Cambridge IGCSE Accounting (9-1) 0985 — 2021 May/June Paper 2 · Variant 2
0985/22/M/J/21 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper16 pages
Mark scheme16 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Leo maintains a petty cash book using the imprest system
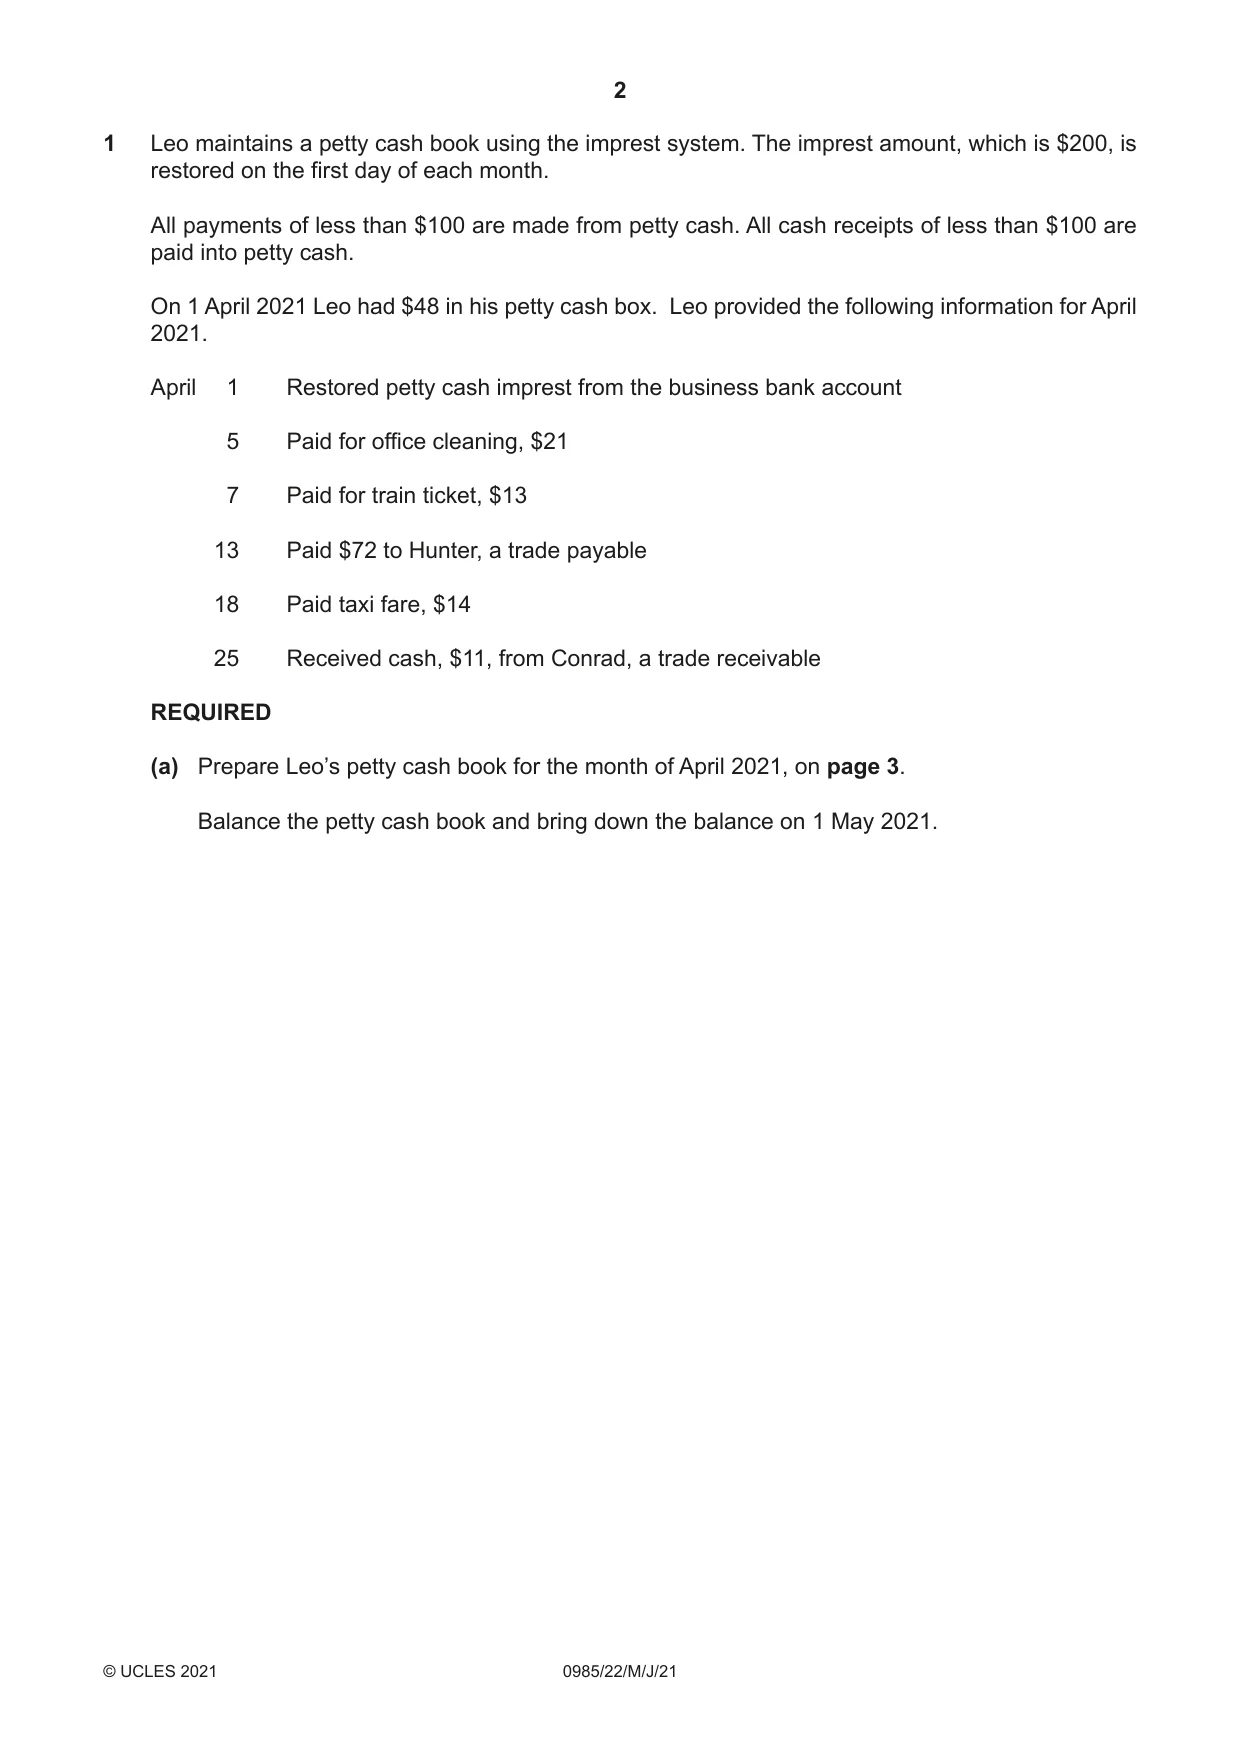
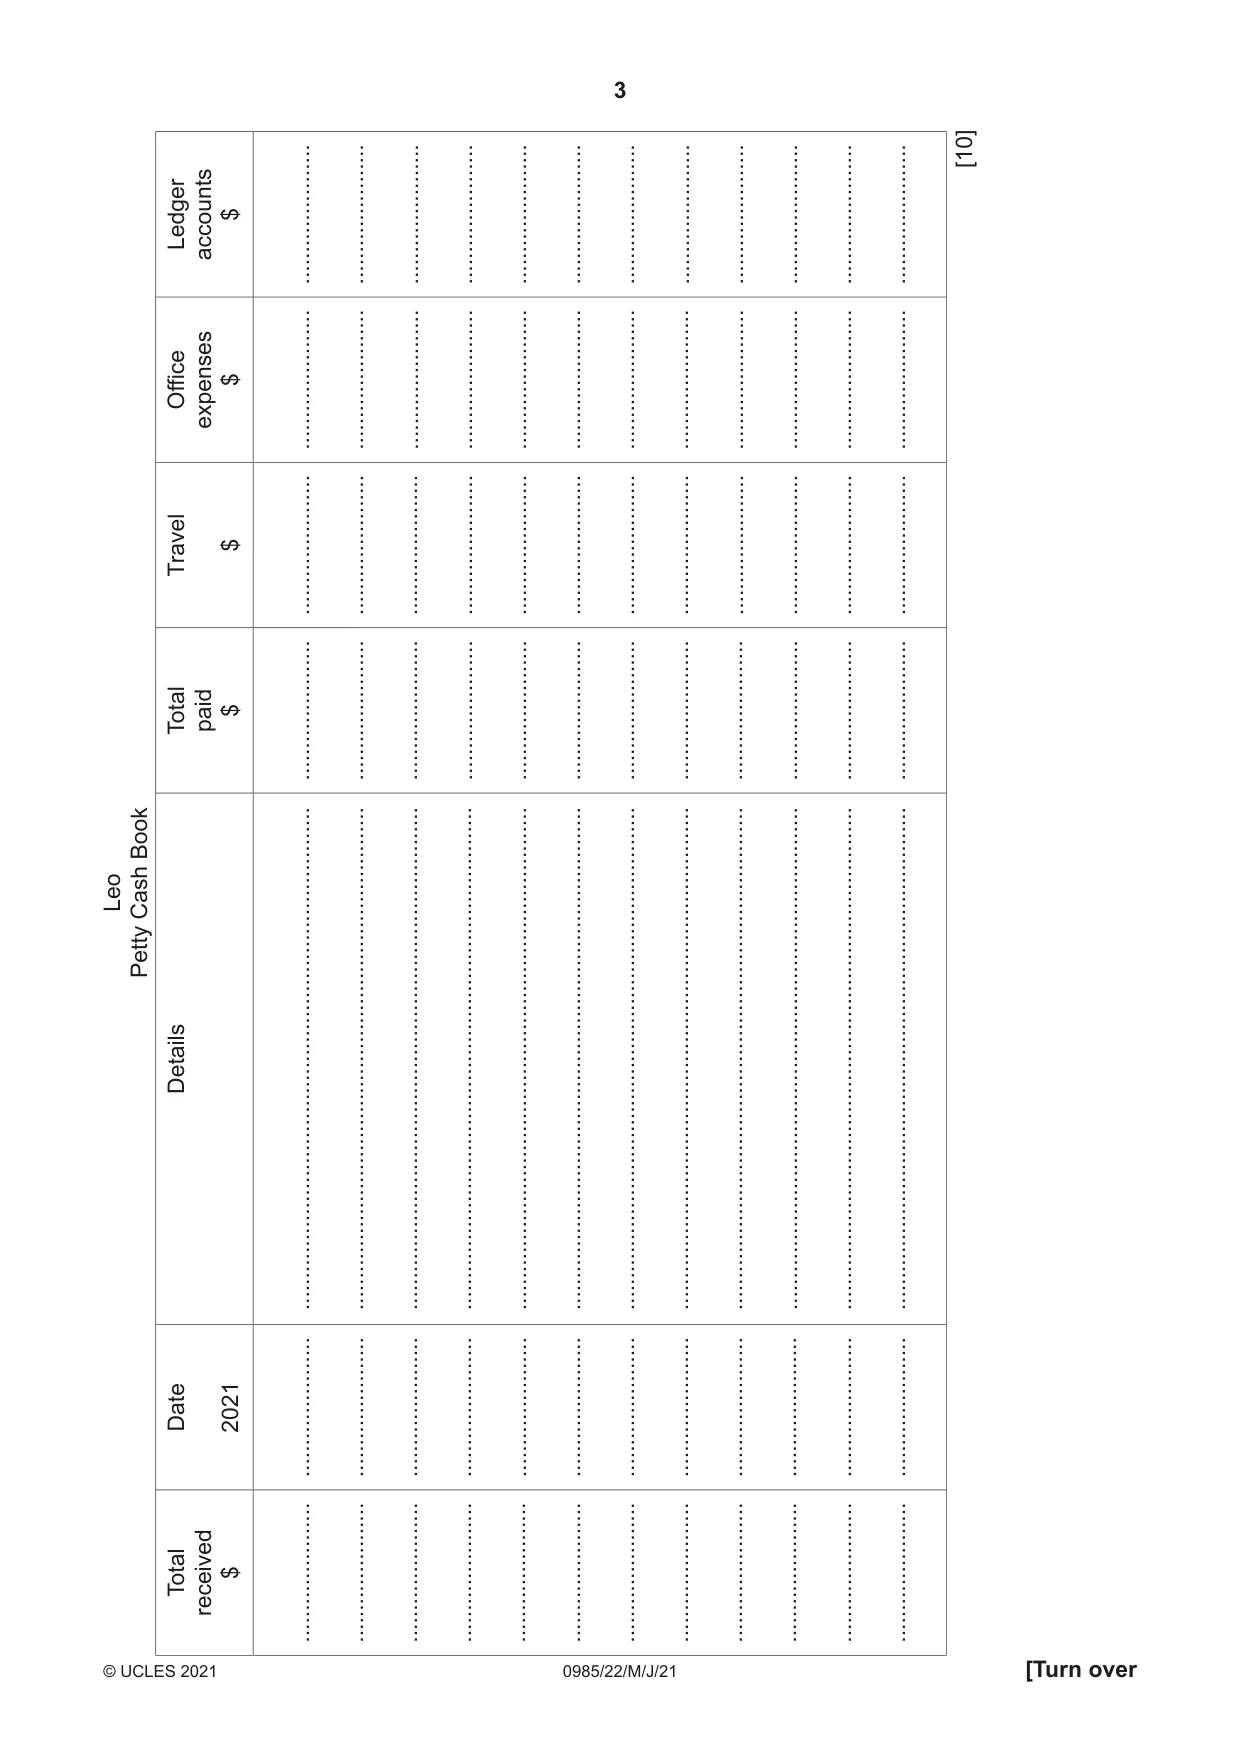
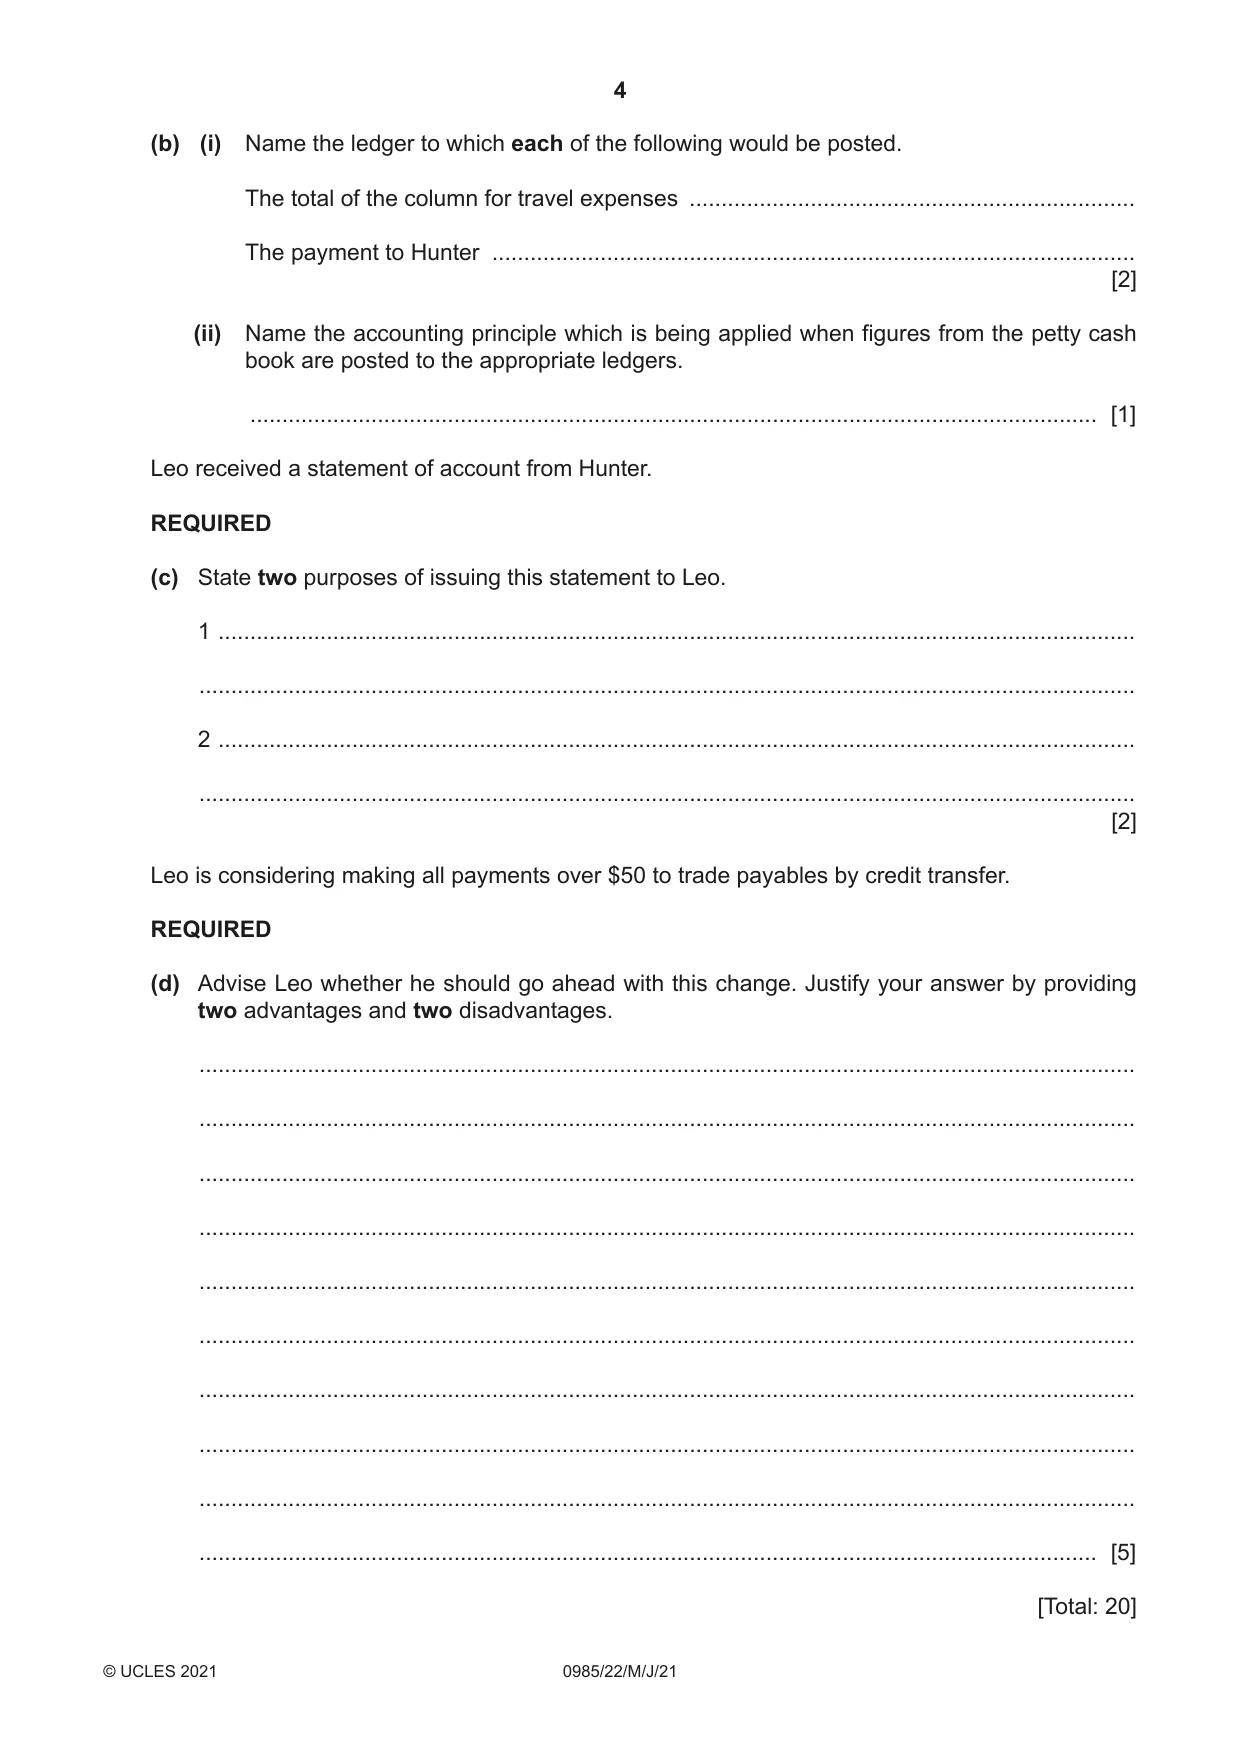
1 Leo maintains a petty cash book using the imprest system. The imprest amount, which is $200, is restored on the first day of each month. All payments of less than $100 are made from petty cash. All cash receipts of less than $100 are paid into petty cash. On 1 April 2021 Leo had $48 in his petty cash box. Leo provided the following information for April 2021. April 1 Restored petty cash imprest from the business bank account 5 Paid for office cleaning, $21 7 Paid for train ticket, $13 13 Paid $72 to Hunter, a trade payable 18 Paid taxi fare, $14 25 Received cash, $11, from Conrad, a trade receivable REQUIRED (a) Prepare Leo’s petty cash book for the month of April 2021, on page 3. Balance the petty cash book and bring down the balance on 1 May 2021. [10] $ Ledger accounts ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... $ Office expenses ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... $ Travel ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... $ Totalpaid ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... Book Leo Cash Petty Details ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... ............................................................................... Date 2021 ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... ...................... (b) (i) Name the ledger to which each of the following would be posted. The total of the column for travel expenses ...................................................................... The payment to Hunter ..................................................................................................... [2] (ii) Name the accounting principle which is being applied when figures from the petty cash book are posted to the appropriate ledgers. ..................................................................................................................................... [1] Leo received a statement of account from Hunter. REQUIRED (c) State two purposes of issuing this statement to Leo. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] Leo is considering making all payments over $50 to trade payables by credit transfer. REQUIRED (d) Advise Leo whether he should go ahead with this change. Justify your answer by providing two advantages and two disadvantages. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
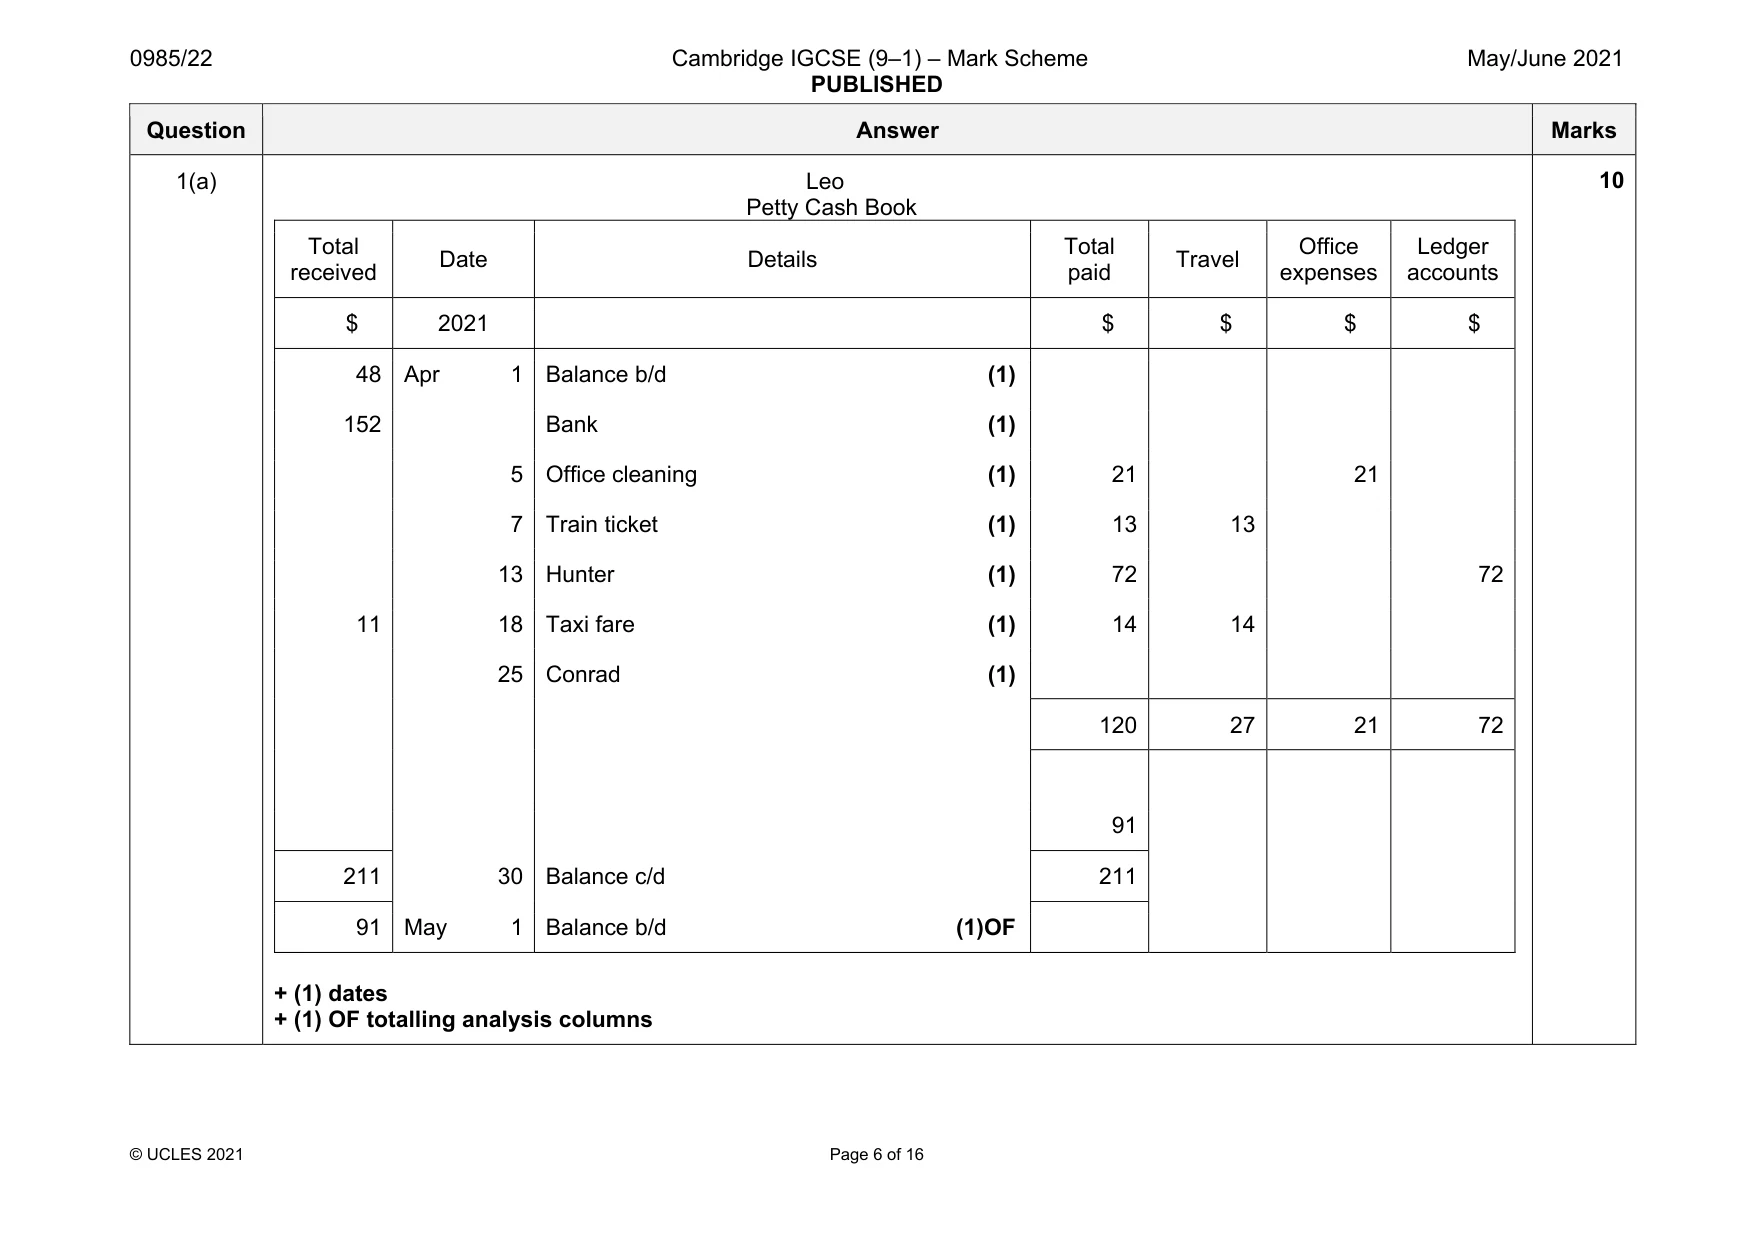
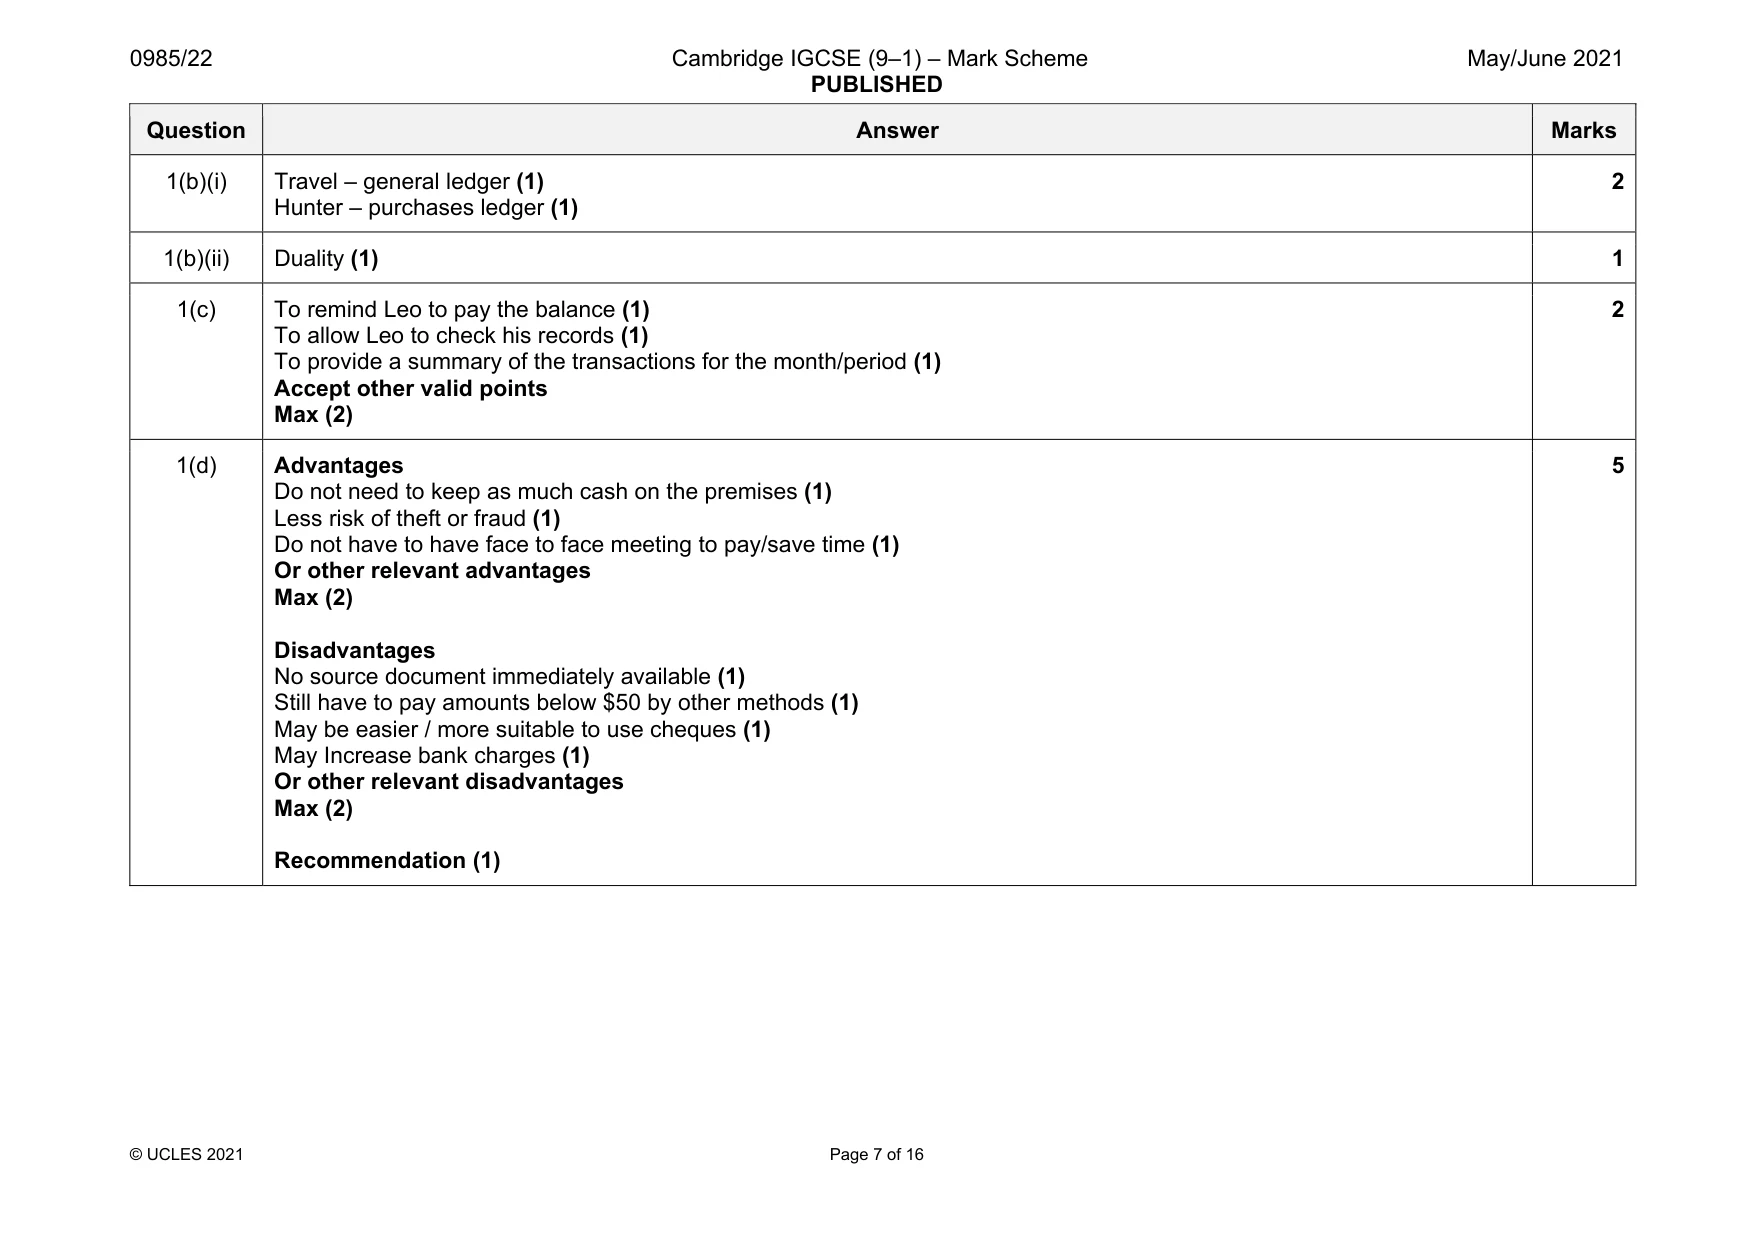
Mark scheme: 1(a) Leo Petty Cash Book Total received Date Details Total paid Travel Office expenses Ledger accounts $ 2021 $ $ $ $ 48 Apr 1 Balance b/d (1) 152 Bank (1) 5 Office cleaning (1) 21 21 7 Train ticket (1) 13 13 13 Hunter (1) 72 72 11 18 Taxi fare (1) 14 14 25 Conrad (1) 120 27 21 72 91 211 30 Balance c/d 211 91 May 1 Balance b/d (1)OF + (1) dates + (1) OF totalling analysis columns Question Answer Marks 1(b)(i) Travel – general ledger (1) Hunter – purchases ledger (1) 2 1(b)(ii) Duality (1) 1 1(c) To remind Leo to pay the balance (1) To allow Leo to check his records (1) To provide a summary of the transactions for the month/period (1) Accept other valid points Max (2) 2 1(d) Advantages Do not need to keep as much cash on the premises (1) Less risk of theft or fraud (1) Do not have to have face to face meeting to pay/save time (1) Or other relevant advantages Max (2) Disadvantages No source document immediately available (1) Still have to pay amounts below $50 by other methods (1) May be easier / more suitable to use cheques (1) May Increase bank charges (1) Or other relevant disadvantages Max (2) Recommendation (1) 5
Q2 · Tej is a trader who sells goods on credit
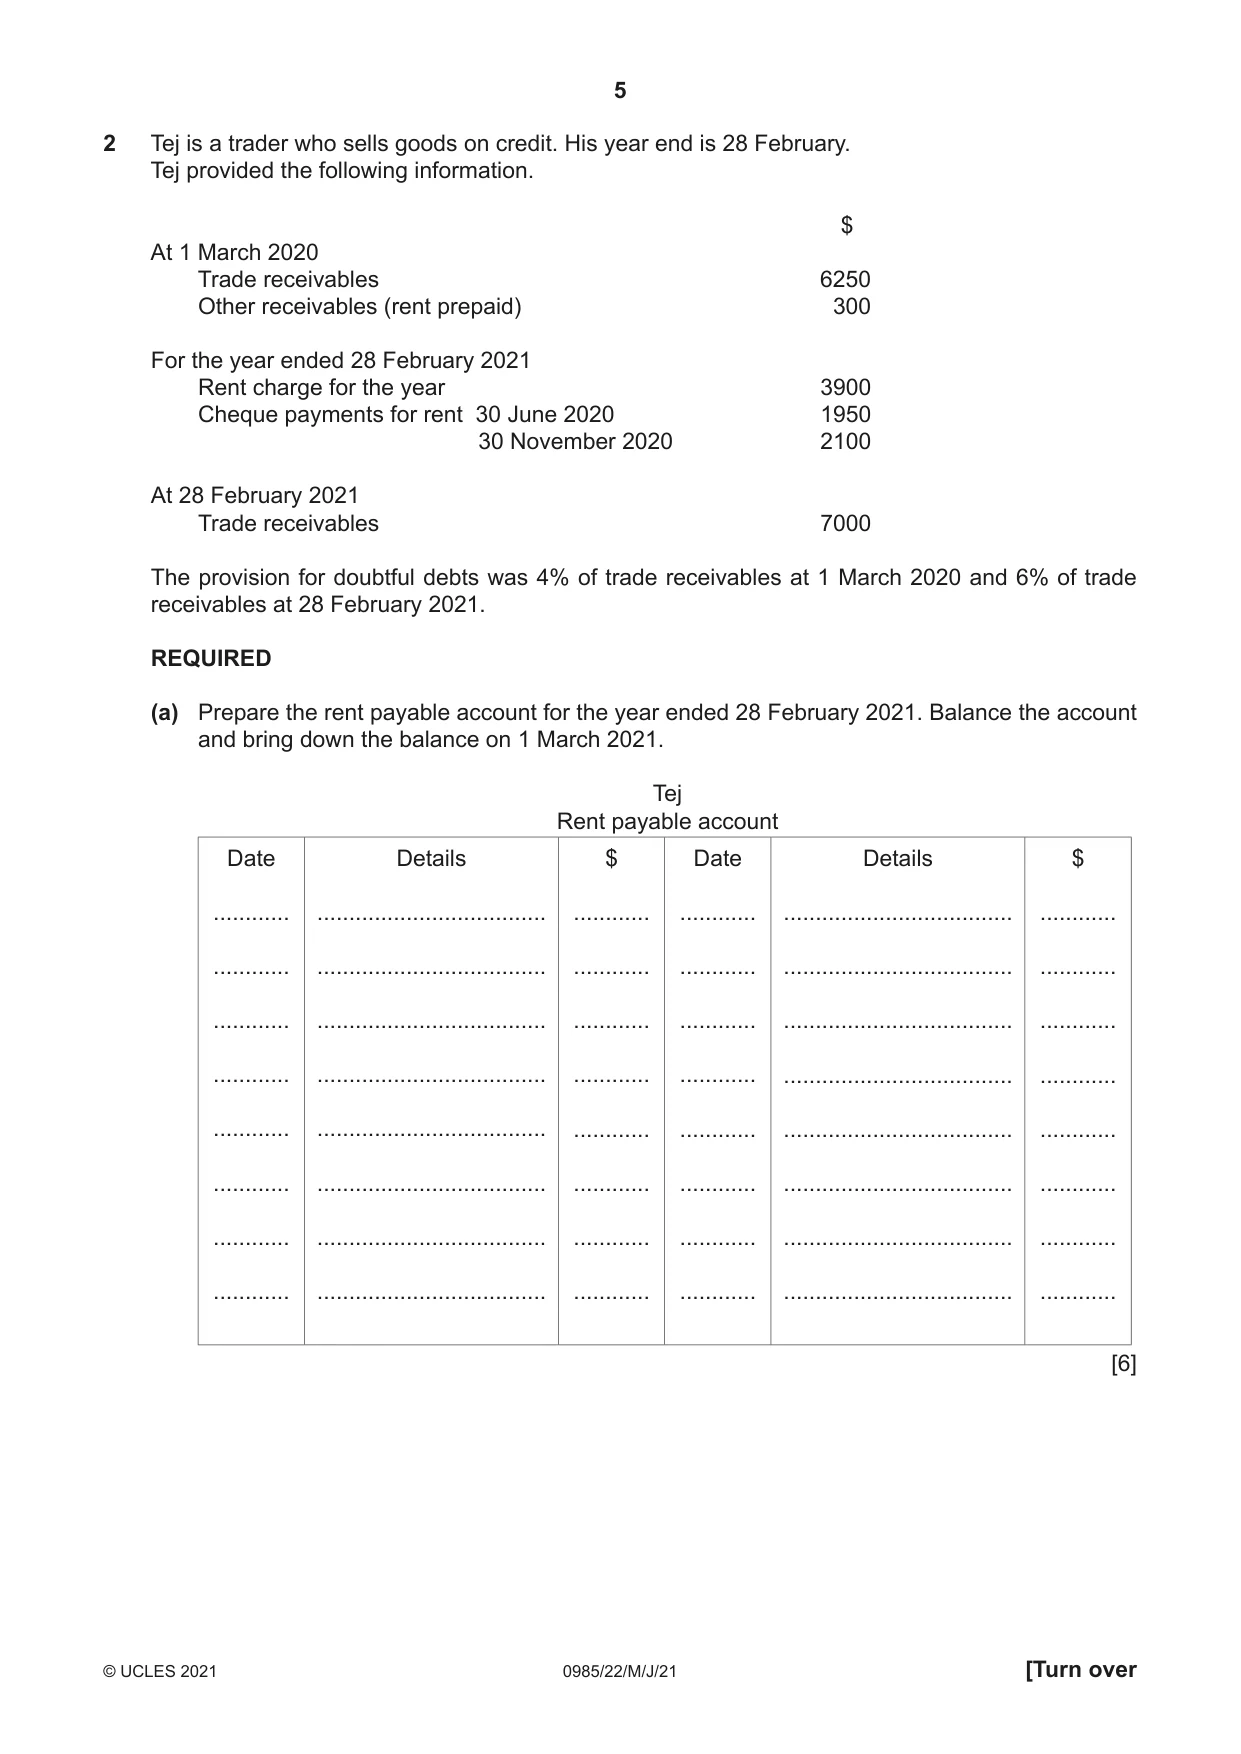
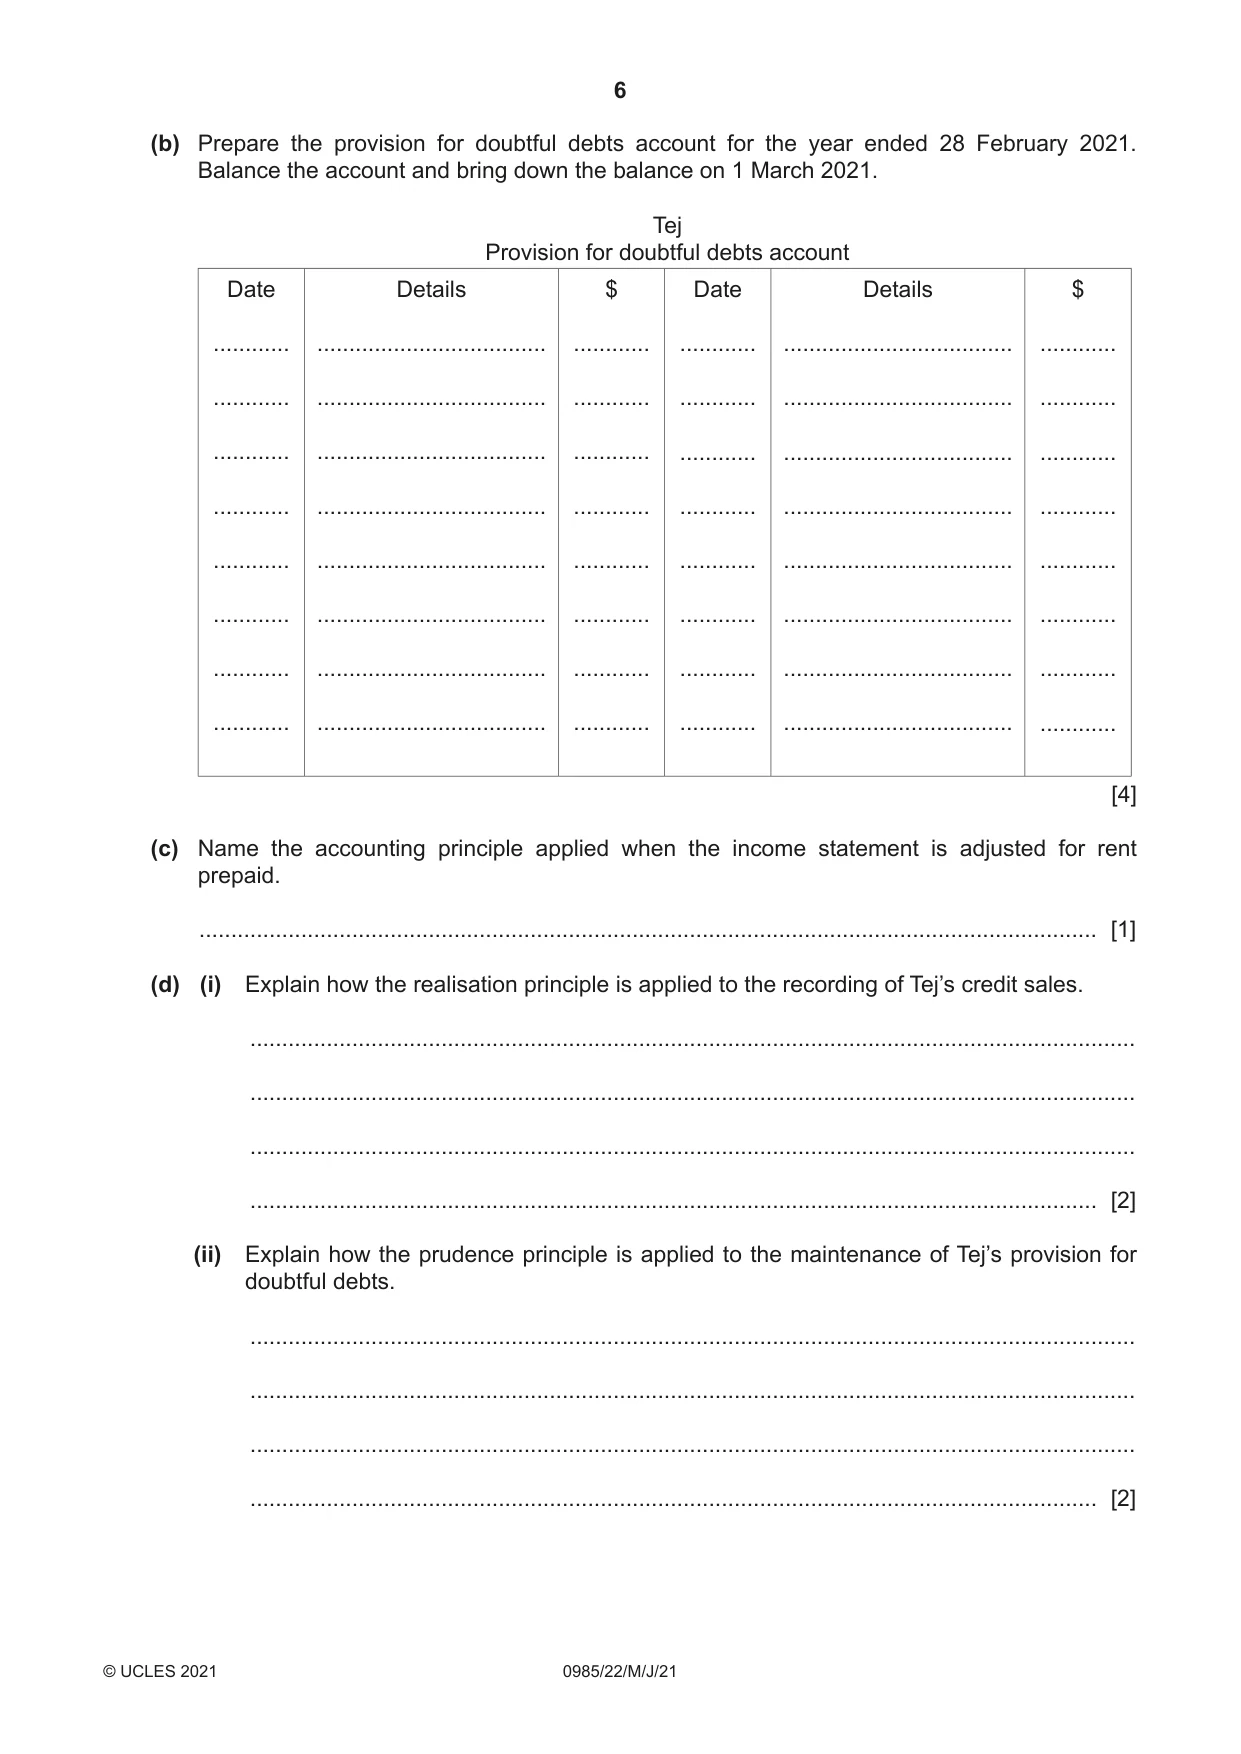
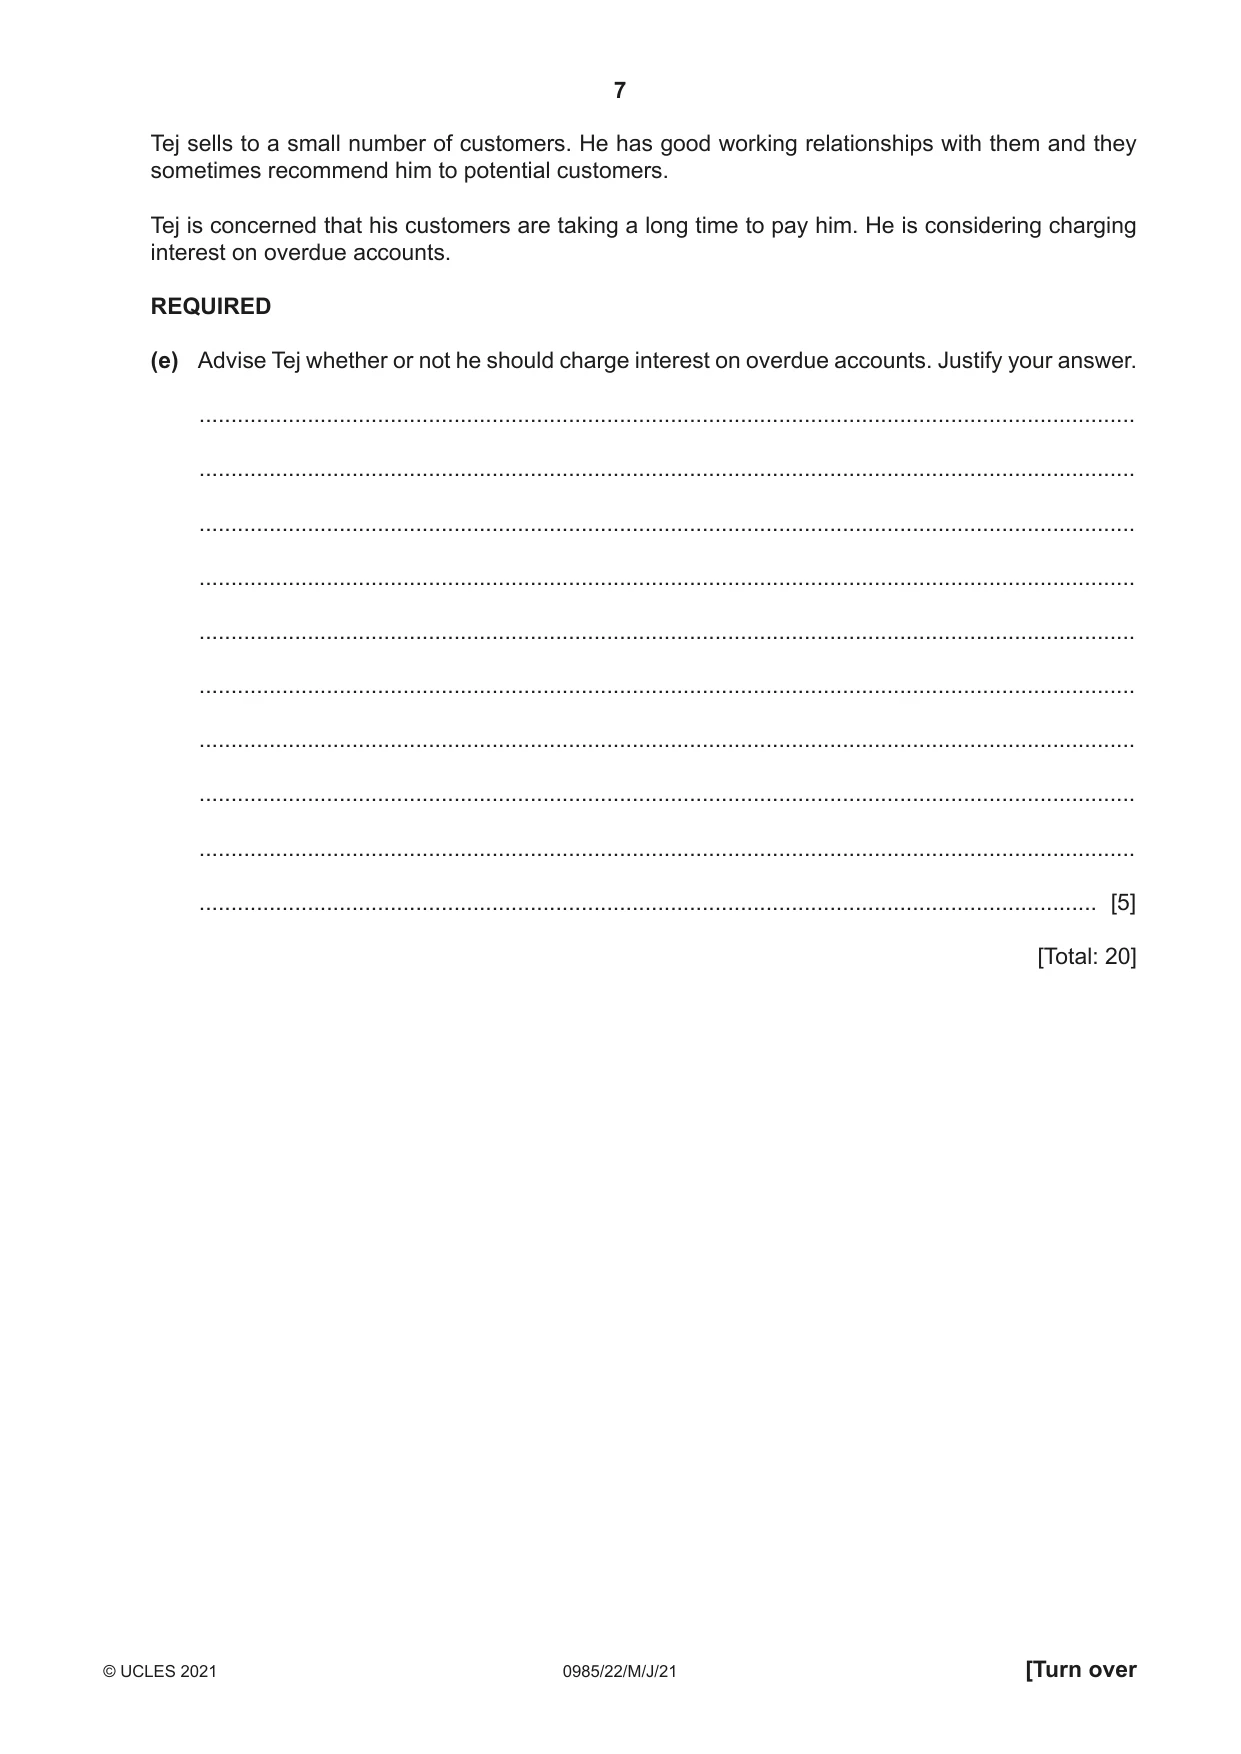
2 Tej is a trader who sells goods on credit. His year end is 28 February. Tej provided the following information. $ At 1 March 2020 Trade receivables 6250 Other receivables (rent prepaid) 300 For the year ended 28 February 2021 Rent charge for the year 3900 Cheque payments for rent 30 June 2020 1950 30 November 2020 2100 At 28 February 2021 Trade receivables 7000 The provision for doubtful debts was 4% of trade receivables at 1 March 2020 and 6% of trade receivables at 28 February 2021. REQUIRED (a) Prepare the rent payable account for the year ended 28 February 2021. Balance the account and bring down the balance on 1 March 2021. Tej Rent payable account Date Details $ Date Details $ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ [6] (b) Prepare the provision for doubtful debts account for the year ended 28 February 2021. Balance the account and bring down the balance on 1 March 2021. Tej Provision for doubtful debts account Date Details $ Date Details $ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ [4] (c) Name the accounting principle applied when the income statement is adjusted for rent prepaid. ............................................................................................................................................. [1] (d) (i) Explain how the realisation principle is applied to the recording of Tej’s credit sales. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] (ii) Explain how the prudence principle is applied to the maintenance of Tej’s provision for doubtful debts. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] Tej sells to a small number of customers. He has good working relationships with them and they sometimes recommend him to potential customers. Tej is concerned that his customers are taking a long time to pay him. He is considering charging interest on overdue accounts. REQUIRED (e) Advise Tej whether or not he should charge interest on overdue accounts. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
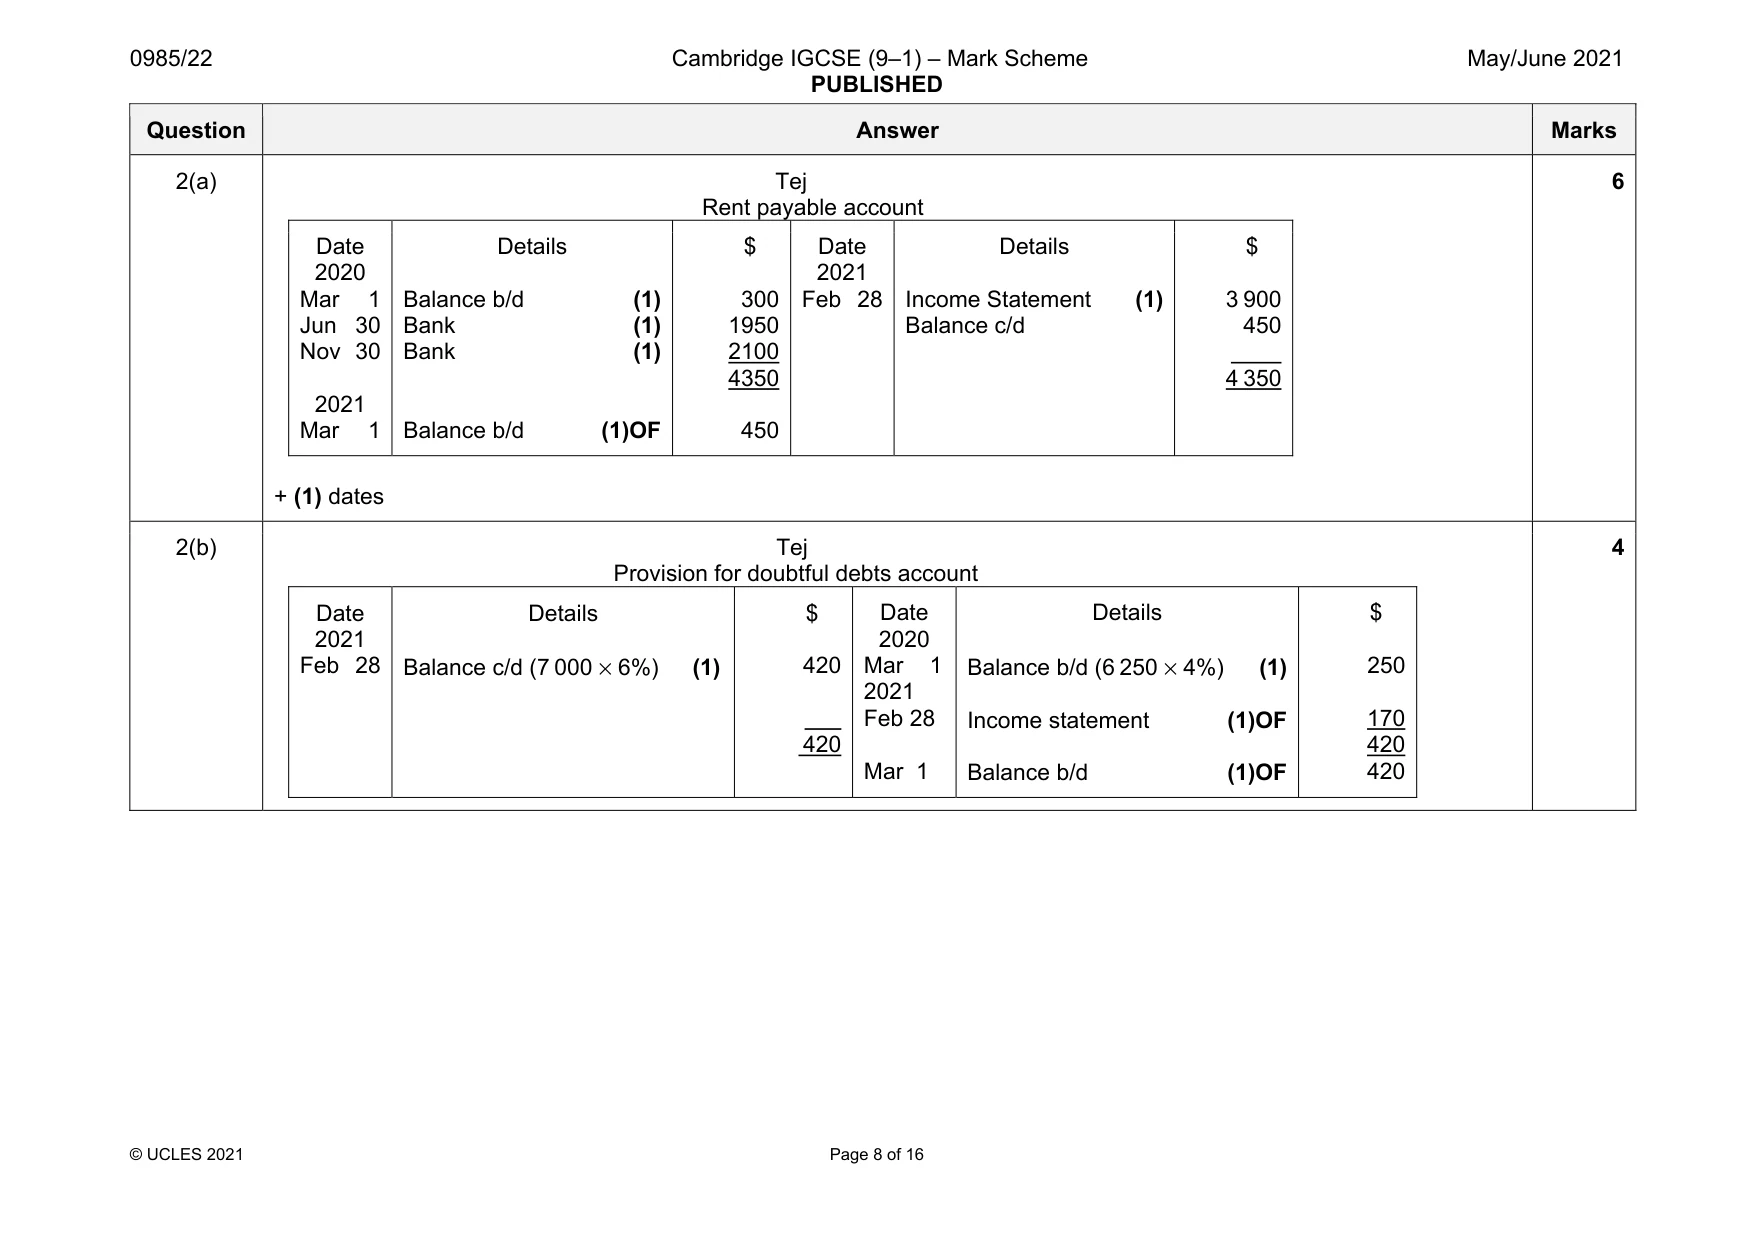
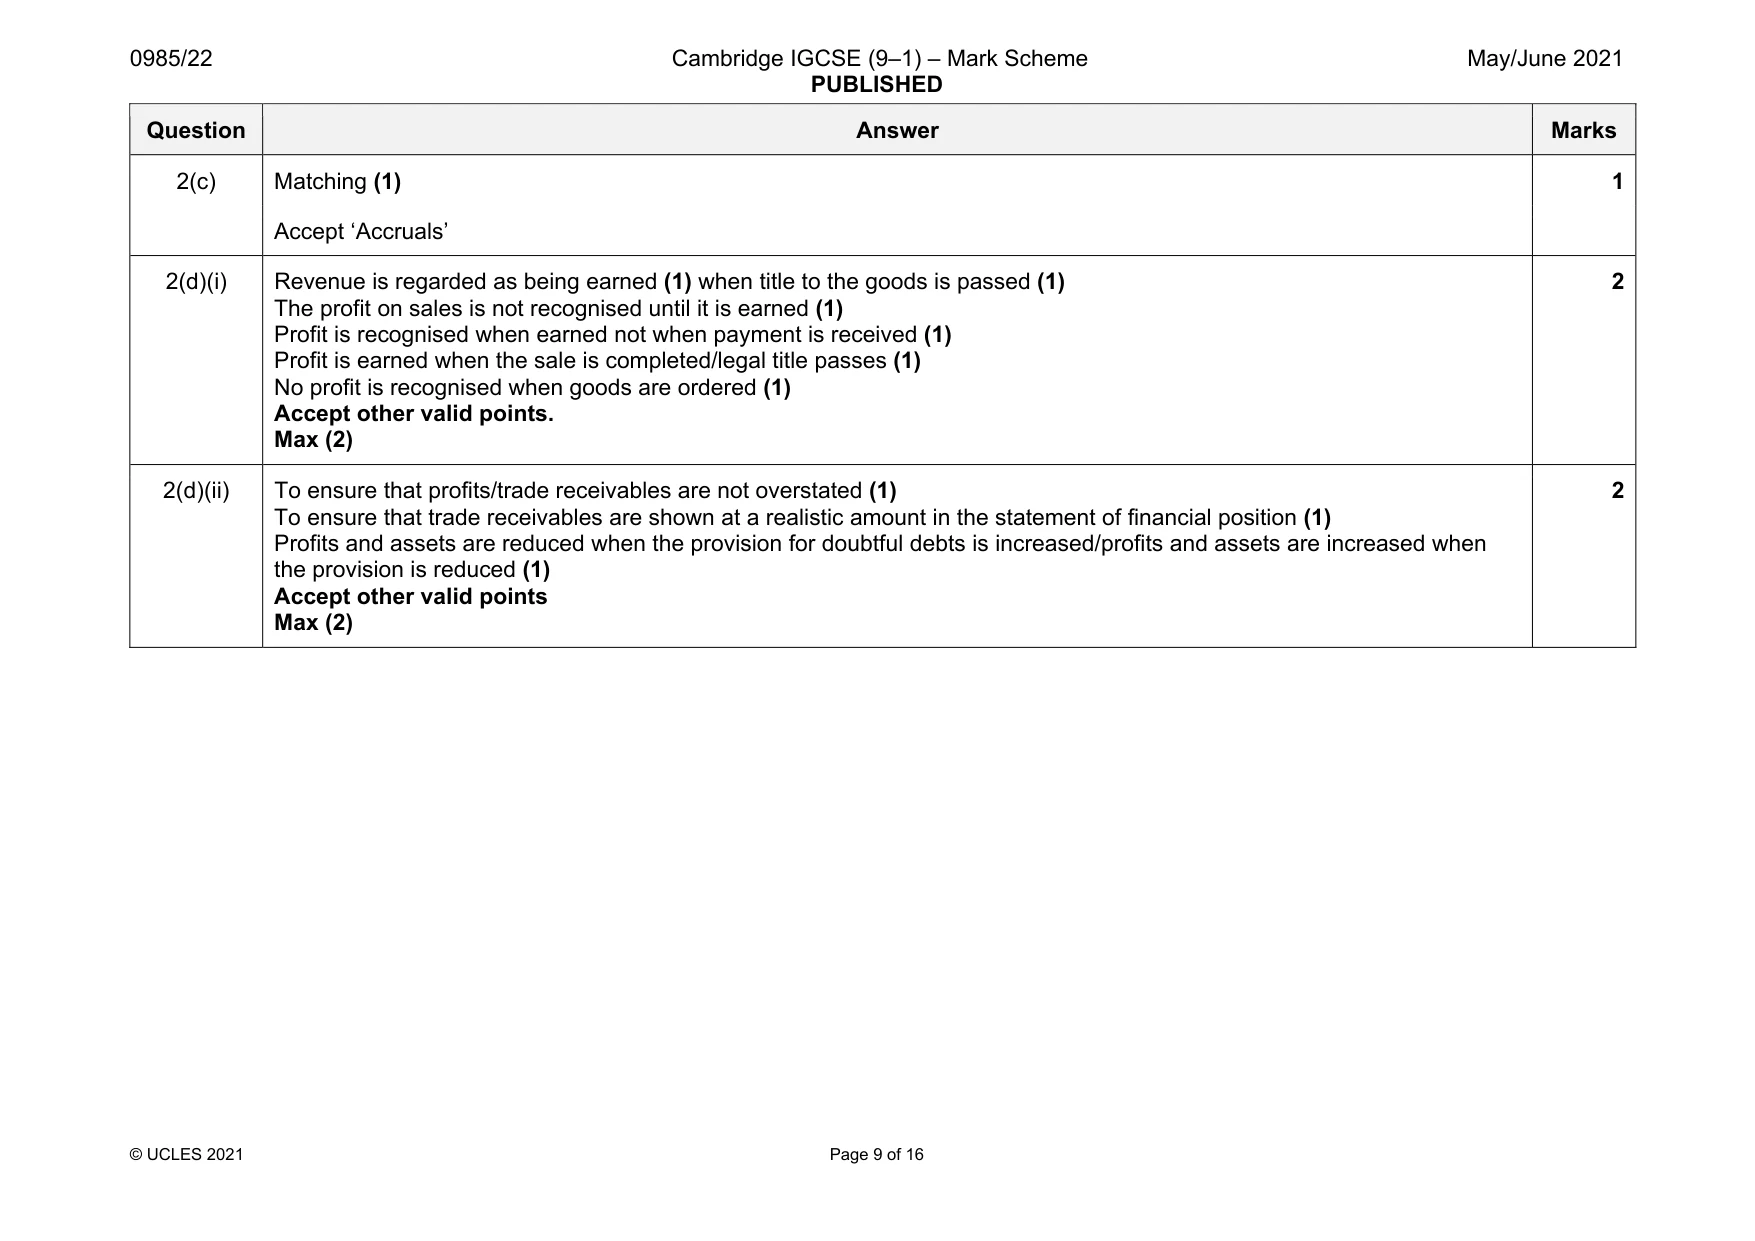
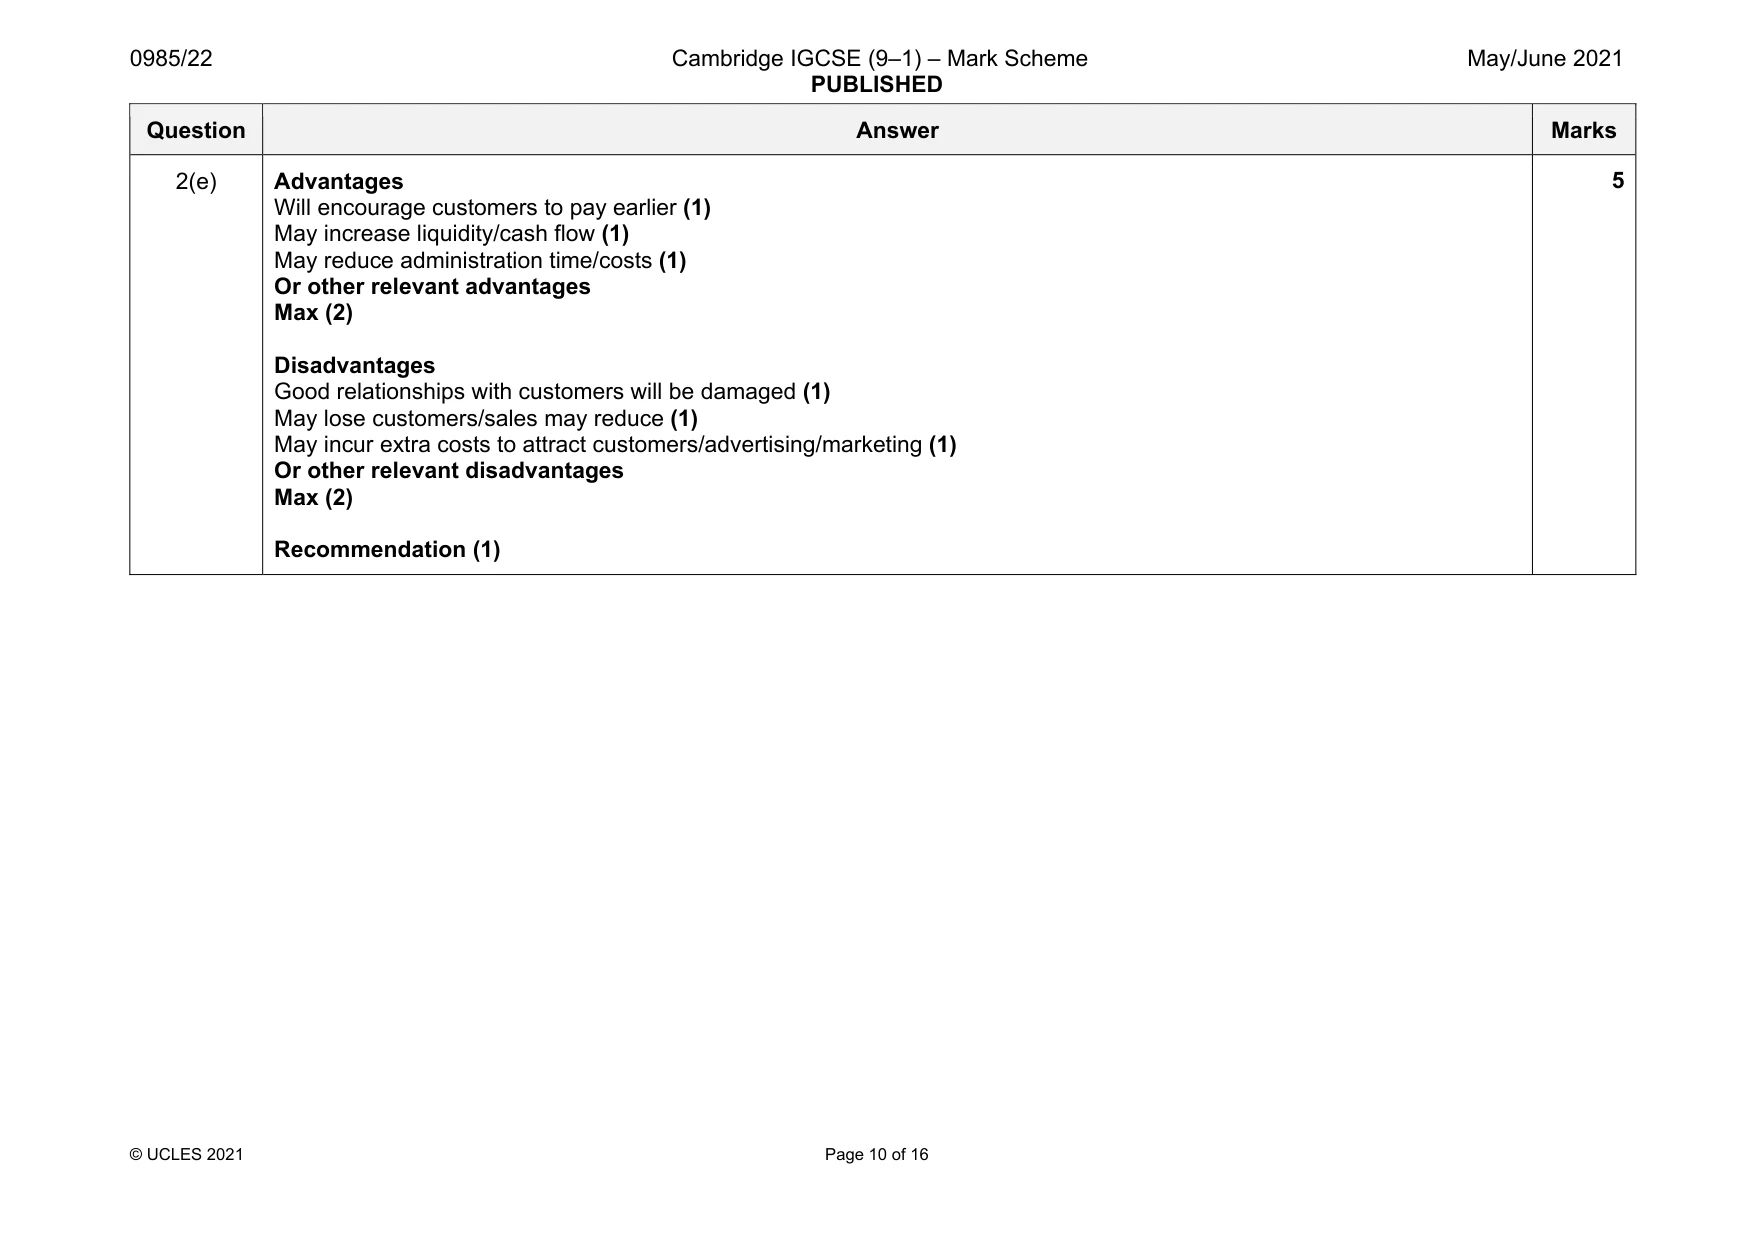
Mark scheme: 2(a) Tej Rent payable account Date 2020 Mar 1 Jun 30 Nov 30 2021 Mar 1 Details Balance b/d (1) Bank (1) Bank (1) Balance b/d (1)OF $ 300 1950 2100 4350 450 Date 2021 Feb 28 Details Income Statement (1) Balance c/d $ 3 900 450 4 350 + (1) dates 6 2(b) Tej Provision for doubtful debts account Date 2021 Feb 28 Details Balance c/d (7 000 × 6%) (1) $ 420 420 Date 2020 Mar 1 2021 Feb 28 Mar 1 Details Balance b/d (6 250 × 4%) (1) Income statement (1)OF Balance b/d (1)OF $ 250 170 420 420 4 Question Answer Marks 2(c) Matching (1) 1 Accept ‘Accruals’ 2(d)(i) Revenue is regarded as being earned (1) when title to the goods is passed (1) The profit on sales is not recognised until it is earned (1) Profit is recognised when earned not when payment is received (1) Profit is earned when the sale is completed/legal title passes (1) No profit is recognised when goods are ordered (1) Accept other valid points. Max (2) 2 2(d)(ii) To ensure that profits/trade receivables are not overstated (1) To ensure that trade receivables are shown at a realistic amount in the statement of financial position (1) Profits and assets are reduced when the provision for doubtful debts is increased/profits and assets are increased when the provision is reduced (1) Accept other valid points Max (2) 2 Question Answer Marks 2(e) Advantages Will encourage customers to pay earlier (1) May increase liquidity/cash flow (1) May reduce administration time/costs (1) Or other relevant advantages Max (2) Disadvantages Good relationships with customers will be damaged (1) May lose customers/sales may reduce (1) May incur extra costs to attract customers/advertising/marketing (1) Or other relevant disadvantages Max (2) Recommendation (1) 5
Q3 · The trial balance of HV Limited at 31 March 2021 was as follows
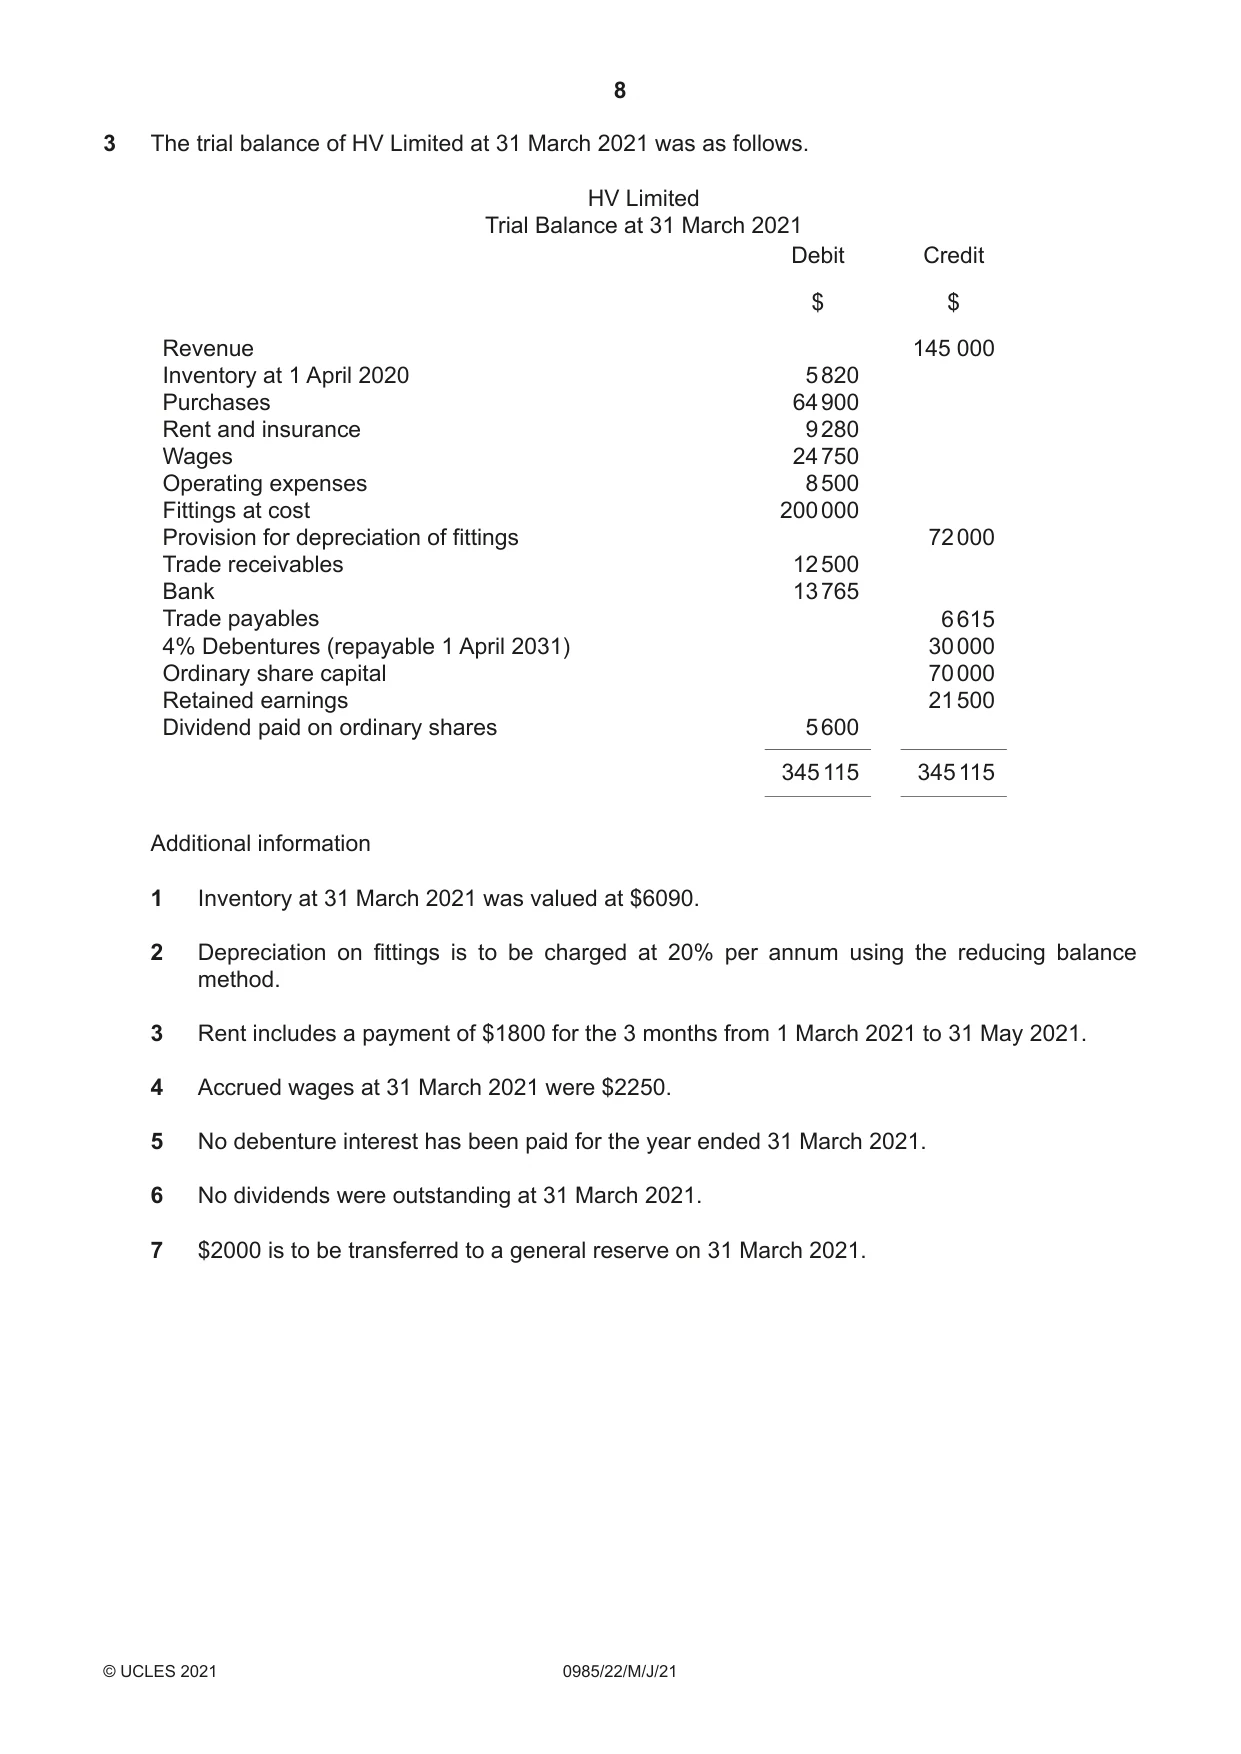
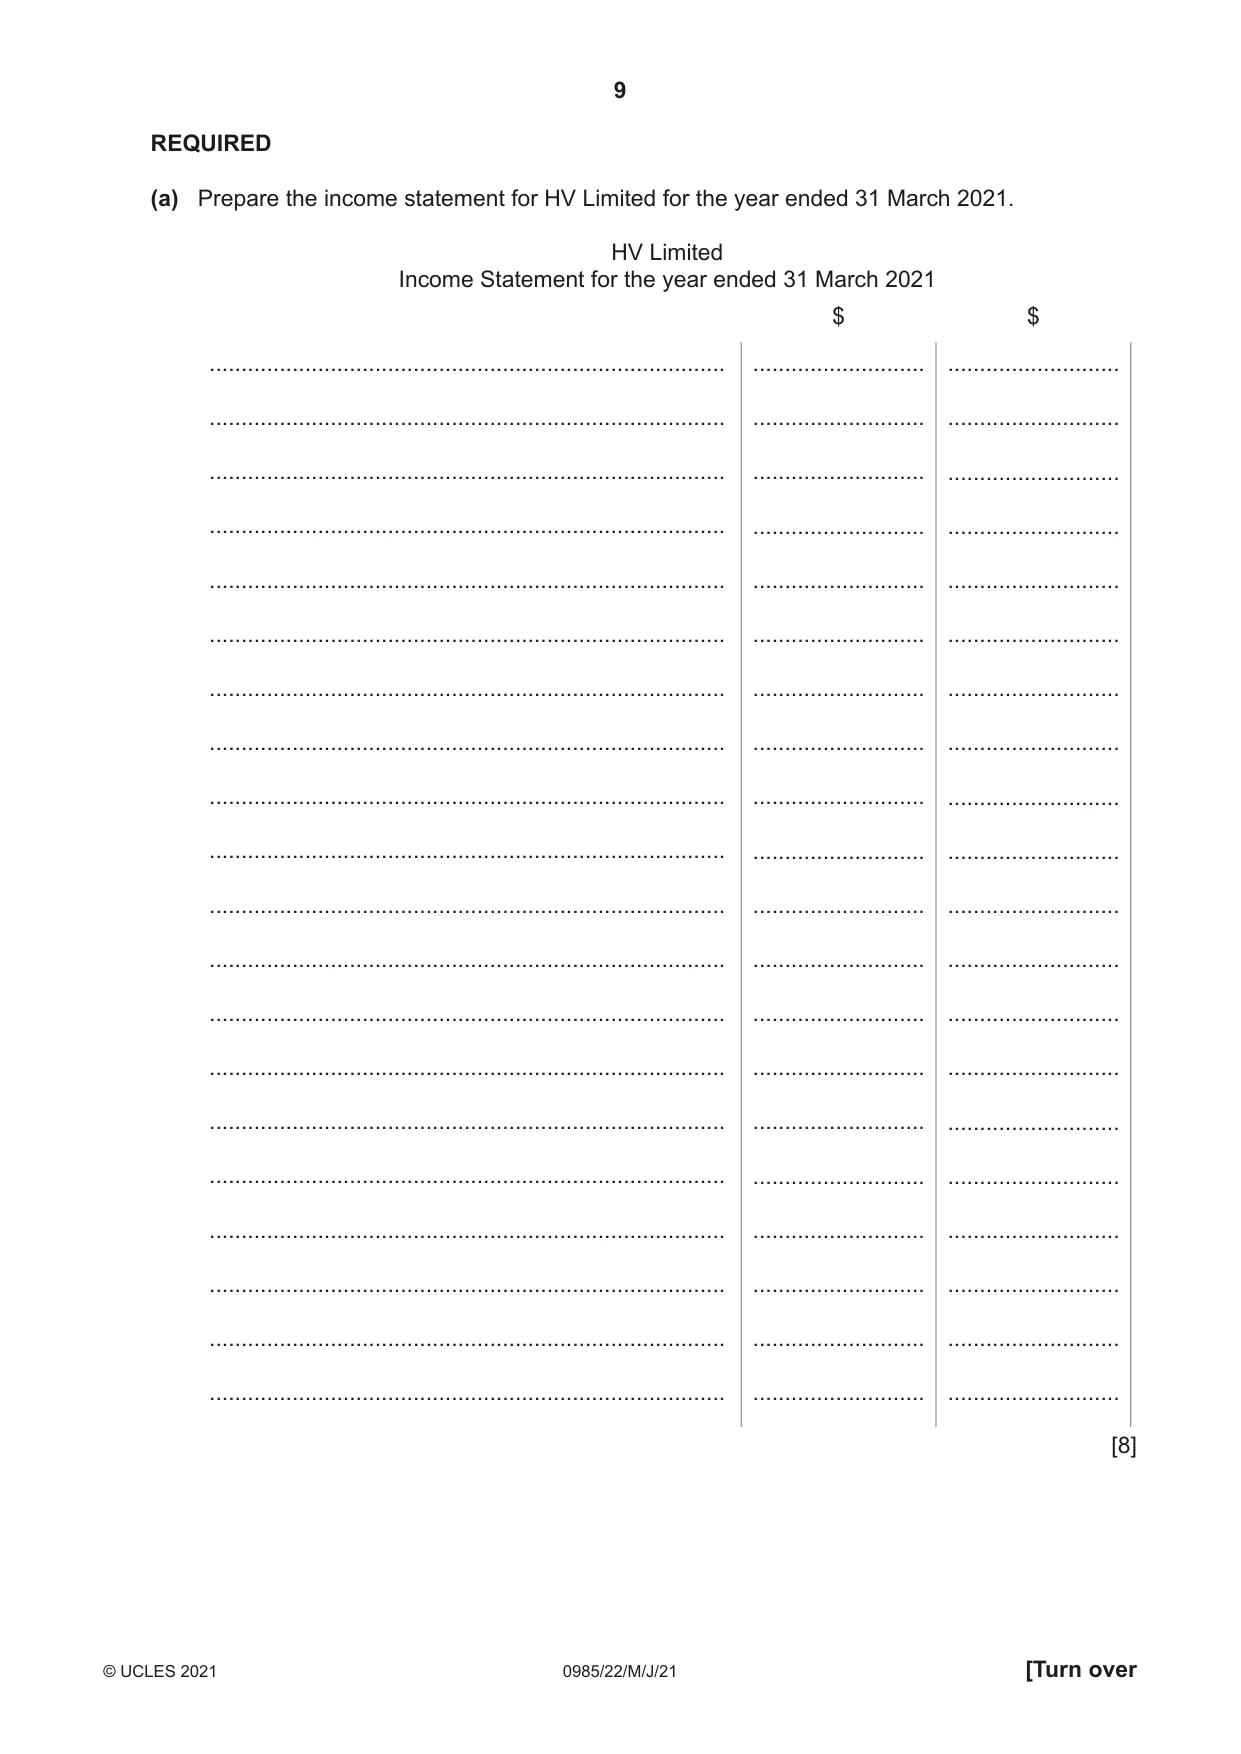
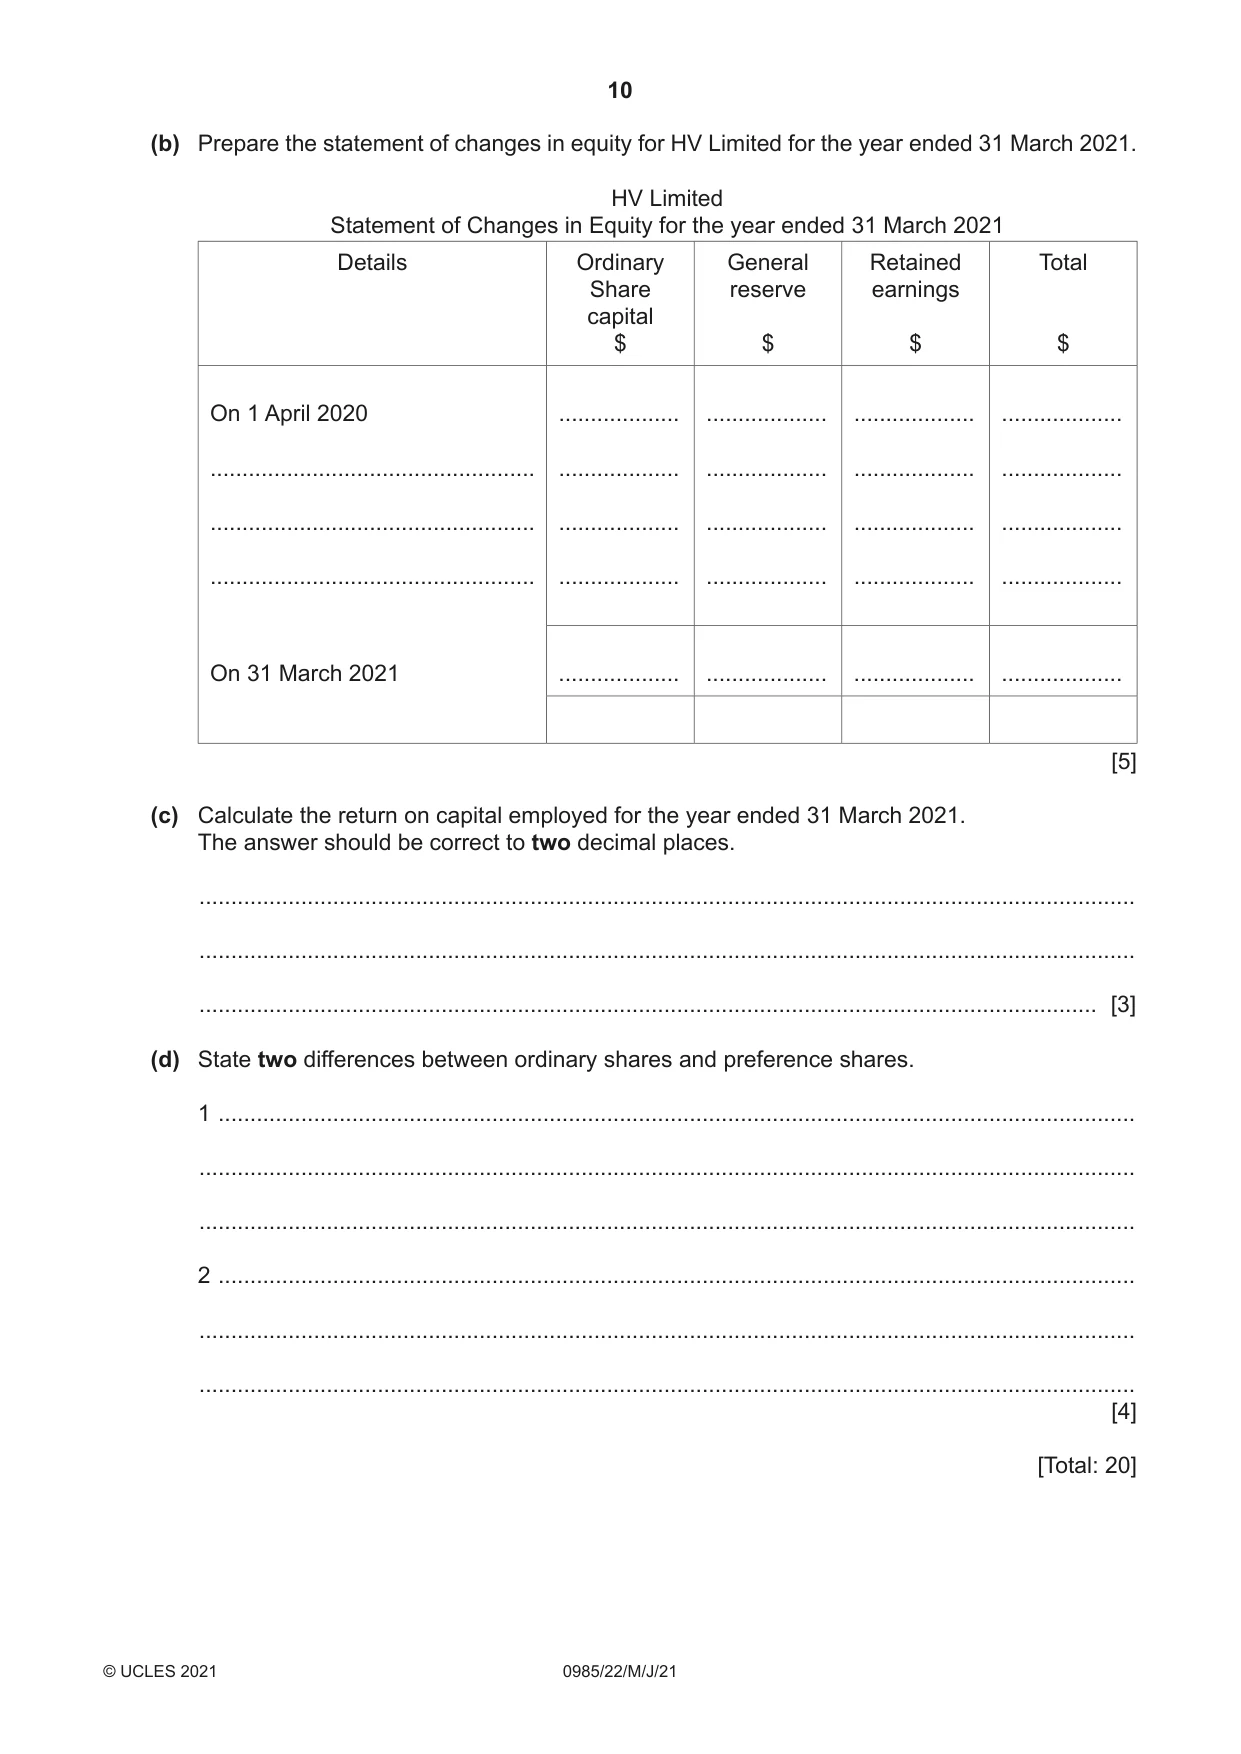
3 The trial balance of HV Limited at 31 March 2021 was as follows. HV Limited Trial Balance at 31 March 2021 Debit Credit $ $ Revenue 145 000 Inventory at 1 April 2020 5 820 Purchases 64 900 Rent and insurance 9 280 Wages 24 750 Operating expenses 8 500 Fittings at cost 200 000 Provision for depreciation of fittings 72 000 Trade receivables 12 500 Bank 13 765 Trade payables 6 615 4% Debentures (repayable 1 April 2031) 30 000 Ordinary share capital 70 000 Retained earnings 21 500 Dividend paid on ordinary shares 5 600 345 115 345 115 Additional information 1 Inventory at 31 March 2021 was valued at $6090. 2 Depreciation on fittings is to be charged at 20% per annum using the reducing balance method. 3 Rent includes a payment of $1800 for the 3 months from 1 March 2021 to 31 May 2021. 4 Accrued wages at 31 March 2021 were $2250. 5 No debenture interest has been paid for the year ended 31 March 2021. 6 No dividends were outstanding at 31 March 2021. 7 $2000 is to be transferred to a general reserve on 31 March 2021. REQUIRED (a) Prepare the income statement for HV Limited for the HV Limited Income Statement for the year e ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. ................................................................................. (b) Prepare the statement of changes in equity for HV Limited for the year ended 31 March 2021. HV Limited Statement of Changes in Equity for the year ended 31 March 2021 Details Ordinary General Retained Total Share reserve earnings capital $ $ $ $ On 1 April 2020 ................... ................... ................... ................... ................................................... ................... ................... ................... ................... ................................................... ................... ................... ................... ................... ................................................... ................... ................... ................... ................... On 31 March 2021 ................... ................... ................... ................... [5] (c) Calculate the return on capital employed for the year ended 31 March 2021. The answer should be correct to two decimal places. ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] (d) State two differences between ordinary shares and preference shares. 1 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... [4] [Total: 20]
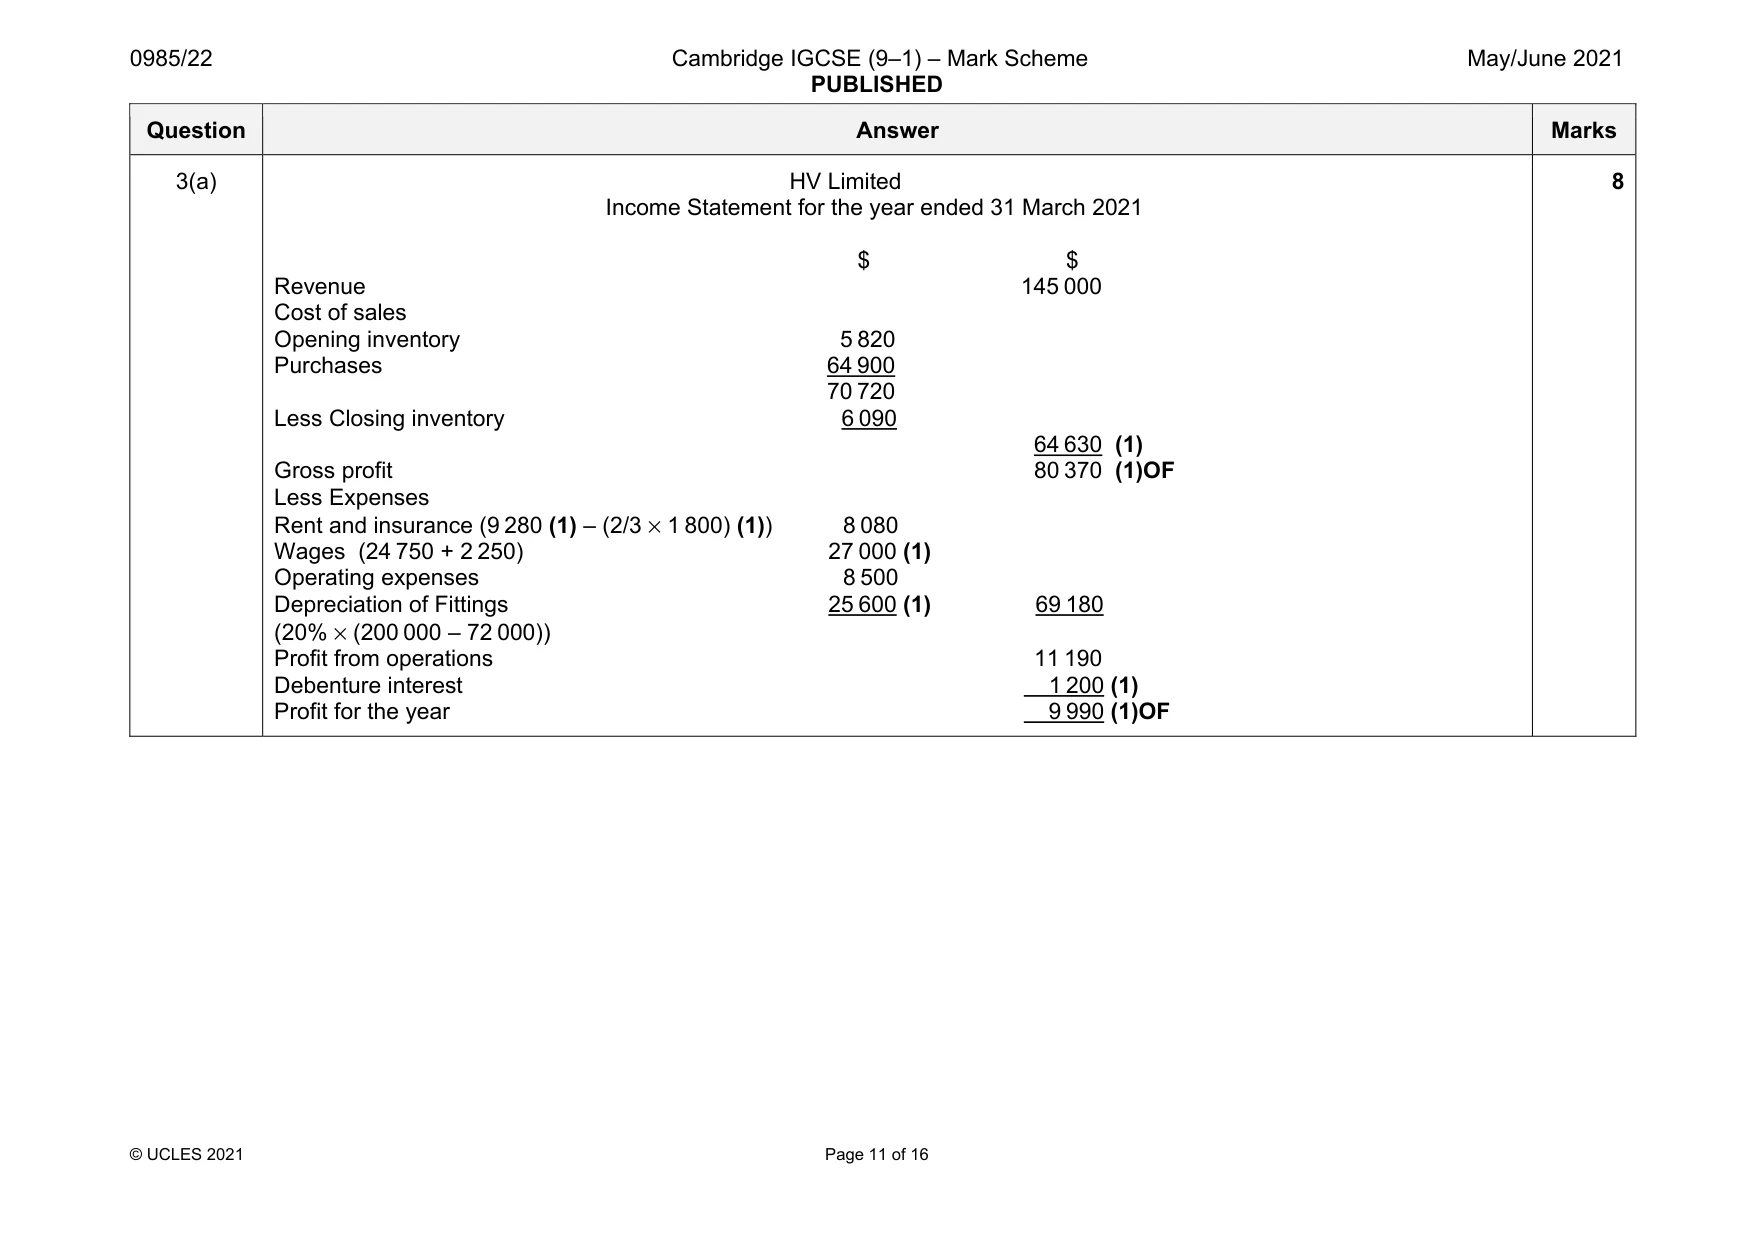
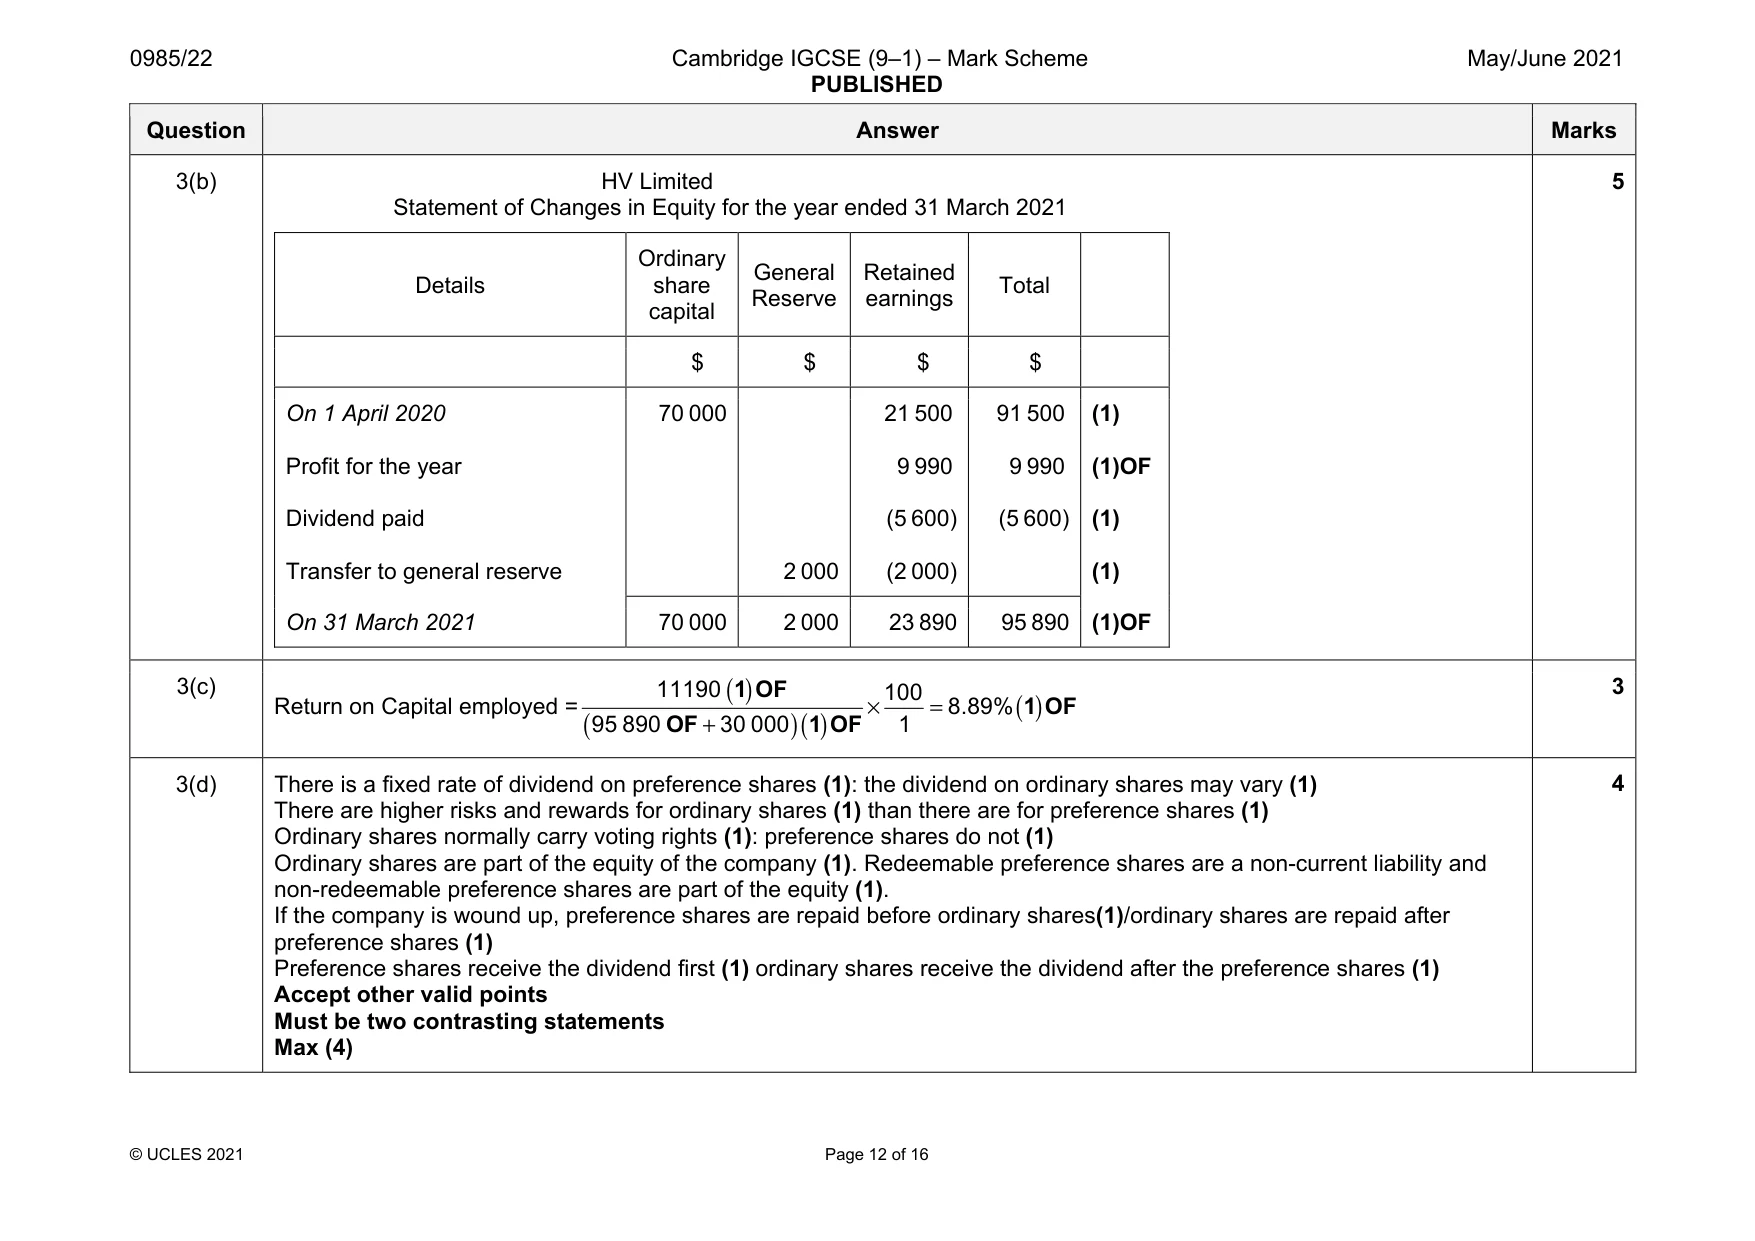
Mark scheme: 3(a) HV Limited Income Statement for the year ended 31 March 2021 $ $ Revenue 145 000 Cost of sales Opening inventory 5 820 Purchases 64 900 70 720 Less Closing inventory 6 090 64 630 (1) Gross profit 80 370 (1)OF Less Expenses Rent and insurance (9 280 (1) – (2/3 × 1 800) (1)) 8 080 Wages (24 750 + 2 250) 27 000 (1) Operating expenses 8 500 Depreciation of Fittings 25 600 (1) 69 180 (20% × (200 000 – 72 000)) Profit from operations 11 190 Debenture interest 1 200 (1) Profit for the year 9 990 (1)OF 8 Question Answer Marks 3(b) HV Limited Statement of Changes in Equity for the year ended 31 March 2021 Details Ordinary share capital General Reserve Retained earnings Total $ $ $ $ On 1 April 2020 Profit for the year Dividend paid Transfer to general reserve 70 000 2 000 21 500 9 990 (5 600) (2 000) 91 500 9 990 (5 600) (1) (1)OF (1) (1) On 31 March 2021 70 000 2 000 23 890 95 890 (1)OF 5 3(c) Return on Capital employed = ( ) ( )( ) ( ) 11190 100 8.89% 95 890 30 000 1 × = + 1 OF 1 OF OF 1 OF 3 3(d) There is a fixed rate of dividend on preference shares (1): the dividend on ordinary shares may vary (1) There are higher risks and rewards for ordinary shares (1) than there are for preference shares (1) Ordinary shares normally carry voting rights (1): preference shares do not (1) Ordinary shares are part of the equity of the company (1). Redeemable preference shares are a non-current liability and non-redeemable preference shares are part of the equity (1). If the company is wound up, preference shares are repaid before ordinary shares(1)/ordinary shares are repaid after preference shares (1) Preference shares receive the dividend first (1) ordinary shares receive the dividend after the preference shares (1) Accept other valid points Must be two contrasting statements Max (4) 4
Q4 · RIA Music Club owns its premises where it has a shop and a number of music rooms
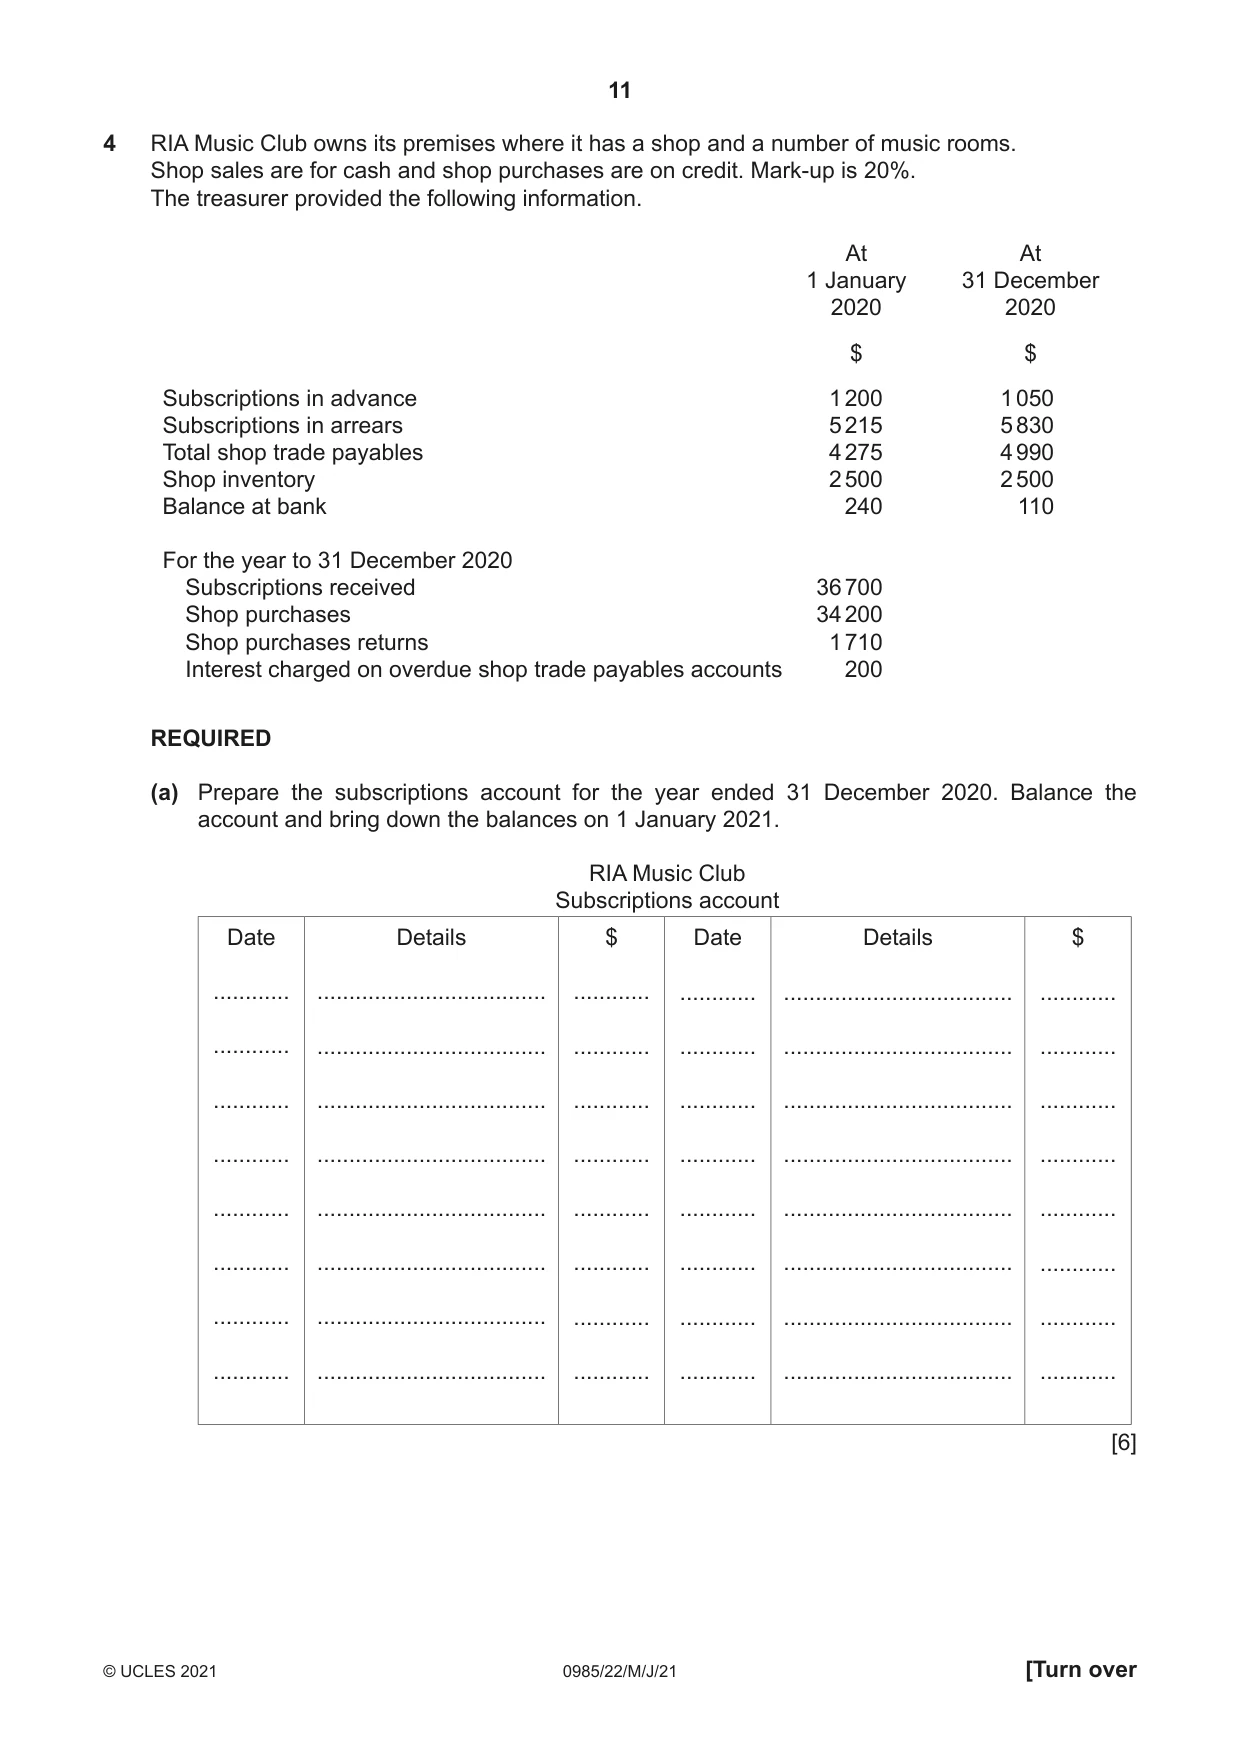
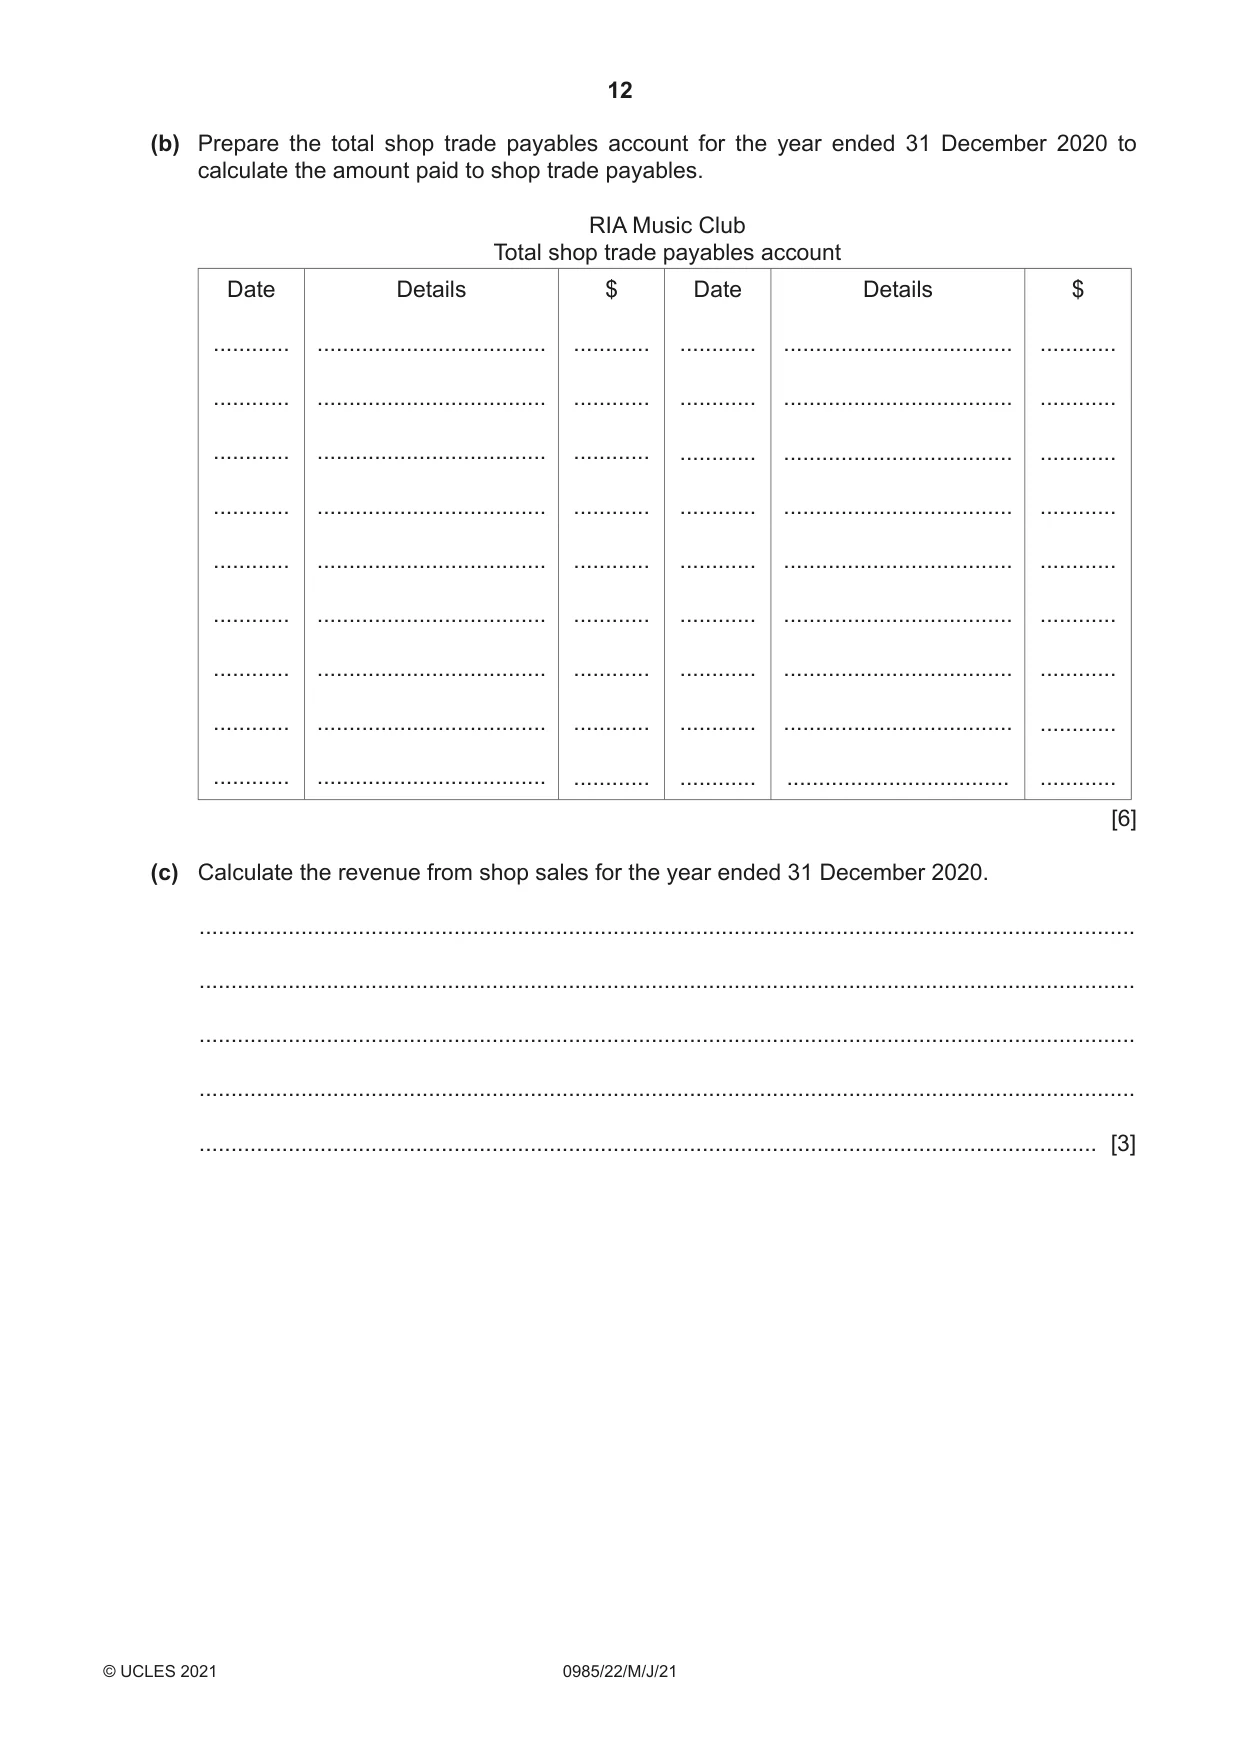
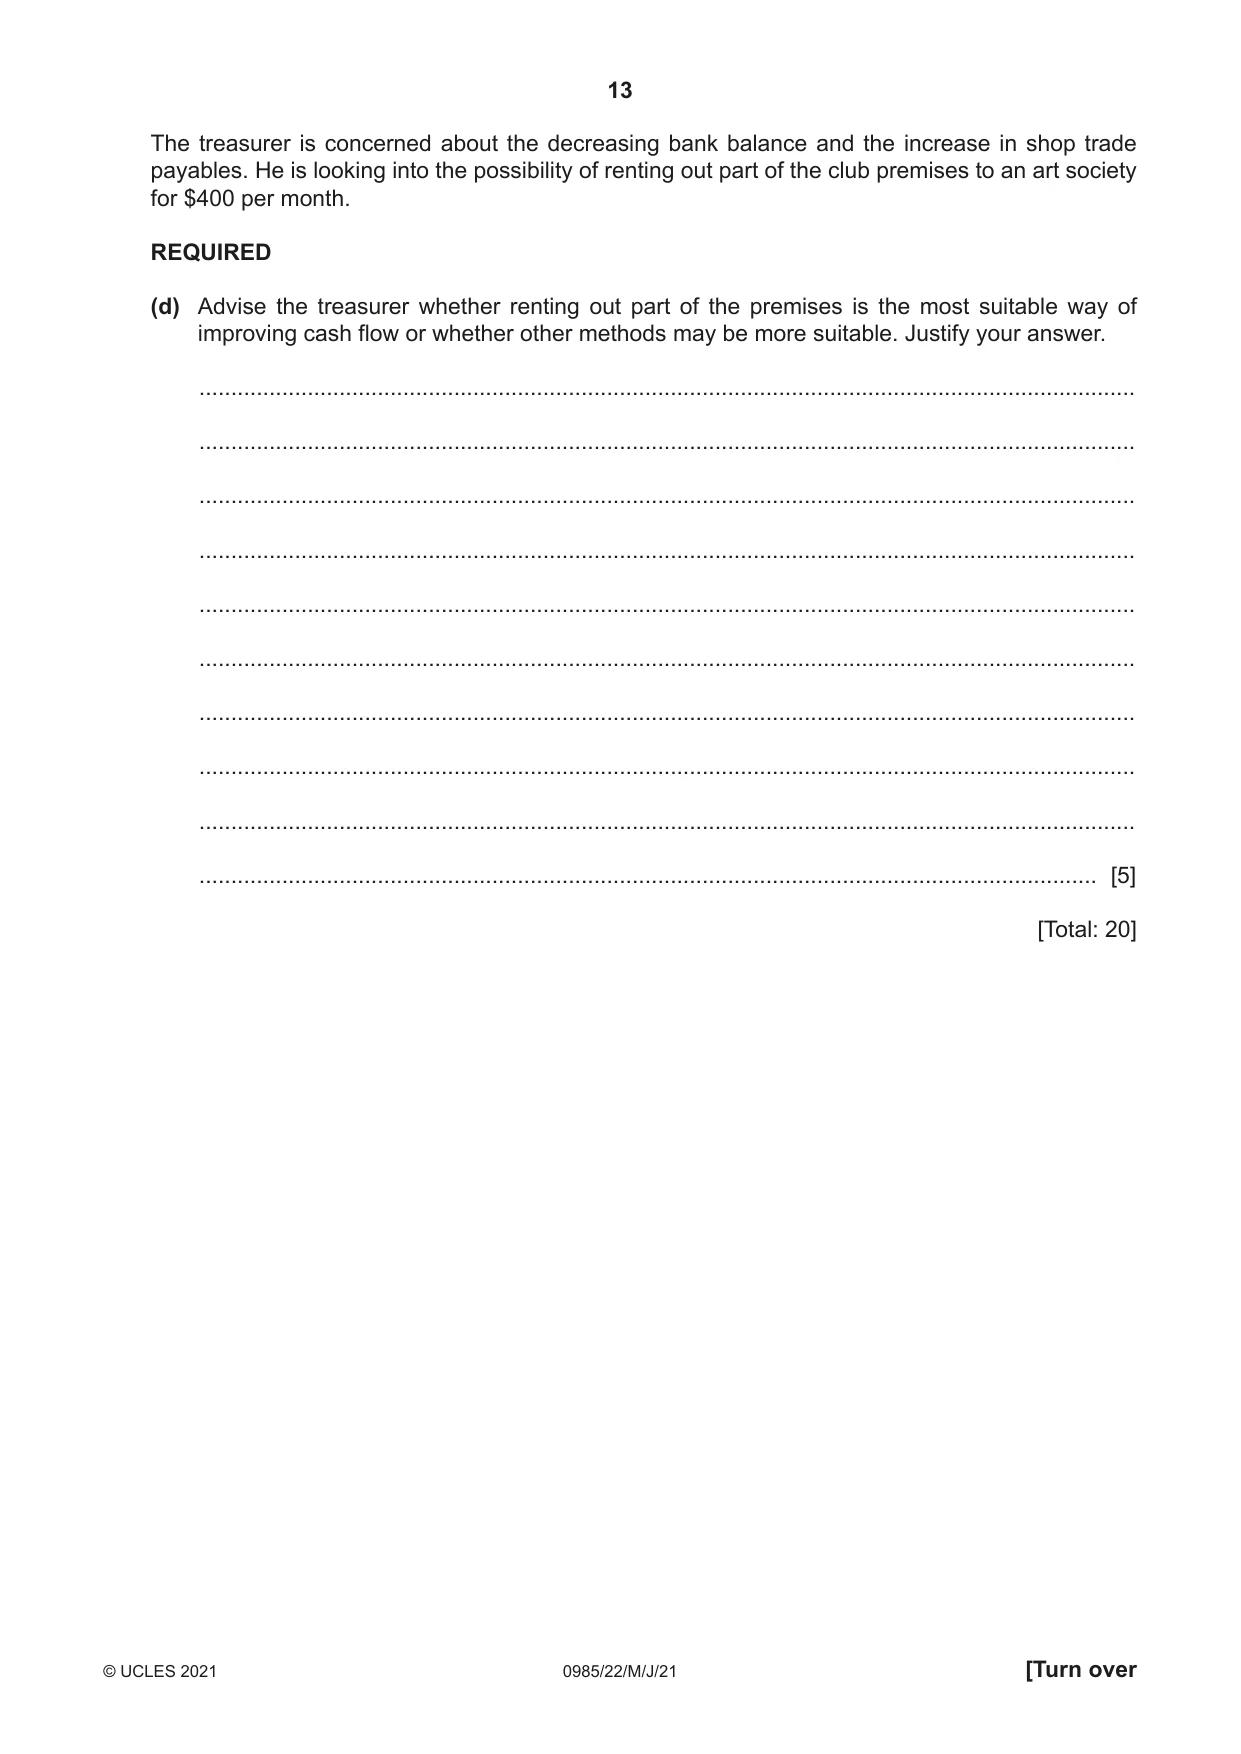
4 RIA Music Club owns its premises where it has a shop and a number of music rooms. Shop sales are for cash and shop purchases are on credit. Mark-up is 20%. The treasurer provided the following information. At At 1 January 31 December 2020 2020 $ $ Subscriptions in advance 1 200 1 050 Subscriptions in arrears 5 215 5 830 Total shop trade payables 4 275 4 990 Shop inventory 2 500 2 500 Balance at bank 240 110 For the year to 31 December 2020 Subscriptions received 36 700 Shop purchases 34 200 Shop purchases returns 1 710 Interest charged on overdue shop trade payables accounts 200 REQUIRED (a) Prepare the subscriptions account for the year ended 31 December 2020. Balance the account and bring down the balances on 1 January 2021. RIA Music Club Subscriptions account Date Details $ Date Details $ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ [6] (b) Prepare the total shop trade payables account for the year ended 31 December 2020 to calculate the amount paid to shop trade payables. RIA Music Club Total shop trade payables account Date Details $ Date Details $ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ ................................... ............ [6] (c) Calculate the revenue from shop sales for the year ended 31 December 2020. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] The treasurer is concerned about the decreasing bank balance and the increase in shop trade payables. He is looking into the possibility of renting out part of the club premises to an art society for $400 per month. REQUIRED (d) Advise the treasurer whether renting out part of the premises is the most suitable way of improving cash flow or whether other methods may be more suitable. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
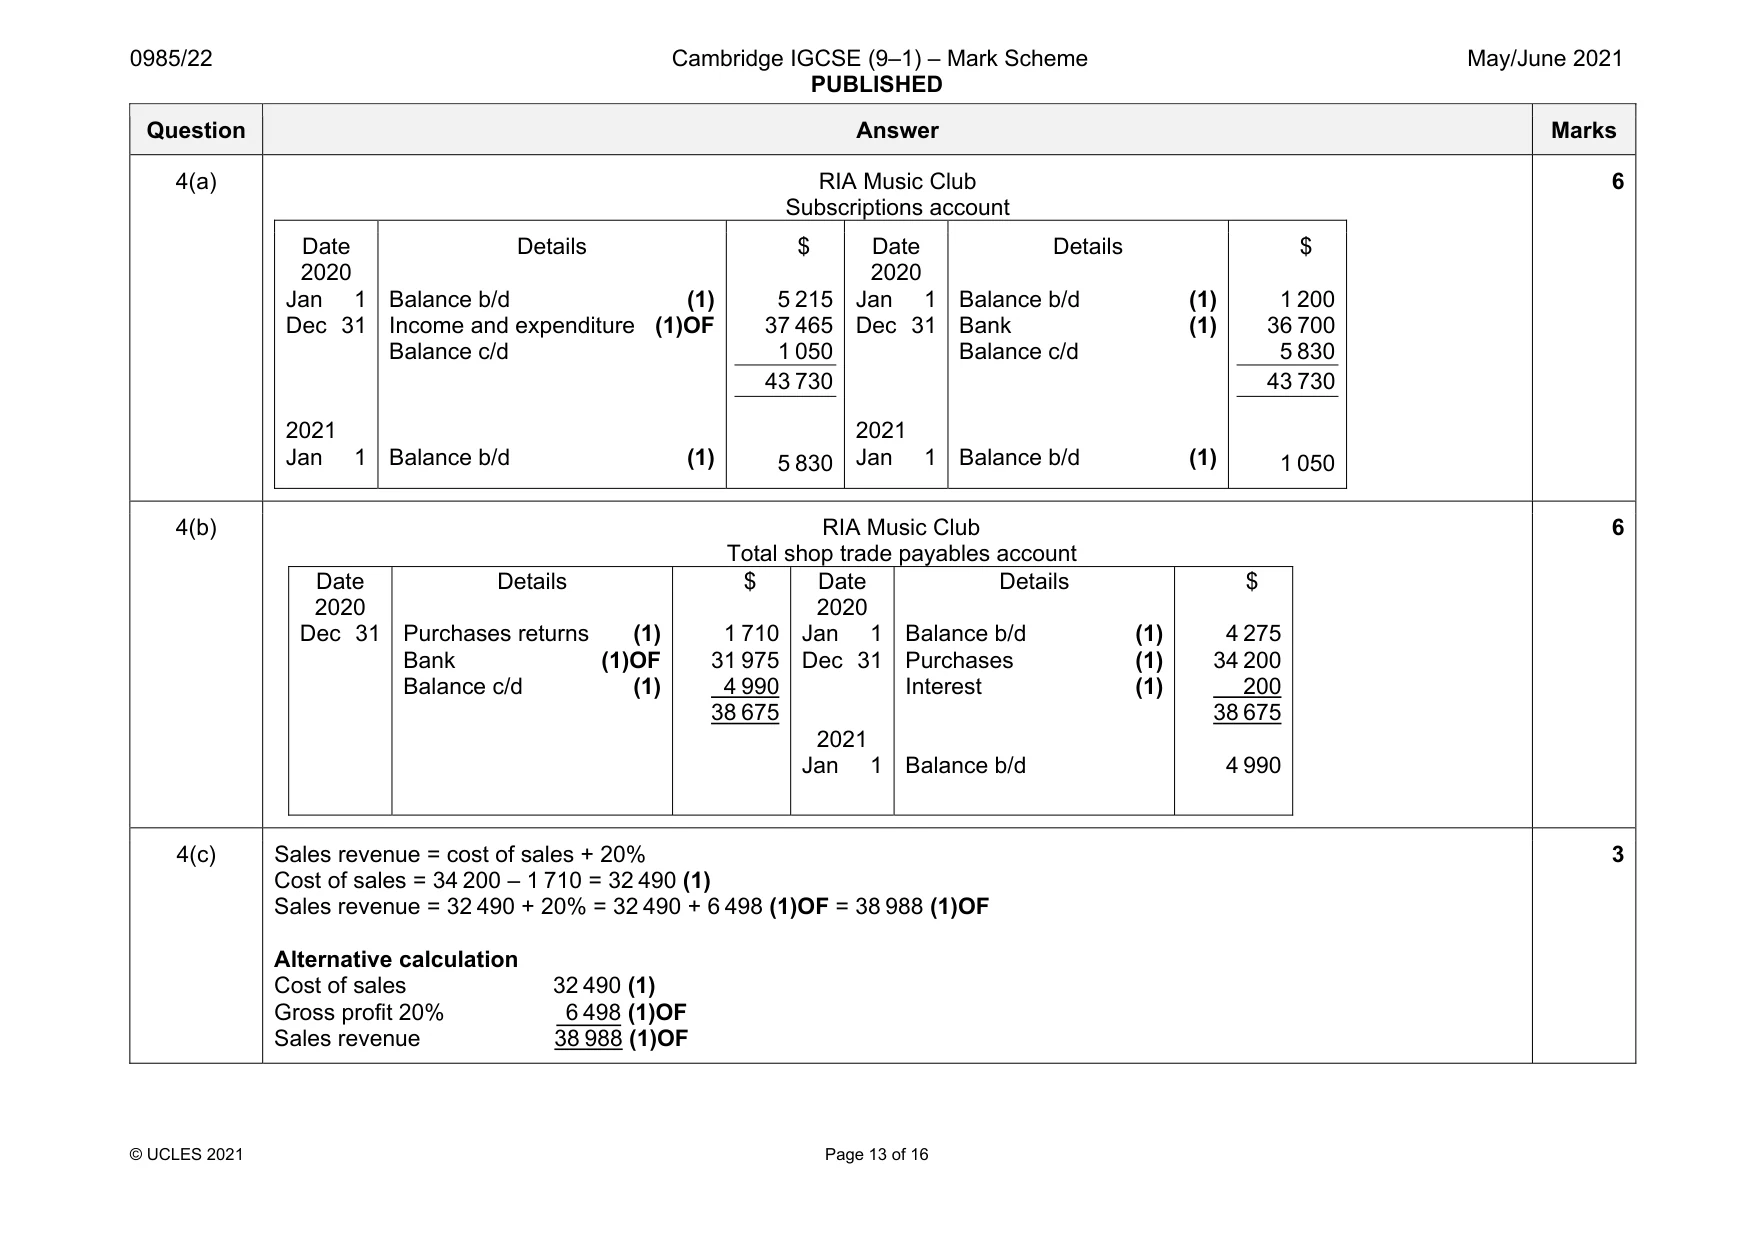
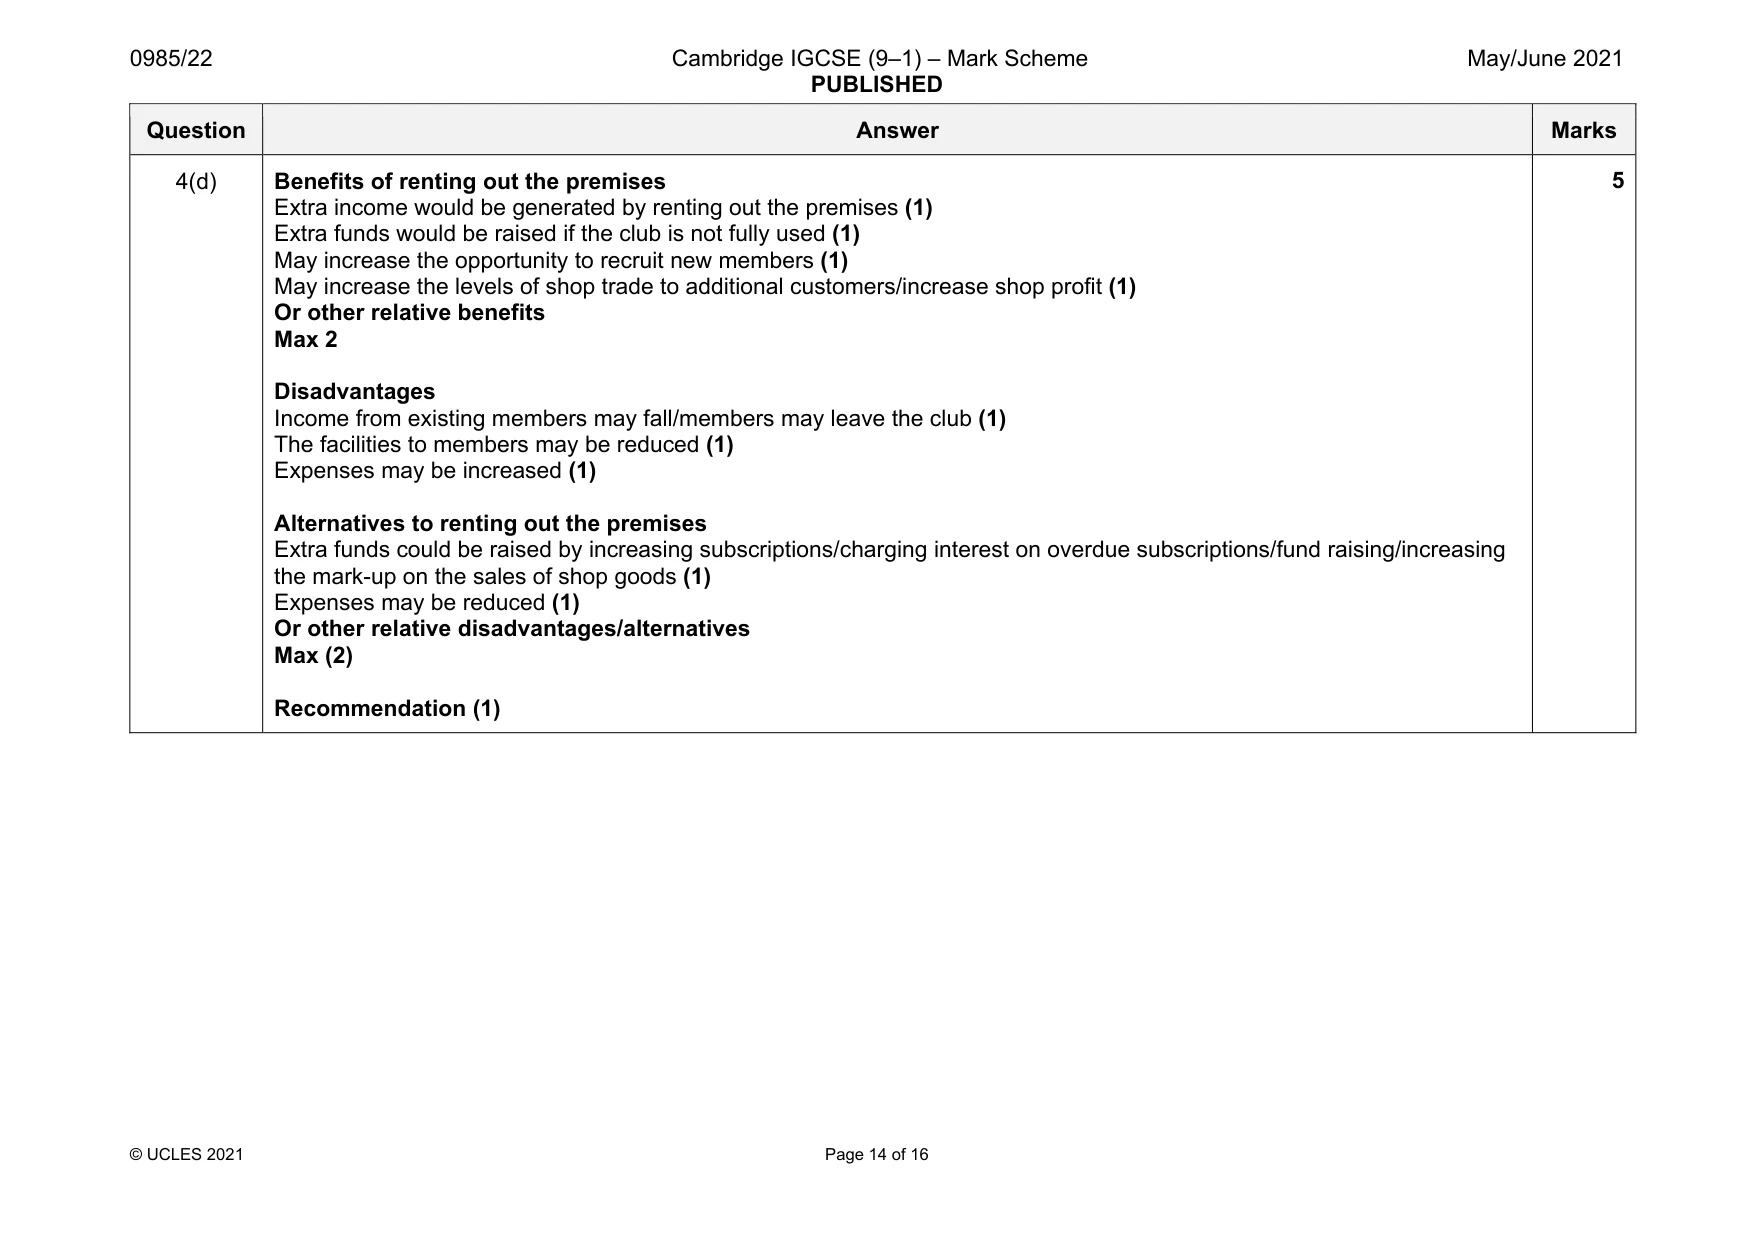
Mark scheme: 4(a) RIA Music Club Subscriptions account Date 2020 Jan 1 Dec 31 2021 Jan 1 Details Balance b/d (1) Income and expenditure (1)OF Balance c/d Balance b/d (1) $ 5 215 37 465 1 050 43 730 5 830 Date 2020 Jan 1 Dec 31 2021 Jan 1 Details Balance b/d (1) Bank (1) Balance c/d Balance b/d (1) $ 1 200 36 700 5 830 43 730 1 050 6 4(b) RIA Music Club Total shop trade payables account Date 2020 Dec 31 Details Purchases returns (1) Bank (1)OF Balance c/d (1) $ 1 710 31 975 4 990 38 675 Date 2020 Jan 1 Dec 31 2021 Jan 1 Details Balance b/d (1) Purchases (1) Interest (1) Balance b/d $ 4 275 34 200 200 38 675 4 990 6 4(c) Sales revenue = cost of sales + 20% Cost of sales = 34 200 – 1 710 = 32 490 (1) Sales revenue = 32 490 + 20% = 32 490 + 6 498 (1)OF = 38 988 (1)OF Alternative calculation Cost of sales 32 490 (1) Gross profit 20% 6 498 (1)OF Sales revenue 38 988 (1)OF 3 Question Answer Marks 4(d) Benefits of renting out the premises Extra income would be generated by renting out the premises (1) Extra funds would be raised if the club is not fully used (1) May increase the opportunity to recruit new members (1) May increase the levels of shop trade to additional customers/increase shop profit (1) Or other relative benefits Max 2 Disadvantages Income from existing members may fall/members may leave the club (1) The facilities to members may be reduced (1) Expenses may be increased (1) Alternatives to renting out the premises Extra funds could be raised by increasing subscriptions/charging interest on overdue subscriptions/fund raising/increasing the mark-up on the sales of shop goods (1) Expenses may be reduced (1) Or other relative disadvantages/alternatives Max (2) Recommendation (1) 5
Q5 · Kia is a trader
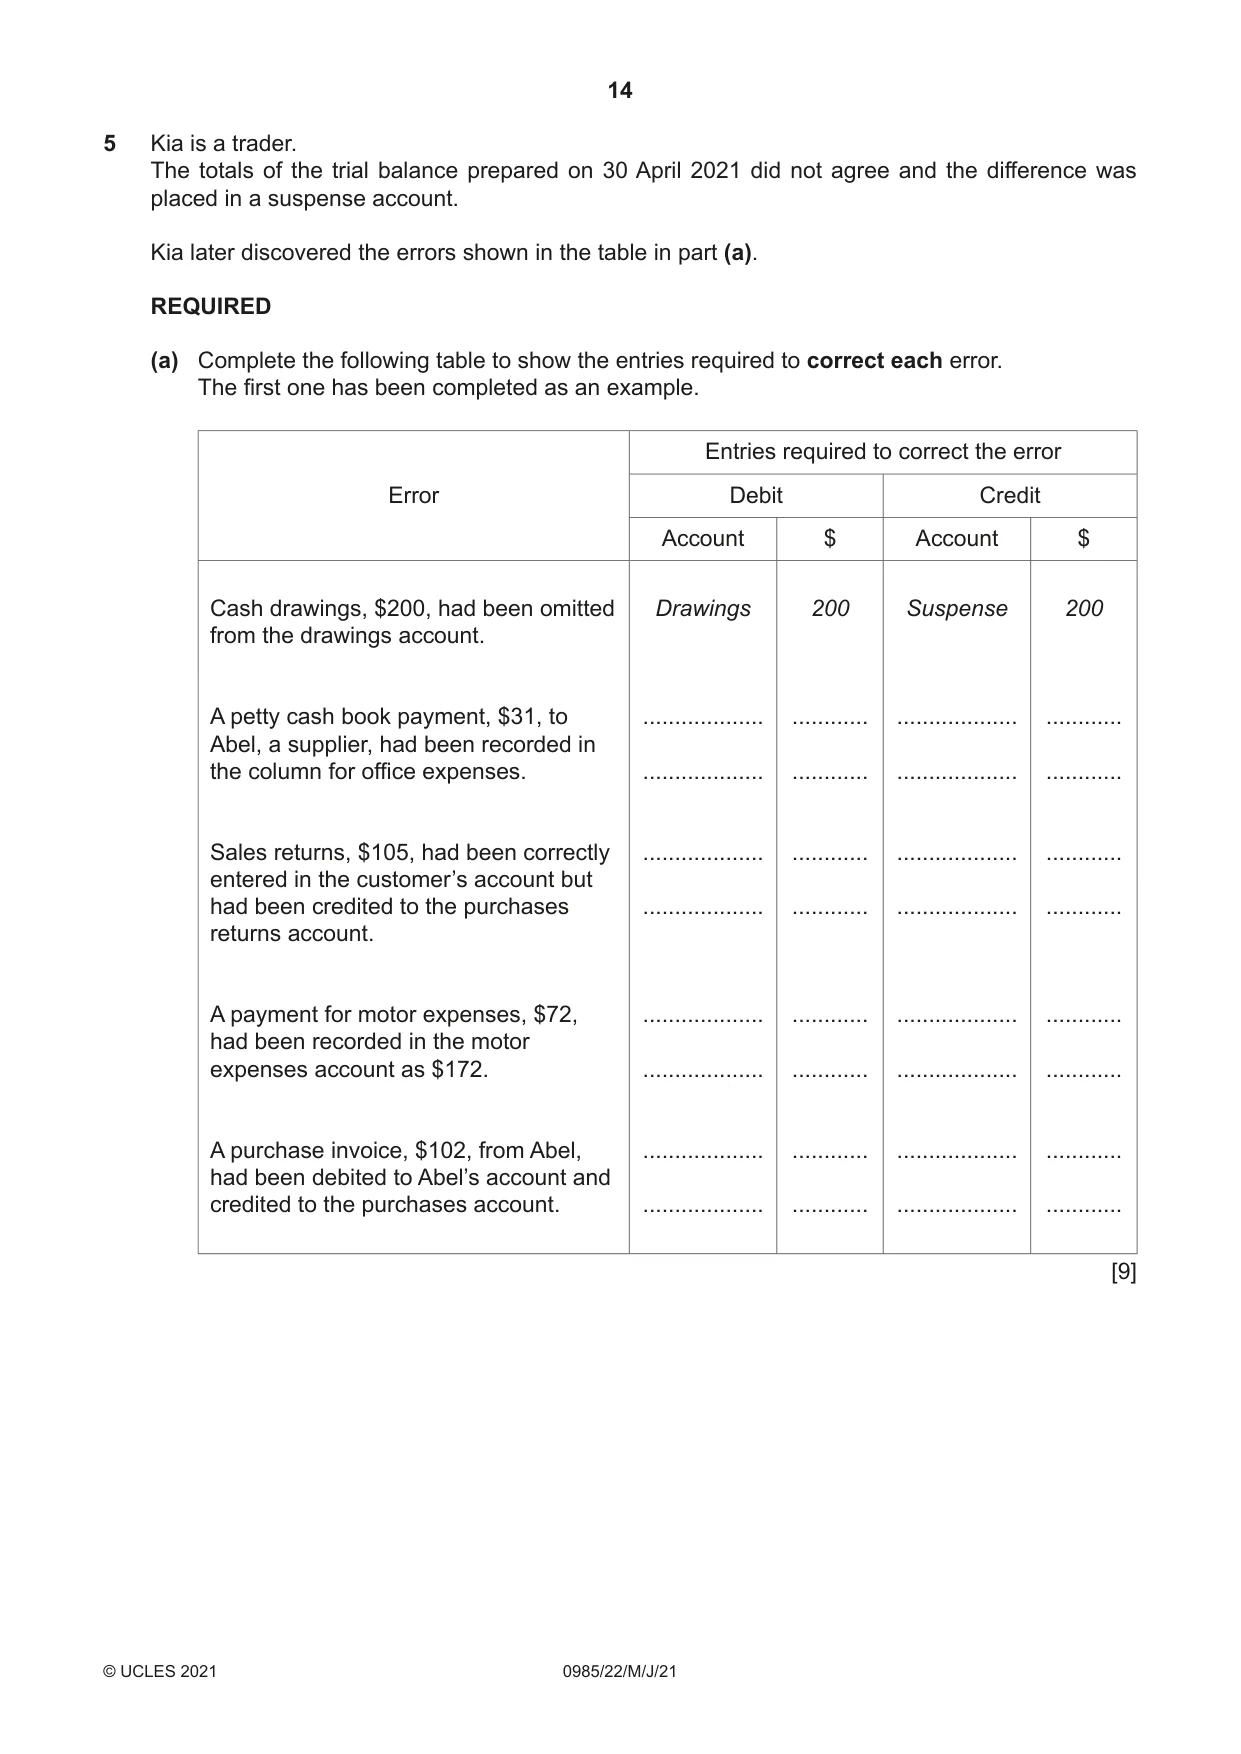
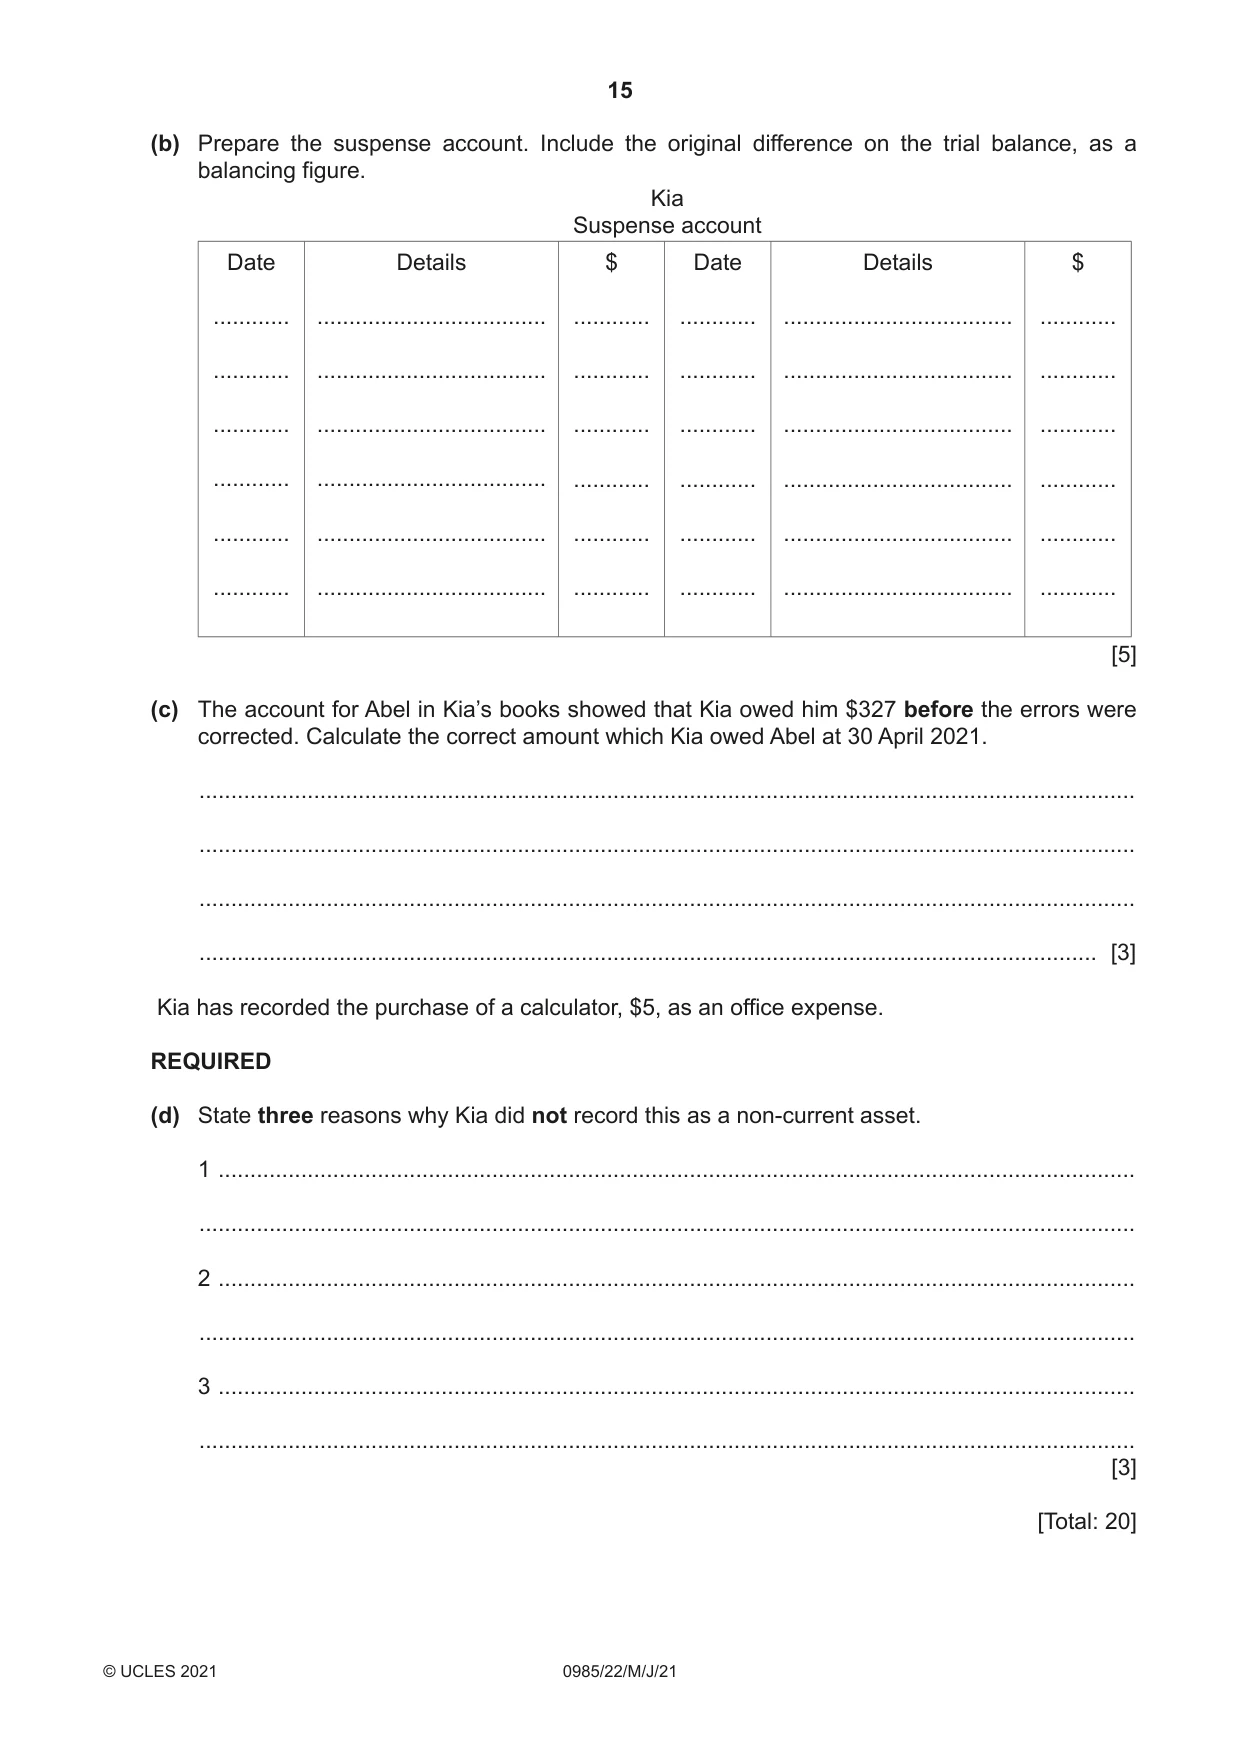
5 Kia is a trader. The totals of the trial balance prepared on 30 April 2021 did not agree and the difference was placed in a suspense account. Kia later discovered the errors shown in the table in part (a). REQUIRED (a) Complete the following table to show the entries required to correct each error. The first one has been completed as an example. Entries required to correct the error Error Debit Credit Account $ Account $ Cash drawings, $200, had been omitted Drawings 200 Suspense 200 from the drawings account. A petty cash book payment, $31, to ................... ............ ................... ............ Abel, a supplier, had been recorded in the column for office expenses. ................... ............ ................... ............ Sales returns, $105, had been correctly ................... ............ ................... ............ entered in the customer’s account but had been credited to the purchases ................... ............ ................... ............ returns account. A payment for motor expenses, $72, ................... ............ ................... ............ had been recorded in the motor expenses account as $172. ................... ............ ................... ............ A purchase invoice, $102, from Abel, ................... ............ ................... ............ had been debited to Abel’s account and credited to the purchases account. ................... ............ ................... ............ [9] (b) Prepare the suspense account. Include the original difference on the trial balance, as a balancing figure. Kia Suspense account Date Details $ Date Details $ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ ............ .................................... ............ [5] (c) The account for Abel in Kia’s books showed that Kia owed him $327 before the errors were corrected. Calculate the correct amount which Kia owed Abel at 30 April 2021. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] Kia has recorded the purchase of a calculator, $5, as an office expense. REQUIRED (d) State three reasons why Kia did not record this as a non-current asset. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... 3 ................................................................................................................................................ ................................................................................................................................................... [3] [Total: 20]
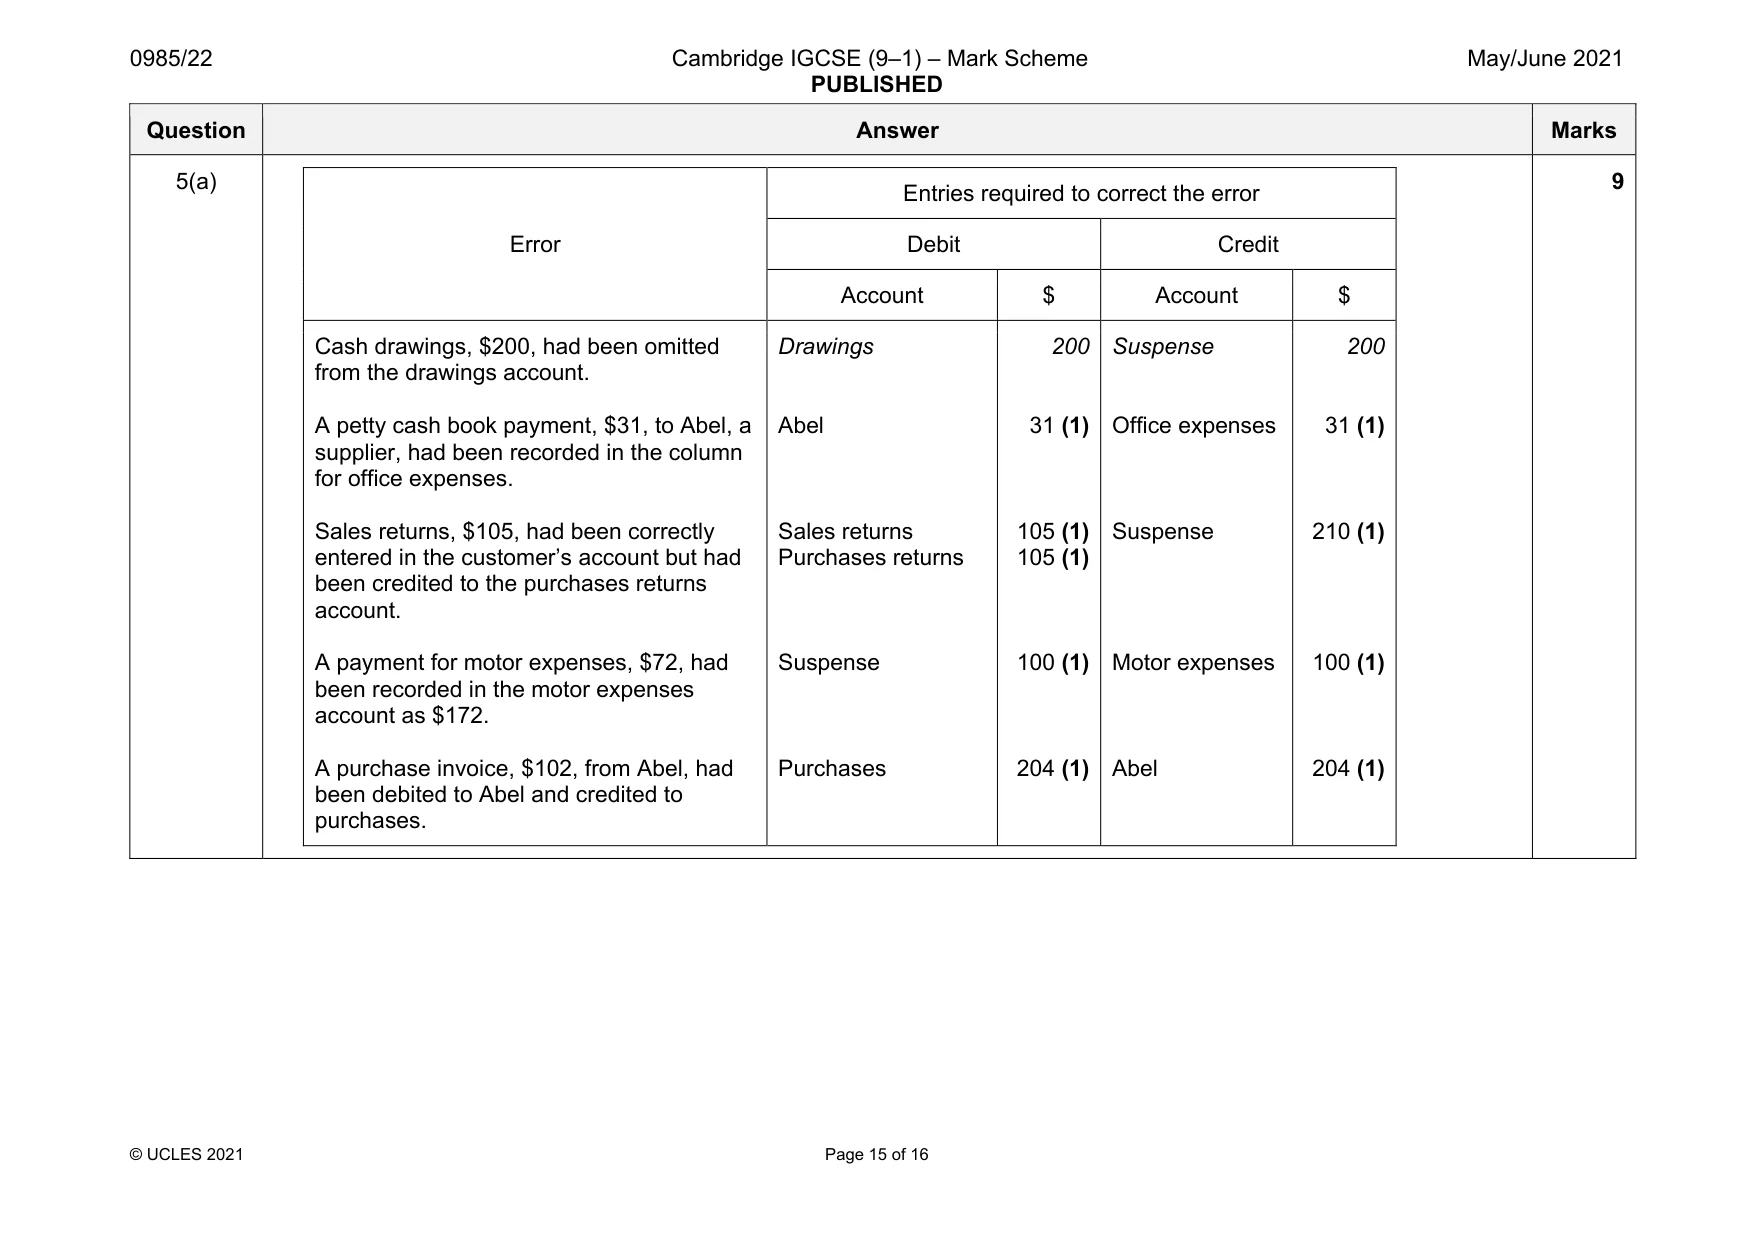
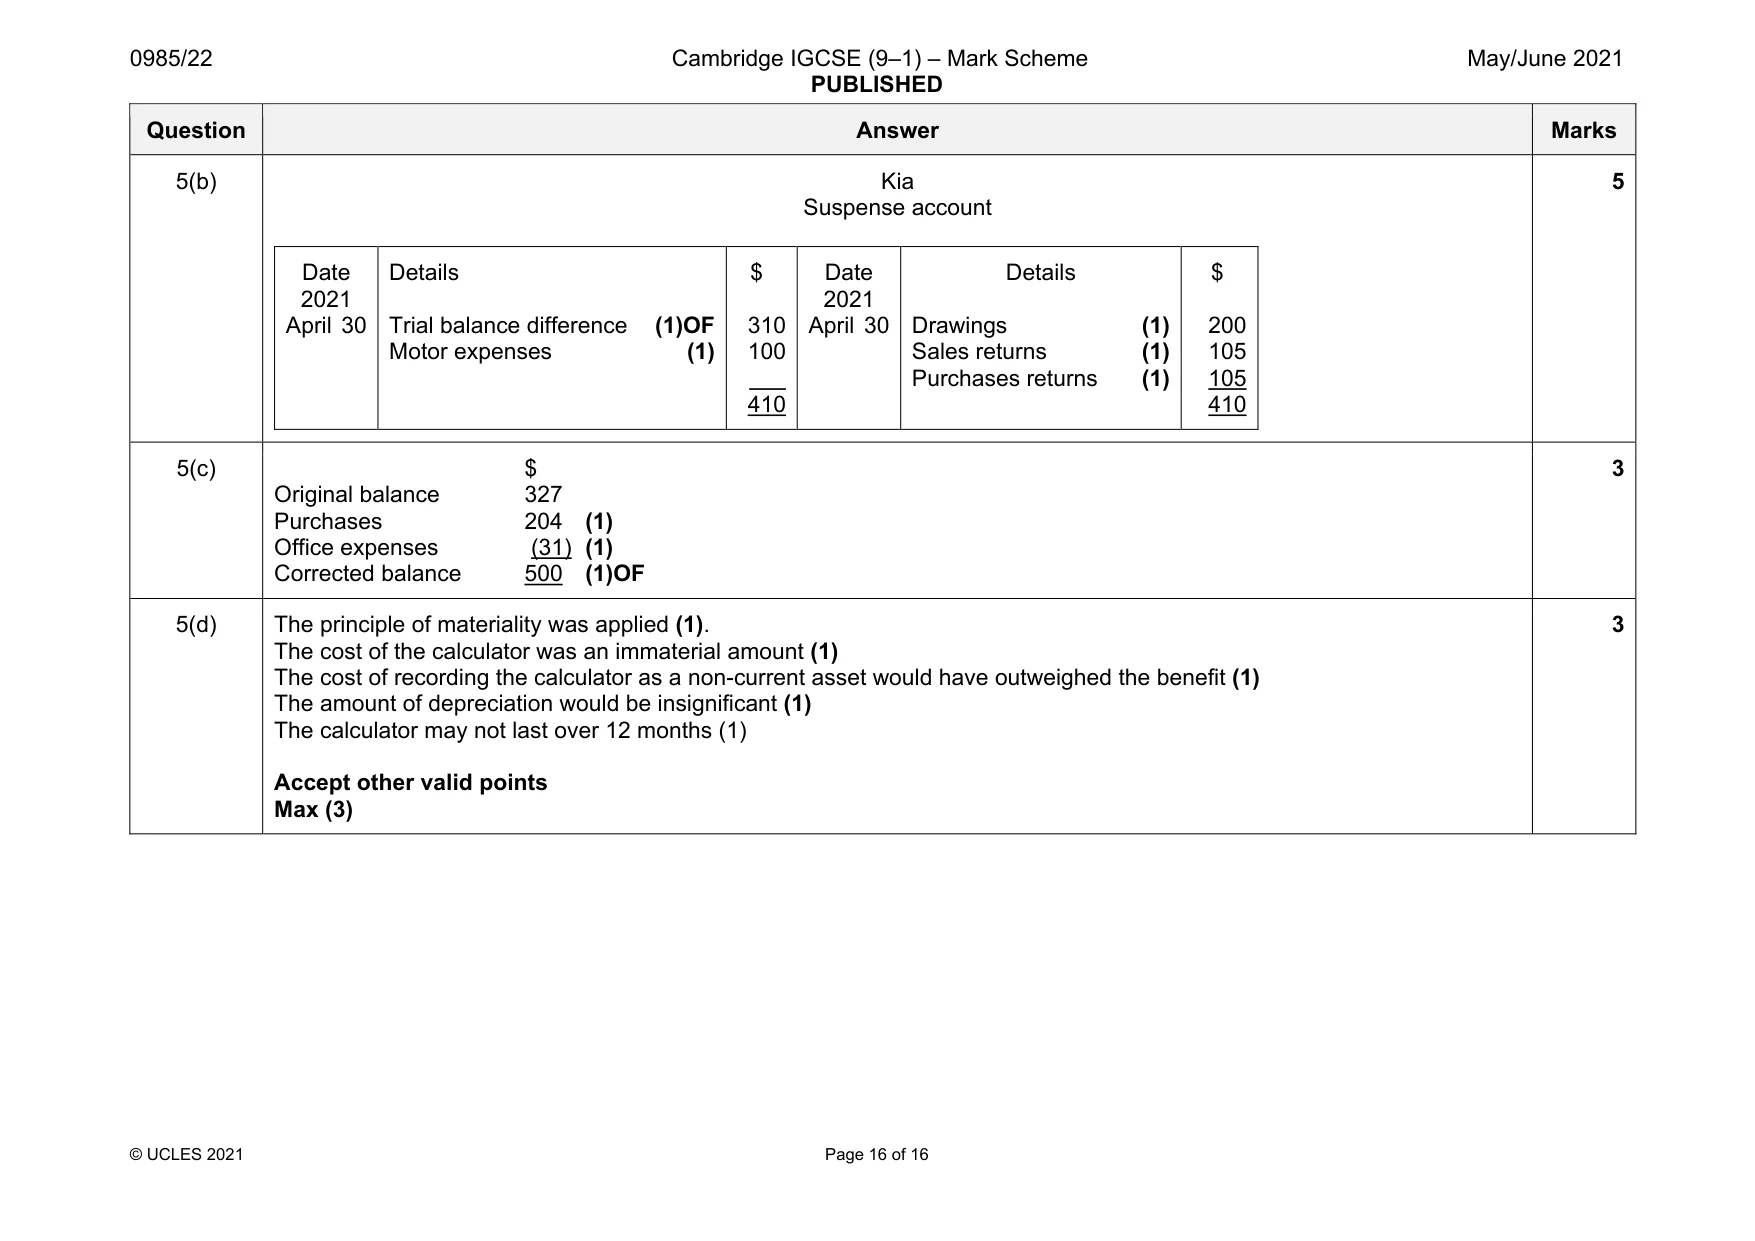
Mark scheme: 5(a) Error Entries required to correct the error Debit Credit Account $ Account $ Cash drawings, $200, had been omitted from the drawings account. A petty cash book payment, $31, to Abel, a supplier, had been recorded in the column for office expenses. Sales returns, $105, had been correctly entered in the customer’s account but had been credited to the purchases returns account. A payment for motor expenses, $72, had been recorded in the motor expenses account as $172. A purchase invoice, $102, from Abel, had been debited to Abel and credited to purchases. Drawings Abel Sales returns Purchases returns Suspense Purchases 200 31 (1) 105 (1) 105 (1) 100 (1) 204 (1) Suspense Office expenses Suspense Motor expenses Abel 200 31 (1) 210 (1) 100 (1) 204 (1) 9 Question Answer Marks 5(b) Kia Suspense account Date 2021 April 30 Details Trial balance difference (1)OF Motor expenses (1) $ 310 100 410 Date 2021 April 30 Details Drawings (1) Sales returns (1) Purchases returns (1) $ 200 105 105 410 5 5(c) $ Original balance 327 Purchases 204 (1) Office expenses (31) (1) Corrected balance 500 (1)OF 3 5(d) The principle of materiality was applied (1). The cost of the calculator was an immaterial amount (1) The cost of recording the calculator as a non-current asset would have outweighed the benefit (1) The amount of depreciation would be insignificant (1) The calculator may not last over 12 months (1) Accept other valid points Max (3) 3
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2021 May/June, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.