Cambridge IGCSE Accounting (9-1) 0985 — 2022 May/June Paper 2 · Variant 1
0985/21/M/J/22 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme14 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Nakul is a trader
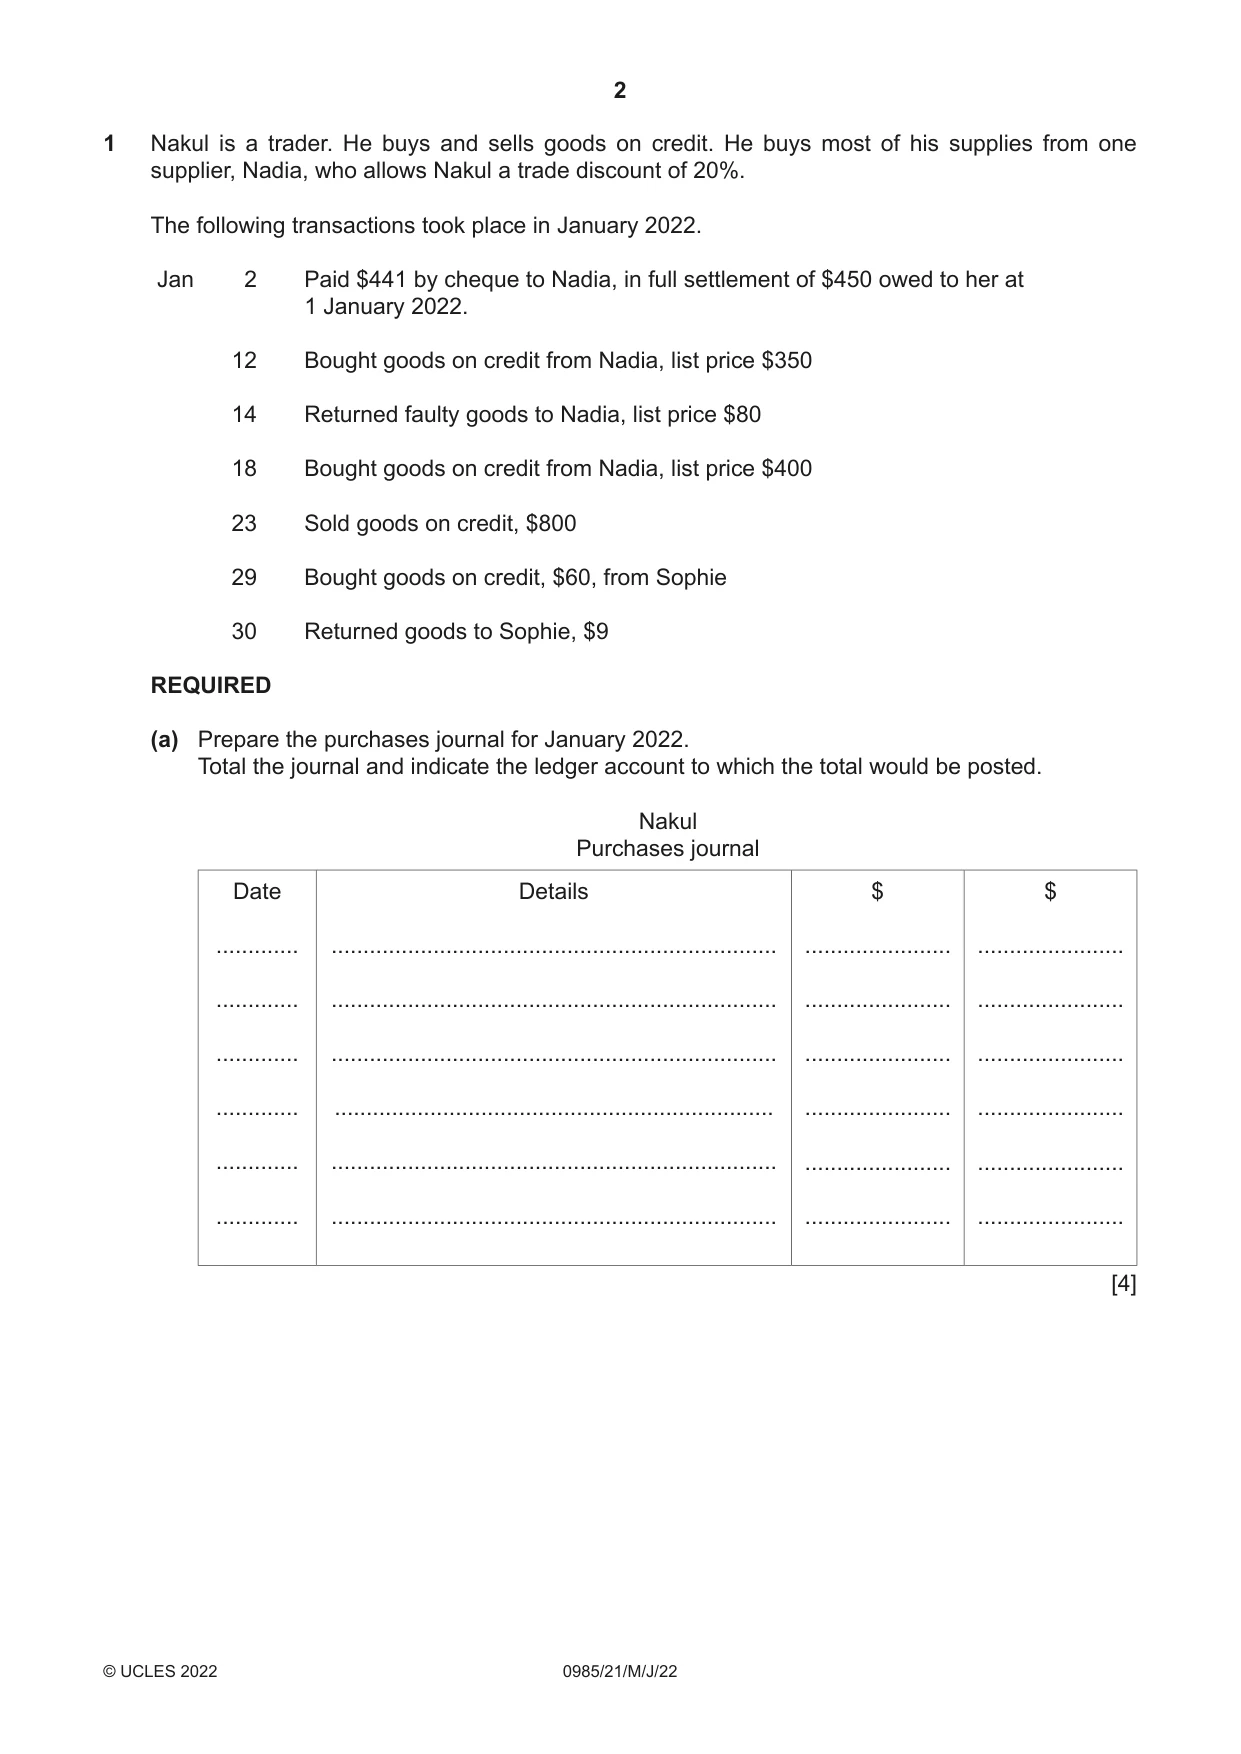
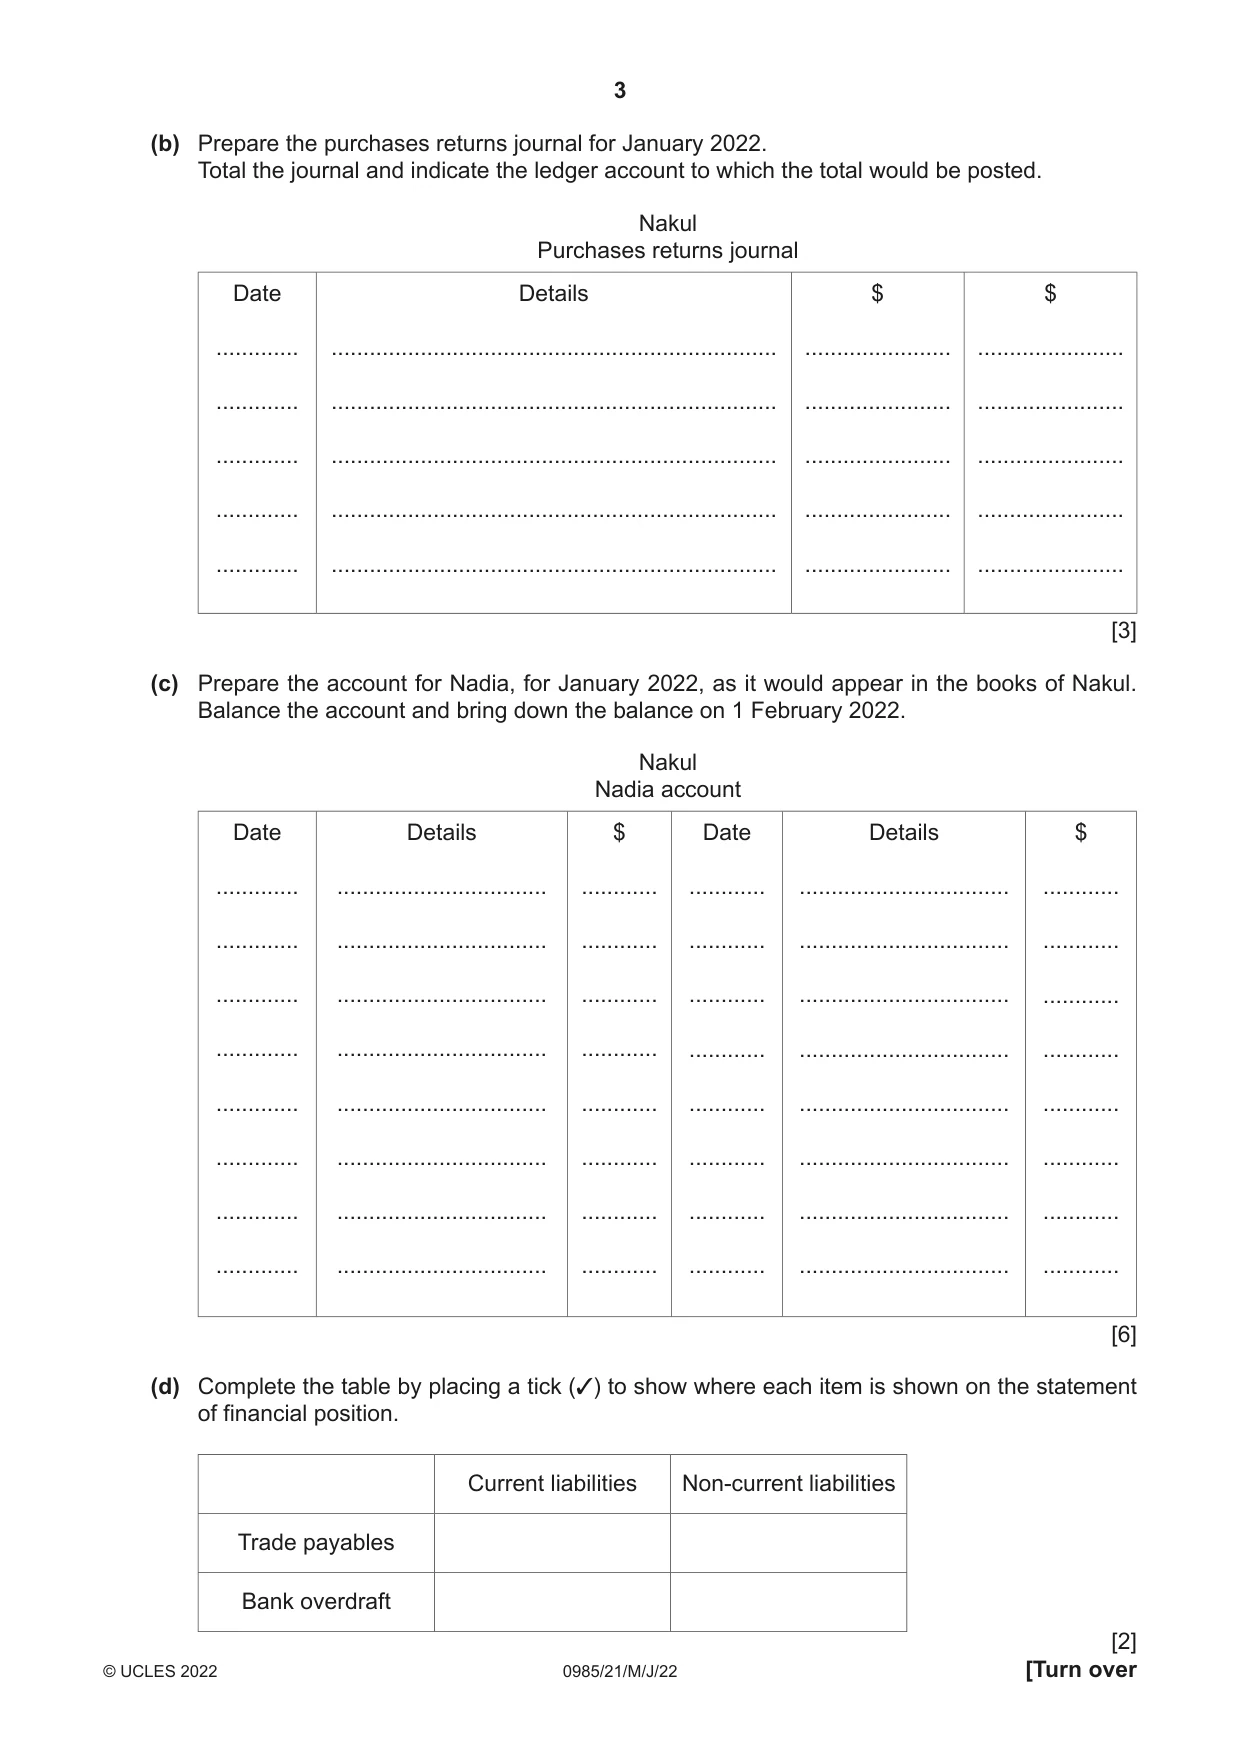
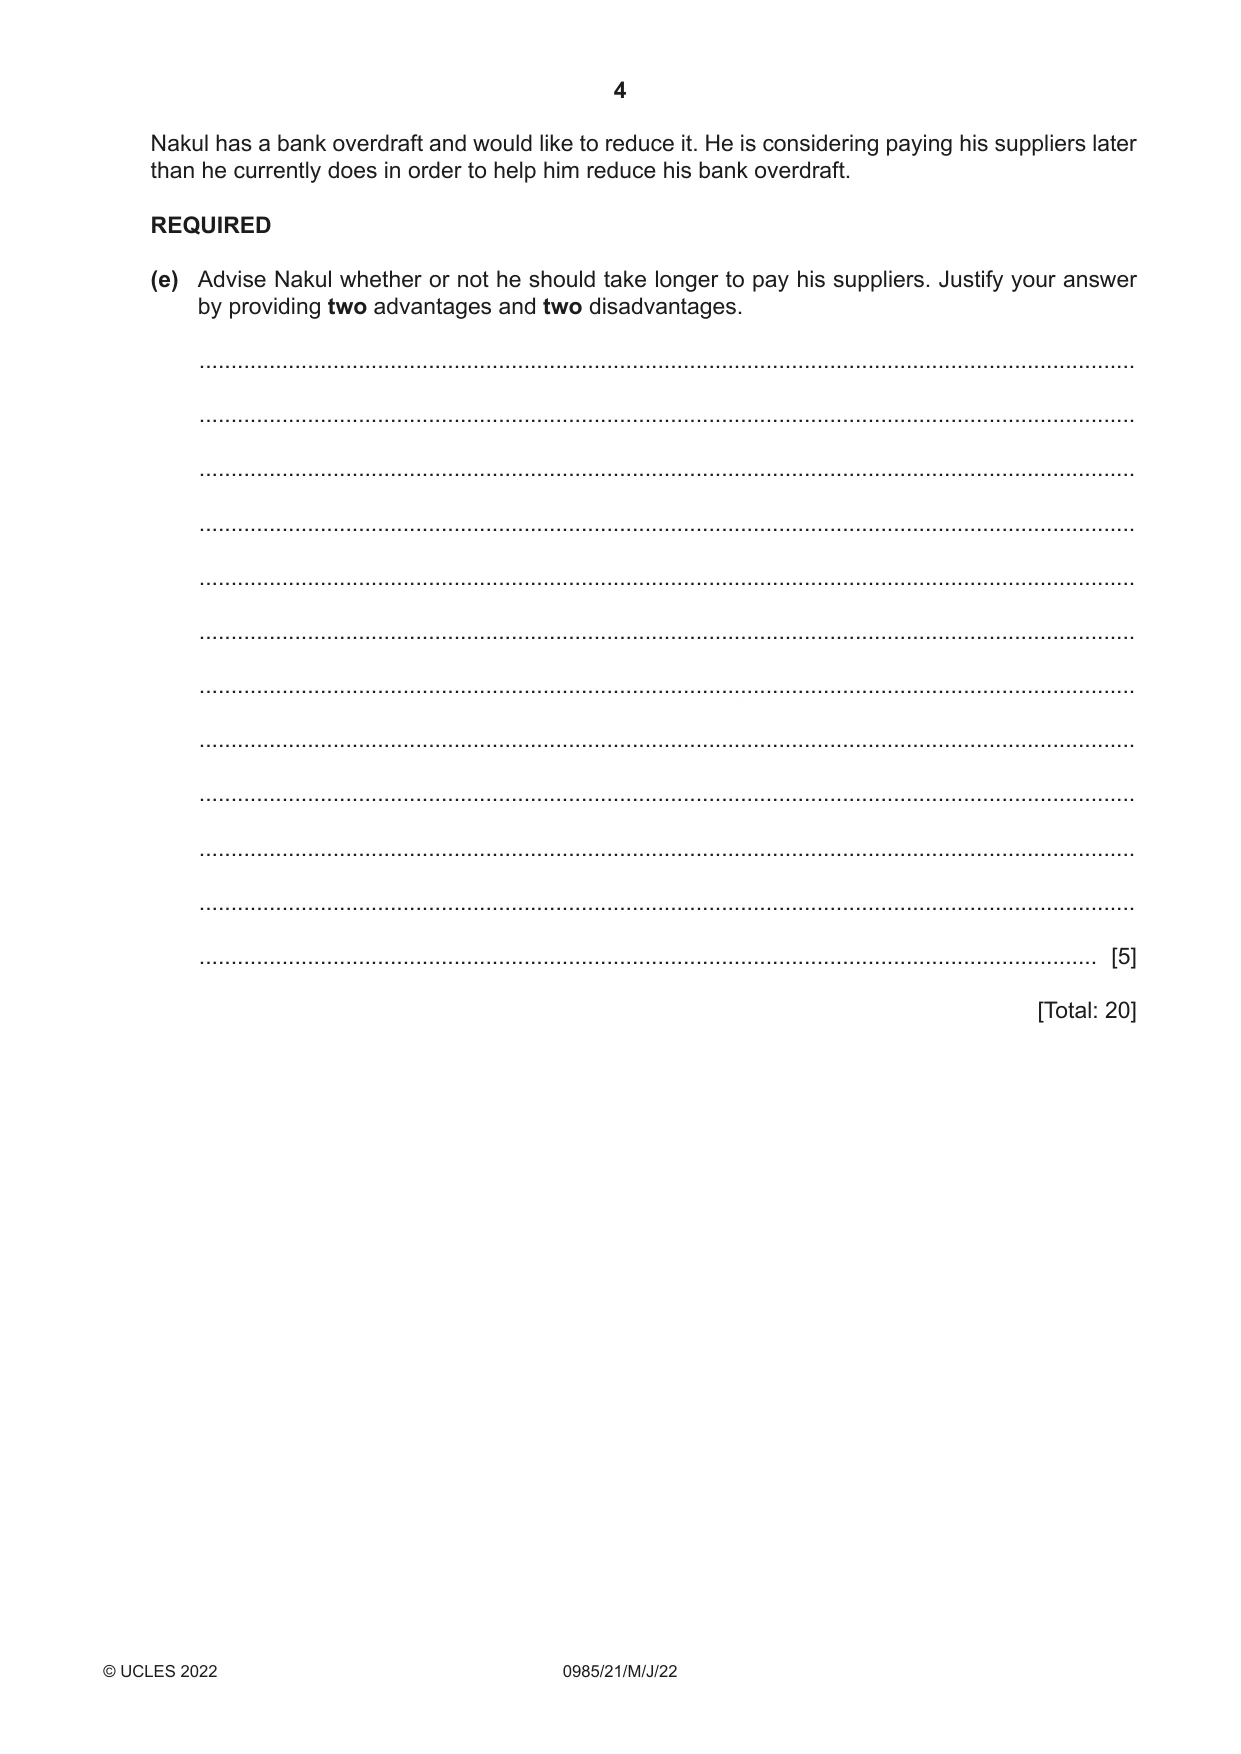
1 Nakul is a trader. He buys and sells goods on credit. He buys most of his supplies from one supplier, Nadia, who allows Nakul a trade discount of 20%. The following transactions took place in January 2022. Jan 2 Paid $441 by cheque to Nadia, in full settlement of $450 owed to her at 1 January 2022. 12 Bought goods on credit from Nadia, list price $350 14 Returned faulty goods to Nadia, list price $80 18 Bought goods on credit from Nadia, list price $400 23 Sold goods on credit, $800 29 Bought goods on credit, $60, from Sophie 30 Returned goods to Sophie, $9 REQUIRED (a) Prepare the purchases journal for January 2022. Total the journal and indicate the ledger account to which the total would be posted. Nakul Purchases journal Date Details $ $ ............. ...................................................................... ....................... ....................... ............. ...................................................................... ....................... ....................... ............. ...................................................................... ....................... ....................... ............. ..................................................................... ....................... ....................... ............. ...................................................................... ....................... ....................... ............. ...................................................................... ....................... ....................... [4] (b) Prepare the purchases returns journal for January 2022. Total the journal and indicate the ledger account to which the total would be posted. Nakul Purchases returns journal Date Details $ $ ............. ...................................................................... ....................... ....................... ............. ...................................................................... ....................... ....................... ............. ...................................................................... ....................... ....................... ............. ...................................................................... ....................... ....................... ............. ...................................................................... ....................... ....................... [3] (c) Prepare the account for Nadia, for January 2022, as it would appear in the books of Nakul. Balance the account and bring down the balance on 1 February 2022. Nakul Nadia account Date Details $ Date Details $ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ ............. ................................. ............ ............ ................................. ............ [6] (d) Complete the table by placing a tick (3) to show where each item is shown on the statement of financial position. Current liabilities Non-current liabilities Trade payables Bank overdraft [2] Nakul has a bank overdraft and would like to reduce it. He is considering paying his suppliers later than he currently does in order to help him reduce his bank overdraft. REQUIRED (e) Advise Nakul whether or not he should take longer to pay his suppliers. Justify your answer by providing two advantages and two disadvantages. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
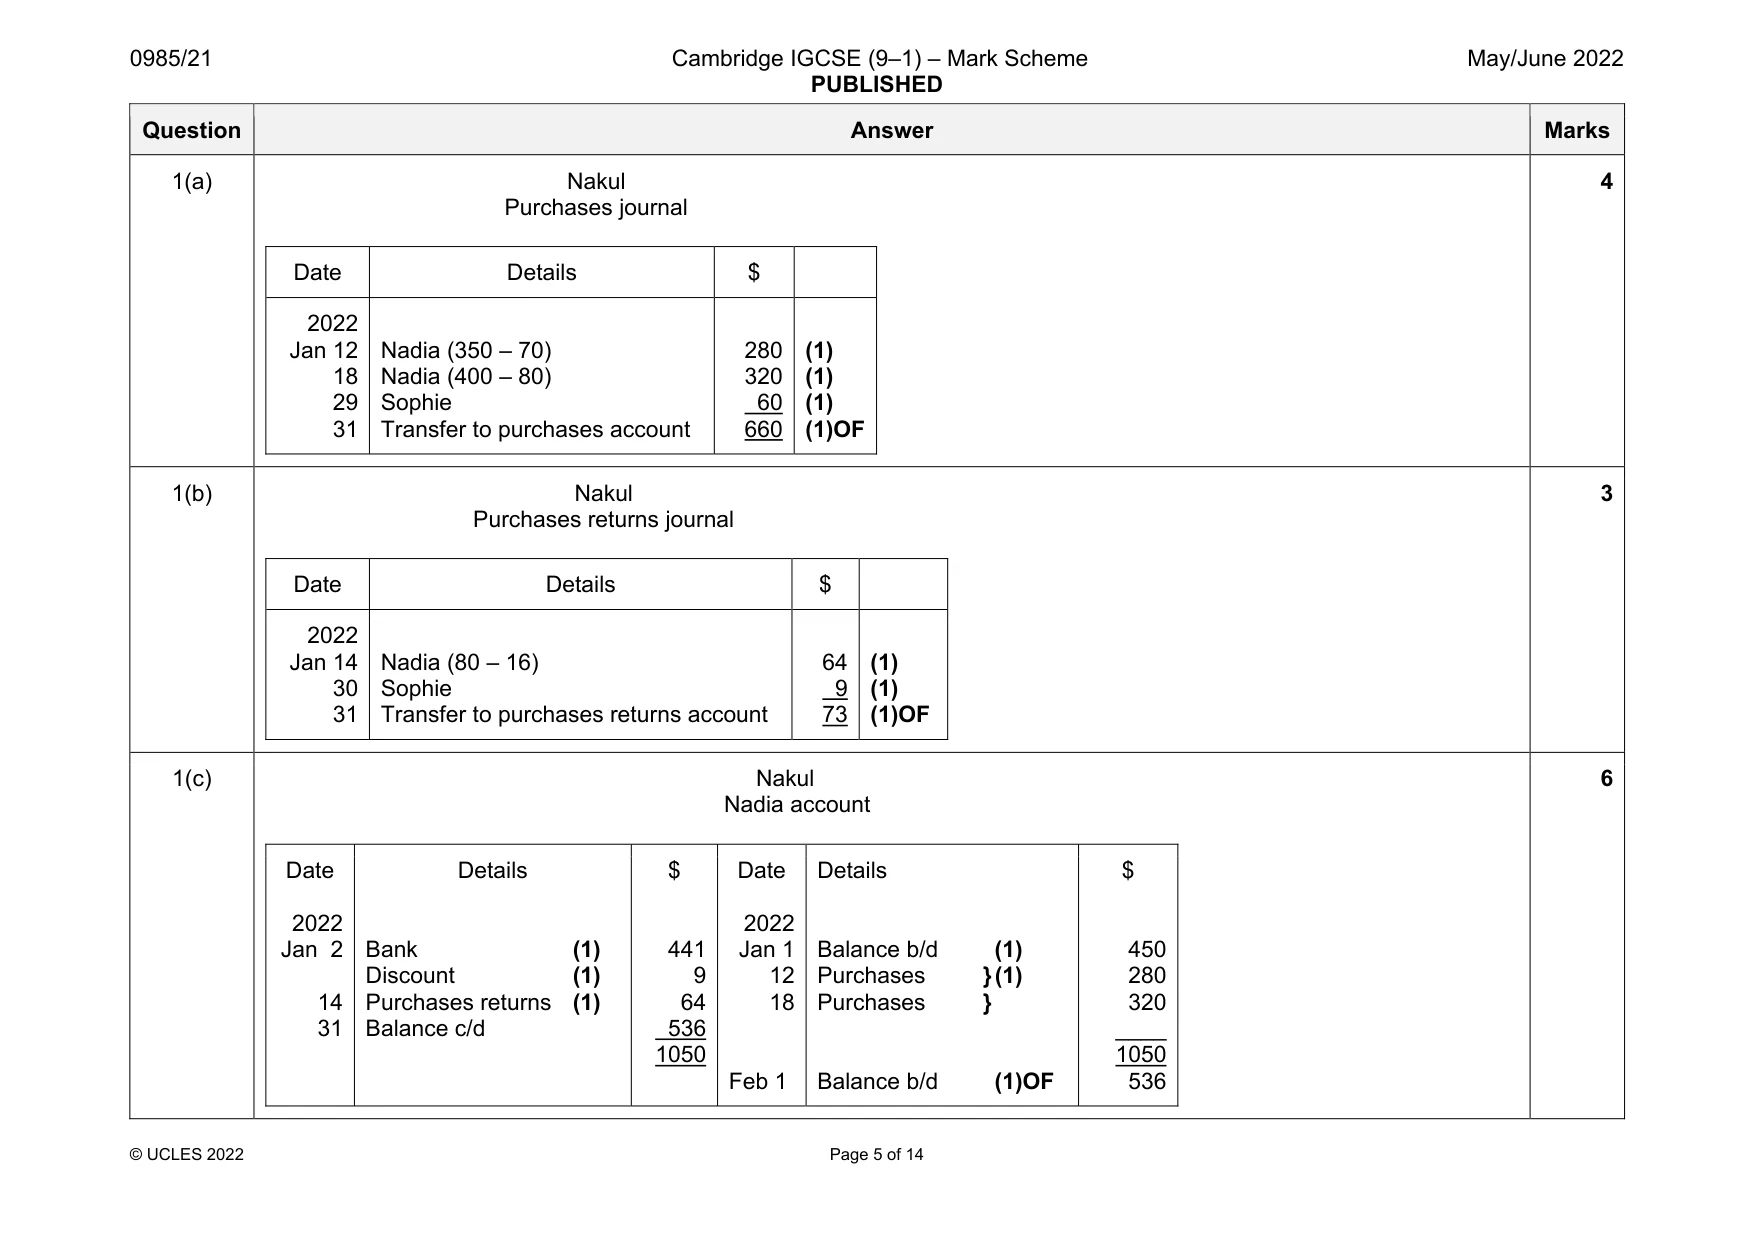
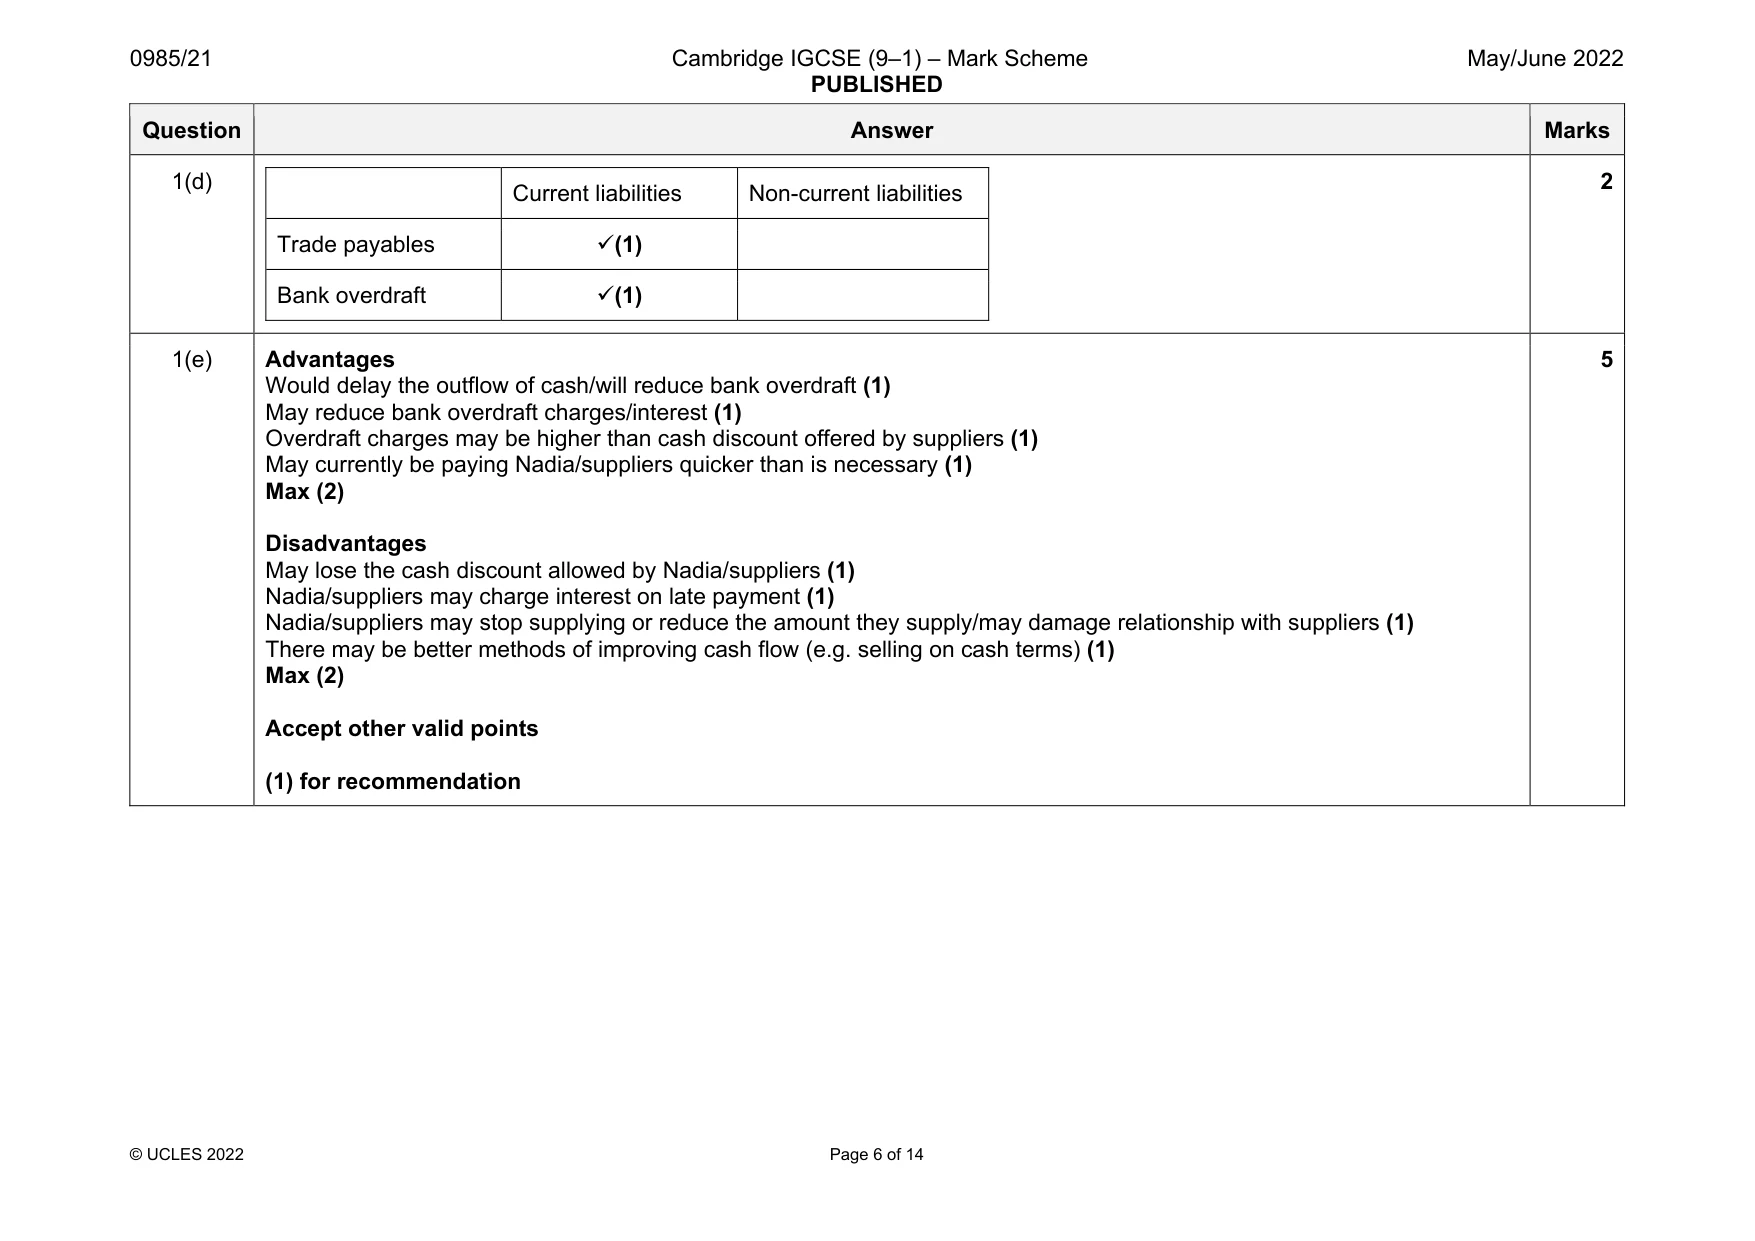
Mark scheme: 1(a) Nakul Purchases journal Date Details $ 2022 Jan 12 18 29 31 Nadia (350 – 70) Nadia (400 – 80) Sophie Transfer to purchases account 280 320 60 660 (1) (1) (1) (1)OF 4 1(b) Nakul Purchases returns journal Date Details $ 2022 Jan 14 30 31 Nadia (80 – 16) Sophie Transfer to purchases returns account 64 9 73 (1) (1) (1)OF 3 1(c) Nakul Nadia account Date 2022 Jan 2 14 31 Details Bank (1) Discount (1) Purchases returns (1) Balance c/d $ 441 9 64 536 1050 Date 2022 Jan 1 12 18 Feb 1 Details Balance b/d (1) Purchases } (1) Purchases } Balance b/d (1)OF $ 450 280 320 ____ 1050 536 6 Question Answer Marks 1(d) Current liabilities Non-current liabilities Trade payables (1) Bank overdraft (1) 2 1(e) Advantages Would delay the outflow of cash/will reduce bank overdraft (1) May reduce bank overdraft charges/interest (1) Overdraft charges may be higher than cash discount offered by suppliers (1) May currently be paying Nadia/suppliers quicker than is necessary (1) Max (2) Disadvantages May lose the cash discount allowed by Nadia/suppliers (1) Nadia/suppliers may charge interest on late payment (1) Nadia/suppliers may stop supplying or reduce the amount they supply/may damage relationship with suppliers (1) There may be better methods of improving cash flow (e.g. selling on cash terms) (1) Max (2) Accept other valid points (1) for recommendation 5
Q2 · Fatima is a sole trader
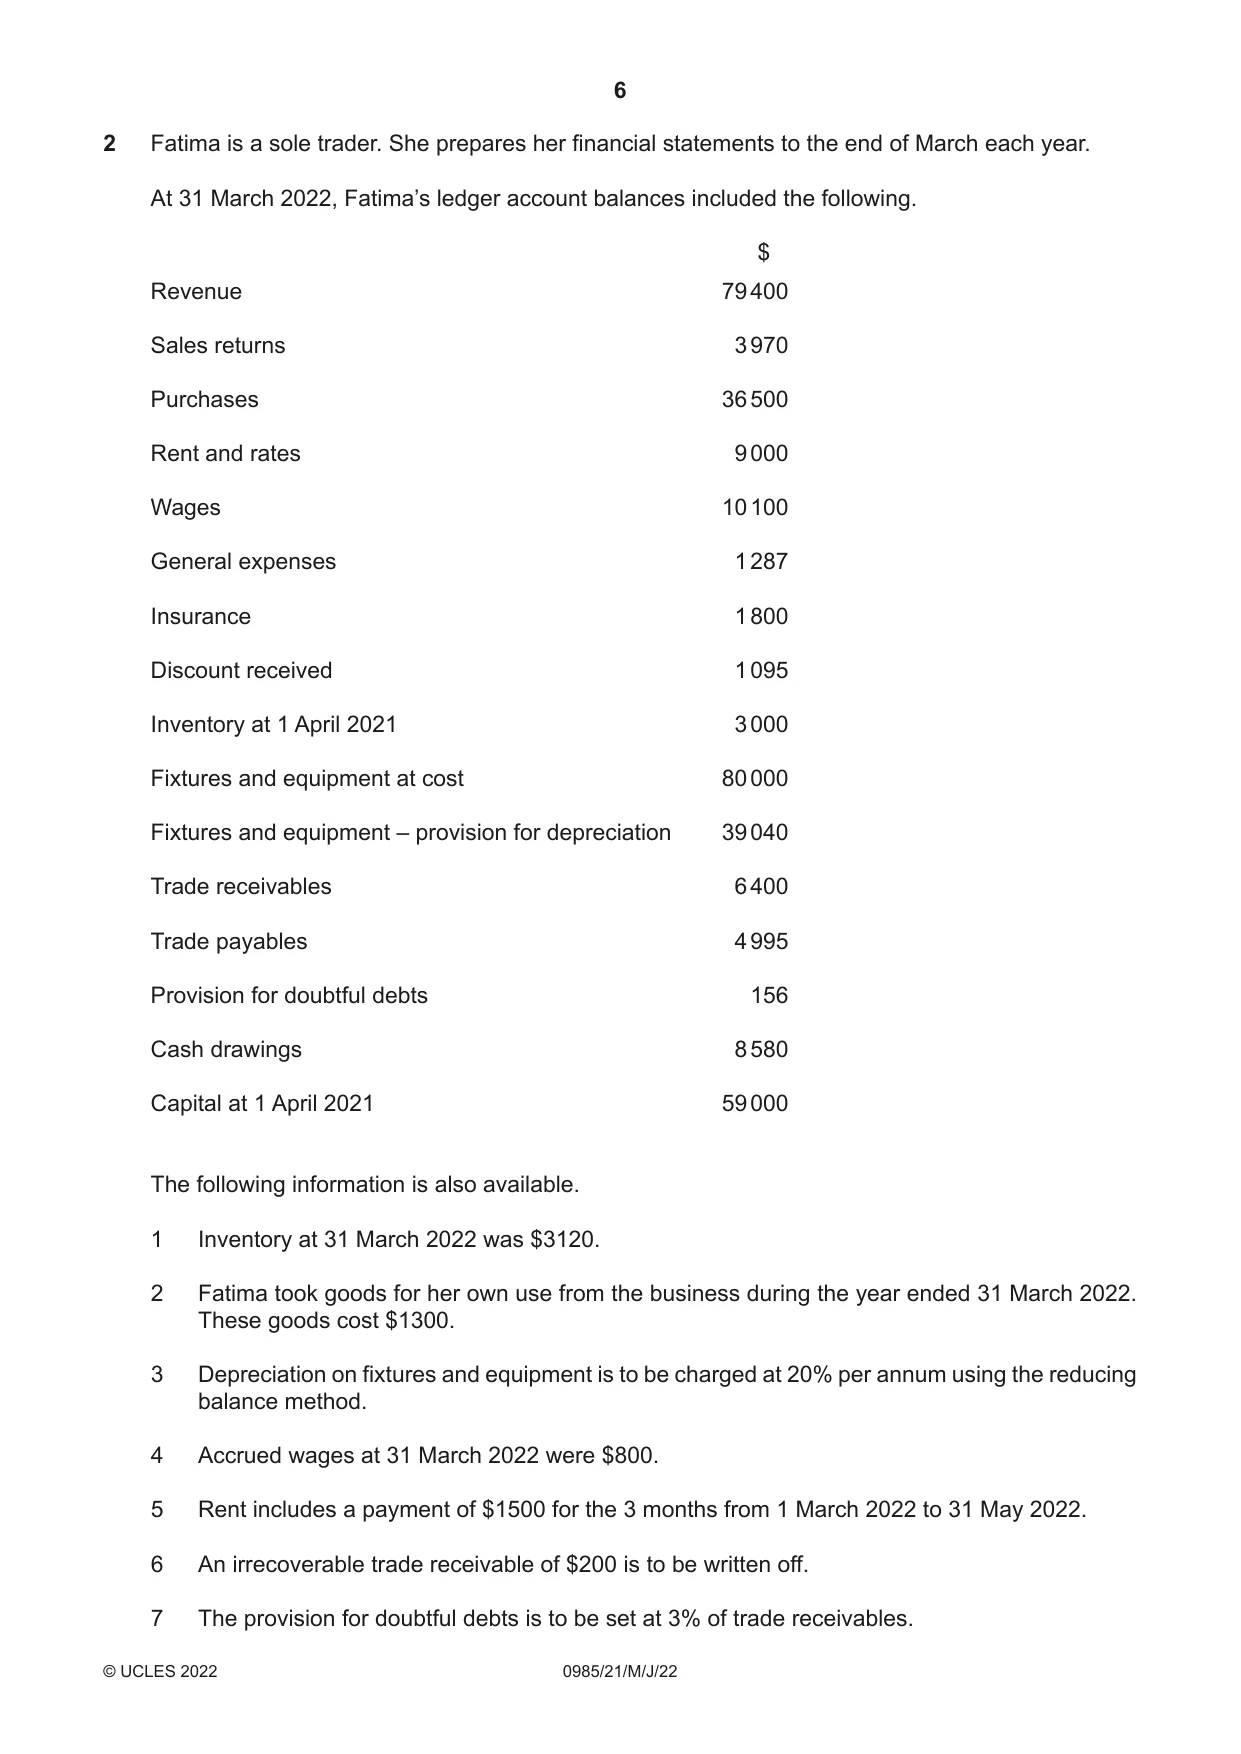
2 Fatima is a sole trader. She prepares her financial statements to the end of March each year. At 31 March 2022, Fatima’s ledger account balances included the following. $ Revenue 79 400 Sales returns 3 970 Purchases 36 500 Rent and rates 9 000 Wages 10 100 General expenses 1 287 Insurance 1 800 Discount received 1 095 Inventory at 1 April 2021 3 000 Fixtures and equipment at cost 80 000 Fixtures and equipment – provision for depreciation 39 040 Trade receivables 6 400 Trade payables 4 995 Provision for doubtful debts 156 Cash drawings 8 580 Capital at 1 April 2021 59 000 The following information is also available. 1 Inventory at 31 March 2022 was $3120. 2 Fatima took goods for her own use from the business during the year ended 31 March 2022. These goods cost $1300. 3 Depreciation on fixtures and equipment is to be charged at 20% per annum using the reducing balance method. 4 Accrued wages at 31 March 2022 were $800. 5 Rent includes a payment of $1500 for the 3 months from 1 March 2022 to 31 May 2022. 6 An irrecoverable trade receivable of $200 is to be written off. 7 The provision for doubtful debts is to be set at 3% of trade receivables. REQUIRED (a) Prepare Fatima’s income statement for the year ended 31 Mar Fatima Income Statement for the year ended 31 ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. ................................................................................................. (b) Prepare Fatima’s capital account for the year ended 31 March 2022. Balance the account and bring down the balance on 1 April 2022. Fatima Capital account Date Details $ Date Details $ ........... ................................. ............ ........... ................................. ............ ........... ................................. ............ ........... ................................. ............ ........... ................................. ............ ........... ................................. ............ ........... ................................. ............ ........... ................................. ............ ........... ................................. ............ ........... ................................. ............ ........... ................................. ............ ........... ................................. ............ [4] Fatima would like to expand the business. She thinks that additional finance of $20 000 would be required for the equipment which she would need. Fatima’s bank have offered to lend her $20 000, to be repaid after four years at interest of 6% per annum. REQUIRED (c) Advise Fatima whether or not to agree to the bank loan. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
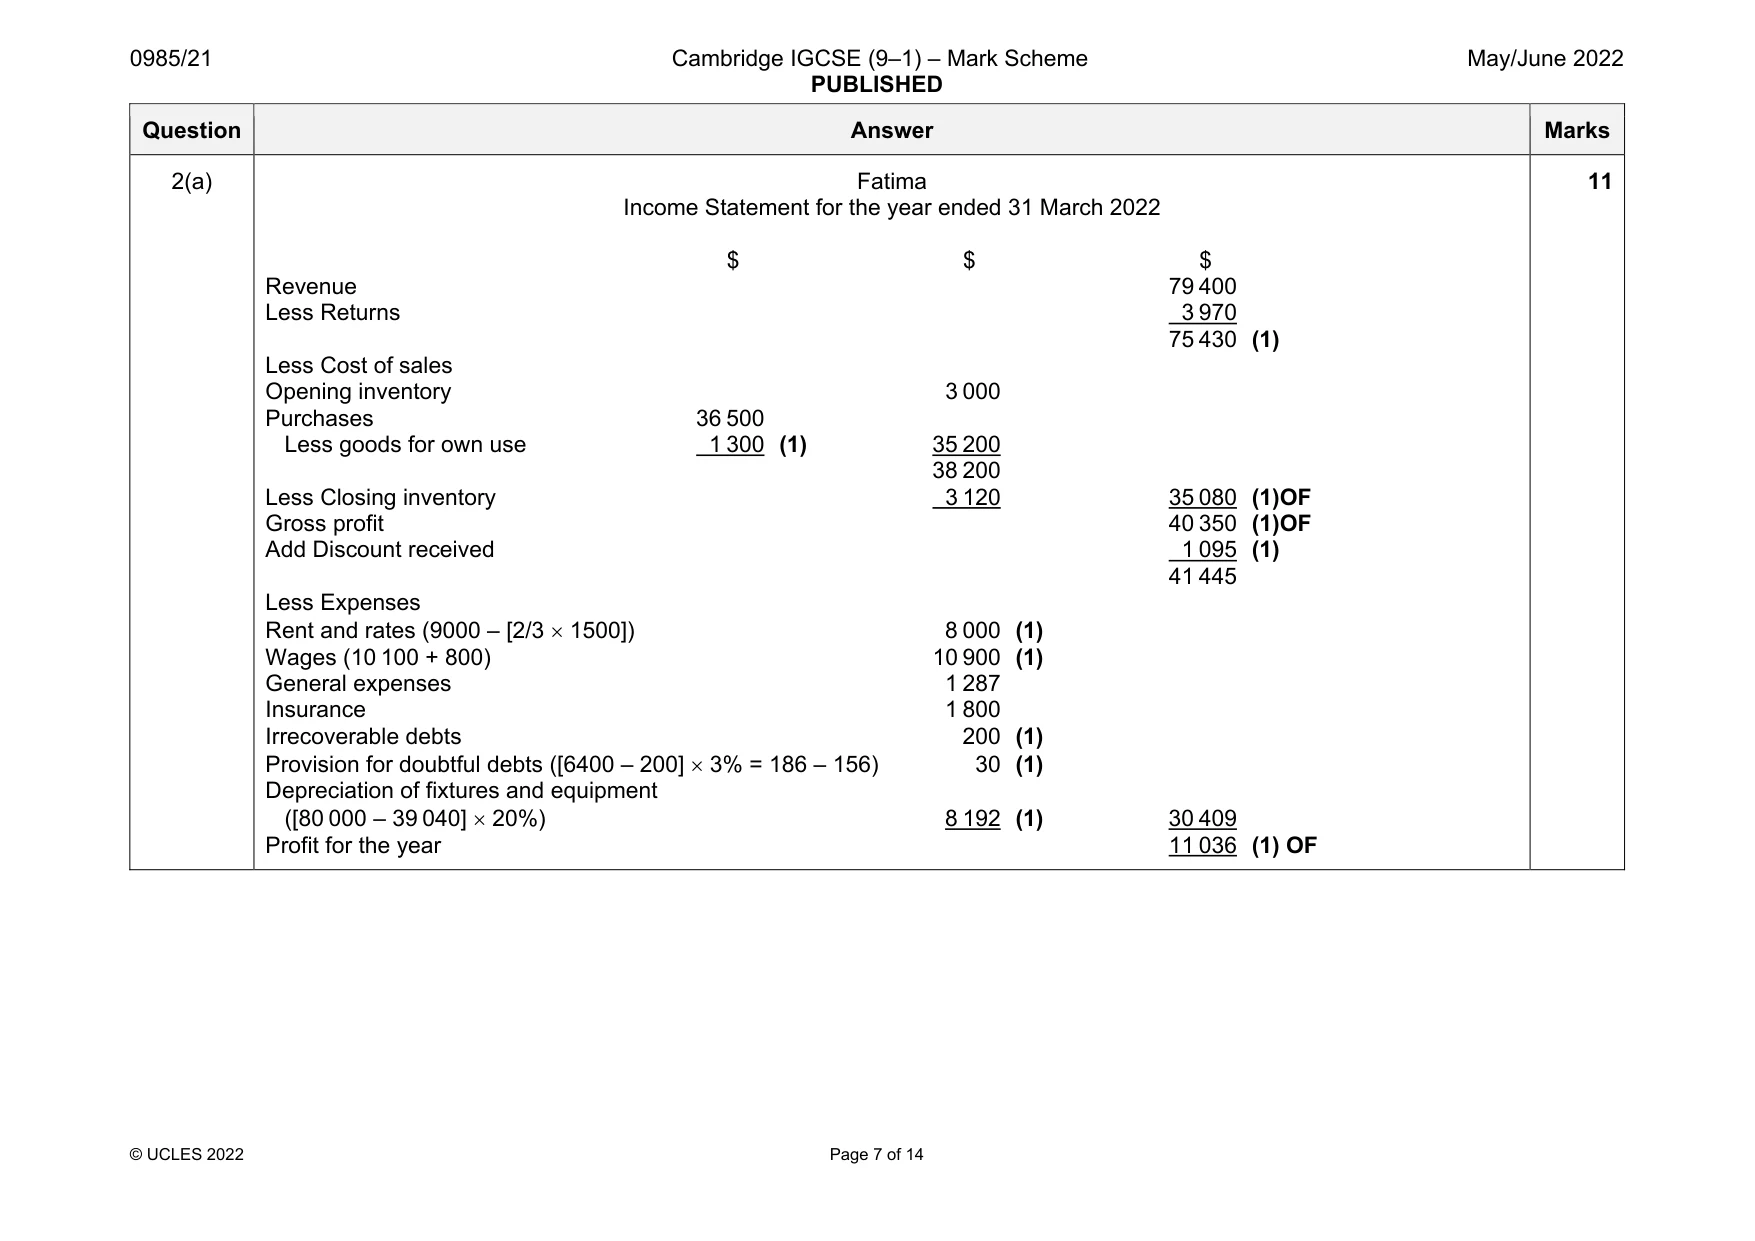
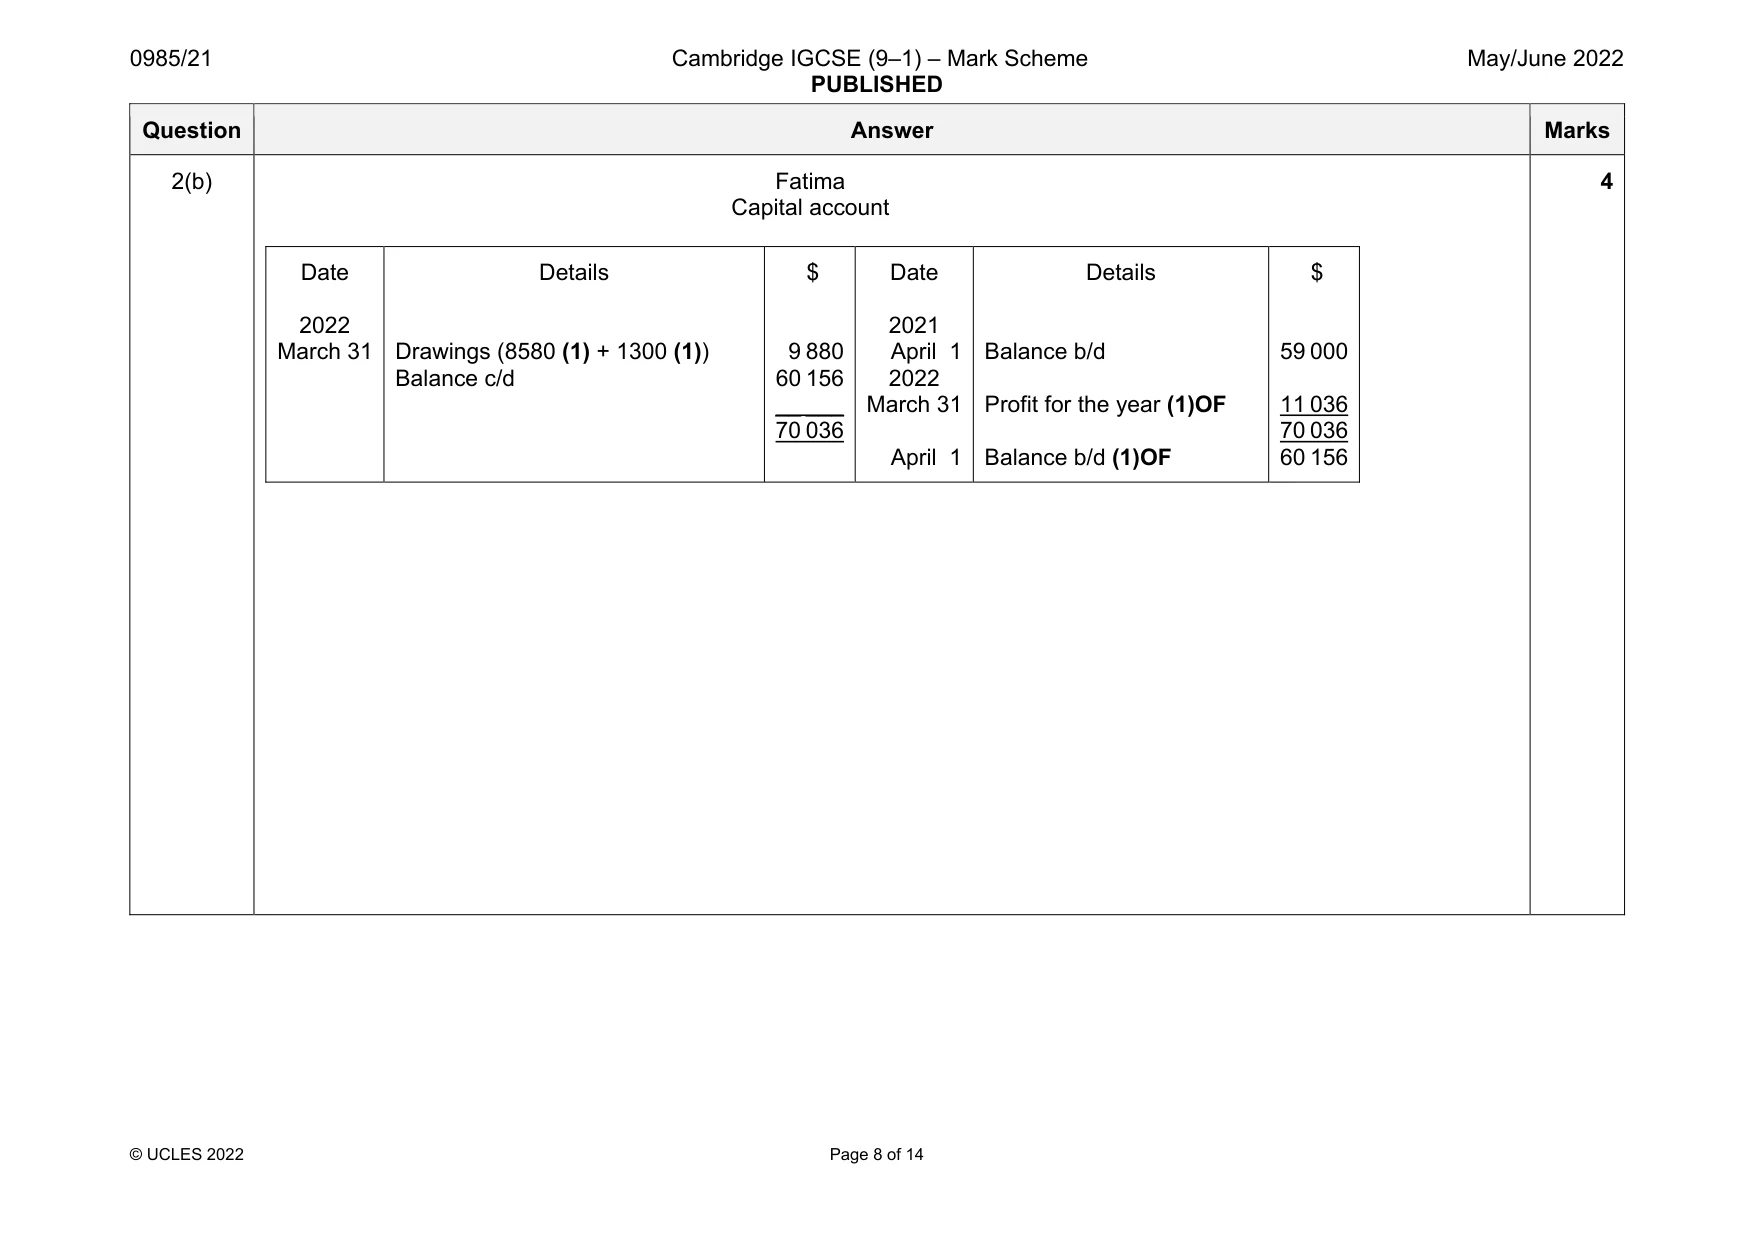
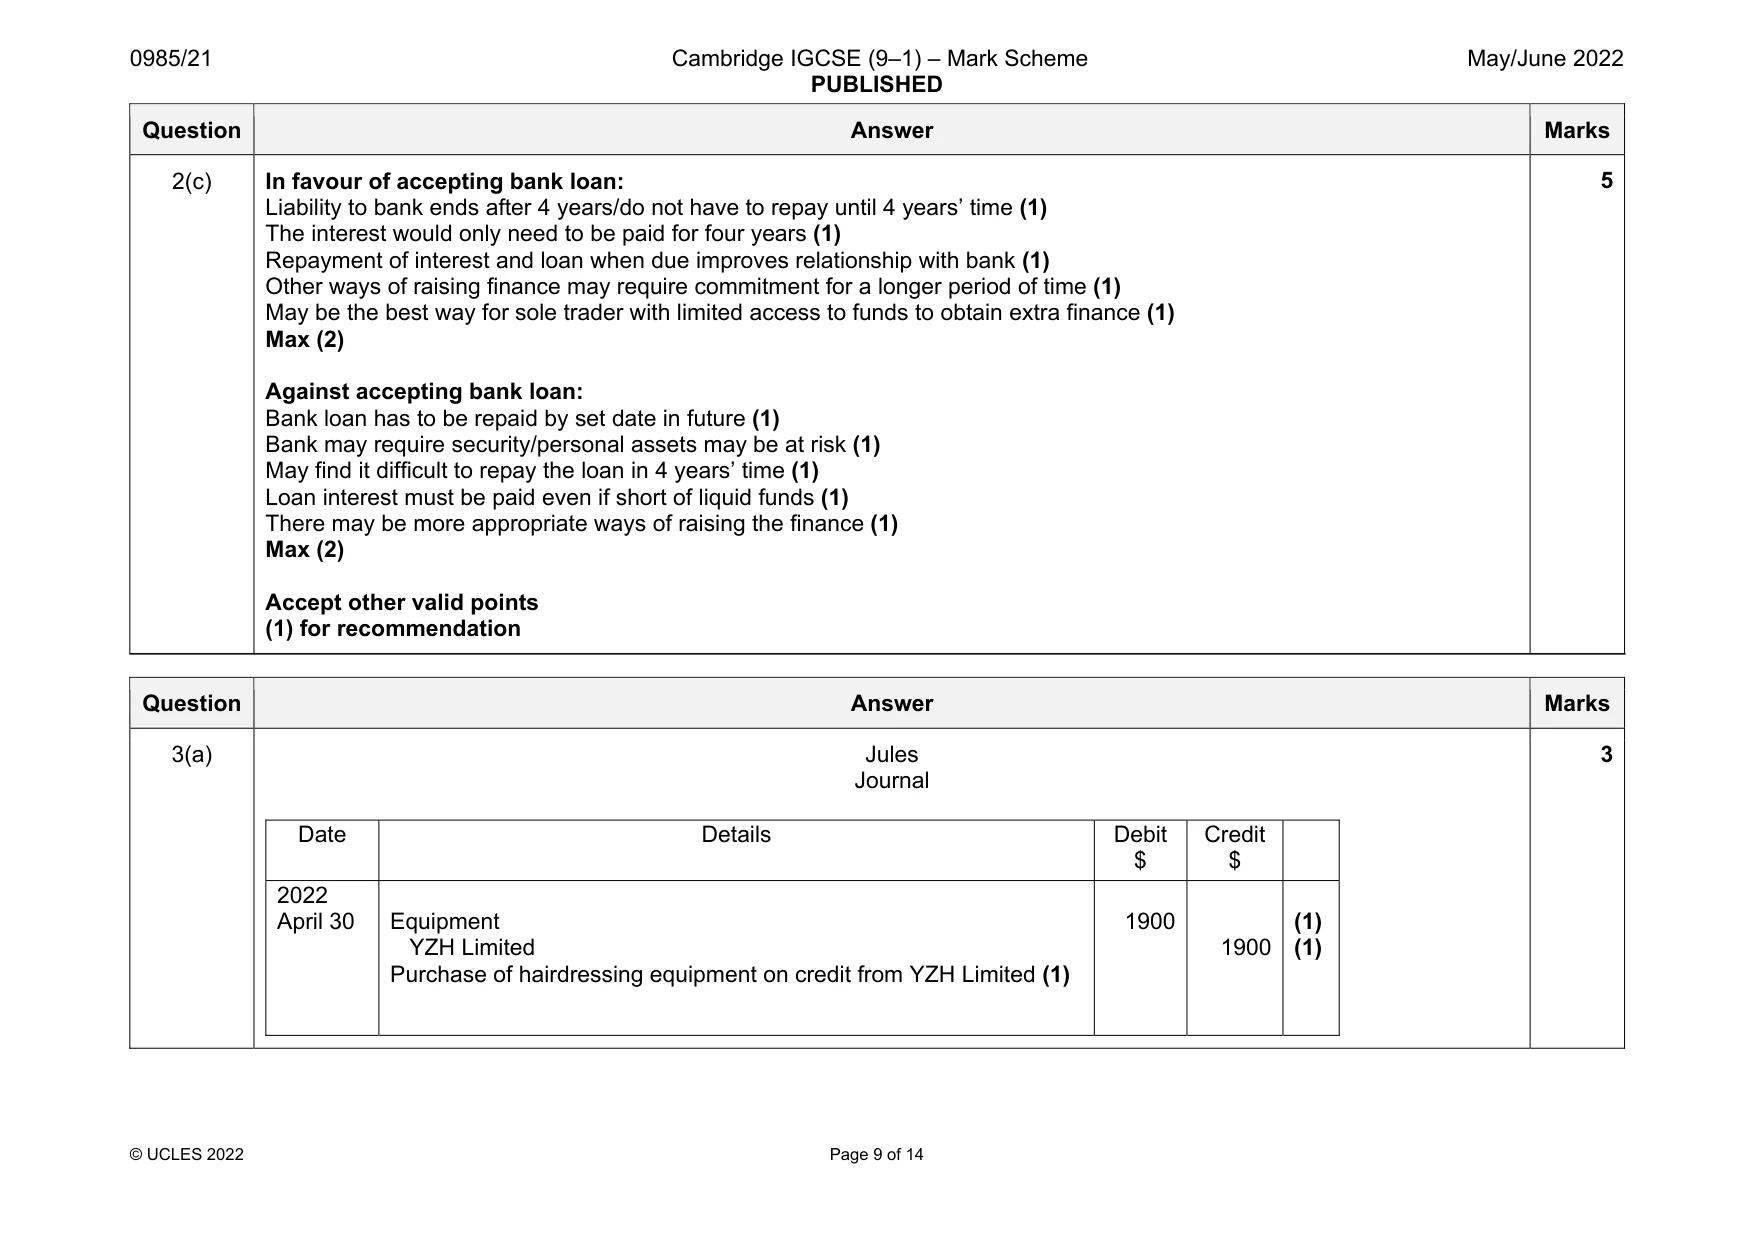
Mark scheme: 2(a) Fatima Income Statement for the year ended 31 March 2022 $ $ $ Revenue 79 400 Less Returns 3 970 75 430 (1) Less Cost of sales Opening inventory 3 000 Purchases 36 500 Less goods for own use 1 300 (1) 35 200 38 200 Less Closing inventory 3 120 35 080 (1)OF Gross profit 40 350 (1)OF Add Discount received 1 095 (1) 41 445 Less Expenses Rent and rates (9000 – [2/3 1500]) 8 000 (1) Wages (10 100 + 800) 10 900 (1) General expenses 1 287 Insurance 1 800 Irrecoverable debts 200 (1) Provision for doubtful debts ([6400 – 200] 3% = 186 – 156) 30 (1) Depreciation of fixtures and equipment ([80 000 – 39 040] 20%) 8 192 (1) 30 409 Profit for the year 11 036 (1) OF 11 Question Answer Marks 2(b) Fatima Capital account Date 2022 March 31 Details Drawings (8580 (1) + 1300 (1)) Balance c/d $ 9 880 60 156 __ ___ 70 036 Date 2021 April 1 2022 March 31 April 1 Details Balance b/d Profit for the year (1)OF Balance b/d (1)OF $ 59 000 11 036 70 036 60 156 4 Question Answer Marks 2(c) In favour of accepting bank loan: Liability to bank ends after 4 years/do not have to repay until 4 years’ time (1) The interest would only need to be paid for four years (1) Repayment of interest and loan when due improves relationship with bank (1) Other ways of raising finance may require commitment for a longer period of time (1) May be the best way for sole trader with limited access to funds to obtain extra finance (1) Max (2) Against accepting bank loan: Bank loan has to be repaid by set date in future (1) Bank may require security/personal assets may be at risk (1) May find it difficult to repay the loan in 4 years’ time (1) Loan interest must be paid even if short of liquid funds (1) There may be more appropriate ways of raising the finance (1) Max (2) Accept other valid points (1) for recommendation 5
Q3 · Jules is a hairdresser
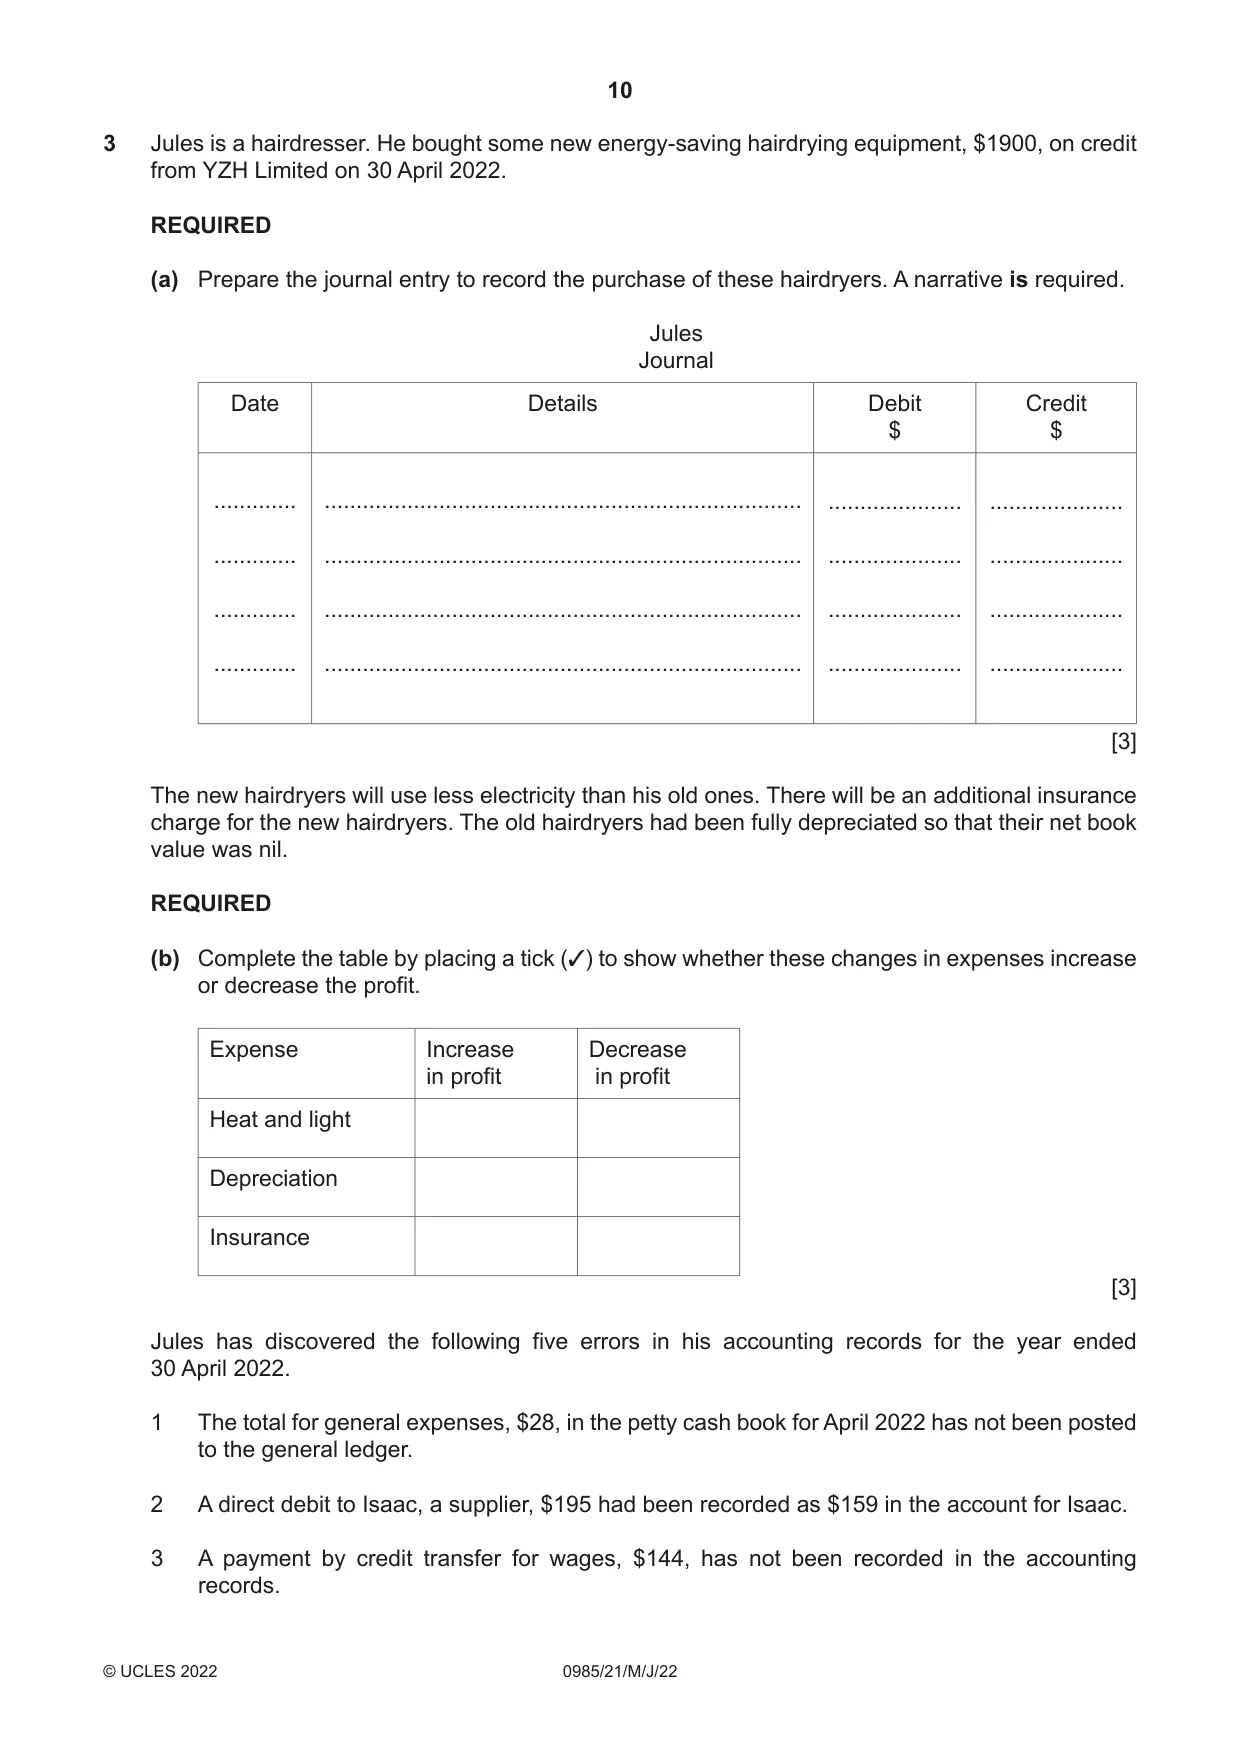
3 Jules is a hairdresser. He bought some new energy-saving hairdrying equipment, $1900, on credit from YZH Limited on 30 April 2022. REQUIRED (a) Prepare the journal entry to record the purchase of these hairdryers. A narrative is required. Jules Journal Date Details Debit Credit $ $ ............. ........................................................................... ..................... ..................... ............. ........................................................................... ..................... ..................... ............. ........................................................................... ..................... ..................... ............. ........................................................................... ..................... ..................... [3] The new hairdryers will use less electricity than his old ones. There will be an additional insurance charge for the new hairdryers. The old hairdryers had been fully depreciated so that their net book value was nil. REQUIRED (b) Complete the table by placing a tick (3) to show whether these changes in expenses increase or decrease the profit. Expense Increase Decrease in profit in profit Heat and light Depreciation Insurance [3] Jules has discovered the following five errors in his accounting records for the year ended 30 April 2022. 1 The total for general expenses, $28, in the petty cash book for April 2022 has not been posted to the general ledger. 2 A direct debit to Isaac, a supplier, $195 had been recorded as $159 in the account for Isaac. 3 A payment by credit transfer for wages, $144, has not been recorded in the accounting records.
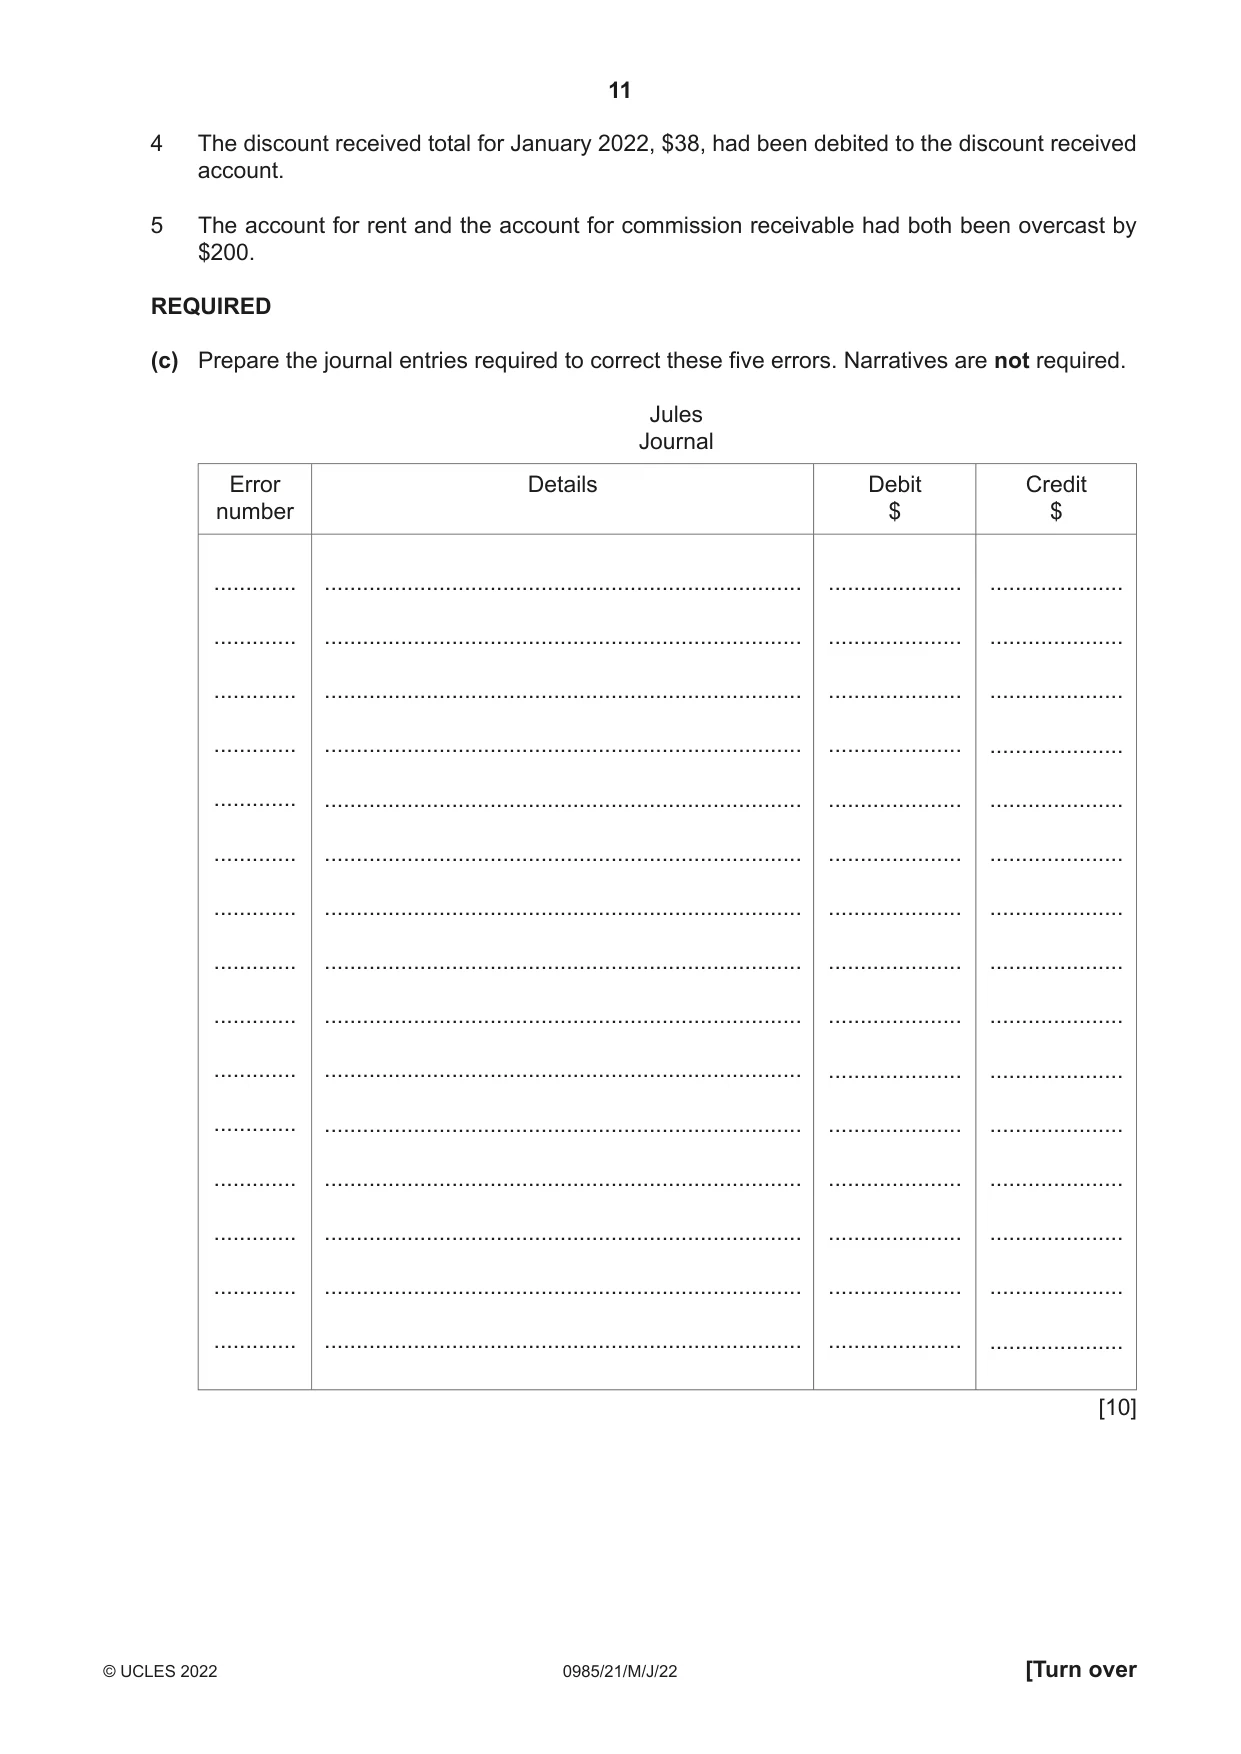
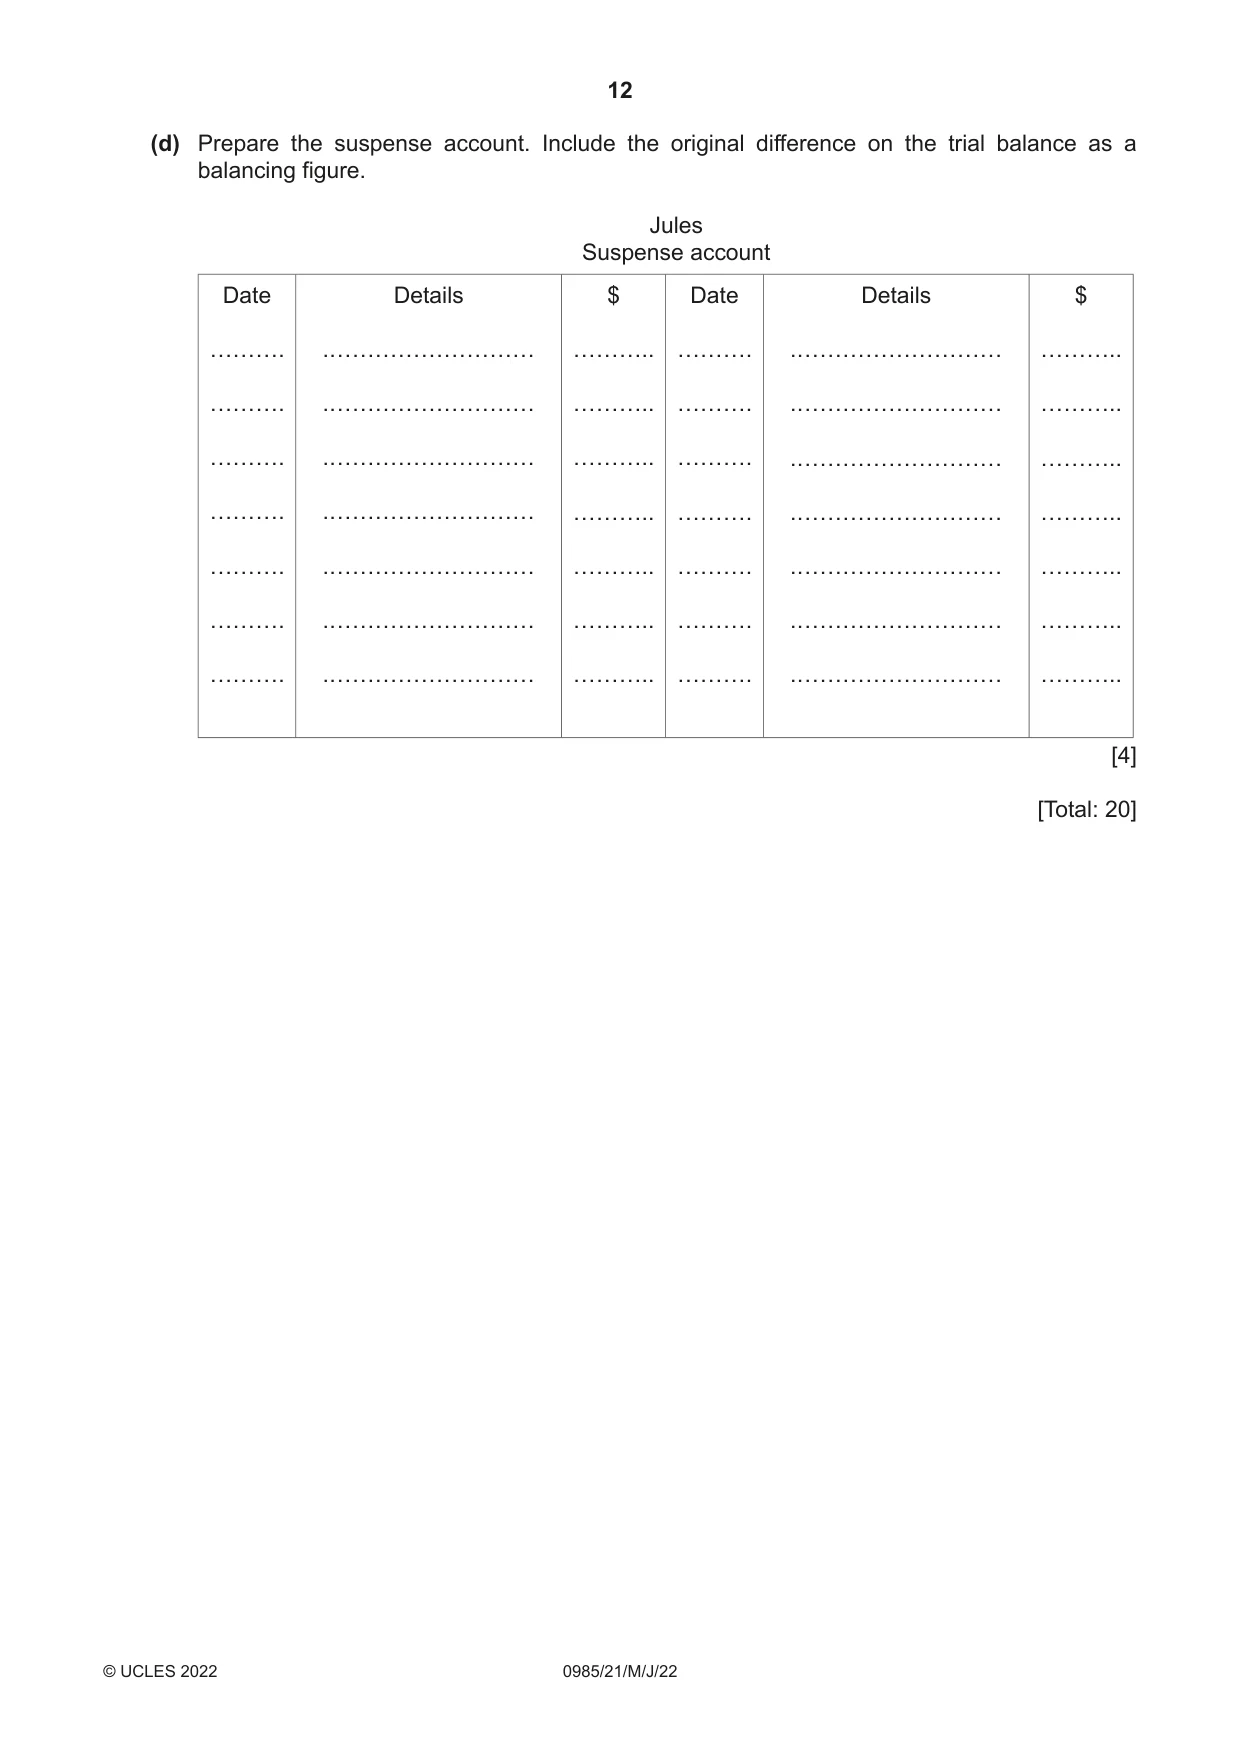
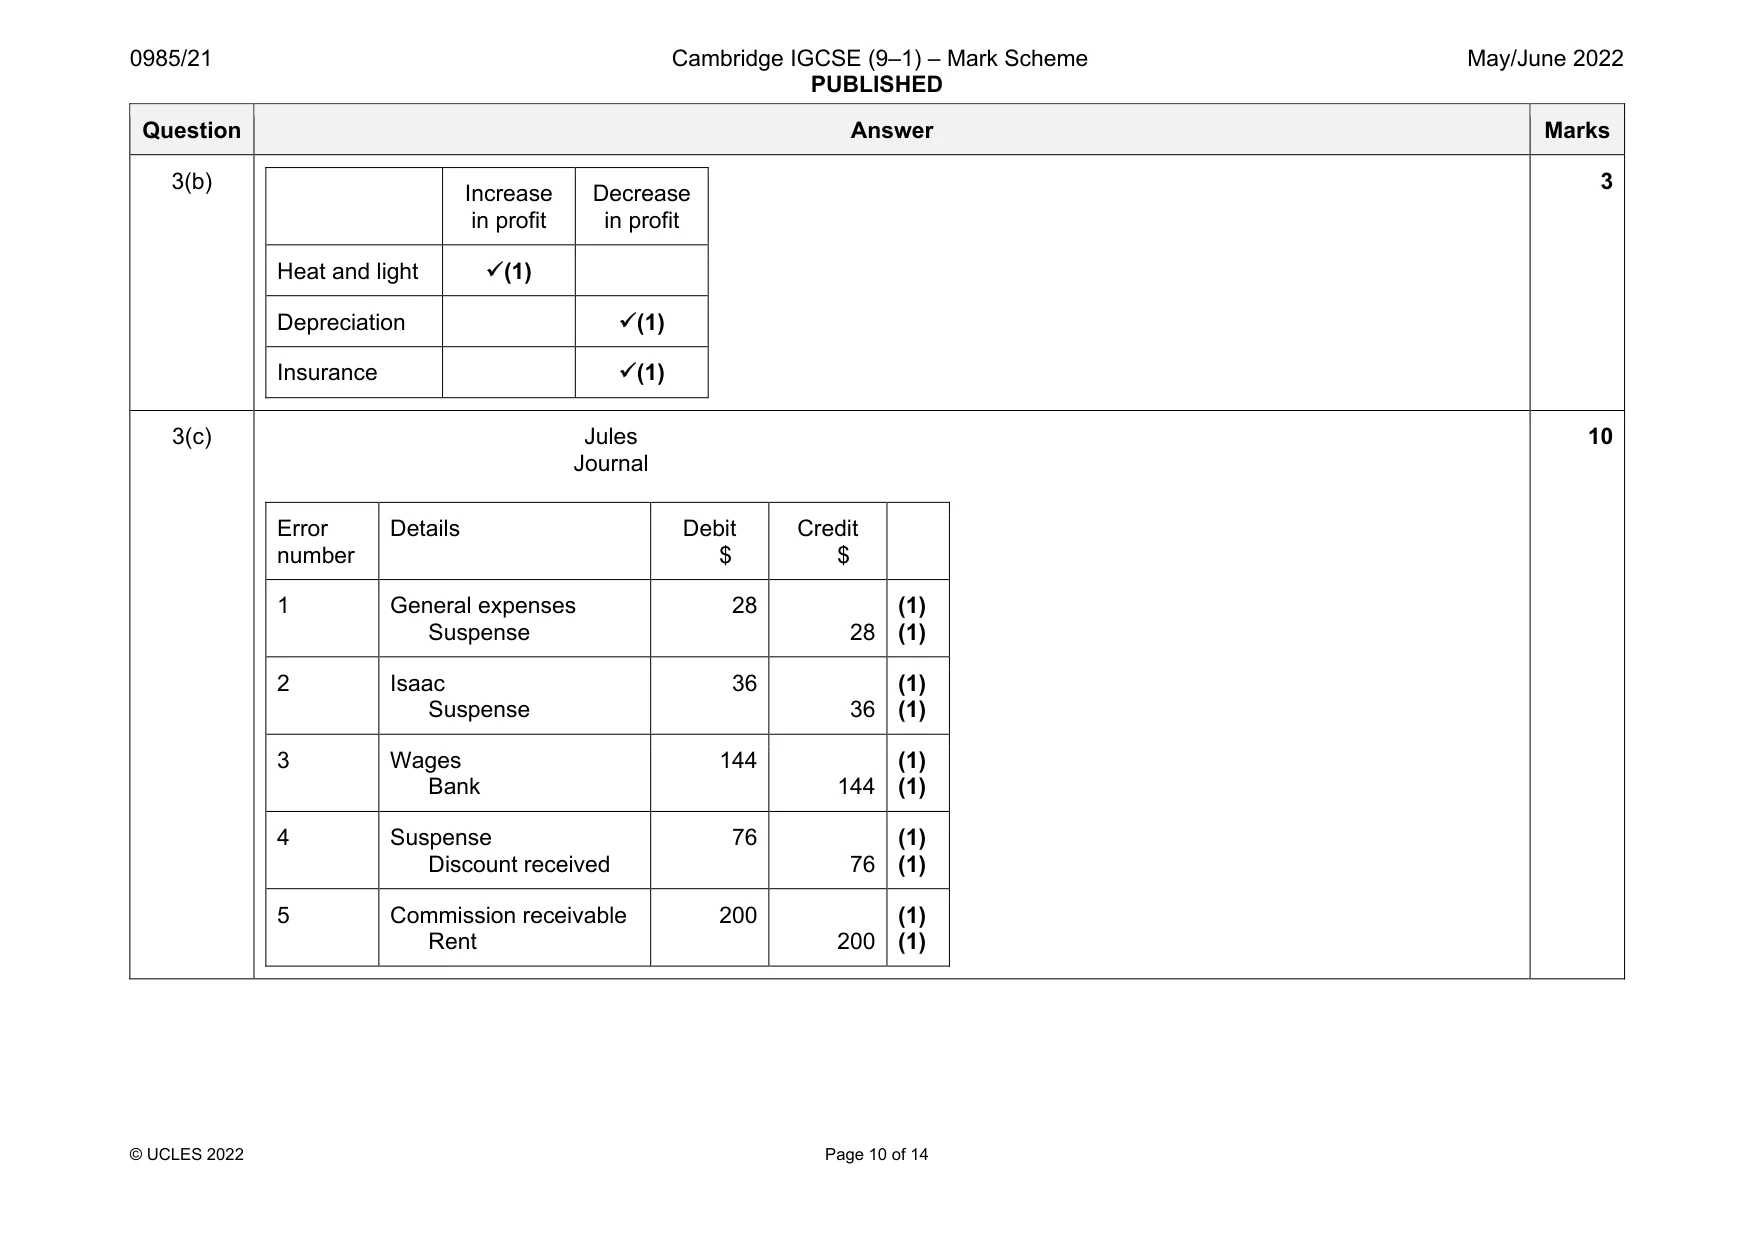
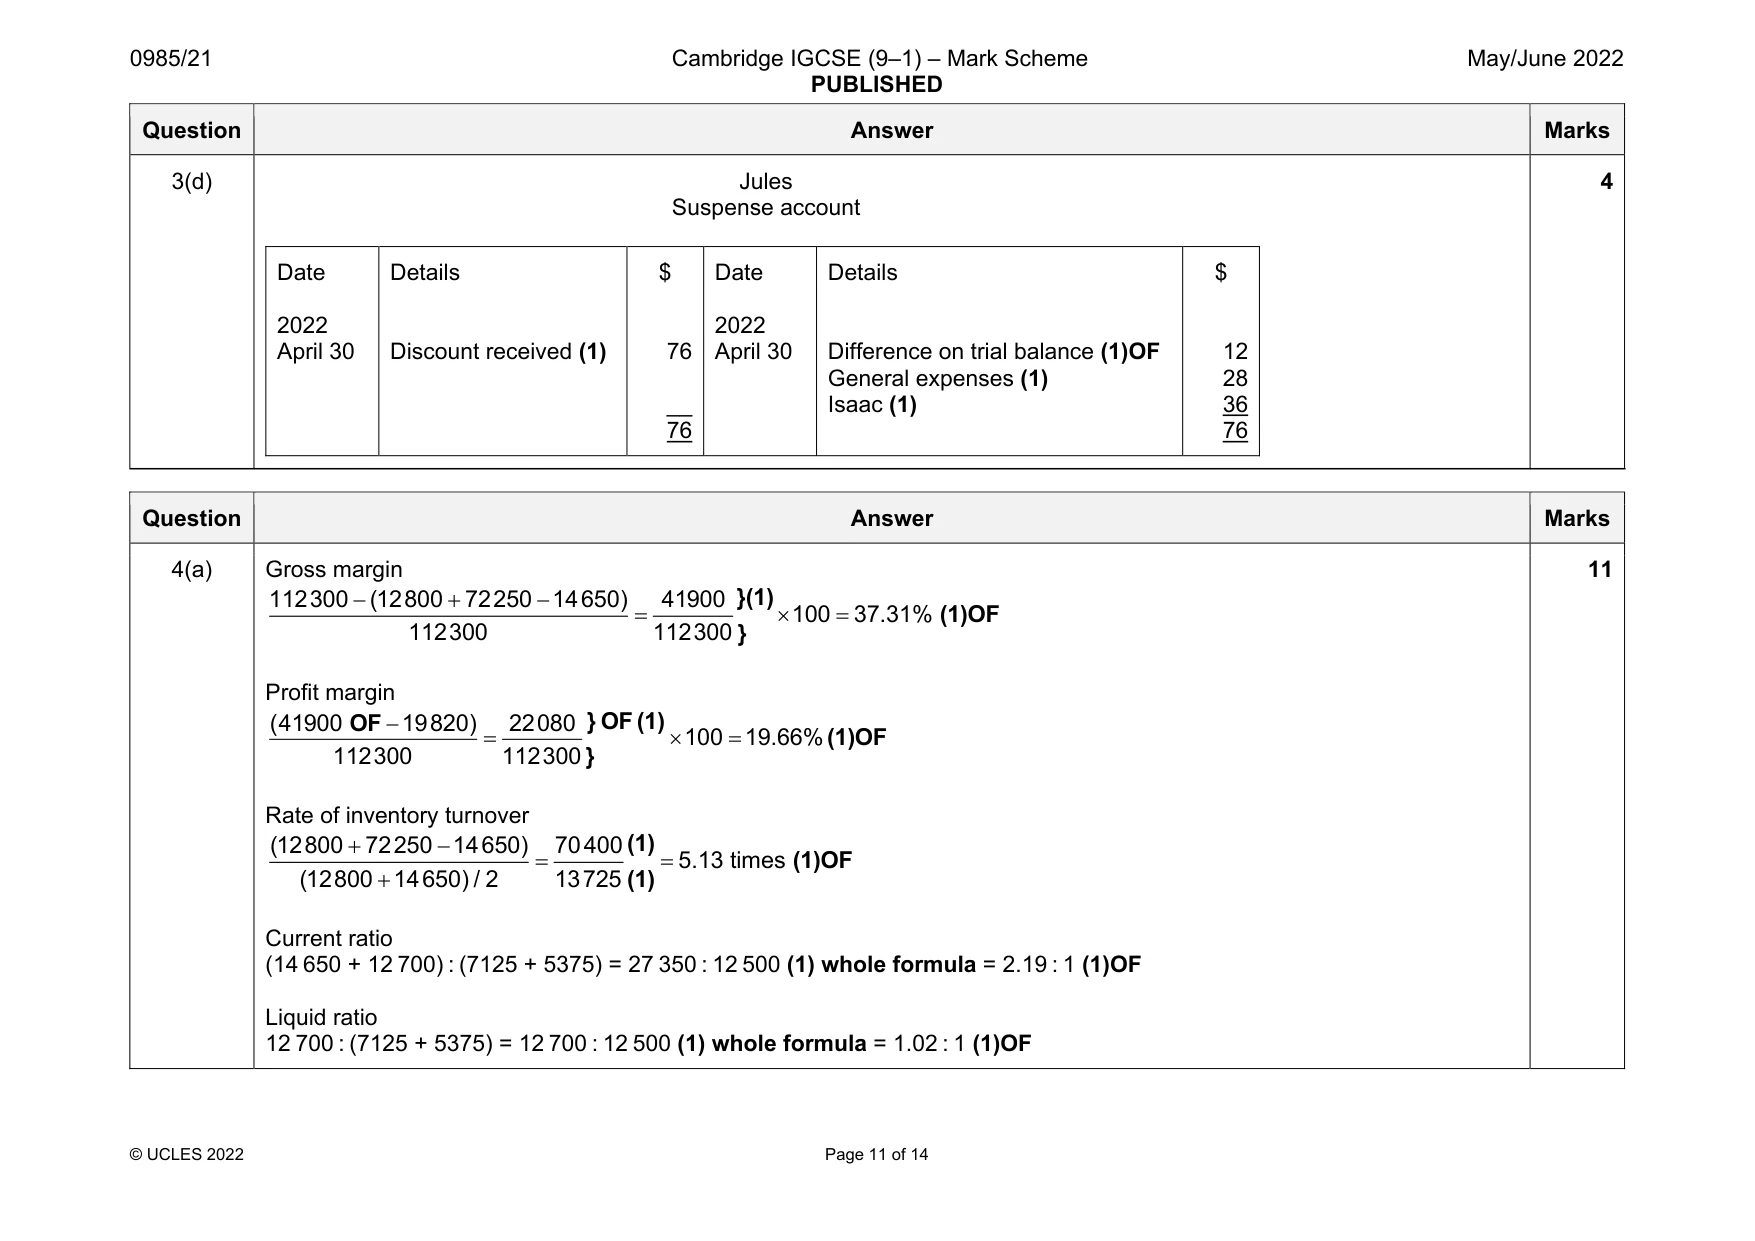
Mark scheme: 3(a) Jules Journal Date Details Debit $ Credit $ 2022 April 30 Equipment YZH Limited Purchase of hairdressing equipment on credit from YZH Limited (1) 1900 1900 (1) (1) 3 Question Answer Marks 3(b) Increase in profit Decrease in profit Heat and light (1) Depreciation (1) Insurance (1) 3 3(c) Jules Journal Error number Details Debit $ Credit $ 1 General expenses Suspense 28 28 (1) (1) 2 Isaac Suspense 36 36 (1) (1) 3 Wages Bank 144 144 (1) (1) 4 Suspense Discount received 76 76 (1) (1) 5 Commission receivable Rent 200 200 (1) (1) 10 Question Answer Marks 3(d) Jules Suspense account Date 2022 April 30 Details Discount received (1) $ 76 __ 76 Date 2022 April 30 Details Difference on trial balance (1)OF General expenses (1) Isaac (1) $ 12 28 36 76 4
Q4 · The discount received total for January 2022, $38, had been debited to the discount…
4 The discount received total for January 2022, $38, had been debited to the discount received account.
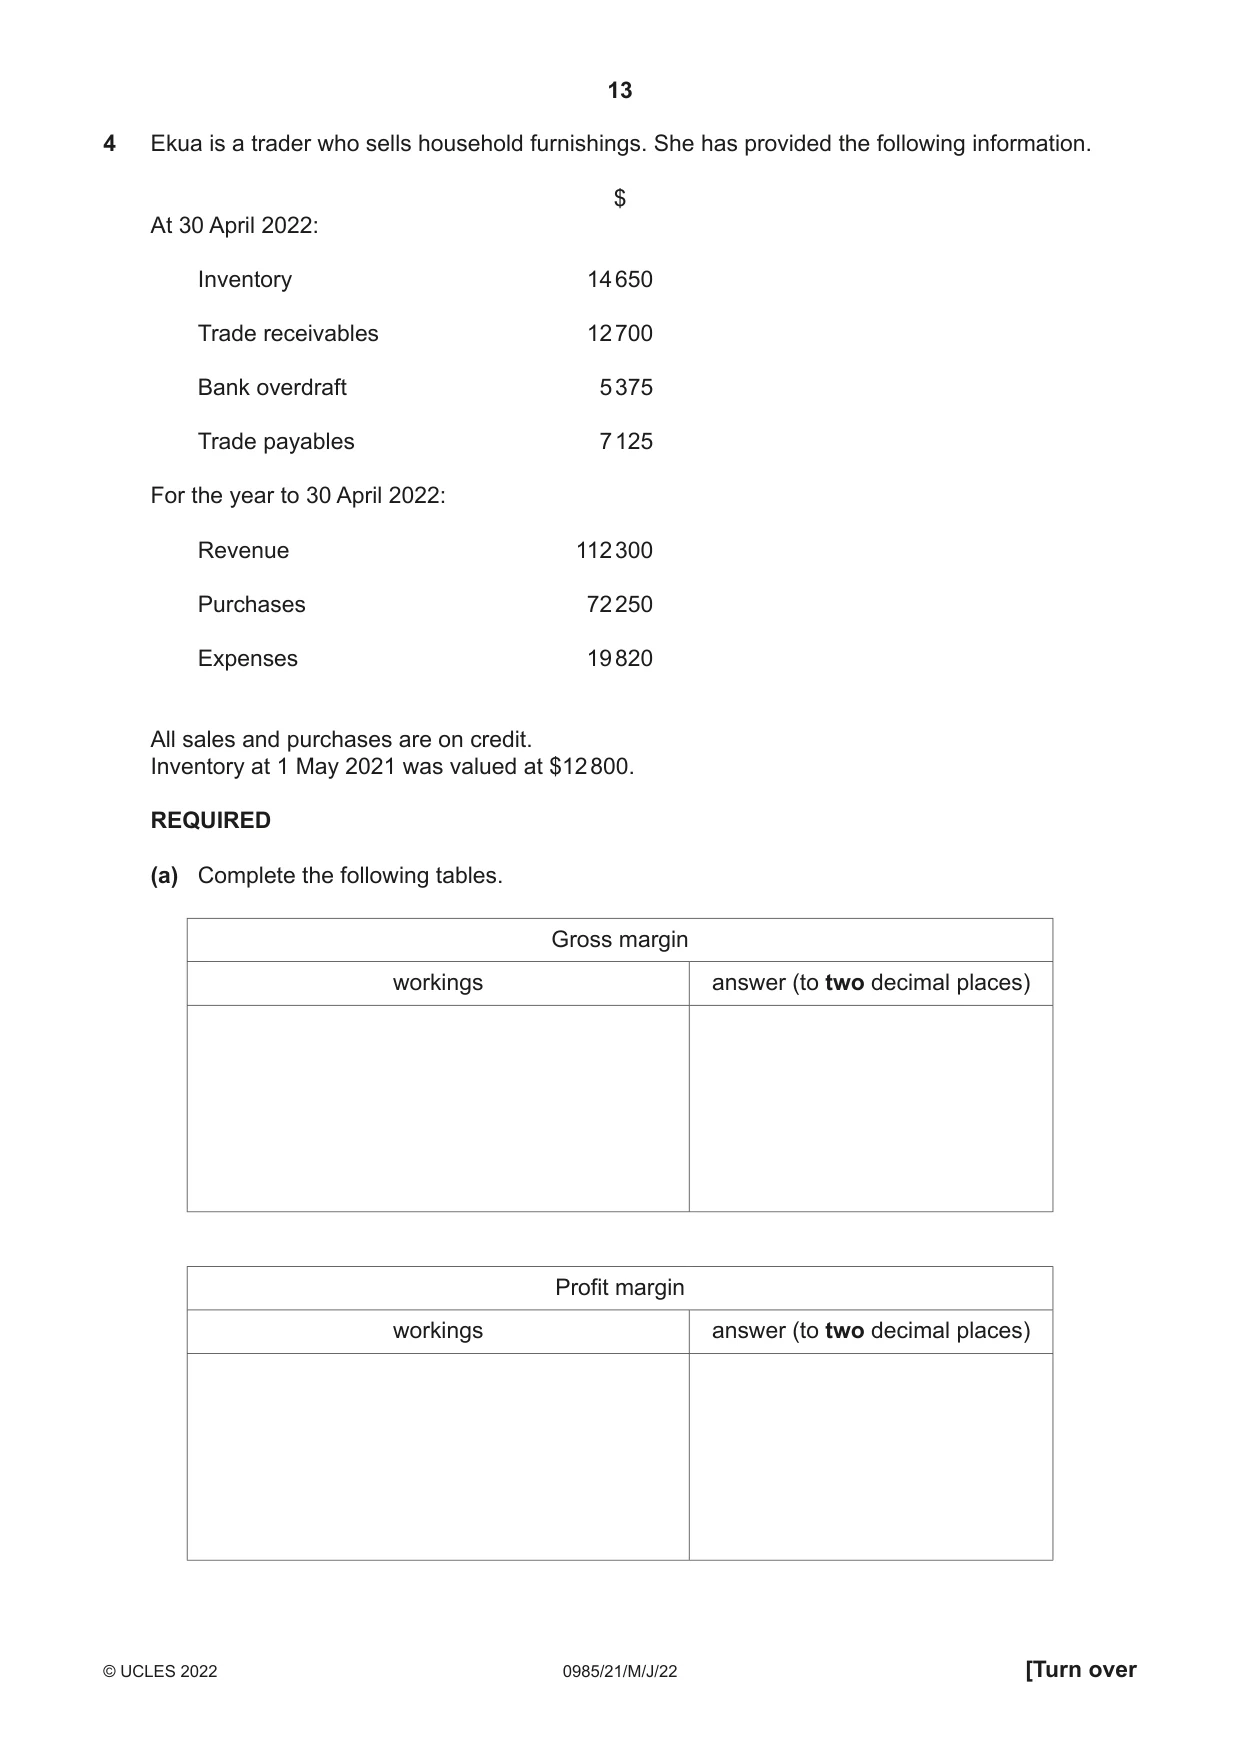
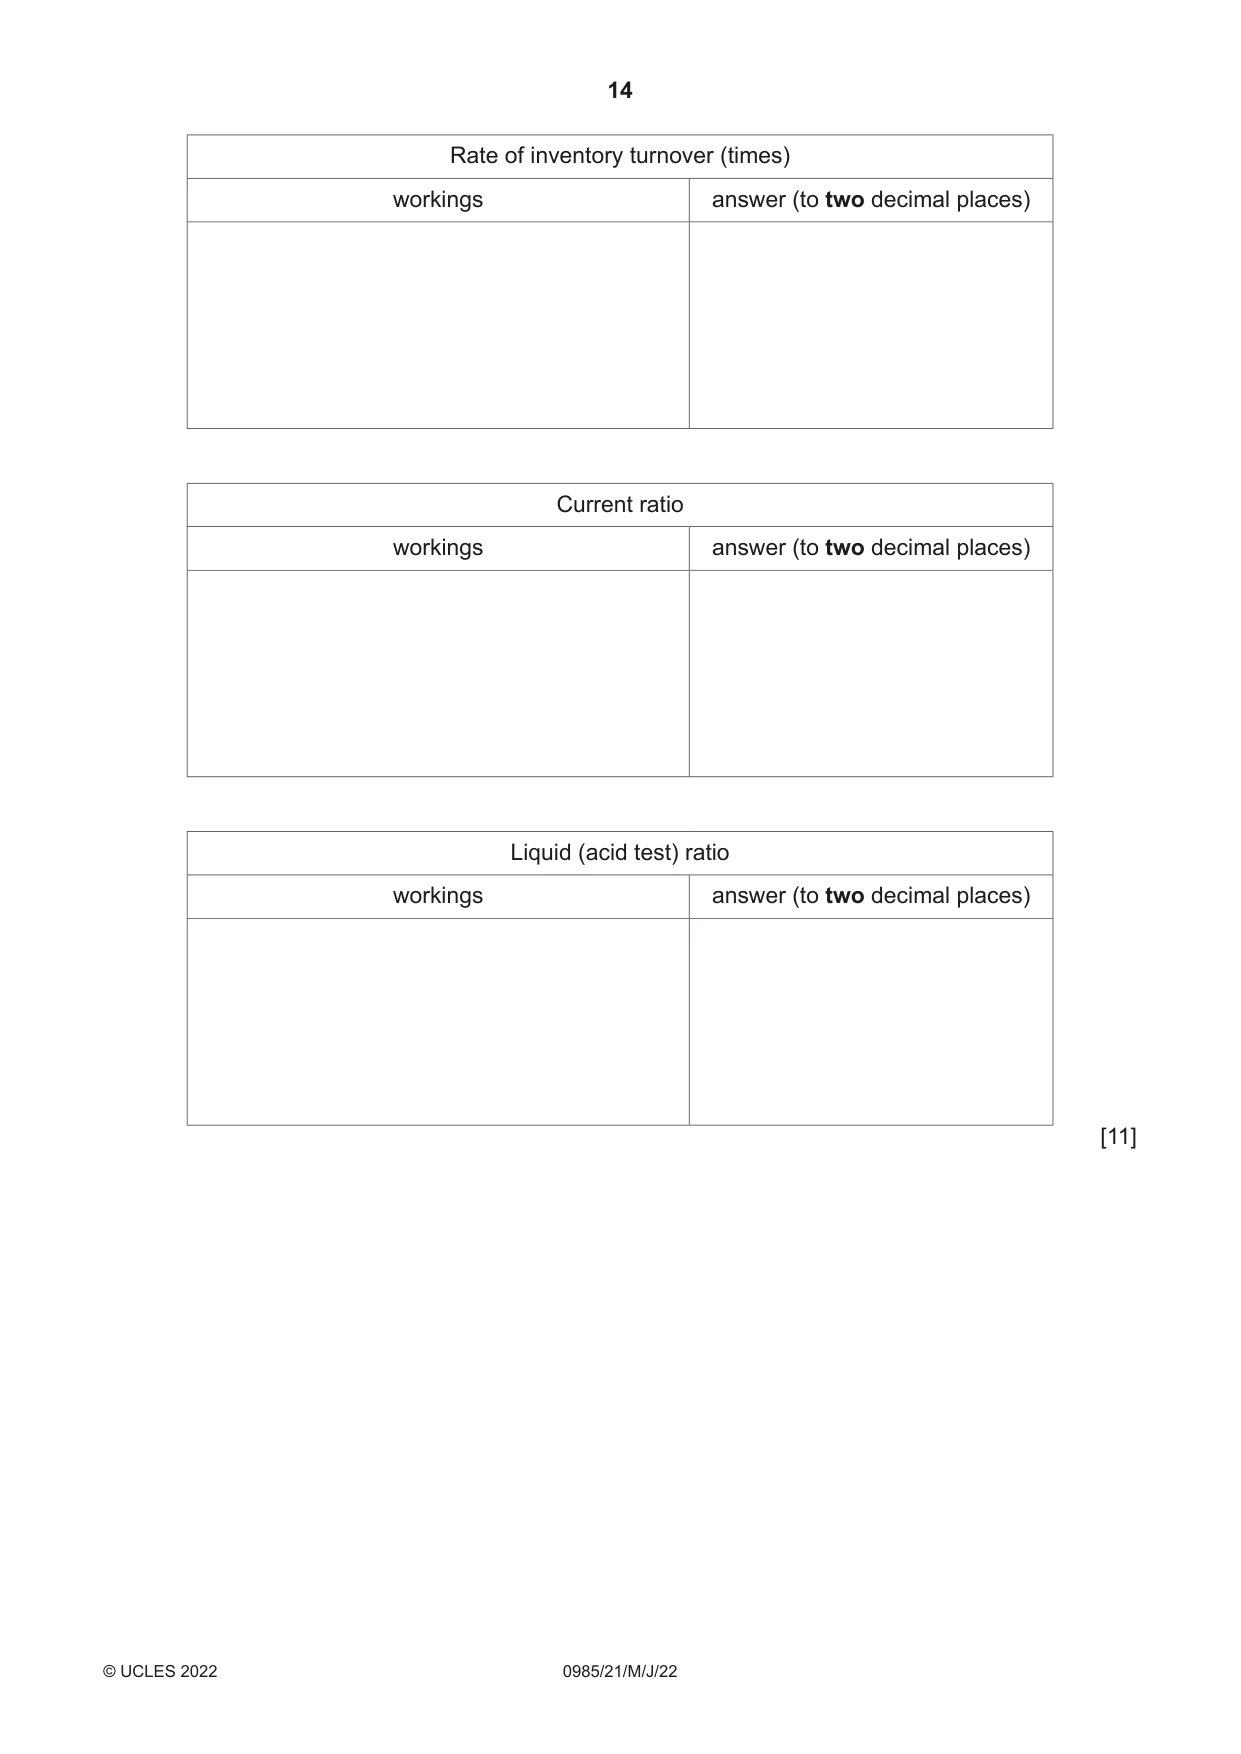
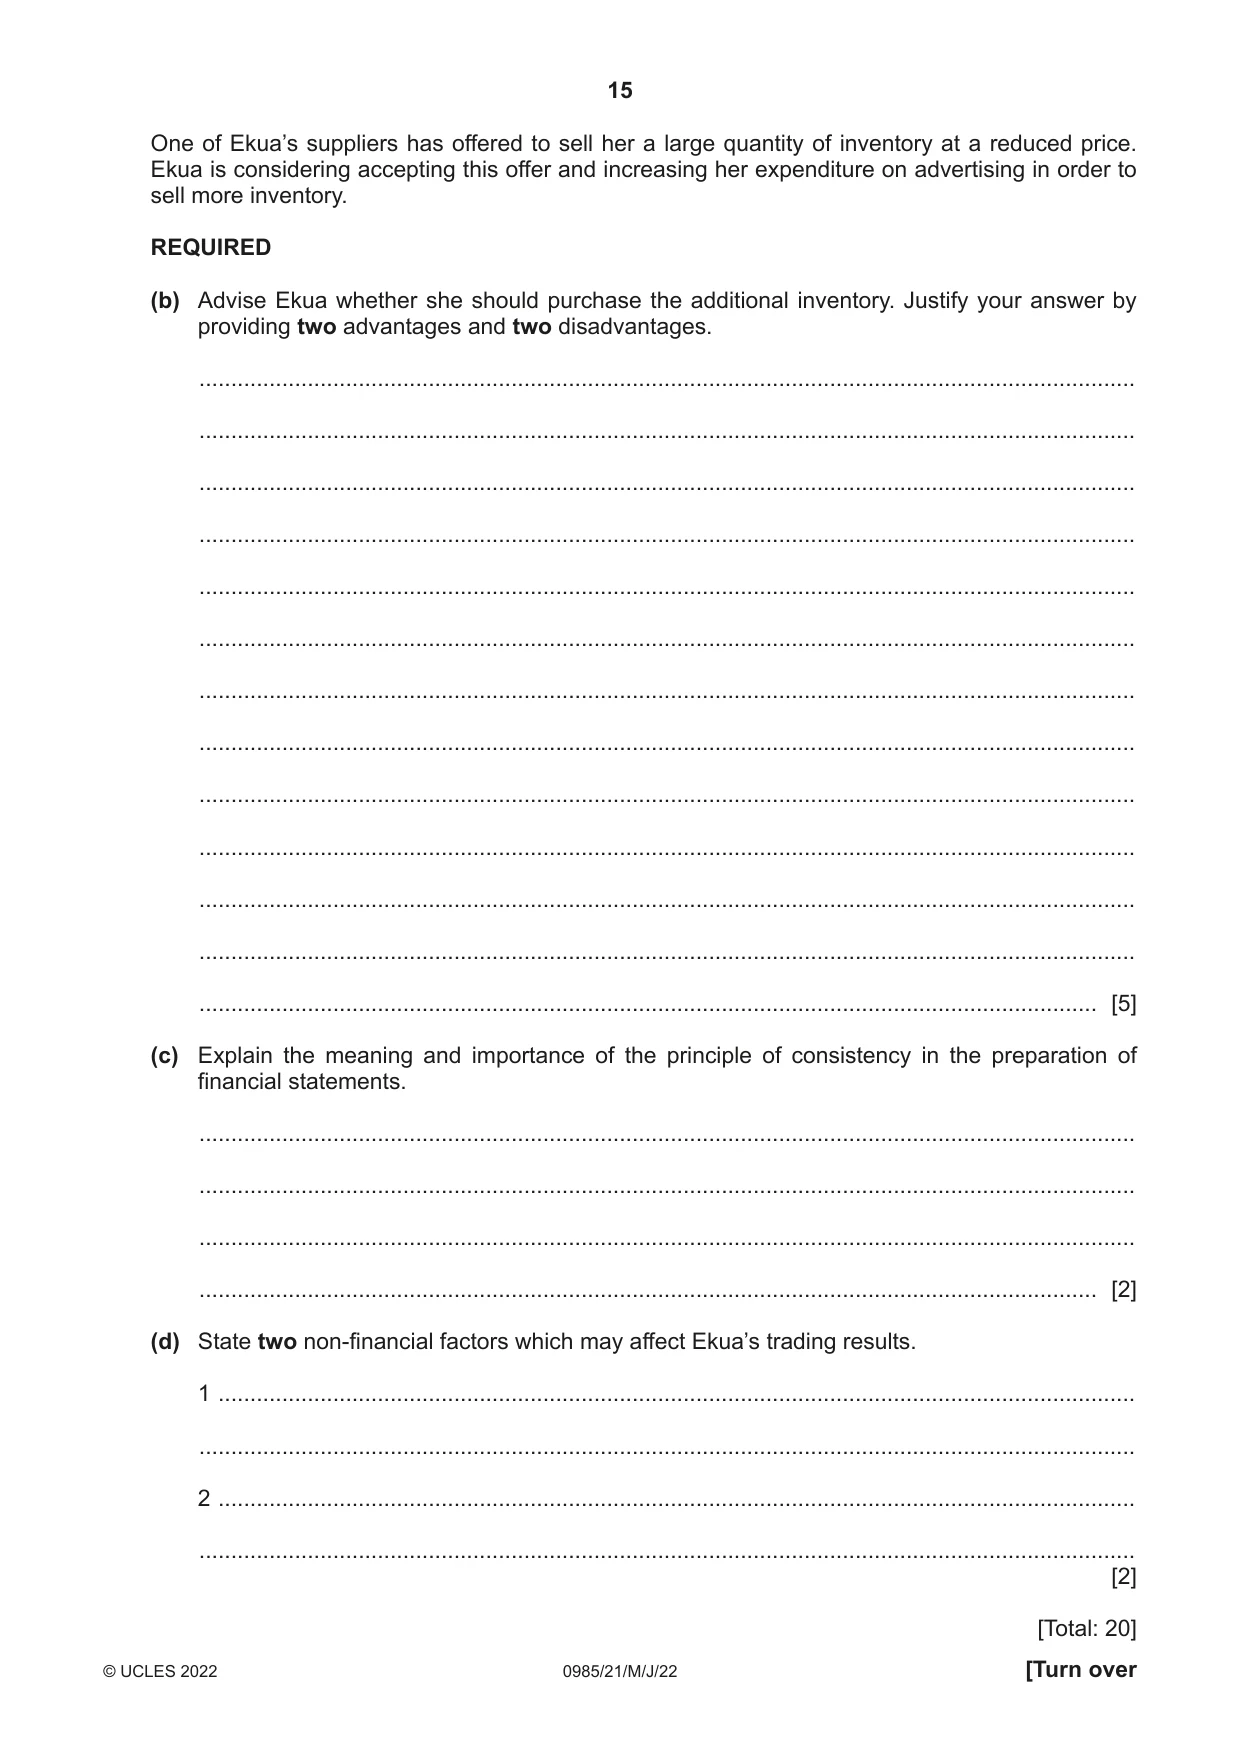
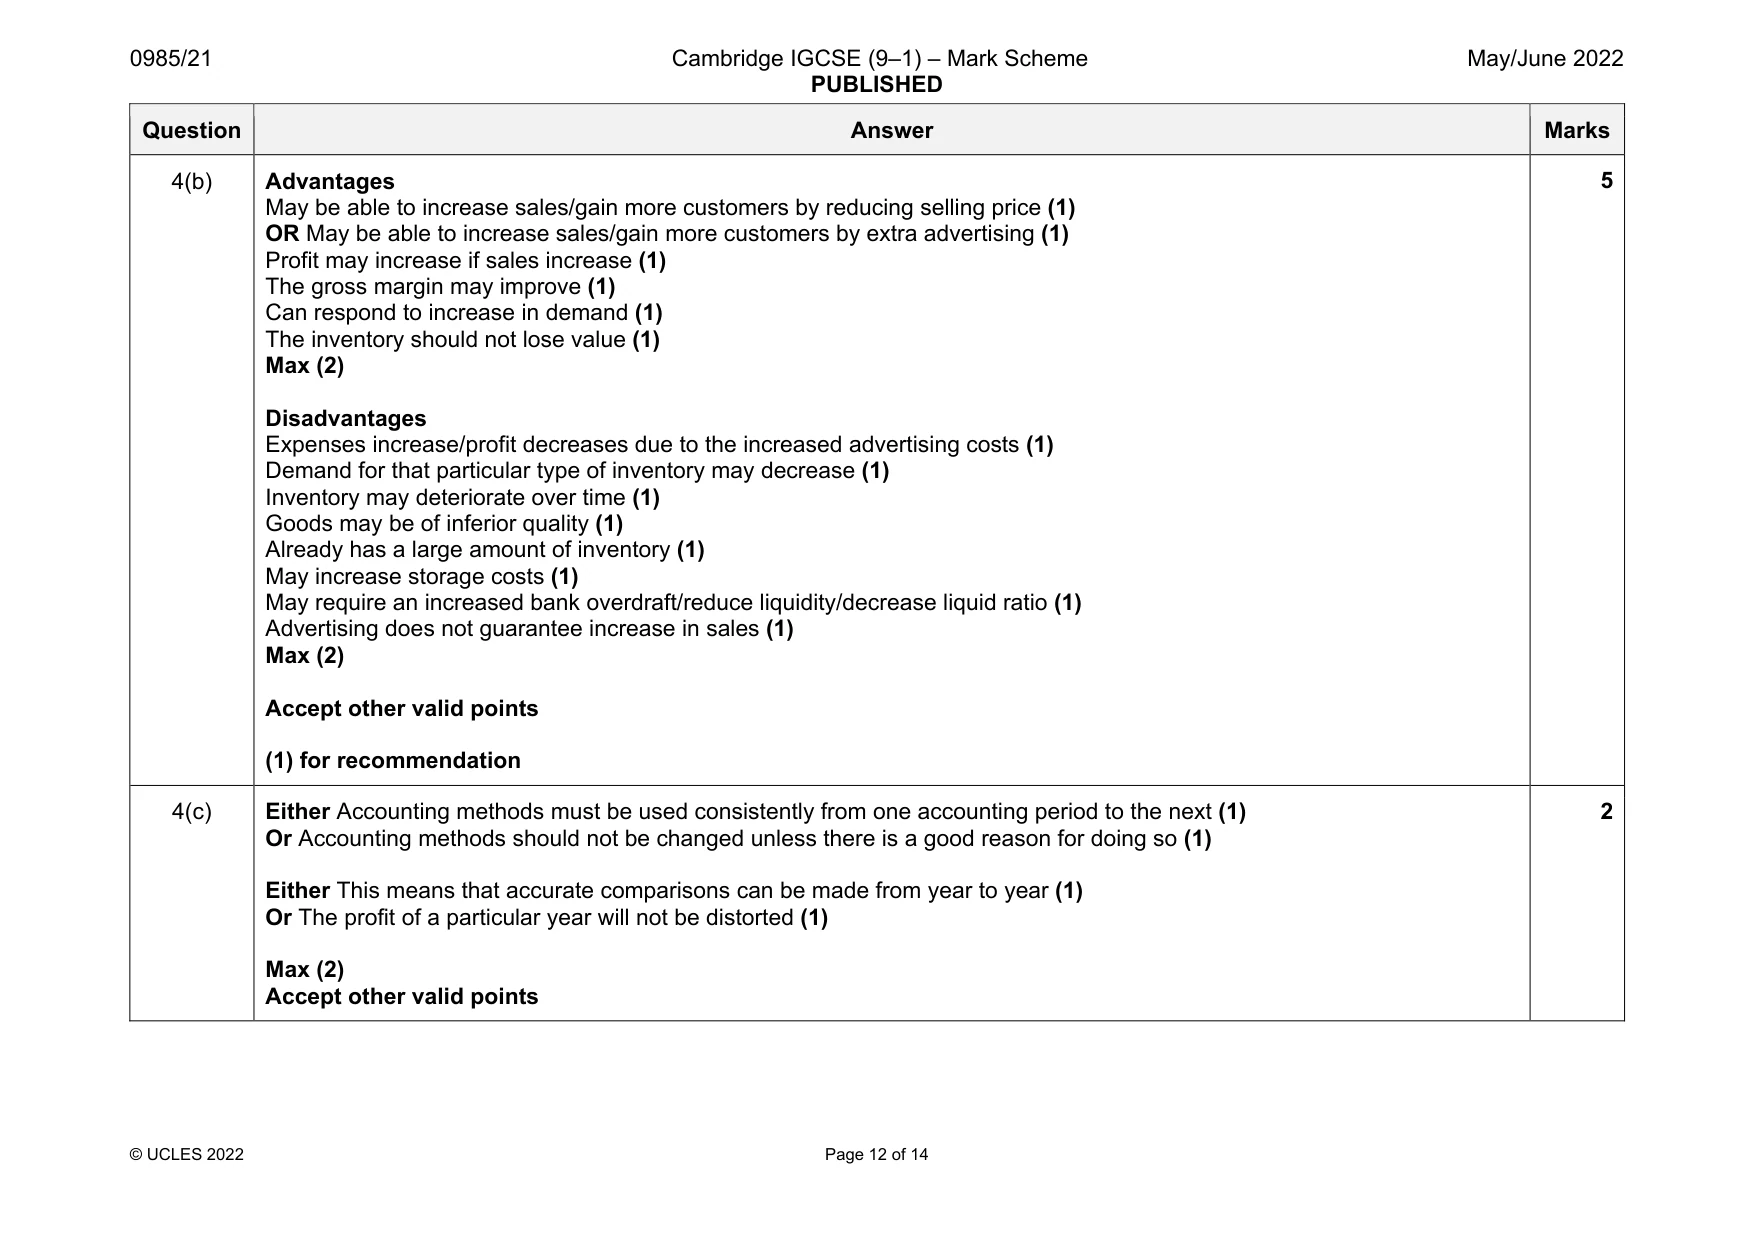
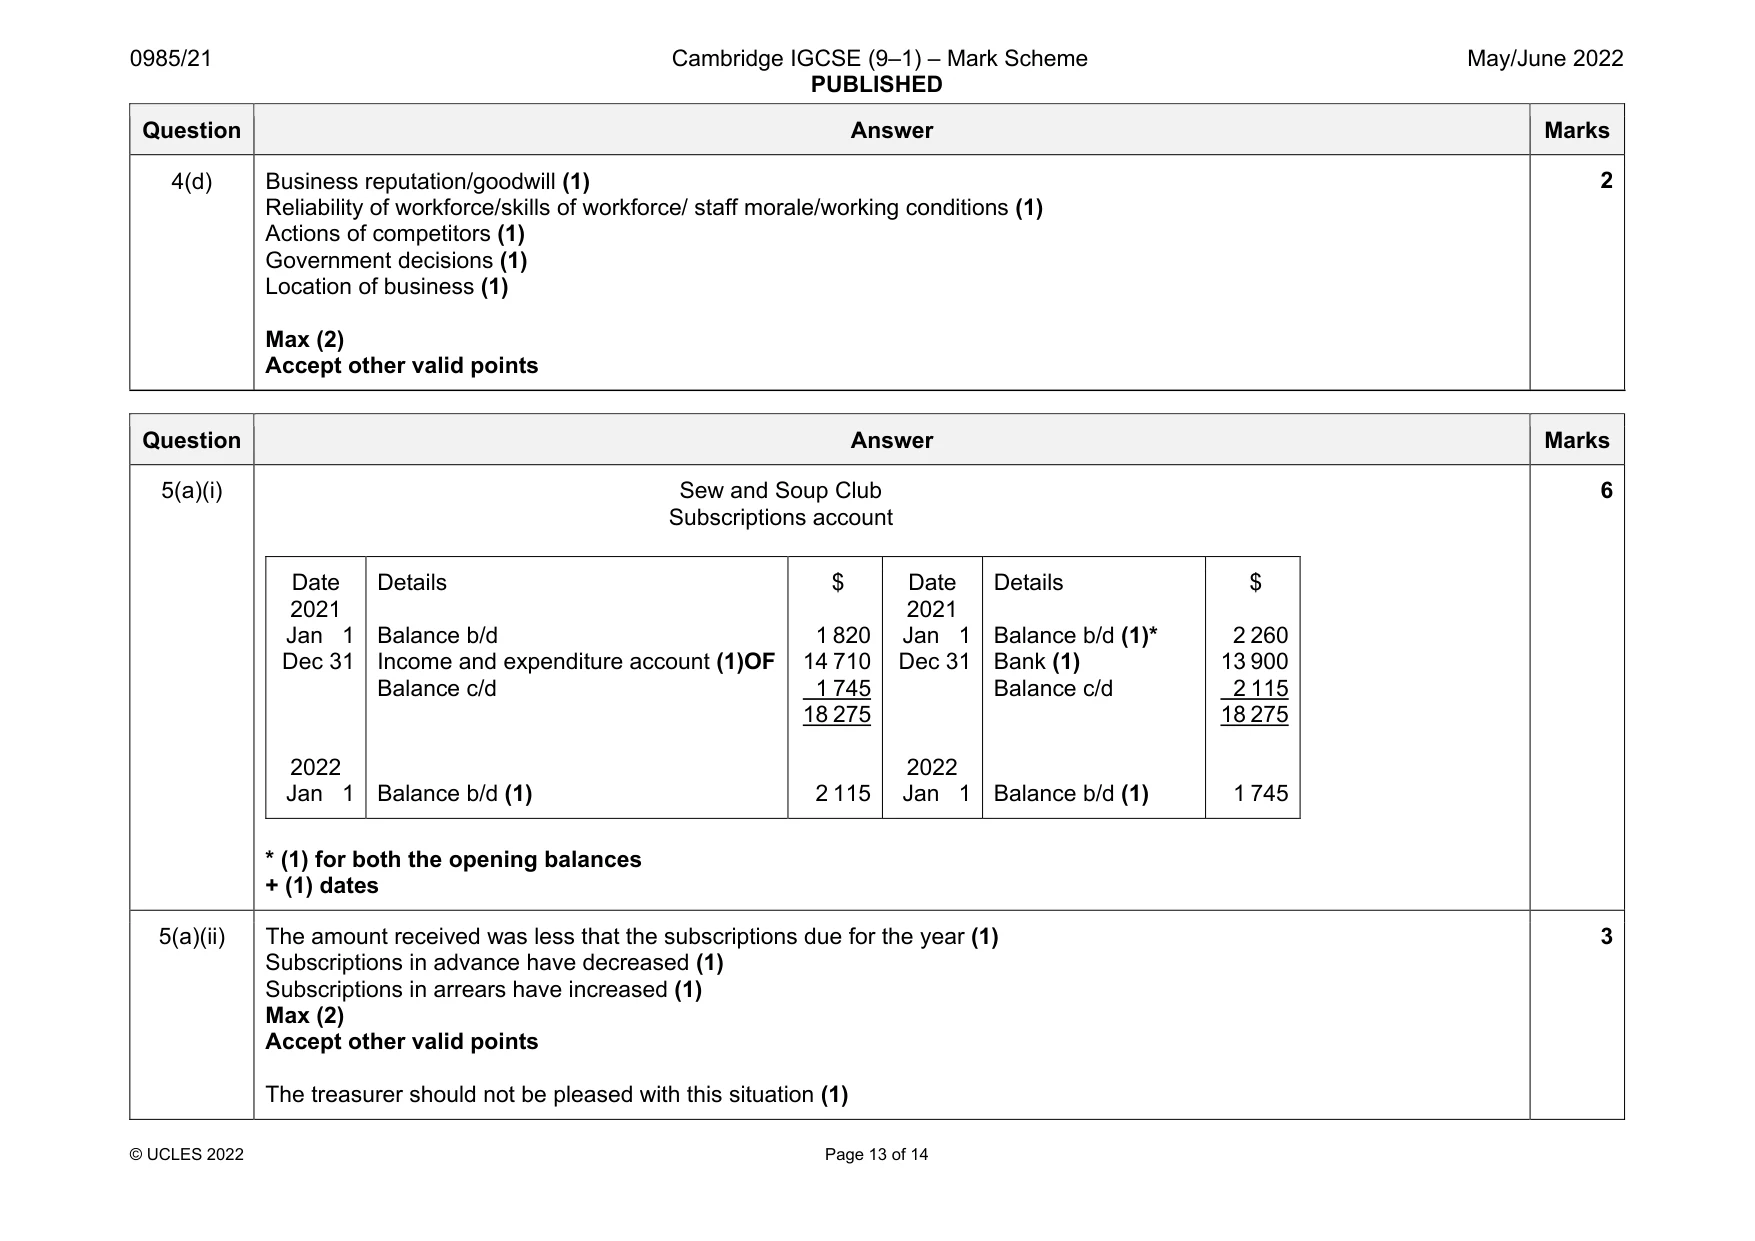
Mark scheme: 4(a) Gross margin 112300 (12800 72250 14650) 41900 100 37.31% 112300 112300 }(1) (1)OF } Profit margin (41900 19820) 22080 100 19.66% 112300 112300 } OF (1) OF (1)OF } Rate of inventory turnover (12800 72250 14650) 70400 5.13 times (12800 14650) / 2 13725 (1) (1)OF (1) Current ratio (14 650 + 12 700) : (7125 + 5375) = 27 350 : 12 500 (1) whole formula = 2.19 : 1 (1)OF Liquid ratio 12 700 : (7125 + 5375) = 12 700 : 12 500 (1) whole formula = 1.02 : 1 (1)OF Question Answer Marks 4(b) Advantages May be able to increase sales/gain more customers by reducing selling price (1) OR May be able to increase sales/gain more customers by extra advertising (1) Profit may increase if sales increase (1) The gross margin may improve (1) Can respond to increase in demand (1) The inventory should not lose value (1) Max (2) Disadvantages Expenses increase/profit decreases due to the increased advertising costs (1) Demand for that particular type of inventory may decrease (1) Inventory may deteriorate over time (1) Goods may be of inferior quality (1) Already has a large amount of inventory (1) May increase storage costs (1) May require an increased bank overdraft/reduce liquidity/decrease liquid ratio (1) Advertising does not guarantee increase in sales (1) Max (2) Accept other valid points (1) for recommendation 5 4(c) Either Accounting methods must be used consistently from one accounting period to the next (1) Or Accounting methods should not be changed unless there is a good reason for doing so (1) Either This means that accurate comparisons can be made from year to year (1) Or The profit of a particular year will not be distorted (1) Max (2) Accept other valid points 2 Question Answer Marks 4(d) Business reputation/goodwill (1) Reliability of workforce/skills of workforce/ staff morale/working conditions (1) Actions of competitors (1) Government decisions (1) Location of business (1) Max (2) Accept other valid points 2
Q5 · The account for rent and the account for commission receivable had both been overcast by…
5 The account for rent and the account for commission receivable had both been overcast by $200. REQUIRED (c) Prepare the journal entries required to correct these five errors. Narratives are not required. Jules Journal Error Details Debit Credit number $ $ ............. ........................................................................... ..................... ..................... ............. ........................................................................... ..................... ..................... ............. ........................................................................... ..................... ..................... ............. ........................................................................... ..................... ..................... ............. ........................................................................... ..................... ..................... ............. ........................................................................... ..................... ..................... ............. ........................................................................... ..................... ..................... ............. ........................................................................... ..................... ..................... ............. ........................................................................... ..................... ..................... ............. ........................................................................... ..................... ..................... ............. ........................................................................... ..................... ..................... ............. ........................................................................... ..................... ..................... ............. ........................................................................... ..................... ..................... ............. ........................................................................... ..................... ..................... ............. ........................................................................... ..................... ..................... [10] (d) Prepare the suspense account. Include the original difference on the trial balance as a balancing figure. Jules Suspense account Date Details $ Date Details $ ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. ………. ……….. [4] [Total: 20] 4 Ekua is a trader who sells household furnishings. She has provided the following information. $ At 30 April 2022: Inventory 14 650 Trade receivables 12 700 Bank overdraft 5 375 Trade payables 7 125 For the year to 30 April 2022: Revenue 112 300 Purchases 72 250 Expenses 19 820 All sales and purchases are on credit. Inventory at 1 May 2021 was valued at $12 800. REQUIRED (a) Complete the following tables. Gross margin workings answer (to two decimal places) Profit margin workings answer (to two decimal places)
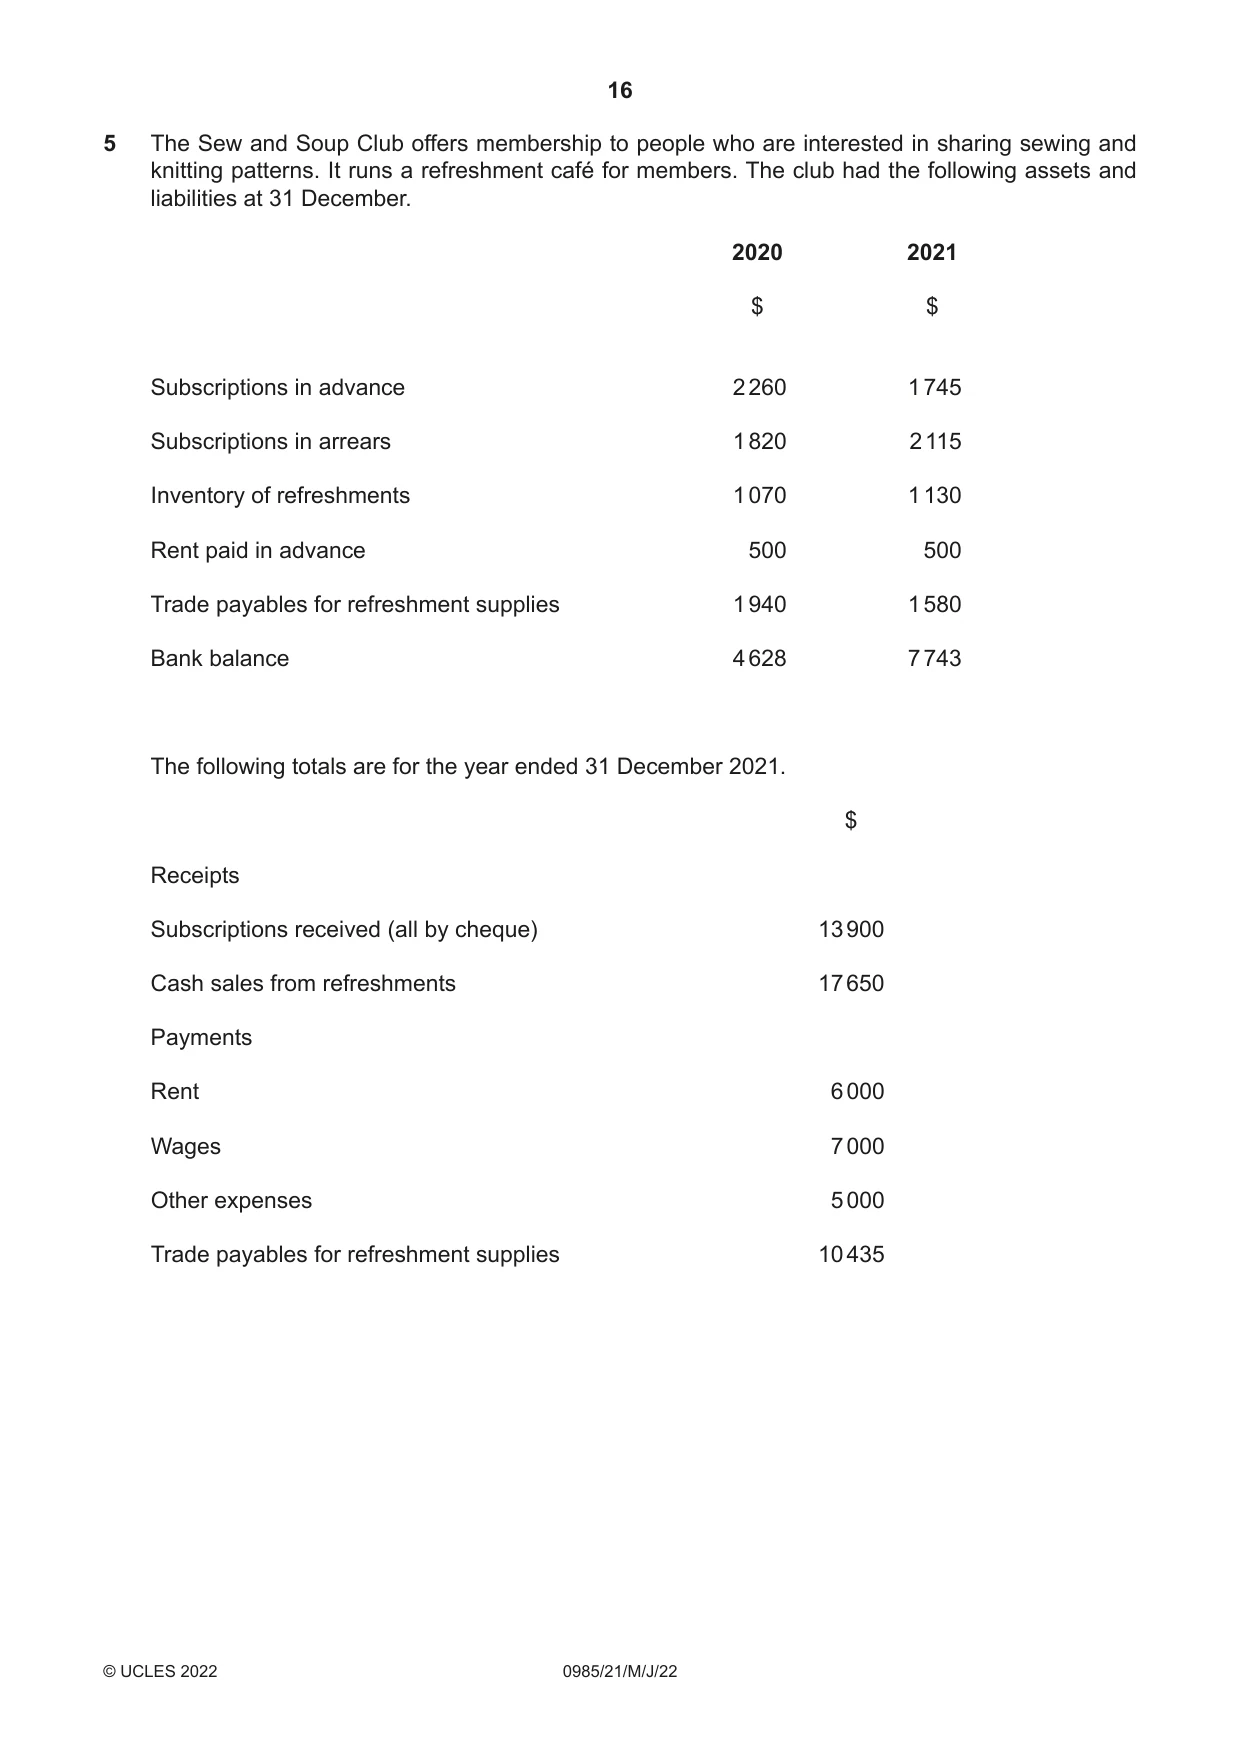
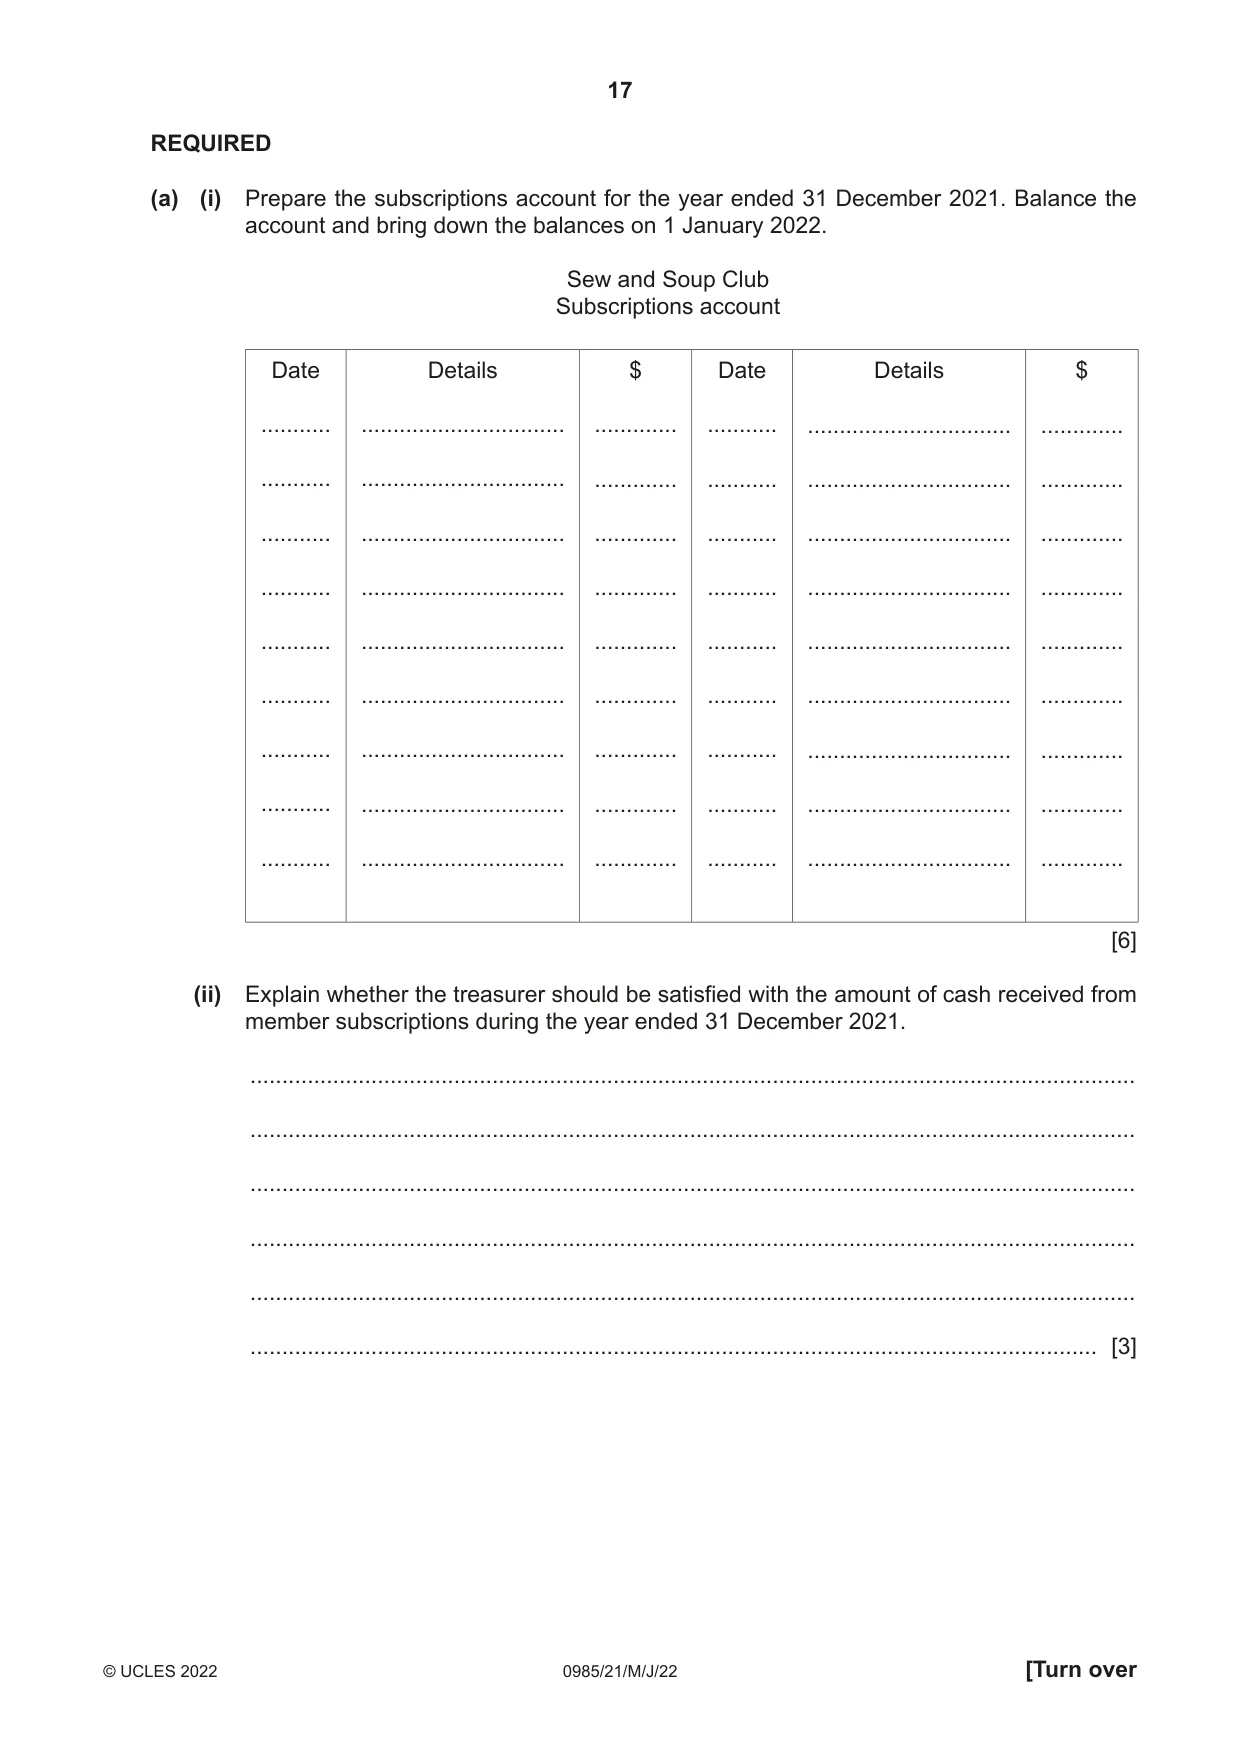
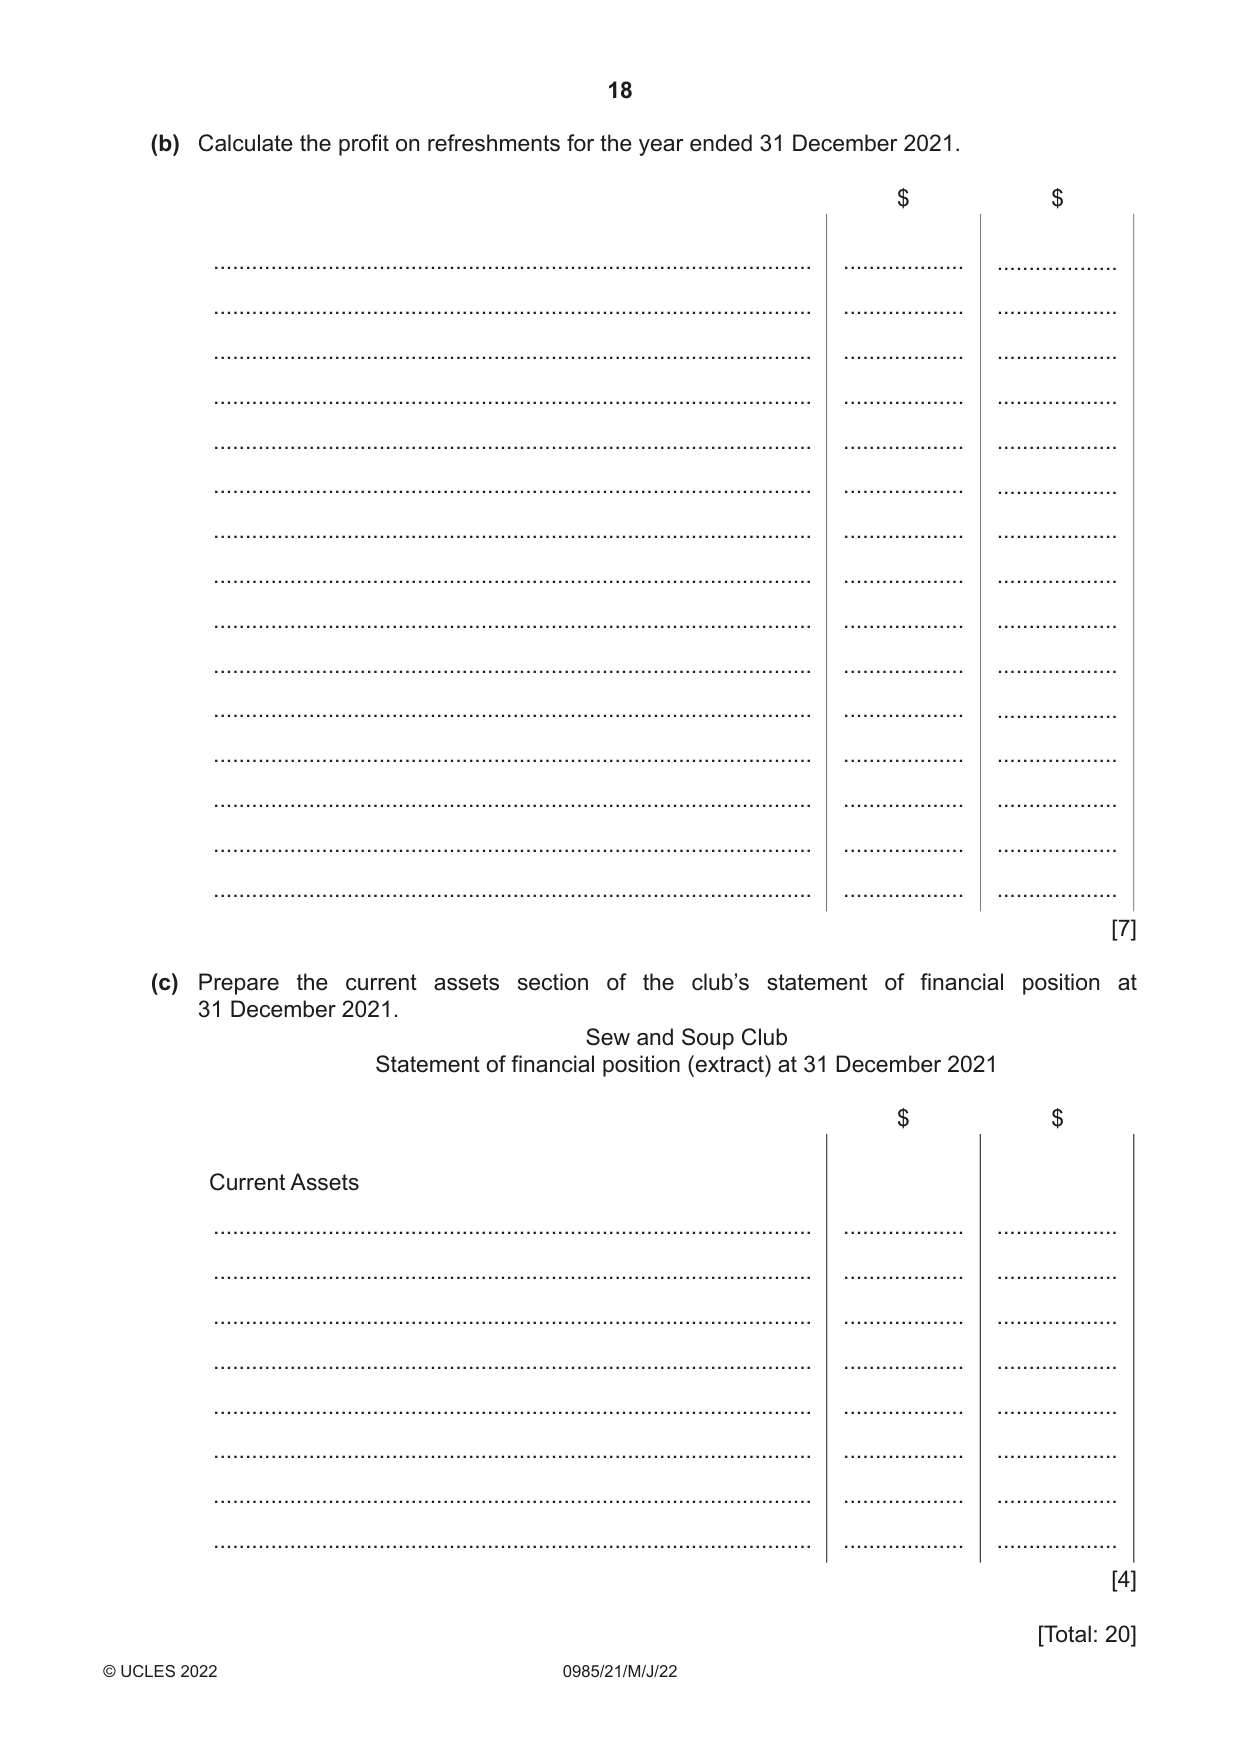
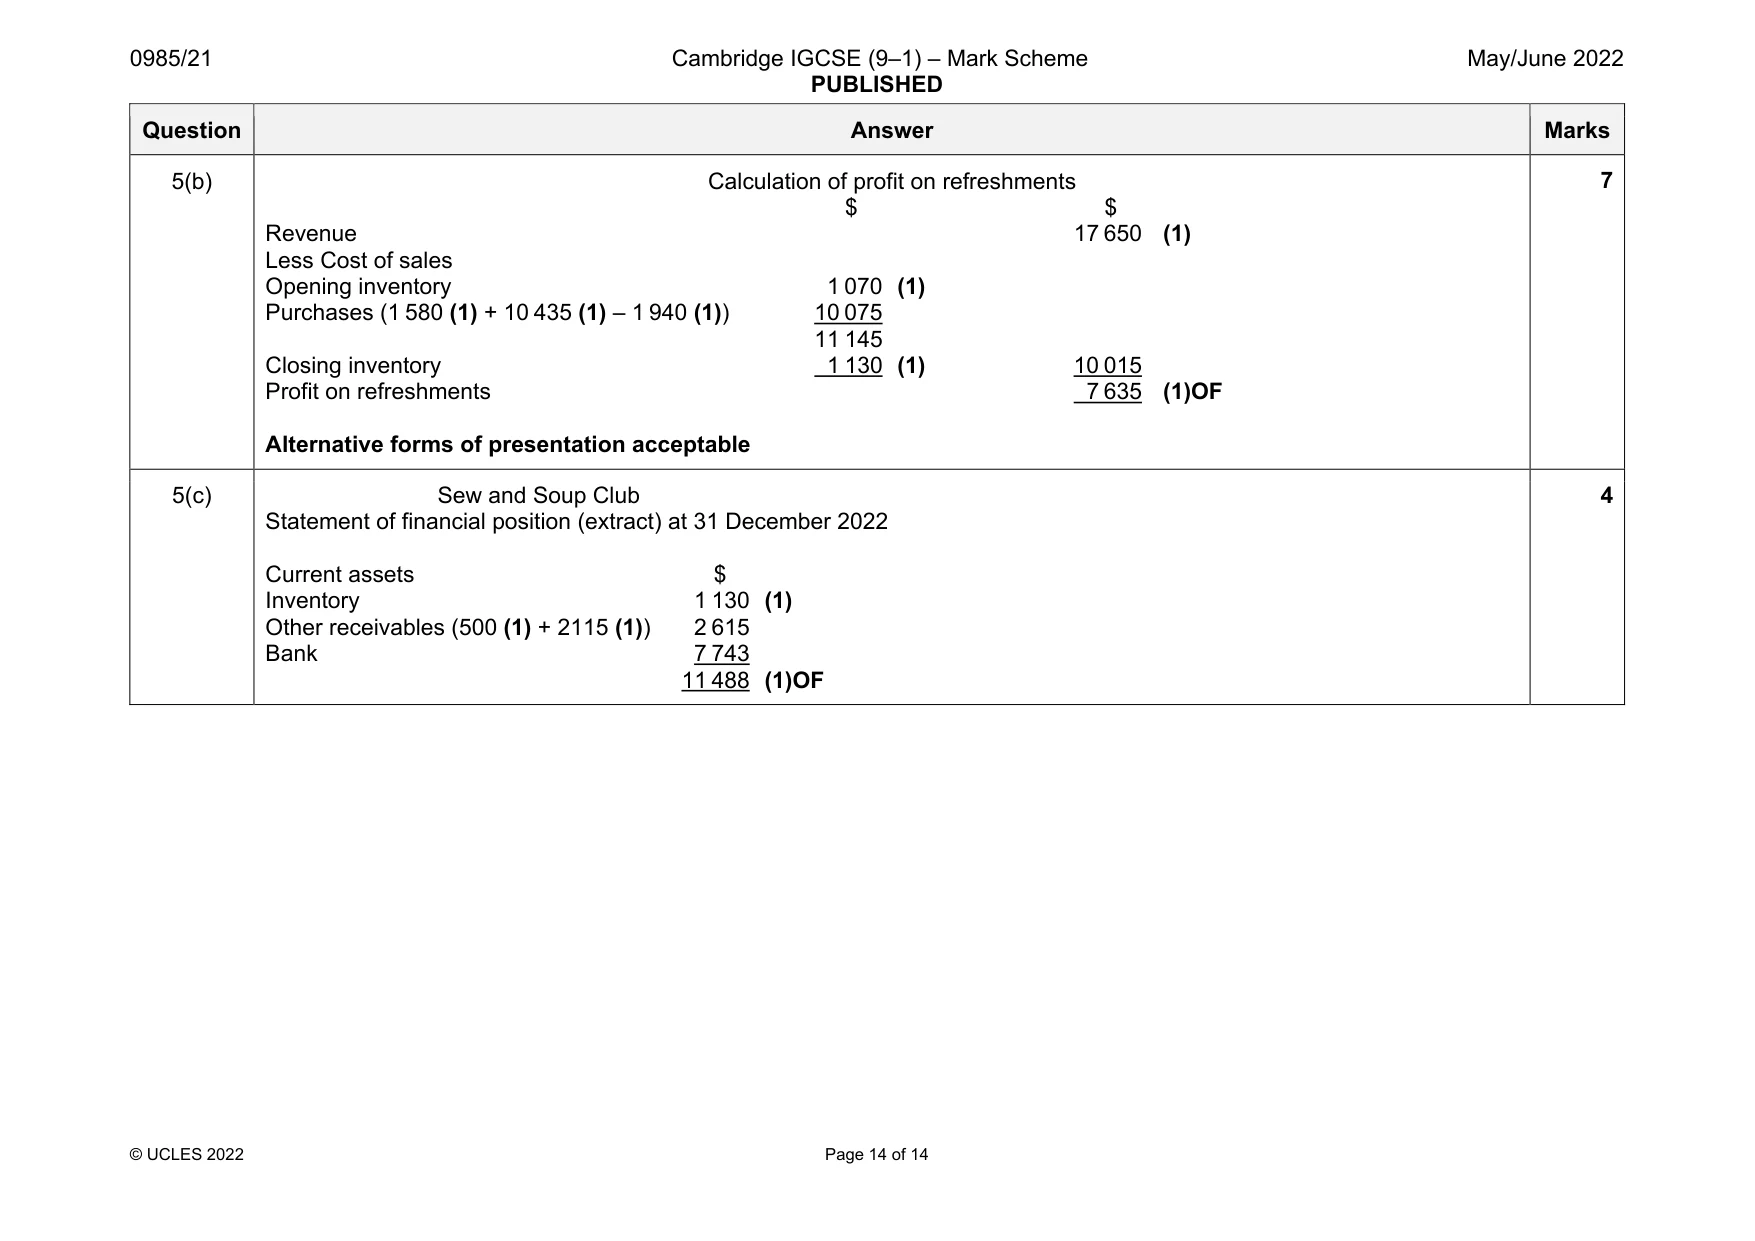
Mark scheme: 5(a)(i) Sew and Soup Club Subscriptions account Date 2021 Jan 1 Dec 31 2022 Jan 1 Details Balance b/d Income and expenditure account (1)OF Balance c/d Balance b/d (1) $ 1 820 14 710 1 745 18 275 2 115 Date 2021 Jan 1 Dec 31 2022 Jan 1 Details Balance b/d (1)* Bank (1) Balance c/d Balance b/d (1) $ 2 260 13 900 2 115 18 275 1 745 * (1) for both the opening balances + (1) dates 5(a)(ii) The amount received was less that the subscriptions due for the year (1) Subscriptions in advance have decreased (1) Subscriptions in arrears have increased (1) Max (2) Accept other valid points The treasurer should not be pleased with this situation (1) 3 Question Answer Marks 5(b) Calculation of profit on refreshments $ $ Revenue 17 650 (1) Less Cost of sales Opening inventory 1 070 (1) Purchases (1 580 (1) + 10 435 (1) – 1 940 (1)) 10 075 11 145 Closing inventory 1 130 (1) 10 015 Profit on refreshments 7 635 (1)OF Alternative forms of presentation acceptable 7 5(c) Sew and Soup Club Statement of financial position (extract) at 31 December 2022 Current assets $ Inventory 1 130 (1) Other receivables (500 (1) + 2115 (1)) 2 615 Bank 7 743 11 488 (1)OF 4
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2022 May/June, Paper 2 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.