Cambridge IGCSE Accounting (9-1) 0985 — 2024 May/June Paper 2 · Variant 2
0985/22/M/J/24 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme14 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Lottie is a trader
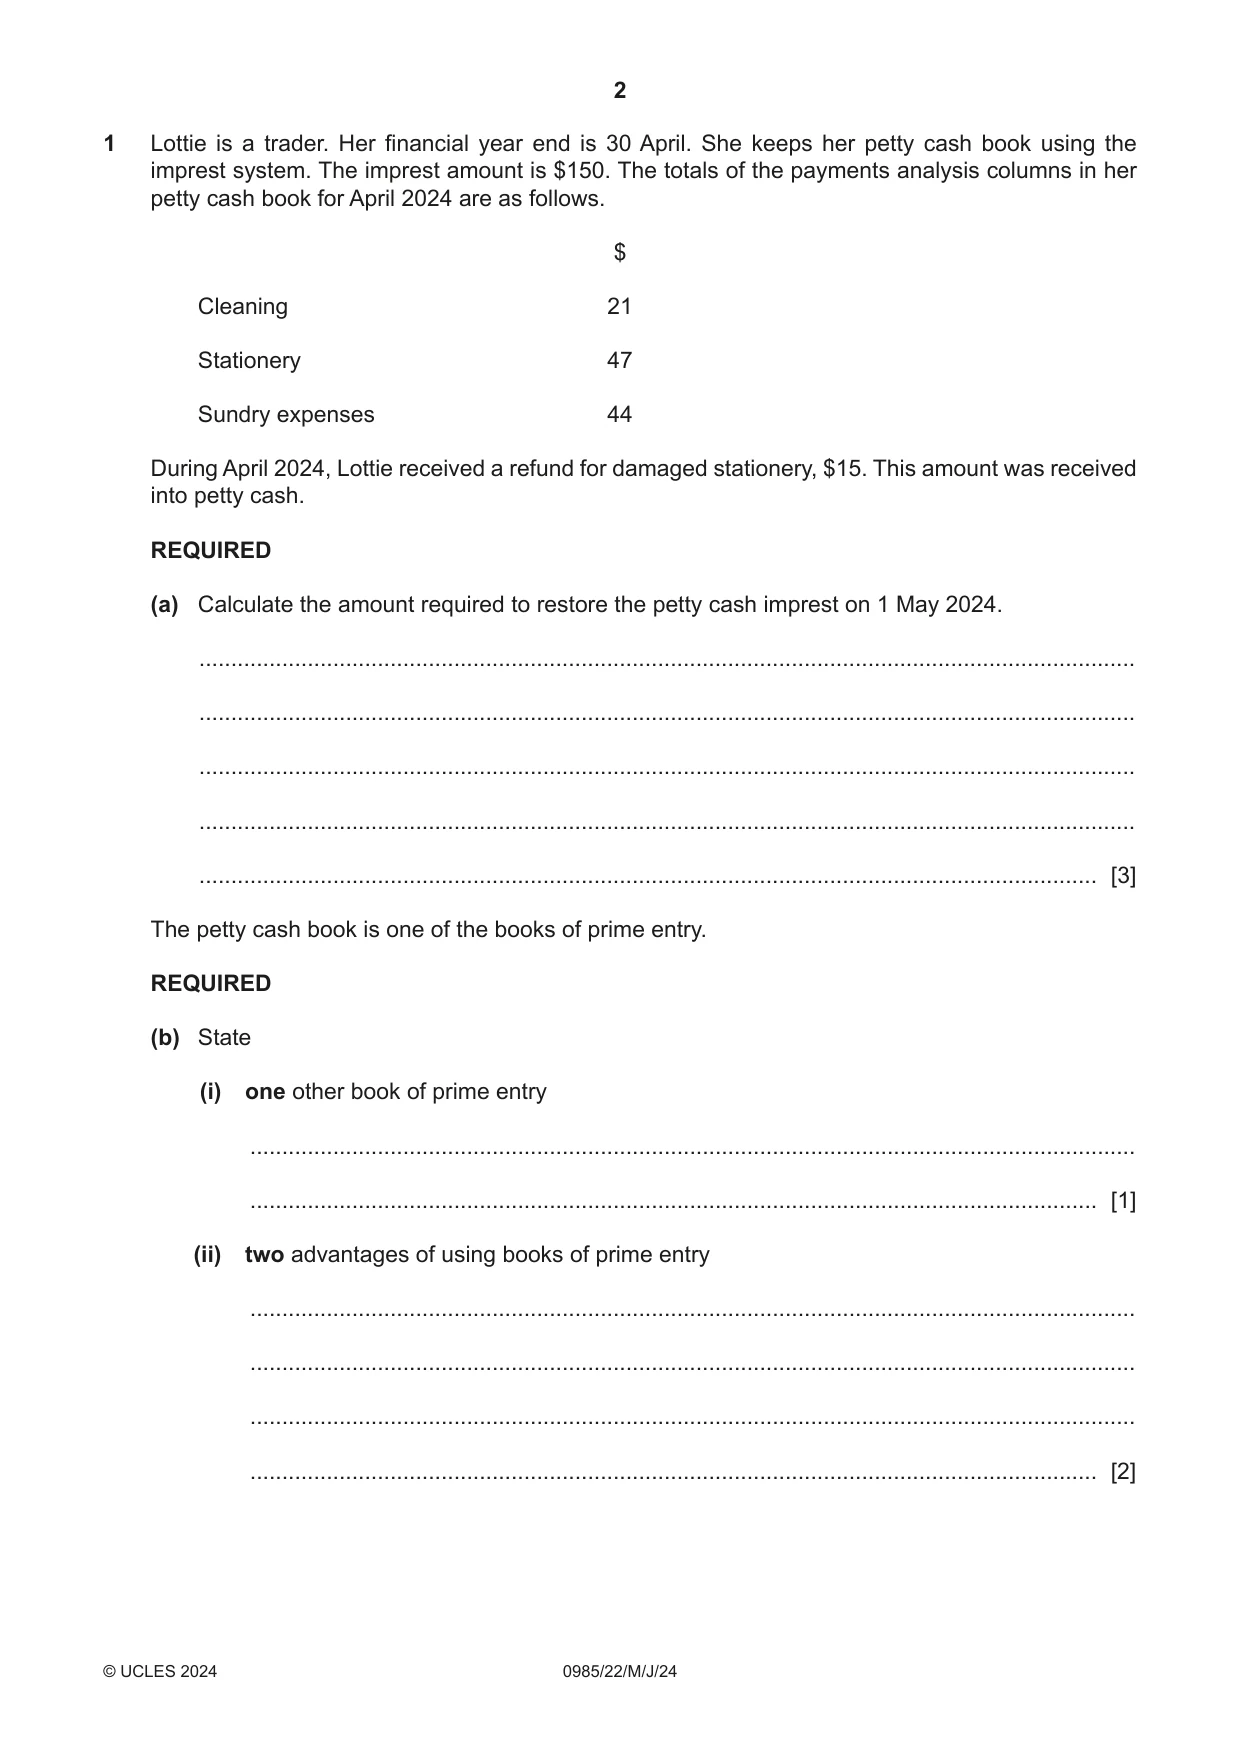
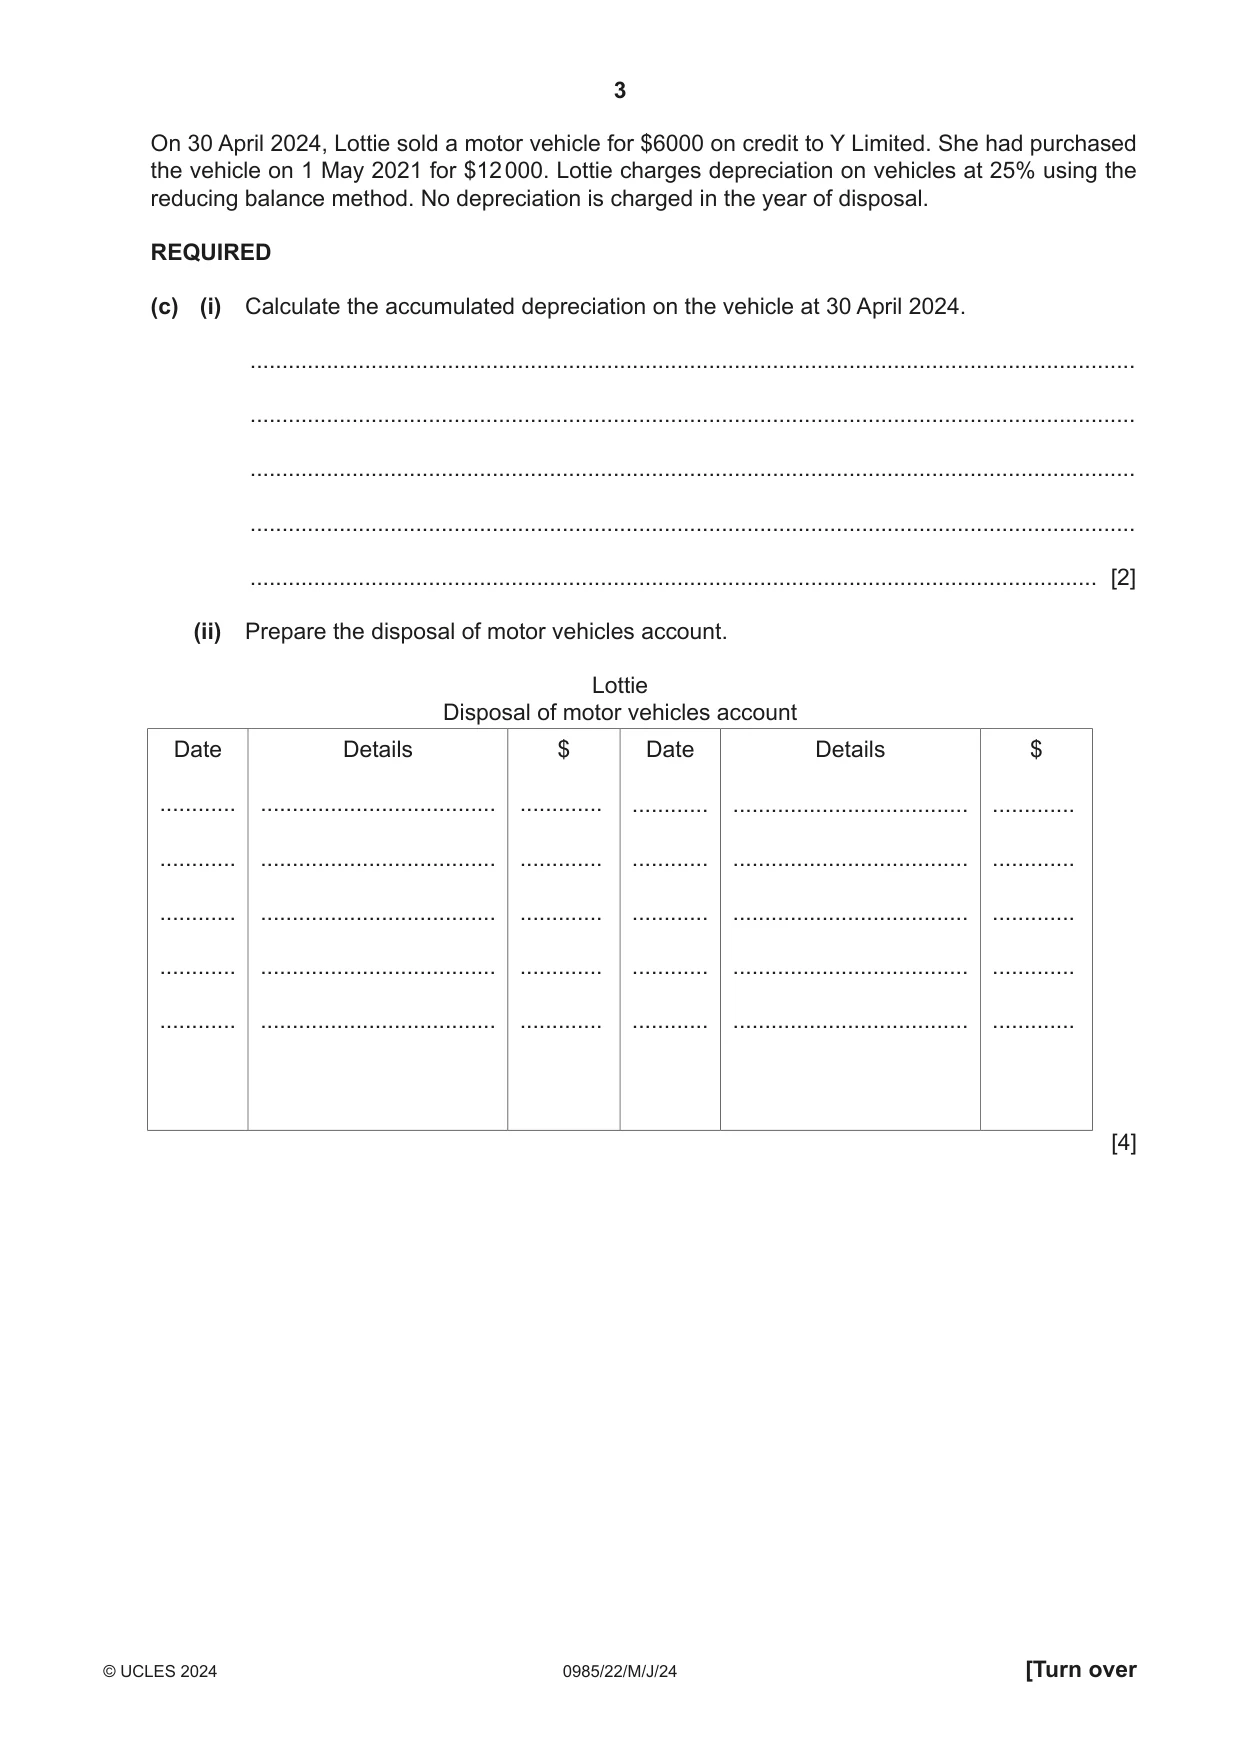
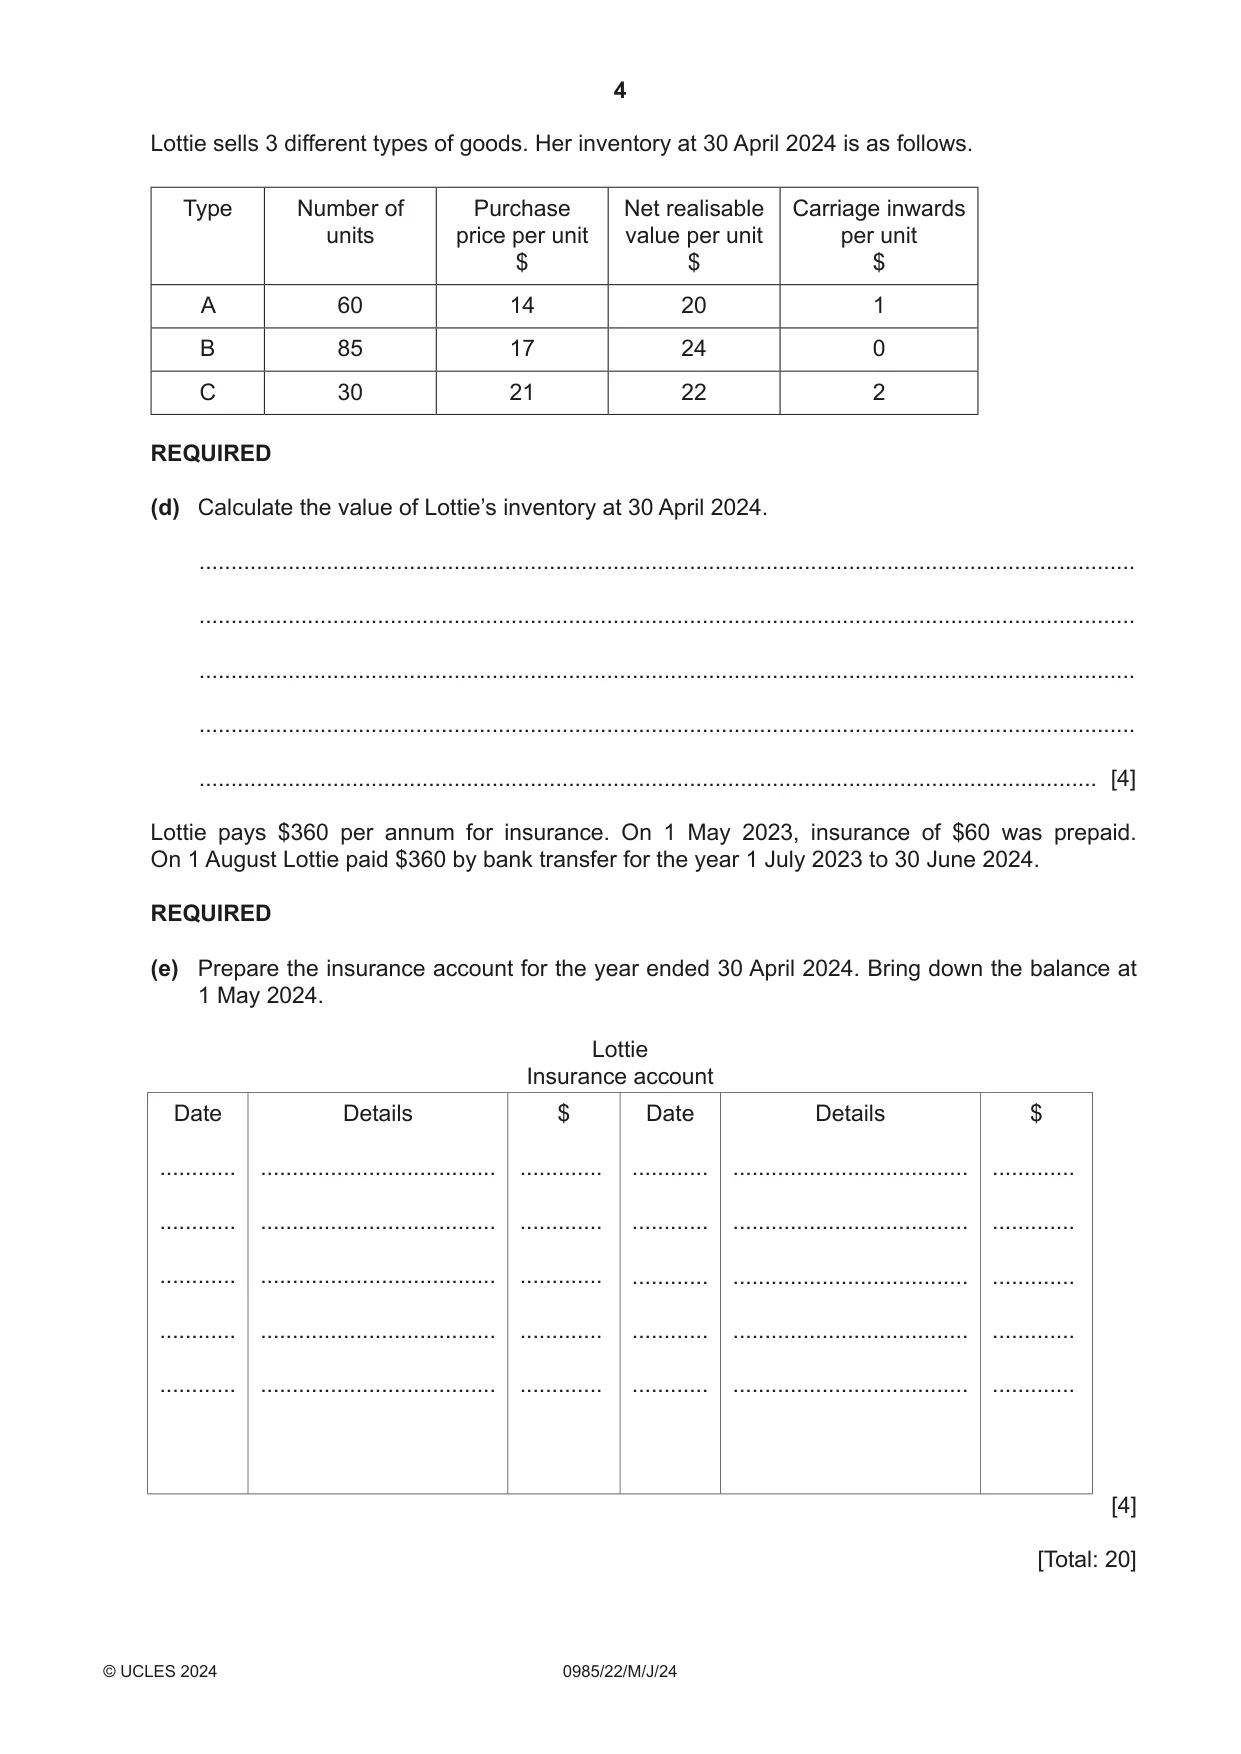
1 Lottie is a trader. Her financial year end is 30 April. She keeps her petty cash book using the imprest system. The imprest amount is $150. The totals of the payments analysis columns in her petty cash book for April 2024 are as follows. $ Cleaning 21 Stationery 47 Sundry expenses 44 During April 2024, Lottie received a refund for damaged stationery, $15. This amount was received into petty cash. REQUIRED (a) Calculate the amount required to restore the petty cash imprest on 1 May 2024. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] The petty cash book is one of the books of prime entry. REQUIRED (b) State (i) one other book of prime entry ........................................................................................................................................... ..................................................................................................................................... [1] (ii) two advantages of using books of prime entry ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] On 30 April 2024, Lottie sold a motor vehicle for $6000 on credit to Y Limited. She had purchased the vehicle on 1 May 2021 for $12 000. Lottie charges depreciation on vehicles at 25% using the reducing balance method. No depreciation is charged in the year of disposal. REQUIRED (c) (i) Calculate the accumulated depreciation on the vehicle at 30 April 2024. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] (ii) Prepare the disposal of motor vehicles account. Lottie Disposal of motor vehicles account Date Details $ Date Details $ ............ ..................................... ............. ............ ..................................... ............. ............ ..................................... ............. ............ ..................................... ............. ............ ..................................... ............. ............ ..................................... ............. ............ ..................................... ............. ............ ..................................... ............. ............ ..................................... ............. ............ ..................................... ............. [4] Lottie sells 3 different types of goods. Her inventory at 30 April 2024 is as follows. Type Number of Purchase Net realisable Carriage inwards units price per unit value per unit per unit $ $ $ A 60 14 20 1 B 85 17 24 0 C 30 21 22 2 REQUIRED (d) Calculate the value of Lottie’s inventory at 30 April 2024. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] Lottie pays $360 per annum for insurance. On 1 May 2023, insurance of $60 was prepaid. On 1 August Lottie paid $360 by bank transfer for the year 1 July 2023 to 30 June 2024. REQUIRED (e) Prepare the insurance account for the year ended 30 April 2024. Bring down the balance at 1 May 2024. Lottie Insurance account Date Details $ Date Details $ ............ ..................................... ............. ............ ..................................... ............. ............ ..................................... ............. ............ ..................................... ............. ............ ..................................... ............. ............ ..................................... ............. ............ ..................................... ............. ............ ..................................... ............. ............ ..................................... ............. ............ ..................................... ............. [4] [Total: 20]
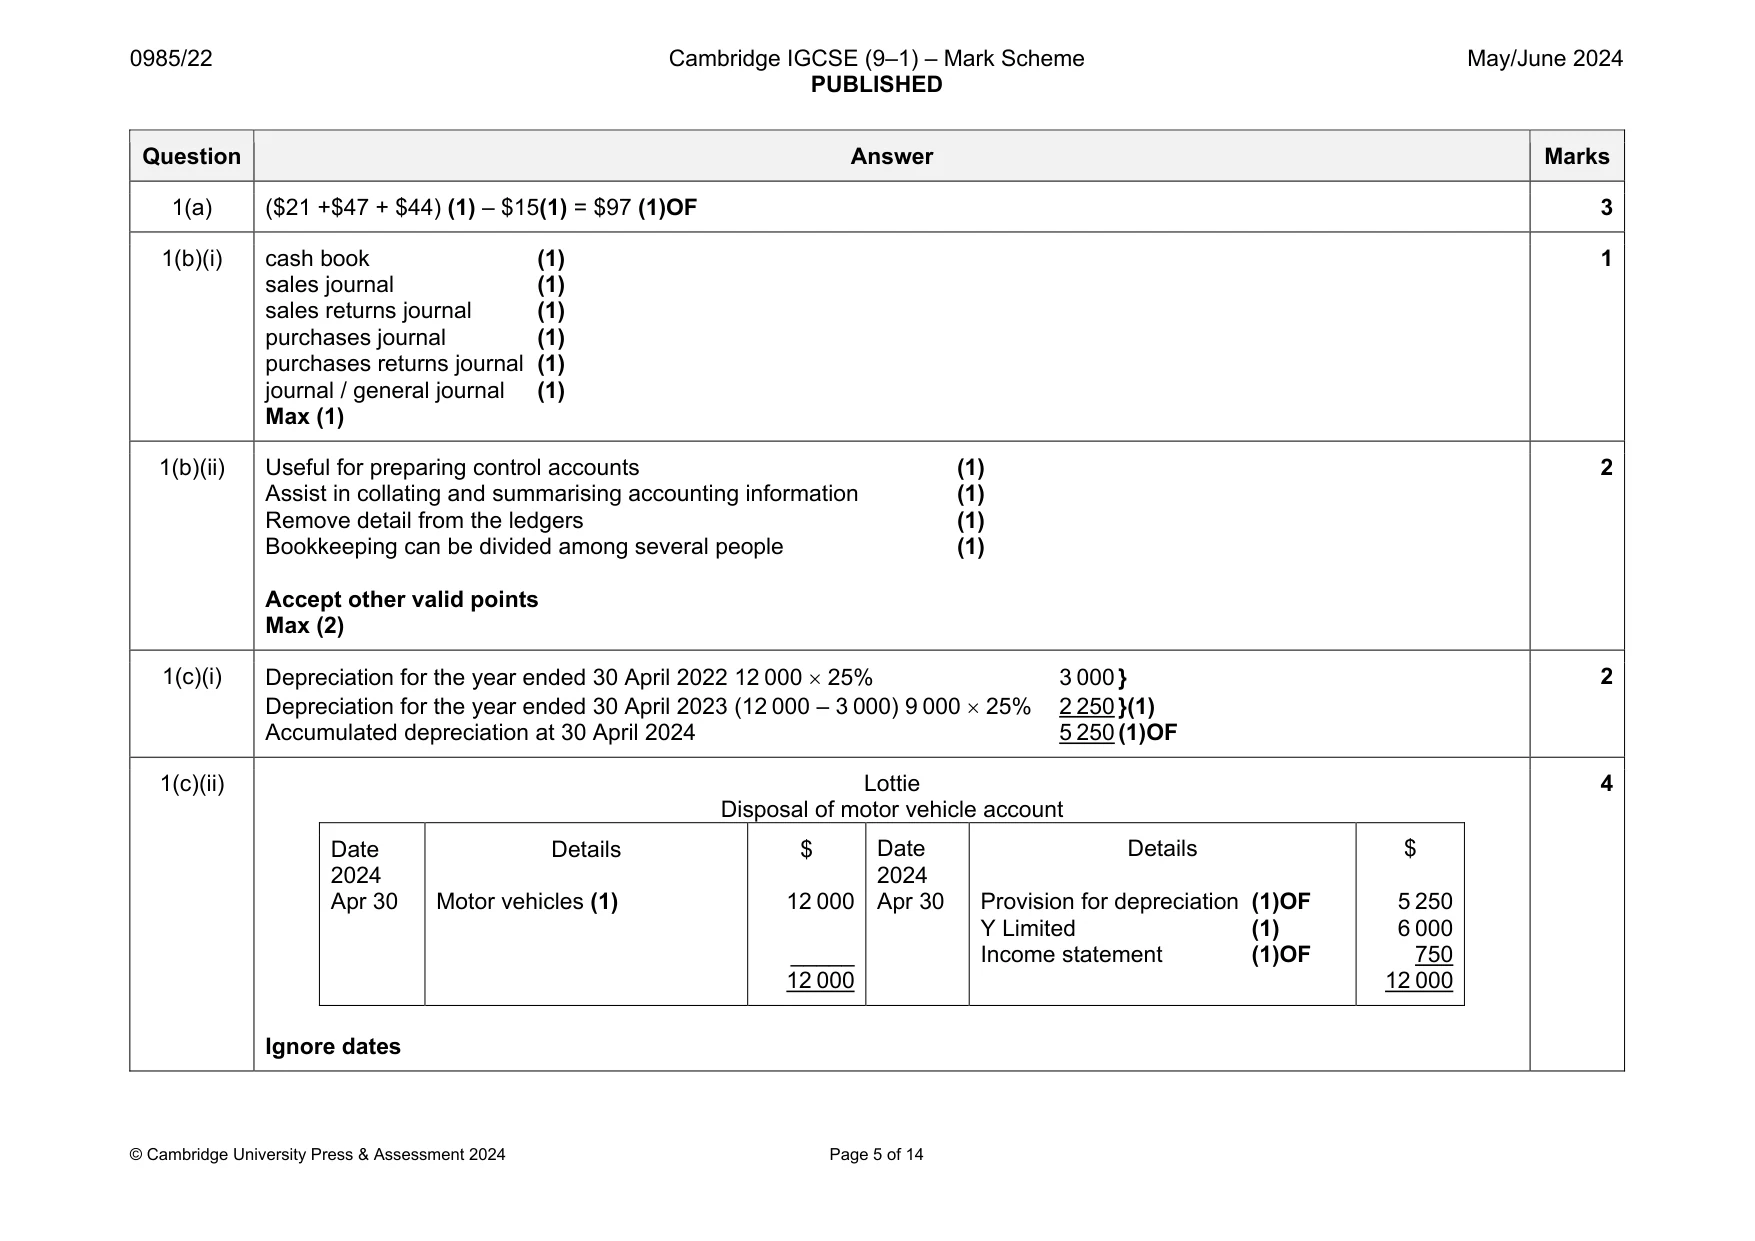
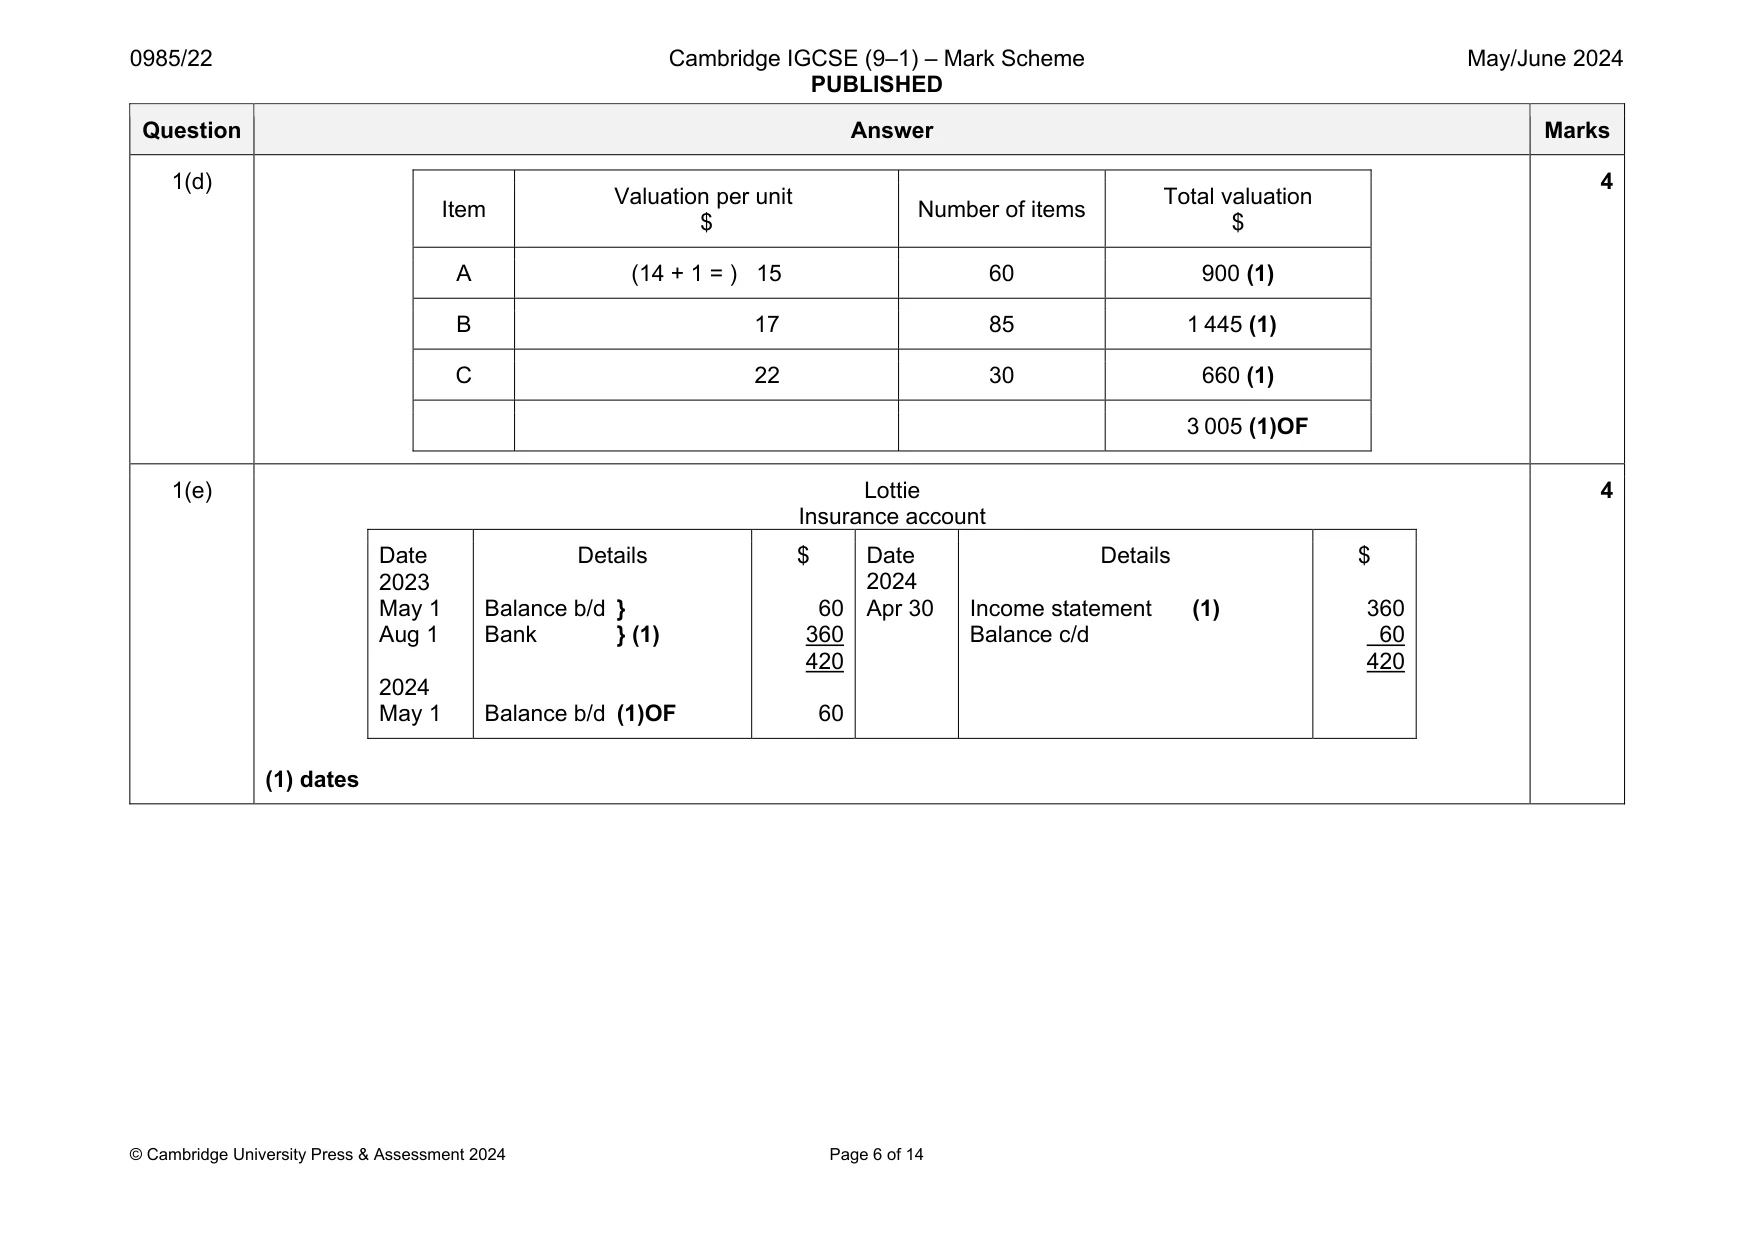
Mark scheme: 1(a) ($21 +$47 + $44) (1) – $15(1) = $97 (1)OF 3 1(b)(i) cash book (1) sales journal (1) sales returns journal (1) purchases journal (1) purchases returns journal (1) journal / general journal (1) Max (1) 1 1(b)(ii) Useful for preparing control accounts (1) Assist in collating and summarising accounting information (1) Remove detail from the ledgers (1) Bookkeeping can be divided among several people (1) Accept other valid points Max (2) 2 1(c)(i) Depreciation for the year ended 30 April 2022 12 000 25% 3 000 } Depreciation for the year ended 30 April 2023 (12 000 – 3 000) 9 000 25% 2 250 }(1) Accumulated depreciation at 30 April 2024 5 250 (1)OF 2 1(c)(ii) Lottie Disposal of motor vehicle account Date 2024 Apr 30 Details Motor vehicles (1) $ 12 000 _____ 12 000 Date 2024 Apr 30 Details Provision for depreciation (1)OF Y Limited (1) Income statement (1)OF $ 5 250 6 000 750 12 000 Ignore dates 4 Question Answer Marks 1(d) Item Valuation per unit $ Number of items Total valuation $ A (14 + 1 = ) 15 60 900 (1) B 17 85 1 445 (1) C 22 30 660 (1) 3 005 (1)OF 4 1(e) Lottie Insurance account Date 2023 May 1 Aug 1 2024 May 1 Details Balance b/d } Bank } (1) Balance b/d (1)OF $ 60 360 420 60 Date 2024 Apr 30 Details Income statement (1) Balance c/d $ 360 60 420 (1) dates 4
Q2 · Toyah owns a factory which makes dolls’ houses
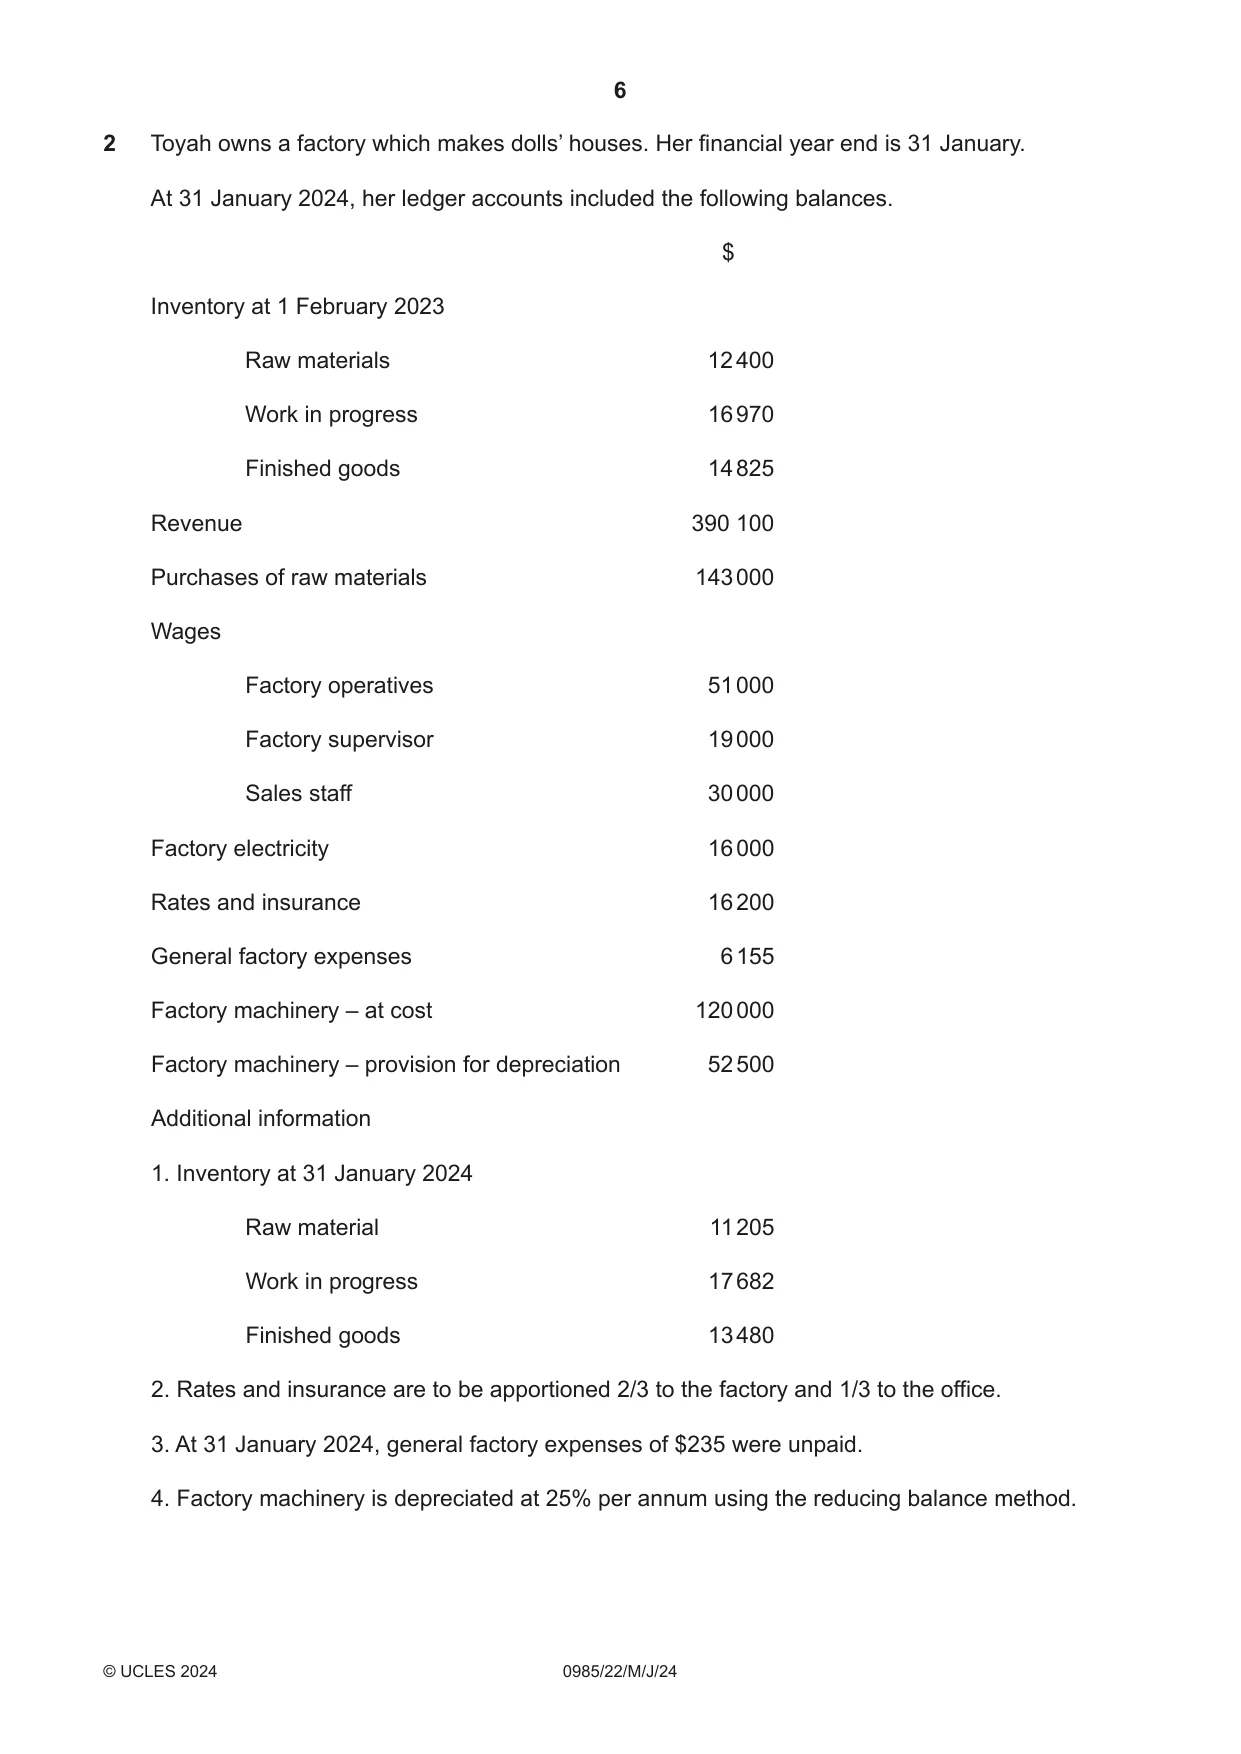
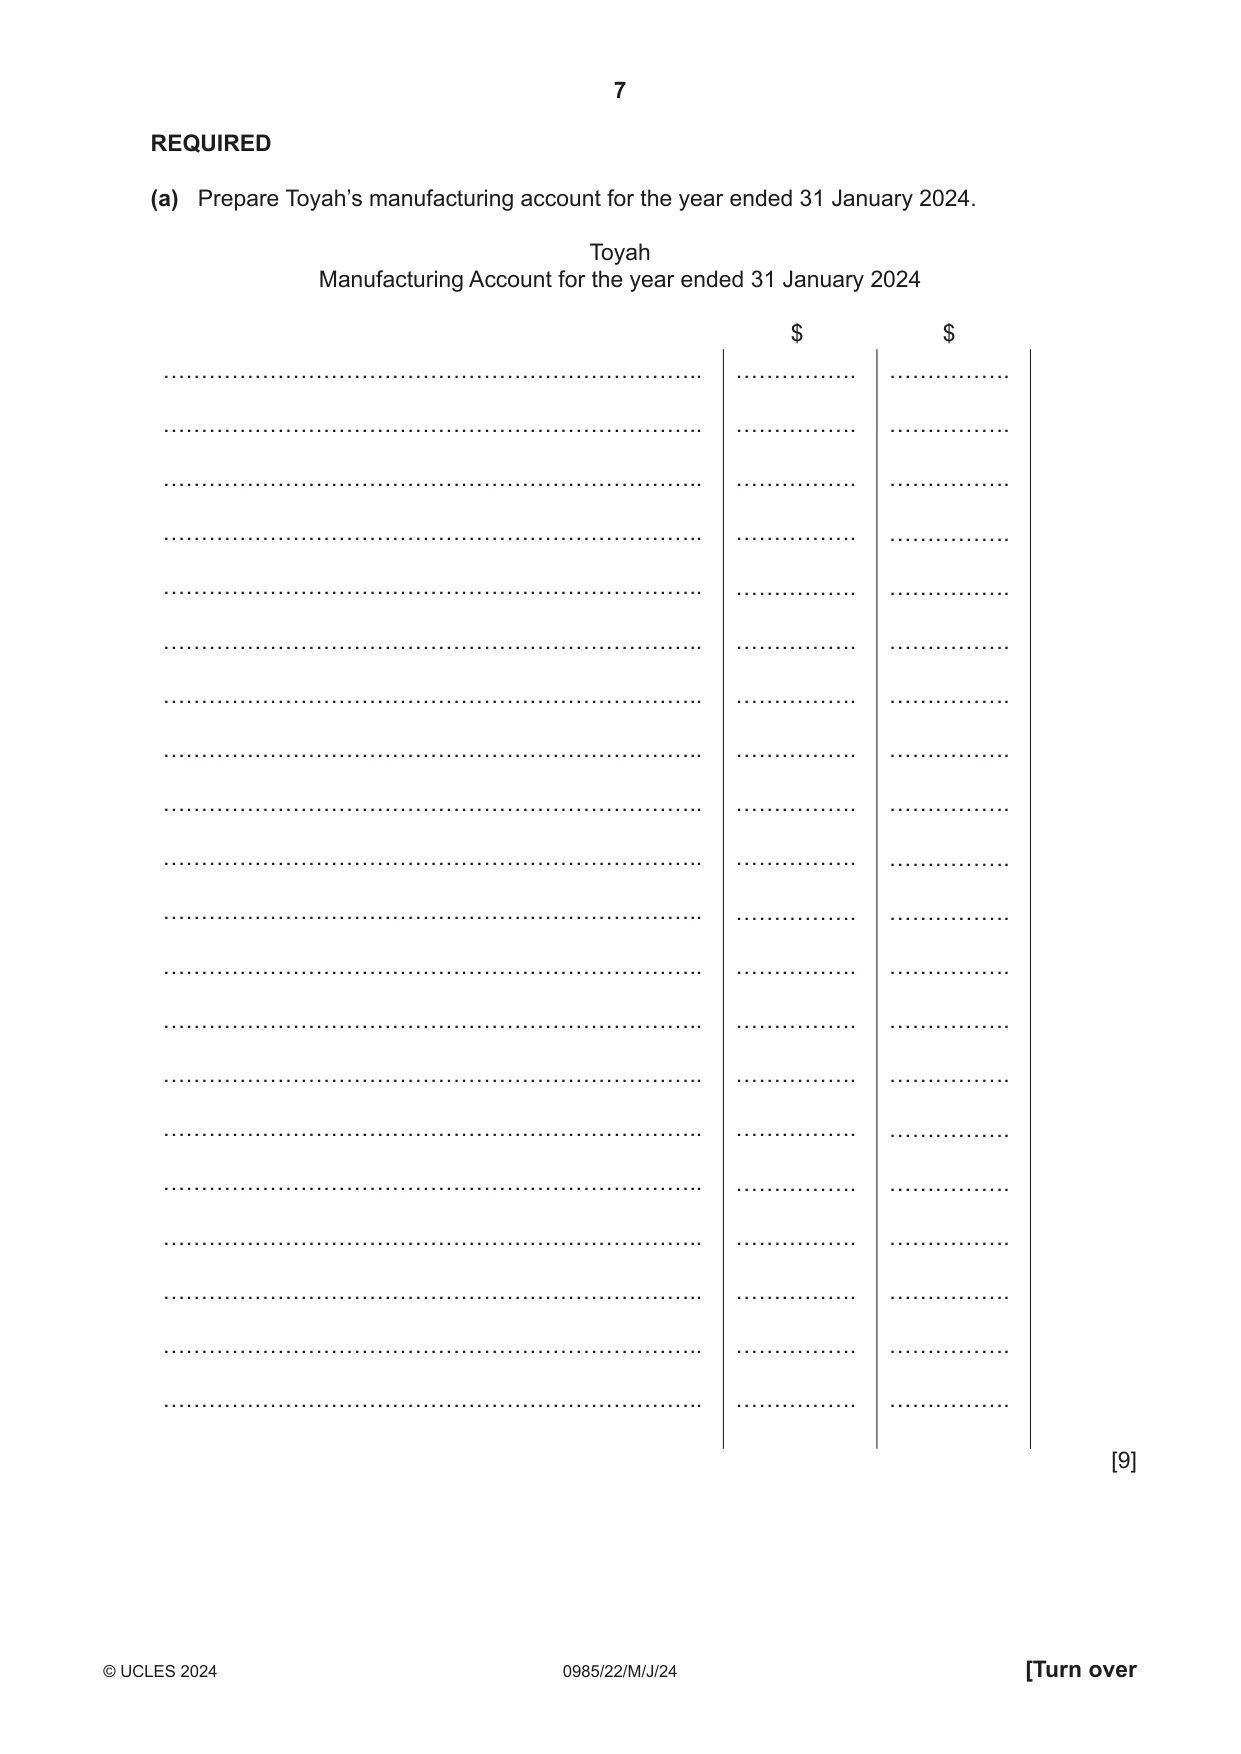
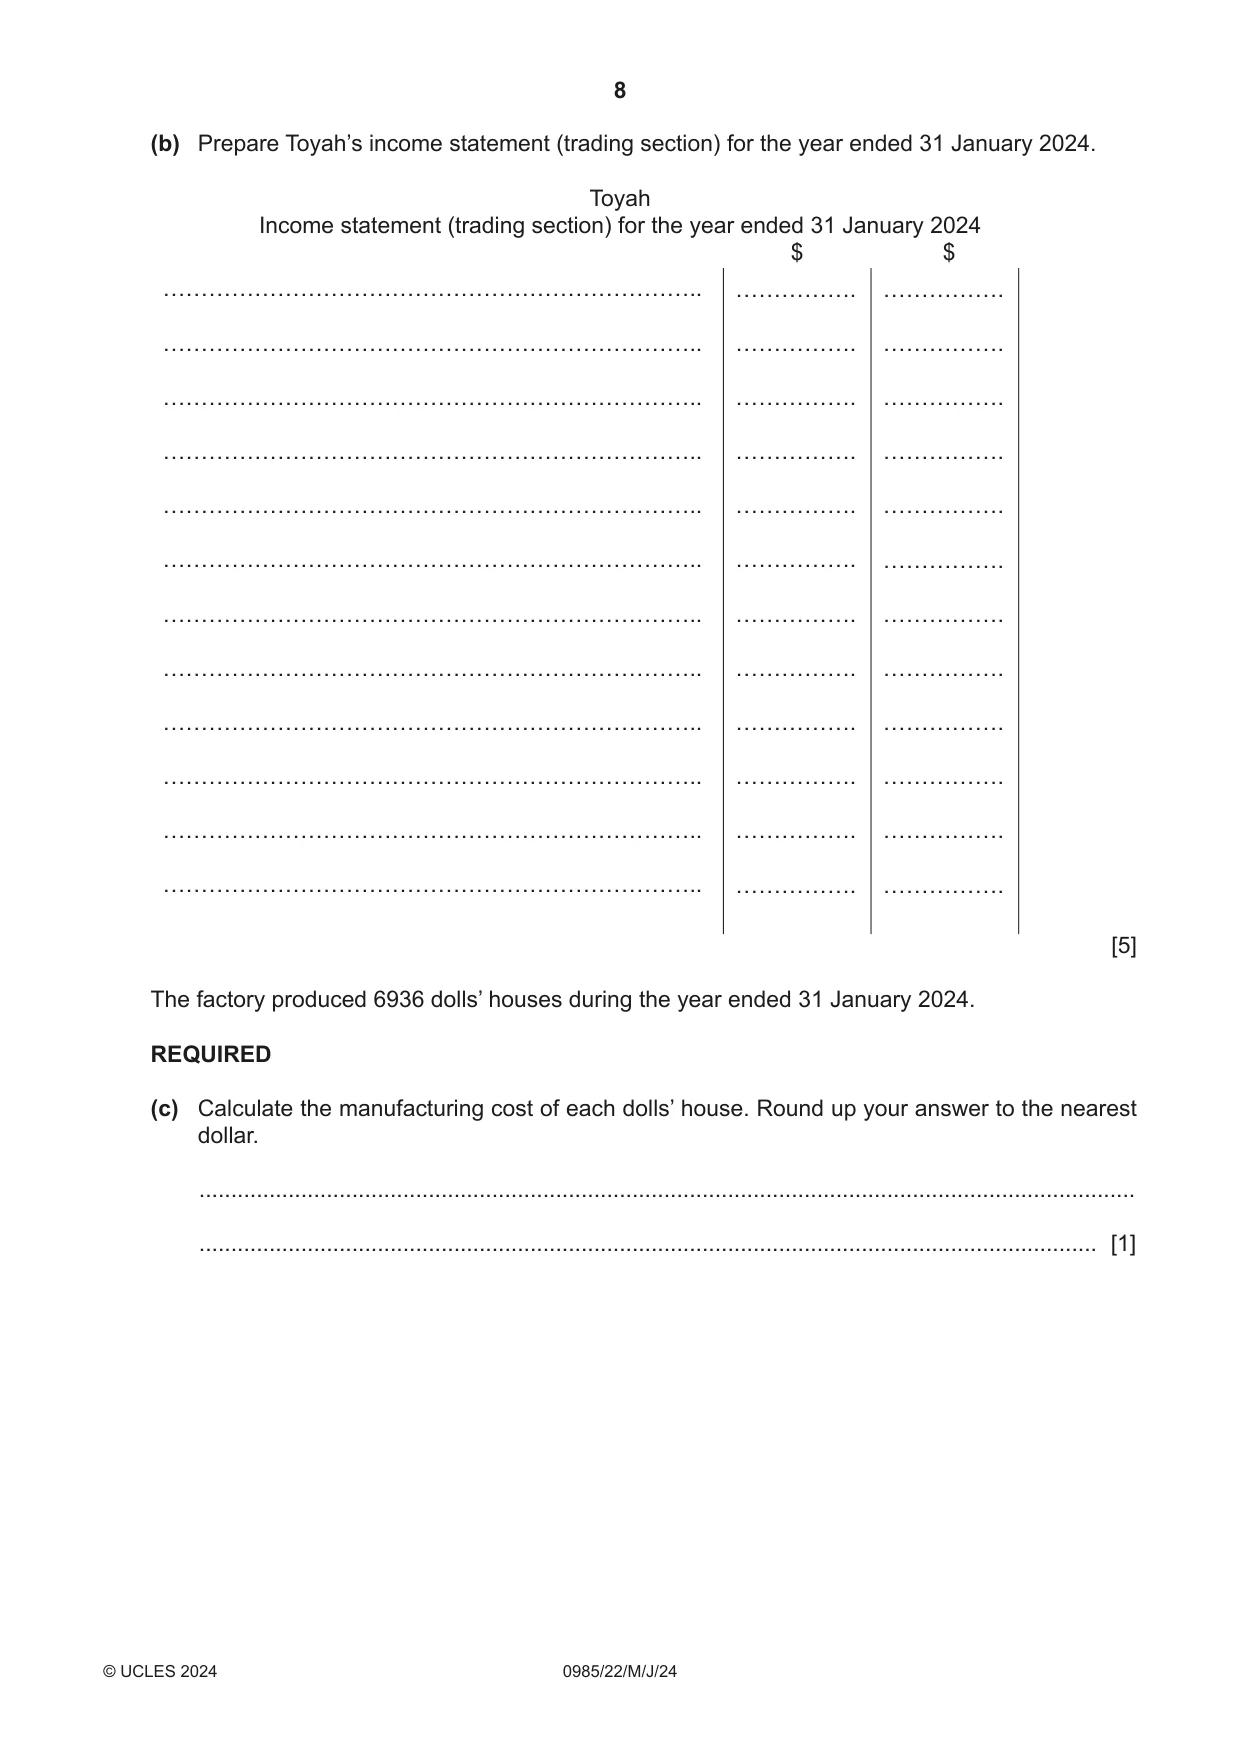
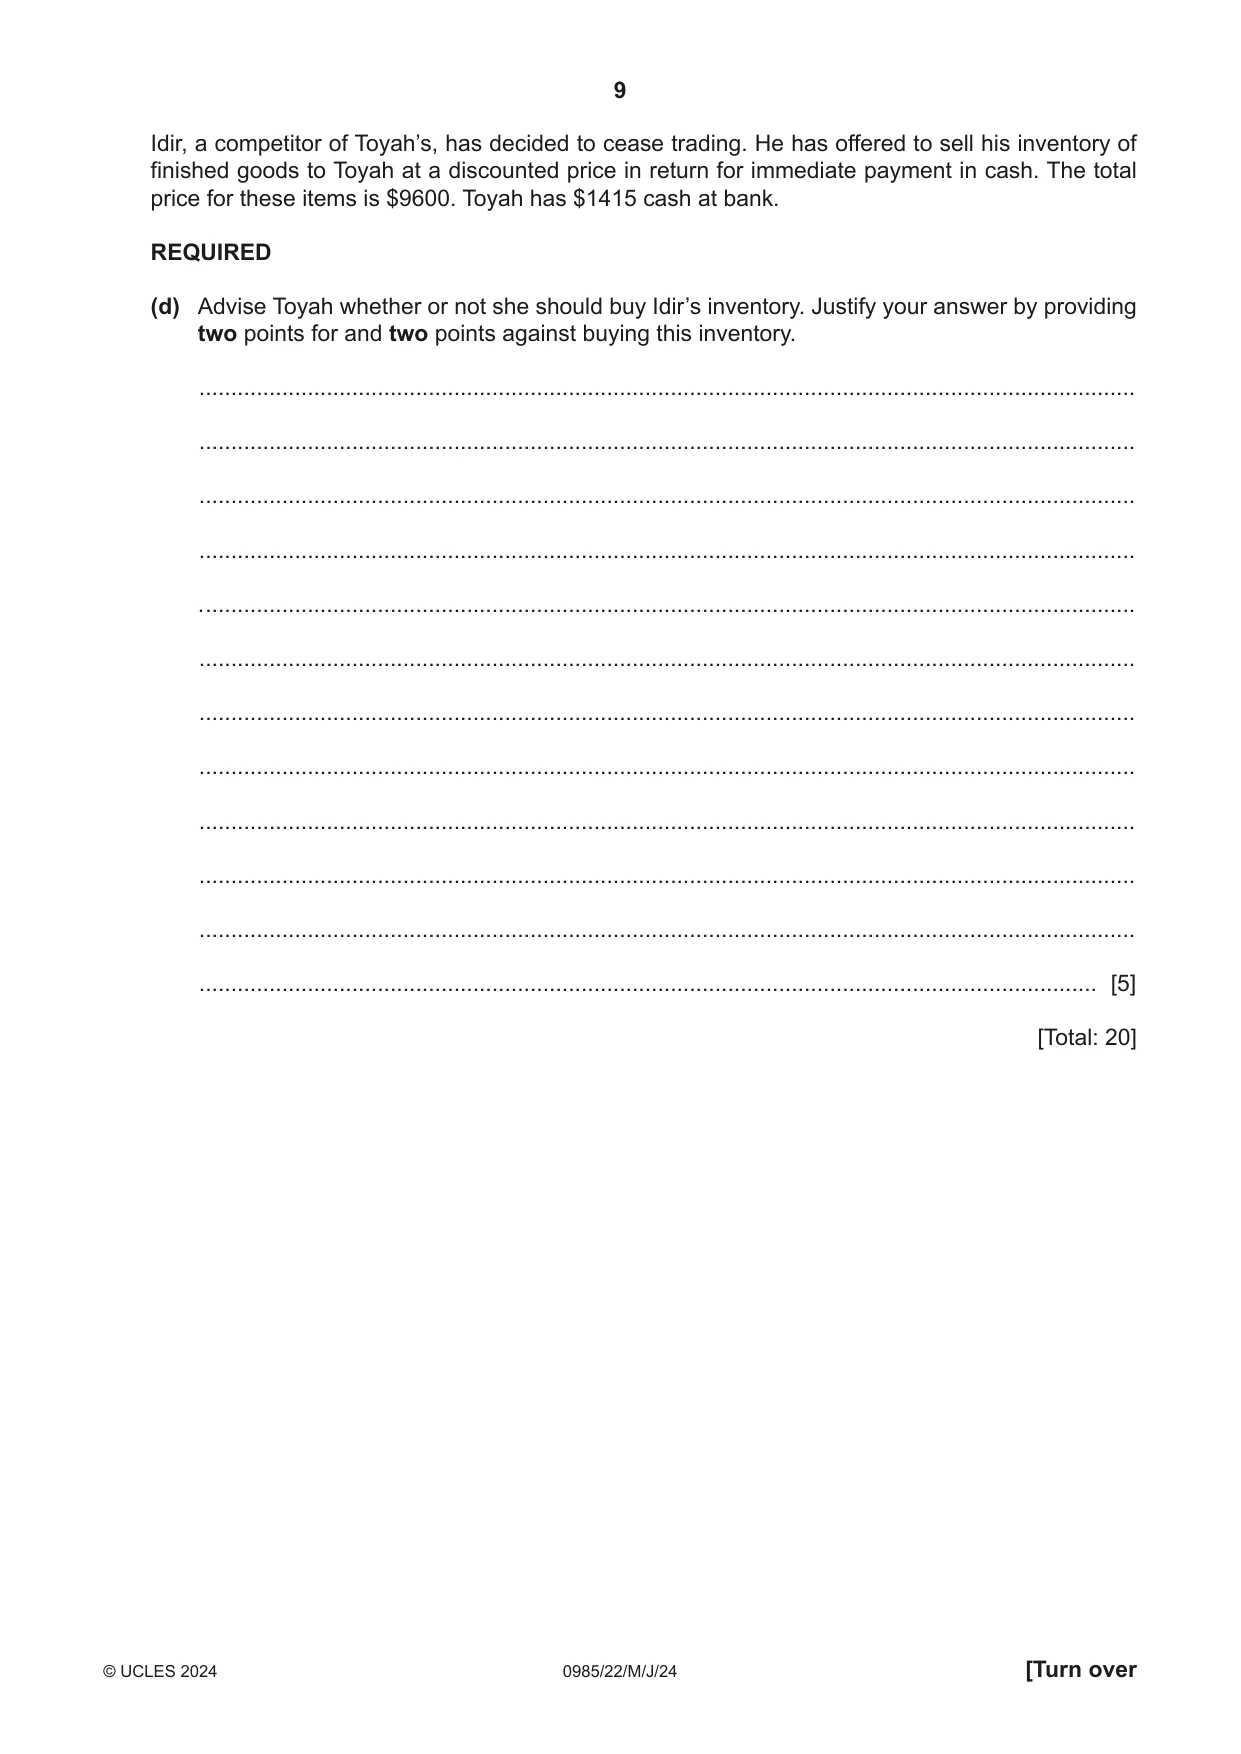
2 Toyah owns a factory which makes dolls’ houses. Her financial year end is 31 January. At 31 January 2024, her ledger accounts included the following balances. $ Inventory at 1 February 2023 Raw materials 12 400 Work in progress 16 970 Finished goods 14 825 Revenue 390 100 Purchases of raw materials 143 000 Wages Factory operatives 51 000 Factory supervisor 19 000 Sales staff 30 000 Factory electricity 16 000 Rates and insurance 16 200 General factory expenses 6 155 Factory machinery – at cost 120 000 Factory machinery – provision for depreciation 52 500 Additional information 1. Inventory at 31 January 2024 Raw material 11 205 Work in progress 17 682 Finished goods 13 480 2. Rates and insurance are to be apportioned 2/3 to the factory and 1/3 to the office. 3. At 31 January 2024, general factory expenses of $235 were unpaid. 4. Factory machinery is depreciated at 25% per annum using the reducing balance method. REQUIRED (a) Prepare Toyah’s manufacturing account for the yea Toyah Manufacturing Account for the year end (b) Prepare Toyah’s income statement (trading section) for the year ended 31 January 2024. Toyah Income statement (trading section) for the year ended 31 January 2024 $ $ ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. [5] The factory produced 6936 dolls’ houses during the year ended 31 January 2024. REQUIRED (c) Calculate the manufacturing cost of each dolls’ house. Round up your answer to the nearest dollar. ................................................................................................................................................... ............................................................................................................................................. [1] Idir, a competitor of Toyah’s, has decided to cease trading. He has offered to sell his inventory of finished goods to Toyah at a discounted price in return for immediate payment in cash. The total price for these items is $9600. Toyah has $1415 cash at bank. REQUIRED (d) Advise Toyah whether or not she should buy Idir’s inventory. Justify your answer by providing two points for and two points against buying this inventory. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... . .................................................................................................................................................. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
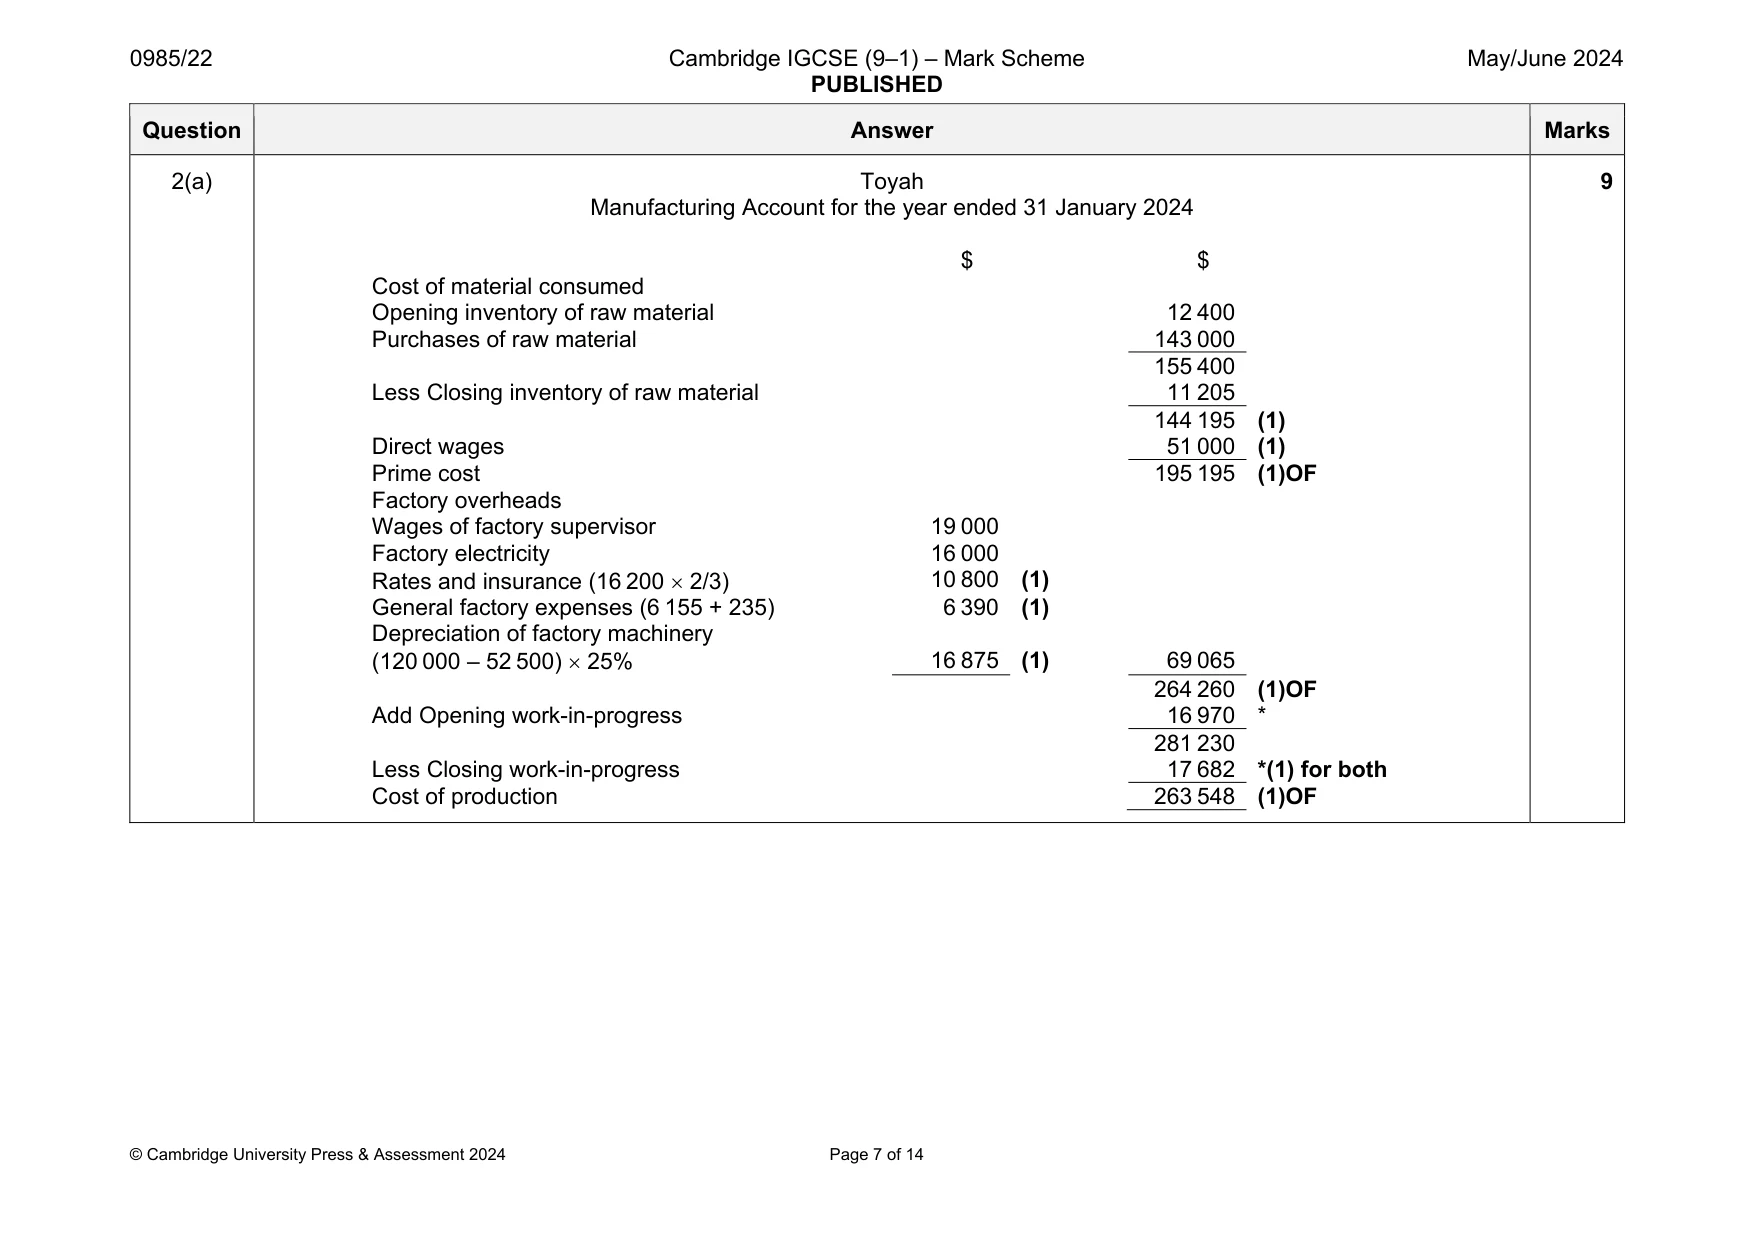
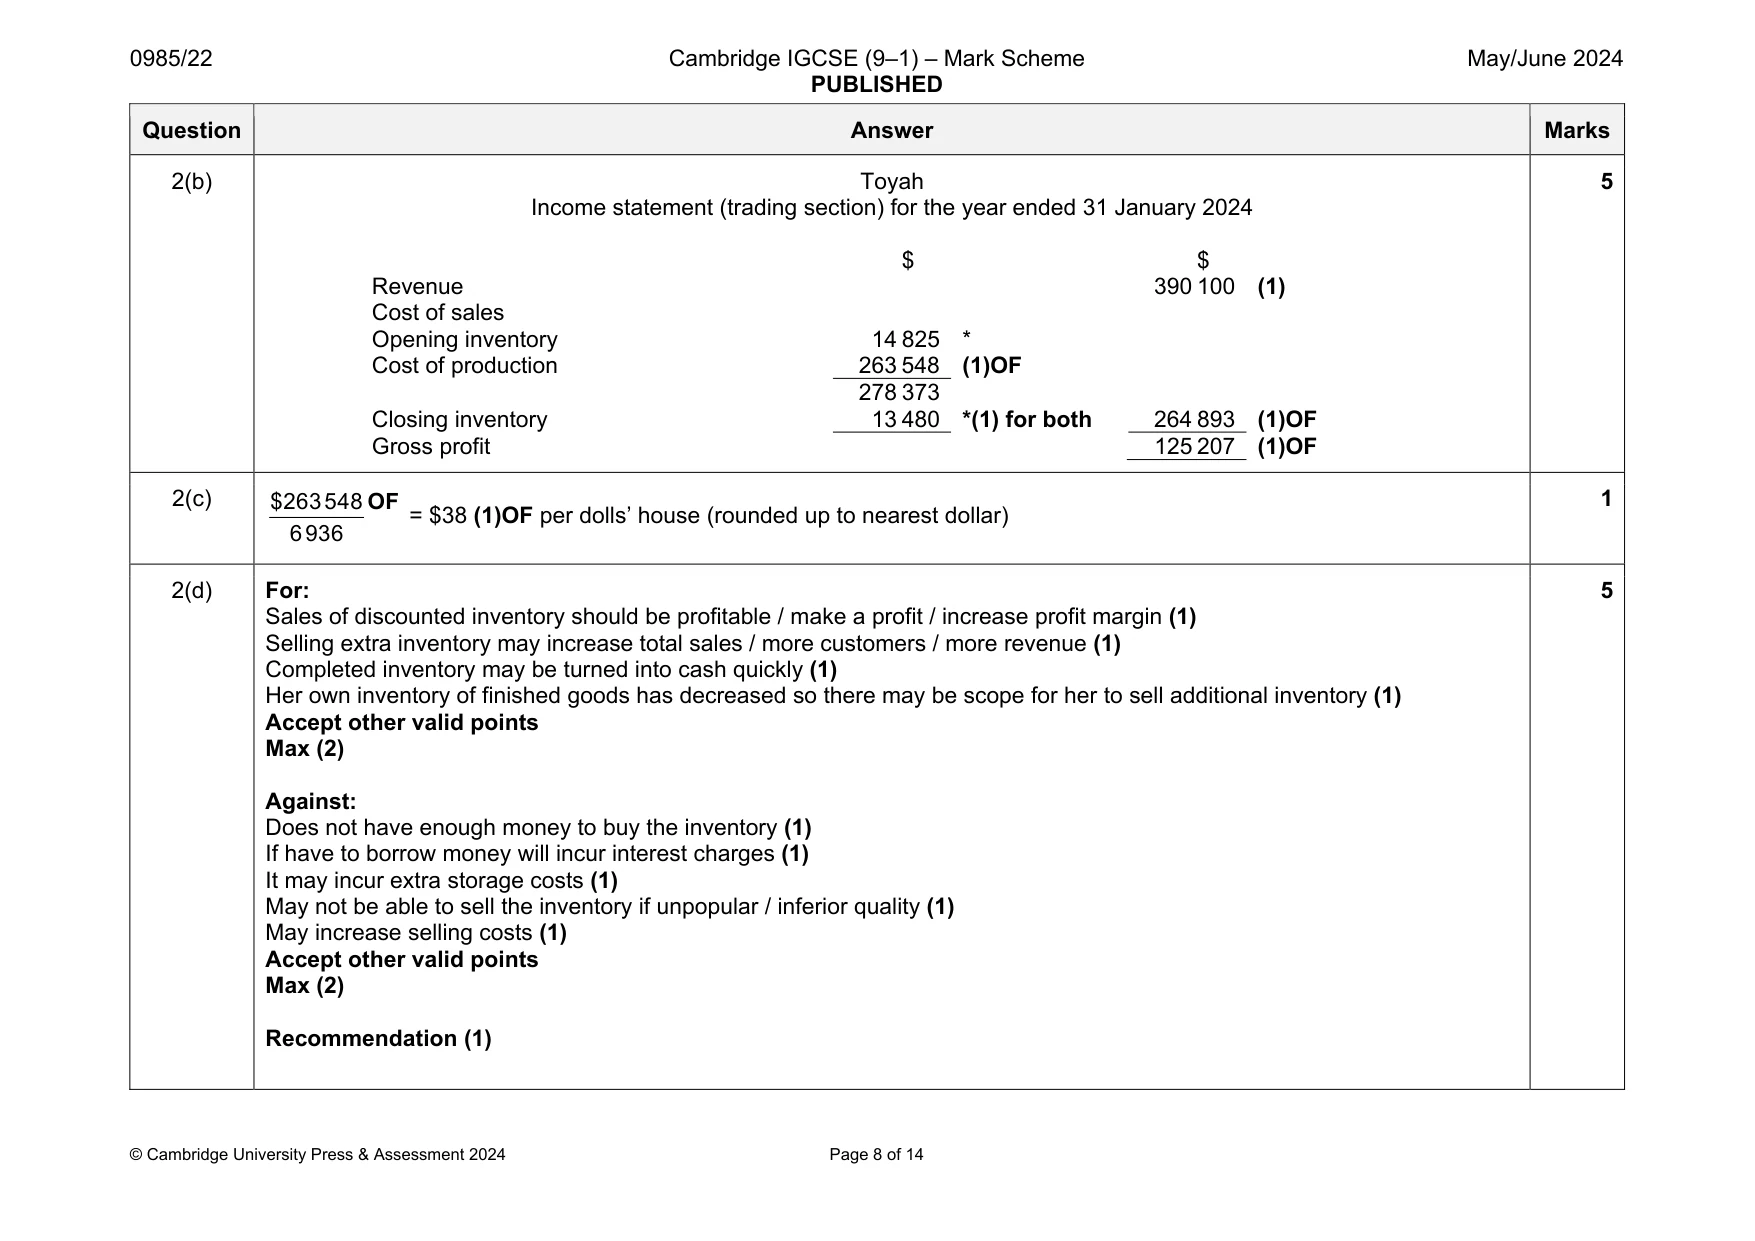
Mark scheme: 2(a) Toyah Manufacturing Account for the year ended 31 January 2024 $ $ Cost of material consumed Opening inventory of raw material 12 400 Purchases of raw material 143 000 155 400 Less Closing inventory of raw material 11 205 144 195 (1) Direct wages 51 000 (1) Prime cost 195 195 (1)OF Factory overheads Wages of factory supervisor 19 000 Factory electricity 16 000 Rates and insurance (16 200 2/3) 10 800 (1) General factory expenses (6 155 + 235) 6 390 (1) Depreciation of factory machinery (120 000 – 52 500) 25% 16 875 (1) 69 065 264 260 (1)OF Add Opening work-in-progress 16 970 * 281 230 Less Closing work-in-progress 17 682 *(1) for both Cost of production 263 548 (1)OF 9 Question Answer Marks 2(b) Toyah Income statement (trading section) for the year ended 31 January 2024 $ $ Revenue 390 100 (1) Cost of sales Opening inventory 14 825 * Cost of production 263 548 (1)OF 278 373 Closing inventory 13 480 *(1) for both 264 893 (1)OF Gross profit 125 207 (1)OF 5 2(c) $263548 6936 OF = $38 (1)OF per dolls’ house (rounded up to nearest dollar) 1 2(d) For: Sales of discounted inventory should be profitable / make a profit / increase profit margin (1) Selling extra inventory may increase total sales / more customers / more revenue (1) Completed inventory may be turned into cash quickly (1) Her own inventory of finished goods has decreased so there may be scope for her to sell additional inventory (1) Accept other valid points Max (2) Against: Does not have enough money to buy the inventory (1) If have to borrow money will incur interest charges (1) It may incur extra storage costs (1) May not be able to sell the inventory if unpopular / inferior quality (1) May increase selling costs (1) Accept other valid points Max (2) Recommendation (1) 5
Q3 · Akil prepared his trial balance at 29 February 2024
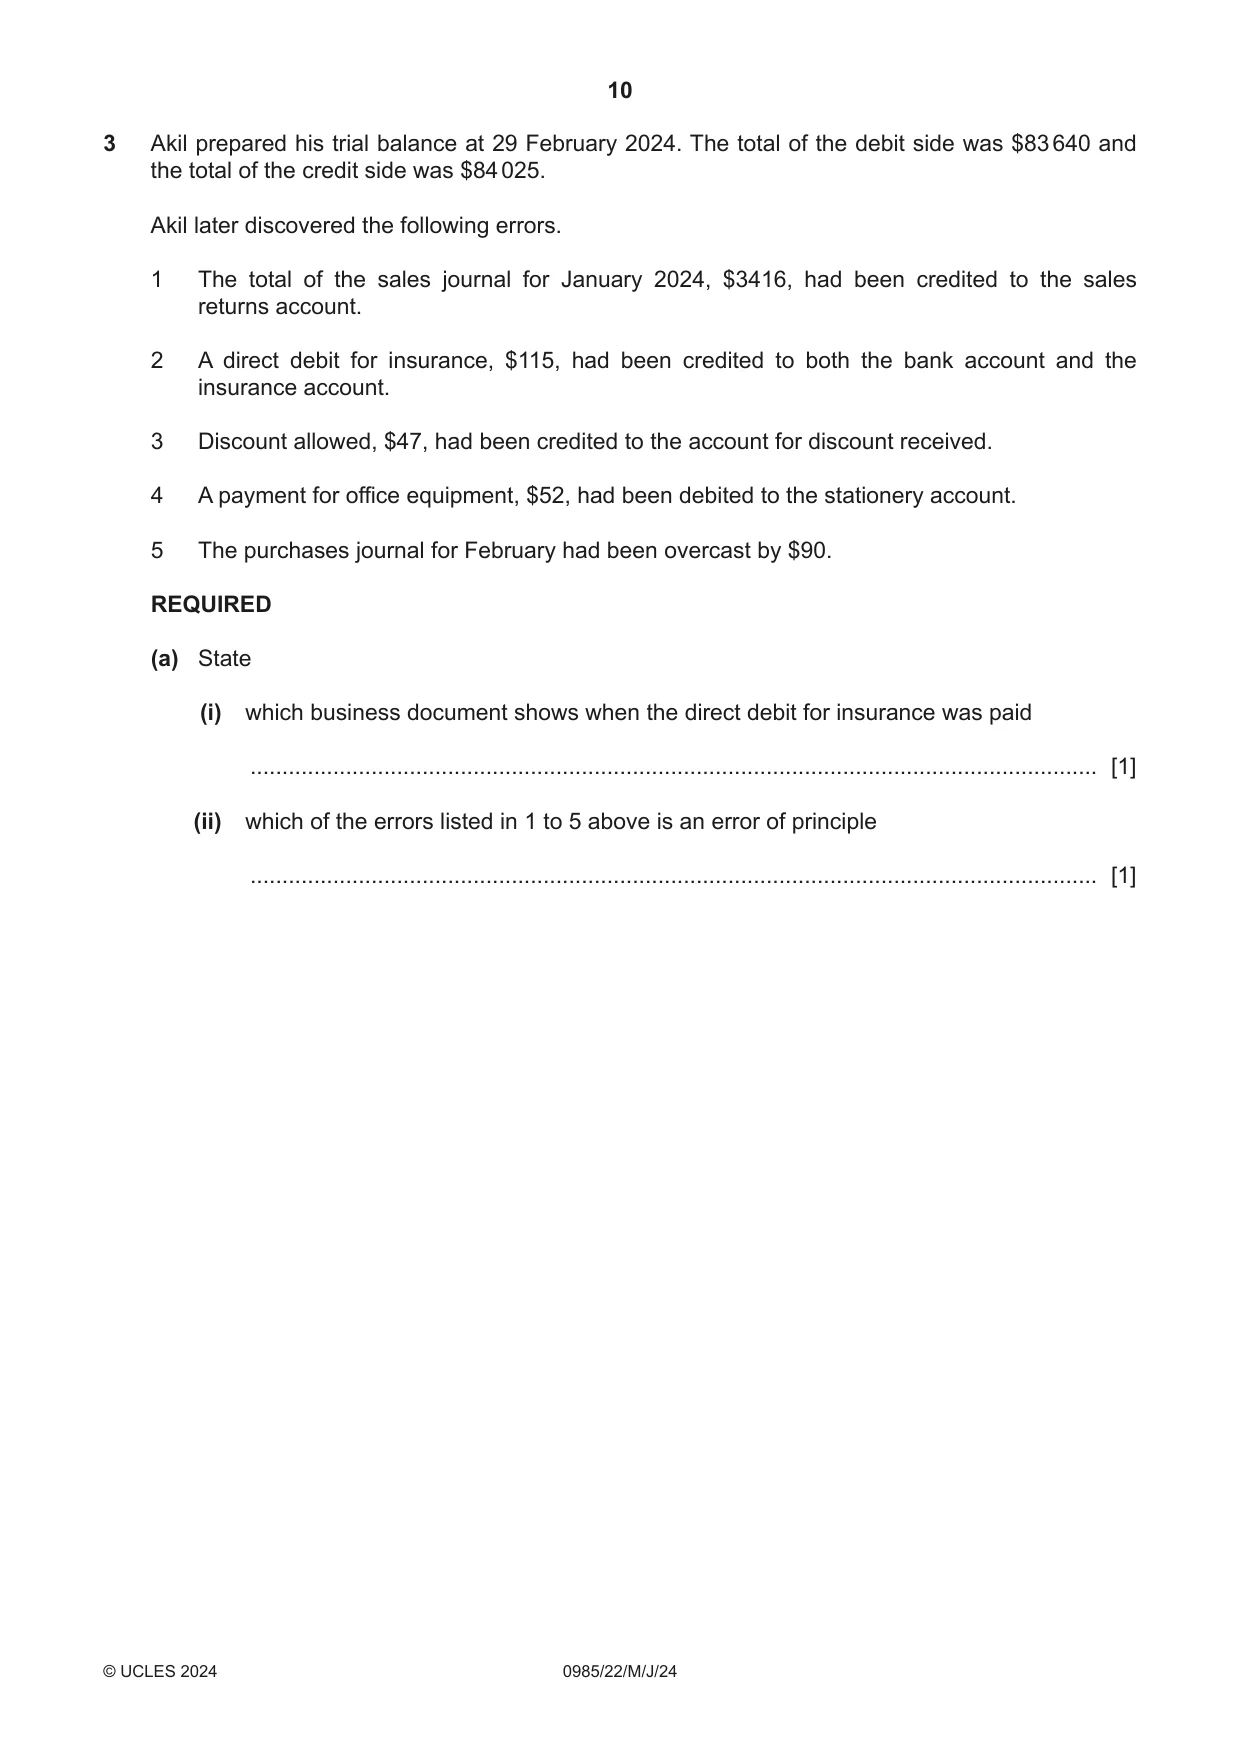
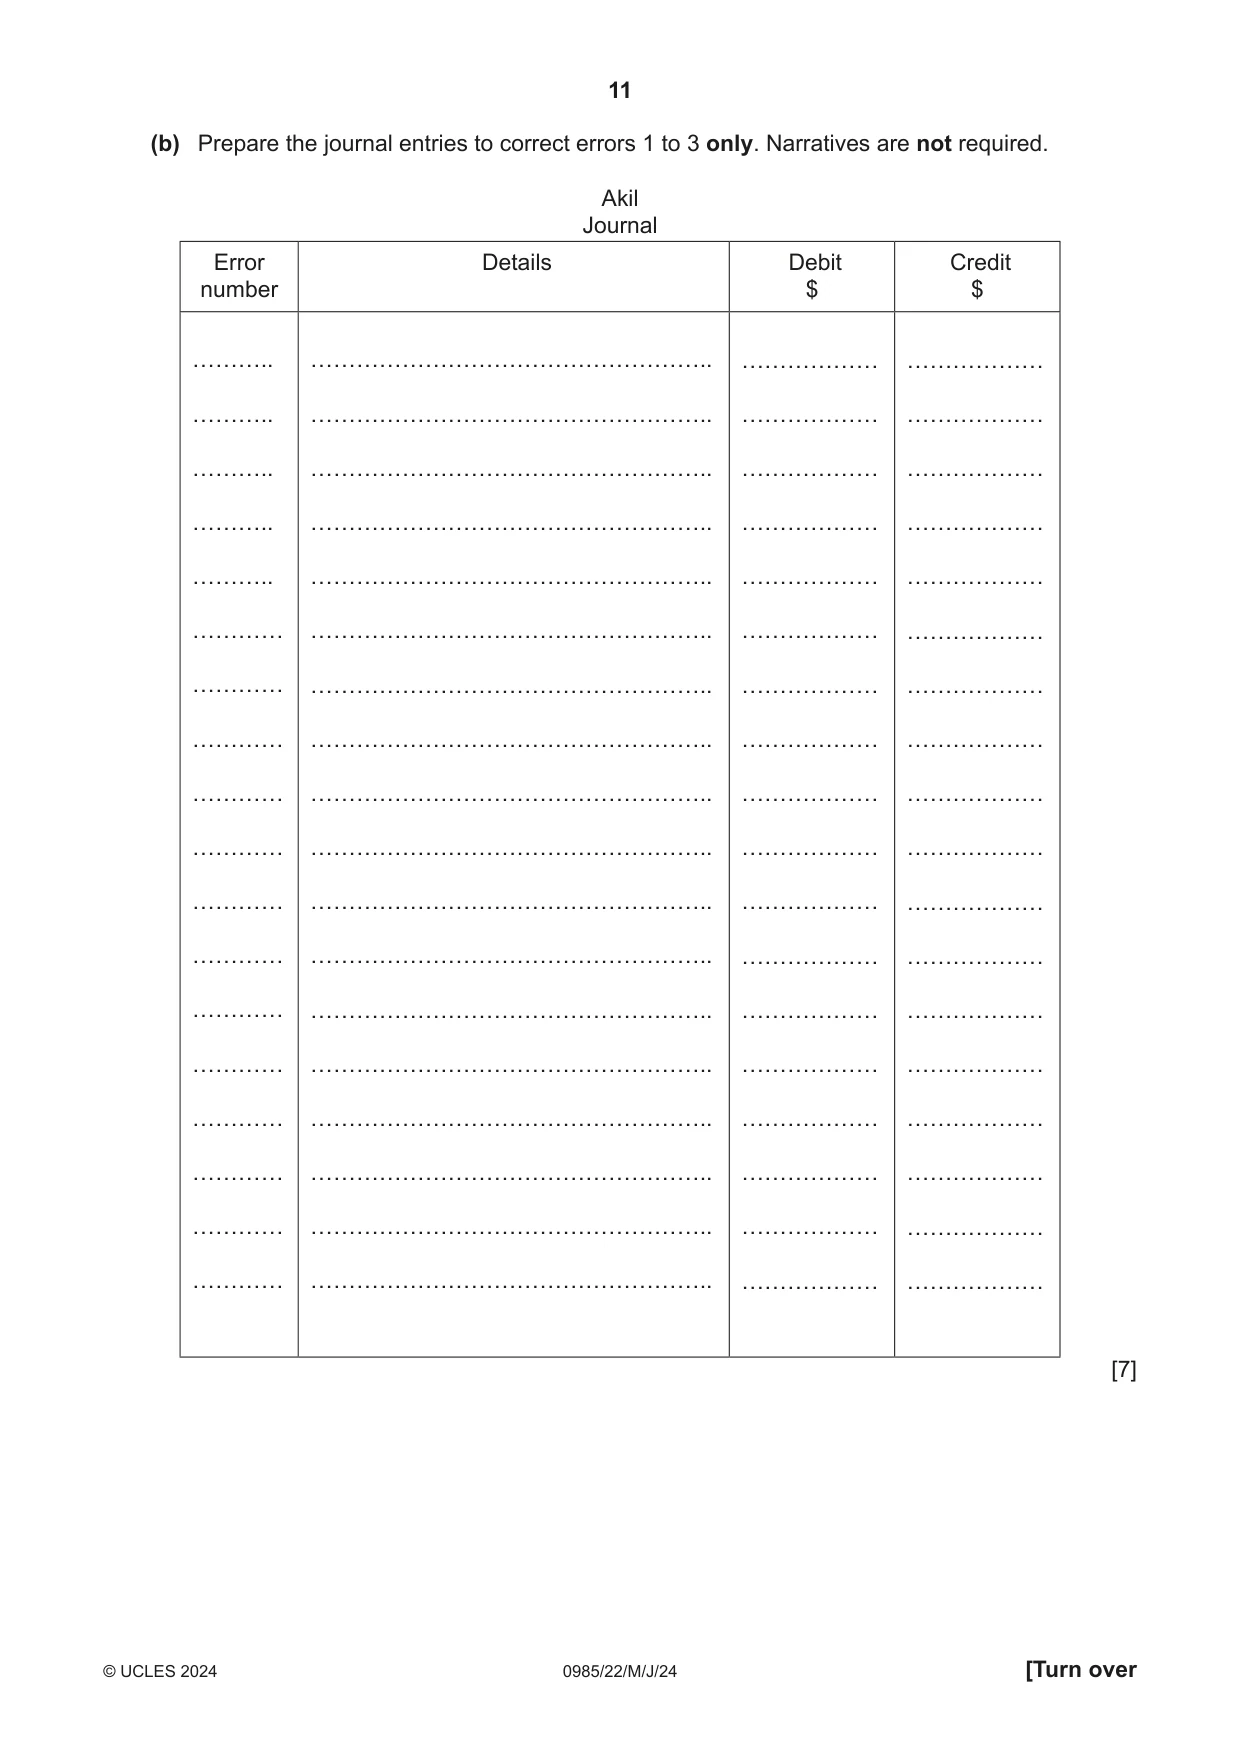
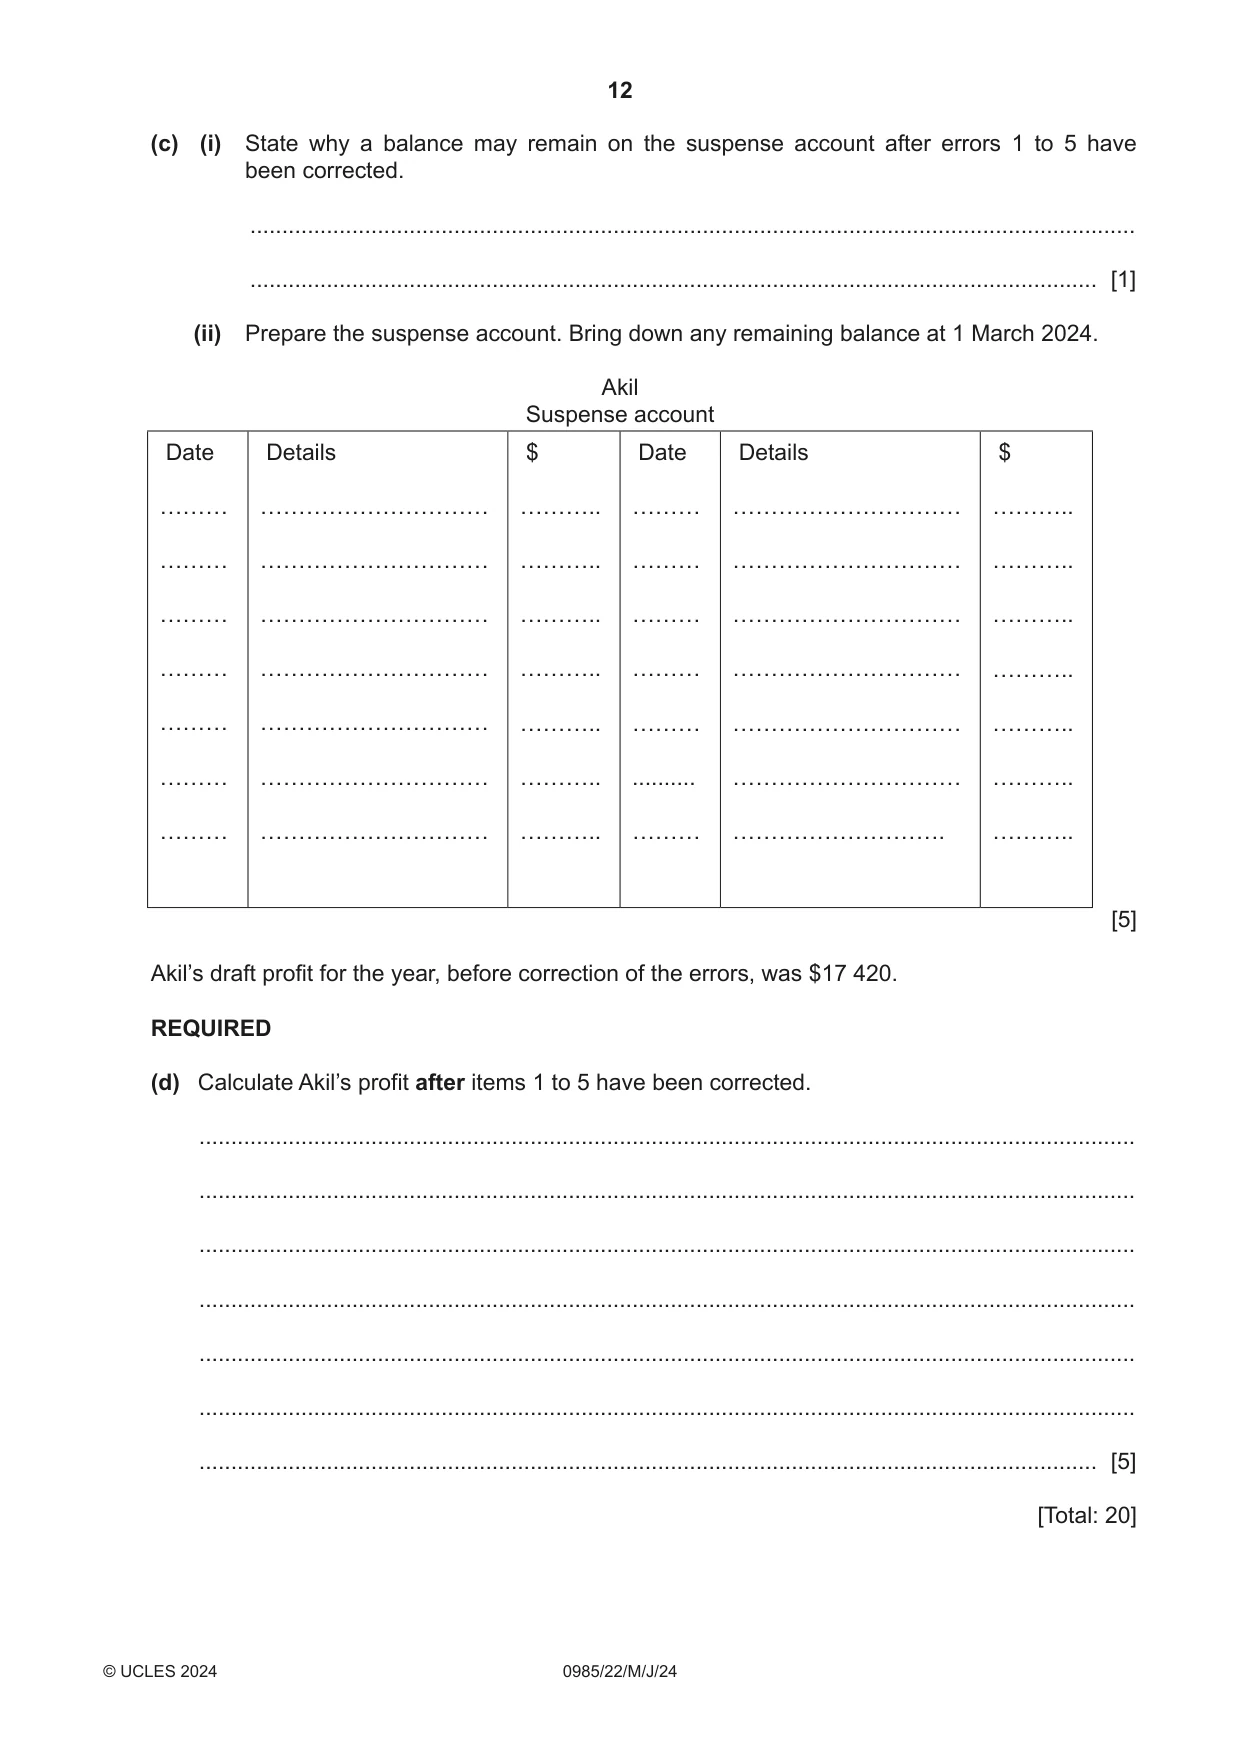
3 Akil prepared his trial balance at 29 February 2024. The total of the debit side was $83 640 and the total of the credit side was $84 025. Akil later discovered the following errors. 1 The total of the sales journal for January 2024, $3416, had been credited to the sales returns account. 2 A direct debit for insurance, $115, had been credited to both the bank account and the insurance account. 3 Discount allowed, $47, had been credited to the account for discount received. 4 A payment for office equipment, $52, had been debited to the stationery account. 5 The purchases journal for February had been overcast by $90. REQUIRED (a) State (i) which business document shows when the direct debit for insurance was paid ..................................................................................................................................... [1] (ii) which of the errors listed in 1 to 5 above is an error of principle ..................................................................................................................................... [1] (b) Prepare the journal entries to correct errors 1 to 3 only. Narratives are not required. Akil Journal Error Details Debit Credit number $ $ ……….. ……………… ……………… ……….. ……………… ……………… ……….. ……………… ……………… ……….. ……………… ……………… ……….. ……………… ……………… ………… ……………… ……………… ………… ……………… ……………… ………… ……………… ……………… ………… ……………… ……………… ………… ……………… ……………… ………… ……………… ……………… ………… ……………… ……………… ………… ……………… ……………… ………… ……………… ……………… ………… ……………… ……………… ………… ……………… ……………… ………… ……………… ……………… ………… ……………… ……………… [7] (c) (i) State why a balance may remain on the suspense account after errors 1 to 5 have been corrected. ........................................................................................................................................... ..................................................................................................................................... [1] (ii) Prepare the suspense account. Bring down any remaining balance at 1 March 2024. Akil Suspense account Date Details $ Date Details $ ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. ……… ……….. .......... ……….. ……… ……….. ……… ……….. [5] Akil’s draft profit for the year, before correction of the errors, was $17 420. REQUIRED (d) Calculate Akil’s profit after items 1 to 5 have been corrected. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
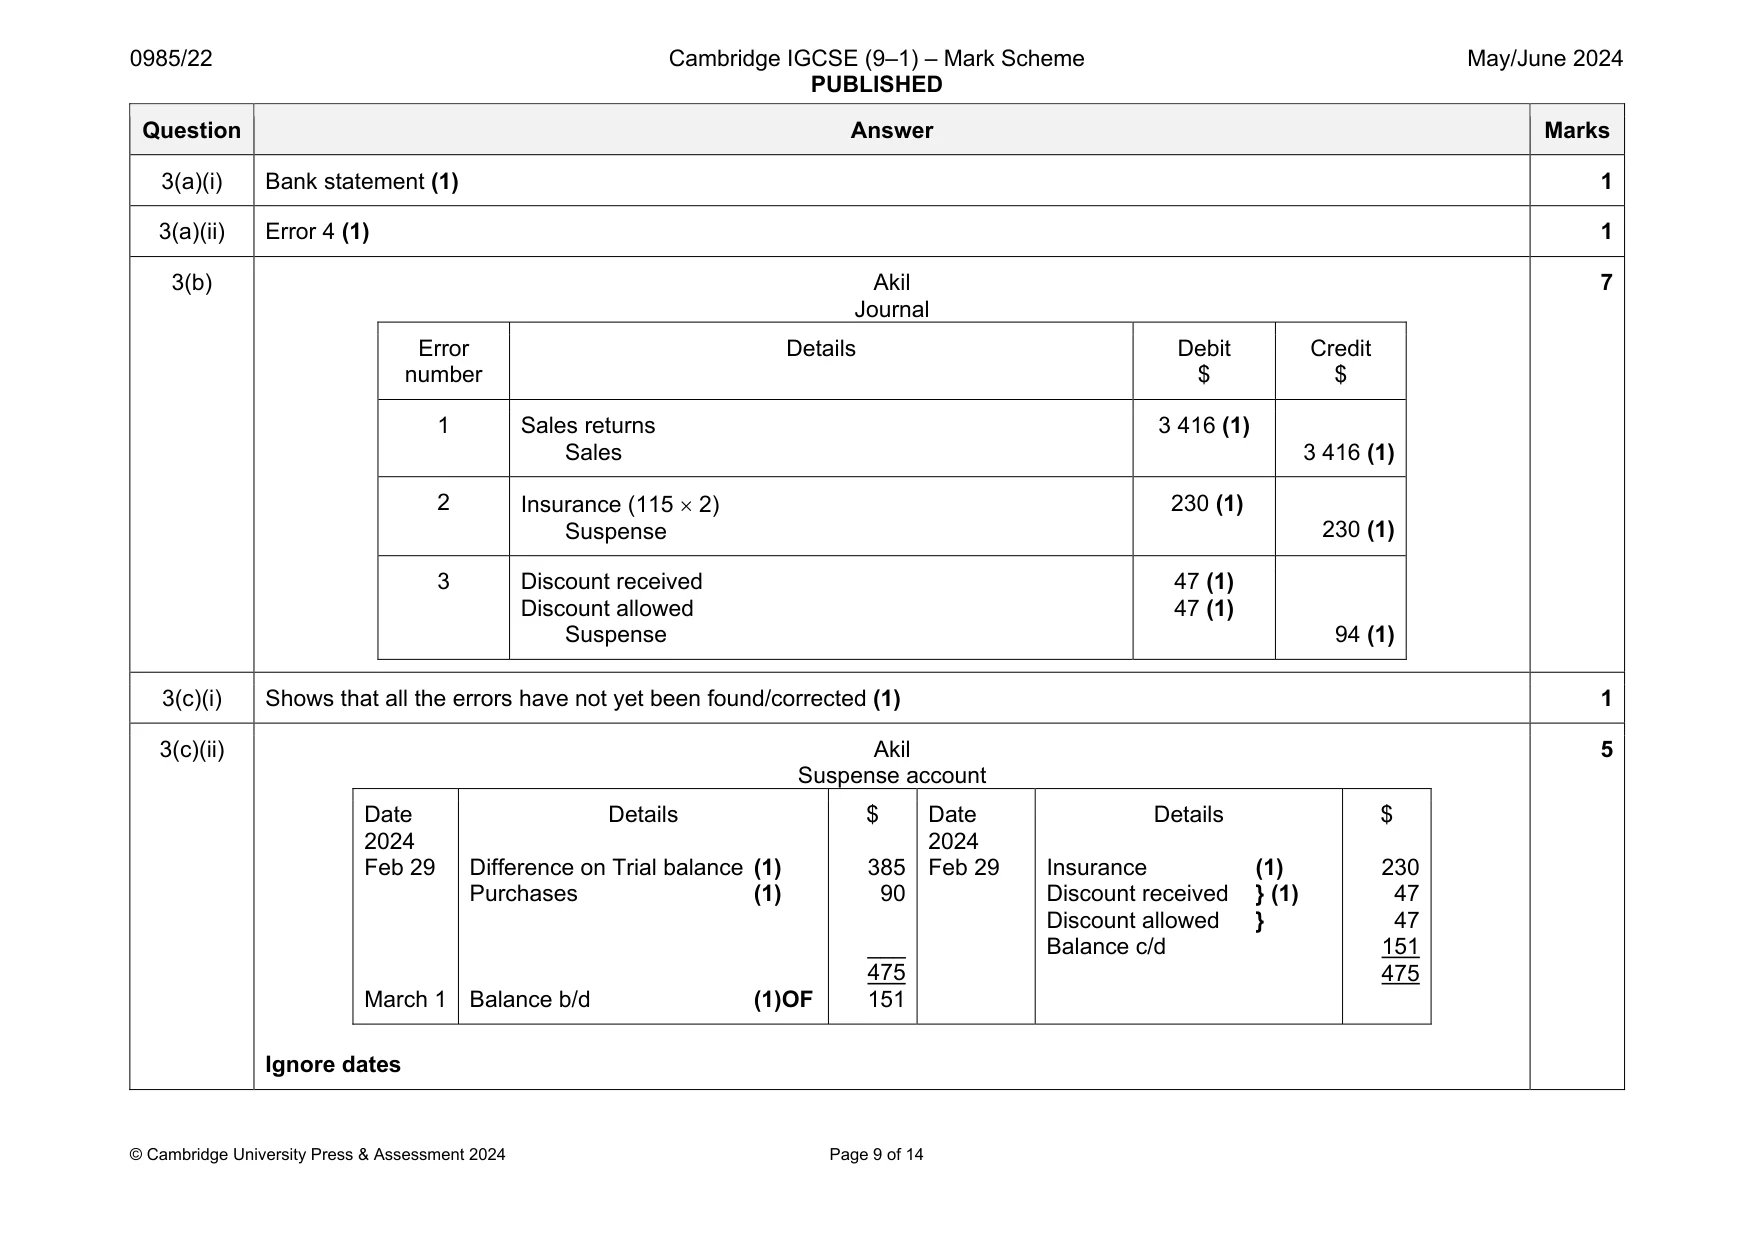
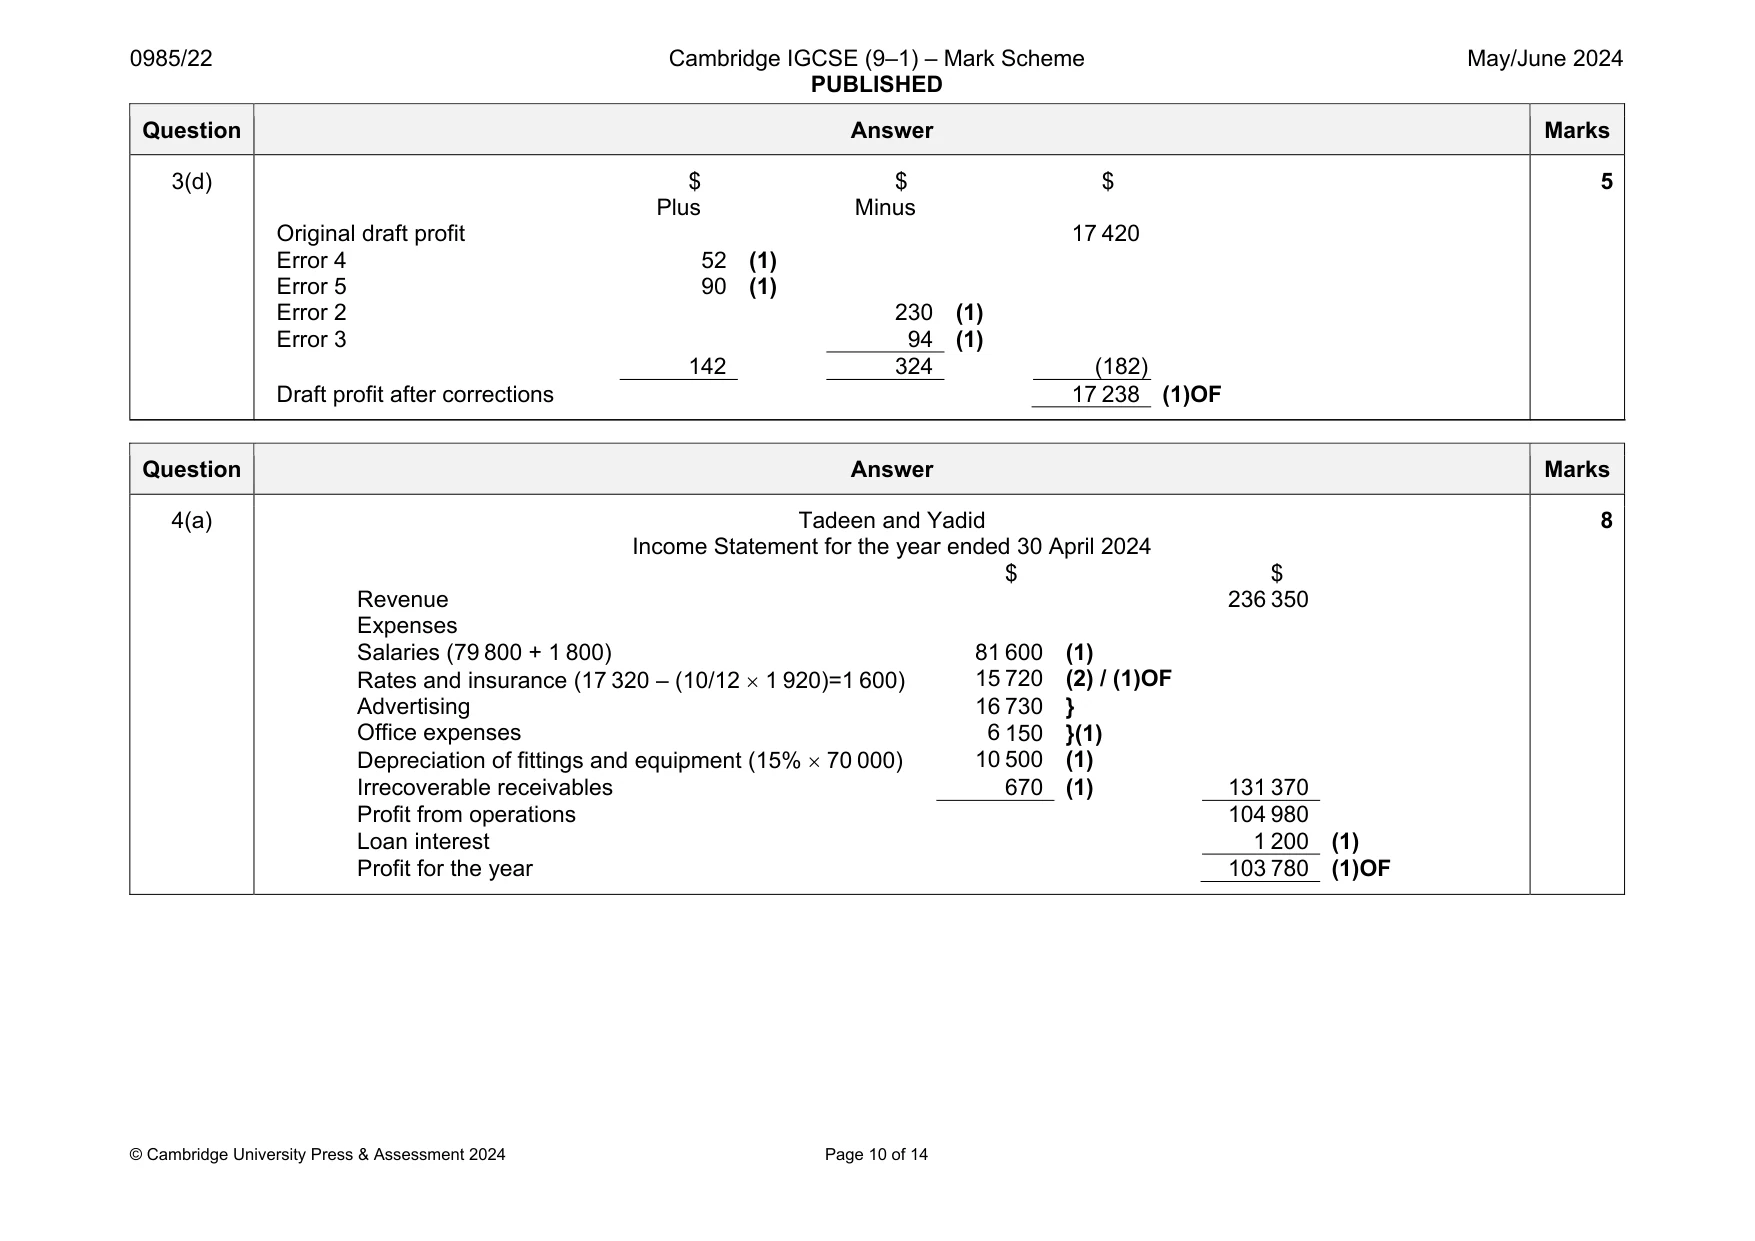
Mark scheme: 3(a)(i) Bank statement (1) 1 3(a)(ii) Error 4 (1) 1 3(b) Akil Journal Error number Details Debit $ Credit $ 1 Sales returns Sales 3 416 (1) 3 416 (1) 2 Insurance (115 2) Suspense 230 (1) 230 (1) 3 Discount received Discount allowed Suspense 47 (1) 47 (1) 94 (1) 7 3(c)(i) Shows that all the errors have not yet been found/corrected (1) 1 3(c)(ii) Akil Suspense account Date 2024 Feb 29 March 1 Details Difference on Trial balance (1) Purchases (1) Balance b/d (1)OF $ 385 90 ___ 475 151 Date 2024 Feb 29 Details Insurance (1) Discount received } (1) Discount allowed } Balance c/d $ 230 47 47 151 475 Ignore dates 5 Question Answer Marks 3(d) $ $ $ Plus Minus Original draft profit 17 420 Error 4 52 (1) Error 5 90 (1) Error 2 230 (1) Error 3 94 (1) 142 324 (182) Draft profit after corrections 17 238 (1)OF 5
Q4 · Tadeen and Yadid are lawyers who have been in partnership for many years
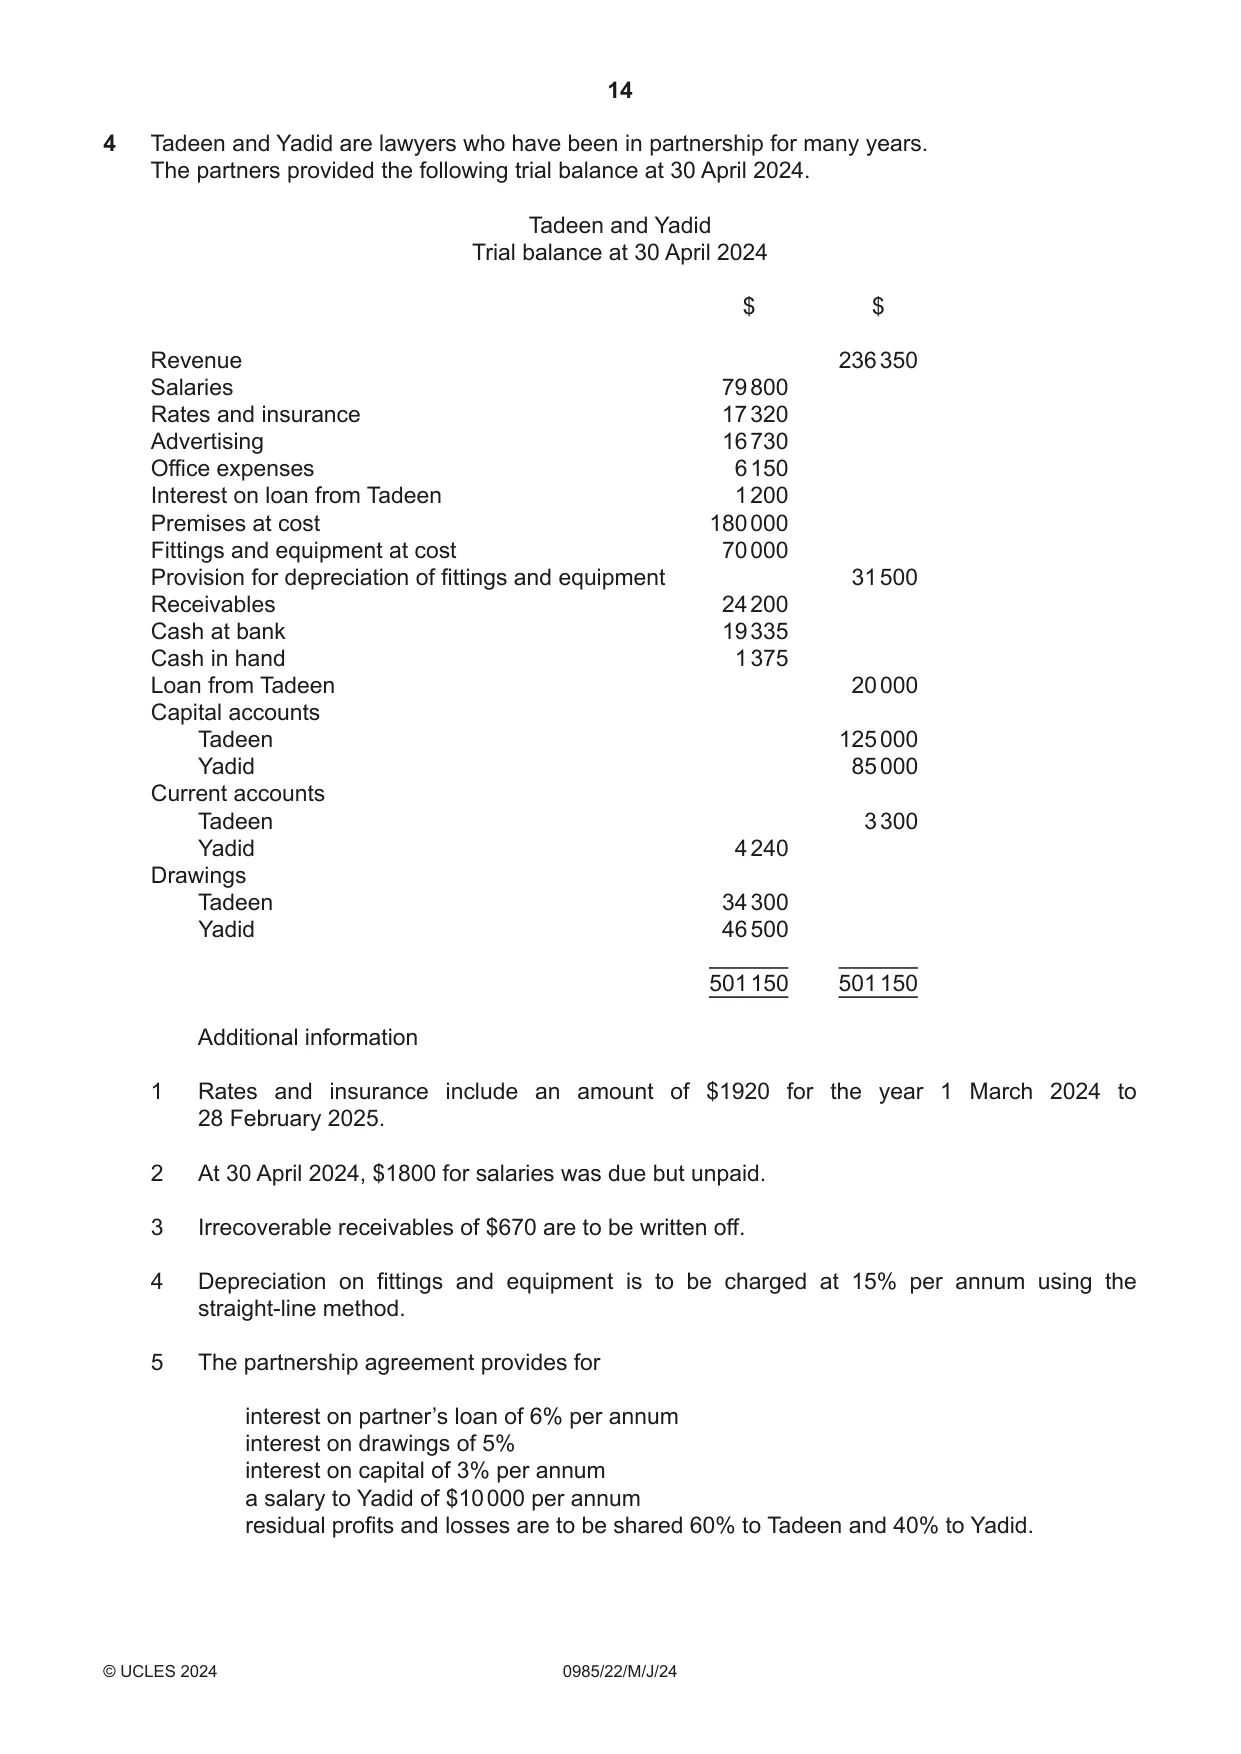
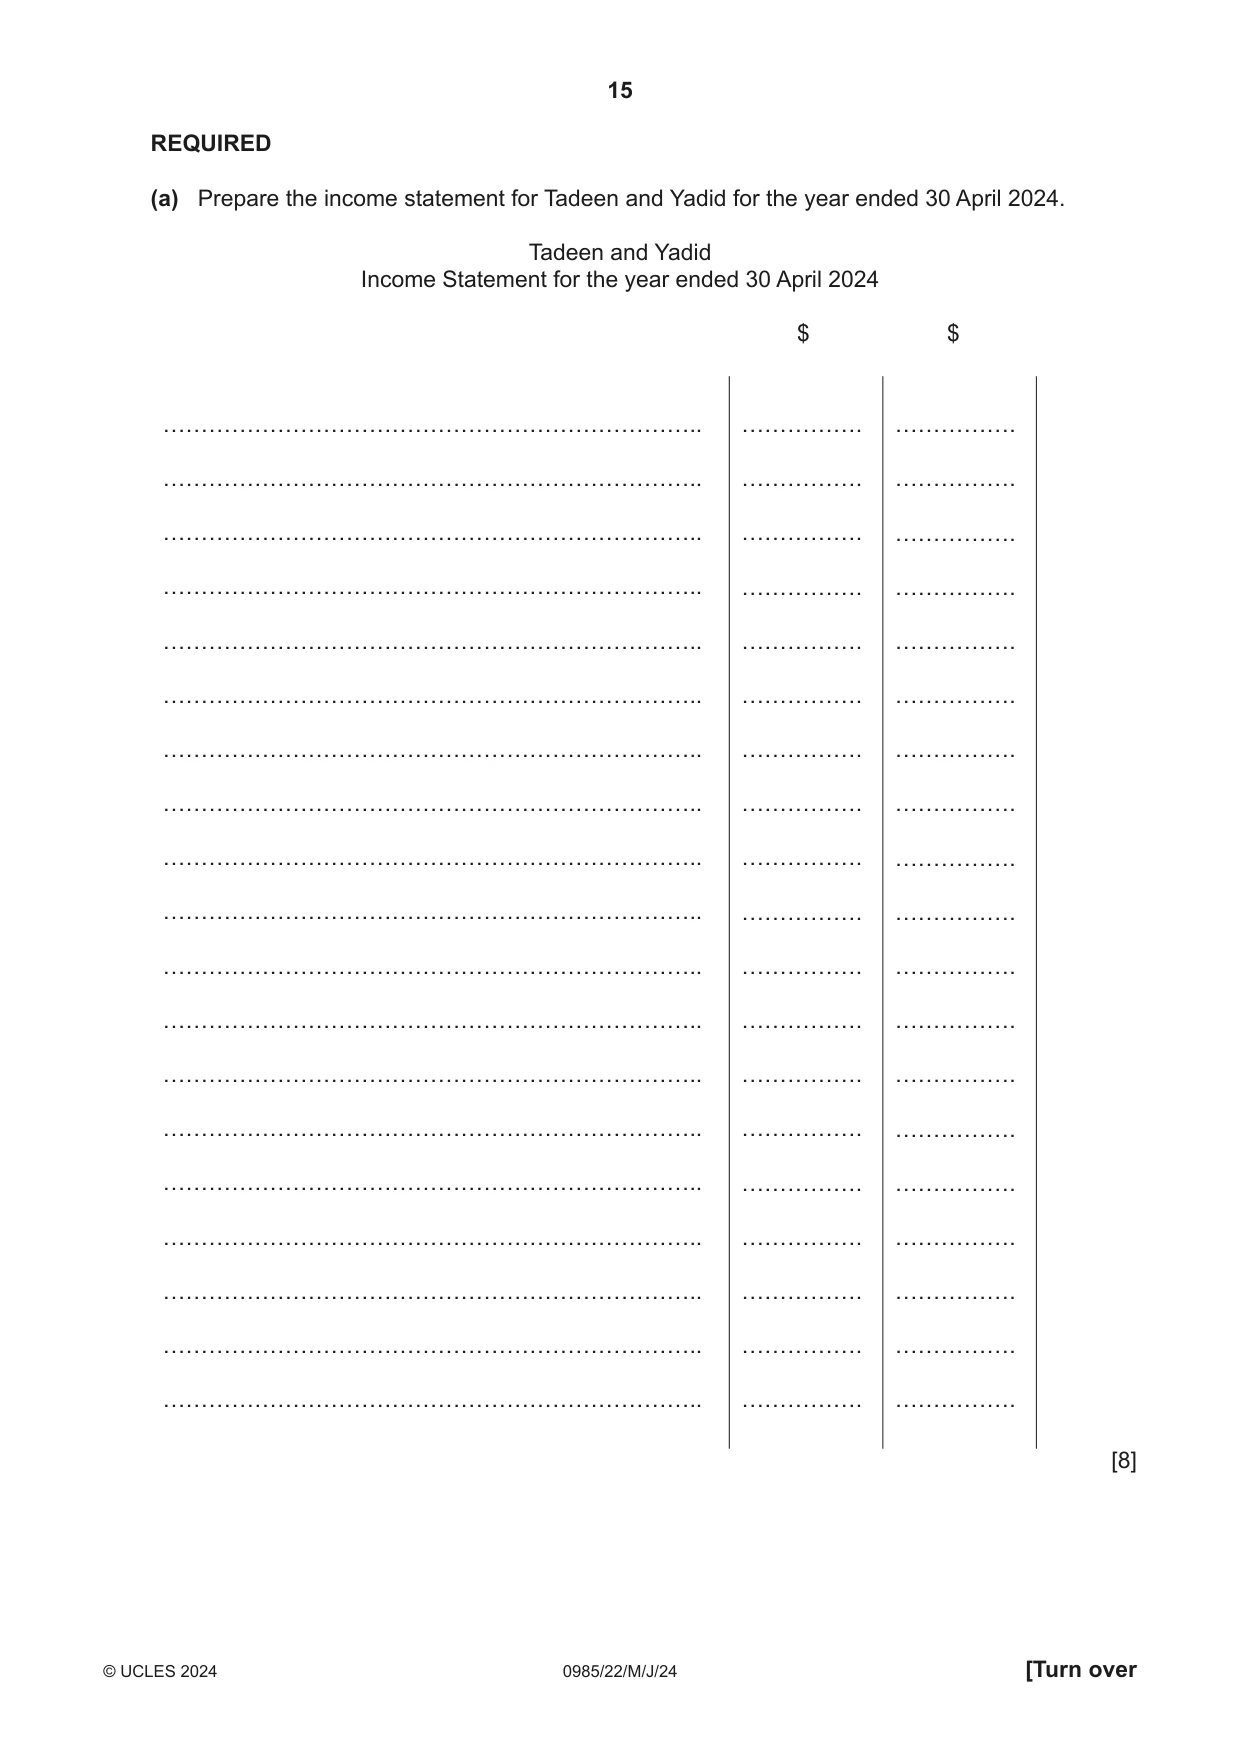
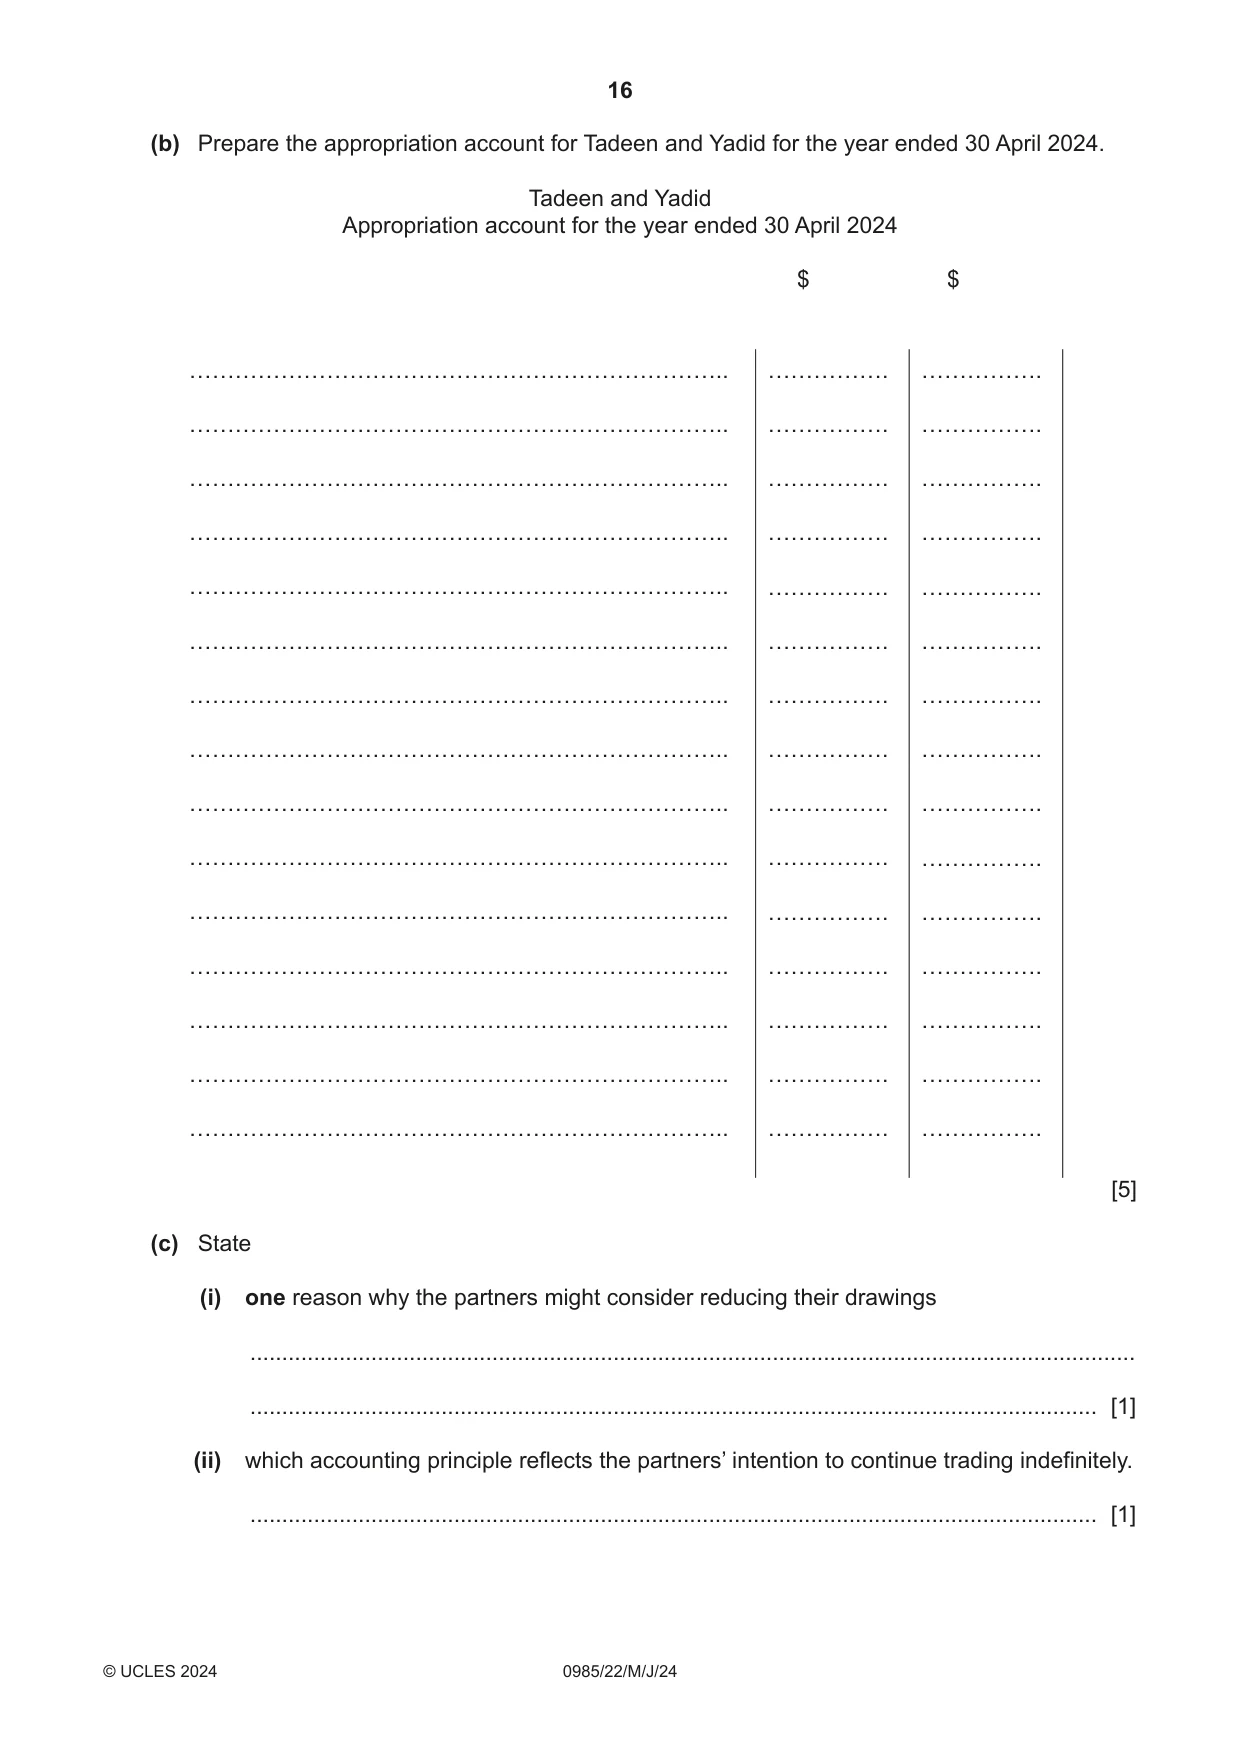
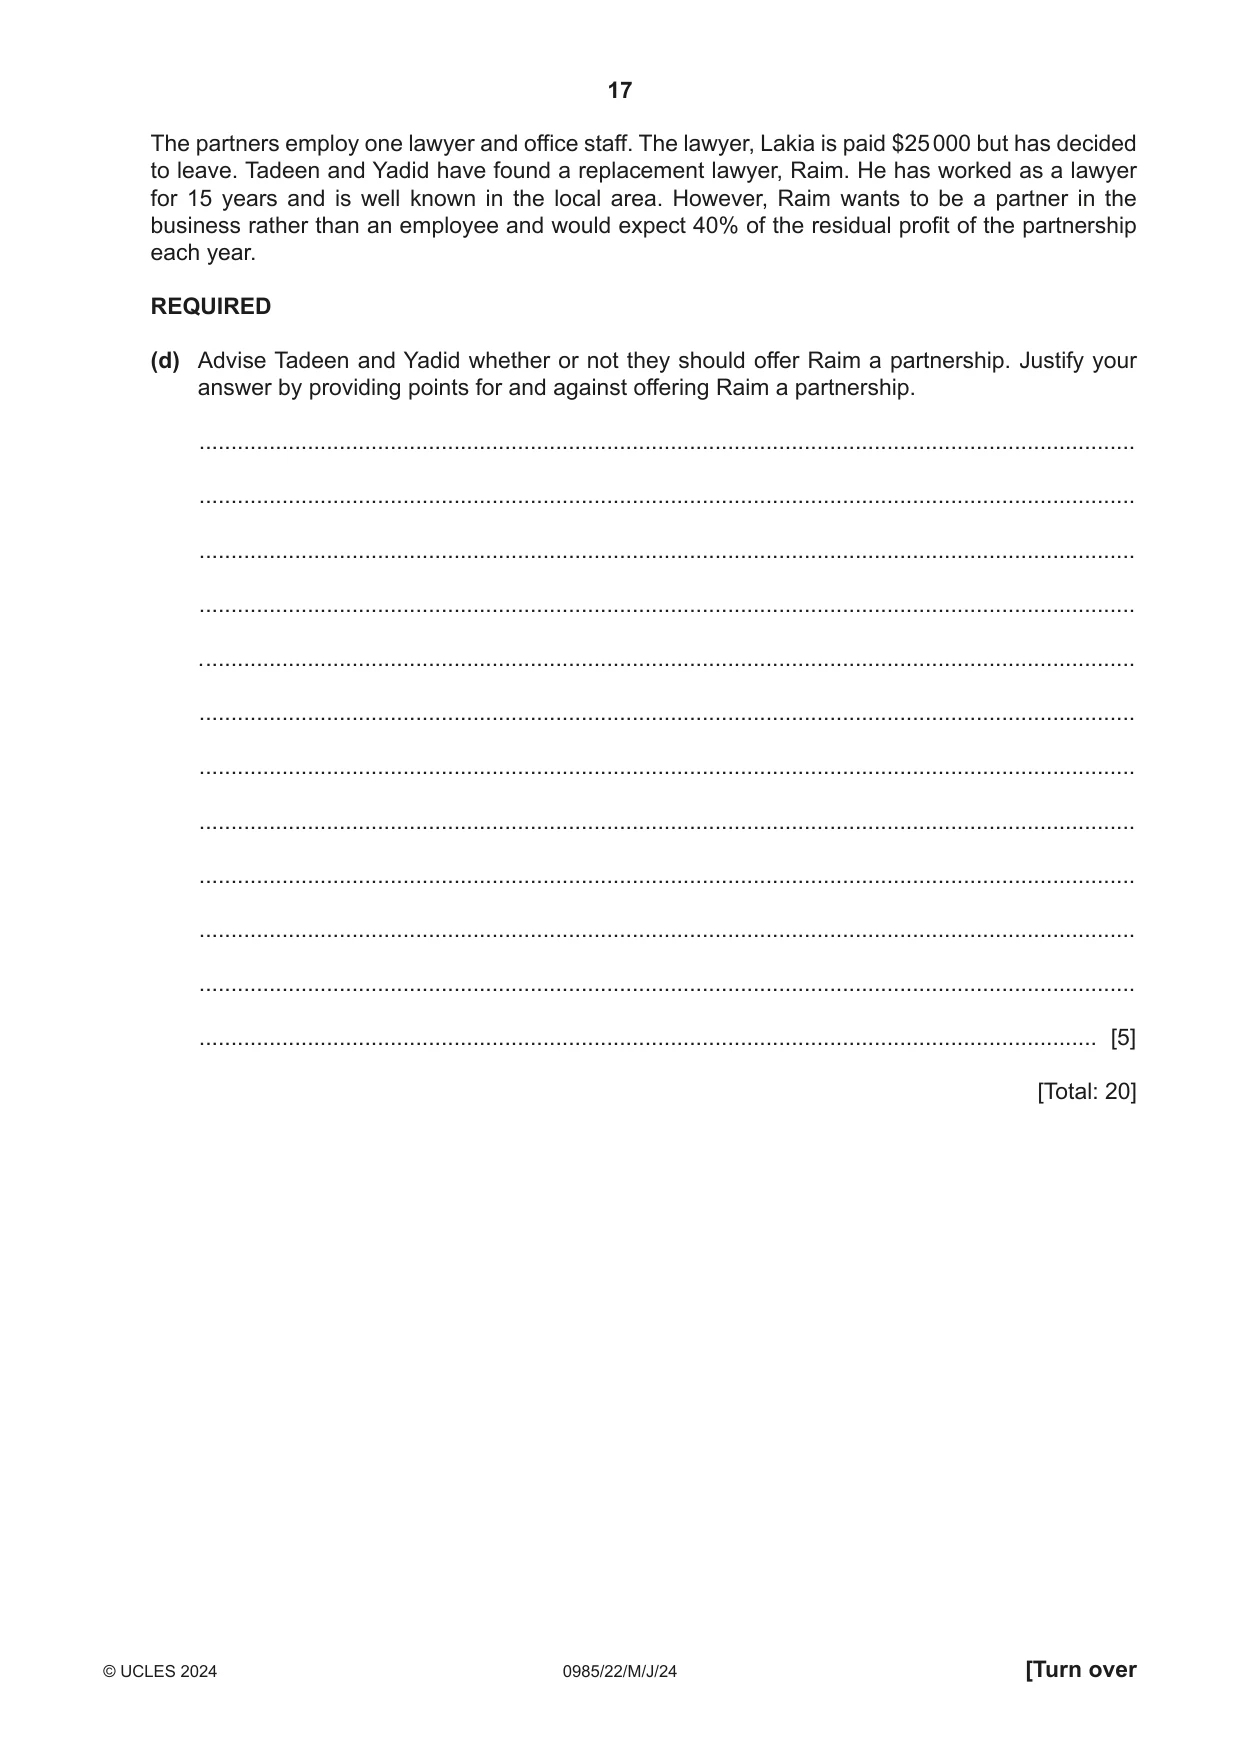
4 Tadeen and Yadid are lawyers who have been in partnership for many years. The partners provided the following trial balance at 30 April 2024. Tadeen and Yadid Trial balance at 30 April 2024 $ $ Revenue 236 350 Salaries 79 800 Rates and insurance 17 320 Advertising 16 730 Office expenses 6 150 Interest on loan from Tadeen 1 200 Premises at cost 180 000 Fittings and equipment at cost 70 000 Provision for depreciation of fittings and equipment 31 500 Receivables 24 200 Cash at bank 19 335 Cash in hand 1 375 Loan from Tadeen 20 000 Capital accounts Tadeen 125 000 Yadid 85 000 Current accounts Tadeen 3 300 Yadid 4 240 Drawings Tadeen 34 300 Yadid 46 500 501 150 501 150 Additional information 1 Rates and insurance include an amount of $1920 for the year 1 March 2024 to 28 February 2025. 2 At 30 April 2024, $1800 for salaries was due but unpaid. 3 Irrecoverable receivables of $670 are to be written off. 4 Depreciation on fittings and equipment is to be charged at 15% per annum using the straight‑line method. 5 The partnership agreement provides for interest on partner’s loan of 6% per annum interest on drawings of 5% interest on capital of 3% per annum a salary to Yadid of $10 000 per annum residual profits and losses are to be shared 60% to Tadeen and 40% to Yadid. REQUIRED (a) Prepare the income statement for Tadeen and Yadi Tadeen and Yadid Income Statement for the year ende (b) Prepare the appropriation account for Tadeen and Yadid for the year ended 30 April 2024. Tadeen and Yadid Appropriation account for the year ended 30 April 2024 $ $ ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. [5] (c) State (i) one reason why the partners might consider reducing their drawings ........................................................................................................................................... ..................................................................................................................................... [1] (ii) which accounting principle reflects the partners’ intention to continue trading indefinitely. ..................................................................................................................................... [1] The partners employ one lawyer and office staff. The lawyer, Lakia is paid $25 000 but has decided to leave. Tadeen and Yadid have found a replacement lawyer, Raim. He has worked as a lawyer for 15 years and is well known in the local area. However, Raim wants to be a partner in the business rather than an employee and would expect 40% of the residual profit of the partnership each year. REQUIRED (d) Advise Tadeen and Yadid whether or not they should offer Raim a partnership. Justify your answer by providing points for and against offering Raim a partnership. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... . .................................................................................................................................................. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
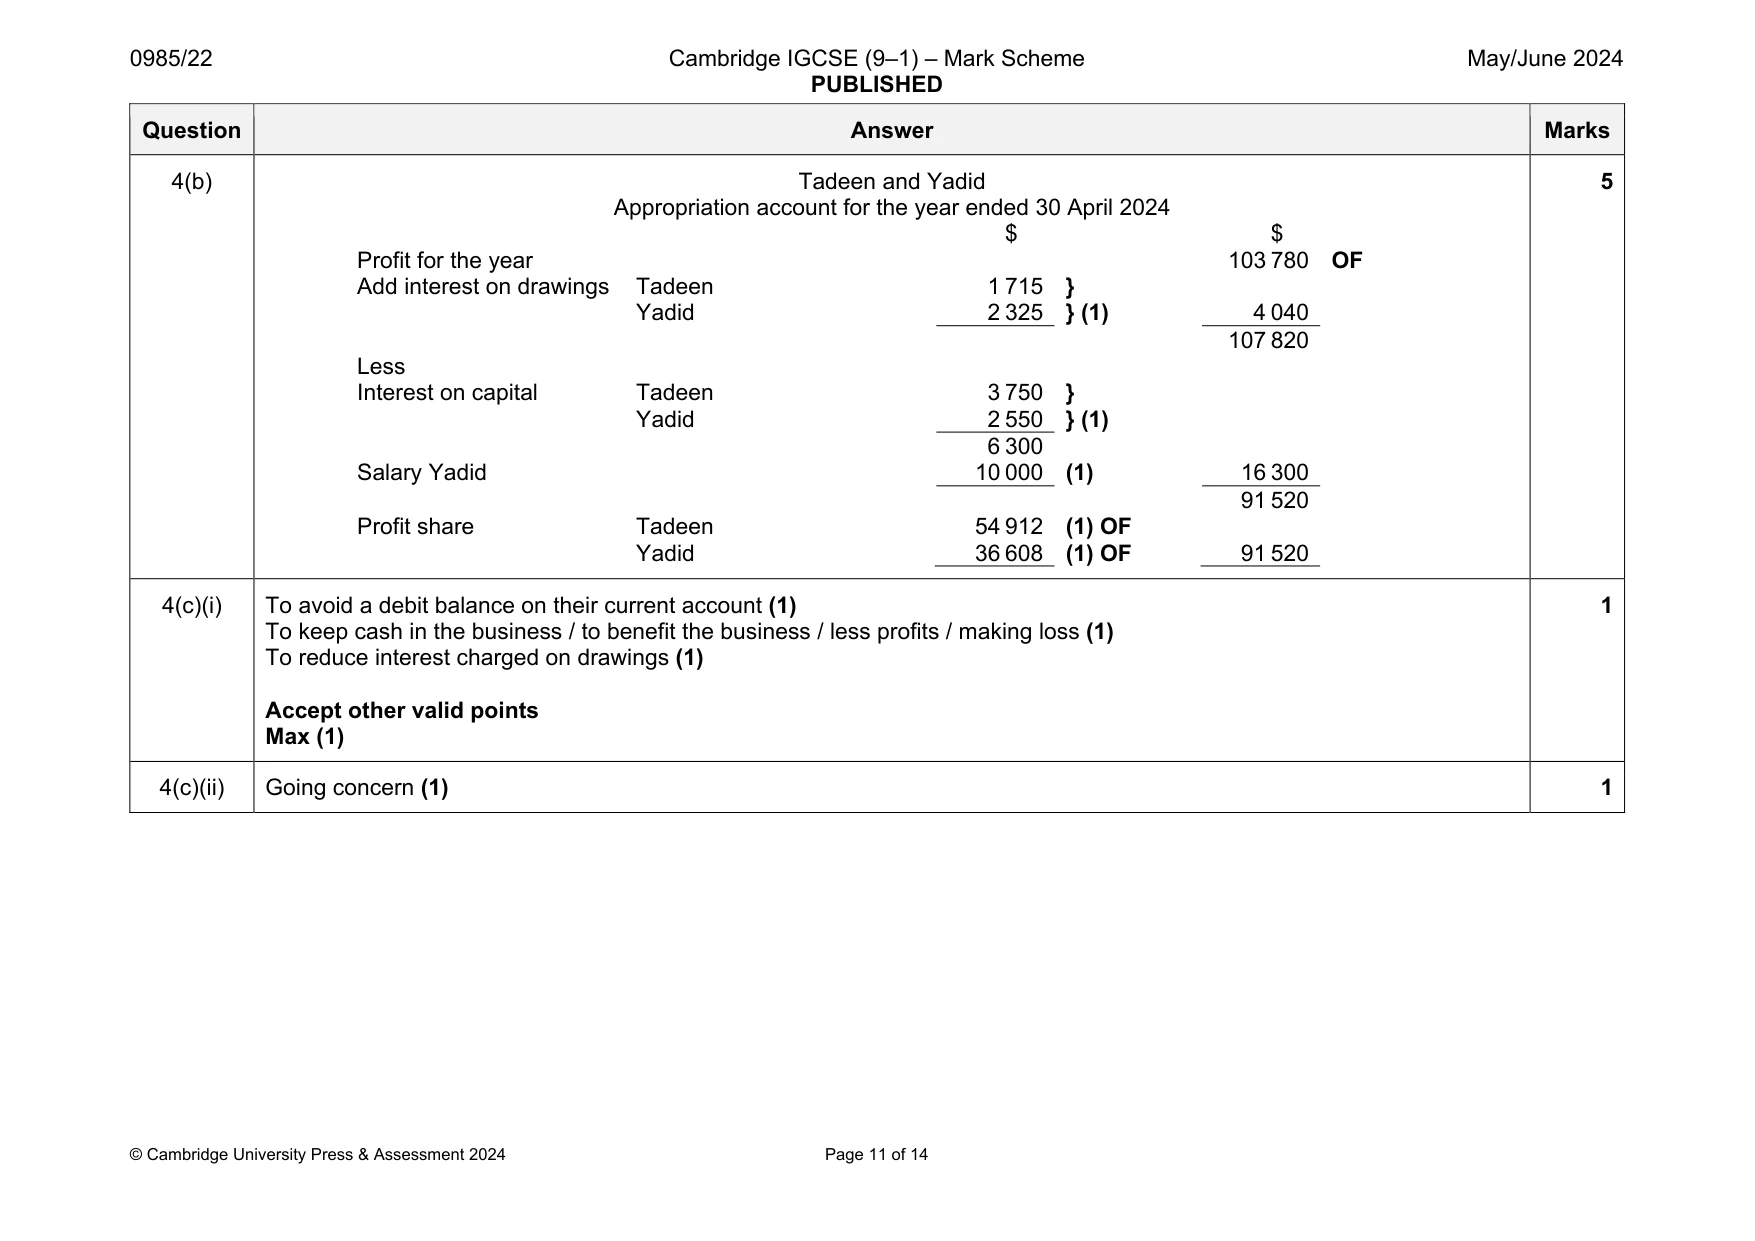
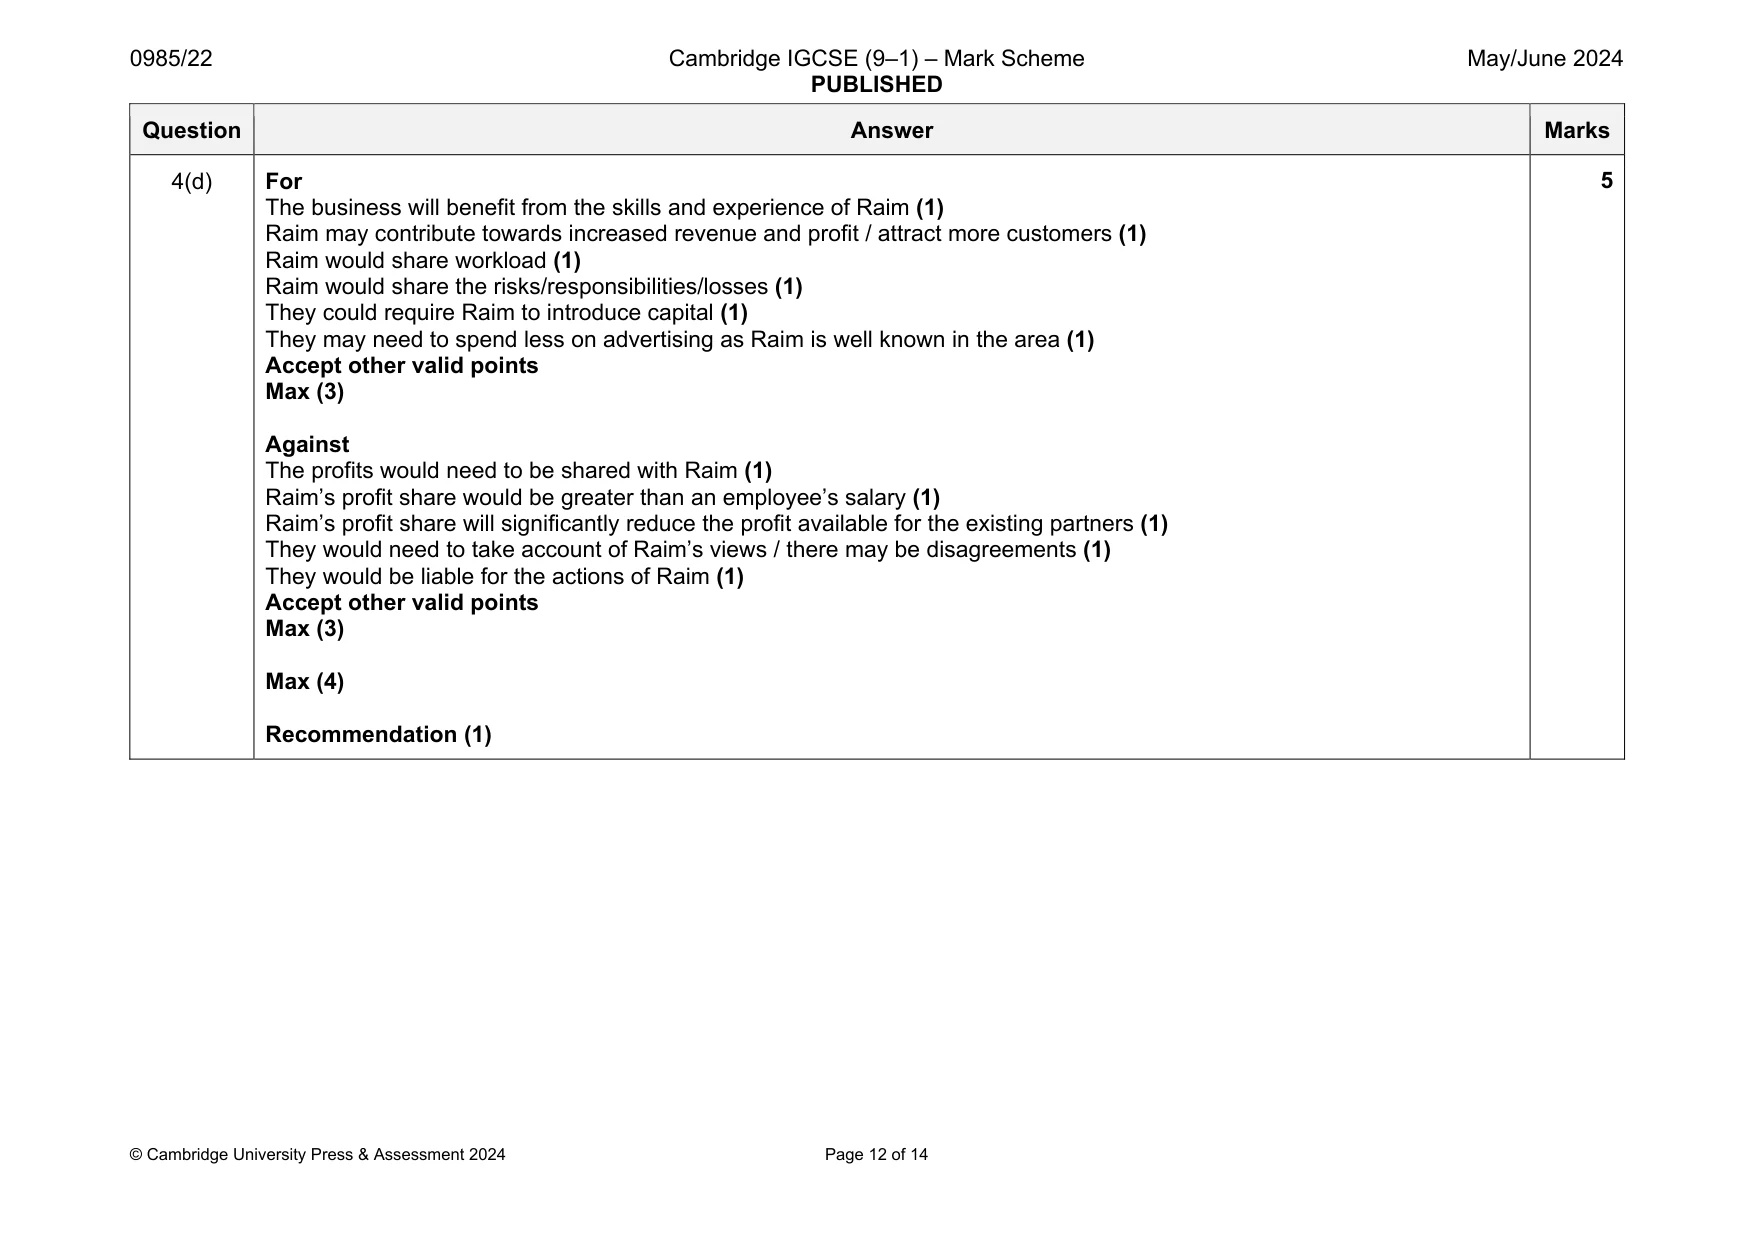
Mark scheme: 4(a) Tadeen and Yadid Income Statement for the year ended 30 April 2024 $ $ Revenue 236 350 Expenses Salaries (79 800 + 1 800) 81 600 (1) Rates and insurance (17 320 – (10/12 1 920)=1 600) 15 720 (2) / (1)OF Advertising 16 730 } Office expenses 6 150 }(1) Depreciation of fittings and equipment (15% 70 000) 10 500 (1) Irrecoverable receivables 670 (1) 131 370 Profit from operations 104 980 Loan interest 1 200 (1) Profit for the year 103 780 (1)OF 8 Question Answer Marks 4(b) Tadeen and Yadid Appropriation account for the year ended 30 April 2024 $ $ Profit for the year 103 780 OF Add interest on drawings Tadeen 1 715 } Yadid 2 325 } (1) 4 040 107 820 Less Interest on capital Tadeen 3 750 } Yadid 2 550 } (1) 6 300 Salary Yadid 10 000 (1) 16 300 91 520 Profit share Tadeen 54 912 (1) OF Yadid 36 608 (1) OF 91 520 5 4(c)(i) To avoid a debit balance on their current account (1) To keep cash in the business / to benefit the business / less profits / making loss (1) To reduce interest charged on drawings (1) Accept other valid points Max (1) 1 4(c)(ii) Going concern (1) 1 Question Answer Marks 4(d) For The business will benefit from the skills and experience of Raim (1) Raim may contribute towards increased revenue and profit / attract more customers (1) Raim would share workload (1) Raim would share the risks/responsibilities/losses (1) They could require Raim to introduce capital (1) They may need to spend less on advertising as Raim is well known in the area (1) Accept other valid points Max (3) Against The profits would need to be shared with Raim (1) Raim’s profit share would be greater than an employee’s salary (1) Raim’s profit share will significantly reduce the profit available for the existing partners (1) They would need to take account of Raim’s views / there may be disagreements (1) They would be liable for the actions of Raim (1) Accept other valid points Max (3) Max (4) Recommendation (1) 5
Q5 · Ajay is a retailer
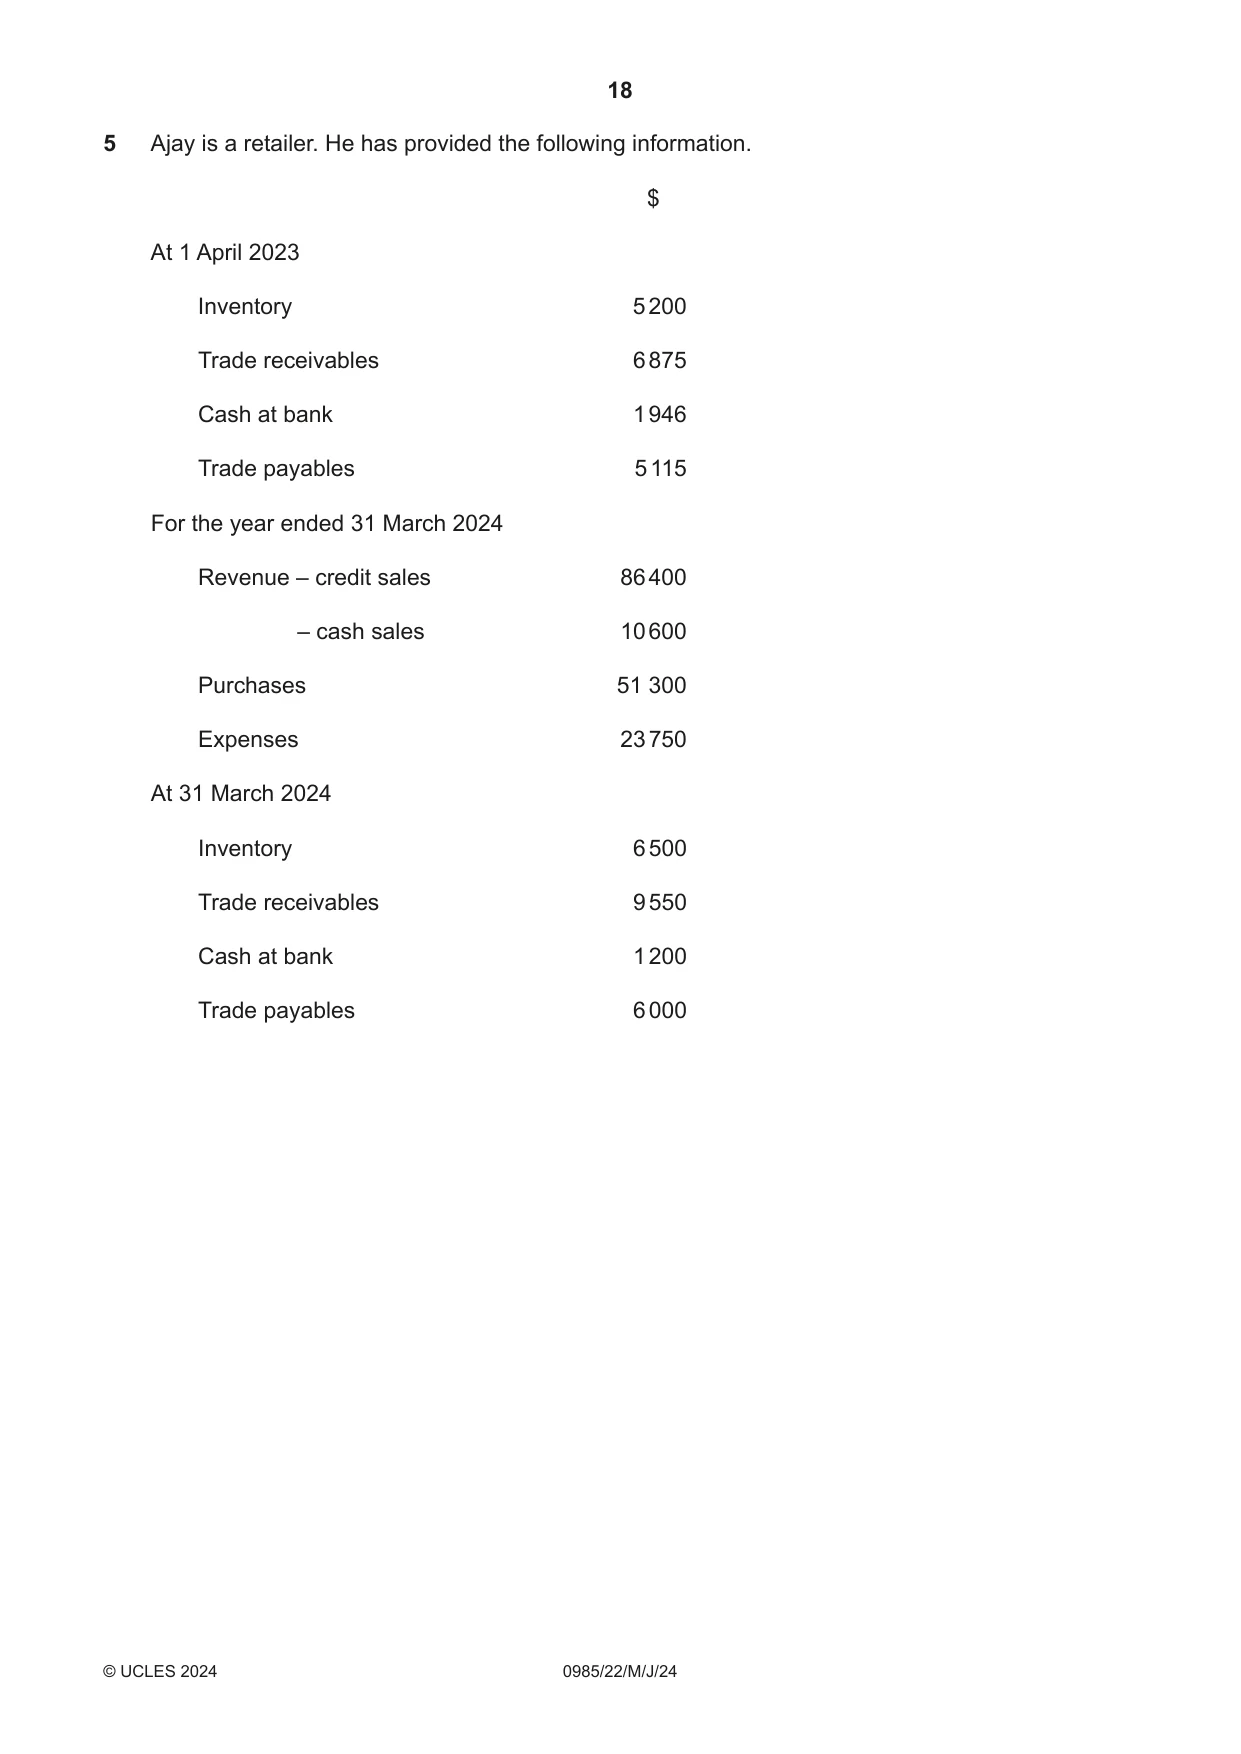
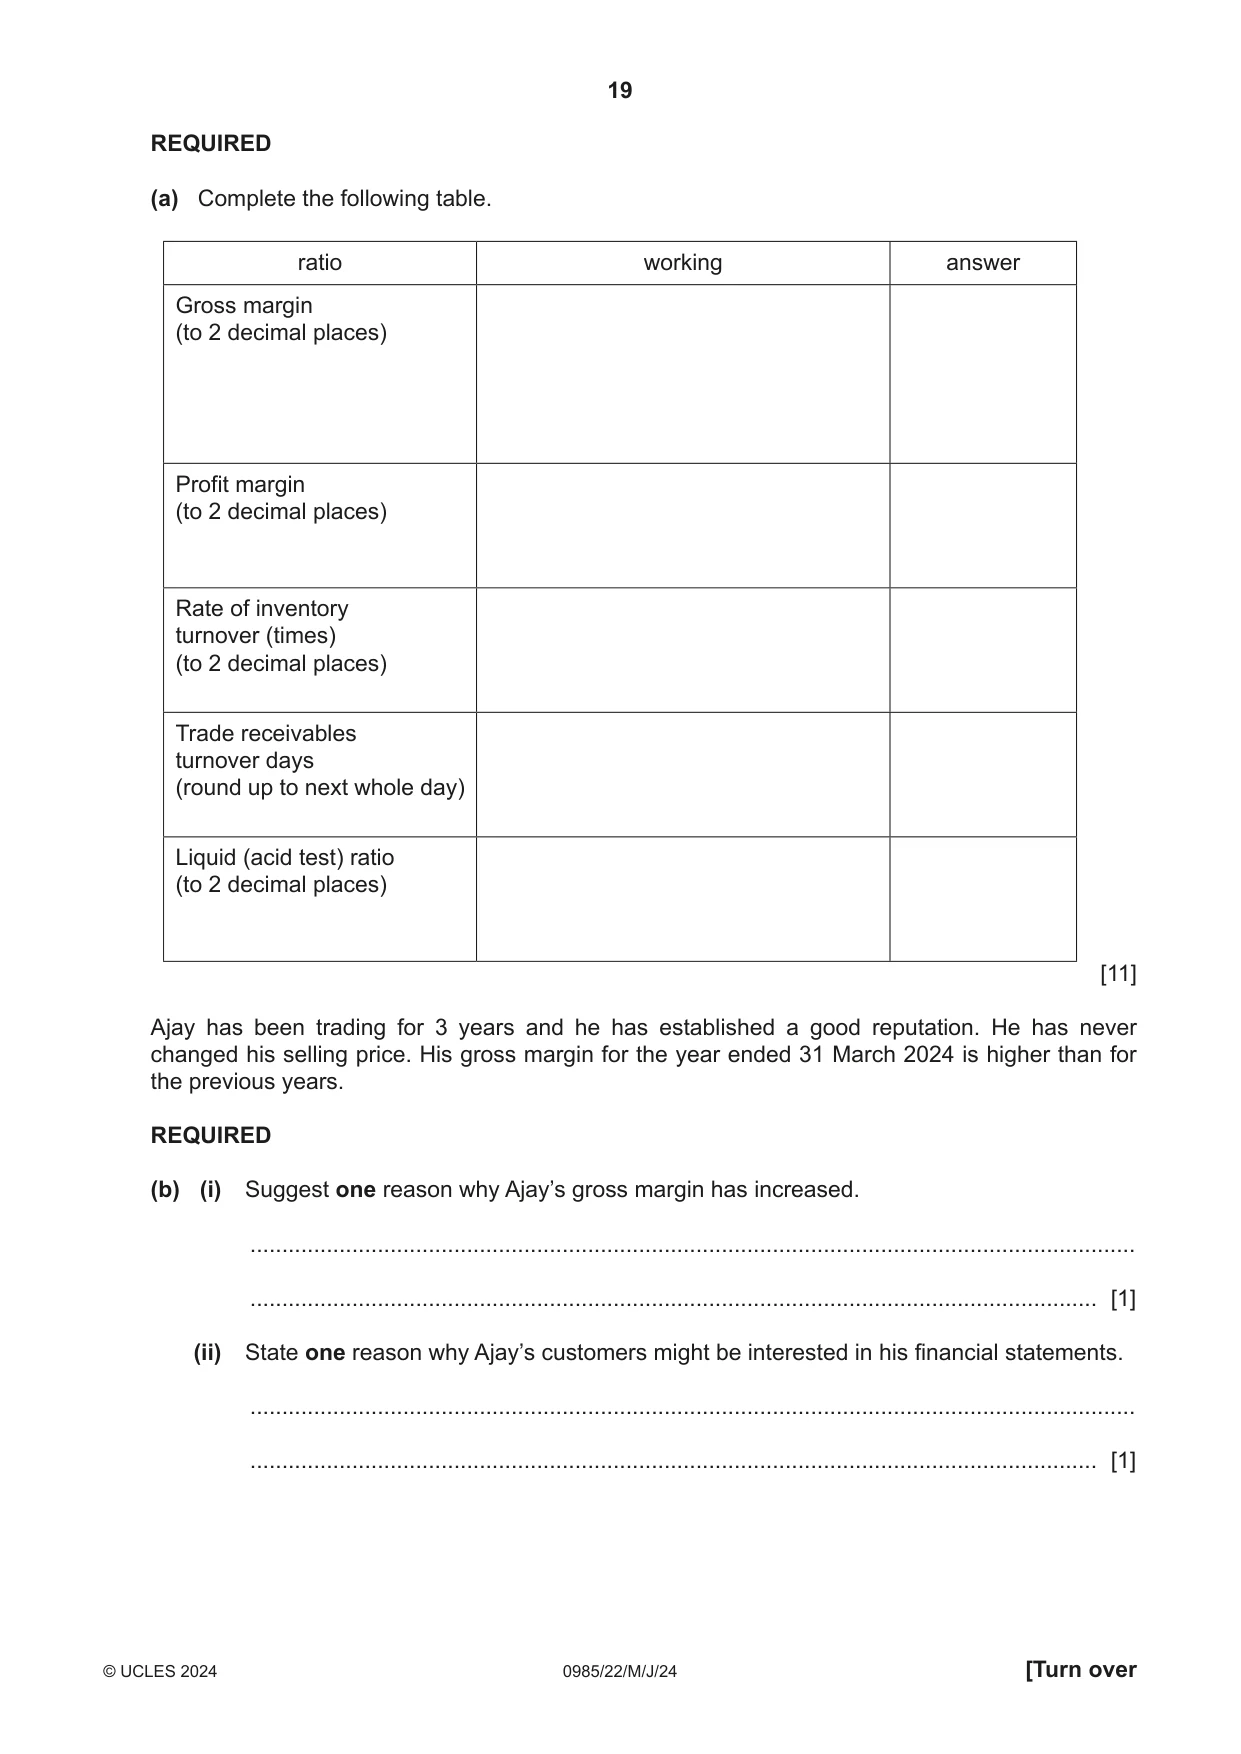
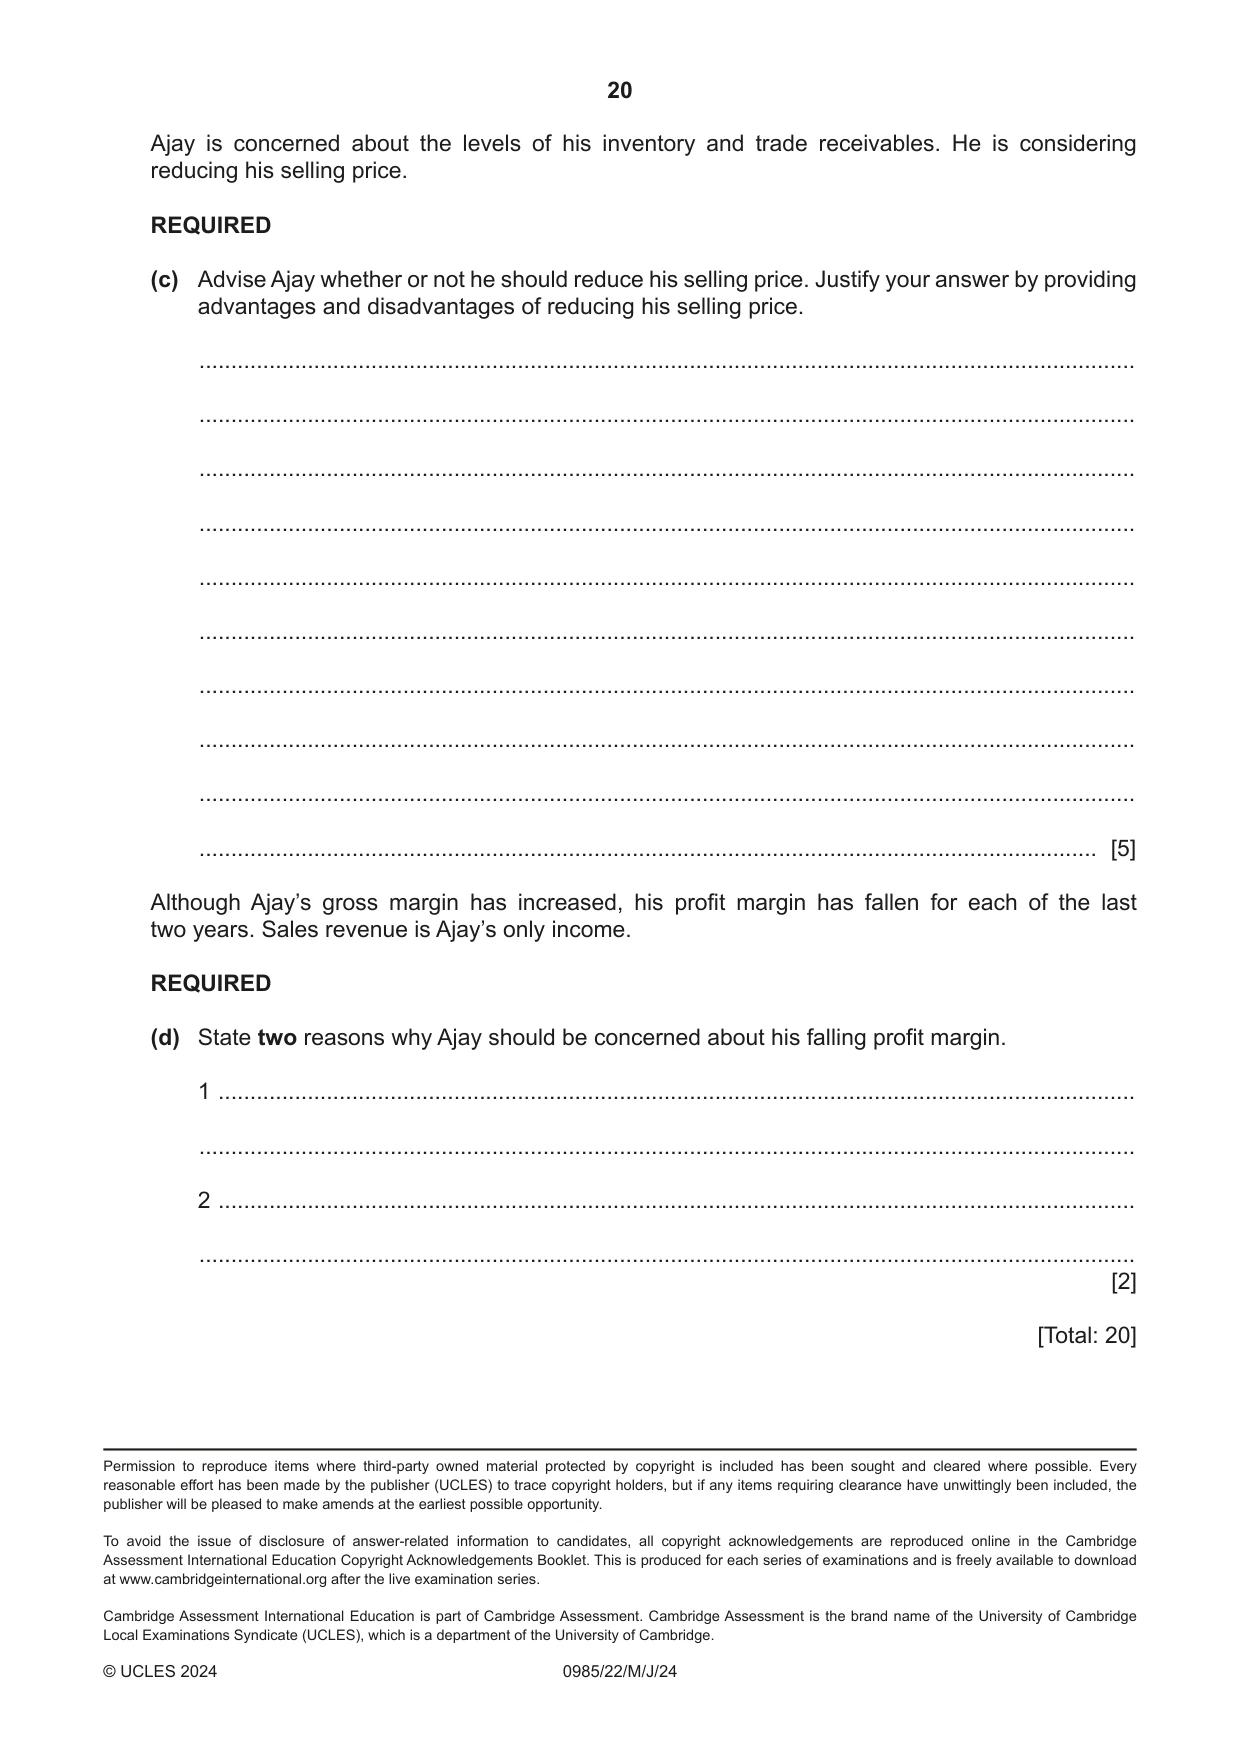
5 Ajay is a retailer. He has provided the following information. $ At 1 April 2023 Inventory 5 200 Trade receivables 6 875 Cash at bank 1 946 Trade payables 5 115 For the year ended 31 March 2024 Revenue – credit sales 86 400 – cash sales 10 600 Purchases 51 300 Expenses 23 750 At 31 March 2024 Inventory 6 500 Trade receivables 9 550 Cash at bank 1 200 Trade payables 6 000 REQUIRED (a) Complete the following table. ratio working answer Gross margin (to 2 decimal places) Profit margin (to 2 decimal places) Rate of inventory turnover (times) (to 2 decimal places) Trade receivables turnover days (round up to next whole day) Liquid (acid test) ratio (to 2 decimal places) [11] Ajay has been trading for 3 years and he has established a good reputation. He has never changed his selling price. His gross margin for the year ended 31 March 2024 is higher than for the previous years. REQUIRED (b) (i) Suggest one reason why Ajay’s gross margin has increased. ........................................................................................................................................... ..................................................................................................................................... [1] (ii) State one reason why Ajay’s customers might be interested in his financial statements. ........................................................................................................................................... ..................................................................................................................................... [1] Ajay is concerned about the levels of his inventory and trade receivables. He is considering reducing his selling price. REQUIRED (c) Advise Ajay whether or not he should reduce his selling price. Justify your answer by providing advantages and disadvantages of reducing his selling price. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] Although Ajay’s gross margin has increased, his profit margin has fallen for each of the last two years. Sales revenue is Ajay’s only income. REQUIRED (d) State two reasons why Ajay should be concerned about his falling profit margin. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] [Total: 20]
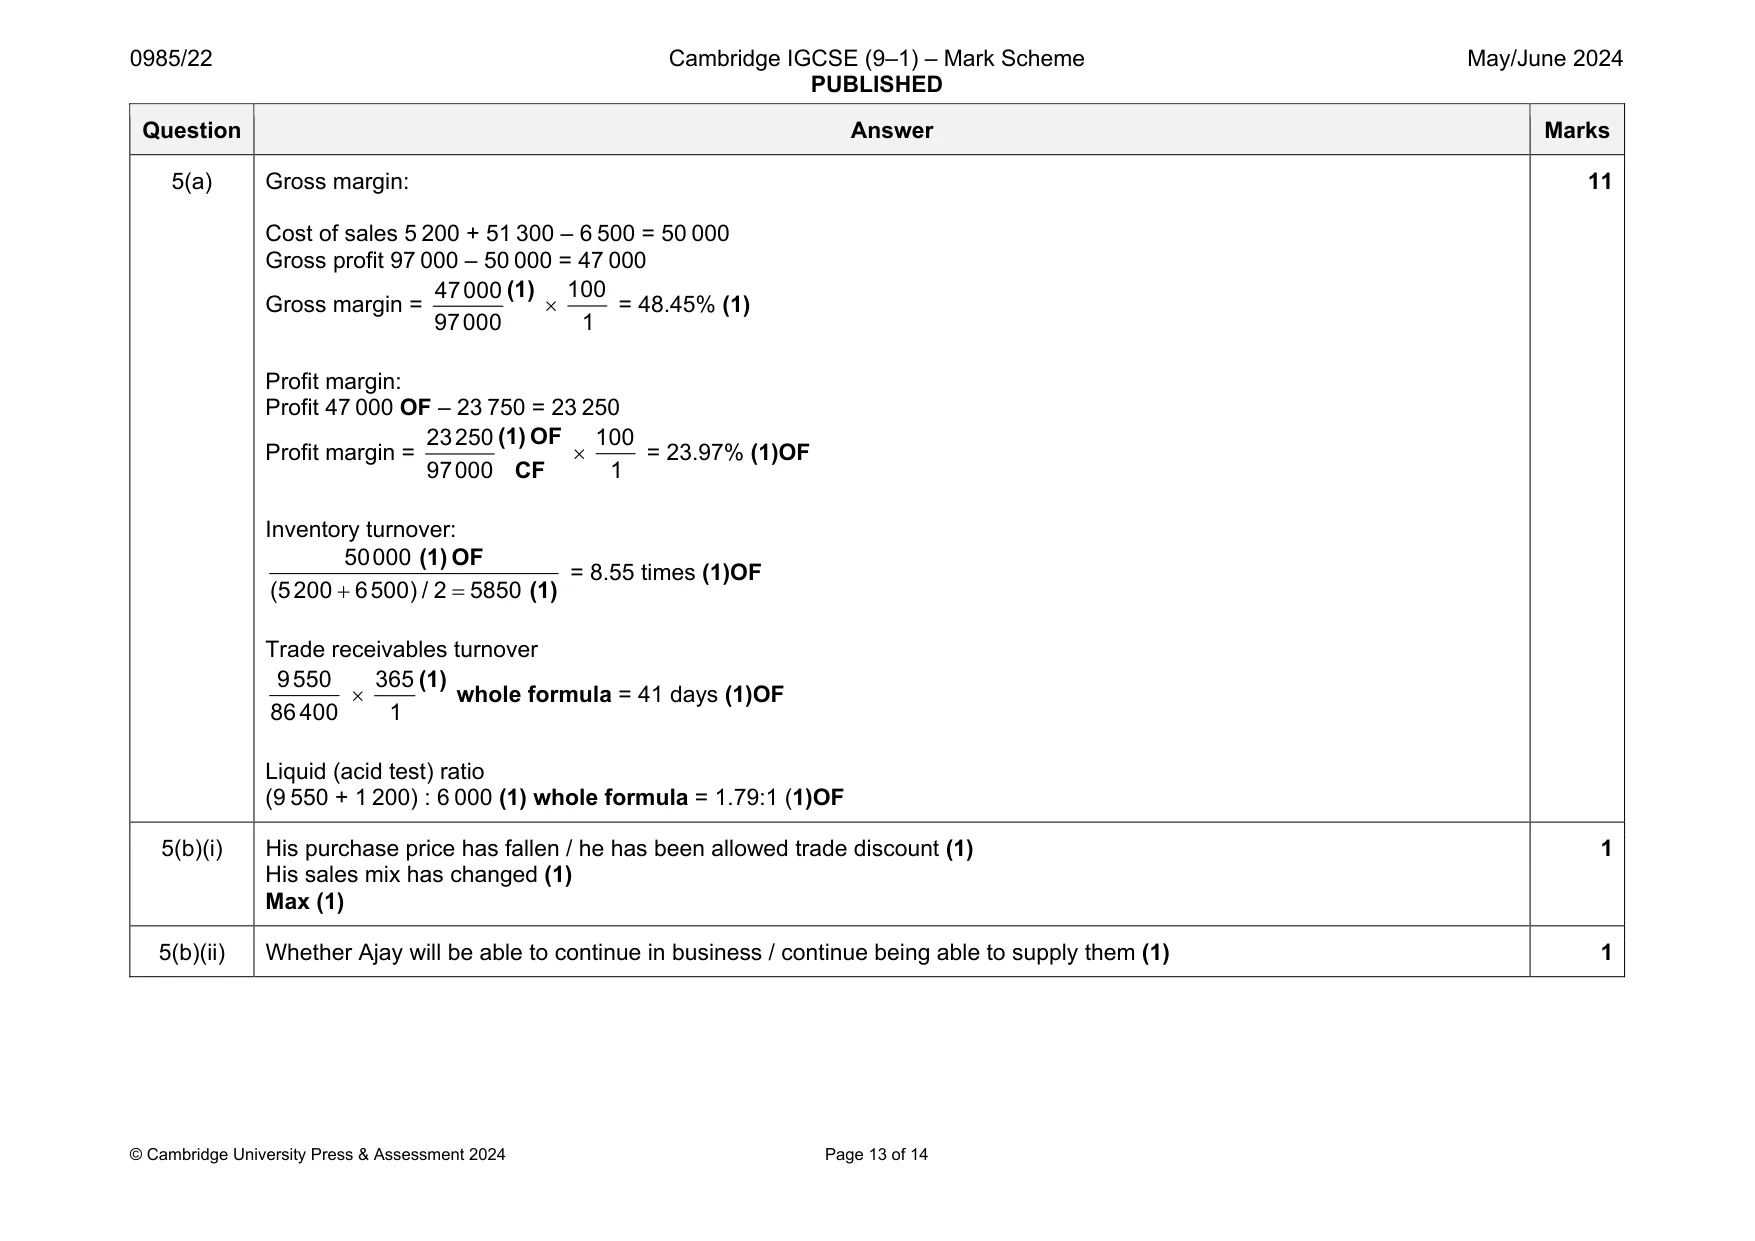
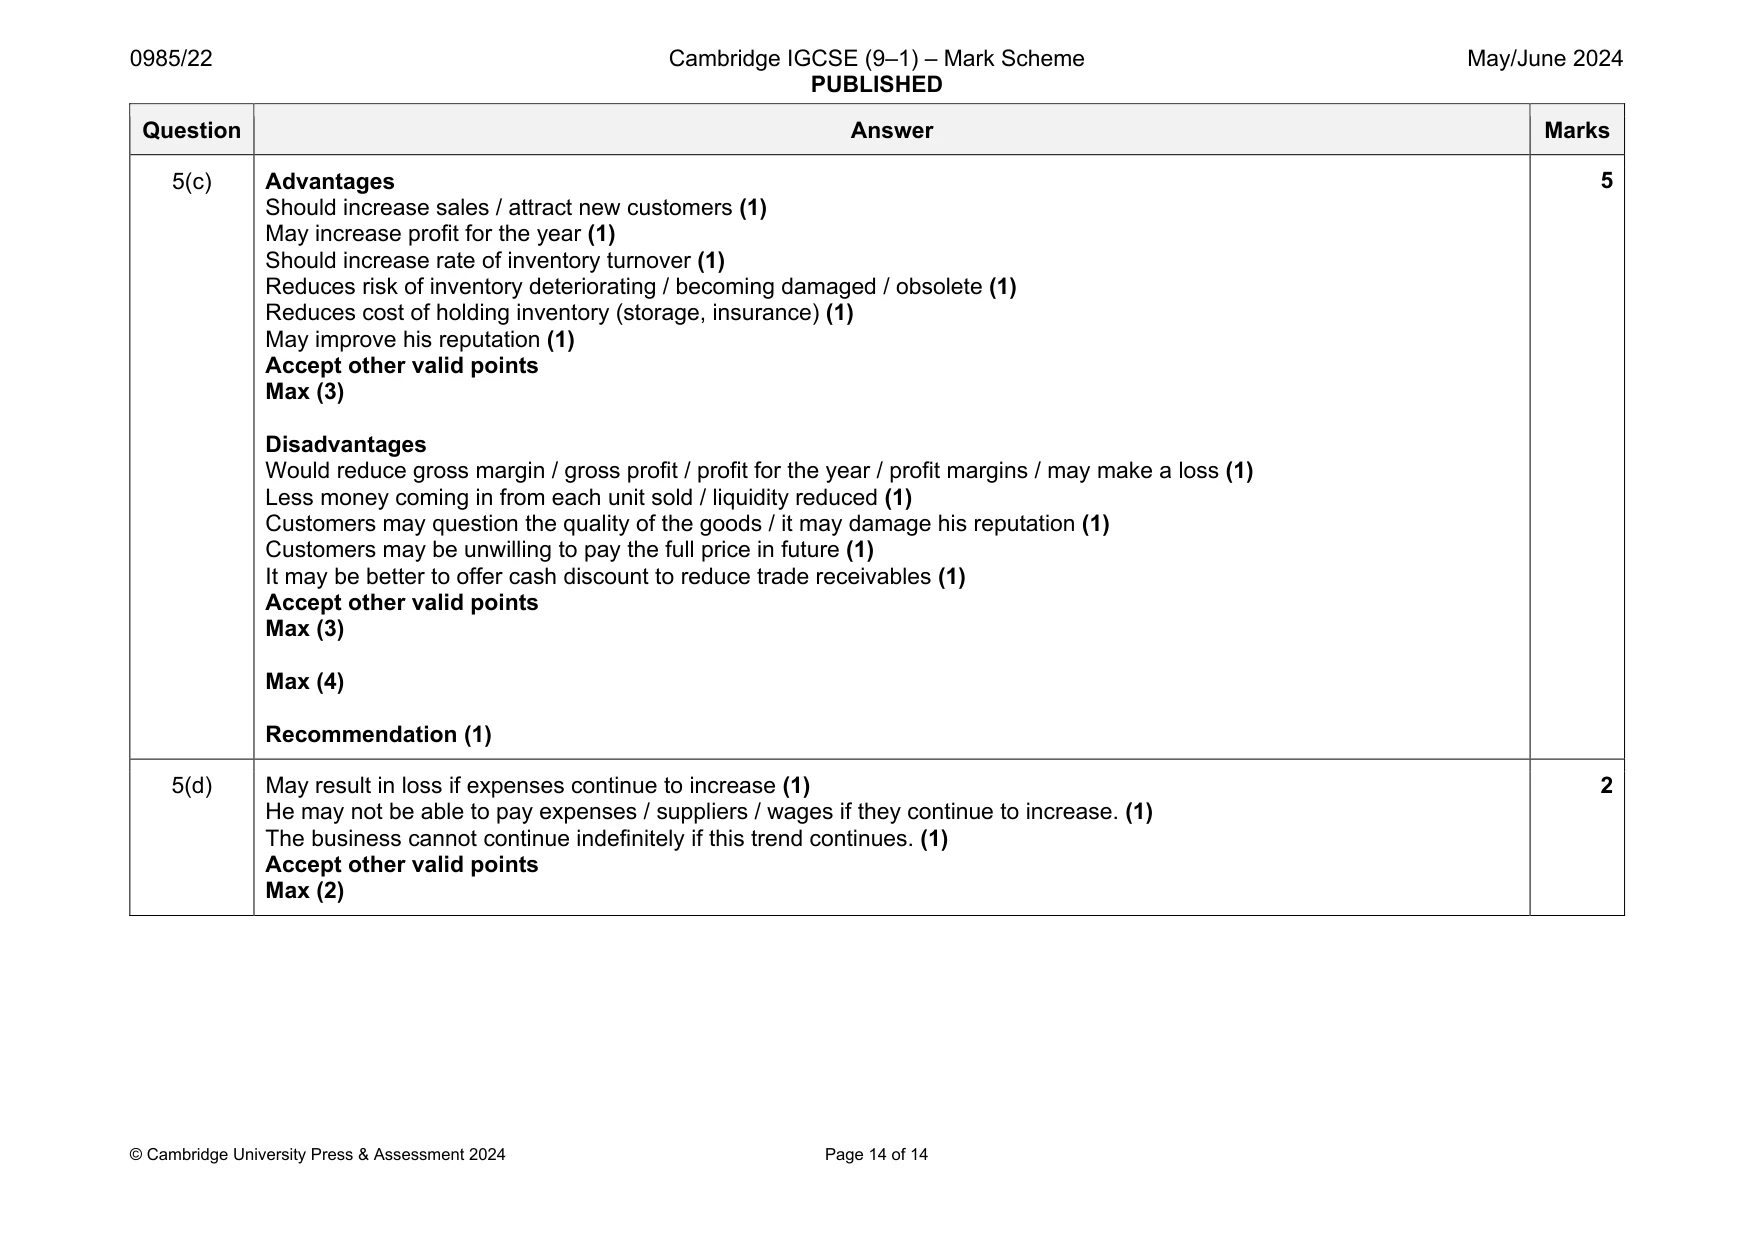
Mark scheme: 5(a) Gross margin: Cost of sales 5 200 + 51 300 – 6 500 = 50 000 Gross profit 97 000 – 50 000 = 47 000 Gross margin = 47000 97000 (1) 100 1 = 48.45% (1) Profit margin: Profit 47 000 OF – 23 750 = 23 250 Profit margin = 23250 97000 (1) OF CF 100 1 = 23.97% (1)OF Inventory turnover: 50000 (5200 6500) / 2 5850 (1) OF (1) = 8.55 times (1)OF Trade receivables turnover 9550 86400 365 1 (1) whole formula = 41 days (1)OF Liquid (acid test) ratio (9 550 + 1 200) : 6 000 (1) whole formula = 1.79:1 (1)OF 11 5(b)(i) His purchase price has fallen / he has been allowed trade discount (1) His sales mix has changed (1) Max (1) 1 5(b)(ii) Whether Ajay will be able to continue in business / continue being able to supply them (1) 1 Question Answer Marks 5(c) Advantages Should increase sales / attract new customers (1) May increase profit for the year (1) Should increase rate of inventory turnover (1) Reduces risk of inventory deteriorating / becoming damaged / obsolete (1) Reduces cost of holding inventory (storage, insurance) (1) May improve his reputation (1) Accept other valid points Max (3) Disadvantages Would reduce gross margin / gross profit / profit for the year / profit margins / may make a loss (1) Less money coming in from each unit sold / liquidity reduced (1) Customers may question the quality of the goods / it may damage his reputation (1) Customers may be unwilling to pay the full price in future (1) It may be better to offer cash discount to reduce trade receivables (1) Accept other valid points Max (3) Max (4) Recommendation (1) 5 5(d) May result in loss if expenses continue to increase (1) He may not be able to pay expenses / suppliers / wages if they continue to increase. (1) The business cannot continue indefinitely if this trend continues. (1) Accept other valid points Max (2) 2
More questions on Calculation and understanding of accounting ratios
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2024 May/June, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.