Cambridge IGCSE Accounting (9-1) 0985 — 2022 May/June Paper 2 · Variant 2
0985/22/M/J/22 · 6 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme16 pages
Answers below. Sit the paper first if you are practising.

Questions as text
Q1 · Peter is a trader
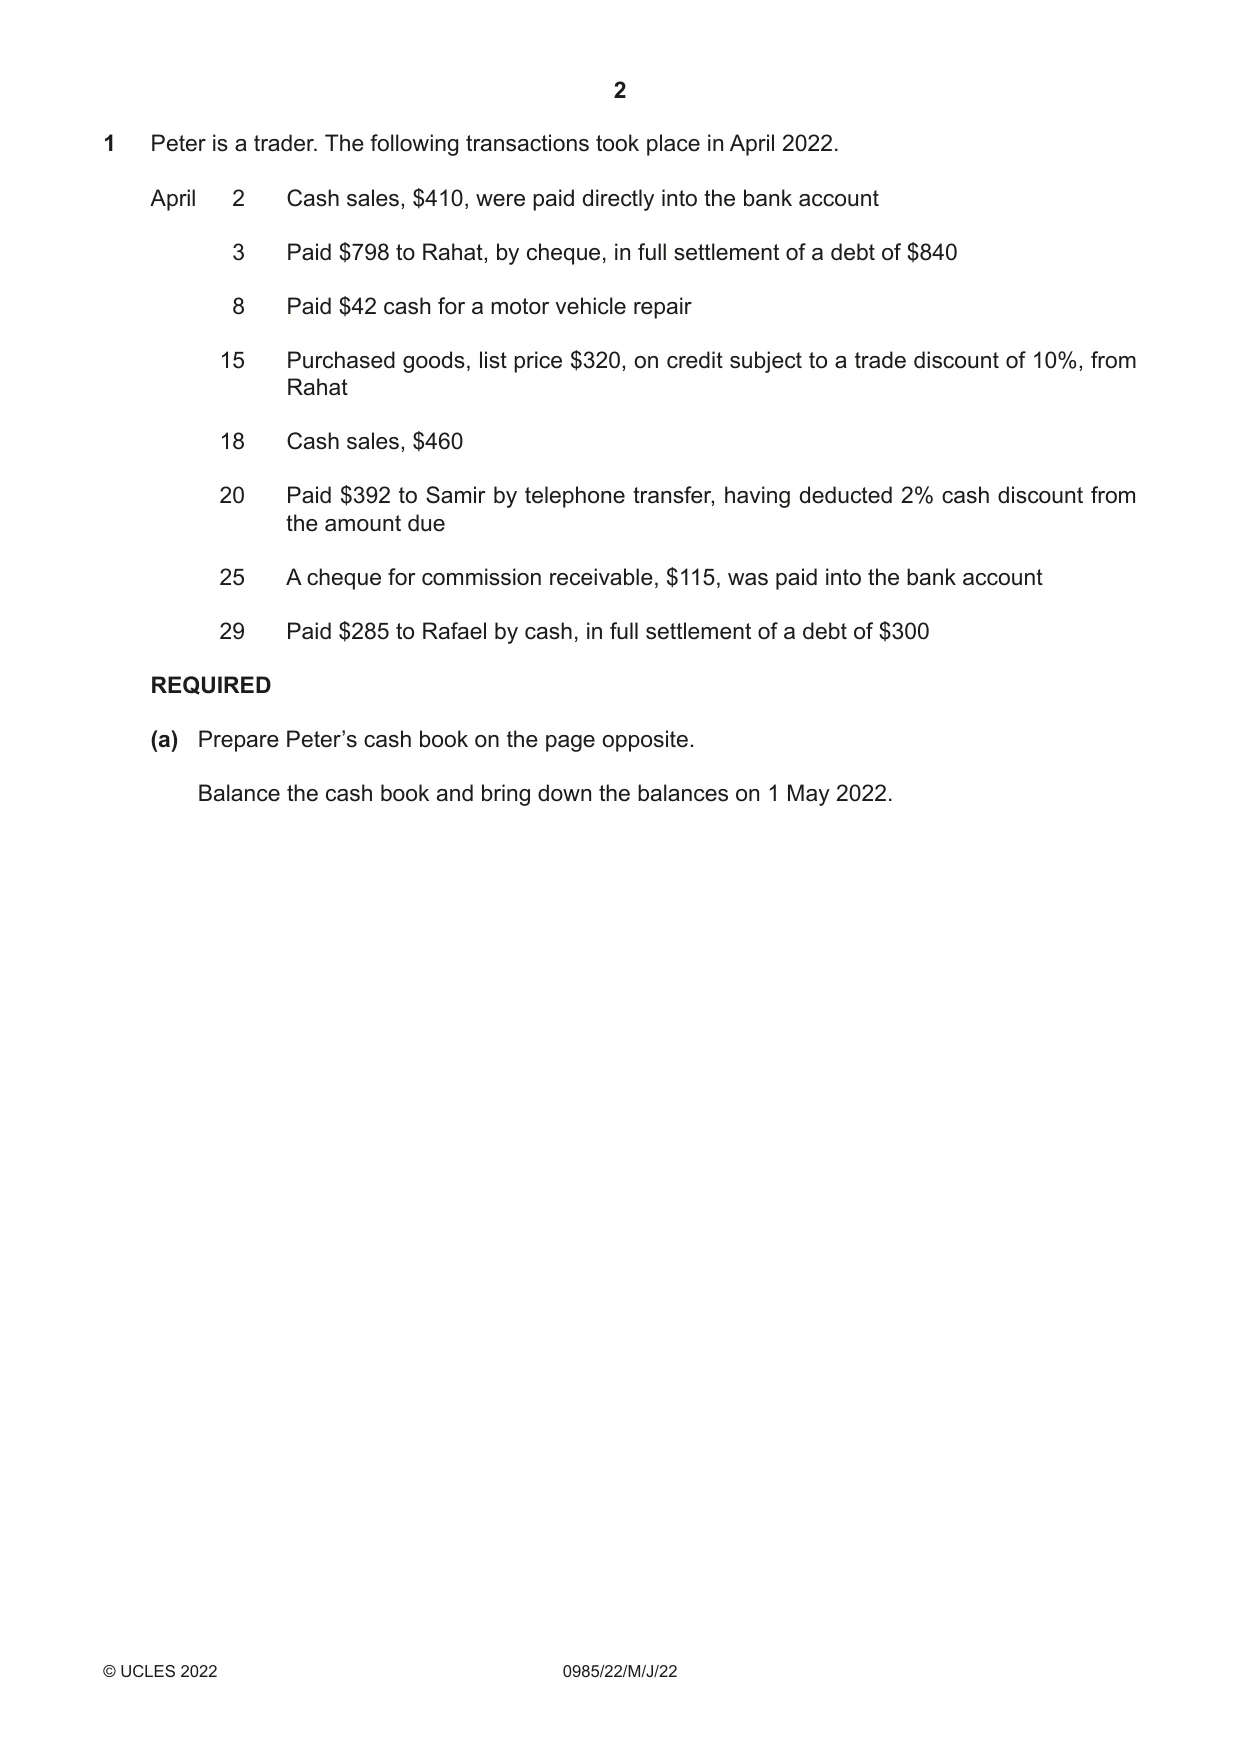
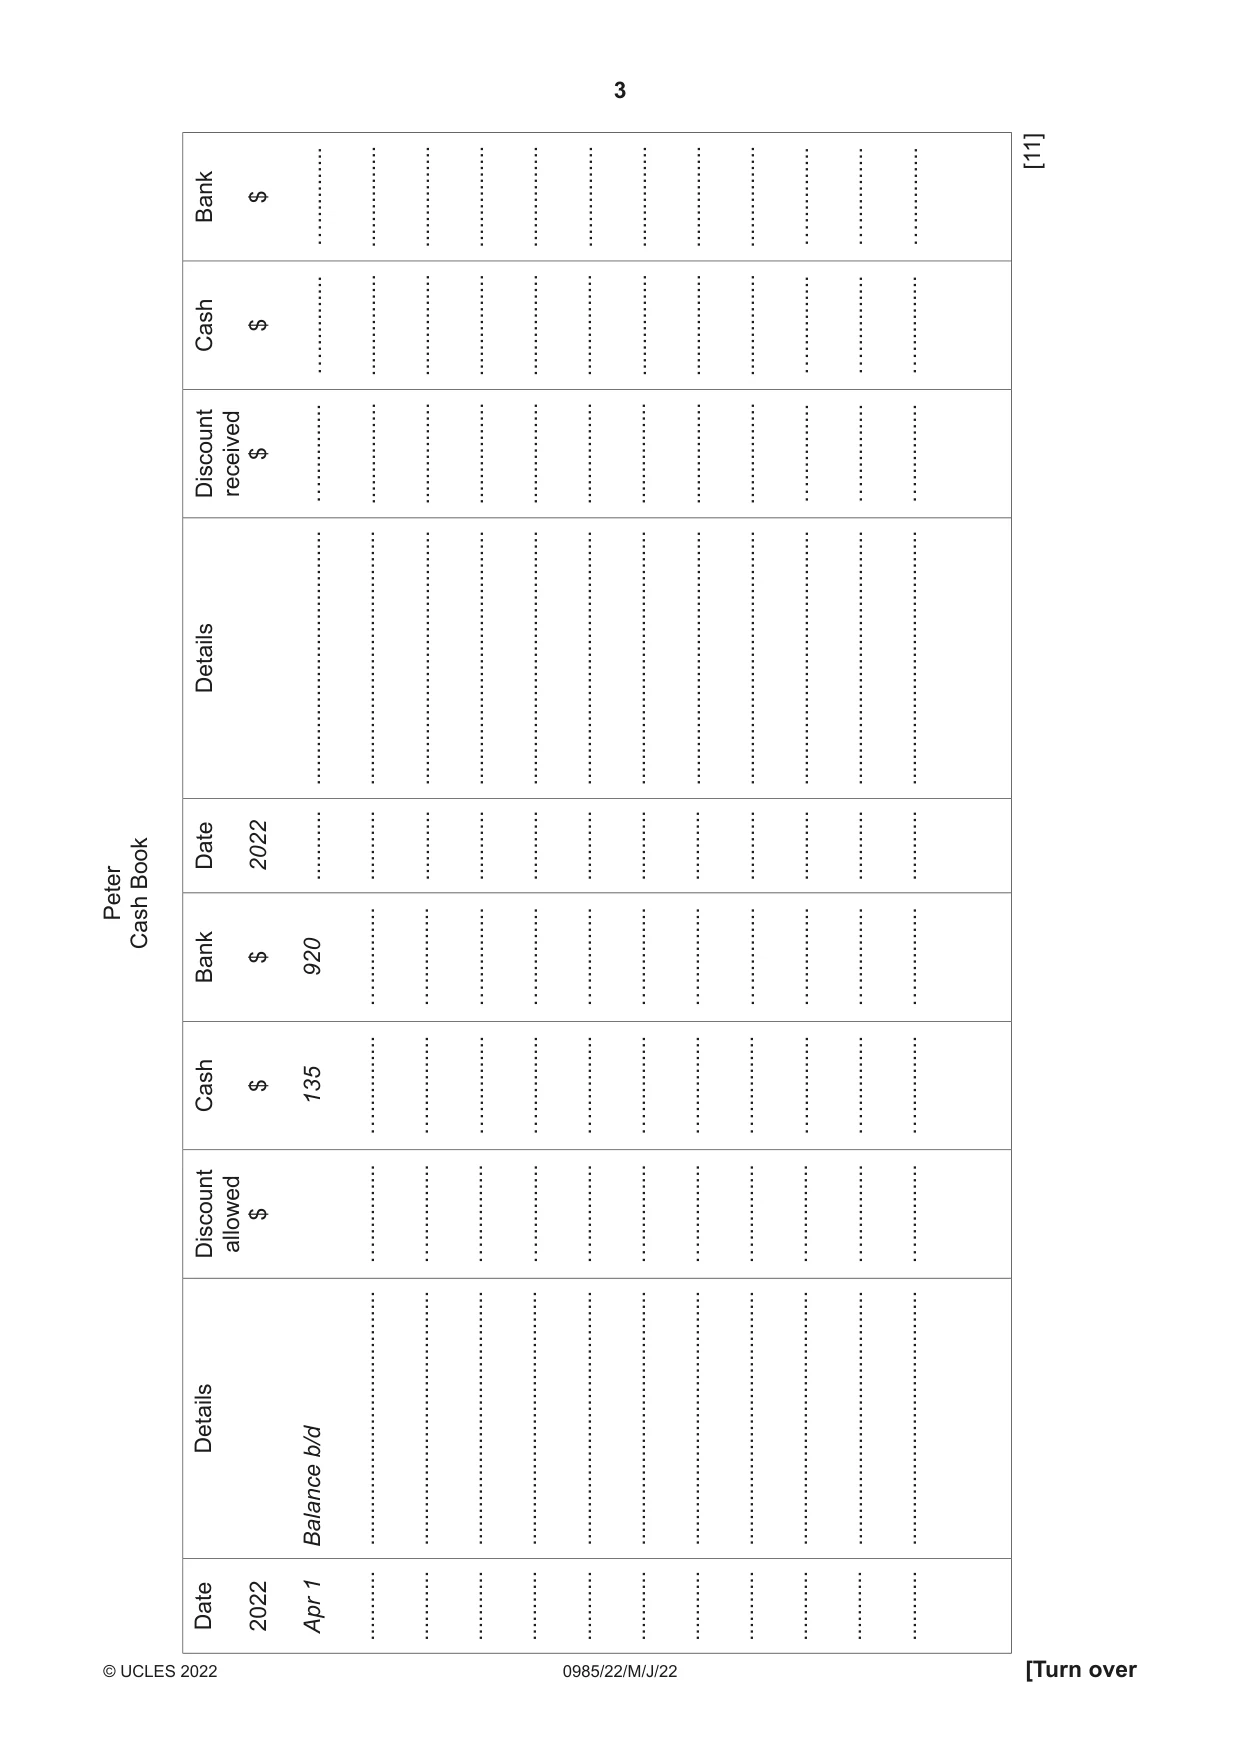
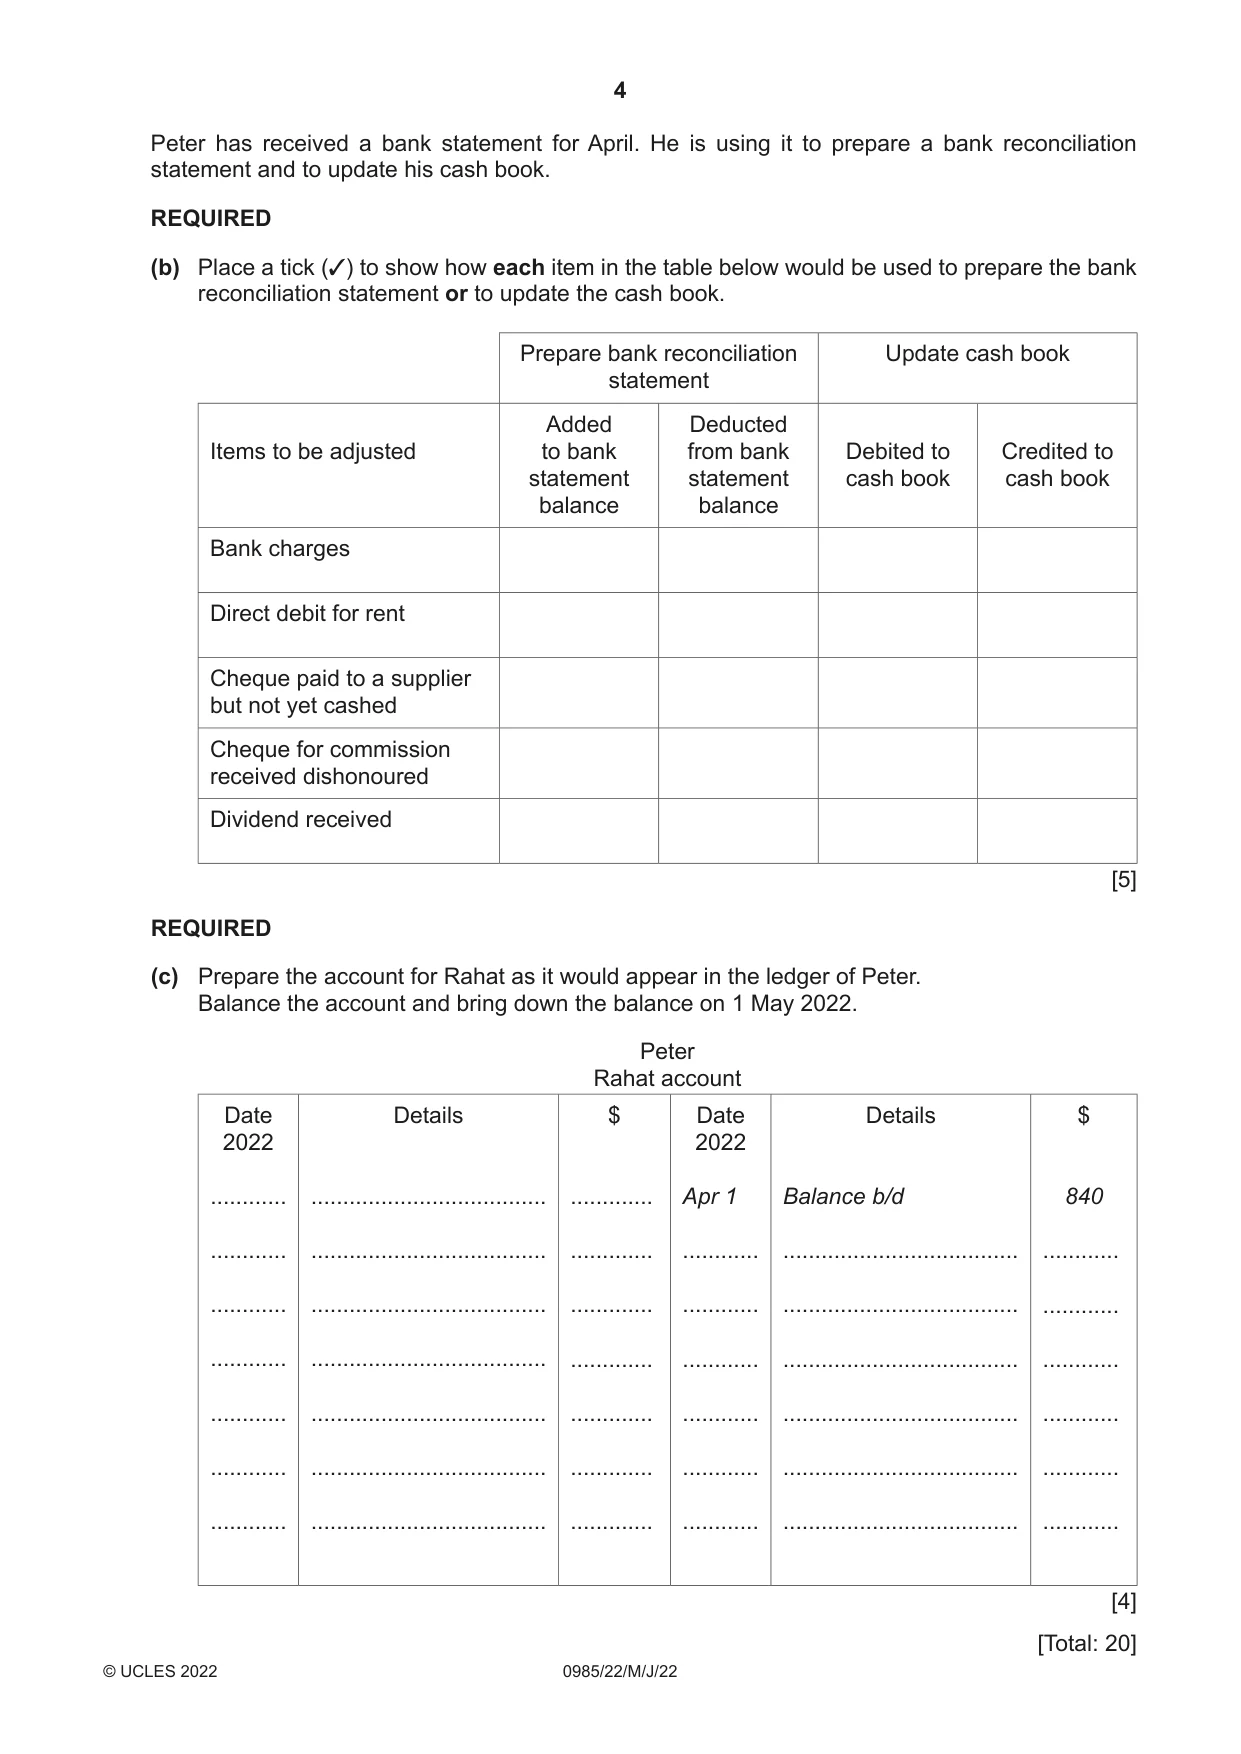
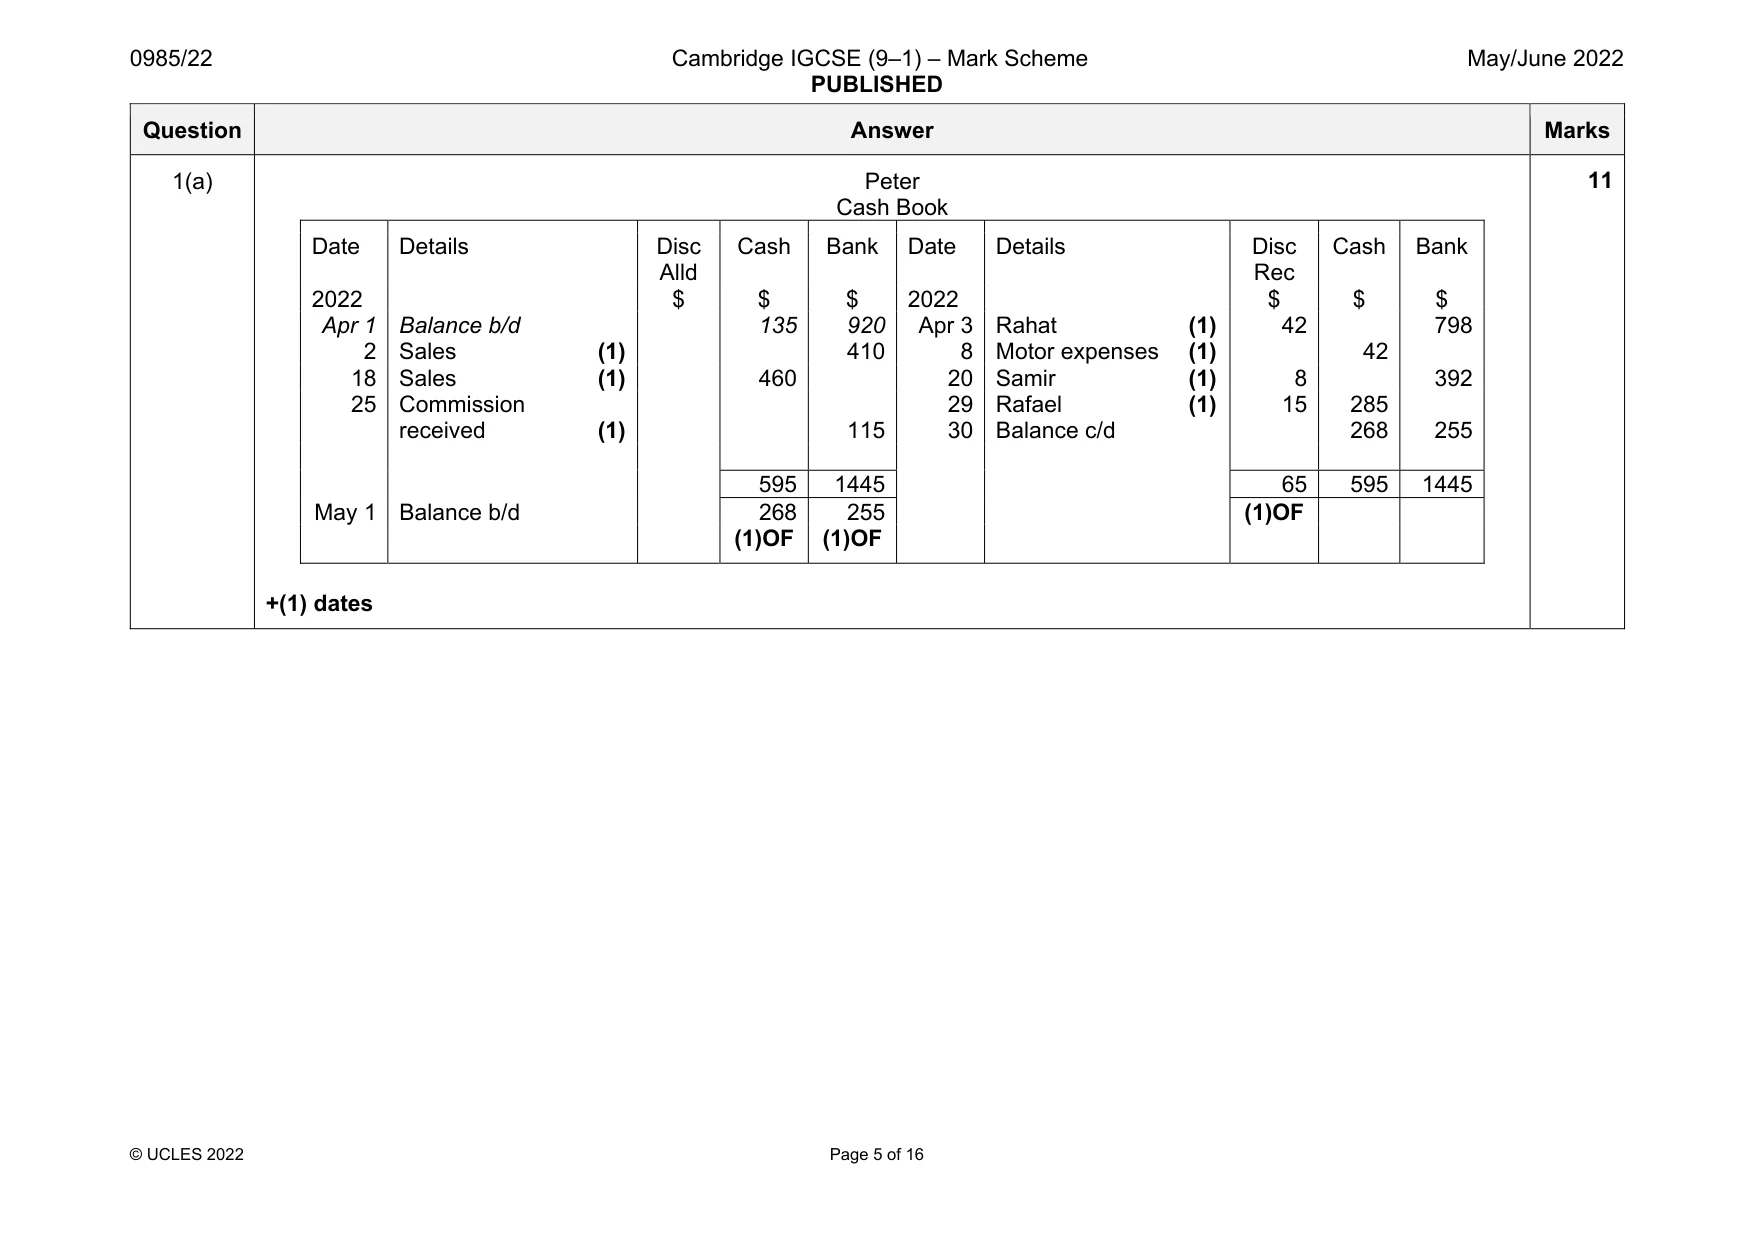
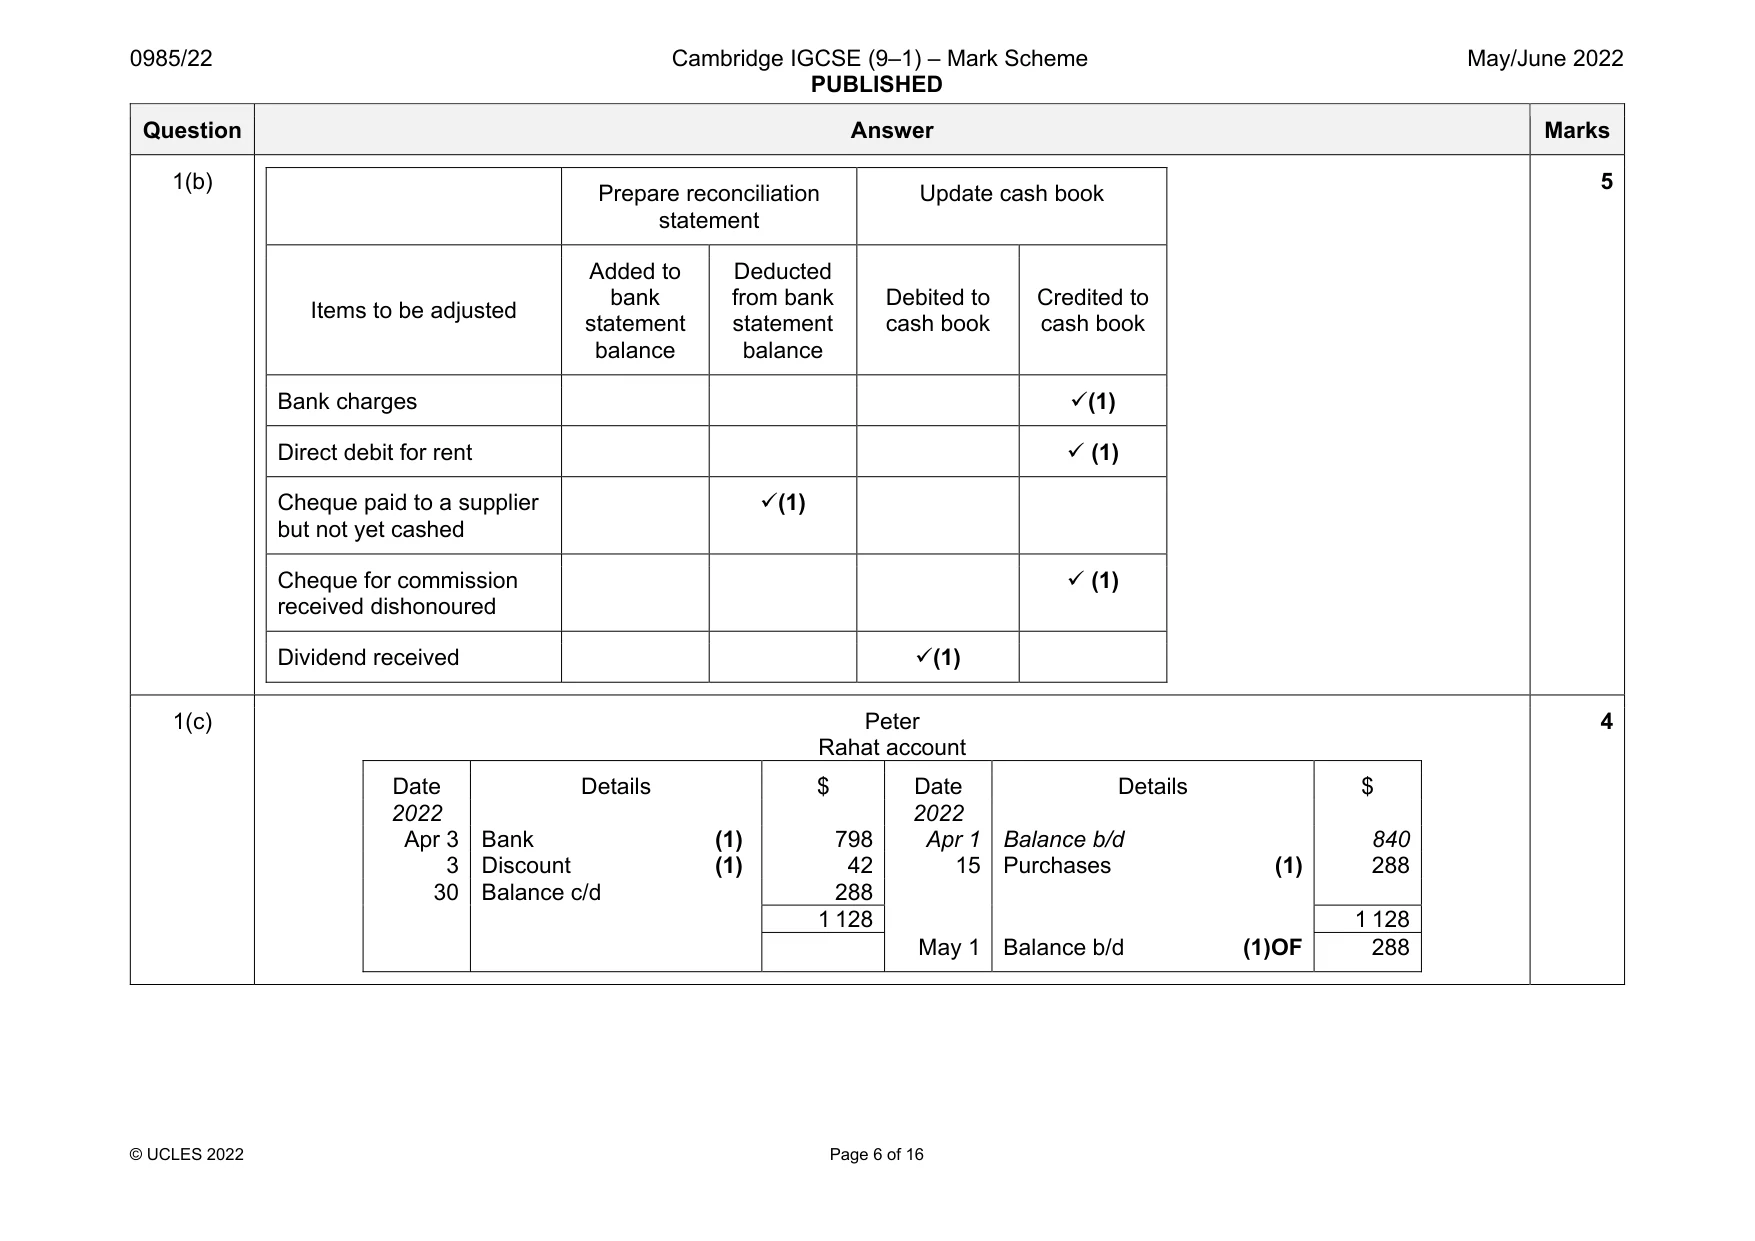
1 Peter is a trader. The following transactions took place in April 2022. April 2 Cash sales, $410, were paid directly into the bank account 3 Paid $798 to Rahat, by cheque, in full settlement of a debt of $840 8 Paid $42 cash for a motor vehicle repair 15 Purchased goods, list price $320, on credit subject to a trade discount of 10%, from Rahat 18 Cash sales, $460 20 Paid $392 to Samir by telephone transfer, having deducted 2% cash discount from the amount due 25 A cheque for commission receivable, $115, was paid into the bank account 29 Paid $285 to Rafael by cash, in full settlement of a debt of $300 REQUIRED (a) Prepare Peter’s cash book on the page opposite. Balance the cash book and bring down the balances on 1 May 2022. [11] $ Bank …............ ................ ................ ................ ................ ................ ................ ................ ................ …............ …............ …............ $ Cash …............ ................ ................ ................ ................ ................ ................ ................ ................ …............ …............ …............ $ Discountreceived …............ ................ ................ ................ ................ ................ ................ ................ ................ …............ …............ …............ Details ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ Date 2022 ........... ........... ........... ........... ........... ........... ........... ........... ........... ........... ........... ........... Book Peter Cash $ 920 Bank …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ $ 135 Cash …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ $ Discountallowed …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ Details b/d Balance ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ Peter has received a bank statement for April. He is using it to prepare a bank reconciliation statement and to update his cash book. REQUIRED (b) Place a tick (✓) to show how each item in the table below would be used to prepare the bank reconciliation statement or to update the cash book. Prepare bank reconciliation Update cash book statement Added Deducted Items to be adjusted to bank from bank Debited to Credited to statement statement cash book cash book balance balance Bank charges Direct debit for rent Cheque paid to a supplier but not yet cashed Cheque for commission received dishonoured Dividend received [5] REQUIRED (c) Prepare the account for Rahat as it would appear in the ledger of Peter. Balance the account and bring down the balance on 1 May 2022. Peter Rahat account Date Details $ Date Details $ 2022 2022 ............ ..................................... ............. Apr 1 Balance b/d 840 ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ [4] [Total: 20]
Mark scheme: 1(a) Peter Cash Book Date Details Disc Alld Cash Bank Date Details Disc Rec Cash Bank 2022 $ $ $ 2022 $ $ $ Apr 1 Balance b/d 135 920 Apr 3 Rahat (1) 42 798 2 Sales (1) 410 8 Motor expenses (1) 42 18 Sales (1) 460 20 Samir (1) 8 392 25 Commission 29 Rafael (1) 15 285 received (1) 115 30 Balance c/d 268 255 595 1445 65 595 1445 May 1 Balance b/d 268 255 (1)OF (1)OF (1)OF +(1) dates Question Answer Marks 1(b) Prepare reconciliation statement Update cash book Items to be adjusted Added to bank statement balance Deducted from bank statement balance Debited to cash book Credited to cash book Bank charges (1) Direct debit for rent (1) Cheque paid to a supplier but not yet cashed (1) Cheque for commission received dishonoured (1) Dividend received (1) 5 1(c) Peter Rahat account Date Details $ Date Details $ 2022 2022 Apr 3 Bank (1) 798 Apr 1 Balance b/d 840 3 Discount (1) 42 15 Purchases (1) 288 30 Balance c/d 288 1 128 1 128 May 1 Balance b/d (1)OF 288 4
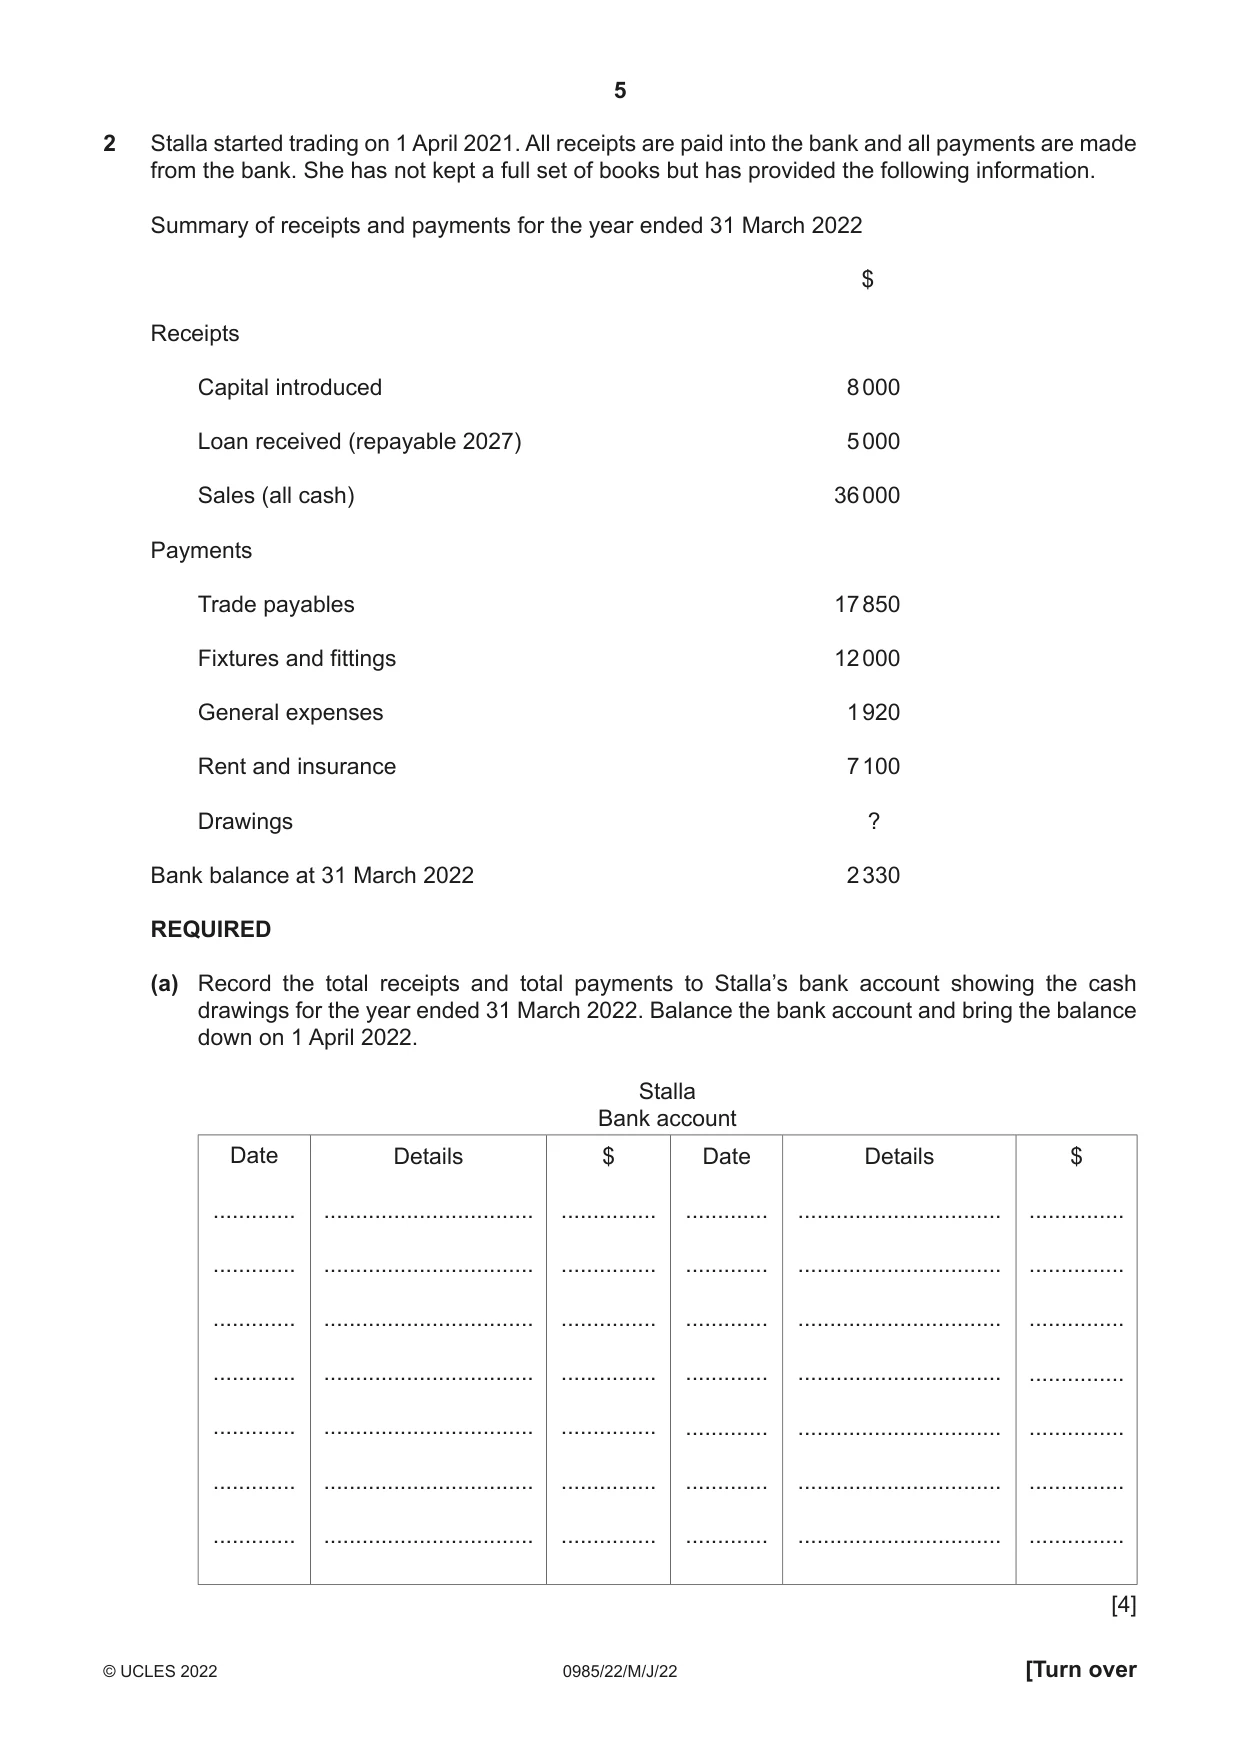
Q2 · Stalla started trading on 1 April 2021
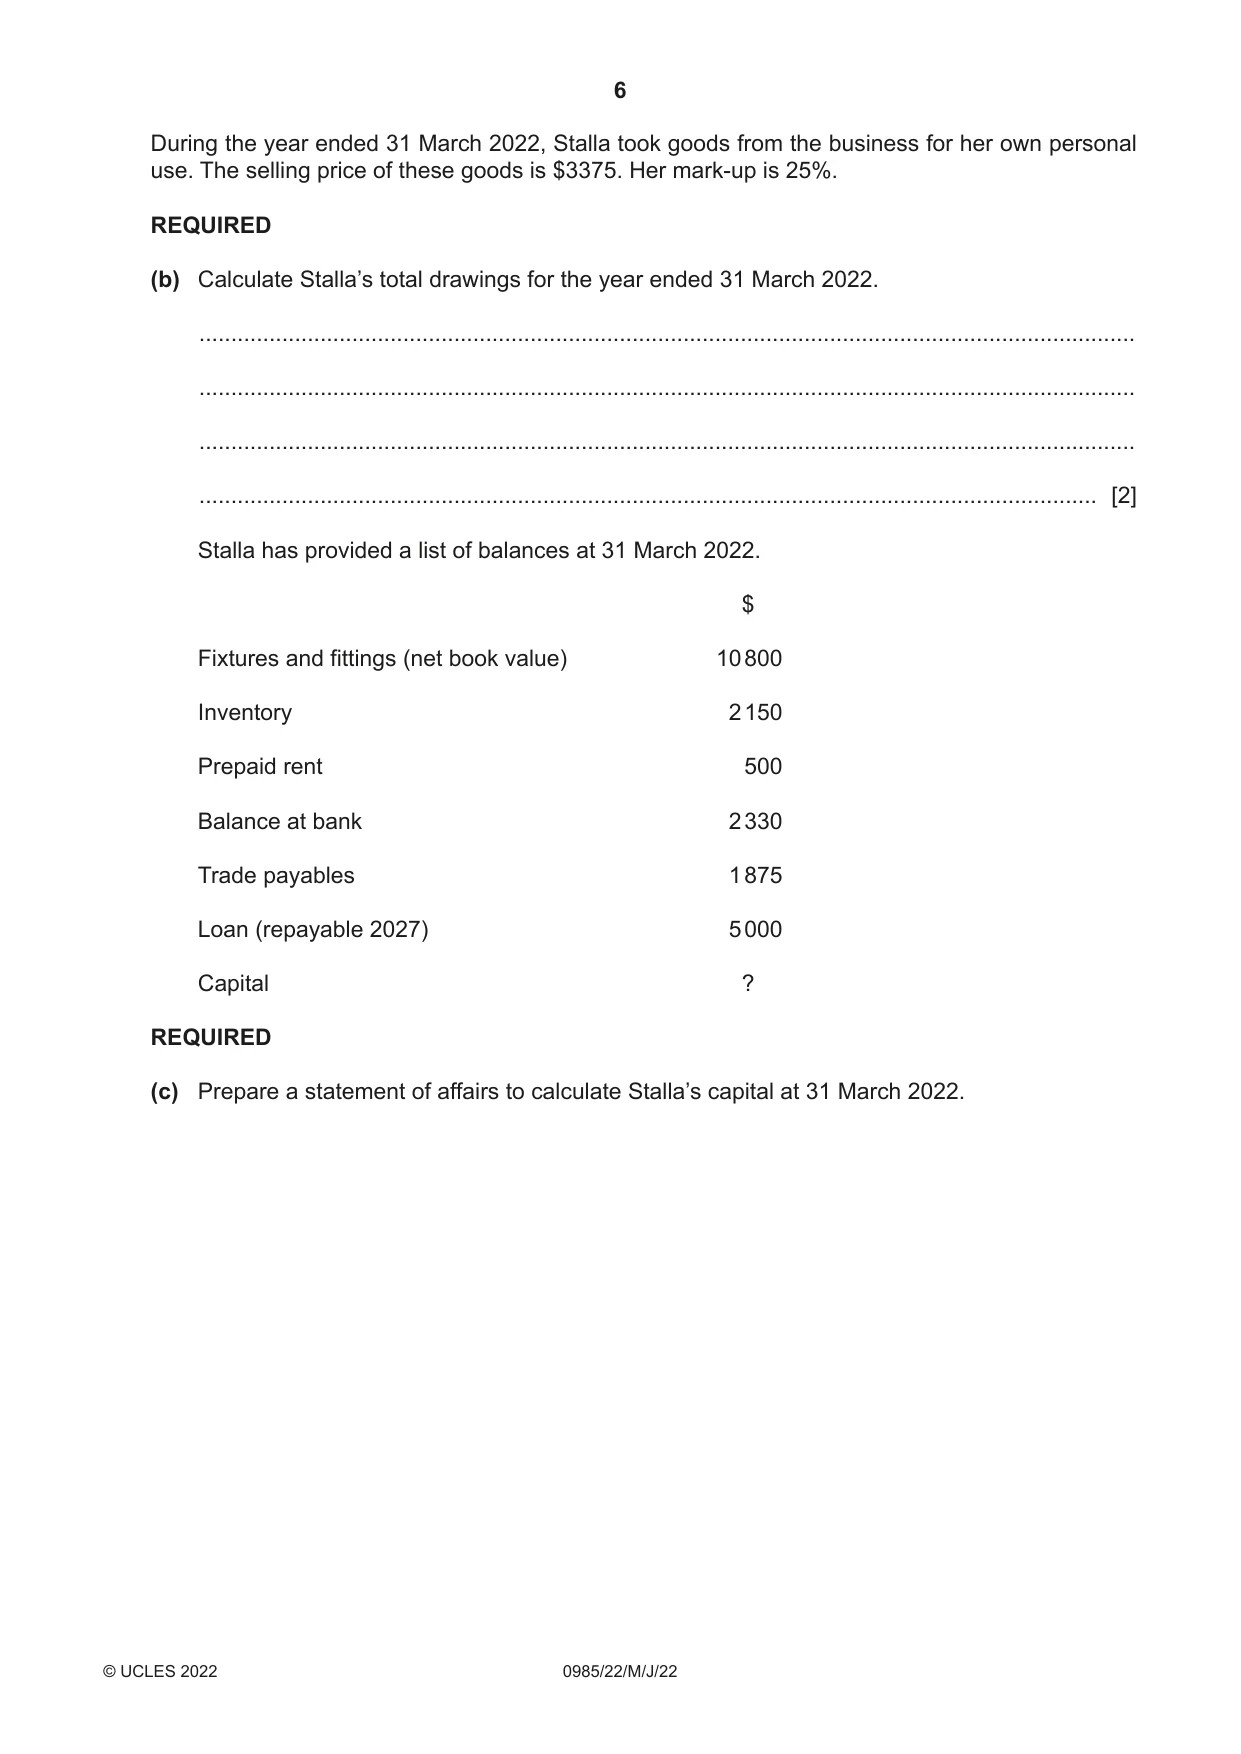
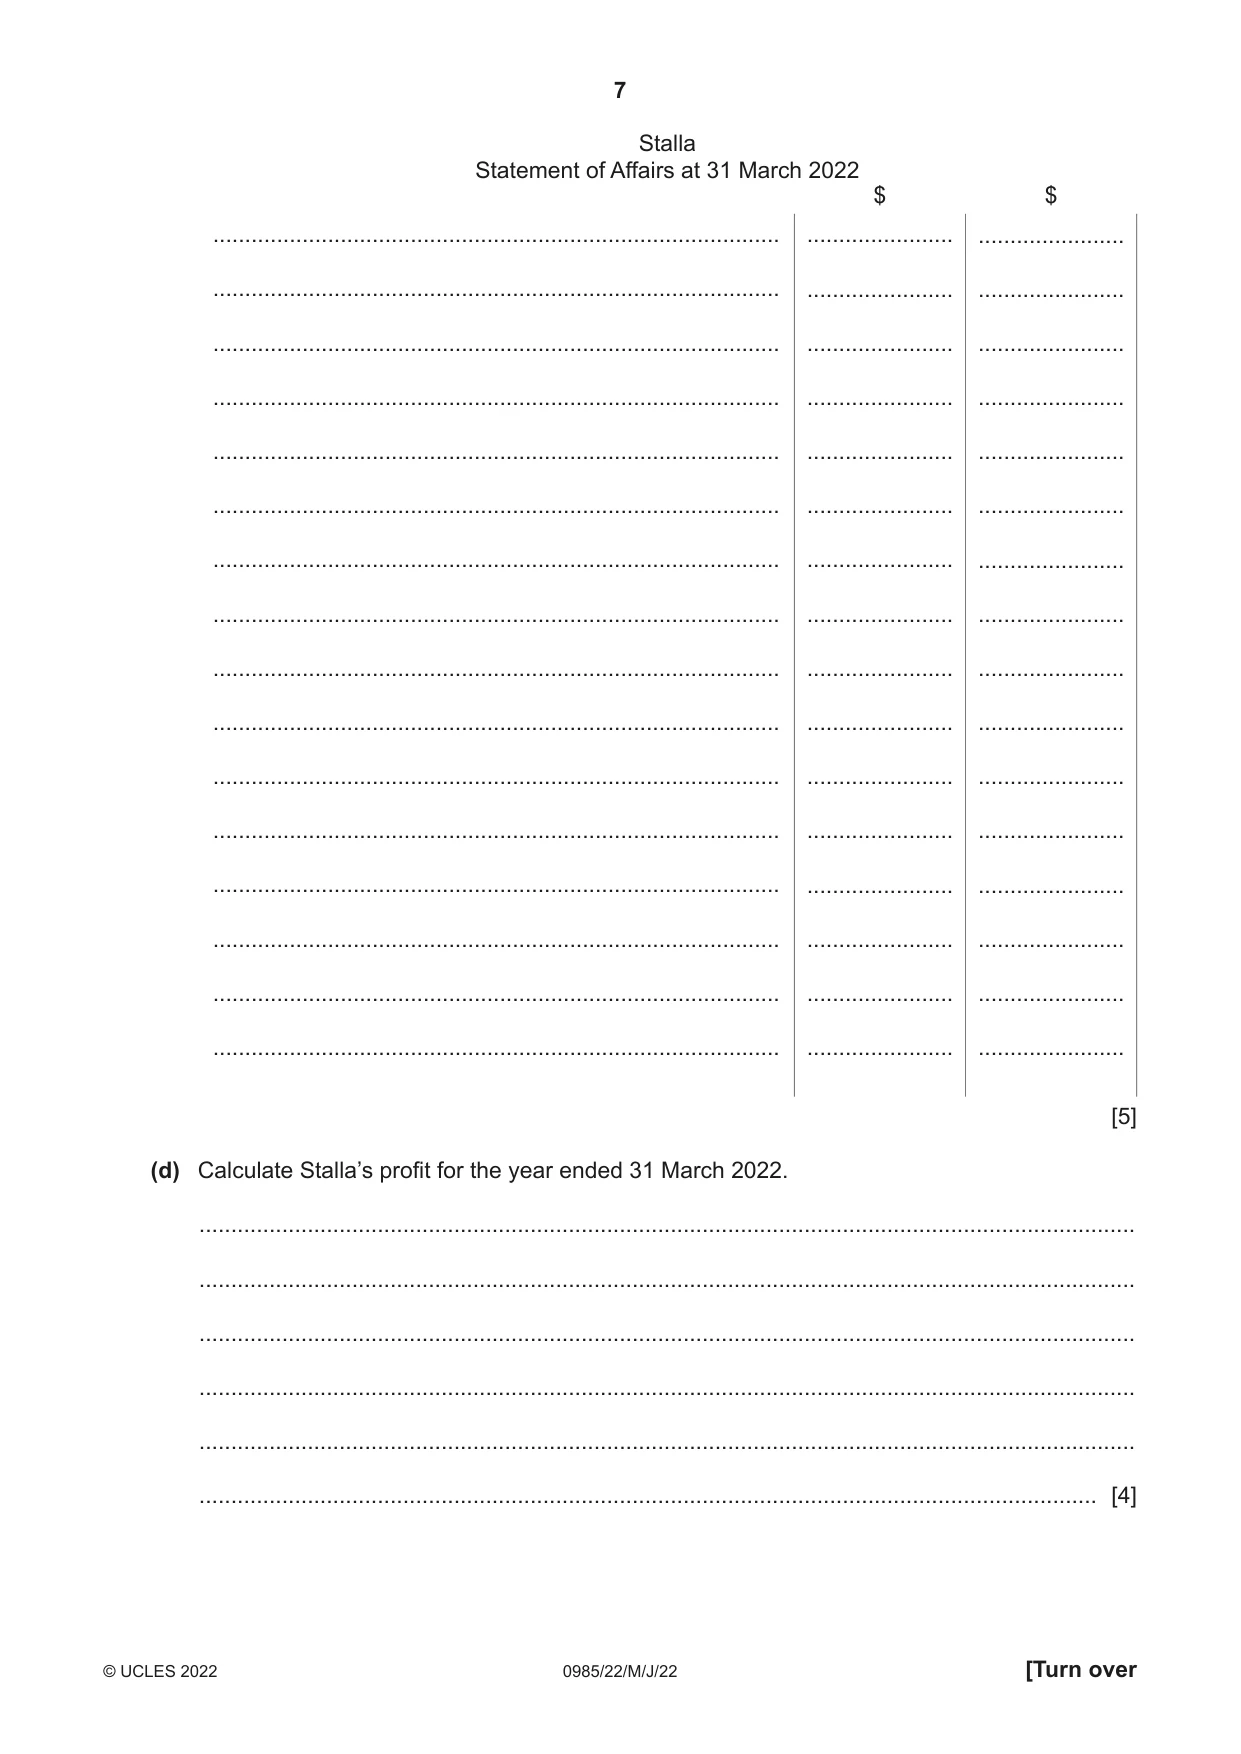
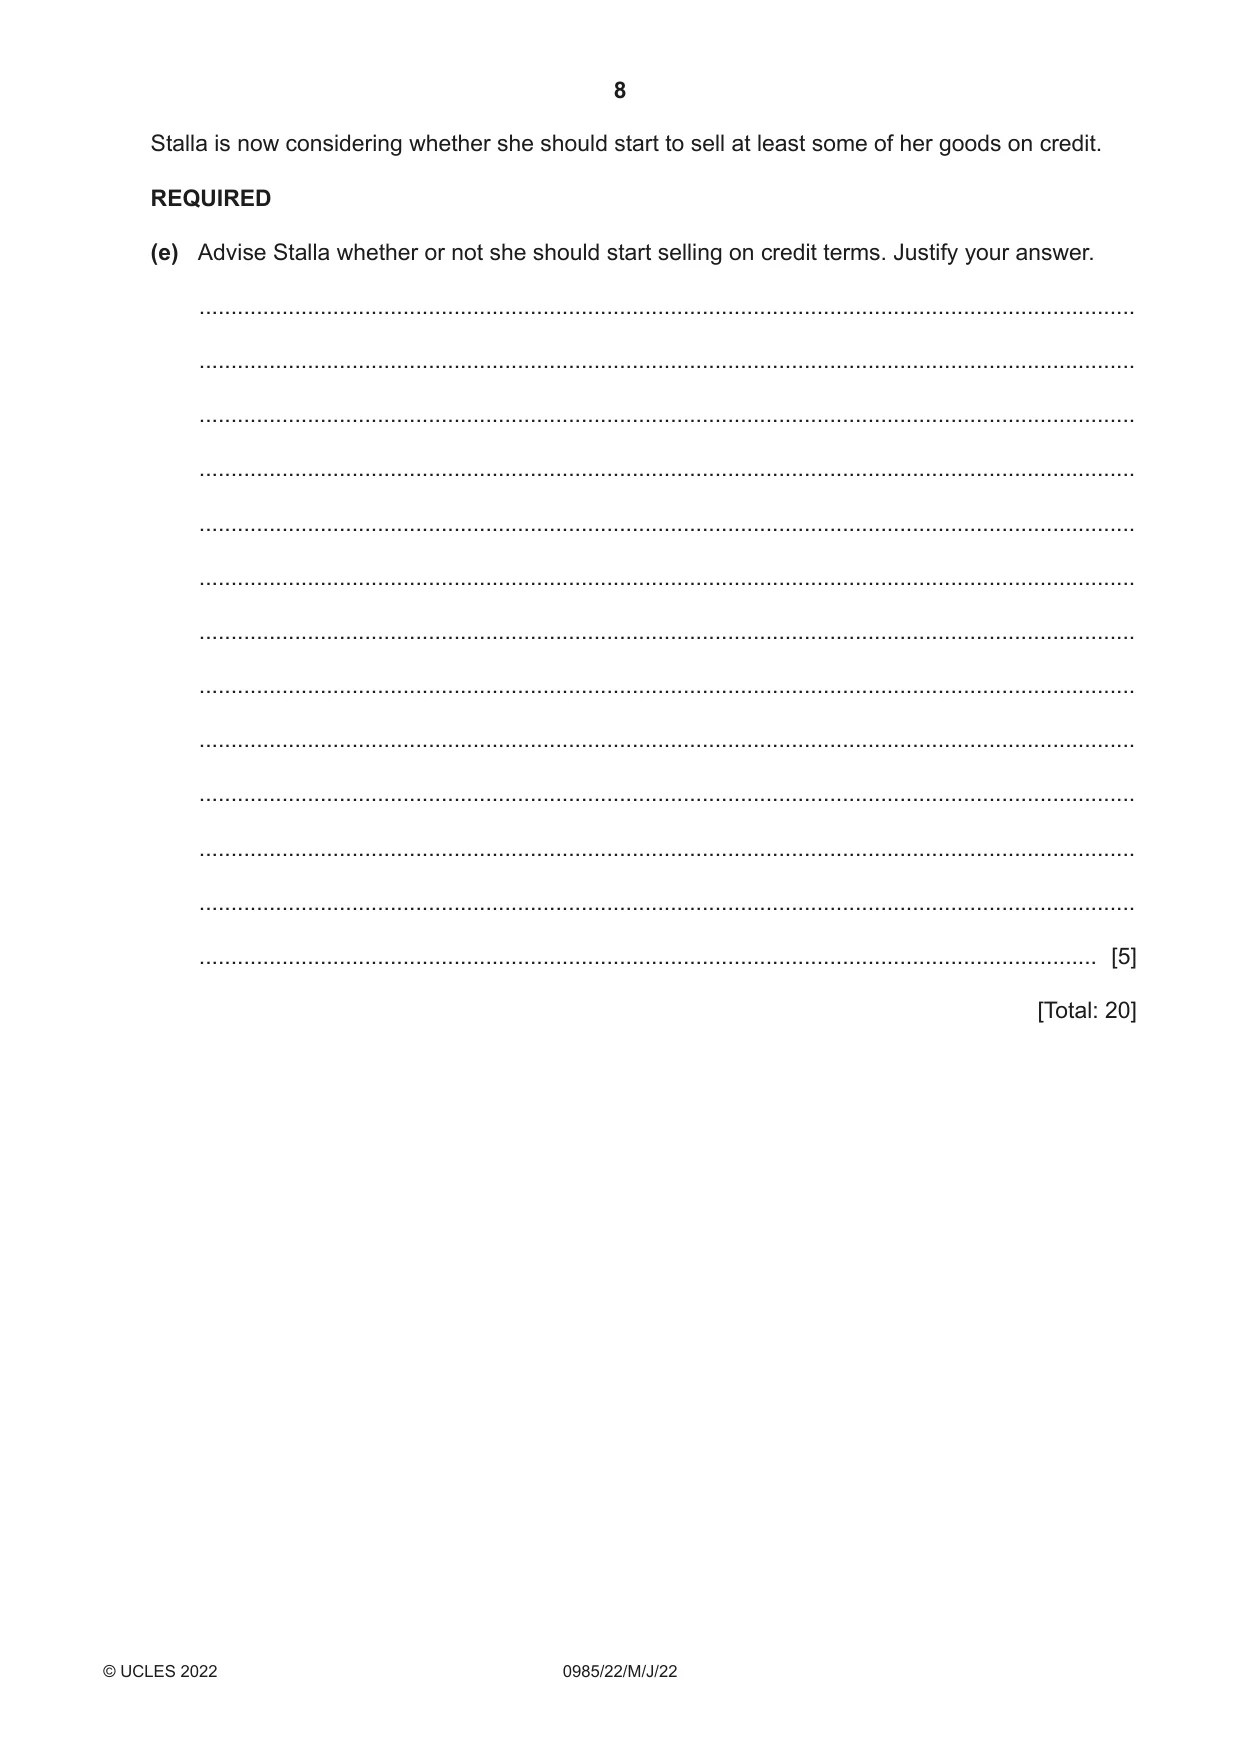
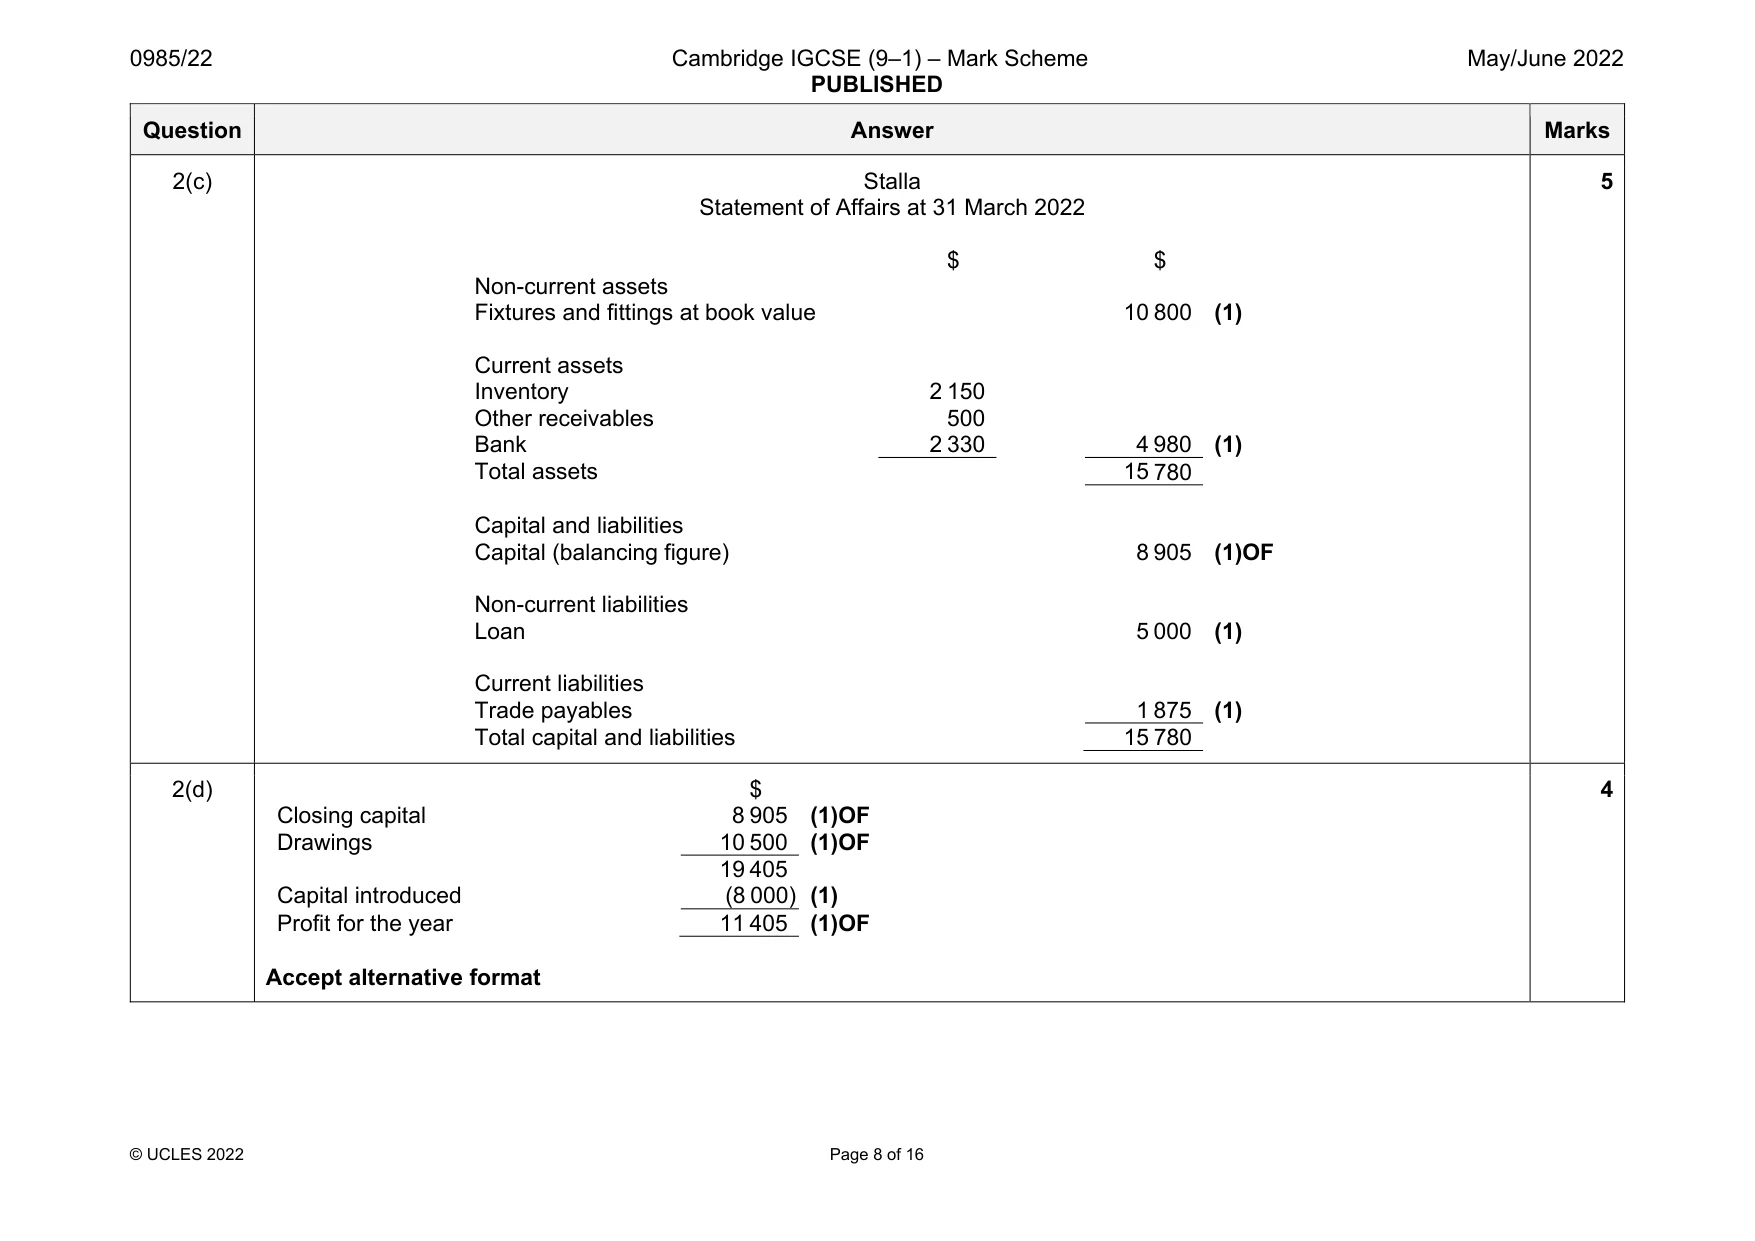
2 Stalla started trading on 1 April 2021. All receipts are paid into the bank and all payments are made from the bank. She has not kept a full set of books but has provided the following information. Summary of receipts and payments for the year ended 31 March 2022 $ Receipts Capital introduced 8 000 Loan received (repayable 2027) 5 000 Sales (all cash) 36 000 Payments Trade payables 17 850 Fixtures and fittings 12 000 General expenses 1 920 Rent and insurance 7 100 Drawings ? Bank balance at 31 March 2022 2 330 REQUIRED (a) Record the total receipts and total payments to Stalla’s bank account showing the cash drawings for the year ended 31 March 2022. Balance the bank account and bring the balance down on 1 April 2022. Stalla Bank account Date Details $ Date Details $ ............. ................................. ............... ............. ................................ ............... ............. ................................. ............... ............. ................................ ............... ............. ................................. ............... ............. ................................ ............... ............. ................................. ............... ............. ................................ ............... ............. ................................. ............... ............. ................................ ............... ............. ................................. ............... ............. ................................ ............... ............. ................................. ............... ............. ................................ ............... [4] During the year ended 31 March 2022, Stalla took goods from the business for her own personal use. The selling price of these goods is $3375. Her mark-up is 25%. REQUIRED (b) Calculate Stalla’s total drawings for the year ended 31 March 2022. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] Stalla has provided a list of balances at 31 March 2022. $ Fixtures and fittings (net book value) 10 800 Inventory 2 150 Prepaid rent 500 Balance at bank 2 330 Trade payables 1 875 Loan (repayable 2027) 5 000 Capital ? REQUIRED (c) Prepare a statement of affairs to calculate Stalla’s capital at 31 March 2022. Stalla Statement of Affairs at 31 March 2022 $ $ ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... [5] (d) Calculate Stalla’s profit for the year ended 31 March 2022. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] Stalla is now considering whether she should start to sell at least some of her goods on credit. REQUIRED (e) Advise Stalla whether or not she should start selling on credit terms. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
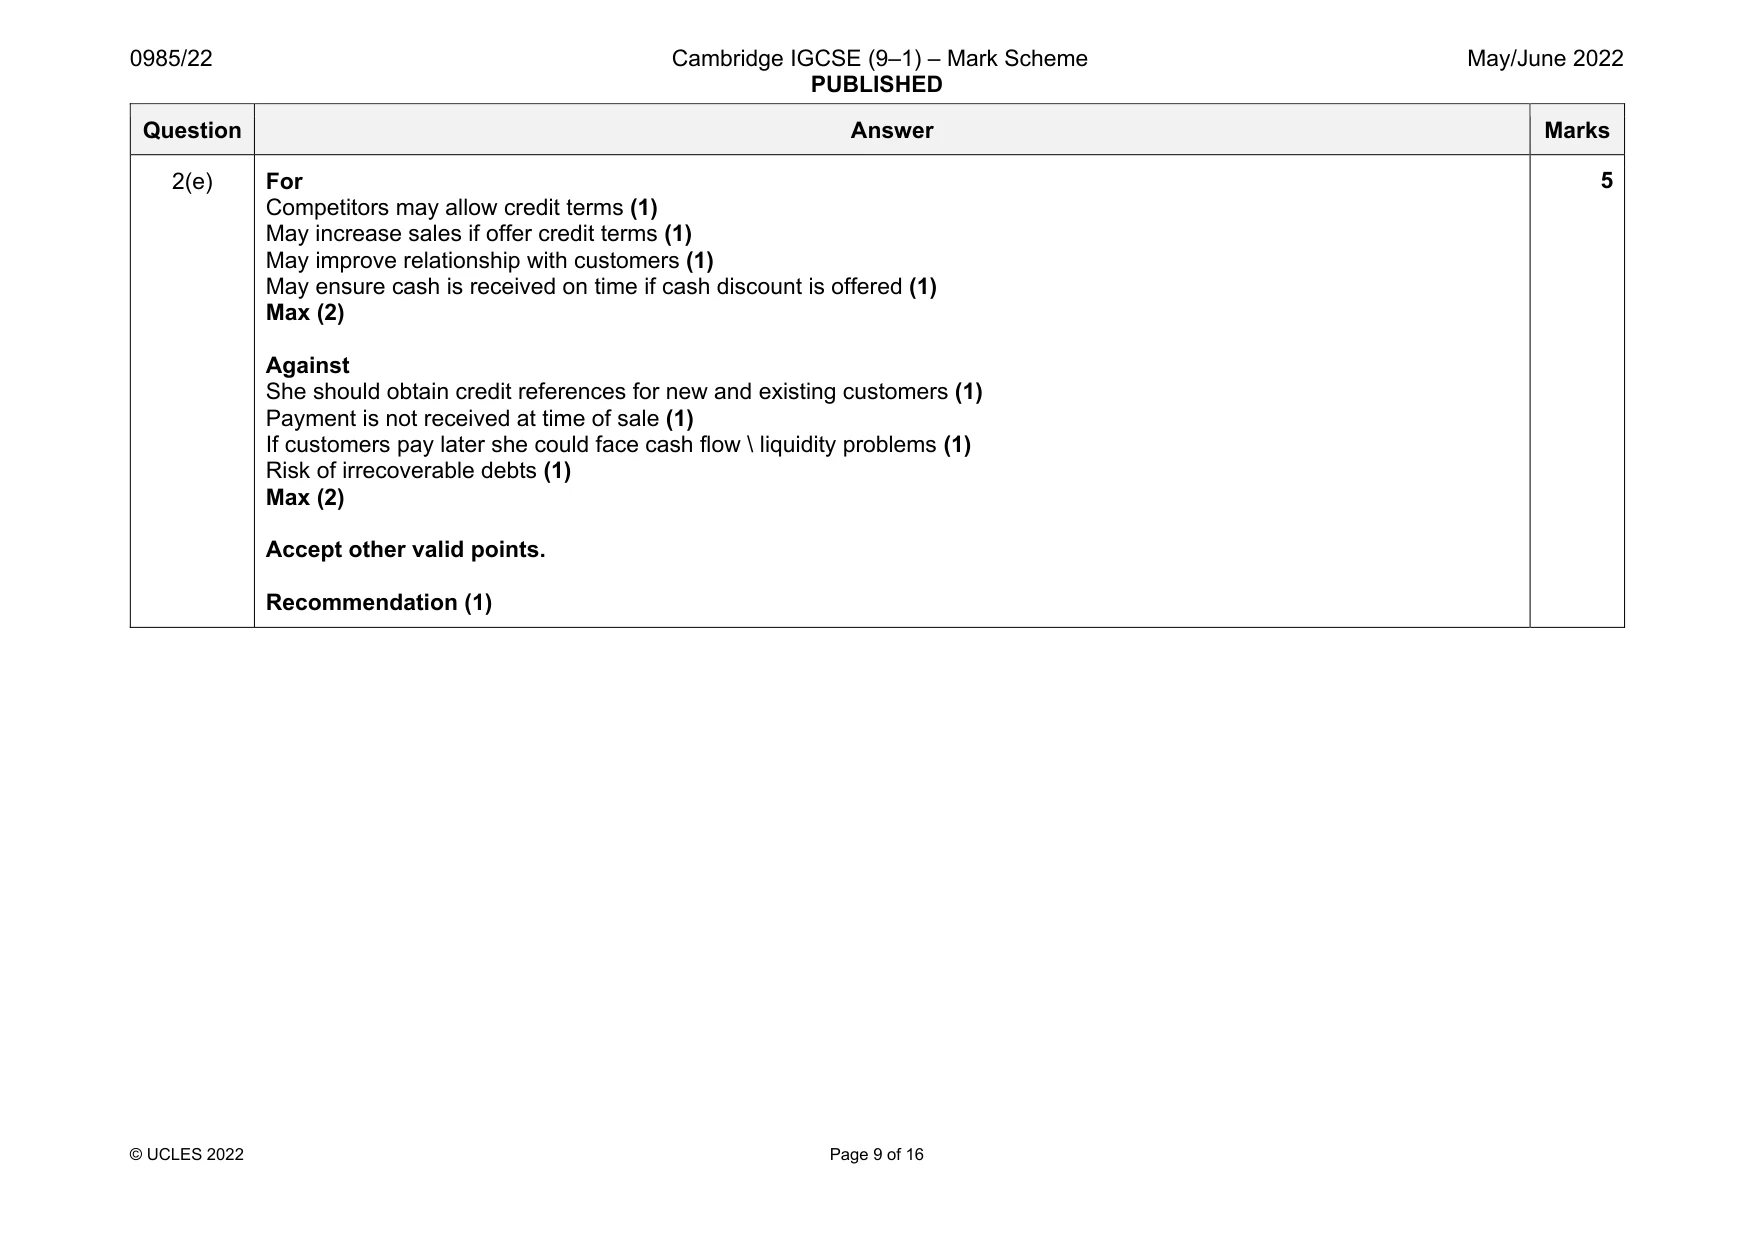
Mark scheme: 2(a) Stalla Bank account Date Details $ Date Details $ 2022 2022 Mar 31 Total receipts (1) 49 000 Mar 31 Total payments (1) 38 870 Drawings (1)OF 7 800 Balance c/d 2 330 49 000 49 000 Apr 1 Balance b/d (1) 2 330 4 2(b) $ Drawings – goods 3 375 100/125 2 700 (1) Drawings – cash 7 800 Total drawings 10 500 (1)OF Accept alternative format 2 Question Answer Marks 2(c) Stalla Statement of Affairs at 31 March 2022 $ $ Non-current assets Fixtures and fittings at book value 10 800 (1) Current assets Inventory 2 150 Other receivables 500 Bank 2 330 4 980 (1) Total assets 15 780 Capital and liabilities Capital (balancing figure) 8 905 (1)OF Non-current liabilities Loan 5 000 (1) Current liabilities Trade payables 1 875 (1) Total capital and liabilities 15 780 5 2(d) $ Closing capital 8 905 (1)OF Drawings 10 500 (1)OF 19 405 Capital introduced (8 000) (1) Profit for the year 11 405 (1)OF Accept alternative format 4 Question Answer Marks 2(e) For Competitors may allow credit terms (1) May increase sales if offer credit terms (1) May improve relationship with customers (1) May ensure cash is received on time if cash discount is offered (1) Max (2) Against She should obtain credit references for new and existing customers (1) Payment is not received at time of sale (1) If customers pay later she could face cash flow \ liquidity problems (1) Risk of irrecoverable debts (1) Max (2) Accept other valid points. Recommendation (1) 5
Q3 · Mosi is a trader
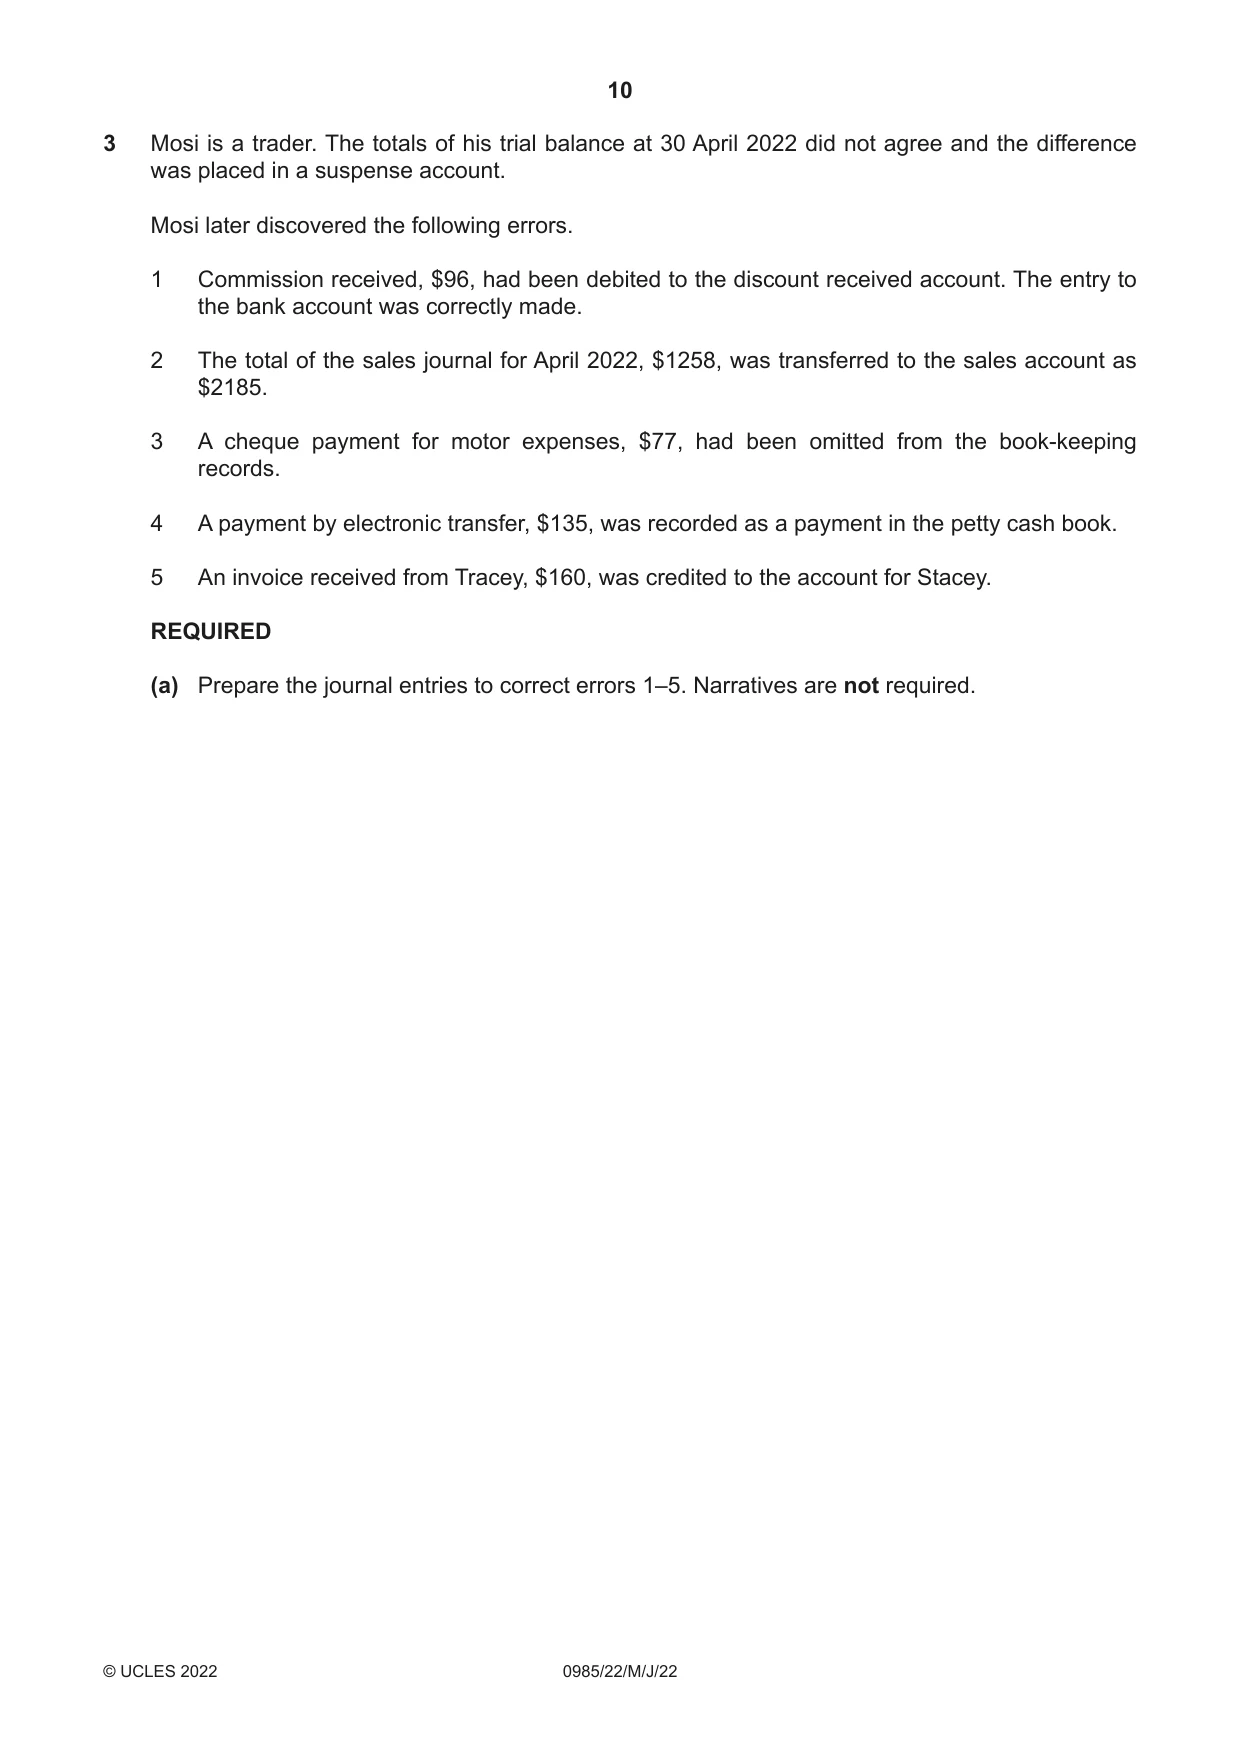
3 Mosi is a trader. The totals of his trial balance at 30 April 2022 did not agree and the difference was placed in a suspense account. Mosi later discovered the following errors. 1 Commission received, $96, had been debited to the discount received account. The entry to the bank account was correctly made. 2 The total of the sales journal for April 2022, $1258, was transferred to the sales account as $2185. 3 A cheque payment for motor expenses, $77, had been omitted from the book-keeping records. 4 A payment by electronic transfer, $135, was recorded as a payment in the petty cash book. 5 An invoice received from Tracey, $160, was credited to the account for Stacey. REQUIRED (a) Prepare the journal entries to correct errors 1–5. Narratives are not required. Mosi Journal Details ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ (b) Prepare the suspense account. Include the original difference on the trial balance as a balancing figure. Mosi Suspense account Date Details $ Date Details $ .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. [4] Mosi’s original draft profit, before correcting the errors, was $39 970. REQUIRED (c) Calculate Mosi’s corrected profit for the year ended 30 April 2022. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
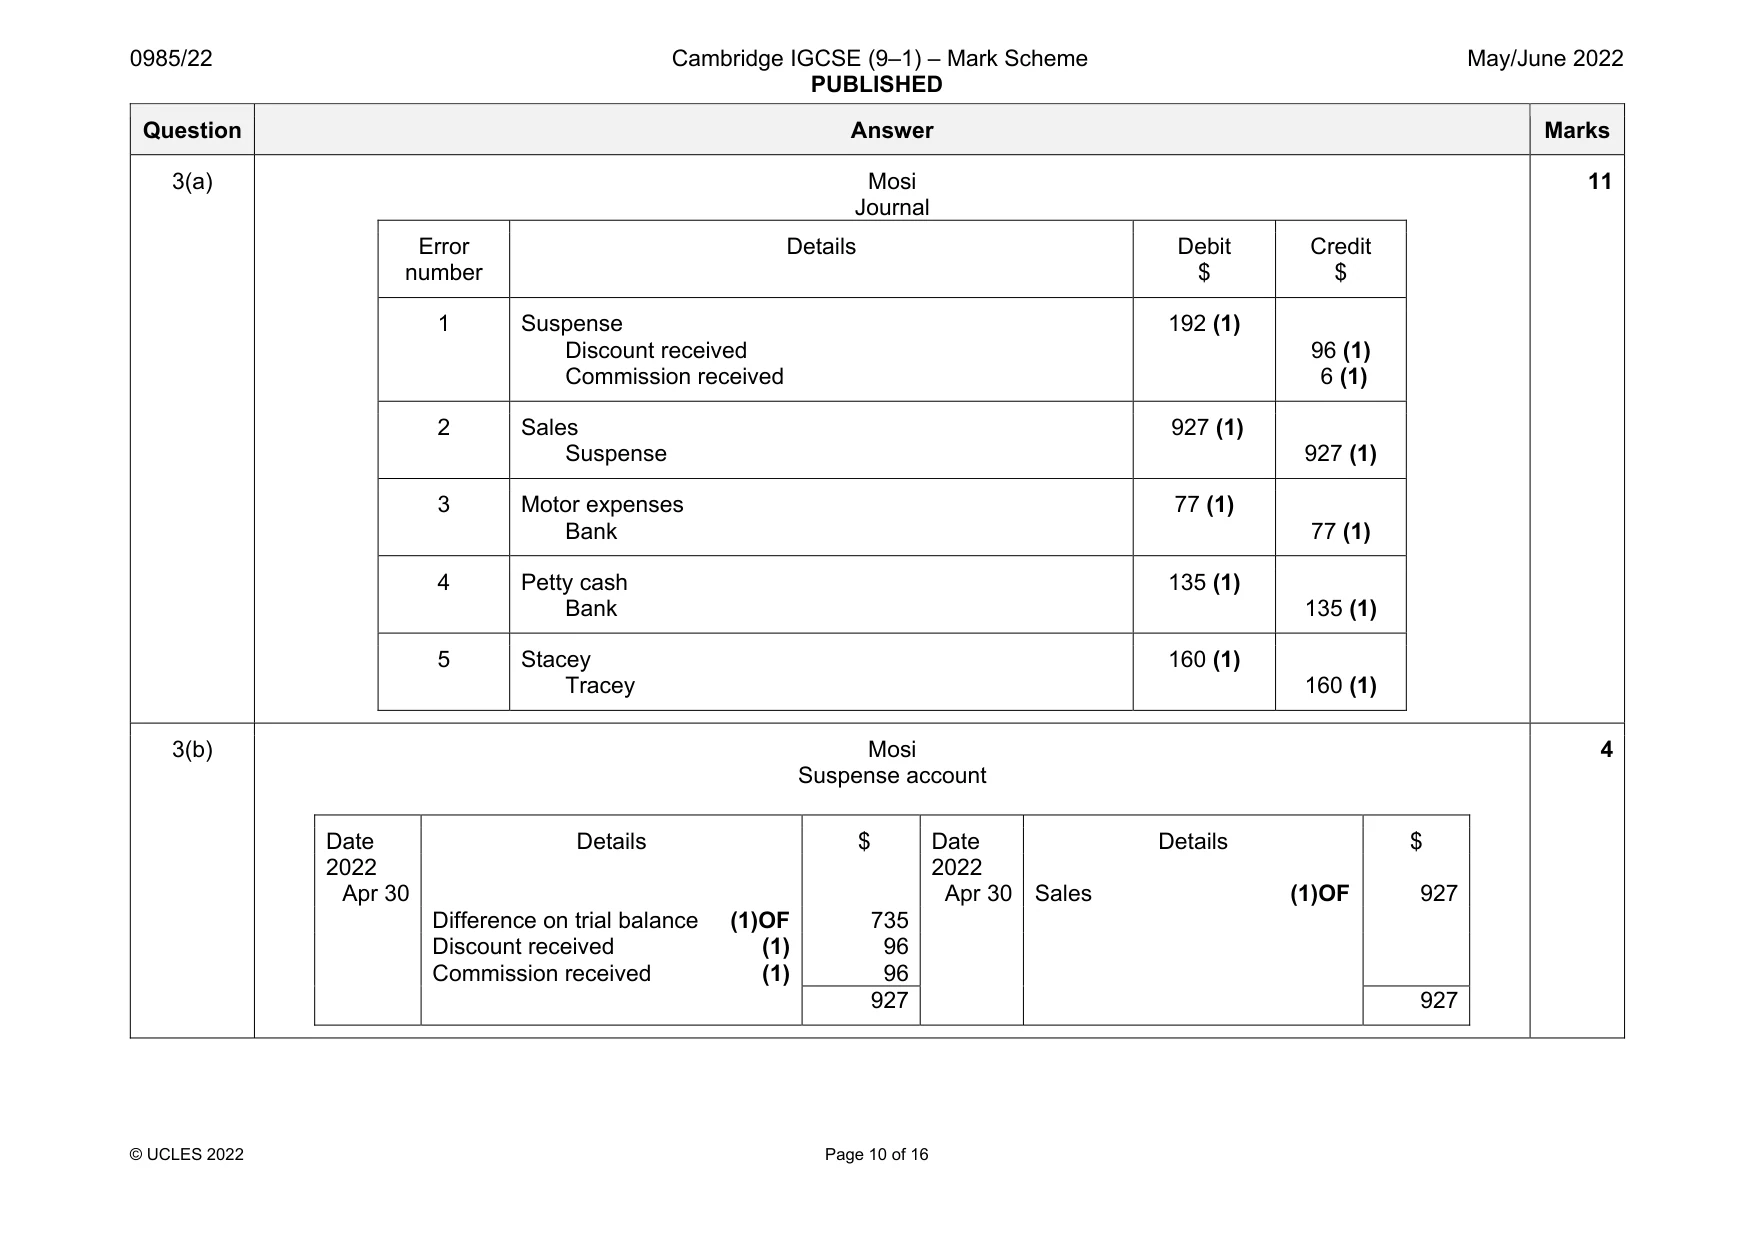
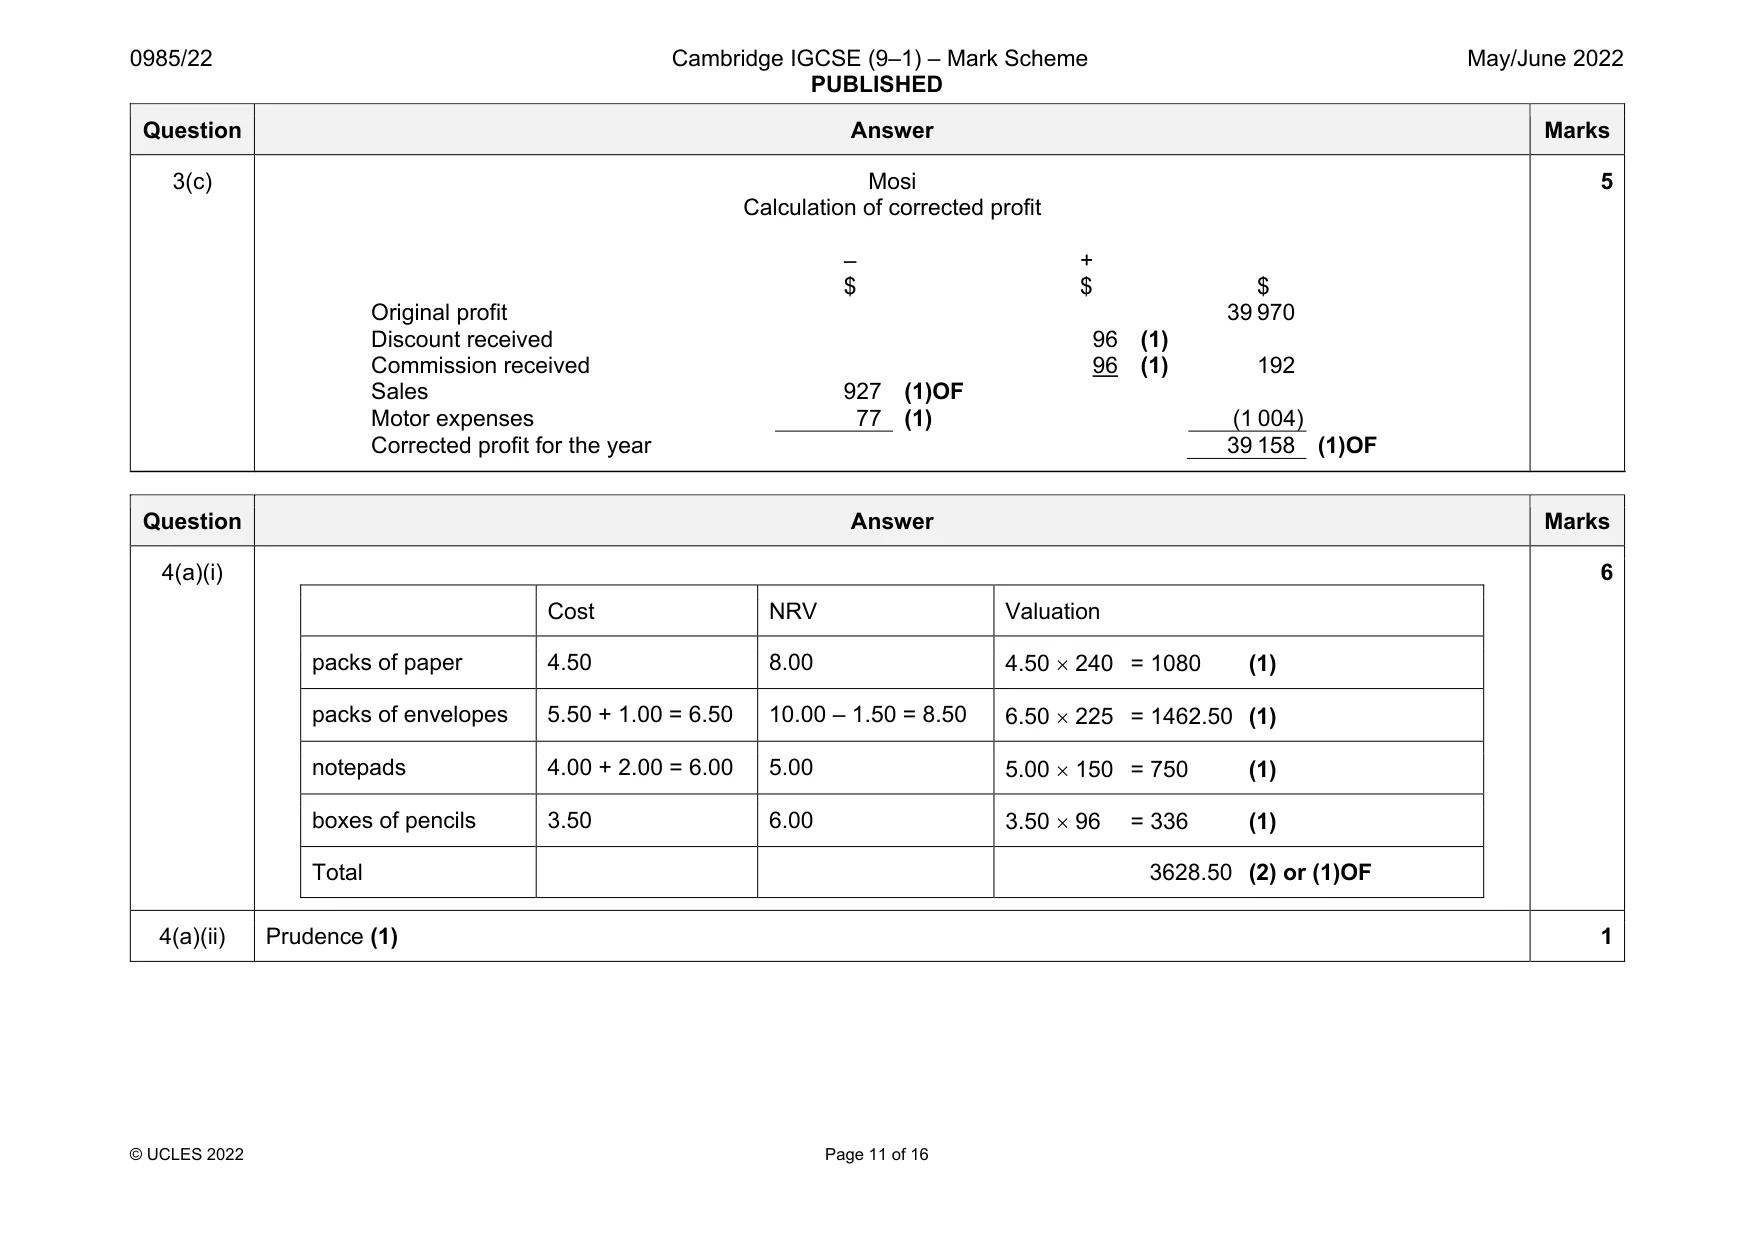
Mark scheme: 3(a) Mosi Journal Error number Details Debit $ Credit $ 1 Suspense Discount received Commission received 192 (1) 96 (1) 6 (1) 2 Sales Suspense 927 (1) 927 (1) 3 Motor expenses Bank 77 (1) 77 (1) 4 Petty cash Bank 135 (1) 135 (1) 5 Stacey Tracey 160 (1) 160 (1) 11 3(b) Mosi Suspense account Date Details $ Date Details $ 2022 2022 Apr 30 Apr 30 Sales (1)OF 927 Difference on trial balance (1)OF 735 Discount received (1) 96 Commission received (1) 96 927 927 4 Question Answer Marks 3(c) Mosi Calculation of corrected profit – $ + $ $ Original profit 39 970 Discount received 96 (1) Commission received 96 (1) 192 Sales 927 (1)OF Motor expenses 77 (1) (1 004) Corrected profit for the year 39 158 (1)OF 5
Q4 · Nala is a trader who buys and sells stationery
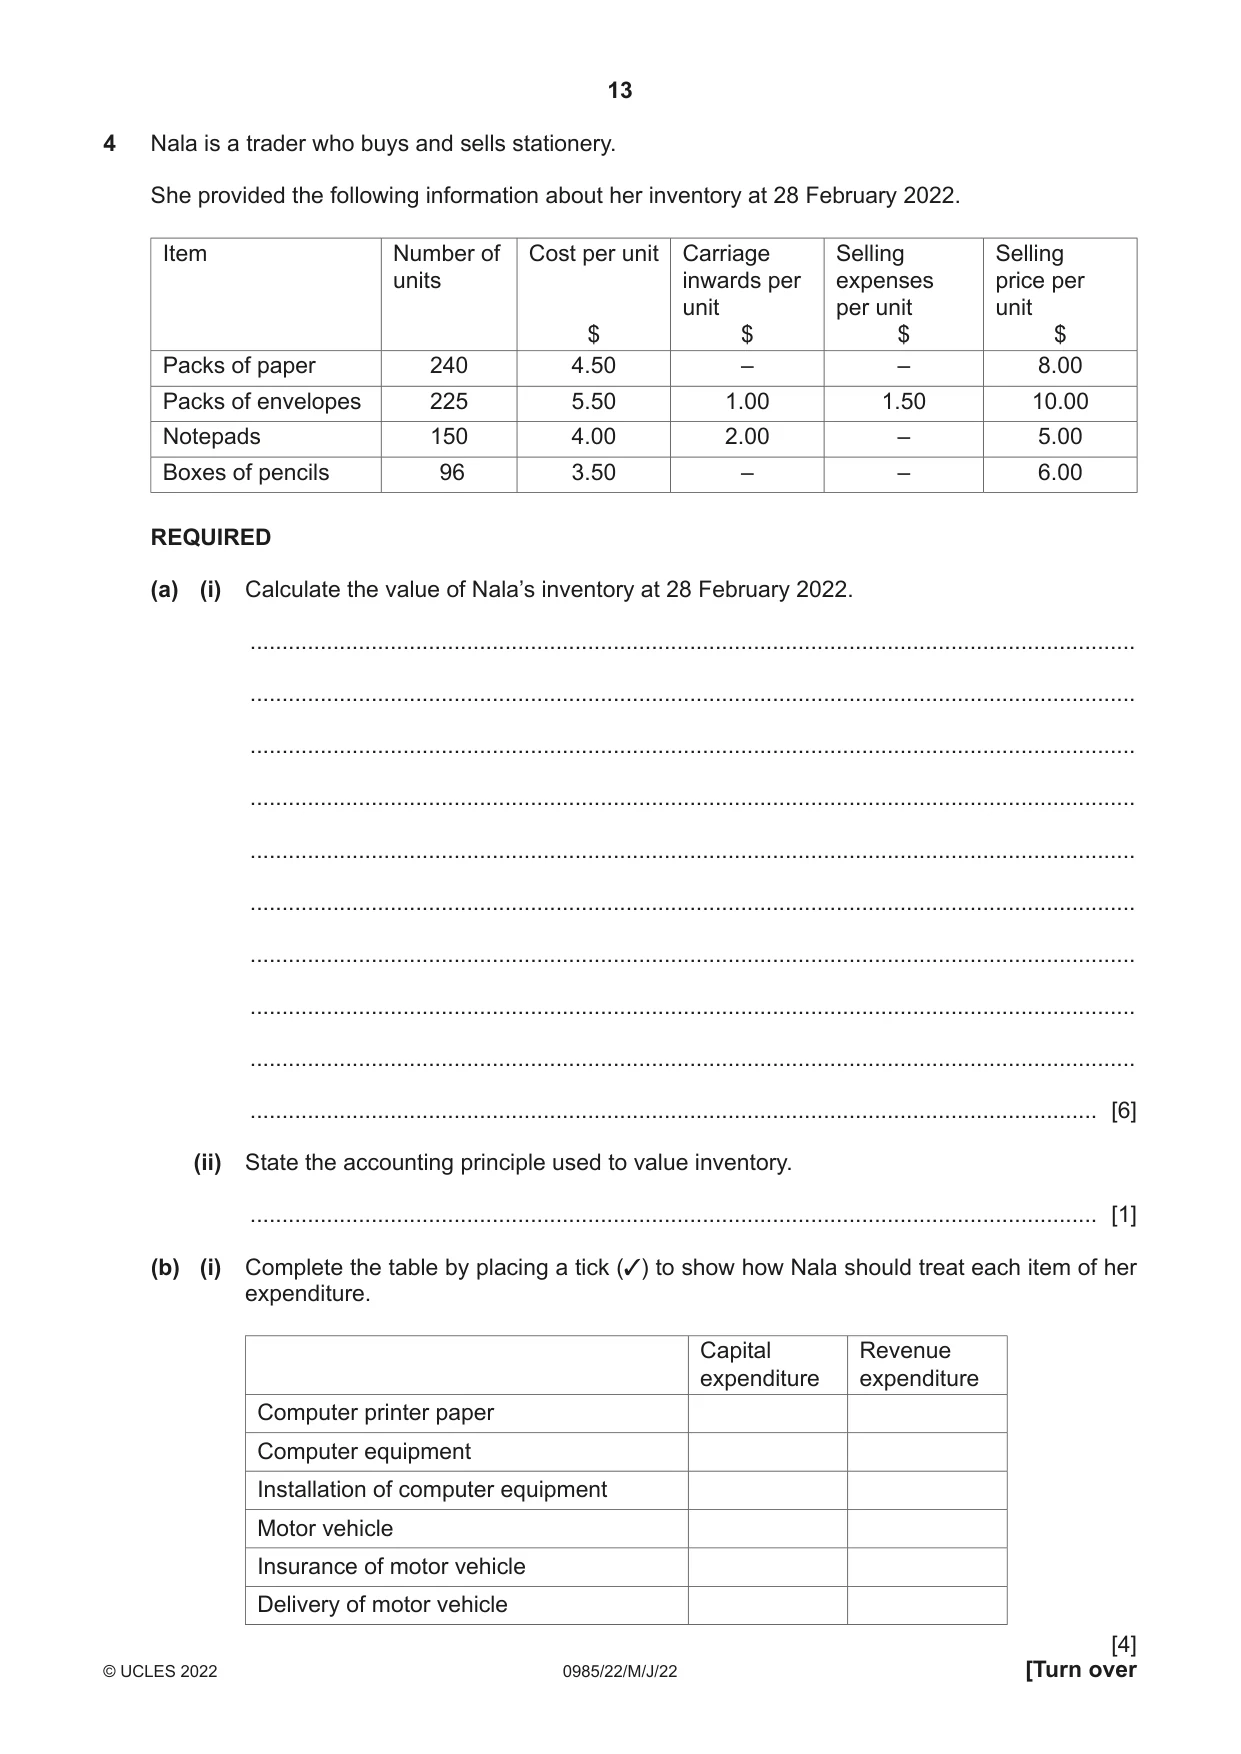
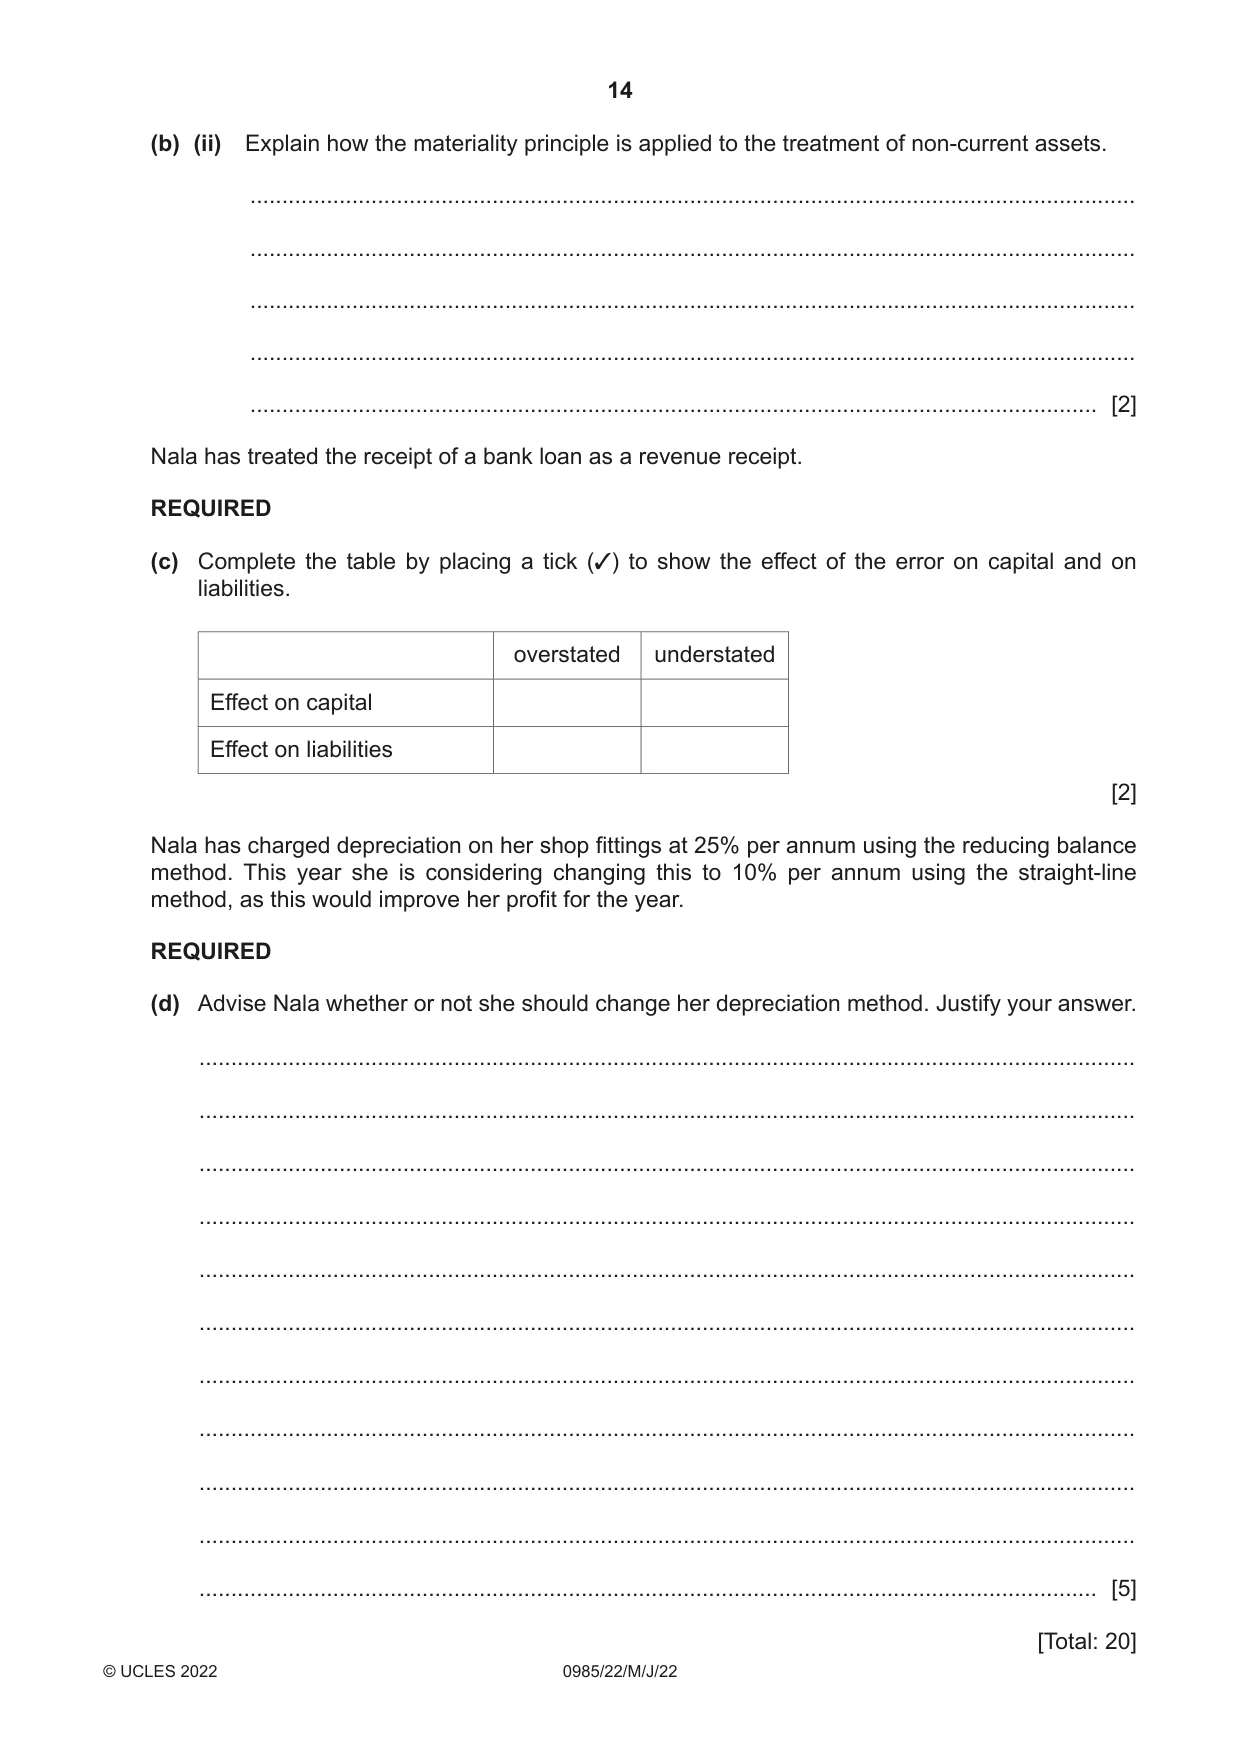
4 Nala is a trader who buys and sells stationery. She provided the following information about her inventory at 28 February 2022. Item Number of Cost per unit Carriage Selling Selling units inwards per expenses price per unit per unit unit $ $ $ $ Packs of paper 240 4.50 – – 8.00 Packs of envelopes 225 5.50 1.00 1.50 10.00 Notepads 150 4.00 2.00 – 5.00 Boxes of pencils 96 3.50 – – 6.00 REQUIRED (a) (i) Calculate the value of Nala’s inventory at 28 February 2022. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [6] (ii) State the accounting principle used to value inventory. ..................................................................................................................................... [1] (b) (i) Complete the table by placing a tick (✓) to show how Nala should treat each item of her expenditure. Capital Revenue expenditure expenditure Computer printer paper Computer equipment Installation of computer equipment Motor vehicle Insurance of motor vehicle Delivery of motor vehicle (b) (ii) Explain how the materiality principle is applied to the treatment of non-current assets. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] Nala has treated the receipt of a bank loan as a revenue receipt. REQUIRED (c) Complete the table by placing a tick (✓) to show the effect of the error on capital and on liabilities. overstated understated Effect on capital Effect on liabilities [2] Nala has charged depreciation on her shop fittings at 25% per annum using the reducing balance method. This year she is considering changing this to 10% per annum using the straight-line method, as this would improve her profit for the year. REQUIRED (d) Advise Nala whether or not she should change her depreciation method. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
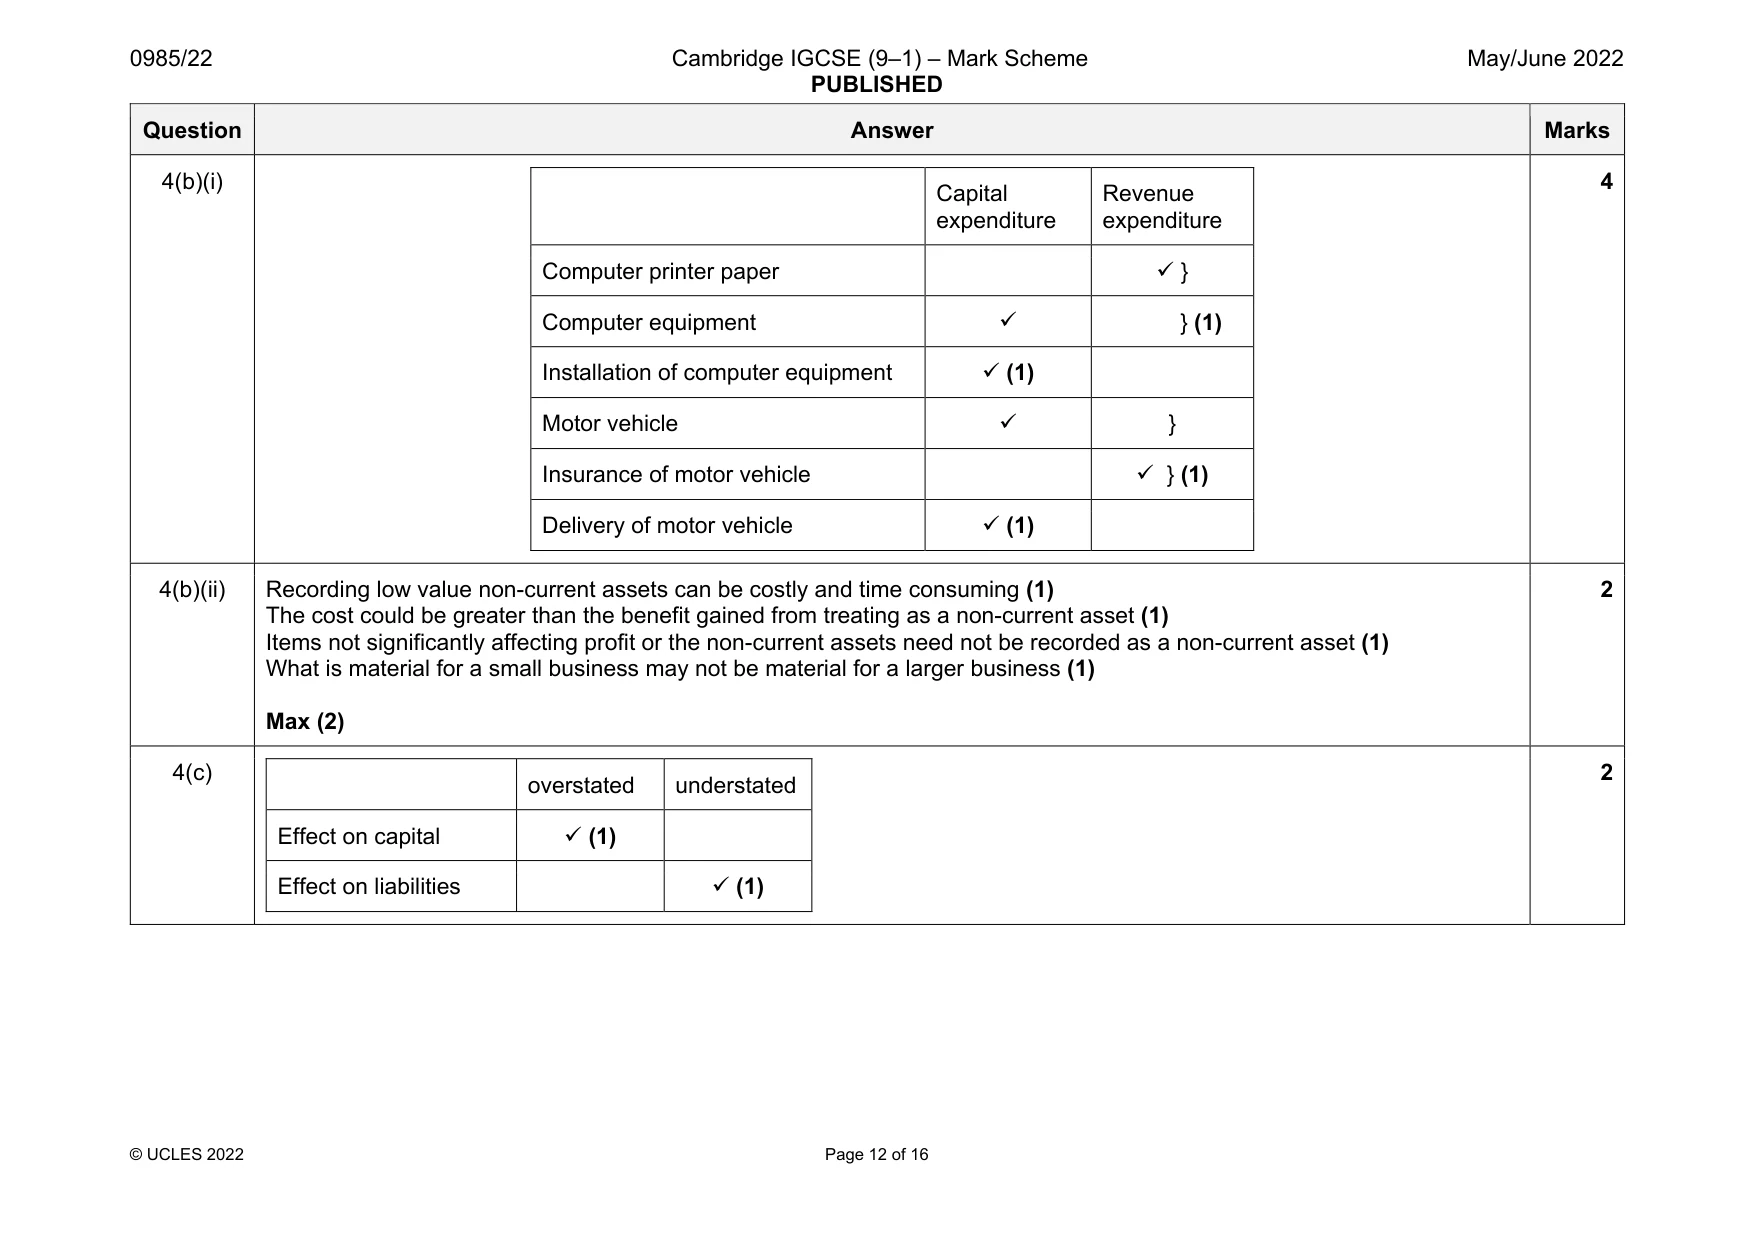
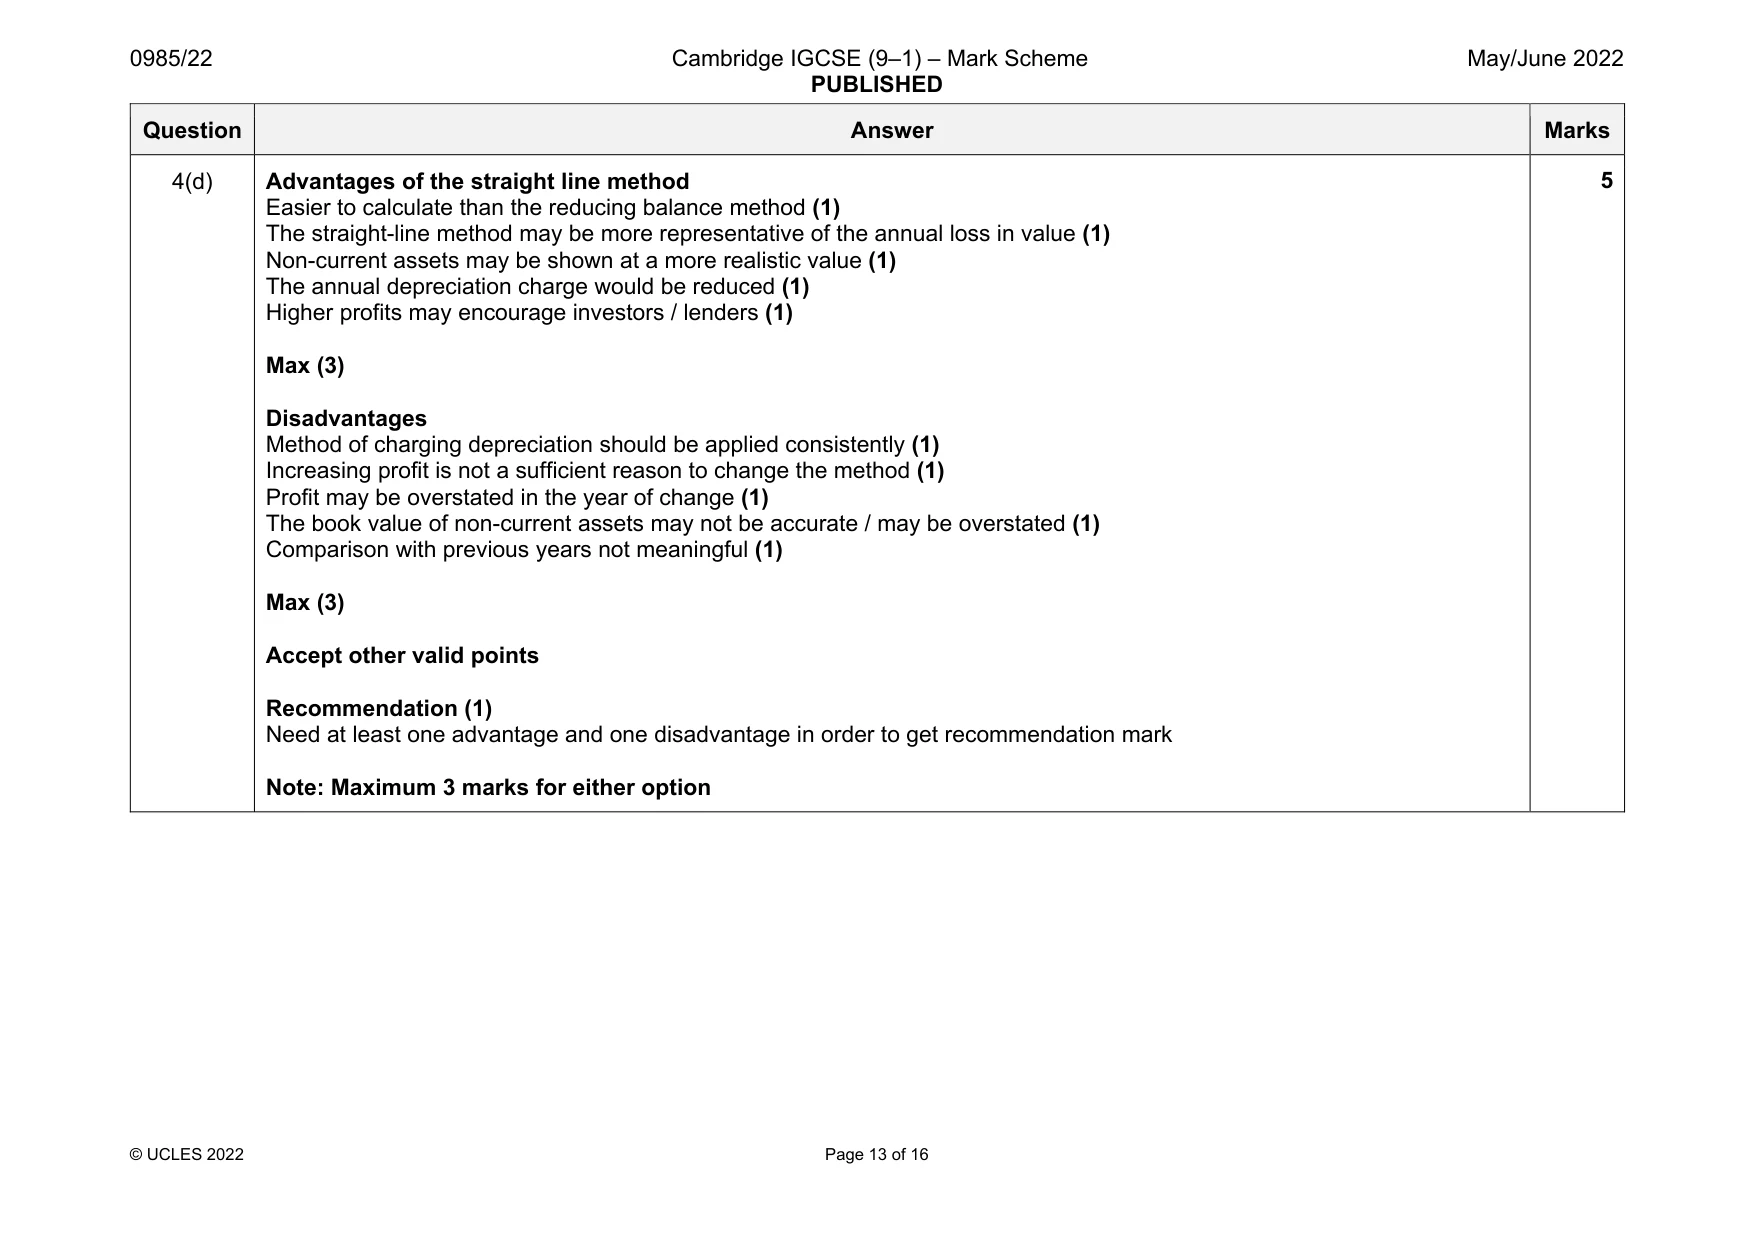
Mark scheme: 4(a)(i) Cost NRV Valuation packs of paper 4.50 8.00 4.50 240 = 1080 (1) packs of envelopes 5.50 + 1.00 = 6.50 10.00 – 1.50 = 8.50 6.50 225 = 1462.50 (1) notepads 4.00 + 2.00 = 6.00 5.00 5.00 150 = 750 (1) boxes of pencils 3.50 6.00 3.50 96 = 336 (1) Total 3628.50 (2) or (1)OF 6 4(a)(ii) Prudence (1) 1 Question Answer Marks 4(b)(i) Capital expenditure Revenue expenditure Computer printer paper } Computer equipment } (1) Installation of computer equipment (1) Motor vehicle } Insurance of motor vehicle } (1) Delivery of motor vehicle (1) 4 4(b)(ii) Recording low value non-current assets can be costly and time consuming (1) The cost could be greater than the benefit gained from treating as a non-current asset (1) Items not significantly affecting profit or the non-current assets need not be recorded as a non-current asset (1) What is material for a small business may not be material for a larger business (1) Max (2) 2 4(c) overstated understated Effect on capital (1) Effect on liabilities (1) 2 Question Answer Marks 4(d) Advantages of the straight line method Easier to calculate than the reducing balance method (1) The straight-line method may be more representative of the annual loss in value (1) Non-current assets may be shown at a more realistic value (1) The annual depreciation charge would be reduced (1) Higher profits may encourage investors / lenders (1) Max (3) Disadvantages Method of charging depreciation should be applied consistently (1) Increasing profit is not a sufficient reason to change the method (1) Profit may be overstated in the year of change (1) The book value of non-current assets may not be accurate / may be overstated (1) Comparison with previous years not meaningful (1) Max (3) Accept other valid points Recommendation (1) Need at least one advantage and one disadvantage in order to get recommendation mark Note: Maximum 3 marks for either option 5
Q5 · The trial balance of M Limited at 30 November 2021 was as follows
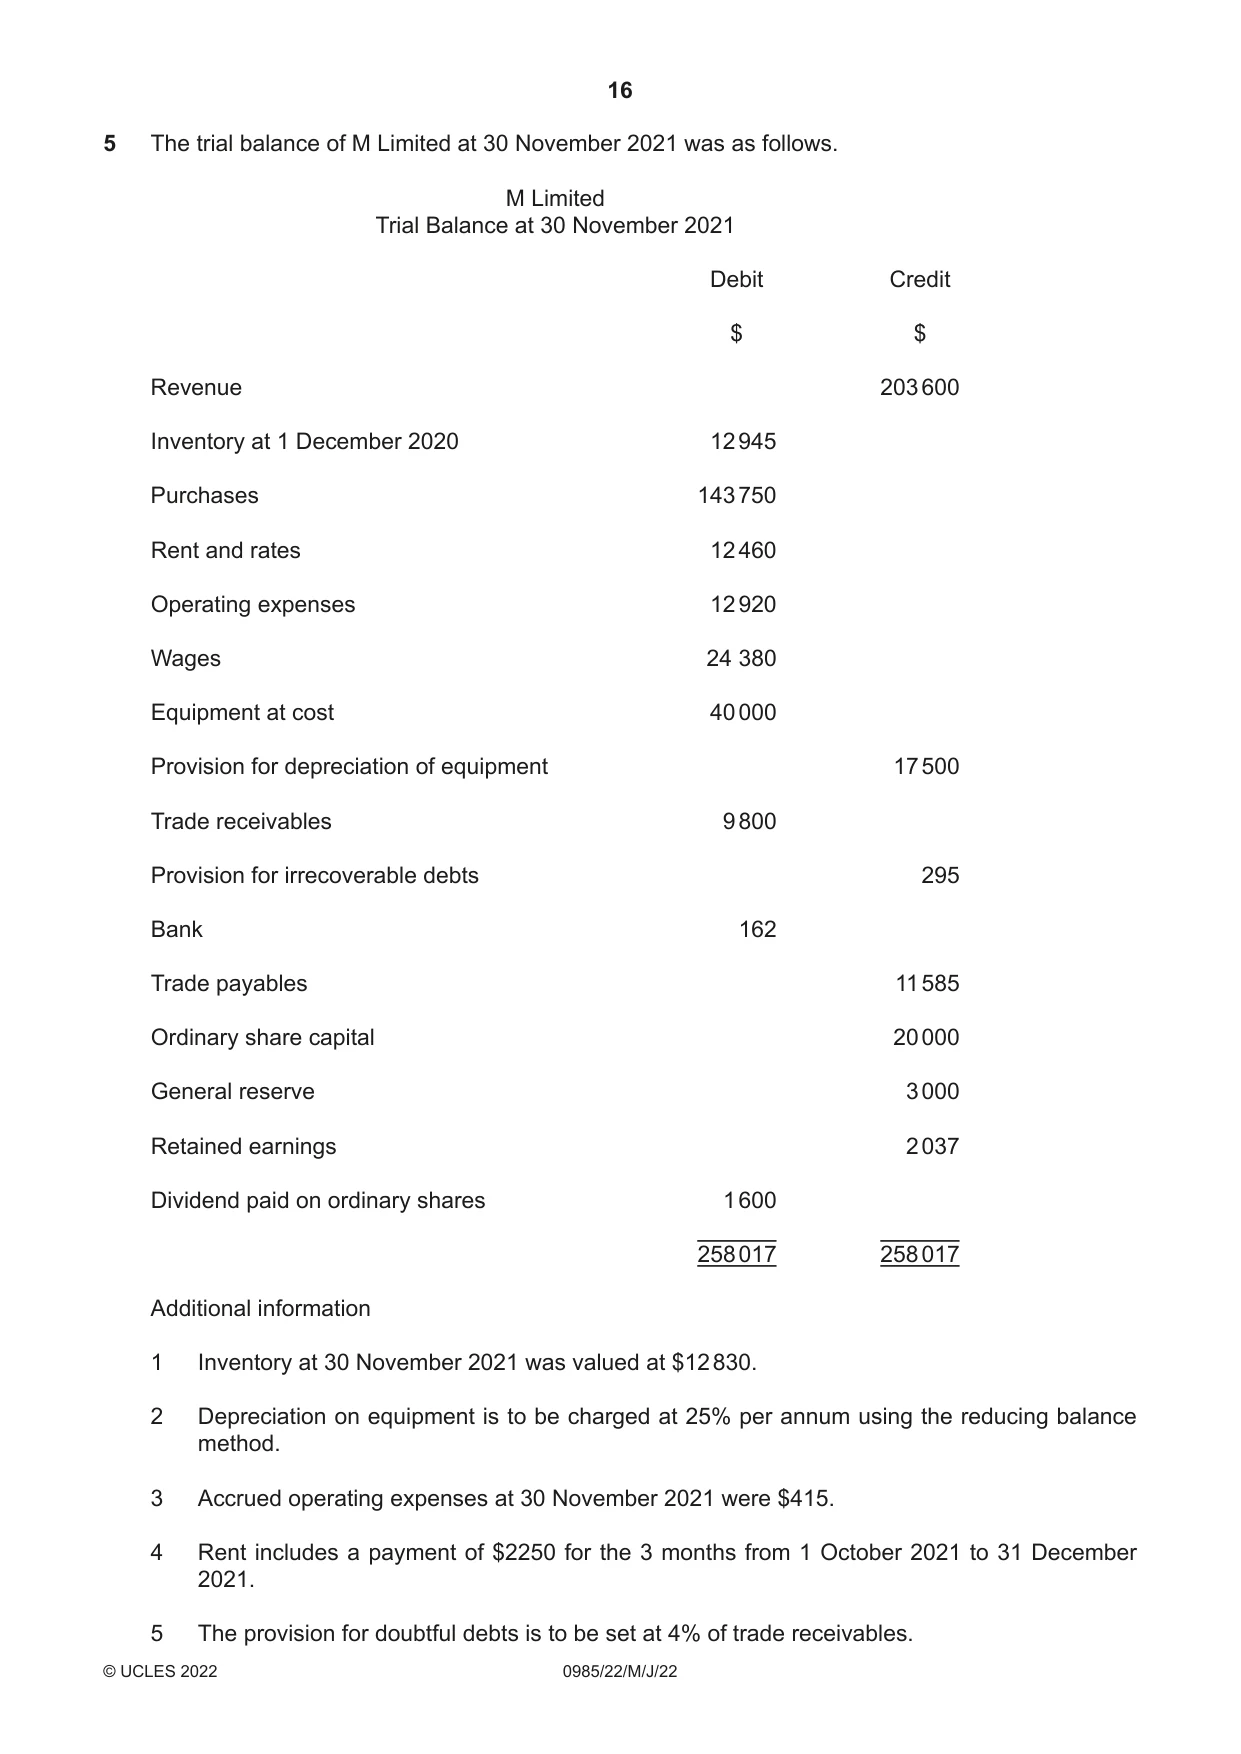
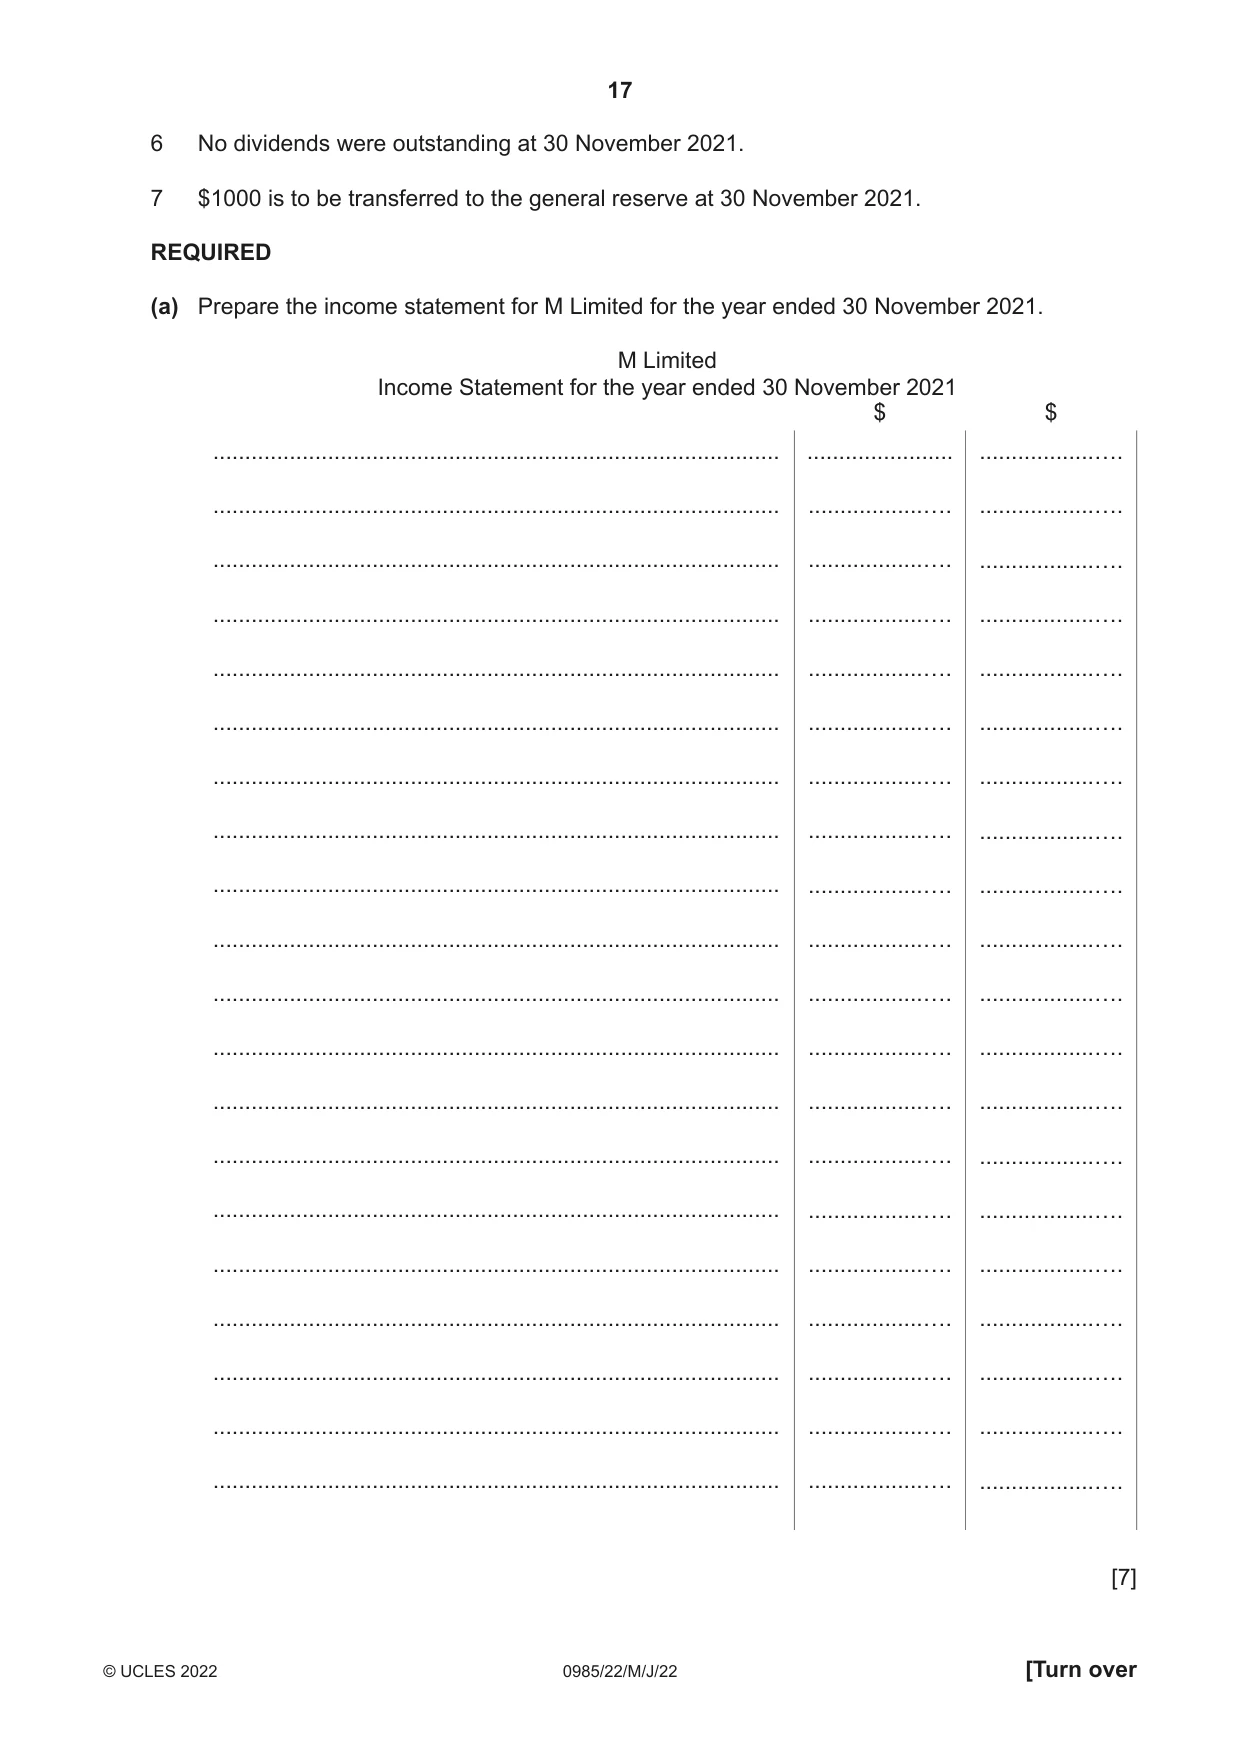
5 The trial balance of M Limited at 30 November 2021 was as follows. M Limited Trial Balance at 30 November 2021 Debit Credit $ $ Revenue 203 600 Inventory at 1 December 2020 12 945 Purchases 143 750 Rent and rates 12 460 Operating expenses 12 920 Wages 24 380 Equipment at cost 40 000 Provision for depreciation of equipment 17 500 Trade receivables 9 800 Provision for irrecoverable debts 295 Bank 162 Trade payables 11 585 Ordinary share capital 20 000 General reserve 3 000 Retained earnings 2 037 Dividend paid on ordinary shares 1 600 258 017 258 017 Additional information 1 Inventory at 30 November 2021 was valued at $12 830. 2 Depreciation on equipment is to be charged at 25% per annum using the reducing balance method. 3 Accrued operating expenses at 30 November 2021 were $415. 4 Rent includes a payment of $2250 for the 3 months from 1 October 2021 to 31 December 2021. 5 The provision for doubtful debts is to be set at 4% of trade receivables.
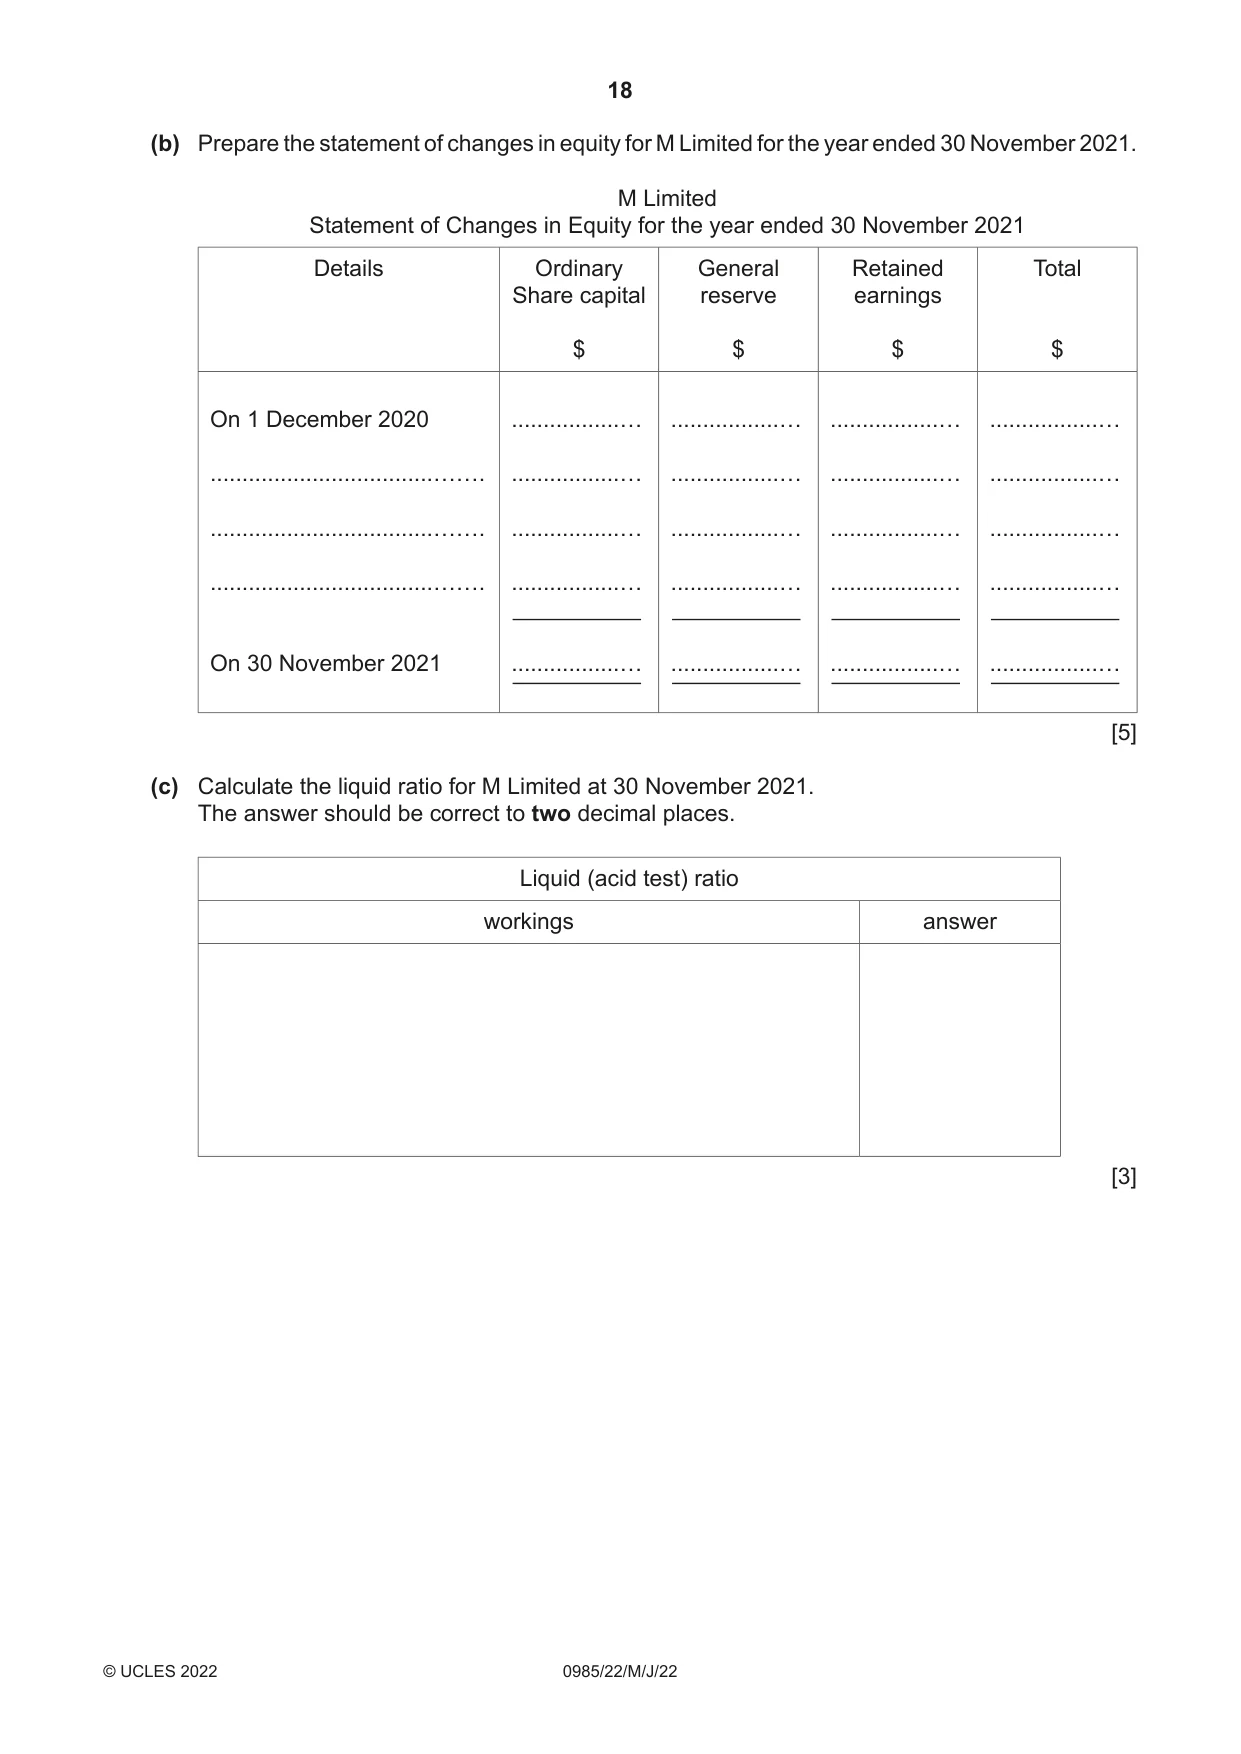
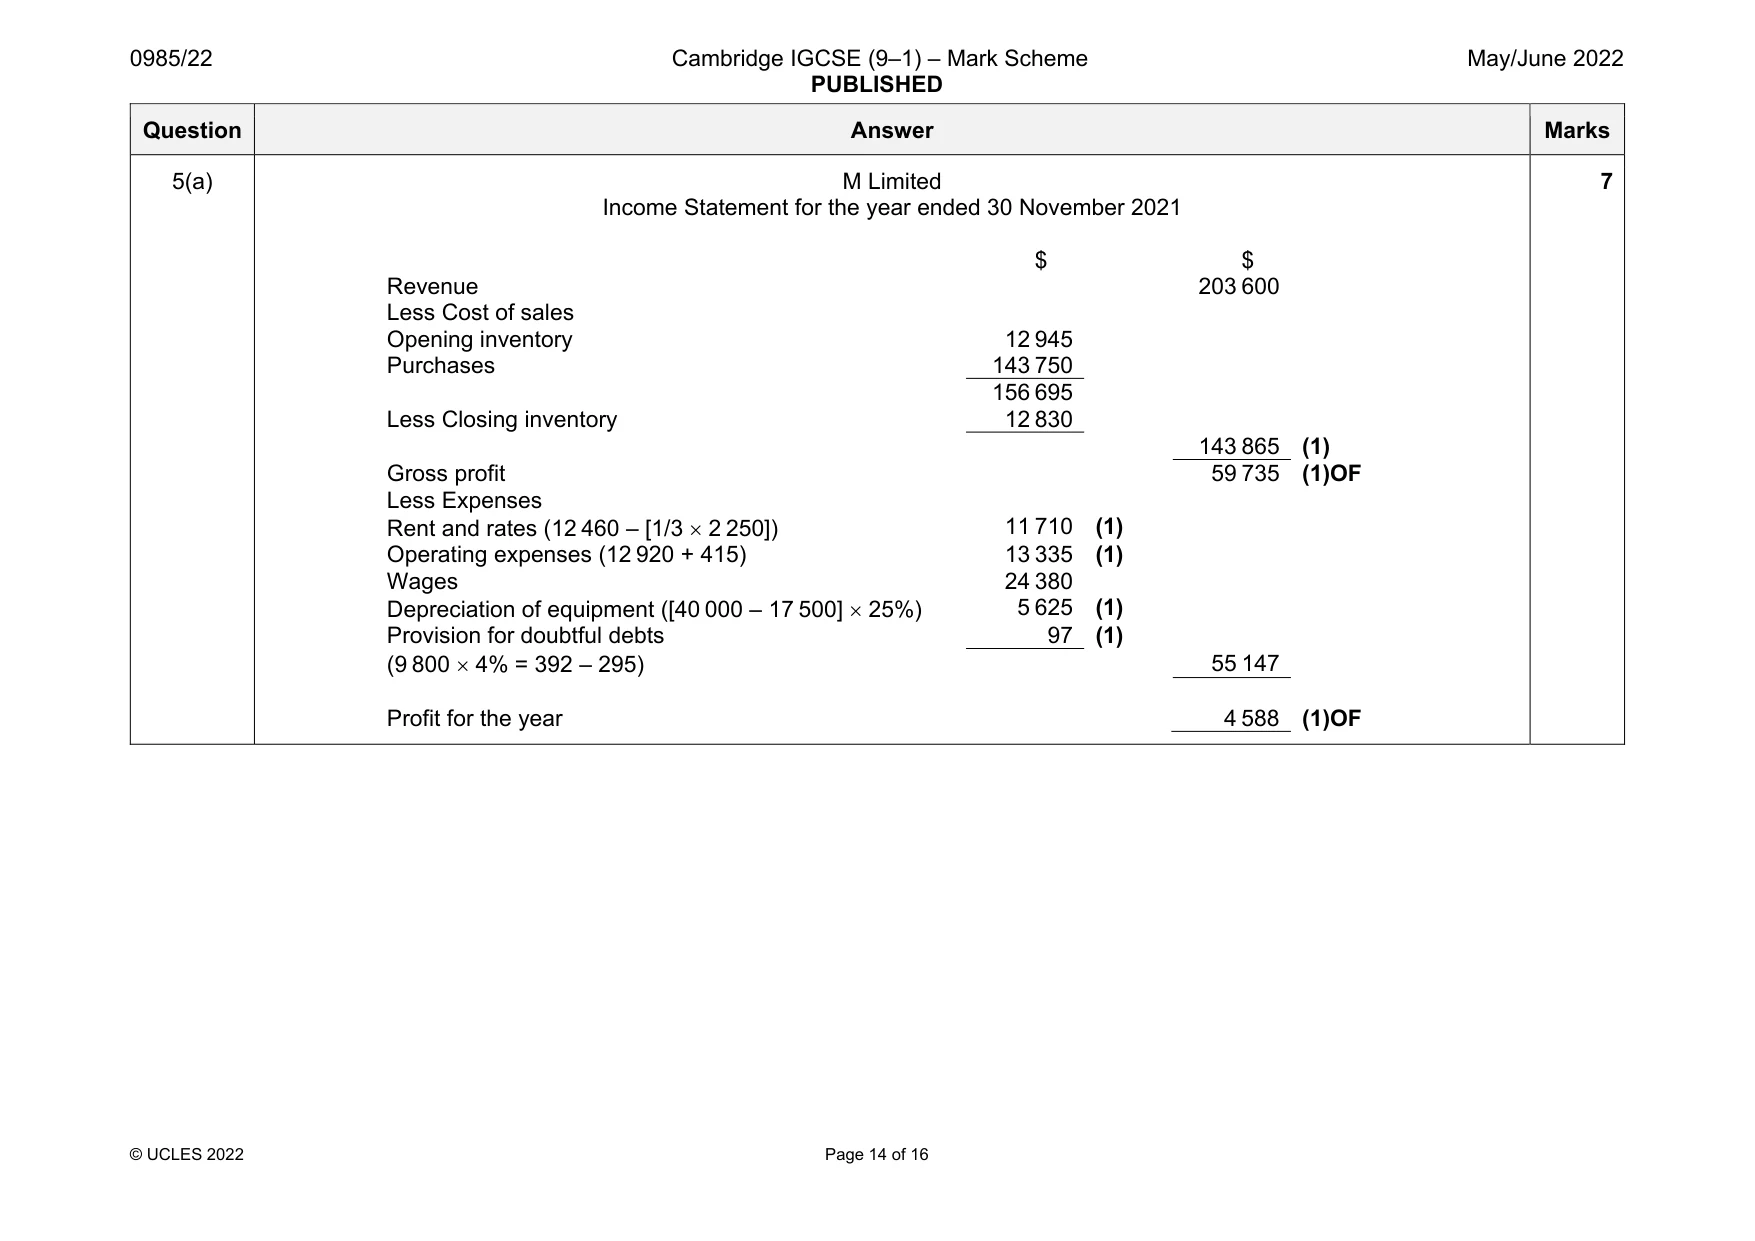
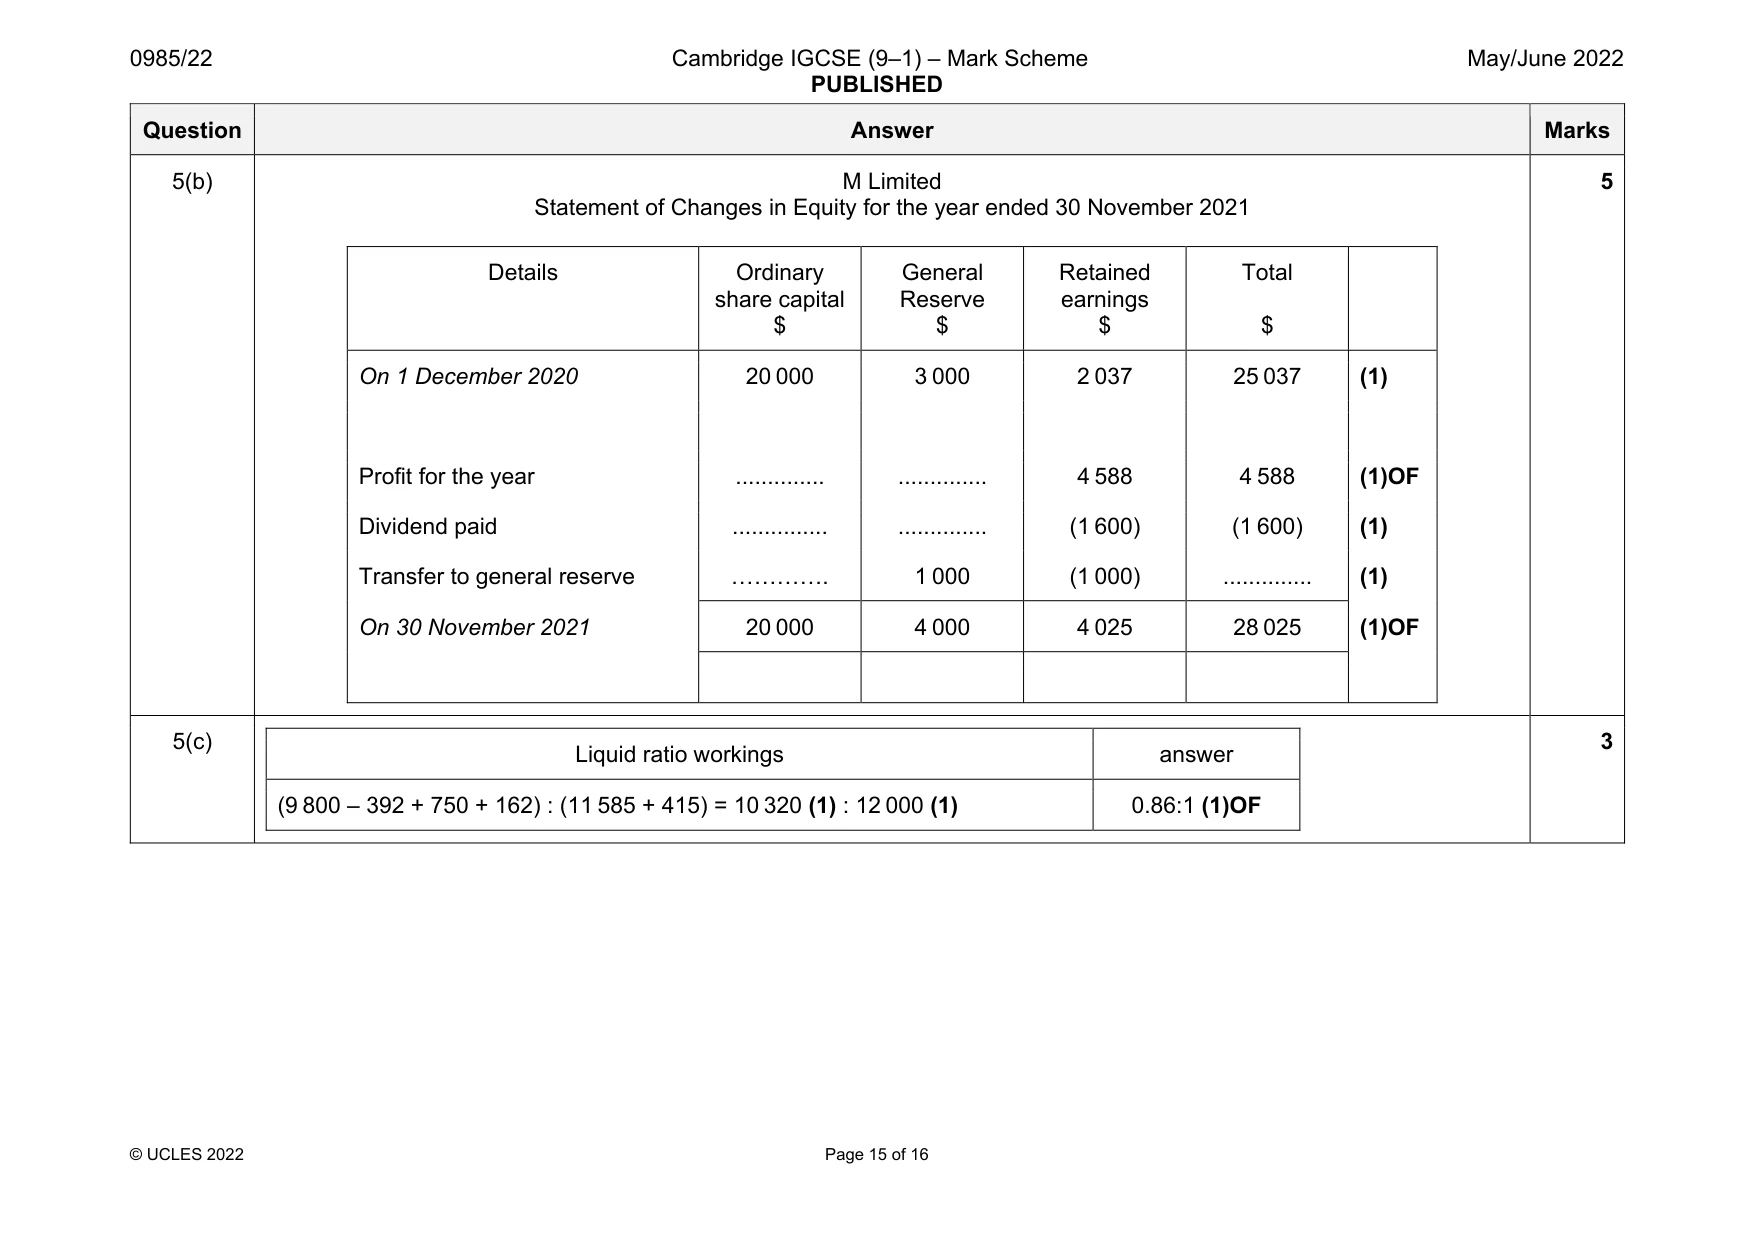
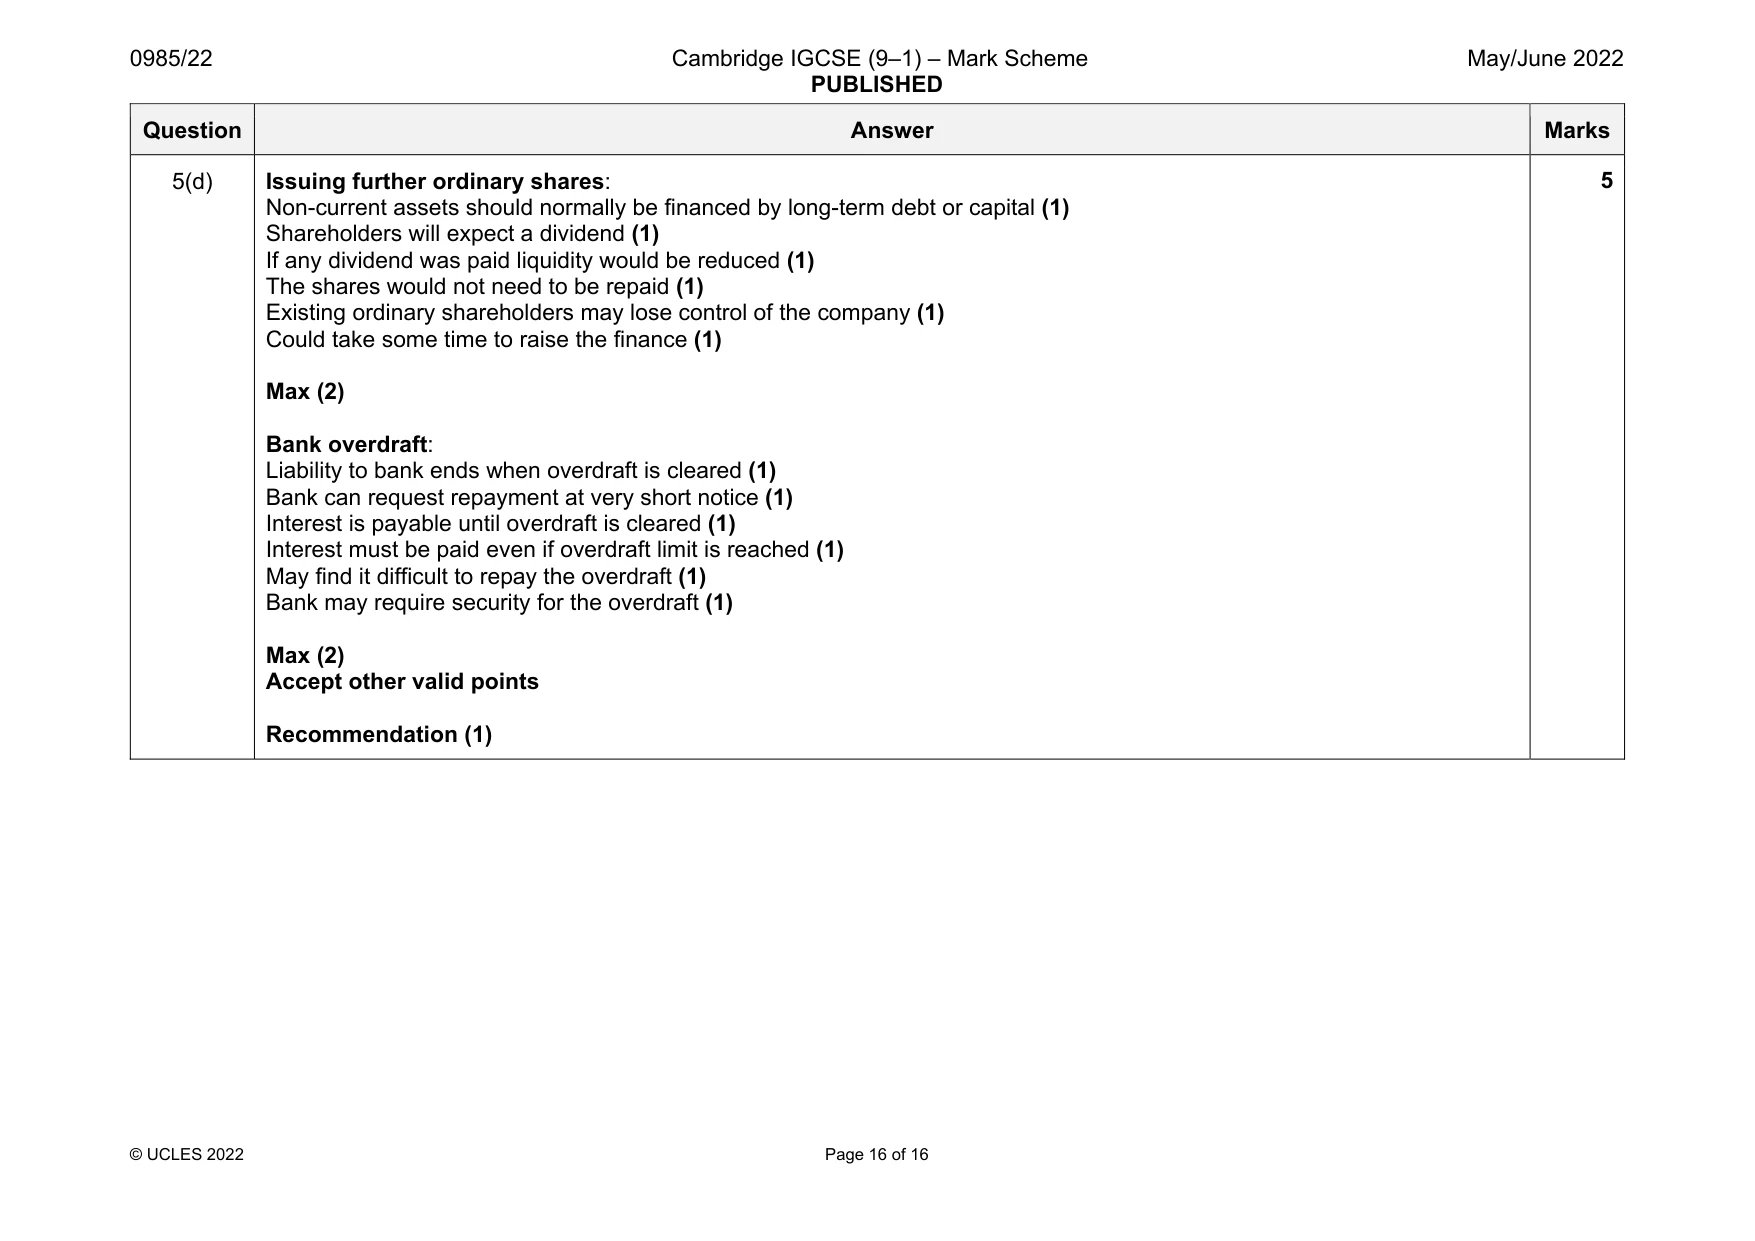
Mark scheme: 5(a) M Limited Income Statement for the year ended 30 November 2021 $ $ Revenue 203 600 Less Cost of sales Opening inventory 12 945 Purchases 143 750 156 695 Less Closing inventory 12 830 143 865 (1) Gross profit 59 735 (1)OF Less Expenses Rent and rates (12 460 – [1/3 2 250]) 11 710 (1) Operating expenses (12 920 + 415) 13 335 (1) Wages 24 380 Depreciation of equipment ([40 000 – 17 500] 25%) 5 625 (1) Provision for doubtful debts 97 (1) (9 800 4% = 392 – 295) 55 147 Profit for the year 4 588 (1)OF 7 Question Answer Marks 5(b) M Limited Statement of Changes in Equity for the year ended 30 November 2021 Details Ordinary share capital $ General Reserve $ Retained earnings $ Total $ On 1 December 2020 20 000 3 000 2 037 25 037 (1) Profit for the year .............. .............. 4 588 4 588 (1)OF Dividend paid ............... .............. (1 600) (1 600) (1) Transfer to general reserve …………. 1 000 (1 000) .............. (1) On 30 November 2021 20 000 4 000 4 025 28 025 (1)OF 5 5(c) Liquid ratio workings answer (9 800 – 392 + 750 + 162) : (11 585 + 415) = 10 320 (1) : 12 000 (1) 0.86:1 (1)OF 3 Question Answer Marks 5(d) Issuing further ordinary shares: Non-current assets should normally be financed by long-term debt or capital (1) Shareholders will expect a dividend (1) If any dividend was paid liquidity would be reduced (1) The shares would not need to be repaid (1) Existing ordinary shareholders may lose control of the company (1) Could take some time to raise the finance (1) Max (2) Bank overdraft: Liability to bank ends when overdraft is cleared (1) Bank can request repayment at very short notice (1) Interest is payable until overdraft is cleared (1) Interest must be paid even if overdraft limit is reached (1) May find it difficult to repay the overdraft (1) Bank may require security for the overdraft (1) Max (2) Accept other valid points Recommendation (1) 5
Q7 · $1000 is to be transferred to the general reserve at 30 No REQUIRED (a) Prepare the…
7 $1000 is to be transferred to the general reserve at 30 No REQUIRED (a) Prepare the income statement for M Limited for the year e M Limited Income Statement for the year ended 30 ......................................................................................... ......................................................................................... ......................................................................................... ......................................................................................... ......................................................................................... ......................................................................................... ......................................................................................... ......................................................................................... ......................................................................................... ......................................................................................... ......................................................................................... ......................................................................................... ......................................................................................... ......................................................................................... ......................................................................................... ......................................................................................... ......................................................................................... ......................................................................................... ......................................................................................... ......................................................................................... (b) Prepare the statement of changes in equity for M Limited for the year ended 30 November 2021. M Limited Statement of Changes in Equity for the year ended 30 November 2021 Details Ordinary General Retained Total Share capital reserve earnings $ $ $ $ On 1 December 2020 .................… .................… .................… .................… ...................................……. .................… .................… .................… .................… ...................................……. .................… .................… .................… .................… ...................................……. .................… .................… .................… .................… On 30 November 2021 .................… .................… .................… .................… [5] (c) Calculate the liquid ratio for M Limited at 30 November 2021. The answer should be correct to two decimal places. Liquid (acid test) ratio workings answer [3] The managing director, Emily, plans to buy new equipment to be used to improve the profitability of the company. She is considering whether to fund the equipment by issuing further ordinary shares or requesting a bank overdraft. REQUIRED (d) Advise Emily whether to fund the purchase of the equipment by issuing further ordinary shares or by requesting a bank overdraft. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
What was in this paper
The subtopics covered by these 6 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2022 May/June, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.