Cambridge IGCSE Accounting (9-1) 0985 — 2023 May/June Paper 2 · Variant 2
0985/22/M/J/23 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme19 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Omer is a trader
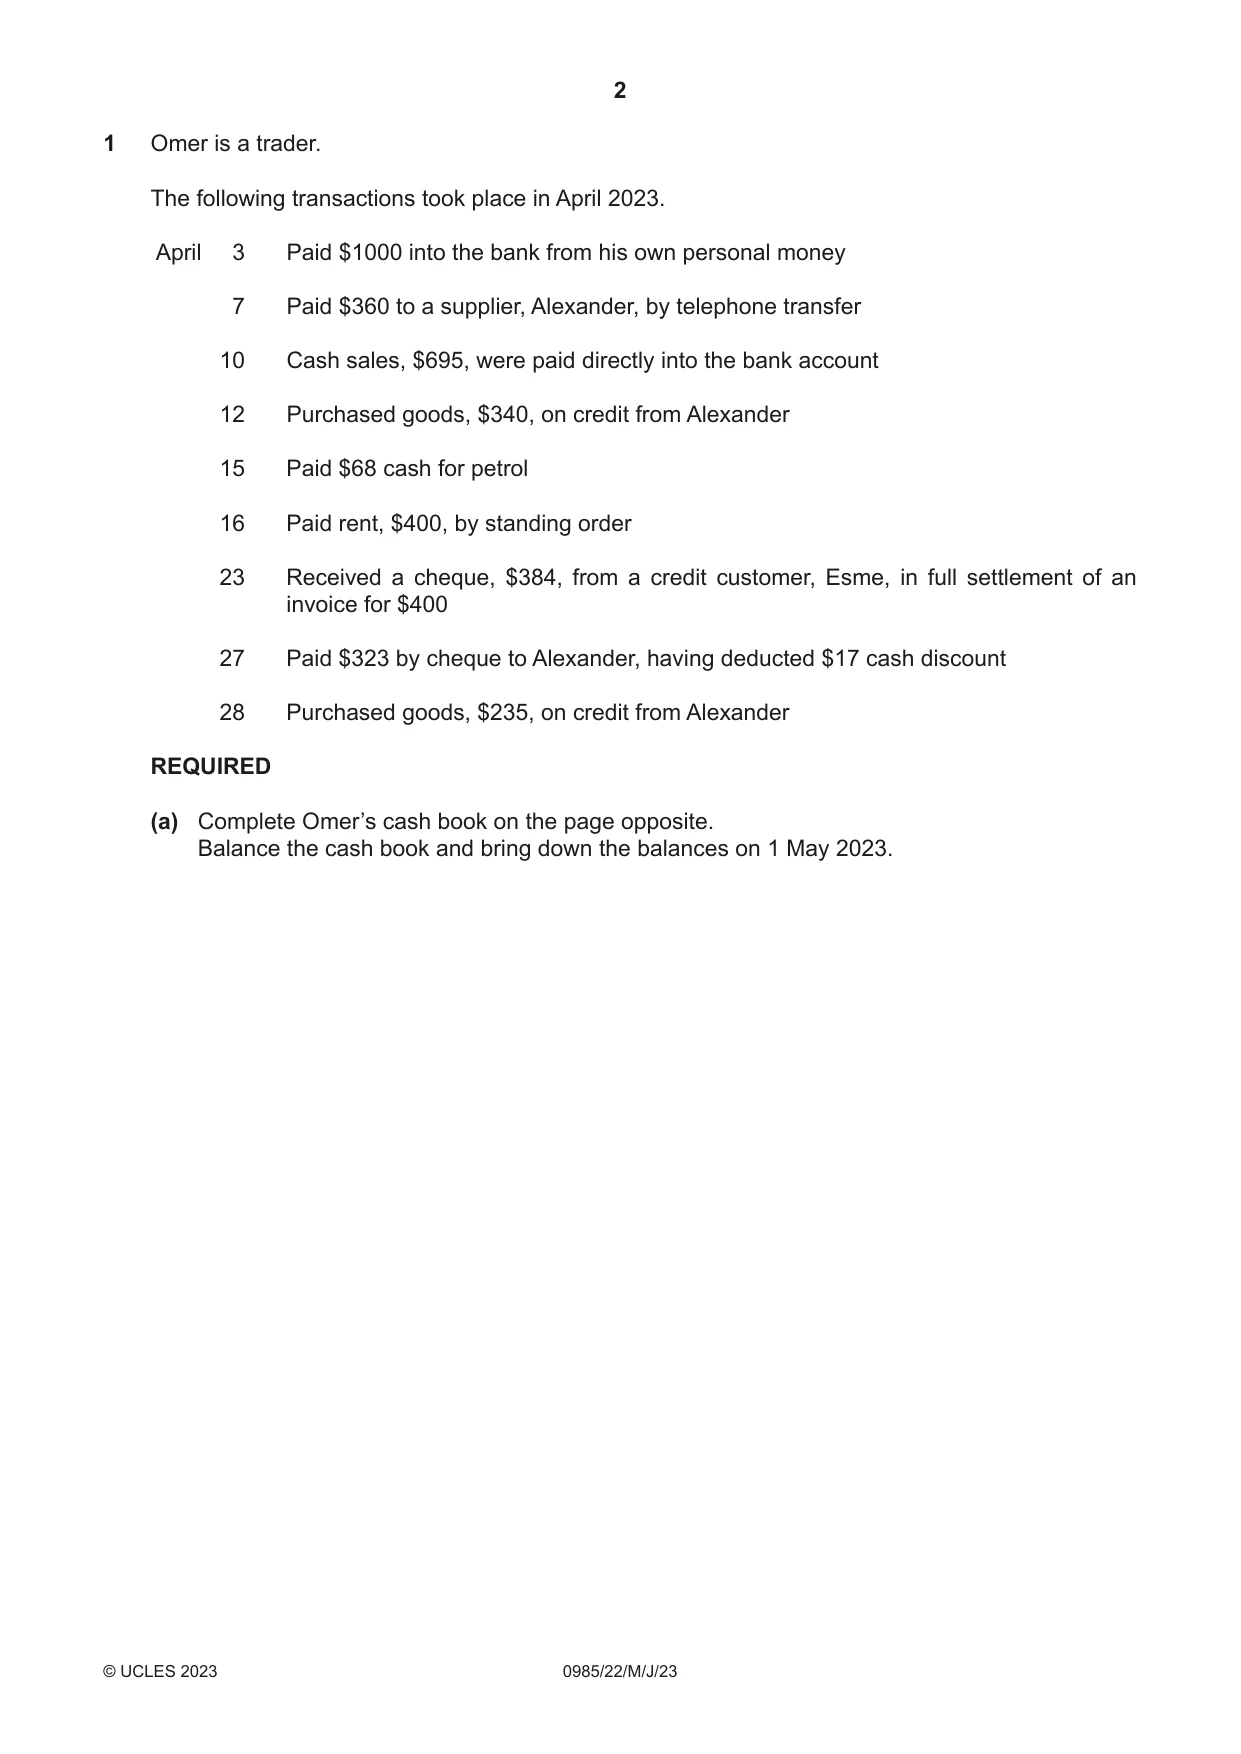
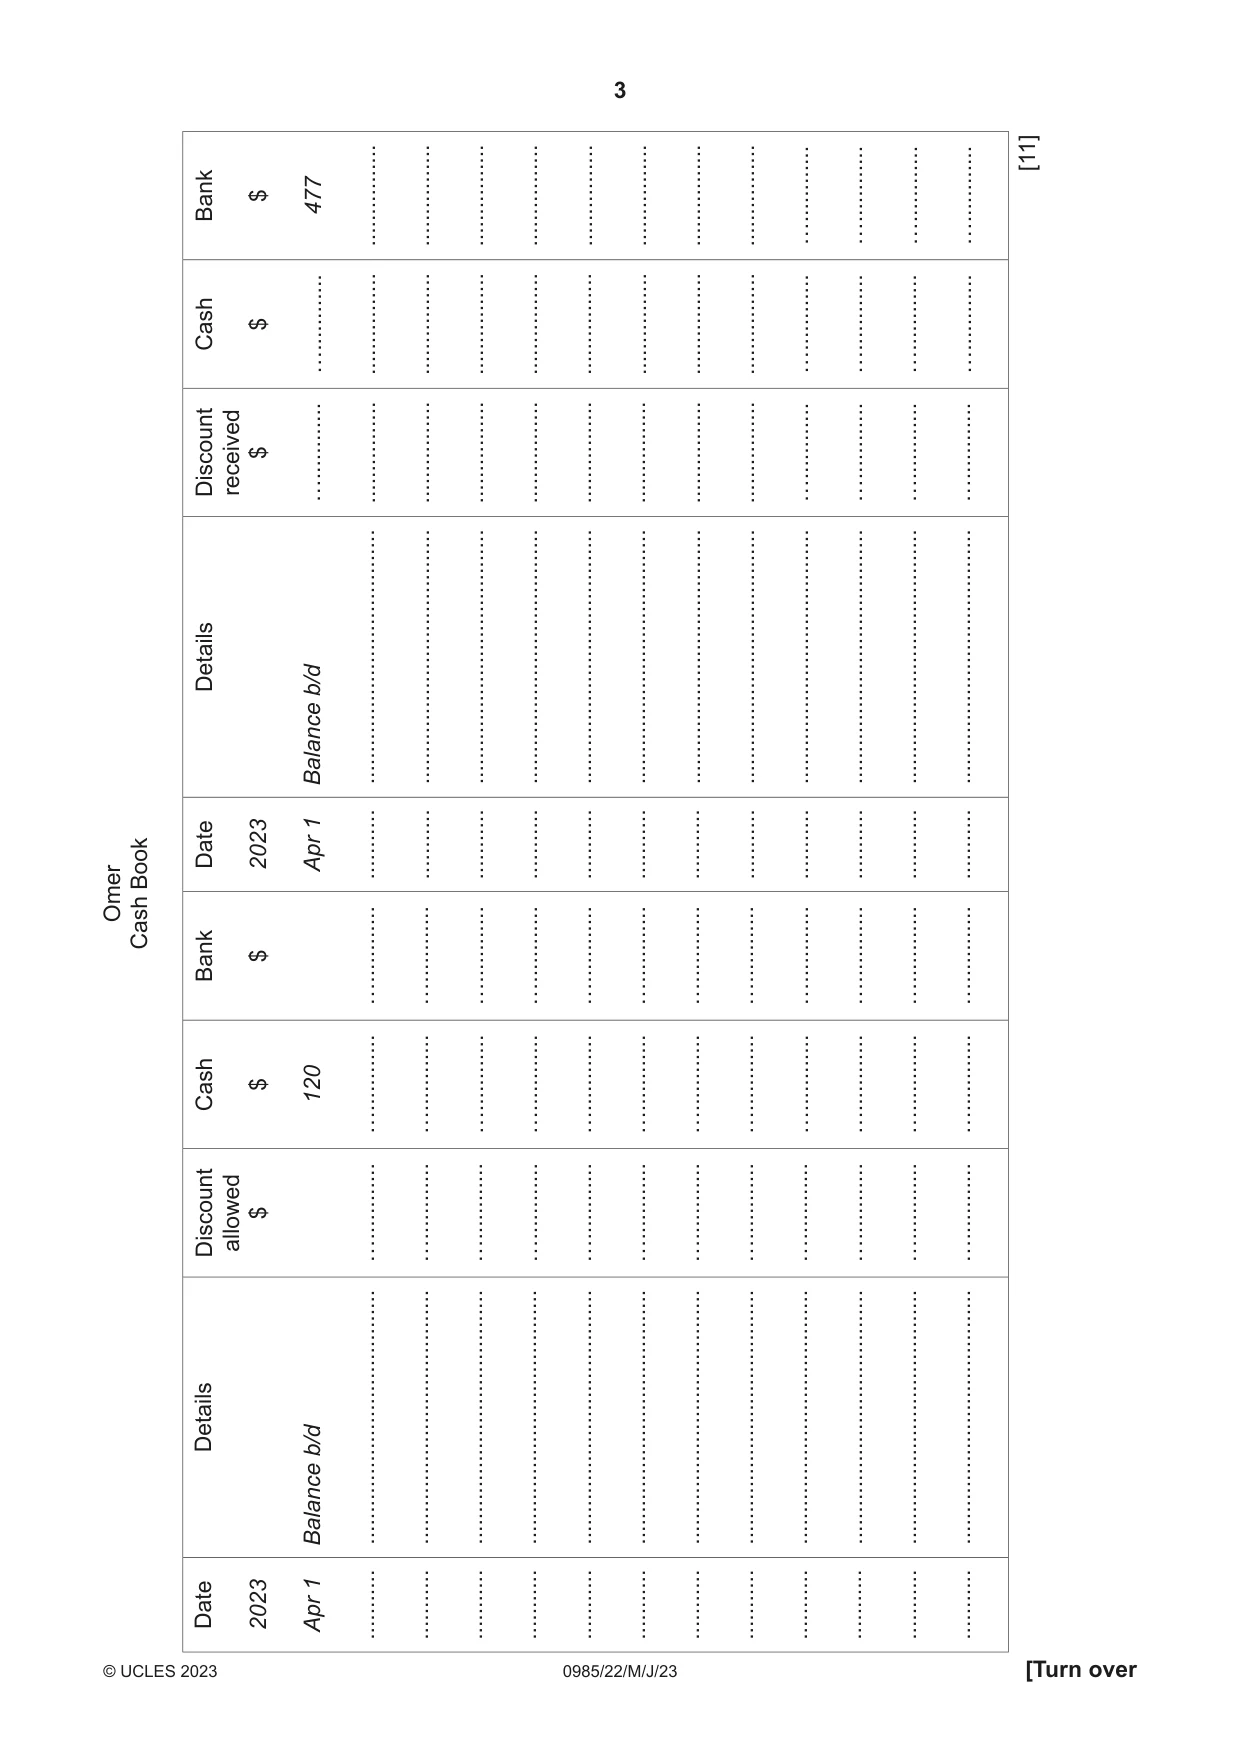
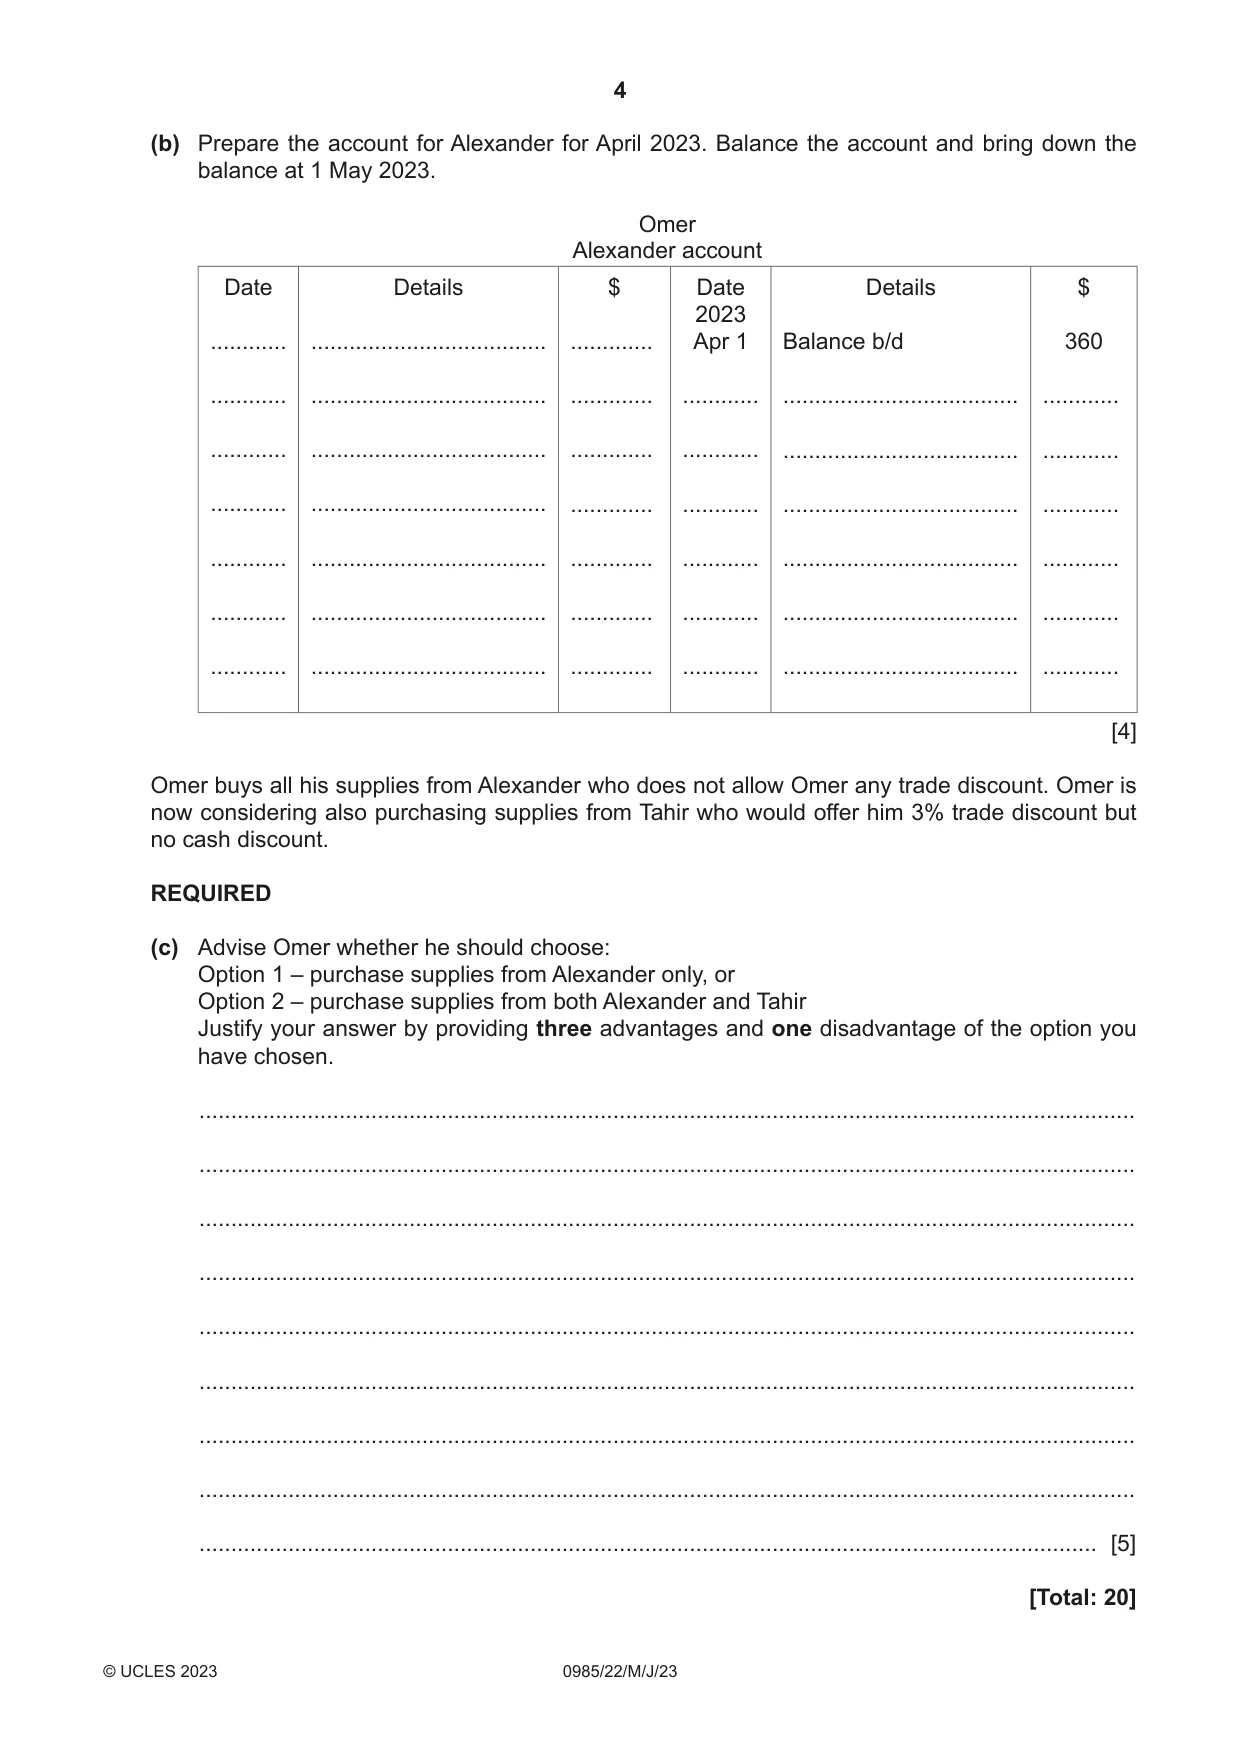
1 Omer is a trader. The following transactions took place in April 2023. April 3 Paid $1000 into the bank from his own personal money 7 Paid $360 to a supplier, Alexander, by telephone transfer 10 Cash sales, $695, were paid directly into the bank account 12 Purchased goods, $340, on credit from Alexander 15 Paid $68 cash for petrol 16 Paid rent, $400, by standing order 23 Received a cheque, $384, from a credit customer, Esme, in full settlement of an invoice for $400 27 Paid $323 by cheque to Alexander, having deducted $17 cash discount 28 Purchased goods, $235, on credit from Alexander REQUIRED (a) Complete Omer’s cash book on the page opposite. Balance the cash book and bring down the balances on 1 May 2023. [11] $ 477 Bank ................ ................ ................ ................ ................ ................ ................ ................ …............ …............ …............ …............ $ Cash …............ ................ ................ ................ ................ ................ ................ ................ ................ …............ …............ …............ …............ $ Discountreceived …............ ................ ................ ................ ................ ................ ................ ................ ................ …............ …............ …............ …............ Details b/d Balance ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ Date 2023 1Apr ........... ........... ........... ........... ........... ........... ........... ........... ........... ........... ........... ........... Book Omer Cash $ Bank …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ $ 120 Cash …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ $ Discountallowed …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ Details b/d Balance ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ (b) Prepare the account for Alexander for April 2023. Balance the account and bring down the balance at 1 May 2023. Omer Alexander account Date Details $ Date Details $ 2023 ............ ..................................... ............. Apr 1 Balance b/d 360 ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ [4] Omer buys all his supplies from Alexander who does not allow Omer any trade discount. Omer is now considering also purchasing supplies from Tahir who would offer him 3% trade discount but no cash discount. REQUIRED (c) Advise Omer whether he should choose: Option 1 – purchase supplies from Alexander only, or Option 2 – purchase supplies from both Alexander and Tahir Justify your answer by providing three advantages and one disadvantage of the option you have chosen. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
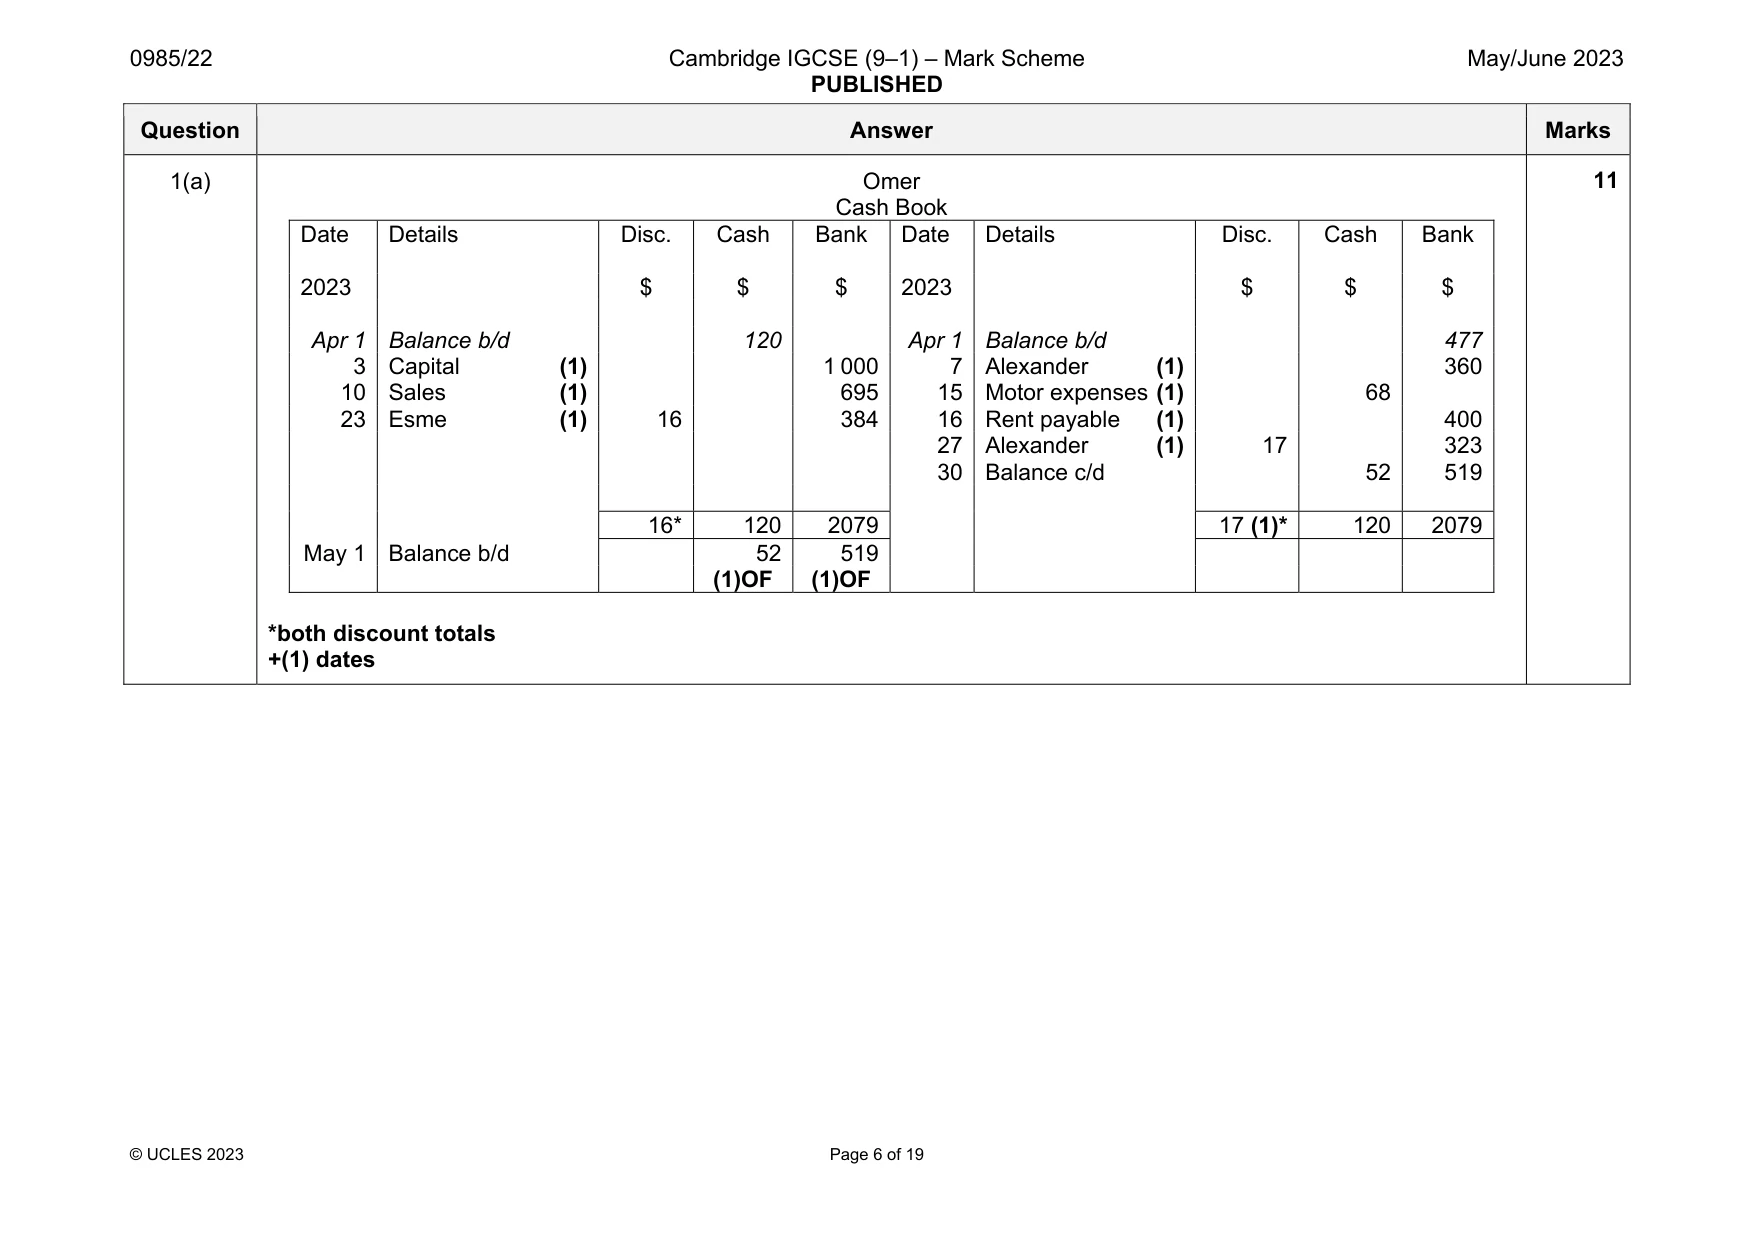
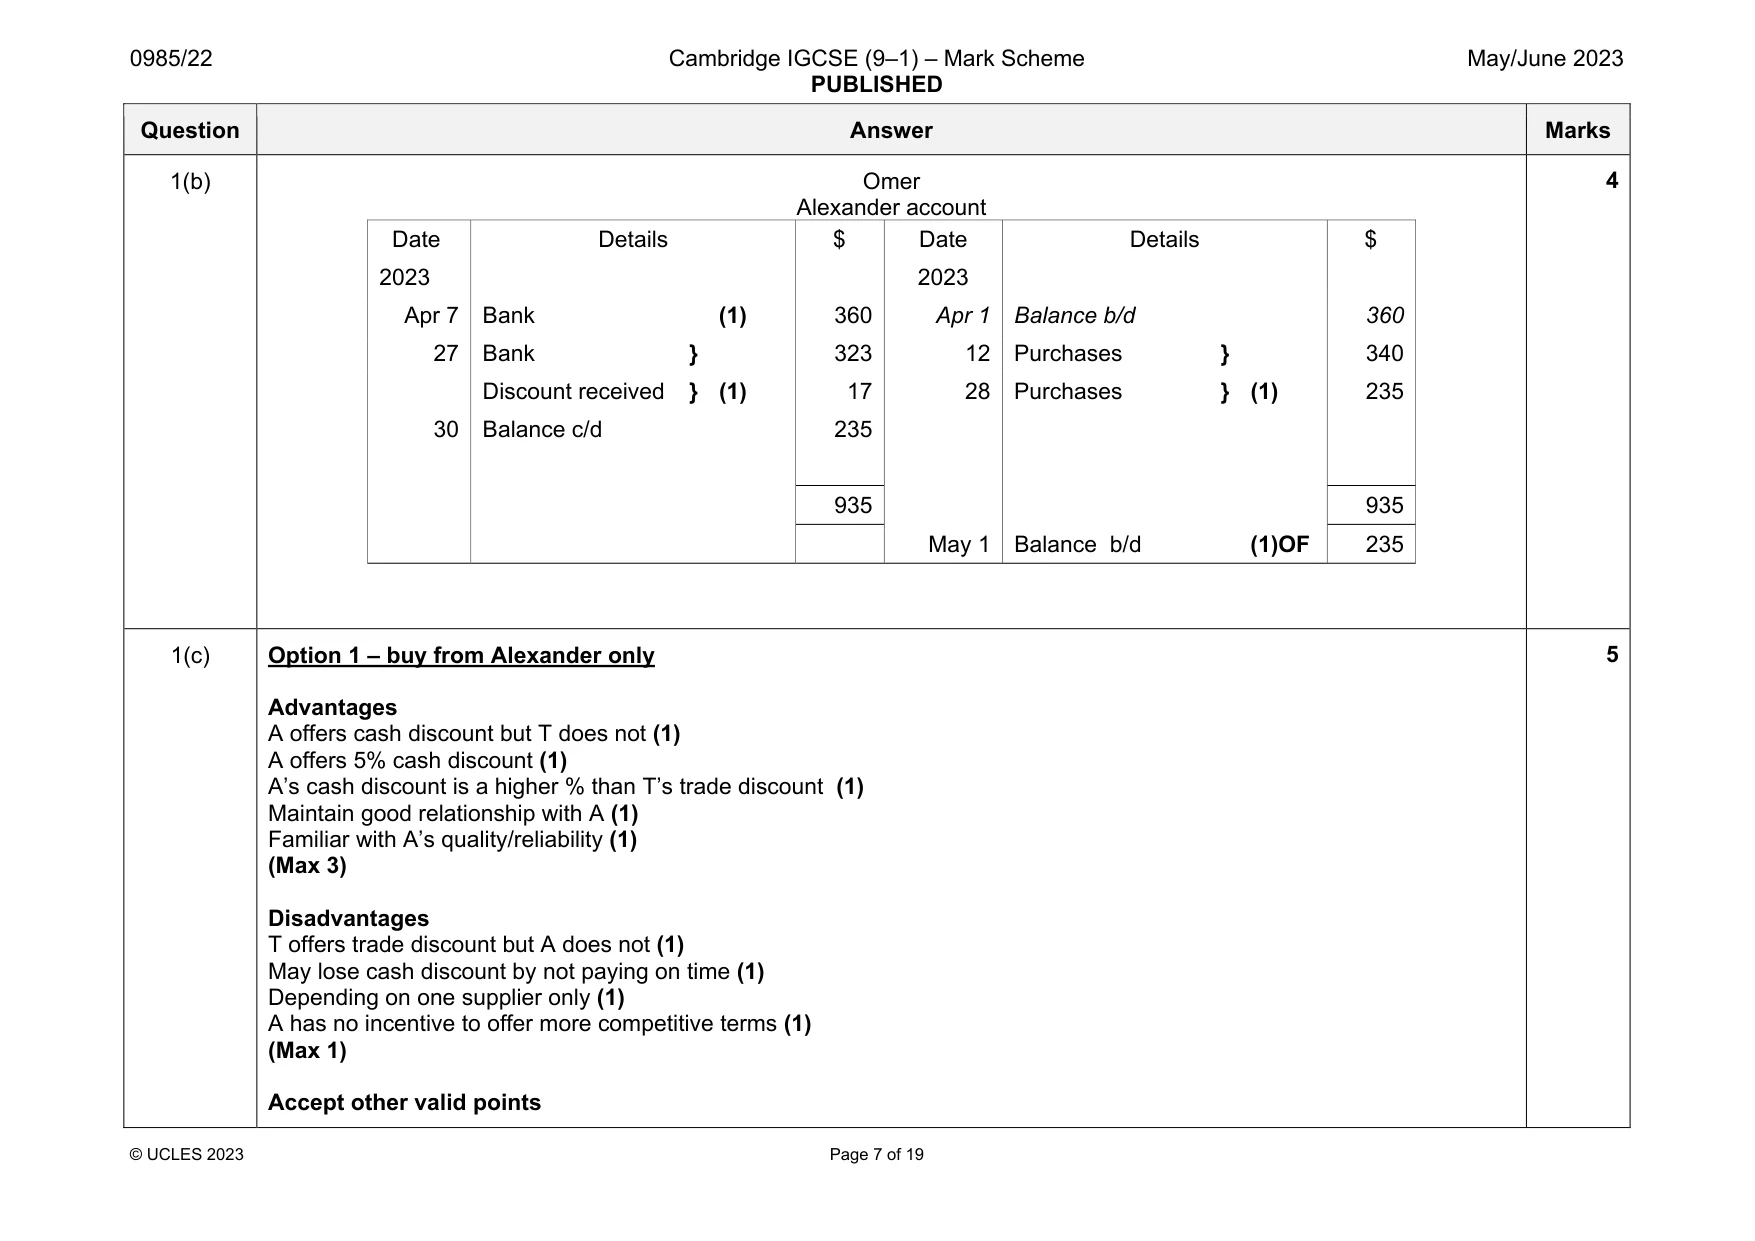
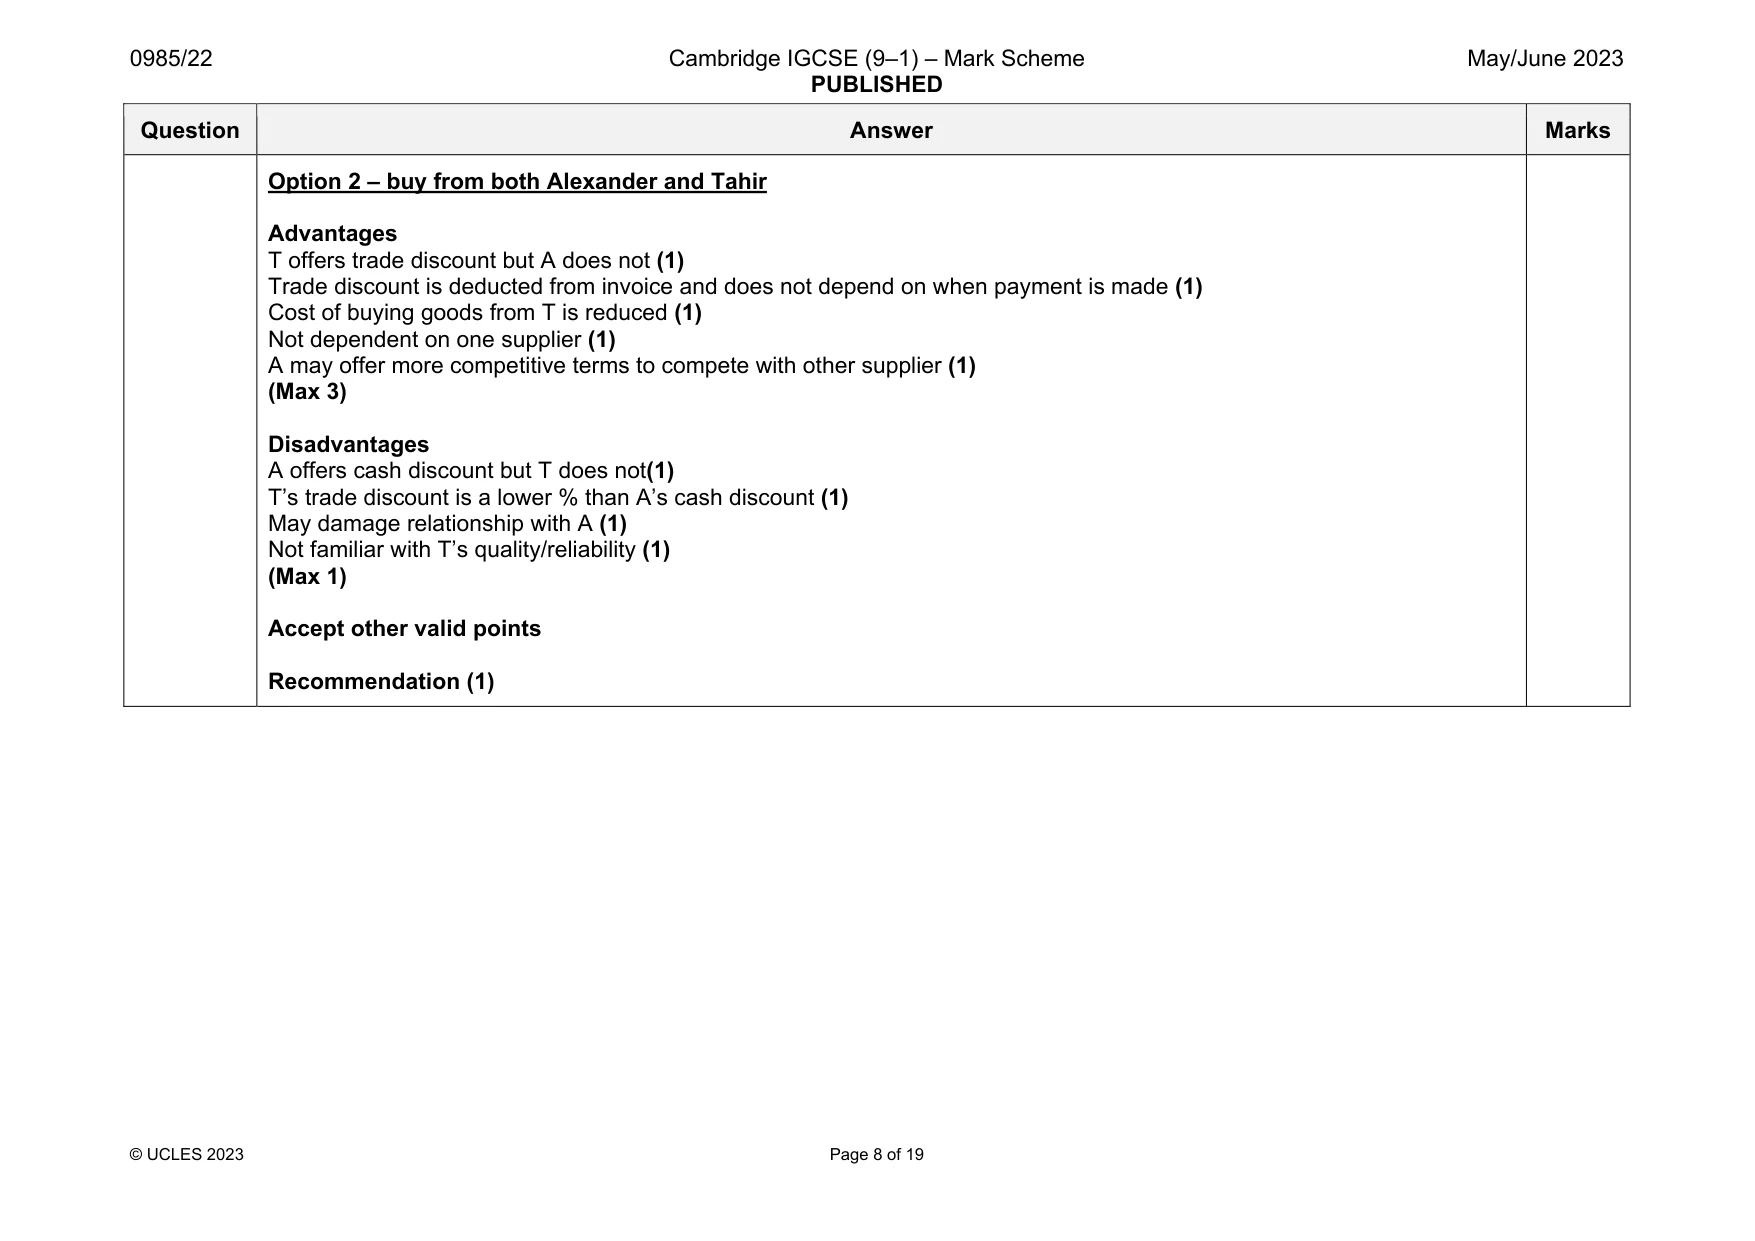
Mark scheme: 1(a) Omer Cash Book Date Details Disc. Cash Bank Date Details Disc. Cash Bank 2023 $ $ $ 2023 $ $ $ Apr 1 Balance b/d 120 Apr 1 Balance b/d 477 3 Capital (1) 1 000 7 Alexander (1) 360 10 Sales (1) 695 15 Motor expenses (1) 68 23 Esme (1) 16 384 16 Rent payable (1) 400 27 Alexander (1) 17 323 30 Balance c/d 52 519 16* 120 2079 17 (1)* 120 2079 May 1 Balance b/d 52 519 (1)OF (1)OF *both discount totals +(1) dates Question Answer Marks 1(b) Omer Alexander account Date Details $ Date Details $ 2023 2023 Apr 7 Bank (1) 360 Apr 1 Balance b/d 360 27 Bank } 323 12 Purchases } 340 Discount received } (1) 17 28 Purchases } (1) 235 30 Balance c/d 235 935 935 May 1 Balance b/d (1)OF 235 4 1(c) Option 1 – buy from Alexander only Advantages A offers cash discount but T does not (1) A offers 5% cash discount (1) A’s cash discount is a higher % than T’s trade discount (1) Maintain good relationship with A (1) Familiar with A’s quality/reliability (1) (Max 3) Disadvantages T offers trade discount but A does not (1) May lose cash discount by not paying on time (1) Depending on one supplier only (1) A has no incentive to offer more competitive terms (1) (Max 1) Accept other valid points 5 Question Answer Marks Option 2 – buy from both Alexander and Tahir Advantages T offers trade discount but A does not (1) Trade discount is deducted from invoice and does not depend on when payment is made (1) Cost of buying goods from T is reduced (1) Not dependent on one supplier (1) A may offer more competitive terms to compete with other supplier (1) (Max 3) Disadvantages A offers cash discount but T does not(1) T’s trade discount is a lower % than A’s cash discount (1) May damage relationship with A (1) Not familiar with T’s quality/reliability (1) (Max 1) Accept other valid points Recommendation (1)
Q2 · Ramla has calculated her draft profit figure for the year ended 28 February 2023
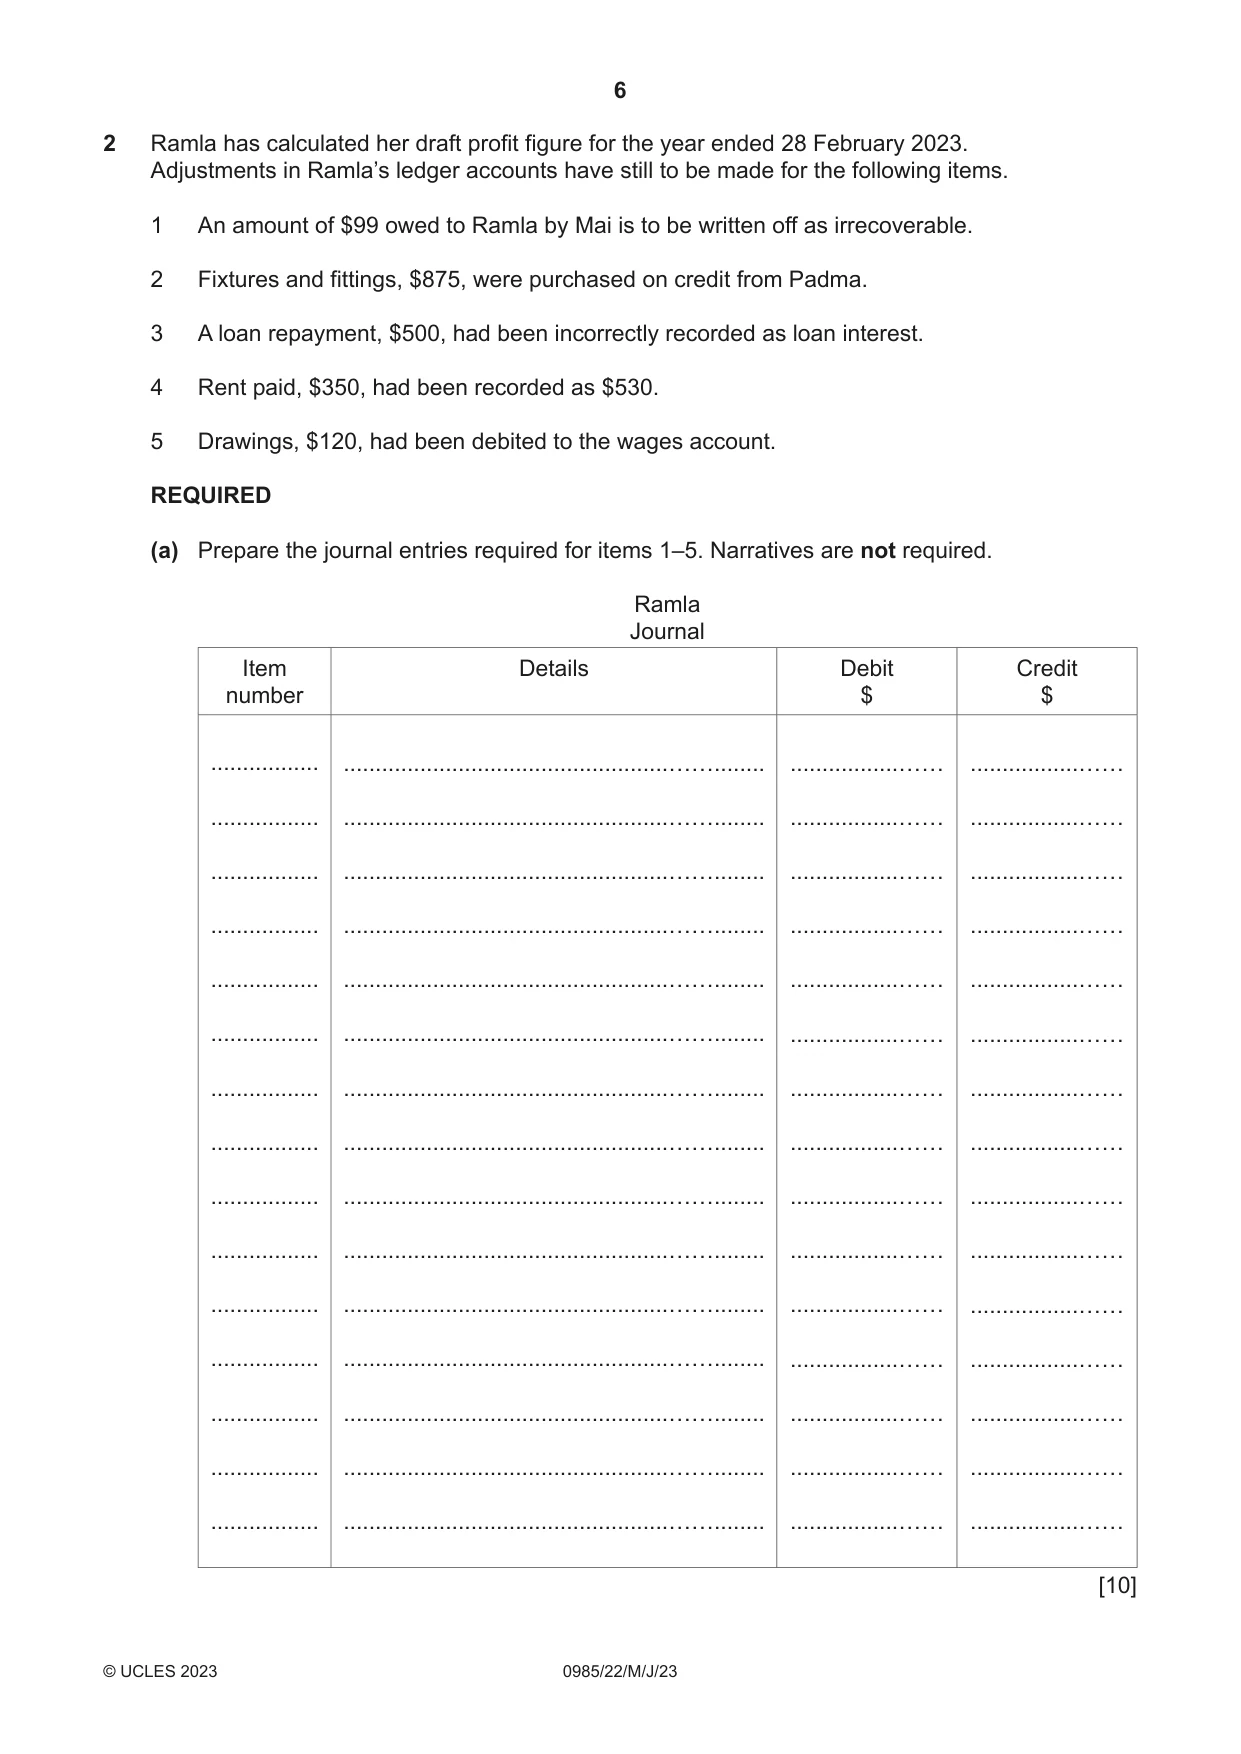
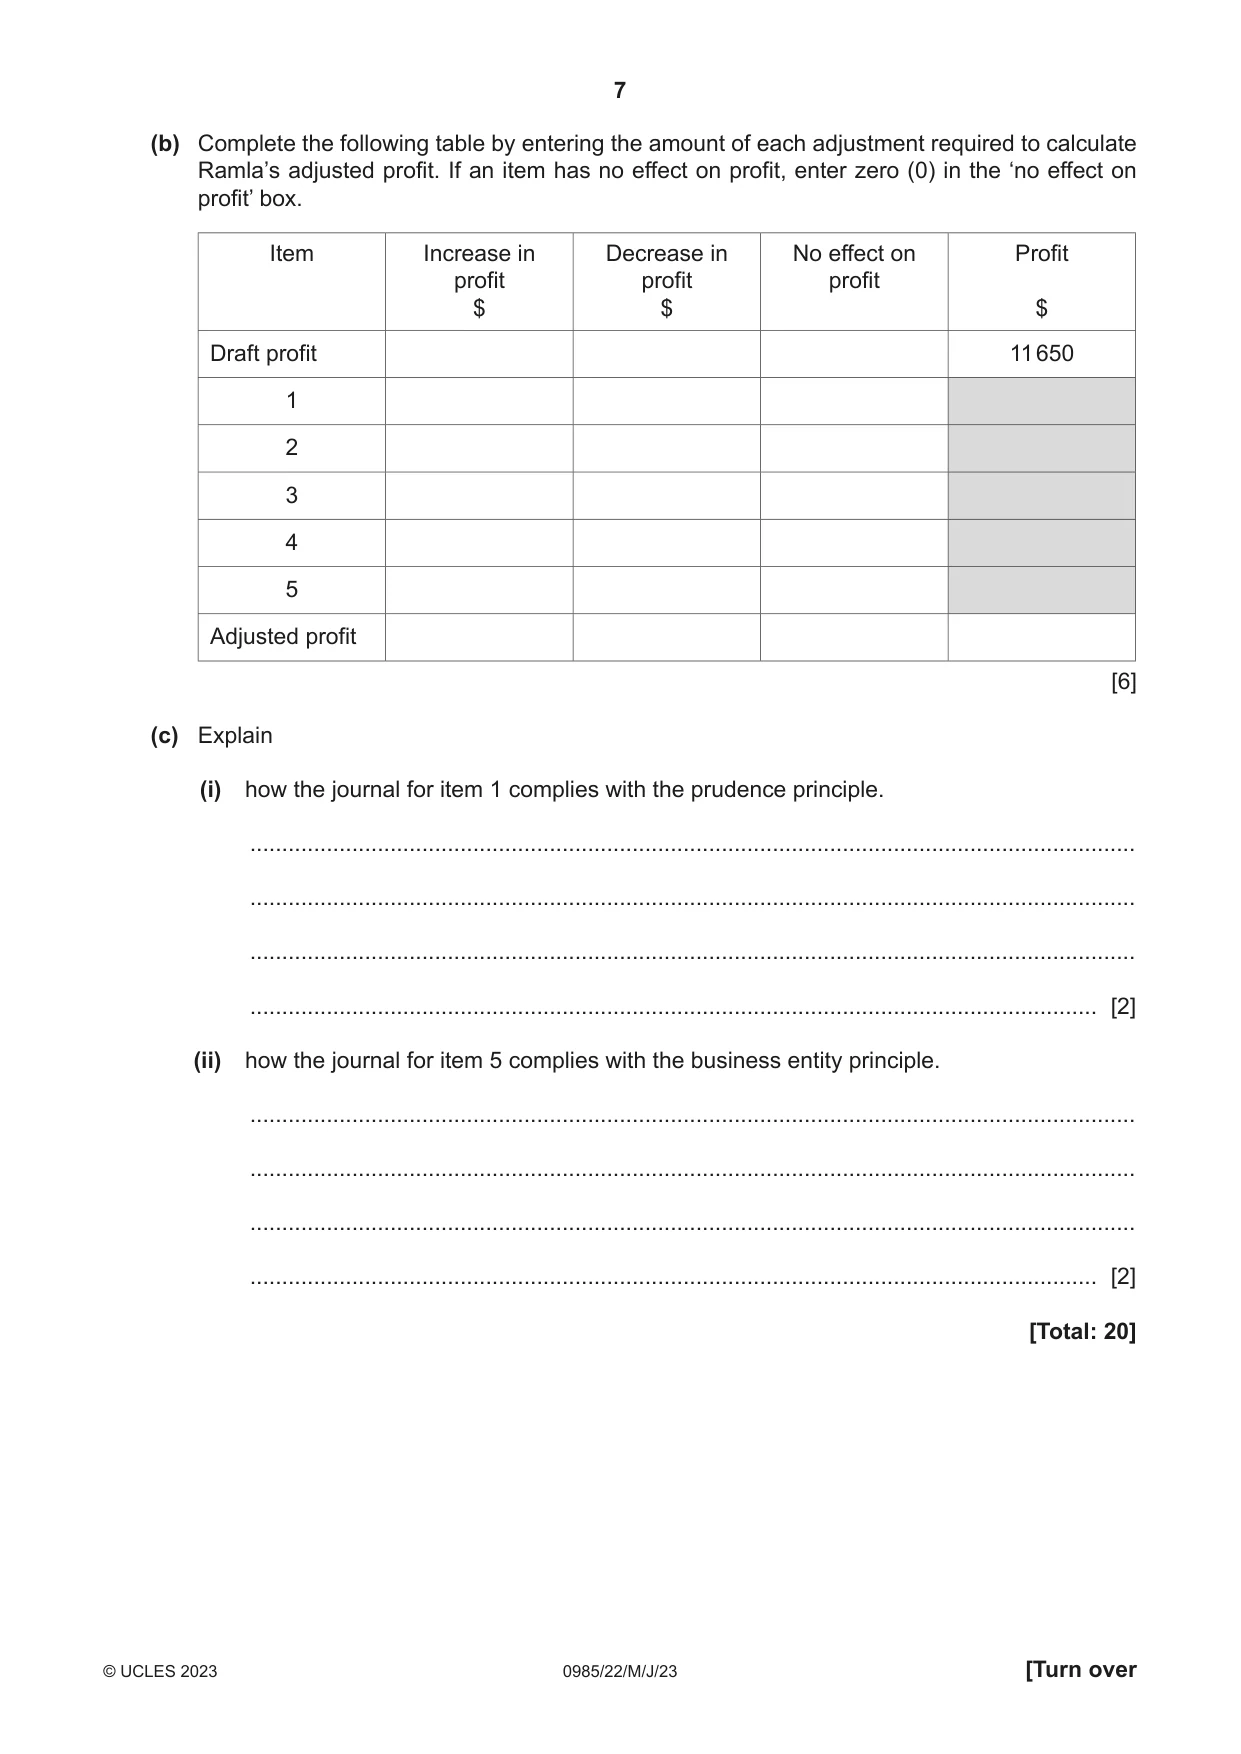
2 Ramla has calculated her draft profit figure for the year ended 28 February 2023. Adjustments in Ramla’s ledger accounts have still to be made for the following items. 1 An amount of $99 owed to Ramla by Mai is to be written off as irrecoverable. 2 Fixtures and fittings, $875, were purchased on credit from Padma. 3 A loan repayment, $500, had been incorrectly recorded as loan interest. 4 Rent paid, $350, had been recorded as $530. 5 Drawings, $120, had been debited to the wages account. REQUIRED (a) Prepare the journal entries required for items 1–5. Narratives are not required. Ramla Journal Item Details Debit Credit number $ $ ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… [10] (b) Complete the following table by entering the amount of each adjustment required to calculate Ramla’s adjusted profit. If an item has no effect on profit, enter zero (0) in the ‘no effect on profit’ box. Item Increase in Decrease in No effect on Profit profit profit profit $ $ $ Draft profit 11 650 1 2 3 4 5 Adjusted profit [6] (c) Explain (i) how the journal for item 1 complies with the prudence principle. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] (ii) how the journal for item 5 complies with the business entity principle. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] [Total: 20]
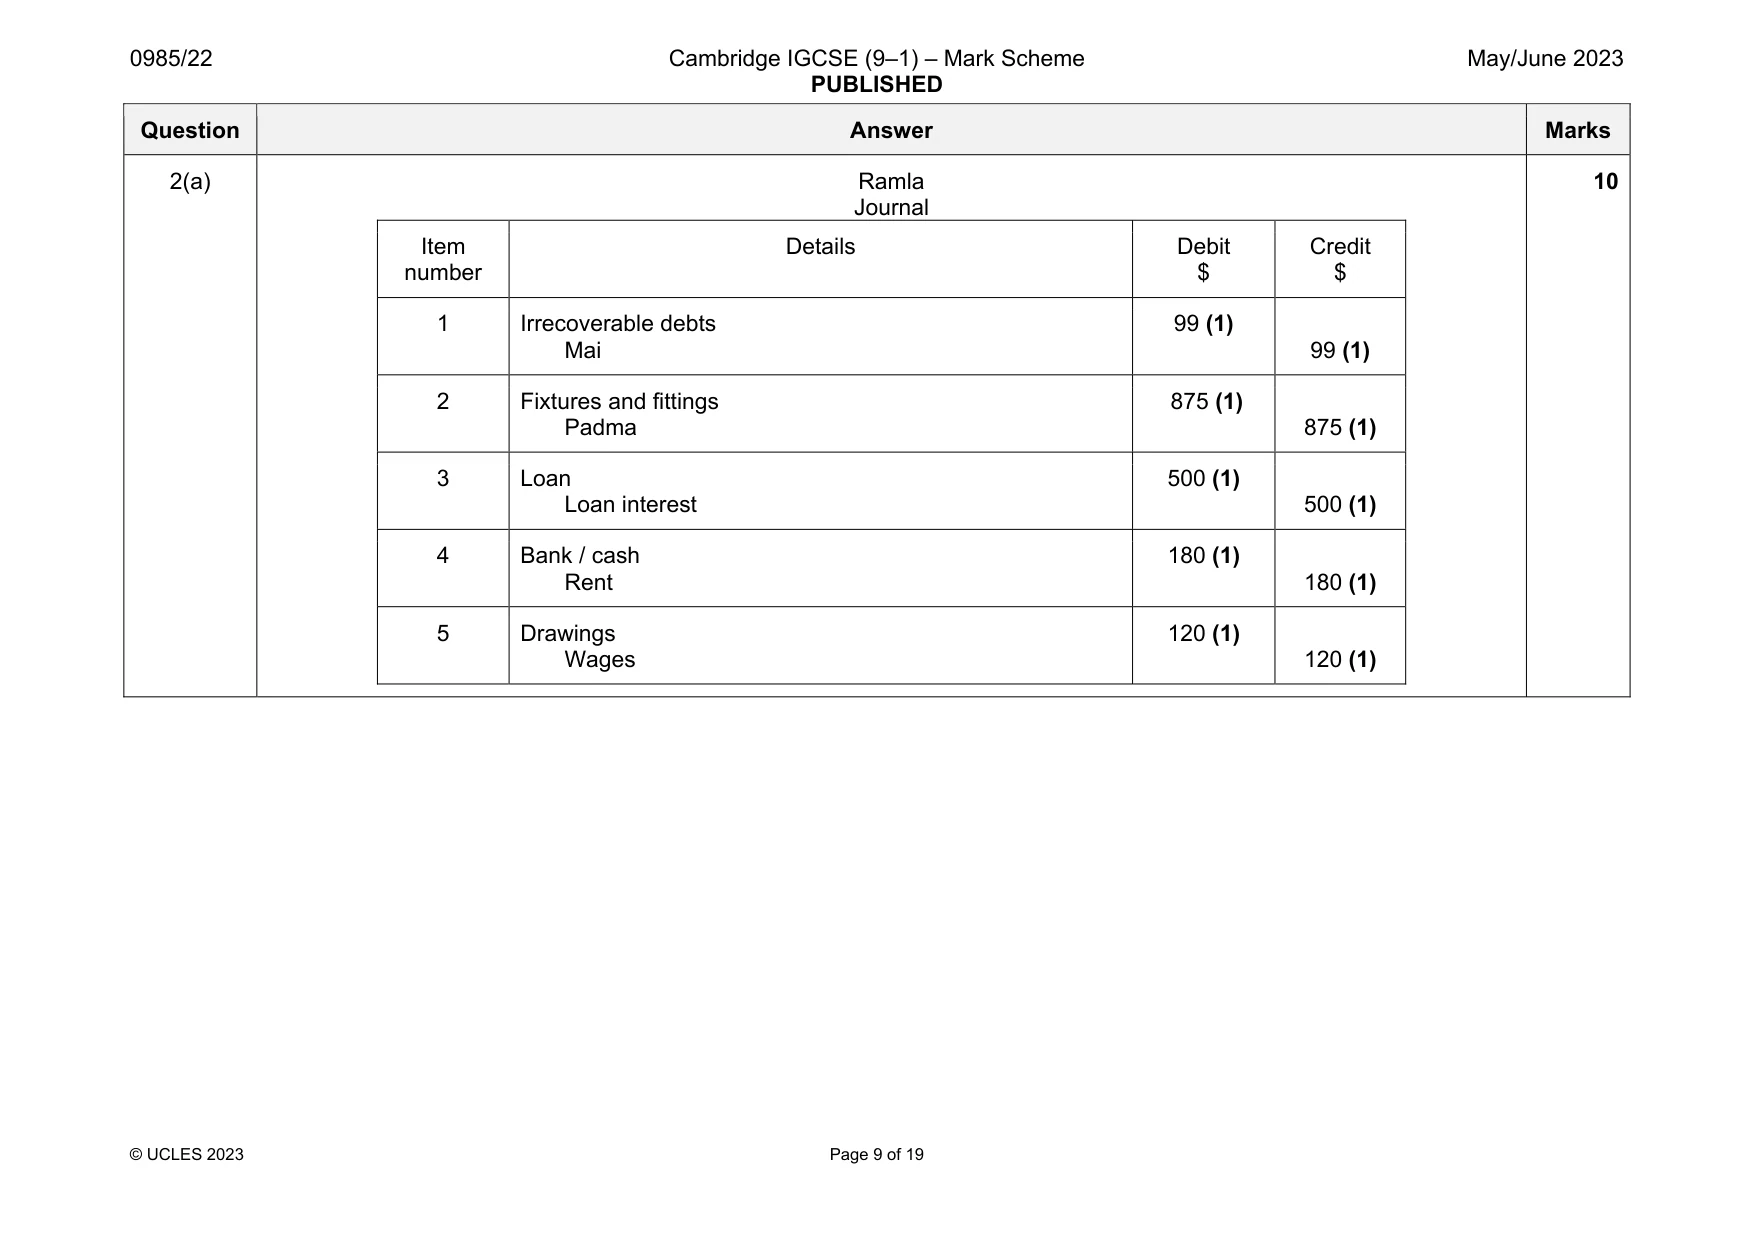
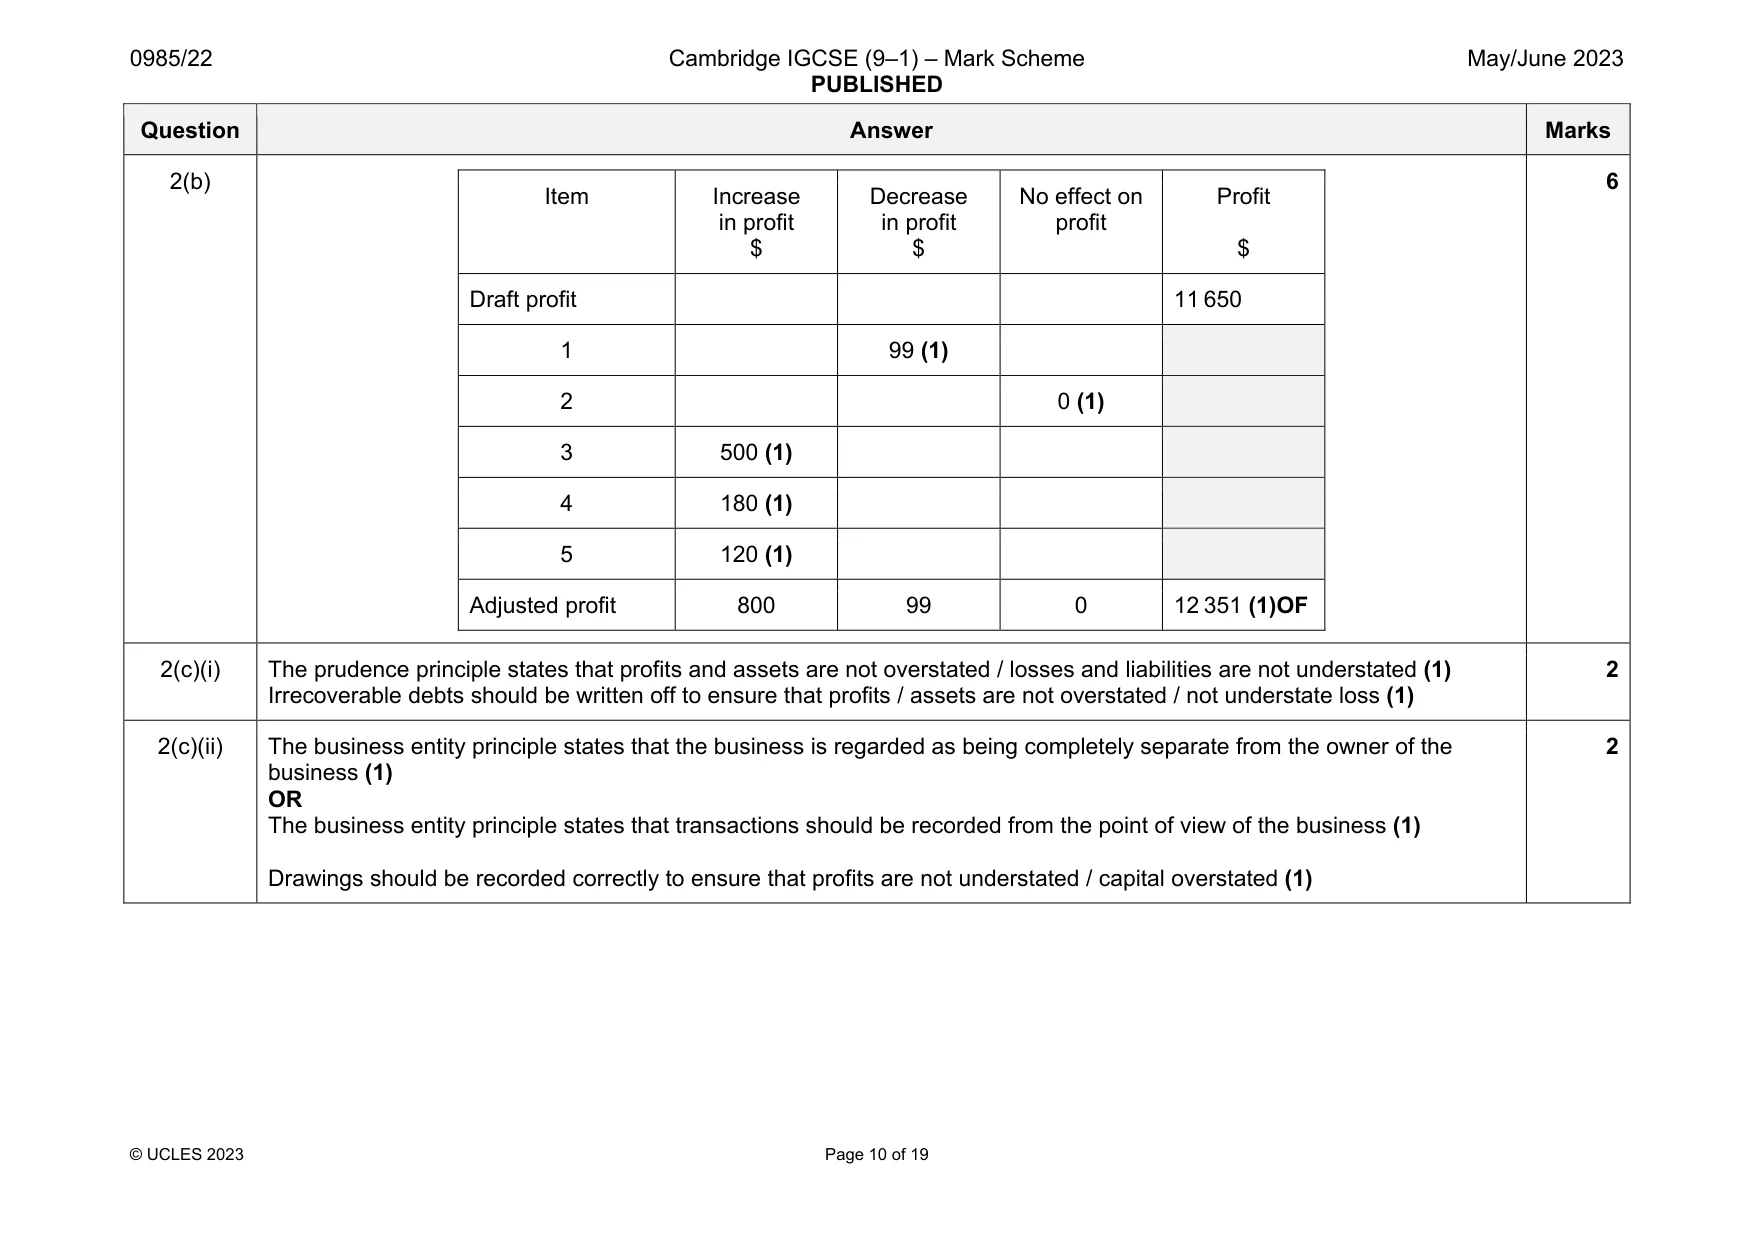
Mark scheme: 2(a) Ramla Journal Item number Details Debit $ Credit $ 1 Irrecoverable debts Mai 99 (1) 99 (1) 2 Fixtures and fittings Padma 875 (1) 875 (1) 3 Loan Loan interest 500 (1) 500 (1) 4 Bank / cash Rent 180 (1) 180 (1) 5 Drawings Wages 120 (1) 120 (1) 10 Question Answer Marks 2(b) Item Increase in profit $ Decrease in profit $ No effect on profit Profit $ Draft profit 11 650 1 99 (1) 2 0 (1) 3 500 (1) 4 180 (1) 5 120 (1) Adjusted profit 800 99 0 12 351 (1)OF 6 2(c)(i) The prudence principle states that profits and assets are not overstated / losses and liabilities are not understated (1) Irrecoverable debts should be written off to ensure that profits / assets are not overstated / not understate loss (1) 2 2(c)(ii) The business entity principle states that the business is regarded as being completely separate from the owner of the business (1) OR The business entity principle states that transactions should be recorded from the point of view of the business (1) Drawings should be recorded correctly to ensure that profits are not understated / capital overstated (1) 2
Q3 · The Favourite Book Club was formed several years ago
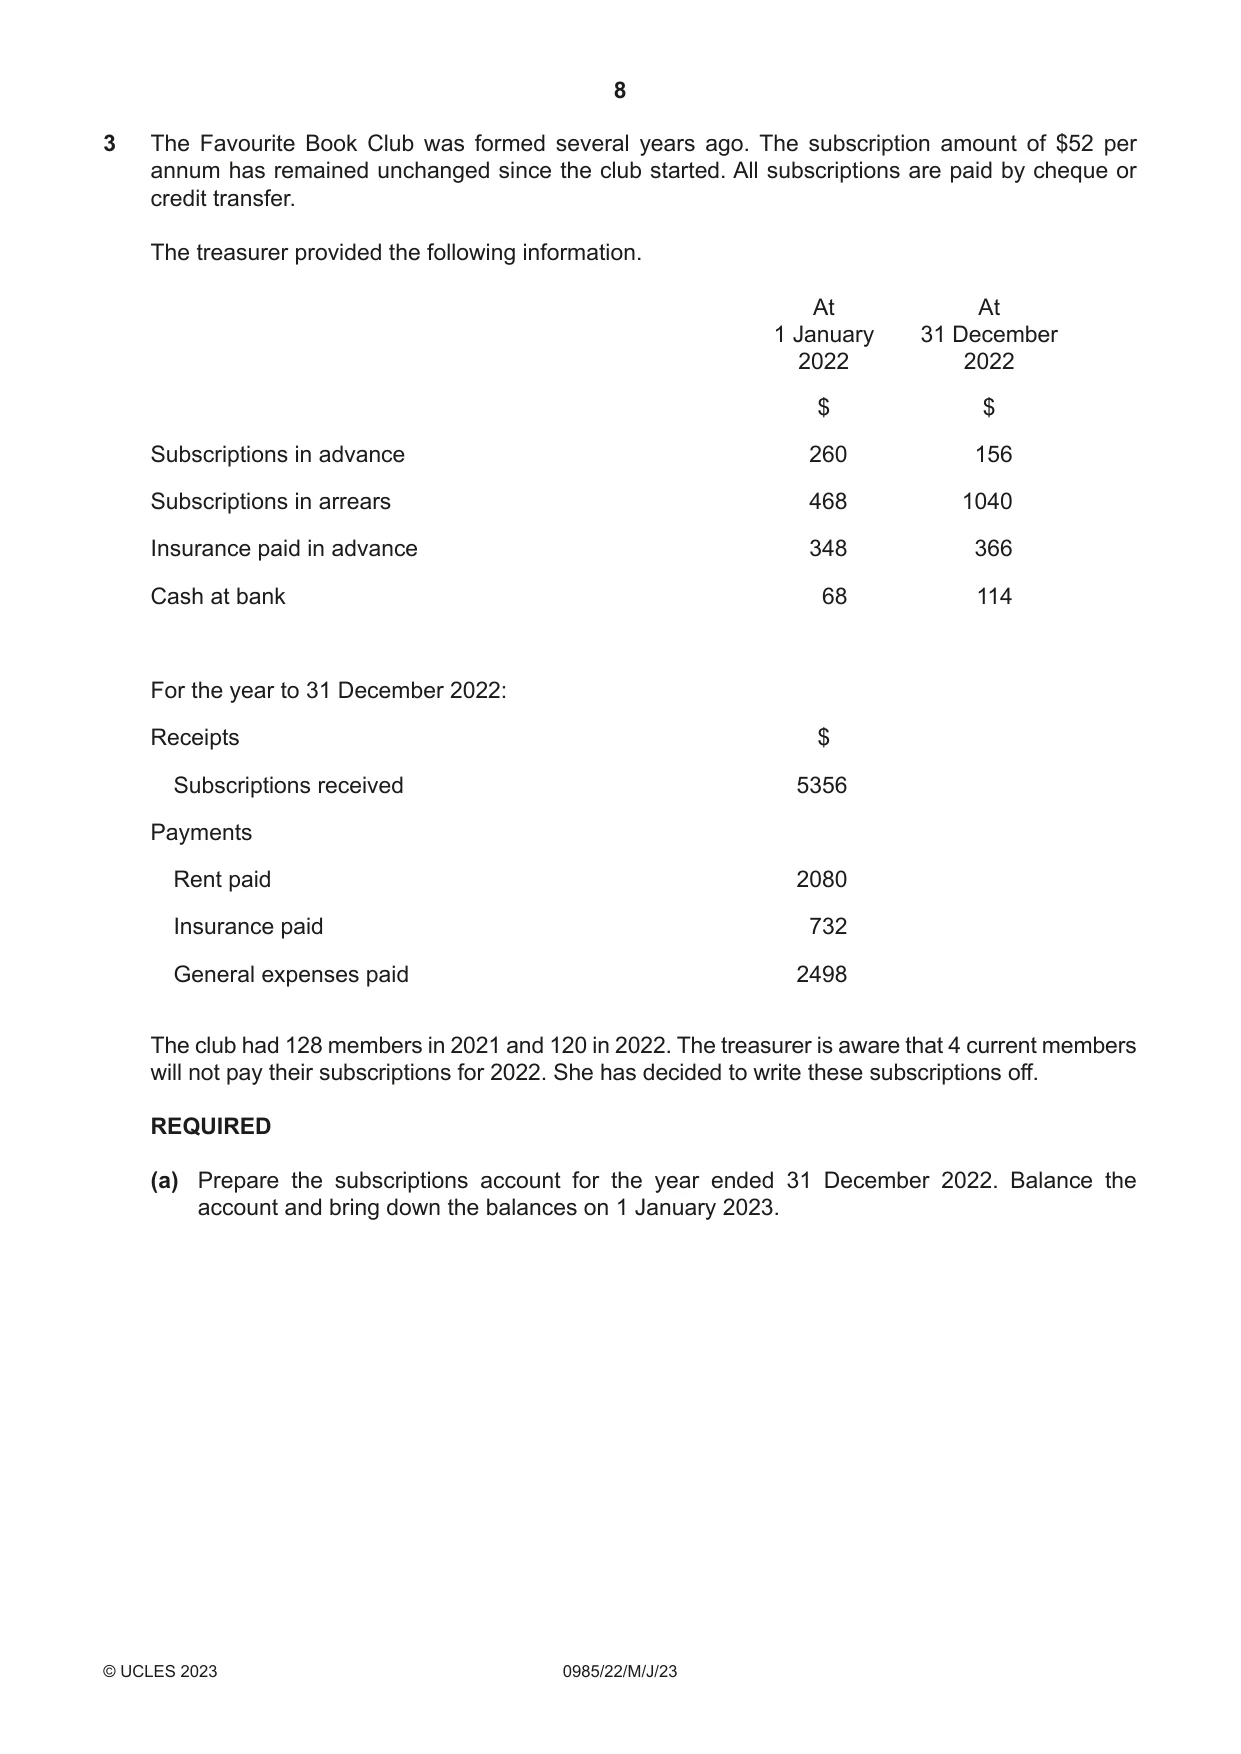
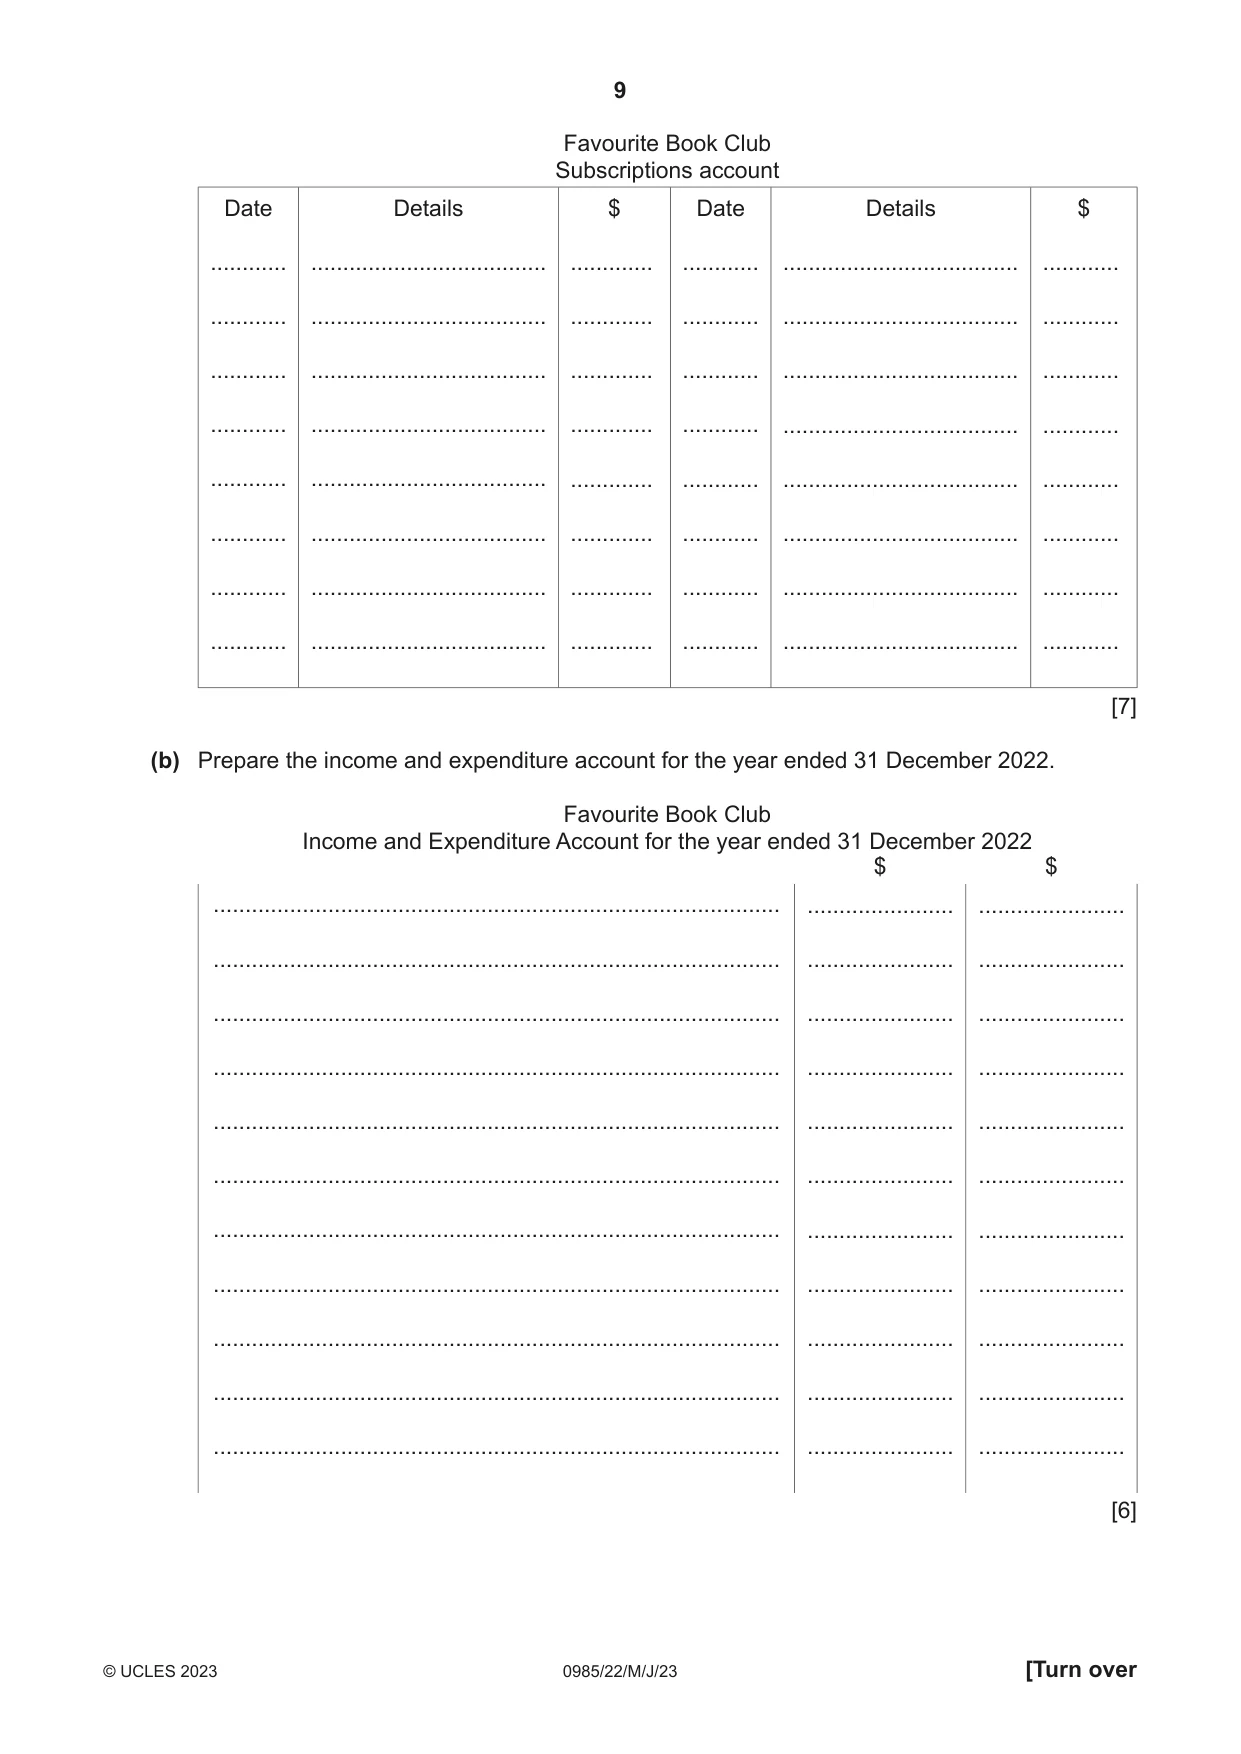
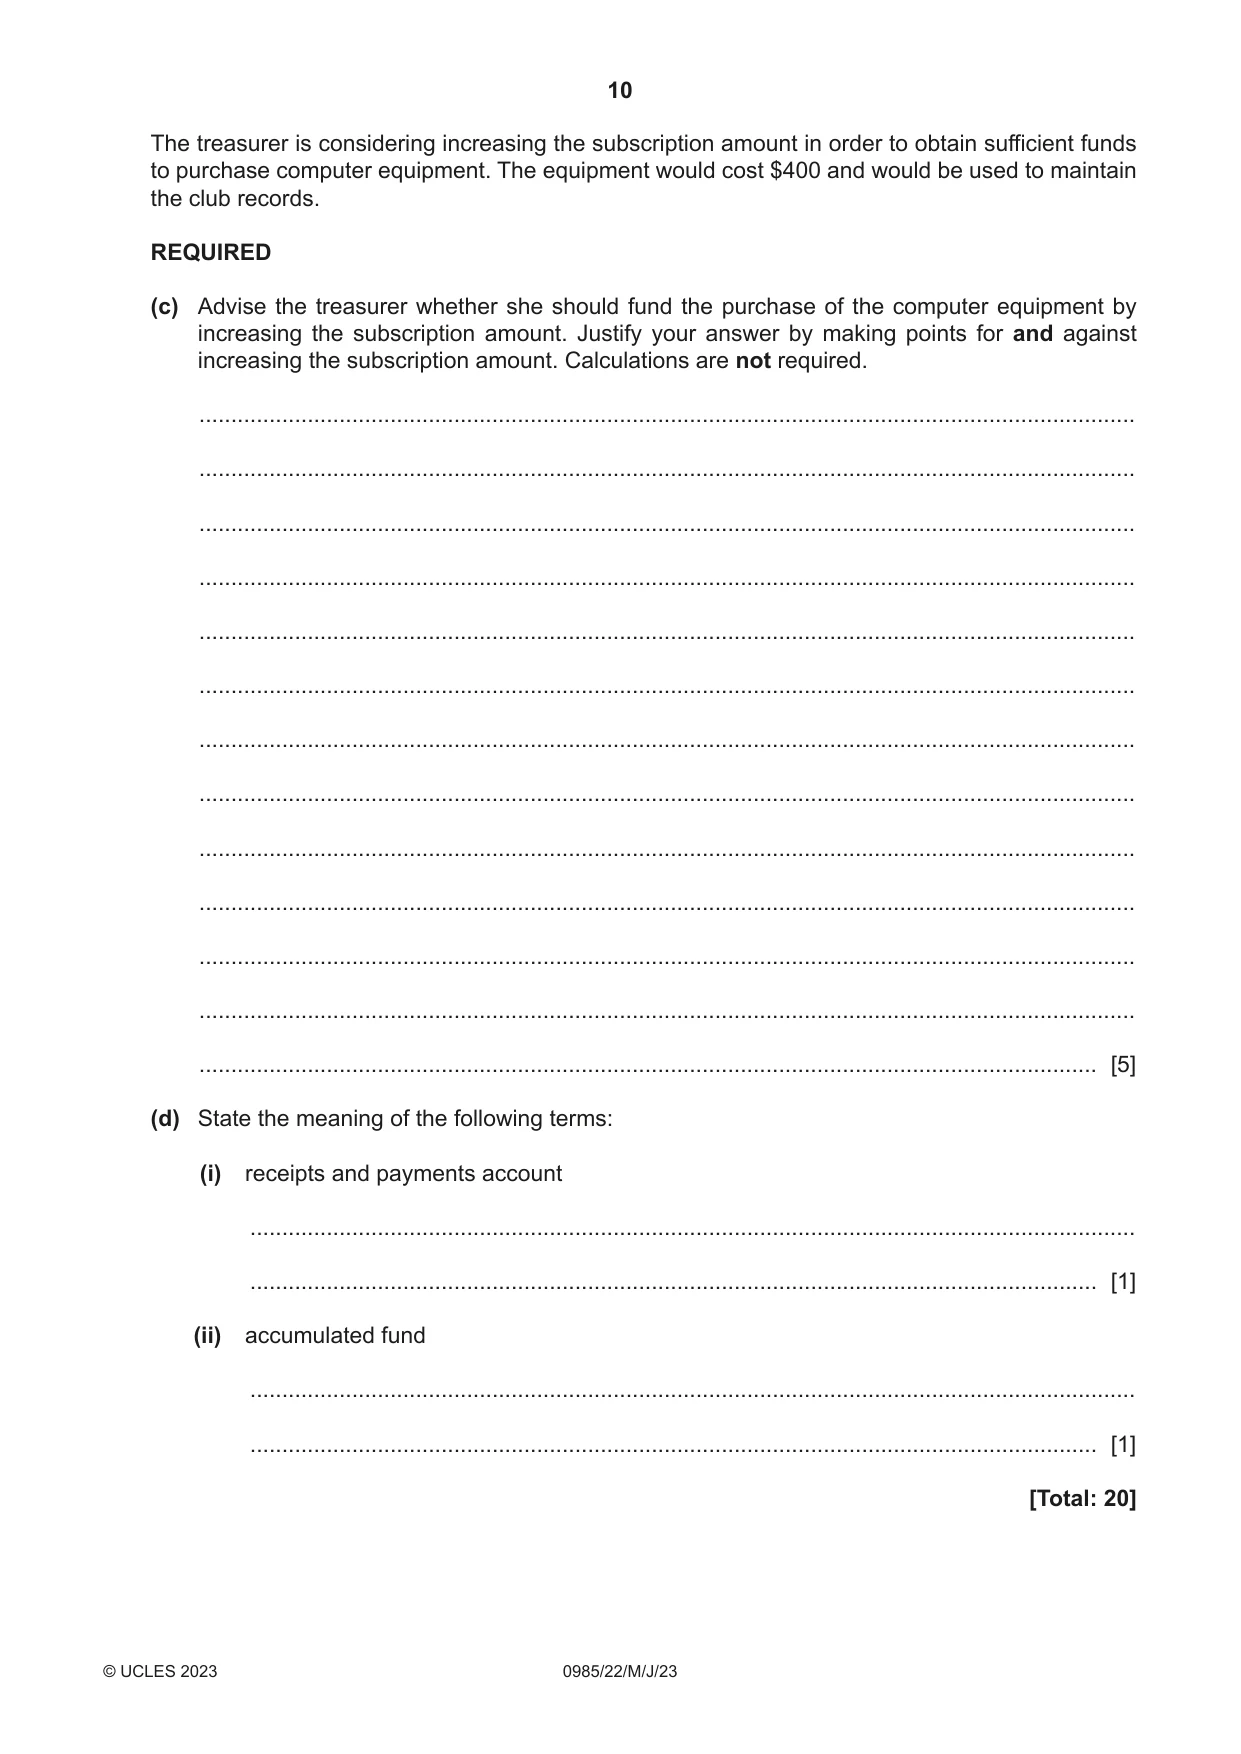
3 The Favourite Book Club was formed several years ago. The subscription amount of $52 per annum has remained unchanged since the club started. All subscriptions are paid by cheque or credit transfer. The treasurer provided the following information. At At 1 January 31 December 2022 2022 $ $ Subscriptions in advance 260 156 Subscriptions in arrears 468 1040 Insurance paid in advance 348 366 Cash at bank 68 114 For the year to 31 December 2022: Receipts $ Subscriptions received 5356 Payments Rent paid 2080 Insurance paid 732 General expenses paid 2498 The club had 128 members in 2021 and 120 in 2022. The treasurer is aware that 4 current members will not pay their subscriptions for 2022. She has decided to write these subscriptions off. REQUIRED (a) Prepare the subscriptions account for the year ended 31 December 2022. Balance the account and bring down the balances on 1 January 2023. Favourite Book Club Subscriptions account Date Details $ Date Details $ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ [7] (b) Prepare the income and expenditure account for the year ended 31 December 2022. Favourite Book Club Income and Expenditure Account for the year ended 31 December 2022 $ $ ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... [6] The treasurer is considering increasing the subscription amount in order to obtain sufficient funds to purchase computer equipment. The equipment would cost $400 and would be used to maintain the club records. REQUIRED (c) Advise the treasurer whether she should fund the purchase of the computer equipment by increasing the subscription amount. Justify your answer by making points for and against increasing the subscription amount. Calculations are not required. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] (d) State the meaning of the following terms: (i) receipts and payments account ........................................................................................................................................... ..................................................................................................................................... [1] (ii) accumulated fund ........................................................................................................................................... ..................................................................................................................................... [1] [Total: 20]
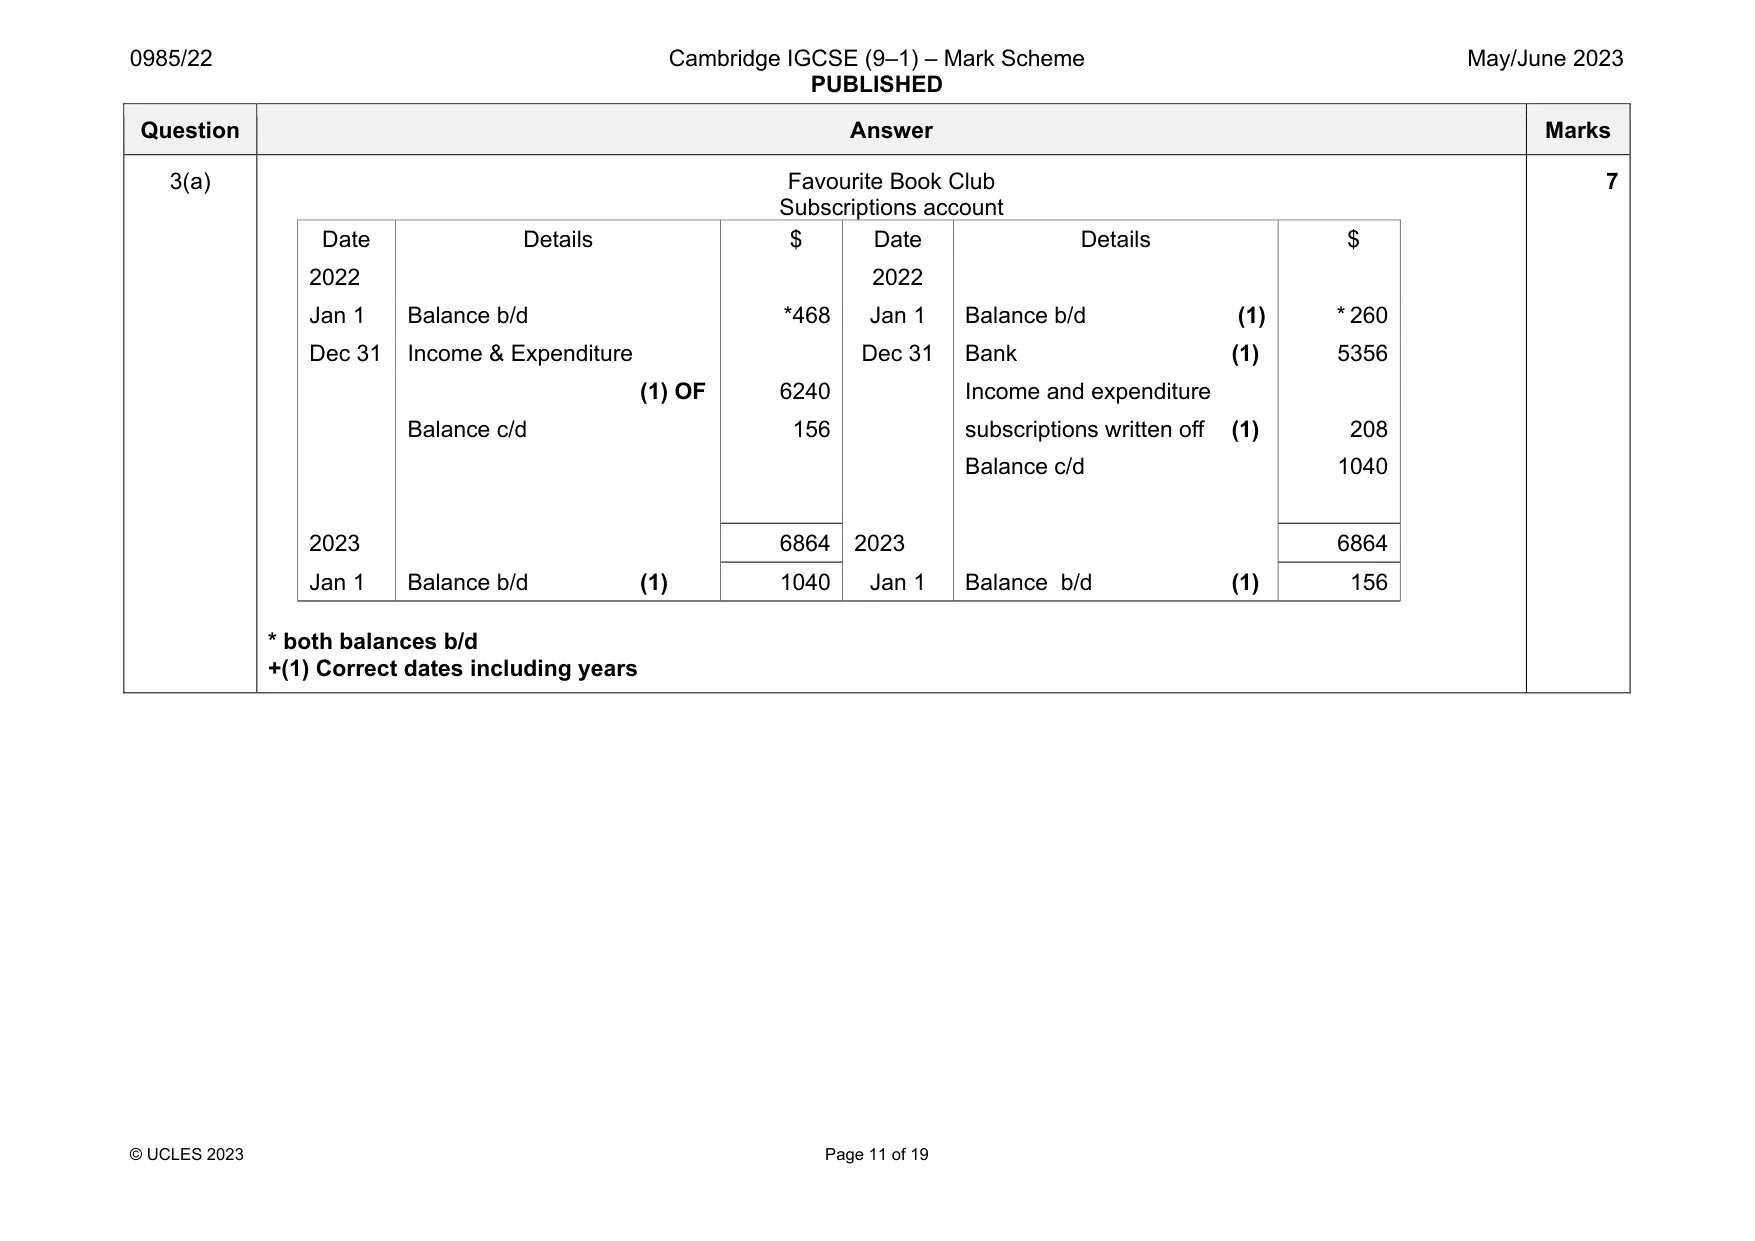
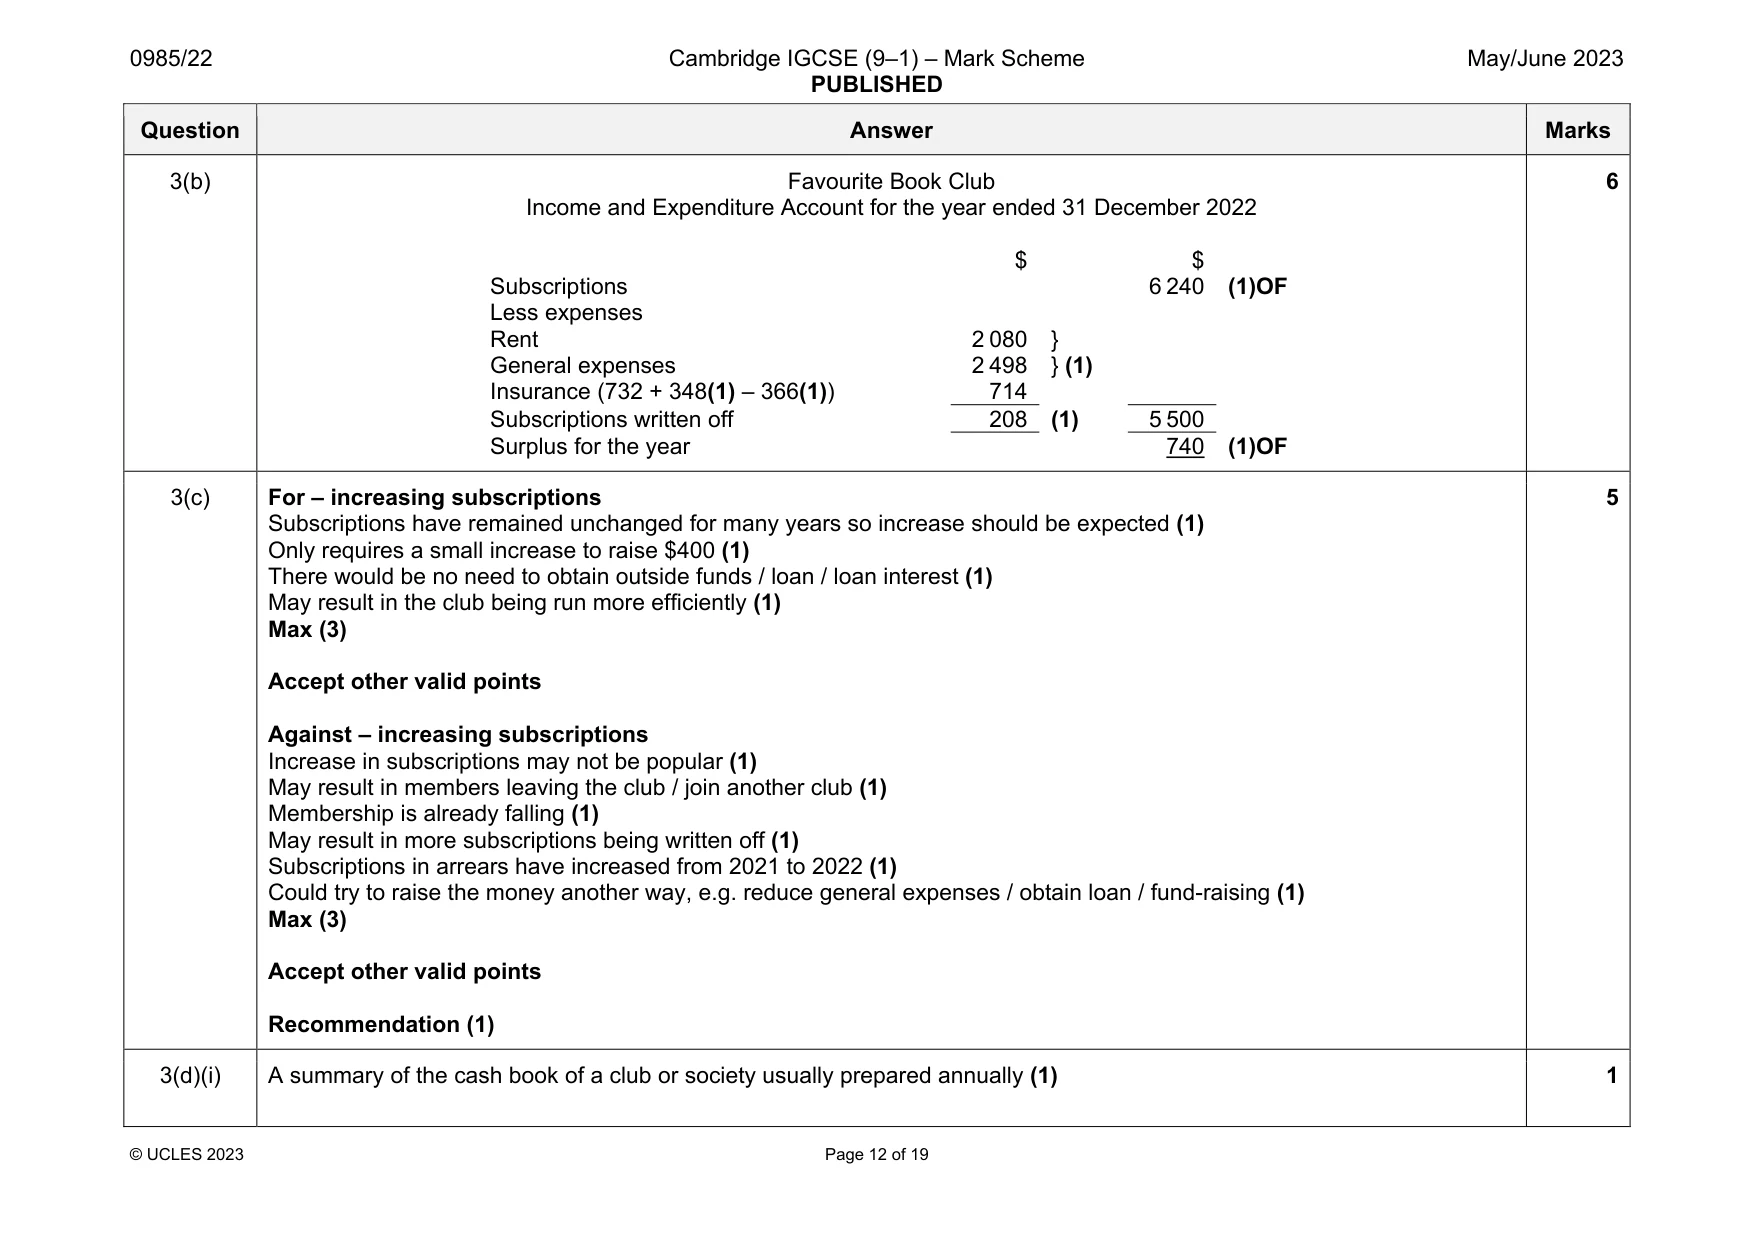
Mark scheme: 3(a) Favourite Book Club Subscriptions account Date Details $ Date Details $ 2022 2022 Jan 1 Balance b/d *468 Jan 1 Balance b/d (1) * 260 Dec 31 Income & Expenditure Dec 31 Bank (1) 5356 (1) OF 6240 Income and expenditure Balance c/d 156 subscriptions written off (1) 208 Balance c/d 1040 2023 6864 2023 6864 Jan 1 Balance b/d (1) 1040 Jan 1 Balance b/d (1) 156 * both balances b/d +(1) Correct dates including years 7 Question Answer Marks 3(b) Favourite Book Club Income and Expenditure Account for the year ended 31 December 2022 $ $ Subscriptions 6 240 (1)OF Less expenses Rent 2 080 } General expenses 2 498 } (1) Insurance (732 + 348(1) – 366(1)) 714 Subscriptions written off 208 (1) 5 500 Surplus for the year 740 (1)OF 6 3(c) For – increasing subscriptions Subscriptions have remained unchanged for many years so increase should be expected (1) Only requires a small increase to raise $400 (1) There would be no need to obtain outside funds / loan / loan interest (1) May result in the club being run more efficiently (1) Max (3) Accept other valid points Against – increasing subscriptions Increase in subscriptions may not be popular (1) May result in members leaving the club / join another club (1) Membership is already falling (1) May result in more subscriptions being written off (1) Subscriptions in arrears have increased from 2021 to 2022 (1) Could try to raise the money another way, e.g. reduce general expenses / obtain loan / fund-raising (1) Max (3) Accept other valid points Recommendation (1) 5 3(d)(i) A summary of the cash book of a club or society usually prepared annually (1) 1 Question Answer Marks 3(d)(ii) Assets less liabilities of a club/society (1) OR accumulated surpluses less accumulated deficits of a club/society (1) 1
Q4 · Akila and Darius are in partnership
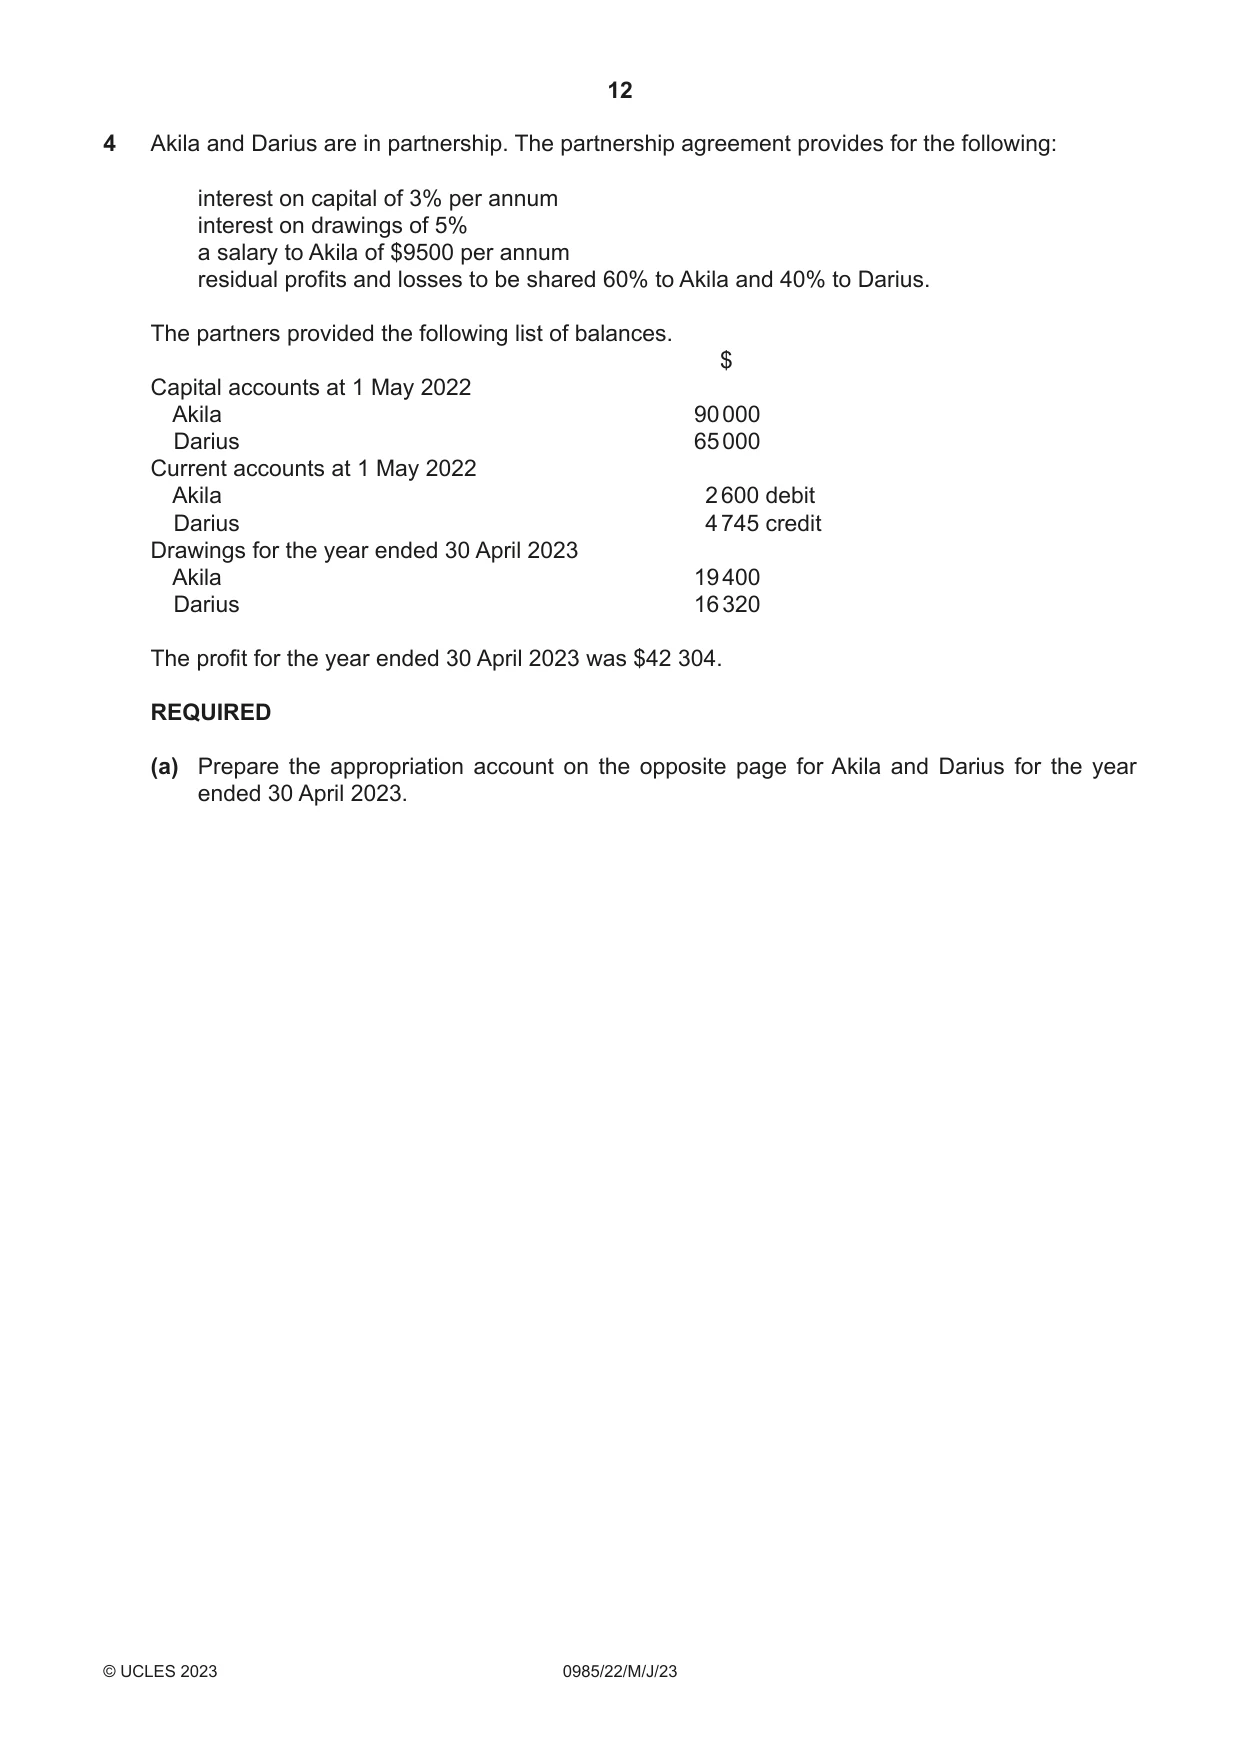
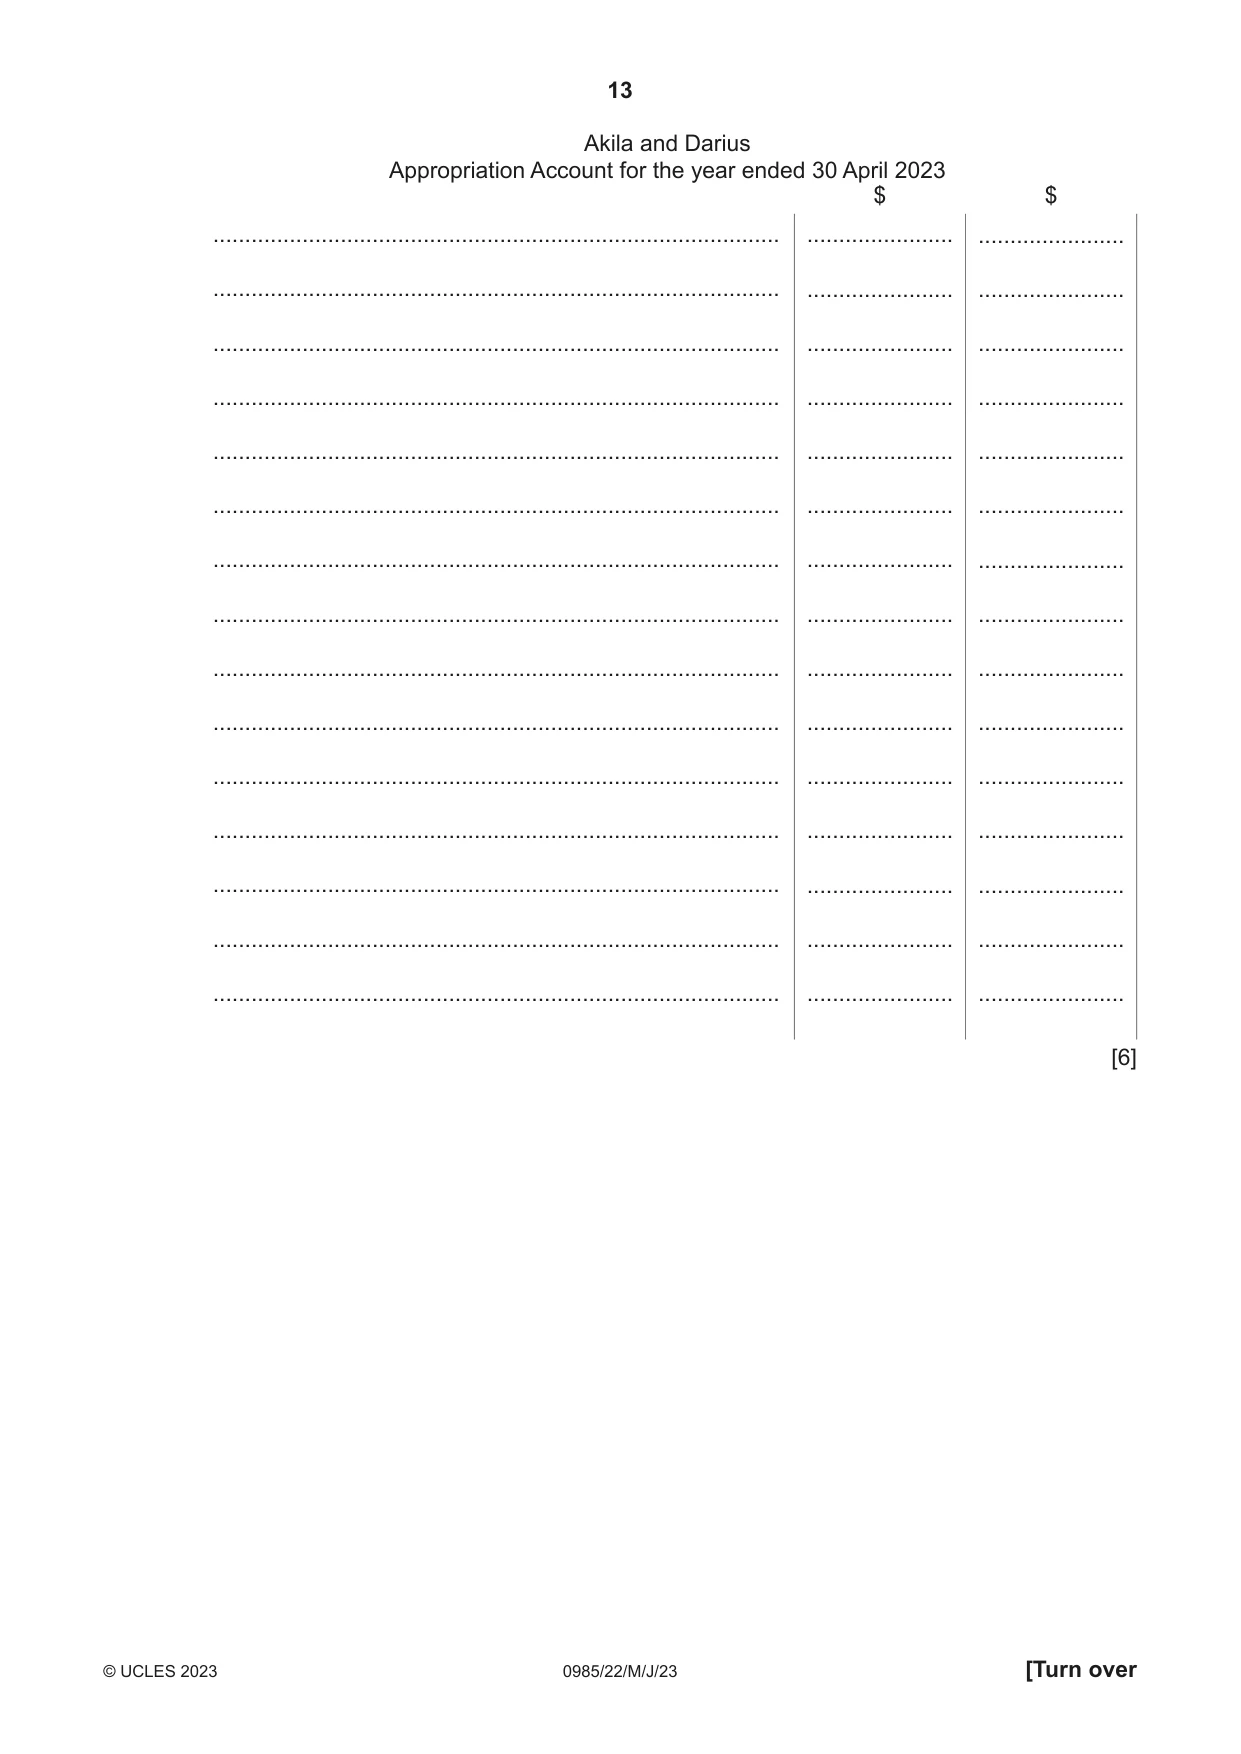
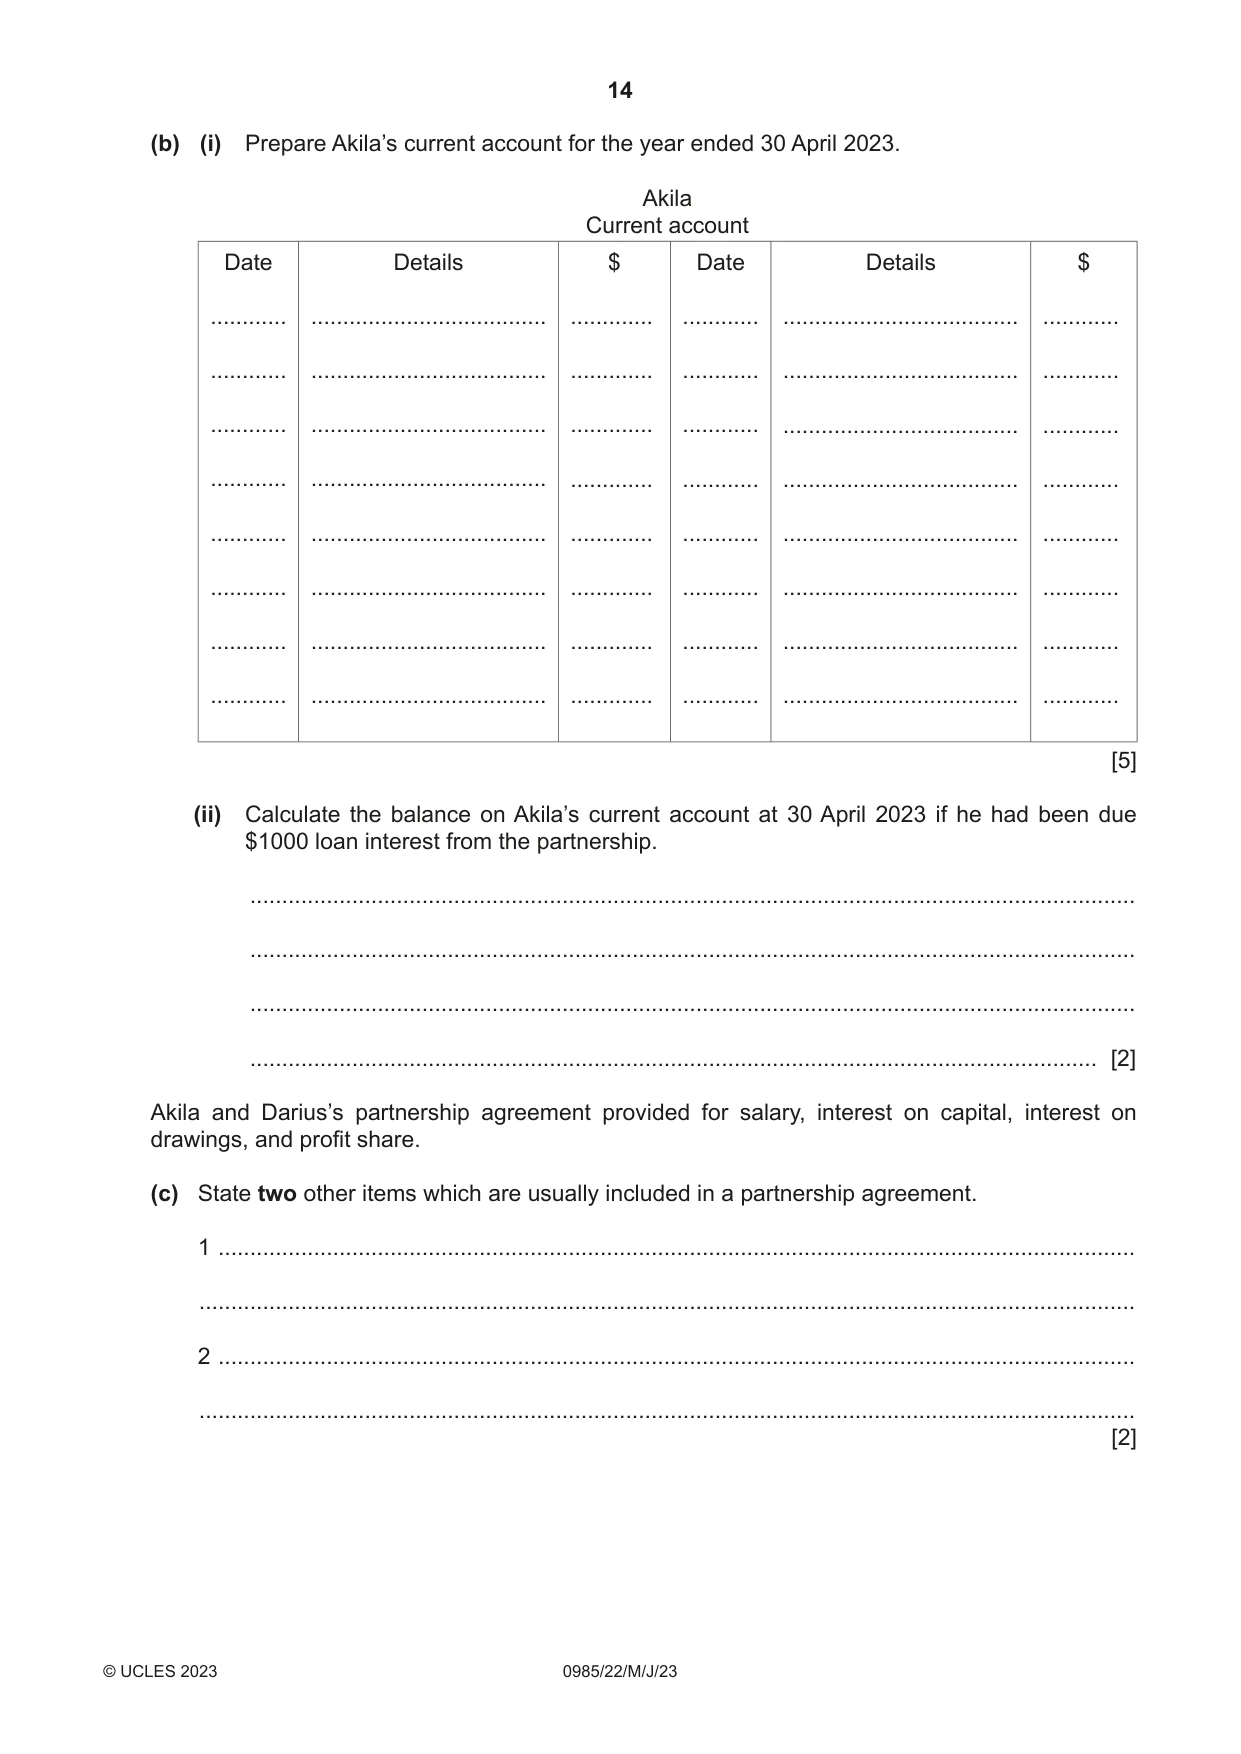
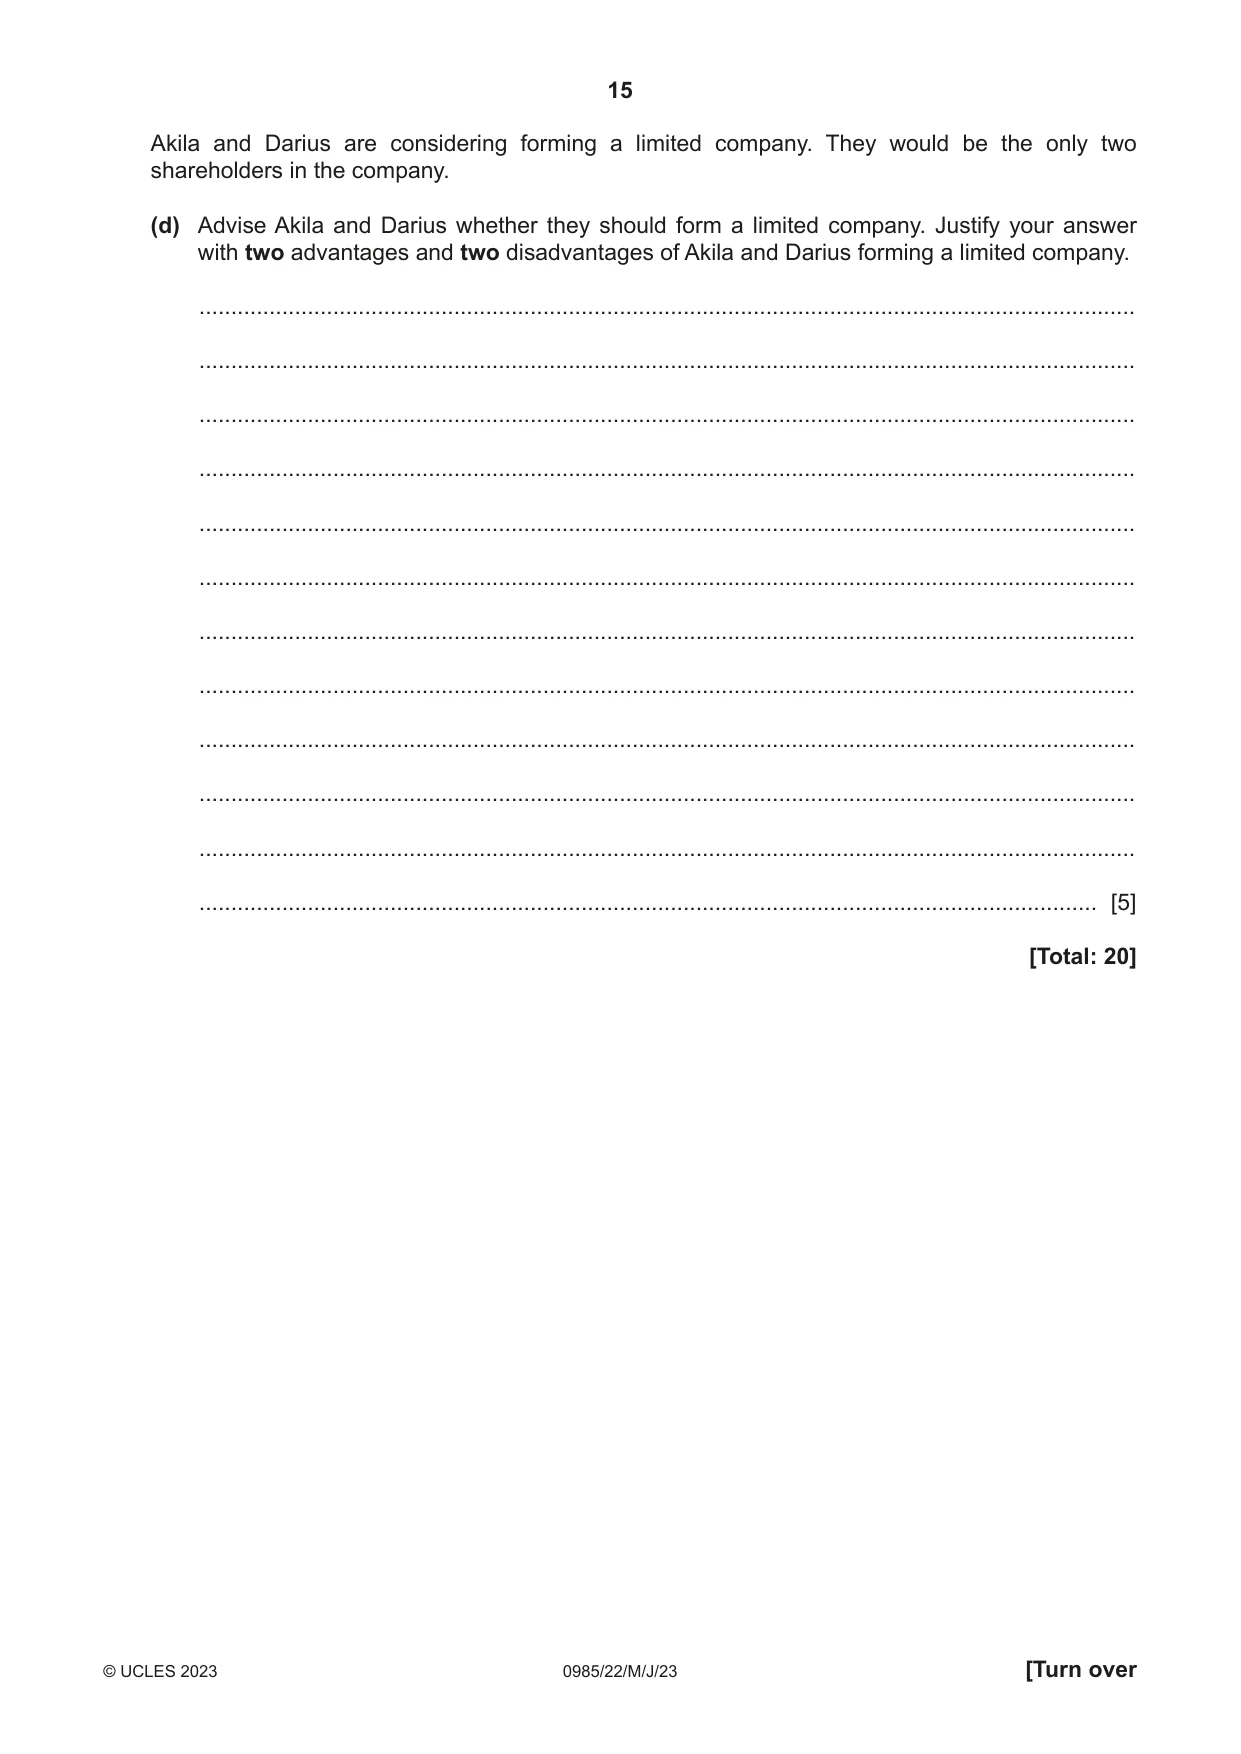
4 Akila and Darius are in partnership. The partnership agreement provides for the following: interest on capital of 3% per annum interest on drawings of 5% a salary to Akila of $9500 per annum residual profits and losses to be shared 60% to Akila and 40% to Darius. The partners provided the following list of balances. $ Capital accounts at 1 May 2022 Akila 90 000 Darius 65 000 Current accounts at 1 May 2022 Akila 2 600 debit Darius 4 745 credit Drawings for the year ended 30 April 2023 Akila 19 400 Darius 16 320 The profit for the year ended 30 April 2023 was $42 304. REQUIRED (a) Prepare the appropriation account on the opposite page for Akila and Darius for the year ended 30 April 2023. Akila and Darius Appropriation Account for the year ended 30 April 2023 $ $ ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... ......................................................................................... ....................... ....................... [6] (b) (i) Prepare Akila’s current account for the year ended 30 April 2023. Akila Current account Date Details $ Date Details $ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ [5] (ii) Calculate the balance on Akila’s current account at 30 April 2023 if he had been due $1000 loan interest from the partnership. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] Akila and Darius’s partnership agreement provided for salary, interest on capital, interest on drawings, and profit share. (c) State two other items which are usually included in a partnership agreement. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] Akila and Darius are considering forming a limited company. They would be the only two shareholders in the company. (d) Advise Akila and Darius whether they should form a limited company. Justify your answer with two advantages and two disadvantages of Akila and Darius forming a limited company. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
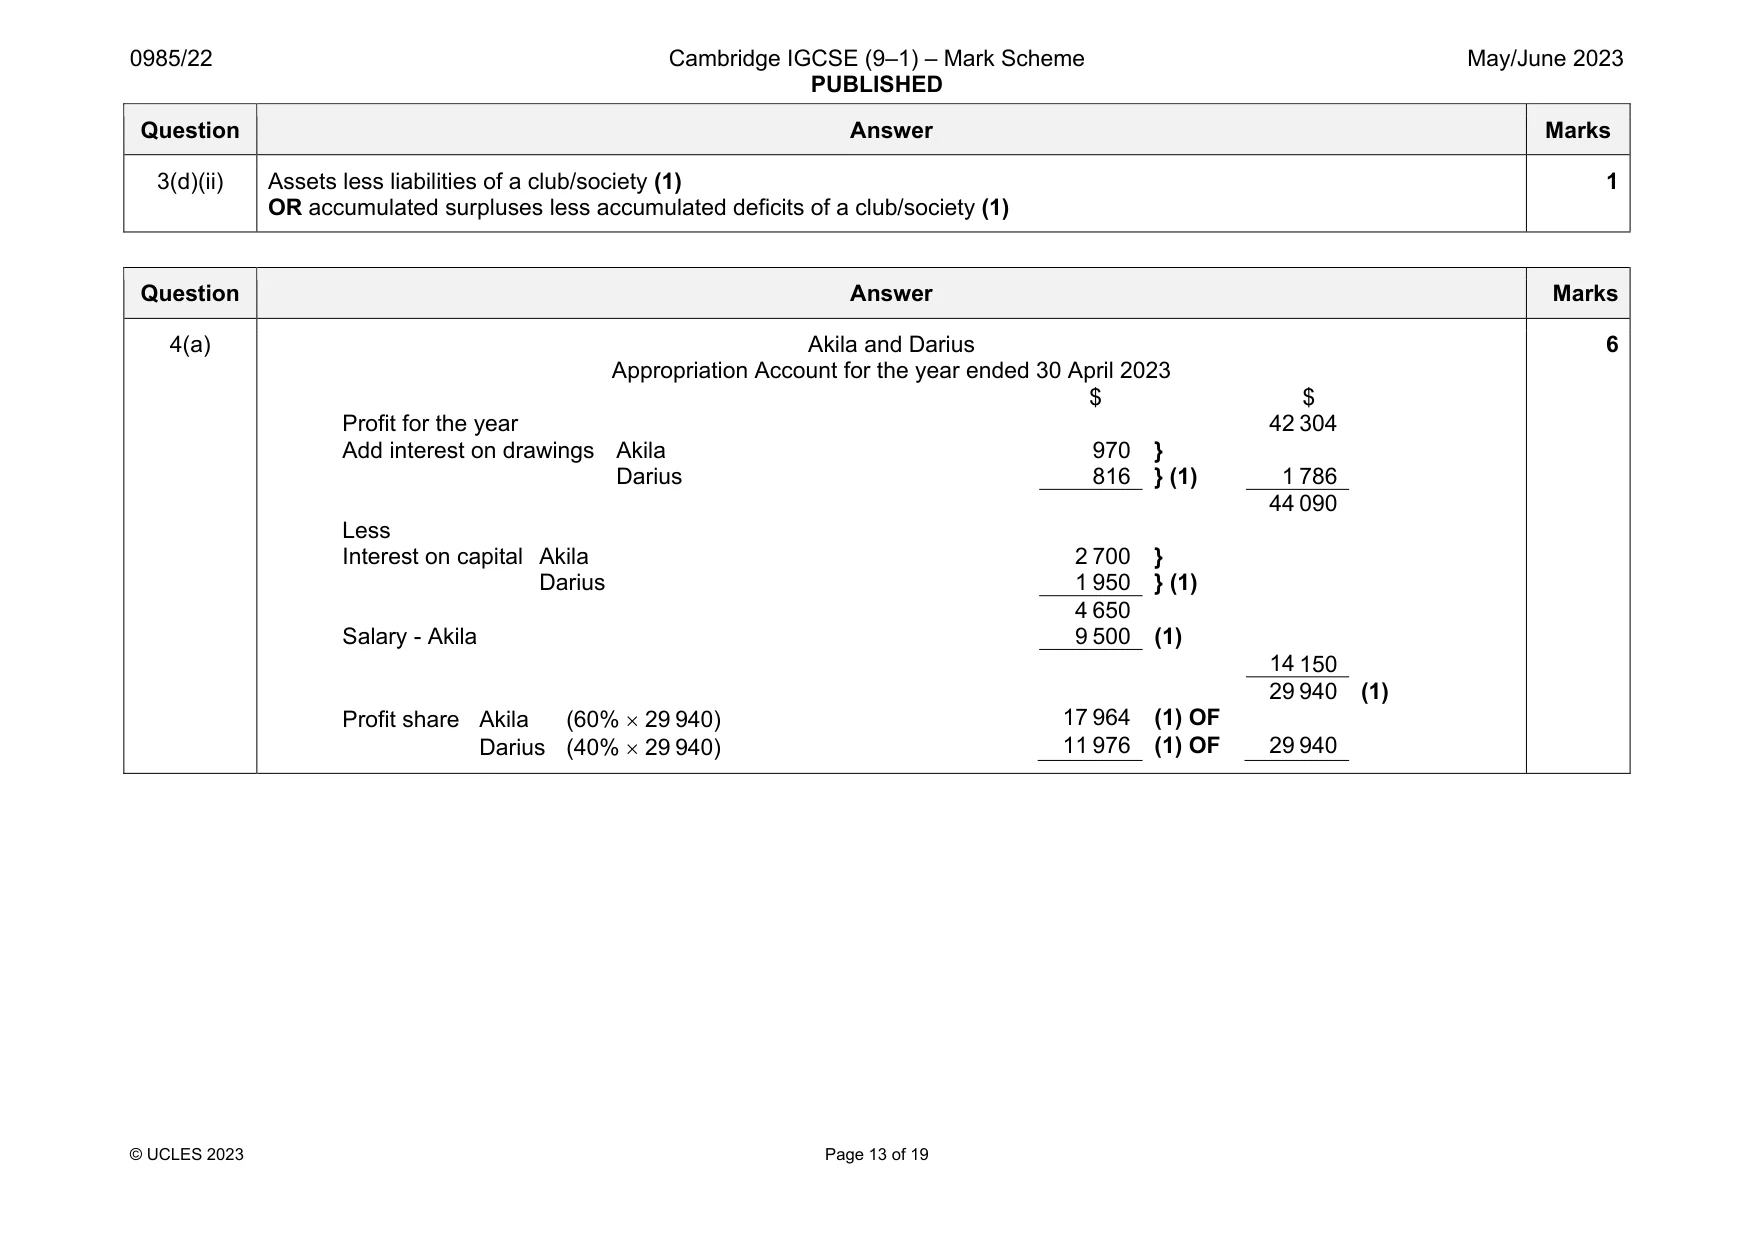
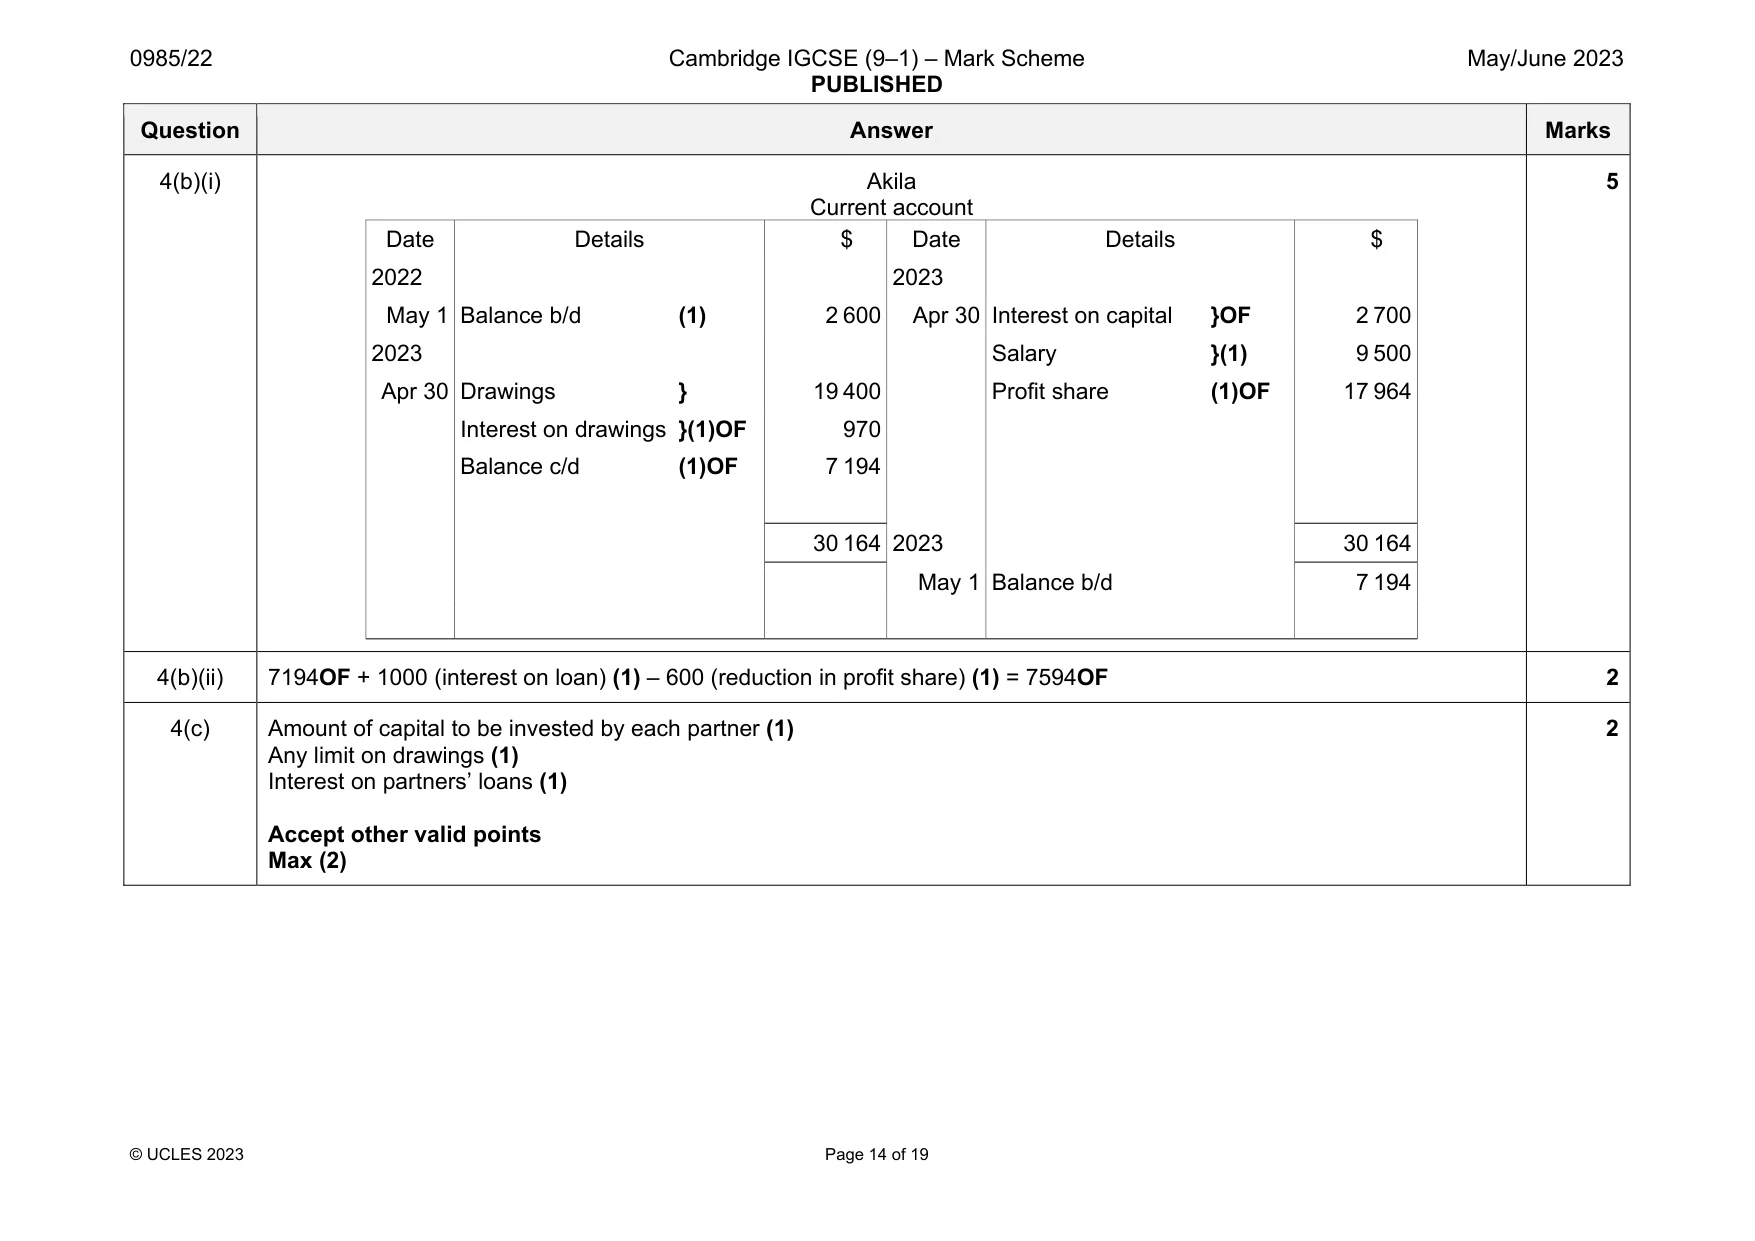
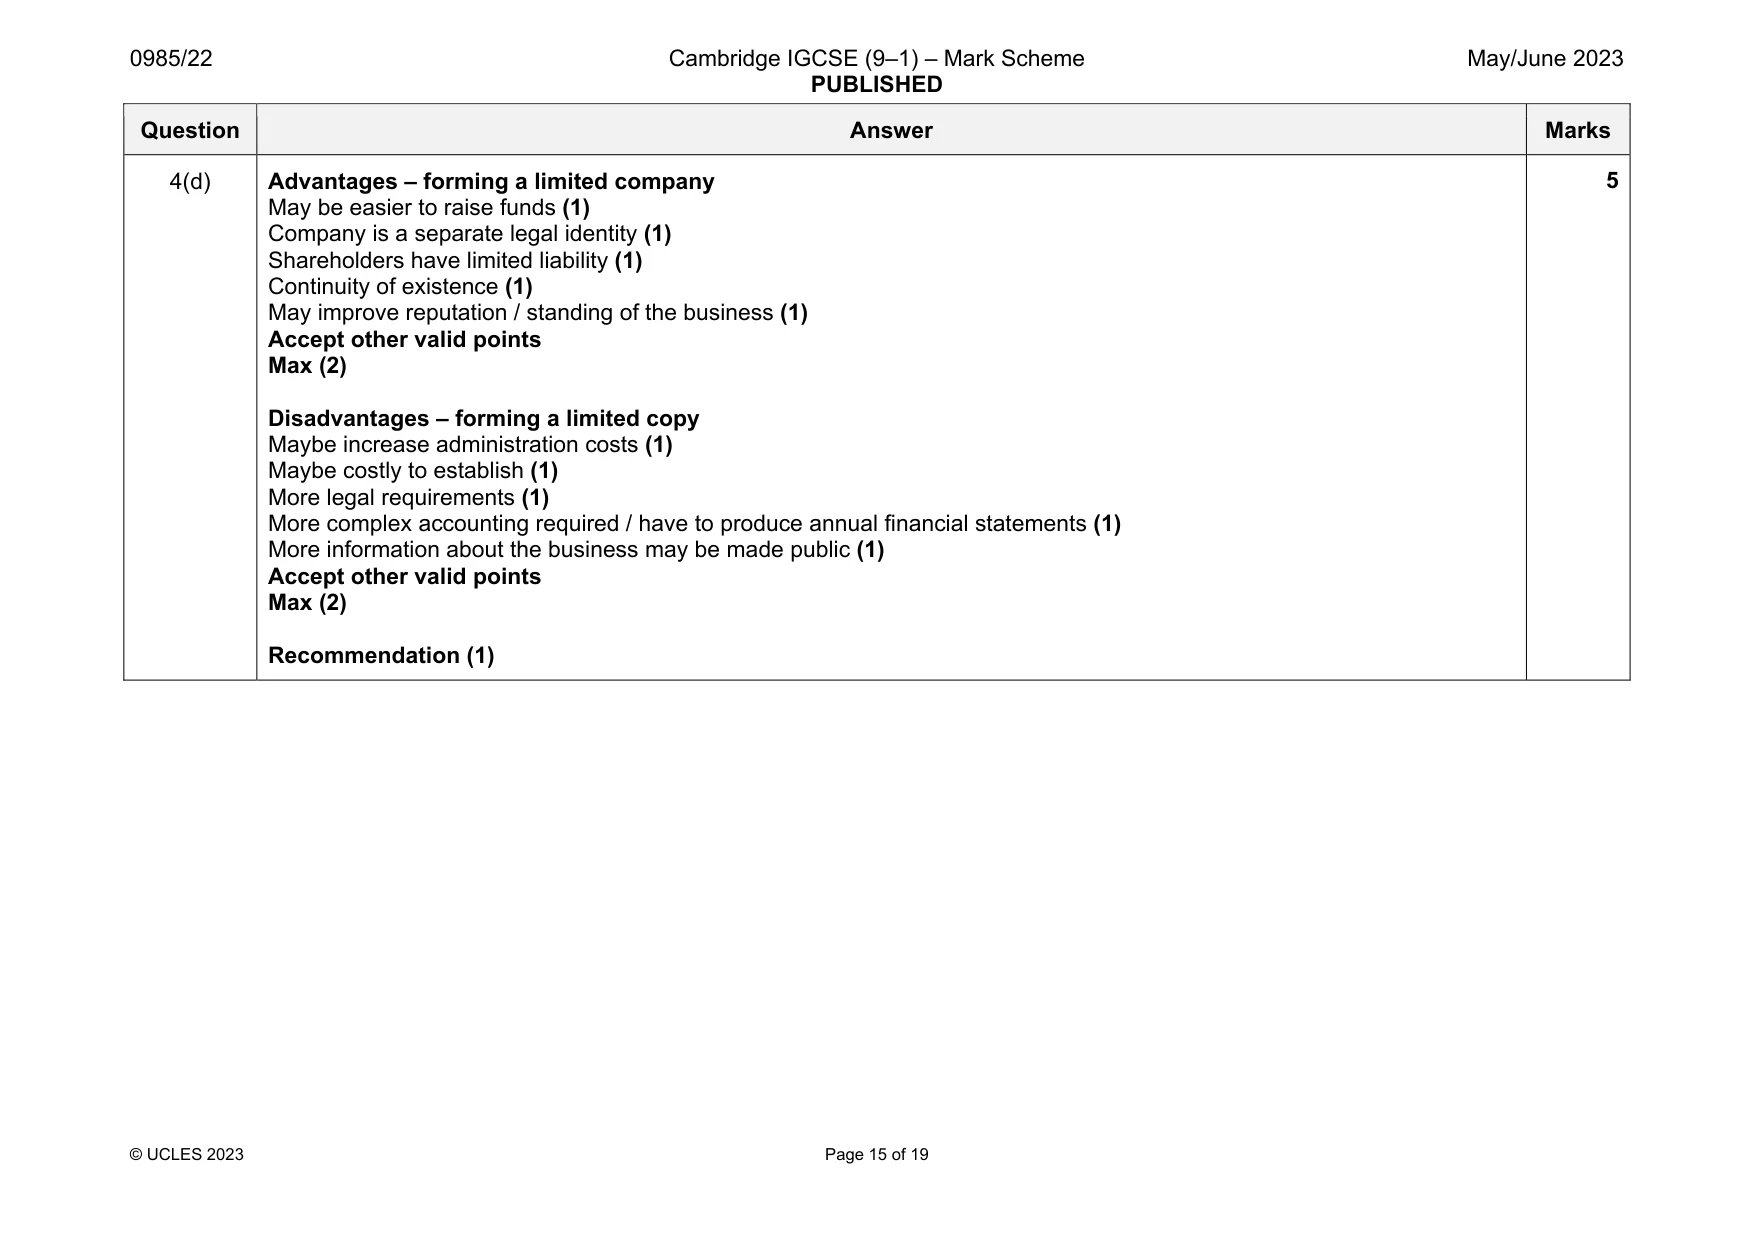
Mark scheme: 4(a) Akila and Darius Appropriation Account for the year ended 30 April 2023 $ $ Profit for the year 42 304 Add interest on drawings Akila 970 } Darius 816 } (1) 1 786 44 090 Less Interest on capital Akila 2 700 } Darius 1 950 } (1) 4 650 Salary - Akila 9 500 (1) 14 150 29 940 (1) Profit share Akila (60% 29 940) 17 964 (1) OF Darius (40% 29 940) 11 976 (1) OF 29 940 6 Question Answer Marks 4(b)(i) Akila Current account Date Details $ Date Details $ 2022 2023 May 1 Balance b/d (1) 2 600 Apr 30 Interest on capital }OF 2 700 2023 Salary }(1) 9 500 Apr 30 Drawings } 19 400 Profit share (1)OF 17 964 Interest on drawings }(1)OF 970 Balance c/d (1)OF 7 194 30 164 2023 30 164 May 1 Balance b/d 7 194 5 4(b)(ii) 7194OF + 1000 (interest on loan) (1) – 600 (reduction in profit share) (1) = 7594OF 2 4(c) Amount of capital to be invested by each partner (1) Any limit on drawings (1) Interest on partners’ loans (1) Accept other valid points Max (2) 2 Question Answer Marks 4(d) Advantages – forming a limited company May be easier to raise funds (1) Company is a separate legal identity (1) Shareholders have limited liability (1) Continuity of existence (1) May improve reputation / standing of the business (1) Accept other valid points Max (2) Disadvantages – forming a limited copy Maybe increase administration costs (1) Maybe costly to establish (1) More legal requirements (1) More complex accounting required / have to produce annual financial statements (1) More information about the business may be made public (1) Accept other valid points Max (2) Recommendation (1) 5
Q5 · Amadi prepared the following trial balance which is not yet totalled and contains errors
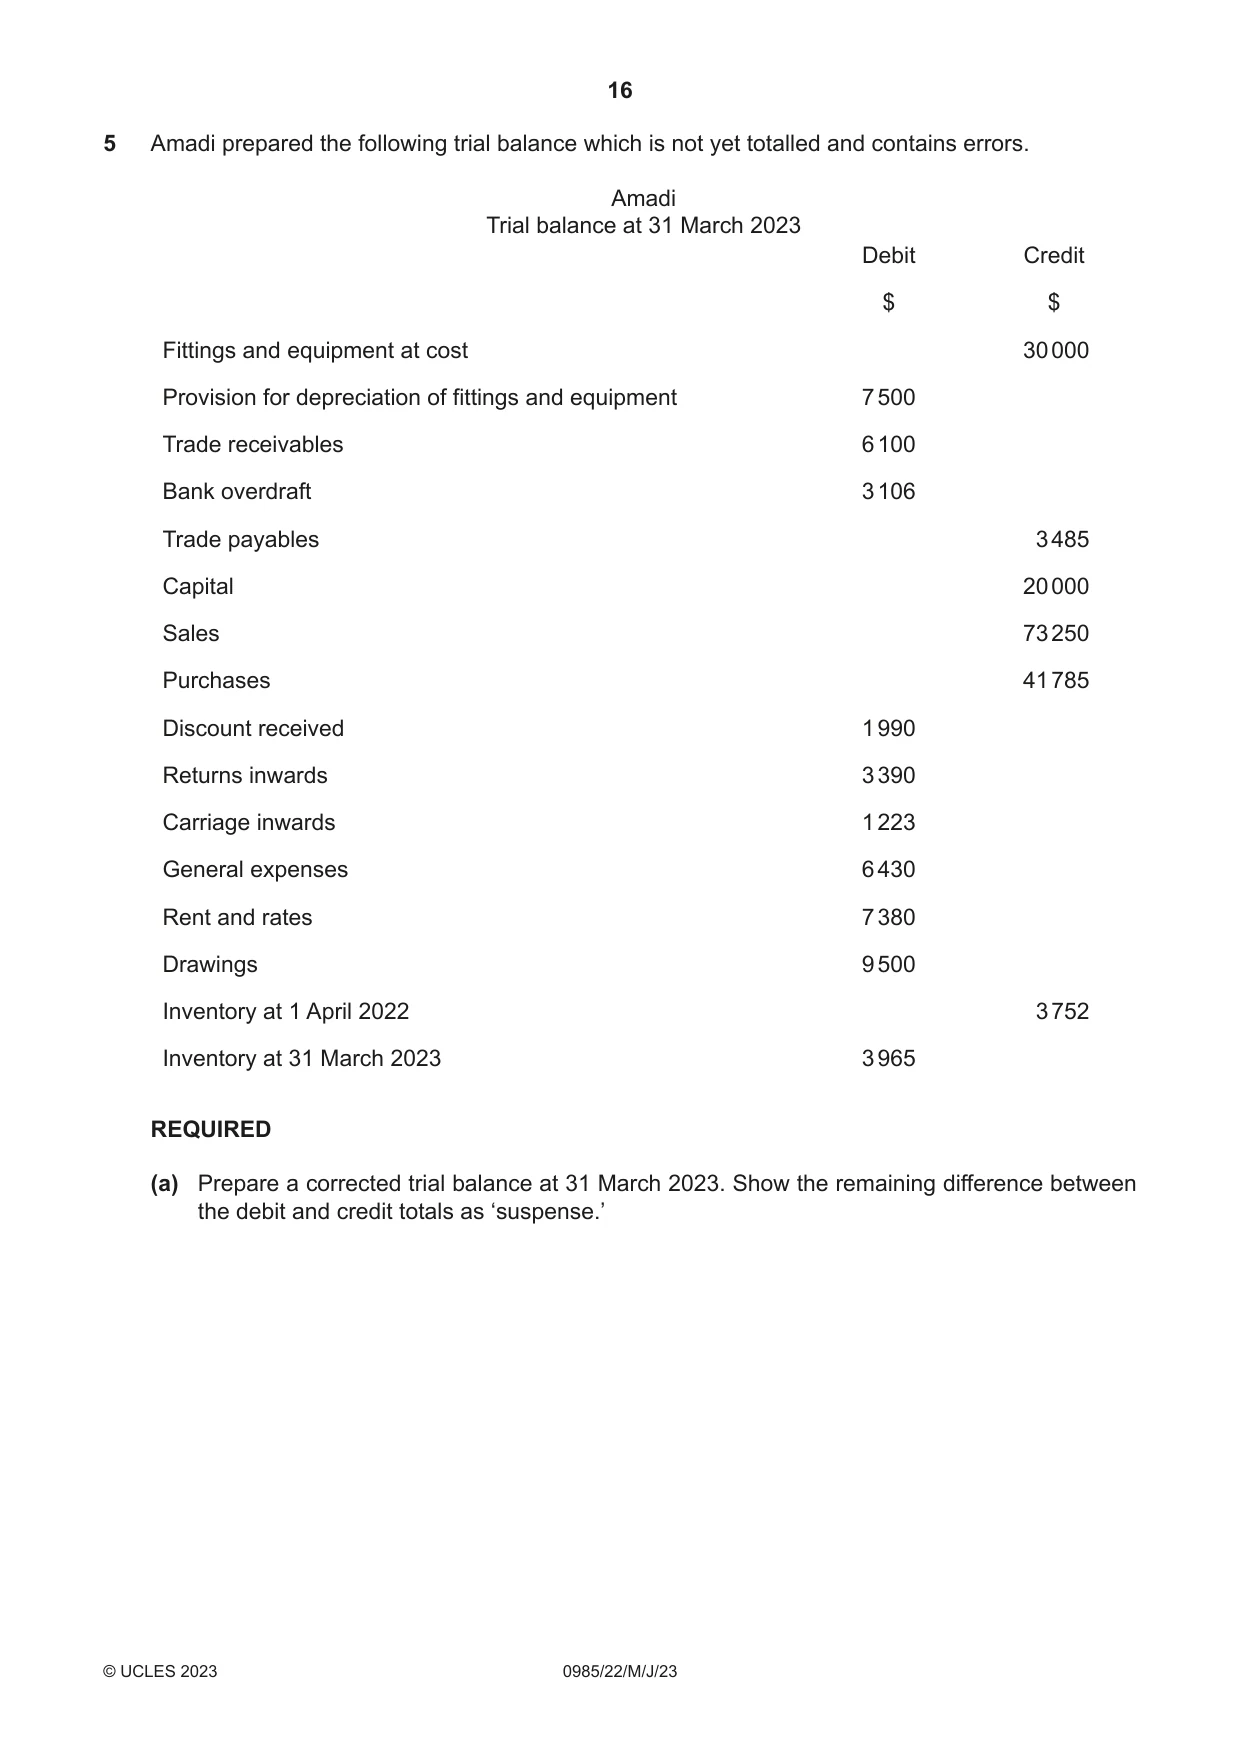
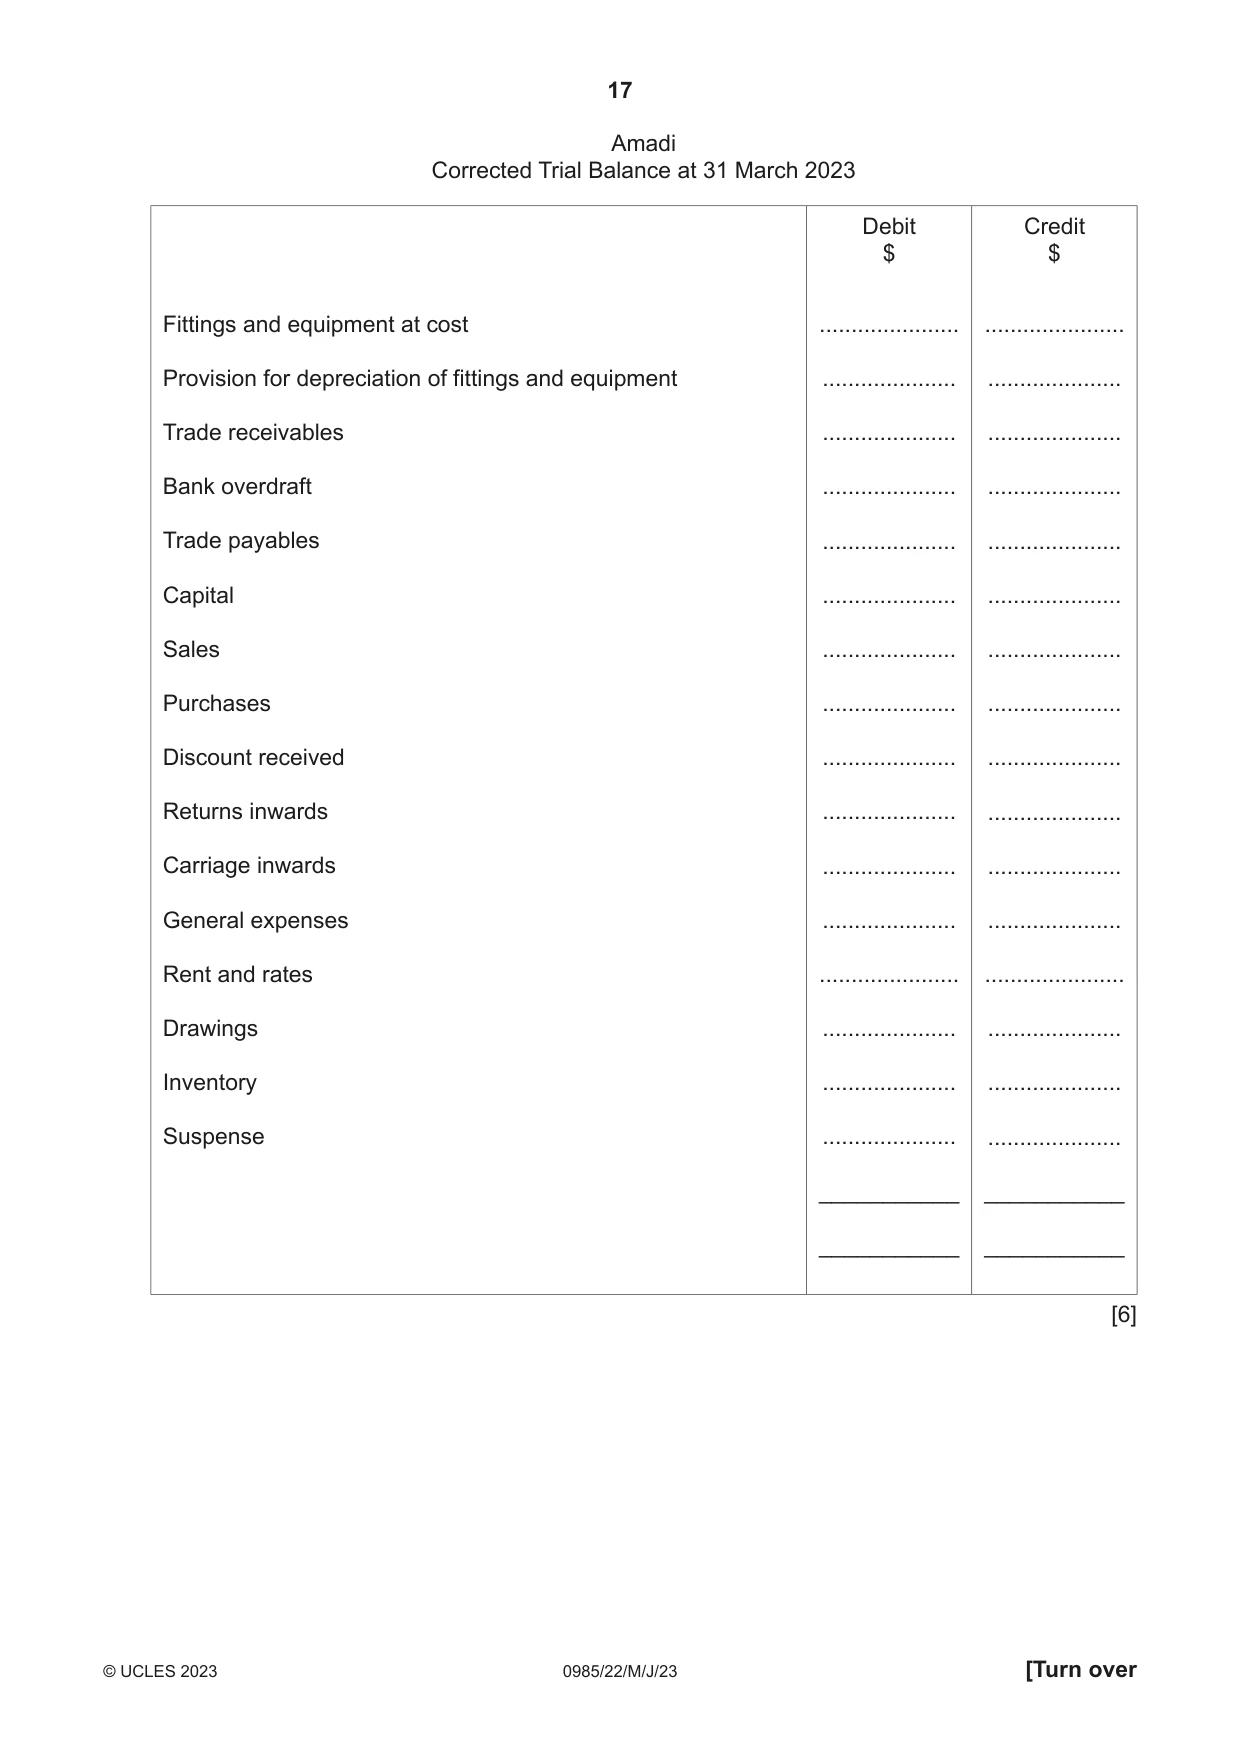
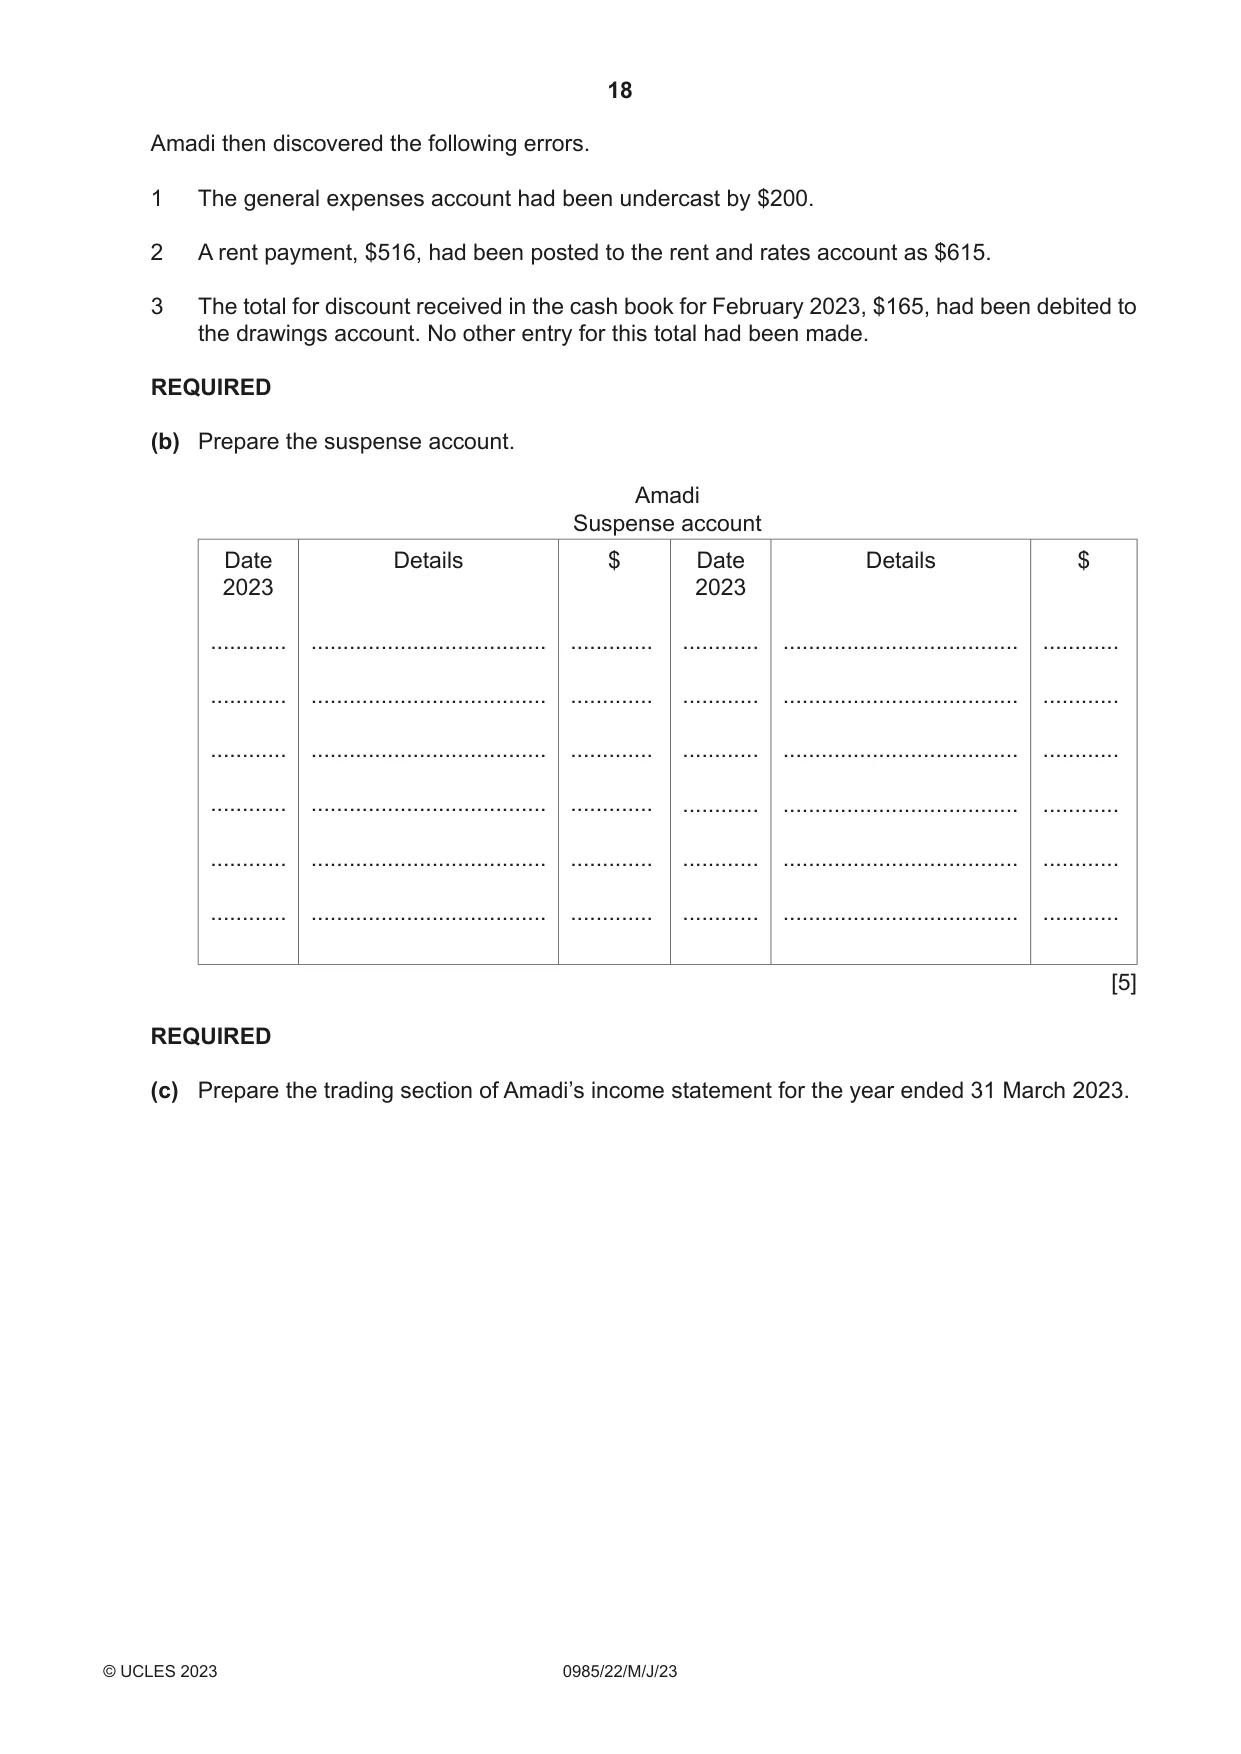
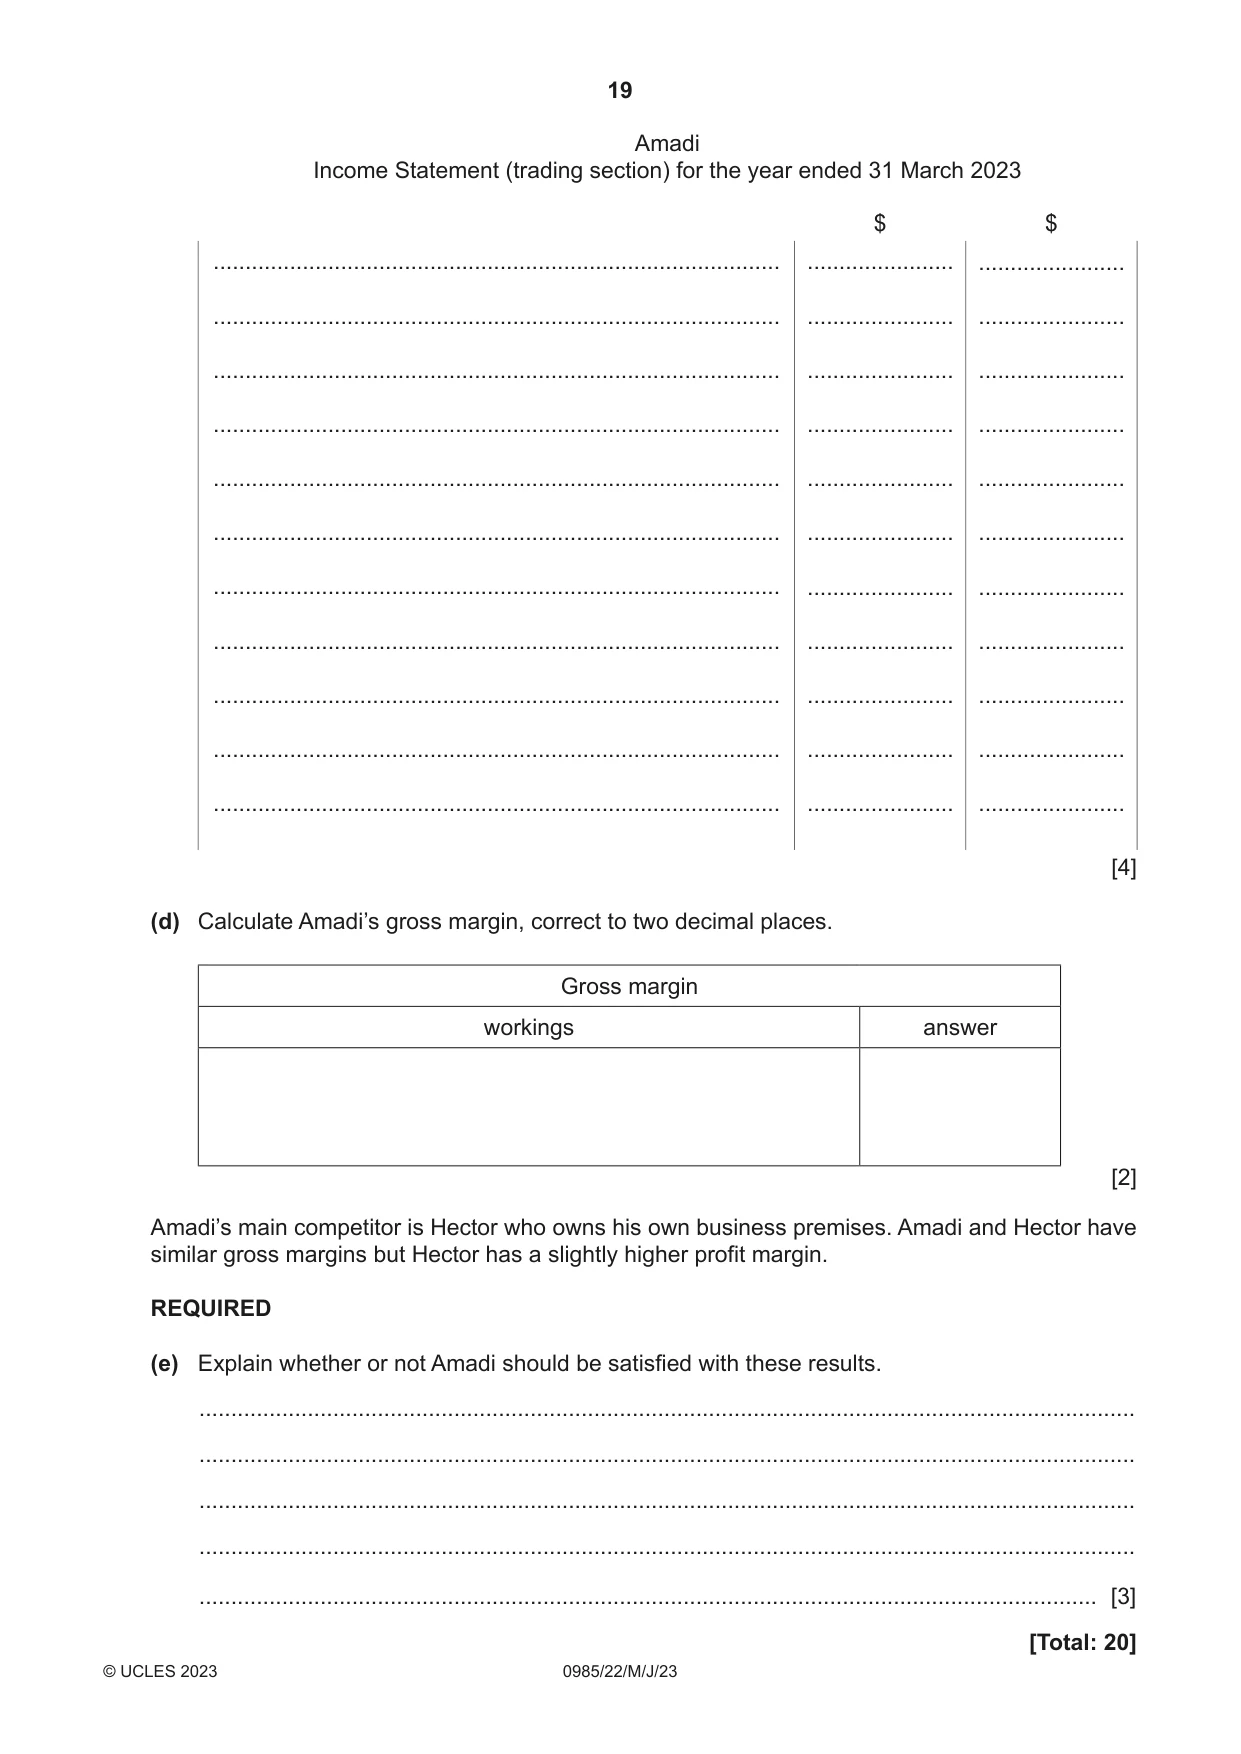
5 Amadi prepared the following trial balance which is not yet totalled and contains errors. Amadi Trial balance at 31 March 2023 Debit Credit $ $ Fittings and equipment at cost 30 000 Provision for depreciation of fittings and equipment 7 500 Trade receivables 6 100 Bank overdraft 3 106 Trade payables 3 485 Capital 20 000 Sales 73 250 Purchases 41 785 Discount received 1 990 Returns inwards 3 390 Carriage inwards 1 223 General expenses 6 430 Rent and rates 7 380 Drawings 9 500 Inventory at 1 April 2022 3 752 Inventory at 31 March 2023 3 965 REQUIRED (a) Prepare a corrected trial balance at 31 March 2023. Show the remaining difference between the debit and credit totals as ‘suspense.’ Amadi Corrected Trial Balance at 31 March 2023 Debit Credit $ $ Fittings and equipment at cost ...................... ...................... Provision for depreciation of fittings and equipment ..................... ..................... Trade receivables ..................... ..................... Bank overdraft ..................... ..................... Trade payables ..................... ..................... Capital ..................... ..................... Sales ..................... ..................... Purchases ..................... ..................... Discount received ..................... ..................... Returns inwards ..................... ..................... Carriage inwards ..................... ..................... General expenses ..................... ..................... Rent and rates ...................... ...................... Drawings ..................... ..................... Inventory ..................... ..................... Suspense ..................... ..................... ___________ ___________ ___________ ___________ [6] Amadi then discovered the following errors. 1 The general expenses account had been undercast by $200. 2 A rent payment, $516, had been posted to the rent and rates account as $615. 3 The total for discount received in the cash book for February 2023, $165, had been debited to the drawings account. No other entry for this total had been made. REQUIRED (b) Prepare the suspense account. Amadi Suspense account Date Details $ Date Details $ 2023 2023 ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ ............ ..................................... ............. ............ ..................................... ............ [5] REQUIRED (c) Prepare the trading section of Amadi’s income statement for the year ended 31 March 2023.
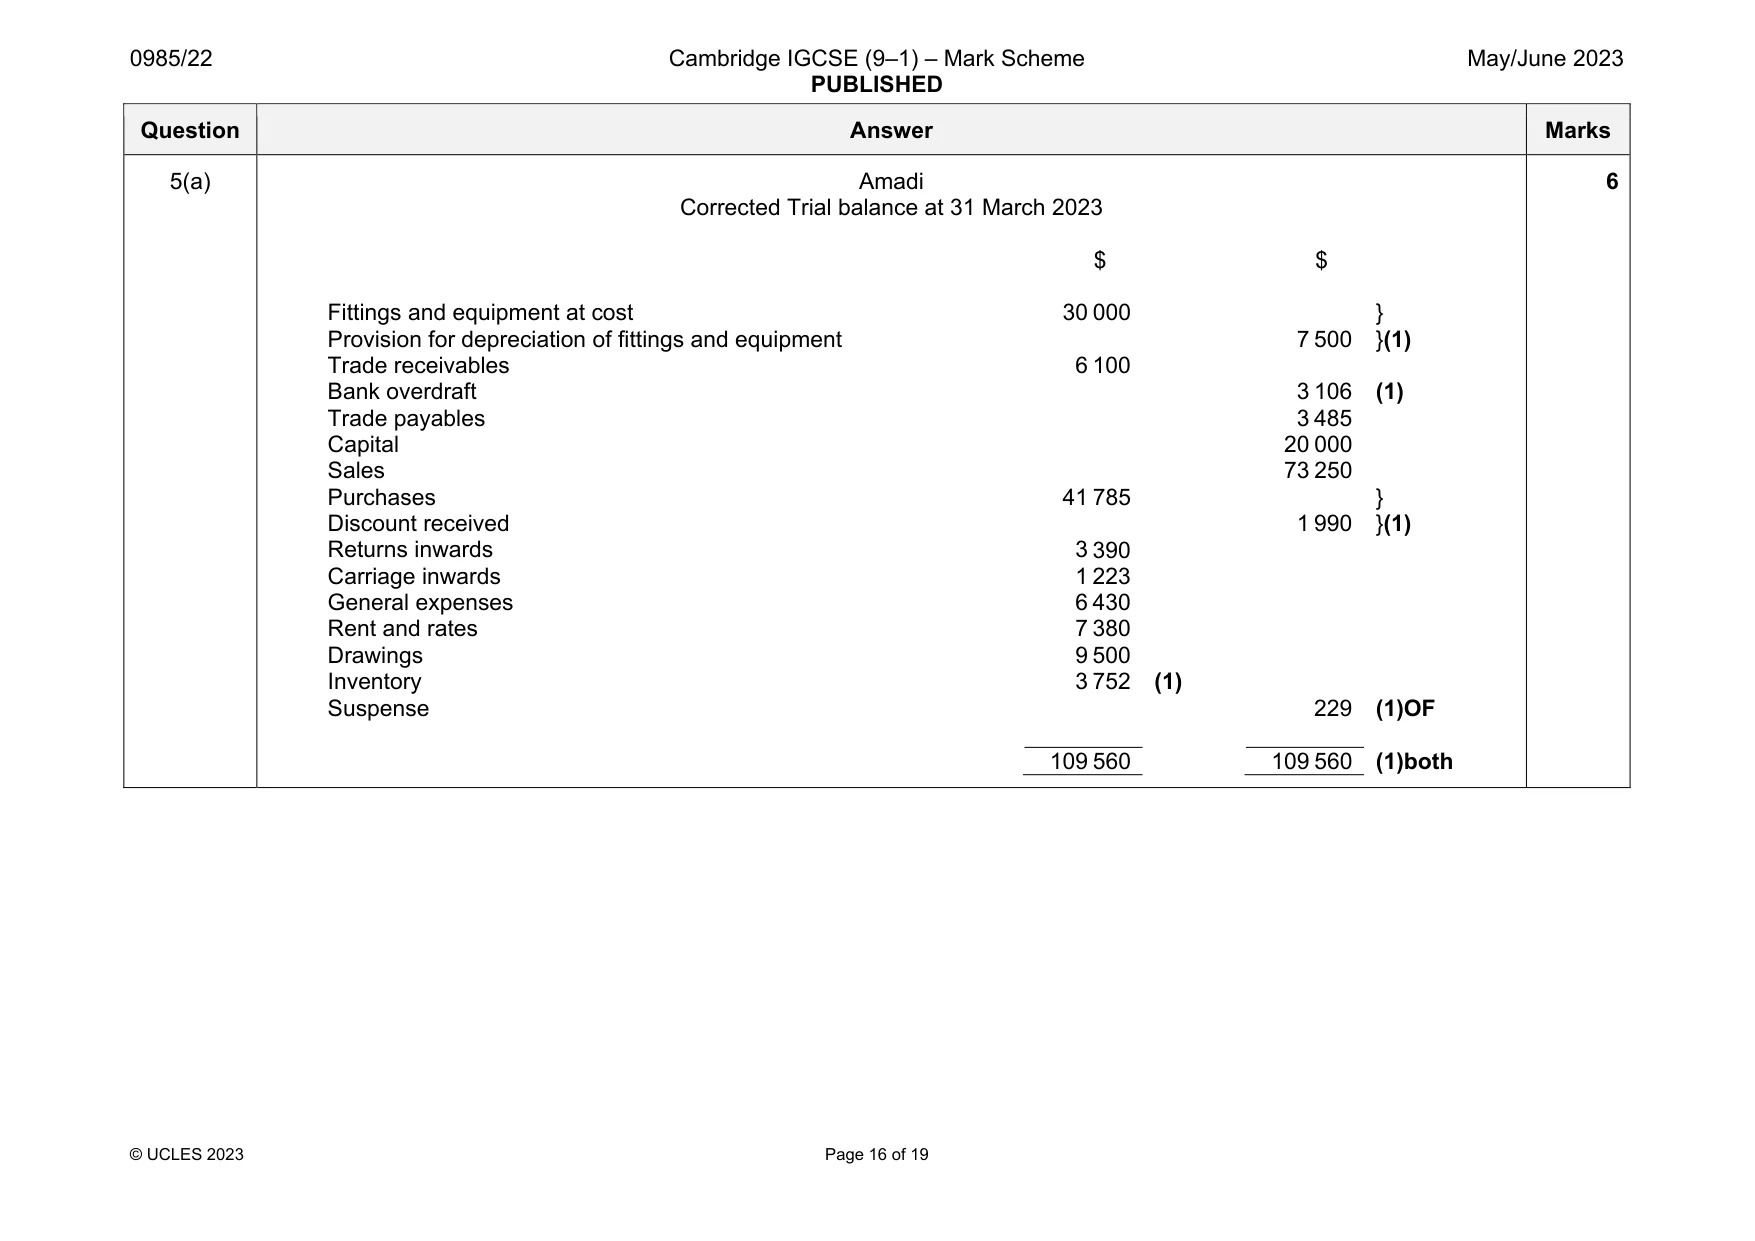
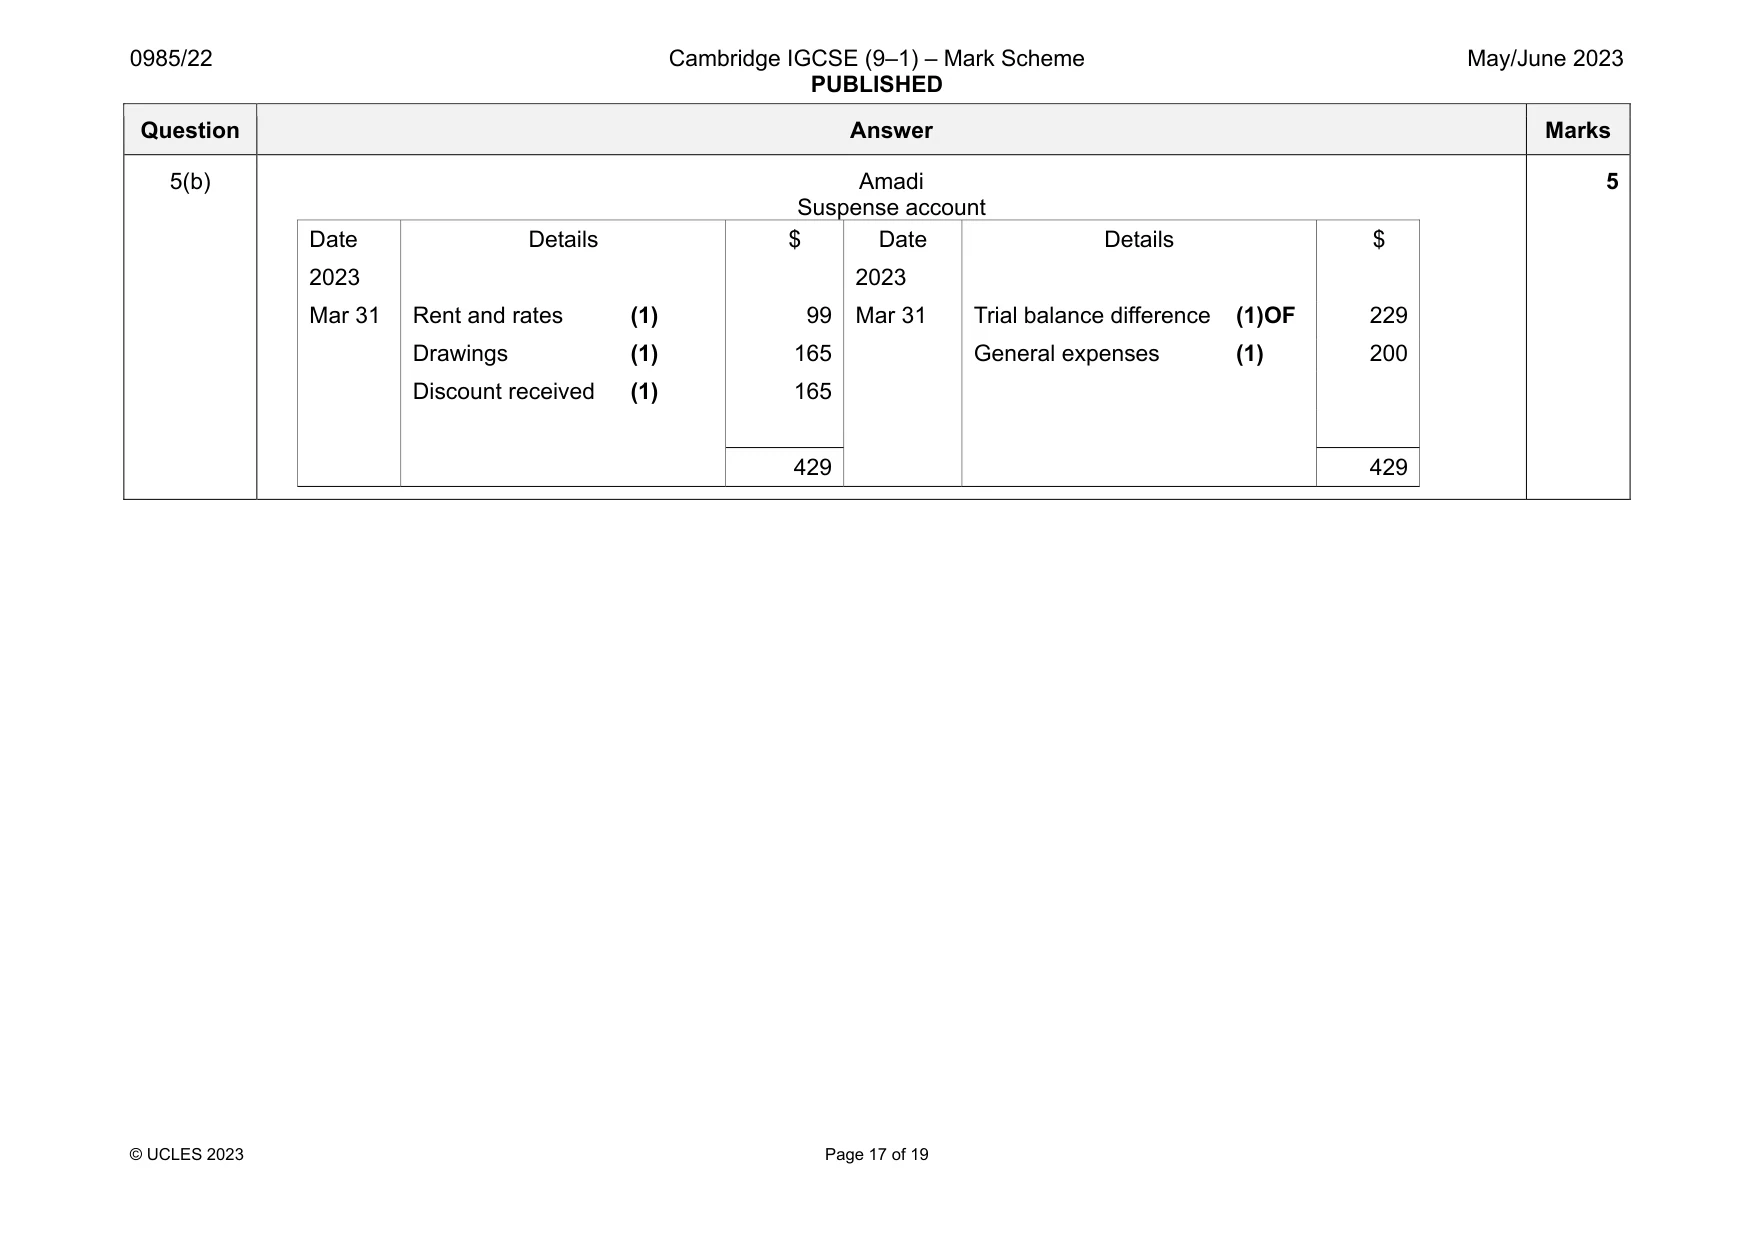
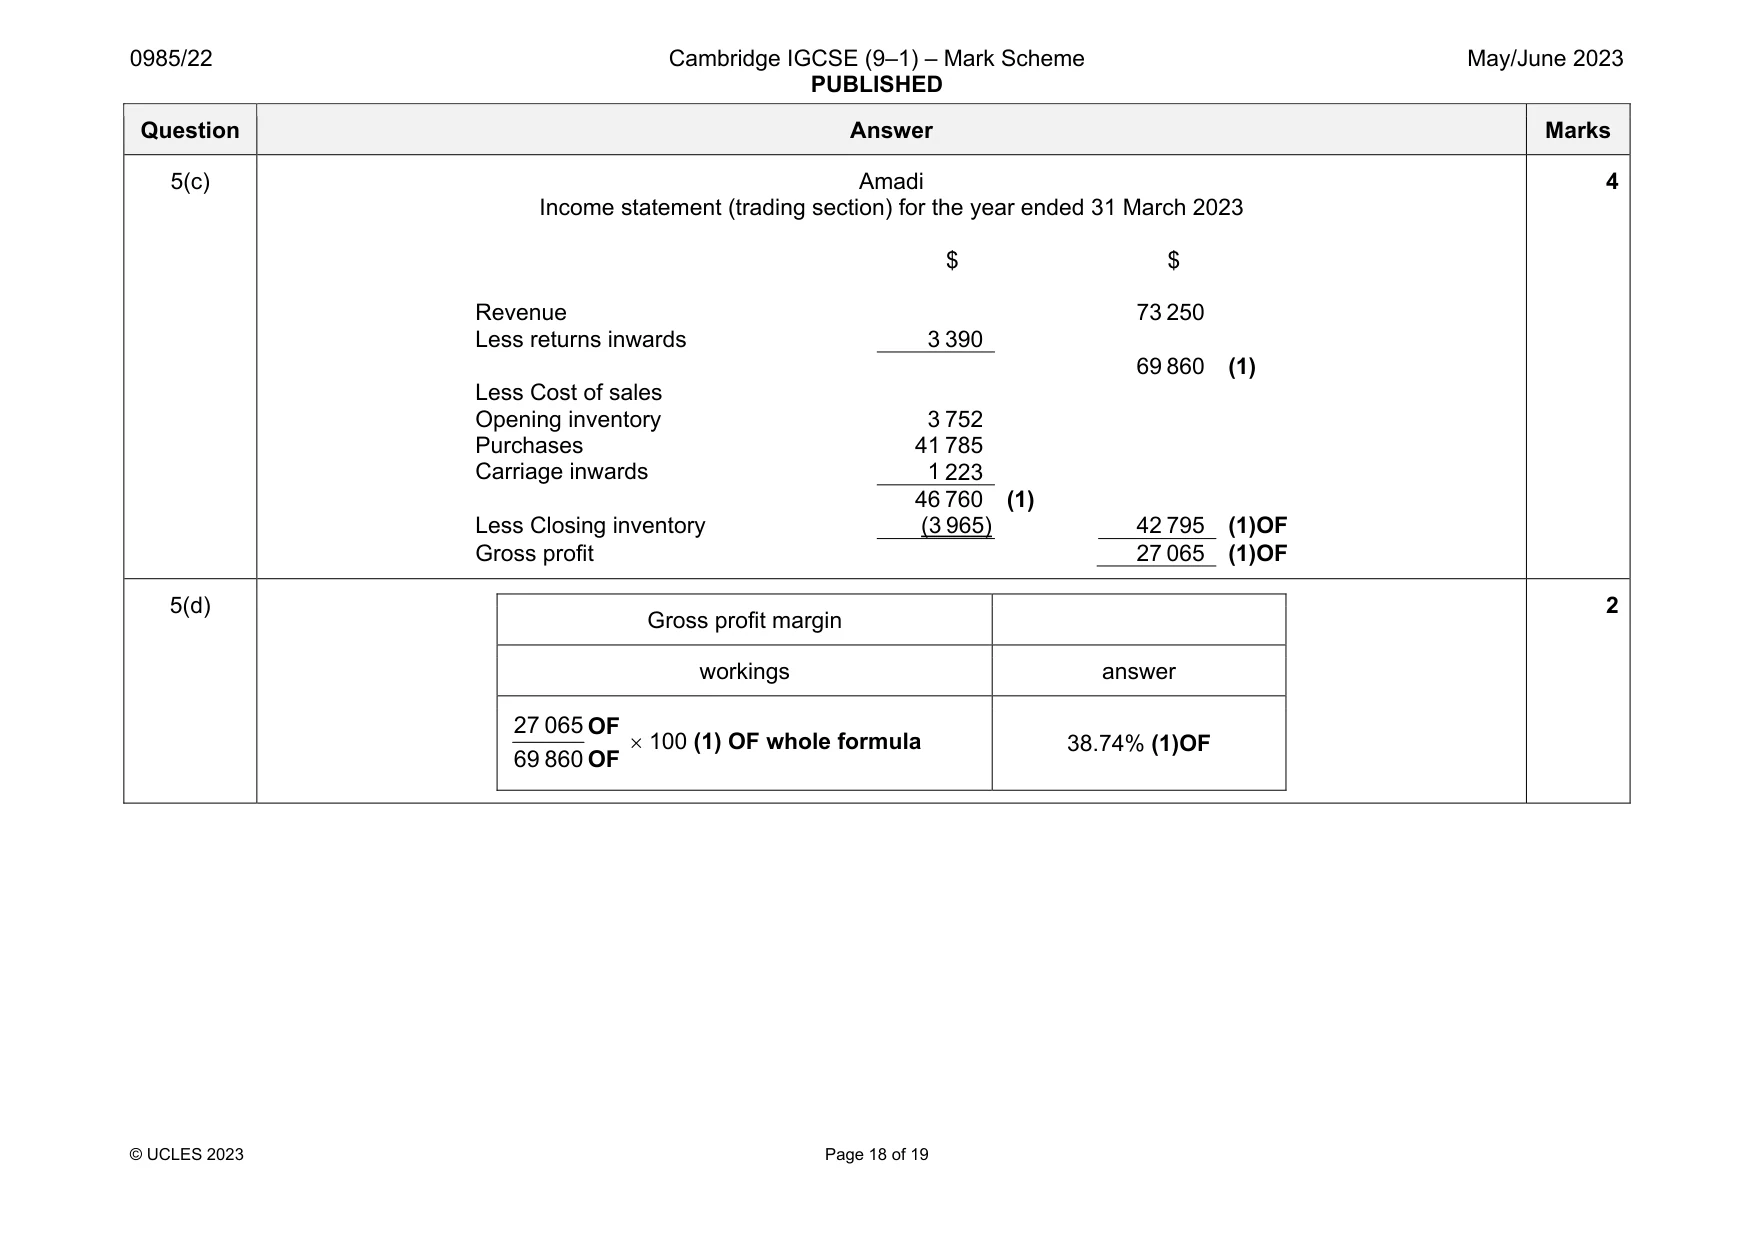
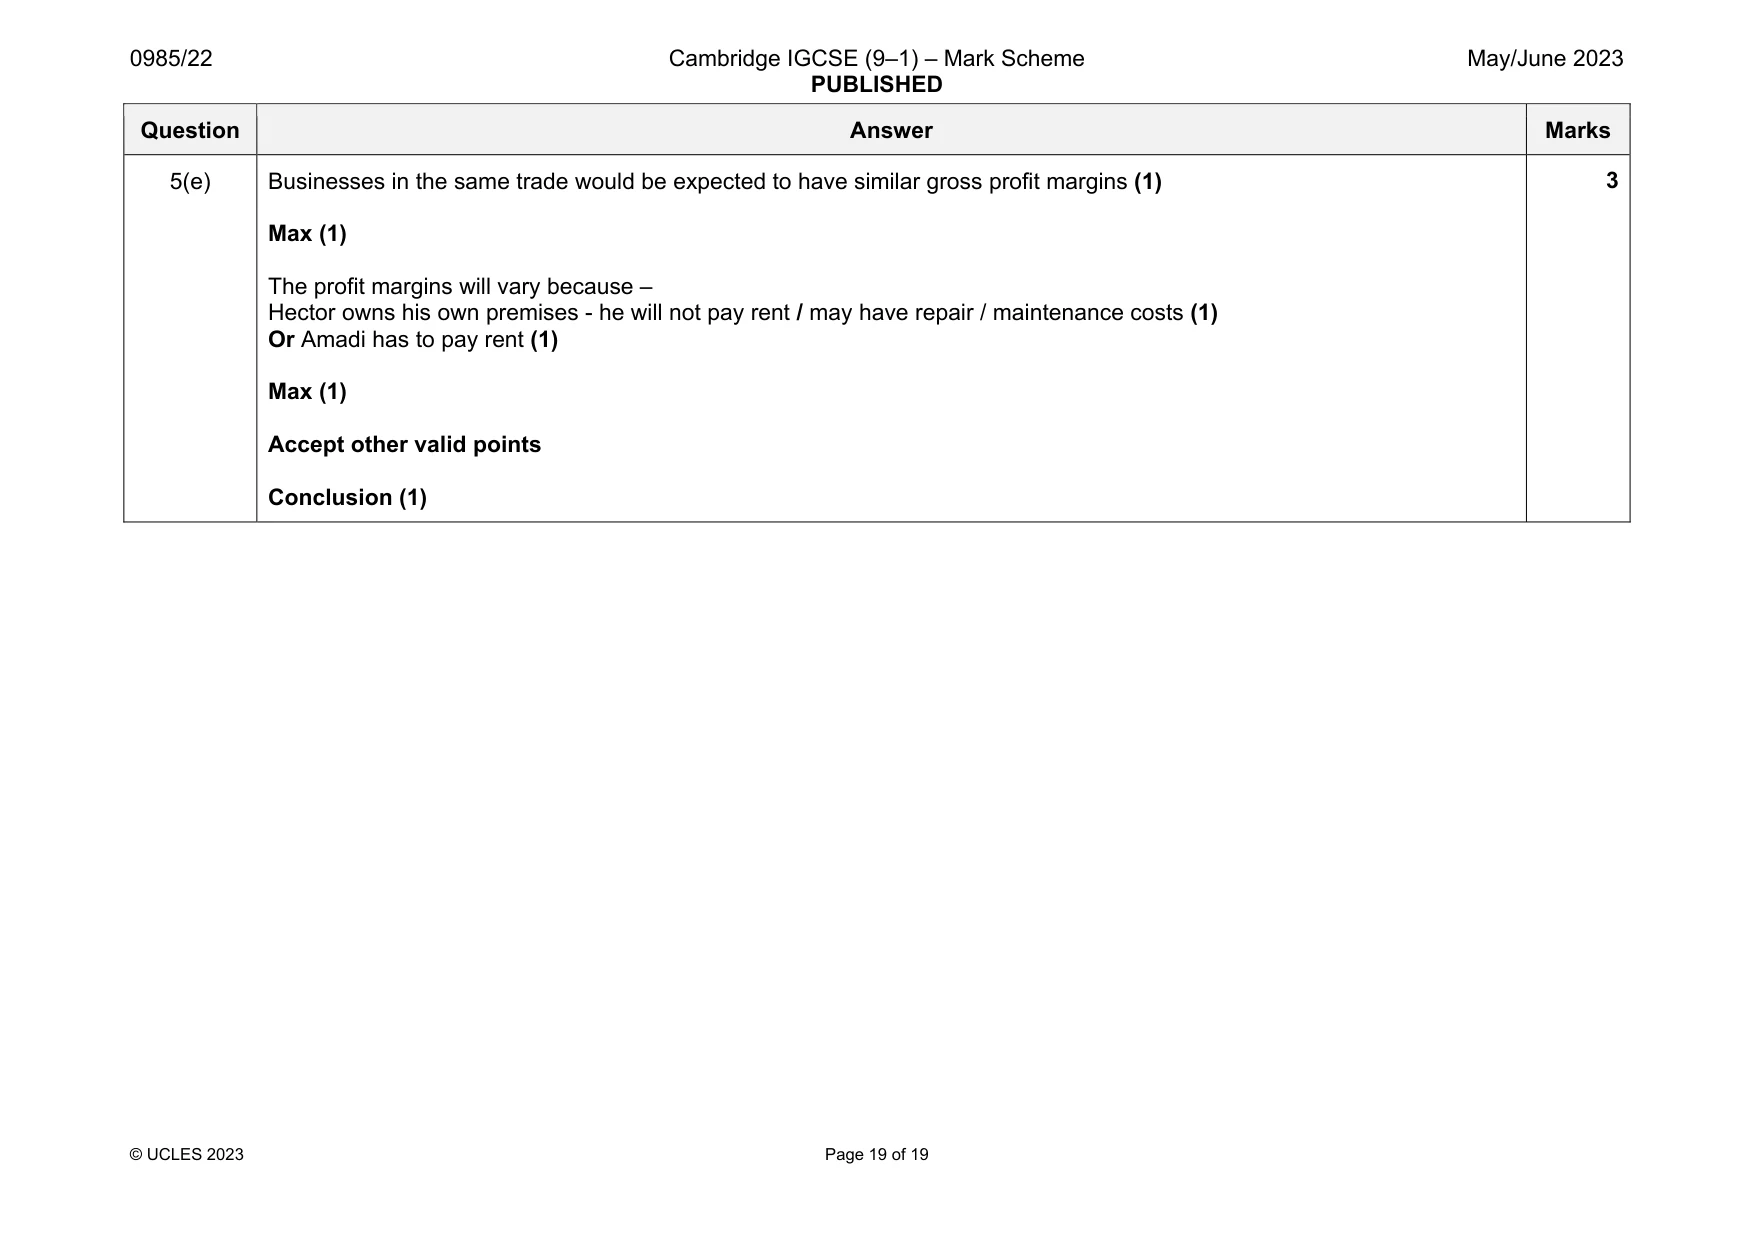
Mark scheme: 5(a) Amadi Corrected Trial balance at 31 March 2023 $ $ Fittings and equipment at cost 30 000 } Provision for depreciation of fittings and equipment 7 500 }(1) Trade receivables 6 100 Bank overdraft 3 106 (1) Trade payables 3 485 Capital 20 000 Sales 73 250 Purchases 41 785 } Discount received 1 990 }(1) Returns inwards 3 390 Carriage inwards 1 223 General expenses 6 430 Rent and rates 7 380 Drawings 9 500 Inventory 3 752 (1) Suspense 229 (1)OF 109 560 109 560 (1)both 6 Question Answer Marks 5(b) Amadi Suspense account Date Details $ Date Details $ 2023 2023 Mar 31 Rent and rates (1) 99 Mar 31 Trial balance difference (1)OF 229 Drawings (1) 165 General expenses (1) 200 Discount received (1) 165 429 429 5 Question Answer Marks 5(c) Amadi Income statement (trading section) for the year ended 31 March 2023 $ $ Revenue 73 250 Less returns inwards 3 390 69 860 (1) Less Cost of sales Opening inventory 3 752 Purchases 41 785 Carriage inwards 1 223 46 760 (1) Less Closing inventory (3 965) 42 795 (1)OF Gross profit 27 065 (1)OF 4 5(d) Gross profit margin workings answer 27 065 69 860 OF OF 100 (1) OF whole formula 38.74% (1)OF 2 Question Answer Marks 5(e) Businesses in the same trade would be expected to have similar gross profit margins (1) Max (1) The profit margins will vary because – Hector owns his own premises - he will not pay rent / may have repair / maintenance costs (1) Or Amadi has to pay rent (1) Max (1) Accept other valid points Conclusion (1) 3
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2023 May/June, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.