Cambridge IGCSE Accounting (9-1) 0985 — 2025 May/June Paper 2 · Variant 2
0985/22/M/J/25 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme14 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Kadima is a trader
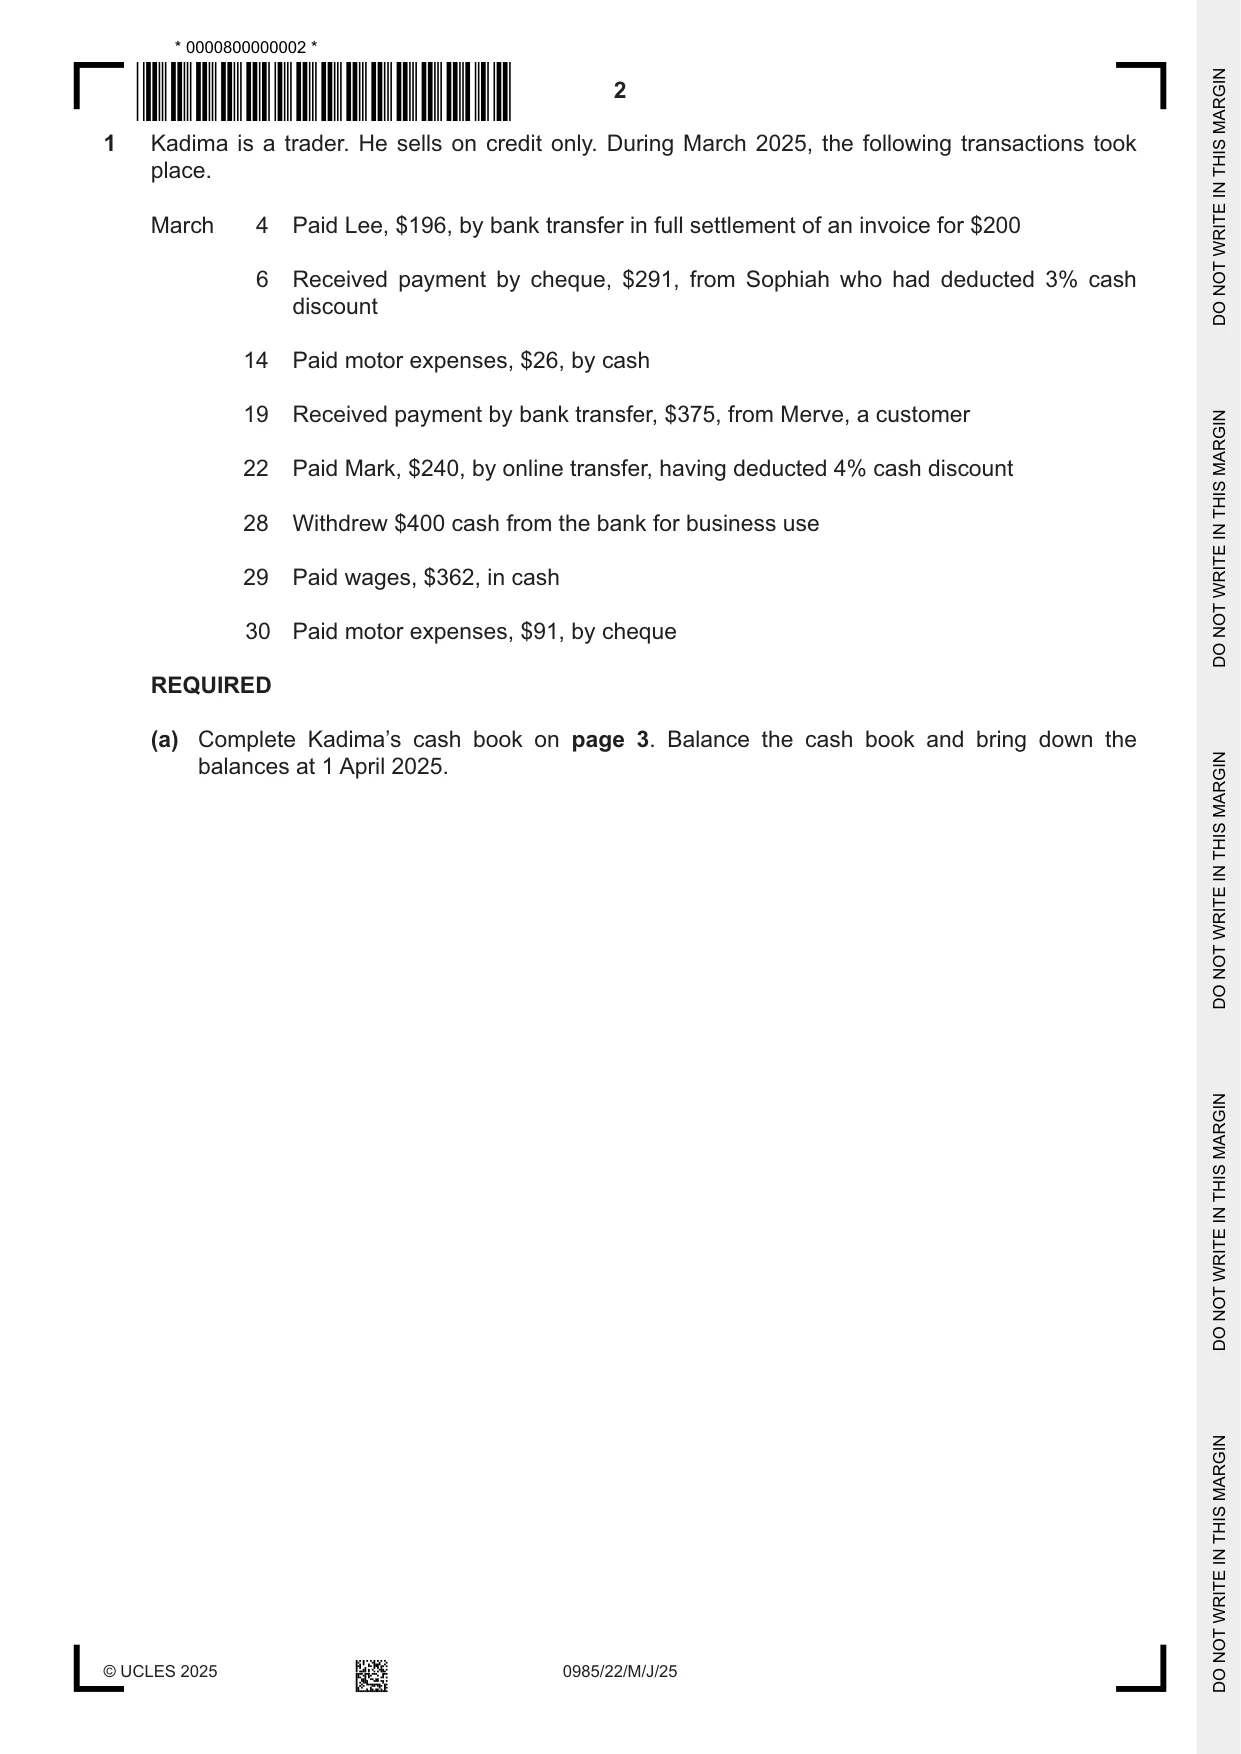
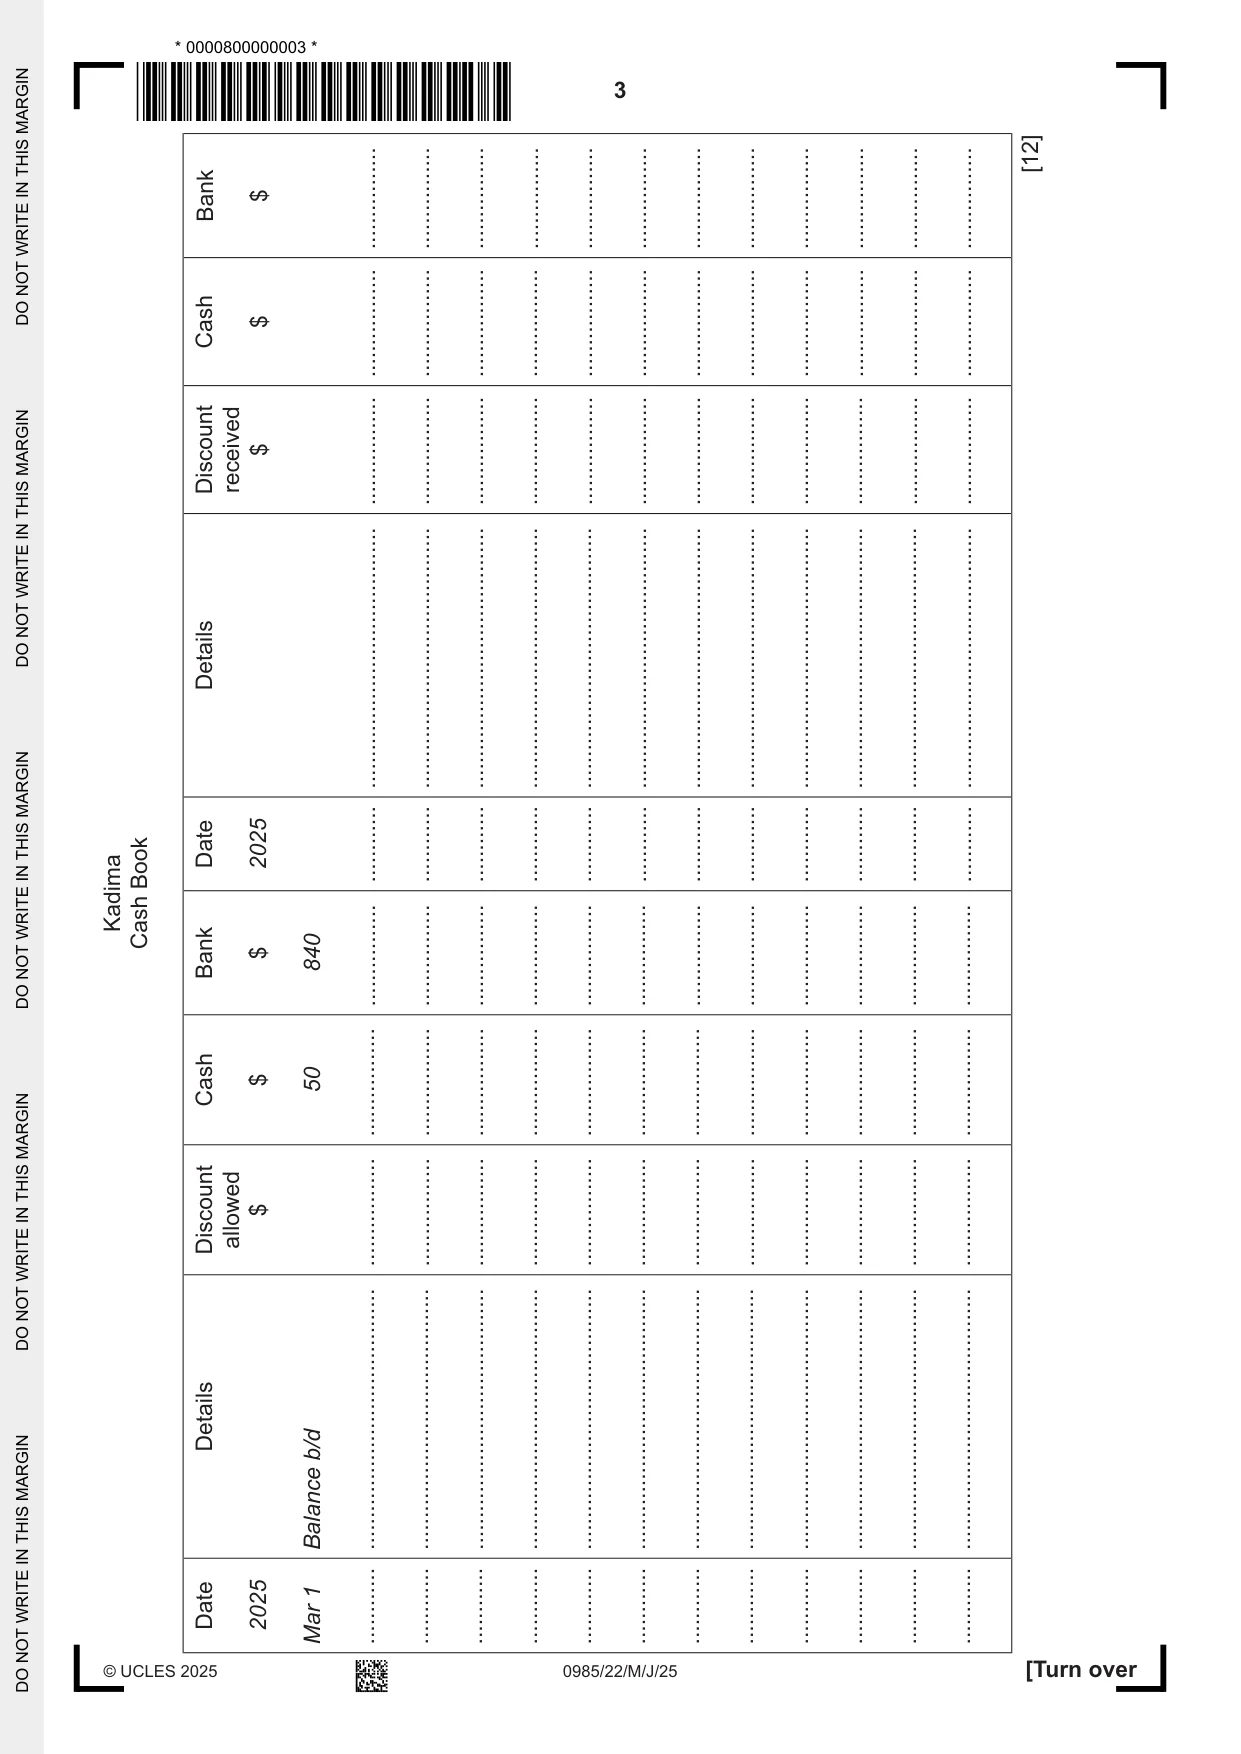
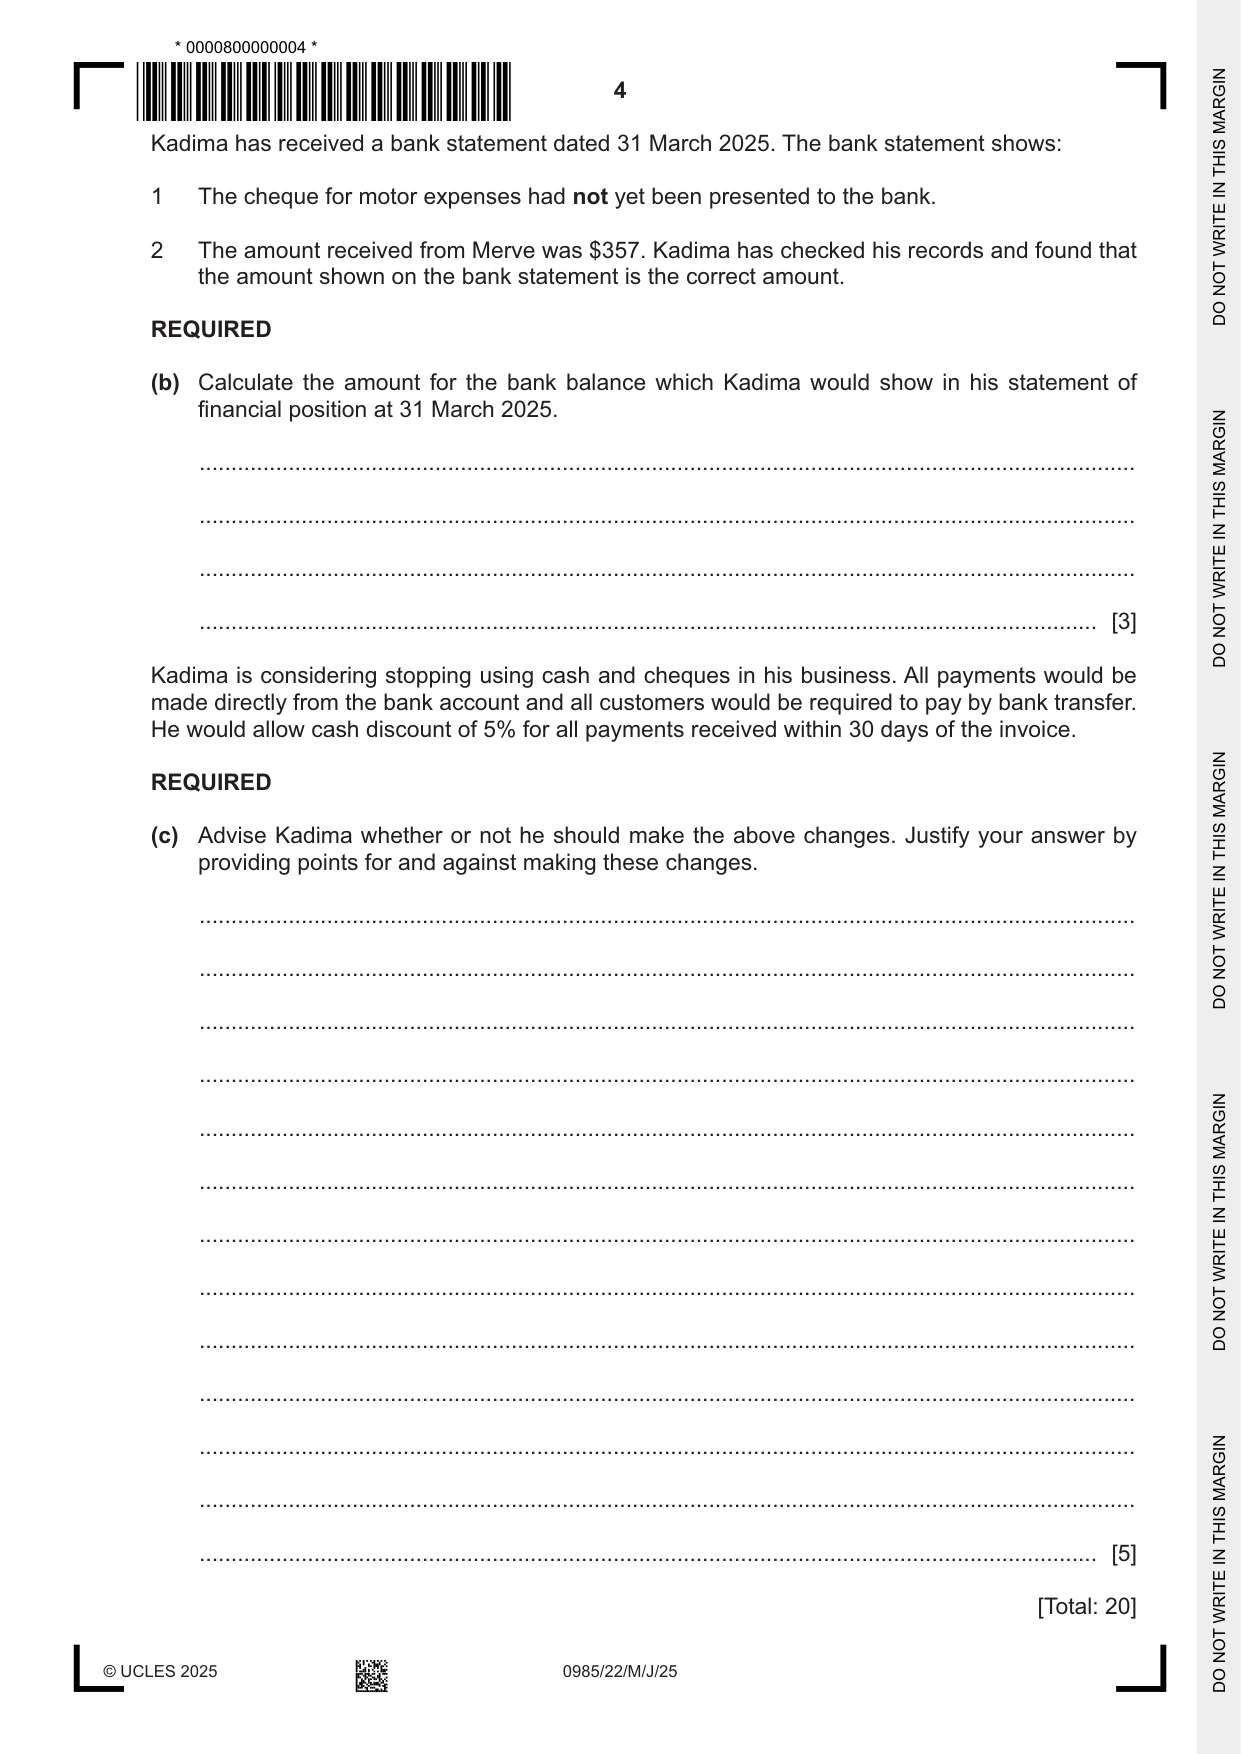
1 Kadima is a trader. He sells on credit only. During March 2025, the following transactions took place. March 4 Paid Lee, $196, by bank transfer in full settlement of an invoice for $200 6 Received payment by cheque, $291, from Sophiah who had deducted 3% cash discount 14 Paid motor expenses, $26, by cash 19 Received payment by bank transfer, $375, from Merve, a customer 22 Paid Mark, $240, by online transfer, having deducted 4% cash discount 28 Withdrew $400 cash from the bank for business use 29 Paid wages, $362, in cash 30 Paid motor expenses, $91, by cheque REQUIRED (a) Complete Kadima’s cash book on page 3. Balance the cash book and bring down the balances at 1 April 2025. [12] $ Bank ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ $ Cash ................. ................. ................. ................. ................. ................. ................. ................. ................. ................. ................. ................. $ Discount received ................. ................. ................. ................. ................. ................. ................. ................. ................. ................. ................. ................. Details ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... Date 2025 ............ ............ ............ ............ ............ ............ ............ ............ ............ ............ ............ ............ Book Kadima Cash $ 840 Bank ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ $ 50 Cash ................. ................. ................. ................. ................. ................. ................. ................. ................. ................. ................. ................. $ Discount allowed ................. ................. ................. ................. ................. ................. ................. ................. ................. ................. ................. ................. Details b/d Balance ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... Kadima has received a bank statement dated 31 March 2025. The bank statement shows: 1 The cheque for motor expenses had not yet been presented to the bank.
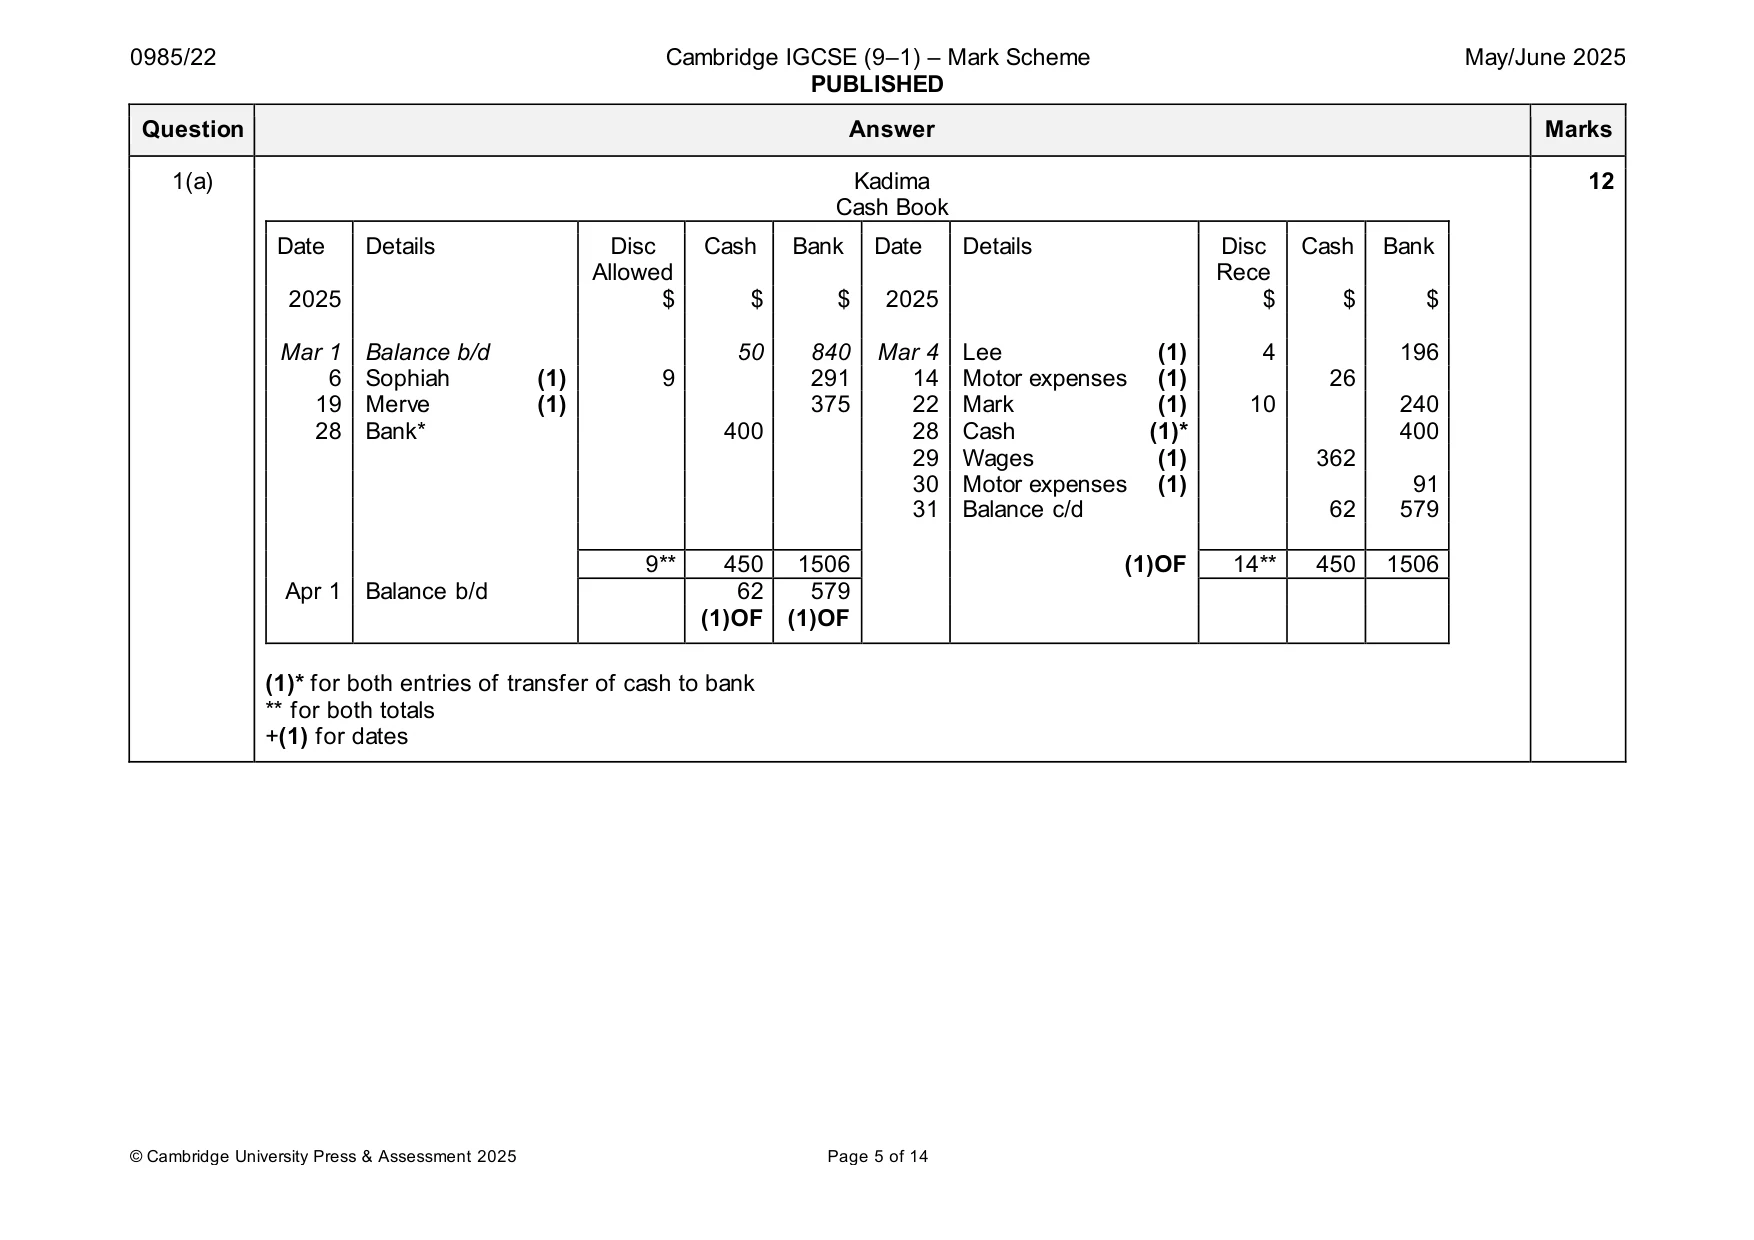
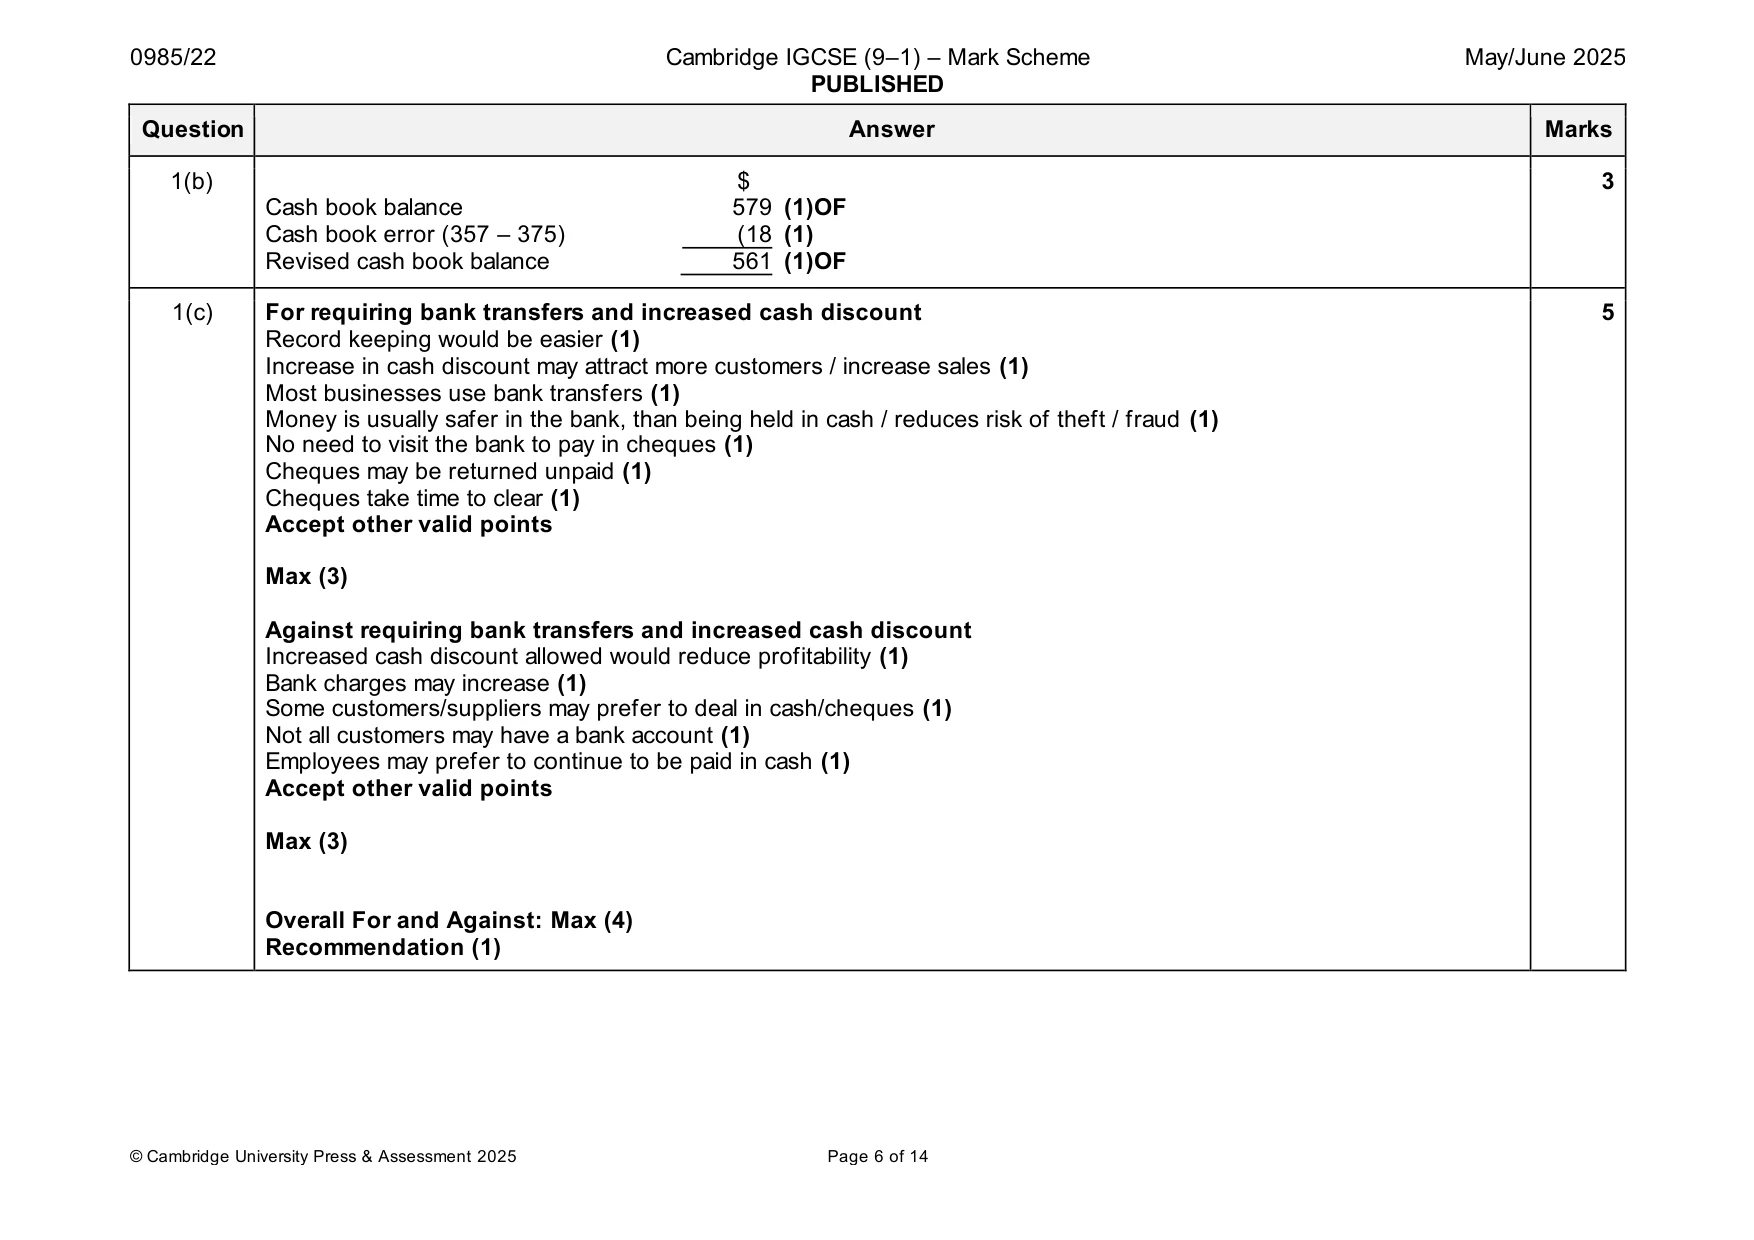
Mark scheme: Question Answer Marks 1(a) Kadima 12 Cash Book Date Details Disc Cash Bank Date Details Disc Cash Bank Allowed Rece 2025 $ $ $ 2025 $ $ $ Mar 1 Balance b/d 50 840 Mar 4 Lee (1) 4 196 6 Sophiah (1) 9 291 14 Motor expenses (1) 26 19 Merve (1) 375 22 Mark (1) 10 240 28 Bank* 400 28 Cash (1)* 400 29 Wages (1) 362 30 Motor expenses (1) 91 31 Balance c/d 62 579 9** 450 1506 (1)OF 14** 450 1506 Apr 1 Balance b/d 62 579 (1)OF (1)OF (1)* for both entries of transfer of cash to bank ** for both totals +(1) for dates 1(b) $ 3 Cash book balance 579 (1)OF Cash book error (357 – 375) (18 (1) Revised cash book balance 561 (1)OF 1(c) For requiring bank transfers and increased cash discount 5 Record keeping would be easier (1) Increase in cash discount may attract more customers / increase sales (1) Most businesses use bank transfers (1) Money is usually safer in the bank, than being held in cash / reduces risk of theft / fraud (1) No need to visit the bank to pay in cheques (1) Cheques may be returned unpaid (1) Cheques take time to clear (1) Accept other valid points Max (3) Against requiring bank transfers and increased cash discount Increased cash discount allowed would reduce profitability (1) Bank charges may increase (1) Some customers/suppliers may prefer to deal in cash/cheques (1) Not all customers may have a bank account (1) Employees may prefer to continue to be paid in cash (1) Accept other valid points Max (3) Overall For and Against: Max (4) Recommendation (1)
Q2 · The amount received from Merve was $357
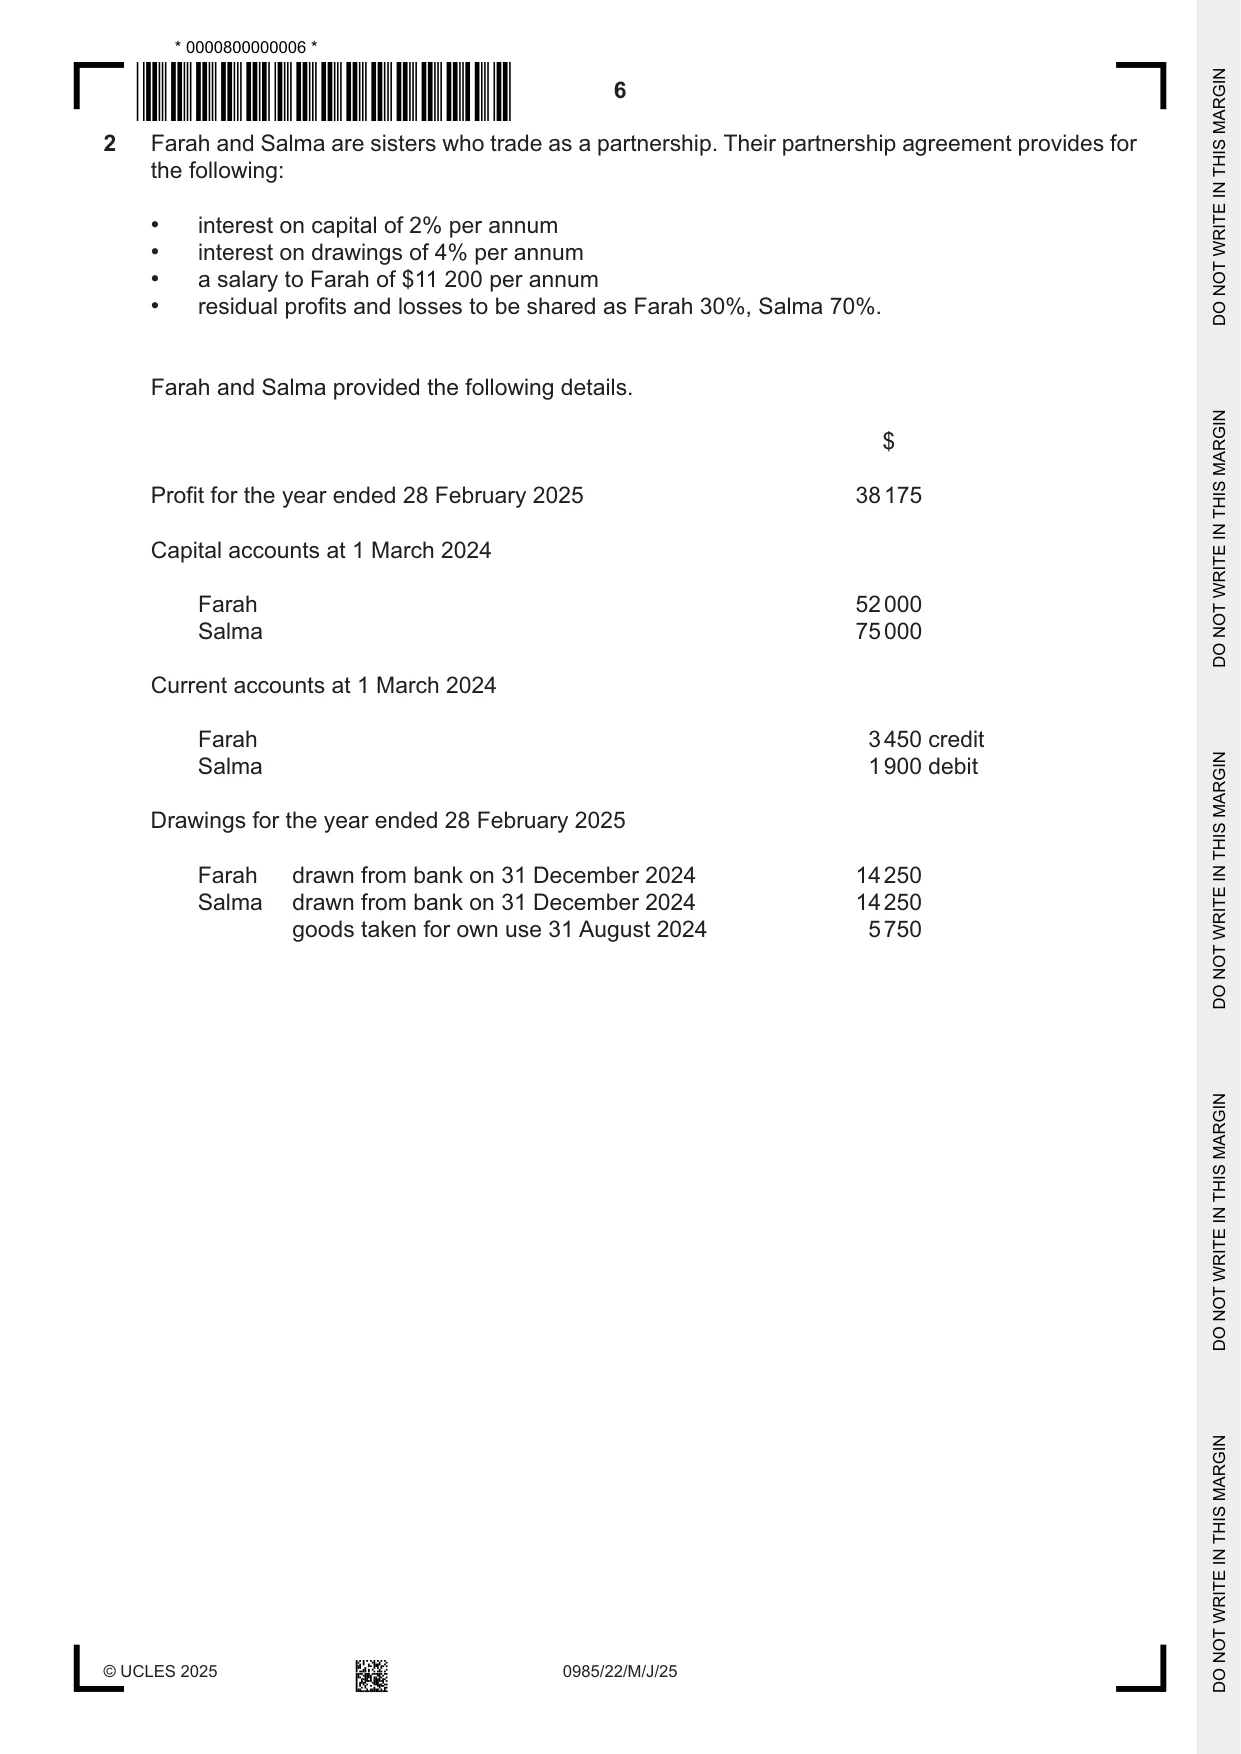
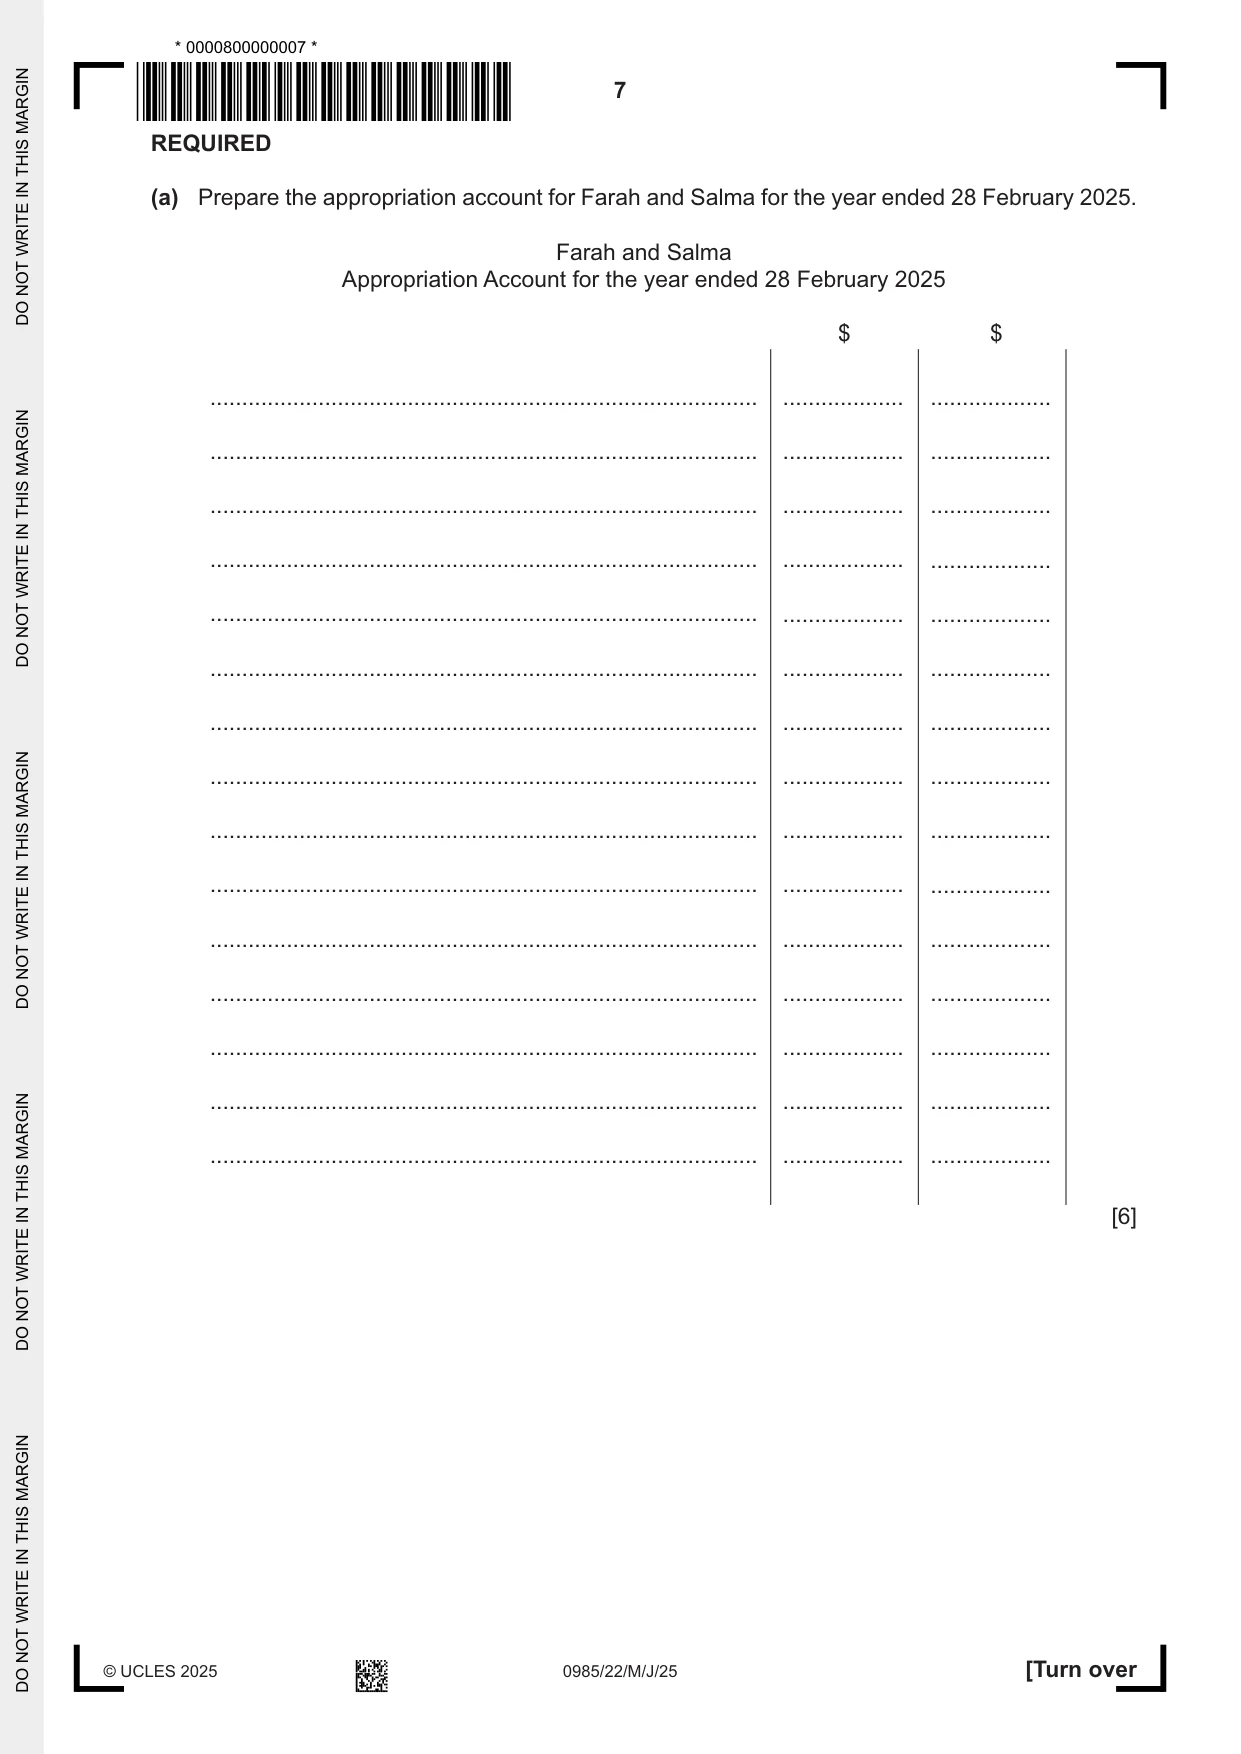
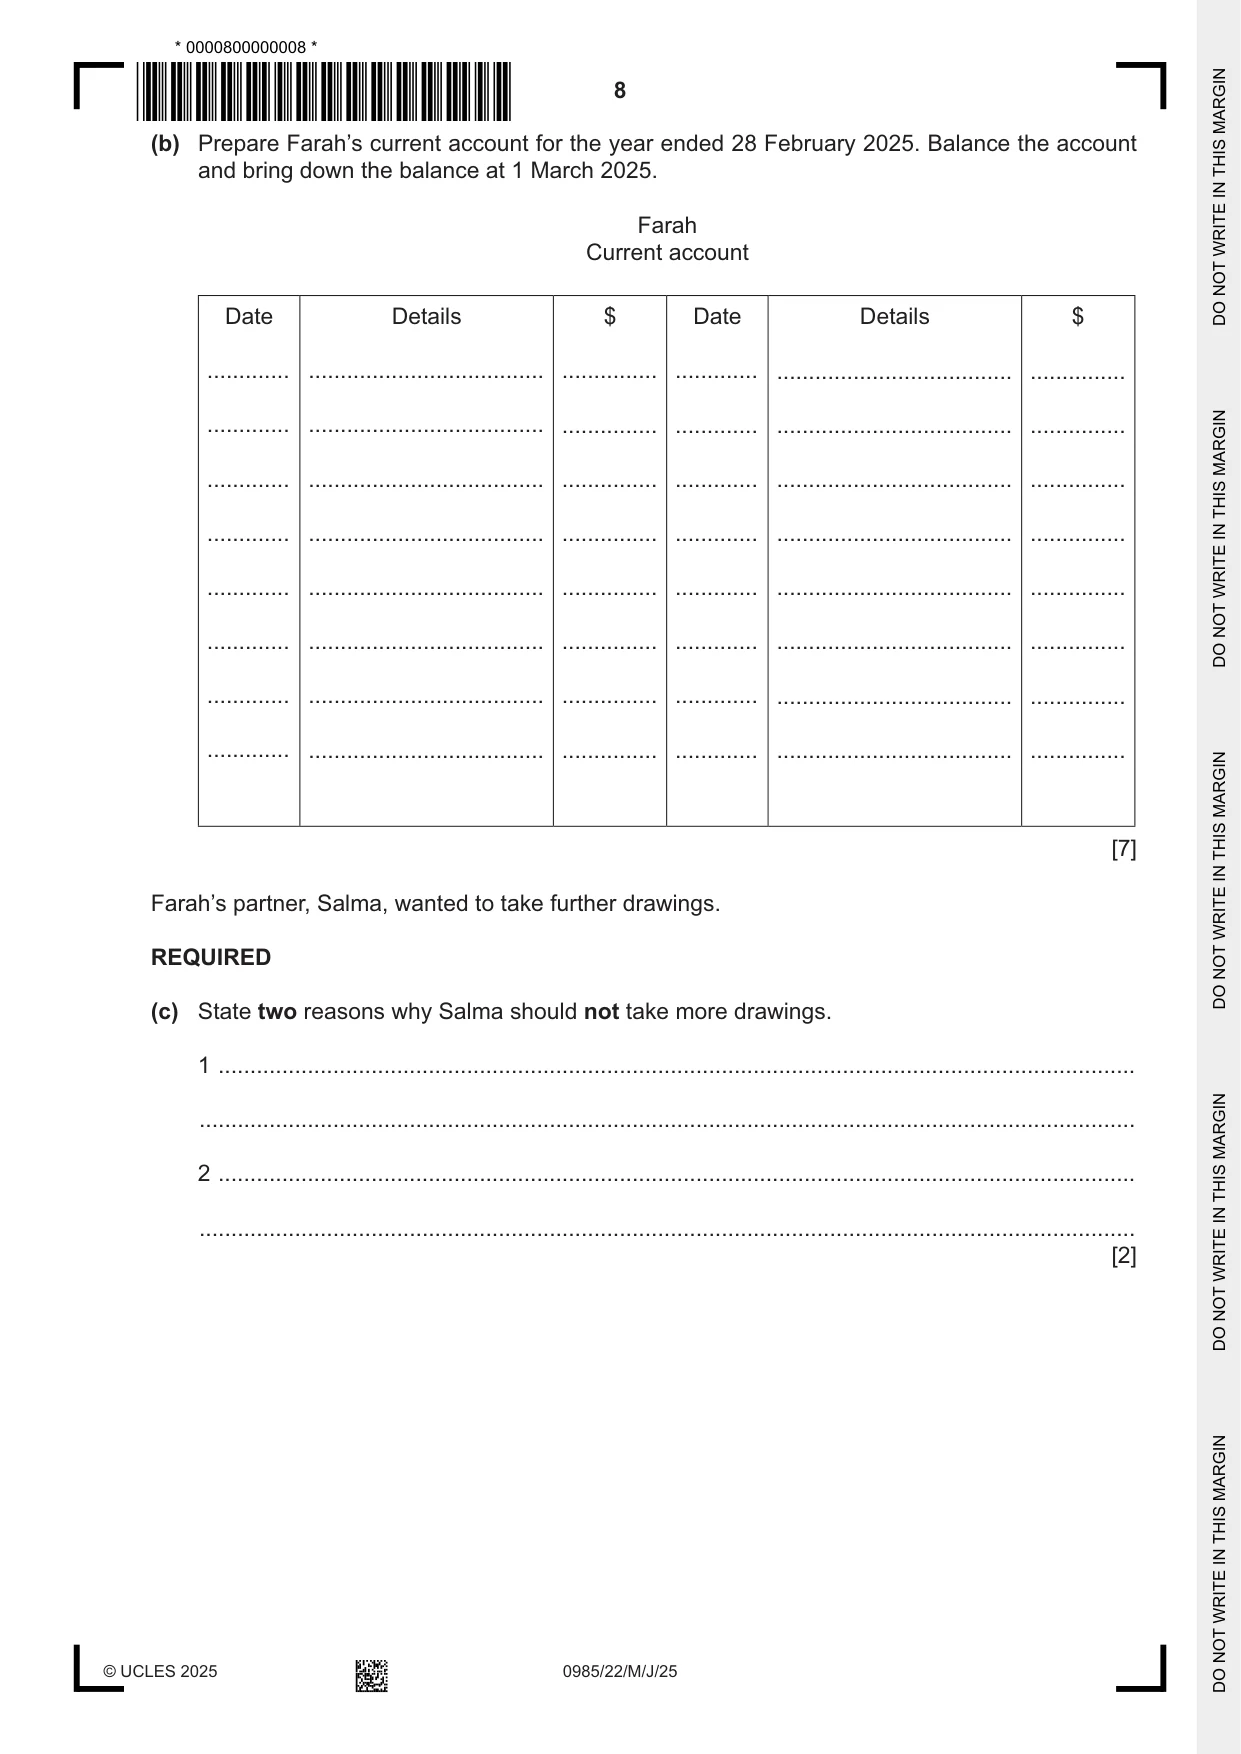
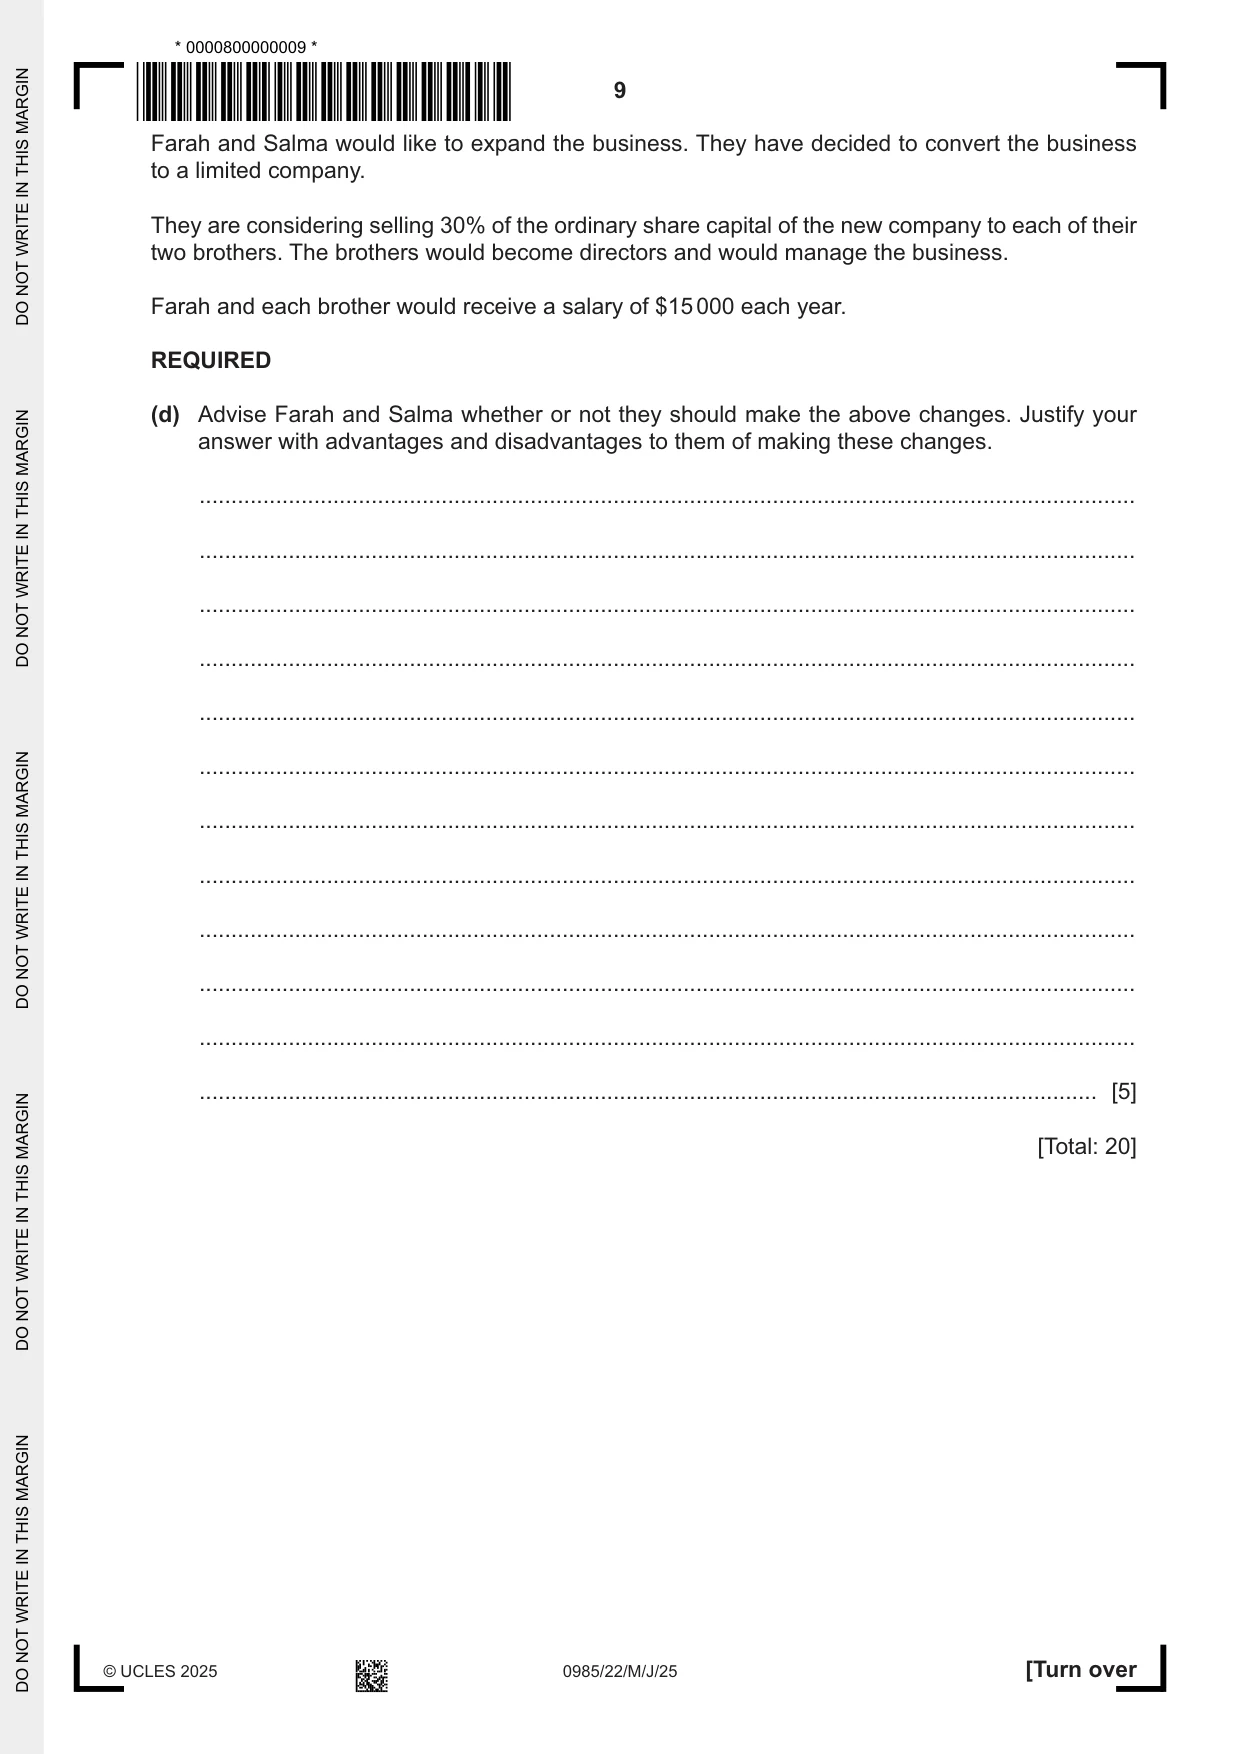
2 The amount received from Merve was $357. Kadima has checked his records and found that the amount shown on the bank statement is the correct amount. REQUIRED (b) Calculate the amount for the bank balance which Kadima would show in his statement of financial position at 31 March 2025. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] Kadima is considering stopping using cash and cheques in his business. All payments would be made directly from the bank account and all customers would be required to pay by bank transfer. He would allow cash discount of 5% for all payments received within 30 days of the invoice. REQUIRED (c) Advise Kadima whether or not he should make the above changes. Justify your answer by providing points for and against making these changes. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20] 2 Farah and Salma are sisters who trade as a partnership. Their partnership agreement provides for the following: • interest on capital of 2% per annum • interest on drawings of 4% per annum • a salary to Farah of $11 200 per annum • residual profits and losses to be shared as Farah 30%, Salma 70%. Farah and Salma provided the following details. $ Profit for the year ended 28 February 2025 38 175 Capital accounts at 1 March 2024 Farah 52 000 Salma 75 000 Current accounts at 1 March 2024 Farah 3 450 credit Salma 1 900 debit Drawings for the year ended 28 February 2025 Farah drawn from bank on 31 December 2024 14 250 Salma drawn from bank on 31 December 2024 14 250 goods taken for own use 31 August 2024 5 750 REQUIRED (a) Prepare the appropriation account for Farah and Salma for the year ended 28 February 2025. Farah and Salma Appropriation Account for the year ended 28 February 2025 $ $ ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... [6] (b) Prepare Farah’s current account for the year ended 28 February 2025. Balance the account and bring down the balance at 1 March 2025. Farah Current account Date Details $ Date Details $ ............. ..................................... ............... ............. ..................................... ............... ............. ..................................... ............... ............. ..................................... ............... ............. ..................................... ............... ............. ..................................... ............... ............. ..................................... ............... ............. ..................................... ............... ............. ..................................... ............... ............. ..................................... ............... ............. ..................................... ............... ............. ..................................... ............... ............. ..................................... ............... ............. ..................................... ............... ............. ..................................... ............... ............. ..................................... ............... [7] Farah’s partner, Salma, wanted to take further drawings. REQUIRED (c) State two reasons why Salma should not take more drawings. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] Farah and Salma would like to expand the business. They have decided to convert the business to a limited company. They are considering selling 30% of the ordinary share capital of the new company to each of their two brothers. The brothers would become directors and would manage the business. Farah and each brother would receive a salary of $15 000 each year. REQUIRED (d) Advise Farah and Salma whether or not they should make the above changes. Justify your answer with advantages and disadvantages to them of making these changes. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
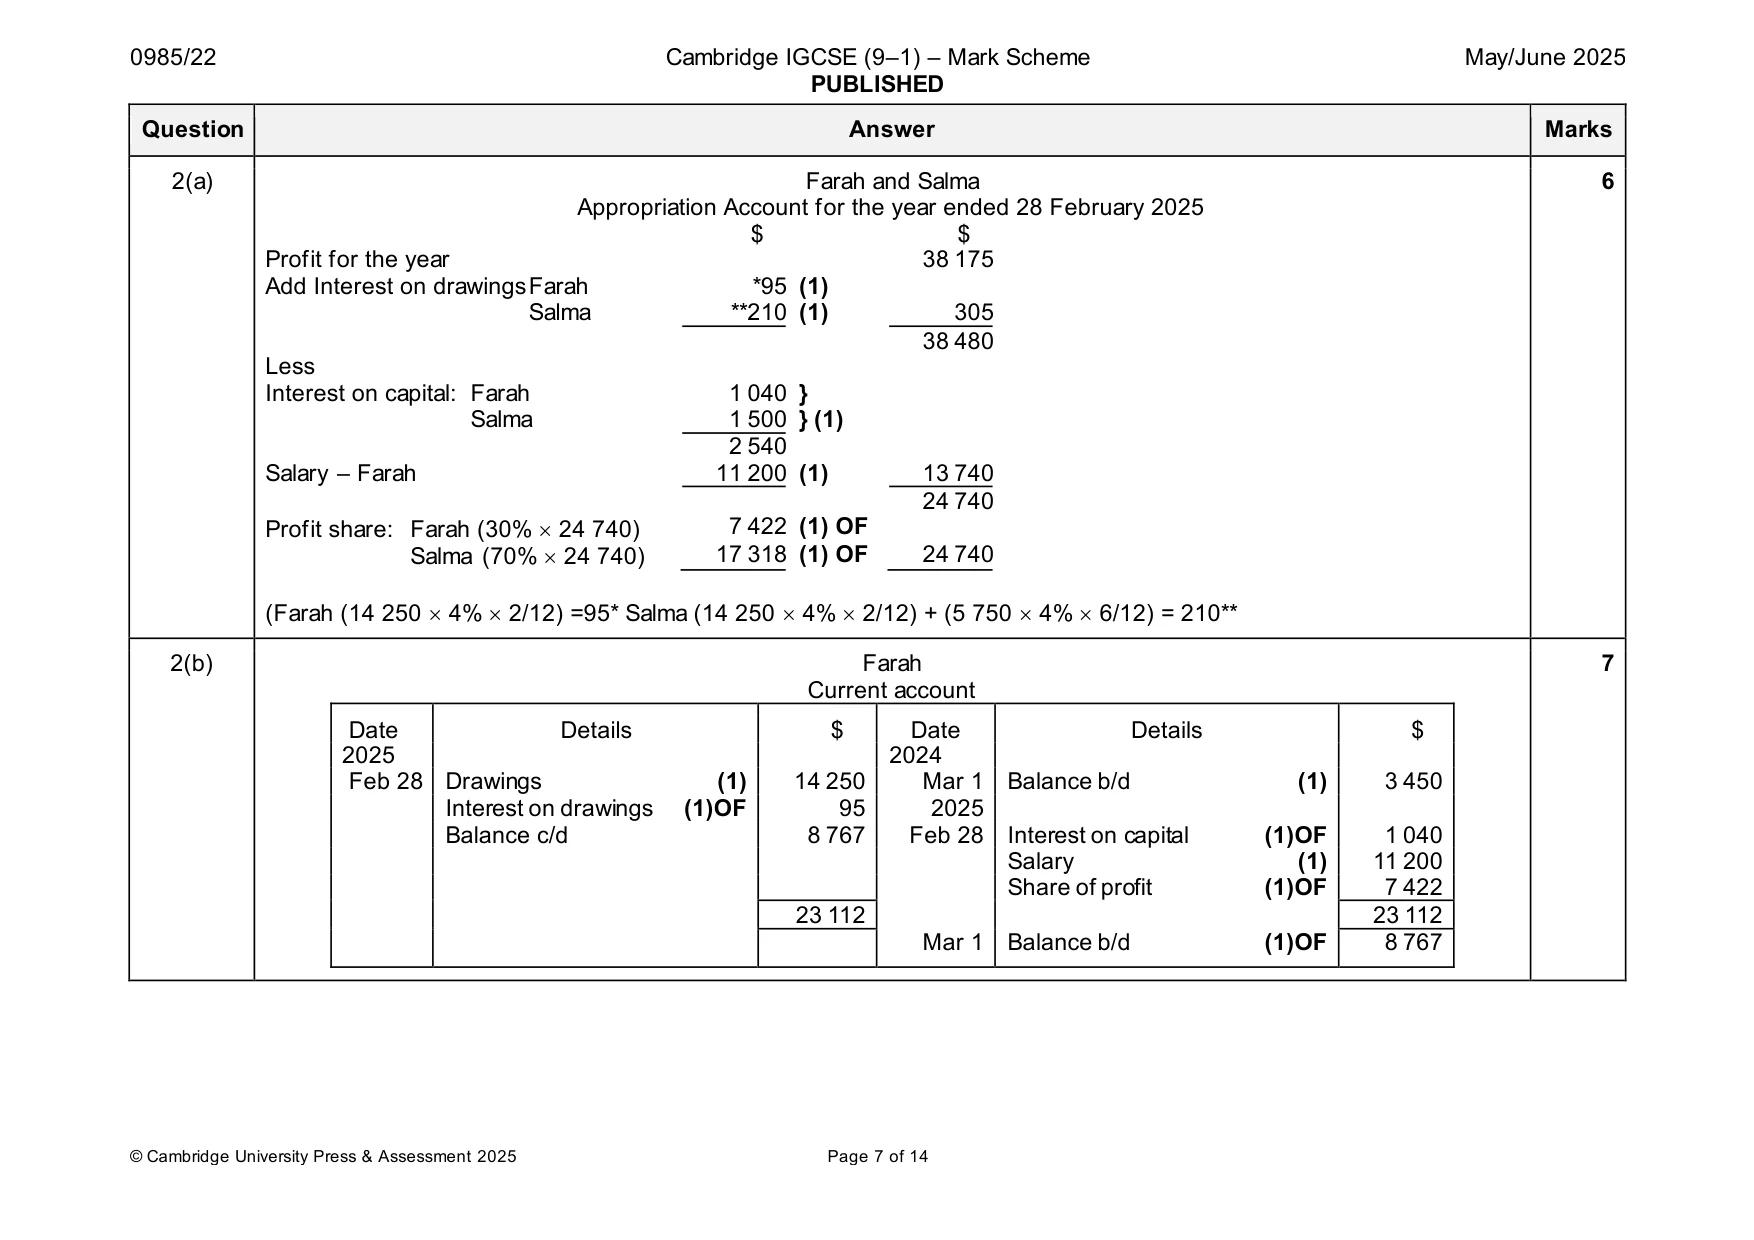
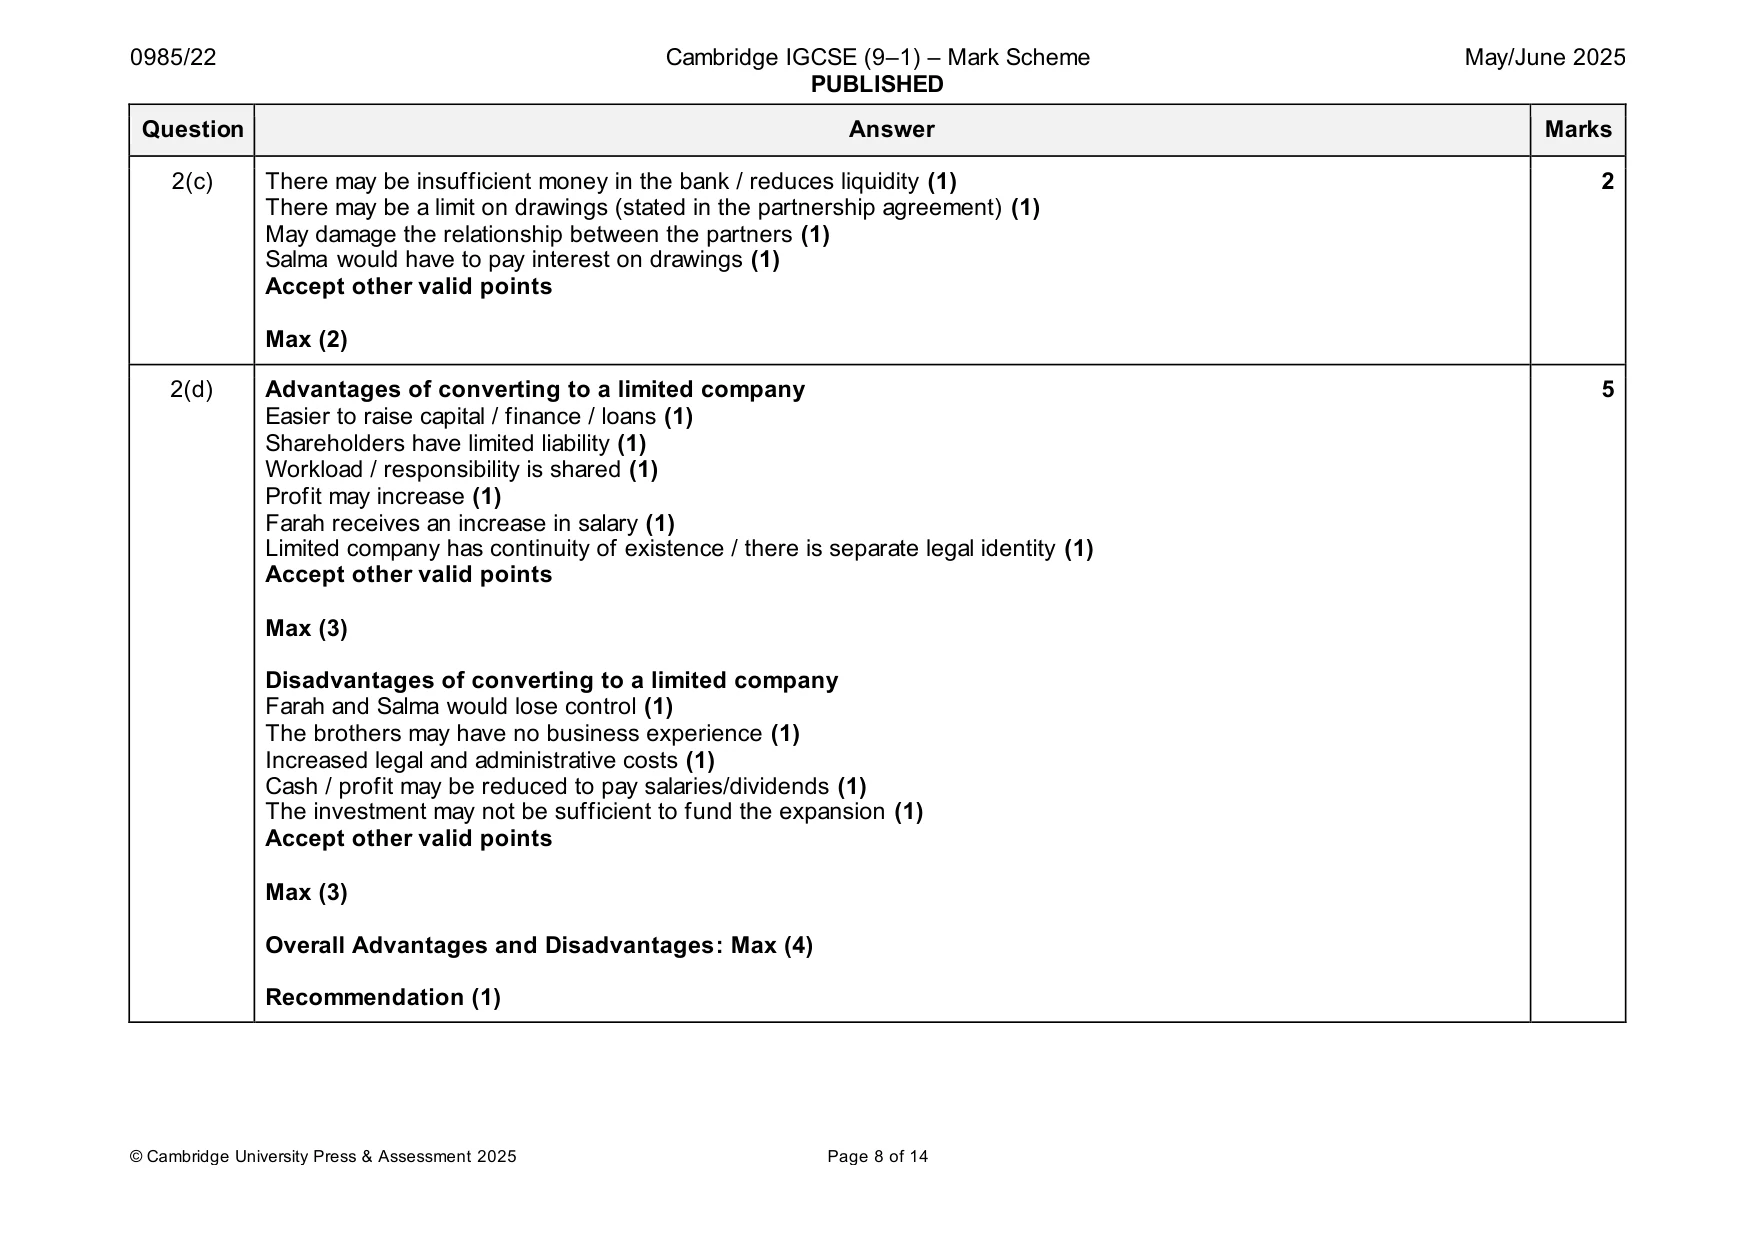
Mark scheme: 2(a) Farah and Salma 6 Appropriation Account for the year ended 28 February 2025 $ $ Profit for the year 38 175 Add Interest on drawings Farah *95 (1) Salma **210 (1) 305 38 480 Less Interest on capital: Farah 1 040 } Salma 1 500 } (1) 2 540 Salary – Farah 11 200 (1) 13 740 24 740 Profit share: Farah (30% 24 740) 7 422 (1) OF Salma (70% 24 740) 17 318 (1) OF 24 740 (Farah (14 250 4% 2/12) =95* Salma (14 250 4% 2/12) + (5 750 4% 6/12) = 210** 2(b) Farah 7 Current account Date Details $ Date Details $ 2025 2024 Feb 28 Drawings (1) 14 250 Mar 1 Balance b/d (1) 3 450 Interest on drawings (1)OF 95 2025 Balance c/d 8 767 Feb 28 Interest on capital (1)OF 1 040 Salary (1) 11 200 Share of profit (1)OF 7 422 23 112 23 112 Mar 1 Balance b/d (1)OF 8 767 2(c) There may be insufficient money in the bank / reduces liquidity (1) 2 There may be a limit on drawings (stated in the partnership agreement) (1) May damage the relationship between the partners (1) Salma would have to pay interest on drawings (1) Accept other valid points Max (2) 2(d) Advantages of converting to a limited company 5 Easier to raise capital / finance / loans (1) Shareholders have limited liability (1) Workload / responsibility is shared (1) Profit may increase (1) Farah receives an increase in salary (1) Limited company has continuity of existence / there is separate legal identity (1) Accept other valid points Max (3) Disadvantages of converting to a limited company Farah and Salma would lose control (1) The brothers may have no business experience (1) Increased legal and administrative costs (1) Cash / profit may be reduced to pay salaries/dividends (1) The investment may not be sufficient to fund the expansion (1) Accept other valid points Max (3) Overall Advantages and Disadvantages: Max (4) Recommendation (1)
Q3 · Jasmine owns a consulting business
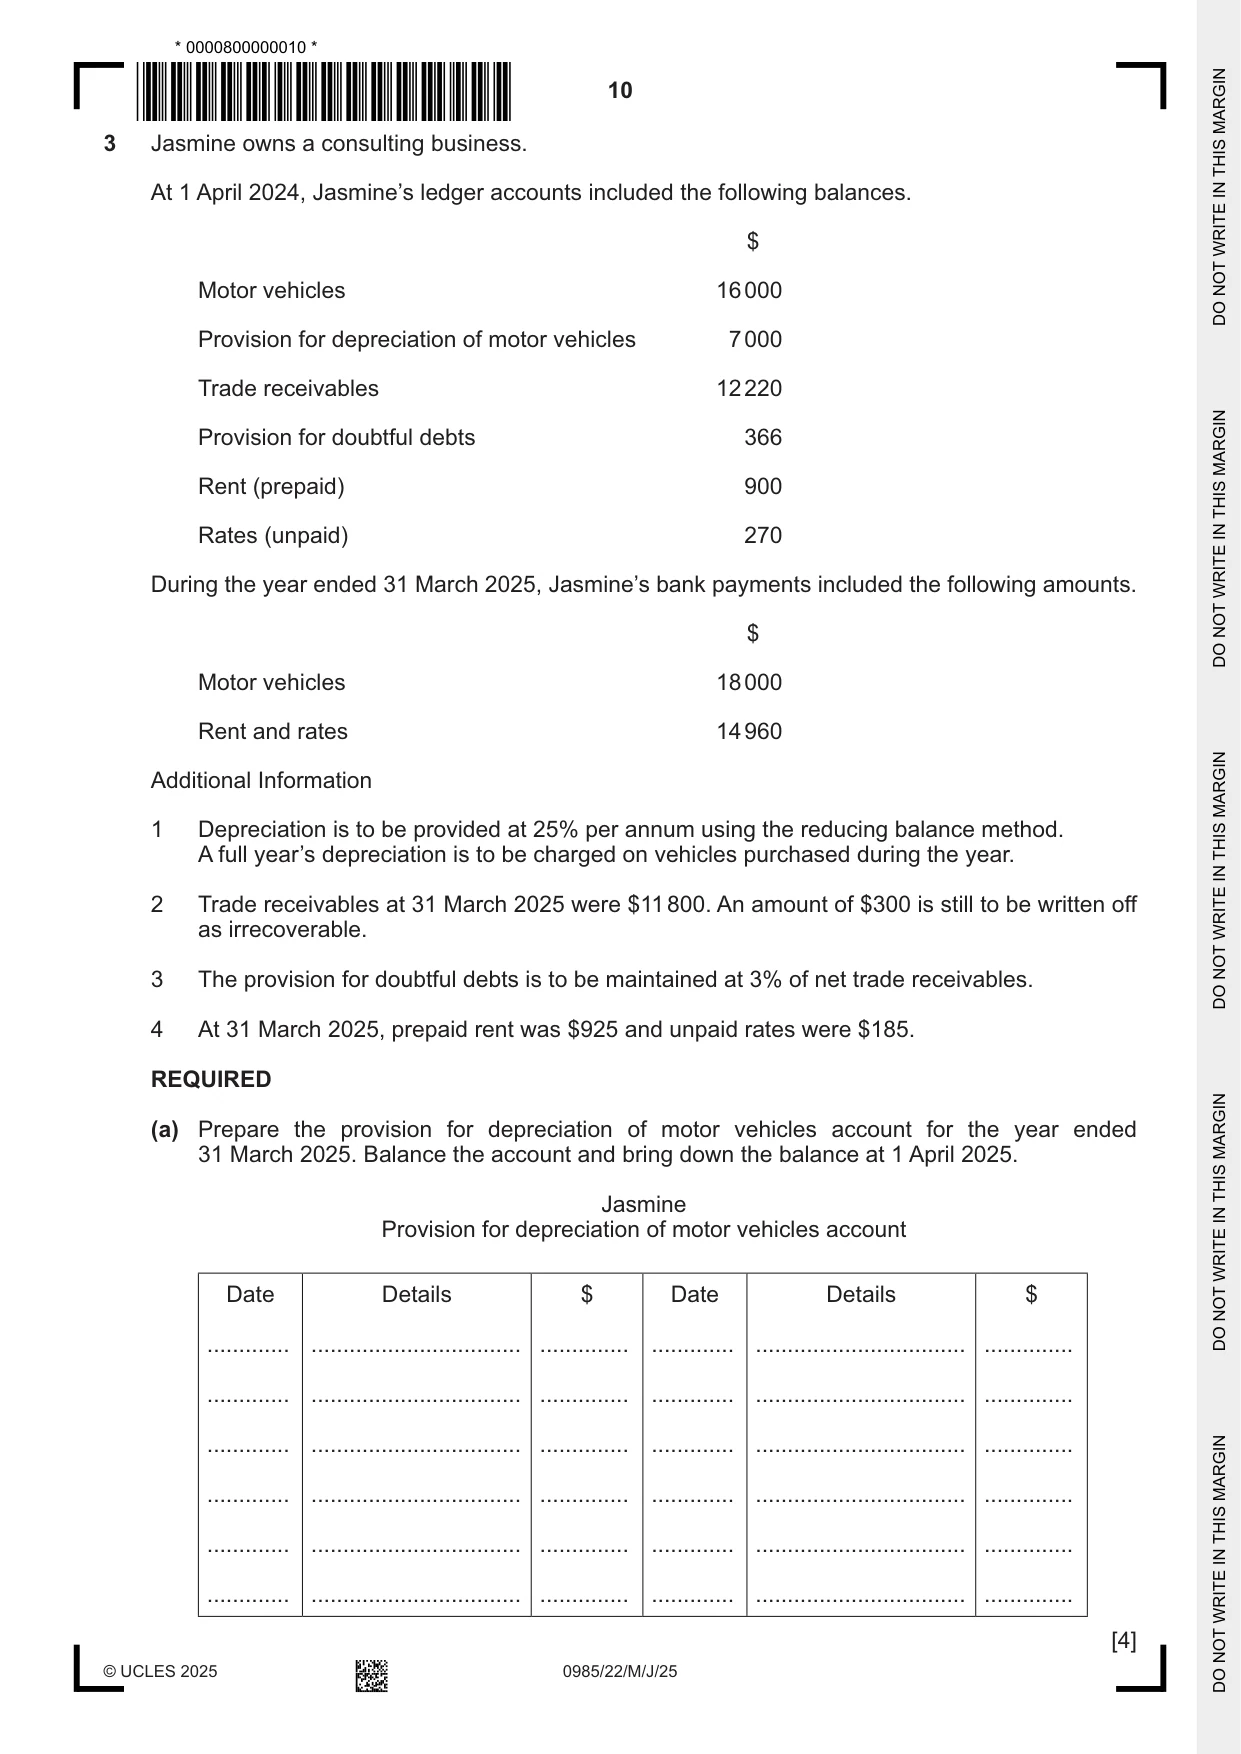
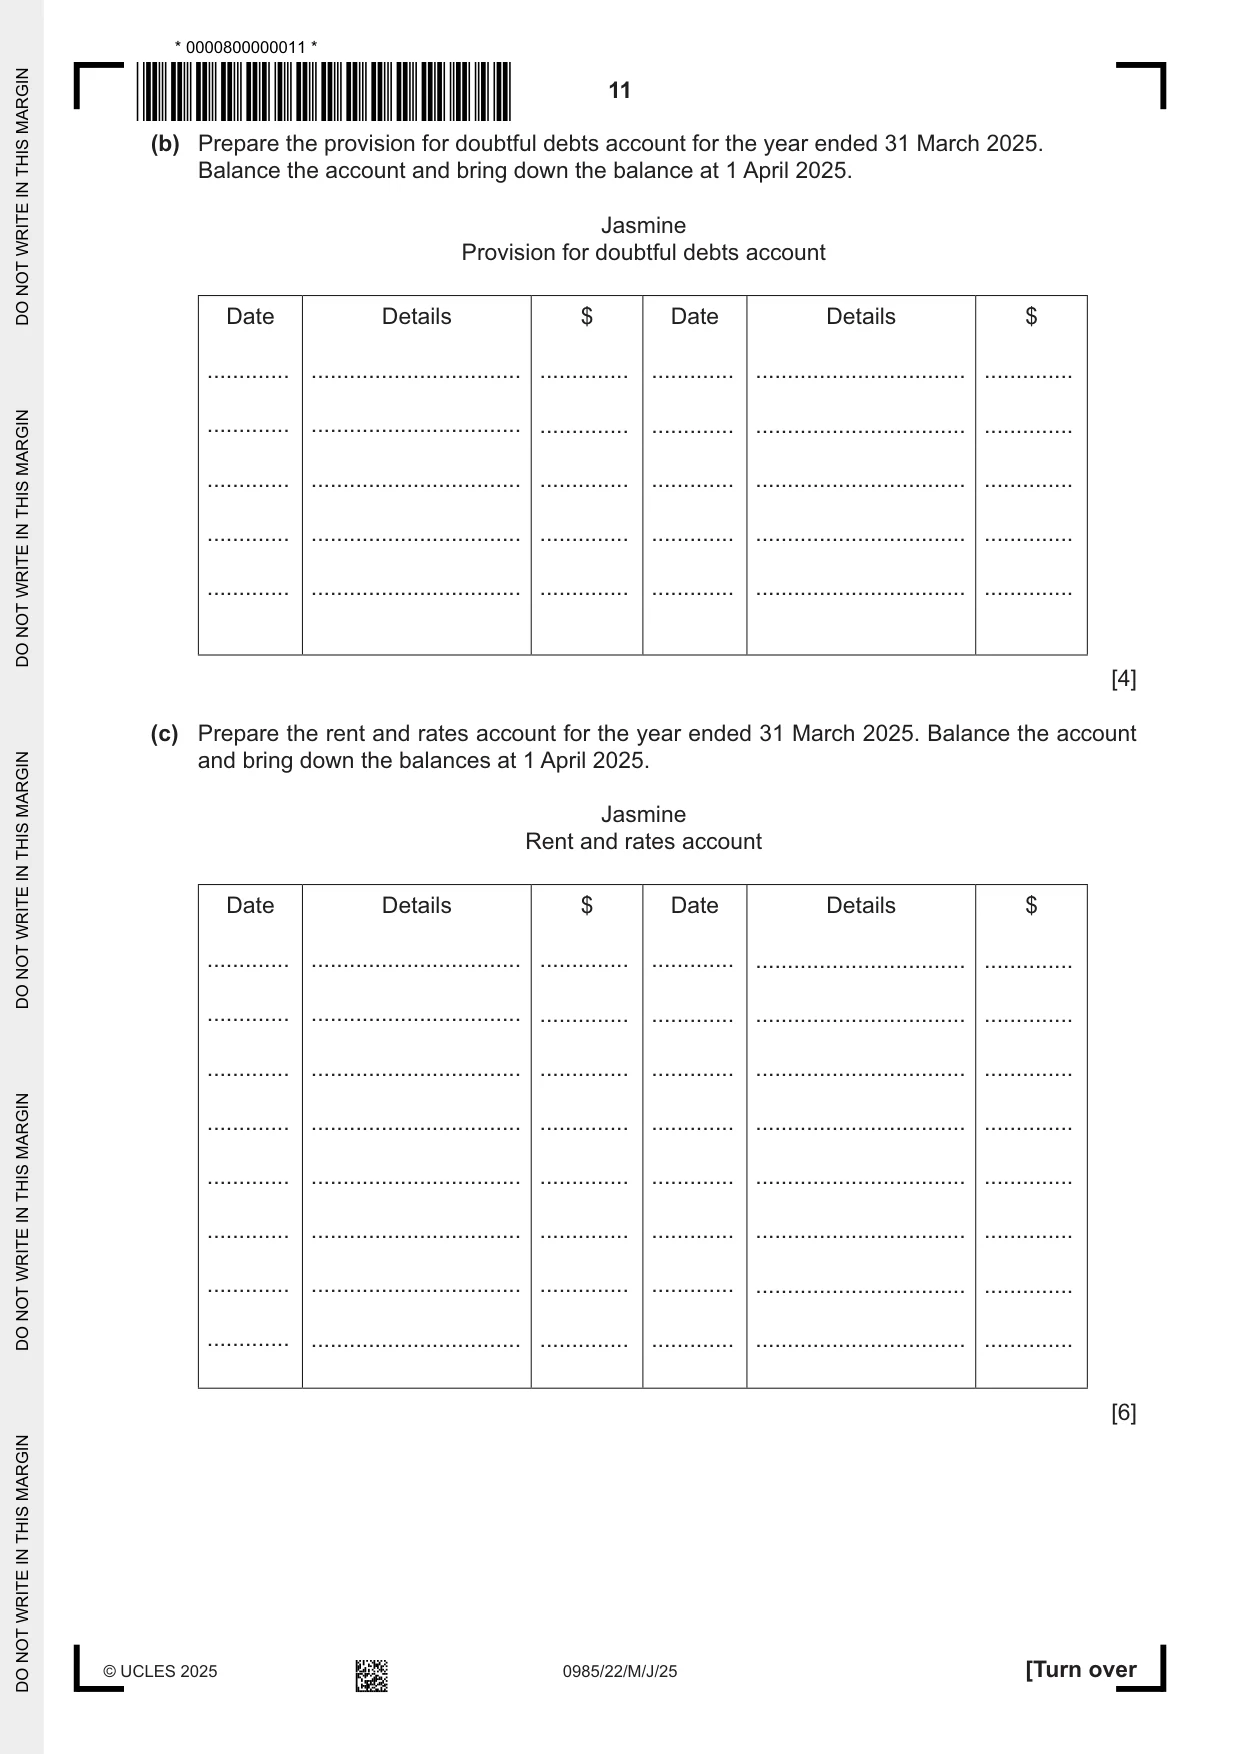
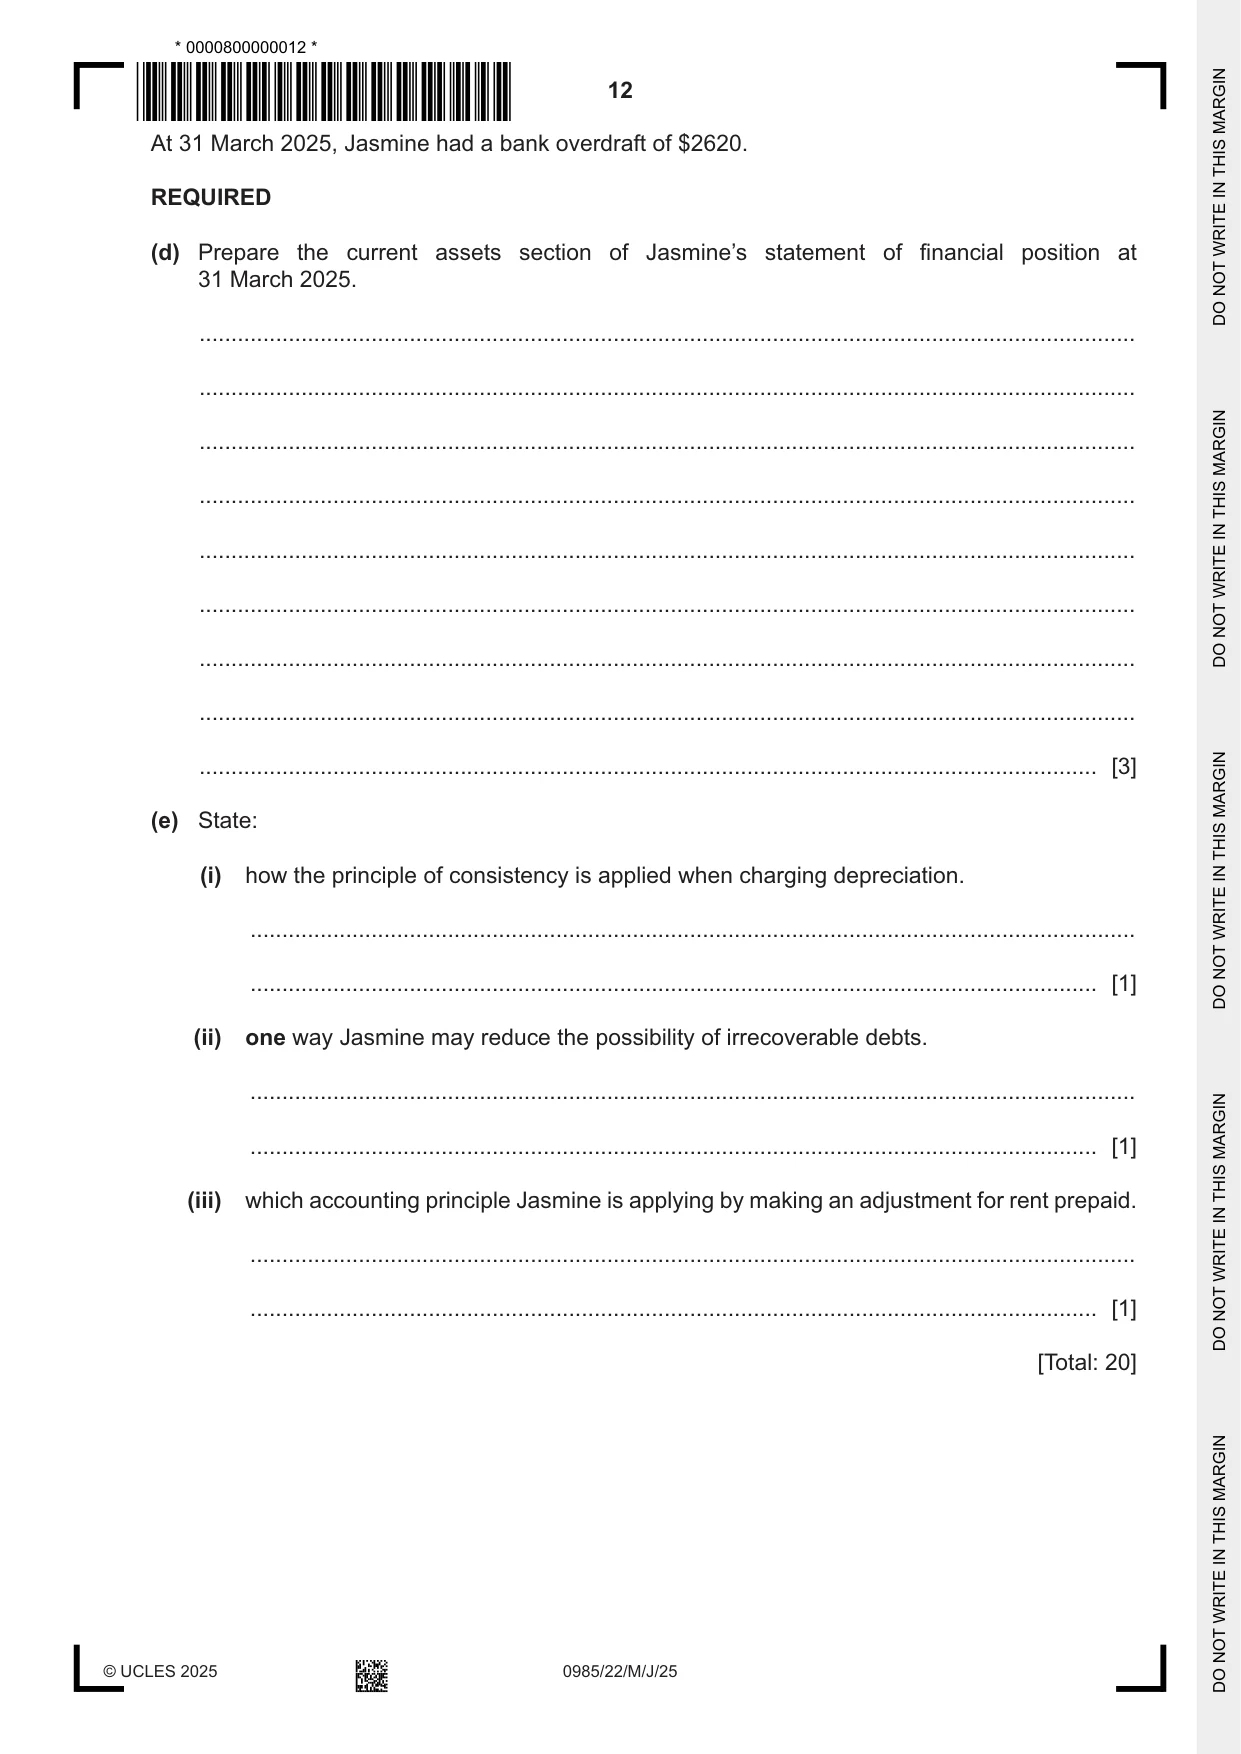
3 Jasmine owns a consulting business. At 1 April 2024, Jasmine’s ledger accounts included the following balances. $ Motor vehicles 16 000 Provision for depreciation of motor vehicles 7 000 Trade receivables 12 220 Provision for doubtful debts 366 Rent (prepaid) 900 Rates (unpaid) 270 During the year ended 31 March 2025, Jasmine’s bank payments included the following amounts. $ Motor vehicles 18 000 Rent and rates 14 960 Additional Information 1 Depreciation is to be provided at 25% per annum using the reducing balance method. A full year’s depreciation is to be charged on vehicles purchased during the year. 2 Trade receivables at 31 March 2025 were $11 800. An amount of $300 is still to be written off as irrecoverable. 3 The provision for doubtful debts is to be maintained at 3% of net trade receivables. 4 At 31 March 2025, prepaid rent was $925 and unpaid rates were $185. REQUIRED (a) Prepare the provision for depreciation of motor vehicles account for the year ended 31 March 2025. Balance the account and bring down the balance at 1 April 2025. Jasmine Provision for depreciation of motor vehicles account Date Details $ Date Details $ ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. [4] (b) Prepare the provision for doubtful debts account for the year ended 31 March 2025. Balance the account and bring down the balance at 1 April 2025. Jasmine Provision for doubtful debts account Date Details $ Date Details $ ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. [4] (c) Prepare the rent and rates account for the year ended 31 March 2025. Balance the account and bring down the balances at 1 April 2025. Jasmine Rent and rates account Date Details $ Date Details $ ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. [6] At 31 March 2025, Jasmine had a bank overdraft of $2620. REQUIRED (d) Prepare the current assets section of Jasmine’s statement of financial position at 31 March 2025. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] (e) State: (i) how the principle of consistency is applied when charging depreciation. ........................................................................................................................................... ..................................................................................................................................... [1] (ii) one way Jasmine may reduce the possibility of irrecoverable debts. ........................................................................................................................................... ..................................................................................................................................... [1] (iii) which accounting principle Jasmine is applying by making an adjustment for rent prepaid. ........................................................................................................................................... ..................................................................................................................................... [1] [Total: 20]
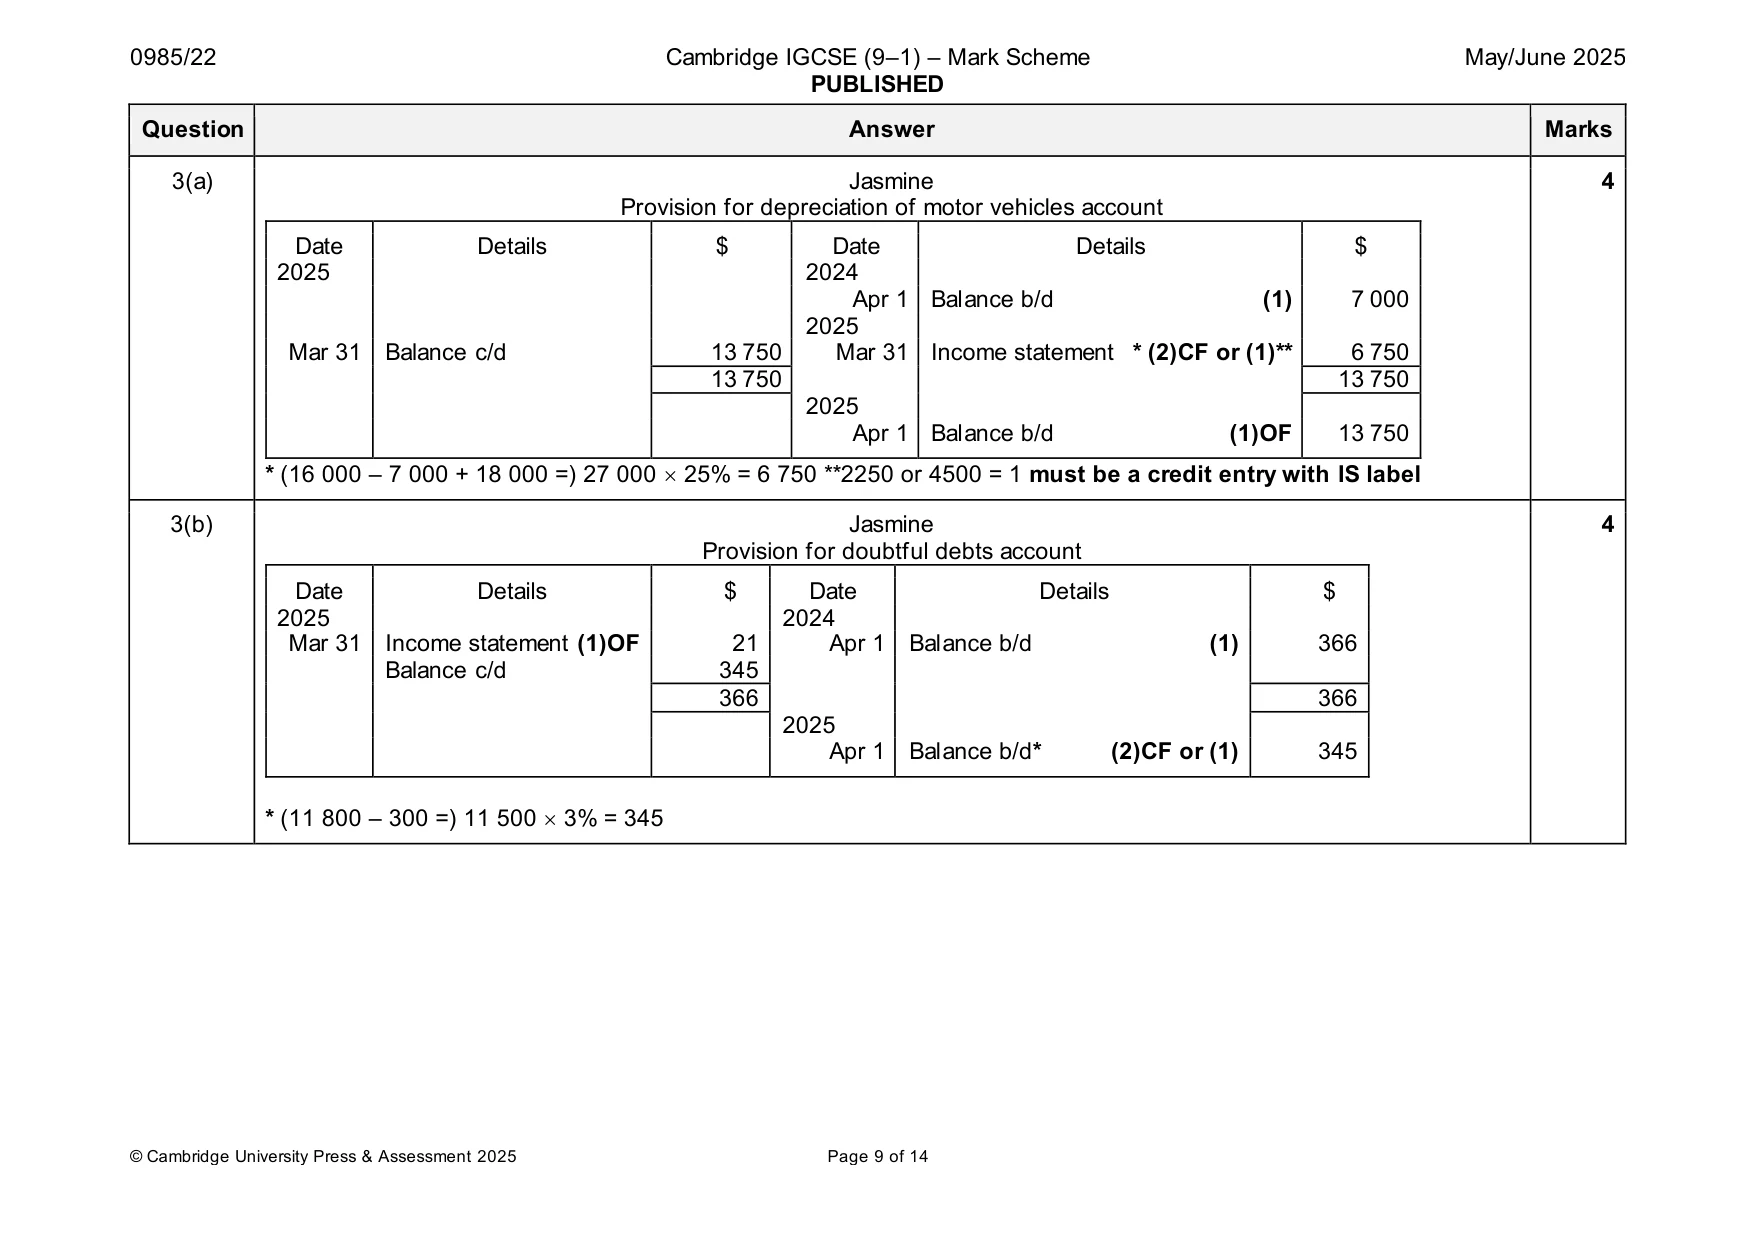
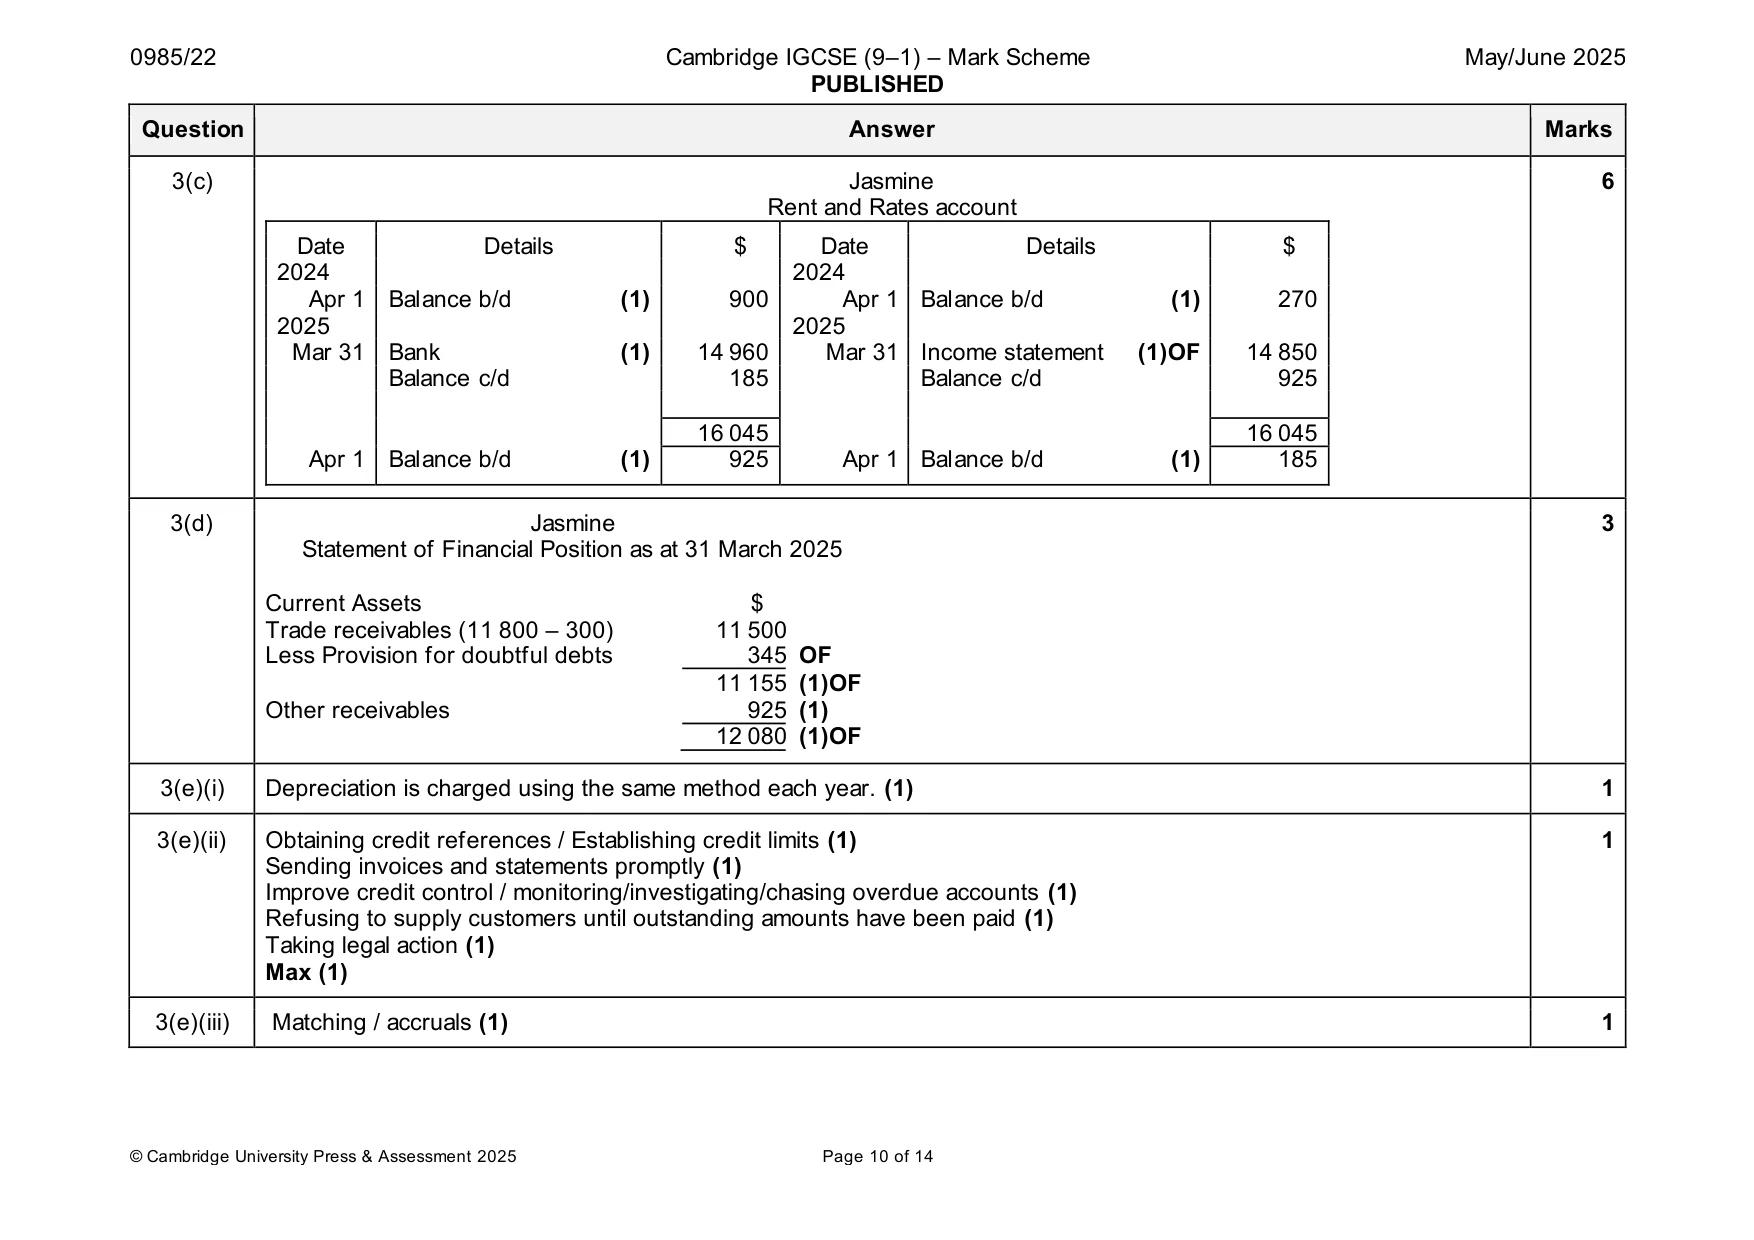
Mark scheme: 3(a) Jasmine 4 Provision for depreciation of motor vehicles account Date Details $ Date Details $ 2025 2024 Apr 1 Balance b/d (1) 7 000 2025 Mar 31 Balance c/d 13 750 Mar 31 Income statement * (2)CF or (1)** 6 750 13 750 13 750 2025 Apr 1 Balance b/d (1)OF 13 750 * (16 000 – 7 000 + 18 000 =) 27 000 25% = 6 750 **2250 or 4500 = 1 must be a credit entry with IS label 3(b) Jasmine 4 Provision for doubtful debts account Date Details $ Date Details $ 2025 2024 Mar 31 Income statement (1)OF 21 Apr 1 Balance b/d (1) 366 Balance c/d 345 366 366 2025 Apr 1 Balance b/d* (2)CF or (1) 345 * (11 800 – 300 =) 11 500 3% = 345 3(c) Jasmine 6 Rent and Rates account Date Details $ Date Details $ 2024 2024 Apr 1 Balance b/d (1) 900 Apr 1 Balance b/d (1) 270 2025 2025 Mar 31 Bank (1) 14 960 Mar 31 Income statement (1)OF 14 850 Balance c/d 185 Balance c/d 925 16 045 16 045 Apr 1 Balance b/d (1) 925 Apr 1 Balance b/d (1) 185 3(d) Jasmine 3 Statement of Financial Position as at 31 March 2025 Current Assets $ Trade receivables (11 800 – 300) 11 500 Less Provision for doubtful debts 345 OF 11 155 (1)OF Other receivables 925 (1) 12 080 (1)OF 3(e)(i) Depreciation is charged using the same method each year. (1) 1 3(e)(ii) Obtaining credit references / Establishing credit limits (1) 1 Sending invoices and statements promptly (1) Improve credit control / monitoring/investigating/chasing overdue accounts (1) Refusing to supply customers until outstanding amounts have been paid (1) Taking legal action (1) Max (1) 3(e)(iii) Matching / accruals (1) 1
Q4 · Bilal prepared a trial balance at 31 December 2024
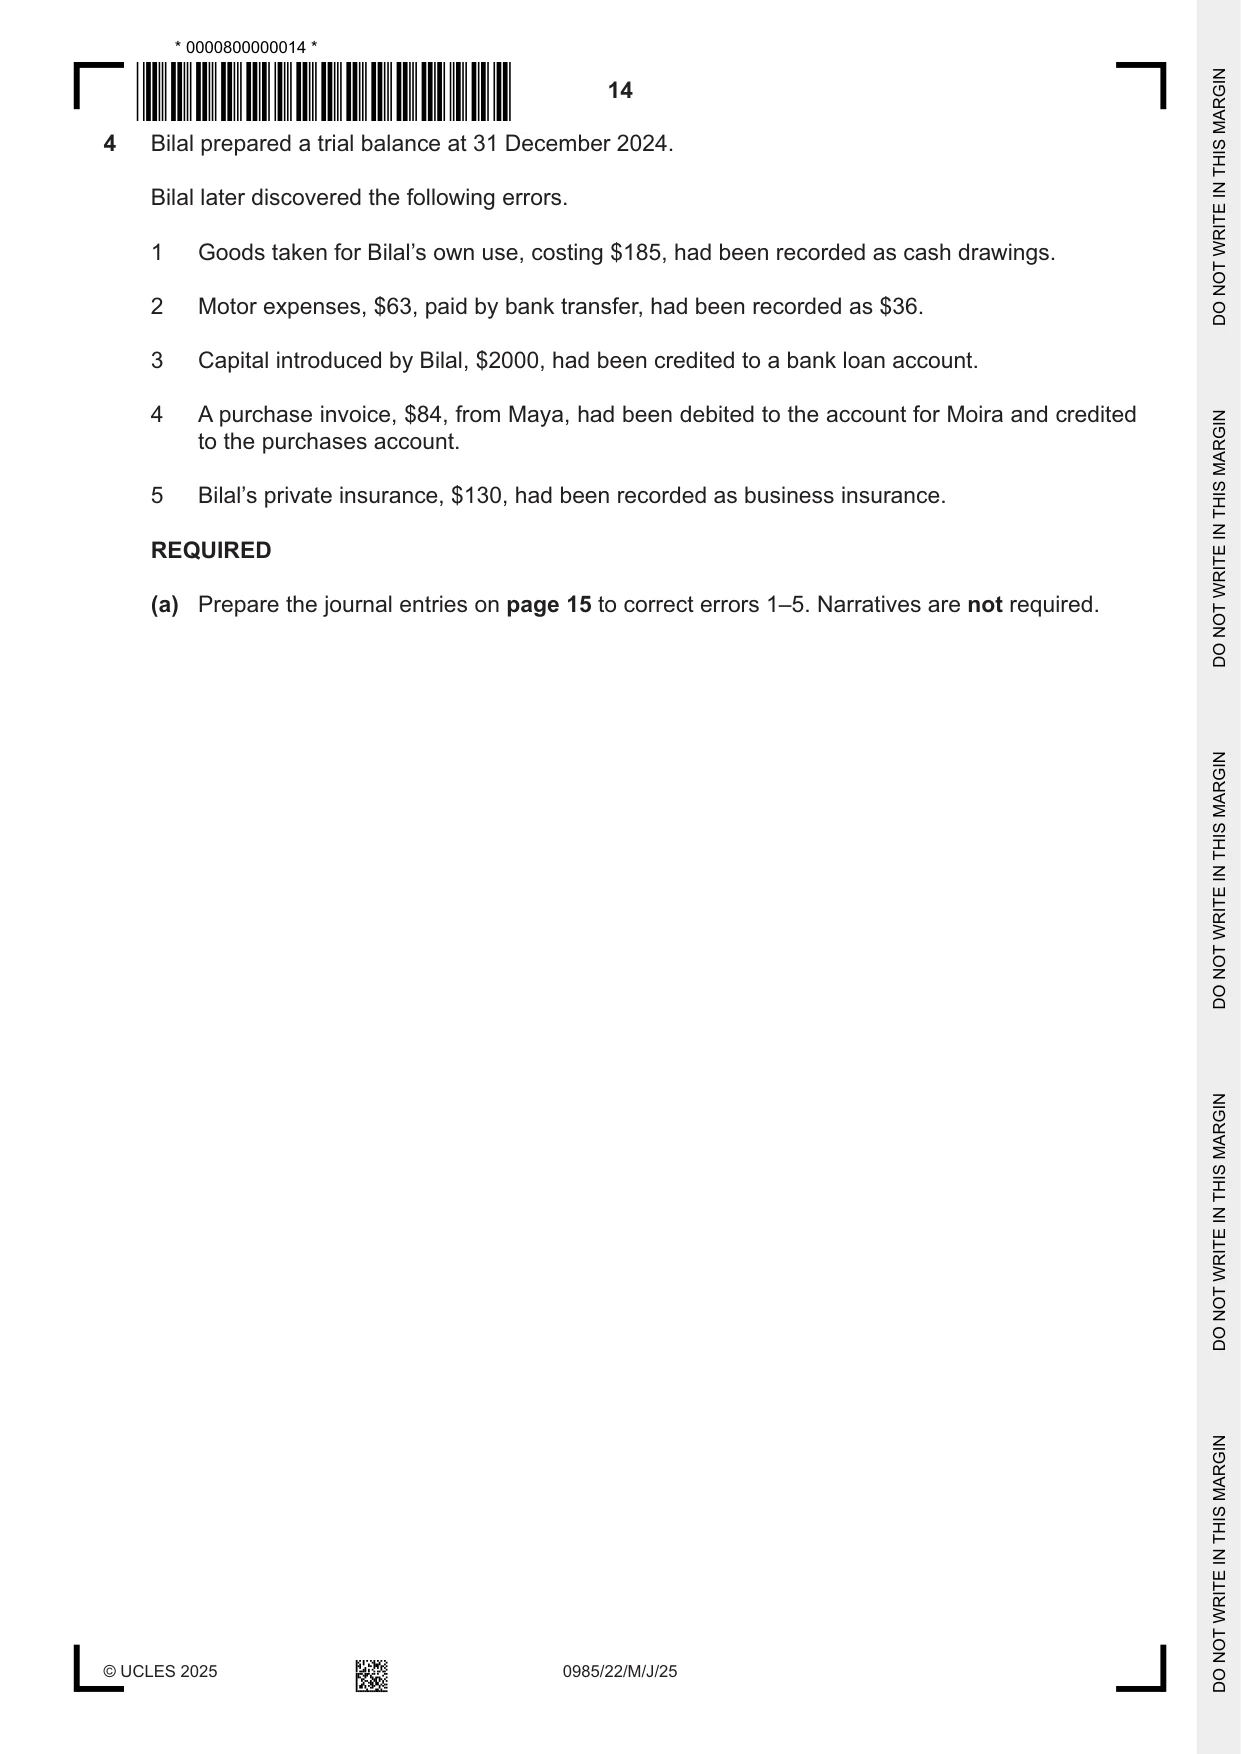
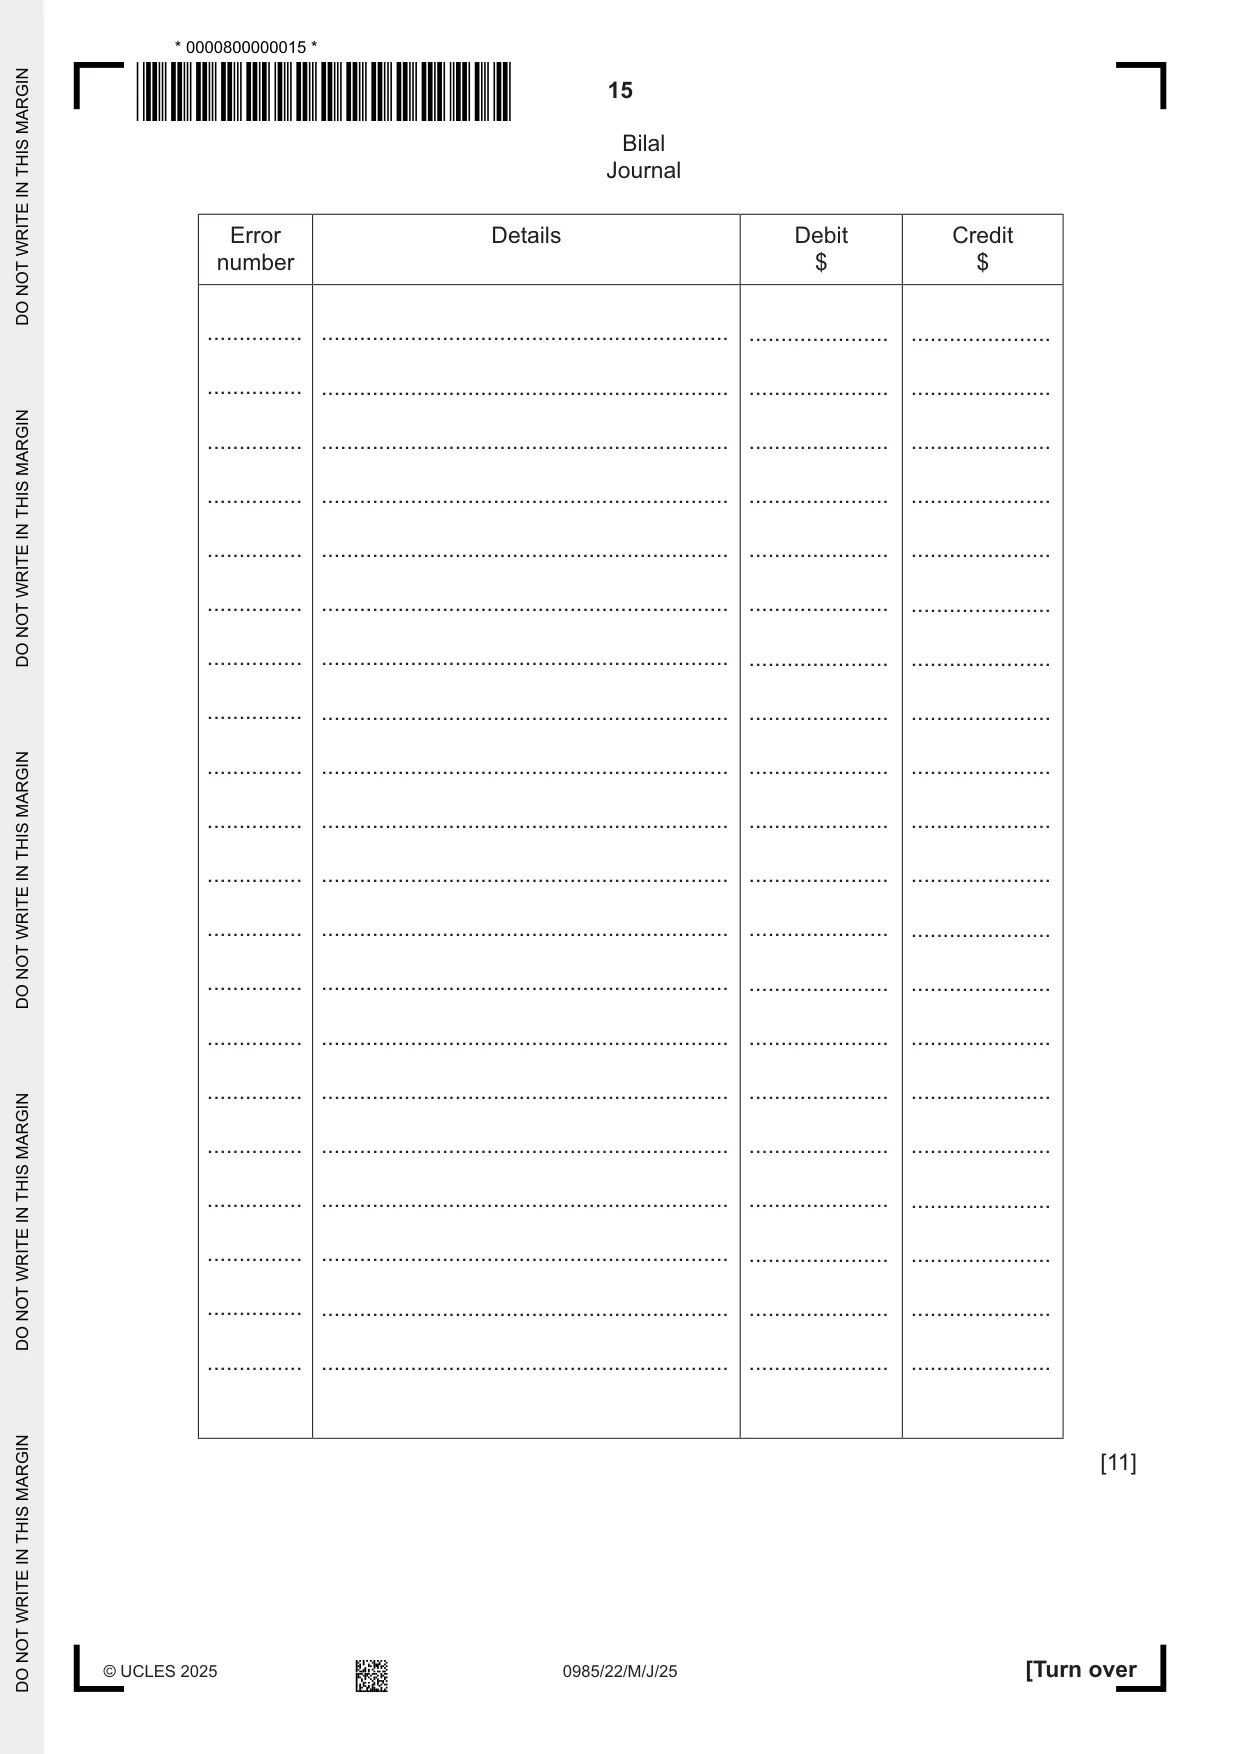
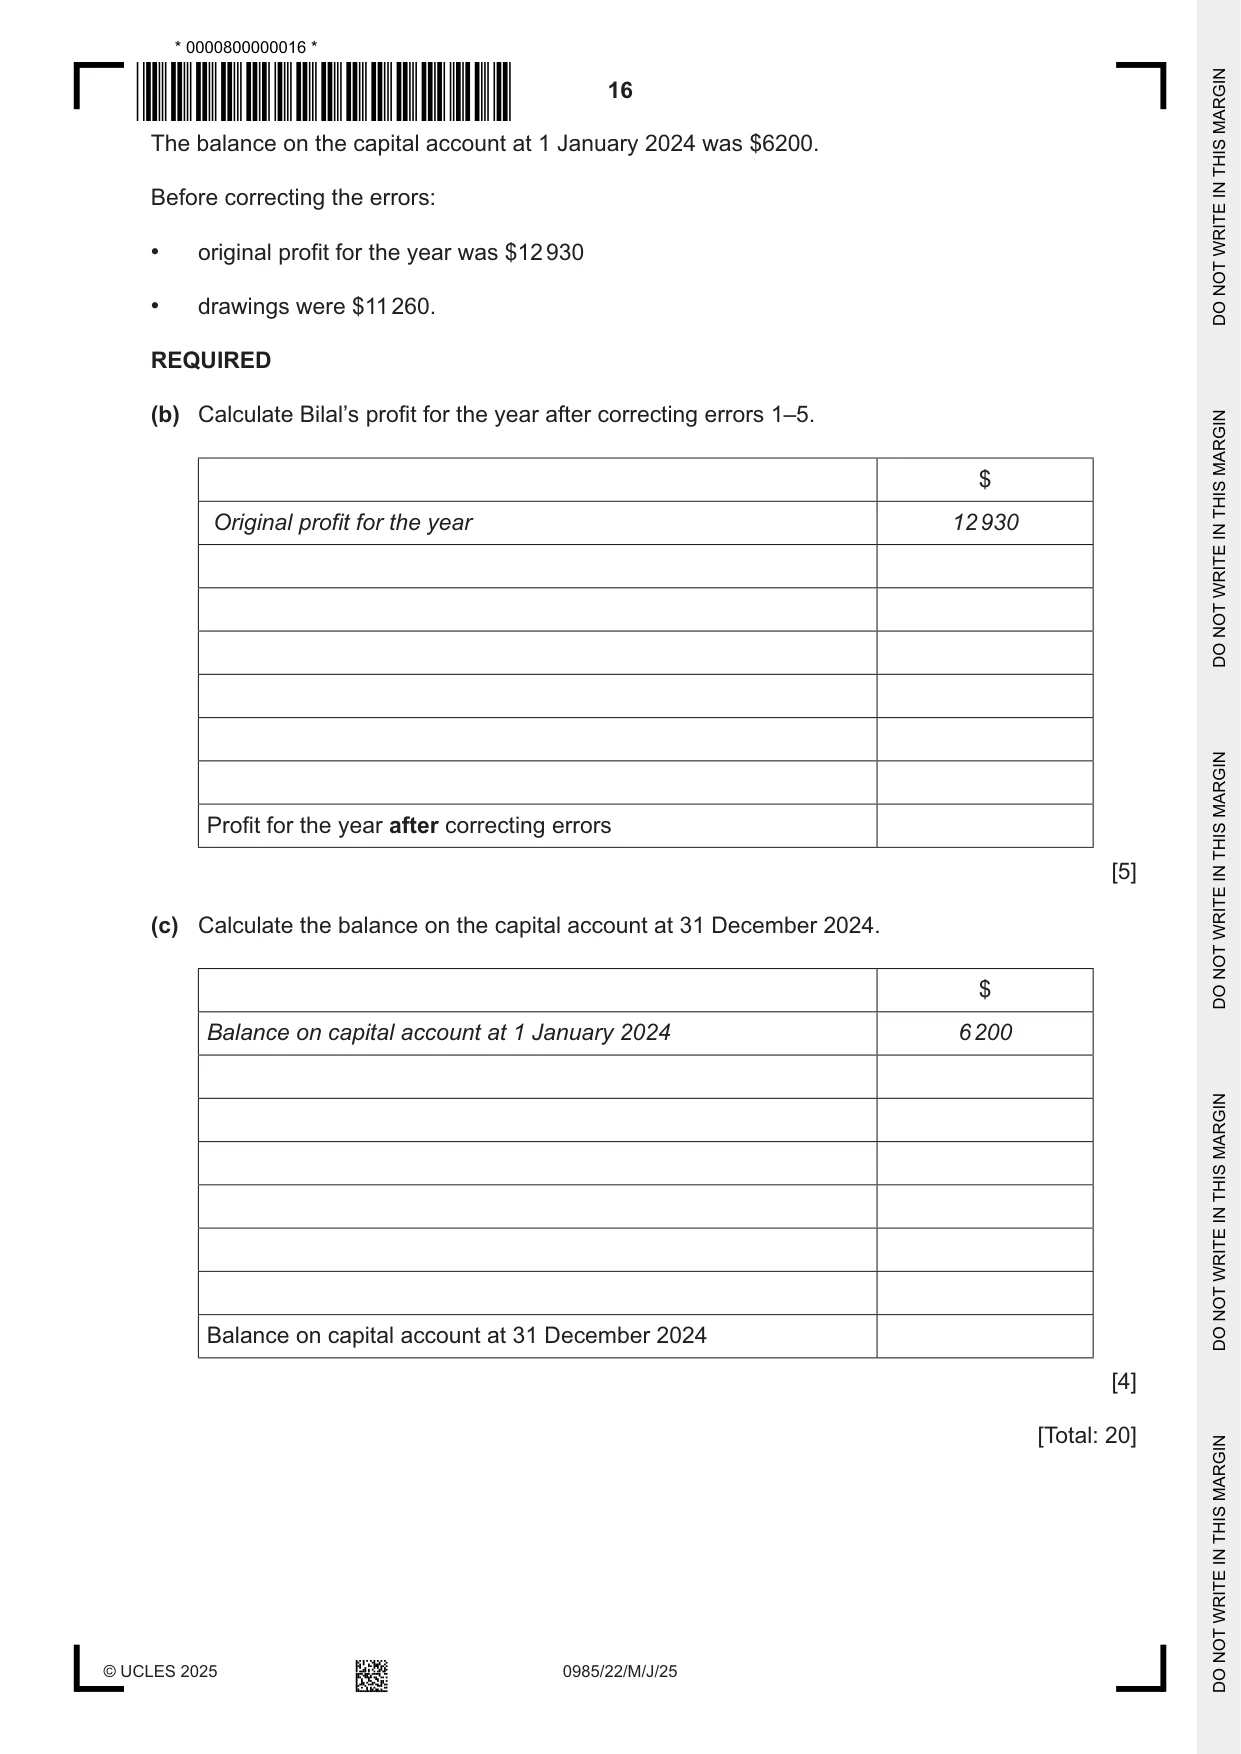
4 Bilal prepared a trial balance at 31 December 2024. Bilal later discovered the following errors. 1 Goods taken for Bilal’s own use, costing $185, had been recorded as cash drawings. 2 Motor expenses, $63, paid by bank transfer, had been recorded as $36. 3 Capital introduced by Bilal, $2000, had been credited to a bank loan account. 4 A purchase invoice, $84, from Maya, had been debited to the account for Moira and credited to the purchases account. 5 Bilal’s private insurance, $130, had been recorded as business insurance. REQUIRED (a) Prepare the journal entries on page 15 to correct errors 1–5. Narratives are not required. Bilal Journal Details ................................................................ ................................................................ ................................................................ ................................................................ ................................................................ ................................................................ ................................................................ ................................................................ ................................................................ ................................................................ ................................................................ ................................................................ ................................................................ ................................................................ ................................................................ ................................................................ ................................................................ ................................................................ ................................................................ ................................................................ The balance on the capital account at 1 January 2024 was $6200. Before correcting the errors: • original profit for the year was $12 930 • drawings were $11 260. REQUIRED (b) Calculate Bilal’s profit for the year after correcting errors 1–5. $ Original profit for the year 12 930 Profit for the year after correcting errors [5] (c) Calculate the balance on the capital account at 31 December 2024. $ Balance on capital account at 1 January 2024 6 200 Balance on capital account at 31 December 2024 [4] [Total: 20]
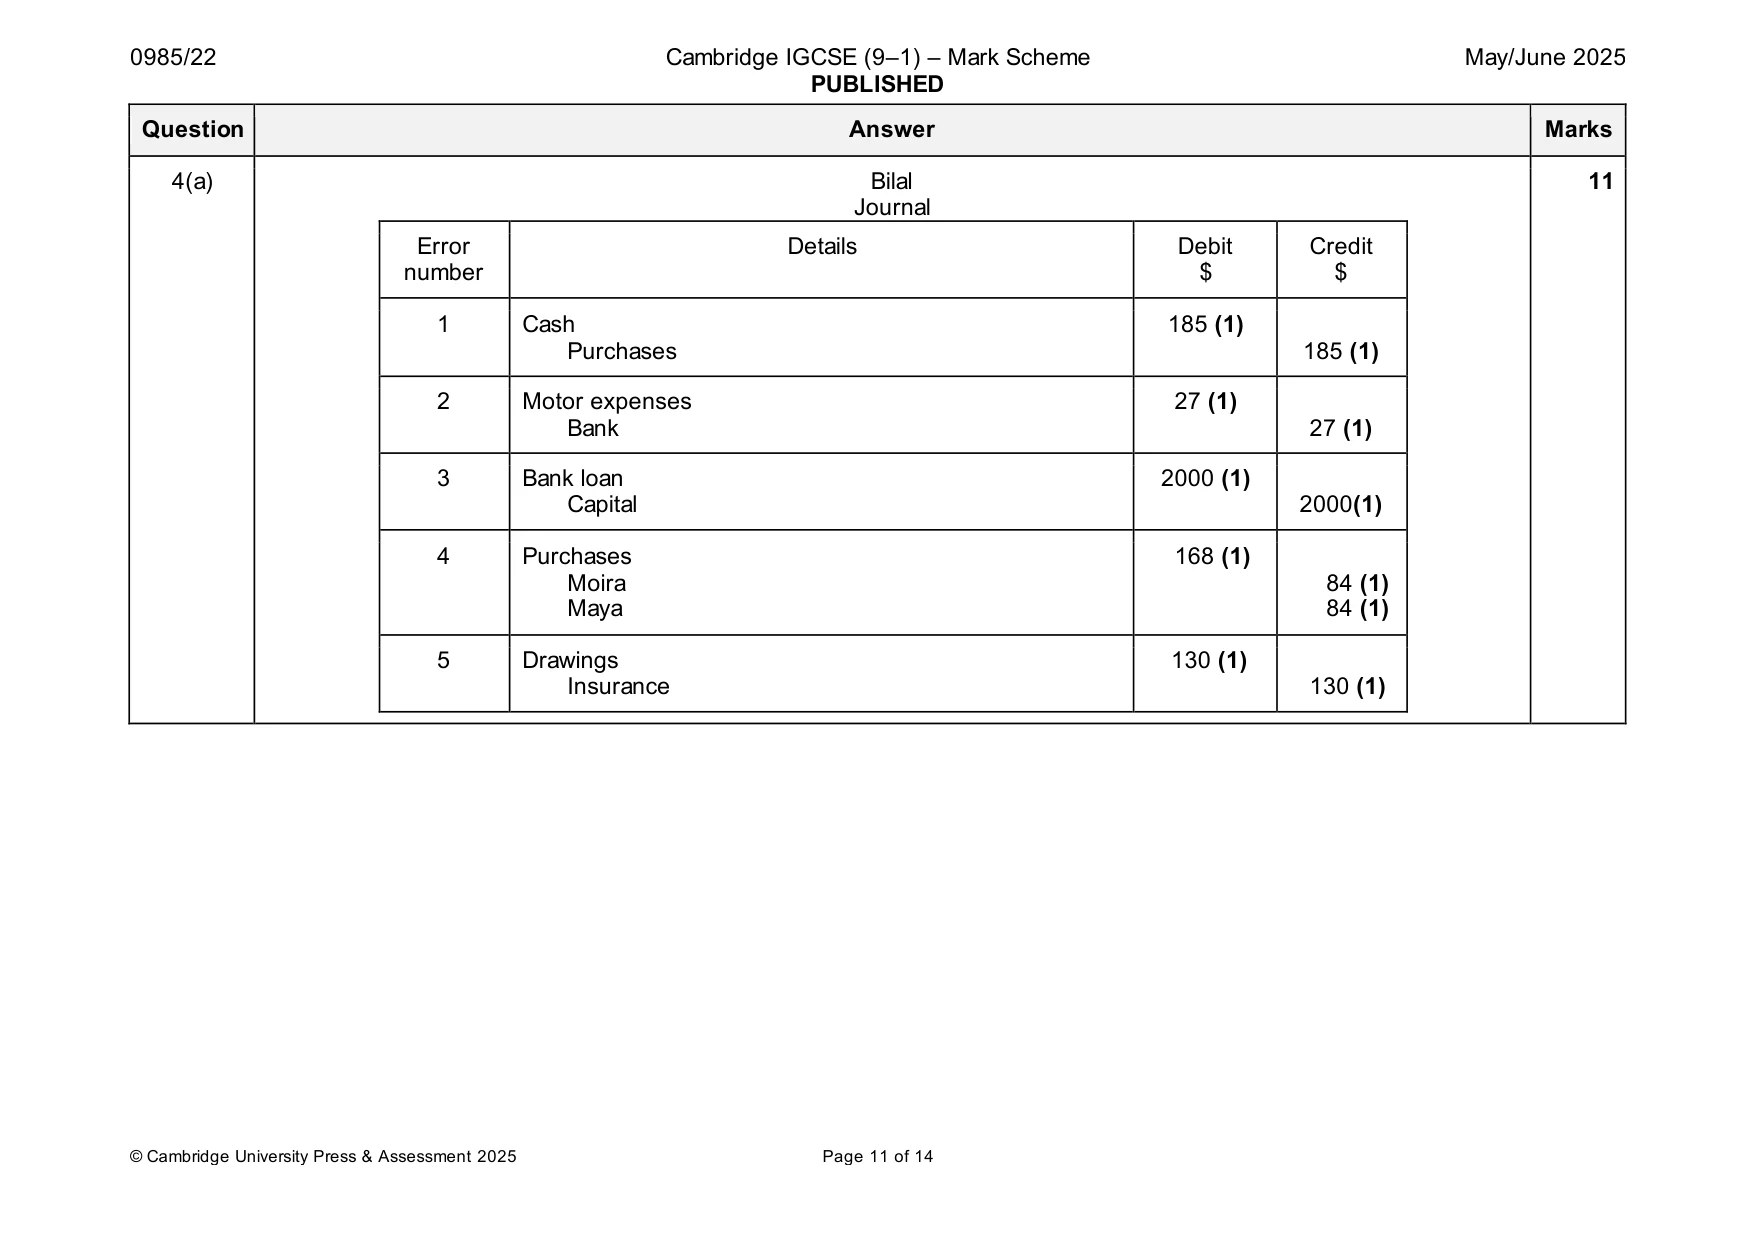
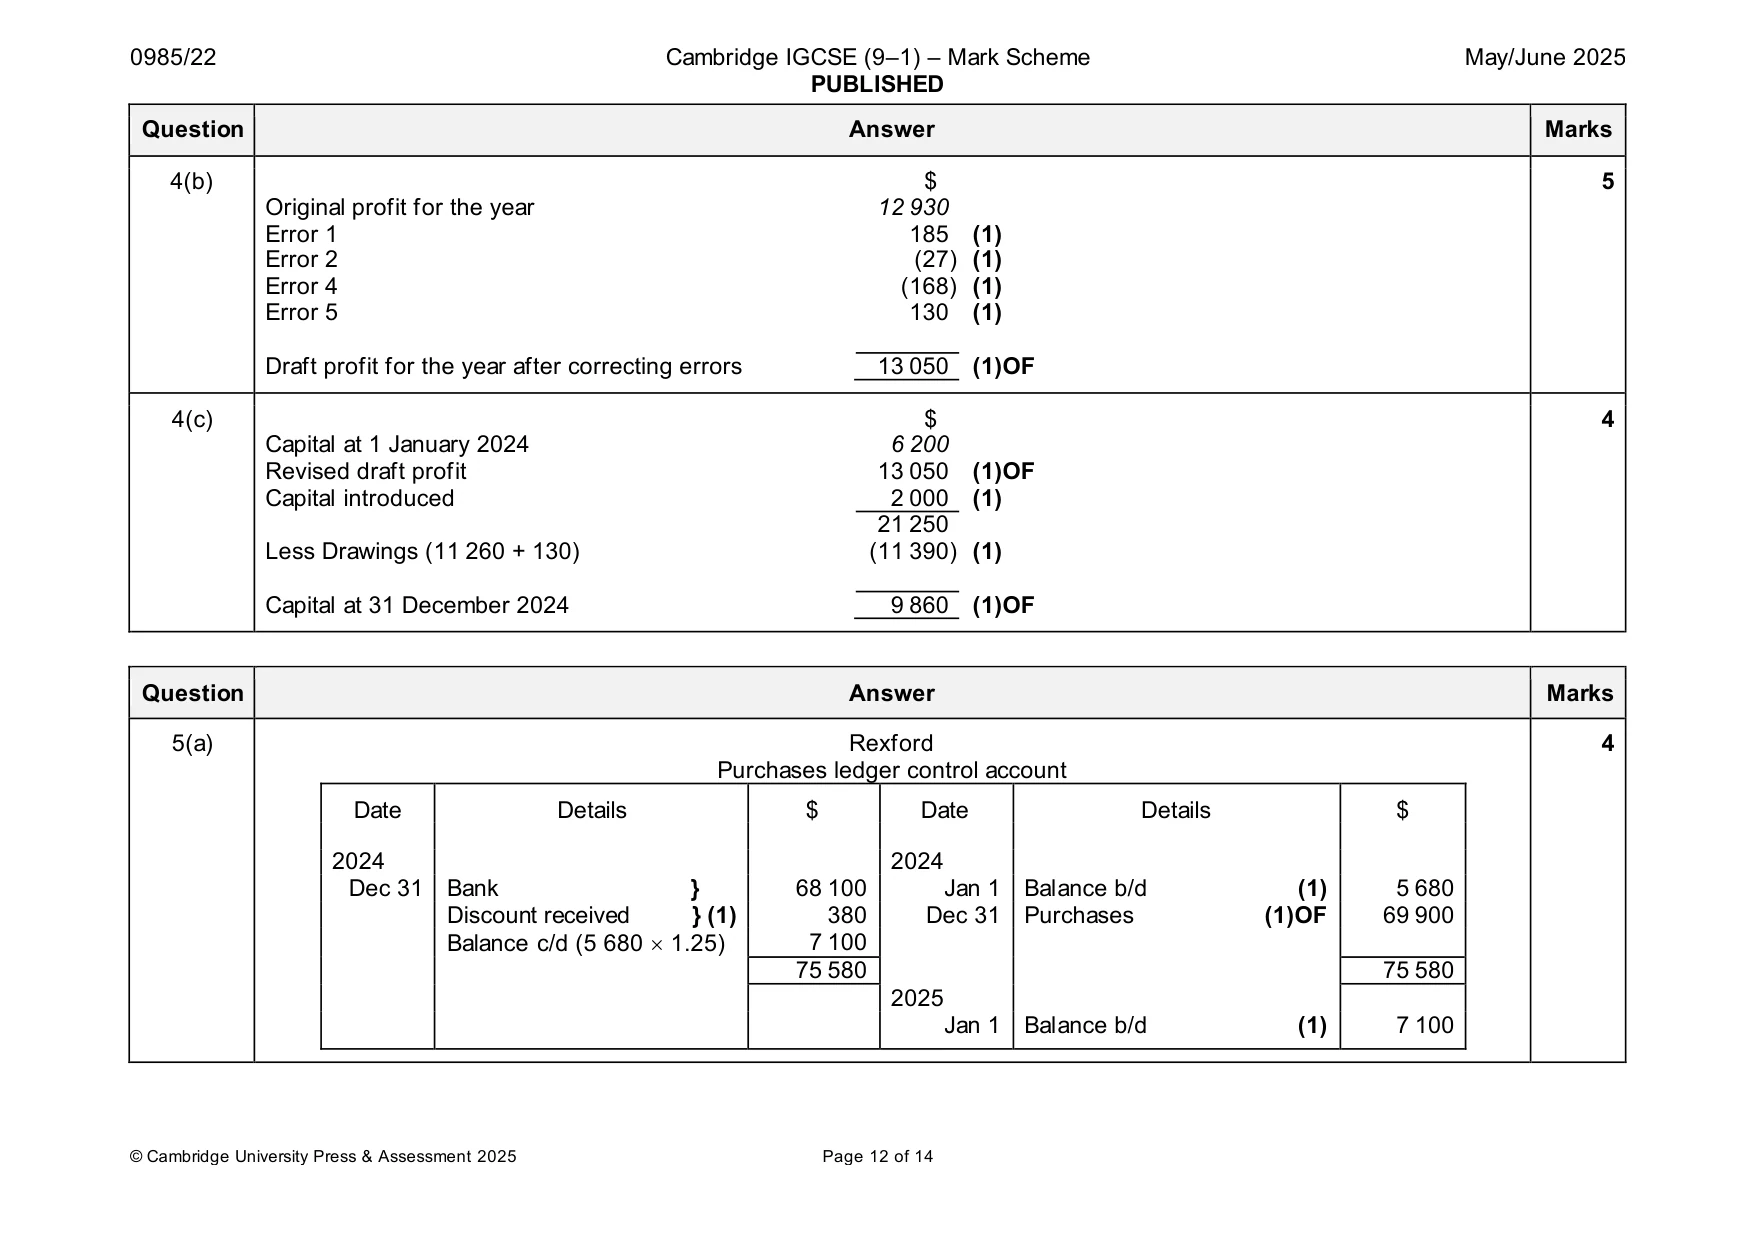
Mark scheme: 4(a) Bilal 11 Journal Error Details Debit Credit number $ $ 1 Cash 185 (1) Purchases 185 (1) 2 Motor expenses 27 (1) Bank 27 (1) 3 Bank loan 2000 (1) Capital 2000(1) 4 Purchases 168 (1) Moira 84 (1) Maya 84 (1) 5 Drawings 130 (1) Insurance 130 (1) 4(b) $ 5 Original profit for the year 12 930 Error 1 185 (1) Error 2 (27) (1) Error 4 (168) (1) Error 5 130 (1) Draft profit for the year after correcting errors 13 050 (1)OF 4(c) $ 4 Capital at 1 January 2024 6 200 Revised draft profit 13 050 (1)OF Capital introduced 2 000 (1) 21 250 Less Drawings (11 260 + 130) (11 390) (1) Capital at 31 December 2024 9 860 (1)OF
Q5 · Rexford is a trader
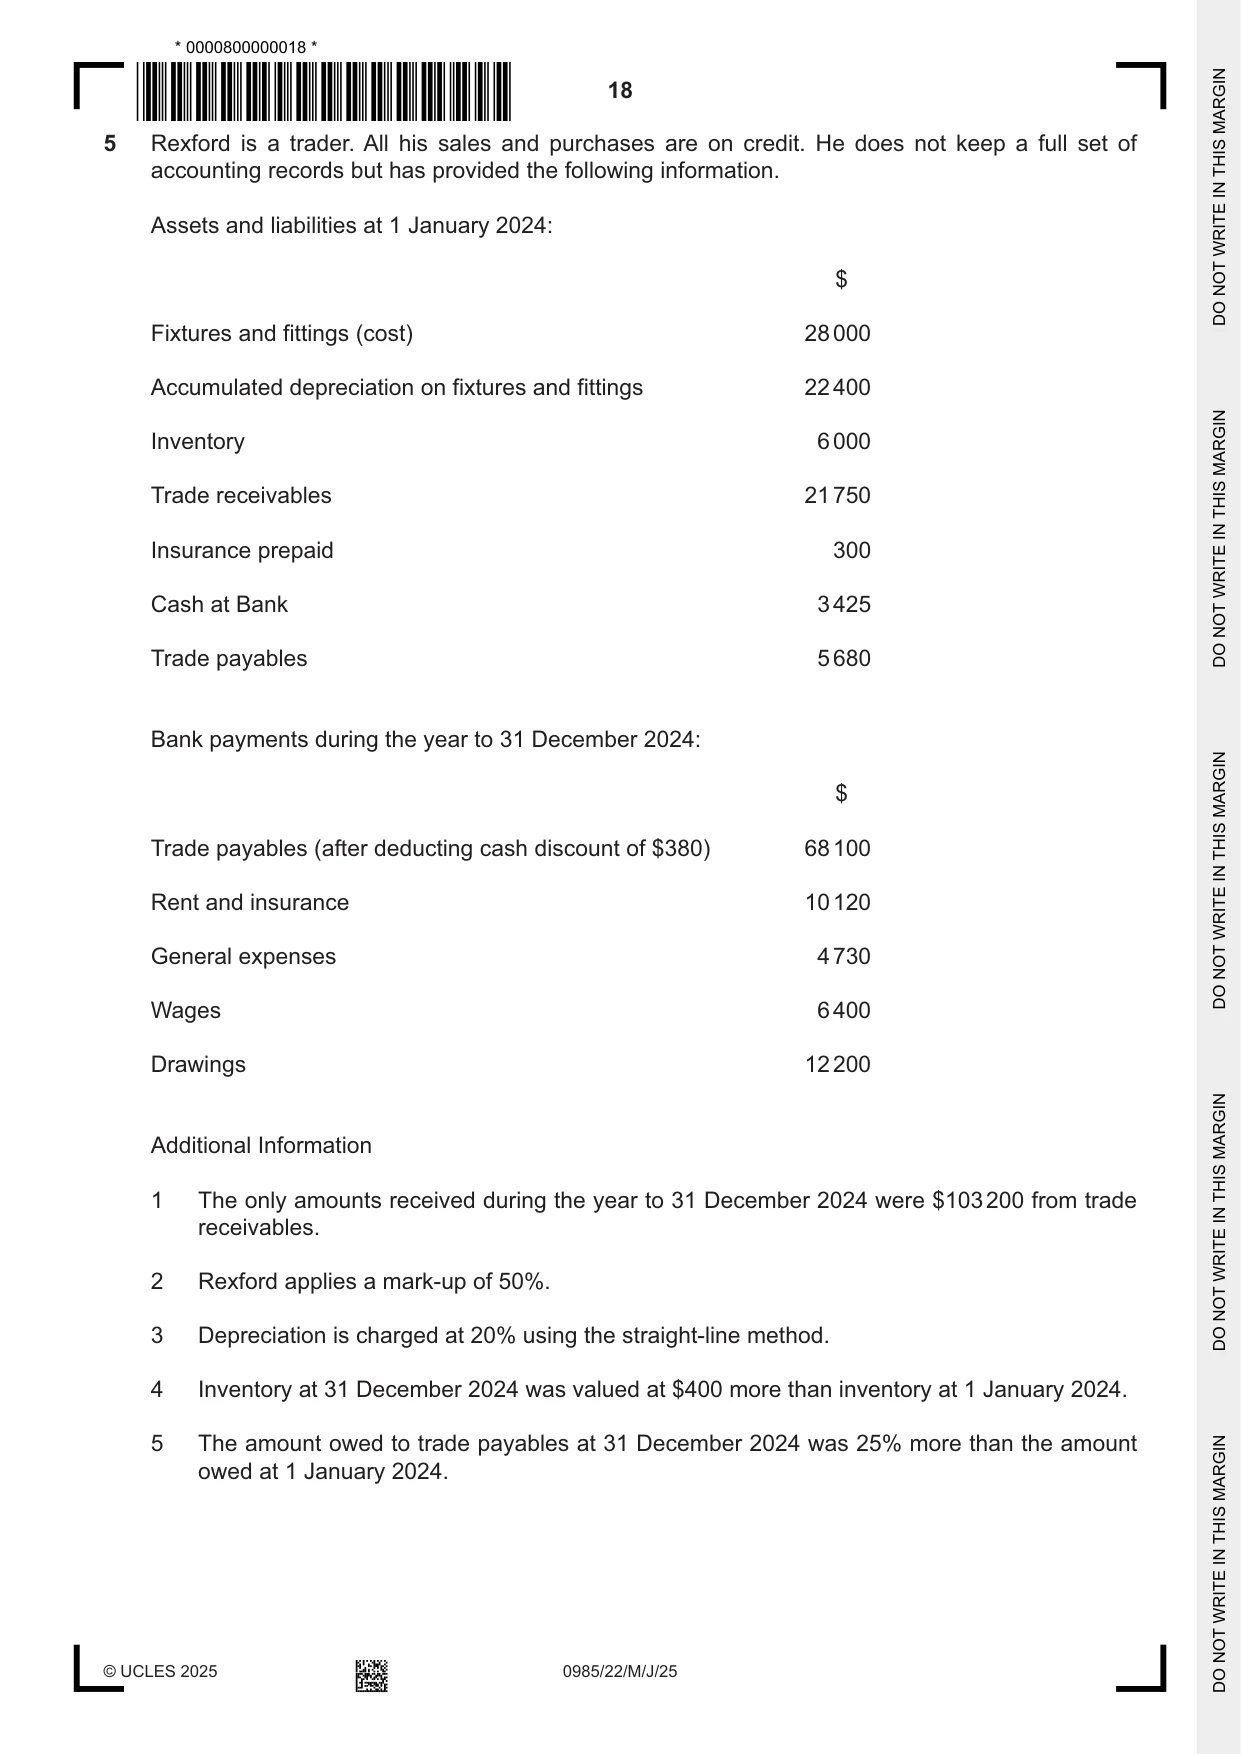
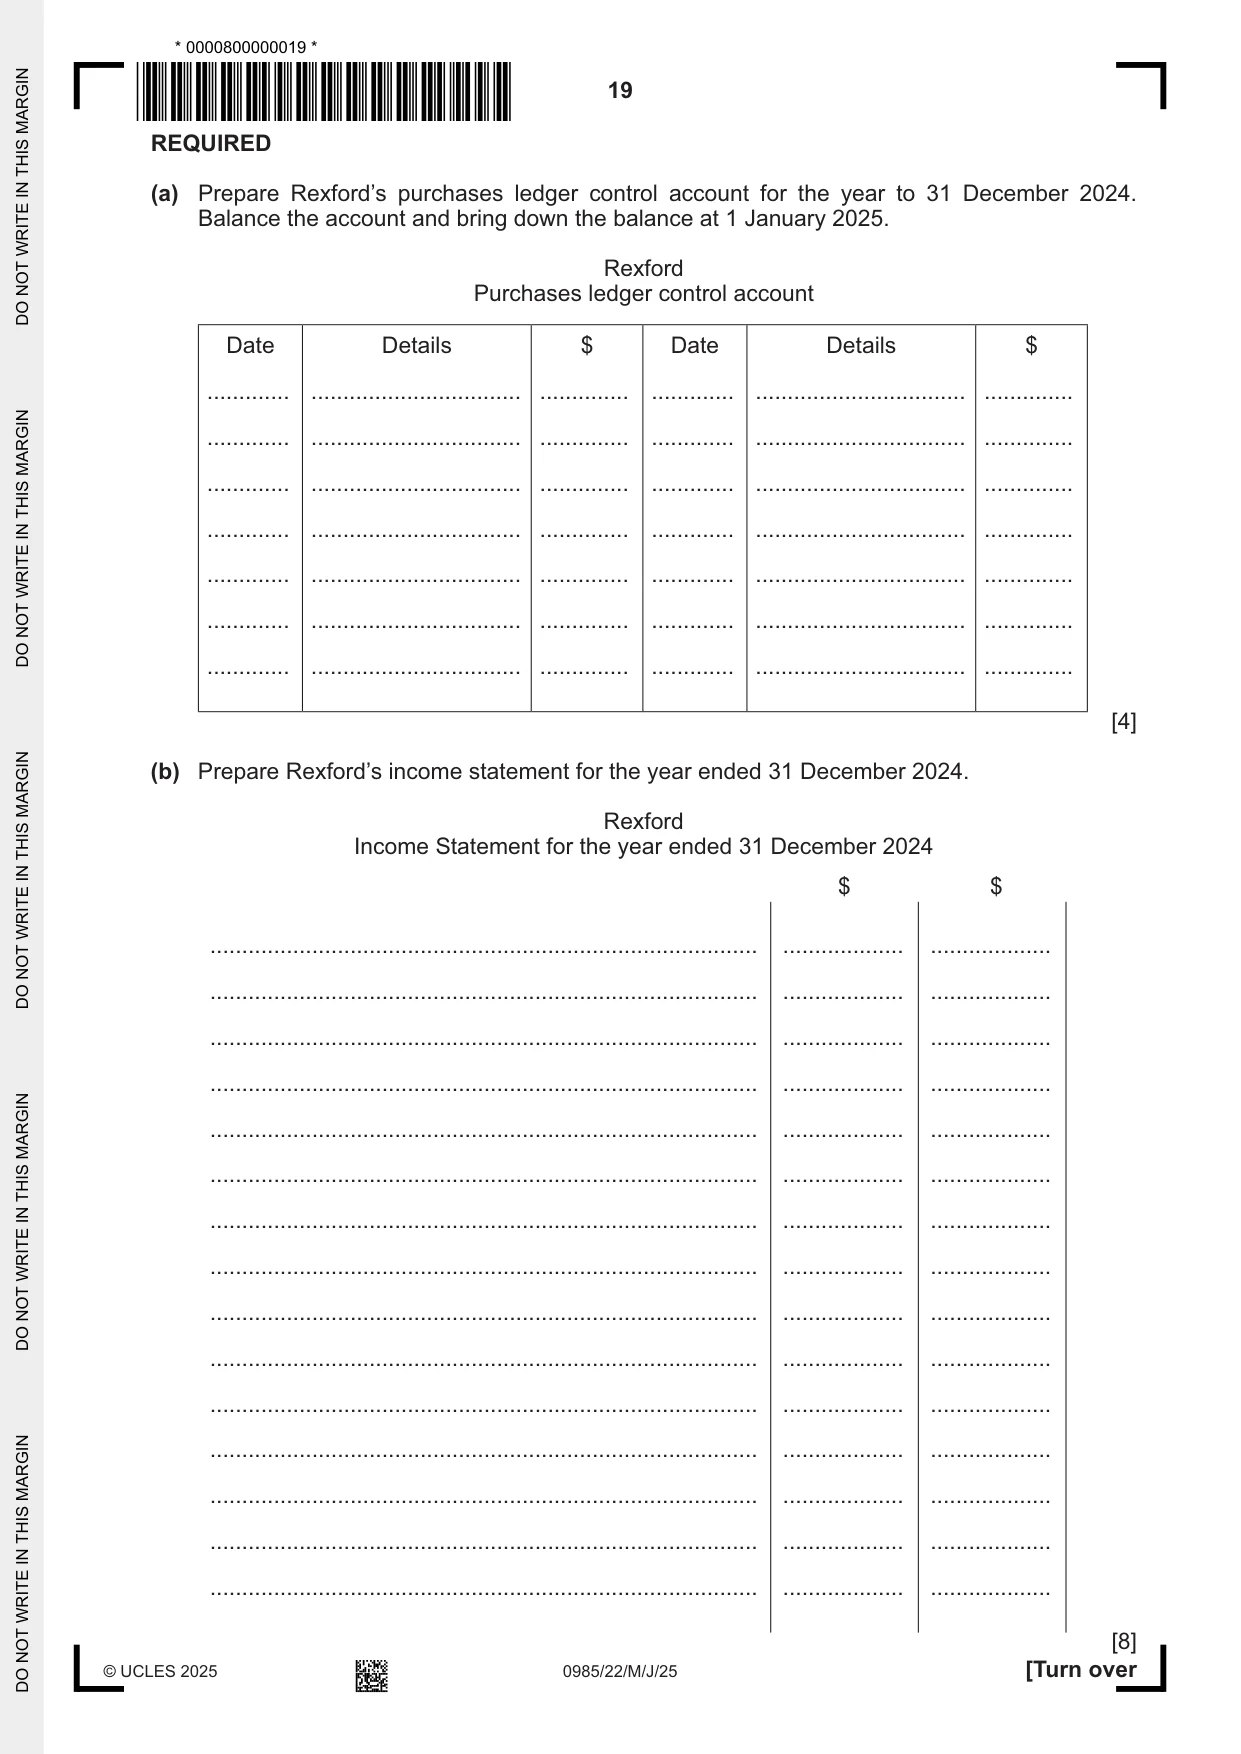
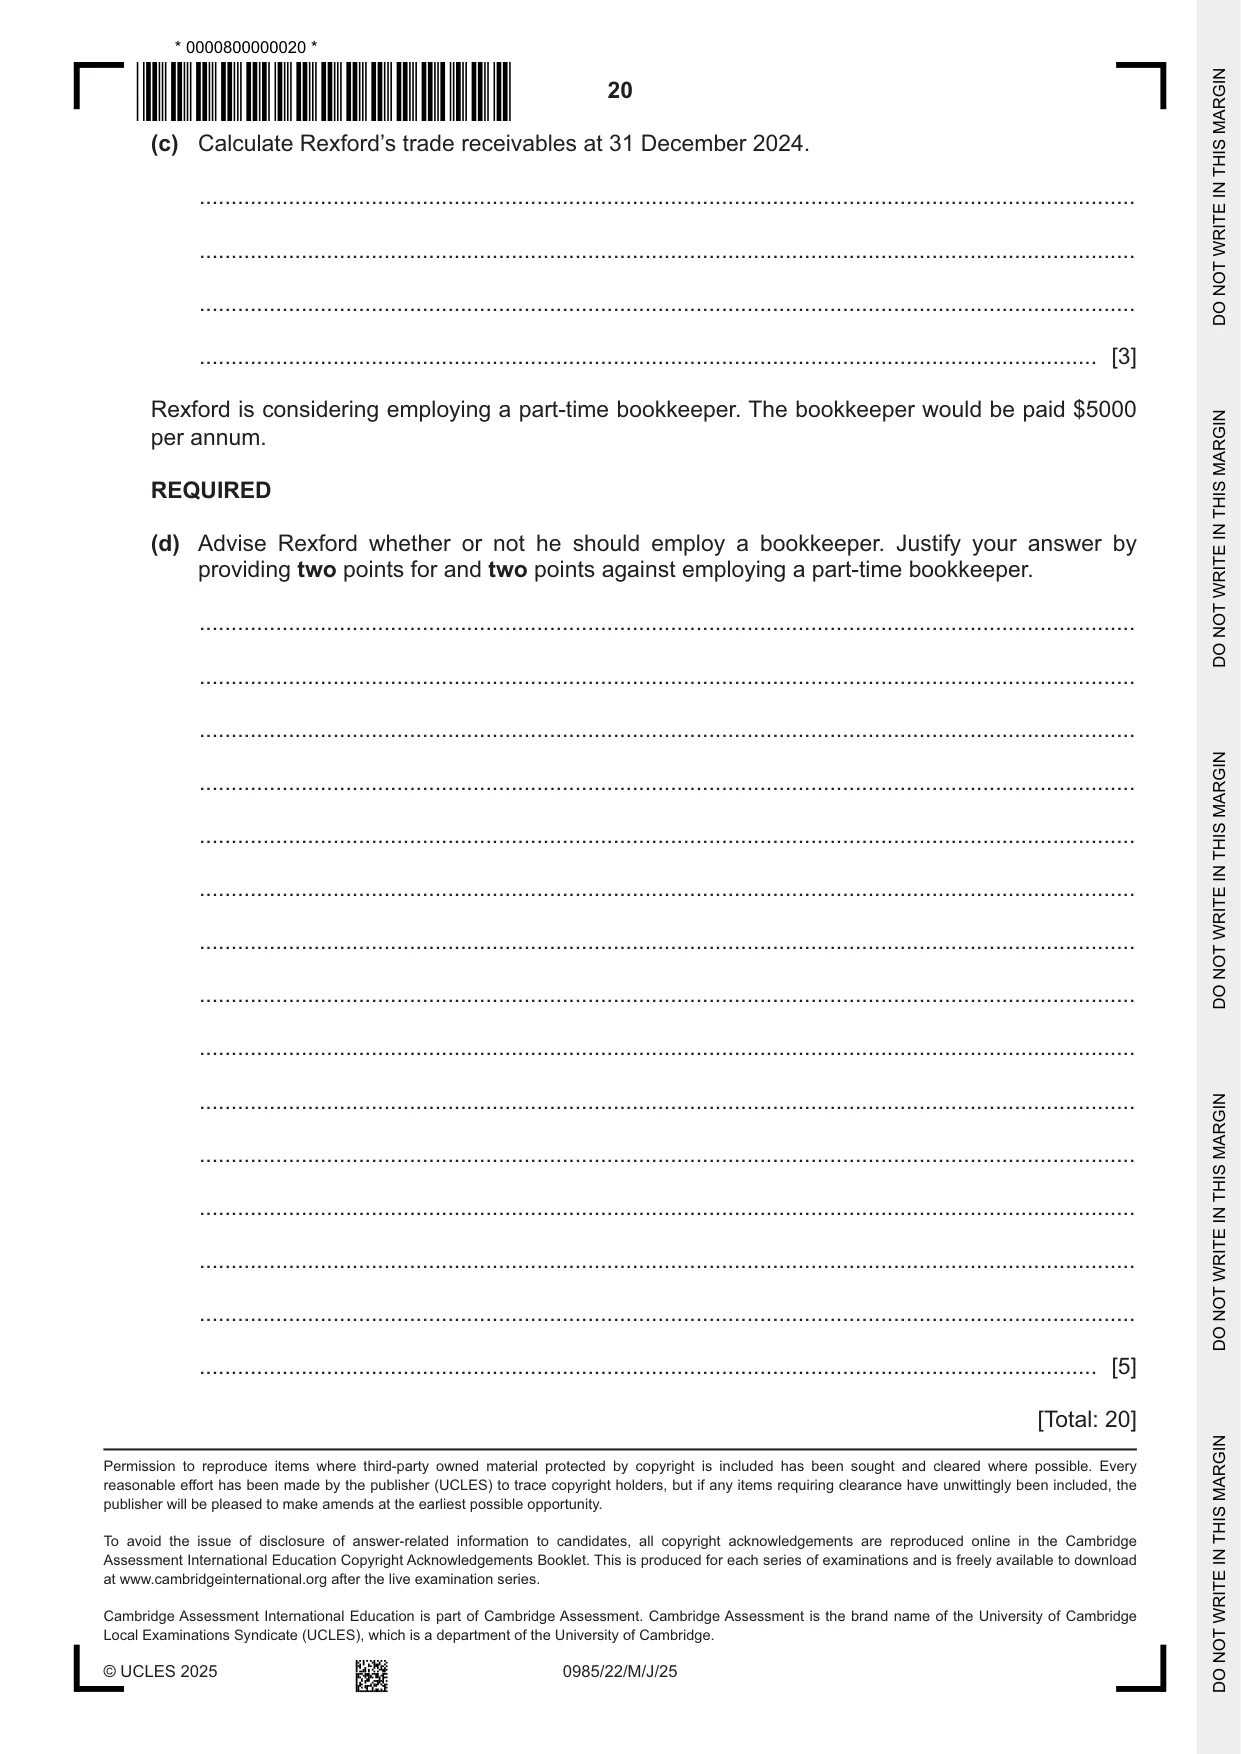
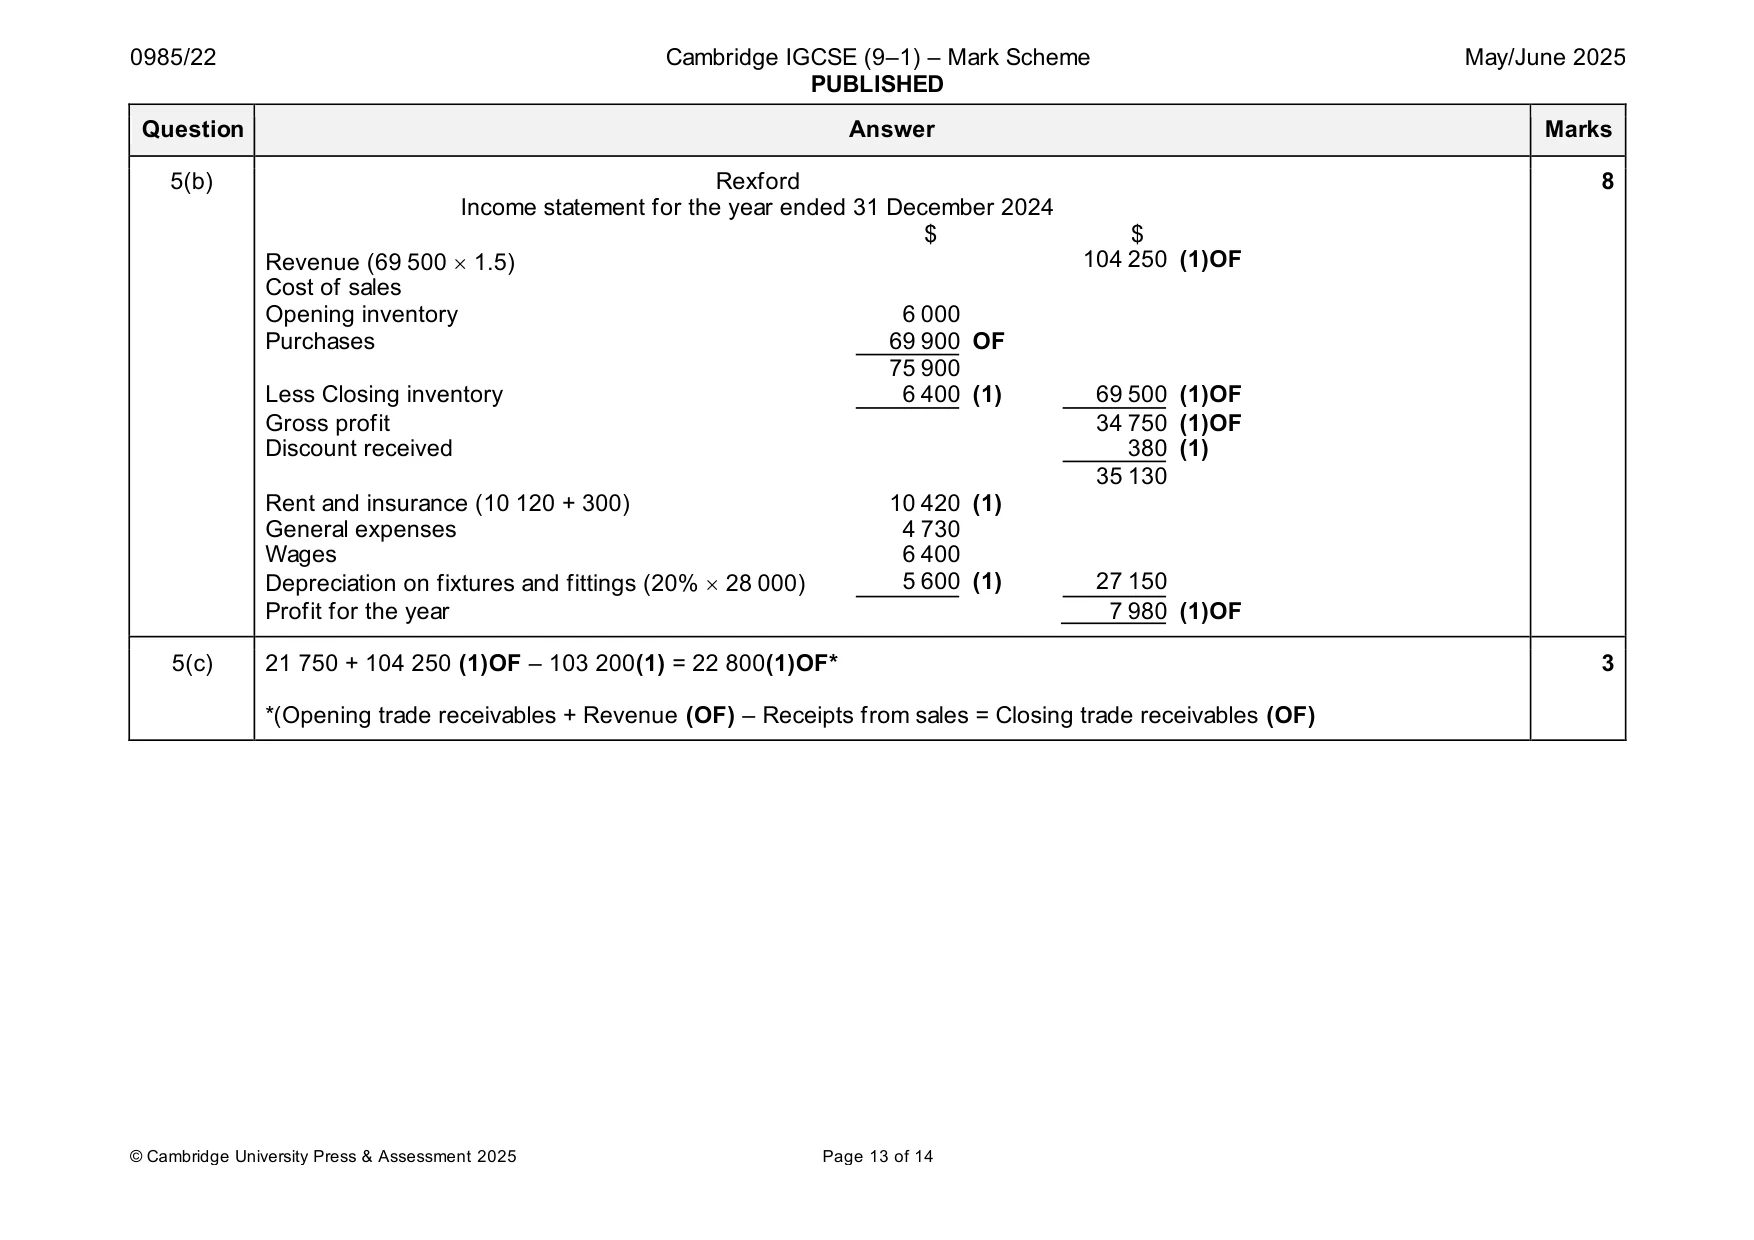
5 Rexford is a trader. All his sales and purchases are on credit. He does not keep a full set of accounting records but has provided the following information. Assets and liabilities at 1 January 2024: $ Fixtures and fittings (cost) 28 000 Accumulated depreciation on fixtures and fittings 22 400 Inventory 6 000 Trade receivables 21 750 Insurance prepaid 300 Cash at Bank 3 425 Trade payables 5 680 Bank payments during the year to 31 December 2024: $ Trade payables (after deducting cash discount of $380) 68 100 Rent and insurance 10 120 General expenses 4 730 Wages 6 400 Drawings 12 200 Additional Information 1 The only amounts received during the year to 31 December 2024 were $103 200 from trade receivables. 2 Rexford applies a mark-up of 50%. 3 Depreciation is charged at 20% using the straight-line method. 4 Inventory at 31 December 2024 was valued at $400 more than inventory at 1 January 2024. 5 The amount owed to trade payables at 31 December 2024 was 25% more than the amount owed at 1 January 2024. REQUIRED (a) Prepare Rexford’s purchases ledger control account for the year to 31 December 2024. Balance the account and bring down the balance at 1 January 2025. Rexford Purchases ledger control account Date Details $ Date Details $ ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. ............. ................................. .............. [4] (b) Prepare Rexford’s income statement for the year ended 31 December 2024. Rexford Income Statement for the year ended 31 December 2024 $ $ ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... ...................................................................................... ................... ................... [8] (c) Calculate Rexford’s trade receivables at 31 December 2024. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] Rexford is considering employing a part-time bookkeeper. The bookkeeper would be paid $5000 per annum. REQUIRED (d) Advise Rexford whether or not he should employ a bookkeeper. Justify your answer by providing two points for and two points against employing a part-time bookkeeper. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
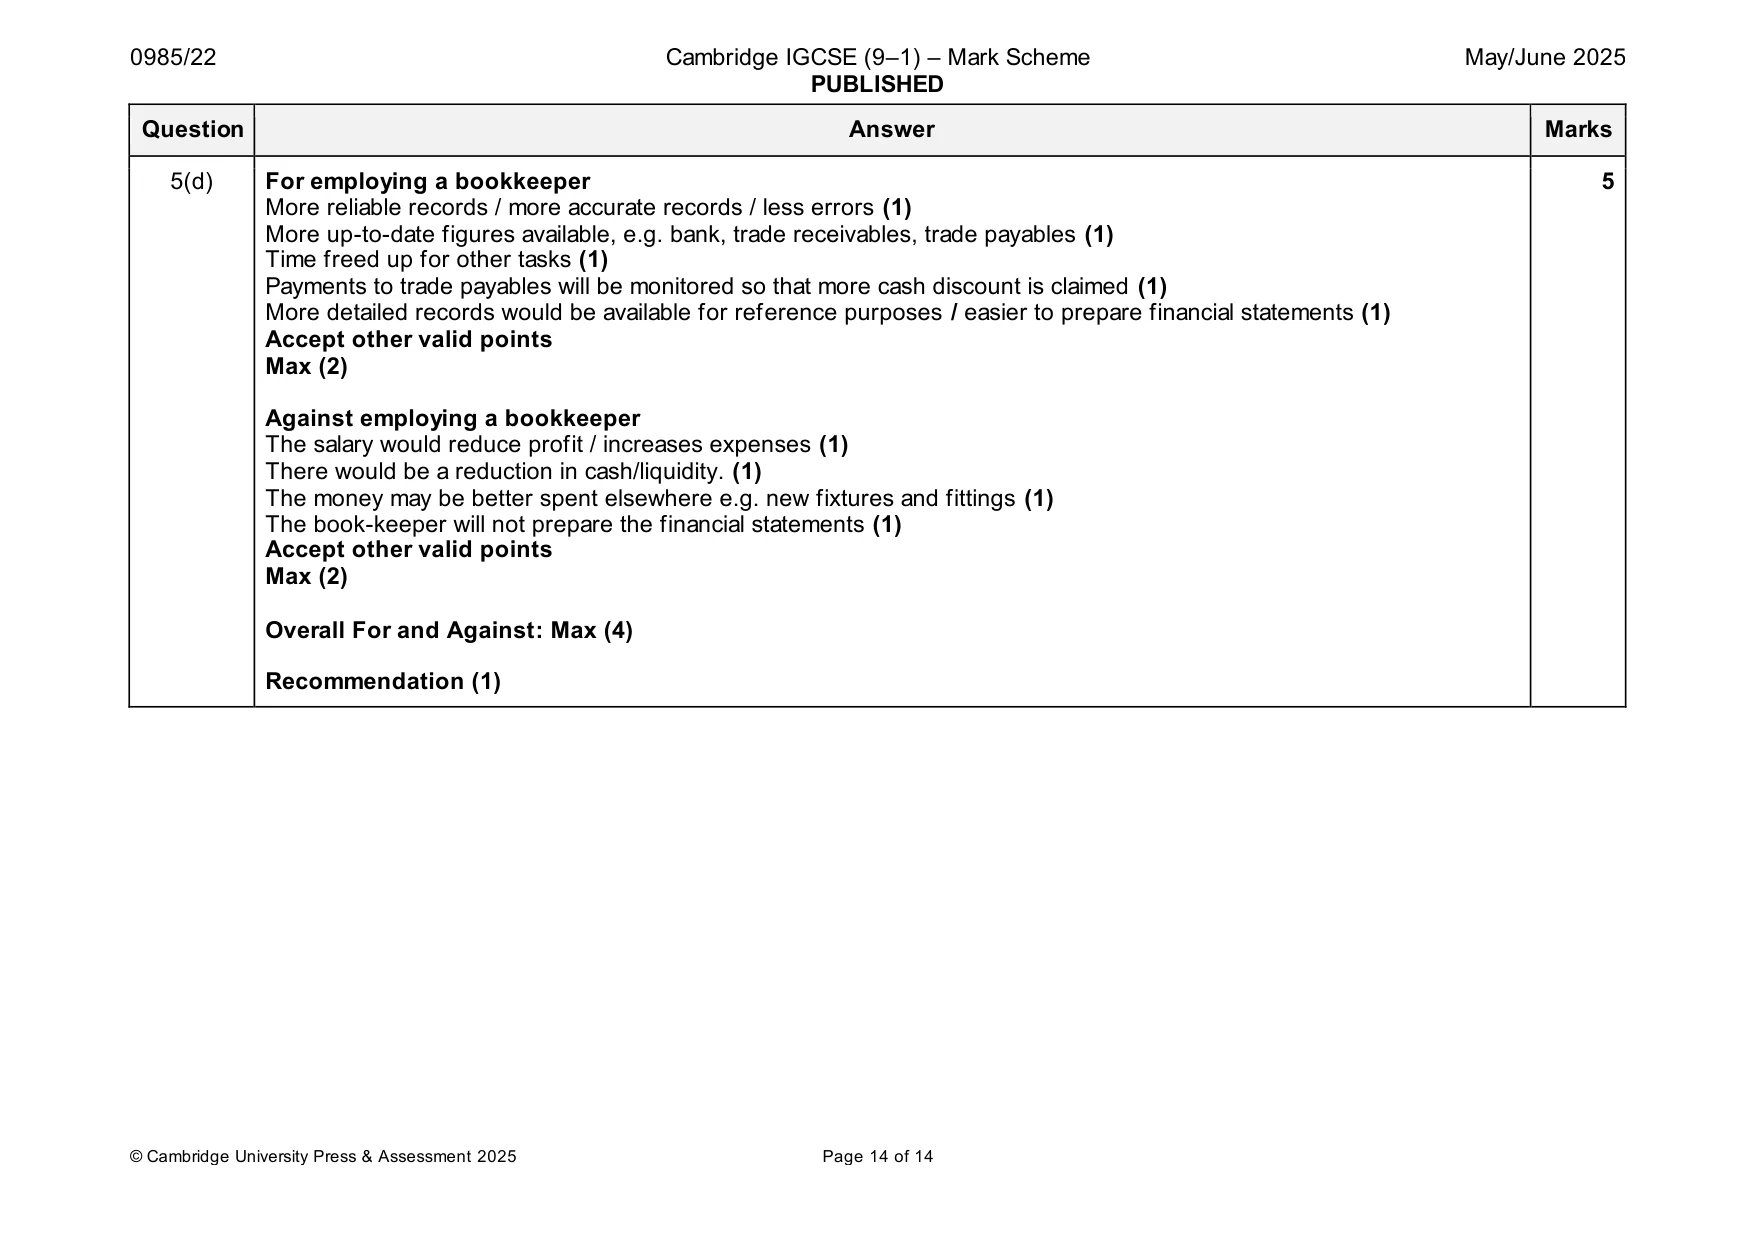
Mark scheme: 5(a) Rexford 4 Purchases ledger control account Date Details $ Date Details $ 2024 2024 Dec 31 Bank } 68 100 Jan 1 Balance b/d (1) 5 680 Discount received } (1) 380 Dec 31 Purchases (1)OF 69 900 Balance c/d (5 680 1.25) 7 100 75 580 75 580 2025 Jan 1 Balance b/d (1) 7 100 5(b) Rexford 8 Income statement for the year ended 31 December 2024 $ $ Revenue (69 500 1.5) 104 250 (1)OF Cost of sales Opening inventory 6 000 Purchases 69 900 OF 75 900 Less Closing inventory 6 400 (1) 69 500 (1)OF Gross profit 34 750 (1)OF Discount received 380 (1) 35 130 Rent and insurance (10 120 + 300) 10 420 (1) General expenses 4 730 Wages 6 400 Depreciation on fixtures and fittings (20% 28 000) 5 600 (1) 27 150 Profit for the year 7 980 (1)OF 5(c) 21 750 + 104 250 (1)OF – 103 200(1) = 22 800(1)OF* 3 *(Opening trade receivables + Revenue (OF) – Receipts from sales = Closing trade receivables (OF) 5(d) For employing a bookkeeper 5 More reliable records / more accurate records / less errors (1) More up-to-date figures available, e.g. bank, trade receivables, trade payables (1) Time freed up for other tasks (1) Payments to trade payables will be monitored so that more cash discount is claimed (1) More detailed records would be available for reference purposes / easier to prepare financial statements (1) Accept other valid points Max (2) Against employing a bookkeeper The salary would reduce profit / increases expenses (1) There would be a reduction in cash/liquidity. (1) The money may be better spent elsewhere e.g. new fixtures and fittings (1) The book-keeper will not prepare the financial statements (1) Accept other valid points Max (2) Overall For and Against: Max (4) Recommendation (1)
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2025 May/June, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.