Questions as text
Q1 · Gok is a wholesaler 0985/22 May/June 2020
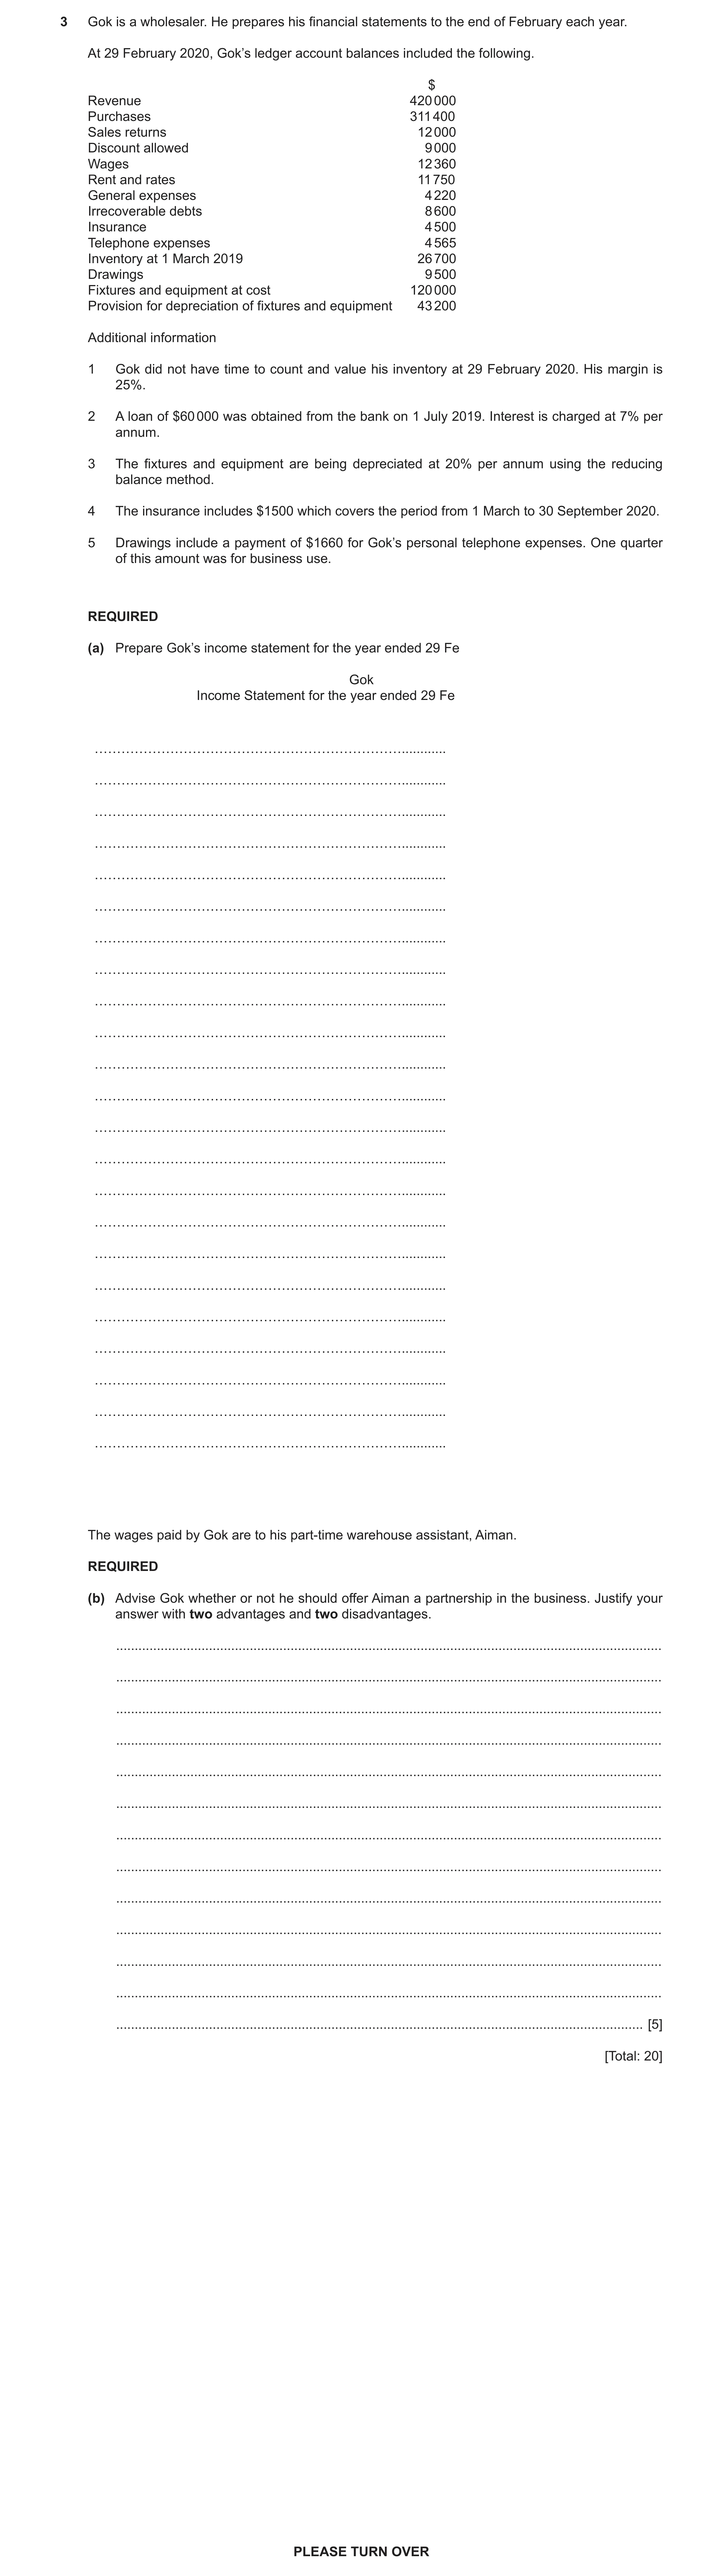
3 Gok is a wholesaler. He prepares his financial statements to the end of February each year. At 29 February 2020, Gok’s ledger account balances included the following. $ Revenue 420 000 Purchases 311 400 Sales returns 12 000 Discount allowed 9 000 Wages 12 360 Rent and rates 11 750 General expenses 4 220 Irrecoverable debts 8 600 Insurance 4 500 Telephone expenses 4 565 Inventory at 1 March 2019 26 700 Drawings 9 500 Fixtures and equipment at cost 120 000 Provision for depreciation of fixtures and equipment 43 200 Additional information 1 Gok did not have time to count and value his inventory at 29 February 2020. His margin is 25%. 2 A loan of $60 000 was obtained from the bank on 1 July 2019. Interest is charged at 7% per annum. 3 The fixtures and equipment are being depreciated at 20% per annum using the reducing balance method. 4 The insurance includes $1500 which covers the period from 1 March to 30 September 2020. 5 Drawings include a payment of $1660 for Gok’s personal telephone expenses. One quarter of this amount was for business use. REQUIRED (a) Prepare Gok’s income statement for the year ended 29 Fe Gok Income Statement for the year ended 29 Fe …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … The wages paid by Gok are to his part-time warehouse assistant, Aiman. REQUIRED (b) Advise Gok whether or not he should offer Aiman a partnership in the business. Justify your answer with two advantages and two disadvantages. … … … … … … … … … … … … … [5] [Total: 20] PLEASE TURN OVER
20 marks
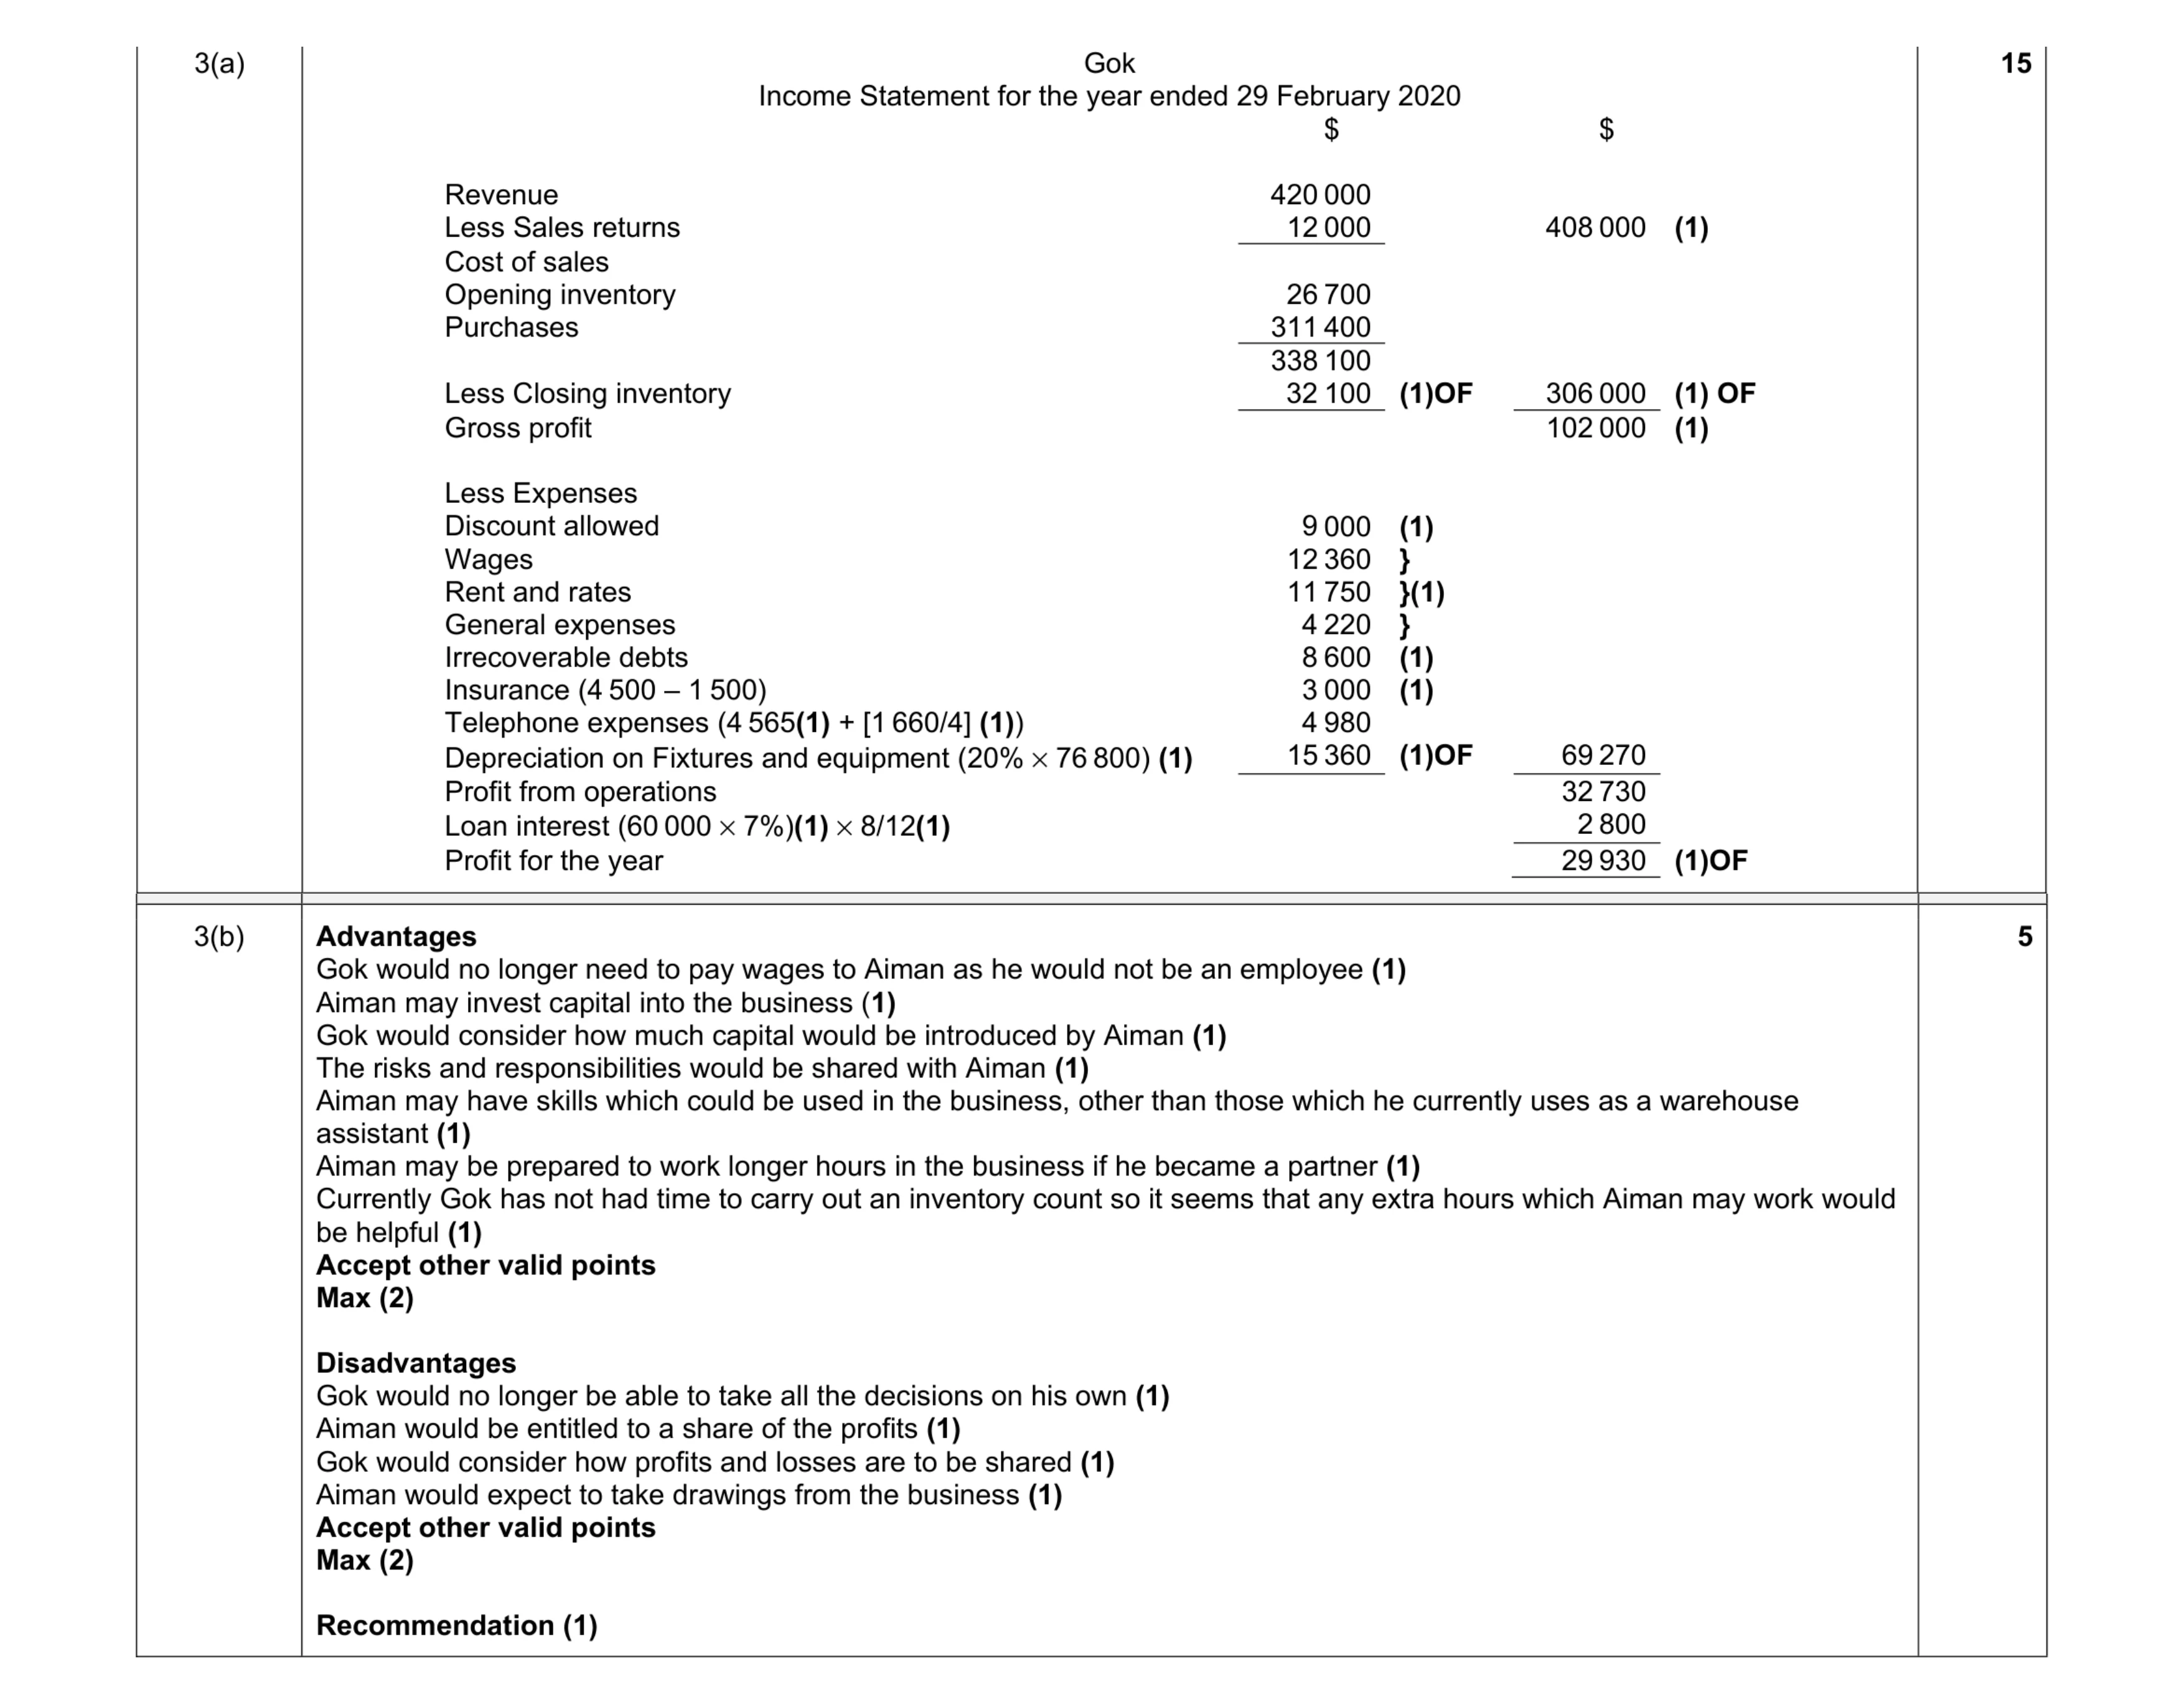
Mark scheme: 3(a) Gok Income Statement for the year ended 29 February 2020 $ $ Revenue 420 000 Less Sales returns 12 000 408 000 (1) Cost of sales Opening inventory 26 700 Purchases 311 400 338 100 Less Closing inventory 32 100 (1)OF 306 000 (1) OF Gross profit 102 000 (1) Less Expenses Discount allowed 9 000 (1) Wages 12 360 } Rent and rates 11 750 }(1) General expenses 4 220 } Irrecoverable debts 8 600 (1) Insurance (4 500 – 1 500) 3 000 (1) Telephone expenses (4 565(1) + [1 660/4] (1)) 4 980 Depreciation on Fixtures and equipment (20% × 76 800) (1) 15 360 (1)OF 69 270 Profit from operations 32 730 Loan interest (60 000 × 7%)(1) × 8/12(1) 2 800 Profit for the year 29 930 (1)OF 15 Question Answer Marks 3(b) Advantages Gok would no longer need to pay wages to Aiman as he would not be an employee (1) Aiman may invest capital into the business (1) Gok would consider how much capital would be introduced by Aiman (1) The risks and responsibilities would be shared with Aiman (1) Aiman may have skills which could be used in the business, other than those which he currently uses as a warehouse assistant (1) Aiman may be prepared to work longer hours in the business if he became a partner (1) Currently Gok has not had time to carry out an inventory count so it seems that any extra hours which Aiman may work would be helpful (1) Accept other valid points Max (2) Disadvantages Gok would no longer be able to take all the decisions on his own (1) Aiman would be entitled to a share of the profits (1) Gok would consider how profits and losses are to be shared (1) Aiman would expect to take drawings from the business (1) Accept other valid points Max (2) Recommendation (1) 5
This question in 0985/22 May/June 2020
Q2 · Carlos owns a business selling computer equipment 0985/22 Oct/Nov 2020
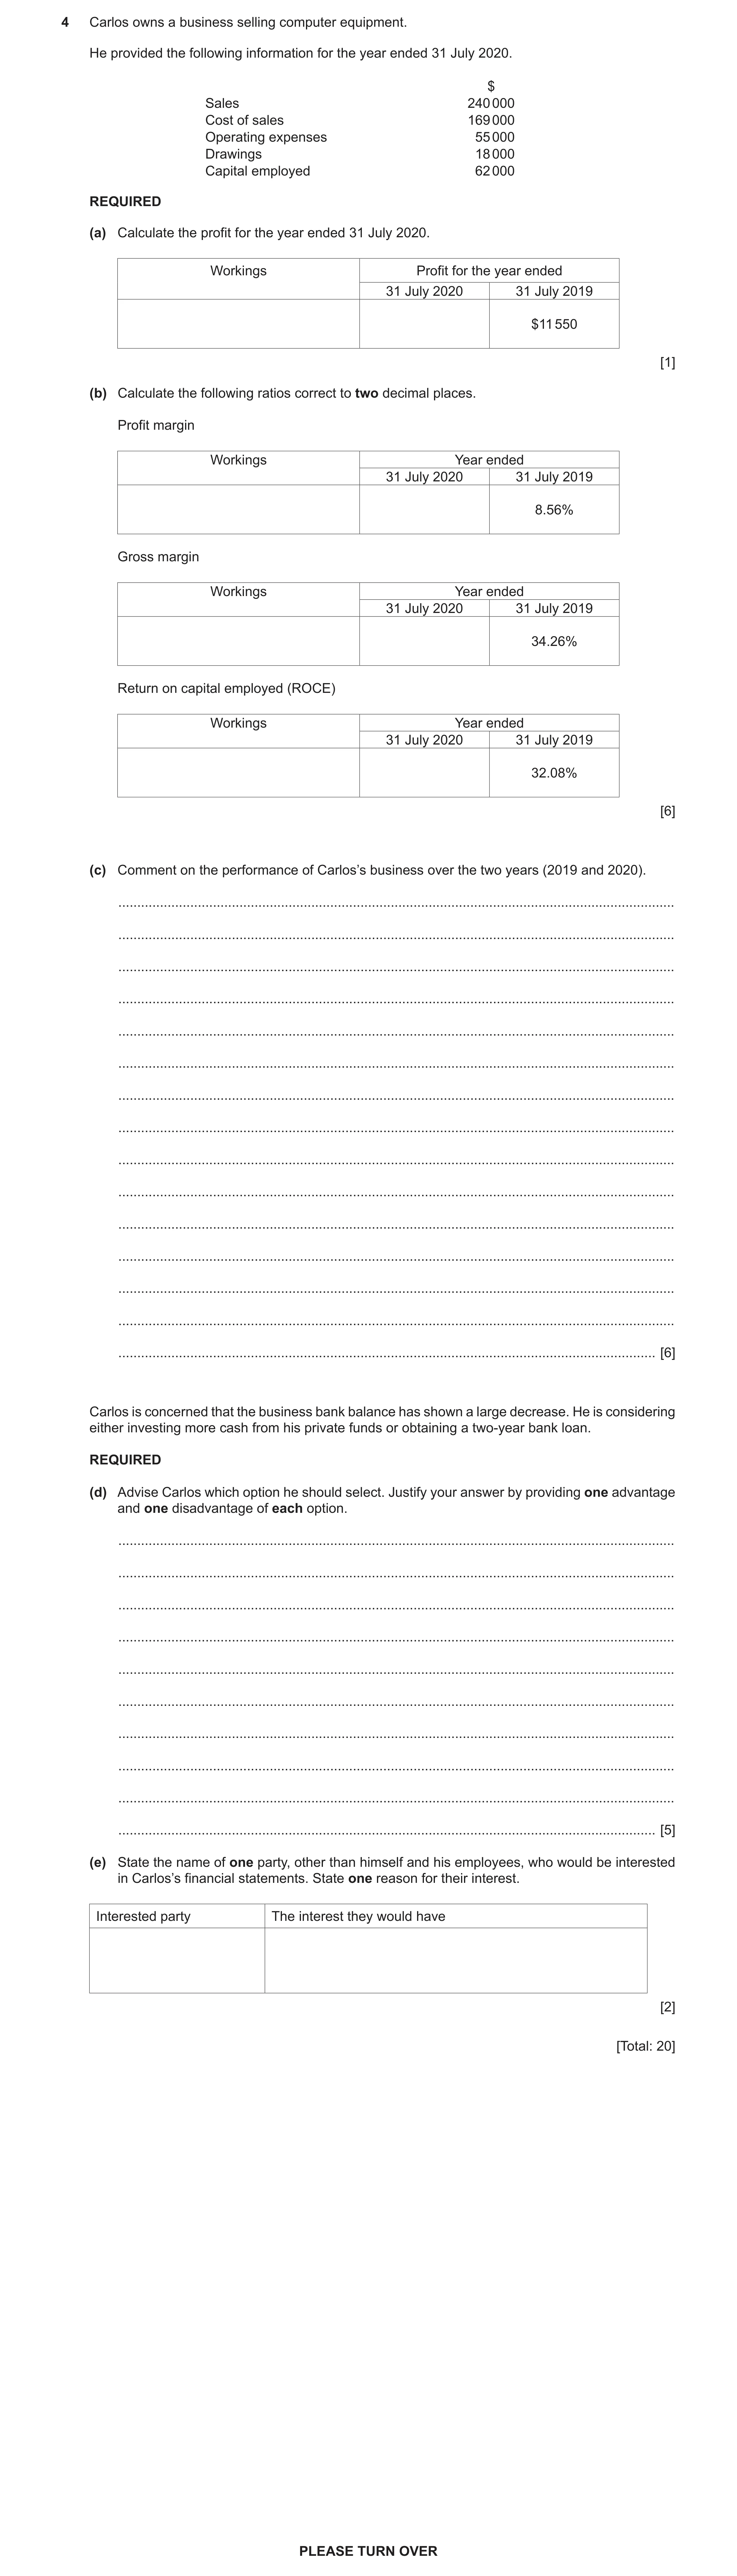
4 Carlos owns a business selling computer equipment. He provided the following information for the year ended 31 July 2020. $ Sales 240 000 Cost of sales 169 000 Operating expenses 55 000 Drawings 18 000 Capital employed 62 000 REQUIRED (a) Calculate the profit for the year ended 31 July 2020. Workings Profit for the year ended 31 July 2020 31 July 2019 $11 550 [1] (b) Calculate the following ratios correct to two decimal places. Profit margin Workings Year ended 31 July 2020 31 July 2019 8.56% Gross margin Workings Year ended 31 July 2020 31 July 2019 34.26% Return on capital employed (ROCE) Workings Year ended 31 July 2020 31 July 2019 32.08% [6] (c) Comment on the performance of Carlos’s business over the two years (2019 and 2020). … … … … … … … … … … … … … … … [6] Carlos is concerned that the business bank balance has shown a large decrease. He is considering either investing more cash from his private funds or obtaining a two-year bank loan. REQUIRED (d) Advise Carlos which option he should select. Justify your answer by providing one advantage and one disadvantage of each option. … … … … … … … … … … [5] (e) State the name of one party, other than himself and his employees, who would be interested in Carlos’s financial statements. State one reason for their interest. Interested party The interest they would have [2] [Total: 20] PLEASE TURN OVER
20 marks
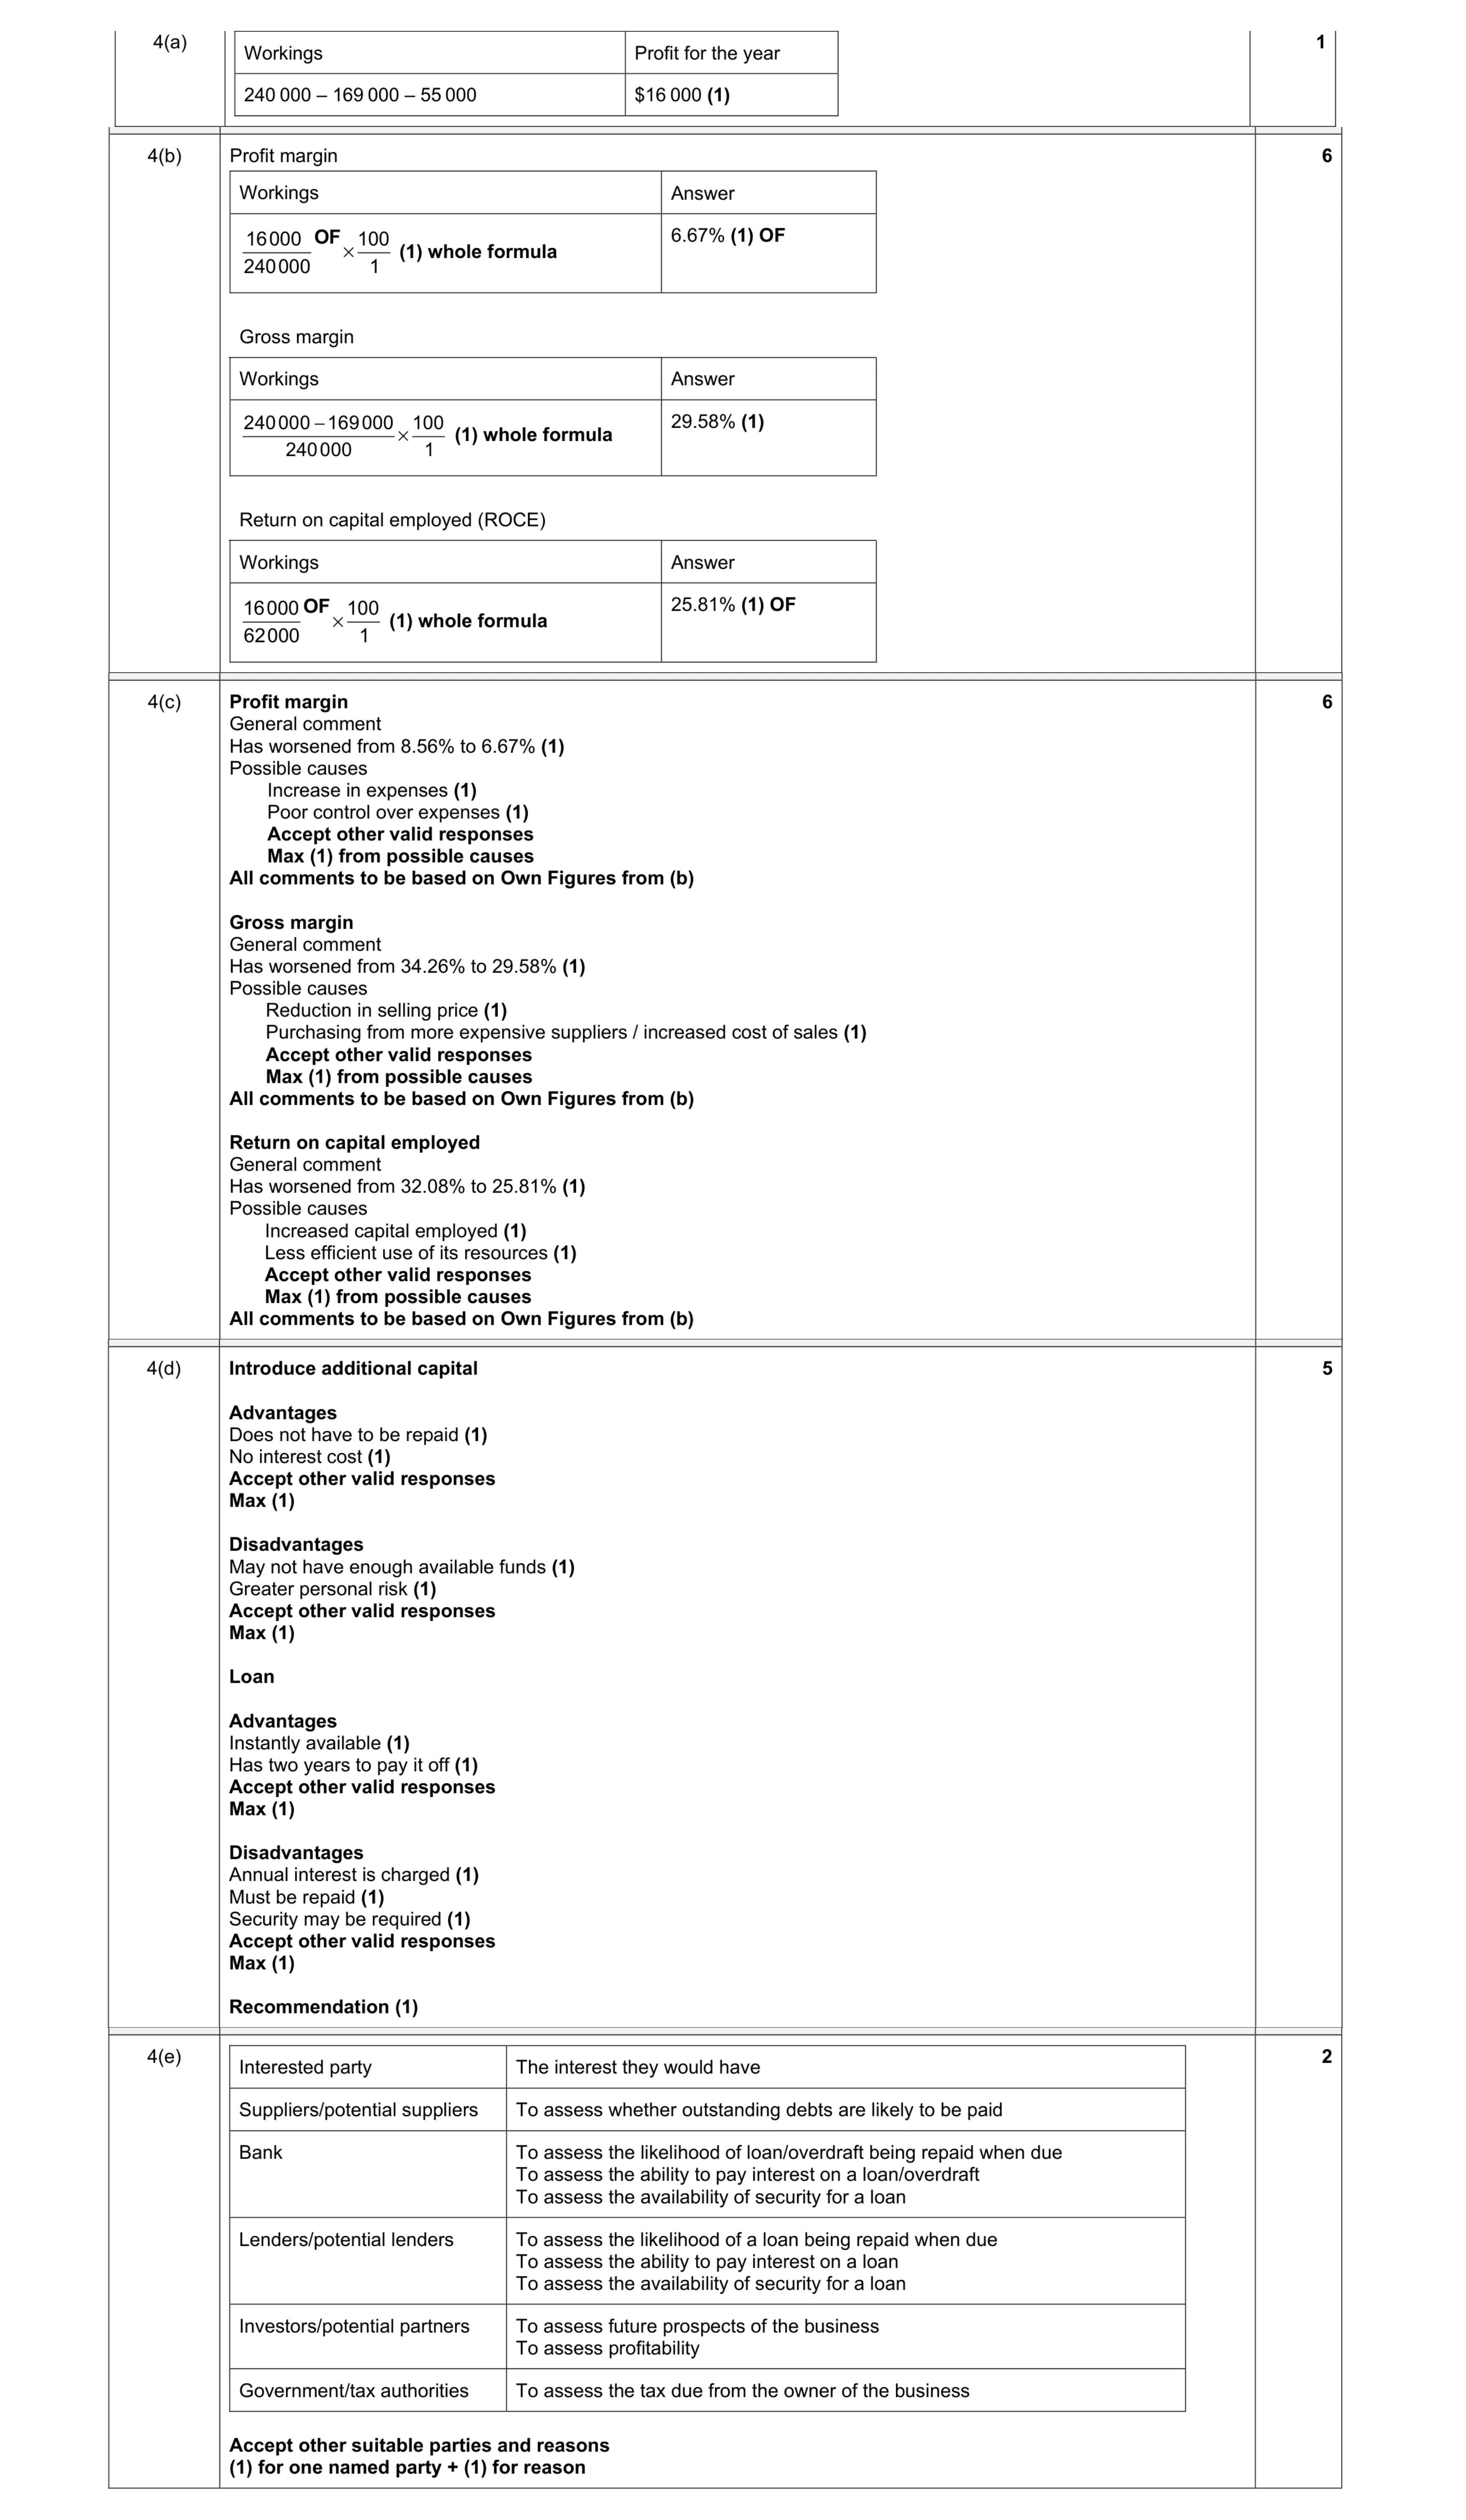
Mark scheme: 4(a) Workings Profit for the year 240 000 – 169 000 – 55 000 $16 000 (1) 1 Question Answer Marks 4(b) Profit margin Workings Answer × 16000 100 240000 1 OF (1) whole formula 6.67% (1) OF Gross margin Workings Answer − × 240000 169000 100 240000 1 (1) whole formula 29.58% (1) Return on capital employed (ROCE) Workings Answer × 16000 100 62000 1 OF (1) whole formula 25.81% (1) OF 6 Question Answer Marks 4(c) Profit margin General comment Has worsened from 8.56% to 6.67% (1) Possible causes Increase in expenses (1) Poor control over expenses (1) Accept other valid responses Max (1) from possible causes All comments to be based on Own Figures from (b) Gross margin General comment Has worsened from 34.26% to 29.58% (1) Possible causes Reduction in selling price (1) Purchasing from more expensive suppliers / increased cost of sales (1) Accept other valid responses Max (1) from possible causes All comments to be based on Own Figures from (b) Return on capital employed General comment Has worsened from 32.08% to 25.81% (1) Possible causes Increased capital employed (1) Less efficient use of its resources (1) Accept other valid responses Max (1) from possible causes All comments to be based on Own Figures from (b) 6 Question Answer Marks 4(d) Introduce additional capital Advantages Does not have to be repaid (1) No interest cost (1) Accept other valid responses Max (1) Disadvantages May not have enough available funds (1) Greater personal risk (1) Accept other valid responses Max (1) Loan Advantages Instantly available (1) Has two years to pay it off (1) Accept other valid responses Max (1) Disadvantages Annual interest is charged (1) Must be repaid (1) Security may be required (1) Accept other valid responses Max (1) Recommendation (1) 5 Question Answer Marks 4(e) Interested party The interest they would have Suppliers/potential suppliers To assess whether outstanding debts are likely to be paid Bank To assess the likelihood of loan/overdraft being repaid when due To assess the ability to pay interest on a loan/overdraft To assess the availability of security for a loan Lenders/potential lenders To assess the likelihood of a loan being repaid when due To assess the ability to pay interest on a loan To assess the availability of security for a loan Investors/potential partners To assess future prospects of the business To assess profitability Government/tax authorities To assess the tax due from the owner of the business Accept other suitable parties and reasons (1) for one named party + (1) for reason 2
This question in 0985/22 Oct/Nov 2020
Q3 · Razia’s financial year ends on 30 September 0985/22 Oct/Nov 2020
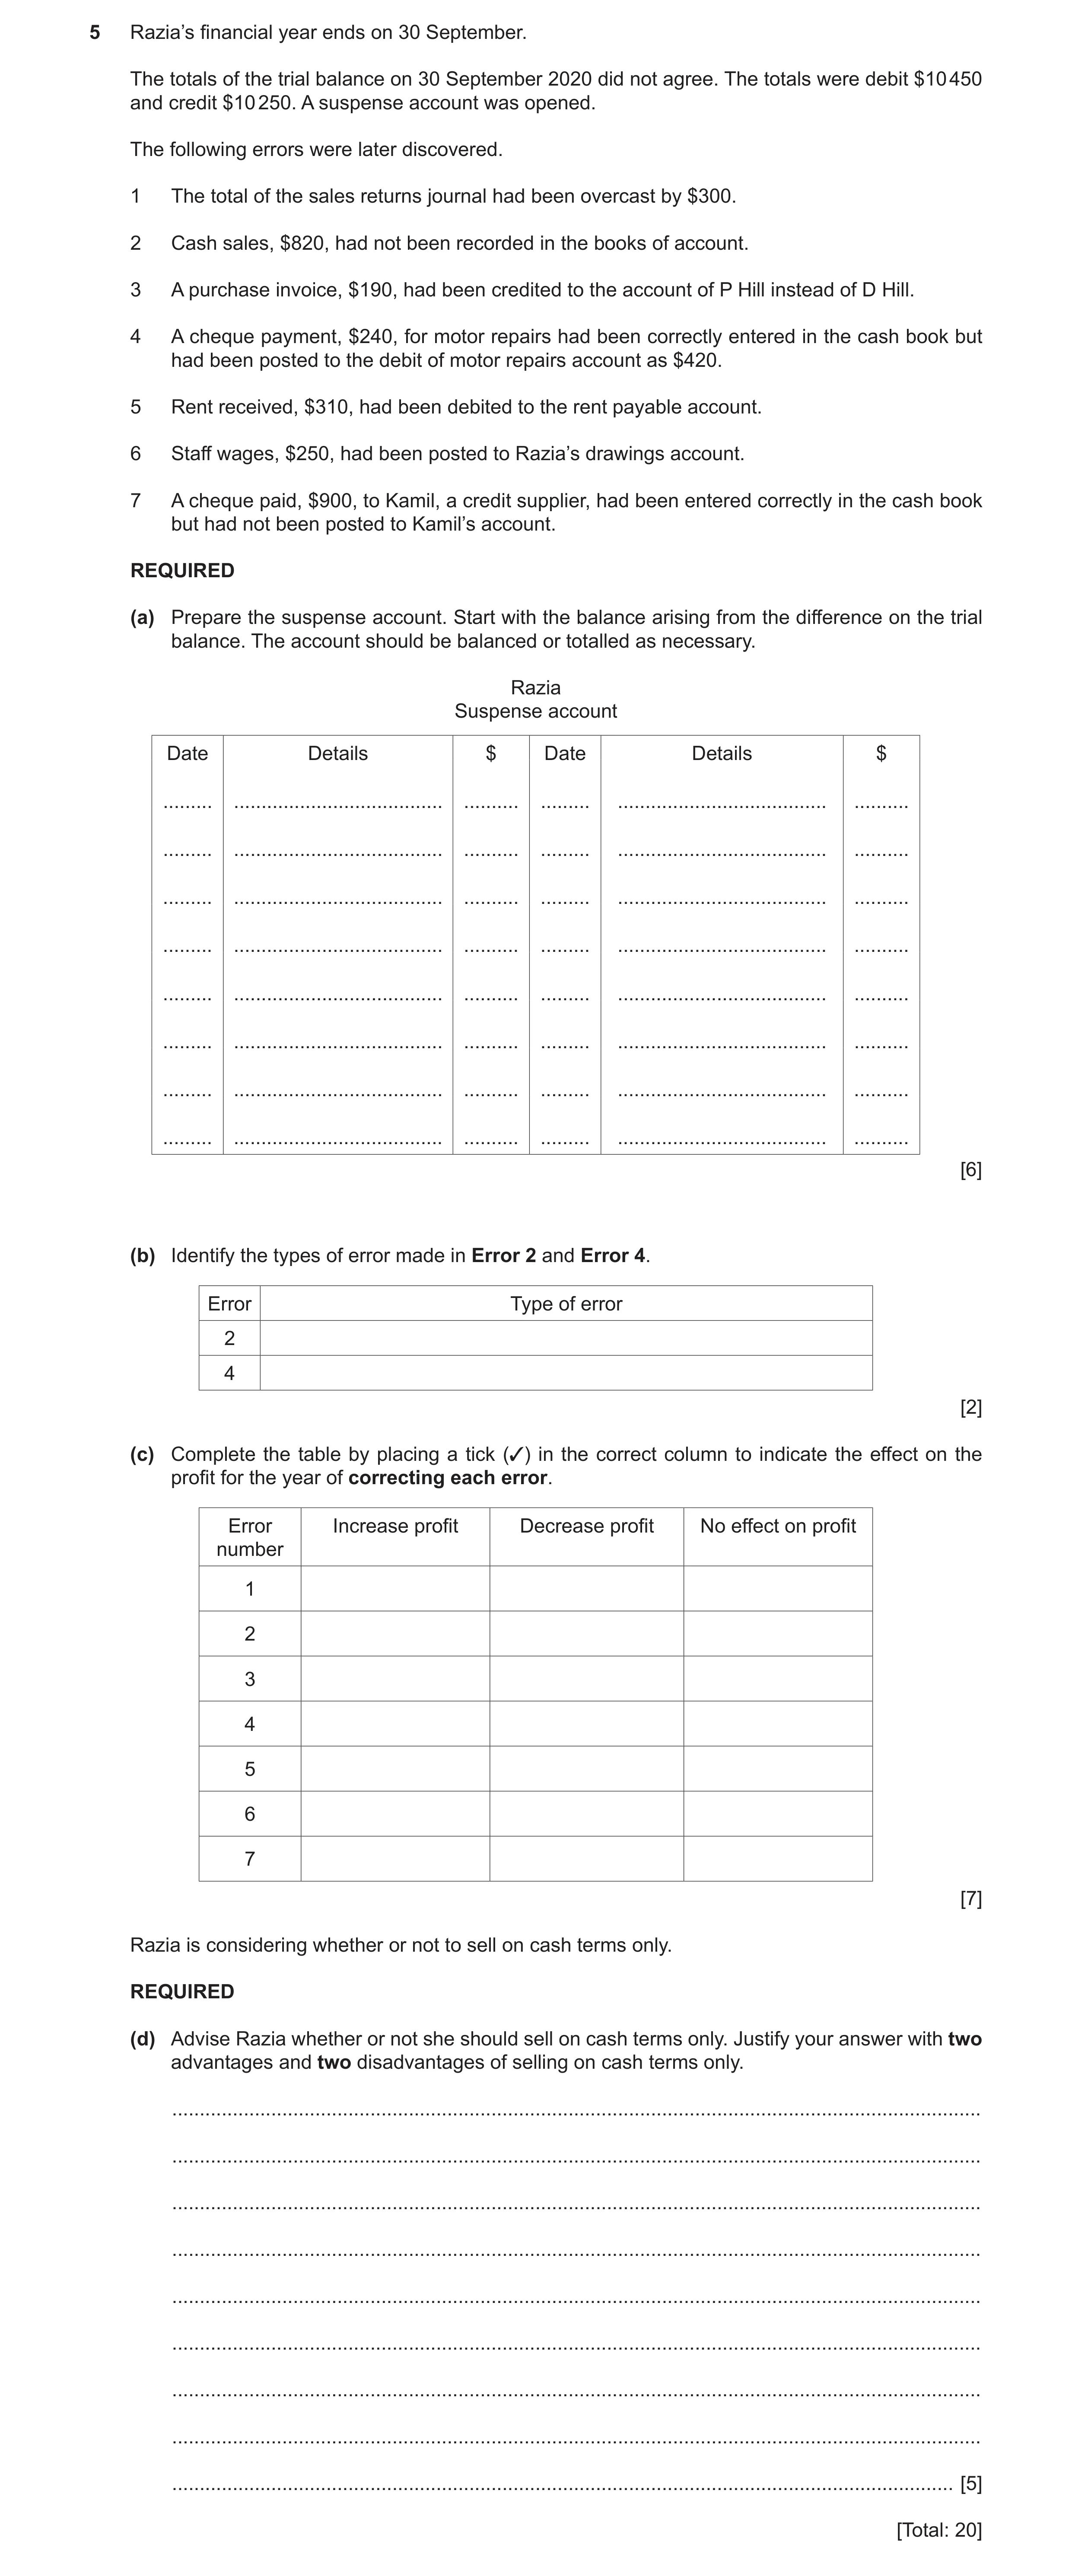
5 Razia’s financial year ends on 30 September. The totals of the trial balance on 30 September 2020 did not agree. The totals were debit $10 450 and credit $10 250. A suspense account was opened. The following errors were later discovered. 1 The total of the sales returns journal had been overcast by $300. 2 Cash sales, $820, had not been recorded in the books of account. 3 A purchase invoice, $190, had been credited to the account of P Hill instead of D Hill. 4 A cheque payment, $240, for motor repairs had been correctly entered in the cash book but had been posted to the debit of motor repairs account as $420. 5 Rent received, $310, had been debited to the rent payable account. 6 Staff wages, $250, had been posted to Razia’s drawings account. 7 A cheque paid, $900, to Kamil, a credit supplier, had been entered correctly in the cash book but had not been posted to Kamil’s account. REQUIRED (a) Prepare the suspense account. Start with the balance arising from the difference on the trial balance. The account should be balanced or totalled as necessary. Razia Suspense account Date Details $ Date Details $ … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [6] (b) Identify the types of error made in Error 2 and Error 4. Error Type of error 2 4 [2] (c) Complete the table by placing a tick (✓) in the correct column to indicate the effect on the profit for the year of correcting each error. Error Increase profit Decrease profit No effect on profit number 1 2 3 4 5 6 7 [7] Razia is considering whether or not to sell on cash terms only. REQUIRED (d) Advise Razia whether or not she should sell on cash terms only. Justify your answer with two advantages and two disadvantages of selling on cash terms only. … … … … … … … … … [5] [Total: 20]
20 marks
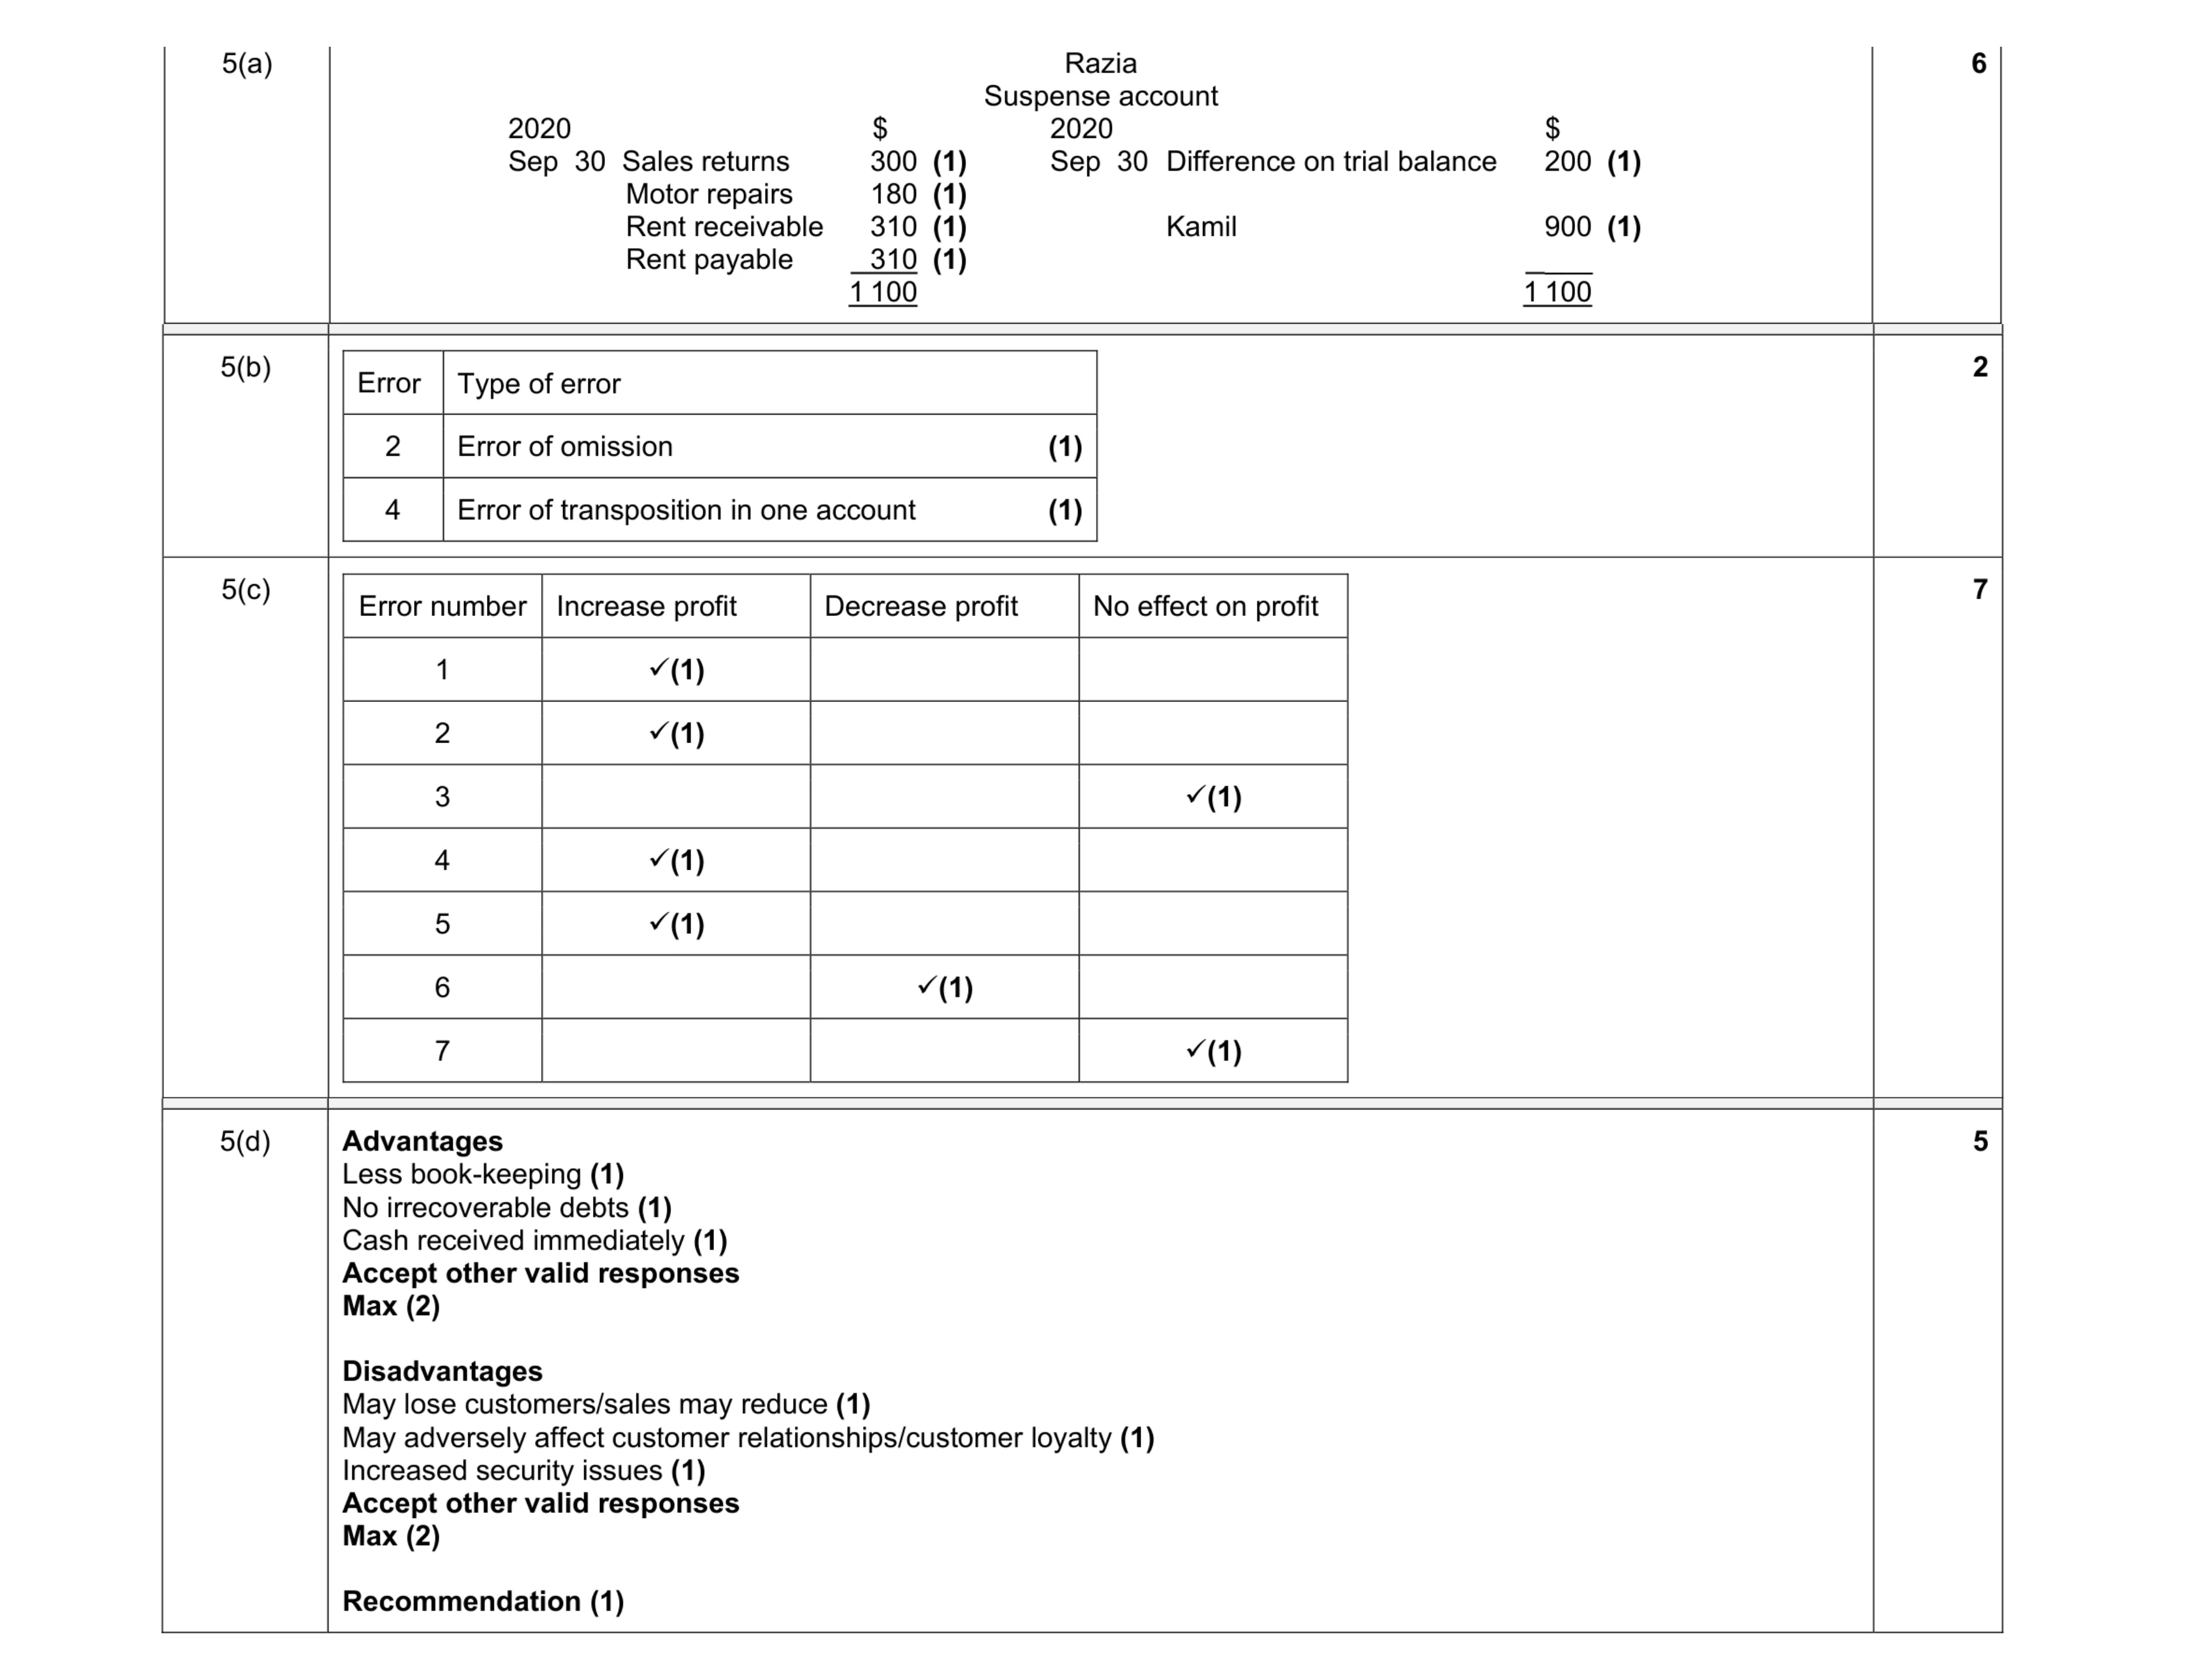
Mark scheme: 5(a) Razia Suspense account 2020 $ 2020 $ Sep 30 Sales returns 300 (1) Sep 30 Difference on trial balance 200 (1) Motor repairs 180 (1) Rent receivable 310 (1) Kamil 900 (1) Rent payable 310 (1) ___ 1 100 1 100 6 Question Answer Marks 5(b) Error Type of error 2 Error of omission (1) 4 Error of transposition in one account (1) 2 5(c) Error number Increase profit Decrease profit No effect on profit 1 (1) 2 (1) 3 (1) 4 (1) 5 (1) 6 (1) 7 (1) 7 Question Answer Marks 5(d) Advantages Less book-keeping (1) No irrecoverable debts (1) Cash received immediately (1) Accept other valid responses Max (2) Disadvantages May lose customers/sales may reduce (1) May adversely affect customer relationships/customer loyalty (1) Increased security issues (1) Accept other valid responses Max (2) Recommendation (1) 5
This question in 0985/22 Oct/Nov 2020
Q4 · John and Banu are partners 0985/21 May/June 2021
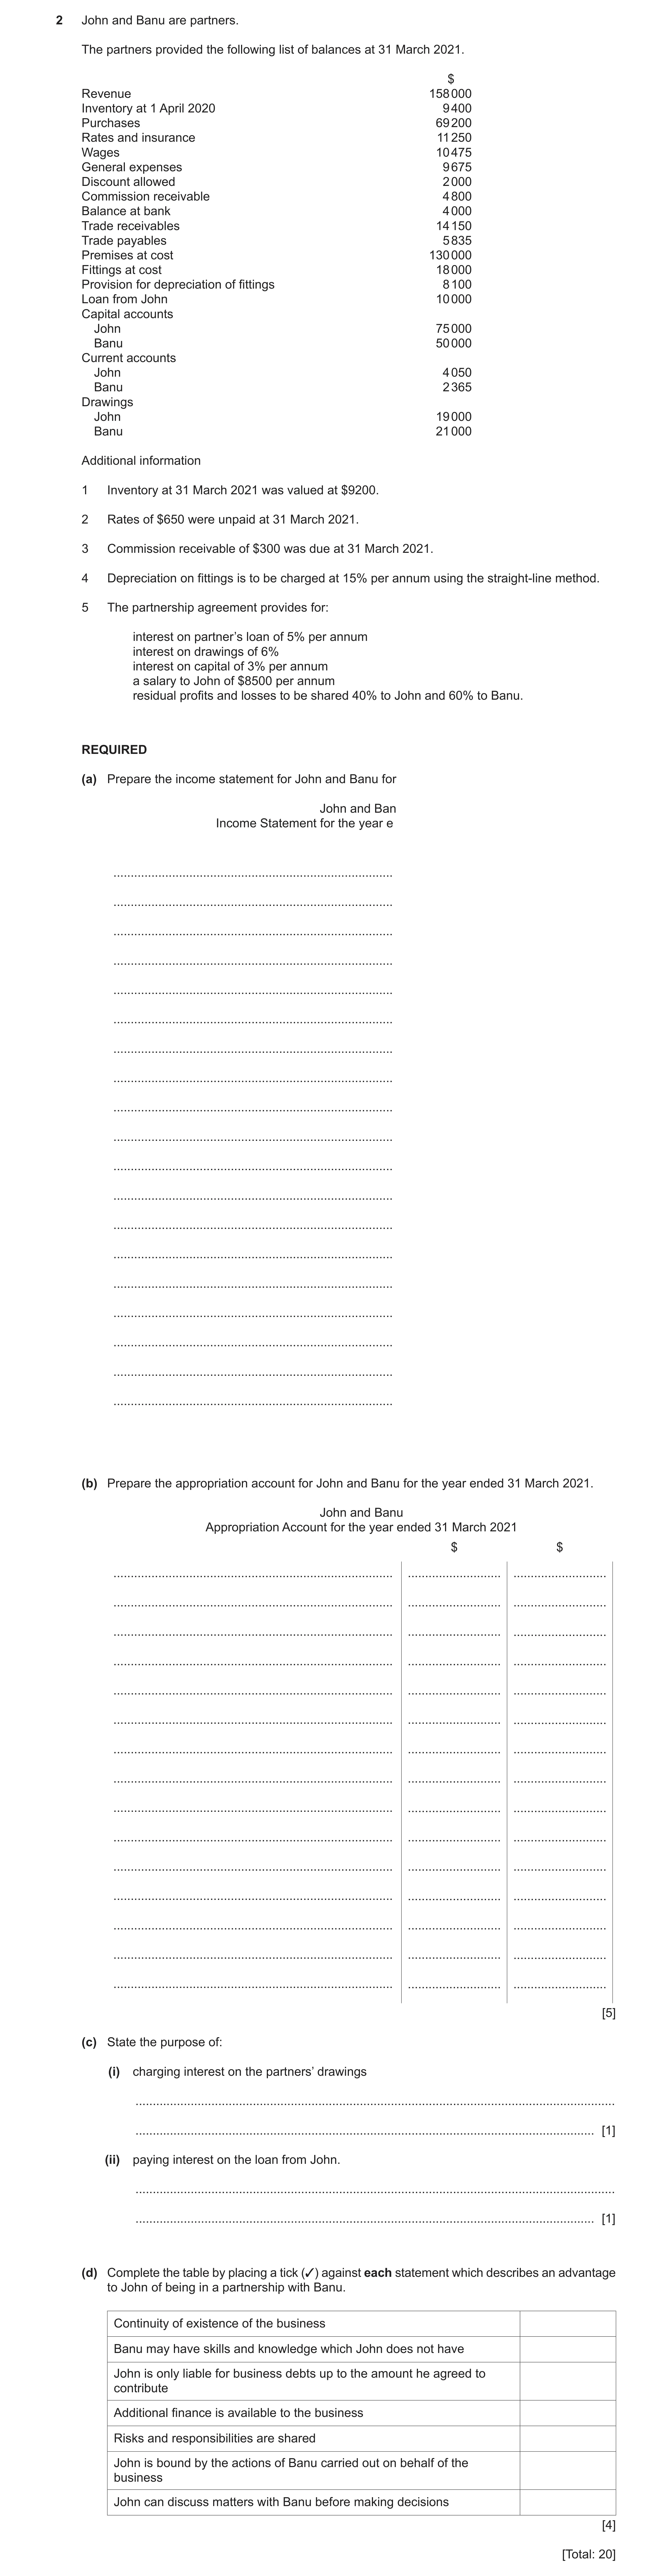
2 John and Banu are partners. The partners provided the following list of balances at 31 March 2021. $ Revenue 158 000 Inventory at 1 April 2020 9 400 Purchases 69 200 Rates and insurance 11 250 Wages 10 475 General expenses 9 675 Discount allowed 2 000 Commission receivable 4 800 Balance at bank 4 000 Trade receivables 14 150 Trade payables 5 835 Premises at cost 130 000 Fittings at cost 18 000 Provision for depreciation of fittings 8 100 Loan from John 10 000 Capital accounts John 75 000 Banu 50 000 Current accounts John 4 050 Banu 2 365 Drawings John 19 000 Banu 21 000 Additional information 1 Inventory at 31 March 2021 was valued at $9200. 2 Rates of $650 were unpaid at 31 March 2021. 3 Commission receivable of $300 was due at 31 March 2021. 4 Depreciation on fittings is to be charged at 15% per annum using the straight-line method. 5 The partnership agreement provides for: interest on partner’s loan of 5% per annum interest on drawings of 6% interest on capital of 3% per annum a salary to John of $8500 per annum residual profits and losses to be shared 40% to John and 60% to Banu. REQUIRED (a) Prepare the income statement for John and Banu for John and Ban Income Statement for the year e … … … … … … … … … … … … … … … … … … … (b) Prepare the appropriation account for John and Banu for the year ended 31 March 2021. John and Banu Appropriation Account for the year ended 31 March 2021 $ $ … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [5] (c) State the purpose of: (i) charging interest on the partners’ drawings … … [1] (ii) paying interest on the loan from John. … … [1] (d) Complete the table by placing a tick (3) against each statement which describes an advantage to John of being in a partnership with Banu. Continuity of existence of the business Banu may have skills and knowledge which John does not have John is only liable for business debts up to the amount he agreed to contribute Additional finance is available to the business Risks and responsibilities are shared John is bound by the actions of Banu carried out on behalf of the business John can discuss matters with Banu before making decisions [4] [Total: 20]
20 marks
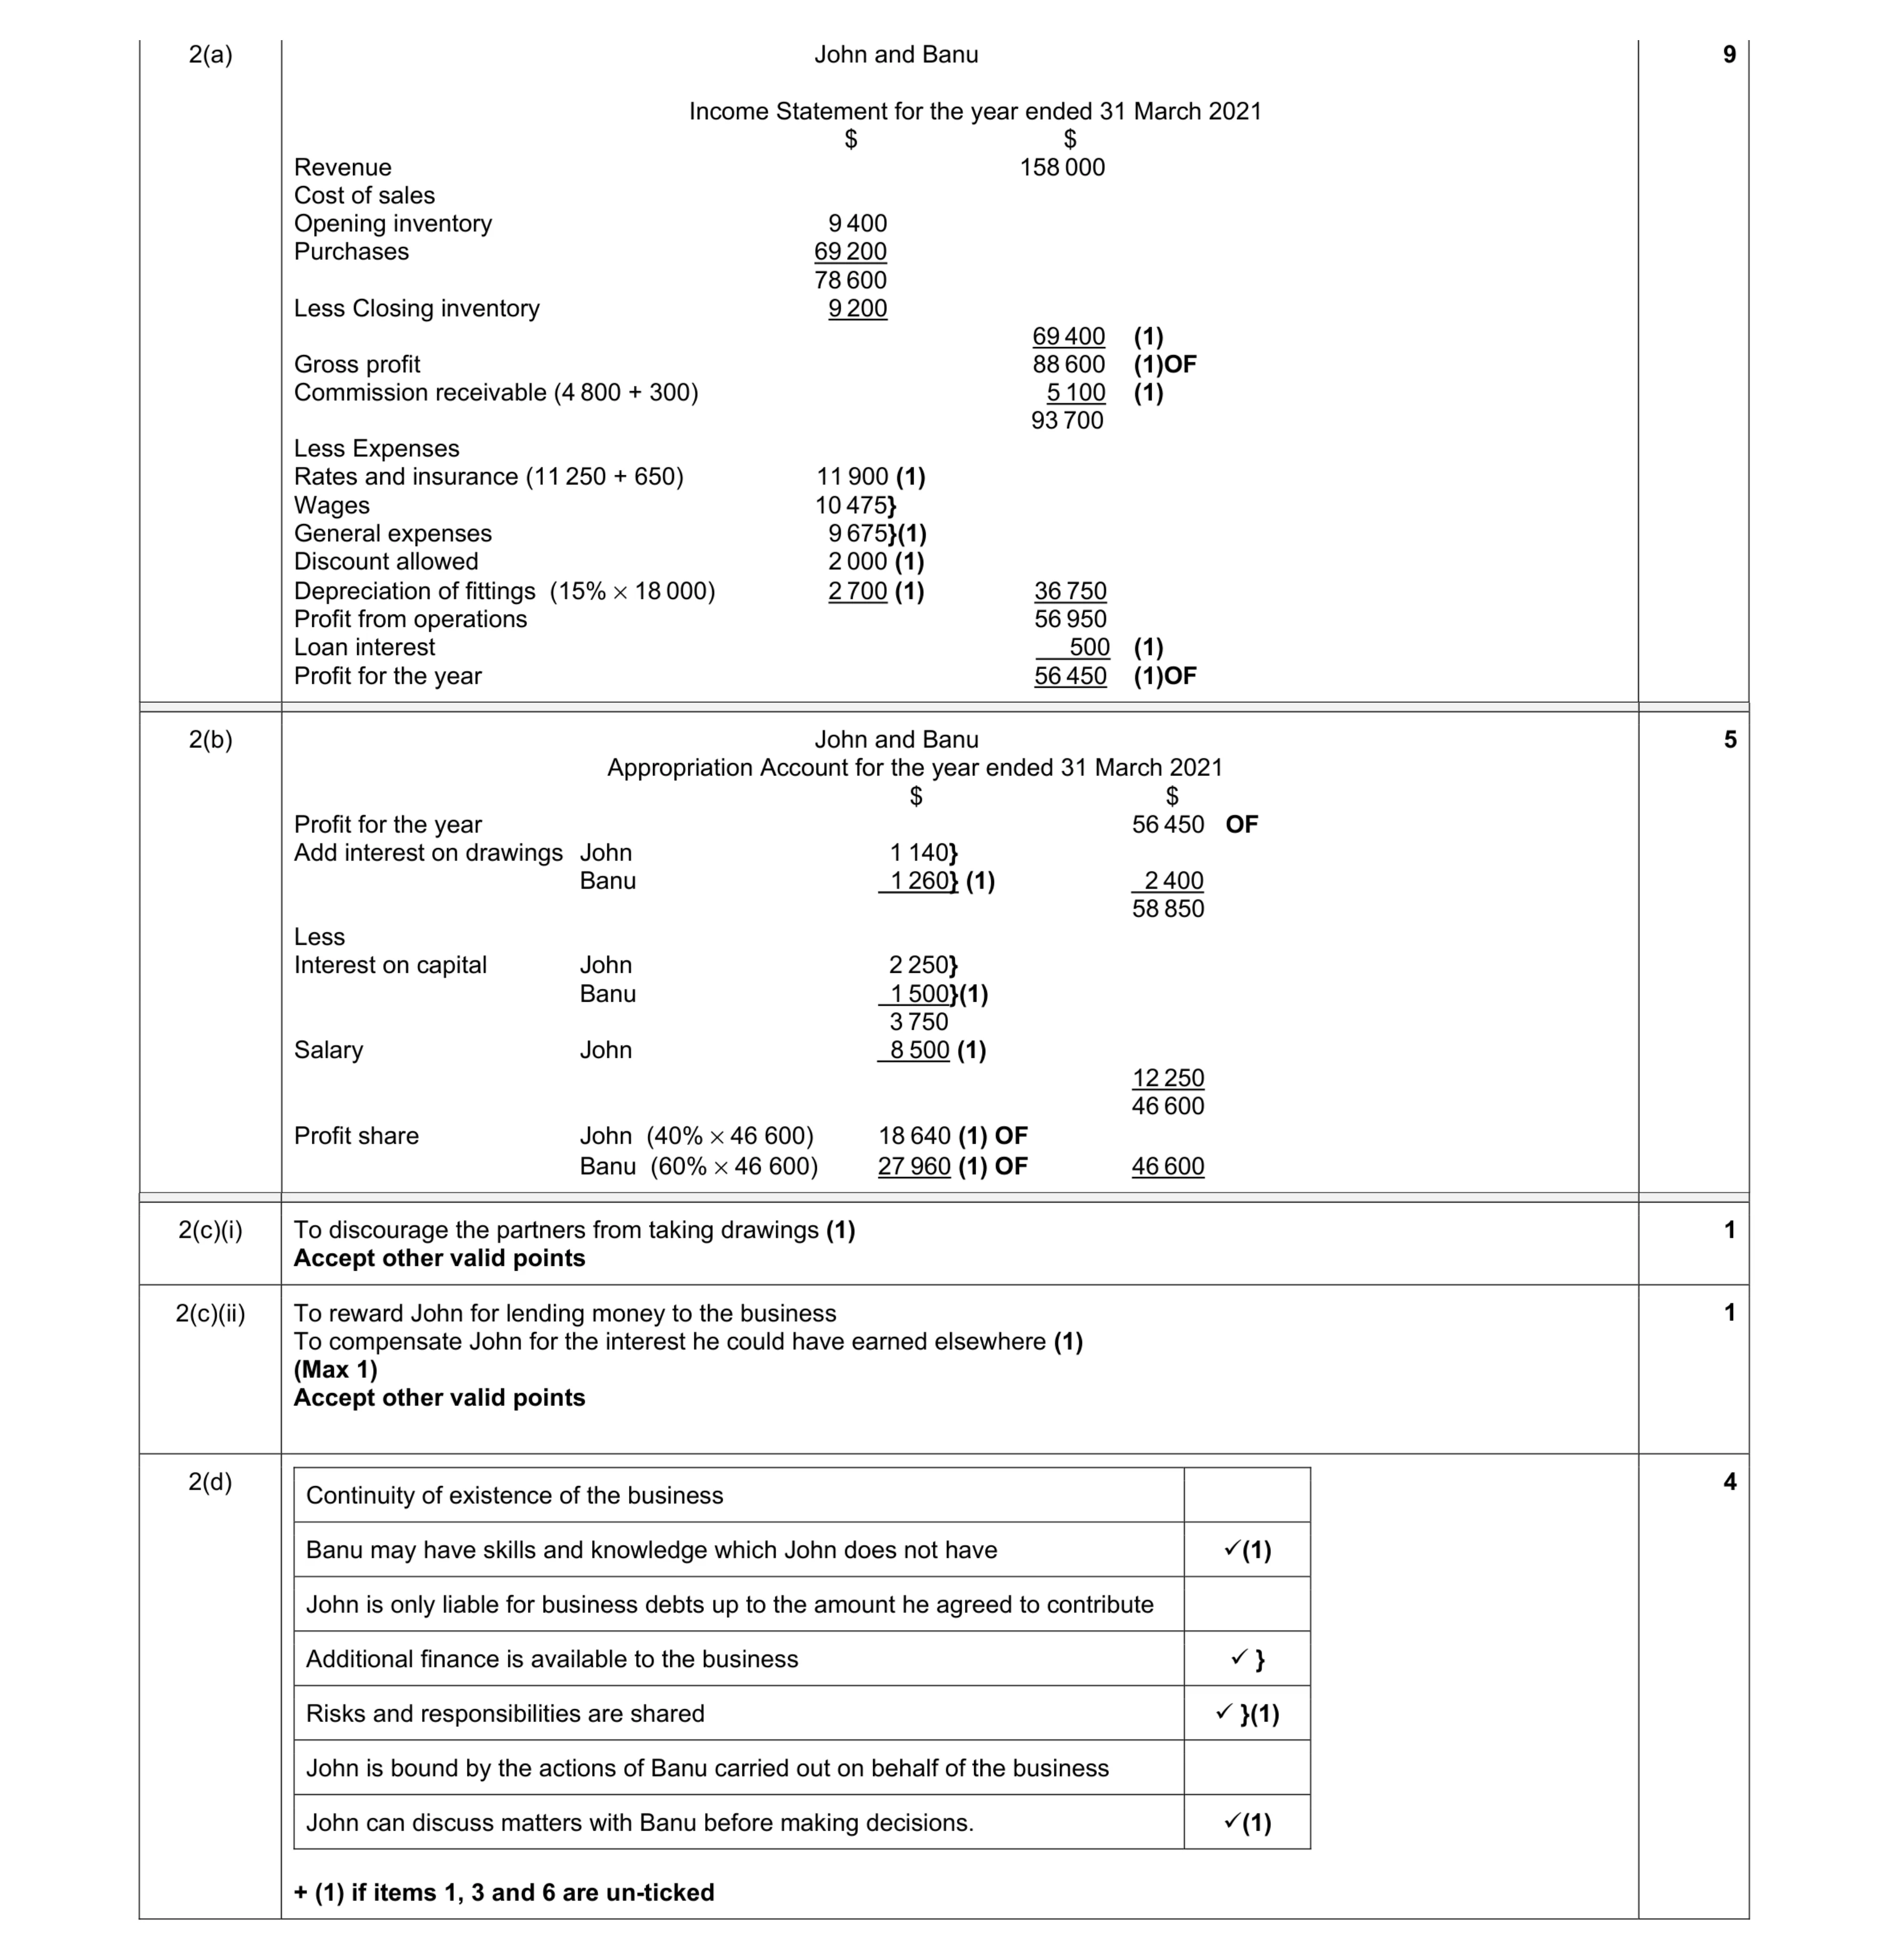
Mark scheme: 2(a) John and Banu Income Statement for the year ended 31 March 2021 $ $ Revenue 158 000 Cost of sales Opening inventory 9 400 Purchases 69 200 78 600 Less Closing inventory 9 200 69 400 (1) Gross profit 88 600 (1)OF Commission receivable (4 800 + 300) 5 100 (1) 93 700 Less Expenses Rates and insurance (11 250 + 650) 11 900 (1) Wages 10 475} General expenses 9 675}(1) Discount allowed 2 000 (1) Depreciation of fittings (15% × 18 000) 2 700 (1) 36 750 Profit from operations 56 950 Loan interest 500 (1) Profit for the year 56 450 (1)OF 9 Question Answer Marks 2(b) John and Banu Appropriation Account for the year ended 31 March 2021 $ $ Profit for the year 56 450 OF Add interest on drawings John 1 140} Banu 1 260} (1) 2 400 58 850 Less Interest on capital John 2 250} Banu 1 500}(1) 3 750 Salary John 8 500 (1) 12 250 46 600 Profit share John (40% × 46 600) 18 640 (1) OF Banu (60% × 46 600) 27 960 (1) OF 46 600 5 Question Answer Marks 2(c)(i) To discourage the partners from taking drawings (1) Accept other valid points 1 2(c)(ii) To reward John for lending money to the business To compensate John for the interest he could have earned elsewhere (1) (Max 1) Accept other valid points 1 2(d) Continuity of existence of the business Banu may have skills and knowledge which John does not have (1) John is only liable for business debts up to the amount he agreed to contribute Additional finance is available to the business } Risks and responsibilities are shared }(1) John is bound by the actions of Banu carried out on behalf of the business John can discuss matters with Banu before making decisions. (1) + (1) if items 1, 3 and 6 are un-ticked 4
This question in 0985/21 May/June 2021
Q5 · Jabir owns an electrical wholesale business 0985/22 Oct/Nov 2021
2 Jabir owns an electrical wholesale business. The following balances appeared in his books on 30 September 2021. $ Inventory 8 000 Purchases 109 000 Trade payables 11 600 Revenue 160 000 Trade receivables 22 600 Operating expenses 35 200 The inventory on 1 October 2020 was $11 000. All sales and purchases were on a credit basis. REQUIRED (a) Calculate the gross profit and profit for the year. … … … … … … … … … … … … [2] (b) (i) Calculate the gross margin. … … … [2] (ii) Advise Jabir on two actions he could take to improve his gross margin. 1 … … 2 … … [2] (c) Calculate the trade receivables turnover. Round up your answer to the next whole day. … … … [2] Jabir wants to increase his credit sales and is considering allowing his credit customers an extra 14 days above his current trade receivables turnover. REQUIRED (d) Advise Jabir whether he should allow his credit customers an extra 14 days above his current trade receivables turnover. Justify your answer. … … … … … … … … … … [5] (e) Calculate the trade payables turnover. Round up your answer to the next whole day. … … … [2] Jabir’s credit suppliers are prepared to double the rate of his trade discount provided he increases his current monthly purchases by 20%. REQUIRED (f) Advise Jabir whether he should increase his current monthly purchases by 20% to earn the additional trade discount. Justify your answer. … … … … … … … … … … [5] [Total: 20]
20 marks
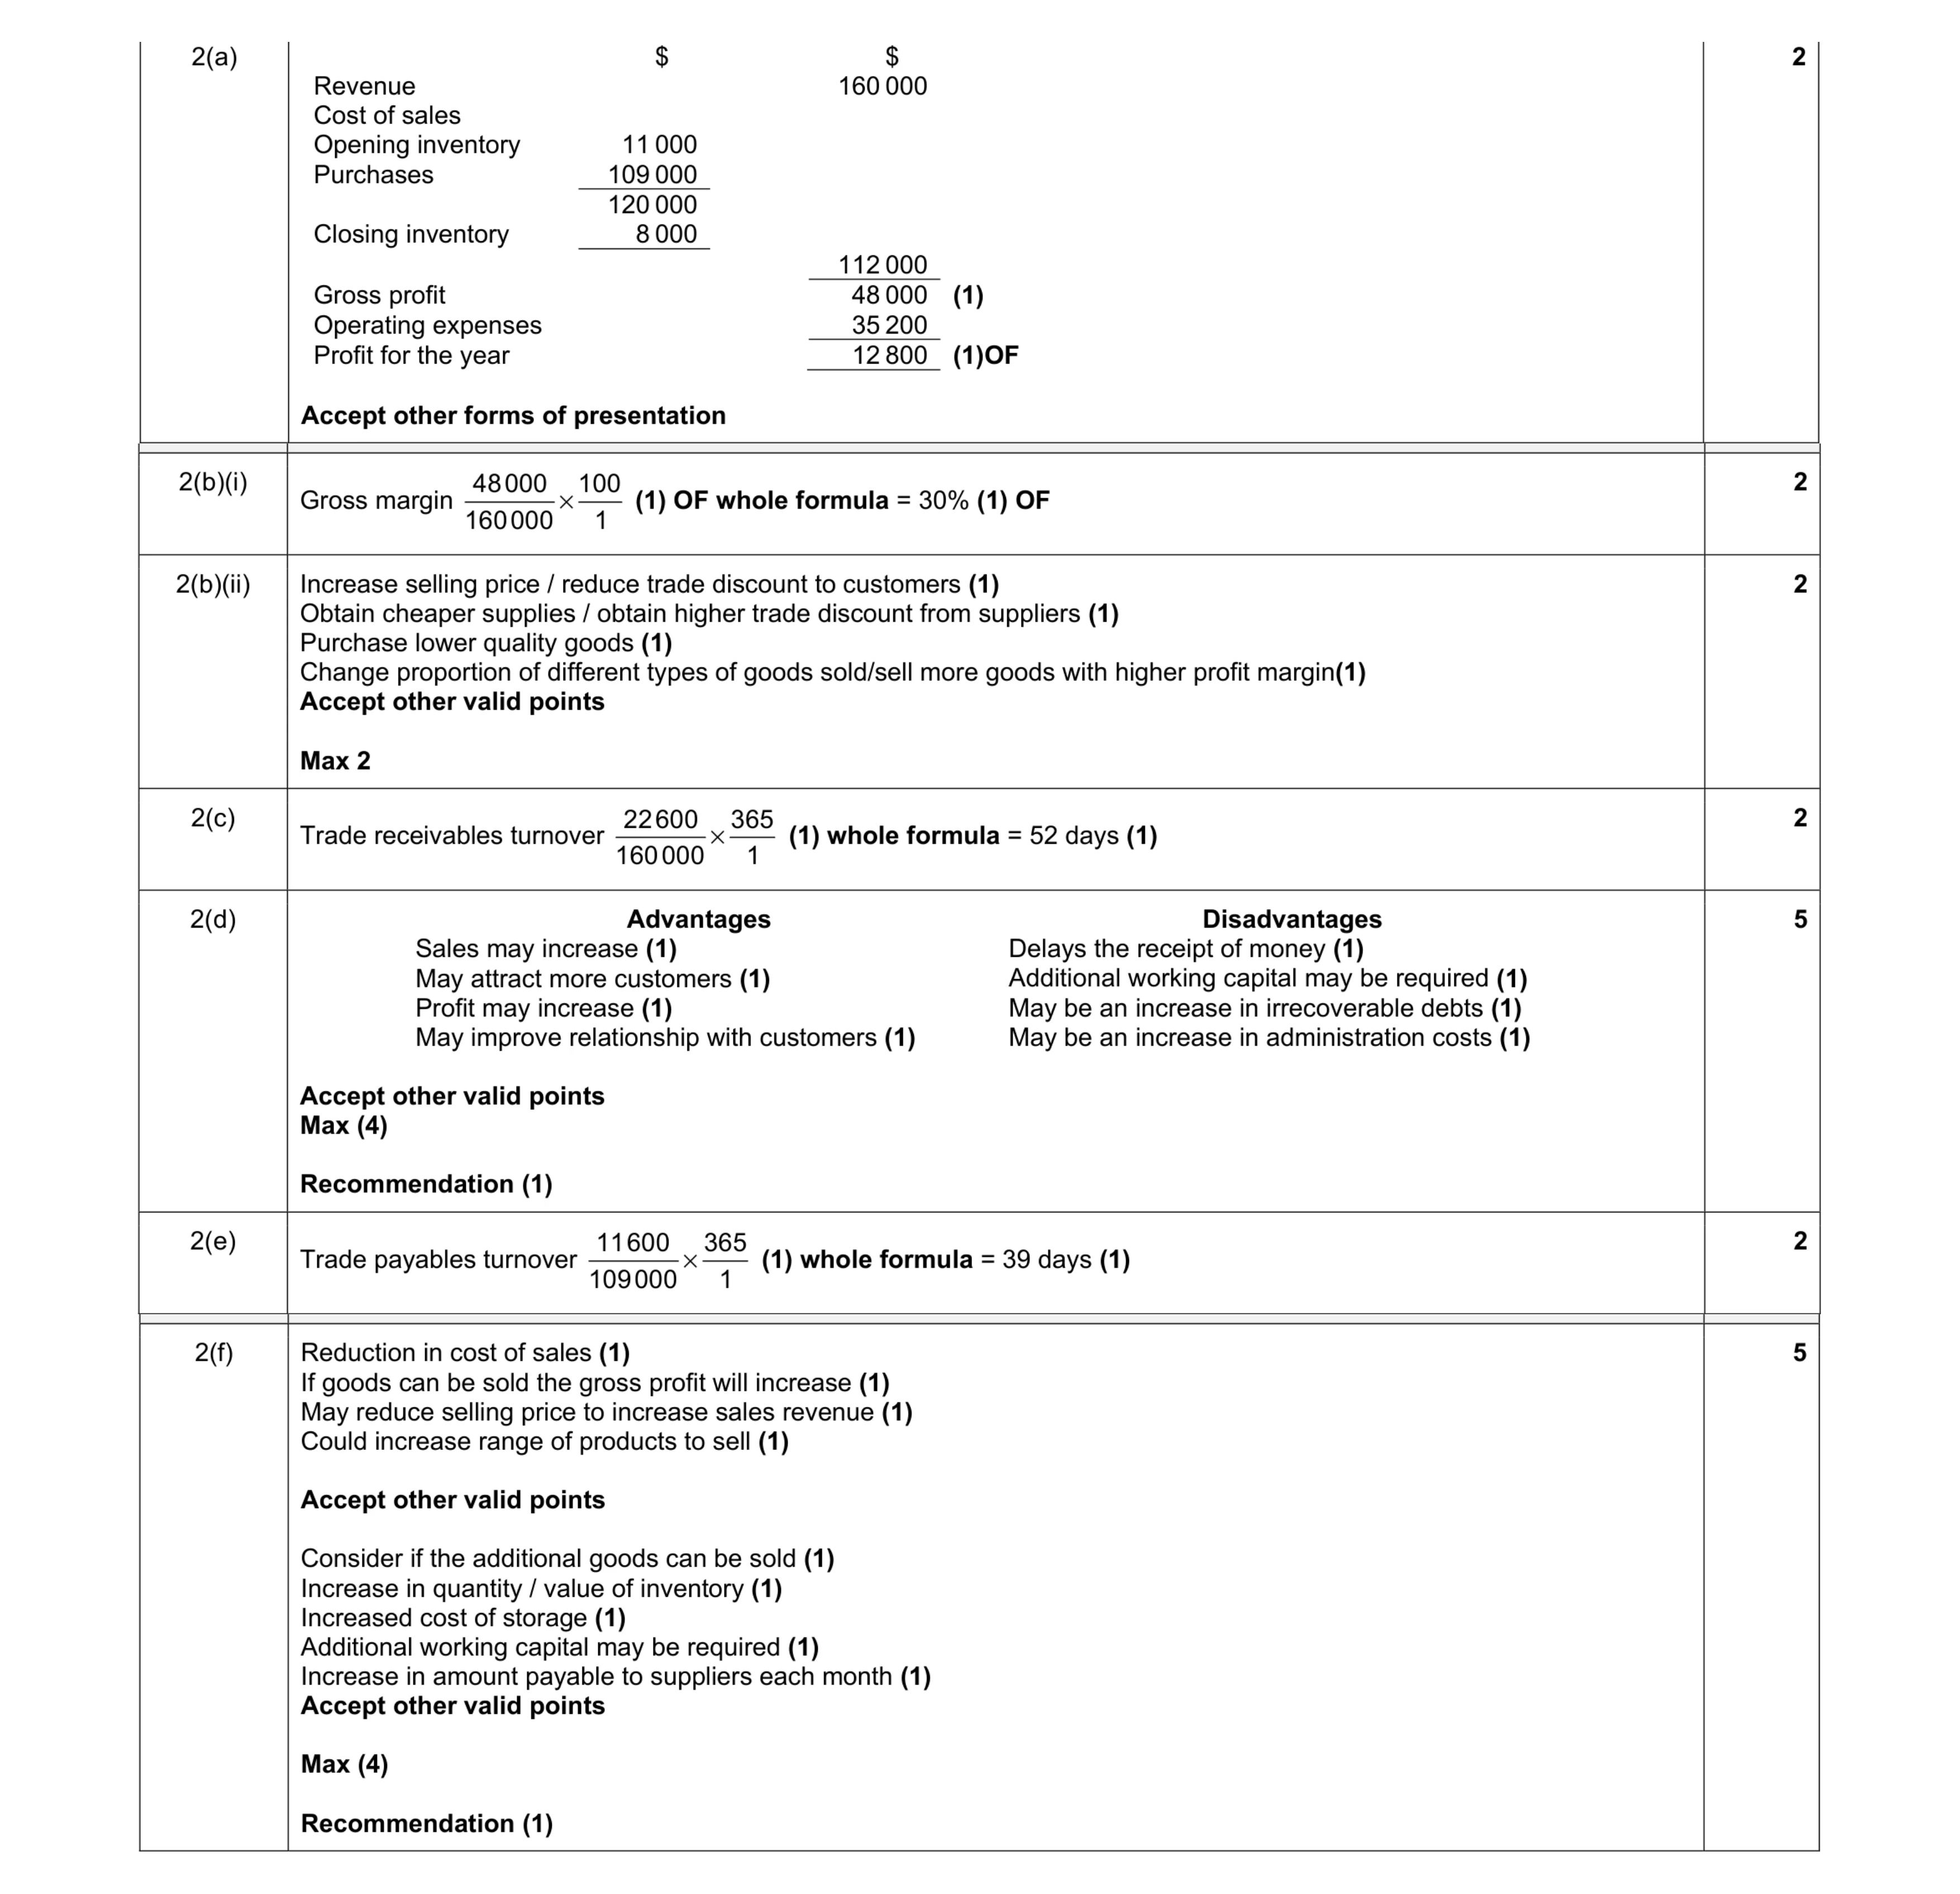
Mark scheme: 2(a) $ $ Revenue 160 000 Cost of sales Opening inventory 11 000 Purchases 109 000 120 000 Closing inventory 8 000 112 000 Gross profit 48 000 (1) Operating expenses 35 200 Profit for the year 12 800 (1)OF Accept other forms of presentation 2 Question Answer Marks 2(b)(i) Gross margin × 48000 100 160000 1 (1) OF whole formula = 30% (1) OF 2 2(b)(ii) Increase selling price / reduce trade discount to customers (1) Obtain cheaper supplies / obtain higher trade discount from suppliers (1) Purchase lower quality goods (1) Change proportion of different types of goods sold/sell more goods with higher profit margin(1) Accept other valid points Max 2 2 2(c) Trade receivables turnover × 22600 365 160000 1 (1) whole formula = 52 days (1) 2 2(d) Advantages Sales may increase (1) May attract more customers (1) Profit may increase (1) May improve relationship with customers (1) Disadvantages Delays the receipt of money (1) Additional working capital may be required (1) May be an increase in irrecoverable debts (1) May be an increase in administration costs (1) Accept other valid points Max (4) Recommendation (1) 5 2(e) Trade payables turnover × 11600 365 109000 1 (1) whole formula = 39 days (1) 2 Question Answer Marks 2(f) Reduction in cost of sales (1) If goods can be sold the gross profit will increase (1) May reduce selling price to increase sales revenue (1) Could increase range of products to sell (1) Accept other valid points Consider if the additional goods can be sold (1) Increase in quantity / value of inventory (1) Increased cost of storage (1) Additional working capital may be required (1) Increase in amount payable to suppliers each month (1) Accept other valid points Max (4) Recommendation (1) 5
This question in 0985/22 Oct/Nov 2021
Q6 · Fatima is a sole trader 0985/21 May/June 2022
2 Fatima is a sole trader. She prepares her financial statements to the end of March each year. At 31 March 2022, Fatima’s ledger account balances included the following. $ Revenue 79 400 Sales returns 3 970 Purchases 36 500 Rent and rates 9 000 Wages 10 100 General expenses 1 287 Insurance 1 800 Discount received 1 095 Inventory at 1 April 2021 3 000 Fixtures and equipment at cost 80 000 Fixtures and equipment – provision for depreciation 39 040 Trade receivables 6 400 Trade payables 4 995 Provision for doubtful debts 156 Cash drawings 8 580 Capital at 1 April 2021 59 000 The following information is also available. 1 Inventory at 31 March 2022 was $3120. 2 Fatima took goods for her own use from the business during the year ended 31 March 2022. These goods cost $1300. 3 Depreciation on fixtures and equipment is to be charged at 20% per annum using the reducing balance method. 4 Accrued wages at 31 March 2022 were $800. 5 Rent includes a payment of $1500 for the 3 months from 1 March 2022 to 31 May 2022. 6 An irrecoverable trade receivable of $200 is to be written off. 7 The provision for doubtful debts is to be set at 3% of trade receivables. REQUIRED (a) Prepare Fatima’s income statement for the year ended 31 Mar Fatima Income Statement for the year ended 31 … … … … … … … … … … … … … … … … … … … … … … … … … … … … … (b) Prepare Fatima’s capital account for the year ended 31 March 2022. Balance the account and bring down the balance on 1 April 2022. Fatima Capital account Date Details $ Date Details $ … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [4] Fatima would like to expand the business. She thinks that additional finance of $20 000 would be required for the equipment which she would need. Fatima’s bank have offered to lend her $20 000, to be repaid after four years at interest of 6% per annum. REQUIRED (c) Advise Fatima whether or not to agree to the bank loan. Justify your answer. … … … … … … … … … … … … [5] [Total: 20]
20 marks
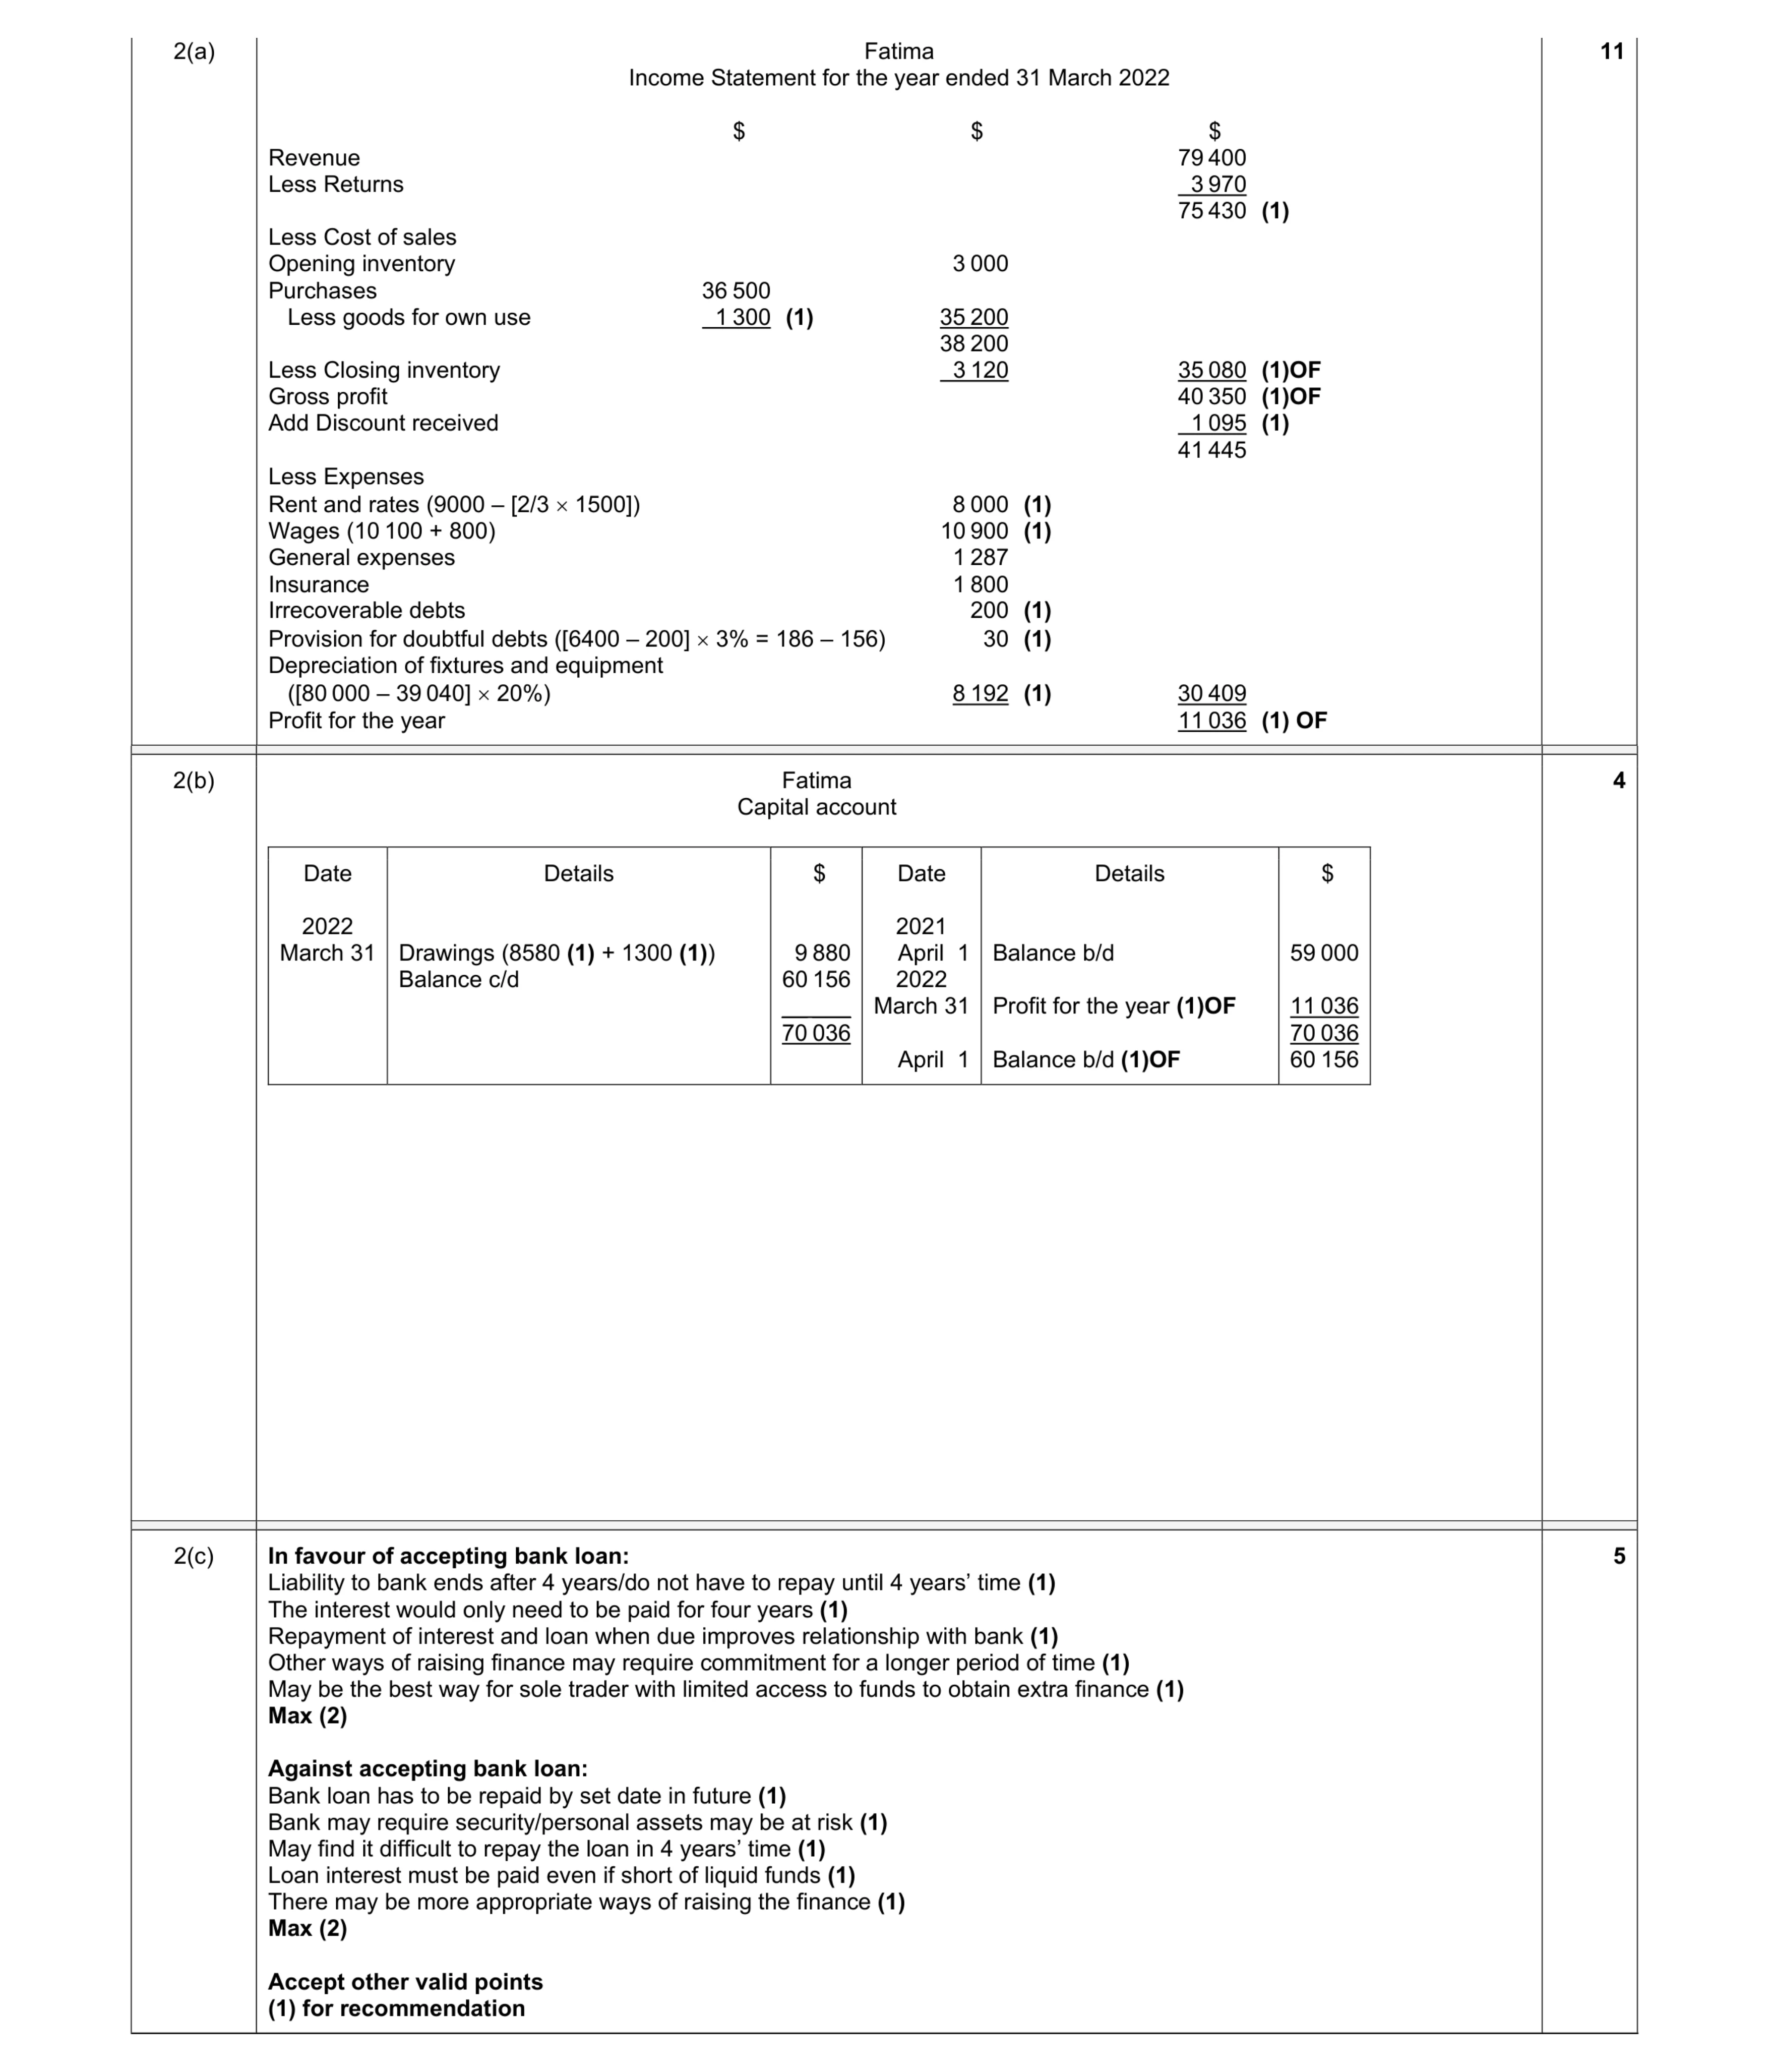
Mark scheme: 2(a) Fatima Income Statement for the year ended 31 March 2022 $ $ $ Revenue 79 400 Less Returns 3 970 75 430 (1) Less Cost of sales Opening inventory 3 000 Purchases 36 500 Less goods for own use 1 300 (1) 35 200 38 200 Less Closing inventory 3 120 35 080 (1)OF Gross profit 40 350 (1)OF Add Discount received 1 095 (1) 41 445 Less Expenses Rent and rates (9000 – [2/3 1500]) 8 000 (1) Wages (10 100 + 800) 10 900 (1) General expenses 1 287 Insurance 1 800 Irrecoverable debts 200 (1) Provision for doubtful debts ([6400 – 200] 3% = 186 – 156) 30 (1) Depreciation of fixtures and equipment ([80 000 – 39 040] 20%) 8 192 (1) 30 409 Profit for the year 11 036 (1) OF 11 Question Answer Marks 2(b) Fatima Capital account Date 2022 March 31 Details Drawings (8580 (1) + 1300 (1)) Balance c/d $ 9 880 60 156 __ ___ 70 036 Date 2021 April 1 2022 March 31 April 1 Details Balance b/d Profit for the year (1)OF Balance b/d (1)OF $ 59 000 11 036 70 036 60 156 4 Question Answer Marks 2(c) In favour of accepting bank loan: Liability to bank ends after 4 years/do not have to repay until 4 years’ time (1) The interest would only need to be paid for four years (1) Repayment of interest and loan when due improves relationship with bank (1) Other ways of raising finance may require commitment for a longer period of time (1) May be the best way for sole trader with limited access to funds to obtain extra finance (1) Max (2) Against accepting bank loan: Bank loan has to be repaid by set date in future (1) Bank may require security/personal assets may be at risk (1) May find it difficult to repay the loan in 4 years’ time (1) Loan interest must be paid even if short of liquid funds (1) There may be more appropriate ways of raising the finance (1) Max (2) Accept other valid points (1) for recommendation 5
This question in 0985/21 May/June 2022
Q7 · BC a sole trader prepared the following trial balance from his accounts on 31 August 2022 0985/22 Oct/Nov 2022
1 BC a sole trader prepared the following trial balance from his accounts on 31 August 2022. Dr Cr $ $ Purchases 120 000 Revenue 231 500 Sales returns 3 600 Inventory 1 September 2021 11 100 Capital 111 900 Bank 4 100 Non-current assets at cost Premises 98 000 Machinery 52 000 Provision for depreciation of non-current assets Machinery 28 400 Commission receivable 2 200 Trade receivables 19 200 Trade payables 7 300 Discount allowed 600 Discount received 1 400 Insurance 9 600 Repairs 12 400 Salaries 53 900 Rates 6 000 Carriage inwards 400 386 800 386 800 Additional information 1 The closing inventory at 31 August 2022 was valued at $12 000. 2 Commission received of $800 was owing at 31 August 2022. 3 The balance shown for salaries covers the 11 months to 31 July 2022. Salaries for August 2022 are due and unpaid. There have been no salary increases over the previous 12 months and an equal amount is paid each month. 4 At 31 August 2022 rates were prepaid by $300. 5 The insurance included $700 covering a private insurance premium for BC. 6 The repairs included $4000 that related to a new attachment for machinery. 7 Machinery is to be depreciated at the rate of 20% per annum by the reducing balance method. A full year’s depreciation is charged regardless of the date of any purchases. There were no disposals during the year. Premises are not depreciated. REQUIRED (a) Prepare the income statement of BC for the year ended BC Income Statement for the year ended 31 …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … (b) Calculate the working capital at 31 August 2022. … … … … … … … … … … … … … … [3] BC has been making future plans for the business and he needs to purchase $6000 of machinery immediately. There are two options to finance the purchase. Option 1 On credit with the full amount of $6000 payable in 60 days Option 2 Obtain a $6000 8% loan repayable in 5 years REQUIRED (c) Advise BC on which option he should use. Justify your answer. … … … … … … … … … … … … … [5] [Total: 20]
20 marks
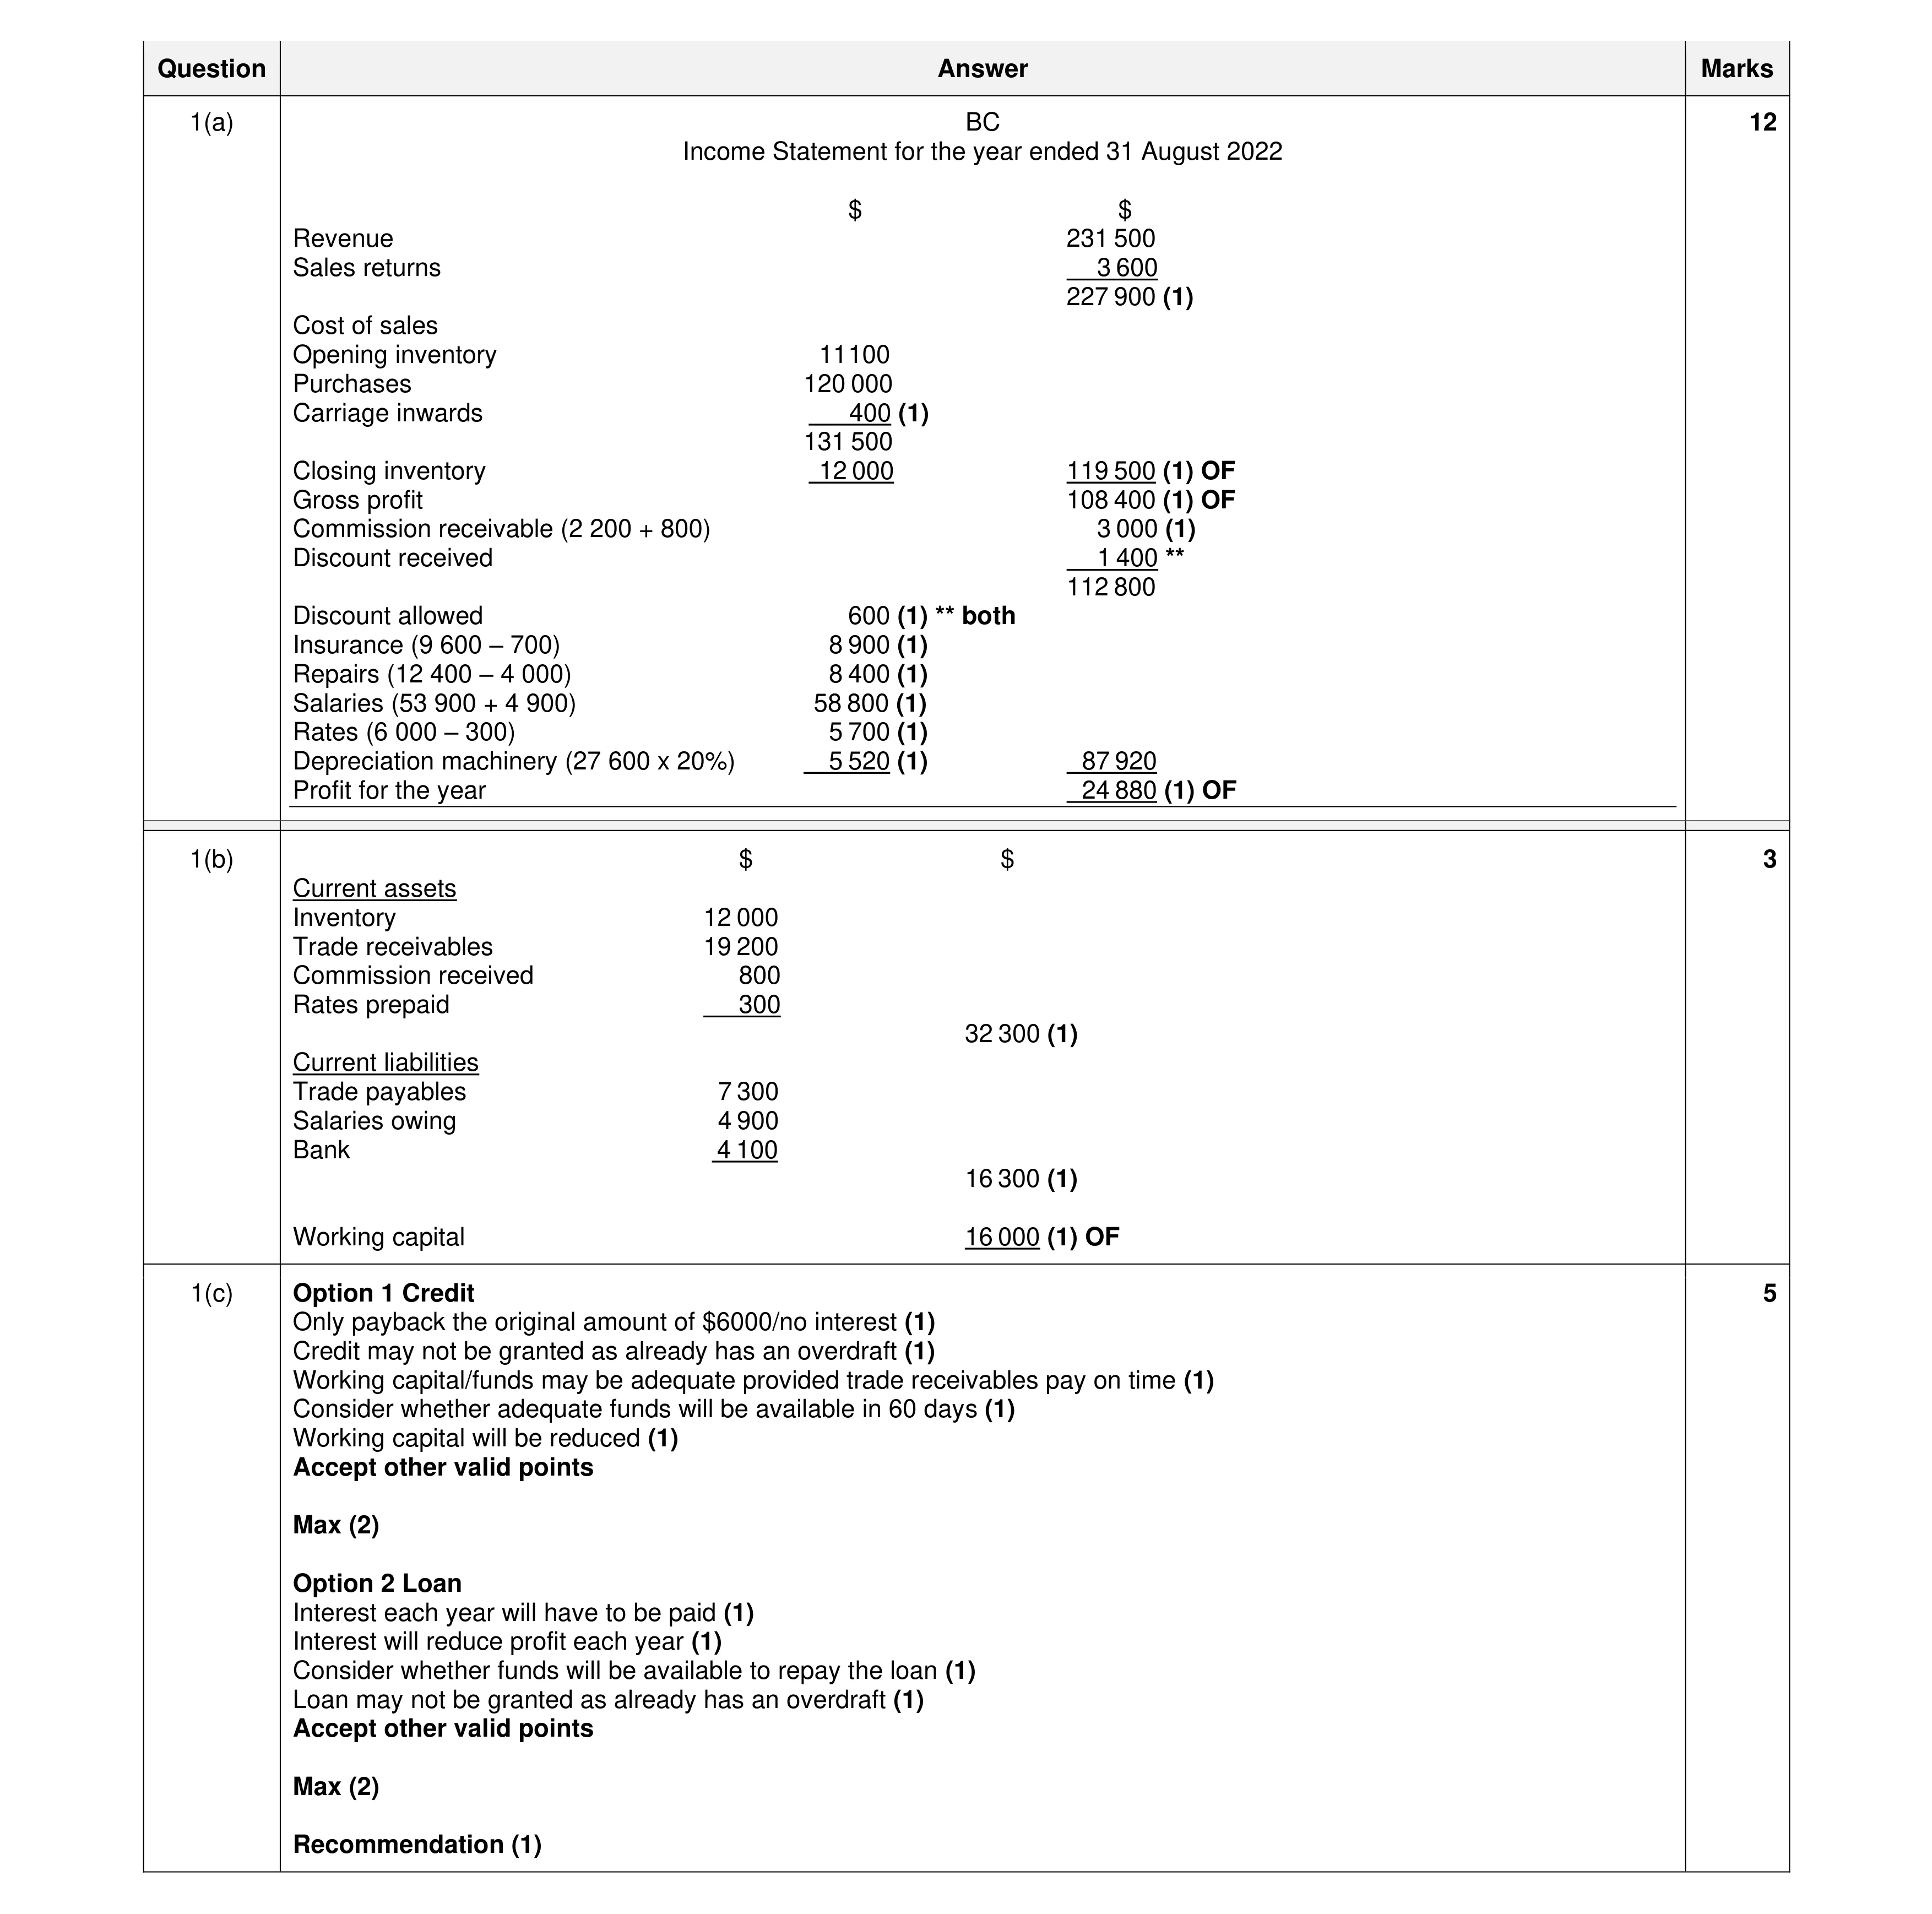
Mark scheme: Question Answer Marks 1(a) BC 12 Income Statement for the year ended 31 August 2022 $ $ Revenue 231 500 Sales returns 3 600 227 900 (1) Cost of sales Opening inventory 11 100 Purchases 120 000 Carriage inwards 400 (1) 131 500 Closing inventory 12 000 119 500 (1) OF Gross profit 108 400 (1) OF Commission receivable (2 200 + 800) 3 000 (1) Discount received 1 400 ** 112 800 Discount allowed 600 (1) ** both Insurance (9 600 – 700) 8 900 (1) Repairs (12 400 – 4 000) 8 400 (1) Salaries (53 900 + 4 900) 58 800 (1) Rates (6 000 – 300) 5 700 (1) Depreciation machinery (27 600 x 20%) 5 520 (1) 87 920 Profit for the year 24 880 (1) OF 1(b) $ $ 3 Current assets Inventory 12 000 Trade receivables 19 200 Commission received 800 Rates prepaid 300 32 300 (1) Current liabilities Trade payables 7 300 Salaries owing 4 900 Bank 4 100 16 300 (1) Working capital 16 000 (1) OF 1(c) Option 1 Credit 5 Only payback the original amount of $6000/no interest (1) Credit may not be granted as already has an overdraft (1) Working capital/funds may be adequate provided trade receivables pay on time (1) Consider whether adequate funds will be available in 60 days (1) Working capital will be reduced (1) Accept other valid points Max (2) Option 2 Loan Interest each year will have to be paid (1) Interest will reduce profit each year (1) Consider whether funds will be available to repay the loan (1) Loan may not be granted as already has an overdraft (1) Accept other valid points Max (2) Recommendation (1)
This question in 0985/22 Oct/Nov 2022
Q8 · Eshe is a trader 0985/21 May/June 2023
3 Eshe is a trader. She has prepared a trial balance at 31 March 2023. The totals did not agree and the difference was placed in a suspense account. Eshe later discovered the errors shown in the following table. REQUIRED (a) Complete the table to show the entries required to correct each error. The first one has been completed as an example. Entries required to correct the error Error Debit Credit Account $ Account $ A payment for rent, $300, had been Rent paid 300 Insurance 300 debited to the insurance account. Credit sales to Raymond of $105 … … … … had been debited to the sales account and credited to Raymond’s … … … … account. Eshe’s total drawings from the bank … … … … for her own use, $9500, had been debited to the cash account. … … … … A purchases invoice from Danika … … … … for $137 had been recorded in her account and in the purchases journal … … … … as $173. Returns inwards, $44, had not been … … … … recorded in the returns inwards account. … … … … The motor expenses account had … … … … been overcast by $100. … … … … [10] (b) Prepare the suspense account. Include the balancing figure as the original difference on the trial balance. Eshe Suspense account Date Details $ Date Details $ … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [3] Eshe’s capital at 1 April 2022 was $31 000. Her draft profit for the year ended 31 March 2023 before correction of the errors was $15 600. REQUIRED (c) Calculate Eshe’s capital at 31 March 2023 after the errors have been corrected. … … … … … … … … … … … … [7] [Total: 20]
20 marks
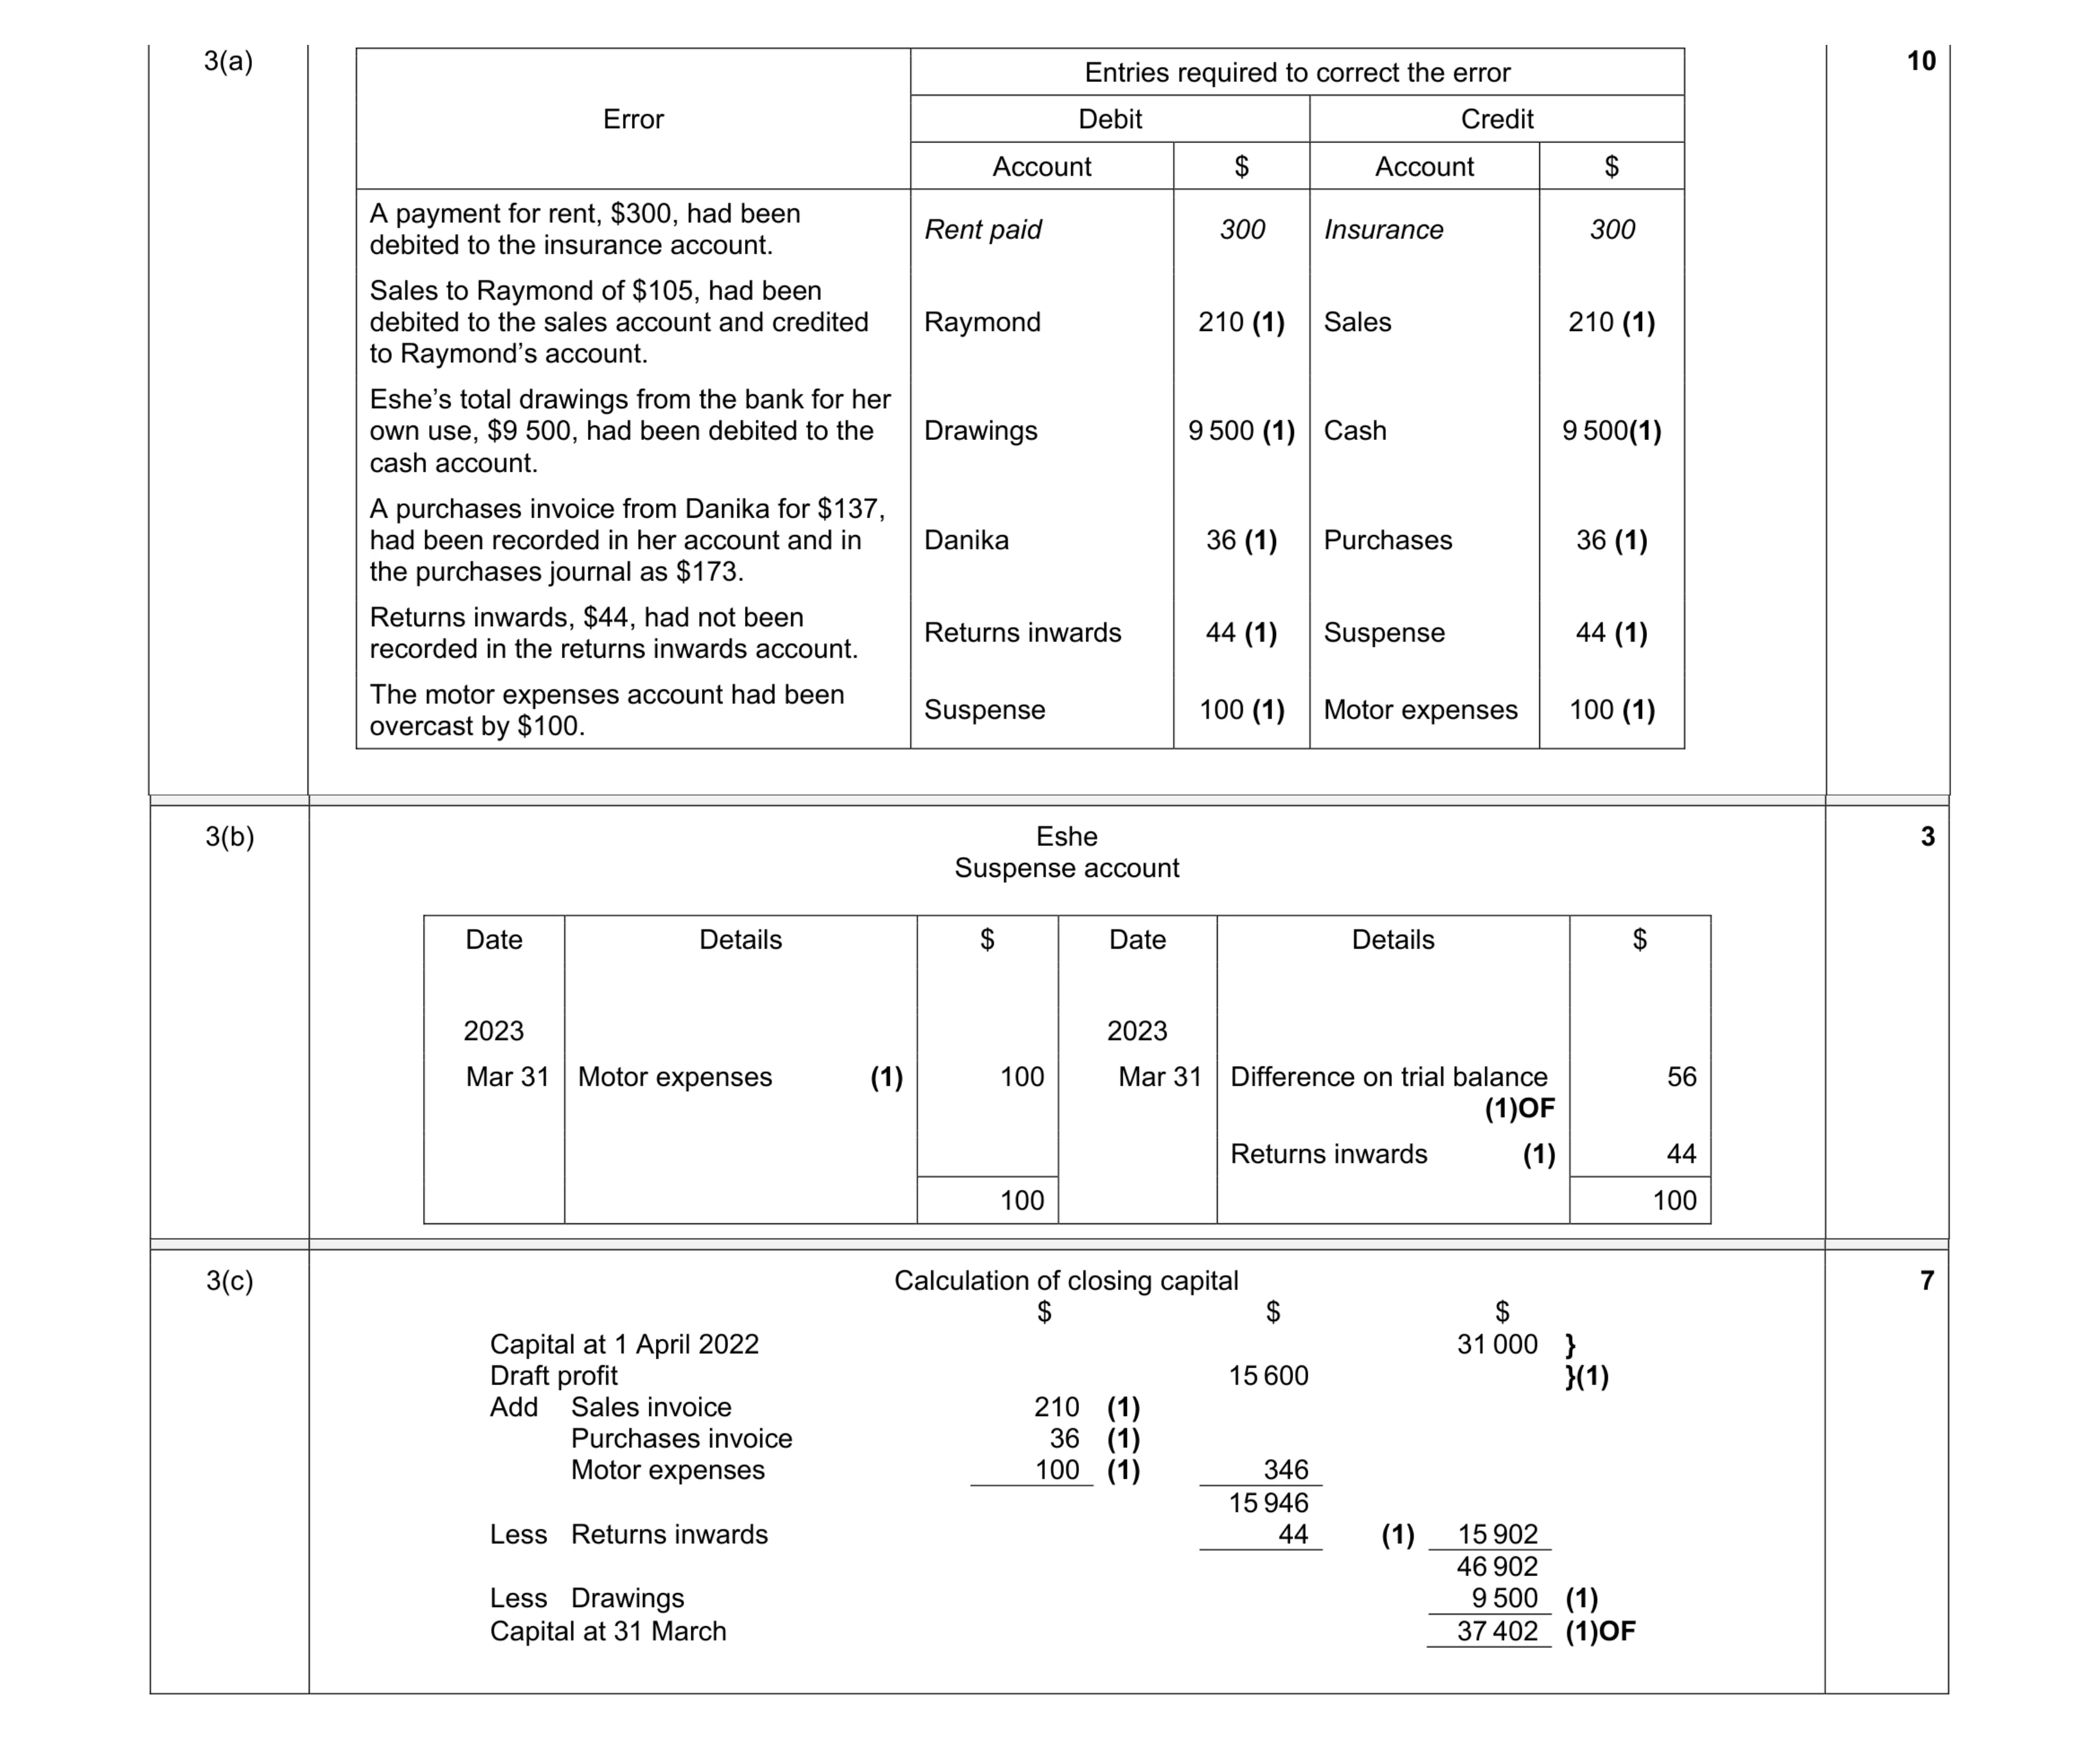
Mark scheme: 3(a) Error Entries required to correct the error Debit Credit Account $ Account $ A payment for rent, $300, had been debited to the insurance account. Rent paid 300 Insurance 300 Sales to Raymond of $105, had been debited to the sales account and credited to Raymond’s account. Raymond 210 (1) Sales 210 (1) Eshe’s total drawings from the bank for her own use, $9 500, had been debited to the cash account. Drawings 9 500 (1) Cash 9 500(1) A purchases invoice from Danika for $137, had been recorded in her account and in the purchases journal as $173. Danika 36 (1) Purchases 36 (1) Returns inwards, $44, had not been recorded in the returns inwards account. Returns inwards 44 (1) Suspense 44 (1) The motor expenses account had been overcast by $100. Suspense 100 (1) Motor expenses 100 (1) Question Answer Marks 3(b) Eshe Suspense account Date Details $ Date Details $ 2023 2023 Mar 31 Motor expenses (1) 100 Mar 31 Difference on trial balance (1)OF 56 Returns inwards (1) 44 100 100 3 Question Answer Marks 3(c) Calculation of closing capital $ $ $ Capital at 1 April 2022 31 000 } Draft profit 15 600 }(1) Add Sales invoice 210 (1) Purchases invoice 36 (1) Motor expenses 100 (1) 346 15 946 Less Returns inwards 44 (1) 15 902 46 902 Less Drawings 9 500 (1) Capital at 31 March 37 402 (1)OF 7
This question in 0985/21 May/June 2023
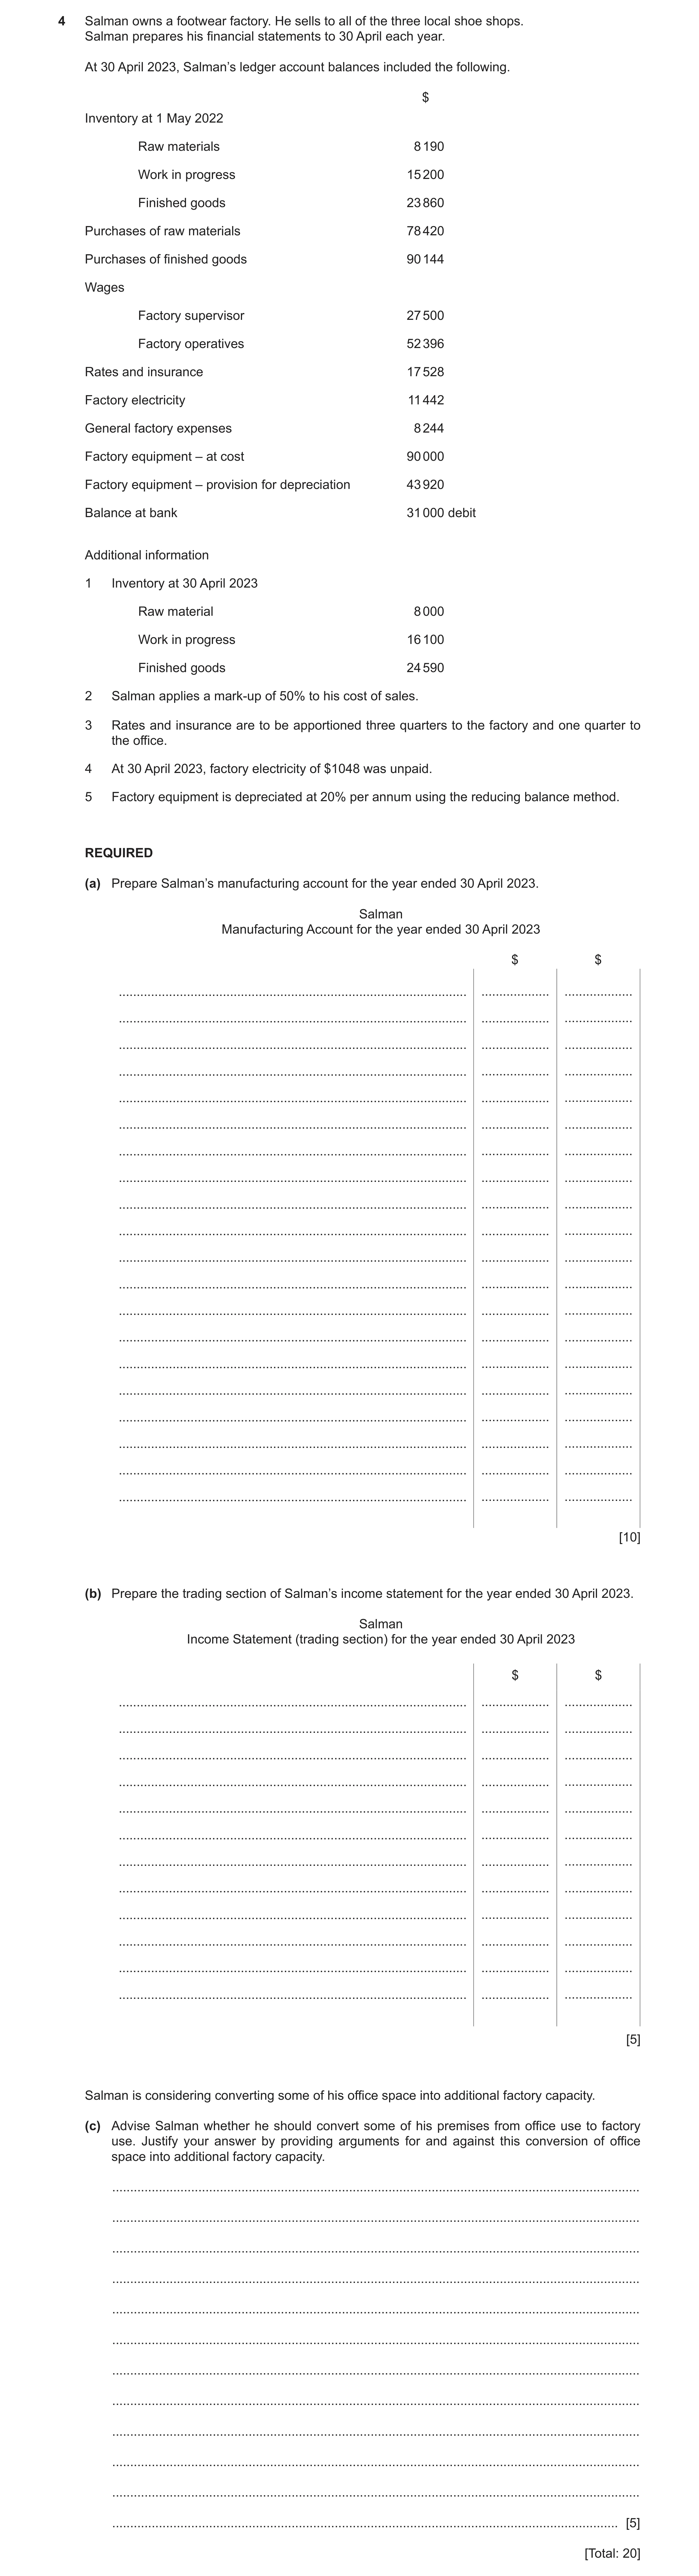
Q9 · Salman owns a footwear factory 0985/21 May/June 2023
4 Salman owns a footwear factory. He sells to all of the three local shoe shops. Salman prepares his financial statements to 30 April each year. At 30 April 2023, Salman’s ledger account balances included the following. $ Inventory at 1 May 2022 Raw materials 8 190 Work in progress 15 200 Finished goods 23 860 Purchases of raw materials 78 420 Purchases of finished goods 90 144 Wages Factory supervisor 27 500 Factory operatives 52 396 Rates and insurance 17 528 Factory electricity 11 442 General factory expenses 8 244 Factory equipment – at cost 90 000 Factory equipment – provision for depreciation 43 920 Balance at bank 31 000 debit Additional information 1 Inventory at 30 April 2023 Raw material 8 000 Work in progress 16 100 Finished goods 24 590 2 Salman applies a mark-up of 50% to his cost of sales. 3 Rates and insurance are to be apportioned three quarters to the factory and one quarter to the office. 4 At 30 April 2023, factory electricity of $1048 was unpaid. 5 Factory equipment is depreciated at 20% per annum using the reducing balance method. REQUIRED (a) Prepare Salman’s manufacturing account for the year ended 30 April 2023. Salman Manufacturing Account for the year ended 30 April 2023 $ $ … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [10] (b) Prepare the trading section of Salman’s income statement for the year ended 30 April 2023. Salman Income Statement (trading section) for the year ended 30 April 2023 $ $ … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [5] Salman is considering converting some of his office space into additional factory capacity. (c) Advise Salman whether he should convert some of his premises from office use to factory use. Justify your answer by providing arguments for and against this conversion of office space into additional factory capacity. … … … … … … … … … … … … [5] [Total: 20]
20 marks
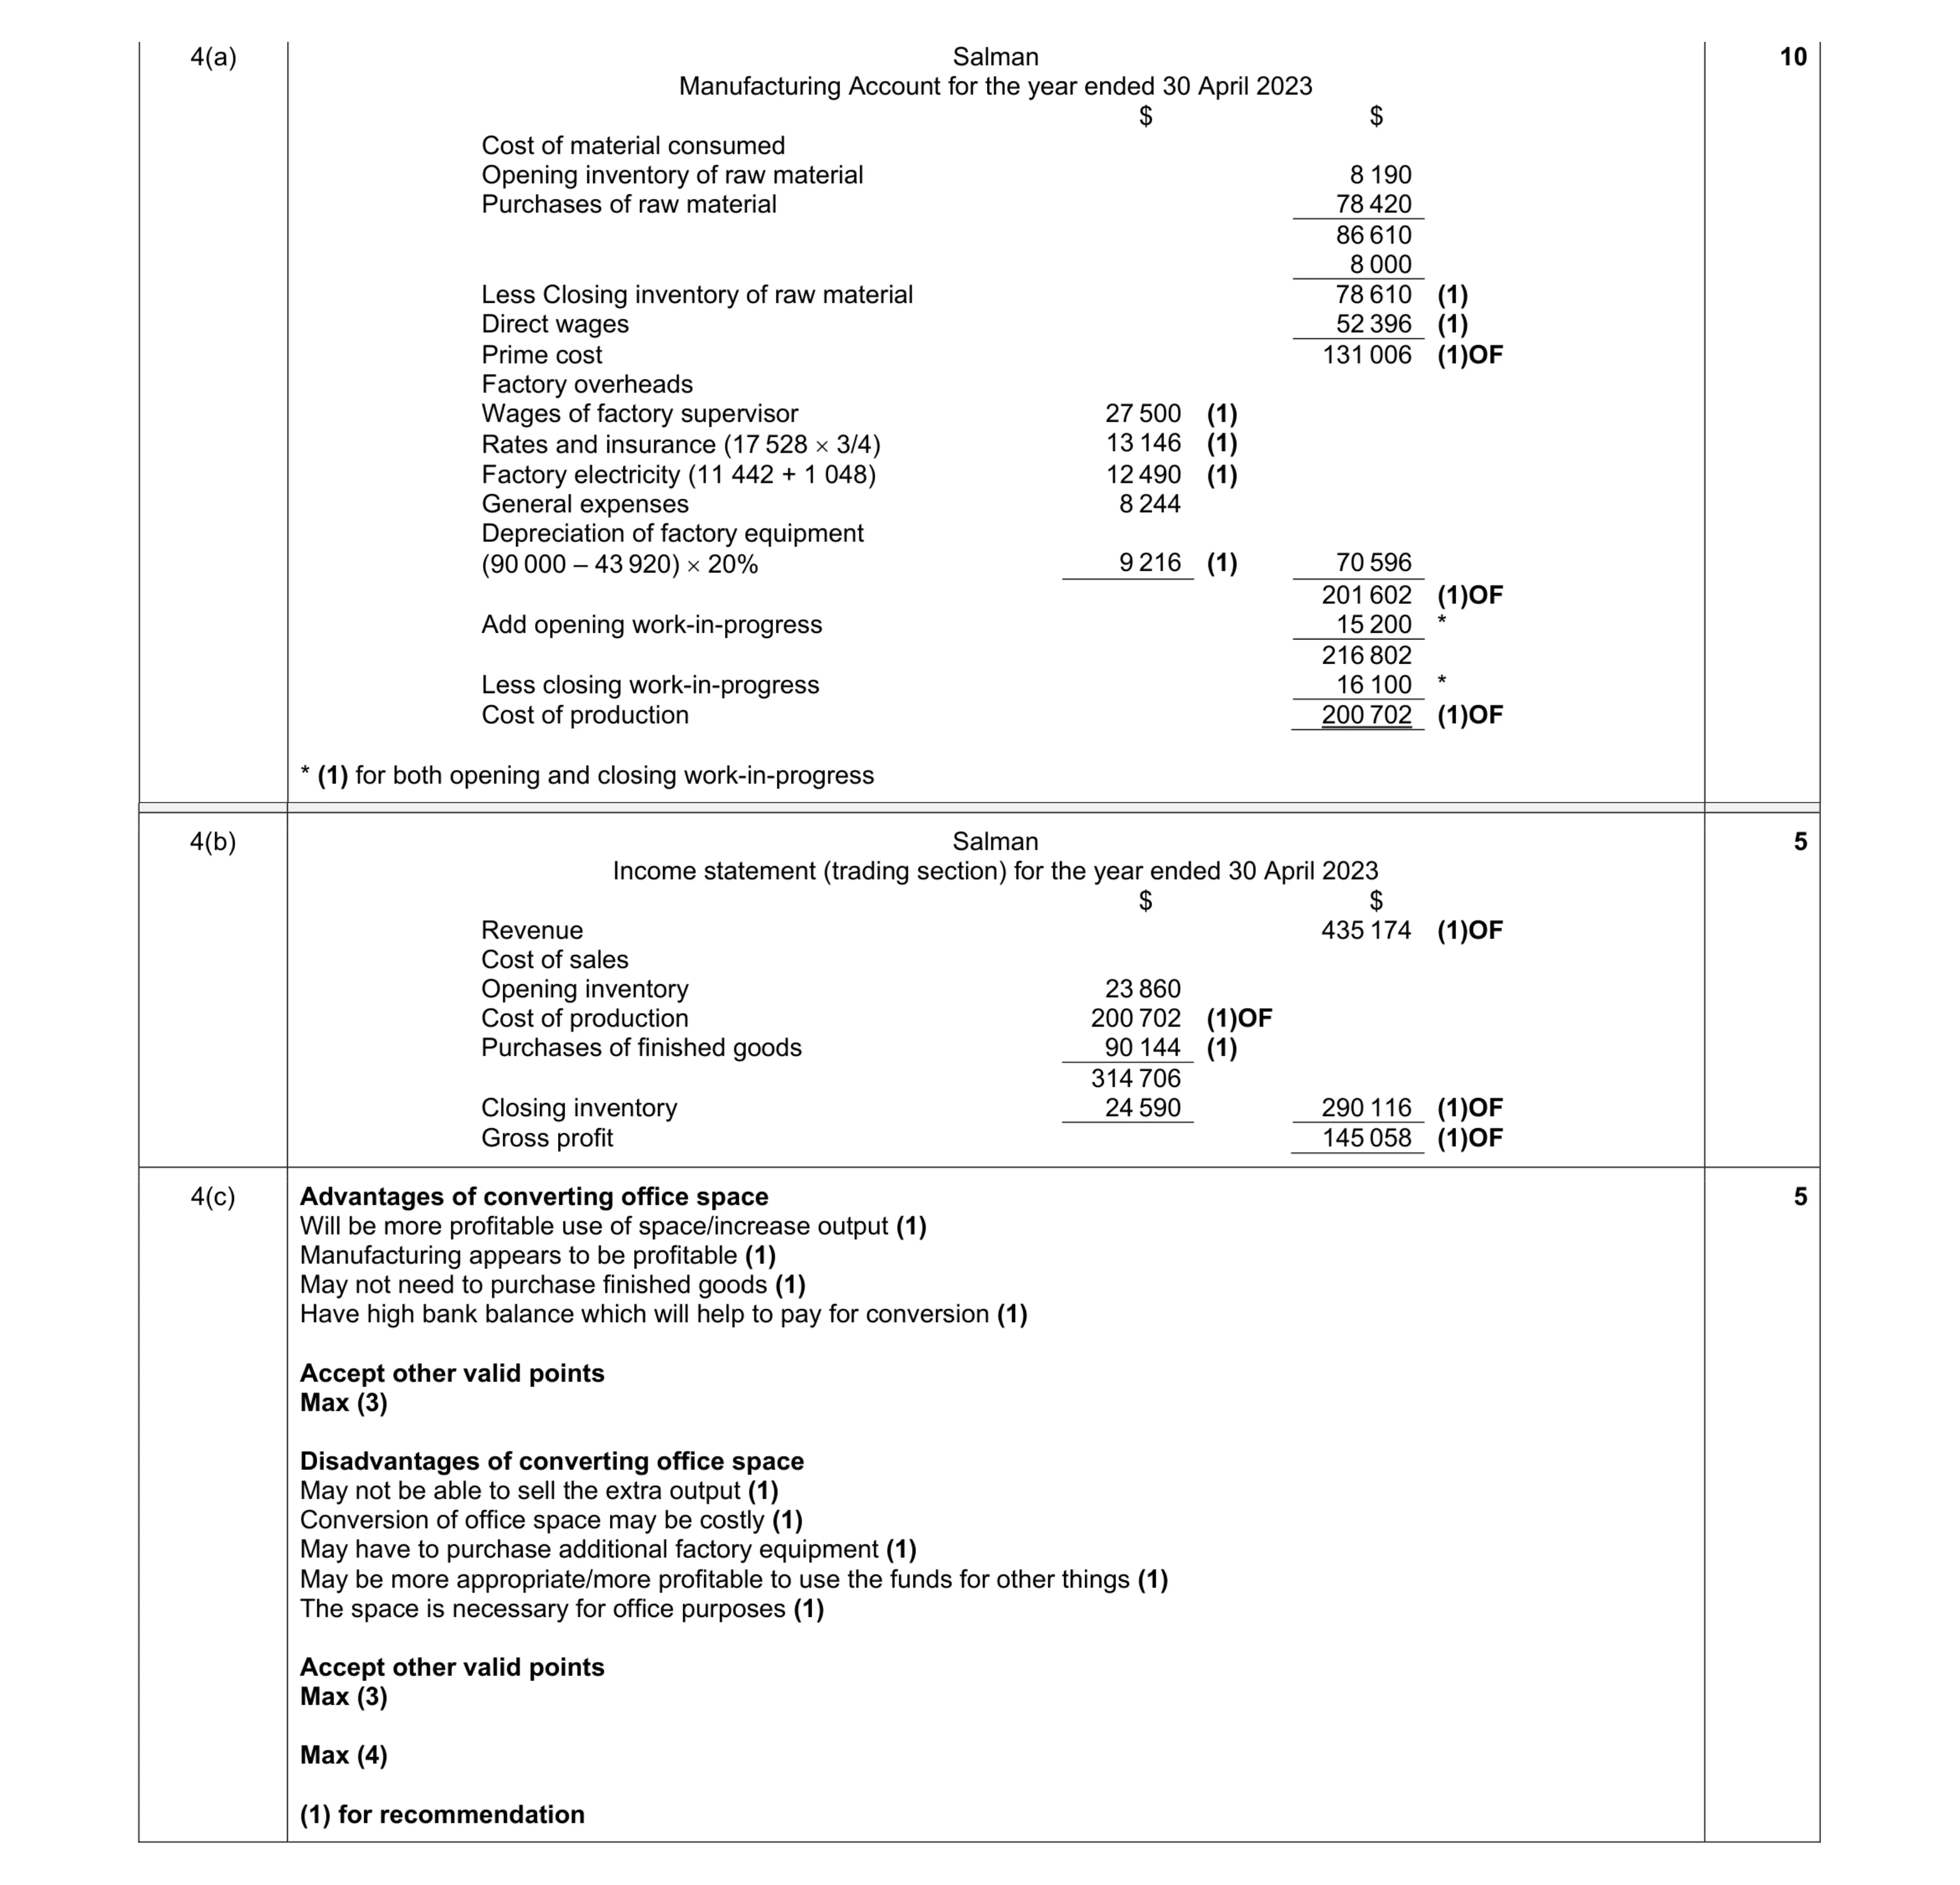
Mark scheme: 4(a) Salman Manufacturing Account for the year ended 30 April 2023 $ $ Cost of material consumed Opening inventory of raw material 8 190 Purchases of raw material 78 420 86 610 8 000 Less Closing inventory of raw material 78 610 (1) Direct wages 52 396 (1) Prime cost 131 006 (1)OF Factory overheads Wages of factory supervisor 27 500 (1) Rates and insurance (17 528 3/4) 13 146 (1) Factory electricity (11 442 + 1 048) 12 490 (1) General expenses 8 244 Depreciation of factory equipment (90 000 – 43 920) 20% 9 216 (1) 70 596 201 602 (1)OF Add opening work-in-progress 15 200 * 216 802 Less closing work-in-progress 16 100 * Cost of production 200 702 (1)OF * (1) for both opening and closing work-in-progress 10 Question Answer Marks 4(b) Salman Income statement (trading section) for the year ended 30 April 2023 $ $ Revenue 435 174 (1)OF Cost of sales Opening inventory 23 860 Cost of production 200 702 (1)OF Purchases of finished goods 90 144 (1) 314 706 Closing inventory 24 590 290 116 (1)OF Gross profit 145 058 (1)OF 5 4(c) Advantages of converting office space Will be more profitable use of space/increase output (1) Manufacturing appears to be profitable (1) May not need to purchase finished goods (1) Have high bank balance which will help to pay for conversion (1) Accept other valid points Max (3) Disadvantages of converting office space May not be able to sell the extra output (1) Conversion of office space may be costly (1) May have to purchase additional factory equipment (1) May be more appropriate/more profitable to use the funds for other things (1) The space is necessary for office purposes (1) Accept other valid points Max (3) Max (4) (1) for recommendation 5
This question in 0985/21 May/June 2023
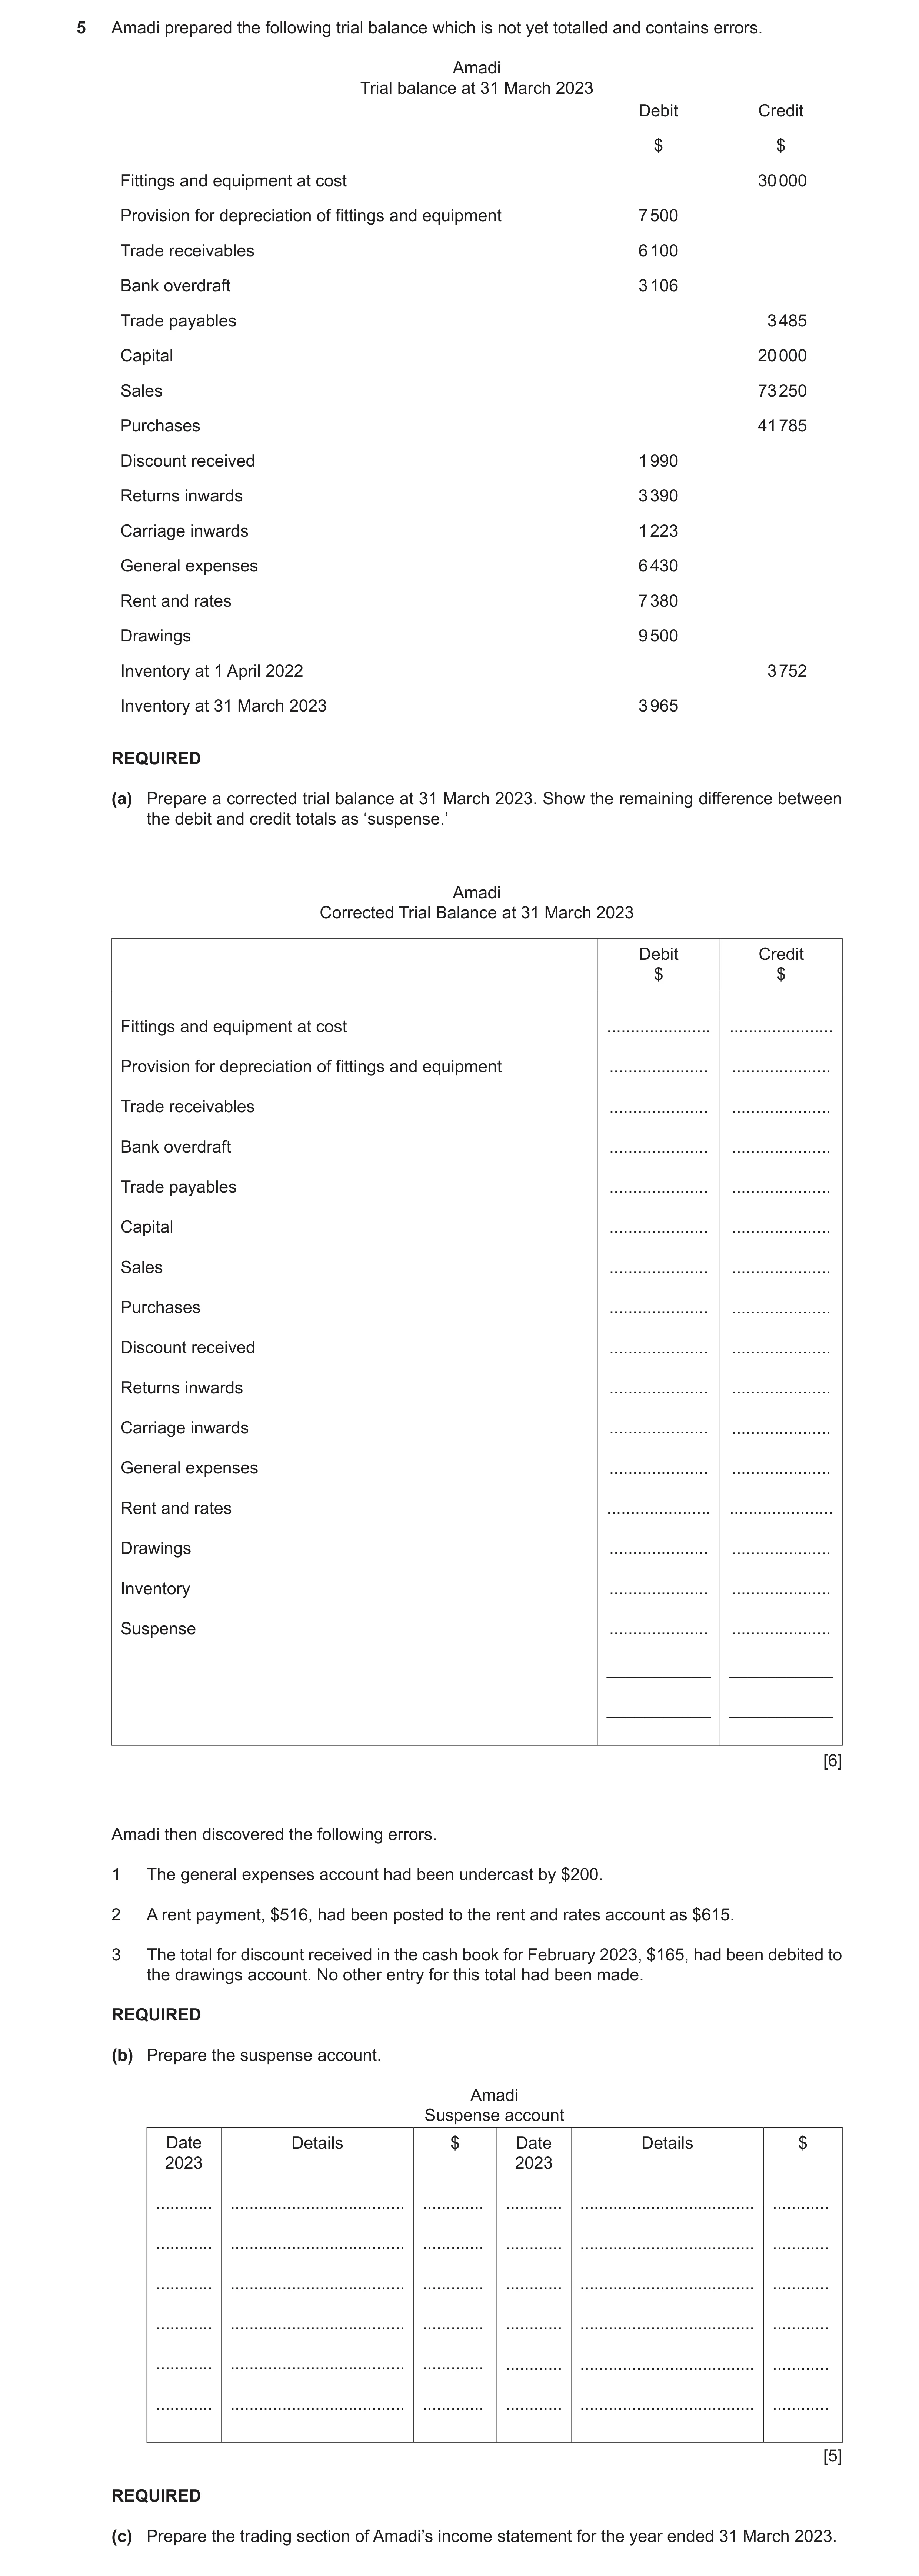
Q10 · Amadi prepared the following trial balance which is not yet totalled and contains errors 0985/22 May/June 2023
5 Amadi prepared the following trial balance which is not yet totalled and contains errors. Amadi Trial balance at 31 March 2023 Debit Credit $ $ Fittings and equipment at cost 30 000 Provision for depreciation of fittings and equipment 7 500 Trade receivables 6 100 Bank overdraft 3 106 Trade payables 3 485 Capital 20 000 Sales 73 250 Purchases 41 785 Discount received 1 990 Returns inwards 3 390 Carriage inwards 1 223 General expenses 6 430 Rent and rates 7 380 Drawings 9 500 Inventory at 1 April 2022 3 752 Inventory at 31 March 2023 3 965 REQUIRED (a) Prepare a corrected trial balance at 31 March 2023. Show the remaining difference between the debit and credit totals as ‘suspense.’ Amadi Corrected Trial Balance at 31 March 2023 Debit Credit $ $ Fittings and equipment at cost … … Provision for depreciation of fittings and equipment … … Trade receivables … … Bank overdraft … … Trade payables … … Capital … … Sales … … Purchases … … Discount received … … Returns inwards … … Carriage inwards … … General expenses … … Rent and rates … … Drawings … … Inventory … … Suspense … … ___________ ___________ ___________ ___________ [6] Amadi then discovered the following errors. 1 The general expenses account had been undercast by $200. 2 A rent payment, $516, had been posted to the rent and rates account as $615. 3 The total for discount received in the cash book for February 2023, $165, had been debited to the drawings account. No other entry for this total had been made. REQUIRED (b) Prepare the suspense account. Amadi Suspense account Date Details $ Date Details $ 2023 2023 … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [5] REQUIRED (c) Prepare the trading section of Amadi’s income statement for the year ended 31 March 2023.
11 marks
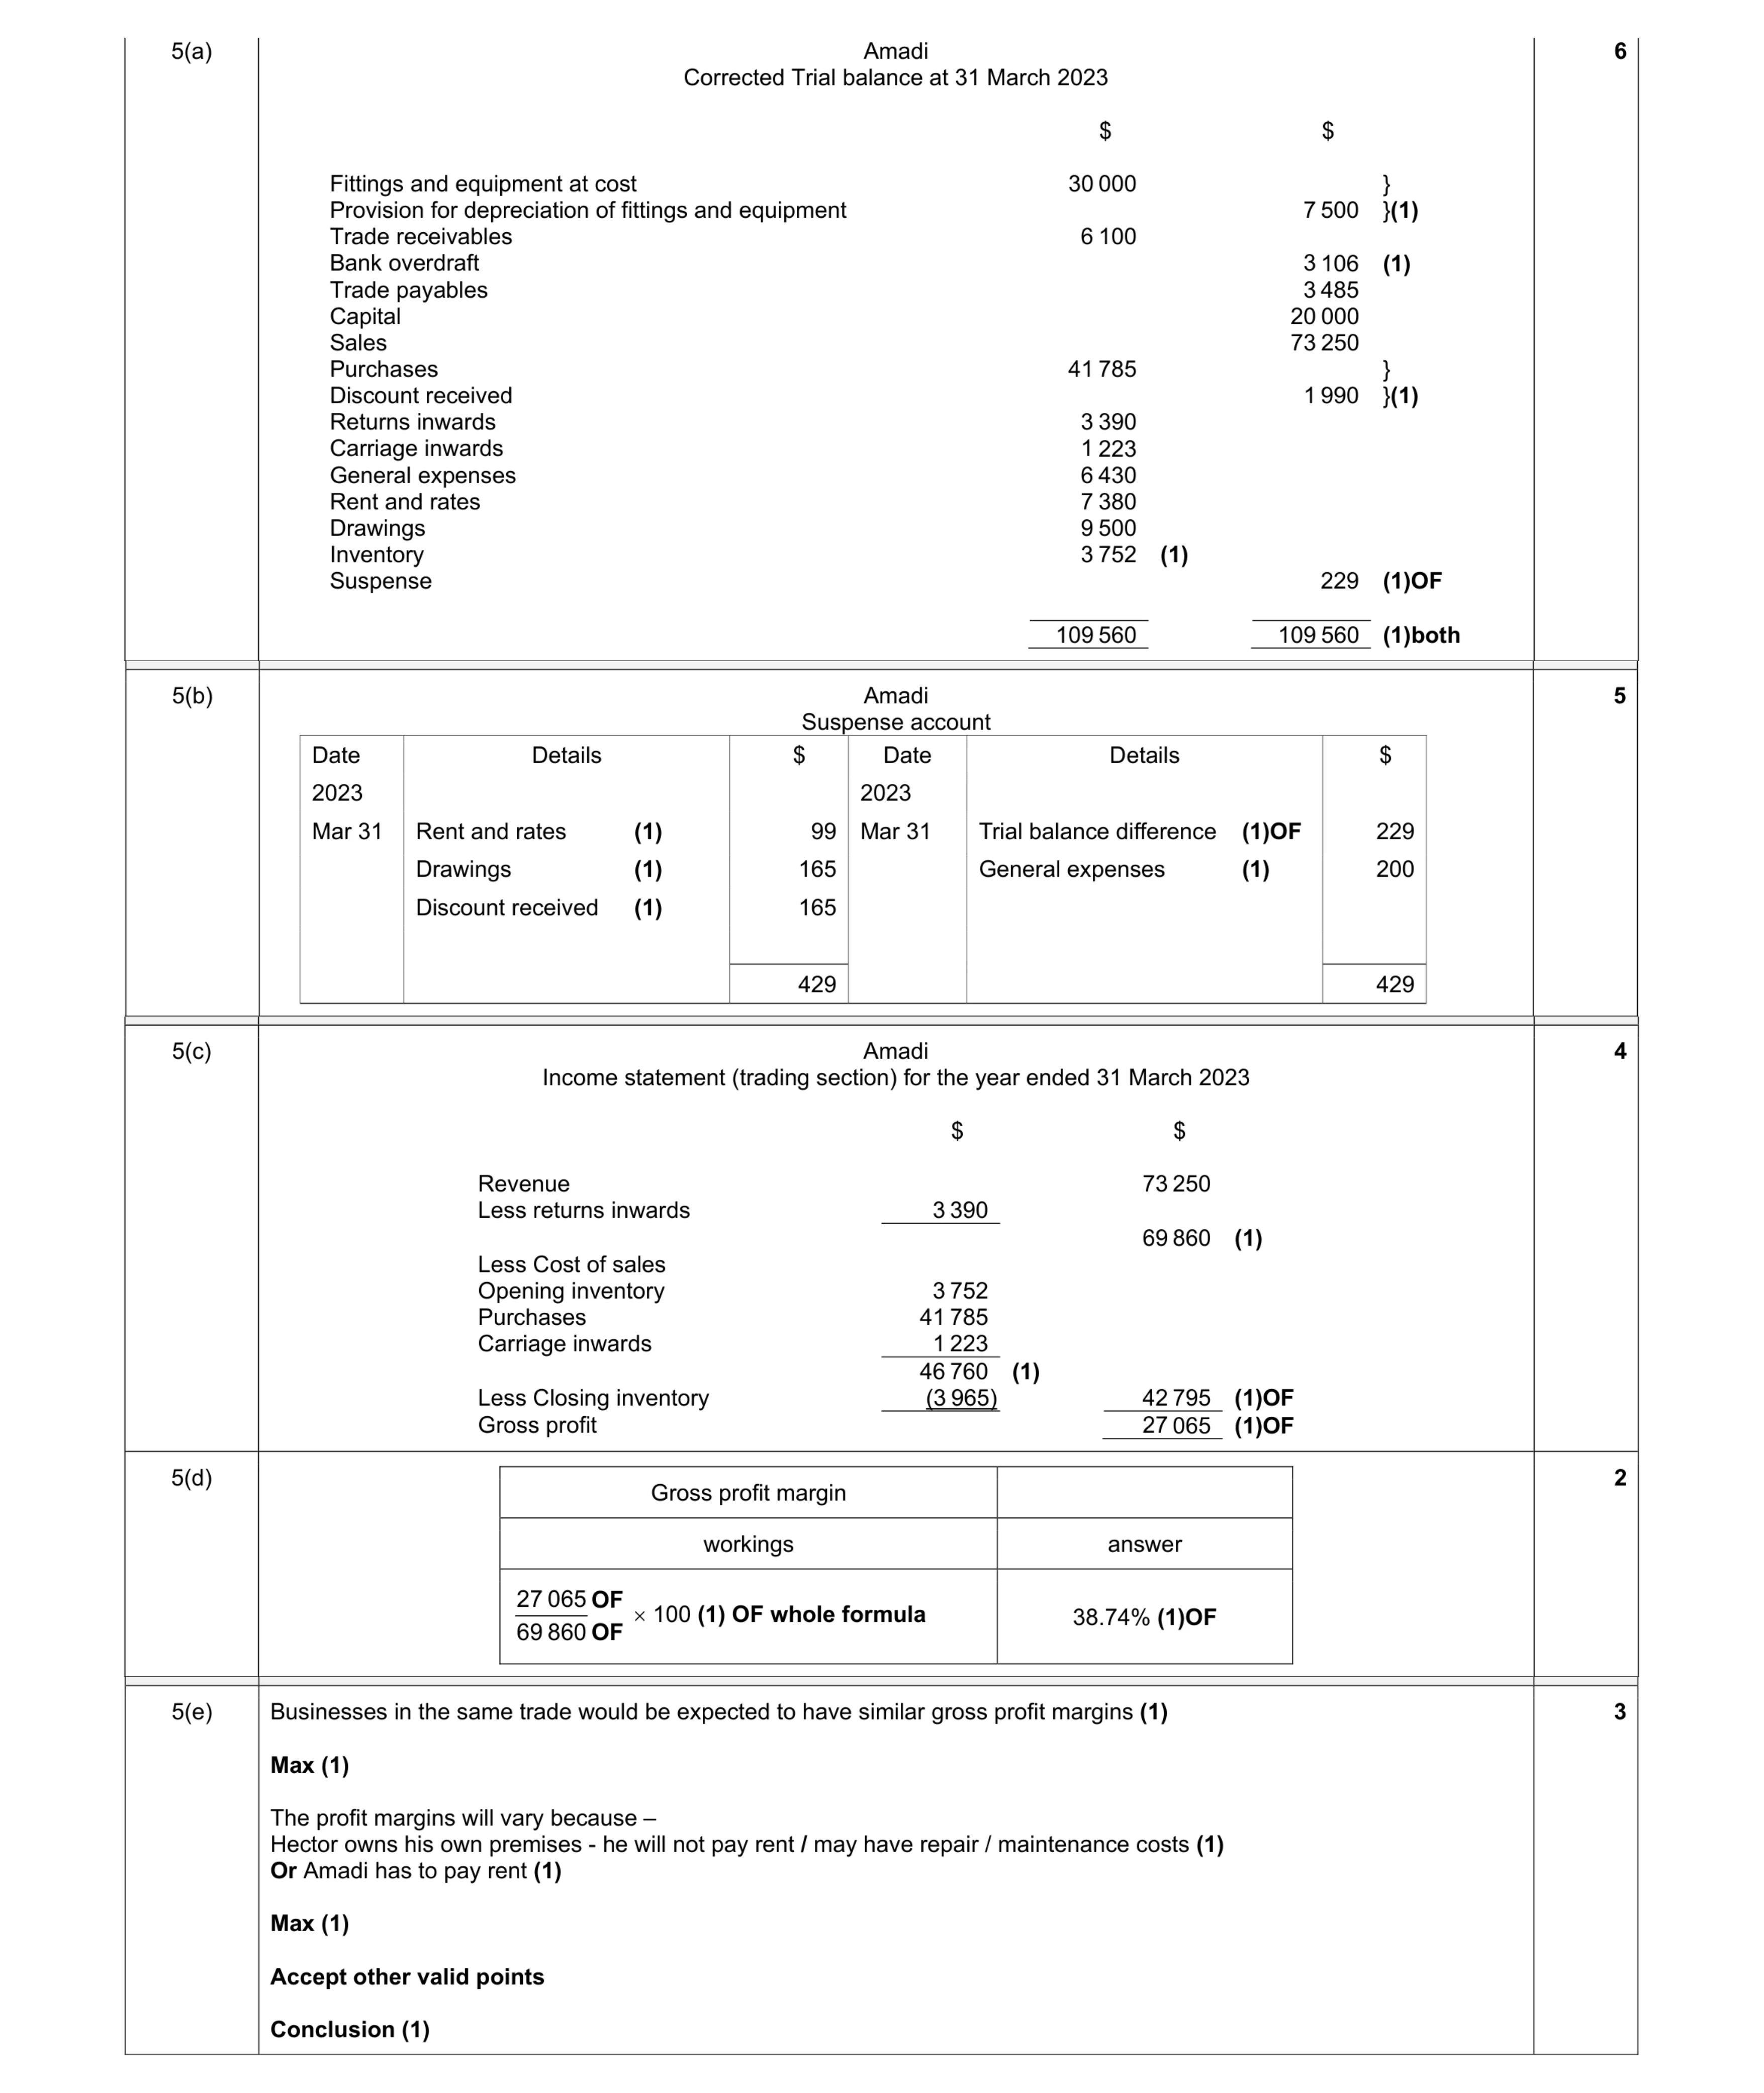
Mark scheme: 5(a) Amadi Corrected Trial balance at 31 March 2023 $ $ Fittings and equipment at cost 30 000 } Provision for depreciation of fittings and equipment 7 500 }(1) Trade receivables 6 100 Bank overdraft 3 106 (1) Trade payables 3 485 Capital 20 000 Sales 73 250 Purchases 41 785 } Discount received 1 990 }(1) Returns inwards 3 390 Carriage inwards 1 223 General expenses 6 430 Rent and rates 7 380 Drawings 9 500 Inventory 3 752 (1) Suspense 229 (1)OF 109 560 109 560 (1)both 6 Question Answer Marks 5(b) Amadi Suspense account Date Details $ Date Details $ 2023 2023 Mar 31 Rent and rates (1) 99 Mar 31 Trial balance difference (1)OF 229 Drawings (1) 165 General expenses (1) 200 Discount received (1) 165 429 429 5 Question Answer Marks 5(c) Amadi Income statement (trading section) for the year ended 31 March 2023 $ $ Revenue 73 250 Less returns inwards 3 390 69 860 (1) Less Cost of sales Opening inventory 3 752 Purchases 41 785 Carriage inwards 1 223 46 760 (1) Less Closing inventory (3 965) 42 795 (1)OF Gross profit 27 065 (1)OF 4 5(d) Gross profit margin workings answer 27 065 69 860 OF OF 100 (1) OF whole formula 38.74% (1)OF 2 Question Answer Marks 5(e) Businesses in the same trade would be expected to have similar gross profit margins (1) Max (1) The profit margins will vary because – Hector owns his own premises - he will not pay rent / may have repair / maintenance costs (1) Or Amadi has to pay rent (1) Max (1) Accept other valid points Conclusion (1) 3
This question in 0985/22 May/June 2023
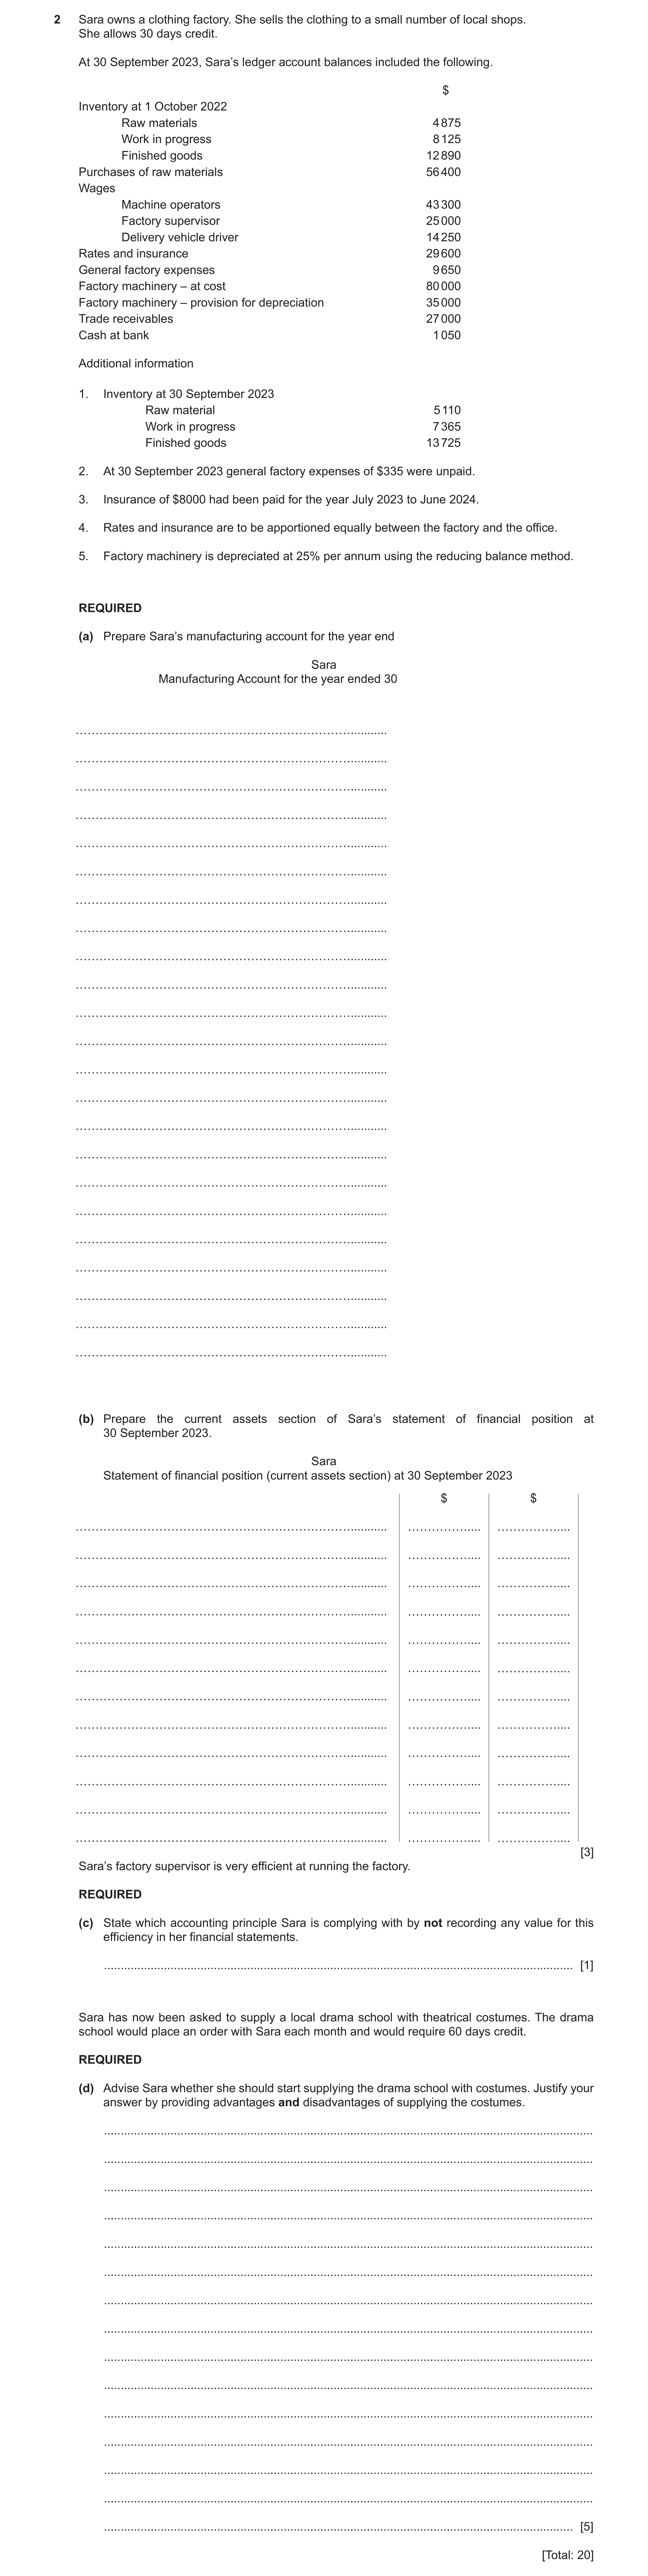
Q11 · Sara owns a clothing factory 0985/22 Oct/Nov 2023
2 Sara owns a clothing factory. She sells the clothing to a small number of local shops. She allows 30 days credit. At 30 September 2023, Sara’s ledger account balances included the following. $ Inventory at 1 October 2022 Raw materials 4 875 Work in progress 8 125 Finished goods 12 890 Purchases of raw materials 56 400 Wages Machine operators 43 300 Factory supervisor 25 000 Delivery vehicle driver 14 250 Rates and insurance 29 600 General factory expenses 9 650 Factory machinery – at cost 80 000 Factory machinery – provision for depreciation 35 000 Trade receivables 27 000 Cash at bank 1 050 Additional information 1. Inventory at 30 September 2023 Raw material 5 110 Work in progress 7 365 Finished goods 13 725 2. At 30 September 2023 general factory expenses of $335 were unpaid. 3. Insurance of $8000 had been paid for the year July 2023 to June 2024. 4. Rates and insurance are to be apportioned equally between the factory and the office. 5. Factory machinery is depreciated at 25% per annum using the reducing balance method. REQUIRED (a) Prepare Sara’s manufacturing account for the year end Sara Manufacturing Account for the year ended 30 …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … …………………………………………………………… … (b) Prepare the current assets section of Sara’s statement of financial position at 30 September 2023. Sara Statement of financial position (current assets section) at 30 September 2023 $ $ …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … [3] Sara’s factory supervisor is very efficient at running the factory. REQUIRED (c) State which accounting principle Sara is complying with by not recording any value for this efficiency in her financial statements. … [1] Sara has now been asked to supply a local drama school with theatrical costumes. The drama school would place an order with Sara each month and would require 60 days credit. REQUIRED (d) Advise Sara whether she should start supplying the drama school with costumes. Justify your answer by providing advantages and disadvantages of supplying the costumes. … … … … … … … … … … … … … … … [5] [Total: 20]
20 marks
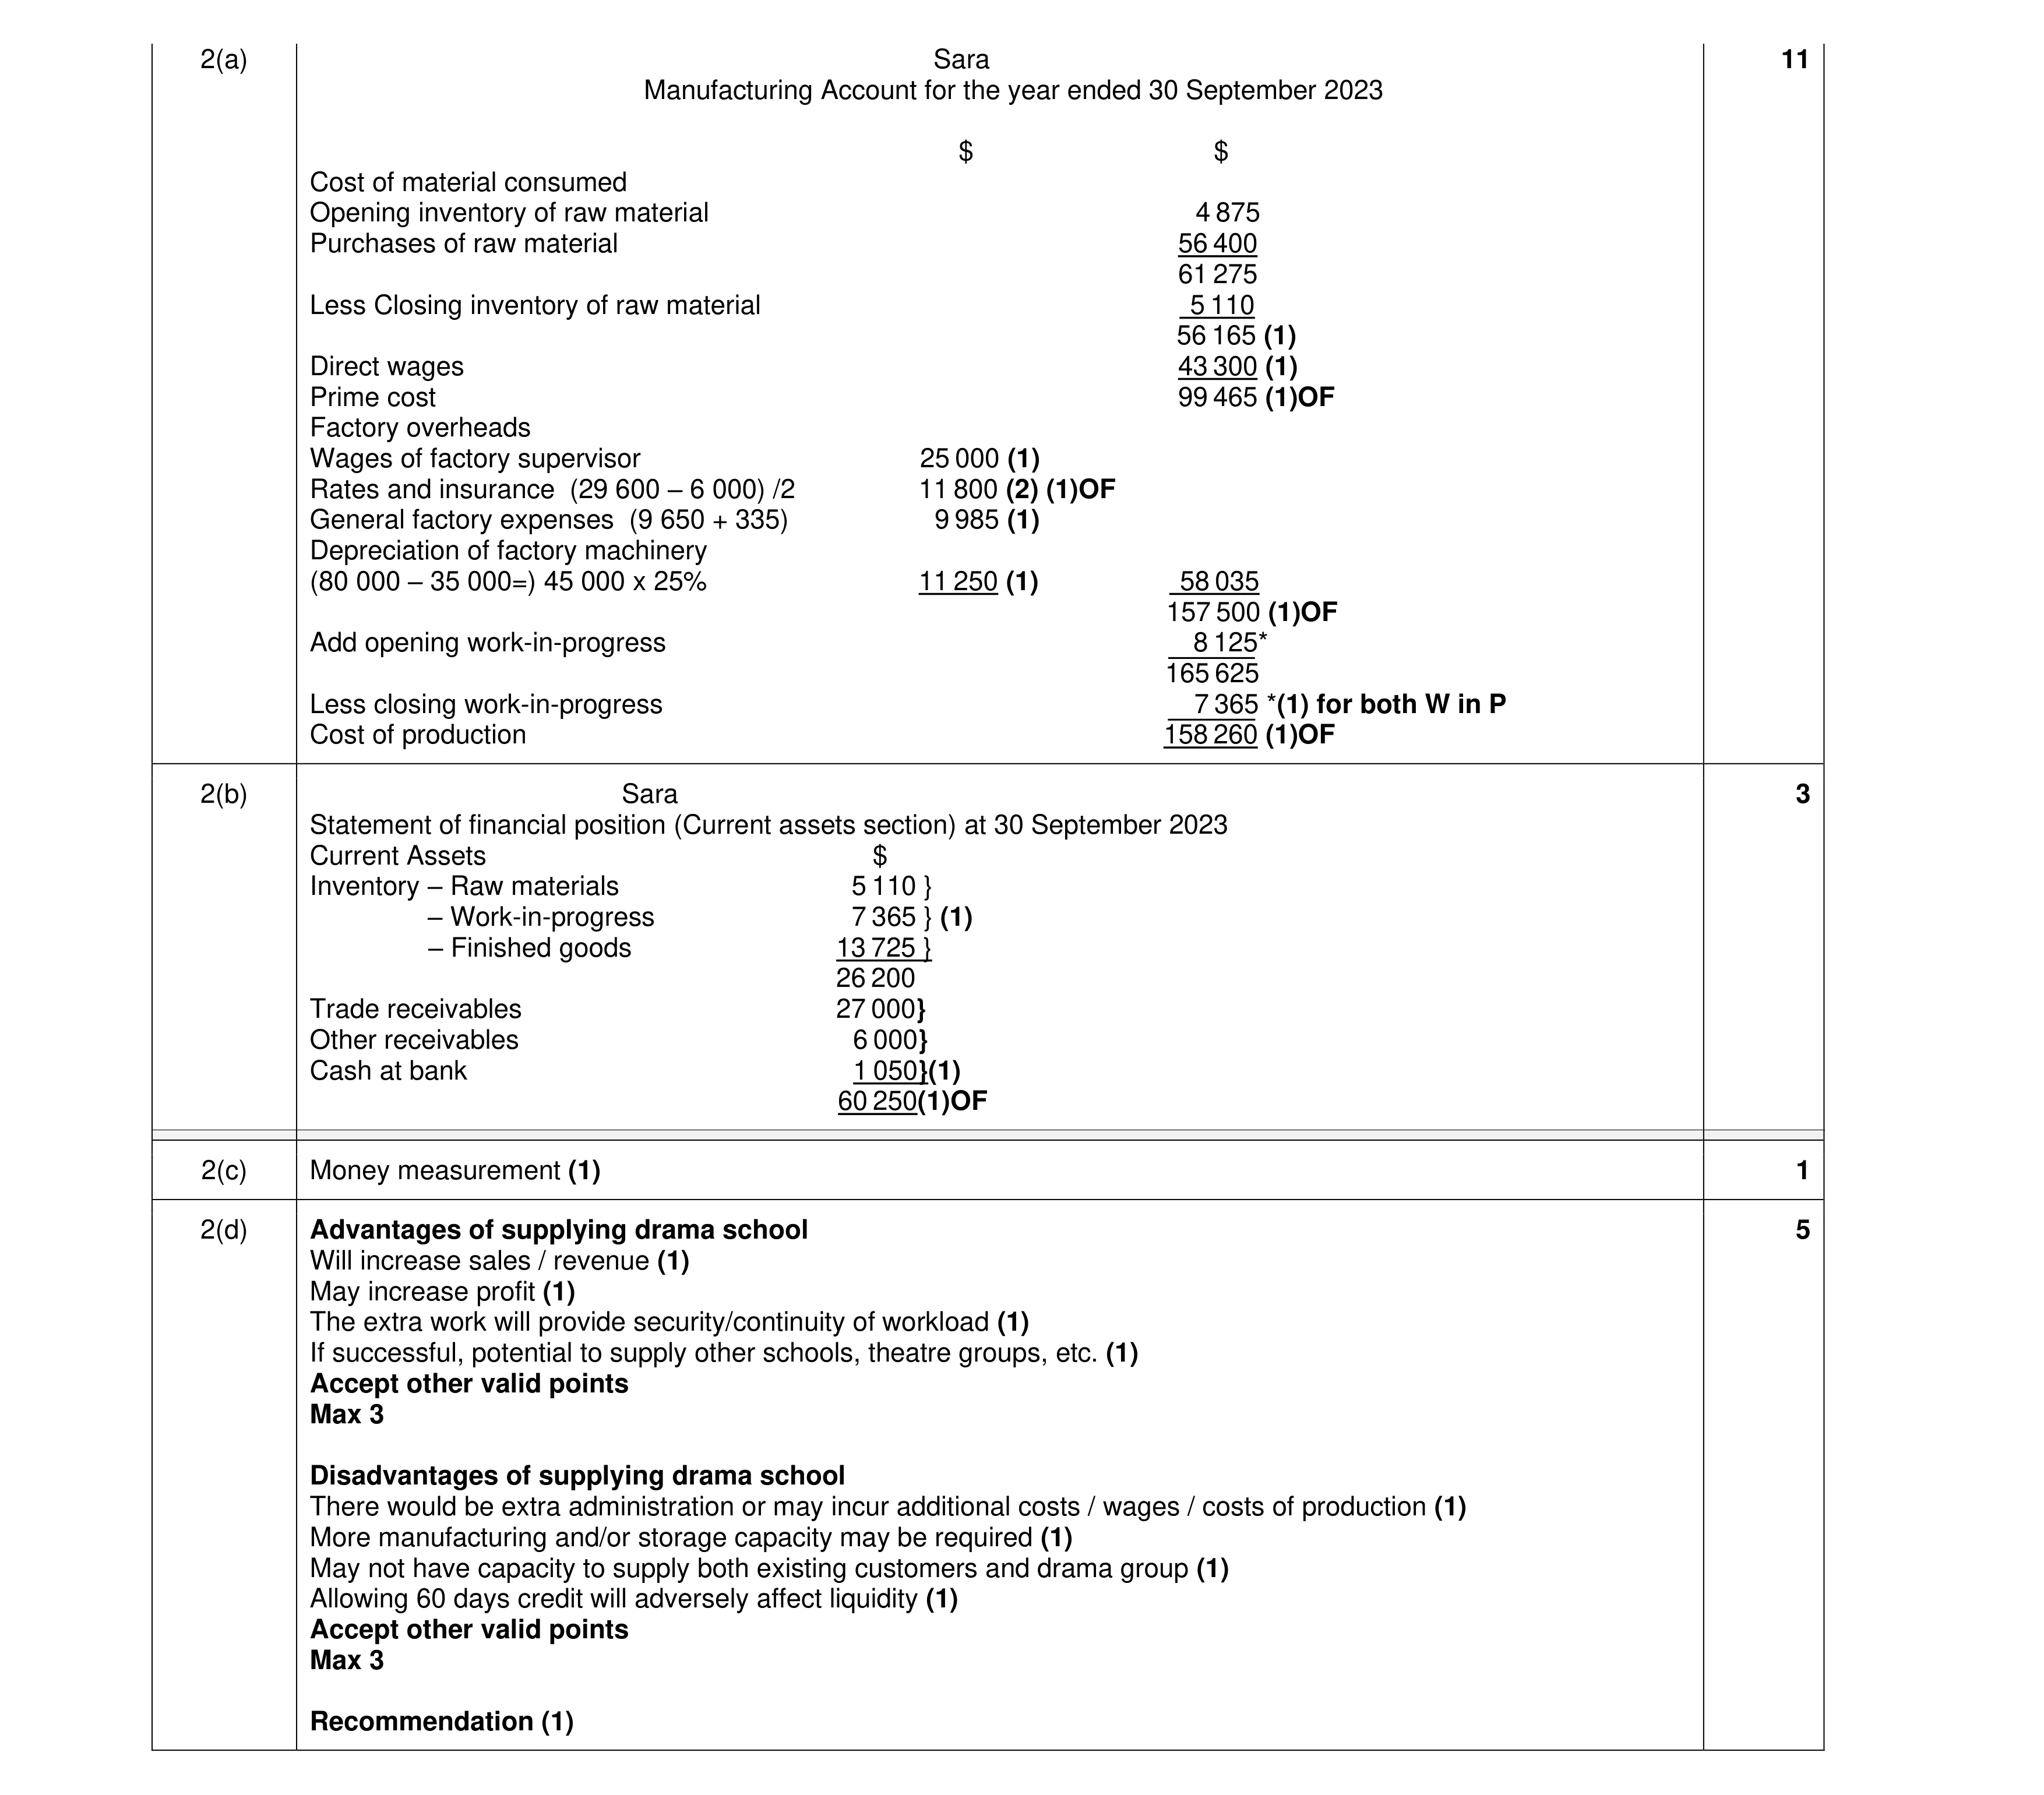
Mark scheme: 2(a) Sara 11 Manufacturing Account for the year ended 30 September 2023 $ $ Cost of material consumed Opening inventory of raw material 4 875 Purchases of raw material 56 400 61 275 Less Closing inventory of raw material 5 110 56 165 (1) Direct wages 43 300 (1) Prime cost 99 465 (1)OF Factory overheads Wages of factory supervisor 25 000 (1) Rates and insurance (29 600 – 6 000) /2 11 800 (2) (1)OF General factory expenses (9 650 + 335) 9 985 (1) Depreciation of factory machinery (80 000 – 35 000=) 45 000 x 25% 11 250 (1) 58 035 157 500 (1)OF Add opening work-in-progress 8 125* 165 625 Less closing work-in-progress 7 365 *(1) for both W in P Cost of production 158 260 (1)OF 2(b) Sara 3 Statement of financial position (Current assets section) at 30 September 2023 Current Assets $ Inventory – Raw materials 5 110 } – Work-in-progress 7 365 } (1) – Finished goods 13 725 } 26 200 Trade receivables 27 000} Other receivables 6 000} Cash at bank 1 050}(1) 60 250(1)OF 2(c) Money measurement (1) 1 2(d) Advantages of supplying drama school 5 Will increase sales / revenue (1) May increase profit (1) The extra work will provide security/continuity of workload (1) If successful, potential to supply other schools, theatre groups, etc. (1) Accept other valid points Max 3 Disadvantages of supplying drama school There would be extra administration or may incur additional costs / wages / costs of production (1) More manufacturing and/or storage capacity may be required (1) May not have capacity to supply both existing customers and drama group (1) Allowing 60 days credit will adversely affect liquidity (1) Accept other valid points Max 3 Recommendation (1)
This question in 0985/22 Oct/Nov 2023
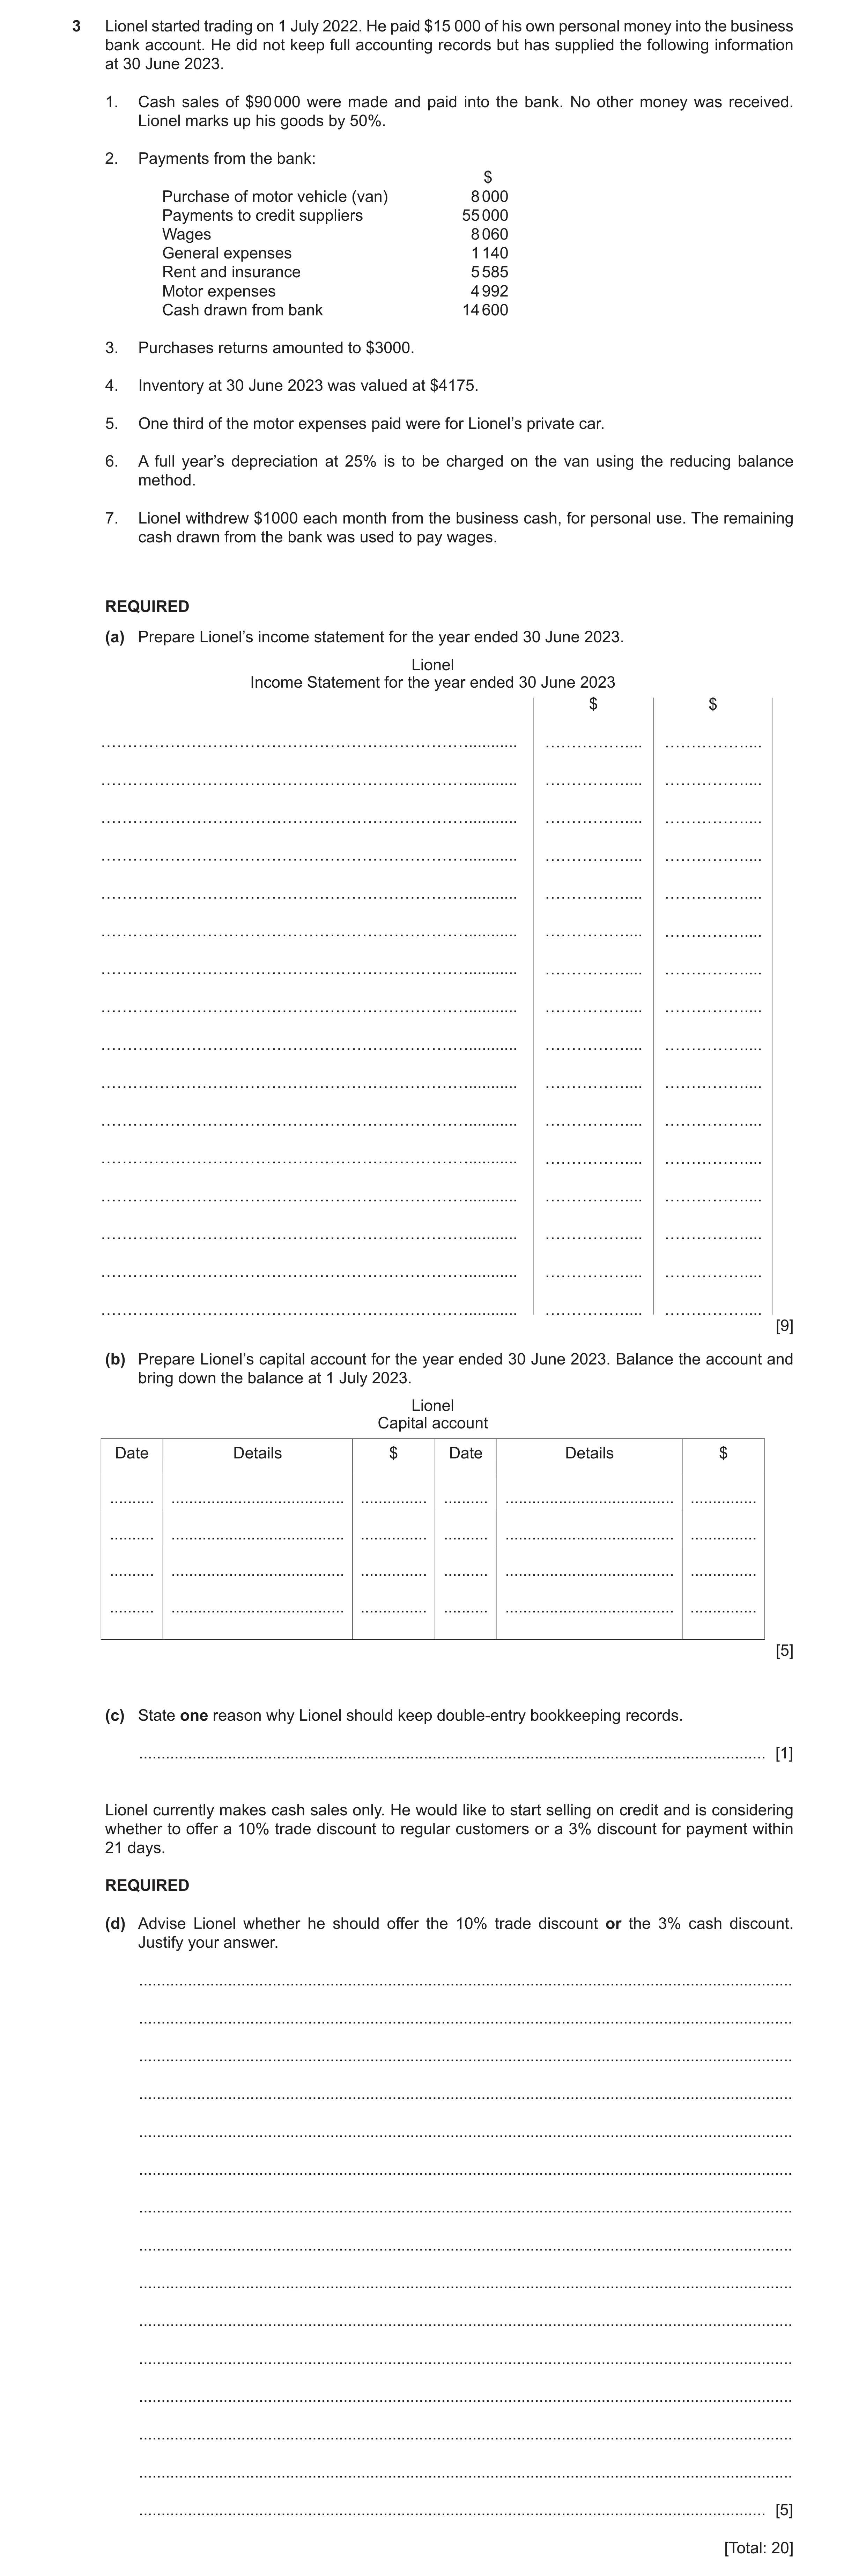
Q12 · Lionel started trading on 1 July 2022 0985/22 Oct/Nov 2023
3 Lionel started trading on 1 July 2022. He paid $15 000 of his own personal money into the business bank account. He did not keep full accounting records but has supplied the following information at 30 June 2023. 1. Cash sales of $90 000 were made and paid into the bank. No other money was received. Lionel marks up his goods by 50%. 2. Payments from the bank: $ Purchase of motor vehicle (van) 8 000 Payments to credit suppliers 55 000 Wages 8 060 General expenses 1 140 Rent and insurance 5 585 Motor expenses 4 992 Cash drawn from bank 14 600 3. Purchases returns amounted to $3000. 4. Inventory at 30 June 2023 was valued at $4175. 5. One third of the motor expenses paid were for Lionel’s private car. 6. A full year’s depreciation at 25% is to be charged on the van using the reducing balance method. 7. Lionel withdrew $1000 each month from the business cash, for personal use. The remaining cash drawn from the bank was used to pay wages. REQUIRED (a) Prepare Lionel’s income statement for the year ended 30 June 2023. Lionel Income Statement for the year ended 30 June 2023 $ $ …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … …………………………………………………………… … …………… … …………… … [9] (b) Prepare Lionel’s capital account for the year ended 30 June 2023. Balance the account and bring down the balance at 1 July 2023. Lionel Capital account Date Details $ Date Details $ … … … … … … … … … … … … … … … … … … … … … … … … [5] (c) State one reason why Lionel should keep double-entry bookkeeping records. … [1] Lionel currently makes cash sales only. He would like to start selling on credit and is considering whether to offer a 10% trade discount to regular customers or a 3% discount for payment within 21 days. REQUIRED (d) Advise Lionel whether he should offer the 10% trade discount or the 3% cash discount. Justify your answer. … … … … … … … … … … … … … … … [5] [Total: 20]
20 marks
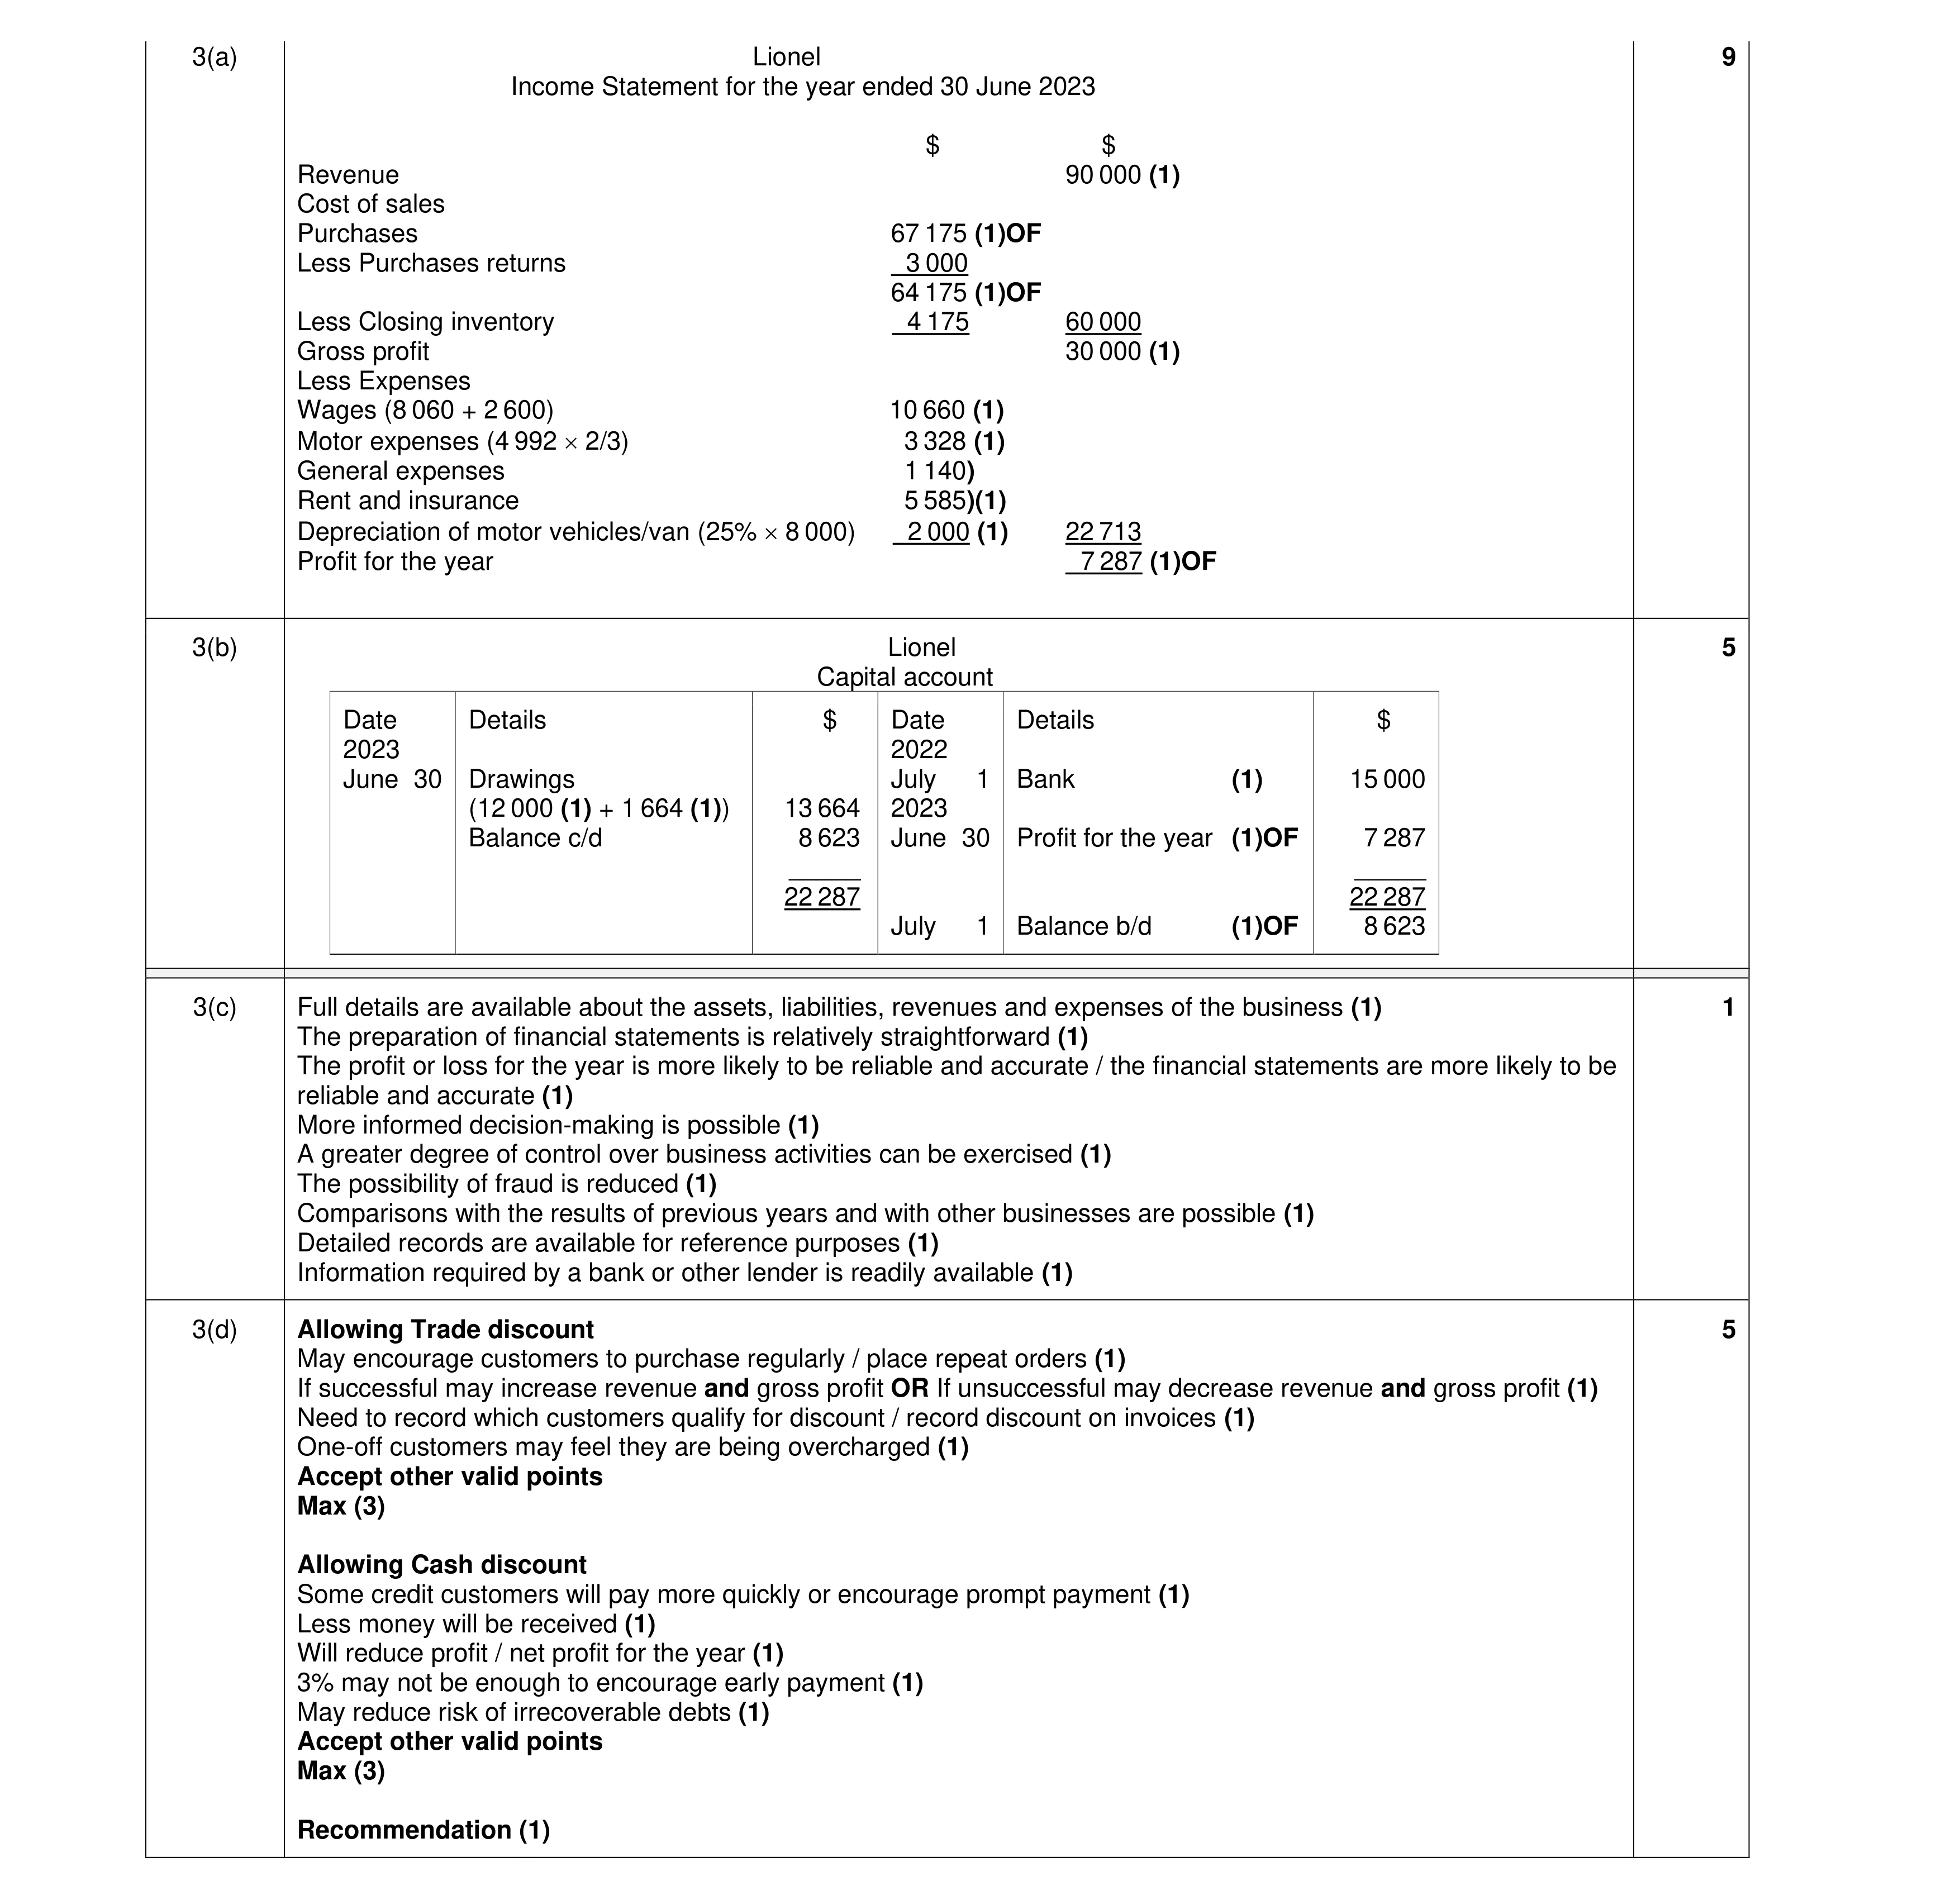
Mark scheme: 3(a) Lionel 9 Income Statement for the year ended 30 June 2023 $ $ Revenue 90 000 (1) Cost of sales Purchases 67 175 (1)OF Less Purchases returns 3 000 64 175 (1)OF Less Closing inventory 4 175 60 000 Gross profit 30 000 (1) Less Expenses Wages (8 060 + 2 600) 10 660 (1) Motor expenses (4 992 2/3) 3 328 (1) General expenses 1 140) Rent and insurance 5 585)(1) Depreciation of motor vehicles/van (25% 8 000) 2 000 (1) 22 713 Profit for the year 7 287 (1)OF 3(b) Lionel 5 Capital account Date Details $ Date Details $ 2023 2022 June 30 Drawings July 1 Bank (1) 15 000 (12 000 (1) + 1 664 (1)) 13 664 2023 Balance c/d 8 623 June 30 Profit for the year (1)OF 7 287 _____ _____ 22 287 22 287 July 1 Balance b/d (1)OF 8 623 3(c) Full details are available about the assets, liabilities, revenues and expenses of the business (1) 1 The preparation of financial statements is relatively straightforward (1) The profit or loss for the year is more likely to be reliable and accurate / the financial statements are more likely to be reliable and accurate (1) More informed decision-making is possible (1) A greater degree of control over business activities can be exercised (1) The possibility of fraud is reduced (1) Comparisons with the results of previous years and with other businesses are possible (1) Detailed records are available for reference purposes (1) Information required by a bank or other lender is readily available (1) 3(d) Allowing Trade discount 5 May encourage customers to purchase regularly / place repeat orders (1) If successful may increase revenue and gross profit OR If unsuccessful may decrease revenue and gross profit (1) Need to record which customers qualify for discount / record discount on invoices (1) One-off customers may feel they are being overcharged (1) Accept other valid points Max (3) Allowing Cash discount Some credit customers will pay more quickly or encourage prompt payment (1) Less money will be received (1) Will reduce profit / net profit for the year (1) 3% may not be enough to encourage early payment (1) May reduce risk of irrecoverable debts (1) Accept other valid points Max (3) Recommendation (1)
This question in 0985/22 Oct/Nov 2023
Q13 · Stella started in business as a retailer on 1 April 2023 0985/21 May/June 2024
5 Stella started in business as a retailer on 1 April 2023. She sells one type of good only. She has not kept a full set of accounting records but has provided the following information. 1 Half of Stella’s purchases were on cash terms and half on credit terms. During the year ended 31 March 2024, Stella paid $34 250 to credit suppliers. On 31 March 2024, she owed $2960 to credit suppliers. 2 Unlike her competitors, Stella made all of her sales for cash. Stella’s mark-up was 32%. 3 The following amounts were paid for expenses during the year to 31 March 2024. $ Rent and insurance 6750 Wages 8300 Other expenses 1815 4 At 31 March 2024, $300 was unpaid for wages and $500 was paid in advance for rent. 5 Insurance is $2400 per annum. On 1 April 2023, Stella paid $3000 for insurance for the following 15 months. 6 Other expenses included $120 paid for vases and flowers. One third of these were for Stella’s own home. Stella treats business costs of under $150 as revenue expenditure. 7 Inventory was valued at $6420 at 31 March 2024. REQUIRED (a) Calculate total purchases for the year ended 31 March 2024. … … … … [3] (b) Prepare Stella’s income statement for the year ended 31 March 2024. Stella Income Statement for the year ended 31 March 2024 $ $ … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [8] Stella’s sales revenue was the same each month for the year to 31 March 2024. She is now considering selling on credit terms as well as for cash. REQUIRED (c) Advise Stella whether or not to start selling on credit terms. Justify your answer by providing points for and against starting selling on credit. … … … … … … … … … … … [5] (d) State: (i) the accounting principle which Stella is following when she treats payments for small items which may last longer than one year, as revenue expenditure. … … [1] (ii) one advantage of following the principle in 5(d)(i). … … [1] (e) State two advantages of maintaining a full set of double entry accounting records. … … … … [2] [Total: 20]
20 marks
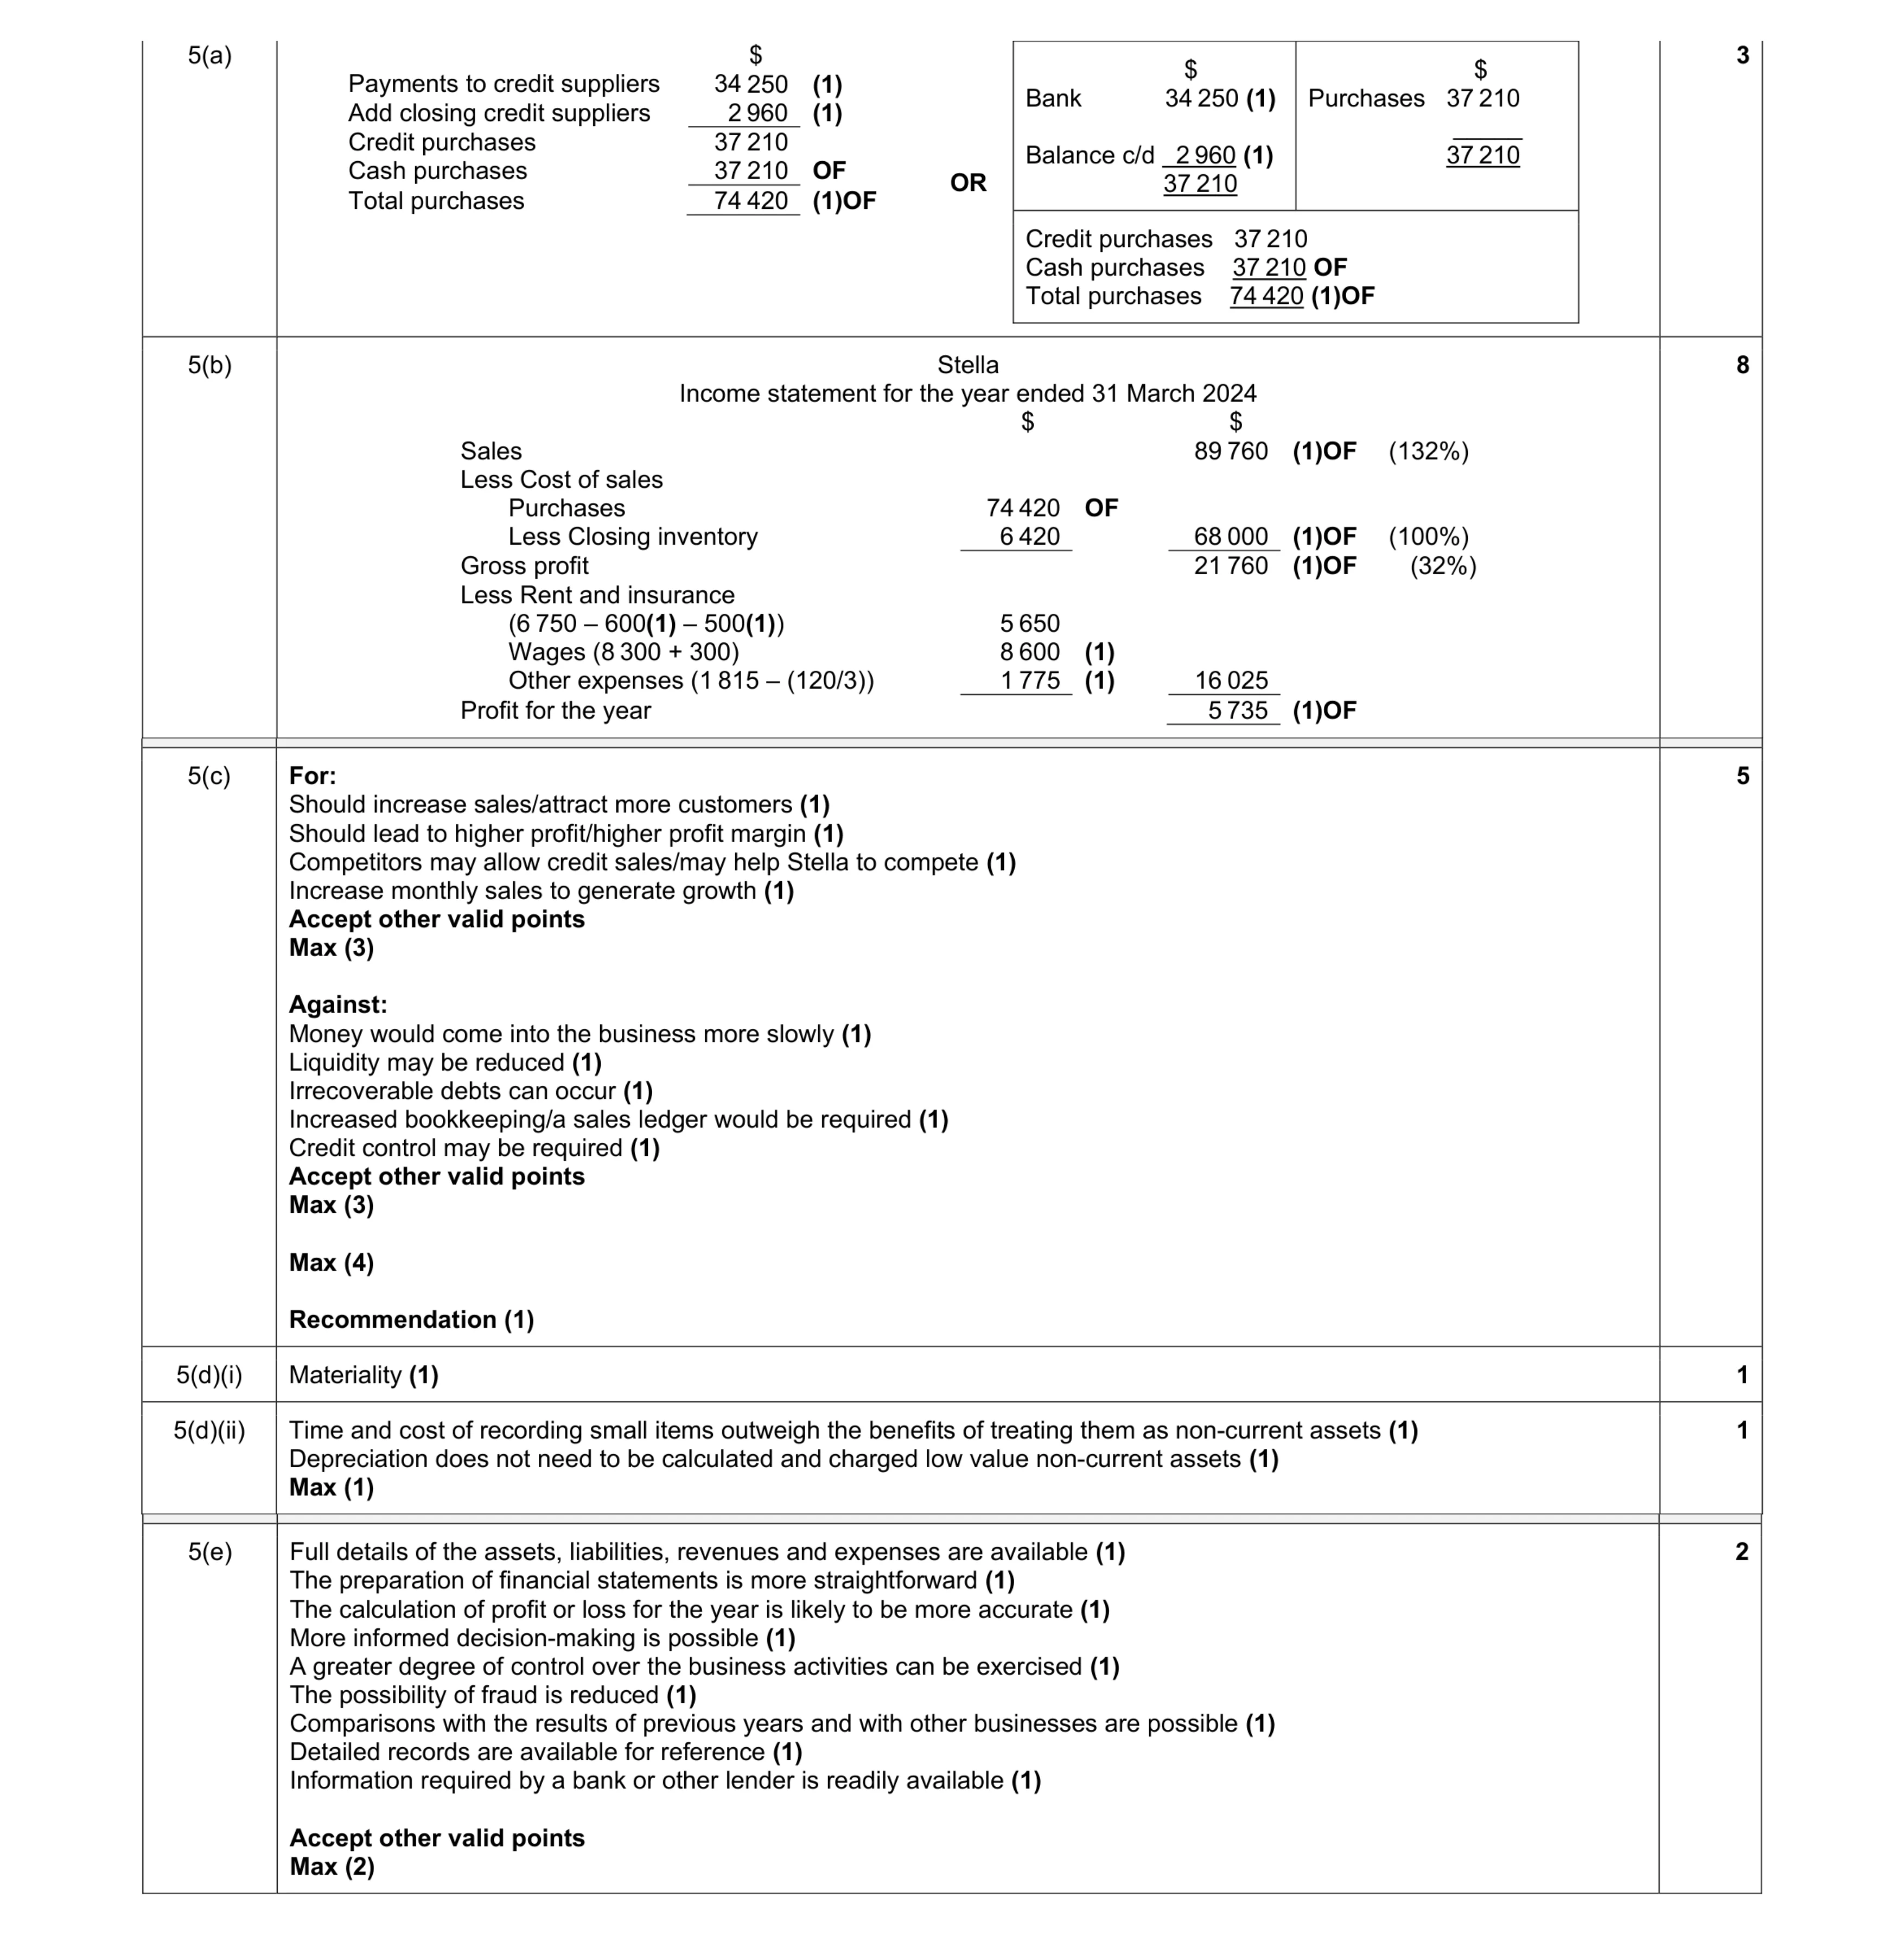
Mark scheme: 5(a) $ Payments to credit suppliers 34 250 (1) Add closing credit suppliers 2 960 (1) Credit purchases 37 210 Cash purchases 37 210 OF Total purchases 74 420 (1)OF OR $ Bank 34 250 (1) Balance c/d 2 960 (1) 37 210 $ Purchases 37 210 _____ 37 210 Credit purchases 37 210 Cash purchases 37 210 OF Total purchases 74 420 (1)OF 3 5(b) Stella Income statement for the year ended 31 March 2024 $ $ Sales 89 760 (1)OF (132%) Less Cost of sales Purchases 74 420 OF Less Closing inventory 6 420 68 000 (1)OF (100%) Gross profit 21 760 (1)OF (32%) Less Rent and insurance (6 750 – 600(1) – 500(1)) 5 650 Wages (8 300 + 300) 8 600 (1) Other expenses (1 815 – (120/3)) 1 775 (1) 16 025 Profit for the year 5 735 (1)OF 8 Question Answer Marks 5(c) For: Should increase sales/attract more customers (1) Should lead to higher profit/higher profit margin (1) Competitors may allow credit sales/may help Stella to compete (1) Increase monthly sales to generate growth (1) Accept other valid points Max (3) Against: Money would come into the business more slowly (1) Liquidity may be reduced (1) Irrecoverable debts can occur (1) Increased bookkeeping/a sales ledger would be required (1) Credit control may be required (1) Accept other valid points Max (3) Max (4) Recommendation (1) 5 5(d)(i) Materiality (1) 1 5(d)(ii) Time and cost of recording small items outweigh the benefits of treating them as non-current assets (1) Depreciation does not need to be calculated and charged low value non-current assets (1) Max (1) 1 Question Answer Marks 5(e) Full details of the assets, liabilities, revenues and expenses are available (1) The preparation of financial statements is more straightforward (1) The calculation of profit or loss for the year is likely to be more accurate (1) More informed decision-making is possible (1) A greater degree of control over the business activities can be exercised (1) The possibility of fraud is reduced (1) Comparisons with the results of previous years and with other businesses are possible (1) Detailed records are available for reference (1) Information required by a bank or other lender is readily available (1) Accept other valid points Max (2) 2
This question in 0985/21 May/June 2024
Q14 · Toyah owns a factory which makes dolls’ houses 0985/22 May/June 2024
2 Toyah owns a factory which makes dolls’ houses. Her financial year end is 31 January. At 31 January 2024, her ledger accounts included the following balances. $ Inventory at 1 February 2023 Raw materials 12 400 Work in progress 16 970 Finished goods 14 825 Revenue 390 100 Purchases of raw materials 143 000 Wages Factory operatives 51 000 Factory supervisor 19 000 Sales staff 30 000 Factory electricity 16 000 Rates and insurance 16 200 General factory expenses 6 155 Factory machinery – at cost 120 000 Factory machinery – provision for depreciation 52 500 Additional information 1. Inventory at 31 January 2024 Raw material 11 205 Work in progress 17 682 Finished goods 13 480 2. Rates and insurance are to be apportioned 2/3 to the factory and 1/3 to the office. 3. At 31 January 2024, general factory expenses of $235 were unpaid. 4. Factory machinery is depreciated at 25% per annum using the reducing balance method. REQUIRED (a) Prepare Toyah’s manufacturing account for the yea Toyah Manufacturing Account for the year end (b) Prepare Toyah’s income statement (trading section) for the year ended 31 January 2024. Toyah Income statement (trading section) for the year ended 31 January 2024 $ $ ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. ……………. [5] The factory produced 6936 dolls’ houses during the year ended 31 January 2024. REQUIRED (c) Calculate the manufacturing cost of each dolls’ house. Round up your answer to the nearest dollar. … … [1] Idir, a competitor of Toyah’s, has decided to cease trading. He has offered to sell his inventory of finished goods to Toyah at a discounted price in return for immediate payment in cash. The total price for these items is $9600. Toyah has $1415 cash at bank. REQUIRED (d) Advise Toyah whether or not she should buy Idir’s inventory. Justify your answer by providing two points for and two points against buying this inventory. … … … … . … … … … … … … … [5] [Total: 20]
20 marks
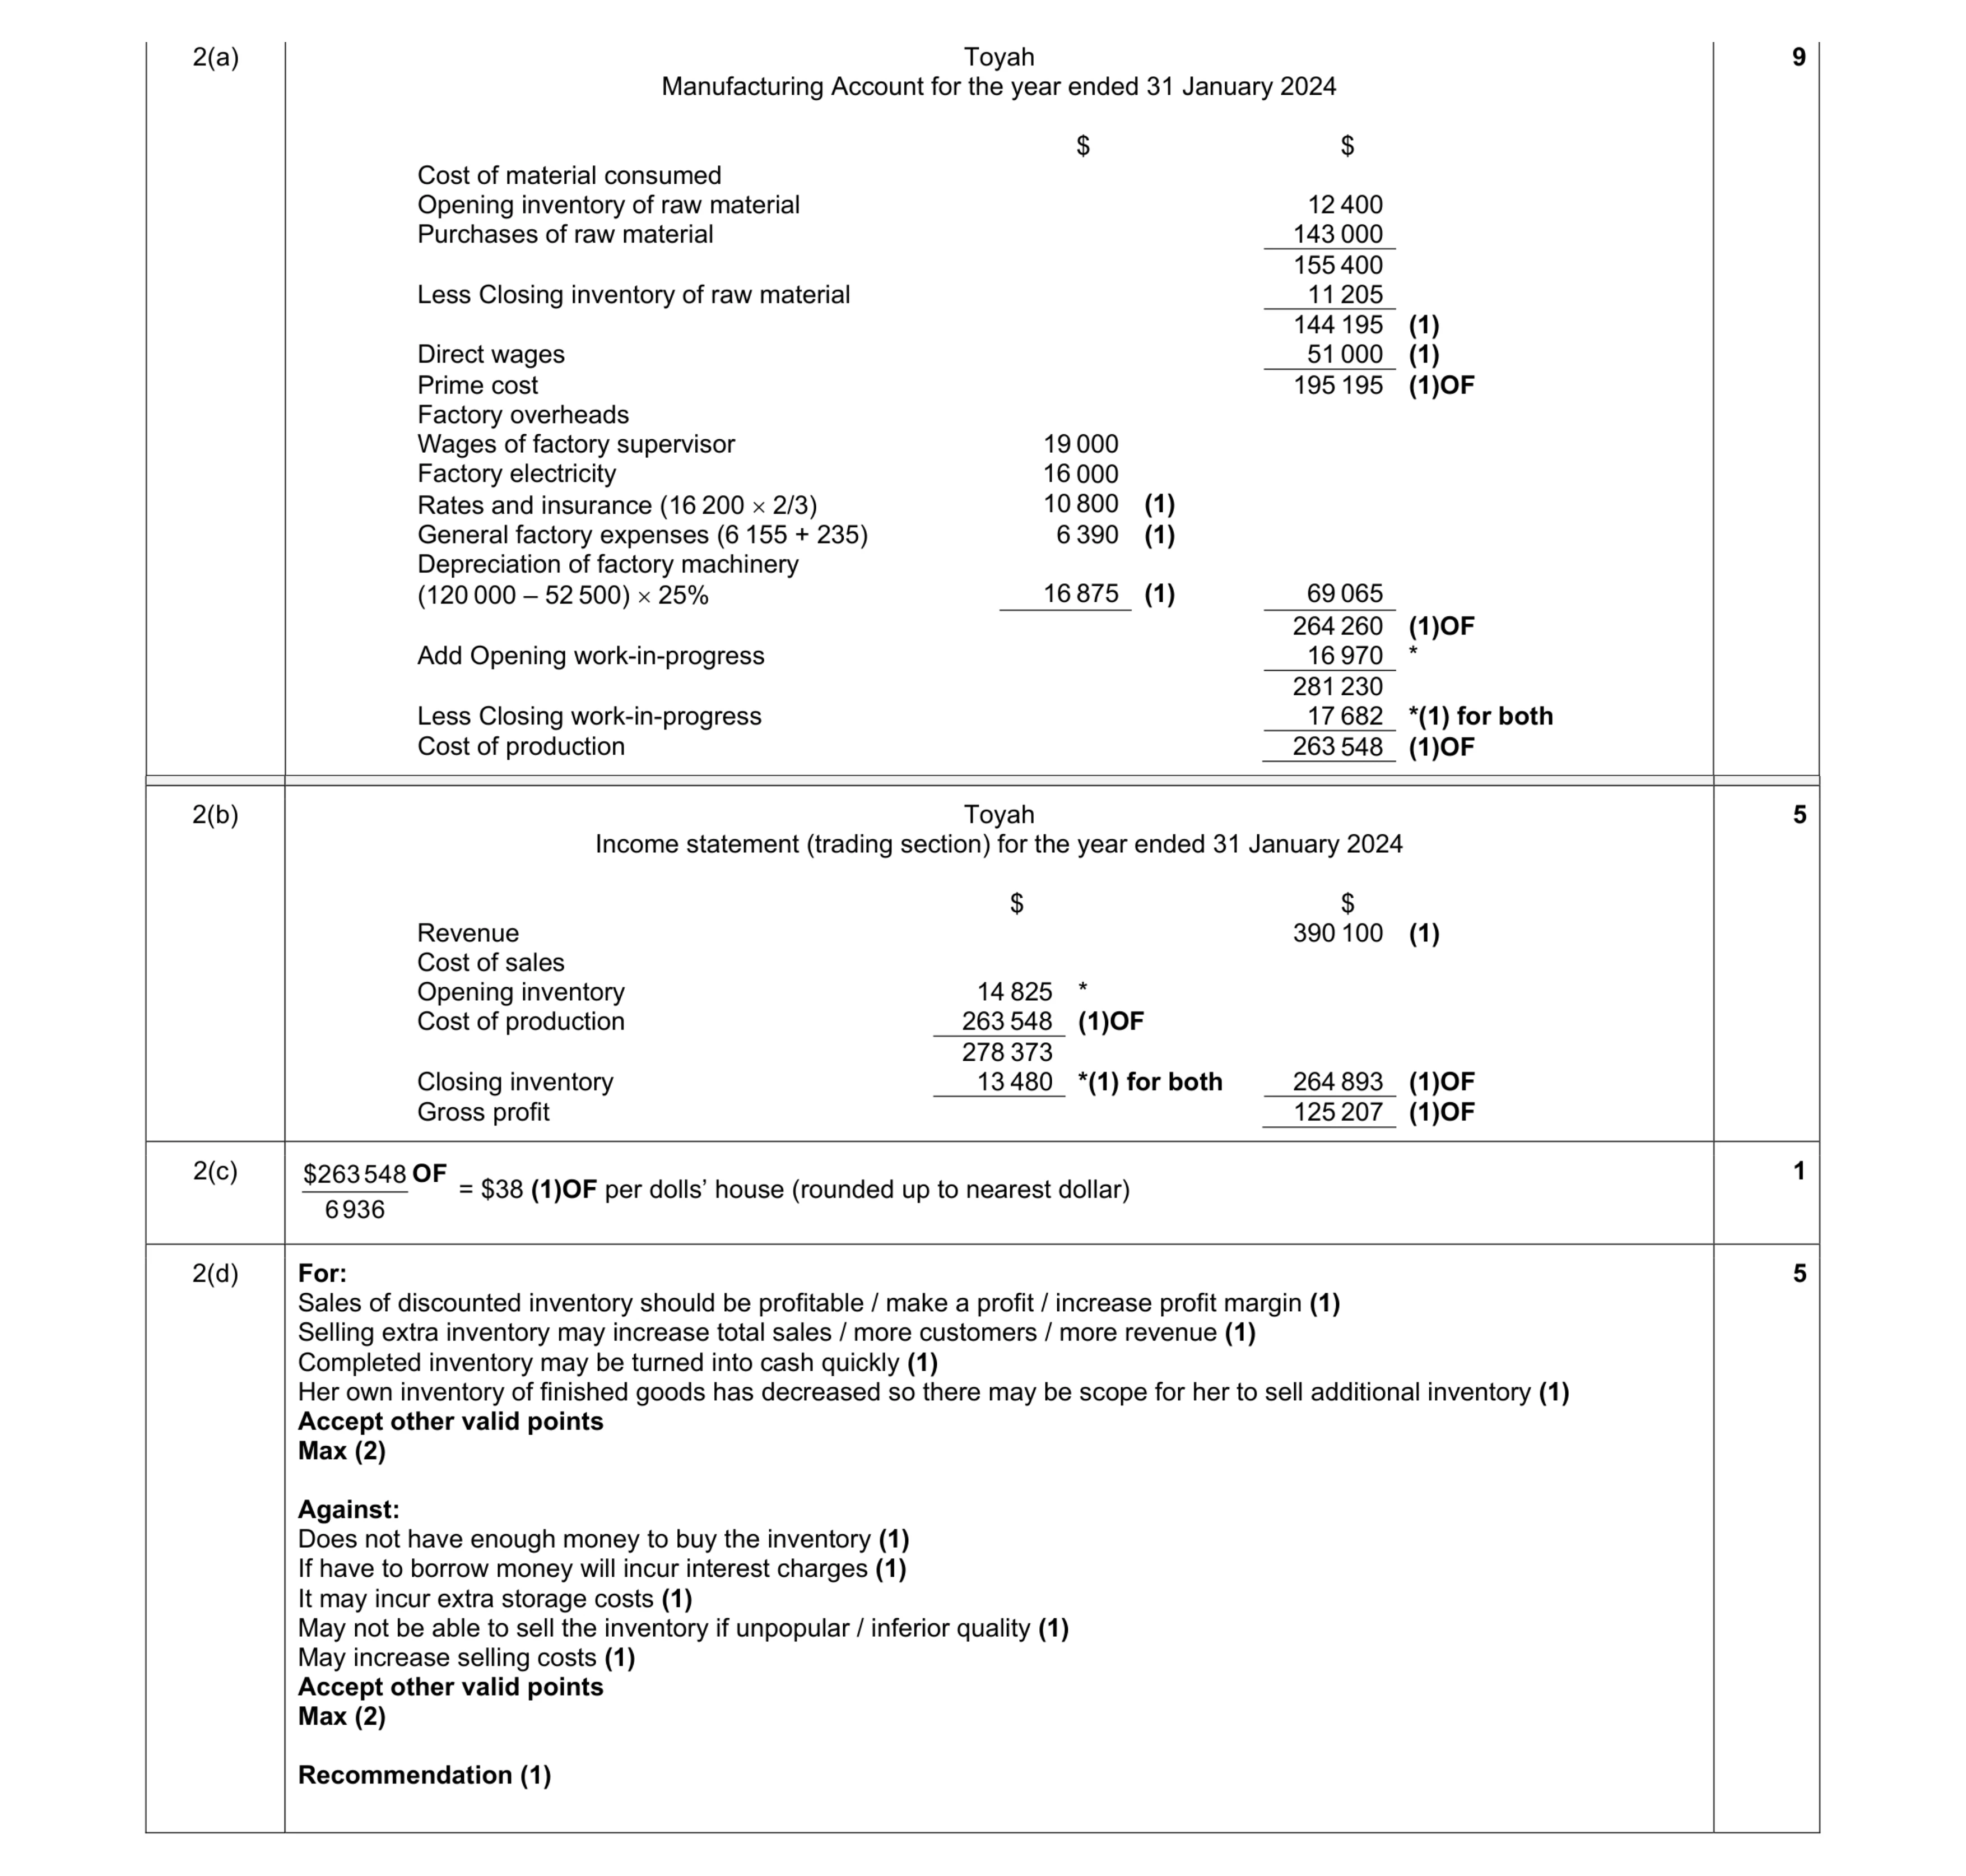
Mark scheme: 2(a) Toyah Manufacturing Account for the year ended 31 January 2024 $ $ Cost of material consumed Opening inventory of raw material 12 400 Purchases of raw material 143 000 155 400 Less Closing inventory of raw material 11 205 144 195 (1) Direct wages 51 000 (1) Prime cost 195 195 (1)OF Factory overheads Wages of factory supervisor 19 000 Factory electricity 16 000 Rates and insurance (16 200 2/3) 10 800 (1) General factory expenses (6 155 + 235) 6 390 (1) Depreciation of factory machinery (120 000 – 52 500) 25% 16 875 (1) 69 065 264 260 (1)OF Add Opening work-in-progress 16 970 * 281 230 Less Closing work-in-progress 17 682 *(1) for both Cost of production 263 548 (1)OF 9 Question Answer Marks 2(b) Toyah Income statement (trading section) for the year ended 31 January 2024 $ $ Revenue 390 100 (1) Cost of sales Opening inventory 14 825 * Cost of production 263 548 (1)OF 278 373 Closing inventory 13 480 *(1) for both 264 893 (1)OF Gross profit 125 207 (1)OF 5 2(c) $263548 6936 OF = $38 (1)OF per dolls’ house (rounded up to nearest dollar) 1 2(d) For: Sales of discounted inventory should be profitable / make a profit / increase profit margin (1) Selling extra inventory may increase total sales / more customers / more revenue (1) Completed inventory may be turned into cash quickly (1) Her own inventory of finished goods has decreased so there may be scope for her to sell additional inventory (1) Accept other valid points Max (2) Against: Does not have enough money to buy the inventory (1) If have to borrow money will incur interest charges (1) It may incur extra storage costs (1) May not be able to sell the inventory if unpopular / inferior quality (1) May increase selling costs (1) Accept other valid points Max (2) Recommendation (1) 5
This question in 0985/22 May/June 2024
Q15 · Kalima is a trader 0985/22 Oct/Nov 2024
1 Kalima is a trader. At the start of September 2024, Kalima had a cash balance of $240, a bank balance of $890 credit and a credit customer, Elizah, owed Kalima $520. The following transactions took place during the month: September 2 Paid stationery in cash, $82 3 Cash sales, $478 A cheque for $30 received at the end of August from Badr, a credit customer, was dishonoured 5 Paid wages by credit transfer, $1390 7 Bought goods from Gulnar on credit, $200 10 Kalima withdrew $150 from the business bank account for personal use 14 Received a cheque from Elizah in full settlement of the amount owed less 2.5% cash discount 16 Paid $120 cash into the business bank account 21 Paid Gulnar the full amount due by credit transfer less a cash discount of 2% 23 Sold goods to Elizah on credit, $1450 29 A credit note totalling $325 was issued to Elizah for goods returned REQUIRED: (a) Prepare Kalima’s cash book on the page opposite, for September 2024. Balance the account and bring down the balances on 1 October 2024. … … … … … … … … … (b) What does the credit balance in the bank on 1 September 2024 represent? … … [1] (c) Prepare the account of Elizah as it would appear in Kalima’s books. Balance the account and bring down any balances on 1 October 2024. Kalima Elizah Account Date Details Amount Date Details Amount 2024 $ 2024 $ … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [5] (d) Name the section heading in Kalima’s statement of financial position where the balance on Elizah’s account would appear. … … [1] [Total: 20]
20 marks
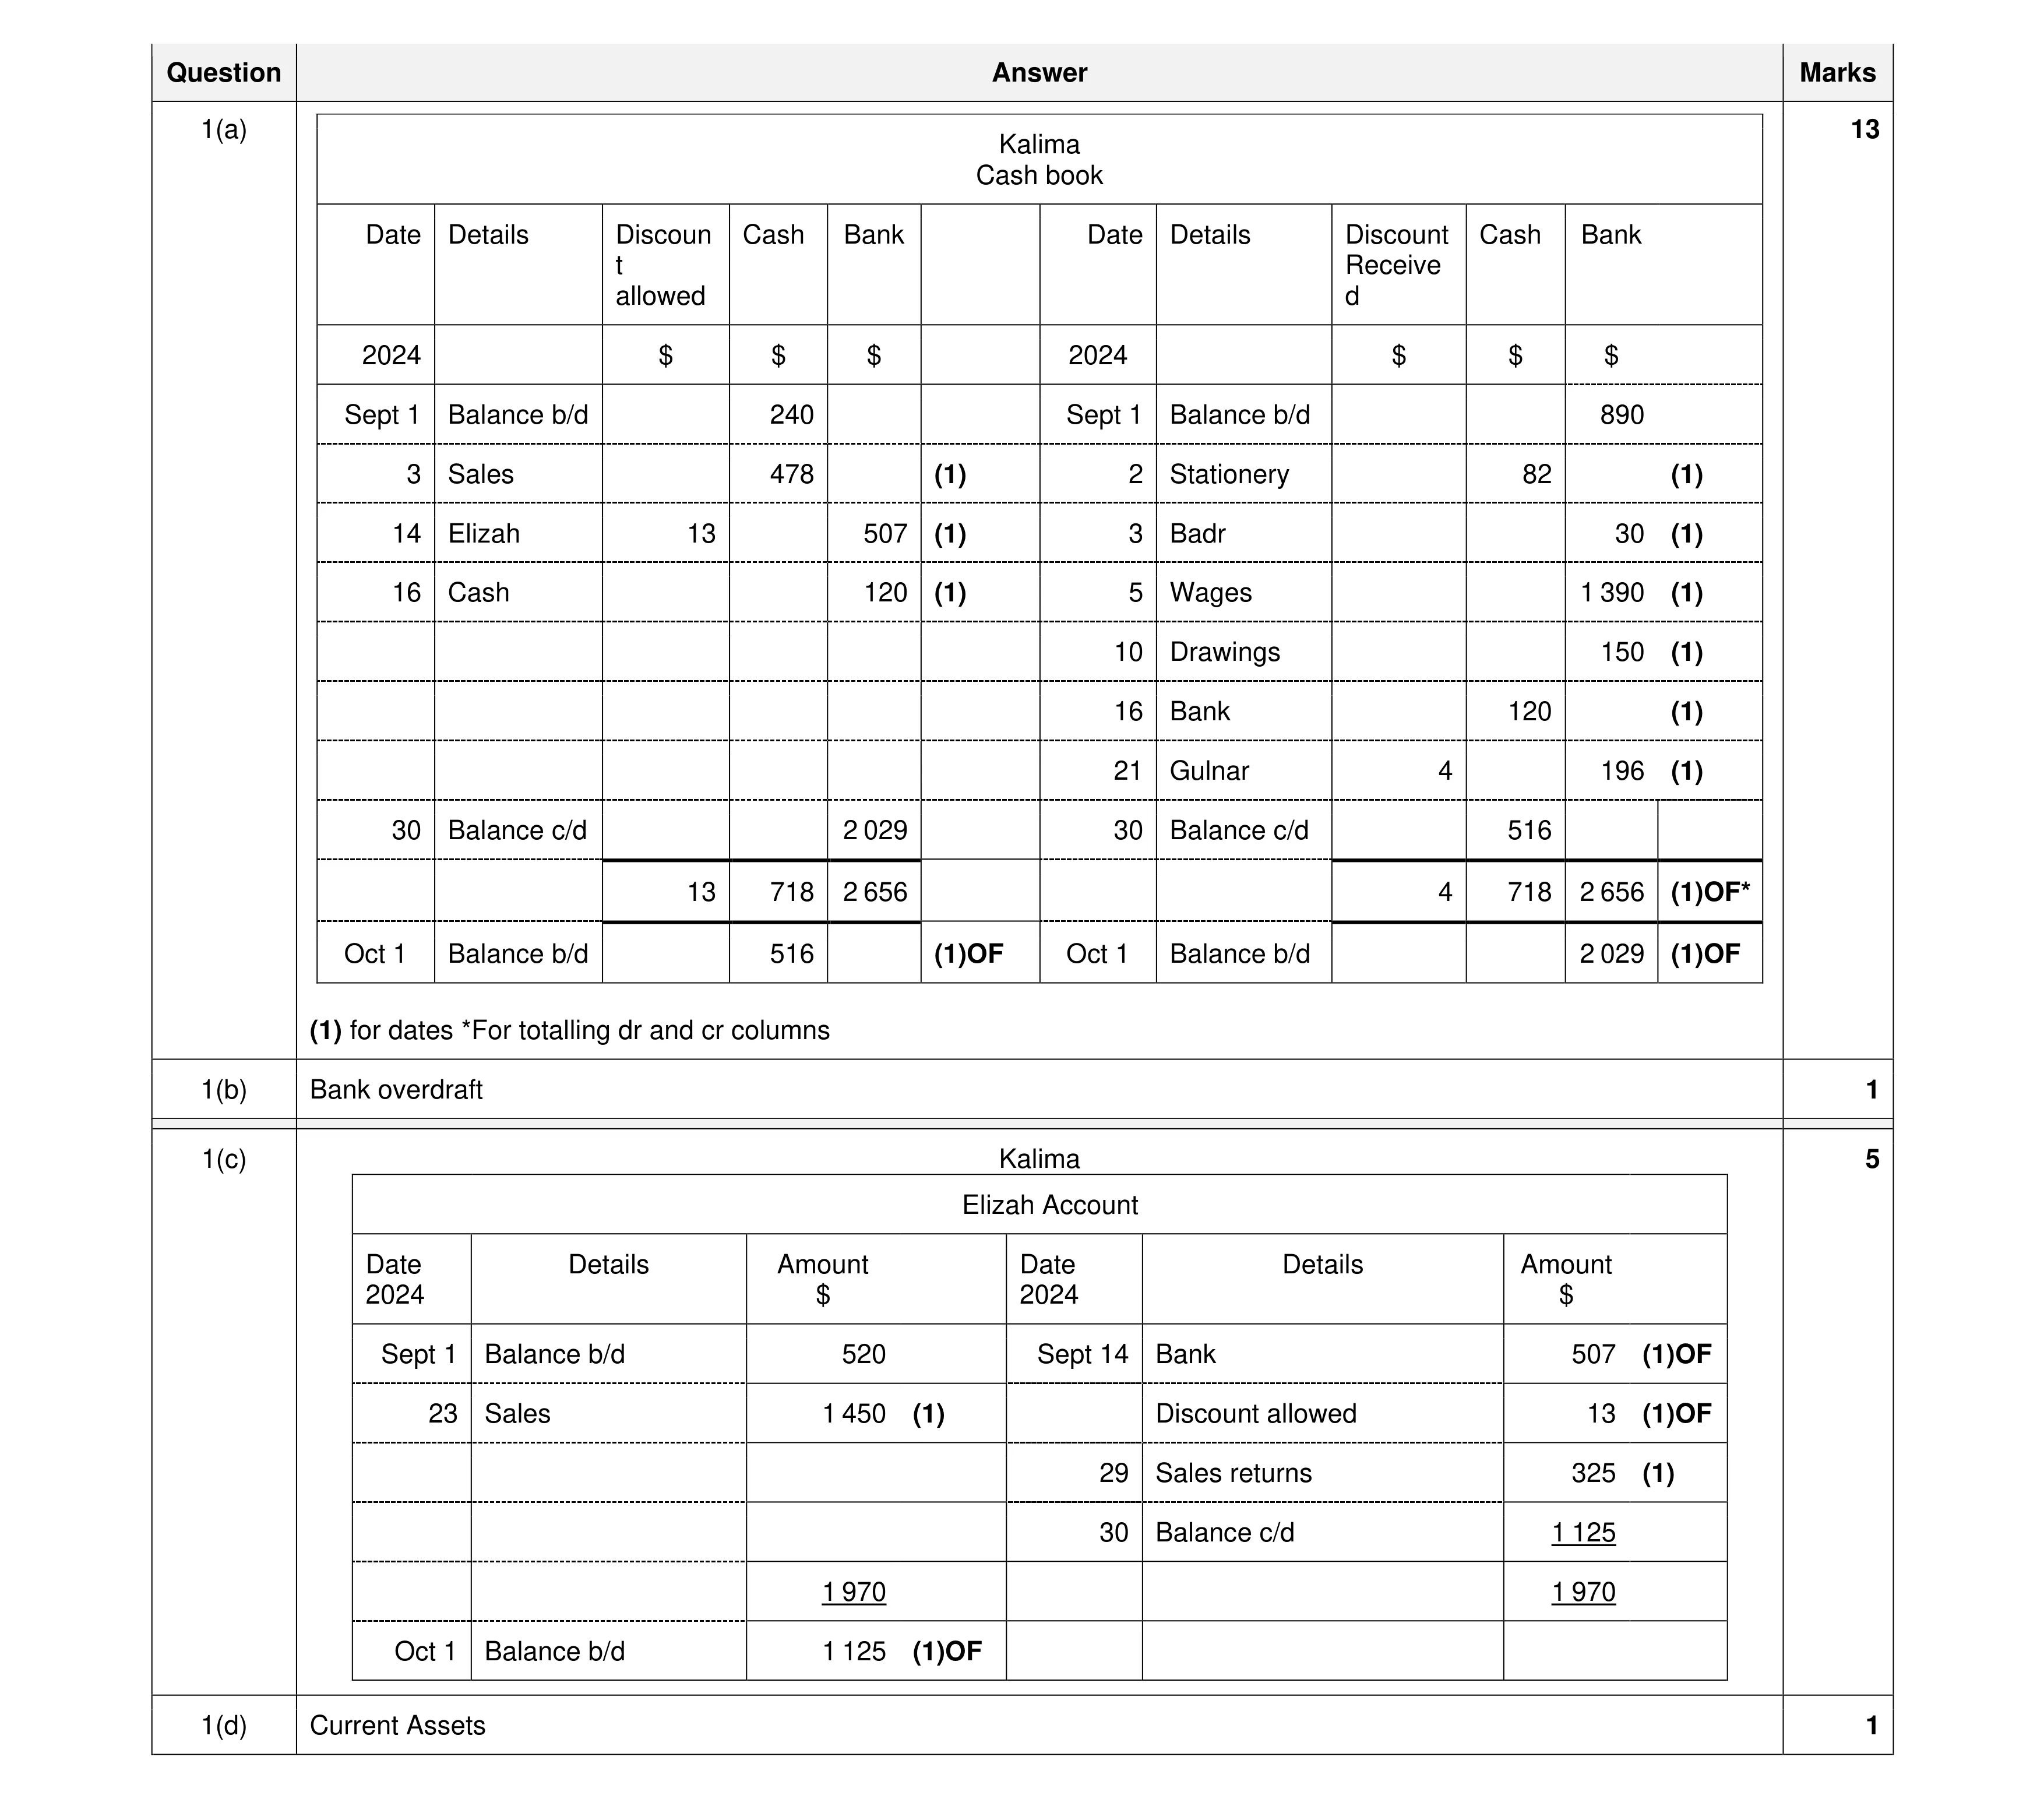
Mark scheme: Question Answer Marks 1(a) 13 Kalima Cash book Date Details Discoun Cash Bank Date Details Discount Cash Bank t Receive allowed d 2024 $ $ $ 2024 $ $ $ Sept 1 Balance b/d 240 Sept 1 Balance b/d 890 3 Sales 478 (1) 2 Stationery 82 (1) 14 Elizah 13 507 (1) 3 Badr 30 (1) 16 Cash 120 (1) 5 Wages 1 390 (1) 10 Drawings 150 (1) 16 Bank 120 (1) 21 Gulnar 4 196 (1) 30 Balance c/d 2 029 30 Balance c/d 516 13 718 2 656 4 718 2 656 (1)OF* Oct 1 Balance b/d 516 (1)OF Oct 1 Balance b/d 2 029 (1)OF (1) for dates *For totalling dr and cr columns 1(b) Bank overdraft 1 1(c) Kalima 5 Elizah Account Date Details Amount Date Details Amount 2024 $ 2024 $ Sept 1 Balance b/d 520 Sept 14 Bank 507 (1)OF 23 Sales 1 450 (1) Discount allowed 13 (1)OF 29 Sales returns 325 (1) 30 Balance c/d 1 125 1 970 1 970 Oct 1 Balance b/d 1 125 (1)OF 1(d) Current Assets 1
This question in 0985/22 Oct/Nov 2024
Q16 · Jasmine owns a consulting business 0985/22 May/June 2025
3 Jasmine owns a consulting business. At 1 April 2024, Jasmine’s ledger accounts included the following balances. $ Motor vehicles 16 000 Provision for depreciation of motor vehicles 7 000 Trade receivables 12 220 Provision for doubtful debts 366 Rent (prepaid) 900 Rates (unpaid) 270 During the year ended 31 March 2025, Jasmine’s bank payments included the following amounts. $ Motor vehicles 18 000 Rent and rates 14 960 Additional Information 1 Depreciation is to be provided at 25% per annum using the reducing balance method. A full year’s depreciation is to be charged on vehicles purchased during the year. 2 Trade receivables at 31 March 2025 were $11 800. An amount of $300 is still to be written off as irrecoverable. 3 The provision for doubtful debts is to be maintained at 3% of net trade receivables. 4 At 31 March 2025, prepaid rent was $925 and unpaid rates were $185. REQUIRED (a) Prepare the provision for depreciation of motor vehicles account for the year ended 31 March 2025. Balance the account and bring down the balance at 1 April 2025. Jasmine Provision for depreciation of motor vehicles account Date Details $ Date Details $ … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [4] (b) Prepare the provision for doubtful debts account for the year ended 31 March 2025. Balance the account and bring down the balance at 1 April 2025. Jasmine Provision for doubtful debts account Date Details $ Date Details $ … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [4] (c) Prepare the rent and rates account for the year ended 31 March 2025. Balance the account and bring down the balances at 1 April 2025. Jasmine Rent and rates account Date Details $ Date Details $ … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [6] At 31 March 2025, Jasmine had a bank overdraft of $2620. REQUIRED (d) Prepare the current assets section of Jasmine’s statement of financial position at 31 March 2025. … … … … … … … … … [3] (e) State: (i) how the principle of consistency is applied when charging depreciation. … … [1] (ii) one way Jasmine may reduce the possibility of irrecoverable debts. … … [1] (iii) which accounting principle Jasmine is applying by making an adjustment for rent prepaid. … … [1] [Total: 20]
20 marks
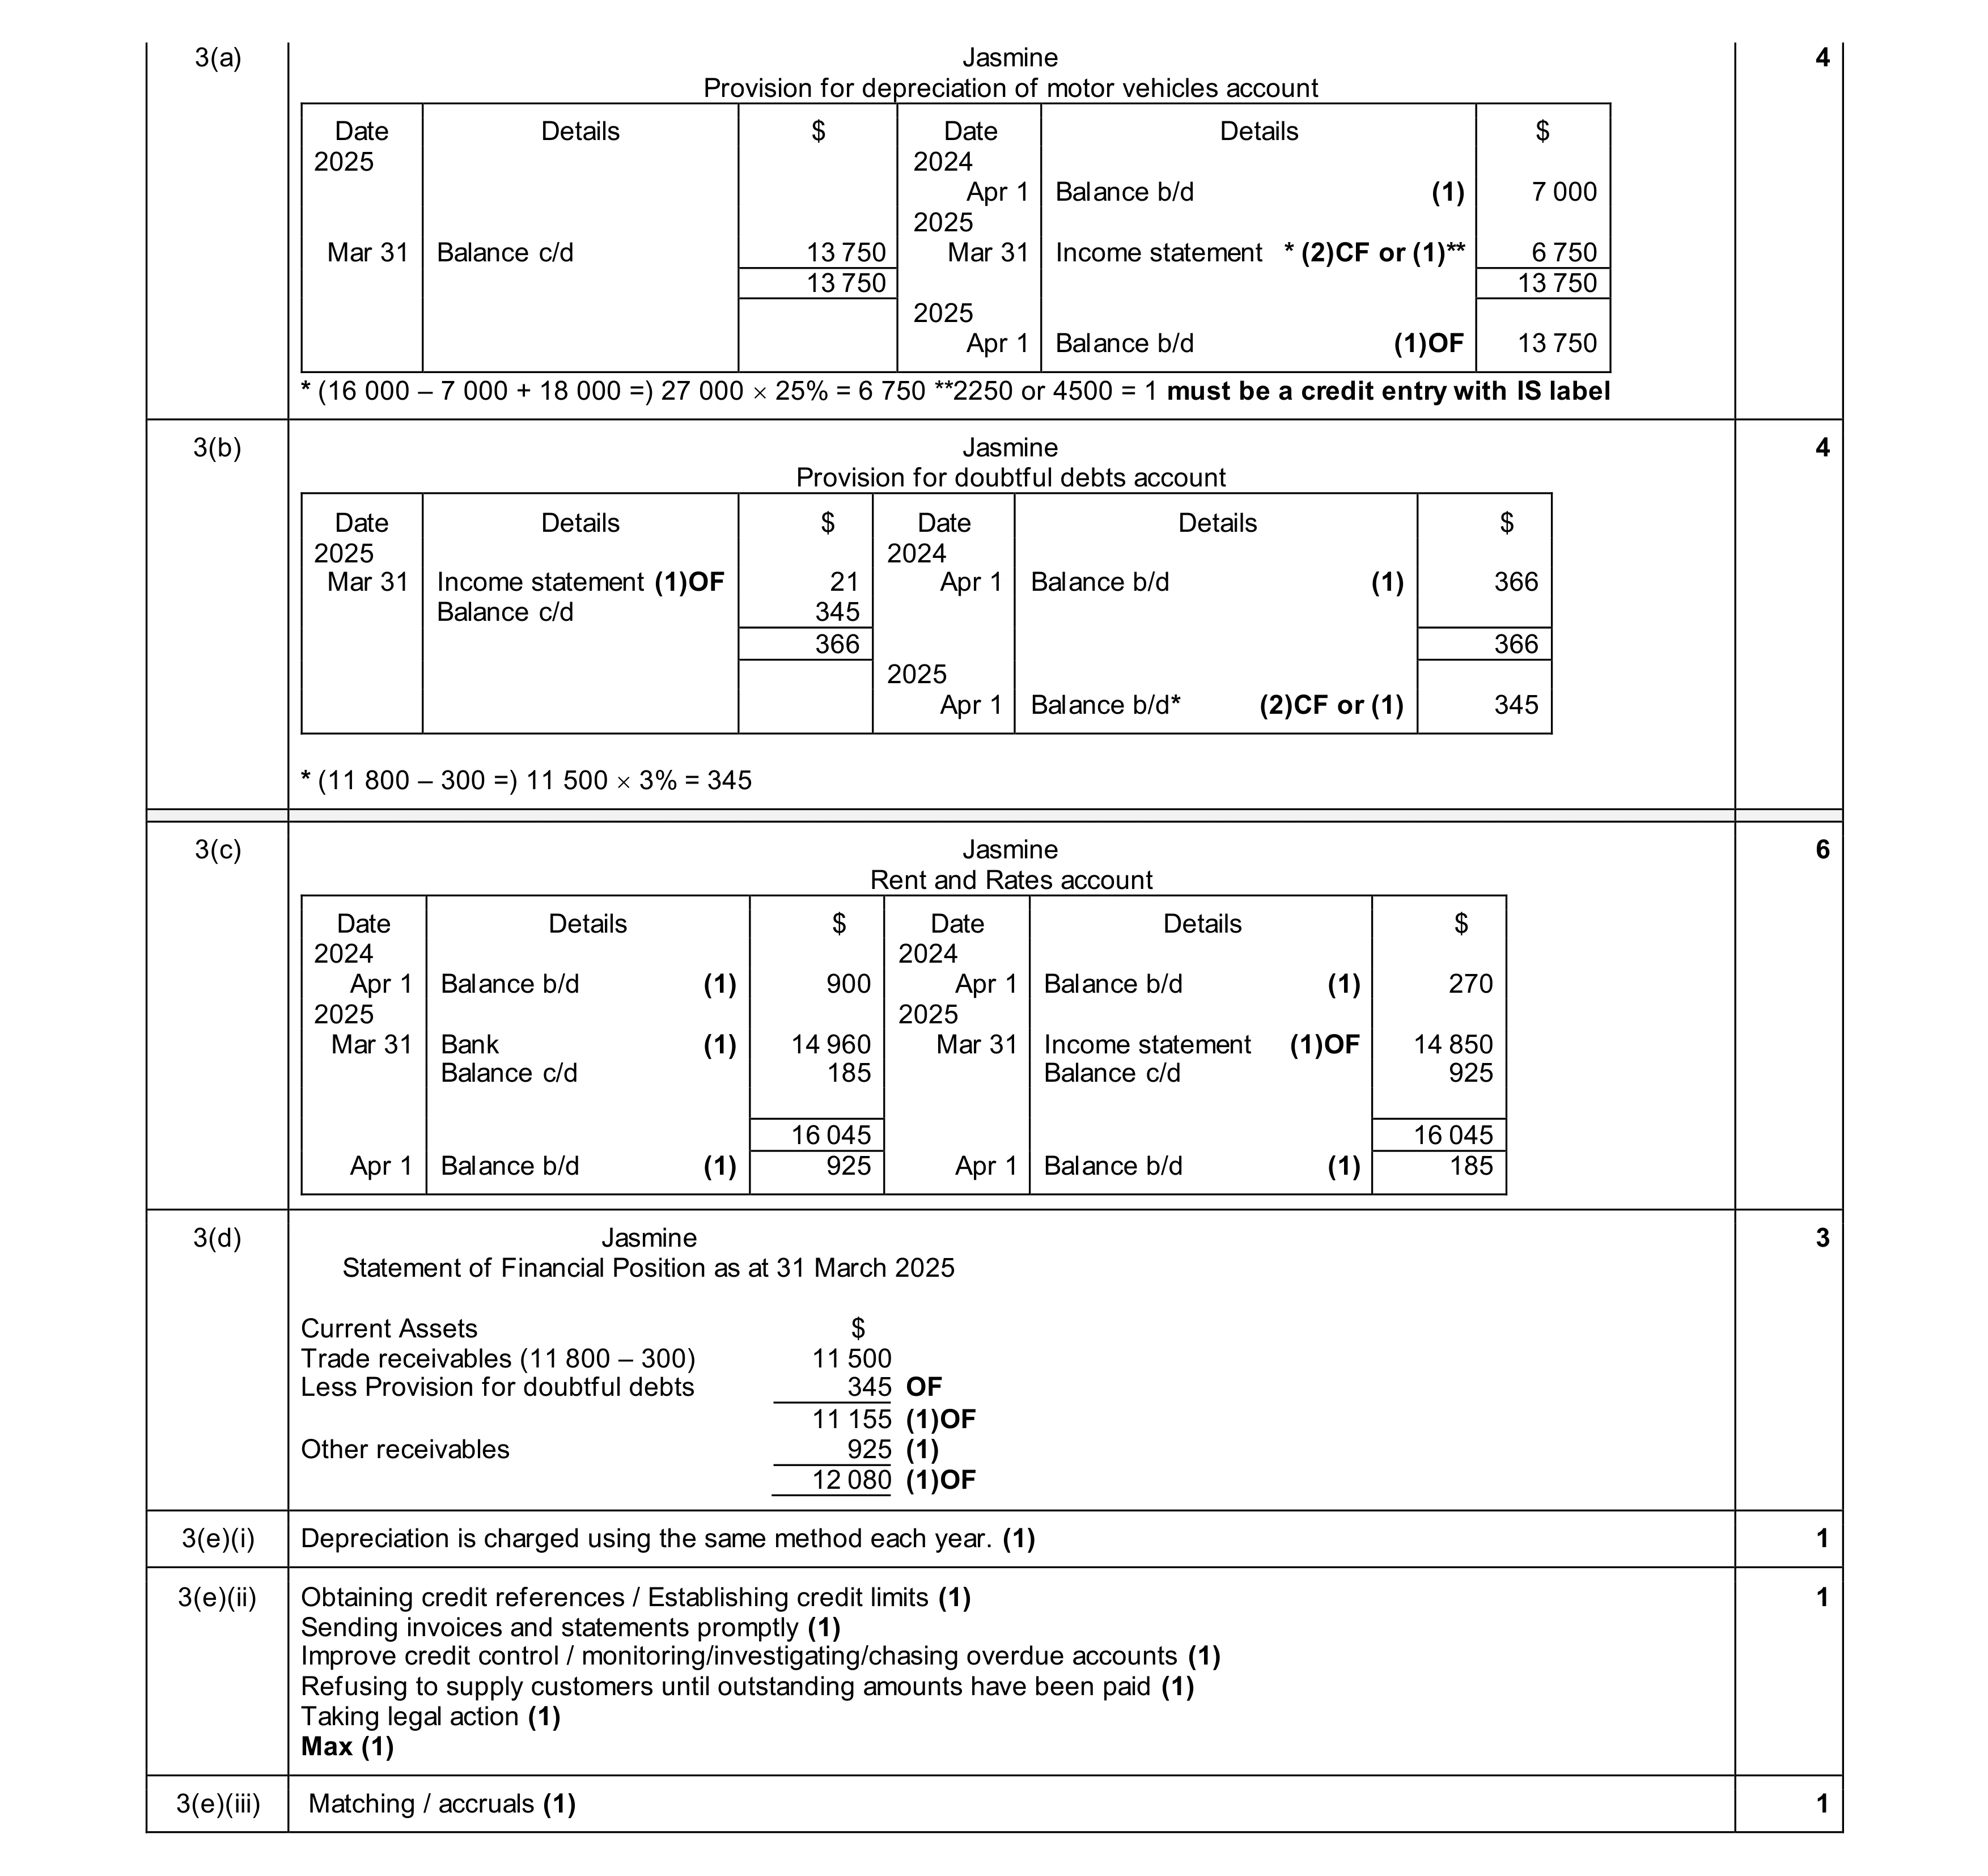
Mark scheme: 3(a) Jasmine 4 Provision for depreciation of motor vehicles account Date Details $ Date Details $ 2025 2024 Apr 1 Balance b/d (1) 7 000 2025 Mar 31 Balance c/d 13 750 Mar 31 Income statement * (2)CF or (1)** 6 750 13 750 13 750 2025 Apr 1 Balance b/d (1)OF 13 750 * (16 000 – 7 000 + 18 000 =) 27 000 25% = 6 750 **2250 or 4500 = 1 must be a credit entry with IS label 3(b) Jasmine 4 Provision for doubtful debts account Date Details $ Date Details $ 2025 2024 Mar 31 Income statement (1)OF 21 Apr 1 Balance b/d (1) 366 Balance c/d 345 366 366 2025 Apr 1 Balance b/d* (2)CF or (1) 345 * (11 800 – 300 =) 11 500 3% = 345 3(c) Jasmine 6 Rent and Rates account Date Details $ Date Details $ 2024 2024 Apr 1 Balance b/d (1) 900 Apr 1 Balance b/d (1) 270 2025 2025 Mar 31 Bank (1) 14 960 Mar 31 Income statement (1)OF 14 850 Balance c/d 185 Balance c/d 925 16 045 16 045 Apr 1 Balance b/d (1) 925 Apr 1 Balance b/d (1) 185 3(d) Jasmine 3 Statement of Financial Position as at 31 March 2025 Current Assets $ Trade receivables (11 800 – 300) 11 500 Less Provision for doubtful debts 345 OF 11 155 (1)OF Other receivables 925 (1) 12 080 (1)OF 3(e)(i) Depreciation is charged using the same method each year. (1) 1 3(e)(ii) Obtaining credit references / Establishing credit limits (1) 1 Sending invoices and statements promptly (1) Improve credit control / monitoring/investigating/chasing overdue accounts (1) Refusing to supply customers until outstanding amounts have been paid (1) Taking legal action (1) Max (1) 3(e)(iii) Matching / accruals (1) 1
This question in 0985/22 May/June 2025
Q17 · Bilal prepared a trial balance at 31 December 2024 0985/22 May/June 2025
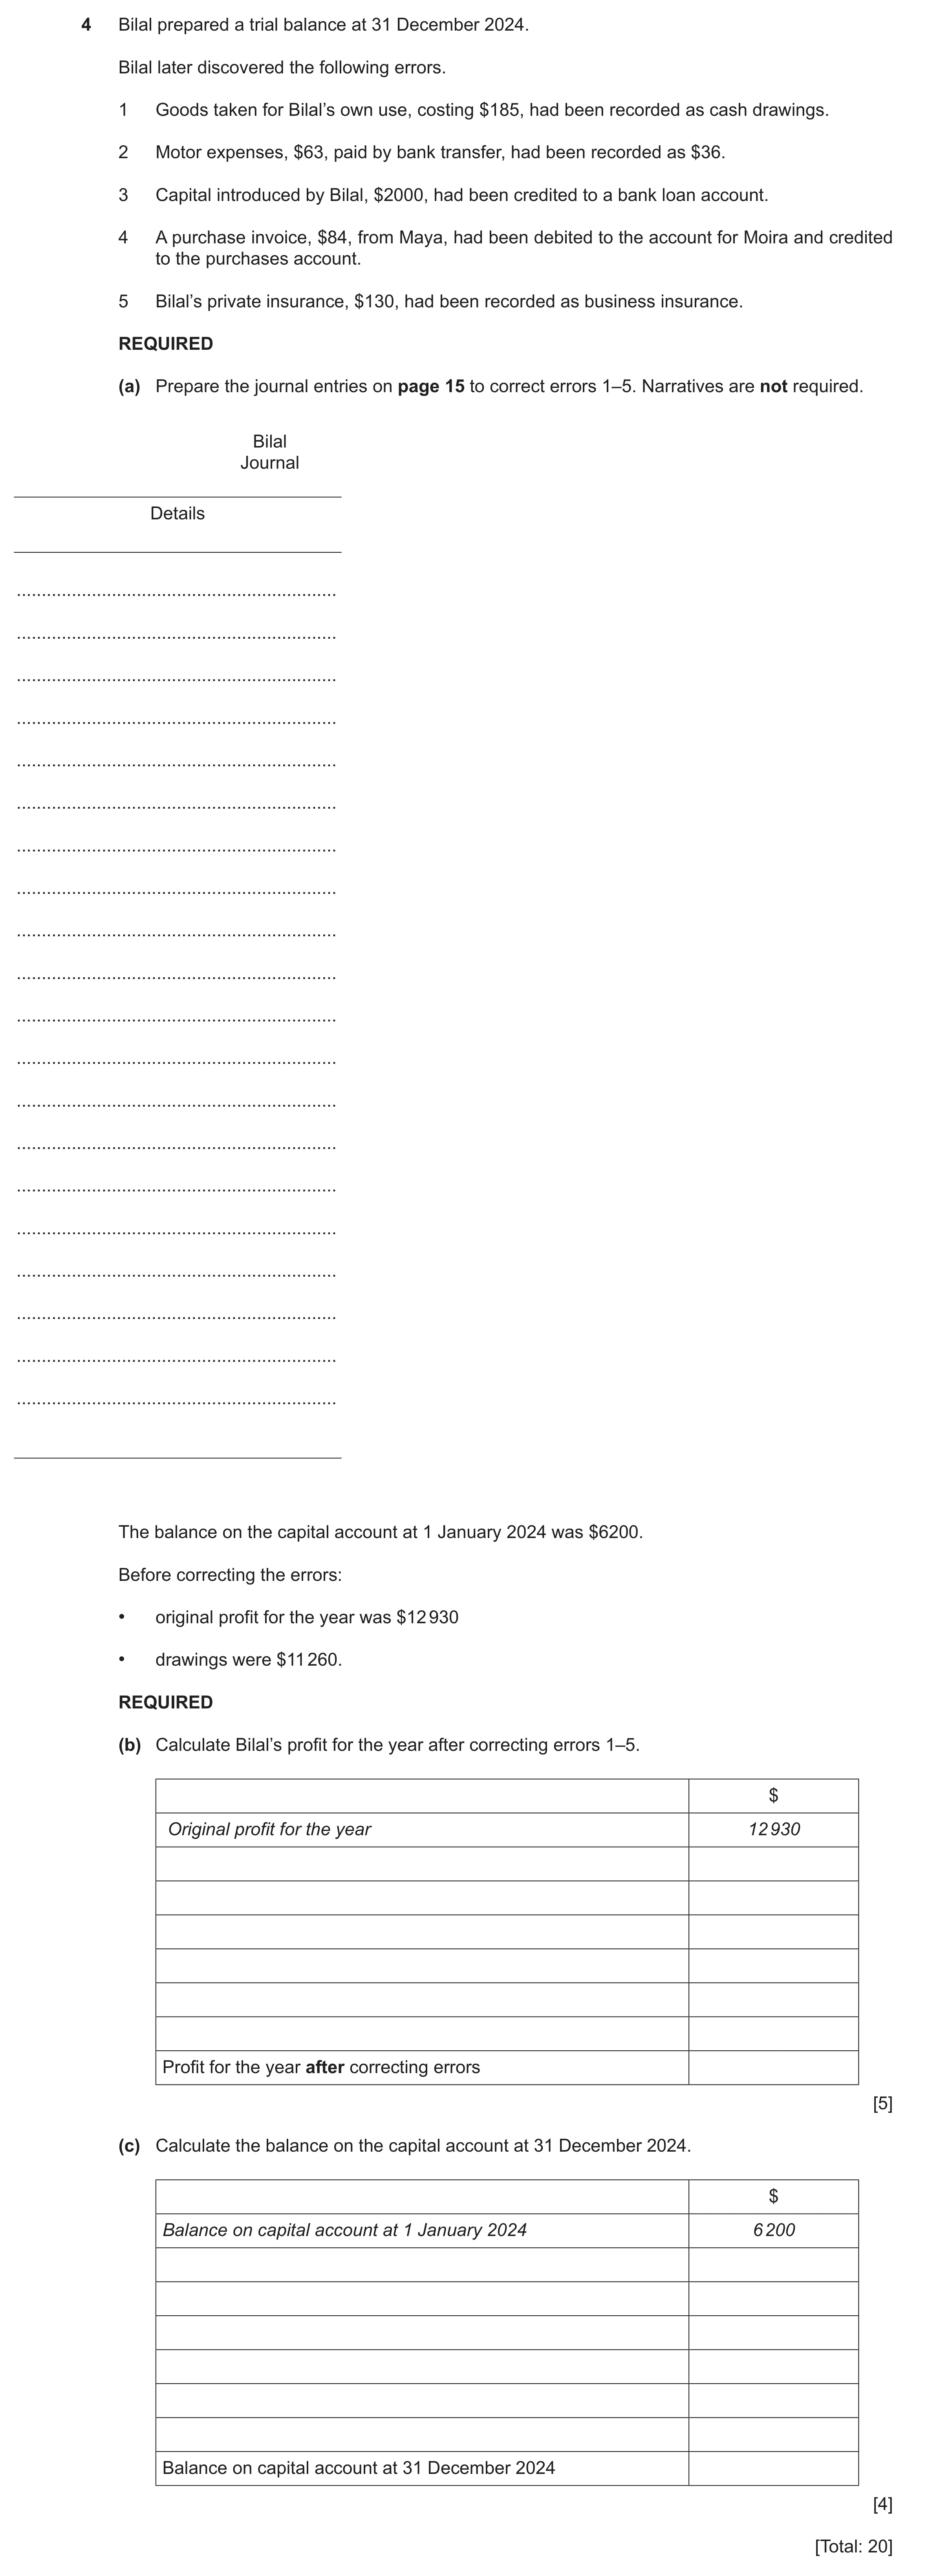
4 Bilal prepared a trial balance at 31 December 2024. Bilal later discovered the following errors. 1 Goods taken for Bilal’s own use, costing $185, had been recorded as cash drawings. 2 Motor expenses, $63, paid by bank transfer, had been recorded as $36. 3 Capital introduced by Bilal, $2000, had been credited to a bank loan account. 4 A purchase invoice, $84, from Maya, had been debited to the account for Moira and credited to the purchases account. 5 Bilal’s private insurance, $130, had been recorded as business insurance. REQUIRED (a) Prepare the journal entries on page 15 to correct errors 1–5. Narratives are not required. Bilal Journal Details … … … … … … … … … … … … … … … … … … … … The balance on the capital account at 1 January 2024 was $6200. Before correcting the errors: • original profit for the year was $12 930 • drawings were $11 260. REQUIRED (b) Calculate Bilal’s profit for the year after correcting errors 1–5. $ Original profit for the year 12 930 Profit for the year after correcting errors [5] (c) Calculate the balance on the capital account at 31 December 2024. $ Balance on capital account at 1 January 2024 6 200 Balance on capital account at 31 December 2024 [4] [Total: 20]
20 marks
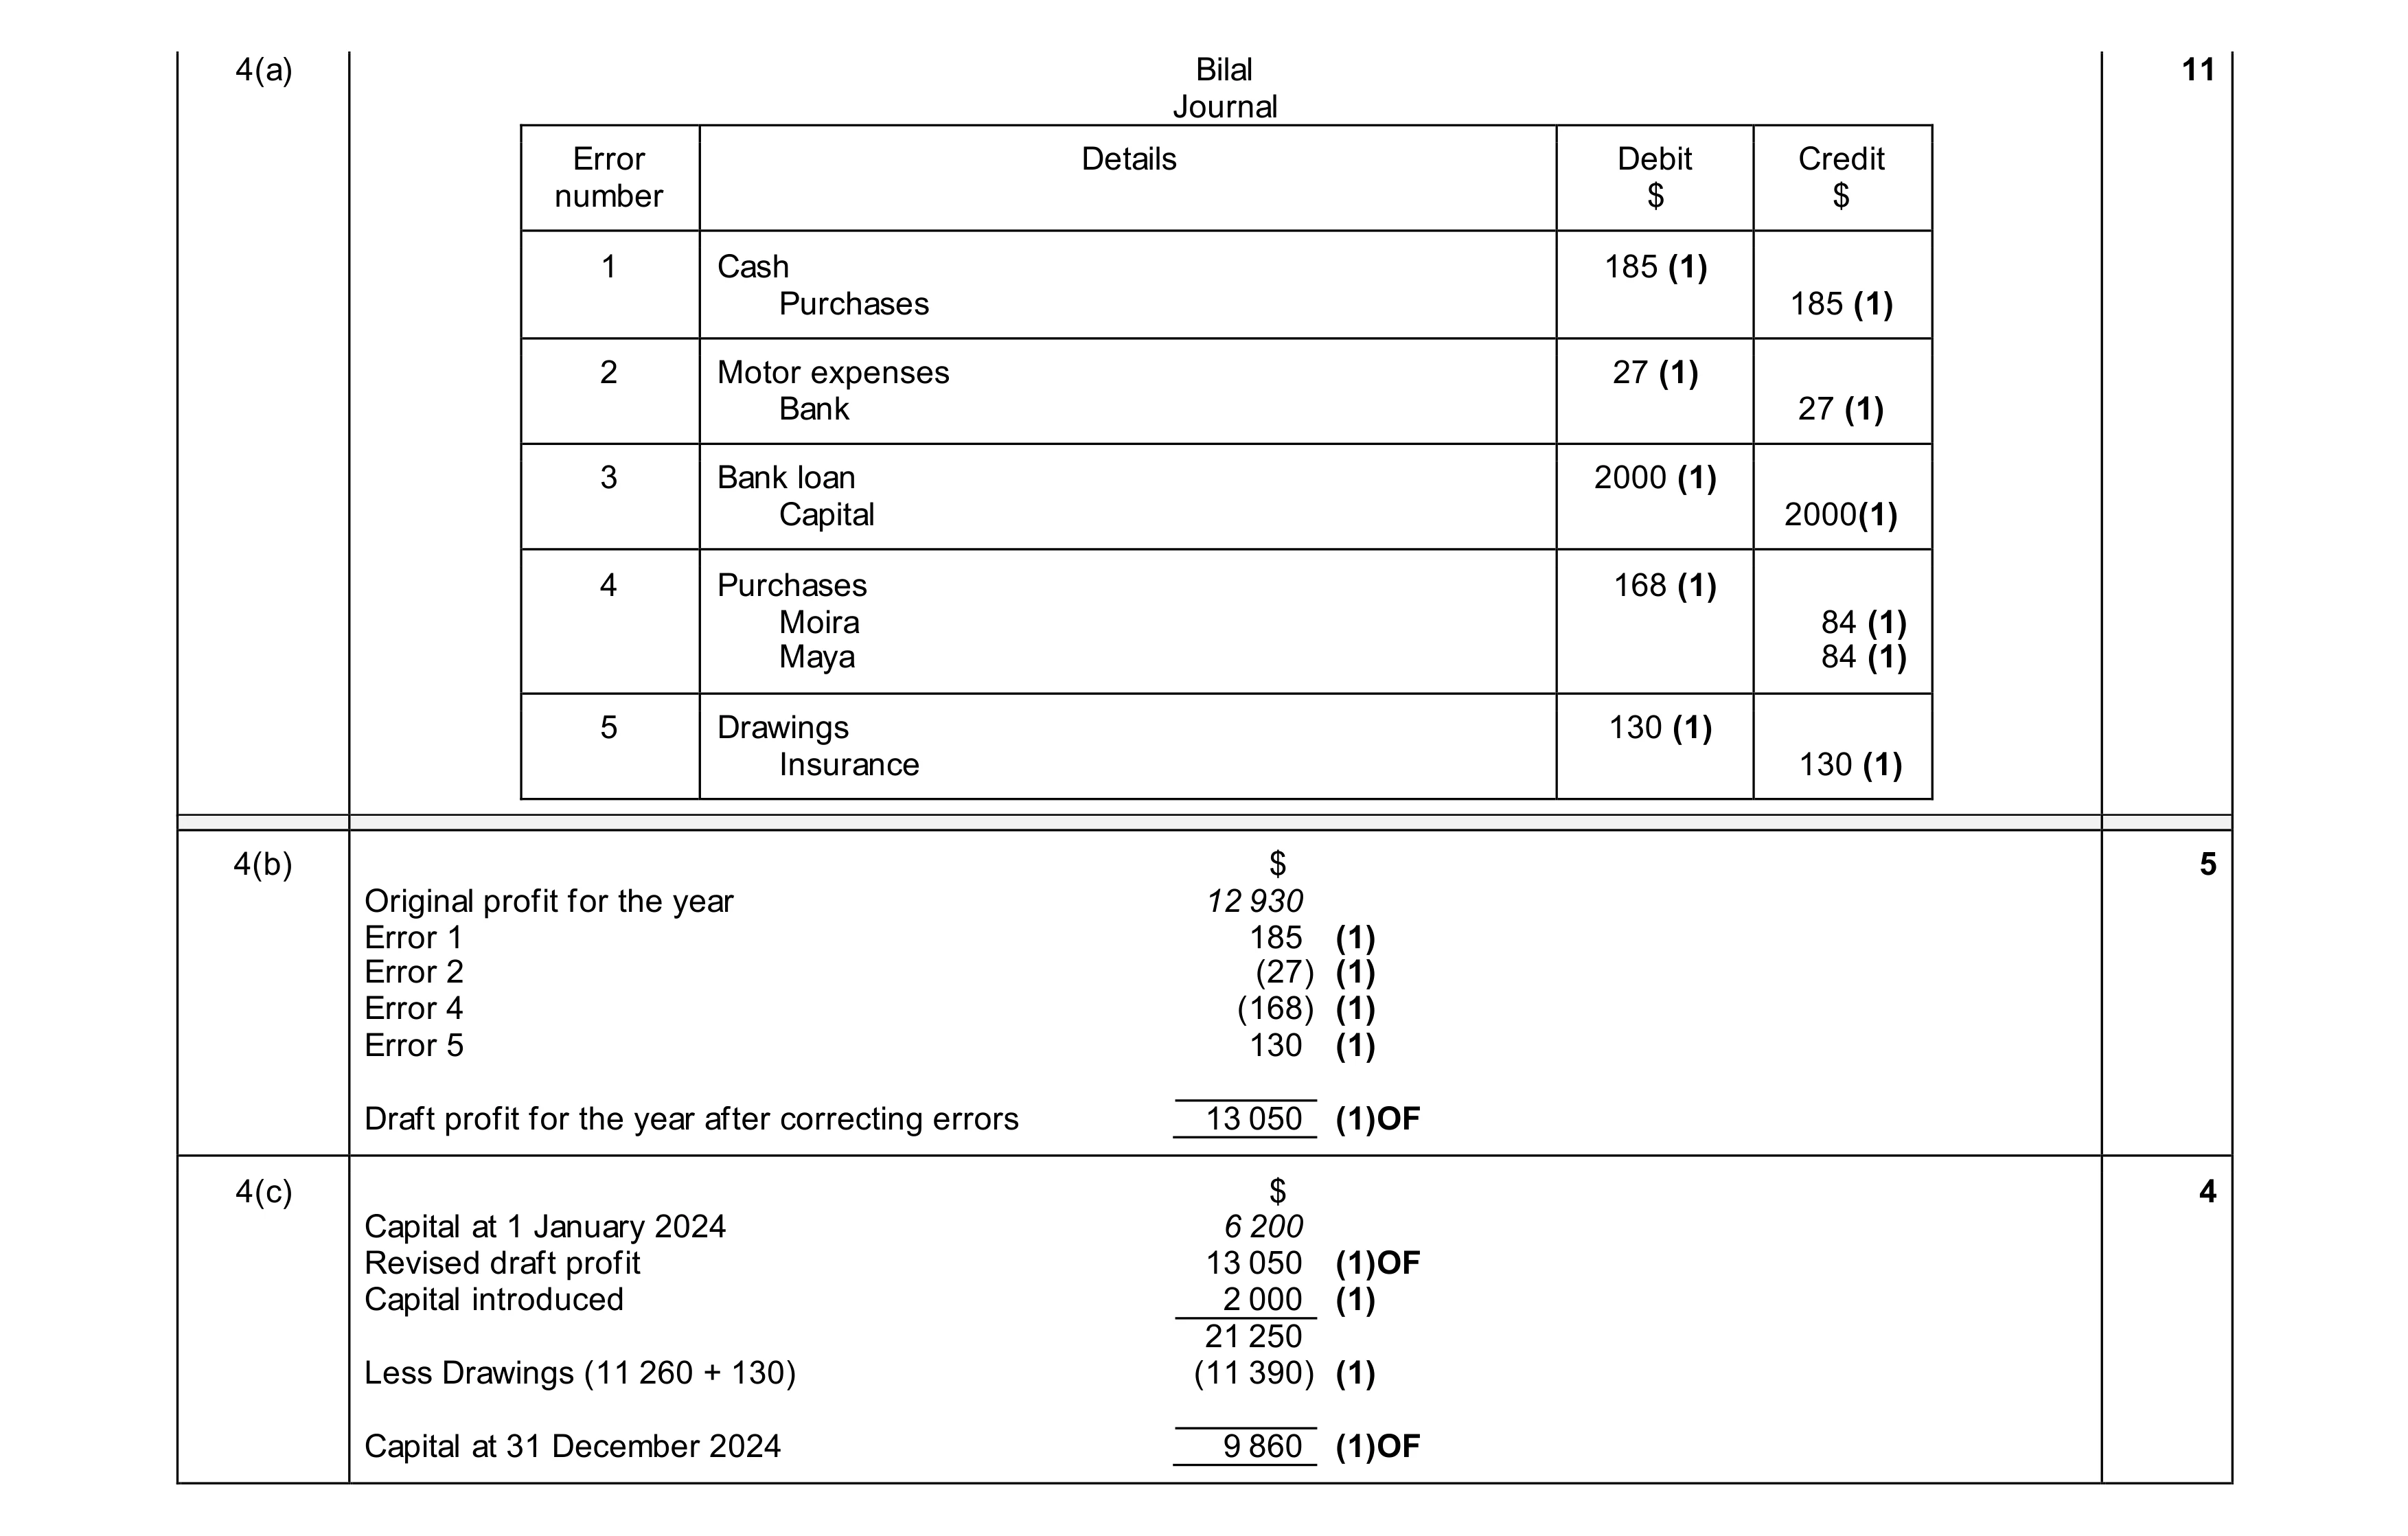
Mark scheme: 4(a) Bilal 11 Journal Error Details Debit Credit number $ $ 1 Cash 185 (1) Purchases 185 (1) 2 Motor expenses 27 (1) Bank 27 (1) 3 Bank loan 2000 (1) Capital 2000(1) 4 Purchases 168 (1) Moira 84 (1) Maya 84 (1) 5 Drawings 130 (1) Insurance 130 (1) 4(b) $ 5 Original profit for the year 12 930 Error 1 185 (1) Error 2 (27) (1) Error 4 (168) (1) Error 5 130 (1) Draft profit for the year after correcting errors 13 050 (1)OF 4(c) $ 4 Capital at 1 January 2024 6 200 Revised draft profit 13 050 (1)OF Capital introduced 2 000 (1) 21 250 Less Drawings (11 260 + 130) (11 390) (1) Capital at 31 December 2024 9 860 (1)OF
This question in 0985/22 May/June 2025
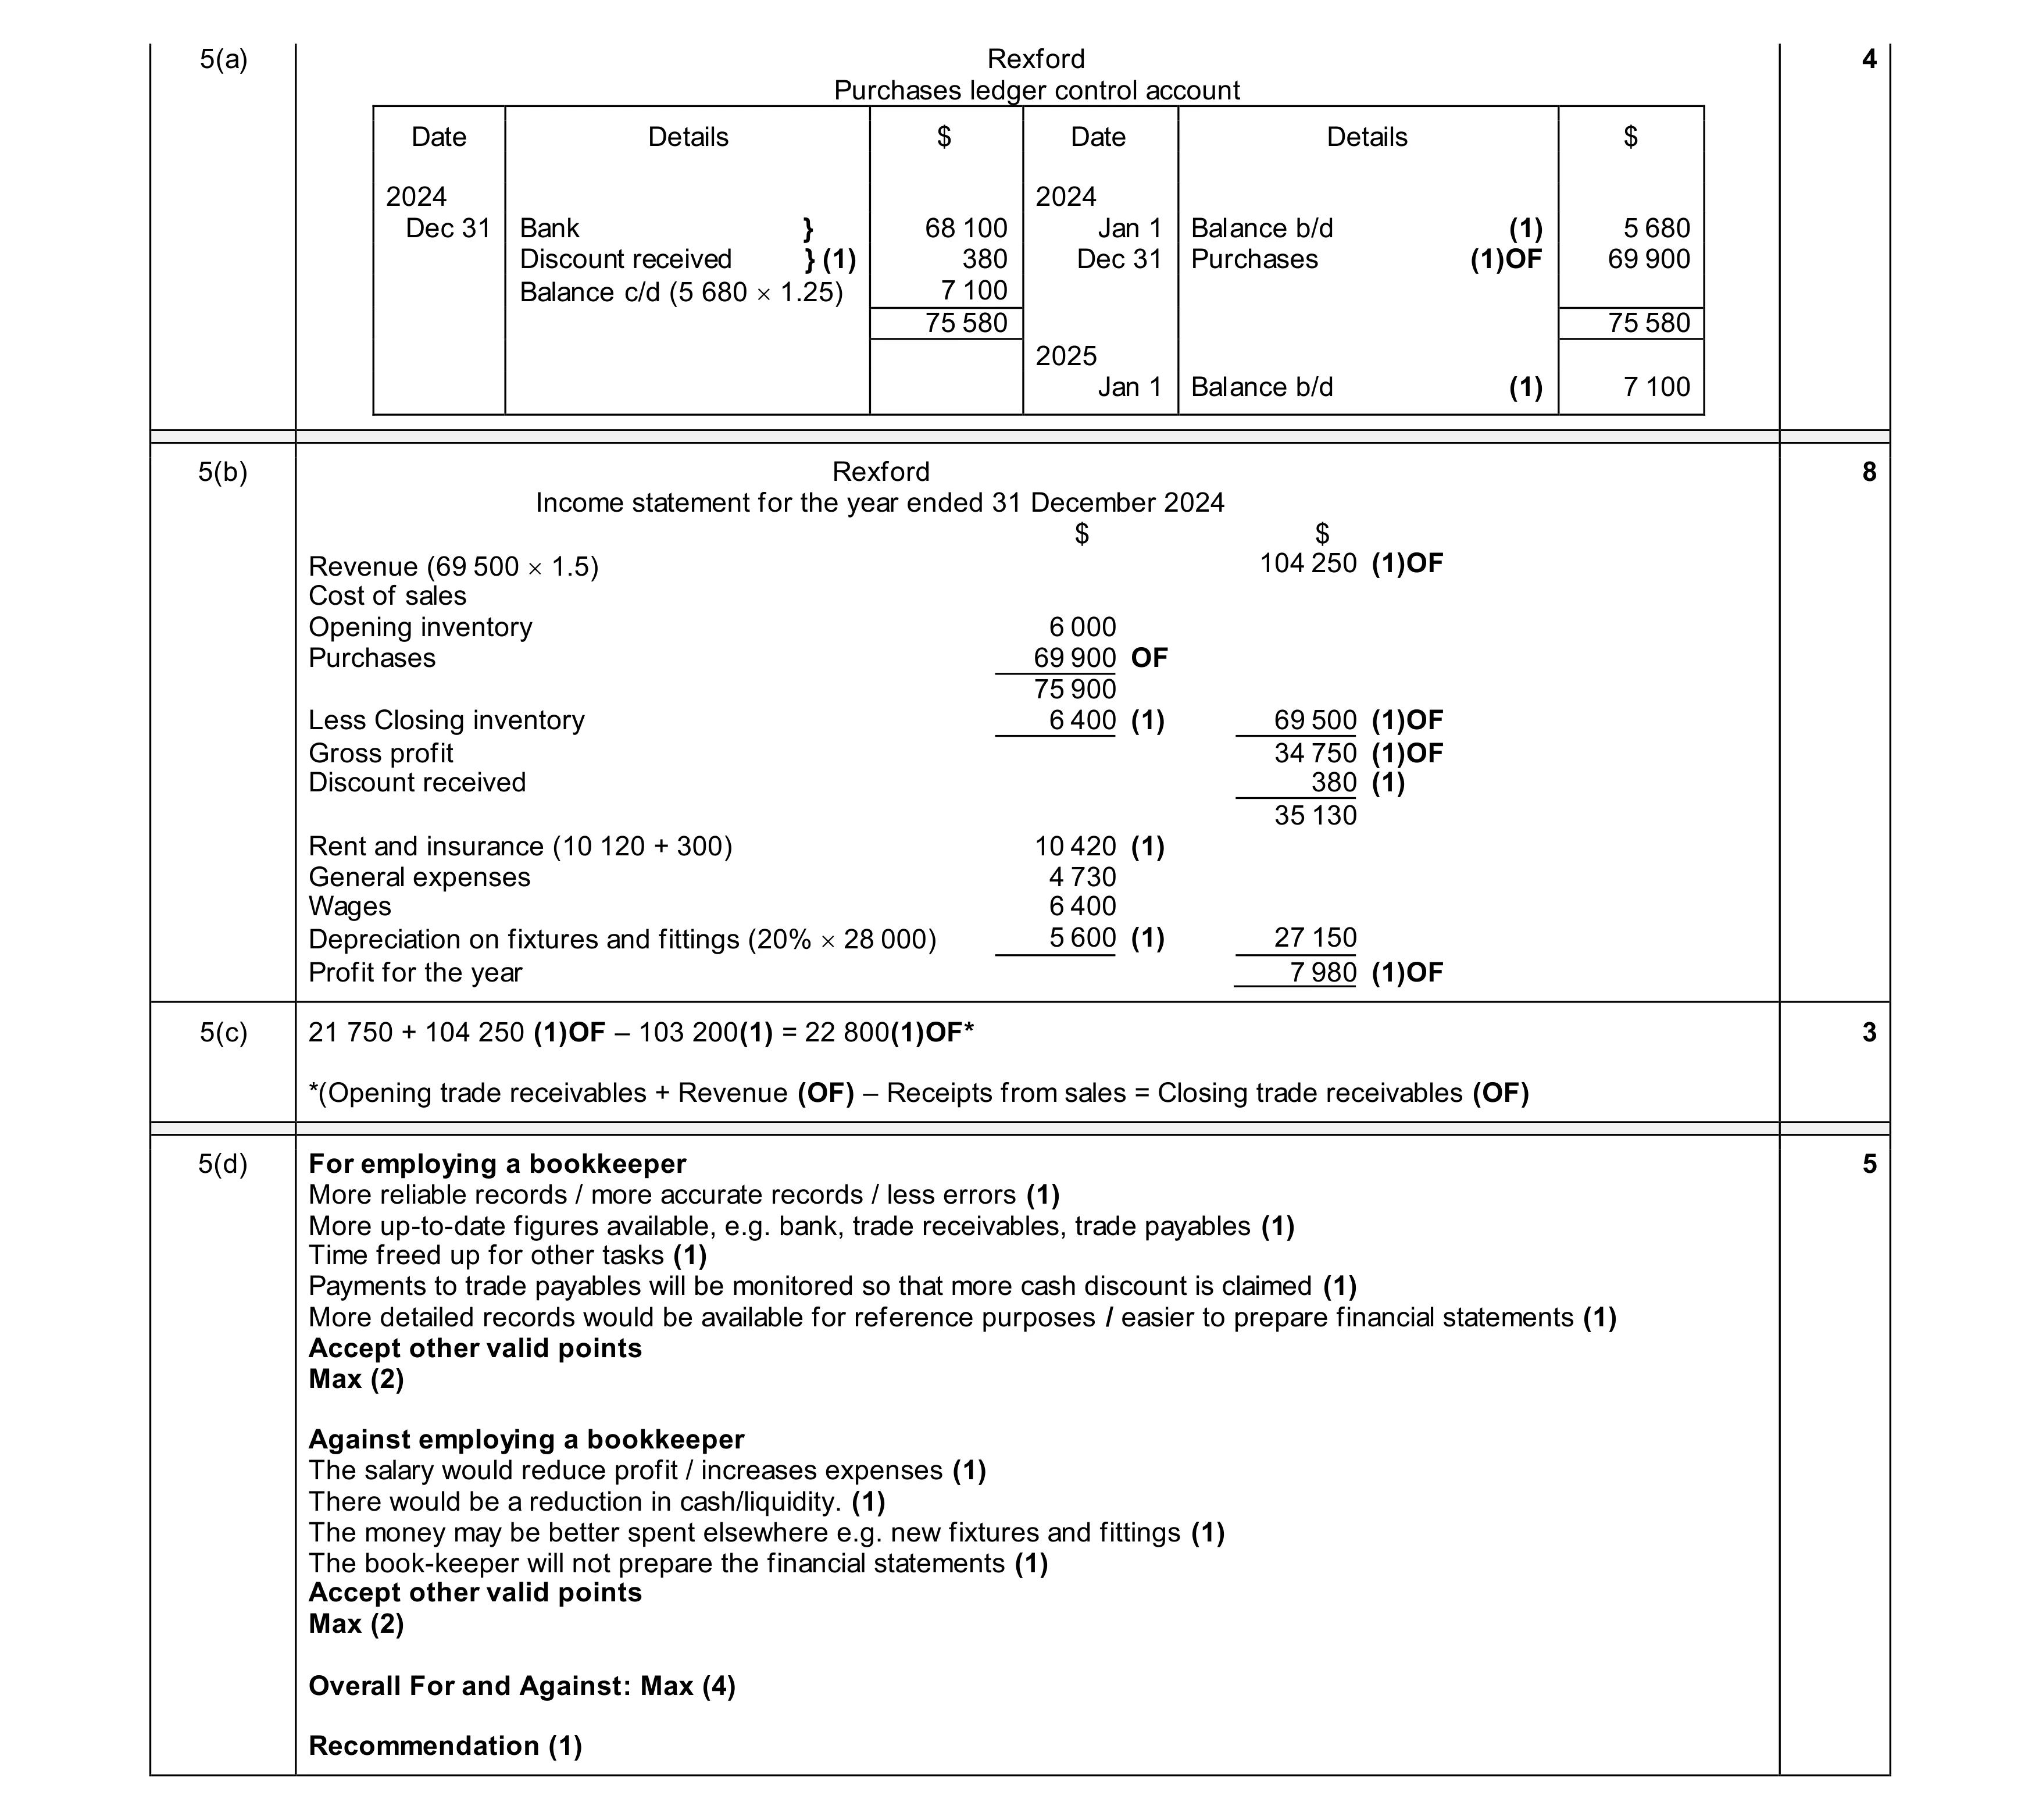
Q18 · Rexford is a trader 0985/22 May/June 2025
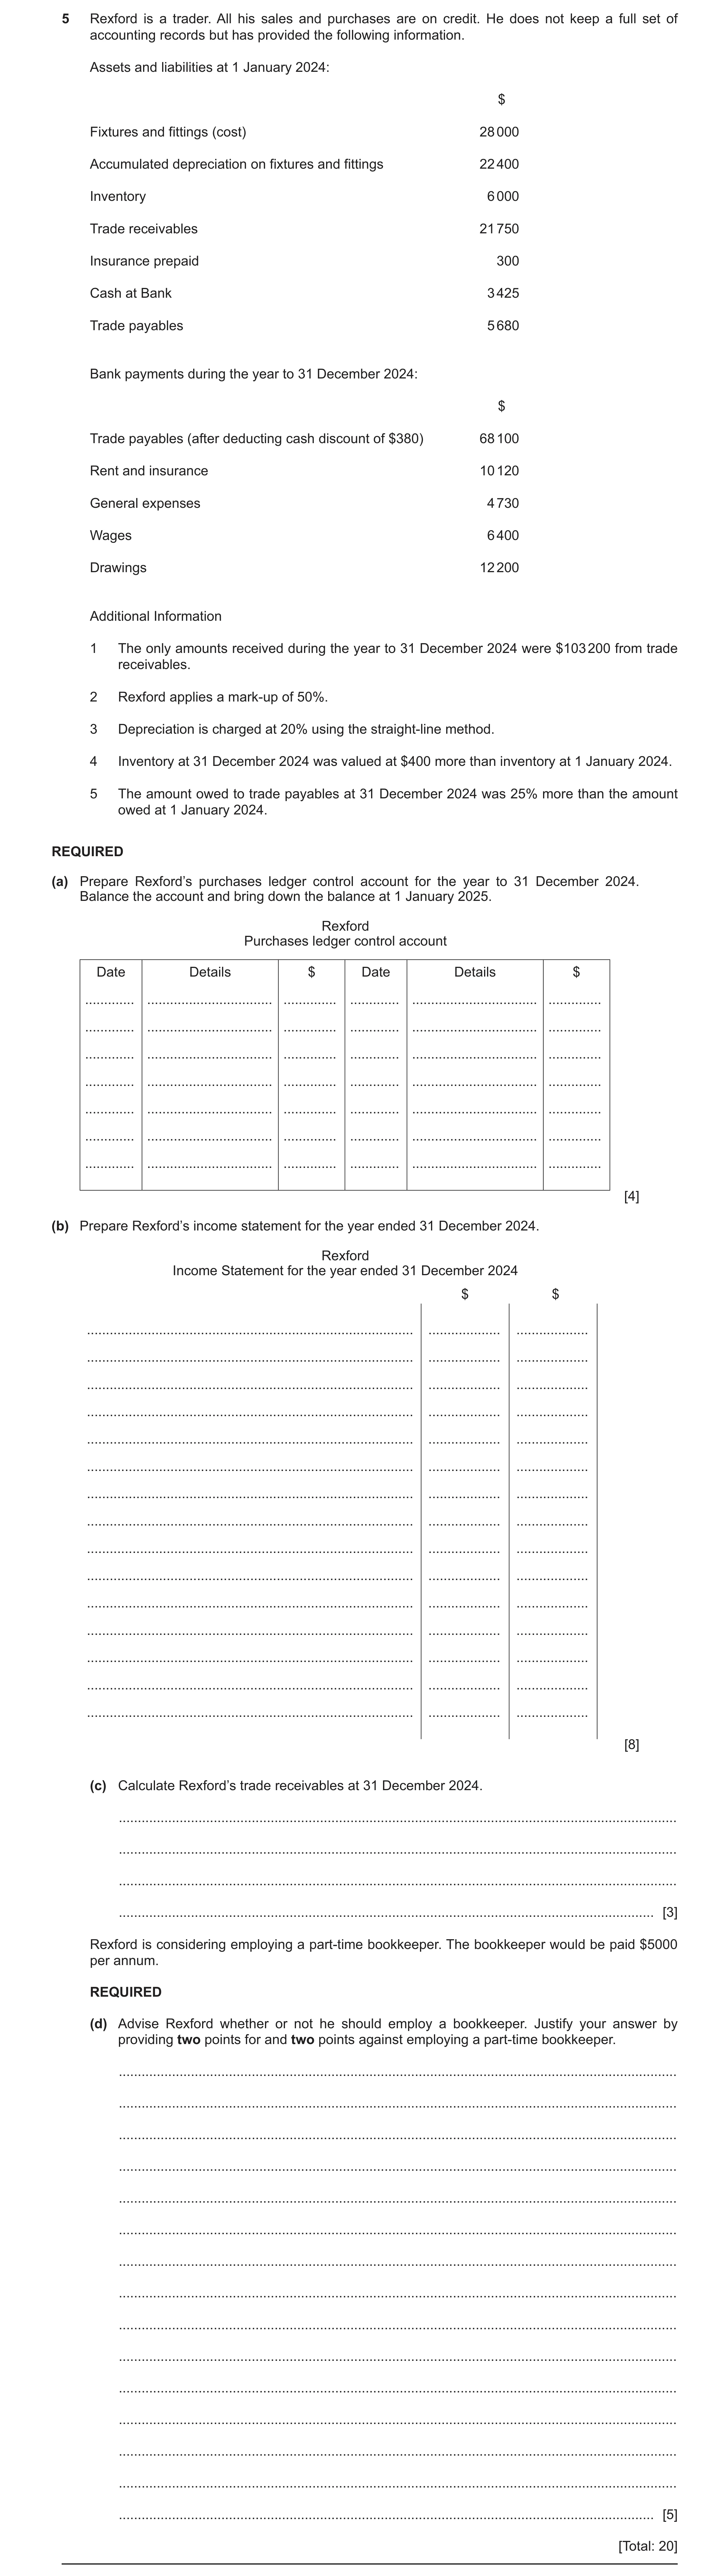
5 Rexford is a trader. All his sales and purchases are on credit. He does not keep a full set of accounting records but has provided the following information. Assets and liabilities at 1 January 2024: $ Fixtures and fittings (cost) 28 000 Accumulated depreciation on fixtures and fittings 22 400 Inventory 6 000 Trade receivables 21 750 Insurance prepaid 300 Cash at Bank 3 425 Trade payables 5 680 Bank payments during the year to 31 December 2024: $ Trade payables (after deducting cash discount of $380) 68 100 Rent and insurance 10 120 General expenses 4 730 Wages 6 400 Drawings 12 200 Additional Information 1 The only amounts received during the year to 31 December 2024 were $103 200 from trade receivables. 2 Rexford applies a mark-up of 50%. 3 Depreciation is charged at 20% using the straight-line method. 4 Inventory at 31 December 2024 was valued at $400 more than inventory at 1 January 2024. 5 The amount owed to trade payables at 31 December 2024 was 25% more than the amount owed at 1 January 2024. REQUIRED (a) Prepare Rexford’s purchases ledger control account for the year to 31 December 2024. Balance the account and bring down the balance at 1 January 2025. Rexford Purchases ledger control account Date Details $ Date Details $ … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [4] (b) Prepare Rexford’s income statement for the year ended 31 December 2024. Rexford Income Statement for the year ended 31 December 2024 $ $ … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [8] (c) Calculate Rexford’s trade receivables at 31 December 2024. … … … … [3] Rexford is considering employing a part-time bookkeeper. The bookkeeper would be paid $5000 per annum. REQUIRED (d) Advise Rexford whether or not he should employ a bookkeeper. Justify your answer by providing two points for and two points against employing a part-time bookkeeper. … … … … … … … … … … … … … … … [5] [Total: 20]
20 marks
Mark scheme: 5(a) Rexford 4 Purchases ledger control account Date Details $ Date Details $ 2024 2024 Dec 31 Bank } 68 100 Jan 1 Balance b/d (1) 5 680 Discount received } (1) 380 Dec 31 Purchases (1)OF 69 900 Balance c/d (5 680 1.25) 7 100 75 580 75 580 2025 Jan 1 Balance b/d (1) 7 100 5(b) Rexford 8 Income statement for the year ended 31 December 2024 $ $ Revenue (69 500 1.5) 104 250 (1)OF Cost of sales Opening inventory 6 000 Purchases 69 900 OF 75 900 Less Closing inventory 6 400 (1) 69 500 (1)OF Gross profit 34 750 (1)OF Discount received 380 (1) 35 130 Rent and insurance (10 120 + 300) 10 420 (1) General expenses 4 730 Wages 6 400 Depreciation on fixtures and fittings (20% 28 000) 5 600 (1) 27 150 Profit for the year 7 980 (1)OF 5(c) 21 750 + 104 250 (1)OF – 103 200(1) = 22 800(1)OF* 3 *(Opening trade receivables + Revenue (OF) – Receipts from sales = Closing trade receivables (OF) 5(d) For employing a bookkeeper 5 More reliable records / more accurate records / less errors (1) More up-to-date figures available, e.g. bank, trade receivables, trade payables (1) Time freed up for other tasks (1) Payments to trade payables will be monitored so that more cash discount is claimed (1) More detailed records would be available for reference purposes / easier to prepare financial statements (1) Accept other valid points Max (2) Against employing a bookkeeper The salary would reduce profit / increases expenses (1) There would be a reduction in cash/liquidity. (1) The money may be better spent elsewhere e.g. new fixtures and fittings (1) The book-keeper will not prepare the financial statements (1) Accept other valid points Max (2) Overall For and Against: Max (4) Recommendation (1)
This question in 0985/22 May/June 2025
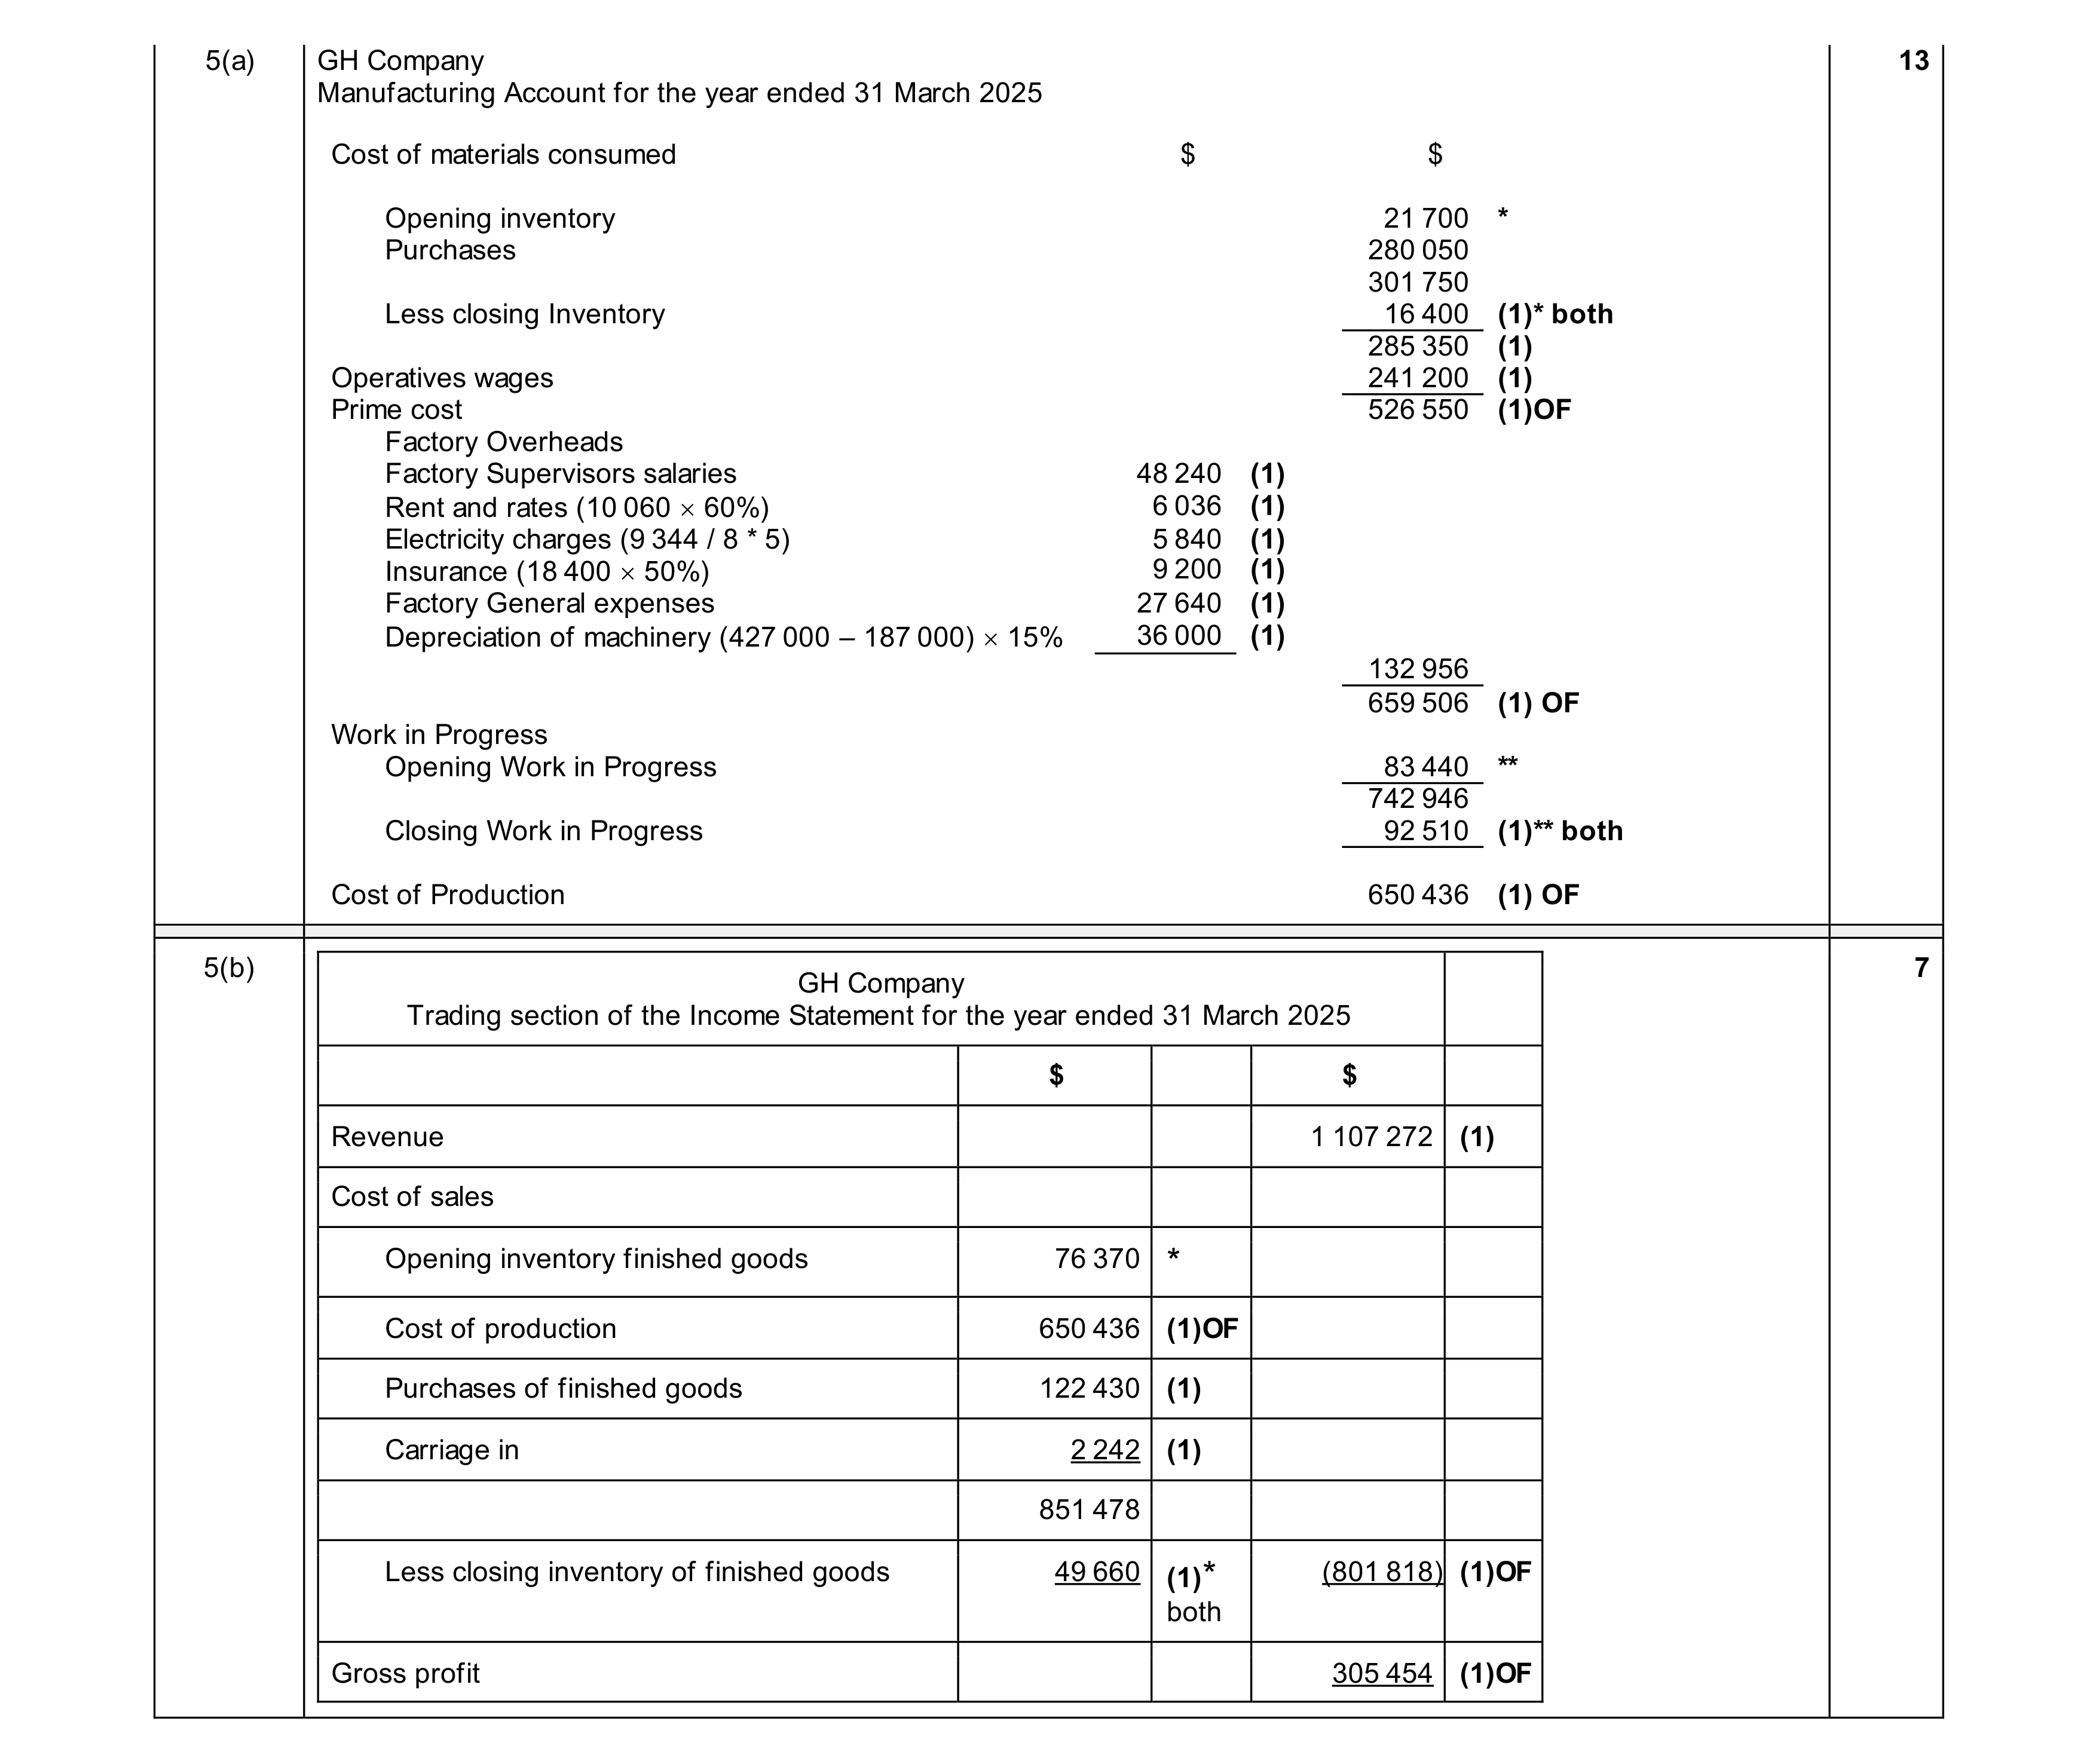
Q19 · GH Company manufactures car parts and has provided the following information relating to… 0985/22 Oct/Nov 2025
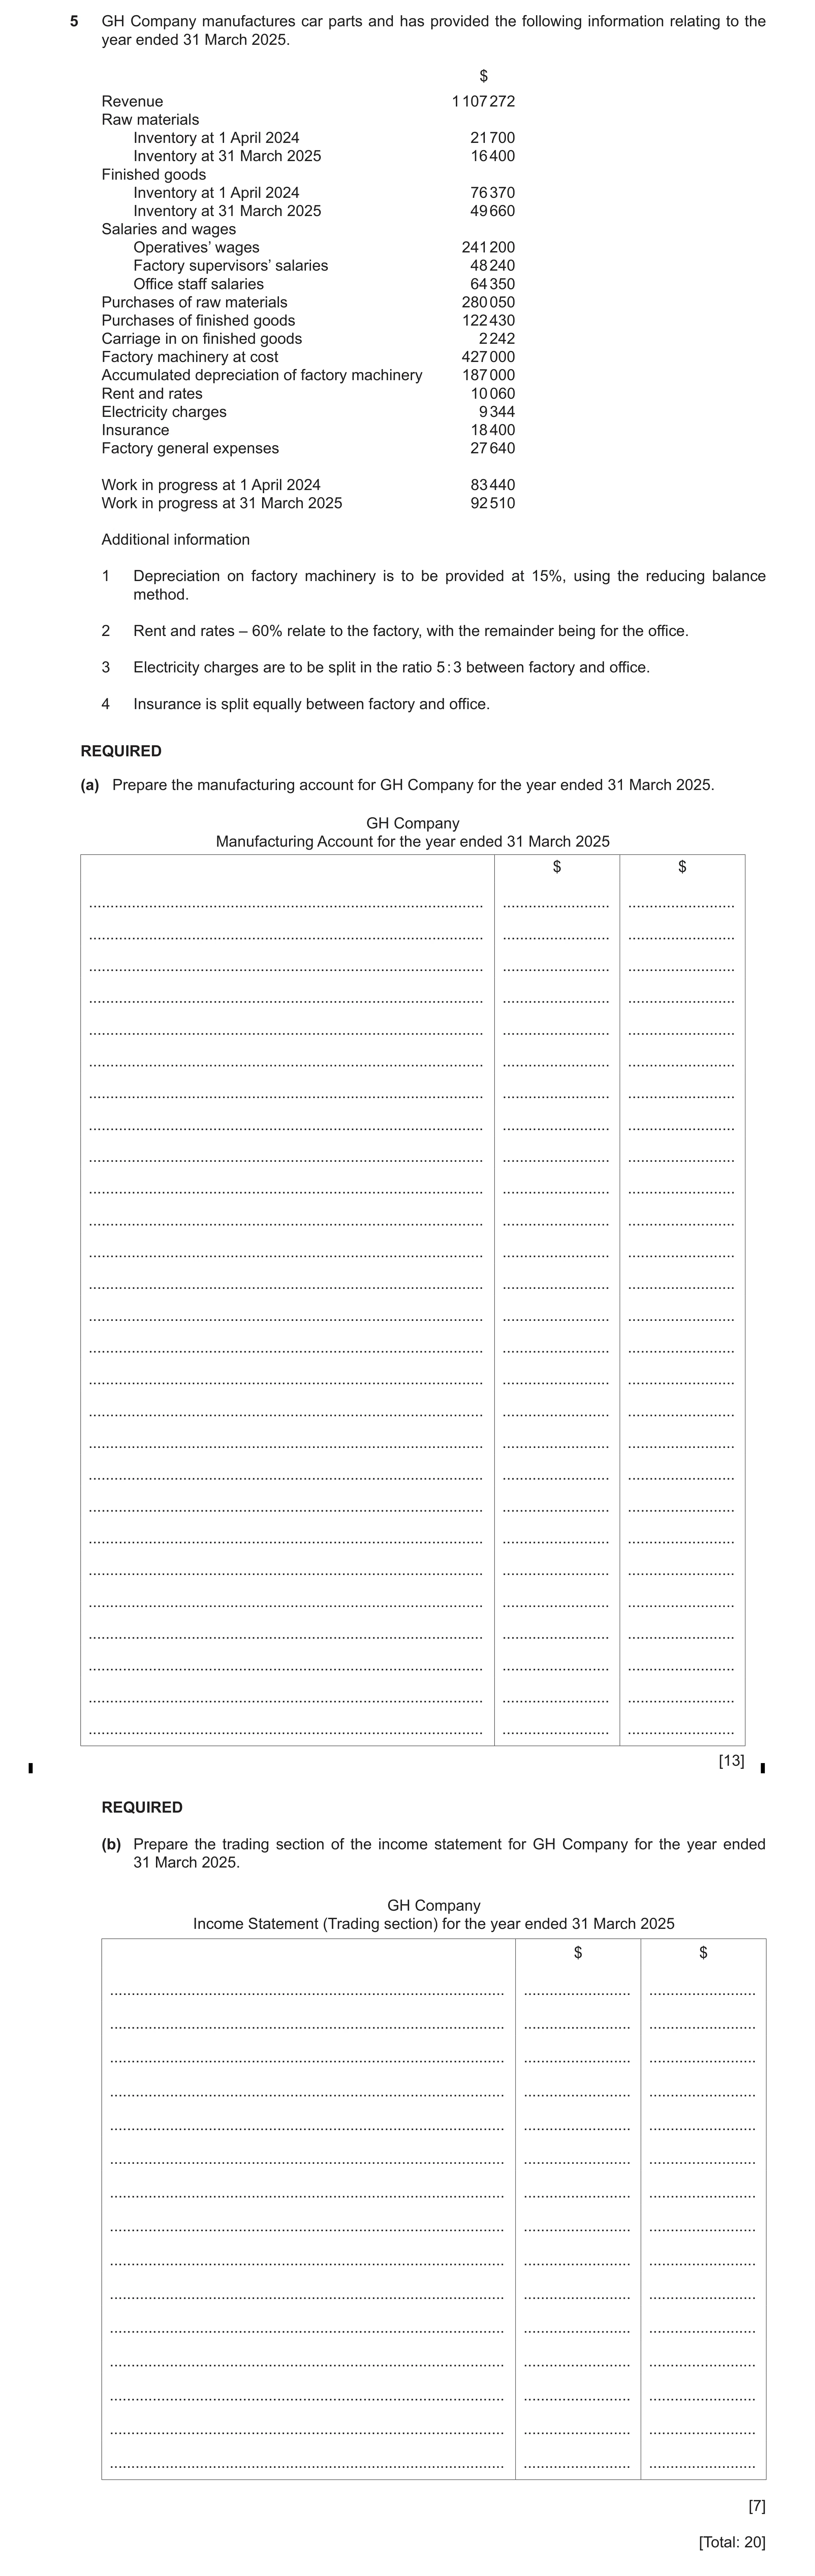
5 GH Company manufactures car parts and has provided the following information relating to the year ended 31 March 2025. $ Revenue 1 107 272 Raw materials Inventory at 1 April 2024 21 700 Inventory at 31 March 2025 16 400 Finished goods Inventory at 1 April 2024 76 370 Inventory at 31 March 2025 49 660 Salaries and wages Operatives’ wages 241 200 Factory supervisors’ salaries 48 240 Office staff salaries 64 350 Purchases of raw materials 280 050 Purchases of finished goods 122 430 Carriage in on finished goods 2 242 Factory machinery at cost 427 000 Accumulated depreciation of factory machinery 187 000 Rent and rates 10 060 Electricity charges 9 344 Insurance 18 400 Factory general expenses 27 640 Work in progress at 1 April 2024 83 440 Work in progress at 31 March 2025 92 510 Additional information 1 Depreciation on factory machinery is to be provided at 15%, using the reducing balance method. 2 Rent and rates – 60% relate to the factory, with the remainder being for the office. 3 Electricity charges are to be split in the ratio 5 : 3 between factory and office. 4 Insurance is split equally between factory and office. REQUIRED (a) Prepare the manufacturing account for GH Company for the year ended 31 March 2025. GH Company Manufacturing Account for the year ended 31 March 2025 $ $ … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [13] REQUIRED (b) Prepare the trading section of the income statement for GH Company for the year ended 31 March 2025. GH Company Income Statement (Trading section) for the year ended 31 March 2025 $ $ … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … … [7] [Total: 20]
20 marks
Mark scheme: 5(a) GH Company 13 Manufacturing Account for the year ended 31 March 2025 Cost of materials consumed $ $ Opening inventory 21 700 * Purchases 280 050 301 750 Less closing Inventory 16 400 (1)* both 285 350 (1) Operatives wages 241 200 (1) Prime cost 526 550 (1)OF Factory Overheads Factory Supervisors salaries 48 240 (1) Rent and rates (10 060 60%) 6 036 (1) Electricity charges (9 344 / 8 * 5) 5 840 (1) Insurance (18 400 50%) 9 200 (1) Factory General expenses 27 640 (1) Depreciation of machinery (427 000 – 187 000) 15% 36 000 (1) 132 956 659 506 (1) OF Work in Progress Opening Work in Progress 83 440 ** 742 946 Closing Work in Progress 92 510 (1)** both Cost of Production 650 436 (1) OF 5(b) 7 GH Company Trading section of the Income Statement for the year ended 31 March 2025 $ $ Revenue 1 107 272 (1) Cost of sales Opening inventory finished goods 76 370 * Cost of production 650 436 (1)OF Purchases of finished goods 122 430 (1) Carriage in 2 242 (1) 851 478 Less closing inventory of finished goods 49 660 (1)* (801 818) (1)OF both Gross profit 305 454 (1)OF
This question in 0985/22 Oct/Nov 2025
 20
 20
 20
 20
 20
 20
 20
 20
 20
 11
 20
 20
 20
 20
 20
 20
 20
 20
 20