Cambridge IGCSE Accounting (9-1) 0985 — 2022 Oct/Nov Paper 2 · Variant 2
0985/22/O/N/22 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme16 pages
Answers below. Sit the paper first if you are practising.
Questions as text
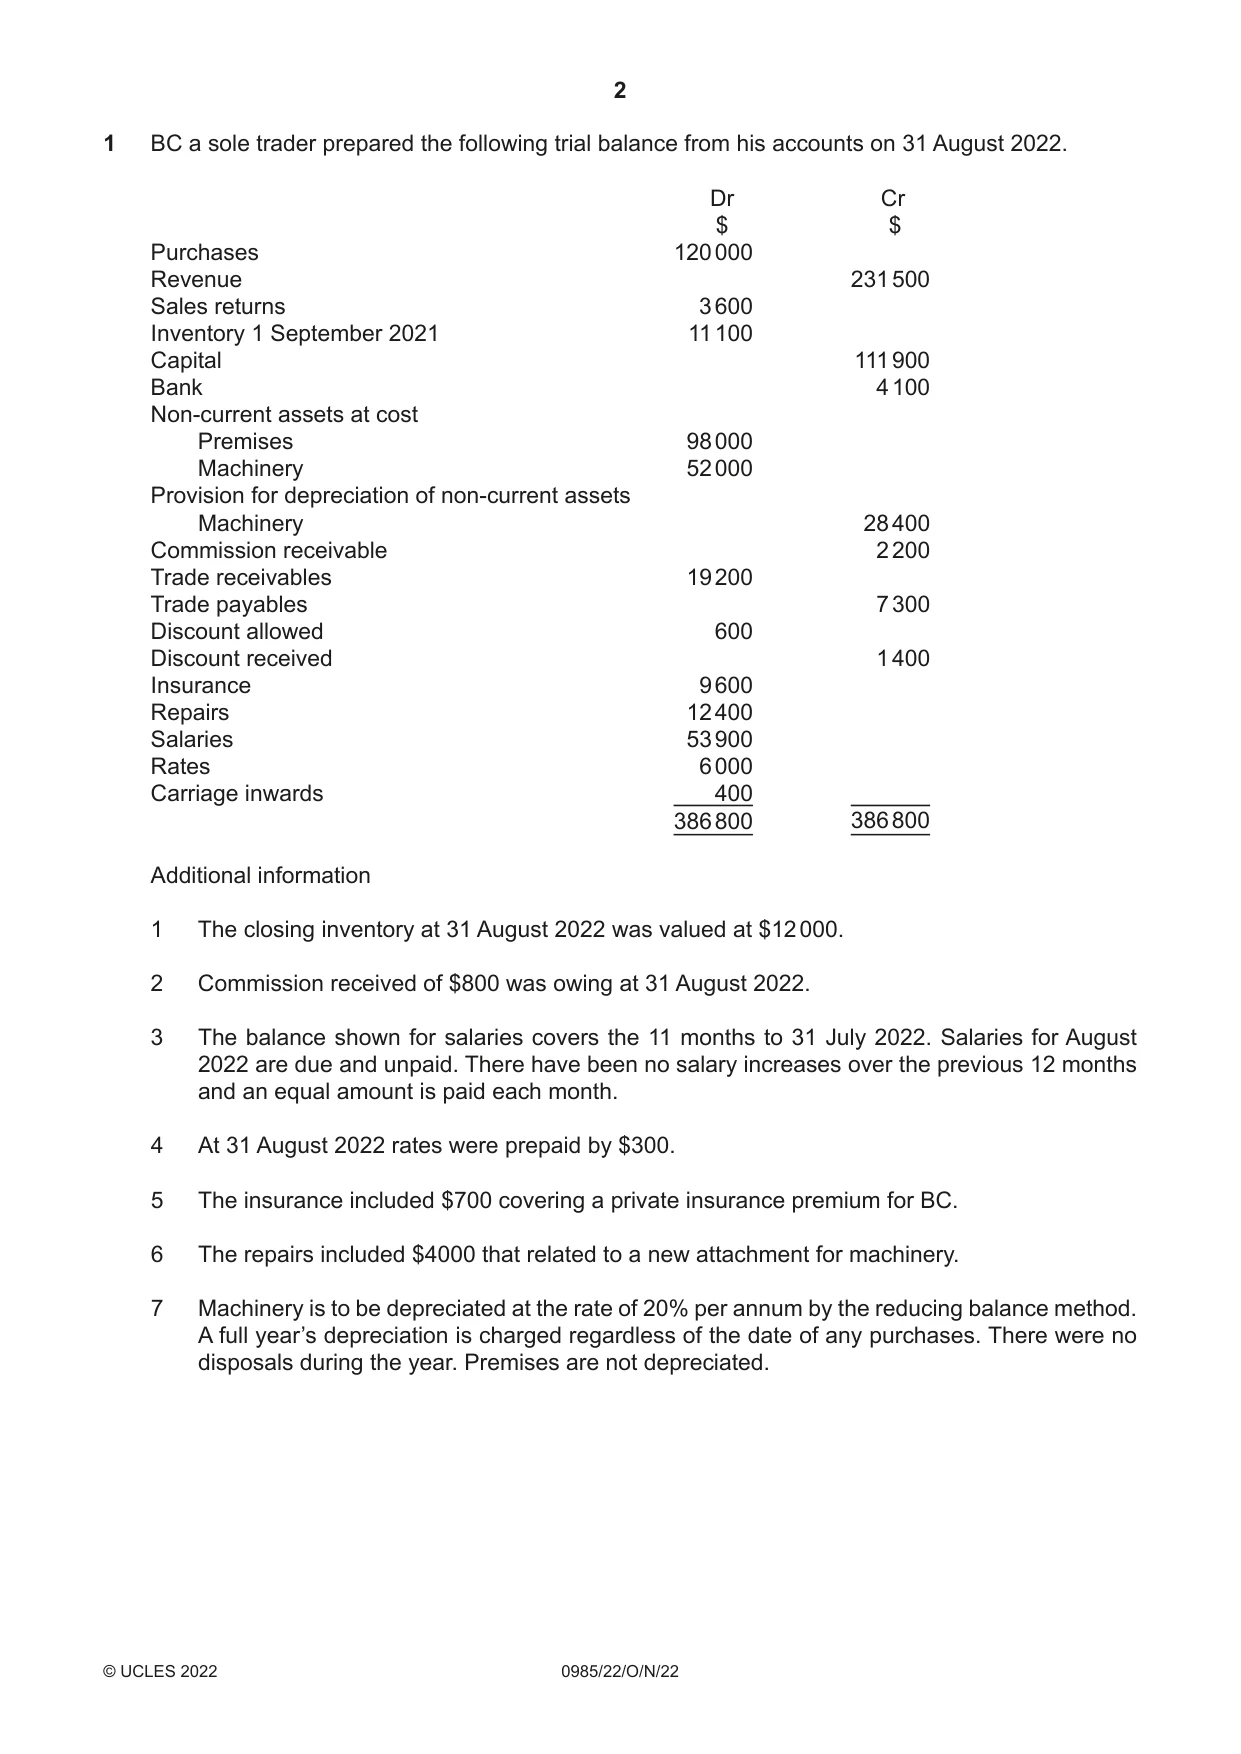
Q1 · BC a sole trader prepared the following trial balance from his accounts on 31 August 2022
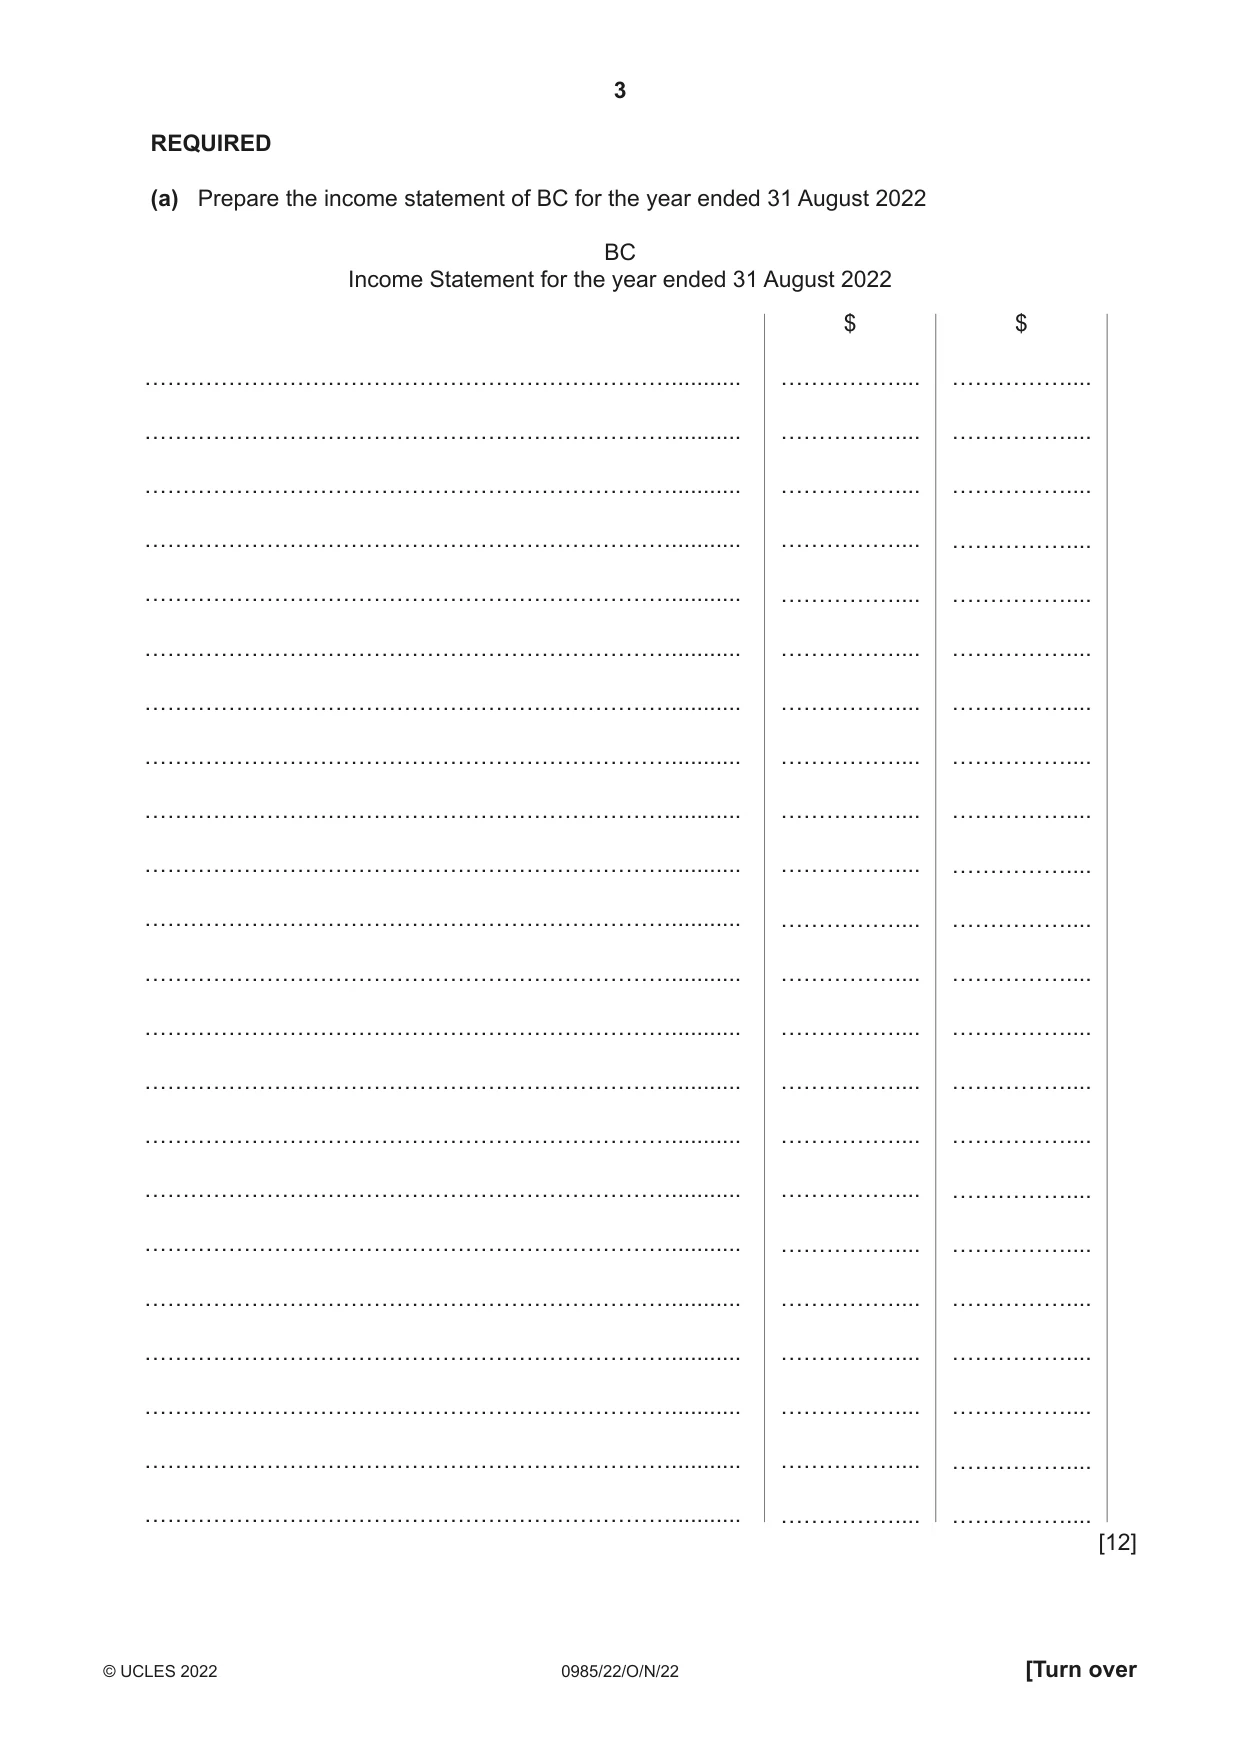
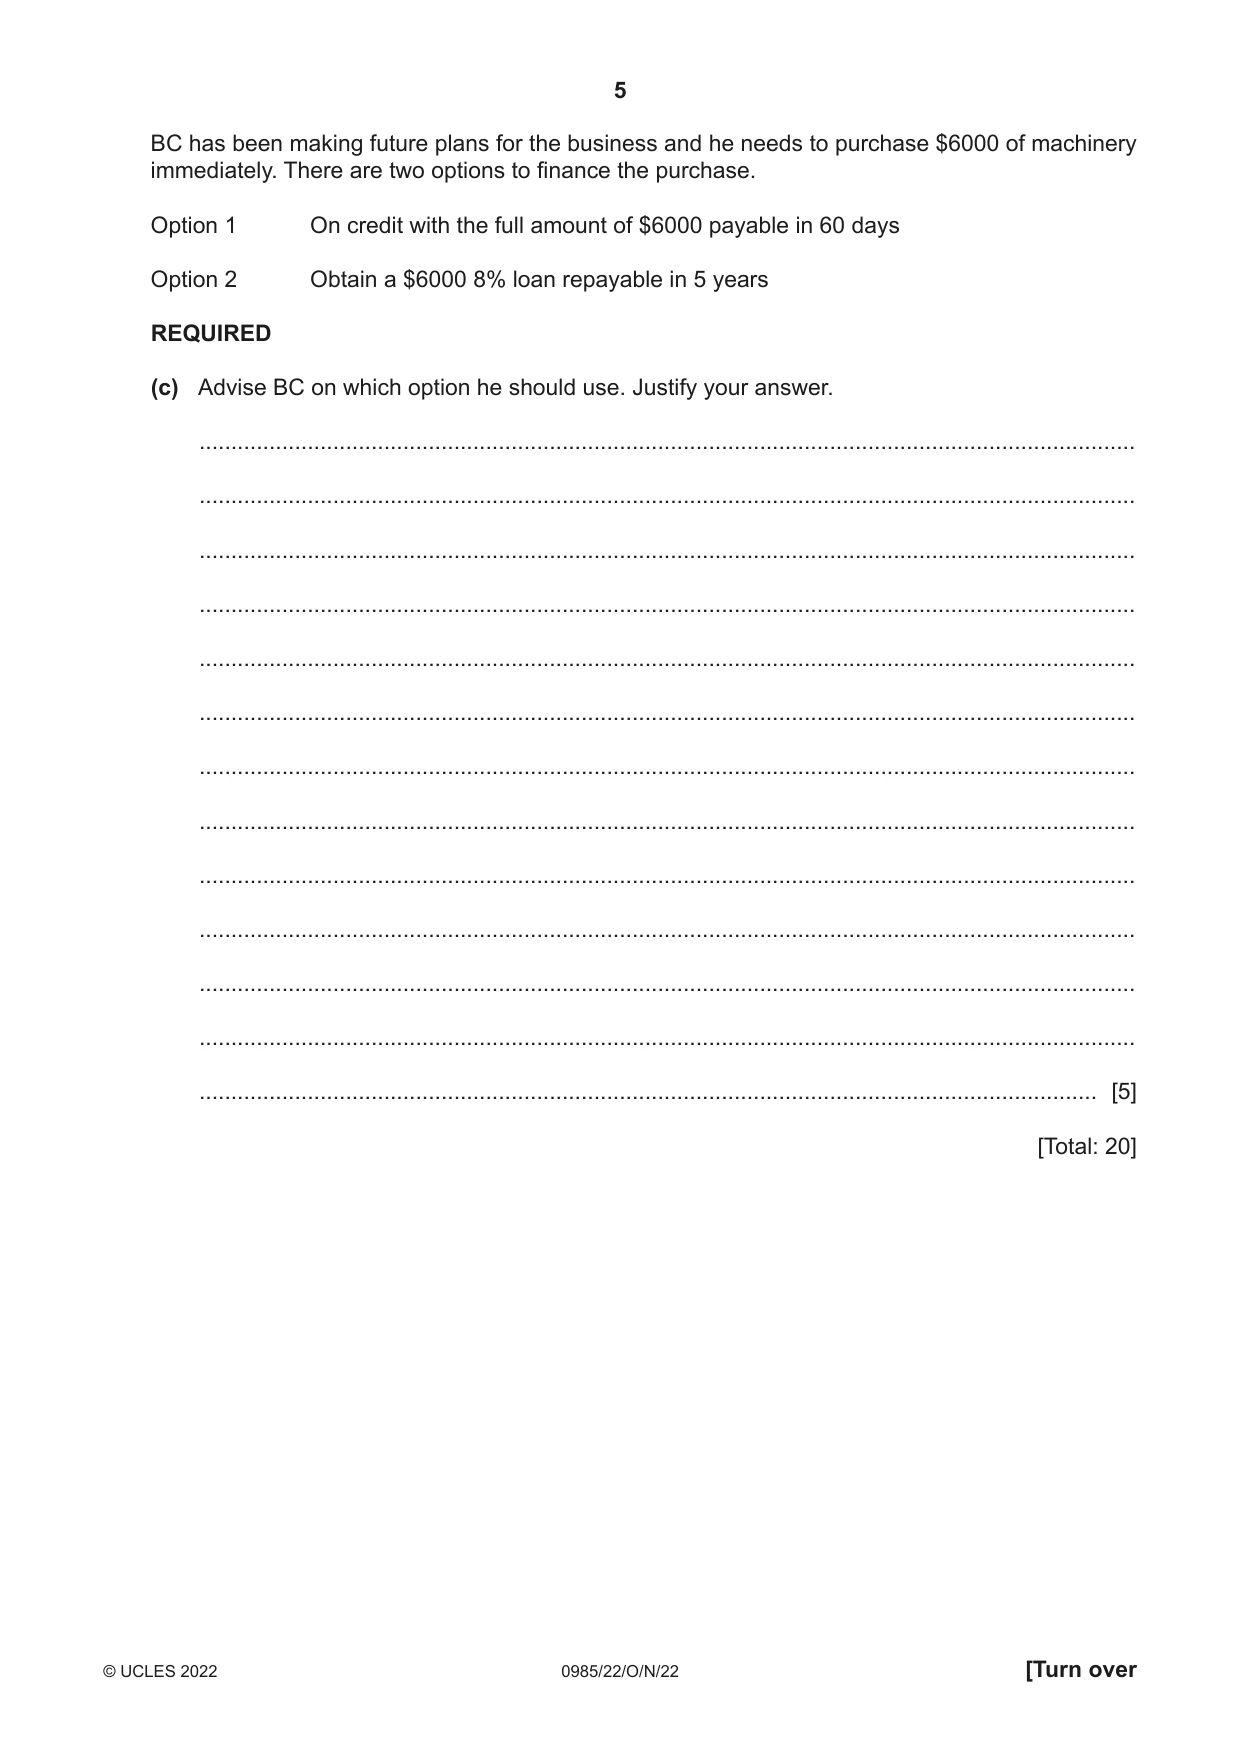
1 BC a sole trader prepared the following trial balance from his accounts on 31 August 2022. Dr Cr $ $ Purchases 120 000 Revenue 231 500 Sales returns 3 600 Inventory 1 September 2021 11 100 Capital 111 900 Bank 4 100 Non-current assets at cost Premises 98 000 Machinery 52 000 Provision for depreciation of non-current assets Machinery 28 400 Commission receivable 2 200 Trade receivables 19 200 Trade payables 7 300 Discount allowed 600 Discount received 1 400 Insurance 9 600 Repairs 12 400 Salaries 53 900 Rates 6 000 Carriage inwards 400 386 800 386 800 Additional information 1 The closing inventory at 31 August 2022 was valued at $12 000. 2 Commission received of $800 was owing at 31 August 2022. 3 The balance shown for salaries covers the 11 months to 31 July 2022. Salaries for August 2022 are due and unpaid. There have been no salary increases over the previous 12 months and an equal amount is paid each month. 4 At 31 August 2022 rates were prepaid by $300. 5 The insurance included $700 covering a private insurance premium for BC. 6 The repairs included $4000 that related to a new attachment for machinery. 7 Machinery is to be depreciated at the rate of 20% per annum by the reducing balance method. A full year’s depreciation is charged regardless of the date of any purchases. There were no disposals during the year. Premises are not depreciated. REQUIRED (a) Prepare the income statement of BC for the year ended BC Income Statement for the year ended 31 ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... (b) Calculate the working capital at 31 August 2022. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] BC has been making future plans for the business and he needs to purchase $6000 of machinery immediately. There are two options to finance the purchase. Option 1 On credit with the full amount of $6000 payable in 60 days Option 2 Obtain a $6000 8% loan repayable in 5 years REQUIRED (c) Advise BC on which option he should use. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
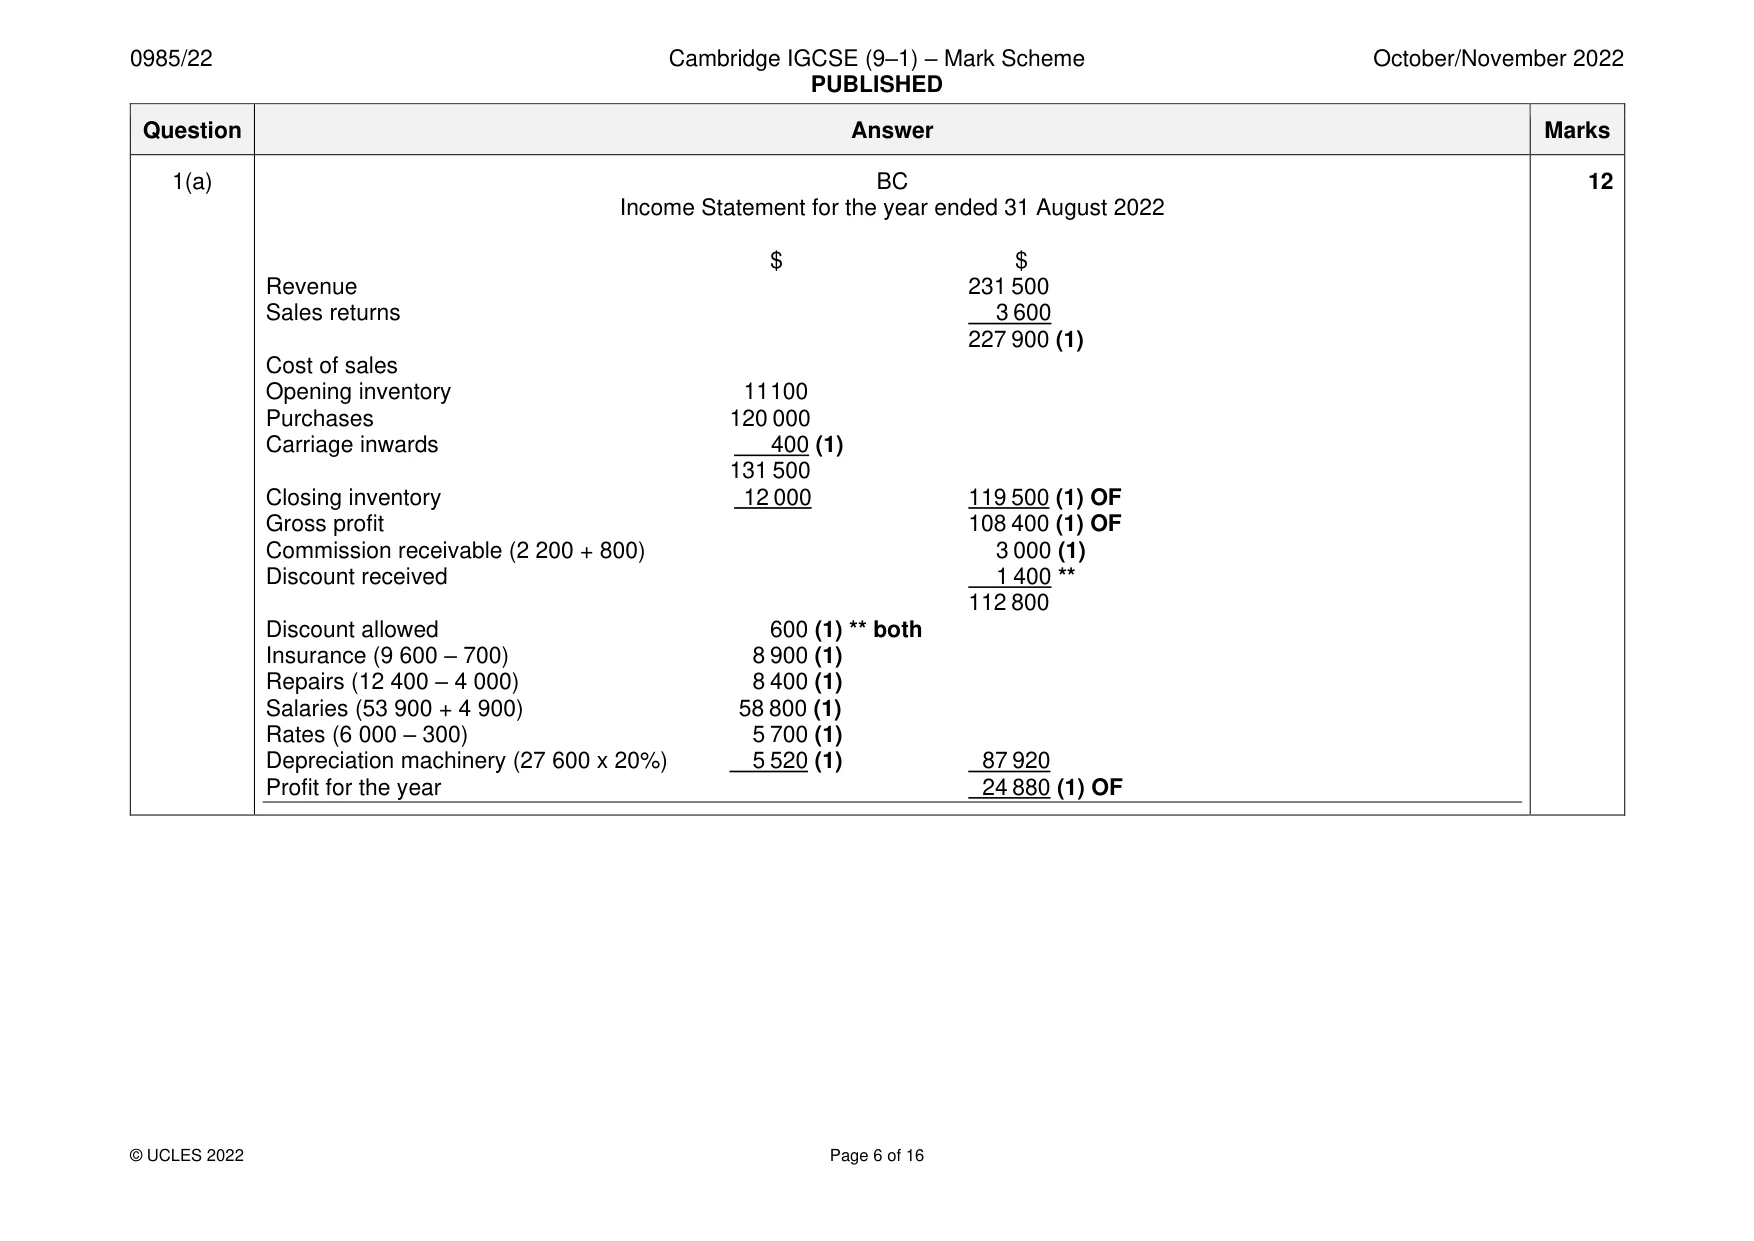
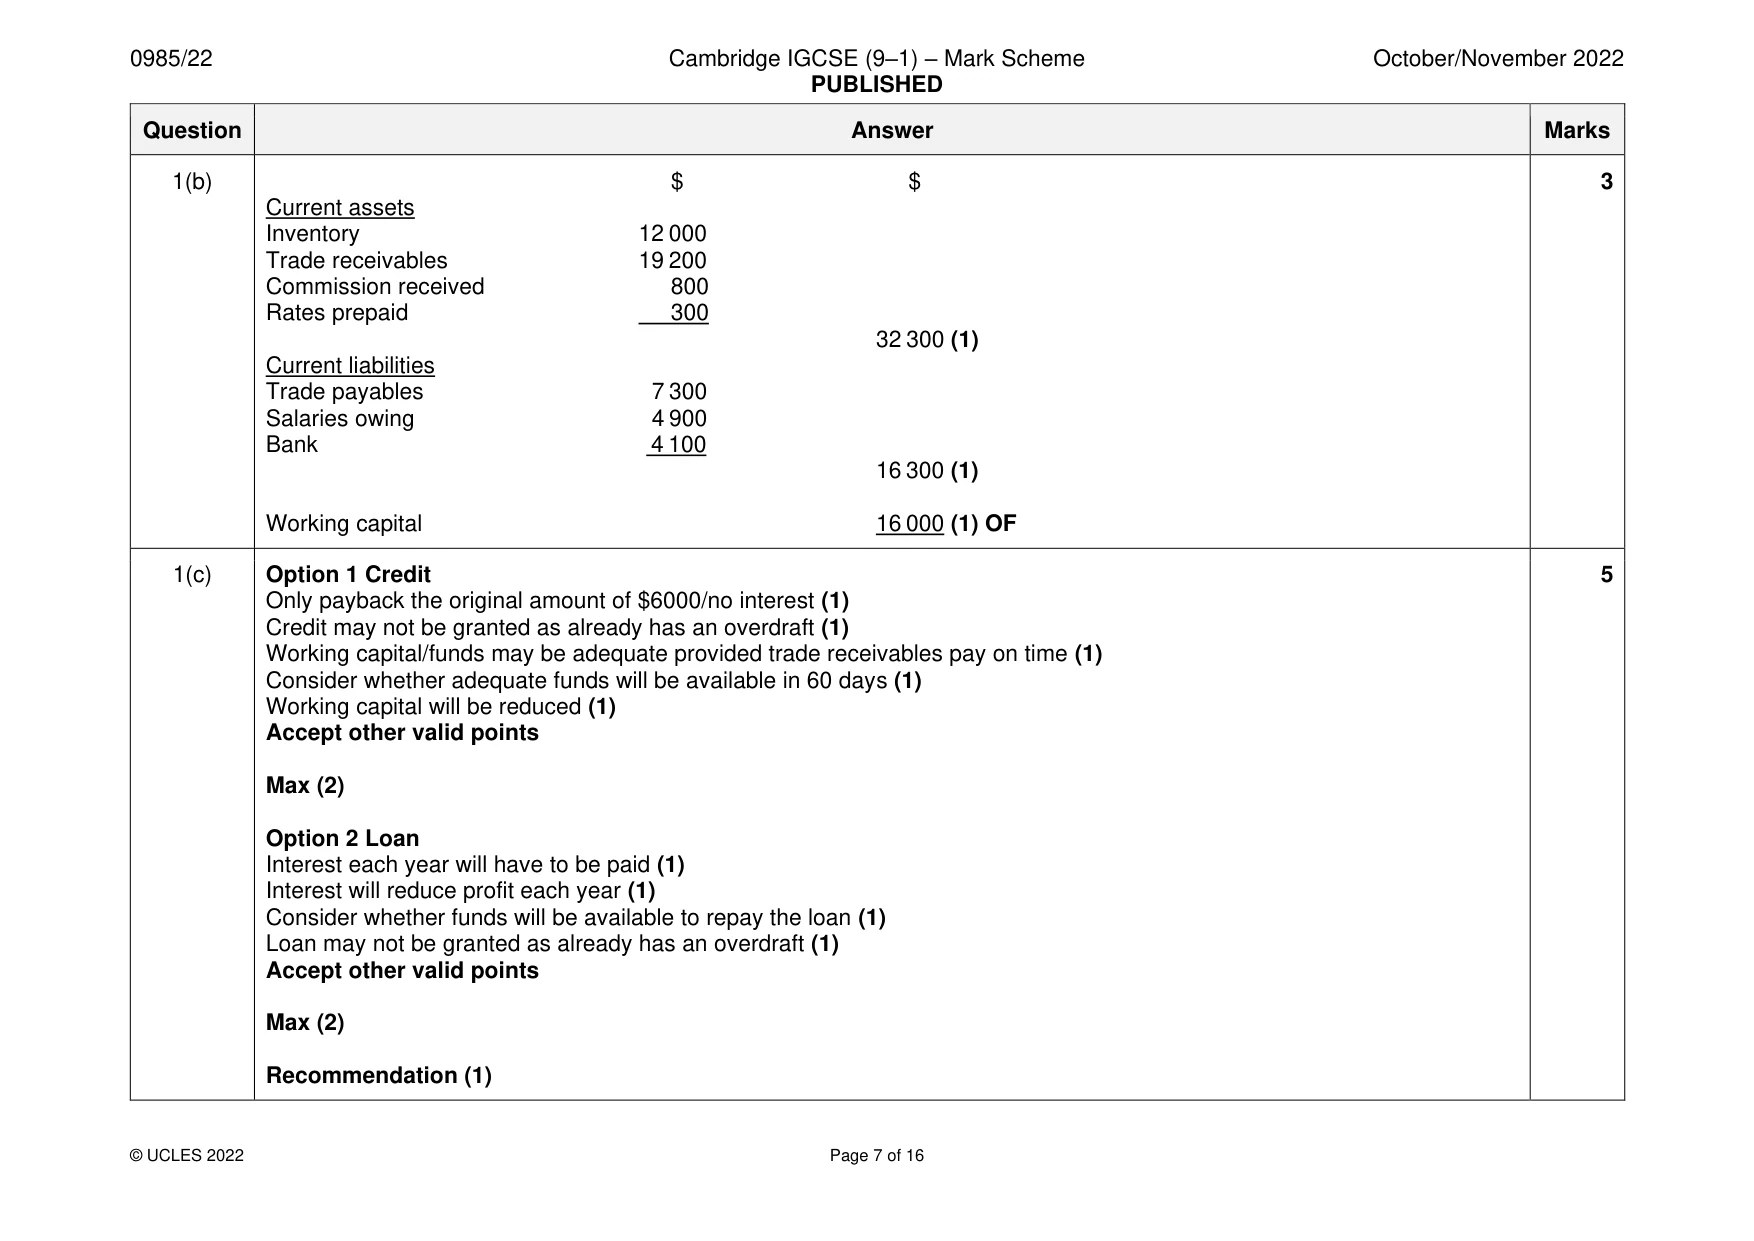
Mark scheme: Question Answer Marks 1(a) BC 12 Income Statement for the year ended 31 August 2022 $ $ Revenue 231 500 Sales returns 3 600 227 900 (1) Cost of sales Opening inventory 11 100 Purchases 120 000 Carriage inwards 400 (1) 131 500 Closing inventory 12 000 119 500 (1) OF Gross profit 108 400 (1) OF Commission receivable (2 200 + 800) 3 000 (1) Discount received 1 400 ** 112 800 Discount allowed 600 (1) ** both Insurance (9 600 – 700) 8 900 (1) Repairs (12 400 – 4 000) 8 400 (1) Salaries (53 900 + 4 900) 58 800 (1) Rates (6 000 – 300) 5 700 (1) Depreciation machinery (27 600 x 20%) 5 520 (1) 87 920 Profit for the year 24 880 (1) OF 1(b) $ $ 3 Current assets Inventory 12 000 Trade receivables 19 200 Commission received 800 Rates prepaid 300 32 300 (1) Current liabilities Trade payables 7 300 Salaries owing 4 900 Bank 4 100 16 300 (1) Working capital 16 000 (1) OF 1(c) Option 1 Credit 5 Only payback the original amount of $6000/no interest (1) Credit may not be granted as already has an overdraft (1) Working capital/funds may be adequate provided trade receivables pay on time (1) Consider whether adequate funds will be available in 60 days (1) Working capital will be reduced (1) Accept other valid points Max (2) Option 2 Loan Interest each year will have to be paid (1) Interest will reduce profit each year (1) Consider whether funds will be available to repay the loan (1) Loan may not be granted as already has an overdraft (1) Accept other valid points Max (2) Recommendation (1)
Q2 · MC is a trader who maintains a full set of accounting records and prepares control…
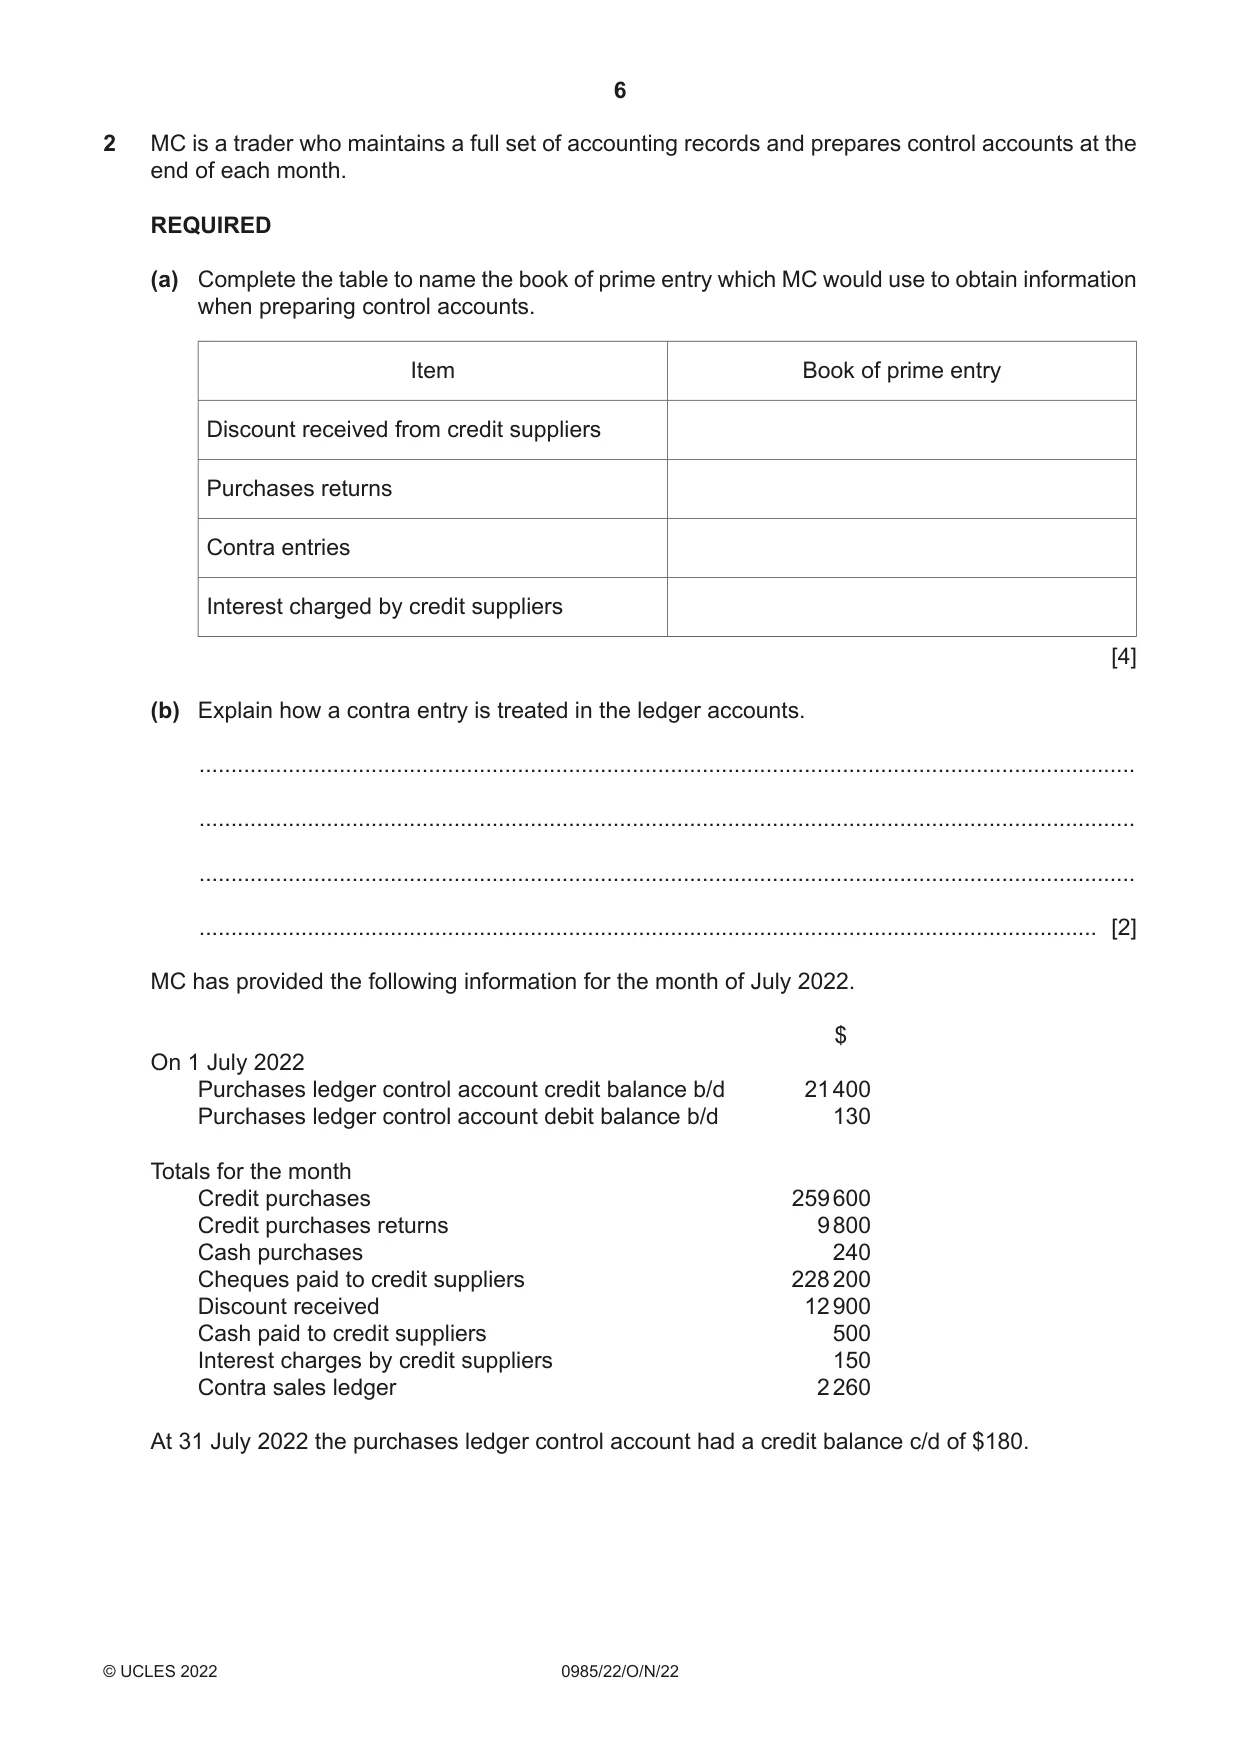
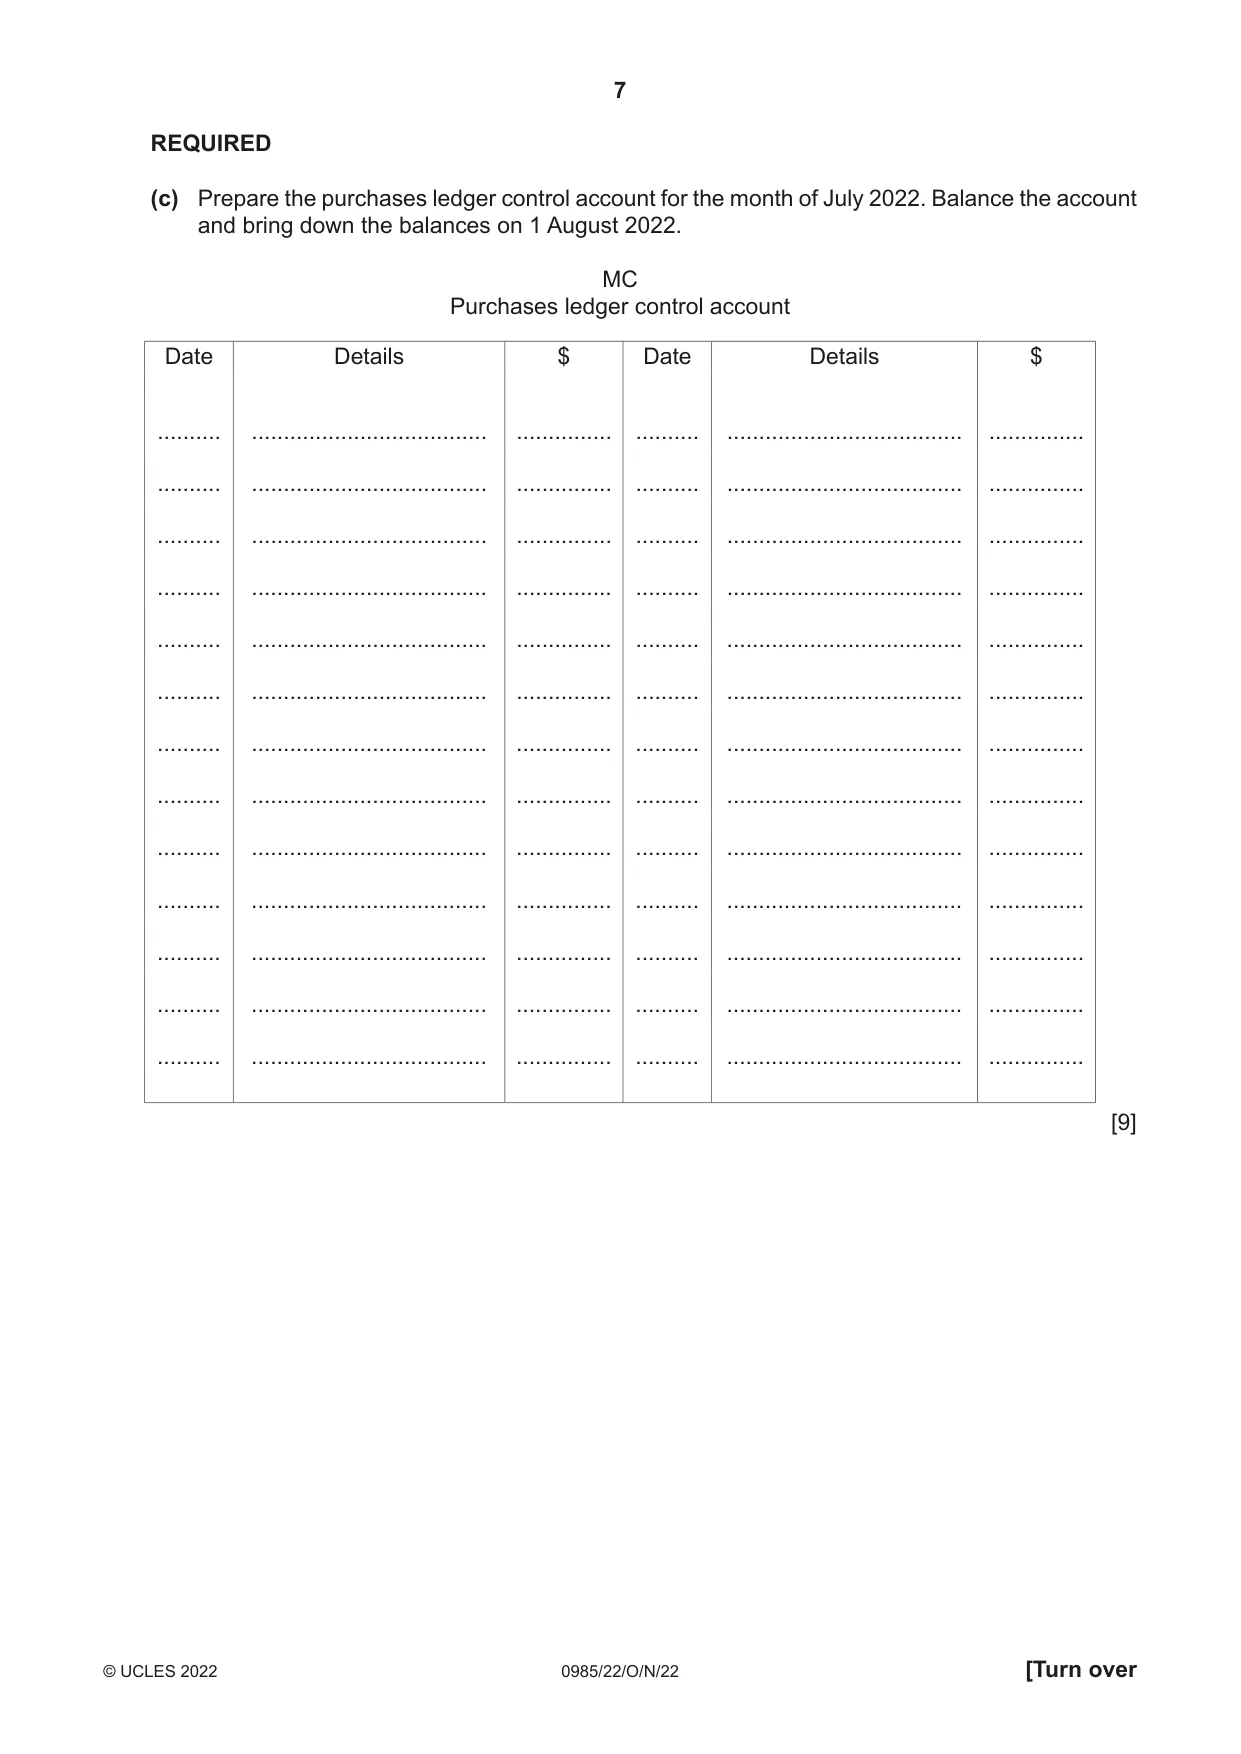
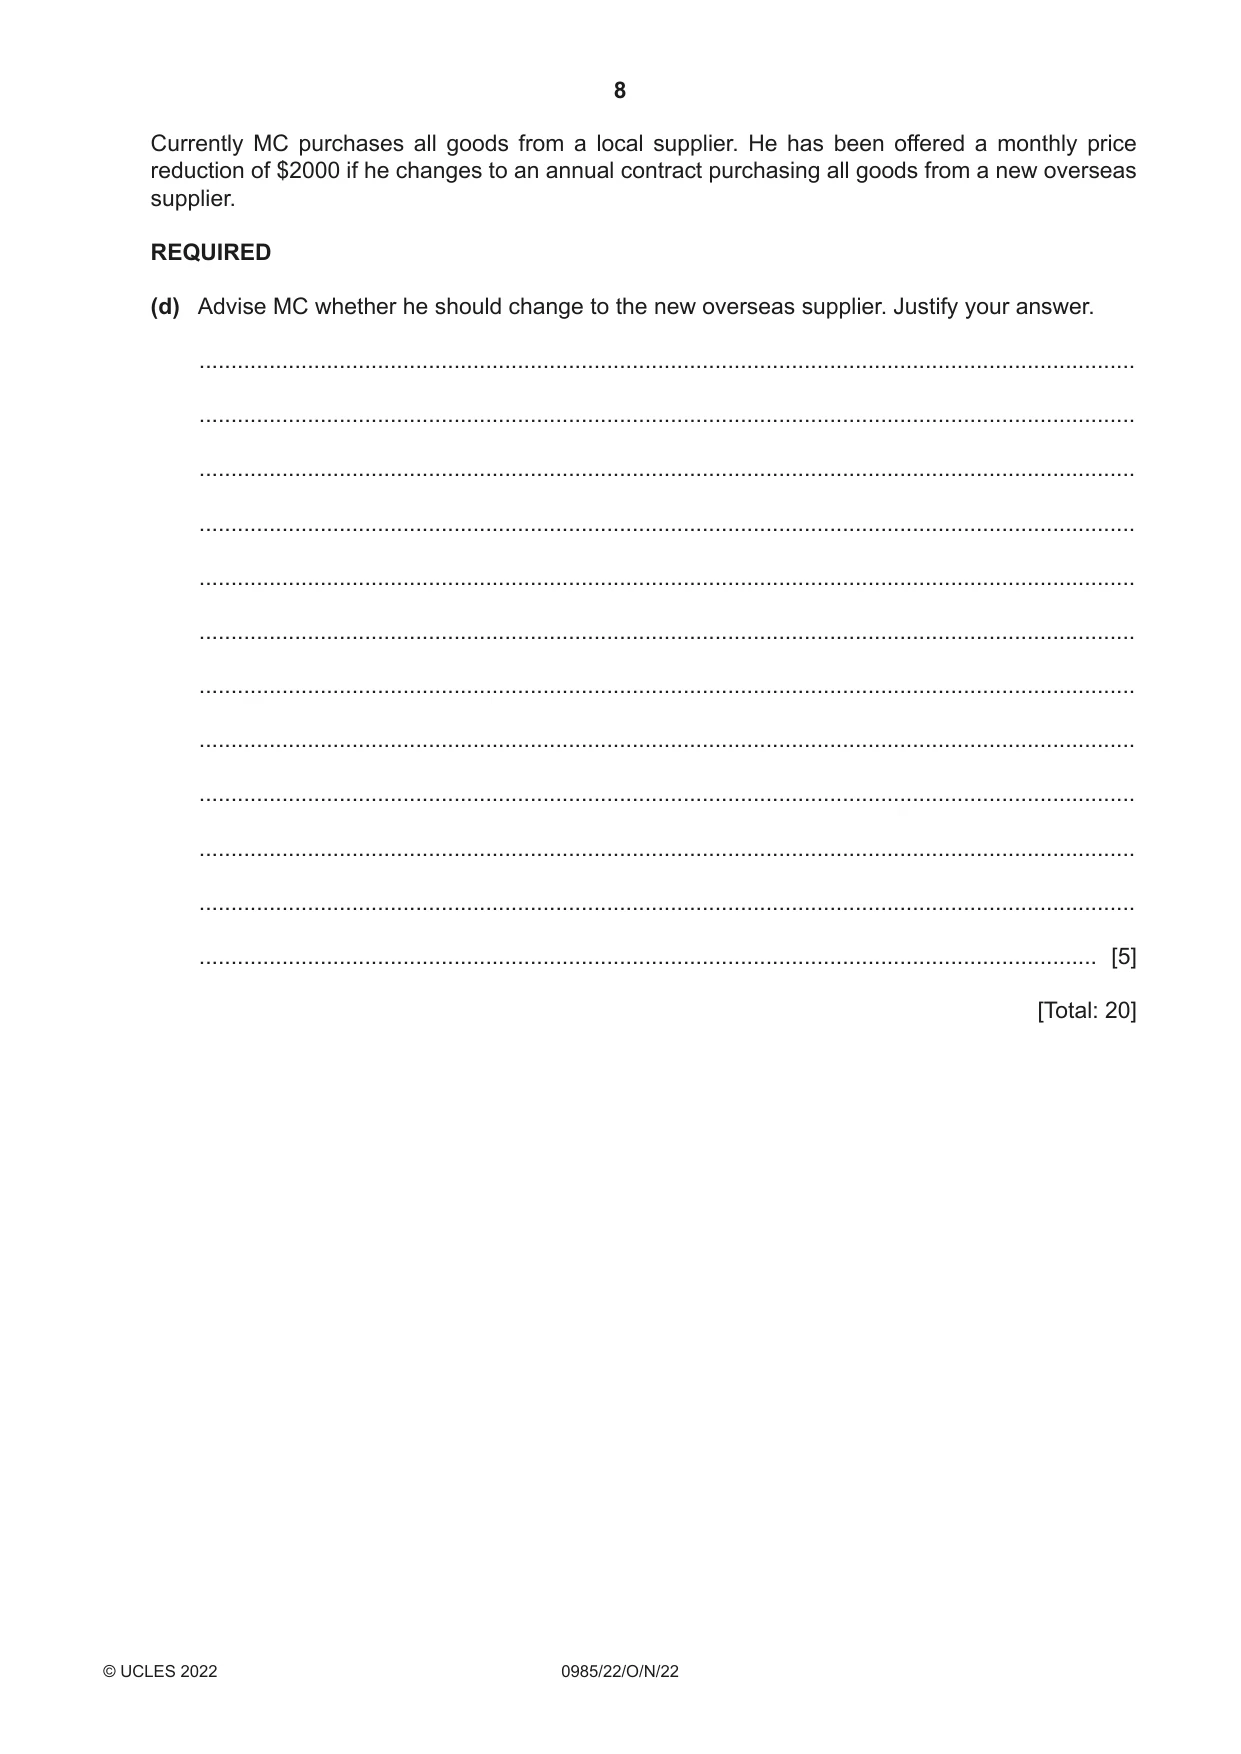
2 MC is a trader who maintains a full set of accounting records and prepares control accounts at the end of each month. REQUIRED (a) Complete the table to name the book of prime entry which MC would use to obtain information when preparing control accounts. Item Book of prime entry Discount received from credit suppliers Purchases returns Contra entries Interest charged by credit suppliers [4] (b) Explain how a contra entry is treated in the ledger accounts. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] MC has provided the following information for the month of July 2022. $ On 1 July 2022 Purchases ledger control account credit balance b/d 21 400 Purchases ledger control account debit balance b/d 130 Totals for the month Credit purchases 259 600 Credit purchases returns 9 800 Cash purchases 240 Cheques paid to credit suppliers 228 200 Discount received 12 900 Cash paid to credit suppliers 500 Interest charges by credit suppliers 150 Contra sales ledger 2 260 At 31 July 2022 the purchases ledger control account had a credit balance c/d of $180. REQUIRED (c) Prepare the purchases ledger control account for the month of July 2022. Balance the account and bring down the balances on 1 August 2022. MC Purchases ledger control account Date Details $ Date Details $ .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... [9] Currently MC purchases all goods from a local supplier. He has been offered a monthly price reduction of $2000 if he changes to an annual contract purchasing all goods from a new overseas supplier. REQUIRED (d) Advise MC whether he should change to the new overseas supplier. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
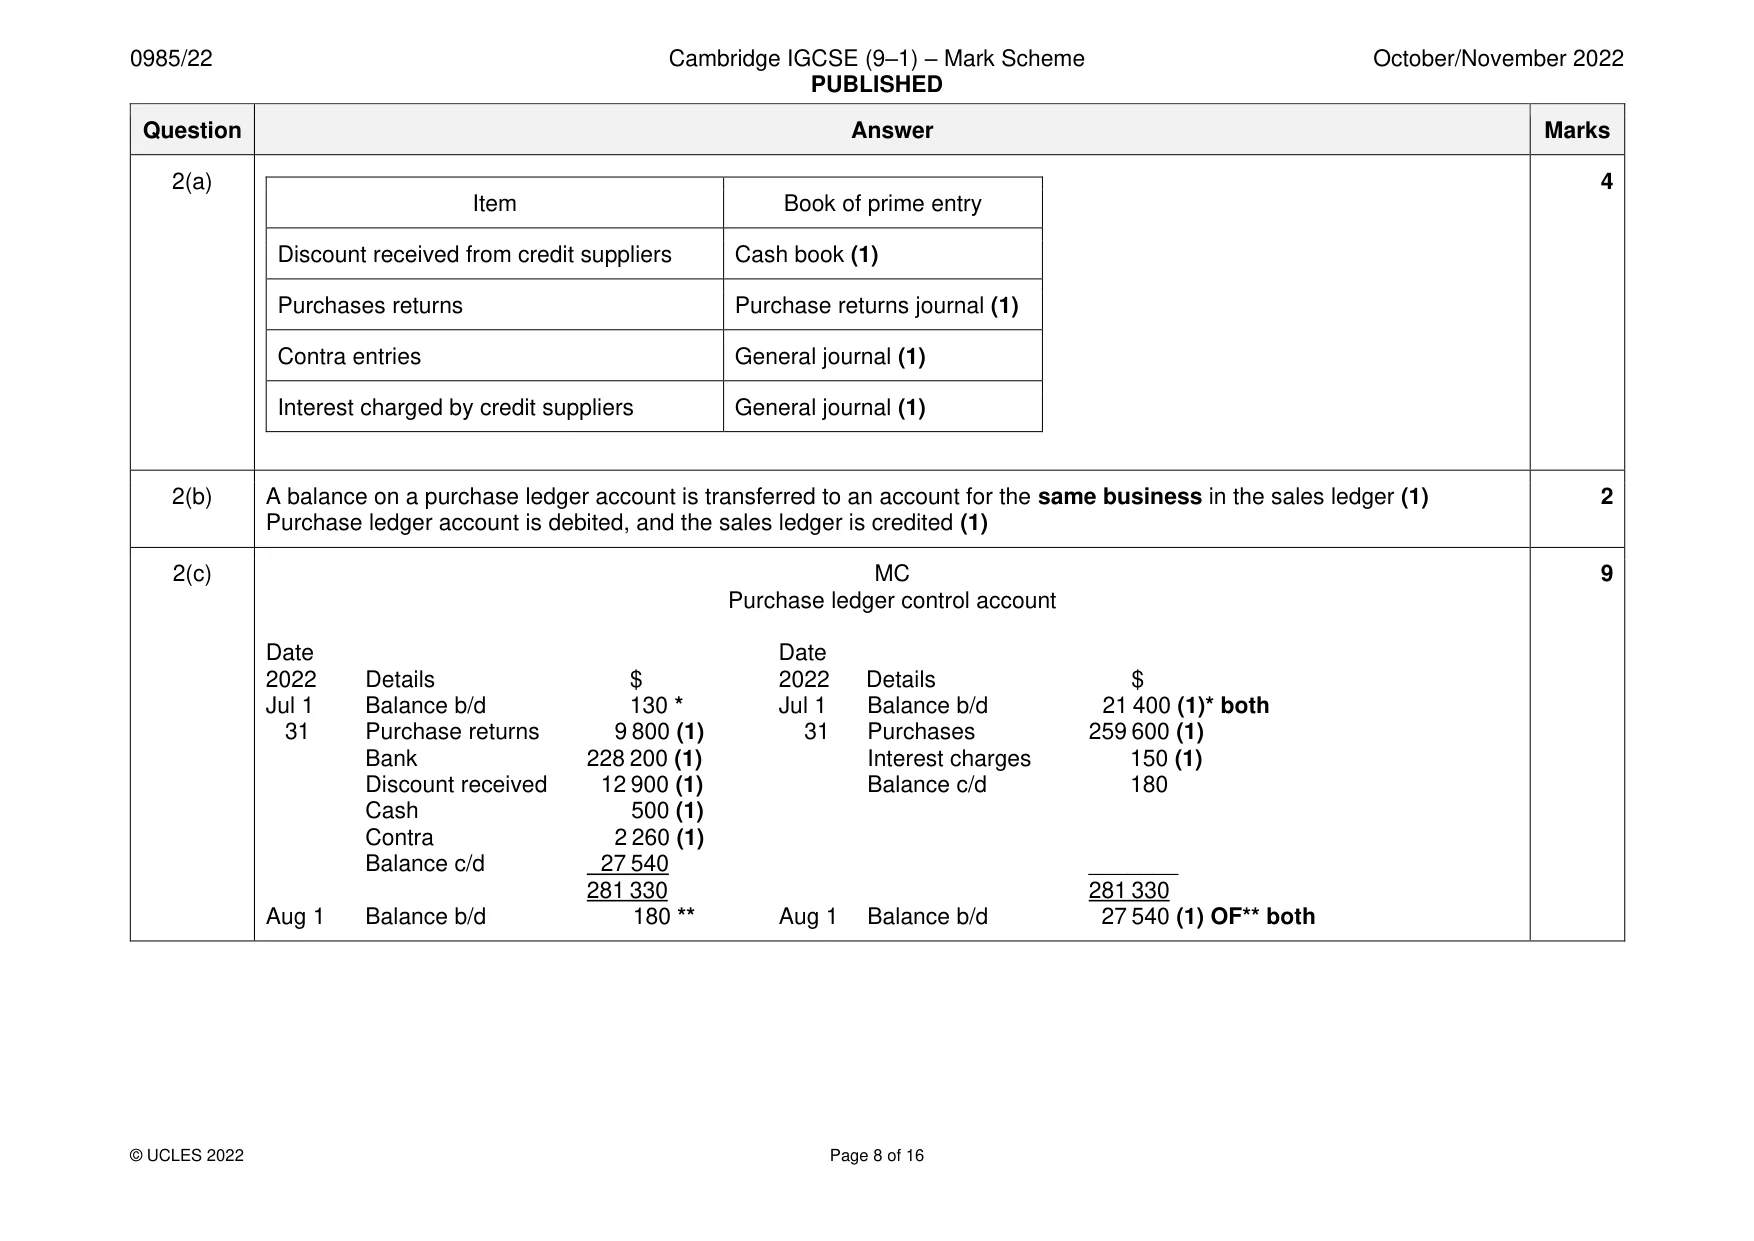
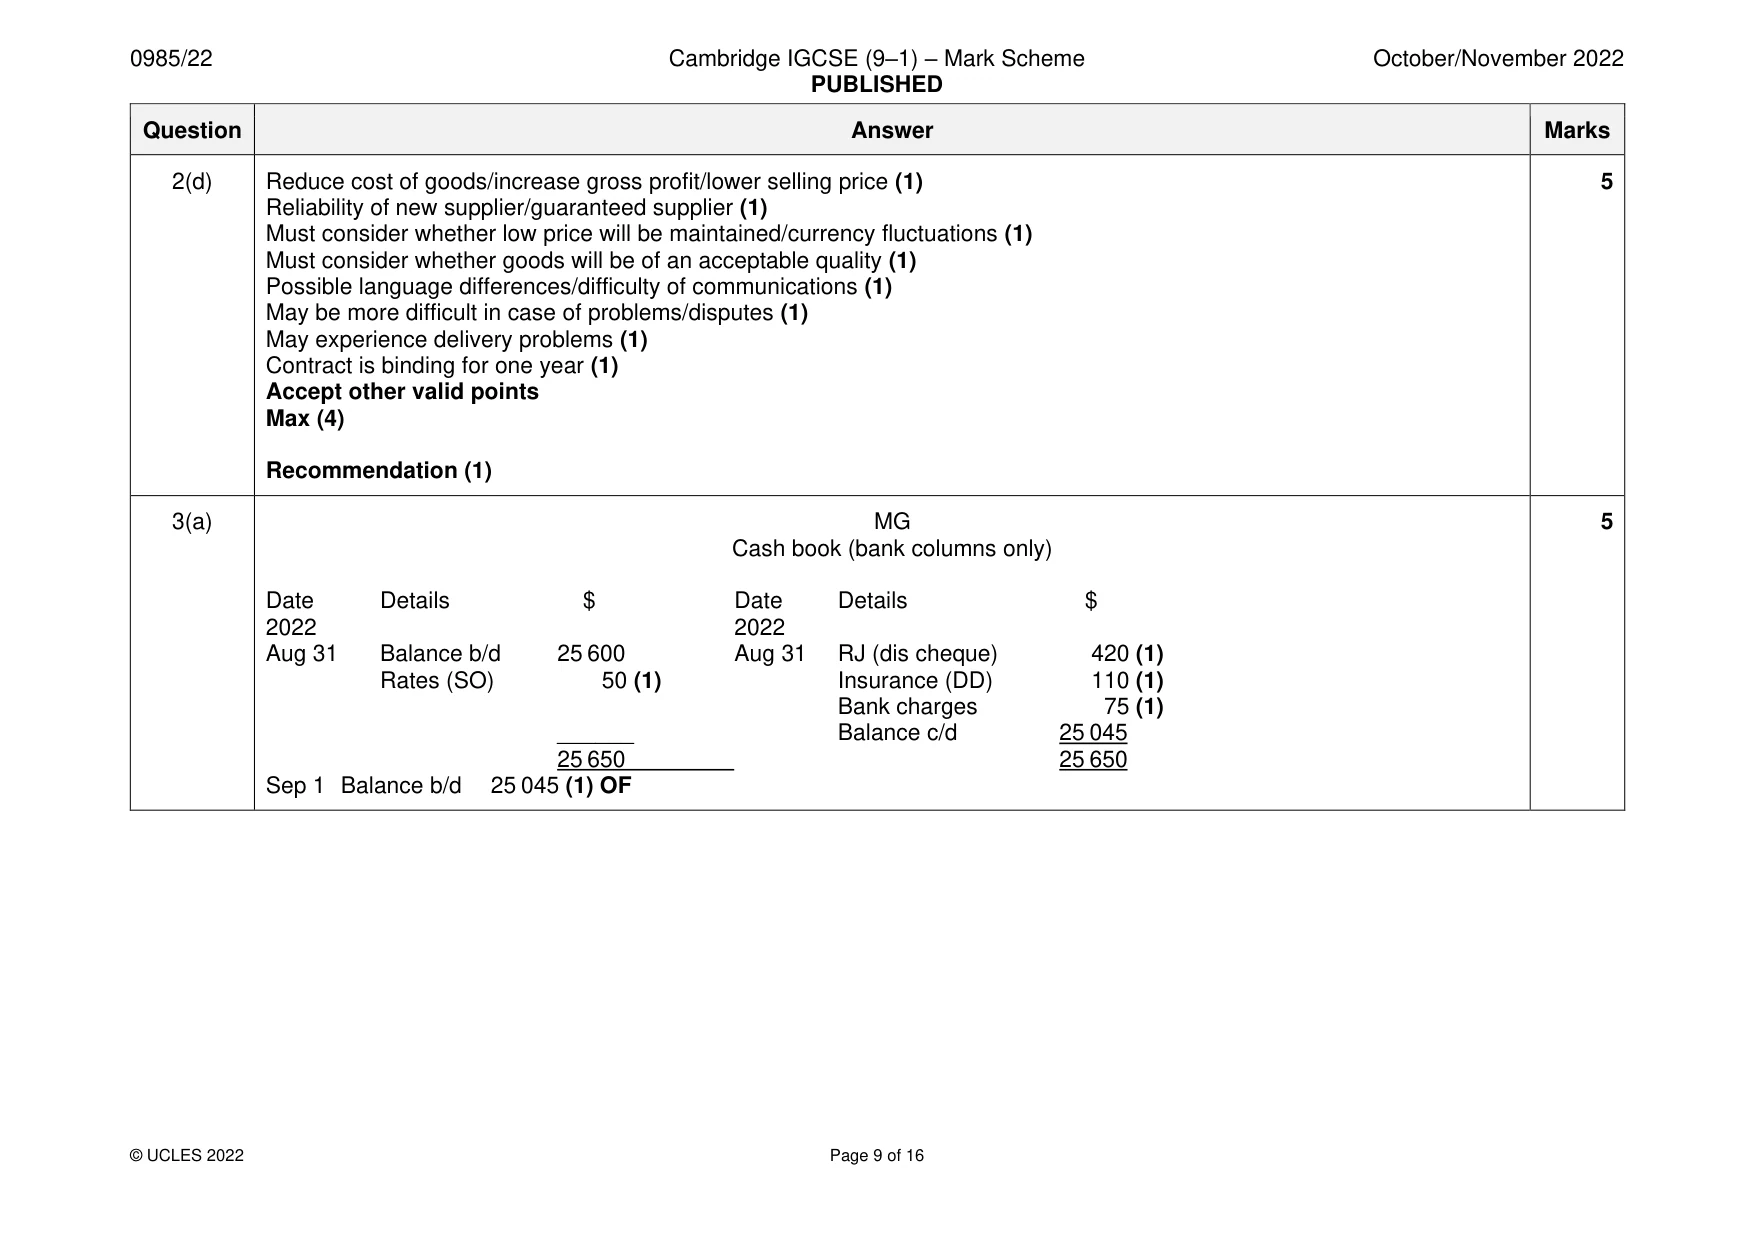
Mark scheme: 2(a) 4 Item Book of prime entry Discount received from credit suppliers Cash book (1) Purchases returns Purchase returns journal (1) Contra entries General journal (1) Interest charged by credit suppliers General journal (1) 2(b) A balance on a purchase ledger account is transferred to an account for the same business in the sales ledger (1) 2 Purchase ledger account is debited, and the sales ledger is credited (1) 2(c) MC 9 Purchase ledger control account Date Date 2022 Details $ 2022 Details $ Jul 1 Balance b/d 130 * Jul 1 Balance b/d 21 400 (1)* both 31 Purchase returns 9 800 (1) 31 Purchases 259 600 (1) Bank 228 200 (1) Interest charges 150 (1) Discount received 12 900 (1) Balance c/d 180 Cash 500 (1) Contra 2 260 (1) Balance c/d 27 540 _______ 281 330 281 330 Aug 1 Balance b/d 180 ** Aug 1 Balance b/d 27 540 (1) OF** both 2(d) Reduce cost of goods/increase gross profit/lower selling price (1) 5 Reliability of new supplier/guaranteed supplier (1) Must consider whether low price will be maintained/currency fluctuations (1) Must consider whether goods will be of an acceptable quality (1) Possible language differences/difficulty of communications (1) May be more difficult in case of problems/disputes (1) May experience delivery problems (1) Contract is binding for one year (1) Accept other valid points Max (4) Recommendation (1)
Q3 · MG has been in business for a number of years as a furniture manufacturer
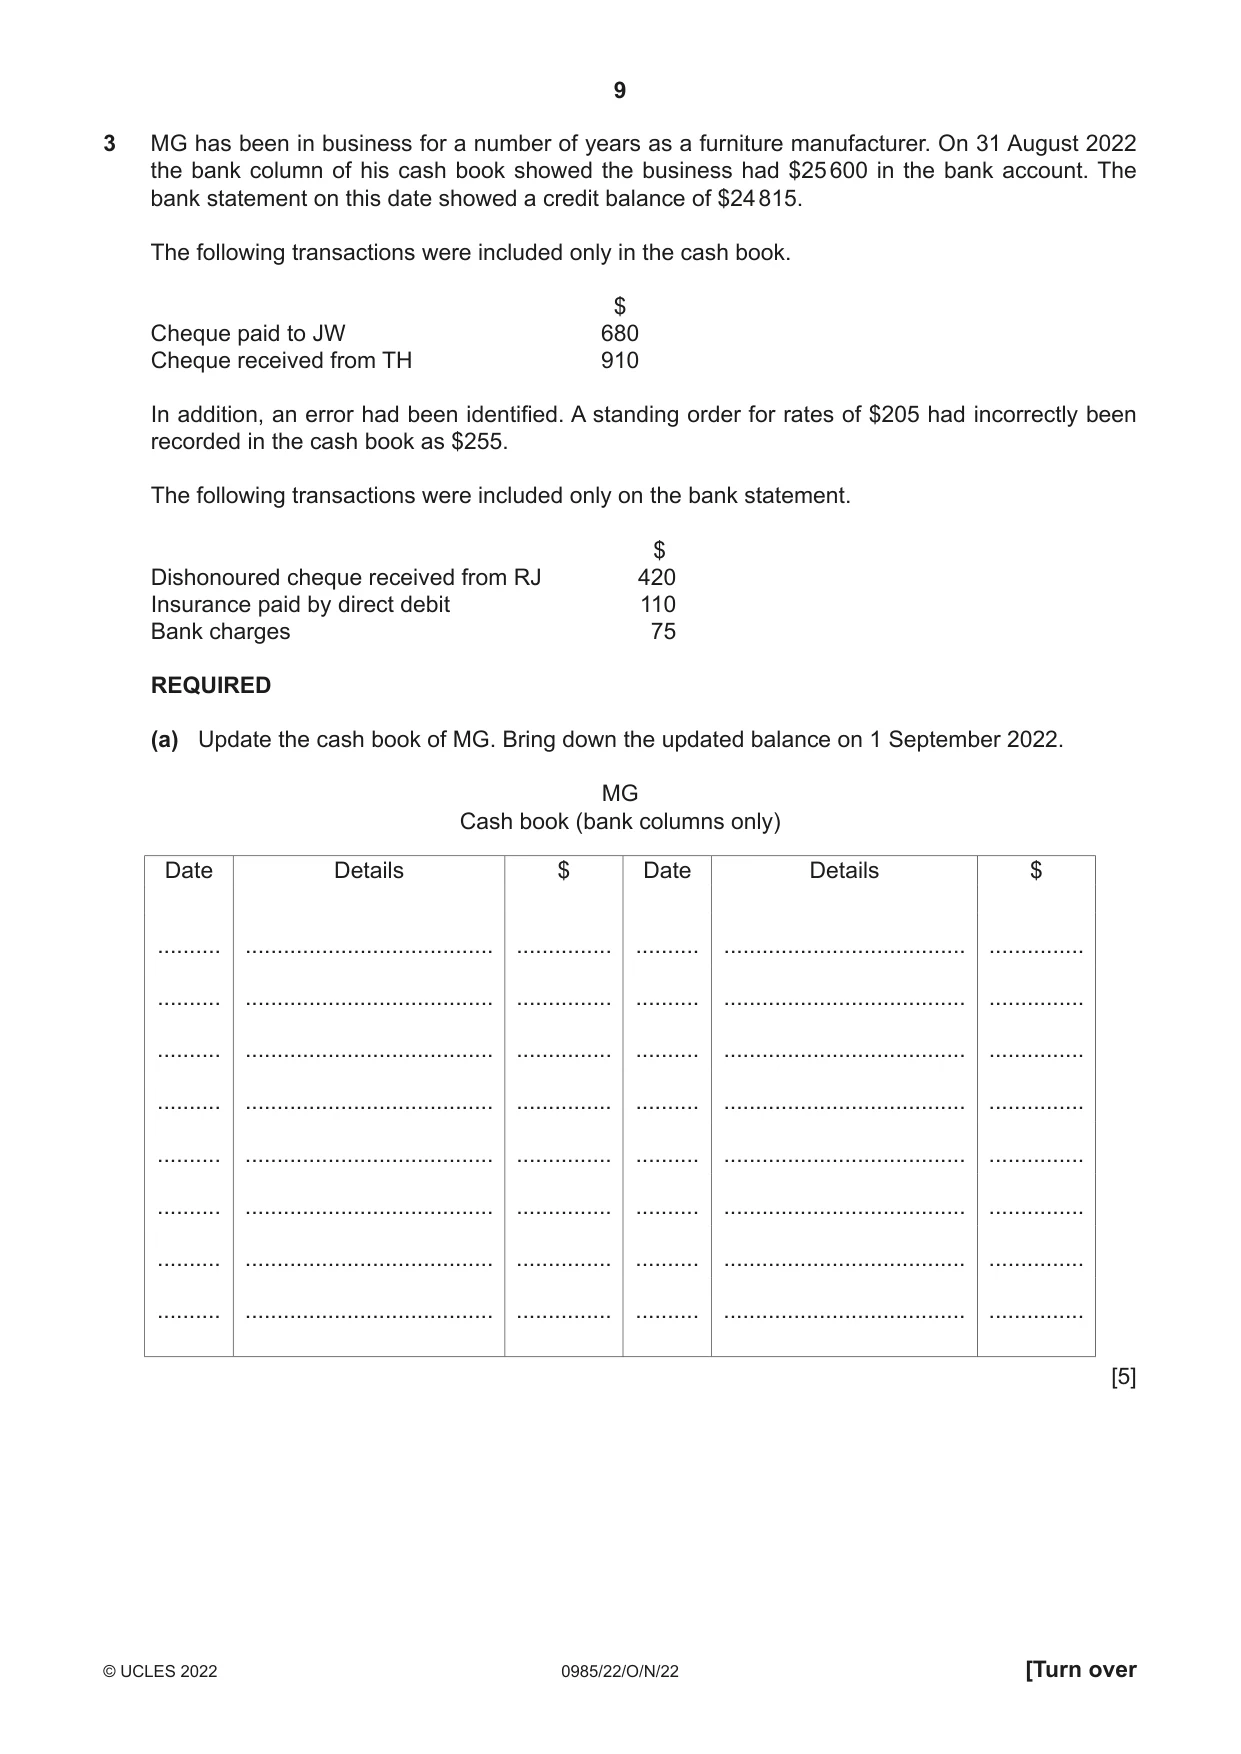
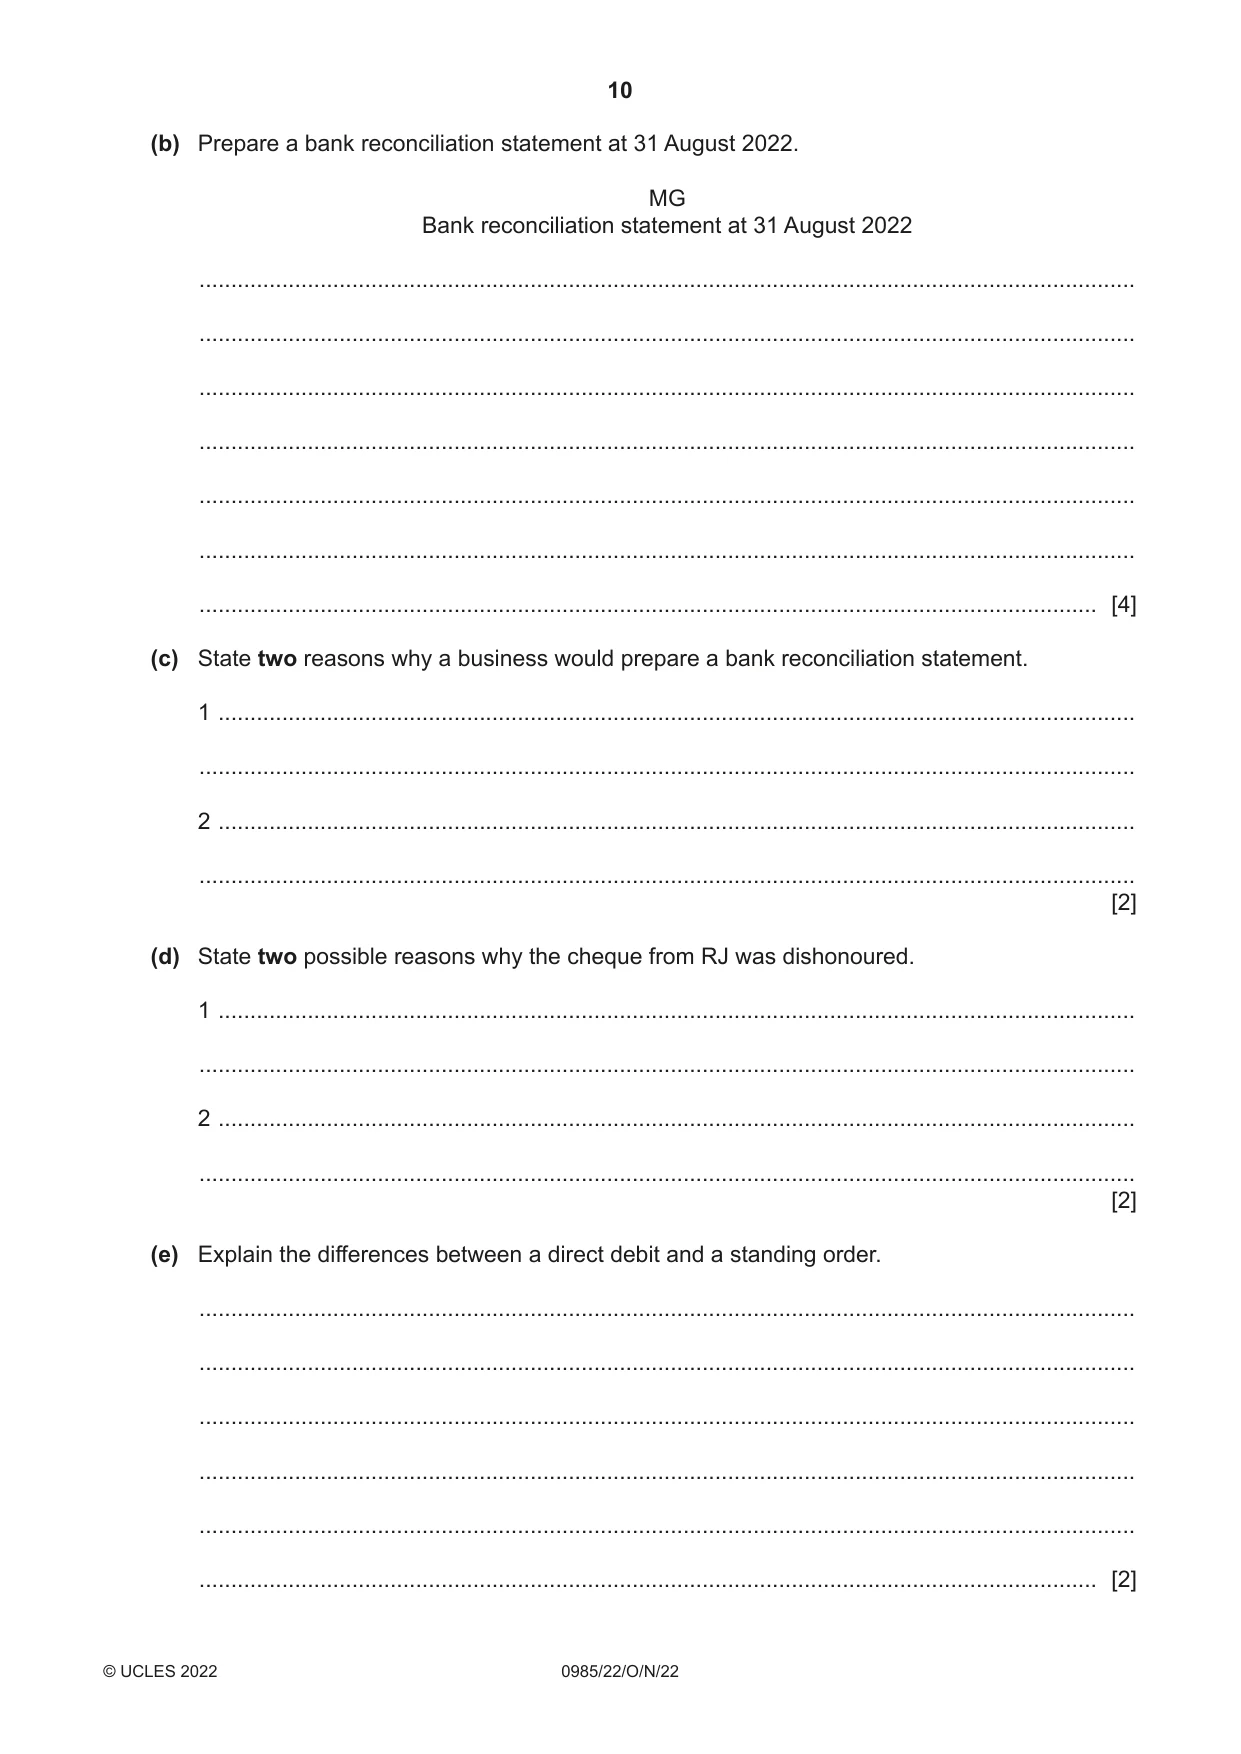
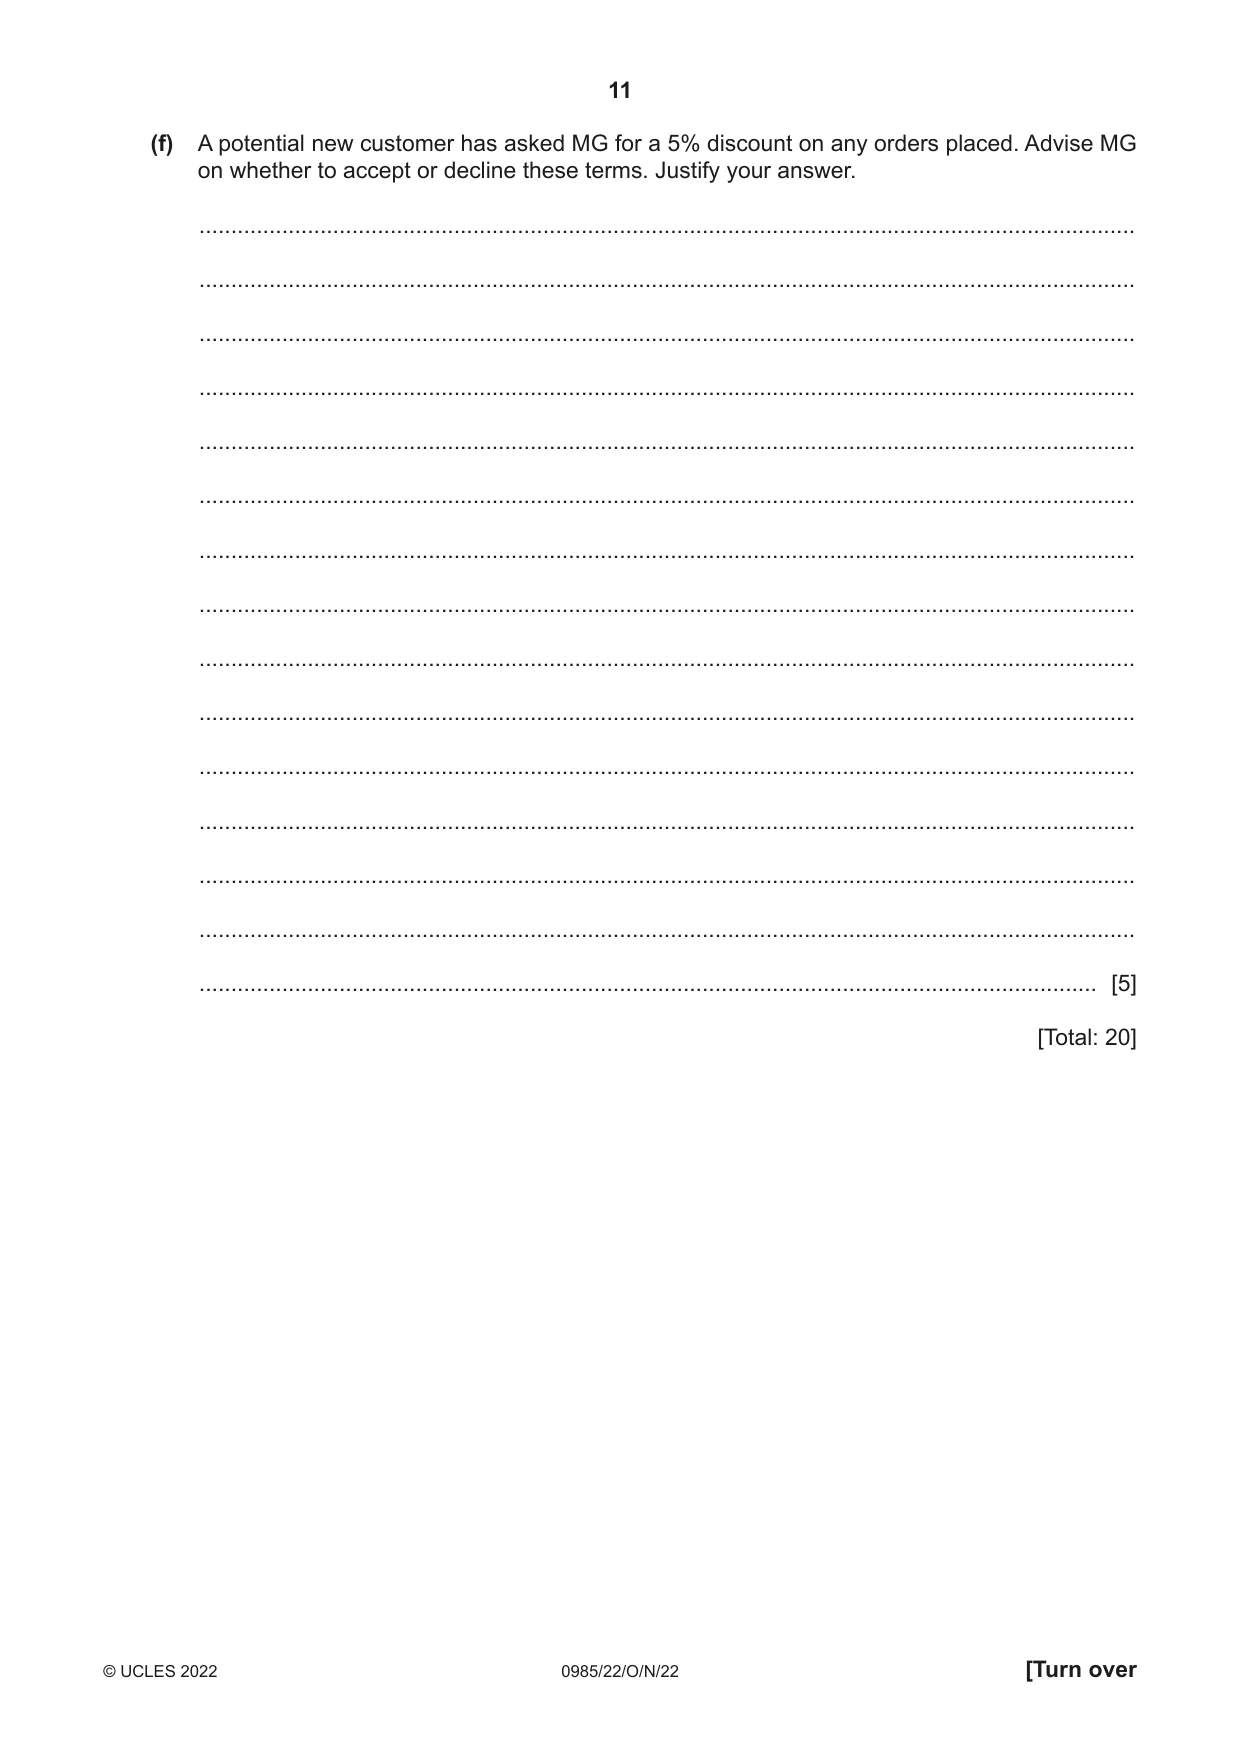
3 MG has been in business for a number of years as a furniture manufacturer. On 31 August 2022 the bank column of his cash book showed the business had $25 600 in the bank account. The bank statement on this date showed a credit balance of $24 815. The following transactions were included only in the cash book. $ Cheque paid to JW 680 Cheque received from TH 910 In addition, an error had been identified. A standing order for rates of $205 had incorrectly been recorded in the cash book as $255. The following transactions were included only on the bank statement. $ Dishonoured cheque received from RJ 420 Insurance paid by direct debit 110 Bank charges 75 REQUIRED (a) Update the cash book of MG. Bring down the updated balance on 1 September 2022. MG Cash book (bank columns only) Date Details $ Date Details $ .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... [5] (b) Prepare a bank reconciliation statement at 31 August 2022. MG Bank reconciliation statement at 31 August 2022 ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] (c) State two reasons why a business would prepare a bank reconciliation statement. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] (d) State two possible reasons why the cheque from RJ was dishonoured. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] (e) Explain the differences between a direct debit and a standing order. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] (f) A potential new customer has asked MG for a 5% discount on any orders placed. Advise MG on whether to accept or decline these terms. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
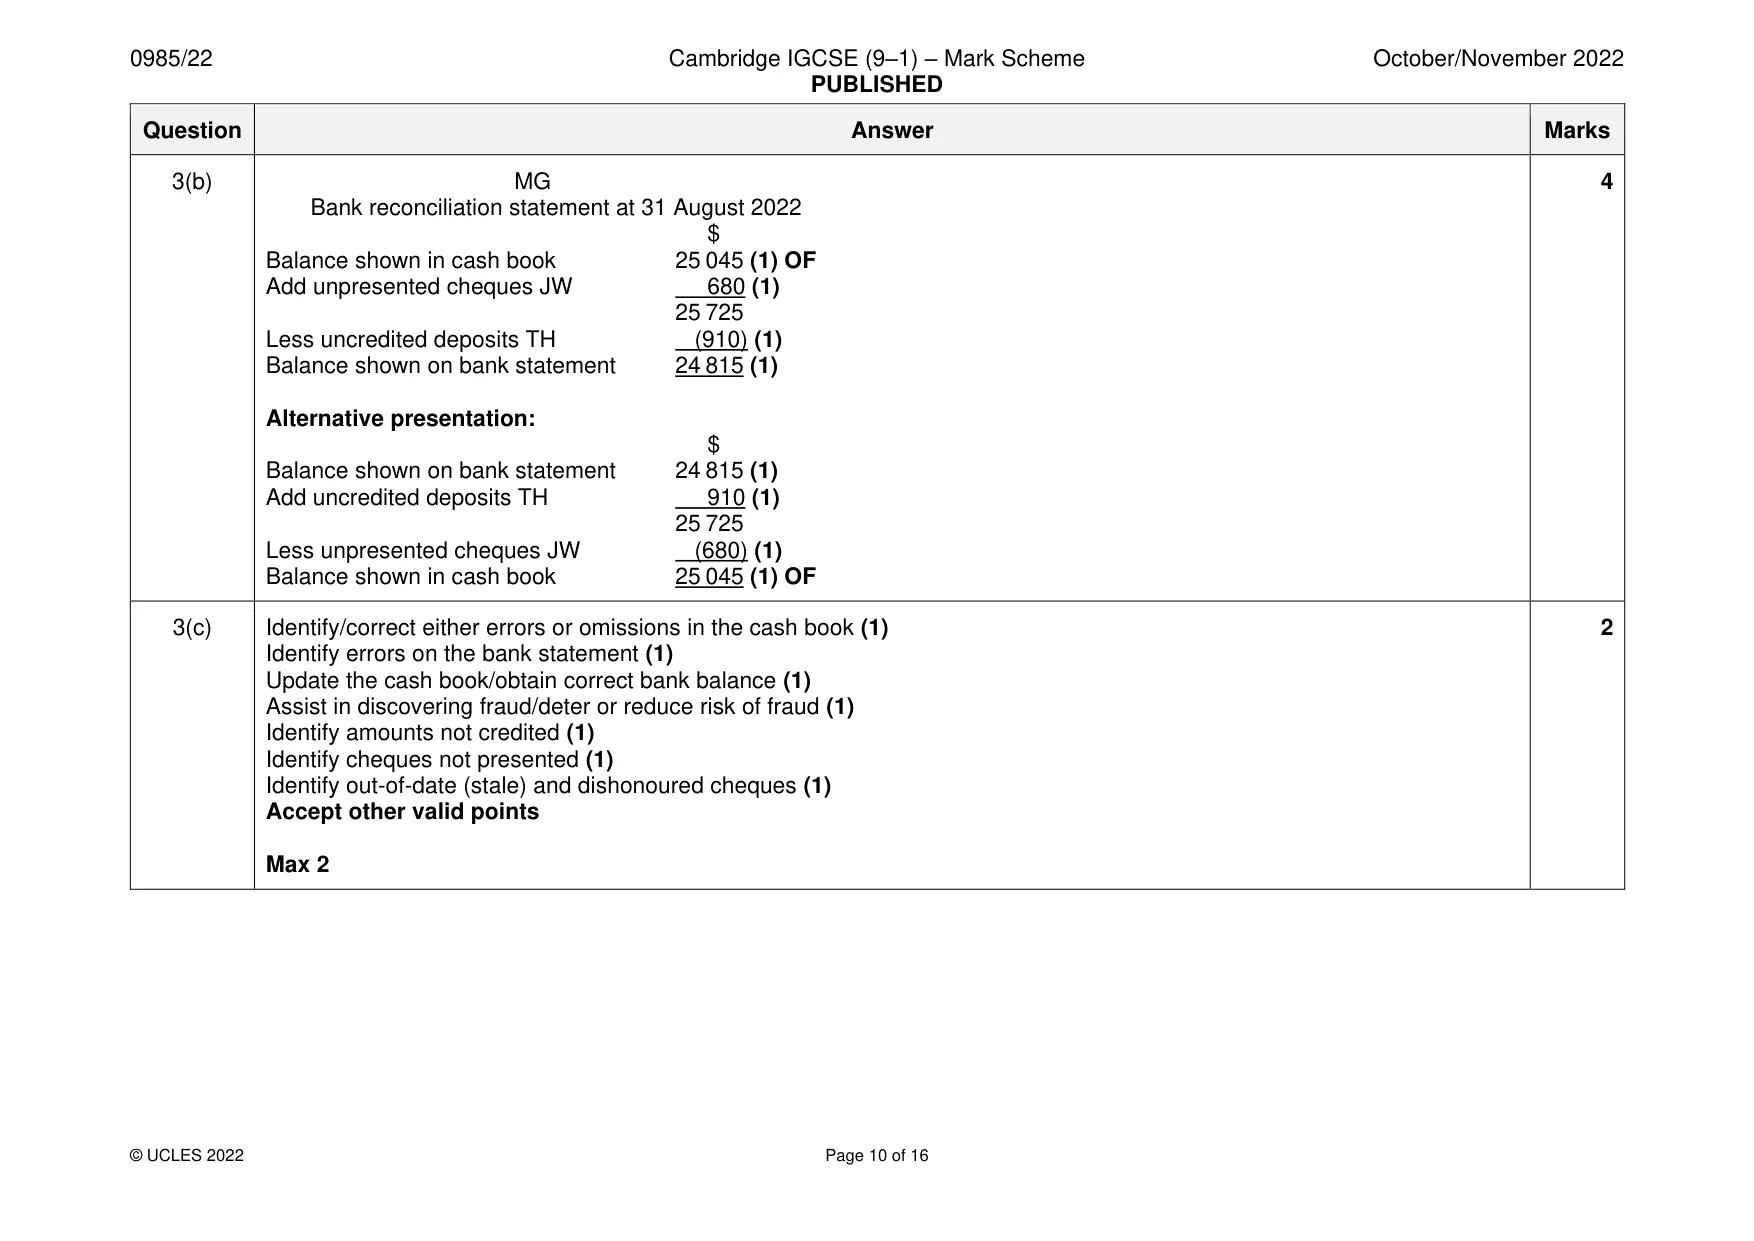
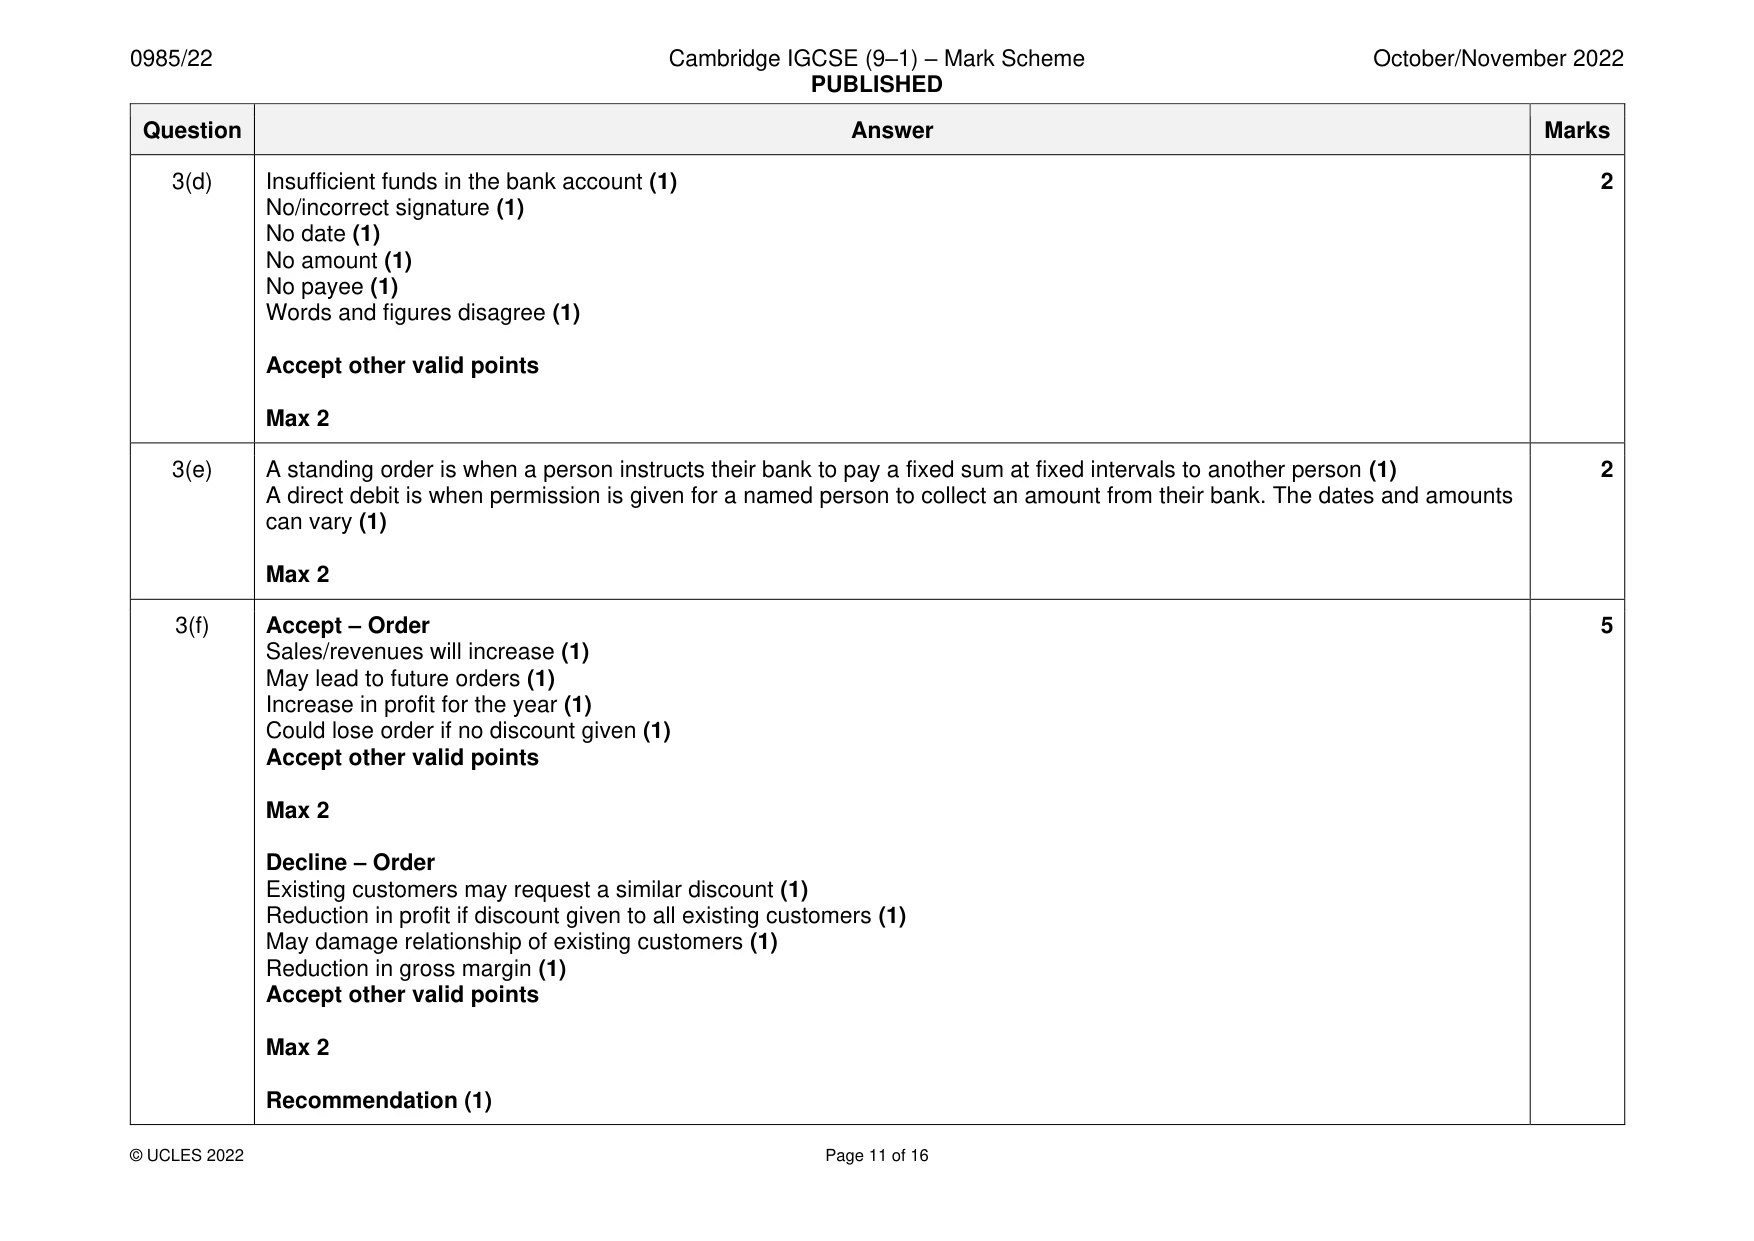
Mark scheme: 3(a) MG 5 Cash book (bank columns only) Date Details $ Date Details $ 2022 2022 Aug 31 Balance b/d 25 600 Aug 31 RJ (dis cheque) 420 (1) Rates (SO) 50 (1) Insurance (DD) 110 (1) Bank charges 75 (1) ______ Balance c/d 25 045 25 650 25 650 Sep 1 Balance b/d 25 045 (1) OF 3(b) MG 4 Bank reconciliation statement at 31 August 2022 $ Balance shown in cash book 25 045 (1) OF Add unpresented cheques JW 680 (1) 25 725 Less uncredited deposits TH (910) (1) Balance shown on bank statement 24 815 (1) Alternative presentation: $ Balance shown on bank statement 24 815 (1) Add uncredited deposits TH 910 (1) 25 725 Less unpresented cheques JW (680) (1) Balance shown in cash book 25 045 (1) OF 3(c) Identify/correct either errors or omissions in the cash book (1) 2 Identify errors on the bank statement (1) Update the cash book/obtain correct bank balance (1) Assist in discovering fraud/deter or reduce risk of fraud (1) Identify amounts not credited (1) Identify cheques not presented (1) Identify out-of-date (stale) and dishonoured cheques (1) Accept other valid points Max 2 3(d) Insufficient funds in the bank account (1) 2 No/incorrect signature (1) No date (1) No amount (1) No payee (1) Words and figures disagree (1) Accept other valid points Max 2 3(e) A standing order is when a person instructs their bank to pay a fixed sum at fixed intervals to another person (1) 2 A direct debit is when permission is given for a named person to collect an amount from their bank. The dates and amounts can vary (1) Max 2 3(f) Accept – Order 5 Sales/revenues will increase (1) May lead to future orders (1) Increase in profit for the year (1) Could lose order if no discount given (1) Accept other valid points Max 2 Decline – Order Existing customers may request a similar discount (1) Reduction in profit if discount given to all existing customers (1) May damage relationship of existing customers (1) Reduction in gross margin (1) Accept other valid points Max 2 Recommendation (1)
Q4 · PG a trader sells electrical components
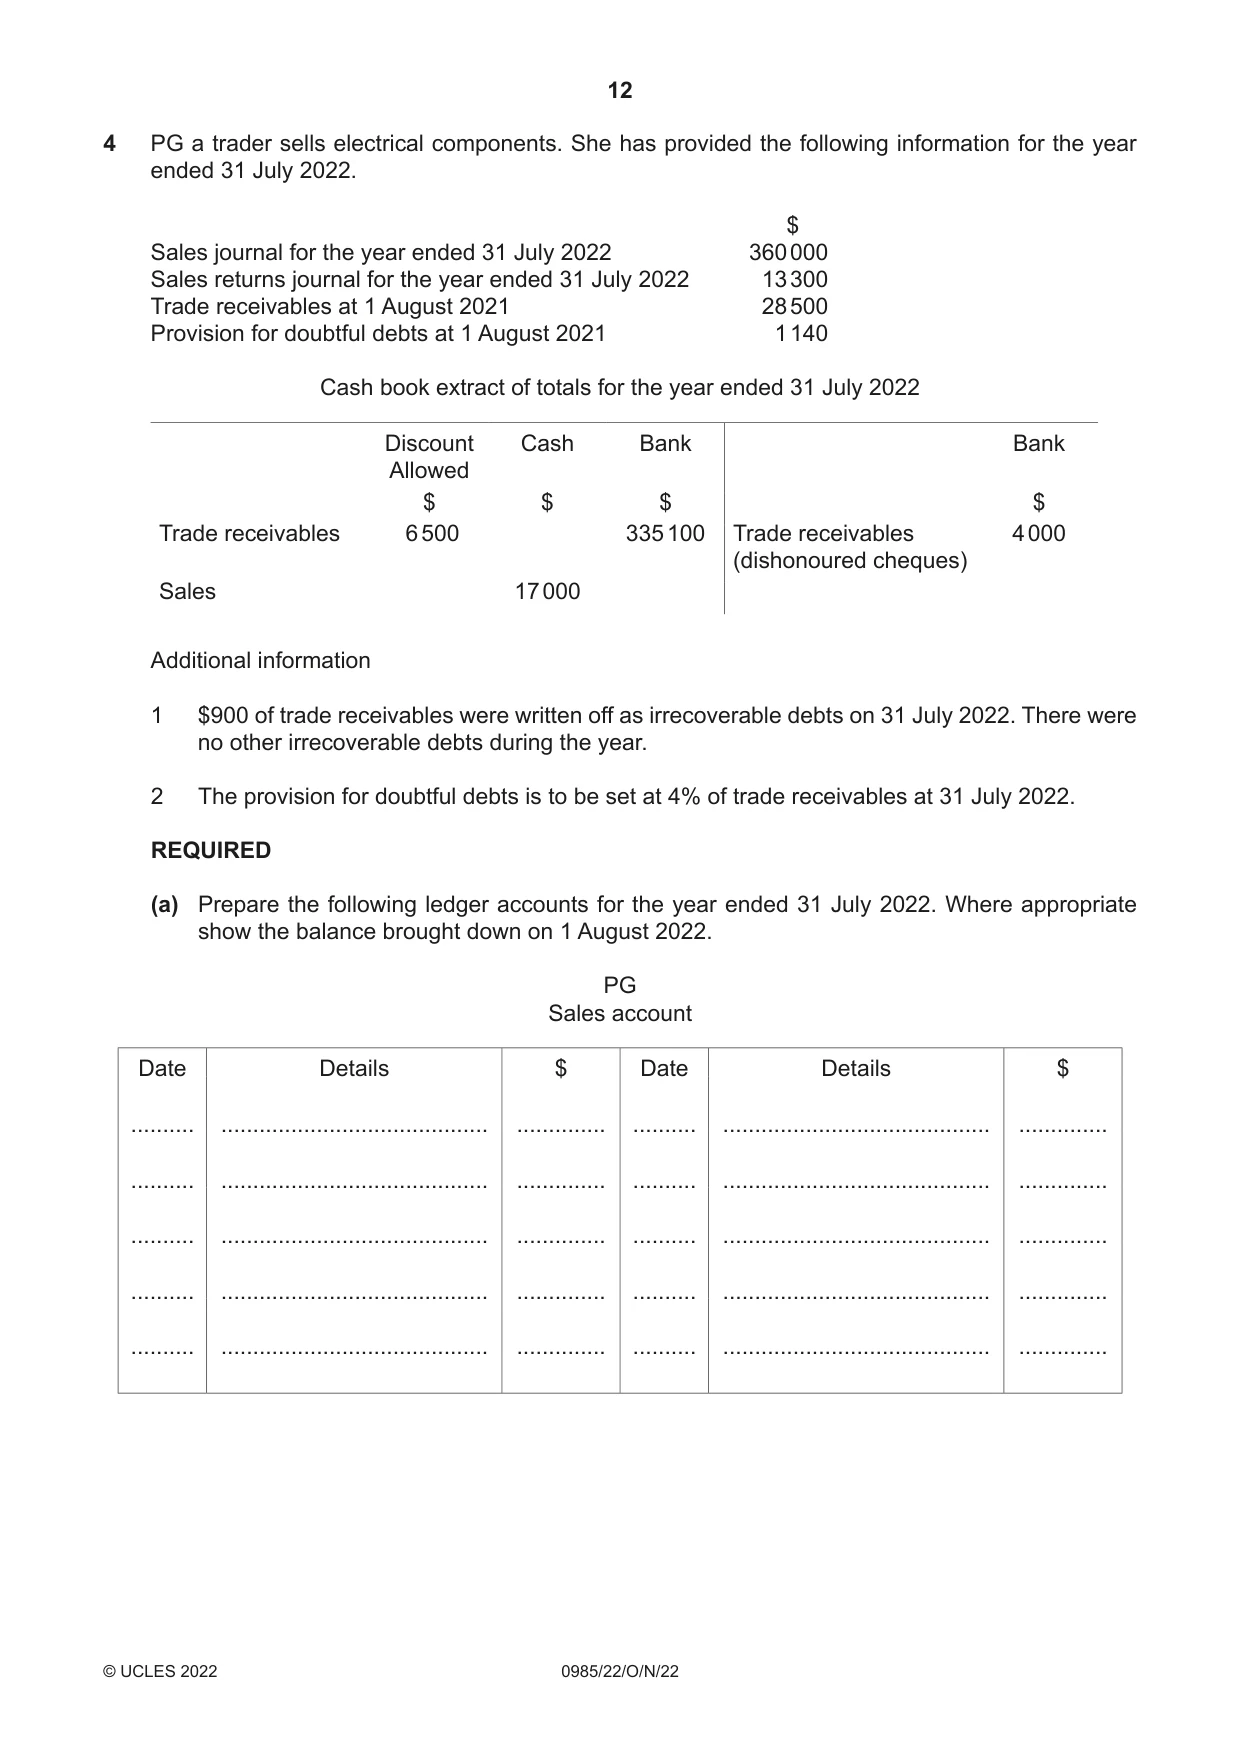
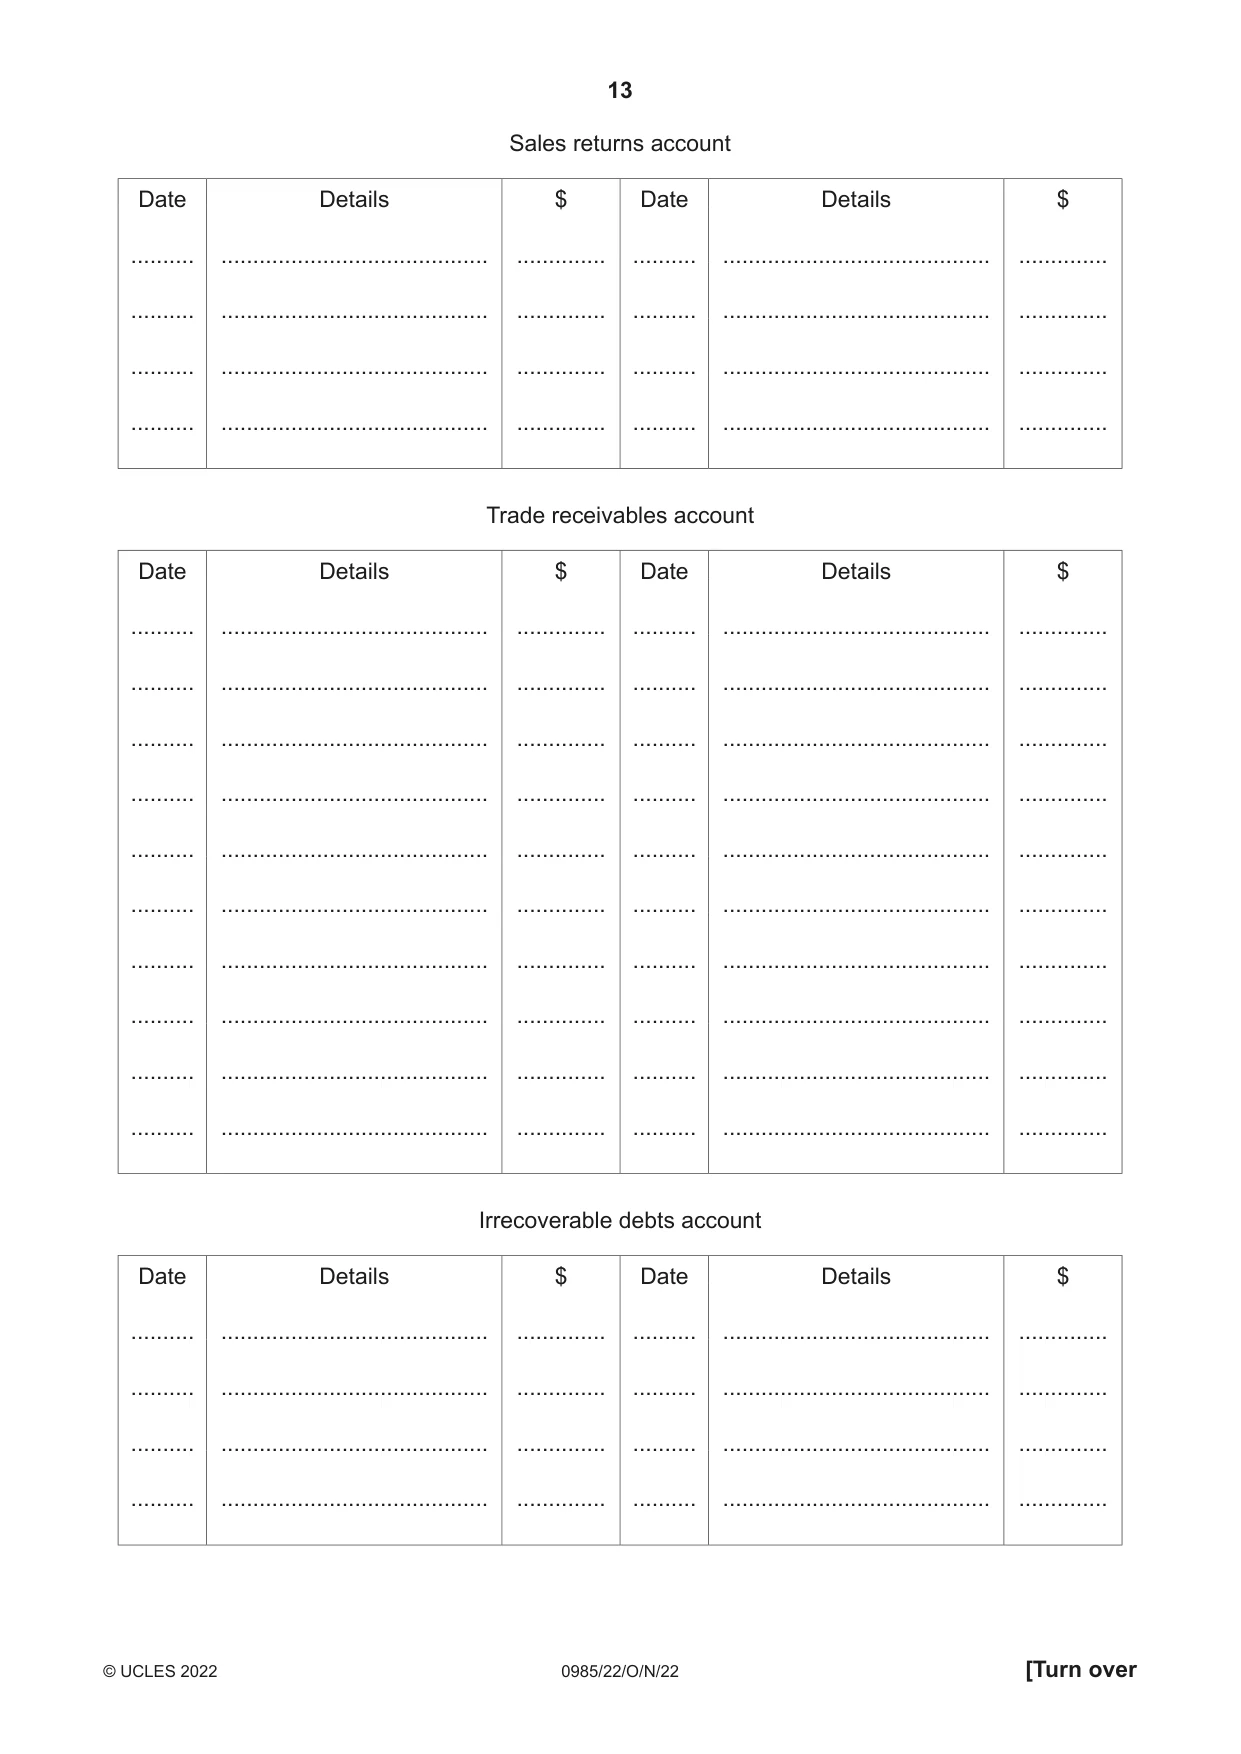
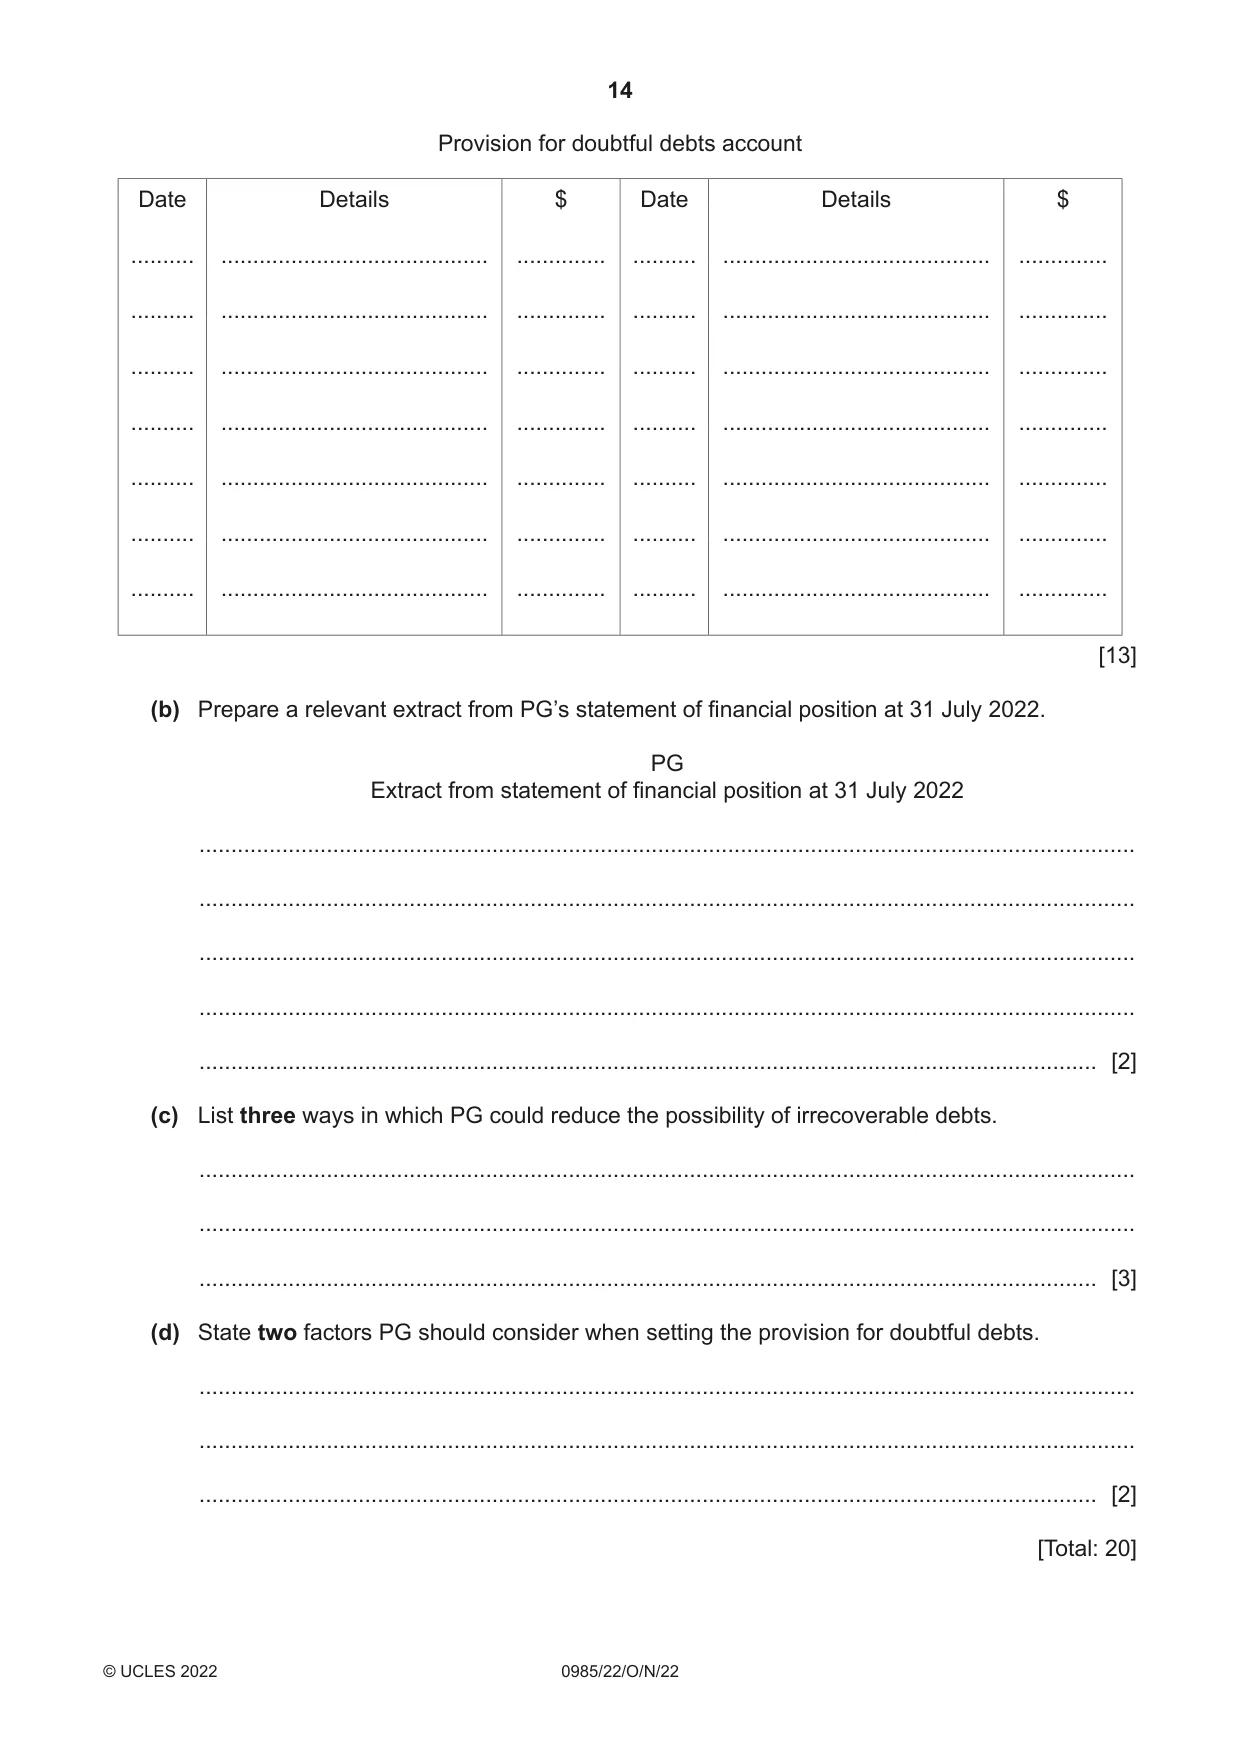
4 PG a trader sells electrical components. She has provided the following information for the year ended 31 July 2022. $ Sales journal for the year ended 31 July 2022 360 000 Sales returns journal for the year ended 31 July 2022 13 300 Trade receivables at 1 August 2021 28 500 Provision for doubtful debts at 1 August 2021 1 140 Cash book extract of totals for the year ended 31 July 2022 Discount Cash Bank Bank Allowed $ $ $ $ Trade receivables 6 500 335 100 Trade receivables 4 000 (dishonoured cheques) Sales 17 000 Additional information 1 $900 of trade receivables were written off as irrecoverable debts on 31 July 2022. There were no other irrecoverable debts during the year. 2 The provision for doubtful debts is to be set at 4% of trade receivables at 31 July 2022. REQUIRED (a) Prepare the following ledger accounts for the year ended 31 July 2022. Where appropriate show the balance brought down on 1 August 2022. PG Sales account Date Details $ Date Details $ .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. Sales returns account Date Details $ Date Details $ .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. Trade receivables account Date Details $ Date Details $ .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. Irrecoverable debts account Date Details $ Date Details $ .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. Provision for doubtful debts account Date Details $ Date Details $ .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. .......... .......................................... .............. [13] (b) Prepare a relevant extract from PG’s statement of financial position at 31 July 2022. PG Extract from statement of financial position at 31 July 2022 ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] (c) List three ways in which PG could reduce the possibility of irrecoverable debts. ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] (d) State two factors PG should consider when setting the provision for doubtful debts. ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] [Total: 20]
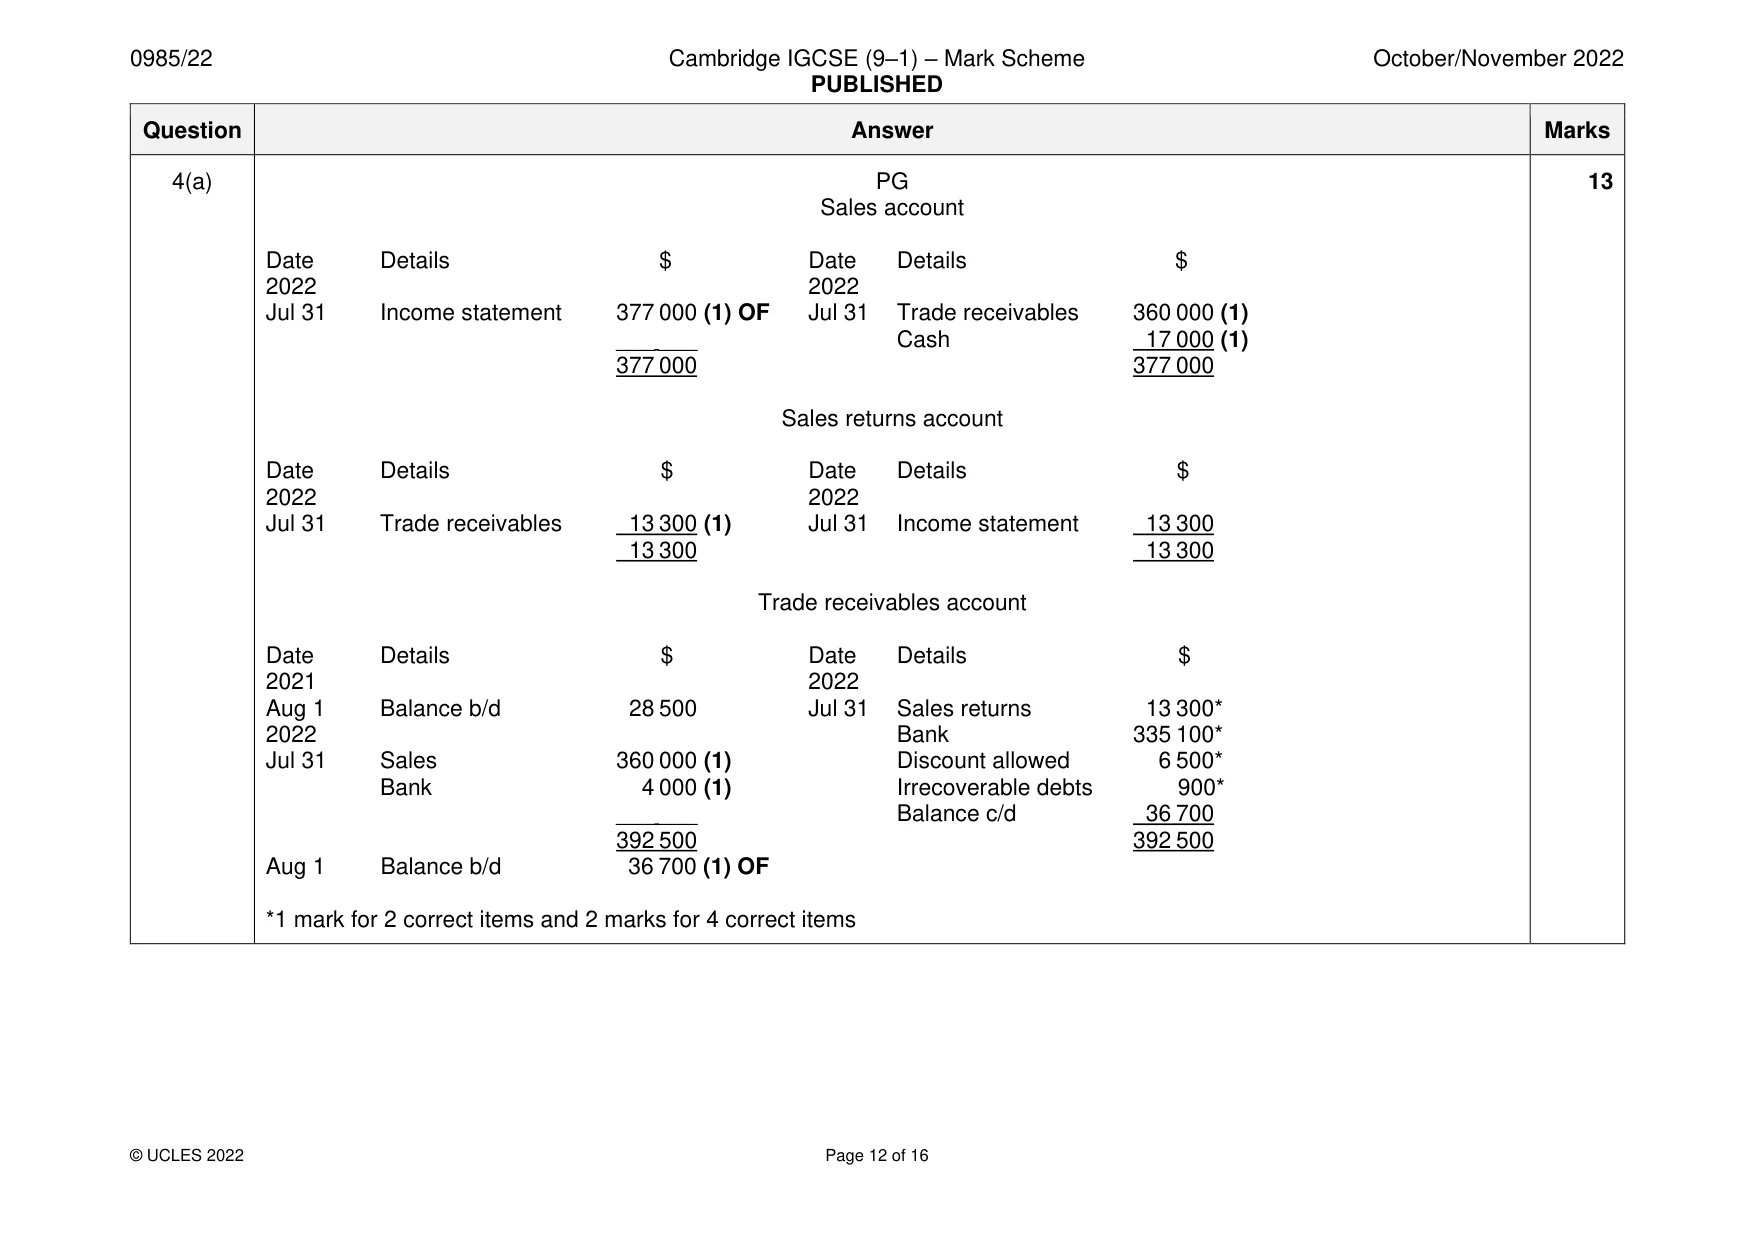
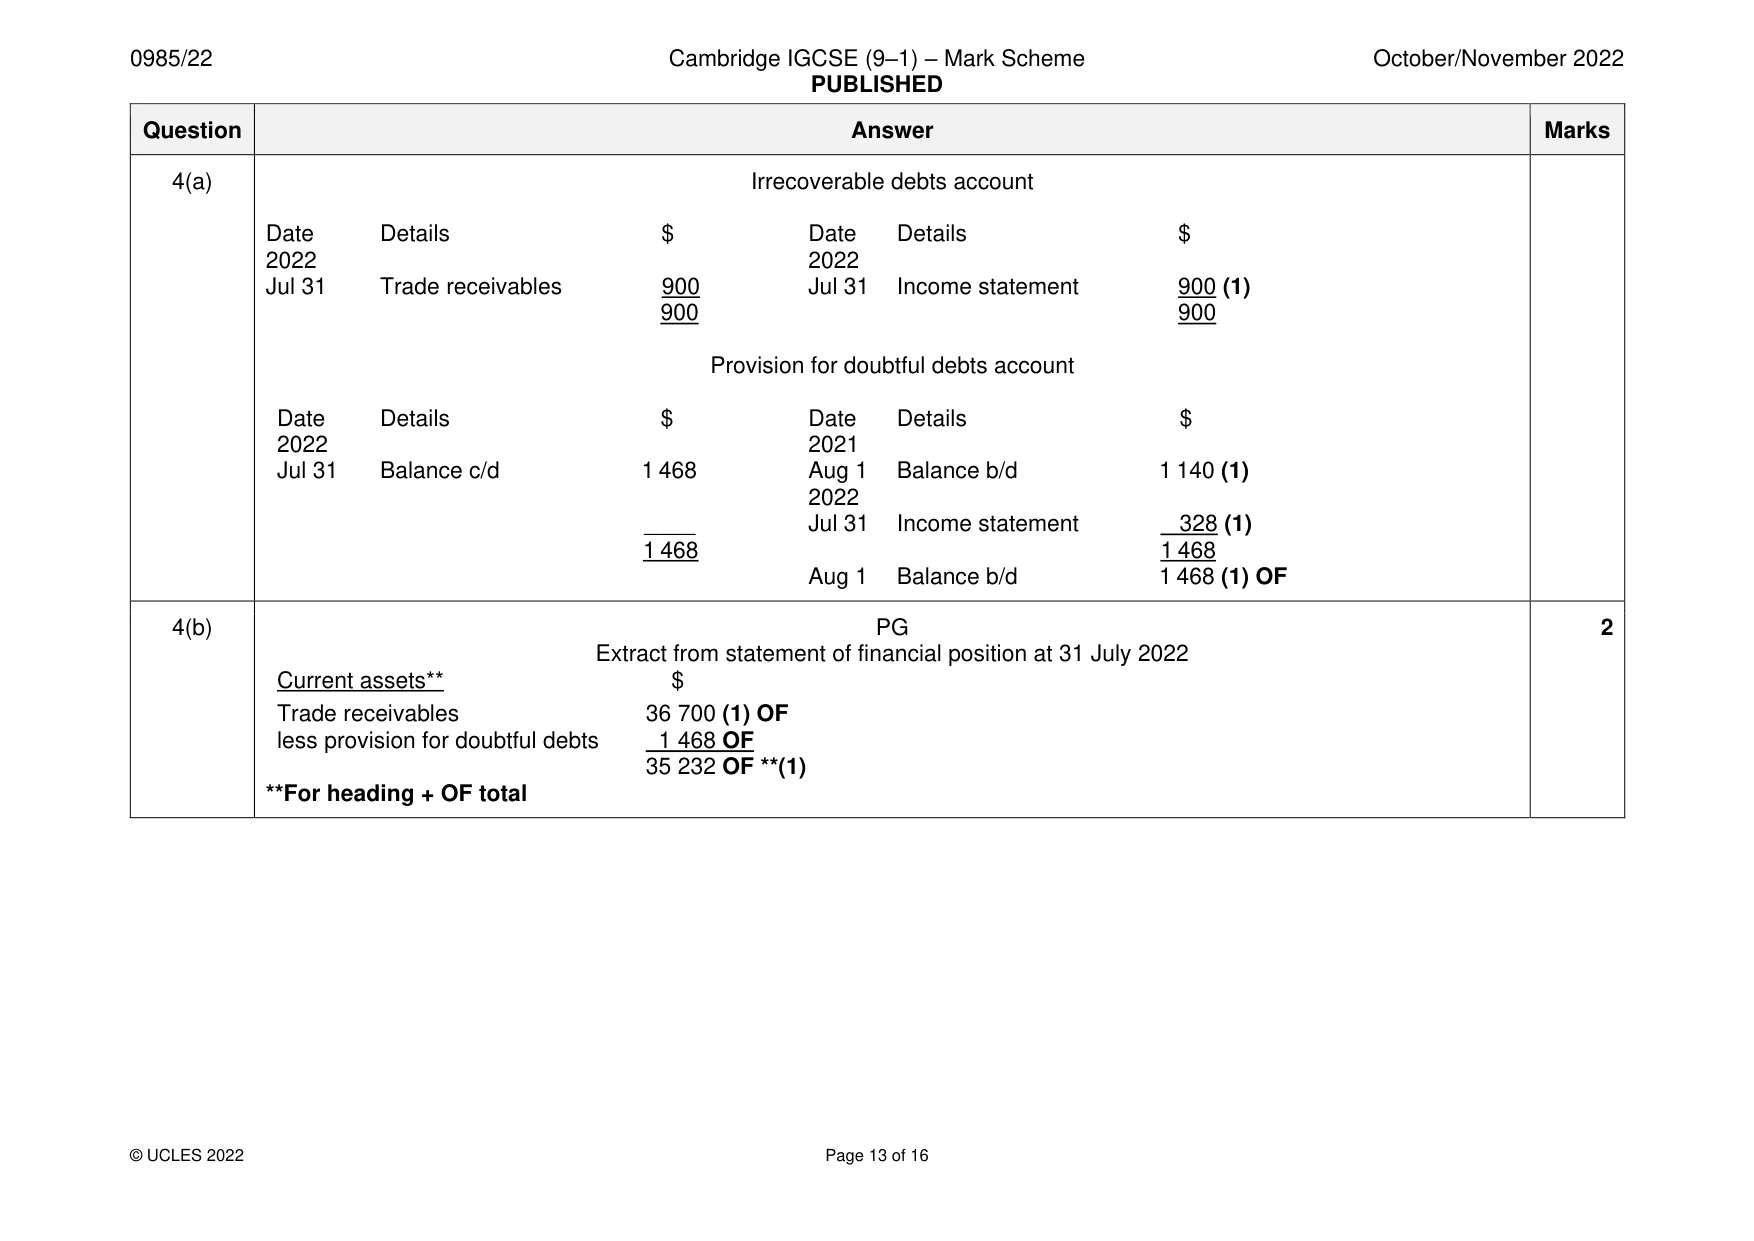
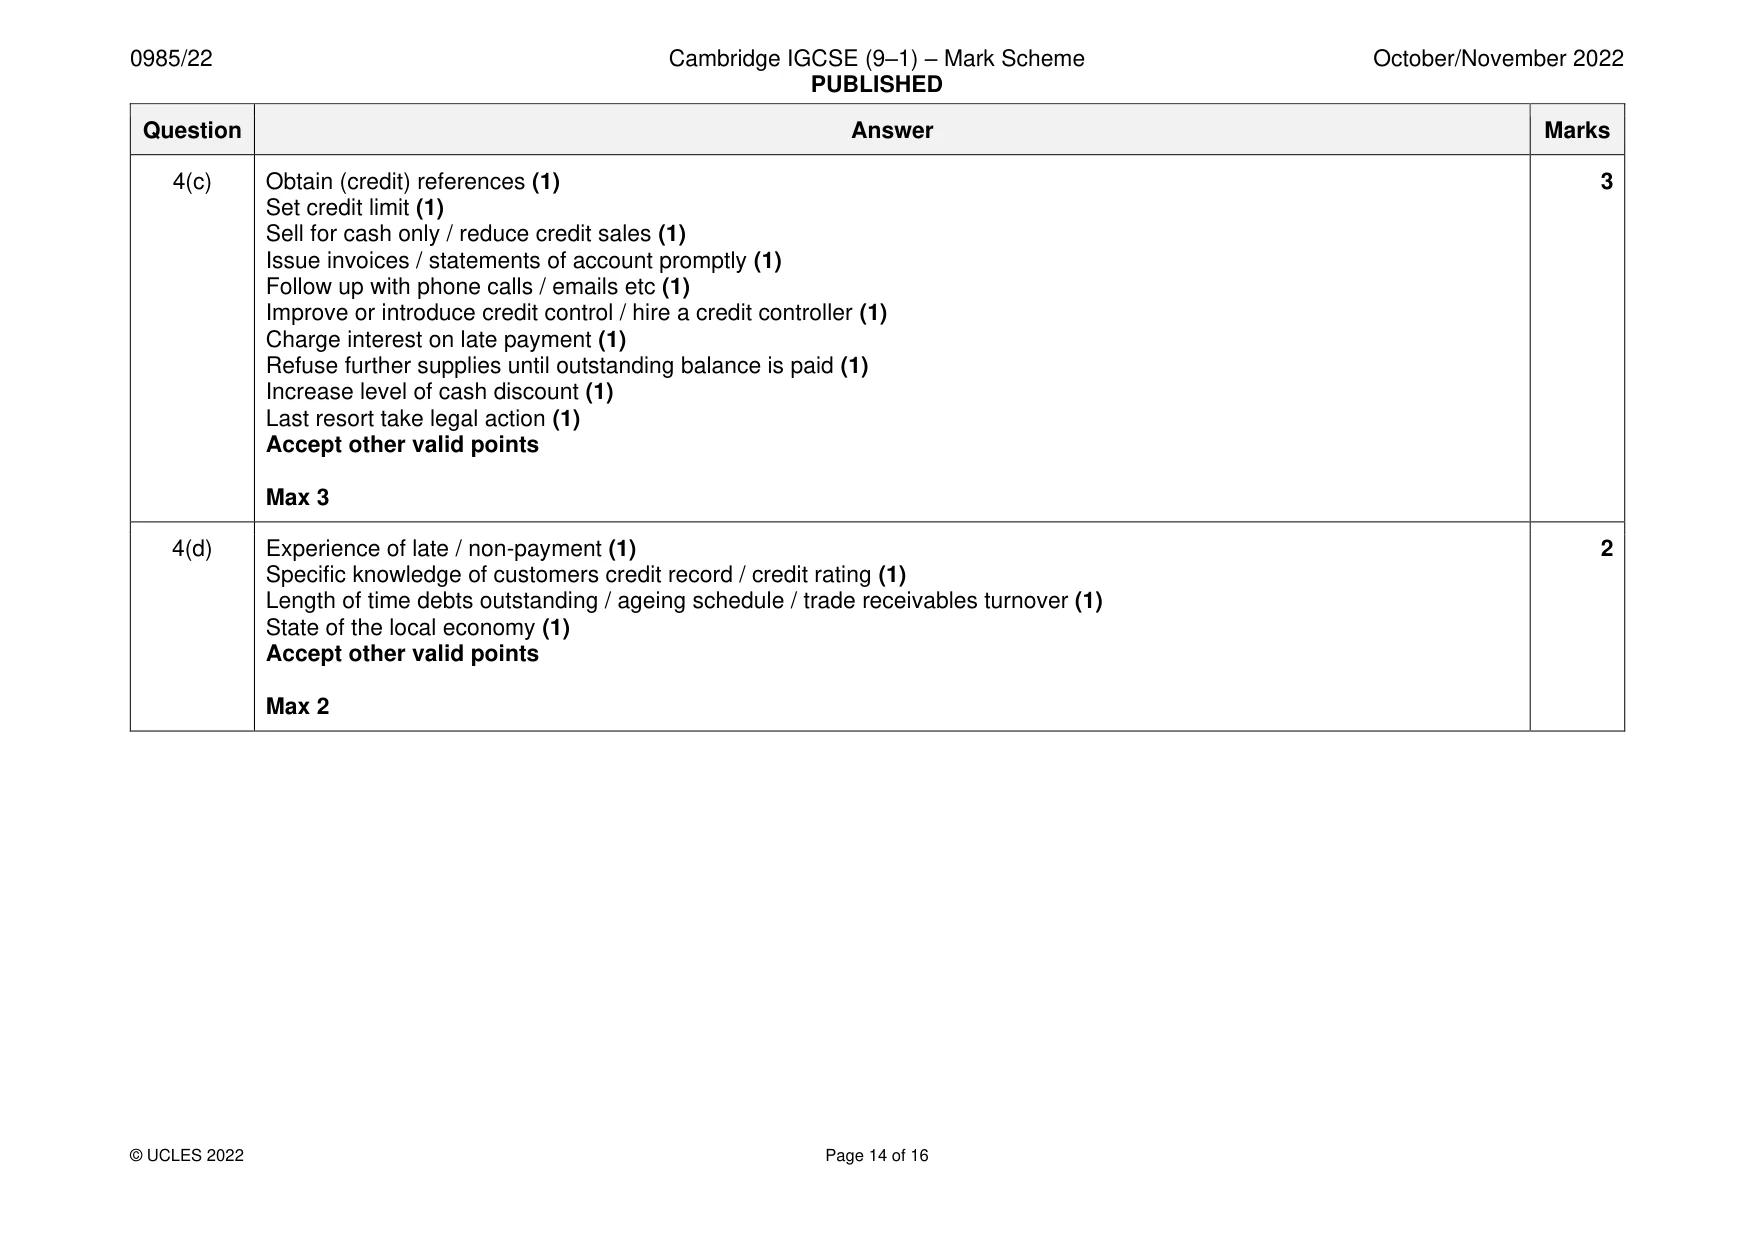
Mark scheme: 4(a) PG 13 Sales account Date Details $ Date Details $ 2022 2022 Jul 31 Income statement 377 000 (1) OF Jul 31 Trade receivables 360 000 (1) ___ ___ Cash 17 000 (1) 377 000 377 000 Sales returns account Date Details $ Date Details $ 2022 2022 Jul 31 Trade receivables 13 300 (1) Jul 31 Income statement 13 300 13 300 13 300 Trade receivables account Date Details $ Date Details $ 2021 2022 Aug 1 Balance b/d 28 500 Jul 31 Sales returns 13 300* 2022 Bank 335 100* Jul 31 Sales 360 000 (1) Discount allowed 6 500* Bank 4 000 (1) Irrecoverable debts 900* ___ ___ Balance c/d 36 700 392 500 392 500 Aug 1 Balance b/d 36 700 (1) OF *1 mark for 2 correct items and 2 marks for 4 correct items 4(a) Irrecoverable debts account Date Details $ Date Details $ 2022 2022 Jul 31 Trade receivables 900 Jul 31 Income statement 900 (1) 900 900 Provision for doubtful debts account Date Details $ Date Details $ 2022 2021 Jul 31 Balance c/d 1 468 Aug 1 Balance b/d 1 140 (1) 2022 ____ Jul 31 Income statement 328 (1) 1 468 1 468 Aug 1 Balance b/d 1 468 (1) OF 4(b) PG 2 Extract from statement of financial position at 31 July 2022 Current assets** $ Trade receivables 36 700 (1) OF less provision for doubtful debts 1 468 OF 35 232 OF **(1) **For heading + OF total 4(c) Obtain (credit) references (1) 3 Set credit limit (1) Sell for cash only / reduce credit sales (1) Issue invoices / statements of account promptly (1) Follow up with phone calls / emails etc (1) Improve or introduce credit control / hire a credit controller (1) Charge interest on late payment (1) Refuse further supplies until outstanding balance is paid (1) Increase level of cash discount (1) Last resort take legal action (1) Accept other valid points Max 3 4(d) Experience of late / non-payment (1) 2 Specific knowledge of customers credit record / credit rating (1) Length of time debts outstanding / ageing schedule / trade receivables turnover (1) State of the local economy (1) Accept other valid points Max 2
Q5 · Sian and Tom are in partnership sharing profits and losses in proportion to capital…
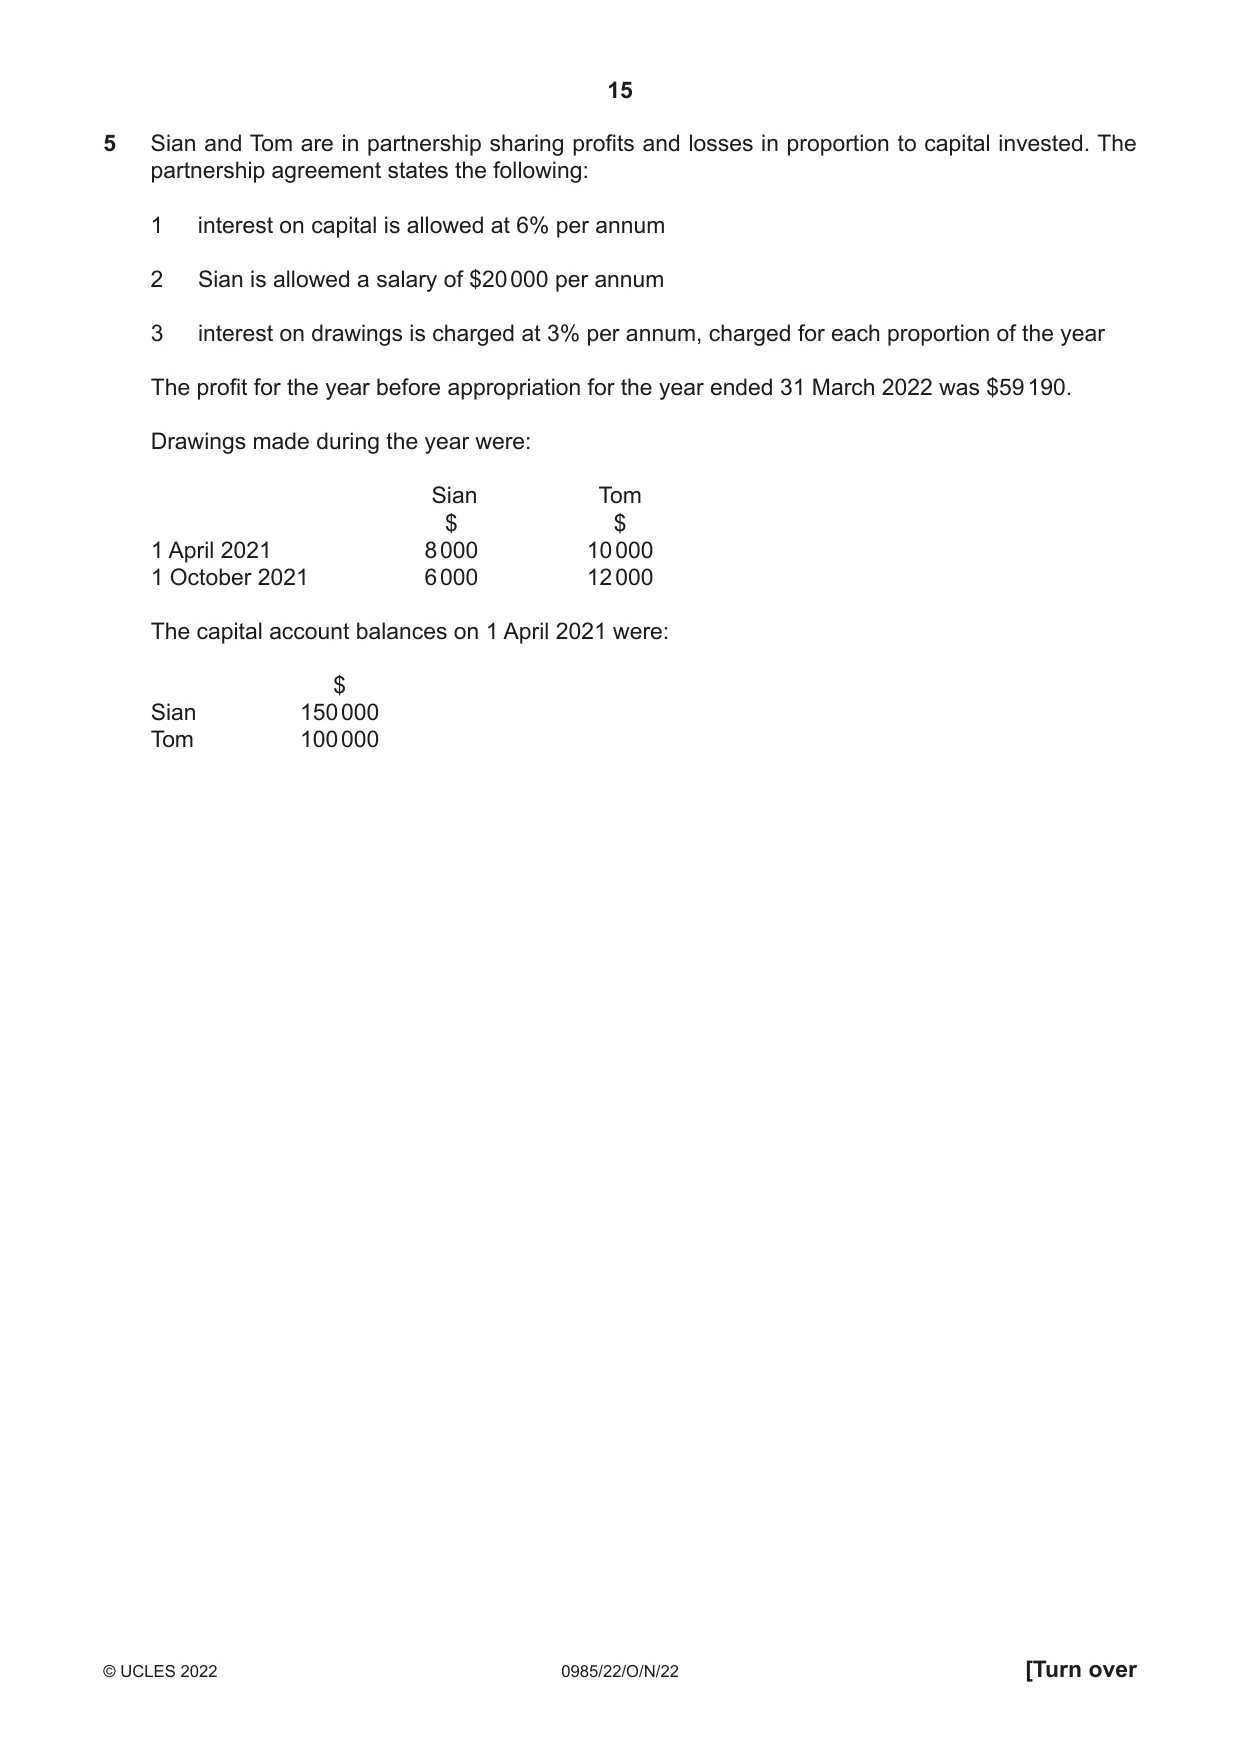
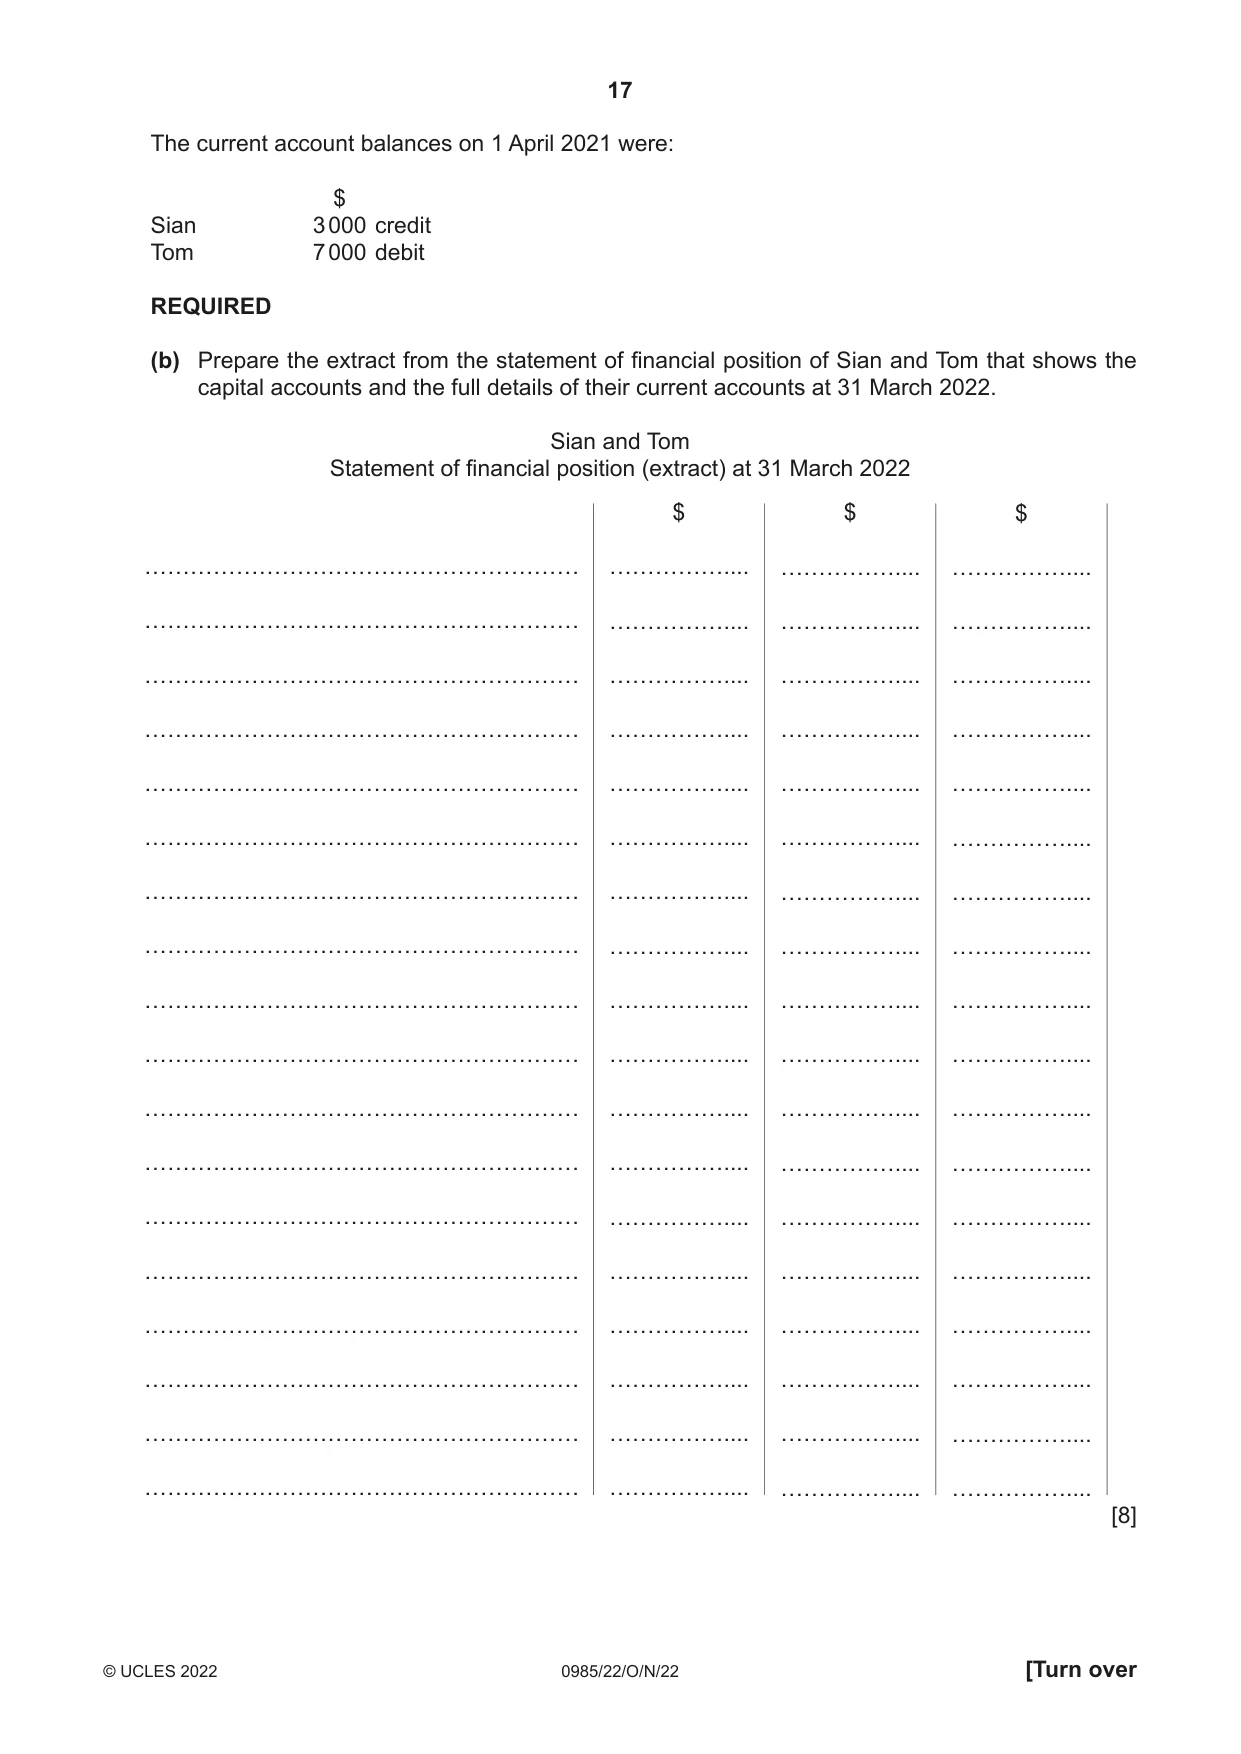
5 Sian and Tom are in partnership sharing profits and losses in proportion to capital invested. The partnership agreement states the following: 1 interest on capital is allowed at 6% per annum 2 Sian is allowed a salary of $20 000 per annum 3 interest on drawings is charged at 3% per annum, charged for each proportion of the year The profit for the year before appropriation for the year ended 31 March 2022 was $59 190. Drawings made during the year were: Sian Tom $ $ 1 April 2021 8 000 10 000 1 October 2021 6 000 12 000 The capital account balances on 1 April 2021 were: $ Sian 150 000 Tom 100 000 REQUIRED (a) Prepare the profit and loss appropriation account fo 31 March 2022. Sian and Tom Profit and loss appropriation account for the year ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... The current account balances on 1 April 2021 were: $ Sian 3 000 credit Tom 7 000 debit REQUIRED (b) Prepare the extract from the statement of financial position of Sian and Tom that shows the capital accounts and the full details of their current accounts at 31 March 2022. Sian and Tom Statement of financial position (extract) at 31 March 2022 $ $ $ …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... …………….... [8]
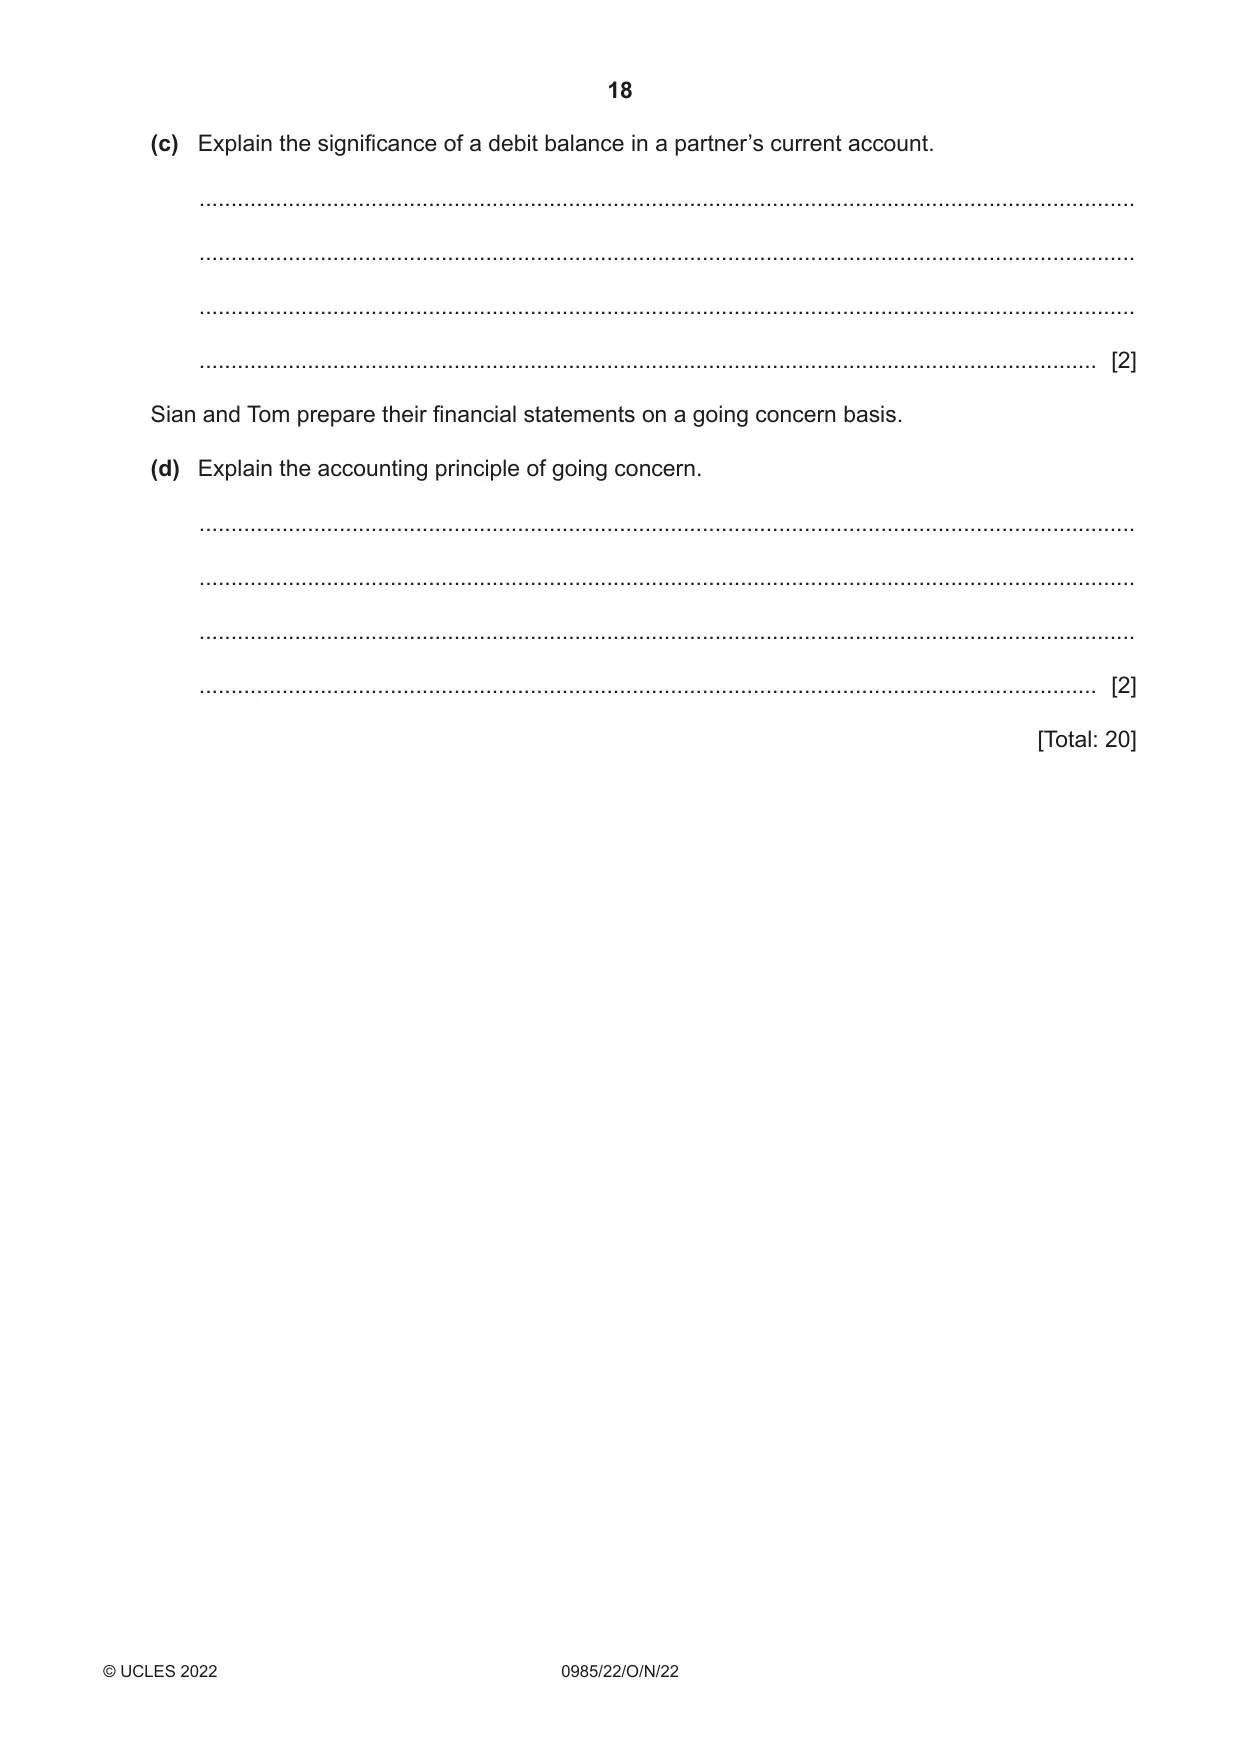
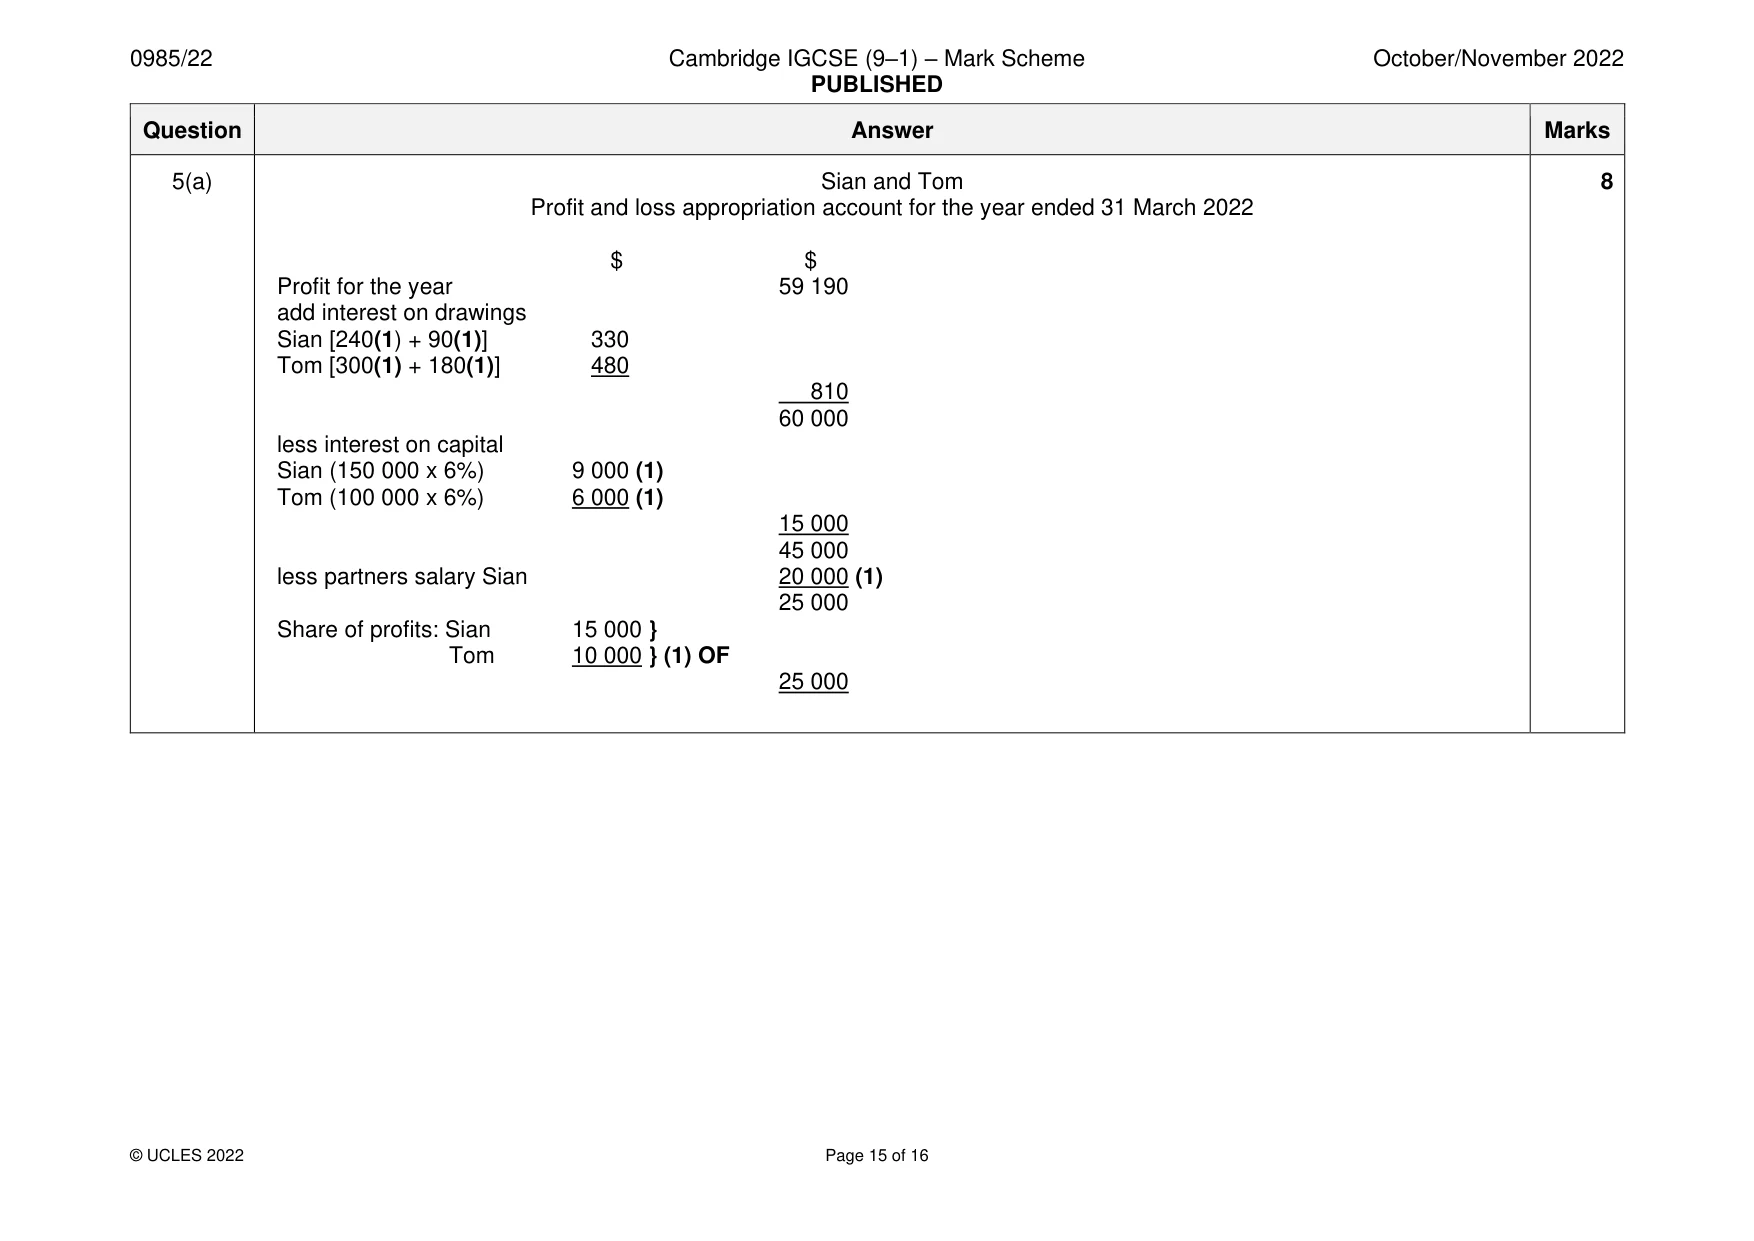
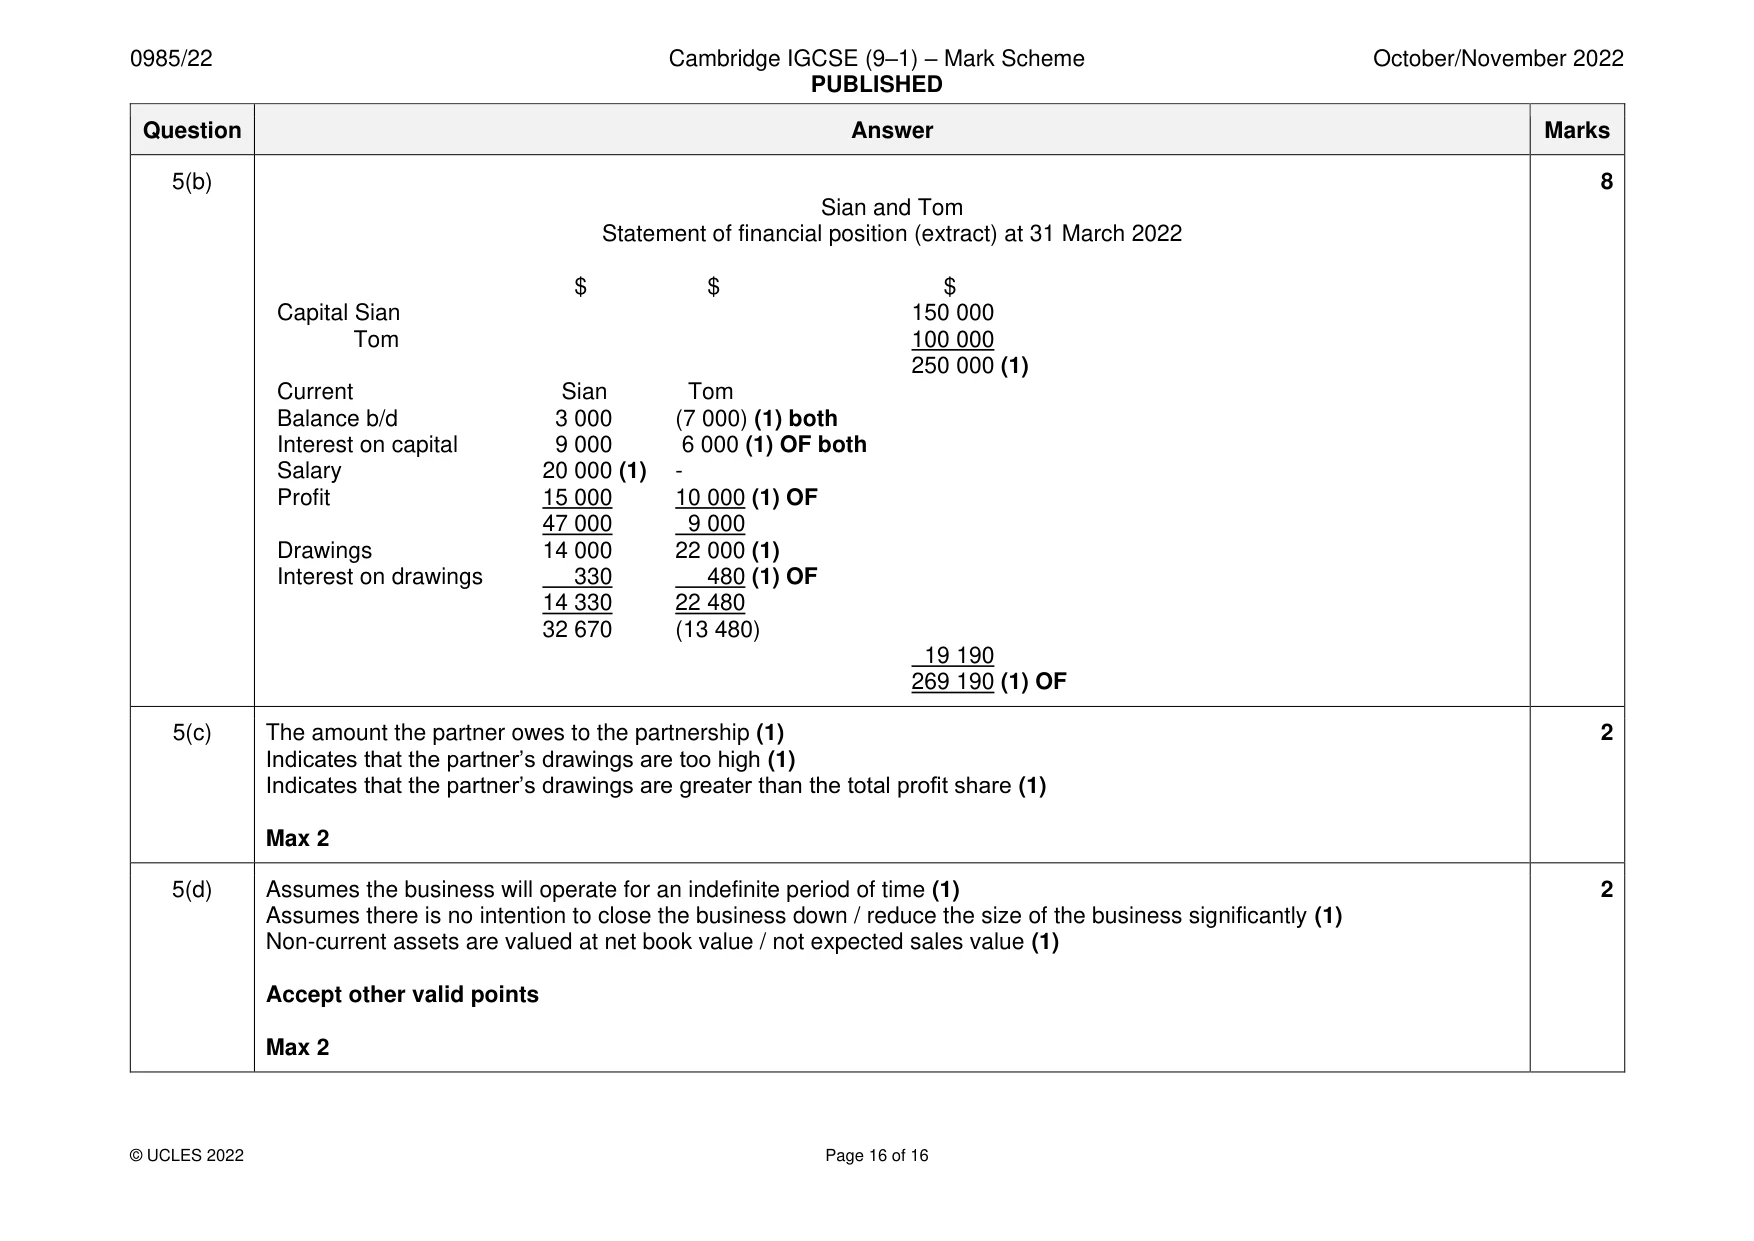
Mark scheme: 5(a) Sian and Tom 8 Profit and loss appropriation account for the year ended 31 March 2022 $ $ Profit for the year 59 190 add interest on drawings Sian [240(1) + 90(1)] 330 Tom [300(1) + 180(1)] 480 810 60 000 less interest on capital Sian (150 000 x 6%) 9 000 (1) Tom (100 000 x 6%) 6 000 (1) 15 000 45 000 less partners salary Sian 20 000 (1) 25 000 Share of profits: Sian 15 000 } Tom 10 000 } (1) OF 25 000 5(b) 8 Sian and Tom Statement of financial position (extract) at 31 March 2022 $ $ $ Capital Sian 150 000 Tom 100 000 250 000 (1) Current Sian Tom Balance b/d 3 000 (7 000) (1) both Interest on capital 9 000 6 000 (1) OF both Salary 20 000 (1) - Profit 15 000 10 000 (1) OF 47 000 9 000 Drawings 14 000 22 000 (1) Interest on drawings 330 480 (1) OF 14 330 22 480 32 670 (13 480) 19 190 269 190 (1) OF 5(c) The amount the partner owes to the partnership (1) 2 Indicates that the partner’s drawings are too high (1) Indicates that the partner’s drawings are greater than the total profit share (1) Max 2 5(d) Assumes the business will operate for an indefinite period of time (1) 2 Assumes there is no intention to close the business down / reduce the size of the business significantly (1) Non-current assets are valued at net book value / not expected sales value (1) Accept other valid points Max 2
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2022 Oct/Nov, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.