Cambridge A Level Accounting 9706 — 2024 Feb/March Paper 2 · Variant 2
9706/22/F/M/24 · 6 questions · 90 marks · ≈101 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme16 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · The following trial balance was extracted from the books of V Limited at 31 December 2023
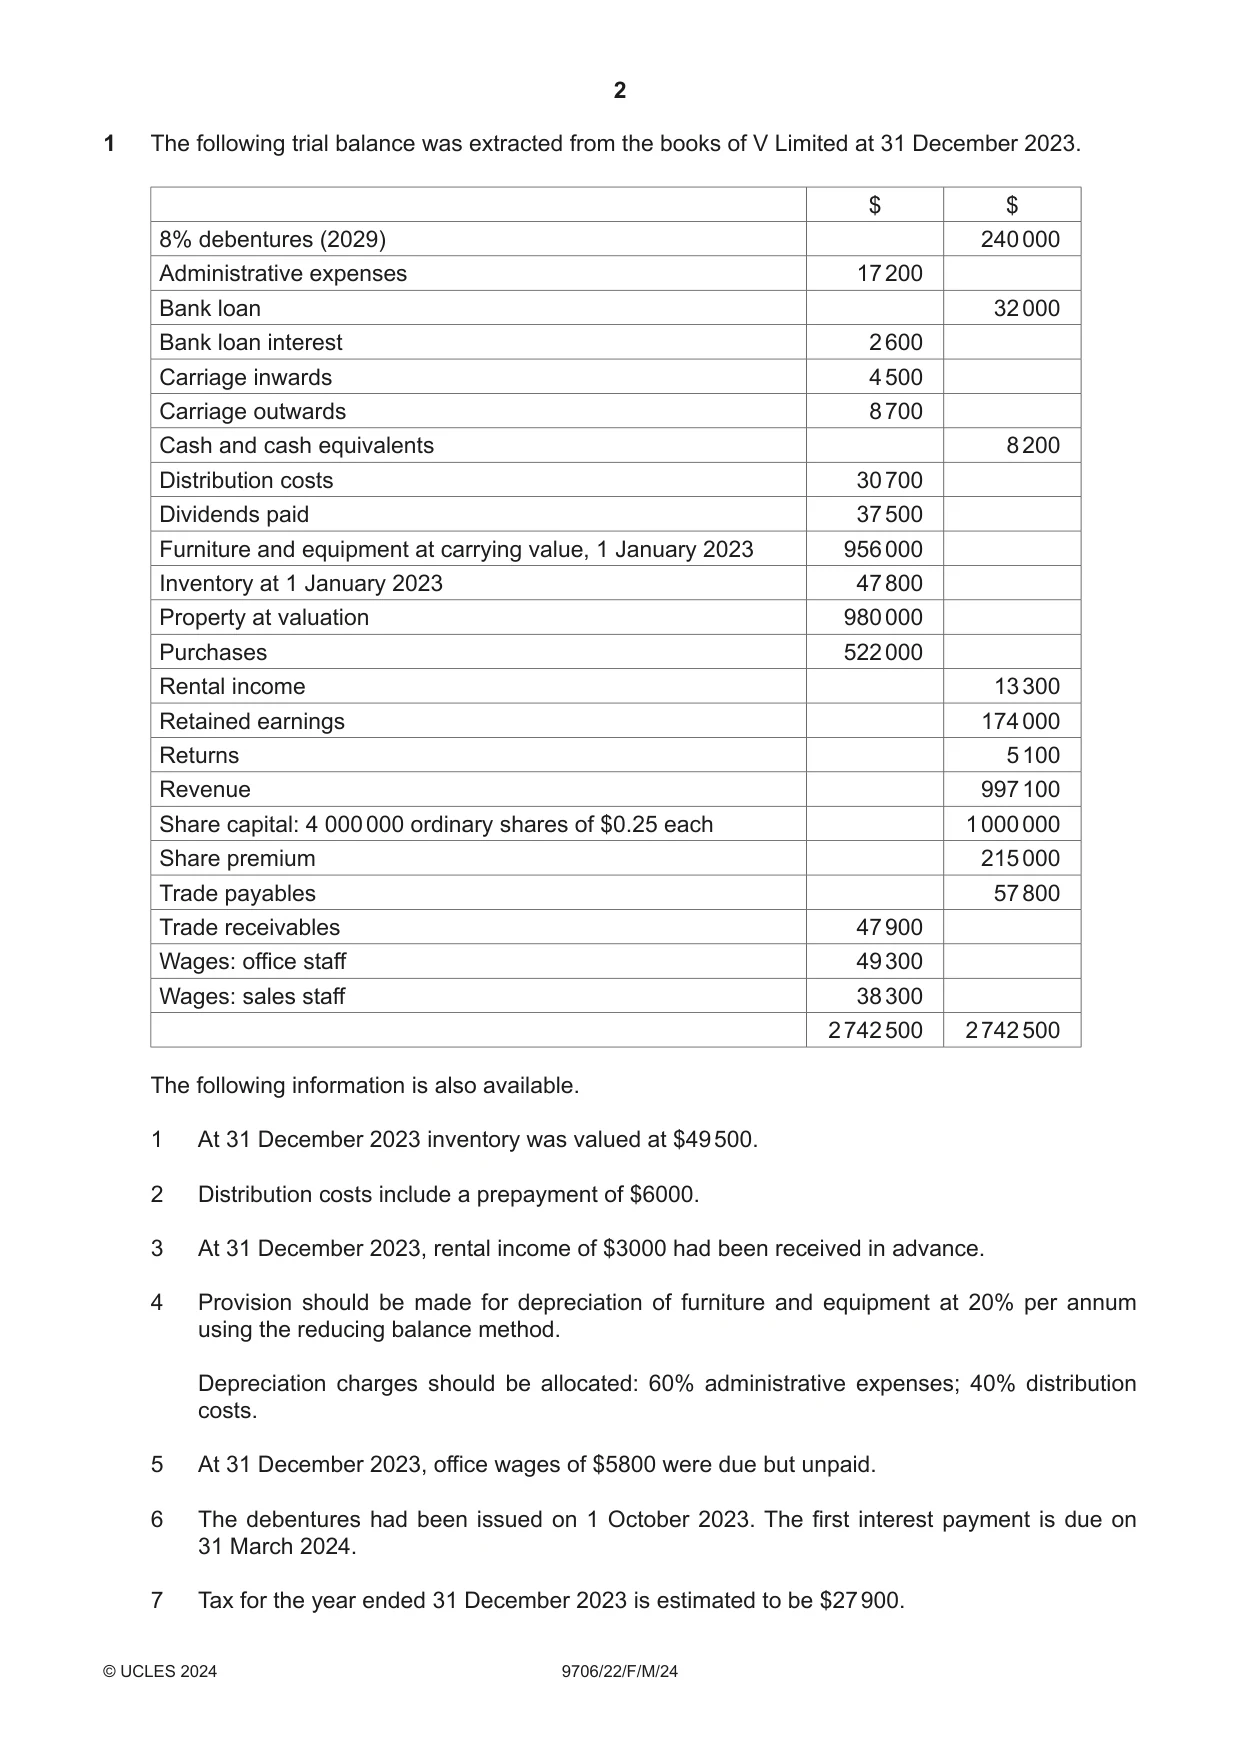
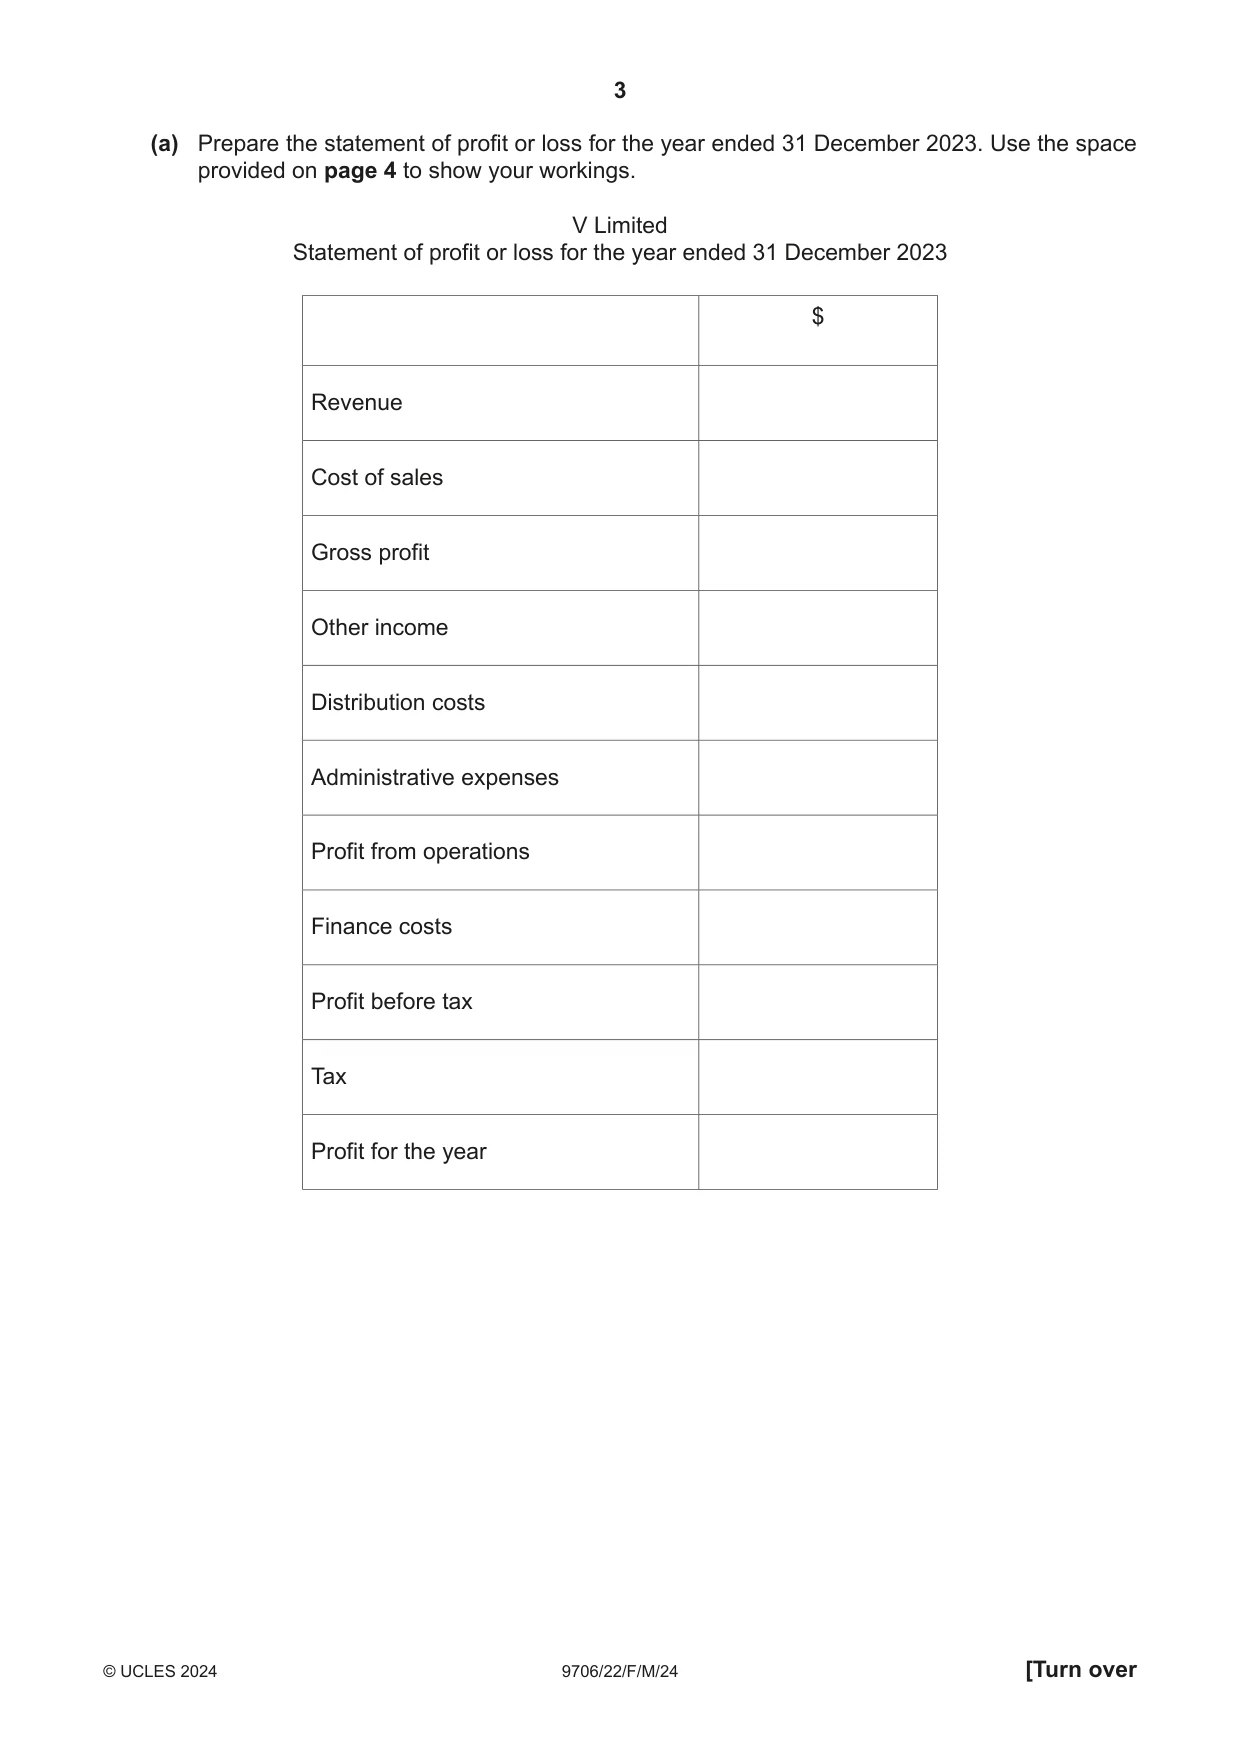
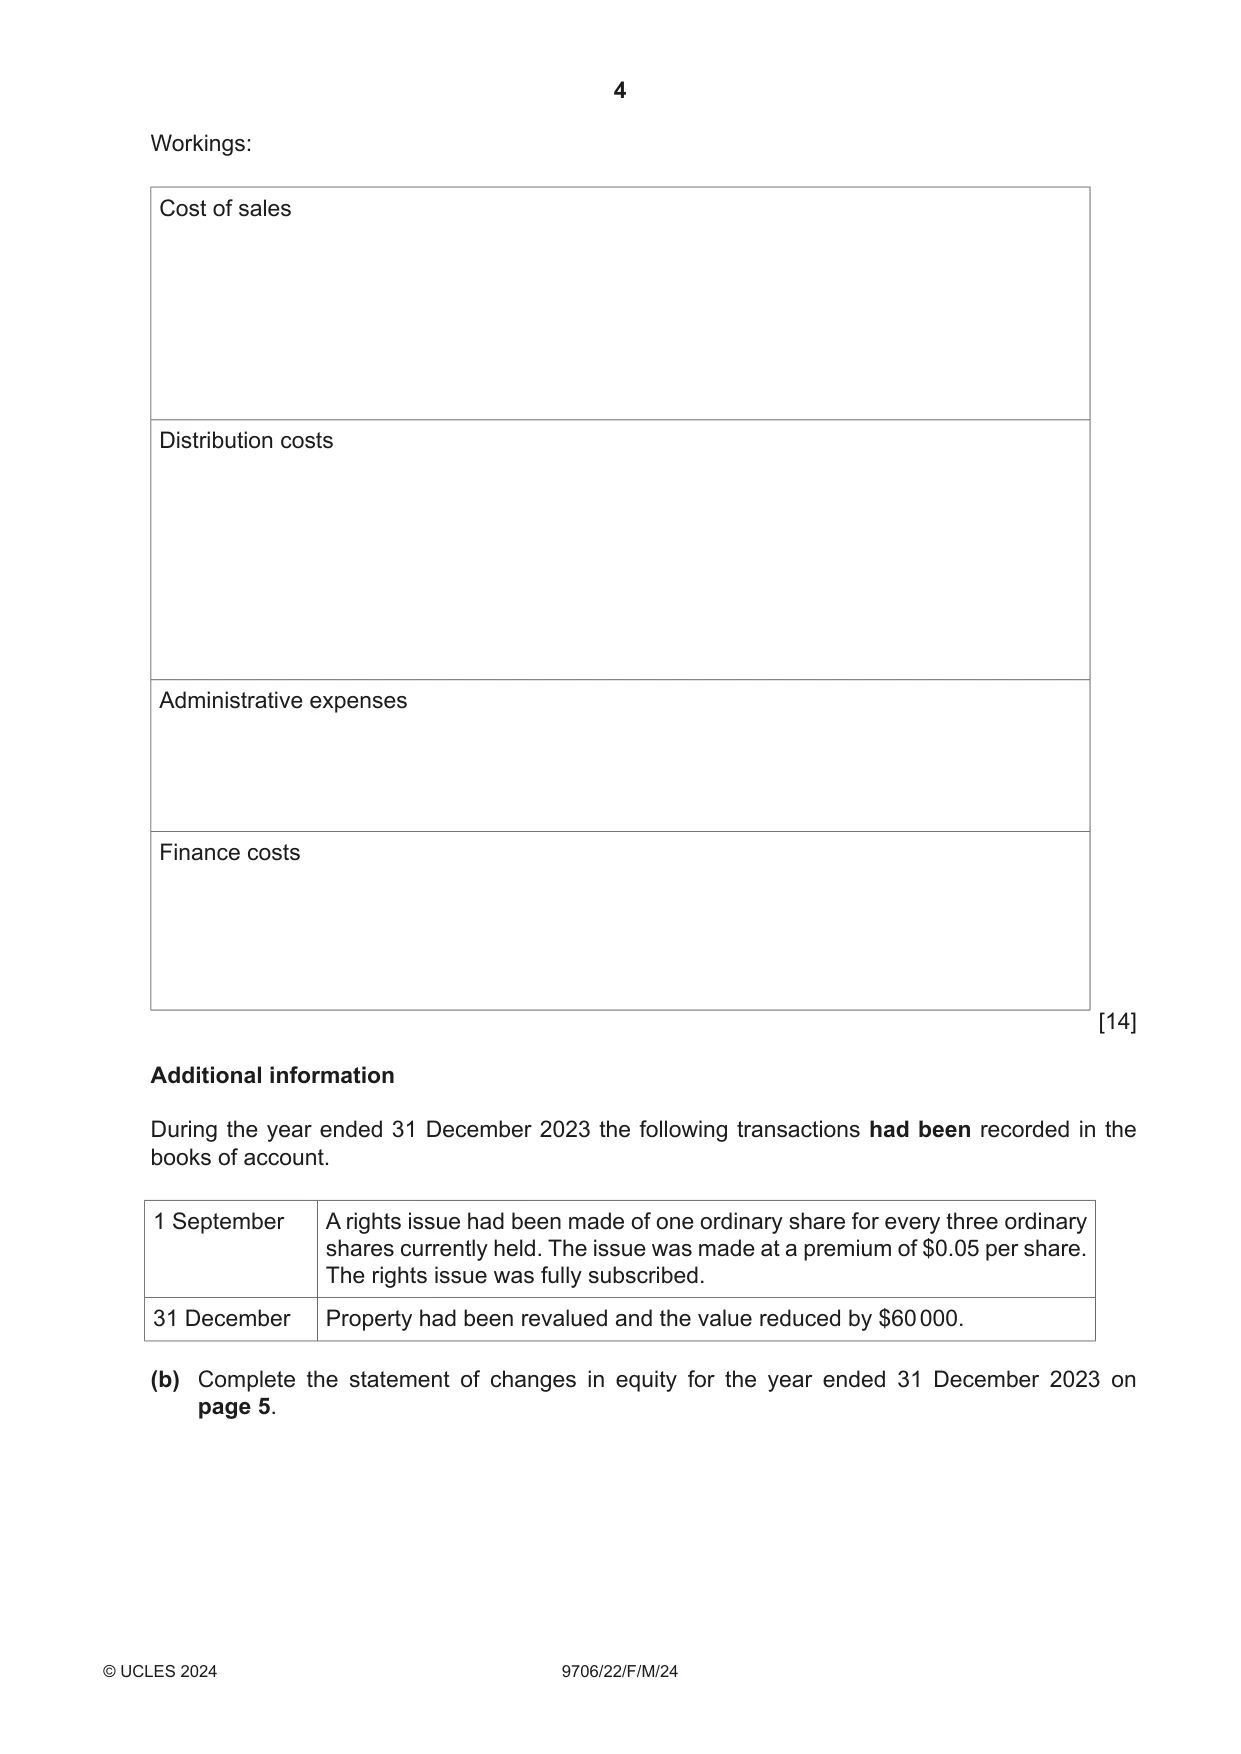
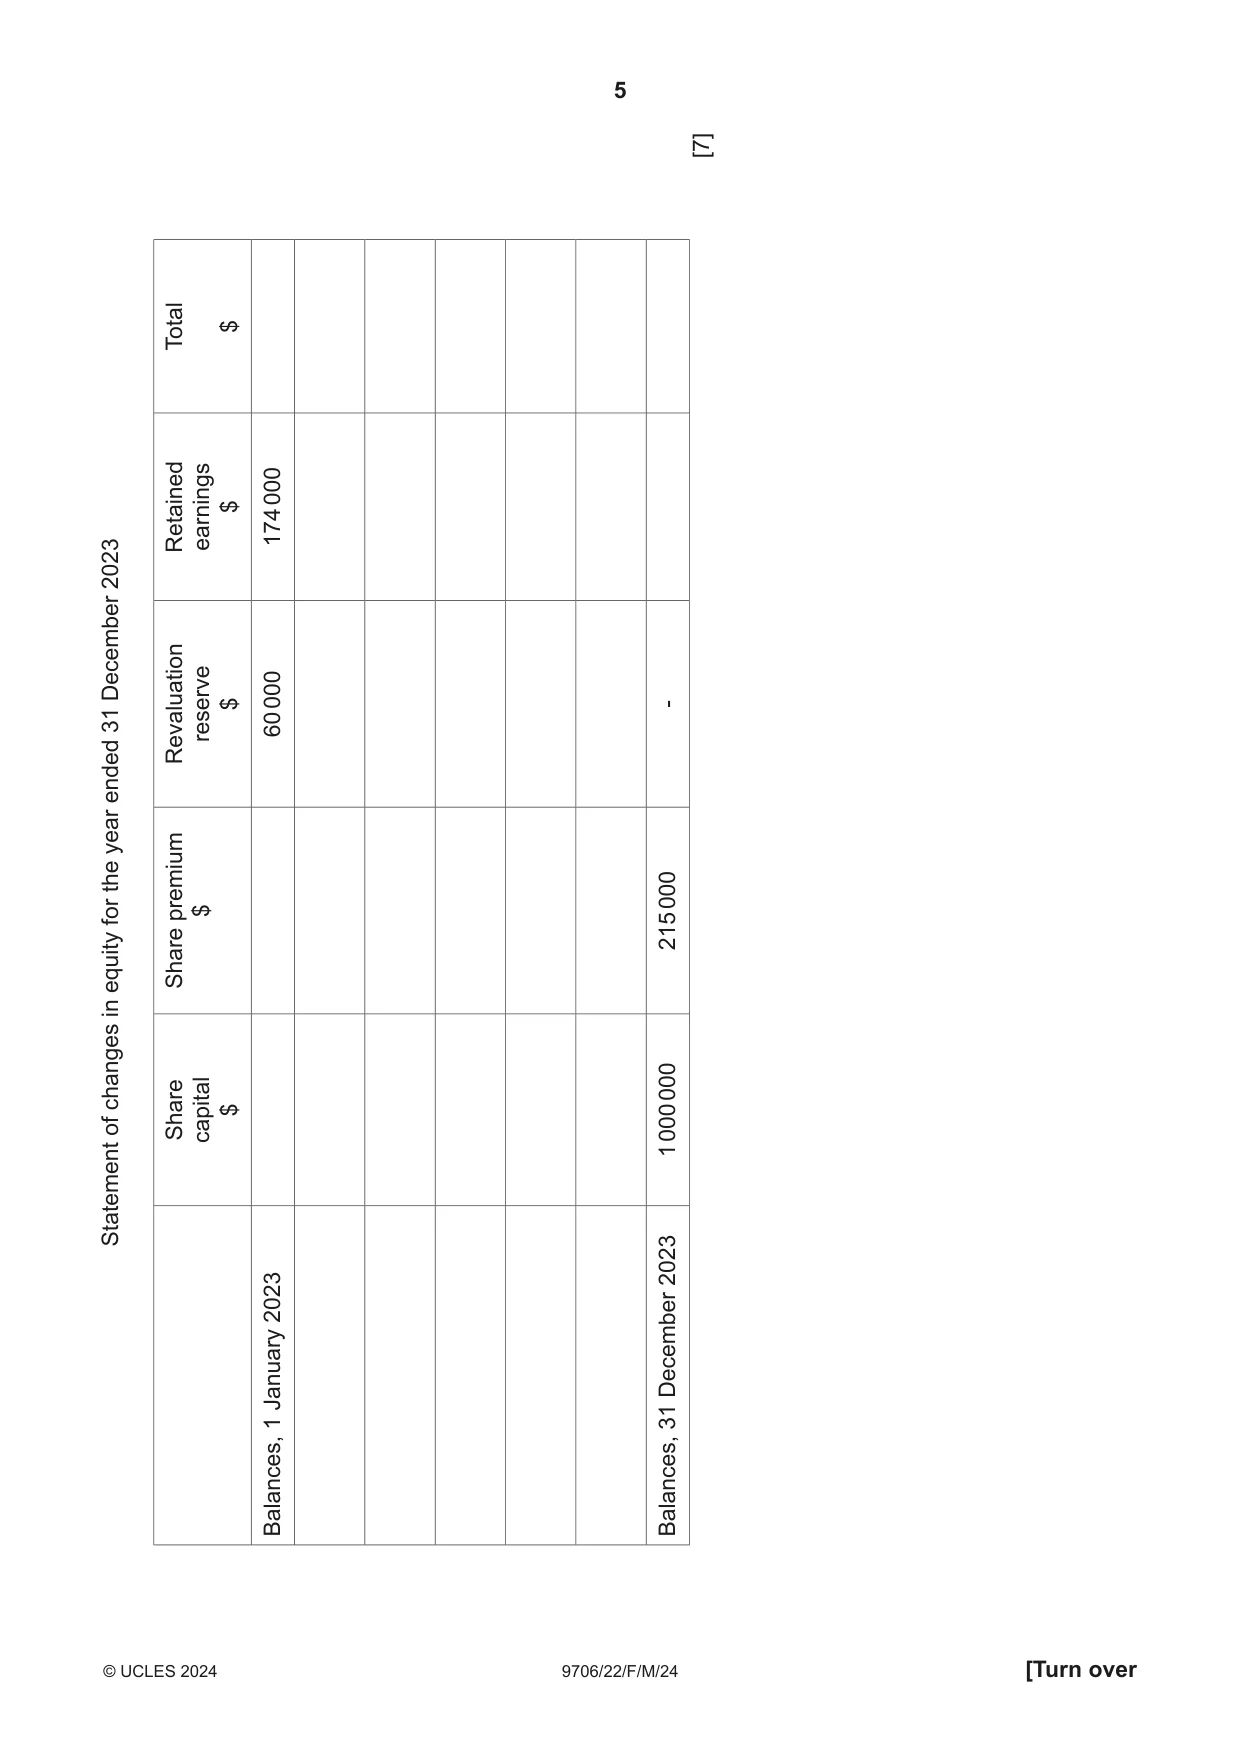
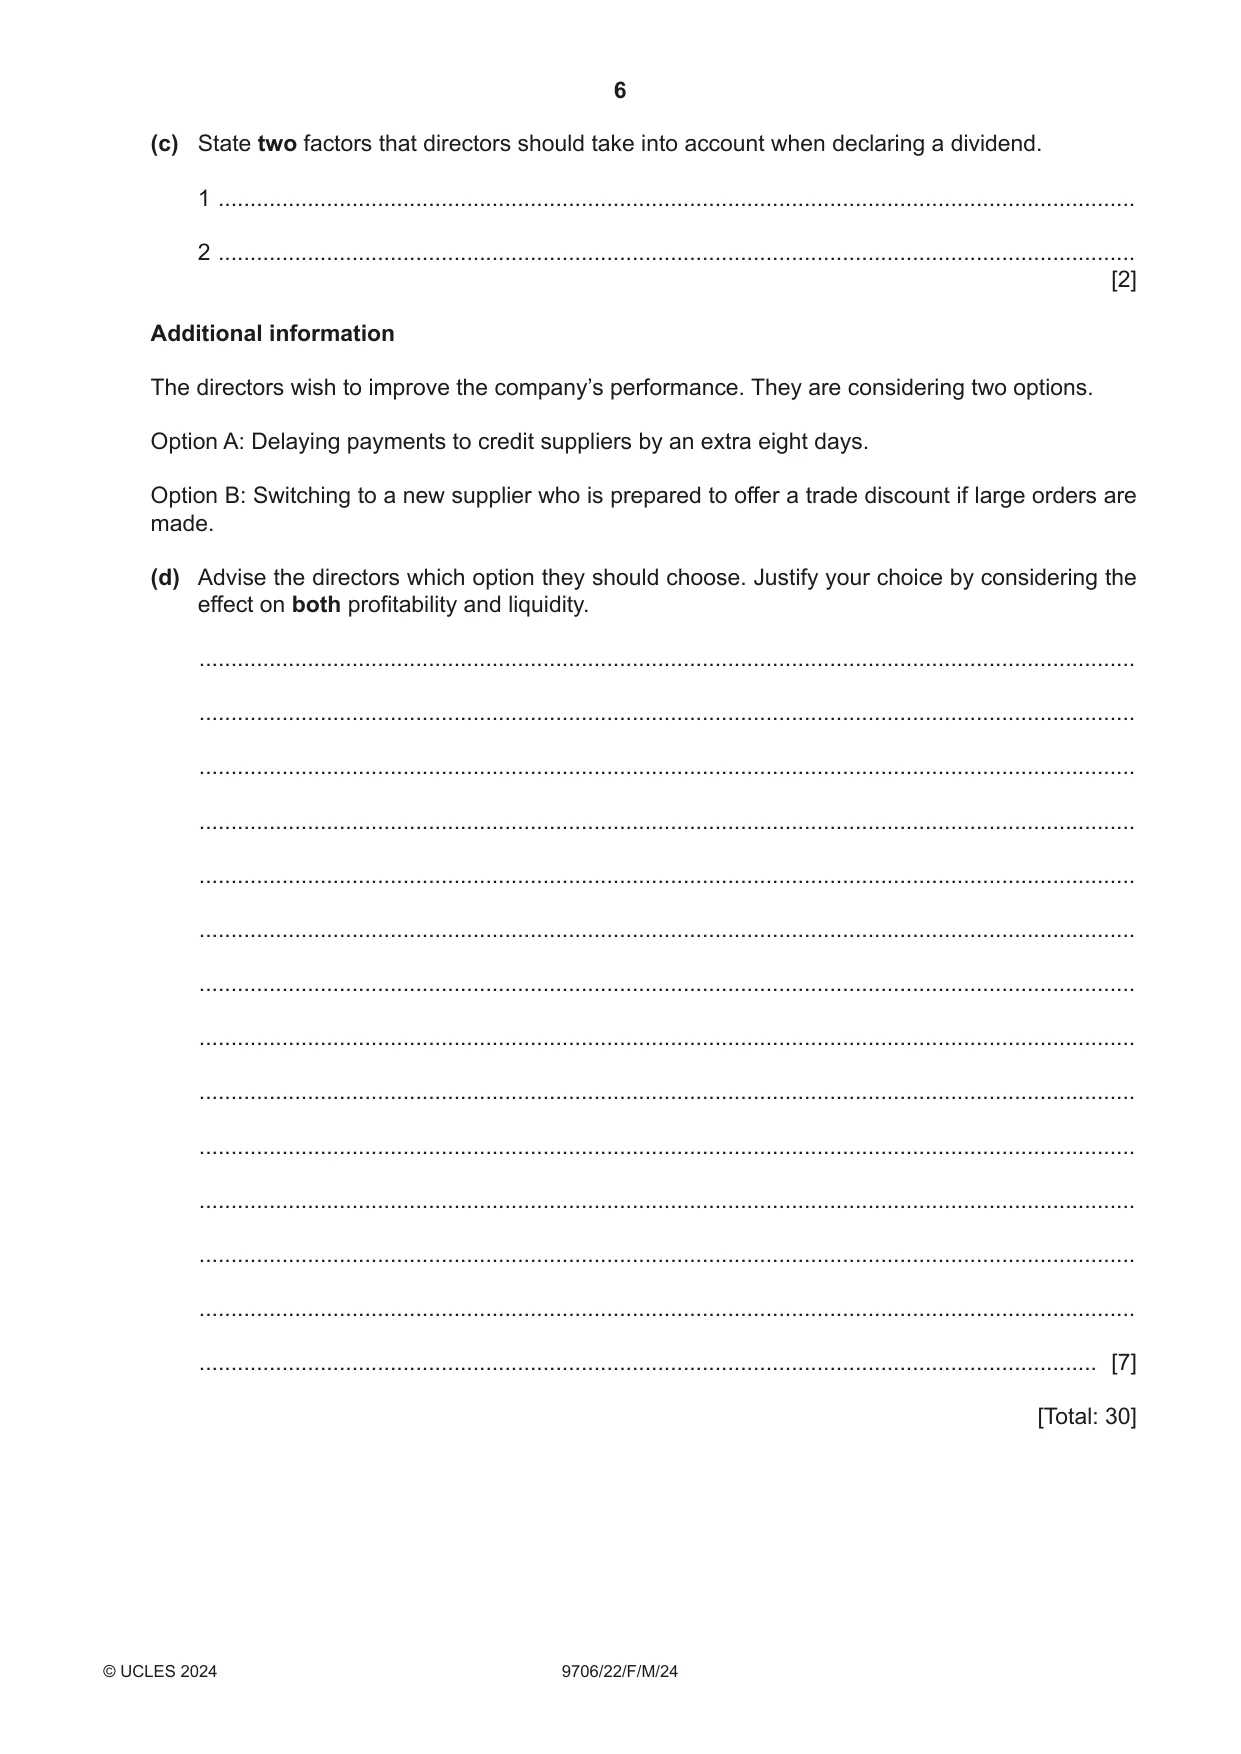
1 The following trial balance was extracted from the books of V Limited at 31 December 2023. $ $ 8% debentures (2029) 240 000 Administrative expenses 17 200 Bank loan 32 000 Bank loan interest 2 600 Carriage inwards 4 500 Carriage outwards 8 700 Cash and cash equivalents 8 200 Distribution costs 30 700 Dividends paid 37 500 Furniture and equipment at carrying value, 1 January 2023 956 000 Inventory at 1 January 2023 47 800 Property at valuation 980 000 Purchases 522 000 Rental income 13 300 Retained earnings 174 000 Returns 5 100 Revenue 997 100 Share capital: 4 000 000 ordinary shares of $0.25 each 1 000 000 Share premium 215 000 Trade payables 57 800 Trade receivables 47 900 Wages: office staff 49 300 Wages: sales staff 38 300 2 742 500 2 742 500 The following information is also available. 1 At 31 December 2023 inventory was valued at $49 500. 2 Distribution costs include a prepayment of $6000. 3 At 31 December 2023, rental income of $3000 had been received in advance. 4 Provision should be made for depreciation of furniture and equipment at 20% per annum using the reducing balance method. Depreciation charges should be allocated: 60% administrative expenses; 40% distribution costs. 5 At 31 December 2023, office wages of $5800 were due but unpaid. 6 The debentures had been issued on 1 October 2023. The first interest payment is due on 31 March 2024. 7 Tax for the year ended 31 December 2023 is estimated to be $27 900. (a) Prepare the statement of profit or loss for the year ended 31 December 2023. Use the space provided on page 4 to show your workings. V Limited Statement of profit or loss for the year ended 31 December 2023 $ Revenue Cost of sales Gross profit Other income Distribution costs Administrative expenses Profit from operations Finance costs Profit before tax Tax Profit for the year Workings: Cost of sales Distribution costs Administrative expenses Finance costs [14] Additional information During the year ended 31 December 2023 the following transactions had been recorded in the books of account. 1 September A rights issue had been made of one ordinary share for every three ordinary shares currently held. The issue was made at a premium of $0.05 per share. The rights issue was fully subscribed. 31 December Property had been revalued and the value reduced by $60 000. (b) Complete the statement of changes in equity for the year ended 31 December 2023 on page 5. [7] $ Total 000 $ Retainedearnings 174 2023 December $ 000 - 31 reserve 60 Revaluation ended year the 000 $for premium 215 equity Share in 000changes $of Sharecapital 000 Statement 1 2023 2023 December January 1 31 Balances, Balances, (c) State two factors that directors should take into account when declaring a dividend. 1 ................................................................................................................................................ 2 ................................................................................................................................................ [2] Additional information The directors wish to improve the company’s performance. They are considering two options. Option A: Delaying payments to credit suppliers by an extra eight days. Option B: Switching to a new supplier who is prepared to offer a trade discount if large orders are made. (d) Advise the directors which option they should choose. Justify your choice by considering the effect on both profitability and liquidity. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [7] [Total: 30]
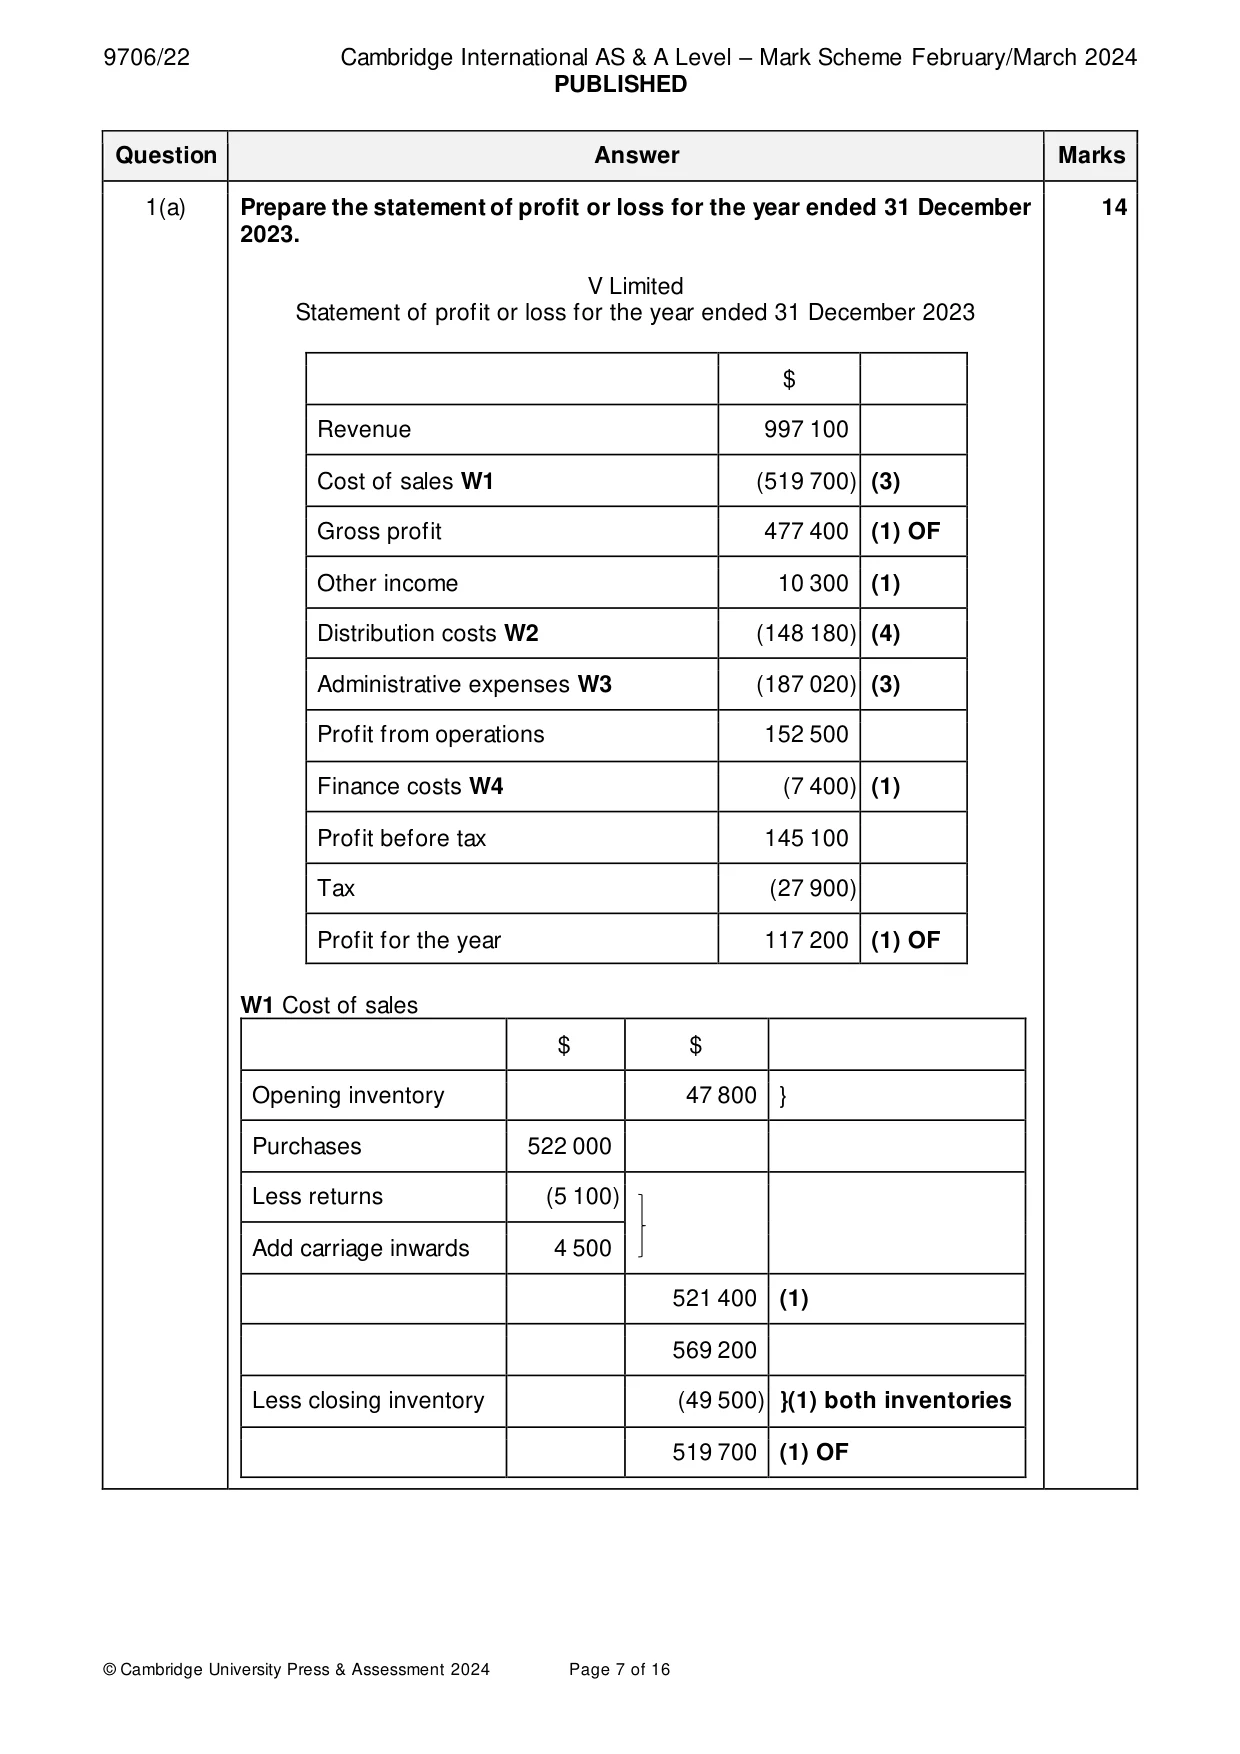
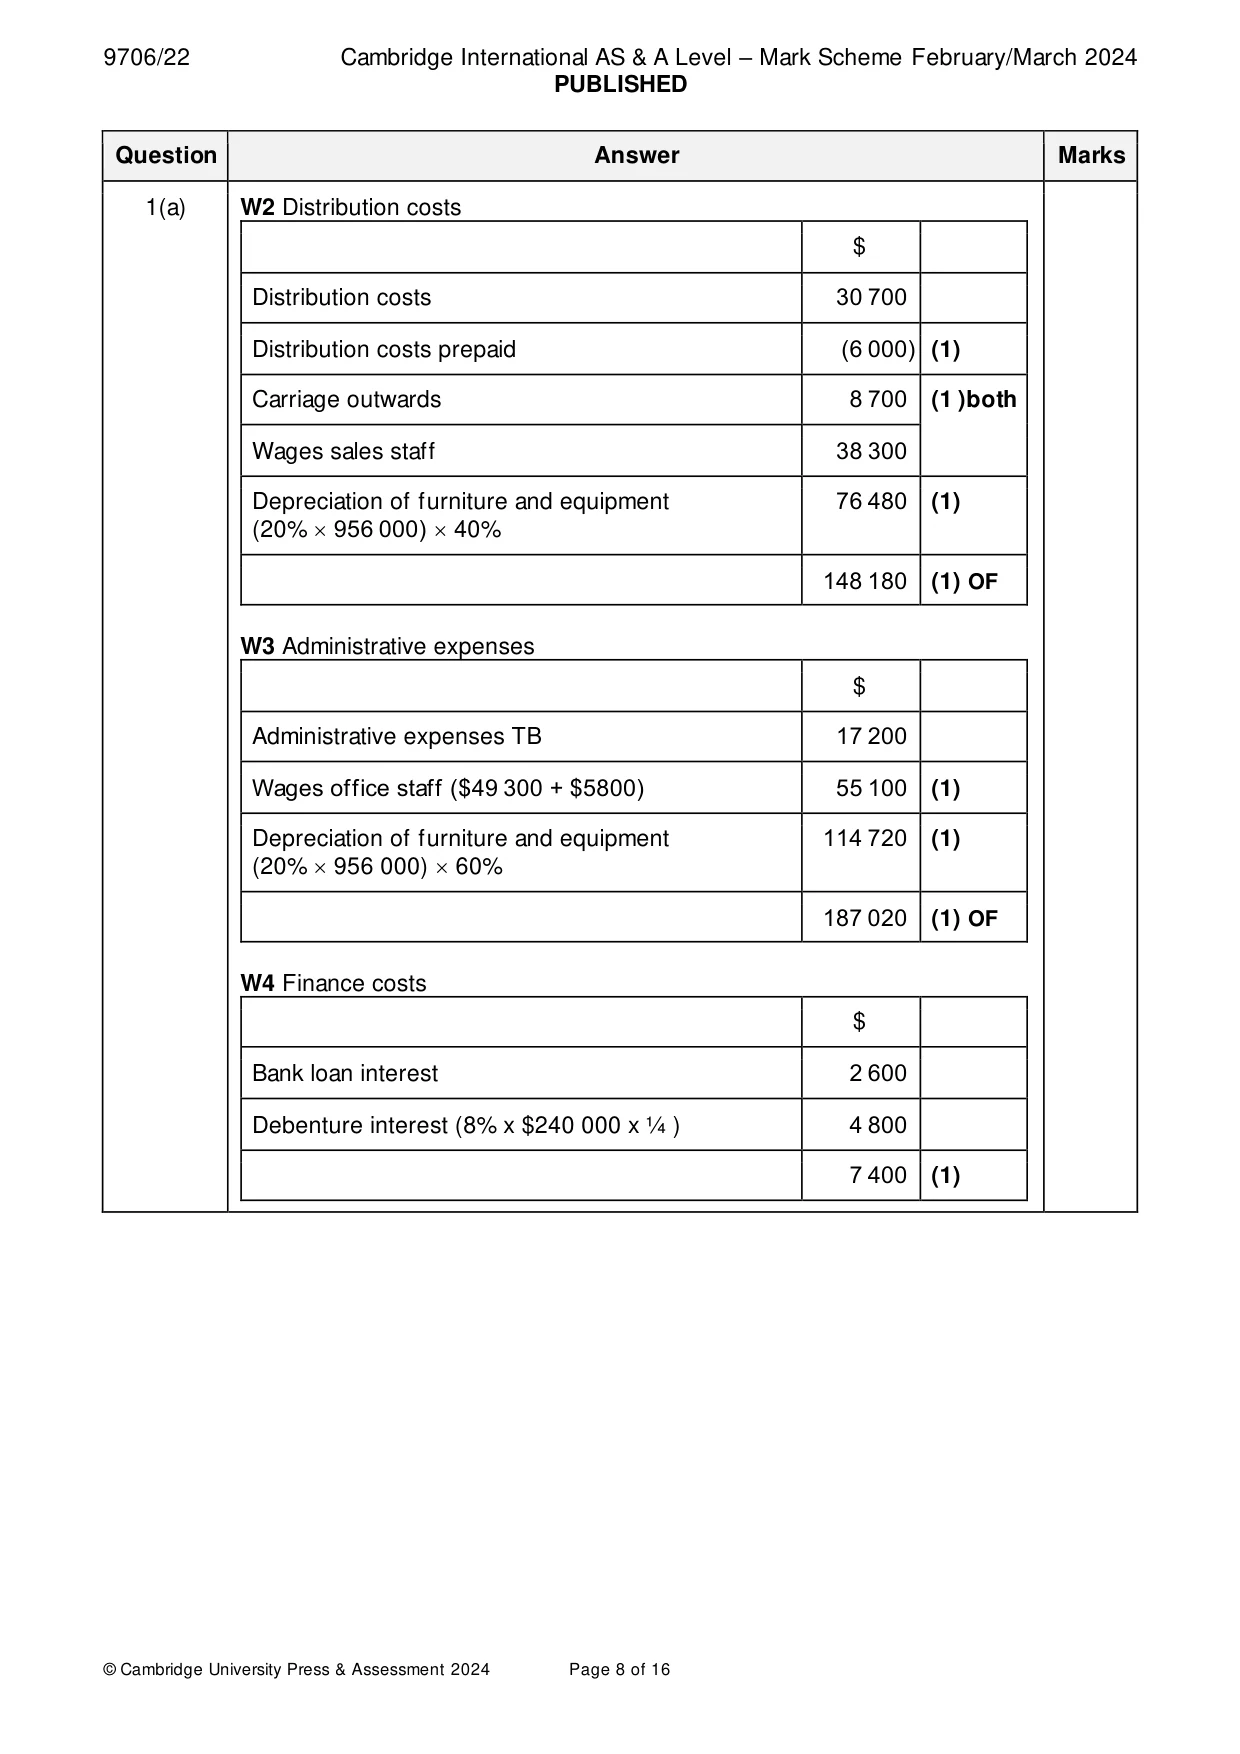
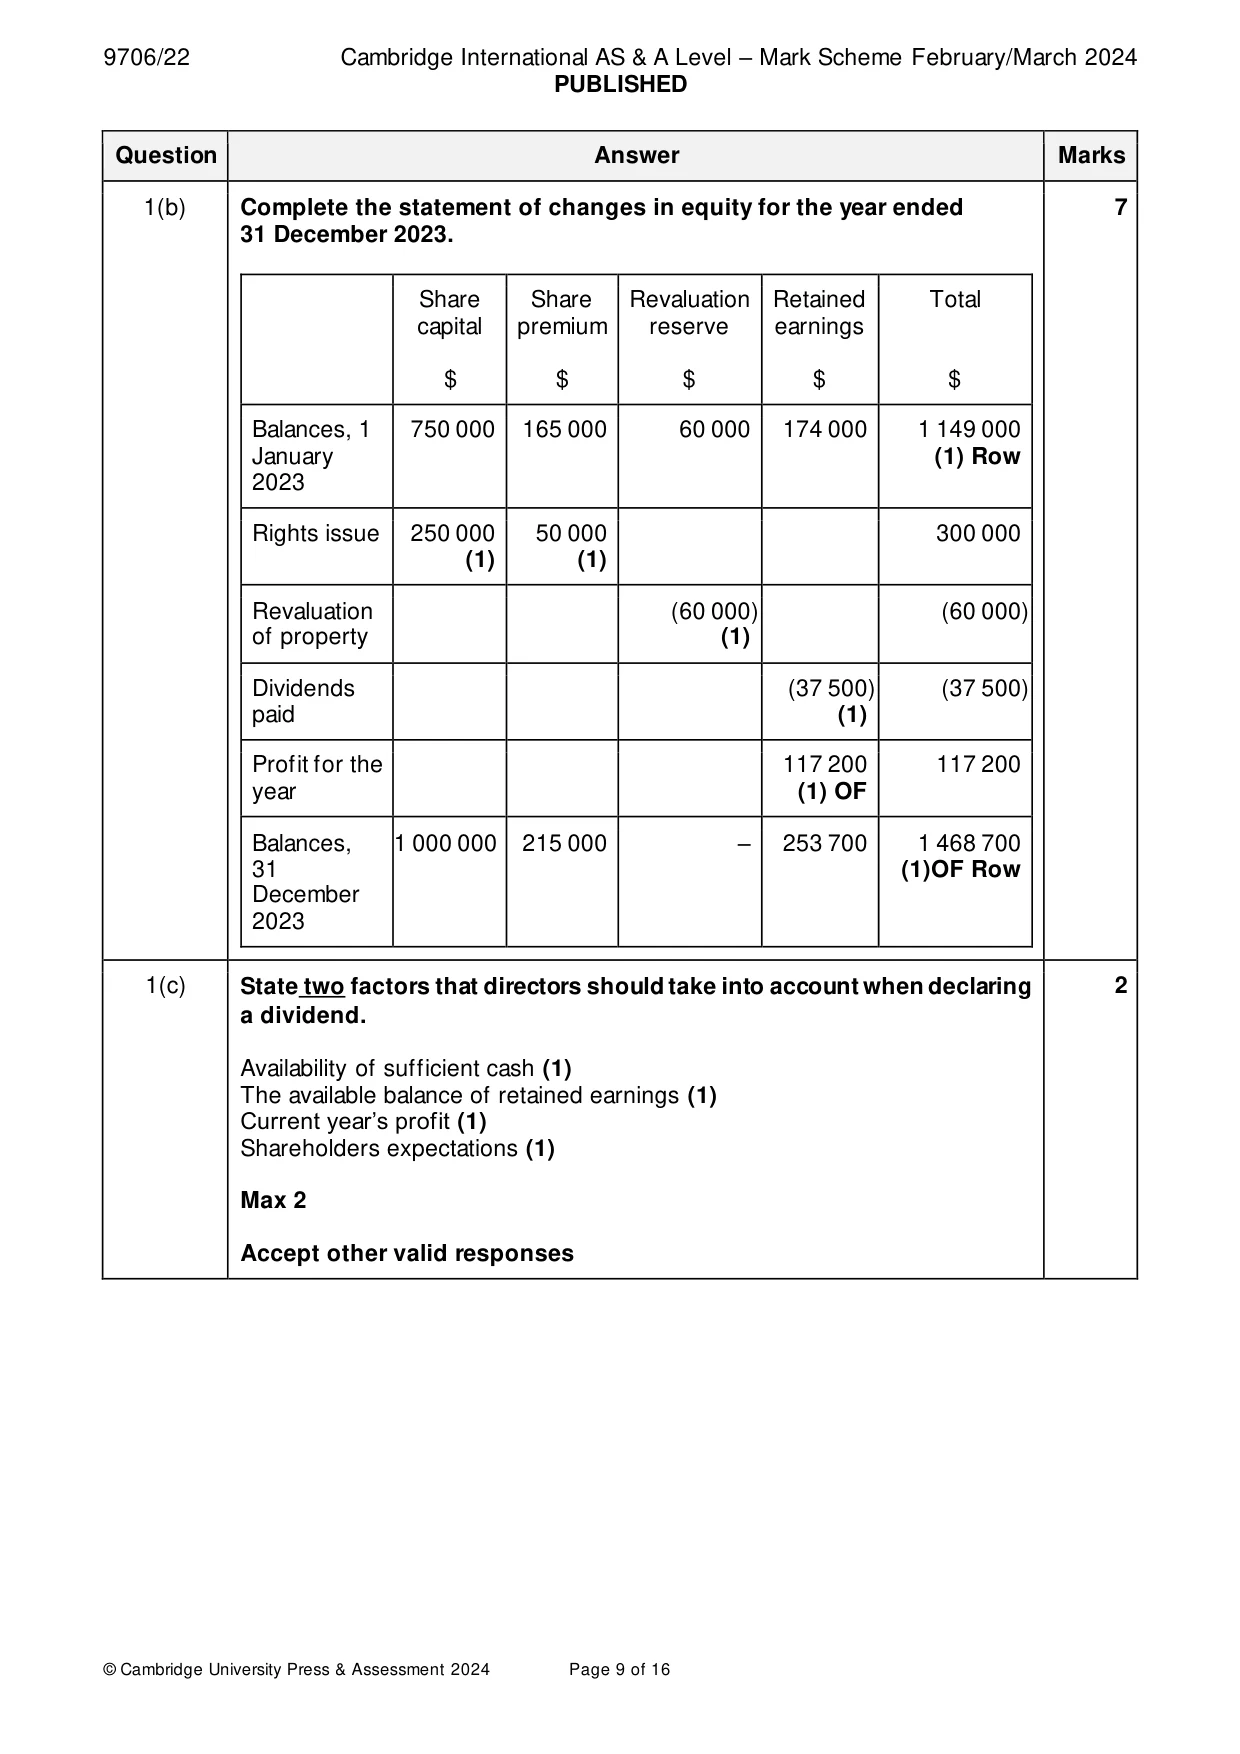
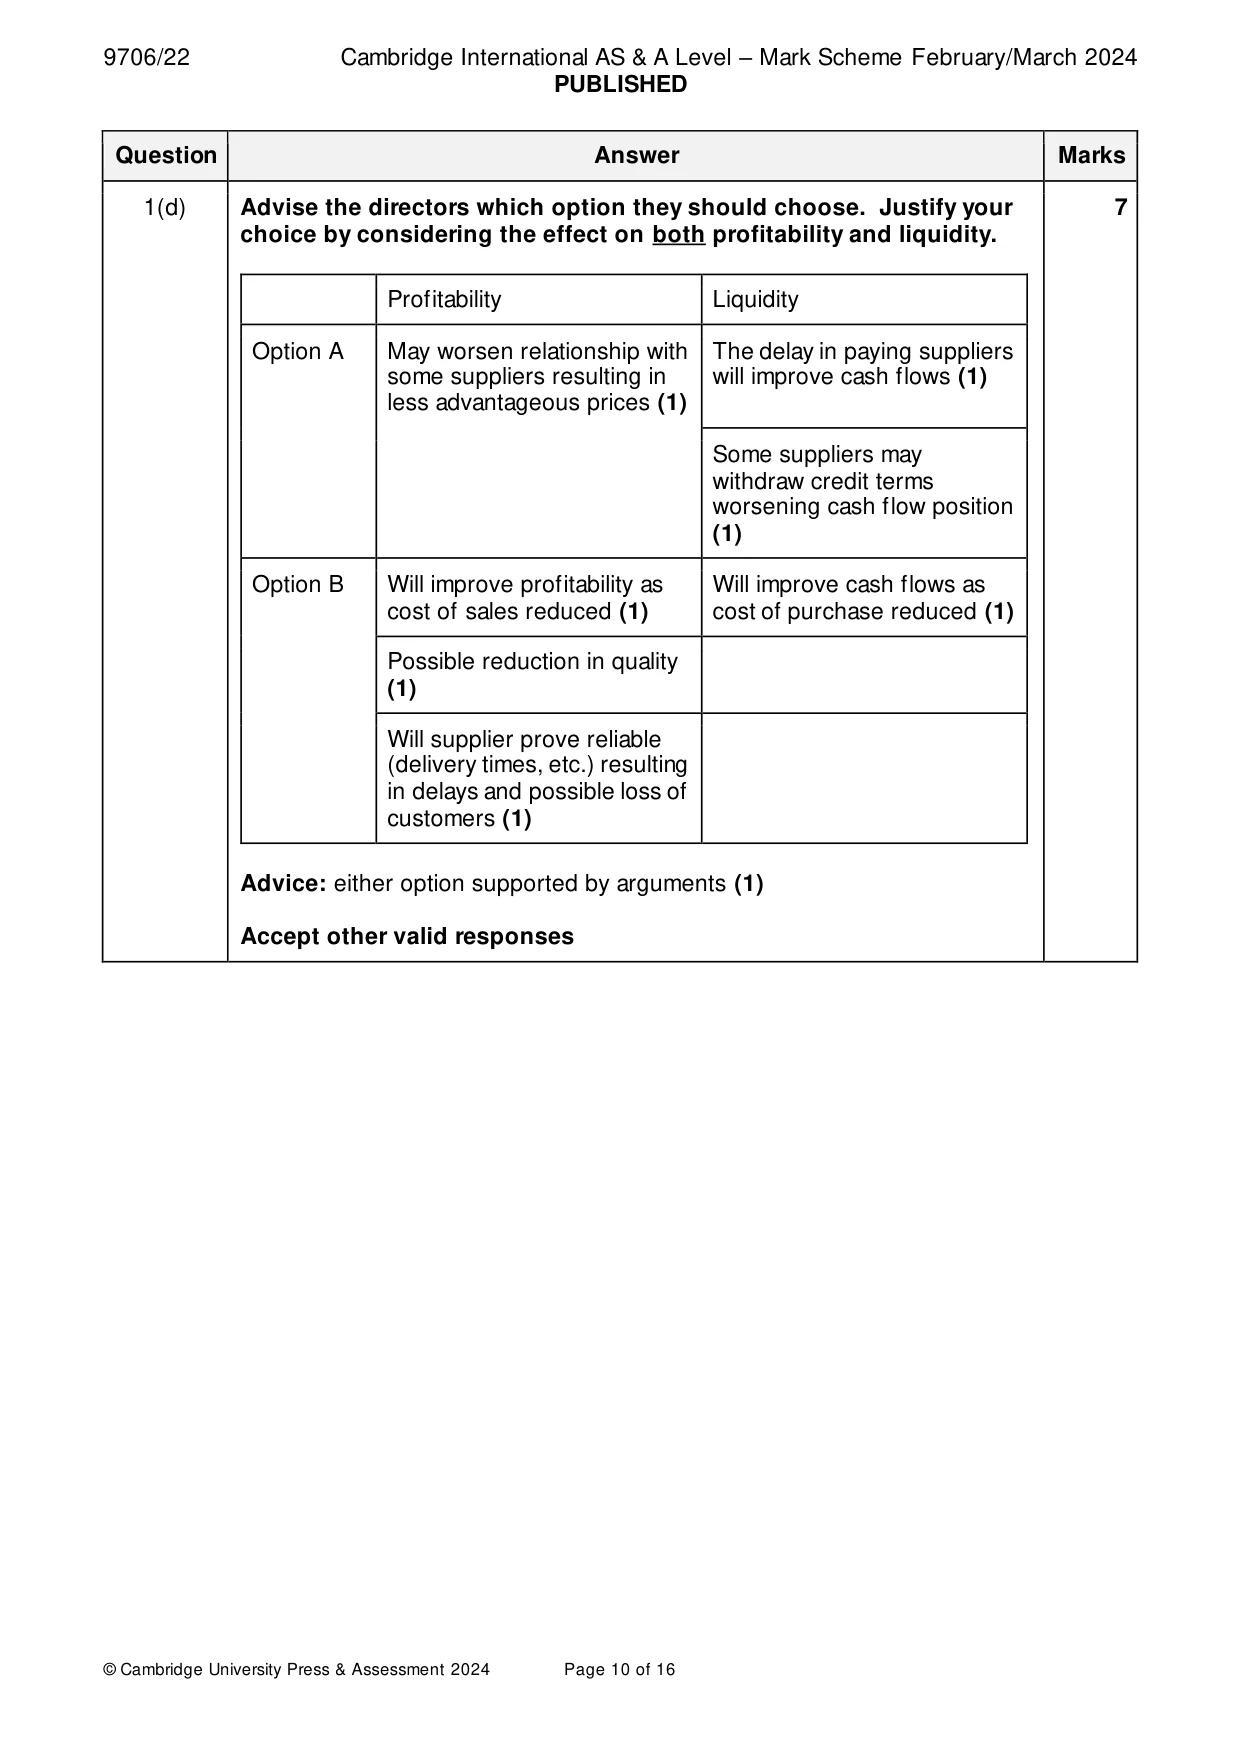
Mark scheme: Question Answer Marks 1(a) Prepare the statement of profit or loss for the year ended 31 December 14 2023. V Limited Statement of profit or loss for the year ended 31 December 2023 $ Revenue 997 100 Cost of sales W1 (519 700) (3) Gross profit 477 400 (1) OF Other income 10 300 (1) Distribution costs W2 (148 180) (4) Administrative expenses W3 (187 020) (3) Profit from operations 152 500 Finance costs W4 (7 400) (1) Profit before tax 145 100 Tax (27 900) Profit for the year 117 200 (1) OF W1 Cost of sales $ $ Opening inventory 47 800 } Purchases 522 000 Less returns (5 100) Add carriage inwards 4 500 521 400 (1) 569 200 Less closing inventory (49 500) }(1) both inventories 519 700 (1) OF 1(a) W2 Distribution costs $ Distribution costs 30 700 Distribution costs prepaid (6 000) (1) Carriage outwards 8 700 (1 )both Wages sales staff 38 300 Depreciation of furniture and equipment 76 480 (1) (20% 956 000) 40% 148 180 (1) OF W3 Administrative expenses $ Administrative expenses TB 17 200 Wages office staff ($49 300 + $5800) 55 100 (1) Depreciation of furniture and equipment 114 720 (1) (20% 956 000) 60% 187 020 (1) OF W4 Finance costs $ Bank loan interest 2 600 Debenture interest (8% x $240 000 x ¼ ) 4 800 7 400 (1) 1(b) Complete the statement of changes in equity for the year ended 7 31 December 2023. Share Share Revaluation Retained Total capital premium reserve earnings $ $ $ $ $ Balances, 1 750 000 165 000 60 000 174 000 1 149 000 January (1) Row 2023 Rights issue 250 000 50 000 300 000 (1) (1) Revaluation (60 000) (60 000) of property (1) Dividends (37 500) (37 500) paid (1) Profit for the 117 200 117 200 year (1) OF Balances, 1 000 000 215 000 – 253 700 1 468 700 31 (1)OF Row December 2023 1(c) State two factors that directors should take into account when declaring 2 a dividend. Availability of sufficient cash (1) The available balance of retained earnings (1) Current year’s profit (1) Shareholders expectations (1) Max 2 Accept other valid responses 1(d) Advise the directors which option they should choose. Justify your 7 choice by considering the effect on both profitability and liquidity. Profitability Liquidity Option A May worsen relationship with The delay in paying suppliers some suppliers resulting in will improve cash flows (1) less advantageous prices (1) Some suppliers may withdraw credit terms worsening cash flow position (1) Option B Will improve profitability as Will improve cash flows as cost of sales reduced (1) cost of purchase reduced (1) Possible reduction in quality (1) Will supplier prove reliable (delivery times, etc.) resulting in delays and possible loss of customers (1) Advice: either option supported by arguments (1) Accept other valid responses
Q2 · Zainab uses the straight-line method of depreciation for business vehicles
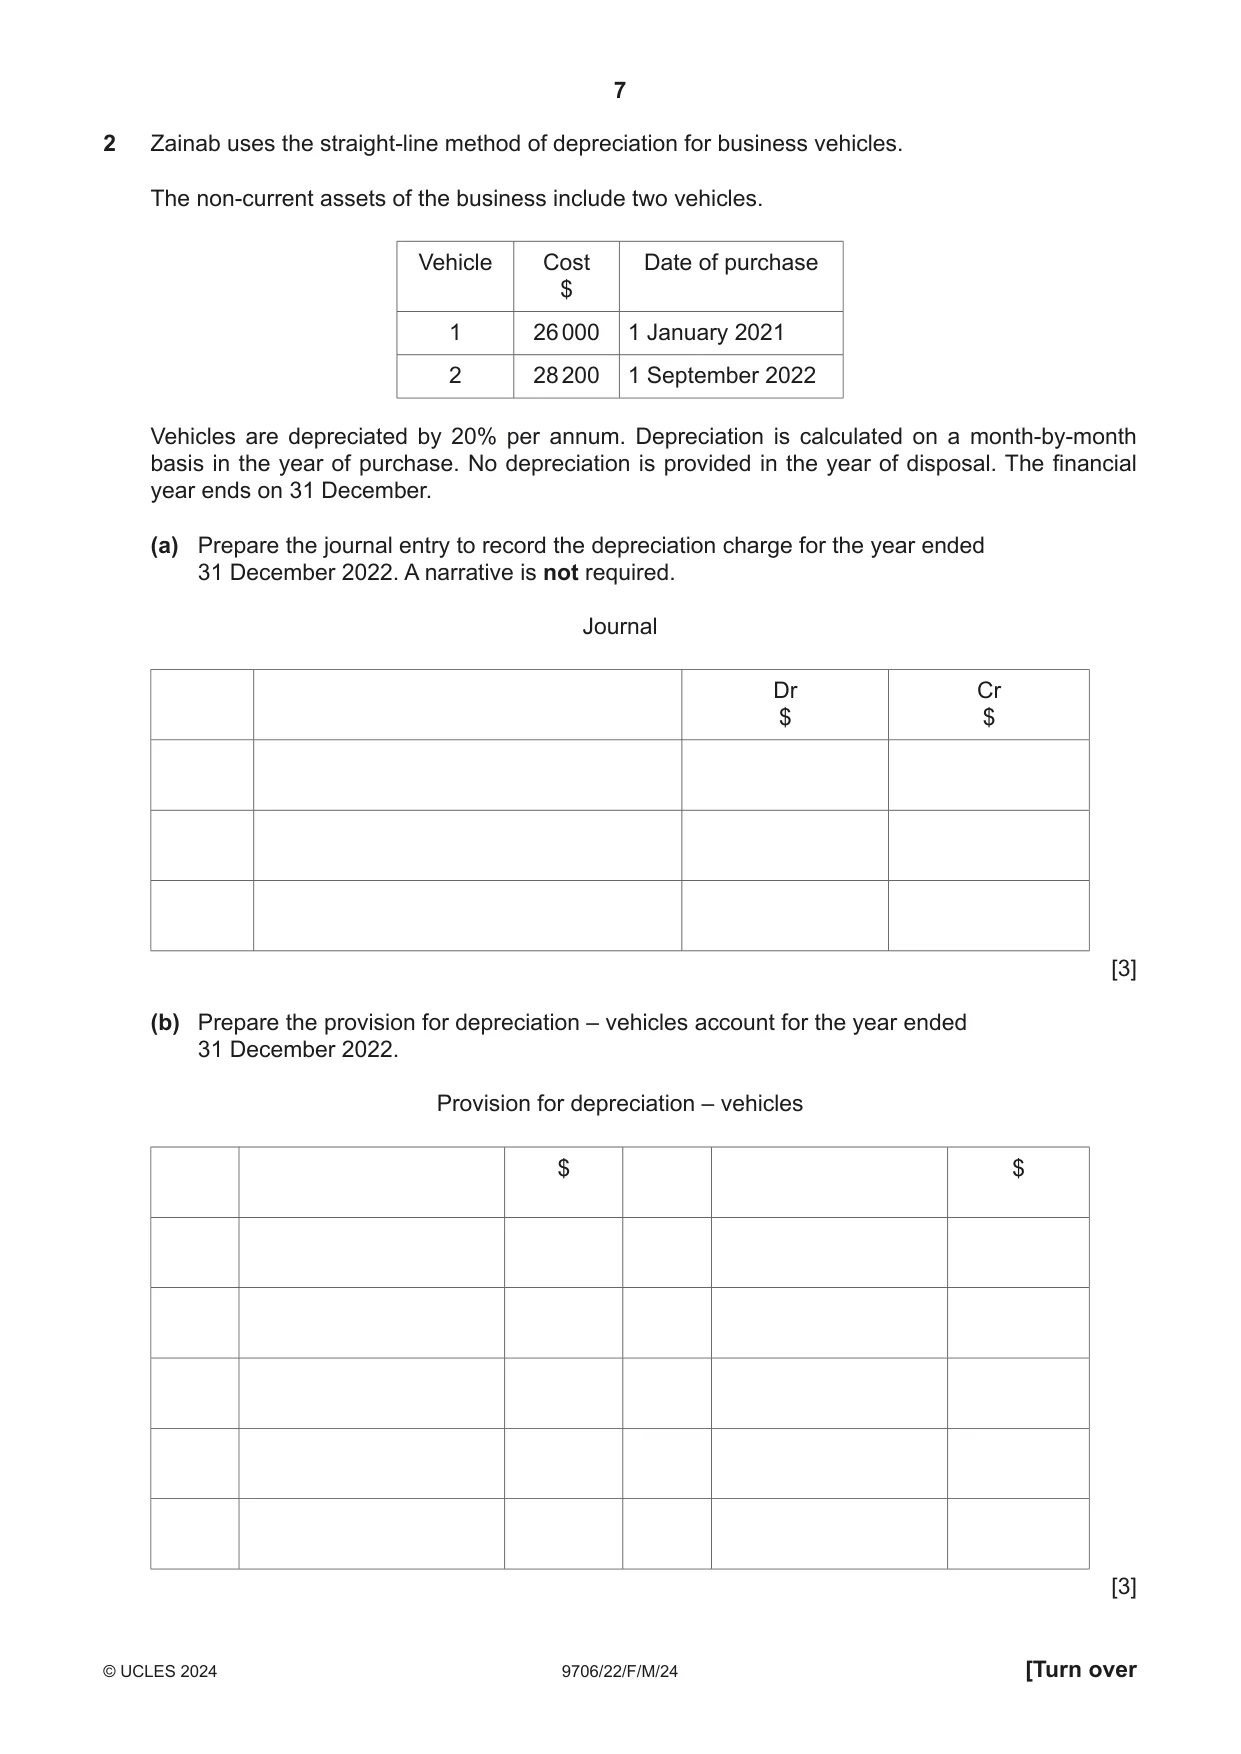
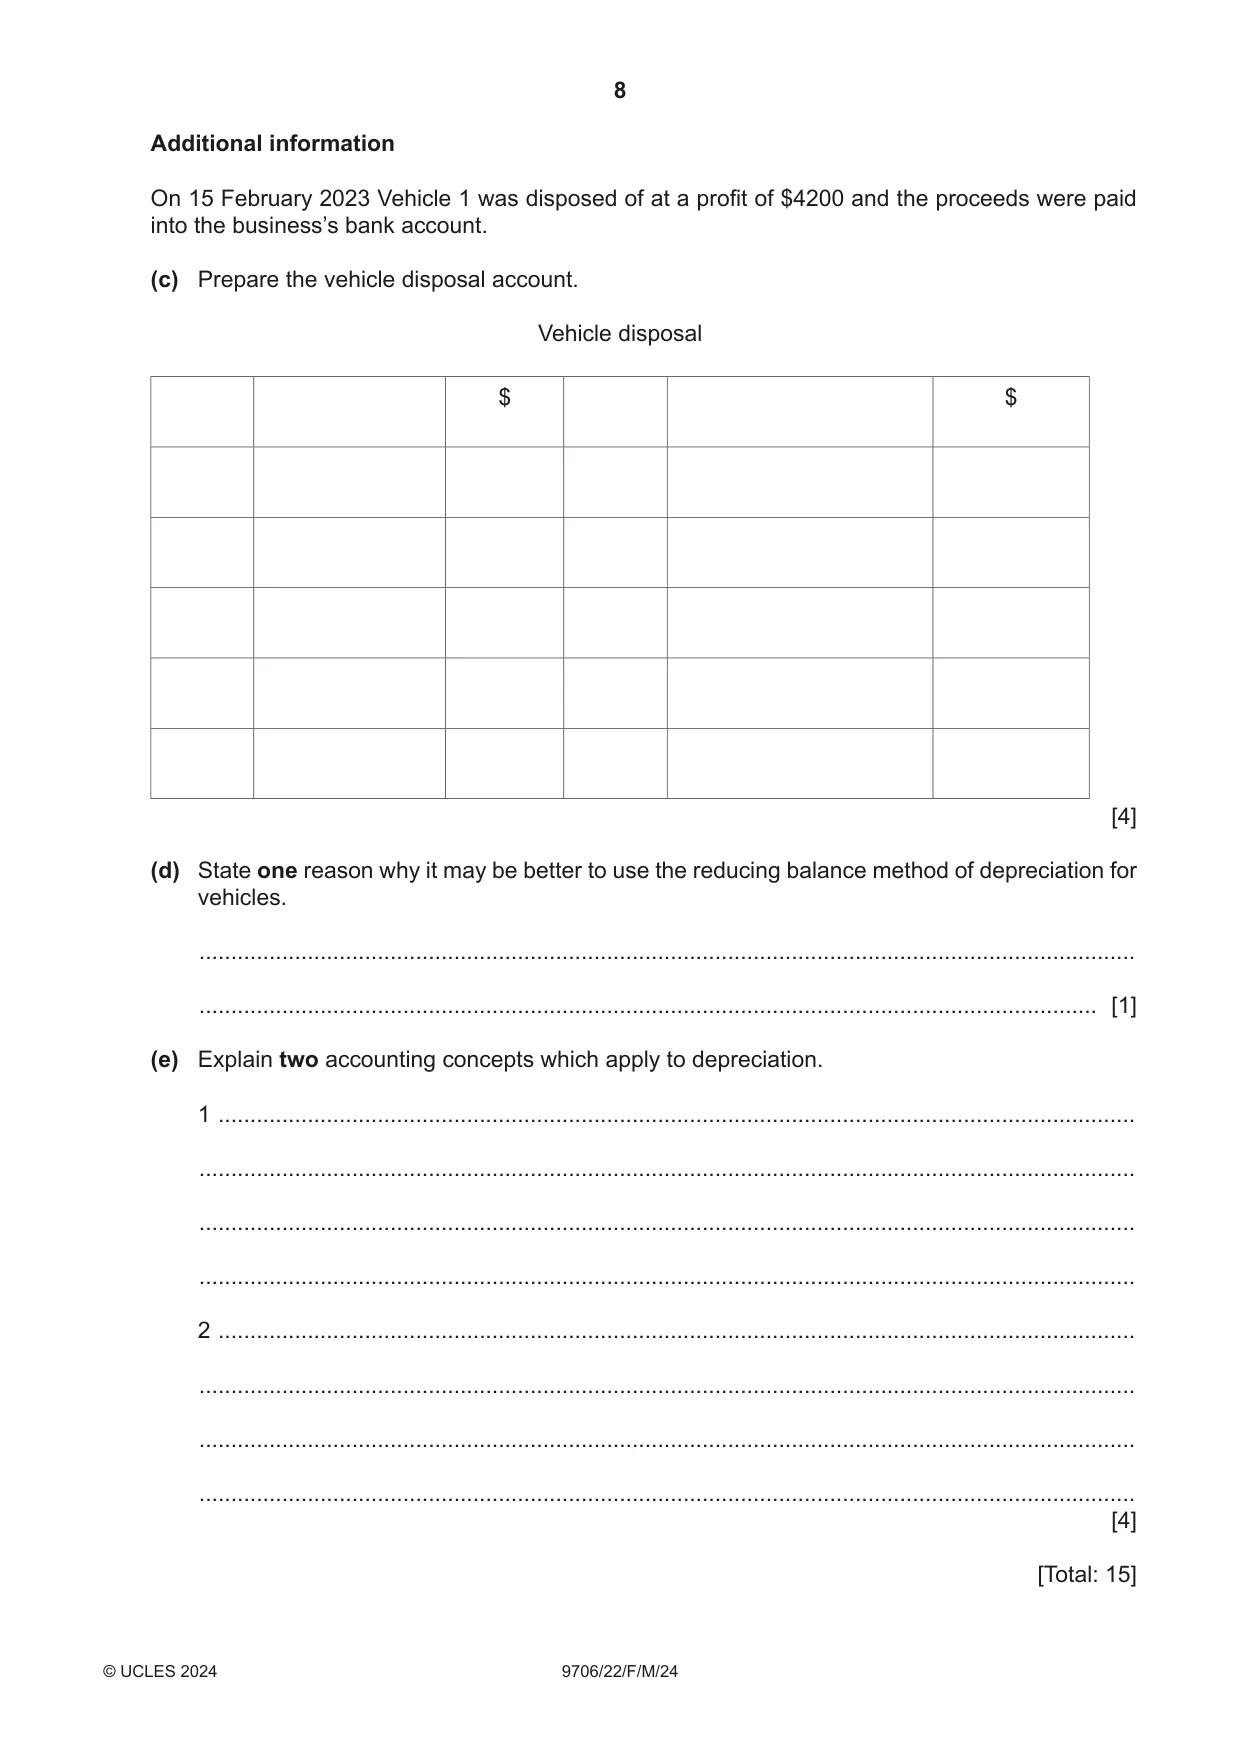
2 Zainab uses the straight-line method of depreciation for business vehicles. The non-current assets of the business include two vehicles. Vehicle Cost Date of purchase $ 1 26 000 1 January 2021 2 28 200 1 September 2022 Vehicles are depreciated by 20% per annum. Depreciation is calculated on a month-by-month basis in the year of purchase. No depreciation is provided in the year of disposal. The financial year ends on 31 December. (a) Prepare the journal entry to record the depreciation charge for the year ended 31 December 2022. A narrative is not required. Journal Dr Cr $ $ [3] (b) Prepare the provision for depreciation – vehicles account for the year ended 31 December 2022. Provision for depreciation – vehicles $ $ [3] Additional information On 15 February 2023 Vehicle 1 was disposed of at a profit of $4200 and the proceeds were paid into the business’s bank account. (c) Prepare the vehicle disposal account. Vehicle disposal $ $ [4] (d) State one reason why it may be better to use the reducing balance method of depreciation for vehicles. ................................................................................................................................................... ............................................................................................................................................. [1] (e) Explain two accounting concepts which apply to depreciation. 1 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... [4] [Total: 15]
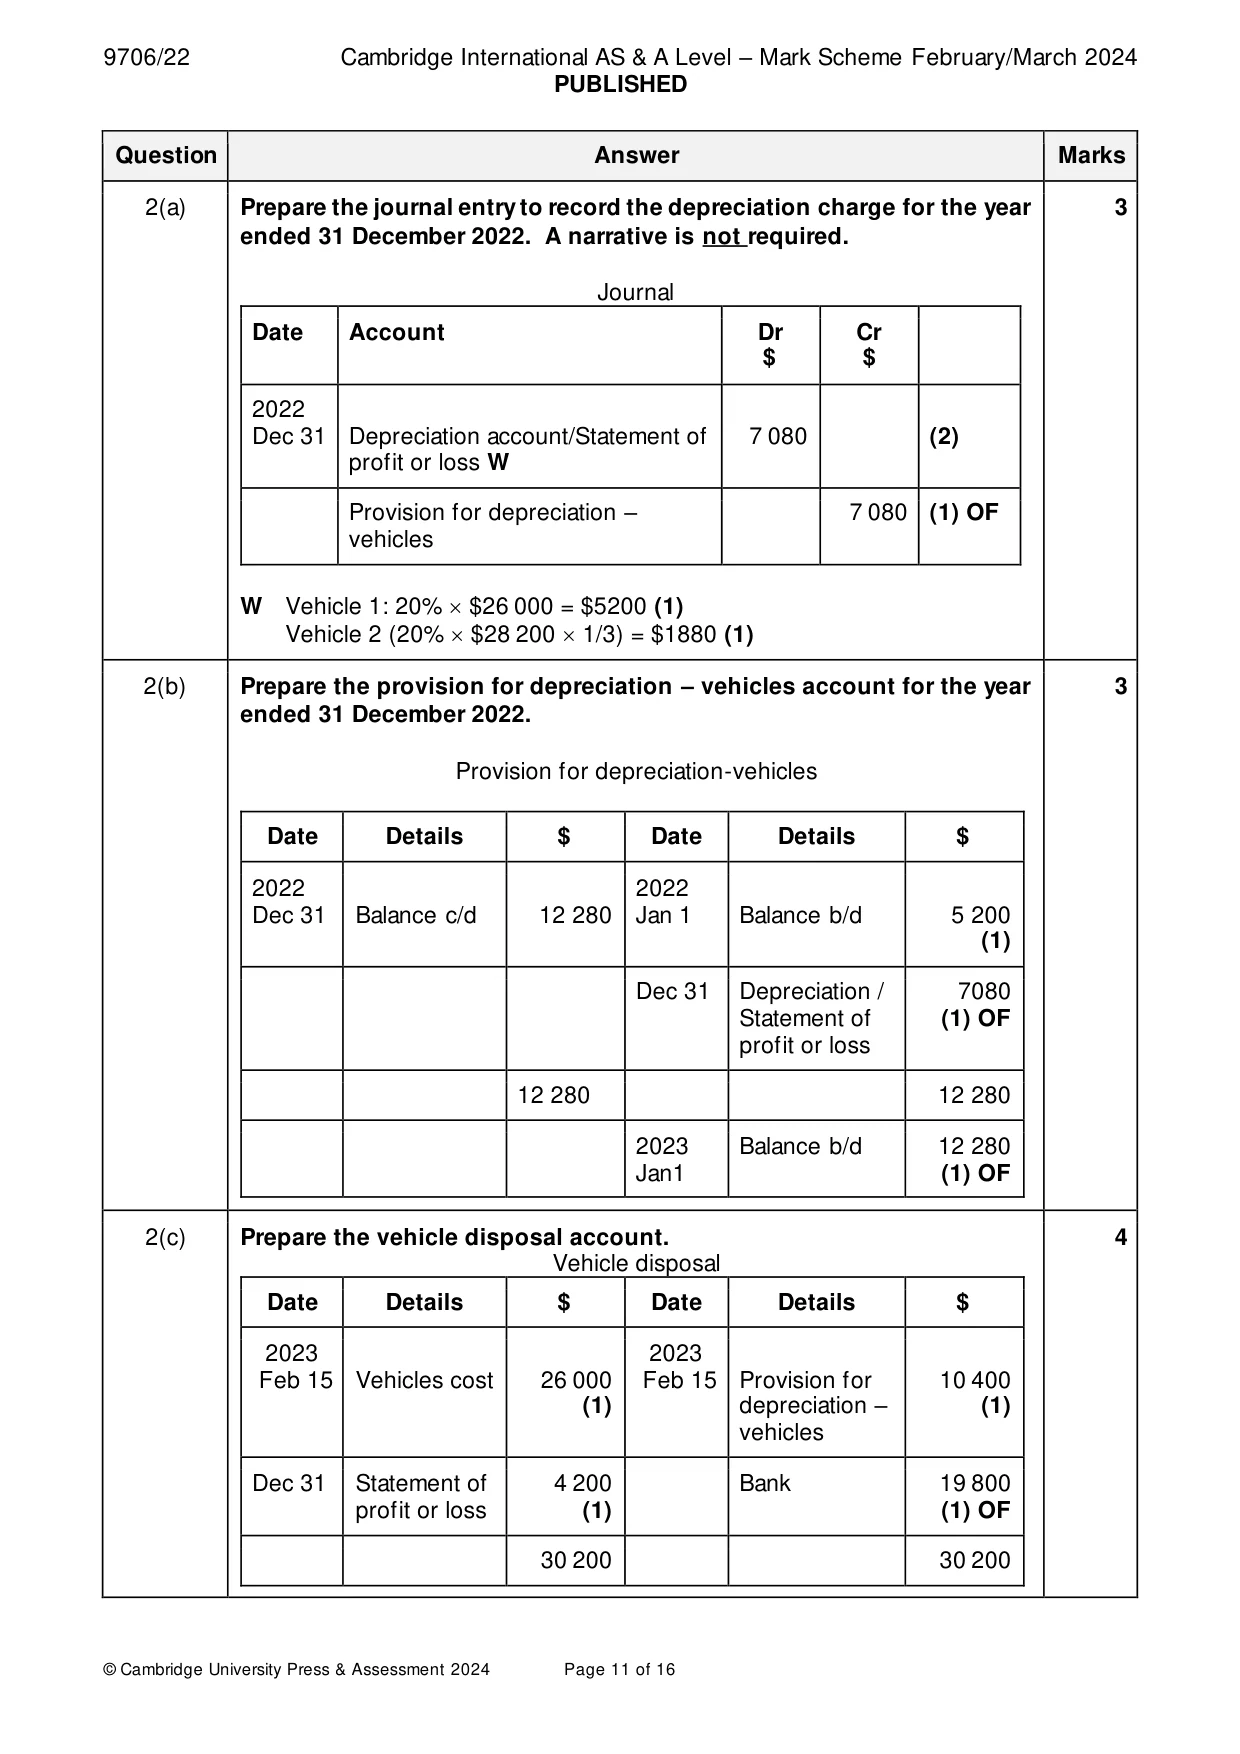
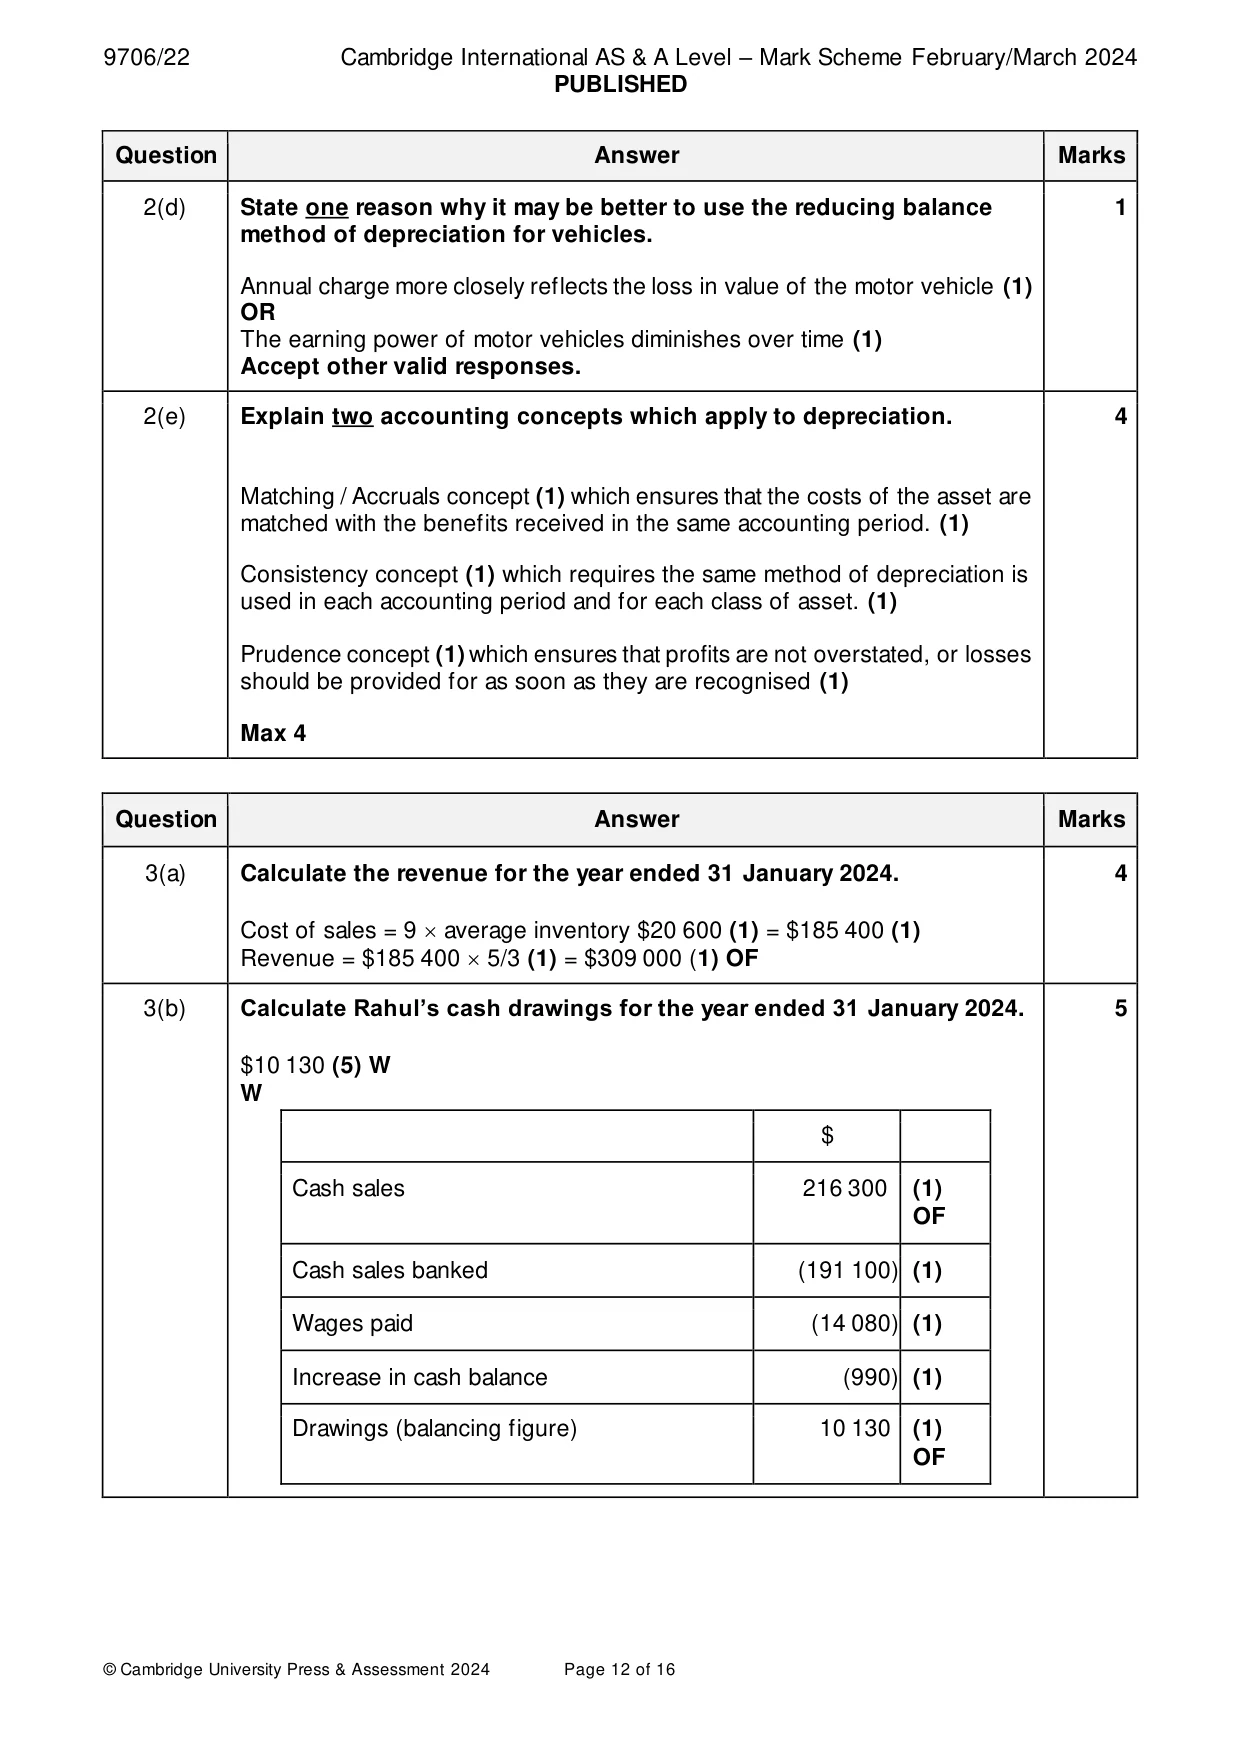
Mark scheme: 2(a) Prepare the journal entry to record the depreciation charge for the year 3 ended 31 December 2022. A narrative is not required. Journal Date Account Dr Cr $ $ 2022 Dec 31 Depreciation account/Statement of 7 080 (2) profit or loss W Provision for depreciation – 7 080 (1) OF vehicles W Vehicle 1: 20% $26 000 = $5200 (1) Vehicle 2 (20% $28 200 1/3) = $1880 (1) 2(b) Prepare the provision for depreciation – vehicles account for the year 3 ended 31 December 2022. Provision for depreciation-vehicles Date Details $ Date Details $ 2022 2022 Dec 31 Balance c/d 12 280 Jan 1 Balance b/d 5 200 (1) Dec 31 Depreciation / 7080 Statement of (1) OF profit or loss 12 280 12 280 2023 Balance b/d 12 280 Jan1 (1) OF 2(c) Prepare the vehicle disposal account. 4 Vehicle disposal Date Details $ Date Details $ 2023 2023 Feb 15 Vehicles cost 26 000 Feb 15 Provision for 10 400 (1) depreciation – (1) vehicles Dec 31 Statement of 4 200 Bank 19 800 profit or loss (1) (1) OF 30 200 30 200 2(d) State one reason why it may be better to use the reducing balance 1 method of depreciation for vehicles. Annual charge more closely reflects the loss in value of the motor vehicle (1) OR The earning power of motor vehicles diminishes over time (1) Accept other valid responses. 2(e) Explain two accounting concepts which apply to depreciation. 4 Matching / Accruals concept (1) which ensures that the costs of the asset are matched with the benefits received in the same accounting period. (1) Consistency concept (1) which requires the same method of depreciation is used in each accounting period and for each class of asset. (1) Prudence concept (1) which ensures that profits are not overstated, or losses should be provided for as soon as they are recognised (1) Max 4
Q3 · Rahul owns a retail business
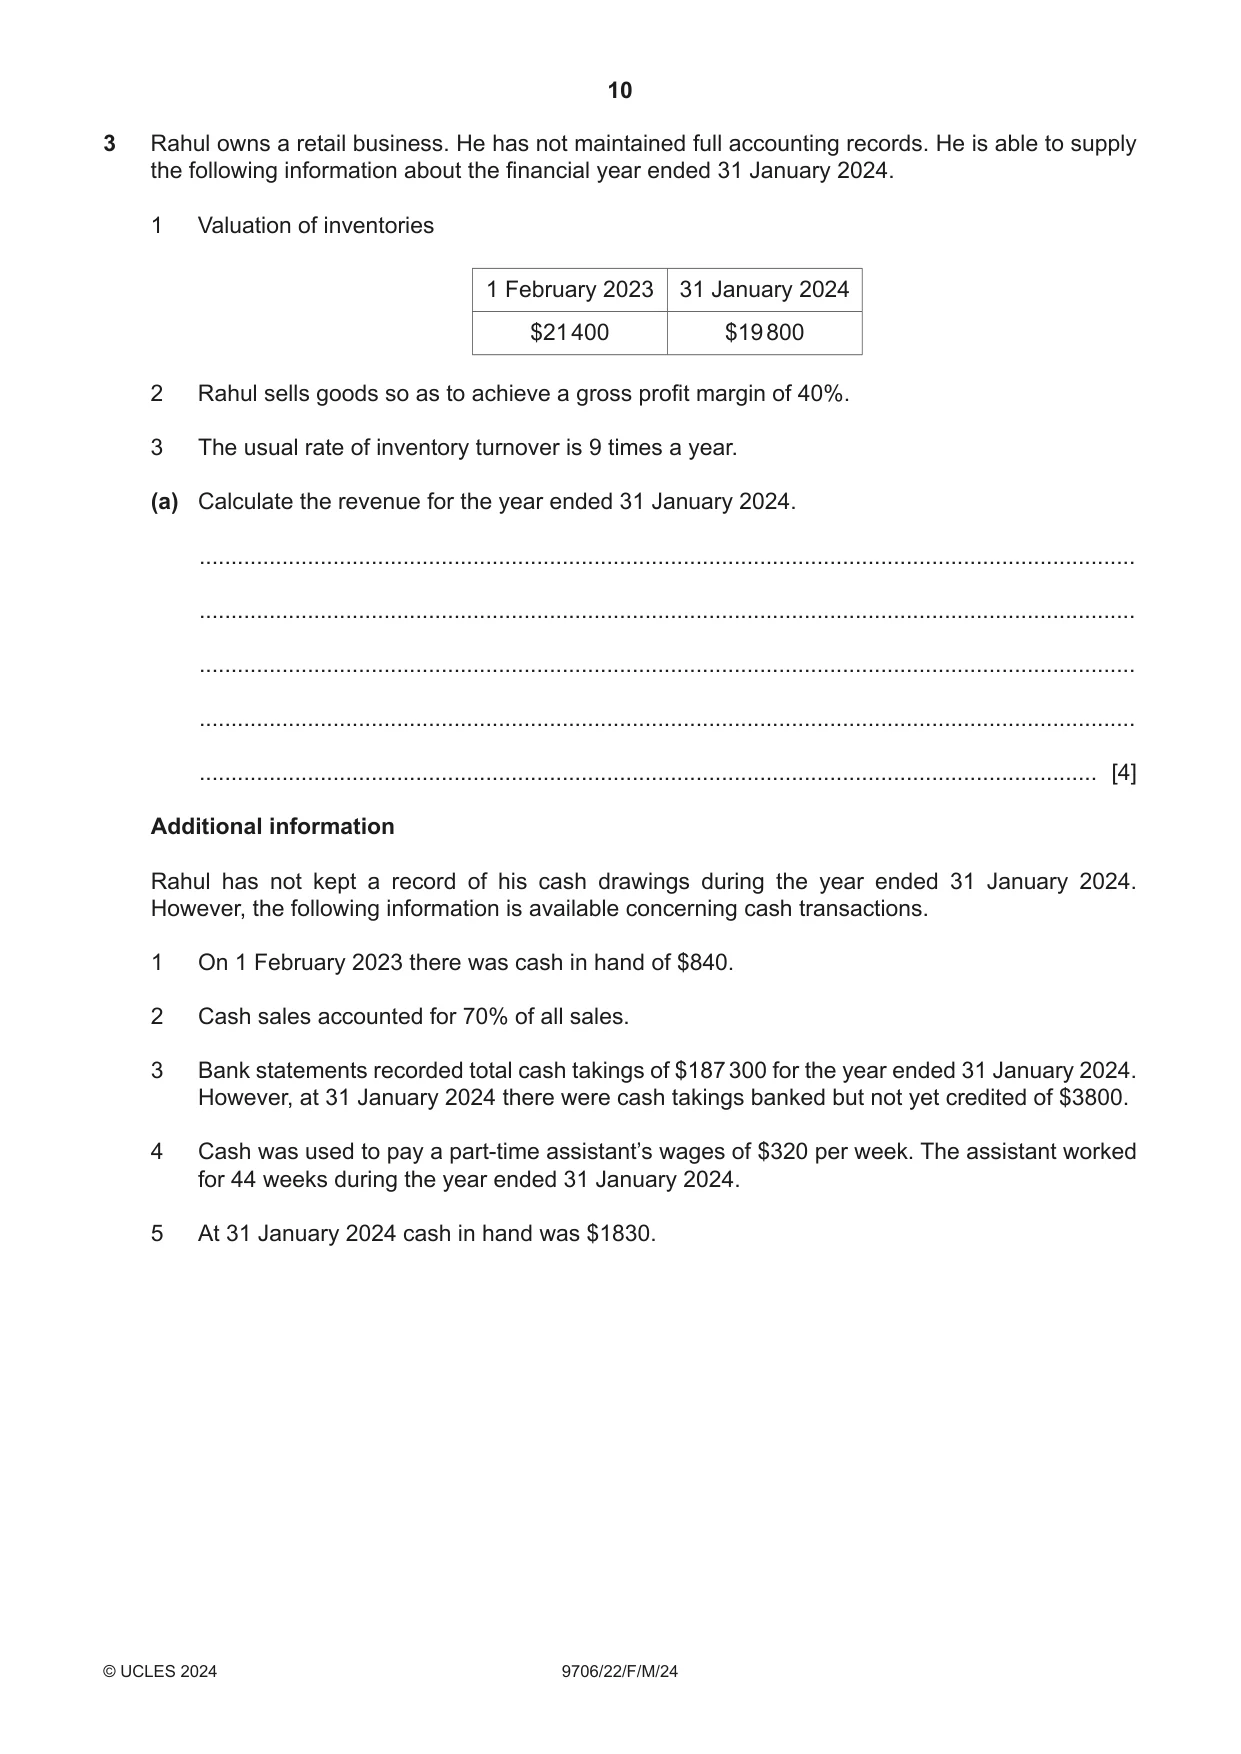
3 Rahul owns a retail business. He has not maintained full accounting records. He is able to supply the following information about the financial year ended 31 January 2024. 1 Valuation of inventories 1 February 2023 31 January 2024 $21 400 $19 800 2 Rahul sells goods so as to achieve a gross profit margin of 40%. 3 The usual rate of inventory turnover is 9 times a year. (a) Calculate the revenue for the year ended 31 January 2024. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] Additional information Rahul has not kept a record of his cash drawings during the year ended 31 January 2024. However, the following information is available concerning cash transactions. 1 On 1 February 2023 there was cash in hand of $840. 2 Cash sales accounted for 70% of all sales. 3 Bank statements recorded total cash takings of $187 300 for the year ended 31 January 2024. However, at 31 January 2024 there were cash takings banked but not yet credited of $3800. 4 Cash was used to pay a part-time assistant’s wages of $320 per week. The assistant worked for 44 weeks during the year ended 31 January 2024. 5 At 31 January 2024 cash in hand was $1830. (b) Calculate Rahul’s cash drawings for the year ended 31 January 2024. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] Additional information Rahul’s accountant has suggested he should start keeping full accounting records and that he should use an accounting software package. (c) State two ways in which Rahul will benefit from the accountant’s suggestions. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] (d) Explain two possible reasons for not accepting the accountant’s suggestions. 1 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... [4] [Total: 15]
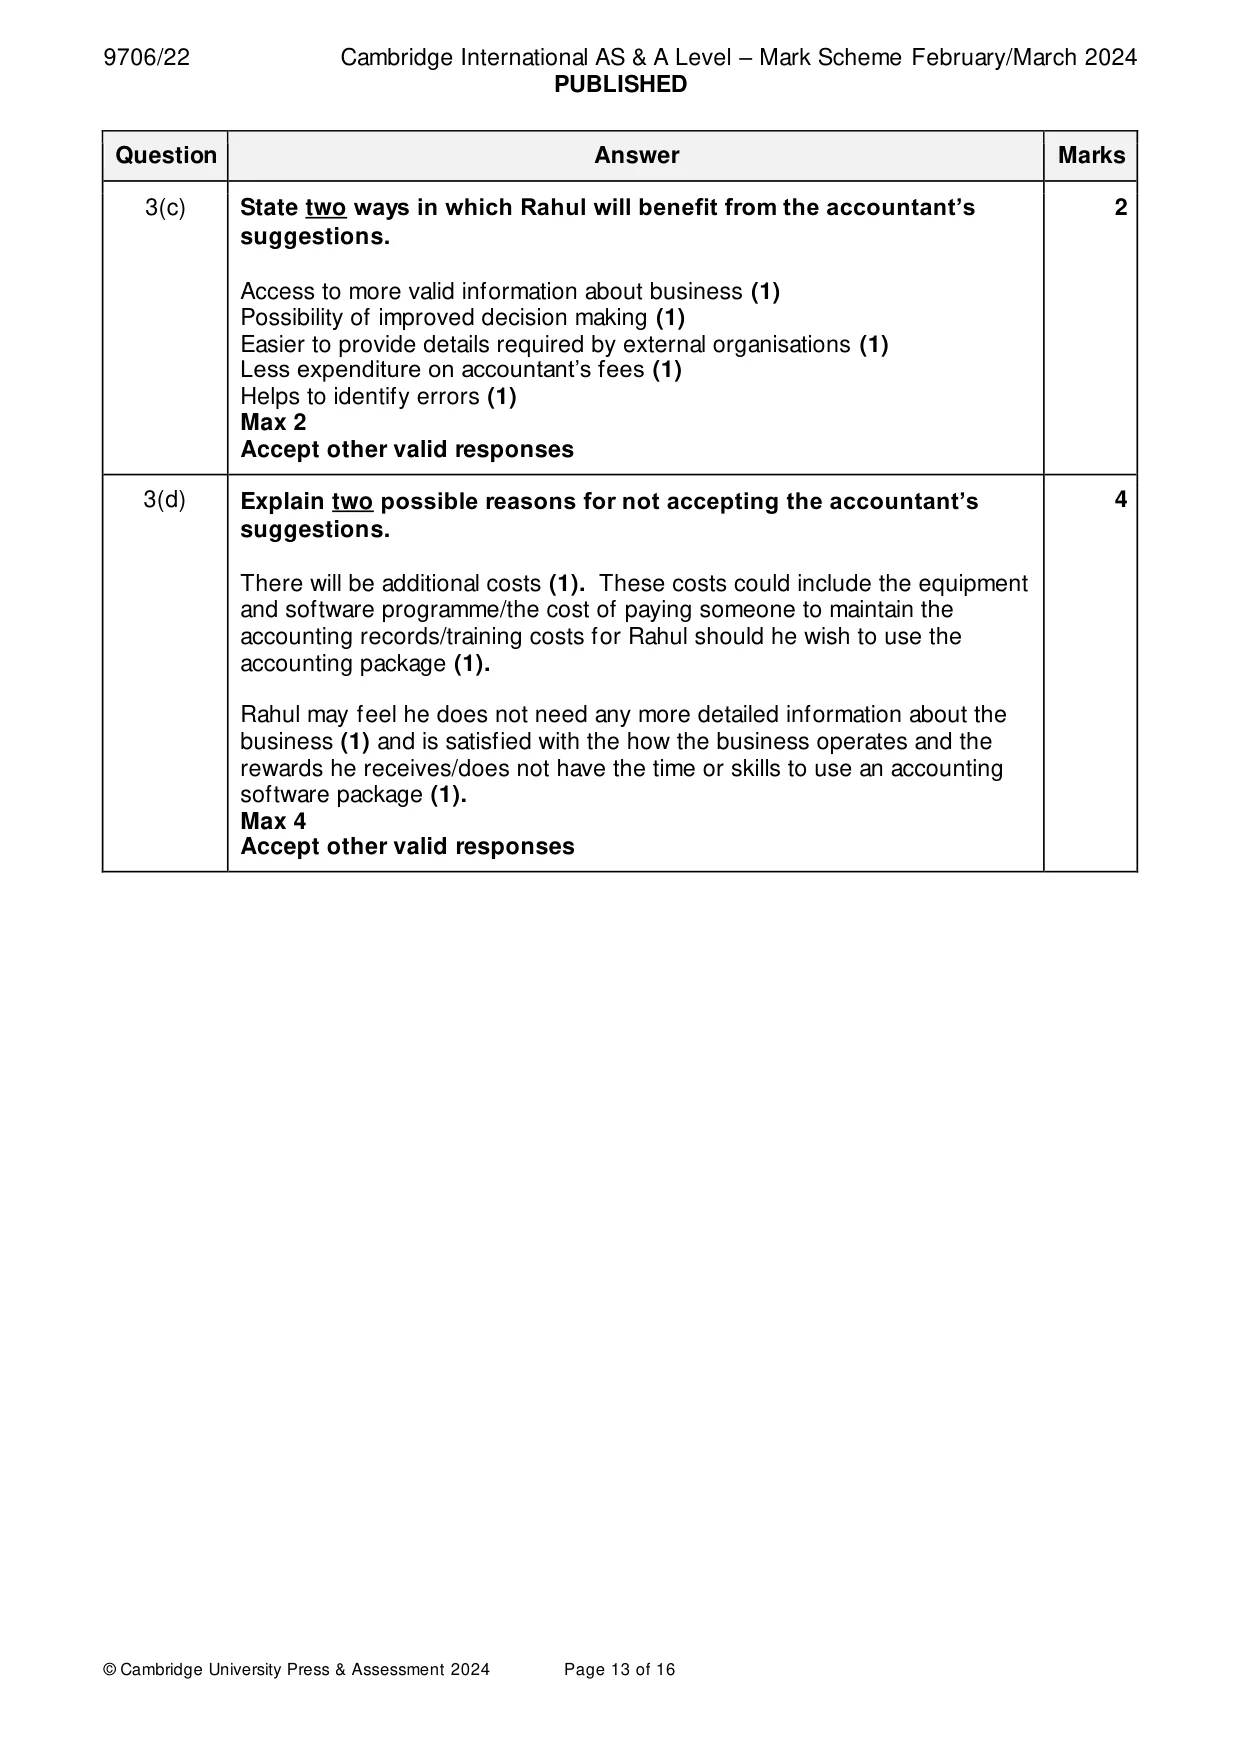
Mark scheme: 3(a) Calculate the revenue for the year ended 31 January 2024. 4 Cost of sales = 9 average inventory $20 600 (1) = $185 400 (1) Revenue = $185 400 5/3 (1) = $309 000 (1) OF 3(b) Calculate Rahul’s cash drawings for the year ended 31 January 2024. 5 $10 130 (5) W W $ Cash sales 216 300 (1) OF Cash sales banked (191 100) (1) Wages paid (14 080) (1) Increase in cash balance (990) (1) Drawings (balancing figure) 10 130 (1) OF 3(c) State two ways in which Rahul will benefit from the accountant’s 2 suggestions. Access to more valid information about business (1) Possibility of improved decision making (1) Easier to provide details required by external organisations (1) Less expenditure on accountant’s fees (1) Helps to identify errors (1) Max 2 Accept other valid responses 3(d) Explain two possible reasons for not accepting the accountant’s 4 suggestions. There will be additional costs (1). These costs could include the equipment and software programme/the cost of paying someone to maintain the accounting records/training costs for Rahul should he wish to use the accounting package (1). Rahul may feel he does not need any more detailed information about the business (1) and is satisfied with the how the business operates and the rewards he receives/does not have the time or skills to use an accounting software package (1). Max 4 Accept other valid responses
Q4 · K Limited uses absorption costing at one of its factories
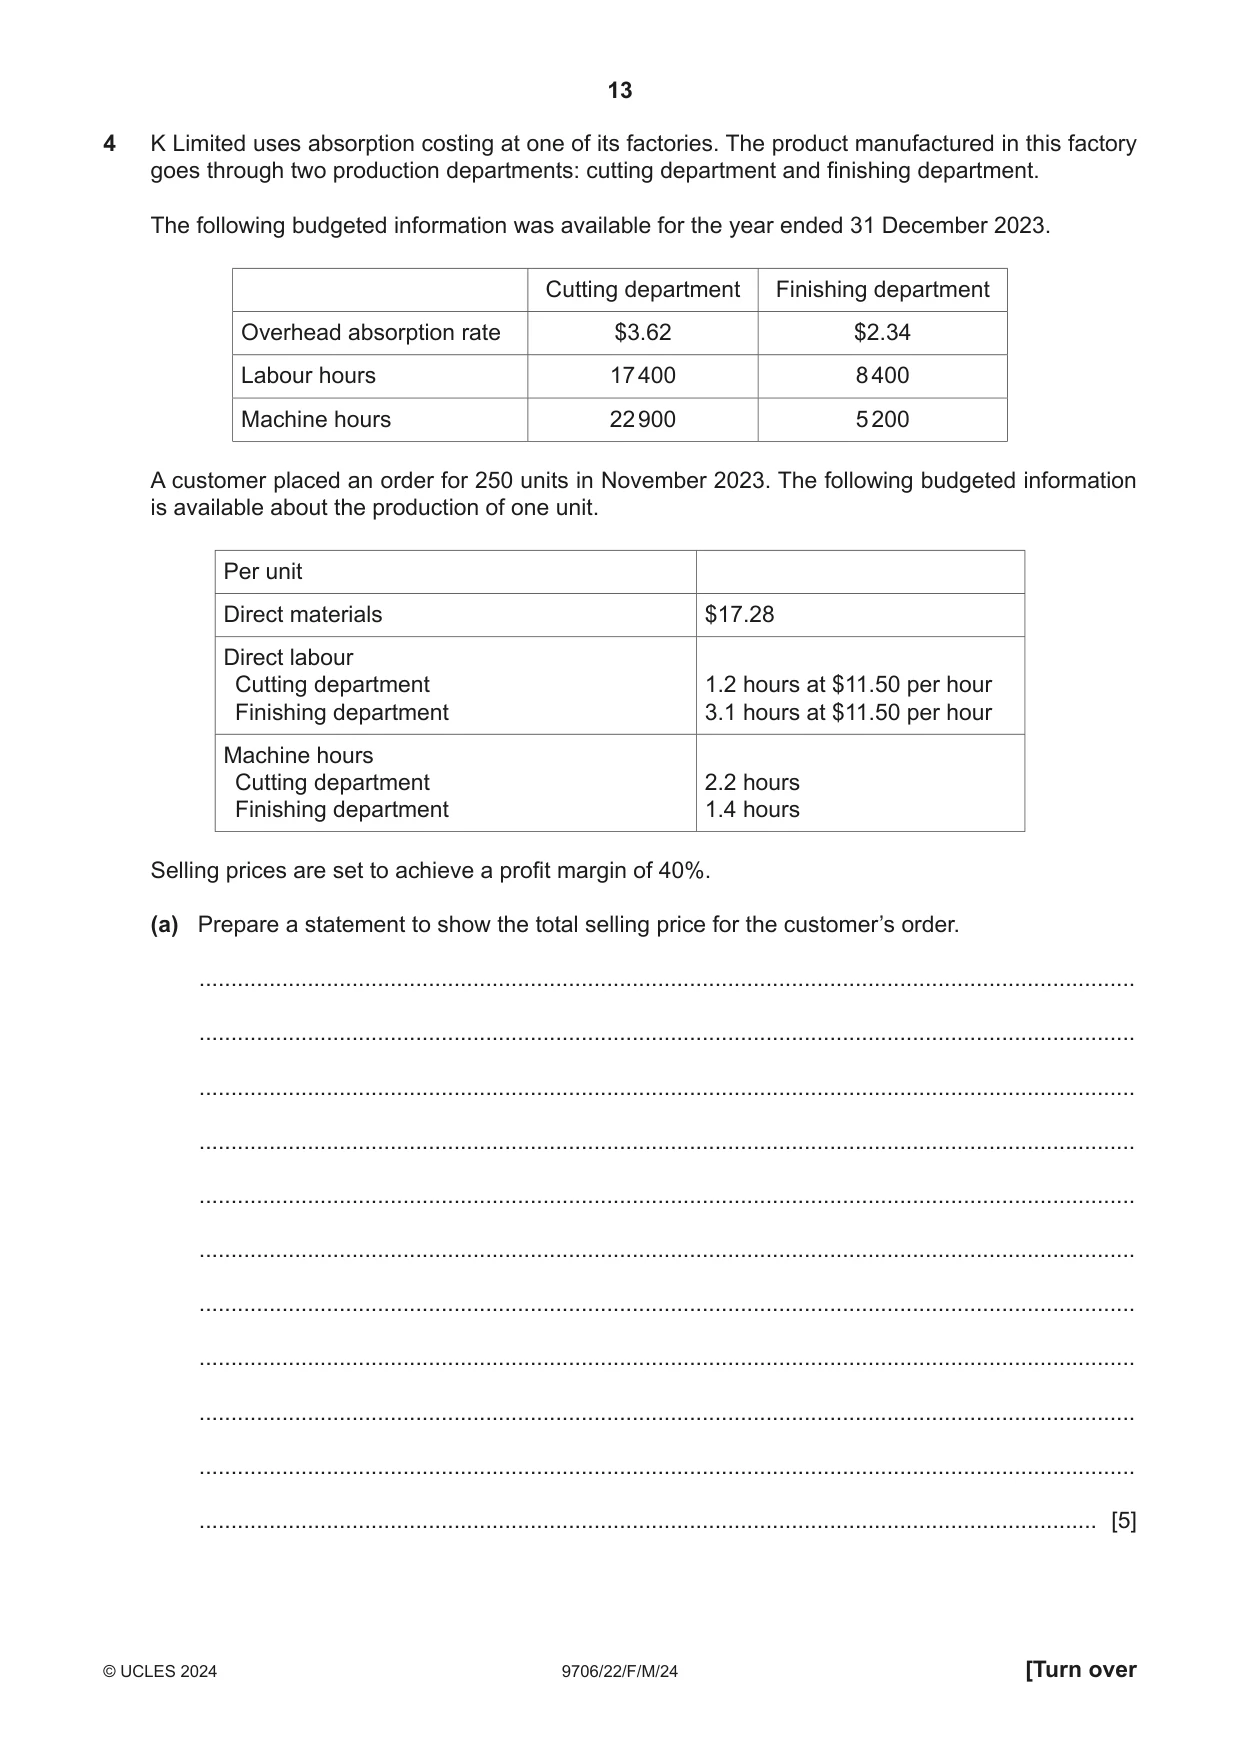
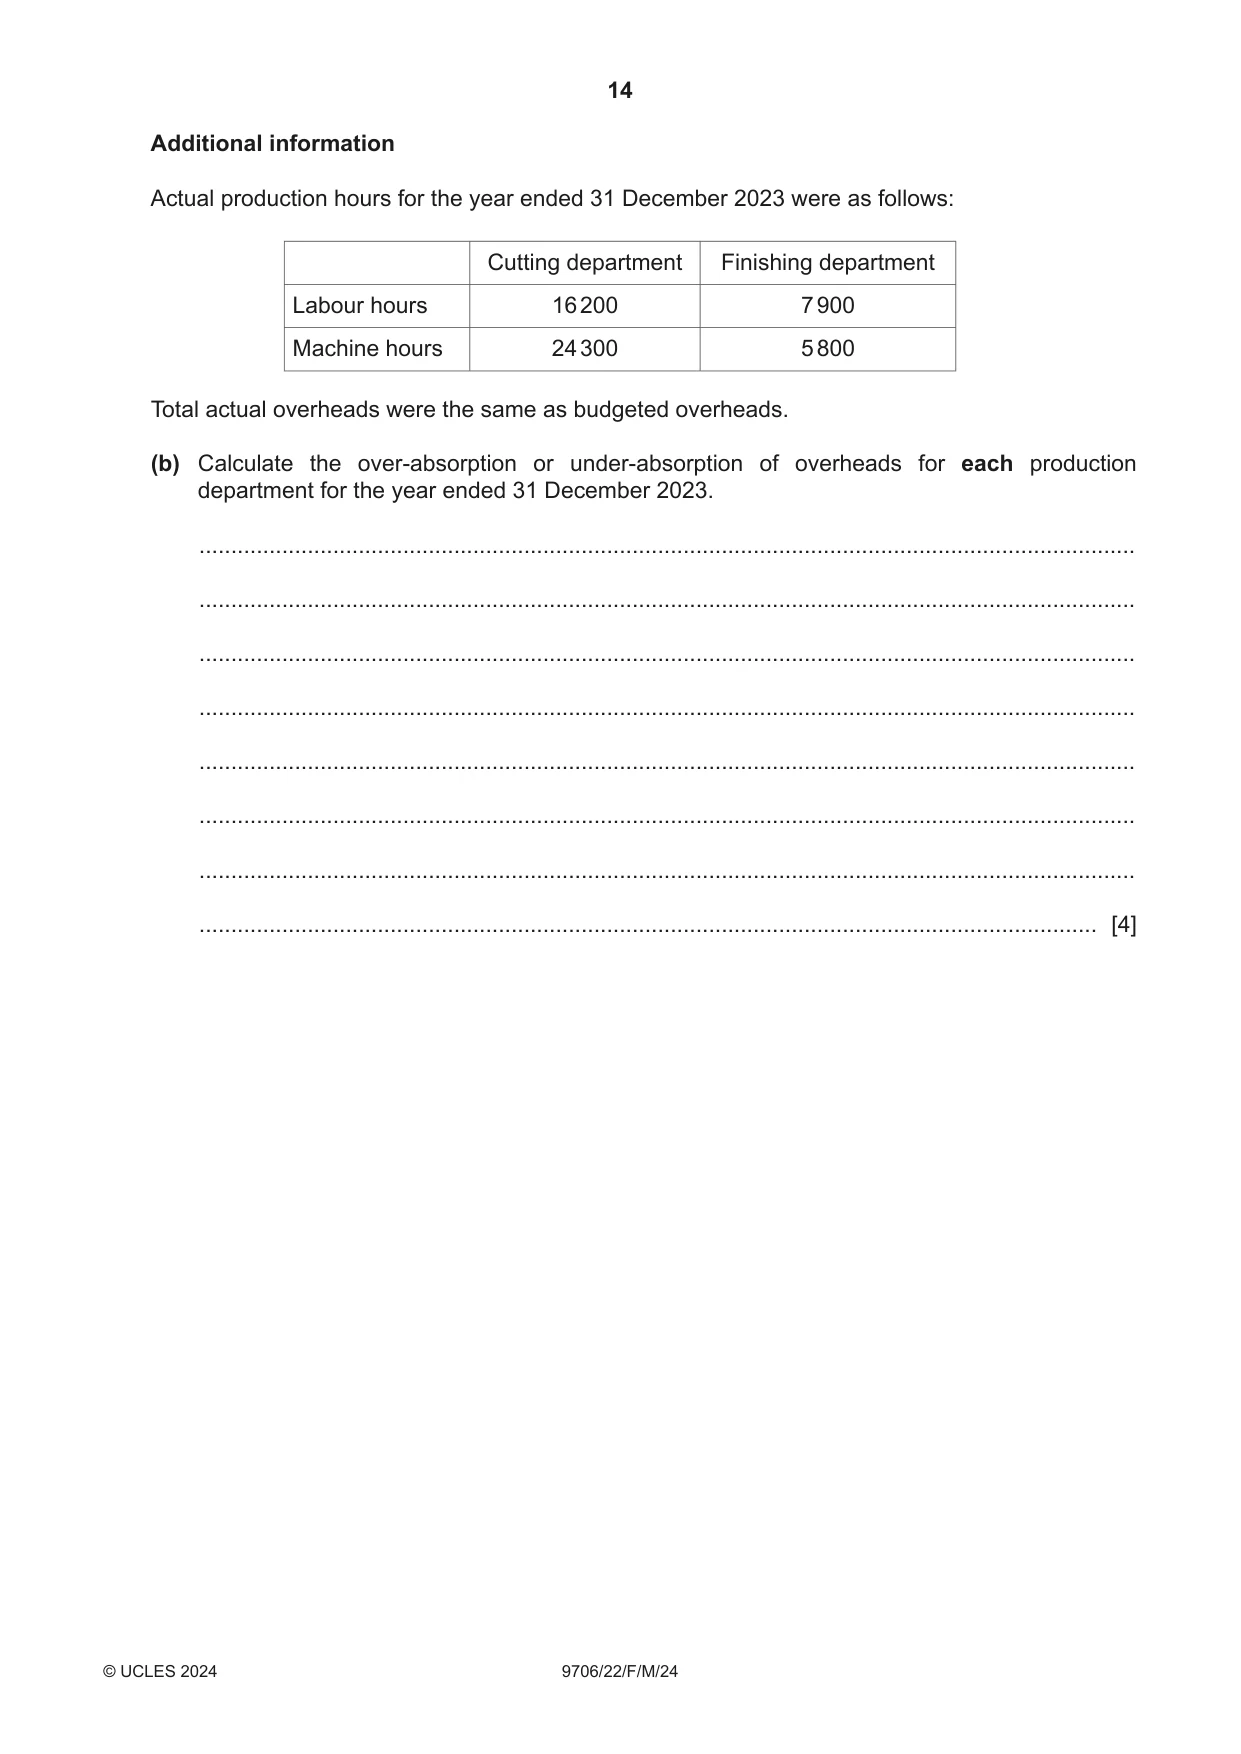
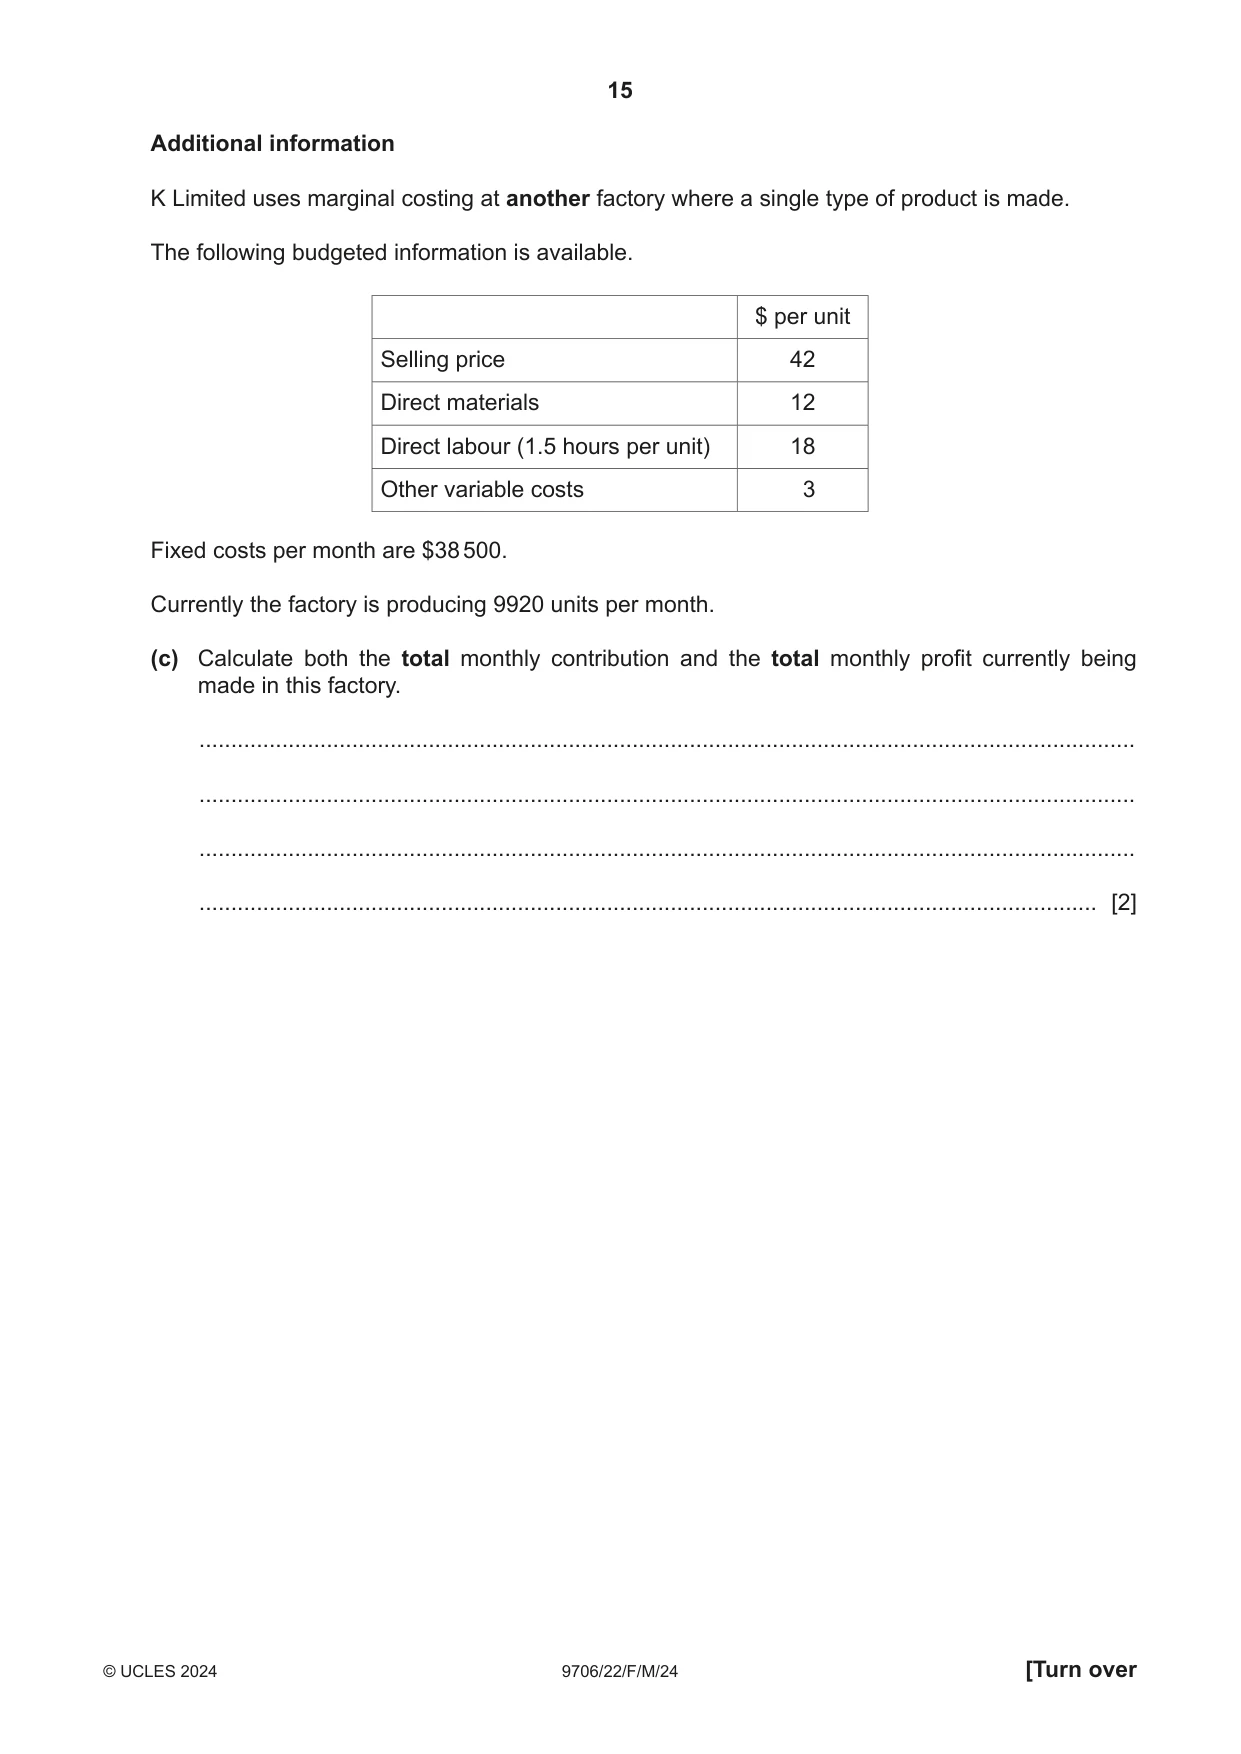
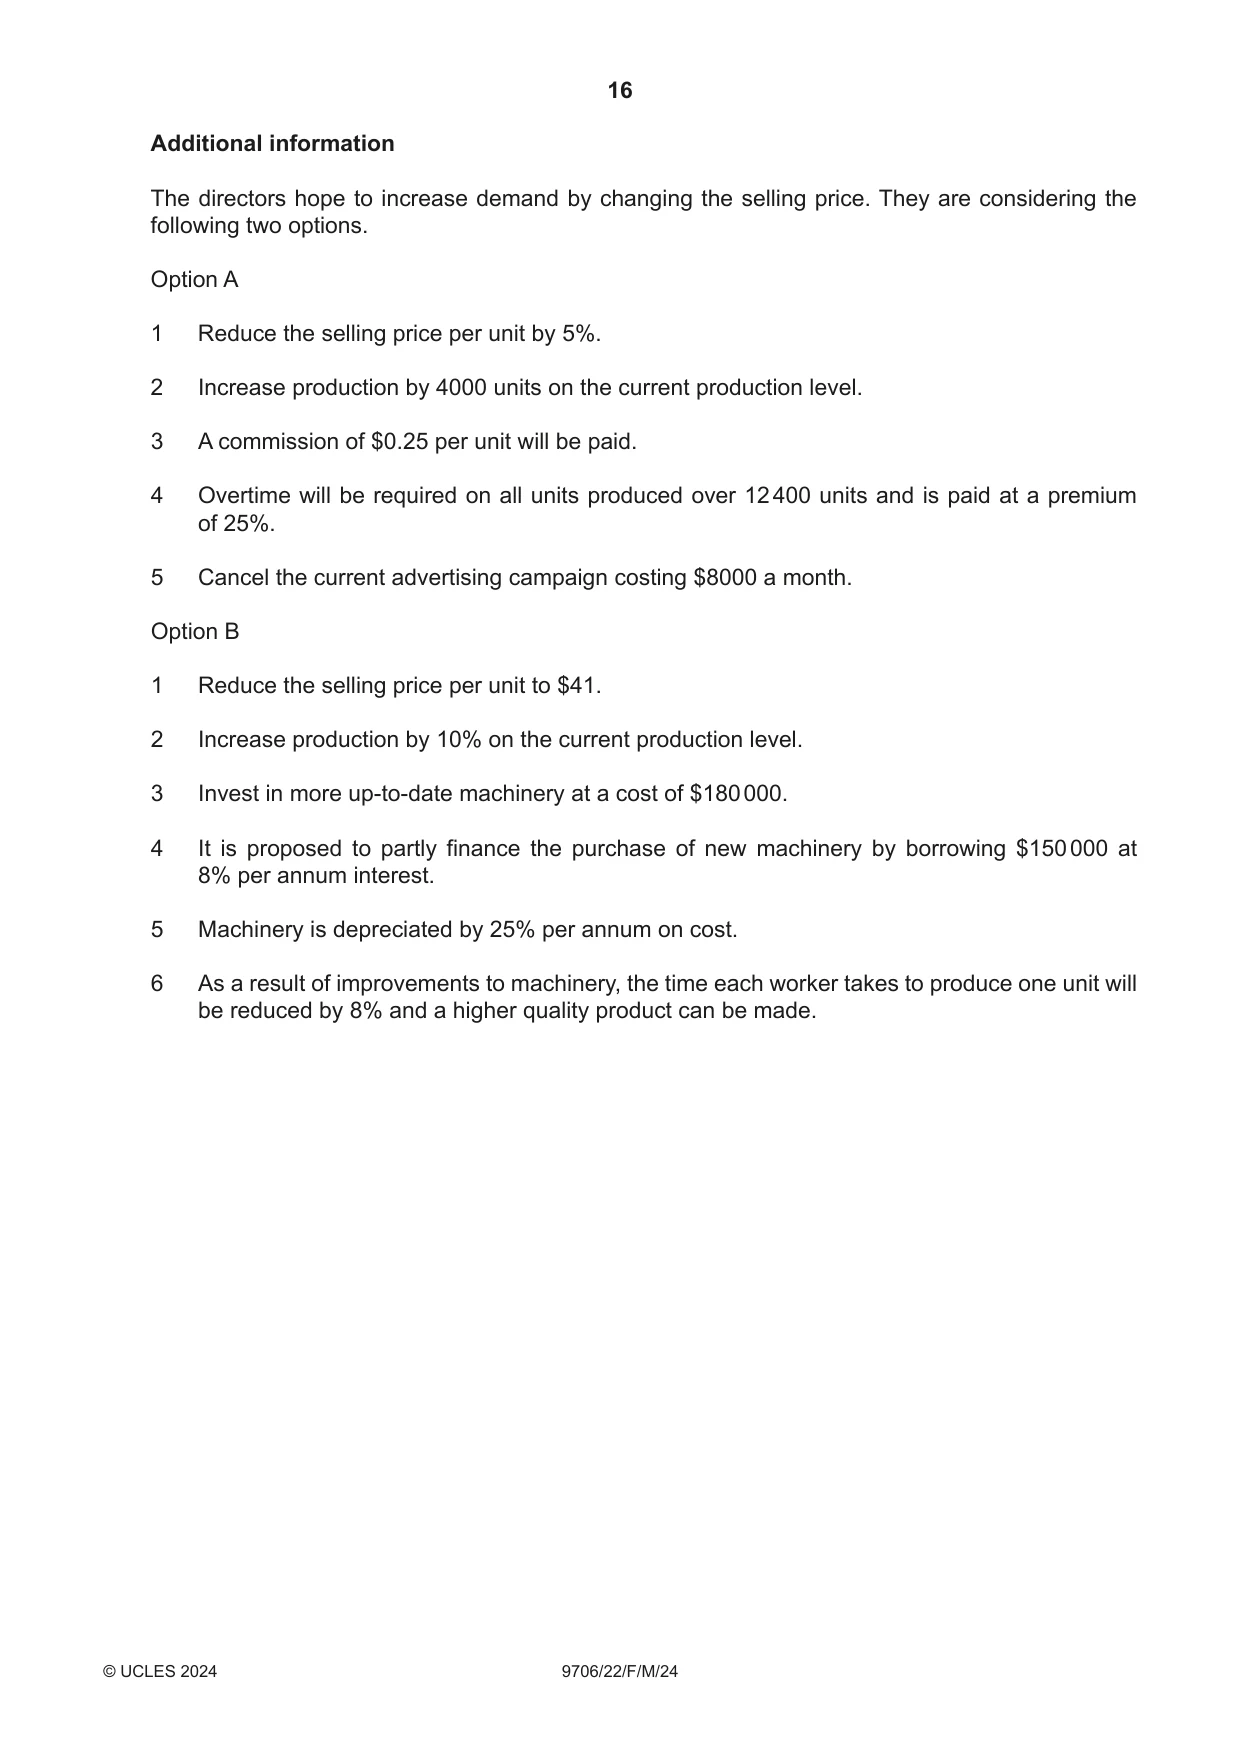
4 K Limited uses absorption costing at one of its factories. The product manufactured in this factory goes through two production departments: cutting department and finishing department. The following budgeted information was available for the year ended 31 December 2023. Cutting department Finishing department Overhead absorption rate $3.62 $2.34 Labour hours 17 400 8 400 Machine hours 22 900 5 200 A customer placed an order for 250 units in November 2023. The following budgeted information is available about the production of one unit. Per unit Direct materials $17.28 Direct labour Cutting department 1.2 hours at $11.50 per hour Finishing department 3.1 hours at $11.50 per hour Machine hours Cutting department 2.2 hours Finishing department 1.4 hours Selling prices are set to achieve a profit margin of 40%. (a) Prepare a statement to show the total selling price for the customer’s order. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] Additional information Actual production hours for the year ended 31 December 2023 were as follows: Cutting department Finishing department Labour hours 16 200 7 900 Machine hours 24 300 5 800 Total actual overheads were the same as budgeted overheads. (b) Calculate the over-absorption or under-absorption of overheads for each production department for the year ended 31 December 2023. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] Additional information K Limited uses marginal costing at another factory where a single type of product is made. The following budgeted information is available. $ per unit Selling price 42 Direct materials 12 Direct labour (1.5 hours per unit) 18 Other variable costs 3 Fixed costs per month are $38 500. Currently the factory is producing 9920 units per month. (c) Calculate both the total monthly contribution and the total monthly profit currently being made in this factory. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] Additional information The directors hope to increase demand by changing the selling price. They are considering the following two options. Option A 1 Reduce the selling price per unit by 5%. 2 Increase production by 4000 units on the current production level. 3 A commission of $0.25 per unit will be paid. 4 Overtime will be required on all units produced over 12 400 units and is paid at a premium of 25%.
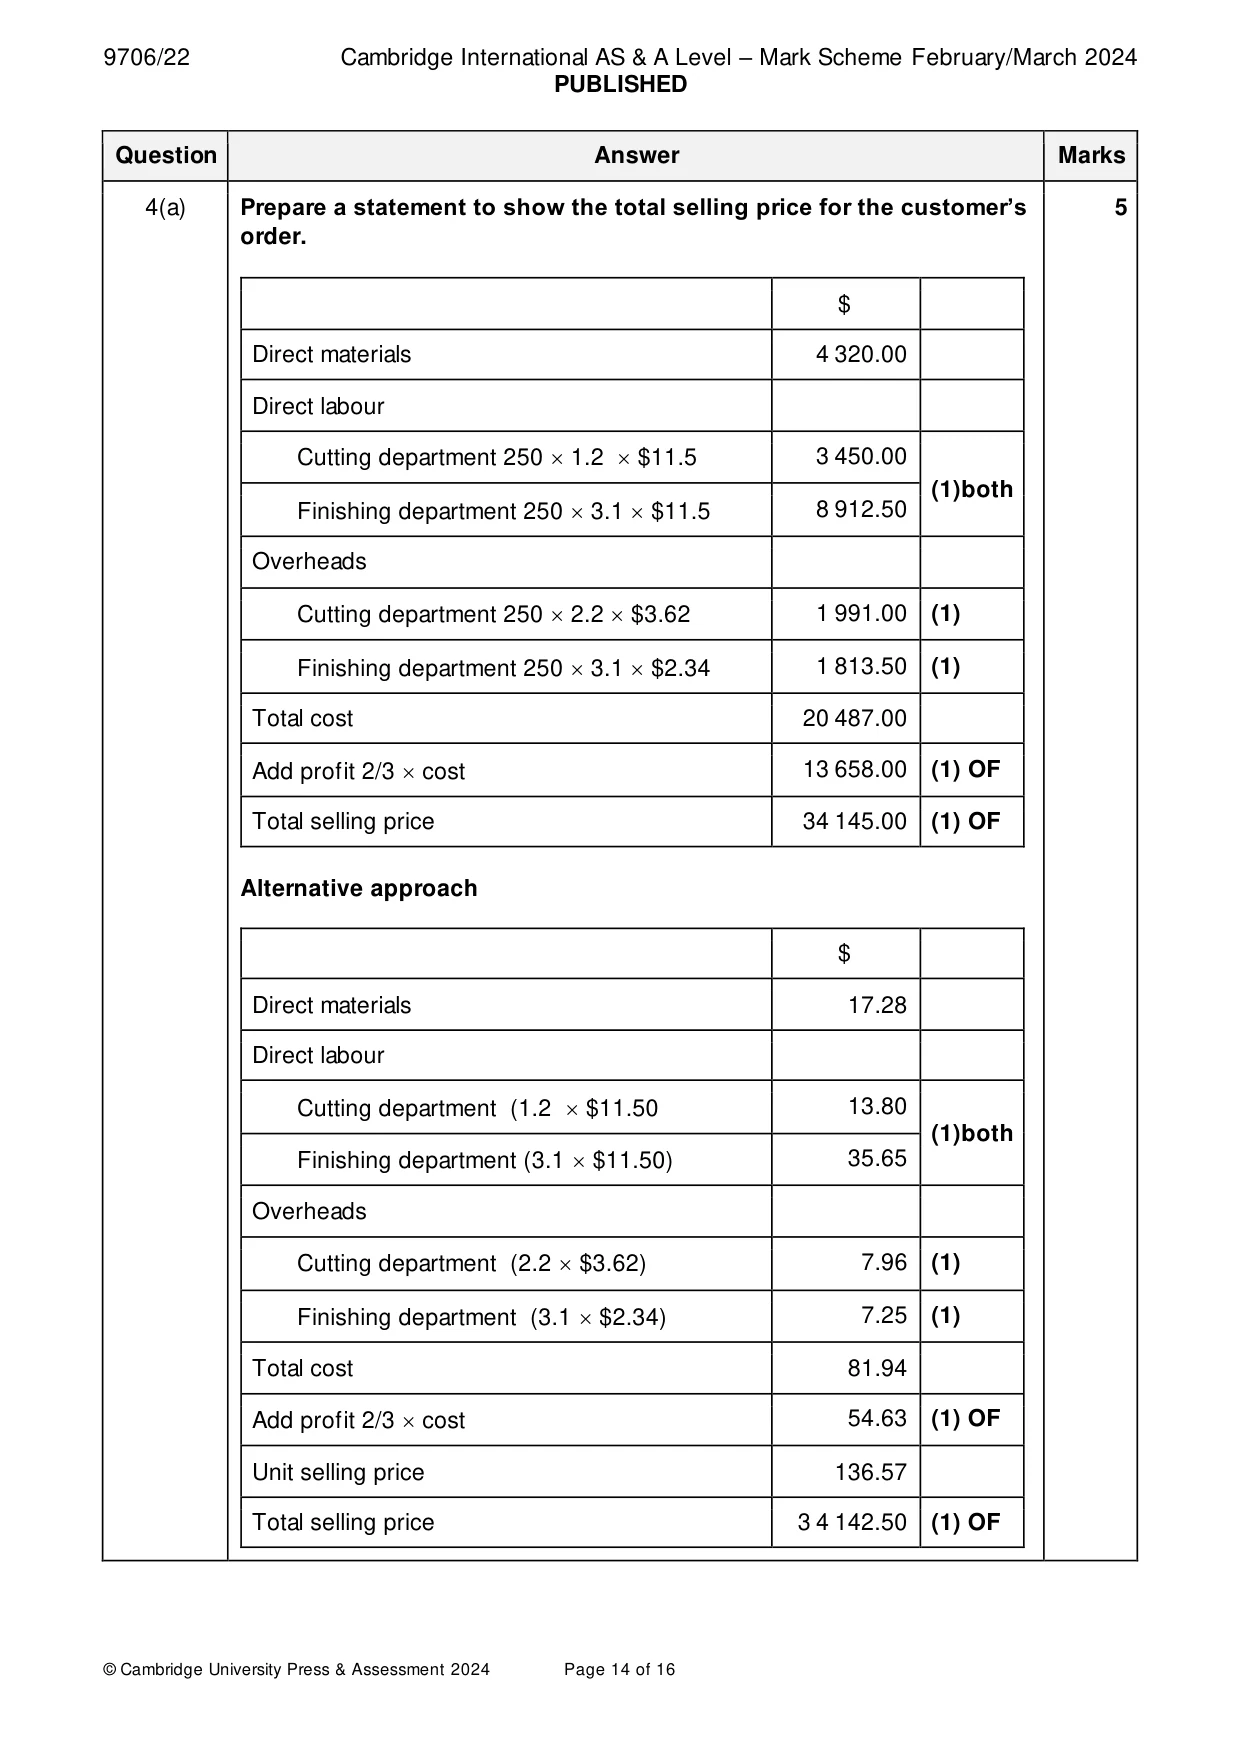
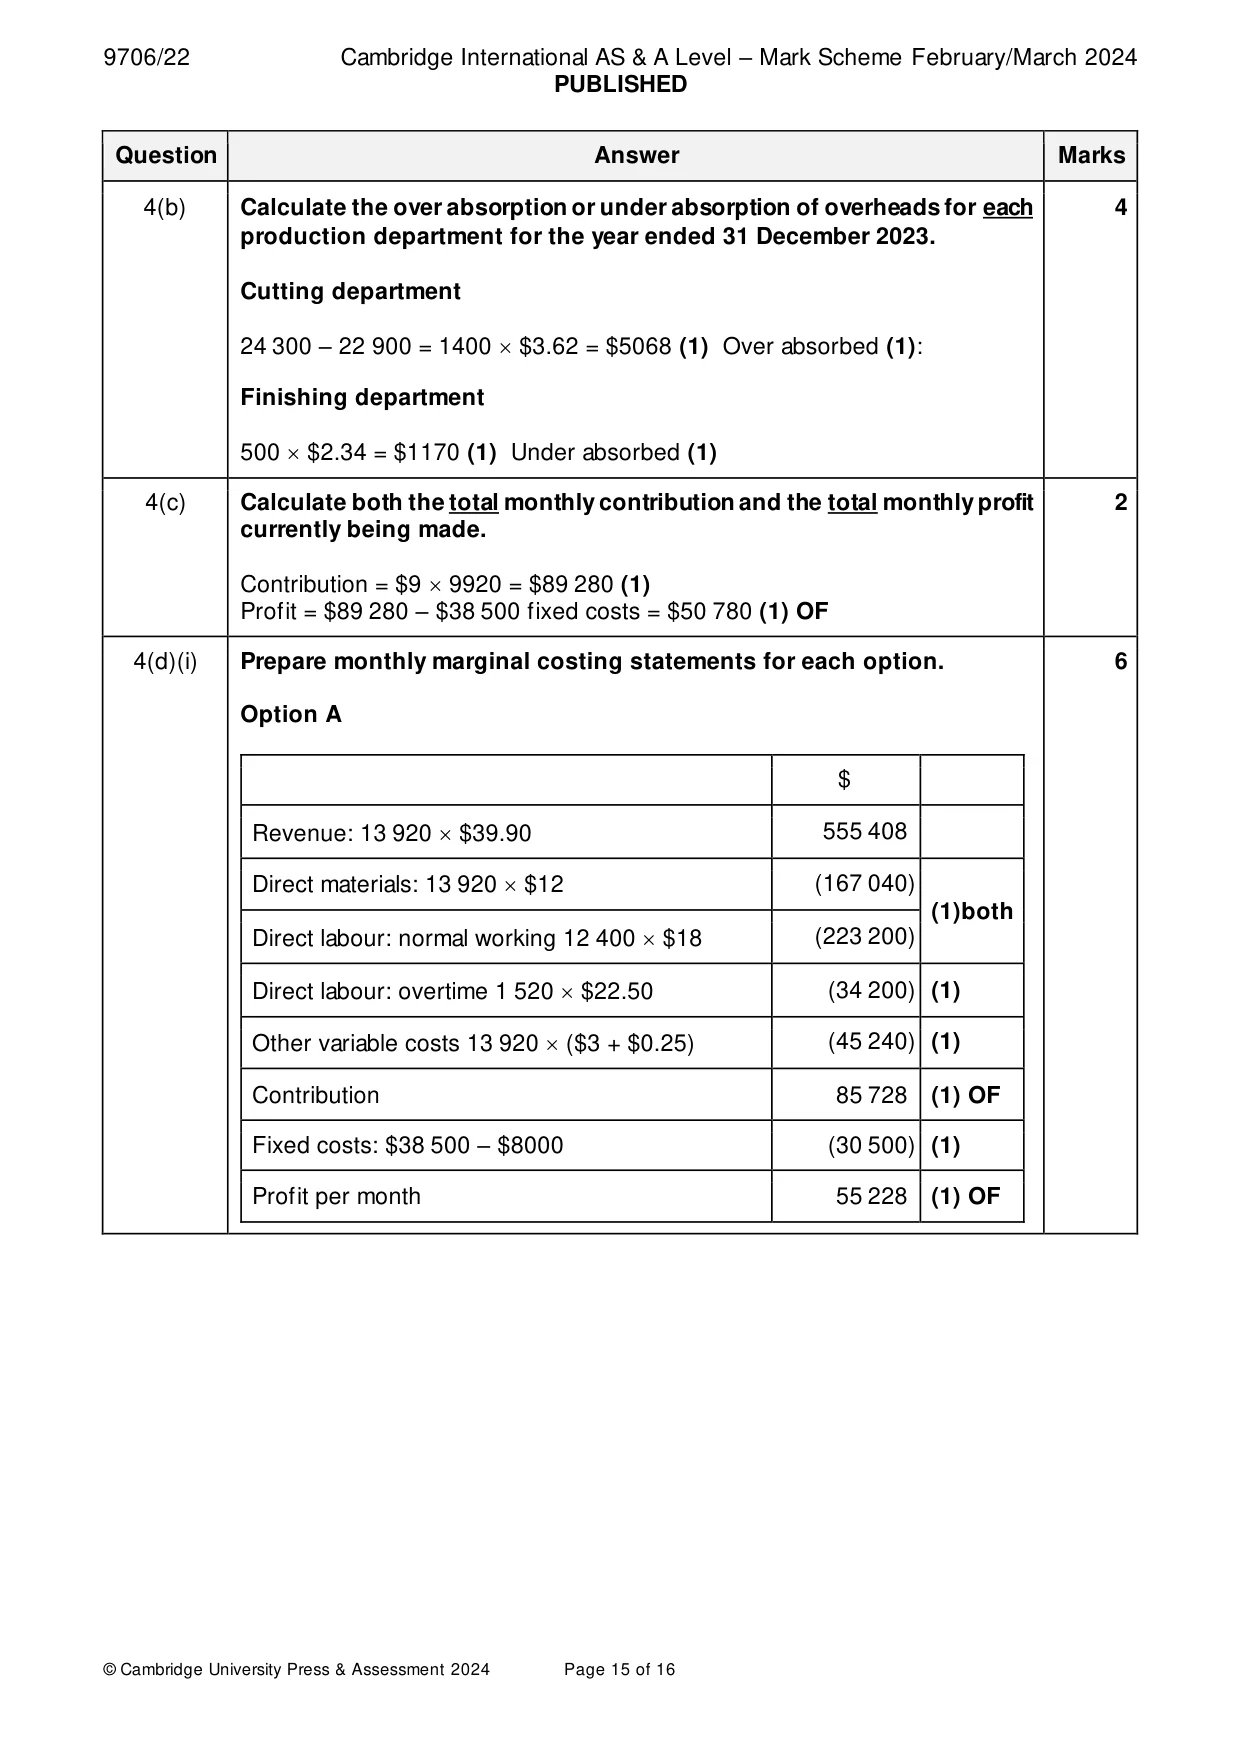
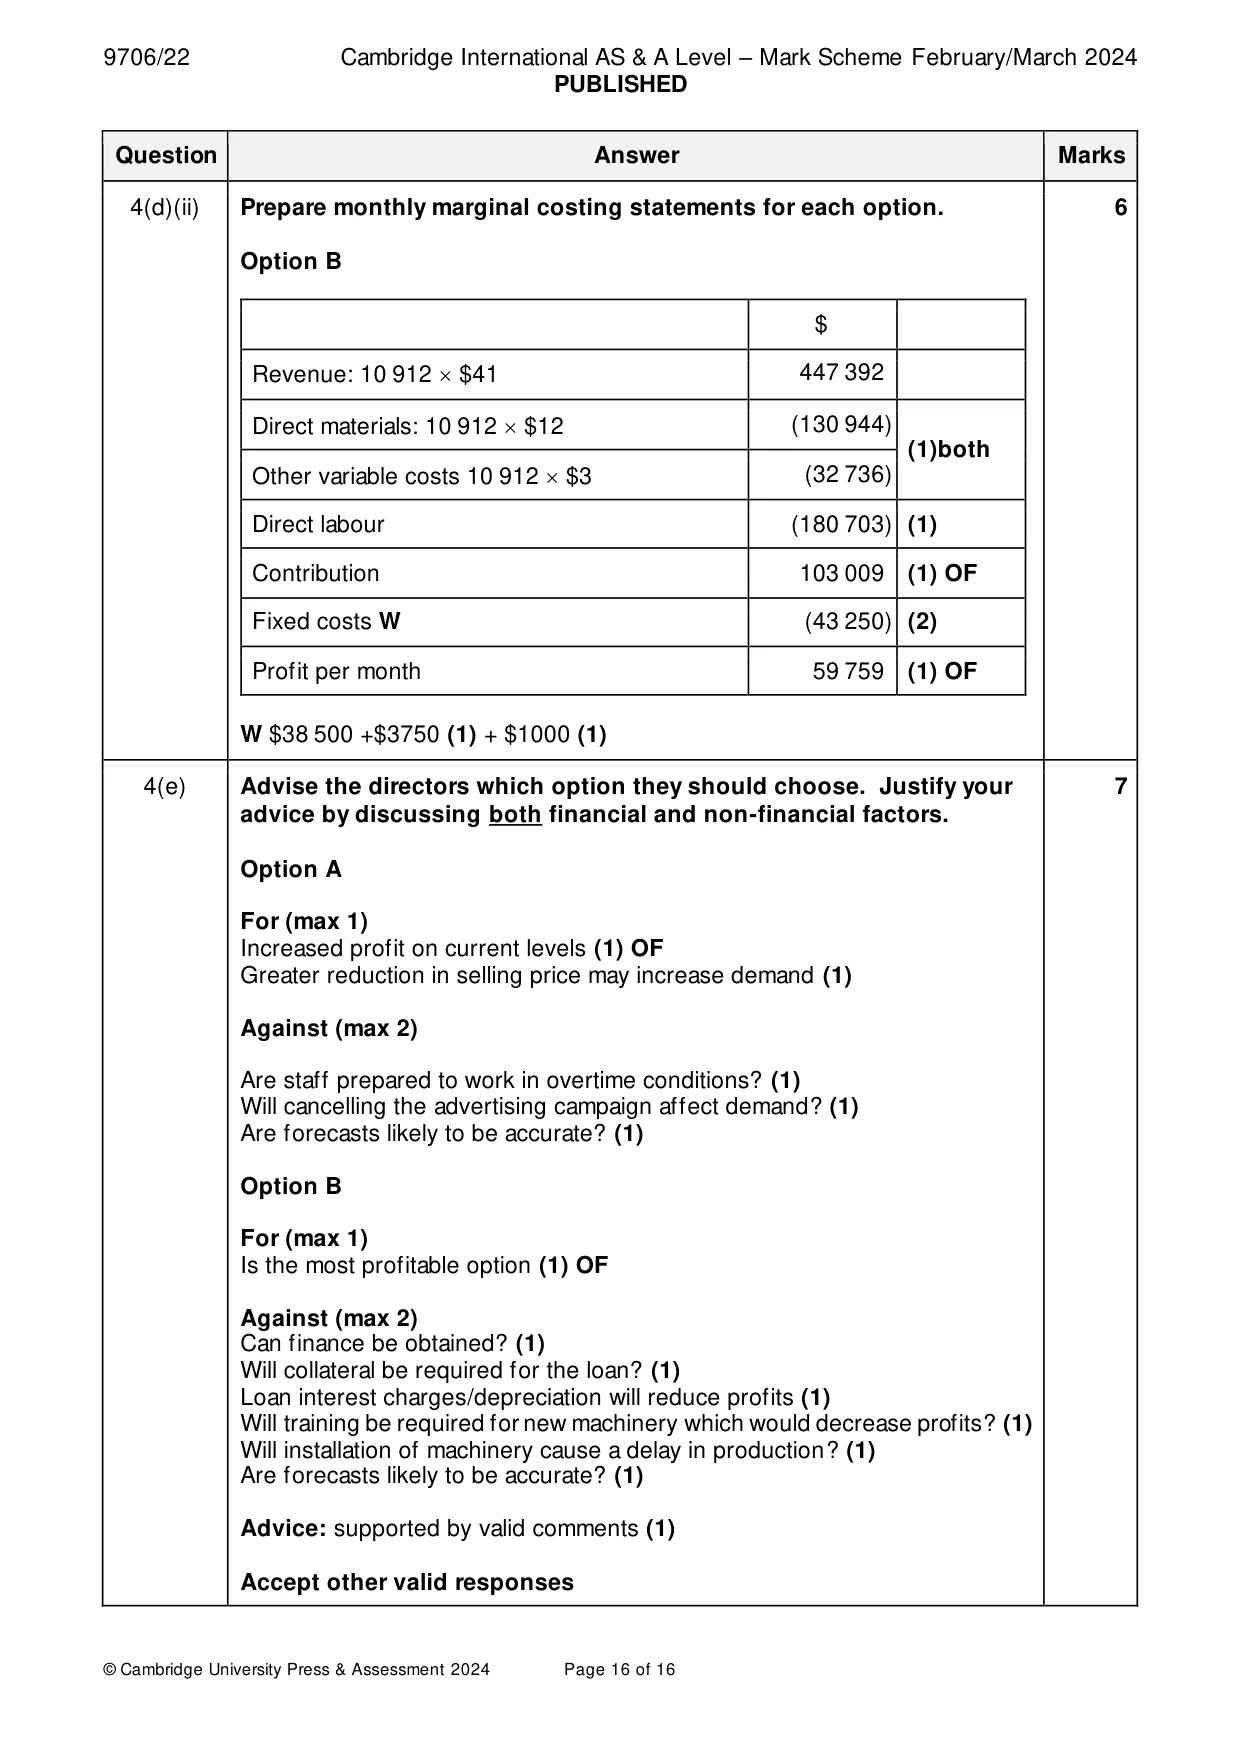
Mark scheme: 4(a) Prepare a statement to show the total selling price for the customer’s 5 order. $ Direct materials 4 320.00 Direct labour Cutting department 250 1.2 $11.5 3 450.00 (1)both Finishing department 250 3.1 $11.5 8 912.50 Overheads Cutting department 250 2.2 $3.62 1 991.00 (1) Finishing department 250 3.1 $2.34 1 813.50 (1) Total cost 20 487.00 Add profit 2/3 cost 13 658.00 (1) OF Total selling price 34 145.00 (1) OF Alternative approach $ Direct materials 17.28 Direct labour Cutting department (1.2 $11.50 13.80 (1)both Finishing department (3.1 $11.50) 35.65 Overheads Cutting department (2.2 $3.62) 7.96 (1) Finishing department (3.1 $2.34) 7.25 (1) Total cost 81.94 Add profit 2/3 cost 54.63 (1) OF Unit selling price 136.57 Total selling price 3 4 142.50 (1) OF 4(b) Calculate the over absorption or under absorption of overheads for each 4 production department for the year ended 31 December 2023. Cutting department 24 300 – 22 900 = 1400 $3.62 = $5068 (1) Over absorbed (1): Finishing department 500 $2.34 = $1170 (1) Under absorbed (1) 4(c) Calculate both the total monthly contribution and the total monthly profit 2 currently being made. Contribution = $9 9920 = $89 280 (1) Profit = $89 280 – $38 500 fixed costs = $50 780 (1) OF 4(d)(i) Prepare monthly marginal costing statements for each option. 6 Option A $ Revenue: 13 920 $39.90 555 408 Direct materials: 13 920 $12 (167 040) (1)both Direct labour: normal working 12 400 $18 (223 200) Direct labour: overtime 1 520 $22.50 (34 200) (1) Other variable costs 13 920 ($3 + $0.25) (45 240) (1) Contribution 85 728 (1) OF Fixed costs: $38 500 – $8000 (30 500) (1) Profit per month 55 228 (1) OF 4(d)(ii) Prepare monthly marginal costing statements for each option. 6 Option B $ Revenue: 10 912 $41 447 392 Direct materials: 10 912 $12 (130 944) (1)both Other variable costs 10 912 $3 (32 736) Direct labour (180 703) (1) Contribution 103 009 (1) OF Fixed costs W (43 250) (2) Profit per month 59 759 (1) OF W $38 500 +$3750 (1) + $1000 (1) 4(e) Advise the directors which option they should choose. Justify your 7 advice by discussing both financial and non-financial factors. Option A For (max 1) Increased profit on current levels (1) OF Greater reduction in selling price may increase demand (1) Against (max 2) Are staff prepared to work in overtime conditions? (1) Will cancelling the advertising campaign affect demand? (1) Are forecasts likely to be accurate? (1) Option B For (max 1) Is the most profitable option (1) OF Against (max 2) Can finance be obtained? (1) Will collateral be required for the loan? (1) Loan interest charges/depreciation will reduce profits (1) Will training be required for new machinery which would decrease profits? (1) Will installation of machinery cause a delay in production? (1) Are forecasts likely to be accurate? (1) Advice: supported by valid comments (1) Accept other valid responses
Q5 · Cancel the current advertising campaign costing $8000 a month
5 Cancel the current advertising campaign costing $8000 a month. Option B 1 Reduce the selling price per unit to $41. 2 Increase production by 10% on the current production level. 3 Invest in more up-to-date machinery at a cost of $180 000. 4 It is proposed to partly finance the purchase of new machinery by borrowing $150 000 at 8% per annum interest. 5 Machinery is depreciated by 25% per annum on cost.
Q6 · Prepare marginal costing statements to show the monthly forecast profit, rounded to the…
(d) Prepare marginal costing statements to show the monthly forecast profit, rounded to the nearest dollar, for each option. (i) Option A ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [6] (ii) Option B ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [6]
What was in this paper
The subtopics covered by these 6 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2024 Feb/March, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.