Cambridge A Level Accounting 9706 — 2022 Oct/Nov Paper 2 · Variant 2
9706/22/O/N/22 · 6 questions · 90 marks · ≈101 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme18 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · The following balances have been extracted from the draft financial statements of H…
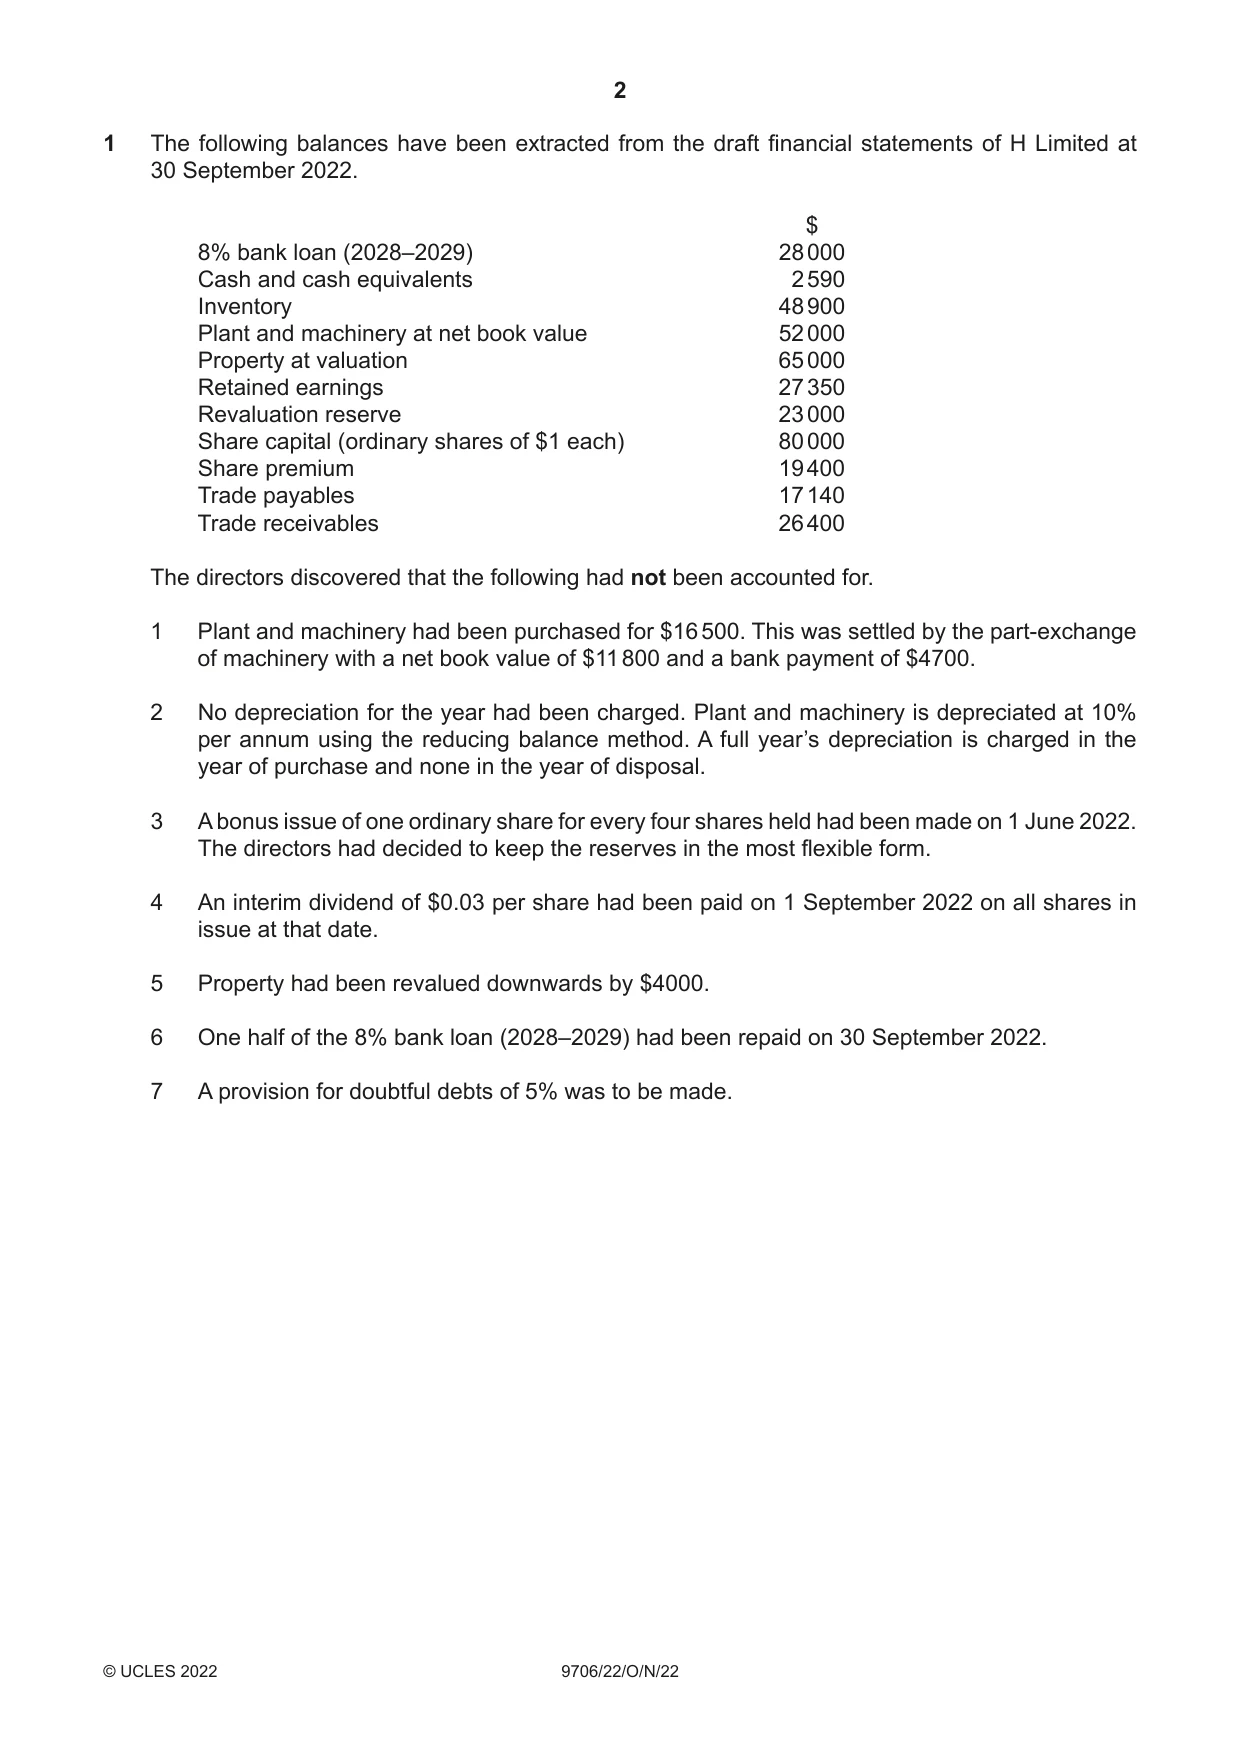
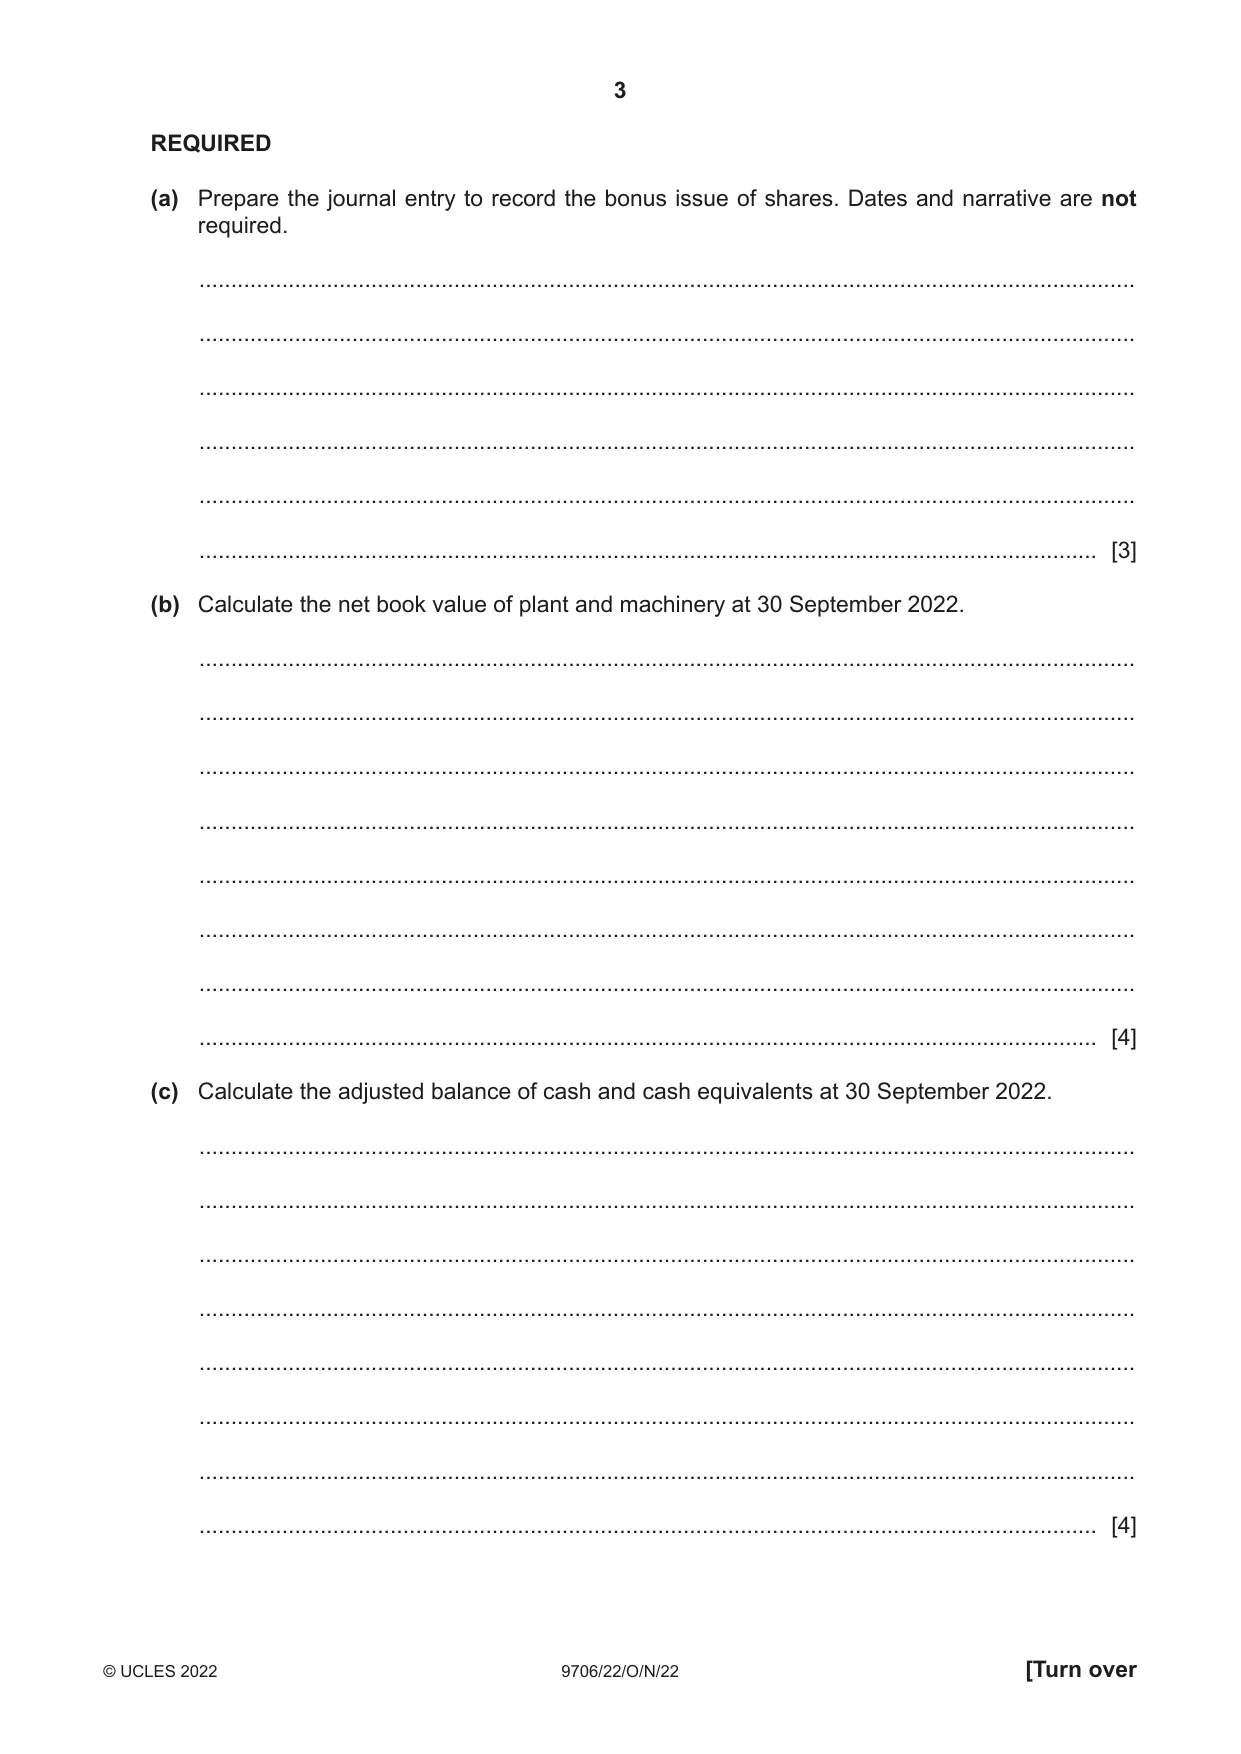
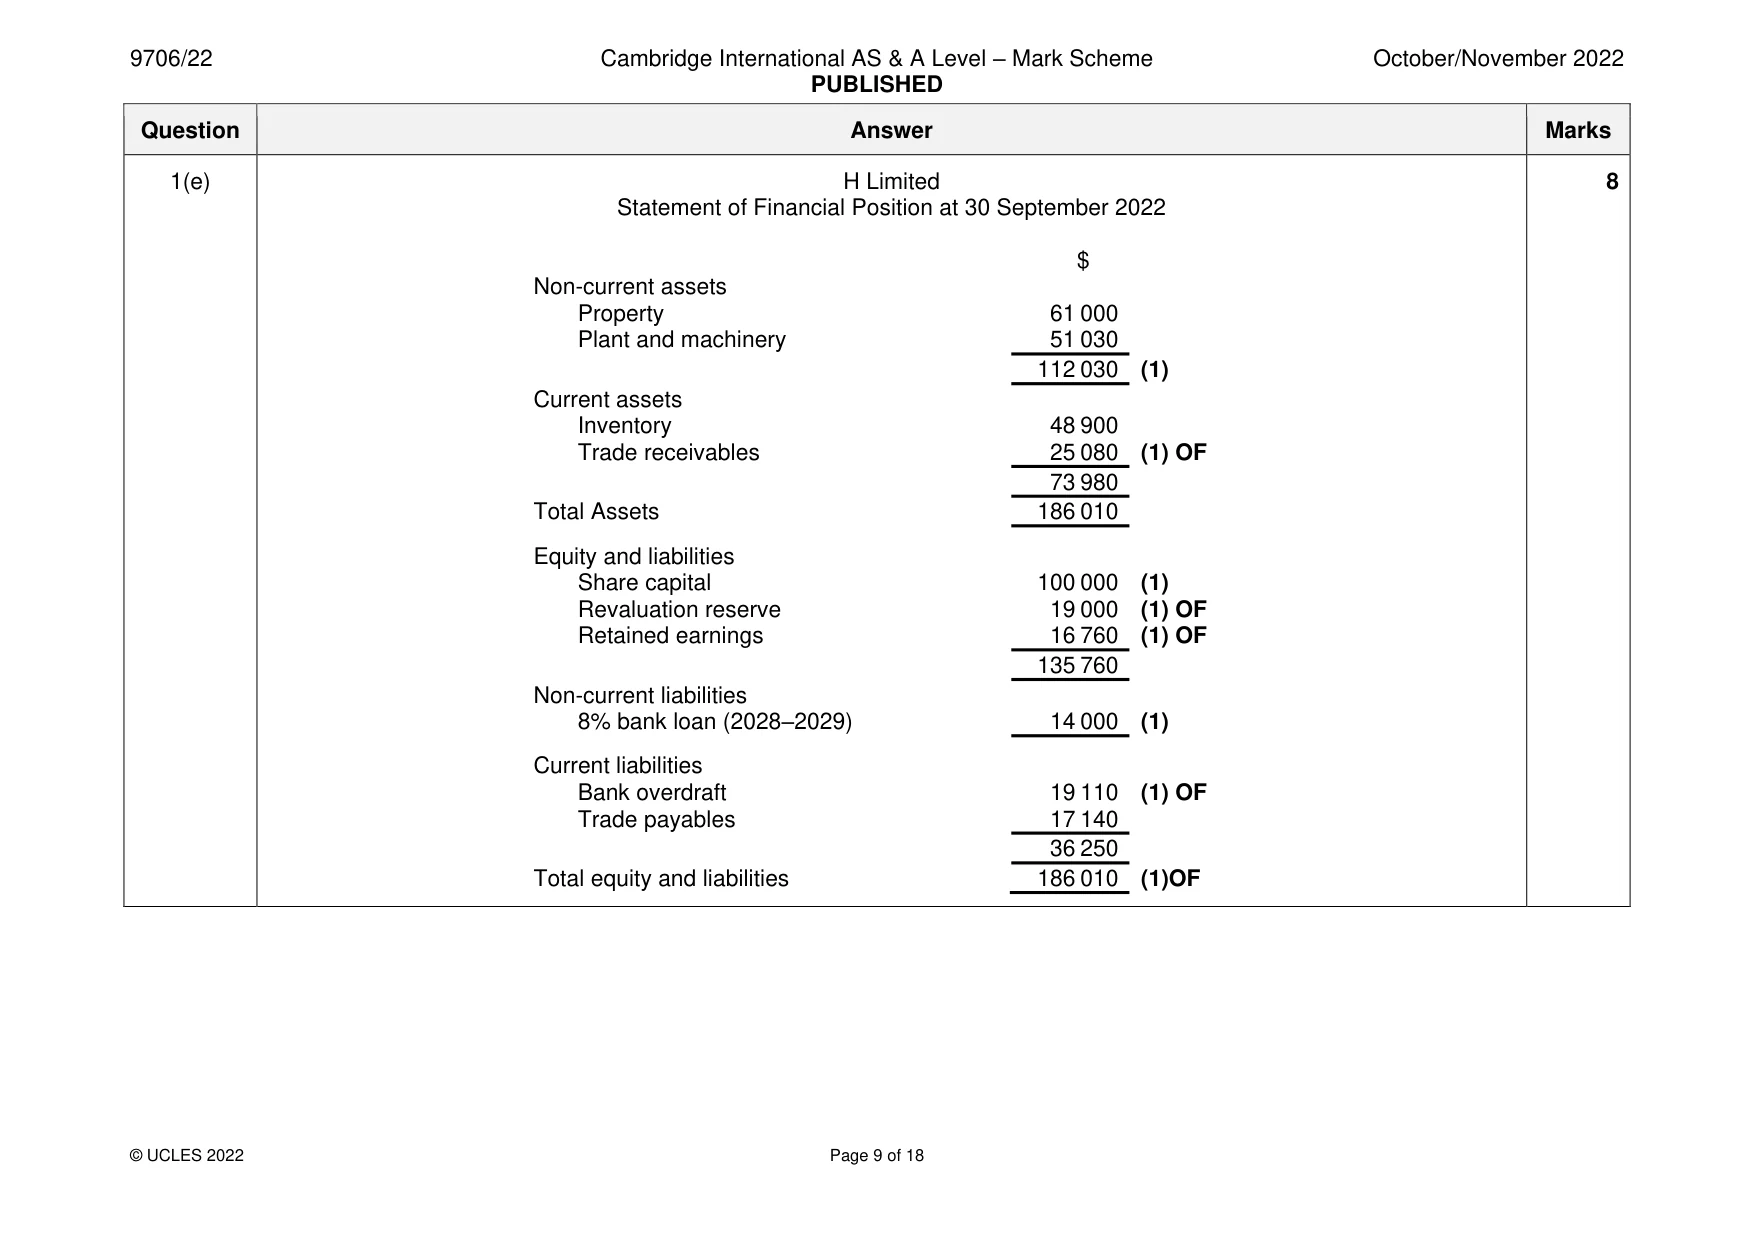
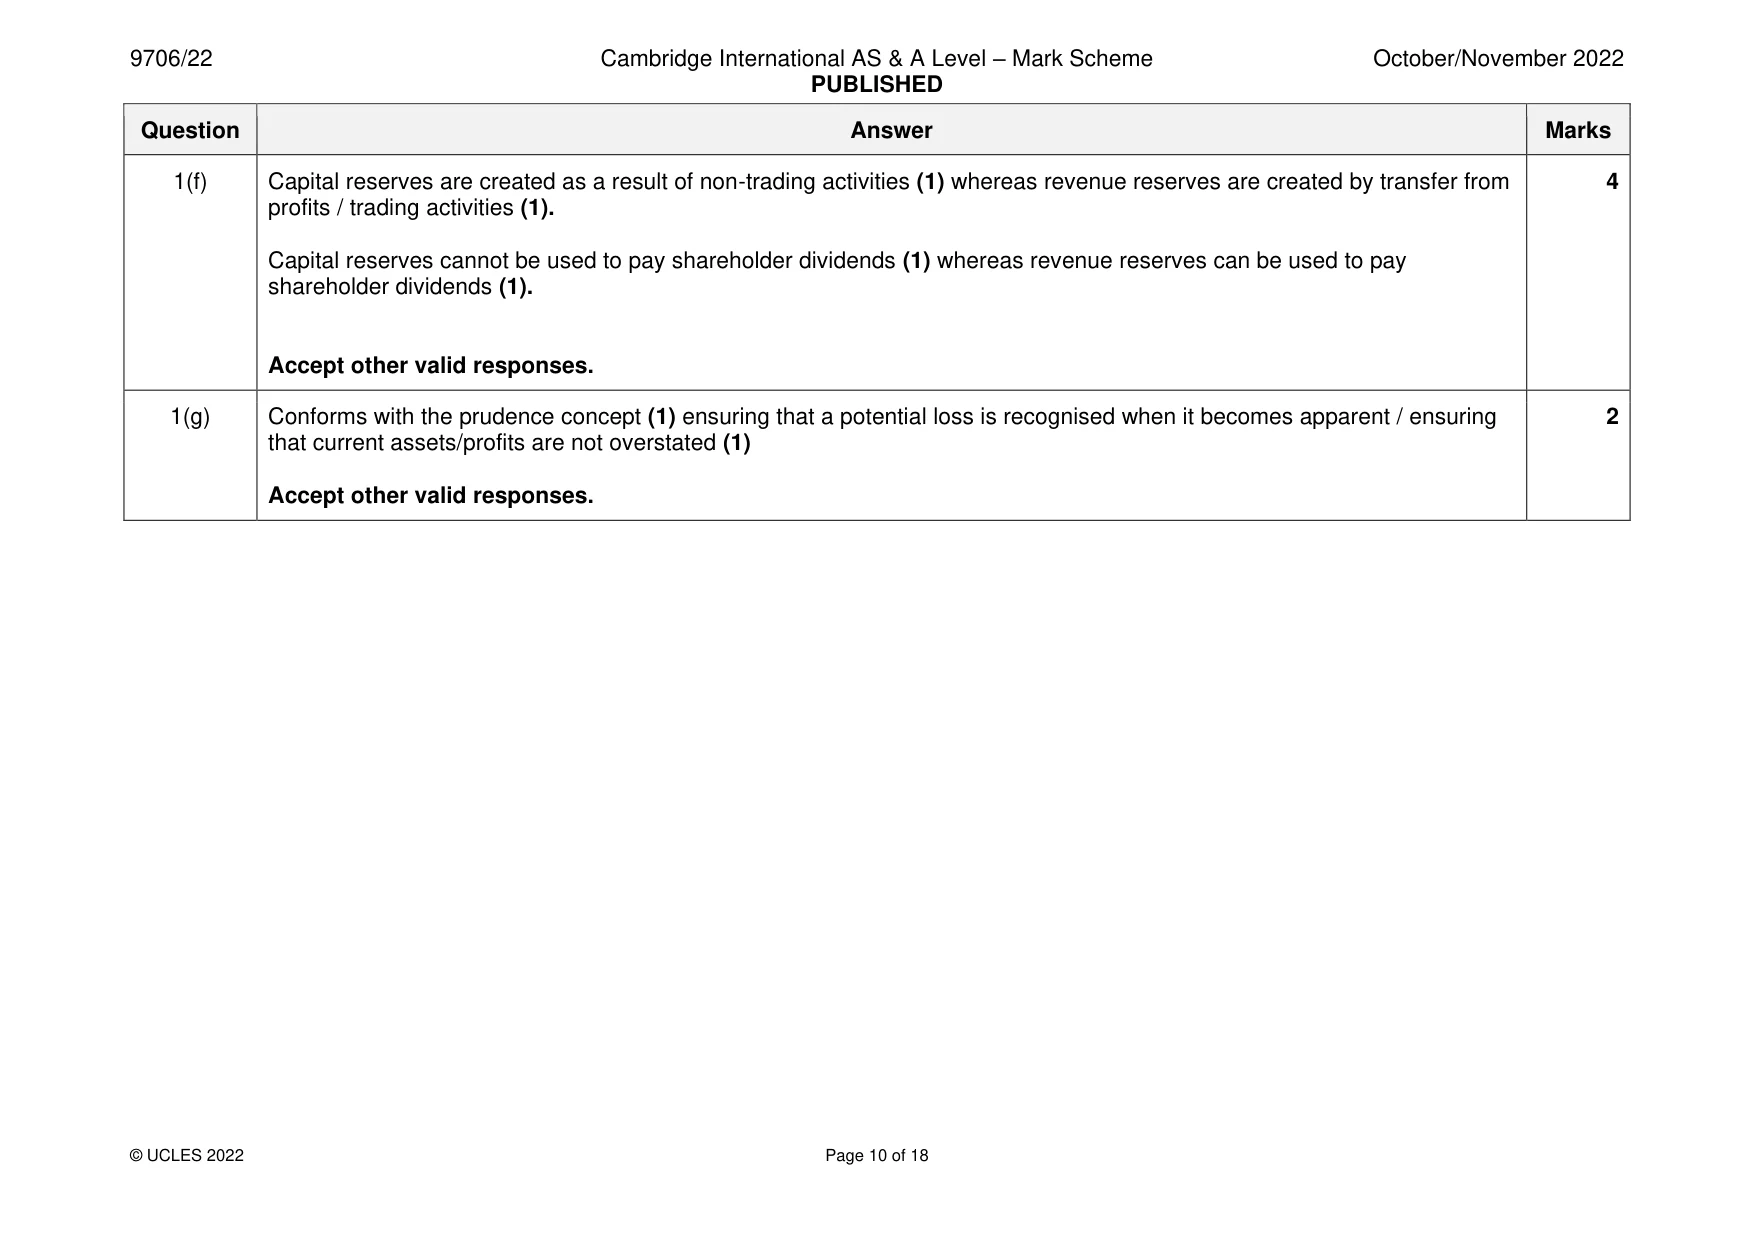
1 The following balances have been extracted from the draft financial statements of H Limited at 30 September 2022. $ 8% bank loan (2028–2029) 28 000 Cash and cash equivalents 2 590 Inventory 48 900 Plant and machinery at net book value 52 000 Property at valuation 65 000 Retained earnings 27 350 Revaluation reserve 23 000 Share capital (ordinary shares of $1 each) 80 000 Share premium 19 400 Trade payables 17 140 Trade receivables 26 400 The directors discovered that the following had not been accounted for. 1 Plant and machinery had been purchased for $16 500. This was settled by the part‑exchange of machinery with a net book value of $11 800 and a bank payment of $4700. 2 No depreciation for the year had been charged. Plant and machinery is depreciated at 10% per annum using the reducing balance method. A full year’s depreciation is charged in the year of purchase and none in the year of disposal. 3 A bonus issue of one ordinary share for every four shares held had been made on 1 June 2022. The directors had decided to keep the reserves in the most flexible form. 4 An interim dividend of $0.03 per share had been paid on 1 September 2022 on all shares in issue at that date. 5 Property had been revalued downwards by $4000. 6 One half of the 8% bank loan (2028–2029) had been repaid on 30 September 2022. 7 A provision for doubtful debts of 5% was to be made. REQUIRED (a) Prepare the journal entry to record the bonus issue of shares. Dates and narrative are not required. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] (b) Calculate the net book value of plant and machinery at 30 September 2022. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] (c) Calculate the adjusted balance of cash and cash equivalents at 30 September 2022. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] (d) Calculate the adjusted balance of retained earnings at 30 September 2022. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] (e) Prepare the statement of financial position at 30 September 2022. H Limited Statement of Financial Position at 30 September 2022 ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [8] (f) Explain two differences between capital reserves and revenue reserves. 1 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... [4] (g) Explain one accounting concept applied when making a provision for doubtful debts. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] [Total: 30] PLEASE TURN OVER
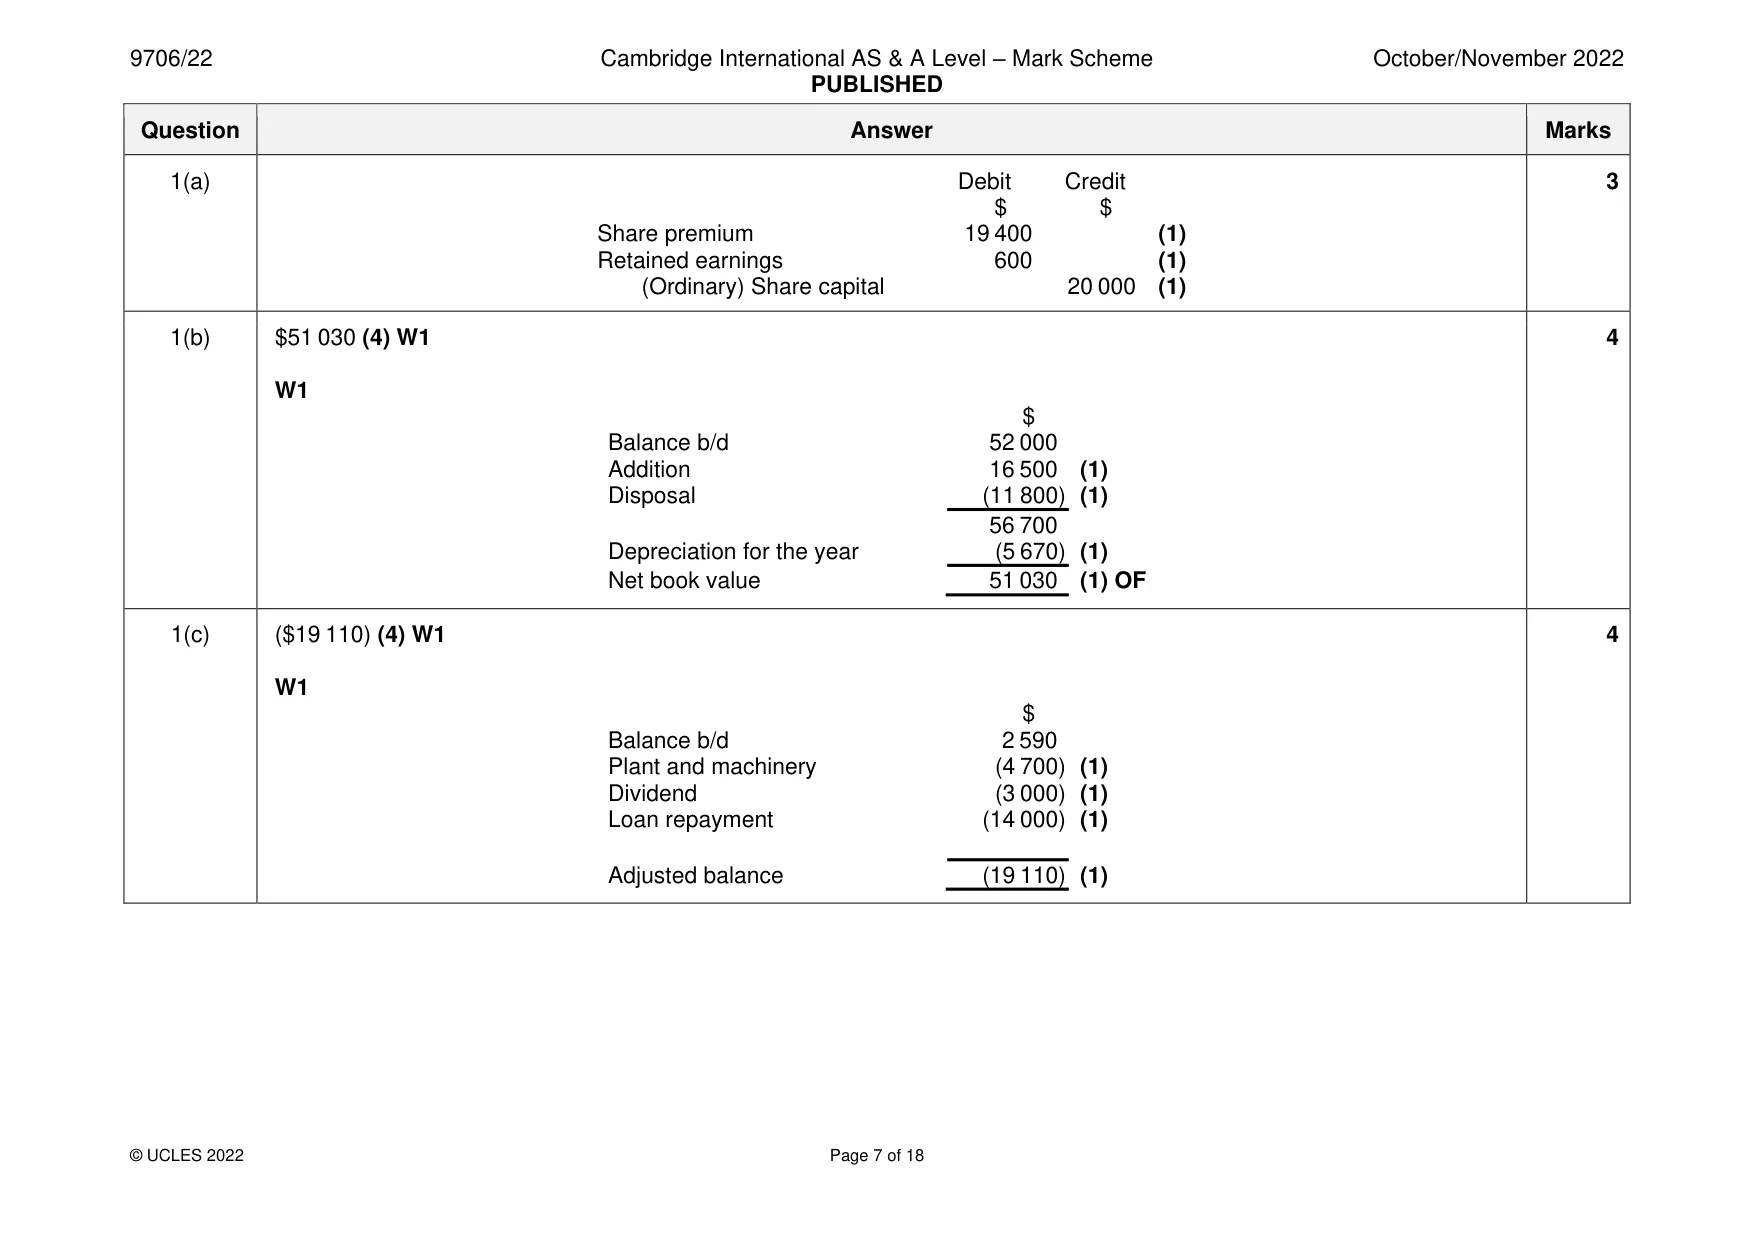
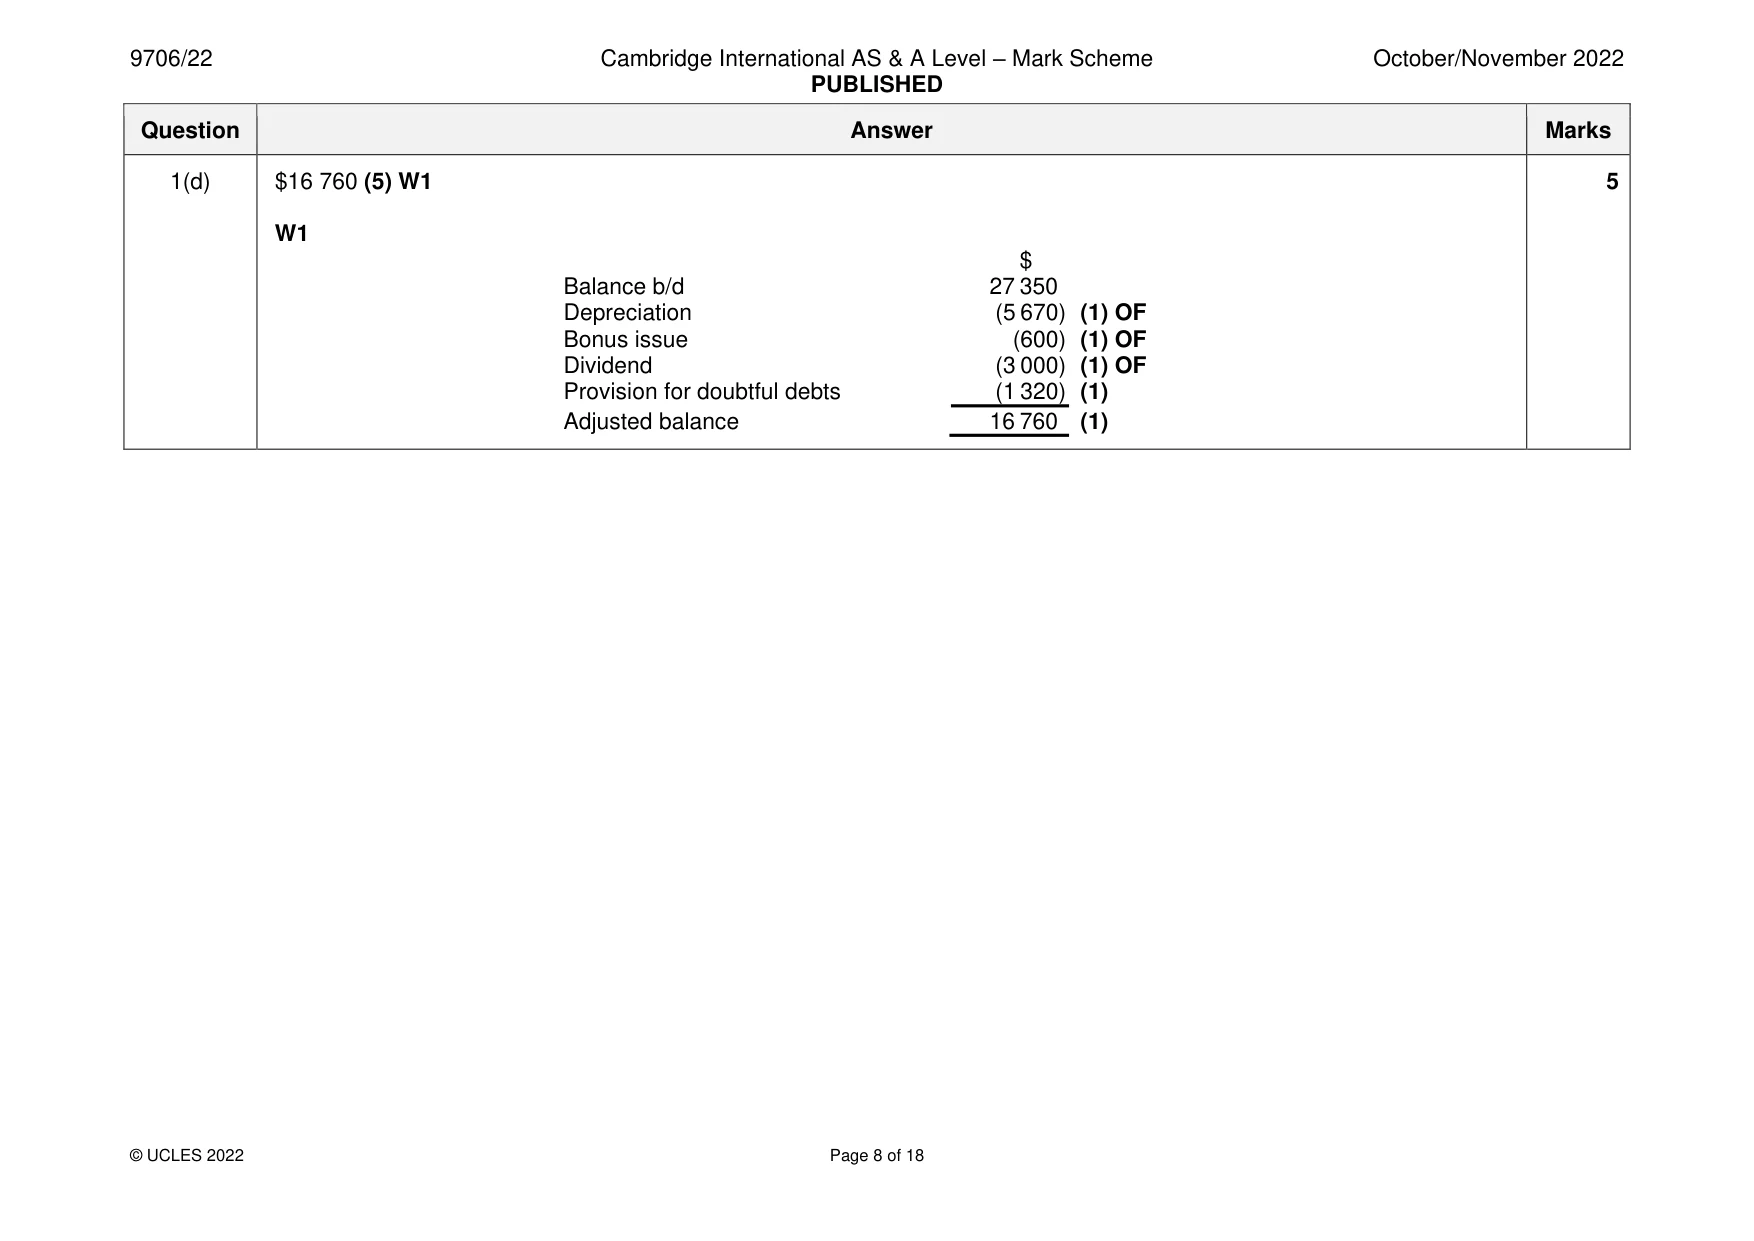
Mark scheme: Question Answer Marks 1(a) Debit Credit 3 $ $ Share premium 19 400 (1) Retained earnings 600 (1) (Ordinary) Share capital 20 000 (1) 1(b) $51 030 (4) W1 4 W1 $ Balance b/d 52 000 Addition 16 500 (1) Disposal (11 800) (1) 56 700 Depreciation for the year (5 670) (1) Net book value 51 030 (1) OF 1(c) ($19 110) (4) W1 4 W1 $ Balance b/d 2 590 Plant and machinery (4 700) (1) Dividend (3 000) (1) Loan repayment (14 000) (1) Adjusted balance (19 110) (1) 1(d) $16 760 (5) W1 5 W1 $ Balance b/d 27 350 Depreciation (5 670) (1) OF Bonus issue (600) (1) OF Dividend (3 000) (1) OF Provision for doubtful debts (1 320) (1) Adjusted balance 16 760 (1) 1(e) H Limited 8 Statement of Financial Position at 30 September 2022 $ Non-current assets Property 61 000 Plant and machinery 51 030 112 030 (1) Current assets Inventory 48 900 Trade receivables 25 080 (1) OF 73 980 Total Assets 186 010 Equity and liabilities Share capital 100 000 (1) Revaluation reserve 19 000 (1) OF Retained earnings 16 760 (1) OF 135 760 Non-current liabilities 8% bank loan (2028–2029) 14 000 (1) Current liabilities Bank overdraft 19 110 (1) OF Trade payables 17 140 36 250 Total equity and liabilities 186 010 (1)OF 1(f) Capital reserves are created as a result of non-trading activities (1) whereas revenue reserves are created by transfer from 4 profits / trading activities (1). Capital reserves cannot be used to pay shareholder dividends (1) whereas revenue reserves can be used to pay shareholder dividends (1). Accept other valid responses. 1(g) Conforms with the prudence concept (1) ensuring that a potential loss is recognised when it becomes apparent / ensuring 2 that current assets/profits are not overstated (1) Accept other valid responses.
Q2 · Usman has extracted the following information from his books of account in order to…
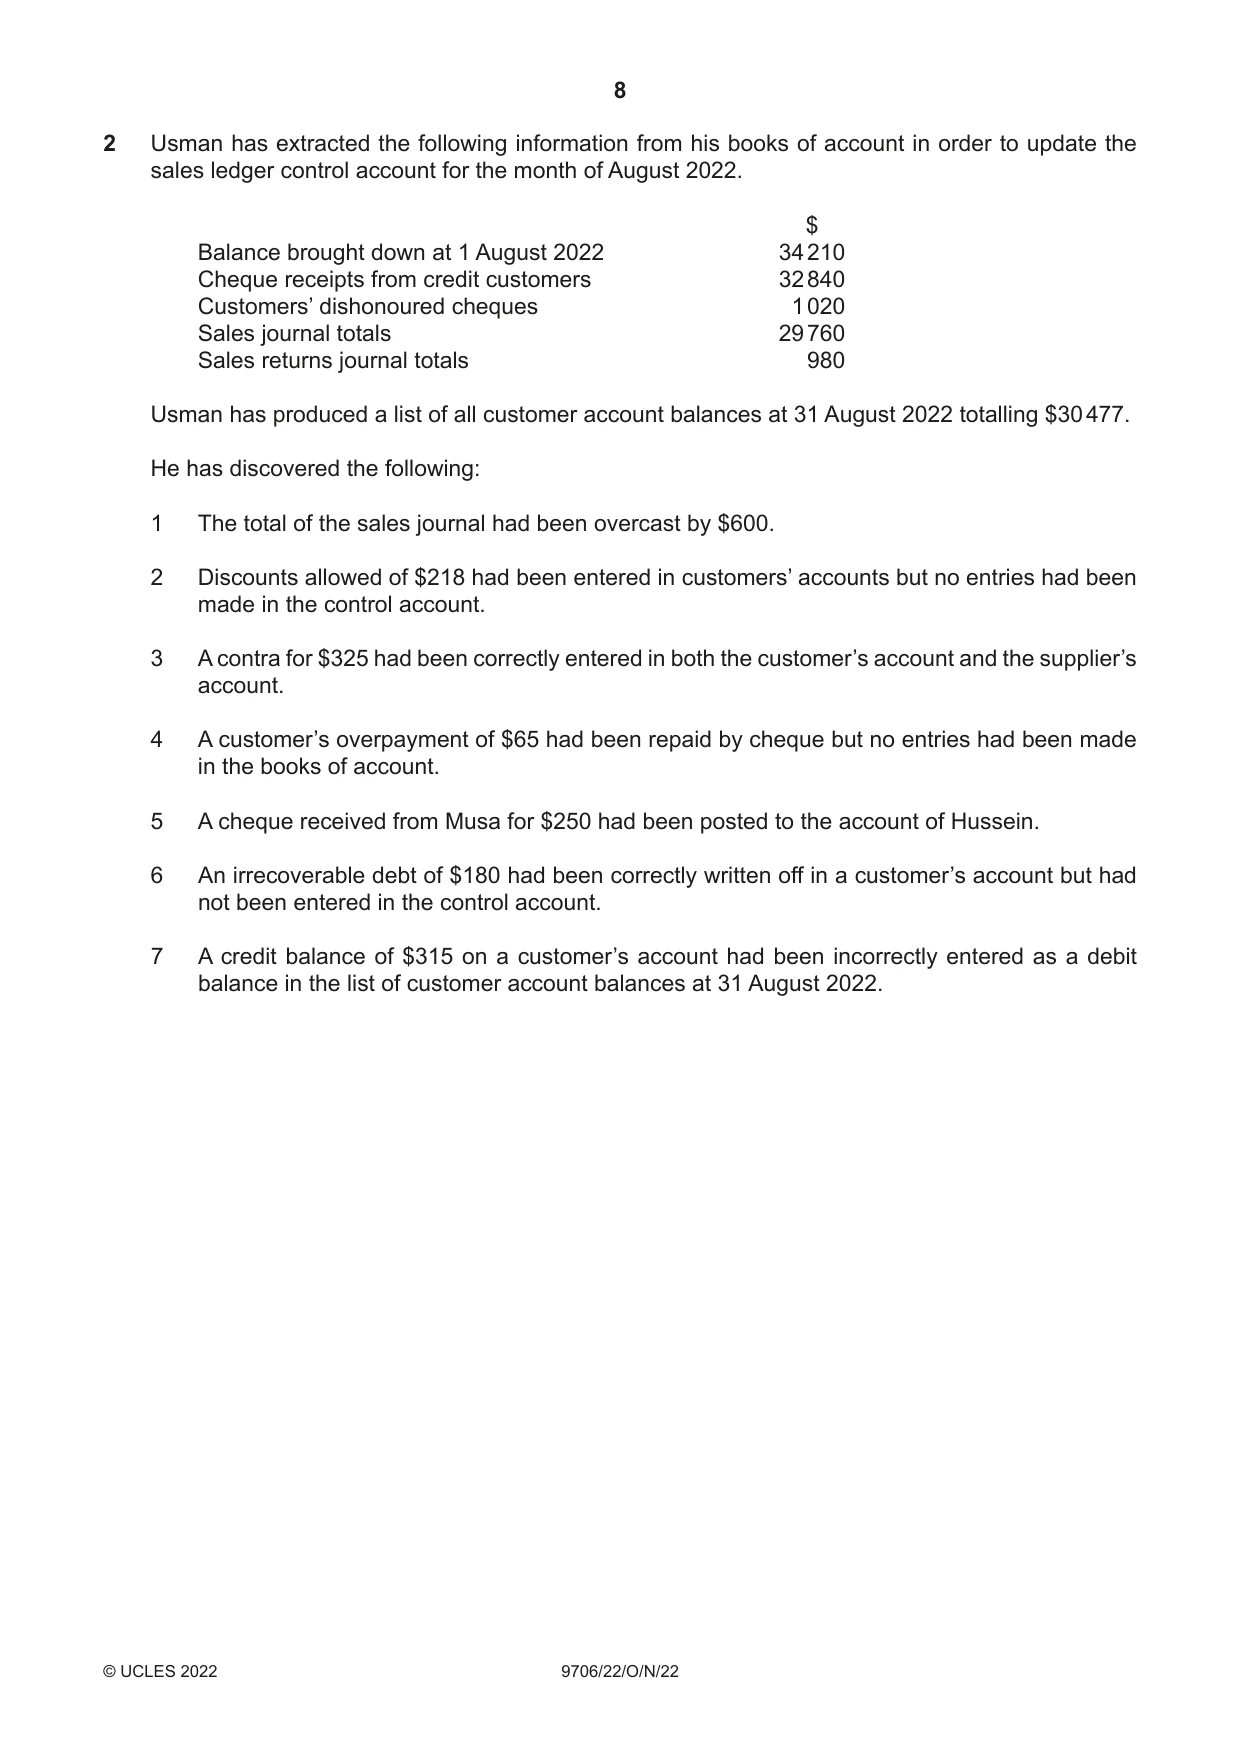
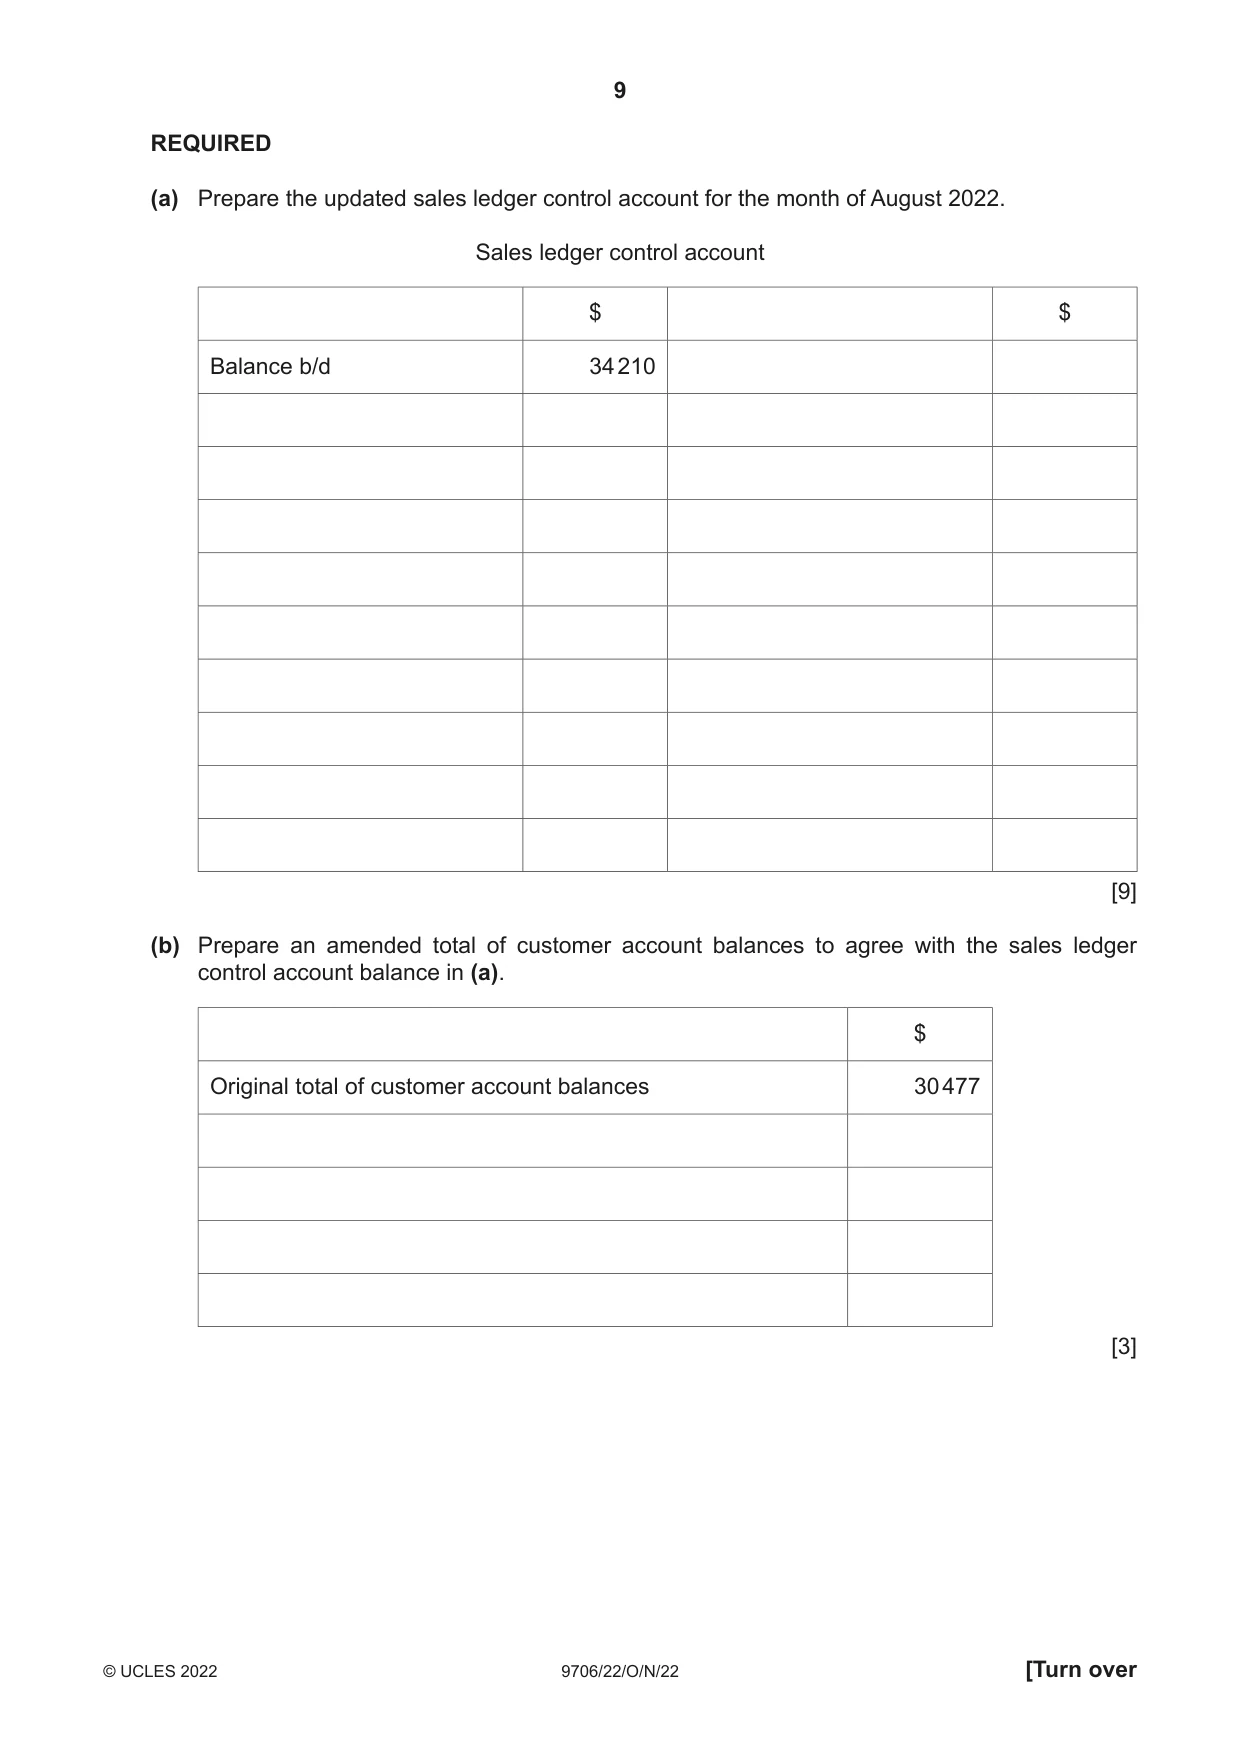
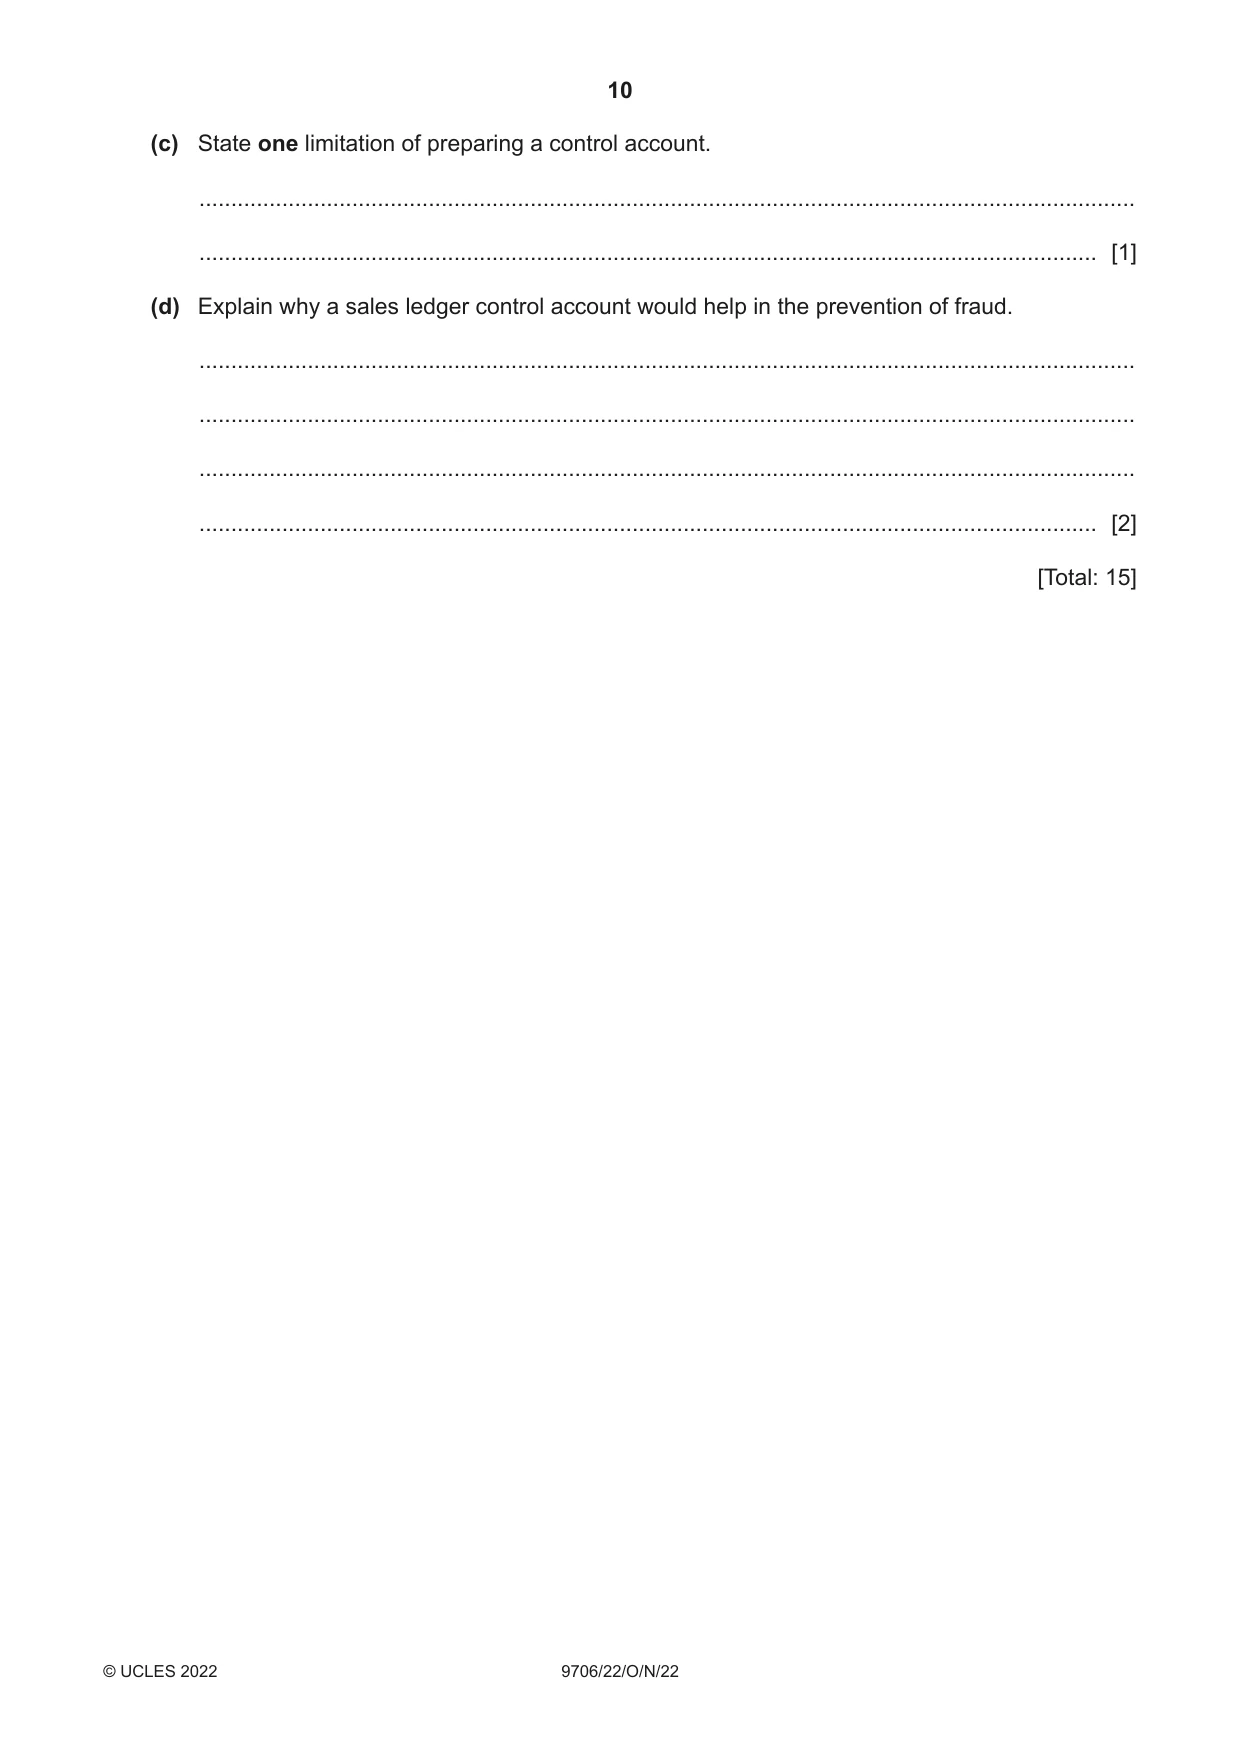
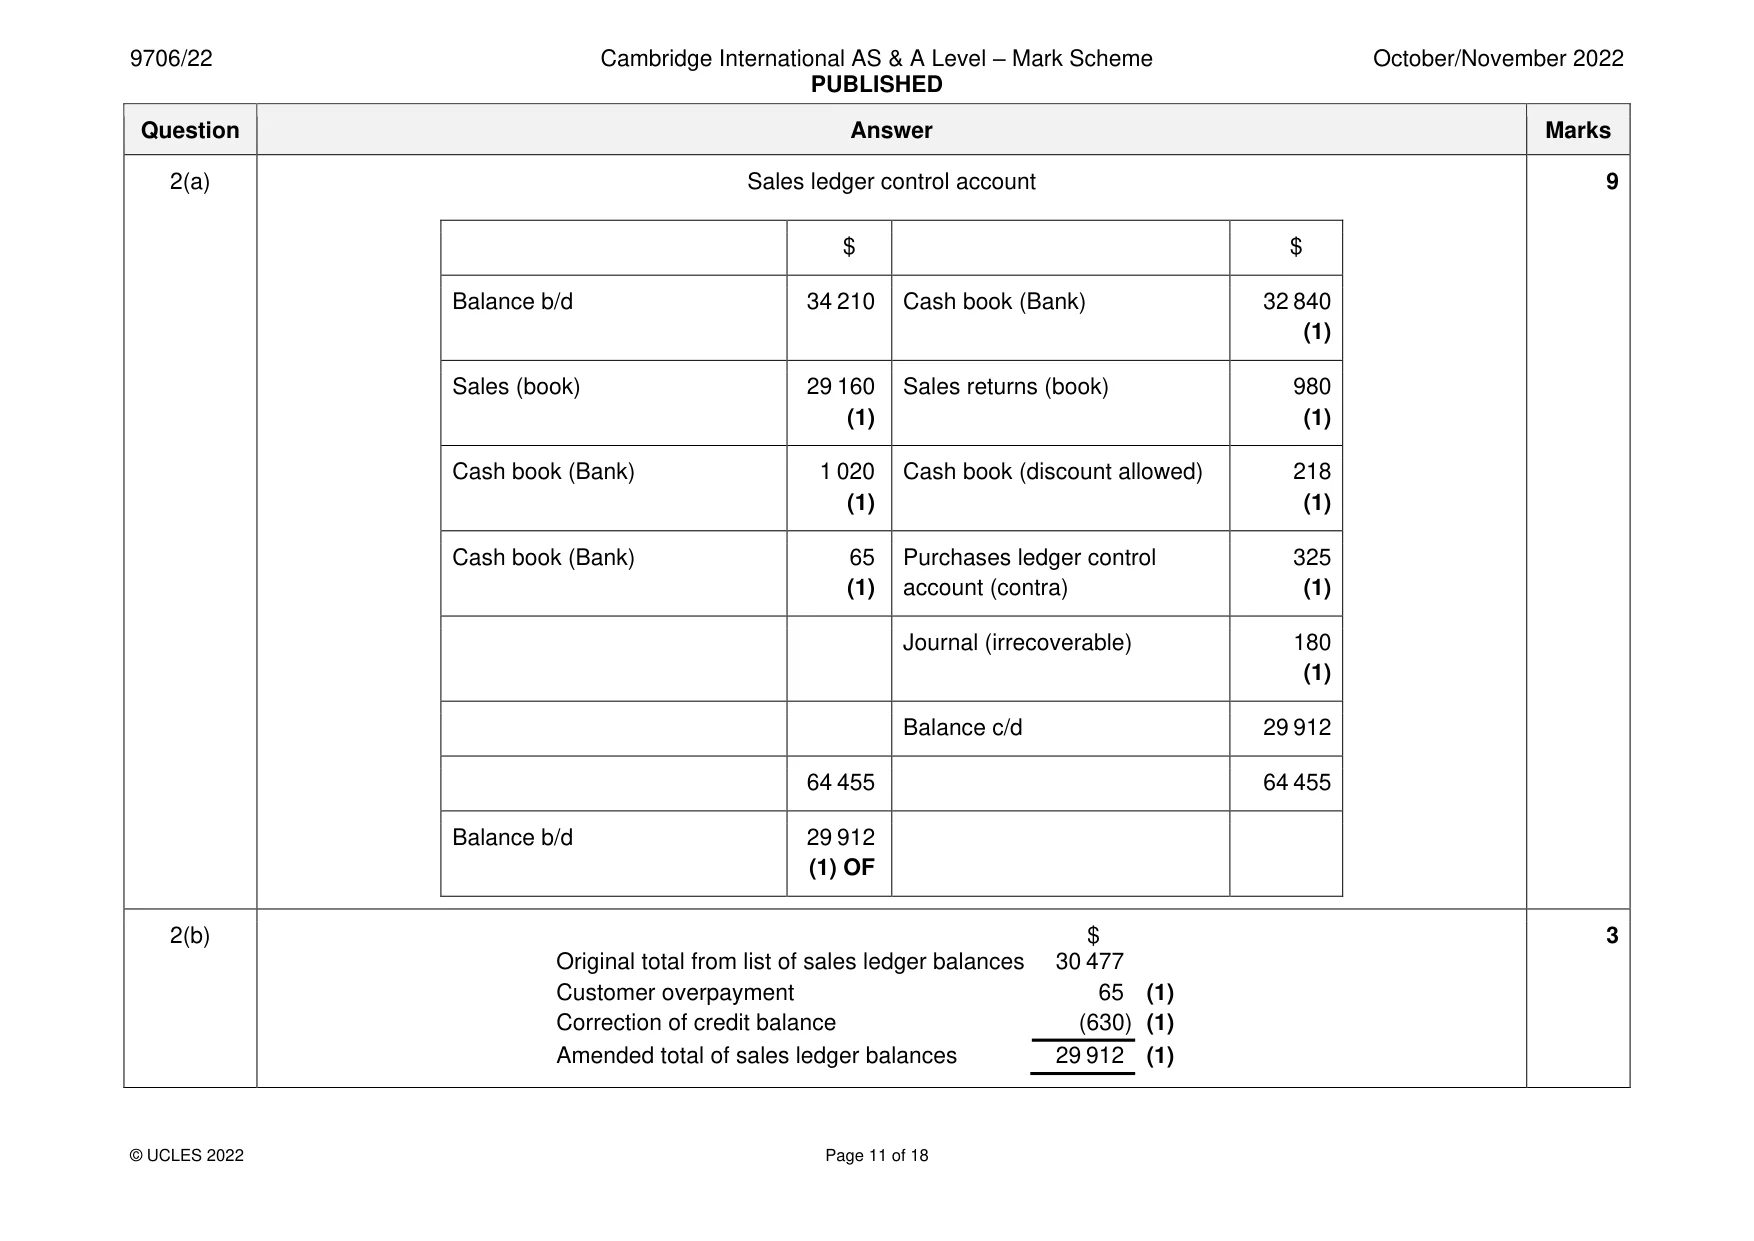
2 Usman has extracted the following information from his books of account in order to update the sales ledger control account for the month of August 2022. $ Balance brought down at 1 August 2022 34 210 Cheque receipts from credit customers 32 840 Customers’ dishonoured cheques 1 020 Sales journal totals 29 760 Sales returns journal totals 980 Usman has produced a list of all customer account balances at 31 August 2022 totalling $30 477. He has discovered the following: 1 The total of the sales journal had been overcast by $600. 2 Discounts allowed of $218 had been entered in customers’ accounts but no entries had been made in the control account. 3 A contra for $325 had been correctly entered in both the customer’s account and the supplier’s account. 4 A customer’s overpayment of $65 had been repaid by cheque but no entries had been made in the books of account. 5 A cheque received from Musa for $250 had been posted to the account of Hussein. 6 An irrecoverable debt of $180 had been correctly written off in a customer’s account but had not been entered in the control account. 7 A credit balance of $315 on a customer’s account had been incorrectly entered as a debit balance in the list of customer account balances at 31 August 2022. REQUIRED (a) Prepare the updated sales ledger control account for the month of August 2022. Sales ledger control account $ $ Balance b/d 34 210 [9] (b) Prepare an amended total of customer account balances to agree with the sales ledger control account balance in (a). $ Original total of customer account balances 30 477 [3] (c) State one limitation of preparing a control account. ................................................................................................................................................... ............................................................................................................................................. [1] (d) Explain why a sales ledger control account would help in the prevention of fraud. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] [Total: 15] PLEASE TURN OVER
Mark scheme: 2(a) Sales ledger control account 9 $ $ Balance b/d 34 210 Cash book (Bank) 32 840 (1) Sales (book) 29 160 Sales returns (book) 980 (1) (1) Cash book (Bank) 1 020 Cash book (discount allowed) 218 (1) (1) Cash book (Bank) 65 Purchases ledger control 325 (1) account (contra) (1) Journal (irrecoverable) 180 (1) Balance c/d 29 912 64 455 64 455 Balance b/d 29 912 (1) OF 2(b) $ 3 Original total from list of sales ledger balances 30 477 Customer overpayment 65 (1) Correction of credit balance (630) (1) Amended total of sales ledger balances 29 912 (1) 2(c) Does not identify all types of error / only proves the arithmetical accuracy of the ledger (1) 1 2(d) Preparation of the sales ledger control account should be carried out by a different member of staff / segregation of 2 duties(1) so collusion between two people would be required for fraud to be present (1) Accept other valid responses.
Q3 · N Limited provided the following information for the year ended 31 August 2022
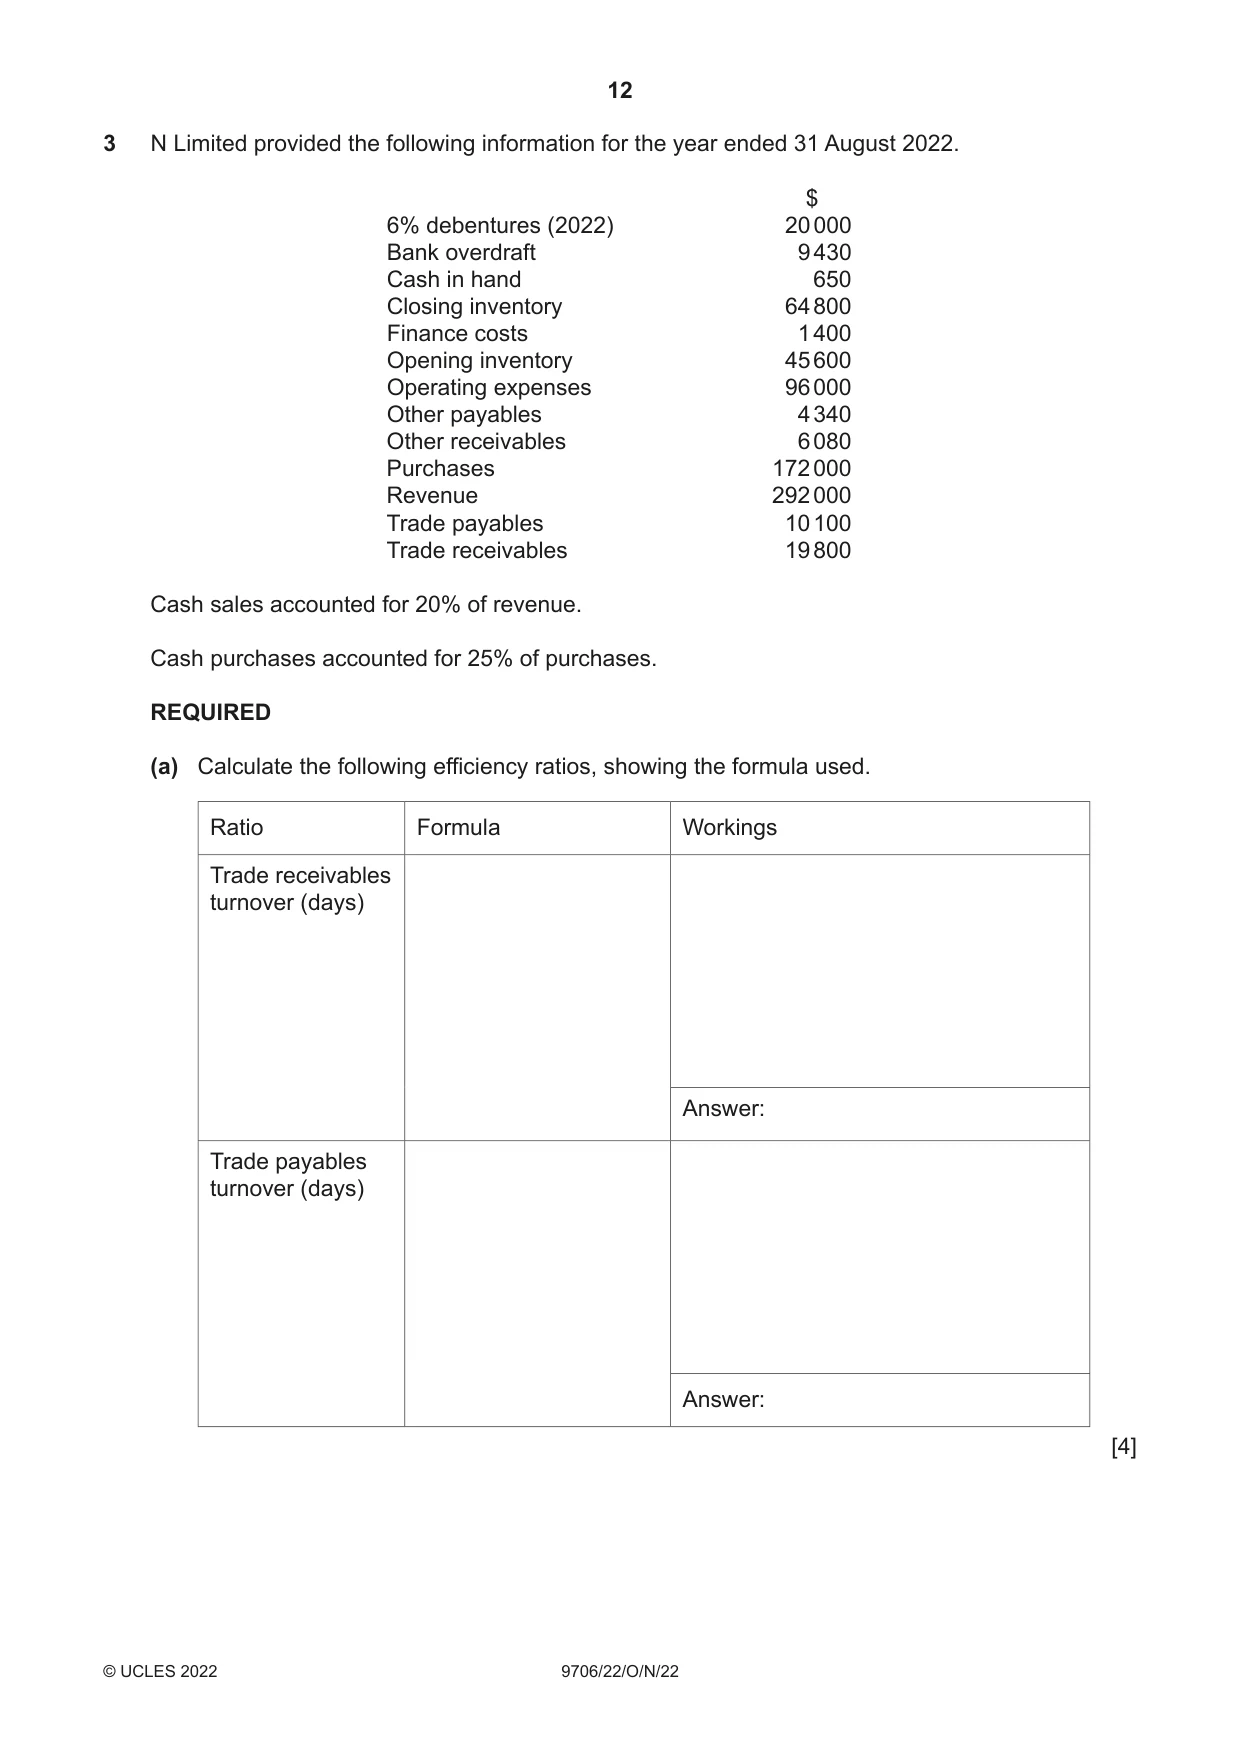
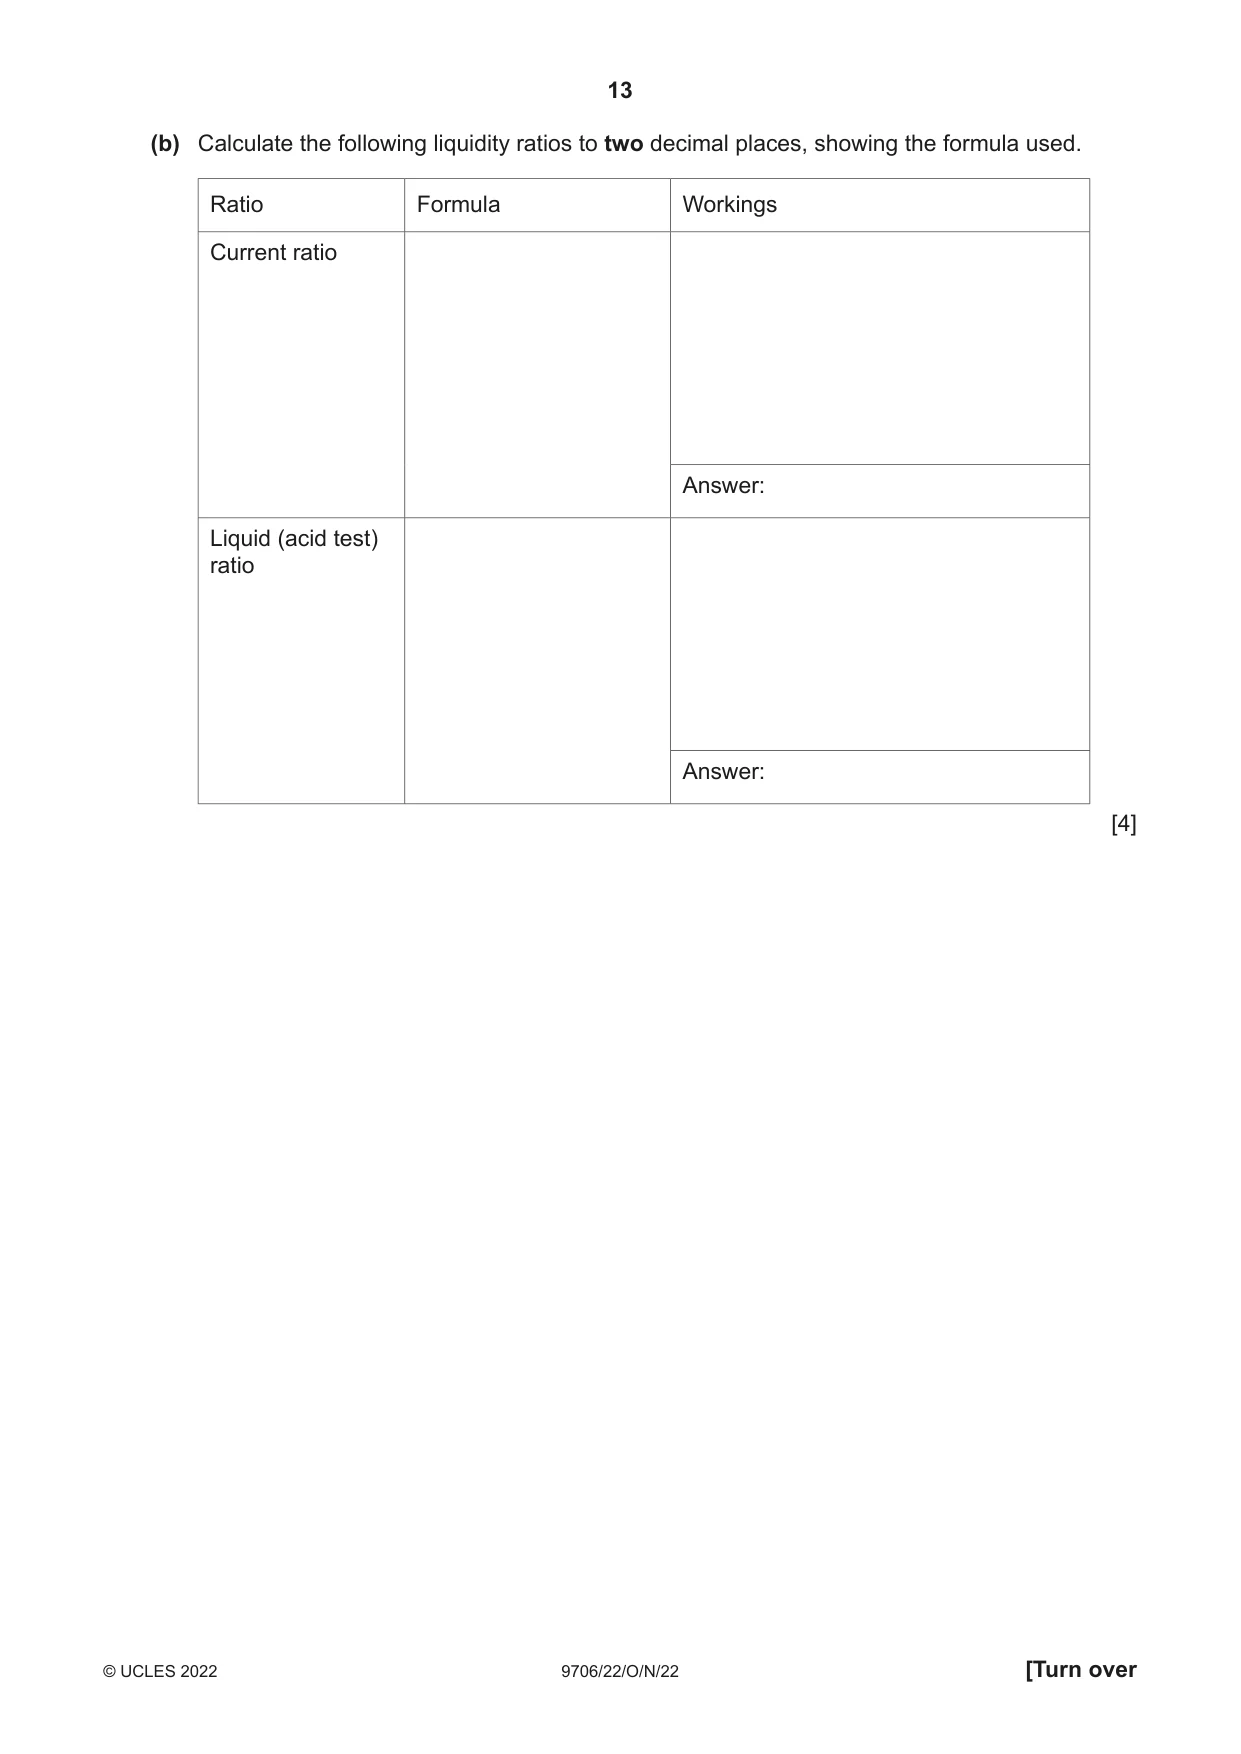
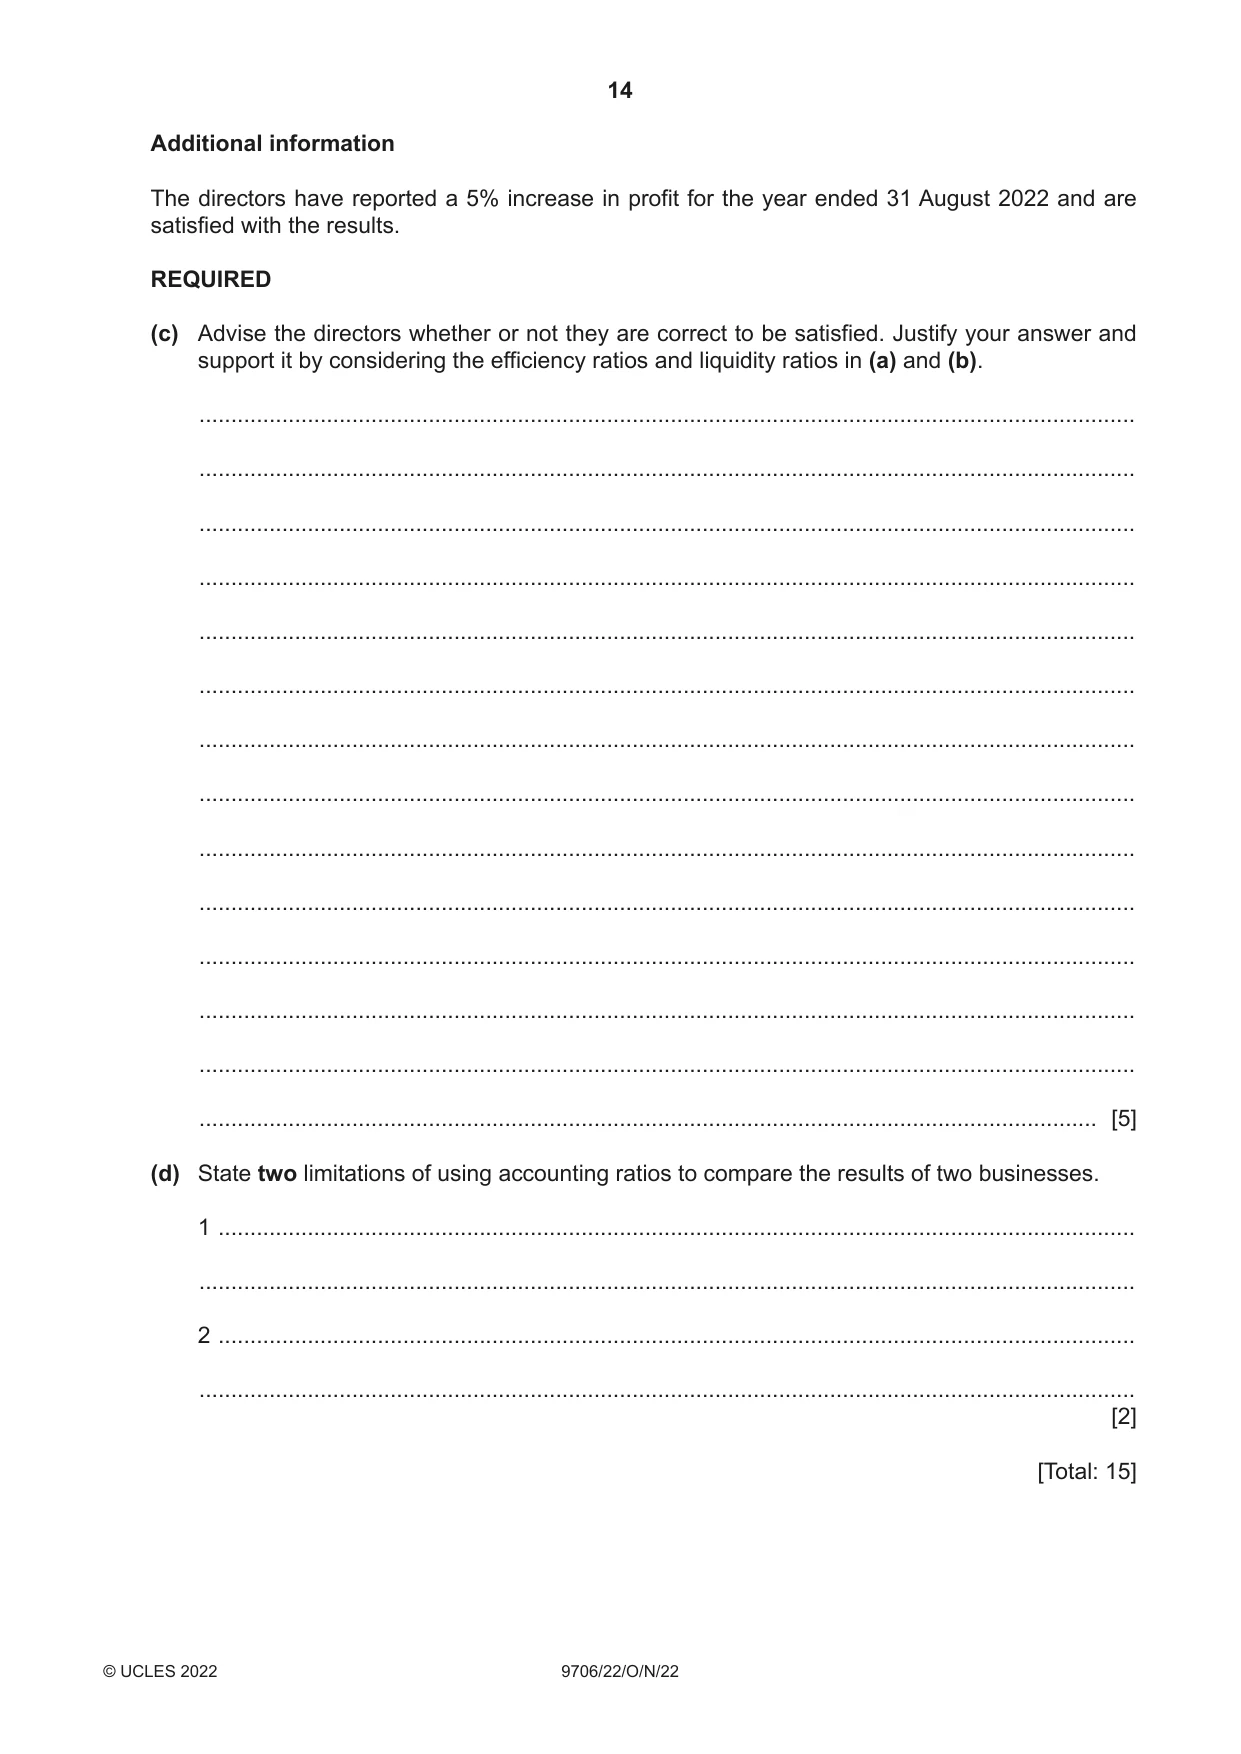
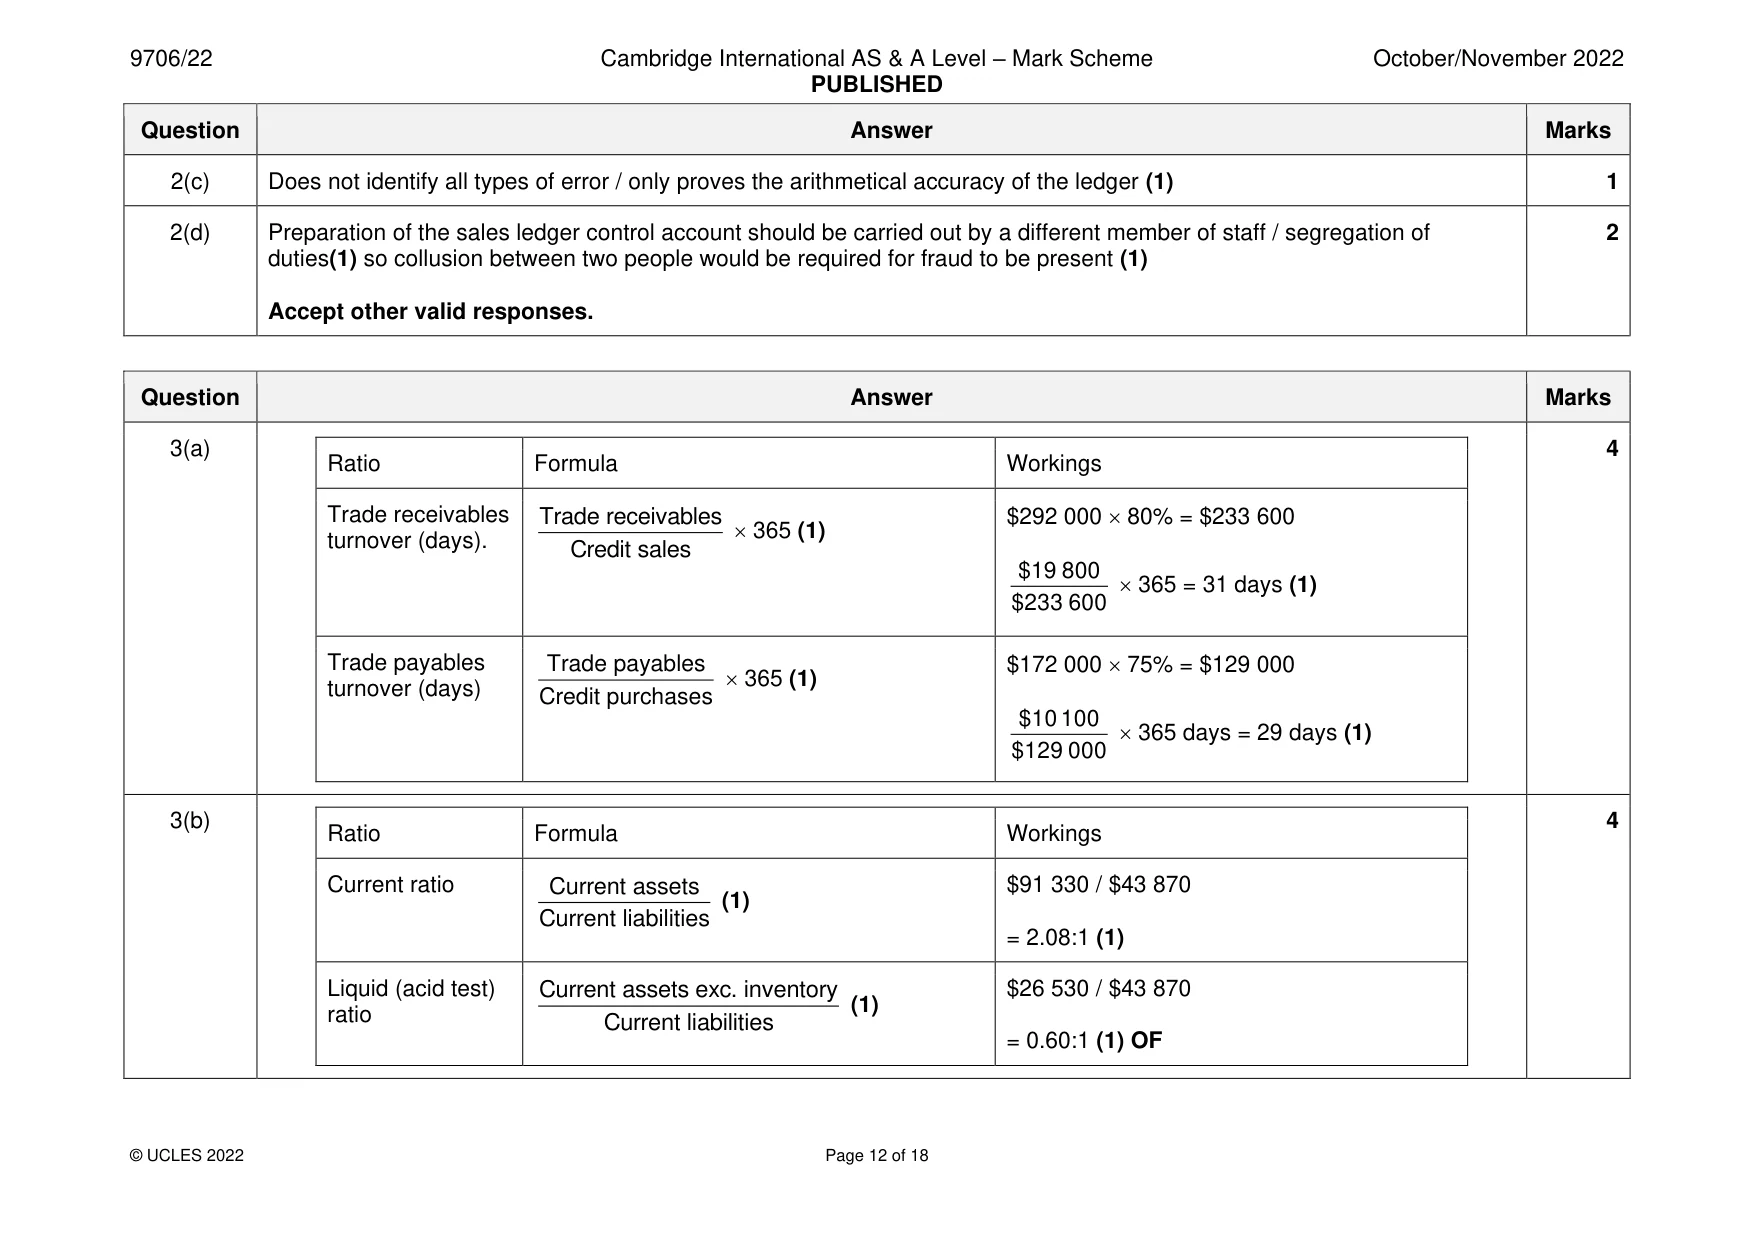
3 N Limited provided the following information for the year ended 31 August 2022. $ 6% debentures (2022) 20 000 Bank overdraft 9 430 Cash in hand 650 Closing inventory 64 800 Finance costs 1 400 Opening inventory 45 600 Operating expenses 96 000 Other payables 4 340 Other receivables 6 080 Purchases 172 000 Revenue 292 000 Trade payables 10 100 Trade receivables 19 800 Cash sales accounted for 20% of revenue. Cash purchases accounted for 25% of purchases. REQUIRED (a) Calculate the following efficiency ratios, showing the formula used. Ratio Formula Workings Trade receivables turnover (days) Answer: Trade payables turnover (days) Answer: [4] (b) Calculate the following liquidity ratios to two decimal places, showing the formula used. Ratio Formula Workings Current ratio Answer: Liquid (acid test) ratio Answer: [4] Additional information The directors have reported a 5% increase in profit for the year ended 31 August 2022 and are satisfied with the results. REQUIRED (c) Advise the directors whether or not they are correct to be satisfied. Justify your answer and support it by considering the efficiency ratios and liquidity ratios in (a) and (b). ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] (d) State two limitations of using accounting ratios to compare the results of two businesses. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] [Total: 15]
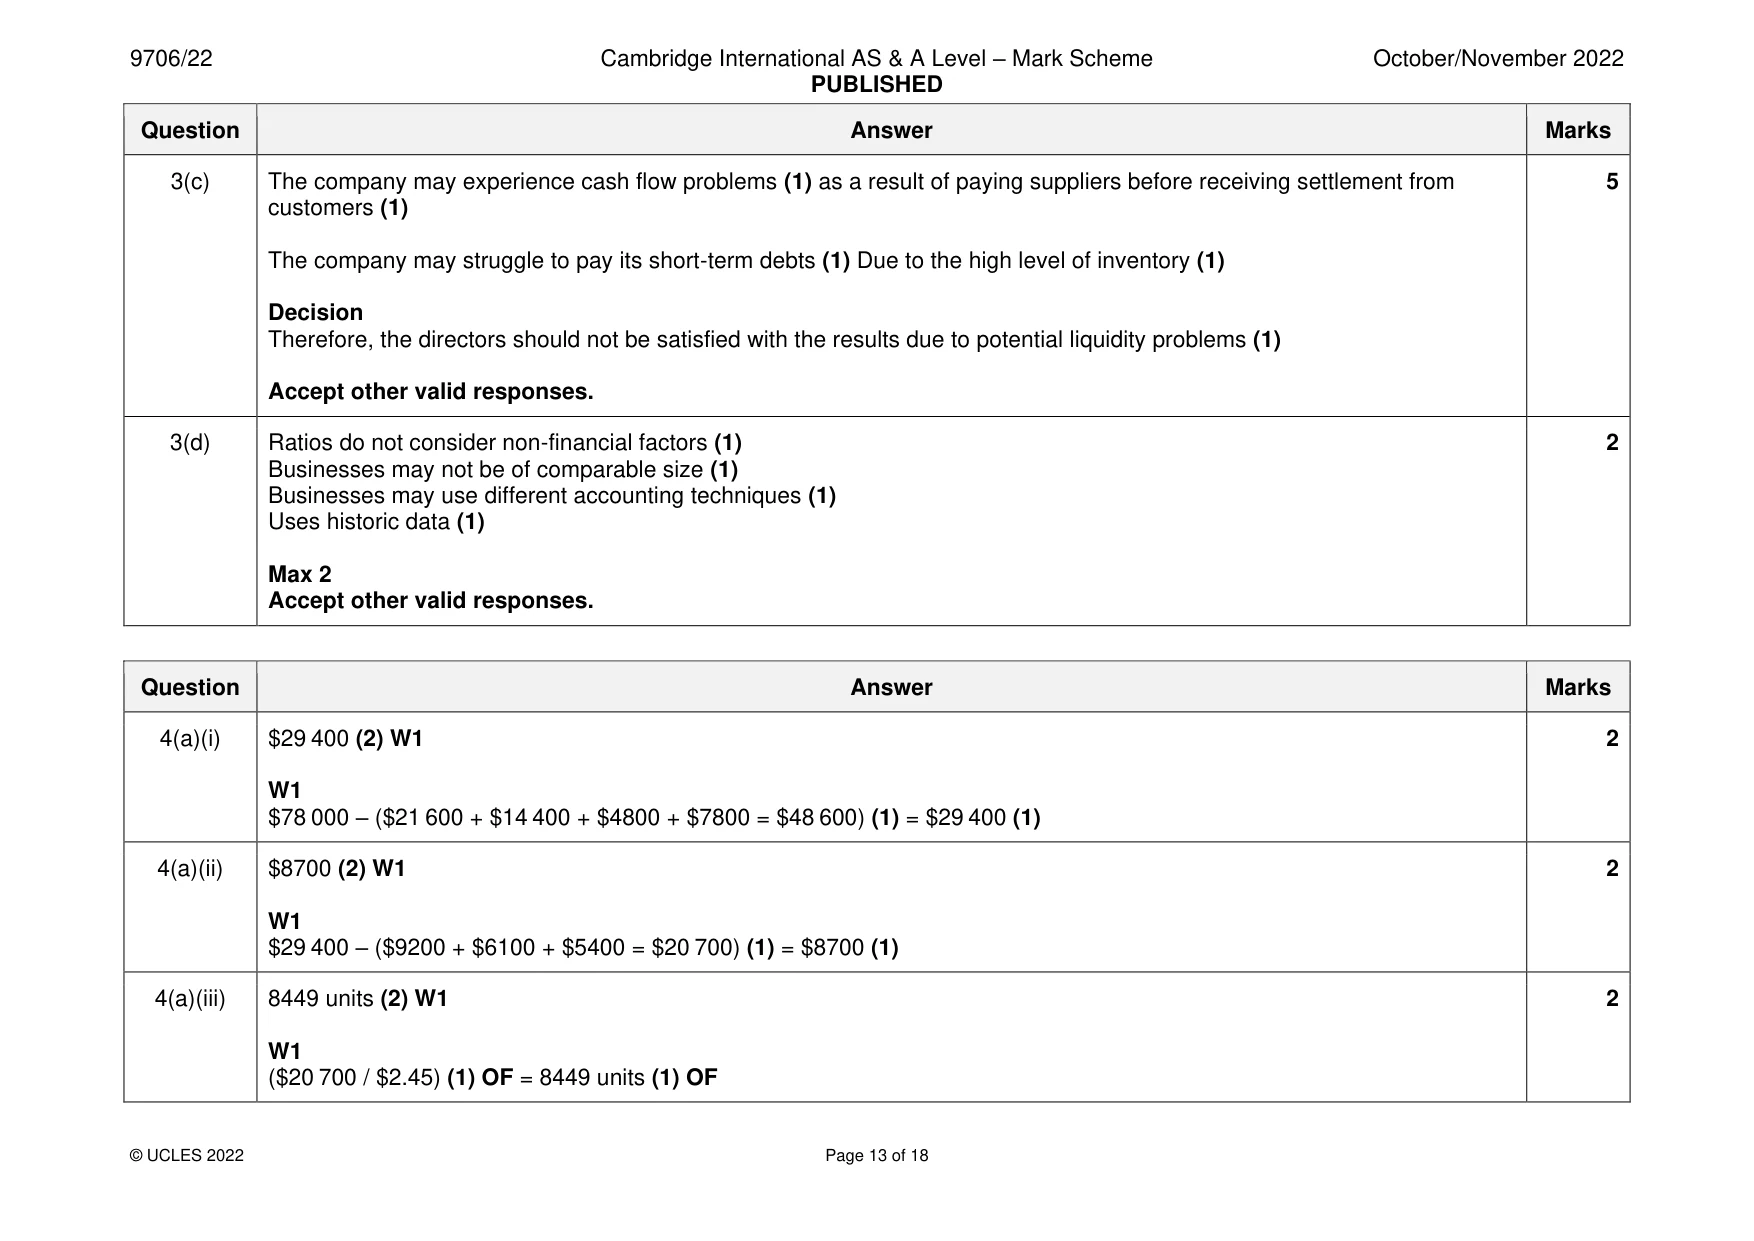
Mark scheme: 3(a) 4 Ratio Formula Workings Trade receivables Trade receivables $292 000 80% = $233 600 365 (1) turnover (days). Credit sales $19 800 365 = 31 days (1) $233 600 Trade payables Trade payables $172 000 75% = $129 000 365 (1) turnover (days) Credit purchases $10 100 365 days = 29 days (1) $129 000 3(b) 4 Ratio Formula Workings Current ratio Current assets $91 330 / $43 870 (1) Current liabilities = 2.08:1 (1) Liquid (acid test) Current assets exc. inventory $26 530 / $43 870 (1) ratio Current liabilities = 0.60:1 (1) OF 3(c) The company may experience cash flow problems (1) as a result of paying suppliers before receiving settlement from 5 customers (1) The company may struggle to pay its short-term debts (1) Due to the high level of inventory (1) Decision Therefore, the directors should not be satisfied with the results due to potential liquidity problems (1) Accept other valid responses. 3(d) Ratios do not consider non-financial factors (1) 2 Businesses may not be of comparable size (1) Businesses may use different accounting techniques (1) Uses historic data (1) Max 2 Accept other valid responses.
More questions on Analysis and communication of accounting information
Q4 · Brady manufactures one product which is sold through agents who receive a 10% commission…
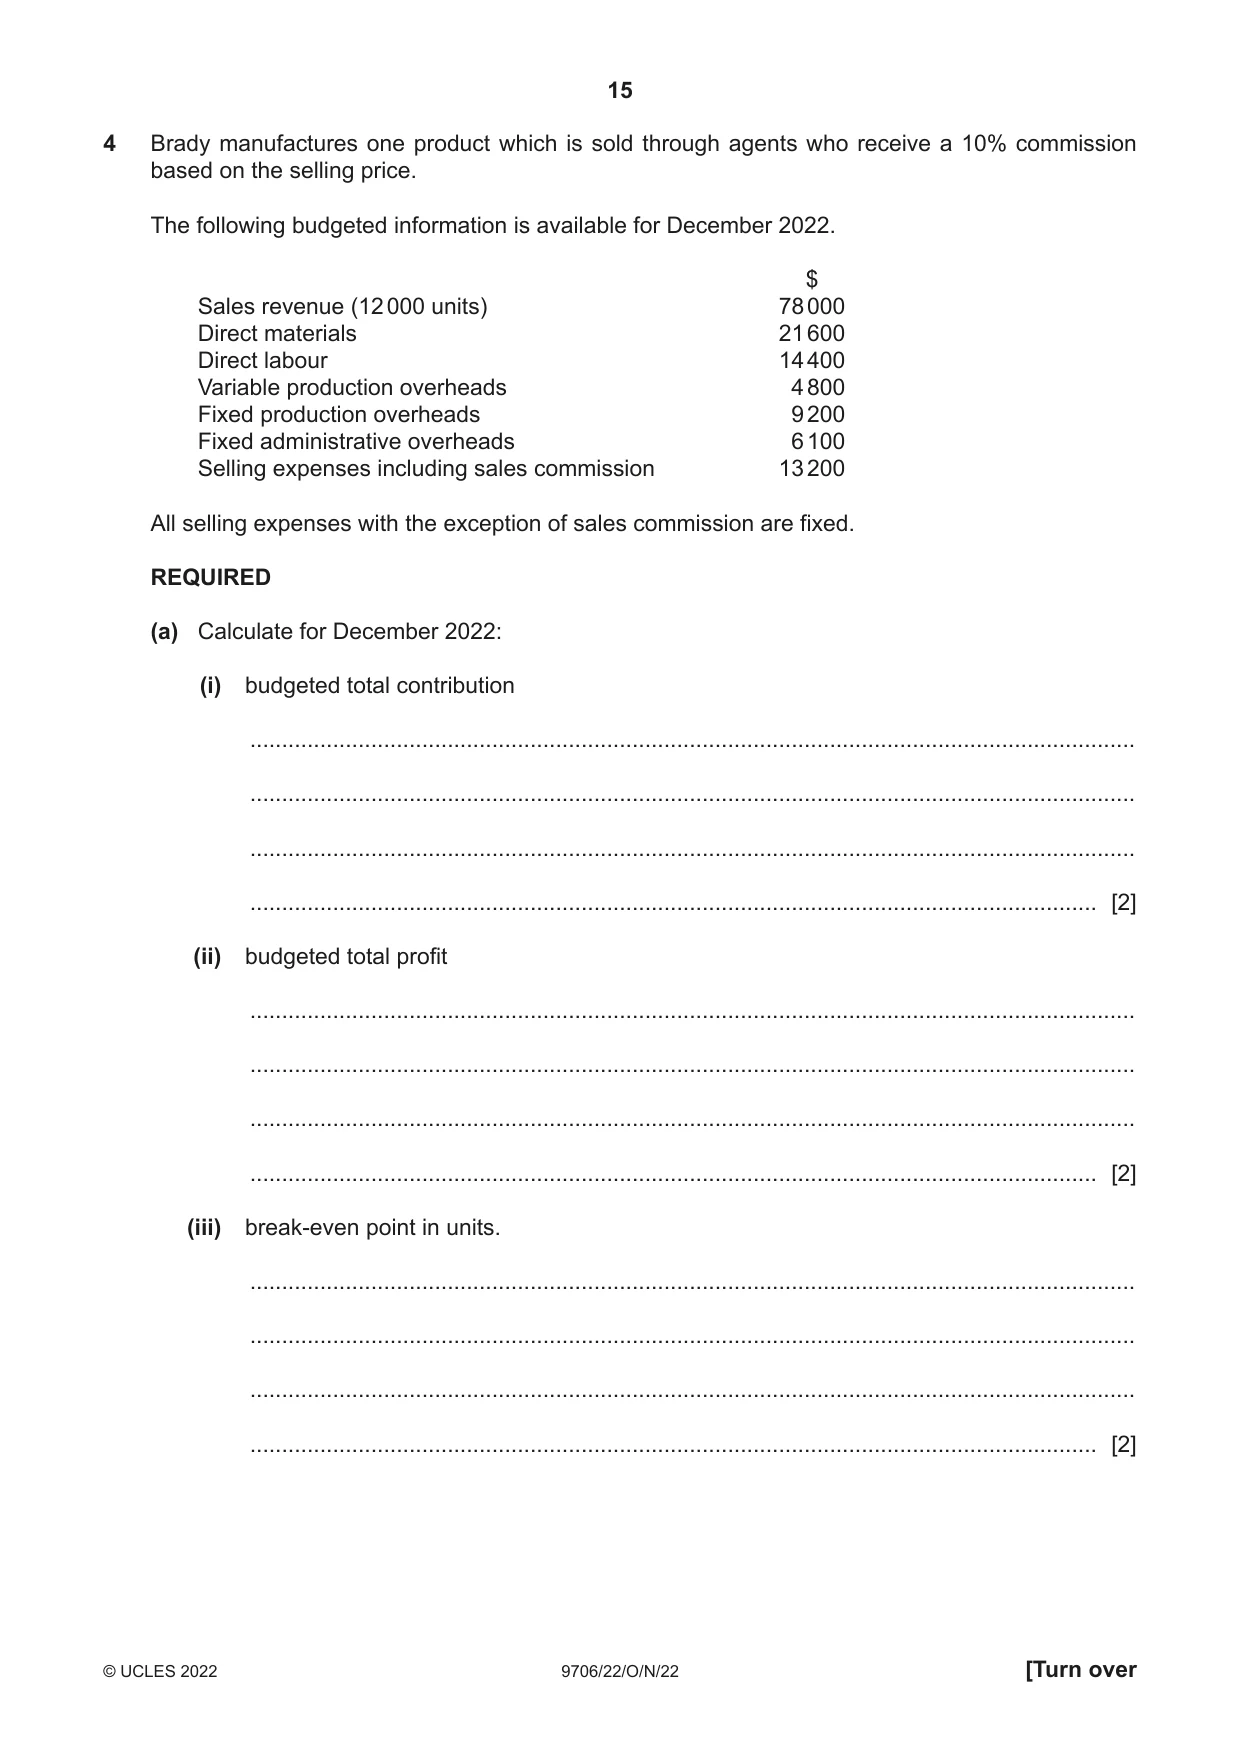
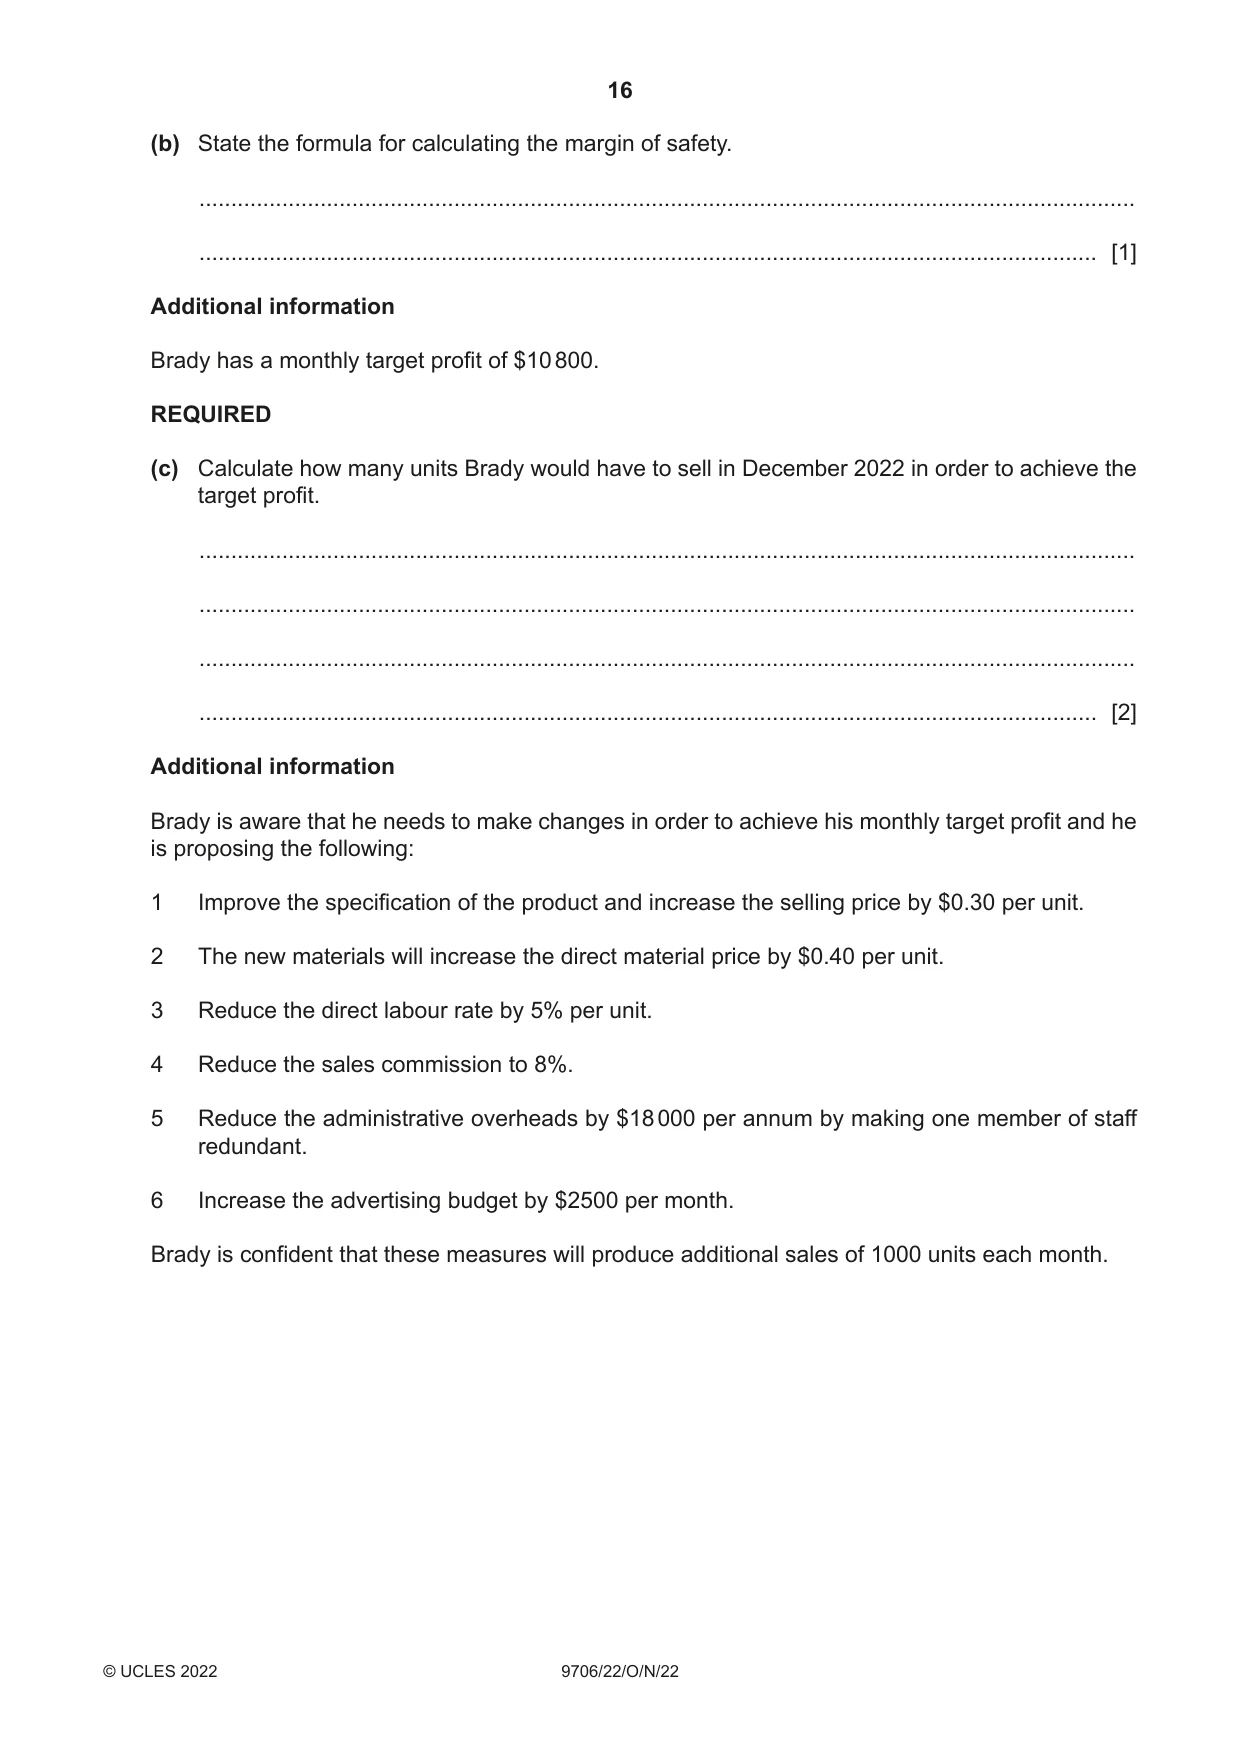
4 Brady manufactures one product which is sold through agents who receive a 10% commission based on the selling price. The following budgeted information is available for December 2022. $ Sales revenue (12 000 units) 78 000 Direct materials 21 600 Direct labour 14 400 Variable production overheads 4 800 Fixed production overheads 9 200 Fixed administrative overheads 6 100 Selling expenses including sales commission 13 200 All selling expenses with the exception of sales commission are fixed. REQUIRED (a) Calculate for December 2022: (i) budgeted total contribution ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] (ii) budgeted total profit ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] (iii) break‑even point in units. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] (b) State the formula for calculating the margin of safety. ................................................................................................................................................... ............................................................................................................................................. [1] Additional information Brady has a monthly target profit of $10 800. REQUIRED (c) Calculate how many units Brady would have to sell in December 2022 in order to achieve the target profit. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] Additional information Brady is aware that he needs to make changes in order to achieve his monthly target profit and he is proposing the following: 1 Improve the specification of the product and increase the selling price by $0.30 per unit. 2 The new materials will increase the direct material price by $0.40 per unit. 3 Reduce the direct labour rate by 5% per unit. 4 Reduce the sales commission to 8%.
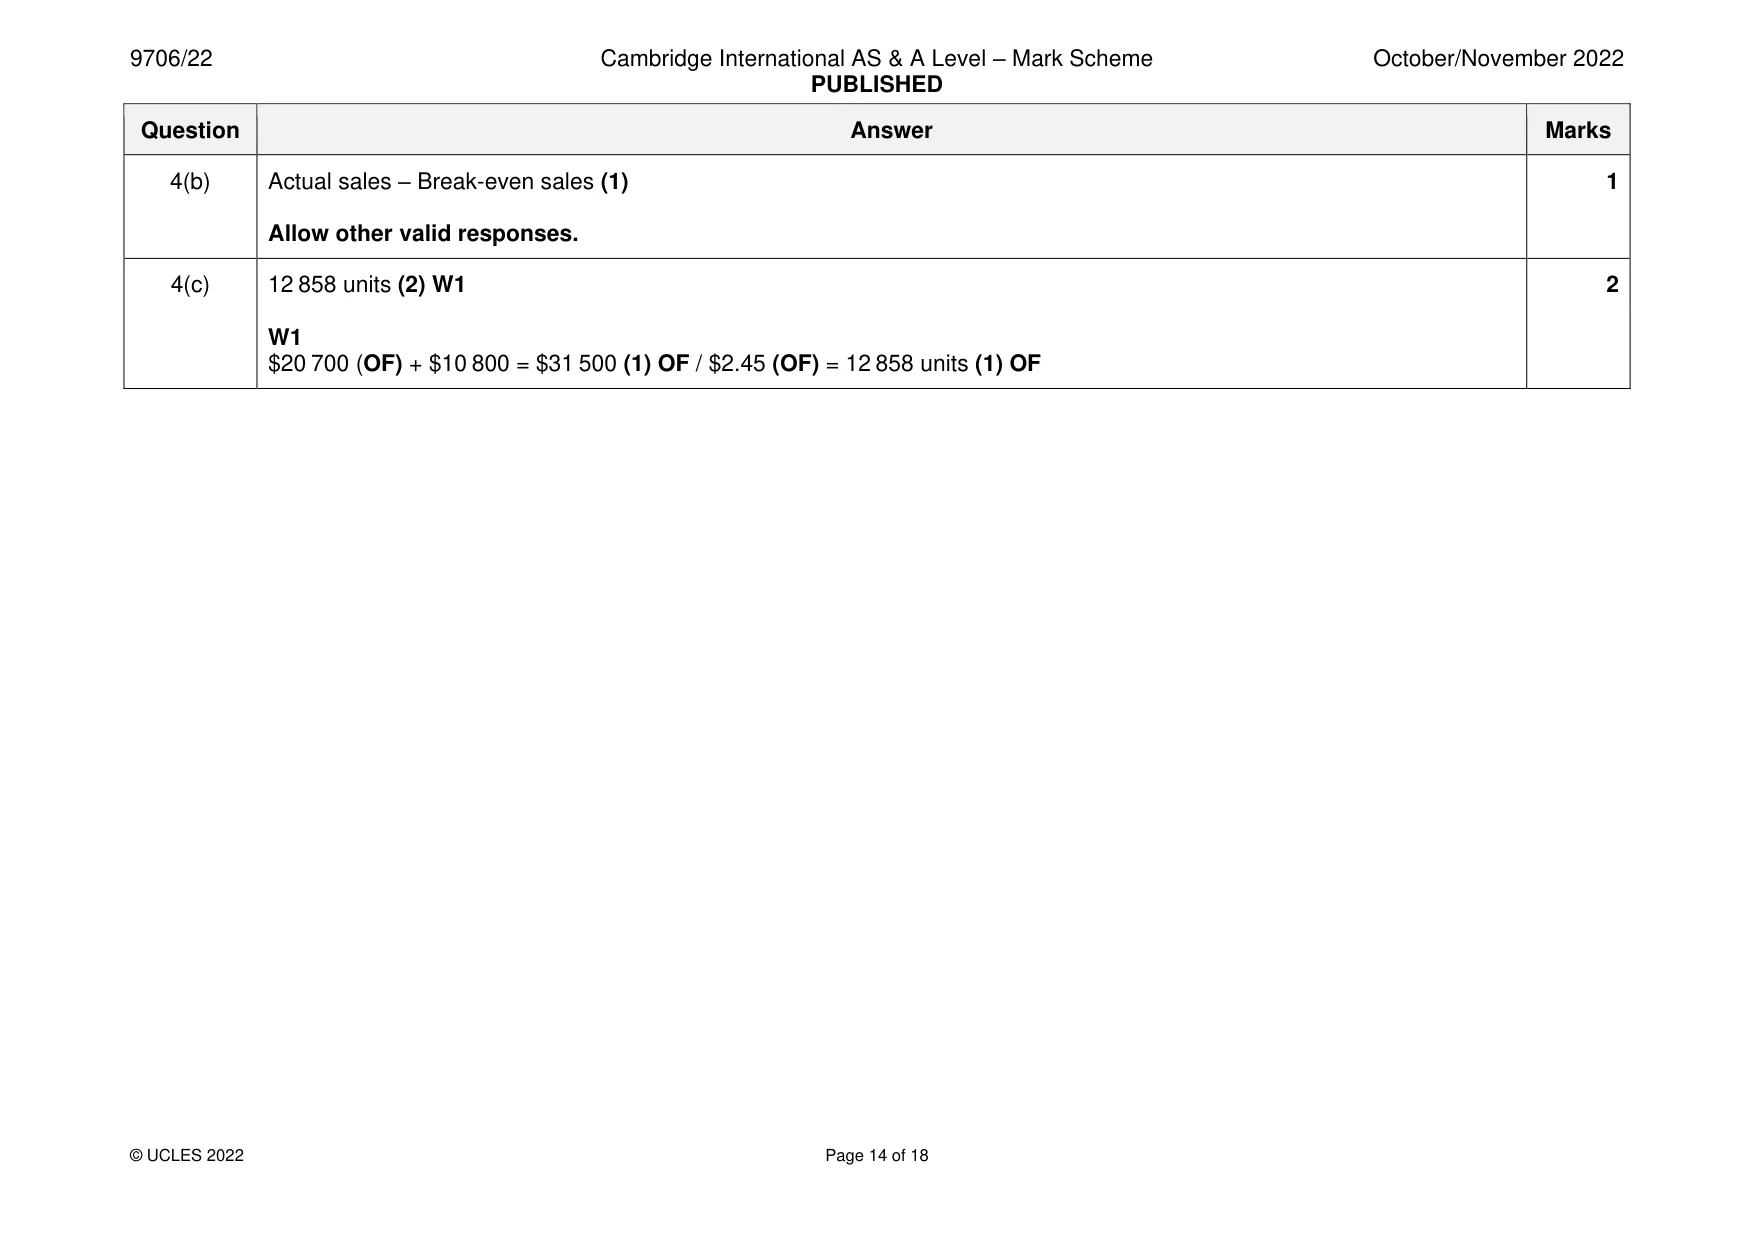
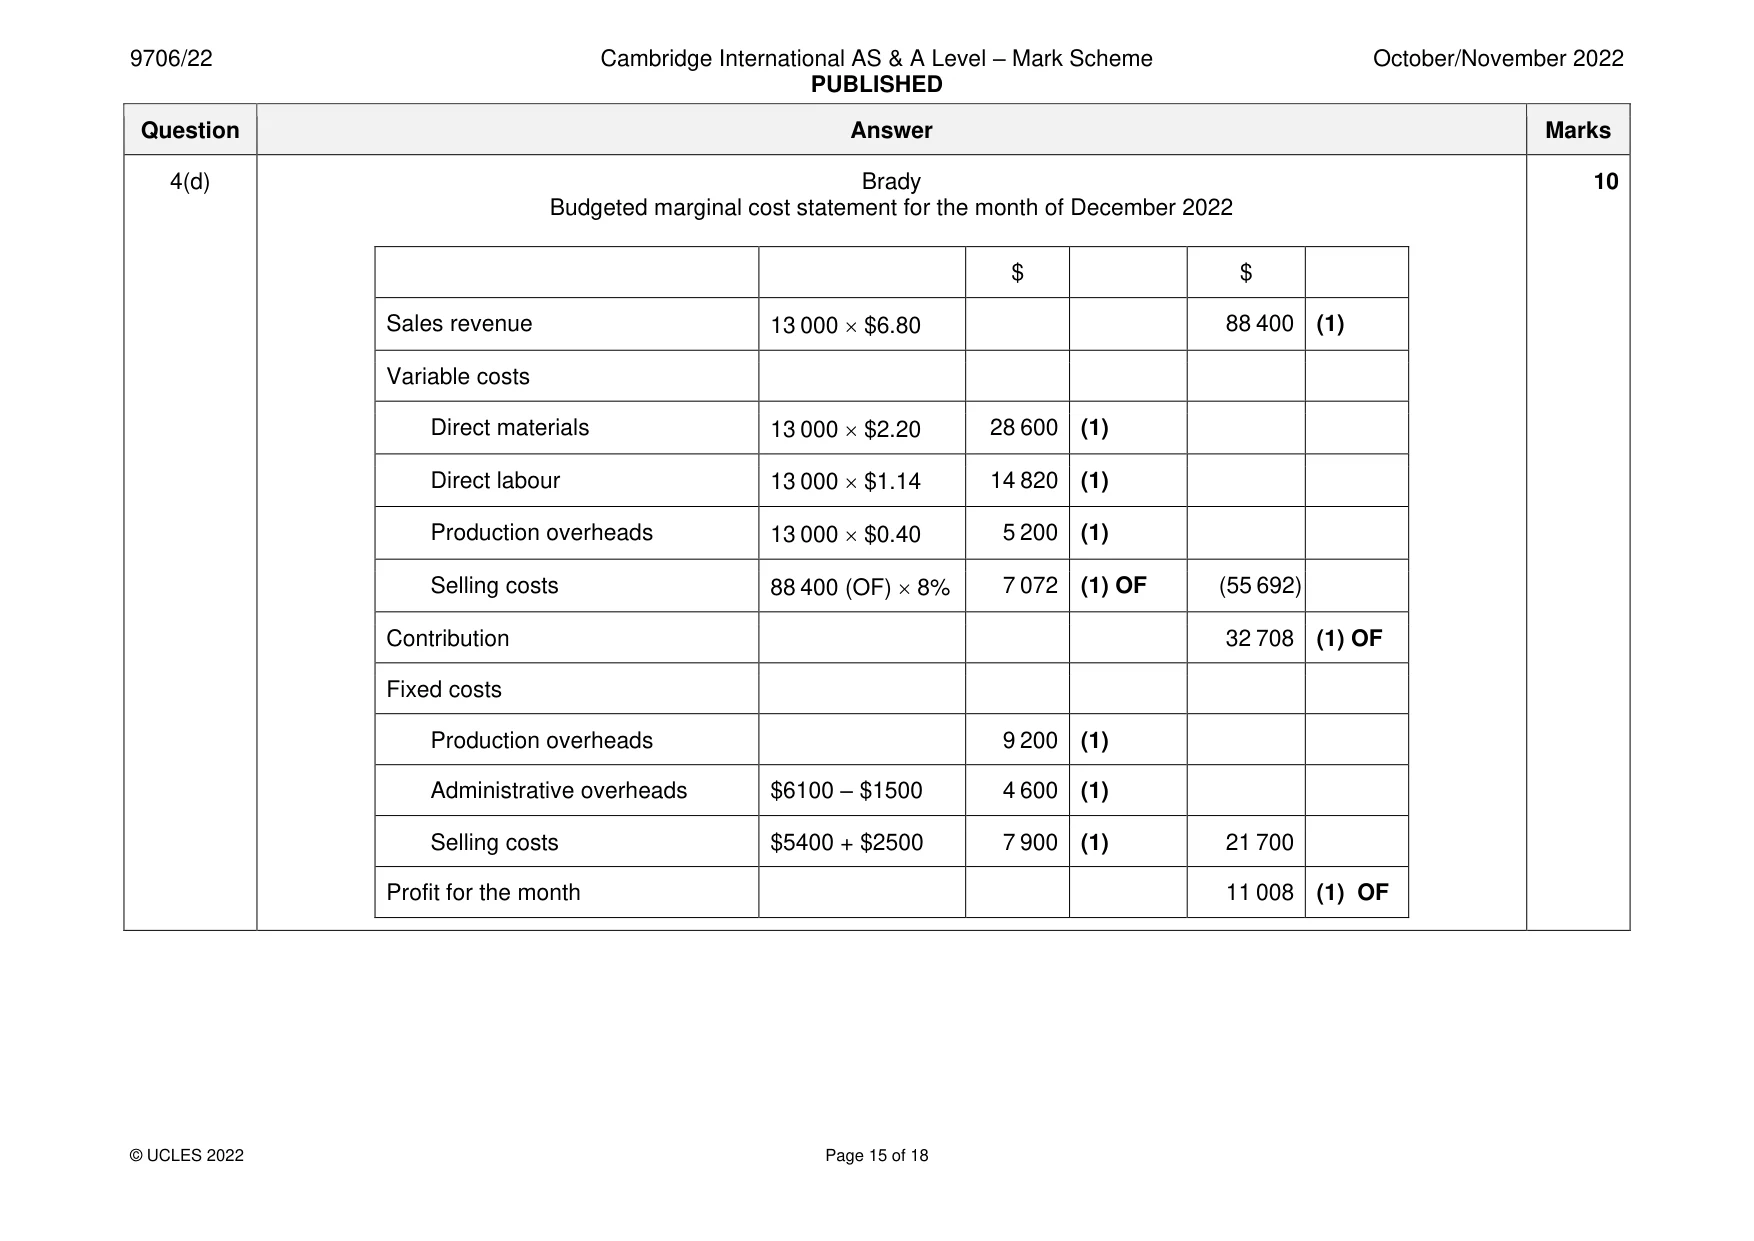
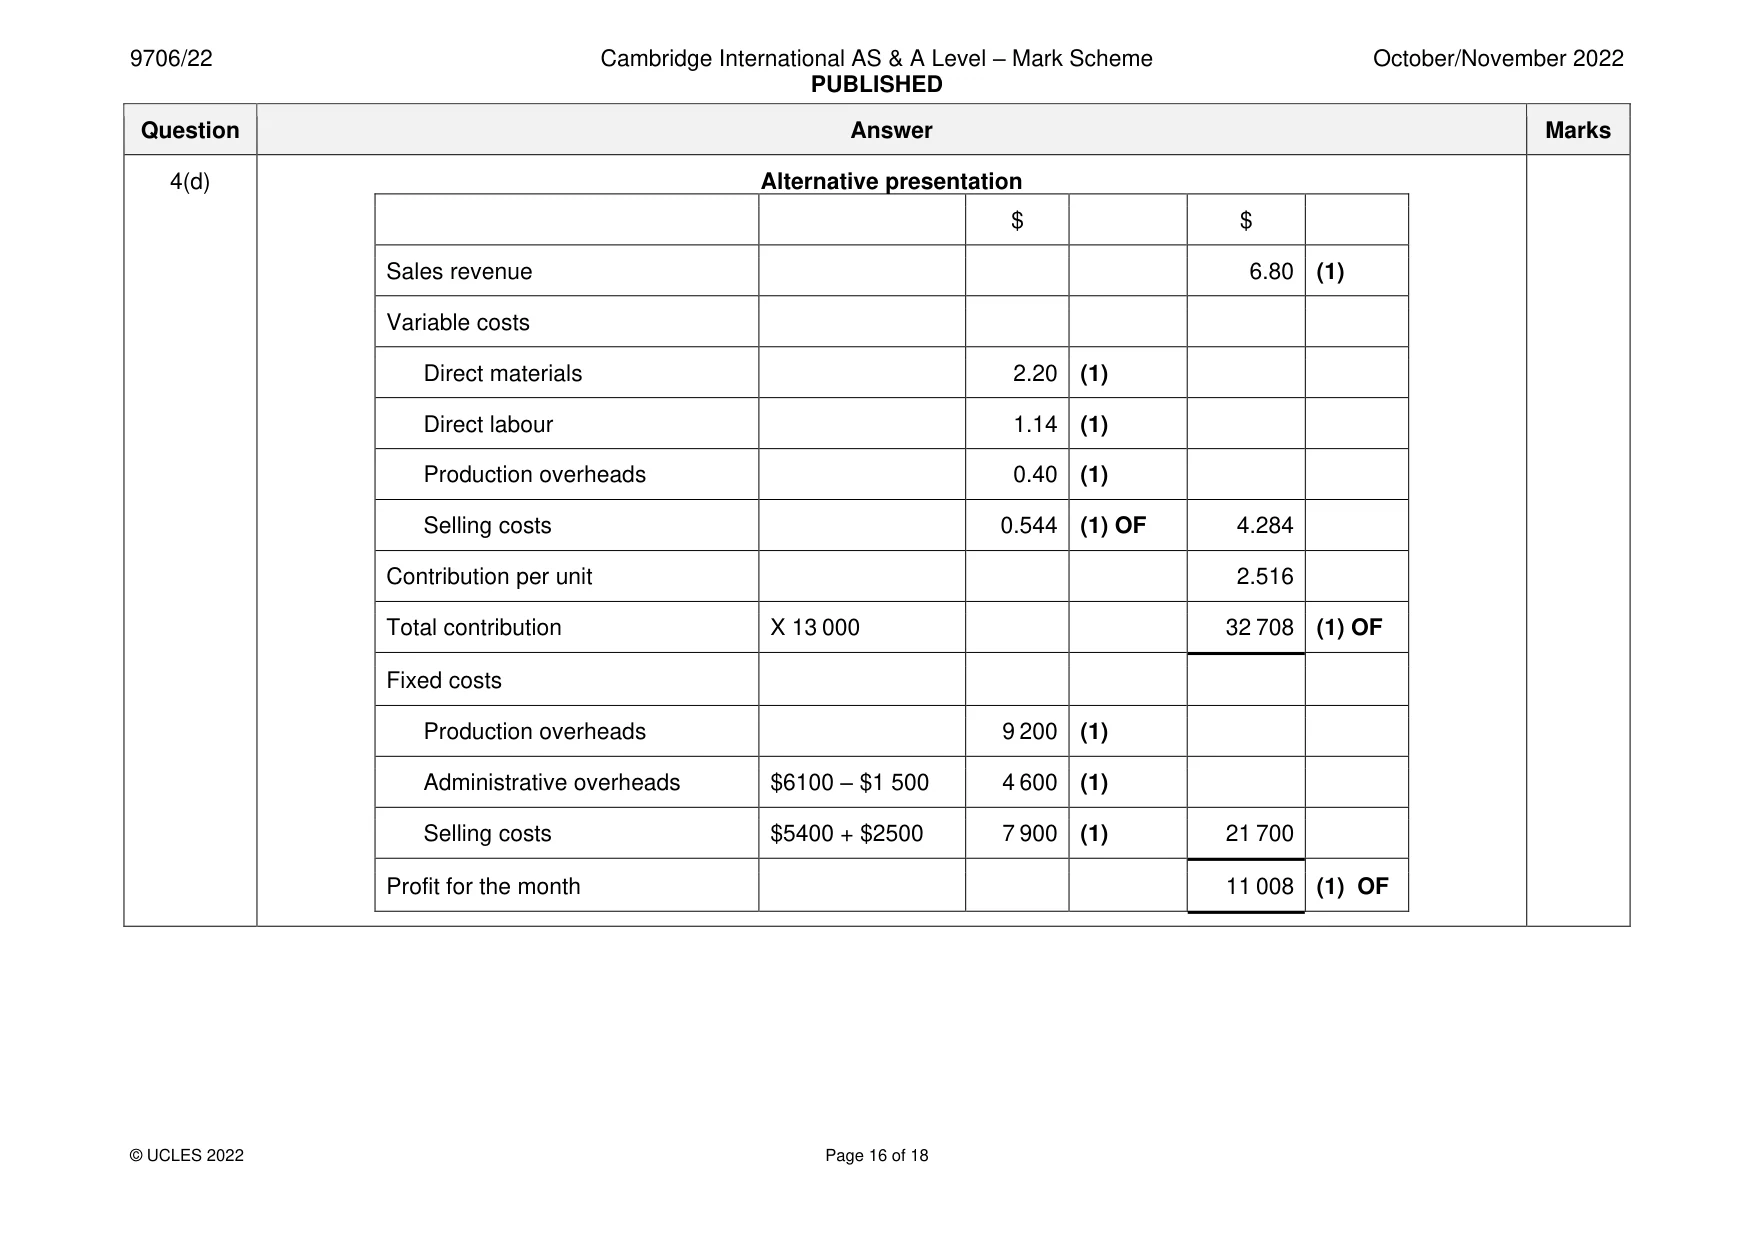
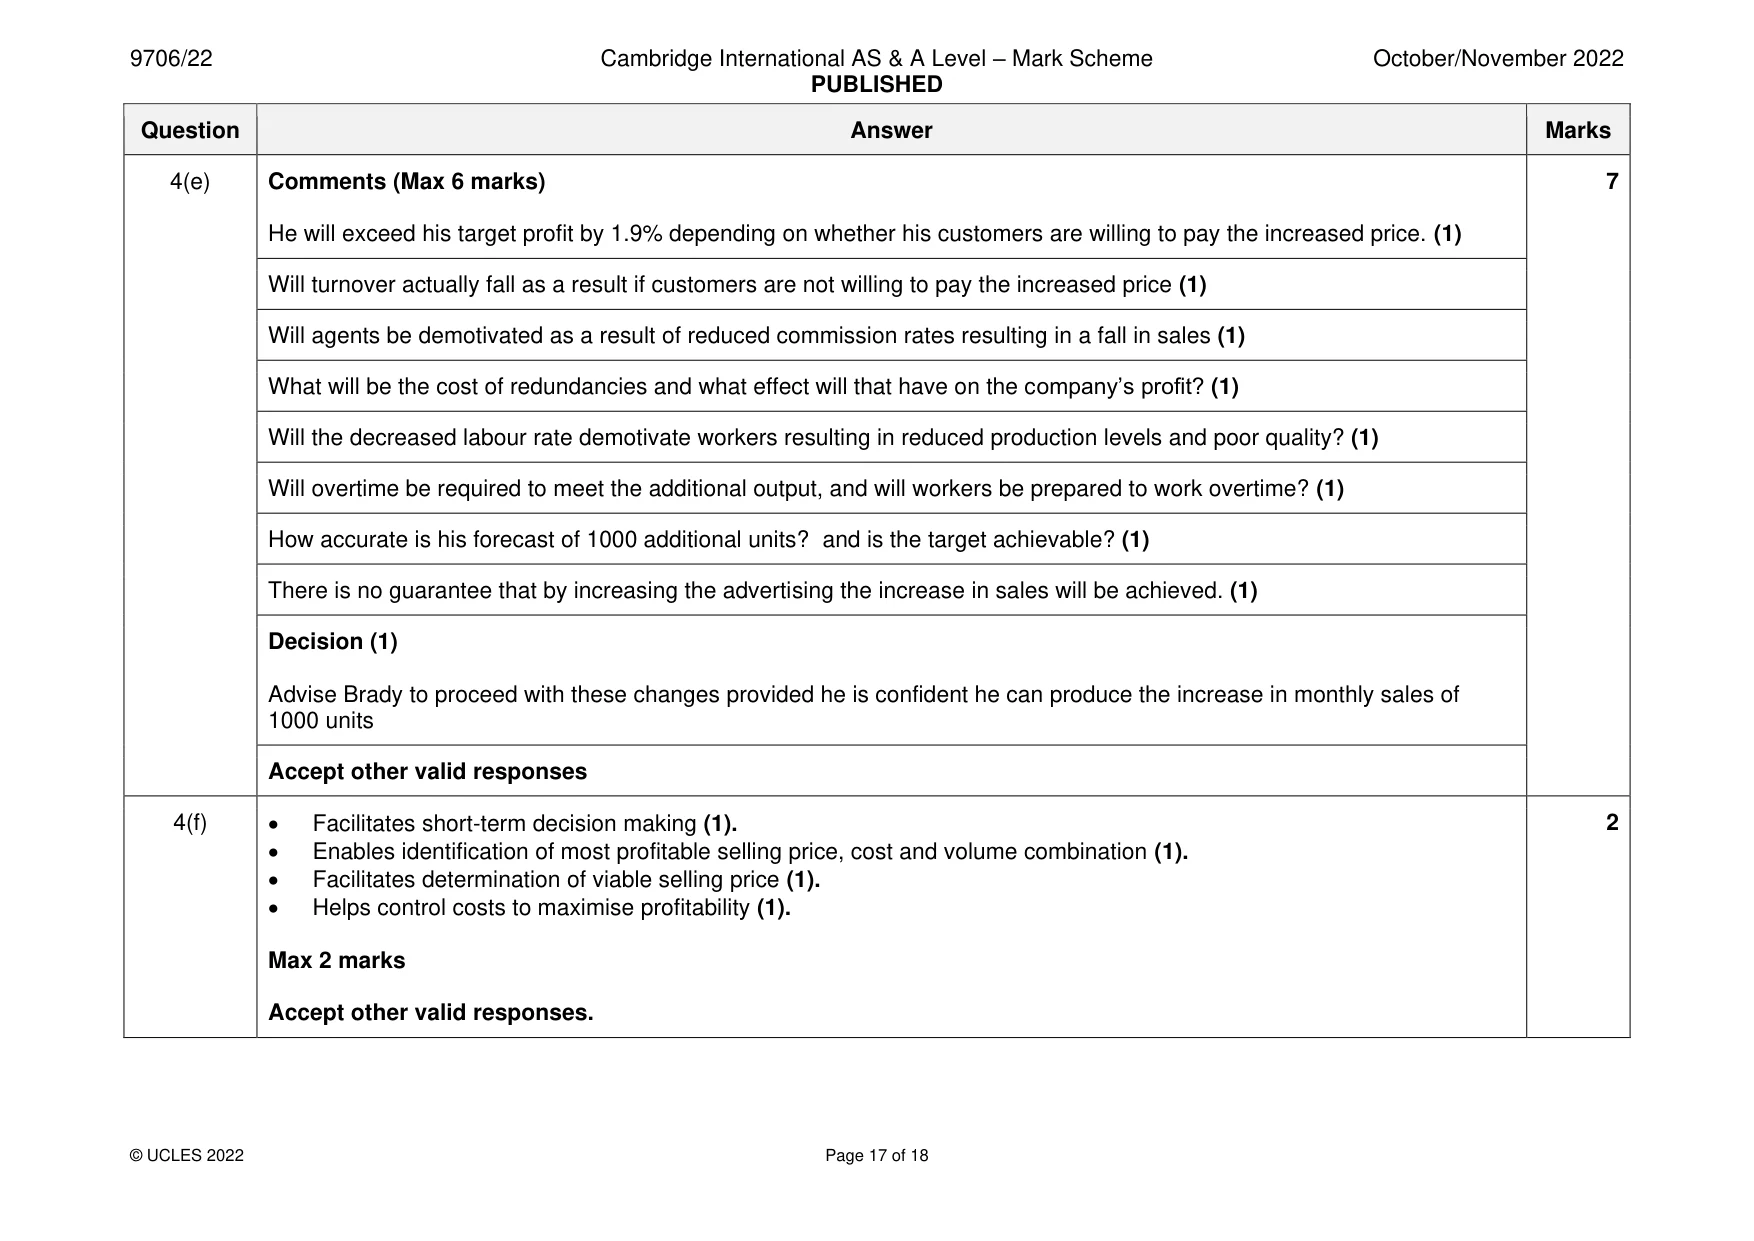
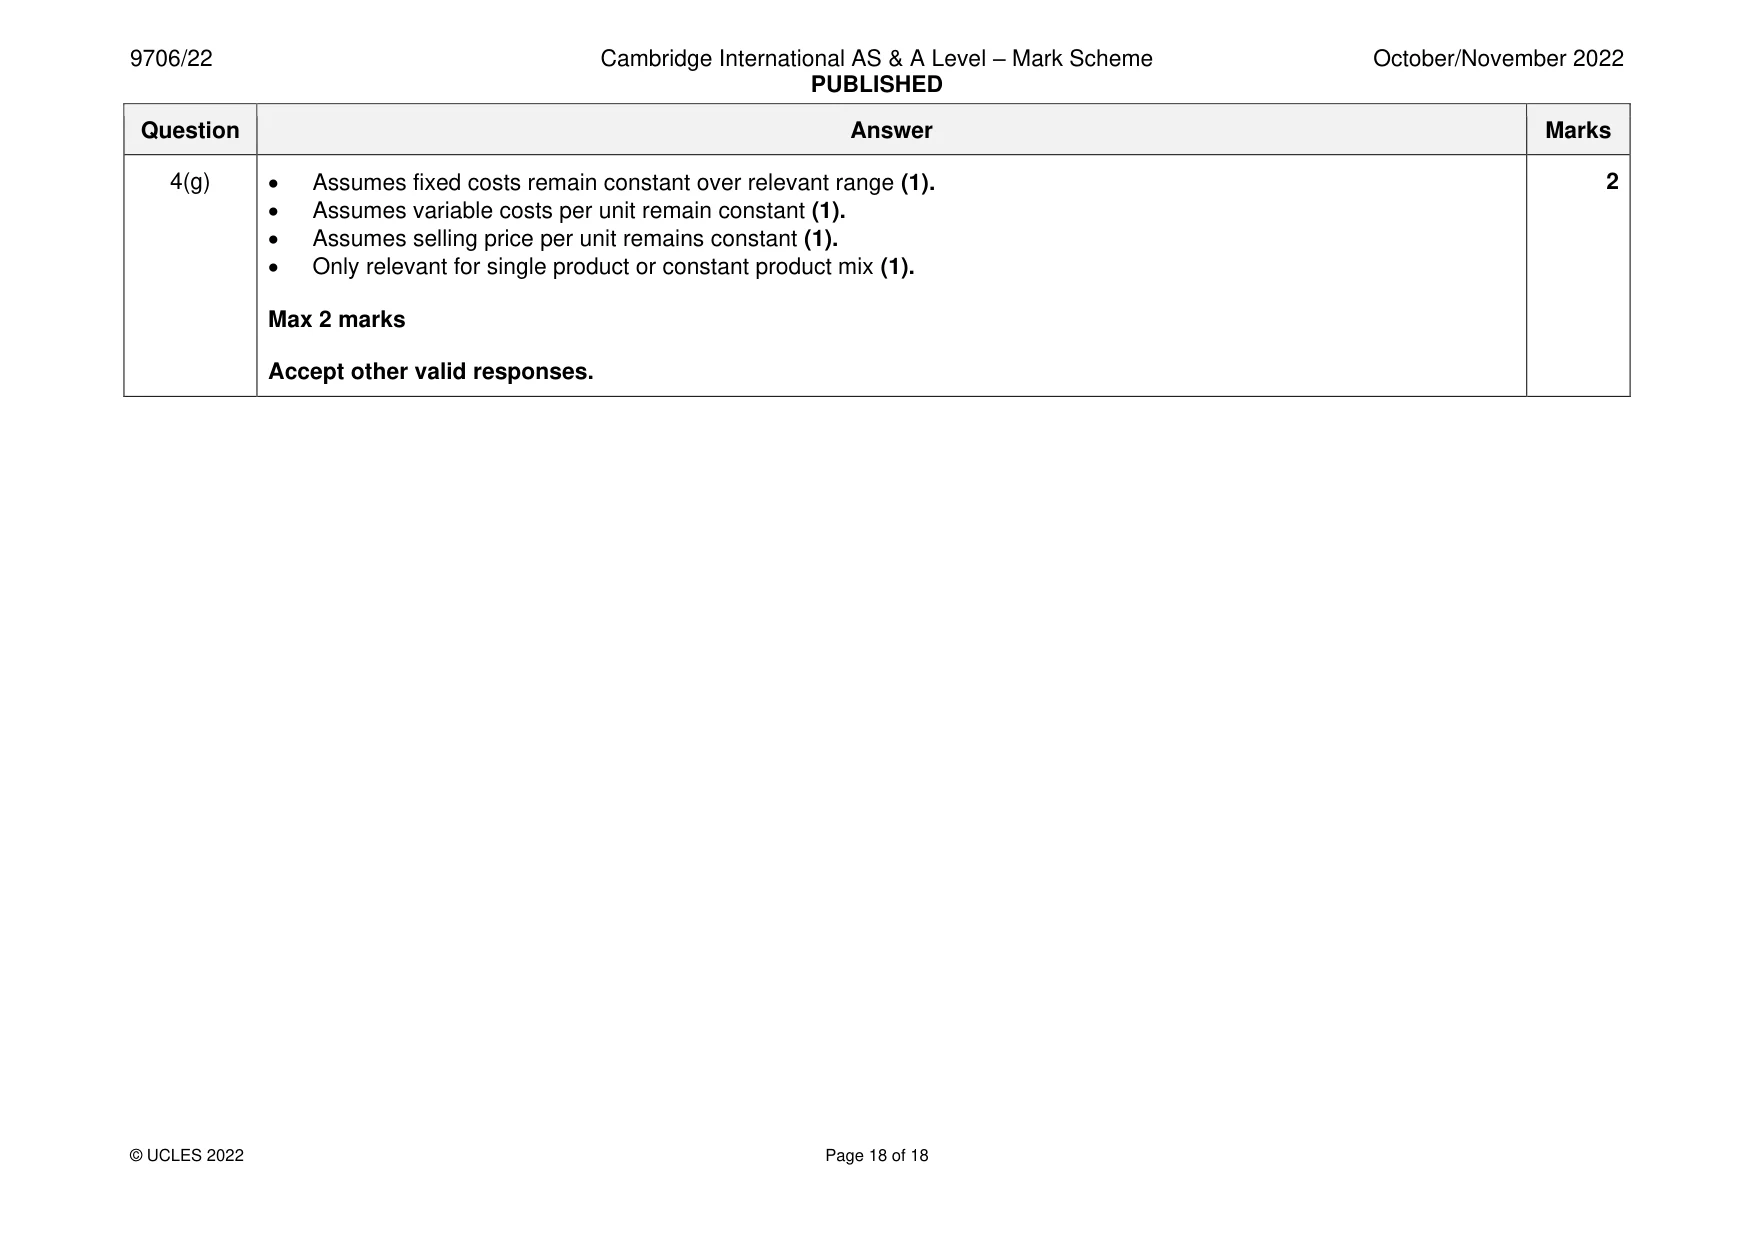
Mark scheme: 4(a)(i) $29 400 (2) W1 2 W1 $78 000 – ($21 600 + $14 400 + $4800 + $7800 = $48 600) (1) = $29 400 (1) 4(a)(ii) $8700 (2) W1 2 W1 $29 400 – ($9200 + $6100 + $5400 = $20 700) (1) = $8700 (1) 4(a)(iii) 8449 units (2) W1 2 W1 ($20 700 / $2.45) (1) OF = 8449 units (1) OF 4(b) Actual sales – Break-even sales (1) 1 Allow other valid responses. 4(c) 12 858 units (2) W1 2 W1 $20 700 (OF) + $10 800 = $31 500 (1) OF / $2.45 (OF) = 12 858 units (1) OF 4(d) Brady 10 Budgeted marginal cost statement for the month of December 2022 $ $ Sales revenue 13 000 $6.80 88 400 (1) Variable costs Direct materials 13 000 $2.20 28 600 (1) Direct labour 13 000 $1.14 14 820 (1) Production overheads 13 000 $0.40 5 200 (1) Selling costs 88 400 (OF) 8% 7 072 (1) OF (55 692) Contribution 32 708 (1) OF Fixed costs Production overheads 9 200 (1) Administrative overheads $6100 – $1500 4 600 (1) Selling costs $5400 + $2500 7 900 (1) 21 700 Profit for the month 11 008 (1) OF 4(d) Alternative presentation $ $ Sales revenue 6.80 (1) Variable costs Direct materials 2.20 (1) Direct labour 1.14 (1) Production overheads 0.40 (1) Selling costs 0.544 (1) OF 4.284 Contribution per unit 2.516 Total contribution X 13 000 32 708 (1) OF Fixed costs Production overheads 9 200 (1) Administrative overheads $6100 – $1 500 4 600 (1) Selling costs $5400 + $2500 7 900 (1) 21 700 Profit for the month 11 008 (1) OF 4(e) Comments (Max 6 marks) 7 He will exceed his target profit by 1.9% depending on whether his customers are willing to pay the increased price. (1) Will turnover actually fall as a result if customers are not willing to pay the increased price (1) Will agents be demotivated as a result of reduced commission rates resulting in a fall in sales (1) What will be the cost of redundancies and what effect will that have on the company’s profit? (1) Will the decreased labour rate demotivate workers resulting in reduced production levels and poor quality? (1) Will overtime be required to meet the additional output, and will workers be prepared to work overtime? (1) How accurate is his forecast of 1000 additional units? and is the target achievable? (1) There is no guarantee that by increasing the advertising the increase in sales will be achieved. (1) Decision (1) Advise Brady to proceed with these changes provided he is confident he can produce the increase in monthly sales of 1000 units Accept other valid responses 4(f) • Facilitates short-term decision making (1). 2 • Enables identification of most profitable selling price, cost and volume combination (1). • Facilitates determination of viable selling price (1). • Helps control costs to maximise profitability (1). Max 2 marks Accept other valid responses. 4(g) • Assumes fixed costs remain constant over relevant range (1). 2 • Assumes variable costs per unit remain constant (1). • Assumes selling price per unit remains constant (1). • Only relevant for single product or constant product mix (1). Max 2 marks Accept other valid responses.
Q5 · Reduce the administrative overheads by $18 000 per annum by making one member of staff…
5 Reduce the administrative overheads by $18 000 per annum by making one member of staff redundant.
Q6 · Increase the advertising budget by $2500 per month
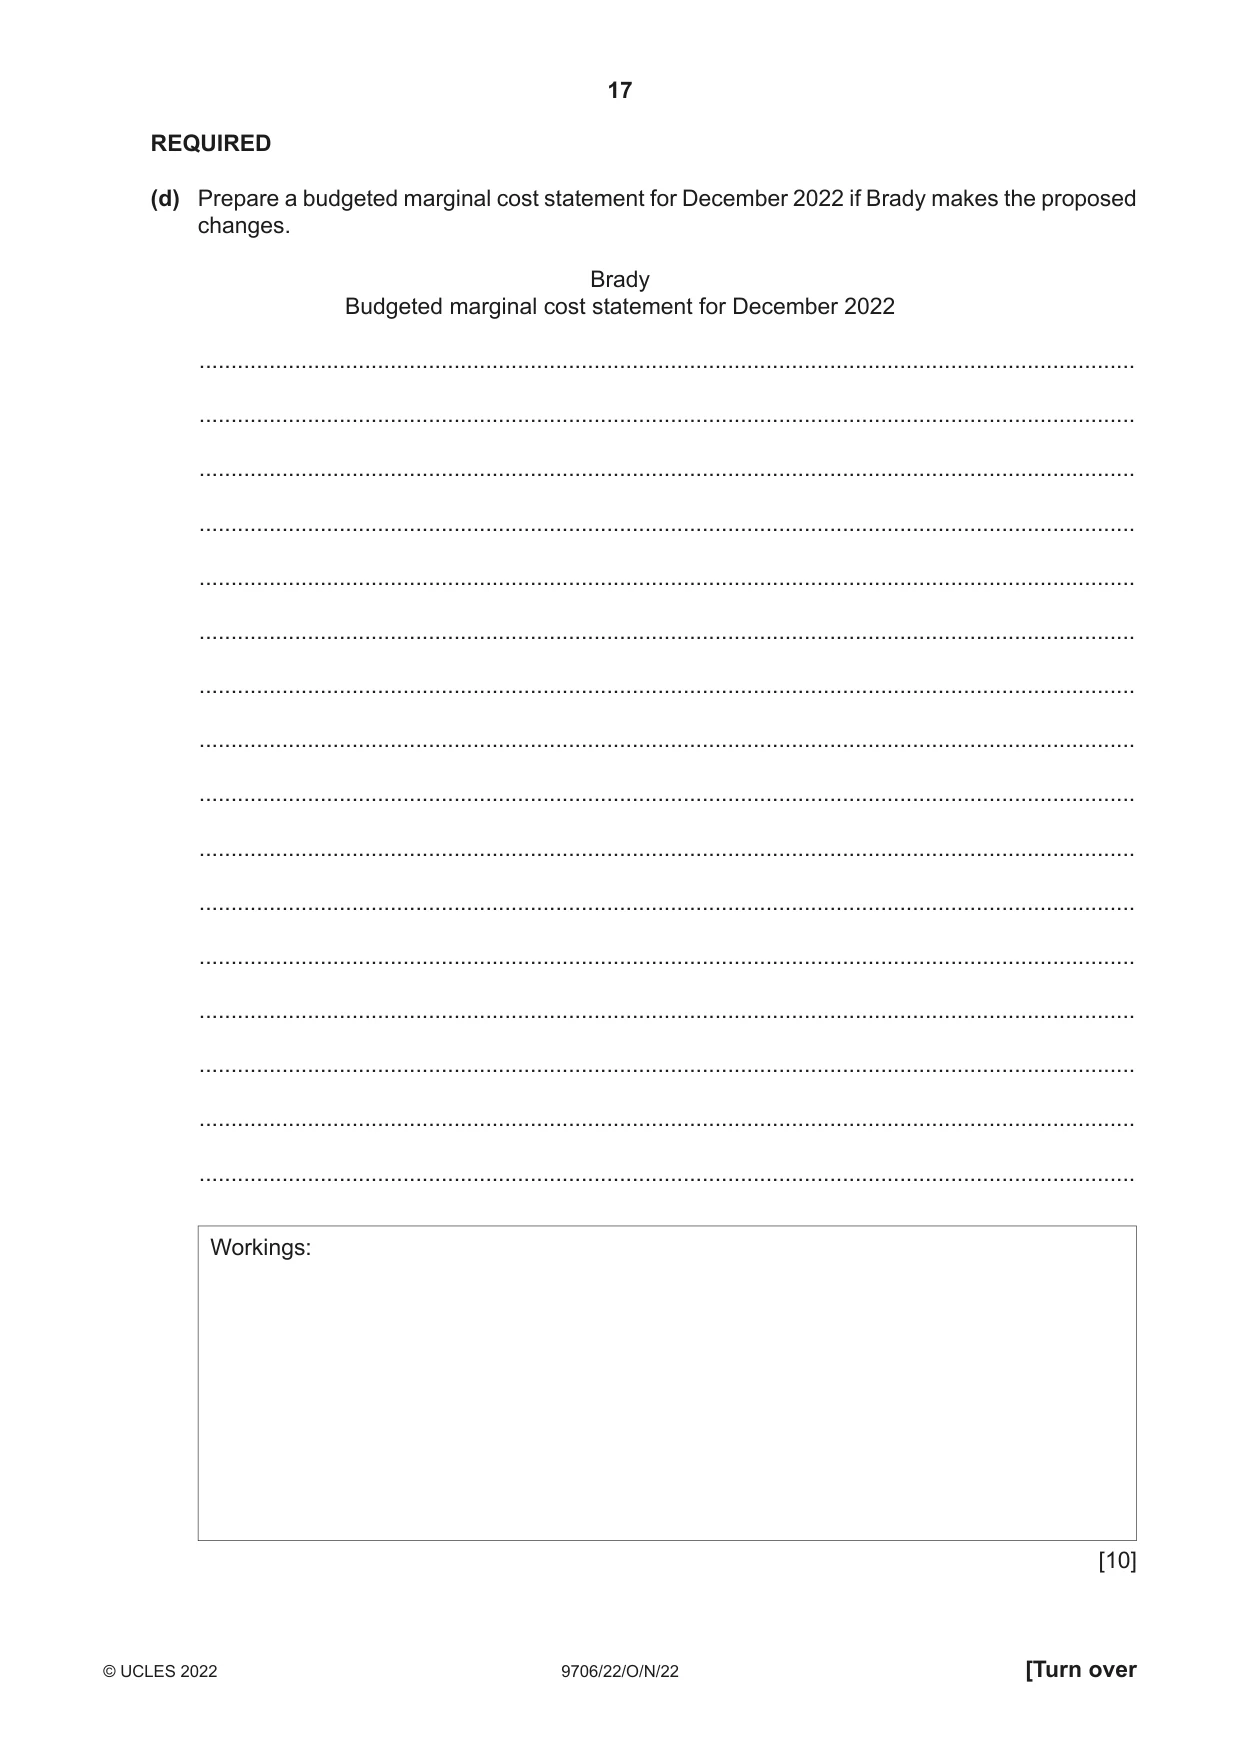
6 Increase the advertising budget by $2500 per month. Brady is confident that these measures will produce additional sales of 1000 units each month. REQUIRED (d) Prepare a budgeted marginal cost statement for December 2022 if Brady makes the proposed changes. Brady Budgeted marginal cost statement for December 2022 ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Workings: [10] (e) Advise Brady whether or not he should make the proposed changes. Justify your advice by discussing the issues that he should consider. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [7] (f) State two advantages of cost–volume–profit analysis. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2]
What was in this paper
The subtopics covered by these 6 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2022 Oct/Nov, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.