Cambridge A Level Accounting 9706 — 2021 Oct/Nov Paper 2 · Variant 1
9706/21/O/N/21 · 4 questions · 90 marks · ≈101 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme13 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Eleni owns a business selling computers
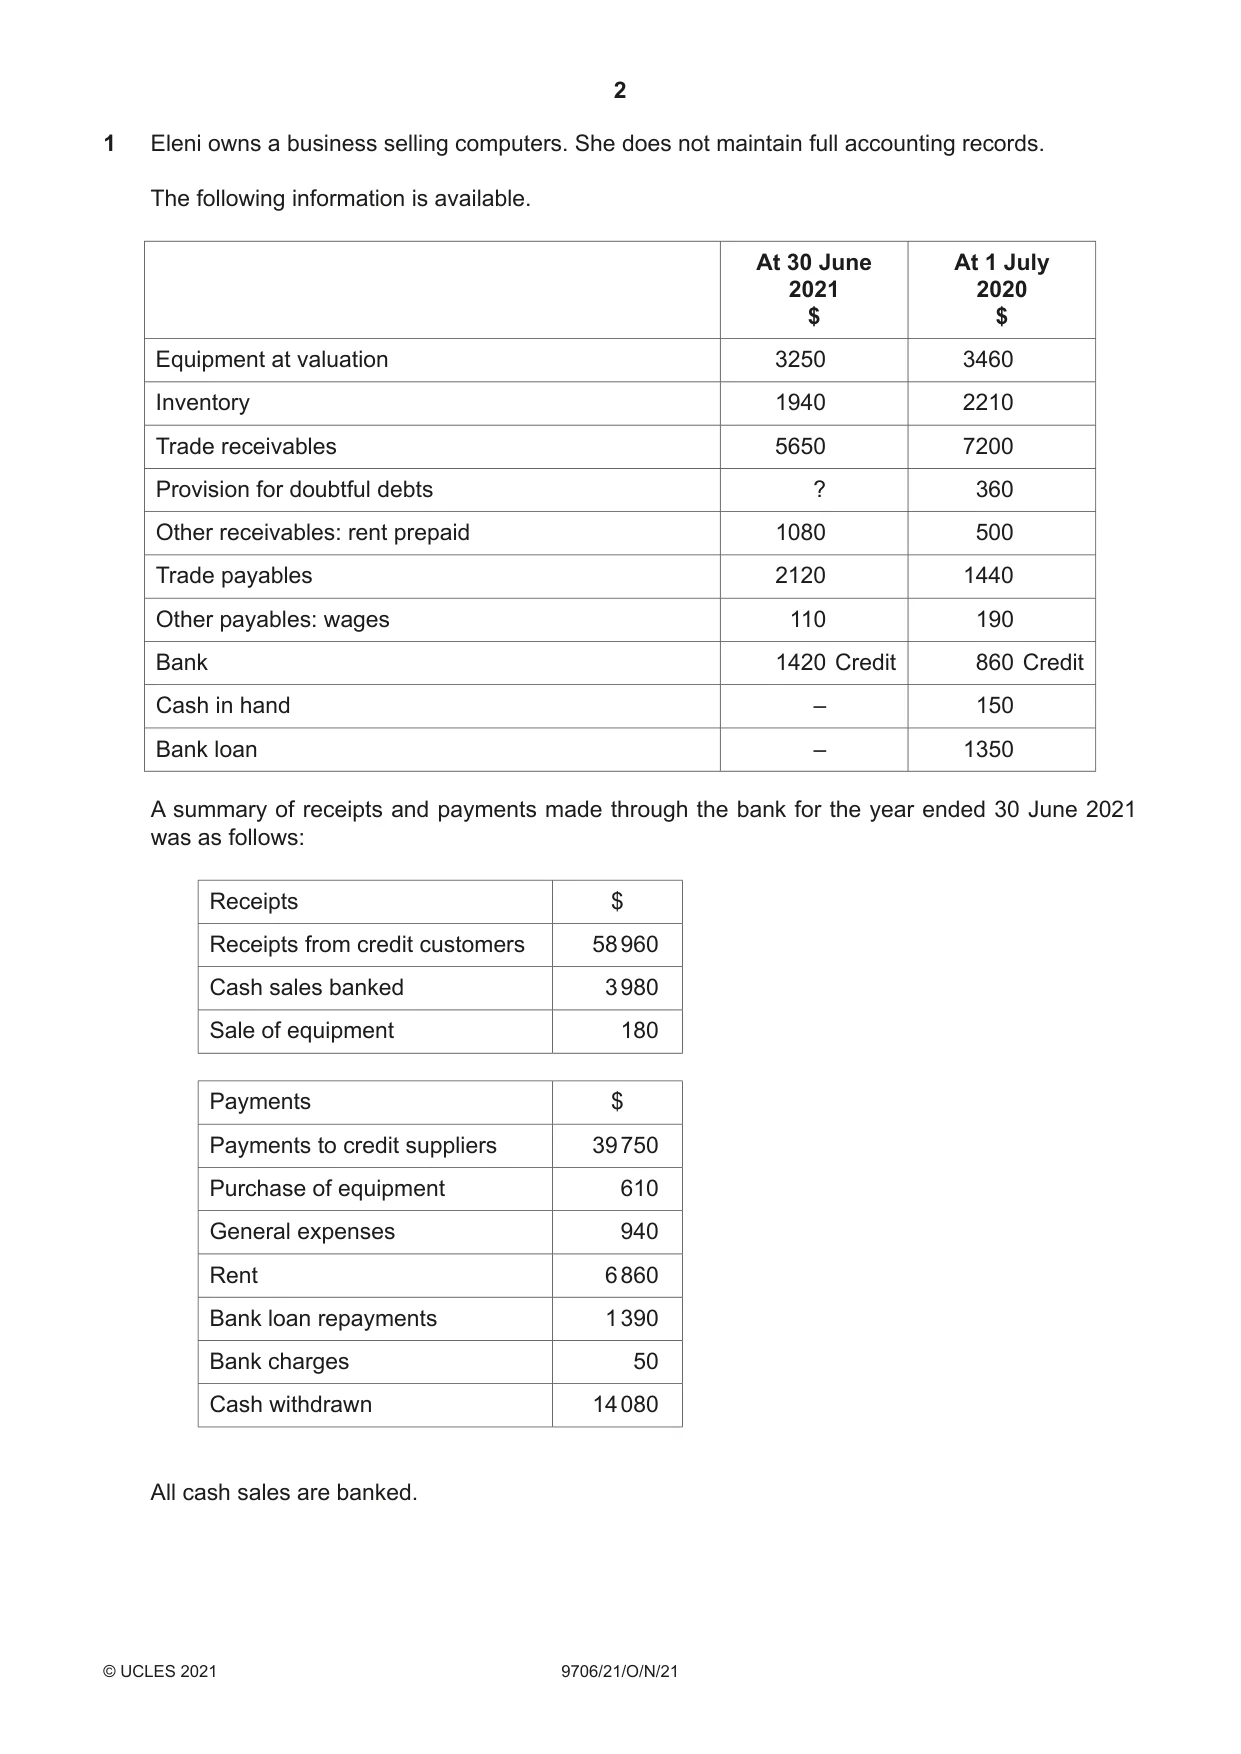
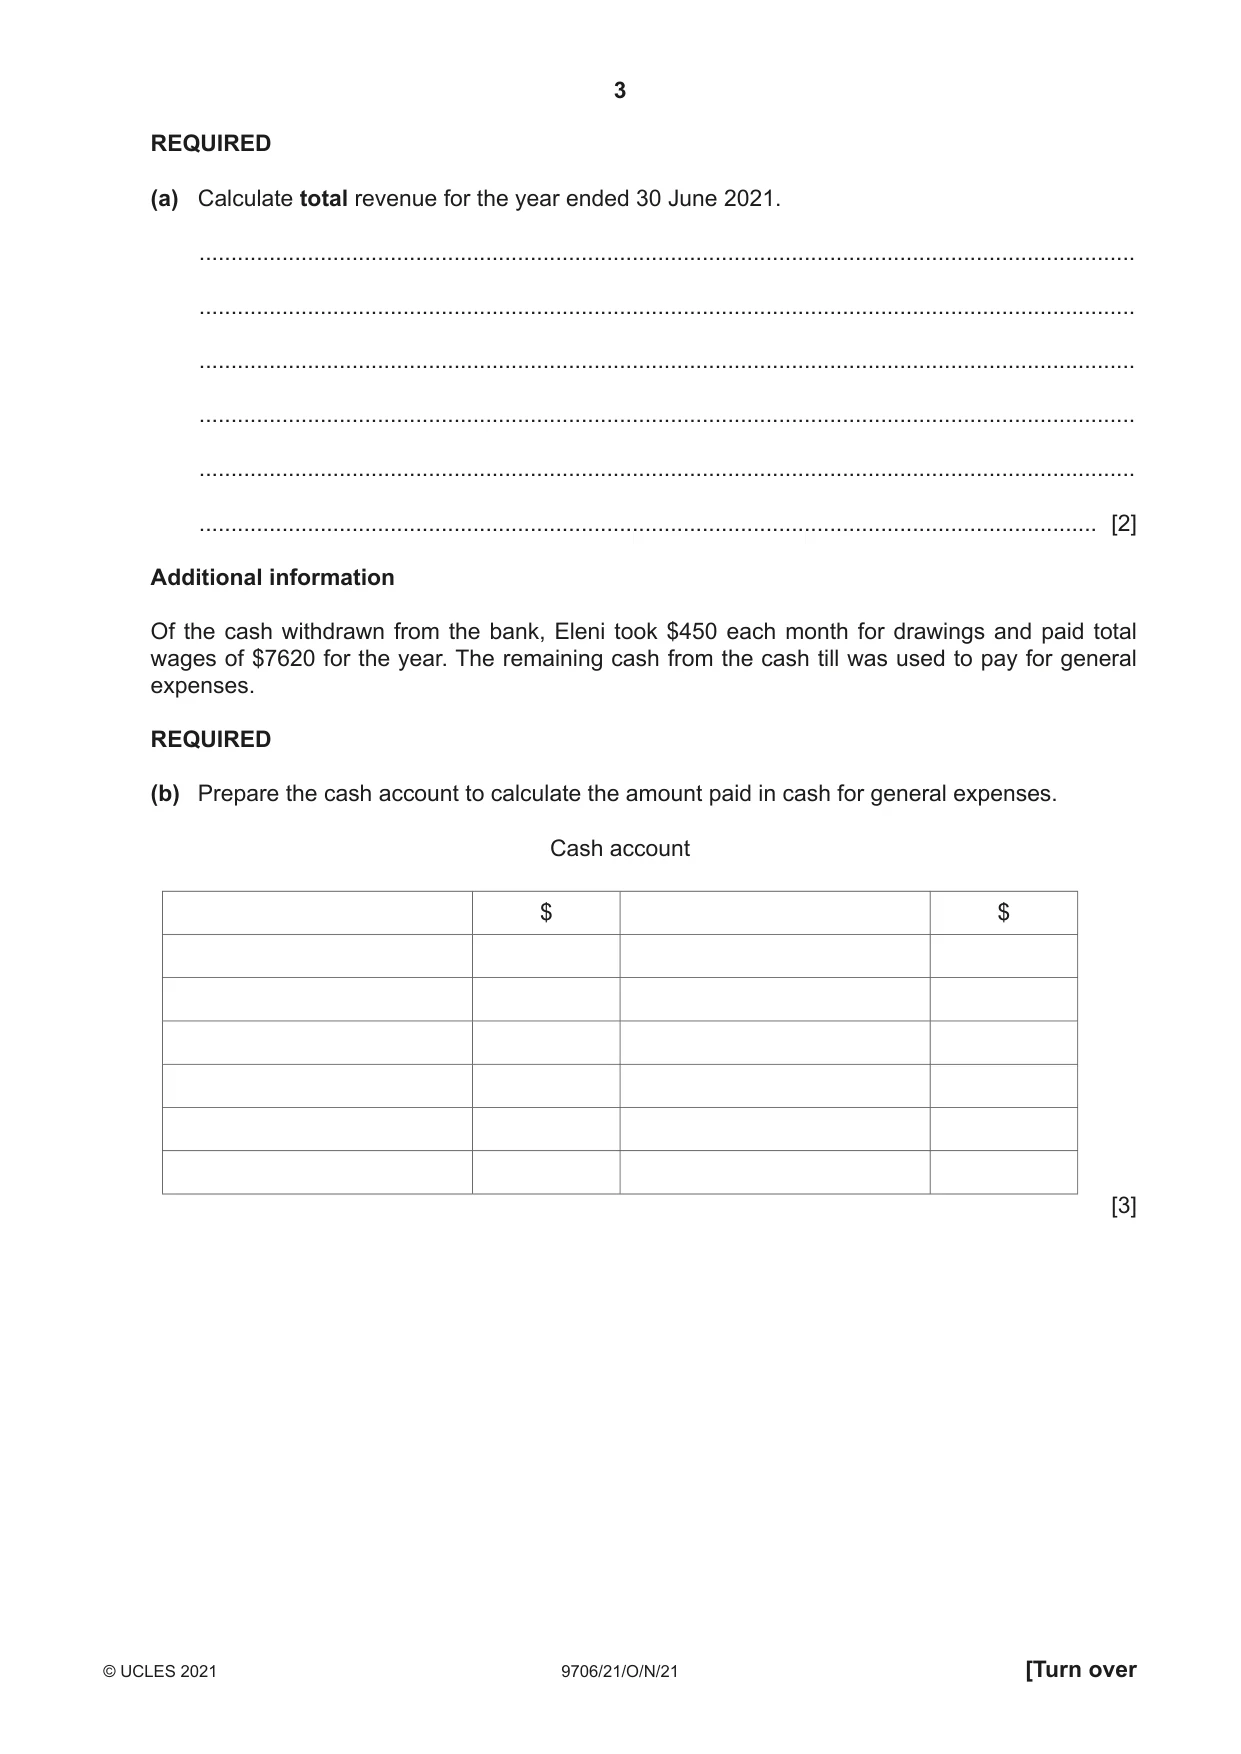
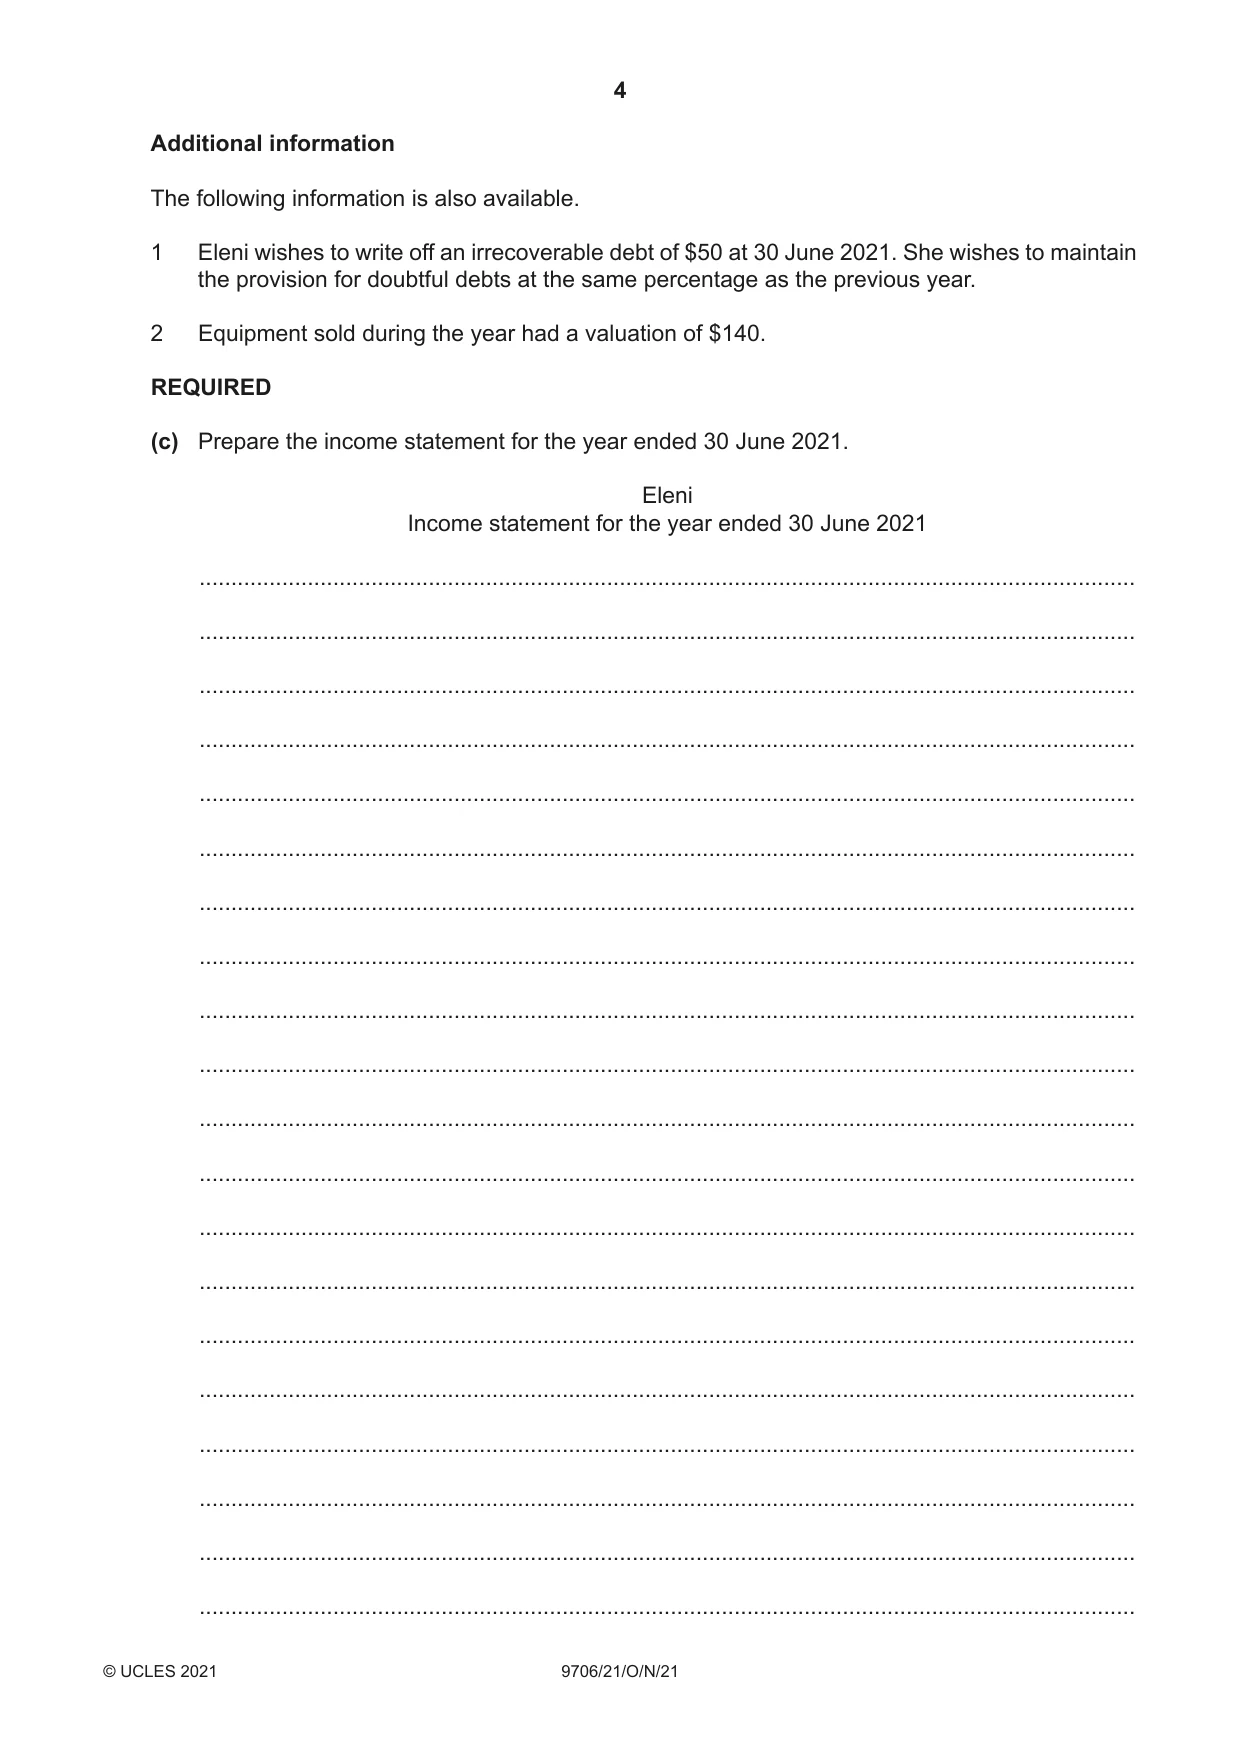
1 Eleni owns a business selling computers. She does not maintain full accounting records. The following information is available. At 30 June At 1 July 2021 2020 $ $ Equipment at valuation 3250 3460 Inventory 1940 2210 Trade receivables 5650 7200 Provision for doubtful debts ? 360 Other receivables: rent prepaid 1080 500 Trade payables 2120 1440 Other payables: wages 110 190 Bank 1420 Credit 860 Credit Cash in hand – 150 Bank loan – 1350 A summary of receipts and payments made through the bank for the year ended 30 June 2021 was as follows: Receipts $ Receipts from credit customers 58 960 Cash sales banked 3 980 Sale of equipment 180 Payments $ Payments to credit suppliers 39 750 Purchase of equipment 610 General expenses 940 Rent 6 860 Bank loan repayments 1 390 Bank charges 50 Cash withdrawn 14 080 All cash sales are banked. REQUIRED (a) Calculate total revenue for the year ended 30 June 2021. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] Additional information Of the cash withdrawn from the bank, Eleni took $450 each month for drawings and paid total wages of $7620 for the year. The remaining cash from the cash till was used to pay for general expenses. REQUIRED (b) Prepare the cash account to calculate the amount paid in cash for general expenses. Cash account $ $ [3] Additional information The following information is also available. 1 Eleni wishes to write off an irrecoverable debt of $50 at 30 June 2021. She wishes to maintain the provision for doubtful debts at the same percentage as the previous year.
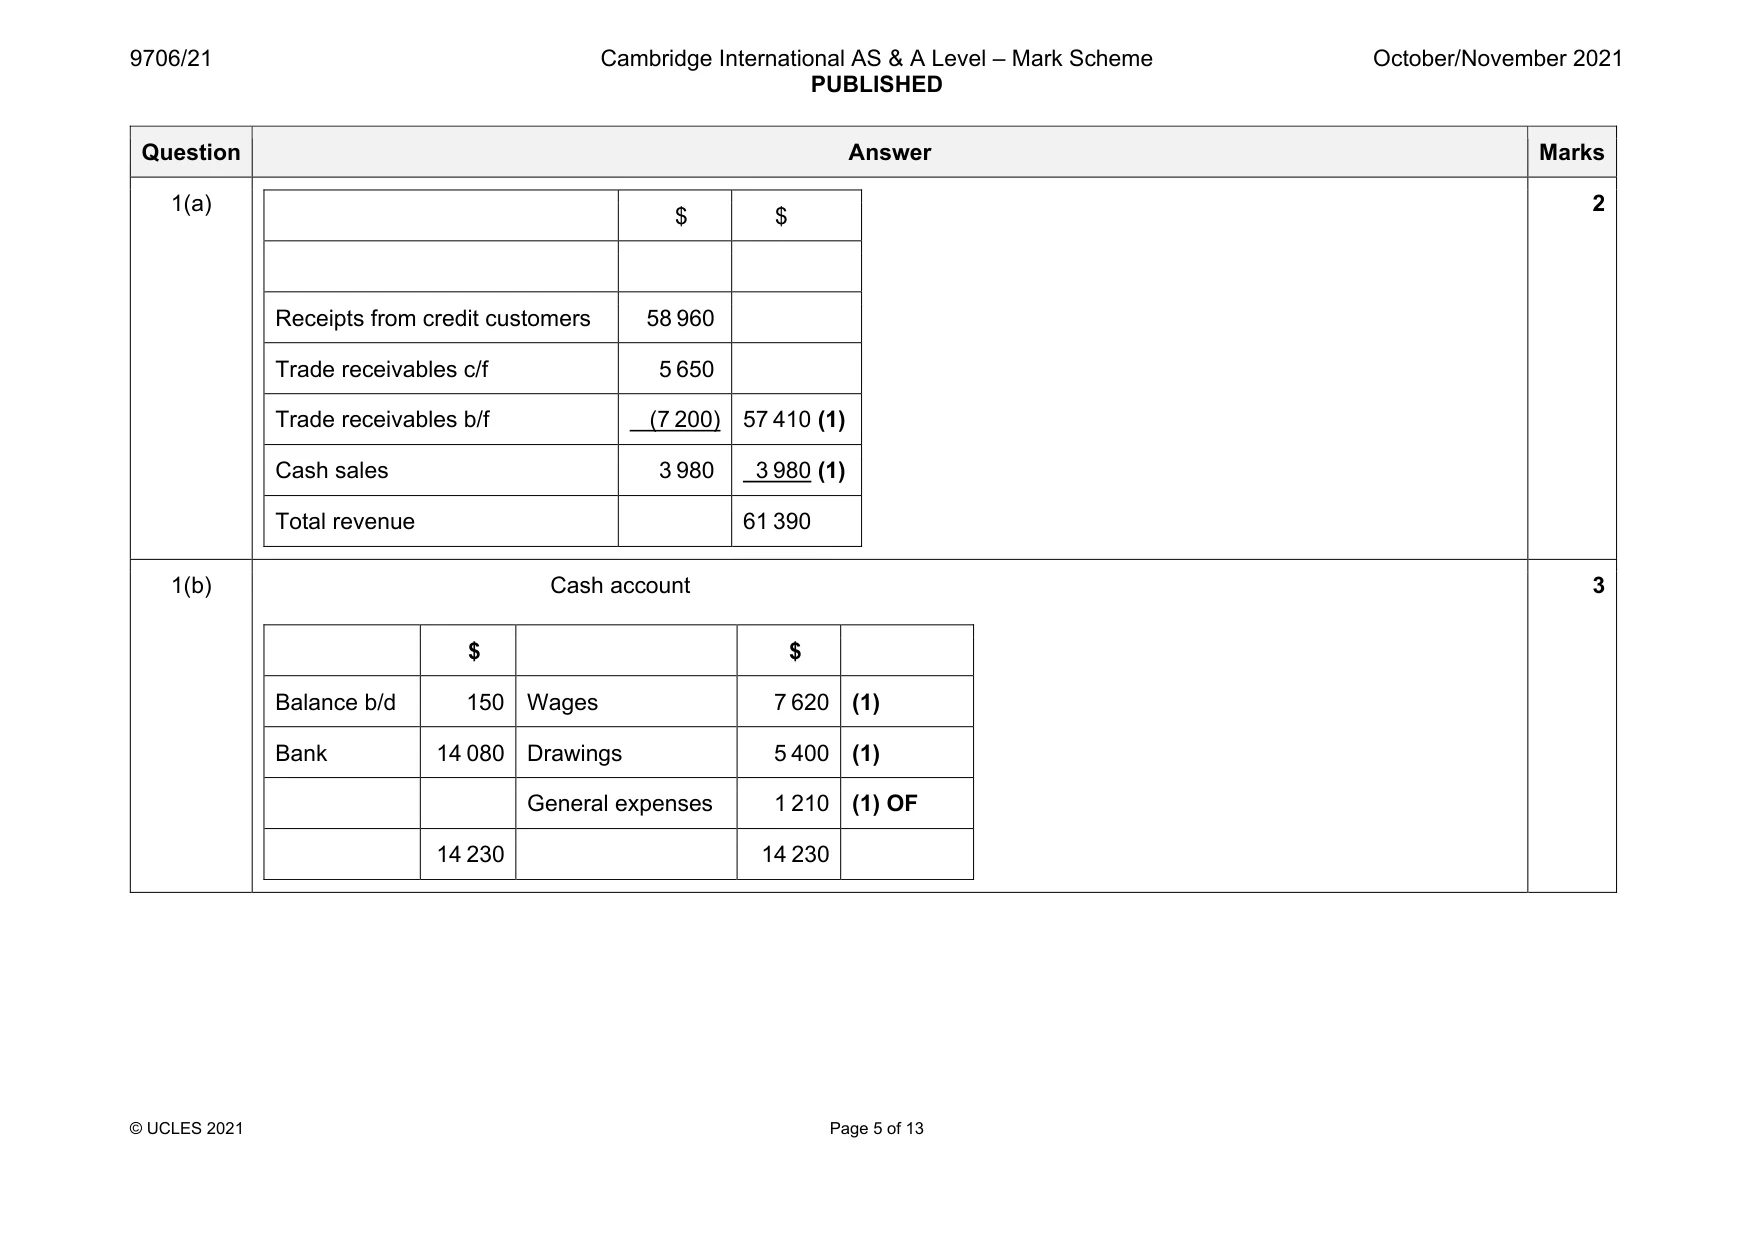
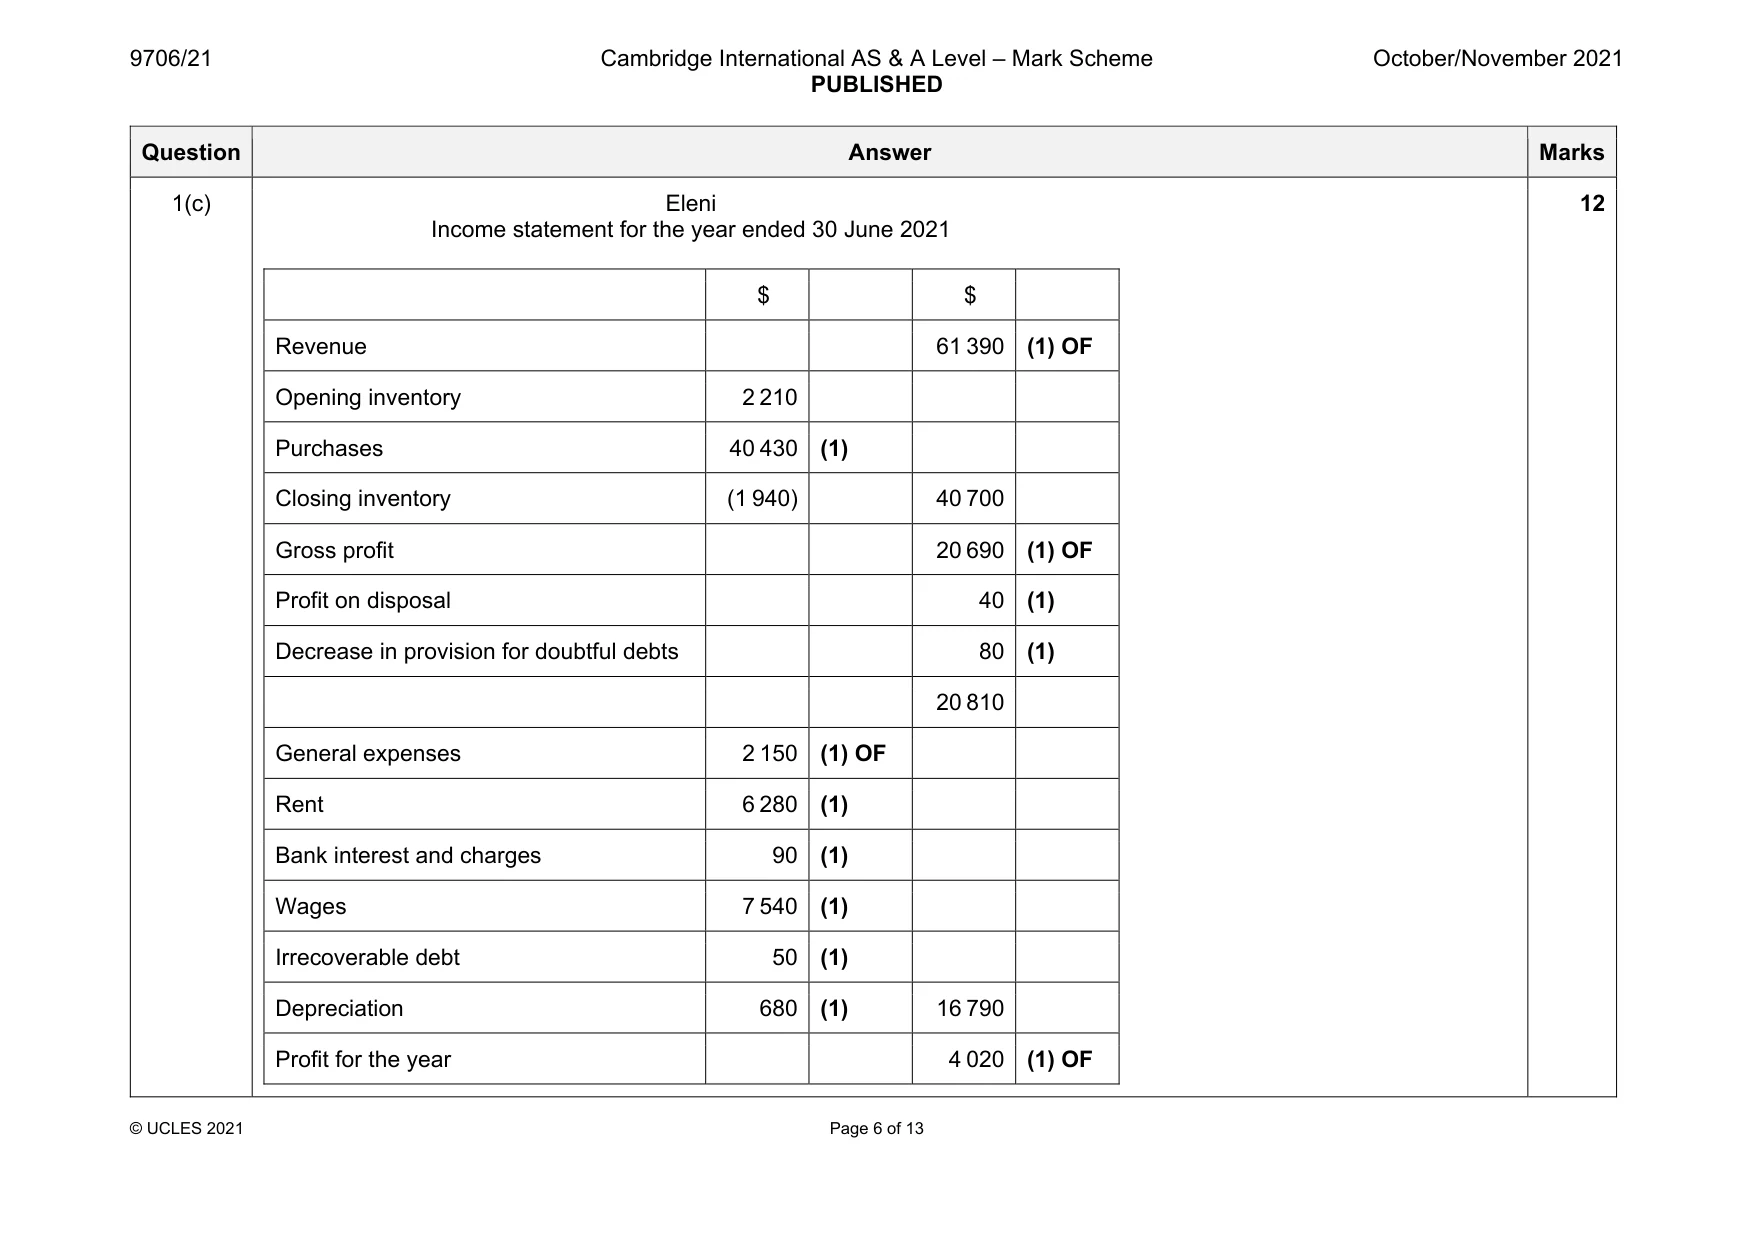
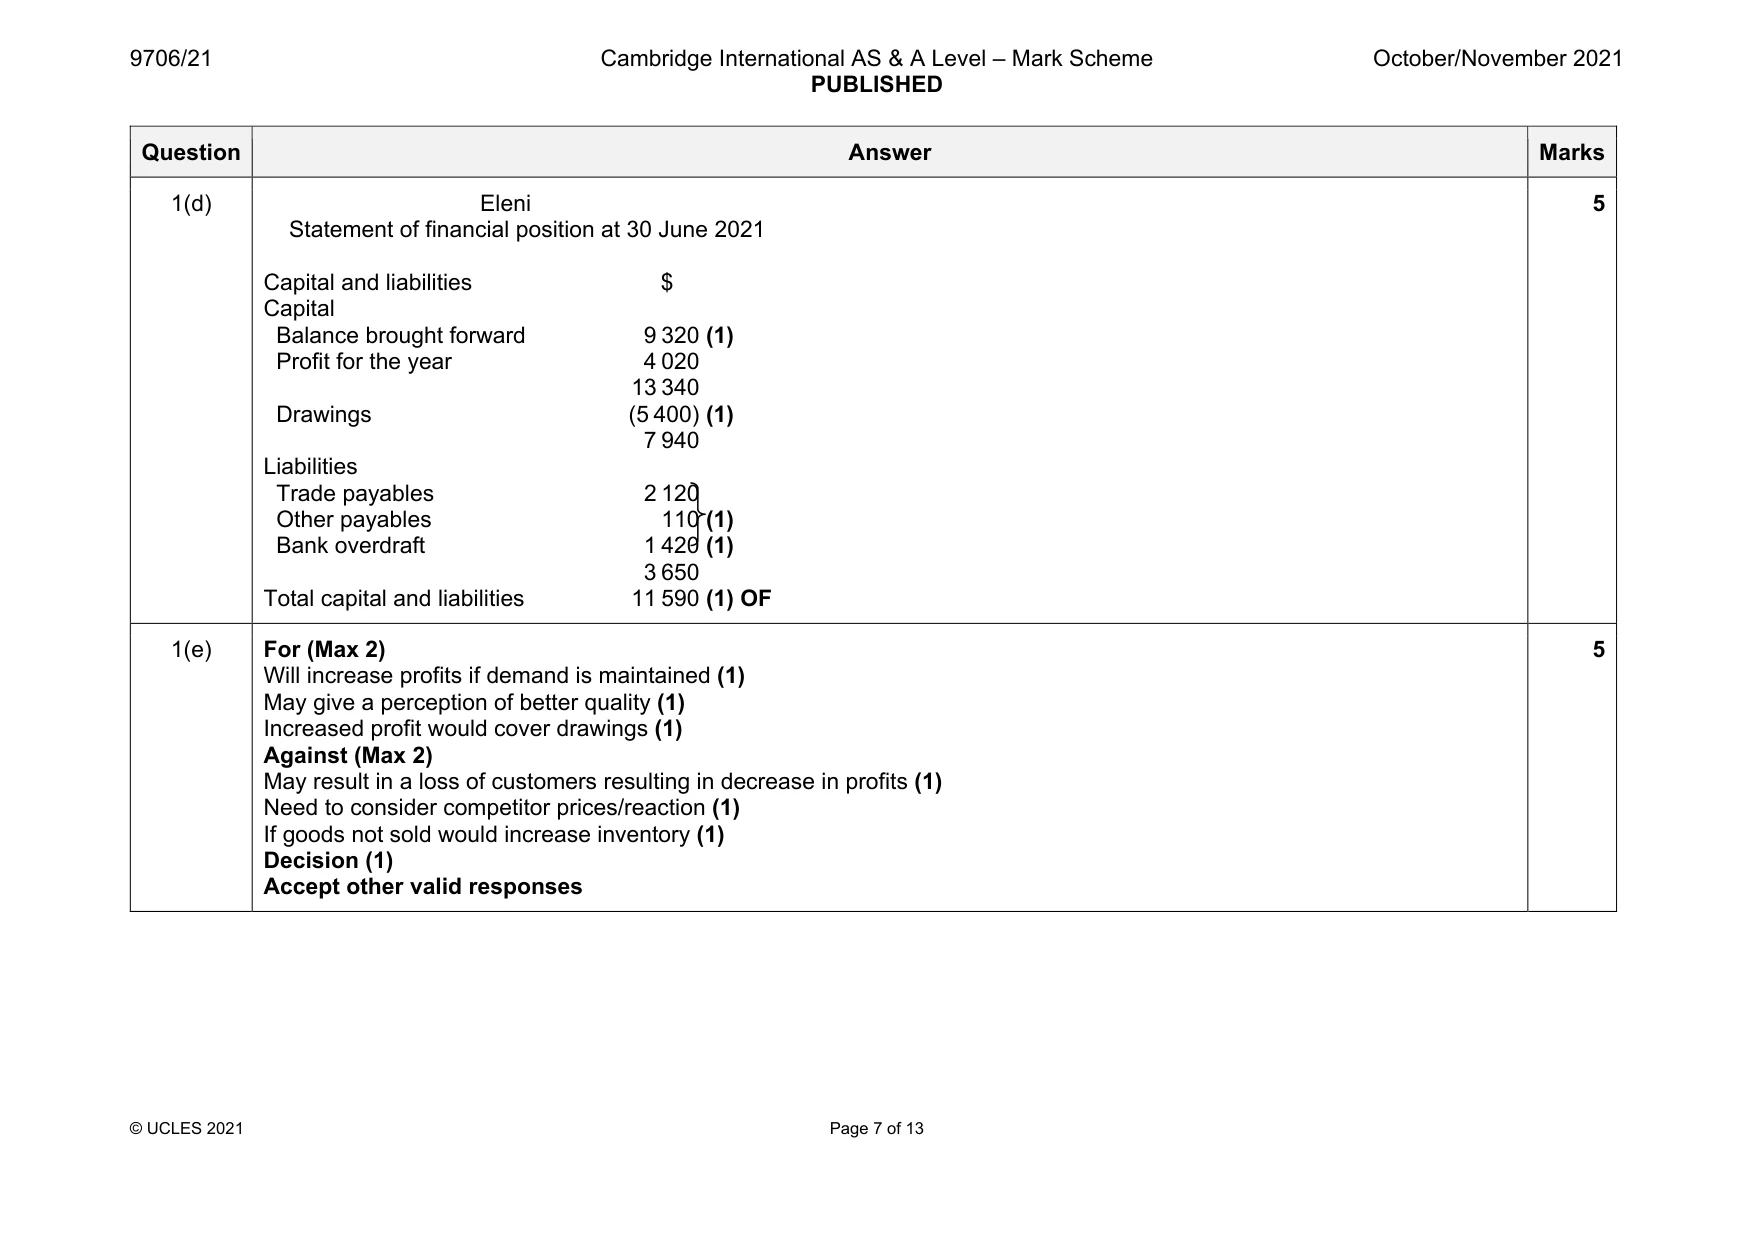
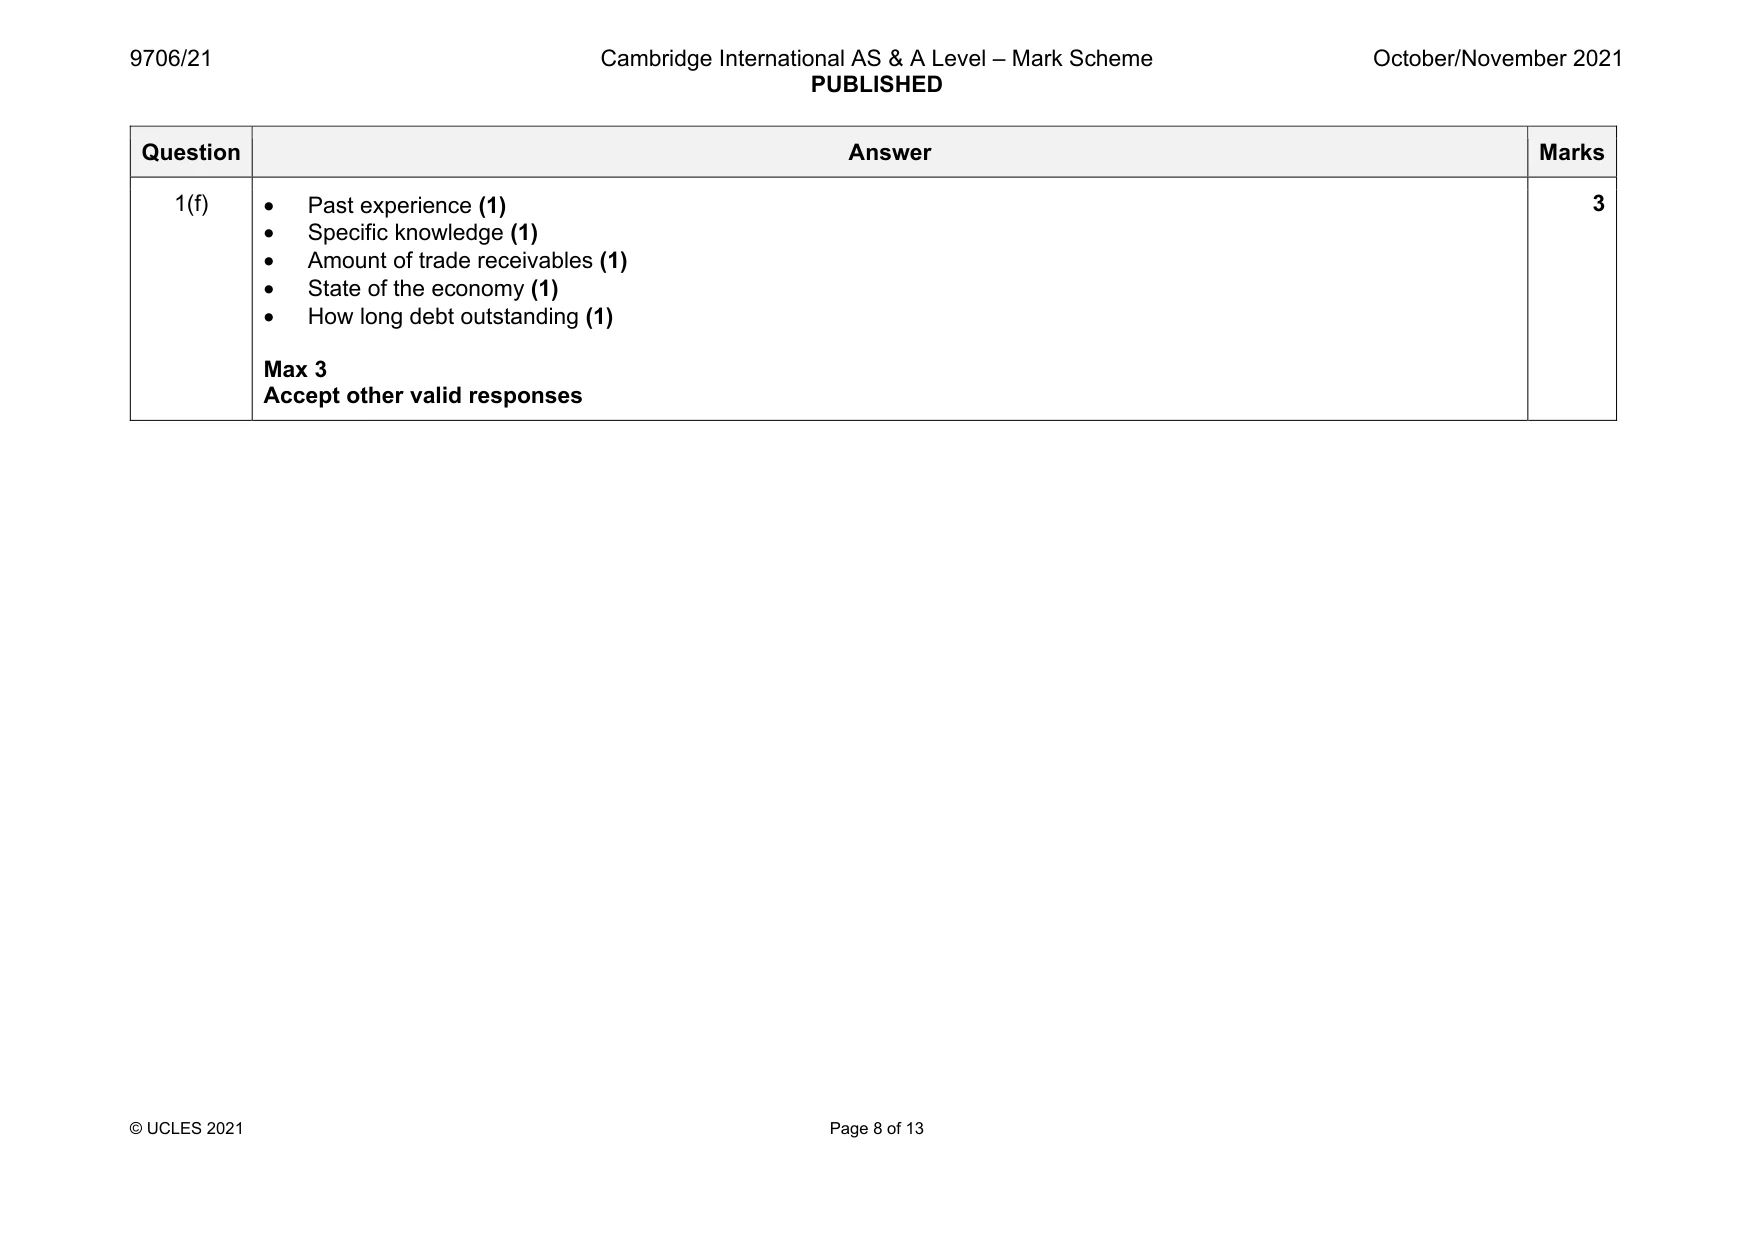
Mark scheme: 1(a) $ $ Receipts from credit customers 58 960 Trade receivables c/f 5 650 Trade receivables b/f (7 200) 57 410 (1) Cash sales 3 980 3 980 (1) Total revenue 61 390 2 1(b) Cash account $ $ Balance b/d 150 Wages 7 620 (1) Bank 14 080 Drawings 5 400 (1) General expenses 1 210 (1) OF 14 230 14 230 3 Question Answer Marks 1(c) Eleni Income statement for the year ended 30 June 2021 $ $ Revenue 61 390 (1) OF Opening inventory 2 210 Purchases 40 430 (1) Closing inventory (1 940) 40 700 Gross profit 20 690 (1) OF Profit on disposal 40 (1) Decrease in provision for doubtful debts 80 (1) 20 810 General expenses 2 150 (1) OF Rent 6 280 (1) Bank interest and charges 90 (1) Wages 7 540 (1) Irrecoverable debt 50 (1) Depreciation 680 (1) 16 790 Profit for the year 4 020 (1) OF 12 Question Answer Marks 1(d) Eleni Statement of financial position at 30 June 2021 Capital and liabilities $ Capital Balance brought forward 9 320 (1) Profit for the year 4 020 13 340 Drawings (5 400) (1) 7 940 Liabilities Trade payables 2 120 (1) Other payables 110 Bank overdraft 1 420 (1) 3 650 Total capital and liabilities 11 590 (1) OF 5 1(e) For (Max 2) Will increase profits if demand is maintained (1) May give a perception of better quality (1) Increased profit would cover drawings (1) Against (Max 2) May result in a loss of customers resulting in decrease in profits (1) Need to consider competitor prices/reaction (1) If goods not sold would increase inventory (1) Decision (1) Accept other valid responses 5 Question Answer Marks 1(f) • Past experience (1) • Specific knowledge (1) • Amount of trade receivables (1) • State of the economy (1) • How long debt outstanding (1) Max 3 Accept other valid responses 3
Q2 · Equipment sold during the year had a valuation of $140
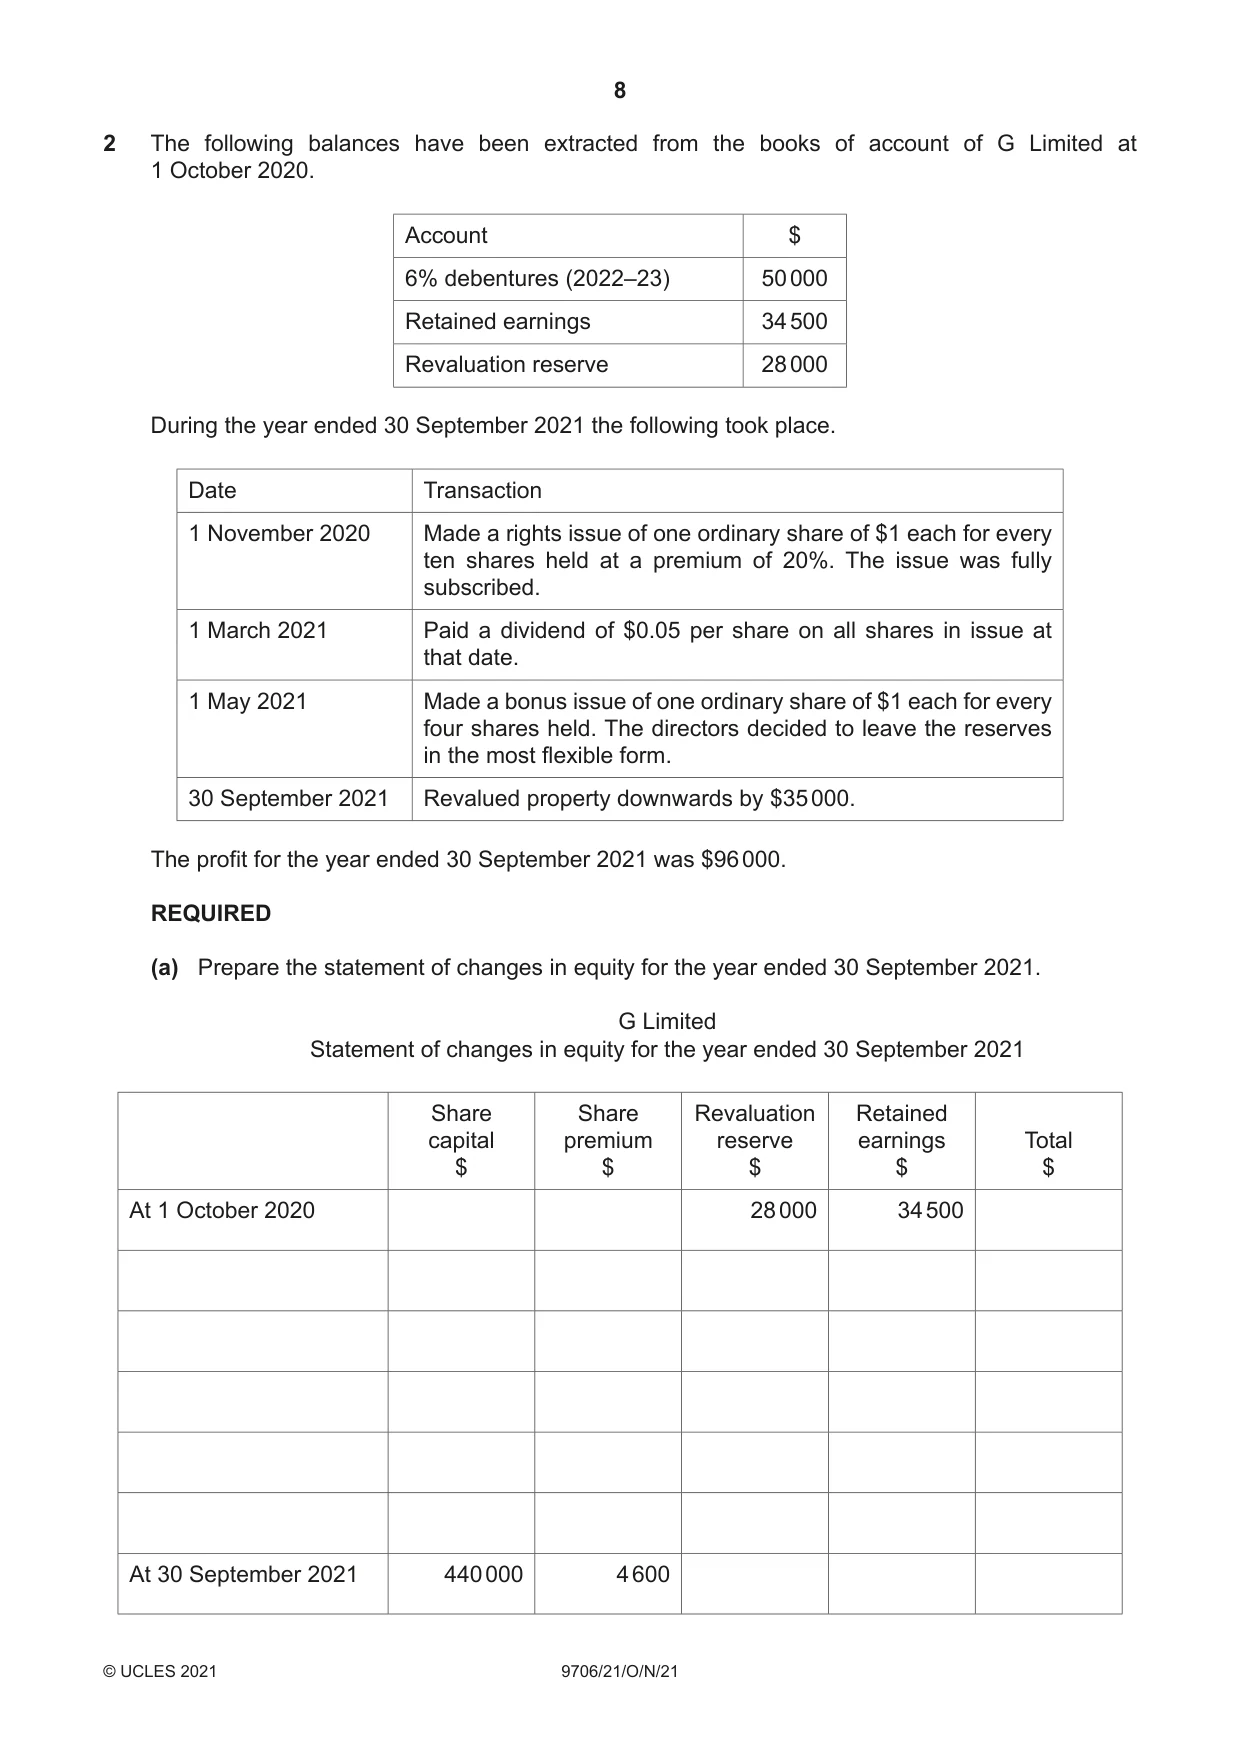
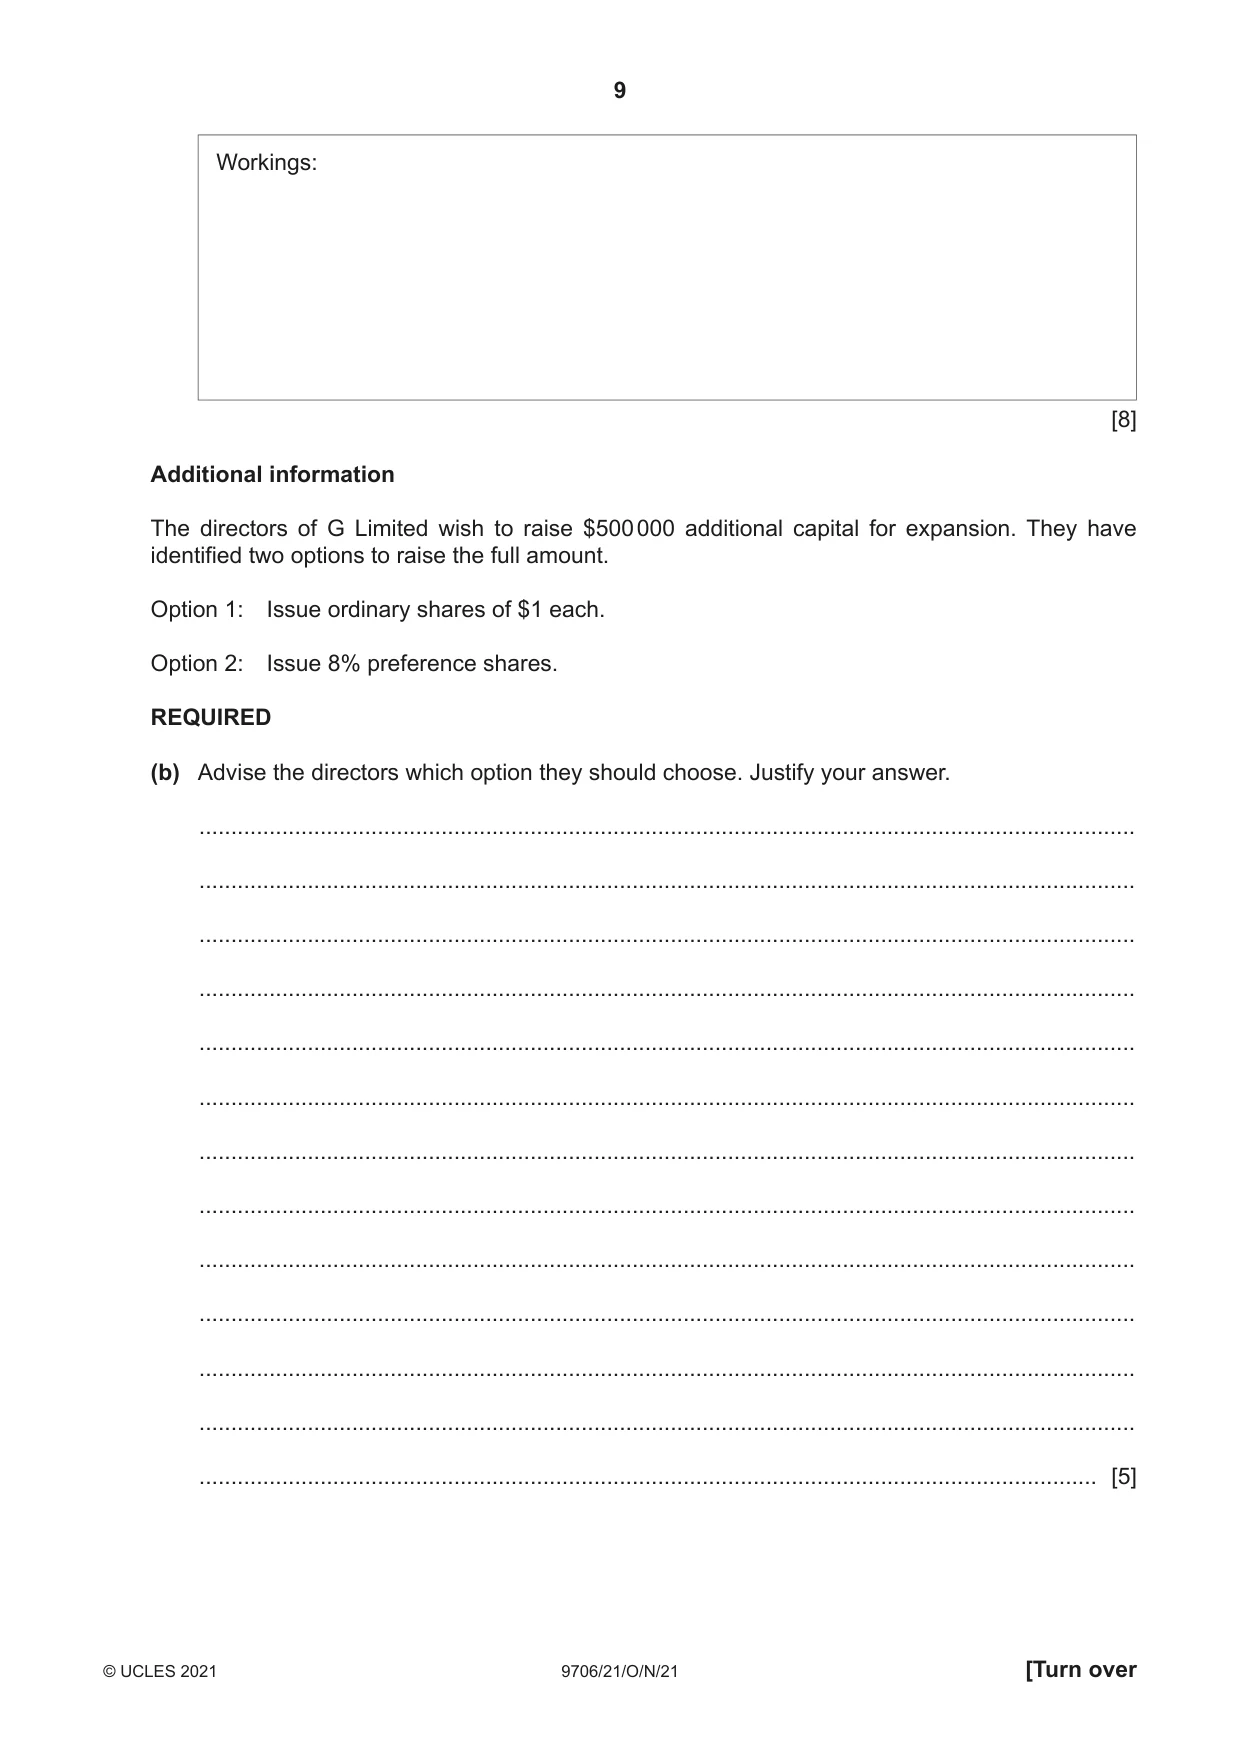
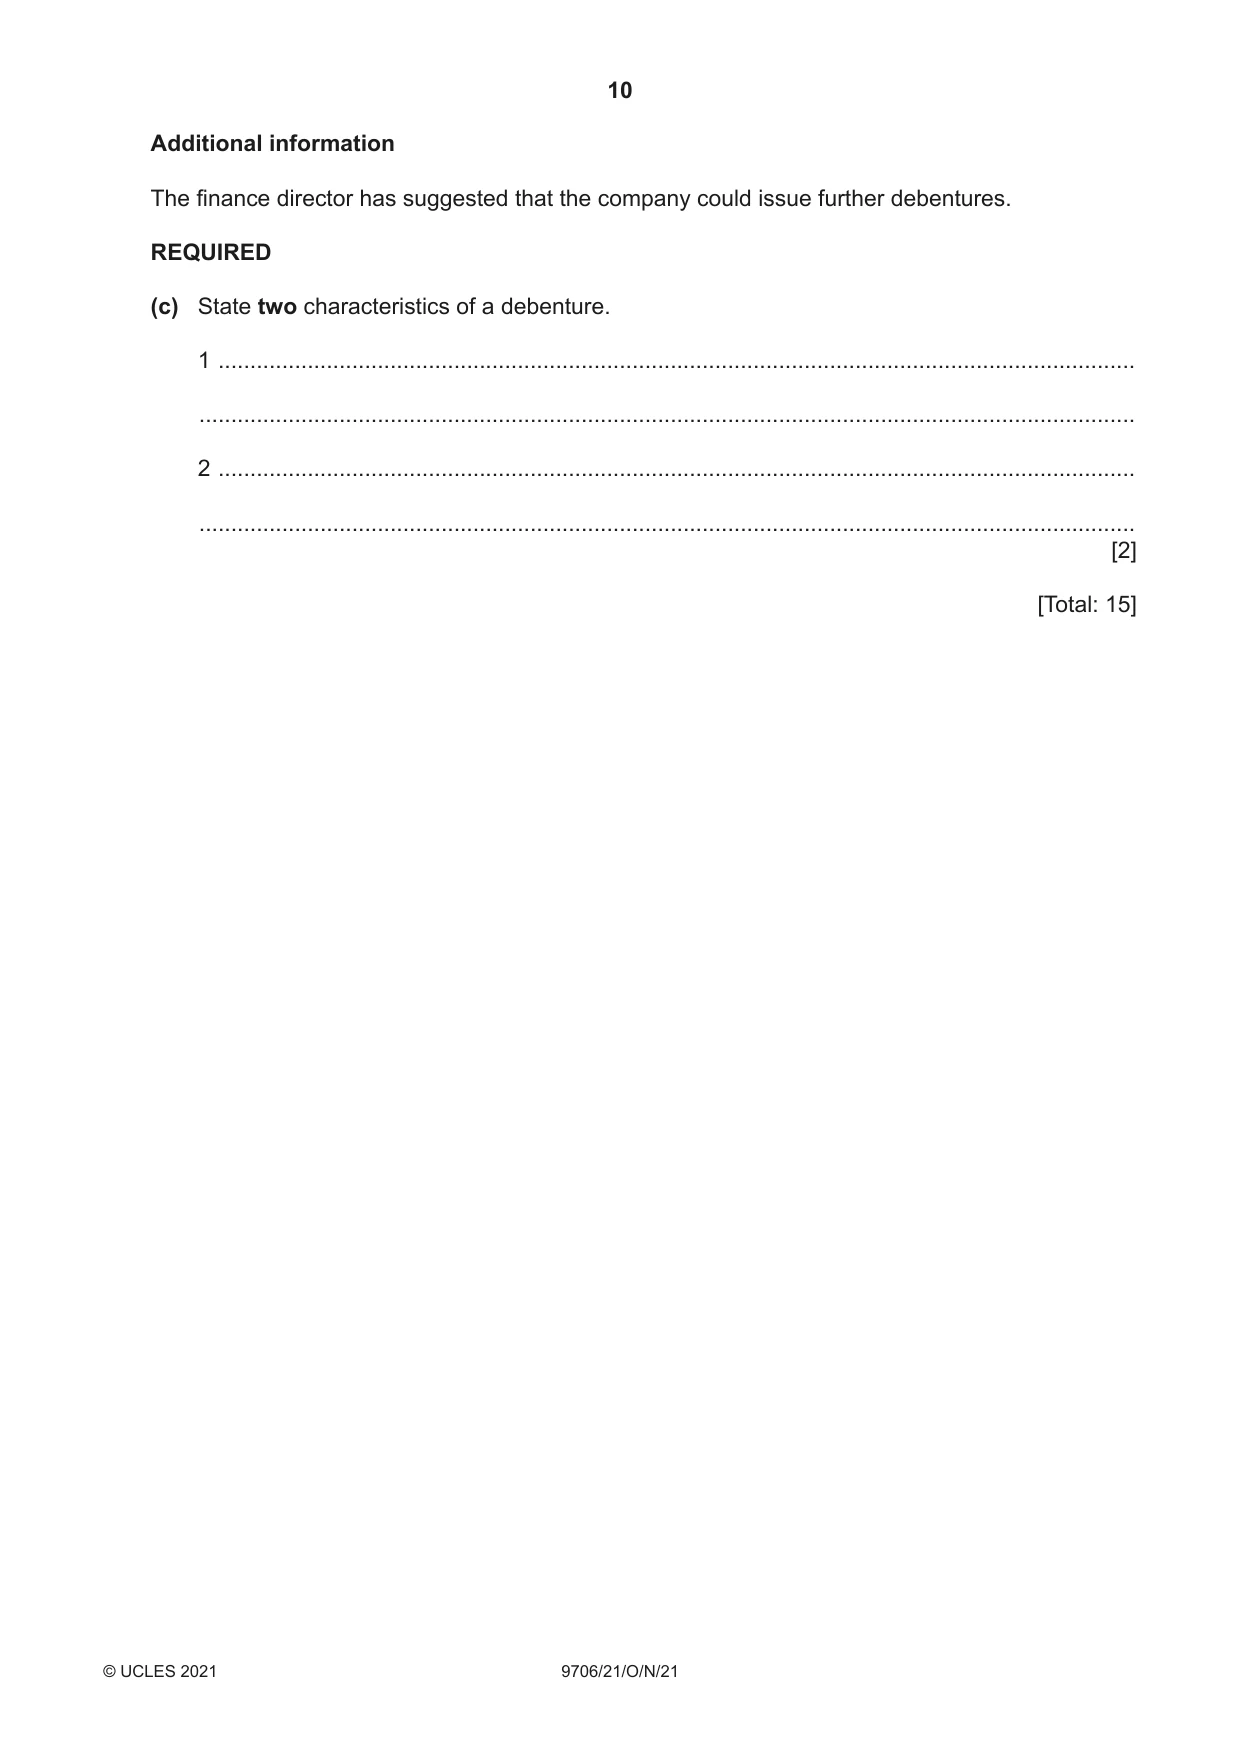
2 Equipment sold during the year had a valuation of $140. REQUIRED (c) Prepare the income statement for the year ended 30 June 2021. Eleni Income statement for the year ended 30 June 2021 ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Workings: [12] (d) Prepare an extract from the statement of financial position at 30 June 2021 to show the capital and liabilities section only. Eleni Statement of financial position at 30 June 2021 Capital and liabilities ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] Additional information Eleni is concerned that she is not earning enough profit. She is considering increasing her prices by 5%. REQUIRED (e) Advise Eleni whether or not she should increase her prices by 5%. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] (f) State three factors that a business should consider when making a provision for doubtful debts. 1 ................................................................................................................................................ 2 ................................................................................................................................................ 3 ................................................................................................................................................ [3] [Total: 30] PLEASE TURN OVER 2 The following balances have been extracted from the books of account of G Limited at 1 October 2020. Account $ 6% debentures (2022–23) 50 000 Retained earnings 34 500 Revaluation reserve 28 000 During the year ended 30 September 2021 the following took place. Date Transaction 1 November 2020 Made a rights issue of one ordinary share of $1 each for every ten shares held at a premium of 20%. The issue was fully subscribed. 1 March 2021 Paid a dividend of $0.05 per share on all shares in issue at that date. 1 May 2021 Made a bonus issue of one ordinary share of $1 each for every four shares held. The directors decided to leave the reserves in the most flexible form. 30 September 2021 Revalued property downwards by $35 000. The profit for the year ended 30 September 2021 was $96 000. REQUIRED (a) Prepare the statement of changes in equity for the year ended 30 September 2021. G Limited Statement of changes in equity for the year ended 30 September 2021 Share Share Revaluation Retained capital premium reserve earnings Total $ $ $ $ $ At 1 October 2020 28 000 34 500 At 30 September 2021 440 000 4 600 Workings: [8] Additional information The directors of G Limited wish to raise $500 000 additional capital for expansion. They have identified two options to raise the full amount. Option 1: Issue ordinary shares of $1 each. Option 2: Issue 8% preference shares. REQUIRED (b) Advise the directors which option they should choose. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] Additional information The finance director has suggested that the company could issue further debentures. REQUIRED (c) State two characteristics of a debenture. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] [Total: 15] PLEASE TURN OVER
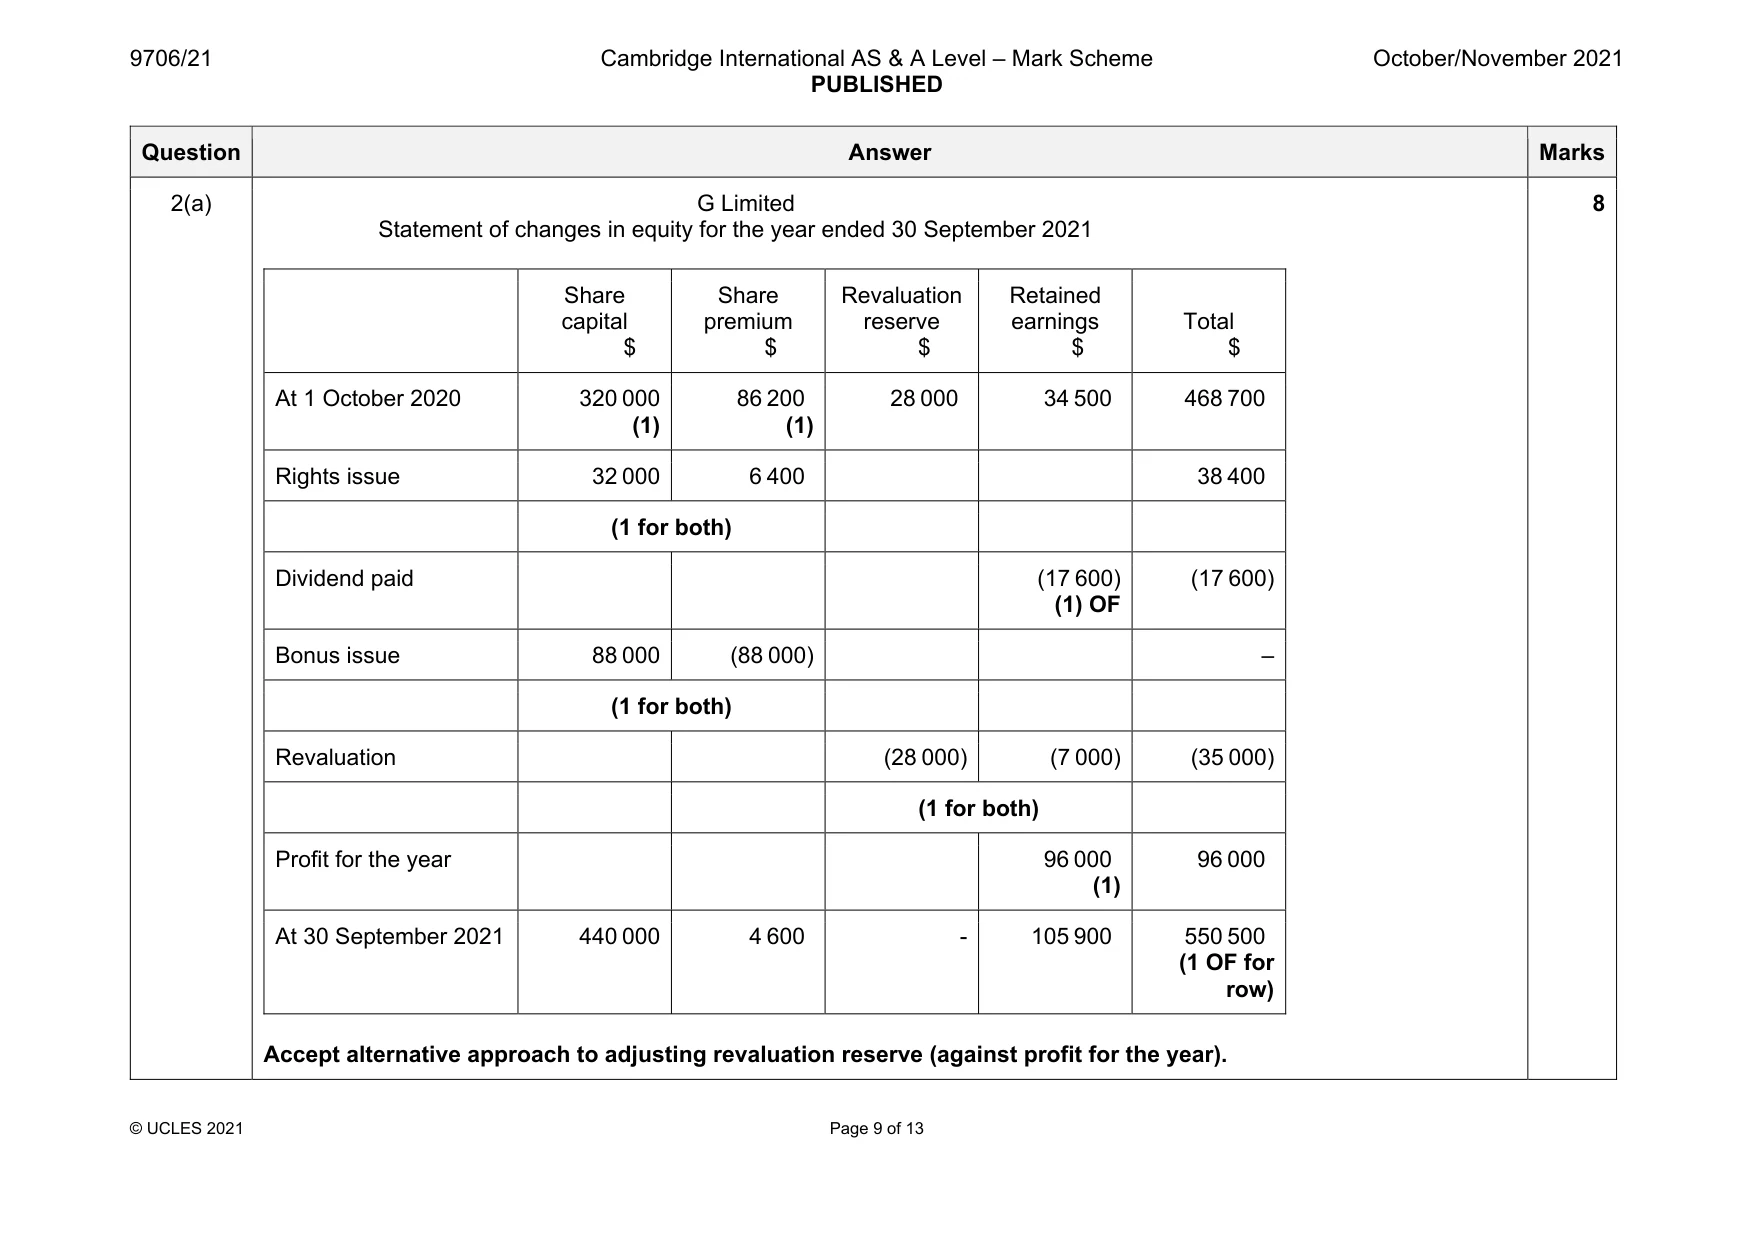
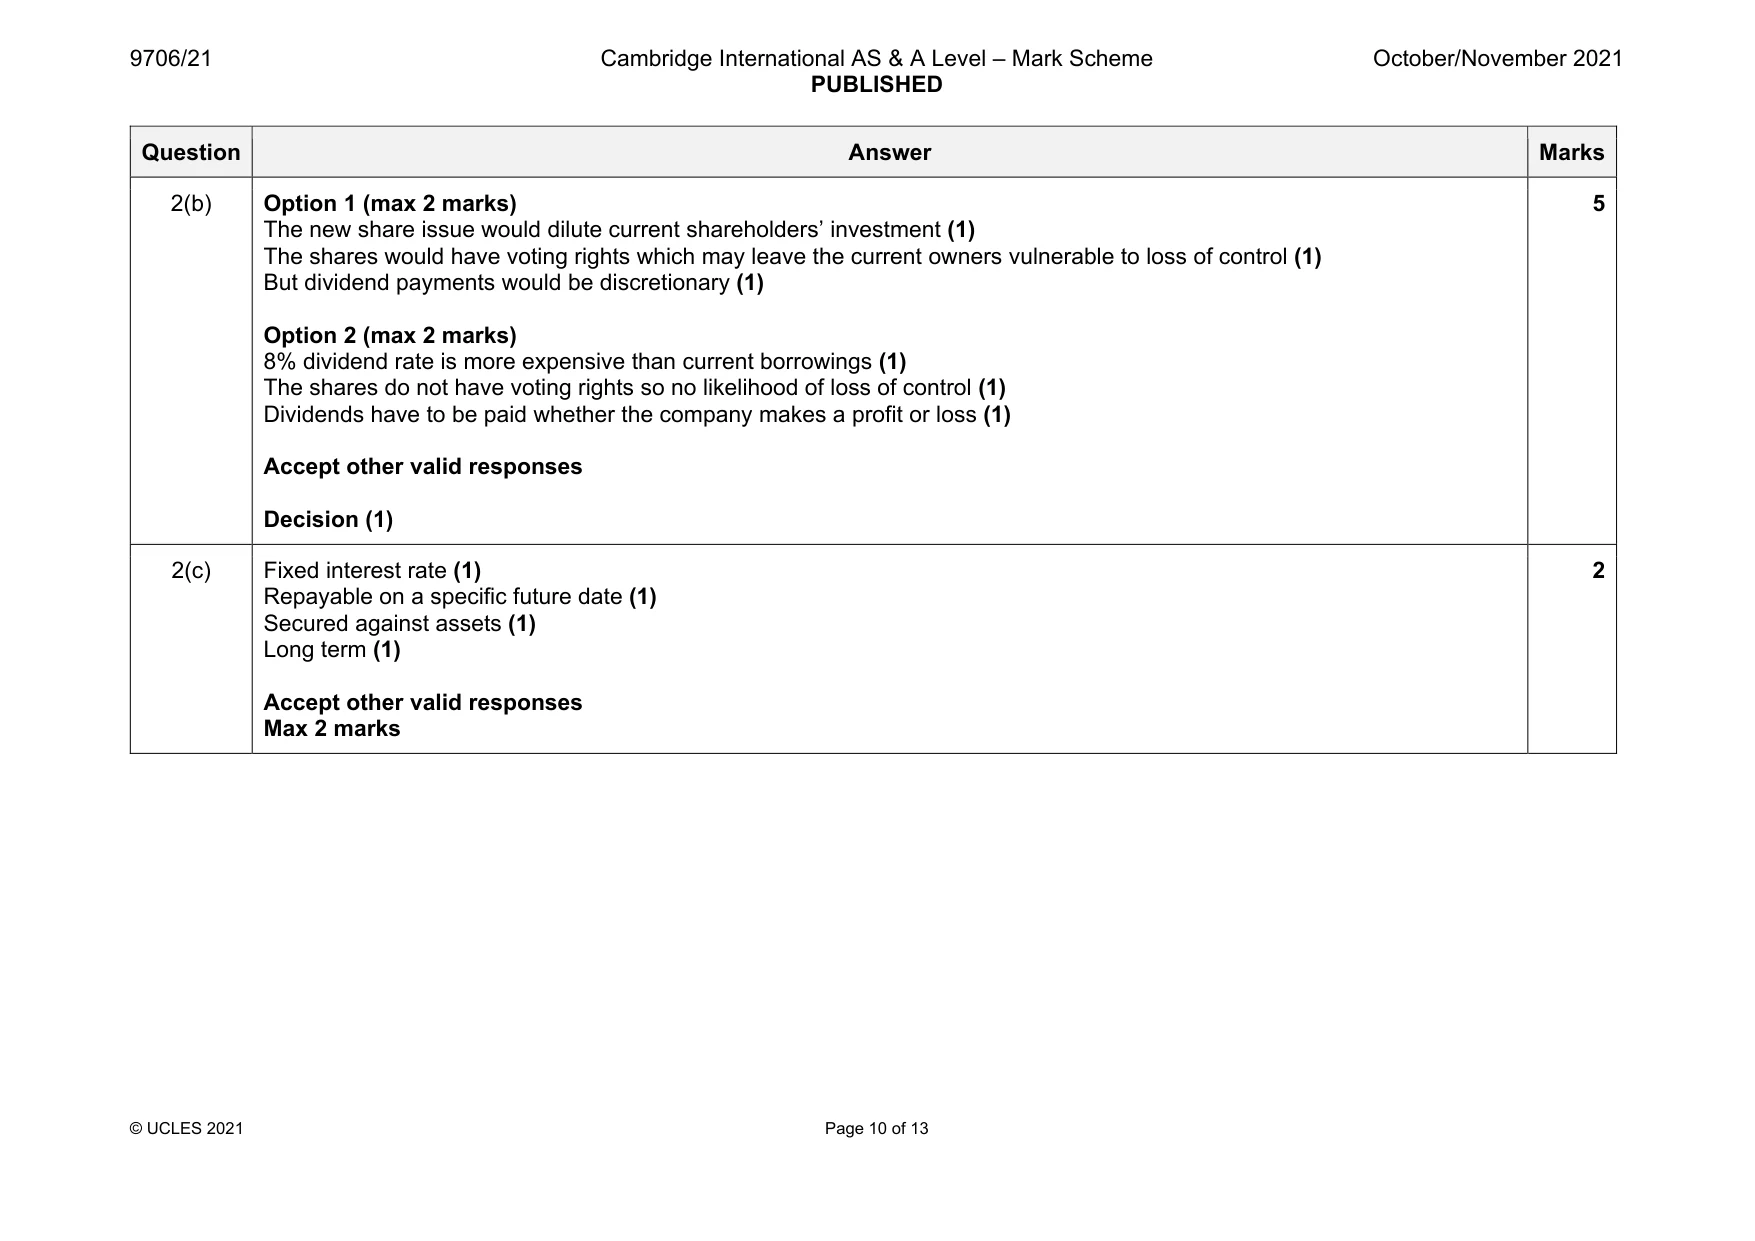
Mark scheme: 2(a) G Limited Statement of changes in equity for the year ended 30 September 2021 Share capital $ Share premium $ Revaluation reserve $ Retained earnings $ Total $ At 1 October 2020 320 000 (1) 86 200 (1) 28 000 34 500 468 700 Rights issue 32 000 6 400 38 400 (1 for both) Dividend paid (17 600) (1) OF (17 600) Bonus issue 88 000 (88 000) – (1 for both) Revaluation (28 000) (7 000) (35 000) (1 for both) Profit for the year 96 000 (1) 96 000 At 30 September 2021 440 000 4 600 - 105 900 550 500 (1 OF for row) Accept alternative approach to adjusting revaluation reserve (against profit for the year). 8 Question Answer Marks 2(b) Option 1 (max 2 marks) The new share issue would dilute current shareholders’ investment (1) The shares would have voting rights which may leave the current owners vulnerable to loss of control (1) But dividend payments would be discretionary (1) Option 2 (max 2 marks) 8% dividend rate is more expensive than current borrowings (1) The shares do not have voting rights so no likelihood of loss of control (1) Dividends have to be paid whether the company makes a profit or loss (1) Accept other valid responses Decision (1) 5 2(c) Fixed interest rate (1) Repayable on a specific future date (1) Secured against assets (1) Long term (1) Accept other valid responses Max 2 marks 2
Q3 · Martina has prepared the following sales ledger control account for the month of August…
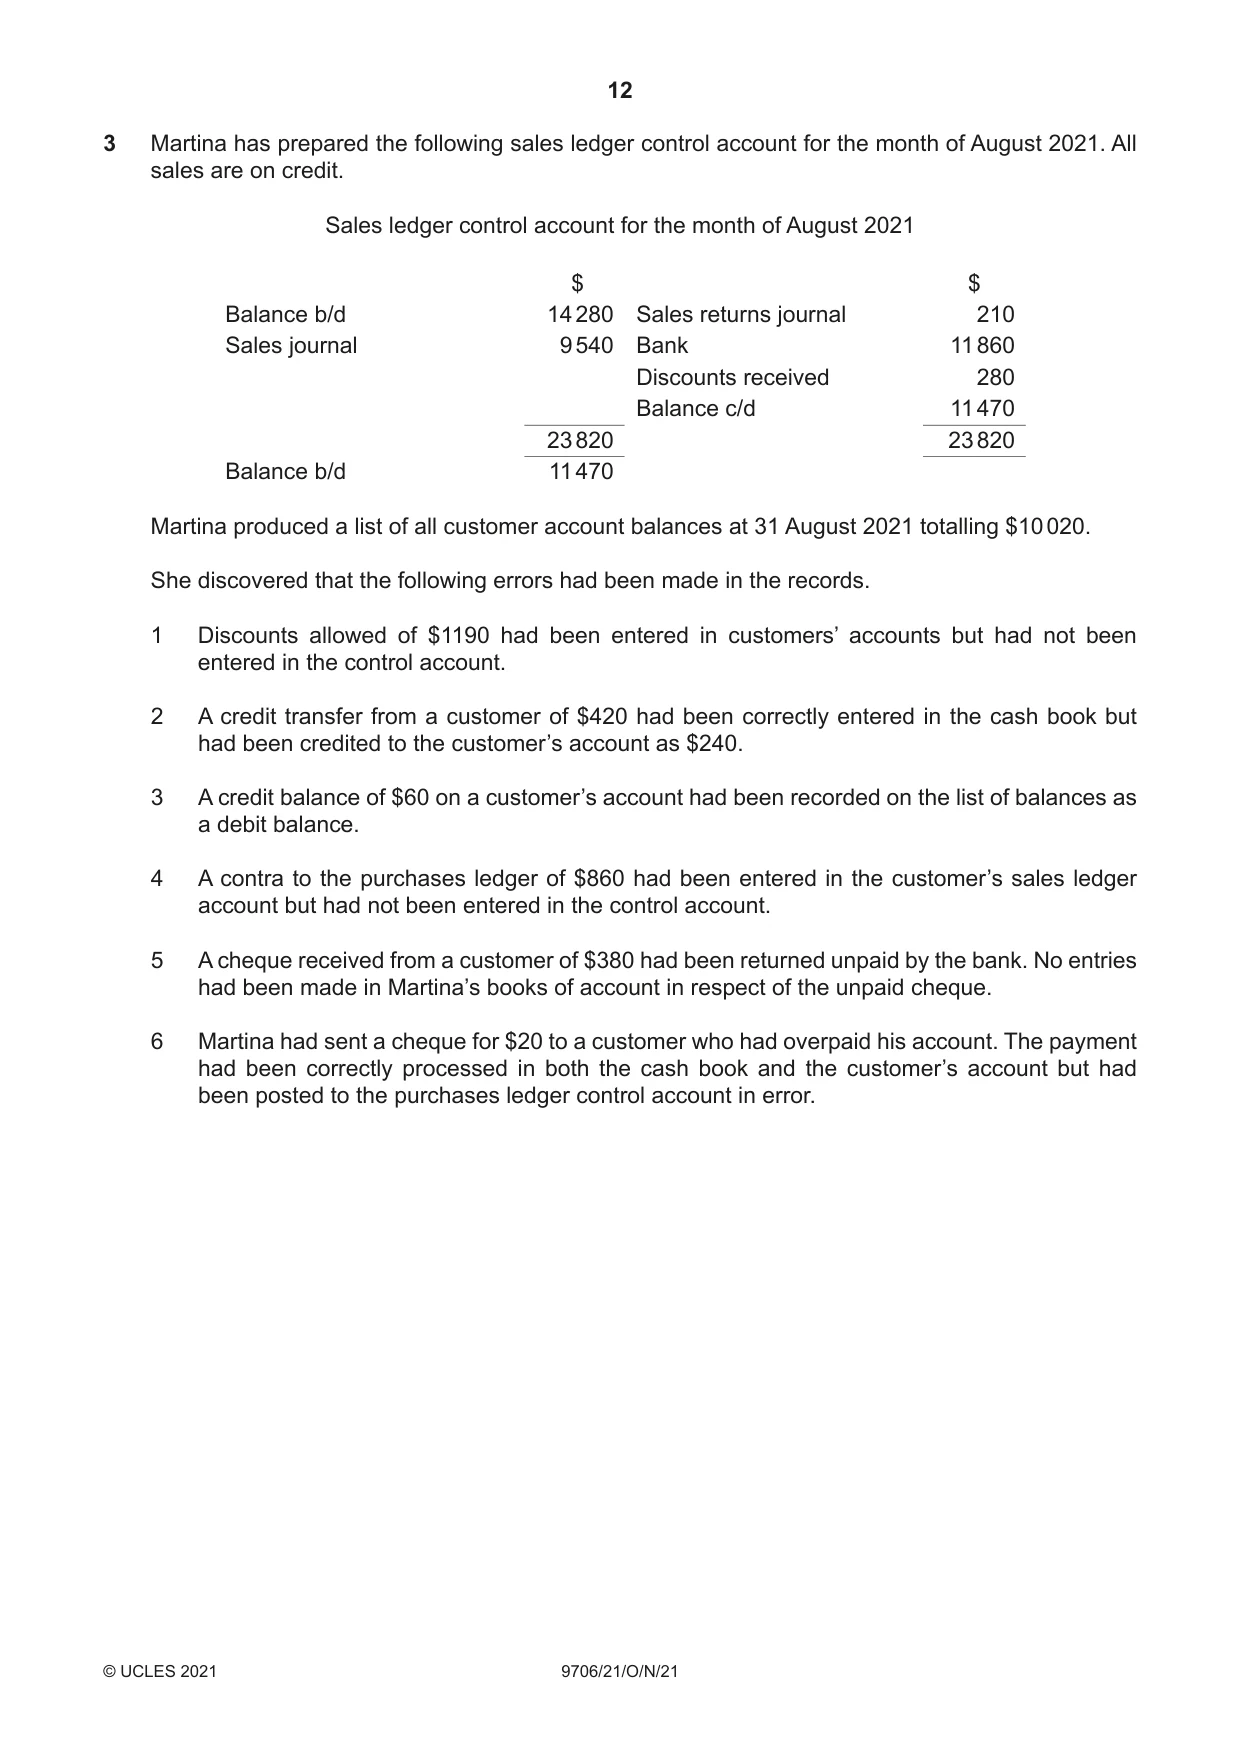
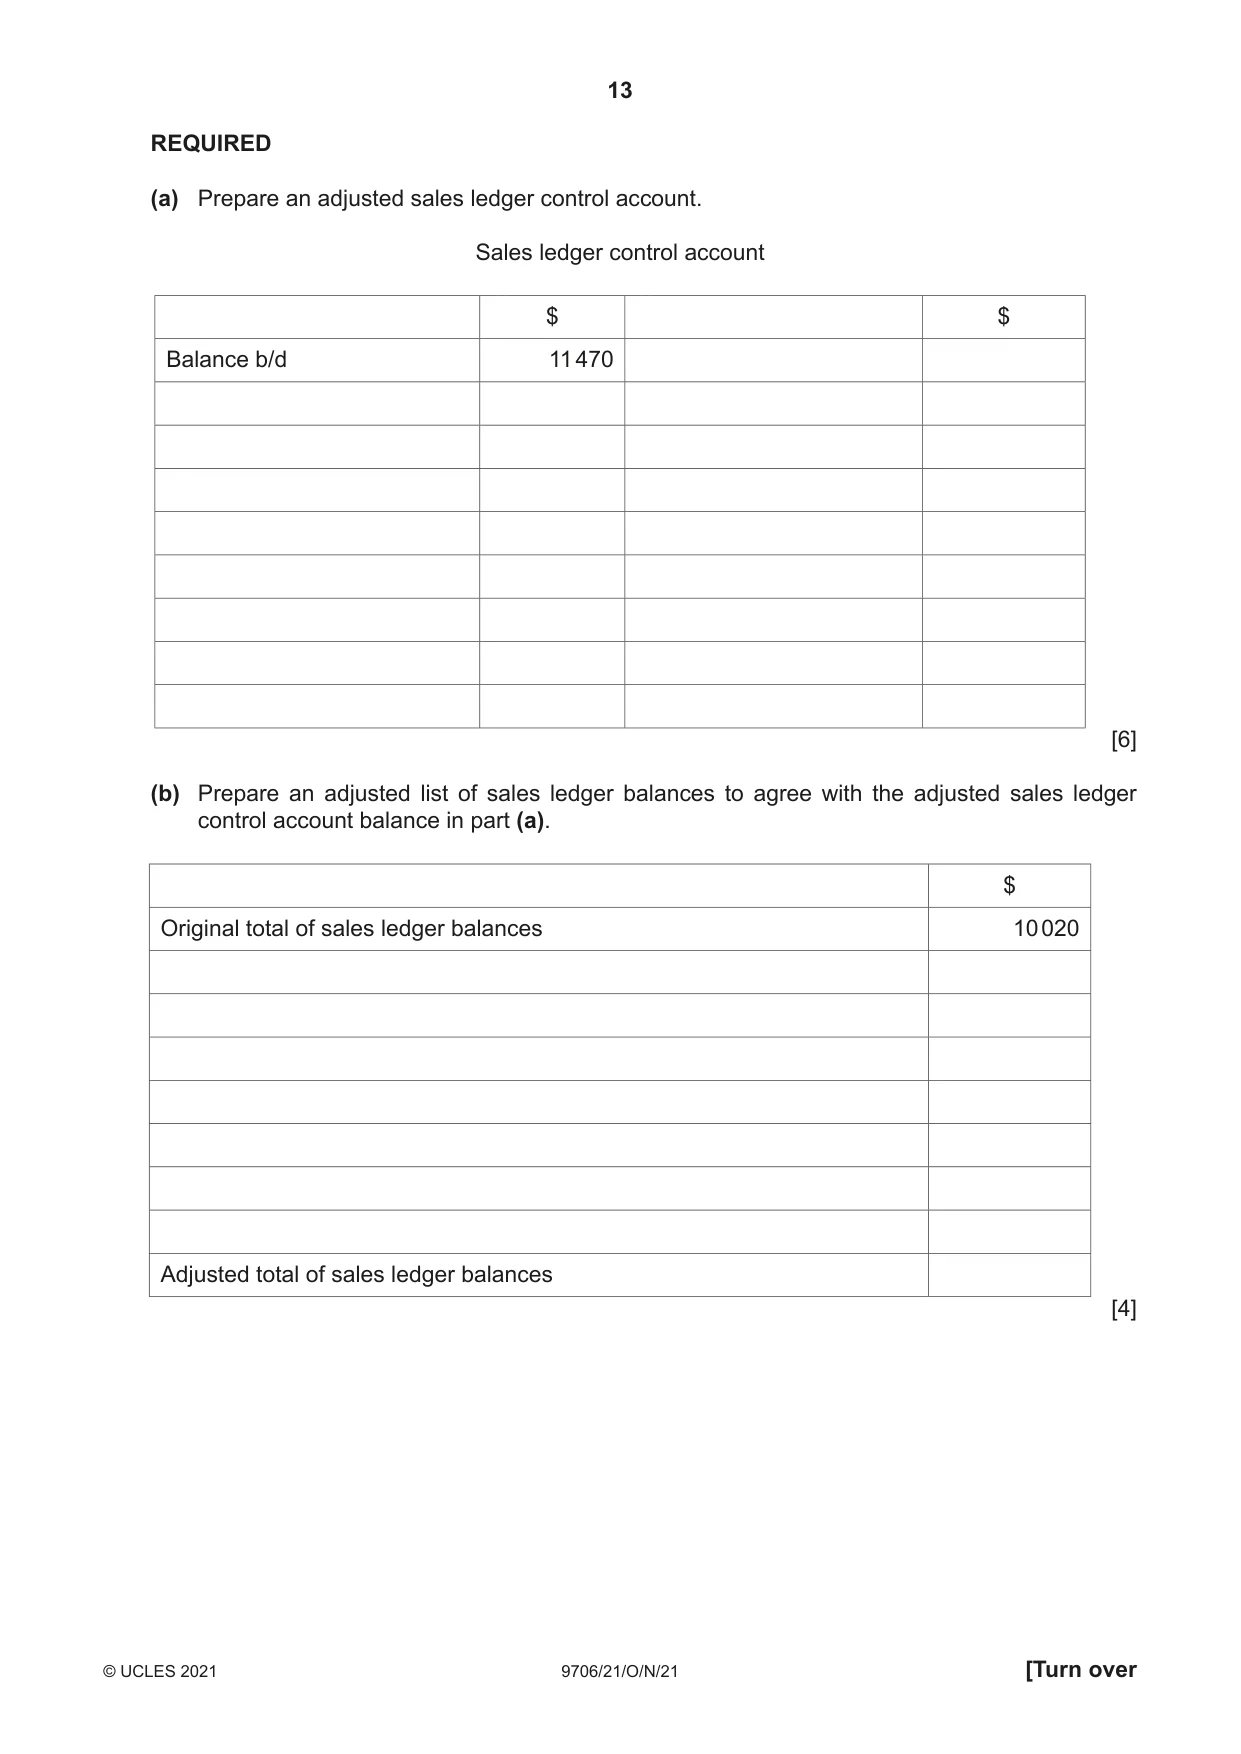
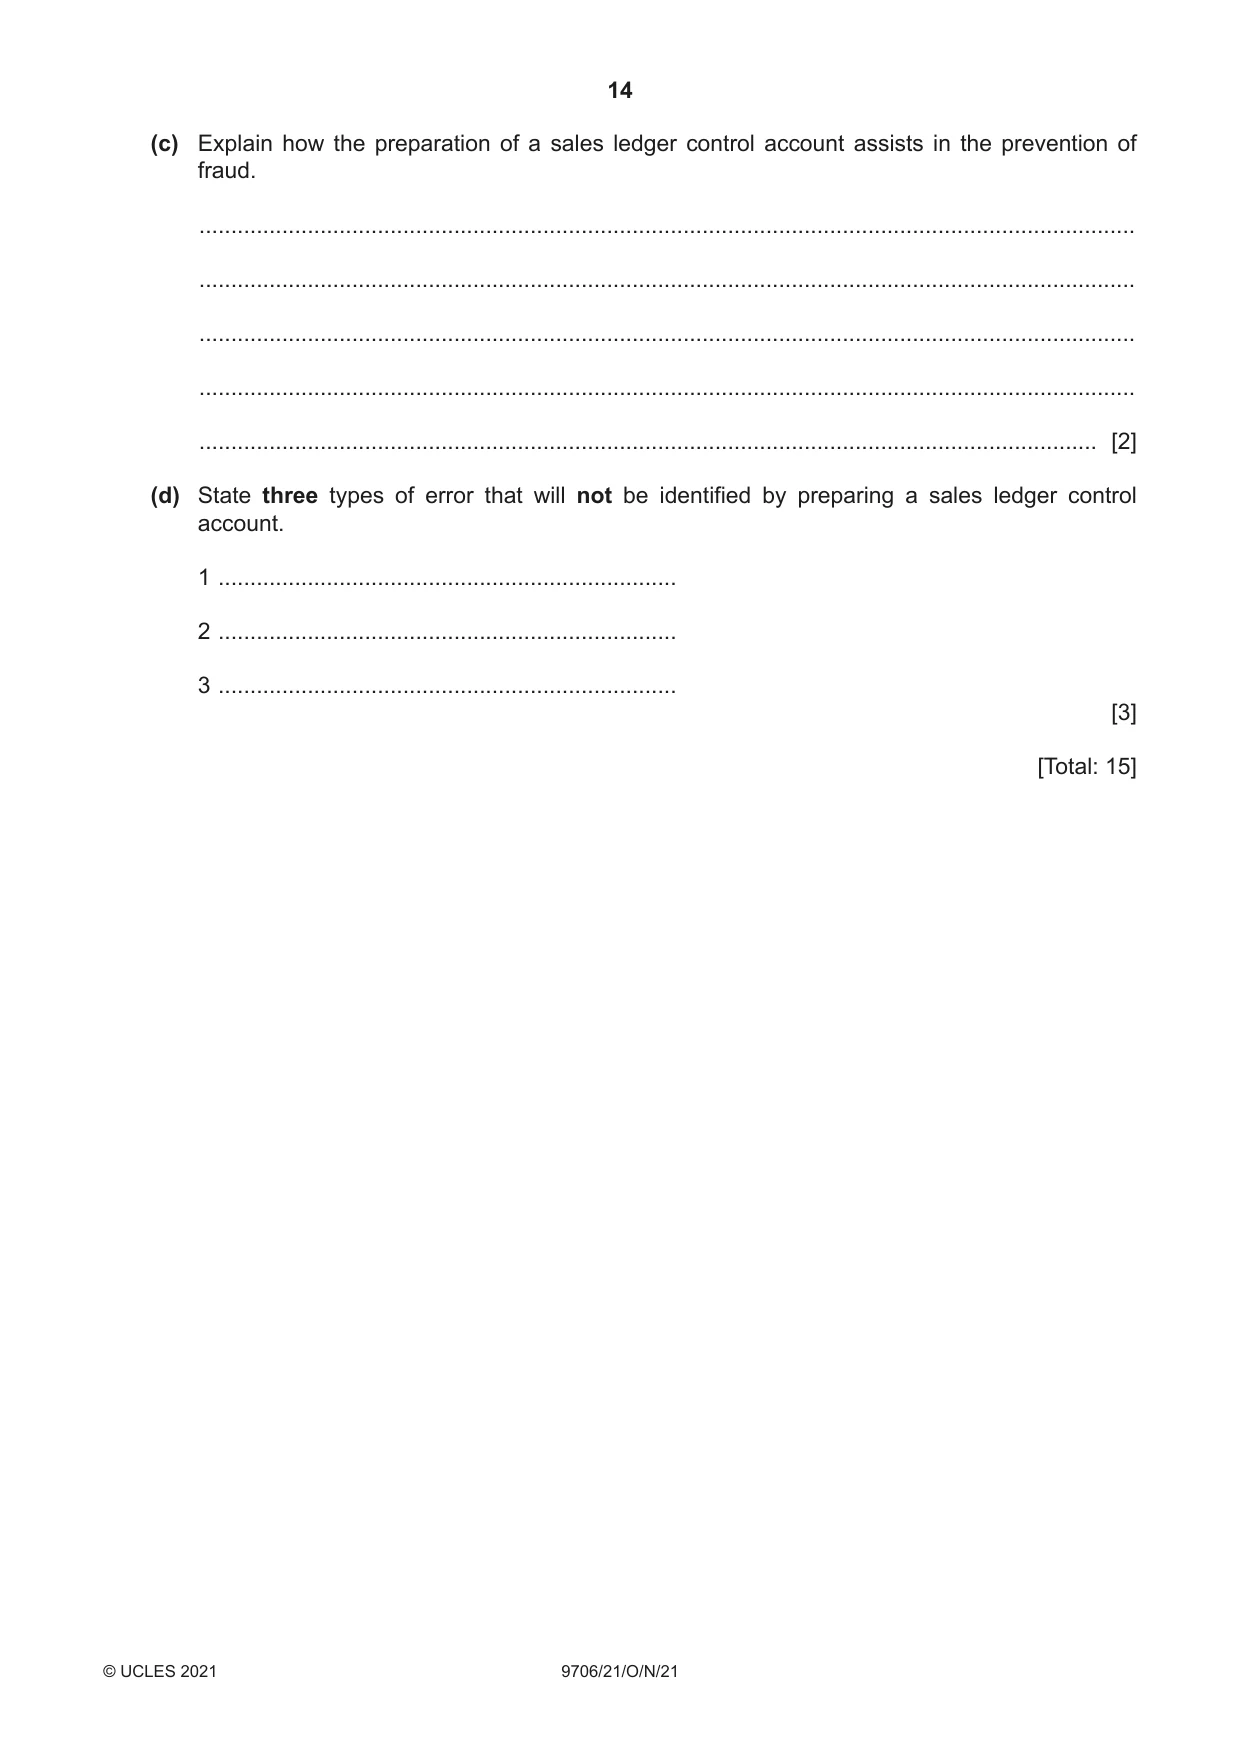
3 Martina has prepared the following sales ledger control account for the month of August 2021. All sales are on credit. Sales ledger control account for the month of August 2021 $ $ Balance b/d 14 280 Sales returns journal 210 Sales journal 9 540 Bank 11 860 Discounts received 280 Balance c/d 11 470 23 820 23 820 Balance b/d 11 470 Martina produced a list of all customer account balances at 31 August 2021 totalling $10 020. She discovered that the following errors had been made in the records. 1 Discounts allowed of $1190 had been entered in customers’ accounts but had not been entered in the control account. 2 A credit transfer from a customer of $420 had been correctly entered in the cash book but had been credited to the customer’s account as $240. 3 A credit balance of $60 on a customer’s account had been recorded on the list of balances as a debit balance. 4 A contra to the purchases ledger of $860 had been entered in the customer’s sales ledger account but had not been entered in the control account. 5 A cheque received from a customer of $380 had been returned unpaid by the bank. No entries had been made in Martina’s books of account in respect of the unpaid cheque. 6 Martina had sent a cheque for $20 to a customer who had overpaid his account. The payment had been correctly processed in both the cash book and the customer’s account but had been posted to the purchases ledger control account in error. REQUIRED (a) Prepare an adjusted sales ledger control account. Sales ledger control account $ $ Balance b/d 11 470 [6] (b) Prepare an adjusted list of sales ledger balances to agree with the adjusted sales ledger control account balance in part (a). $ Original total of sales ledger balances 10 020 Adjusted total of sales ledger balances [4] (c) Explain how the preparation of a sales ledger control account assists in the prevention of fraud. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] (d) State three types of error that will not be identified by preparing a sales ledger control account. 1 ........................................................................ 2 ........................................................................ 3 ........................................................................ [3] [Total: 15]
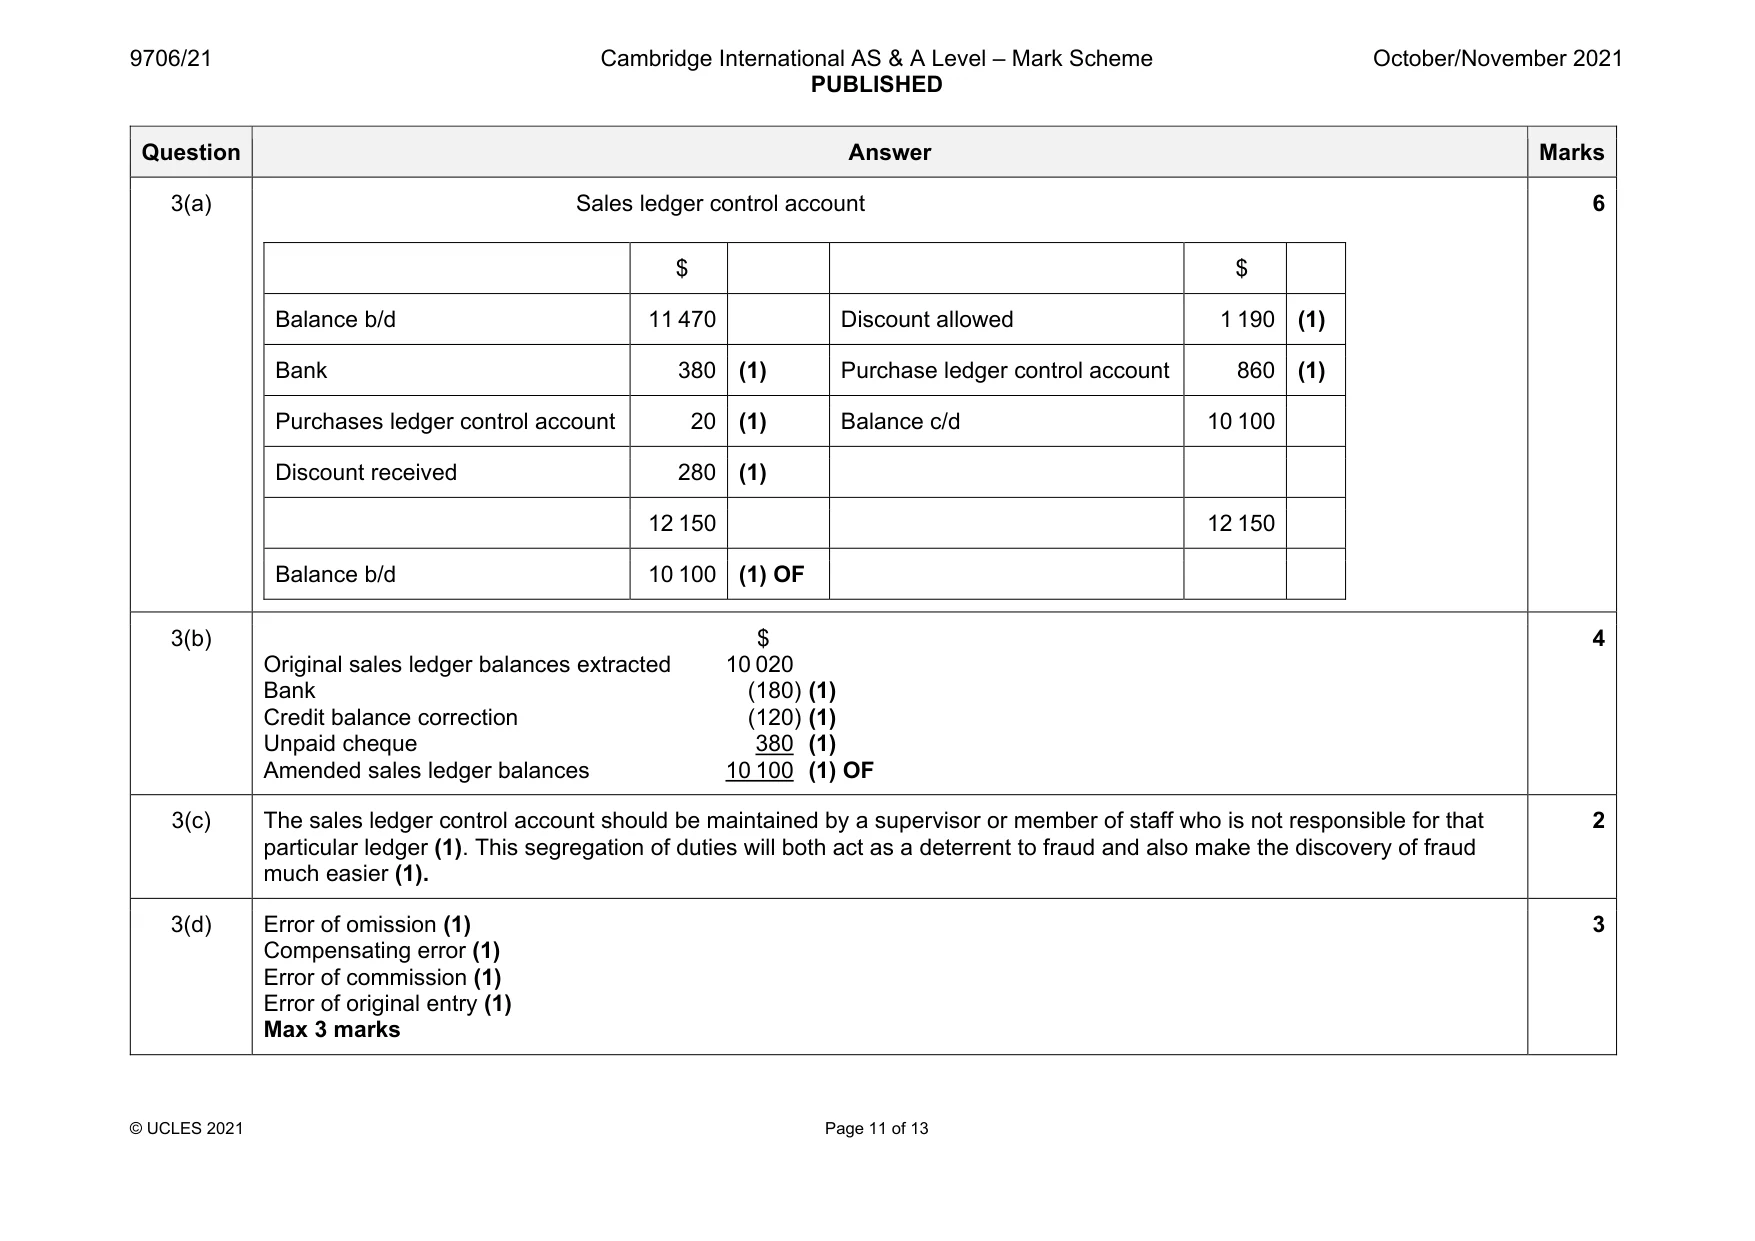
Mark scheme: 3(a) Sales ledger control account $ $ Balance b/d 11 470 Discount allowed 1 190 (1) Bank 380 (1) Purchase ledger control account 860 (1) Purchases ledger control account 20 (1) Balance c/d 10 100 Discount received 280 (1) 12 150 12 150 Balance b/d 10 100 (1) OF 6 3(b) $ Original sales ledger balances extracted 10 020 Bank (180) (1) Credit balance correction (120) (1) Unpaid cheque 380 (1) Amended sales ledger balances 10 100 (1) OF 4 3(c) The sales ledger control account should be maintained by a supervisor or member of staff who is not responsible for that particular ledger (1). This segregation of duties will both act as a deterrent to fraud and also make the discovery of fraud much easier (1). 2 3(d) Error of omission (1) Compensating error (1) Error of commission (1) Error of original entry (1) Max 3 marks 3
Q4 · B Limited is a manufacturing business
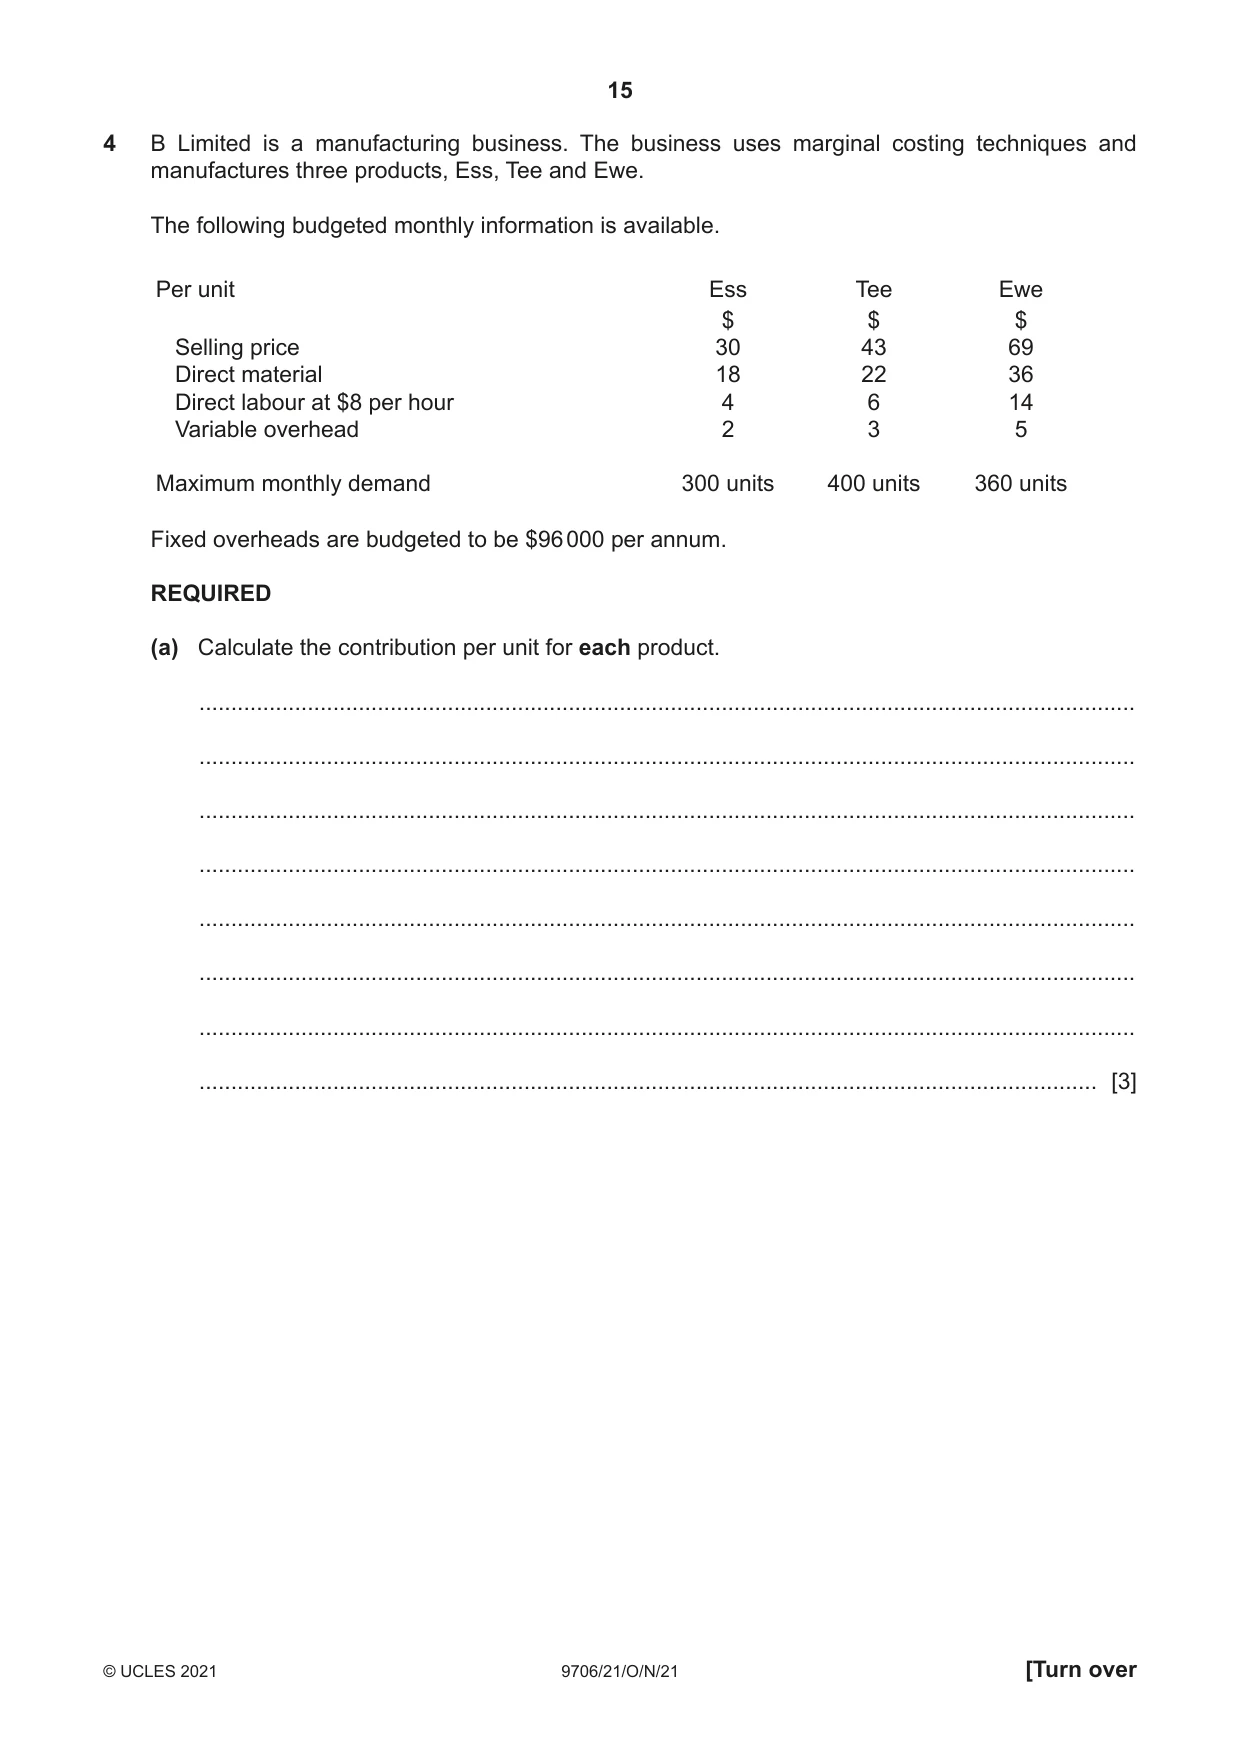
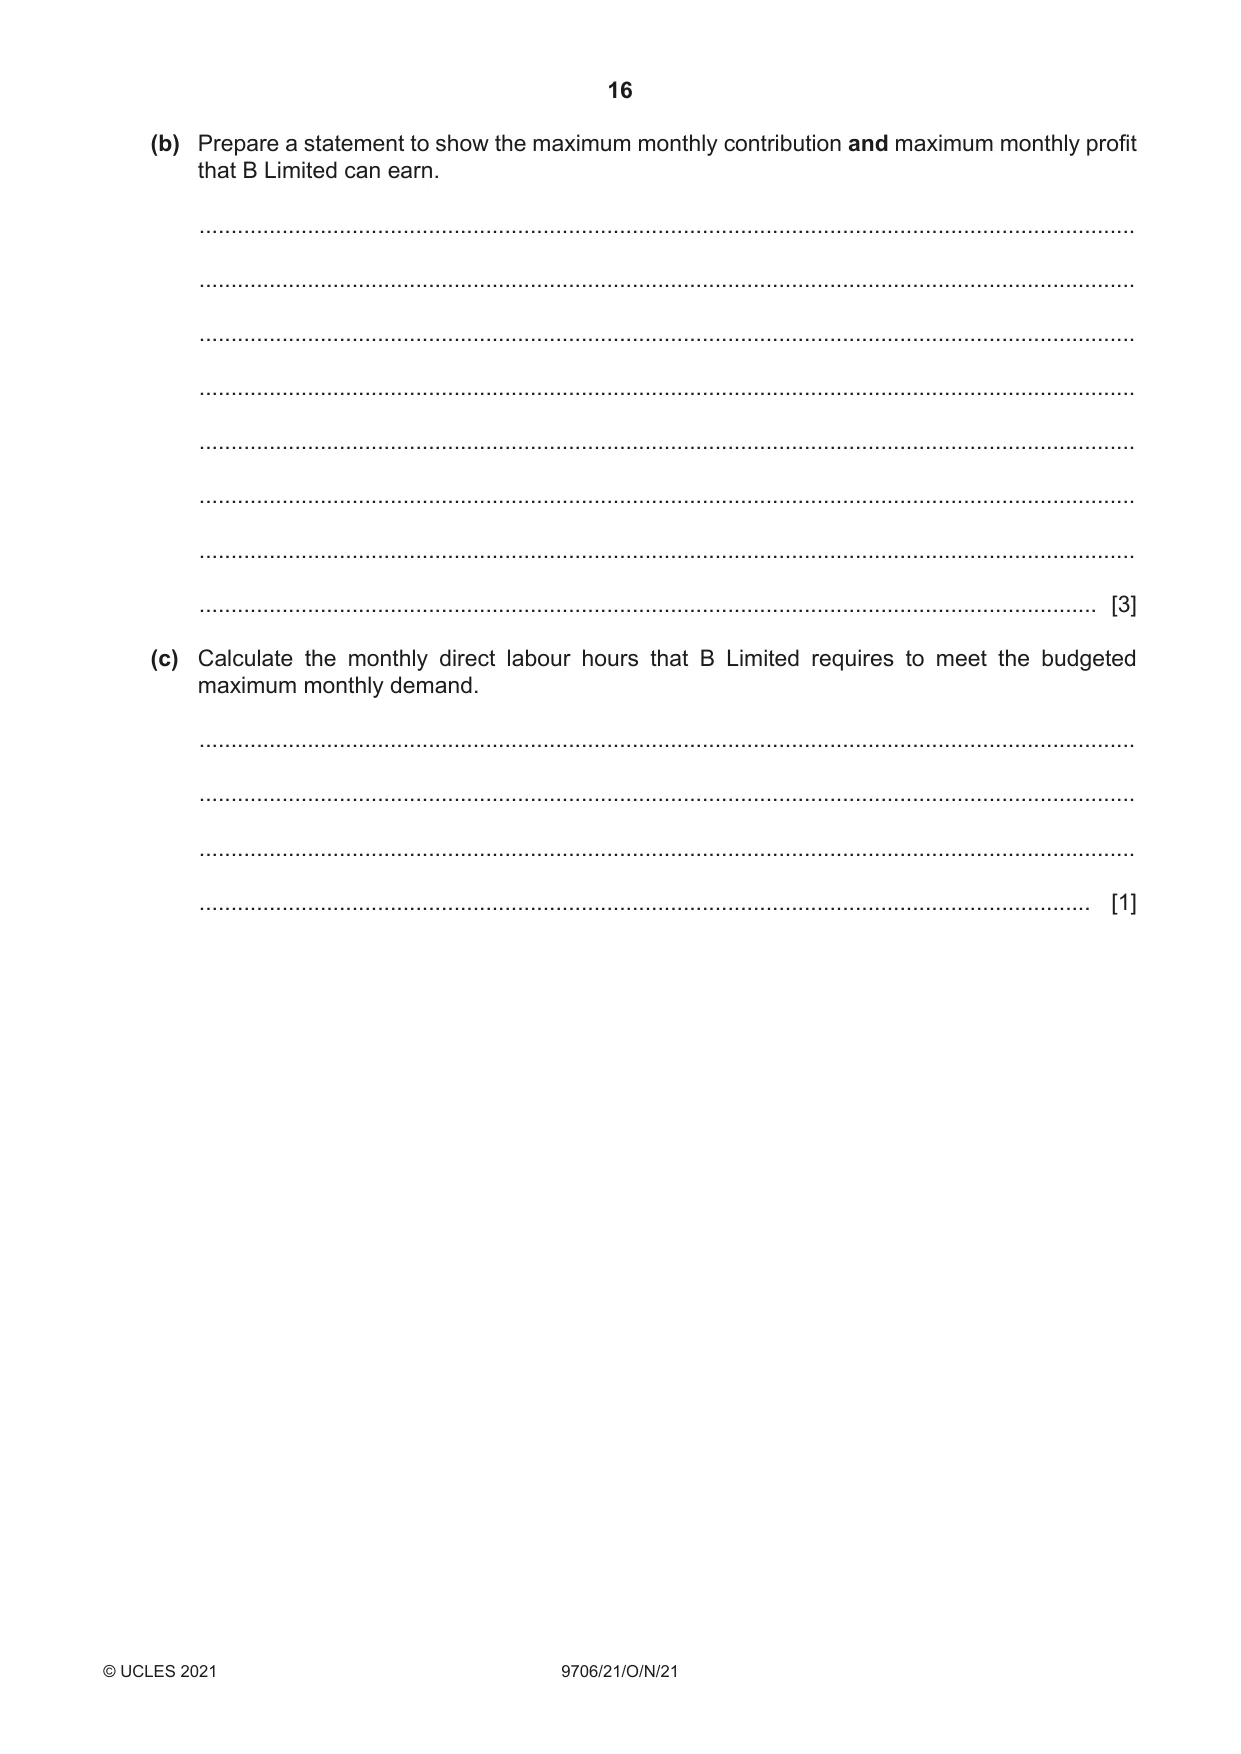
4 B Limited is a manufacturing business. The business uses marginal costing techniques and manufactures three products, Ess, Tee and Ewe. The following budgeted monthly information is available. Per unit Ess Tee Ewe $ $ $ Selling price 30 43 69 Direct material 18 22 36 Direct labour at $8 per hour 4 6 14 Variable overhead 2 3 5 Maximum monthly demand 300 units 400 units 360 units Fixed overheads are budgeted to be $96 000 per annum. REQUIRED (a) Calculate the contribution per unit for each product. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] (b) Prepare a statement to show the maximum monthly contribution and maximum monthly profit that B Limited can earn. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] (c) Calculate the monthly direct labour hours that B Limited requires to meet the budgeted maximum monthly demand. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................ [1] Additional information Due to a shortage of skilled labour, the directors are aware that only 900 direct labour hours per month will be available from 1 December 2021. REQUIRED (d) Calculate the maximum contribution and maximum profit for December 2021, taking into account the limited direct labour hours available. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ........................................................................................................................................... [11]
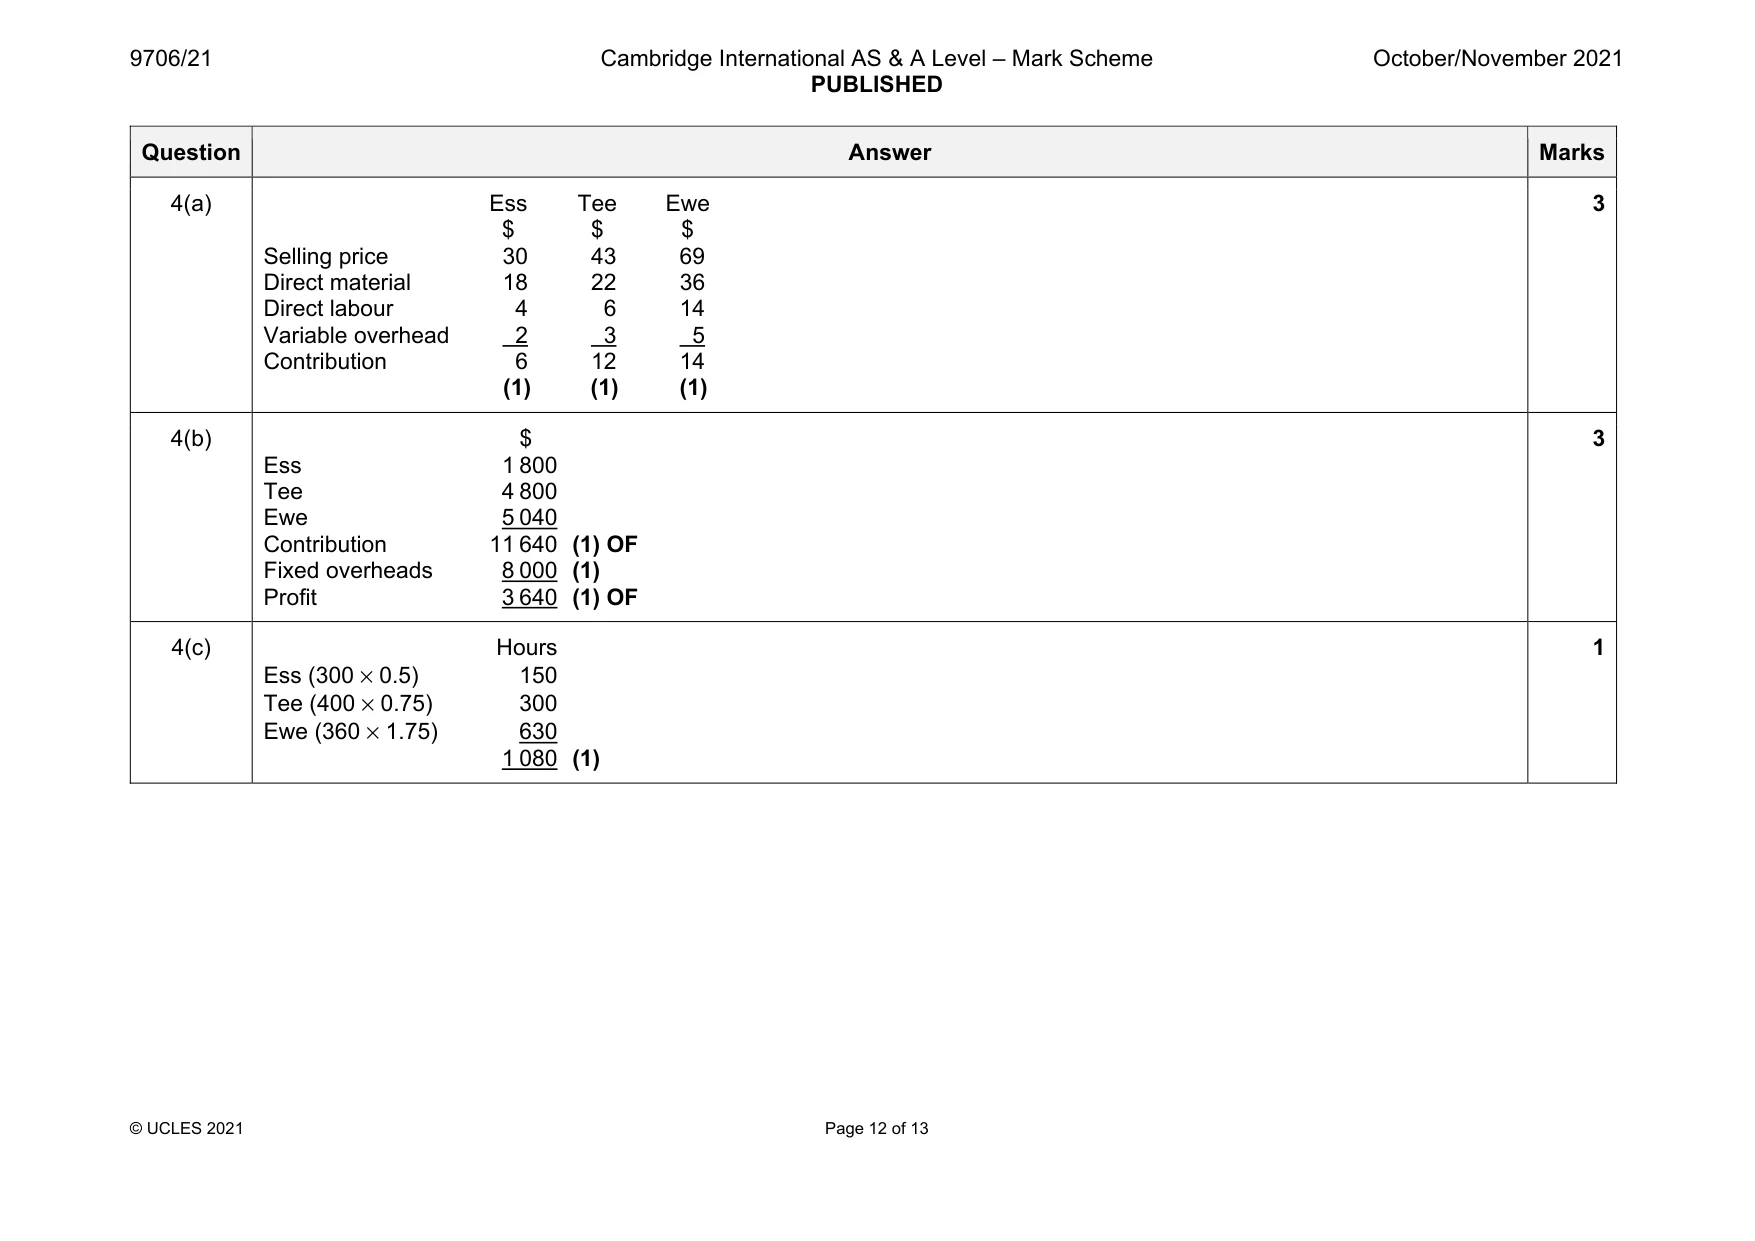
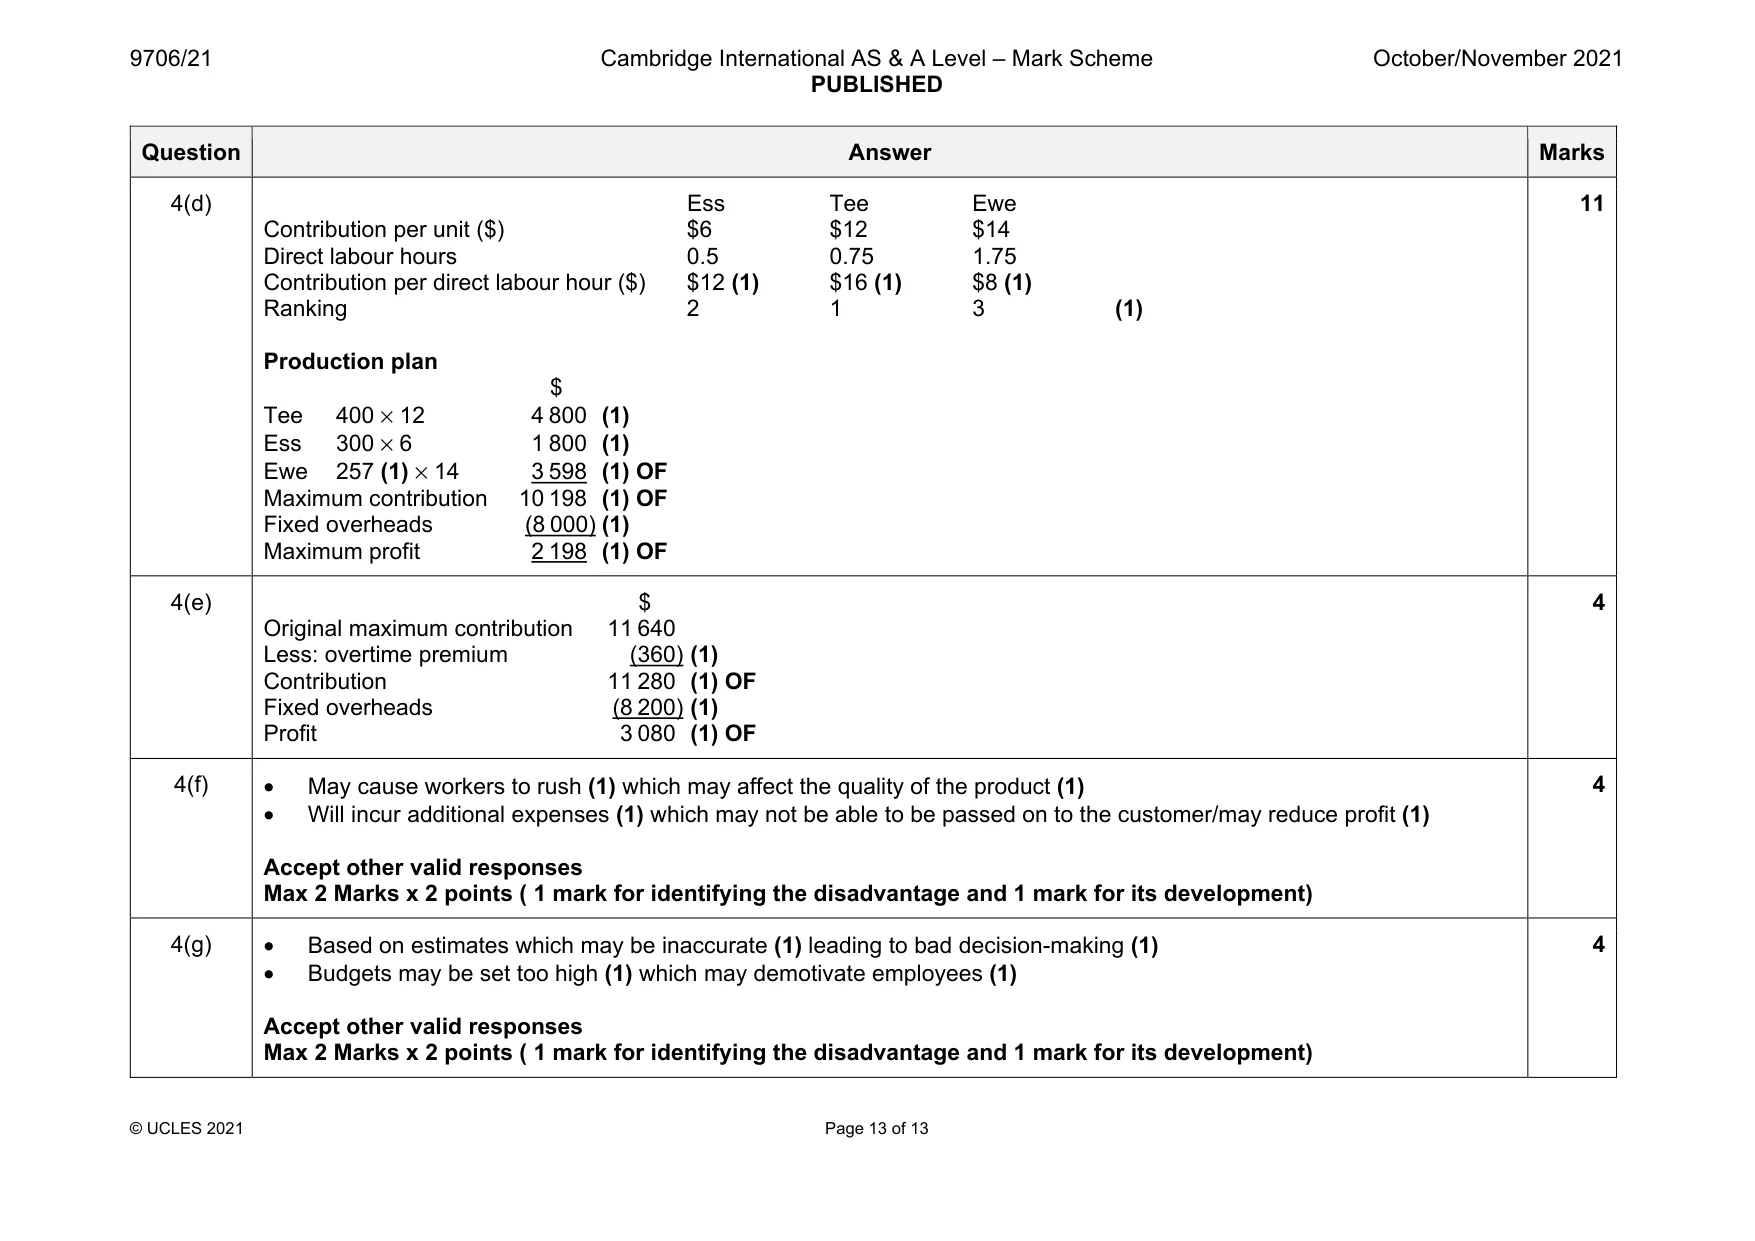
Mark scheme: 4(a) Ess Tee Ewe $ $ $ Selling price 30 43 69 Direct material 18 22 36 Direct labour 4 6 14 Variable overhead 2 3 5 Contribution 6 12 14 (1) (1) (1) 3 4(b) $ Ess 1 800 Tee 4 800 Ewe 5 040 Contribution 11 640 (1) OF Fixed overheads 8 000 (1) Profit 3 640 (1) OF 3 4(c) Hours Ess (300 × 0.5) 150 Tee (400 × 0.75) 300 Ewe (360 × 1.75) 630 1 080 (1) 1 Question Answer Marks 4(d) Ess Tee Ewe Contribution per unit ($) $6 $12 $14 Direct labour hours 0.5 0.75 1.75 Contribution per direct labour hour ($) $12 (1) $16 (1) $8 (1) Ranking 2 1 3 (1) Production plan $ Tee 400 × 12 4 800 (1) Ess 300 × 6 1 800 (1) Ewe 257 (1) × 14 3 598 (1) OF Maximum contribution 10 198 (1) OF Fixed overheads (8 000) (1) Maximum profit 2 198 (1) OF 11 4(e) $ Original maximum contribution 11 640 Less: overtime premium (360) (1) Contribution 11 280 (1) OF Fixed overheads (8 200) (1) Profit 3 080 (1) OF 4 4(f) • May cause workers to rush (1) which may affect the quality of the product (1) • Will incur additional expenses (1) which may not be able to be passed on to the customer/may reduce profit (1) Accept other valid responses Max 2 Marks x 2 points ( 1 mark for identifying the disadvantage and 1 mark for its development) 4 4(g) • Based on estimates which may be inaccurate (1) leading to bad decision-making (1) • Budgets may be set too high (1) which may demotivate employees (1) Accept other valid responses Max 2 Marks x 2 points ( 1 mark for identifying the disadvantage and 1 mark for its development) 4
What was in this paper
The subtopics covered by these 4 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2021 Oct/Nov, Paper 2 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.