Cambridge A Level Accounting 9706 — 2021 Oct/Nov Paper 2 · Variant 3
9706/23/O/N/21 · 8 questions · 90 marks · ≈101 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme16 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · The following information has been extracted from the accounting records of T Limited at…
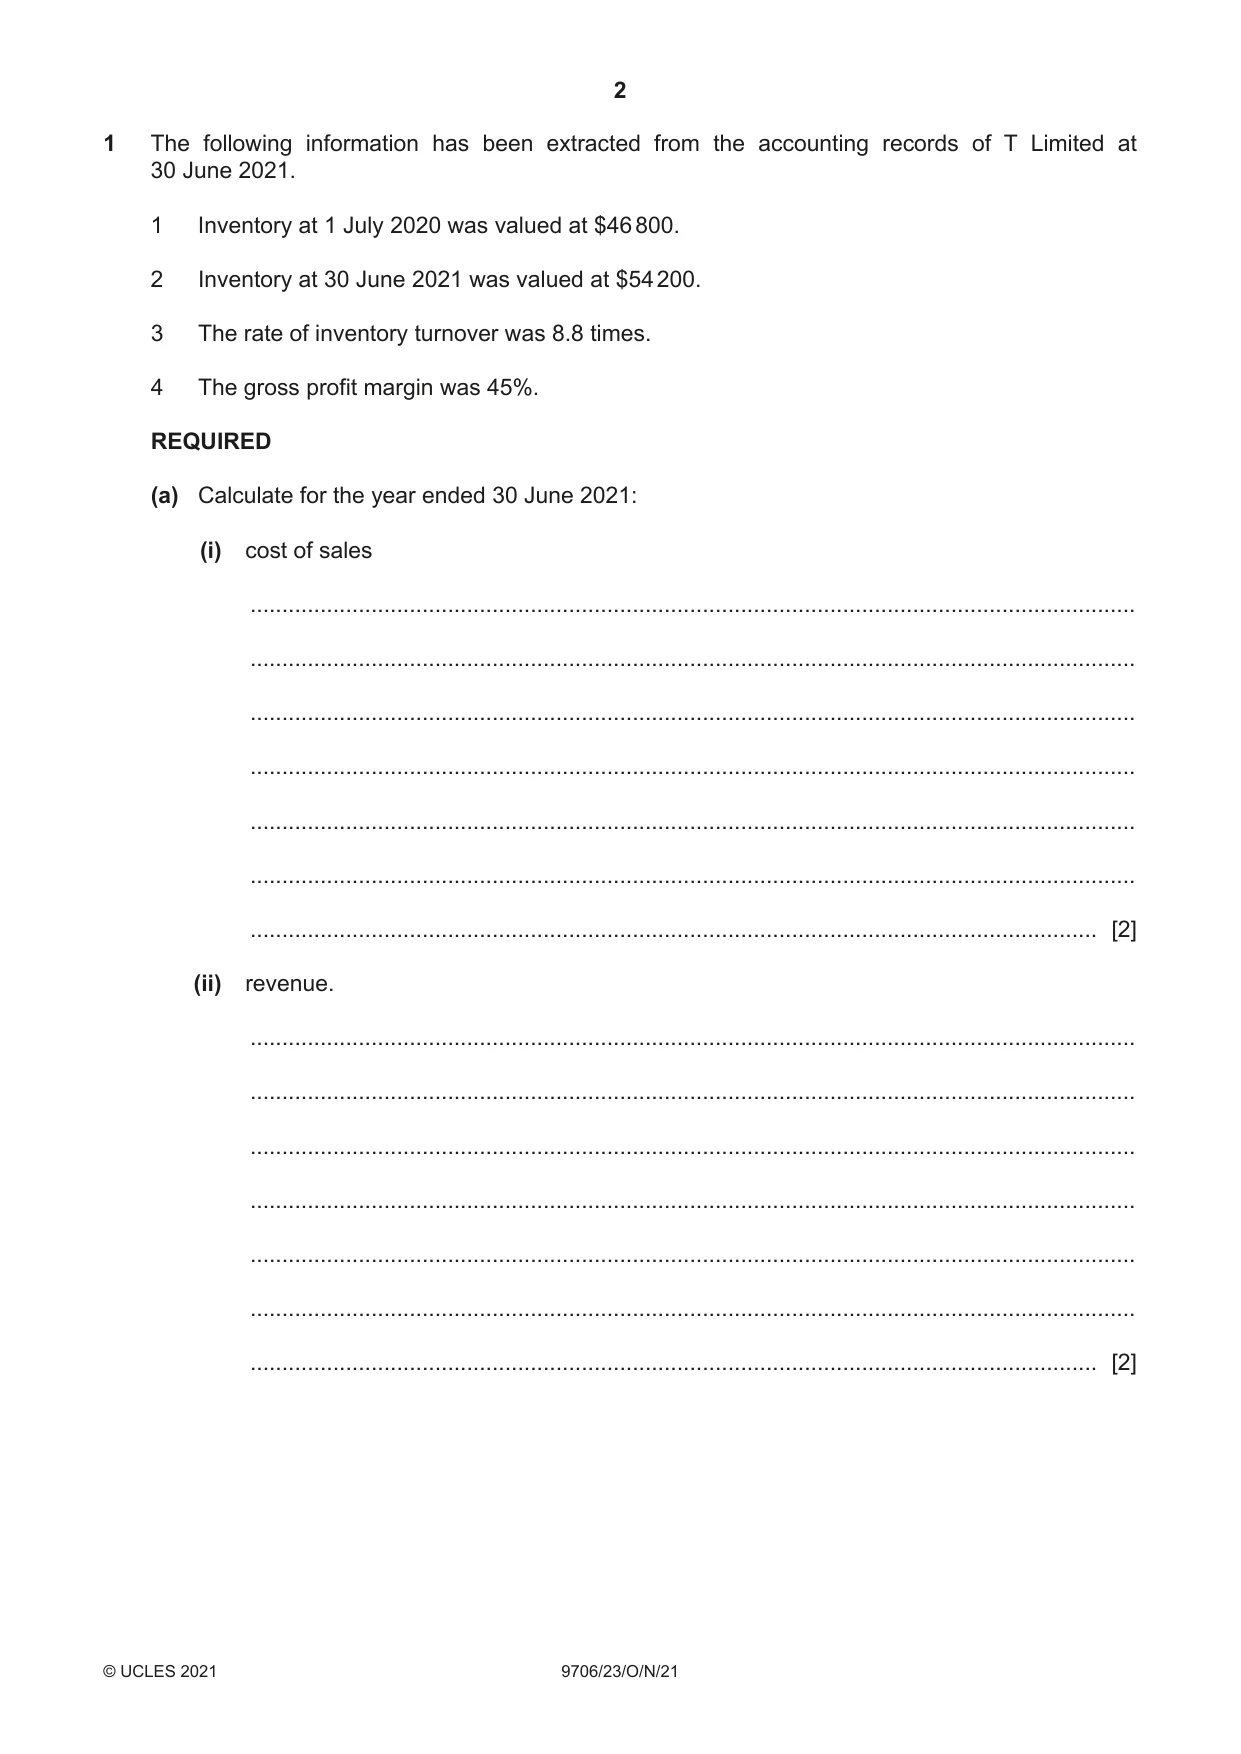
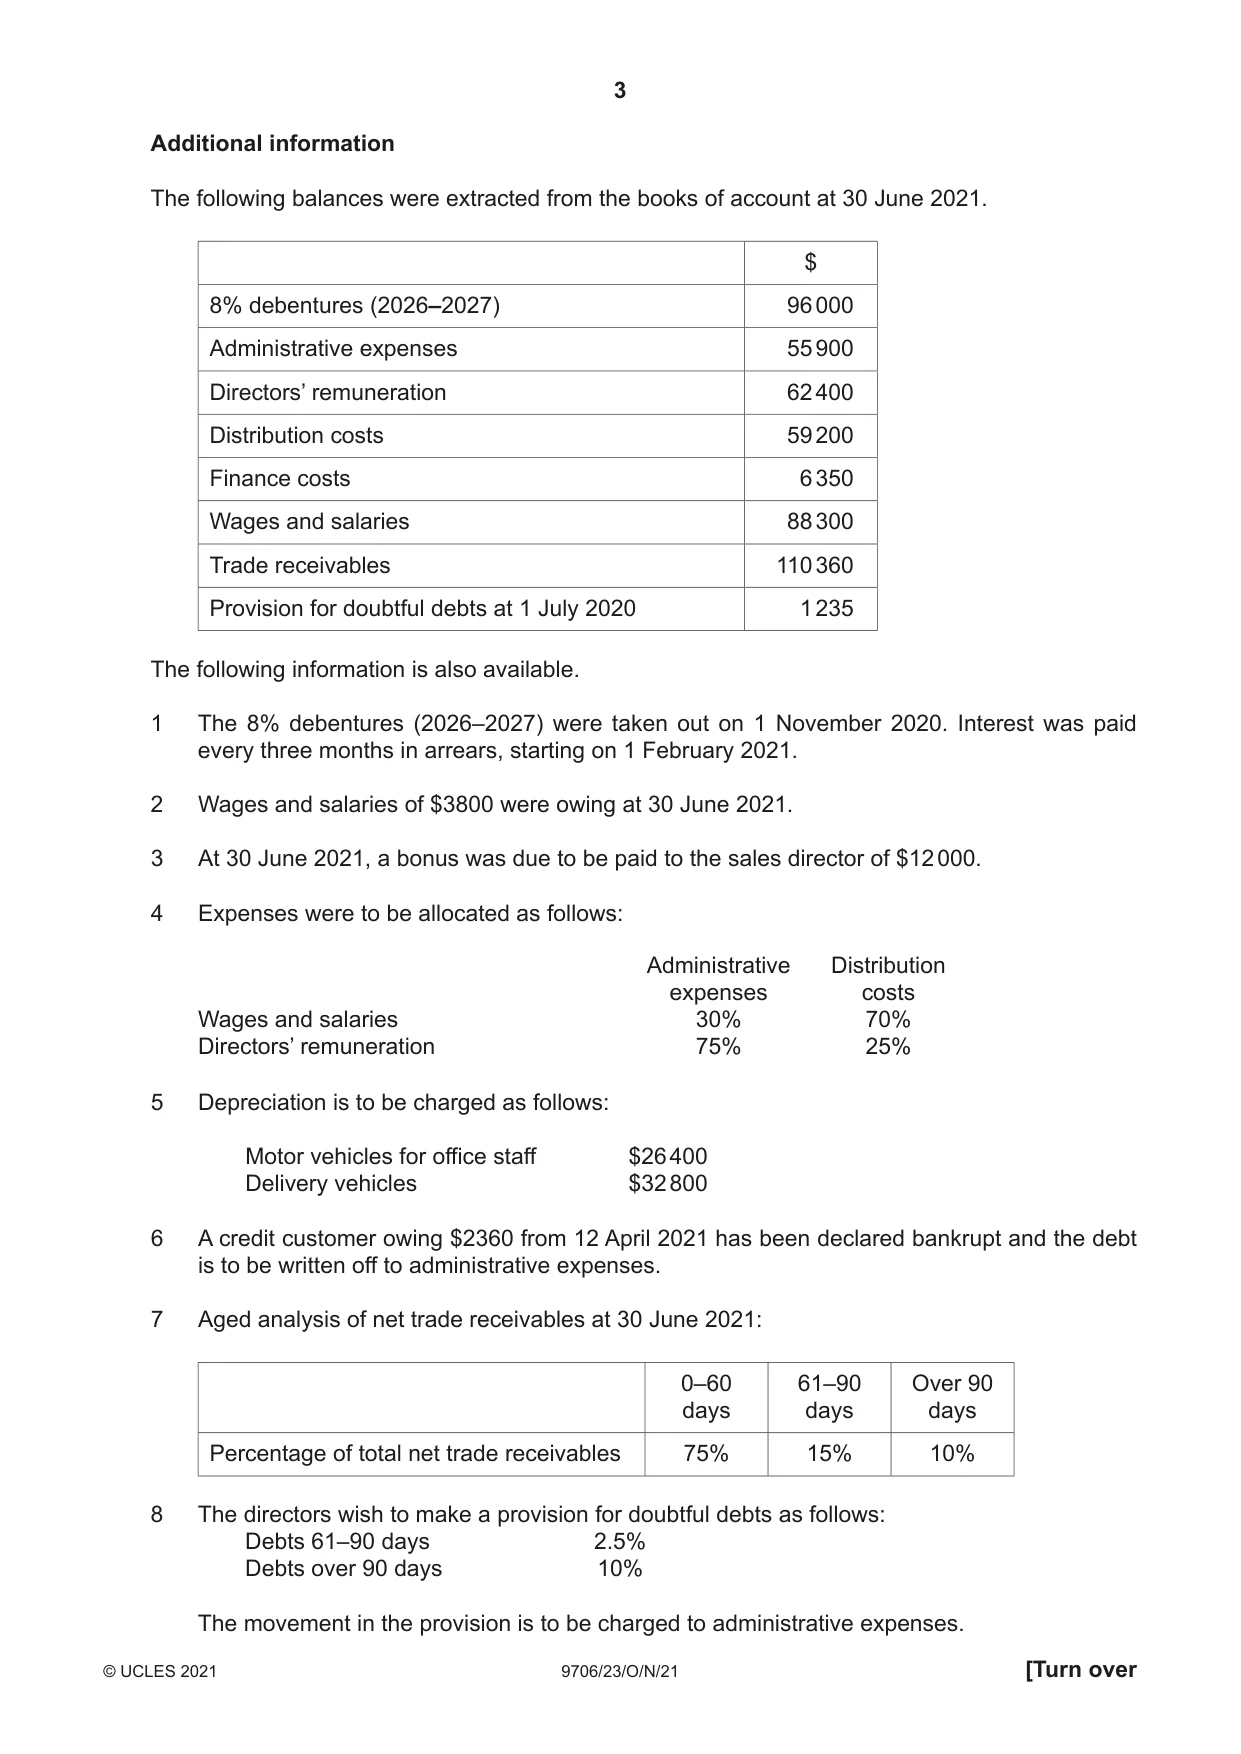
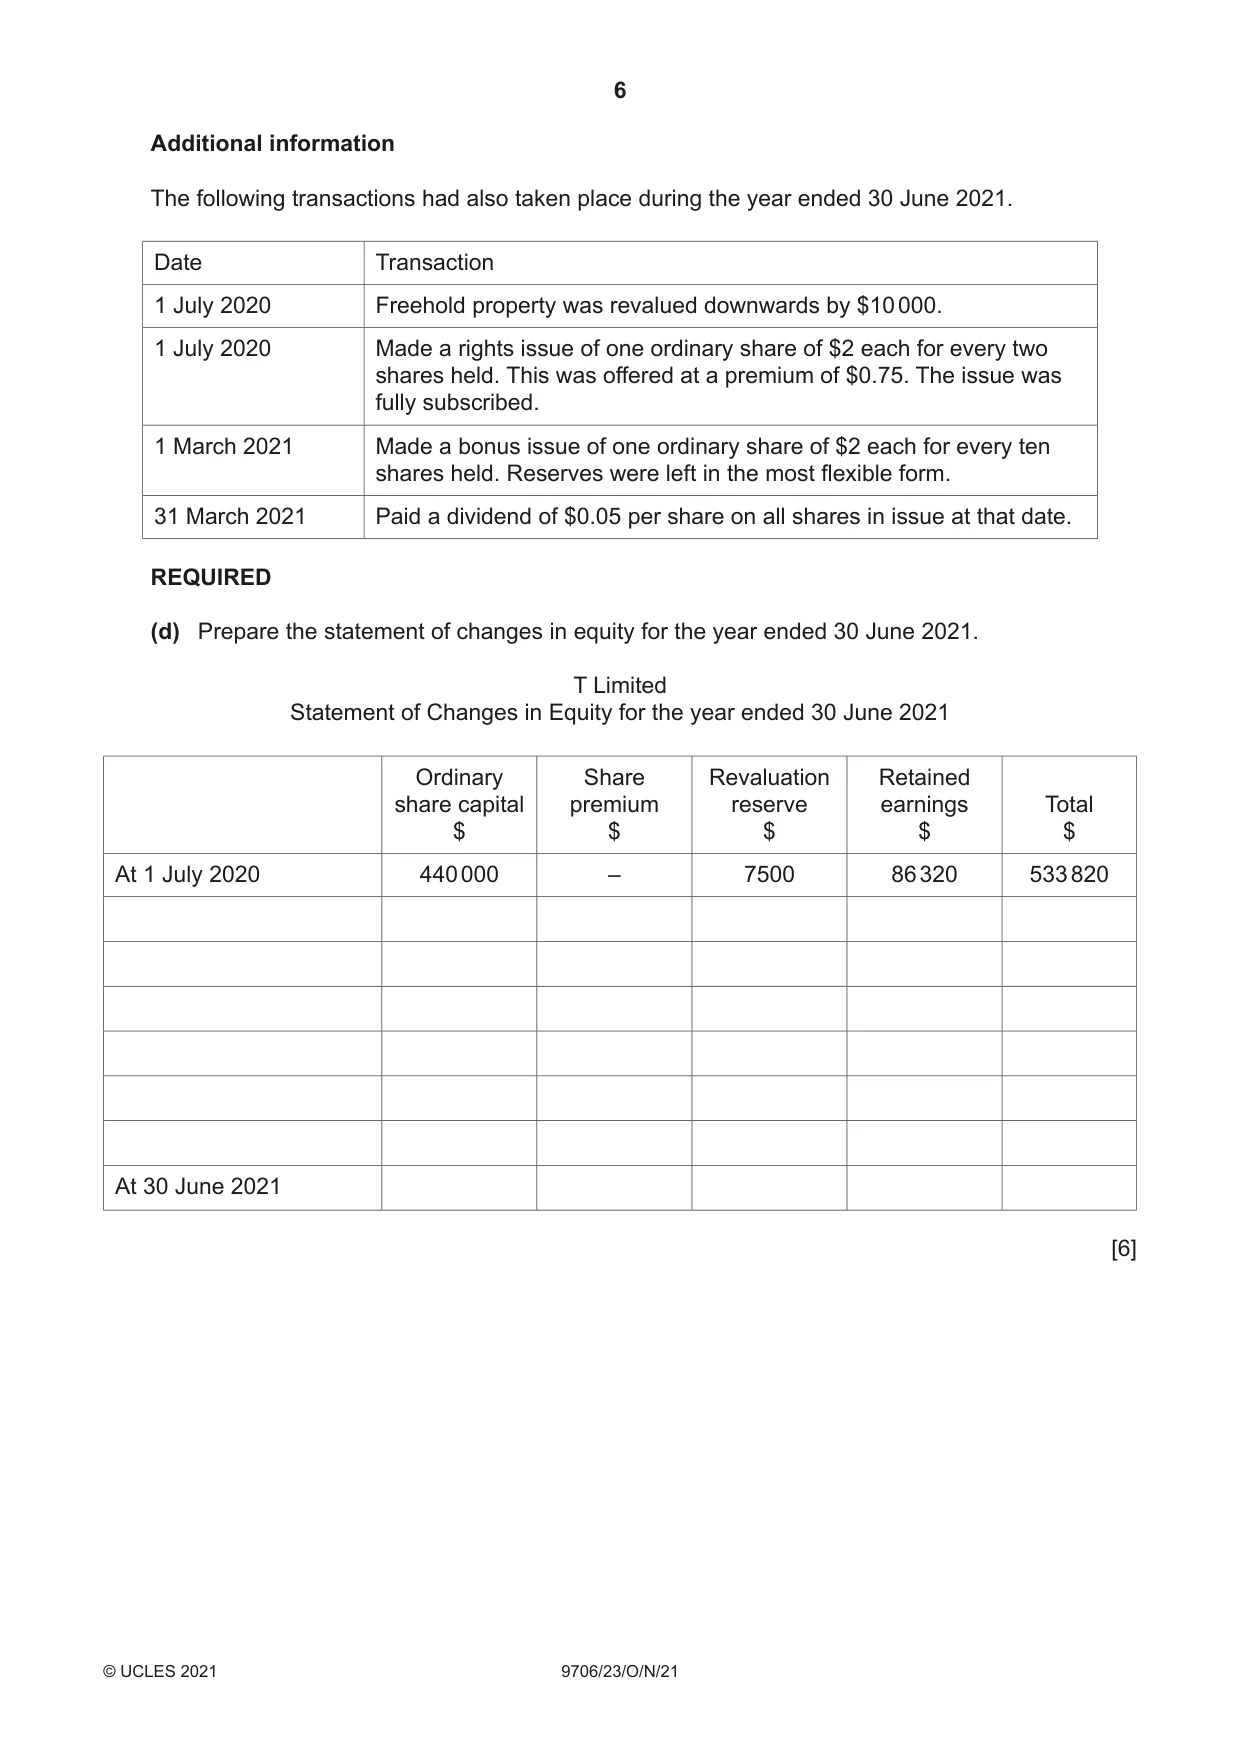
1 The following information has been extracted from the accounting records of T Limited at 30 June 2021. 1 Inventory at 1 July 2020 was valued at $46 800. 2 Inventory at 30 June 2021 was valued at $54 200. 3 The rate of inventory turnover was 8.8 times. 4 The gross profit margin was 45%. REQUIRED (a) Calculate for the year ended 30 June 2021: (i) cost of sales ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] (ii) revenue. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] Additional information The following balances were extracted from the books of account at 30 June 2021. $ 8% debentures (2026–2027) 96 000 Administrative expenses 55 900 Directors’ remuneration 62 400 Distribution costs 59 200 Finance costs 6 350 Wages and salaries 88 300 Trade receivables 110 360 Provision for doubtful debts at 1 July 2020 1 235 The following information is also available. 1 The 8% debentures (2026–2027) were taken out on 1 November 2020. Interest was paid every three months in arrears, starting on 1 February 2021.
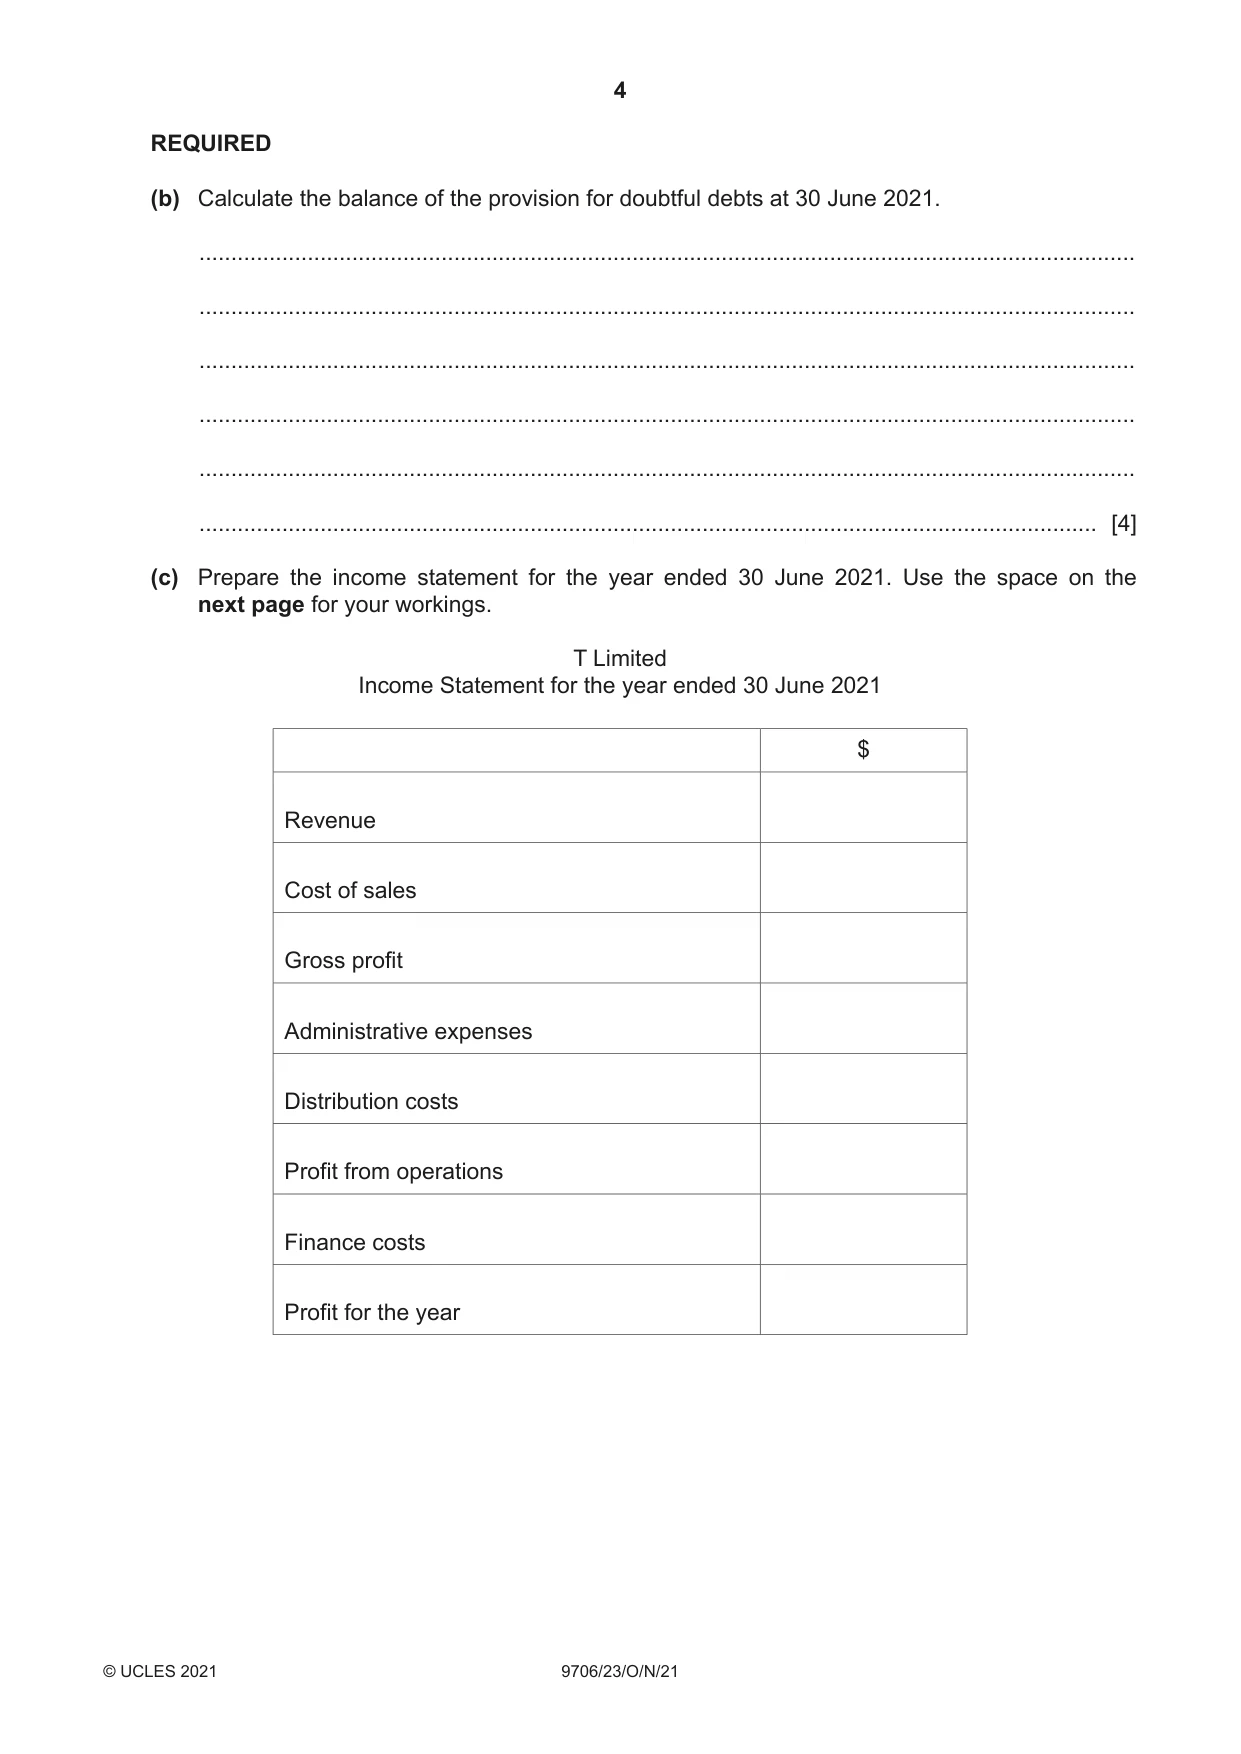
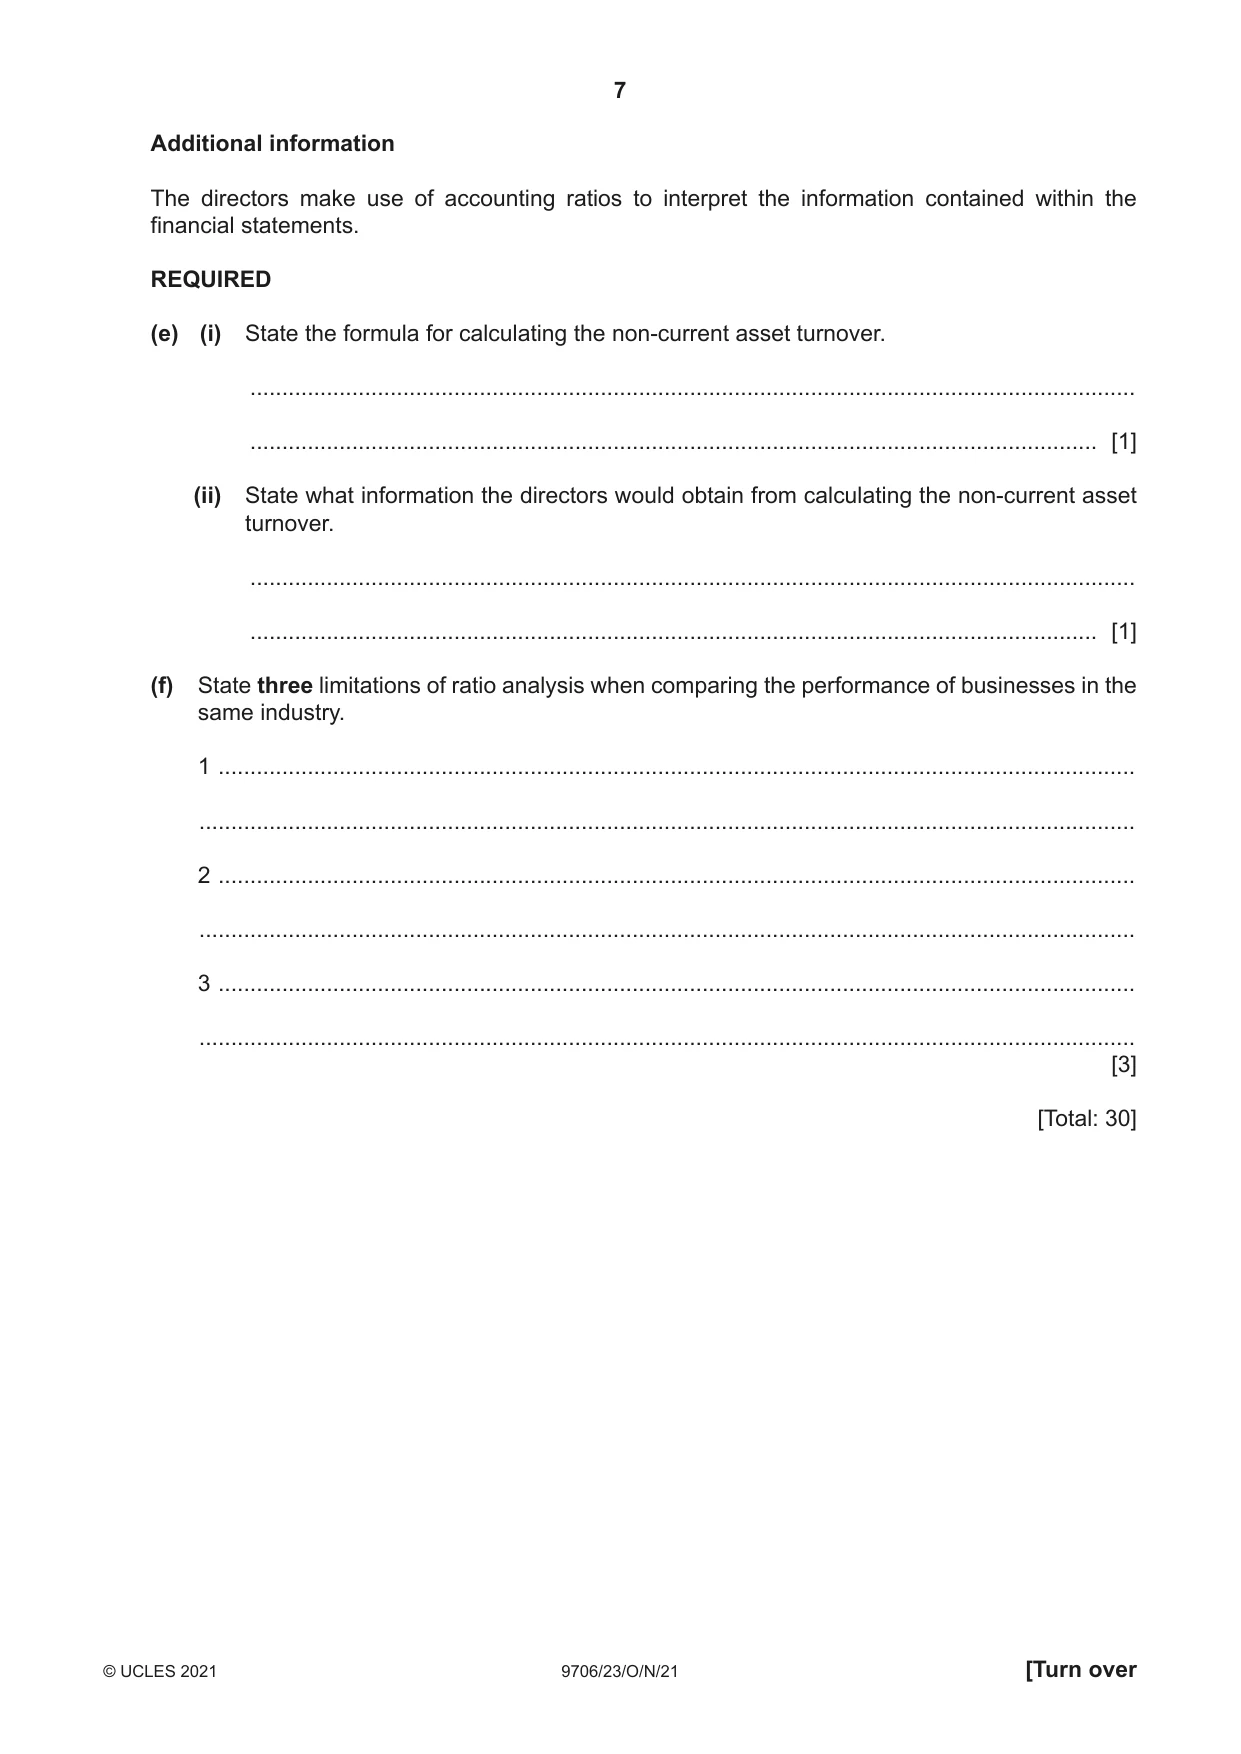
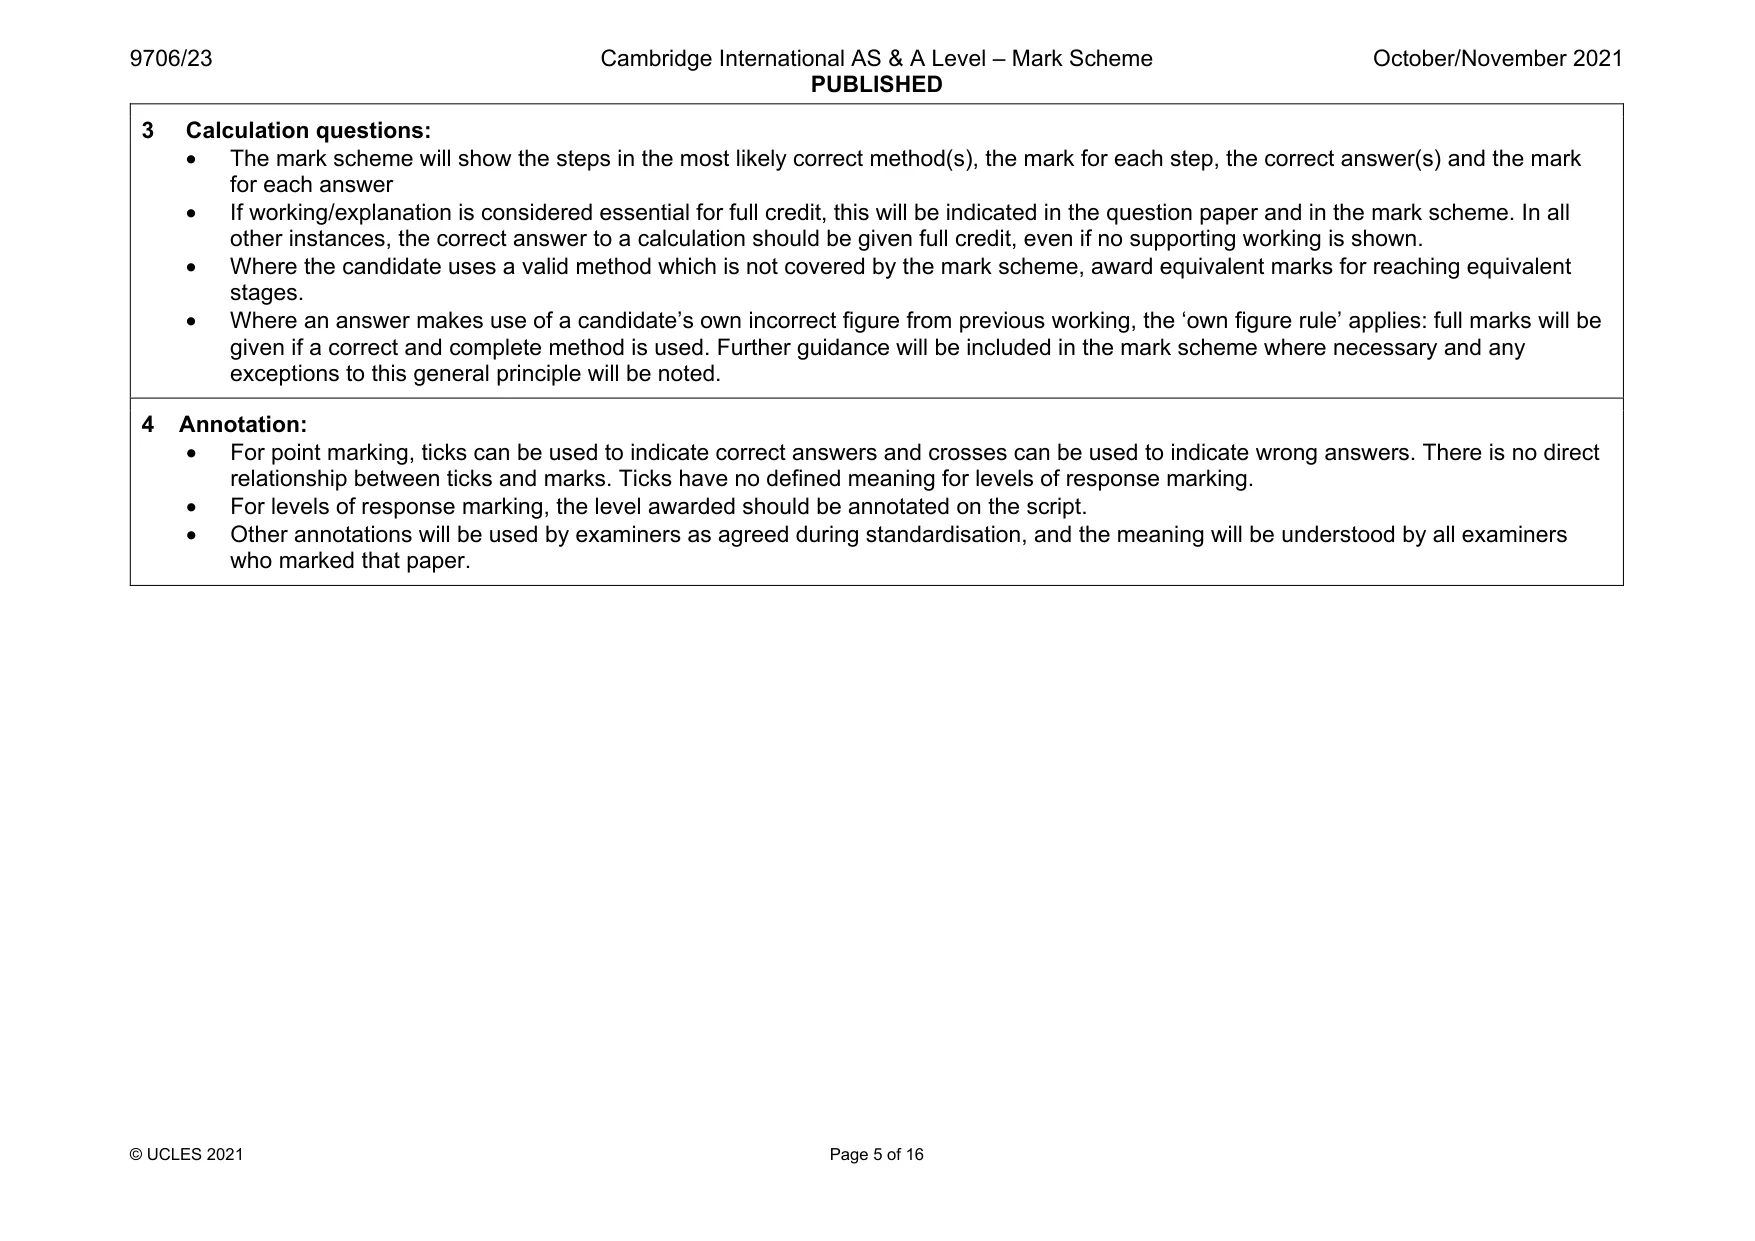
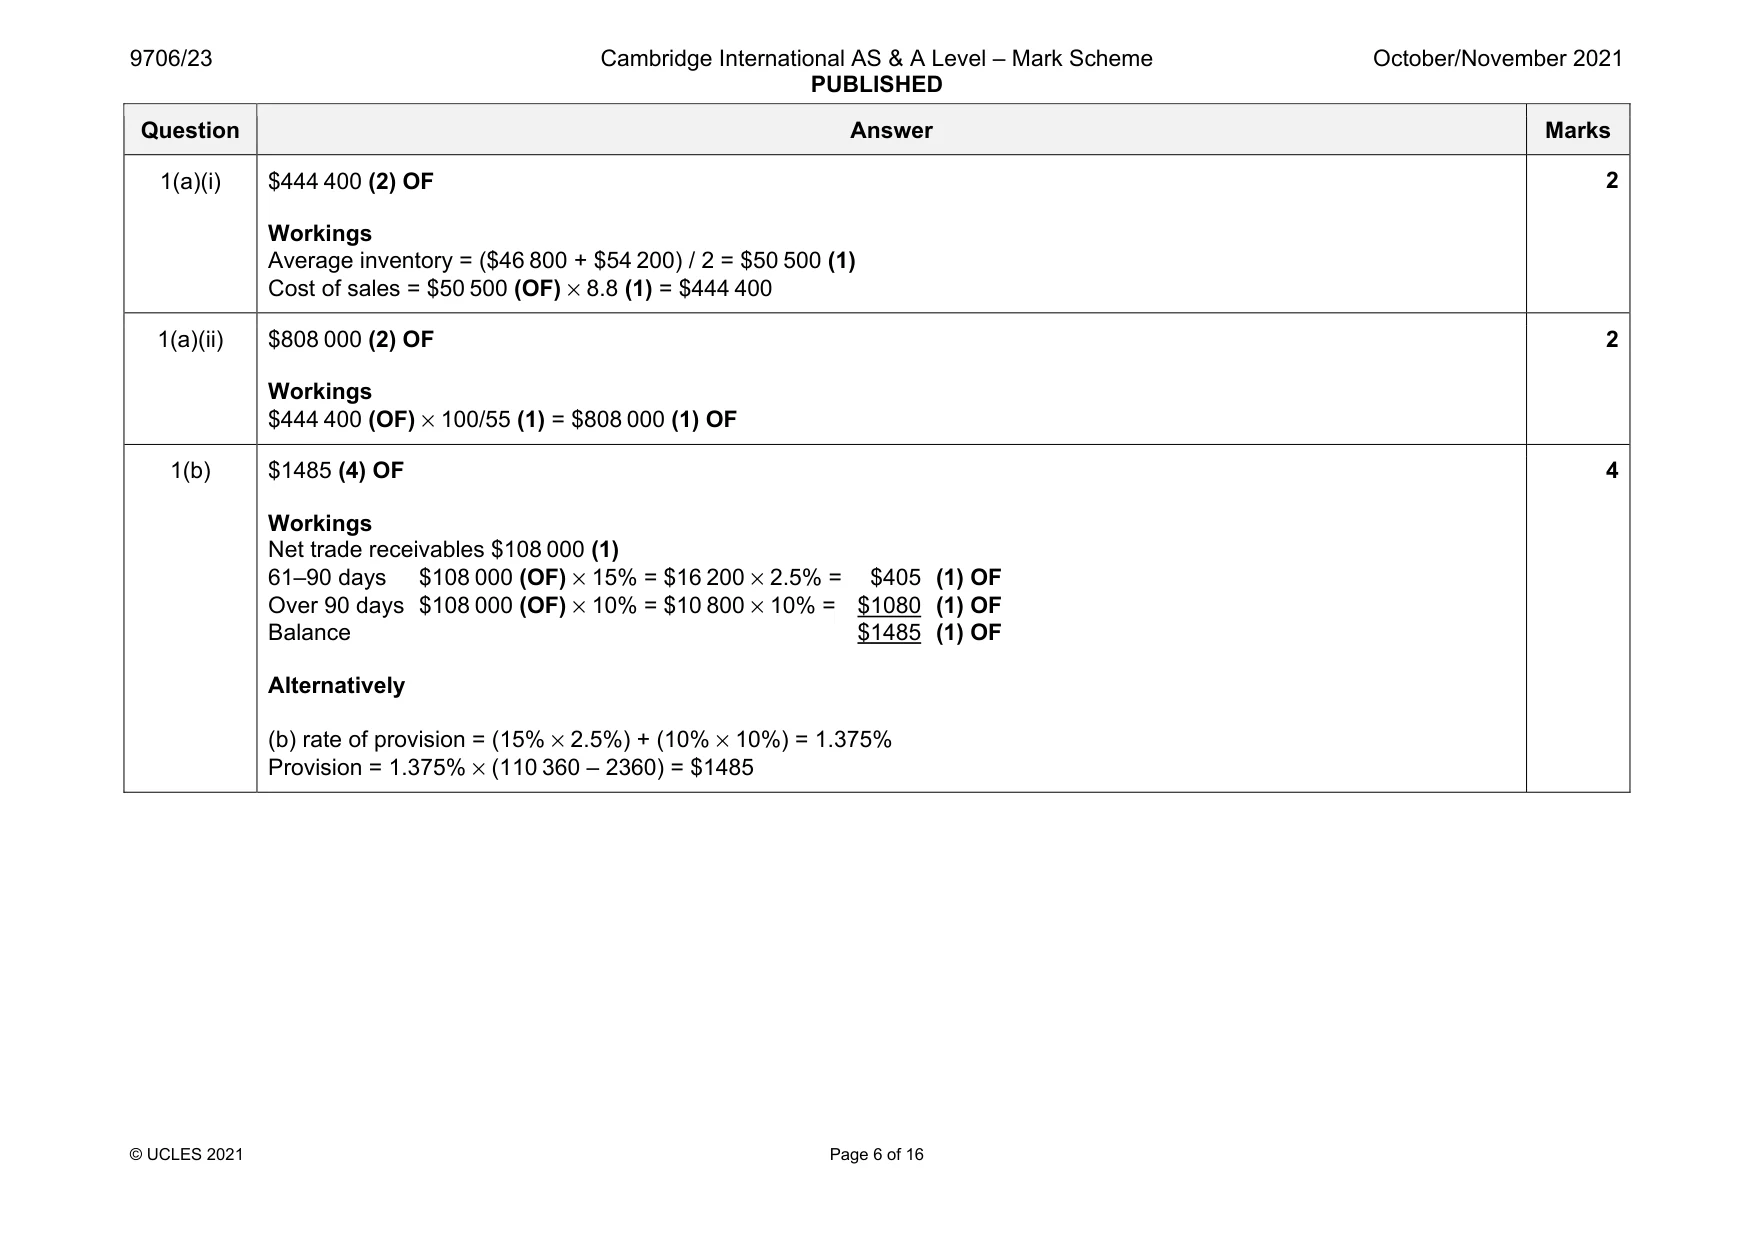
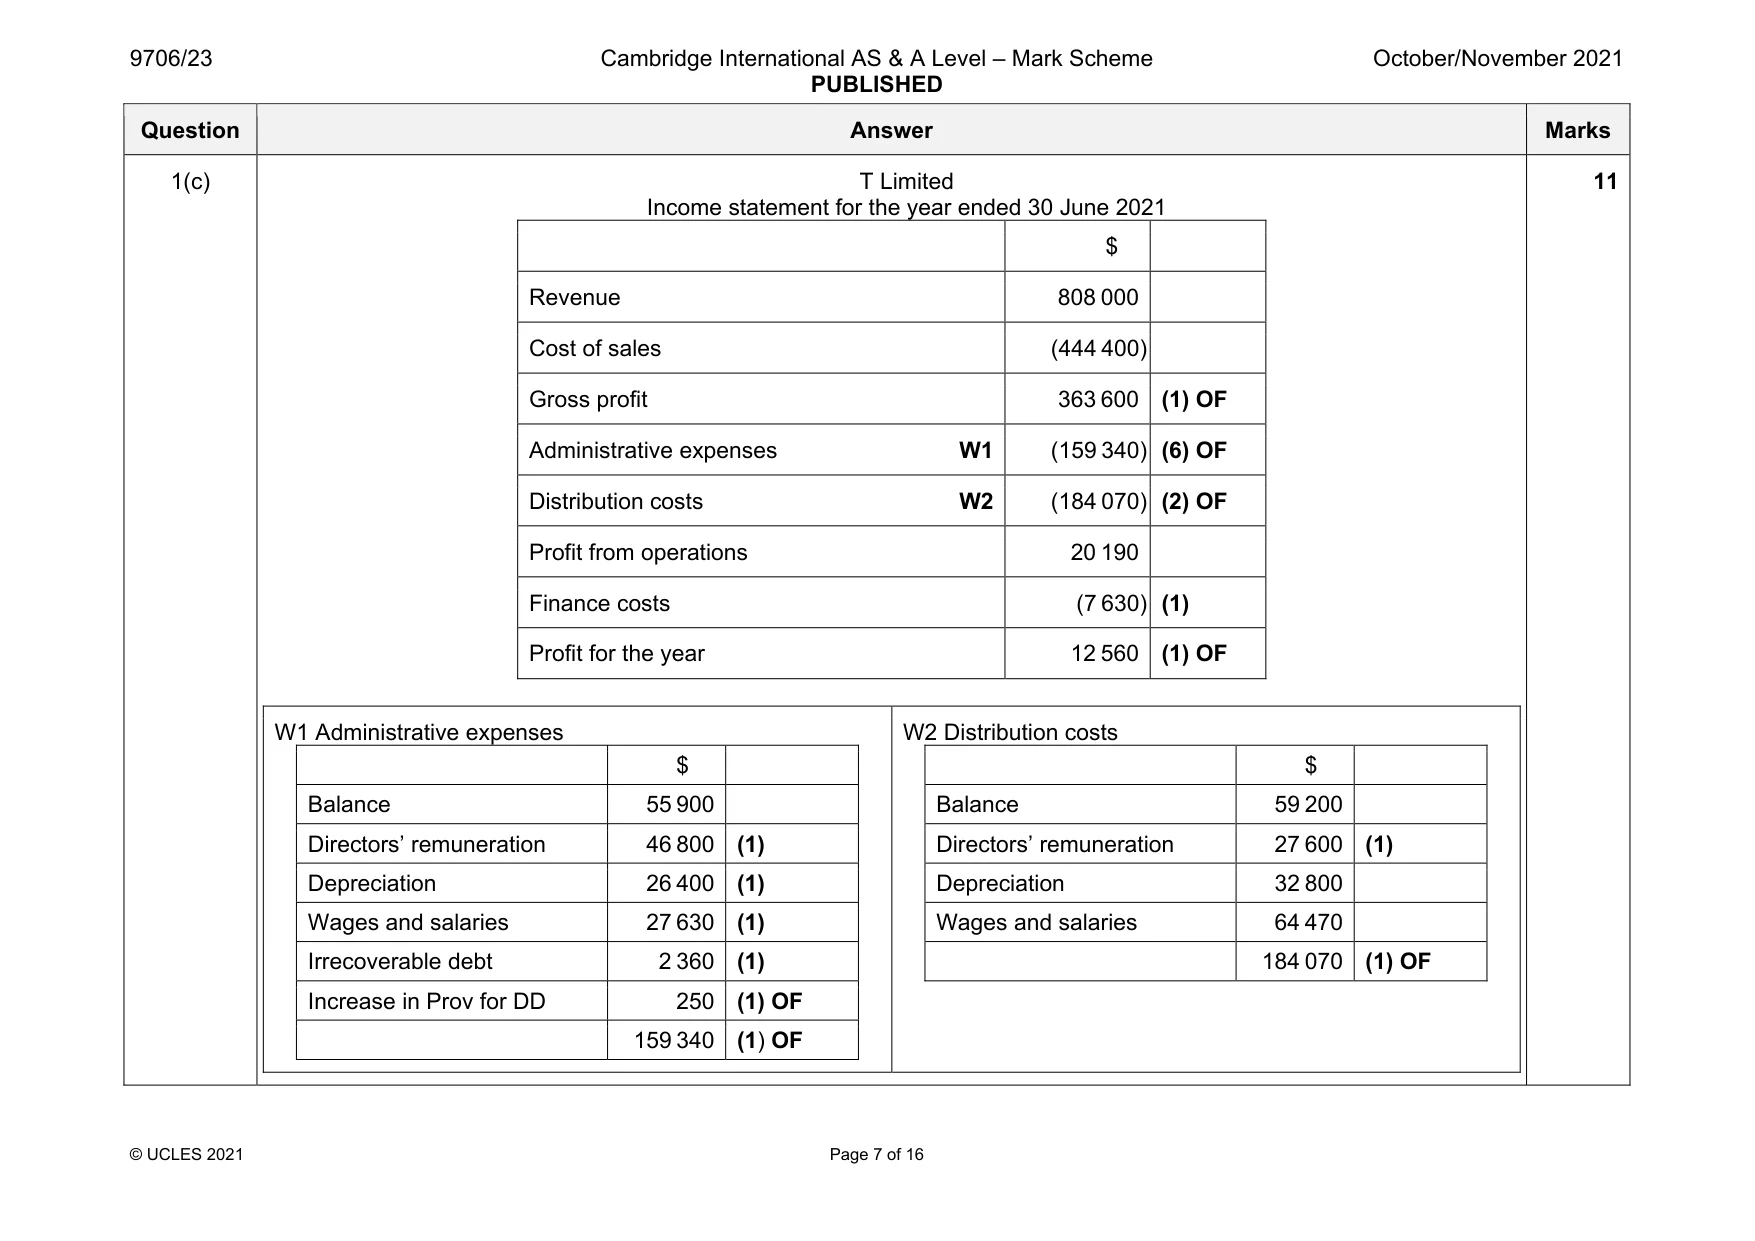
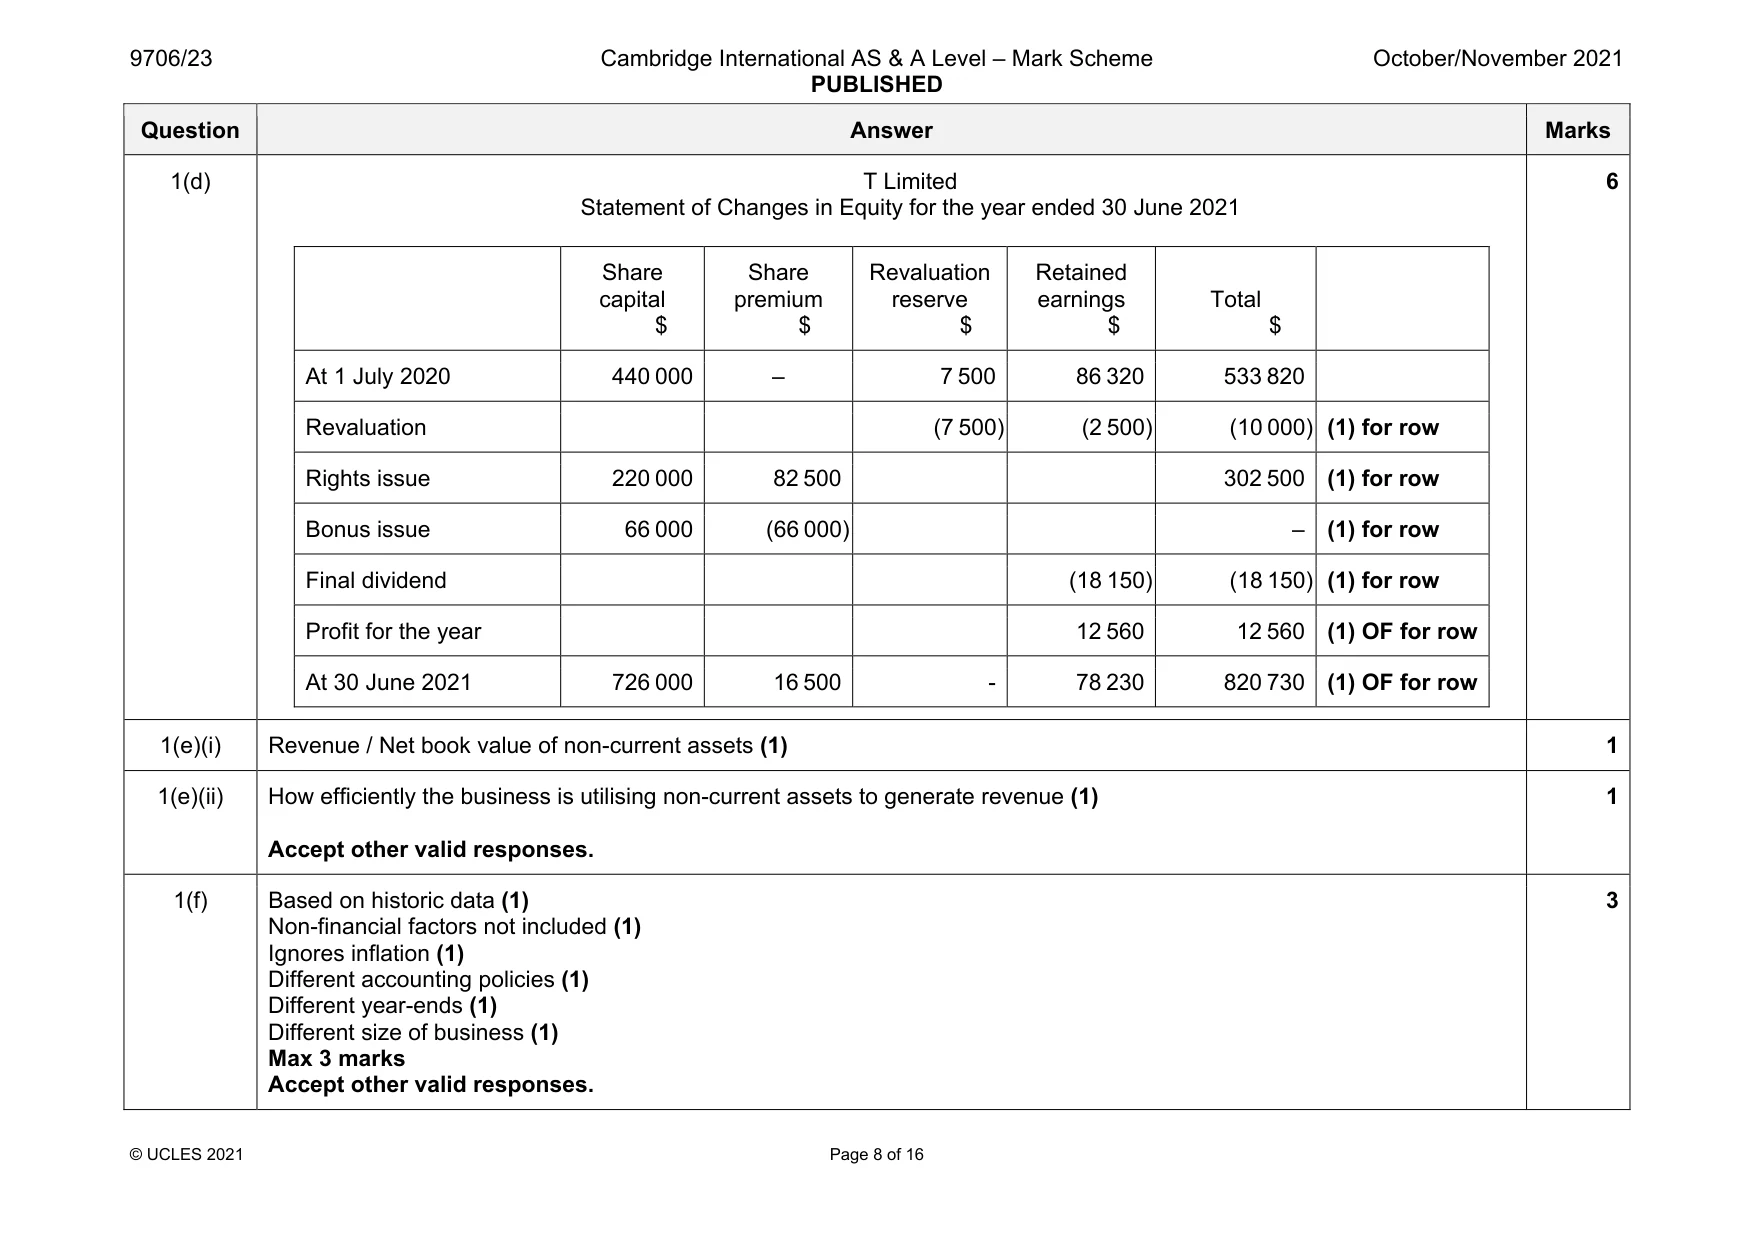
Mark scheme: 1(a)(i) $444 400 (2) OF Workings Average inventory = ($46 800 + $54 200) / 2 = $50 500 (1) Cost of sales = $50 500 (OF) × 8.8 (1) = $444 400 1(a)(ii) $808 000 (2) OF Workings $444 400 (OF) × 100/55 (1) = $808 000 (1) OF 2 1(b) $1485 (4) OF Workings Net trade receivables $108 000 (1) 61–90 days $108 000 (OF) × 15% = $16 200 × 2.5% = $405 (1) OF Over 90 days $108 000 (OF) × 10% = $10 800 × 10% = $1080 (1) OF Balance $1485 (1) OF Alternatively (b) rate of provision = (15% × 2.5%) + (10% × 10%) = 1.375% Provision = 1.375% × (110 360 – 2360) = $1485 4 Question Answer Marks 1(c) T Limited Income statement for the year ended 30 June 2021 $ Revenue 808 000 Cost of sales (444 400) Gross profit 363 600 (1) OF Administrative expenses W1 (159 340) (6) OF Distribution costs W2 (184 070) (2) OF Profit from operations 20 190 Finance costs (7 630) (1) Profit for the year 12 560 (1) OF W1 Administrative expenses $ Balance 55 900 Directors’ remuneration 46 800 (1) Depreciation 26 400 (1) Wages and salaries 27 630 (1) Irrecoverable debt 2 360 (1) Increase in Prov for DD 250 (1) OF 159 340 (1) OF W2 Distribution costs $ Balance 59 200 Directors’ remuneration 27 600 (1) Depreciation 32 800 Wages and salaries 64 470 184 070 (1) OF 11 Question Answer Marks 1(d) T Limited Statement of Changes in Equity for the year ended 30 June 2021 Share capital $ Share premium $ Revaluation reserve $ Retained earnings $ Total $ At 1 July 2020 440 000 – 7 500 86 320 533 820 Revaluation (7 500) (2 500) (10 000) (1) for row Rights issue 220 000 82 500 302 500 (1) for row Bonus issue 66 000 (66 000) – (1) for row Final dividend (18 150) (18 150) (1) for row Profit for the year 12 560 12 560 (1) OF for row At 30 June 2021 726 000 16 500 - 78 230 820 730 (1) OF for row 6 1(e)(i) Revenue / Net book value of non-current assets (1) 1 1(e)(ii) How efficiently the business is utilising non-current assets to generate revenue (1) Accept other valid responses. 1 1(f) Based on historic data (1) Non-financial factors not included (1) Ignores inflation (1) Different accounting policies (1) Different year-ends (1) Different size of business (1) Max 3 marks Accept other valid responses. 3
More questions on Analysis and communication of accounting information
Q2 · Abbie, Ben and Cain have been in partnership for many years sharing profits and losses in…
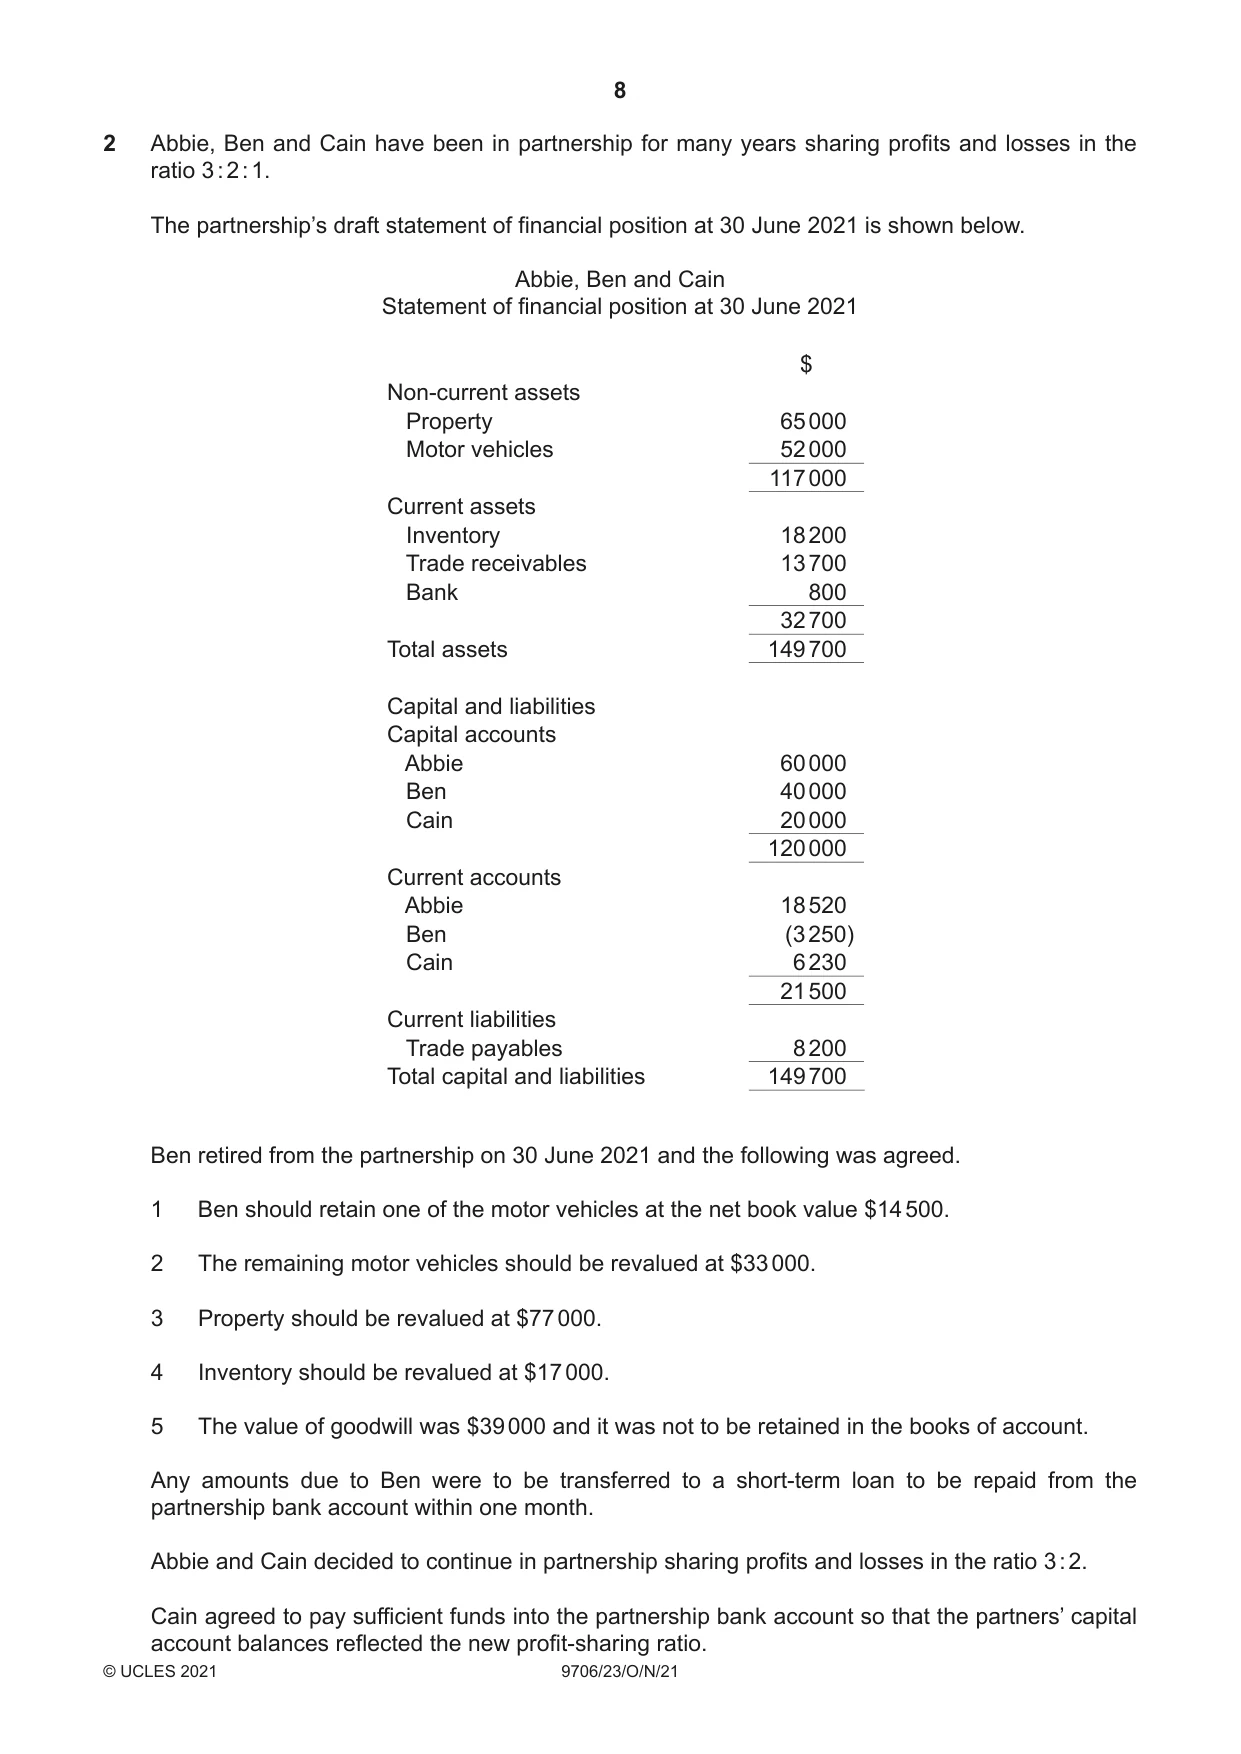
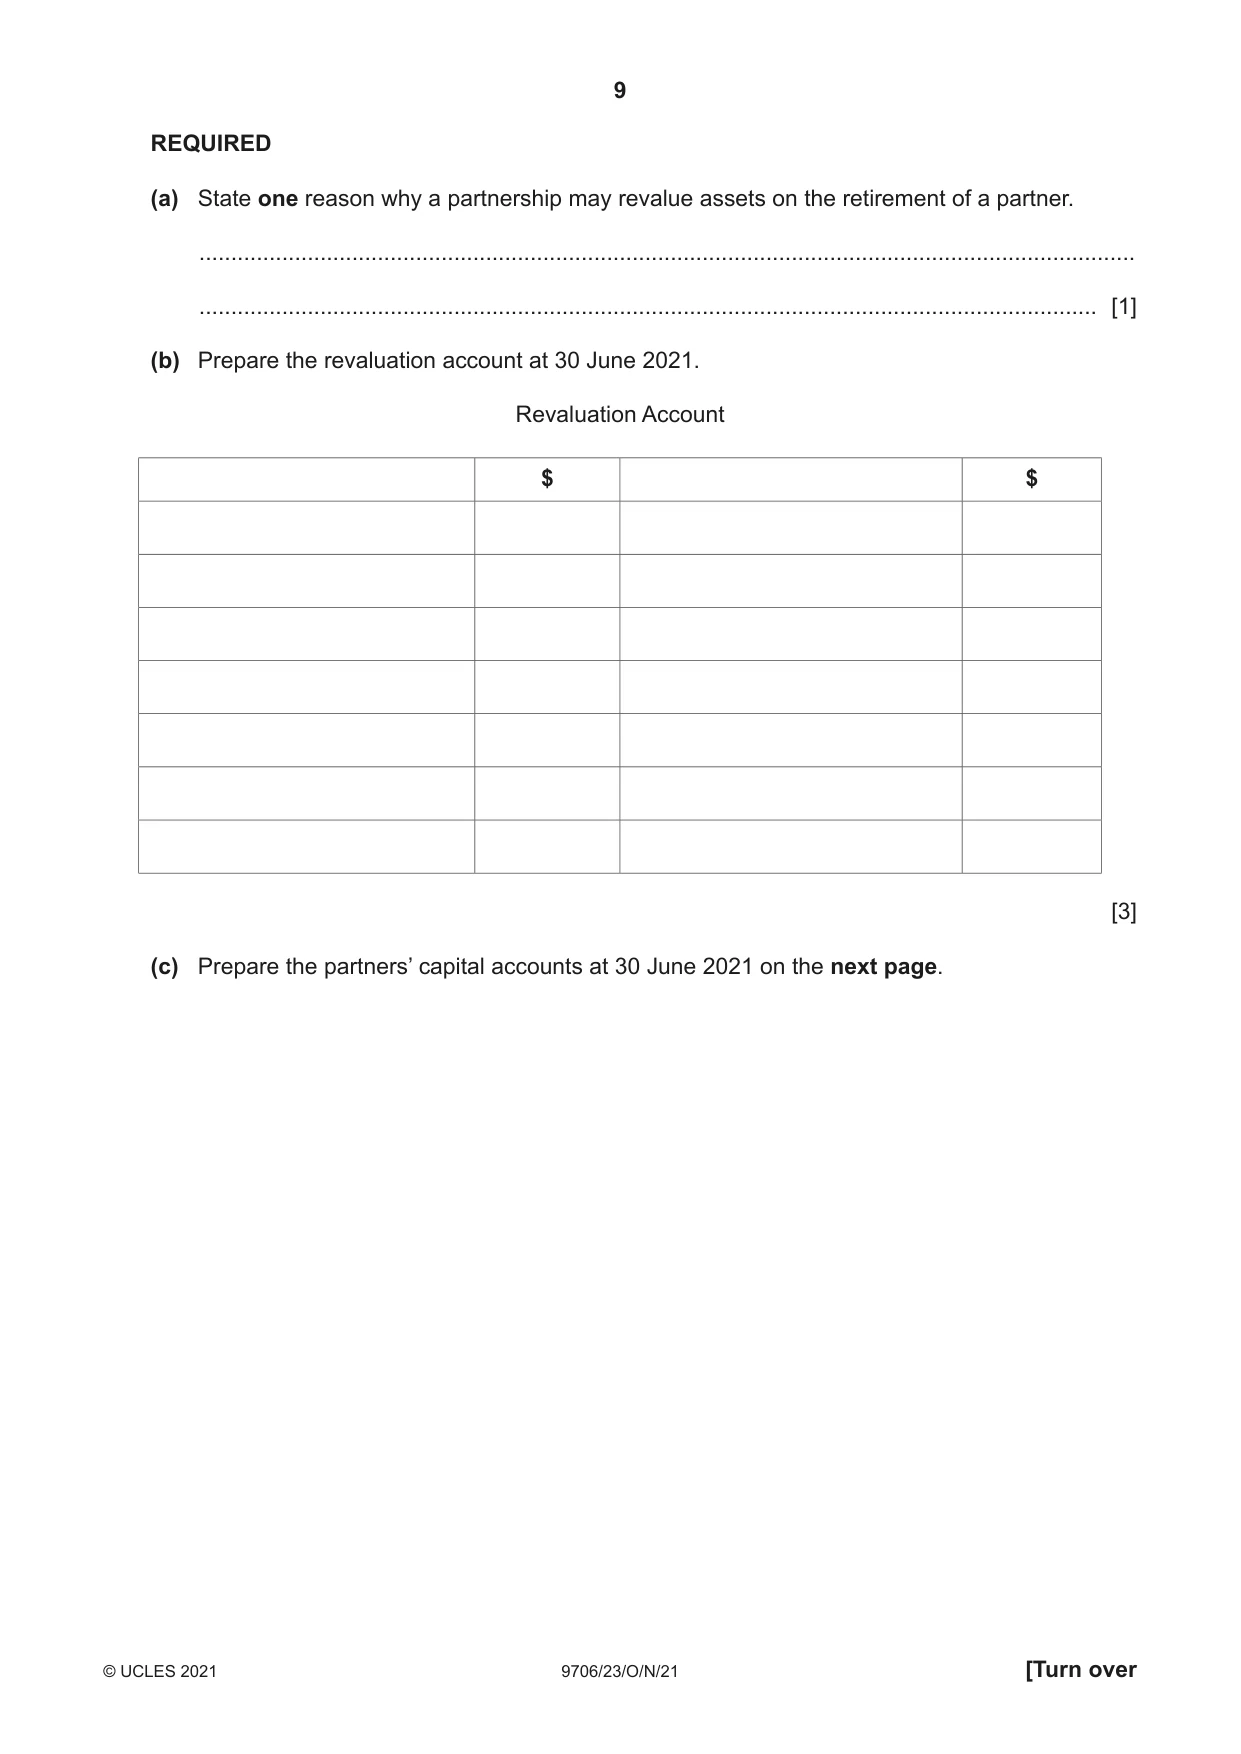
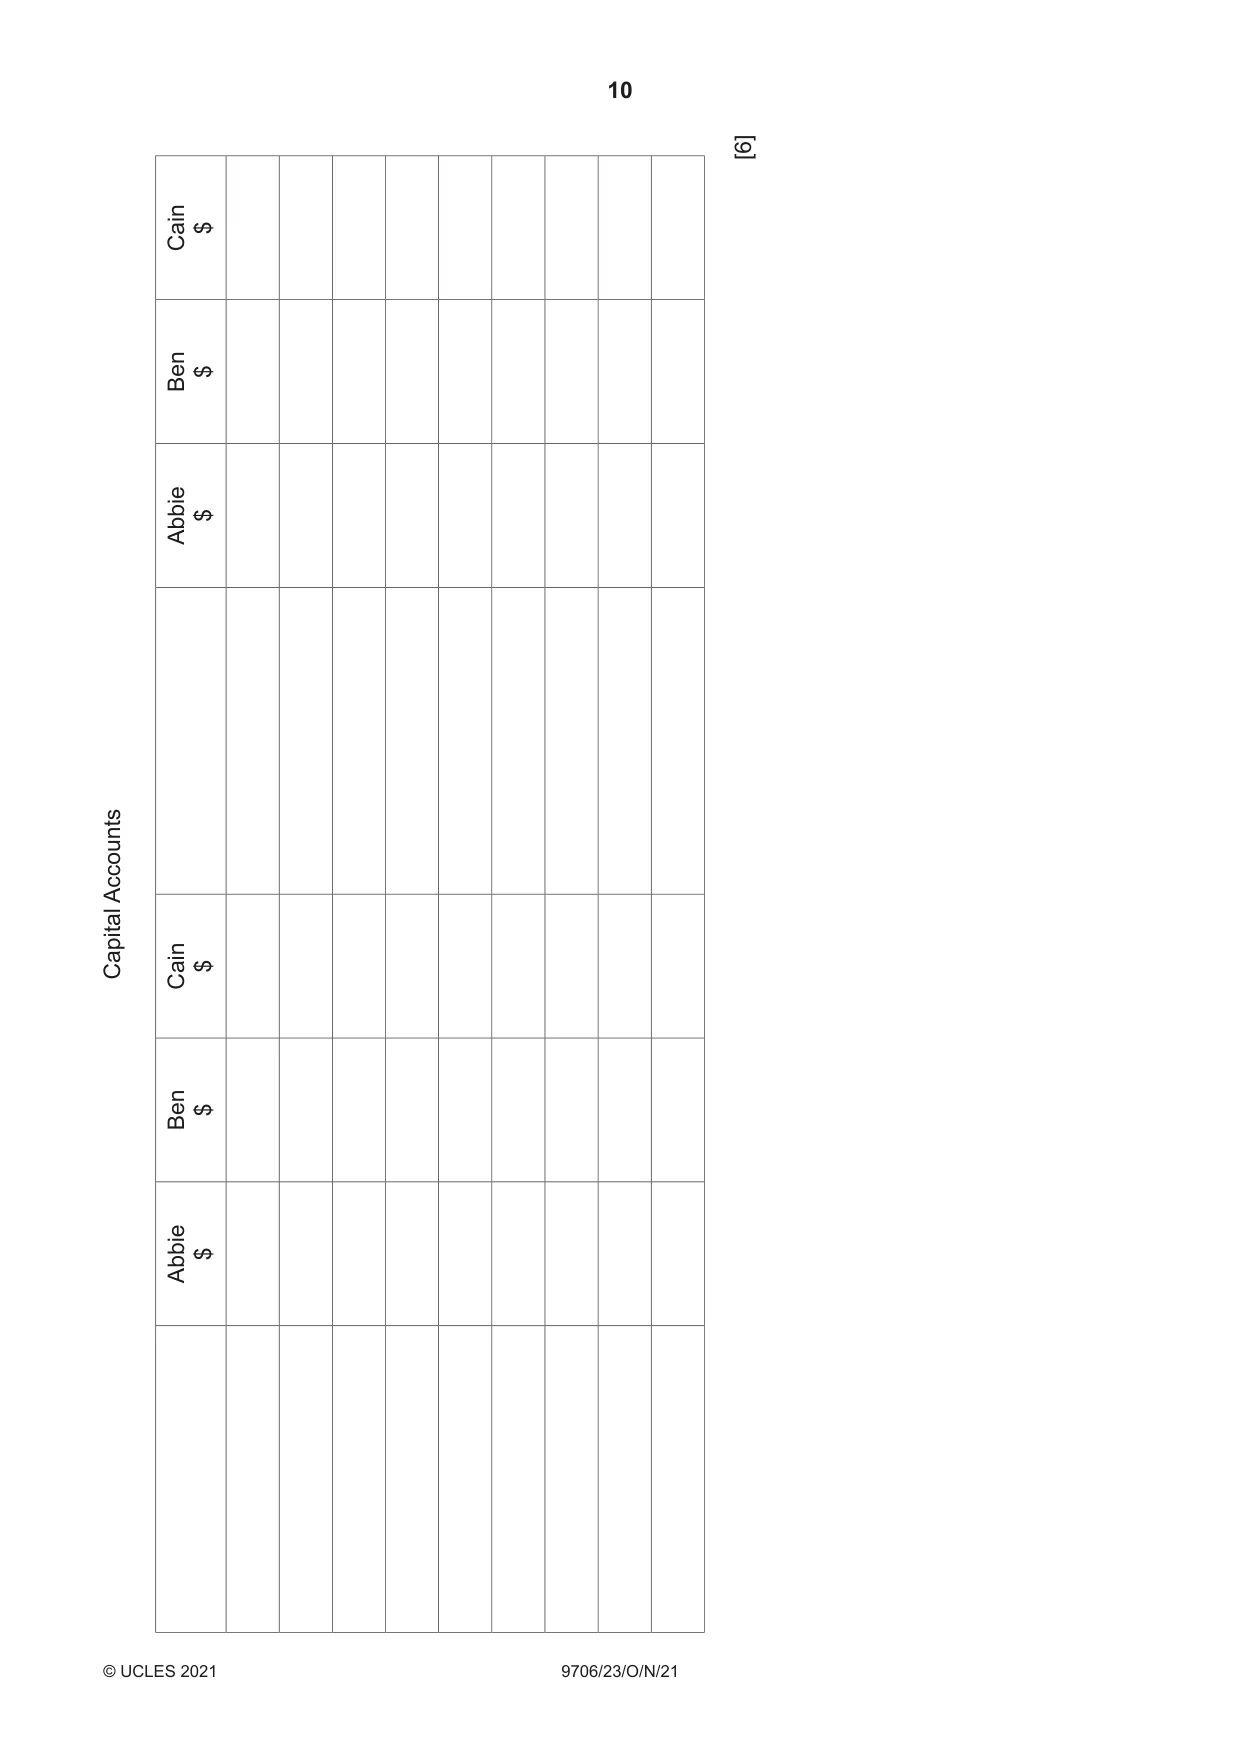
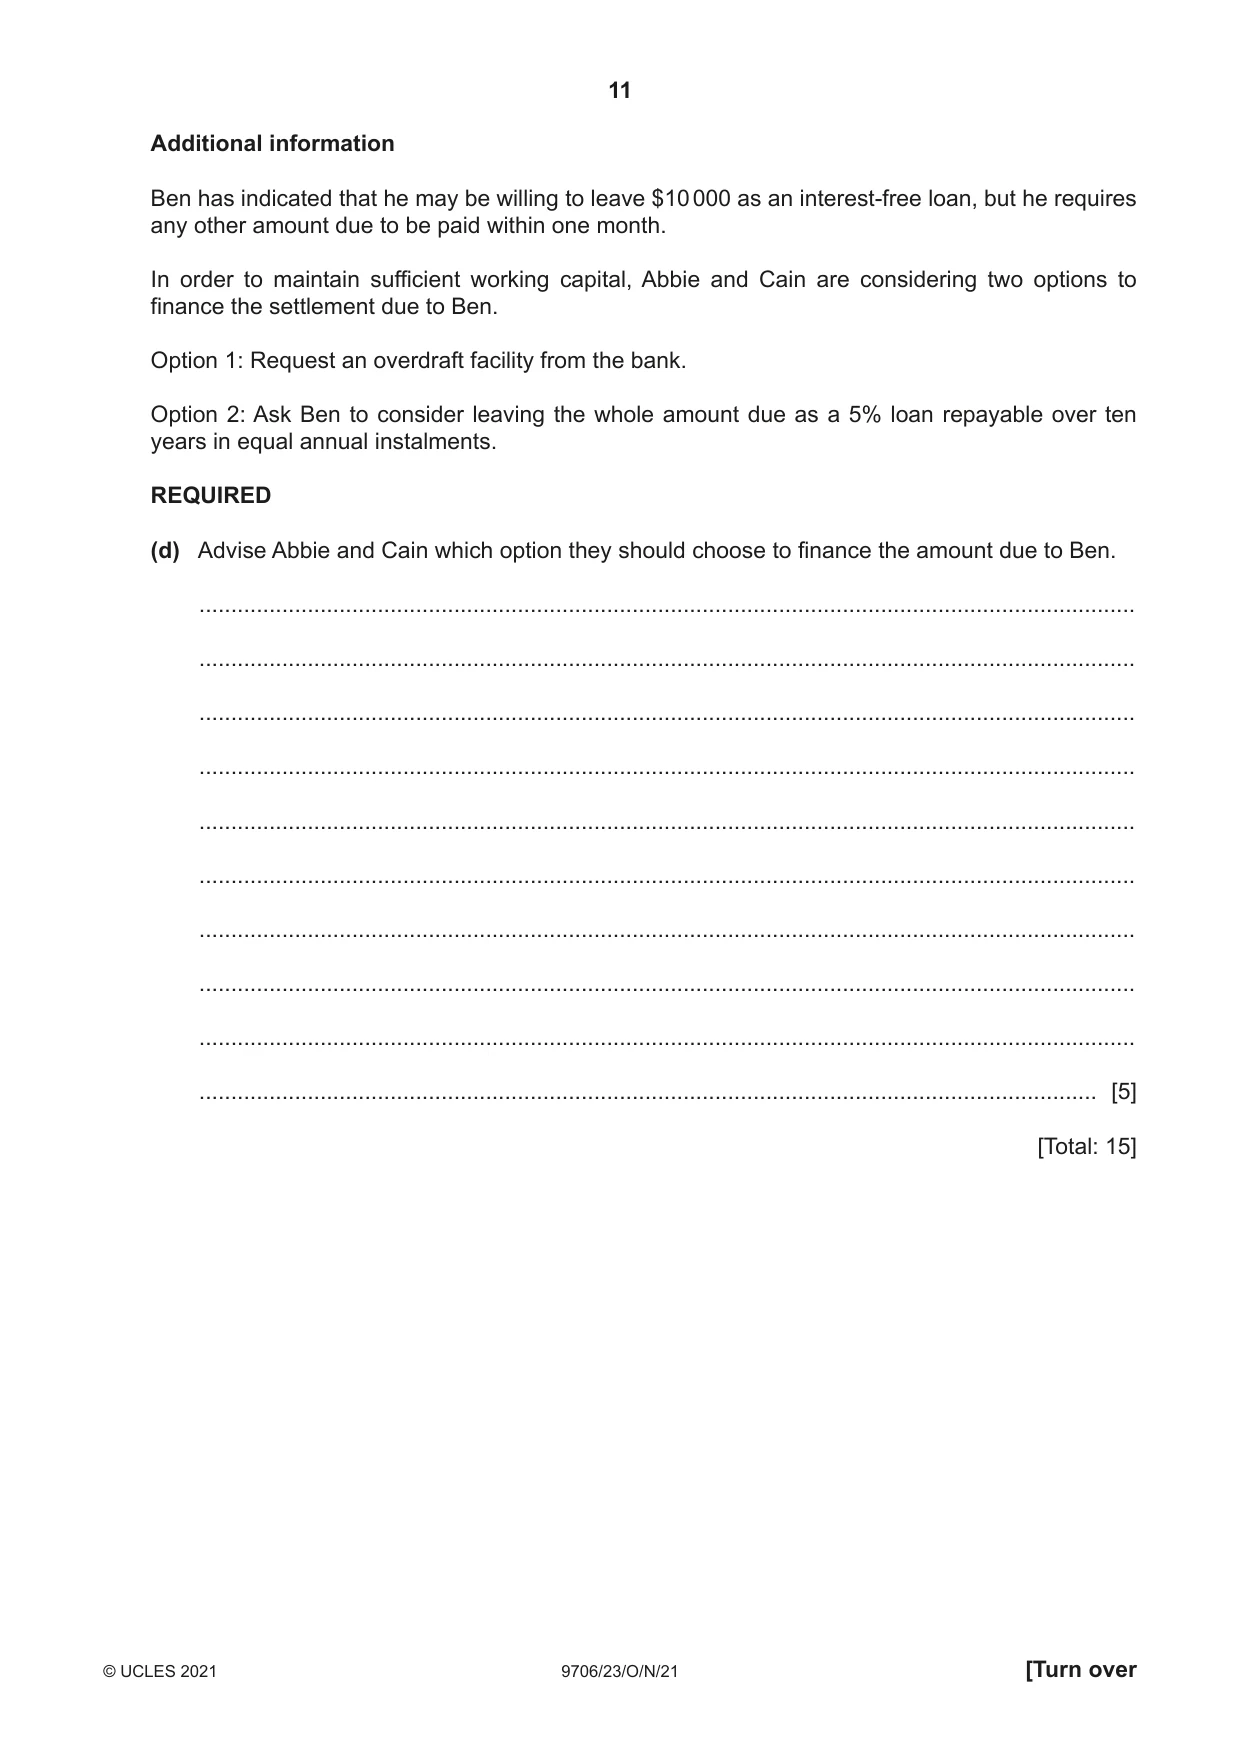
2 Abbie, Ben and Cain have been in partnership for many years sharing profits and losses in the ratio 3 : 2 : 1. The partnership’s draft statement of financial position at 30 June 2021 is shown below. Abbie, Ben and Cain Statement of financial position at 30 June 2021 $ Non-current assets Property 65 000 Motor vehicles 52 000 117 000 Current assets Inventory 18 200 Trade receivables 13 700 Bank 800 32 700 Total assets 149 700 Capital and liabilities Capital accounts Abbie 60 000 Ben 40 000 Cain 20 000 120 000 Current accounts Abbie 18 520 Ben (3 250) Cain 6 230 21 500 Current liabilities Trade payables 8 200 Total capital and liabilities 149 700 Ben retired from the partnership on 30 June 2021 and the following was agreed. 1 Ben should retain one of the motor vehicles at the net book value $14 500. 2 The remaining motor vehicles should be revalued at $33 000. 3 Property should be revalued at $77 000. 4 Inventory should be revalued at $17 000. 5 The value of goodwill was $39 000 and it was not to be retained in the books of account. Any amounts due to Ben were to be transferred to a short-term loan to be repaid from the partnership bank account within one month. Abbie and Cain decided to continue in partnership sharing profits and losses in the ratio 3 : 2. Cain agreed to pay sufficient funds into the partnership bank account so that the partners’ capital account balances reflected the new profit-sharing ratio. REQUIRED (a) State one reason why a partnership may revalue assets on the retirement of a partner. ................................................................................................................................................... ............................................................................................................................................. [1] (b) Prepare the revaluation account at 30 June 2021. Revaluation Account $ $ [3] (c) Prepare the partners’ capital accounts at 30 June 2021 on the next page. [6] $ Cain $ Ben $ Abbie Accounts $Capital Cain $ Ben $ Abbie Additional information Ben has indicated that he may be willing to leave $10 000 as an interest-free loan, but he requires any other amount due to be paid within one month. In order to maintain sufficient working capital, Abbie and Cain are considering two options to finance the settlement due to Ben. Option 1: Request an overdraft facility from the bank. Option 2: Ask Ben to consider leaving the whole amount due as a 5% loan repayable over ten years in equal annual instalments. REQUIRED (d) Advise Abbie and Cain which option they should choose to finance the amount due to Ben. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 15]
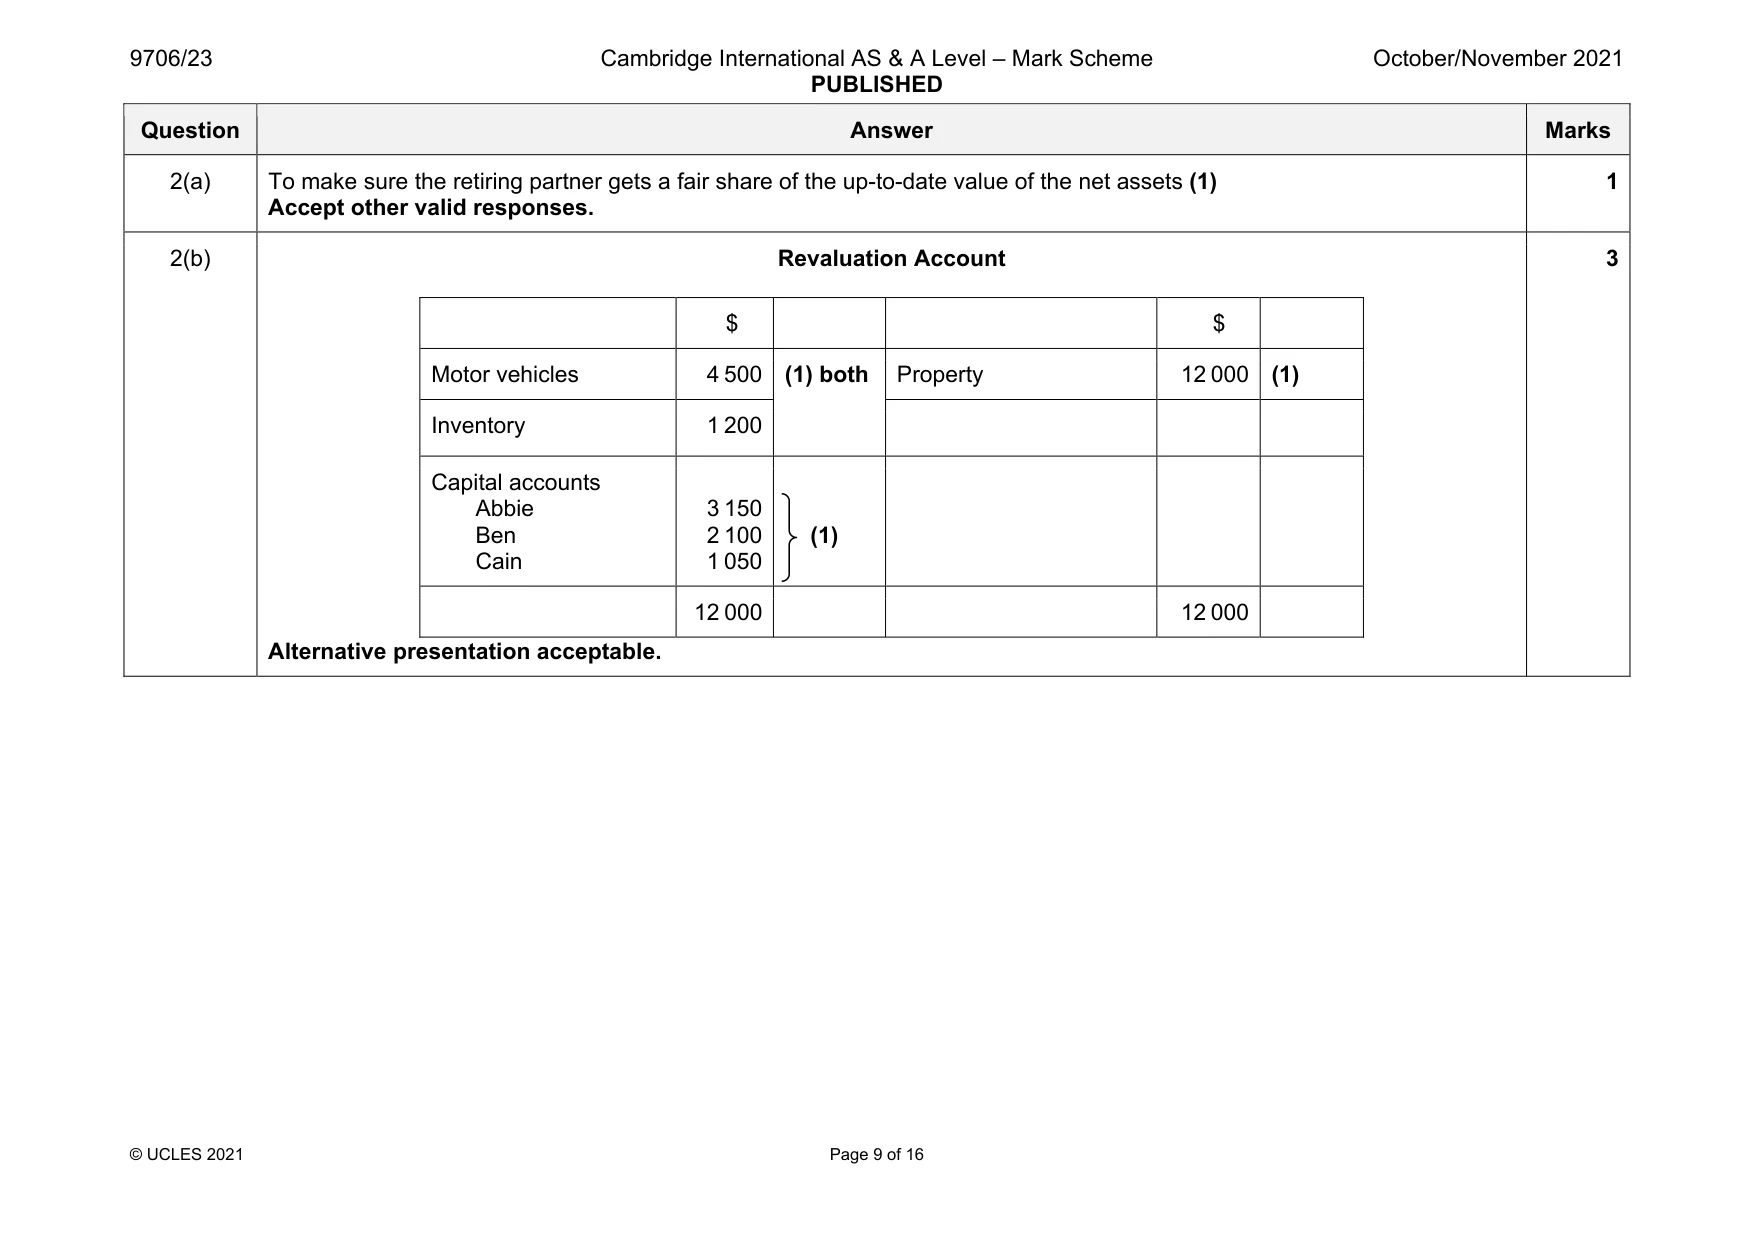
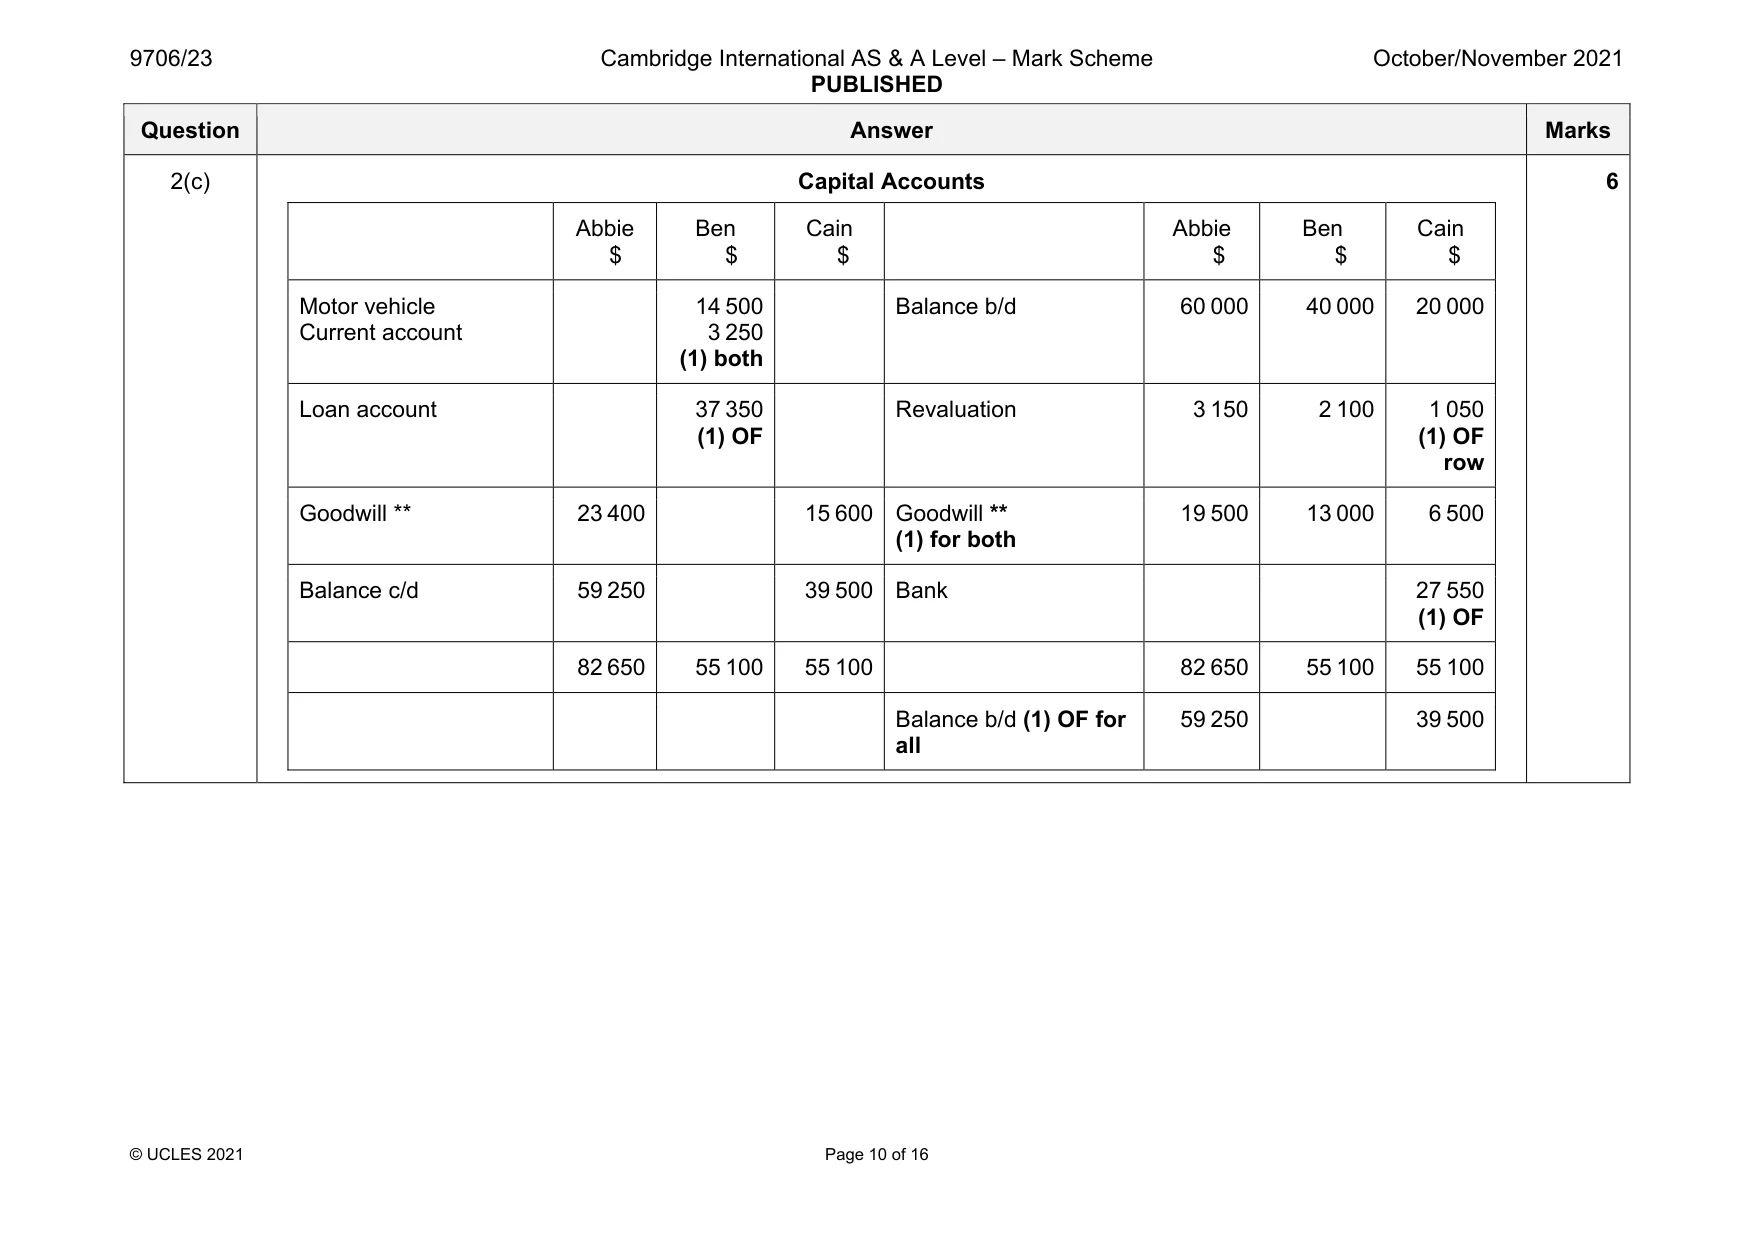
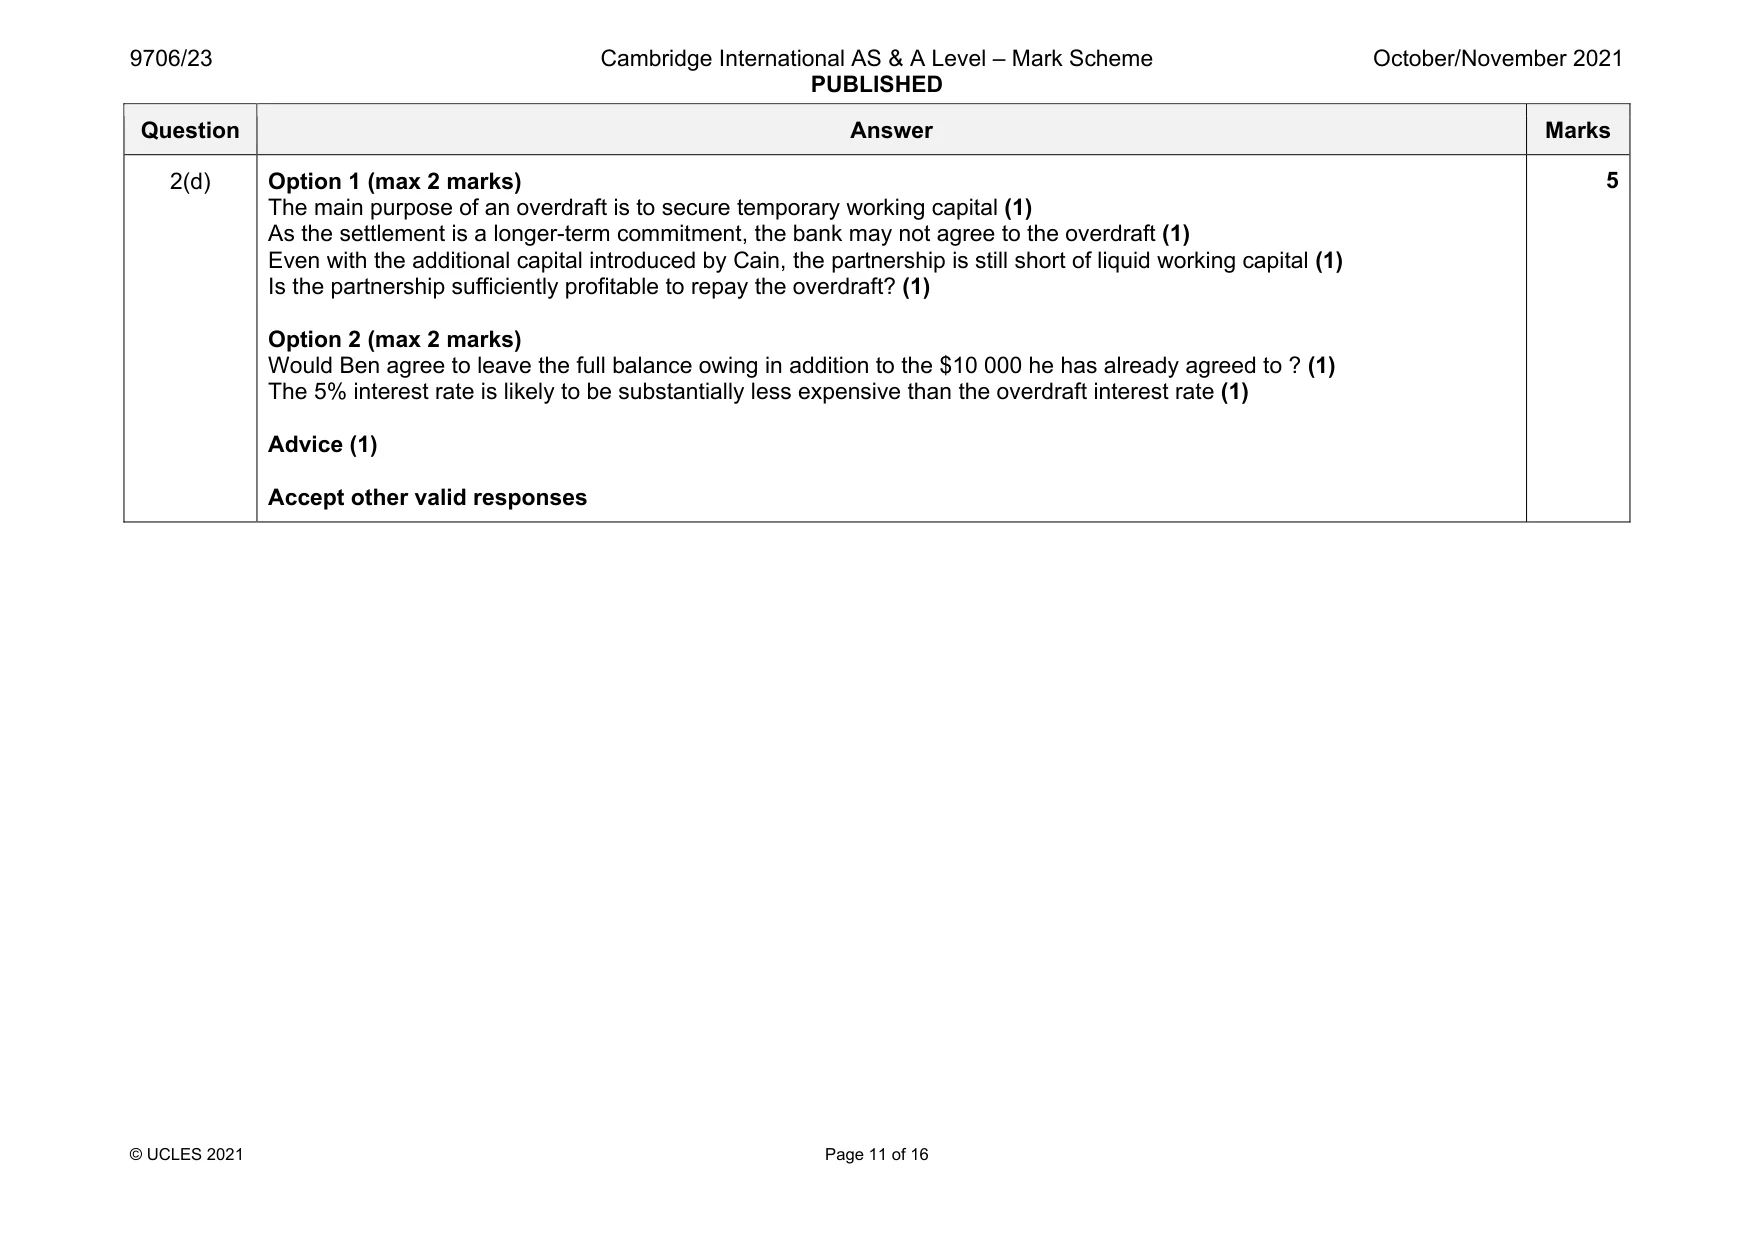
Mark scheme: 2(a) To make sure the retiring partner gets a fair share of the up-to-date value of the net assets (1) Accept other valid responses. 1 2(b) Revaluation Account $ $ Motor vehicles 4 500 (1) both Property 12 000 (1) Inventory 1 200 Capital accounts Abbie Ben Cain 3 150 2 100 1 050 (1) 12 000 12 000 Alternative presentation acceptable. 3 Question Answer Marks 2(c) Capital Accounts Abbie $ Ben $ Cain $ Abbie $ Ben $ Cain $ Motor vehicle Current account 14 500 3 250 (1) both Balance b/d 60 000 40 000 20 000 Loan account 37 350 (1) OF Revaluation 3 150 2 100 1 050 (1) OF row Goodwill ** 23 400 15 600 Goodwill ** (1) for both 19 500 13 000 6 500 Balance c/d 59 250 39 500 Bank 27 550 (1) OF 82 650 55 100 55 100 82 650 55 100 55 100 Balance b/d (1) OF for all 59 250 39 500 6 Question Answer Marks 2(d) Option 1 (max 2 marks) The main purpose of an overdraft is to secure temporary working capital (1) As the settlement is a longer-term commitment, the bank may not agree to the overdraft (1) Even with the additional capital introduced by Cain, the partnership is still short of liquid working capital (1) Is the partnership sufficiently profitable to repay the overdraft? (1) Option 2 (max 2 marks) Would Ben agree to leave the full balance owing in addition to the $10 000 he has already agreed to ? (1) The 5% interest rate is likely to be substantially less expensive than the overdraft interest rate (1) Advice (1) Accept other valid responses 5
Q3 · Petra owns a small manufacturing business
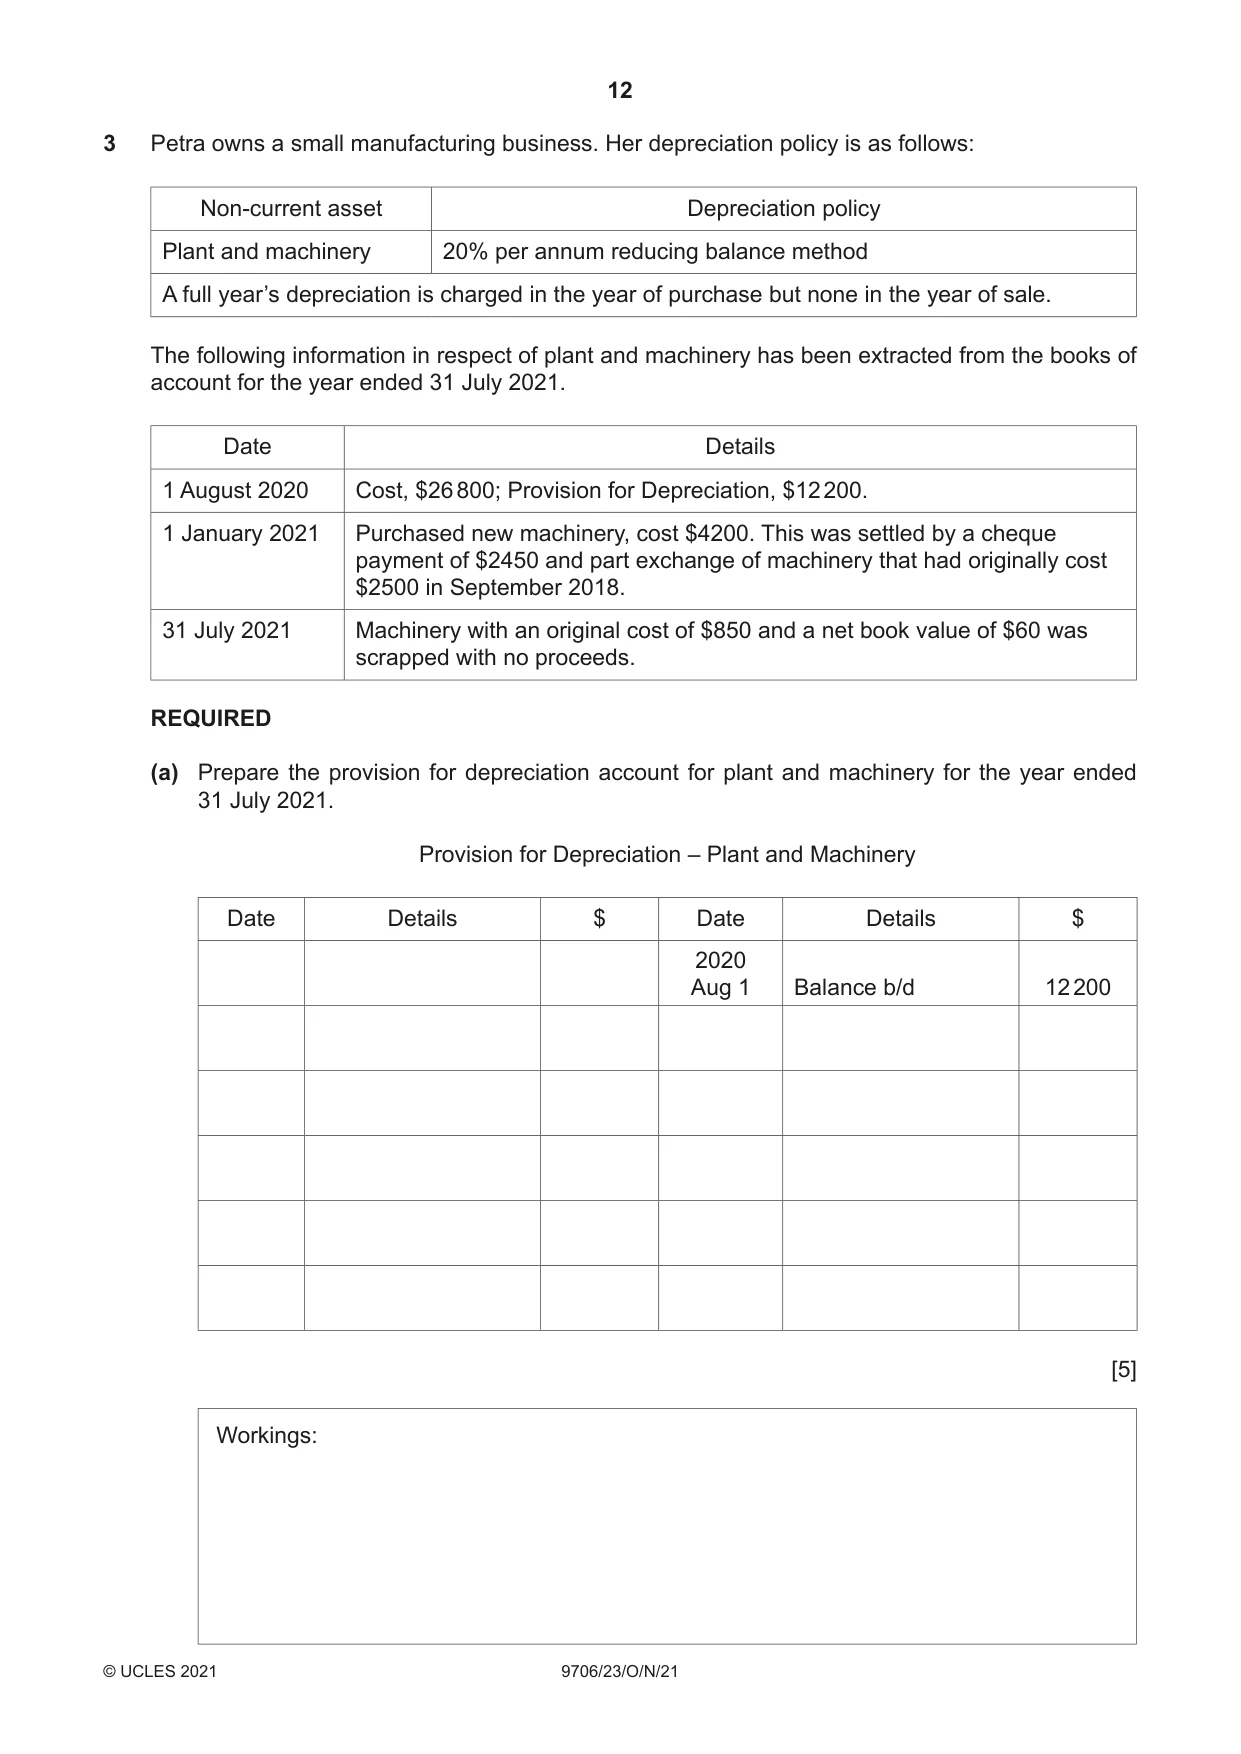
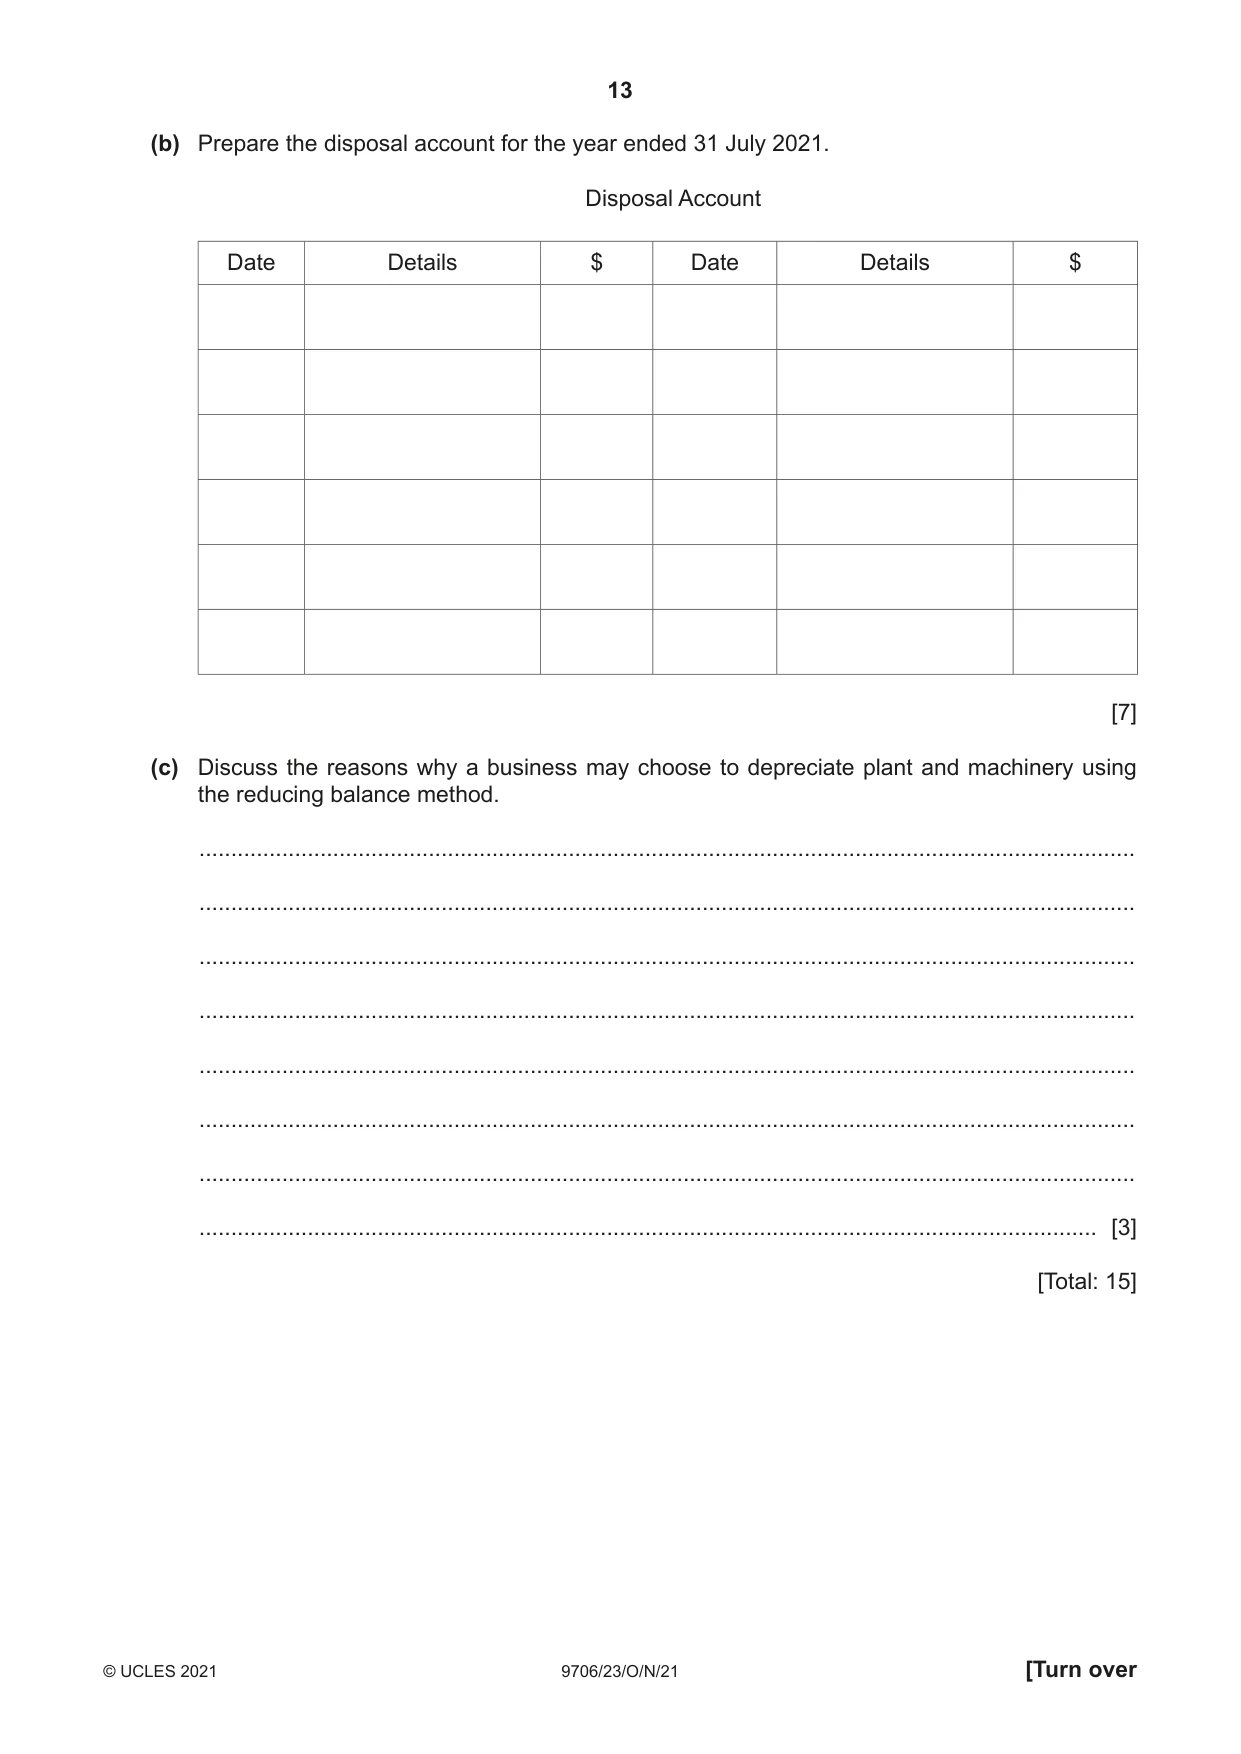
3 Petra owns a small manufacturing business. Her depreciation policy is as follows: Non-current asset Depreciation policy Plant and machinery 20% per annum reducing balance method A full year’s depreciation is charged in the year of purchase but none in the year of sale. The following information in respect of plant and machinery has been extracted from the books of account for the year ended 31 July 2021. Date Details 1 August 2020 Cost, $26 800; Provision for Depreciation, $12 200. 1 January 2021 Purchased new machinery, cost $4200. This was settled by a cheque payment of $2450 and part exchange of machinery that had originally cost $2500 in September 2018. 31 July 2021 Machinery with an original cost of $850 and a net book value of $60 was scrapped with no proceeds. REQUIRED (a) Prepare the provision for depreciation account for plant and machinery for the year ended 31 July 2021. Provision for Depreciation – Plant and Machinery Date Details $ Date Details $ 2020 Aug 1 Balance b/d 12 200 [5] Workings: (b) Prepare the disposal account for the year ended 31 July 2021. Disposal Account Date Details $ Date Details $ [7] (c) Discuss the reasons why a business may choose to depreciate plant and machinery using the reducing balance method. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] [Total: 15]
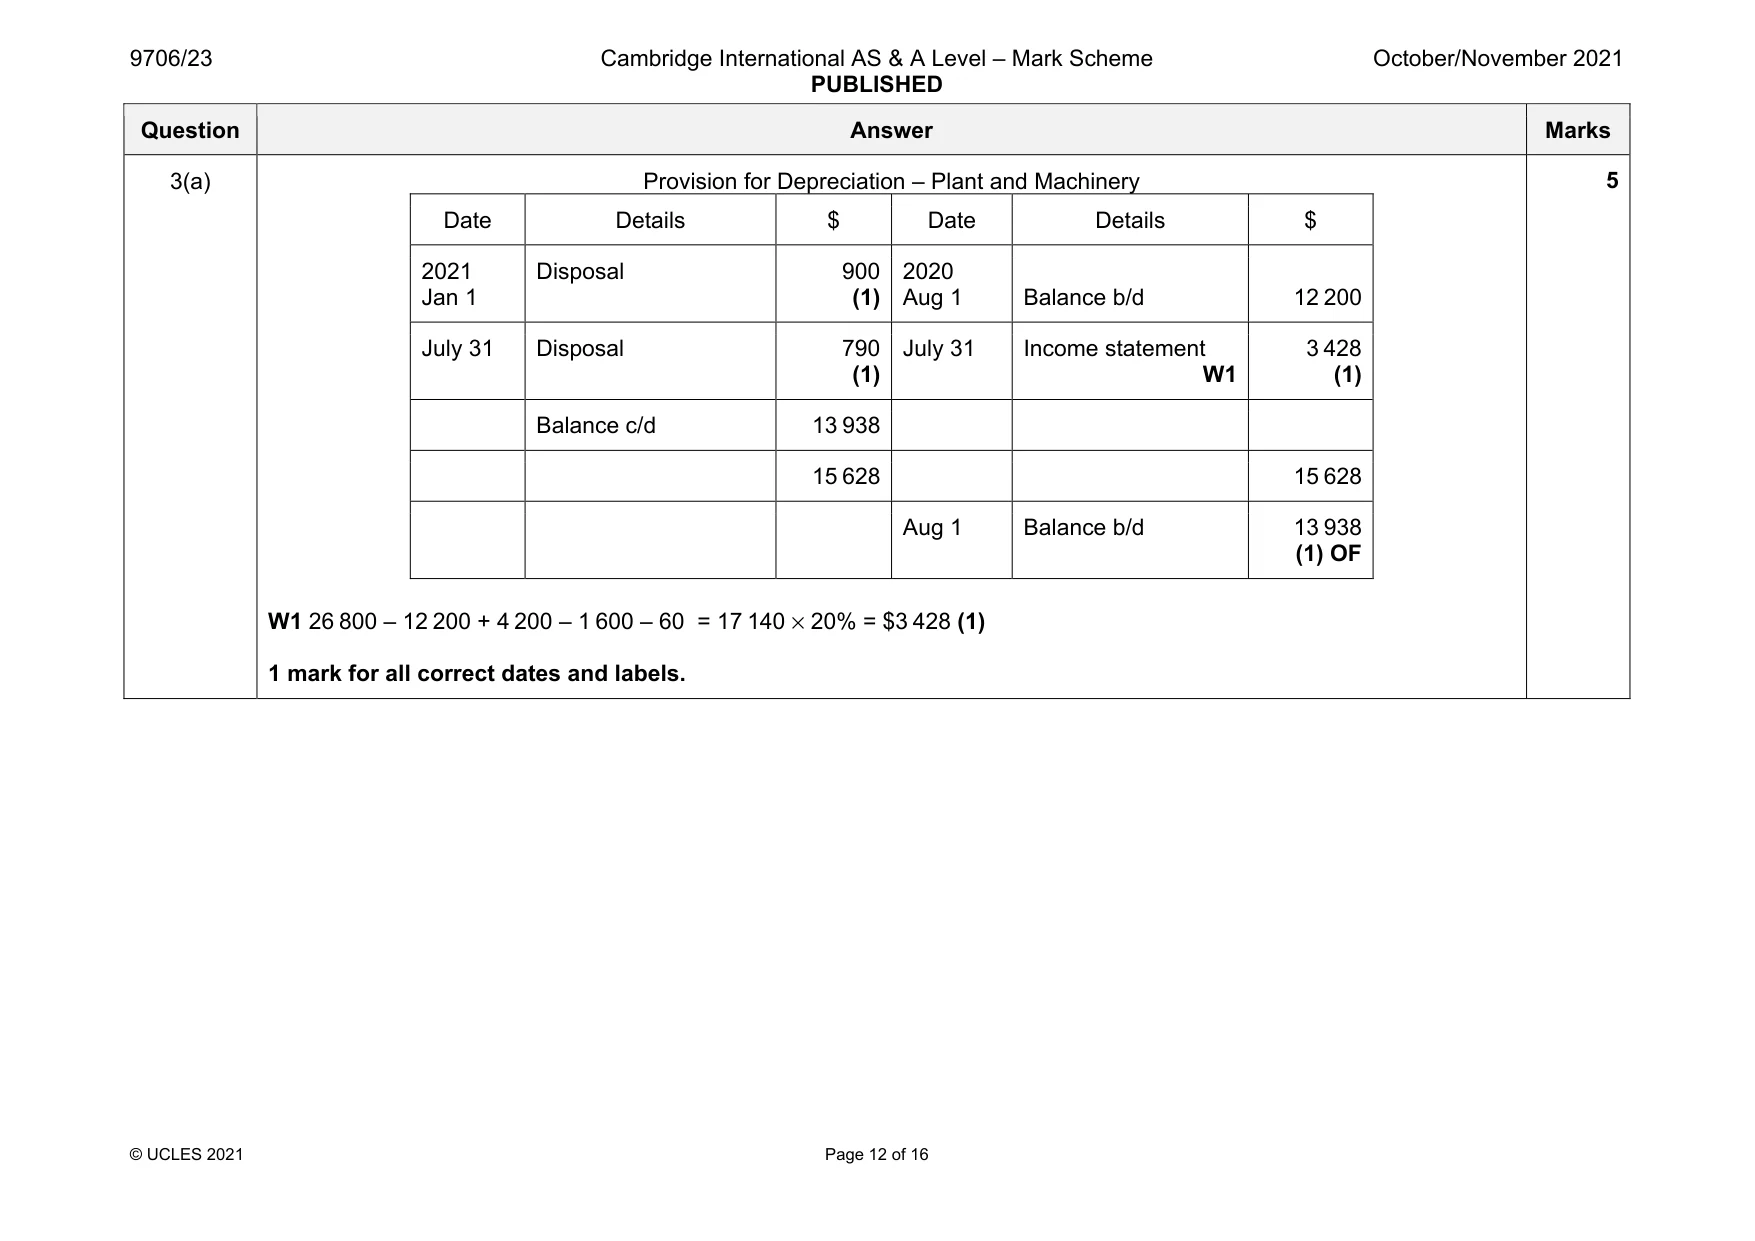
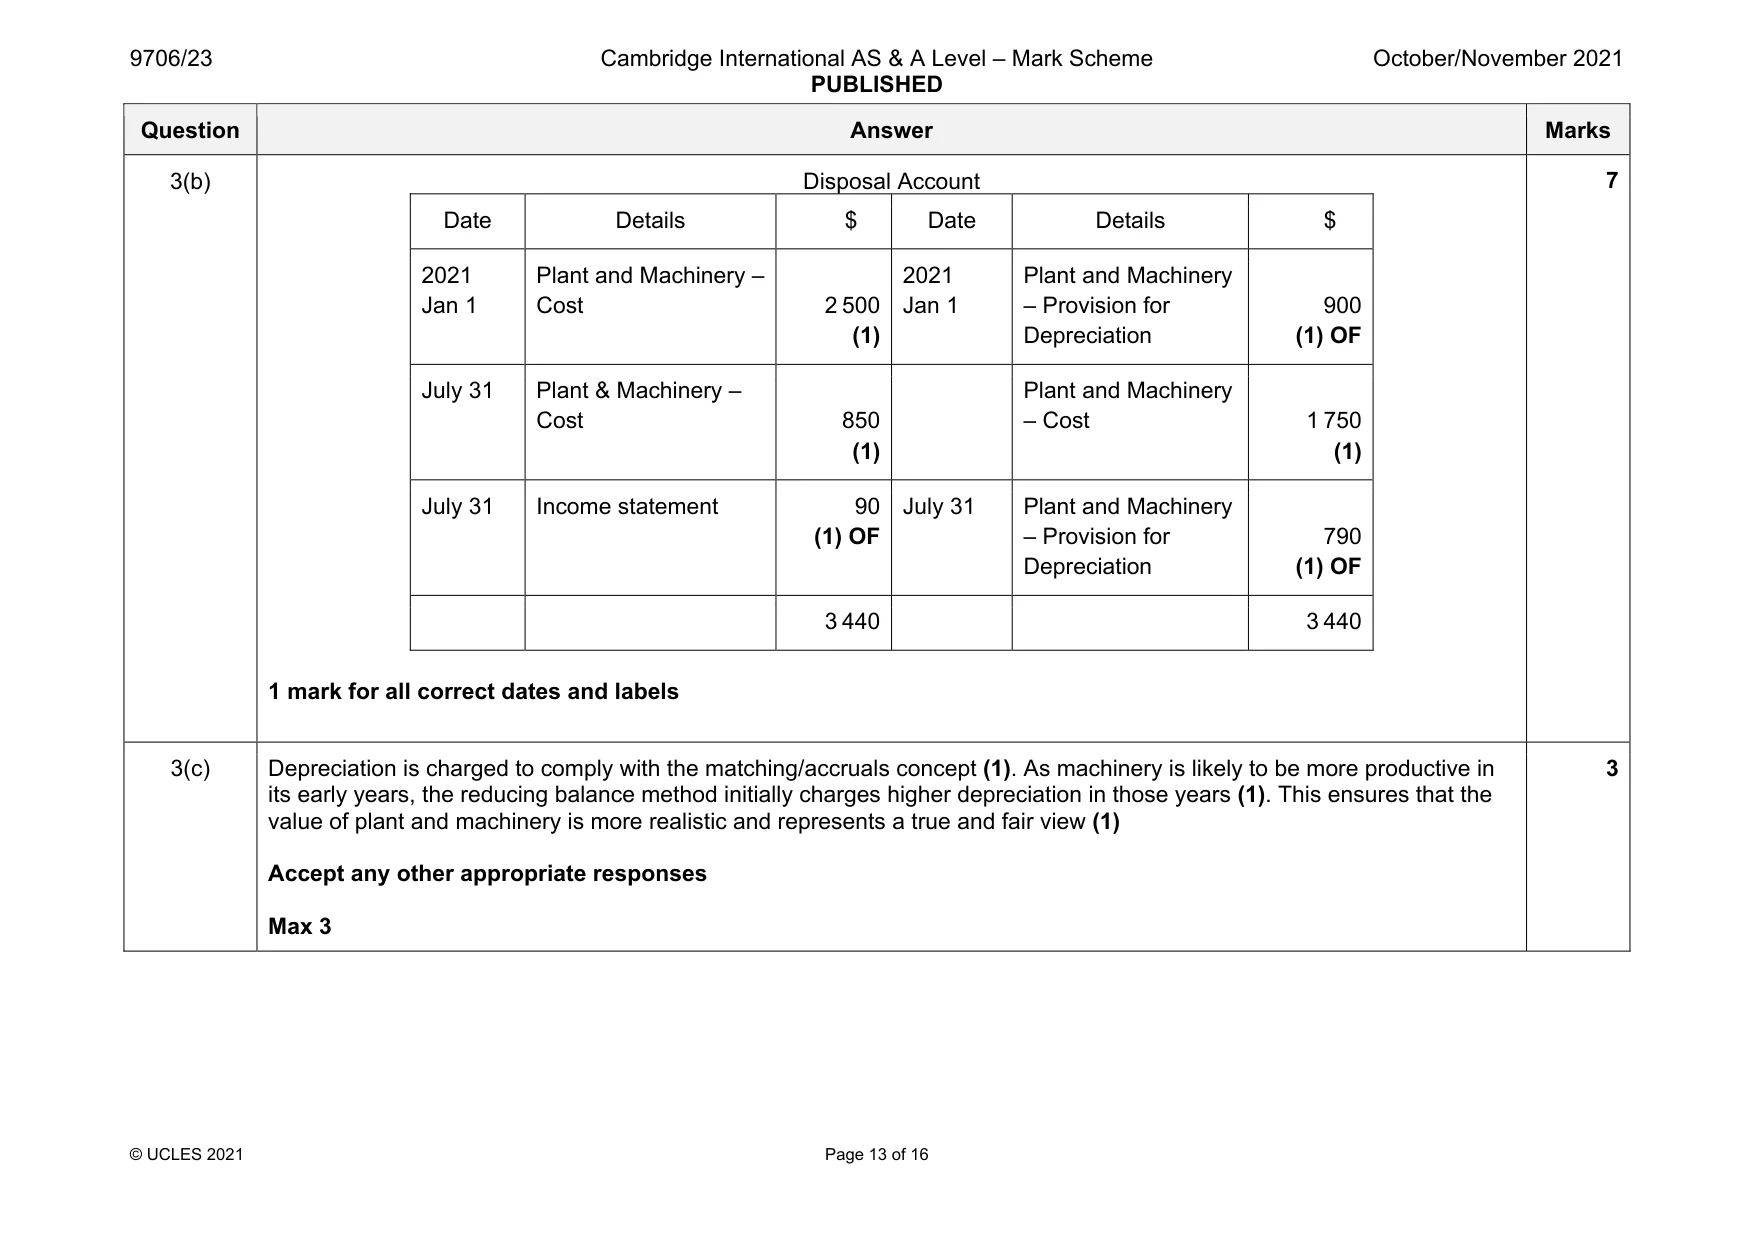
Mark scheme: 3(a) Provision for Depreciation – Plant and Machinery Date Details $ Date Details $ 2021 Jan 1 Disposal 900 (1) 2020 Aug 1 Balance b/d 12 200 July 31 Disposal 790 (1) July 31 Income statement W1 3 428 (1) Balance c/d 13 938 15 628 15 628 Aug 1 Balance b/d 13 938 (1) OF W1 26 800 – 12 200 + 4 200 – 1 600 – 60 = 17 140 × 20% = $3 428 (1) 1 mark for all correct dates and labels. Question Answer Marks 3(b) Disposal Account Date Details $ Date Details $ 2021 Jan 1 Plant and Machinery – Cost 2 500 (1) 2021 Jan 1 Plant and Machinery – Provision for Depreciation 900 (1) OF July 31 Plant & Machinery – Cost 850 (1) Plant and Machinery – Cost 1 750 (1) July 31 Income statement 90 (1) OF July 31 Plant and Machinery – Provision for Depreciation 790 (1) OF 3 440 3 440 1 mark for all correct dates and labels 7 3(c) Depreciation is charged to comply with the matching/accruals concept (1). As machinery is likely to be more productive in its early years, the reducing balance method initially charges higher depreciation in those years (1). This ensures that the value of plant and machinery is more realistic and represents a true and fair view (1) Accept any other appropriate responses Max 3 3
Q4 · Expenses were to be allocated as follows: Administrative Distribution expenses costs…
4 Expenses were to be allocated as follows: Administrative Distribution expenses costs Wages and salaries 30% 70% Directors’ remuneration 75% 25%
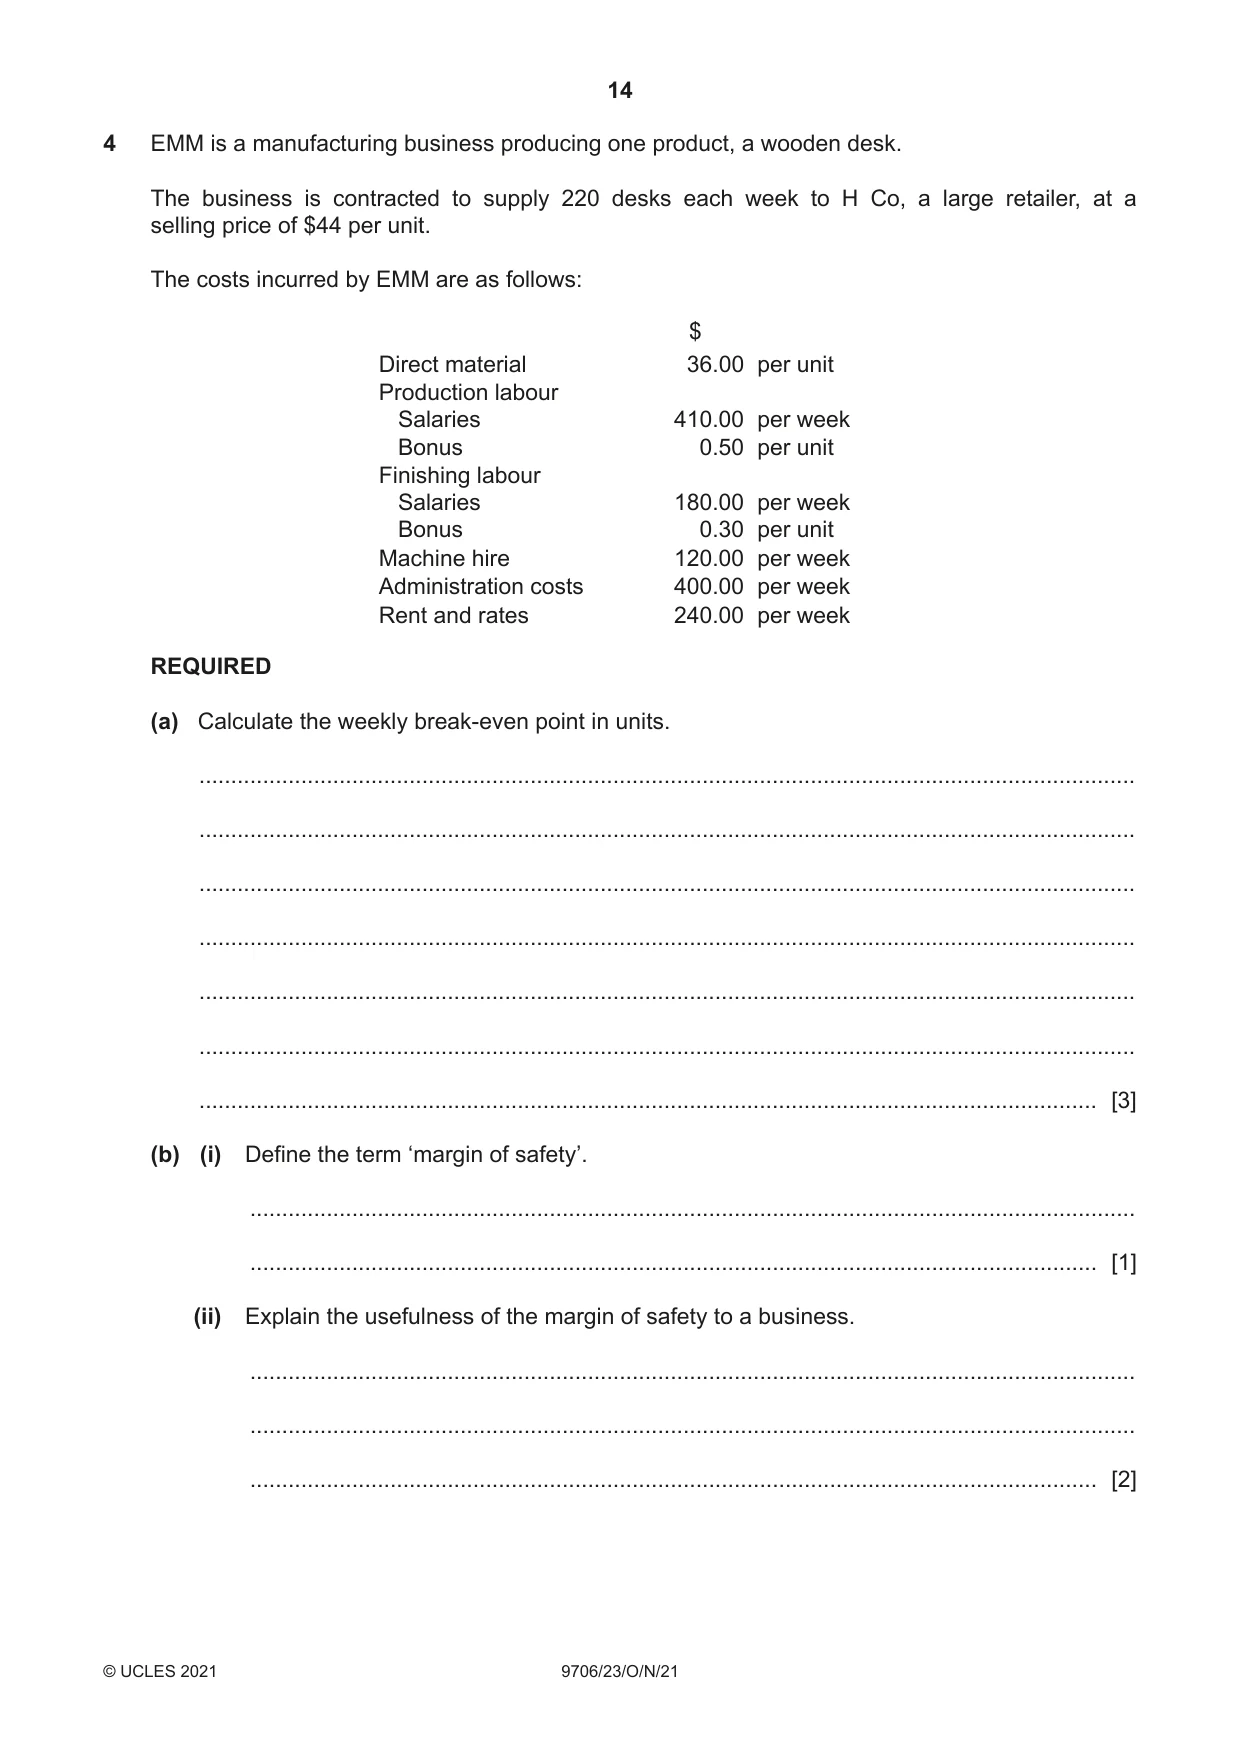
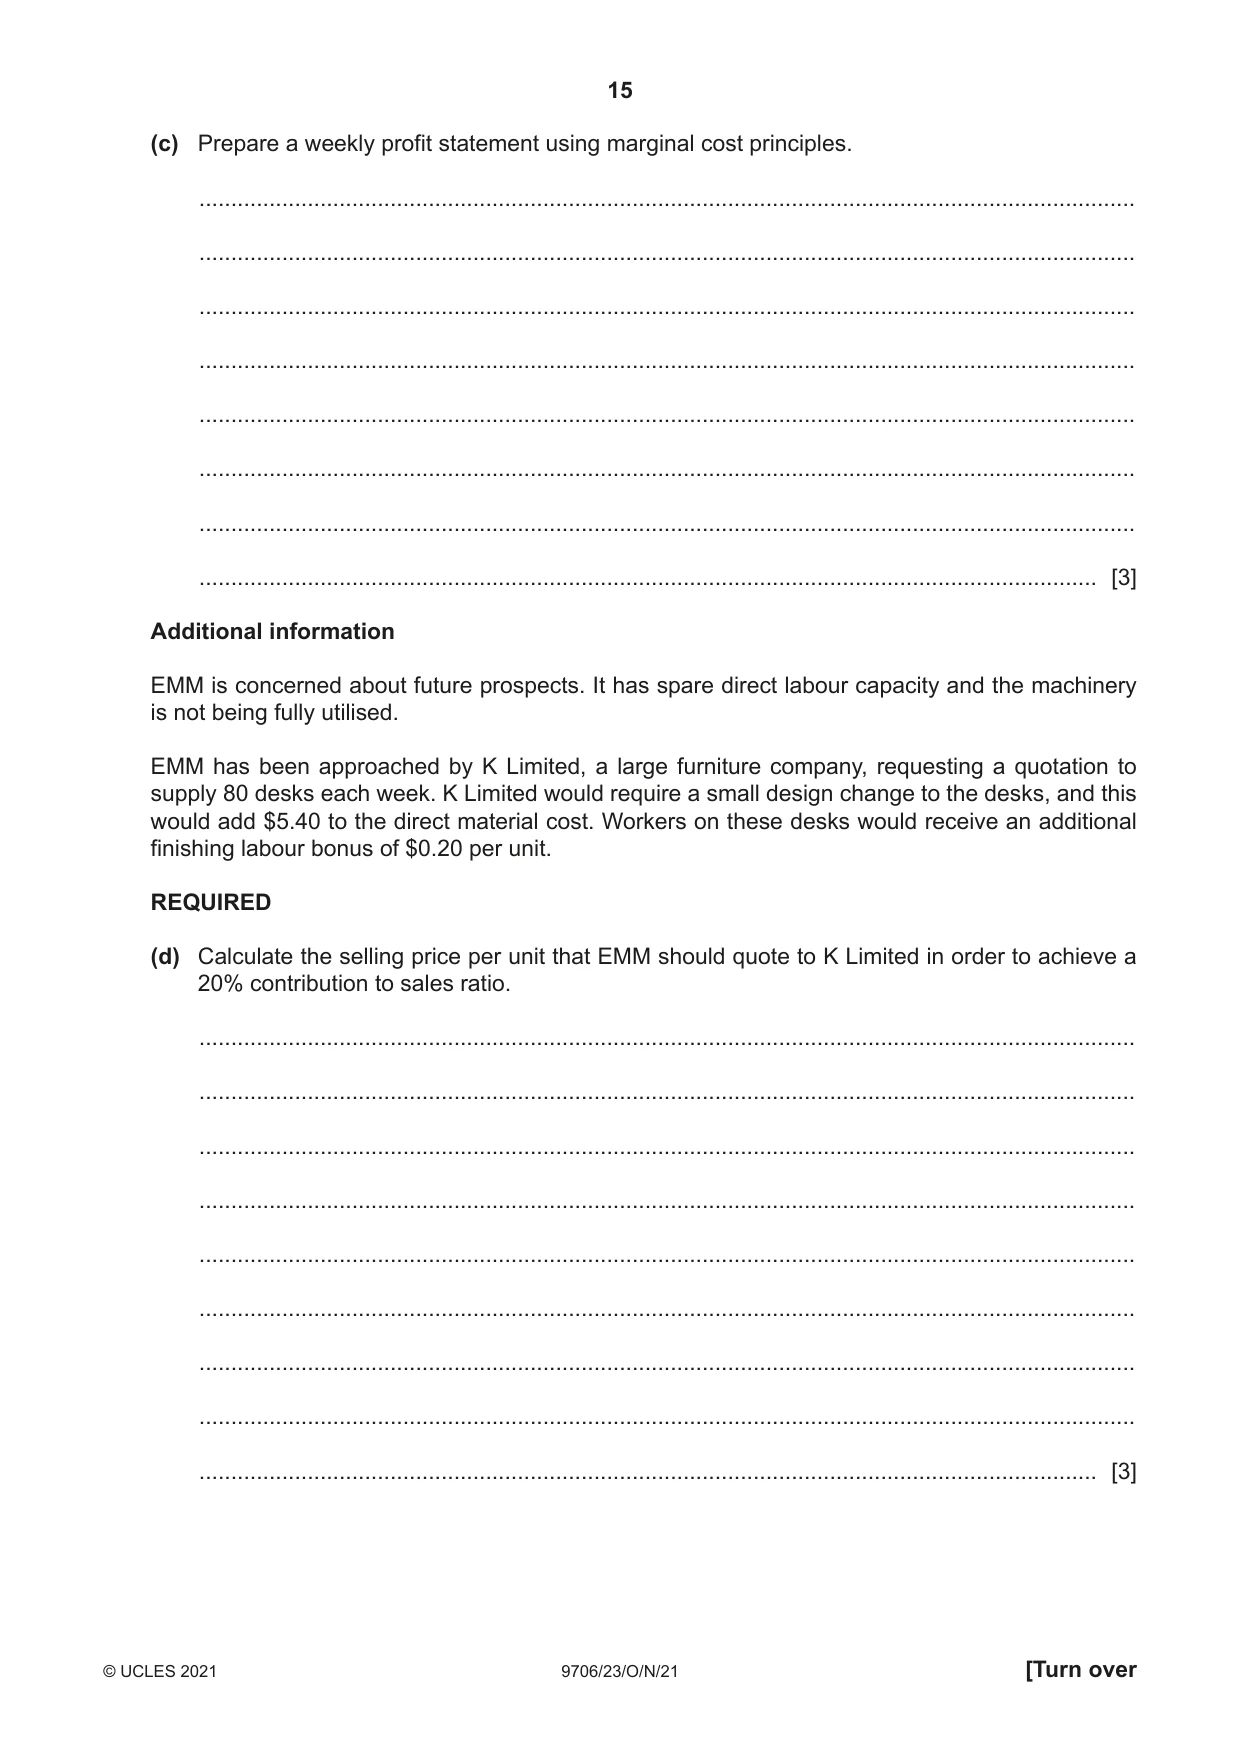
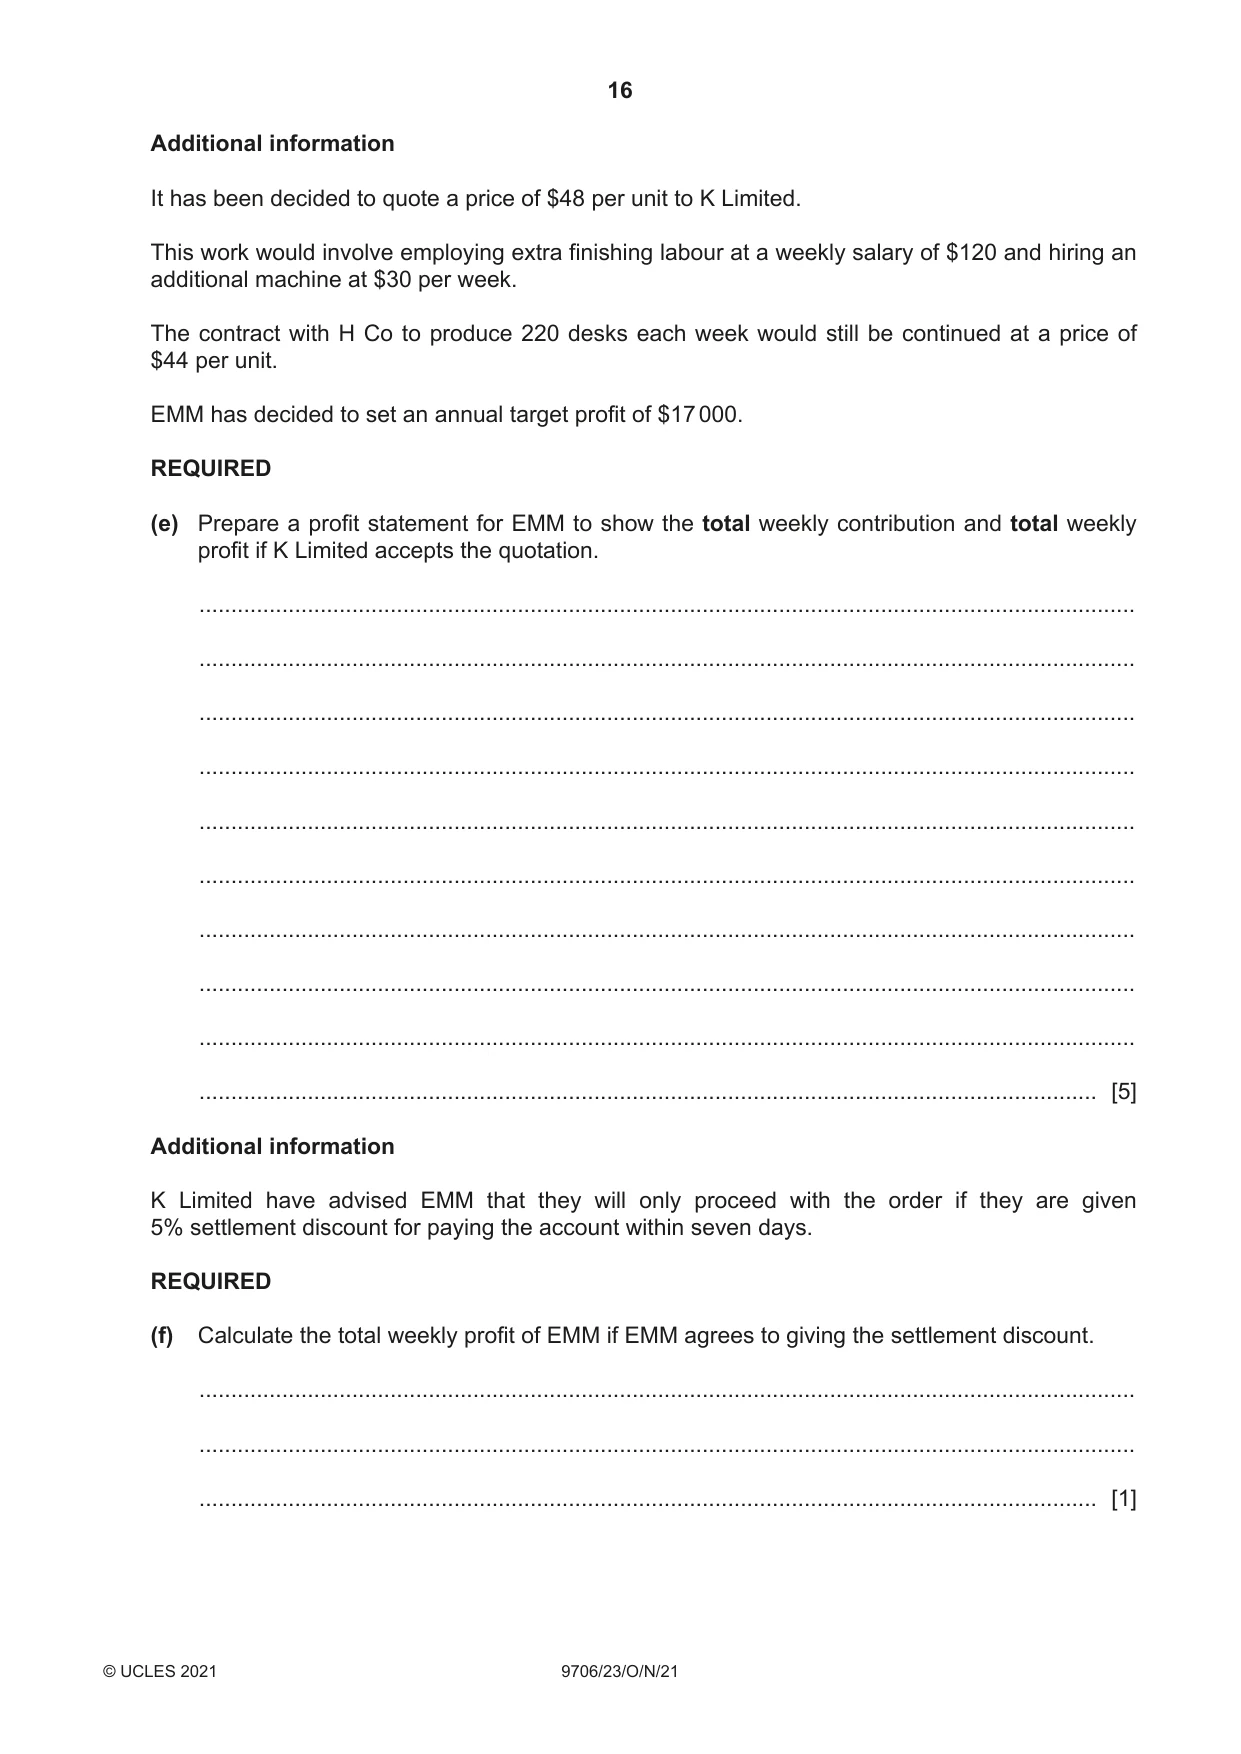
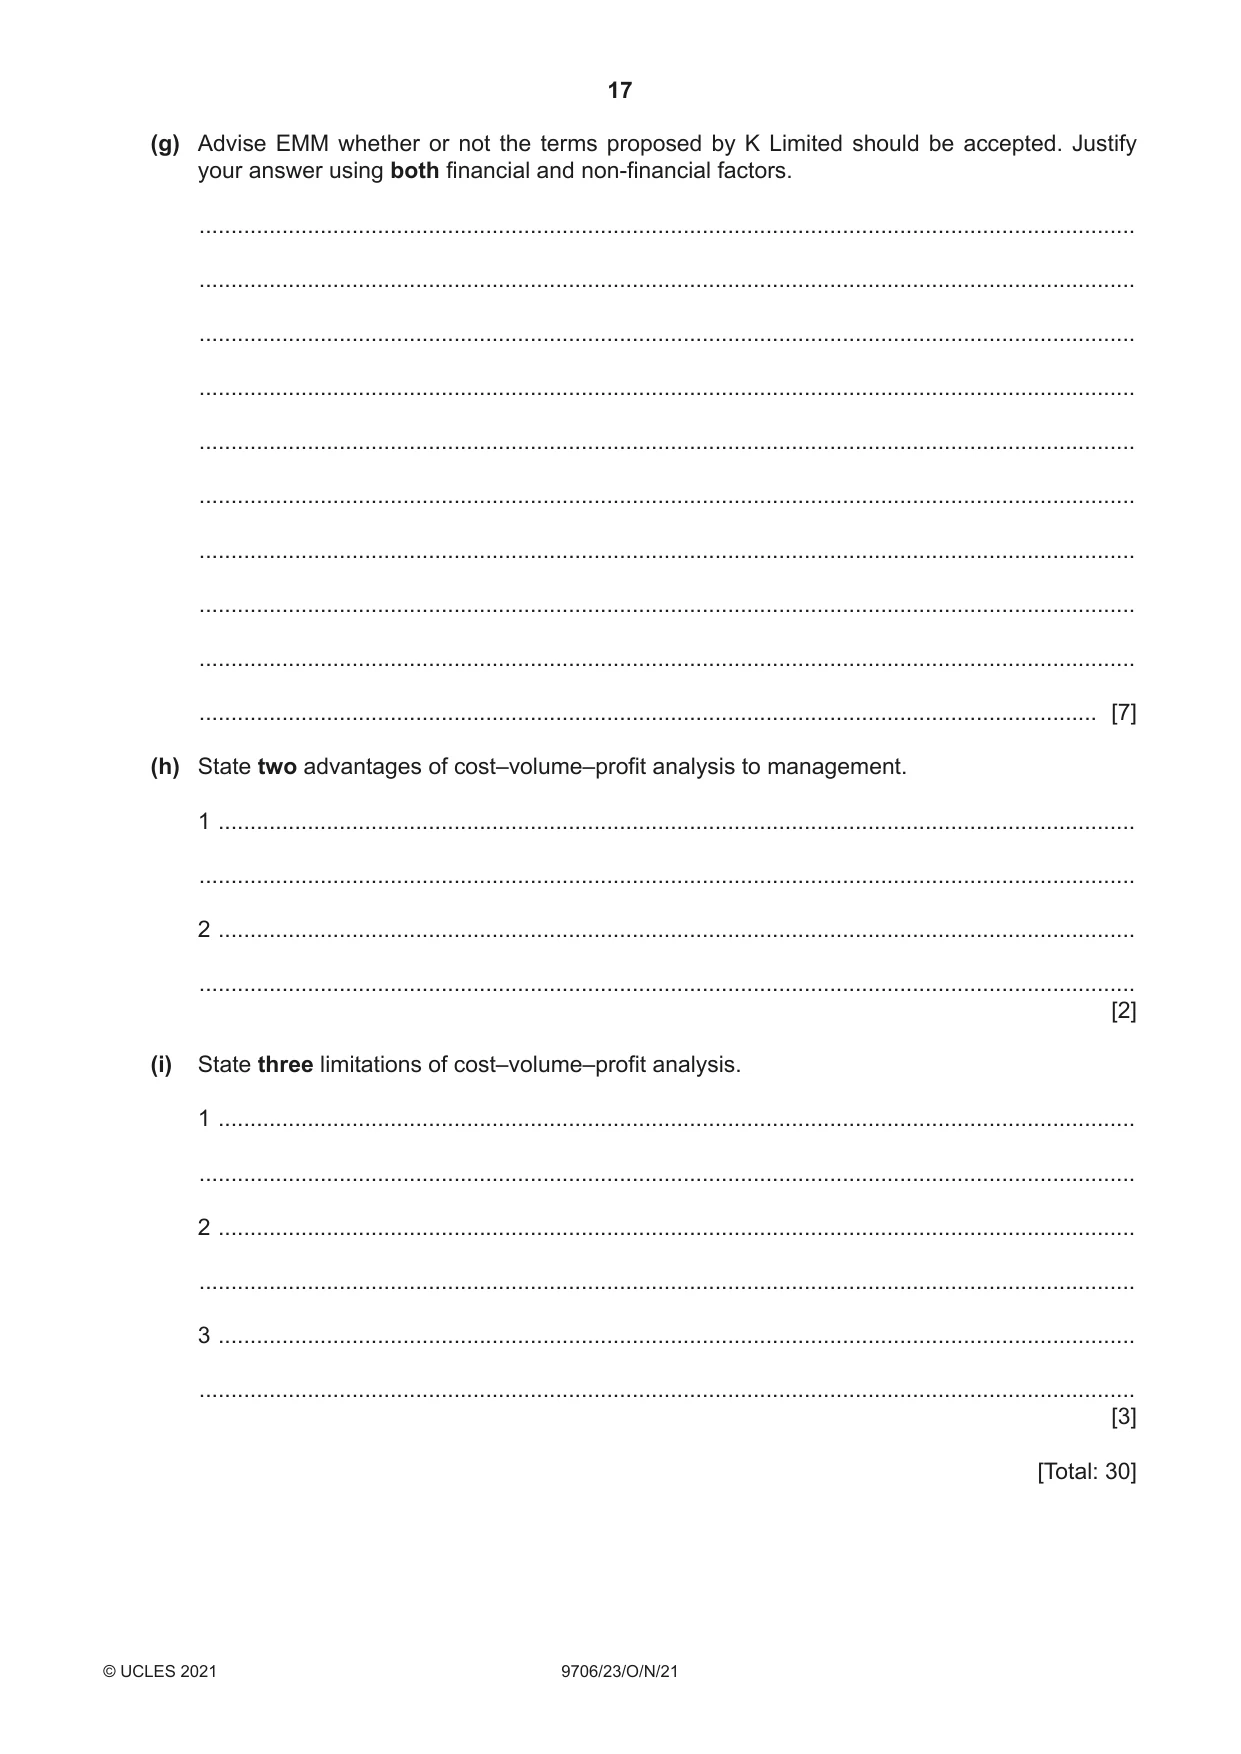
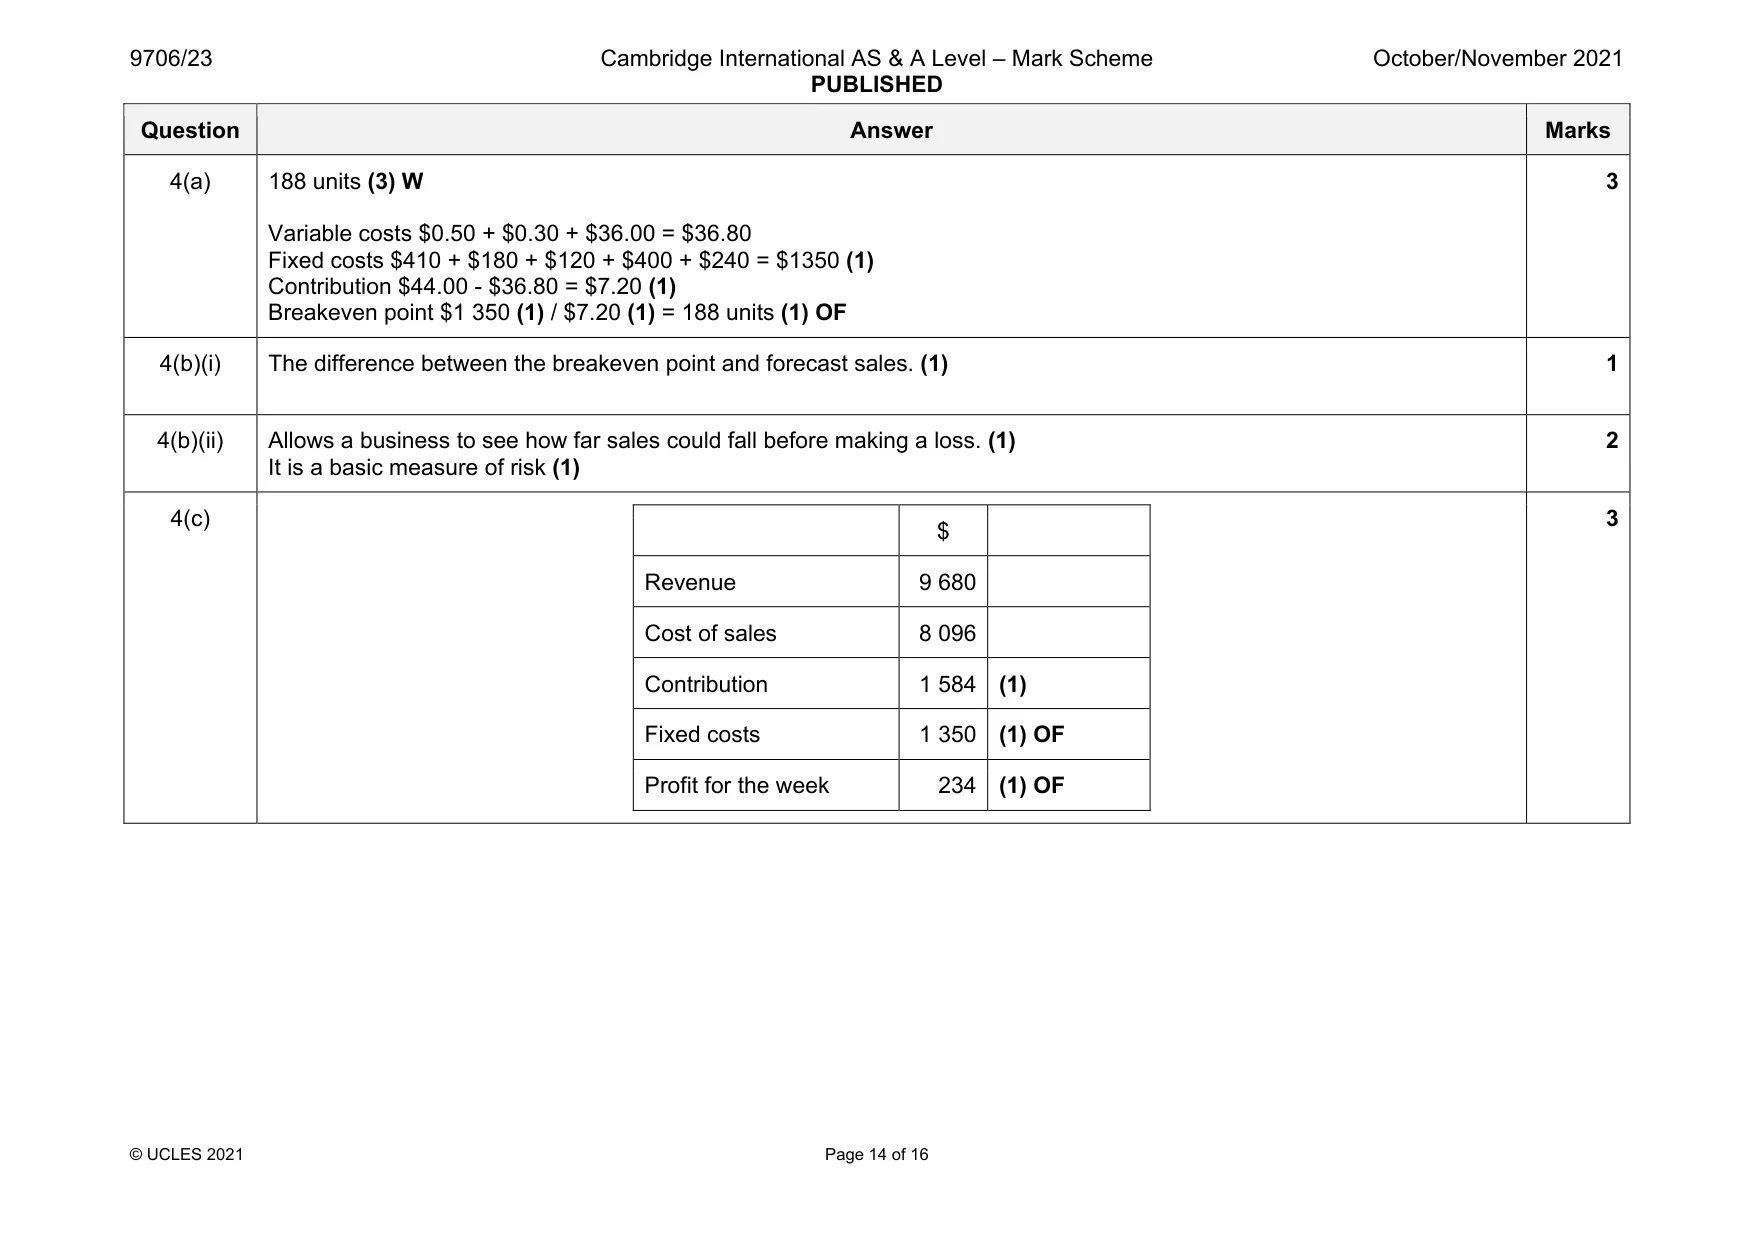
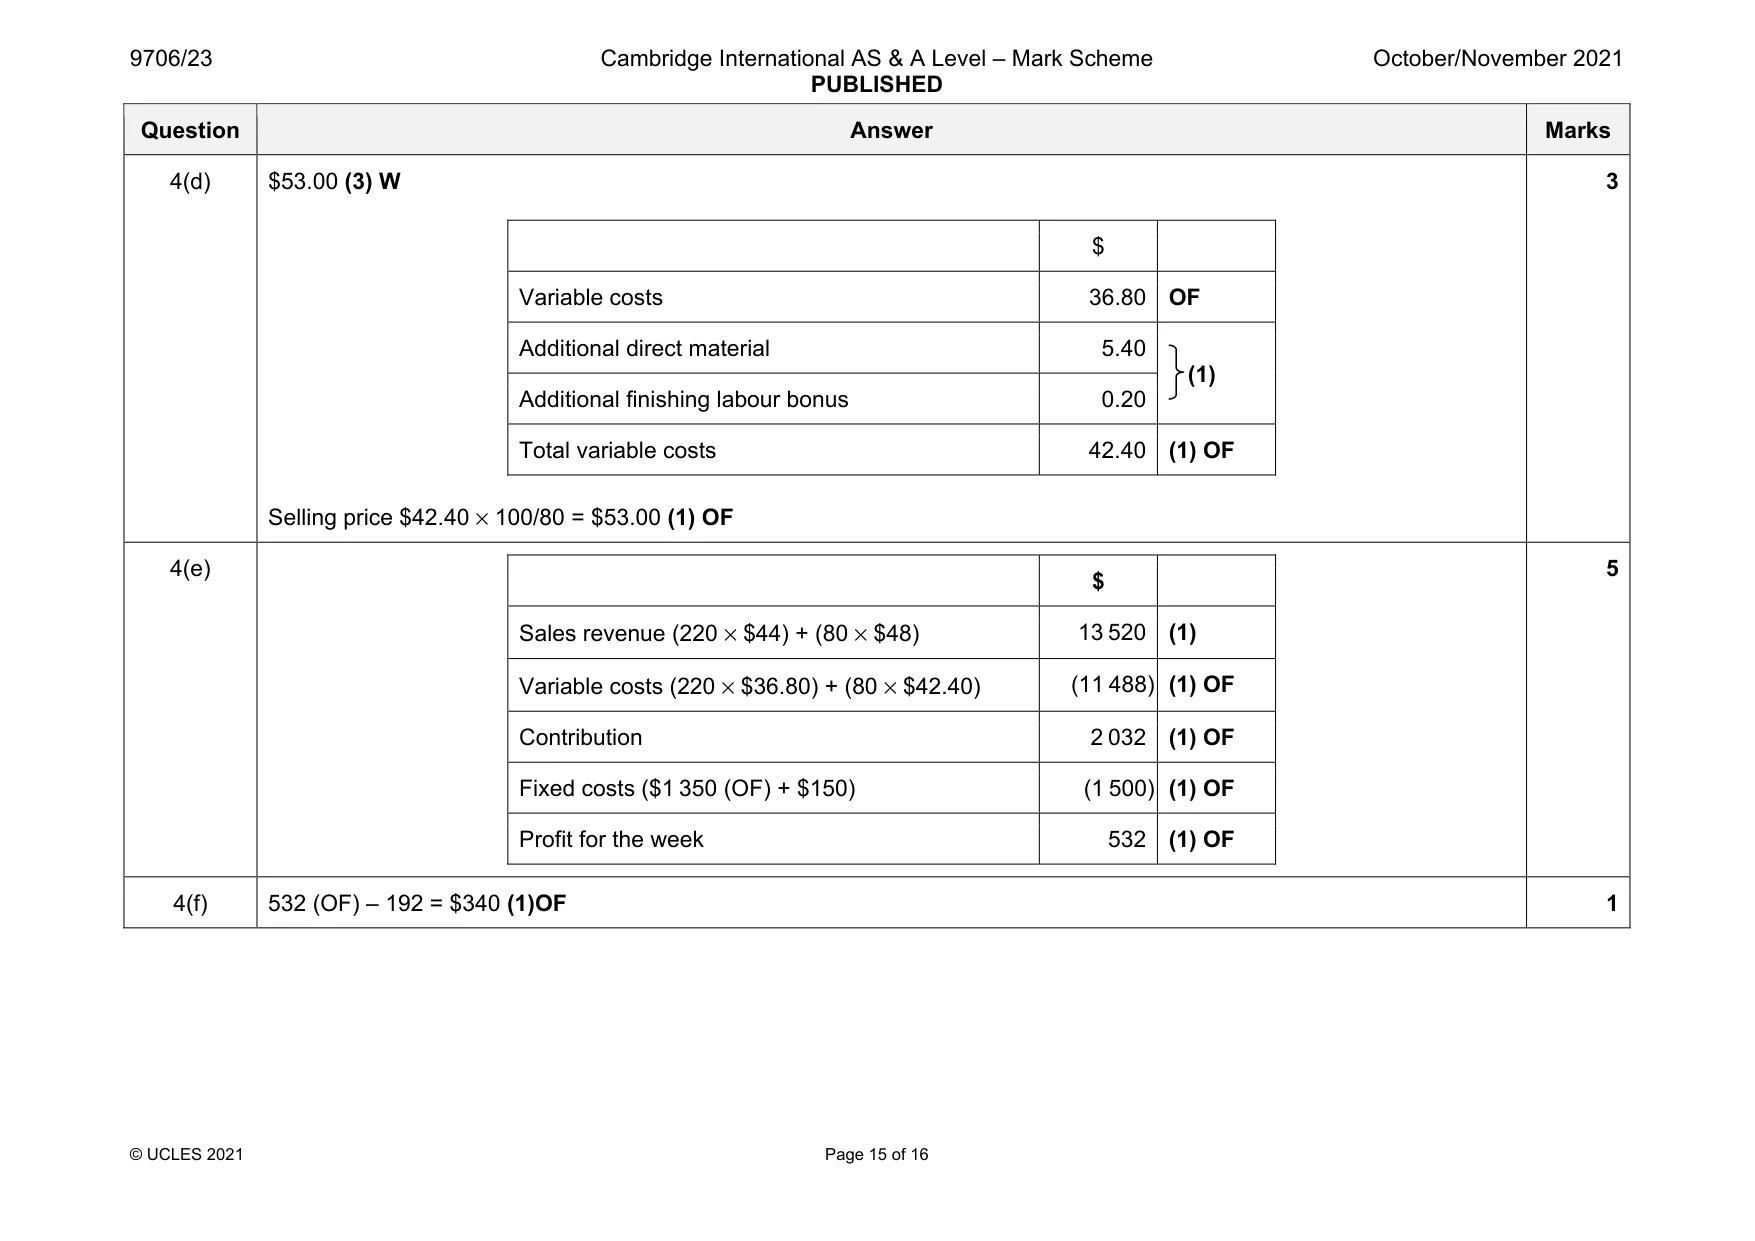
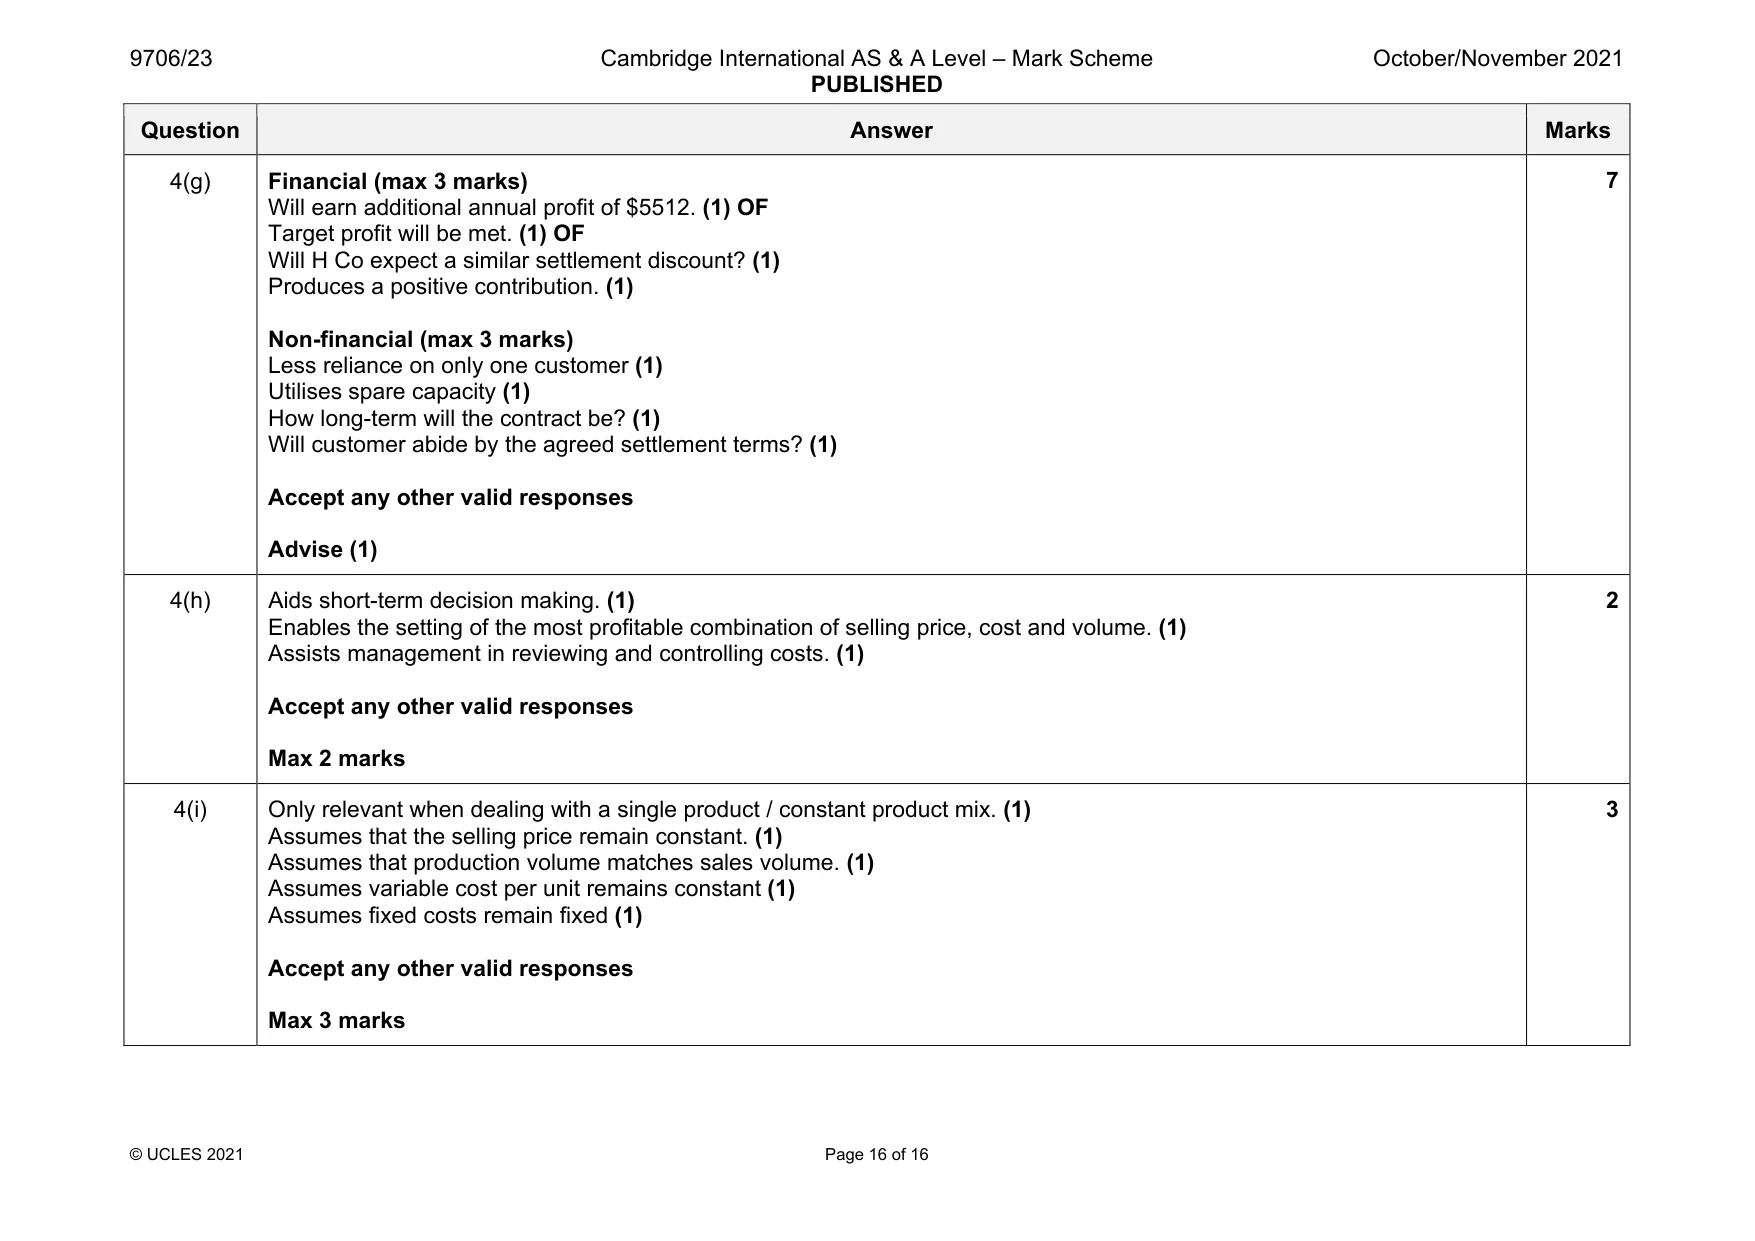
Mark scheme: 4(a) 188 units (3) W Variable costs $0.50 + $0.30 + $36.00 = $36.80 Fixed costs $410 + $180 + $120 + $400 + $240 = $1350 (1) Contribution $44.00 - $36.80 = $7.20 (1) Breakeven point $1 350 (1) / $7.20 (1) = 188 units (1) OF 3 4(b)(i) The difference between the breakeven point and forecast sales. (1) 1 4(b)(ii) Allows a business to see how far sales could fall before making a loss. (1) It is a basic measure of risk (1) 2 4(c) $ Revenue 9 680 Cost of sales 8 096 Contribution 1 584 (1) Fixed costs 1 350 (1) OF Profit for the week 234 (1) OF 3 Question Answer Marks 4(d) $53.00 (3) W $ Variable costs 36.80 OF Additional direct material 5.40 (1) Additional finishing labour bonus 0.20 Total variable costs 42.40 (1) OF Selling price $42.40 × 100/80 = $53.00 (1) OF 3 4(e) $ Sales revenue (220 × $44) + (80 × $48) 13 520 (1) Variable costs (220 × $36.80) + (80 × $42.40) (11 488) (1) OF Contribution 2 032 (1) OF Fixed costs ($1 350 (OF) + $150) (1 500) (1) OF Profit for the week 532 (1) OF 5 4(f) 532 (OF) – 192 = $340 (1)OF 1 Question Answer Marks 4(g) Financial (max 3 marks) Will earn additional annual profit of $5512. (1) OF Target profit will be met. (1) OF Will H Co expect a similar settlement discount? (1) Produces a positive contribution. (1) Non-financial (max 3 marks) Less reliance on only one customer (1) Utilises spare capacity (1) How long-term will the contract be? (1) Will customer abide by the agreed settlement terms? (1) Accept any other valid responses Advise (1) 7 4(h) Aids short-term decision making. (1) Enables the setting of the most profitable combination of selling price, cost and volume. (1) Assists management in reviewing and controlling costs. (1) Accept any other valid responses Max 2 marks 2 4(i) Only relevant when dealing with a single product / constant product mix. (1) Assumes that the selling price remain constant. (1) Assumes that production volume matches sales volume. (1) Assumes variable cost per unit remains constant (1) Assumes fixed costs remain fixed (1) Accept any other valid responses Max 3 marks 3
Q5 · Depreciation is to be charged as follows: Motor vehicles for office staff $26 400…
5 Depreciation is to be charged as follows: Motor vehicles for office staff $26 400 Delivery vehicles $32 800
Q6 · A credit customer owing $2360 from 12 April 2021 has been declared bankrupt and the debt…
6 A credit customer owing $2360 from 12 April 2021 has been declared bankrupt and the debt is to be written off to administrative expenses.
Q7 · Aged analysis of net trade receivables at 30 June 2021: 0–60 61–90 Over 90 days days days…
7 Aged analysis of net trade receivables at 30 June 2021: 0–60 61–90 Over 90 days days days Percentage of total net trade receivables 75% 15% 10%
More questions on Analysis and communication of accounting information
Q8 · The directors wish to make a provision for doubtful debts as follows: Debts 61–90 days…
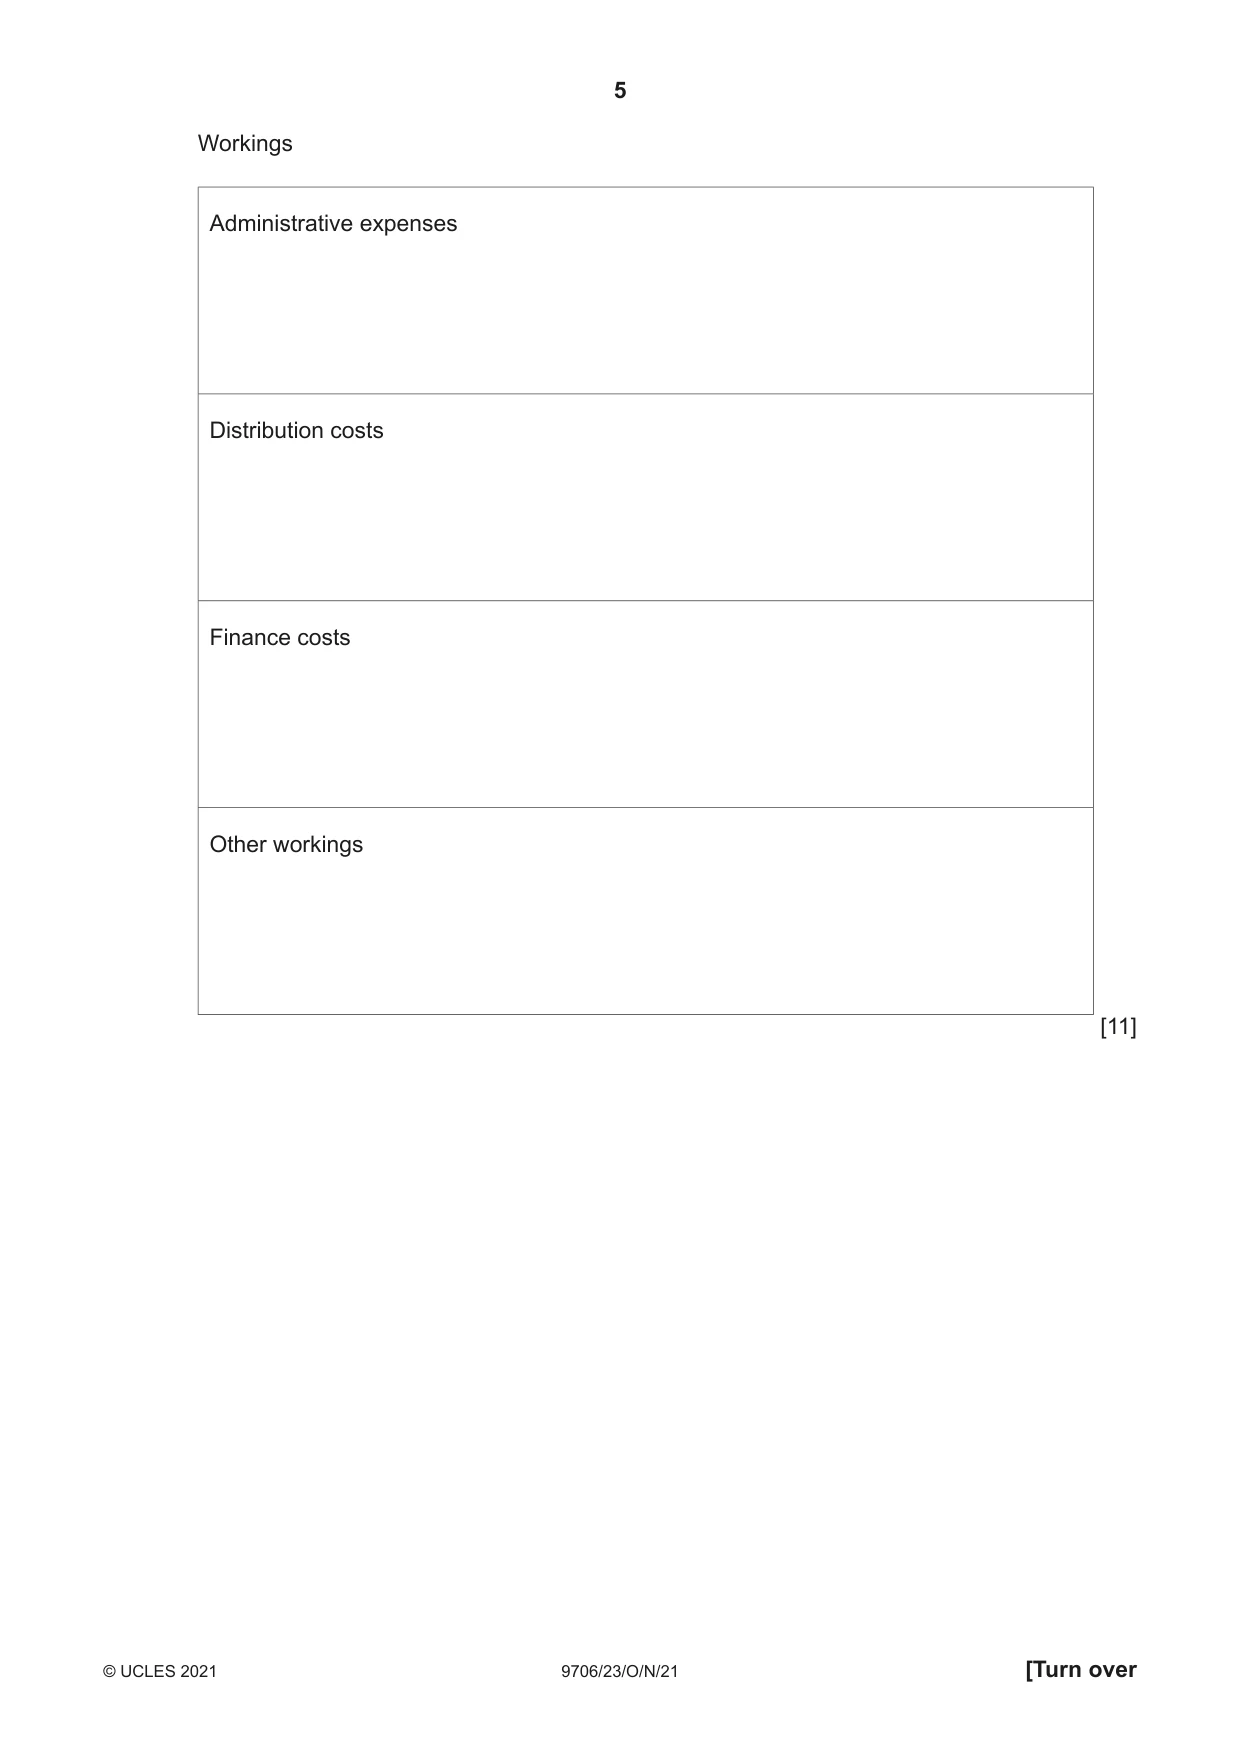
8 The directors wish to make a provision for doubtful debts as follows: Debts 61–90 days 2.5% Debts over 90 days 10% The movement in the provision is to be charged to administrative expenses. REQUIRED (b) Calculate the balance of the provision for doubtful debts at 30 June 2021. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] (c) Prepare the income statement for the year ended 30 June 2021. Use the space on the next page for your workings. T Limited Income Statement for the year ended 30 June 2021 $ Revenue Cost of sales Gross profit Administrative expenses Distribution costs Profit from operations Finance costs Profit for the year Workings Administrative expenses Distribution costs Finance costs Other workings [11]
What was in this paper
The subtopics covered by these 8 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2021 Oct/Nov, Paper 2 · Variant 3. A higher threshold means an easier paper — the bar moves with how the cohort did.