Cambridge A Level Accounting 9706 — 2012 Oct/Nov Paper 2 · Variant 2
9706/22/O/N/12 · 90 marks · ≈101 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper16 pages
Mark scheme5 pages
Answers below. Sit the paper first if you are practising.
Paper as text
Question paper, page 1
This document consists of 14 printed pages and 2 blank pages. IB12 11_9706_22/2RP © UCLES 2012 [Turn over *6093861380* For Examiner's Use 1 2 3 Total UNIVERSITY OF CAMBRIDGE INTERNATIONAL EXAMINATIONS General Certificate of Education Advanced Subsidiary Level and Advanced Level ACCOUNTING 9706/22 Paper 2 Structured Questions October/November 2012 1 hour 30 minutes Candidates answer on the Question Paper No Additional Materials are required. READ THESE INSTRUCTIONS FIRST Write your Centre number, candidate number and name on all the work you hand in. Write in dark blue or black pen. You may use a soft pencil for rough working. Do not use staples, paper clips, highlighters, glue or correction fluid. DO NOT WRITE IN ANY BARCODES. Answer all questions. All accounting statements are to be presented in good style. International accounting terms and formats should be used as appropriate. Workings must be shown. You may use a calculator. At the end of the examination, fasten all your work securely together. The number of marks is given in brackets [ ] at the end of each question or part question.
Question paper, page 2
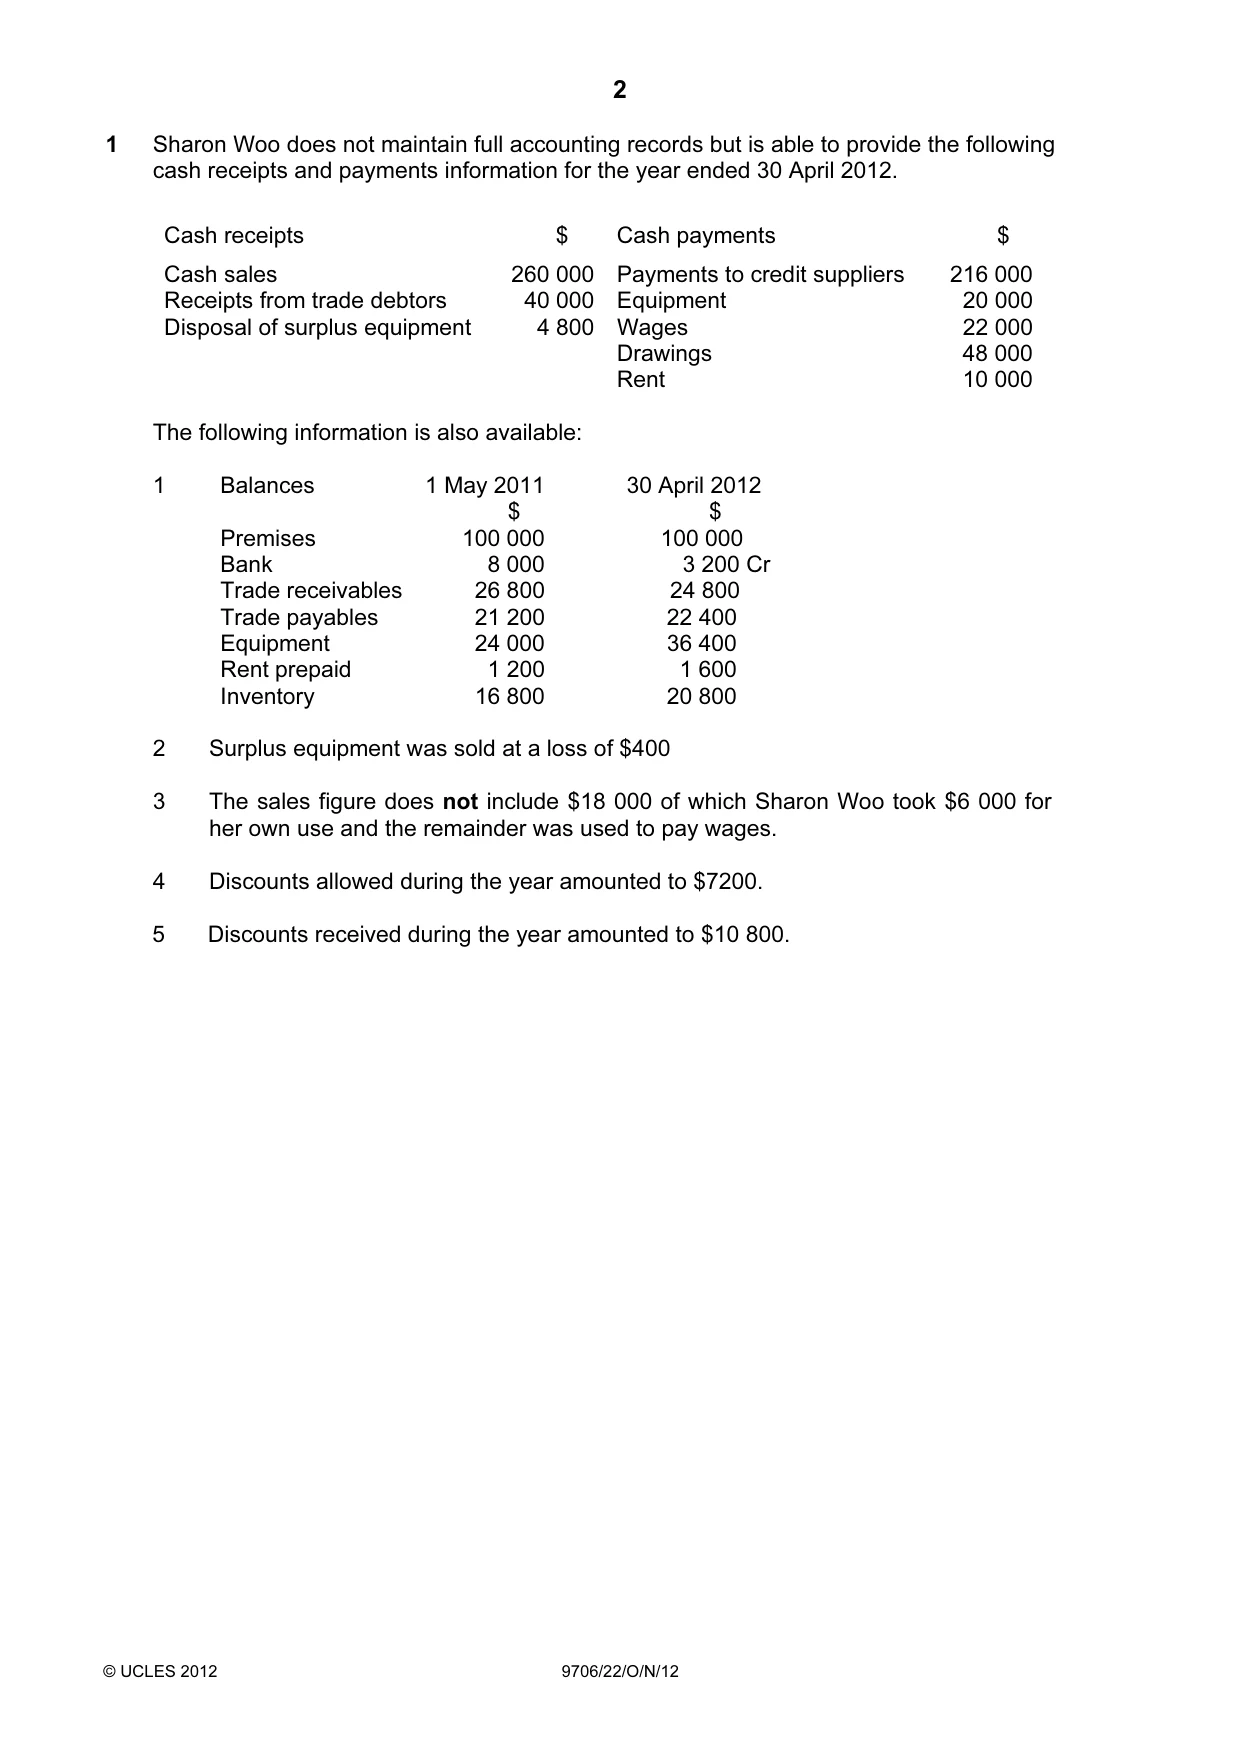
2 © UCLES 2012 9706/22/O/N/12 1 Sharon Woo does not maintain full accounting records but is able to provide the following cash receipts and payments information for the year ended 30 April 2012. Cash receipts $ Cash payments $ Cash sales 260 000 Payments to credit suppliers 216 000 Receipts from trade debtors 40 000 Equipment 20 000 Disposal of surplus equipment 4 800 Wages 22 000 Drawings 48 000 Rent 10 000 The following information is also available: 1 Balances 1 May 2011 30 April 2012 $ $ Premises 100 000 100 000 Bank 8 000 3 200 Cr Trade receivables 26 800 24 800 Trade payables 21 200 22 400 Equipment 24 000 36 400 Rent prepaid 1 200 1 600 Inventory 16 800 20 800 2 Surplus equipment was sold at a loss of $400 3 The sales figure does not include $18 000 of which Sharon Woo took $6 000 for her own use and the remainder was used to pay wages. 4 Discounts allowed during the year amounted to $7200. 5 Discounts received during the year amounted to $10 800.
Question paper, page 3
3 © UCLES 2012 9706/22/O/N/12 [Turn over For Examiner's Use REQUIRED (a) Calculate Sharon Woo’s capital at 1 May 2011. [4]
Question paper, page 4
4 © UCLES 2012 9706/22/O/N/12 For Examiner's Use (b) Prepare Sharon Woo’s income statement for the year ended 30 April 2012. [20]
Question paper, page 5
5 © UCLES 2012 9706/22/O/N/12 [Turn over For Examiner's Use (c) Calculate the return on capital employed for the year ended 30 April 2012 (to two decimal places) using the opening capital figure. [3] (d) Advise Sharon Woo how she can use the figure for return on capital employed to assess the performance of her business. [3] [Total: 30]
Question paper, page 6
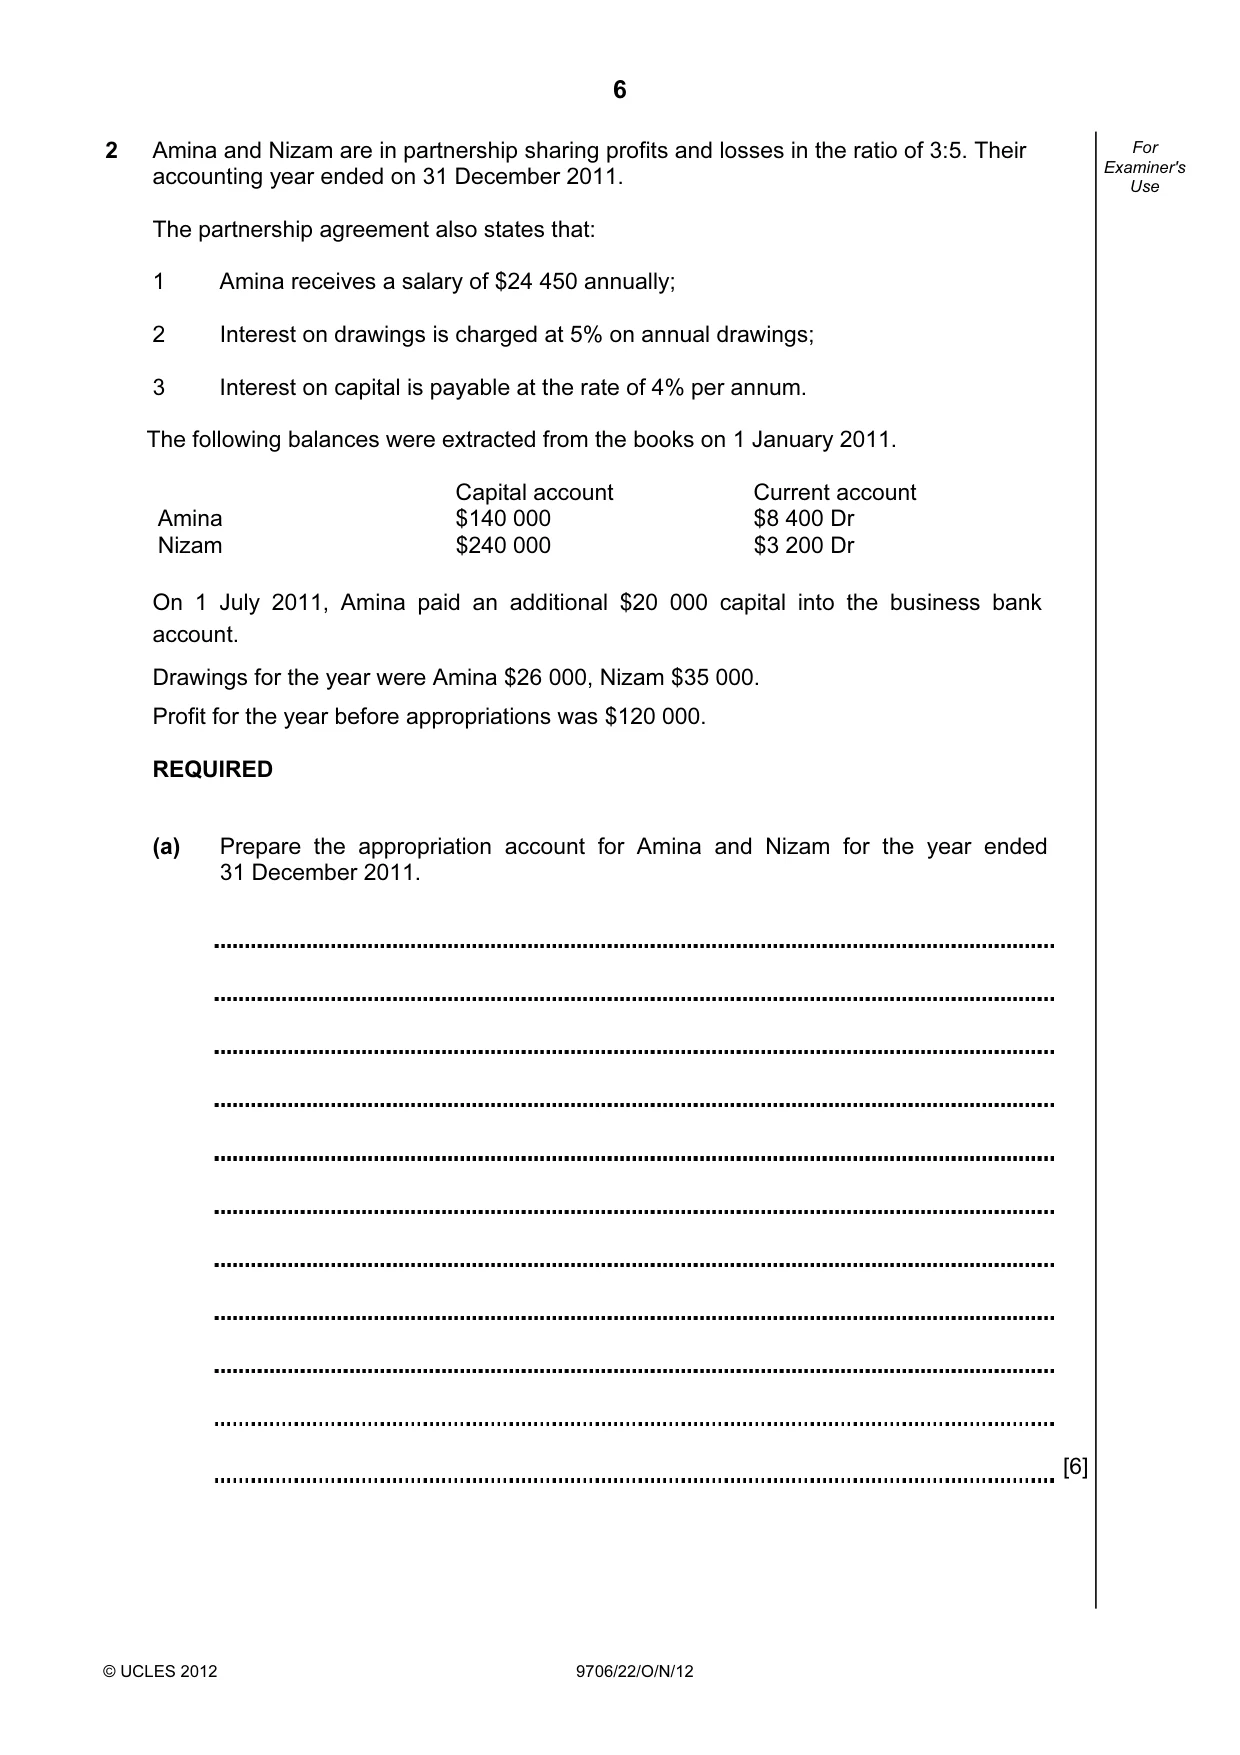
6 © UCLES 2012 9706/22/O/N/12 For Examiner's Use 2 Amina and Nizam are in partnership sharing profits and losses in the ratio of 3:5. Their accounting year ended on 31 December 2011. The partnership agreement also states that: 1 Amina receives a salary of $24 450 annually; 2 Interest on drawings is charged at 5% on annual drawings; 3 Interest on capital is payable at the rate of 4% per annum. The following balances were extracted from the books on 1 January 2011. Capital account Current account Amina $140 000 $8 400 Dr Nizam $240 000 $3 200 Dr On 1 July 2011, Amina paid an additional $20 000 capital into the business bank account. Drawings for the year were Amina $26 000, Nizam $35 000. Profit for the year before appropriations was $120 000. REQUIRED (a) Prepare the appropriation account for Amina and Nizam for the year ended 31 December 2011. [6]
Question paper, page 7
7 © UCLES 2012 9706/22/O/N/12 [Turn over For Examiner's Use (b) Prepare the current accounts for Amina and Nizam for the year ended 31 December 2011. [6]
Question paper, page 8
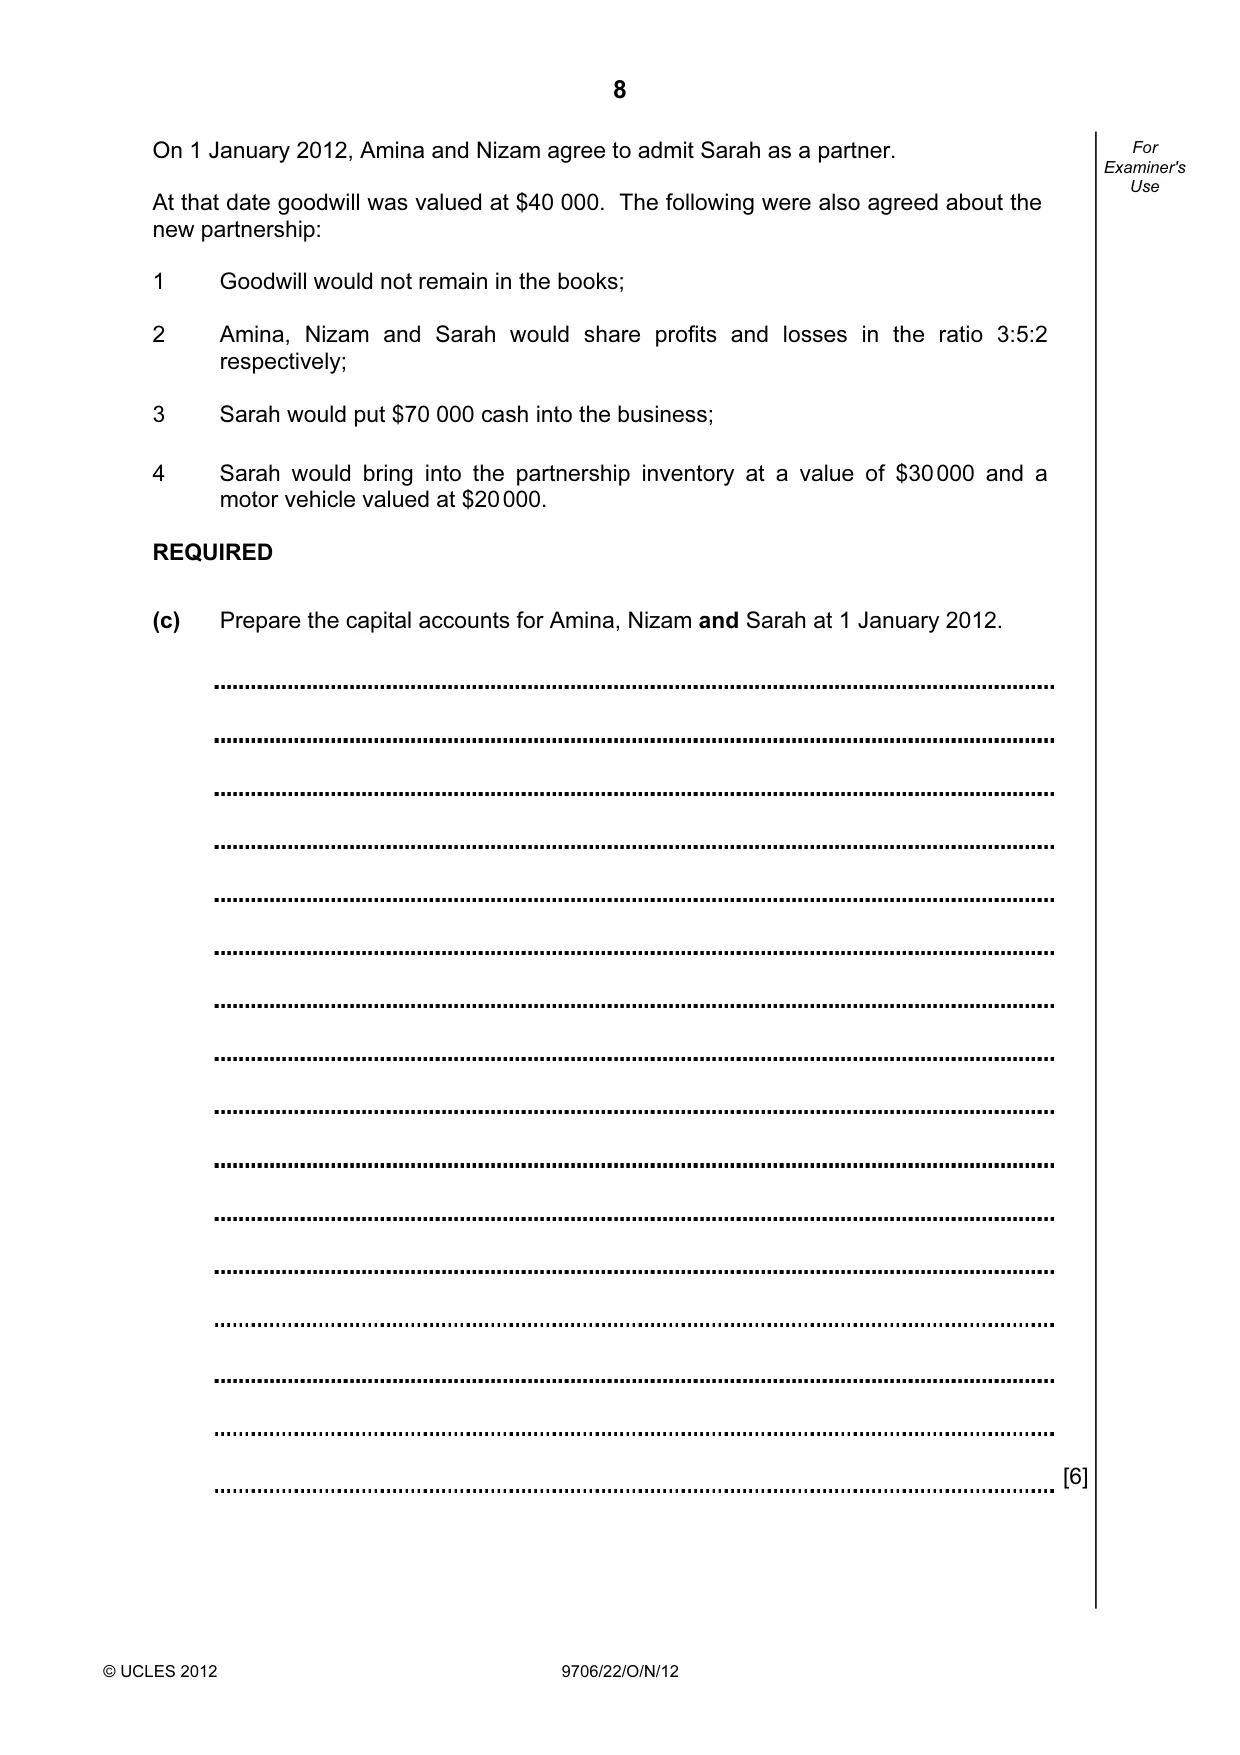
8 © UCLES 2012 9706/22/O/N/12 For Examiner's Use On 1 January 2012, Amina and Nizam agree to admit Sarah as a partner. At that date goodwill was valued at $40 000. The following were also agreed about the new partnership: 1 Goodwill would not remain in the books; 2 Amina, Nizam and Sarah would share profits and losses in the ratio 3:5:2 respectively; 3 Sarah would put $70 000 cash into the business; 4 Sarah would bring into the partnership inventory at a value of $30 000 and a motor vehicle valued at $20 000. REQUIRED (c) Prepare the capital accounts for Amina, Nizam and Sarah at 1 January 2012. [6]
Question paper, page 9
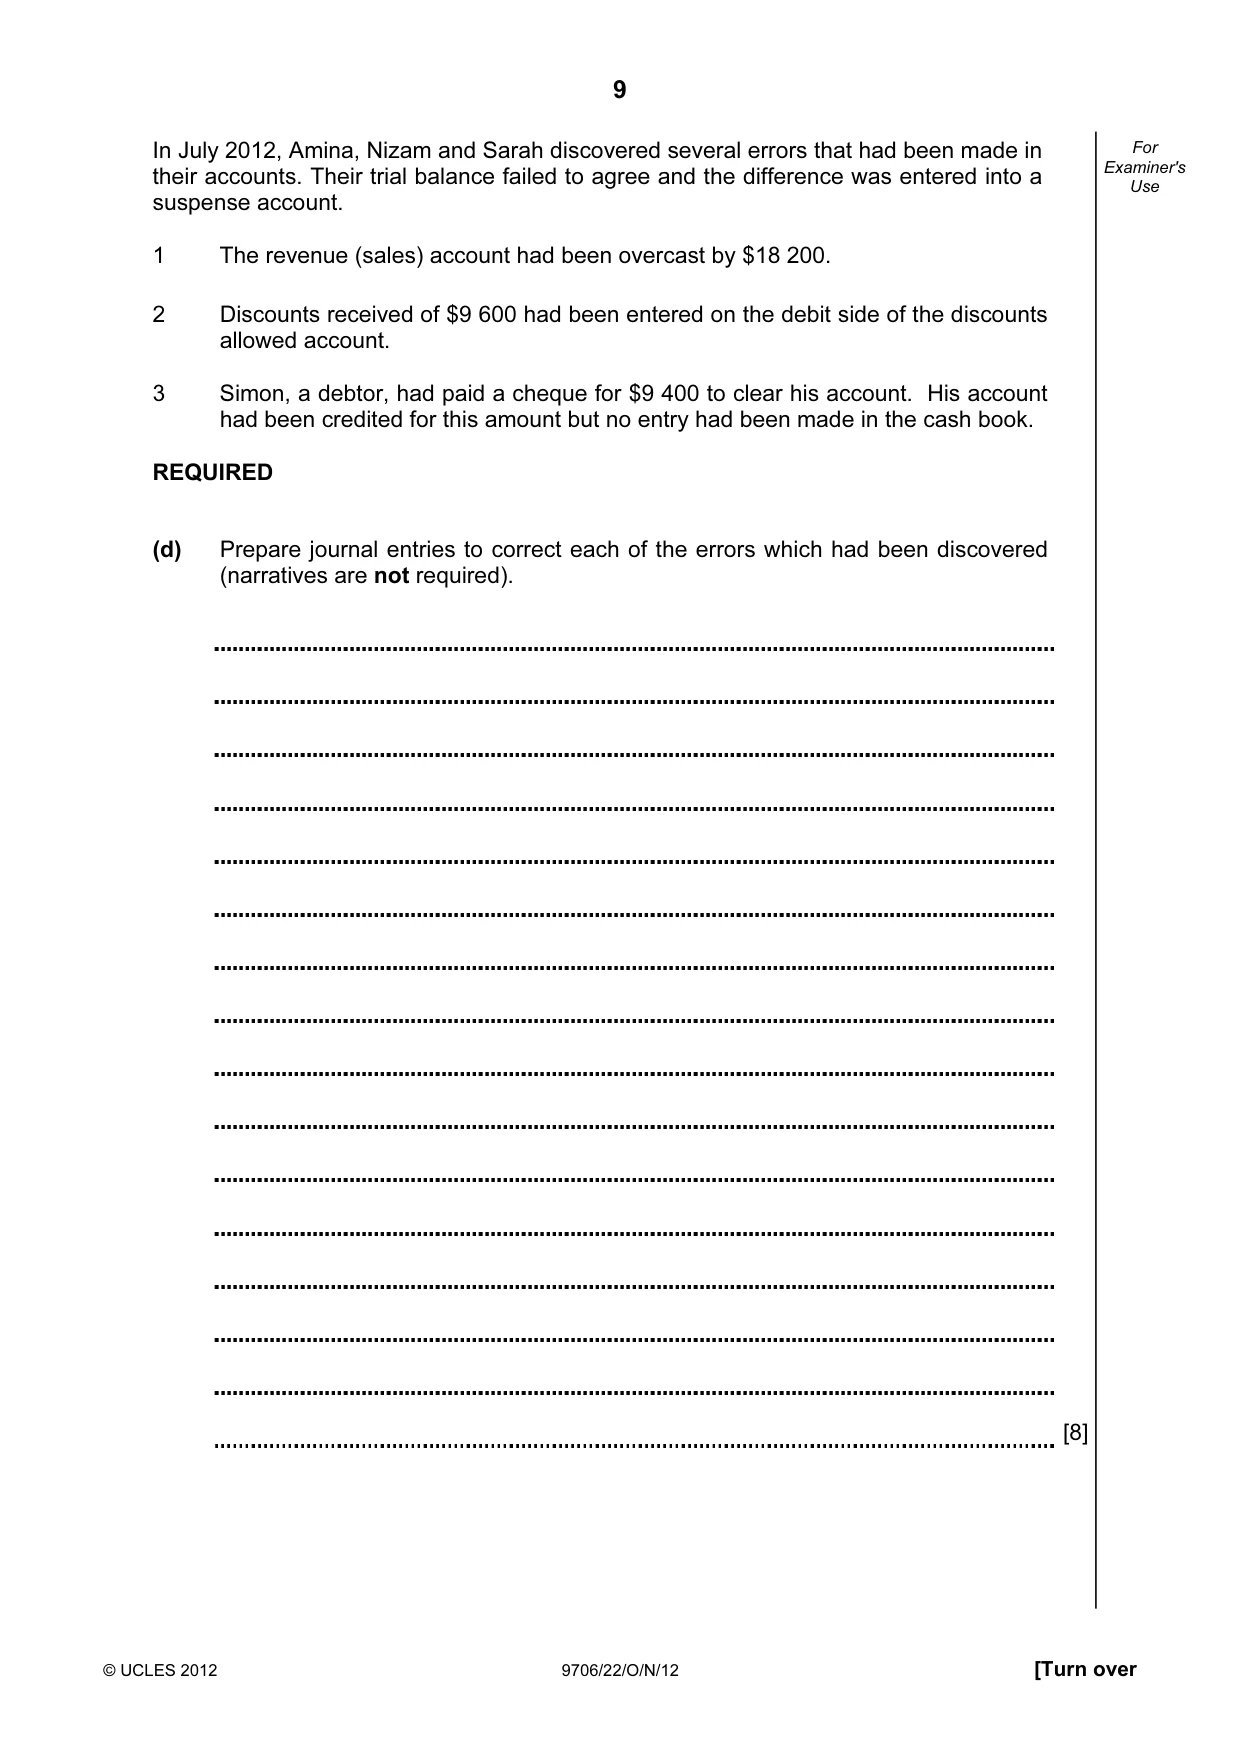
9 © UCLES 2012 9706/22/O/N/12 [Turn over For Examiner's Use In July 2012, Amina, Nizam and Sarah discovered several errors that had been made in their accounts. Their trial balance failed to agree and the difference was entered into a suspense account. 1 The revenue (sales) account had been overcast by $18 200. 2 Discounts received of $9 600 had been entered on the debit side of the discounts allowed account. 3 Simon, a debtor, had paid a cheque for $9 400 to clear his account. His account had been credited for this amount but no entry had been made in the cash book. REQUIRED (d) Prepare journal entries to correct each of the errors which had been discovered (narratives are not required). [8]
Question paper, page 10
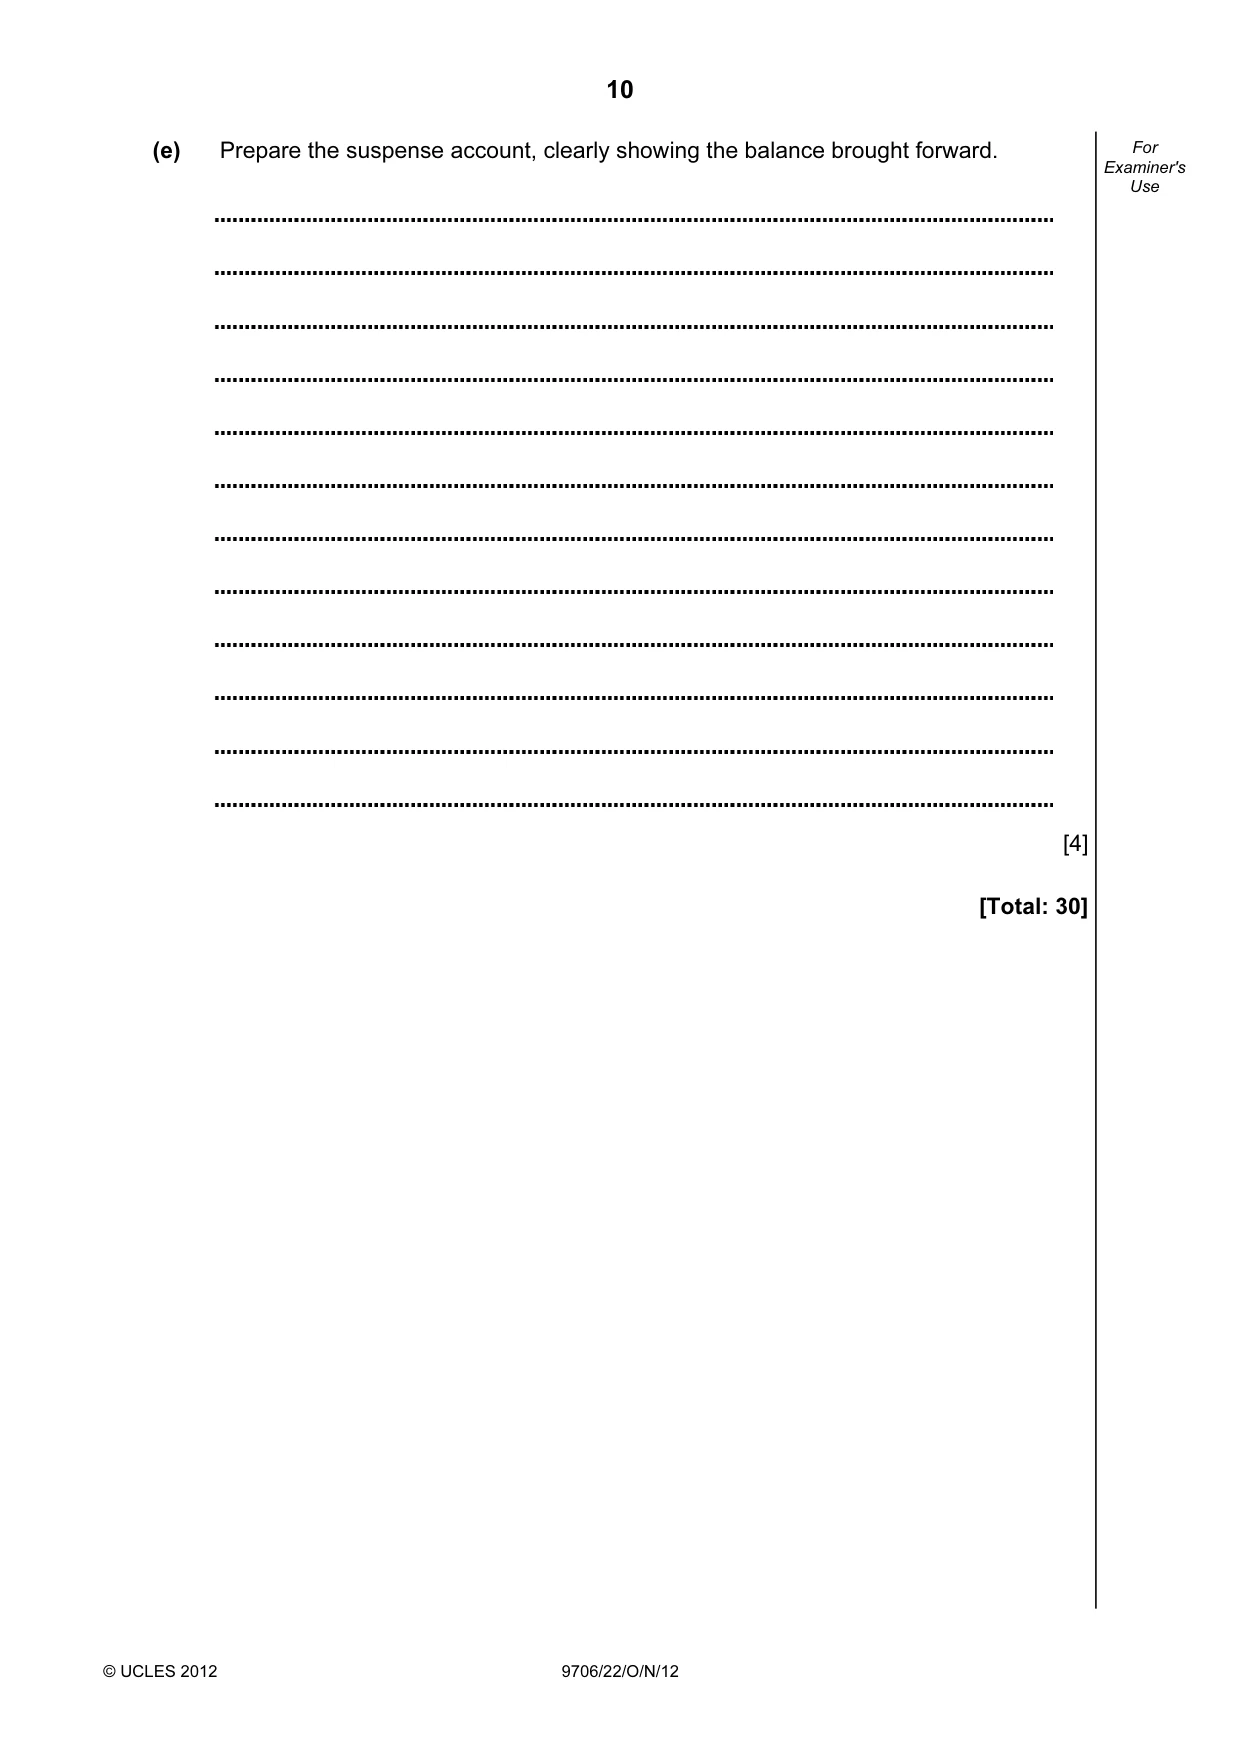
10 © UCLES 2012 9706/22/O/N/12 For Examiner's Use (e) Prepare the suspense account, clearly showing the balance brought forward. [4] [Total: 30]
Question paper, page 11
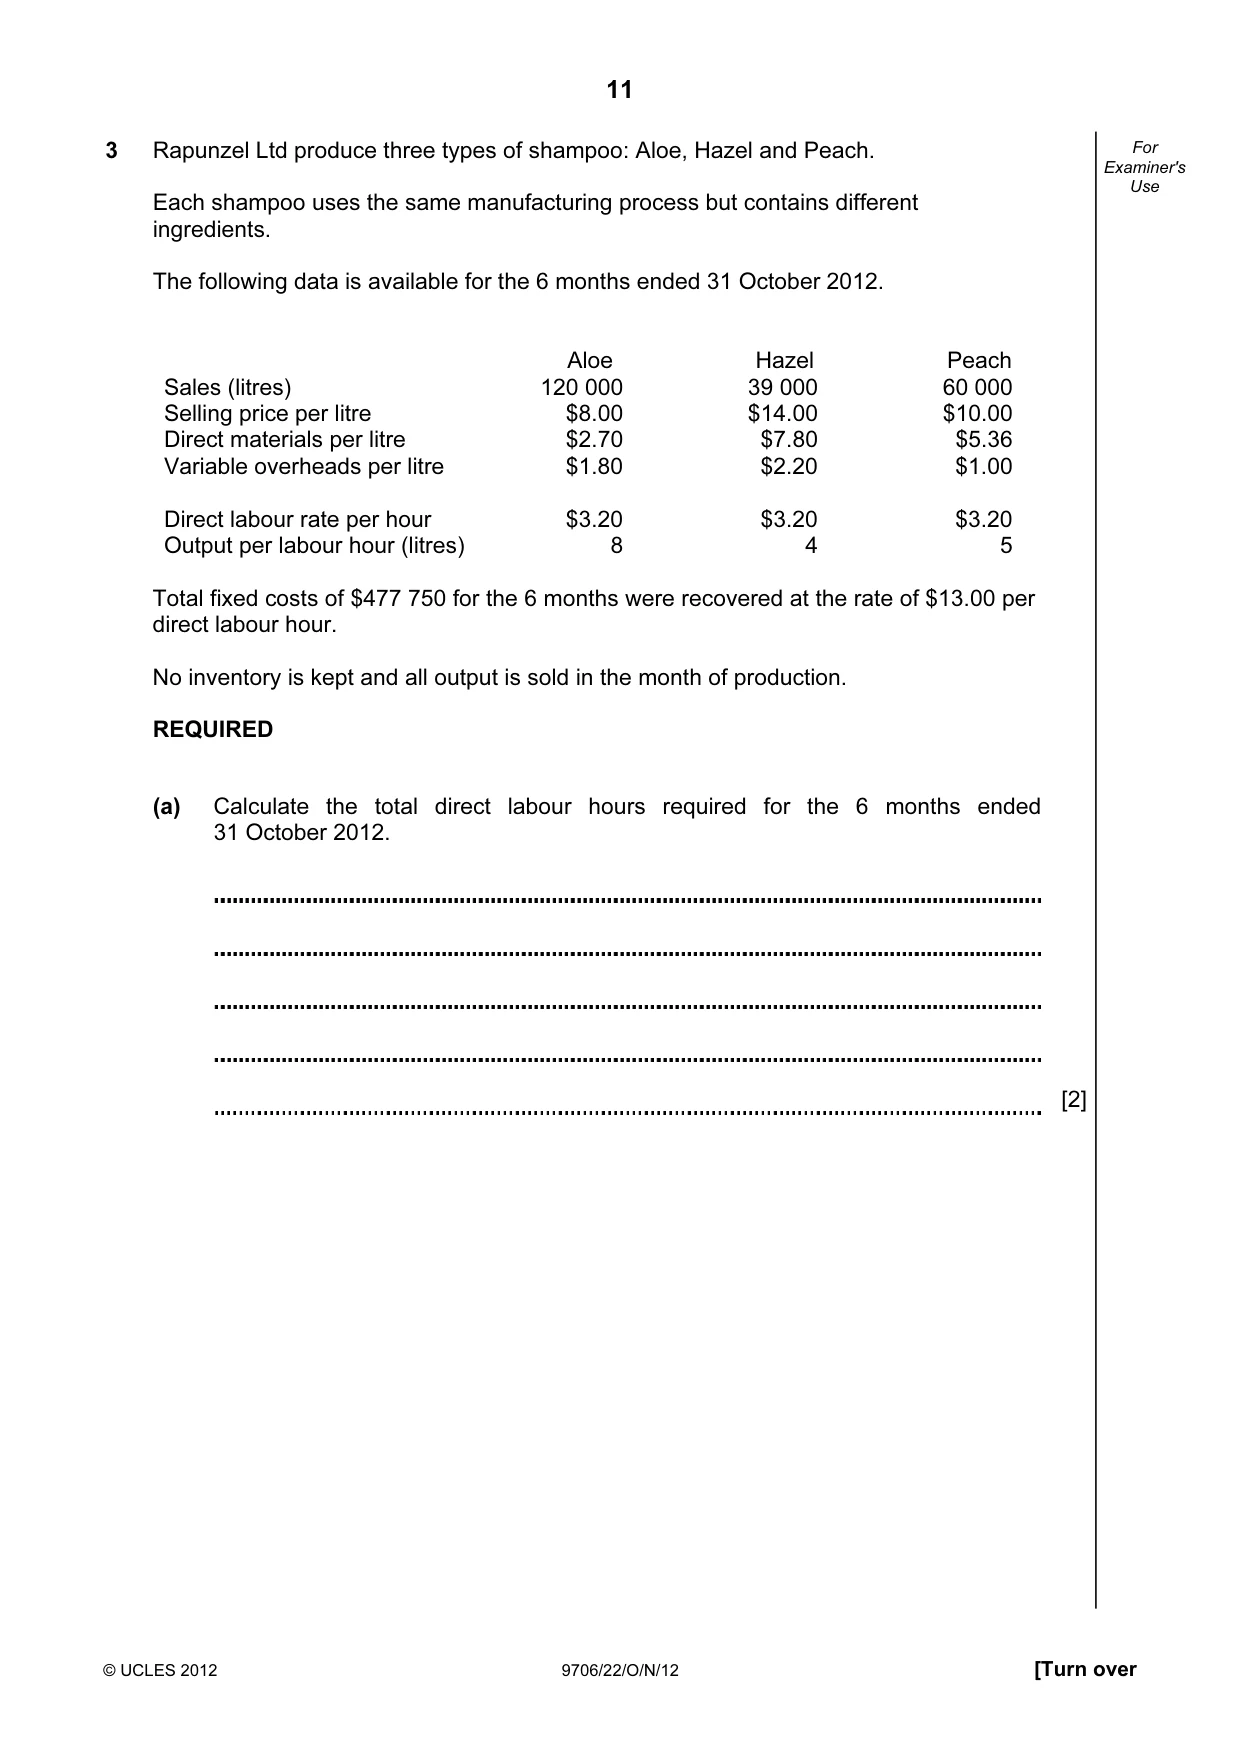
11 © UCLES 2012 9706/22/O/N/12 [Turn over For Examiner's Use 3 Rapunzel Ltd produce three types of shampoo: Aloe, Hazel and Peach. Each shampoo uses the same manufacturing process but contains different ingredients. The following data is available for the 6 months ended 31 October 2012. Aloe Hazel Peach Sales (litres) 120 000 39 000 60 000 Selling price per litre $8.00 $14.00 $10.00 Direct materials per litre $2.70 $7.80 $5.36 Variable overheads per litre $1.80 $2.20 $1.00 Direct labour rate per hour $3.20 $3.20 $3.20 Output per labour hour (litres) 8 4 5 Total fixed costs of $477 750 for the 6 months were recovered at the rate of $13.00 per direct labour hour. No inventory is kept and all output is sold in the month of production. REQUIRED (a) Calculate the total direct labour hours required for the 6 months ended 31 October 2012. [2]
Question paper, page 12
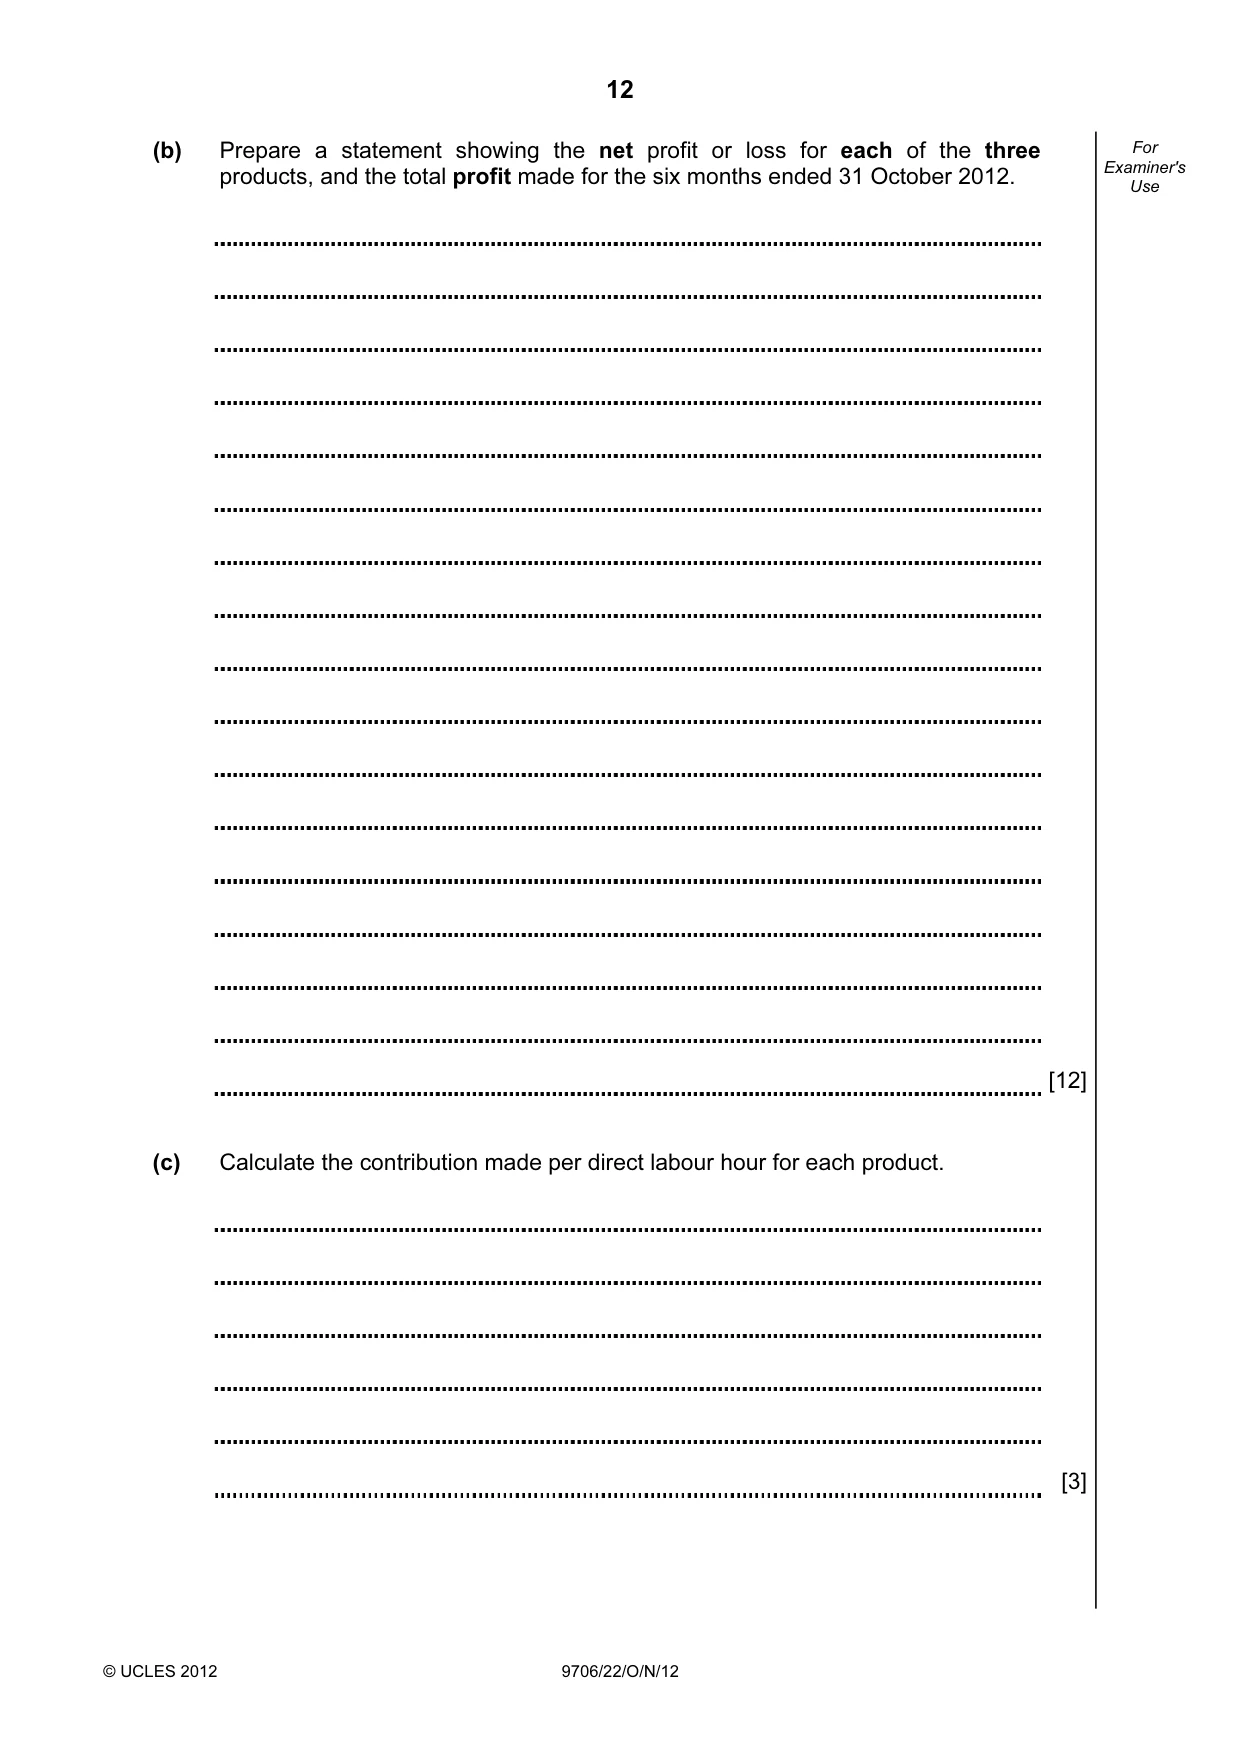
12 © UCLES 2012 9706/22/O/N/12 For Examiner's Use (b) Prepare a statement showing the net profit or loss for each of the three products, and the total profit made for the six months ended 31 October 2012. [12] (c) Calculate the contribution made per direct labour hour for each product. [3]
Question paper, page 13
13 © UCLES 2012 9706/22/O/N/12 [Turn over For Examiner's Use One of the directors suggests that production of the Hazel shampoo should be stopped and resources should be concentrated on the production of the Aloe and Peach shampoos. If this decision is implemented: • The sales of Aloe and Peach shampoos are forecast to increase by 10% each; • There will be no increase in the selling price; • The rates for variable costs will remain unchanged; • Higher marketing costs will increase the total fixed costs to $550 000. REQUIRED (d) Prepare a statement showing the expected net profit or loss for the Aloe and Peach shampoos and the total expected net profit for the 6 months ending 30 April 2013. Using the overhead recovery rate of $13.00 per direct labour hour clearly show any fixed overhead over/under absorbed. [9]
Question paper, page 14
14 © UCLES 2012 9706/22/O/N/12 For Examiner's Use (e) Based on your calculations in (b) and (d) above, advise the Board of Directors regarding the future production of the range of shampoos. [4] [Total: 30]
Question paper, page 15
15 © UCLES 2012 9706/22/O/N/12 BLANK PAGE
Question paper, page 16
16 Permission to reproduce items where third-party owned material protected by copyright is included has been sought and cleared where possible. Every reasonable effort has been made by the publisher (UCLES) to trace copyright holders, but if any items requiring clearance have unwittingly been included, the publisher will be pleased to make amends at the earliest possible opportunity. University of Cambridge International Examinations is part of the Cambridge Assessment Group. Cambridge Assessment is the brand name of University of Cambridge Local Examinations Syndicate (UCLES), which is itself a department of the University of Cambridge. © UCLES 2012 9706/22/O/N/12 BLANK PAGE
Mark scheme, page 1
CAMBRIDGE INTERNATIONAL EXAMINATIONS GCE Advanced Subsidiary Level and GCE Advanced Level MARK SCHEME for the October/November 2012 series 9706 ACCOUNTING 9706/22 Paper 2 (Structured Questions – Core), maximum raw mark 90 This mark scheme is published as an aid to teachers and candidates, to indicate the requirements of the examination. It shows the basis on which Examiners were instructed to award marks. It does not indicate the details of the discussions that took place at an Examiners’ meeting before marking began, which would have considered the acceptability of alternative answers. Mark schemes should be read in conjunction with the question paper and the Principal Examiner Report for Teachers. Cambridge will not enter into discussions about these mark schemes. Cambridge is publishing the mark schemes for the October/November 2012 series for most IGCSE, GCE Advanced Level and Advanced Subsidiary Level components and some Ordinary Level components.
Mark scheme, page 2
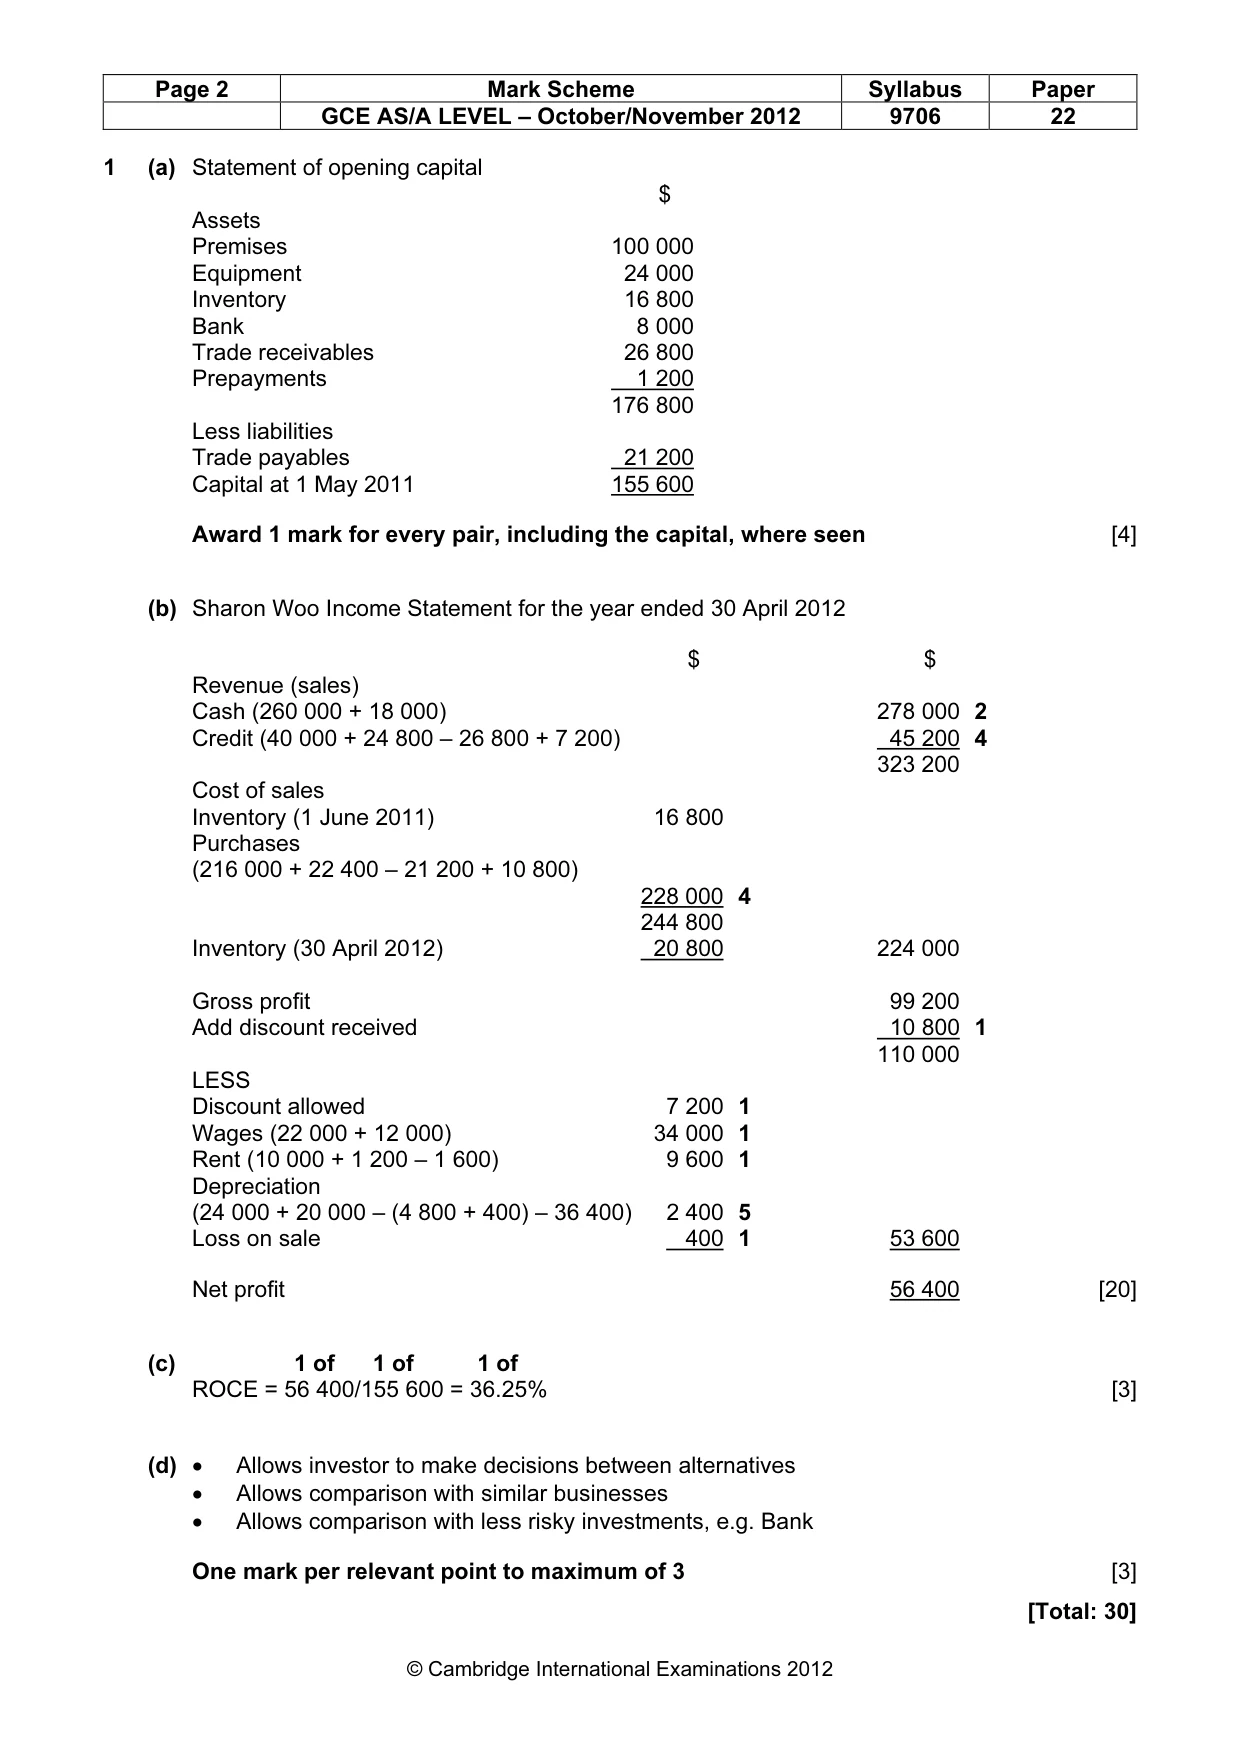
Page 2 Mark Scheme Syllabus Paper GCE AS/A LEVEL – October/November 2012 9706 22 © Cambridge International Examinations 2012 1 (a) Statement of opening capital $ Assets Premises 100 000 Equipment 24 000 Inventory 16 800 Bank 8 000 Trade receivables 26 800 Prepayments 1 200 176 800 Less liabilities Trade payables 21 200 Capital at 1 May 2011 155 600 Award 1 mark for every pair, including the capital, where seen [4] (b) Sharon Woo Income Statement for the year ended 30 April 2012 $ $ Revenue (sales) Cash (260 000 + 18 000) 278 000 2 Credit (40 000 + 24 800 – 26 800 + 7 200) 45 200 4 323 200 Cost of sales Inventory (1 June 2011) 16 800 Purchases (216 000 + 22 400 – 21 200 + 10 800) 228 000 4 244 800 Inventory (30 April 2012) 20 800 224 000 Gross profit 99 200 Add discount received 10 800 1 110 000 LESS Discount allowed 7 200 1 Wages (22 000 + 12 000) 34 000 1 Rent (10 000 + 1 200 – 1 600) 9 600 1 Depreciation (24 000 + 20 000 – (4 800 + 400) – 36 400) 2 400 5 Loss on sale 400 1 53 600 Net profit 56 400 [20] (c) 1 of 1 of 1 of ROCE = 56 400/155 600 = 36.25% [3] (d) • Allows investor to make decisions between alternatives • Allows comparison with similar businesses • Allows comparison with less risky investments, e.g. Bank One mark per relevant point to maximum of 3 [3] [Total: 30]
Mark scheme, page 3
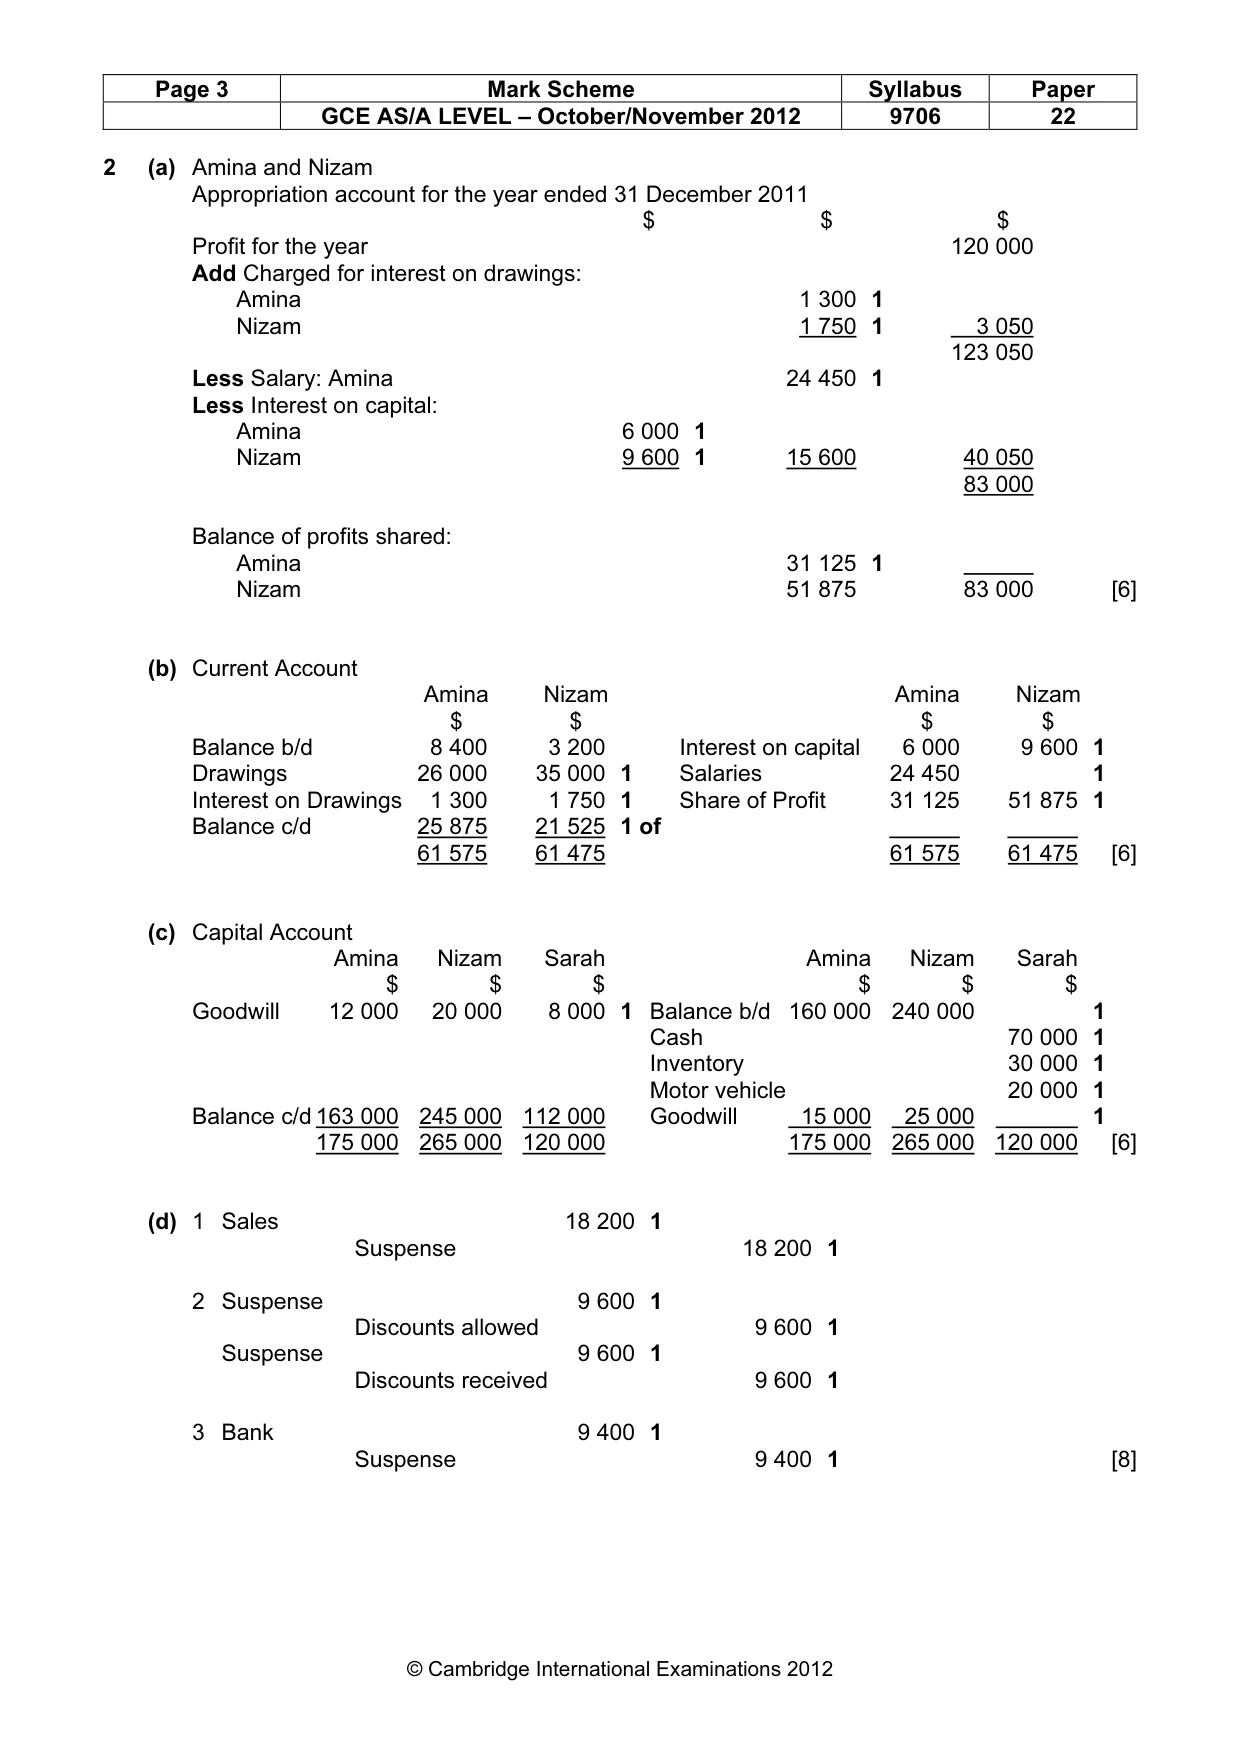
Page 3 Mark Scheme Syllabus Paper GCE AS/A LEVEL – October/November 2012 9706 22 © Cambridge International Examinations 2012 2 (a) Amina and Nizam Appropriation account for the year ended 31 December 2011 $ $ $ Profit for the year 120 000 Add Charged for interest on drawings: Amina 1 300 1 Nizam 1 750 1 3 050 123 050 Less Salary: Amina 24 450 1 Less Interest on capital: Amina 6 000 1 Nizam 9 600 1 15 600 40 050 83 000 Balance of profits shared: Amina 31 125 1 Nizam 51 875 83 000 [6] (b) Current Account Amina Nizam Amina Nizam $ $ $ $ Balance b/d 8 400 3 200 Interest on capital 6 000 9 600 1 Drawings 26 000 35 000 1 Salaries 24 450 1 Interest on Drawings 1 300 1 750 1 Share of Profit 31 125 51 875 1 Balance c/d 25 875 21 525 1 of 61 575 61 475 61 575 61 475 [6] (c) Capital Account Amina Nizam Sarah Amina Nizam Sarah $ $ $ $ $ $ Goodwill 12 000 20 000 8 000 1 Balance b/d 160 000 240 000 1 Cash 70 000 1 Inventory 30 000 1 Motor vehicle 20 000 1 Balance c/d 163 000 245 000 112 000 Goodwill 15 000 25 000 1 175 000 265 000 120 000 175 000 265 000 120 000 [6] (d) 1 Sales 18 200 1 Suspense 18 200 1 2 Suspense 9 600 1 Discounts allowed 9 600 1 Suspense 9 600 1 Discounts received 9 600 1 3 Bank 9 400 1 Suspense 9 400 1 [8]
Mark scheme, page 4
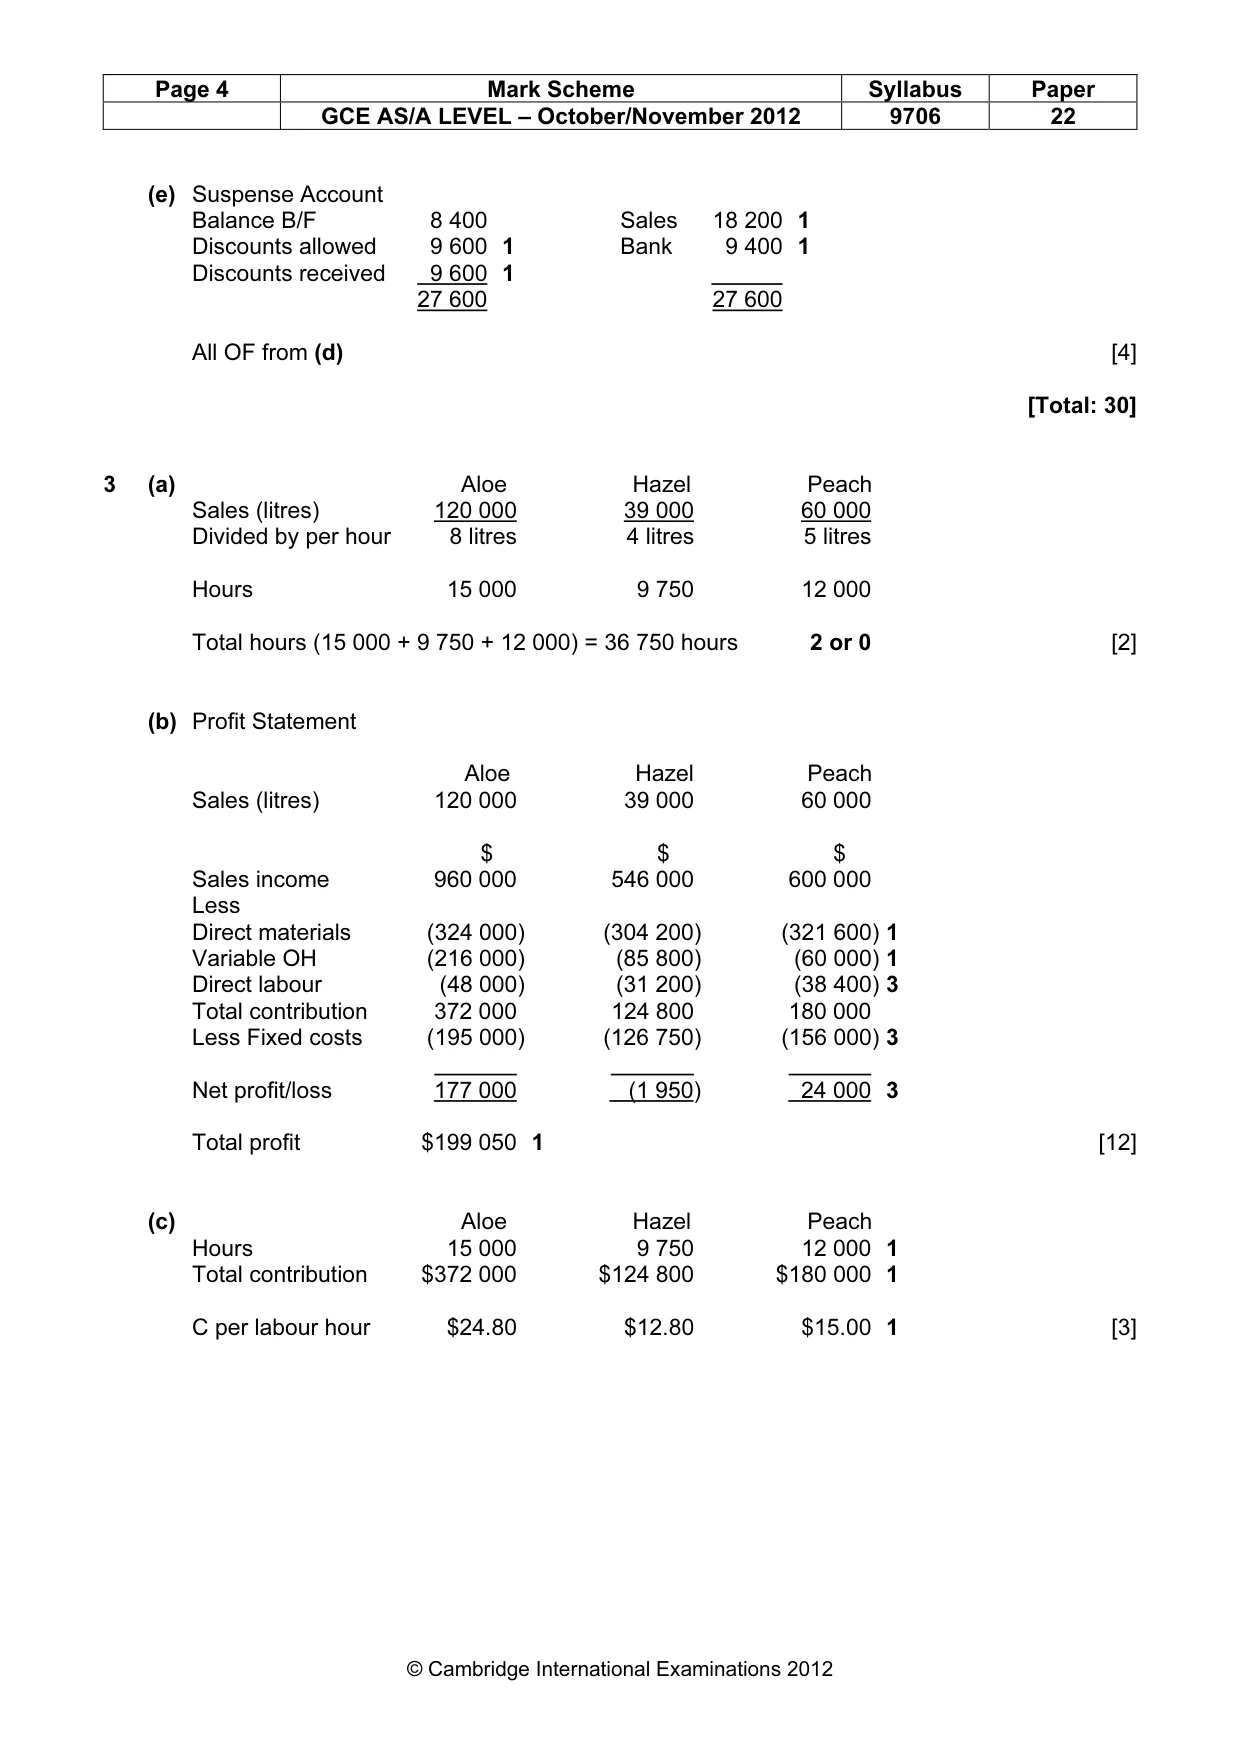
Page 4 Mark Scheme Syllabus Paper GCE AS/A LEVEL – October/November 2012 9706 22 © Cambridge International Examinations 2012 (e) Suspense Account Balance B/F 8 400 Sales 18 200 1 Discounts allowed 9 600 1 Bank 9 400 1 Discounts received 9 600 1 27 600 27 600 All OF from (d) [4] [Total: 30] 3 (a) Aloe Hazel Peach Sales (litres) 120 000 39 000 60 000 Divided by per hour 8 litres 4 litres 5 litres Hours 15 000 9 750 12 000 Total hours (15 000 + 9 750 + 12 000) = 36 750 hours 2 or 0 [2] (b) Profit Statement Aloe Hazel Peach Sales (litres) 120 000 39 000 60 000 $ $ $ Sales income 960 000 546 000 600 000 Less Direct materials (324 000) (304 200) (321 600) 1 Variable OH (216 000) (85 800) (60 000) 1 Direct labour (48 000) (31 200) (38 400) 3 Total contribution 372 000 124 800 180 000 Less Fixed costs (195 000) (126 750) (156 000) 3 Net profit/loss 177 000 (1 950) 24 000 3 Total profit $199 050 1 [12] (c) Aloe Hazel Peach Hours 15 000 9 750 12 000 1 Total contribution $372 000 $124 800 $180 000 1 C per labour hour $24.80 $12.80 $15.00 1 [3]
Mark scheme, page 5
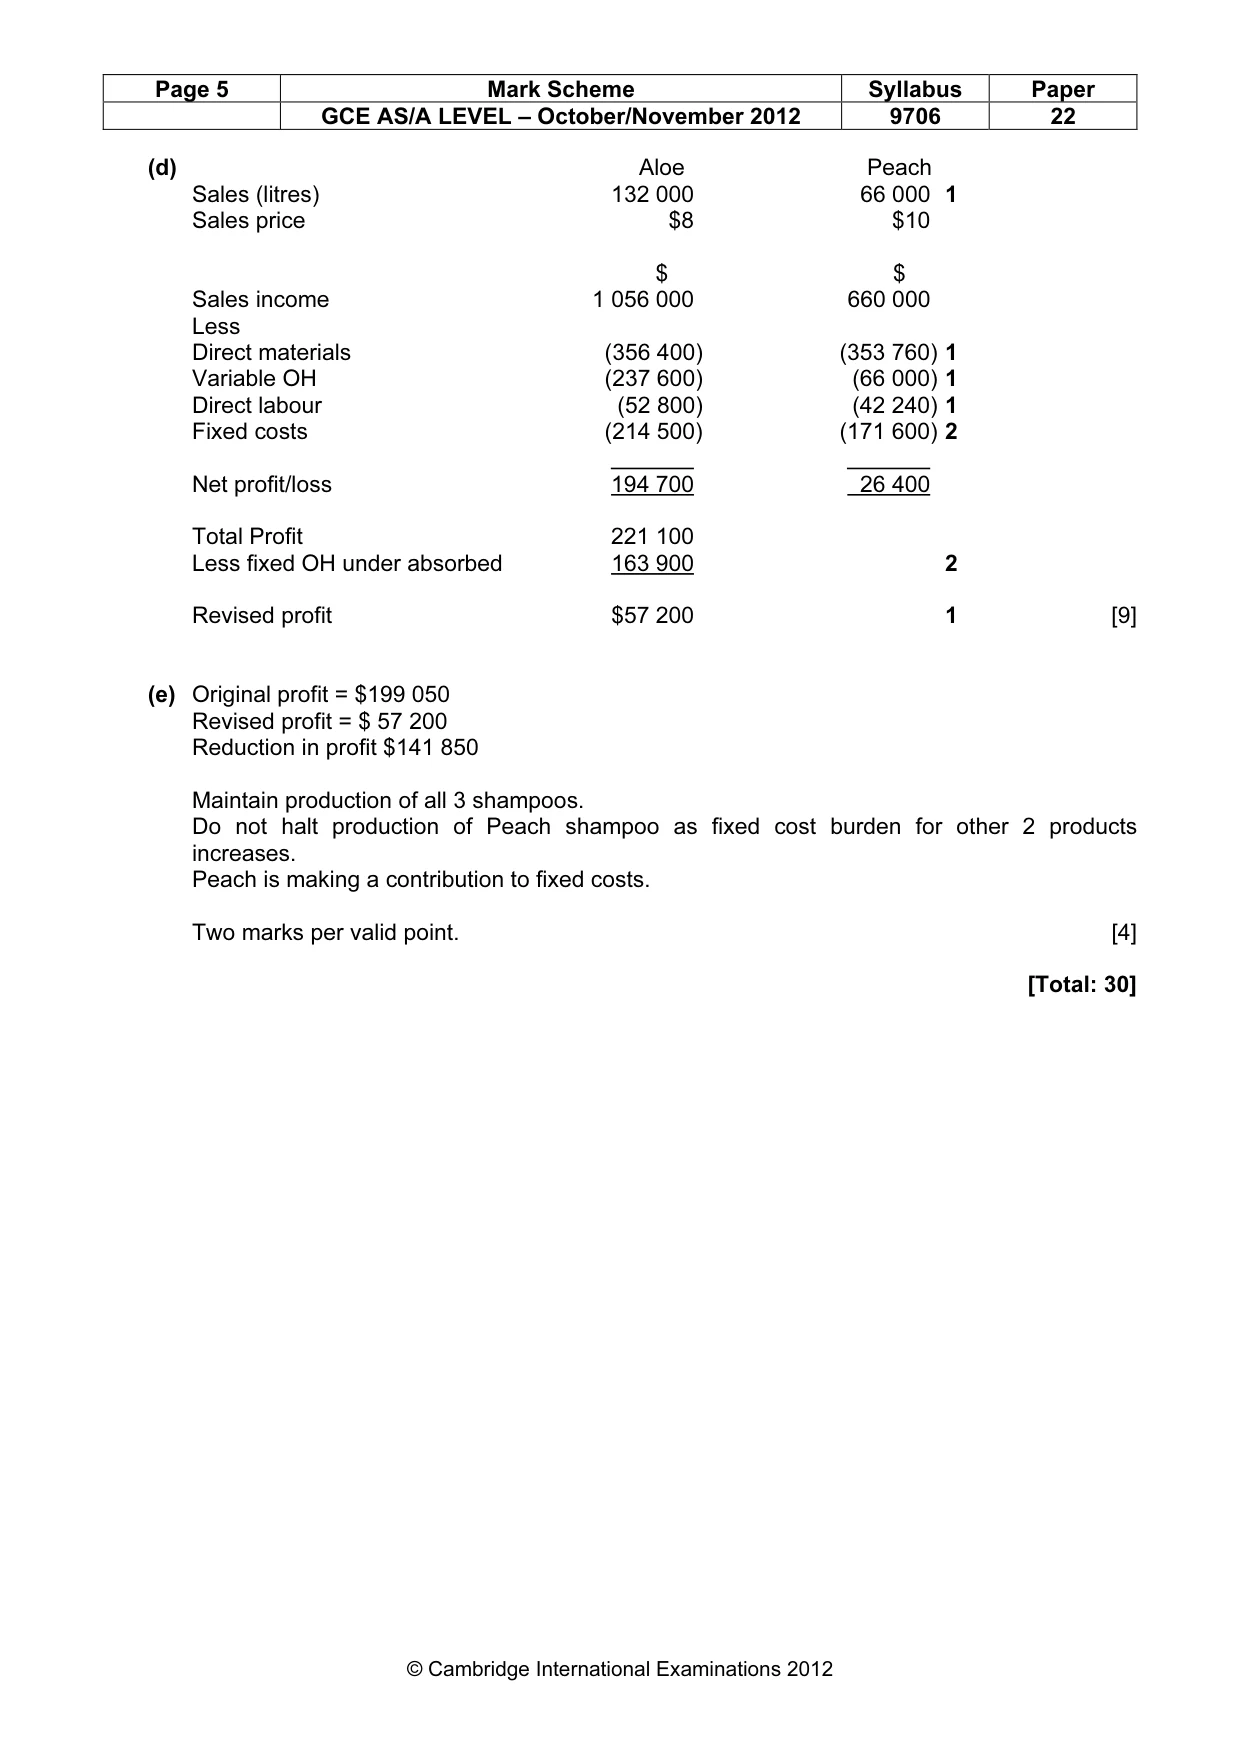
Page 5 Mark Scheme Syllabus Paper GCE AS/A LEVEL – October/November 2012 9706 22 © Cambridge International Examinations 2012 (d) Aloe Peach Sales (litres) 132 000 66 000 1 Sales price $8 $10 $ $ Sales income 1 056 000 660 000 Less Direct materials (356 400) (353 760) 1 Variable OH (237 600) (66 000) 1 Direct labour (52 800) (42 240) 1 Fixed costs (214 500) (171 600) 2 Net profit/loss 194 700 26 400 Total Profit 221 100 Less fixed OH under absorbed 163 900 2 Revised profit $57 200 1 [9] (e) Original profit = $199 050 Revised profit = $ 57 200 Reduction in profit $141 850 Maintain production of all 3 shampoos. Do not halt production of Peach shampoo as fixed cost burden for other 2 products increases. Peach is making a contribution to fixed costs. Two marks per valid point. [4] [Total: 30]
What you needed in this session
Cambridge’s own grade thresholds for 2012 Oct/Nov, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.