Cambridge A Level Accounting 9706 — 2025 Oct/Nov Paper 2 · Variant 3
9706/23/O/N/25 · 4 questions · 90 marks · ≈101 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme
No mark scheme is in the library for this paper.
Questions as text
Q1 · Fazal and Naseem are in partnership
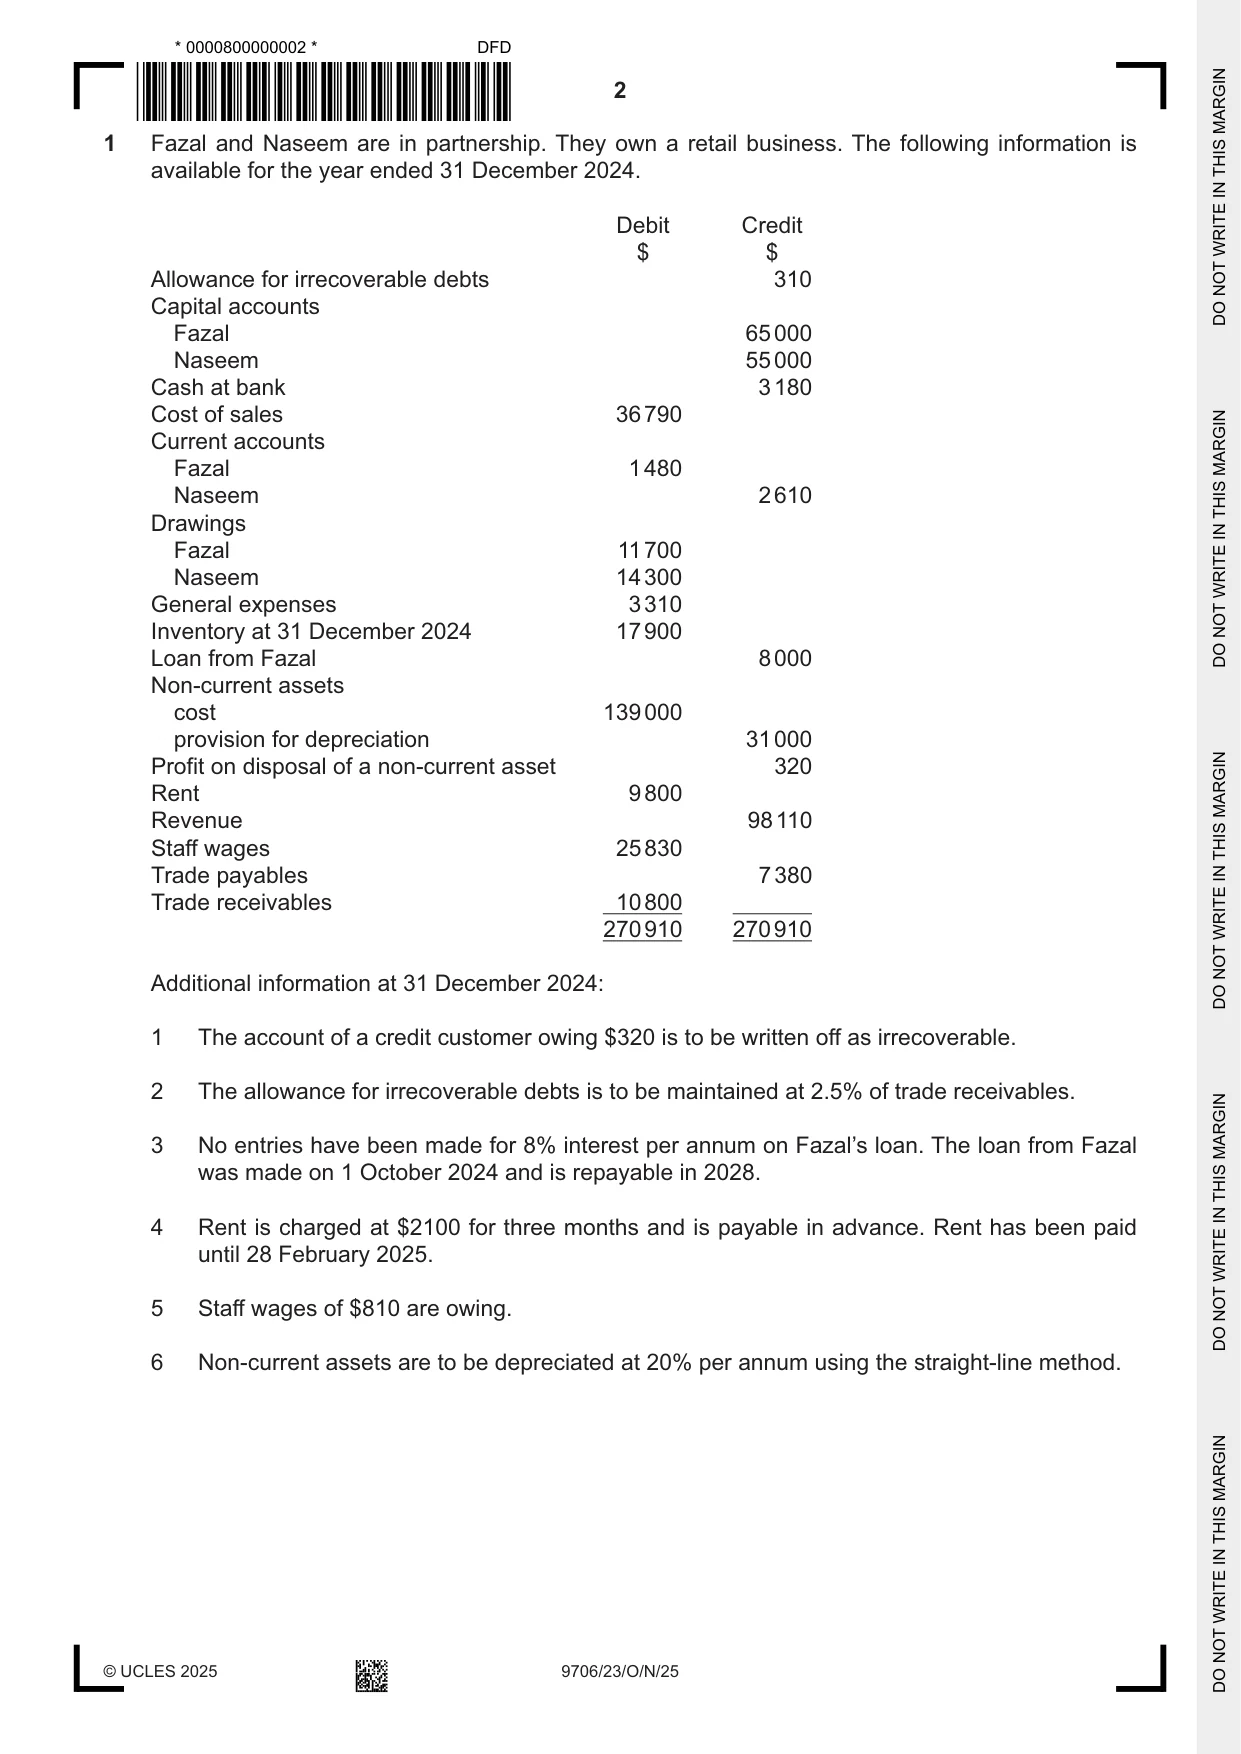
1 Fazal and Naseem are in partnership. They own a retail business. The following information is available for the year ended 31 December 2024. Debit Credit $ $ Allowance for irrecoverable debts 310 Capital accounts Fazal 65 000 Naseem 55 000 Cash at bank 3 180 Cost of sales 36 790 Current accounts Fazal 1 480 Naseem 2 610 Drawings Fazal 11 700 Naseem 14 300 General expenses 3 310 Inventory at 31 December 2024 17 900 Loan from Fazal 8 000 Non‑current assets cost 139 000 provision for depreciation 31 000 Profit on disposal of a non‑current asset 320 Rent 9 800 Revenue 98 110 Staff wages 25 830 Trade payables 7 380 Trade receivables 10 800 270 910 270 910 Additional information at 31 December 2024: 1 The account of a credit customer owing $320 is to be written off as irrecoverable. 2 The allowance for irrecoverable debts is to be maintained at 2.5% of trade receivables. 3 No entries have been made for 8% interest per annum on Fazal’s loan. The loan from Fazal was made on 1 October 2024 and is repayable in 2028. 4 Rent is charged at $2100 for three months and is payable in advance. Rent has been paid until 28 February 2025. 5 Staff wages of $810 are owing. 6 Non‑current assets are to be depreciated at 20% per annum using the straight‑line method. (a) Prepare the statement of profit or loss for the year ended 31 December 2024. Use the space provided on page 4 to show your workings. Fazal and Naseem Statement of profit or loss for the year ended 31 December 2024 ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Workings: [9] Additional information The partners share profits and losses equally after providing for: 1 interest on drawings of 5% per annum
Q2 · Prepare each partner’s current account for the year ended 31 December 2024
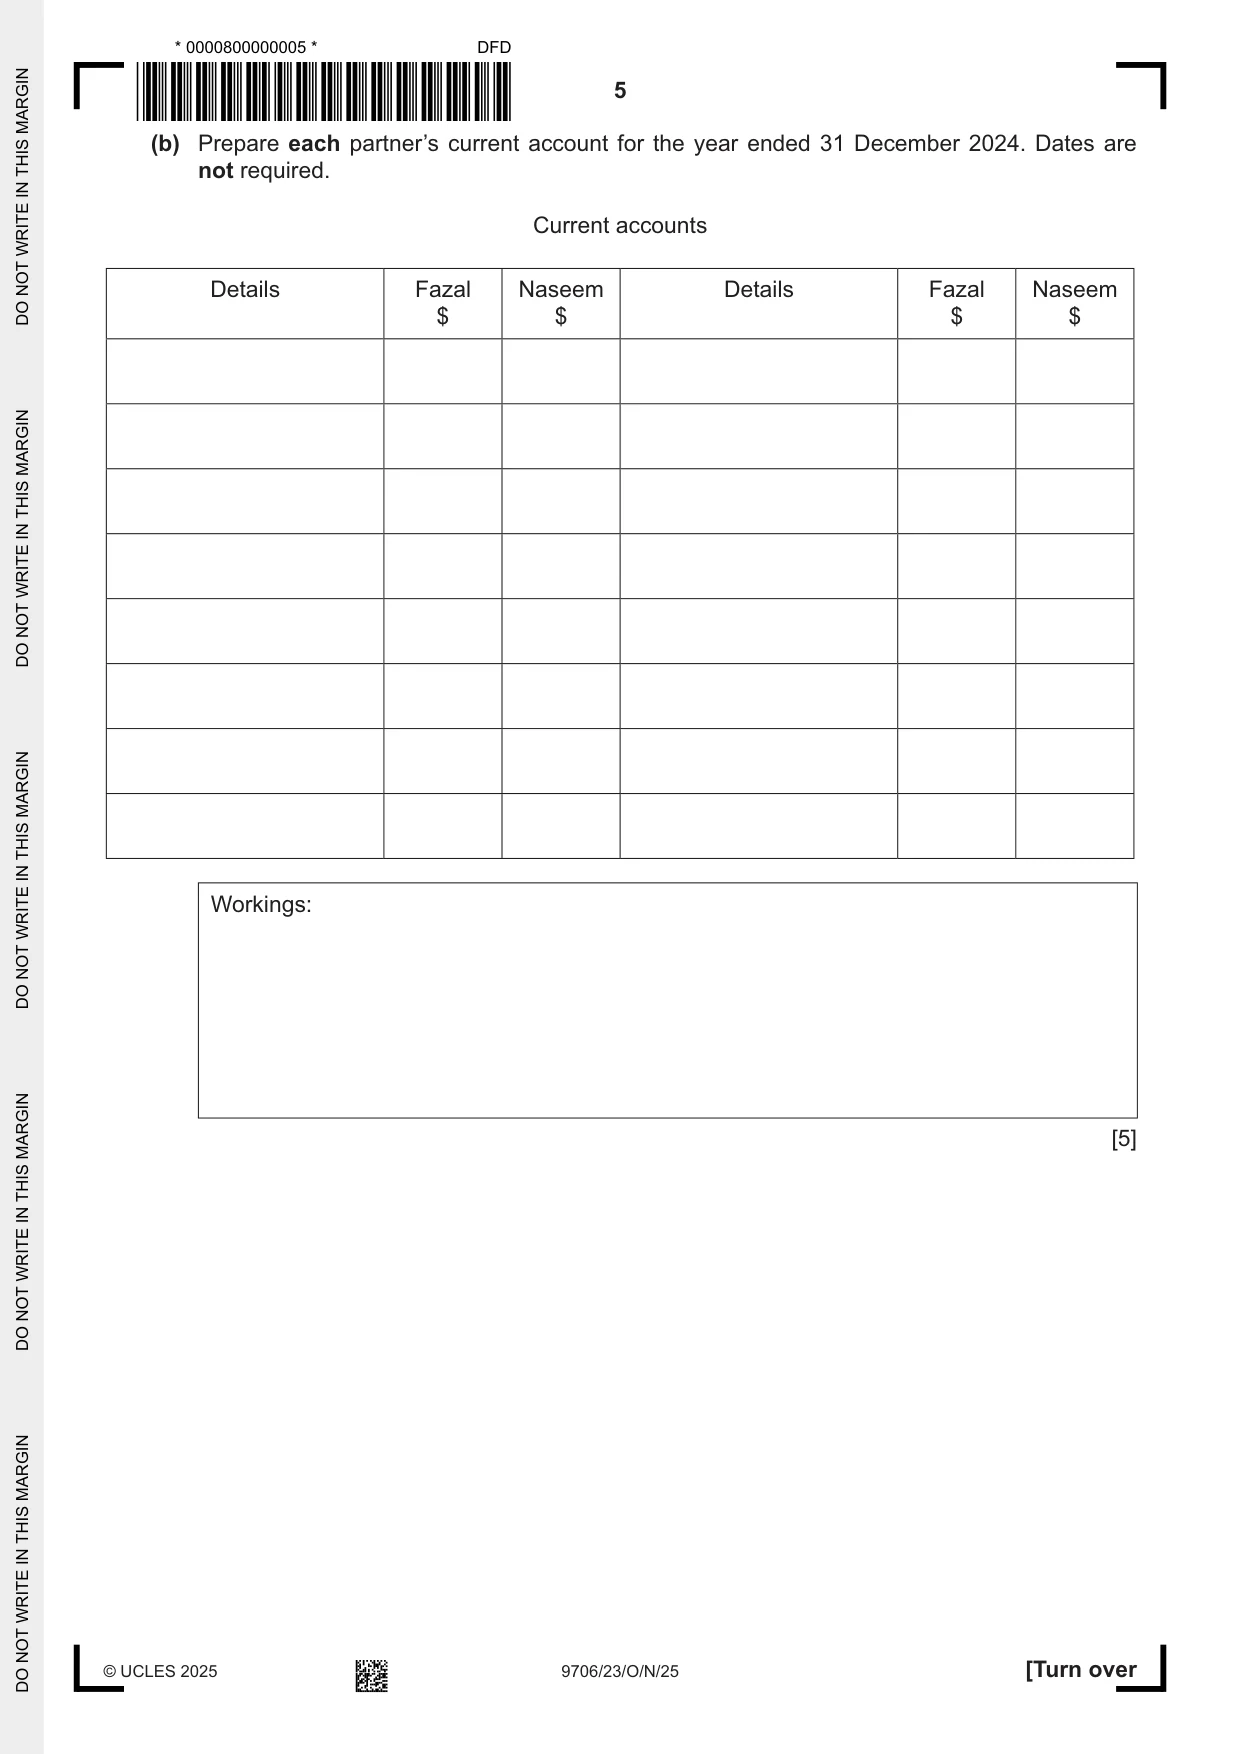
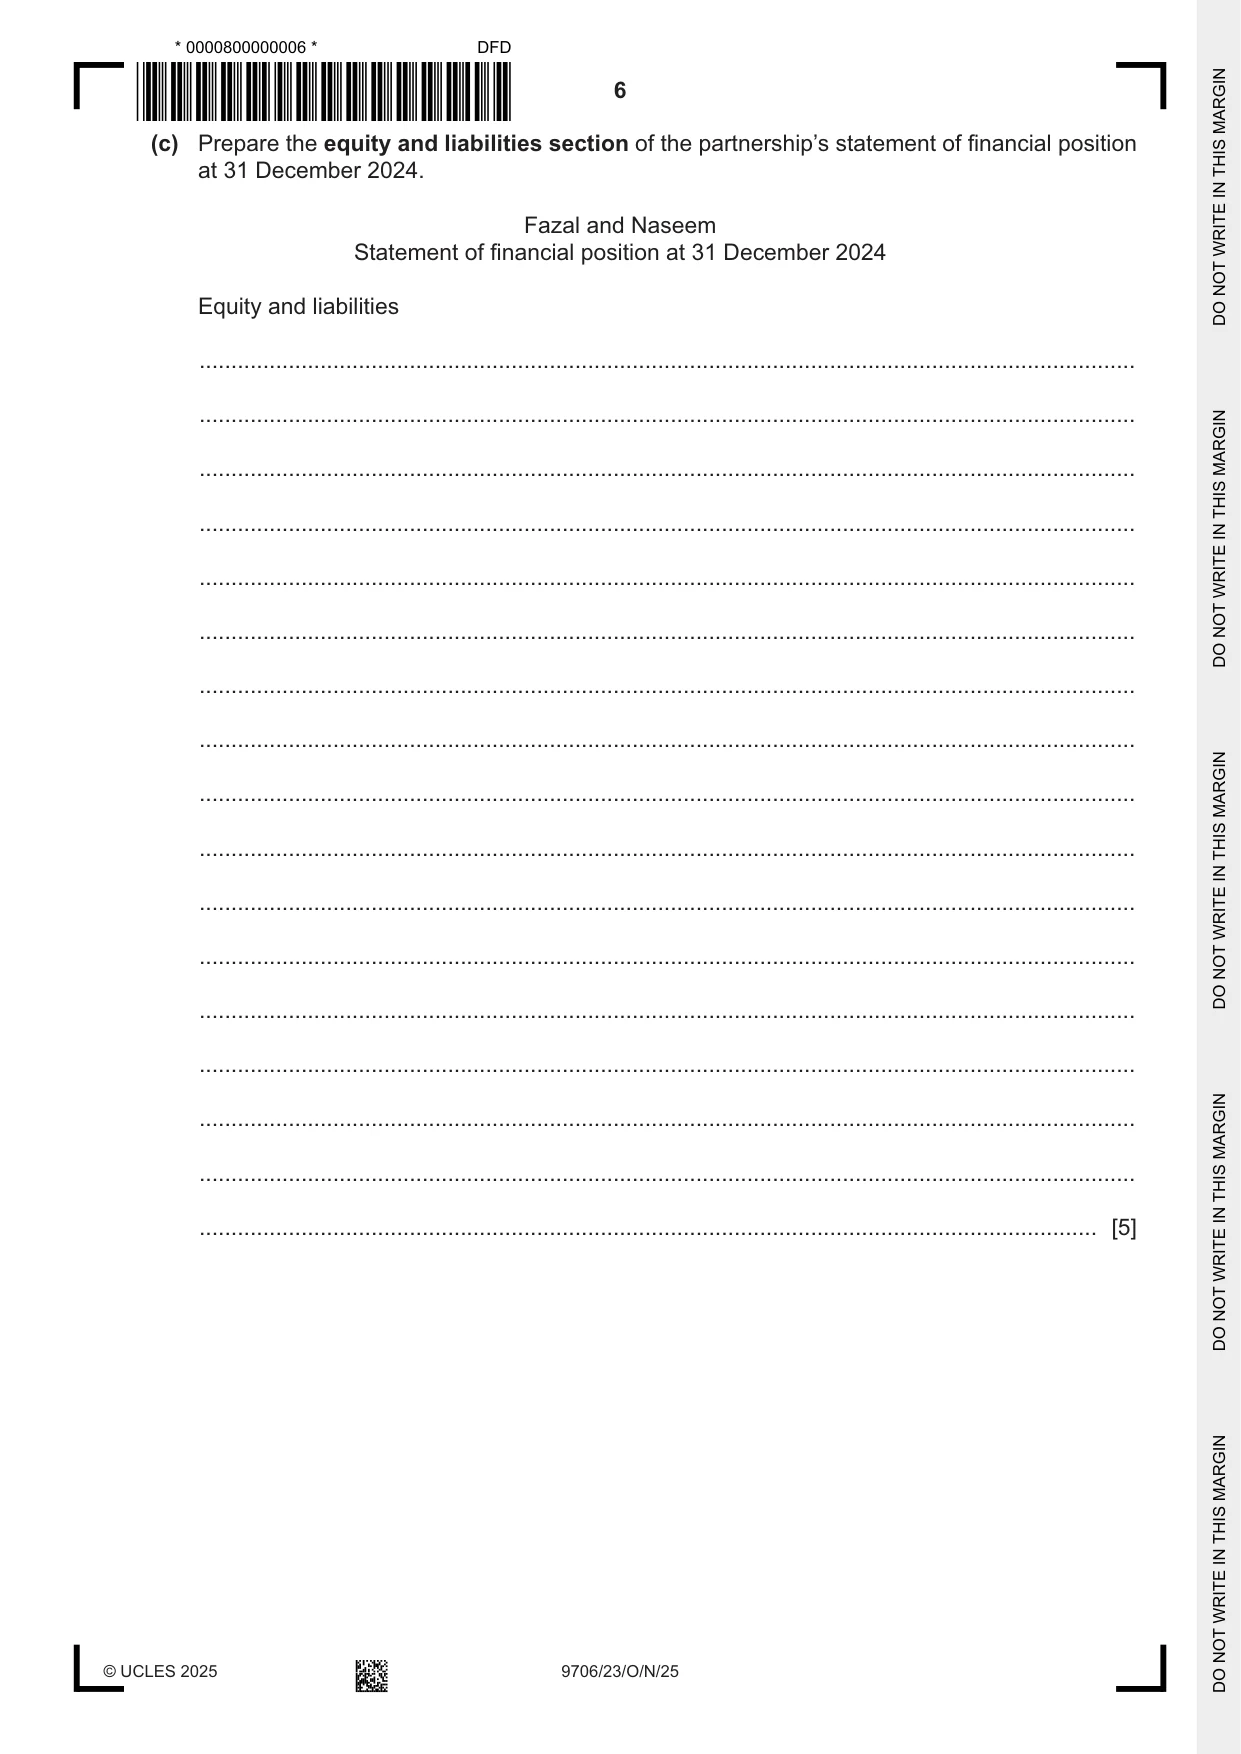
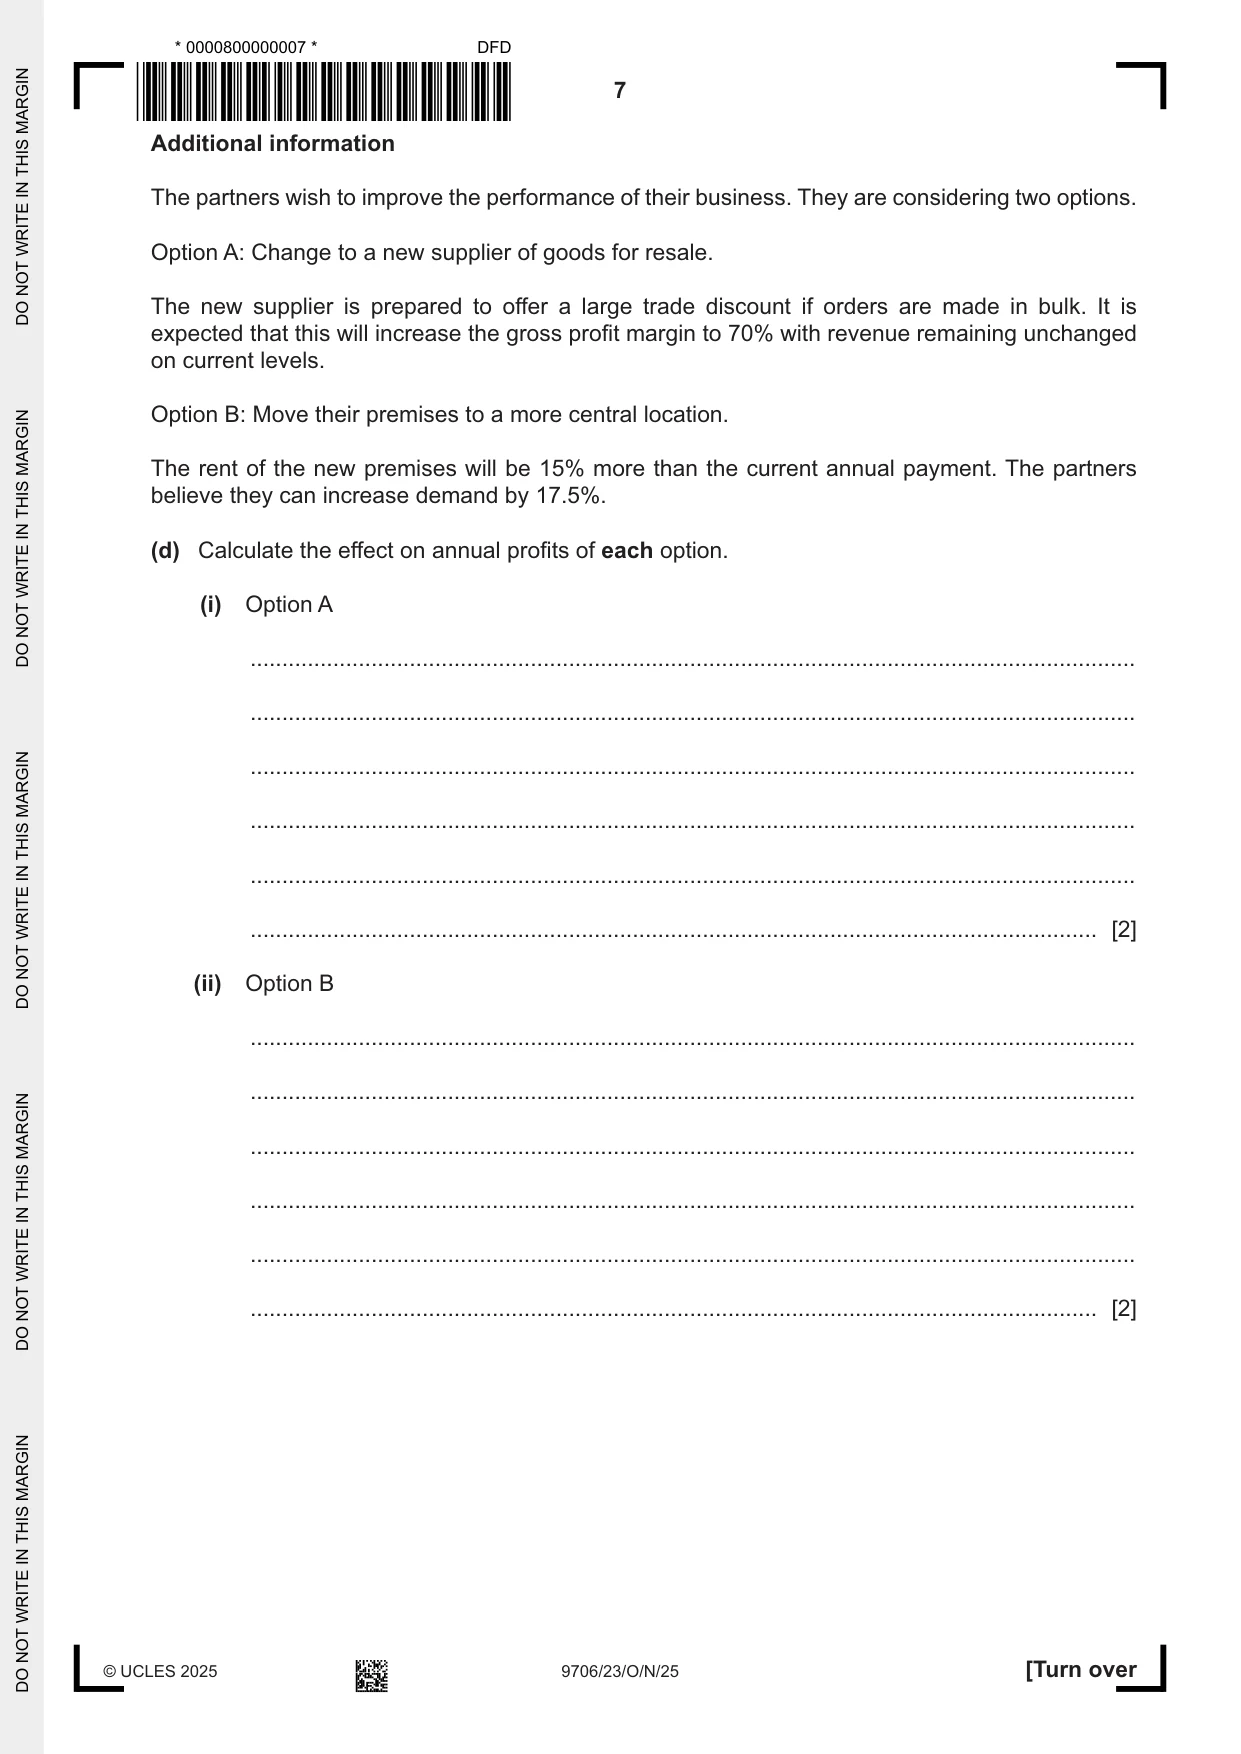
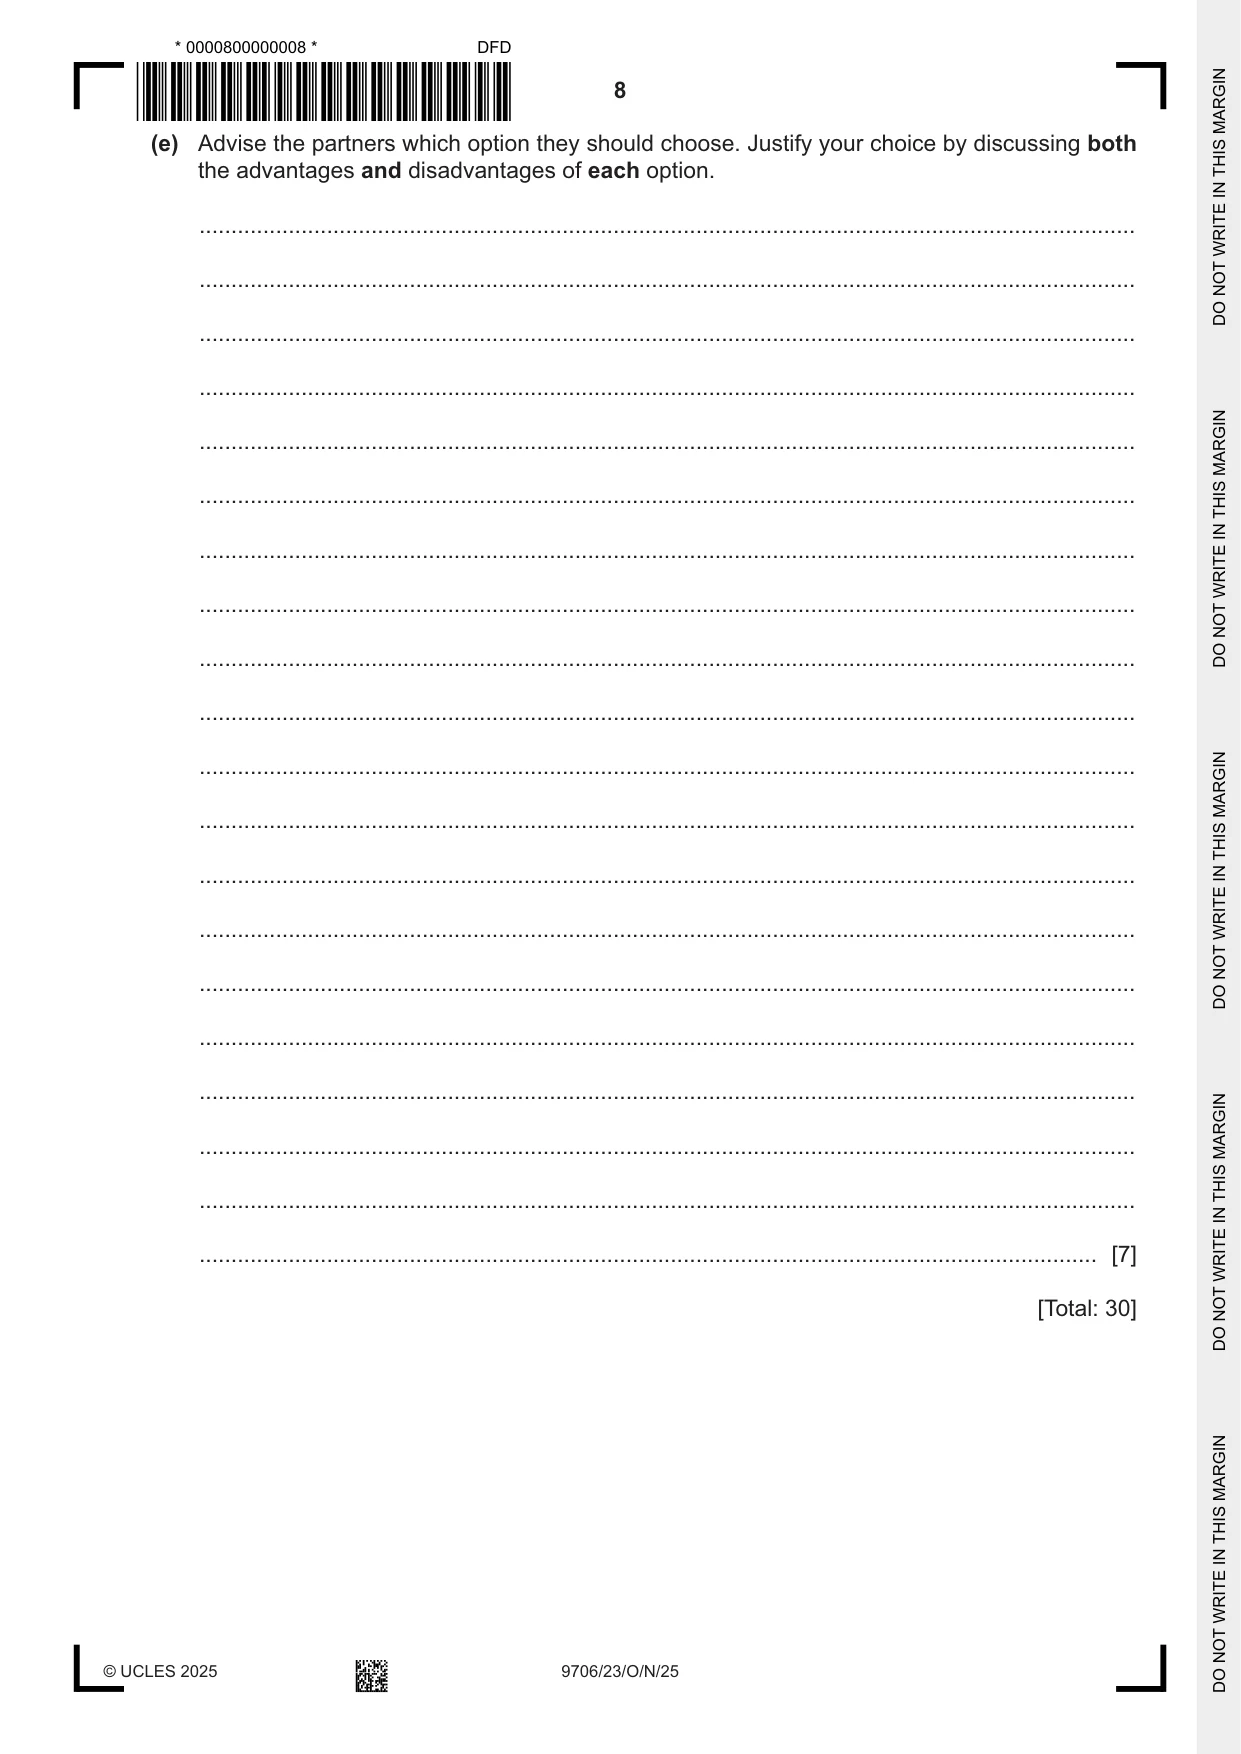
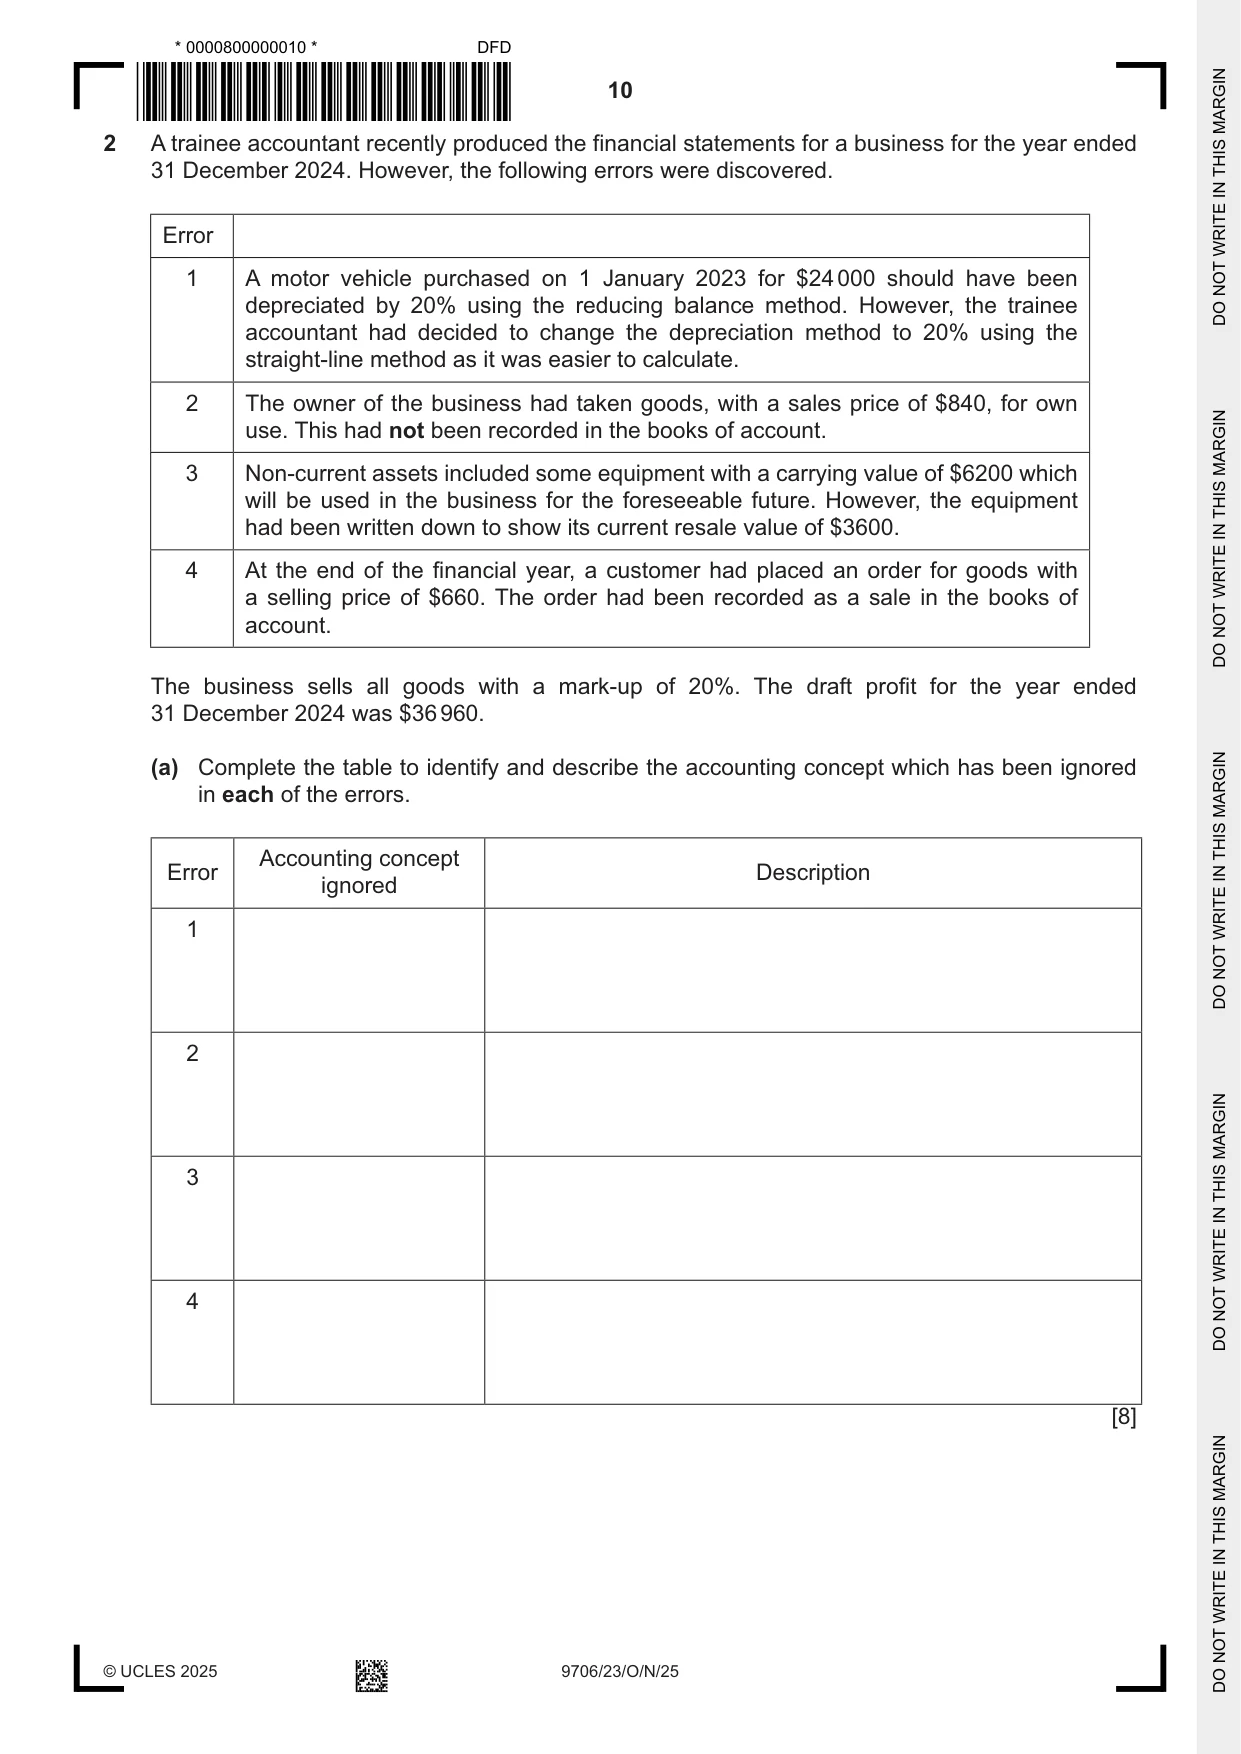
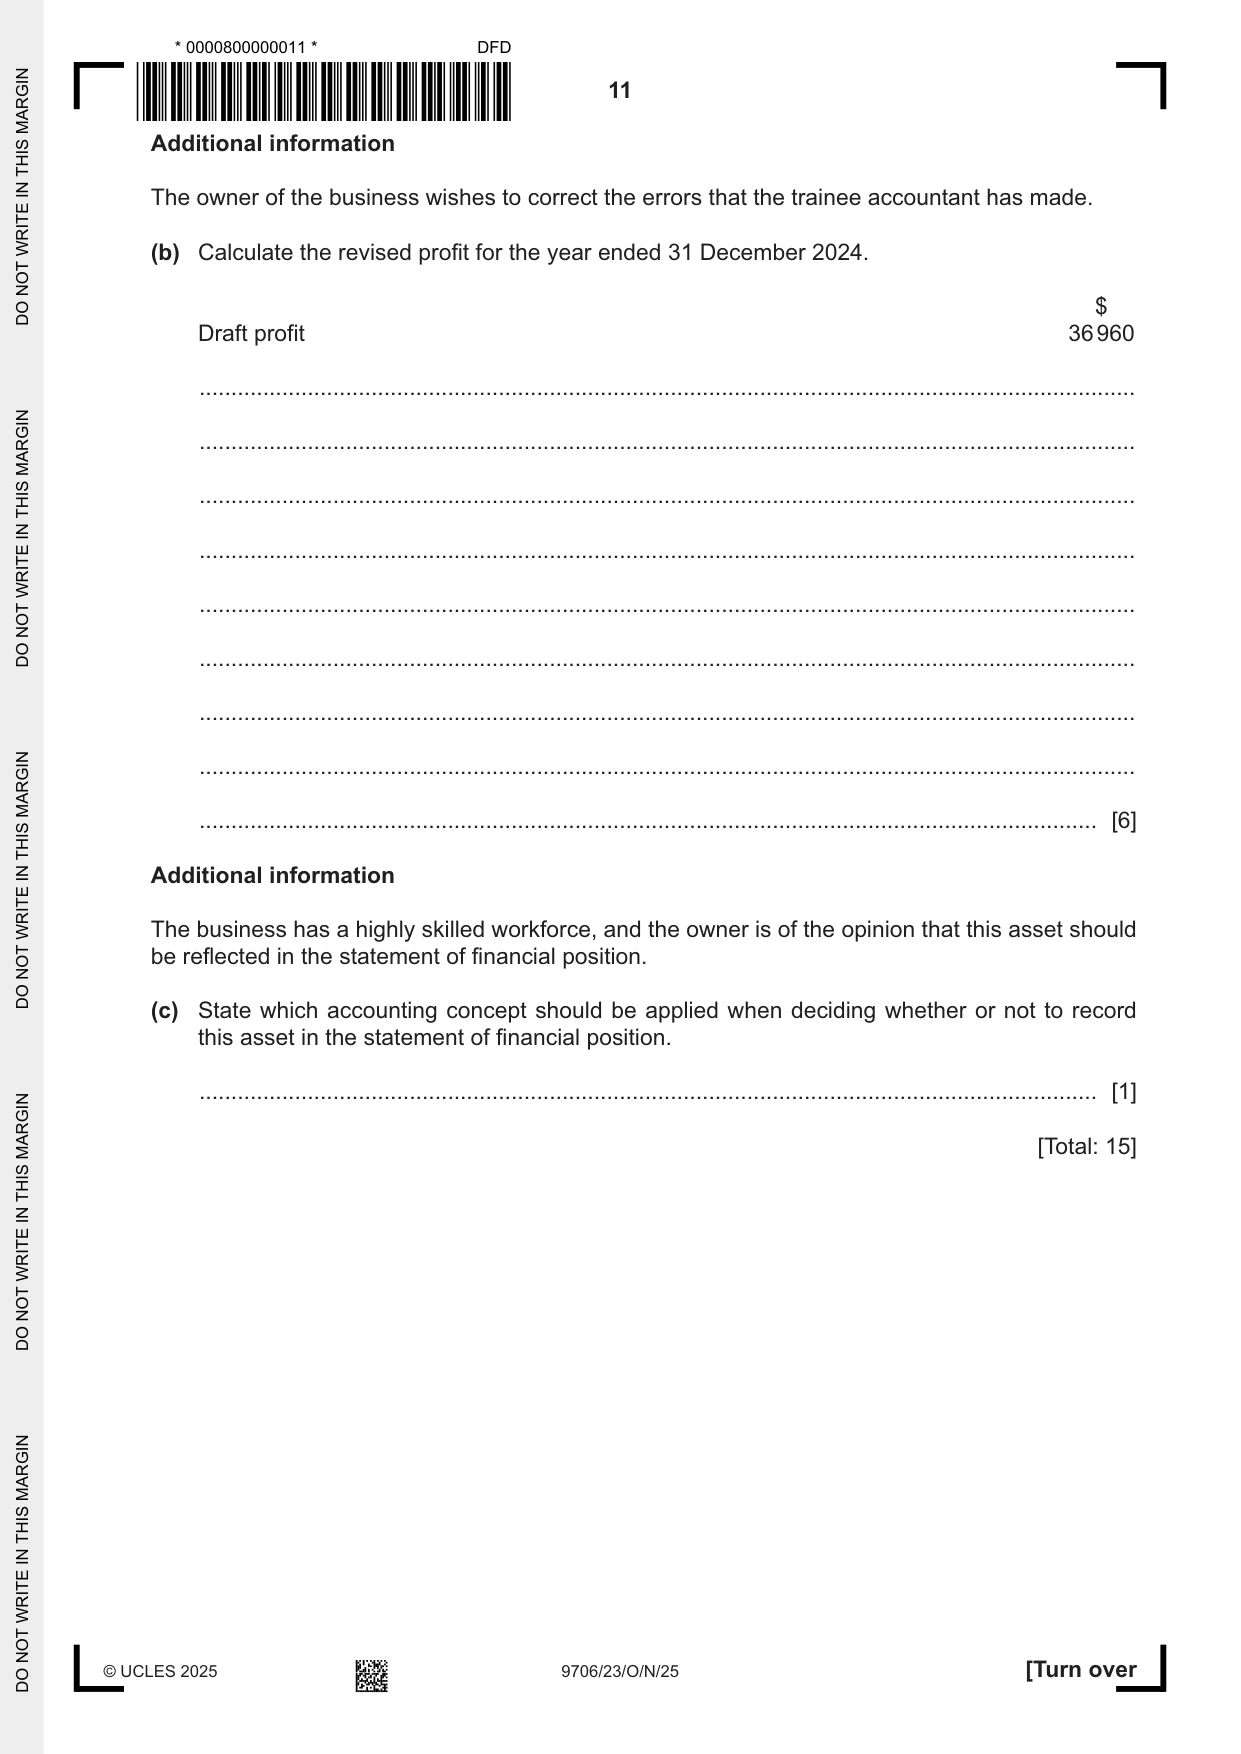
(b) Prepare each partner’s current account for the year ended 31 December 2024. Dates are not required. Current accounts Details Fazal Naseem Details Fazal Naseem $ $ $ $ Workings: [5] (c) Prepare the equity and liabilities section of the partnership’s statement of financial position at 31 December 2024. Fazal and Naseem Statement of financial position at 31 December 2024 Equity and liabilities ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] Additional information The partners wish to improve the performance of their business. They are considering two options. Option A: Change to a new supplier of goods for resale. The new supplier is prepared to offer a large trade discount if orders are made in bulk. It is expected that this will increase the gross profit margin to 70% with revenue remaining unchanged on current levels. Option B: Move their premises to a more central location. The rent of the new premises will be 15% more than the current annual payment. The partners believe they can increase demand by 17.5%. (d) Calculate the effect on annual profits of each option. (i) Option A ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] (ii) Option B ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] (e) Advise the partners which option they should choose. Justify your choice by discussing both the advantages and disadvantages of each option. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [7] [Total: 30] 2 A trainee accountant recently produced the financial statements for a business for the year ended 31 December 2024. However, the following errors were discovered. Error 1 A motor vehicle purchased on 1 January 2023 for $24 000 should have been depreciated by 20% using the reducing balance method. However, the trainee accountant had decided to change the depreciation method to 20% using the straight‑line method as it was easier to calculate. 2 The owner of the business had taken goods, with a sales price of $840, for own use. This had not been recorded in the books of account. 3 Non‑current assets included some equipment with a carrying value of $6200 which will be used in the business for the foreseeable future. However, the equipment had been written down to show its current resale value of $3600. 4 At the end of the financial year, a customer had placed an order for goods with a selling price of $660. The order had been recorded as a sale in the books of account. The business sells all goods with a mark‑up of 20%. The draft profit for the year ended 31 December 2024 was $36 960. (a) Complete the table to identify and describe the accounting concept which has been ignored in each of the errors. Accounting concept Error Description ignored 1 2 3 4 [8] Additional information The owner of the business wishes to correct the errors that the trainee accountant has made. (b) Calculate the revised profit for the year ended 31 December 2024. $ Draft profit 36 960 ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [6] Additional information The business has a highly skilled workforce, and the owner is of the opinion that this asset should be reflected in the statement of financial position. (c) State which accounting concept should be applied when deciding whether or not to record this asset in the statement of financial position. ............................................................................................................................................. [1] [Total: 15]
Q3 · On 1 April 2024, the following balances appeared in the books of P plc
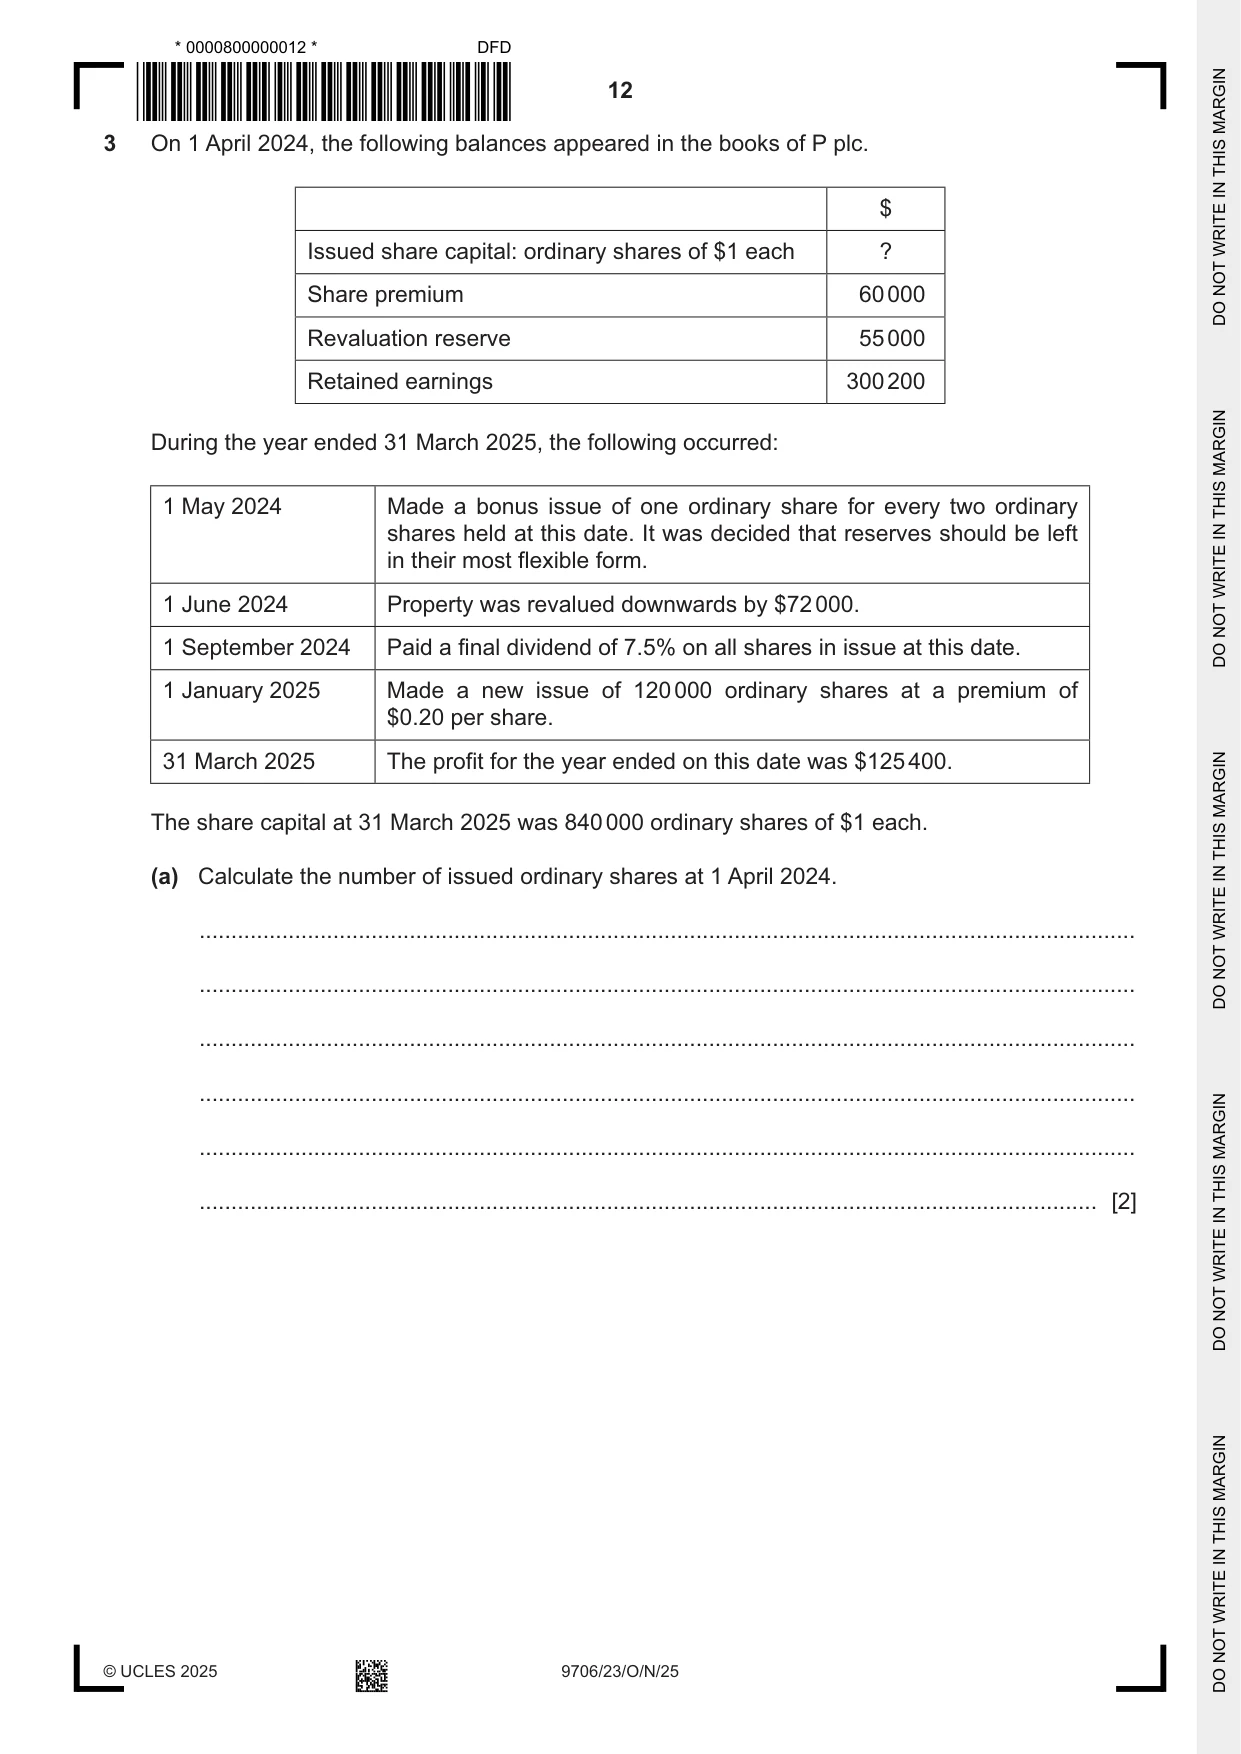
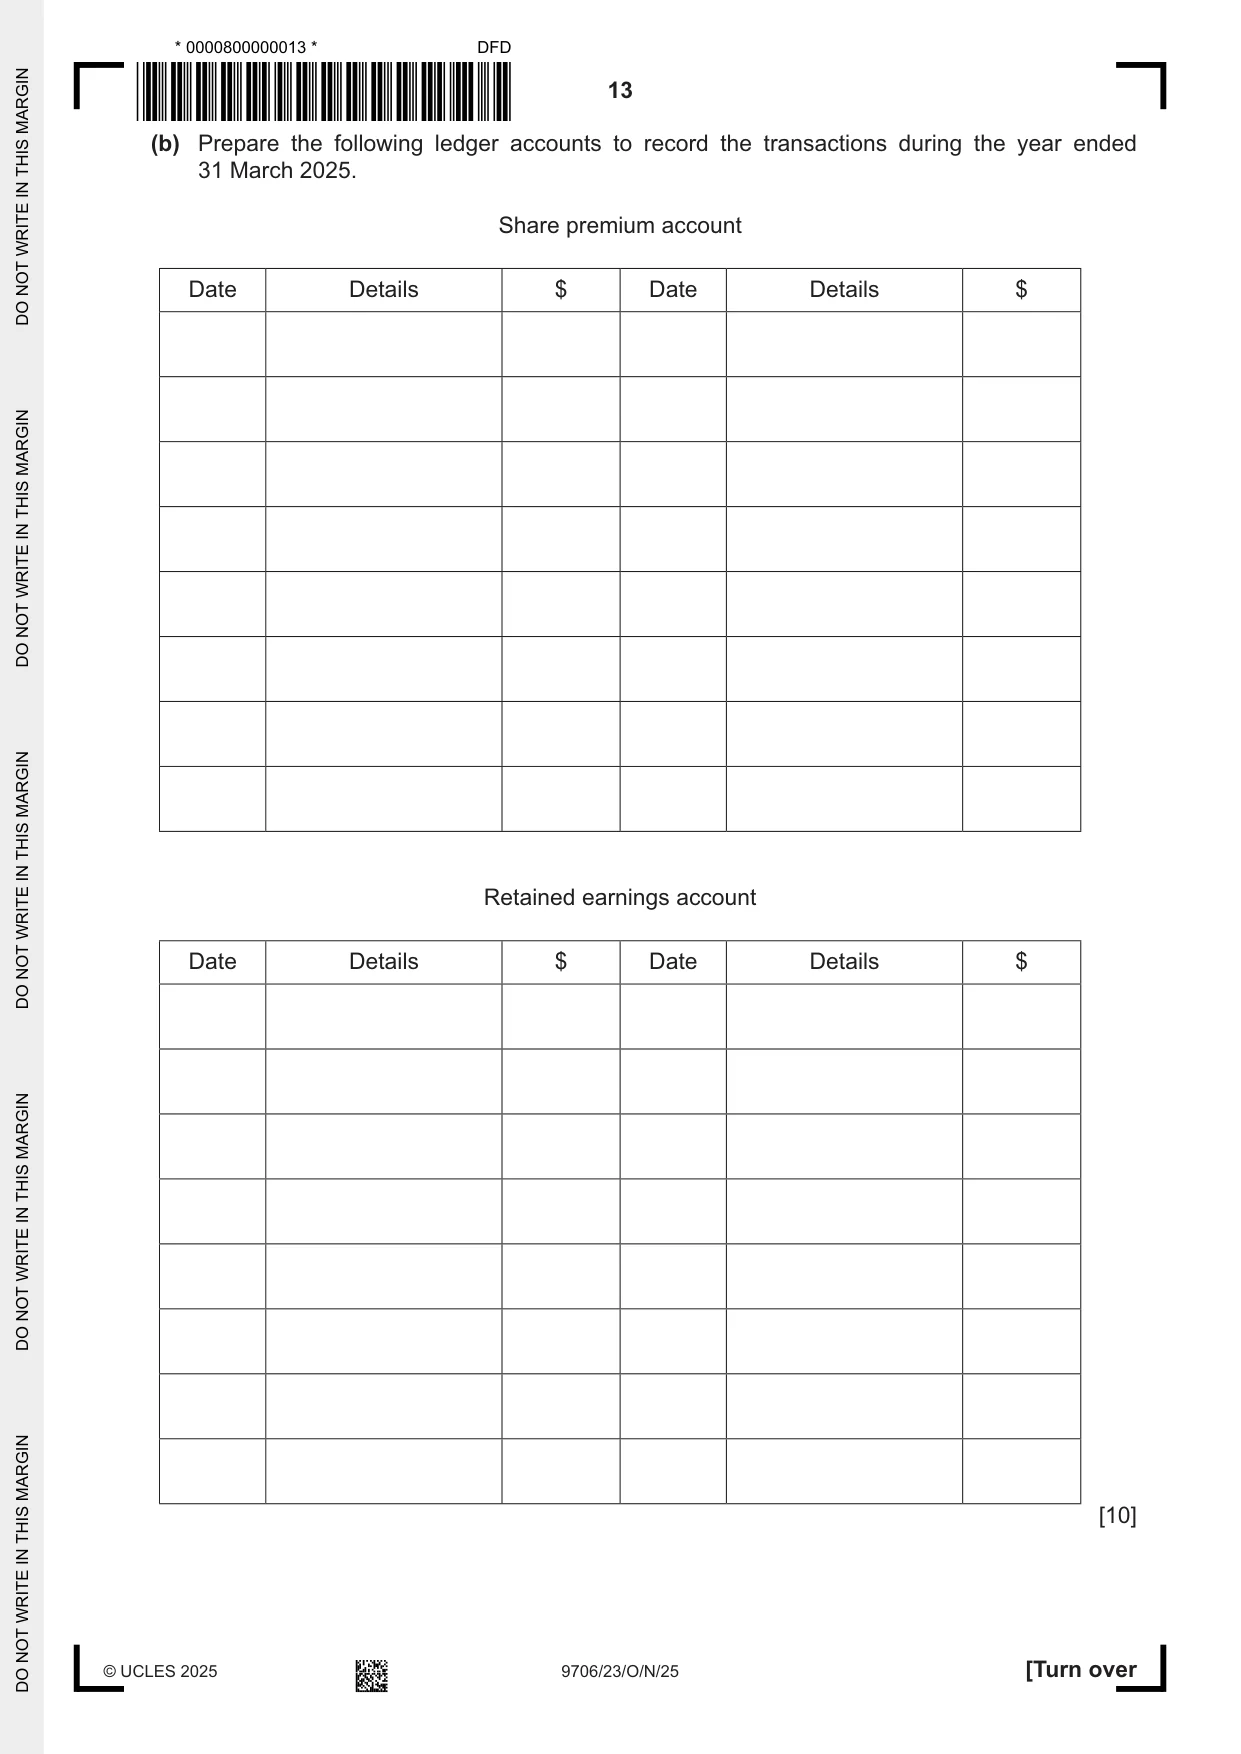
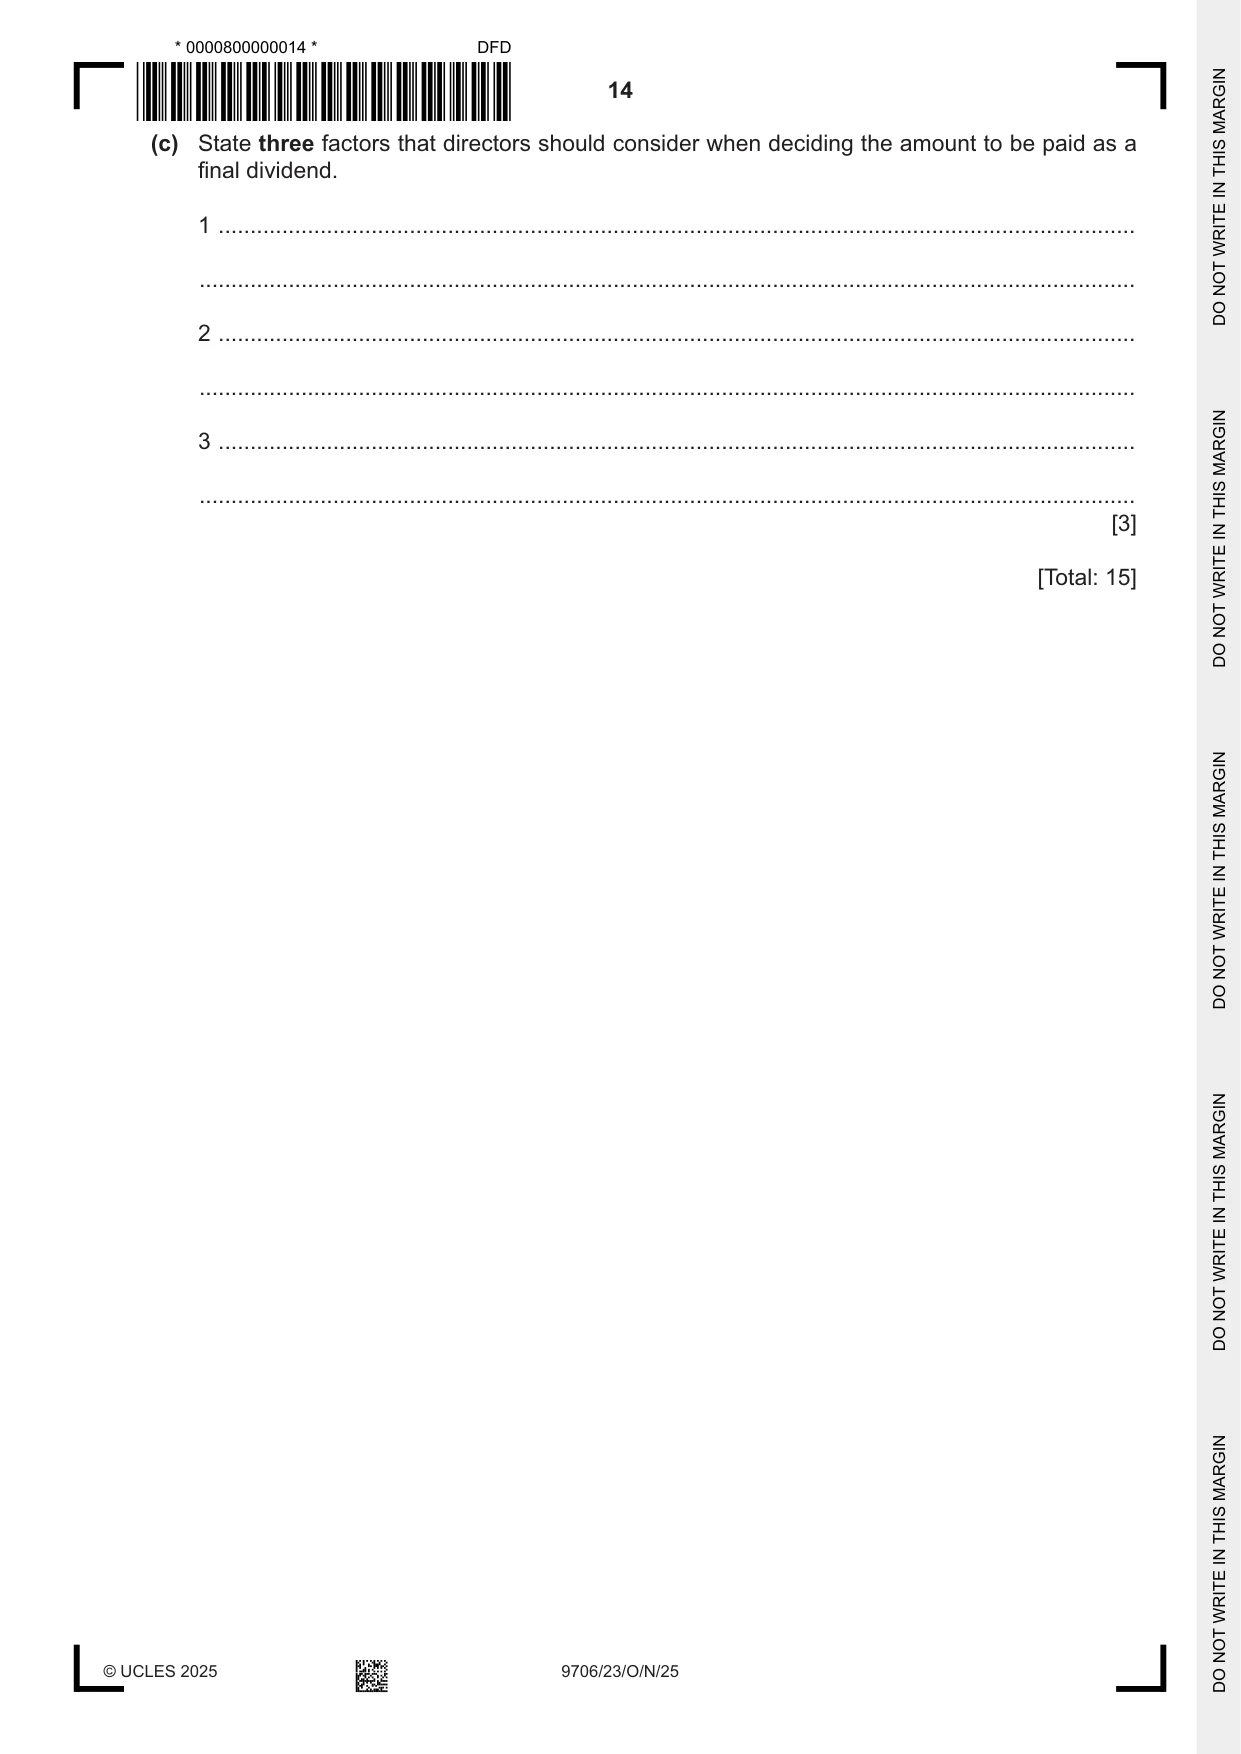
3 On 1 April 2024, the following balances appeared in the books of P plc. $ Issued share capital: ordinary shares of $1 each ? Share premium 60 000 Revaluation reserve 55 000 Retained earnings 300 200 During the year ended 31 March 2025, the following occurred: 1 May 2024 Made a bonus issue of one ordinary share for every two ordinary shares held at this date. It was decided that reserves should be left in their most flexible form. 1 June 2024 Property was revalued downwards by $72 000. 1 September 2024 Paid a final dividend of 7.5% on all shares in issue at this date. 1 January 2025 Made a new issue of 120 000 ordinary shares at a premium of $0.20 per share. 31 March 2025 The profit for the year ended on this date was $125 400. The share capital at 31 March 2025 was 840 000 ordinary shares of $1 each. (a) Calculate the number of issued ordinary shares at 1 April 2024. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] (b) Prepare the following ledger accounts to record the transactions during the year ended 31 March 2025. Share premium account Date Details $ Date Details $ Retained earnings account Date Details $ Date Details $ [10] (c) State three factors that directors should consider when deciding the amount to be paid as a final dividend. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... 3 ................................................................................................................................................ ................................................................................................................................................... [3] [Total: 15]
Q4 · V Limited is a manufacturing company which uses absorption costing at one of its factories
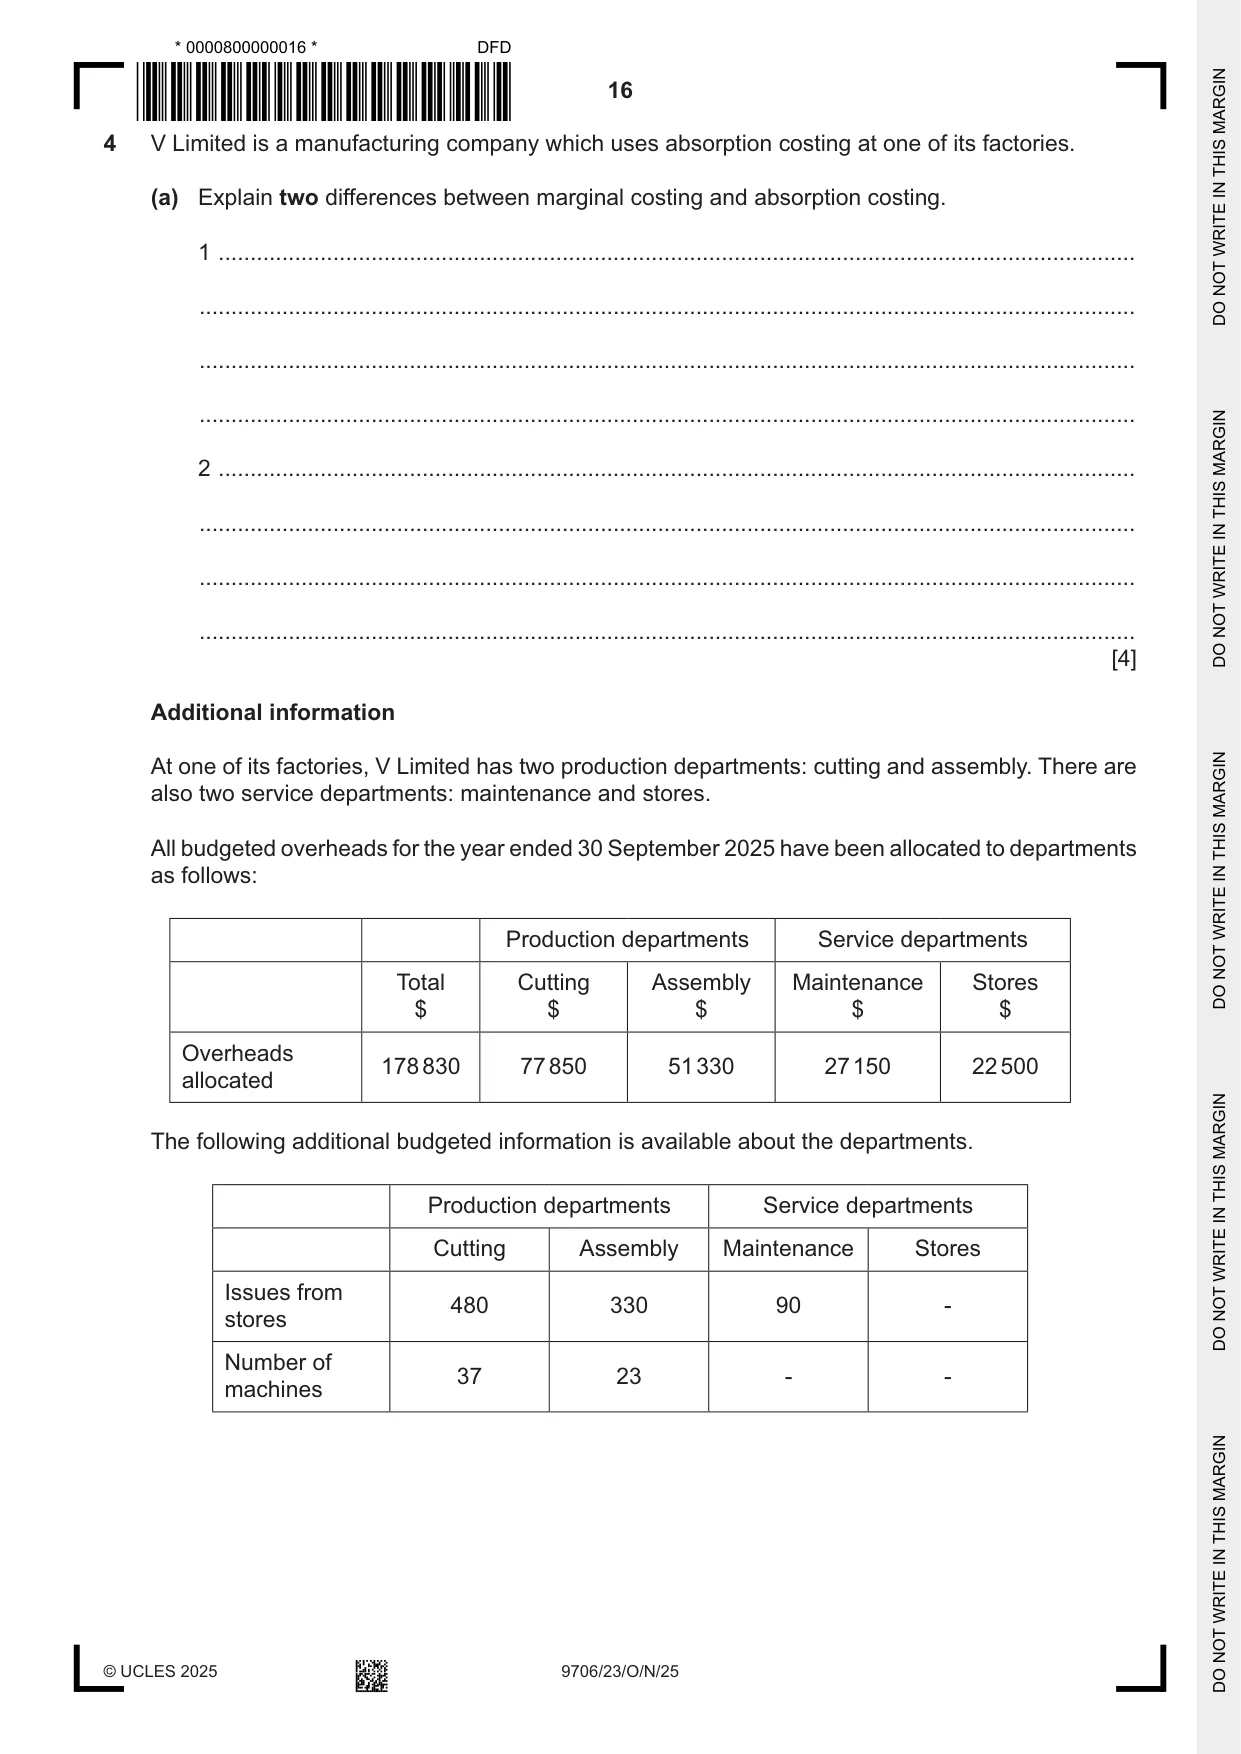
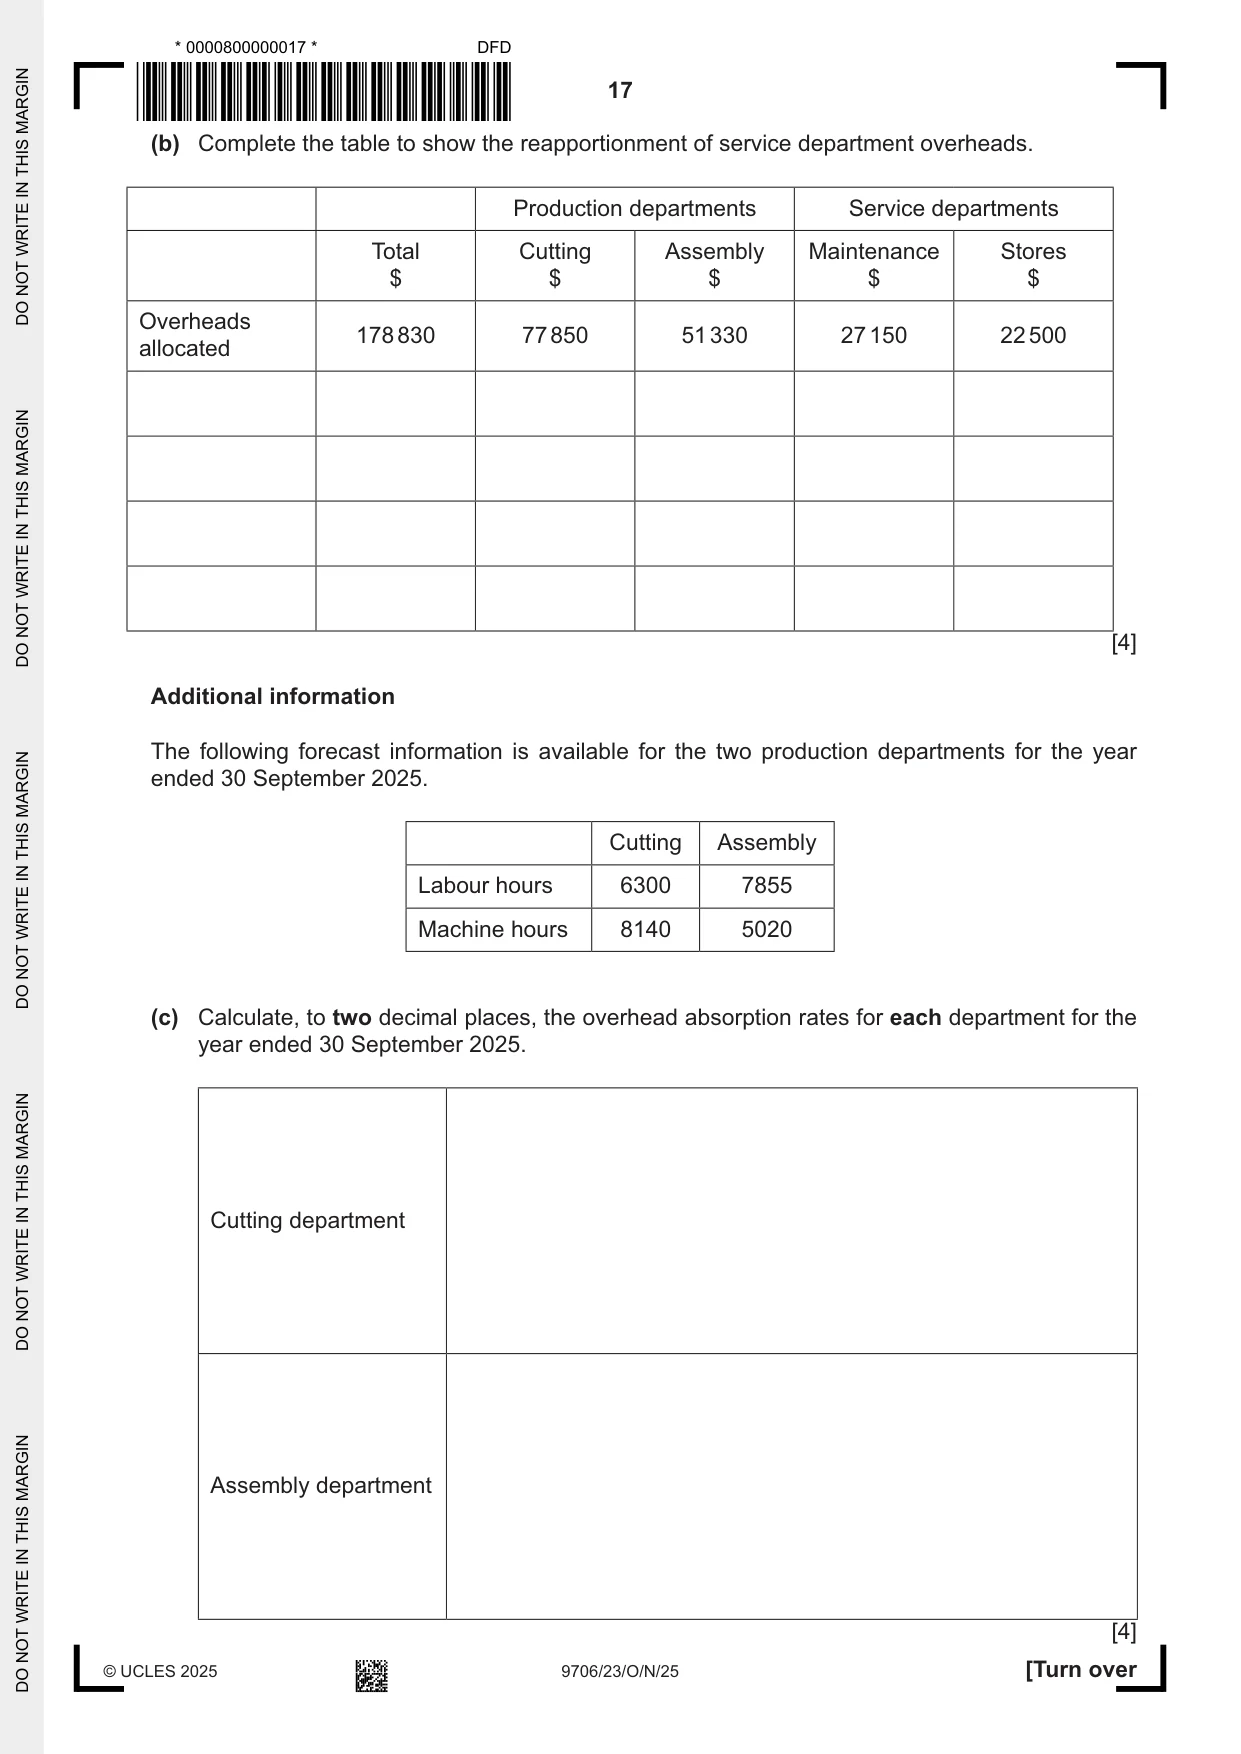
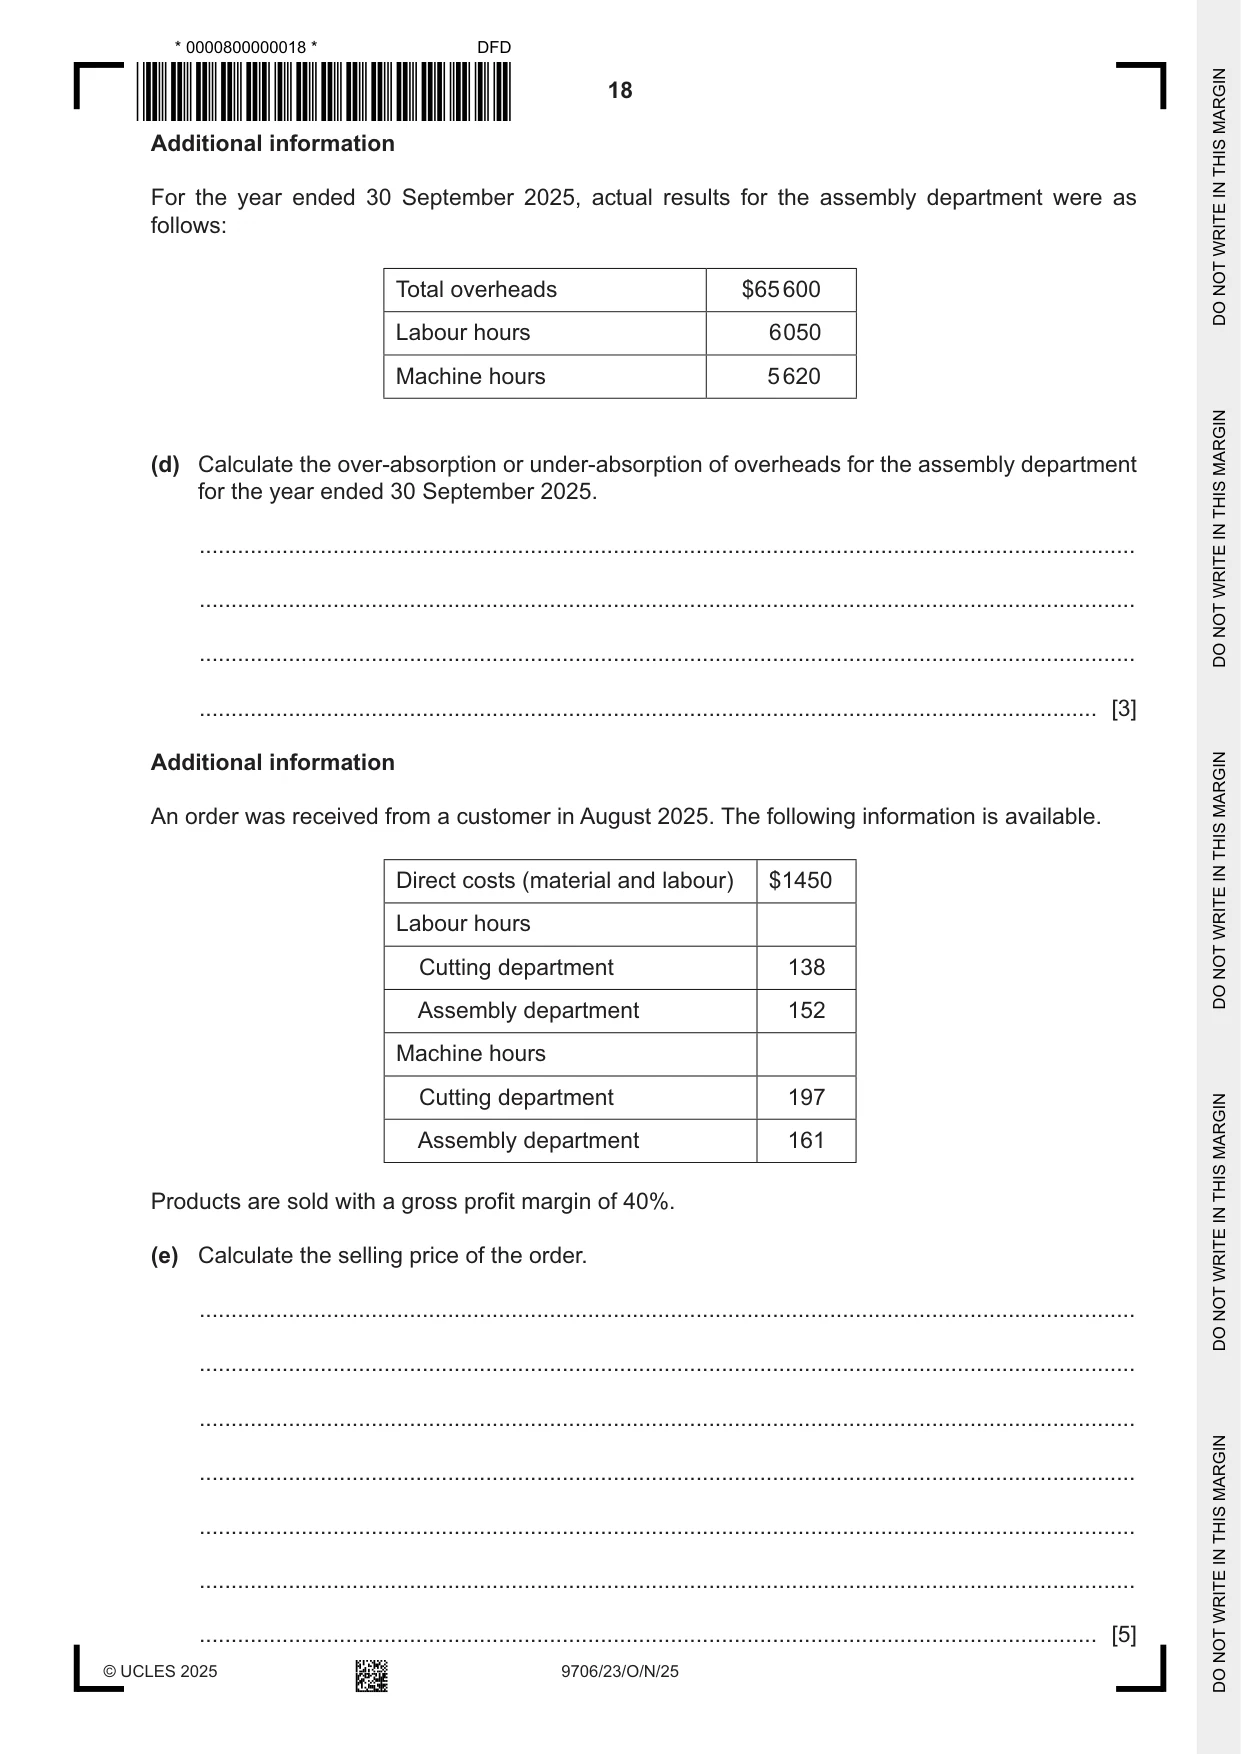
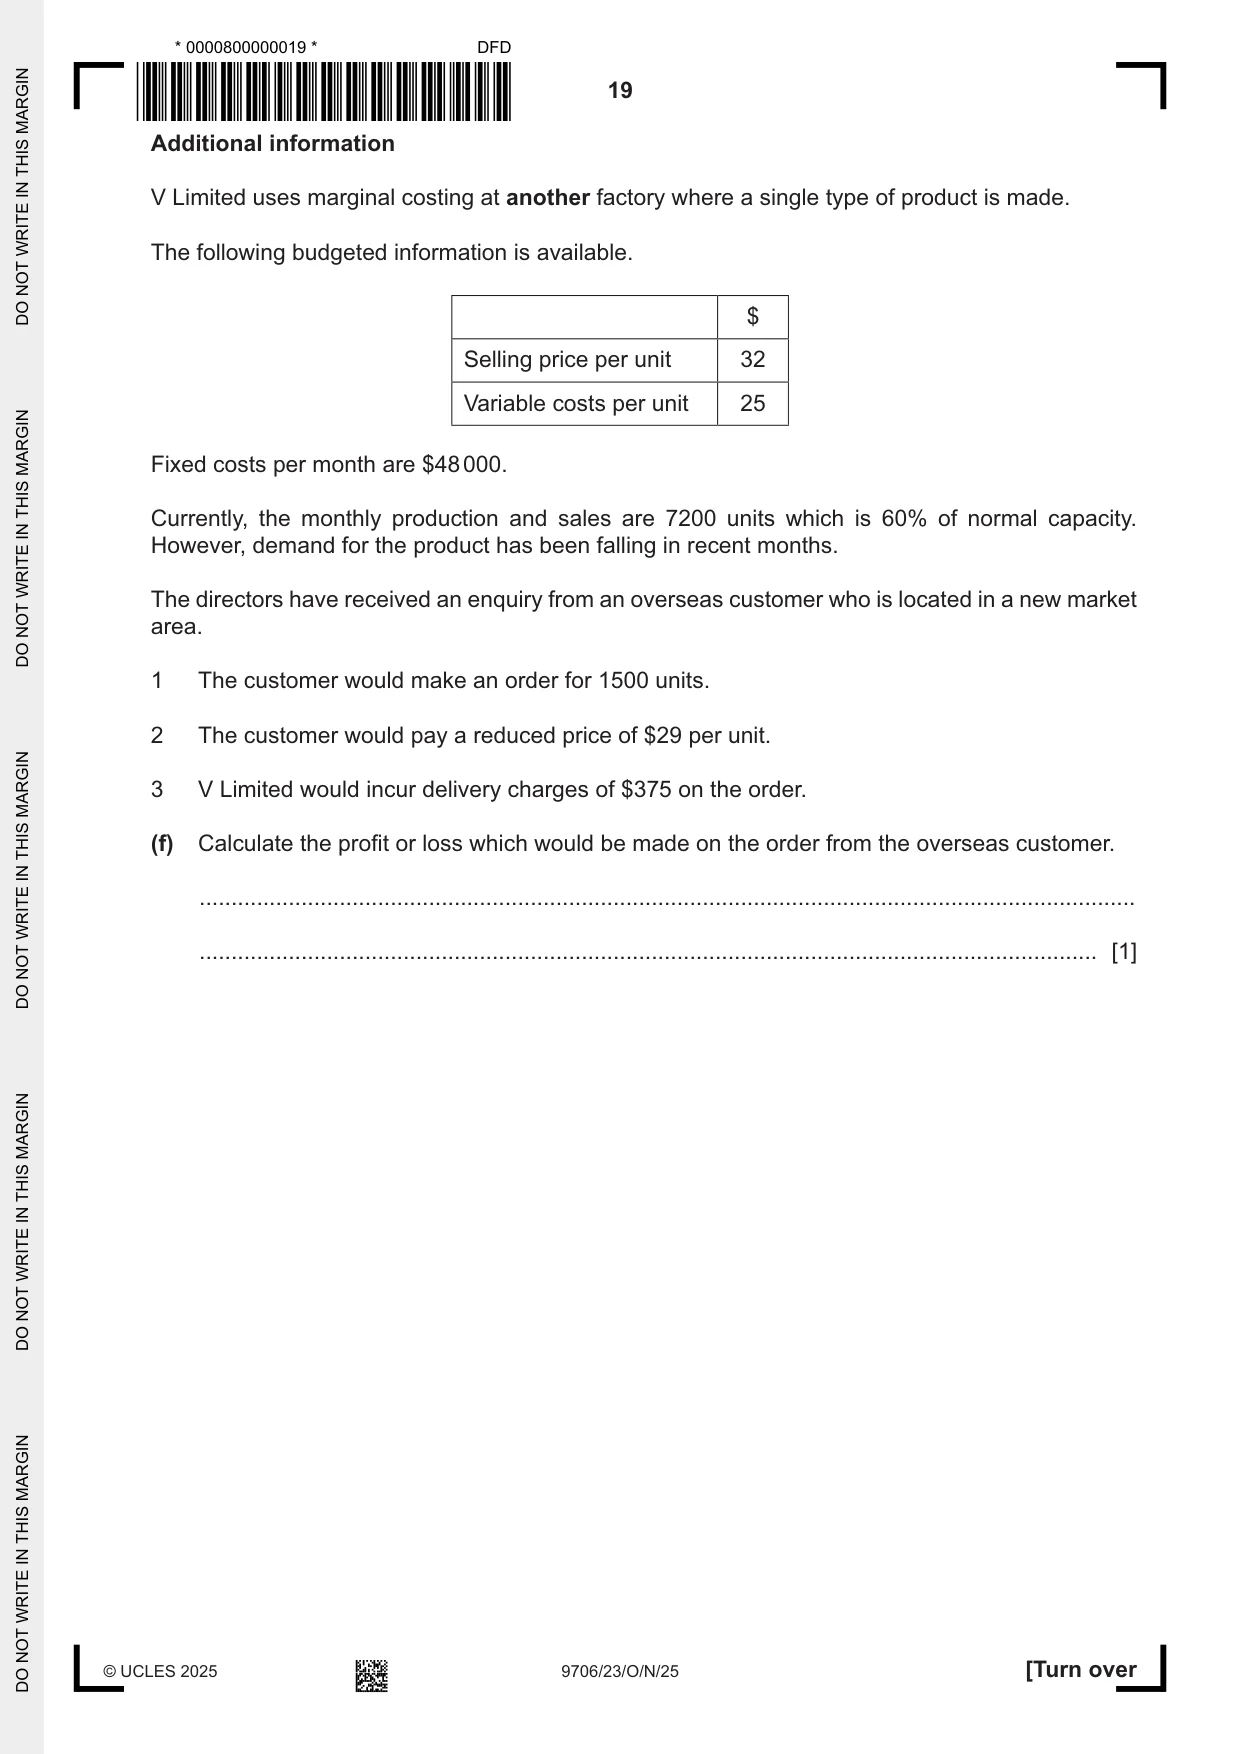
4 V Limited is a manufacturing company which uses absorption costing at one of its factories. (a) Explain two differences between marginal costing and absorption costing. 1 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... [4] Additional information At one of its factories, V Limited has two production departments: cutting and assembly. There are also two service departments: maintenance and stores. All budgeted overheads for the year ended 30 September 2025 have been allocated to departments as follows: Production departments Service departments Total Cutting Assembly Maintenance Stores $ $ $ $ $ Overheads 178 830 77 850 51 330 27 150 22 500 allocated The following additional budgeted information is available about the departments. Production departments Service departments Cutting Assembly Maintenance Stores Issues from 480 330 90 ‑ stores Number of 37 23 ‑ ‑ machines (b) Complete the table to show the reapportionment of service department overheads. Production departments Service departments Total Cutting Assembly Maintenance Stores $ $ $ $ $ Overheads 178 830 77 850 51 330 27 150 22 500 allocated [4] Additional information The following forecast information is available for the two production departments for the year ended 30 September 2025. Cutting Assembly Labour hours 6300 7855 Machine hours 8140 5020 (c) Calculate, to two decimal places, the overhead absorption rates for each department for the year ended 30 September 2025. Cutting department Assembly department [4] Additional information For the year ended 30 September 2025, actual results for the assembly department were as follows: Total overheads $65 600 Labour hours 6 050 Machine hours 5 620 (d) Calculate the over‑absorption or under‑absorption of overheads for the assembly department for the year ended 30 September 2025. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] Additional information An order was received from a customer in August 2025. The following information is available. Direct costs (material and labour) $1450 Labour hours Cutting department 138 Assembly department 152 Machine hours Cutting department 197 Assembly department 161 Products are sold with a gross profit margin of 40%. (e) Calculate the selling price of the order. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ...................................................................................................................................................
What was in this paper
The subtopics covered by these 4 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2025 Oct/Nov, Paper 2 · Variant 3. A higher threshold means an easier paper — the bar moves with how the cohort did.