Cambridge A Level Accounting 9706 — 2024 May/June Paper 1 · Variant 2
9706/12/M/J/24 · 30 marks · ≈34 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
Mark scheme3 pages
Answers below. Sit the paper first if you are practising.
Paper as text
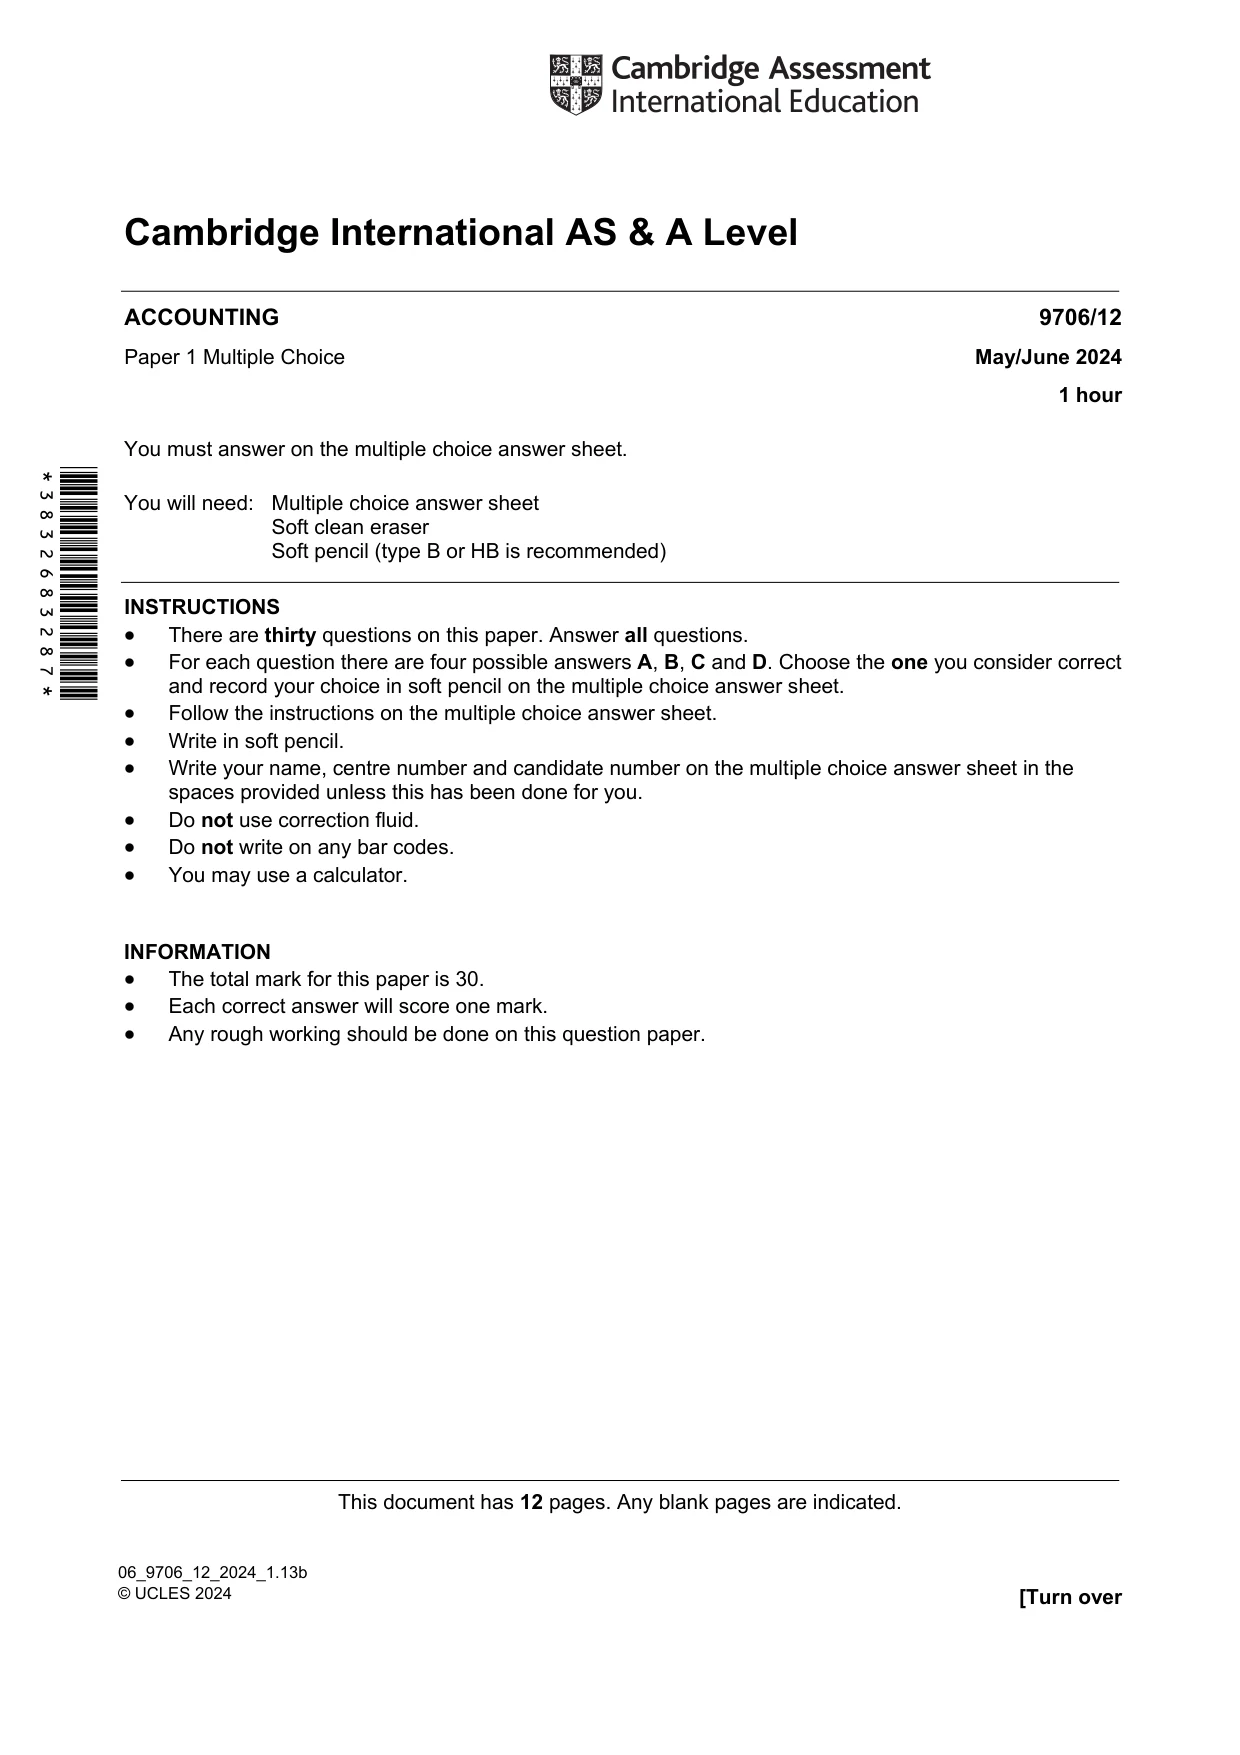
Question paper, page 1
This document has 12 pages. Any blank pages are indicated. 06_9706_12_2024_1.13b © UCLES 2024 [Turn over *3832683287* Cambridge International AS & A Level ACCOUNTING 9706/12 Paper 1 Multiple Choice May/June 2024 1 hour You must answer on the multiple choice answer sheet. You will need: Multiple choice answer sheet Soft clean eraser Soft pencil (type B or HB is recommended) INSTRUCTIONS There are thirty questions on this paper. Answer all questions. For each question there are four possible answers A, B, C and D. Choose the one you consider correct and record your choice in soft pencil on the multiple choice answer sheet. Follow the instructions on the multiple choice answer sheet. Write in soft pencil. Write your name, centre number and candidate number on the multiple choice answer sheet in the spaces provided unless this has been done for you. Do not use correction fluid. Do not write on any bar codes. You may use a calculator. INFORMATION The total mark for this paper is 30. Each correct answer will score one mark. Any rough working should be done on this question paper.
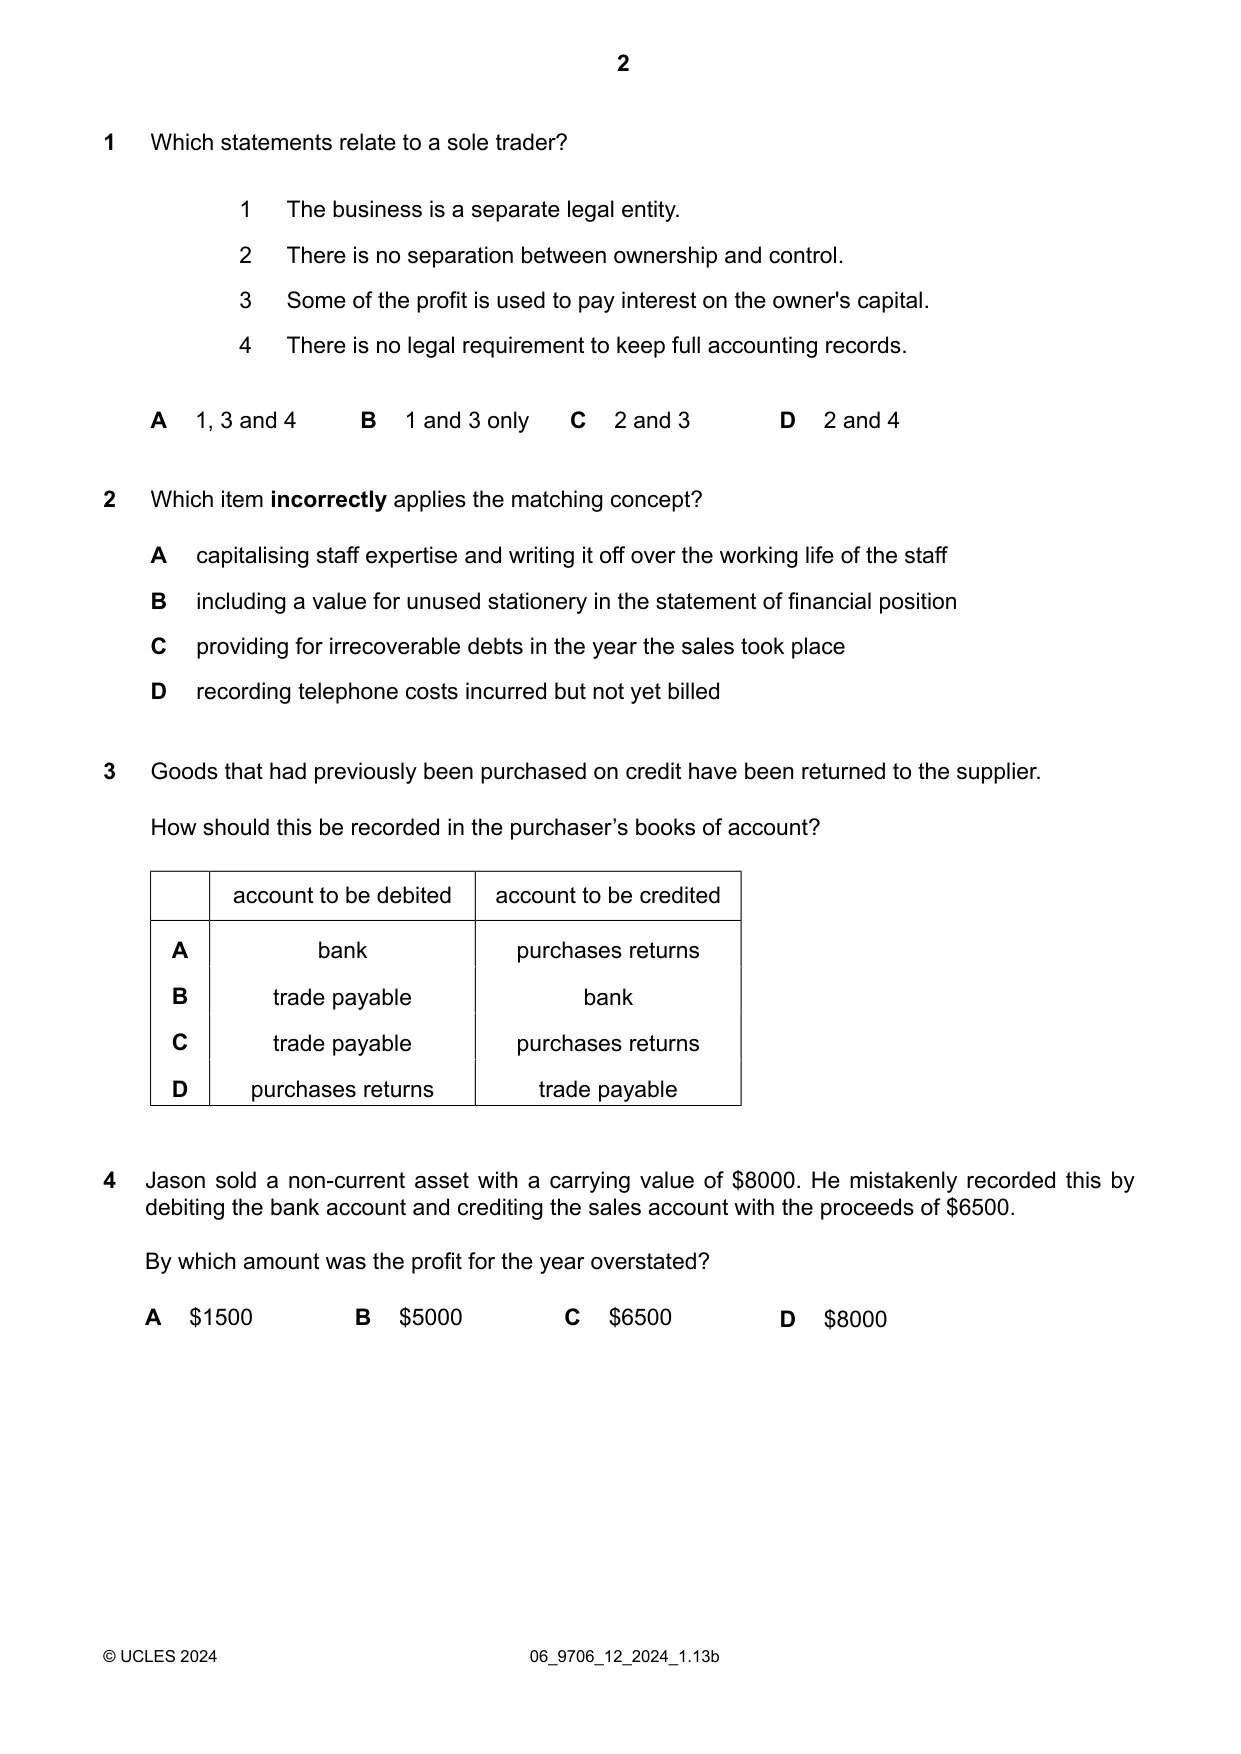
Question paper, page 2
Which statements relate to a sole trader? 1 The business is a separate legal entity. 1 There is no separation between ownership and control. 2 Some of the profit is used to pay interest on the owner's capital. 3 There is no legal requirement to keep full accounting records. 4 2 and 4 D 2 and 3 C 1 and 3 only B 1, 3 and 4 A Which item incorrectly applies the matching concept? 2 capitalising staff expertise and writing it off over the working life of the staff A including a value for unused stationery in the statement of financial position B providing for irrecoverable debts in the year the sales took place C recording telephone costs incurred but not yet billed D Goods that had previously been purchased on credit have been returned to the supplier. How should this be recorded in the purchaser’s books of account? 3 account to be credited account to be debited purchases returns bank A bank trade payable B purchases returns trade payable C trade payable purchases returns D Jason sold a non-current asset with a carrying value of $8000. He mistakenly recorded this by debiting the bank account and crediting the sales account with the proceeds of $6500. 4 $8000 D By which amount was the profit for the year overstated? A $1500 B $5000 C $6500 06_9706_12_2024_1.13b © UCLES 2024 2
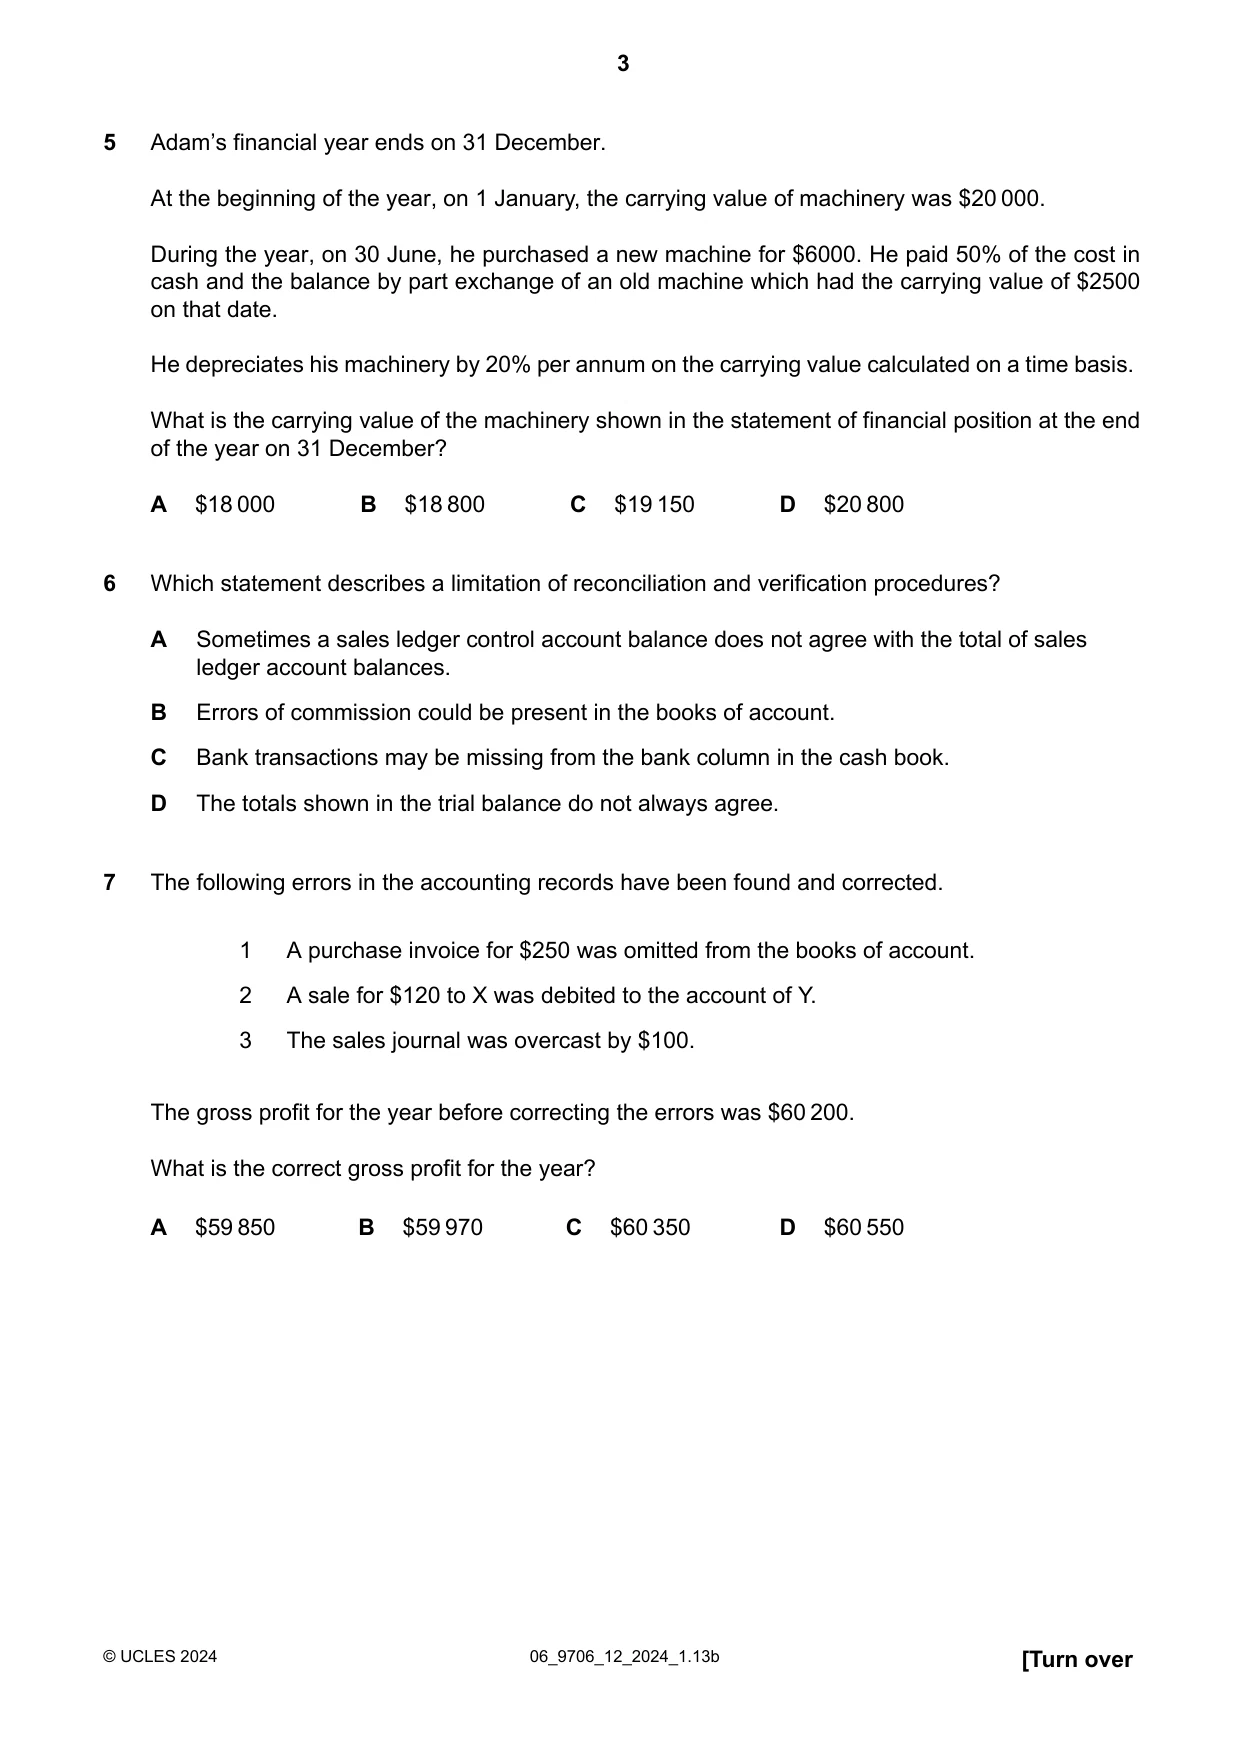
Question paper, page 3
Adam’s financial year ends on 31 December. At the beginning of the year, on 1 January, the carrying value of machinery was $20 000. During the year, on 30 June, he purchased a new machine for $6000. He paid 50% of the cost in cash and the balance by part exchange of an old machine which had the carrying value of $2500 on that date. He depreciates his machinery by 20% per annum on the carrying value calculated on a time basis. What is the carrying value of the machinery shown in the statement of financial position at the end of the year on 31 December? 5 D $20 800 C $19 150 B $18 800 $18 000 A Which statement describes a limitation of reconciliation and verification procedures? 6 Sometimes a sales ledger control account balance does not agree with the total of sales ledger account balances. A Errors of commission could be present in the books of account. B Bank transactions may be missing from the bank column in the cash book. C The totals shown in the trial balance do not always agree. D The following errors in the accounting records have been found and corrected. 7 A purchase invoice for $250 was omitted from the books of account. 1 A sale for $120 to X was debited to the account of Y. 2 The sales journal was overcast by $100. 3 The gross profit for the year before correcting the errors was $60 200. What is the correct gross profit for the year? D $60 550 A $59 850 B $59 970 C $60 350 [Turn over 06_9706_12_2024_1.13b © UCLES 2024 3
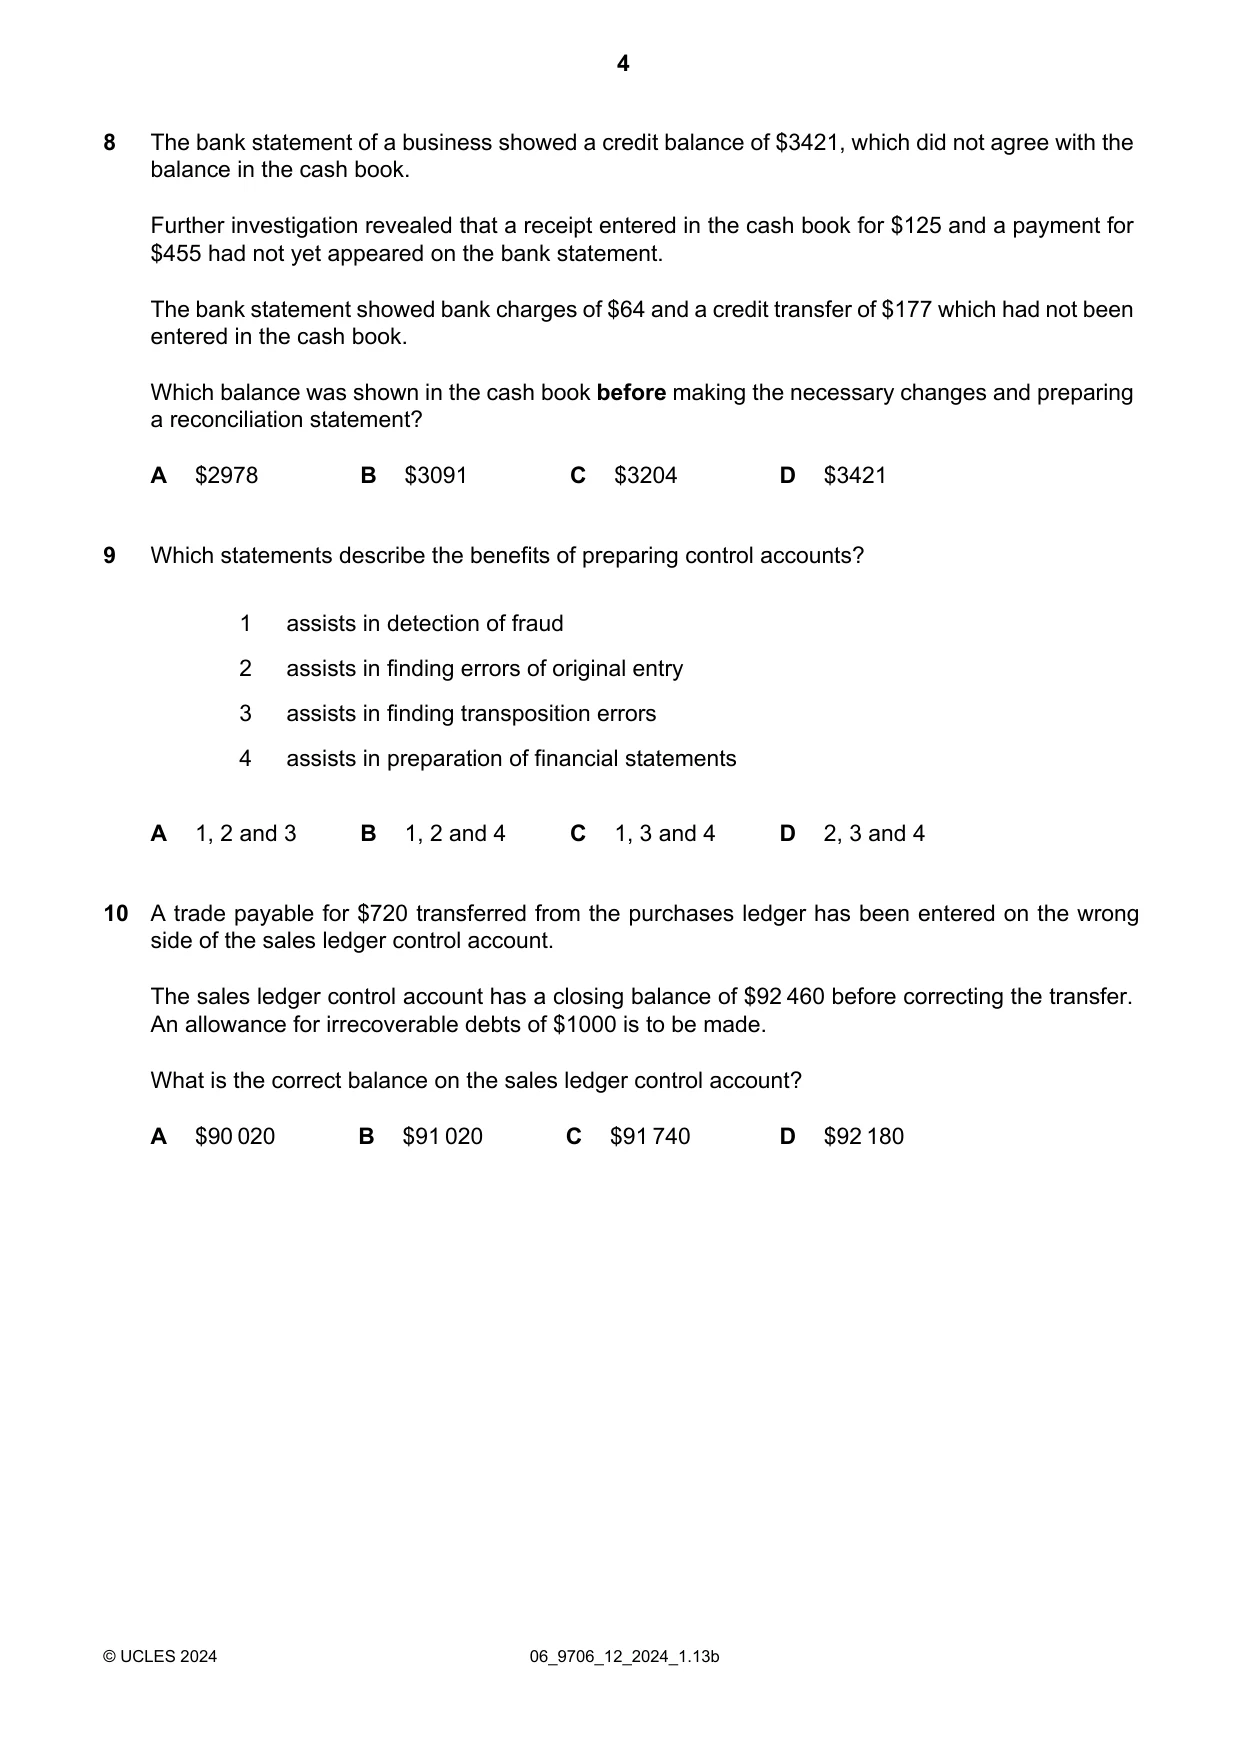
Question paper, page 4
The bank statement of a business showed a credit balance of $3421, which did not agree with the balance in the cash book. Further investigation revealed that a receipt entered in the cash book for $125 and a payment for $455 had not yet appeared on the bank statement. The bank statement showed bank charges of $64 and a credit transfer of $177 which had not been entered in the cash book. Which balance was shown in the cash book before making the necessary changes and preparing a reconciliation statement? 8 $3421 D $3204 C $3091 B $2978 A Which statements describe the benefits of preparing control accounts? 9 assists in detection of fraud 1 assists in finding errors of original entry 2 assists in finding transposition errors 3 assists in preparation of financial statements 4 2, 3 and 4 D 1, 3 and 4 C 1, 2 and 4 B 1, 2 and 3 A A trade payable for $720 transferred from the purchases ledger has been entered on the wrong side of the sales ledger control account. The sales ledger control account has a closing balance of $92 460 before correcting the transfer. An allowance for irrecoverable debts of $1000 is to be made. What is the correct balance on the sales ledger control account? 10 D $92 180 A $90 020 B $91 020 C $91 740 06_9706_12_2024_1.13b © UCLES 2024 4
Question paper, page 5
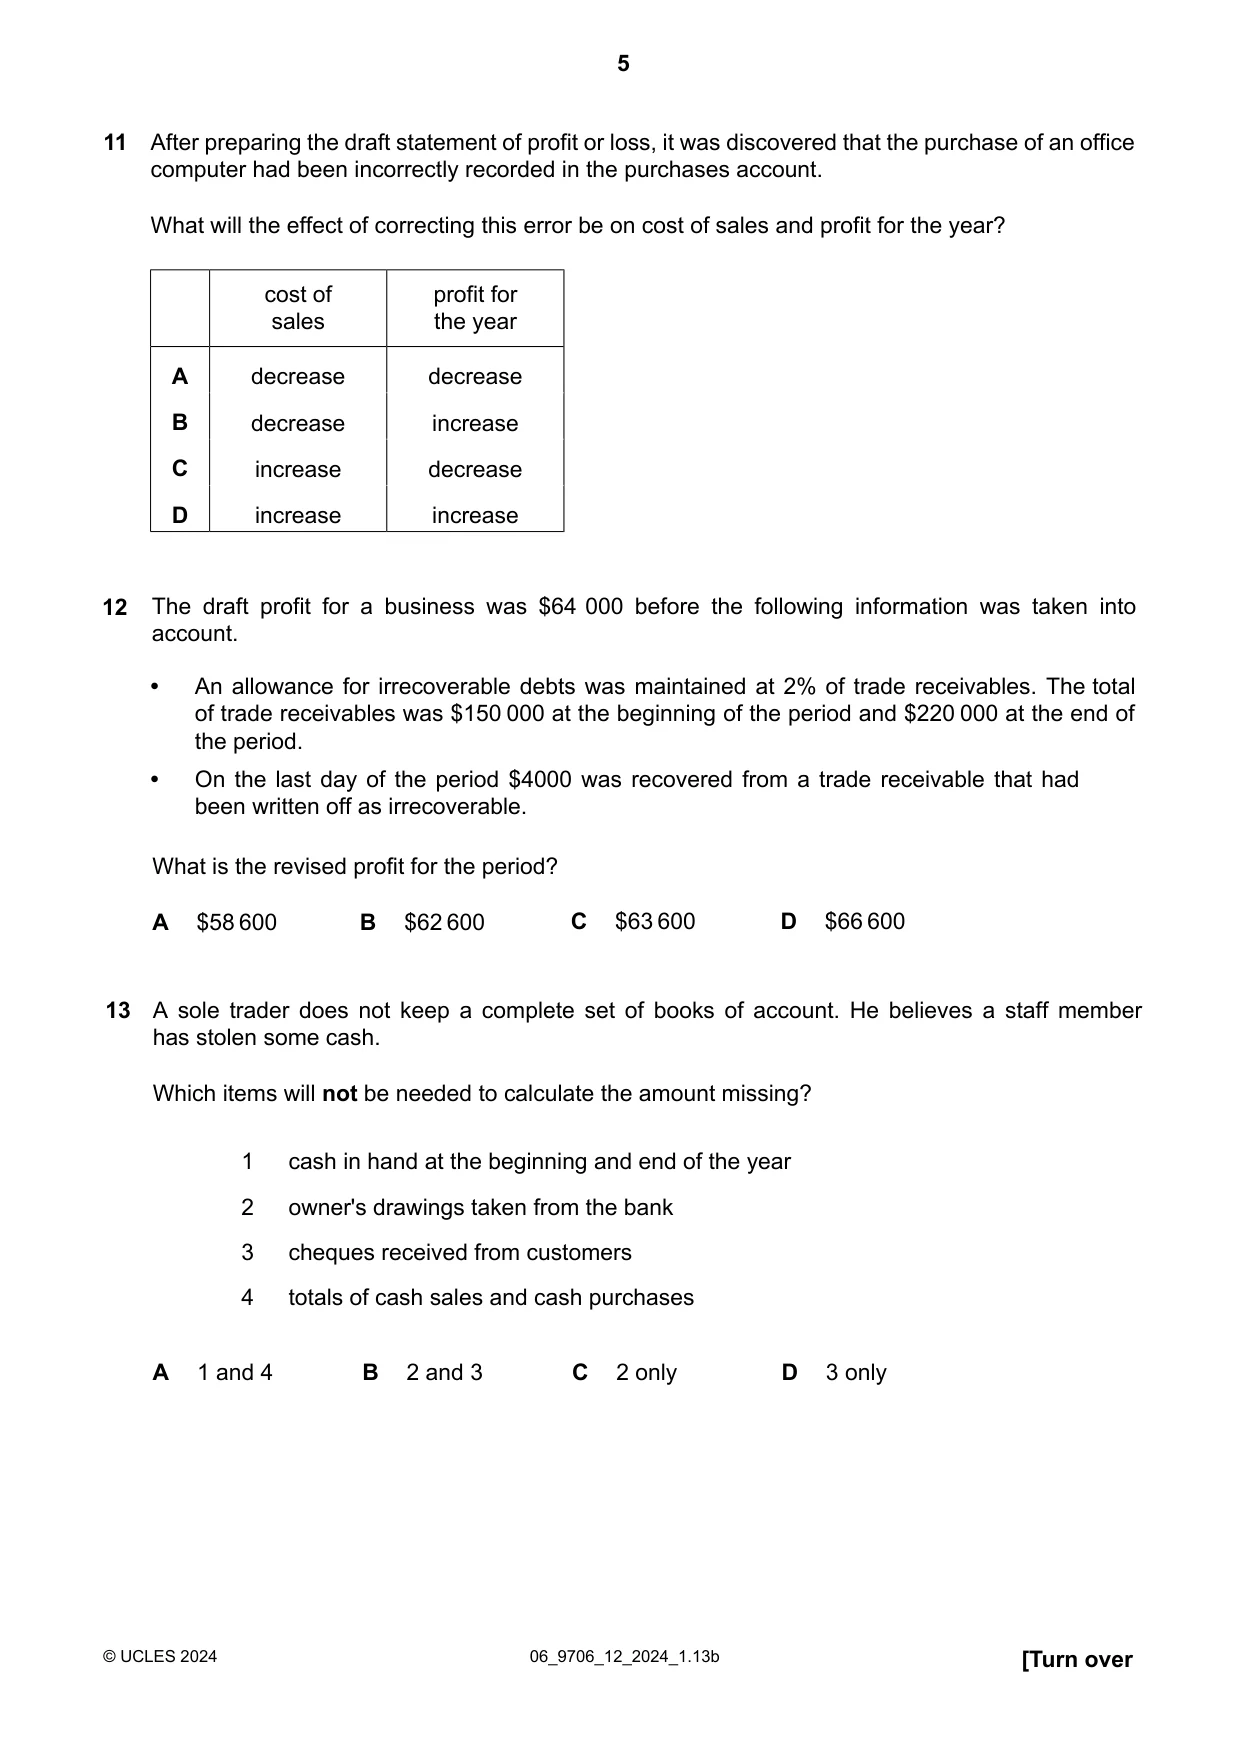
After preparing the draft statement of profit or loss, it was discovered that the purchase of an office computer had been incorrectly recorded in the purchases account. What will the effect of correcting this error be on cost of sales and profit for the year? 11 profit for the year cost of sales decrease decrease A increase decrease B decrease increase C increase increase D The draft profit for a business was $64 000 before the following information was taken into account. • An allowance for irrecoverable debts was maintained at 2% of trade receivables. The total of trade receivables was $150 000 at the beginning of the period and $220 000 at the end of the period. • On the last day of the period $4000 was recovered from a trade receivable that had been written off as irrecoverable. D $66 600 C $63 600 What is the revised profit for the period? A $58 600 B $62 600 A sole trader does not keep a complete set of books of account. He believes a staff member has stolen some cash. Which items will not be needed to calculate the amount missing? 12 cash in hand at the beginning and end of the year 1 owner's drawings taken from the bank 2 cheques received from customers 3 totals of cash sales and cash purchases 4 3 only D 2 only C 2 and 3 B 1 and 4 A [Turn over 06_9706_12_2024_1.13b © UCLES 2024 5 13
Question paper, page 6
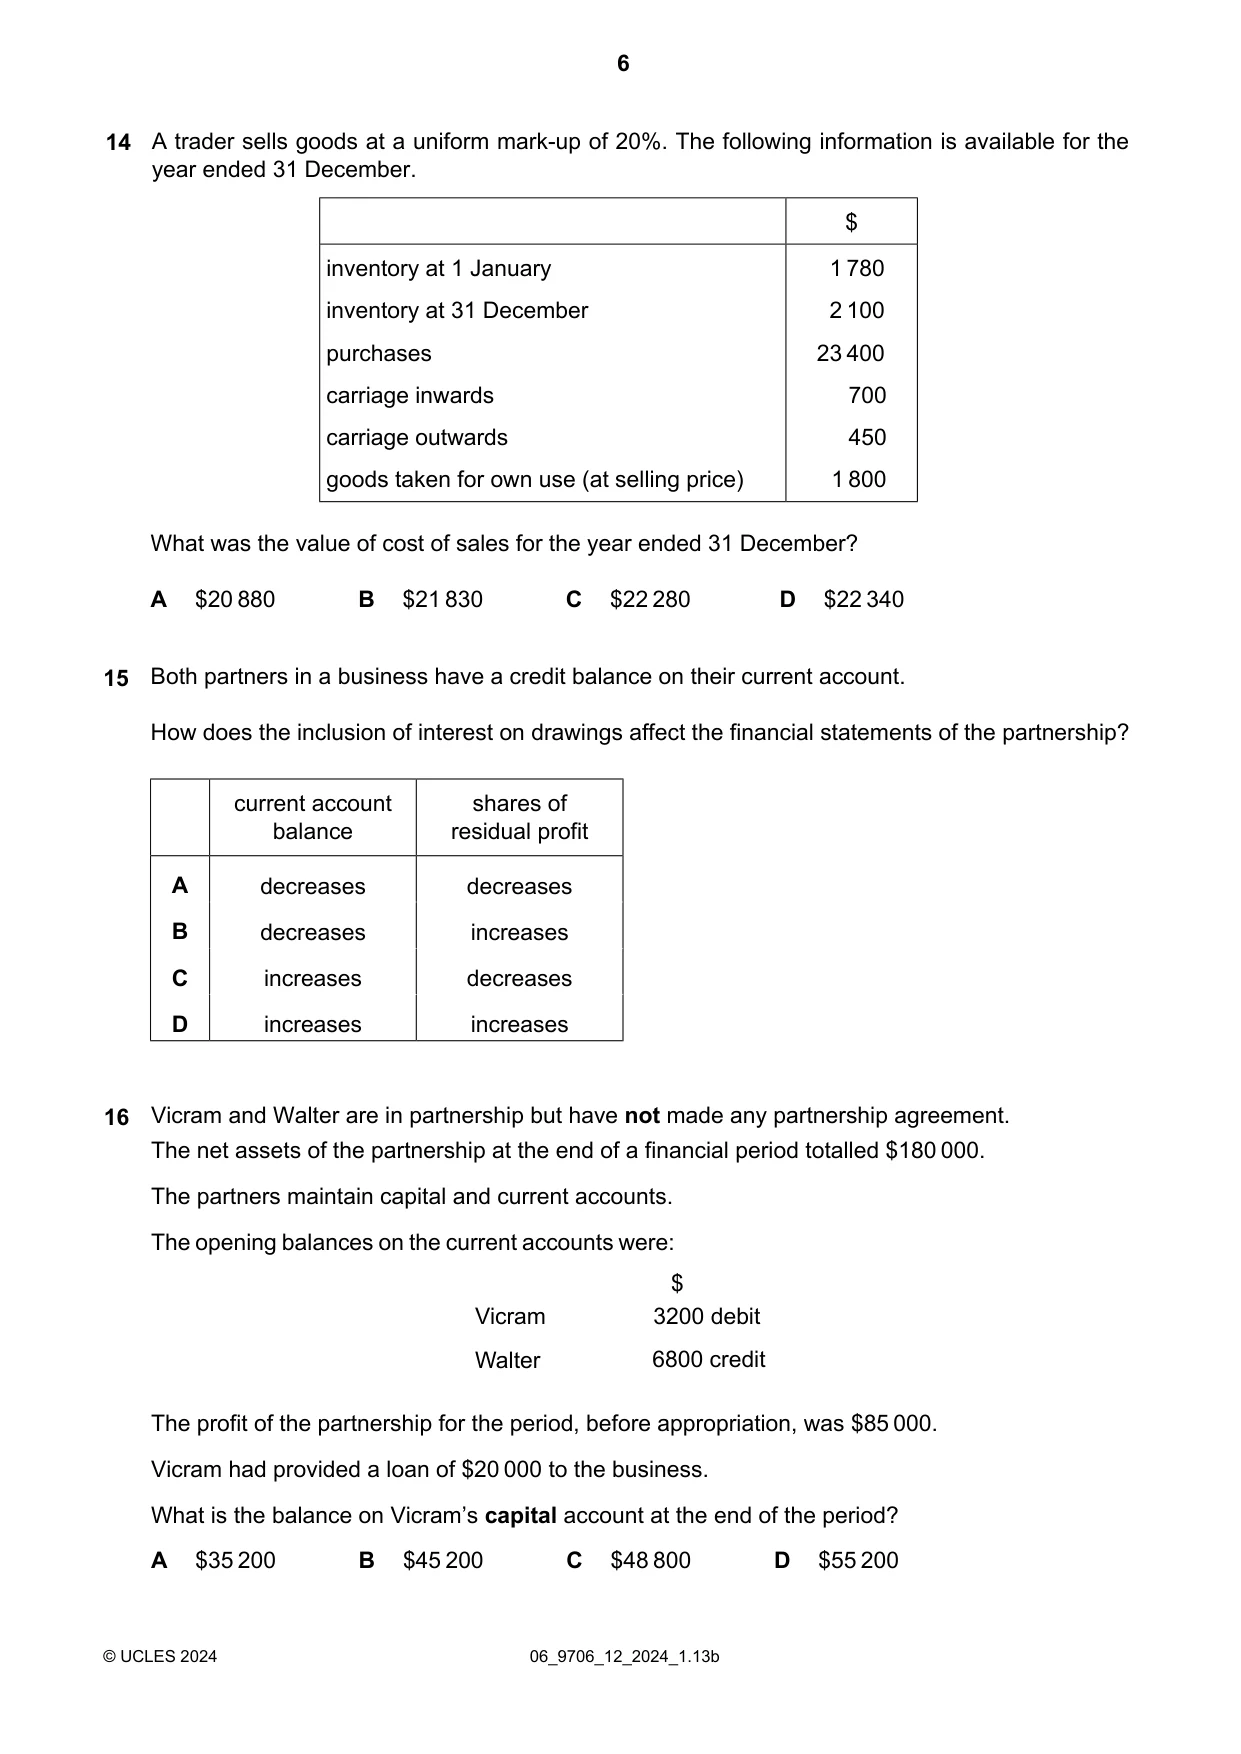
A trader sells goods at a uniform mark-up of 20%. The following information is available for the year ended 31 December. $ 1 780 2 100 23 400 700 450 1 800 inventory at 1 January inventory at 31 December purchases carriage inwards carriage outwards goods taken for own use (at selling price) What was the value of cost of sales for the year ended 31 December? D $22 340 A $20 880 B $21 830 C $22 280 Both partners in a business have a credit balance on their current account. How does the inclusion of interest on drawings affect the financial statements of the partnership? 14 shares of residual profit current account balance decreases decreases A increases decreases B decreases increases C increases increases D 16 Vicram and Walter are in partnership but have not made any partnership agreement. The net assets of the partnership at the end of a financial period totalled $180 000. The partners maintain capital and current accounts. The opening balances on the current accounts were: The profit of the partnership for the period, before appropriation, was $85 000. Vicram had provided a loan of $20 000 to the business. What is the balance on Vicram’s capital account at the end of the period? A $35 200 B $45 200 C $48 800 D $55 200 06_9706_12_2024_1.13b © UCLES 2024 6 15 $ 3200 debit Vicram 6800 credit Walter
Question paper, page 7
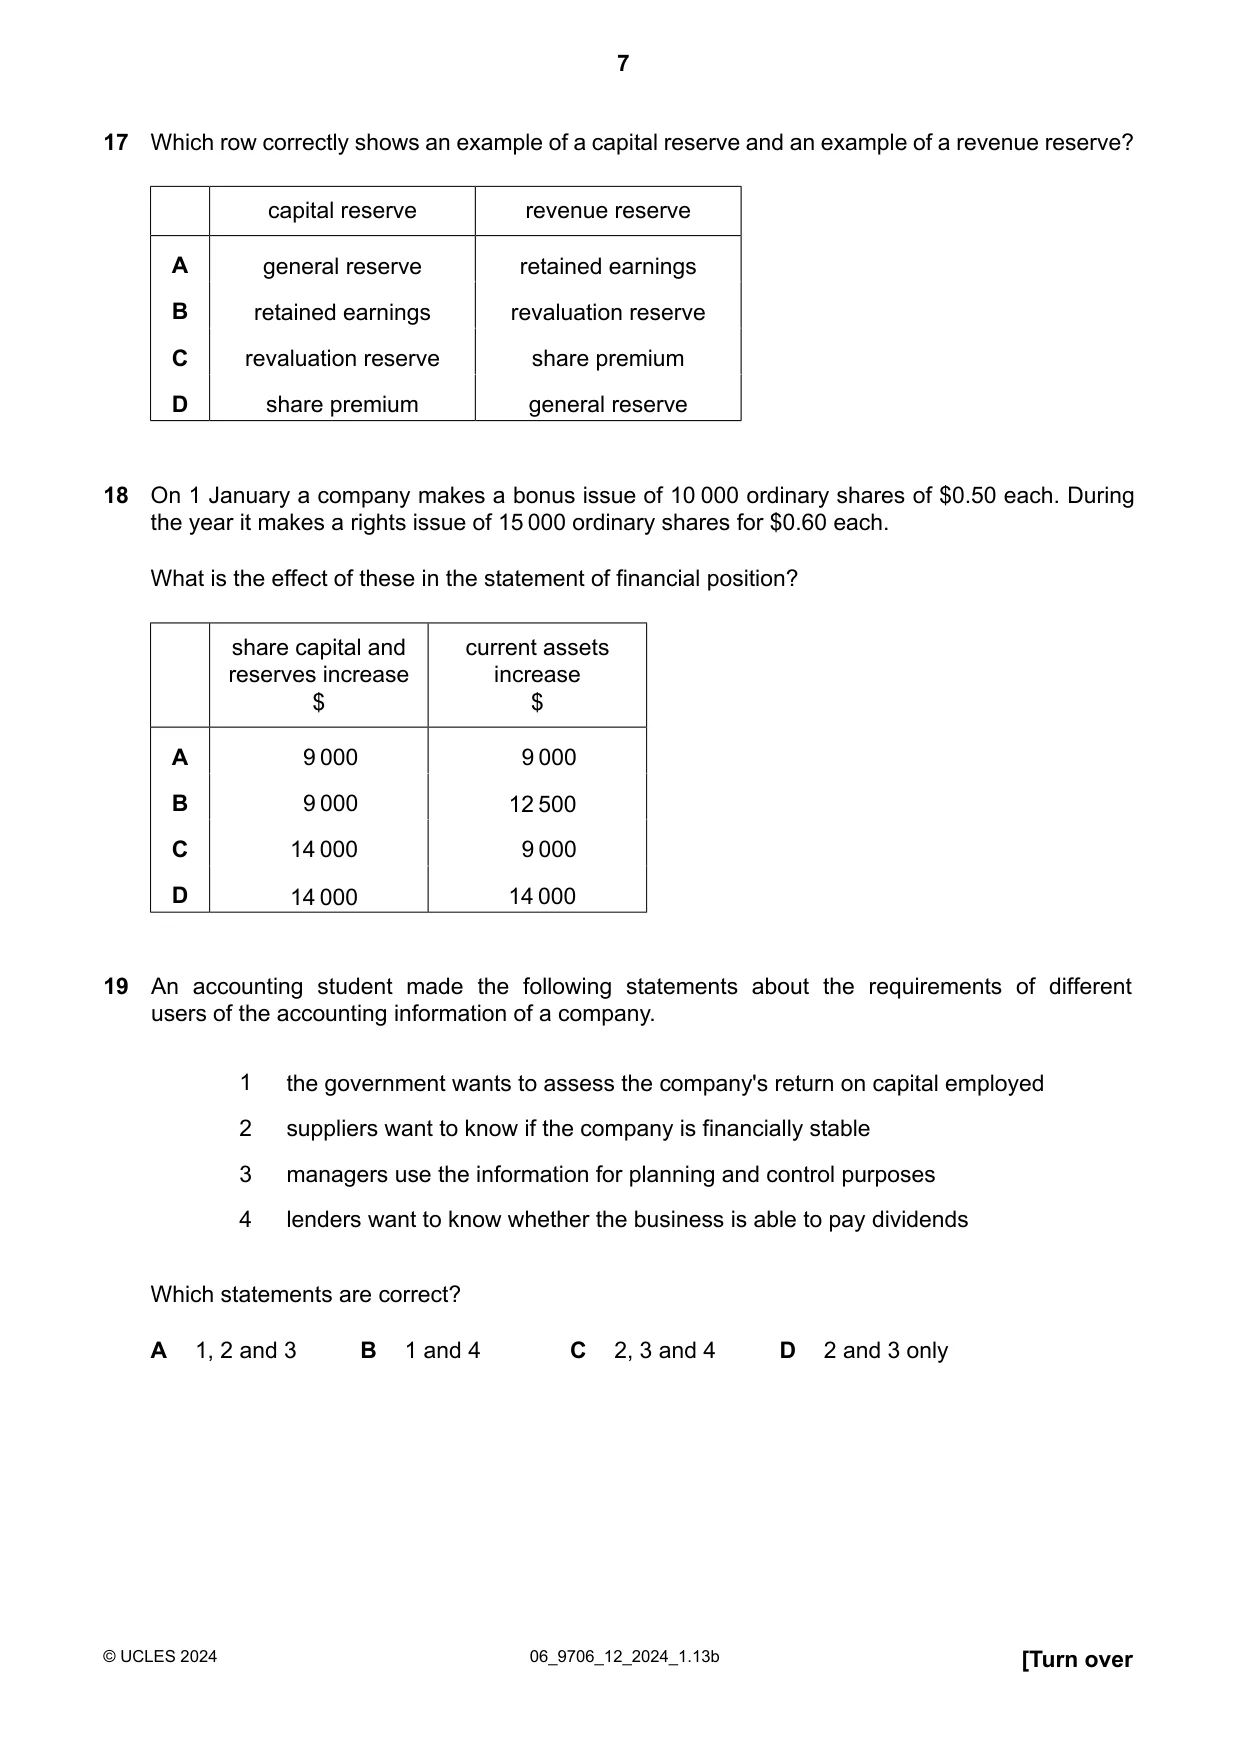
17 Which row correctly shows an example of a capital reserve and an example of a revenue reserve? revenue reserve capital reserve retained earnings general reserve A revaluation reserve retained earnings B share premium revaluation reserve C general reserve share premium D On 1 January a company makes a bonus issue of 10 000 ordinary shares of $0.50 each. During the year it makes a rights issue of 15 000 ordinary shares for $0.60 each. What is the effect of these in the statement of financial position? 18 current assets increase $ share capital and reserves increase $ 9 000 9 000 A 12 500 9 000 B 9 000 14 000 C 14 000 14 000 D An accounting student made the following statements about the requirements of different users of the accounting information of a company. 19 the government wants to assess the company's return on capital employed 1 suppliers want to know if the company is financially stable 2 managers use the information for planning and control purposes 3 lenders want to know whether the business is able to pay dividends 4 Which statements are correct? 2 and 3 only D 2, 3 and 4 C 1 and 4 B 1, 2 and 3 A [Turn over 06_9706_12_2024_1.13b © UCLES 2024 7
Question paper, page 8
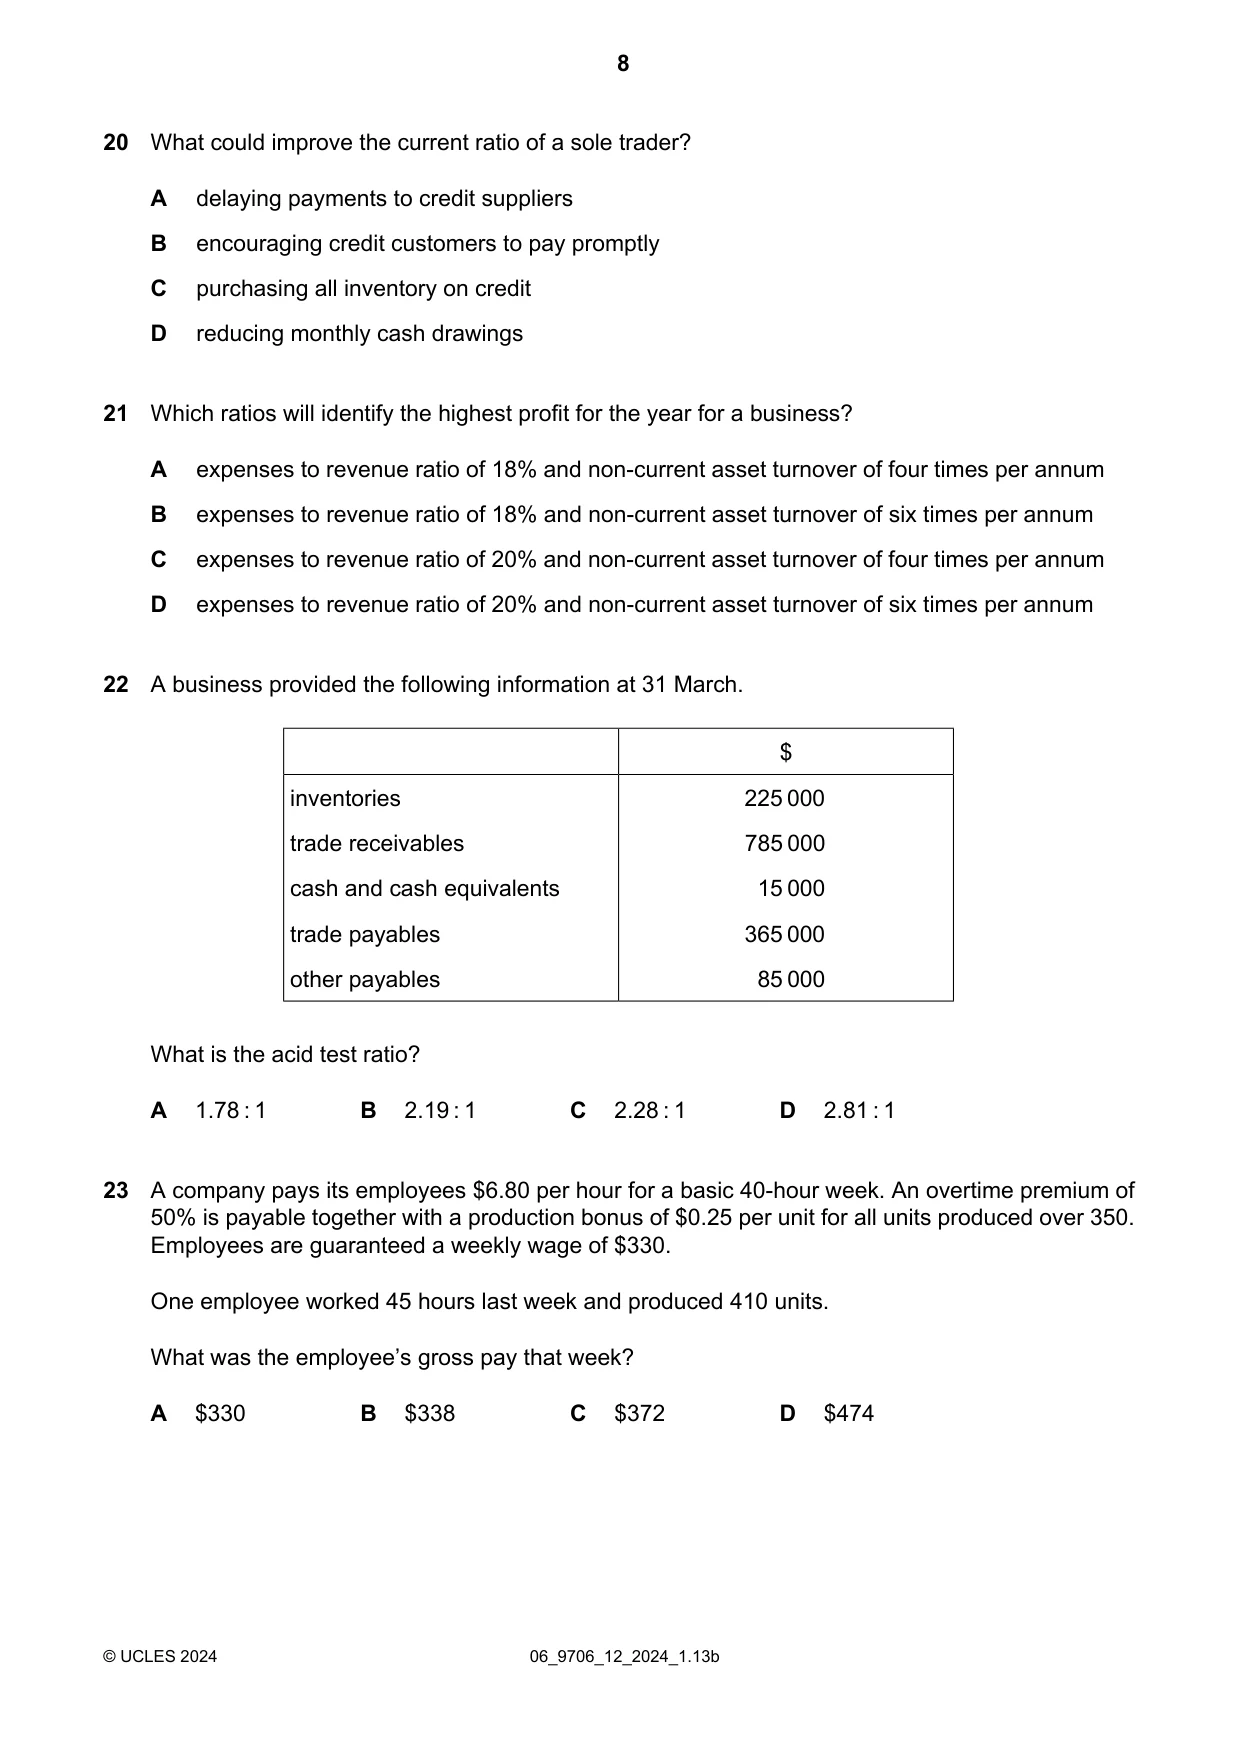
What could improve the current ratio of a sole trader? 20 delaying payments to credit suppliers A encouraging credit customers to pay promptly B purchasing all inventory on credit C reducing monthly cash drawings D Which ratios will identify the highest profit for the year for a business? 21 expenses to revenue ratio of 18% and non-current asset turnover of four times per annum A expenses to revenue ratio of 18% and non-current asset turnover of six times per annum B expenses to revenue ratio of 20% and non-current asset turnover of four times per annum C expenses to revenue ratio of 20% and non-current asset turnover of six times per annum D A business provided the following information at 31 March. 22 $ 225 000 inventories 785 000 trade receivables 15 000 cash and cash equivalents 365 000 trade payables 85 000 other payables What is the acid test ratio? D 2.81 : 1 C 2.28 : 1 B 2.19 : 1 A 1.78 : 1 A company pays its employees $6.80 per hour for a basic 40-hour week. An overtime premium of 50% is payable together with a production bonus of $0.25 per unit for all units produced over 350. Employees are guaranteed a weekly wage of $330. One employee worked 45 hours last week and produced 410 units. What was the employee’s gross pay that week? 23 $474 D $372 C $338 B $330 A 06_9706_12_2024_1.13b © UCLES 2024 8
Question paper, page 9
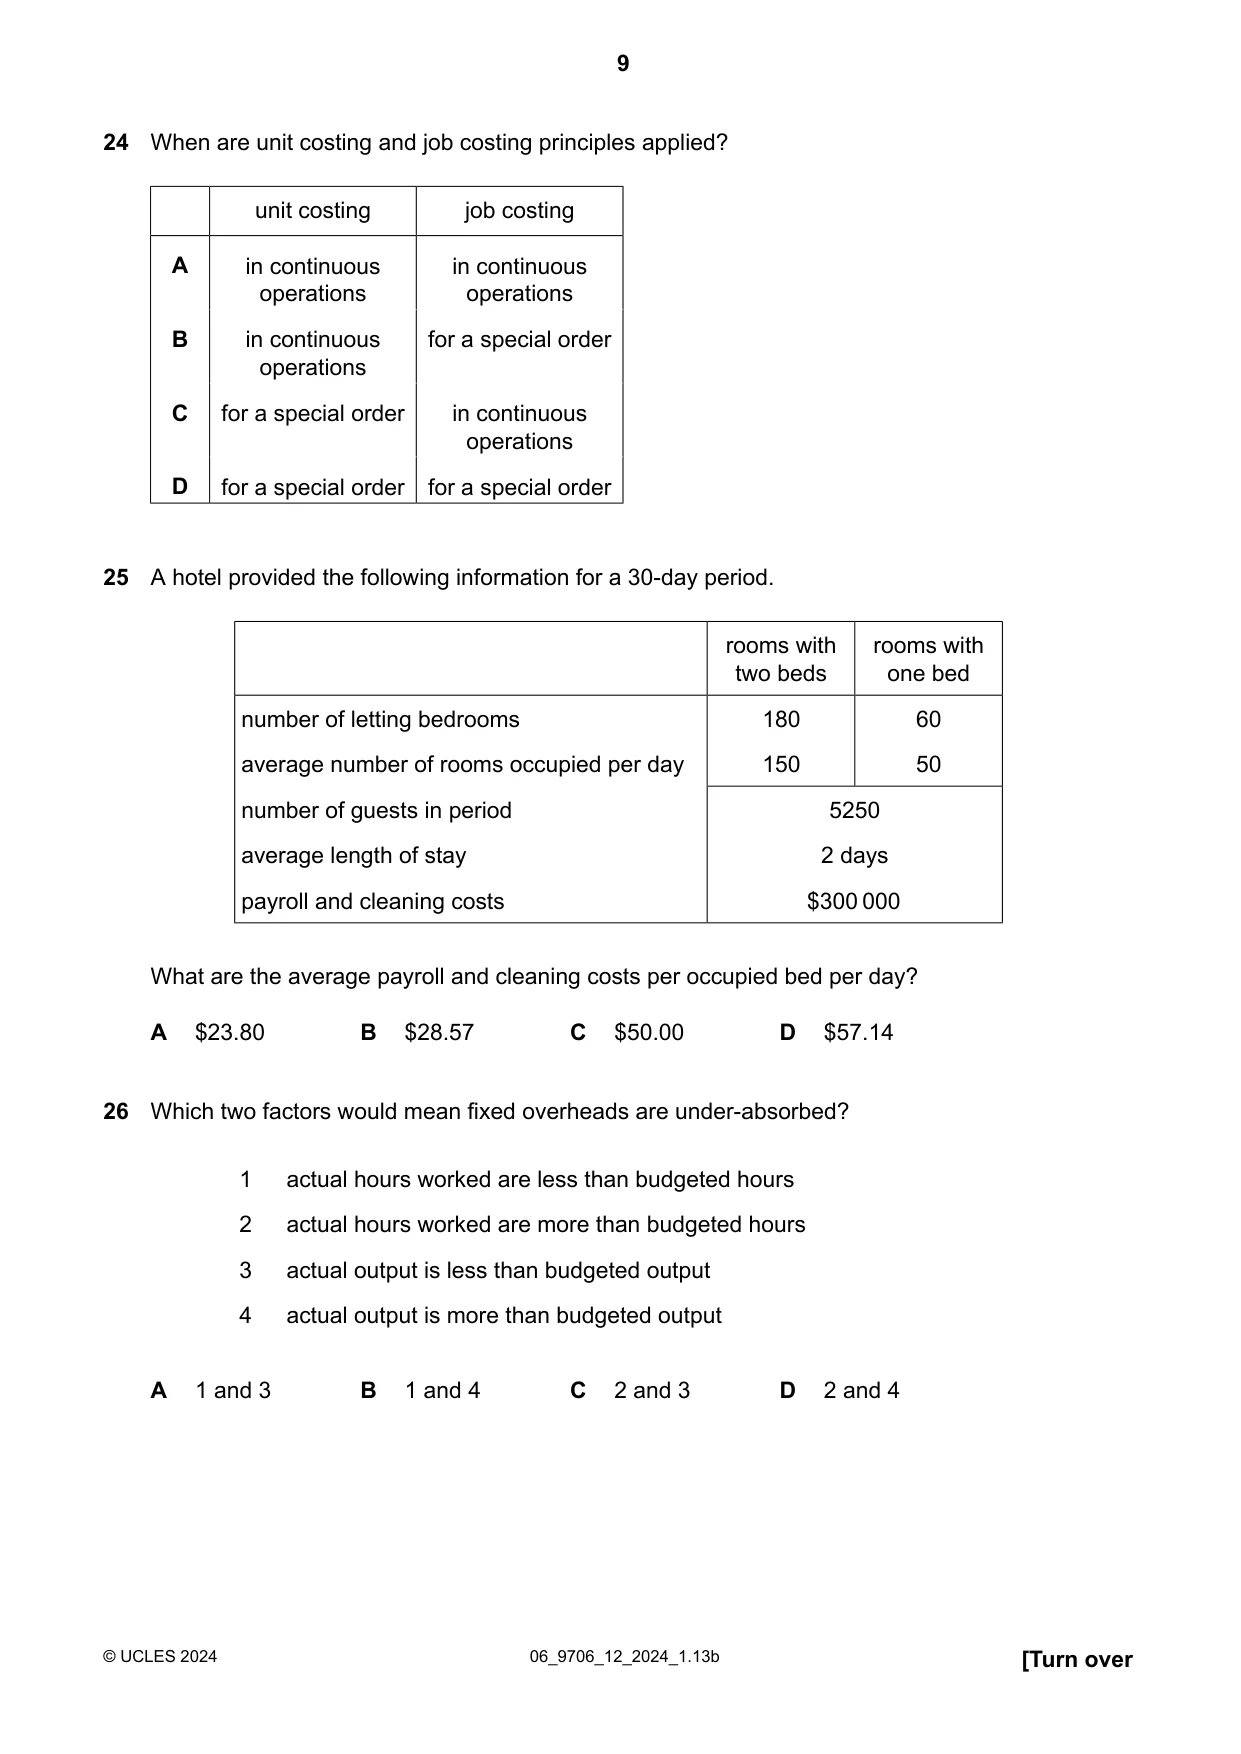
When are unit costing and job costing principles applied? 24 job costing unit costing in continuous operations in continuous operations A for a special order in continuous operations B in continuous operations for a special order C for a special order for a special order D A hotel provided the following information for a 30-day period. 25 rooms with one bed rooms with two beds 60 180 number of letting bedrooms 50 150 average number of rooms occupied per day 5250 number of guests in period 2 days average length of stay $300 000 payroll and cleaning costs What are the average payroll and cleaning costs per occupied bed per day? $57.14 D $50.00 C $28.57 B $23.80 A Which two factors would mean fixed overheads are under-absorbed? 26 actual hours worked are less than budgeted hours 1 actual hours worked are more than budgeted hours 2 actual output is less than budgeted output 3 actual output is more than budgeted output 4 2 and 4 D 2 and 3 C 1 and 4 B 1 and 3 A [Turn over 06_9706_12_2024_1.13b © UCLES 2024 9
Question paper, page 10
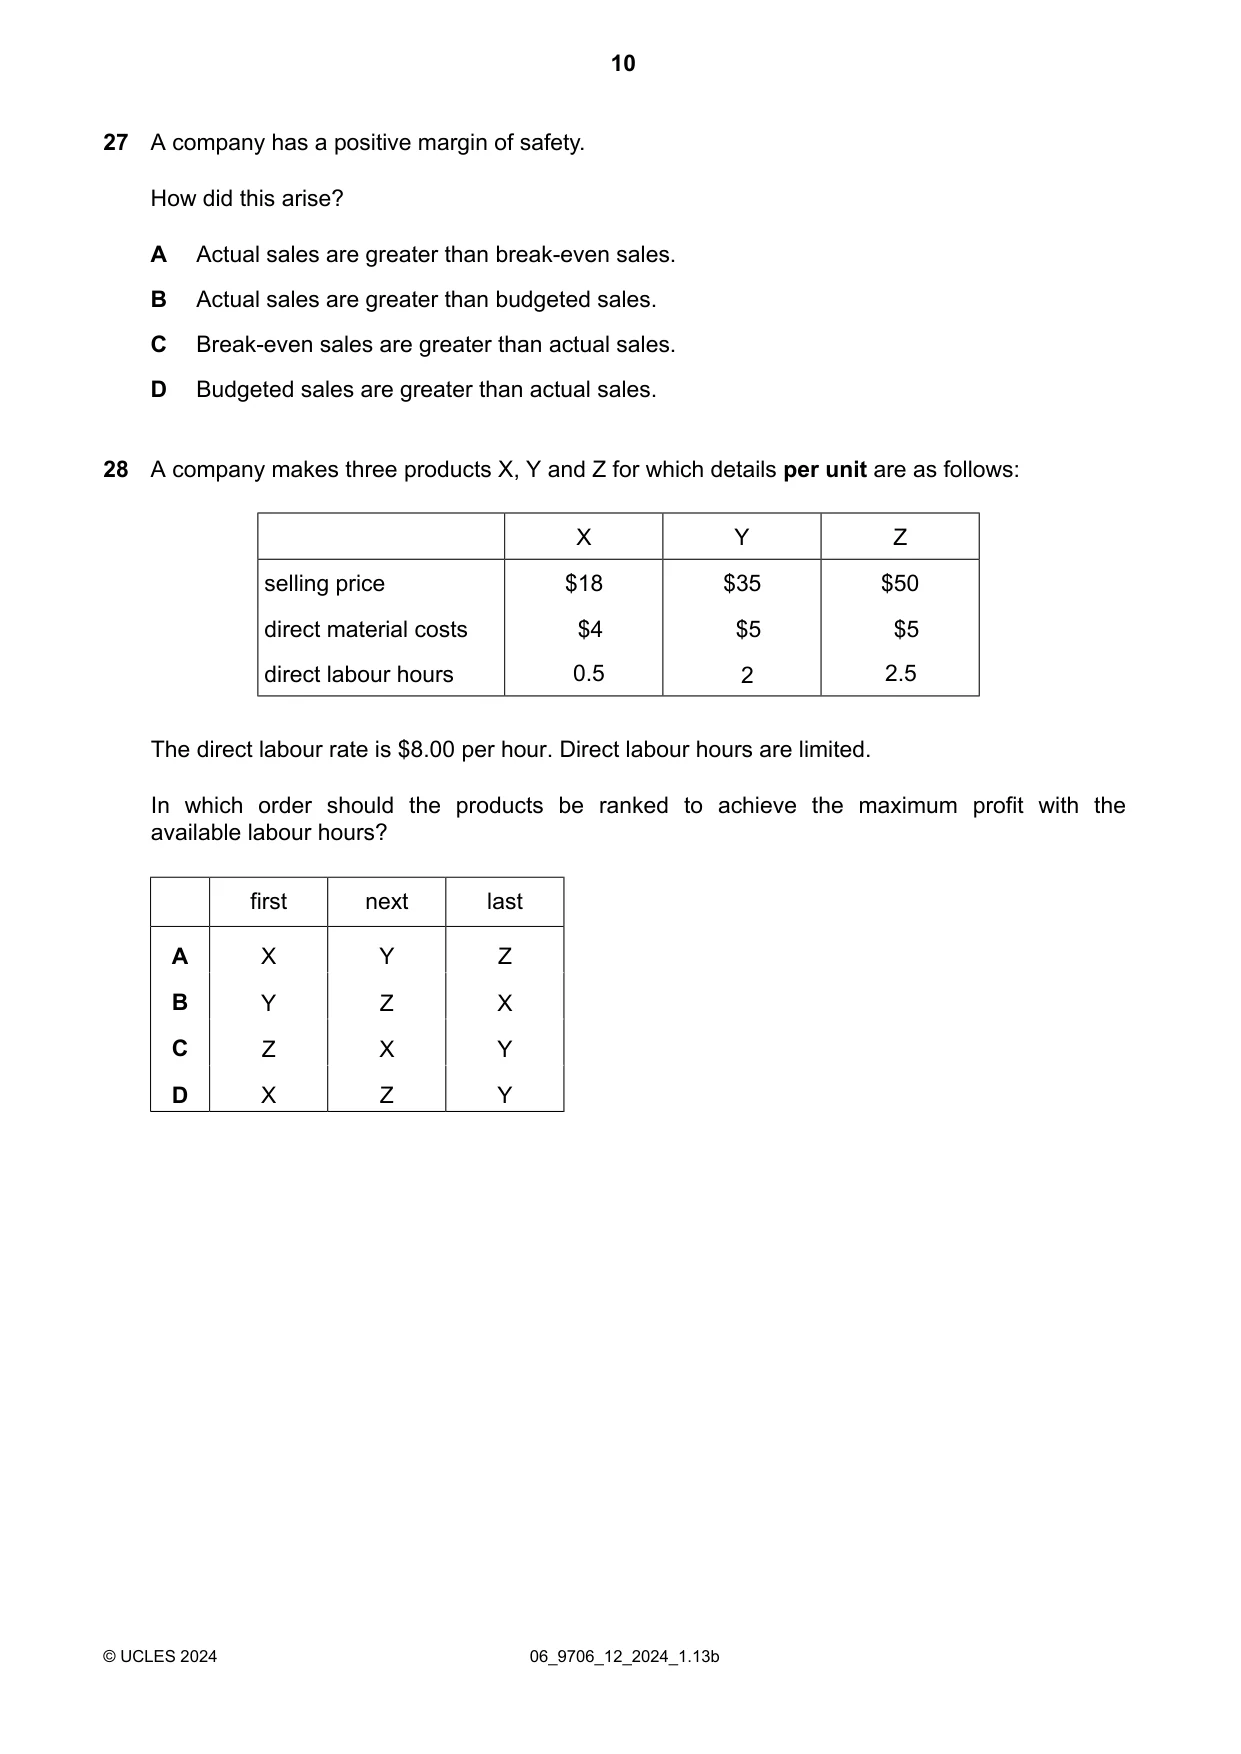
A company has a positive margin of safety. How did this arise? 27 Actual sales are greater than break-even sales. A Actual sales are greater than budgeted sales. B Break-even sales are greater than actual sales. C Budgeted sales are greater than actual sales. D 28 A company makes three products X, Y and Z for which details per unit are as follows: Z Y X $50 $35 $18 selling price $5 $5 $4 direct material costs 2.5 2 0.5 direct labour hours The direct labour rate is $8.00 per hour. Direct labour hours are limited. In which order should the products be ranked to achieve the maximum profit with the available labour hours? last next first Z Y X A X Z Y B Y X Z C Y Z X D 06_9706_12_2024_1.13b © UCLES 2024 10
Question paper, page 11
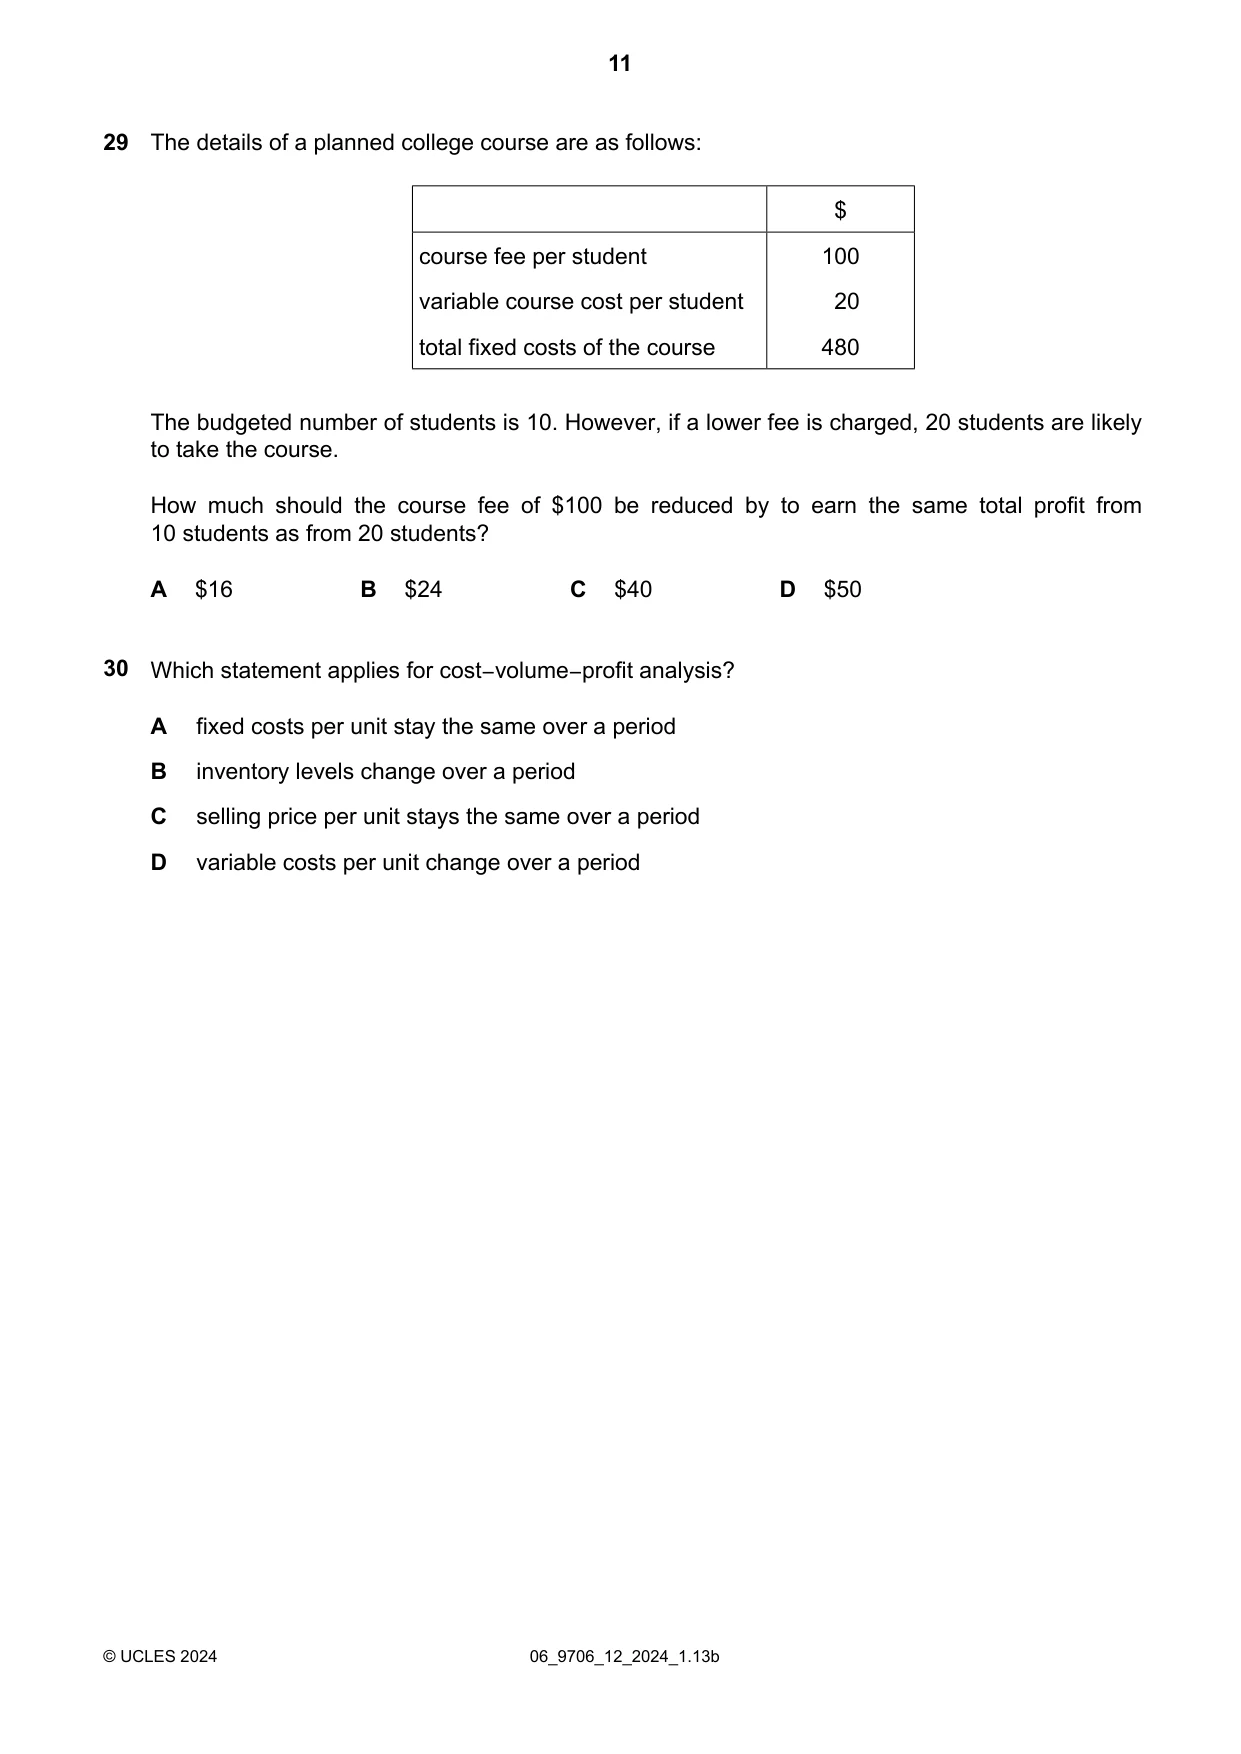
29 The details of a planned college course are as follows: $ 100 course fee per student 20 variable course cost per student 480 total fixed costs of the course The budgeted number of students is 10. However, if a lower fee is charged, 20 students are likely to take the course. How much should the course fee of $100 be reduced by to earn the same total profit from 10 students as from 20 students? $50 D $40 C $24 B $16 A Which statement applies for cost−volume−profit analysis? 30 fixed costs per unit stay the same over a period A inventory levels change over a period B selling price per unit stays the same over a period C variable costs per unit change over a period D 06_9706_12_2024_1.13b © UCLES 2024 11
Question paper, page 12
12 Permission to reproduce items where third-party owned material protected by copyright is included has been sought and cleared where possible. Every reasonable effort has been made by the publisher (UCLES) to trace copyright holders, but if any items requiring clearance have unwittingly been included, the publisher will be pleased to make amends at the earliest possible opportunity. To avoid the issue of disclosure of answer-related information to candidates, all copyright acknowledgements are reproduced online in the Cambridge Assessment International Education Copyright Acknowledgements Booklet. This is produced for each series of examinations and is freely available to download at www.cambridgeinternational.org after the live examination series. Cambridge Assessment International Education is part of Cambridge Assessment. Cambridge Assessment is the brand name of the University of Cambridge Local Examinations Syndicate (UCLES), which is a department of the University of Cambridge. © UCLES 2024 06_9706_12_2024_1.13b BLANK PAGE
Mark scheme, page 1
This document consists of 3 printed pages. © Cambridge University Press & Assessment 2024 [Turn over Cambridge International AS & A Level ACCOUNTING 9706/12 Paper 1 Multiple Choice May/June 2024 MARK SCHEME Maximum Mark: 30 Published This mark scheme is published as an aid to teachers and candidates, to indicate the requirements of the examination. Mark schemes should be read in conjunction with the question paper and the Principal Examiner Report for Teachers. Cambridge International will not enter into discussions about these mark schemes. Cambridge International is publishing the mark schemes for the May/June 2024 series for most Cambridge IGCSE, Cambridge International A and AS Level and Cambridge Pre-U components, and some Cambridge O Level components.
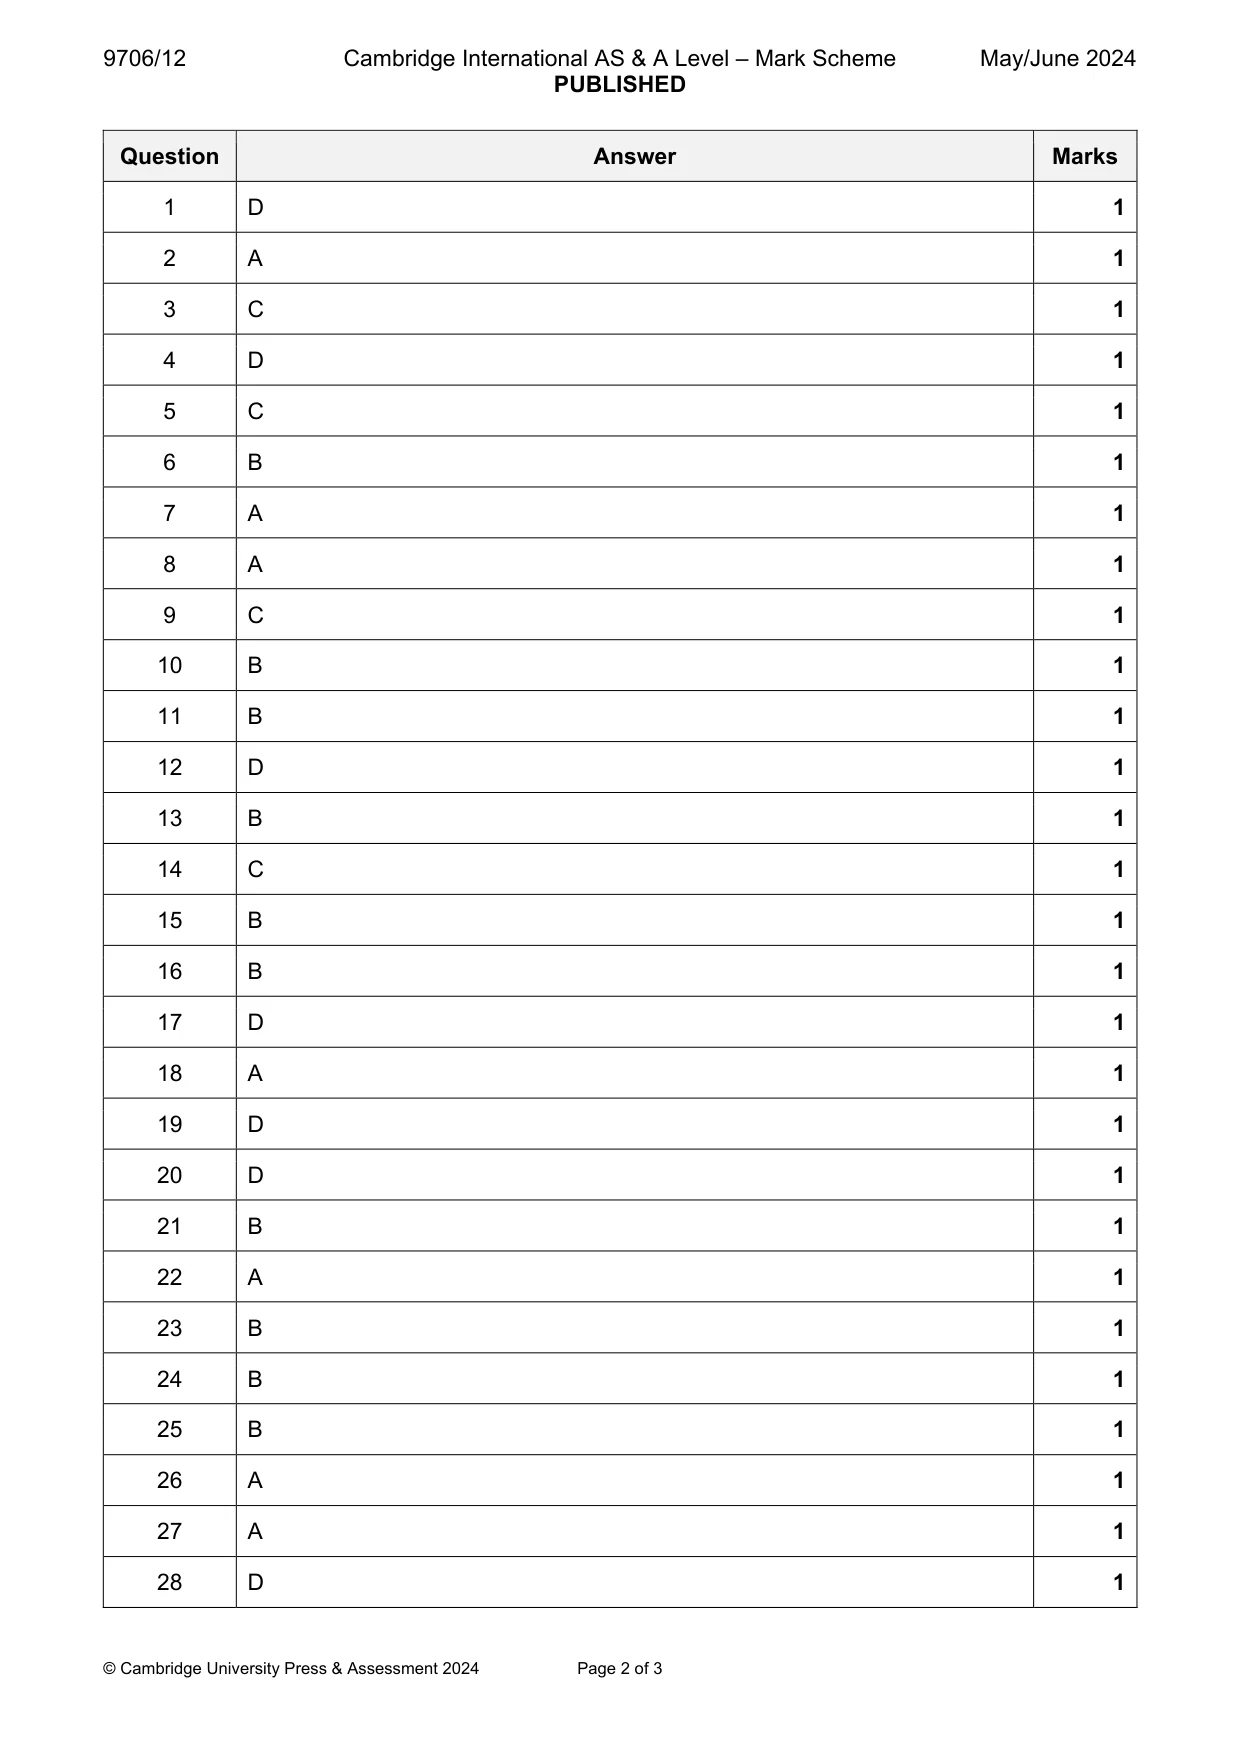
Mark scheme, page 2
9706/12 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 2 of 3 Question Answer Marks 1 D 1 2 A 1 3 C 1 4 D 1 5 C 1 6 B 1 7 A 1 8 A 1 9 C 1 10 B 1 11 B 1 12 D 1 13 B 1 14 C 1 15 B 1 16 B 1 17 D 1 18 A 1 19 D 1 20 D 1 21 B 1 22 A 1 23 B 1 24 B 1 25 B 1 26 A 1 27 A 1 28 D 1
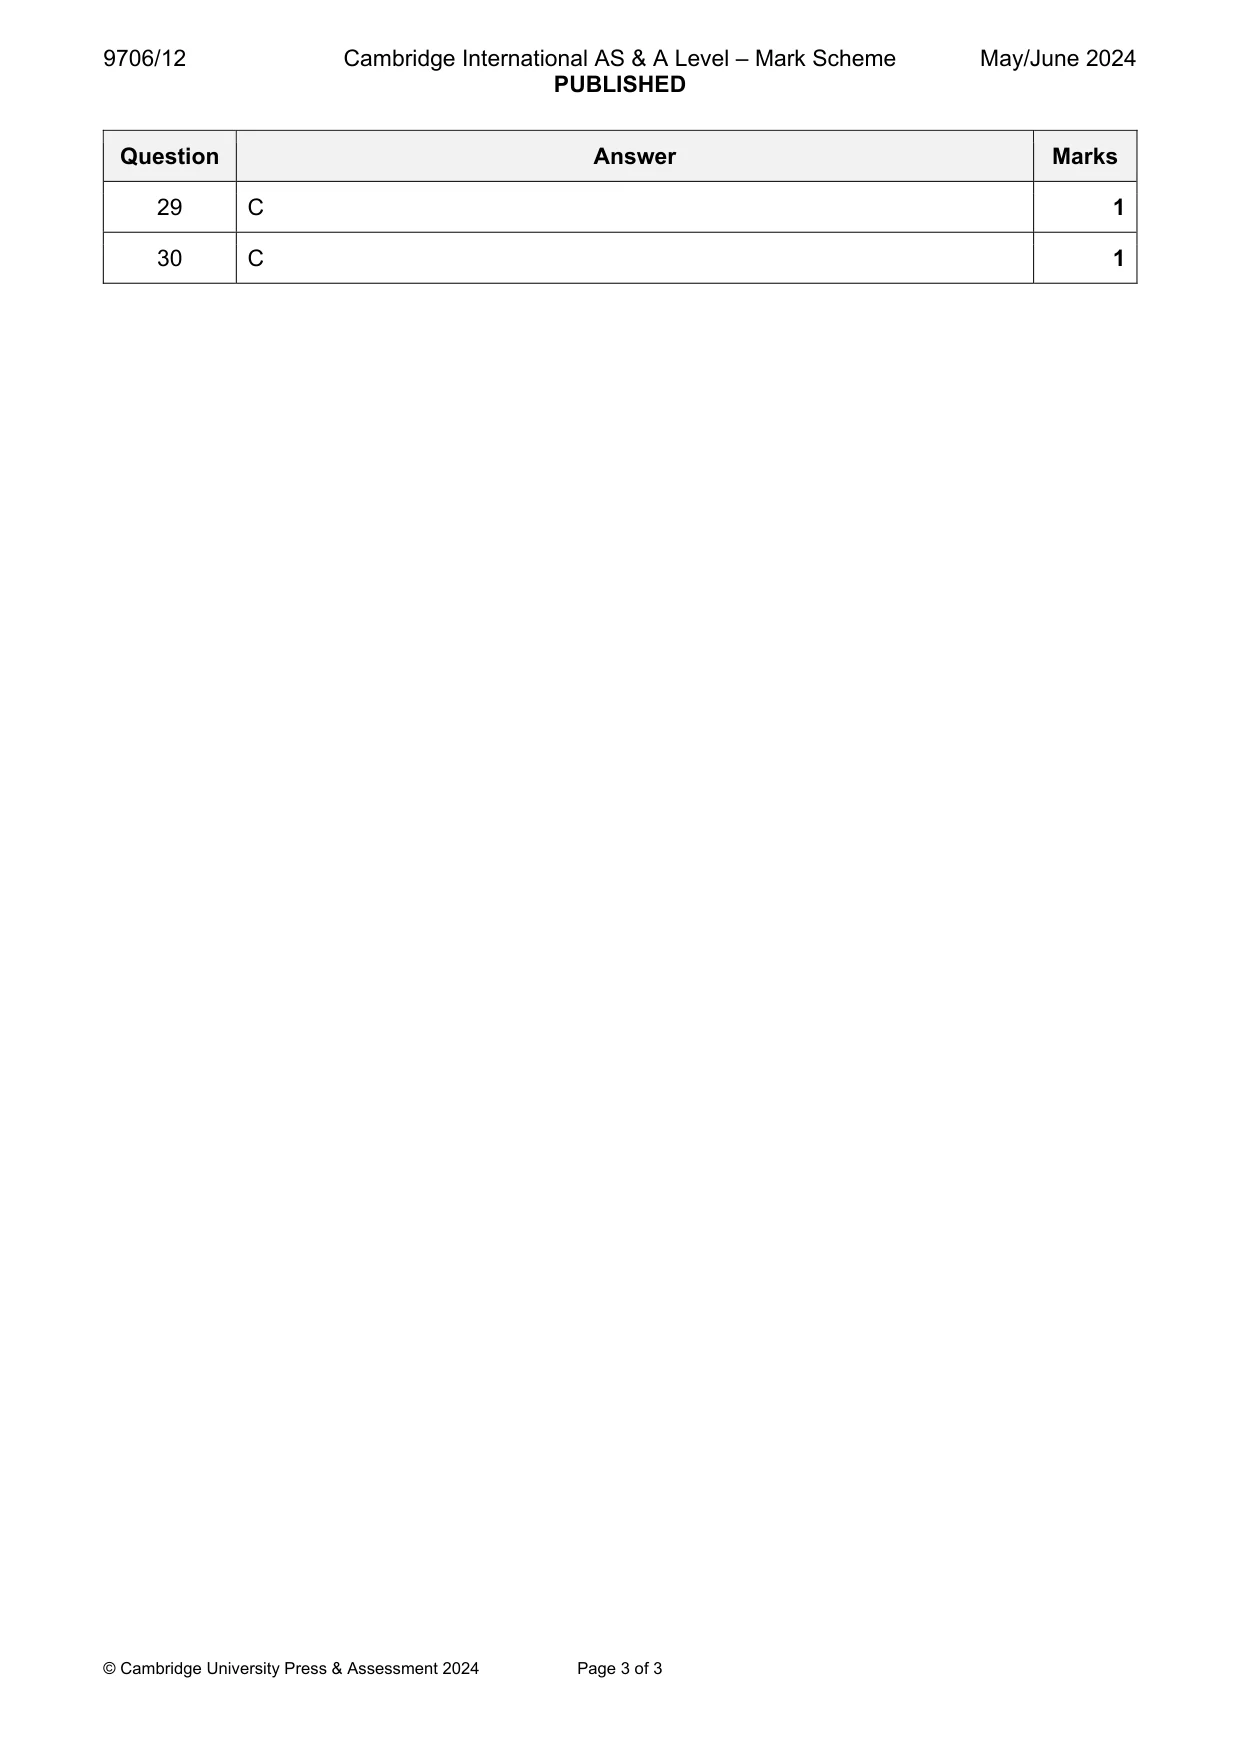
Mark scheme, page 3
9706/12 Cambridge International AS & A Level – Mark Scheme PUBLISHED May/June 2024 © Cambridge University Press & Assessment 2024 Page 3 of 3 Question Answer Marks 29 C 1 30 C 1
What you needed in this session
Cambridge’s own grade thresholds for 2024 May/June, Paper 1 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.