Cambridge A Level Accounting 9706 — 2020 May/June Paper 2 · Variant 3
9706/23/M/J/20 · 5 questions · 63 marks · ≈71 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme9 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · The directors of K Limited are preparing the financial statements for the year ended 31…
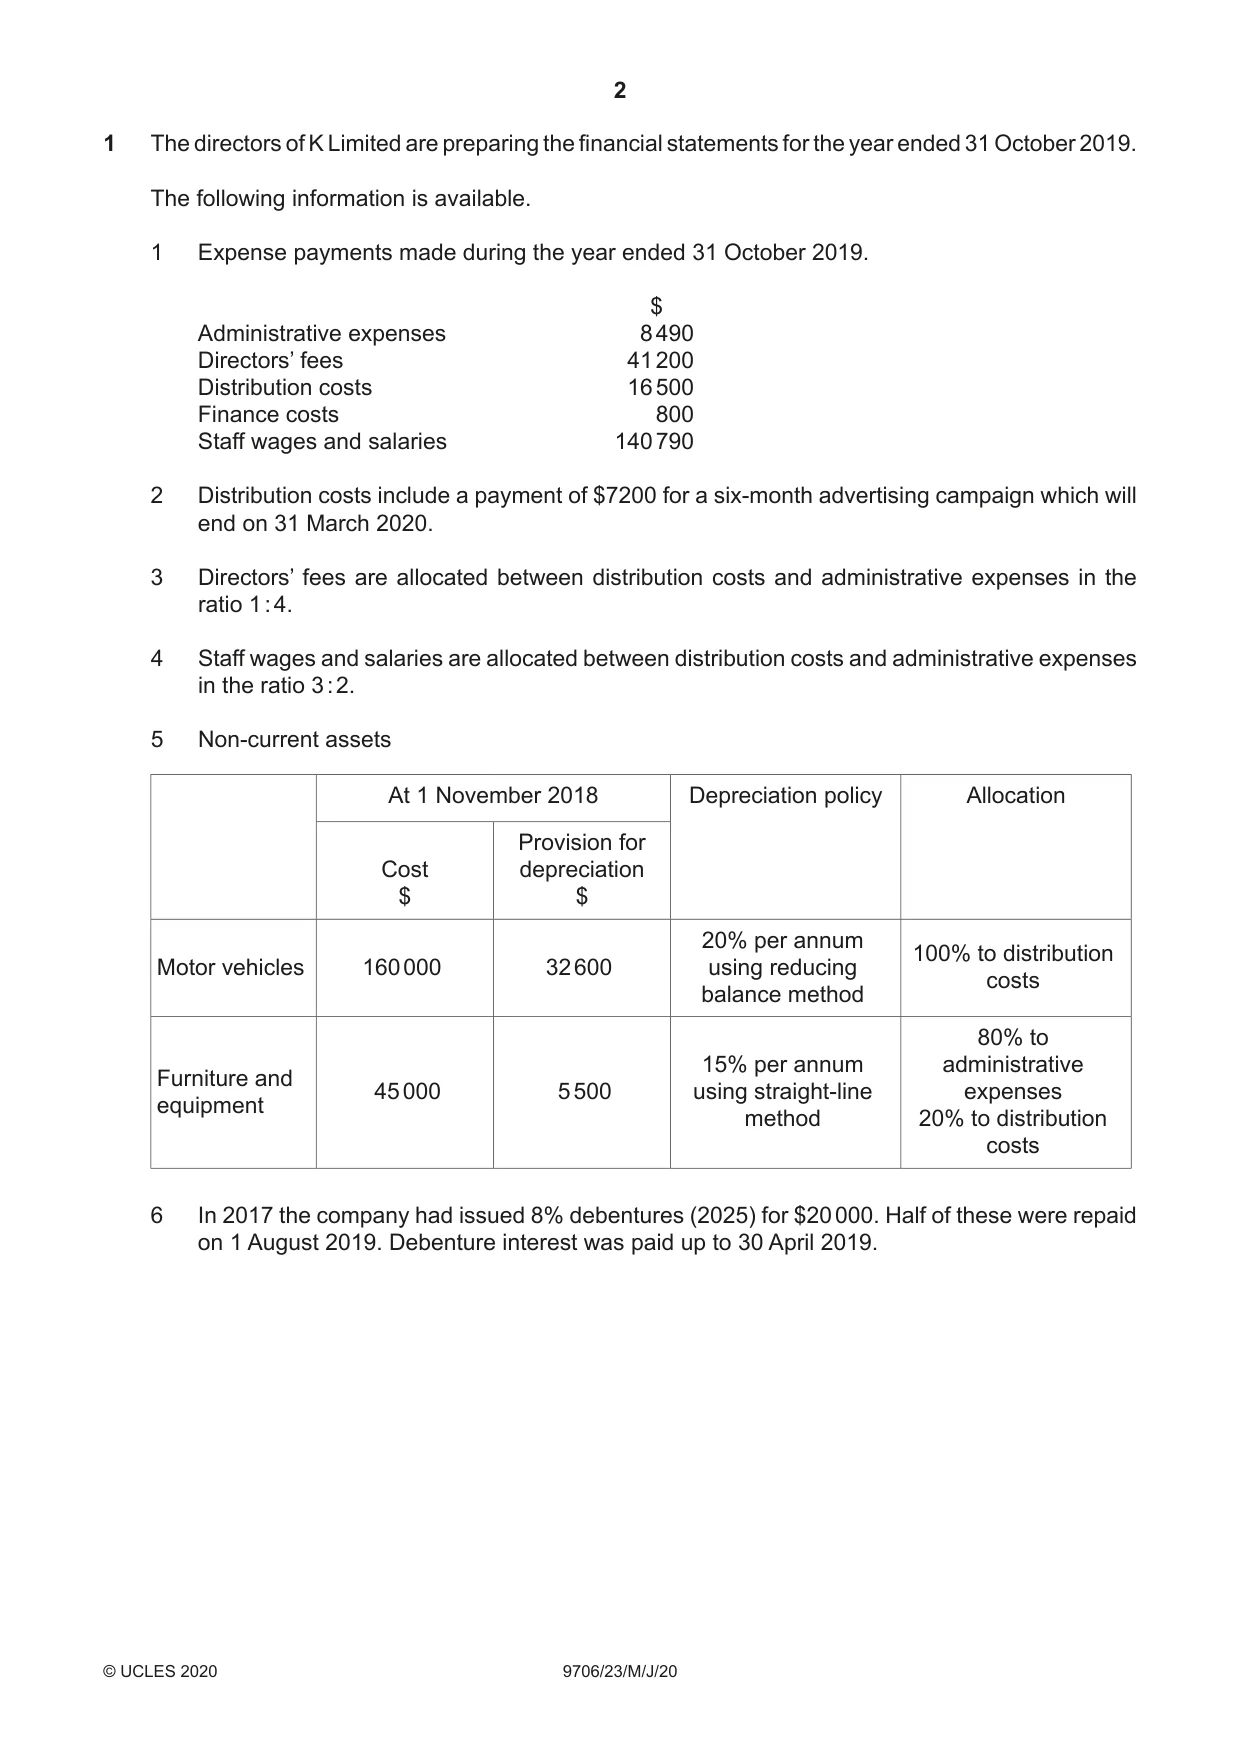
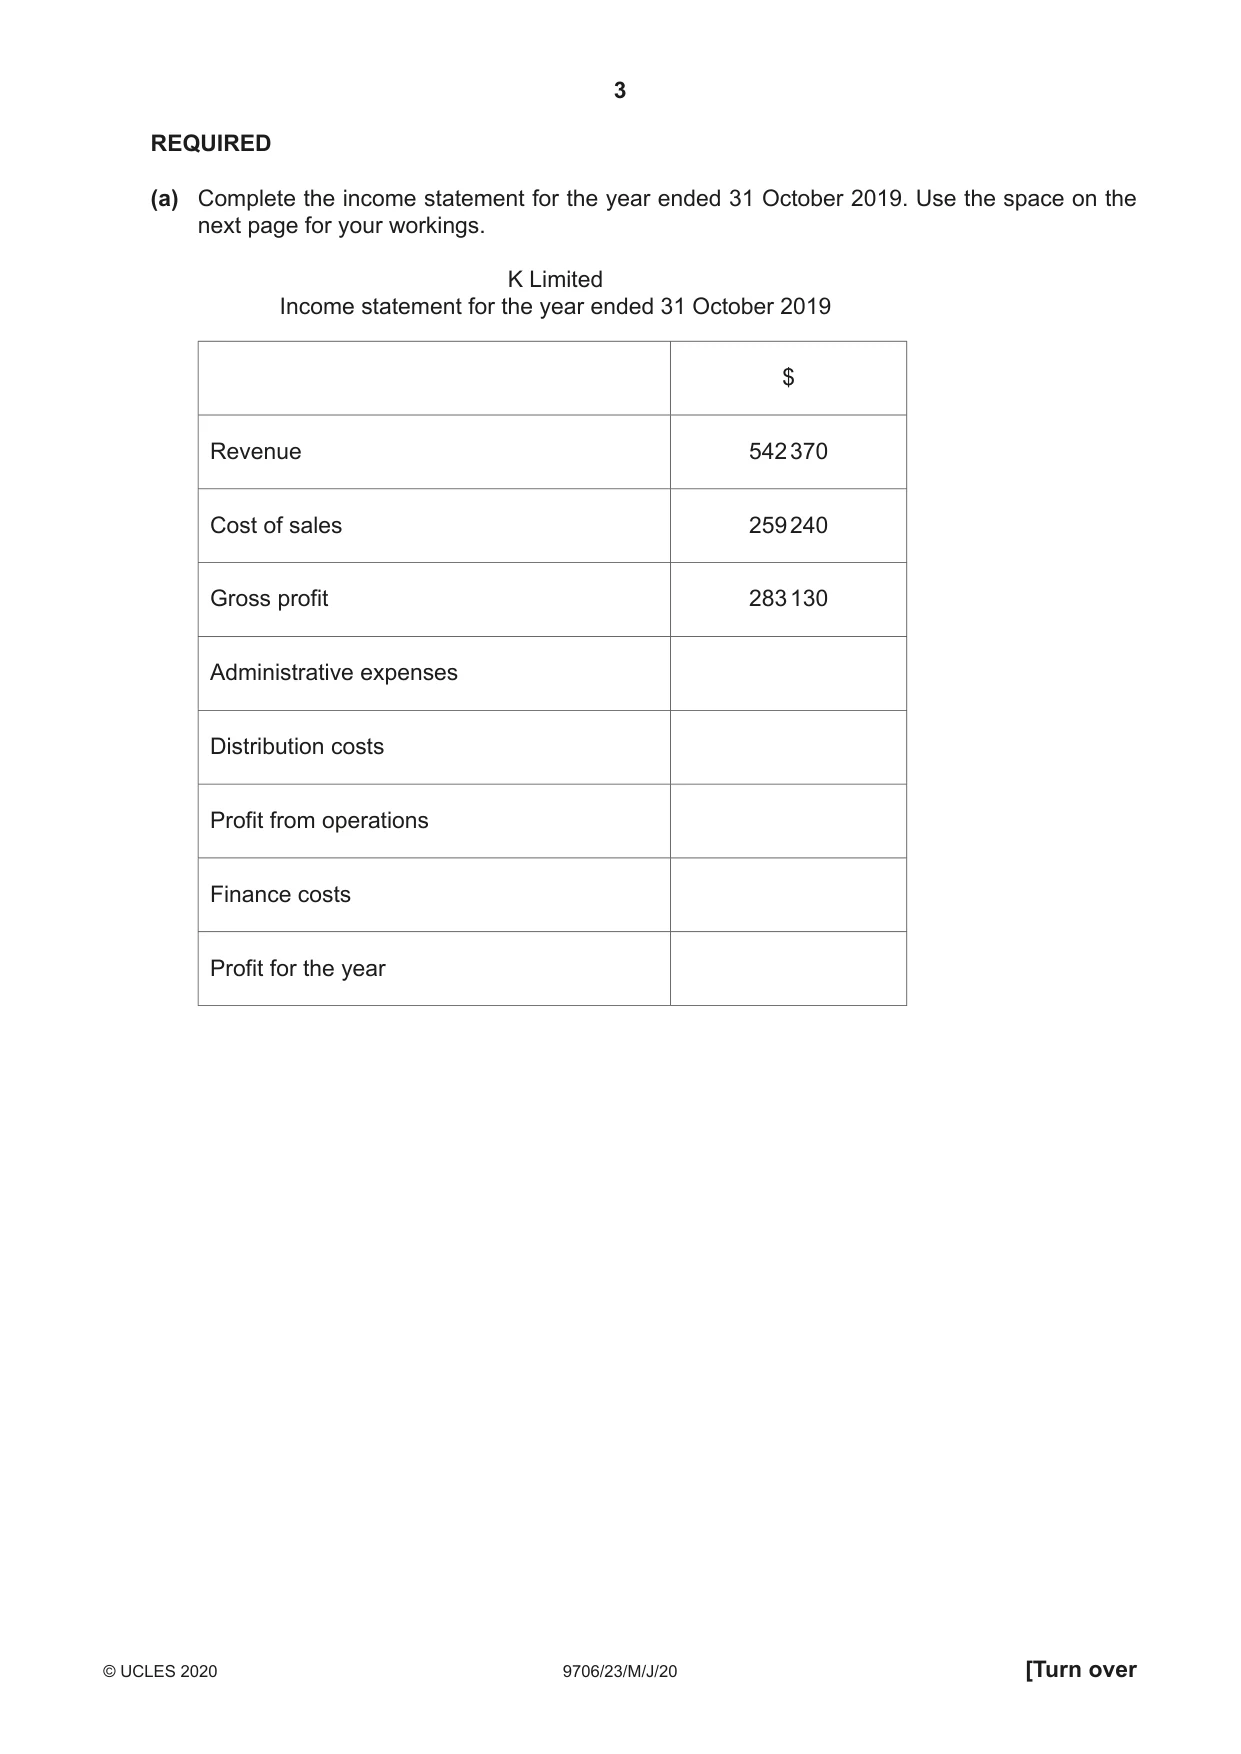
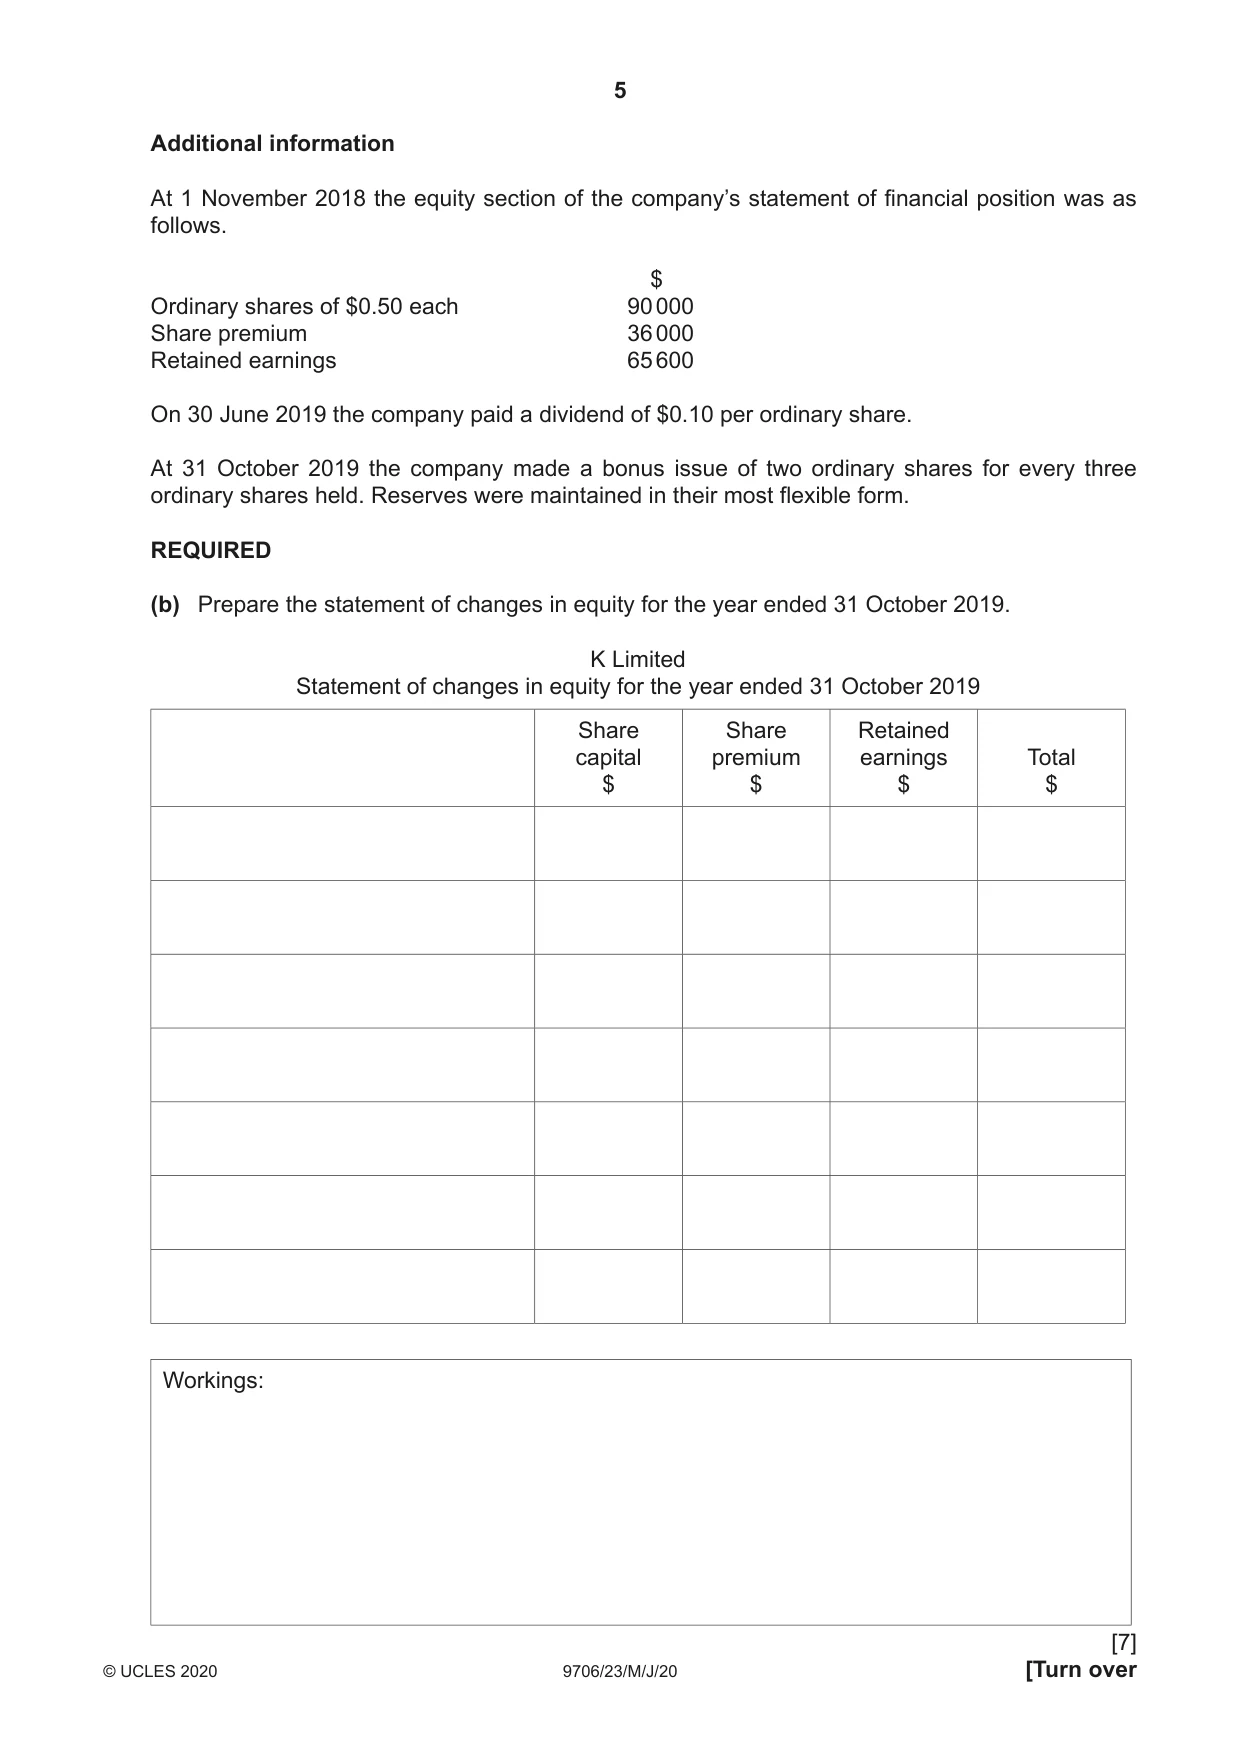
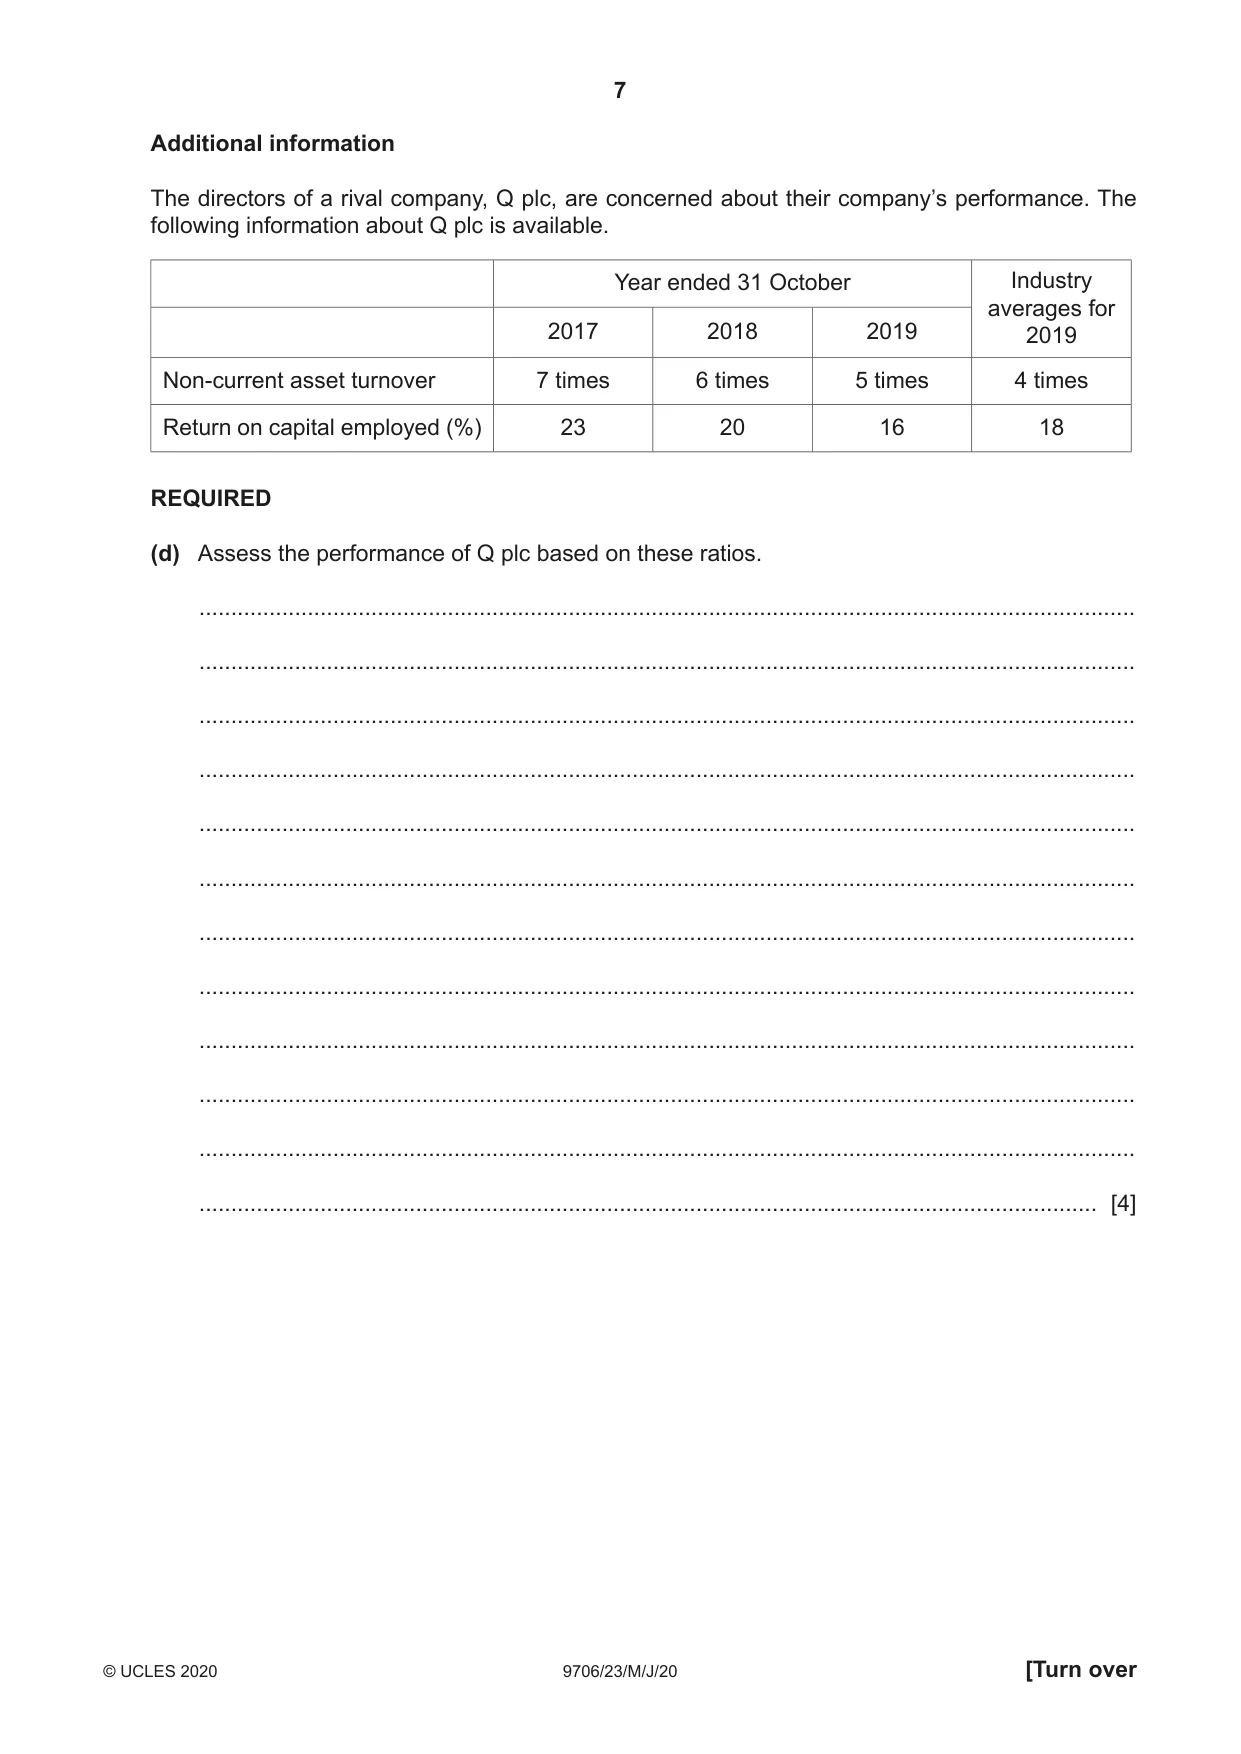
1 The directors of K Limited are preparing the financial statements for the year ended 31 October 2019. The following information is available. 1 Expense payments made during the year ended 31 October 2019. $ Administrative expenses 8 490 Directors’ fees 41 200 Distribution costs 16 500 Finance costs 800 Staff wages and salaries 140 790 2 Distribution costs include a payment of $7200 for a six-month advertising campaign which will end on 31 March 2020. 3 Directors’ fees are allocated between distribution costs and administrative expenses in the ratio 1 : 4. 4 Staff wages and salaries are allocated between distribution costs and administrative expenses in the ratio 3 : 2. 5 Non-current assets At 1 November 2018 Depreciation policy Allocation Provision for Cost depreciation $ $ 20% per annum 100% to distribution Motor vehicles 160 000 32 600 using reducing costs balance method 80% to 15% per annum administrative Furniture and 45 000 5 500 using straight-line expenses equipment method 20% to distribution costs 6 In 2017 the company had issued 8% debentures (2025) for $20 000. Half of these were repaid on 1 August 2019. Debenture interest was paid up to 30 April 2019. REQUIRED (a) Complete the income statement for the year ended 31 October 2019. Use the space on the next page for your workings. K Limited Income statement for the year ended 31 October 2019 $ Revenue 542 370 Cost of sales 259 240 Gross profit 283 130 Administrative expenses Distribution costs Profit from operations Finance costs Profit for the year Workings: Administrative expenses Distribution costs Finance costs [11] Additional information At 1 November 2018 the equity section of the company’s statement of financial position was as follows. $ Ordinary shares of $0.50 each 90 000 Share premium 36 000 Retained earnings 65 600 On 30 June 2019 the company paid a dividend of $0.10 per ordinary share. At 31 October 2019 the company made a bonus issue of two ordinary shares for every three ordinary shares held. Reserves were maintained in their most flexible form. REQUIRED (b) Prepare the statement of changes in equity for the year ended 31 October 2019. K Limited Statement of changes in equity for the year ended 31 October 2019 Share Share Retained capital premium earnings Total $ $ $ $ Workings: Additional information K Limited was formed several years ago by the partners in a business. REQUIRED (c) State three advantages to the shareholders of trading as a limited company. 1 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... 3 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... [3] Additional information The directors of a rival company, Q plc, are concerned about their company’s performance. The following information about Q plc is available. Year ended 31 October Industry averages for 2017 2018 2019 2019 Non-current asset turnover 7 times 6 times 5 times 4 times Return on capital employed (%) 23 20 16 18 REQUIRED (d) Assess the performance of Q plc based on these ratios. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] Additional information Q plc’s liabilities include 8% debentures of $50 000. A director has suggested repaying the debentures to improve the company’s return on capital employed. REQUIRED (e) Advise the director whether or not the company should go ahead with this suggestion. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 30]
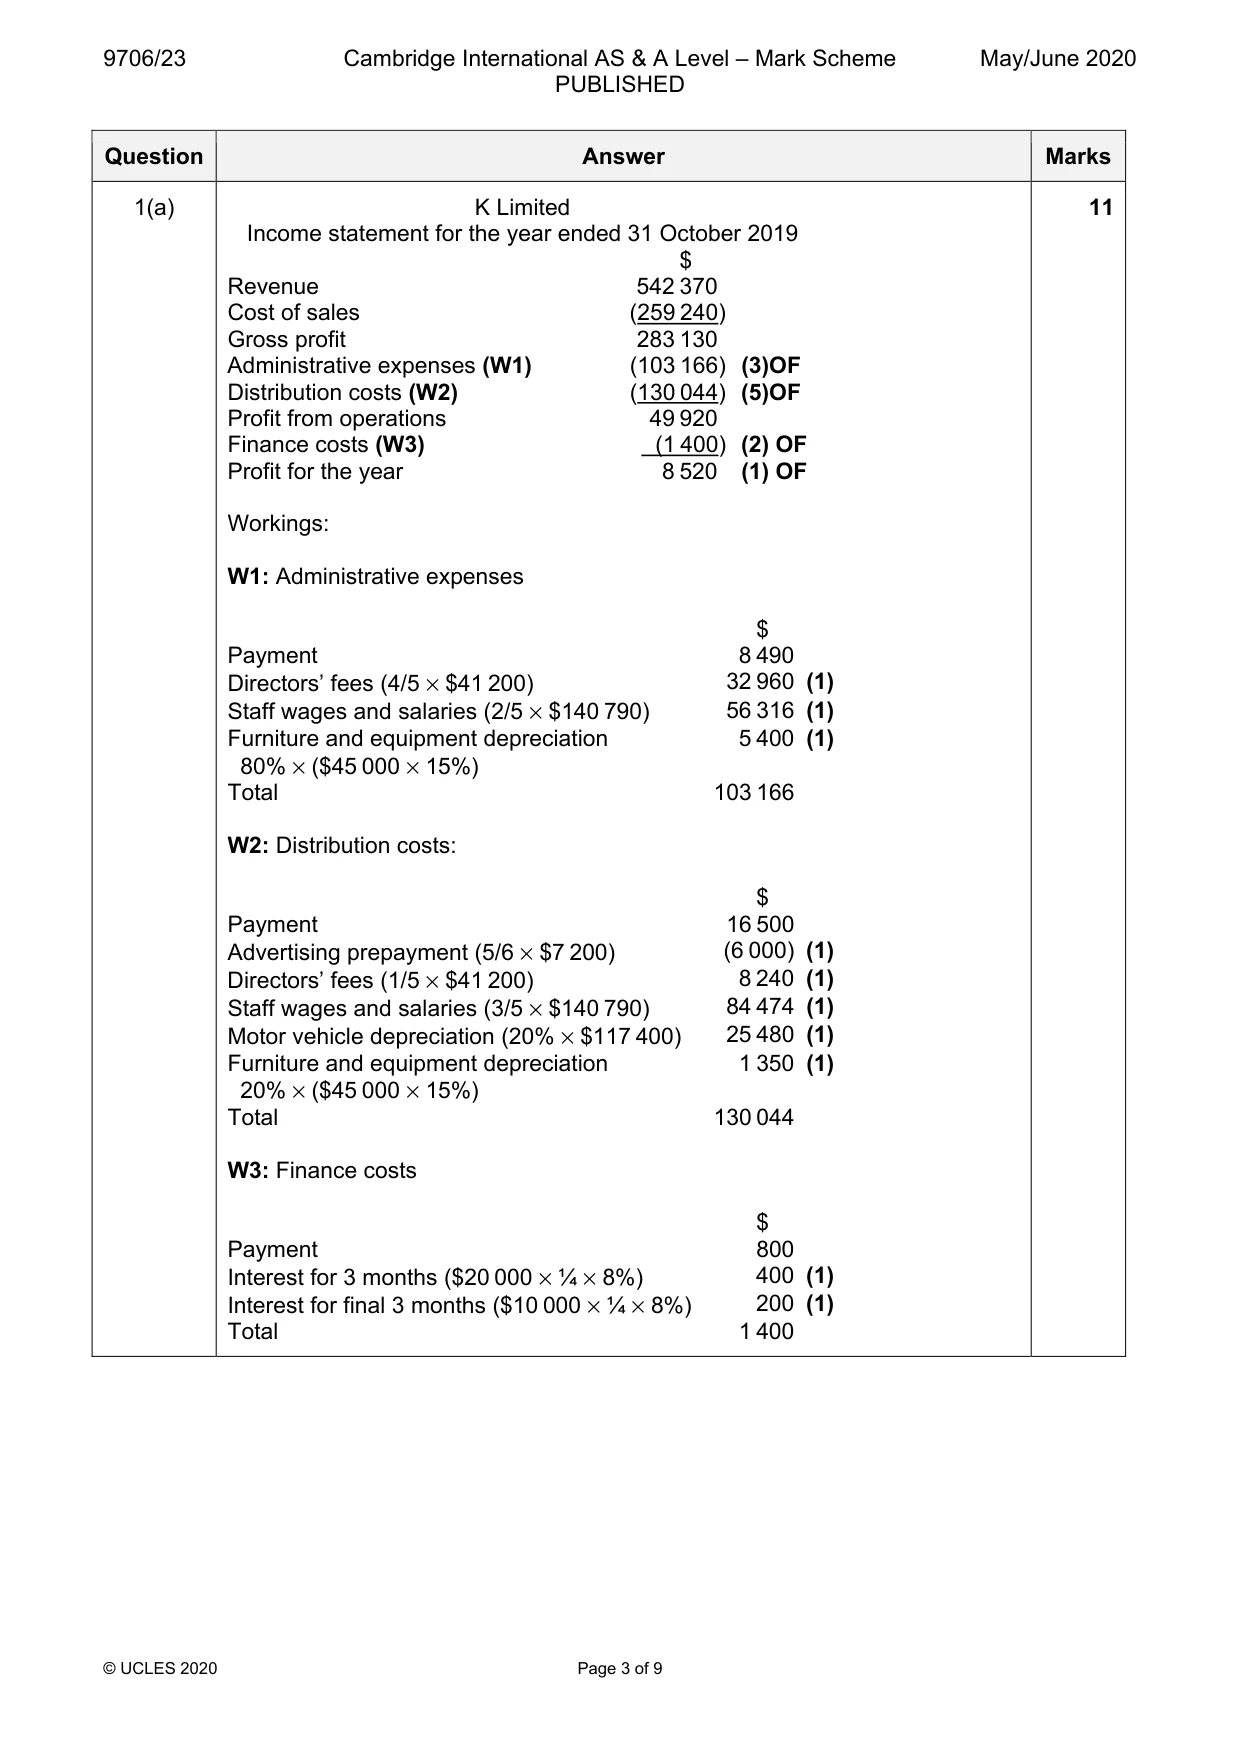
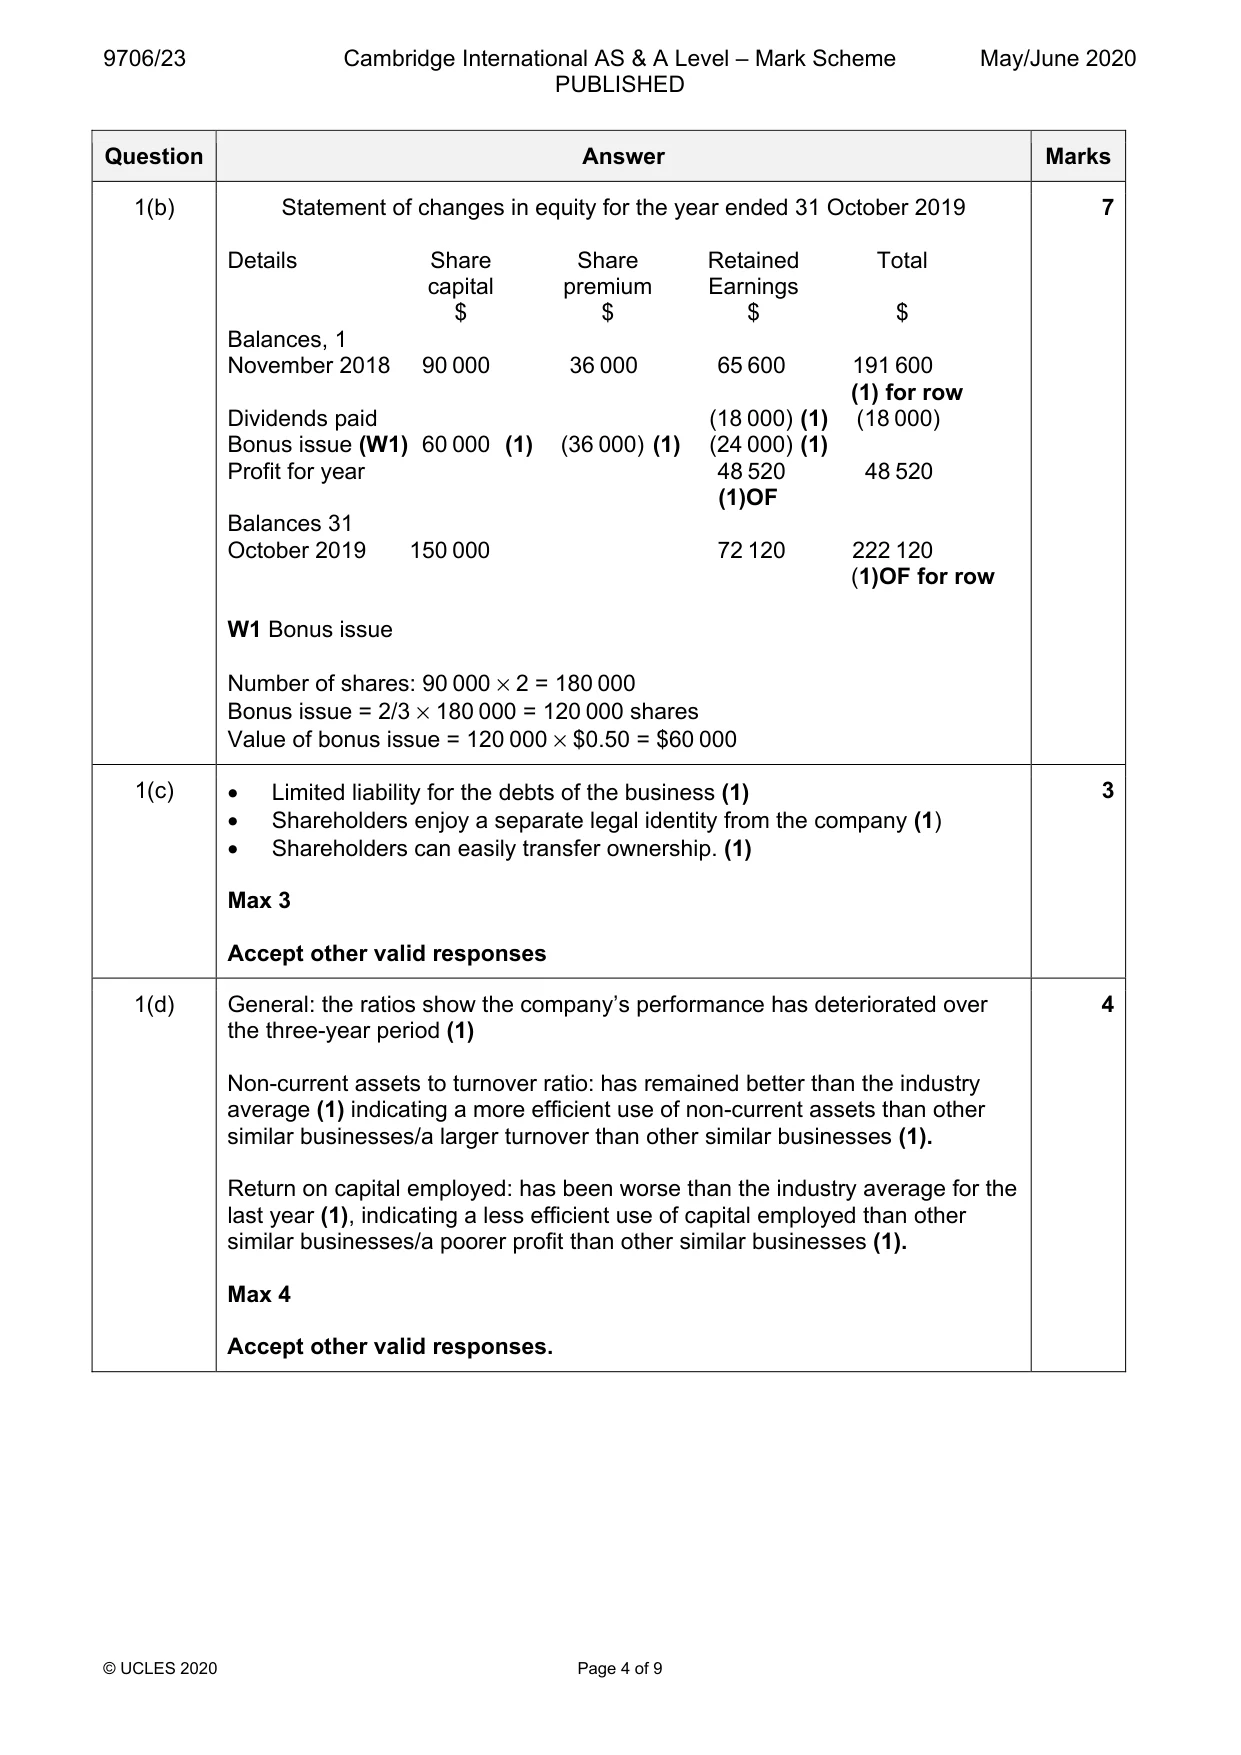
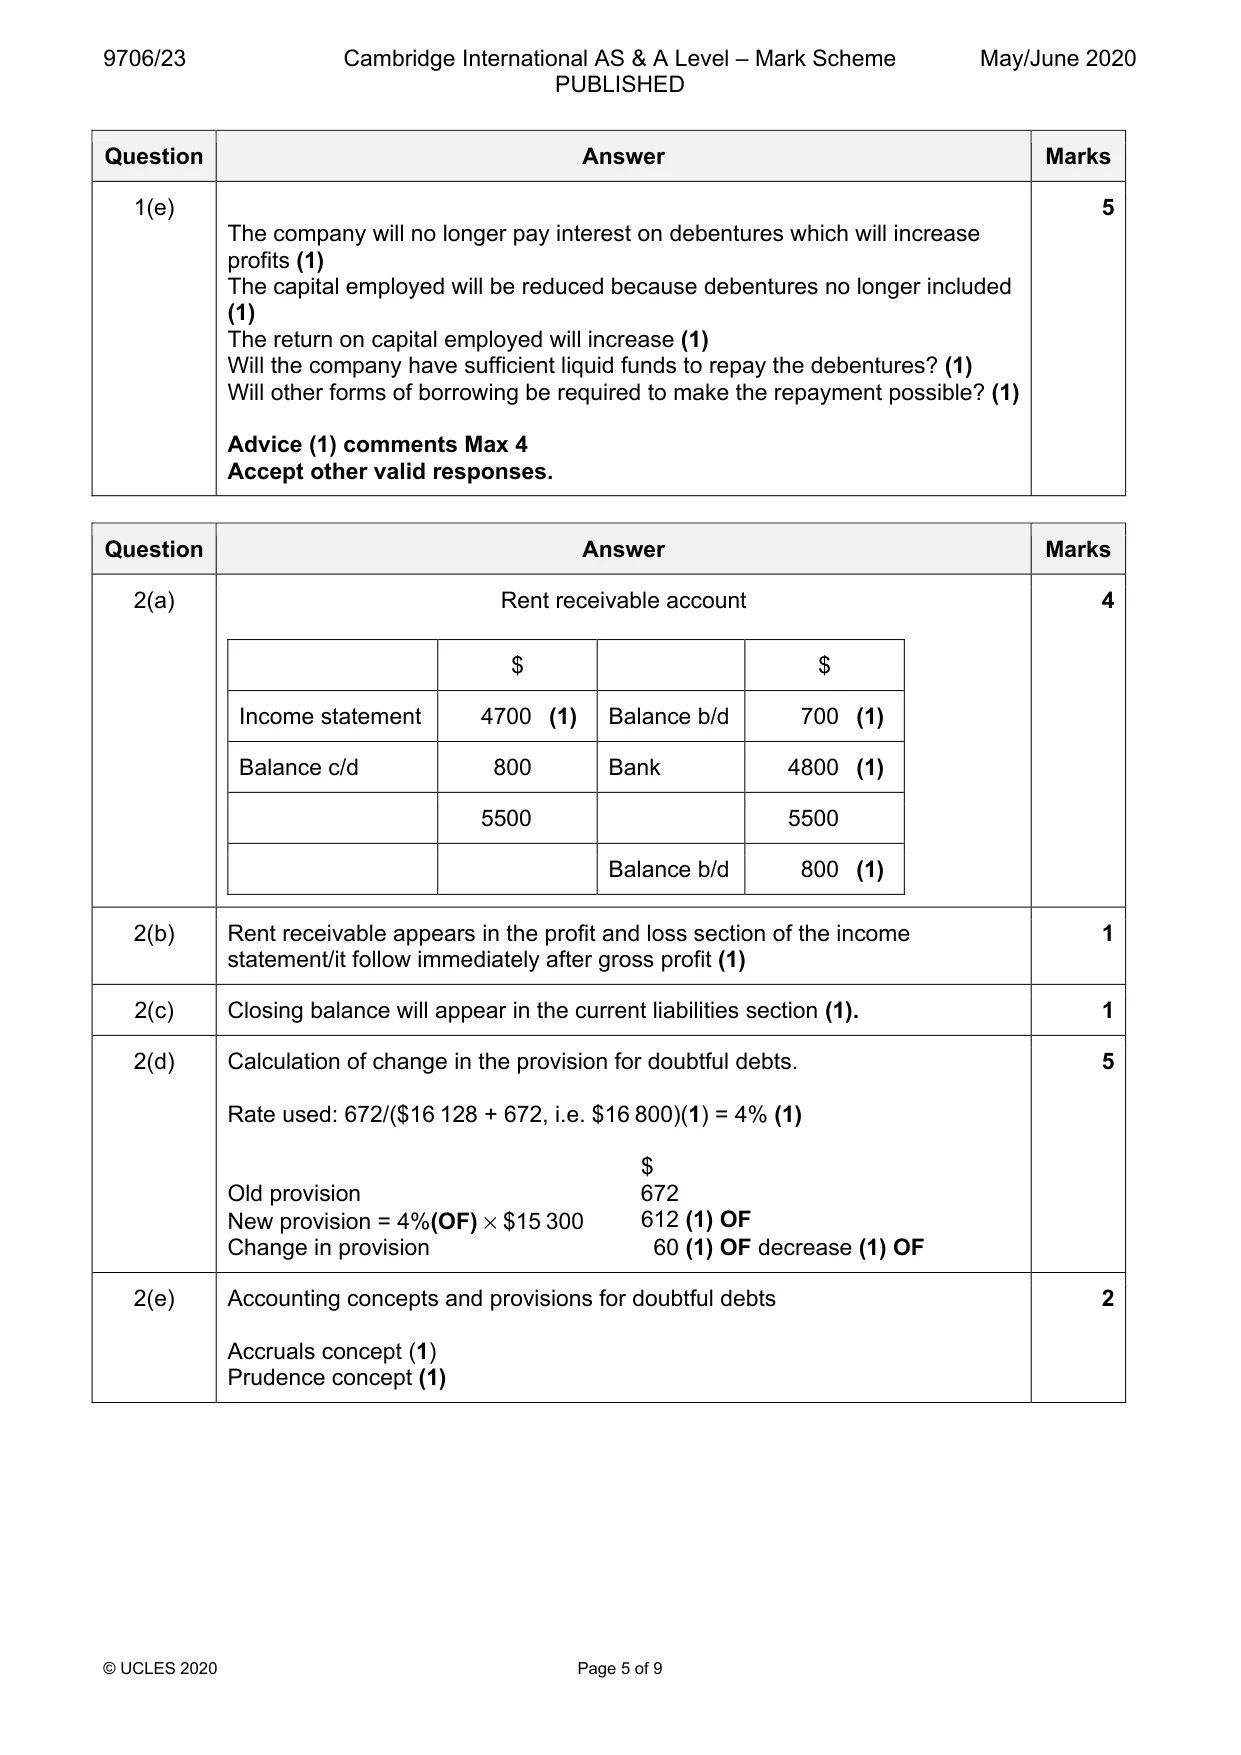
Mark scheme: Question Answer Marks 1(a) K Limited 11 Income statement for the year ended 31 October 2019 $ Revenue 542 370 Cost of sales (259 240) Gross profit 283 130 Administrative expenses (W1) (103 166) (3)OF Distribution costs (W2) (130 044) (5)OF Profit from operations 49 920 Finance costs (W3) (1 400) (2) OF Profit for the year 8 520 (1) OF Workings: W1: Administrative expenses $ Payment 8 490 Directors’ fees (4/5 × $41 200) 32 960 (1) Staff wages and salaries (2/5 × $140 790) 56 316 (1) Furniture and equipment depreciation 5 400 (1) 80% × ($45 000 × 15%) Total 103 166 W2: Distribution costs: $ Payment 16 500 Advertising prepayment (5/6 × $7 200) (6 000) (1) Directors’ fees (1/5 × $41 200) 8 240 (1) Staff wages and salaries (3/5 × $140 790) 84 474 (1) Motor vehicle depreciation (20% × $117 400) 25 480 (1) Furniture and equipment depreciation 1 350 (1) 20% × ($45 000 × 15%) Total 130 044 W3: Finance costs $ Payment 800 Interest for 3 months ($20 000 × ¼ × 8%) 400 (1) Interest for final 3 months ($10 000 × ¼ × 8%) 200 (1) Total 1 400 1(b) Statement of changes in equity for the year ended 31 October 2019 7 Details Share Share Retained Total capital premium Earnings $ $ $ $ Balances, 1 November 2018 90 000 36 000 65 600 191 600 (1) for row Dividends paid (18 000) (1) (18 000) Bonus issue (W1) 60 000 (1) (36 000) (1) (24 000) (1) Profit for year 48 520 48 520 (1)OF Balances 31 October 2019 150 000 72 120 222 120 (1)OF for row W1 Bonus issue Number of shares: 90 000 × 2 = 180 000 Bonus issue = 2/3 × 180 000 = 120 000 shares Value of bonus issue = 120 000 × $0.50 = $60 000 1(c) • Limited liability for the debts of the business (1) 3 • Shareholders enjoy a separate legal identity from the company (1) • Shareholders can easily transfer ownership. (1) Max 3 Accept other valid responses 1(d) General: the ratios show the company’s performance has deteriorated over 4 the three-year period (1) Non-current assets to turnover ratio: has remained better than the industry average (1) indicating a more efficient use of non-current assets than other similar businesses/a larger turnover than other similar businesses (1). Return on capital employed: has been worse than the industry average for the last year (1), indicating a less efficient use of capital employed than other similar businesses/a poorer profit than other similar businesses (1). Max 4 Accept other valid responses. 1(e) 5 The company will no longer pay interest on debentures which will increase profits (1) The capital employed will be reduced because debentures no longer included (1) The return on capital employed will increase (1) Will the company have sufficient liquid funds to repay the debentures? (1) Will other forms of borrowing be required to make the repayment possible? (1) Advice (1) comments Max 4 Accept other valid responses.
Q2 · Daniel, a retailer, receives rent from a tenant
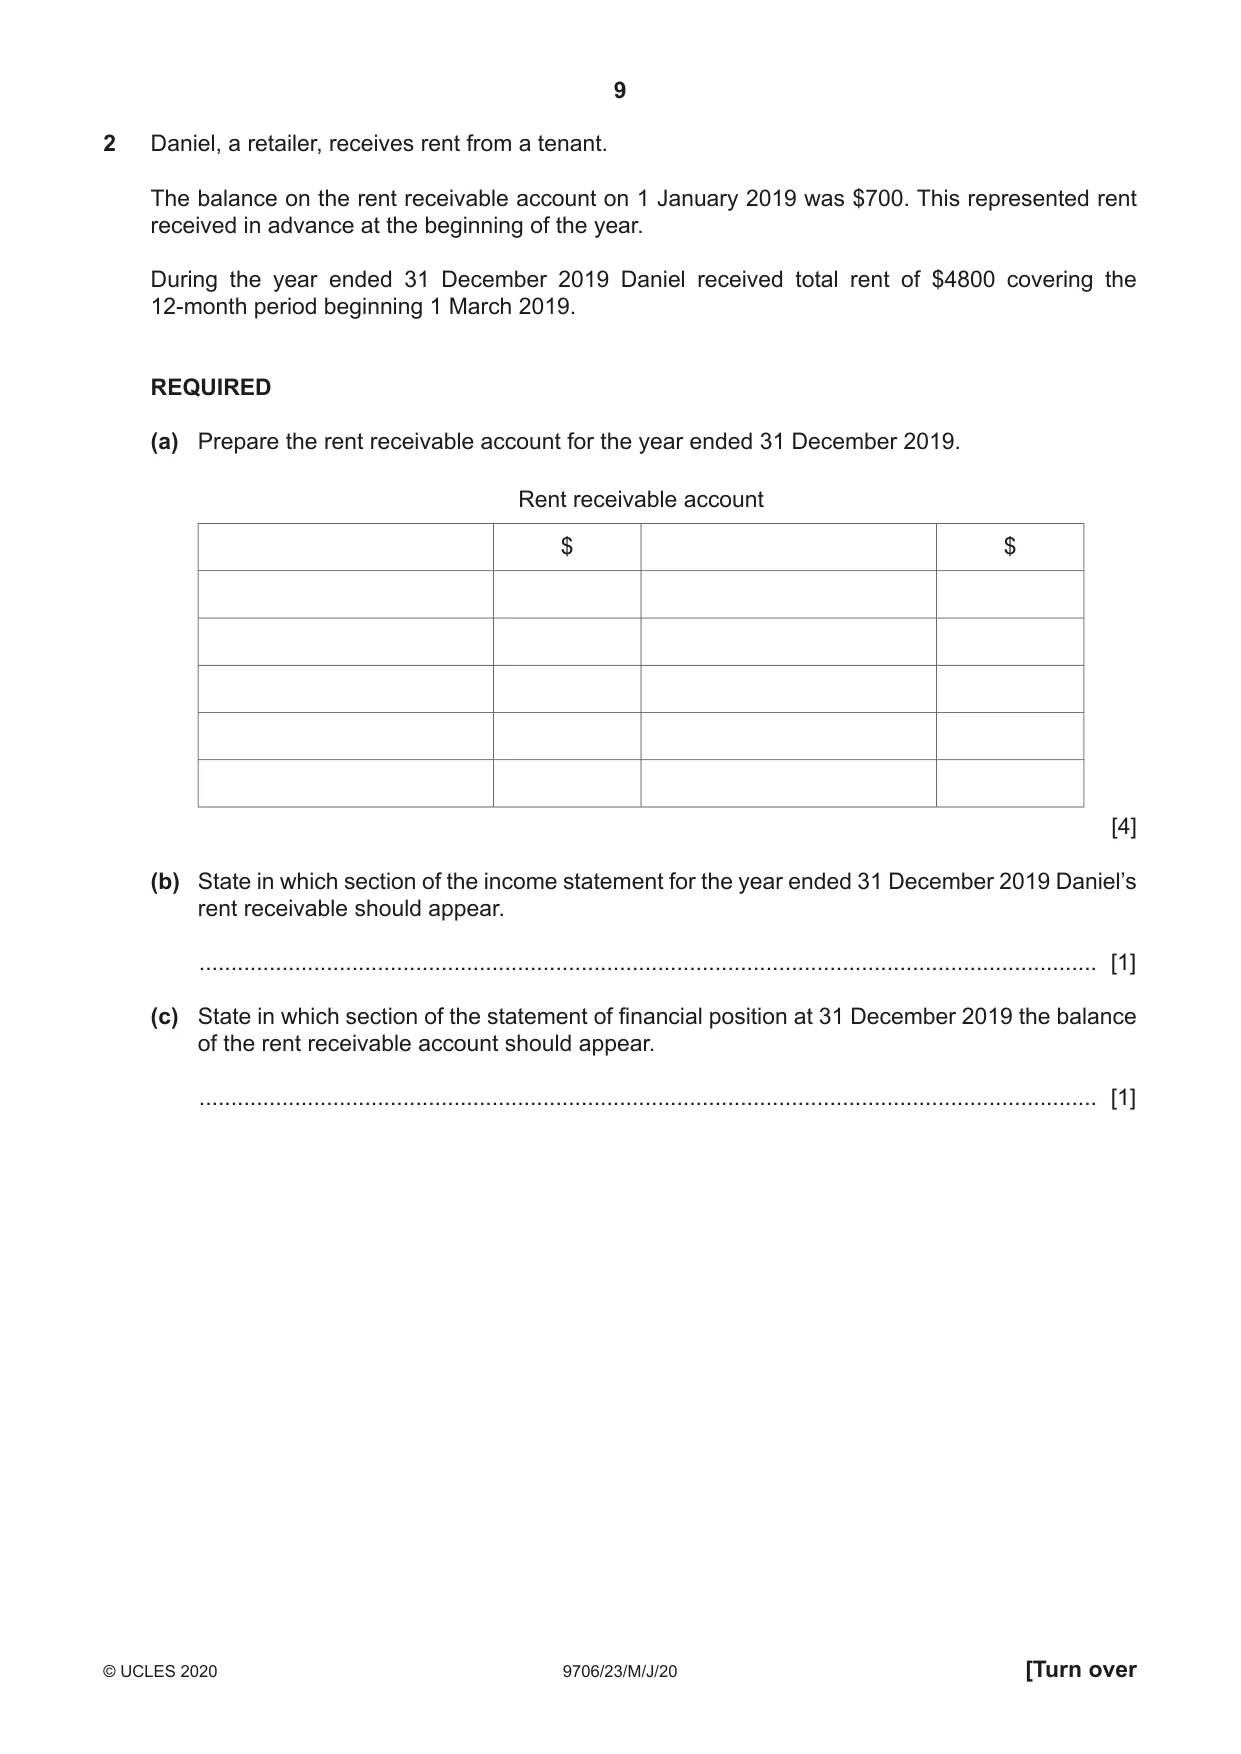
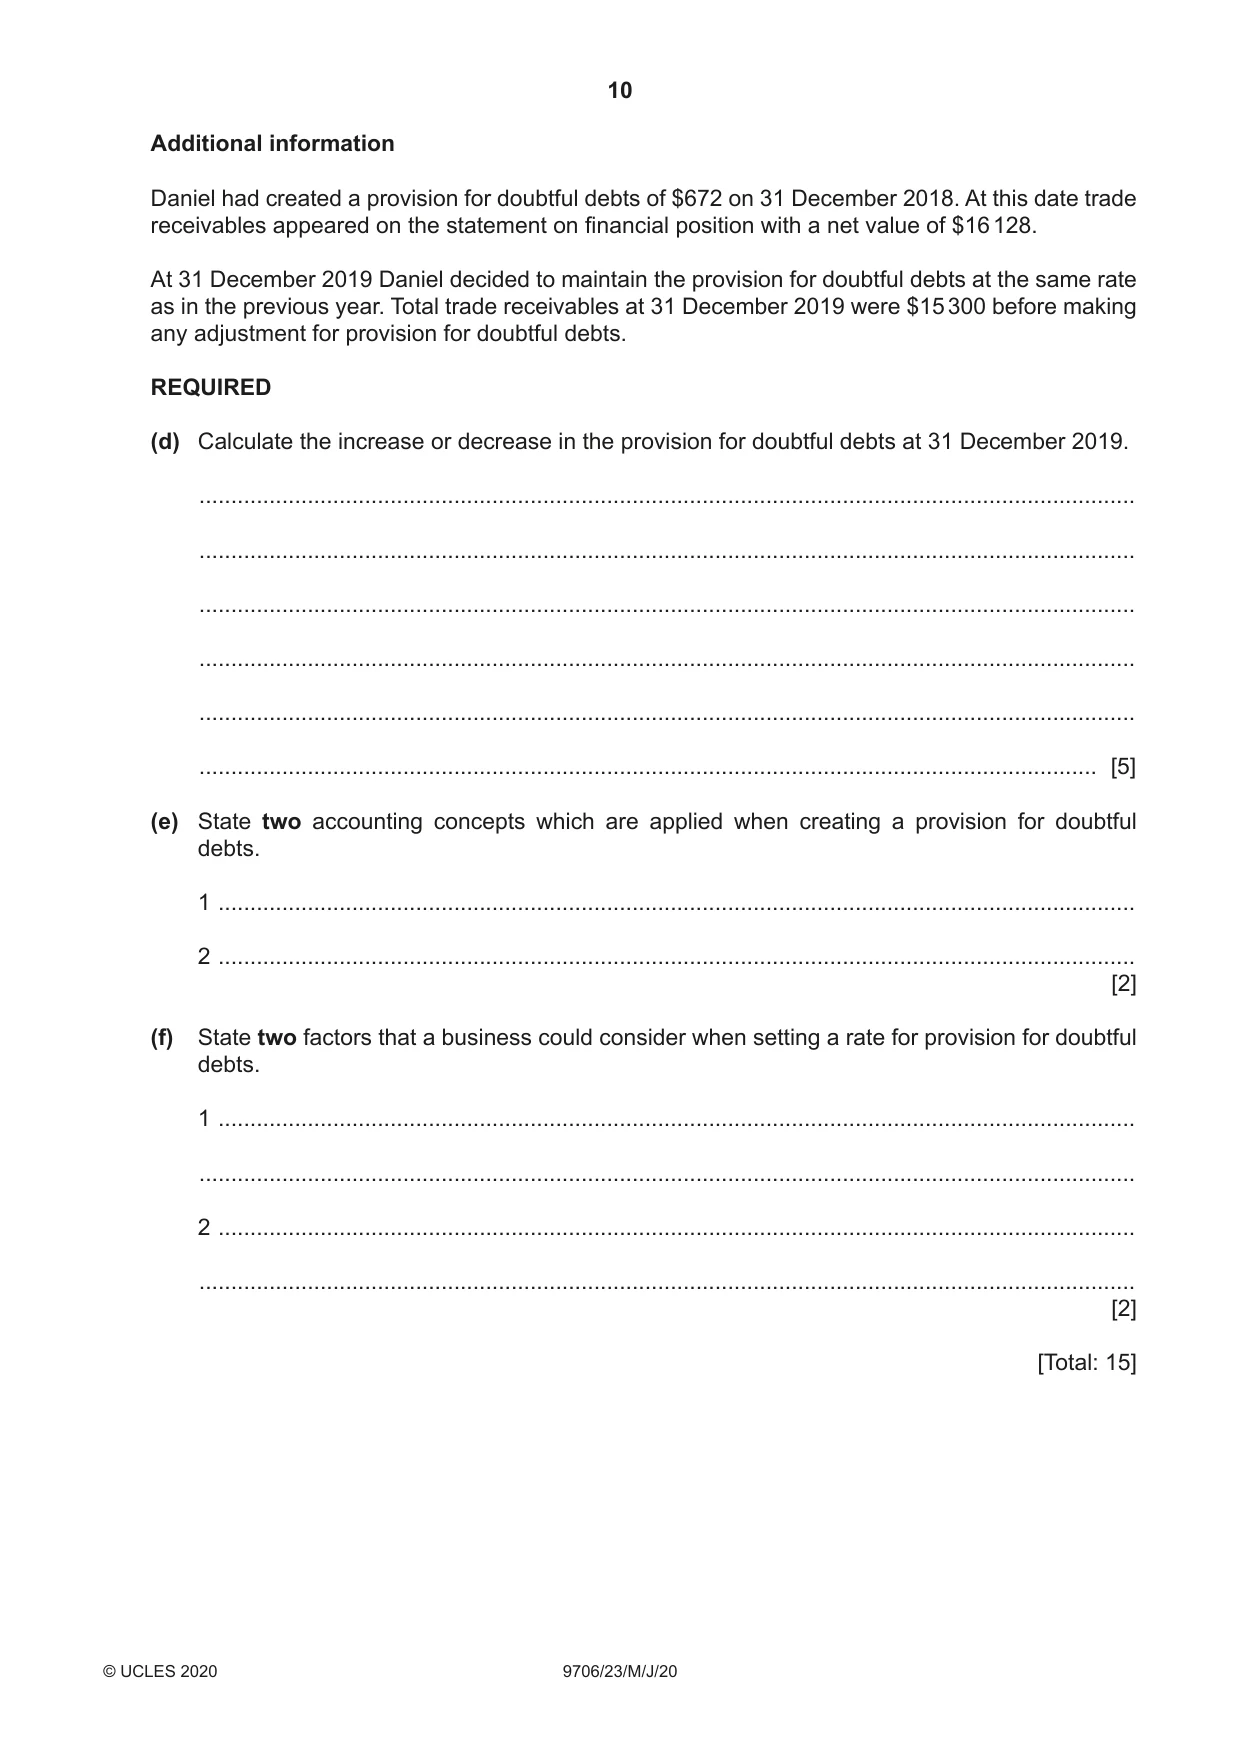
2 Daniel, a retailer, receives rent from a tenant. The balance on the rent receivable account on 1 January 2019 was $700. This represented rent received in advance at the beginning of the year. During the year ended 31 December 2019 Daniel received total rent of $4800 covering the 12-month period beginning 1 March 2019. REQUIRED (a) Prepare the rent receivable account for the year ended 31 December 2019. Rent receivable account $ $ [4] (b) State in which section of the income statement for the year ended 31 December 2019 Daniel’s rent receivable should appear. ............................................................................................................................................. [1] (c) State in which section of the statement of financial position at 31 December 2019 the balance of the rent receivable account should appear. ............................................................................................................................................. [1] Additional information Daniel had created a provision for doubtful debts of $672 on 31 December 2018. At this date trade receivables appeared on the statement on financial position with a net value of $16 128. At 31 December 2019 Daniel decided to maintain the provision for doubtful debts at the same rate as in the previous year. Total trade receivables at 31 December 2019 were $15 300 before making any adjustment for provision for doubtful debts. REQUIRED (d) Calculate the increase or decrease in the provision for doubtful debts at 31 December 2019. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] (e) State two accounting concepts which are applied when creating a provision for doubtful debts. 1 ................................................................................................................................................ 2 ................................................................................................................................................ [2] (f) State two factors that a business could consider when setting a rate for provision for doubtful debts. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] [Total: 15]
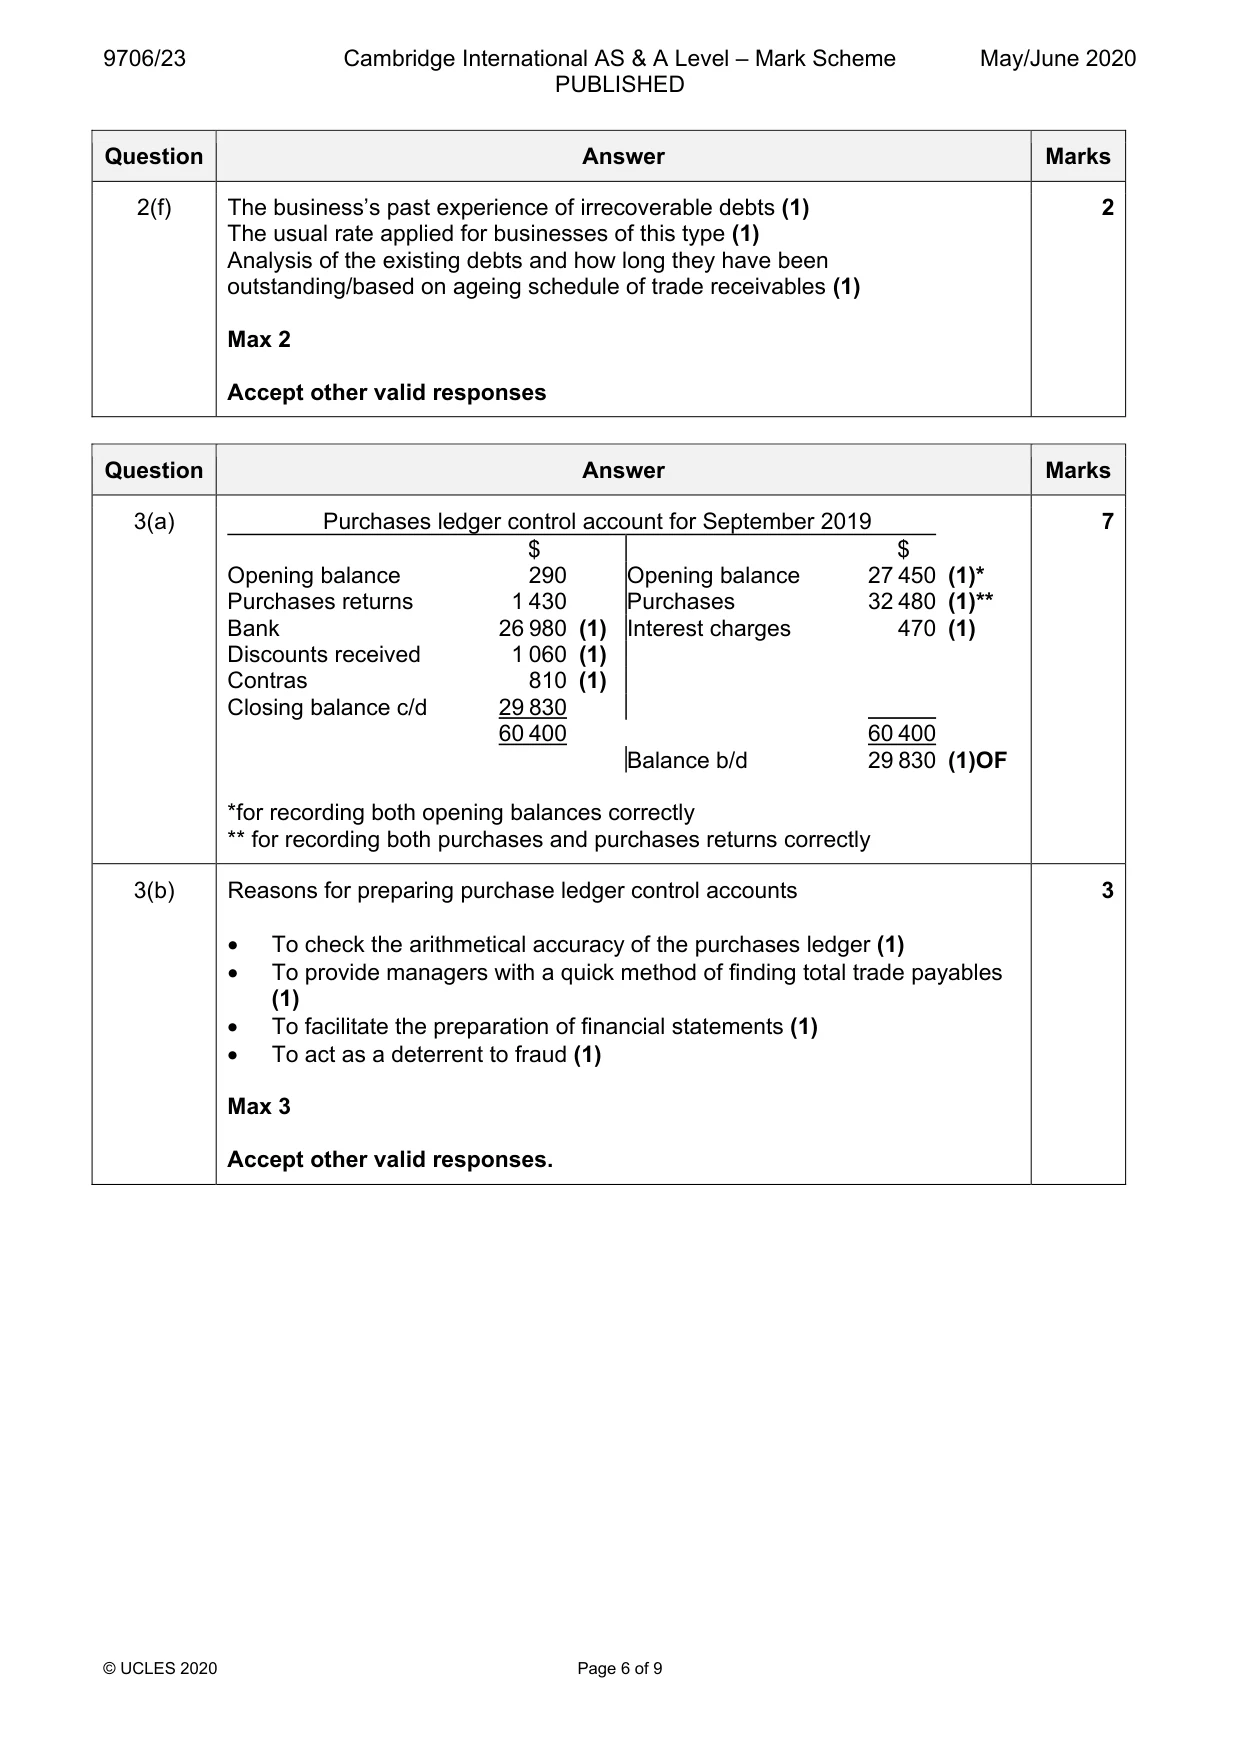
Mark scheme: 2(a) Rent receivable account 4 $ $ Income statement 4700 (1) Balance b/d 700 (1) Balance c/d 800 Bank 4800 (1) 5500 5500 Balance b/d 800 (1) 2(b) Rent receivable appears in the profit and loss section of the income 1 statement/it follow immediately after gross profit (1) 2(c) Closing balance will appear in the current liabilities section (1). 1 2(d) Calculation of change in the provision for doubtful debts. 5 Rate used: 672/($16 128 + 672, i.e. $16 800)(1) = 4% (1) $ Old provision 672 New provision = 4%(OF) × $15 300 612 (1) OF Change in provision 60 (1) OF decrease (1) OF 2(e) Accounting concepts and provisions for doubtful debts 2 Accruals concept (1) Prudence concept (1) 2(f) The business’s past experience of irrecoverable debts (1) 2 The usual rate applied for businesses of this type (1) Analysis of the existing debts and how long they have been outstanding/based on ageing schedule of trade receivables (1) Max 2 Accept other valid responses
Q3 · The following balances appear in Reena’s purchases ledger control account at 29 February…
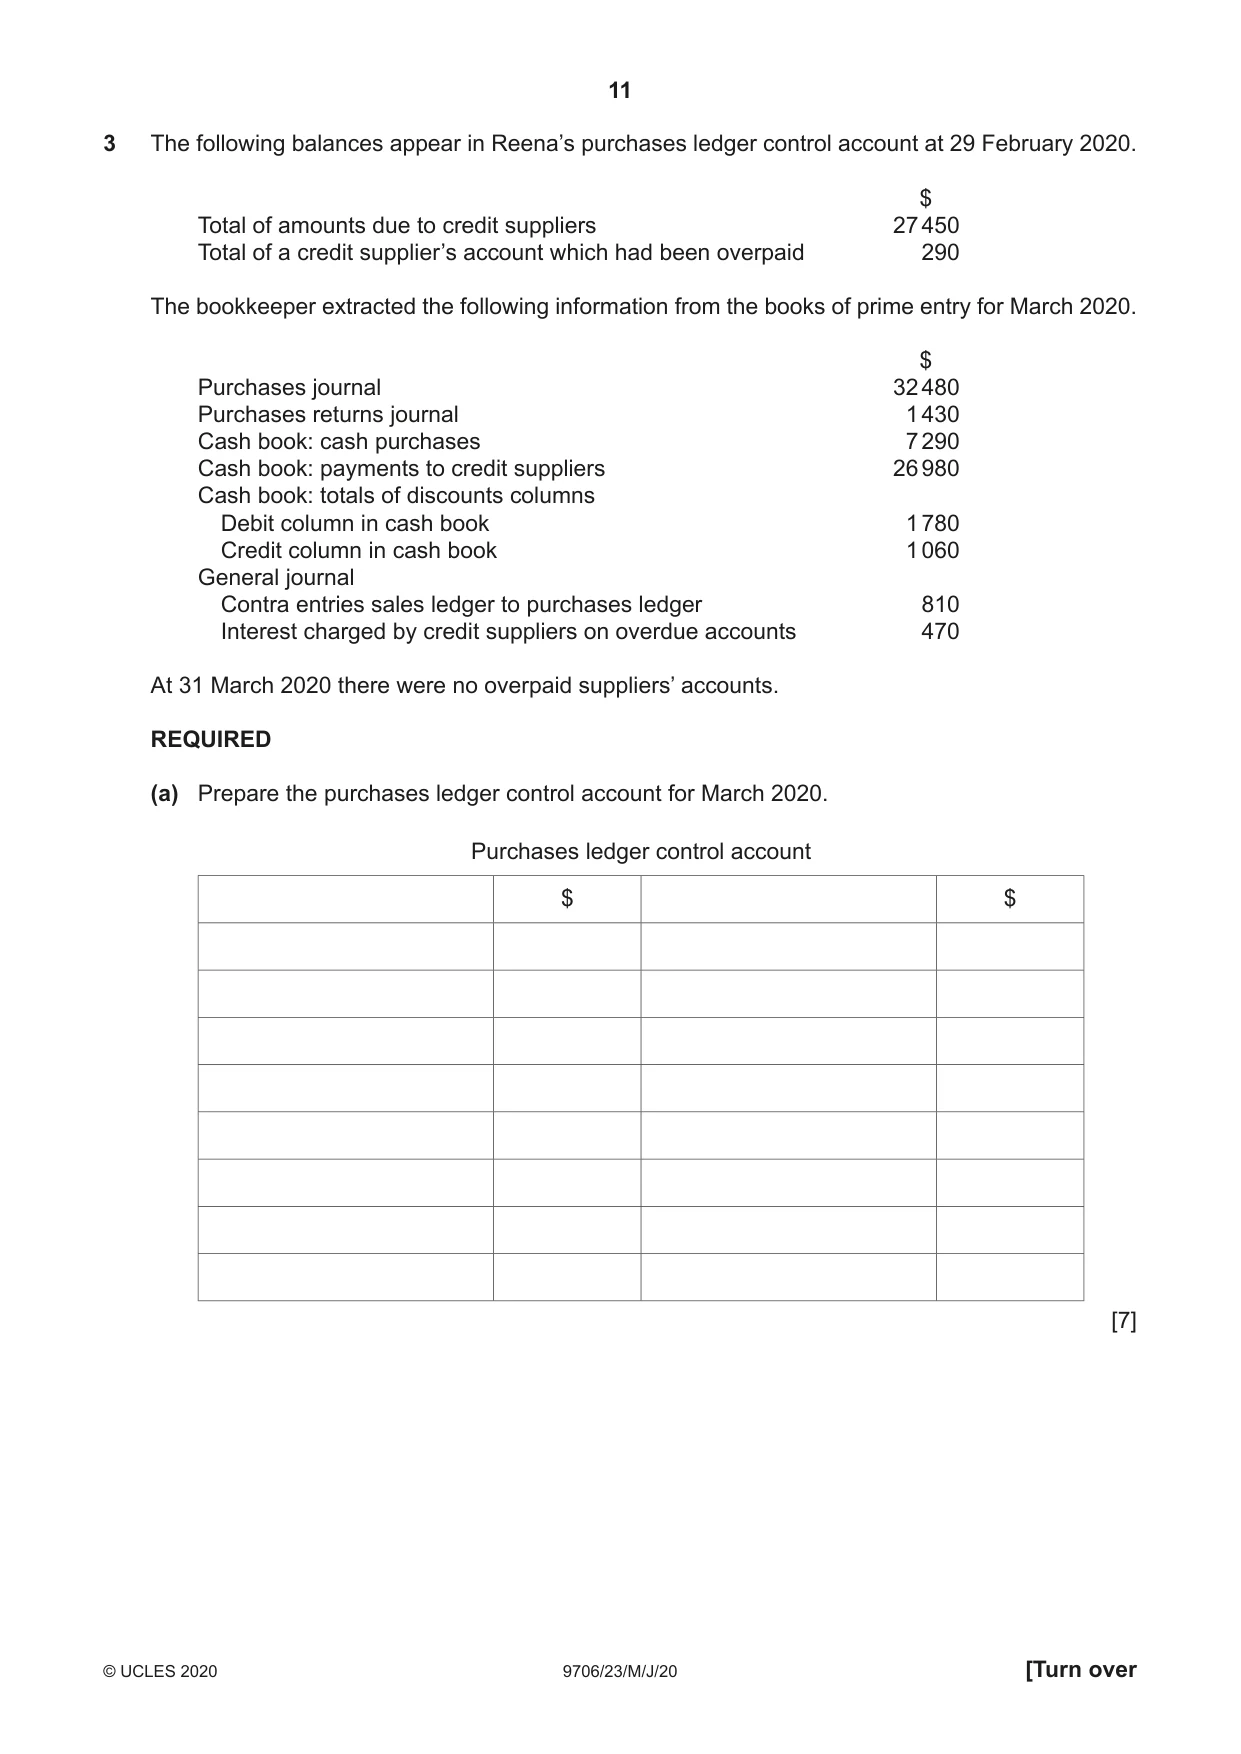
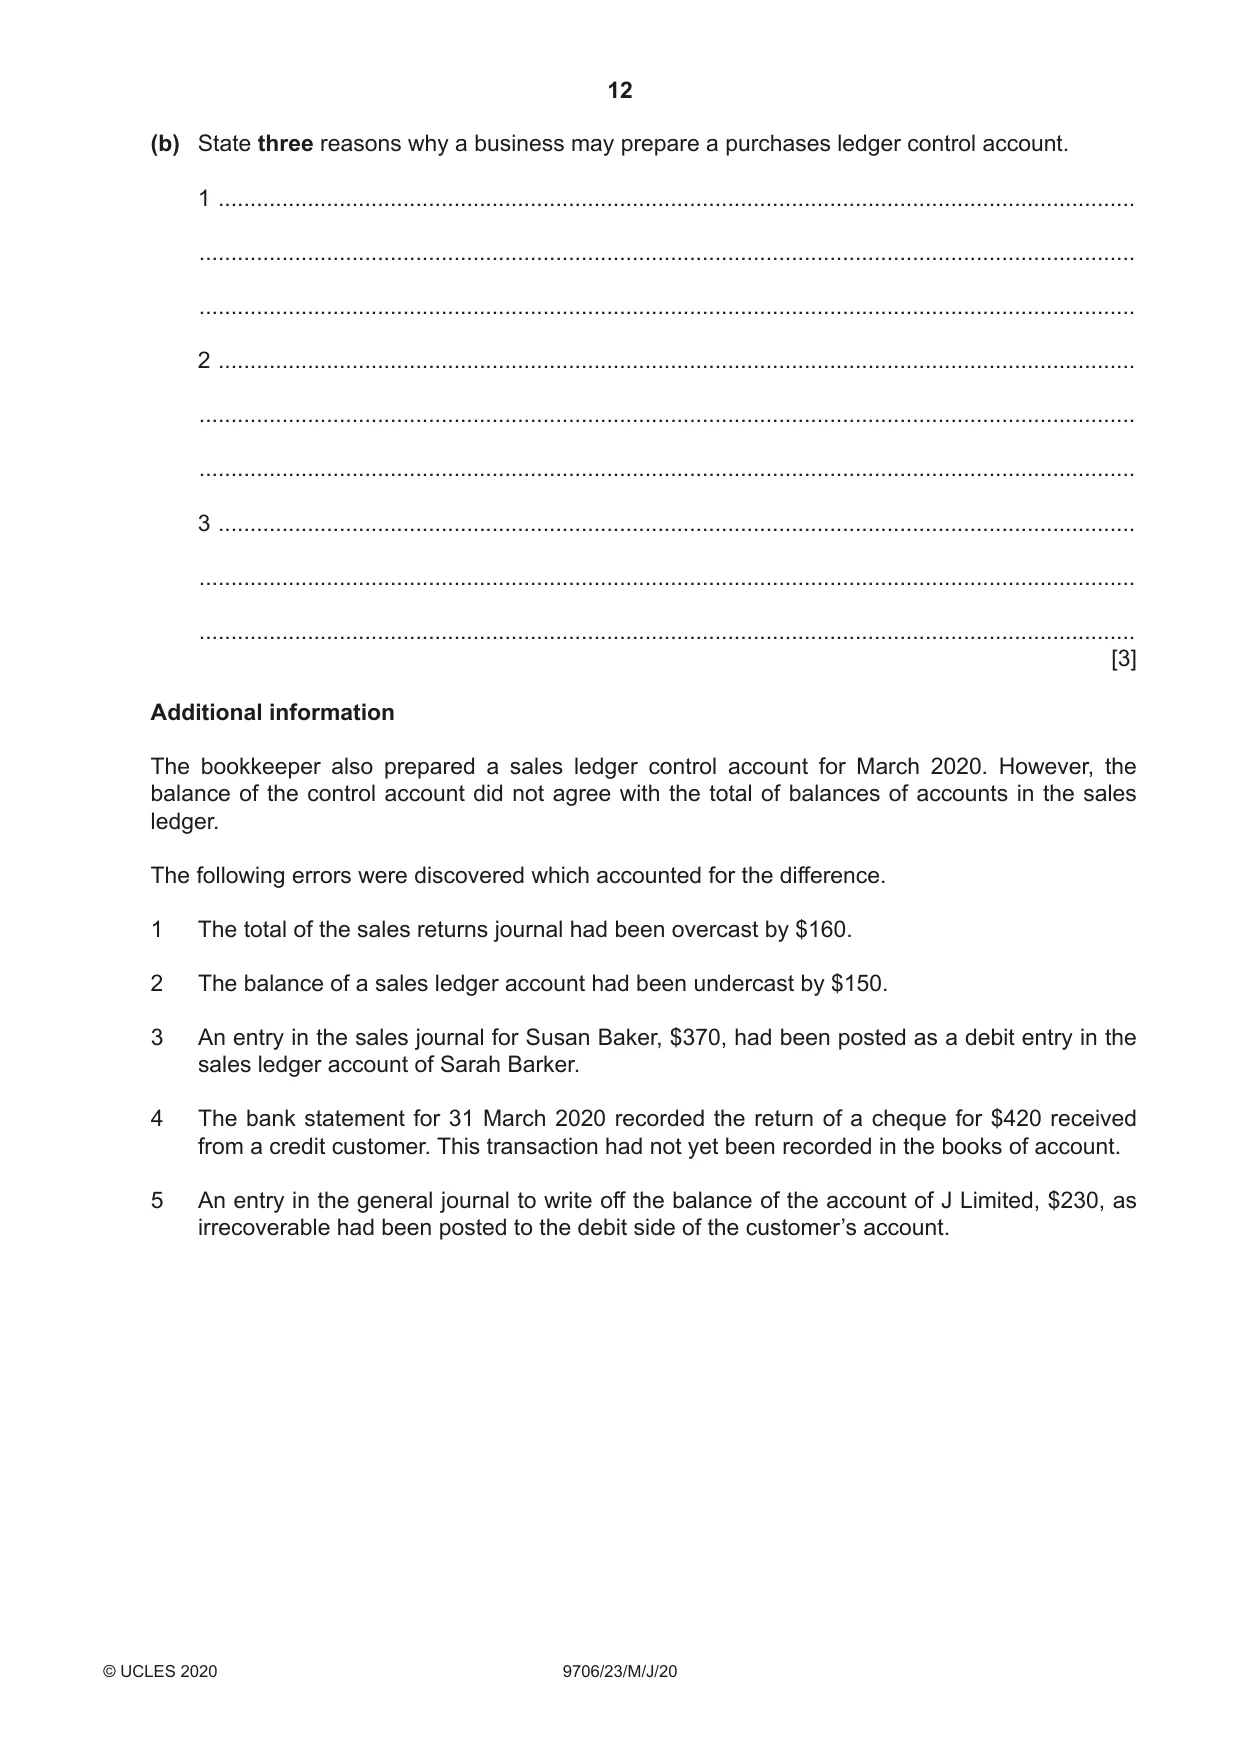
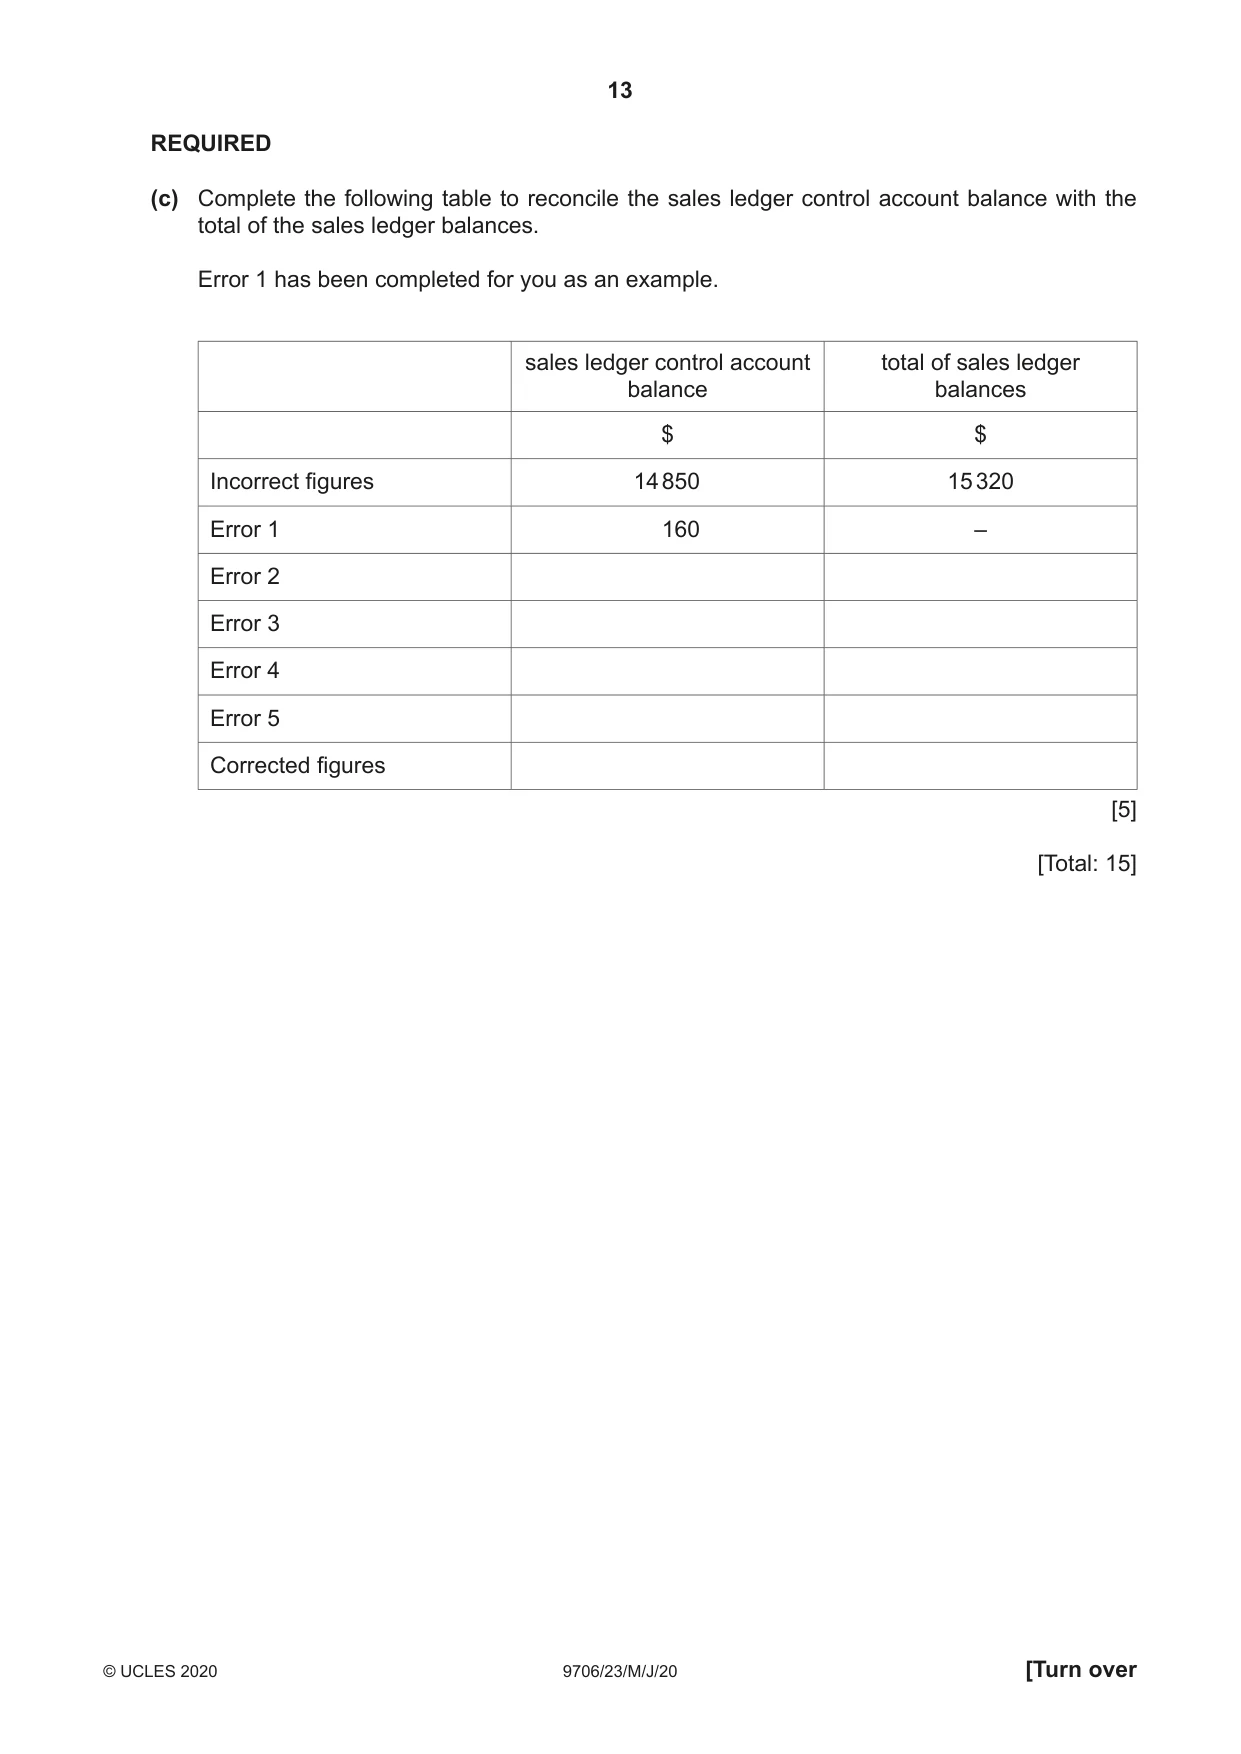
3 The following balances appear in Reena’s purchases ledger control account at 29 February 2020. $ Total of amounts due to credit suppliers 27 450 Total of a credit supplier’s account which had been overpaid 290 The bookkeeper extracted the following information from the books of prime entry for March 2020. $ Purchases journal 32 480 Purchases returns journal 1 430 Cash book: cash purchases 7 290 Cash book: payments to credit suppliers 26 980 Cash book: totals of discounts columns Debit column in cash book 1 780 Credit column in cash book 1 060 General journal Contra entries sales ledger to purchases ledger 810 Interest charged by credit suppliers on overdue accounts 470 At 31 March 2020 there were no overpaid suppliers’ accounts. REQUIRED (a) Prepare the purchases ledger control account for March 2020. Purchases ledger control account $ $ [7] (b) State three reasons why a business may prepare a purchases ledger control account. 1 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... 3 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... [3] Additional information The bookkeeper also prepared a sales ledger control account for March 2020. However, the balance of the control account did not agree with the total of balances of accounts in the sales ledger. The following errors were discovered which accounted for the difference. 1 The total of the sales returns journal had been overcast by $160. 2 The balance of a sales ledger account had been undercast by $150. 3 An entry in the sales journal for Susan Baker, $370, had been posted as a debit entry in the sales ledger account of Sarah Barker.
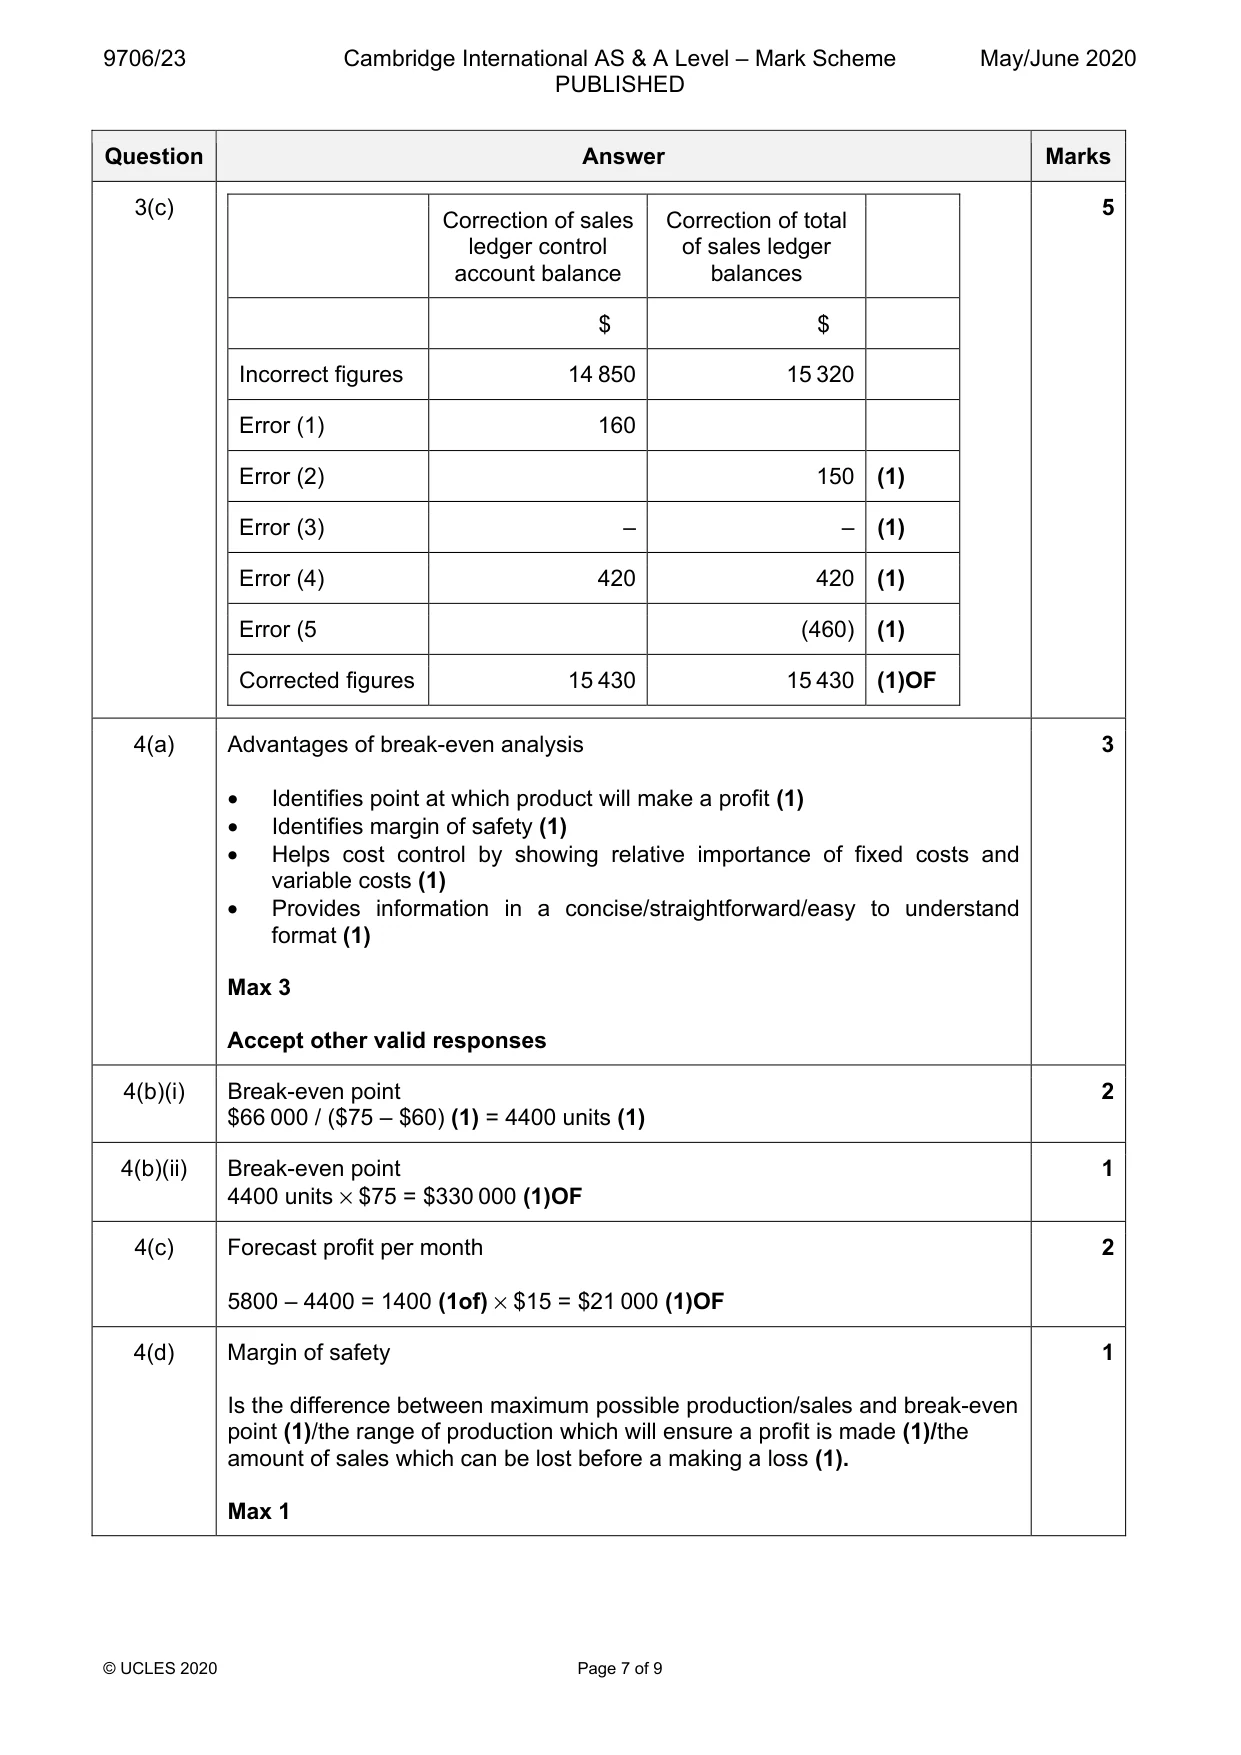
Mark scheme: 3(a) Purchases ledger control account for September 2019 7 $ $ Opening balance 290 Opening balance 27 450 (1)* Purchases returns 1 430 Purchases 32 480 (1)** Bank 26 980 (1) Interest charges 470 (1) Discounts received 1 060 (1) Contras 810 (1) Closing balance c/d 29 830 00 000 60 400 60 400 Balance b/d 29 830 (1)OF *for recording both opening balances correctly ** for recording both purchases and purchases returns correctly 3(b) Reasons for preparing purchase ledger control accounts 3 • To check the arithmetical accuracy of the purchases ledger (1) • To provide managers with a quick method of finding total trade payables (1) • To facilitate the preparation of financial statements (1) • To act as a deterrent to fraud (1) Max 3 Accept other valid responses. 3(c) 5 Correction of sales Correction of total ledger control of sales ledger account balance balances $ $ Incorrect figures 14 850 15 320 Error (1) 160 Error (2) 150 (1) Error (3) – – (1) Error (4) 420 420 (1) Error (5 (460) (1) Corrected figures 15 430 15 430 (1)OF
Q4 · The bank statement for 31 March 2020 recorded the return of a cheque for $420 received…
4 The bank statement for 31 March 2020 recorded the return of a cheque for $420 received from a credit customer. This transaction had not yet been recorded in the books of account.
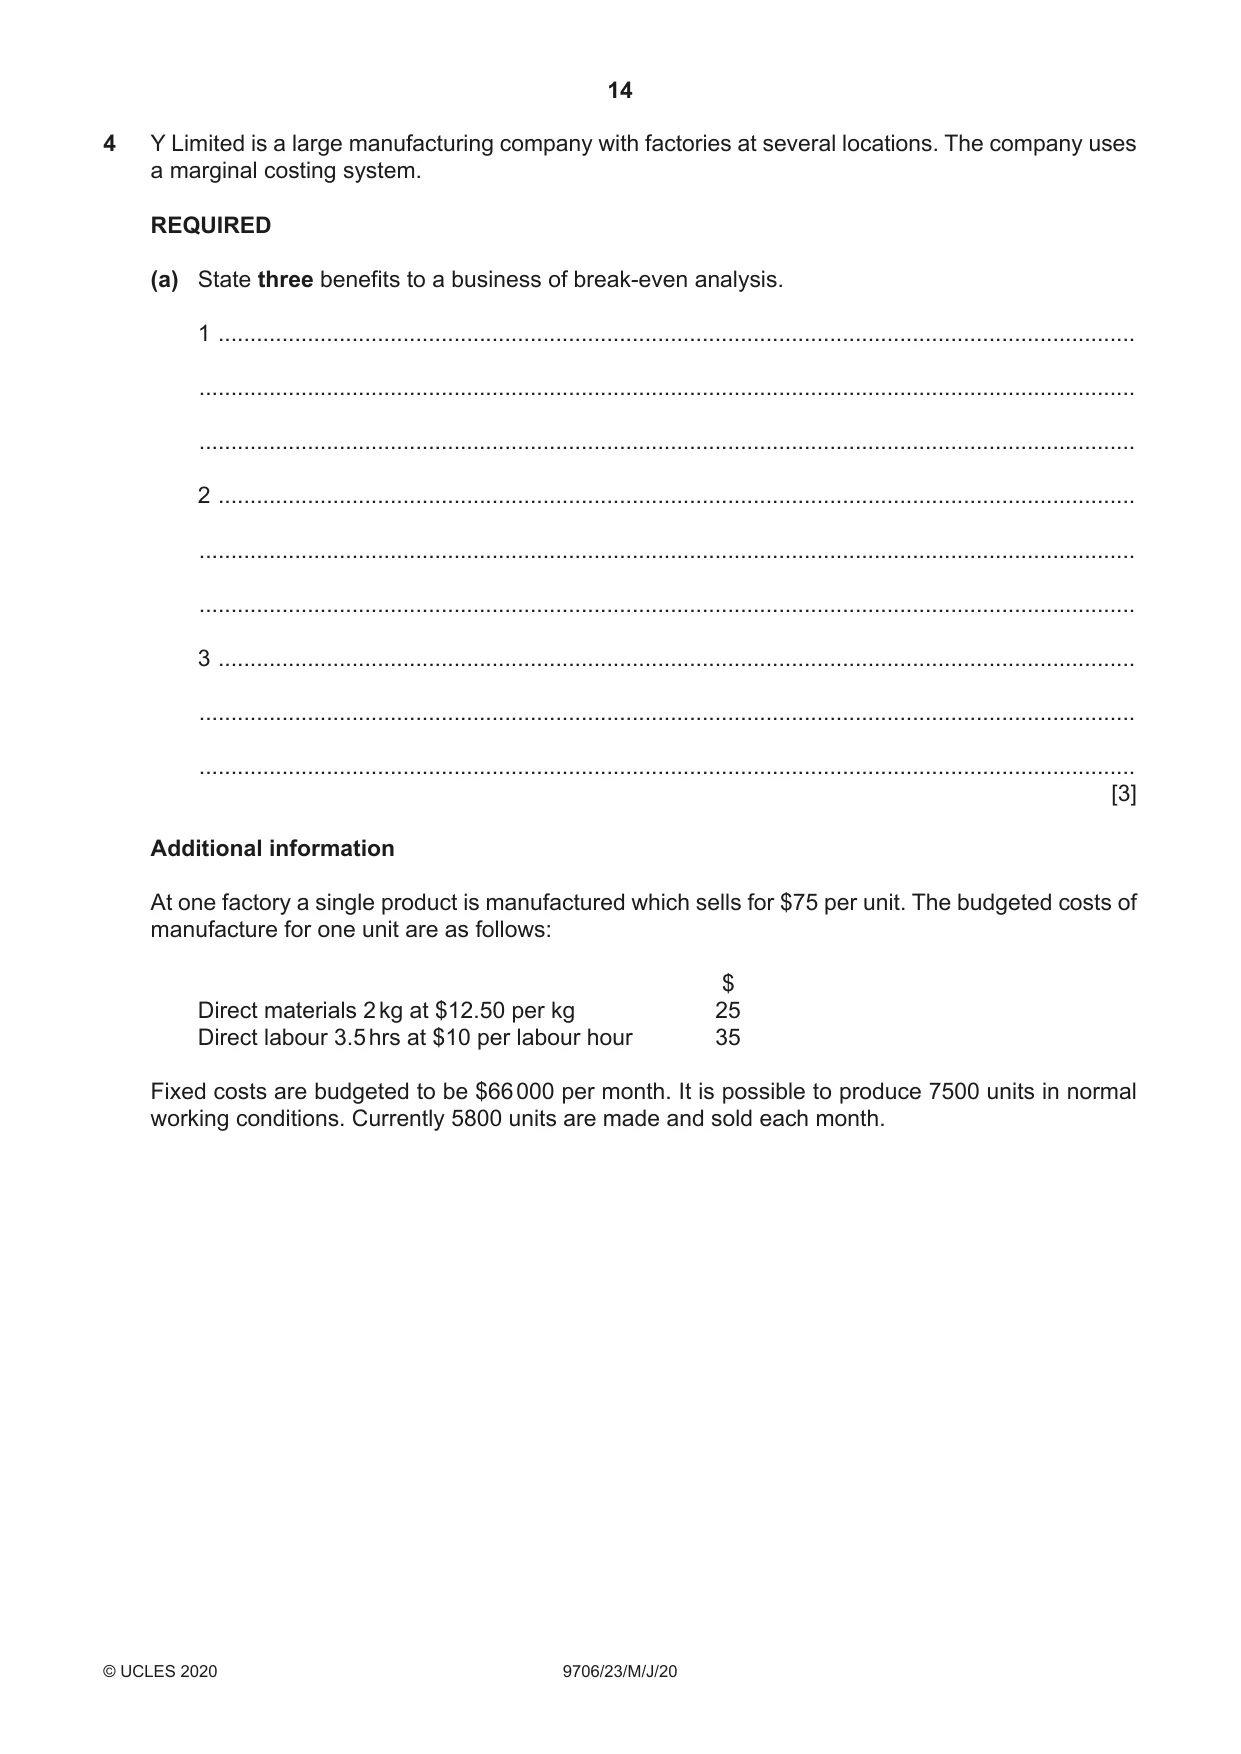
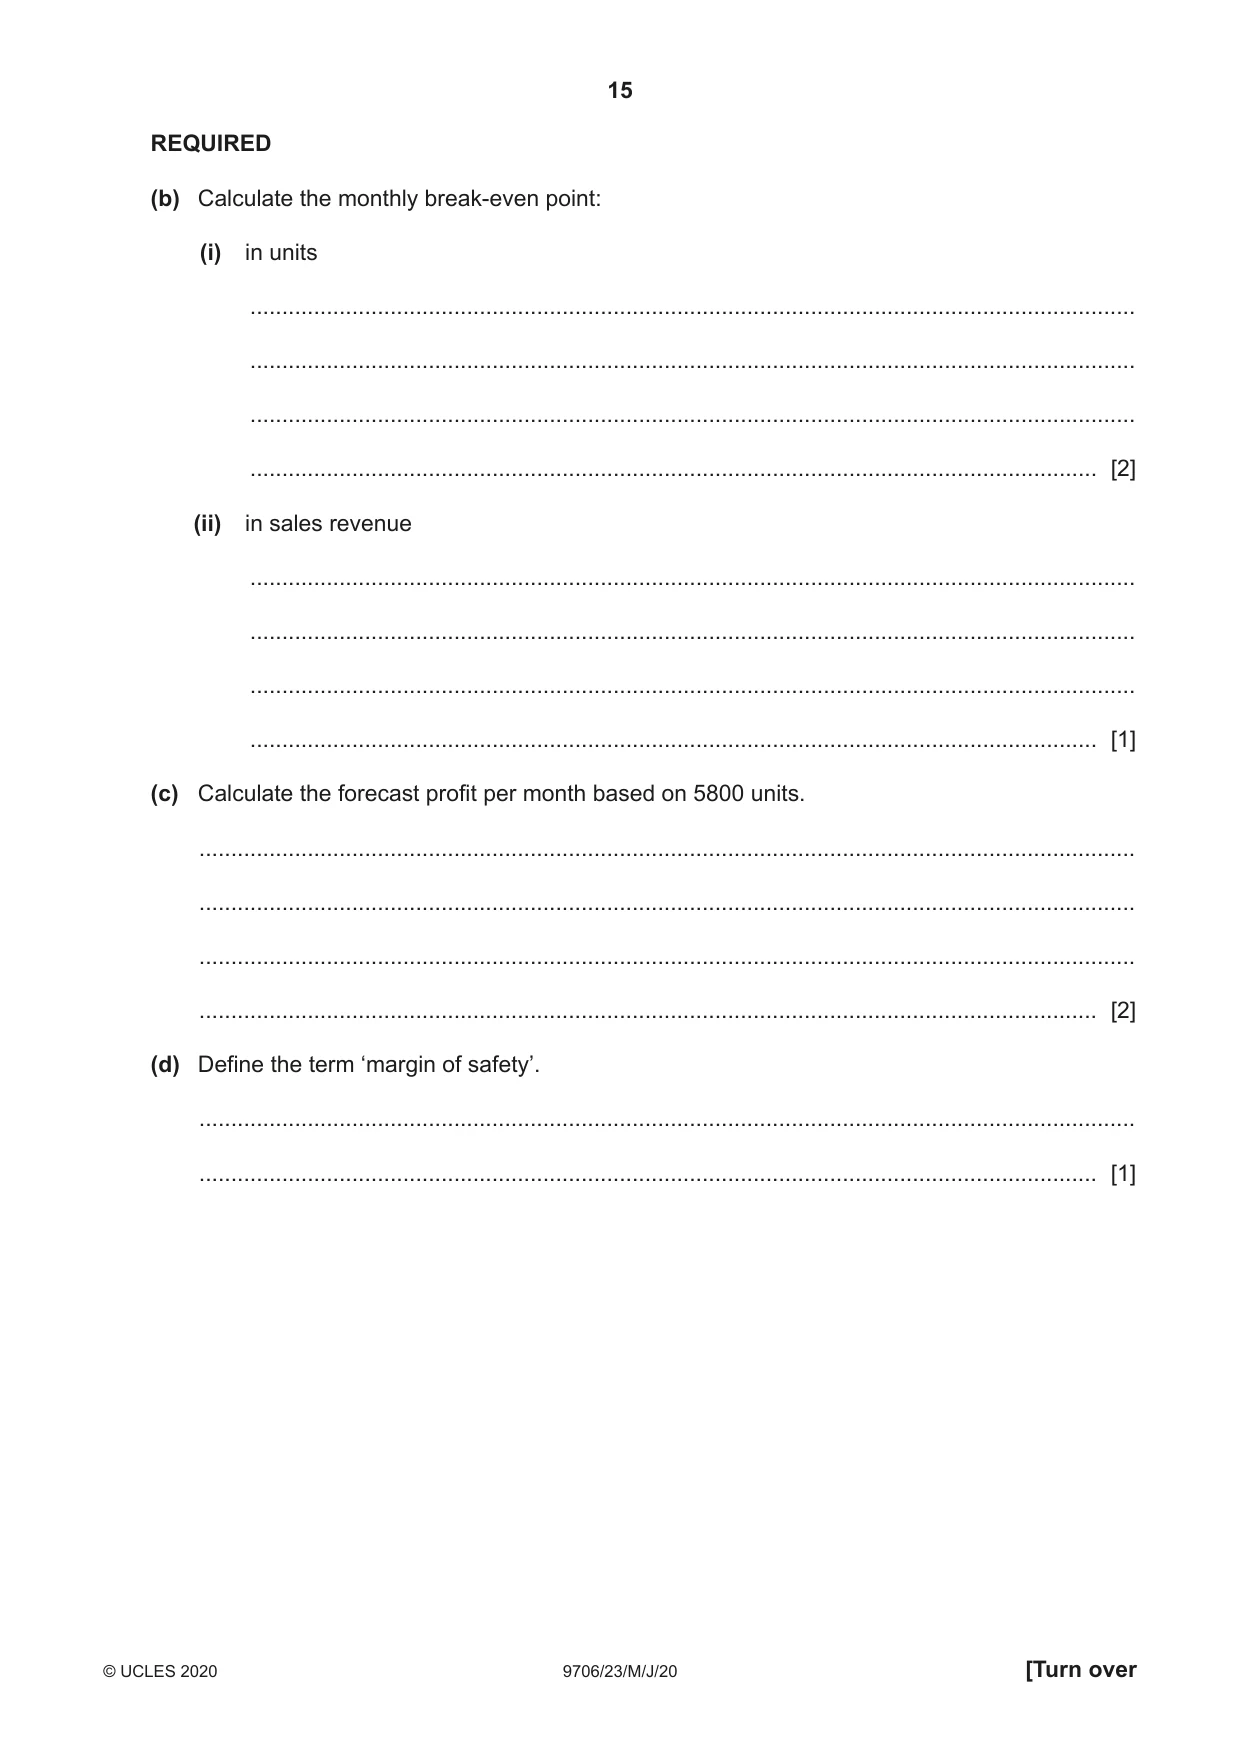
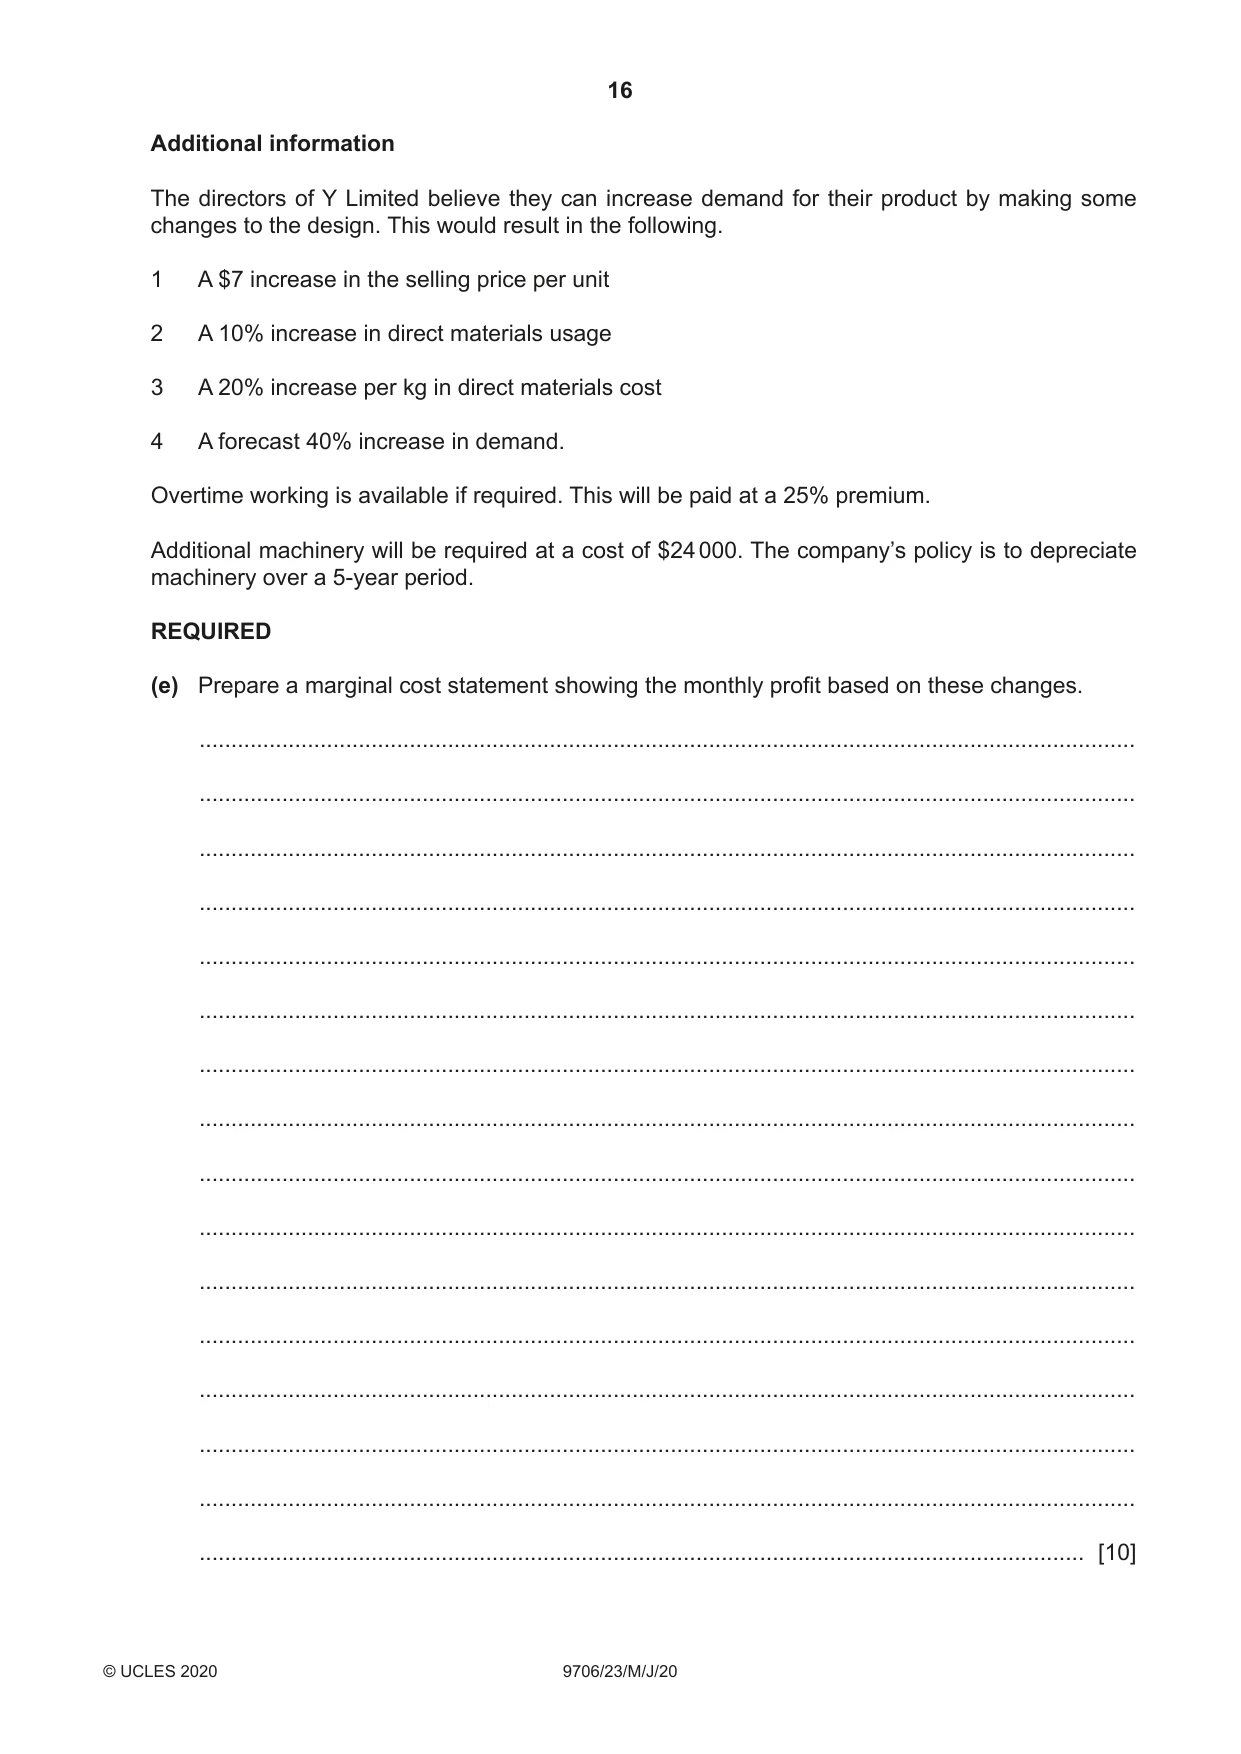
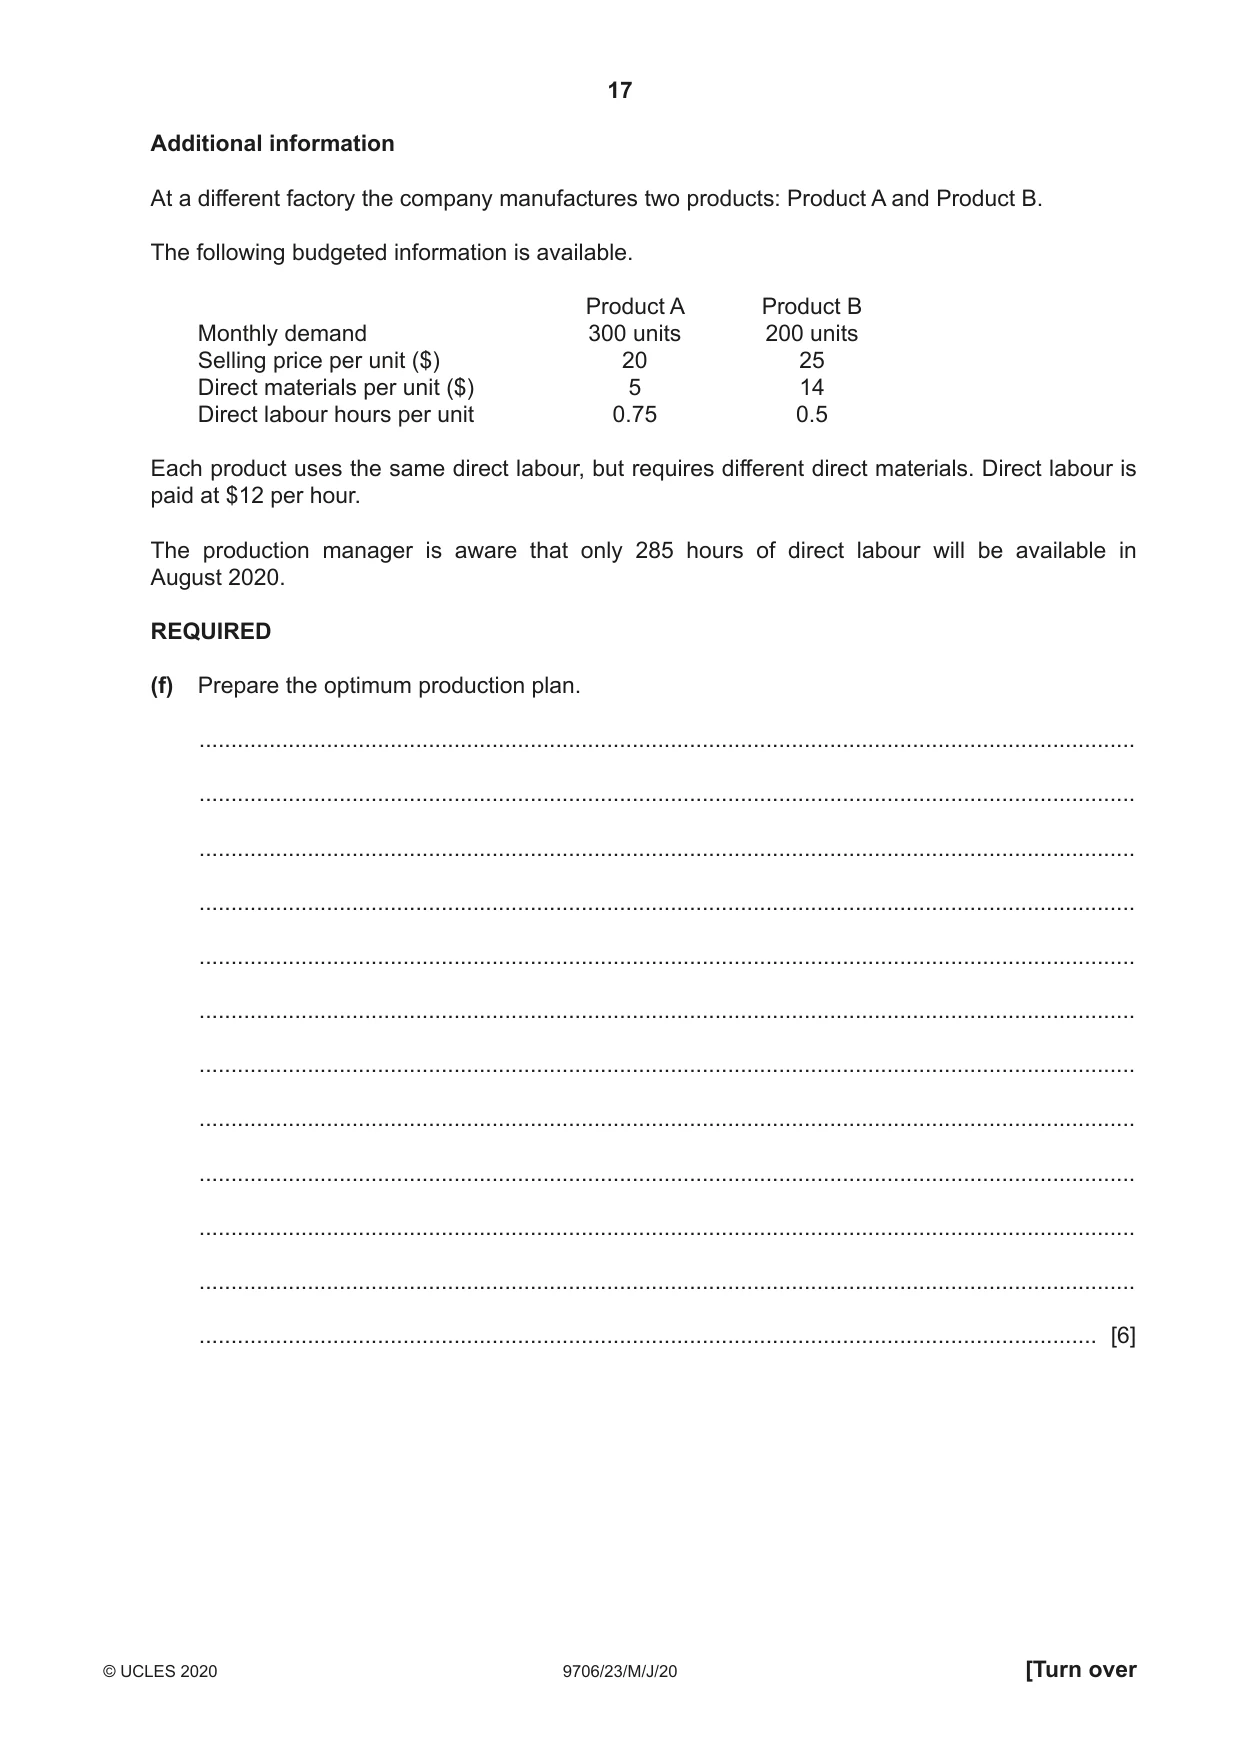
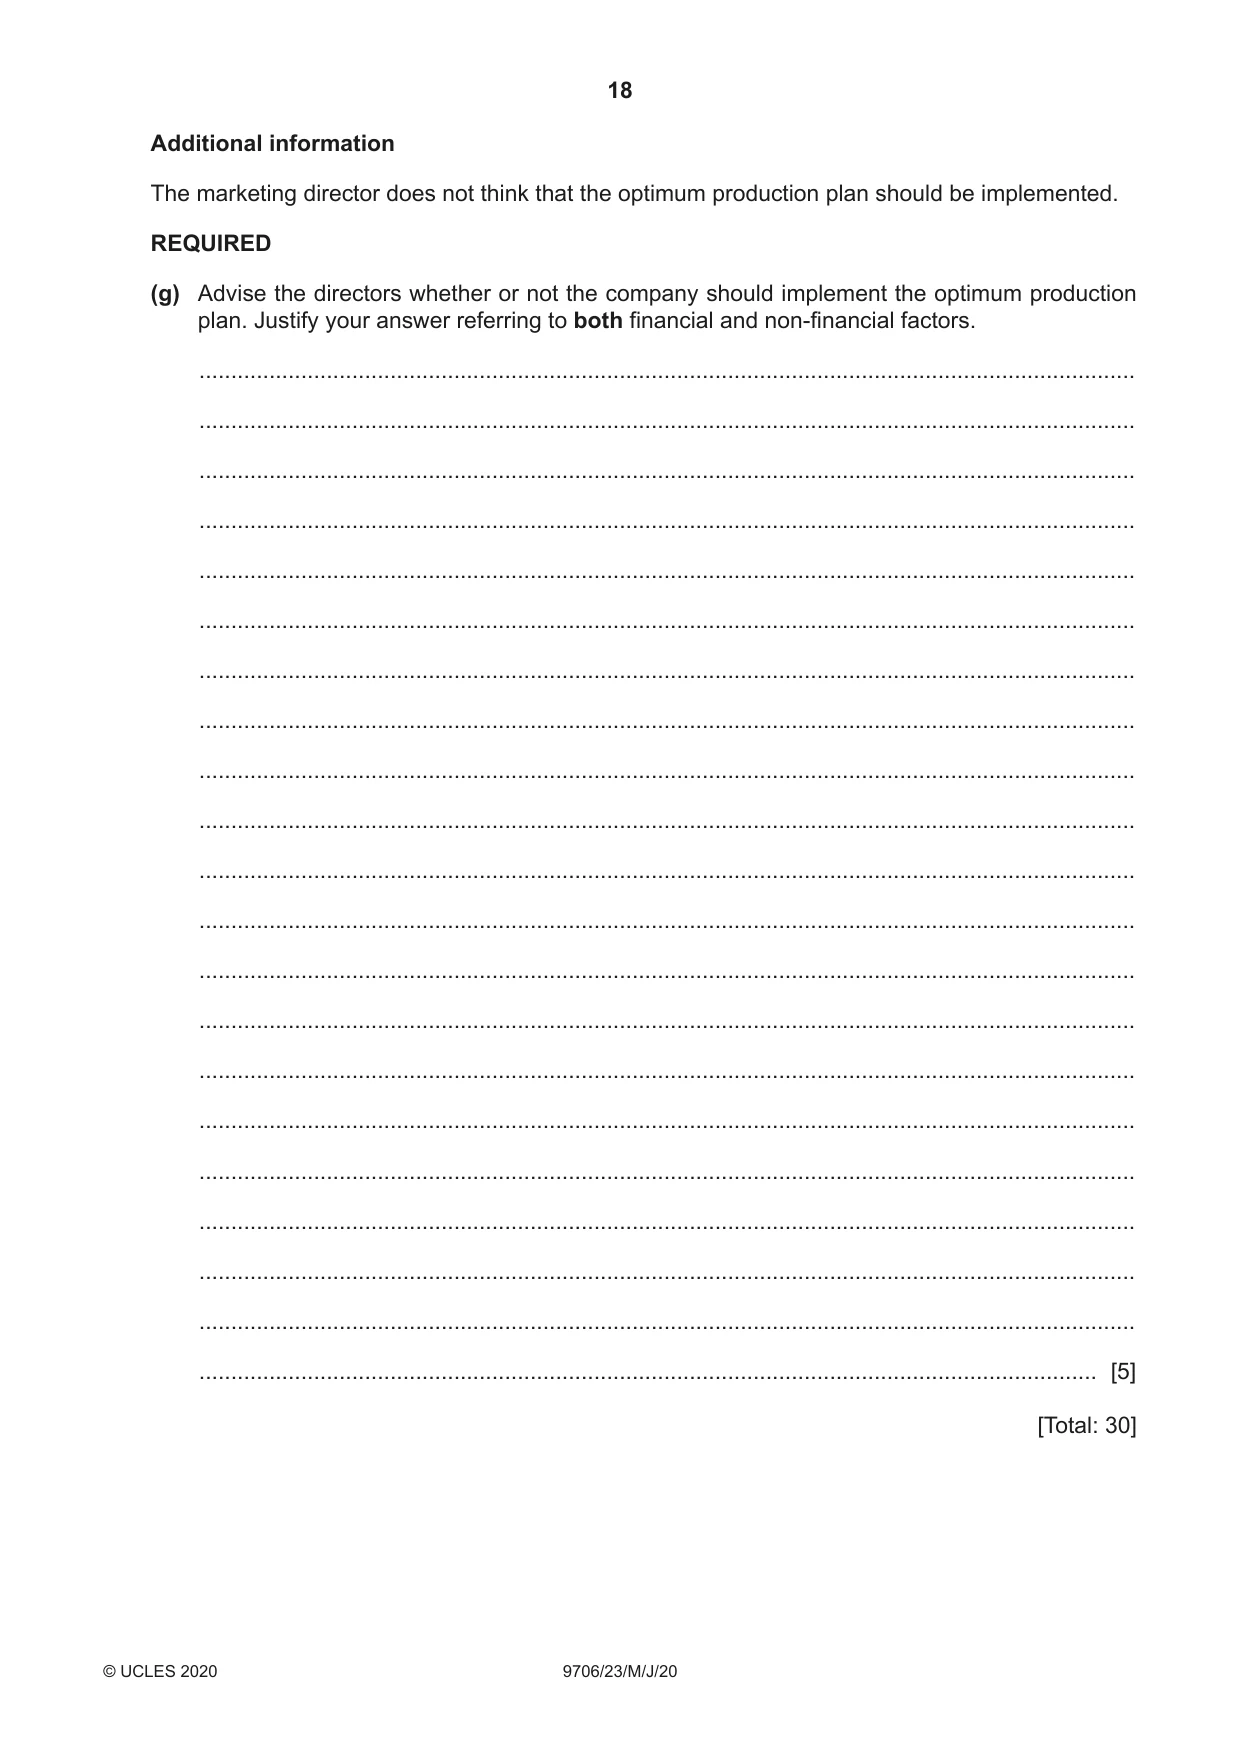
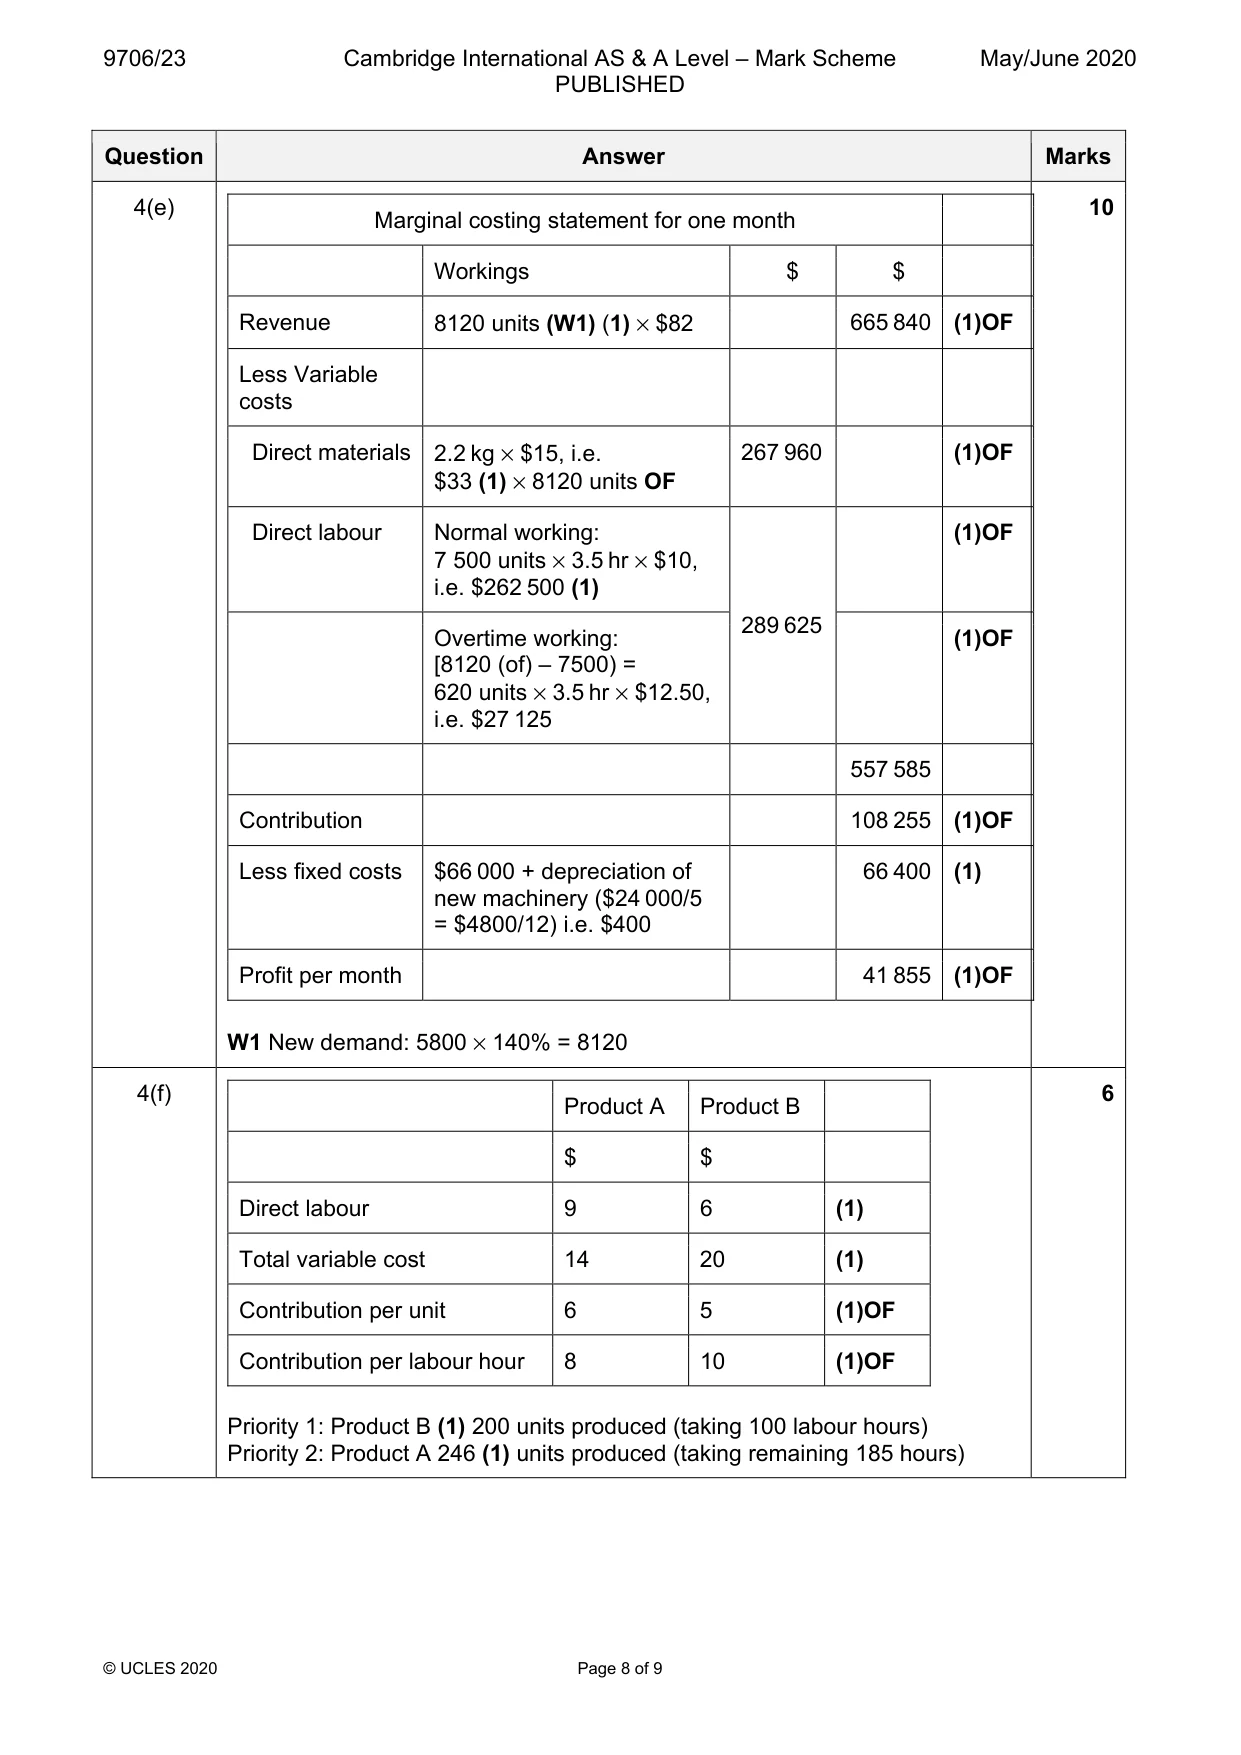
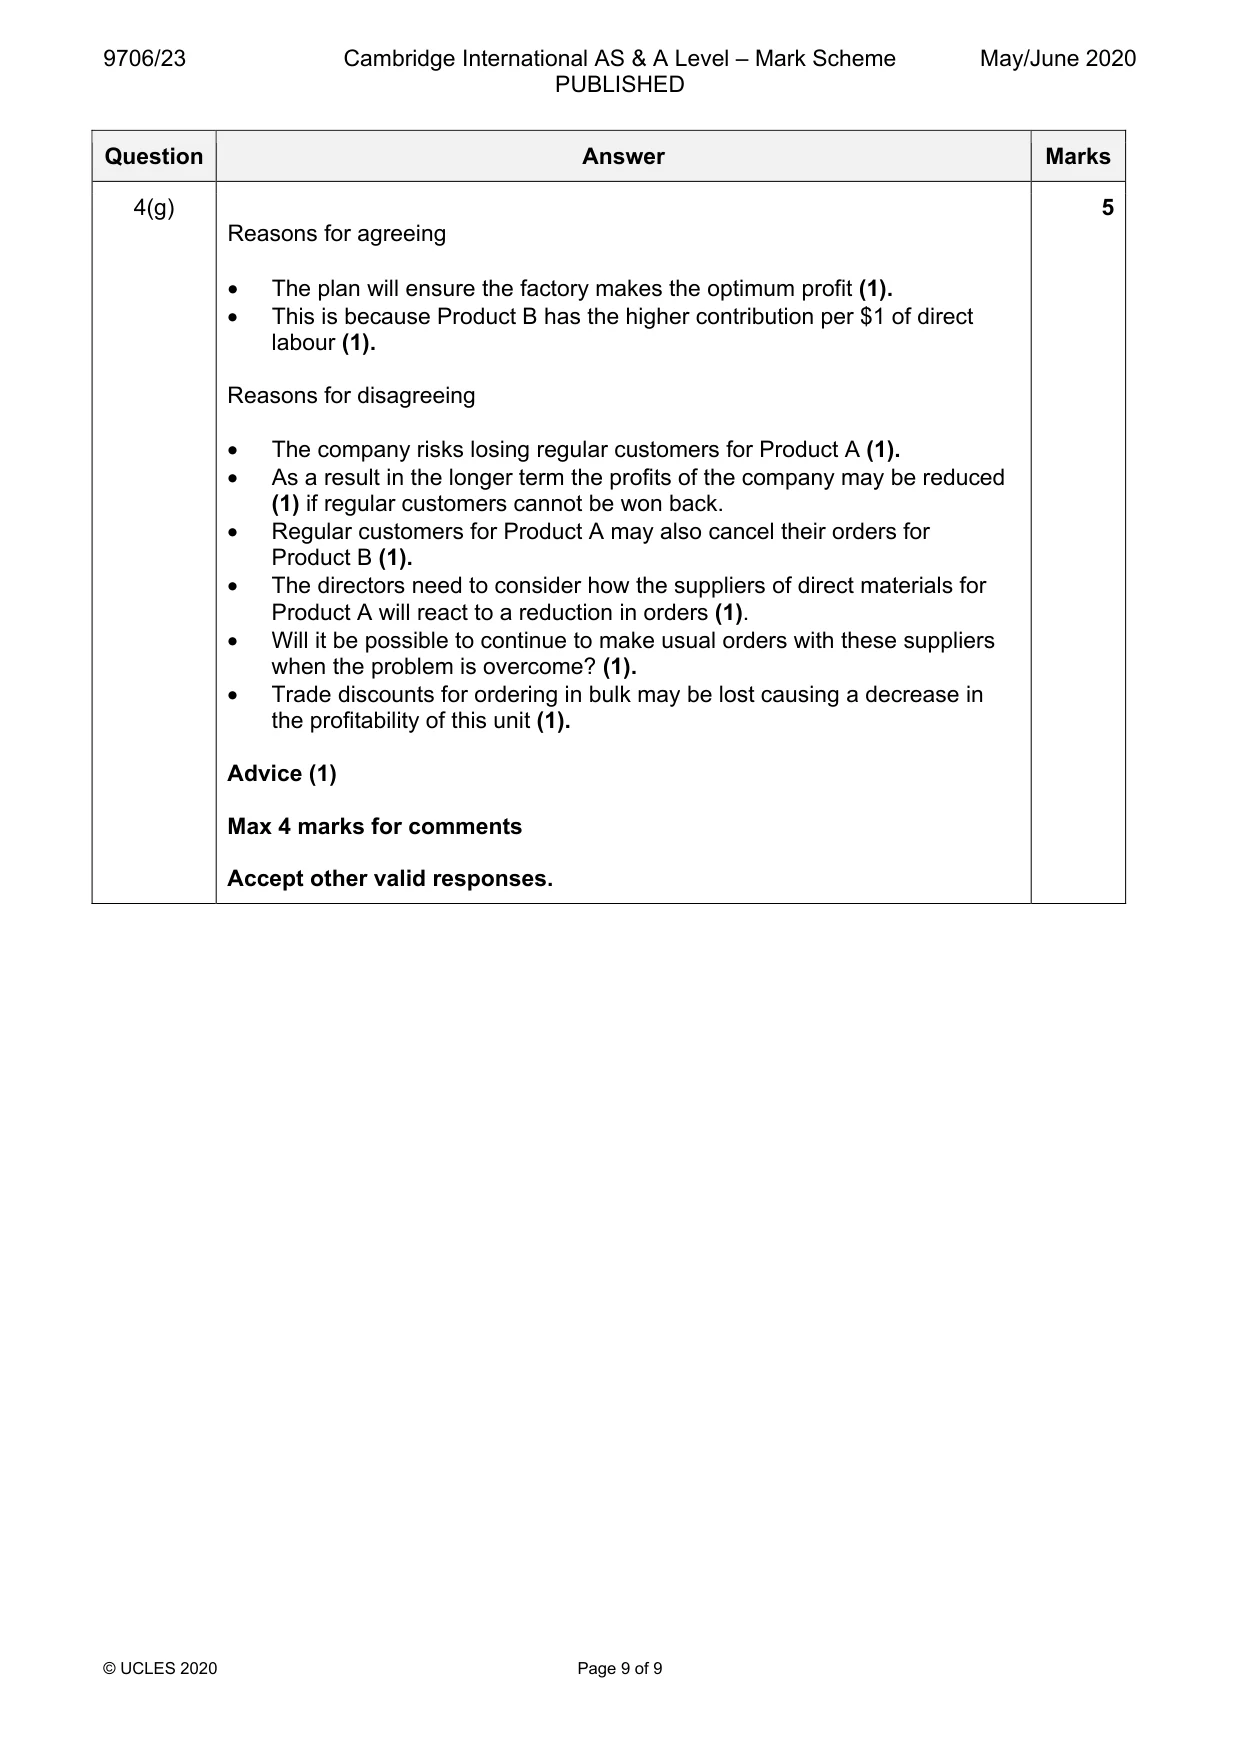
Mark scheme: 4(a) Advantages of break-even analysis 3 • Identifies point at which product will make a profit (1) • Identifies margin of safety (1) • Helps cost control by showing relative importance of fixed costs and variable costs (1) • Provides information in a concise/straightforward/easy to understand format (1) Max 3 Accept other valid responses 4(b)(i) Break-even point 2 $66 000 / ($75 – $60) (1) = 4400 units (1) 4(b)(ii) Break-even point 1 4400 units × $75 = $330 000 (1)OF 4(c) Forecast profit per month 2 5800 – 4400 = 1400 (1of) × $15 = $21 000 (1)OF 4(d) Margin of safety 1 Is the difference between maximum possible production/sales and break-even point (1)/the range of production which will ensure a profit is made (1)/the amount of sales which can be lost before a making a loss (1). Max 1 4(e) 10 Marginal costing statement for one month Workings $ $ Revenue 8120 units (W1) (1) × $82 665 840 (1)OF Less Variable costs Direct materials 2.2 kg × $15, i.e. 267 960 (1)OF $33 (1) × 8120 units OF Direct labour Normal working: (1)OF 7 500 units × 3.5 hr × $10, i.e. $262 500 (1) 289 625 Overtime working: (1)OF [8120 (of) – 7500) = 620 units × 3.5 hr × $12.50, i.e. $27 125 557 585 Contribution 108 255 (1)OF Less fixed costs $66 000 + depreciation of 66 400 (1) new machinery ($24 000/5 = $4800/12) i.e. $400 Profit per month 41 855 (1)OF W1 New demand: 5800 × 140% = 8120 4(f) 6 Product A Product B $ $ Direct labour 9 6 (1) Total variable cost 14 20 (1) Contribution per unit 6 5 (1)OF Contribution per labour hour 8 10 (1)OF Priority 1: Product B (1) 200 units produced (taking 100 labour hours) Priority 2: Product A 246 (1) units produced (taking remaining 185 hours) 4(g) 5 Reasons for agreeing • The plan will ensure the factory makes the optimum profit (1). • This is because Product B has the higher contribution per $1 of direct labour (1). Reasons for disagreeing • The company risks losing regular customers for Product A (1). • As a result in the longer term the profits of the company may be reduced (1) if regular customers cannot be won back. • Regular customers for Product A may also cancel their orders for Product B (1). • The directors need to consider how the suppliers of direct materials for Product A will react to a reduction in orders (1). • Will it be possible to continue to make usual orders with these suppliers when the problem is overcome? (1). • Trade discounts for ordering in bulk may be lost causing a decrease in the profitability of this unit (1). Advice (1) Max 4 marks for comments Accept other valid responses.
Q5 · An entry in the general journal to write off the balance of the account of J Limited…
5 An entry in the general journal to write off the balance of the account of J Limited, $230, as irrecoverable had been posted to the debit side of the customer’s account. REQUIRED (c) Complete the following table to reconcile the sales ledger control account balance with the total of the sales ledger balances. Error 1 has been completed for you as an example. sales ledger control account total of sales ledger balance balances $ $ Incorrect figures 14 850 15 320 Error 1 160 – Error 2 Error 3 Error 4 Error 5 Corrected figures [5] [Total: 15] 4 Y Limited is a large manufacturing company with factories at several locations. The company uses a marginal costing system. REQUIRED (a) State three benefits to a business of break-even analysis. 1 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... 3 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... [3] Additional information At one factory a single product is manufactured which sells for $75 per unit. The budgeted costs of manufacture for one unit are as follows: $ Direct materials 2 kg at $12.50 per kg 25 Direct labour 3.5 hrs at $10 per labour hour 35 Fixed costs are budgeted to be $66 000 per month. It is possible to produce 7500 units in normal working conditions. Currently 5800 units are made and sold each month.
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.