Cambridge A Level Accounting 9706 — 2020 May/June Paper 2 · Variant 1
9706/21/M/J/20 · 4 questions · 73 marks · ≈82 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme14 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Hamza and Noor are in partnership
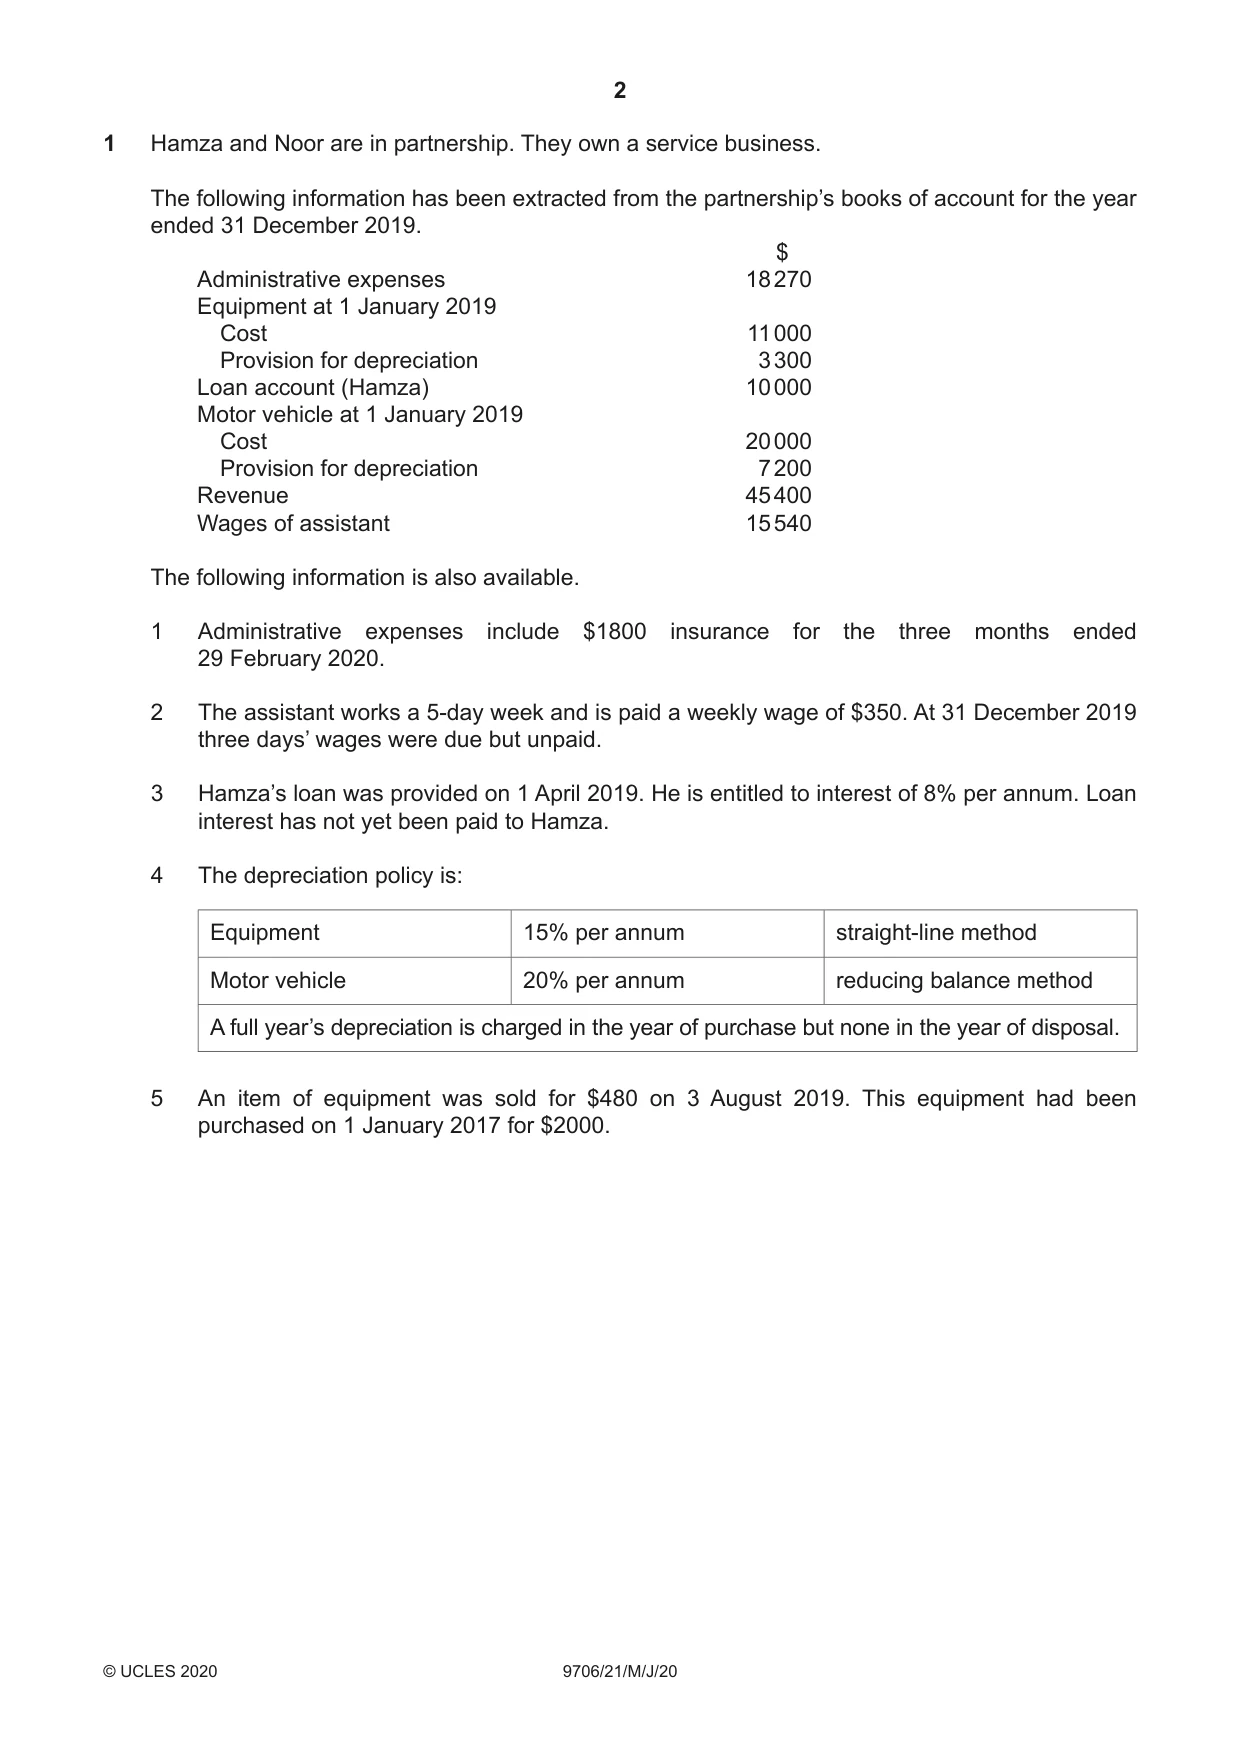
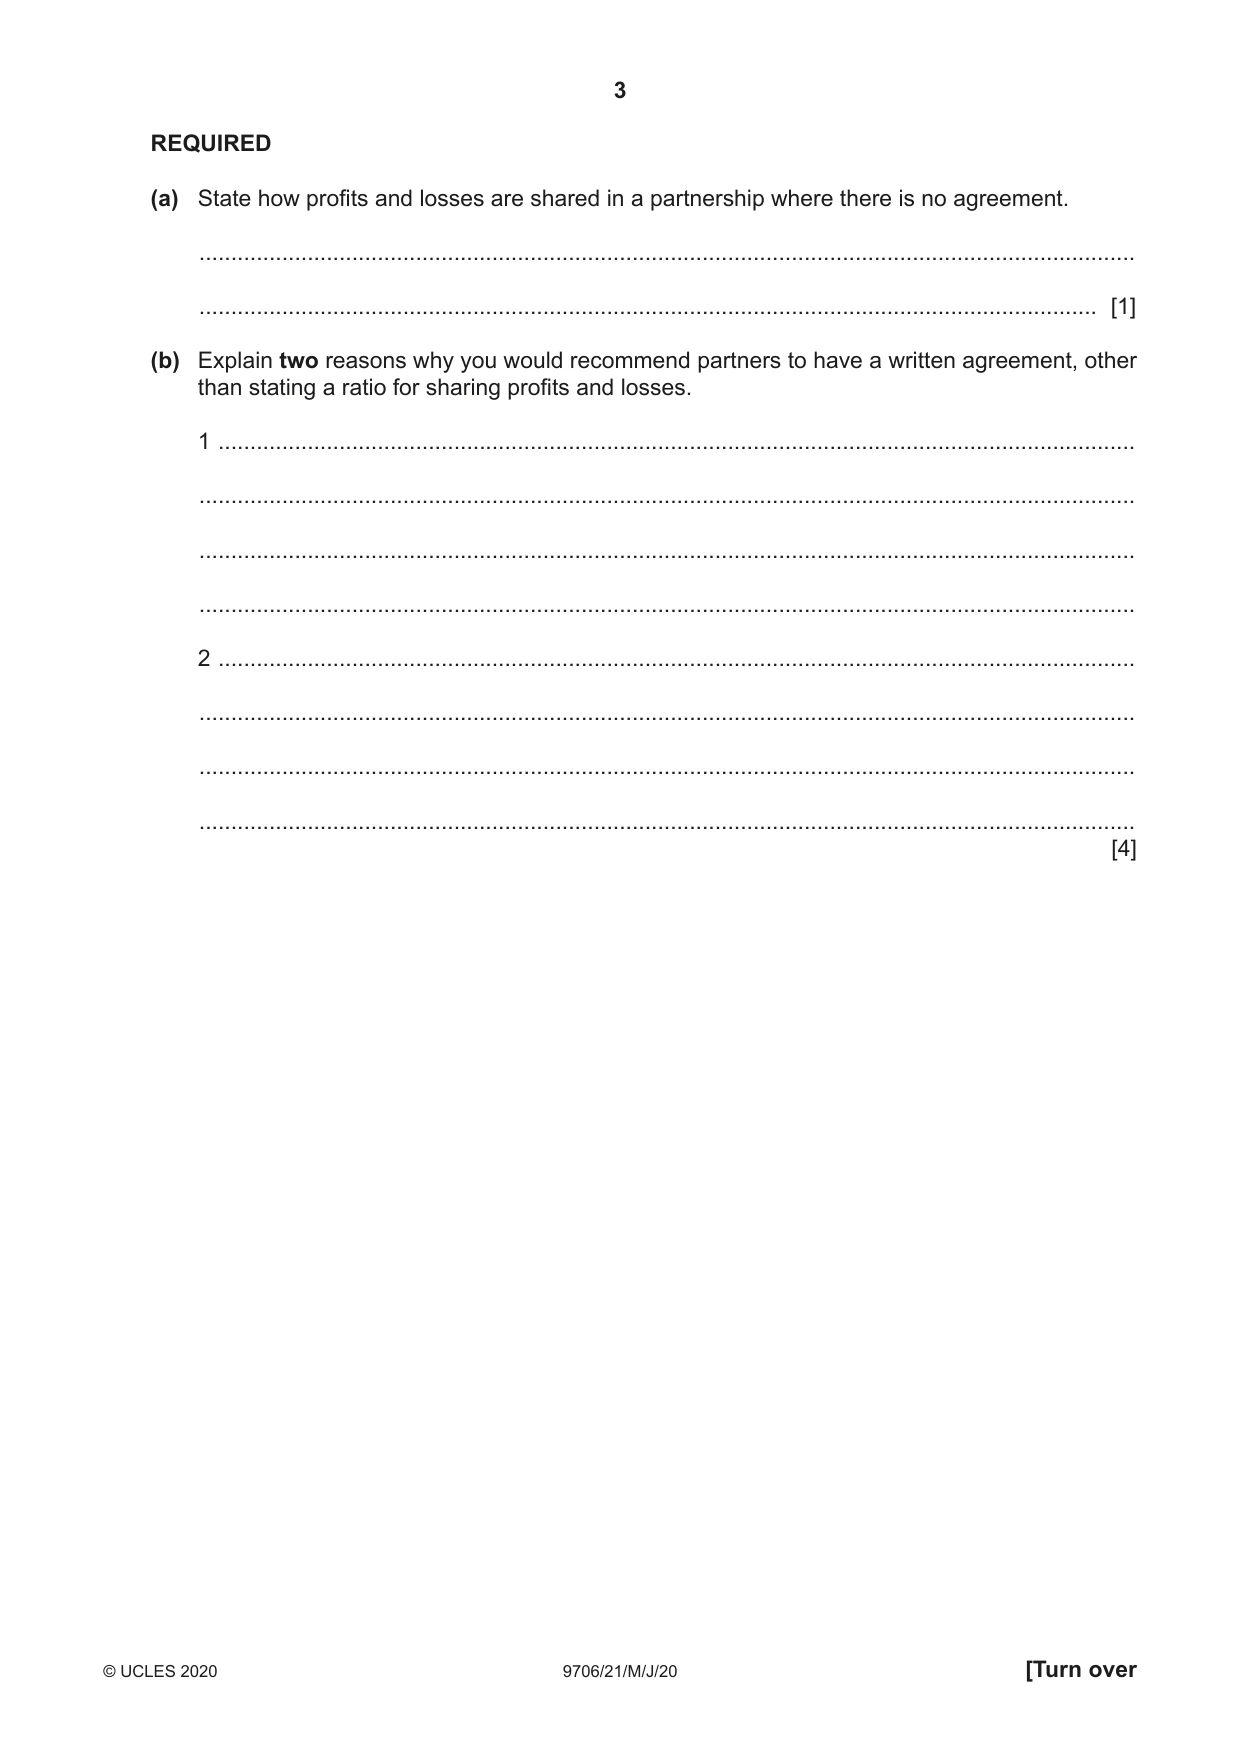
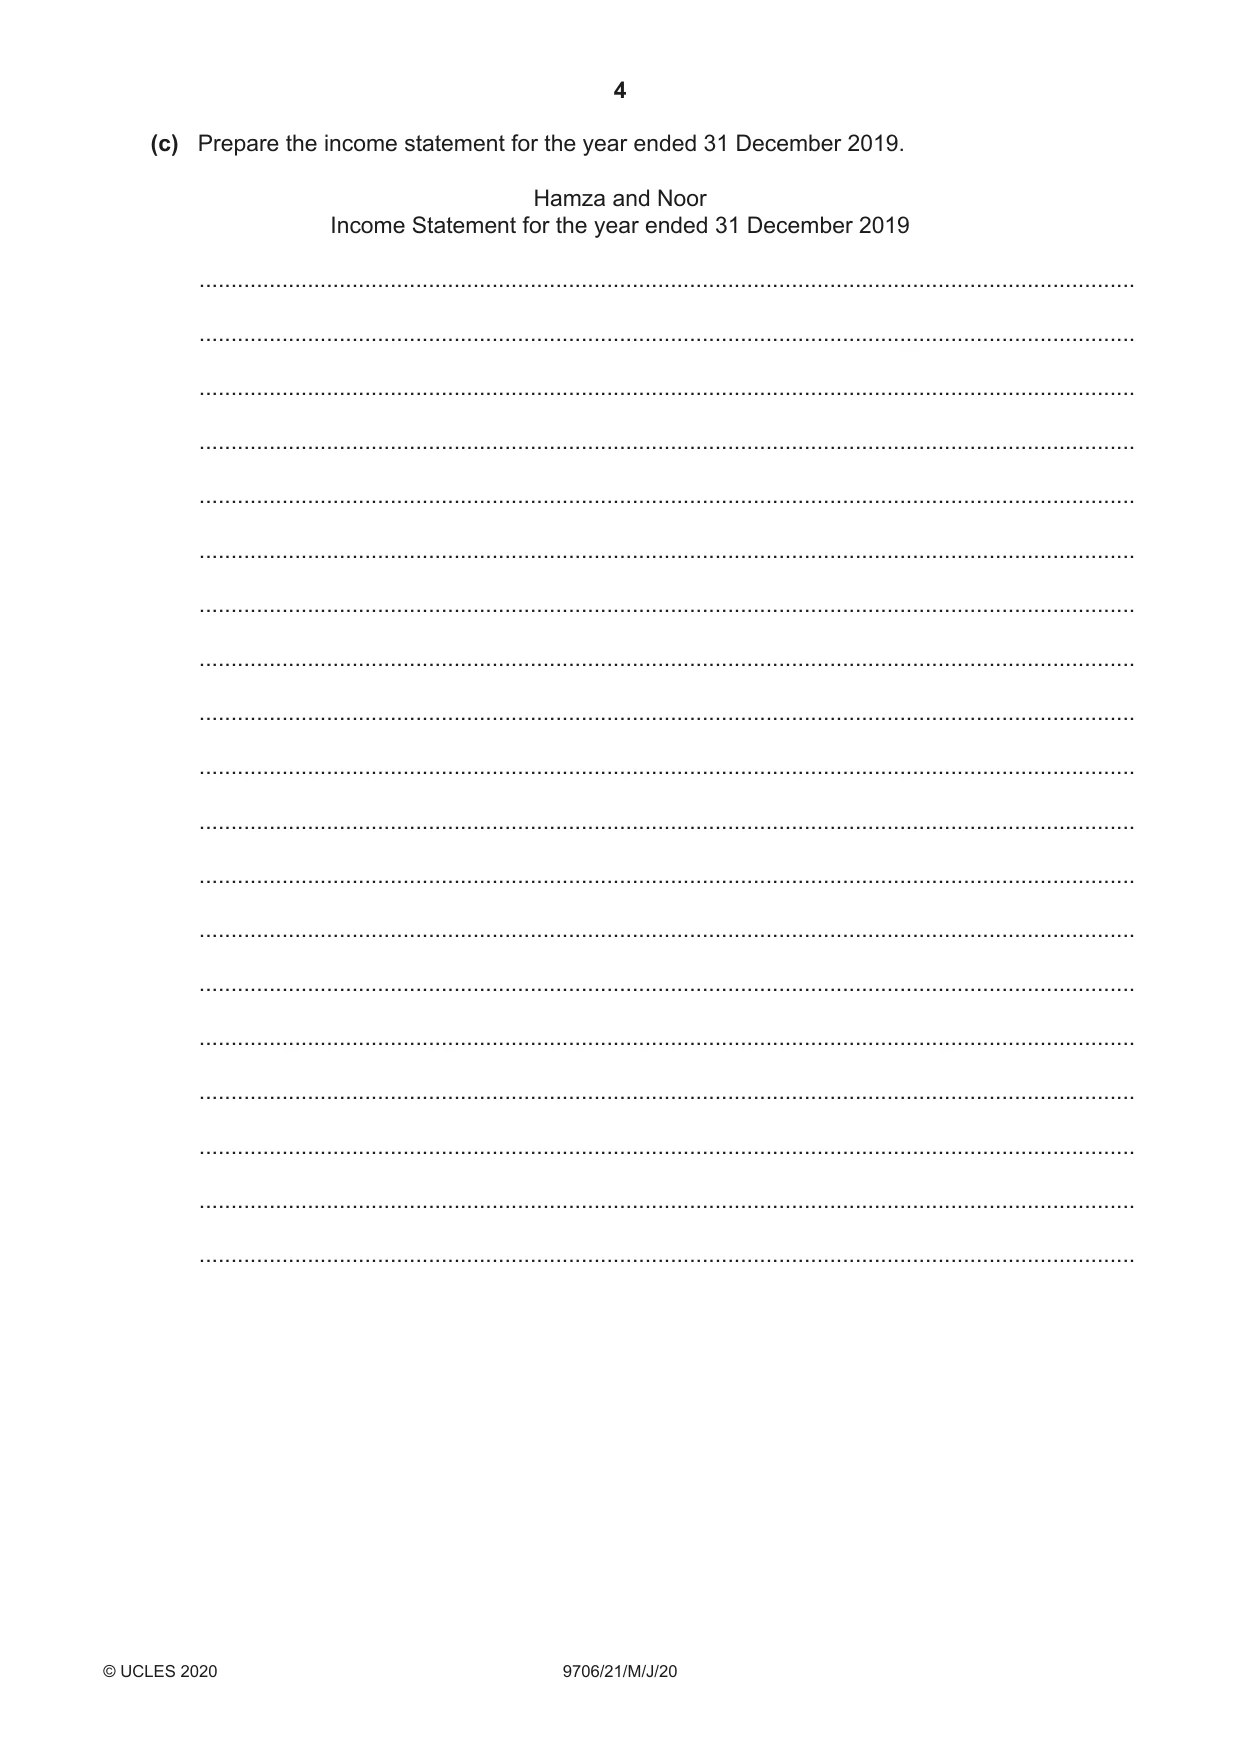
1 Hamza and Noor are in partnership. They own a service business. The following information has been extracted from the partnership’s books of account for the year ended 31 December 2019. $ Administrative expenses 18 270 Equipment at 1 January 2019 Cost 11 000 Provision for depreciation 3 300 Loan account (Hamza) 10 000 Motor vehicle at 1 January 2019 Cost 20 000 Provision for depreciation 7 200 Revenue 45 400 Wages of assistant 15 540 The following information is also available. 1 Administrative expenses include $1800 insurance for the three months ended 29 February 2020. 2 The assistant works a 5-day week and is paid a weekly wage of $350. At 31 December 2019 three days’ wages were due but unpaid. 3 Hamza’s loan was provided on 1 April 2019. He is entitled to interest of 8% per annum. Loan interest has not yet been paid to Hamza. 4 The depreciation policy is: Equipment 15% per annum straight-line method Motor vehicle 20% per annum reducing balance method A full year’s depreciation is charged in the year of purchase but none in the year of disposal. 5 An item of equipment was sold for $480 on 3 August 2019. This equipment had been purchased on 1 January 2017 for $2000. REQUIRED (a) State how profits and losses are shared in a partnership where there is no agreement. ................................................................................................................................................... ............................................................................................................................................. [1] (b) Explain two reasons why you would recommend partners to have a written agreement, other than stating a ratio for sharing profits and losses. 1 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... [4] (c) Prepare the income statement for the year ended 31 December 2019. Hamza and Noor Income Statement for the year ended 31 December 2019 ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Workings: [11] Additional information Hamza and Noor have an agreement about sharing profits and losses. Their agreement is as follows. 1 Noor is to be given a salary of $11 000.
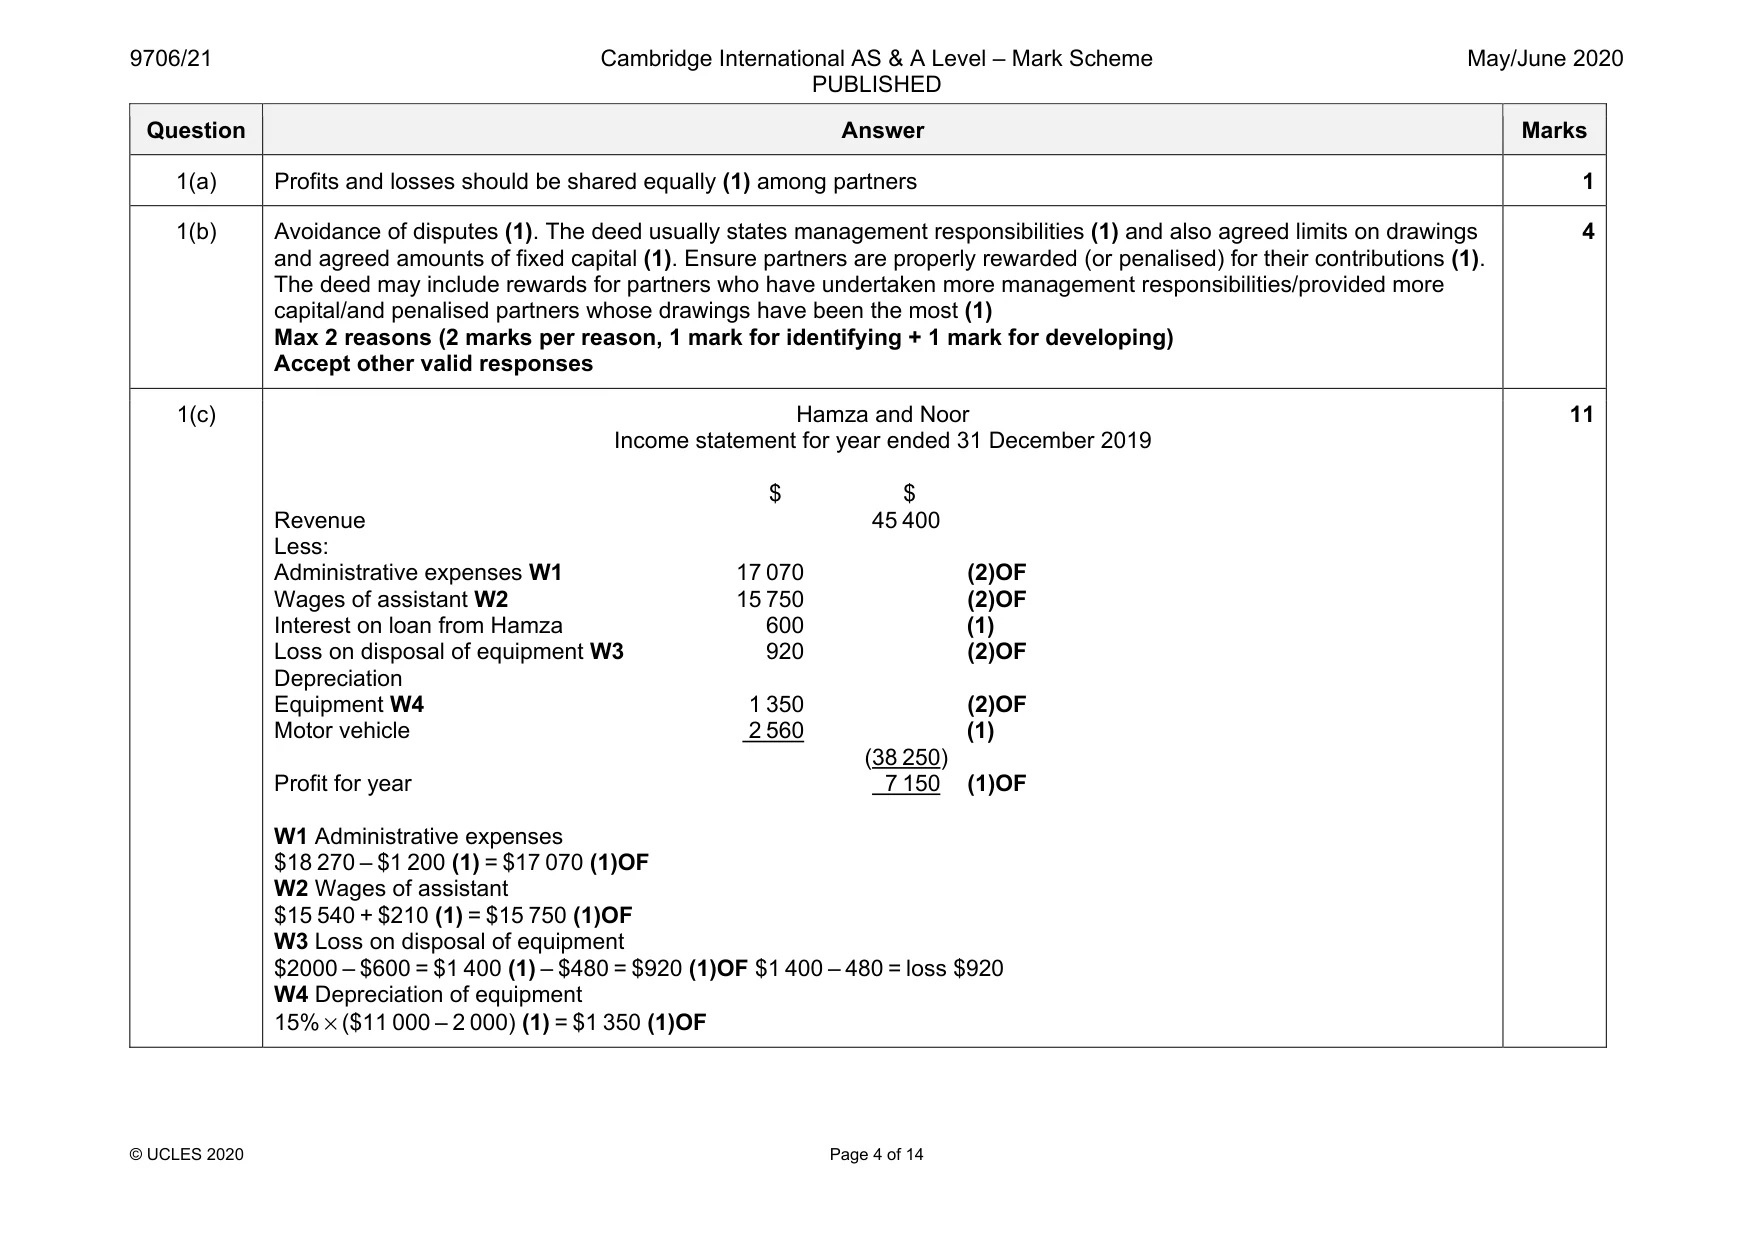
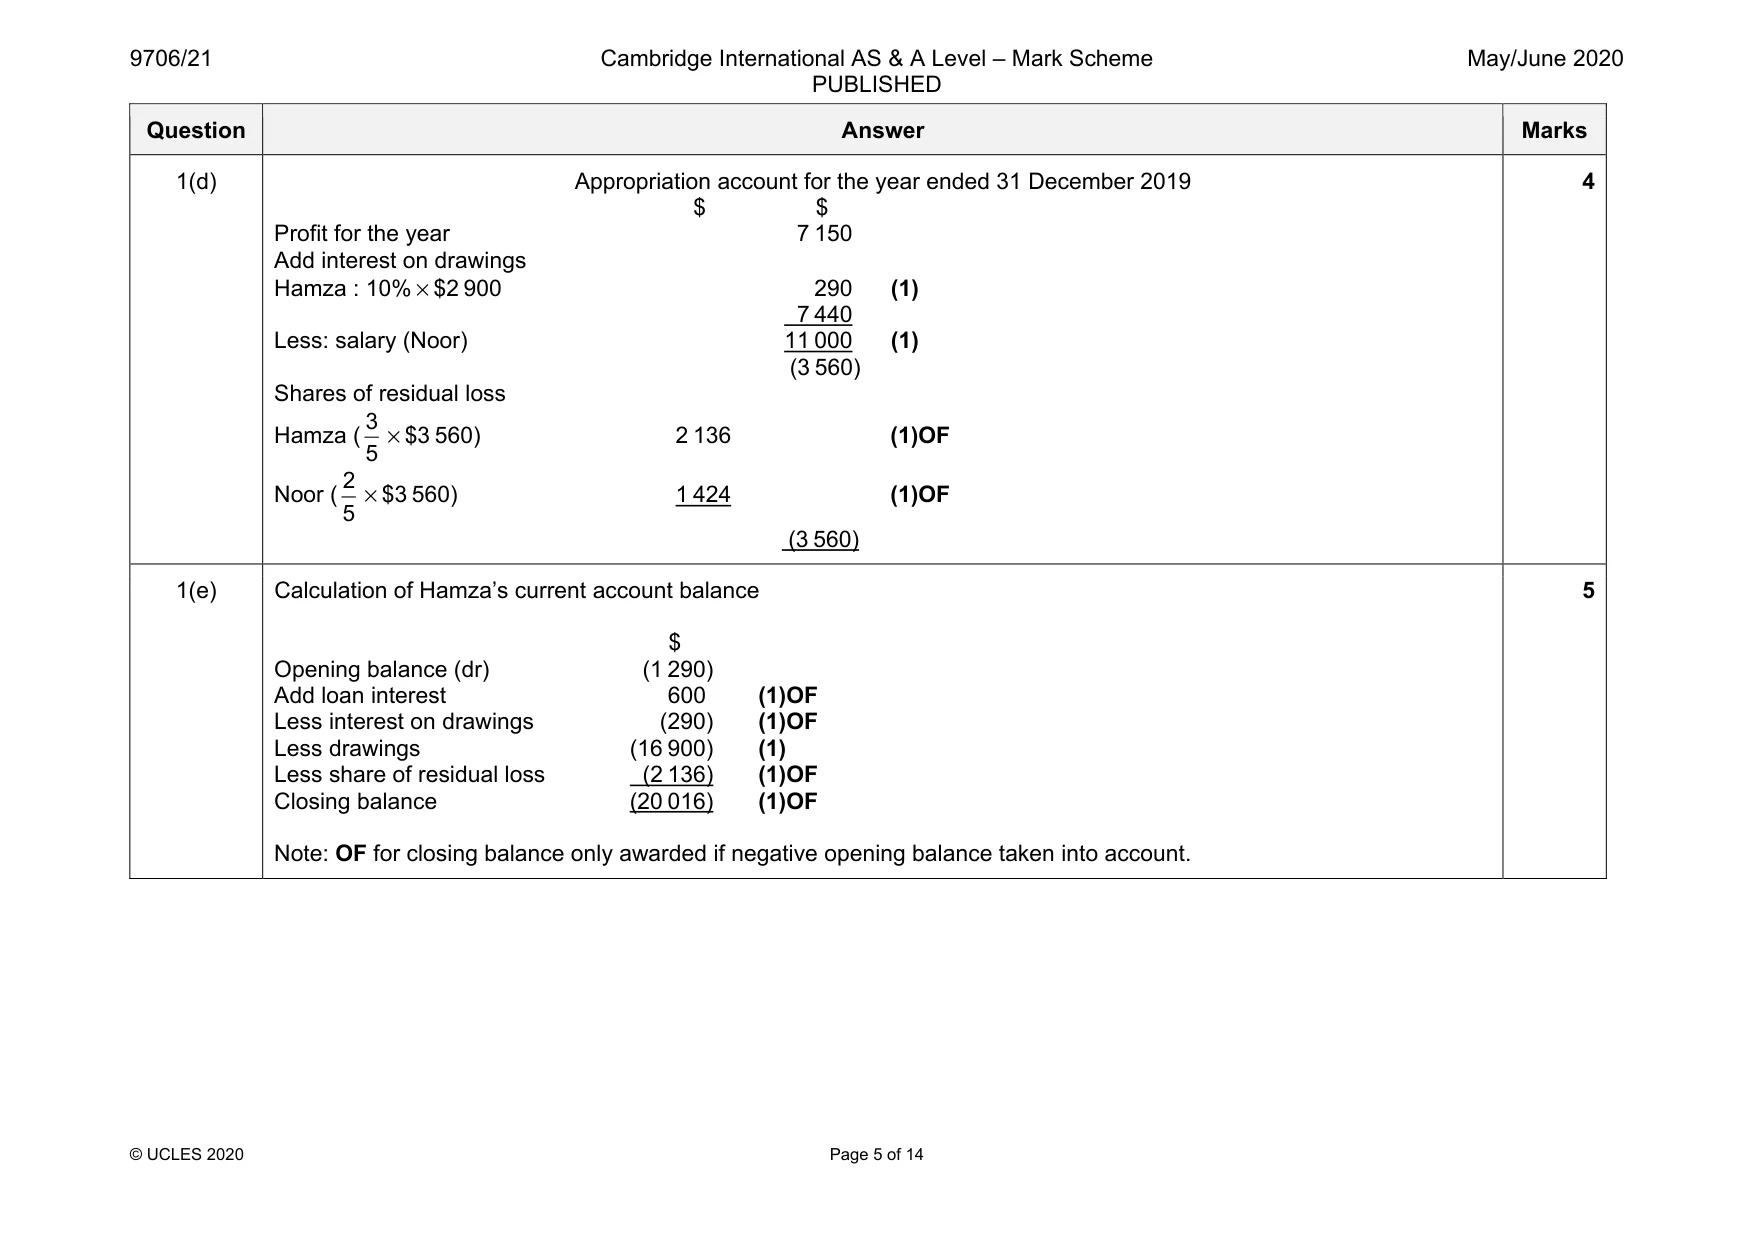
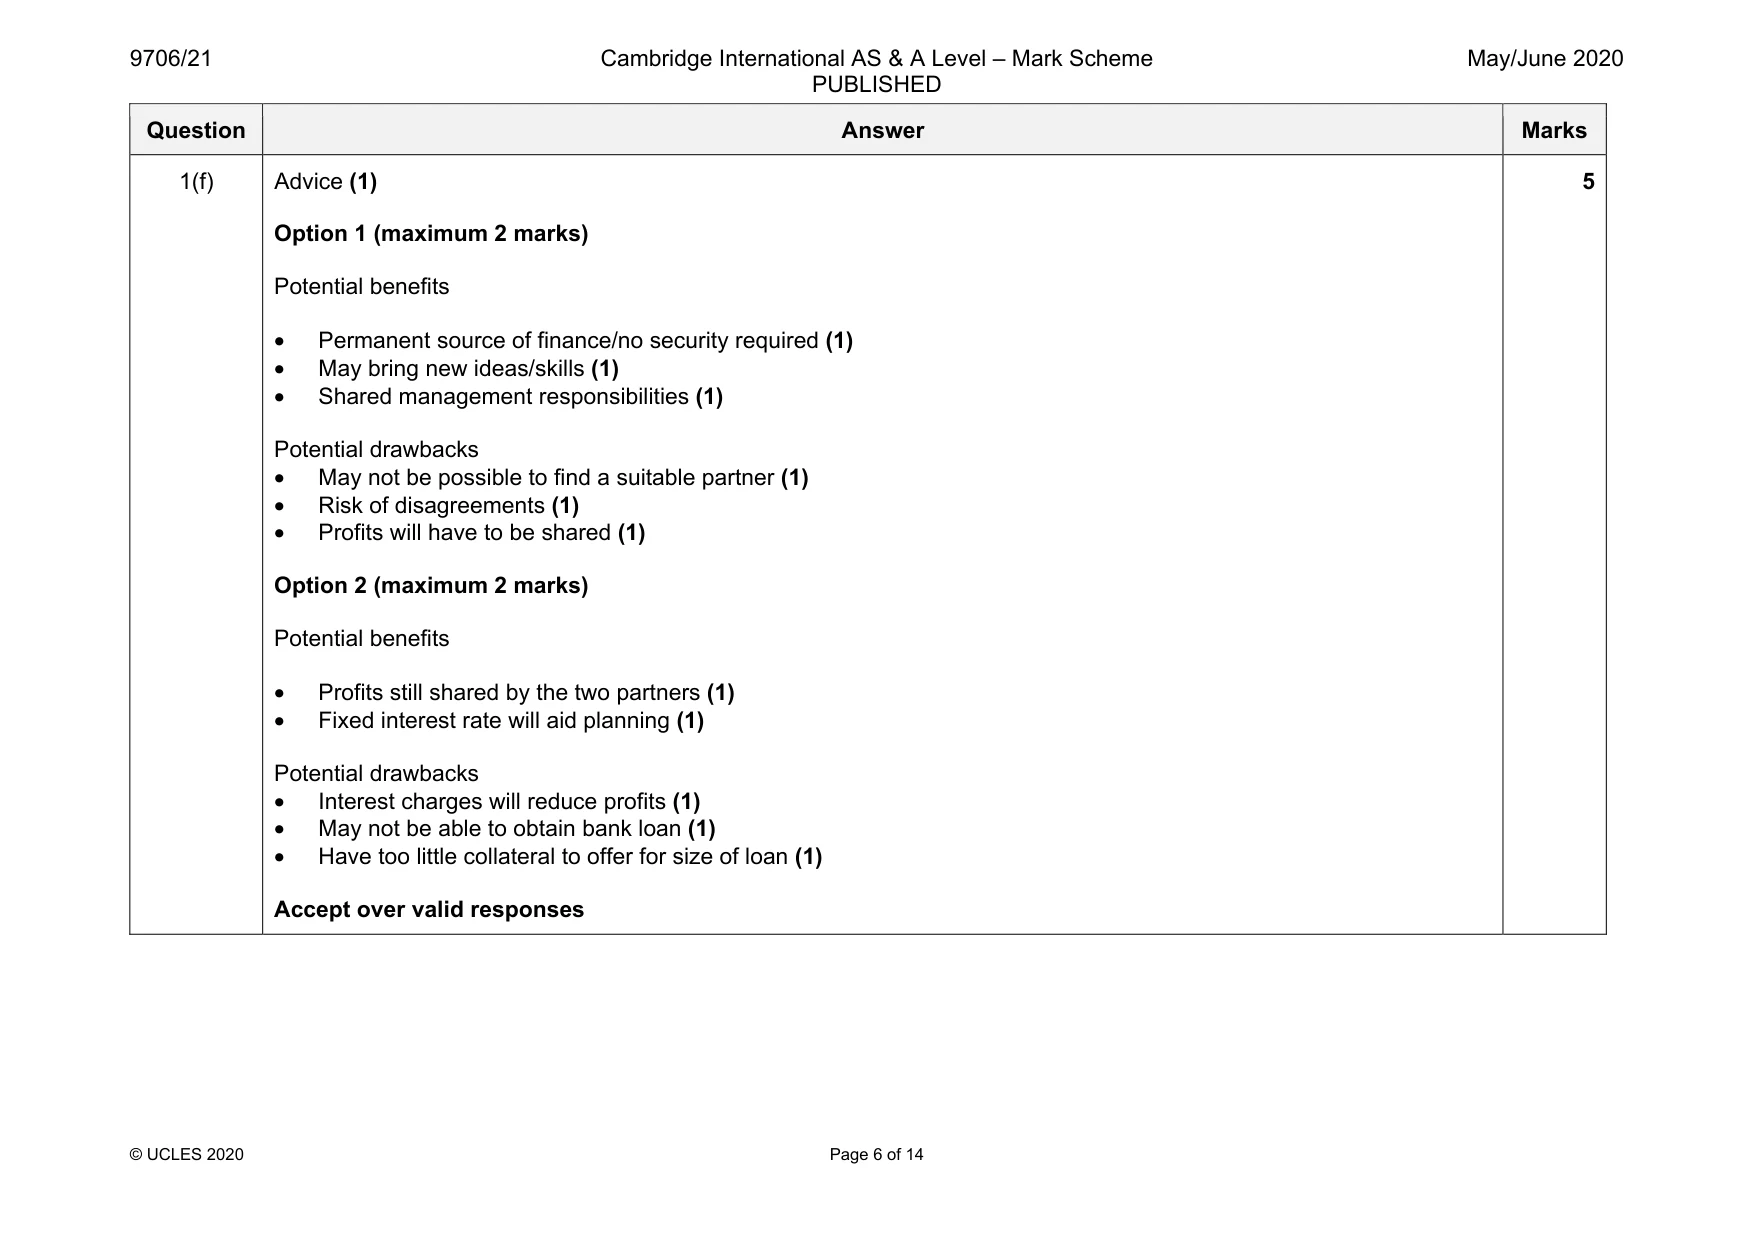
Mark scheme: 1(a) Profits and losses should be shared equally (1) among partners 1 1(b) Avoidance of disputes (1). The deed usually states management responsibilities (1) and also agreed limits on drawings and agreed amounts of fixed capital (1). Ensure partners are properly rewarded (or penalised) for their contributions (1). The deed may include rewards for partners who have undertaken more management responsibilities/provided more capital/and penalised partners whose drawings have been the most (1) Max 2 reasons (2 marks per reason, 1 mark for identifying + 1 mark for developing) Accept other valid responses 4 1(c) Hamza and Noor Income statement for year ended 31 December 2019 $ $ Revenue 45 400 Less: Administrative expenses W1 17 070 (2)OF Wages of assistant W2 15 750 (2)OF Interest on loan from Hamza 600 (1) Loss on disposal of equipment W3 920 (2)OF Depreciation Equipment W4 1 350 (2)OF Motor vehicle 2 560 (1) (38 250) Profit for year 7 150 (1)OF W1 Administrative expenses $18 270 – $1 200 (1) = $17 070 (1)OF W2 Wages of assistant $15 540 + $210 (1) = $15 750 (1)OF W3 Loss on disposal of equipment $2000 – $600 = $1 400 (1) – $480 = $920 (1)OF $1 400 – 480 = loss $920 W4 Depreciation of equipment 15% × ($11 000 – 2 000) (1) = $1 350 (1)OF 11 Question Answer Marks 1(d) Appropriation account for the year ended 31 December 2019 $ $ Profit for the year 7 150 Add interest on drawings Hamza : 10% × $2 900 290 (1) 7 440 Less: salary (Noor) 11 000 (1) (3 560) Shares of residual loss Hamza ( 3 5 × $3 560) 2 136 (1)OF Noor ( 2 5 × $3 560) 1 424 (1)OF (3 560) 4 1(e) Calculation of Hamza’s current account balance $ Opening balance (dr) (1 290) Add loan interest 600 (1)OF Less interest on drawings (290) (1)OF Less drawings (16 900) (1) Less share of residual loss (2 136) (1)OF Closing balance (20 016) (1)OF Note: OF for closing balance only awarded if negative opening balance taken into account. 5 Question Answer Marks 1(f) Advice (1) Option 1 (maximum 2 marks) Potential benefits • Permanent source of finance/no security required (1) • May bring new ideas/skills (1) • Shared management responsibilities (1) Potential drawbacks • May not be possible to find a suitable partner (1) • Risk of disagreements (1) • Profits will have to be shared (1) Option 2 (maximum 2 marks) Potential benefits • Profits still shared by the two partners (1) • Fixed interest rate will aid planning (1) Potential drawbacks • Interest charges will reduce profits (1) • May not be able to obtain bank loan (1) • Have too little collateral to offer for size of loan (1) Accept over valid responses 5
Q2 · Partners are allowed to have drawings of $14 000 per annum
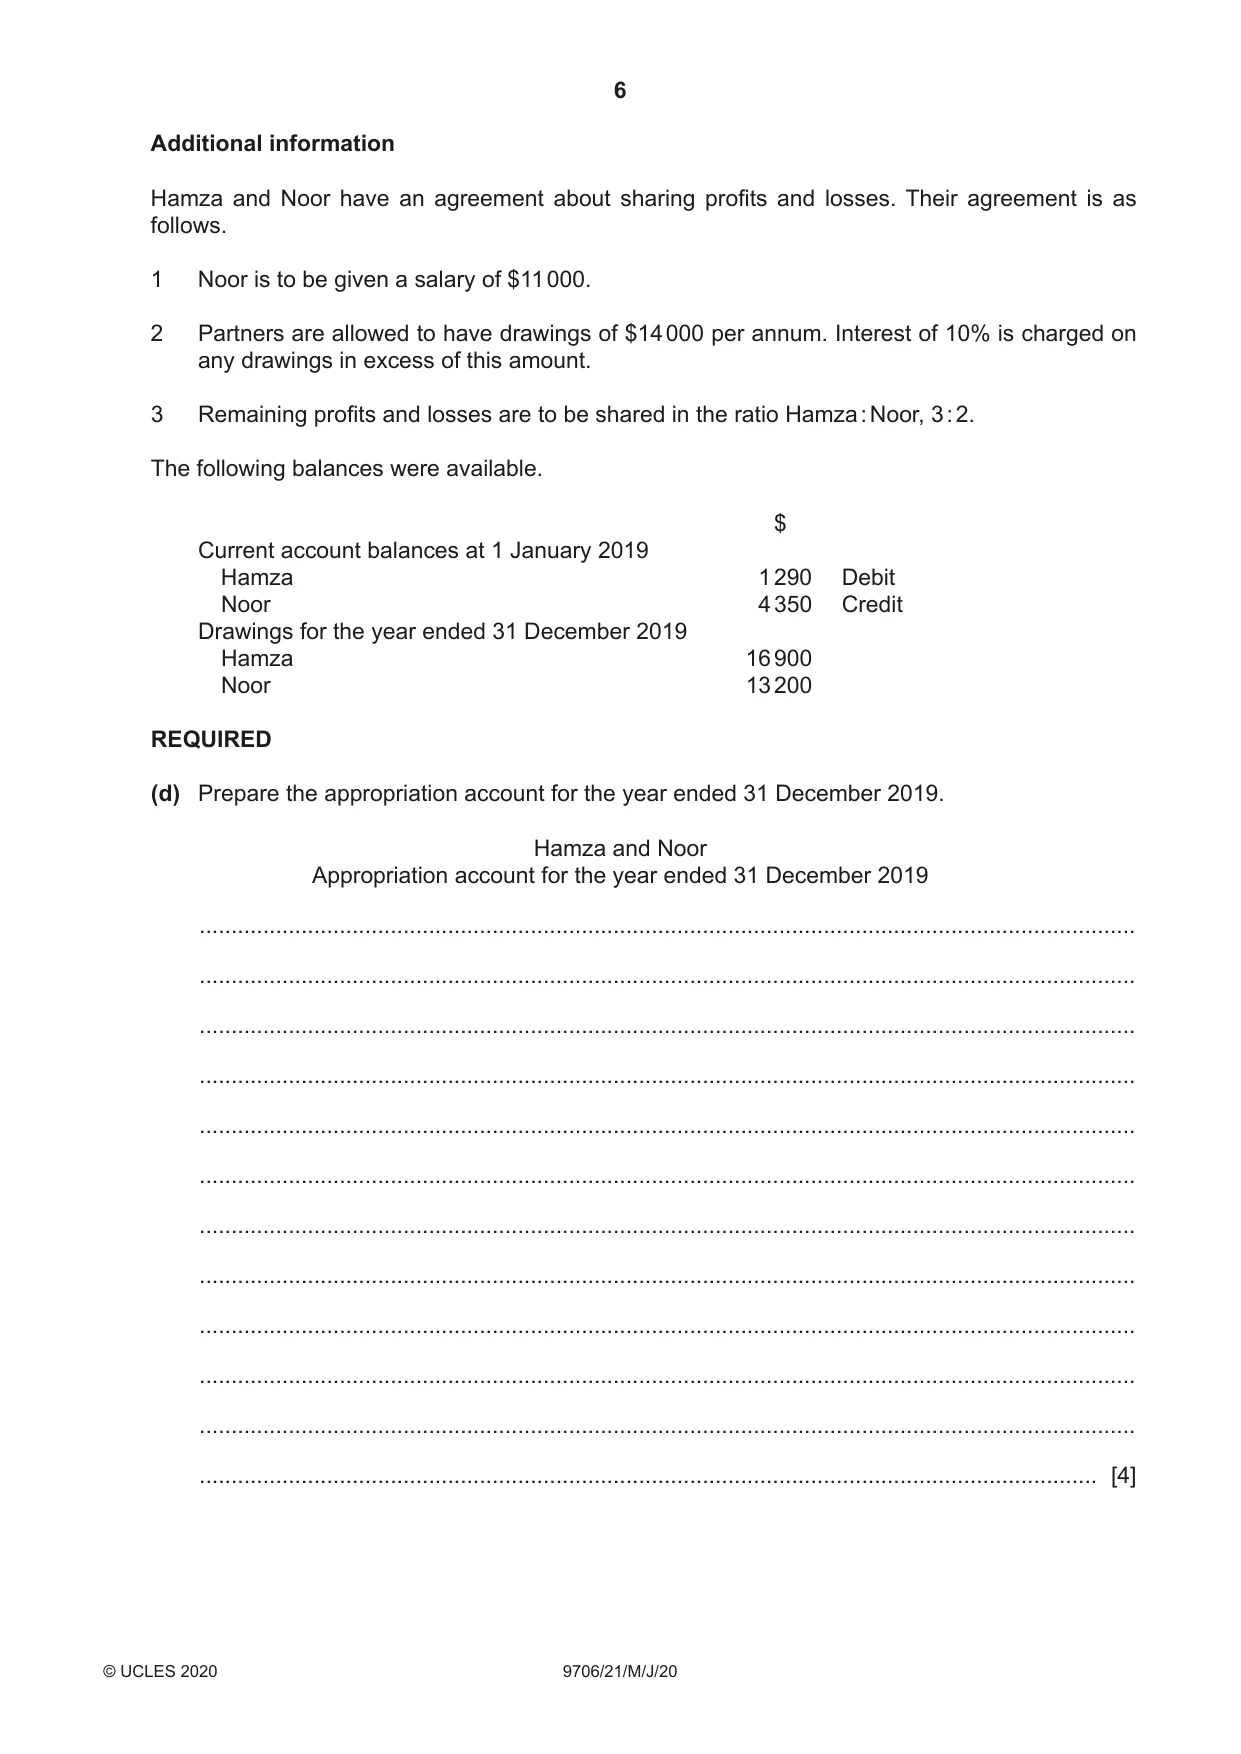
2 Partners are allowed to have drawings of $14 000 per annum. Interest of 10% is charged on any drawings in excess of this amount.
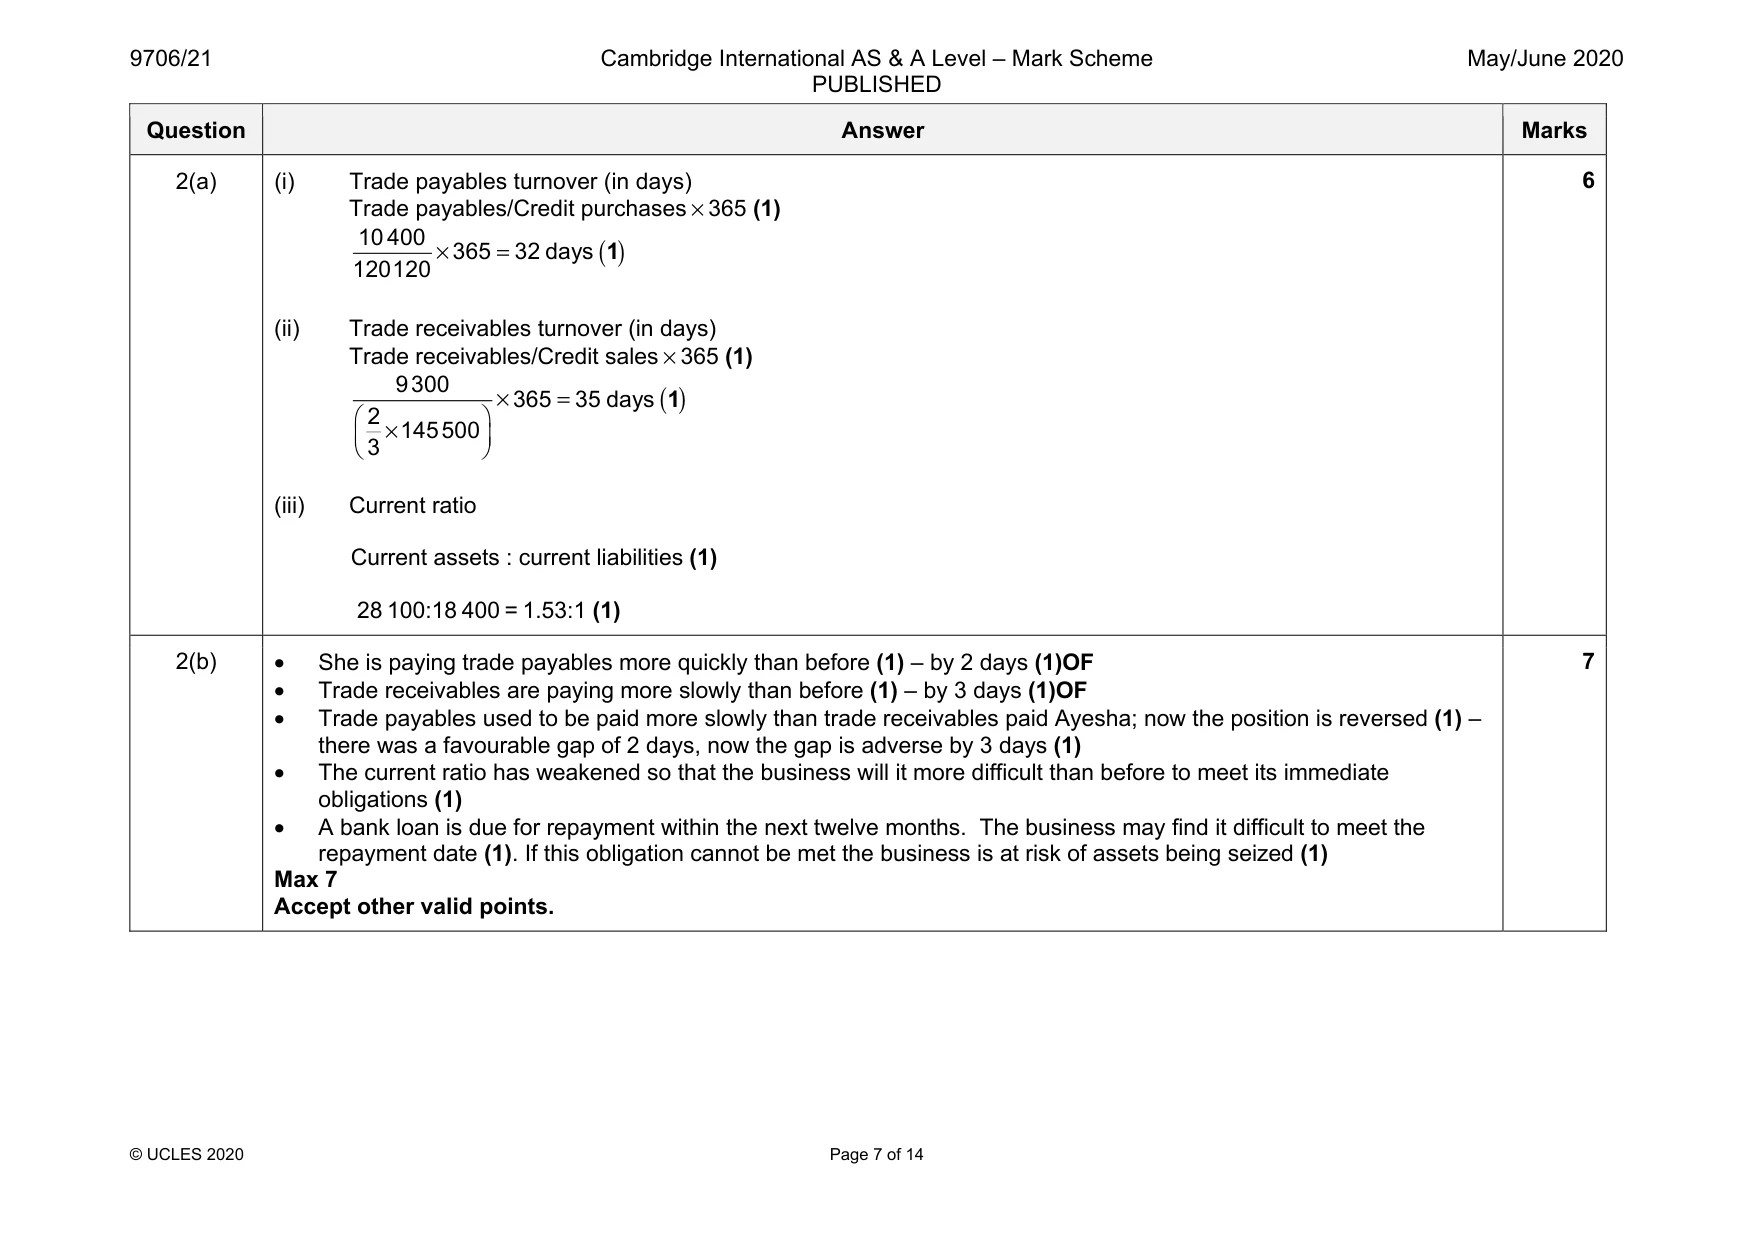
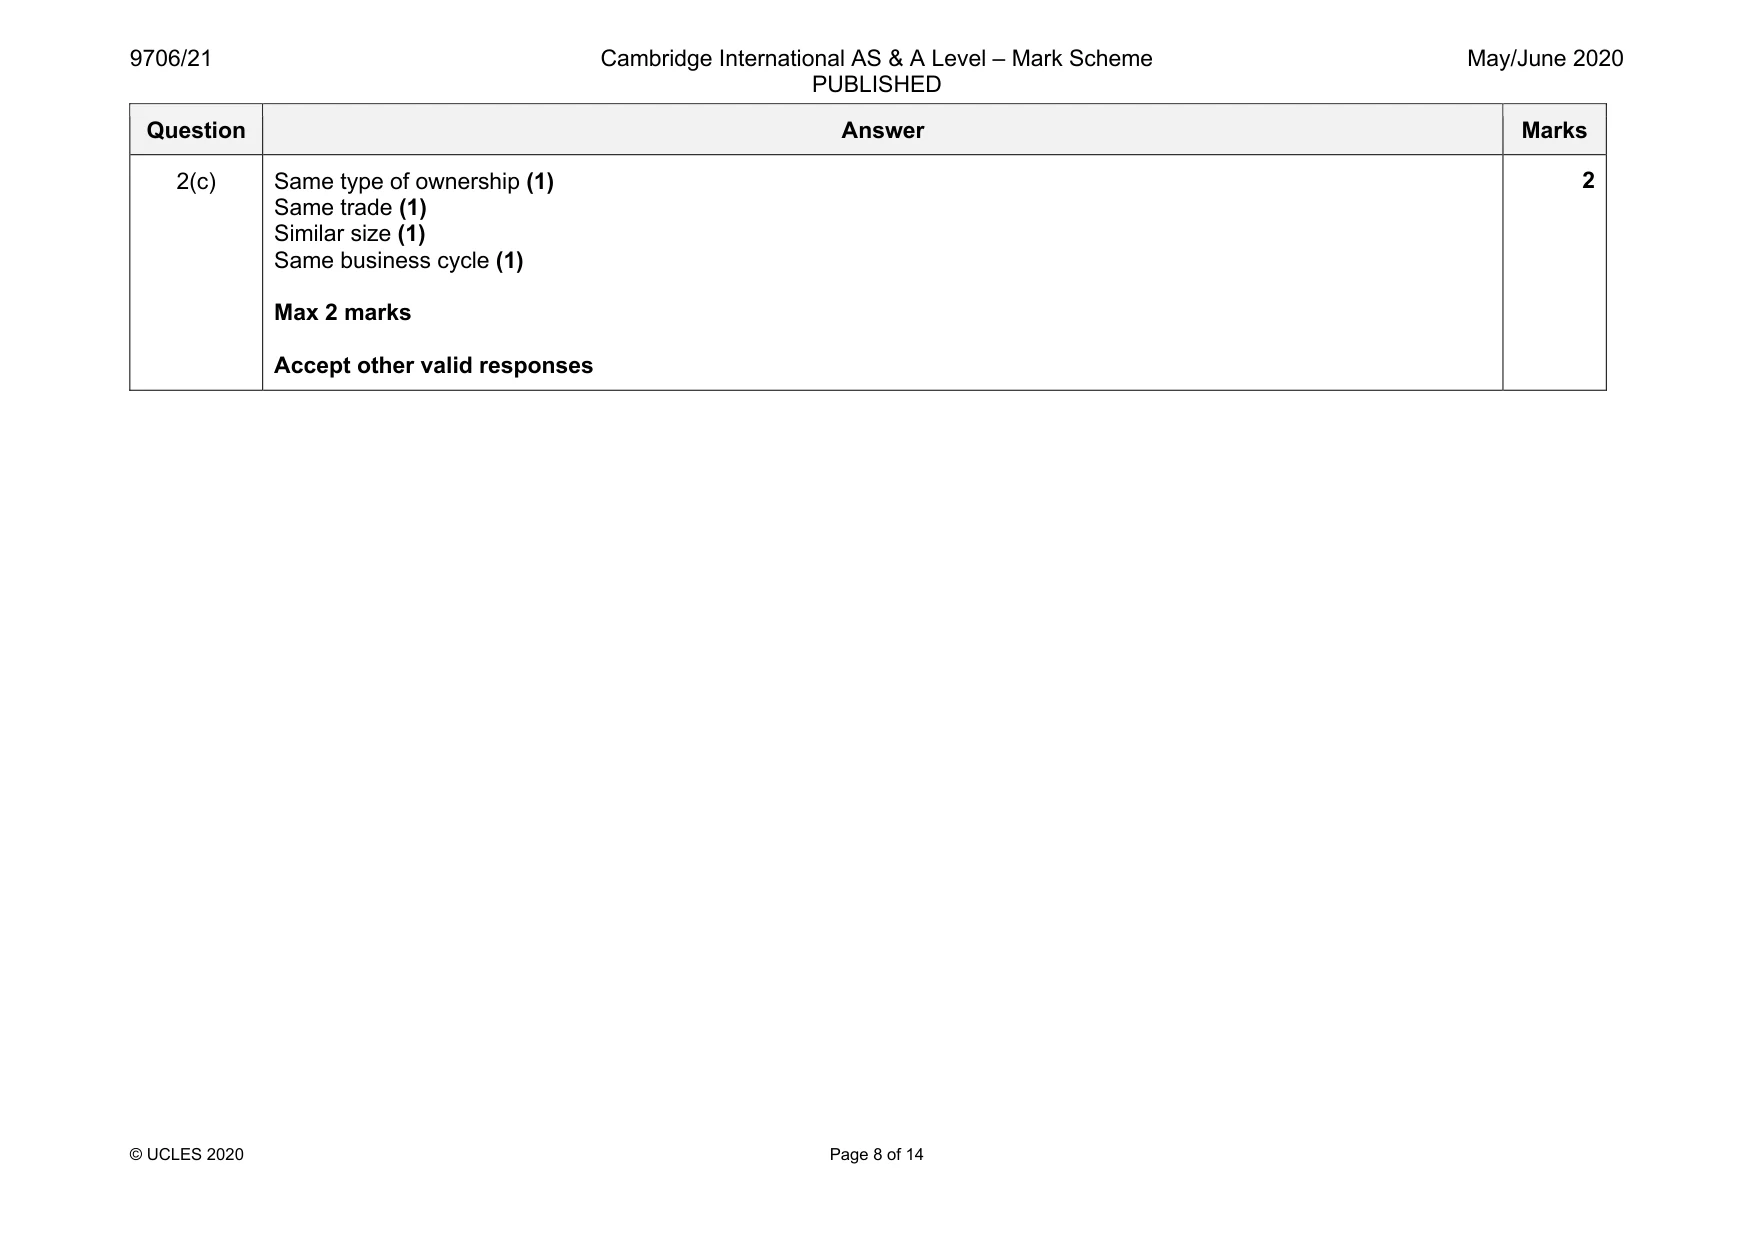
Mark scheme: 2(a) (i) Trade payables turnover (in days) Trade payables/Credit purchases × 365 (1) ( ) × = 10 400 365 32 days 120120 1 (ii) Trade receivables turnover (in days) Trade receivables/Credit sales × 365 (1) ( ) × = × 9300 365 35 days 2 145500 3 1 (iii) Current ratio Current assets : current liabilities (1) 28 100:18 400 = 1.53:1 (1) 2(b) • She is paying trade payables more quickly than before (1) – by 2 days (1)OF • Trade receivables are paying more slowly than before (1) – by 3 days (1)OF • Trade payables used to be paid more slowly than trade receivables paid Ayesha; now the position is reversed (1) – there was a favourable gap of 2 days, now the gap is adverse by 3 days (1) • The current ratio has weakened so that the business will it more difficult than before to meet its immediate obligations (1) • A bank loan is due for repayment within the next twelve months. The business may find it difficult to meet the repayment date (1). If this obligation cannot be met the business is at risk of assets being seized (1) Max 7 Accept other valid points. 7 Question Answer Marks 2(c) Same type of ownership (1) Same trade (1) Similar size (1) Same business cycle (1) Max 2 marks Accept other valid responses 2
Q3 · Remaining profits and losses are to be shared in the ratio Hamza : Noor, 3 : 2
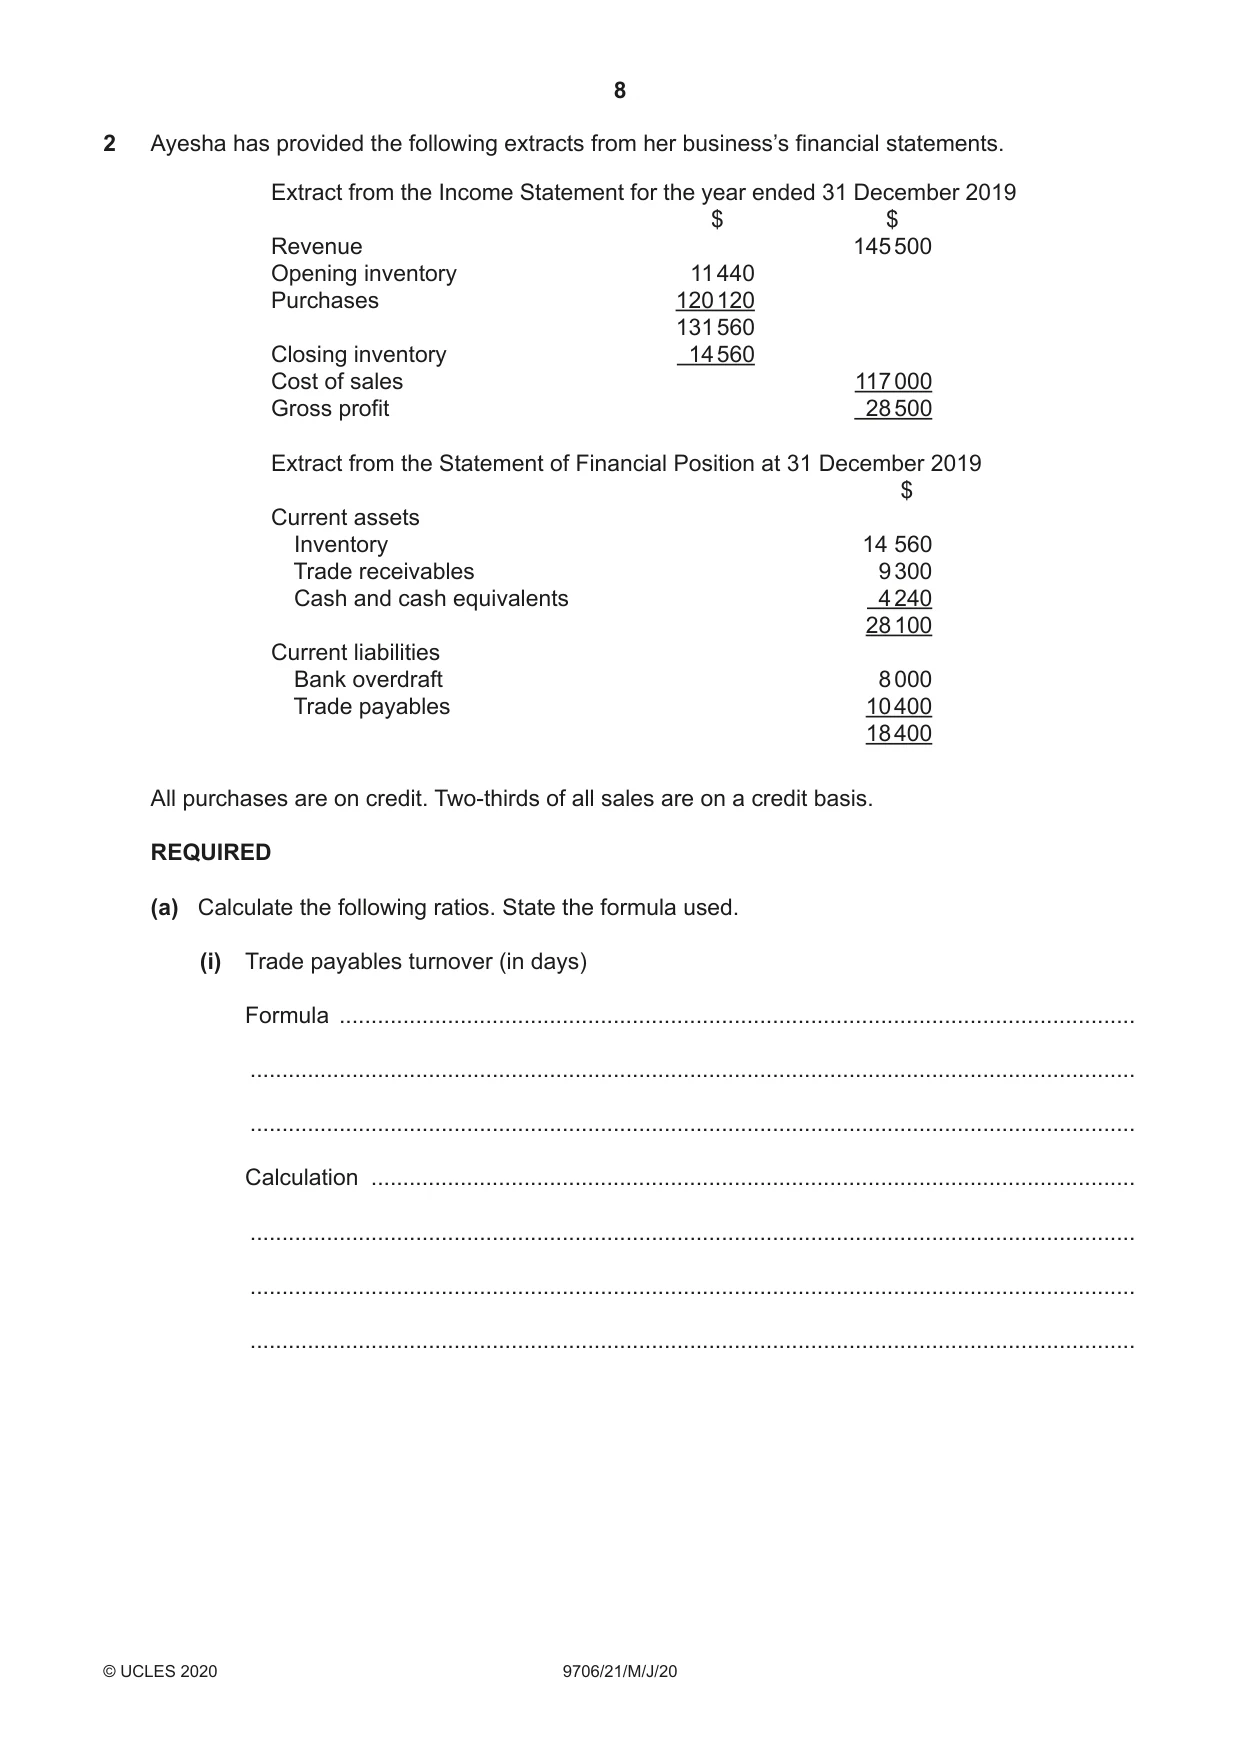
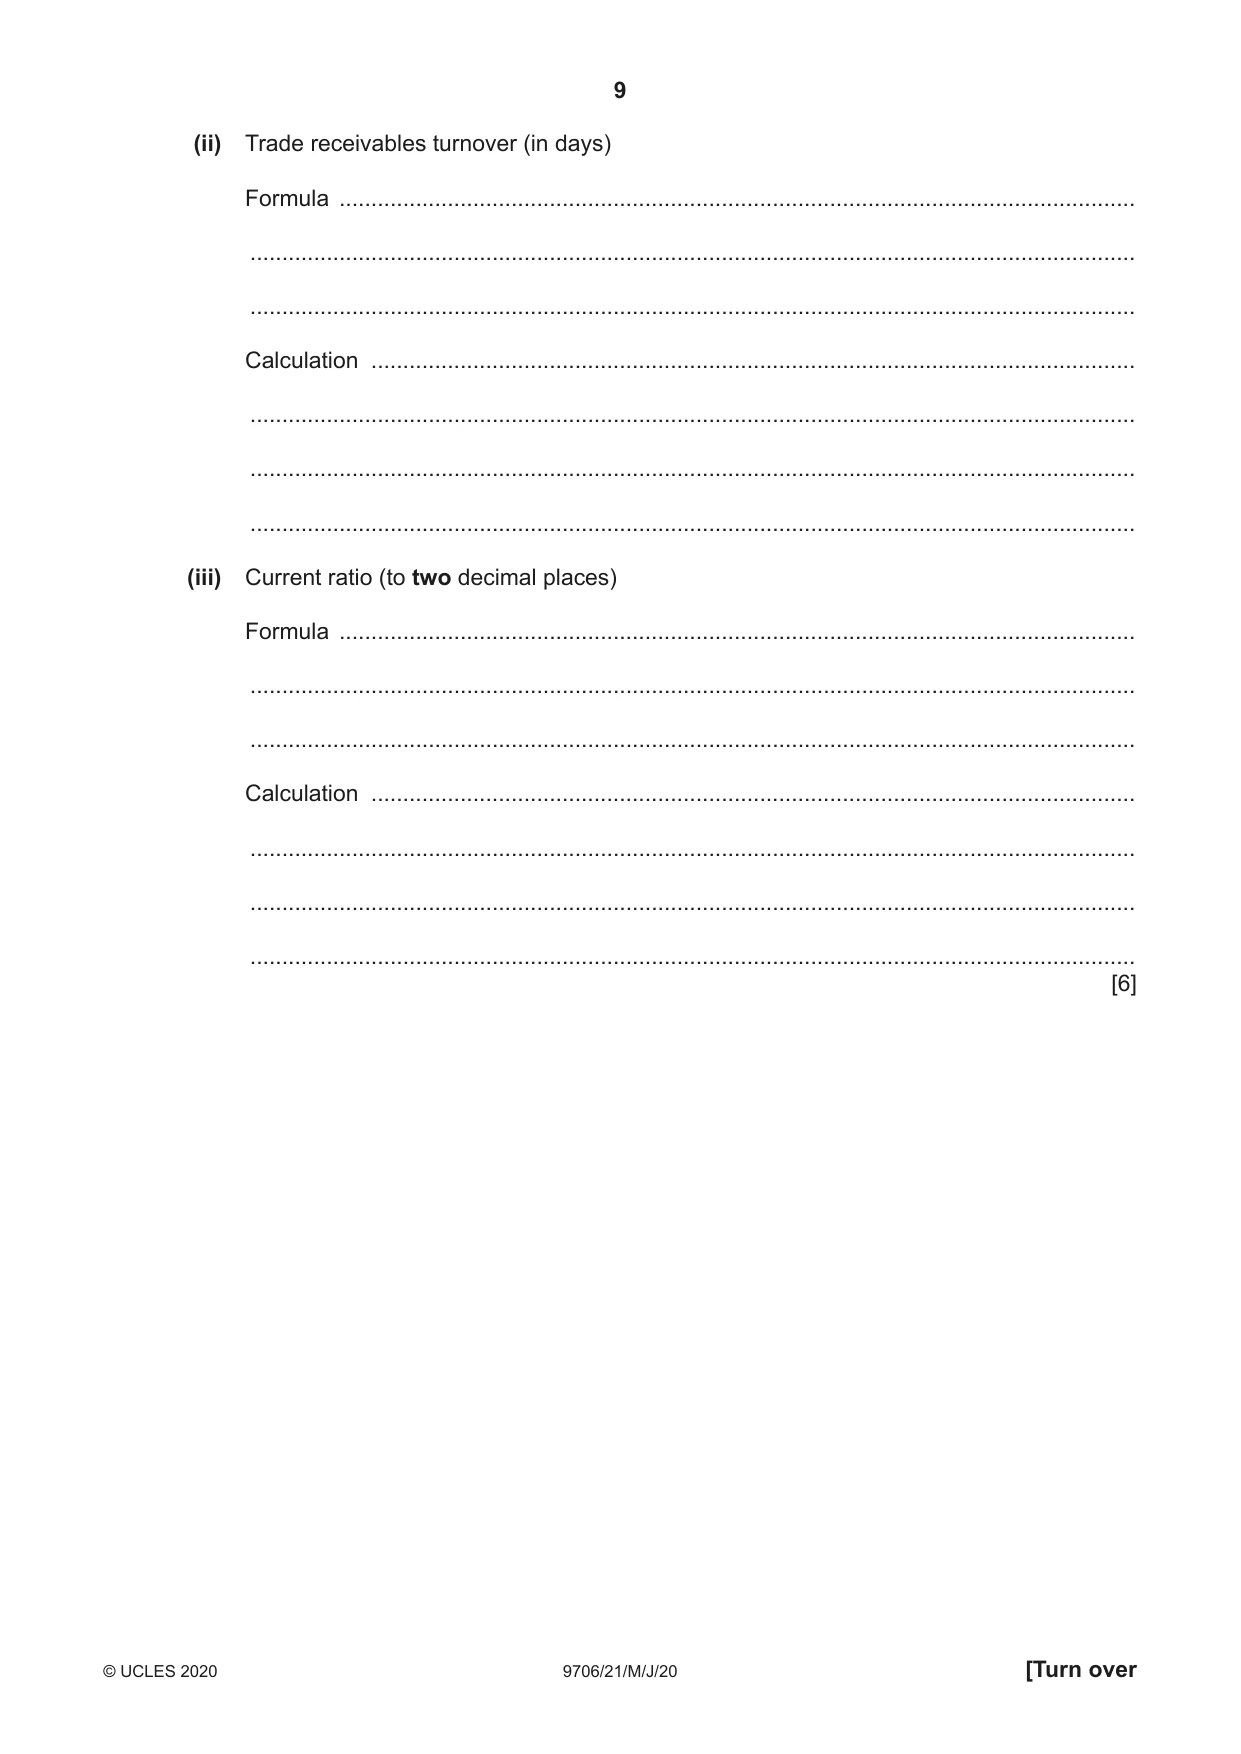
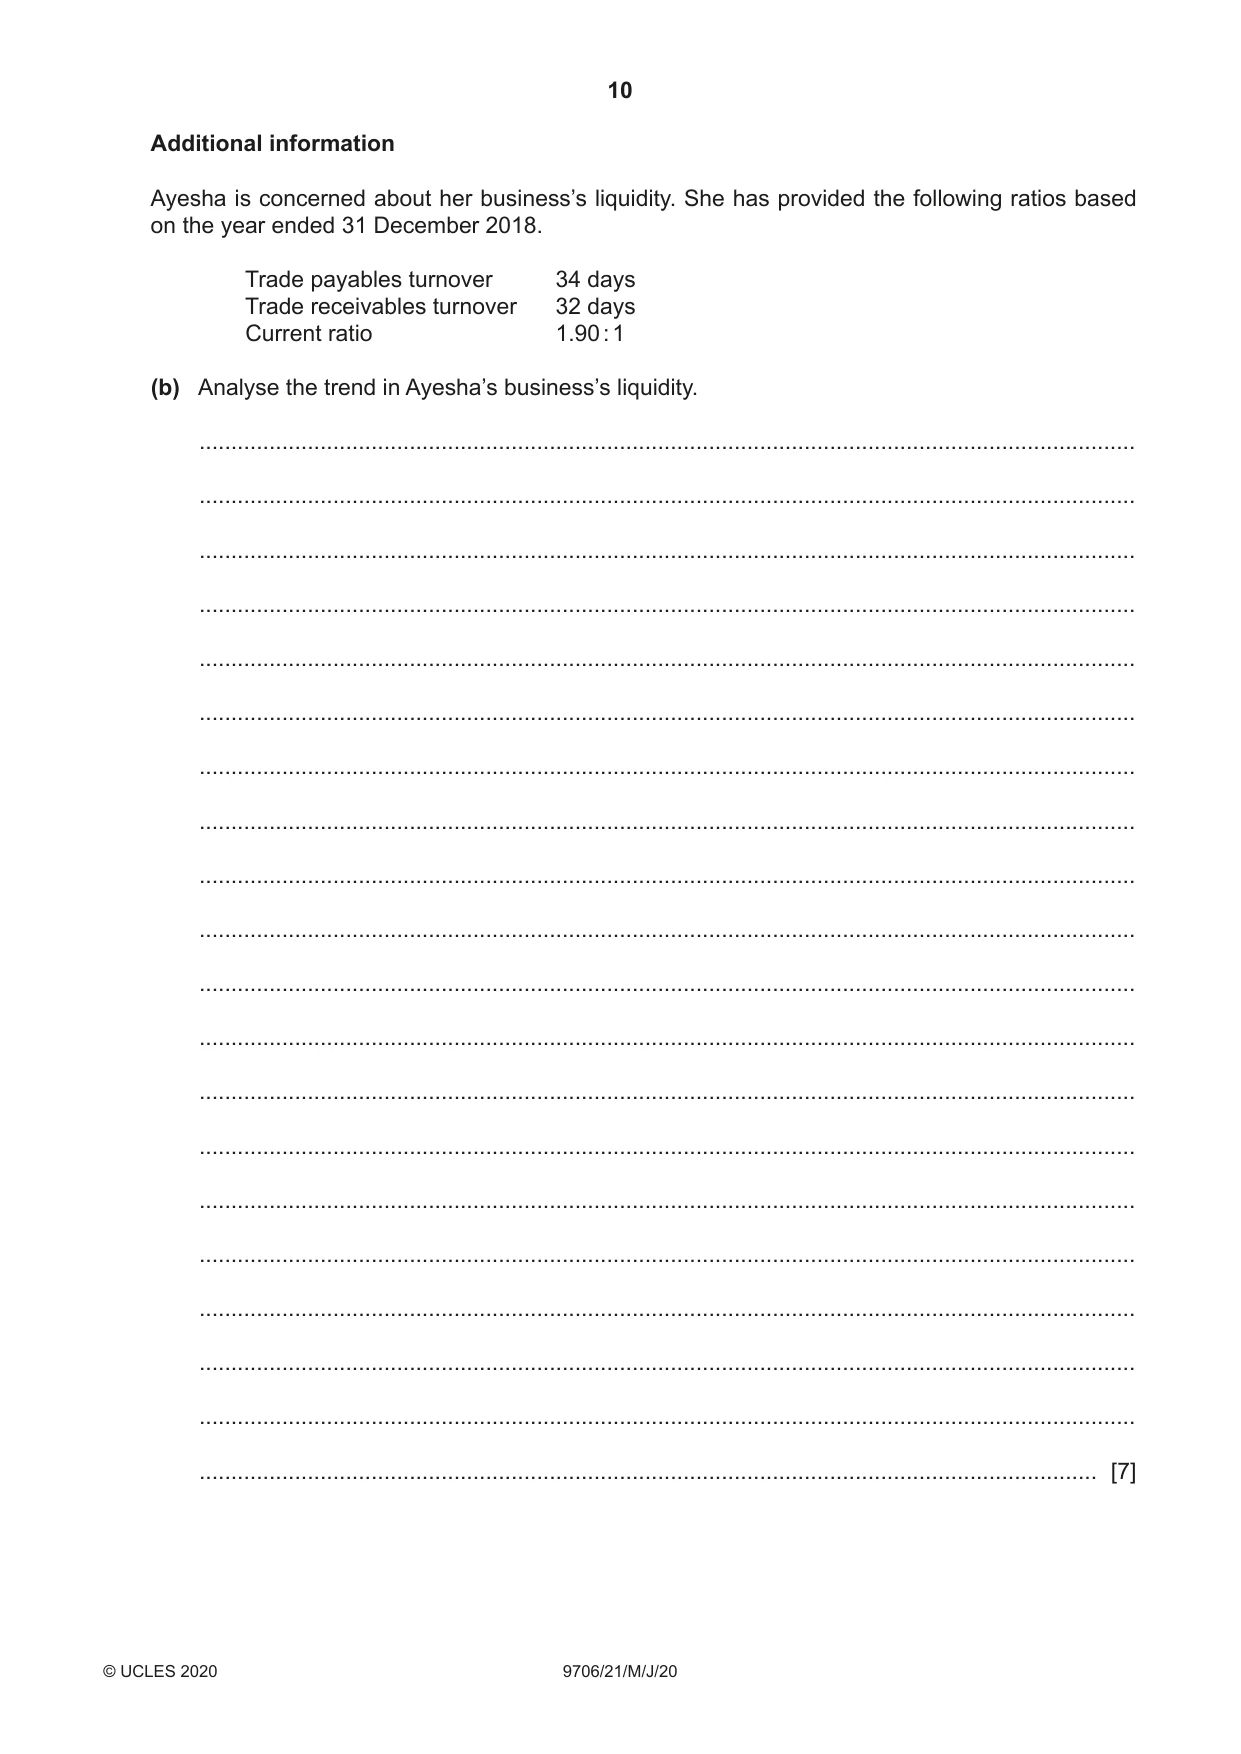
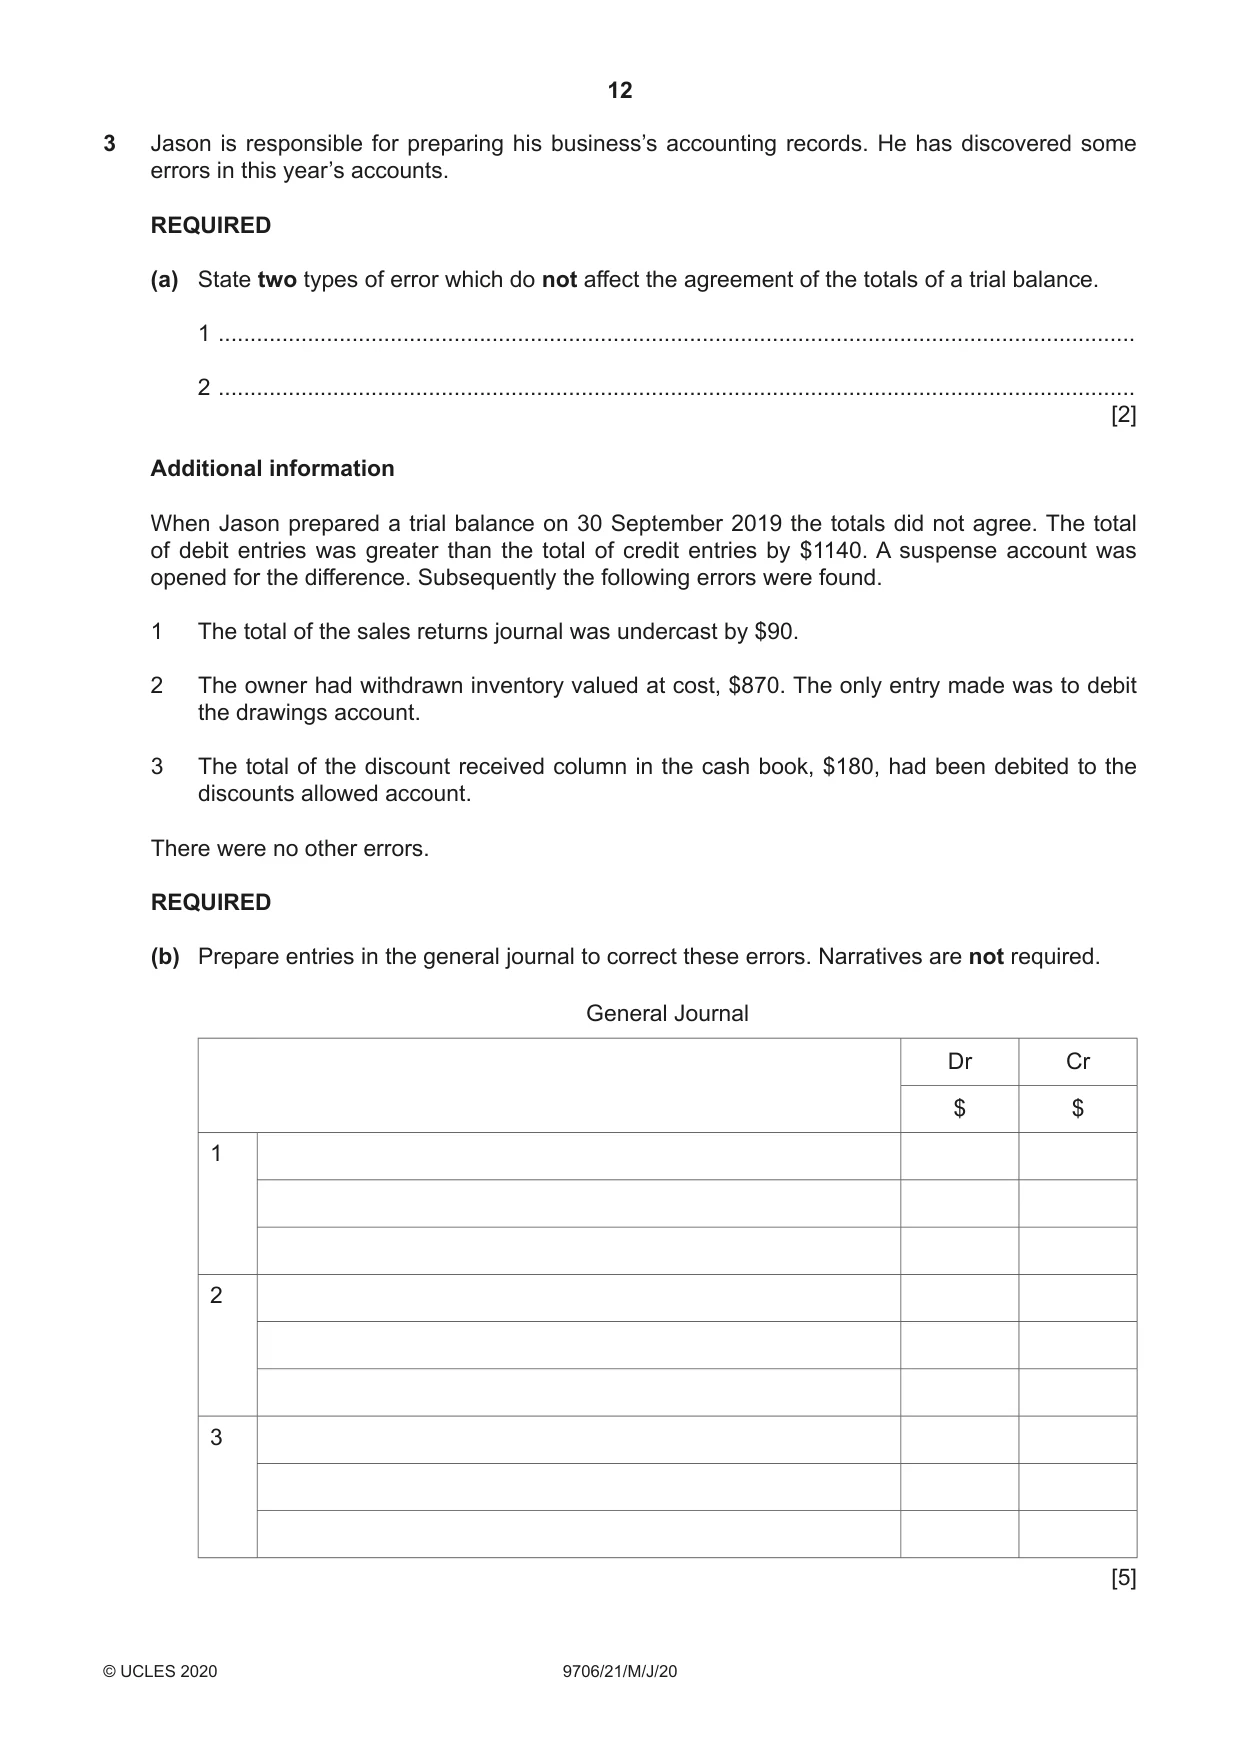
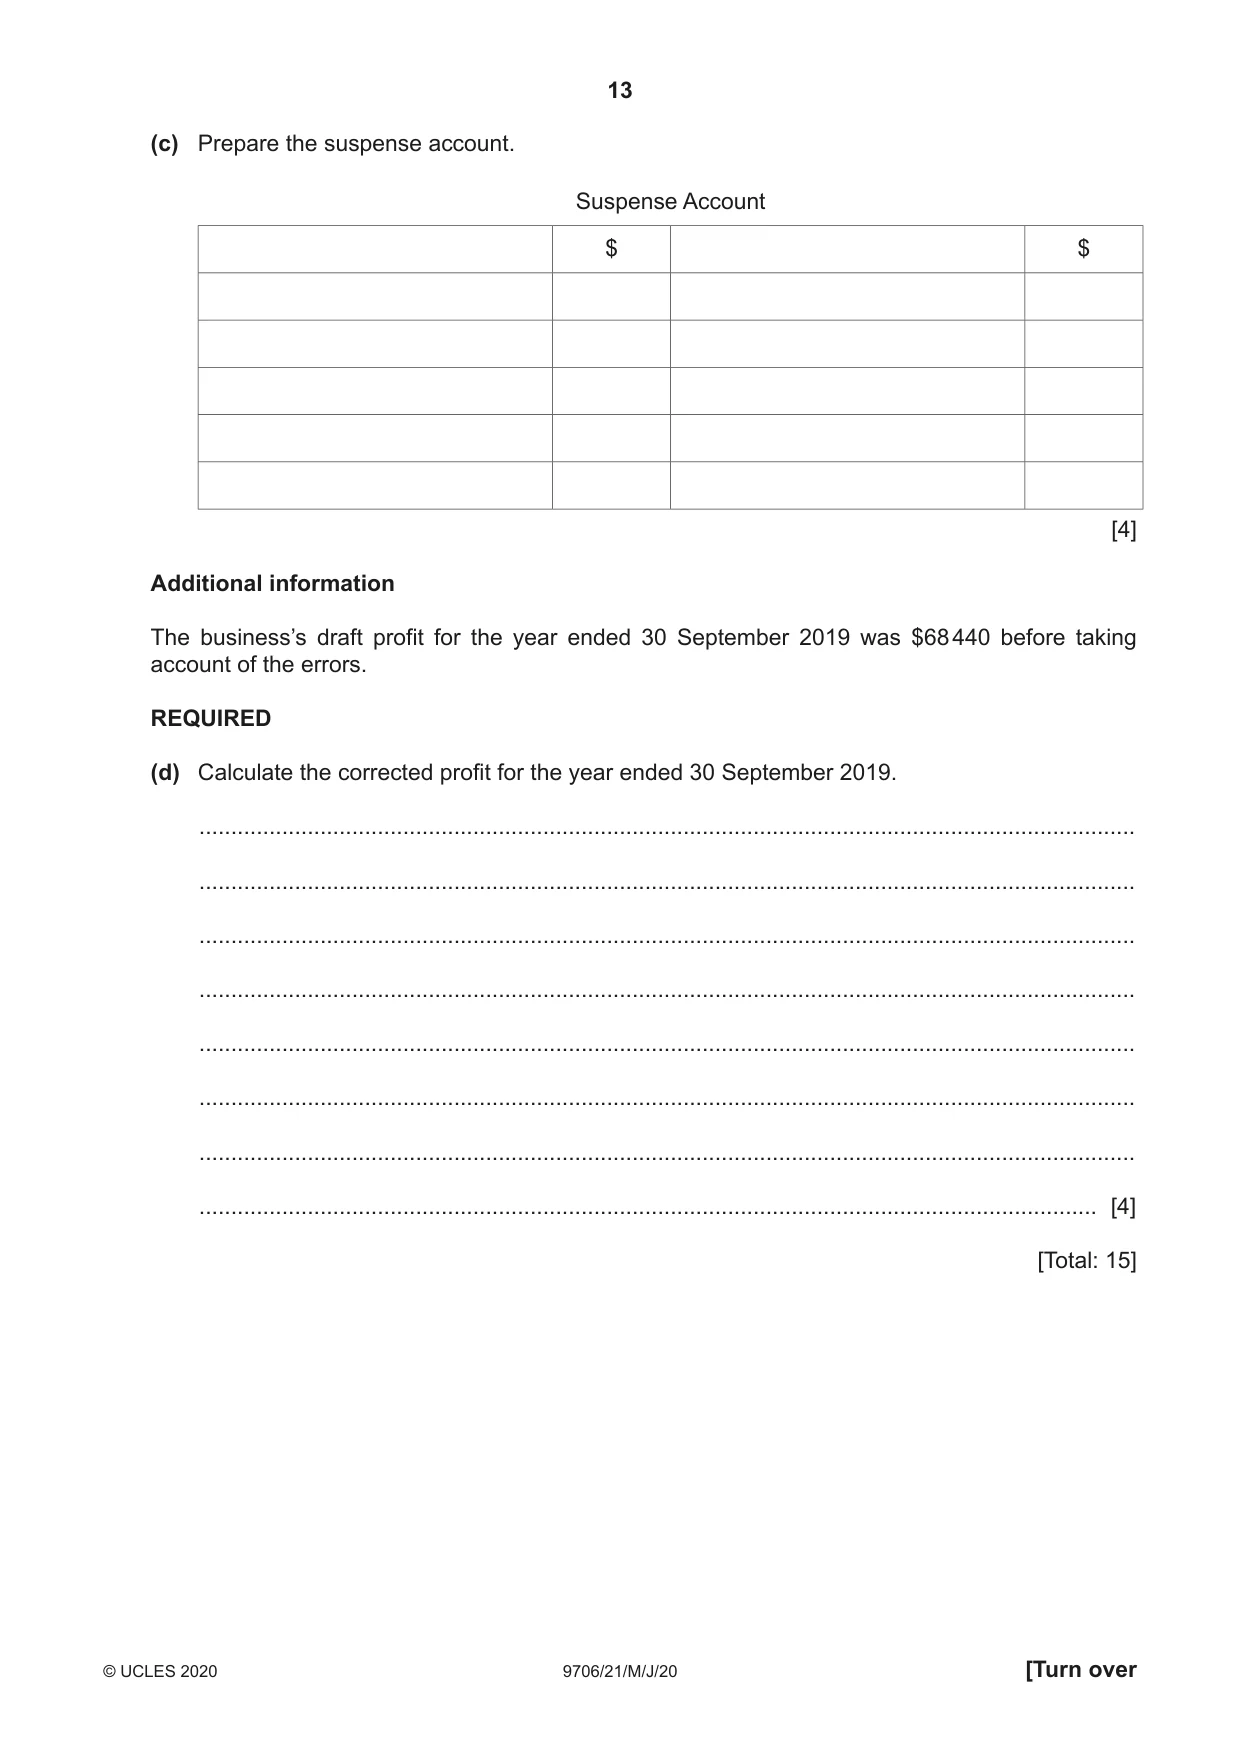
3 Remaining profits and losses are to be shared in the ratio Hamza : Noor, 3 : 2. The following balances were available. $ Current account balances at 1 January 2019 Hamza 1 290 Debit Noor 4 350 Credit Drawings for the year ended 31 December 2019 Hamza 16 900 Noor 13 200 REQUIRED (d) Prepare the appropriation account for the year ended 31 December 2019. Hamza and Noor Appropriation account for the year ended 31 December 2019 ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] (e) Calculate the balance of Hamza’s current account at 31 December 2019. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] Additional information Hamza and Noor have been considering expanding their business which will require additional finance of $90 000. In order to finance the expansion they are considering two options. Option 1: admit a new partner Option 2: apply for a bank loan REQUIRED (f) Advise which option the partners should choose. Justify your advice. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 30] 2 Ayesha has provided the following extracts from her business’s financial statements. Extract from the Income Statement for the year ended 31 December 2019 $ $ Revenue 145 500 Opening inventory 11 440 Purchases 120 120 131 560 Closing inventory 14 560 Cost of sales 117 000 Gross profit 28 500 Extract from the Statement of Financial Position at 31 December 2019 $ Current assets Inventory 14 560 Trade receivables 9 300 Cash and cash equivalents 4 240 28 100 Current liabilities Bank overdraft 8 000 Trade payables 10 400 18 400 All purchases are on credit. Two-thirds of all sales are on a credit basis. REQUIRED (a) Calculate the following ratios. State the formula used. (i) Trade payables turnover (in days) Formula ............................................................................................................................. ........................................................................................................................................... ........................................................................................................................................... Calculation ........................................................................................................................ ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... (ii) Trade receivables turnover (in days) Formula ............................................................................................................................. ........................................................................................................................................... ........................................................................................................................................... Calculation ........................................................................................................................ ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... (iii) Current ratio (to two decimal places) Formula ............................................................................................................................. ........................................................................................................................................... ........................................................................................................................................... Calculation ........................................................................................................................ ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... [6] Additional information Ayesha is concerned about her business’s liquidity. She has provided the following ratios based on the year ended 31 December 2018. Trade payables turnover 34 days Trade receivables turnover 32 days Current ratio 1.90 : 1 (b) Analyse the trend in Ayesha’s business’s liquidity. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [7] (c) State two factors that should be considered when choosing businesses with which to compare a business. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] [Total: 15] 3 Jason is responsible for preparing his business’s accounting records. He has discovered some errors in this year’s accounts. REQUIRED (a) State two types of error which do not affect the agreement of the totals of a trial balance. 1 ................................................................................................................................................ 2 ................................................................................................................................................ [2] Additional information When Jason prepared a trial balance on 30 September 2019 the totals did not agree. The total of debit entries was greater than the total of credit entries by $1140. A suspense account was opened for the difference. Subsequently the following errors were found. 1 The total of the sales returns journal was undercast by $90. 2 The owner had withdrawn inventory valued at cost, $870. The only entry made was to debit the drawings account. 3 The total of the discount received column in the cash book, $180, had been debited to the discounts allowed account. There were no other errors. REQUIRED (b) Prepare entries in the general journal to correct these errors. Narratives are not required. General Journal Dr Cr $ $ 1 2 3 [5] (c) Prepare the suspense account. Suspense Account $ $ [4] Additional information The business’s draft profit for the year ended 30 September 2019 was $68 440 before taking account of the errors. REQUIRED (d) Calculate the corrected profit for the year ended 30 September 2019. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] [Total: 15]
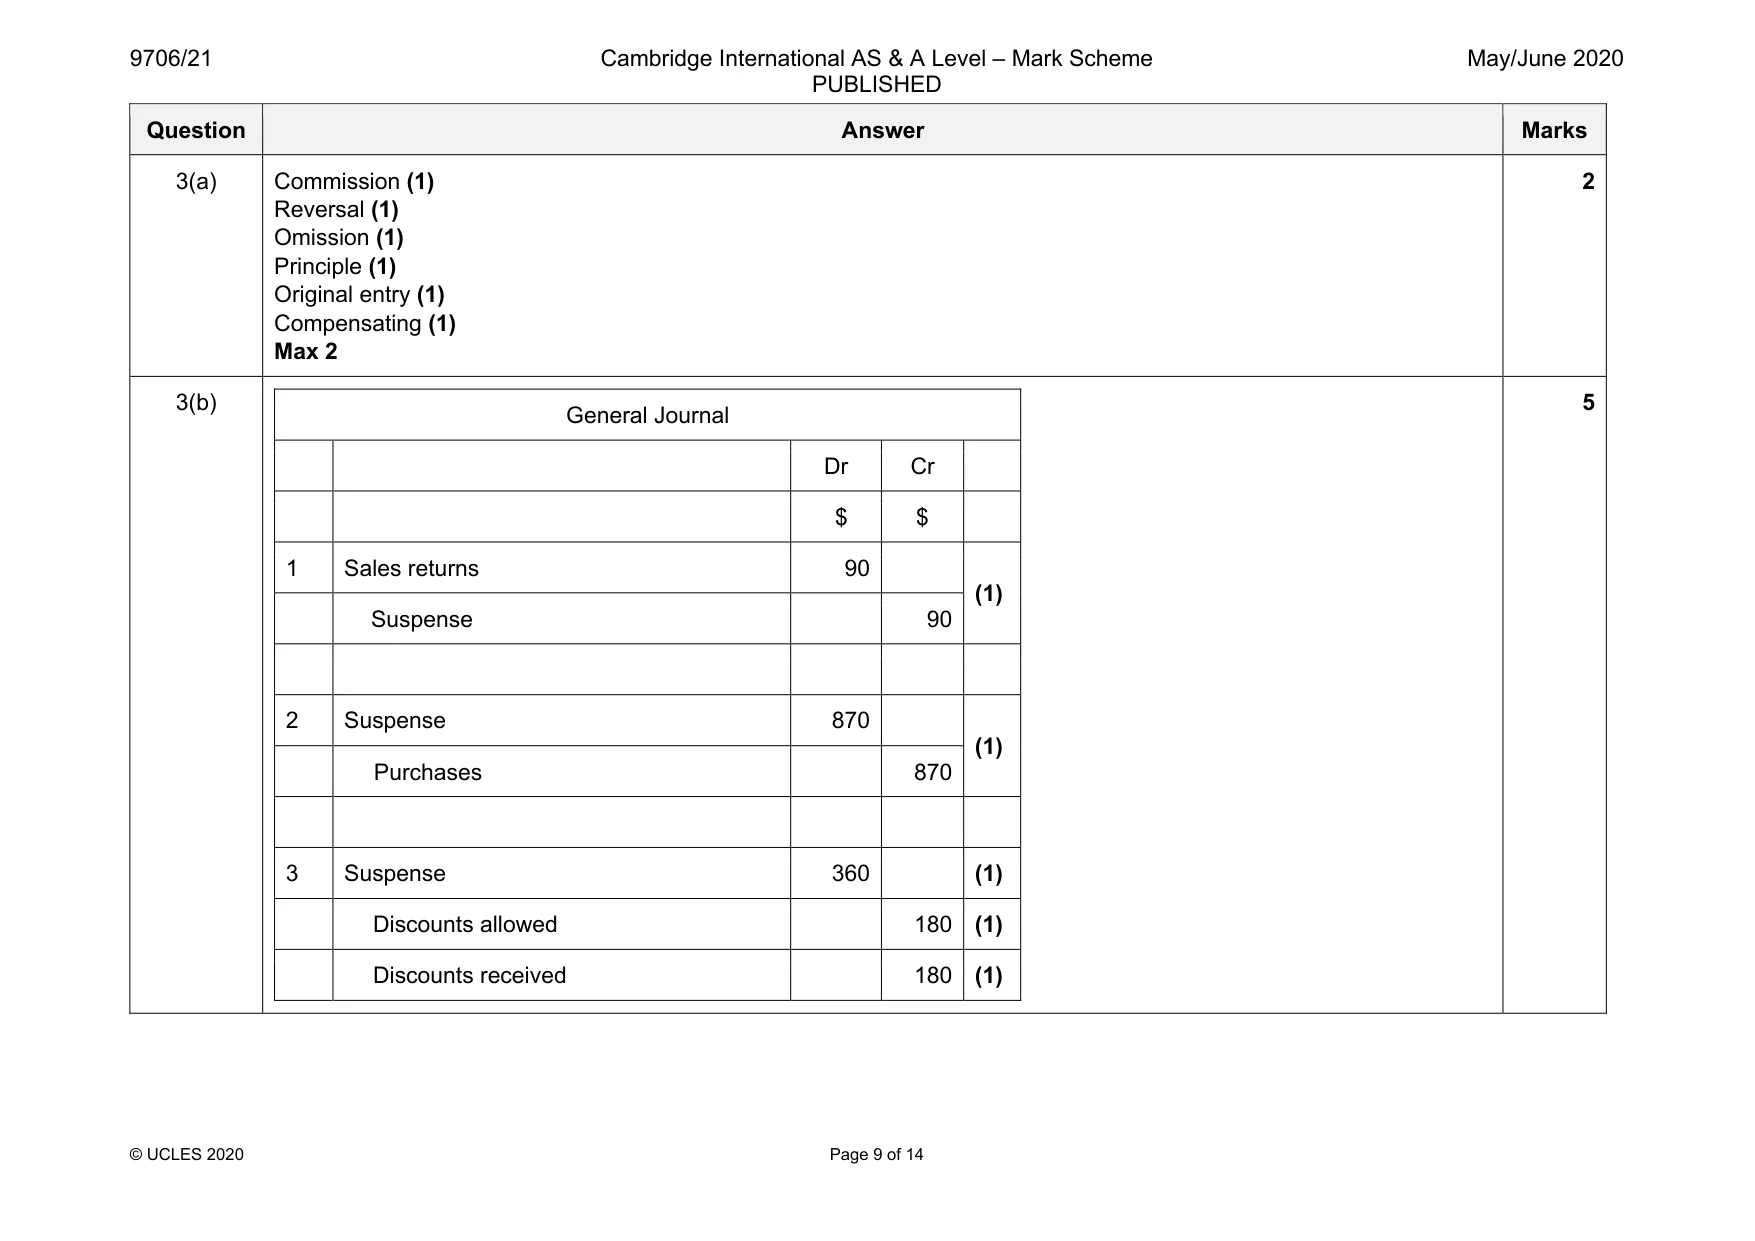
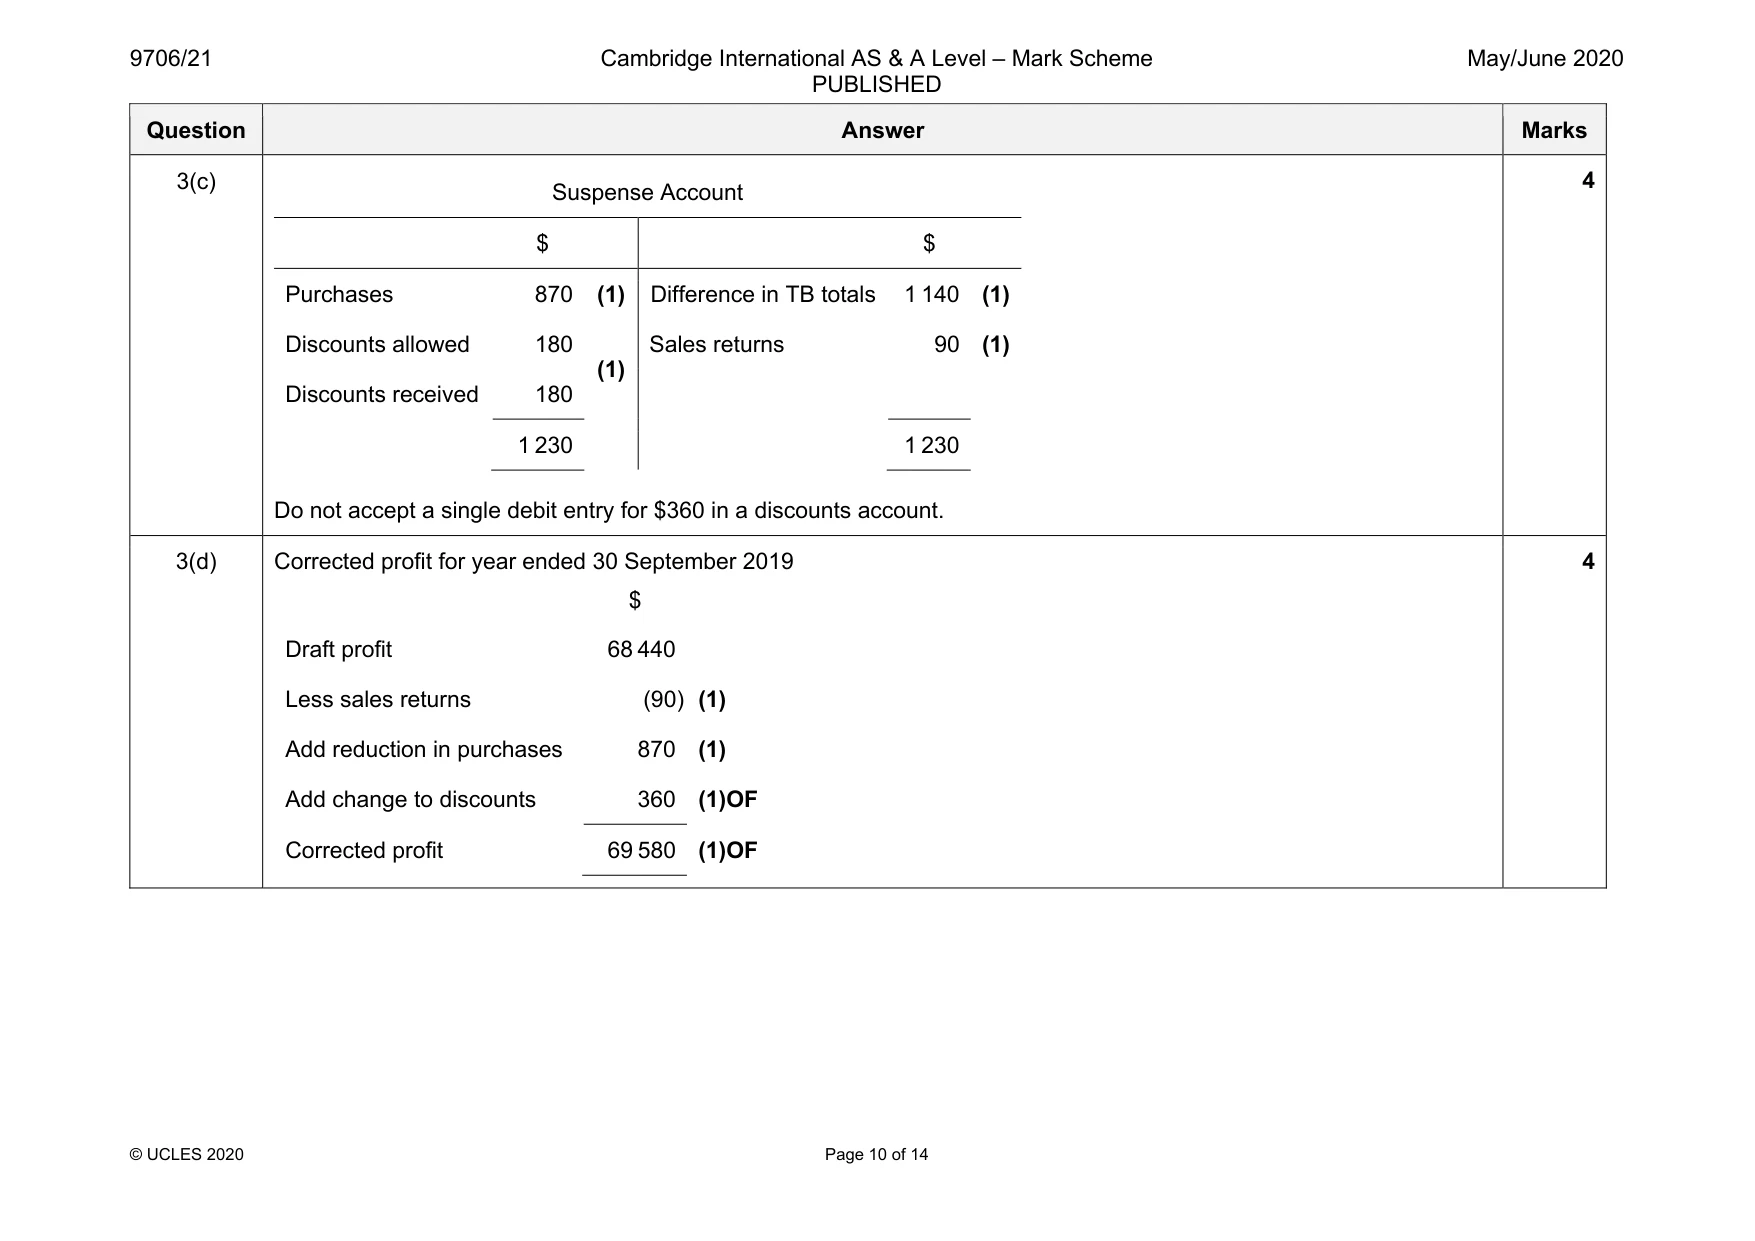
Mark scheme: 3(a) Commission (1) Reversal (1) Omission (1) Principle (1) Original entry (1) Compensating (1) Max 2 2 3(b) General Journal Dr Cr $ $ 1 Sales returns 90 (1) Suspense 90 2 Suspense 870 (1) Purchases 870 3 Suspense 360 (1) Discounts allowed 180 (1) Discounts received 180 (1) 5 Question Answer Marks 3(c) Suspense Account $ $ Purchases 870 (1) Difference in TB totals 1 140 (1) Discounts allowed 180 (1) Sales returns 90 (1) Discounts received 180 1 230 1 230 Do not accept a single debit entry for $360 in a discounts account. 4 3(d) Corrected profit for year ended 30 September 2019 $ Draft profit 68 440 Less sales returns (90) (1) Add reduction in purchases 870 (1) Add change to discounts 360 (1)OF Corrected profit 69 580 (1)OF 4
Q4 · G Limited manufactures cakes for celebrations
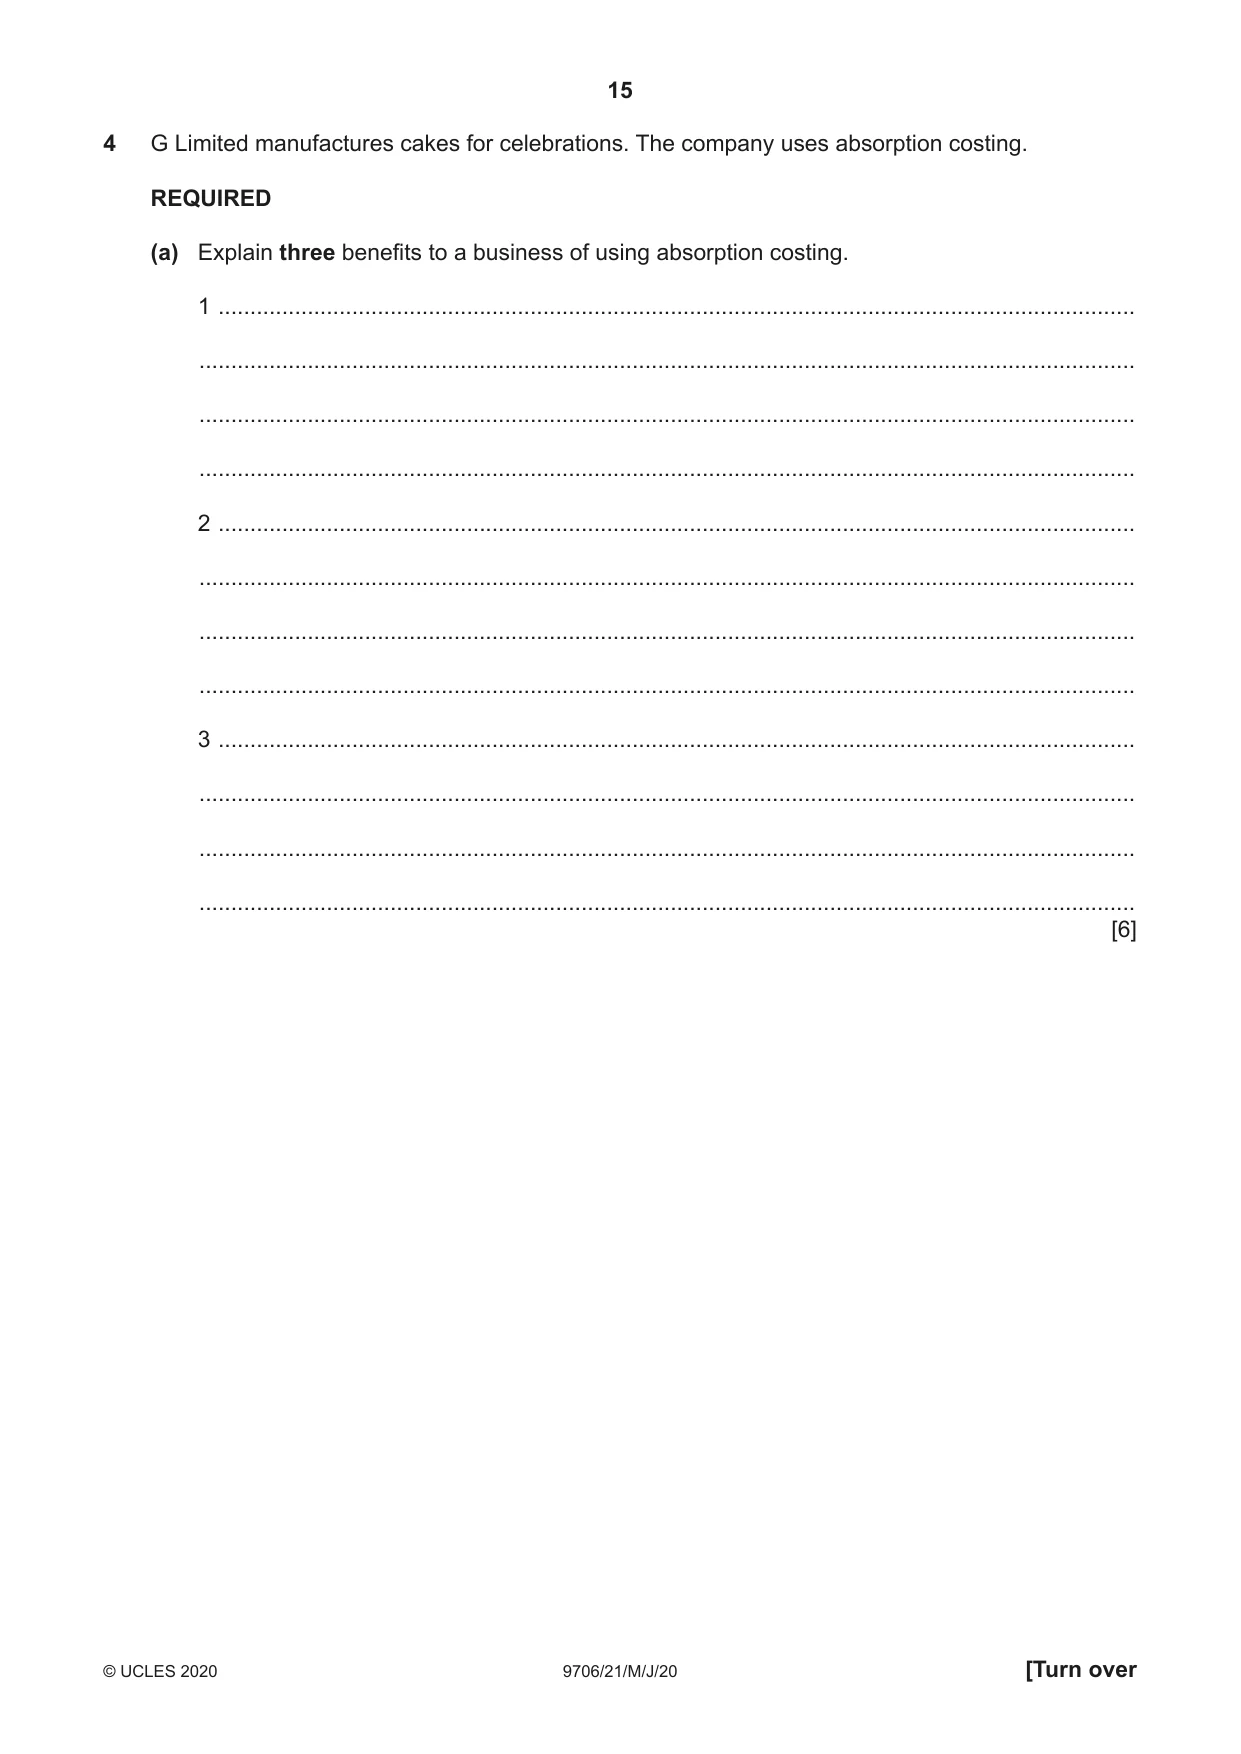
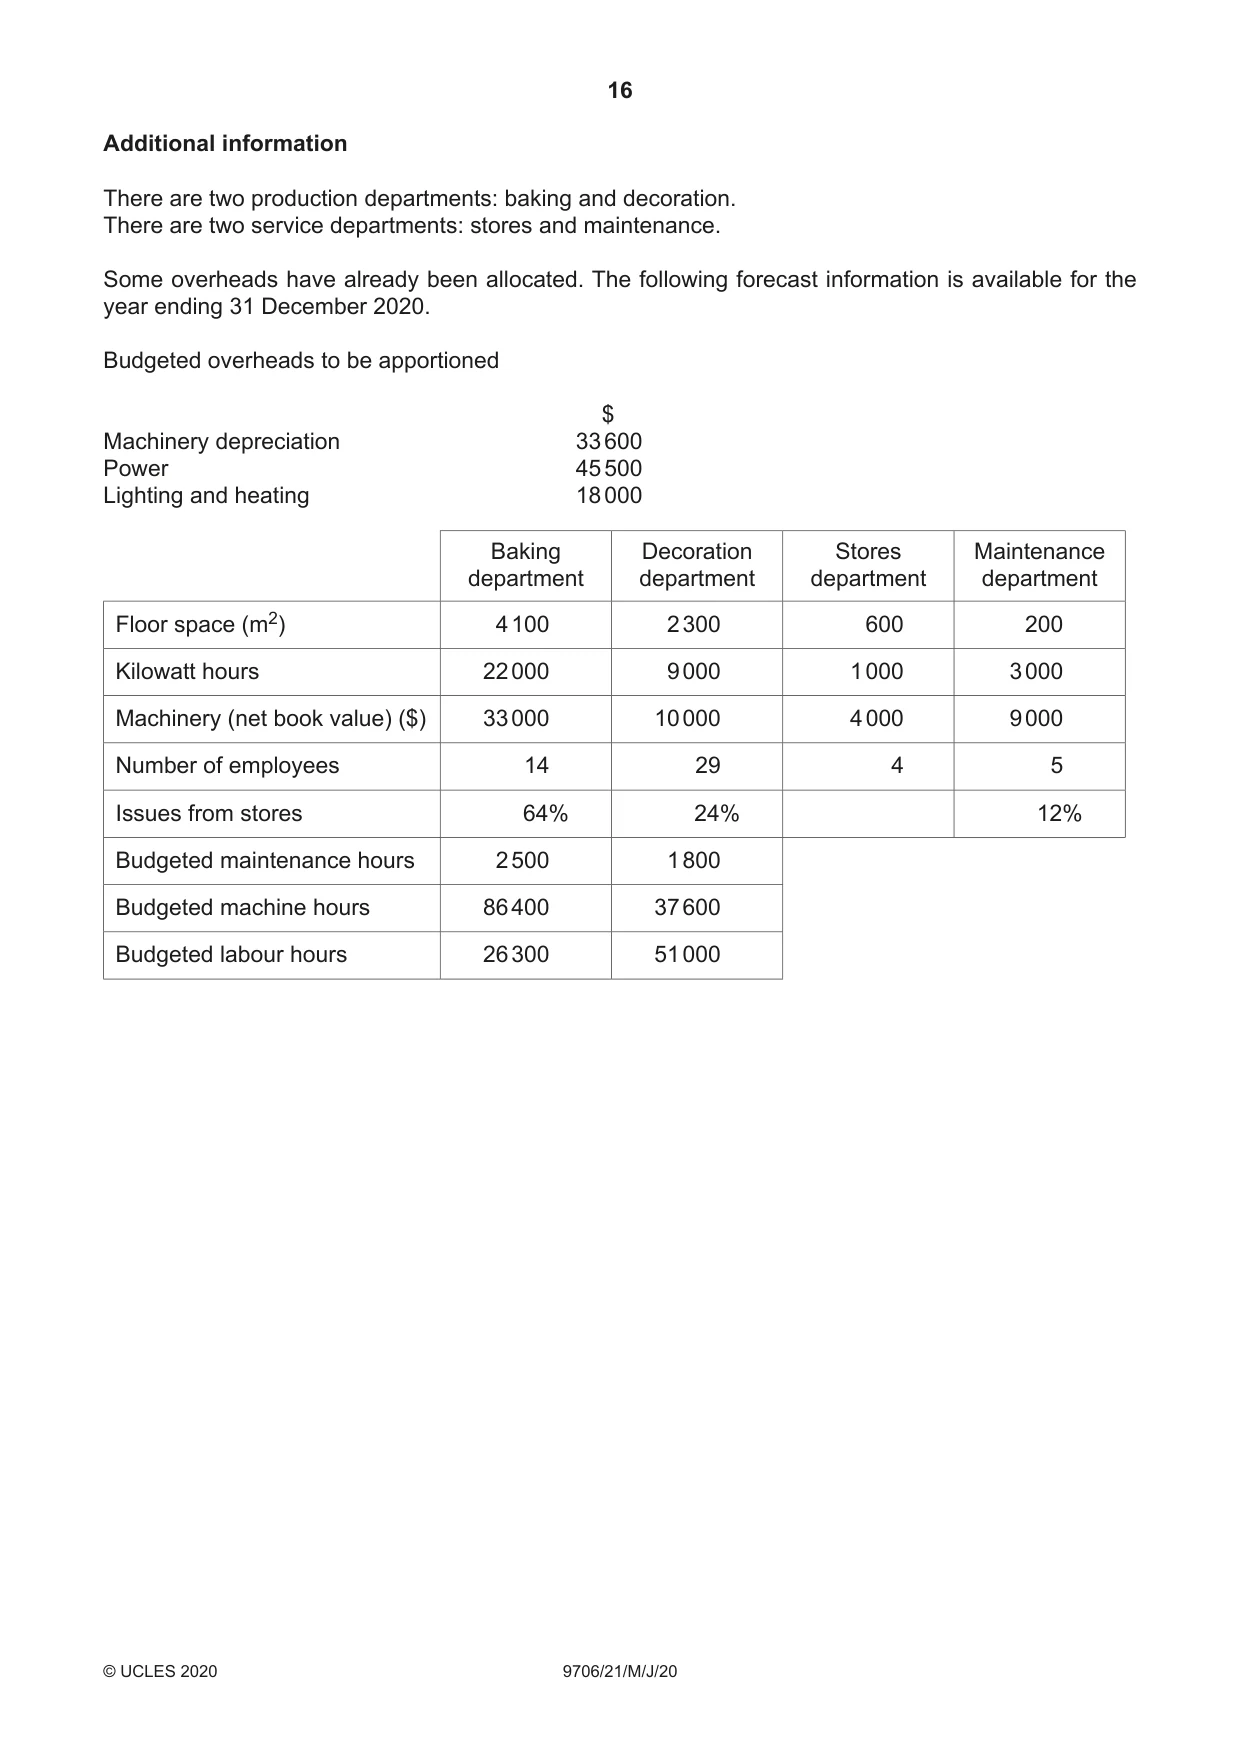
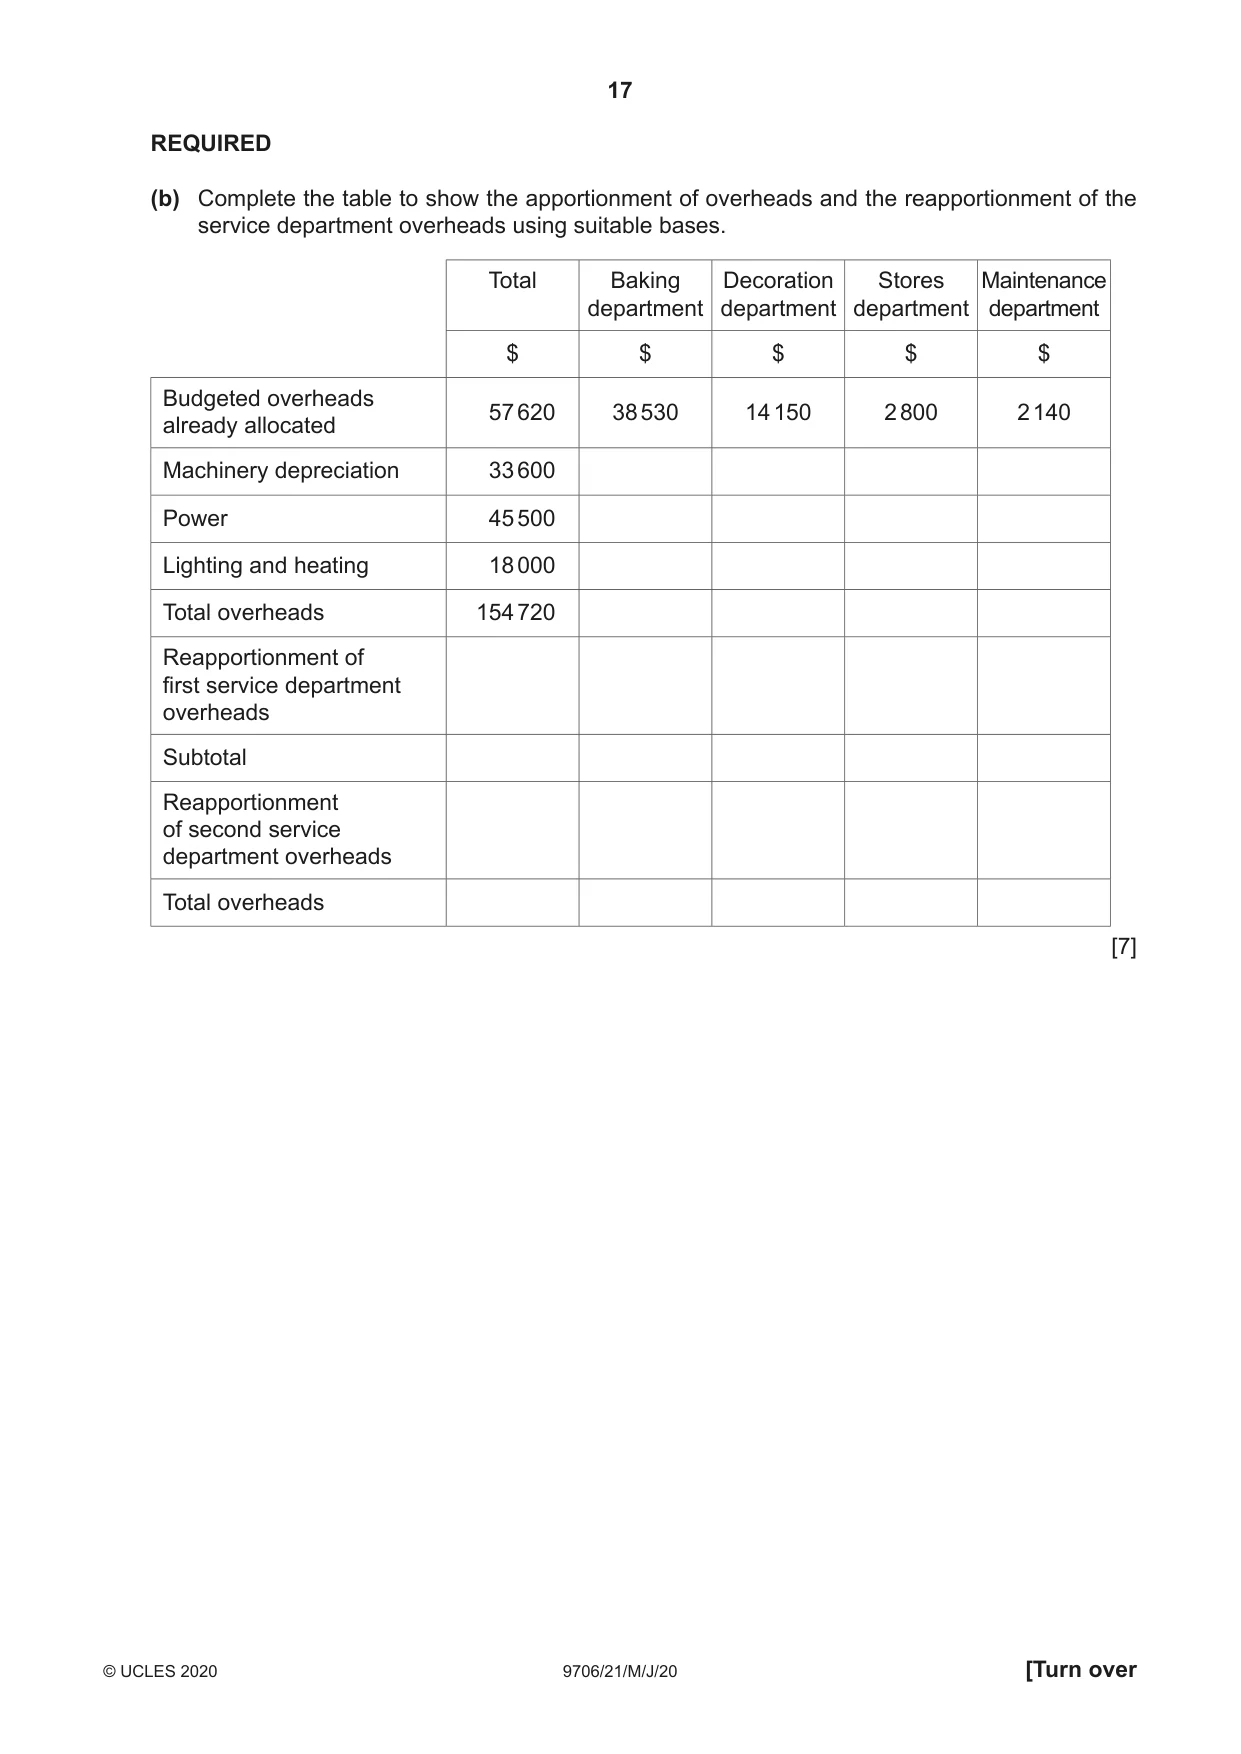
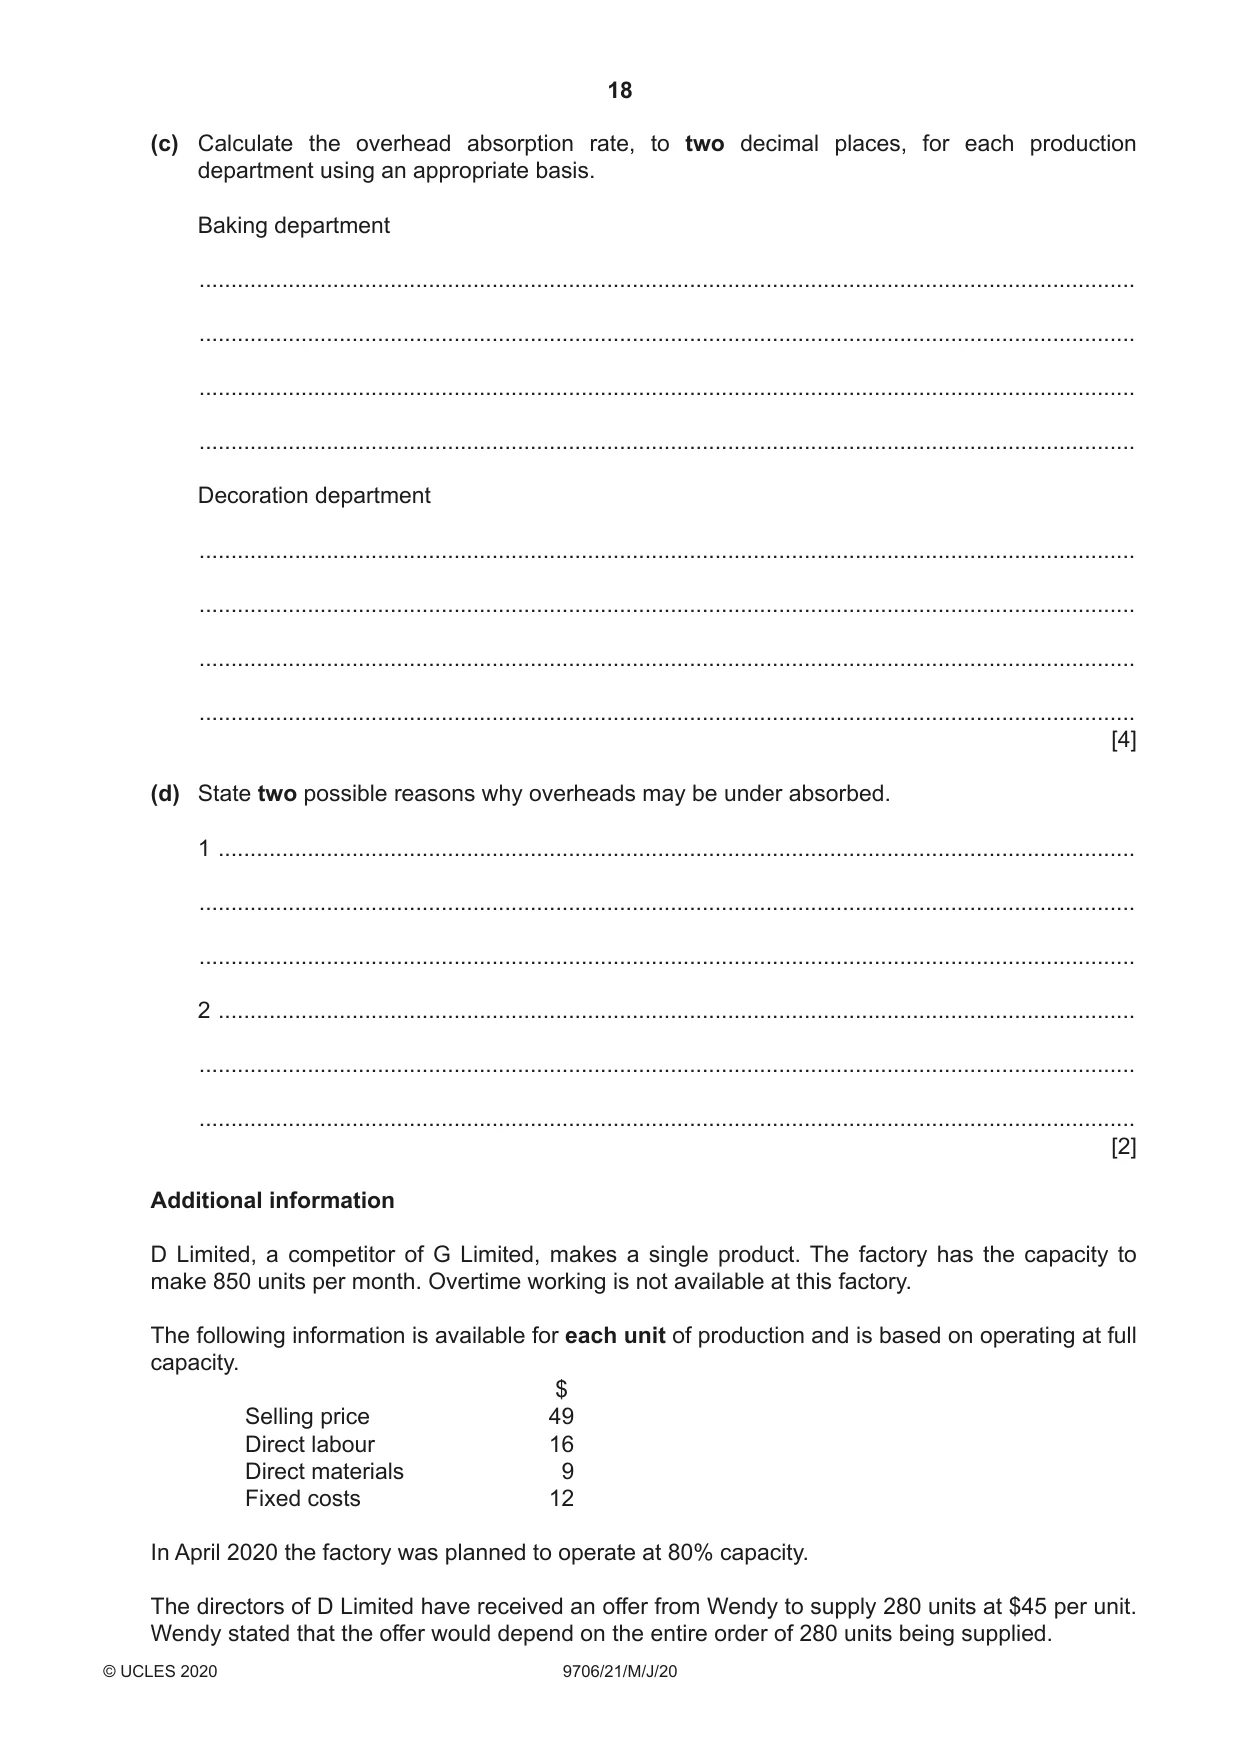
4 G Limited manufactures cakes for celebrations. The company uses absorption costing. REQUIRED (a) Explain three benefits to a business of using absorption costing. 1 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... 3 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... [6] Additional information There are two production departments: baking and decoration. There are two service departments: stores and maintenance. Some overheads have already been allocated. The following forecast information is available for the year ending 31 December 2020. Budgeted overheads to be apportioned $ Machinery depreciation 33 600 Power 45 500 Lighting and heating 18 000 Baking Decoration Stores Maintenance department department department department Floor space (m2) 4 100 2 300 600 200 Kilowatt hours 22 000 9 000 1 000 3 000 Machinery (net book value) ($) 33 000 10 000 4 000 9 000 Number of employees 14 29 4 5 Issues from stores 64% 24% 12% Budgeted maintenance hours 2 500 1 800 Budgeted machine hours 86 400 37 600 Budgeted labour hours 26 300 51 000 REQUIRED (b) Complete the table to show the apportionment of overheads and the reapportionment of the service department overheads using suitable bases. Total Baking Decoration Stores Maintenance department department department department $ $ $ $ $ Budgeted overheads 57 620 38 530 14 150 2 800 2 140 already allocated Machinery depreciation 33 600 Power 45 500 Lighting and heating 18 000 Total overheads 154 720 Reapportionment of first service department overheads Subtotal Reapportionment of second service department overheads Total overheads [7]
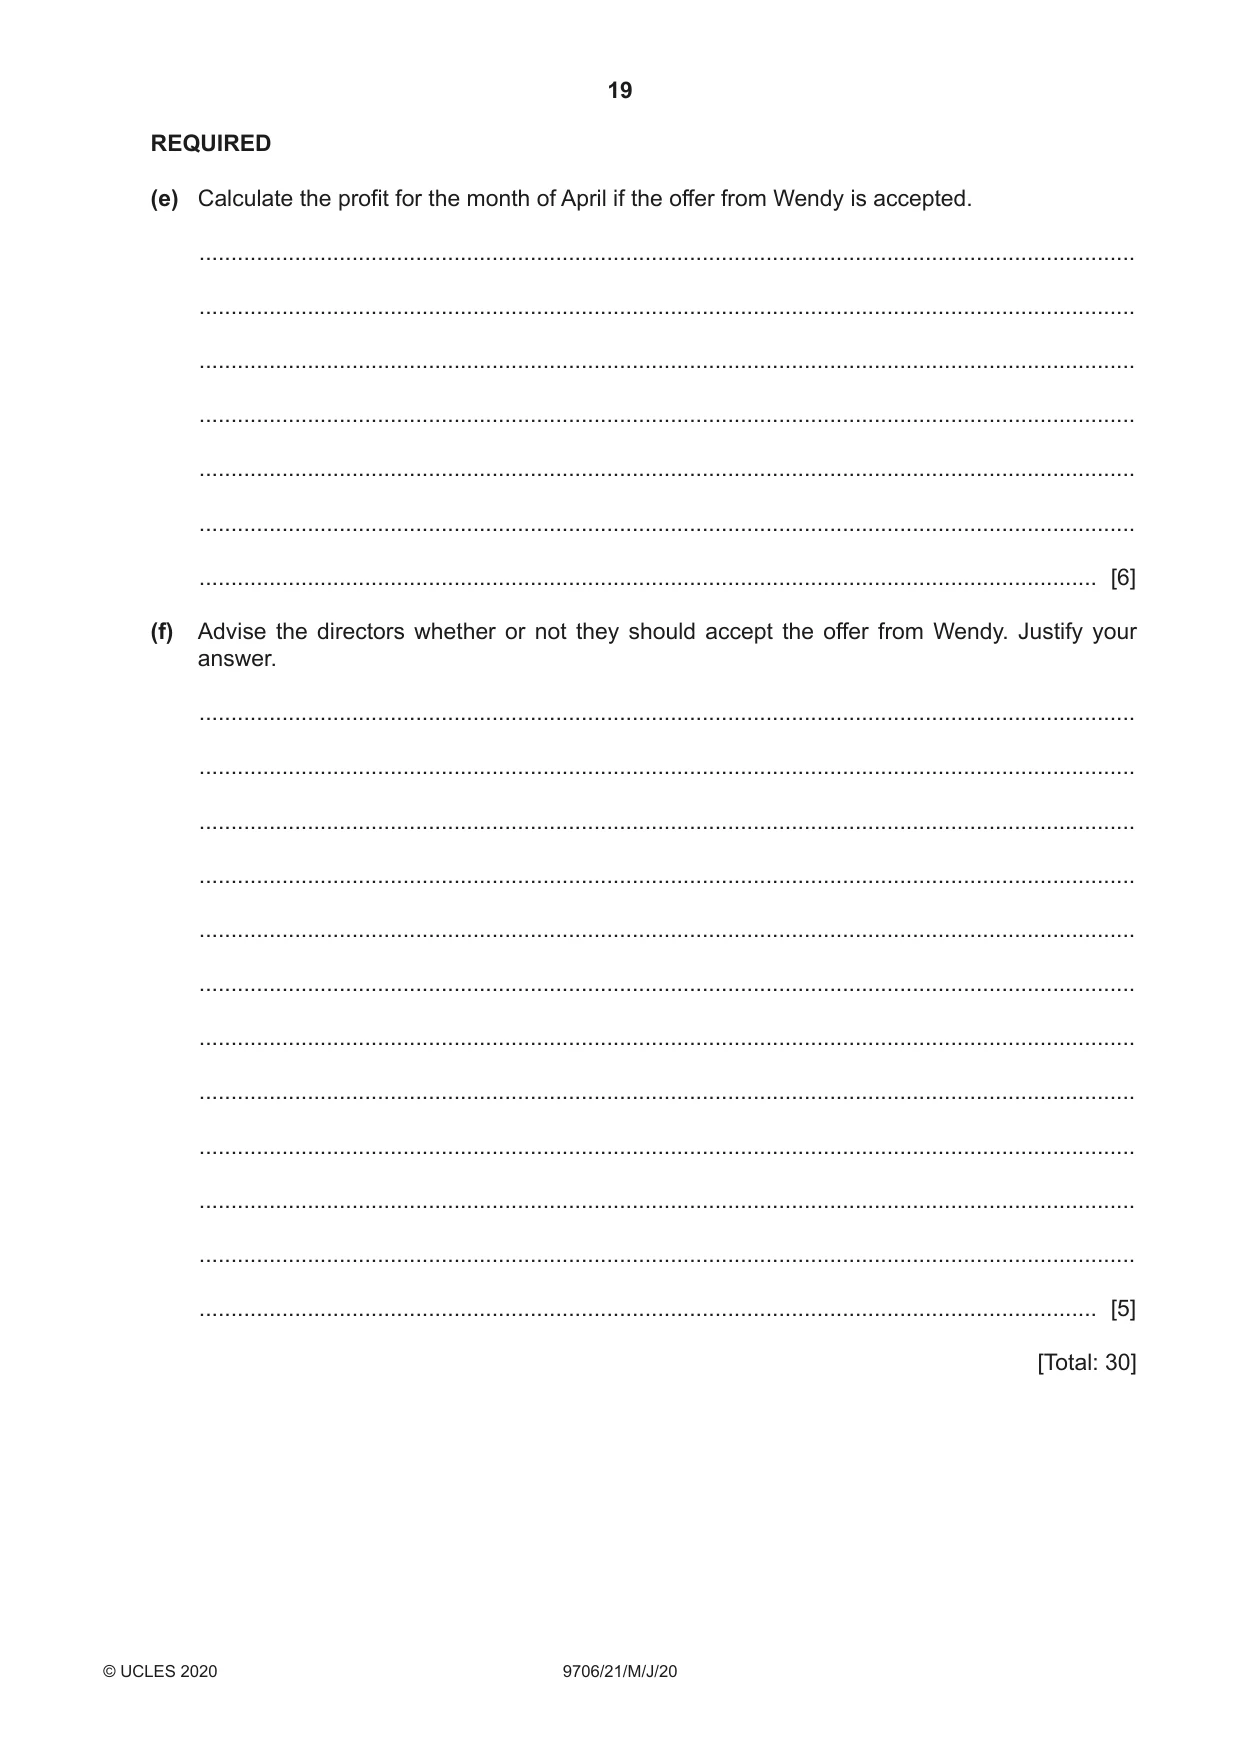
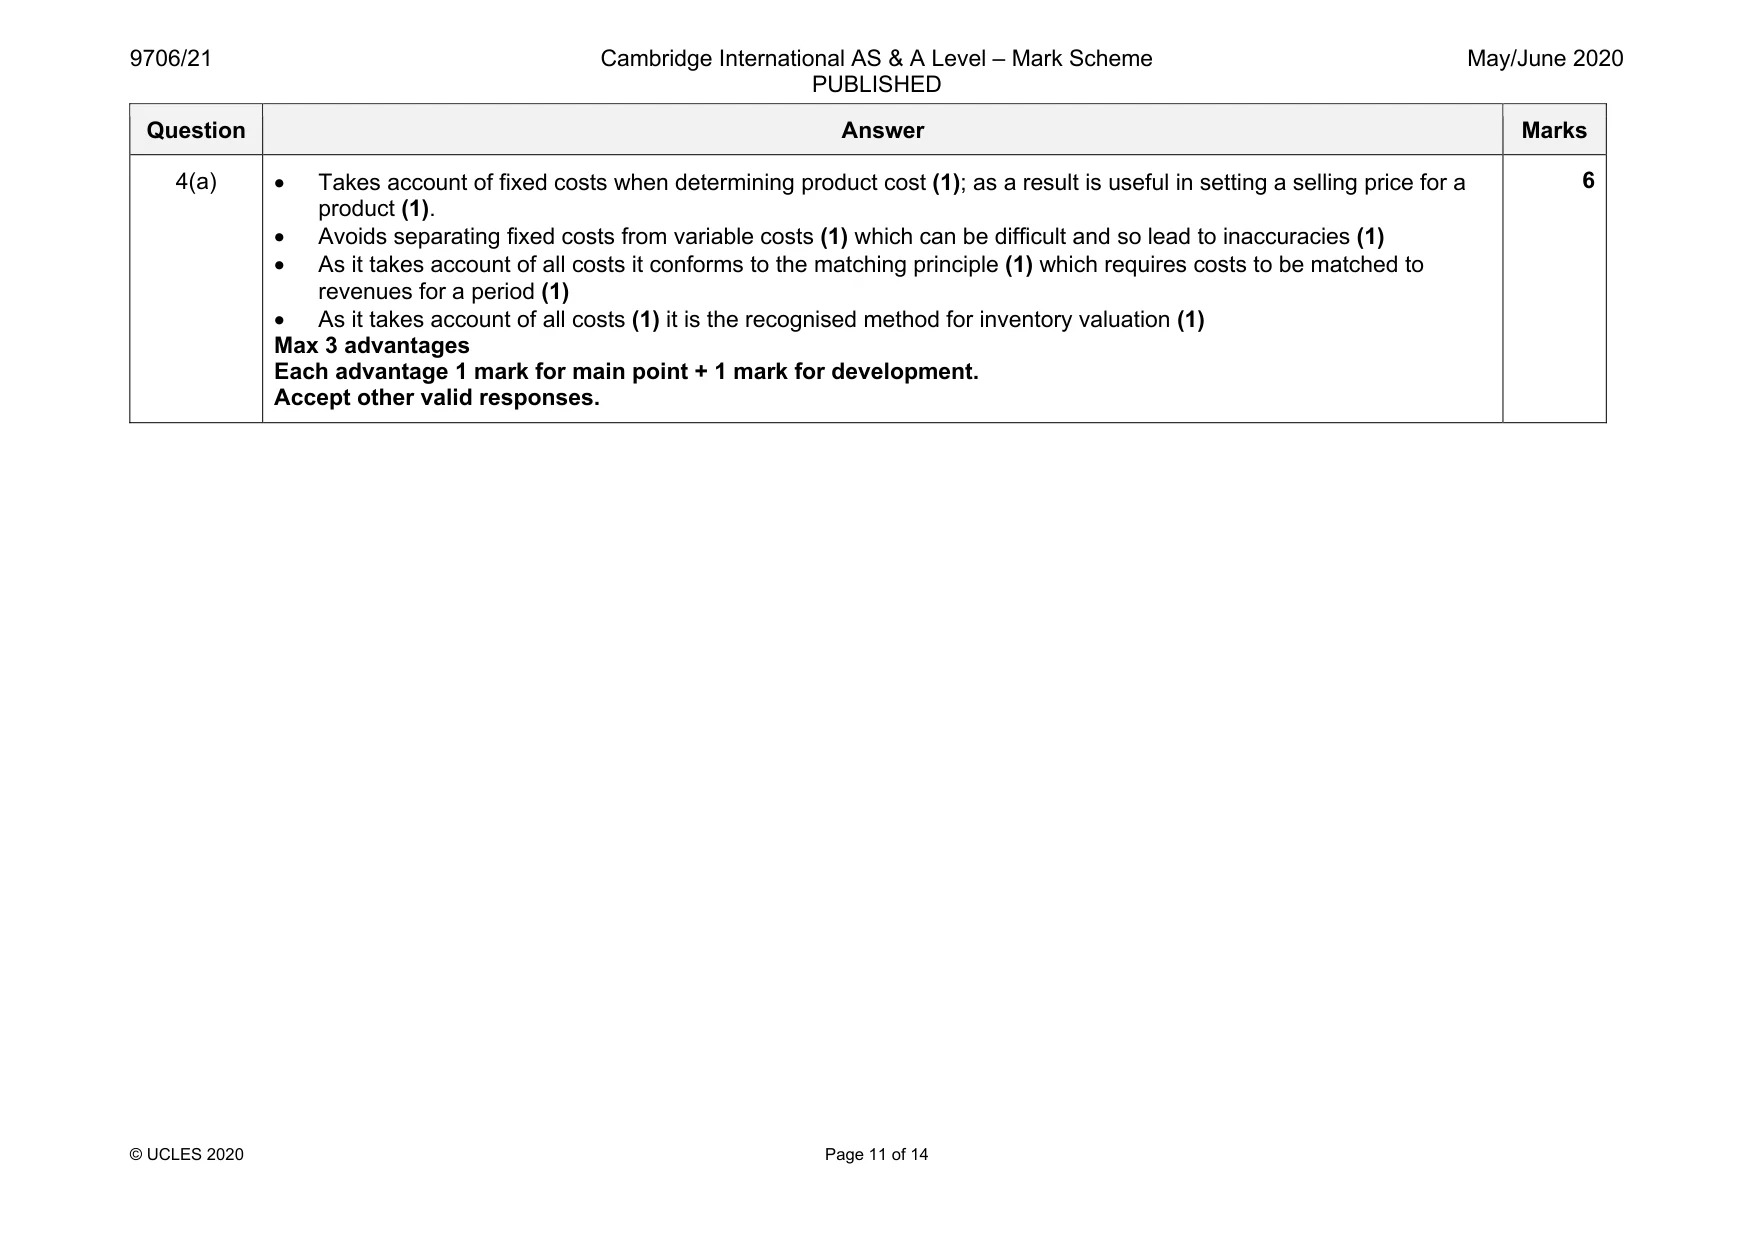
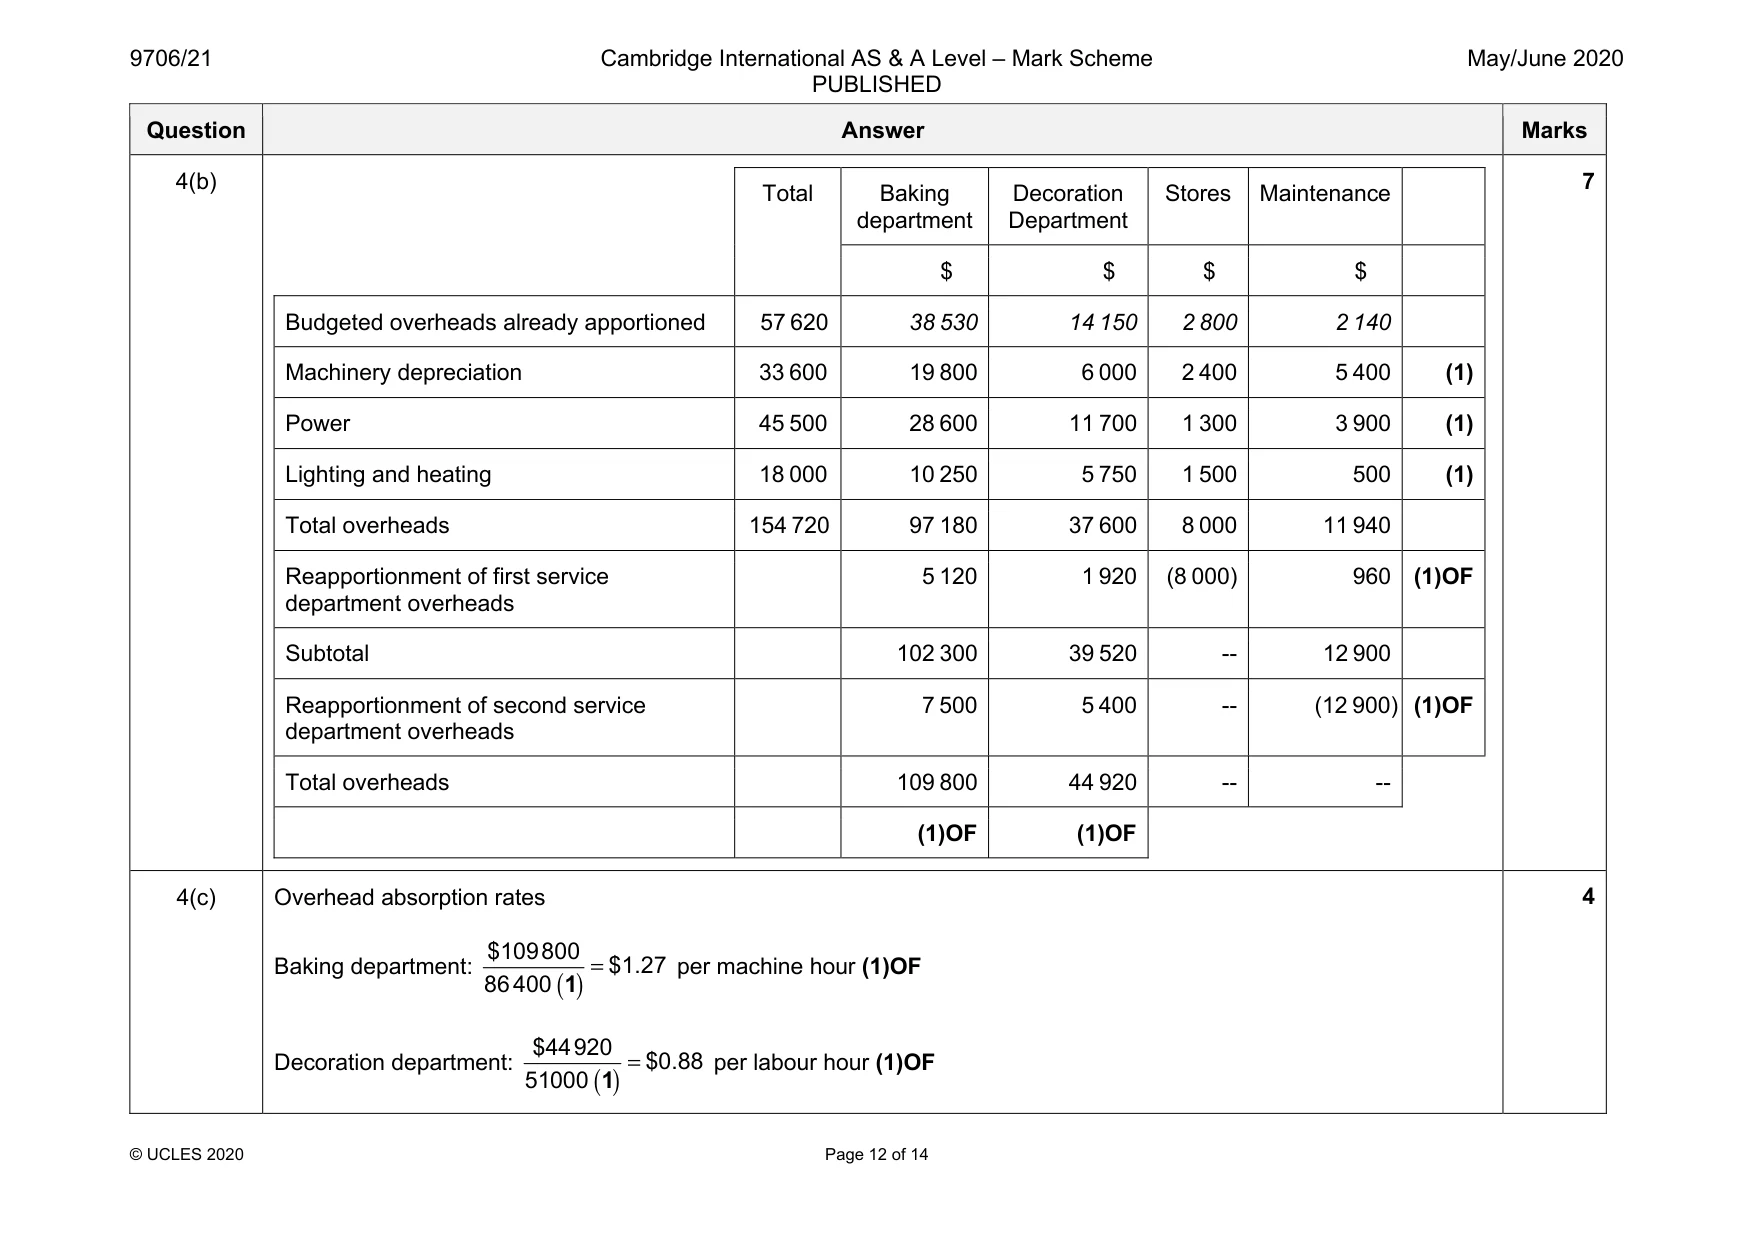
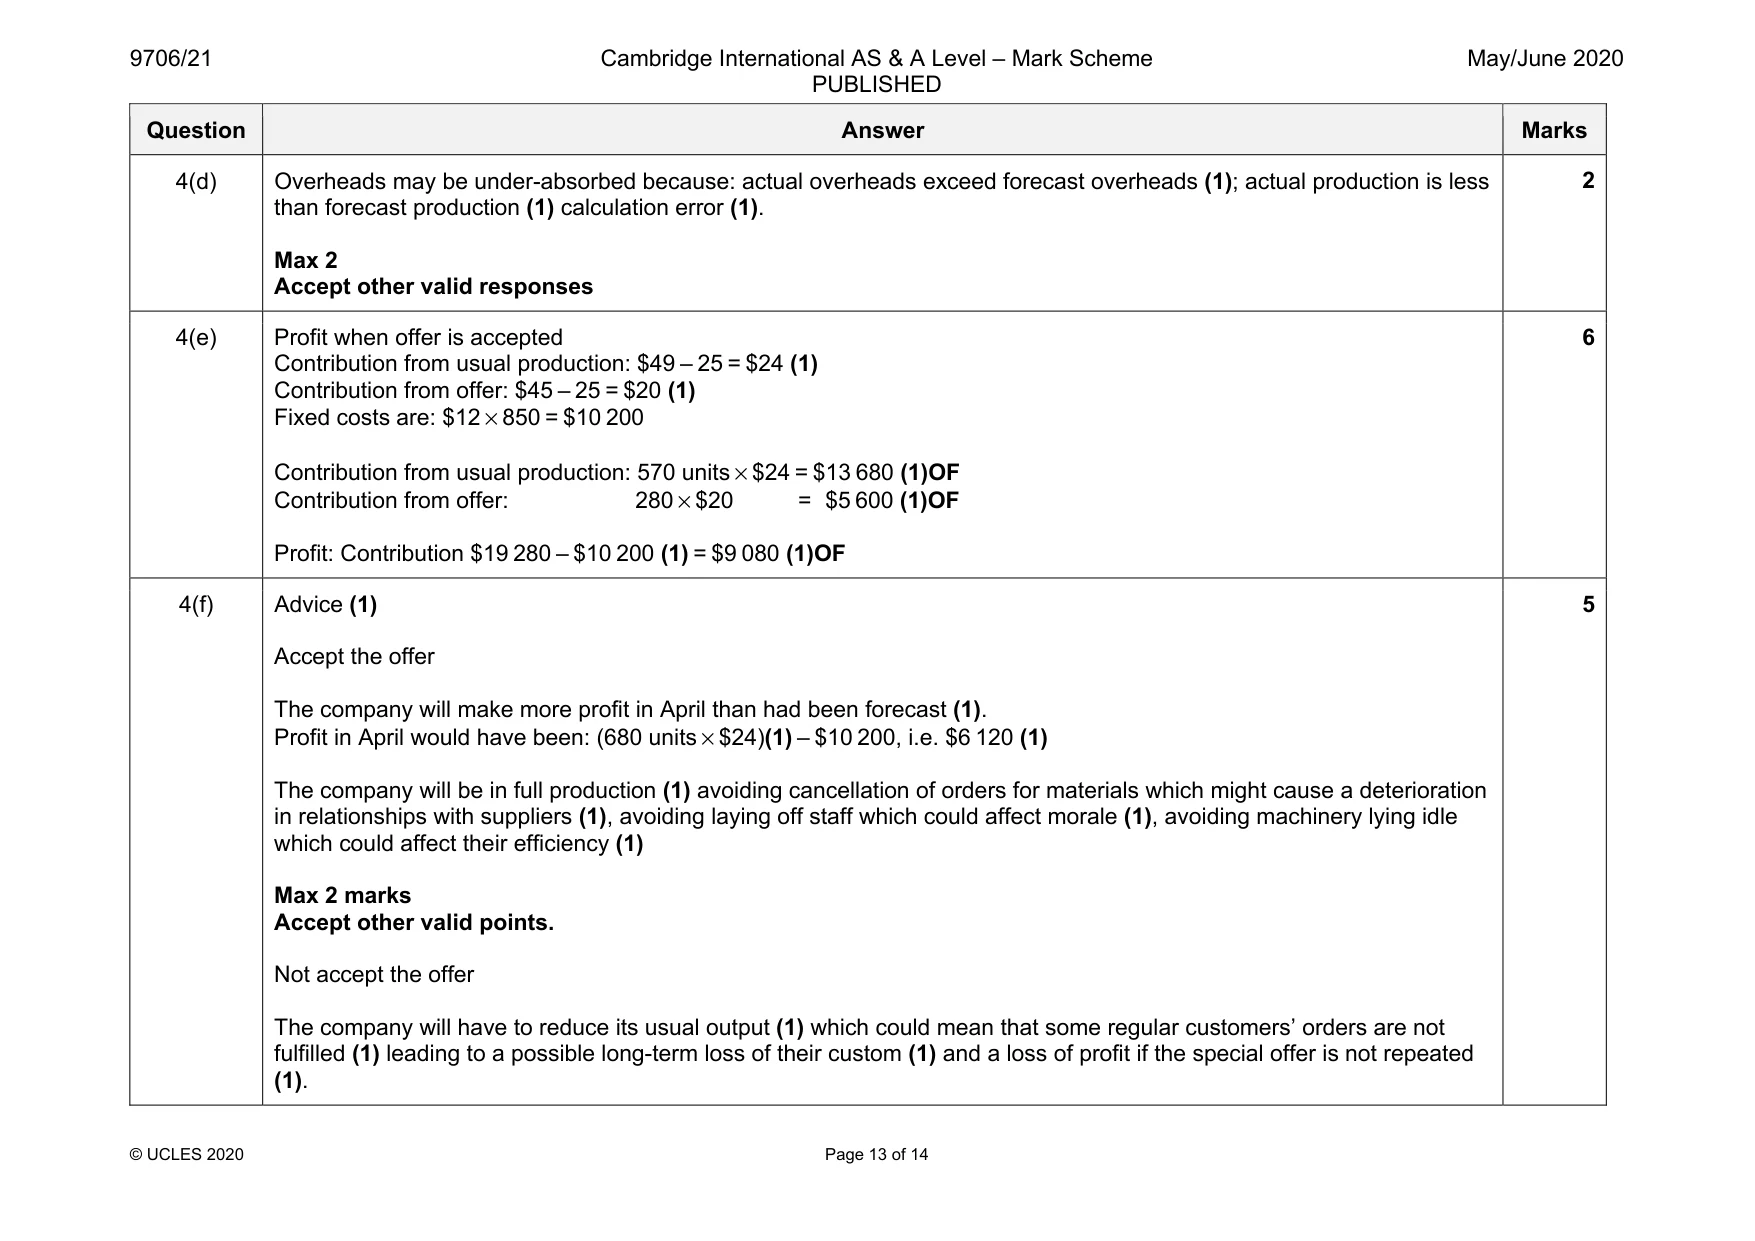
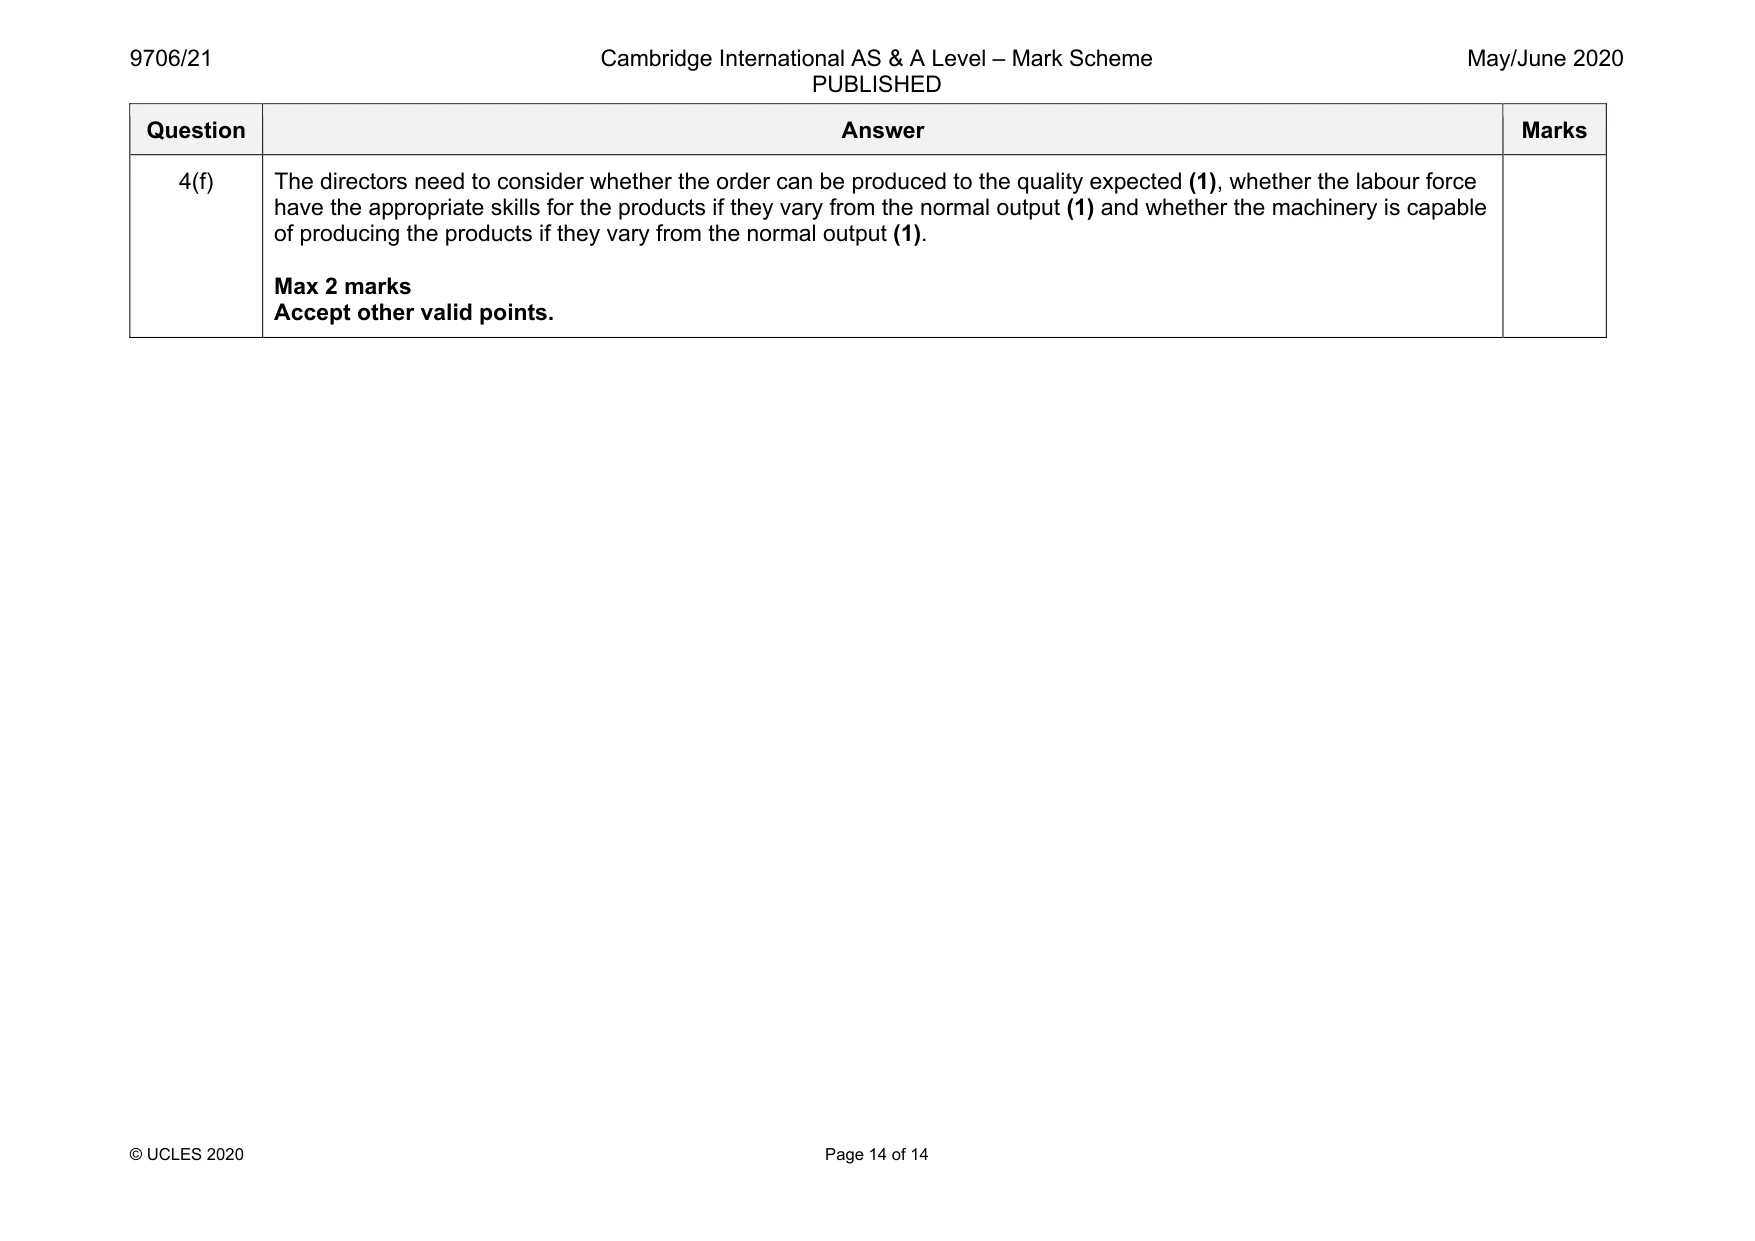
Mark scheme: 4(a) • Takes account of fixed costs when determining product cost (1); as a result is useful in setting a selling price for a product (1). • Avoids separating fixed costs from variable costs (1) which can be difficult and so lead to inaccuracies (1) • As it takes account of all costs it conforms to the matching principle (1) which requires costs to be matched to revenues for a period (1) • As it takes account of all costs (1) it is the recognised method for inventory valuation (1) Max 3 advantages Each advantage 1 mark for main point + 1 mark for development. Accept other valid responses. Question Answer Marks 4(b) Total Baking department Decoration Department Stores Maintenance $ $ $ $ Budgeted overheads already apportioned 57 620 38 530 14 150 2 800 2 140 Machinery depreciation 33 600 19 800 6 000 2 400 5 400 (1) Power 45 500 28 600 11 700 1 300 3 900 (1) Lighting and heating 18 000 10 250 5 750 1 500 500 (1) Total overheads 154 720 97 180 37 600 8 000 11 940 Reapportionment of first service department overheads 5 120 1 920 (8 000) 960 (1)OF Subtotal 102 300 39 520 -- 12 900 Reapportionment of second service department overheads 7 500 5 400 -- (12 900) (1)OF Total overheads 109 800 44 920 -- -- (1)OF (1)OF 7 4(c) Overhead absorption rates Baking department: ( ) = $109800 $1.27 86400 1 per machine hour (1)OF Decoration department: ( ) = $44920 $0.88 51000 1 per labour hour (1)OF 4 Question Answer Marks 4(d) Overheads may be under-absorbed because: actual overheads exceed forecast overheads (1); actual production is less than forecast production (1) calculation error (1). Max 2 Accept other valid responses 2 4(e) Profit when offer is accepted Contribution from usual production: $49 – 25 = $24 (1) Contribution from offer: $45 – 25 = $20 (1) Fixed costs are: $12 × 850 = $10 200 Contribution from usual production: 570 units × $24 = $13 680 (1)OF Contribution from offer: 280 × $20 = $5 600 (1)OF Profit: Contribution $19 280 – $10 200 (1) = $9 080 (1)OF 6 4(f) Advice (1) Accept the offer The company will make more profit in April than had been forecast (1). Profit in April would have been: (680 units × $24)(1) – $10 200, i.e. $6 120 (1) The company will be in full production (1) avoiding cancellation of orders for materials which might cause a deterioration in relationships with suppliers (1), avoiding laying off staff which could affect morale (1), avoiding machinery lying idle which could affect their efficiency (1) Max 2 marks Accept other valid points. Not accept the offer The company will have to reduce its usual output (1) which could mean that some regular customers’ orders are not fulfilled (1) leading to a possible long-term loss of their custom (1) and a loss of profit if the special offer is not repeated (1). 5 Question Answer Marks 4(f) The directors need to consider whether the order can be produced to the quality expected (1), whether the labour force have the appropriate skills for the products if they vary from the normal output (1) and whether the machinery is capable of producing the products if they vary from the normal output (1). Max 2 marks Accept other valid points.
What was in this paper
The subtopics covered by these 4 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.