Cambridge IGCSE Accounting 0452 — 2005 Oct/Nov Paper 3 · Variant 1
0452/31/O/N/05 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages

Mark scheme8 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Maria van Zyl is a trader
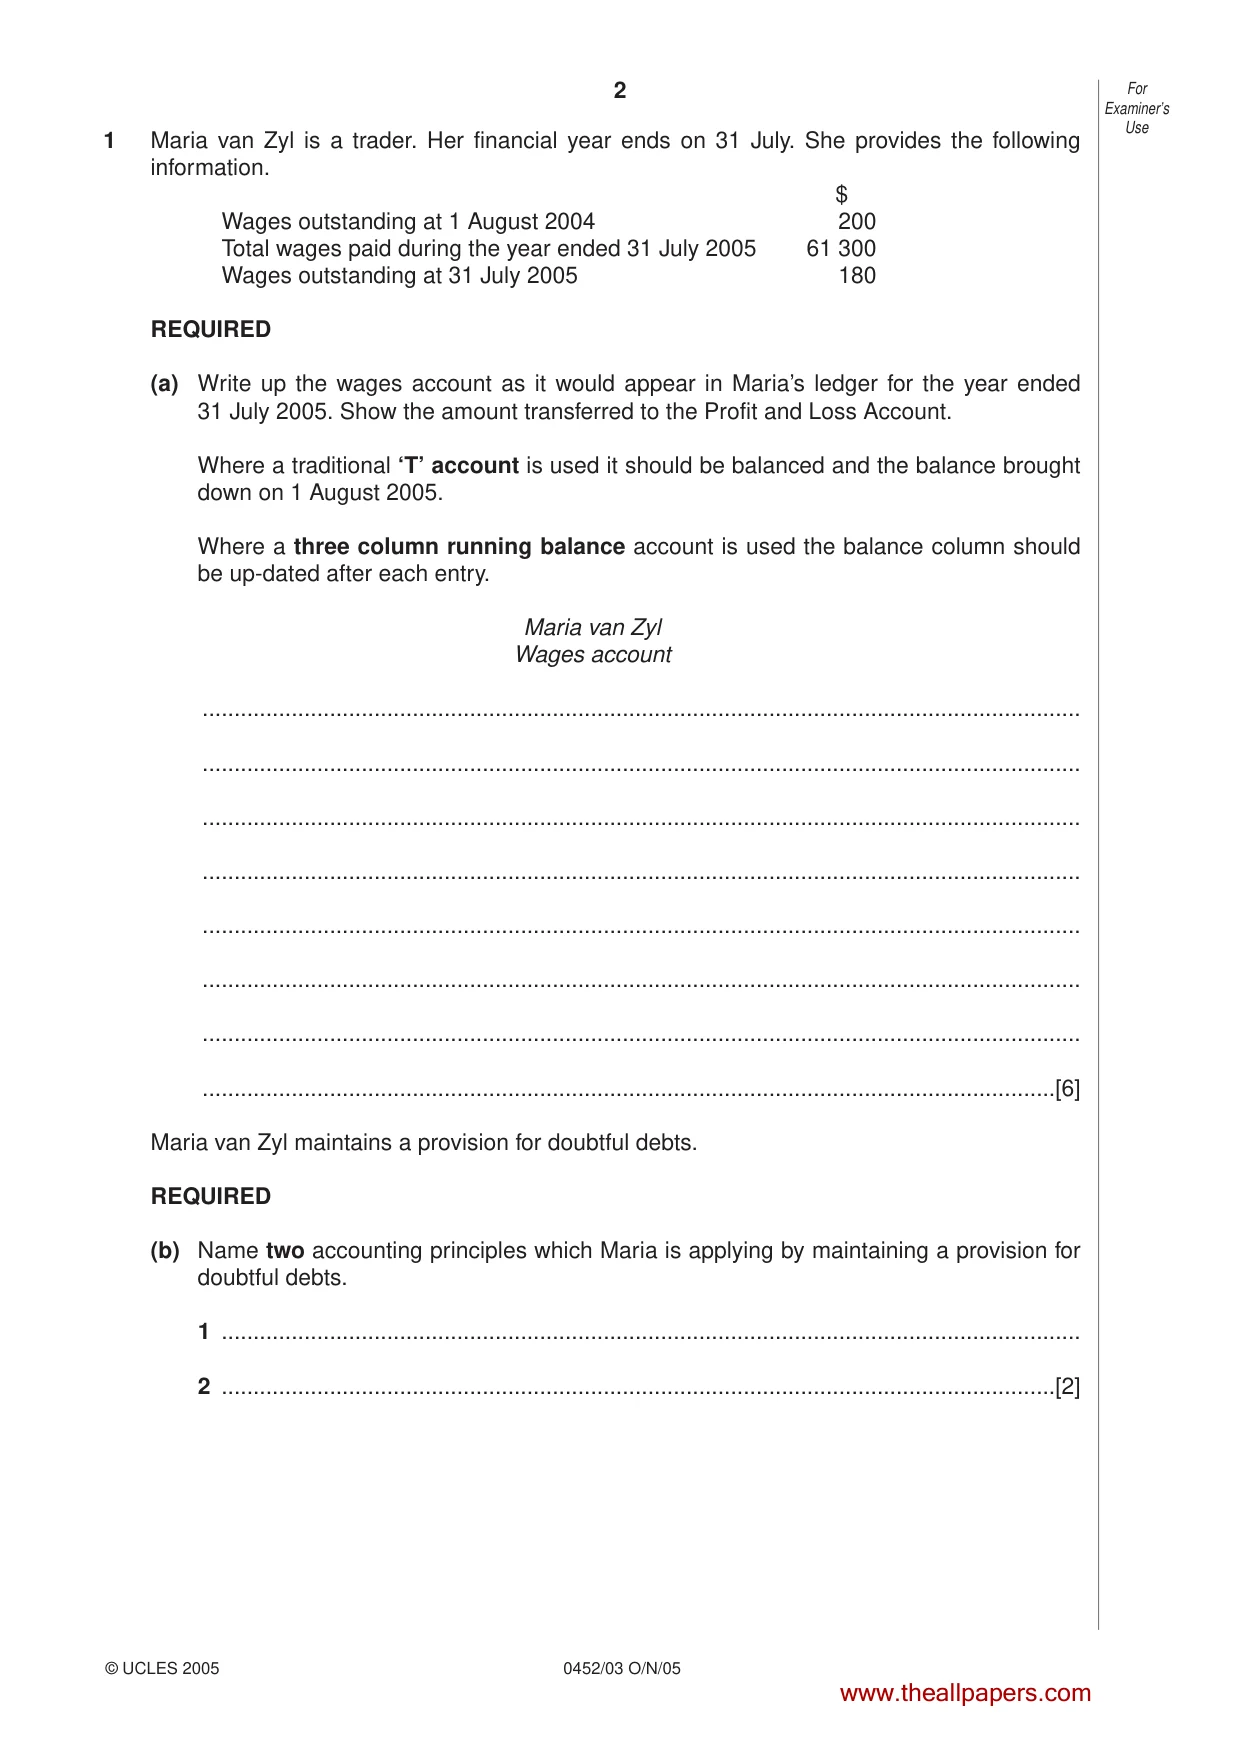
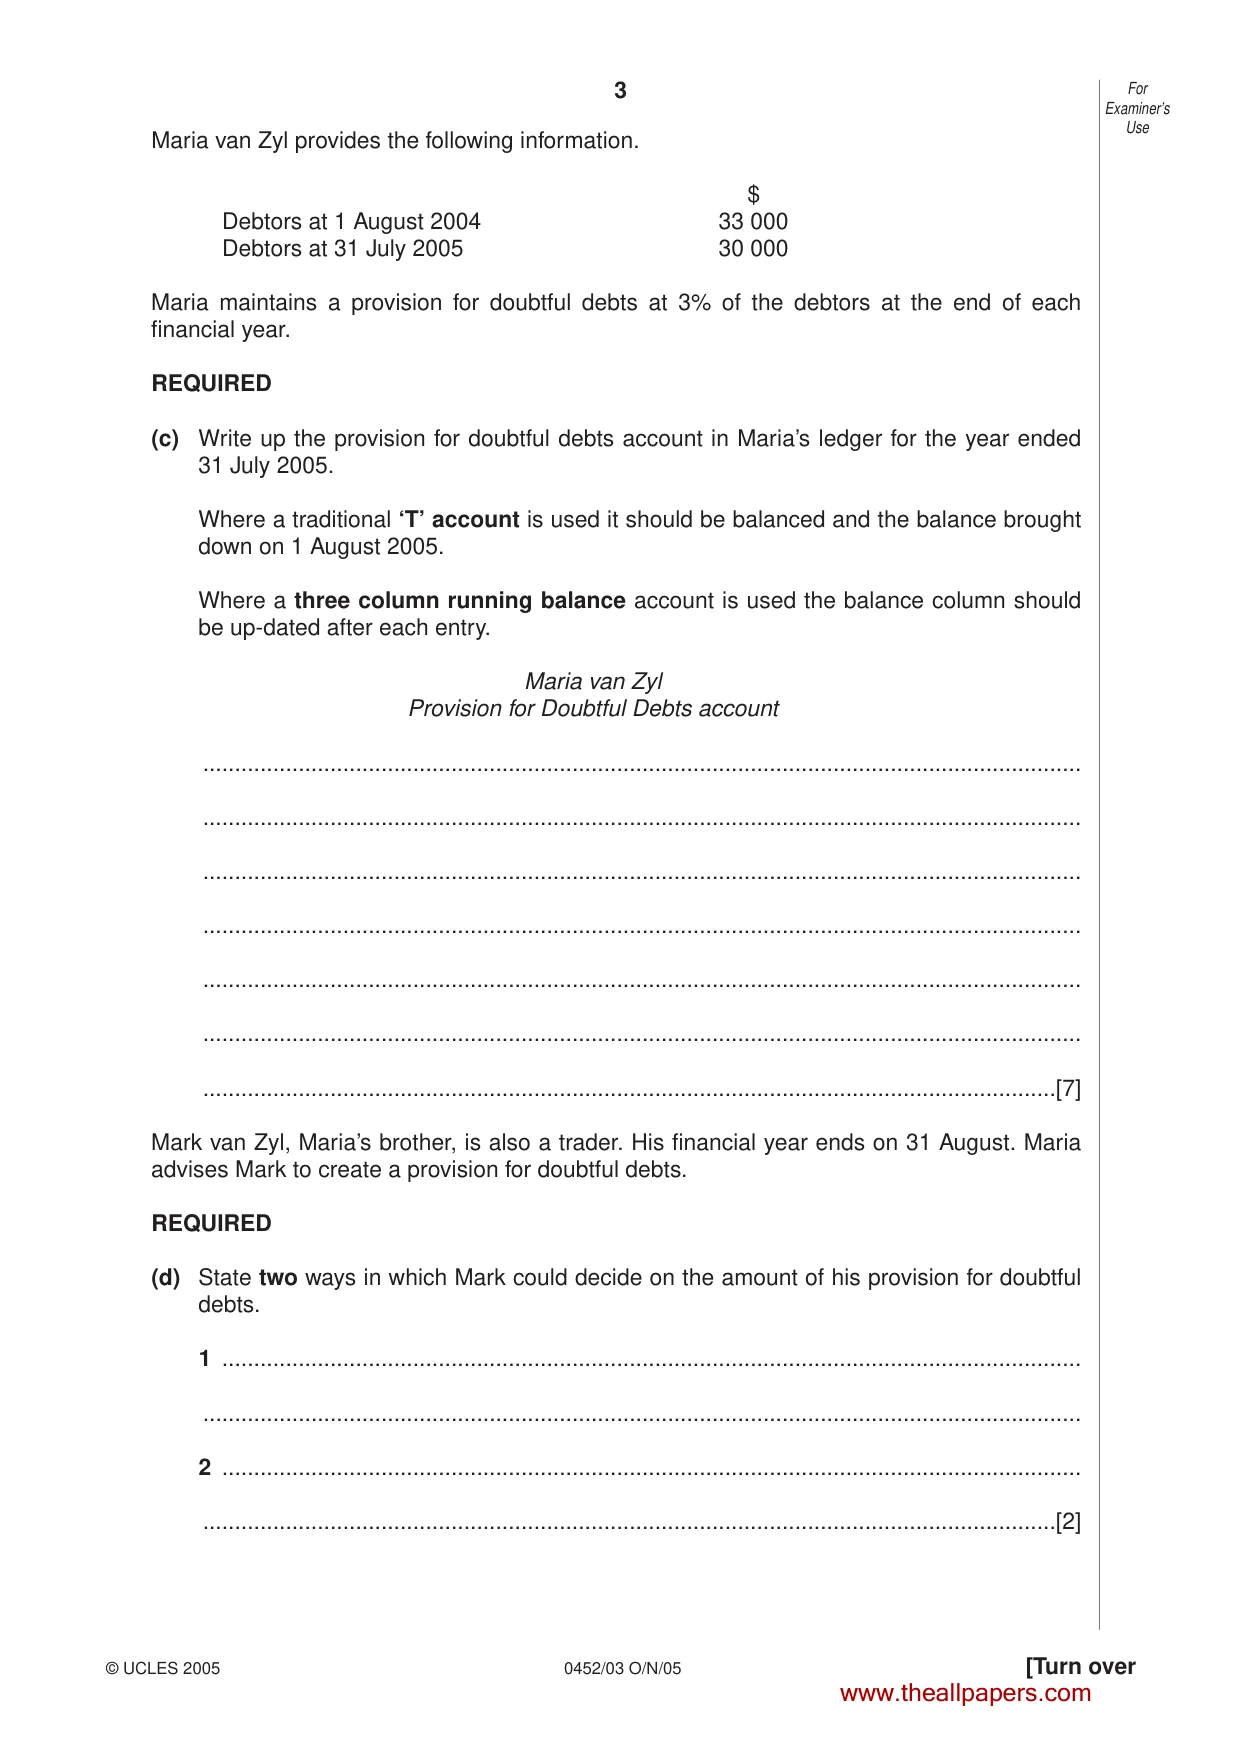
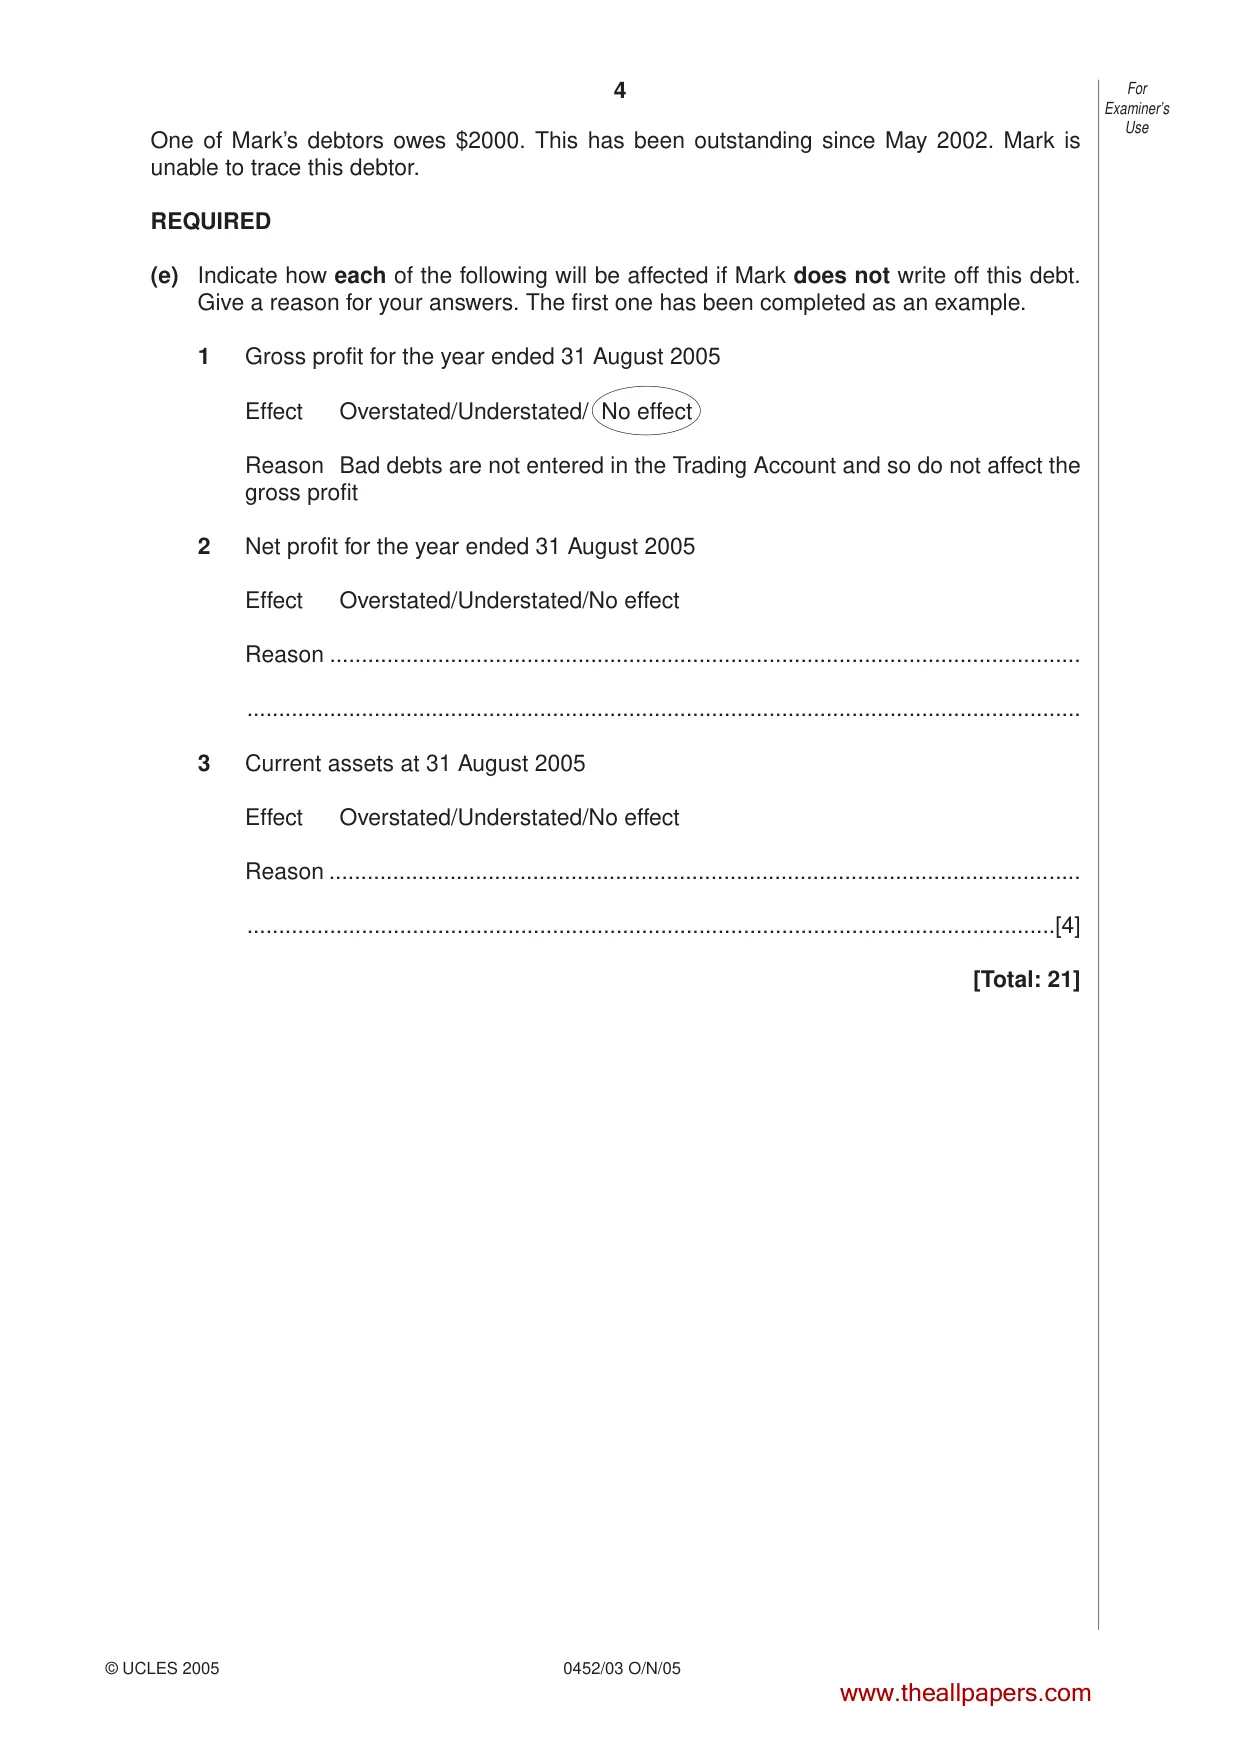
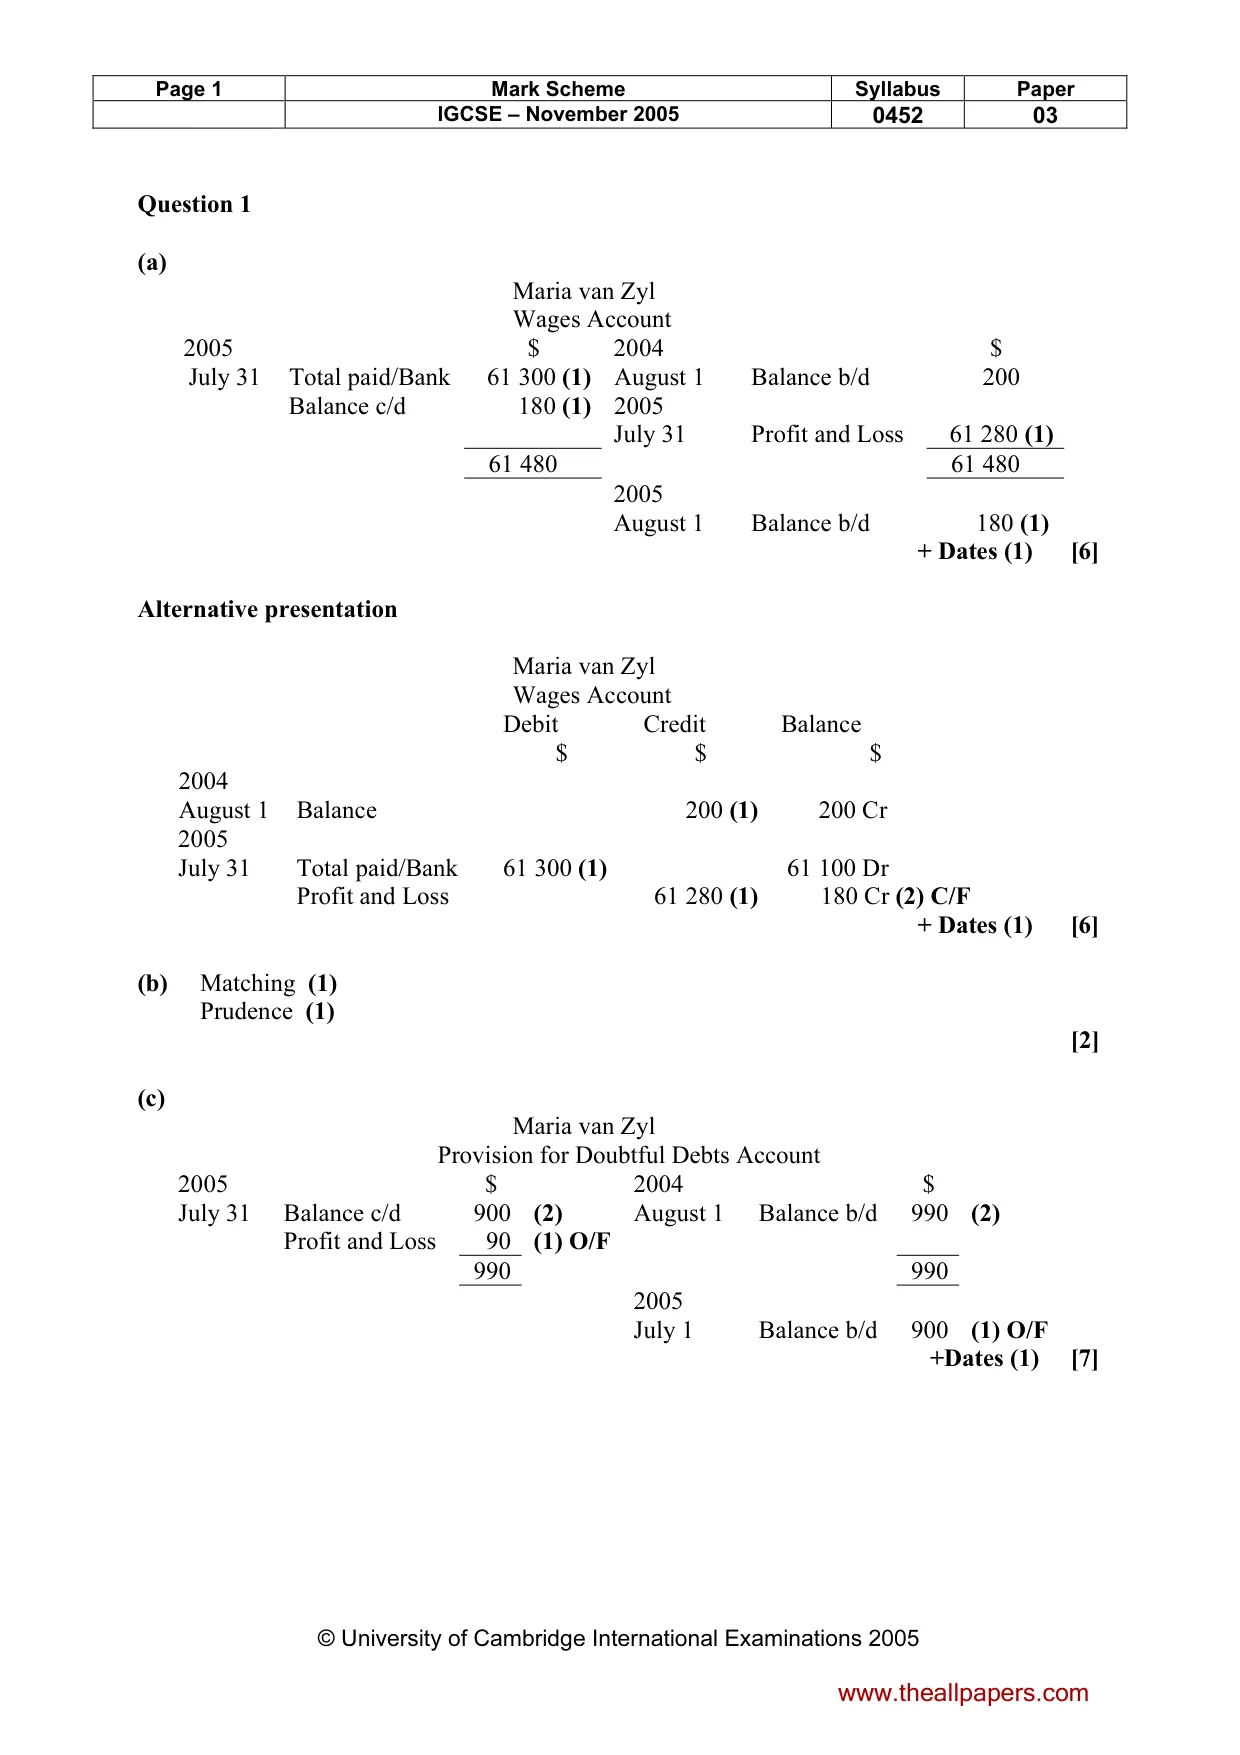
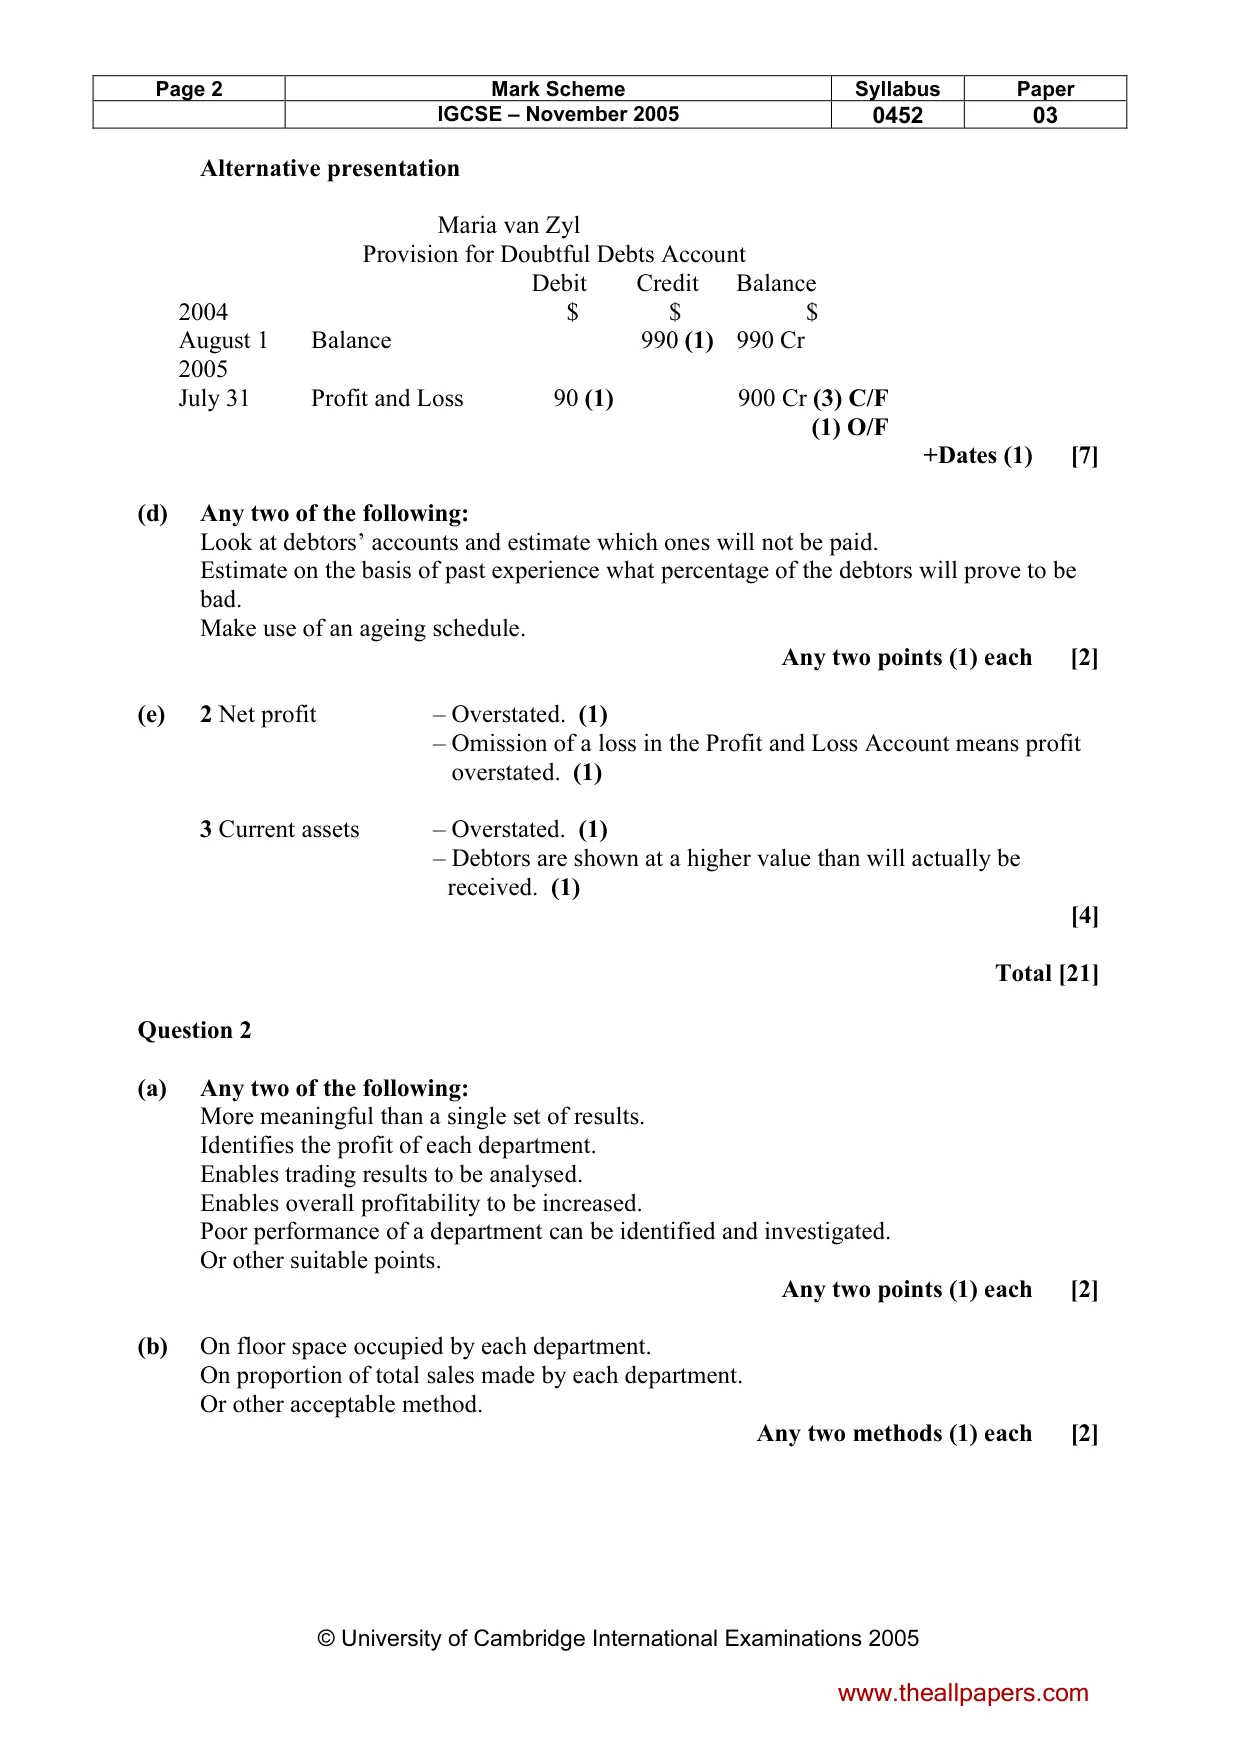
1 Maria van Zyl is a trader. Her financial year ends on 31 July. She provides the following information. $ Wages outstanding at 1 August 2004 200 Total wages paid during the year ended 31 July 2005 61 300 Wages outstanding at 31 July 2005 180 REQUIRED (a) Write up the wages account as it would appear in Maria’s ledger for the year ended 31 July 2005. Show the amount transferred to the Profit and Loss Account. Where a traditional ‘T’ account is used it should be balanced and the balance brought down on 1 August 2005. Where a three column running balance account is used the balance column should be up-dated after each entry. Maria van Zyl Wages account .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... ......................................................................................................................................[6] Maria van Zyl maintains a provision for doubtful debts. REQUIRED (b) Name two accounting principles which Maria is applying by maintaining a provision for doubtful debts. 1 ....................................................................................................................................... 2 ...................................................................................................................................[2] Maria van Zyl provides the following information. $ Debtors at 1 August 2004 33 000 Debtors at 31 July 2005 30 000 Maria maintains a provision for doubtful debts at 3% of the debtors at the end of each financial year. REQUIRED (c) Write up the provision for doubtful debts account in Maria’s ledger for the year ended 31 July 2005. Where a traditional ‘T’ account is used it should be balanced and the balance brought down on 1 August 2005. Where a three column running balance account is used the balance column should be up-dated after each entry. Maria van Zyl Provision for Doubtful Debts account .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... ......................................................................................................................................[7] Mark van Zyl, Maria’s brother, is also a trader. His financial year ends on 31 August. Maria advises Mark to create a provision for doubtful debts. REQUIRED (d) State two ways in which Mark could decide on the amount of his provision for doubtful debts. 1 ....................................................................................................................................... .......................................................................................................................................... 2 ....................................................................................................................................... ......................................................................................................................................[2] One of Mark’s debtors owes $2000. This has been outstanding since May 2002. Mark is unable to trace this debtor. REQUIRED (e) Indicate how each of the following will be affected if Mark does not write off this debt. Give a reason for your answers. The first one has been completed as an example. 1 Gross profit for the year ended 31 August 2005 Effect Overstated/Understated/ No effect Reason Bad debts are not entered in the Trading Account and so do not affect the gross profit 2 Net profit for the year ended 31 August 2005 Effect Overstated/Understated/No effect Reason ...................................................................................................................... ................................................................................................................................... 3 Current assets at 31 August 2005 Effect Overstated/Understated/No effect Reason ...................................................................................................................... ...............................................................................................................................[4] [Total: 21]
More questions on Irrecoverable debts and allowance for irrecoverable debts
Q2 · Abdul El Said is a retailer
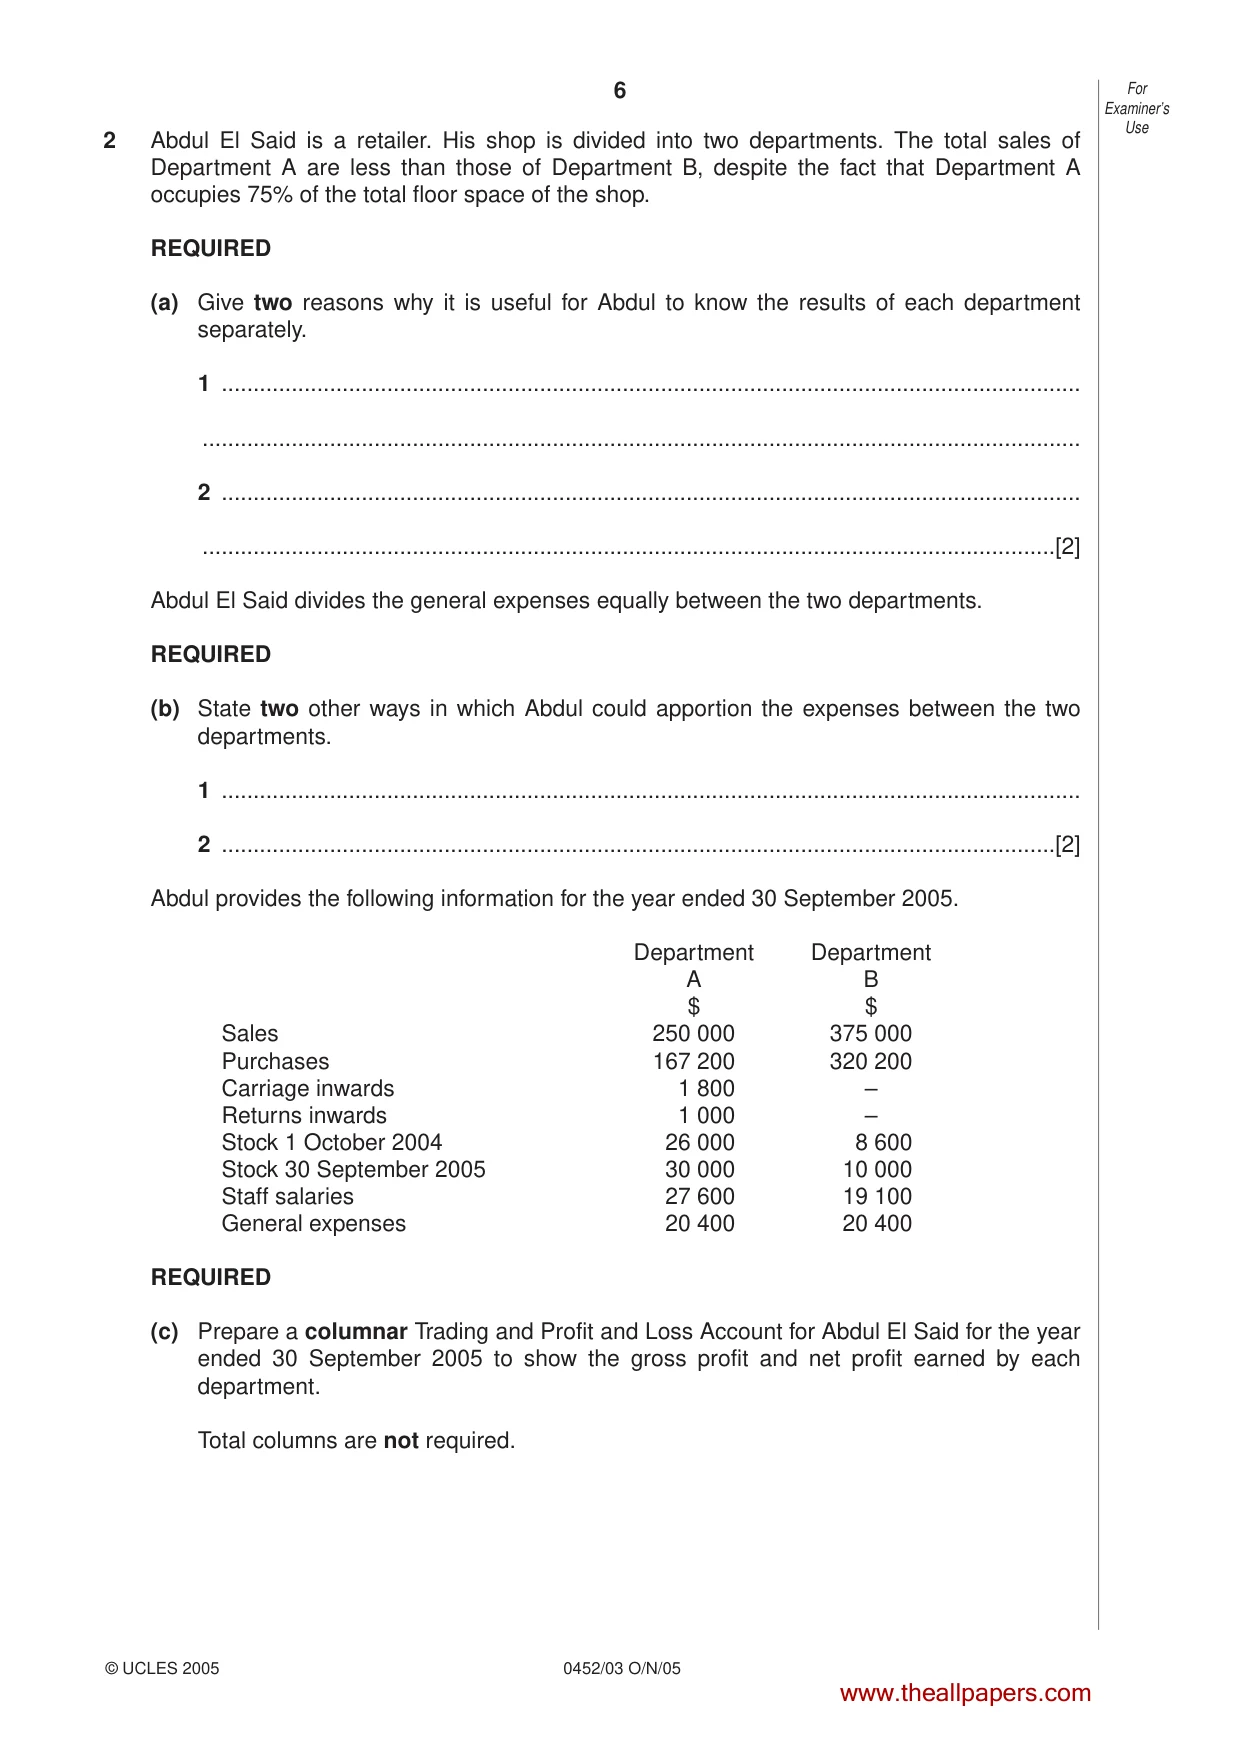
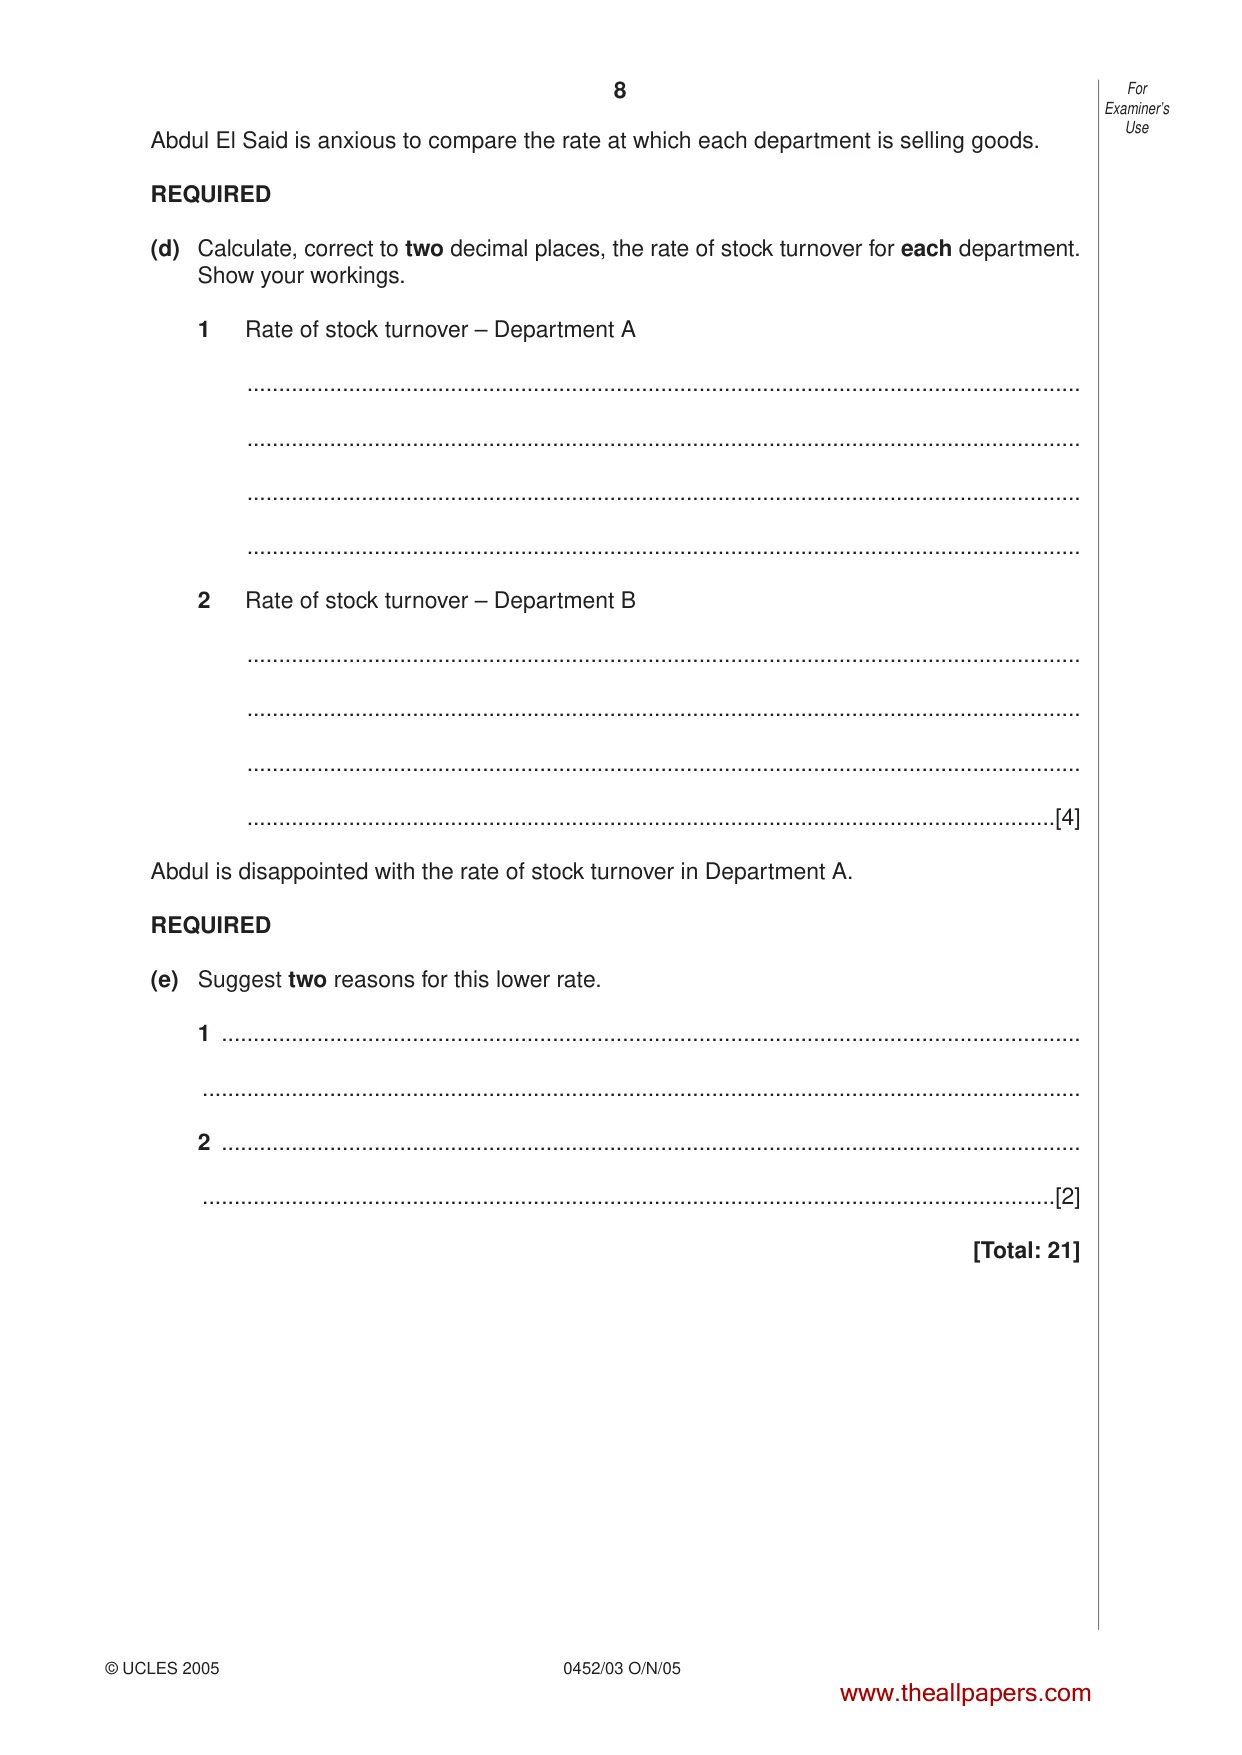
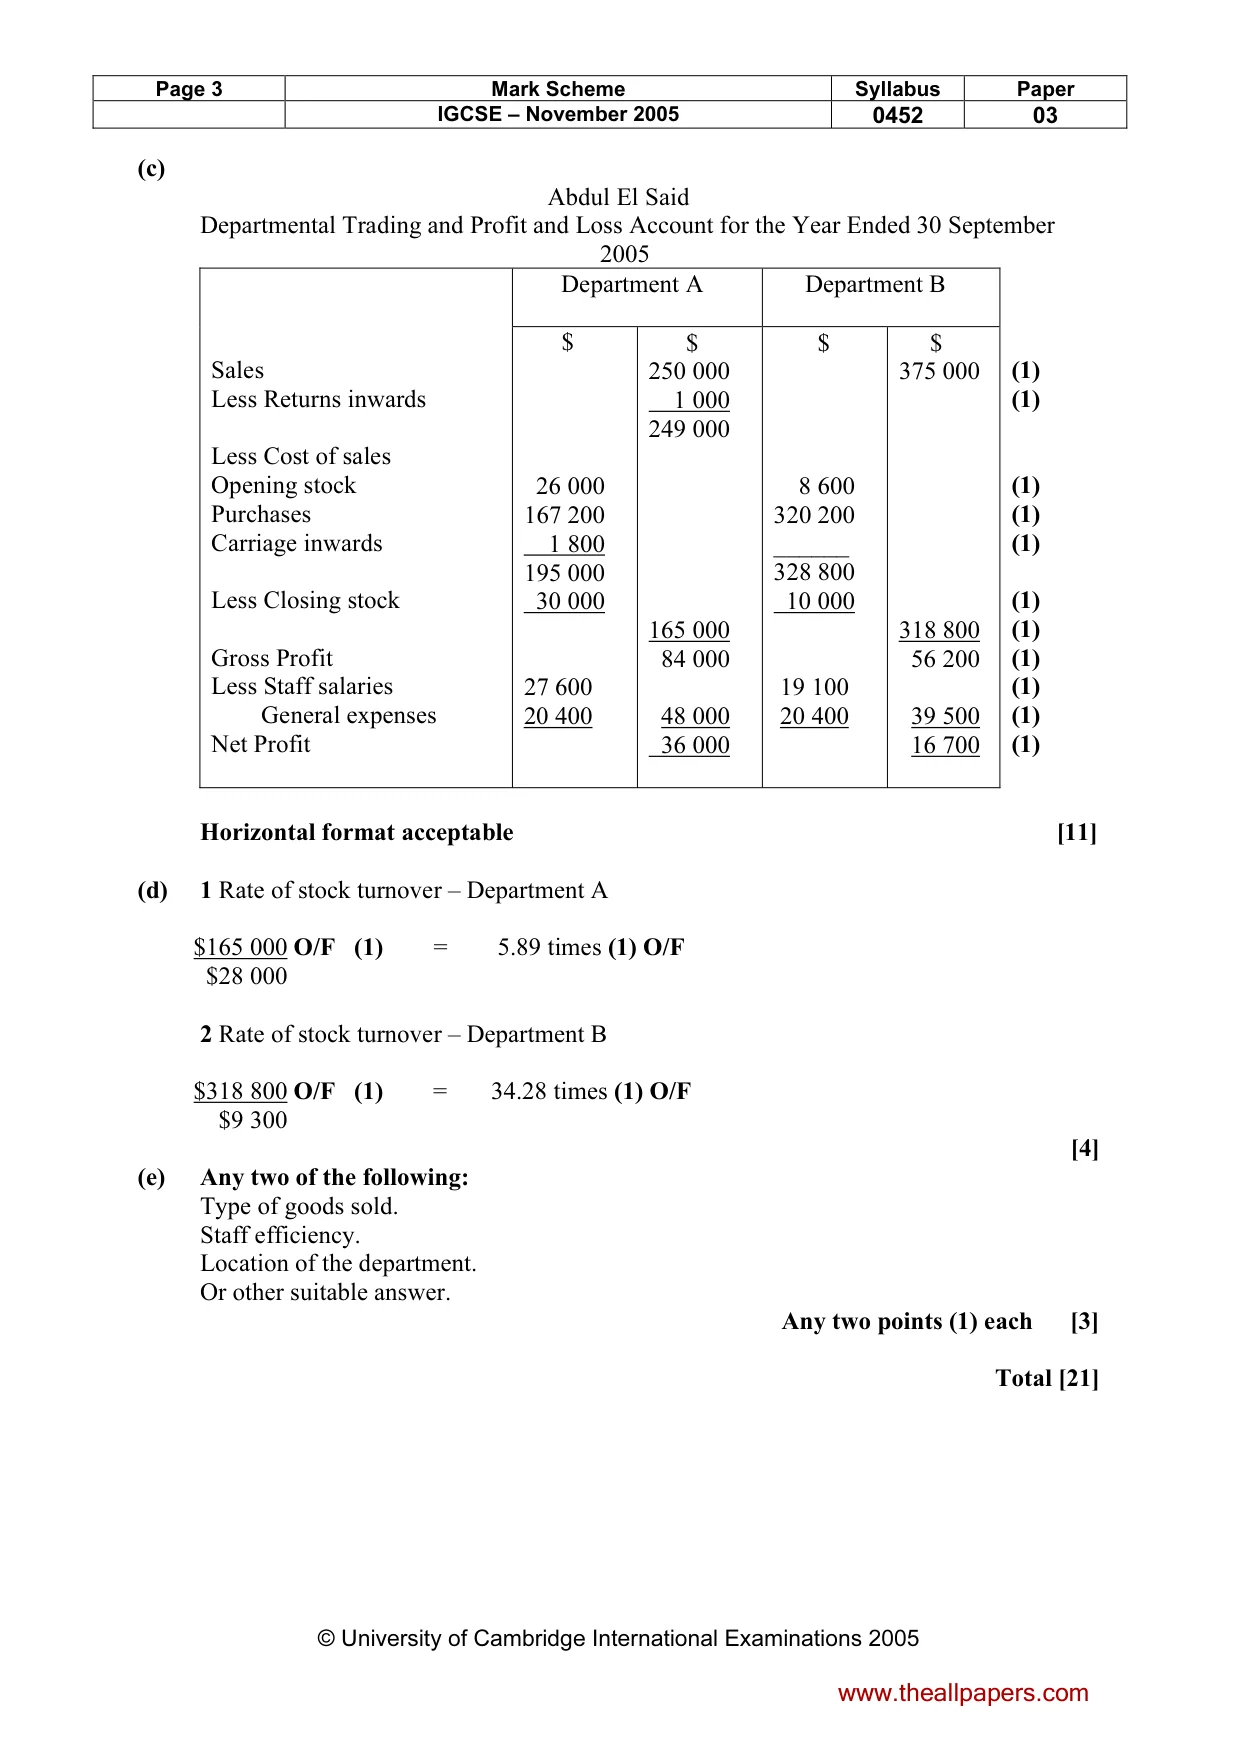
2 Abdul El Said is a retailer. His shop is divided into two departments. The total sales of Department A are less than those of Department B, despite the fact that Department A occupies 75% of the total floor space of the shop. REQUIRED (a) Give two reasons why it is useful for Abdul to know the results of each department separately. 1 ....................................................................................................................................... .......................................................................................................................................... 2 ....................................................................................................................................... ......................................................................................................................................[2] Abdul El Said divides the general expenses equally between the two departments. REQUIRED (b) State two other ways in which Abdul could apportion the expenses between the two departments. 1 ....................................................................................................................................... 2 ...................................................................................................................................[2] Abdul provides the following information for the year ended 30 September 2005. Department Department A B $ $ Sales 250 000 375 000 Purchases 167 200 320 200 Carriage inwards 1 800 – Returns inwards 1 000 – Stock 1 October 2004 26 000 8 600 Stock 30 September 2005 30 000 10 000 Staff salaries 27 600 19 100 General expenses 20 400 20 400 REQUIRED (c) Prepare a columnar Trading and Profit and Loss Account for Abdul El Said for the year ended 30 September 2005 to show the gross profit and net profit earned by each department. Total columns are not required. Abdul El Said Departmental Trading and Profit and Loss Account for the year ended 30 September 2005 .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... ....................................................................................................................................[11] Abdul El Said is anxious to compare the rate at which each department is selling goods. REQUIRED (d) Calculate, correct to two decimal places, the rate of stock turnover for each department. Show your workings. 1 Rate of stock turnover – Department A ................................................................................................................................... ................................................................................................................................... ................................................................................................................................... ................................................................................................................................... 2 Rate of stock turnover – Department B ................................................................................................................................... ................................................................................................................................... ................................................................................................................................... ...............................................................................................................................[4] Abdul is disappointed with the rate of stock turnover in Department A. REQUIRED (e) Suggest two reasons for this lower rate. 1 ....................................................................................................................................... .......................................................................................................................................... 2 ....................................................................................................................................... ......................................................................................................................................[2] [Total: 21]
Q3 · Rebecca Tan is a trader
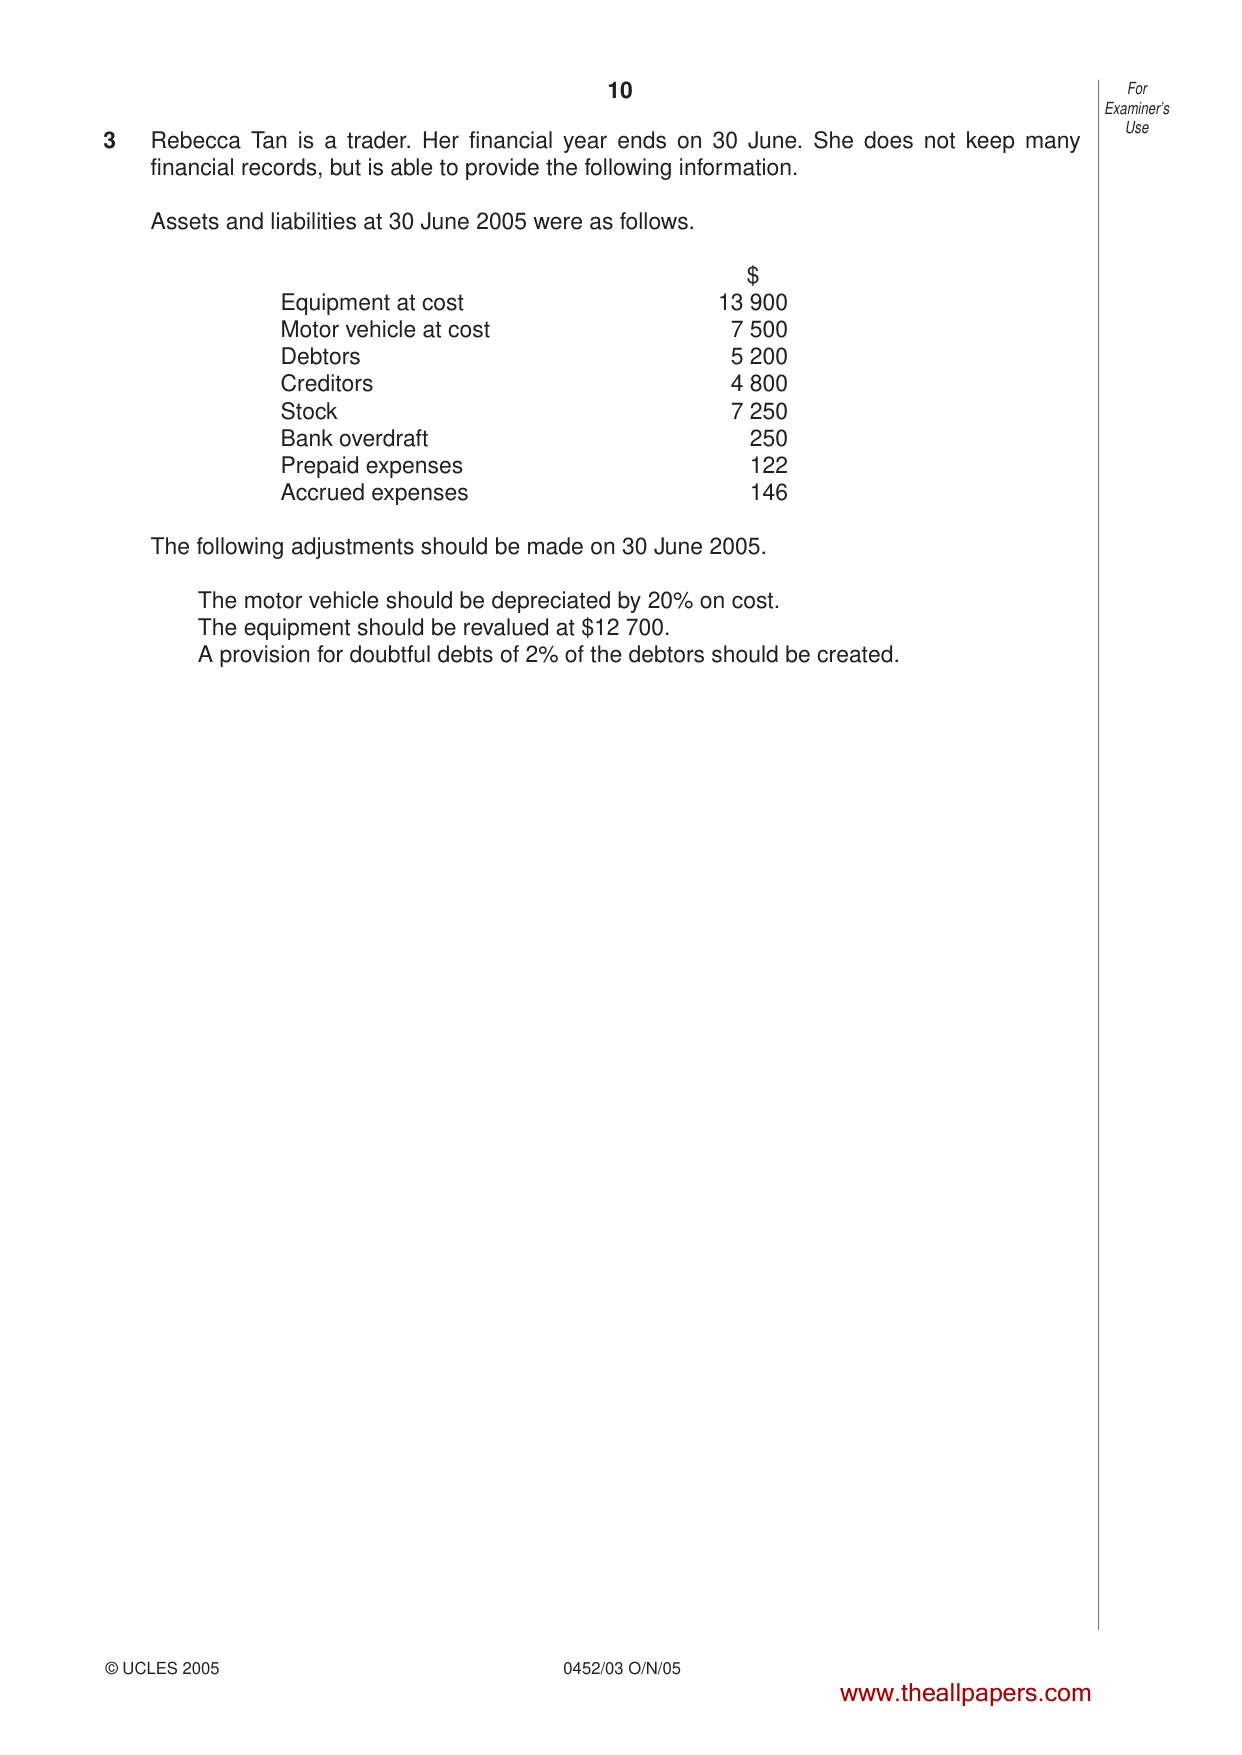
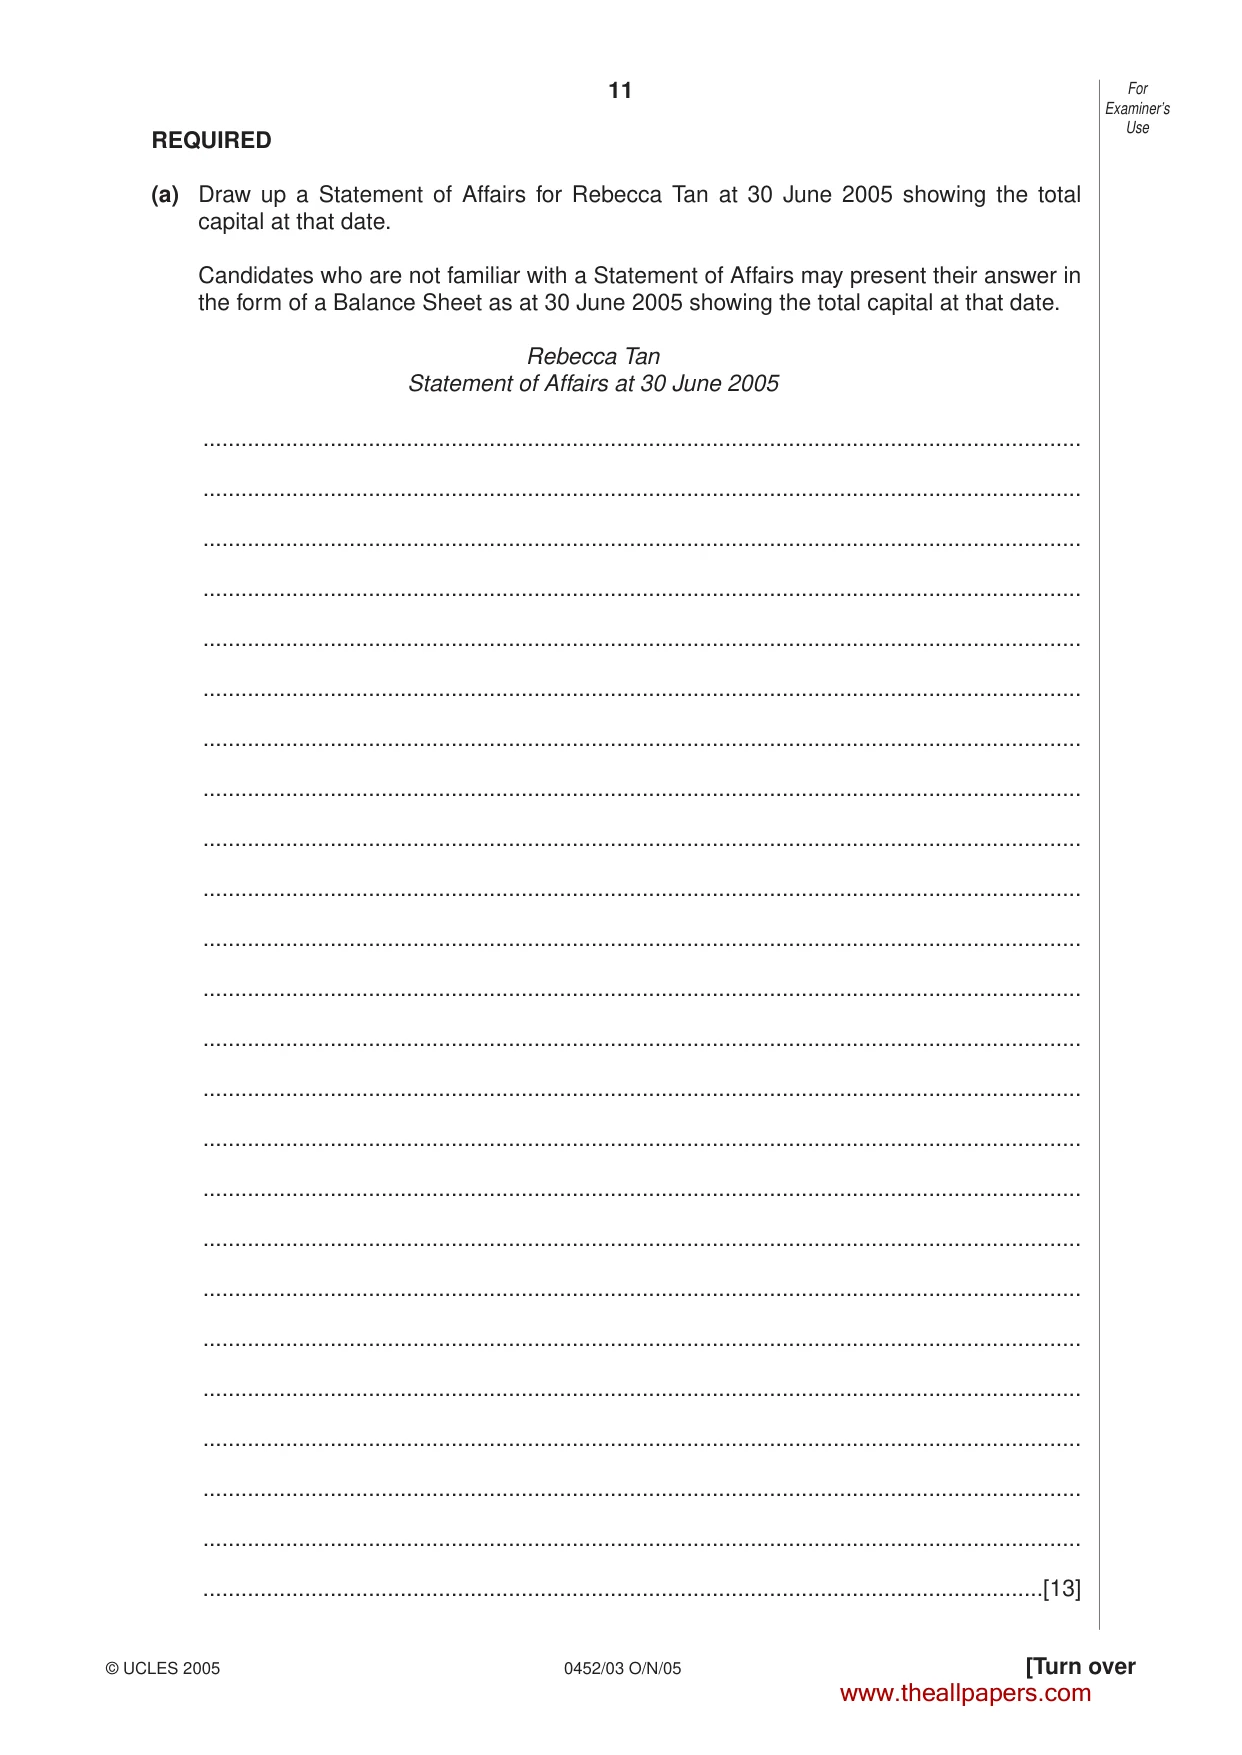
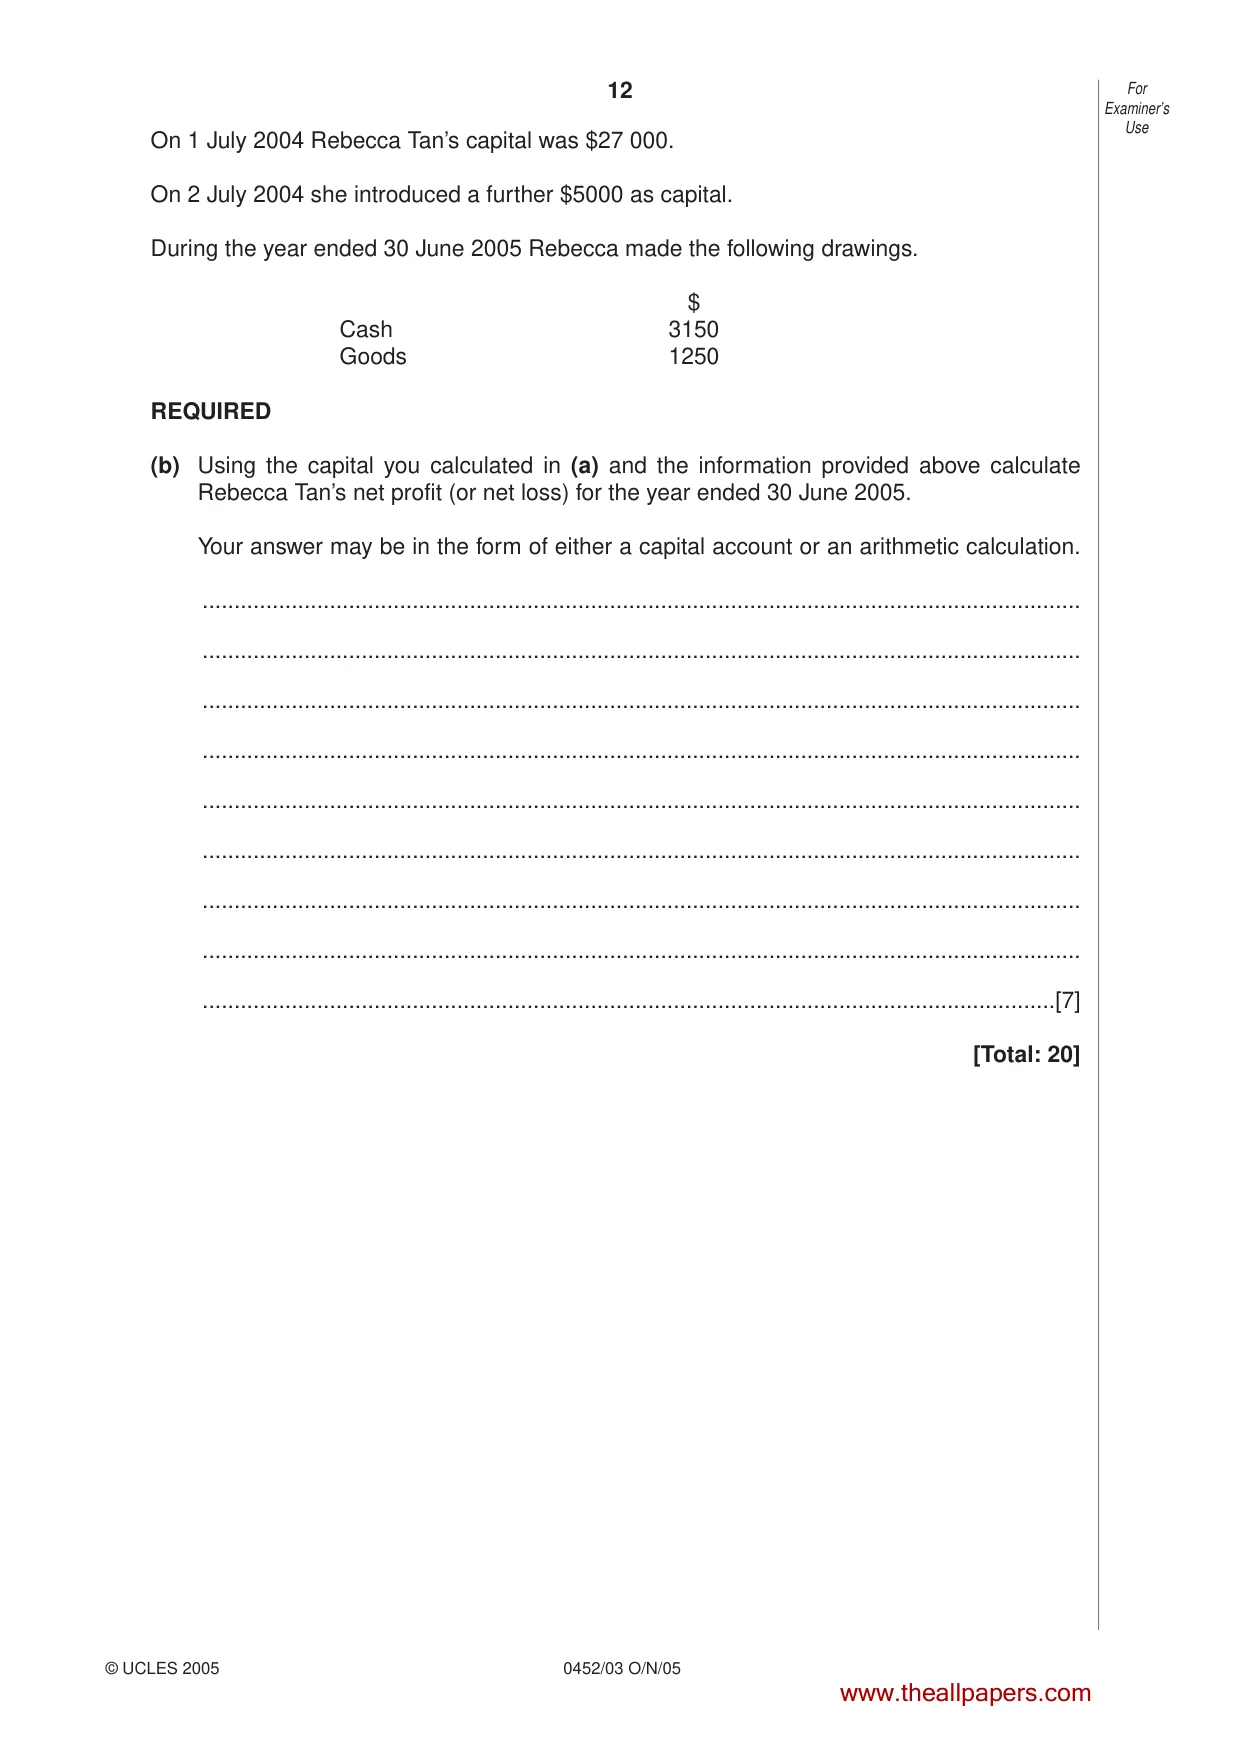
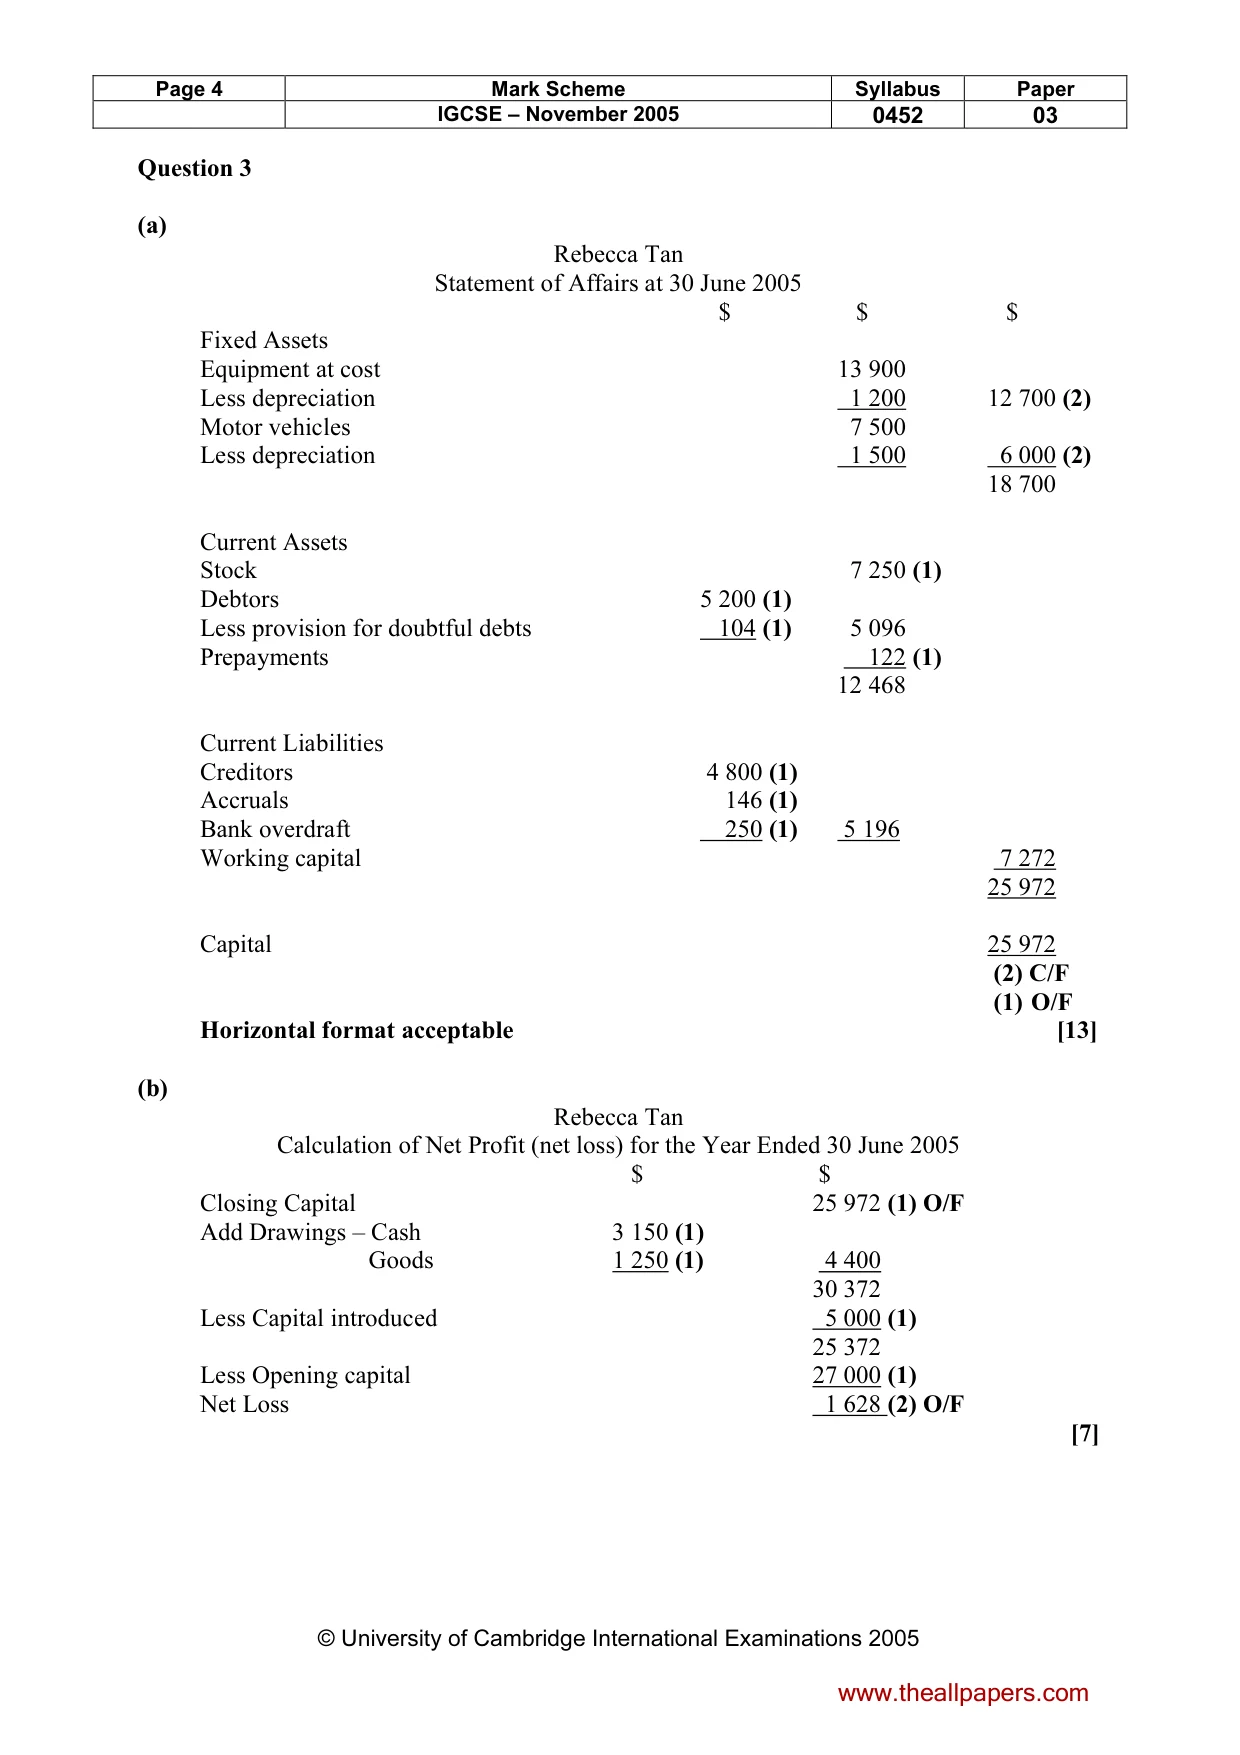
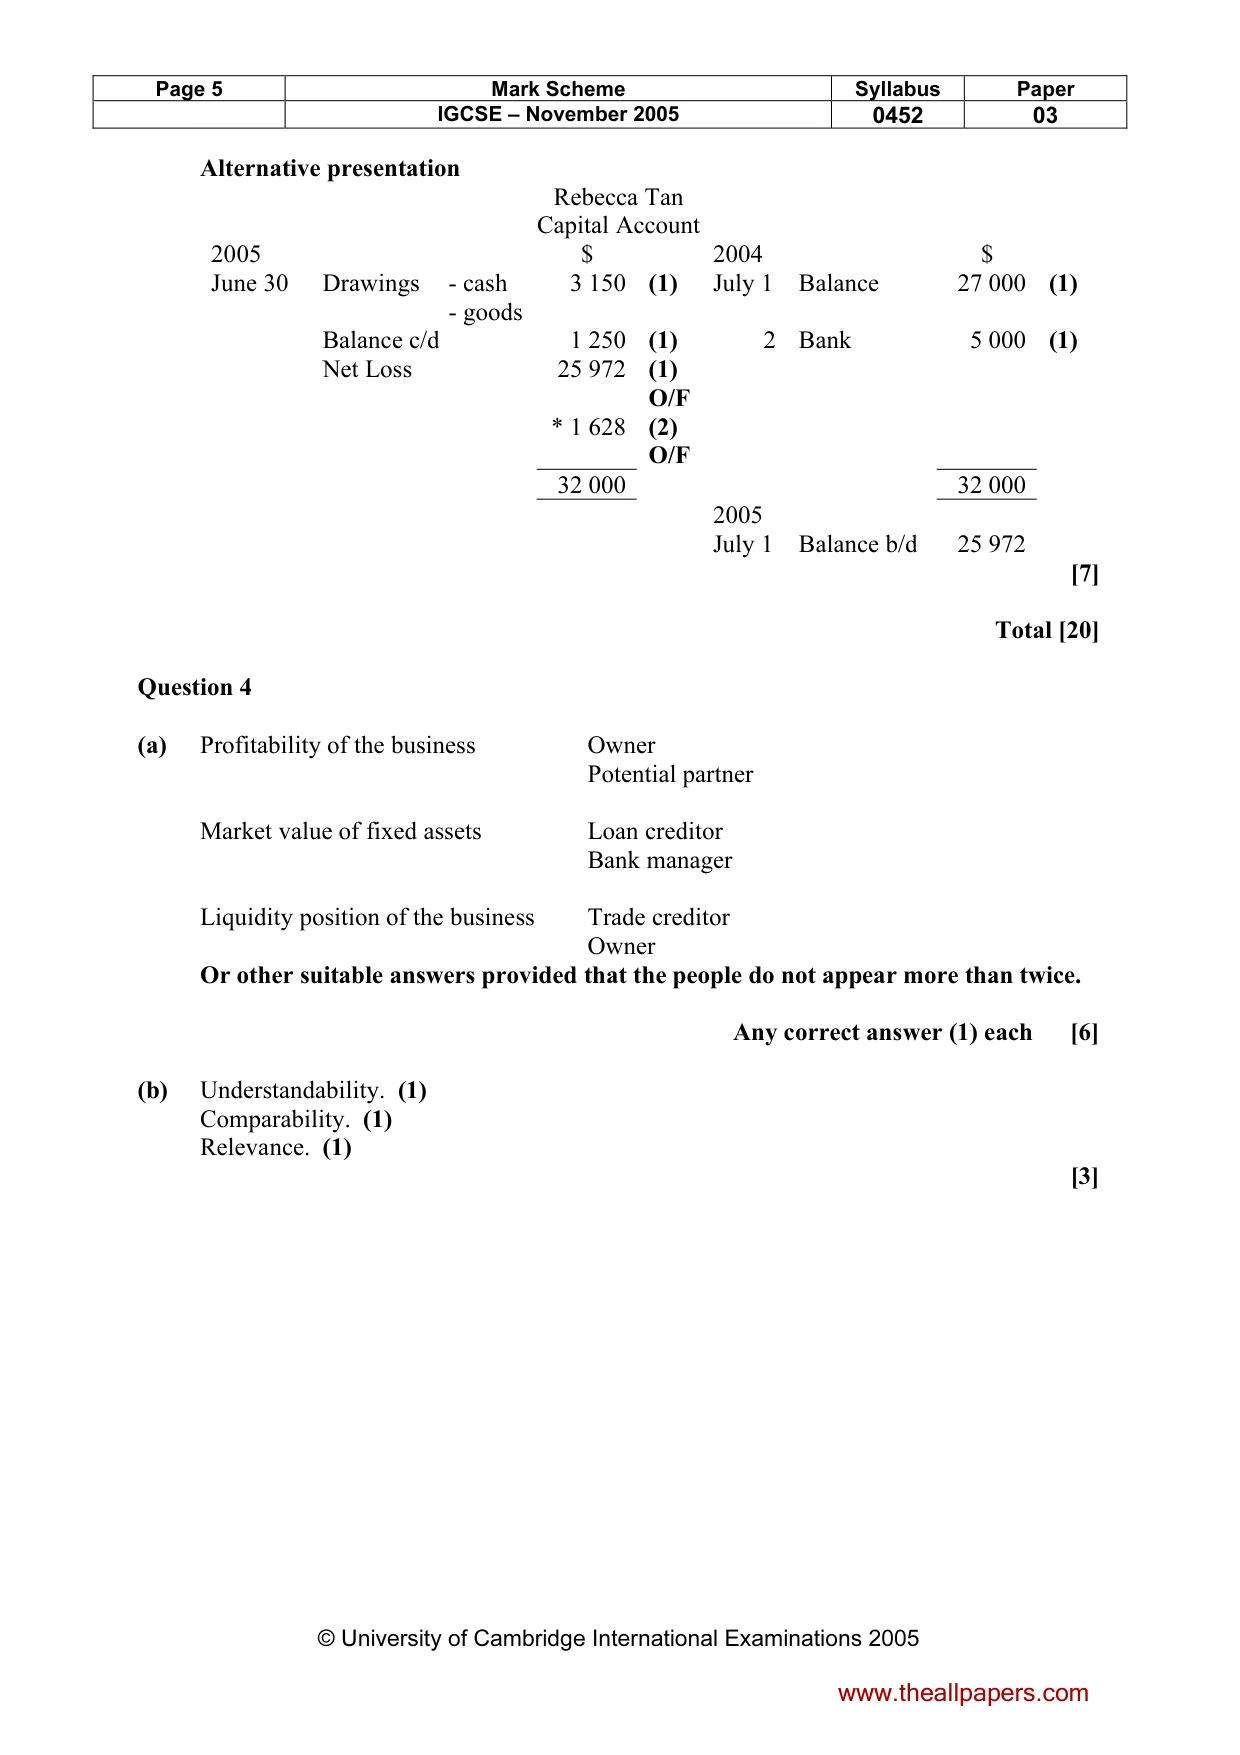
3 Rebecca Tan is a trader. Her financial year ends on 30 June. She does not keep many financial records, but is able to provide the following information. Assets and liabilities at 30 June 2005 were as follows. $ Equipment at cost 13 900 Motor vehicle at cost 7 500 Debtors 5 200 Creditors 4 800 Stock 7 250 Bank overdraft 250 Prepaid expenses 122 Accrued expenses 146 The following adjustments should be made on 30 June 2005. The motor vehicle should be depreciated by 20% on cost. The equipment should be revalued at $12 700. A provision for doubtful debts of 2% of the debtors should be created. REQUIRED (a) Draw up a Statement of Affairs for Rebecca Tan at 30 June 2005 showing the total capital at that date. Candidates who are not familiar with a Statement of Affairs may present their answer in the form of a Balance Sheet as at 30 June 2005 showing the total capital at that date. Rebecca Tan Statement of Affairs at 30 June 2005 .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... ....................................................................................................................................[13] On 1 July 2004 Rebecca Tan’s capital was $27 000. On 2 July 2004 she introduced a further $5000 as capital. During the year ended 30 June 2005 Rebecca made the following drawings. $ Cash 3150 Goods 1250 REQUIRED (b) Using the capital you calculated in (a) and the information provided above calculate Rebecca Tan’s net profit (or net loss) for the year ended 30 June 2005. Your answer may be in the form of either a capital account or an arithmetic calculation. .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... ......................................................................................................................................[7] [Total: 20]
Q4 · Franz Fischer is a sole trader
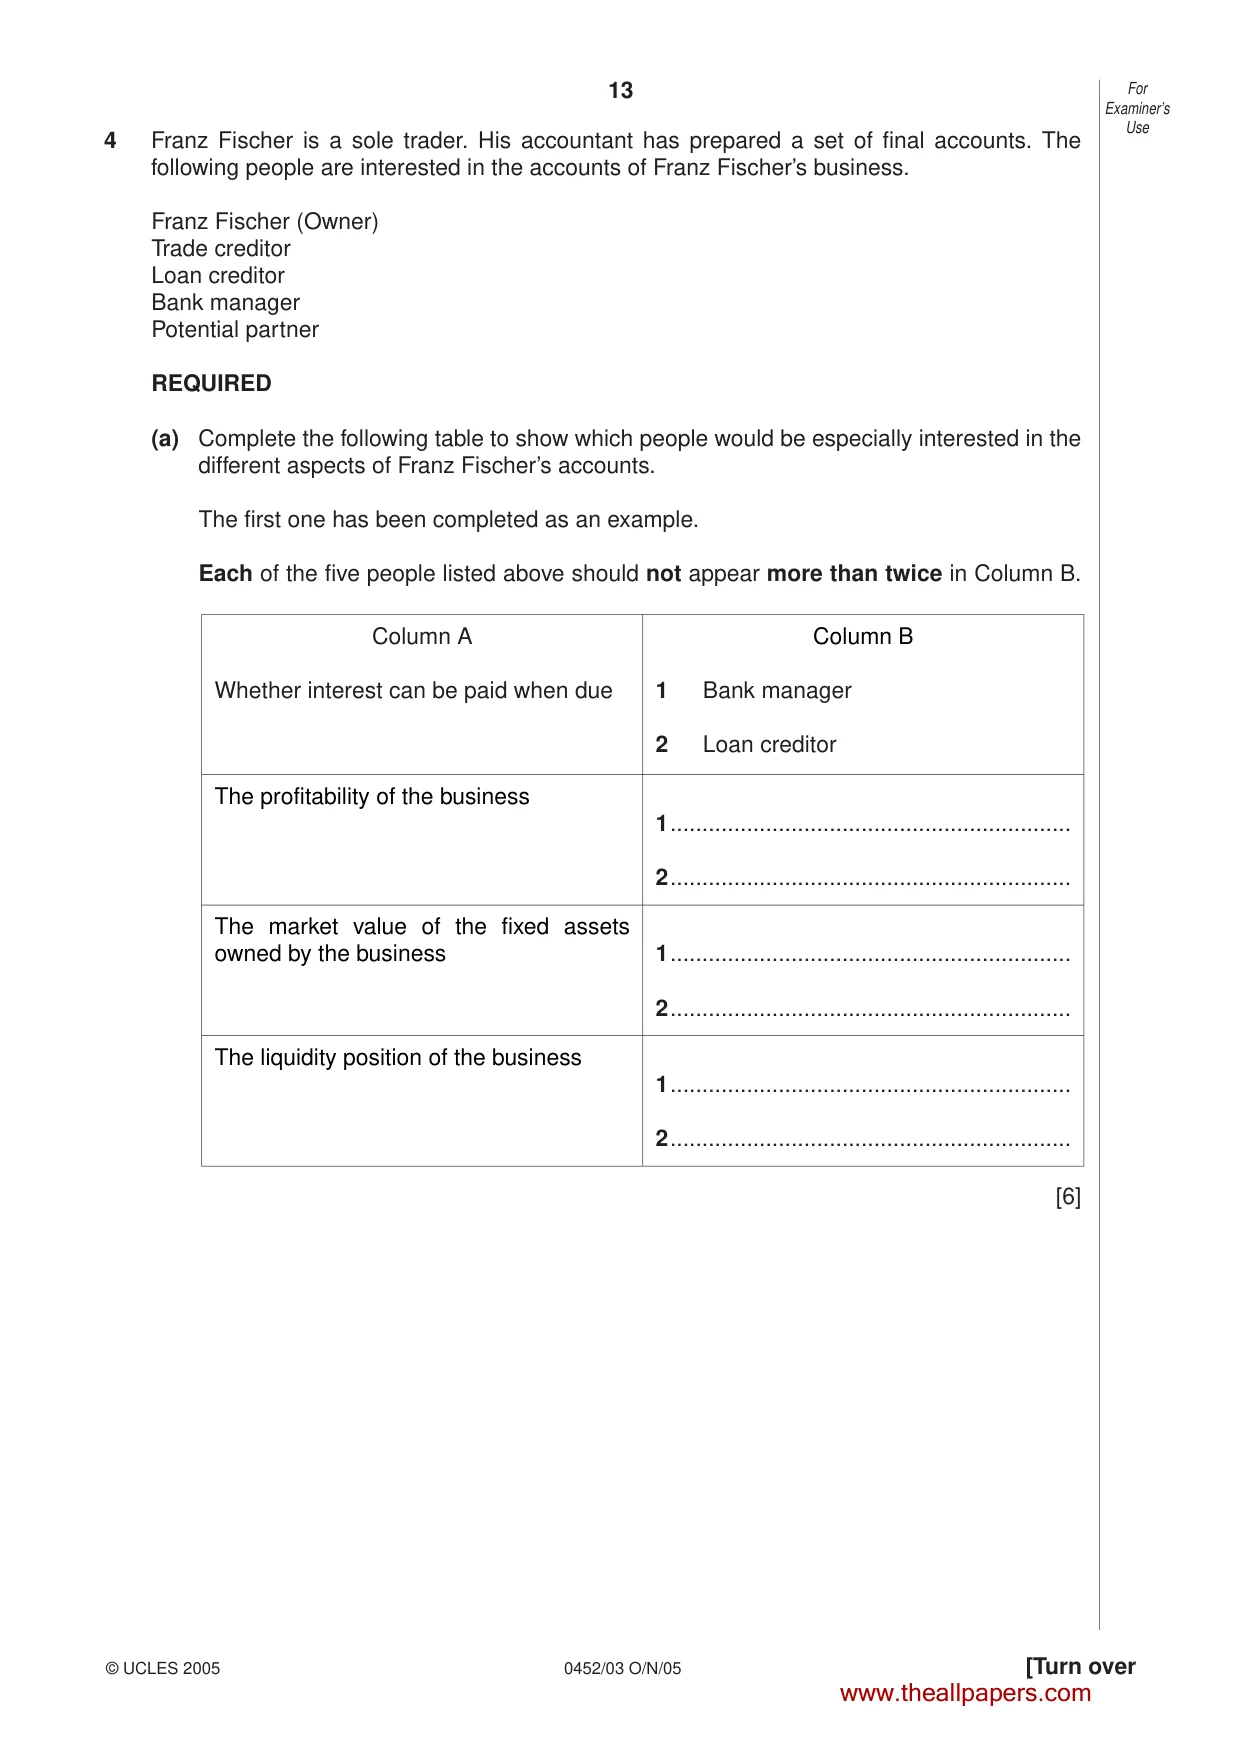
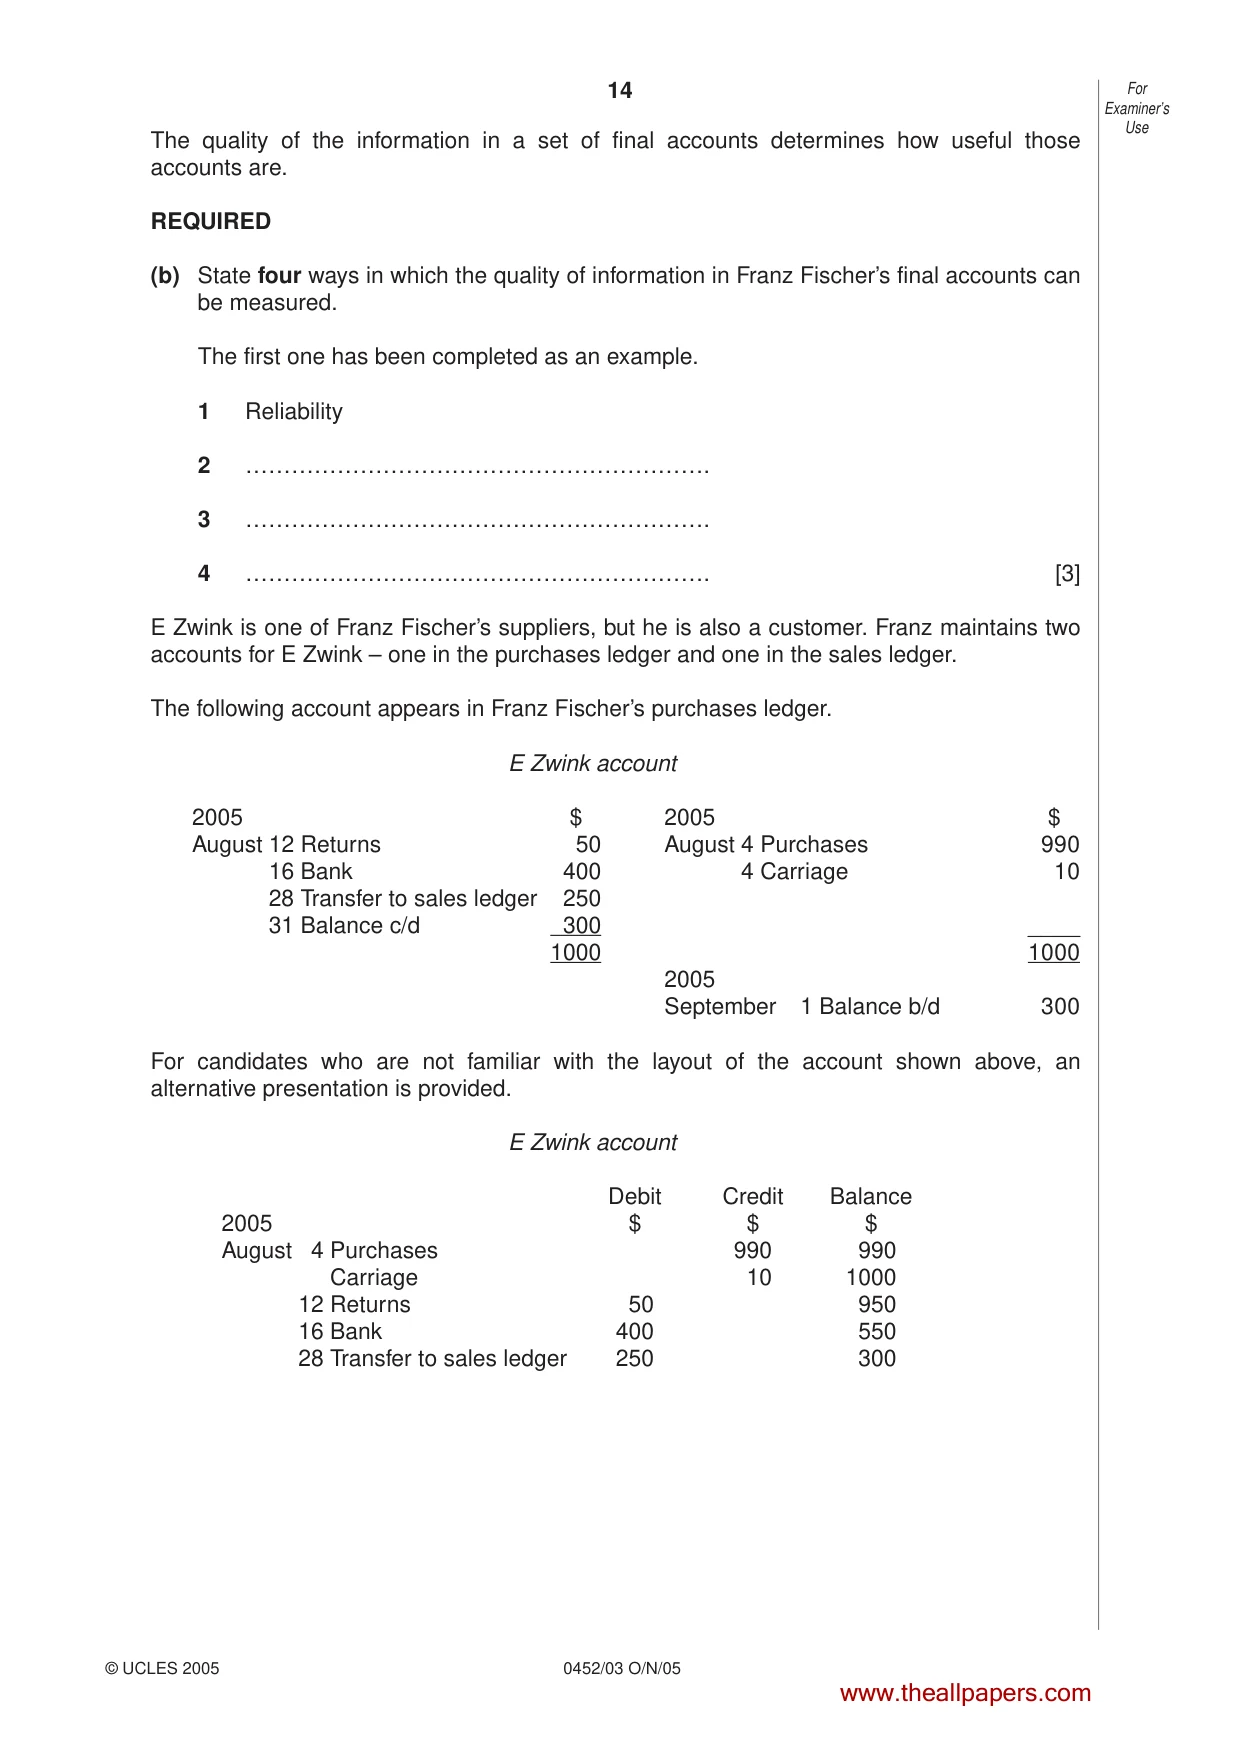
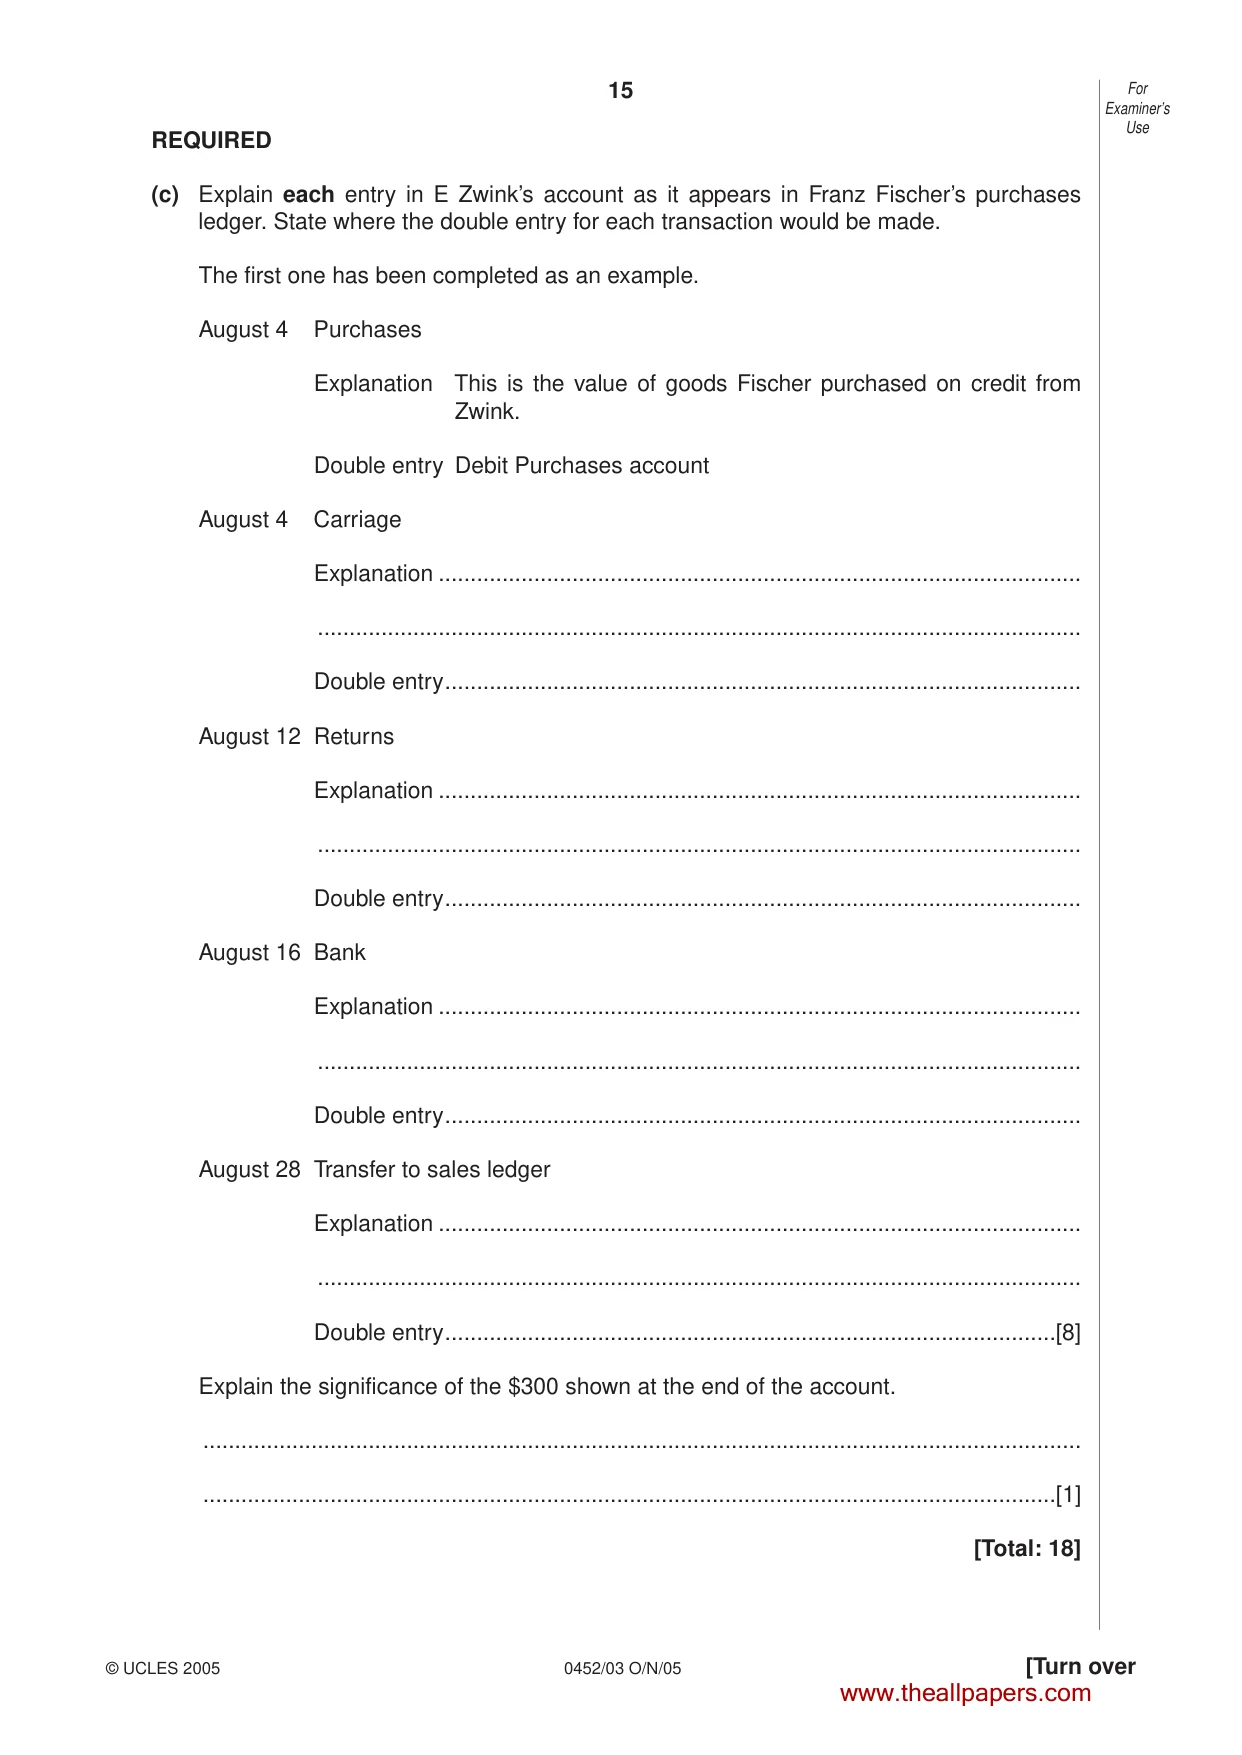
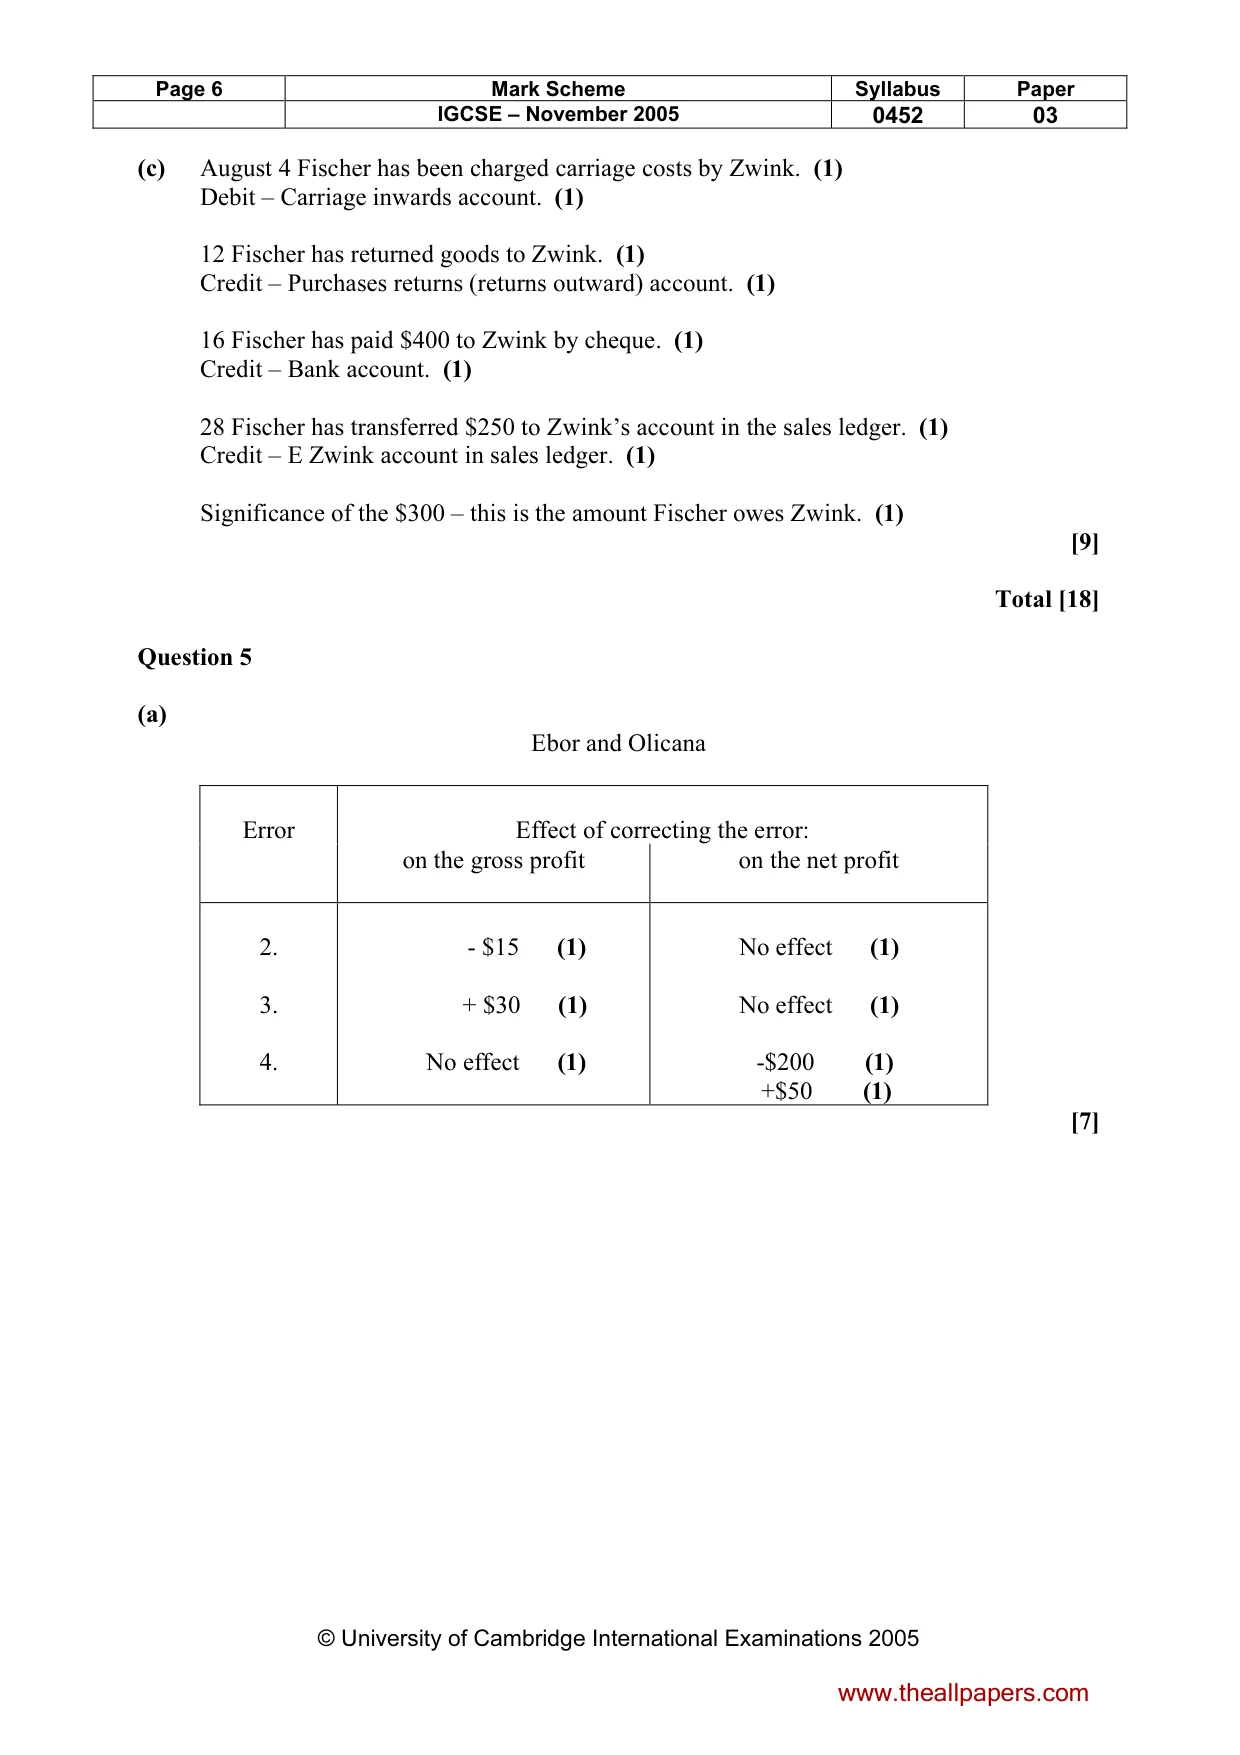
4 Franz Fischer is a sole trader. His accountant has prepared a set of final accounts. The following people are interested in the accounts of Franz Fischer’s business. Franz Fischer (Owner) Trade creditor Loan creditor Bank manager Potential partner REQUIRED (a) Complete the following table to show which people would be especially interested in the different aspects of Franz Fischer’s accounts. The first one has been completed as an example. Each of the five people listed above should not appear more than twice in Column B. Column A Column B Whether interest can be paid when due 1 Bank manager 2 Loan creditor The profitability of the business 1............................................................... 2............................................................... The market value of the fixed assets owned by the business 1............................................................... 2............................................................... The liquidity position of the business 1............................................................... 2............................................................... [6] The quality of the information in a set of final accounts determines how useful those accounts are. REQUIRED (b) State four ways in which the quality of information in Franz Fischer’s final accounts can be measured. The first one has been completed as an example. 1 Reliability 2 3 4 [3] E Zwink is one of Franz Fischer’s suppliers, but he is also a customer. Franz maintains two accounts for E Zwink – one in the purchases ledger and one in the sales ledger. The following account appears in Franz Fischer’s purchases ledger. E Zwink account 2005 $ 2005 $ August 12 Returns 50 August 4 Purchases 990 16 Bank 400 4 Carriage 10 28 Transfer to sales ledger 250 31 Balance c/d 300 ____ 1000 1000 2005 September 1 Balance b/d 300 For candidates who are not familiar with the layout of the account shown above, an alternative presentation is provided. E Zwink account Debit Credit Balance 2005 $ $ $ August 4 Purchases 990 990 Carriage 10 1000 12 Returns 50 950 16 Bank 400 550 28 Transfer to sales ledger 250 300 REQUIRED (c) Explain each entry in E Zwink’s account as it appears in Franz Fischer’s purchases ledger. State where the double entry for each transaction would be made. The first one has been completed as an example. August 4 Purchases Explanation This is the value of goods Fischer purchased on credit from Zwink. Double entry Debit Purchases account August 4 Carriage Explanation ..................................................................................................... ........................................................................................................................ Double entry.................................................................................................... August 12 Returns Explanation ..................................................................................................... ........................................................................................................................ Double entry.................................................................................................... August 16 Bank Explanation ..................................................................................................... ........................................................................................................................ Double entry.................................................................................................... August 28 Transfer to sales ledger Explanation ..................................................................................................... ........................................................................................................................ Double entry................................................................................................[8] Explain the significance of the $300 shown at the end of the account. .......................................................................................................................................... ......................................................................................................................................[1] [Total: 18]
Q5 · Ebor and Olicana are in partnership trading in sports goods
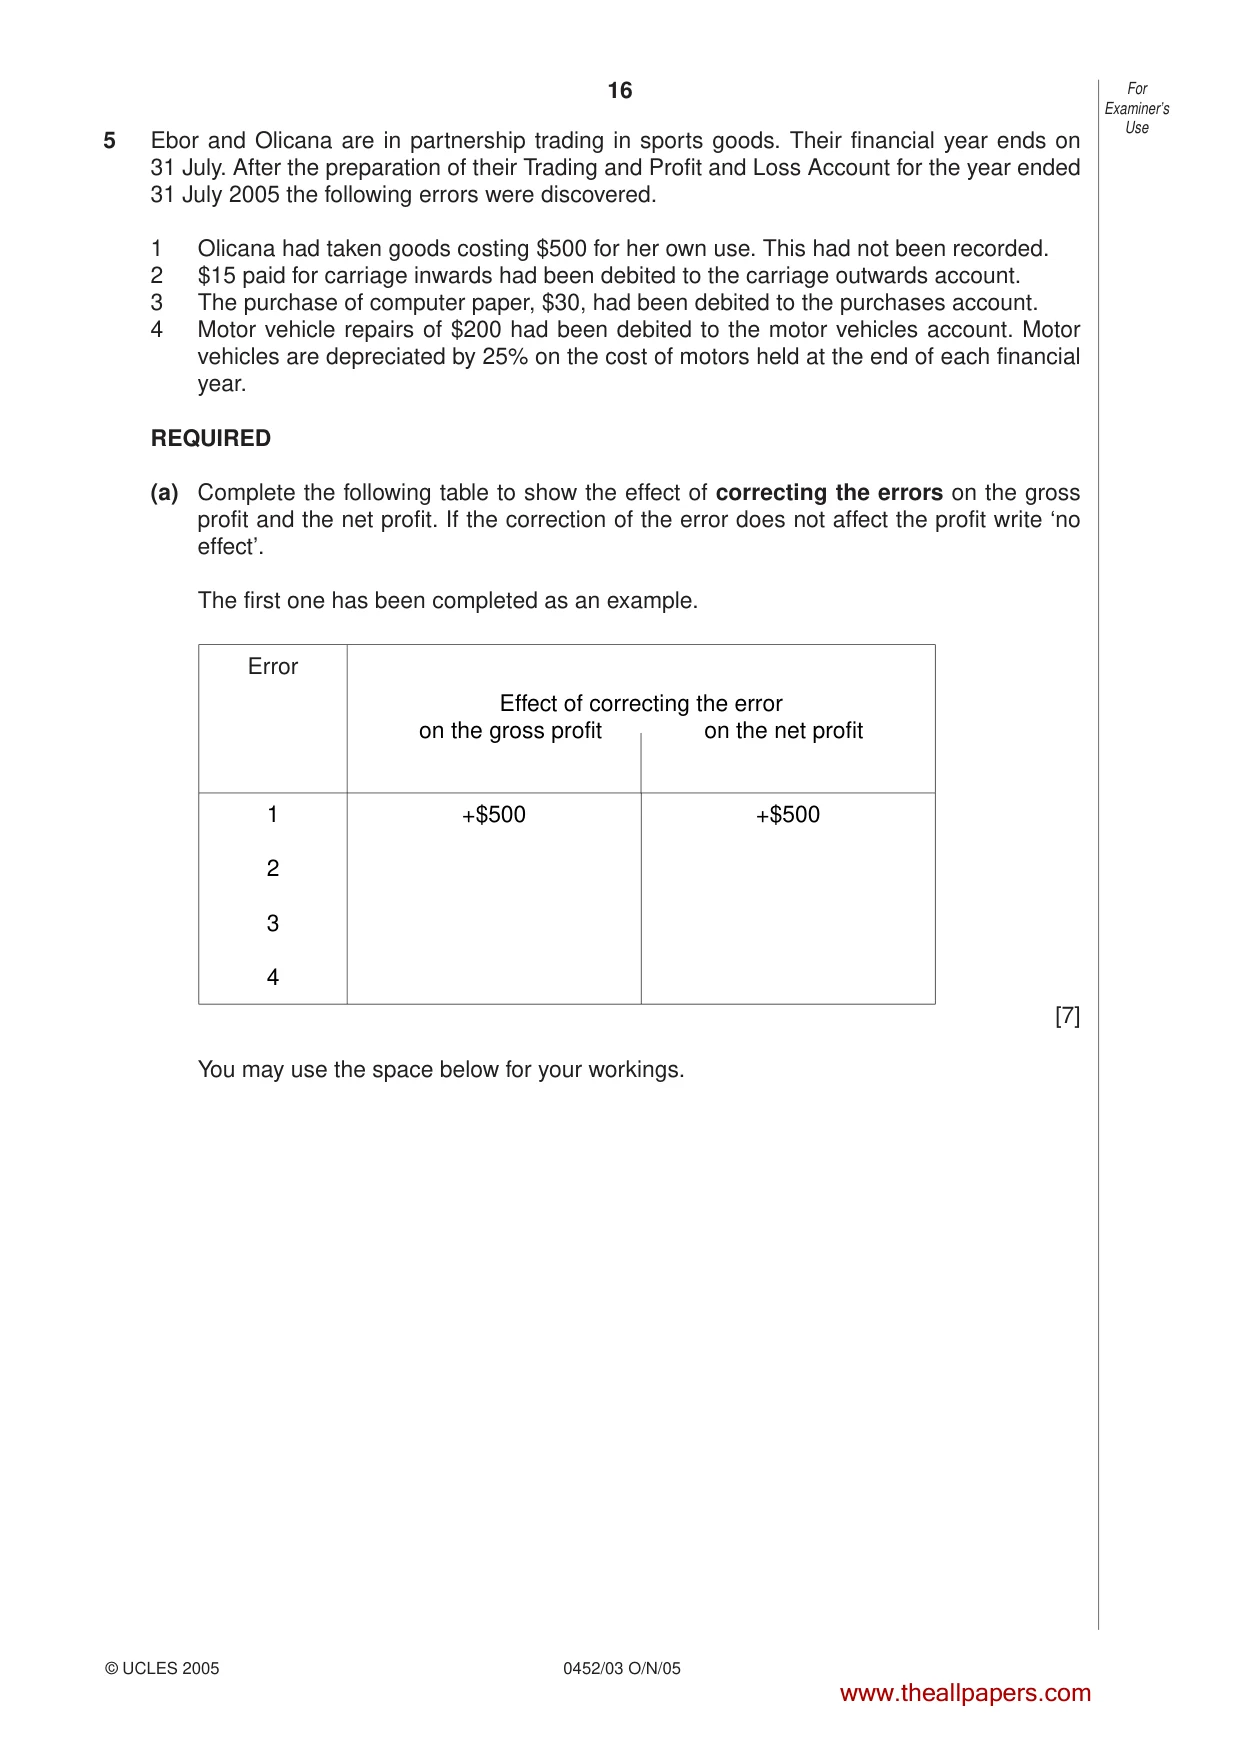
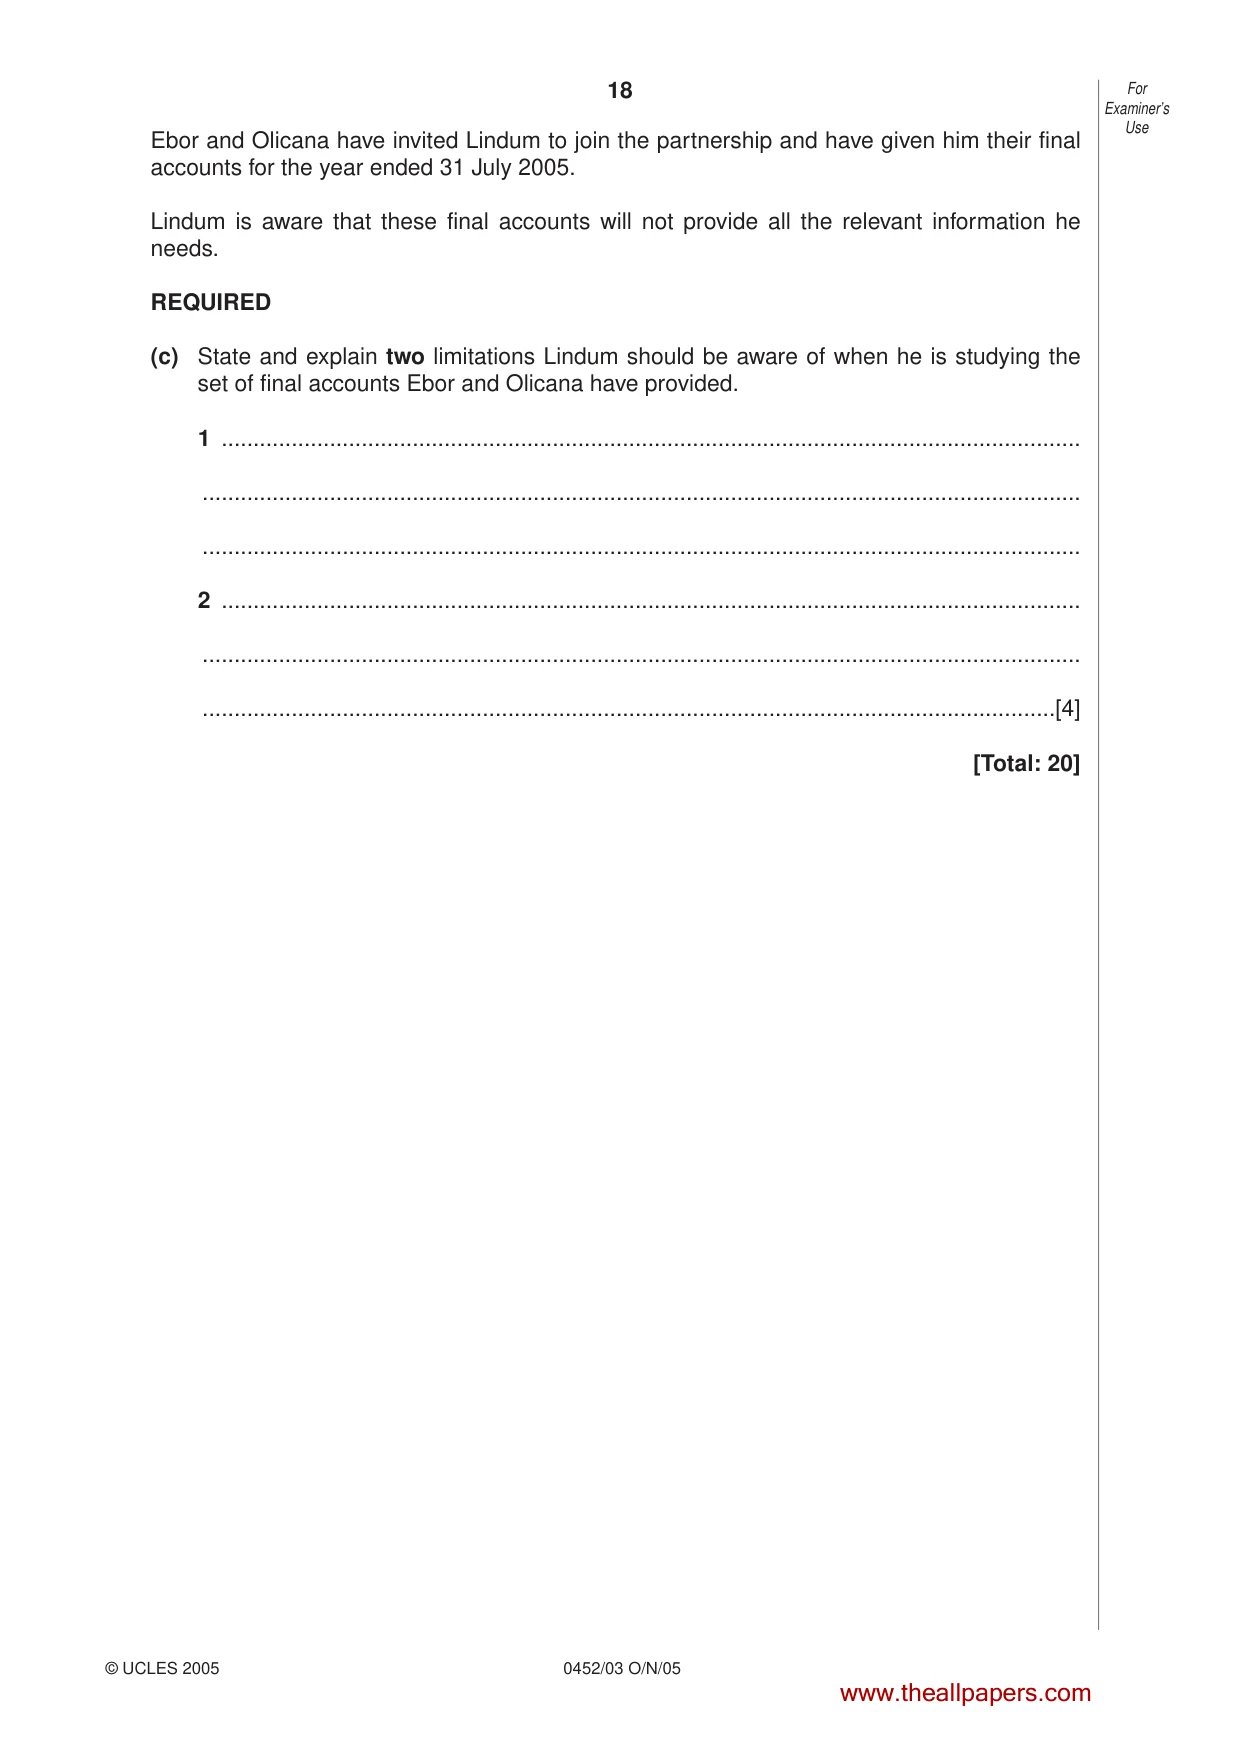
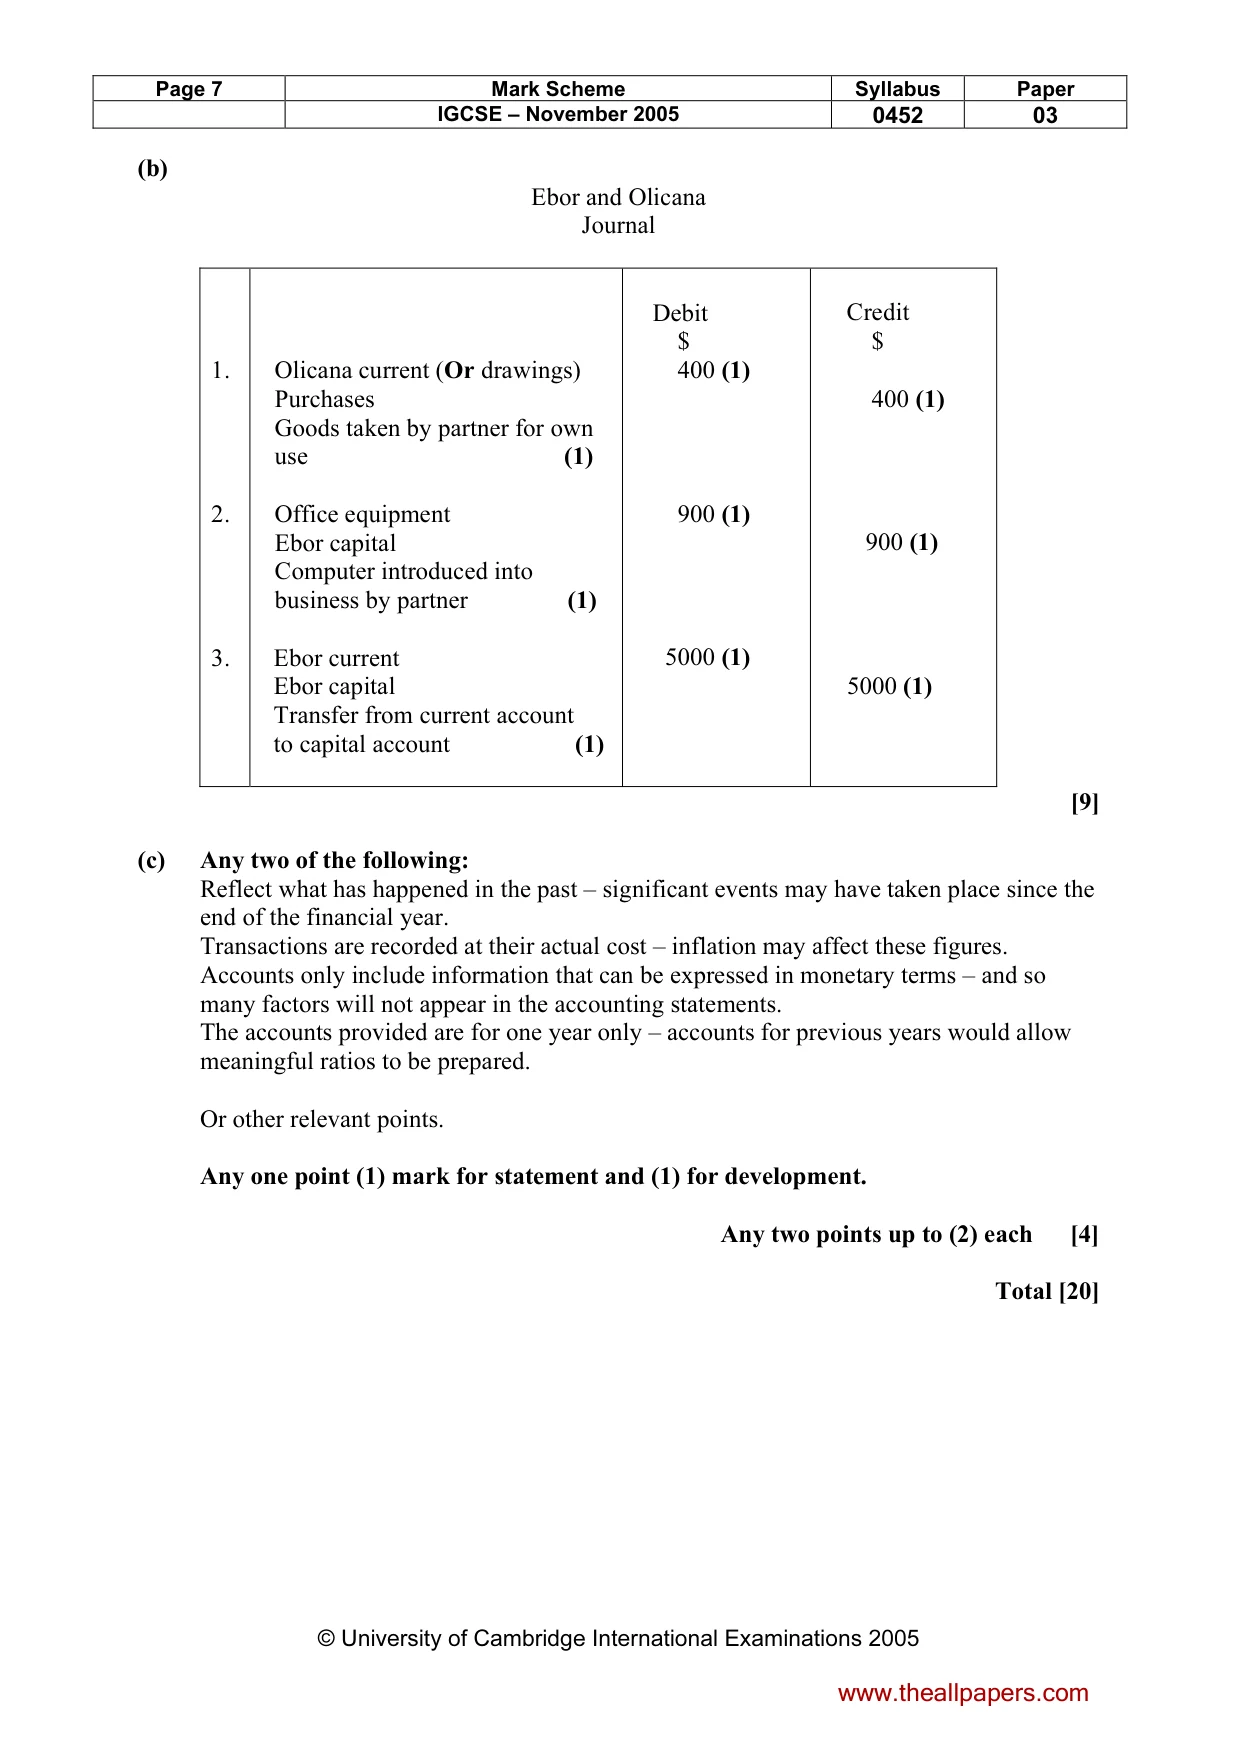
5 Ebor and Olicana are in partnership trading in sports goods. Their financial year ends on 31 July. After the preparation of their Trading and Profit and Loss Account for the year ended 31 July 2005 the following errors were discovered. 1 Olicana had taken goods costing $500 for her own use. This had not been recorded. 2 $15 paid for carriage inwards had been debited to the carriage outwards account. 3 The purchase of computer paper, $30, had been debited to the purchases account. 4 Motor vehicle repairs of $200 had been debited to the motor vehicles account. Motor vehicles are depreciated by 25% on the cost of motors held at the end of each financial year. REQUIRED (a) Complete the following table to show the effect of correcting the errors on the gross profit and the net profit. If the correction of the error does not affect the profit write ‘no effect’. The first one has been completed as an example. Error Effect of correcting the error on the gross profit on the net profit 1 +$500 +$500 2 3 4 [7] You may use the space below for your workings. Ebor and Olicana maintain a full set of books of account. The following transactions took place on 31 August 2005. 1 Olicana took further goods costing $400 for her own use. 2 Ebor brought his own computer, valued at $900, into the business. 3 Ebor’s current account showed a credit balance of $10 000. It was agreed that he should transfer half of this to his capital account. REQUIRED (b) Prepare the necessary journal entries to record the above transactions. Narratives are required. Ebor and Olicana Journal Debit Credit $ $ ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. [9] Ebor and Olicana have invited Lindum to join the partnership and have given him their final accounts for the year ended 31 July 2005. Lindum is aware that these final accounts will not provide all the relevant information he needs. REQUIRED (c) State and explain two limitations Lindum should be aware of when he is studying the set of final accounts Ebor and Olicana have provided. 1 ....................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... 2 ....................................................................................................................................... .......................................................................................................................................... ......................................................................................................................................[4] [Total: 20]
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.