Cambridge IGCSE Accounting 0452 — 2005 May/June Paper 3 · Variant 1
0452/31/M/J/05 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme9 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · James and Susan Mokobi are in partnership, sharing profits and losses equally
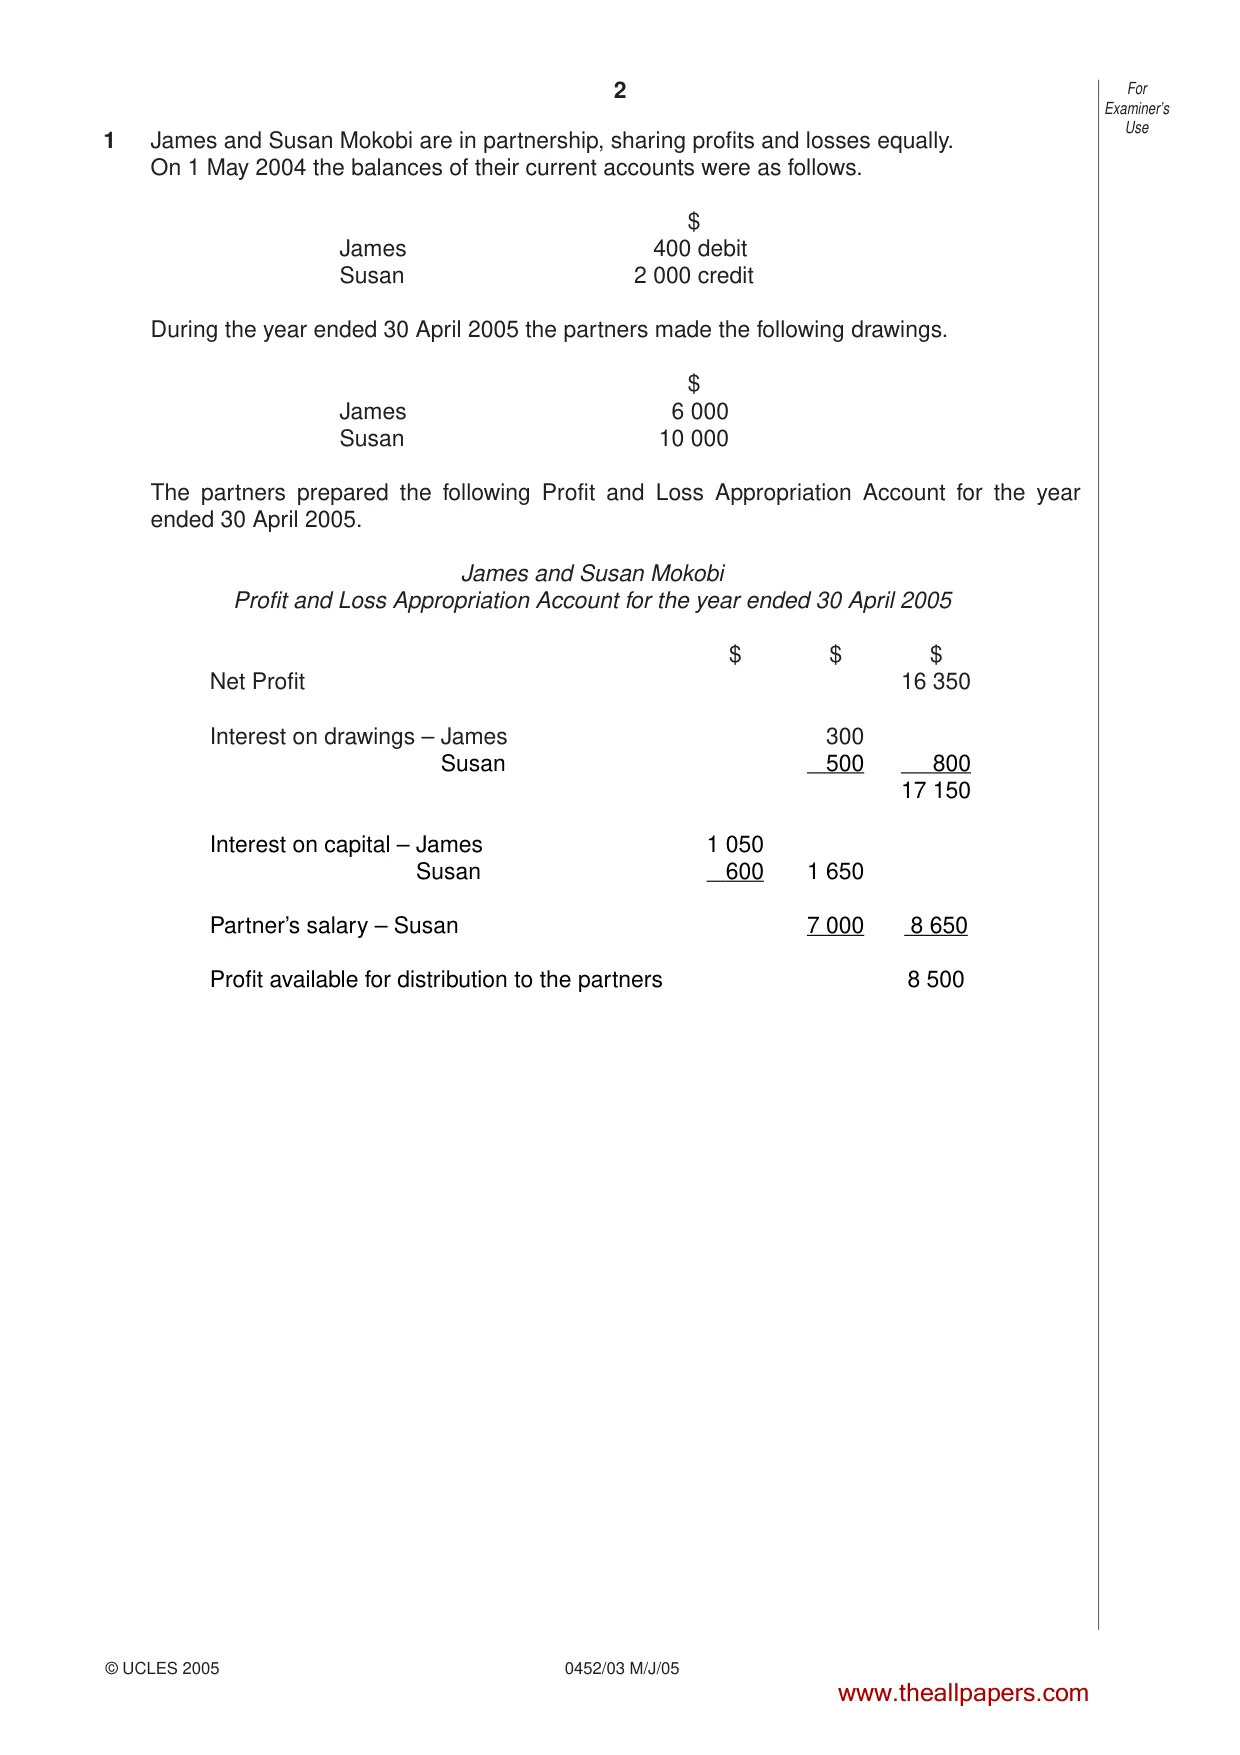
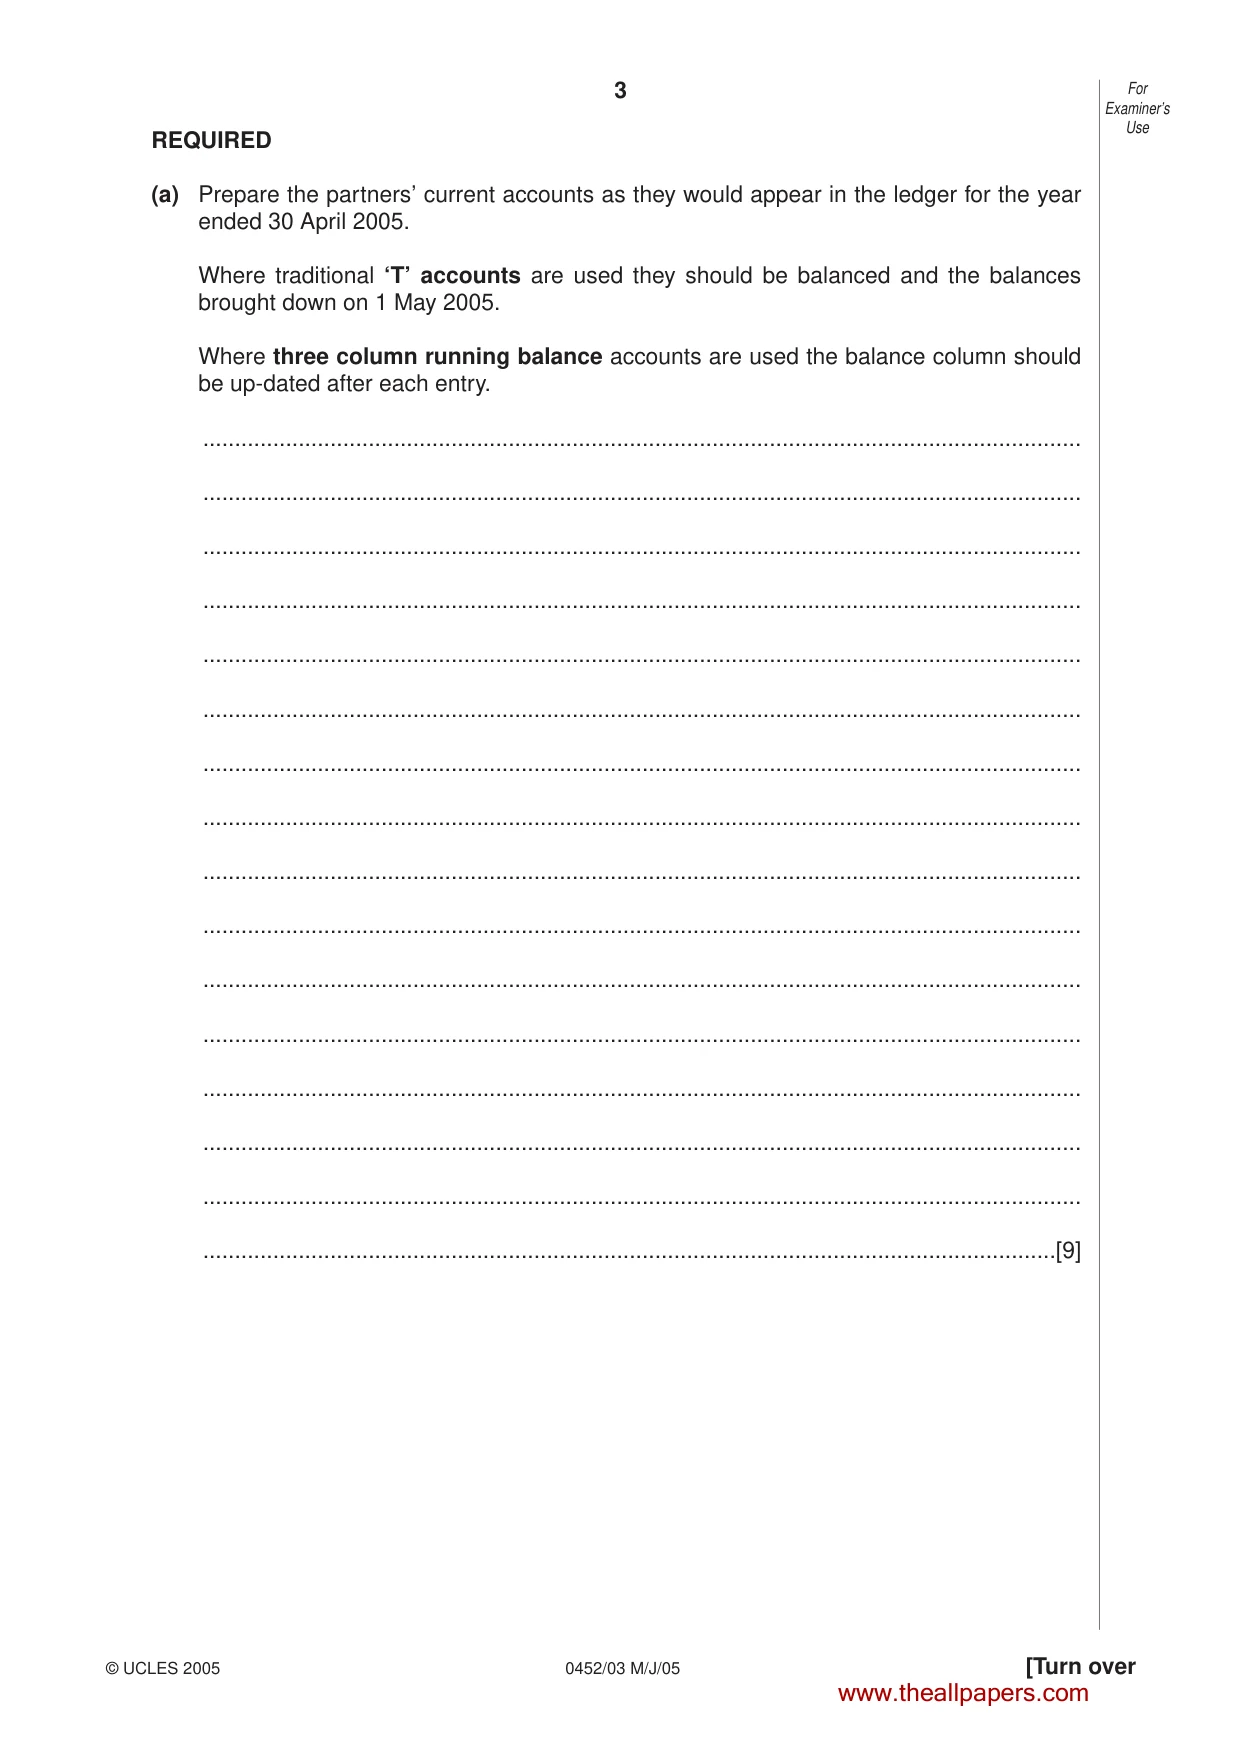
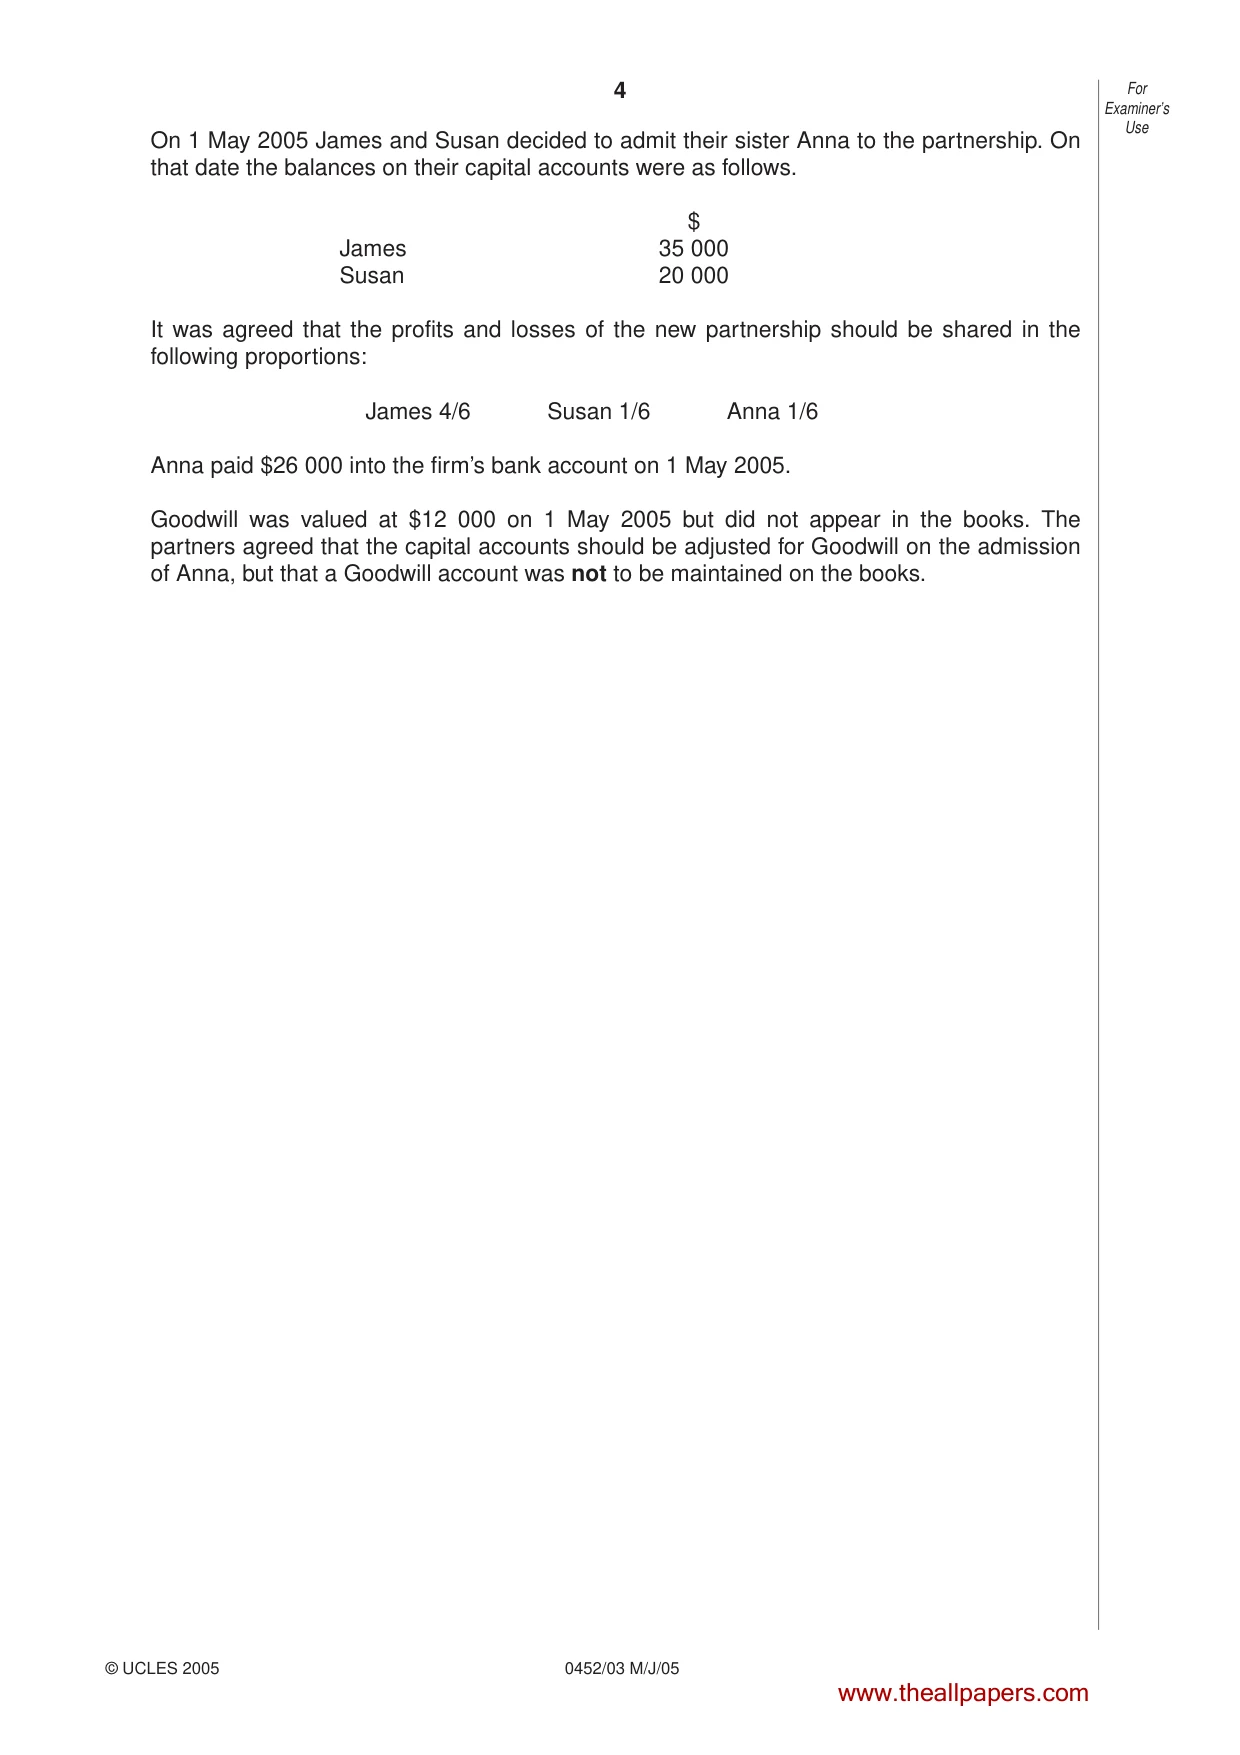
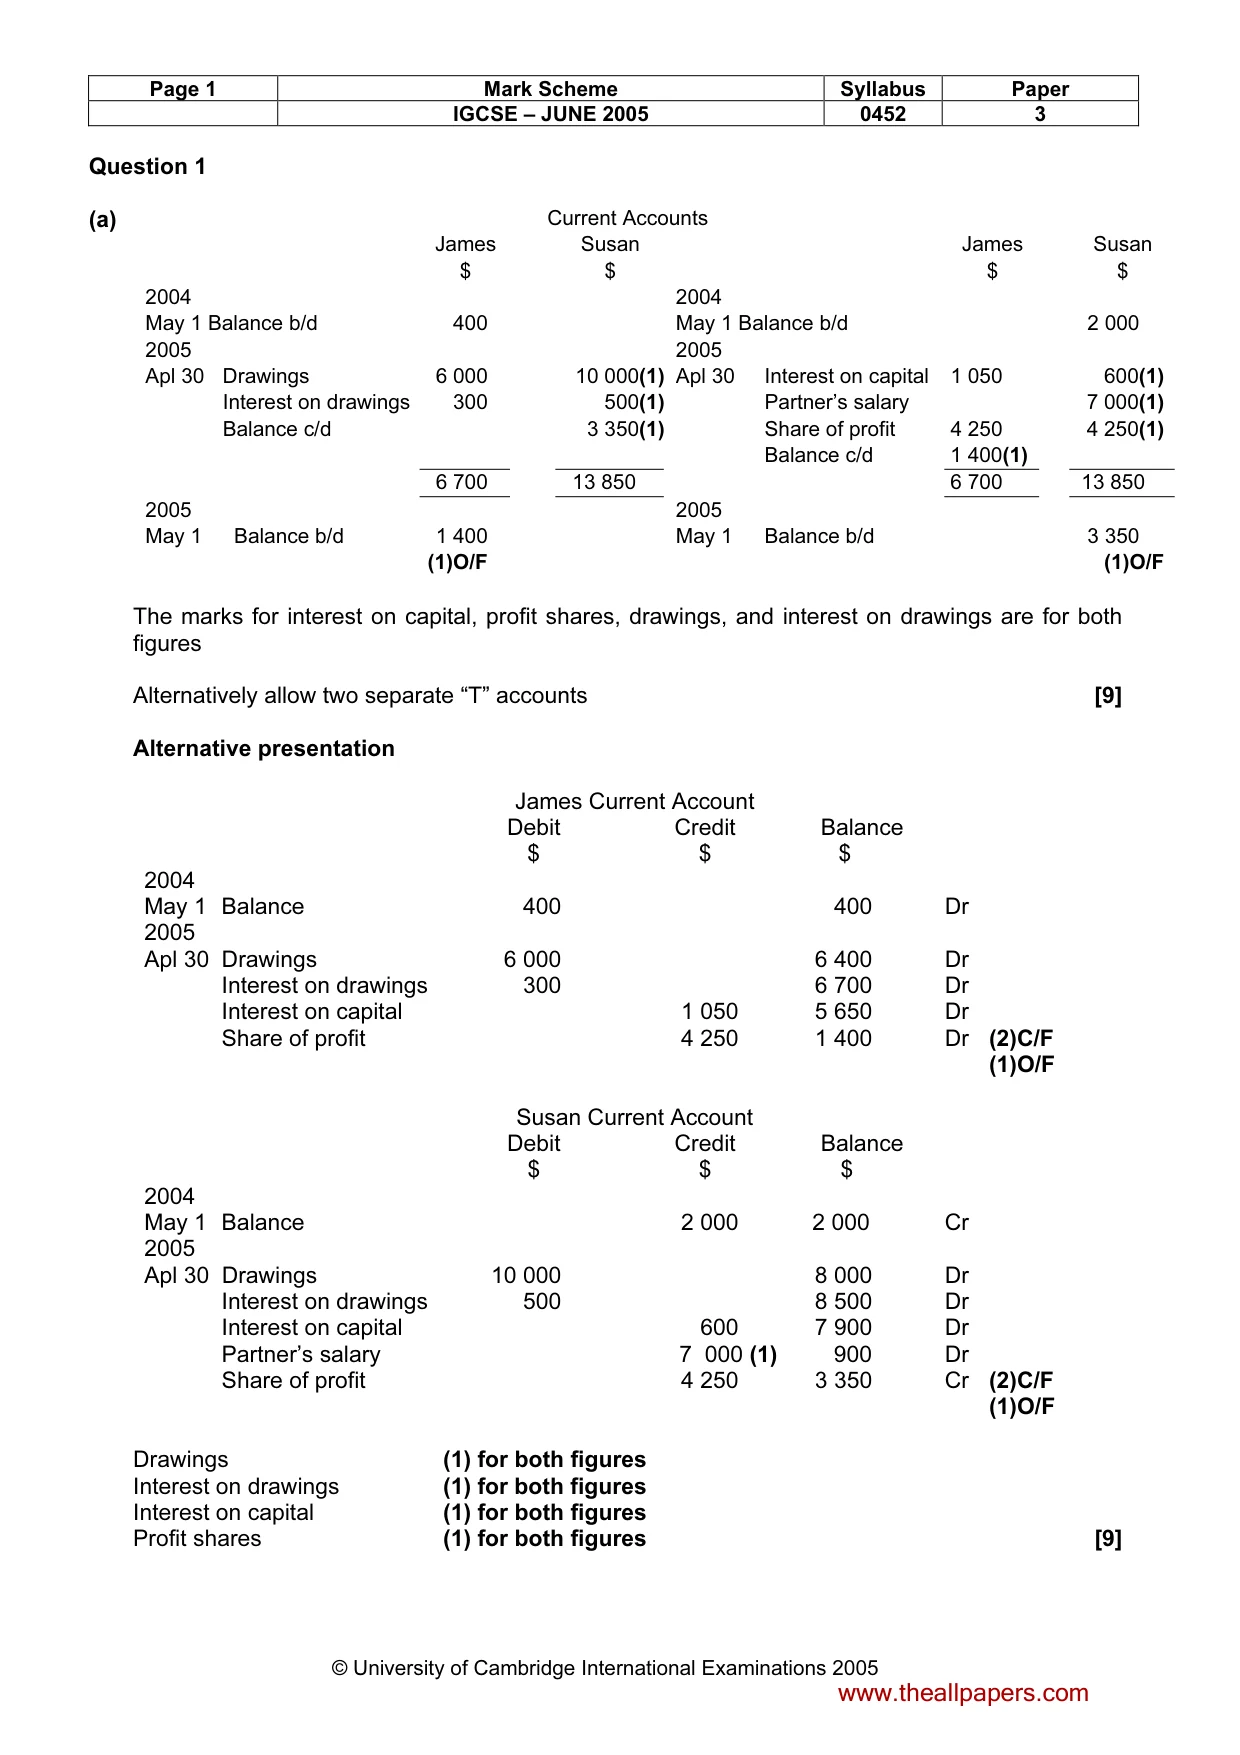
1 James and Susan Mokobi are in partnership, sharing profits and losses equally. On 1 May 2004 the balances of their current accounts were as follows. $ James 400 debit Susan 2 000 credit During the year ended 30 April 2005 the partners made the following drawings. $ James 6 000 Susan 10 000 The partners prepared the following Profit and Loss Appropriation Account for the year ended 30 April 2005. James and Susan Mokobi Profit and Loss Appropriation Account for the year ended 30 April 2005 $ $ $ Net Profit 16 350 Interest on drawings – James 300 Interest on drawings – Susan 500 800 17 150 Interest on capital – James 1 050 Interest on capital – Susan 600 1 650 Partner’s salary – Susan 7 000 8 650 Profit available for distribution to the partners 8 500 REQUIRED (a) Prepare the partners’ current accounts as they would appear in the ledger for the year ended 30 April 2005. Where traditional ‘T’ accounts are used they should be balanced and the balances brought down on 1 May 2005. Where three column running balance accounts are used the balance column should be up-dated after each entry. .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... ......................................................................................................................................[9] On 1 May 2005 James and Susan decided to admit their sister Anna to the partnership. On that date the balances on their capital accounts were as follows. $ James 35 000 Susan 20 000 It was agreed that the profits and losses of the new partnership should be shared in the following proportions: James 4/6 Susan 1/6 Anna 1/6 Anna paid $26 000 into the firm’s bank account on 1 May 2005. Goodwill was valued at $12 000 on 1 May 2005 but did not appear in the books. The partners agreed that the capital accounts should be adjusted for Goodwill on the admission of Anna, but that a Goodwill account was not to be maintained on the books. REQUIRED (b) Prepare the capital accounts of James, Susan and Anna as they would appear in the ledger immediately after Anna was made a partner. Where traditional ‘T’ accounts are used they should be balanced and the balances brought down on 2 May 2005. Where three column running balance accounts are used the balance column should be up-dated after each entry. .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... ....................................................................................................................................[14] [Total: 23]
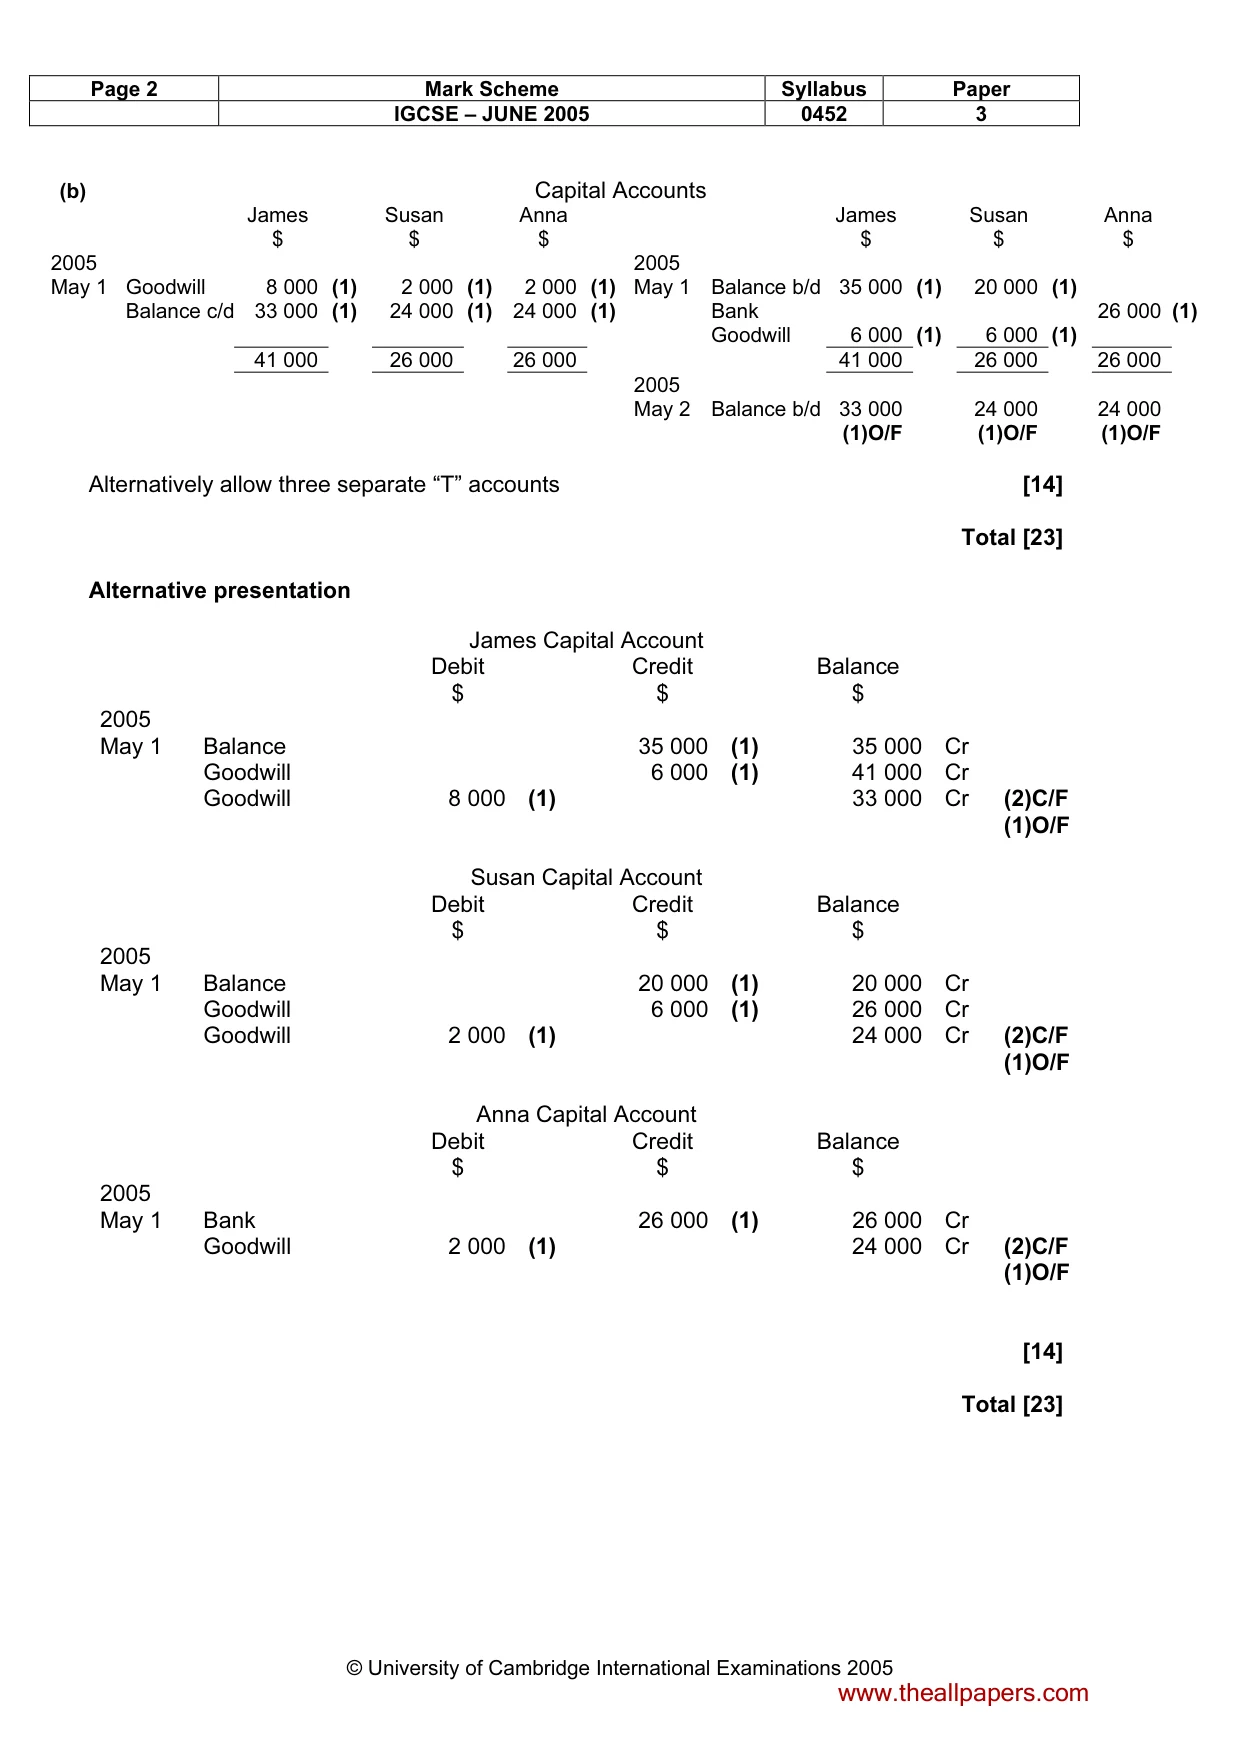
Q2 · Jane Joda started a business on 1 April 2003
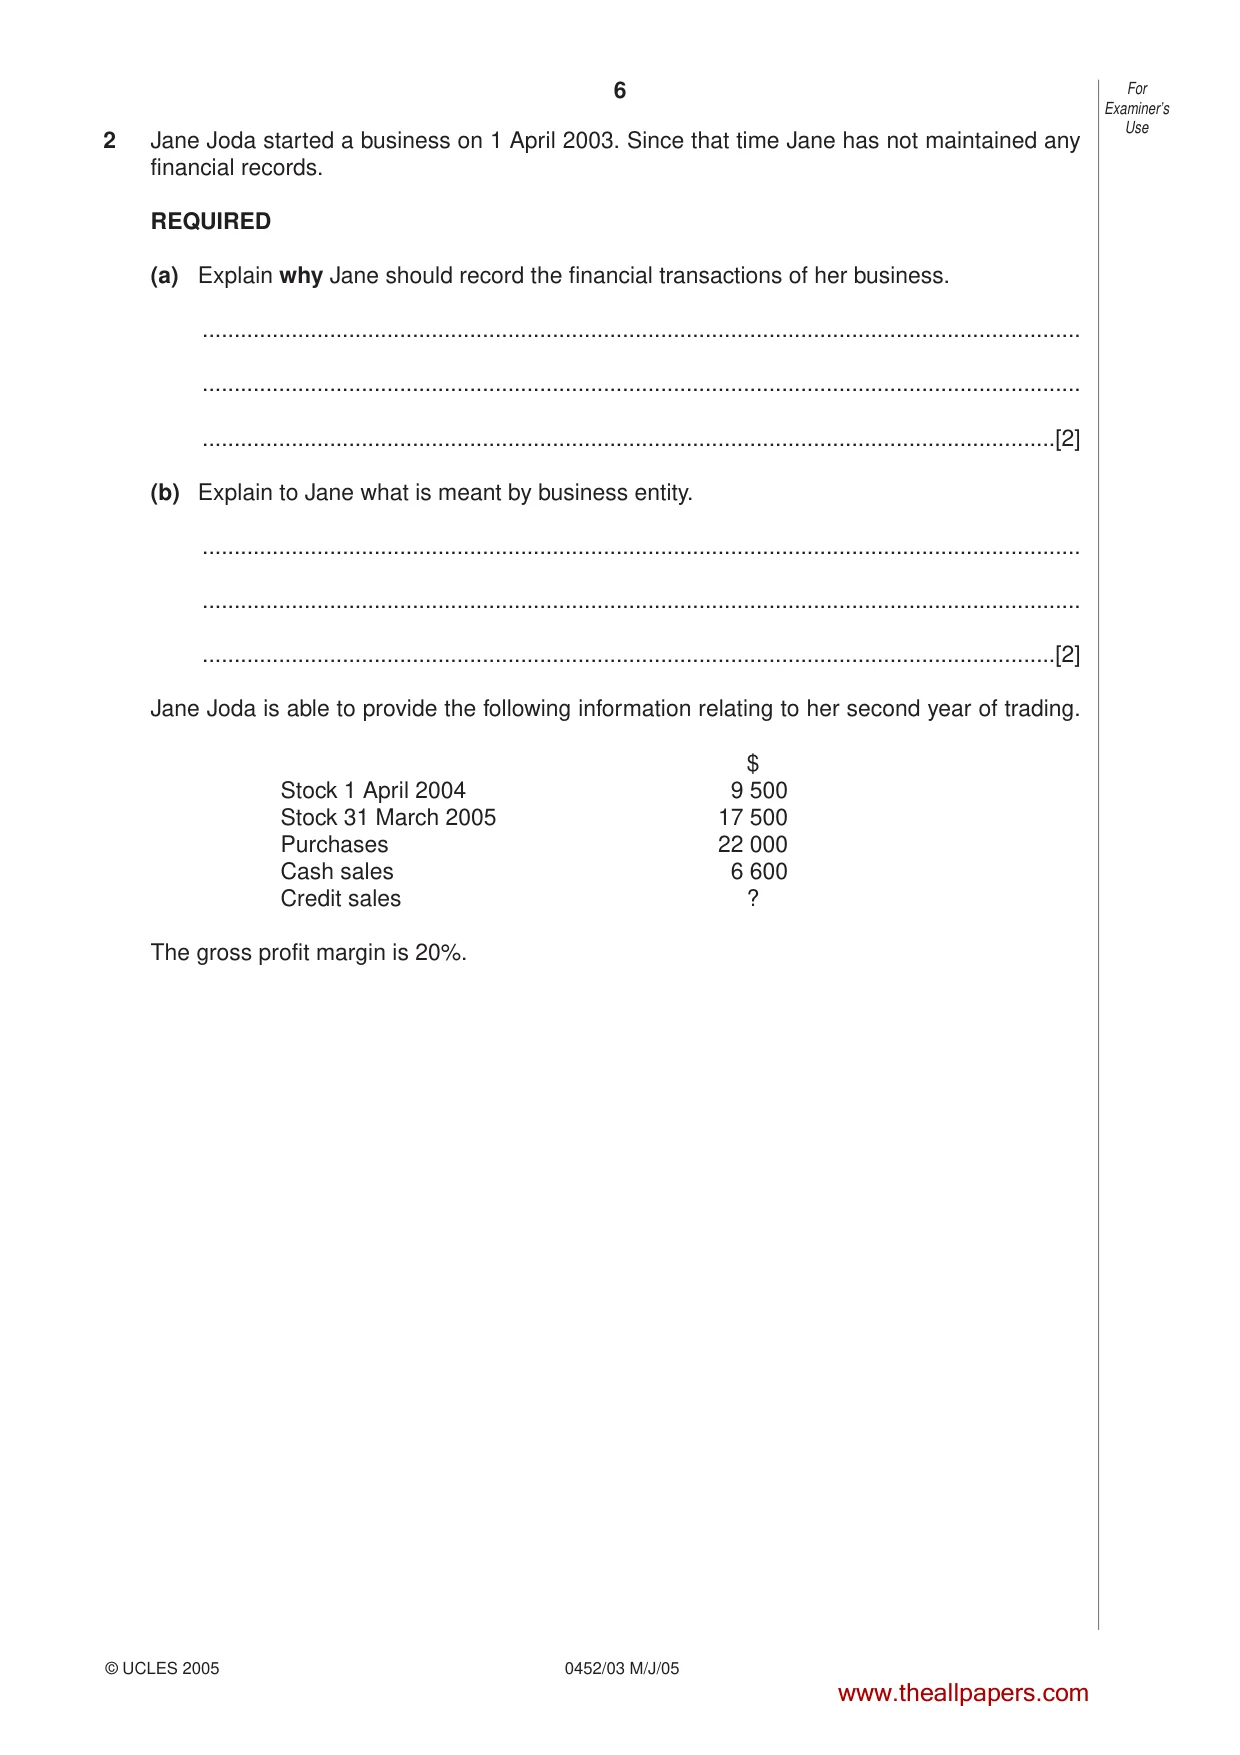
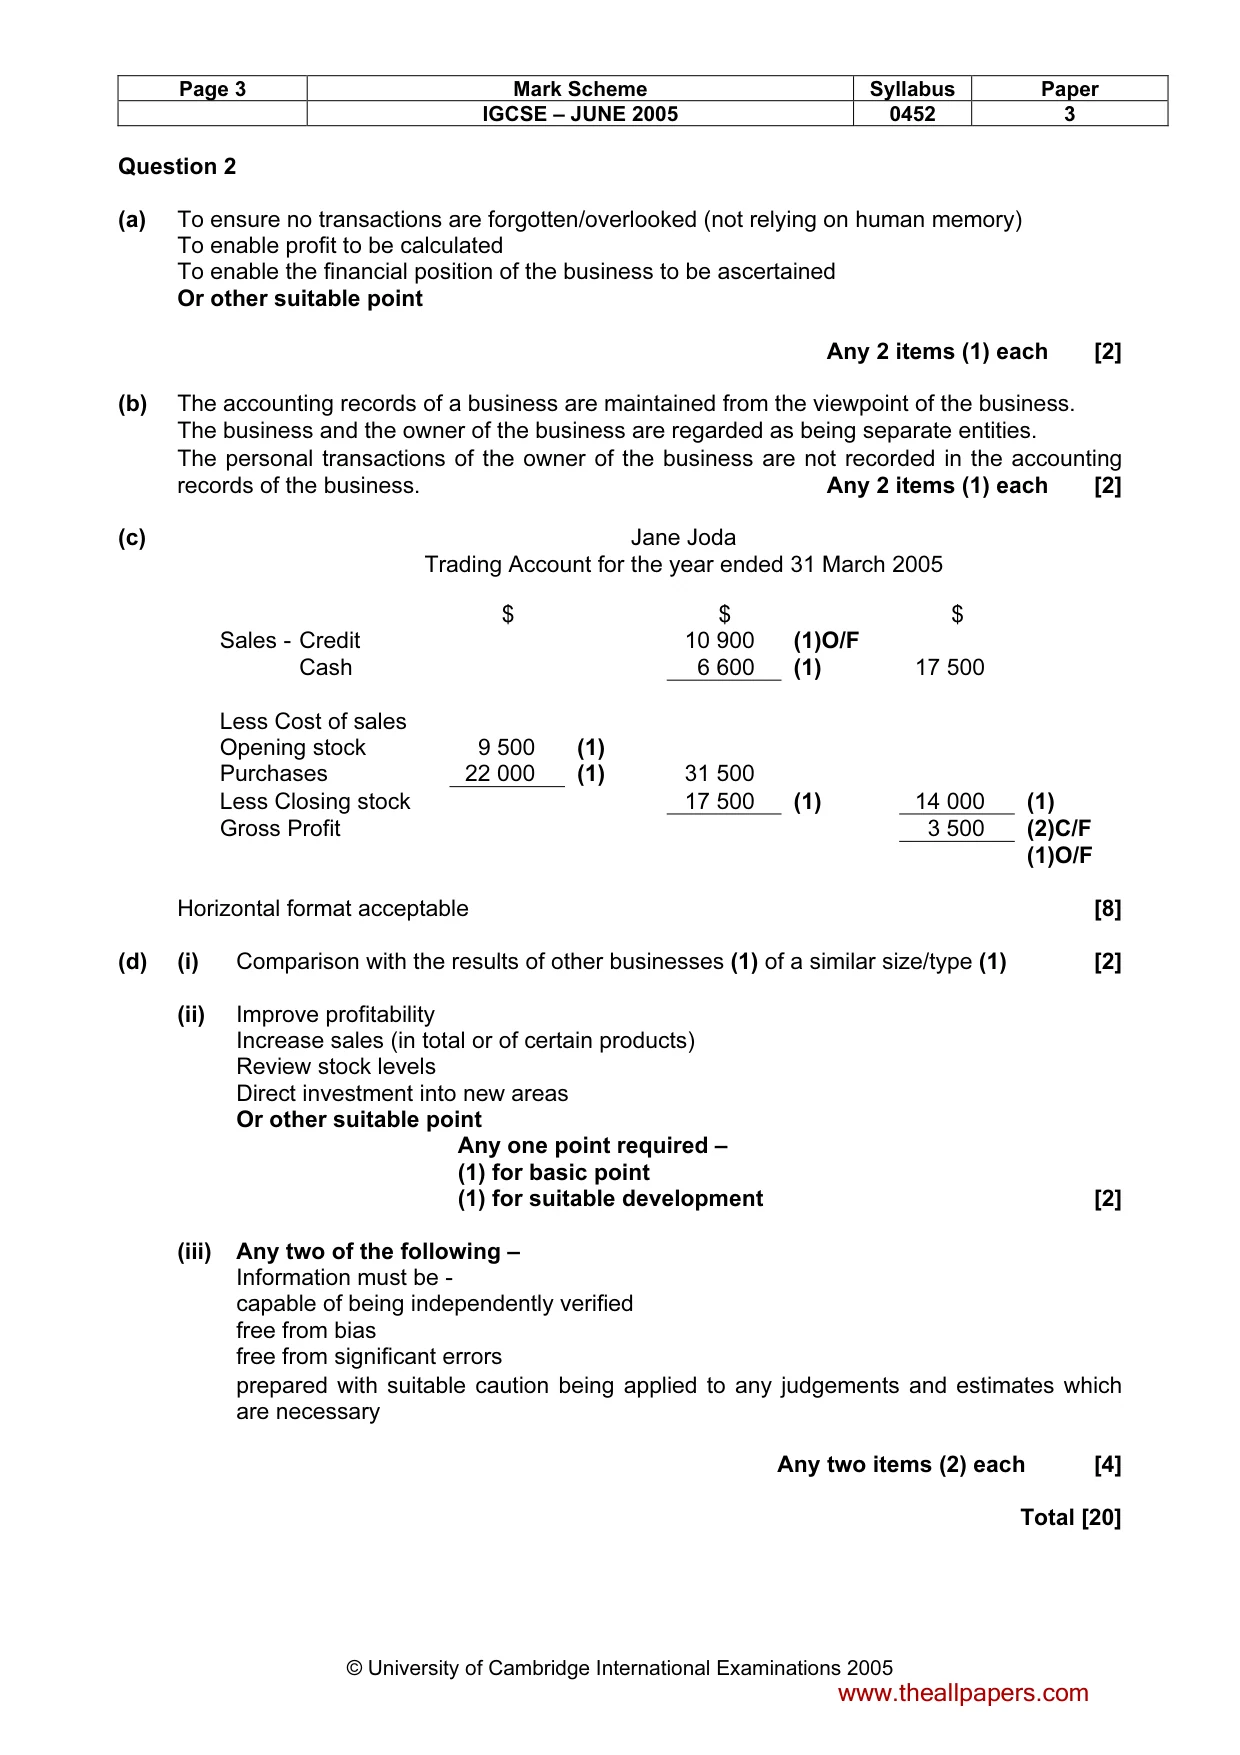
2 Jane Joda started a business on 1 April 2003. Since that time Jane has not maintained any financial records. REQUIRED (a) Explain why Jane should record the financial transactions of her business. .......................................................................................................................................... .......................................................................................................................................... ......................................................................................................................................[2] (b) Explain to Jane what is meant by business entity. .......................................................................................................................................... .......................................................................................................................................... ......................................................................................................................................[2] Jane Joda is able to provide the following information relating to her second year of trading. $ Stock 1 April 2004 9 500 Stock 31 March 2005 17 500 Purchases 22 000 Cash sales 6 600 Credit sales ? The gross profit margin is 20%. REQUIRED (c) Calculate by means of a Trading Account the value of Jane Joda’s credit sales for the year ended 31 March 2005. Jane Joda Trading Account for the year ended 31 March 2005 .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... ......................................................................................................................................[8] The quality of information in financial statements can be measured in terms of comparability and reliability. REQUIRED (d) (i) Jane Joda could compare her results for the year ended 30 April 2005 with those for the previous year. State one other comparison Jane could make. ................................................................................................................................... ...............................................................................................................................[2] (ii) Suggest one way in which Jane might use the results of any comparisons she makes. ................................................................................................................................... ................................................................................................................................... ...............................................................................................................................[2] (iii) Jane Joda must be able to rely on the information provided in the financial statements prepared for her business. One condition which must be present for information to be regarded as reliable is shown below. State two other conditions. 1 The information must be capable of being depended on as being a true statement of the transactions and events which are being recorded. 2 ........................................................................................................................... ........................................................................................................................... 3 ........................................................................................................................... .......................................................................................................................[4] [Total: 20]
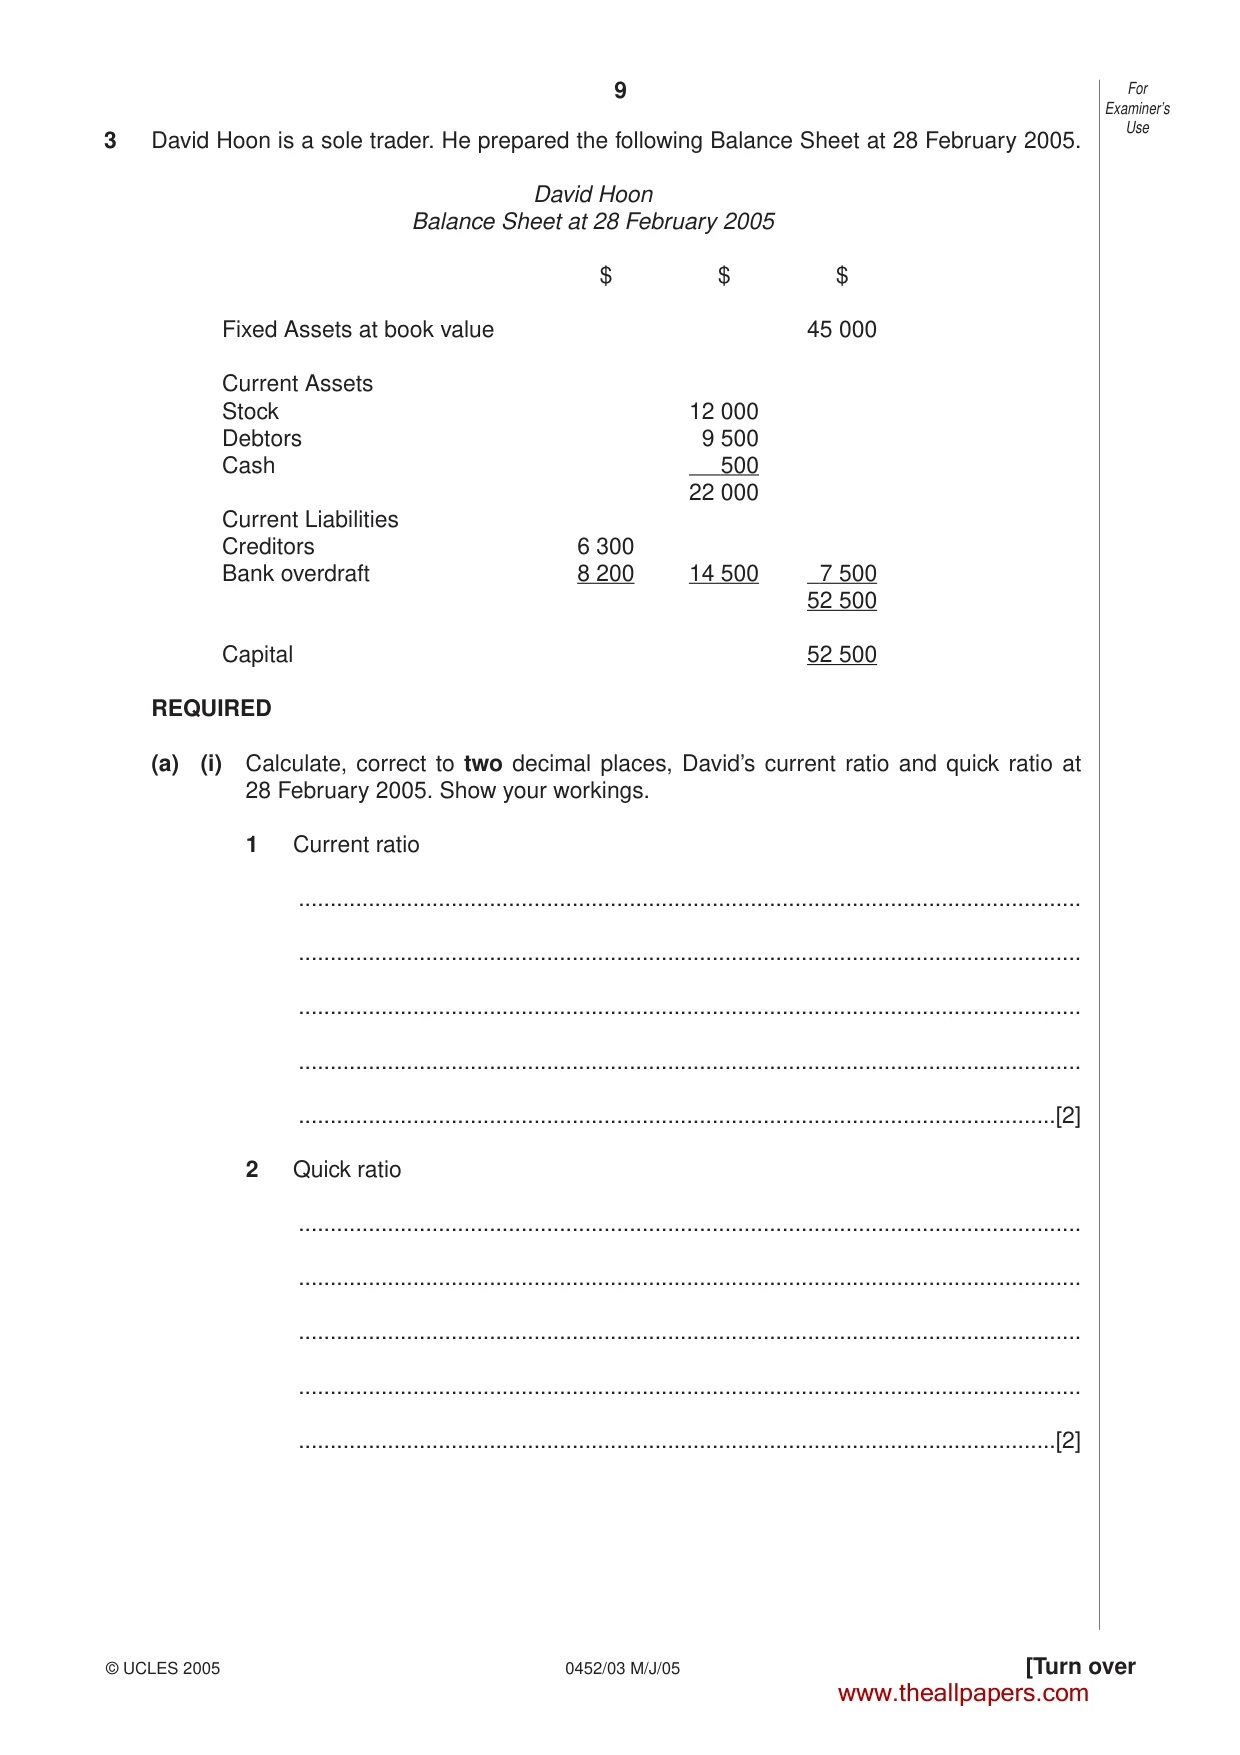
Q3 · David Hoon is a sole trader
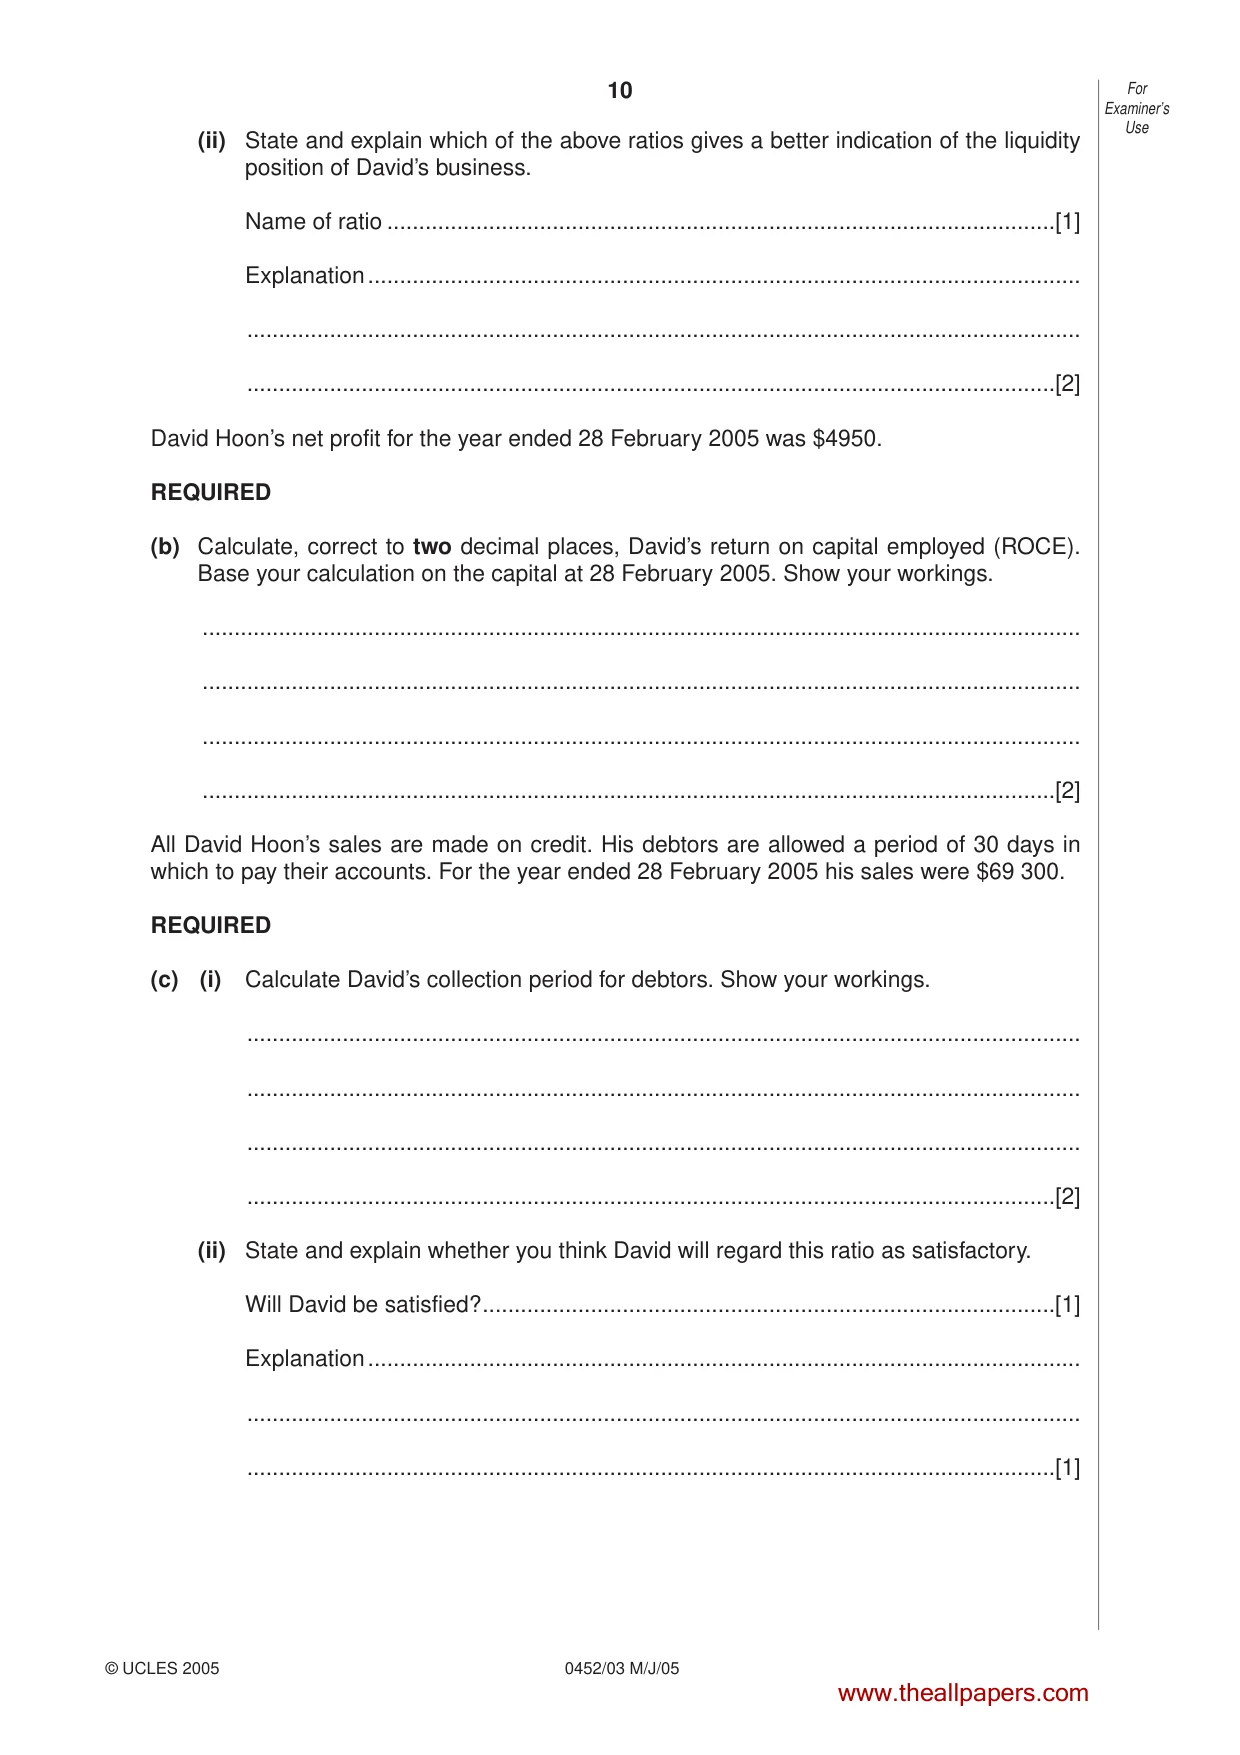
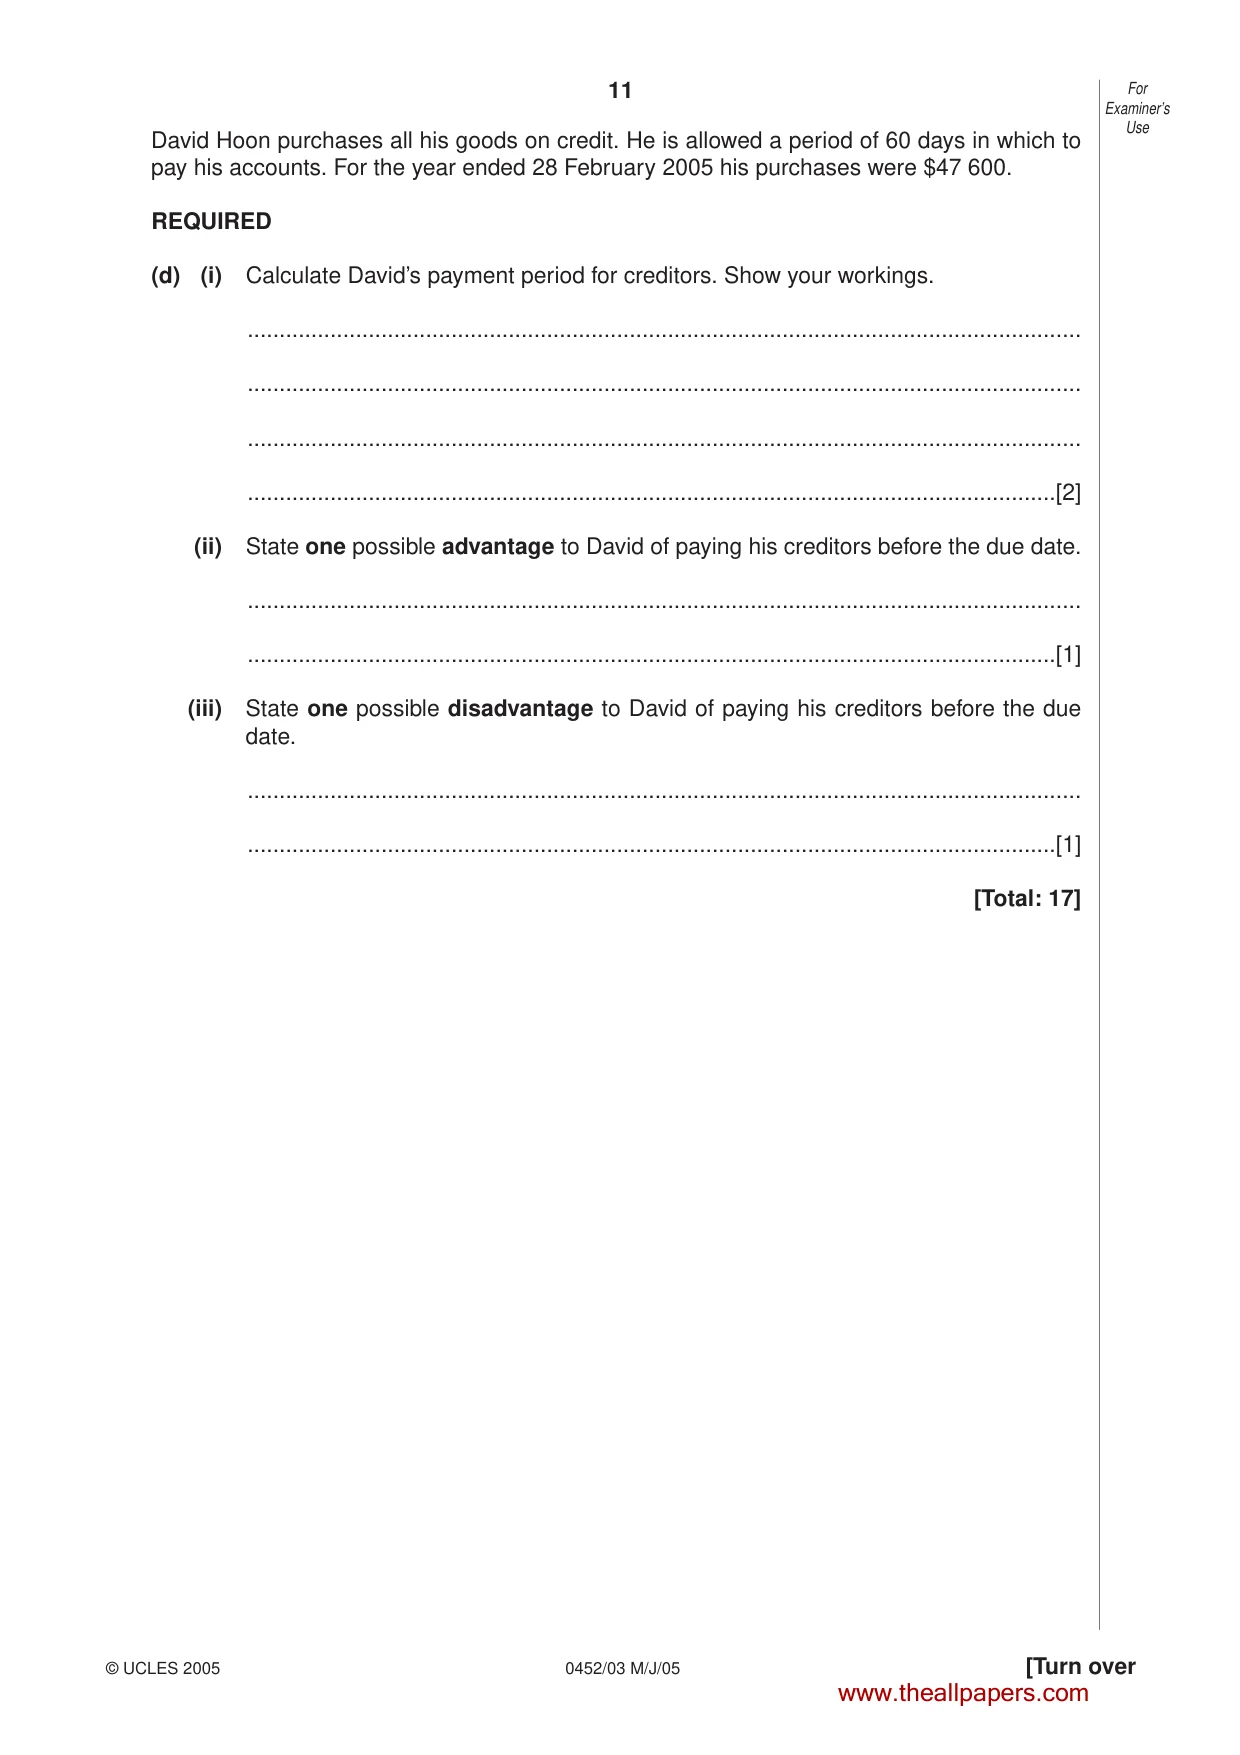
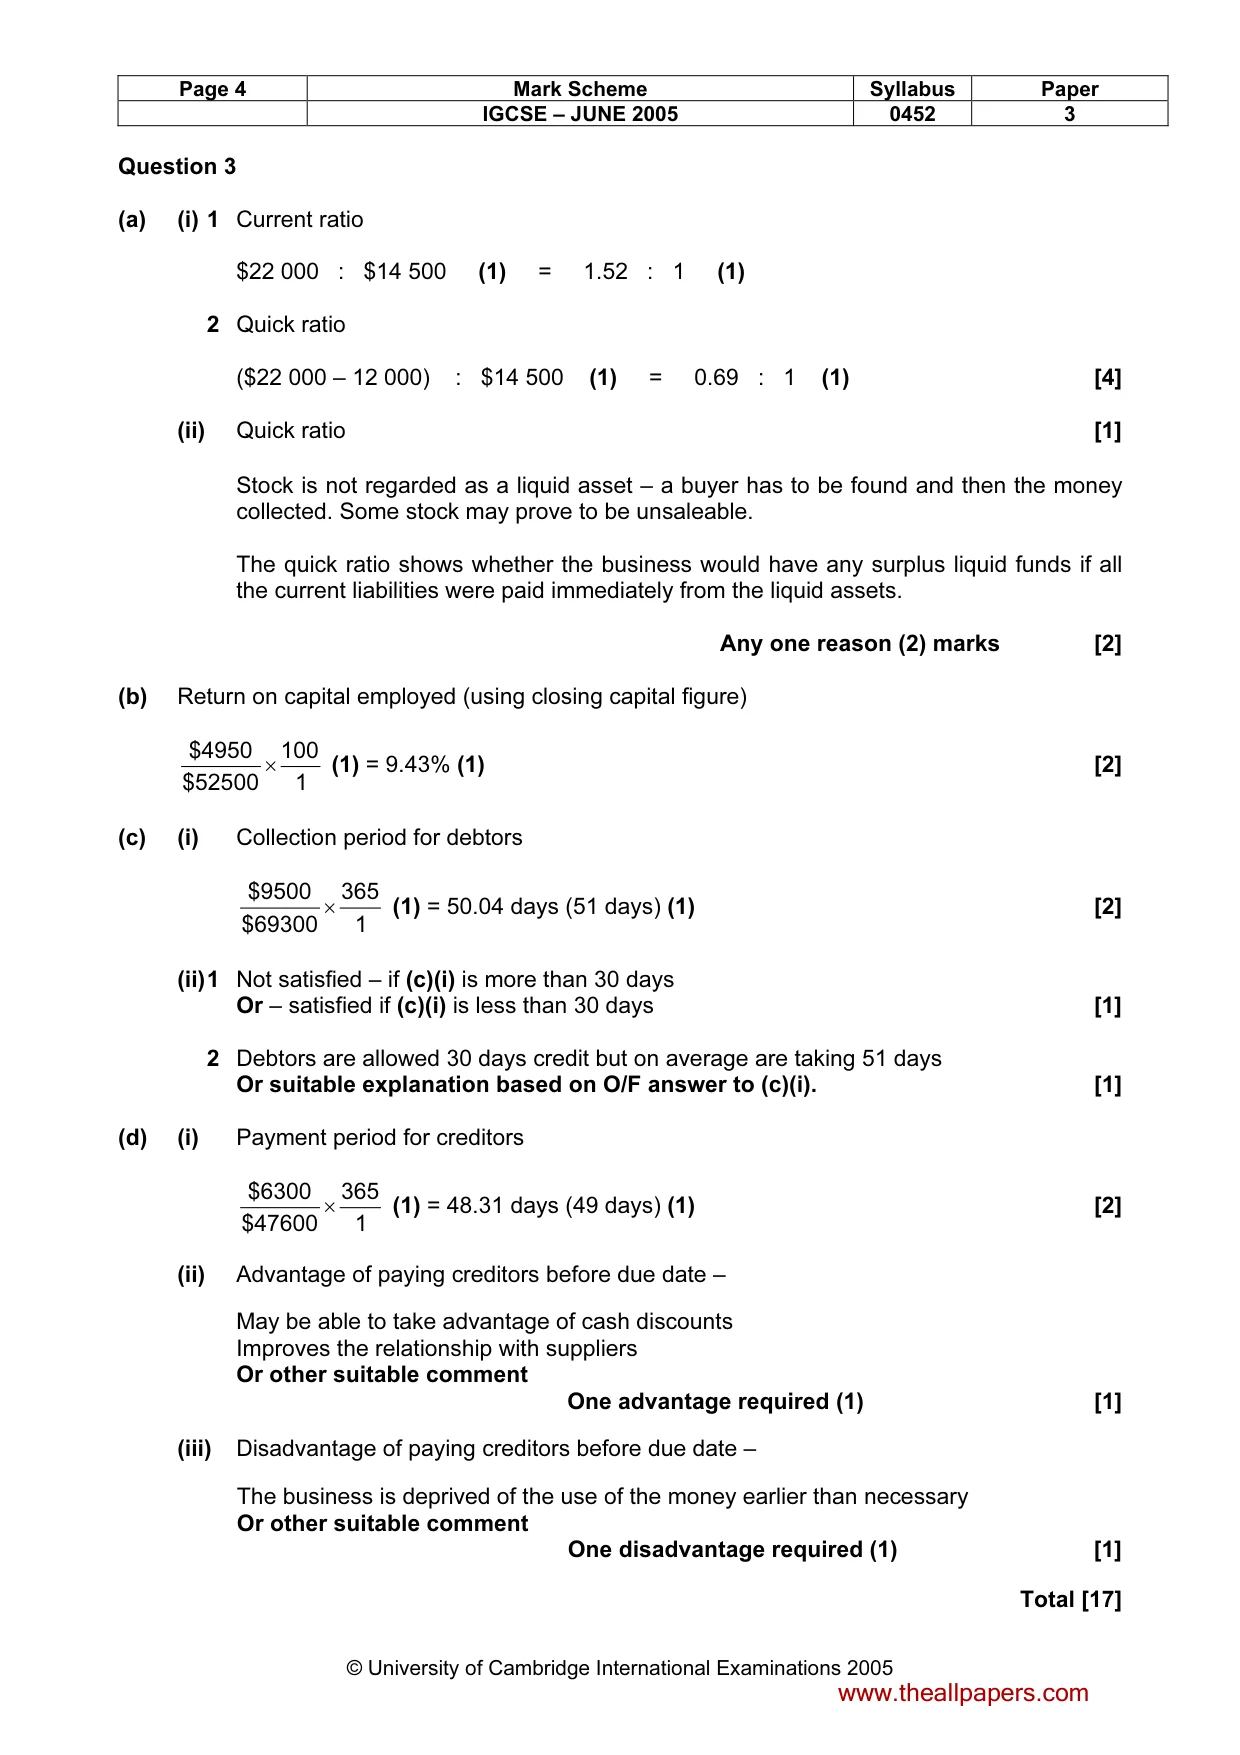
3 David Hoon is a sole trader. He prepared the following Balance Sheet at 28 February 2005. David Hoon Balance Sheet at 28 February 2005 $ $ $ Fixed Assets at book value 45 000 Current Assets Stock 12 000 Debtors 9 500 Cash 500 22 000 Current Liabilities Creditors 6 300 Bank overdraft 8 200 14 500 7 500 52 500 Capital 52 500 REQUIRED (a) (i) Calculate, correct to two decimal places, David’s current ratio and quick ratio at 28 February 2005. Show your workings. 1 Current ratio ........................................................................................................................... ........................................................................................................................... ........................................................................................................................... ........................................................................................................................... .......................................................................................................................[2] 2 Quick ratio ........................................................................................................................... ........................................................................................................................... ........................................................................................................................... ........................................................................................................................... .......................................................................................................................[2] (ii) State and explain which of the above ratios gives a better indication of the liquidity position of David’s business. Name of ratio .........................................................................................................[1] Explanation................................................................................................................ ................................................................................................................................... ...............................................................................................................................[2] David Hoon’s net profit for the year ended 28 February 2005 was $4950. REQUIRED (b) Calculate, correct to two decimal places, David’s return on capital employed (ROCE). Base your calculation on the capital at 28 February 2005. Show your workings. .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... ......................................................................................................................................[2] All David Hoon’s sales are made on credit. His debtors are allowed a period of 30 days in which to pay their accounts. For the year ended 28 February 2005 his sales were $69 300. REQUIRED (c) (i) Calculate David’s collection period for debtors. Show your workings. ................................................................................................................................... ................................................................................................................................... ................................................................................................................................... ...............................................................................................................................[2] (ii) State and explain whether you think David will regard this ratio as satisfactory. Will David be satisfied?..........................................................................................[1] Explanation................................................................................................................ ................................................................................................................................... ...............................................................................................................................[1] David Hoon purchases all his goods on credit. He is allowed a period of 60 days in which to pay his accounts. For the year ended 28 February 2005 his purchases were $47 600. REQUIRED (d) (i) Calculate David’s payment period for creditors. Show your workings. ................................................................................................................................... ................................................................................................................................... ................................................................................................................................... ...............................................................................................................................[2] (ii) State one possible advantage to David of paying his creditors before the due date. ................................................................................................................................... ...............................................................................................................................[1] (iii) State one possible disadvantage to David of paying his creditors before the due date. ................................................................................................................................... ...............................................................................................................................[1] [Total: 17]
More questions on Calculation and understanding of accounting ratios
Q4 · The following terms are used in connection with non-trading organisations such as clubs
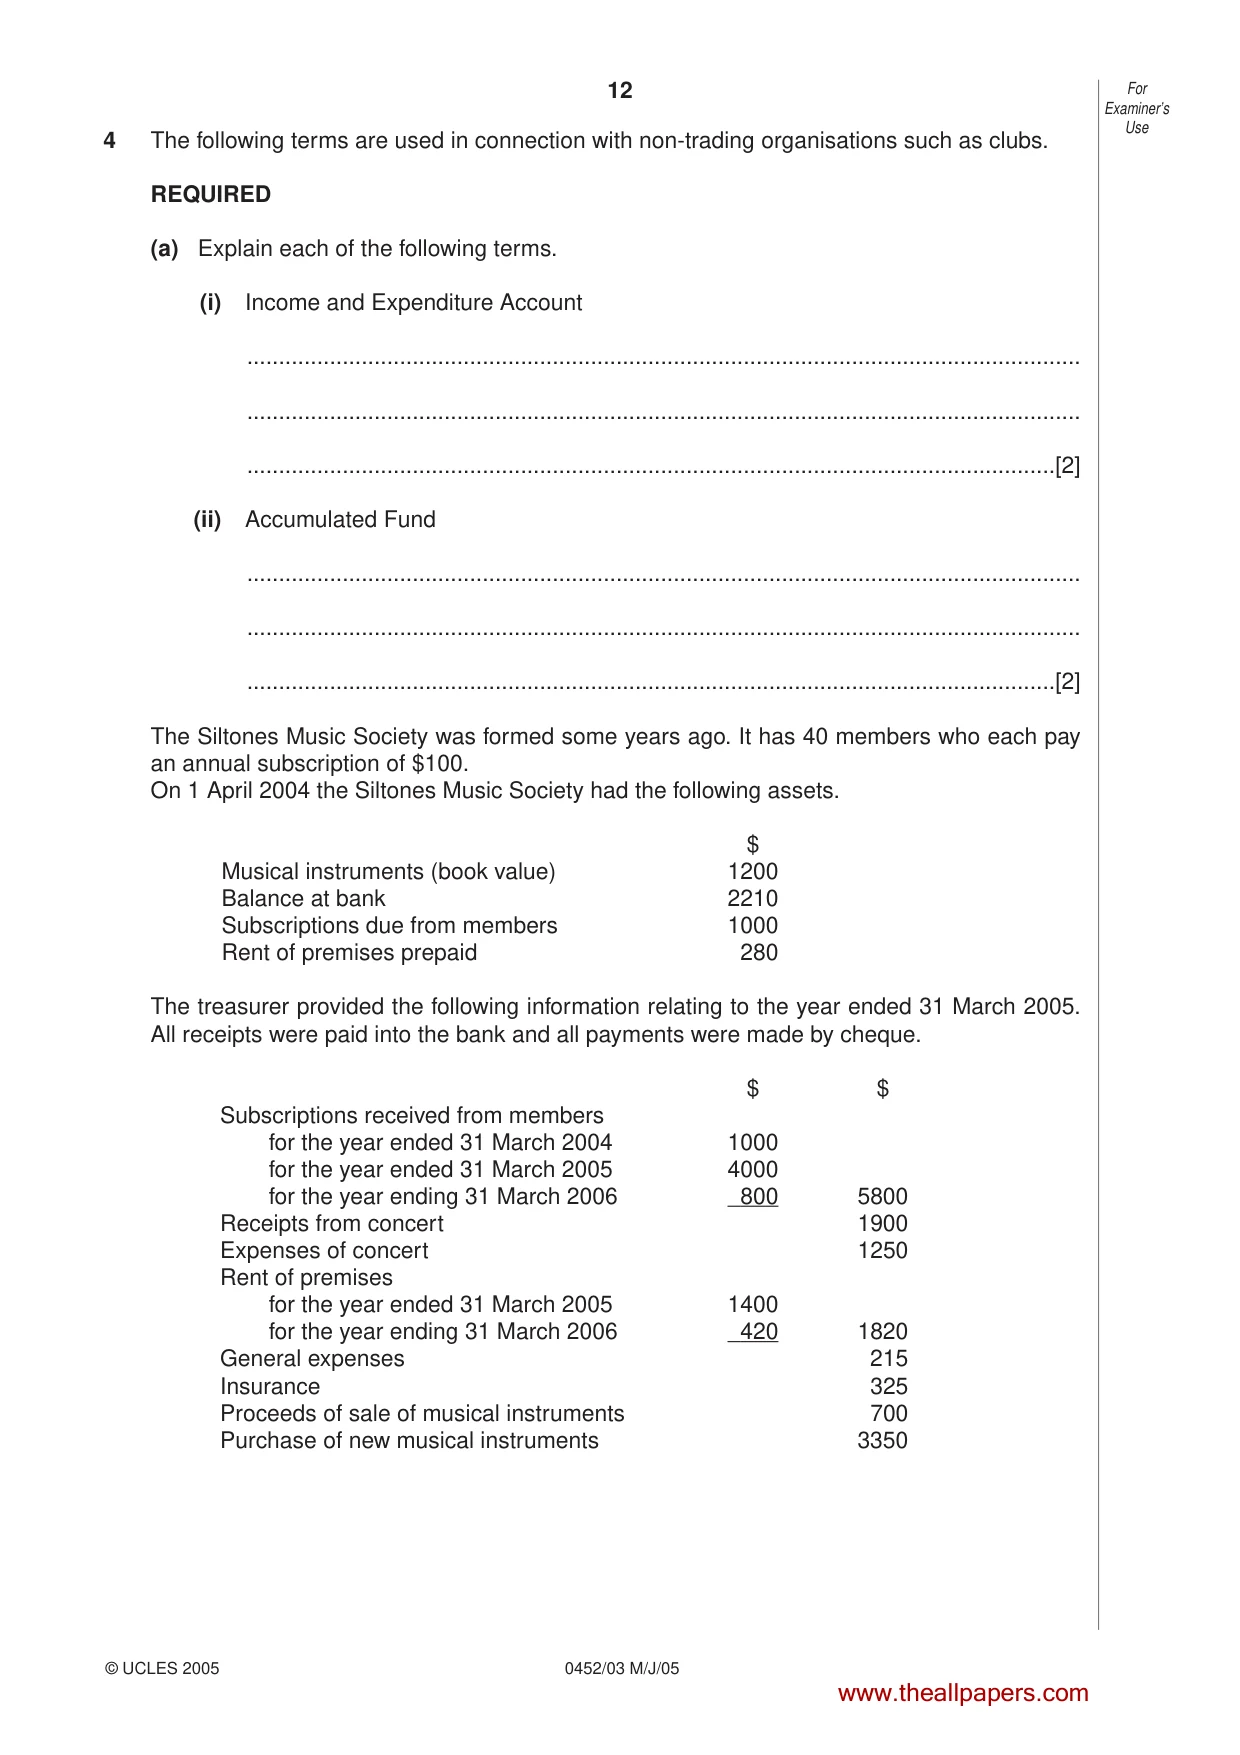
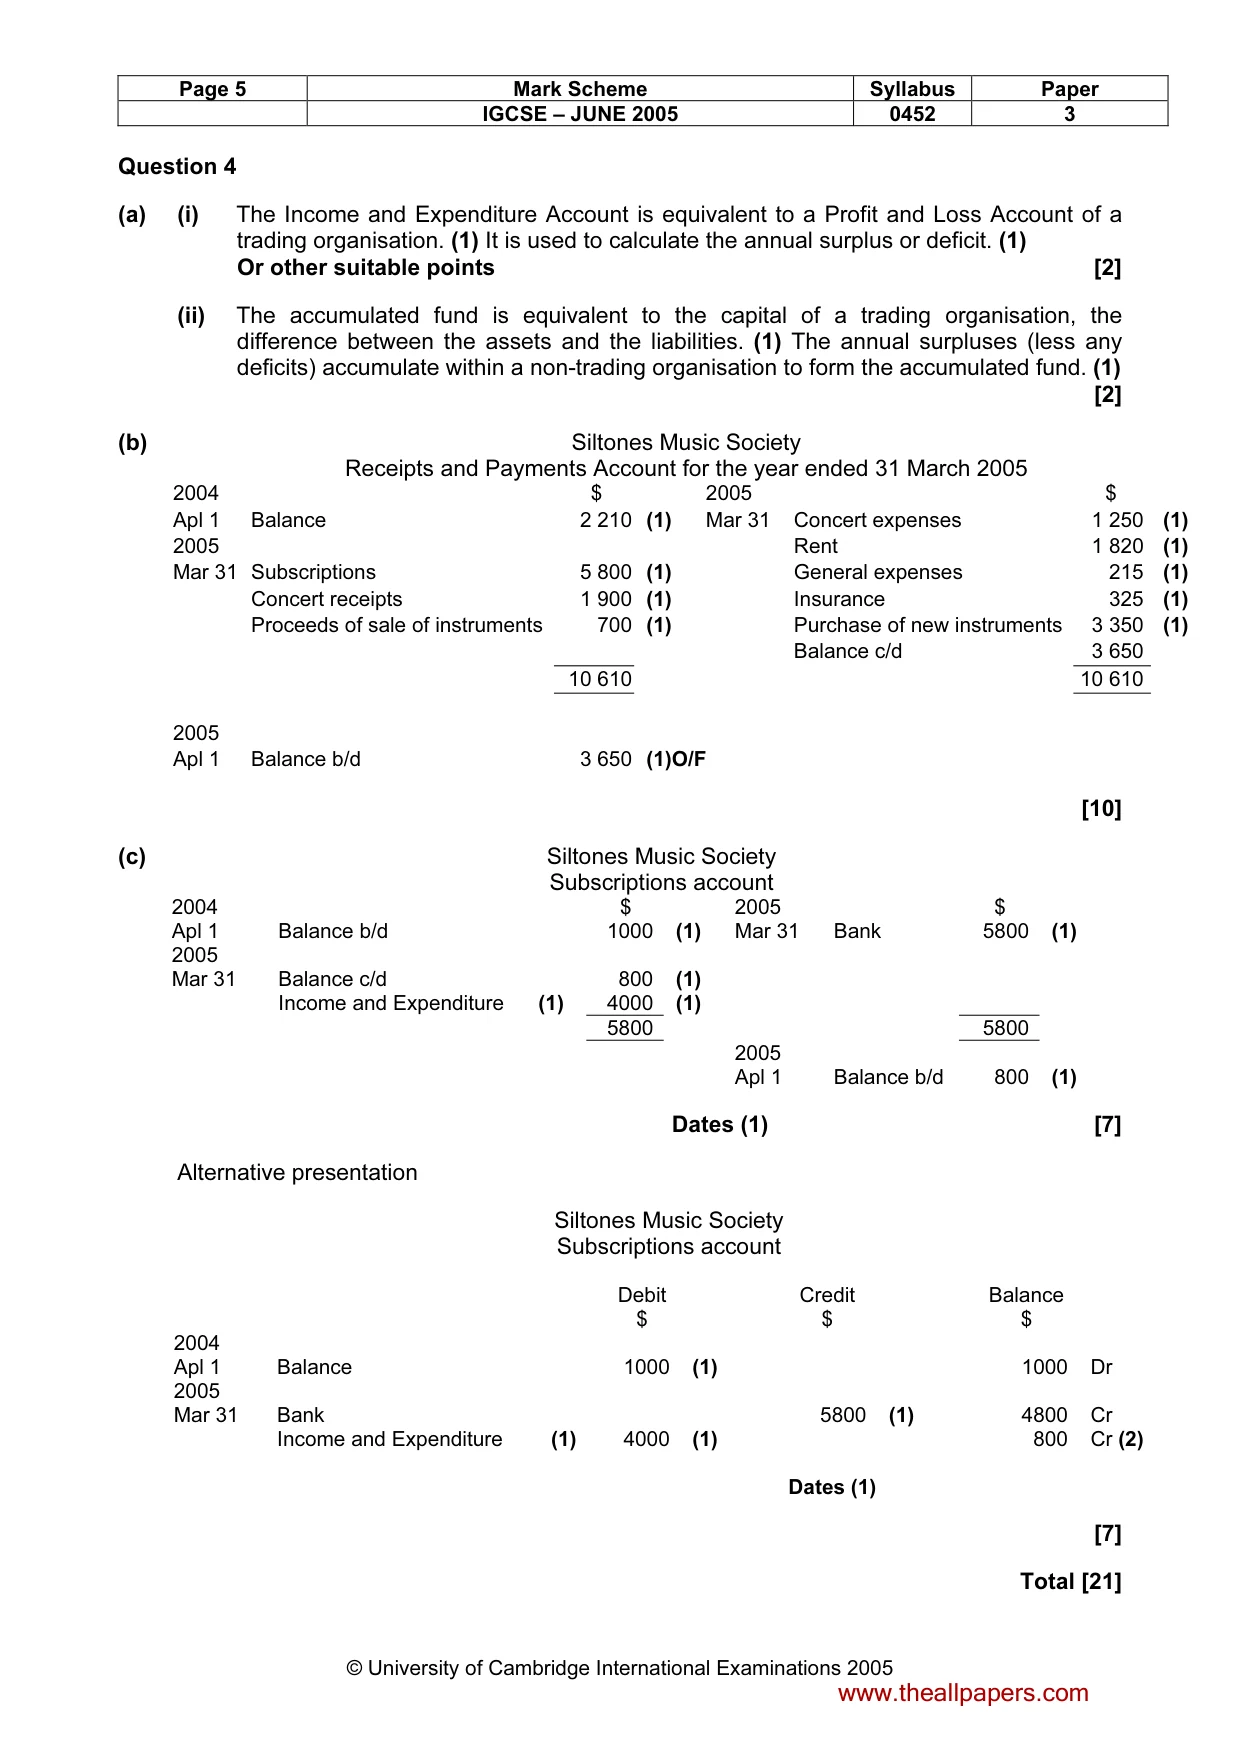
4 The following terms are used in connection with non-trading organisations such as clubs. REQUIRED (a) Explain each of the following terms. (i) Income and Expenditure Account ................................................................................................................................... ................................................................................................................................... ...............................................................................................................................[2] (ii) Accumulated Fund ................................................................................................................................... ................................................................................................................................... ...............................................................................................................................[2] The Siltones Music Society was formed some years ago. It has 40 members who each pay an annual subscription of $100. On 1 April 2004 the Siltones Music Society had the following assets. $ Musical instruments (book value) 1200 Balance at bank 2210 Subscriptions due from members 1000 Rent of premises prepaid 280 The treasurer provided the following information relating to the year ended 31 March 2005. All receipts were paid into the bank and all payments were made by cheque. $ $ Subscriptions received from members for the year ended 31 March 2004 1000 for the year ended 31 March 2005 4000 for the year ending 31 March 2006 800 5800 Receipts from concert 1900 Expenses of concert 1250 Rent of premises for the year ended 31 March 2005 1400 for the year ending 31 March 2006 420 1820 General expenses 215 Insurance 325 Proceeds of sale of musical instruments 700 Purchase of new musical instruments 3350 REQUIRED (b) Prepare the Receipts and Payments Account of the Siltones Music Society for the year ended 31 March 2005. Balance the account at 31 March and bring down the balance on 1 April 2005. Siltones Music Society Receipts and Payments Account for the year ended 31 March 2005 .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... ....................................................................................................................................[10] REQUIRED (c) Prepare the subscriptions account as it would appear in the ledger of the Siltones Music Society for the year ended 31 March 2005. Show the amount transferred to the Income and Expenditure Account. Where a traditional ‘T’ account is used it should be balanced and the balance brought down on 1 April 2005. Where a three column running balance account is used the balance column should be up-dated after each entry. Siltones Music Society Subscriptions account .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... .......................................................................................................................................... ......................................................................................................................................[7] [Total: 21]
Q5 · Ahmed Shafik’s financial year ends on 31 January
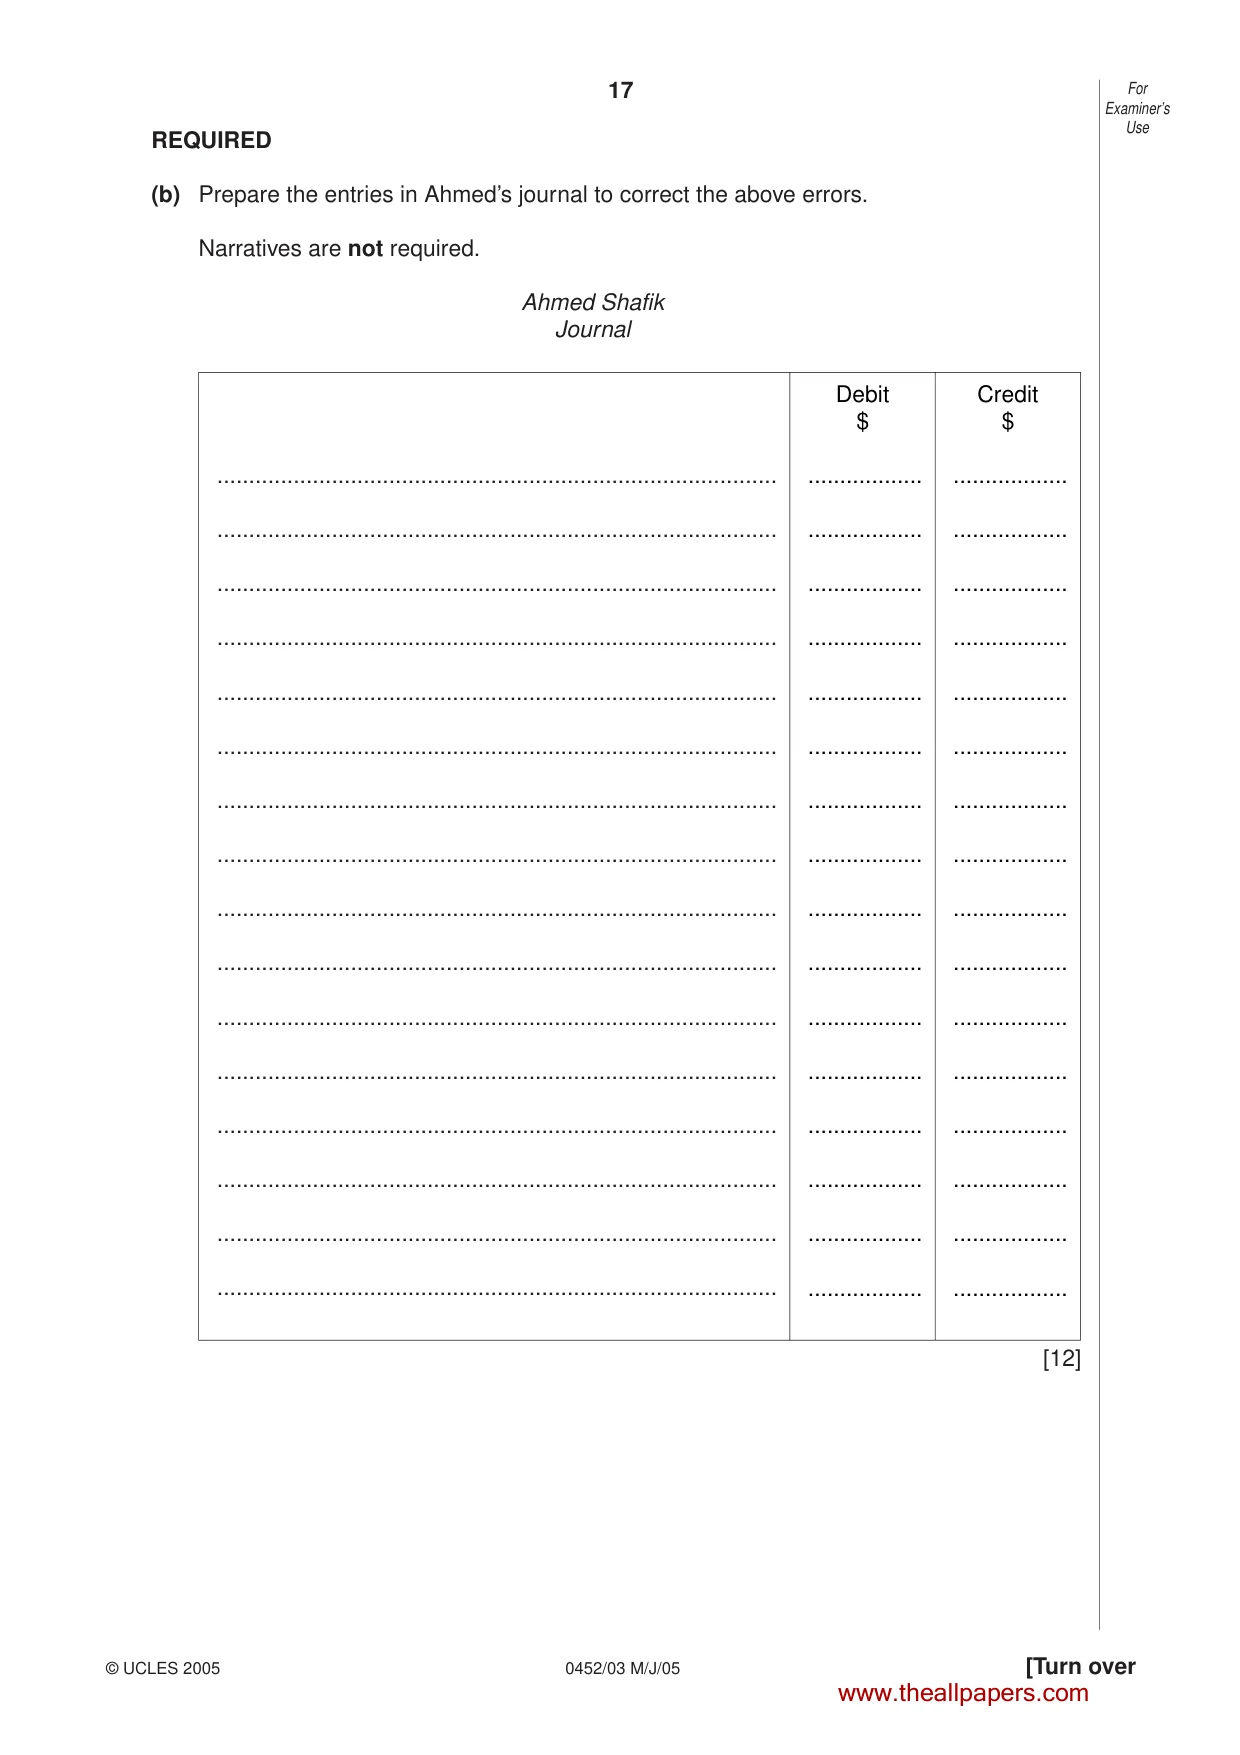
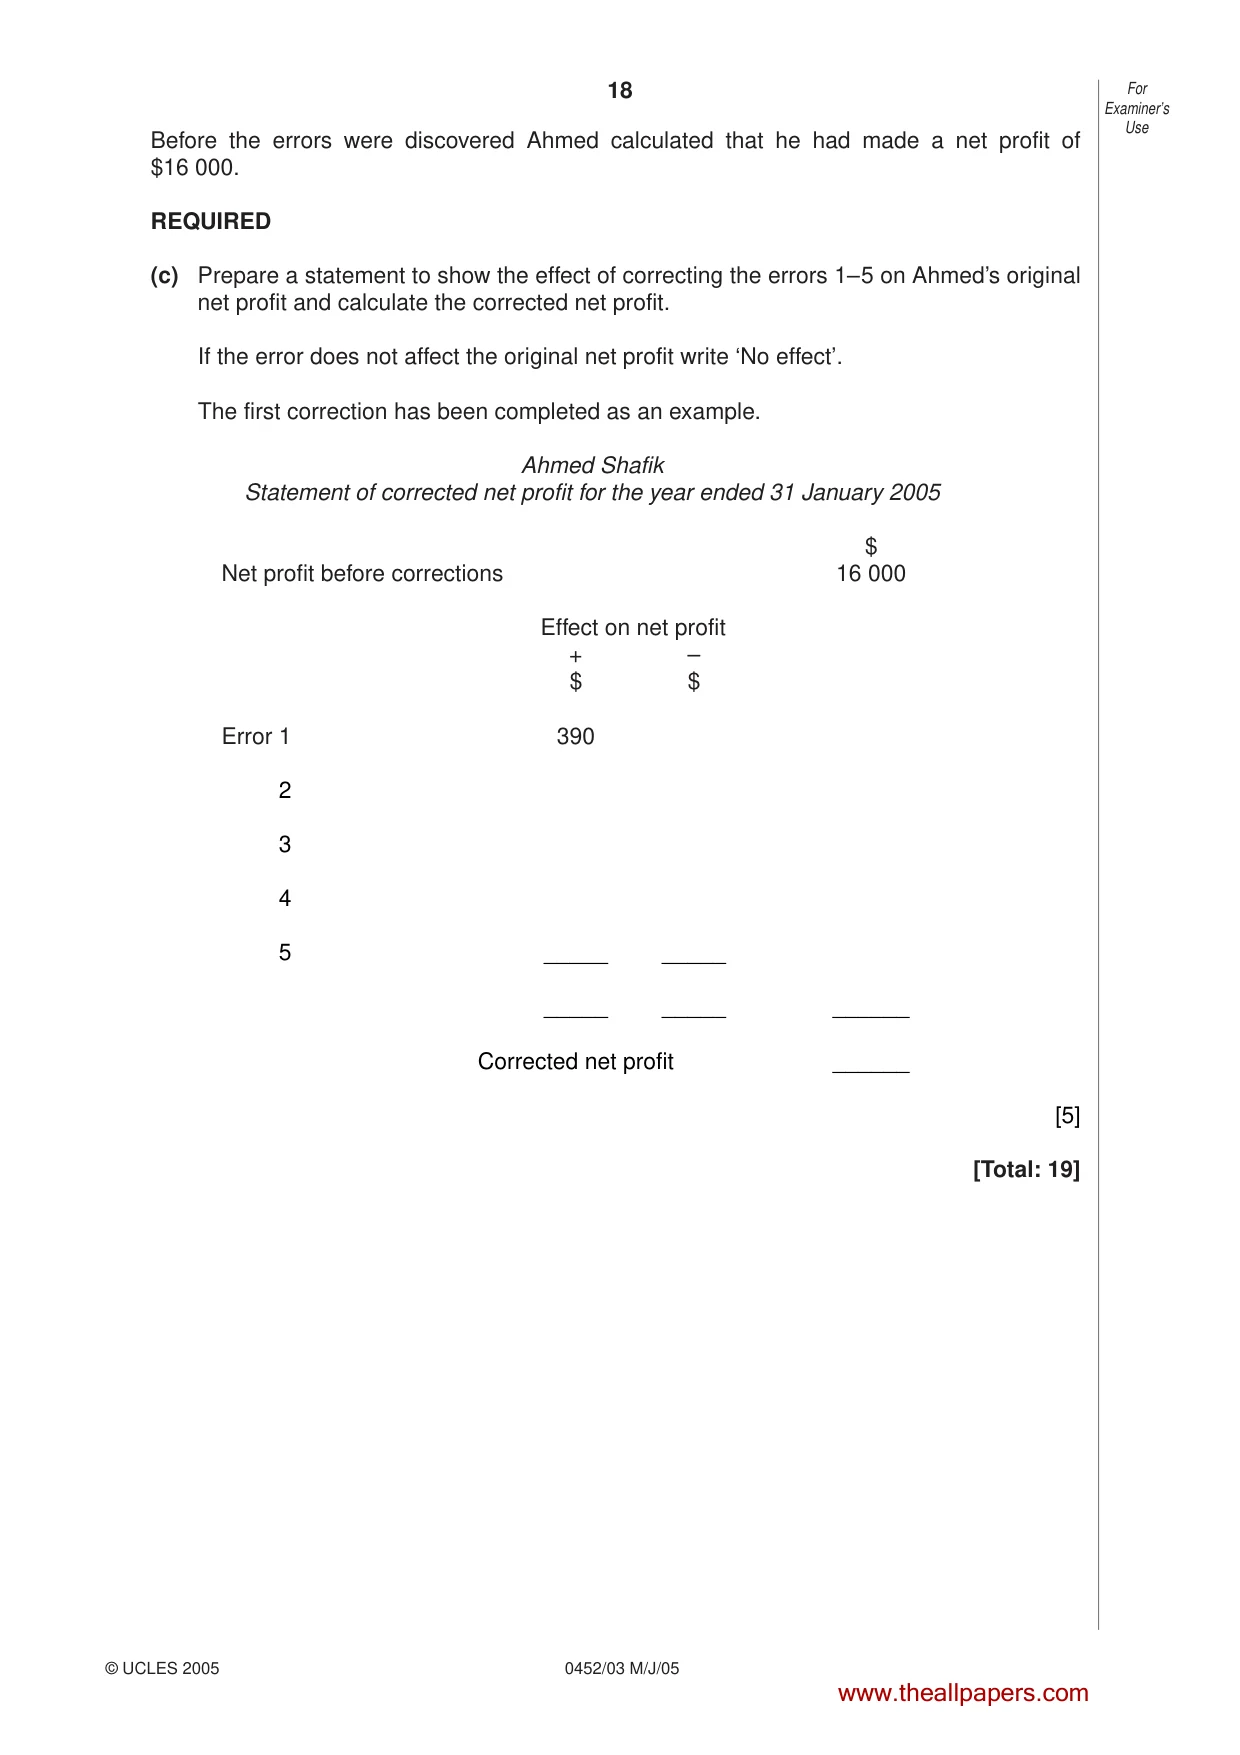
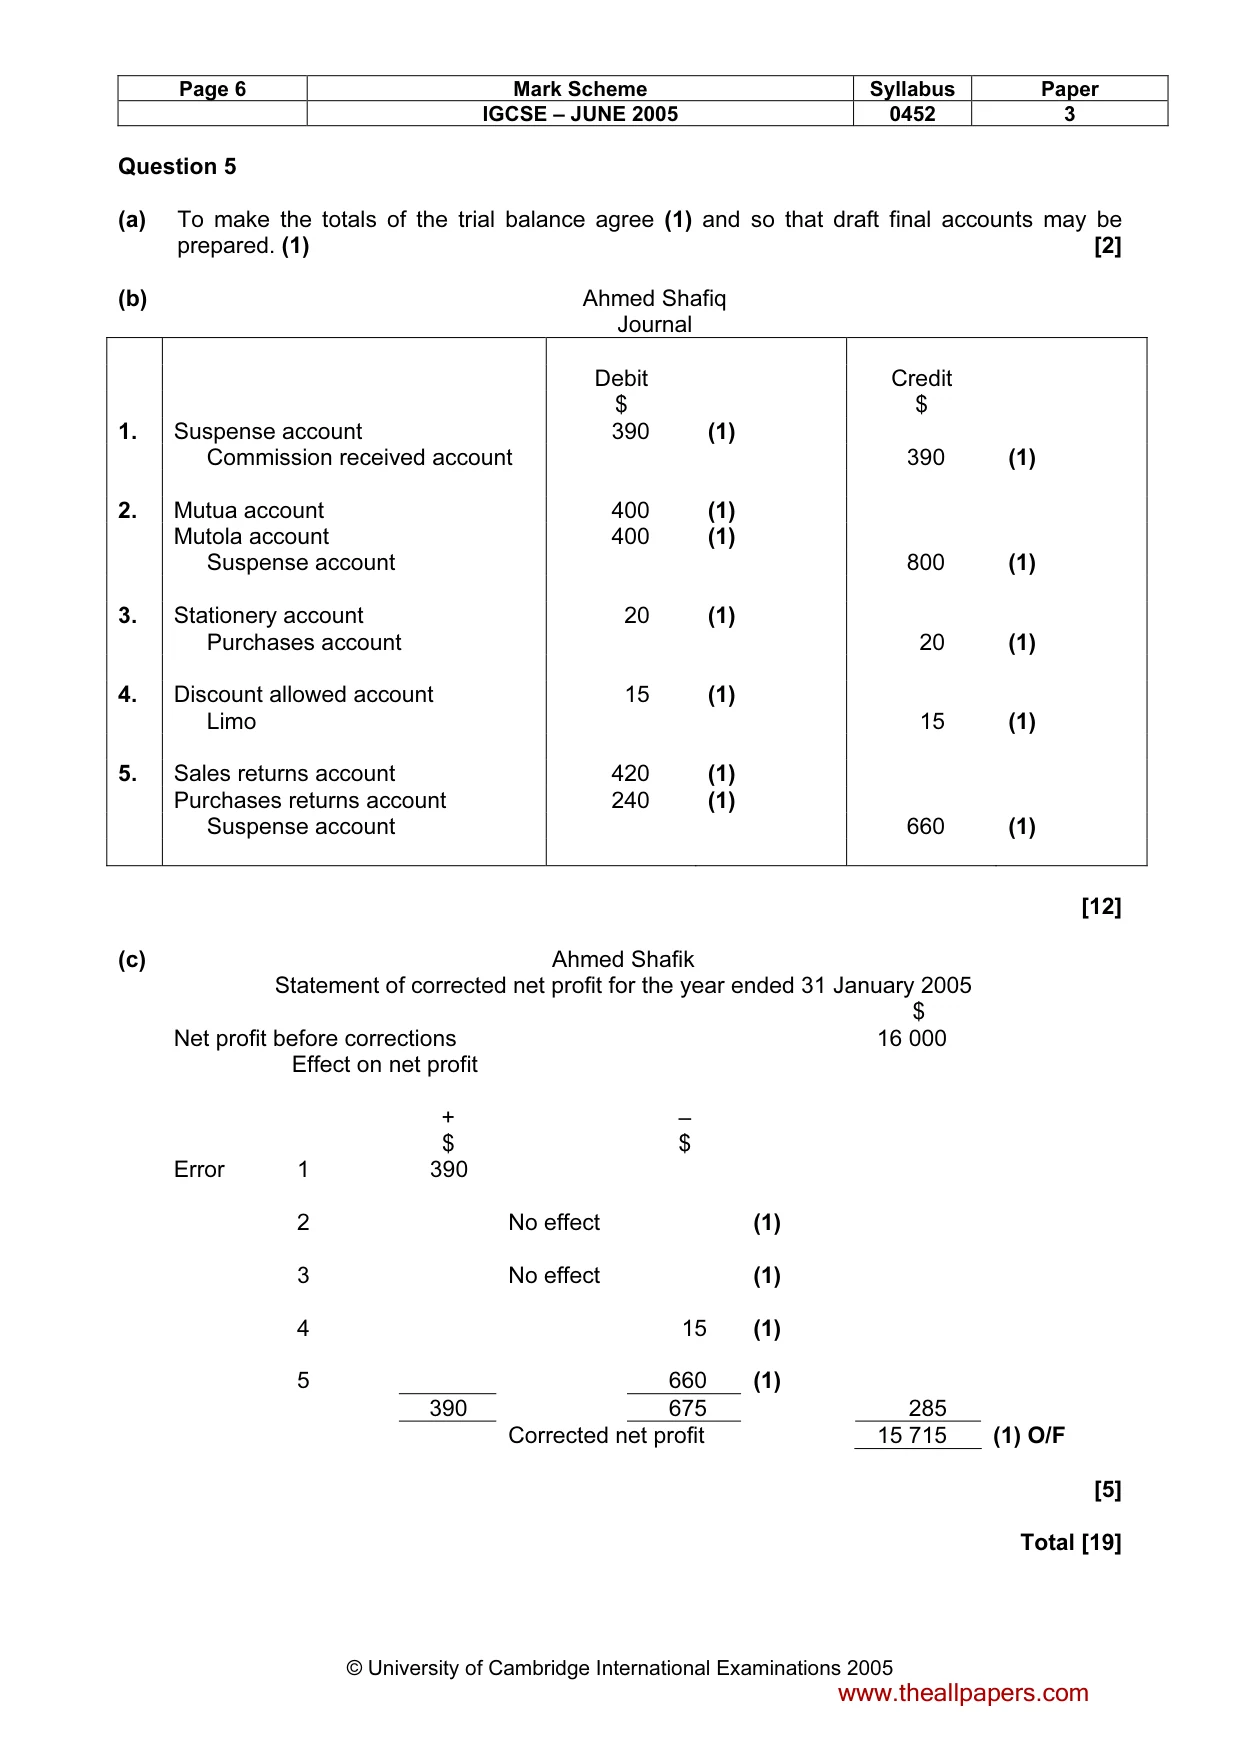
5 Ahmed Shafik’s financial year ends on 31 January. The totals of his trial balance on 31 January 2005 failed to agree. Ahmed entered the difference on the trial balance in a suspense account. REQUIRED (a) Explain why it is necessary to open a suspense account when the totals of a trial balance fail to agree. .......................................................................................................................................... .......................................................................................................................................... ......................................................................................................................................[2] The following errors were later discovered. 1 Commission received, $390, was entered in the cash book but not in the commission received account. 2 $400 paid to Mutua, a supplier, had been credited to the account of Mutola, another supplier. 3 The purchase of stationery, $20, was credited to the cash book and debited to the purchases account. 4 No entry had been made for cash discount, $15, allowed to Limo, a debtor, for prompt payment. 5 The total of the sales returns journal, $420, had been credited to the purchases returns account as $240. REQUIRED (b) Prepare the entries in Ahmed’s journal to correct the above errors. Narratives are not required. Ahmed Shafik Journal Debit Credit $ $ ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. ........................................................................................ .................. .................. [12] Before the errors were discovered Ahmed calculated that he had made a net profit of $16 000. REQUIRED (c) Prepare a statement to show the effect of correcting the errors 1–5 on Ahmed’s original net profit and calculate the corrected net profit. If the error does not affect the original net profit write ‘No effect’. The first correction has been completed as an example. Ahmed Shafik Statement of corrected net profit for the year ended 31 January 2005 $ Net profit before corrections 16 000 Effect on net profit + – $ $ Error 1 390 Error 2 Error 3 Error 4 Error 5 _____ _____ _____ _____ ______ Corrected net profit ______ [5] [Total: 19]
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.