Cambridge IGCSE Accounting 0452 — 2004 Oct/Nov Paper 3 · Variant 1
0452/31/O/N/04
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper16 pages
Mark scheme11 pages
Answers below. Sit the paper first if you are practising.
Paper as text
Question paper, page 1
This document consists of 16 printed pages. SP (BR) S60102/5 © UCLES 2004 [Turn over UNIVERSITY OF CAMBRIDGE INTERNATIONAL EXAMINATIONS International General Certificate of Secondary Education ACCOUNTING 0452/03 Paper 3 October/November 2004 1 hour 45 minutes Candidates answer on the Question Paper. No Additional Materials are required. READ THESE INSTRUCTIONS FIRST Write your Centre number, candidate number and name on all the work you hand in. Write in dark blue or black pen in the spaces provided on the Question Paper. You may use a soft pencil for rough working. Do not use staples, paper clips, highlighters, glue or correction fluid. Answer all questions. At the end of the examination, fasten all your work securely together. The number of marks is given in brackets [ ] at the end of each question or part question. You may use a calculator. Where layouts are to be completed, you may not need all the lines for your answer. The businesses mentioned in this question paper are fictitious. Centre Number Candidate Number Name If you have been given a label, look at the details. If any details are incorrect or missing, please fill in your correct details in the space given at the top of this page. Stick your personal label here, if provided. For Examiner’s Use 1 2 3 4 5 Total www.theallpapers.com
Question paper, page 2
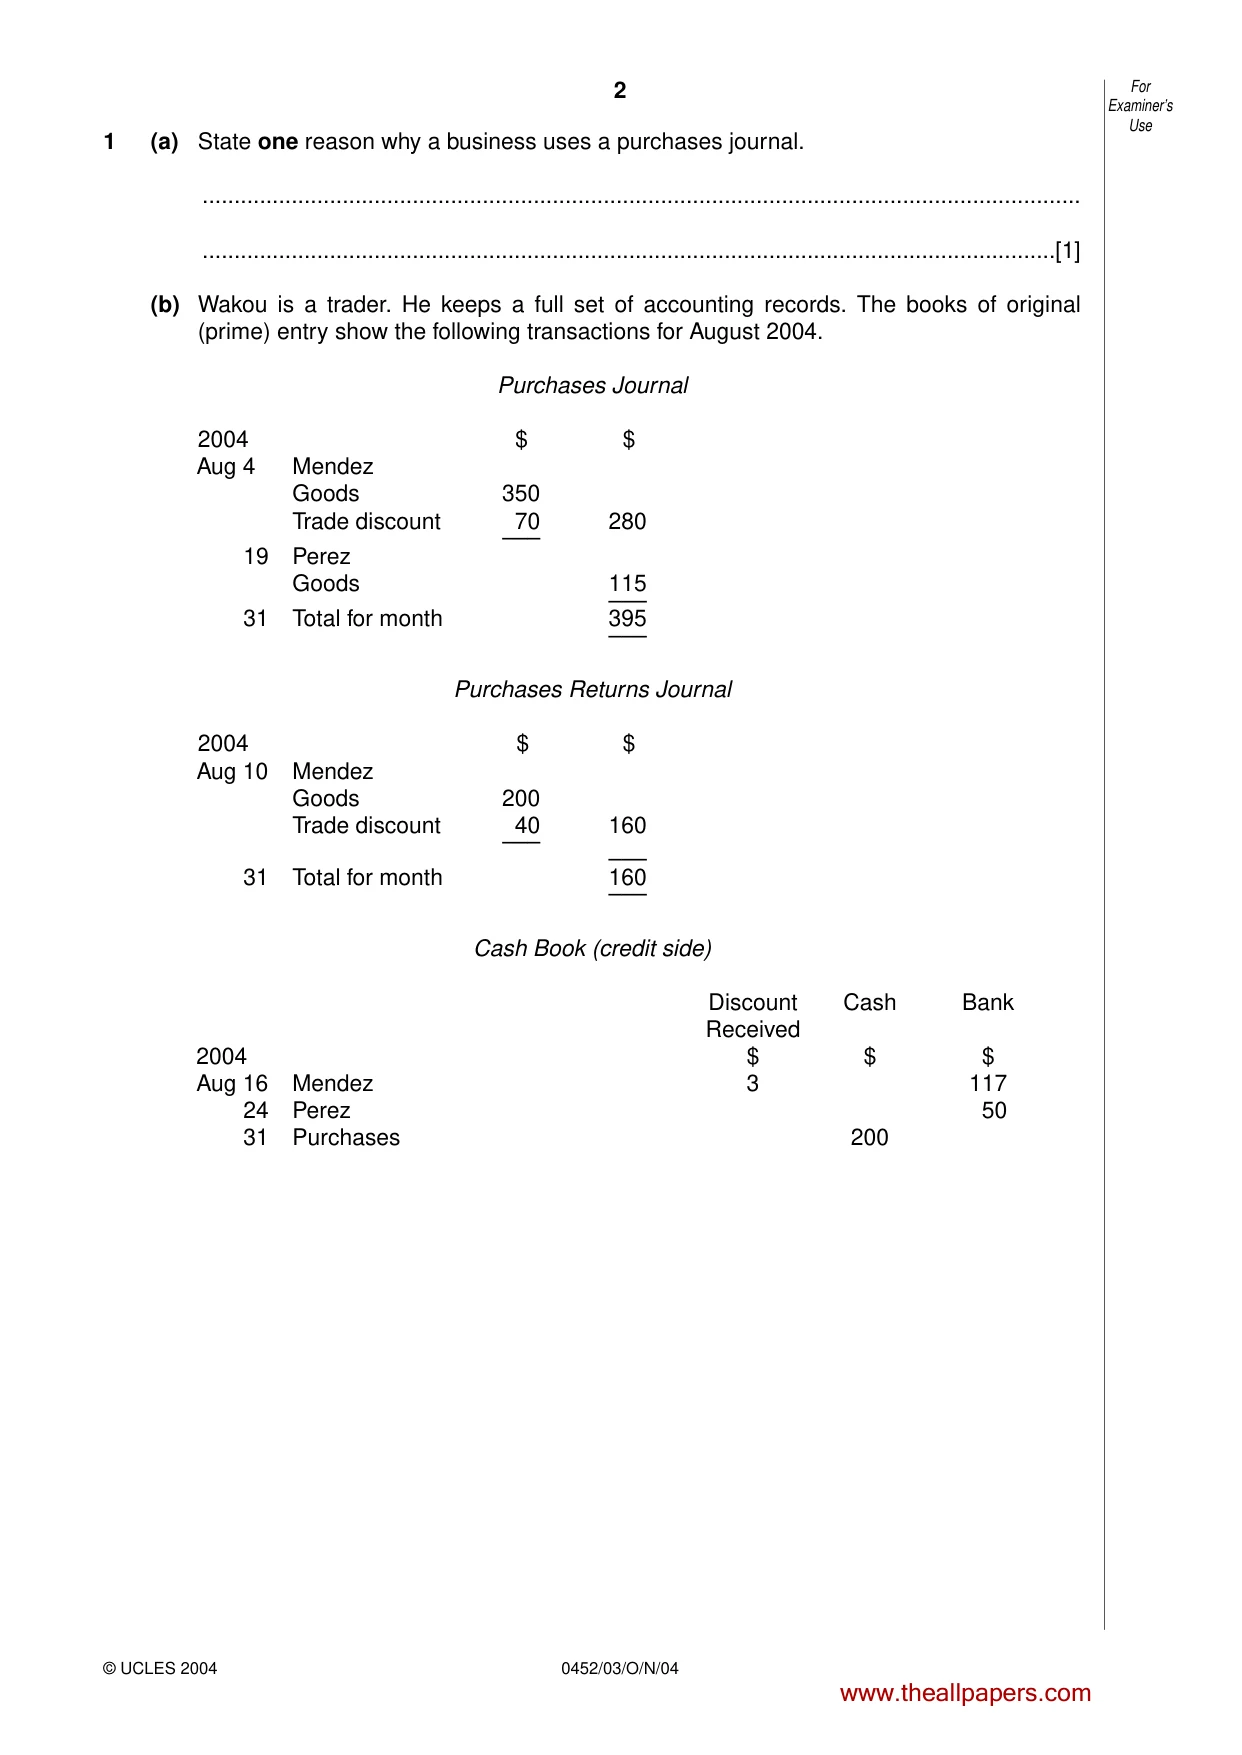
2 © UCLES 2004 0452/03/O/N/04 1 (a) State one reason why a business uses a purchases journal. … …[1] (b) Wakou is a trader. He keeps a full set of accounting records. The books of original (prime) entry show the following transactions for August 2004. Purchases Journal 2004 $ $ Aug 4 Mendez Goods 350 Trade discount 70 280 ––– 19 Perez Goods 115 ––– 31 Total for month 395 ––– Purchases Returns Journal 2004 $ $ Aug 10 Mendez Goods 200 Trade discount 40 160 ––– ––– 31 Total for month 160 ––– Cash Book (credit side) Discount Cash Bank Received 2004 $ $ $ Aug 16 Mendez 3 117 24 Perez 50 31 Purchases 200 For Examiner’s Use www.theallpapers.com
Question paper, page 3
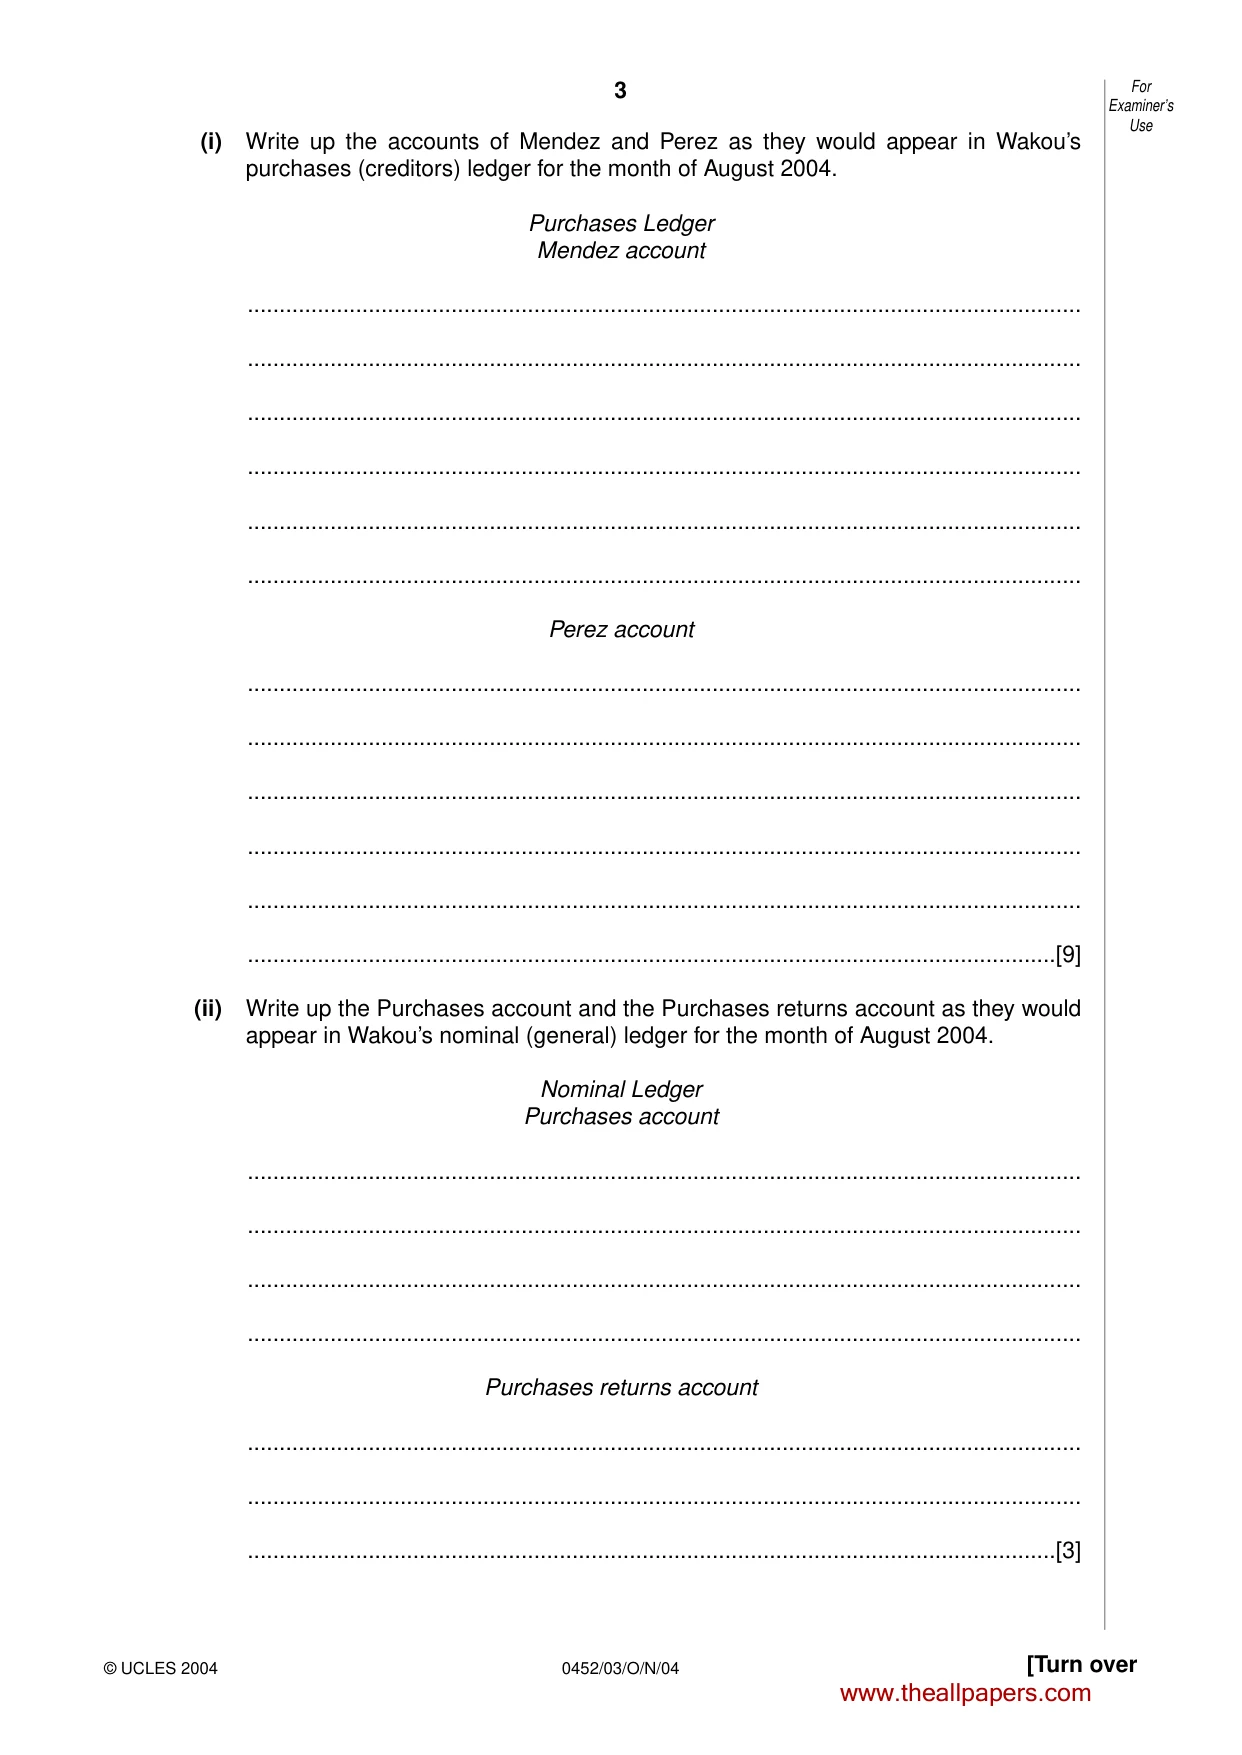
3 © UCLES 2004 0452/03/O/N/04 [Turn over (i) Write up the accounts of Mendez and Perez as they would appear in Wakou’s purchases (creditors) ledger for the month of August 2004. Purchases Ledger Mendez account … … … … … … Perez account … … … … … …[9] (ii) Write up the Purchases account and the Purchases returns account as they would appear in Wakou’s nominal (general) ledger for the month of August 2004. Nominal Ledger Purchases account … … … … Purchases returns account … … …[3] For Examiner’s Use www.theallpapers.com
Question paper, page 4
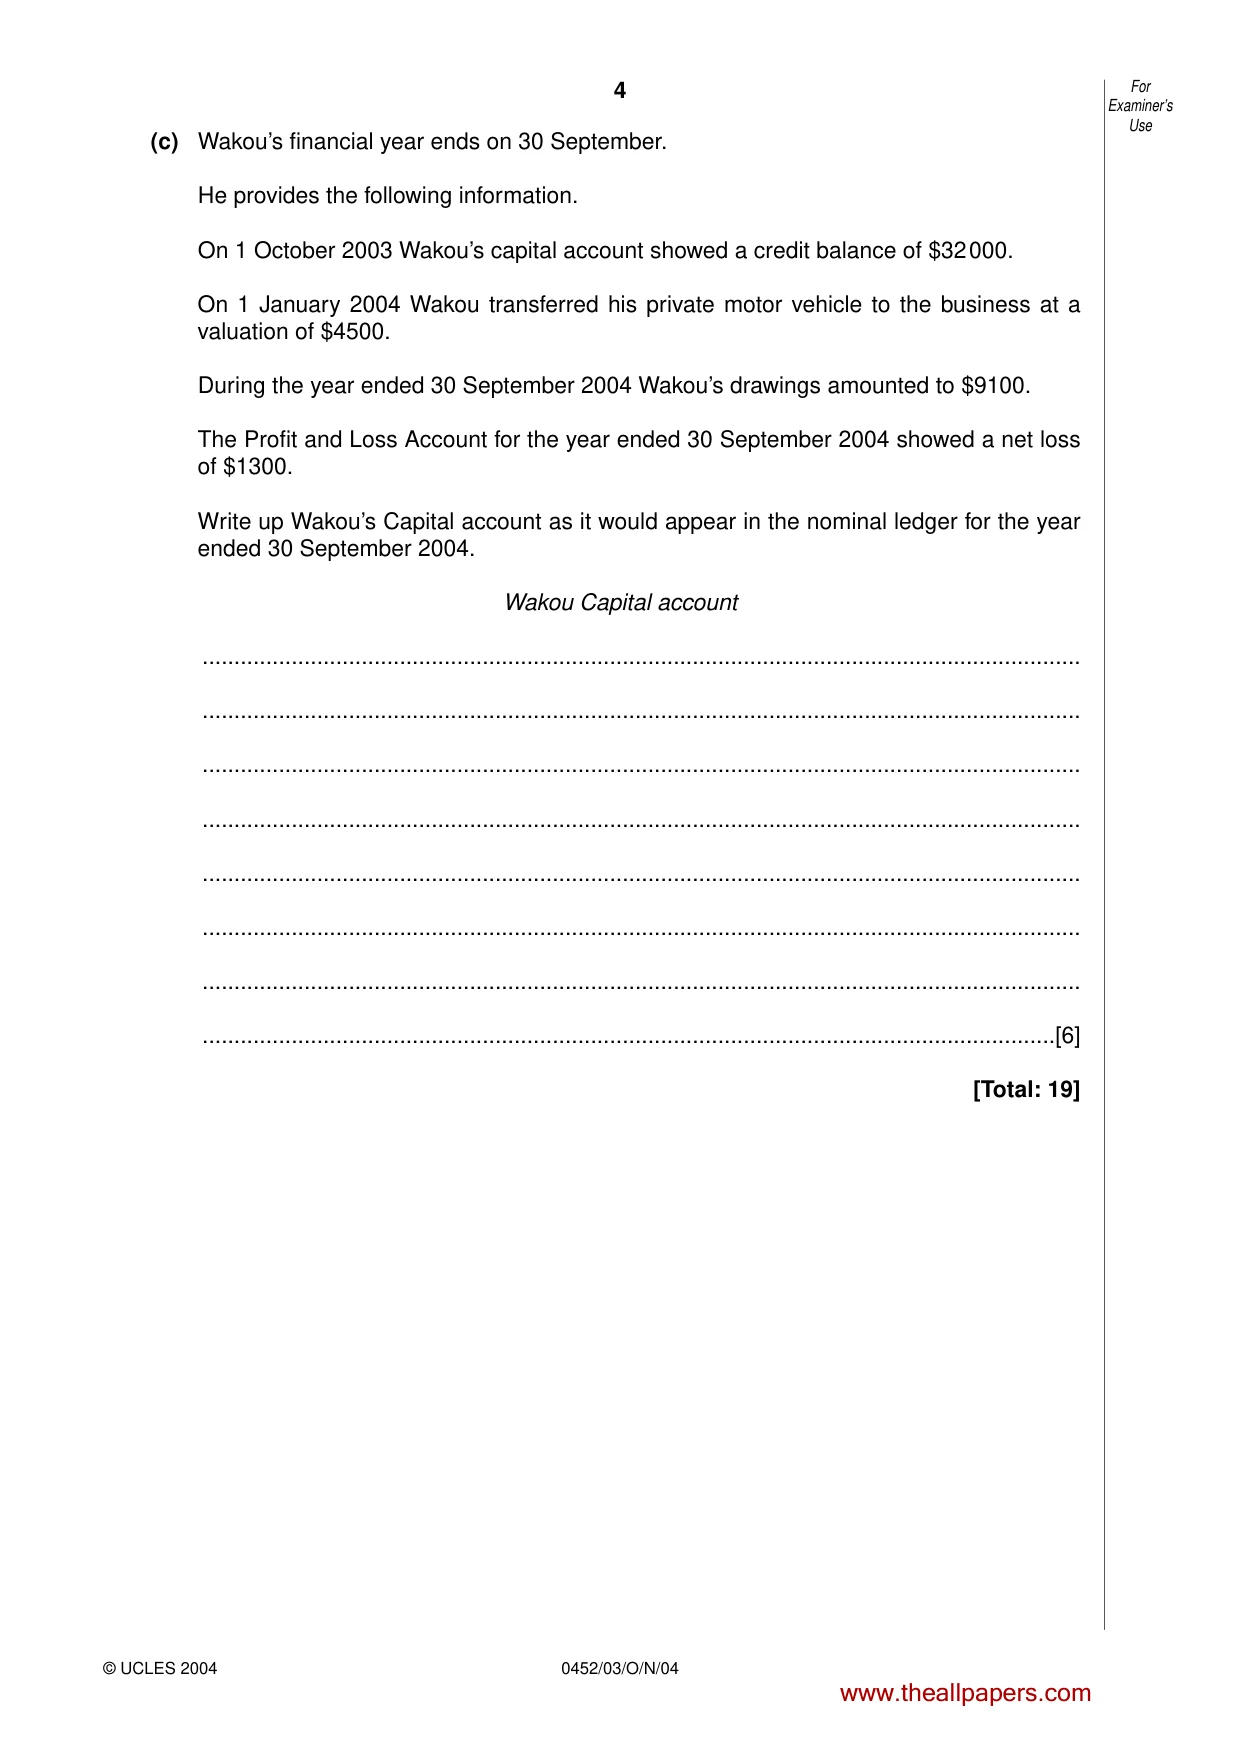
4 © UCLES 2004 0452/03/O/N/04 (c) Wakou’s financial year ends on 30 September. He provides the following information. On 1 October 2003 Wakou’s capital account showed a credit balance of $32000. On 1 January 2004 Wakou transferred his private motor vehicle to the business at a valuation of $4500. During the year ended 30 September 2004 Wakou’s drawings amounted to $9100. The Profit and Loss Account for the year ended 30 September 2004 showed a net loss of $1300. Write up Wakou’s Capital account as it would appear in the nominal ledger for the year ended 30 September 2004. Wakou Capital account … … … … … … … …[6] [Total: 19] For Examiner’s Use www.theallpapers.com
Question paper, page 5
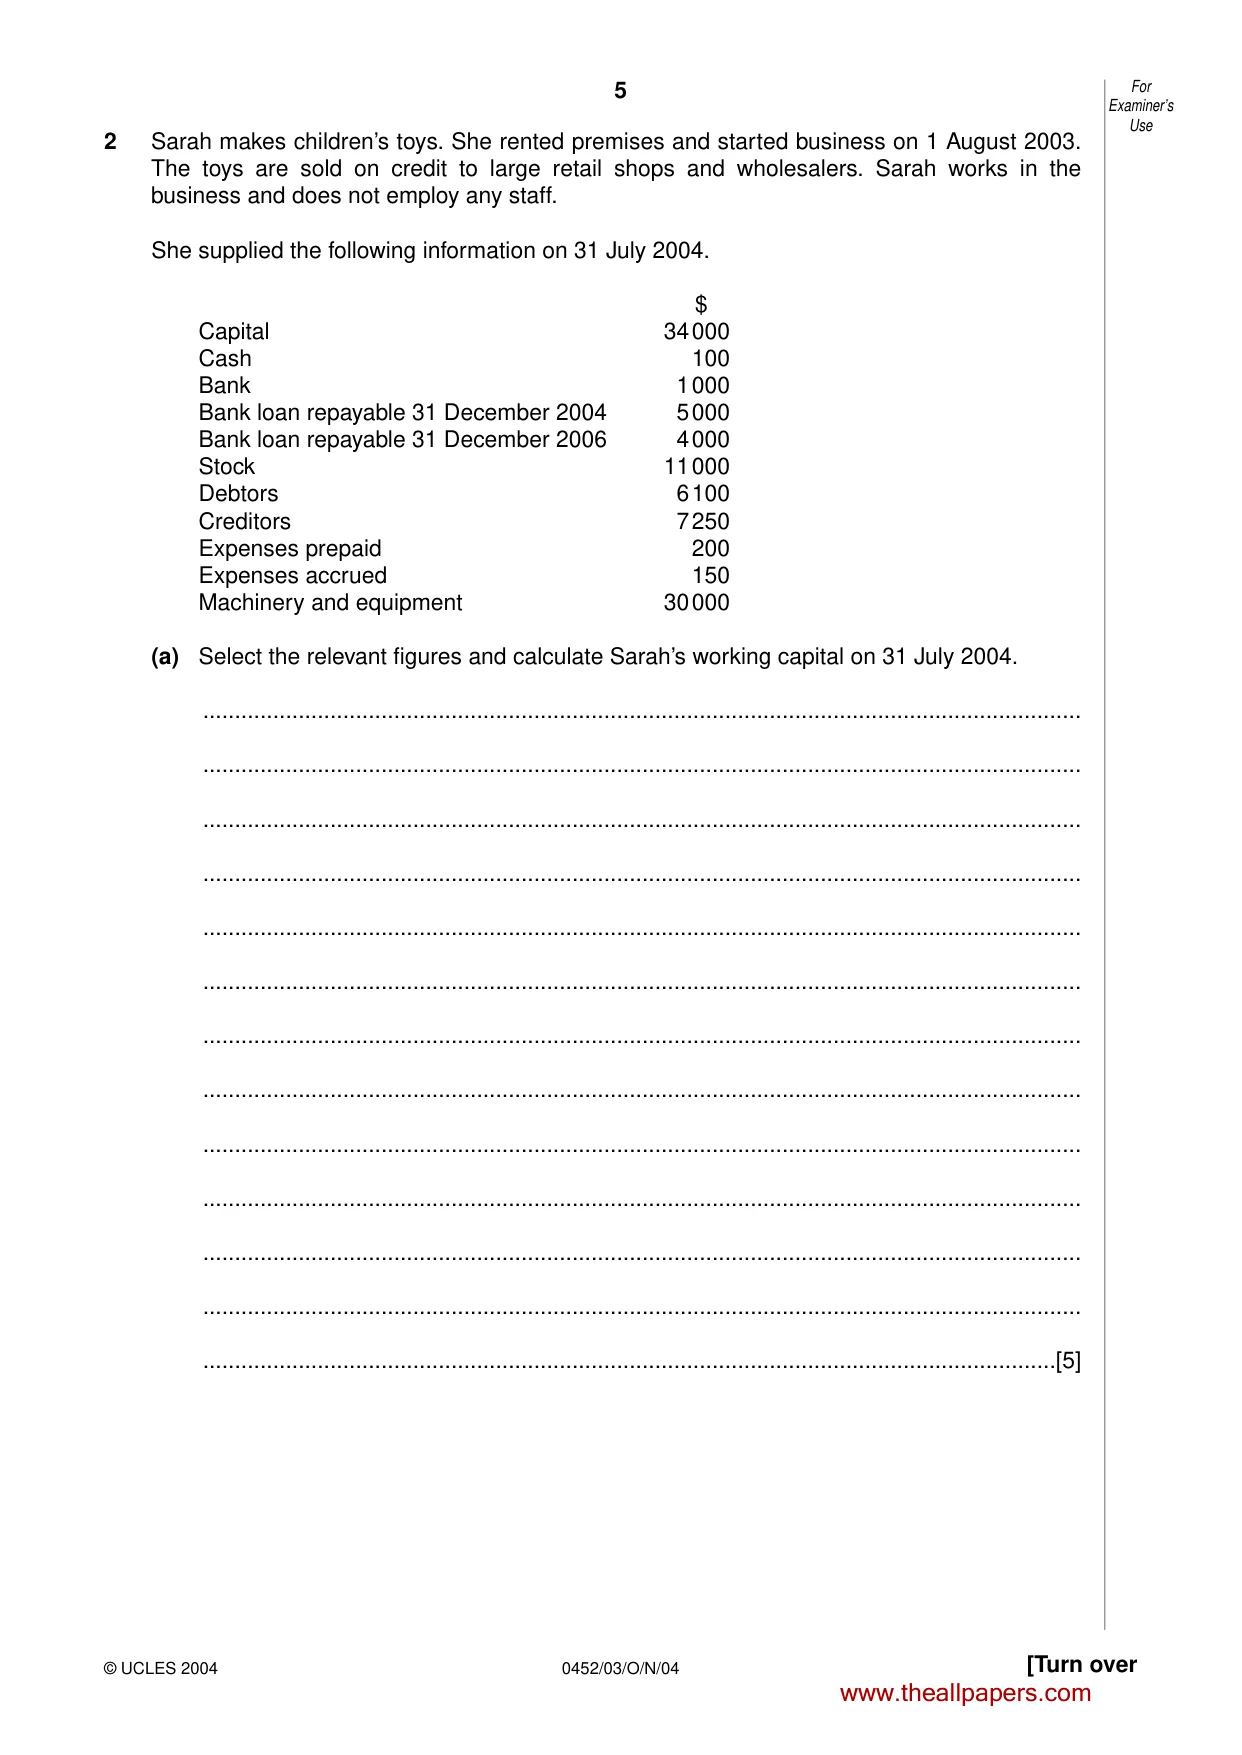
5 © UCLES 2004 0452/03/O/N/04 [Turn over 2 Sarah makes children’s toys. She rented premises and started business on 1 August 2003. The toys are sold on credit to large retail shops and wholesalers. Sarah works in the business and does not employ any staff. She supplied the following information on 31 July 2004. $ Capital 34000 Cash 100 Bank 1000 Bank loan repayable 31 December 2004 5000 Bank loan repayable 31 December 2006 4000 Stock 11000 Debtors 6100 Creditors 7250 Expenses prepaid 200 Expenses accrued 150 Machinery and equipment 30000 (a) Select the relevant figures and calculate Sarah’s working capital on 31 July 2004. … … … … … … … … … … … … …[5] For Examiner’s Use www.theallpapers.com
Question paper, page 6
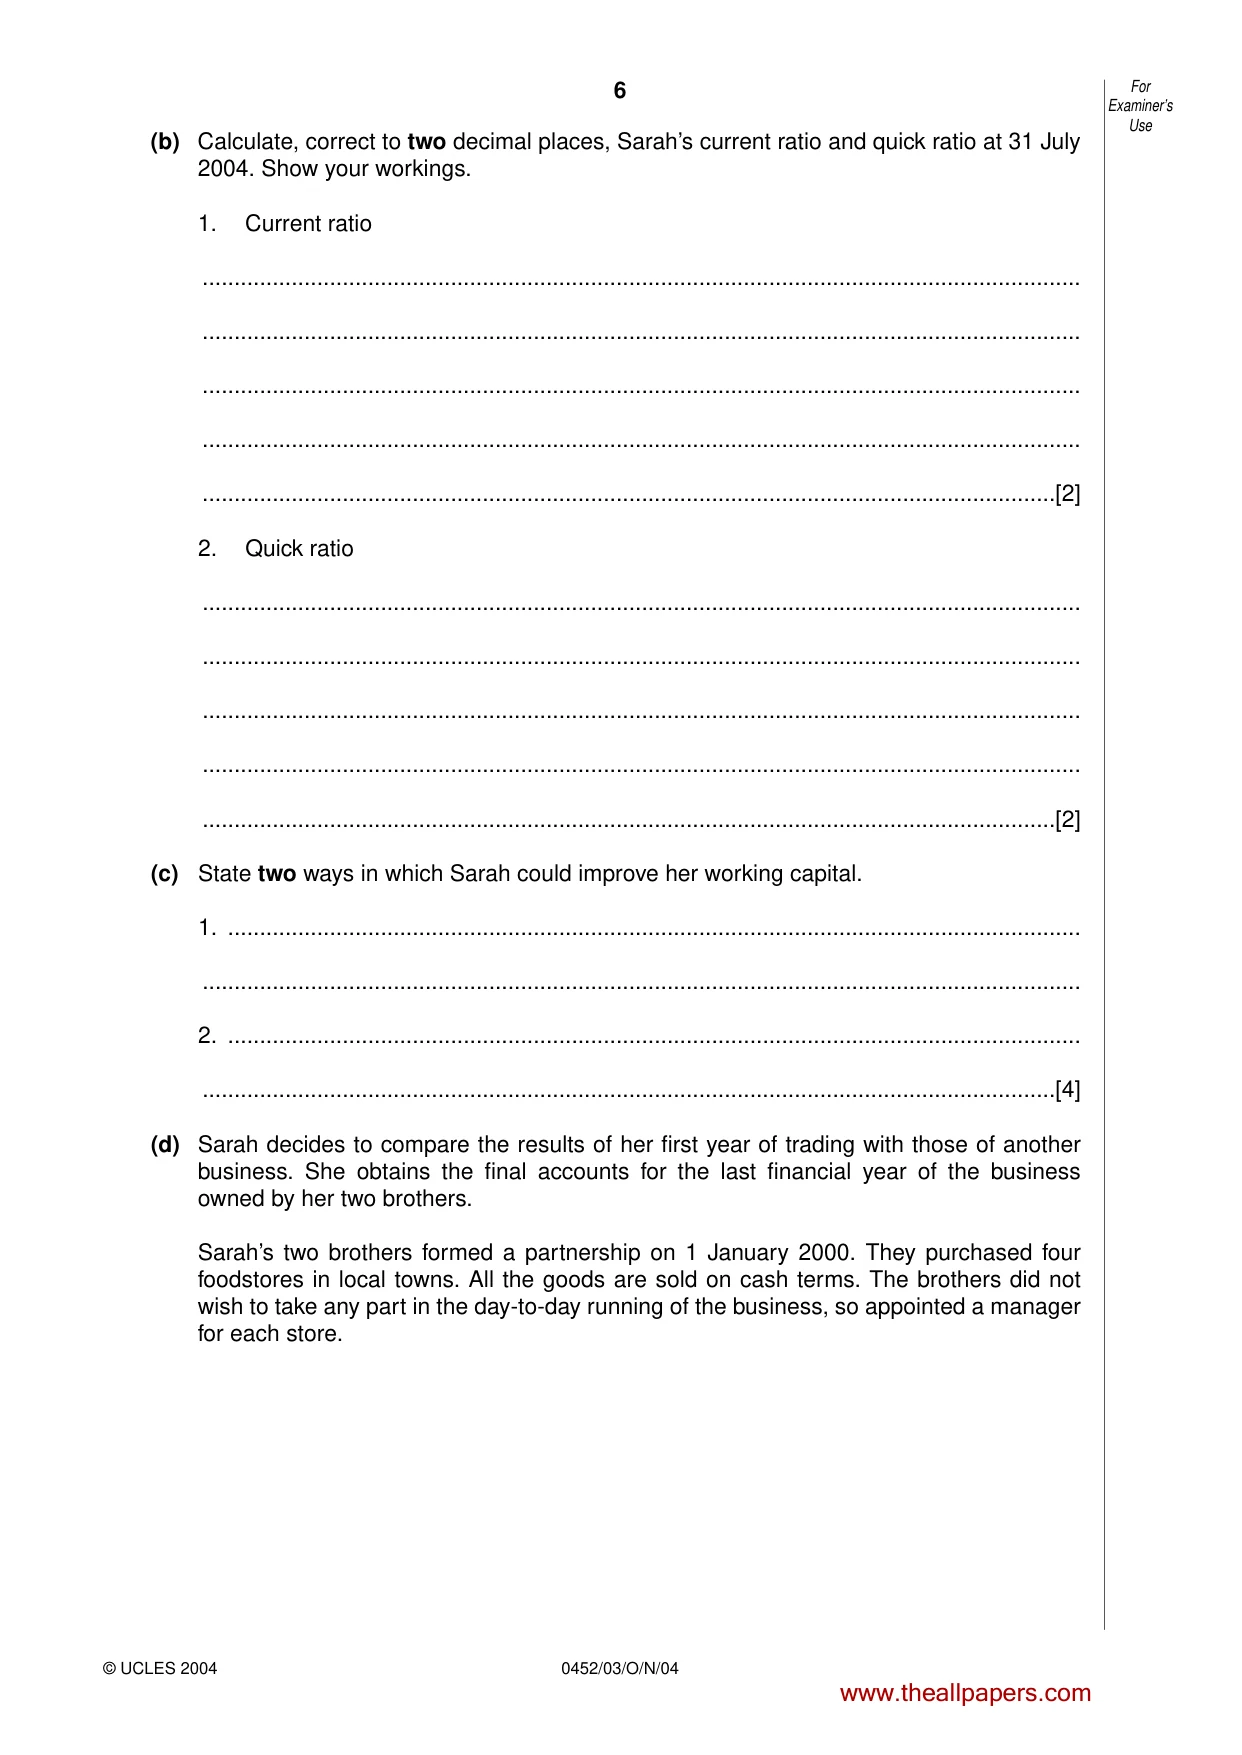
6 © UCLES 2004 0452/03/O/N/04 (b) Calculate, correct to two decimal places, Sarah’s current ratio and quick ratio at 31 July 2004. Show your workings. 1. Current ratio … … … … …[2] 2. Quick ratio … … … … …[2] (c) State two ways in which Sarah could improve her working capital. 1. … … 2. … …[4] (d) Sarah decides to compare the results of her first year of trading with those of another business. She obtains the final accounts for the last financial year of the business owned by her two brothers. Sarah’s two brothers formed a partnership on 1 January 2000. They purchased four foodstores in local towns. All the goods are sold on cash terms. The brothers did not wish to take any part in the day-to-day running of the business, so appointed a manager for each store. For Examiner’s Use www.theallpapers.com
Question paper, page 7
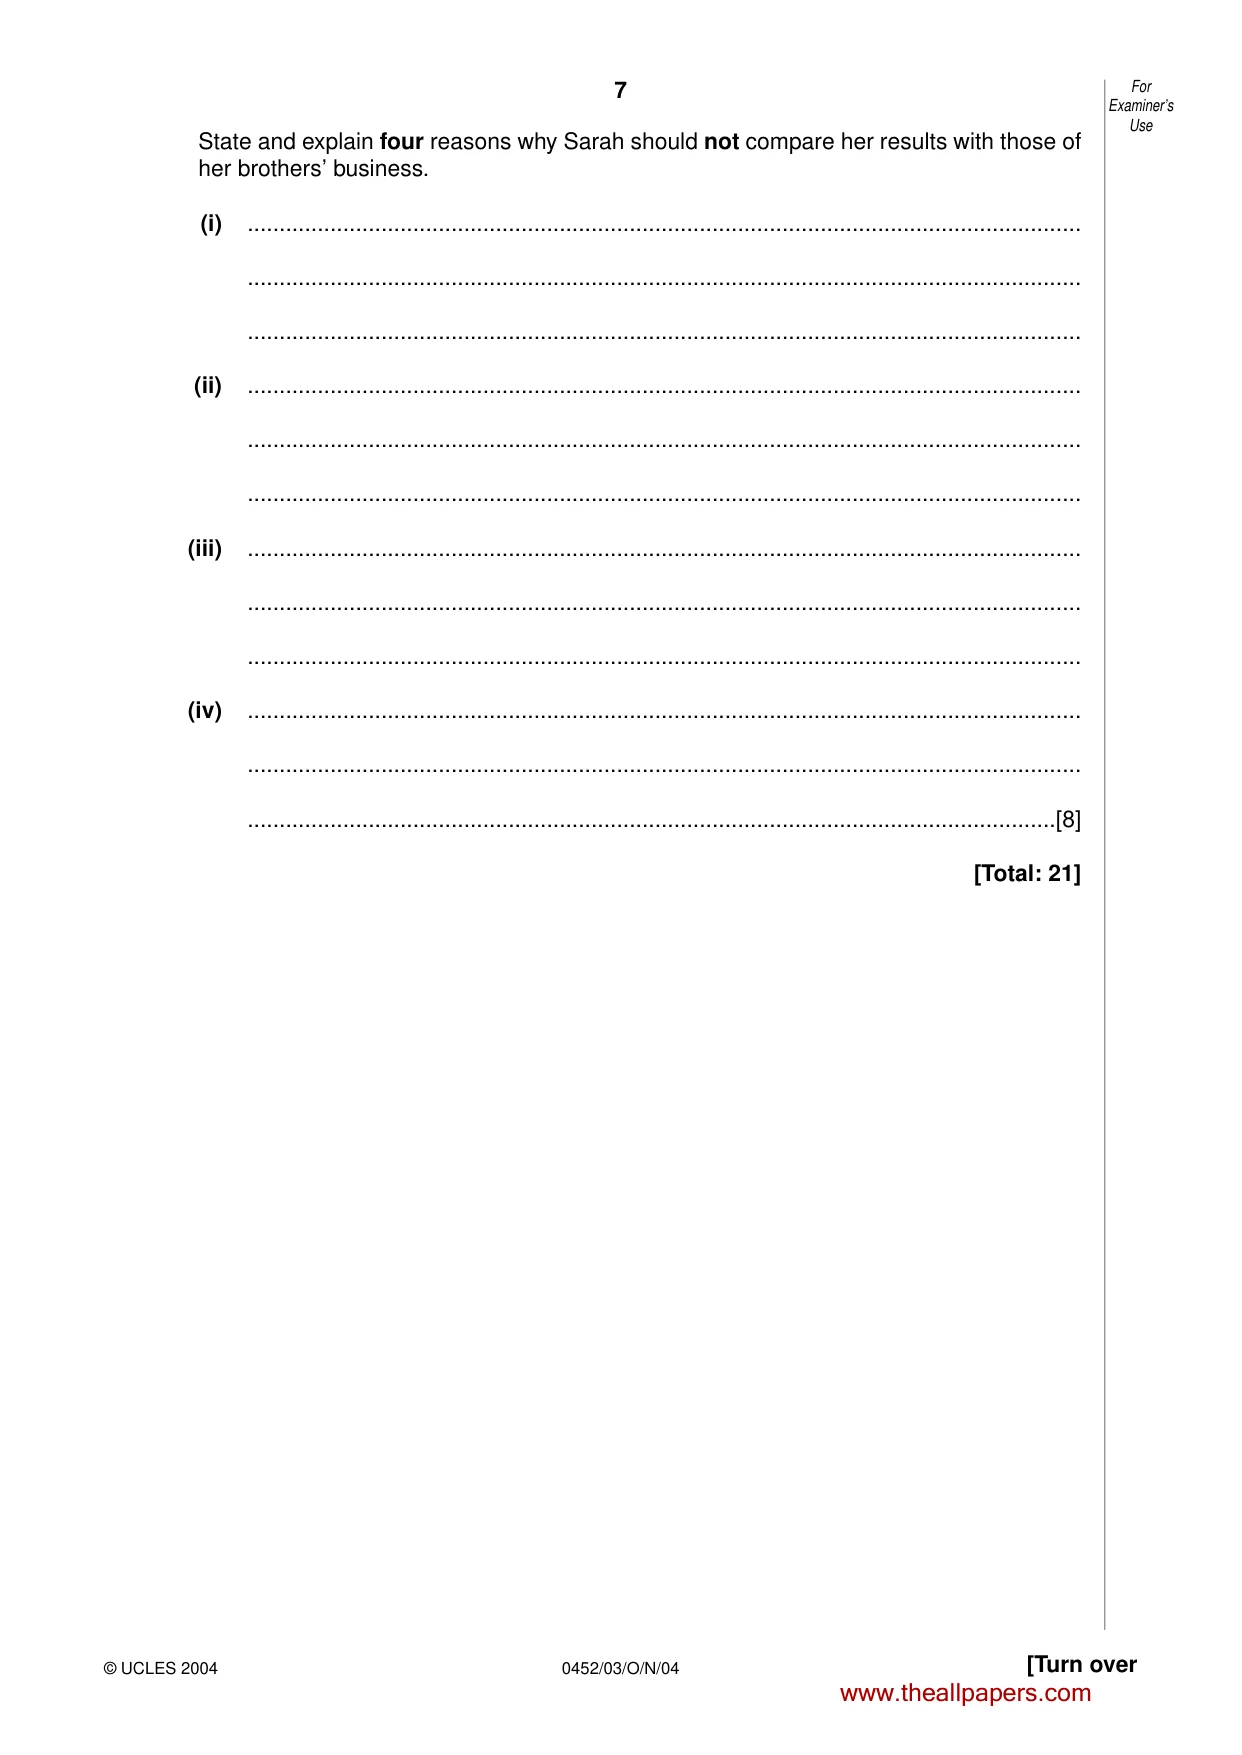
7 © UCLES 2004 0452/03/O/N/04 [Turn over State and explain four reasons why Sarah should not compare her results with those of her brothers’ business. (i) … … … (ii) … … … (iii) … … … (iv) … … …[8] [Total: 21] For Examiner’s Use www.theallpapers.com
Question paper, page 8
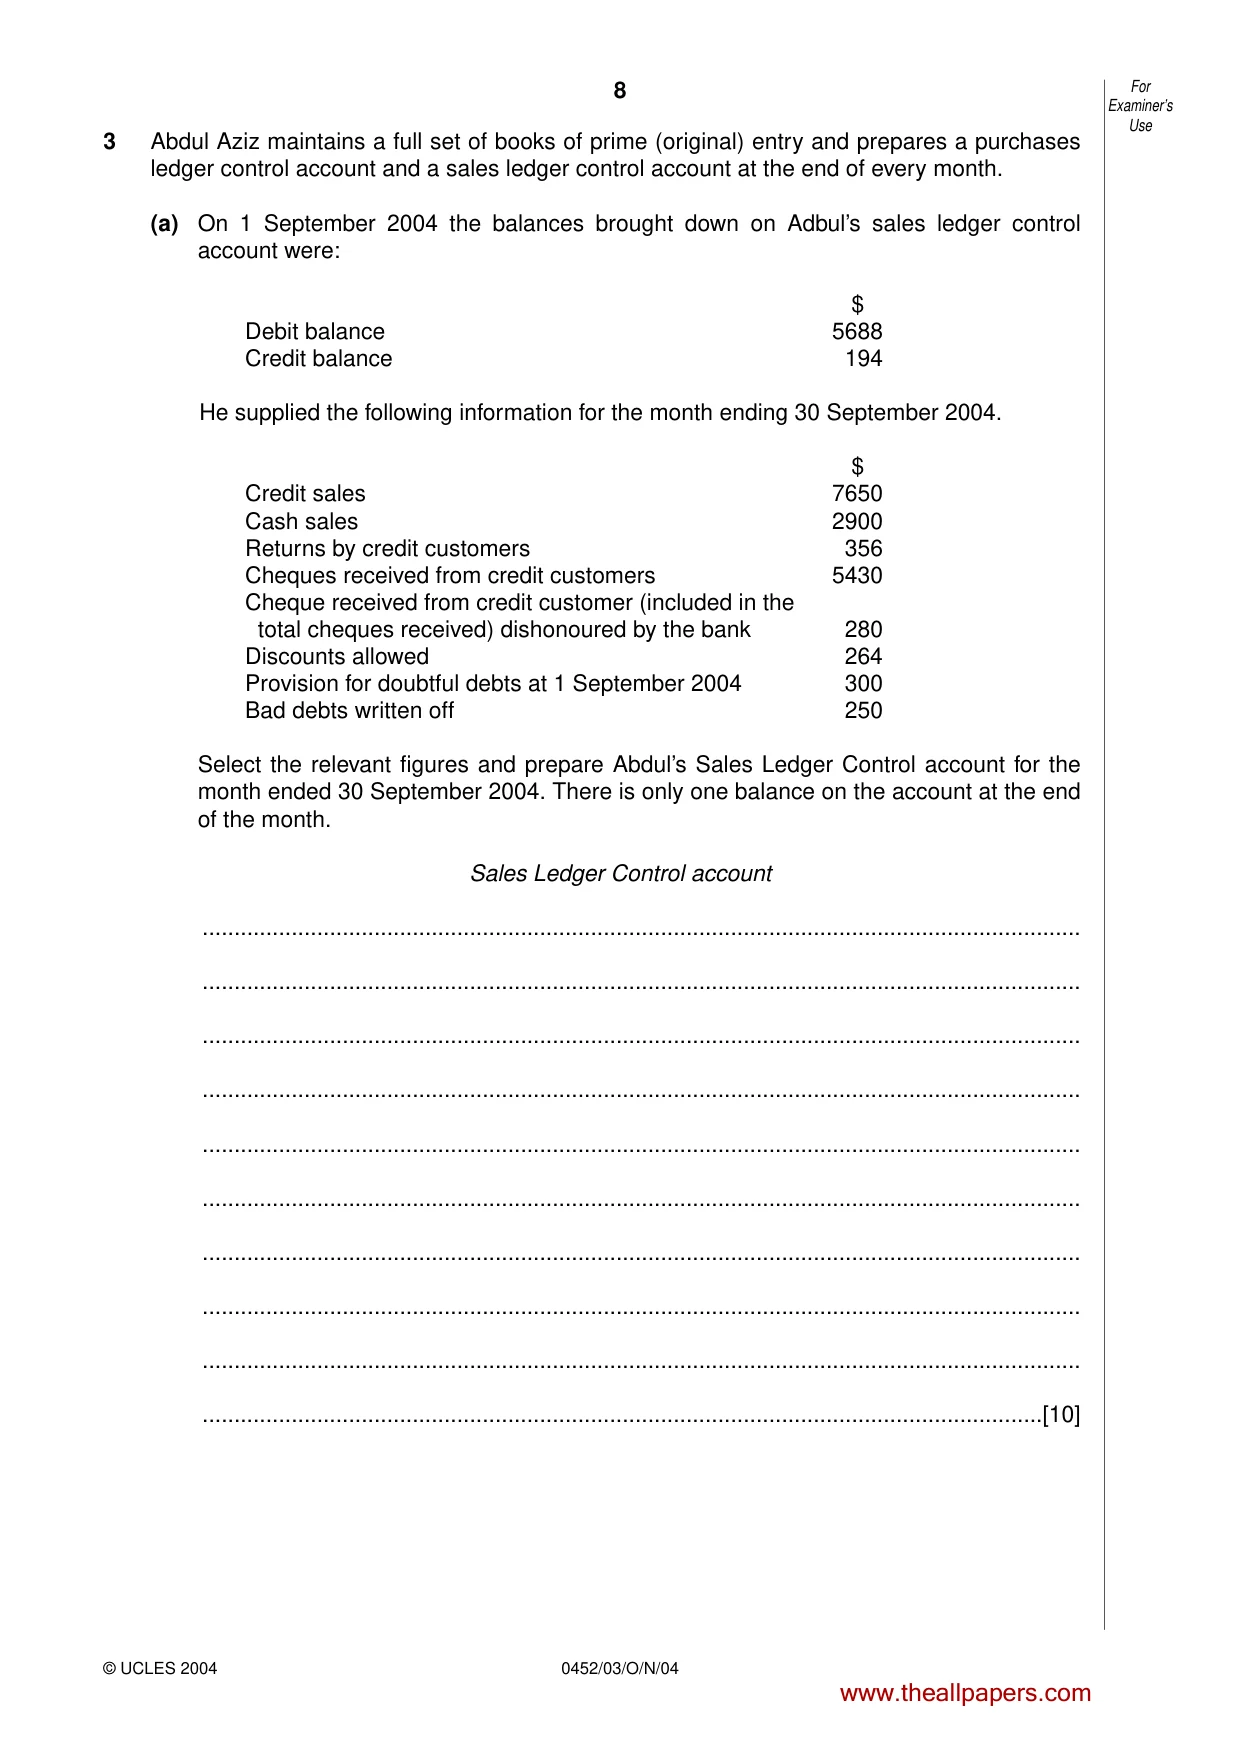
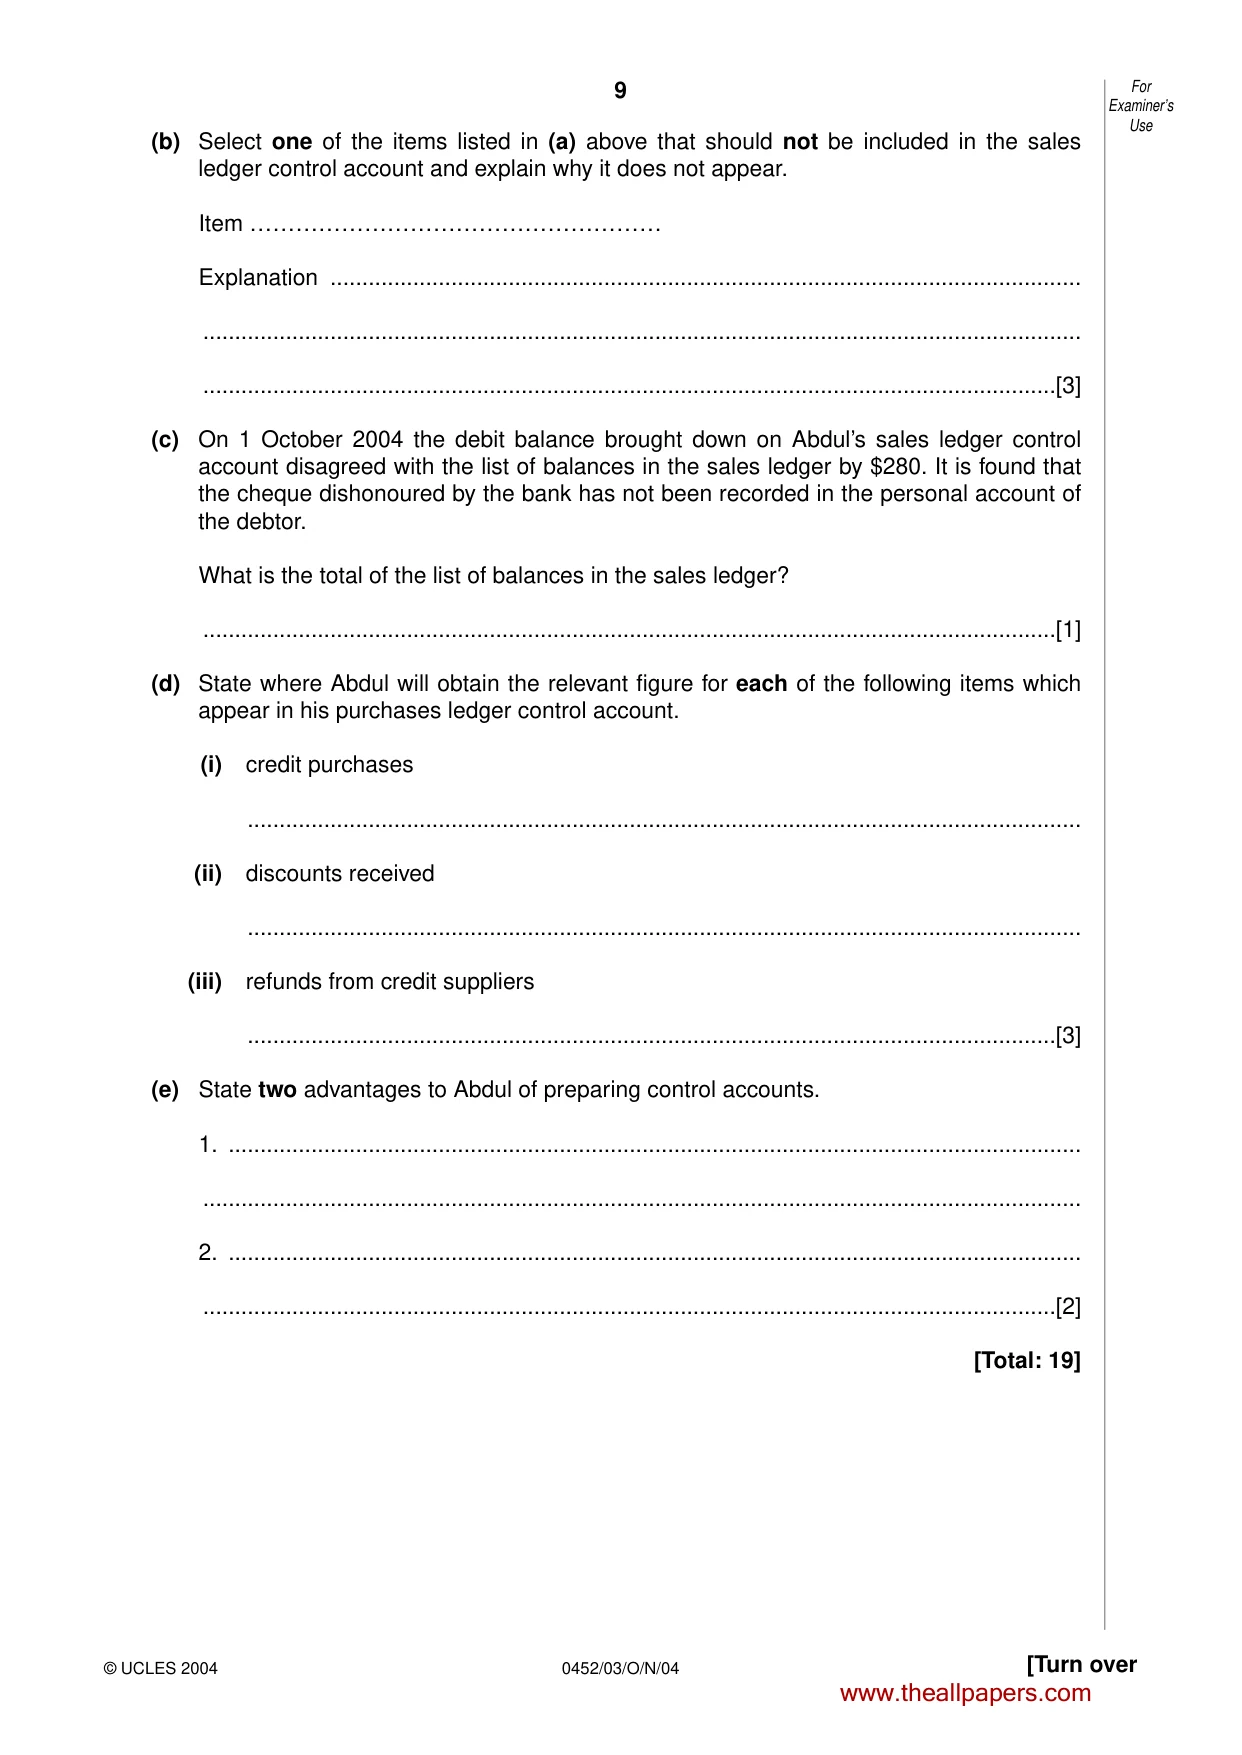
8 © UCLES 2004 0452/03/O/N/04 3 Abdul Aziz maintains a full set of books of prime (original) entry and prepares a purchases ledger control account and a sales ledger control account at the end of every month. (a) On 1 September 2004 the balances brought down on Adbul’s sales ledger control account were: $ Debit balance 5688 Credit balance 194 He supplied the following information for the month ending 30 September 2004. $ Credit sales 7650 Cash sales 2900 Returns by credit customers 356 Cheques received from credit customers 5430 Cheque received from credit customer (included in the total cheques received) dishonoured by the bank 280 Discounts allowed 264 Provision for doubtful debts at 1 September 2004 300 Bad debts written off 250 Select the relevant figures and prepare Abdul’s Sales Ledger Control account for the month ended 30 September 2004. There is only one balance on the account at the end of the month. Sales Ledger Control account … … … … … … … … … …[10] For Examiner’s Use www.theallpapers.com
Question paper, page 9
9 © UCLES 2004 0452/03/O/N/04 [Turn over (b) Select one of the items listed in (a) above that should not be included in the sales ledger control account and explain why it does not appear. Item ……………………………………………… Explanation … … …[3] (c) On 1 October 2004 the debit balance brought down on Abdul’s sales ledger control account disagreed with the list of balances in the sales ledger by $280. It is found that the cheque dishonoured by the bank has not been recorded in the personal account of the debtor. What is the total of the list of balances in the sales ledger? …[1] (d) State where Abdul will obtain the relevant figure for each of the following items which appear in his purchases ledger control account. (i) credit purchases … (ii) discounts received … (iii) refunds from credit suppliers …[3] (e) State two advantages to Abdul of preparing control accounts. 1. … … 2. … …[2] [Total: 19] For Examiner’s Use www.theallpapers.com
Question paper, page 10
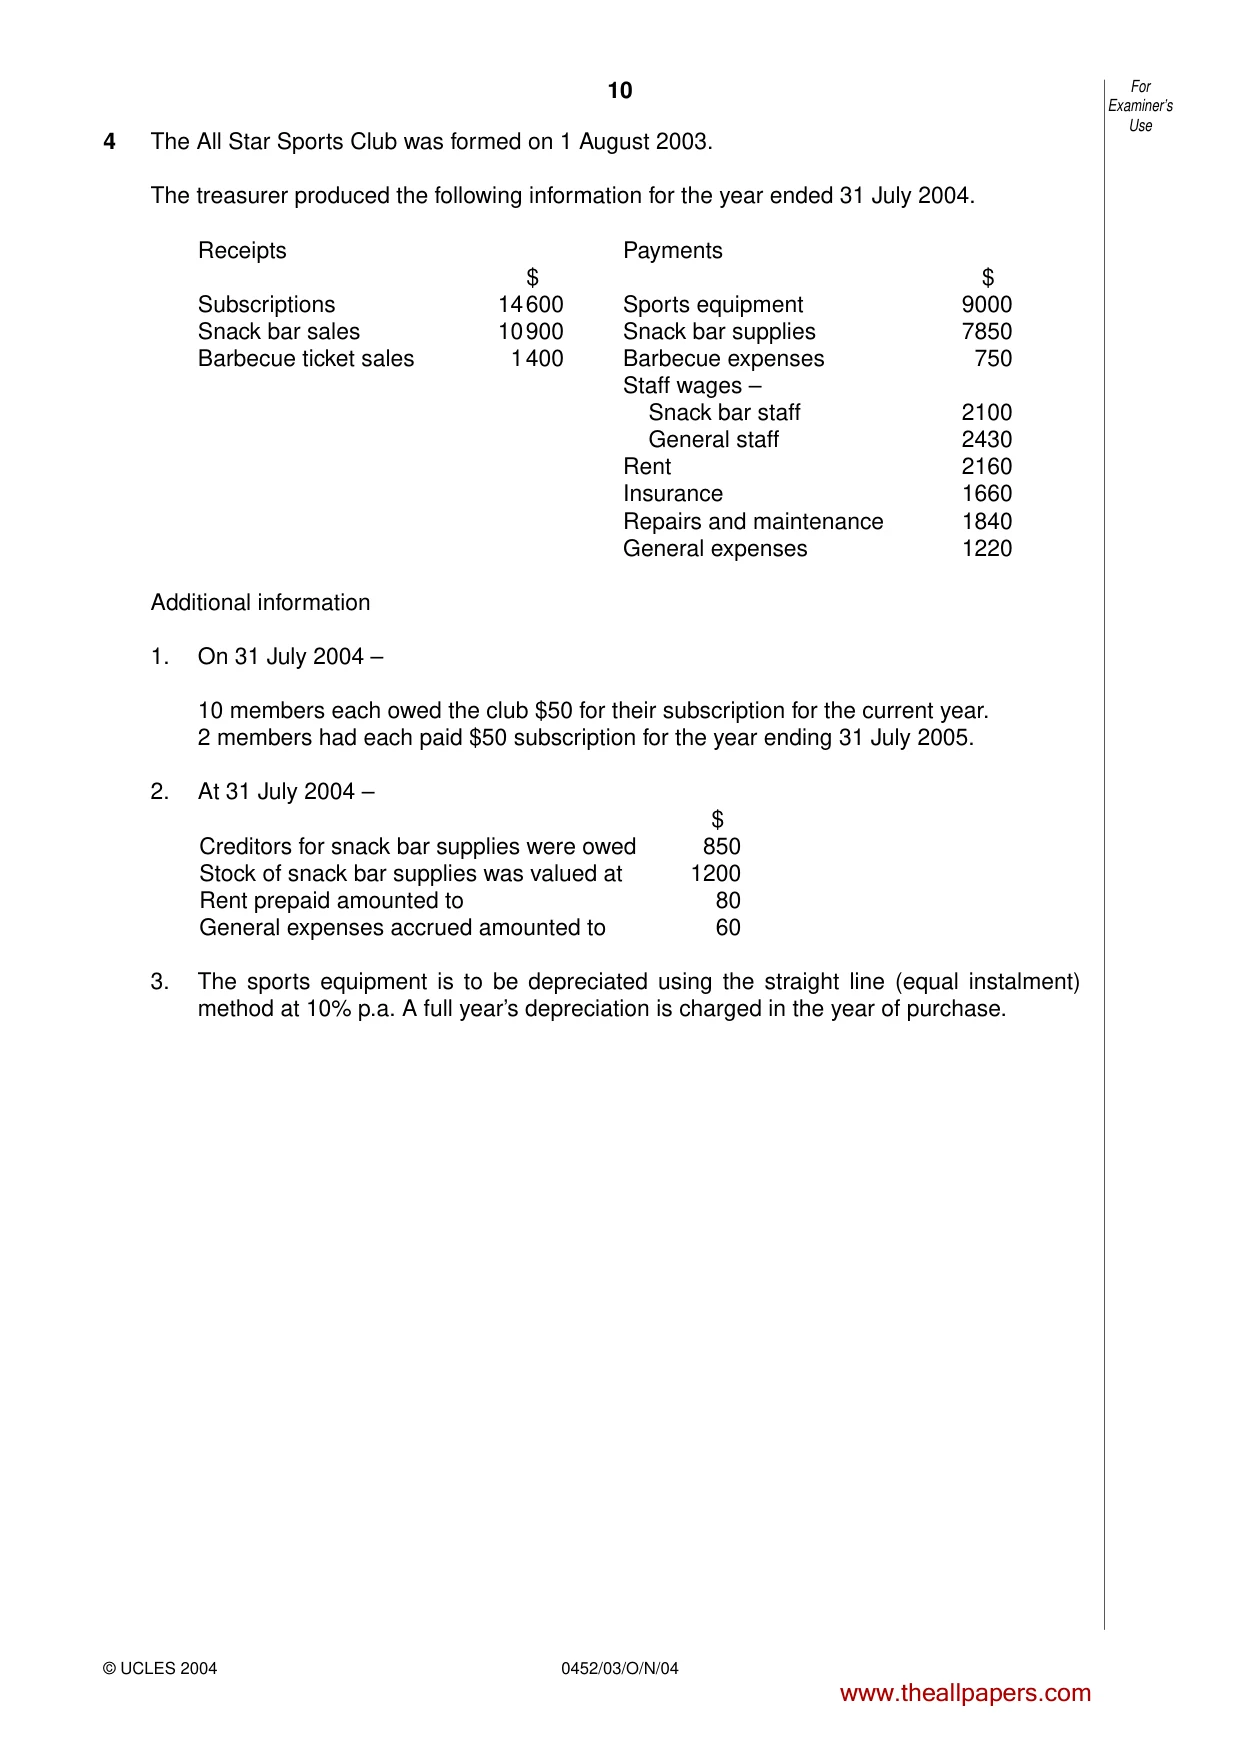
10 © UCLES 2004 0452/03/O/N/04 4 The All Star Sports Club was formed on 1 August 2003. The treasurer produced the following information for the year ended 31 July 2004. Receipts Payments $ $ Subscriptions 14600 Sports equipment 9000 Snack bar sales 10900 Snack bar supplies 7850 Barbecue ticket sales 1400 Barbecue expenses 750 Staff wages – Snack bar staff 2100 General staff 2430 Rent 2160 Insurance 1660 Repairs and maintenance 1840 General expenses 1220 Additional information 1. On 31 July 2004 – 10 members each owed the club $50 for their subscription for the current year. 2 members had each paid $50 subscription for the year ending 31 July 2005. 2. At 31 July 2004 – $ Creditors for snack bar supplies were owed 850 Stock of snack bar supplies was valued at 1200 Rent prepaid amounted to 80 General expenses accrued amounted to 60 3. The sports equipment is to be depreciated using the straight line (equal instalment) method at 10% p.a. A full year’s depreciation is charged in the year of purchase. For Examiner’s Use www.theallpapers.com
Question paper, page 11
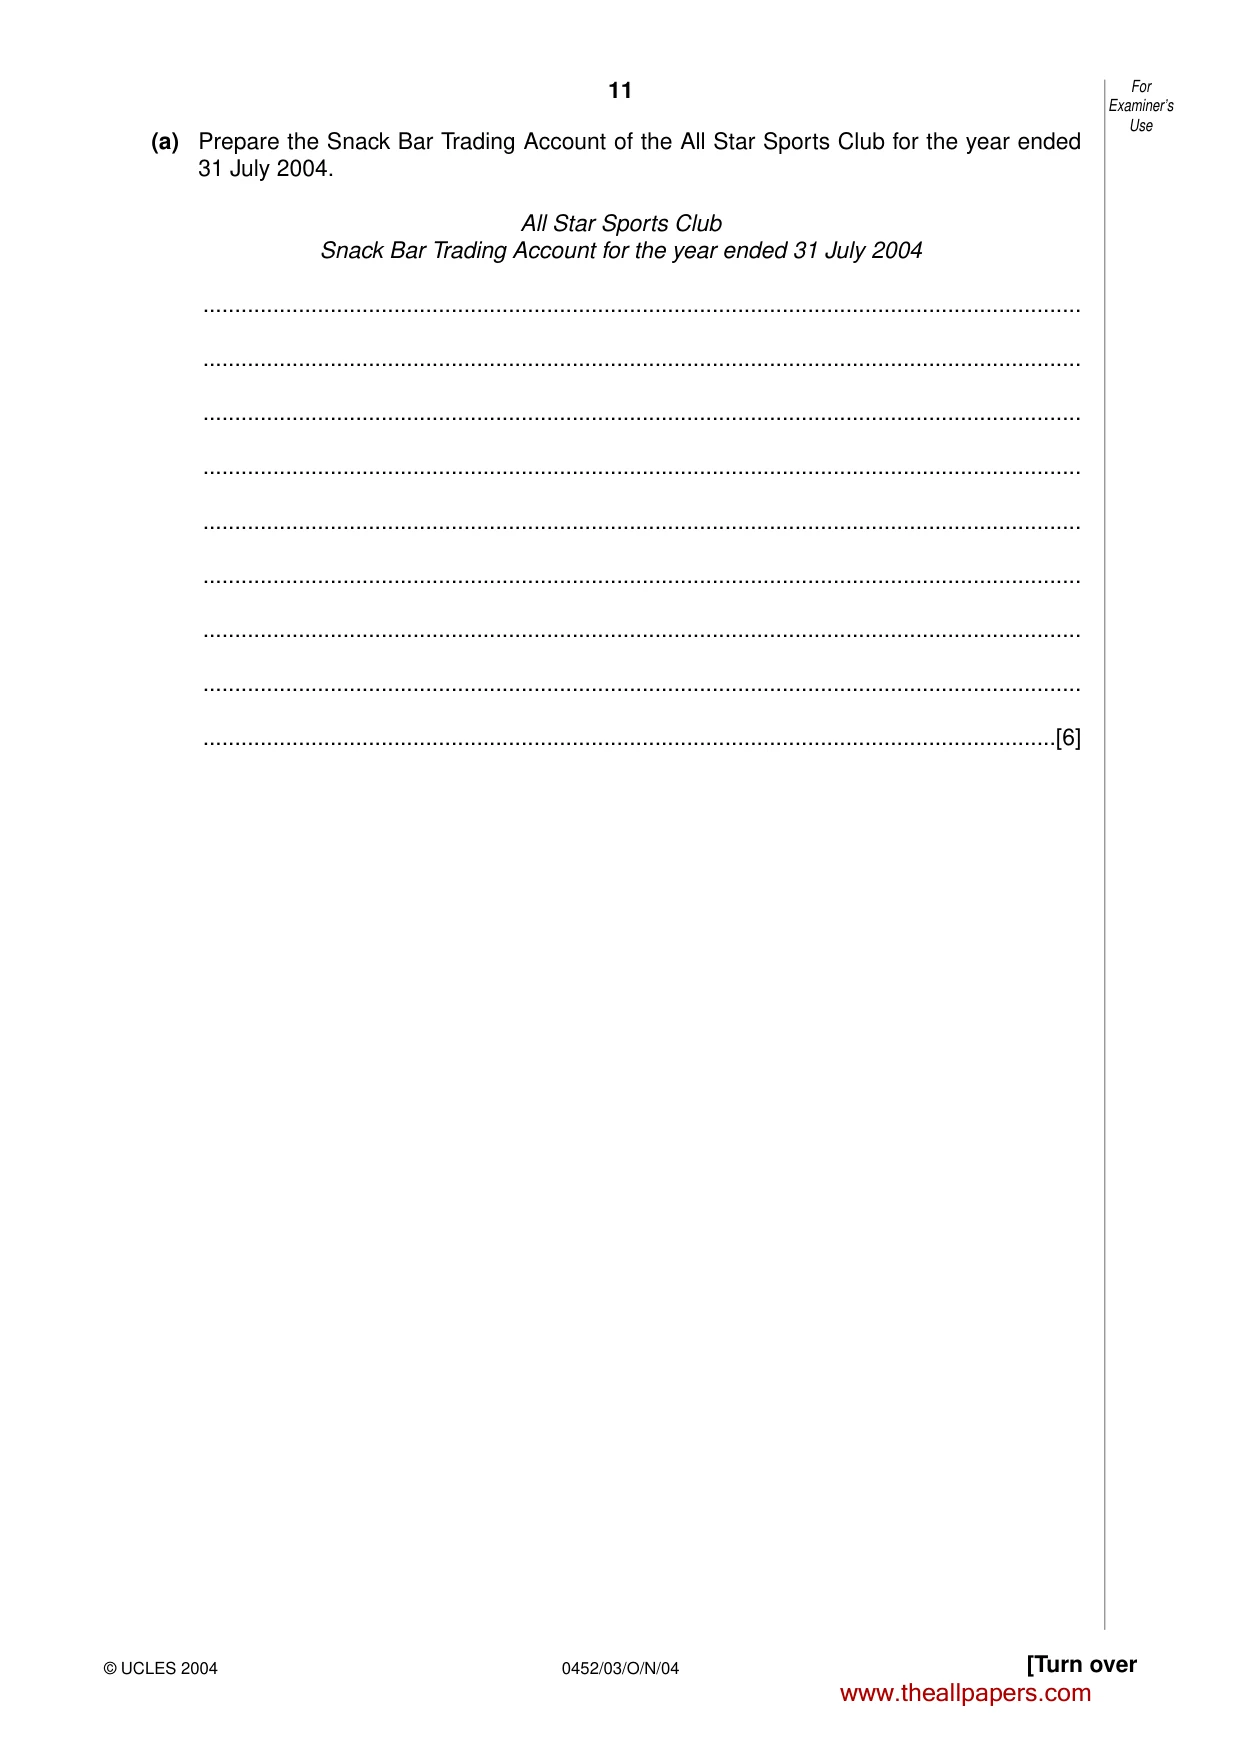
11 © UCLES 2004 0452/03/O/N/04 [Turn over (a) Prepare the Snack Bar Trading Account of the All Star Sports Club for the year ended 31 July 2004. All Star Sports Club Snack Bar Trading Account for the year ended 31 July 2004 … … … … … … … … …[6] For Examiner’s Use www.theallpapers.com
Question paper, page 12
12 © UCLES 2004 0452/03/O/N/04 (b) Prepare the Income and Expenditure Account of the All Star Sports Club for the year ended 31 July 2004. All Star Sports Club Income and Expenditure Account for the year ended 31 July 2004 … … … … … … … … … … … … … … … … … …[12] For Examiner’s Use www.theallpapers.com
Question paper, page 13
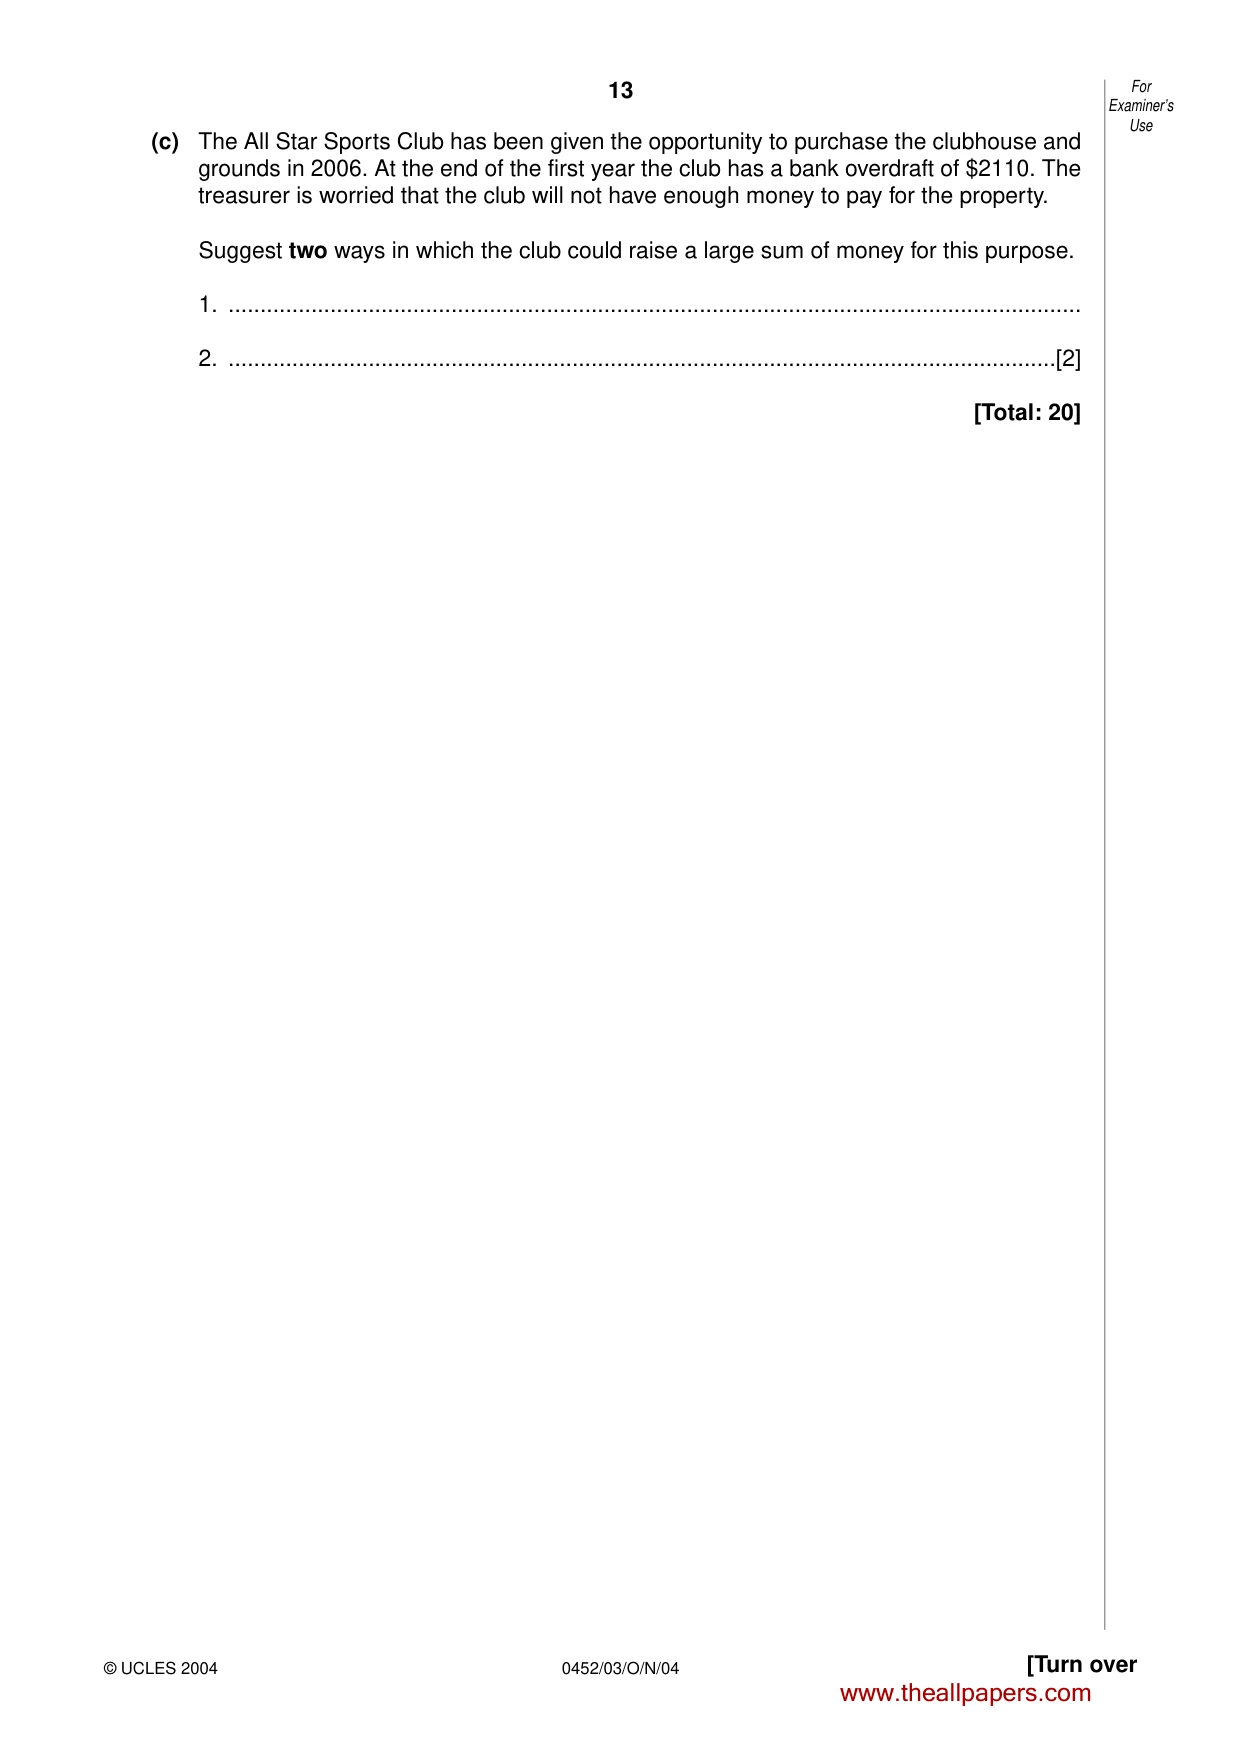
13 © UCLES 2004 0452/03/O/N/04 [Turn over (c) The All Star Sports Club has been given the opportunity to purchase the clubhouse and grounds in 2006. At the end of the first year the club has a bank overdraft of $2110. The treasurer is worried that the club will not have enough money to pay for the property. Suggest two ways in which the club could raise a large sum of money for this purpose. 1. … 2. …[2] [Total: 20] For Examiner’s Use www.theallpapers.com
Question paper, page 14
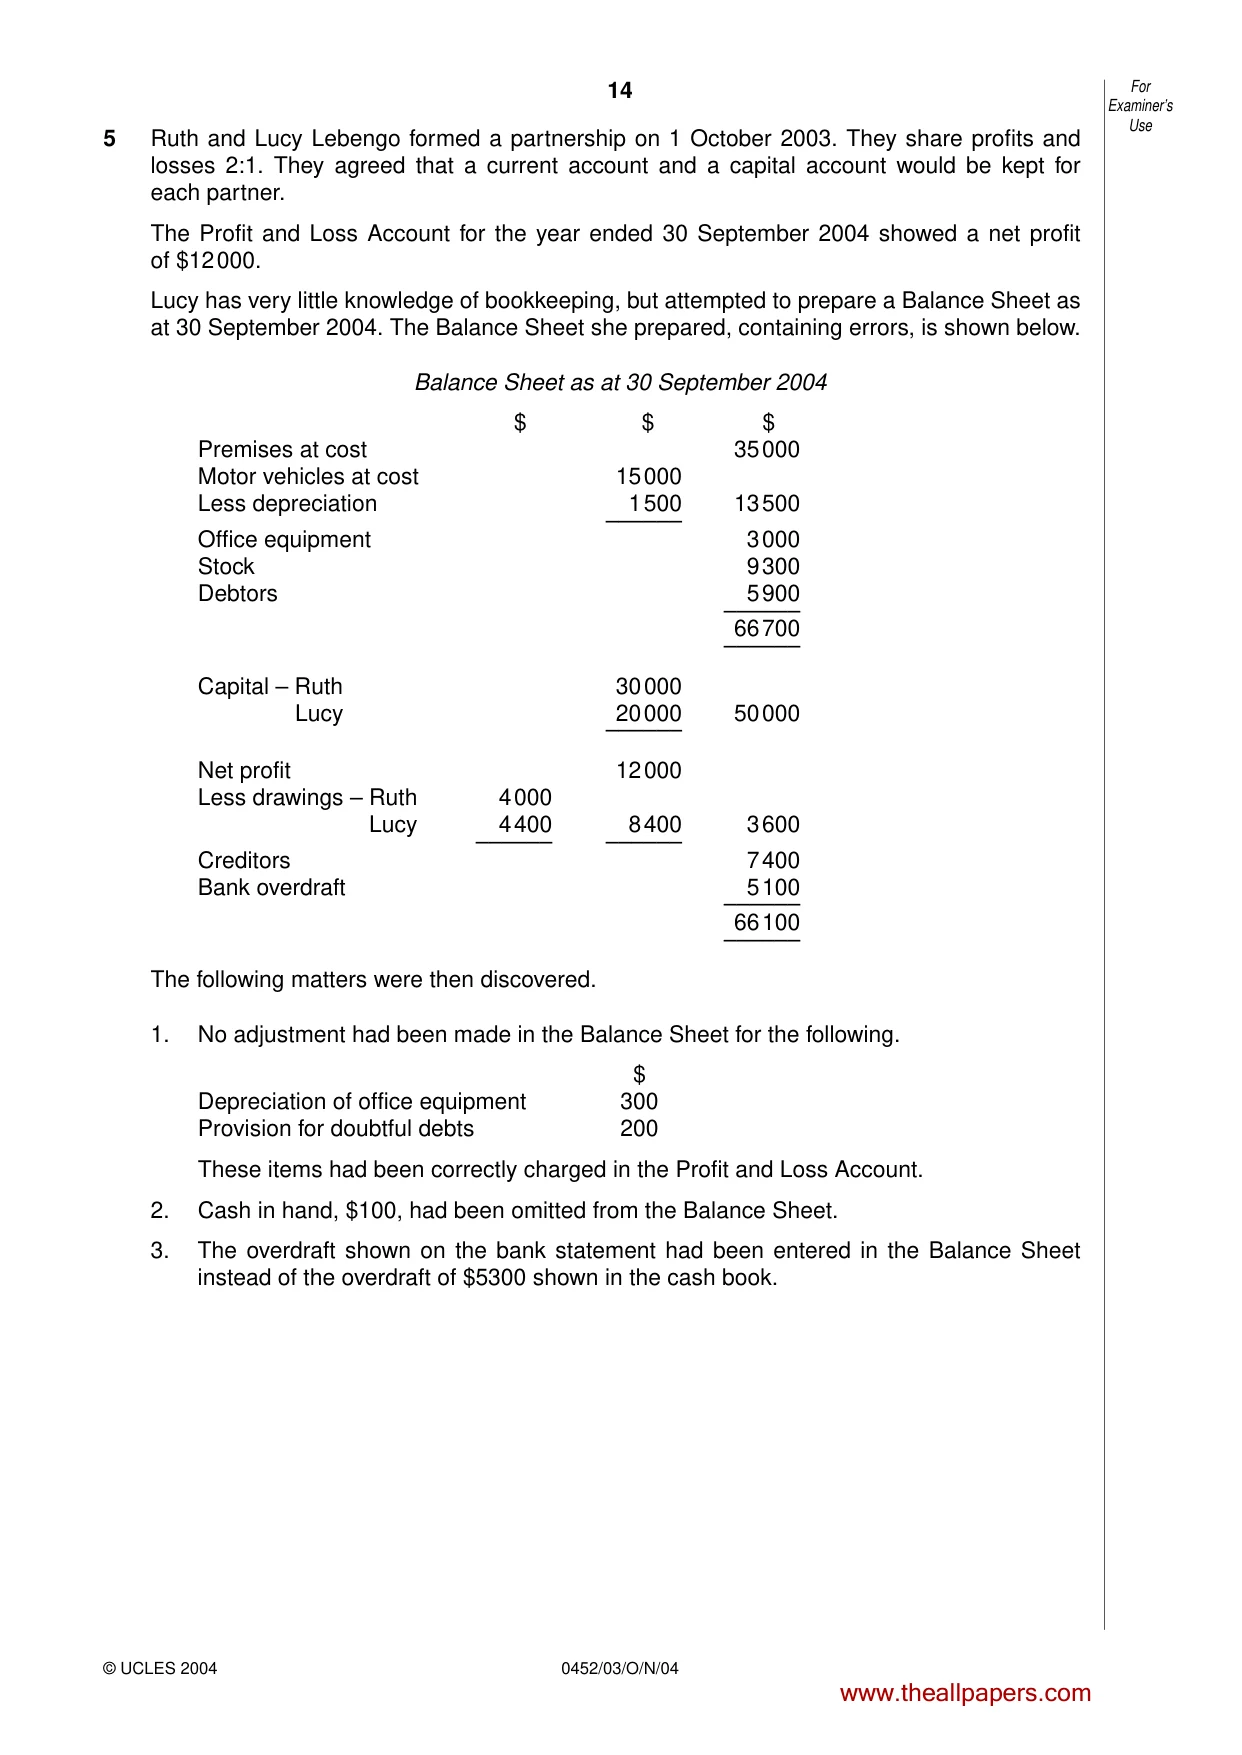
14 © UCLES 2004 0452/03/O/N/04 5 Ruth and Lucy Lebengo formed a partnership on 1 October 2003. They share profits and losses 2:1. They agreed that a current account and a capital account would be kept for each partner. The Profit and Loss Account for the year ended 30 September 2004 showed a net profit of $12000. Lucy has very little knowledge of bookkeeping, but attempted to prepare a Balance Sheet as at 30 September 2004. The Balance Sheet she prepared, containing errors, is shown below. Balance Sheet as at 30 September 2004 $ $ $ Premises at cost 35000 Motor vehicles at cost 15000 Less depreciation 1500 13500 –––––– Office equipment 3000 Stock 9300 Debtors 5900 –––––– 66700 –––––– Capital – Ruth 30000 Lucy 20000 50000 –––––– Net profit 12000 Less drawings – Ruth 4000 Lucy 4400 8400 3600 –––––– –––––– Creditors 7400 Bank overdraft 5100 –––––– 66100 –––––– The following matters were then discovered. 1. No adjustment had been made in the Balance Sheet for the following. $ Depreciation of office equipment 300 Provision for doubtful debts 200 These items had been correctly charged in the Profit and Loss Account. 2. Cash in hand, $100, had been omitted from the Balance Sheet. 3. The overdraft shown on the bank statement had been entered in the Balance Sheet instead of the overdraft of $5300 shown in the cash book. For Examiner’s Use www.theallpapers.com
Question paper, page 15
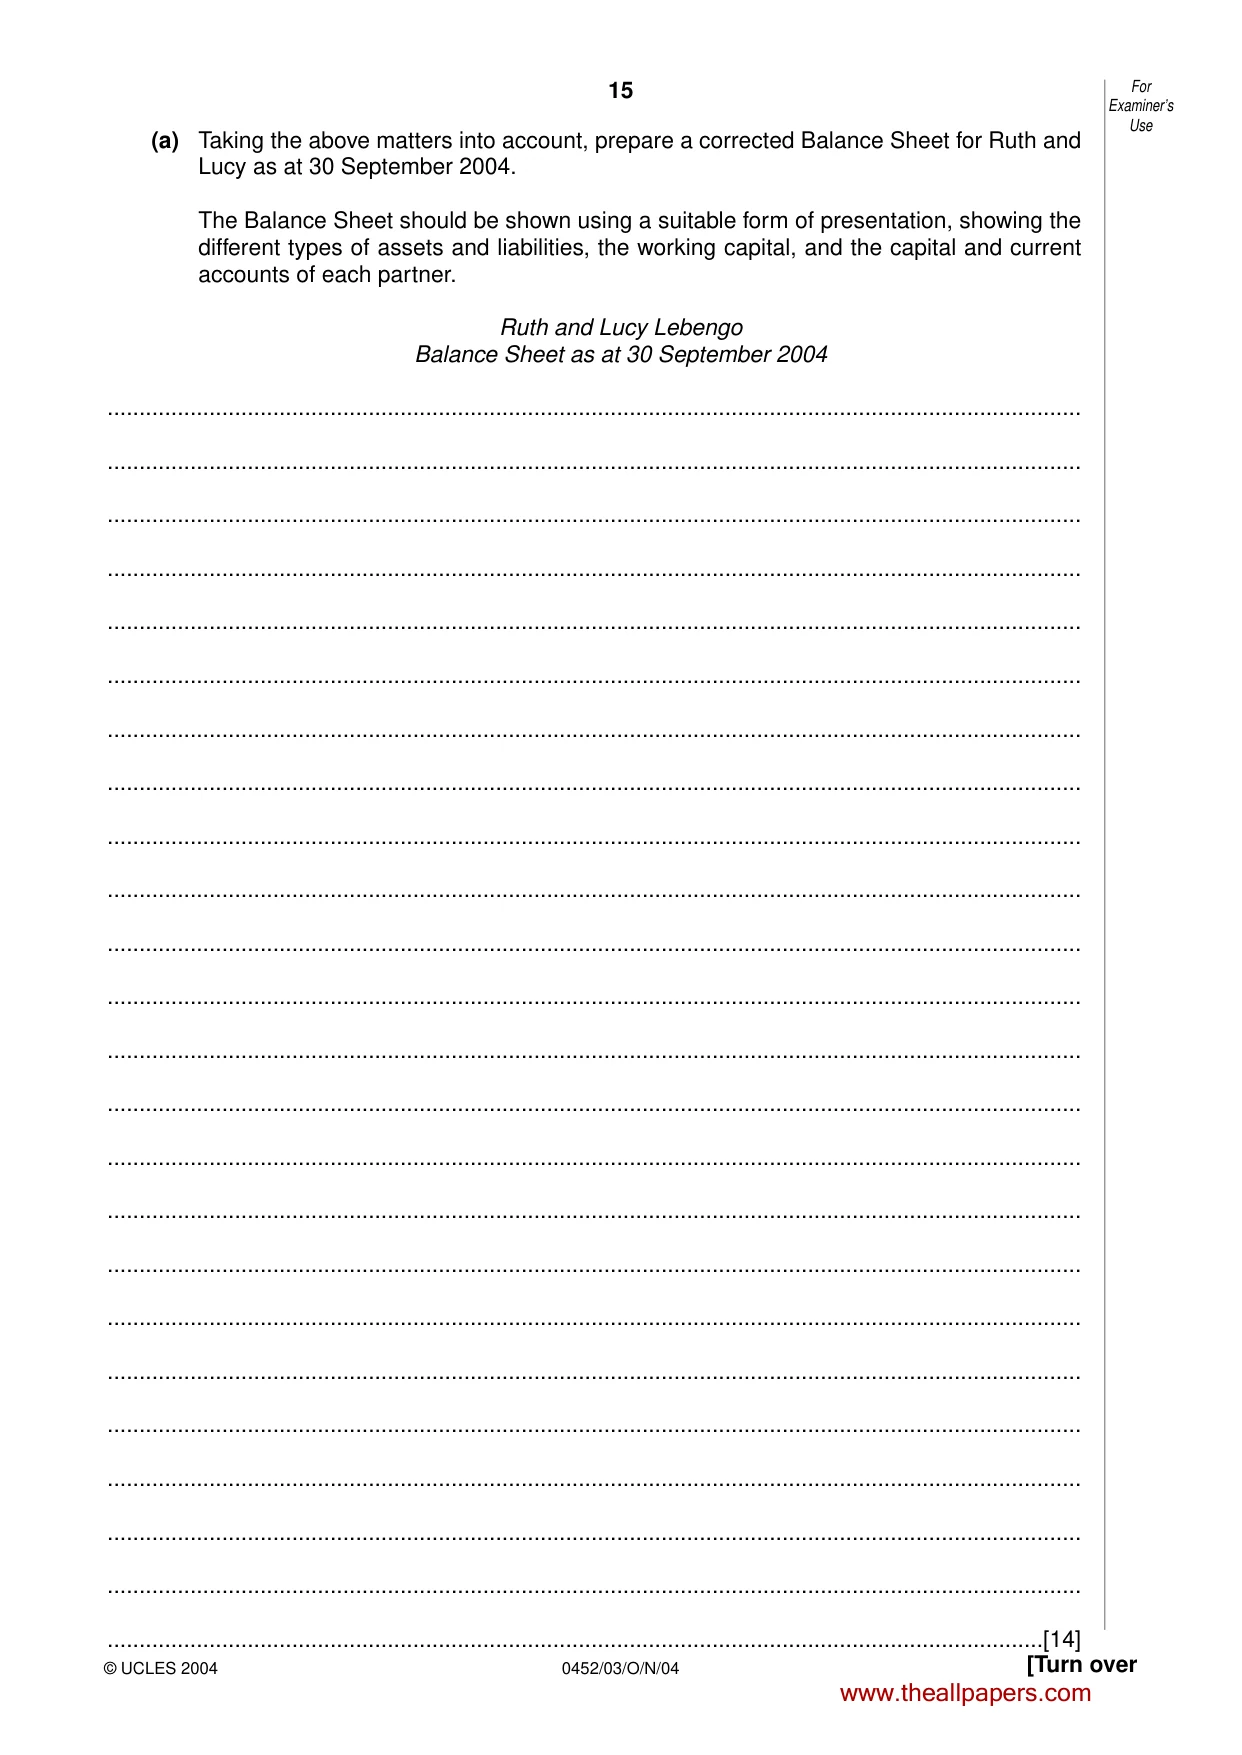
15 © UCLES 2004 0452/03/O/N/04 [Turn over For Examiner’s Use (a) Taking the above matters into account, prepare a corrected Balance Sheet for Ruth and Lucy as at 30 September 2004. The Balance Sheet should be shown using a suitable form of presentation, showing the different types of assets and liabilities, the working capital, and the capital and current accounts of each partner. Ruth and Lucy Lebengo Balance Sheet as at 30 September 2004 … … … … … … … … … … … … … … … … … … … … … … … …[14] www.theallpapers.com
Question paper, page 16
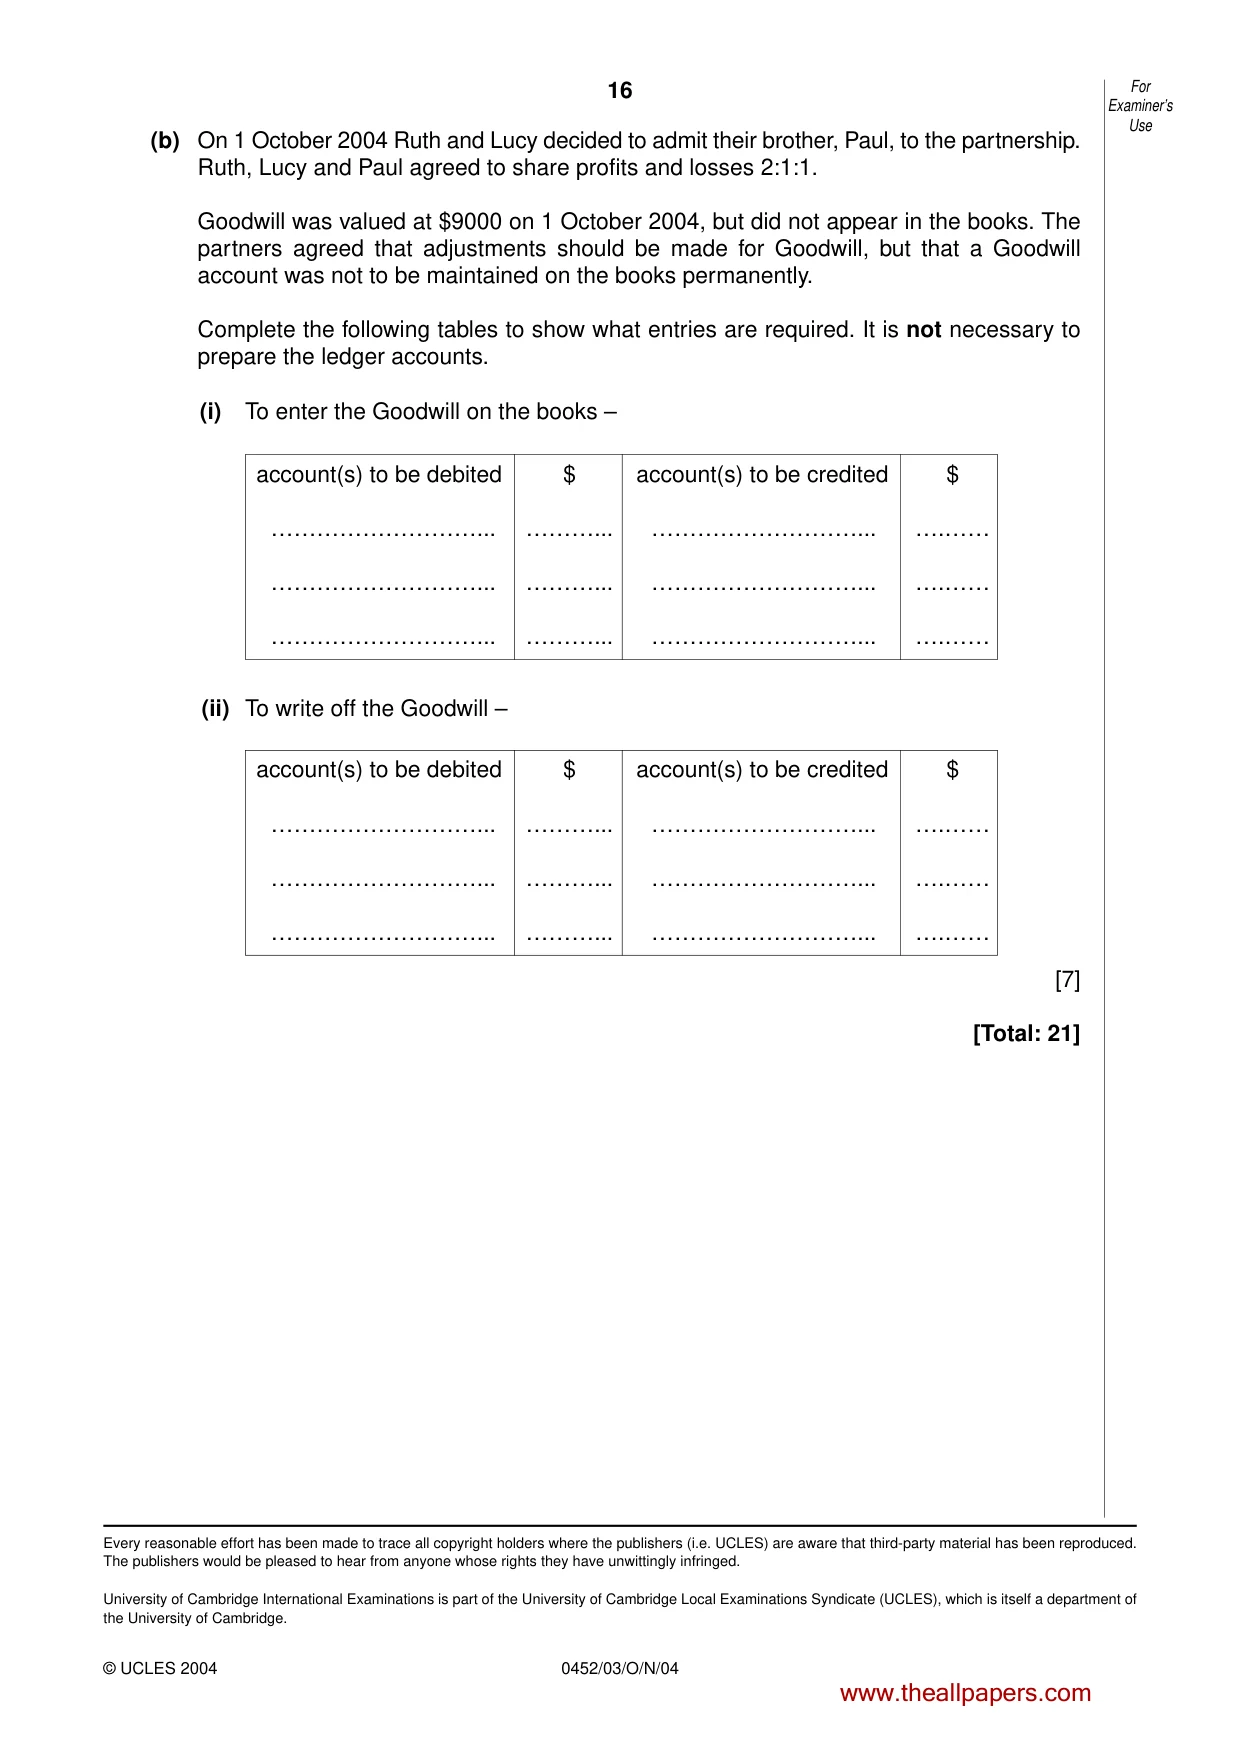
16 © UCLES 2004 0452/03/O/N/04 For Examiner’s Use (b) On 1 October 2004 Ruth and Lucy decided to admit their brother, Paul, to the partnership. Ruth, Lucy and Paul agreed to share profits and losses 2:1:1. Goodwill was valued at $9000 on 1 October 2004, but did not appear in the books. The partners agreed that adjustments should be made for Goodwill, but that a Goodwill account was not to be maintained on the books permanently. Complete the following tables to show what entries are required. It is not necessary to prepare the ledger accounts. (i) To enter the Goodwill on the books – (ii) To write off the Goodwill – [7] [Total: 21] account(s) to be debited $ account(s) to be credited $ ………………………... ………... ………………………... ….…… ………………………... ………... ………………………... ….…… ………………………... ………... ………………………... ….…… account(s) to be debited $ account(s) to be credited $ ………………………... ………... ………………………... ….…… ………………………... ………... ………………………... ….…… ………………………... ………... ………………………... ….…… Every reasonable effort has been made to trace all copyright holders where the publishers (i.e. UCLES) are aware that third-party material has been reproduced. The publishers would be pleased to hear from anyone whose rights they have unwittingly infringed. University of Cambridge International Examinations is part of the University of Cambridge Local Examinations Syndicate (UCLES), which is itself a department of the University of Cambridge. www.theallpapers.com
Mark scheme, page 1
UNIVERSITY OF CAMBRIDGE INTERNATIONAL EXAMINATIONS International General Certificate of Secondary Education MARK SCHEME for the November 2004 question paper 0452 ACCOUNTING 0452/03 Paper 3, maximum raw mark 100 This mark scheme is published as an aid to teachers and students, to indicate the requirements of the examination. It shows the basis on which Examiners were initially instructed to award marks. It does not indicate the details of the discussions that took place at an Examiners’ meeting before marking began. Any substantial changes to the mark scheme that arose from these discussions will be recorded in the published Report on the Examination. All Examiners are instructed that alternative correct answers and unexpected approaches in candidates’ scripts must be given marks that fairly reflect the relevant knowledge and skills demonstrated. Mark schemes must be read in conjunction with the question papers and the Report on the Examination. • CIE will not enter into discussion or correspondence in connection with these mark schemes. CIE is publishing the mark schemes for the November 2004 question papers for most IGCSE and GCE Advanced Level syllabuses. www.theallpapers.com
Mark scheme, page 2
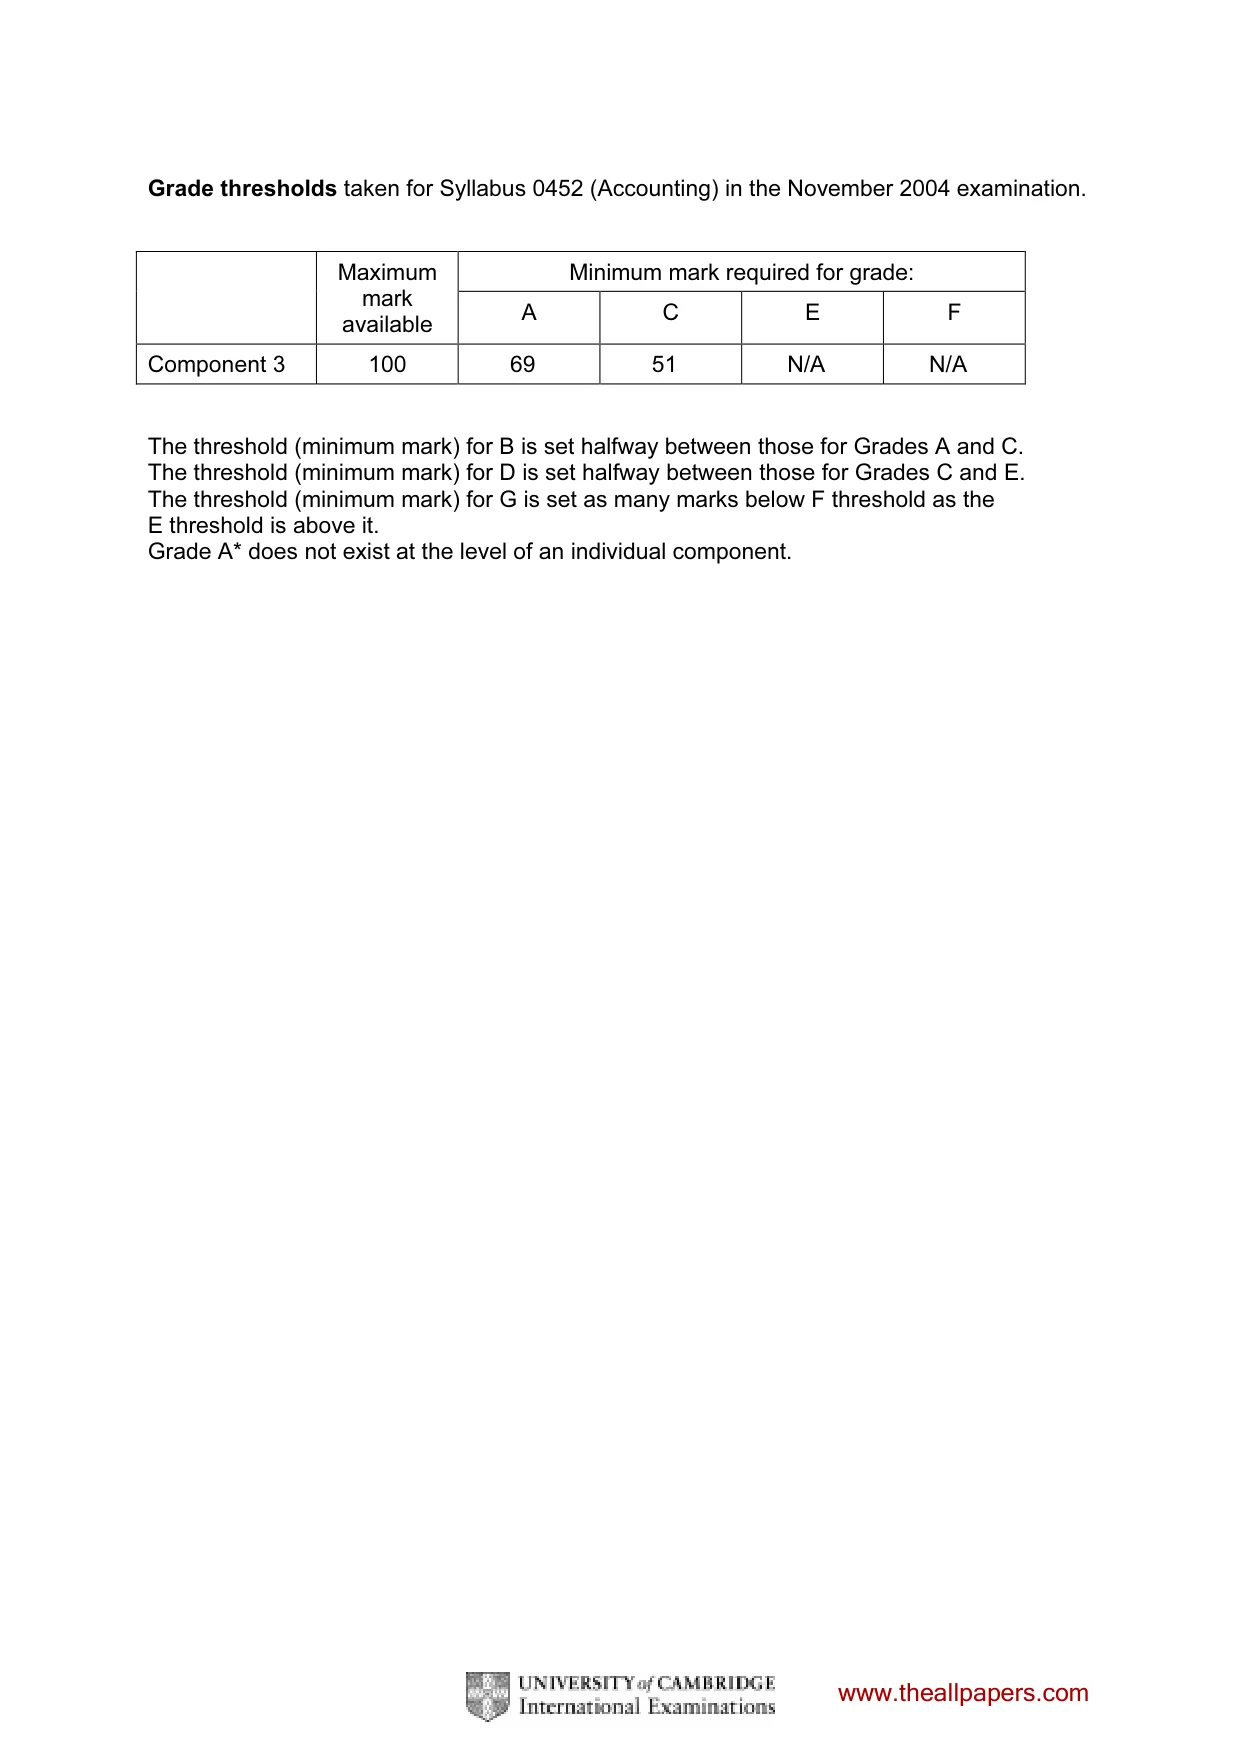
Grade thresholds taken for Syllabus 0452 (Accounting) in the November 2004 examination. Minimum mark required for grade: Maximum mark available A C E F Component 3 100 69 51 N/A N/A The threshold (minimum mark) for B is set halfway between those for Grades A and C. The threshold (minimum mark) for D is set halfway between those for Grades C and E. The threshold (minimum mark) for G is set as many marks below F threshold as the E threshold is above it. Grade A* does not exist at the level of an individual component. www.theallpapers.com
Mark scheme, page 3
NOVEMBER 2004 IGCSE MARK SCHEME MAXIMUM MARK: 100 SYLLABUS/COMPONENT: 0452/03 ACCOUNTING Paper 3 www.theallpapers.com
Mark scheme, page 4
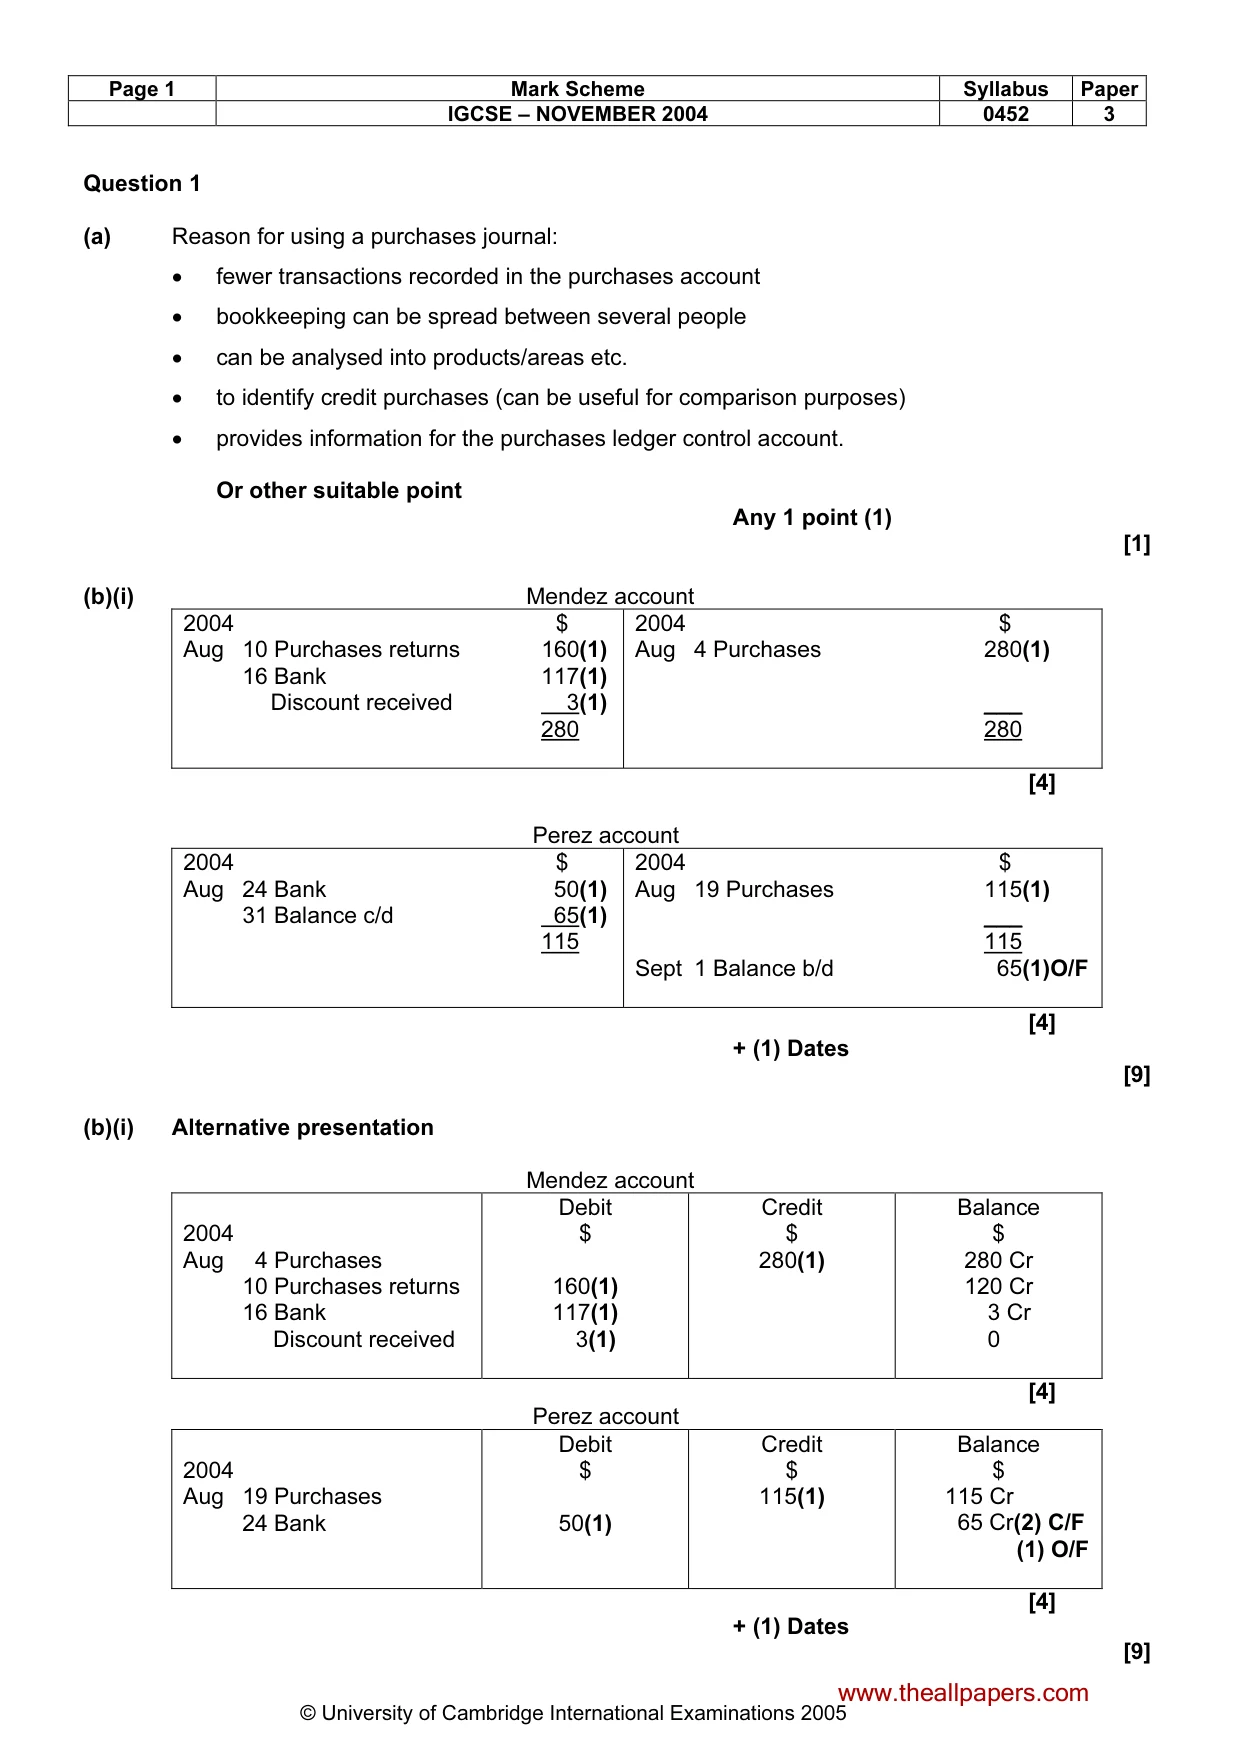
Page 1 Mark Scheme Syllabus Paper IGCSE – NOVEMBER 2004 0452 3 © University of Cambridge International Examinations 2005 Question 1 (a) Reason for using a purchases journal: • fewer transactions recorded in the purchases account • bookkeeping can be spread between several people • can be analysed into products/areas etc. • to identify credit purchases (can be useful for comparison purposes) • provides information for the purchases ledger control account. Or other suitable point Any 1 point (1) [1] (b)(i) Mendez account 2004 $ Aug 10 Purchases returns 160(1) 16 Bank 117(1) Discount received 3(1) 280 2004 $ Aug 4 Purchases 280(1) ___ 280 [4] Perez account 2004 $ Aug 24 Bank 50(1) 31 Balance c/d 65(1) 115 2004 $ Aug 19 Purchases 115(1) ___ 115 Sept 1 Balance b/d 65(1)O/F [4] + (1) Dates [9] (b)(i) Alternative presentation Mendez account 2004 Aug 4 Purchases 10 Purchases returns 16 Bank Discount received Debit $ 160(1) 117(1) 3(1) Credit $ 280(1) Balance $ 280 Cr 120 Cr 3 Cr 0 [4] Perez account 2004 Aug 19 Purchases 24 Bank Debit $ 50(1) Credit $ 115(1) Balance $ 115 Cr 65 Cr(2) C/F (1) O/F [4] + (1) Dates [9] www.theallpapers.com
Mark scheme, page 5
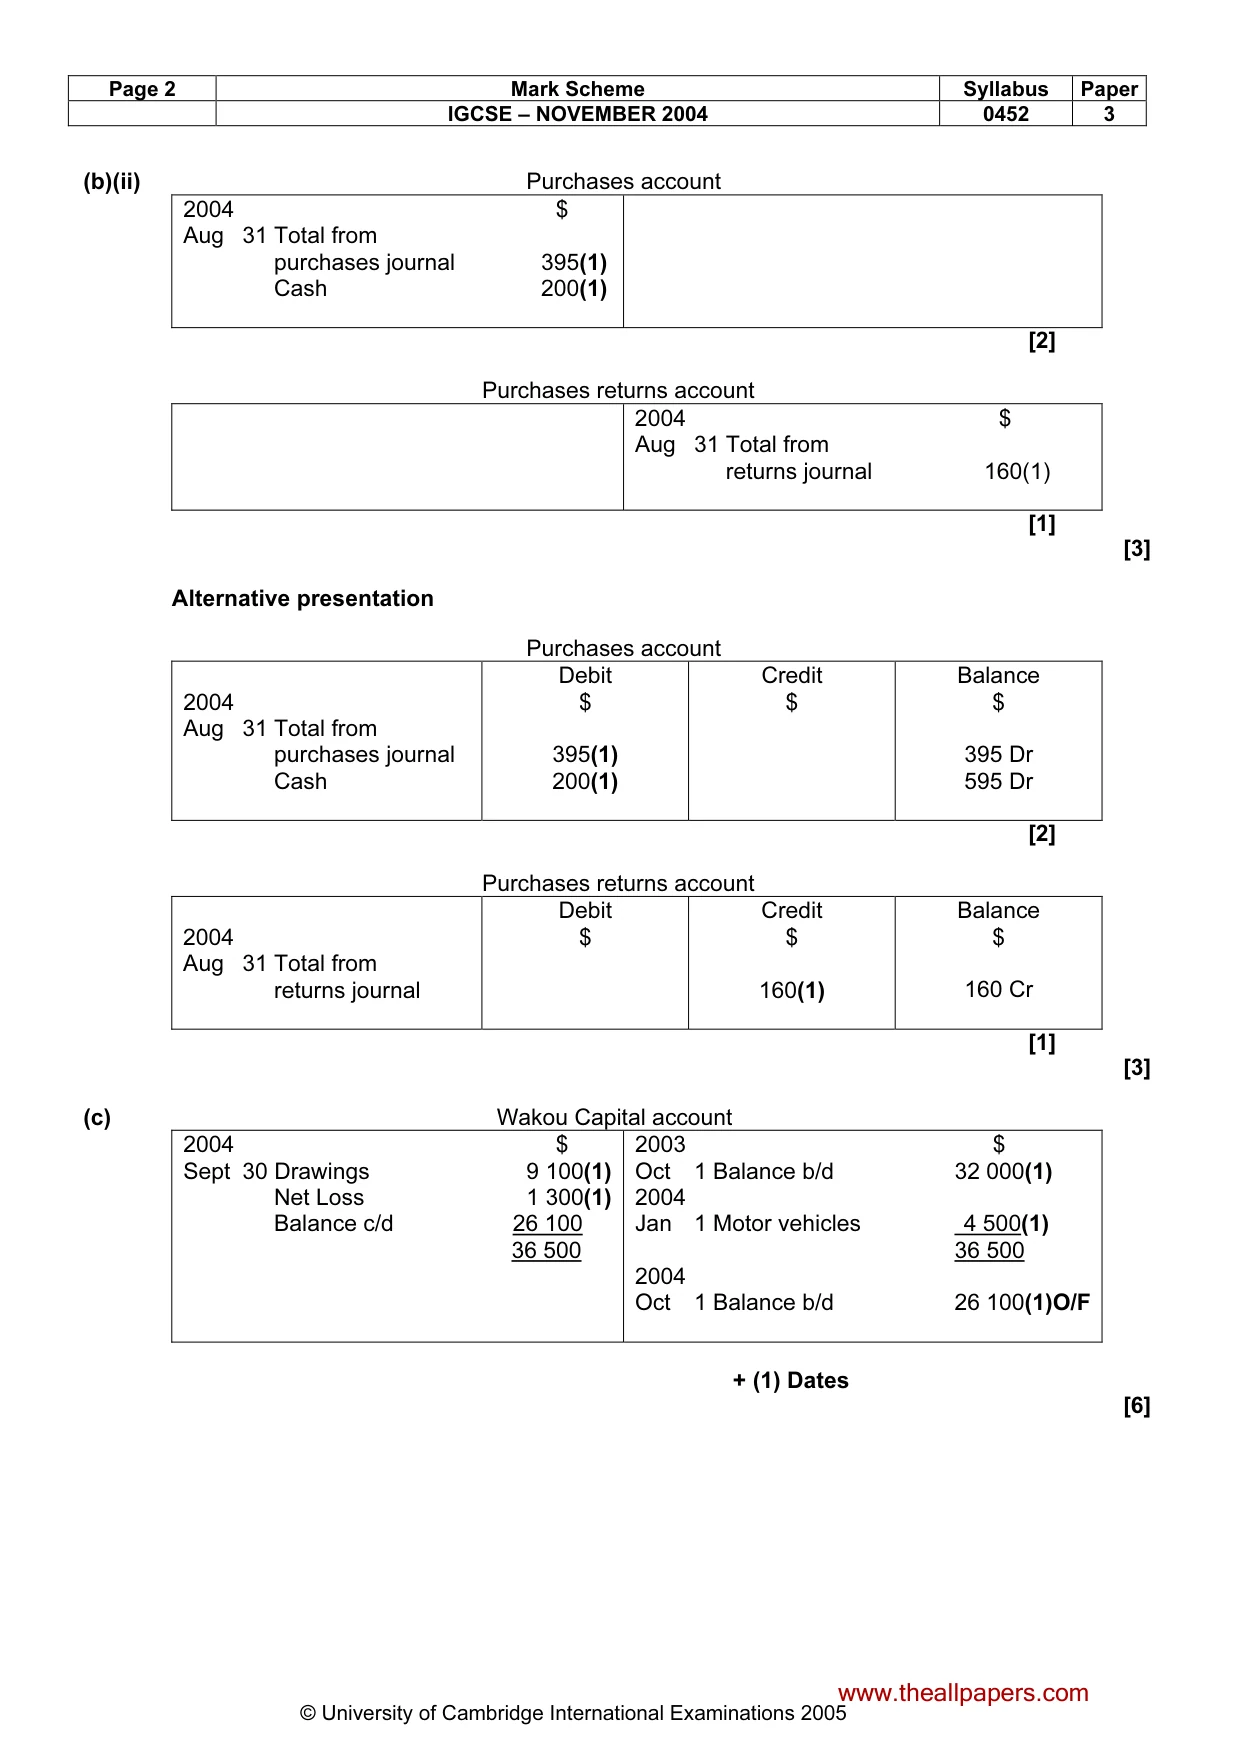
Page 2 Mark Scheme Syllabus Paper IGCSE – NOVEMBER 2004 0452 3 © University of Cambridge International Examinations 2005 (b)(ii) Purchases account 2004 $ Aug 31 Total from purchases journal 395(1) Cash 200(1) [2] Purchases returns account 2004 $ Aug 31 Total from returns journal 160(1) [1] [3] Alternative presentation Purchases account 2004 Aug 31 Total from purchases journal Cash Debit $ 395(1) 200(1) Credit $ Balance $ 395 Dr 595 Dr [2] Purchases returns account 2004 Aug 31 Total from returns journal Debit $ Credit $ 160(1) Balance $ 160 Cr [1] [3] (c) Wakou Capital account 2004 $ Sept 30 Drawings 9 100(1) Net Loss 1 300(1) Balance c/d 26 100 36 500 2003 $ Oct 1 Balance b/d 32 000(1) 2004 Jan 1 Motor vehicles 4 500(1) 36 500 2004 Oct 1 Balance b/d 26 100(1)O/F + (1) Dates [6] www.theallpapers.com
Mark scheme, page 6
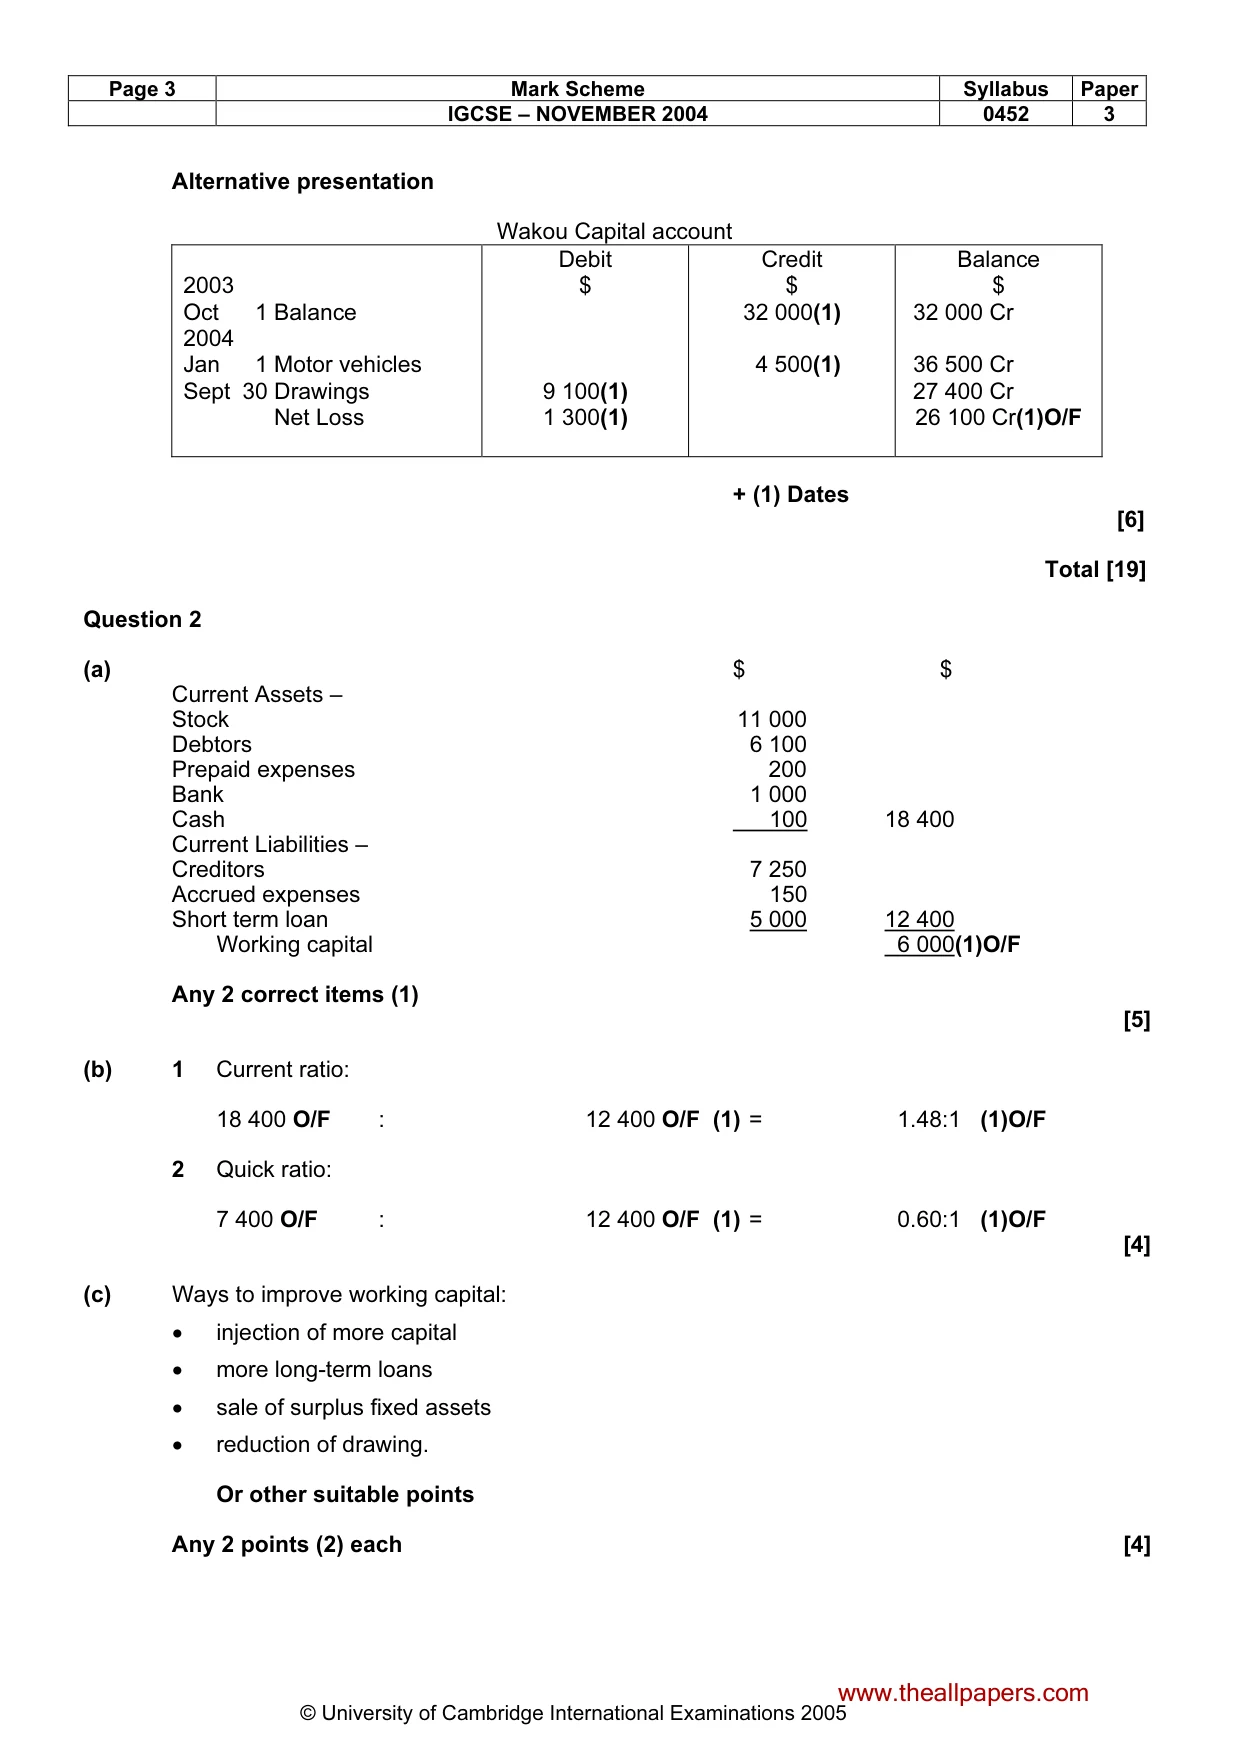
Page 3 Mark Scheme Syllabus Paper IGCSE – NOVEMBER 2004 0452 3 © University of Cambridge International Examinations 2005 Alternative presentation Wakou Capital account 2003 Oct 1 Balance 2004 Jan 1 Motor vehicles Sept 30 Drawings Net Loss Debit $ 9 100(1) 1 300(1) Credit $ 32 000(1) 4 500(1) Balance $ 32 000 Cr 36 500 Cr 27 400 Cr 26 100 Cr(1)O/F + (1) Dates [6] Total [19] Question 2 (a) $ $ Current Assets – Stock 11 000 Debtors 6 100 Prepaid expenses 200 Bank 1 000 Cash 100 18 400 Current Liabilities – Creditors 7 250 Accrued expenses 150 Short term loan 5 000 12 400 Working capital 6 000(1)O/F Any 2 correct items (1) [5] (b) 1 Current ratio: 18 400 O/F : 12 400 O/F (1) = 1.48:1 (1)O/F 2 Quick ratio: 7 400 O/F : 12 400 O/F (1) = 0.60:1 (1)O/F [4] (c) Ways to improve working capital: • injection of more capital • more long-term loans • sale of surplus fixed assets • reduction of drawing. Or other suitable points Any 2 points (2) each [4] www.theallpapers.com
Mark scheme, page 7
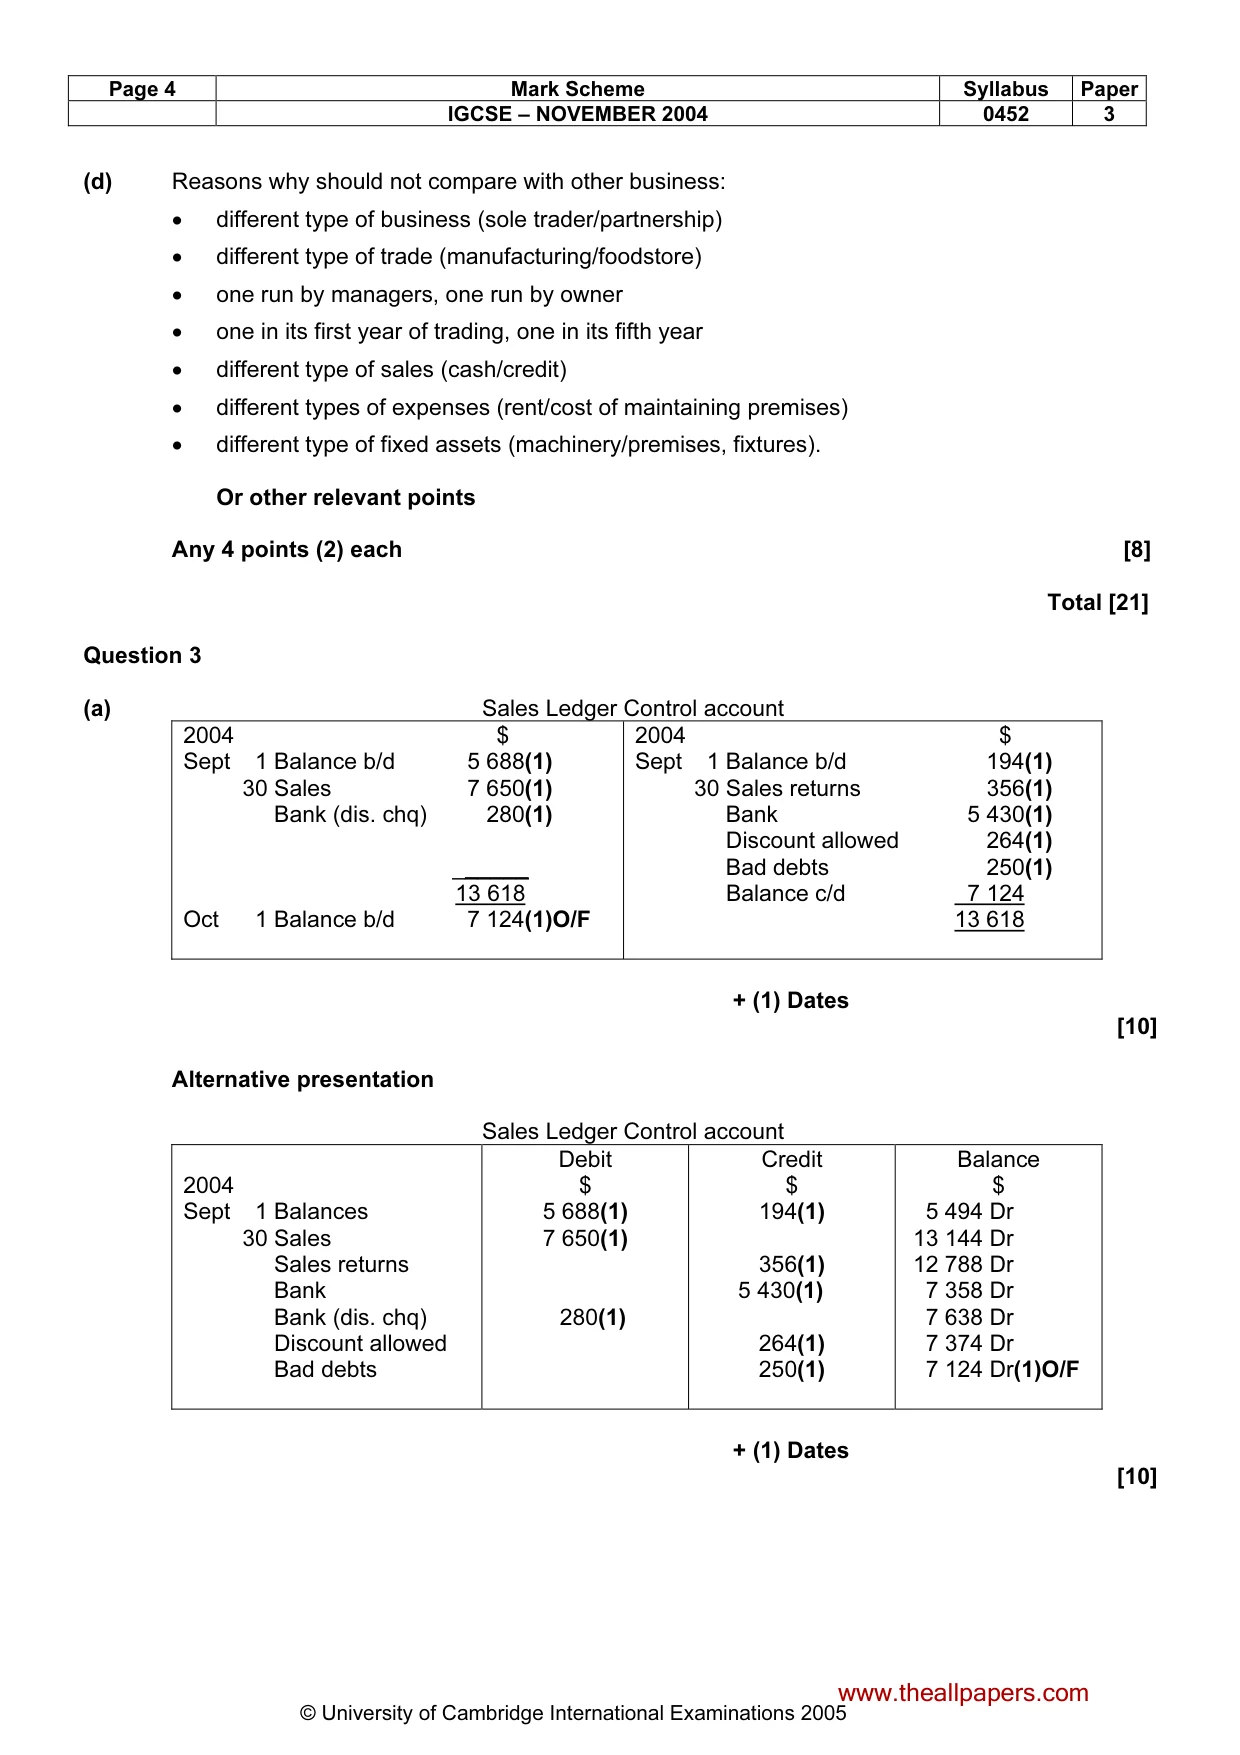
Page 4 Mark Scheme Syllabus Paper IGCSE – NOVEMBER 2004 0452 3 © University of Cambridge International Examinations 2005 (d) Reasons why should not compare with other business: • different type of business (sole trader/partnership) • different type of trade (manufacturing/foodstore) • one run by managers, one run by owner • one in its first year of trading, one in its fifth year • different type of sales (cash/credit) • different types of expenses (rent/cost of maintaining premises) • different type of fixed assets (machinery/premises, fixtures). Or other relevant points Any 4 points (2) each [8] Total [21] Question 3 (a) Sales Ledger Control account 2004 $ Sept 1 Balance b/d 5 688(1) 30 Sales 7 650(1) Bank (dis. chq) 280(1) ______ 13 618 Oct 1 Balance b/d 7 124(1)O/F 2004 $ Sept 1 Balance b/d 194(1) 30 Sales returns 356(1) Bank 5 430(1) Discount allowed 264(1) Bad debts 250(1) Balance c/d 7 124 13 618 + (1) Dates [10] Alternative presentation Sales Ledger Control account 2004 Sept 1 Balances 30 Sales Sales returns Bank Bank (dis. chq) Discount allowed Bad debts Debit $ 5 688(1) 7 650(1) 280(1) Credit $ 194(1) 356(1) 5 430(1) 264(1) 250(1) Balance $ 5 494 Dr 13 144 Dr 12 788 Dr 7 358 Dr 7 638 Dr 7 374 Dr 7 124 Dr(1)O/F + (1) Dates [10] www.theallpapers.com
Mark scheme, page 8
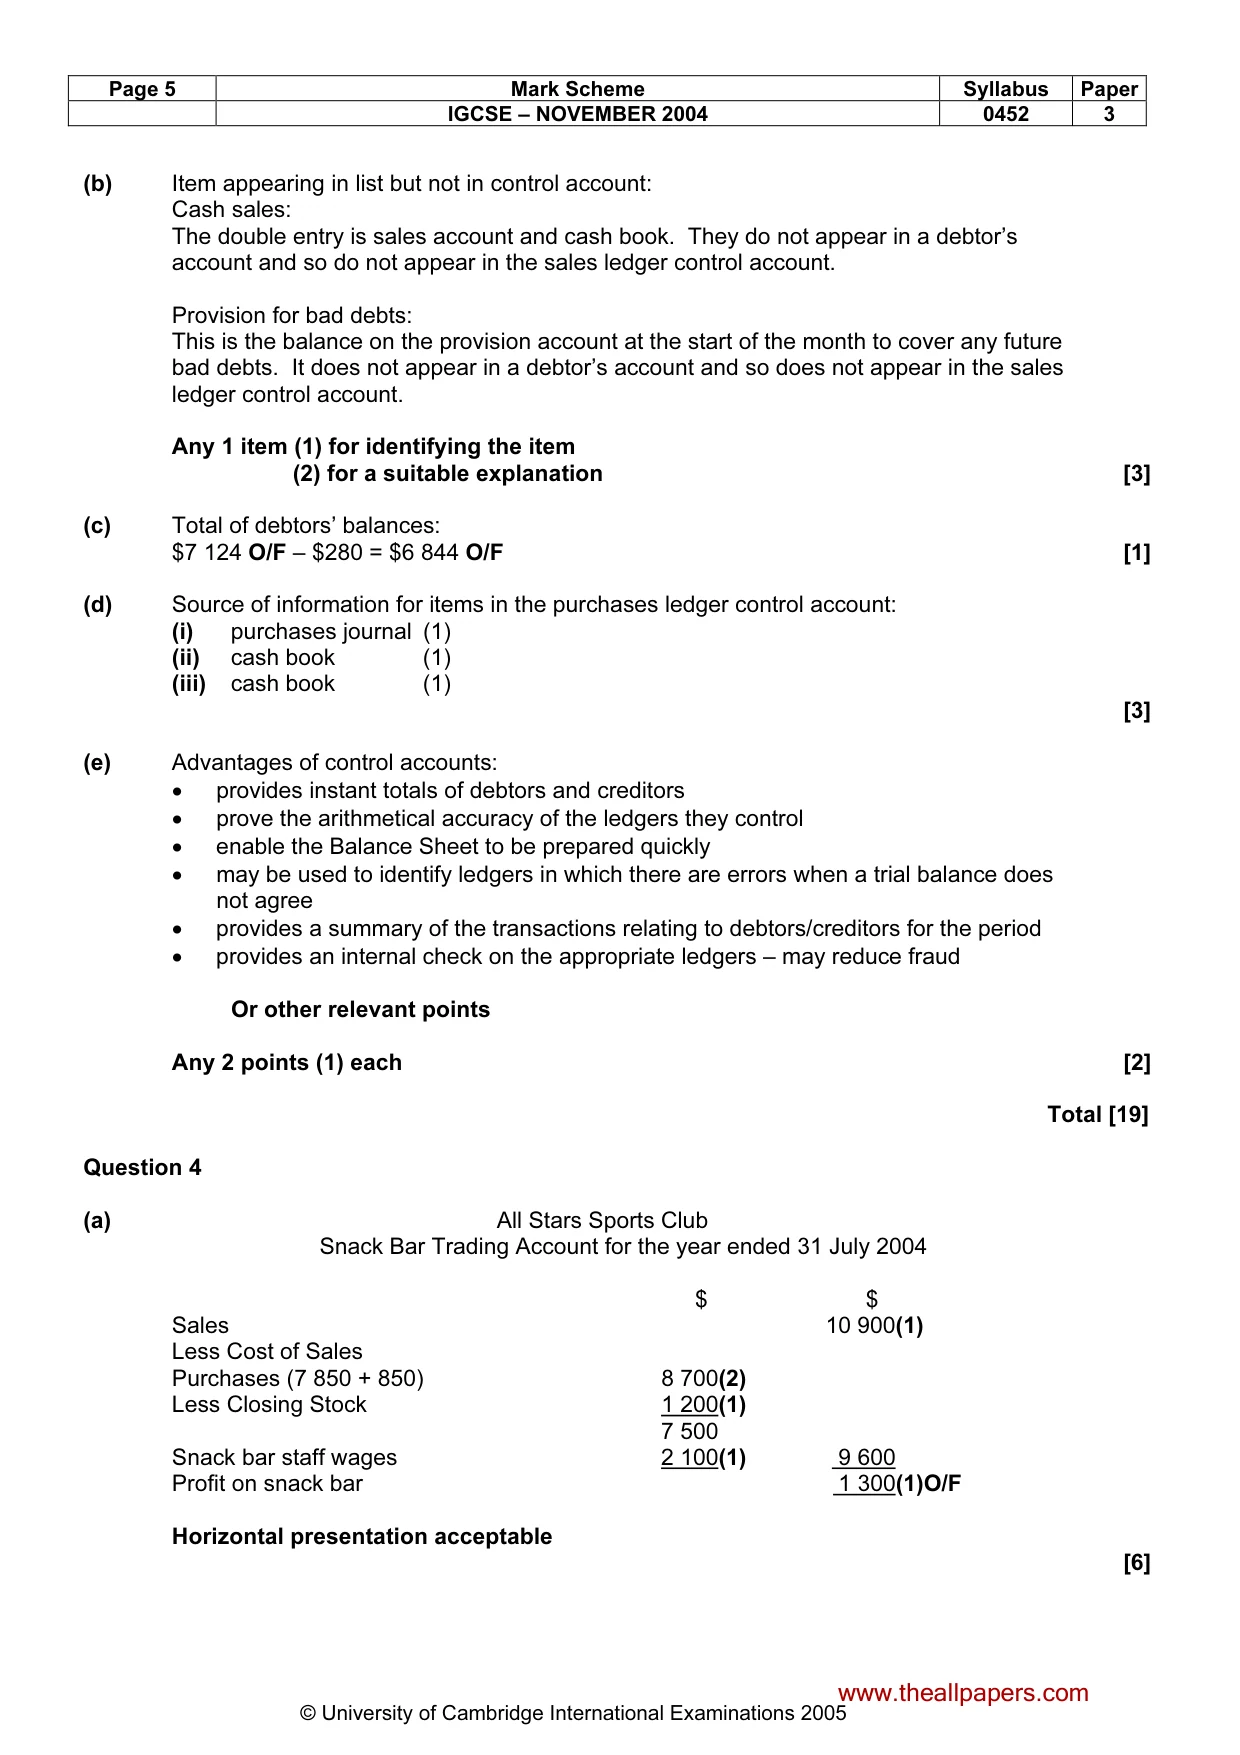
Page 5 Mark Scheme Syllabus Paper IGCSE – NOVEMBER 2004 0452 3 © University of Cambridge International Examinations 2005 (b) Item appearing in list but not in control account: Cash sales: The double entry is sales account and cash book. They do not appear in a debtor’s account and so do not appear in the sales ledger control account. Provision for bad debts: This is the balance on the provision account at the start of the month to cover any future bad debts. It does not appear in a debtor’s account and so does not appear in the sales ledger control account. Any 1 item (1) for identifying the item (2) for a suitable explanation [3] (c) Total of debtors’ balances: $7 124 O/F – $280 = $6 844 O/F [1] (d) Source of information for items in the purchases ledger control account: (i) purchases journal (1) (ii) cash book (1) (iii) cash book (1) [3] (e) Advantages of control accounts: • provides instant totals of debtors and creditors • prove the arithmetical accuracy of the ledgers they control • enable the Balance Sheet to be prepared quickly • may be used to identify ledgers in which there are errors when a trial balance does not agree • provides a summary of the transactions relating to debtors/creditors for the period • provides an internal check on the appropriate ledgers – may reduce fraud Or other relevant points Any 2 points (1) each [2] Total [19] Question 4 (a) All Stars Sports Club Snack Bar Trading Account for the year ended 31 July 2004 $ $ Sales 10 900(1) Less Cost of Sales Purchases (7 850 + 850) 8 700(2) Less Closing Stock 1 200(1) 7 500 Snack bar staff wages 2 100(1) 9 600 Profit on snack bar 1 300(1)O/F Horizontal presentation acceptable [6] www.theallpapers.com
Mark scheme, page 9
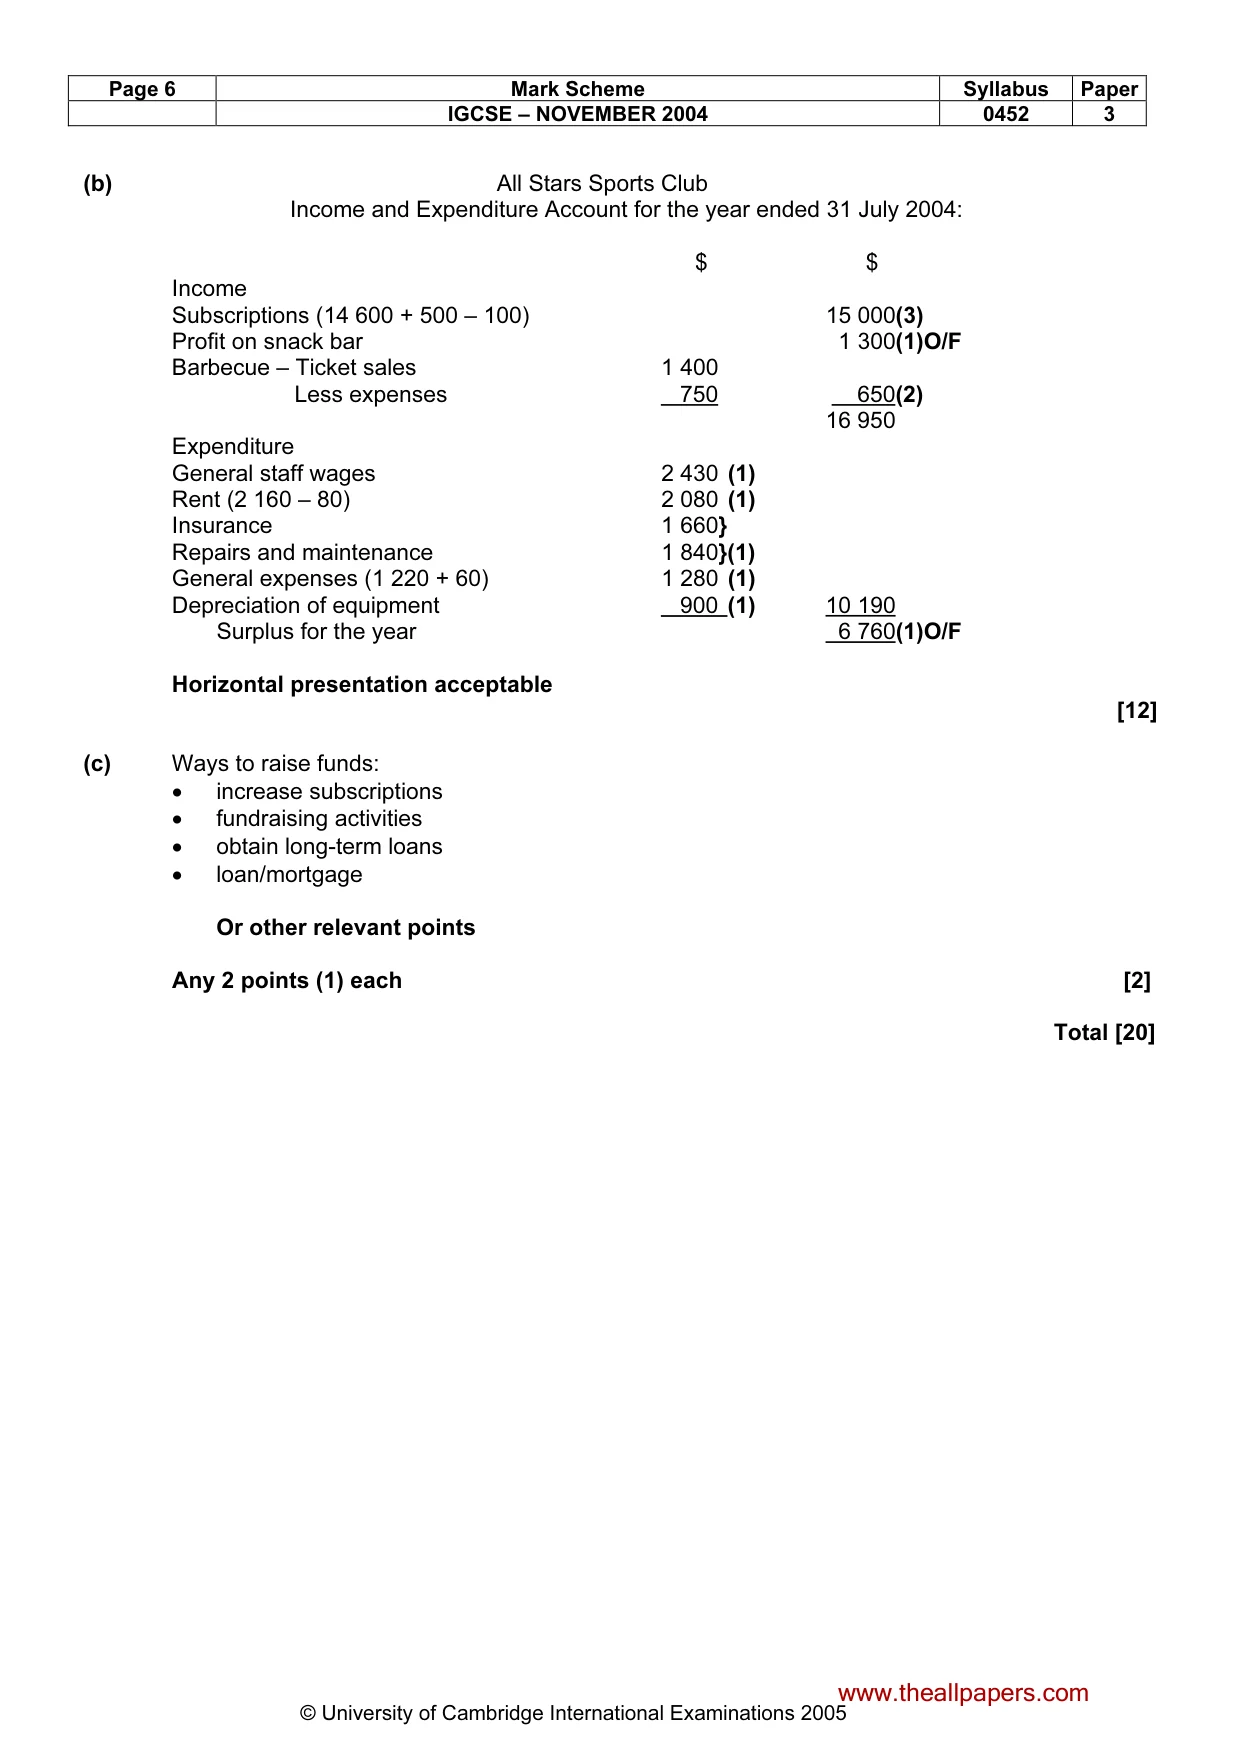
Page 6 Mark Scheme Syllabus Paper IGCSE – NOVEMBER 2004 0452 3 © University of Cambridge International Examinations 2005 (b) All Stars Sports Club Income and Expenditure Account for the year ended 31 July 2004: $ $ Income Subscriptions (14 600 + 500 – 100) 15 000(3) Profit on snack bar 1 300(1)O/F Barbecue – Ticket sales 1 400 Less expenses 750 650(2) 16 950 Expenditure General staff wages 2 430 (1) Rent (2 160 – 80) 2 080 (1) Insurance 1 660} Repairs and maintenance 1 840}(1) General expenses (1 220 + 60) 1 280 (1) Depreciation of equipment 900 (1) 10 190 Surplus for the year 6 760(1)O/F Horizontal presentation acceptable [12] (c) Ways to raise funds: • increase subscriptions • fundraising activities • obtain long-term loans • loan/mortgage Or other relevant points Any 2 points (1) each [2] Total [20] www.theallpapers.com
Mark scheme, page 10
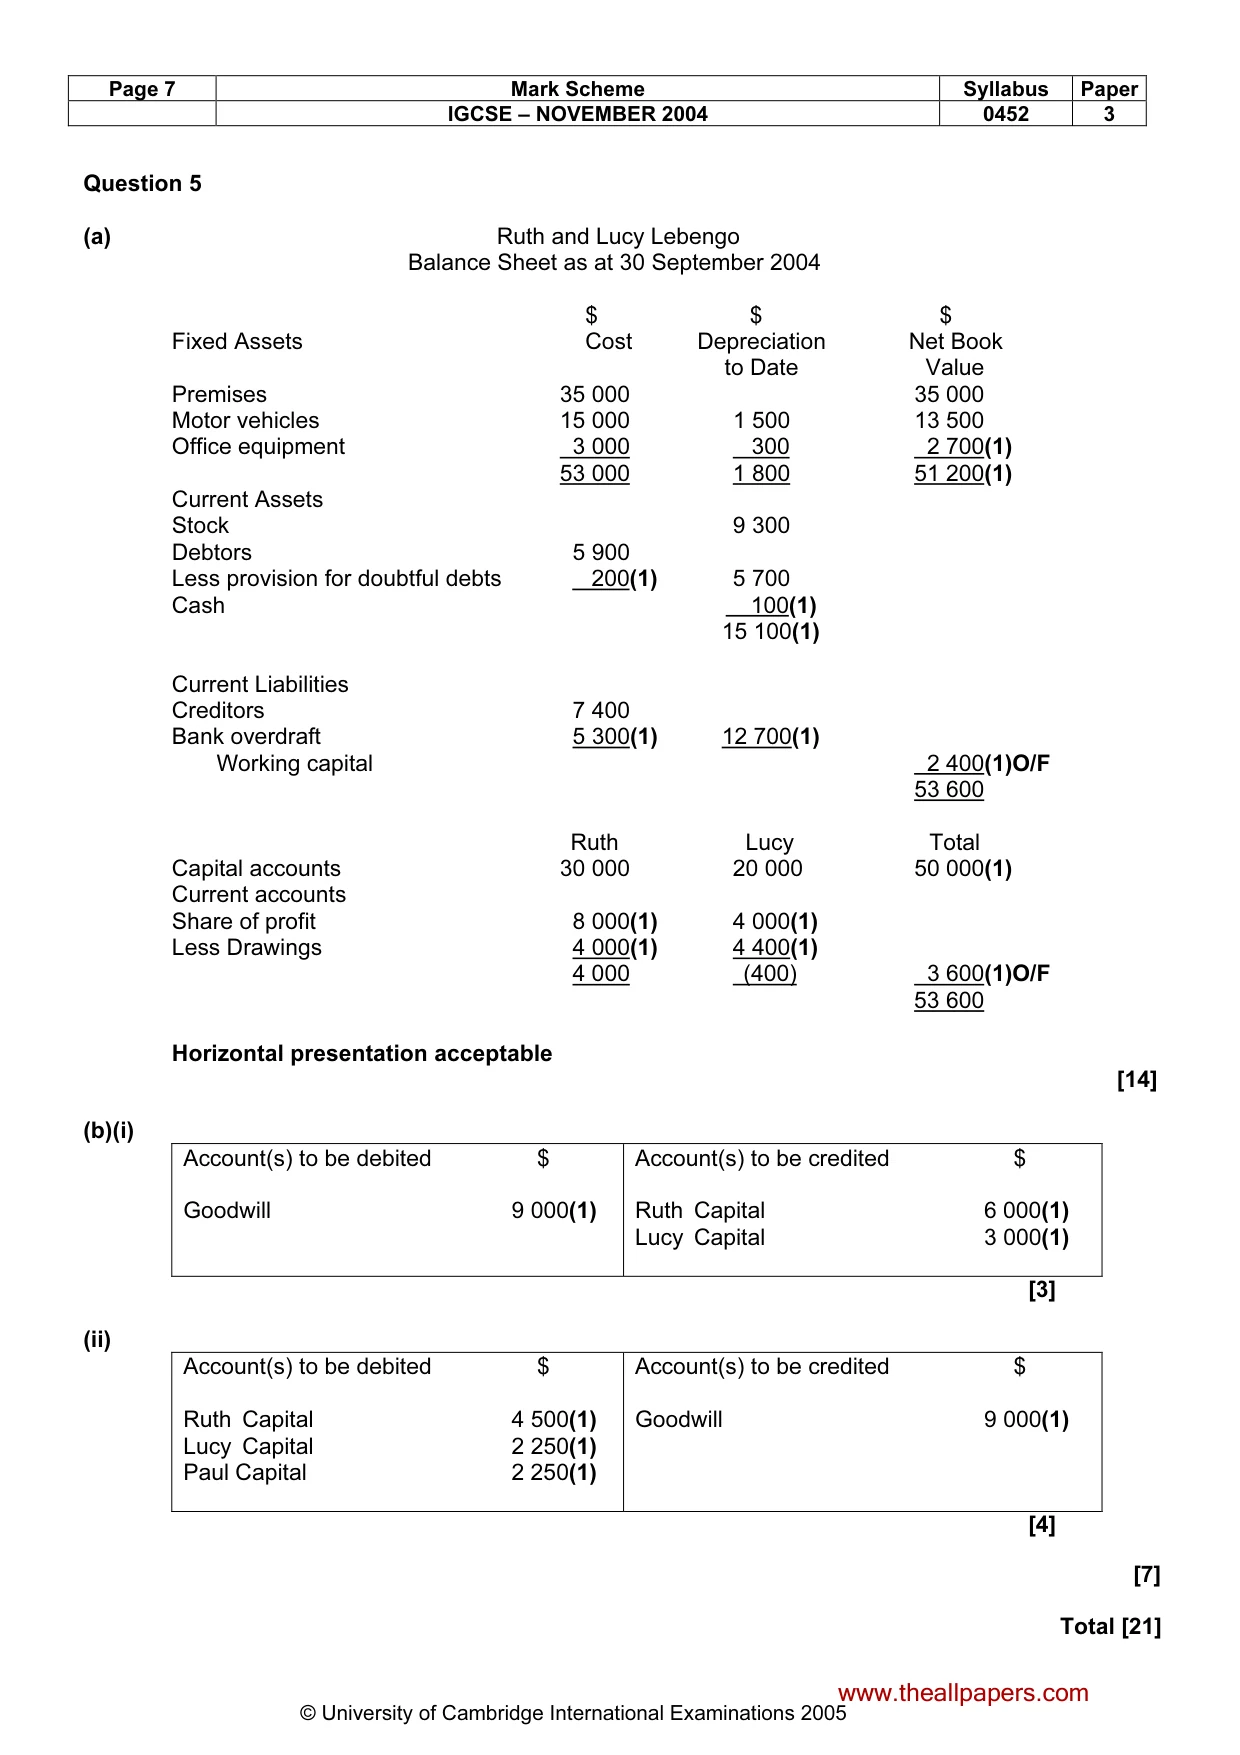
Page 7 Mark Scheme Syllabus Paper IGCSE – NOVEMBER 2004 0452 3 © University of Cambridge International Examinations 2005 Question 5 (a) Ruth and Lucy Lebengo Balance Sheet as at 30 September 2004 $ $ $ Fixed Assets Cost Depreciation Net Book to Date Value Premises 35 000 35 000 Motor vehicles 15 000 1 500 13 500 Office equipment 3 000 300 2 700(1) 53 000 1 800 51 200(1) Current Assets Stock 9 300 Debtors 5 900 Less provision for doubtful debts 200(1) 5 700 Cash 100(1) 15 100(1) Current Liabilities Creditors 7 400 Bank overdraft 5 300(1) 12 700(1) Working capital 2 400(1)O/F 53 600 Ruth Lucy Total Capital accounts 30 000 20 000 50 000(1) Current accounts Share of profit 8 000(1) 4 000(1) Less Drawings 4 000(1) 4 400(1) 4 000 (400) 3 600(1)O/F 53 600 Horizontal presentation acceptable [14] (b)(i) Account(s) to be debited $ Goodwill 9 000(1) Account(s) to be credited $ Ruth Capital 6 000(1) Lucy Capital 3 000(1) [3] (ii) Account(s) to be debited $ Ruth Capital 4 500(1) Lucy Capital 2 250(1) Paul Capital 2 250(1) Account(s) to be credited $ Goodwill 9 000(1) [4] [7] Total [21] www.theallpapers.com