Cambridge IGCSE Accounting 0452 — 2003 Oct/Nov Paper 3 · Variant 1
0452/31/O/N/03
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper16 pages
Mark scheme
No mark scheme is in the library for this paper.
Paper as text
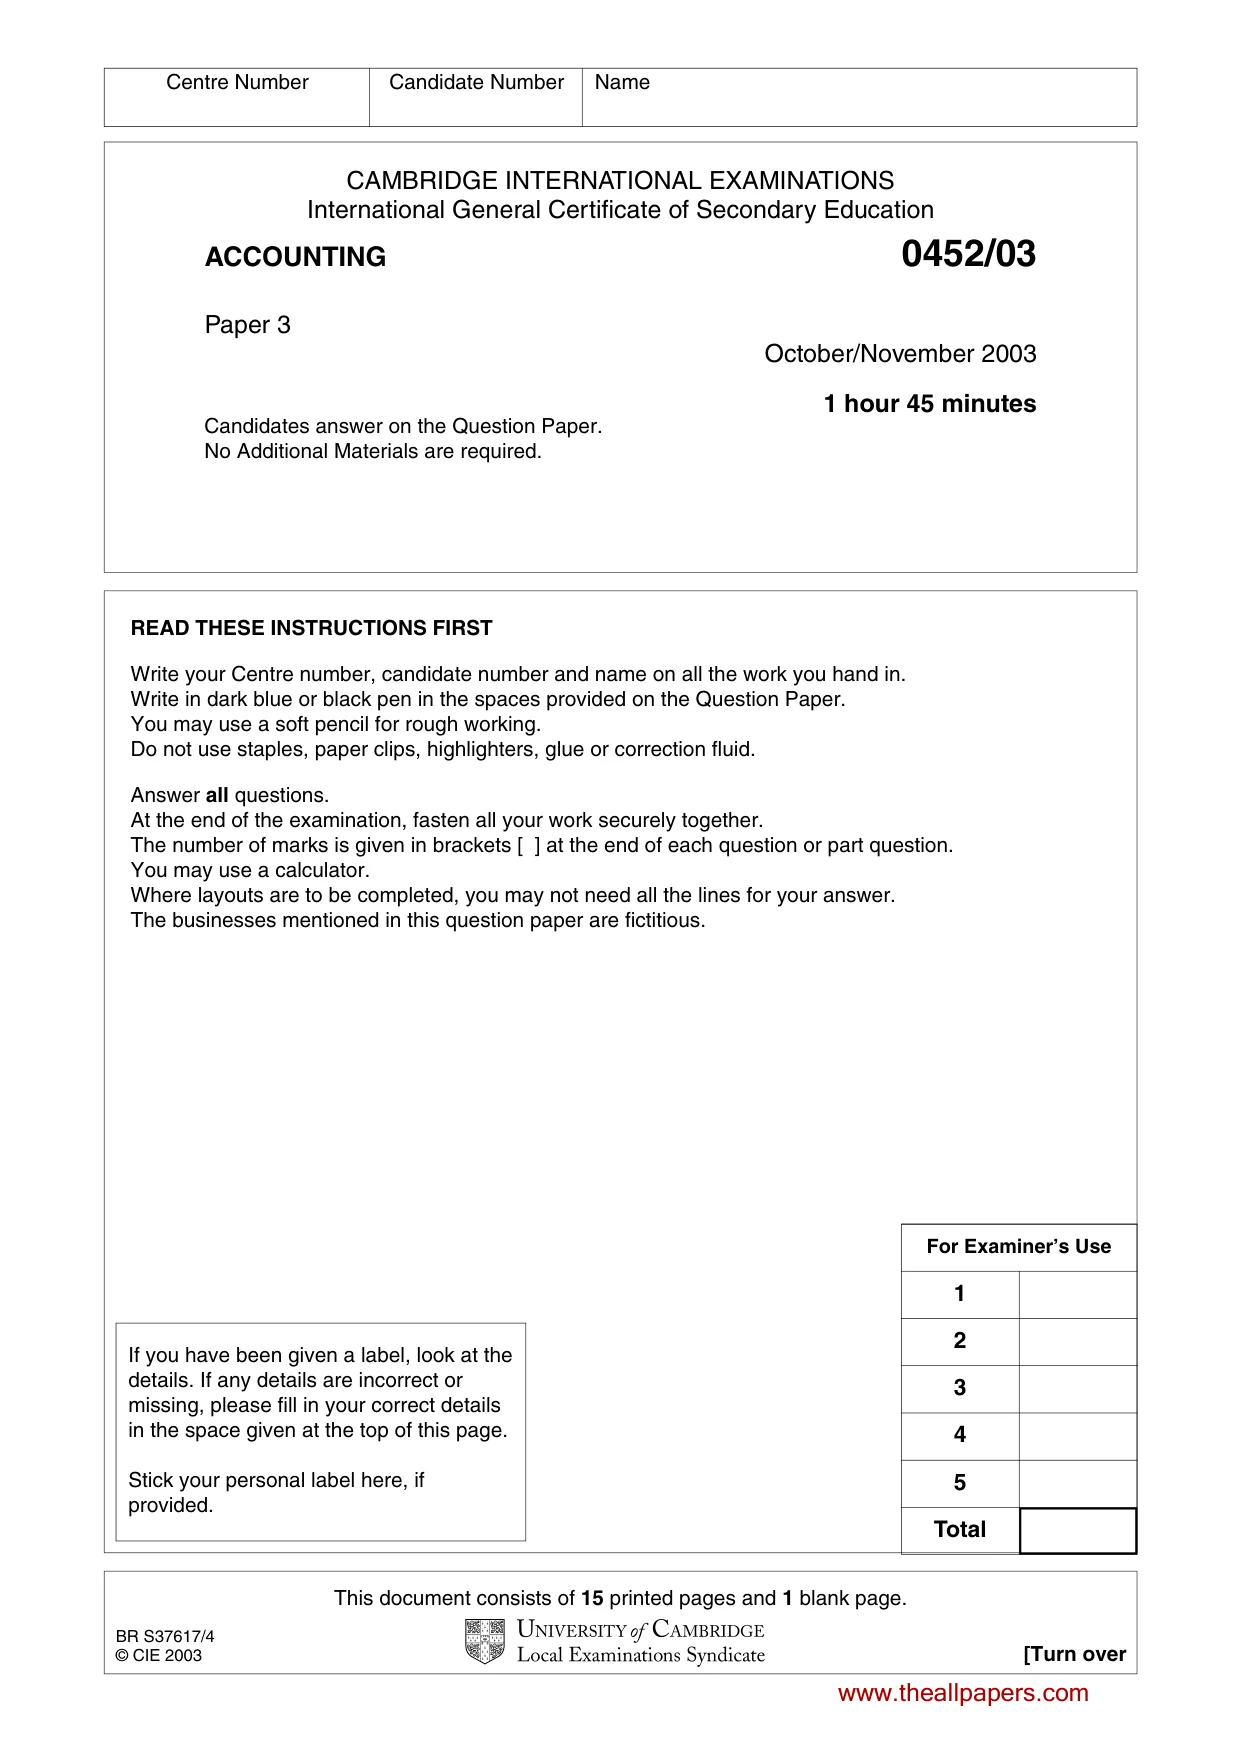
Question paper, page 1
This document consists of 15 printed pages and 1 blank page. BR S37617/4 © CIE 2003 [Turn over CAMBRIDGE INTERNATIONAL EXAMINATIONS International General Certificate of Secondary Education ACCOUNTING 0452/03 Paper 3 October/November 2003 1 hour 45 minutes Candidates answer on the Question Paper. No Additional Materials are required. READ THESE INSTRUCTIONS FIRST Write your Centre number, candidate number and name on all the work you hand in. Write in dark blue or black pen in the spaces provided on the Question Paper. You may use a soft pencil for rough working. Do not use staples, paper clips, highlighters, glue or correction fluid. Answer all questions. At the end of the examination, fasten all your work securely together. The number of marks is given in brackets [ ] at the end of each question or part question. You may use a calculator. Where layouts are to be completed, you may not need all the lines for your answer. The businesses mentioned in this question paper are fictitious. Centre Number Candidate Number Name If you have been given a label, look at the details. If any details are incorrect or missing, please fill in your correct details in the space given at the top of this page. Stick your personal label here, if provided. For Examiner’s Use 1 2 3 4 5 Total www.theallpapers.com
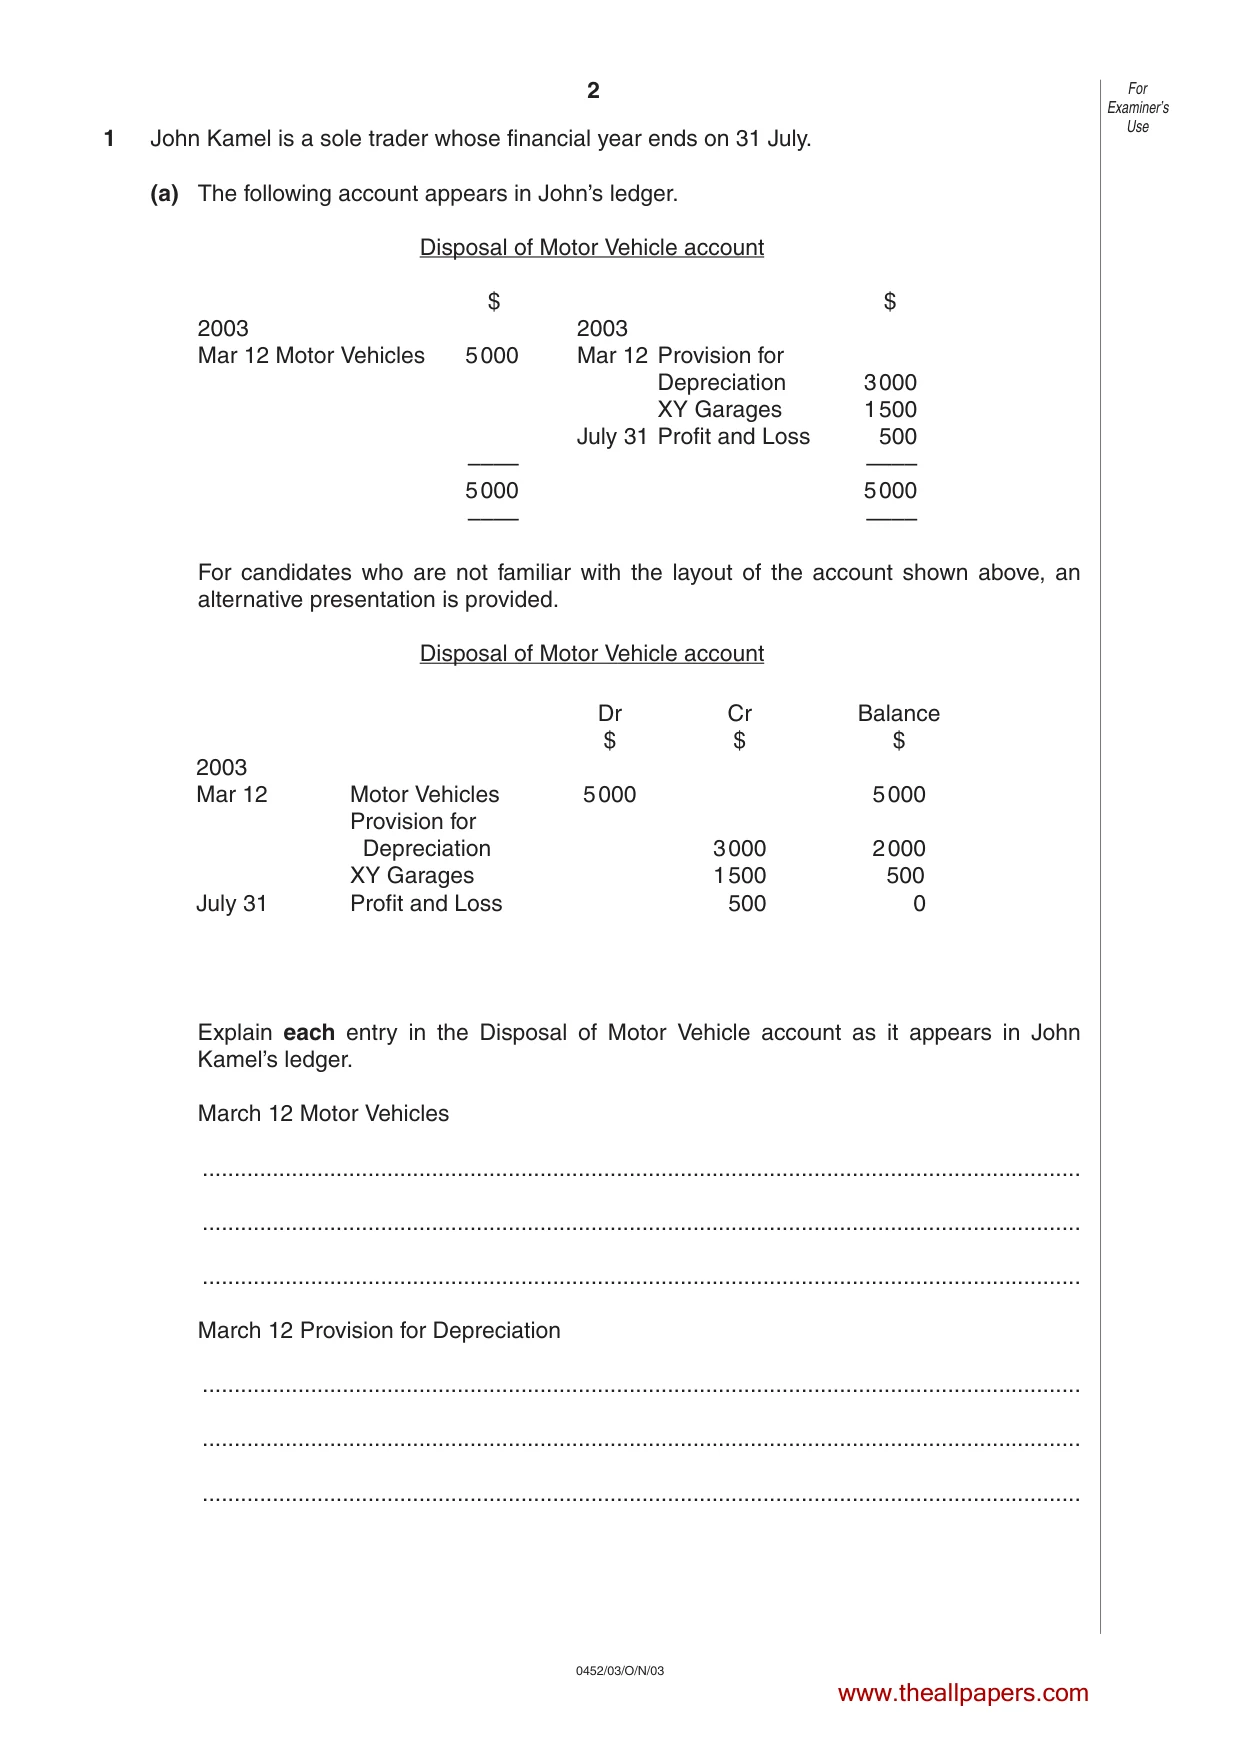
Question paper, page 2
For Examiner’s Use 2 0452/03/O/N/03 1 John Kamel is a sole trader whose financial year ends on 31 July. (a) The following account appears in John’s ledger. Disposal of Motor Vehicle account $ $ 2003 2003 Mar 12 Motor Vehicles 5000 Mar 12 Provision for Depreciation 3000 XY Garages 1500 July 31 Profit and Loss 500 –––– –––– 5000 5000 –––– –––– For candidates who are not familiar with the layout of the account shown above, an alternative presentation is provided. Disposal of Motor Vehicle account Explain each entry in the Disposal of Motor Vehicle account as it appears in John Kamel’s ledger. March 12 Motor Vehicles … … … March 12 Provision for Depreciation … … … Dr Cr Balance $ $ $ 2003 Mar 12 Motor Vehicles 5000 5000 Provision for Depreciation 3000 2000 XY Garages 1500 500 July 31 Profit and Loss 500 0 www.theallpapers.com
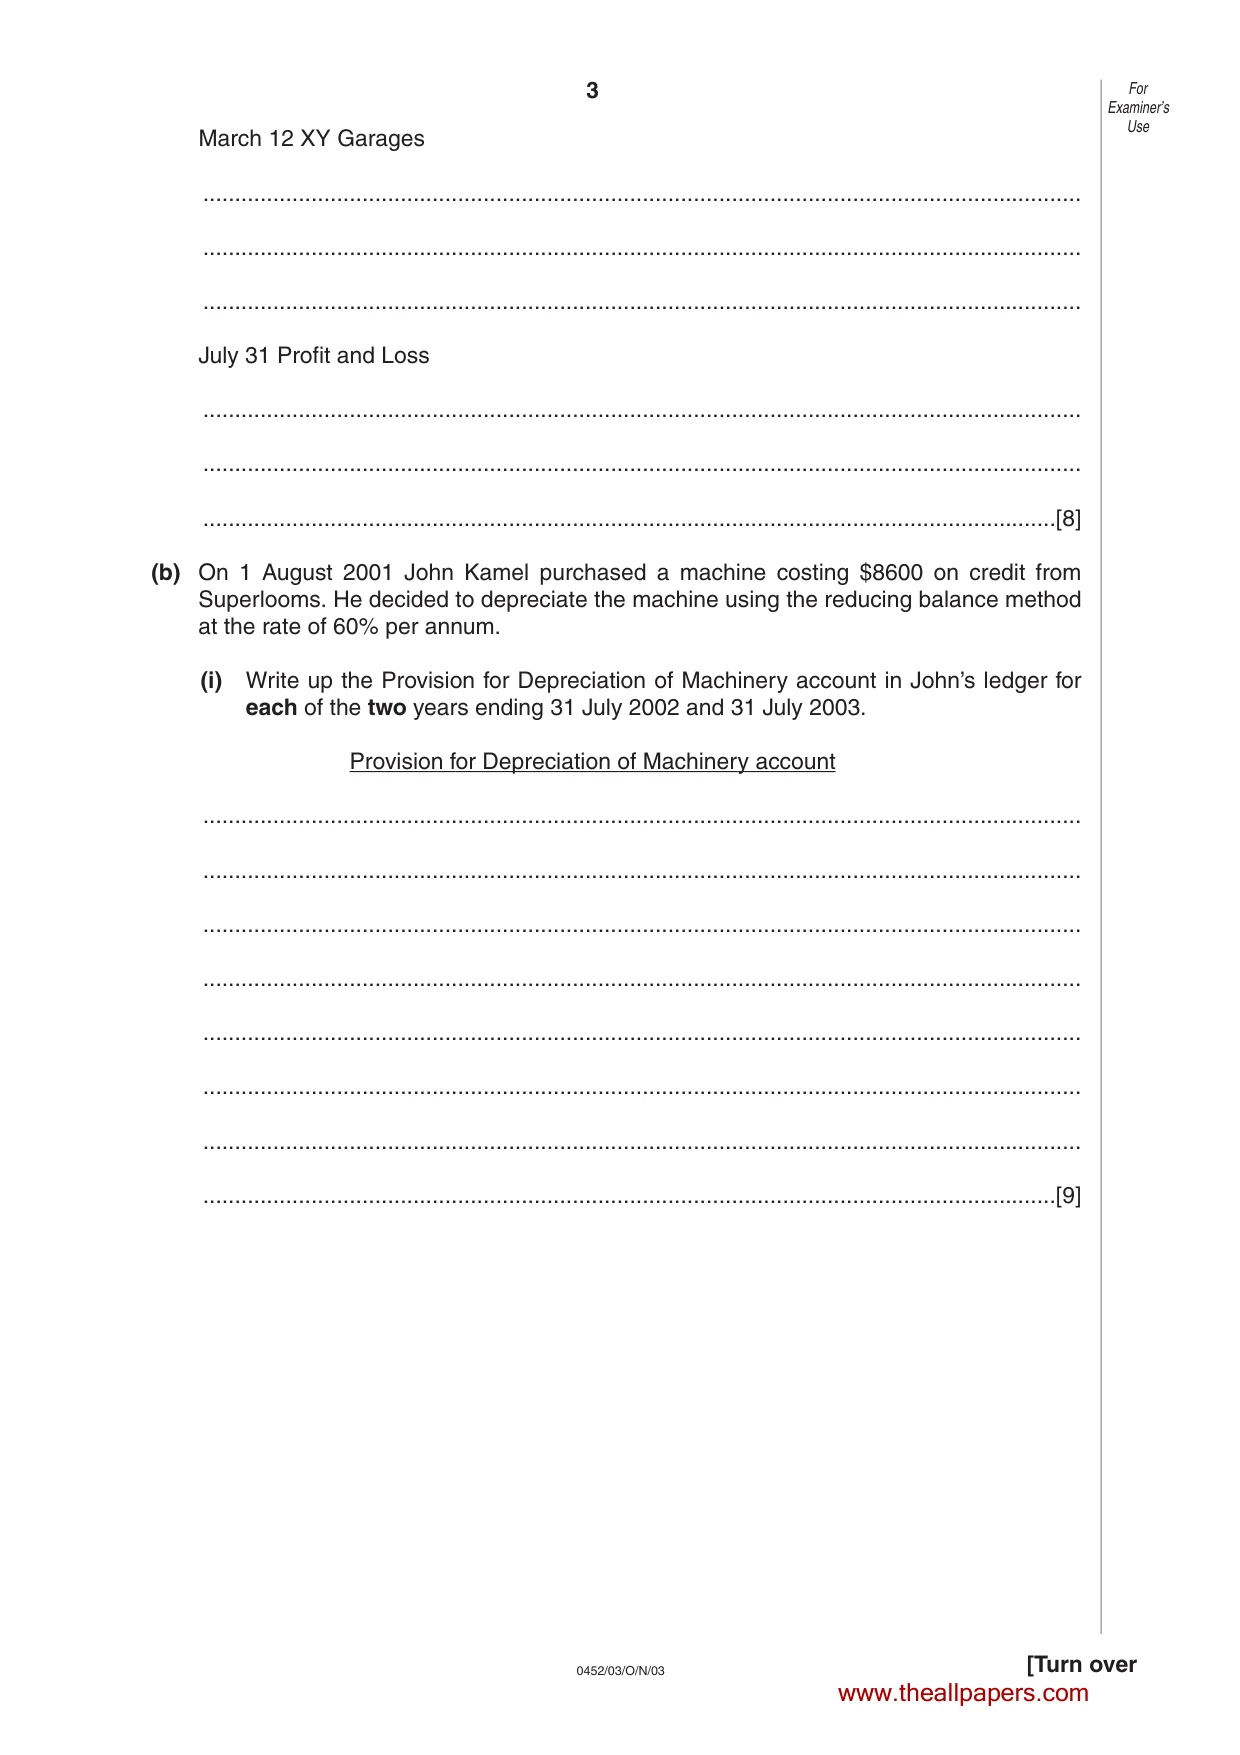
Question paper, page 3
For Examiner’s Use 3 0452/03/O/N/03 [Turn over March 12 XY Garages … … … July 31 Profit and Loss … … …[8] (b) On 1 August 2001 John Kamel purchased a machine costing $8600 on credit from Superlooms. He decided to depreciate the machine using the reducing balance method at the rate of 60% per annum. (i) Write up the Provision for Depreciation of Machinery account in John’s ledger for each of the two years ending 31 July 2002 and 31 July 2003. Provision for Depreciation of Machinery account … … … … … … … …[9] www.theallpapers.com
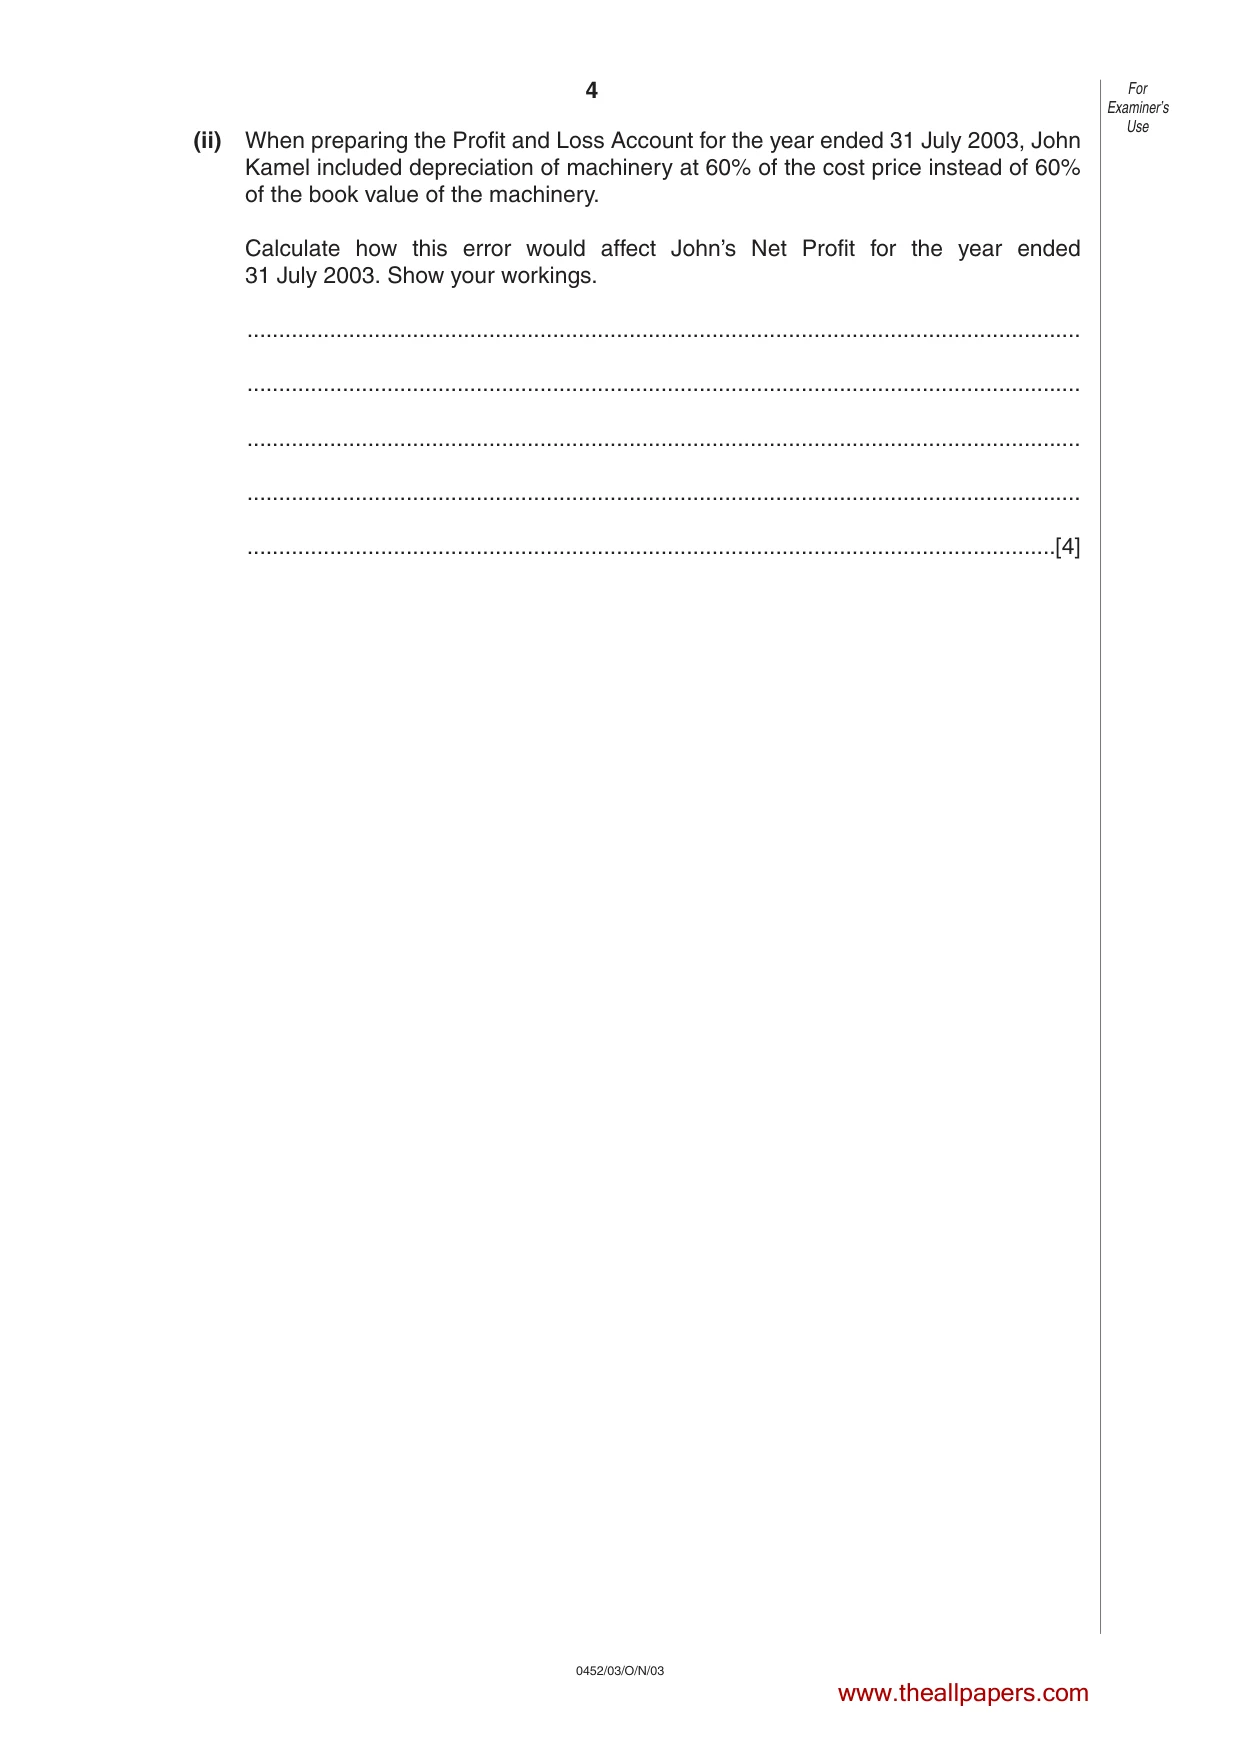
Question paper, page 4
(ii) When preparing the Profit and Loss Account for the year ended 31 July 2003, John Kamel included depreciation of machinery at 60% of the cost price instead of 60% of the book value of the machinery. Calculate how this error would affect John’s Net Profit for the year ended 31 July 2003. Show your workings. … … … … …[4] 4 0452/03/O/N/03 For Examiner’s Use www.theallpapers.com
Question paper, page 5
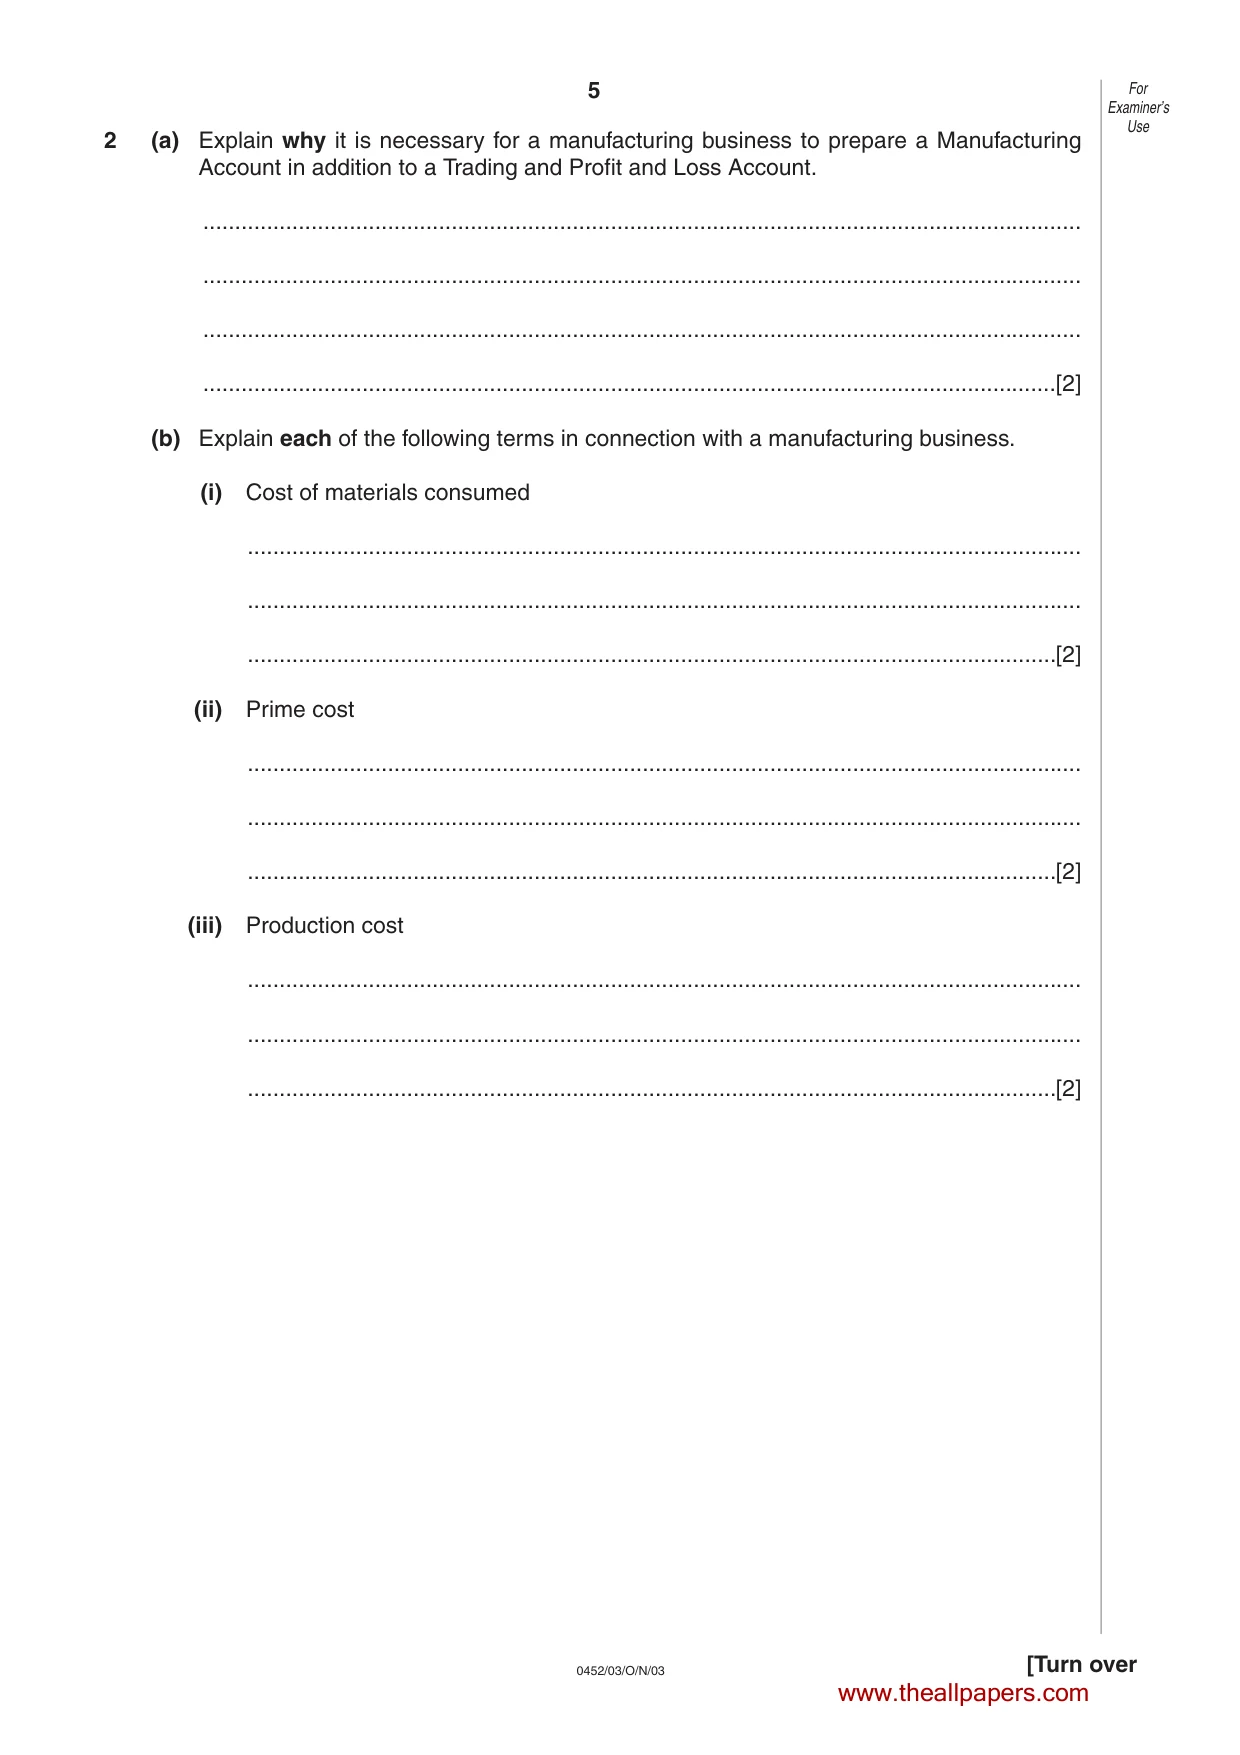
5 0452/03/O/N/03 [Turn over 2 (a) Explain why it is necessary for a manufacturing business to prepare a Manufacturing Account in addition to a Trading and Profit and Loss Account. … … … …[2] (b) Explain each of the following terms in connection with a manufacturing business. (i) Cost of materials consumed … … …[2] (ii) Prime cost … … …[2] (iii) Production cost … … …[2] For Examiner’s Use www.theallpapers.com
Question paper, page 6
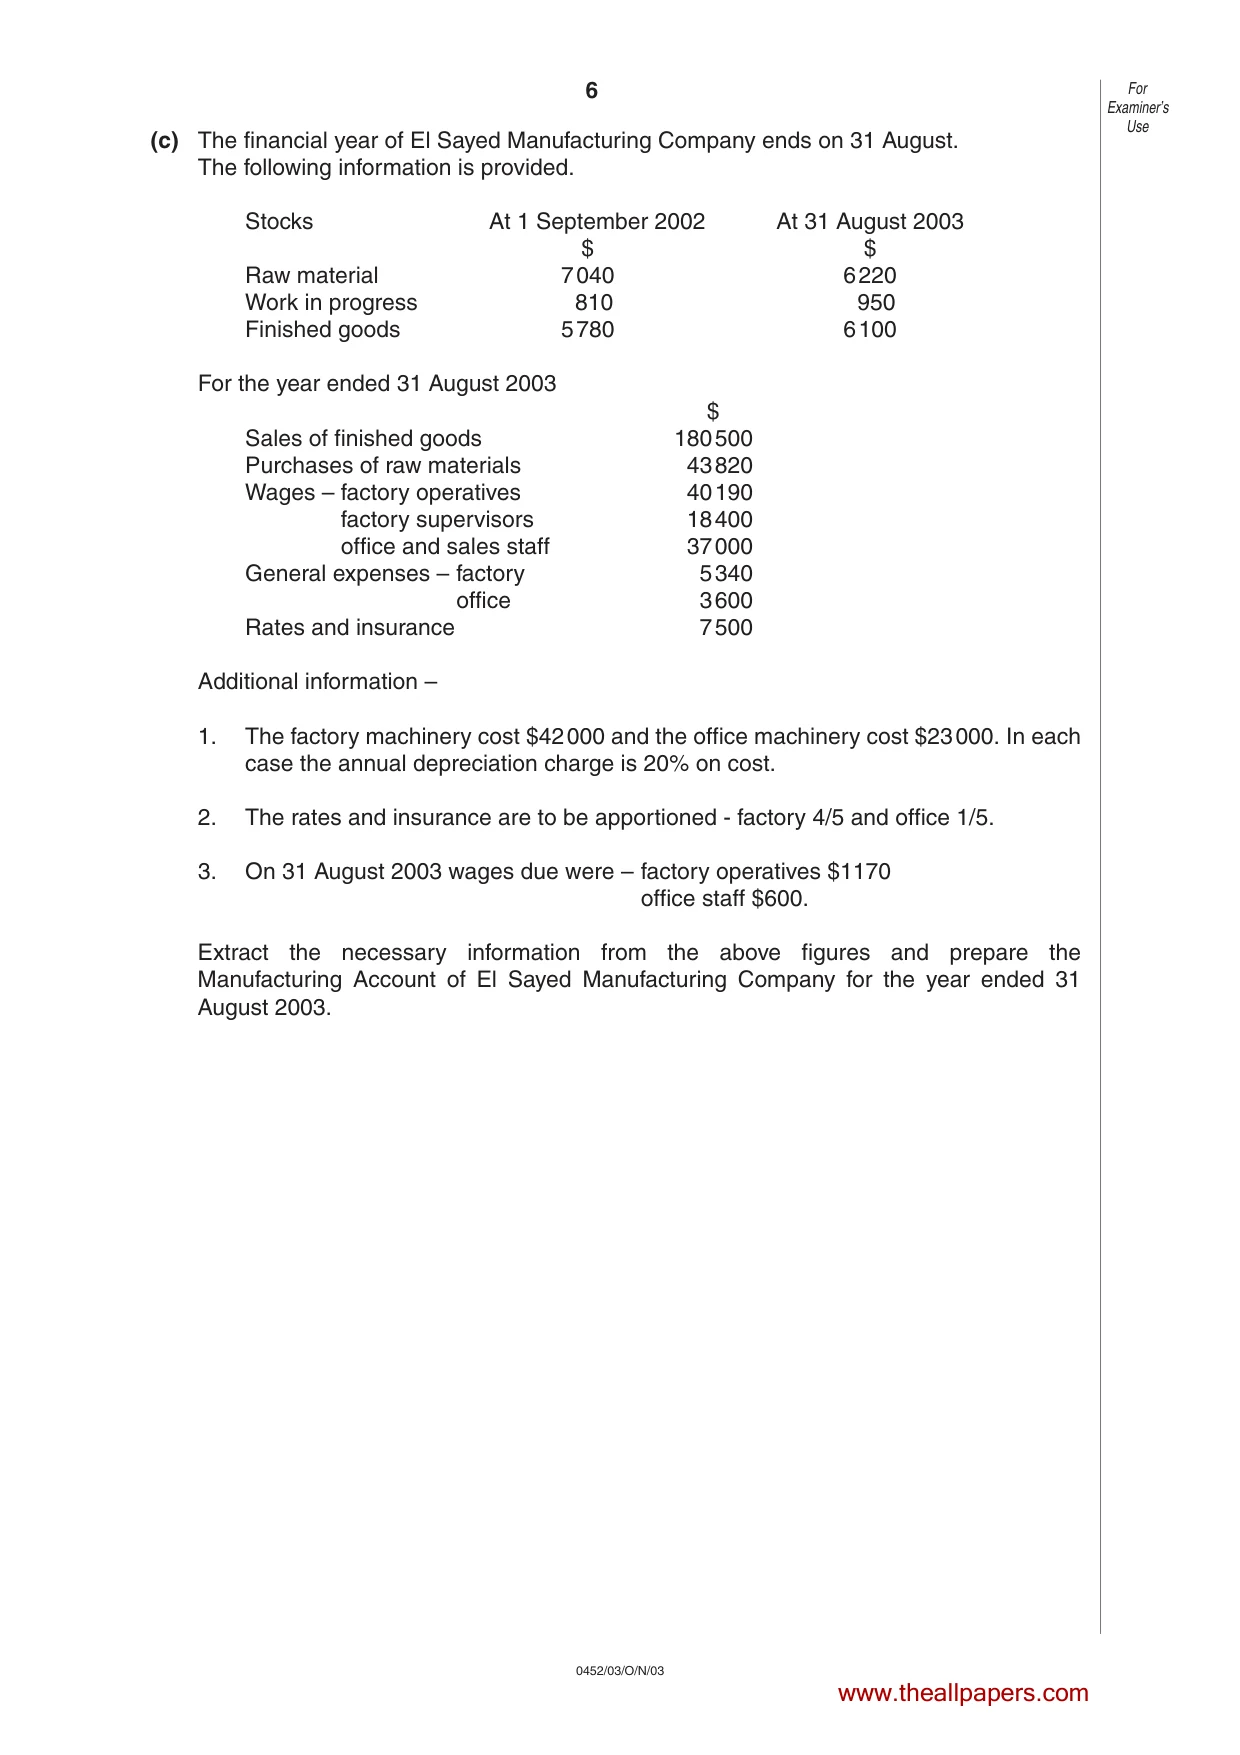
6 0452/03/O/N/03 (c) The financial year of El Sayed Manufacturing Company ends on 31 August. The following information is provided. Stocks At 1 September 2002 At 31 August 2003 $ $ Raw material 7040 6220 Work in progress 810 950 Finished goods 5780 6100 For the year ended 31 August 2003 $ Sales of finished goods 180500 Purchases of raw materials 43820 Wages – factory operatives 40190 factory supervisors 18400 office and sales staff 37000 General expenses – factory 5340 office 3600 Rates and insurance 7500 Additional information – 1. The factory machinery cost $42000 and the office machinery cost $23000. In each case the annual depreciation charge is 20% on cost. 2. The rates and insurance are to be apportioned - factory 4/5 and office 1/5. 3. On 31 August 2003 wages due were – factory operatives $1170 office staff $600. Extract the necessary information from the above figures and prepare the Manufacturing Account of El Sayed Manufacturing Company for the year ended 31 August 2003. For Examiner’s Use www.theallpapers.com
Question paper, page 7
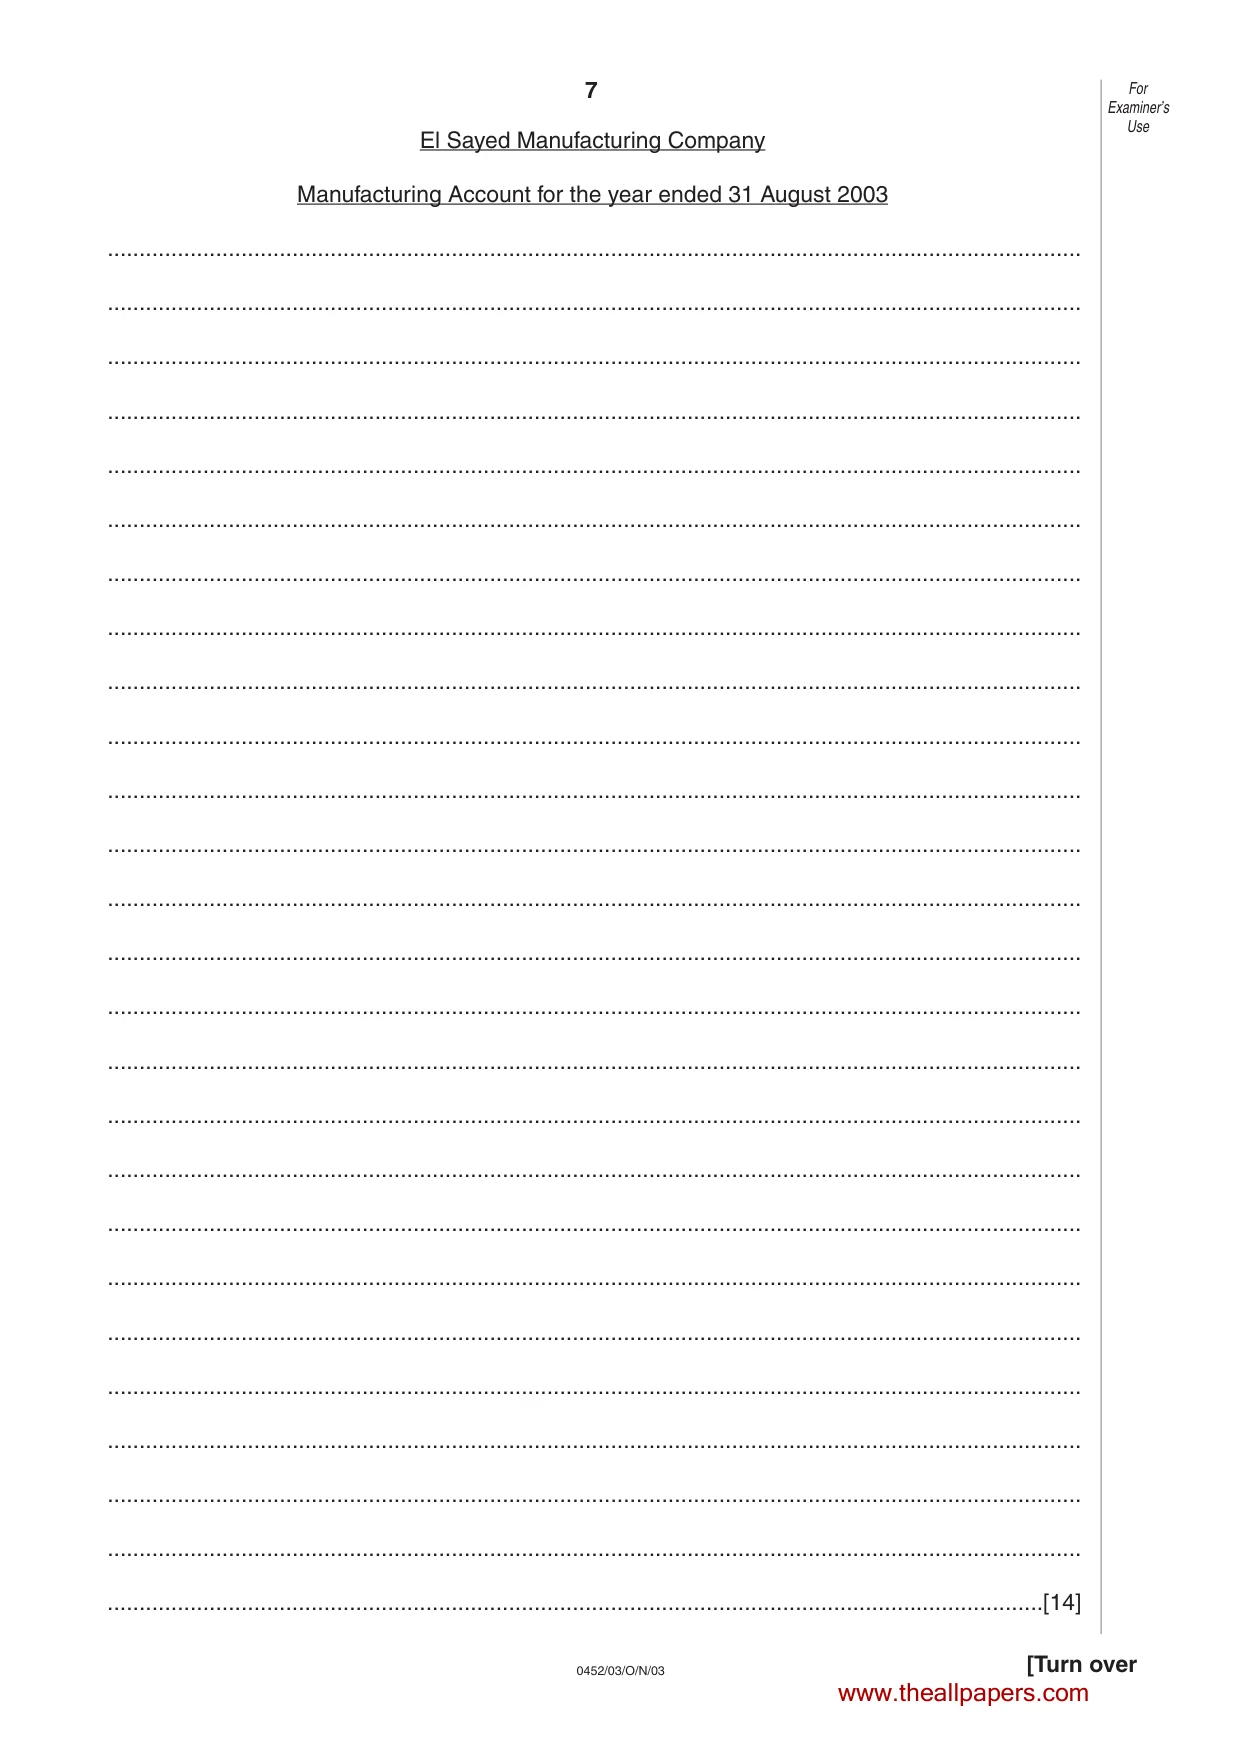
7 0452/03/O/N/03 [Turn over El Sayed Manufacturing Company Manufacturing Account for the year ended 31 August 2003 … … … … … … … … … … … … … … … … … … … … … … … … … …[14] For Examiner’s Use www.theallpapers.com
Question paper, page 8
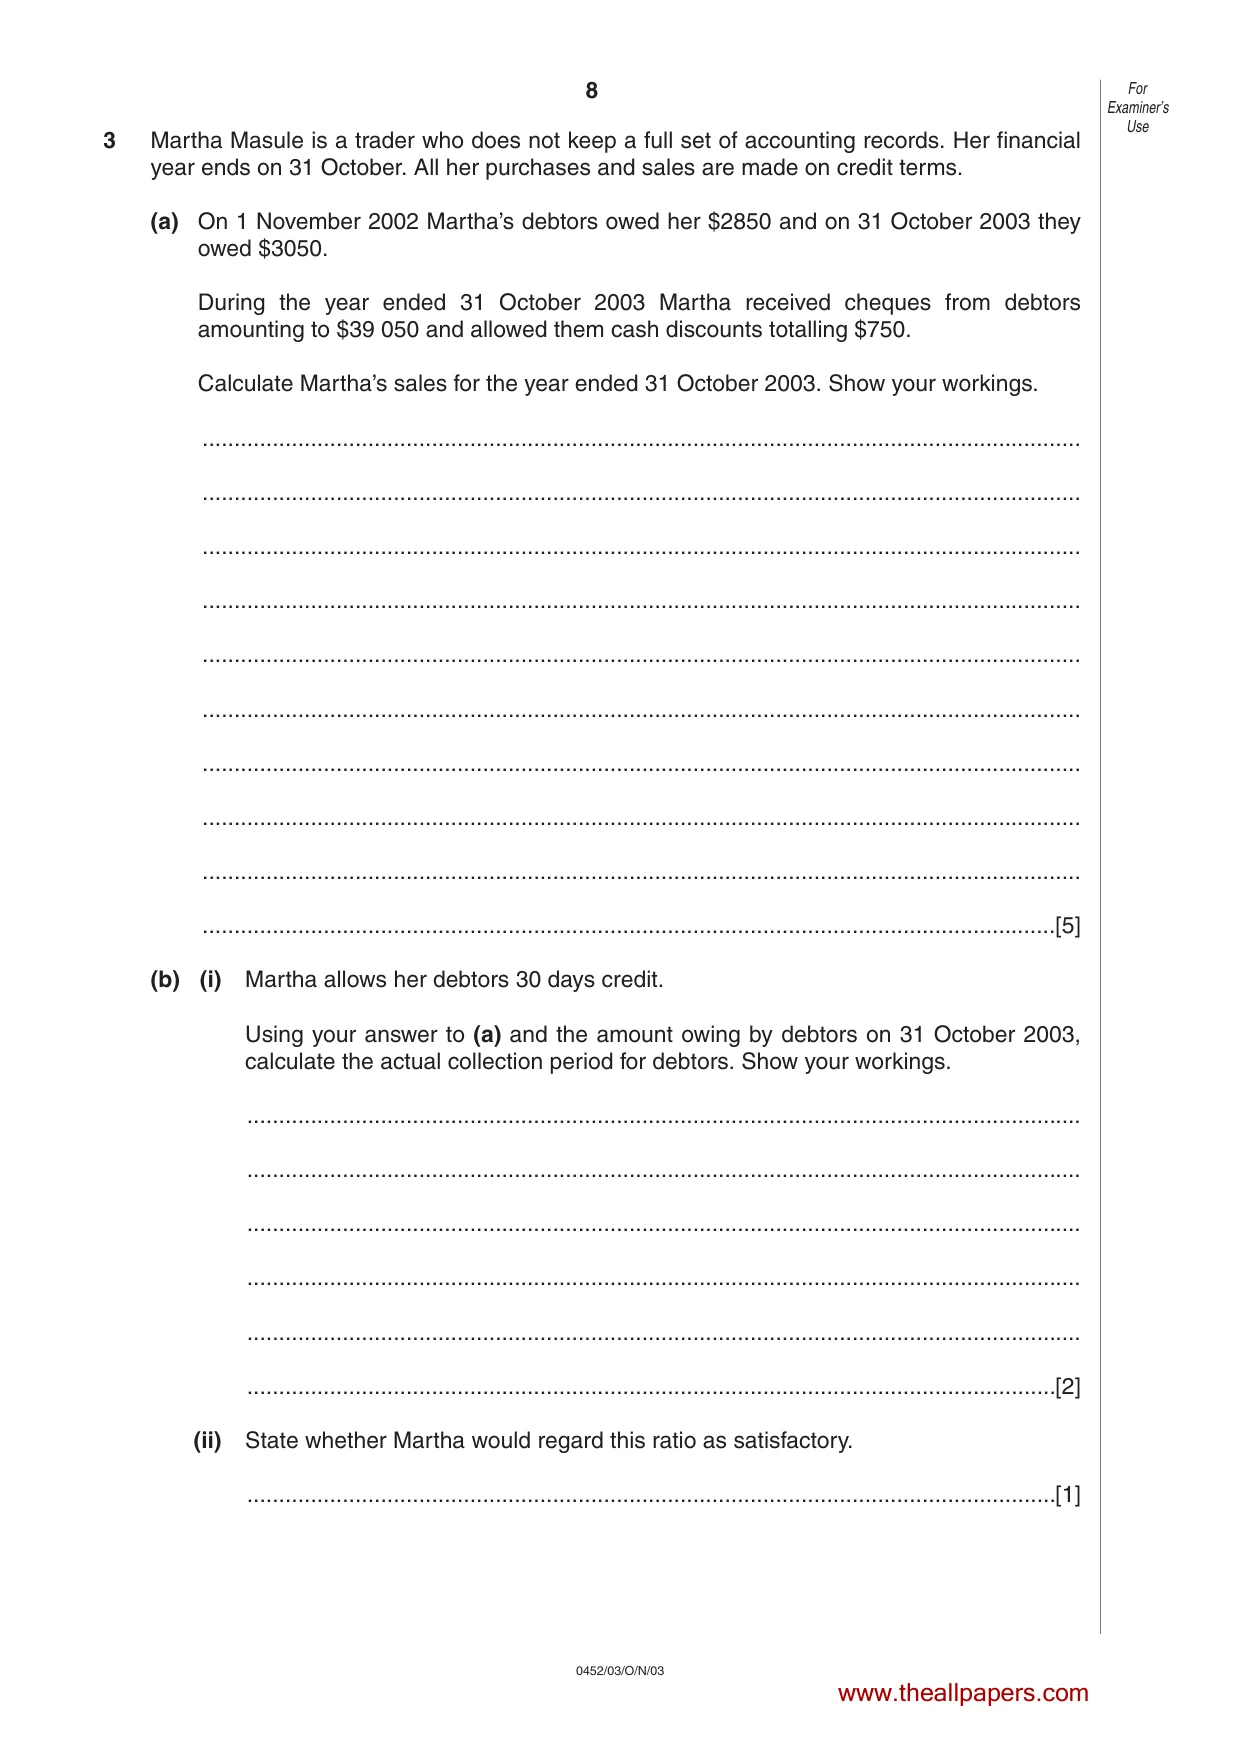
8 0452/03/O/N/03 3 Martha Masule is a trader who does not keep a full set of accounting records. Her financial year ends on 31 October. All her purchases and sales are made on credit terms. (a) On 1 November 2002 Martha’s debtors owed her $2850 and on 31 October 2003 they owed $3050. During the year ended 31 October 2003 Martha received cheques from debtors amounting to $39 050 and allowed them cash discounts totalling $750. Calculate Martha’s sales for the year ended 31 October 2003. Show your workings. … … … … … … … … … …[5] (b) (i) Martha allows her debtors 30 days credit. Using your answer to (a) and the amount owing by debtors on 31 October 2003, calculate the actual collection period for debtors. Show your workings. … … … … … …[2] (ii) State whether Martha would regard this ratio as satisfactory. …[1] For Examiner’s Use www.theallpapers.com
Question paper, page 9
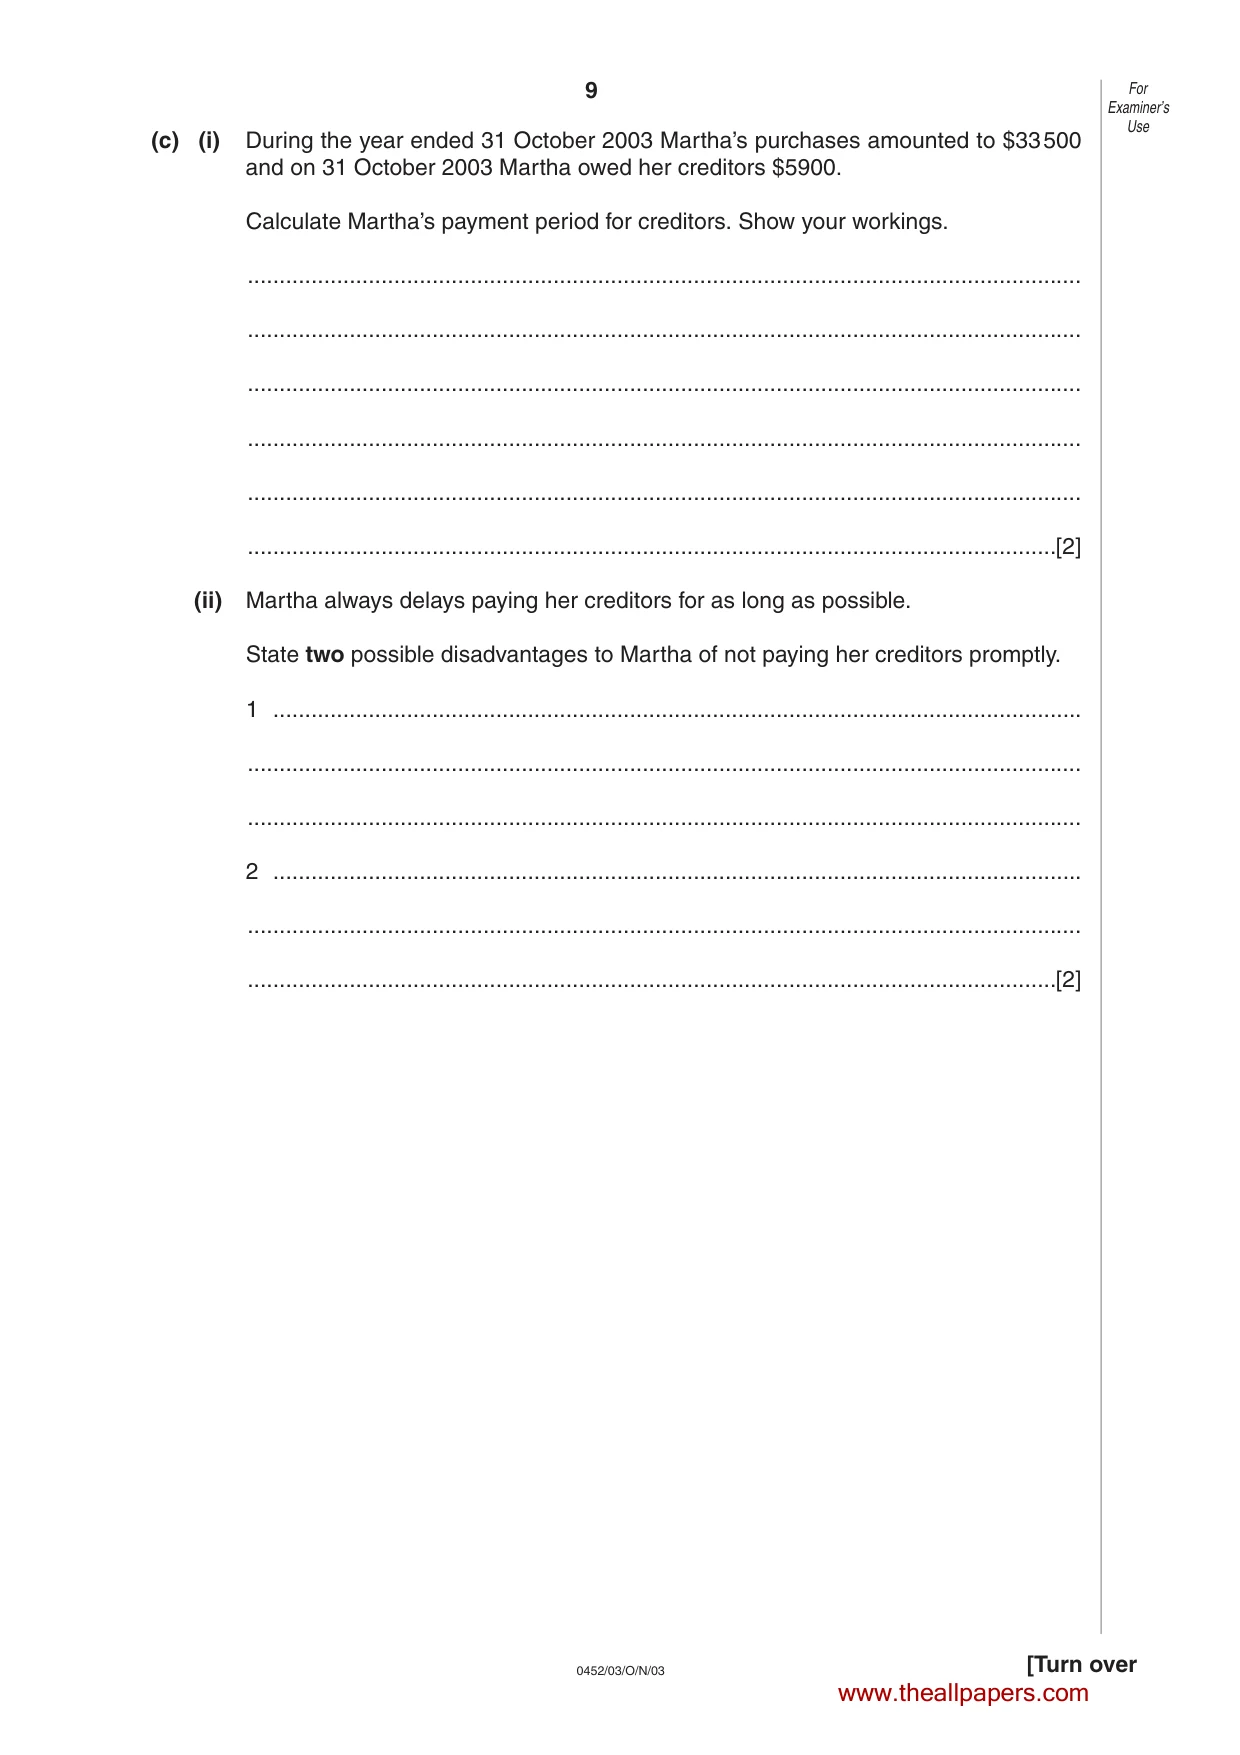
9 0452/03/O/N/03 [Turn over (c) (i) During the year ended 31 October 2003 Martha’s purchases amounted to $33500 and on 31 October 2003 Martha owed her creditors $5900. Calculate Martha’s payment period for creditors. Show your workings. … … … … … …[2] (ii) Martha always delays paying her creditors for as long as possible. State two possible disadvantages to Martha of not paying her creditors promptly. 1 … … … 2 … … …[2] For Examiner’s Use www.theallpapers.com
Question paper, page 10
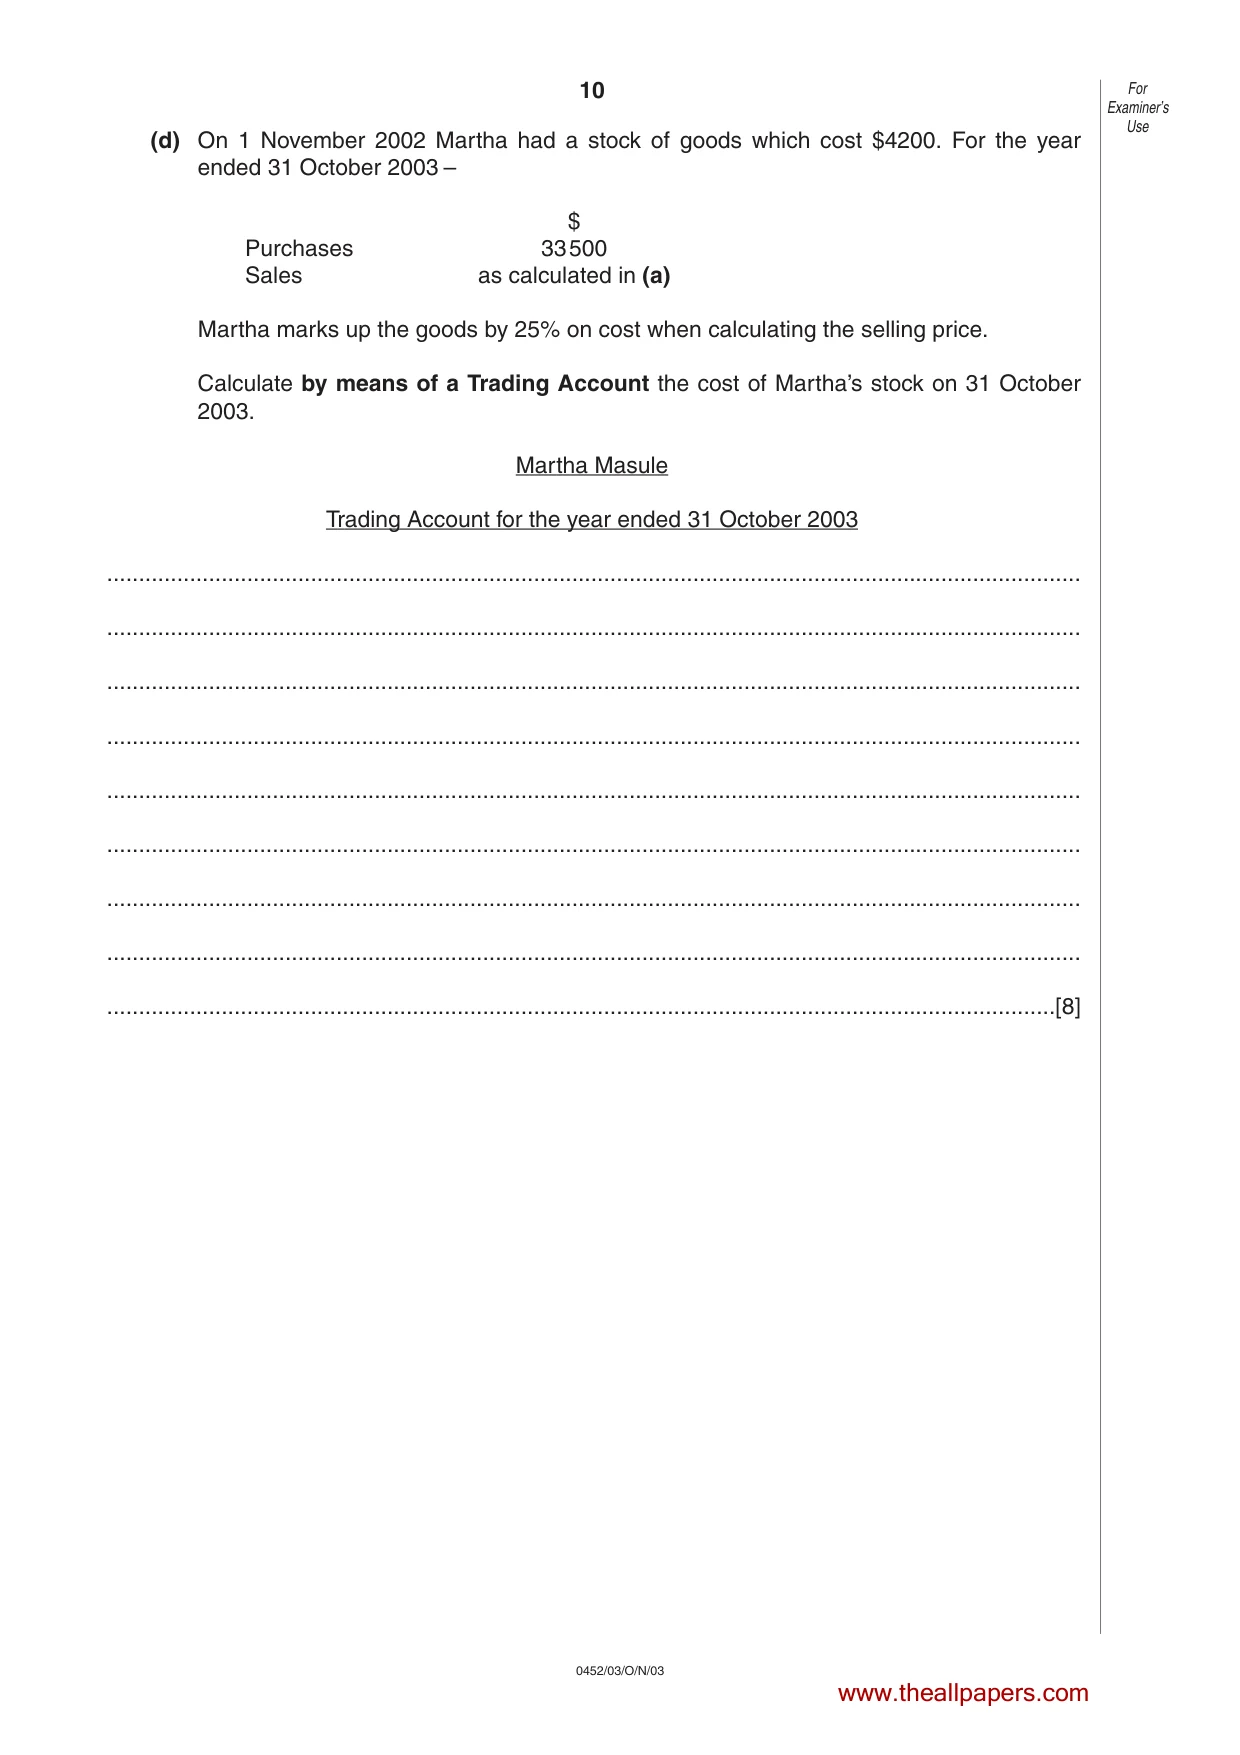
10 0452/03/O/N/03 (d) On 1 November 2002 Martha had a stock of goods which cost $4200. For the year ended 31 October 2003 – $ Purchases 33500 Sales as calculated in (a) Martha marks up the goods by 25% on cost when calculating the selling price. Calculate by means of a Trading Account the cost of Martha’s stock on 31 October 2003. Martha Masule Trading Account for the year ended 31 October 2003 … … … … … … … … …[8] For Examiner’s Use www.theallpapers.com
Question paper, page 11
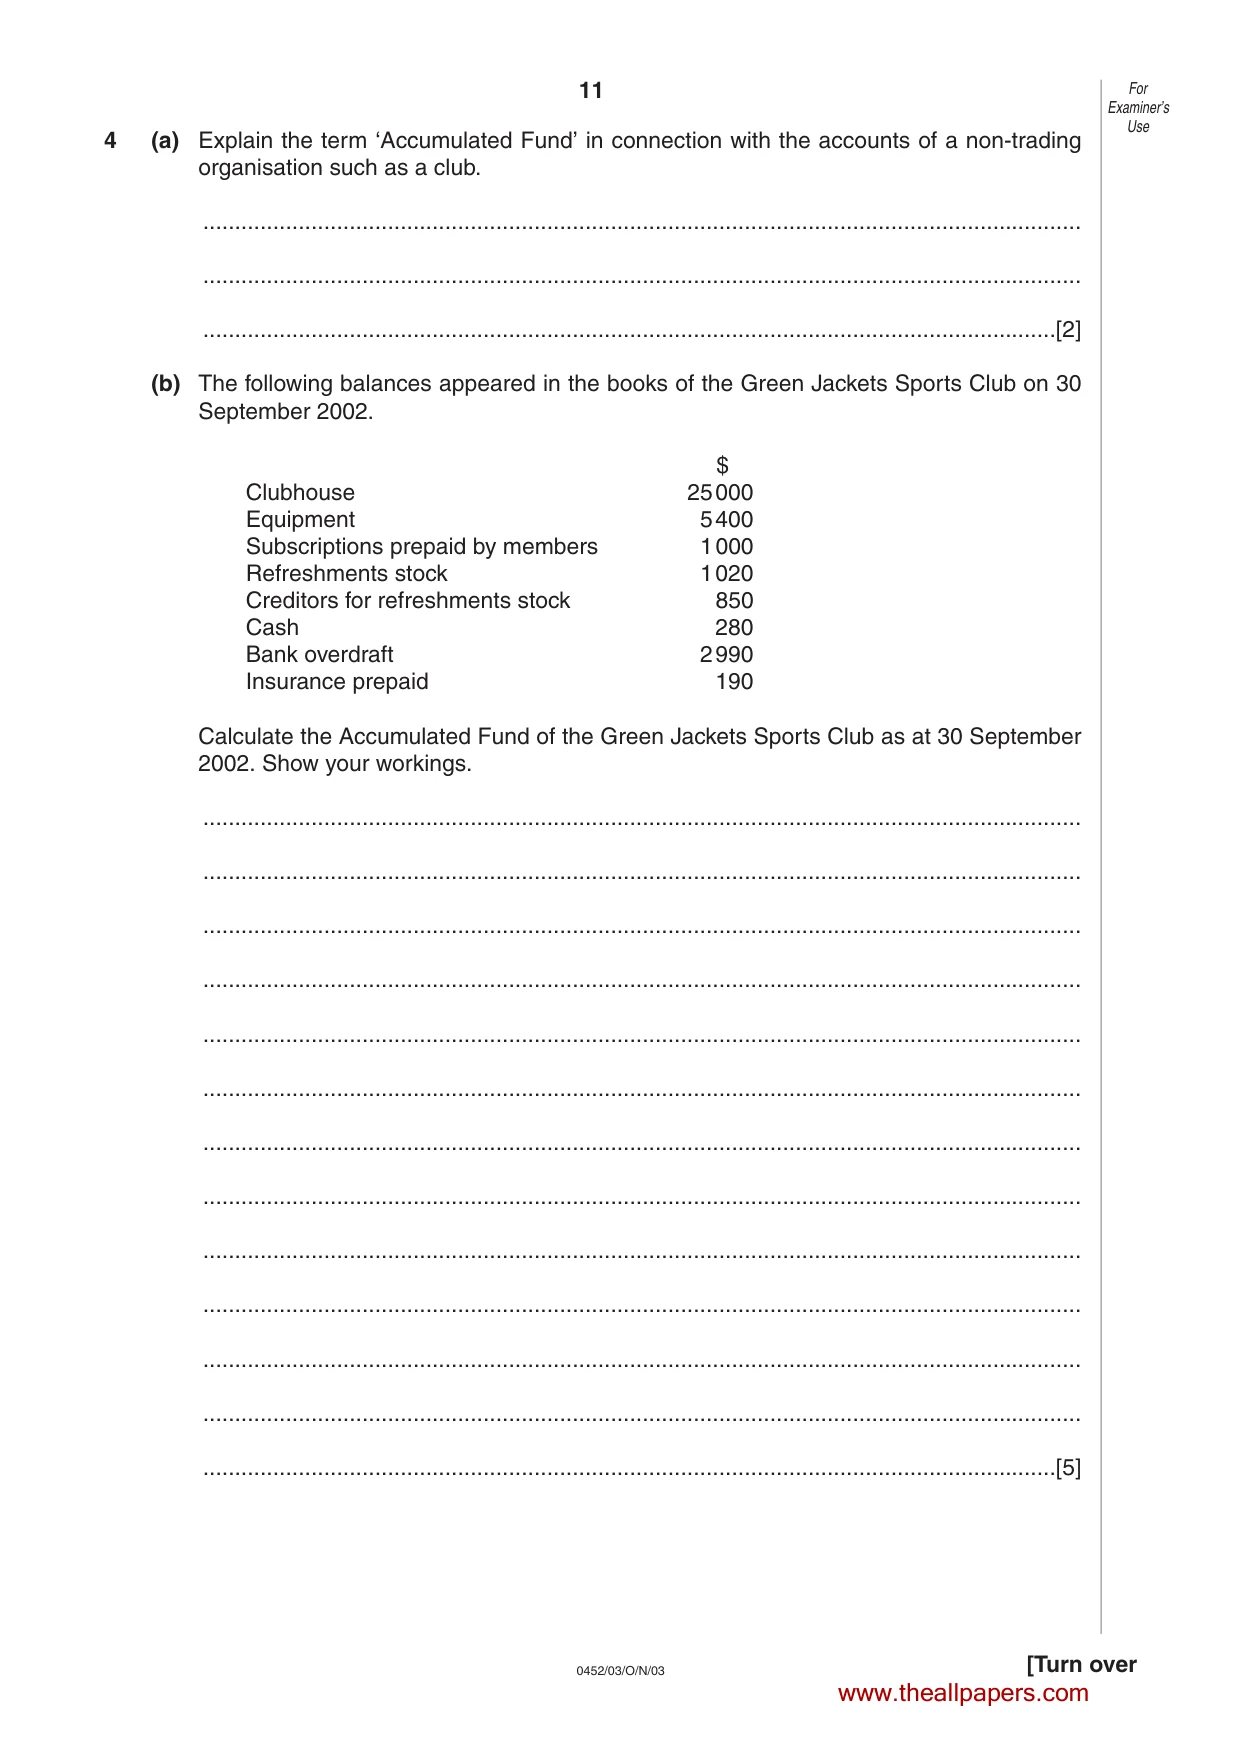
11 0452/03/O/N/03 [Turn over 4 (a) Explain the term ‘Accumulated Fund’ in connection with the accounts of a non-trading organisation such as a club. … … …[2] (b) The following balances appeared in the books of the Green Jackets Sports Club on 30 September 2002. $ Clubhouse 25000 Equipment 5400 Subscriptions prepaid by members 1000 Refreshments stock 1020 Creditors for refreshments stock 850 Cash 280 Bank overdraft 2990 Insurance prepaid 190 Calculate the Accumulated Fund of the Green Jackets Sports Club as at 30 September 2002. Show your workings. … … … … … … … … … … … … …[5] For Examiner’s Use www.theallpapers.com
Question paper, page 12
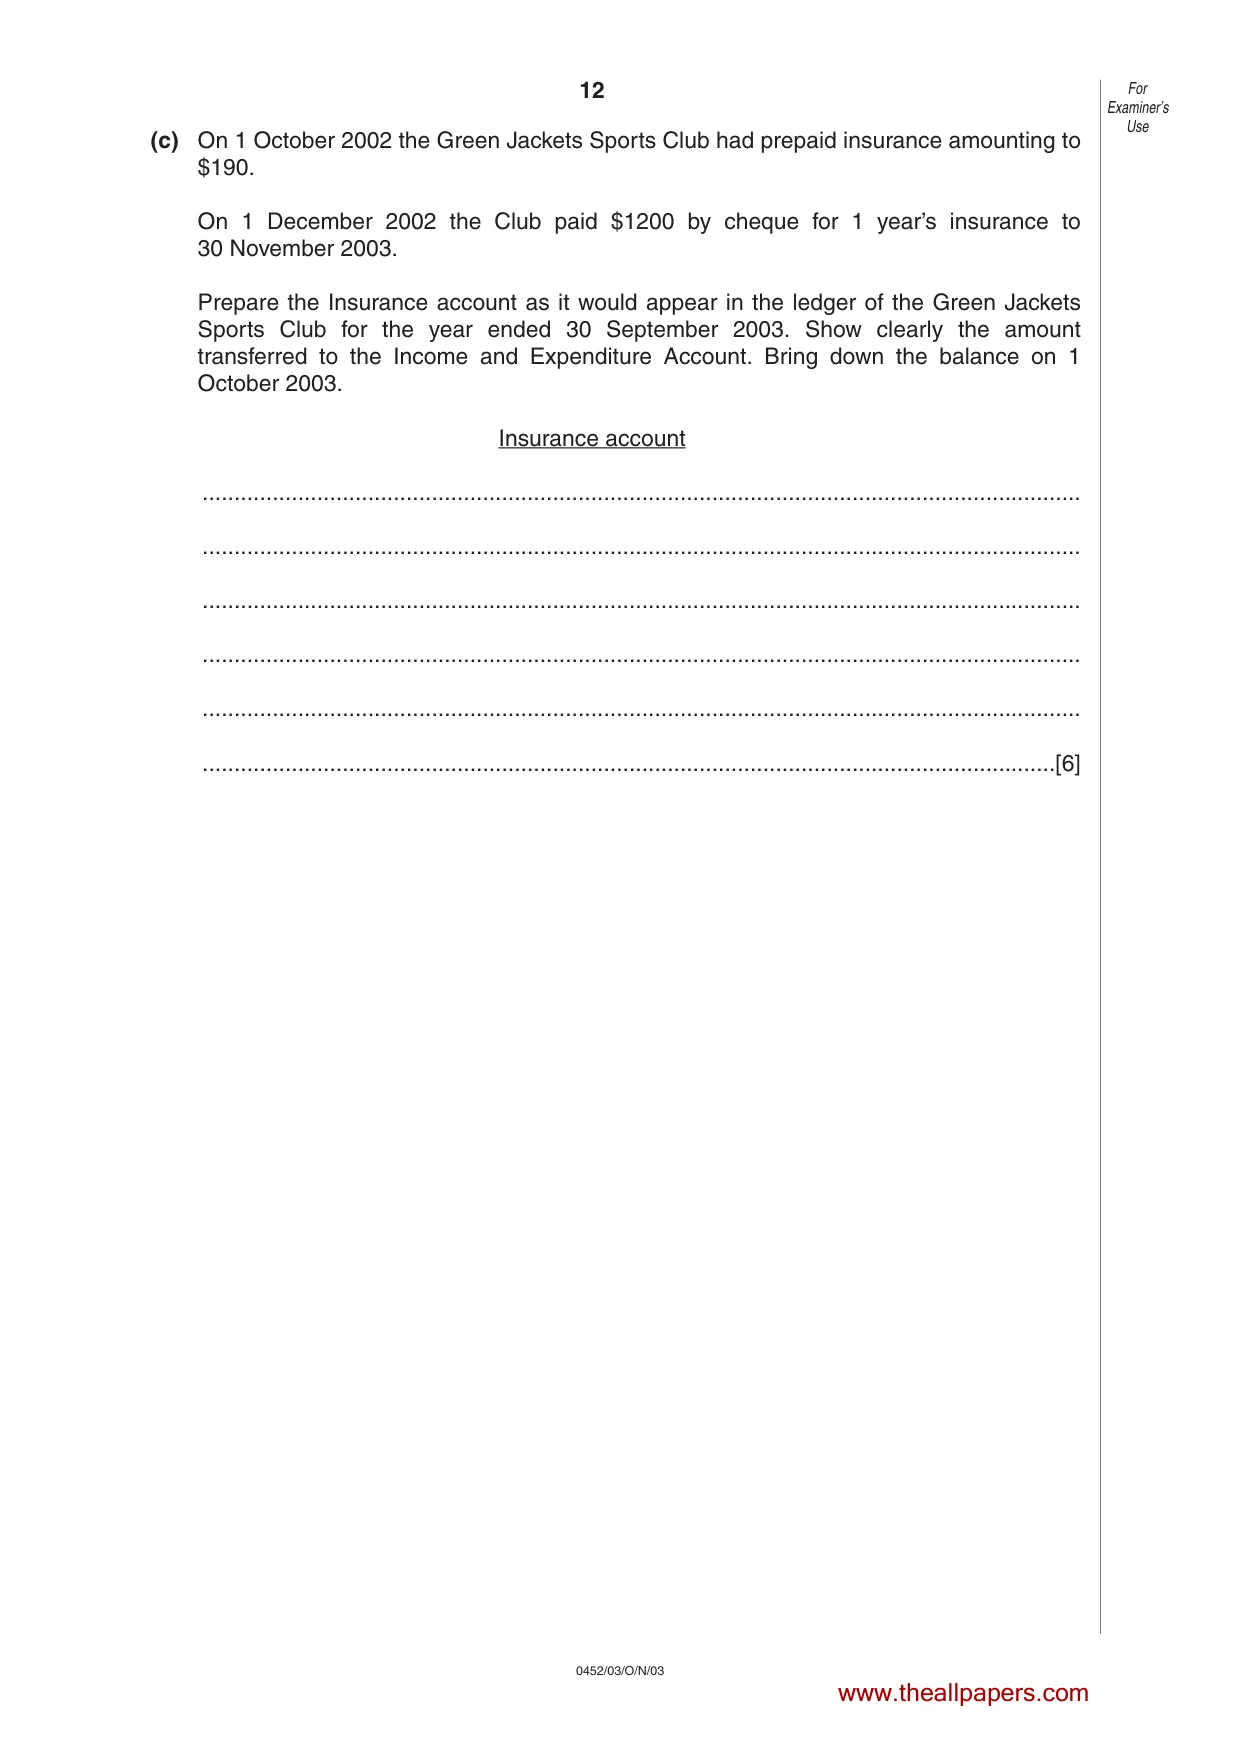
12 0452/03/O/N/03 (c) On 1 October 2002 the Green Jackets Sports Club had prepaid insurance amounting to $190. On 1 December 2002 the Club paid $1200 by cheque for 1 year’s insurance to 30 November 2003. Prepare the Insurance account as it would appear in the ledger of the Green Jackets Sports Club for the year ended 30 September 2003. Show clearly the amount transferred to the Income and Expenditure Account. Bring down the balance on 1 October 2003. Insurance account … … … … … …[6] For Examiner’s Use www.theallpapers.com
Question paper, page 13
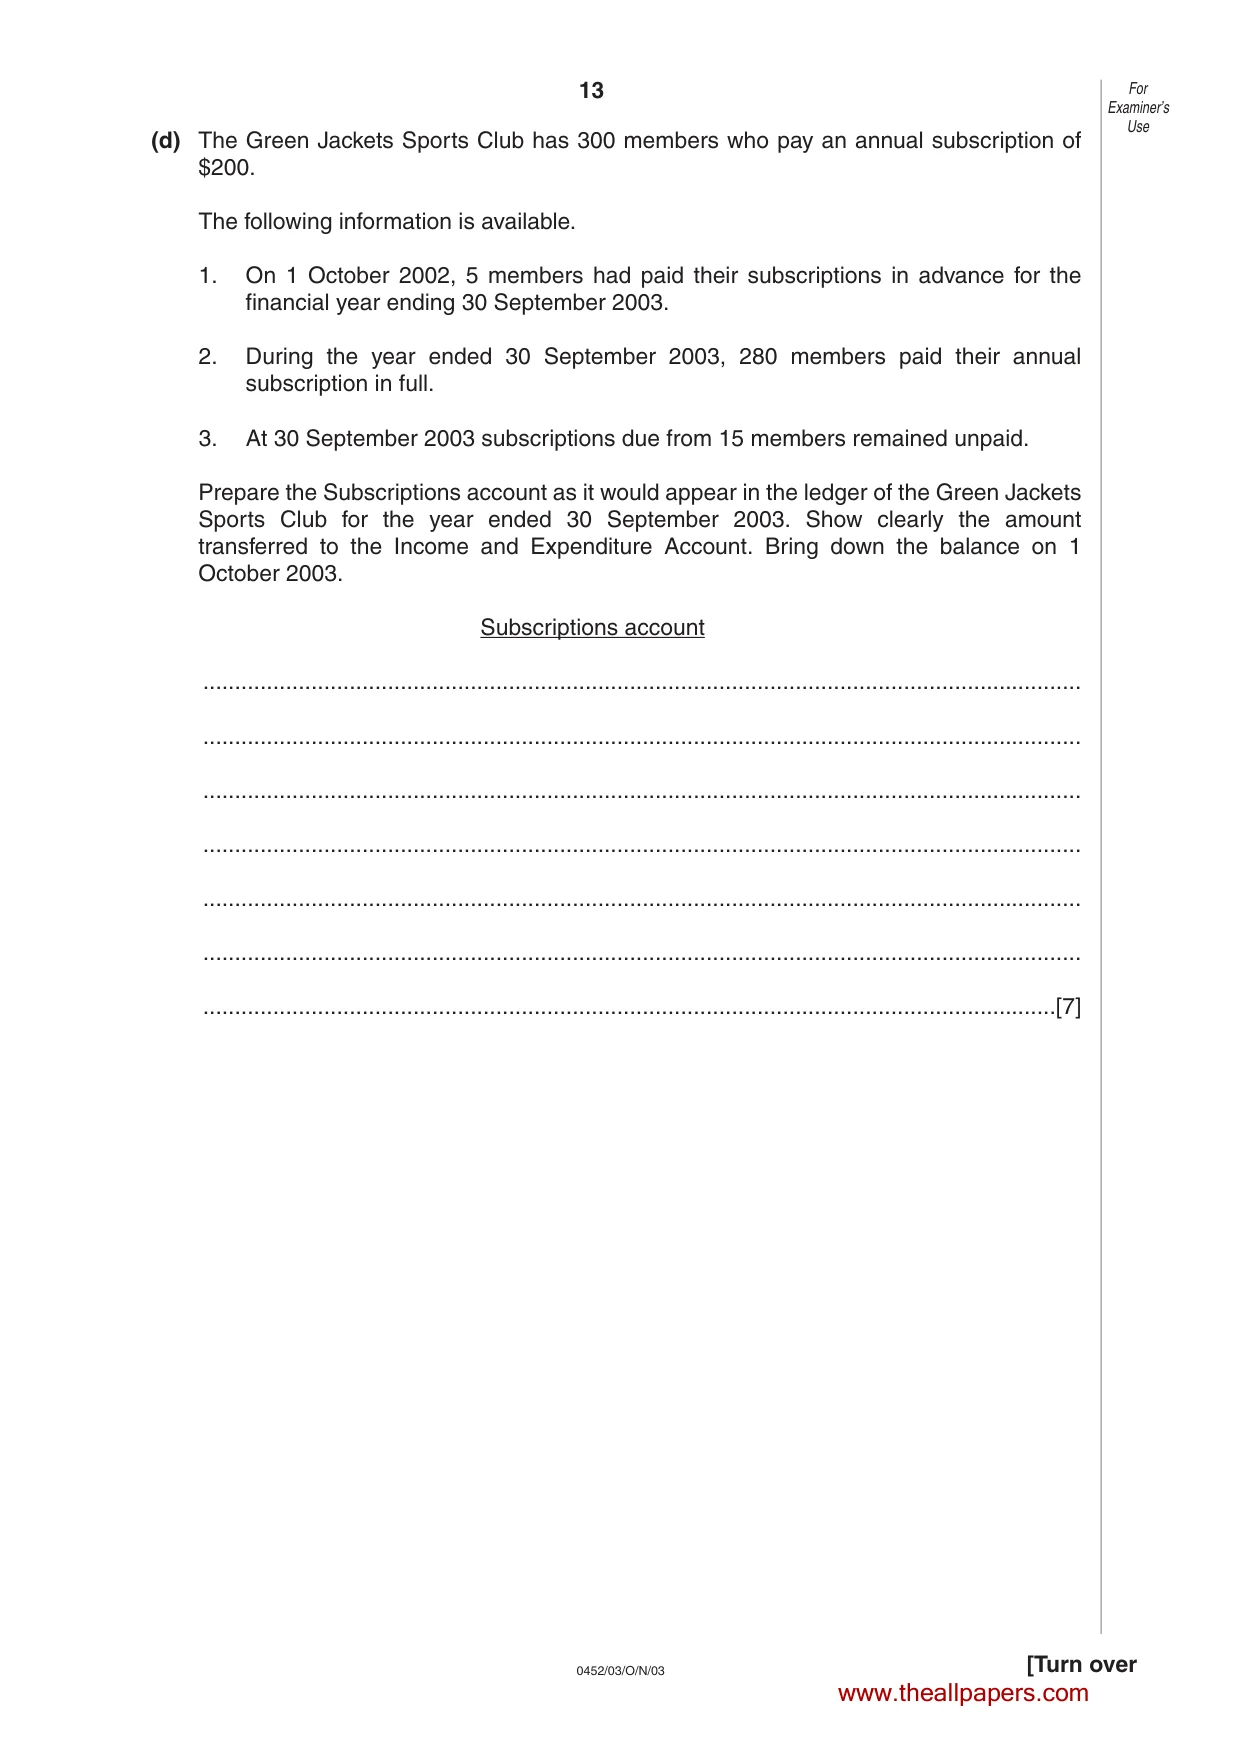
13 0452/03/O/N/03 [Turn over (d) The Green Jackets Sports Club has 300 members who pay an annual subscription of $200. The following information is available. 1. On 1 October 2002, 5 members had paid their subscriptions in advance for the financial year ending 30 September 2003. 2. During the year ended 30 September 2003, 280 members paid their annual subscription in full. 3. At 30 September 2003 subscriptions due from 15 members remained unpaid. Prepare the Subscriptions account as it would appear in the ledger of the Green Jackets Sports Club for the year ended 30 September 2003. Show clearly the amount transferred to the Income and Expenditure Account. Bring down the balance on 1 October 2003. Subscriptions account … … … … … … …[7] For Examiner’s Use www.theallpapers.com
Question paper, page 14
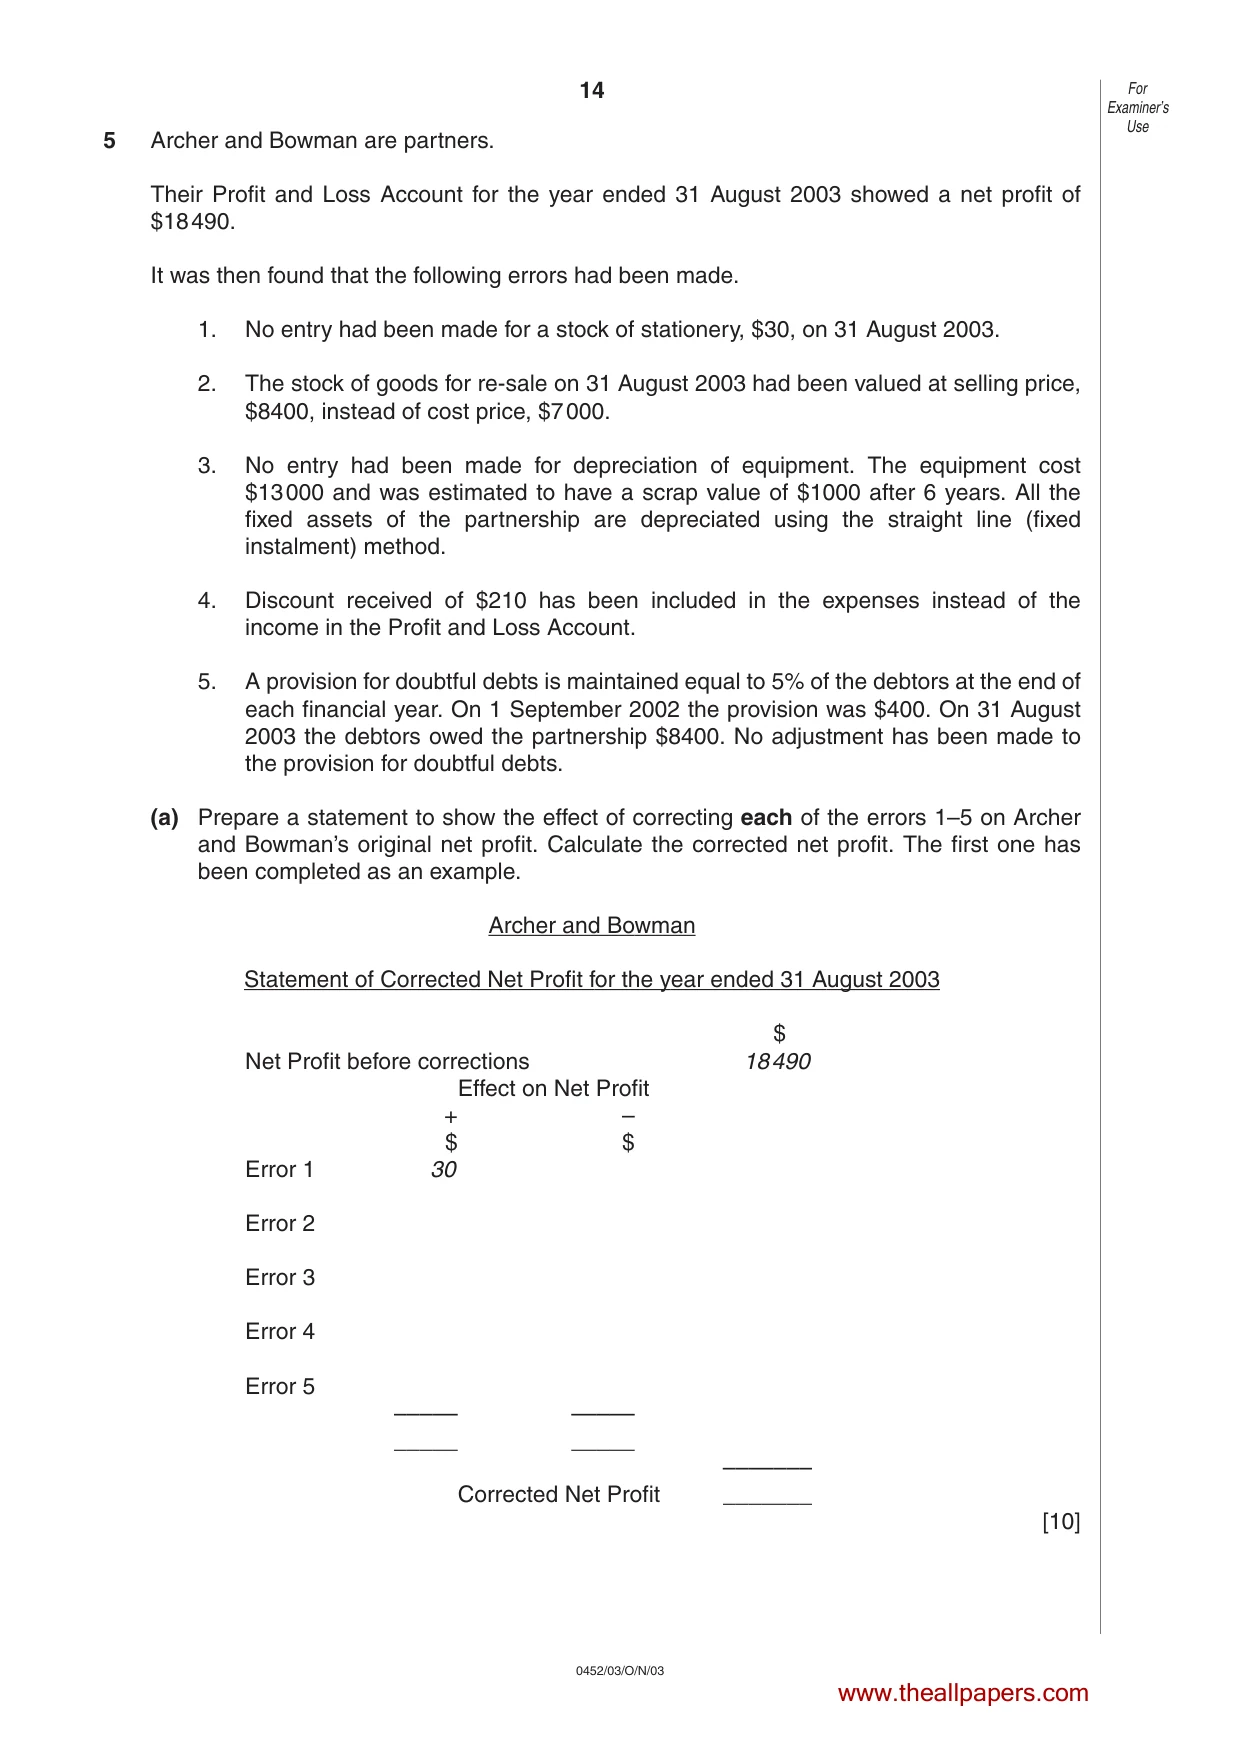
14 0452/03/O/N/03 5 Archer and Bowman are partners. Their Profit and Loss Account for the year ended 31 August 2003 showed a net profit of $18490. It was then found that the following errors had been made. 1. No entry had been made for a stock of stationery, $30, on 31 August 2003. 2. The stock of goods for re-sale on 31 August 2003 had been valued at selling price, $8400, instead of cost price, $7000. 3. No entry had been made for depreciation of equipment. The equipment cost $13000 and was estimated to have a scrap value of $1000 after 6 years. All the fixed assets of the partnership are depreciated using the straight line (fixed instalment) method. 4. Discount received of $210 has been included in the expenses instead of the income in the Profit and Loss Account. 5. A provision for doubtful debts is maintained equal to 5% of the debtors at the end of each financial year. On 1 September 2002 the provision was $400. On 31 August 2003 the debtors owed the partnership $8400. No adjustment has been made to the provision for doubtful debts. (a) Prepare a statement to show the effect of correcting each of the errors 1–5 on Archer and Bowman’s original net profit. Calculate the corrected net profit. The first one has been completed as an example. Archer and Bowman Statement of Corrected Net Profit for the year ended 31 August 2003 $ Net Profit before corrections 18490 Effect on Net Profit + – $ $ Error 1 30 Error 2 Error 3 Error 4 Error 5 ––––– ––––– _____ _____ ––––––– Corrected Net Profit _______ [10] For Examiner’s Use www.theallpapers.com
Question paper, page 15
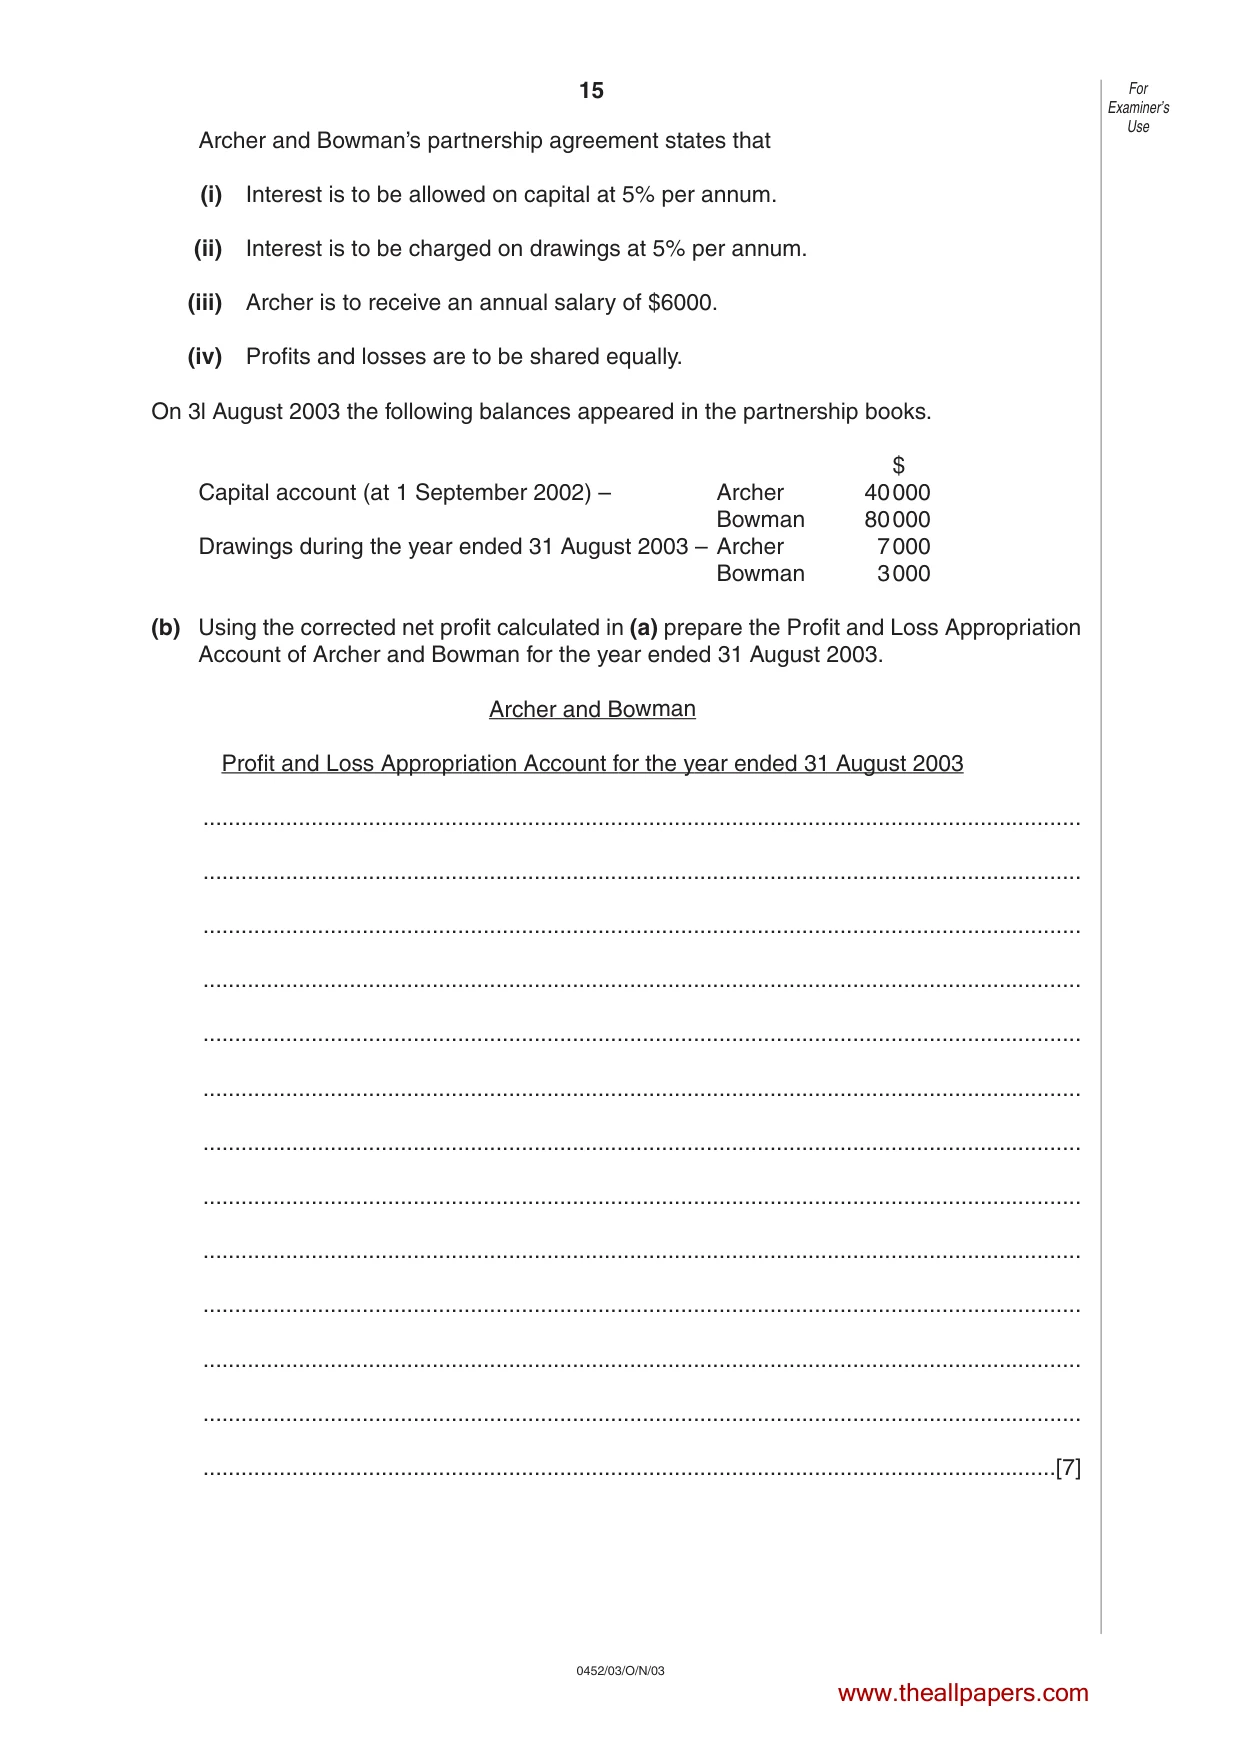
15 0452/03/O/N/03 Archer and Bowman’s partnership agreement states that (i) Interest is to be allowed on capital at 5% per annum. (ii) Interest is to be charged on drawings at 5% per annum. (iii) Archer is to receive an annual salary of $6000. (iv) Profits and losses are to be shared equally. On 3l August 2003 the following balances appeared in the partnership books. $ Capital account (at 1 September 2002) – Archer 40000 Bowman 80000 Drawings during the year ended 31 August 2003 – Archer 7000 Bowman 3000 (b) Using the corrected net profit calculated in (a) prepare the Profit and Loss Appropriation Account of Archer and Bowman for the year ended 31 August 2003. Archer and Bowman Profit and Loss Appropriation Account for the year ended 31 August 2003 … … … … … … … … … … … … …[7] For Examiner’s Use www.theallpapers.com
Question paper, page 16
16 0452/03/O/N/03 BLANK PAGE www.theallpapers.com