Cambridge IGCSE Accounting 0452 — 2003 May/June Paper 3 · Variant 1
0452/31/M/J/03
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper16 pages
Mark scheme
No mark scheme is in the library for this paper.
Paper as text
Question paper, page 1
This document consists of 15 printed pages and 1 blank page. BR S37616/2 © CIE 2003 [Turn over CAMBRIDGE INTERNATIONAL EXAMINATIONS International General Certificate of Secondary Education ACCOUNTING 0452/03 Paper 3 May/June 2003 1 hour 45 minutes Candidates answer on the Question Paper. No Additional Materials are required. READ THESE INSTRUCTIONS FIRST Write your Centre number, candidate number and name on all the work you hand in. Write in dark blue or black pen in the spaces provided on the Question Paper. You may use a soft pencil for rough working. Do not use staples, paper clips, highlighters, glue or correction fluid. Answer all questions. At the end of the examination, fasten all your work securely together. The number of marks is given in brackets [ ] at the end of each question or part question. You may use a calculator. Where layouts are to be completed, you may not need all the lines for your answer. The businesses mentioned in this Question Paper are fictitious. Centre Number Candidate Number Name If you have been given a label, look at the details. If any details are incorrect or missing, please fill in your correct details in the space given at the top of this page. Stick your personal label here, if provided. For Examiner’s Use 1 2 3 4 5 Total www.theallpapers.com
Question paper, page 2
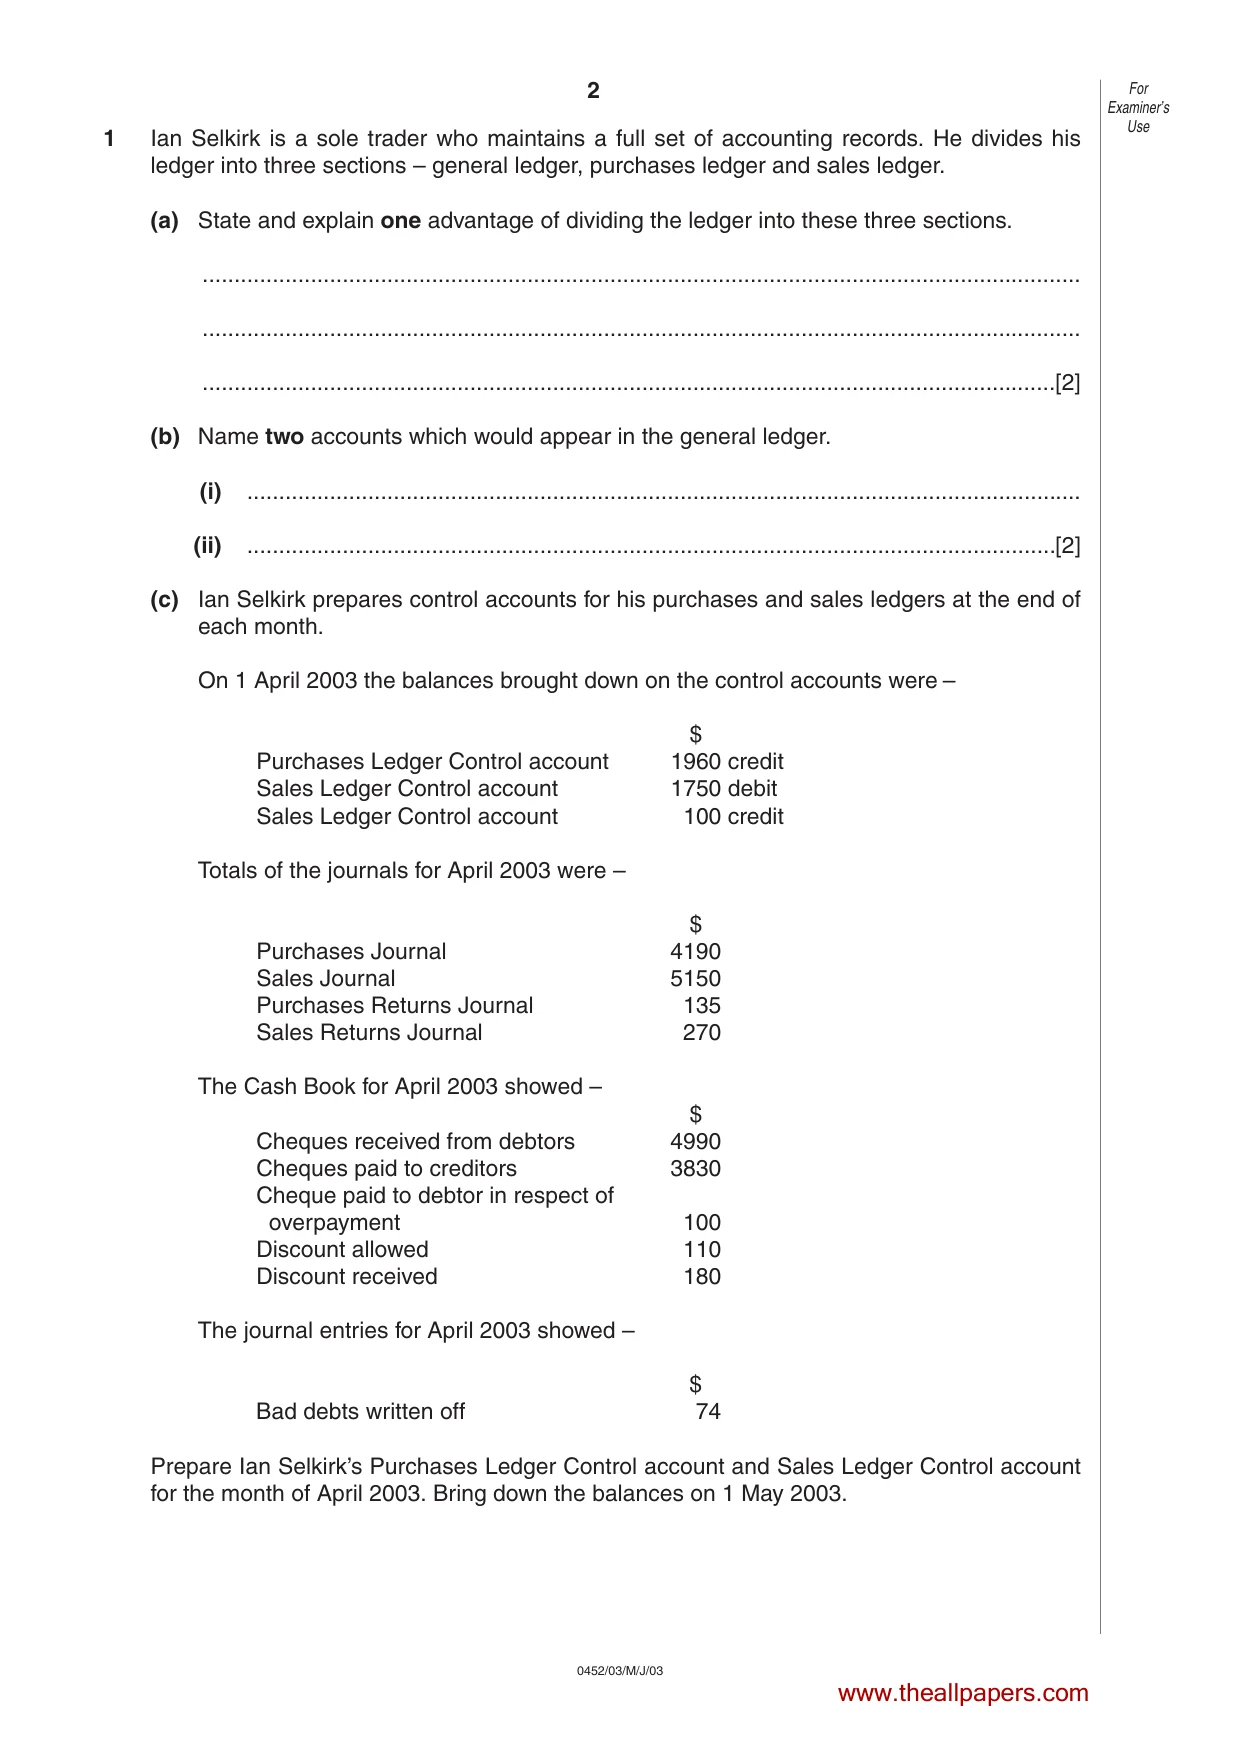
For Examiner’s Use 2 0452/03/M/J/03 1 Ian Selkirk is a sole trader who maintains a full set of accounting records. He divides his ledger into three sections – general ledger, purchases ledger and sales ledger. (a) State and explain one advantage of dividing the ledger into these three sections. … … …[2] (b) Name two accounts which would appear in the general ledger. (i) … (ii) …[2] (c) Ian Selkirk prepares control accounts for his purchases and sales ledgers at the end of each month. On 1 April 2003 the balances brought down on the control accounts were – $ Purchases Ledger Control account 1960 credit Sales Ledger Control account 1750 debit Sales Ledger Control account 100 credit Totals of the journals for April 2003 were – $ Purchases Journal 4190 Sales Journal 5150 Purchases Returns Journal 135 Sales Returns Journal 270 The Cash Book for April 2003 showed – $ Cheques received from debtors 4990 Cheques paid to creditors 3830 Cheque paid to debtor in respect of overpayment 100 Discount allowed 110 Discount received 180 The journal entries for April 2003 showed – $ Bad debts written off 74 Prepare Ian Selkirk’s Purchases Ledger Control account and Sales Ledger Control account for the month of April 2003. Bring down the balances on 1 May 2003. www.theallpapers.com
Question paper, page 3
For Examiner’s Use 3 0452/03/M/J/03 [Turn over Purchases Ledger Control account … … … … … … … … …[6] Sales Ledger Control account … … … … … … … … … … …[8] www.theallpapers.com
Question paper, page 4
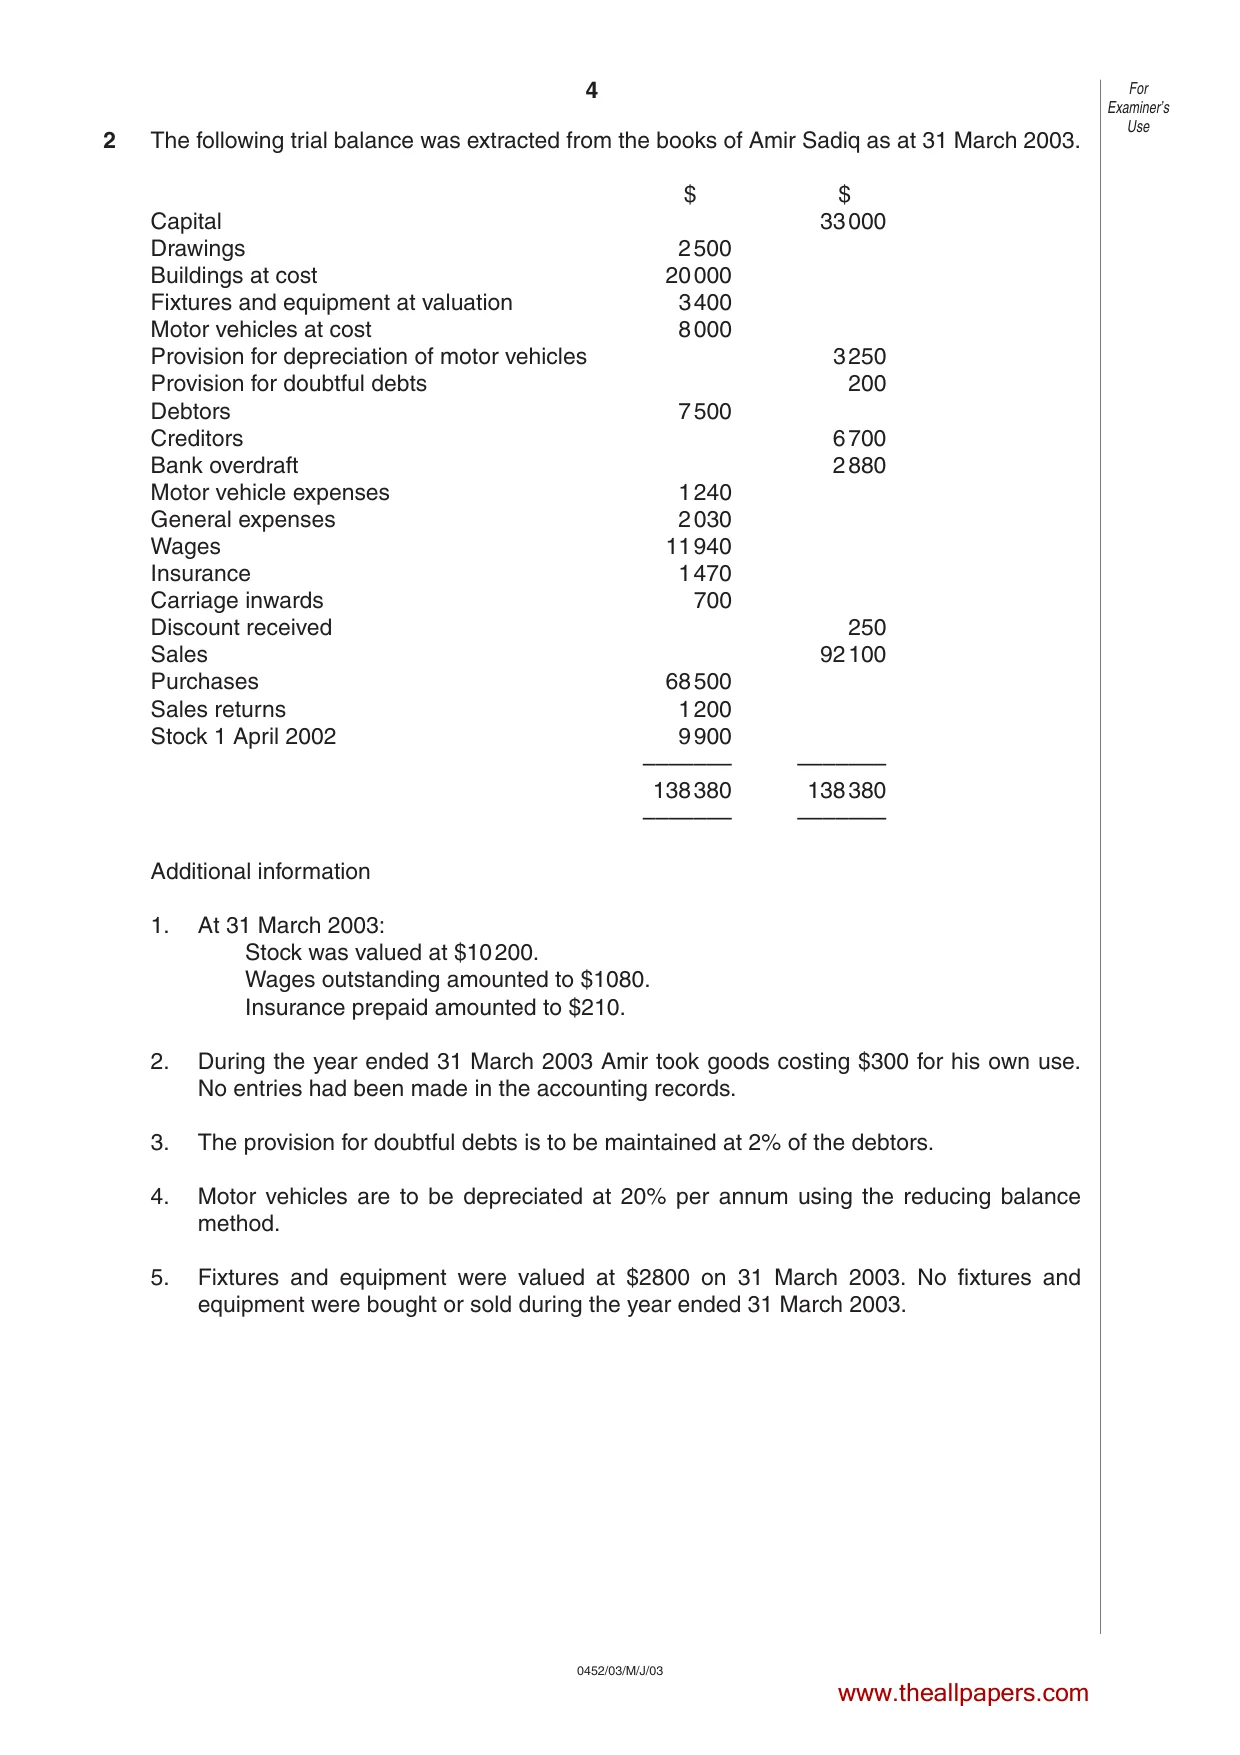
2 The following trial balance was extracted from the books of Amir Sadiq as at 31 March 2003. $ $ Capital 33000 Drawings 2500 Buildings at cost 20000 Fixtures and equipment at valuation 3400 Motor vehicles at cost 8000 Provision for depreciation of motor vehicles 3250 Provision for doubtful debts 200 Debtors 7500 Creditors 6700 Bank overdraft 2880 Motor vehicle expenses 1240 General expenses 2030 Wages 11940 Insurance 1470 Carriage inwards 700 Discount received 250 Sales 92100 Purchases 68500 Sales returns 1200 Stock 1 April 2002 9900 ––––––– ––––––– 138380 138380 ––––––– ––––––– Additional information 1. At 31 March 2003: Stock was valued at $10200. Wages outstanding amounted to $1080. Insurance prepaid amounted to $210. 2. During the year ended 31 March 2003 Amir took goods costing $300 for his own use. No entries had been made in the accounting records. 3. The provision for doubtful debts is to be maintained at 2% of the debtors. 4. Motor vehicles are to be depreciated at 20% per annum using the reducing balance method. 5. Fixtures and equipment were valued at $2800 on 31 March 2003. No fixtures and equipment were bought or sold during the year ended 31 March 2003. 4 0452/03/M/J/03 For Examiner’s Use www.theallpapers.com
Question paper, page 5
5 0452/03/M/J/03 [Turn over (a) Prepare the Trading and Profit and Loss Account of Amir Sadiq for the year ended 31 March 2003. A Balance Sheet is not required. Amir Sadiq Trading and Profit and Loss Account for the year ended 31 March 2003 … … … … … … … … … … … … … … … … … … … … … … … …[17] For Examiner’s Use www.theallpapers.com
Question paper, page 6
6 0452/03/M/J/03 (b) Calculate, correct to two decimal places, Amir’s rate of stock turnover for the year ended 31 March 2003. Show your workings. … … … … …[2] (c) (i) Explain what is meant by the going concern principle. … … … …[2] (ii) On what basis should stock be valued when the going concern principle is applied? … …[1] For Examiner’s Use www.theallpapers.com
Question paper, page 7
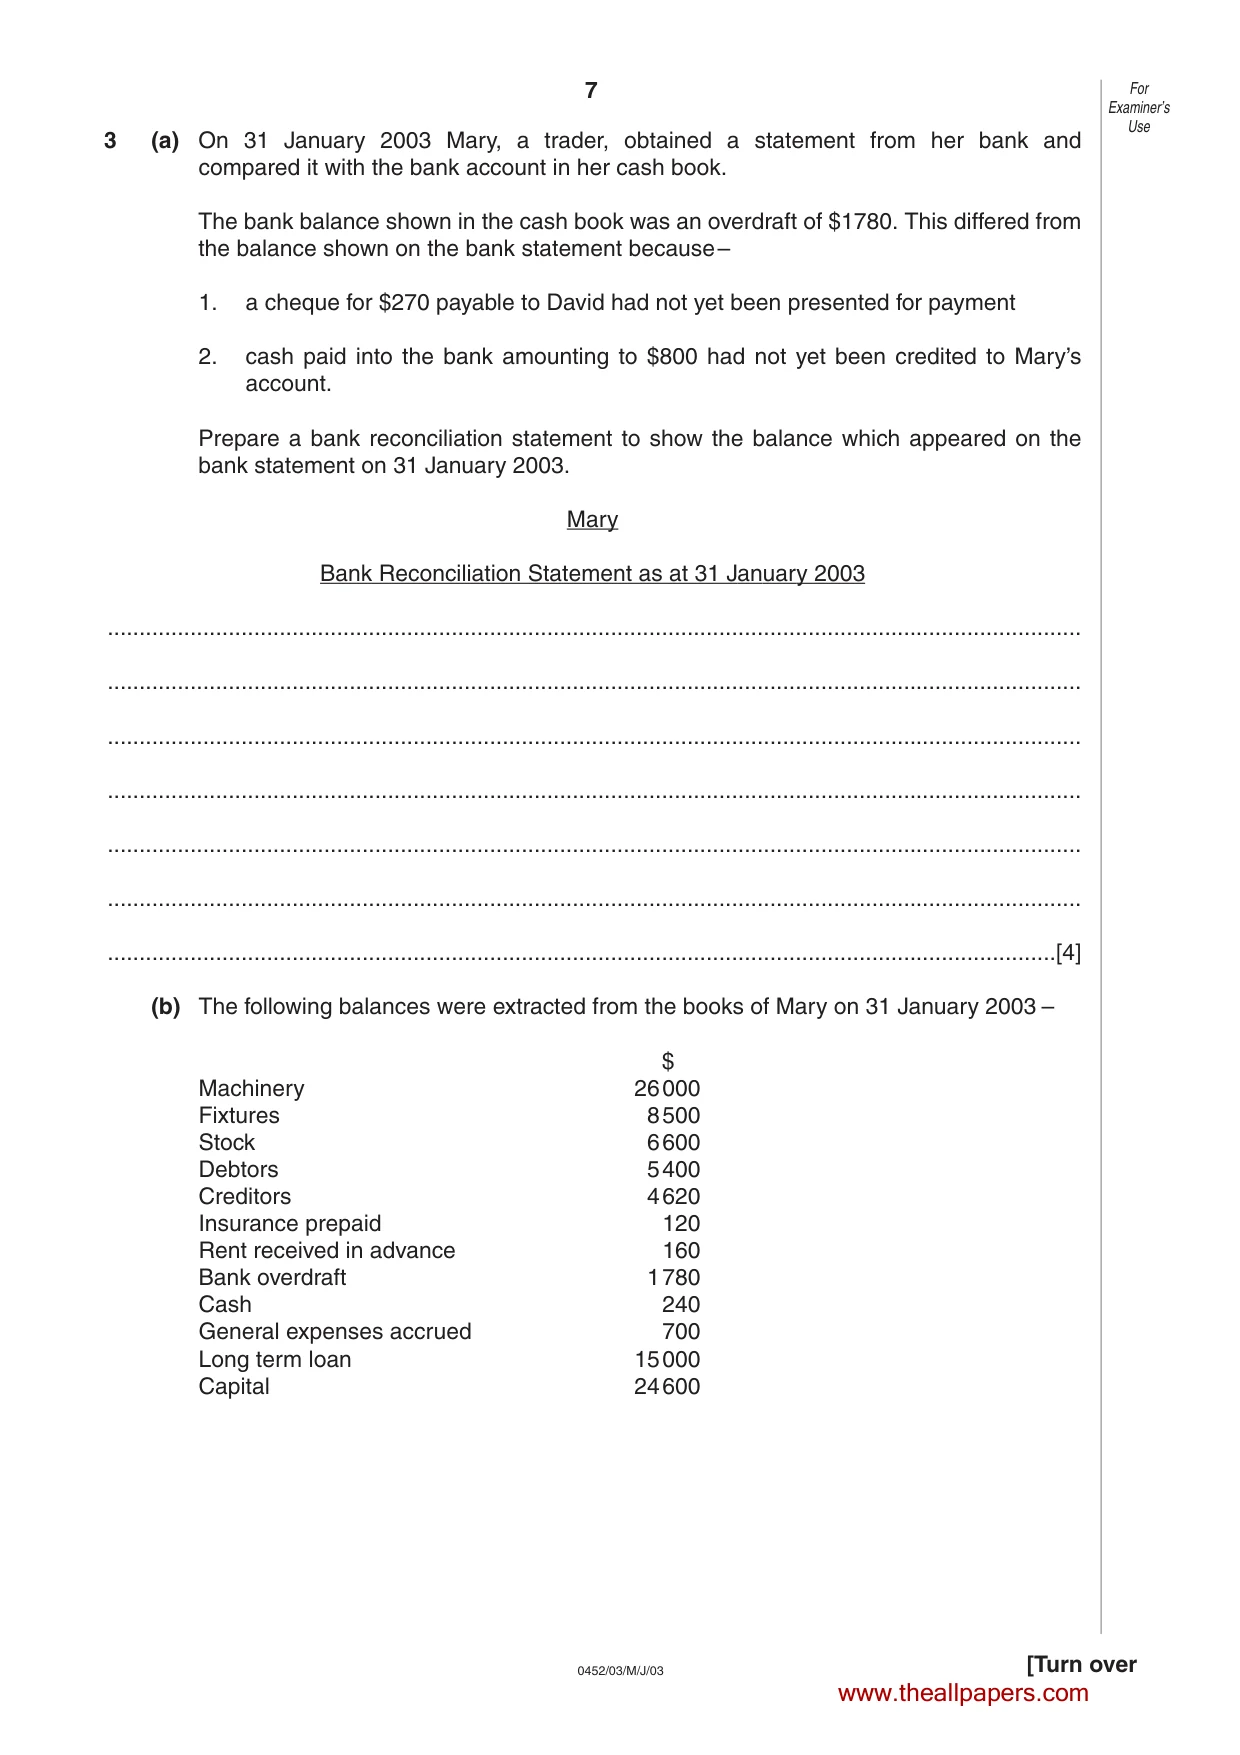
7 0452/03/M/J/03 [Turn over 3 (a) On 31 January 2003 Mary, a trader, obtained a statement from her bank and compared it with the bank account in her cash book. The bank balance shown in the cash book was an overdraft of $1780. This differed from the balance shown on the bank statement because– 1. a cheque for $270 payable to David had not yet been presented for payment 2. cash paid into the bank amounting to $800 had not yet been credited to Mary’s account. Prepare a bank reconciliation statement to show the balance which appeared on the bank statement on 31 January 2003. Mary Bank Reconciliation Statement as at 31 January 2003 … … … … … … …[4] (b) The following balances were extracted from the books of Mary on 31 January 2003 – $ Machinery 26000 Fixtures 8500 Stock 6600 Debtors 5400 Creditors 4620 Insurance prepaid 120 Rent received in advance 160 Bank overdraft 1780 Cash 240 General expenses accrued 700 Long term loan 15000 Capital 24600 For Examiner’s Use www.theallpapers.com
Question paper, page 8
8 0452/03/M/J/03 (i) Select the relevant figures and calculate Mary’s working capital on 31 January 2003. … … … … … … … … … … … … …[5] (ii) Calculate, correct to two decimal places, Mary’s current ratio and quick ratio at 31 January 2003. Show your workings. 1. Current ratio … … … … …[2] 2. Quick ratio … … … … …[2] For Examiner’s Use www.theallpapers.com
Question paper, page 9
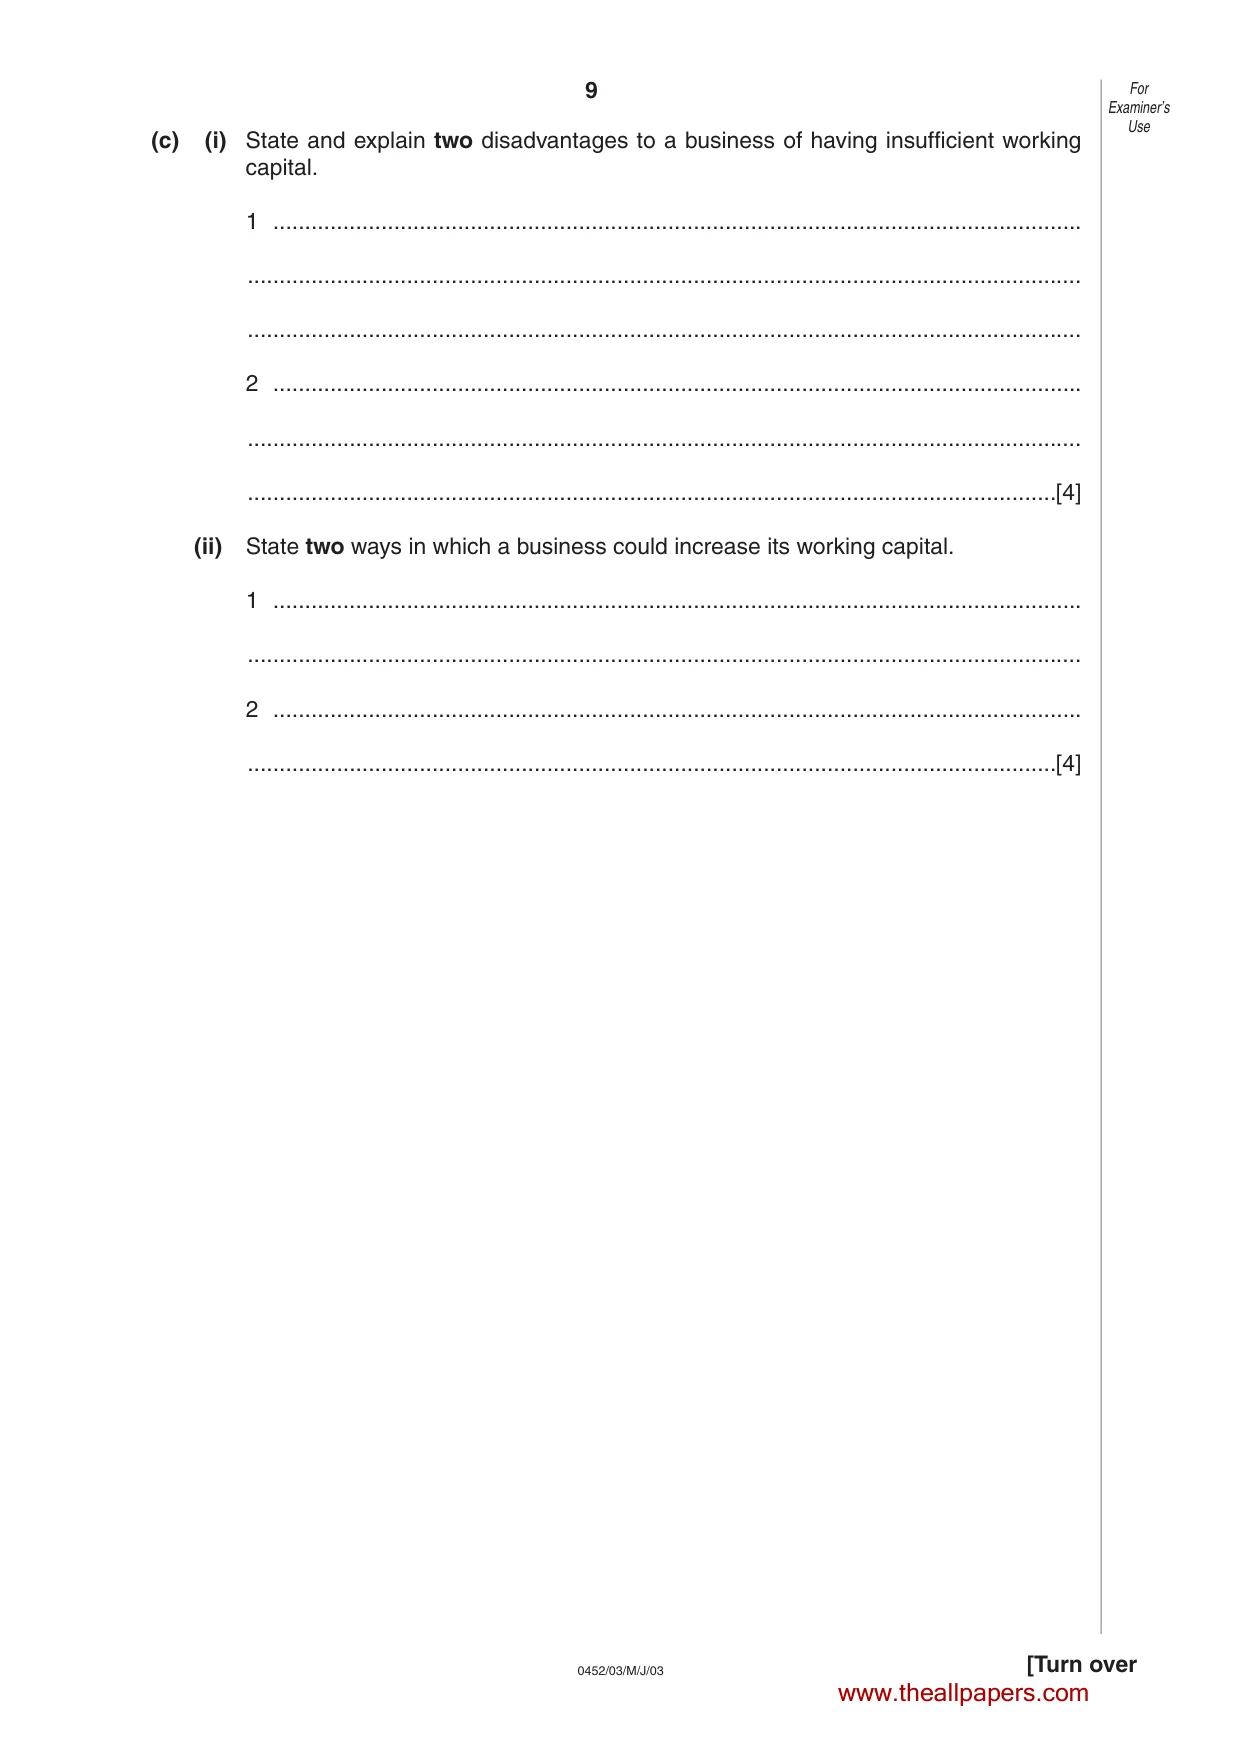
9 0452/03/M/J/03 [Turn over (c) (i) State and explain two disadvantages to a business of having insufficient working capital. 1 … … … 2 … … …[4] (ii) State two ways in which a business could increase its working capital. 1 … … 2 … …[4] For Examiner’s Use www.theallpapers.com
Question paper, page 10
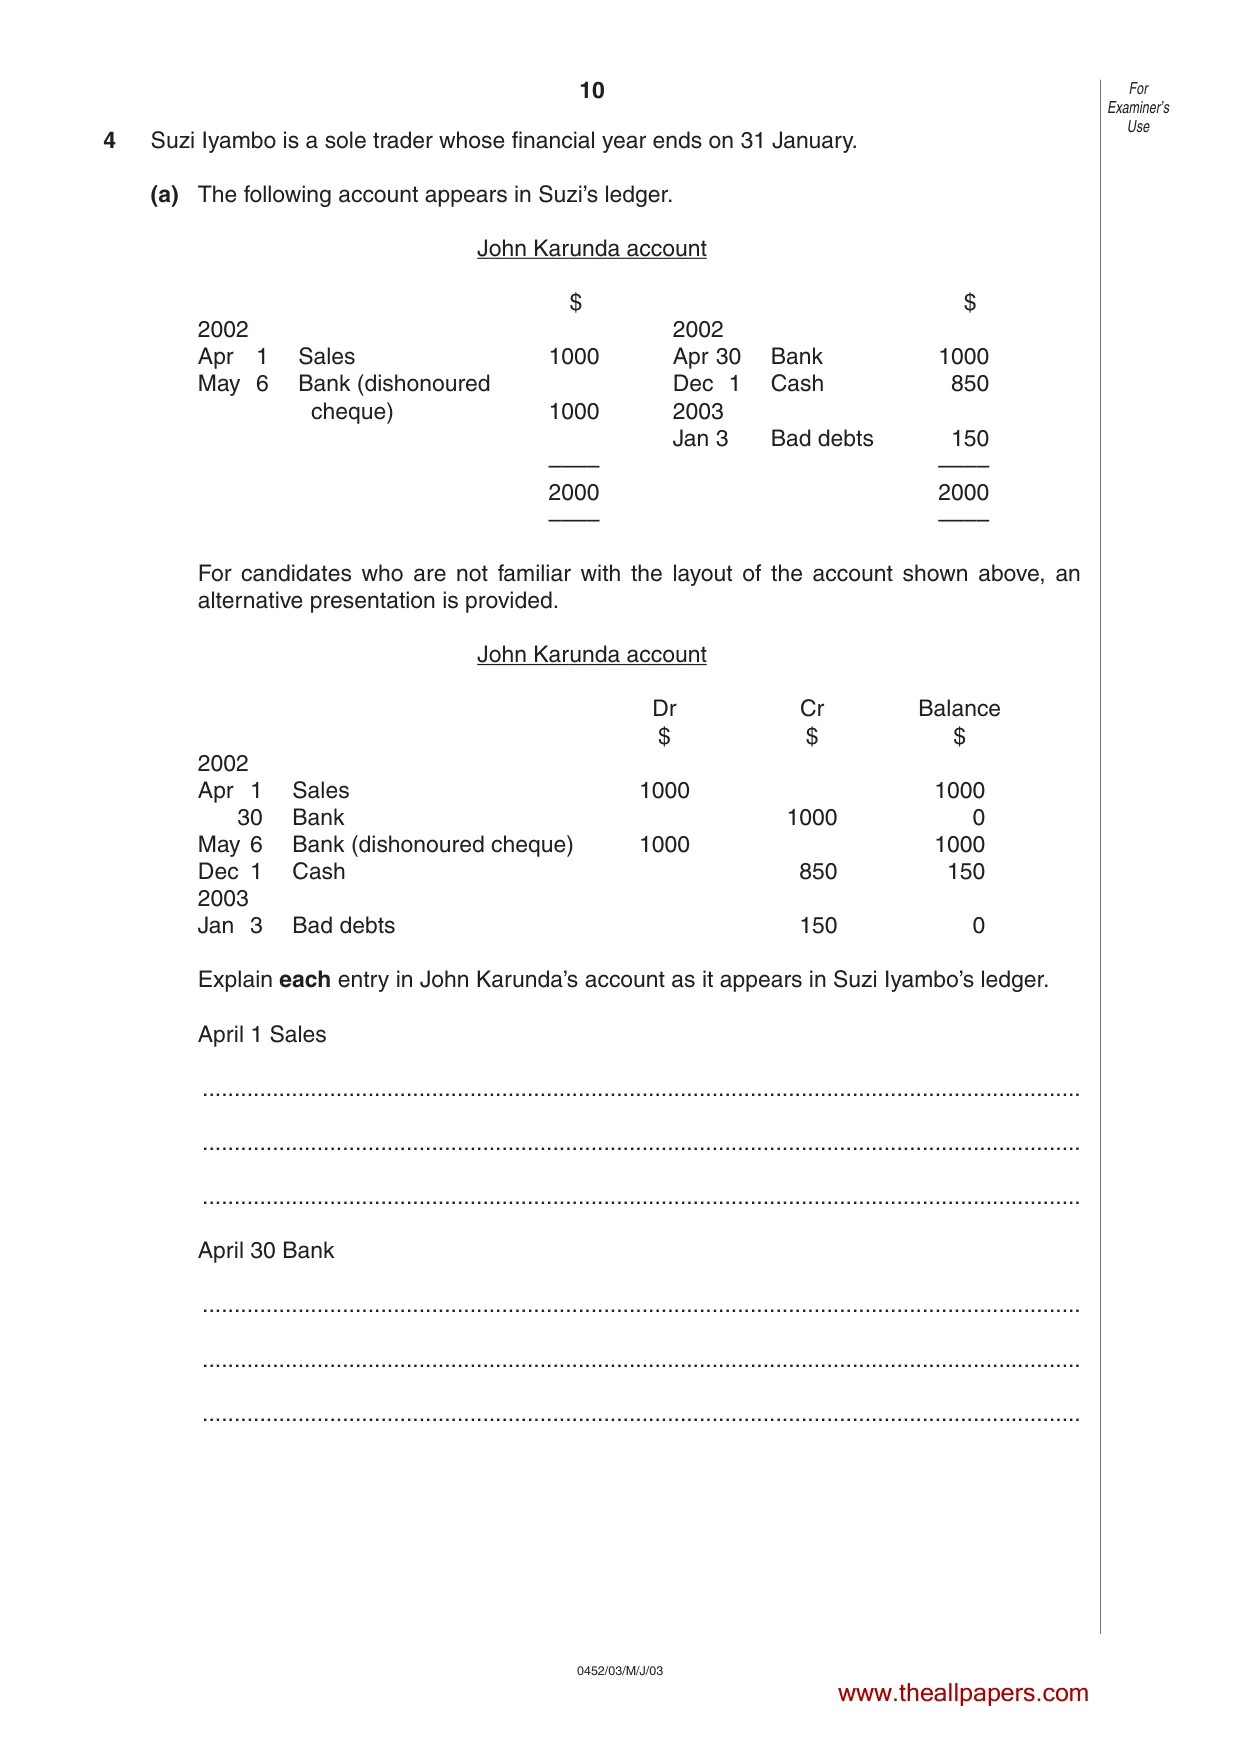
10 0452/03/M/J/03 4 Suzi Iyambo is a sole trader whose financial year ends on 31 January. (a) The following account appears in Suzi’s ledger. John Karunda account $ $ 2002 2002 Apr 1 Sales 1000 Apr 30 Bank 1000 May 6 Bank (dishonoured Dec 1 Cash 850 cheque) 1000 2003 Jan 3 Bad debts 150 –––– –––– 2000 2000 –––– –––– For candidates who are not familiar with the layout of the account shown above, an alternative presentation is provided. John Karunda account Dr Cr Balance $ $ $ 2002 Apr 1 Sales 1000 1000 30 Bank 1000 0 May 6 Bank (dishonoured cheque) 1000 1000 Dec 1 Cash 850 150 2003 Jan 3 Bad debts 150 0 Explain each entry in John Karunda’s account as it appears in Suzi Iyambo’s ledger. April 1 Sales … … … April 30 Bank … … … For Examiner’s Use www.theallpapers.com
Question paper, page 11
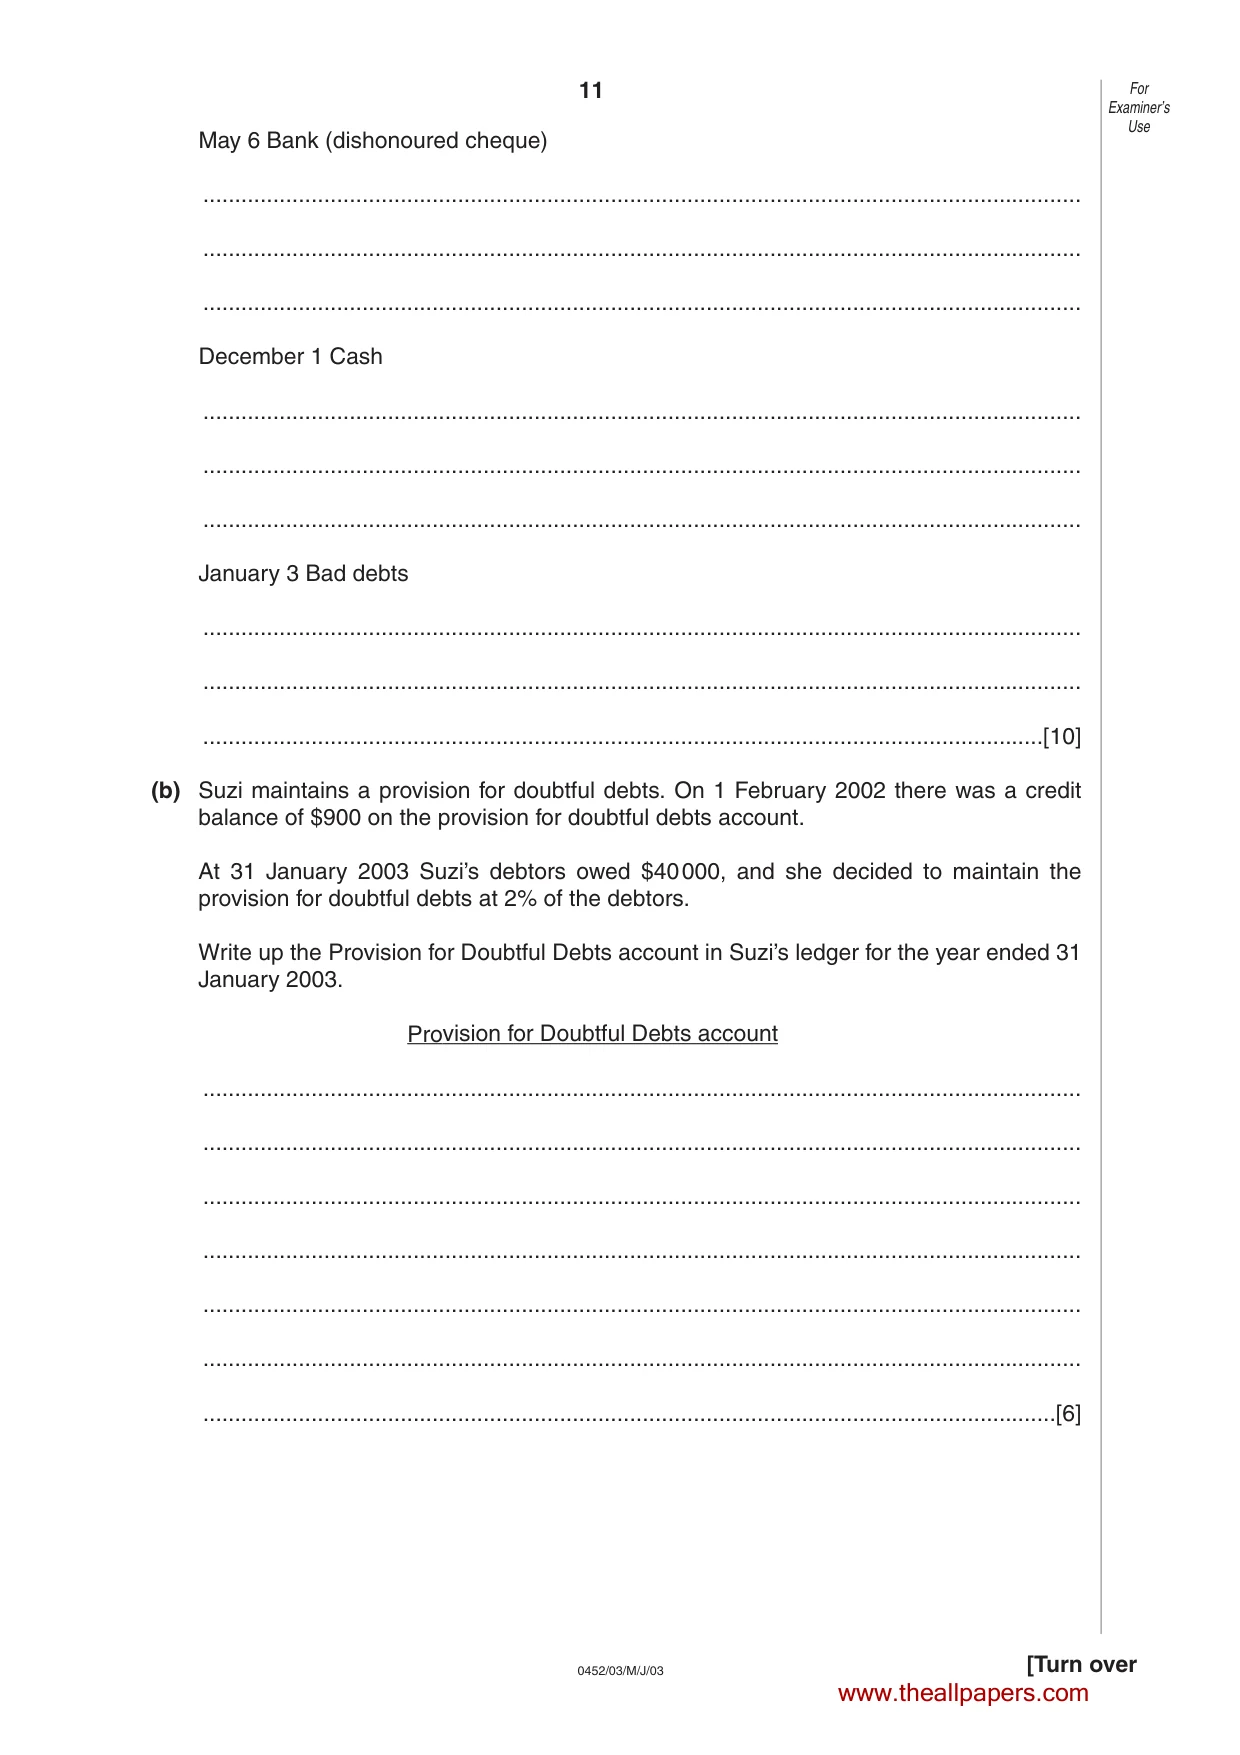
11 0452/03/M/J/03 [Turn over May 6 Bank (dishonoured cheque) … … … December 1 Cash … … … January 3 Bad debts … … …[10] (b) Suzi maintains a provision for doubtful debts. On 1 February 2002 there was a credit balance of $900 on the provision for doubtful debts account. At 31 January 2003 Suzi’s debtors owed $40000, and she decided to maintain the provision for doubtful debts at 2% of the debtors. Write up the Provision for Doubtful Debts account in Suzi’s ledger for the year ended 31 January 2003. Provision for Doubtful Debts account … … … … … … …[6] For Examiner’s Use www.theallpapers.com
Question paper, page 12
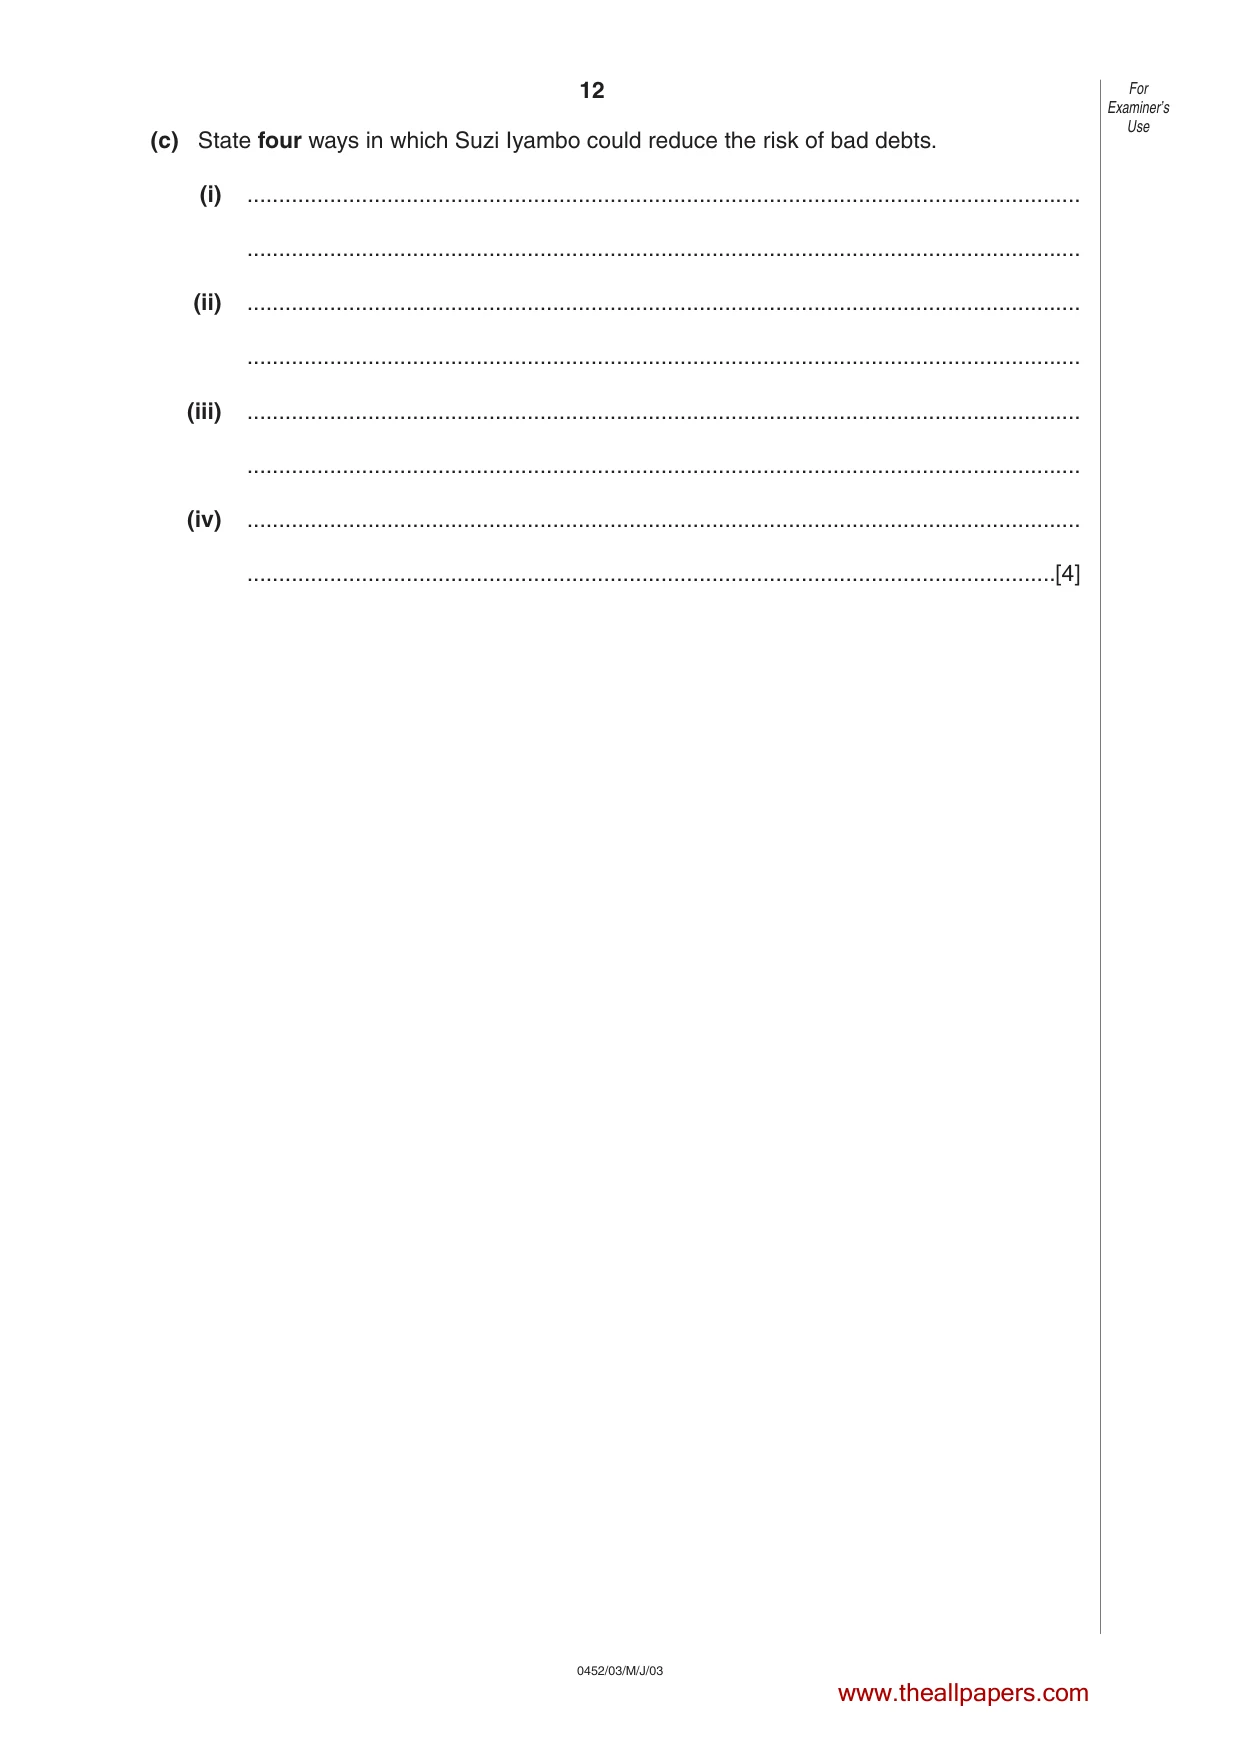
12 0452/03/M/J/03 (c) State four ways in which Suzi Iyambo could reduce the risk of bad debts. (i) … … (ii) … … (iii) … … (iv) … …[4] For Examiner’s Use www.theallpapers.com
Question paper, page 13
13 0452/03/M/J/03 [Turn over BLANK PAGE www.theallpapers.com
Question paper, page 14
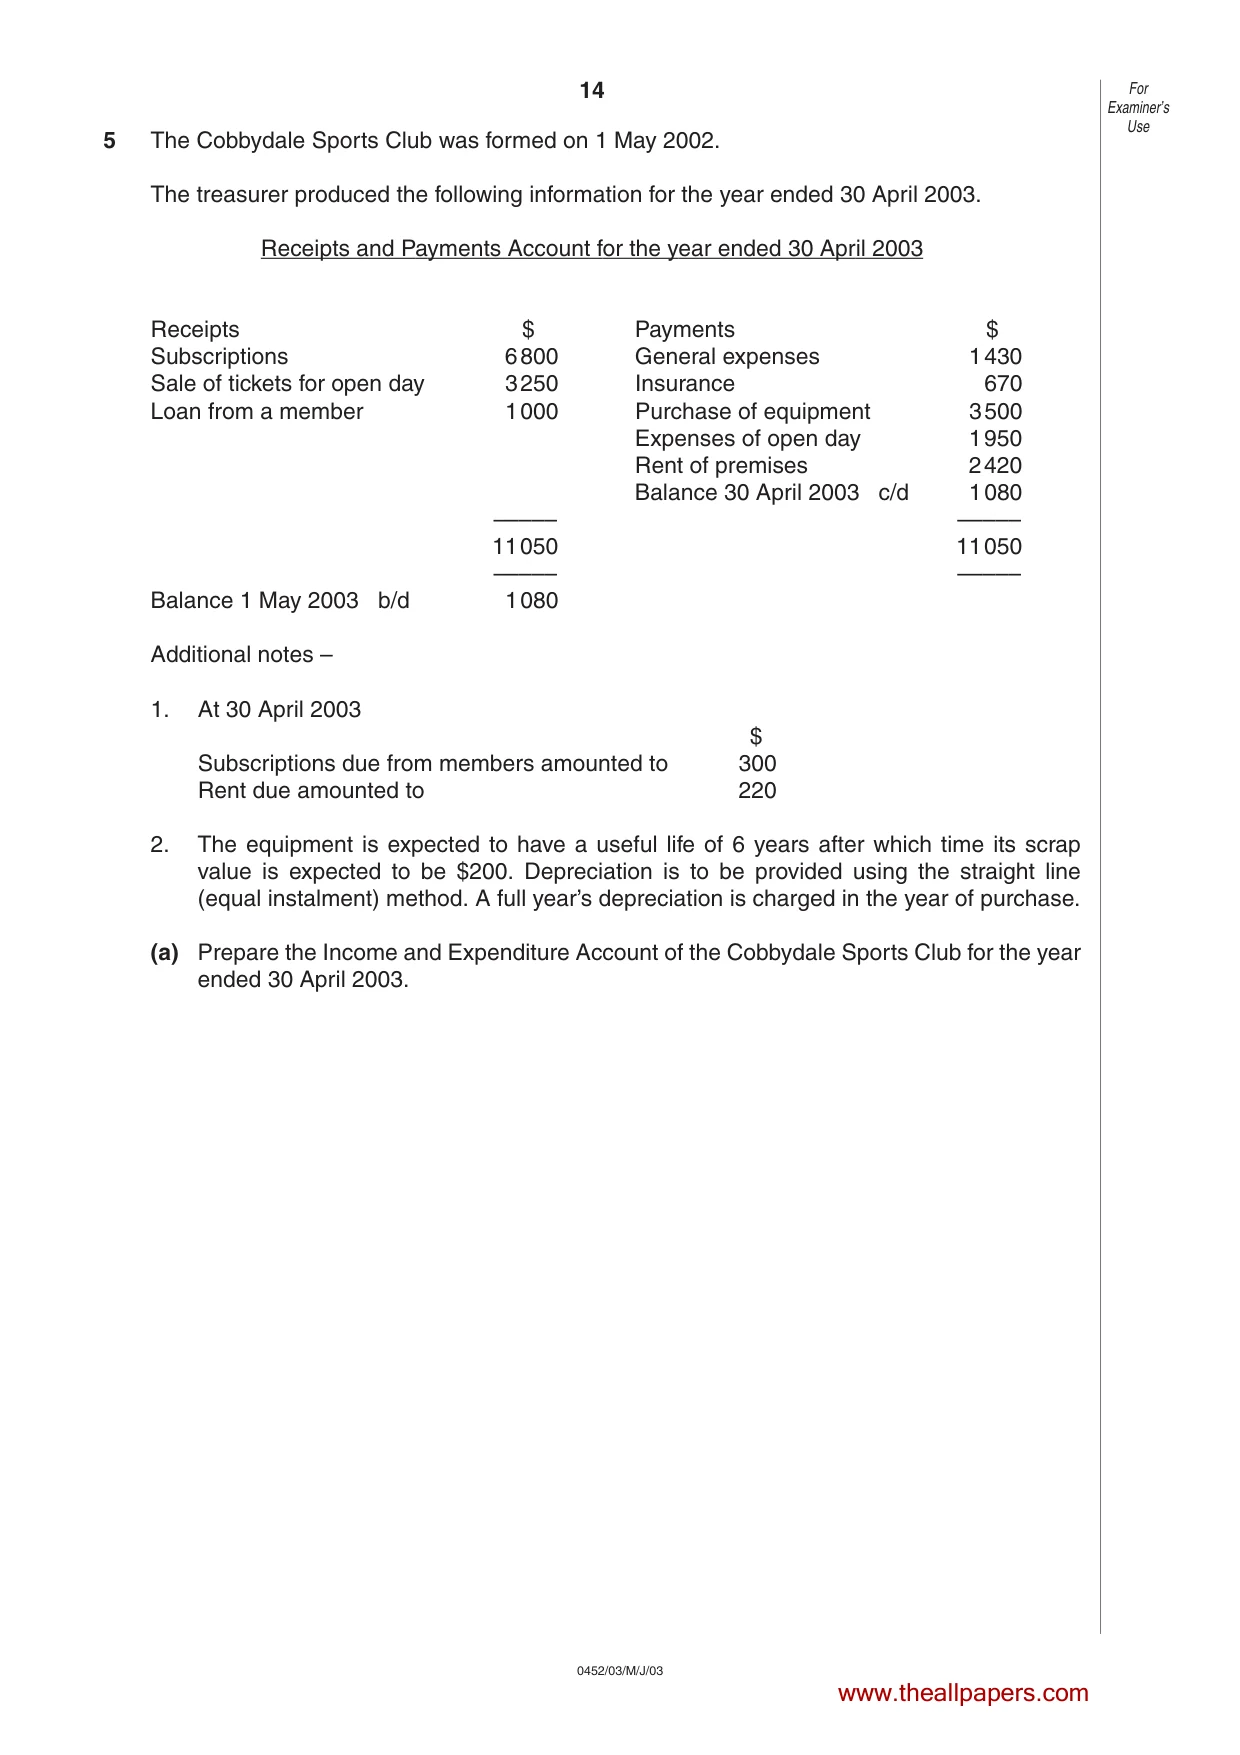
14 0452/03/M/J/03 5 The Cobbydale Sports Club was formed on 1 May 2002. The treasurer produced the following information for the year ended 30 April 2003. Receipts and Payments Account for the year ended 30 April 2003 Receipts $ Payments $ Subscriptions 6800 General expenses 1430 Sale of tickets for open day 3250 Insurance 670 Loan from a member 1000 Purchase of equipment 3500 Expenses of open day 1950 Rent of premises 2420 Balance 30 April 2003 c/d 1080 ––––– ––––– 11050 11050 ––––– ––––– Balance 1 May 2003 b/d 1080 Additional notes – 1. At 30 April 2003 $ Subscriptions due from members amounted to 300 Rent due amounted to 220 2. The equipment is expected to have a useful life of 6 years after which time its scrap value is expected to be $200. Depreciation is to be provided using the straight line (equal instalment) method. A full year’s depreciation is charged in the year of purchase. (a) Prepare the Income and Expenditure Account of the Cobbydale Sports Club for the year ended 30 April 2003. For Examiner’s Use www.theallpapers.com
Question paper, page 15
15 0452/03/M/J/03 [Turn over Cobbydale Sports Club Income and Expenditure Account for the year ended 30 April 2003 … … … … … … … … … … … … … … … …[7] (b) (i) Select one of the items appearing in the Receipts and Payments Account which should not be included in the Income and Expenditure Account and explain why it does not appear. Item … Explanation… … …[2] For Examiner’s Use www.theallpapers.com
Question paper, page 16
16 0452/03/M/J/03 (ii) Select one of the items appearing in the Income and Expenditure Account which does not appear in the Receipts and Payments Account and explain why it does not appear. Item … Explanation… … …[2] (c) Prepare the Balance Sheet of the Cobbydale Sports Club as at 30 April 2003. Cobbydale Sports Club Balance Sheet as at 30 April 2003 … … … … … … … … … … … … … … … … … … …[8] For Examiner’s Use www.theallpapers.com