Cambridge A Level Accounting 9706 — 2025 Oct/Nov Paper 4 · Variant 1
9706/41/O/N/25 · 2 questions · 50 marks · ≈56 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper8 pages
Mark scheme15 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Read Source A in the insert
1 Read Source A in the insert. (a) Calculate the net present value (NPV) of: (i) the new machine ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [3] (ii) the upgraded machine. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [3] (b) Calculate, to two decimal places, the internal rate of return (IRR) of: (i) the new machine ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [3] (ii) the upgraded machine. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [3] (c) Advise the directors which machine they should adopt if Product P were to be made. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [7] Additional information One of the directors raises two issues before making the final decision. 1 In his opinion, the accounting rate of return (ARR) should be the only criterion for making the investment decision.
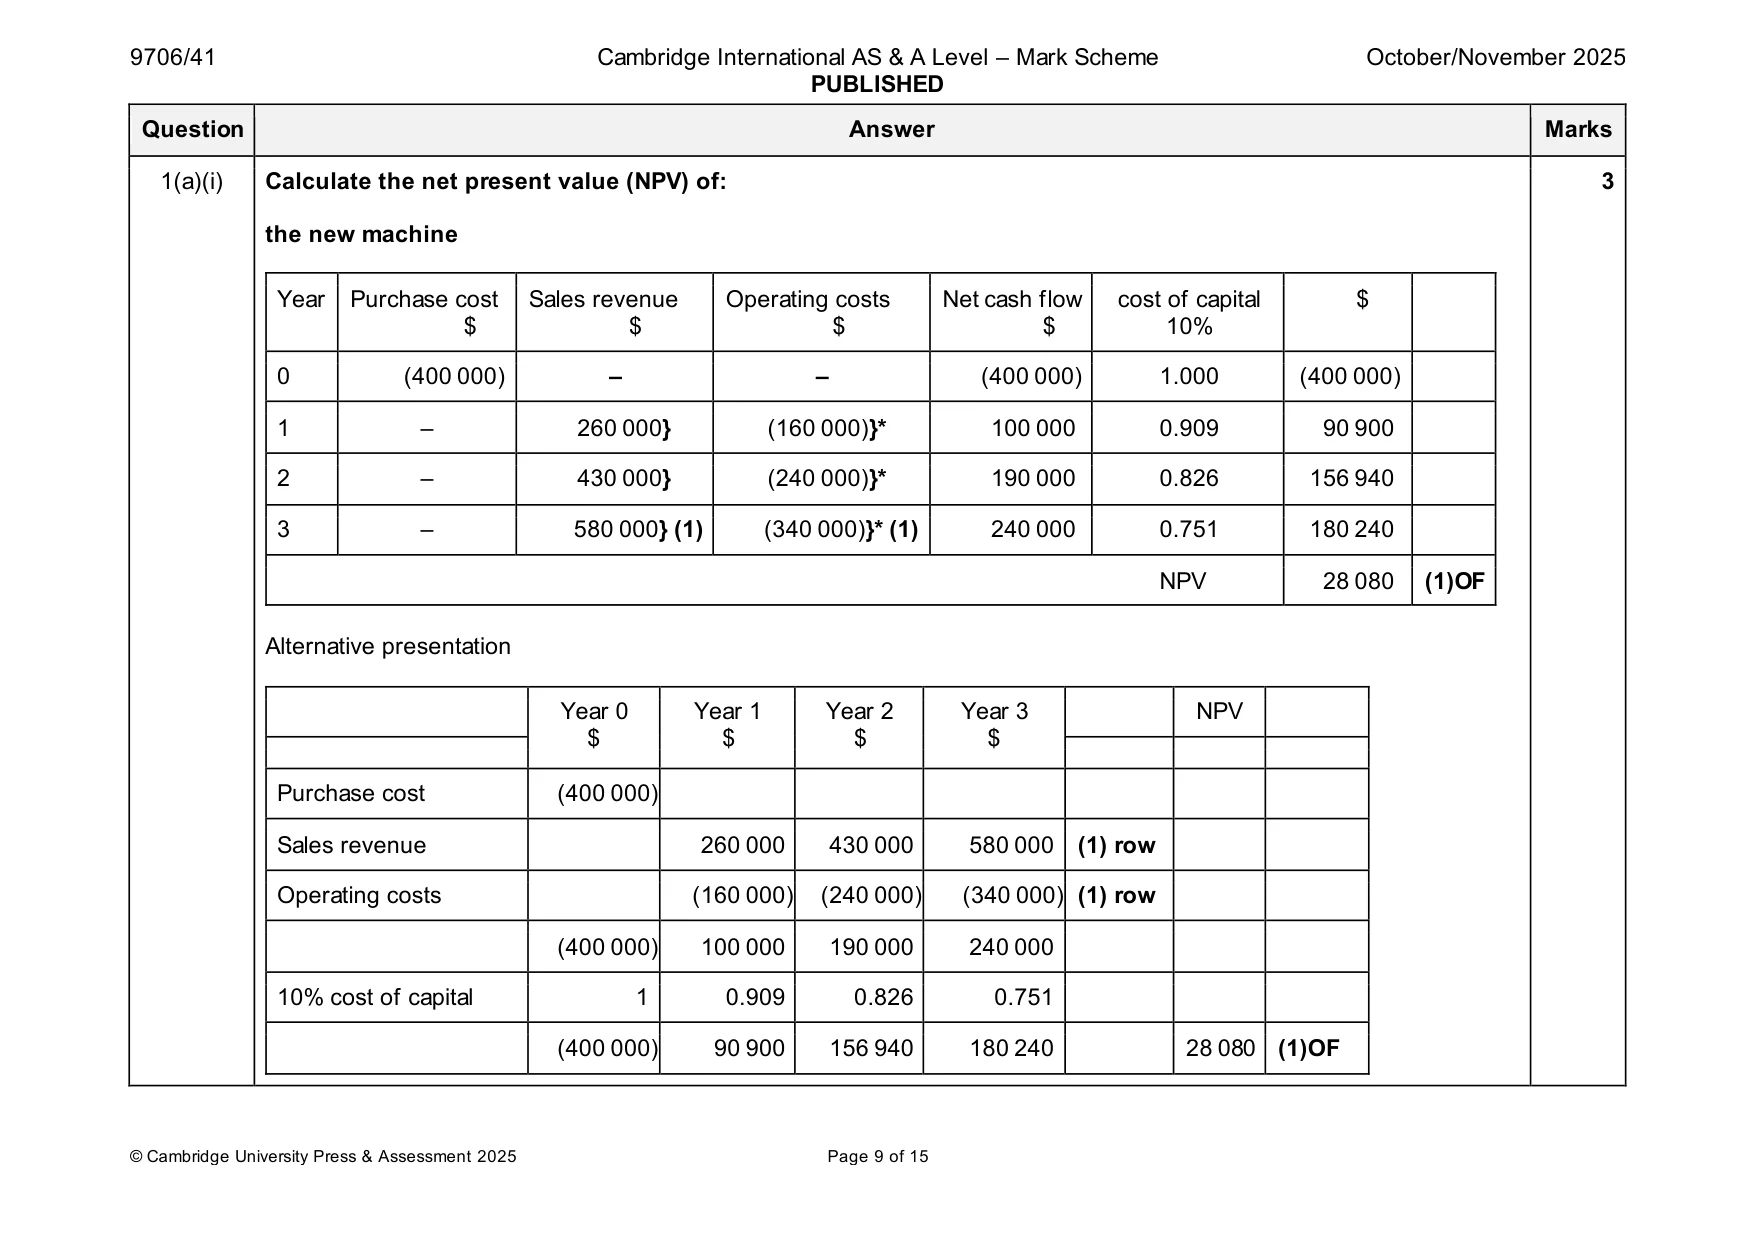
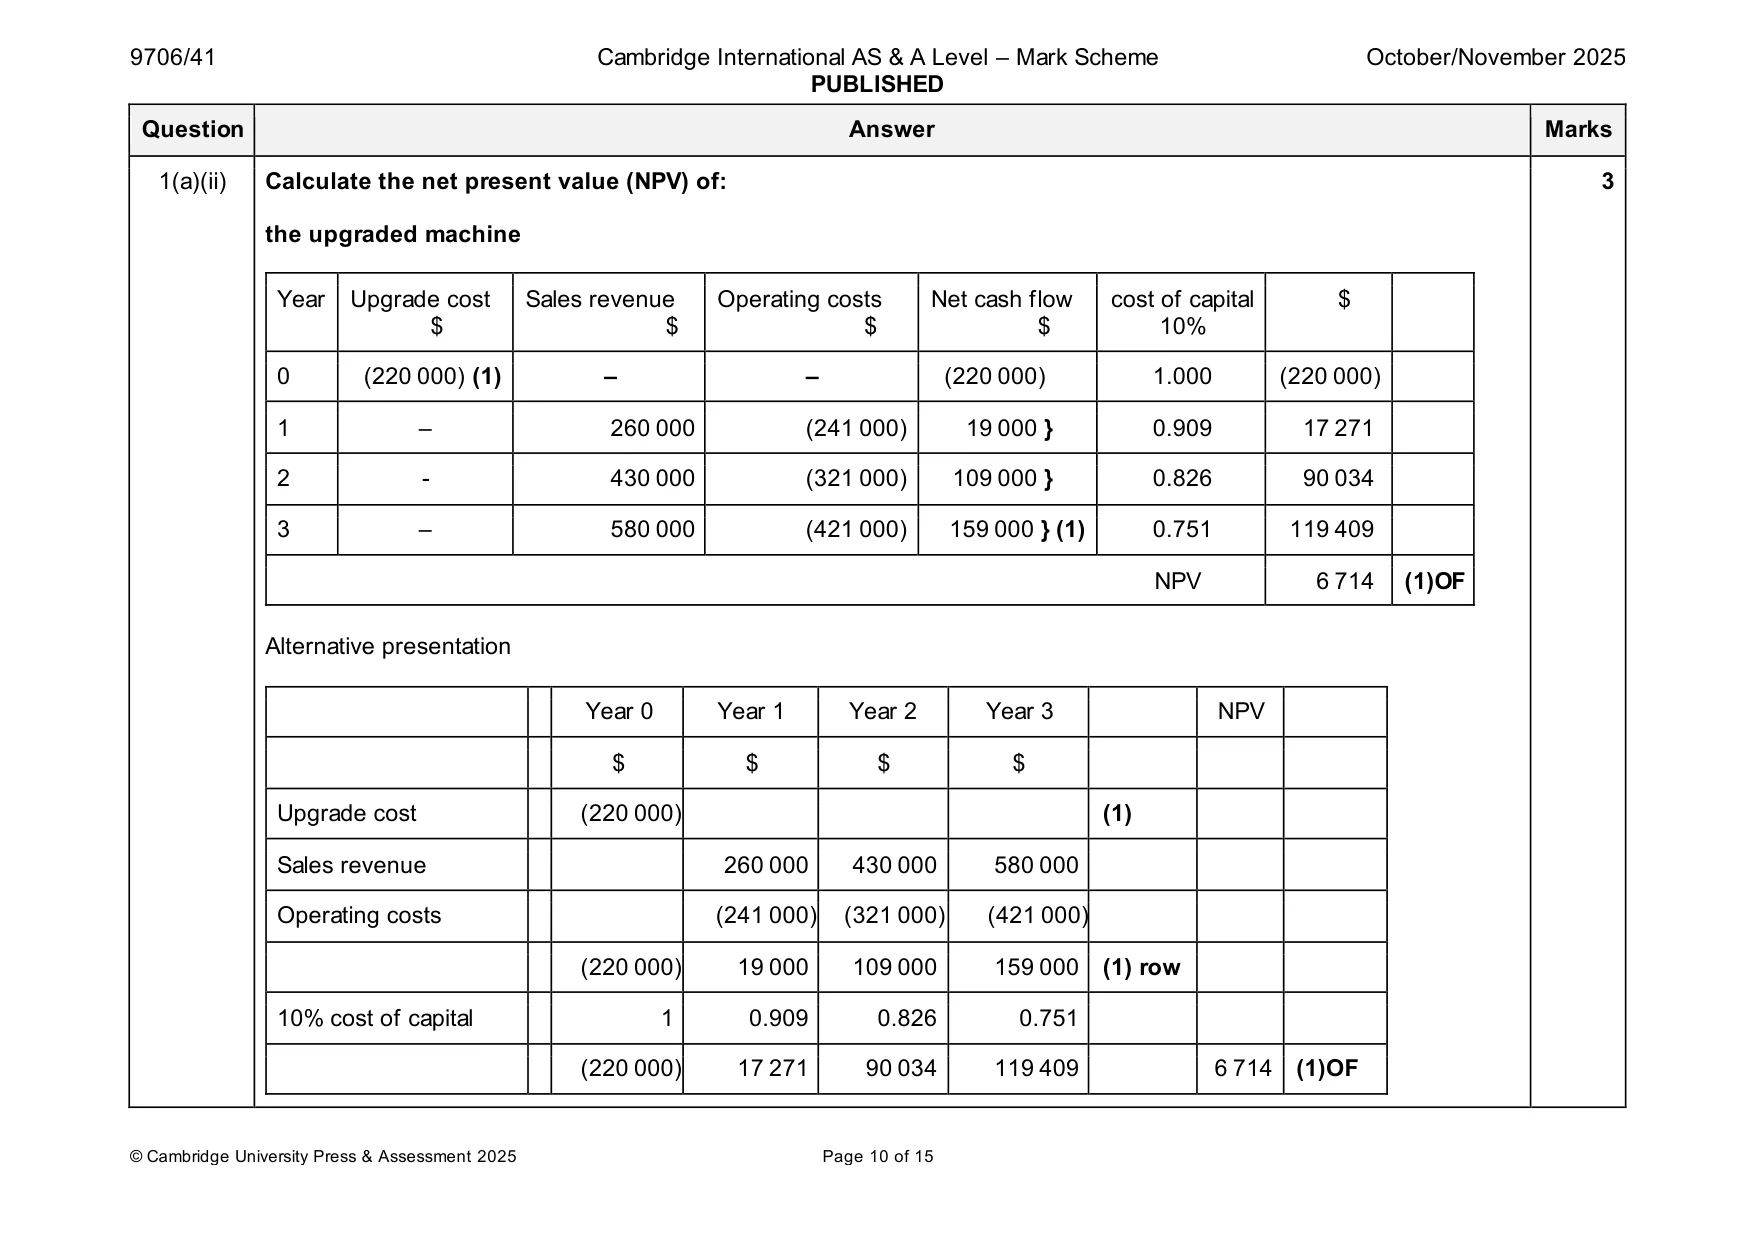
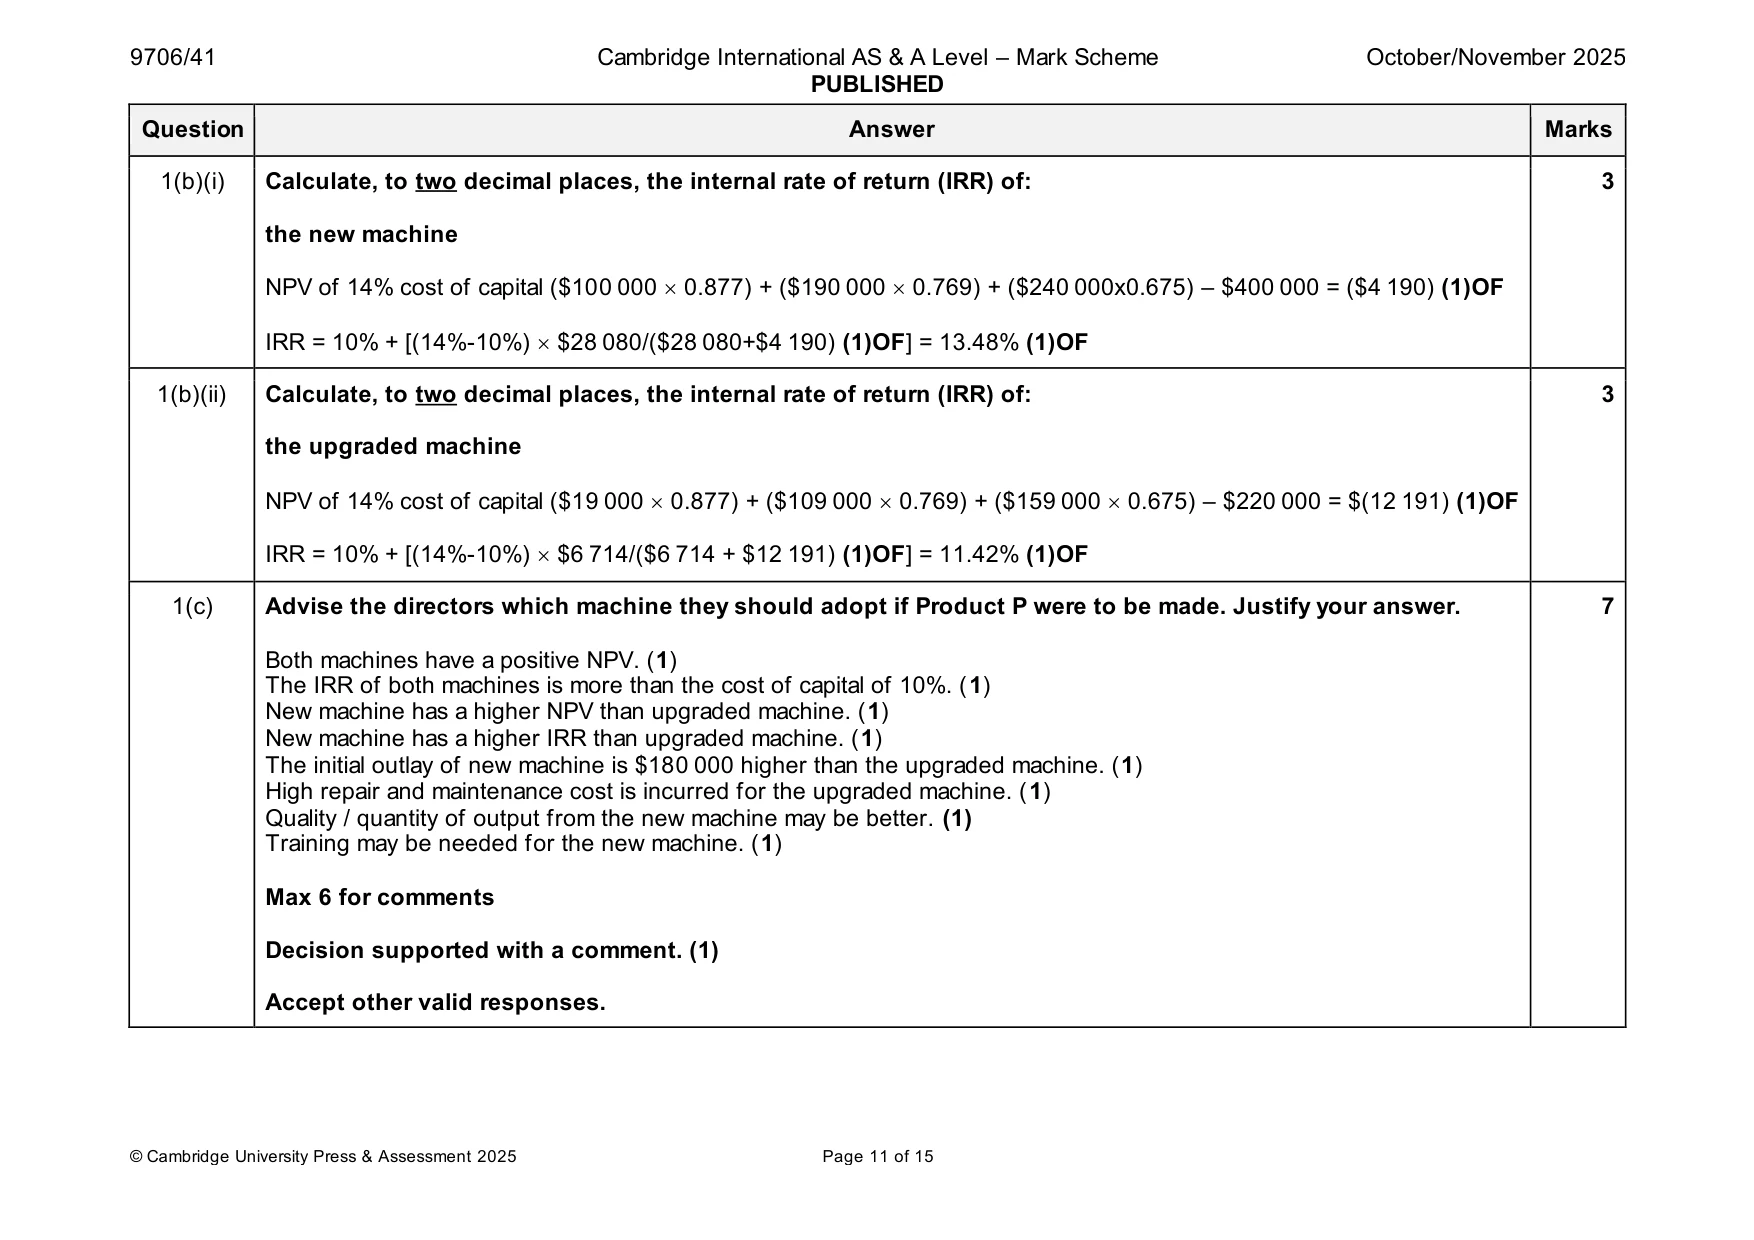
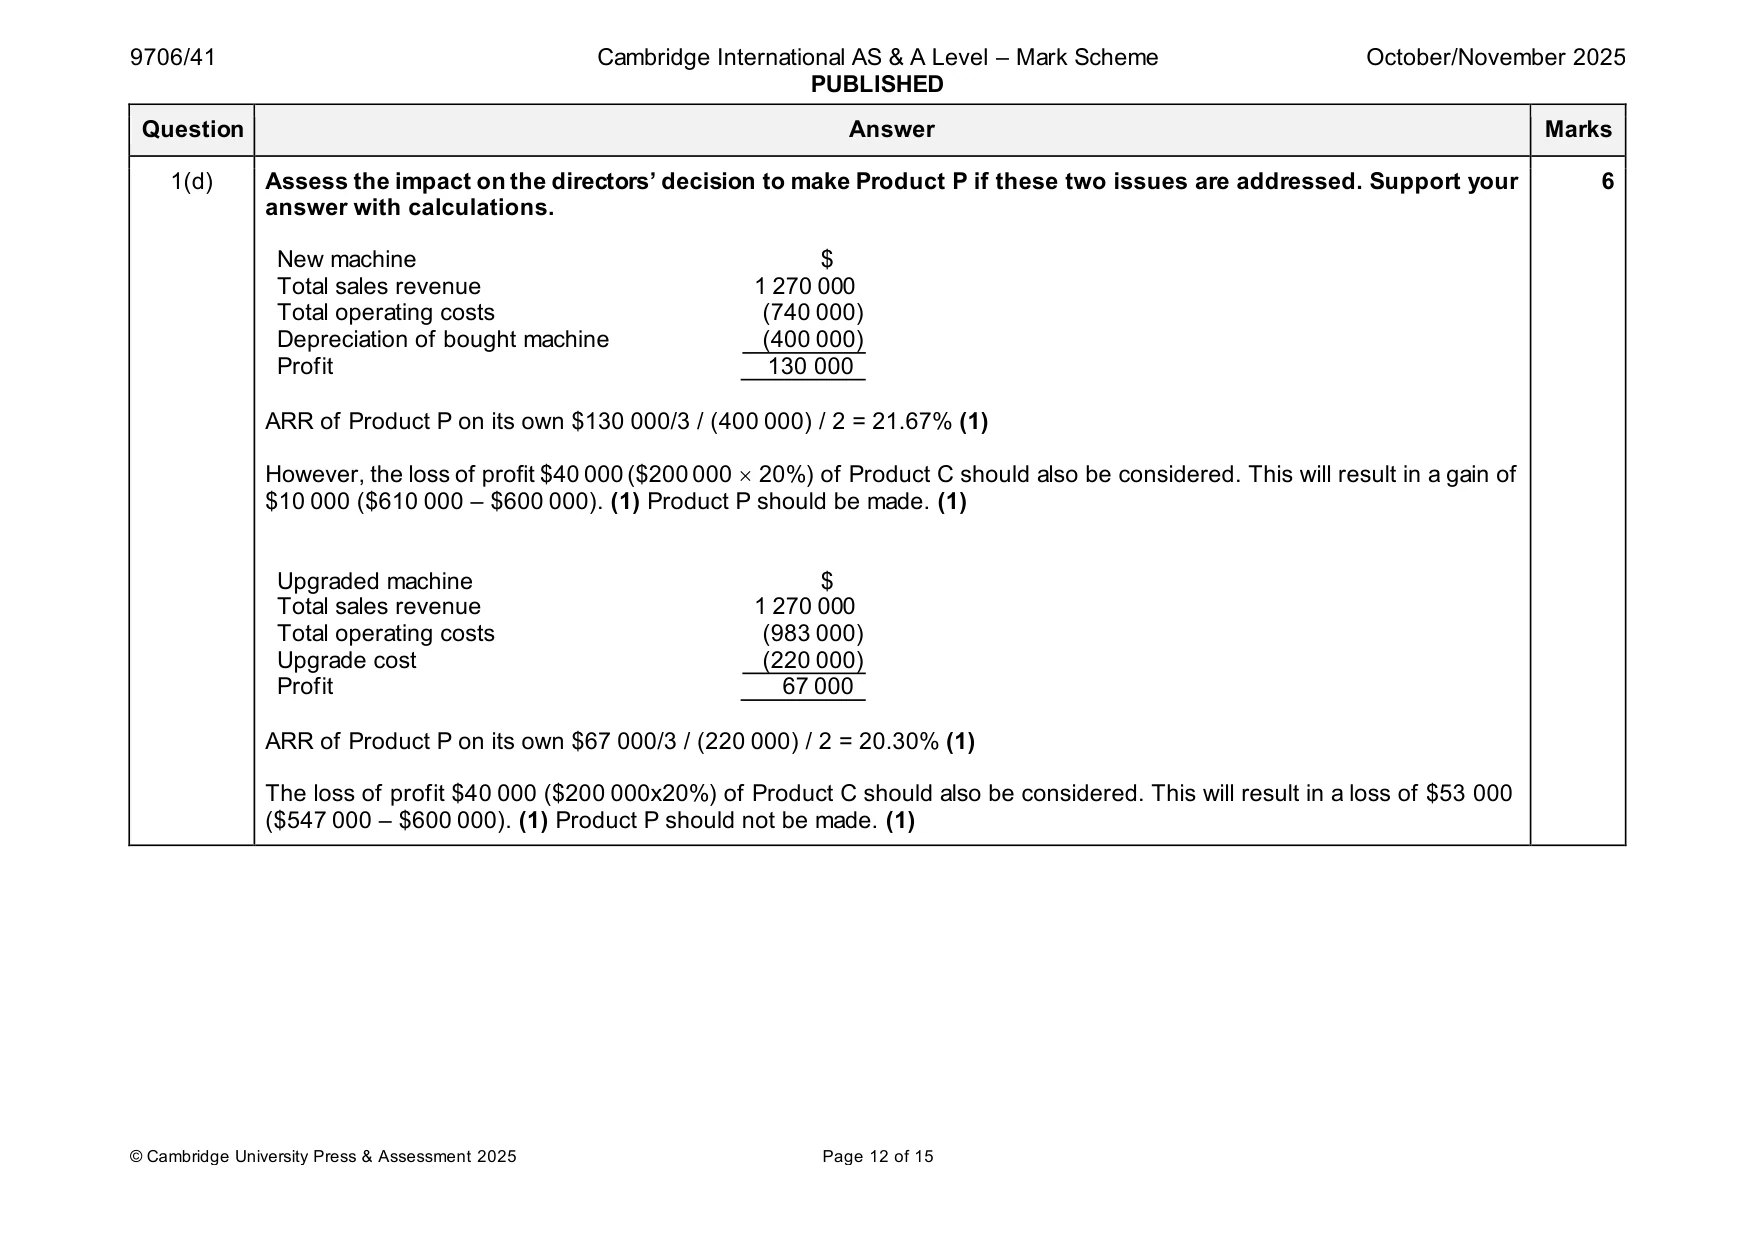
Mark scheme: Question Answer Marks 1(a)(i) Calculate the net present value (NPV) of: 3 the new machine Year Purchase cost Sales revenue Operating costs Net cash flow cost of capital $ $ $ $ $ 10% 0 (400 000) – – (400 000) 1.000 (400 000) 1 – 260 000} (160 000)}* 100 000 0.909 90 900 2 – 430 000} (240 000)}* 190 000 0.826 156 940 3 – 580 000} (1) (340 000)}* (1) 240 000 0.751 180 240 NPV 28 080 (1)OF Alternative presentation Year 0 Year 1 Year 2 Year 3 NPV $ $ $ $ Purchase cost (400 000) Sales revenue 260 000 430 000 580 000 (1) row Operating costs (160 000) (240 000) (340 000) (1) row (400 000) 100 000 190 000 240 000 10% cost of capital 1 0.909 0.826 0.751 (400 000) 90 900 156 940 180 240 28 080 (1)OF 1(a)(ii) Calculate the net present value (NPV) of: 3 the upgraded machine Year Upgrade cost Sales revenue Operating costs Net cash flow cost of capital $ $ $ $ $ 10% 0 (220 000) (1) – – (220 000) 1.000 (220 000) 1 – 260 000 (241 000) 19 000 } 0.909 17 271 2 - 430 000 (321 000) 109 000 } 0.826 90 034 3 – 580 000 (421 000) 159 000 } (1) 0.751 119 409 NPV 6 714 (1)OF Alternative presentation Year 0 Year 1 Year 2 Year 3 NPV $ $ $ $ Upgrade cost (220 000) (1) Sales revenue 260 000 430 000 580 000 Operating costs (241 000) (321 000) (421 000) (220 000) 19 000 109 000 159 000 (1) row 10% cost of capital 1 0.909 0.826 0.751 (220 000) 17 271 90 034 119 409 6 714 (1)OF 1(b)(i) Calculate, to two decimal places, the internal rate of return (IRR) of: 3 the new machine NPV of 14% cost of capital ($100 000 0.877) + ($190 000 0.769) + ($240 000x0.675) – $400 000 = ($4 190) (1)OF IRR = 10% + [(14%-10%) $28 080/($28 080+$4 190) (1)OF] = 13.48% (1)OF 1(b)(ii) Calculate, to two decimal places, the internal rate of return (IRR) of: 3 the upgraded machine NPV of 14% cost of capital ($19 000 0.877) + ($109 000 0.769) + ($159 000 0.675) – $220 000 = $(12 191) (1)OF IRR = 10% + [(14%-10%) $6 714/($6 714 + $12 191) (1)OF] = 11.42% (1)OF 1(c) Advise the directors which machine they should adopt if Product P were to be made. Justify your answer. 7 Both machines have a positive NPV. (1) The IRR of both machines is more than the cost of capital of 10%. (1) New machine has a higher NPV than upgraded machine. (1) New machine has a higher IRR than upgraded machine. (1) The initial outlay of new machine is $180 000 higher than the upgraded machine. (1) High repair and maintenance cost is incurred for the upgraded machine. (1) Quality / quantity of output from the new machine may be better. (1) Training may be needed for the new machine. (1) Max 6 for comments Decision supported with a comment. (1) Accept other valid responses. 1(d) Assess the impact on the directors’ decision to make Product P if these two issues are addressed. Support your 6 answer with calculations. New machine $ Total sales revenue 1 270 000 Total operating costs (740 000) Depreciation of bought machine (400 000) Profit 130 000 ARR of Product P on its own $130 000/3 / (400 000) / 2 = 21.67% (1) However, the loss of profit $40 000 ($200 000 20%) of Product C should also be considered. This will result in a gain of $10 000 ($610 000 – $600 000). (1) Product P should be made. (1) Upgraded machine $ Total sales revenue 1 270 000 Total operating costs (983 000) Upgrade cost (220 000) Profit 67 000 ARR of Product P on its own $67 000/3 / (220 000) / 2 = 20.30% (1) The loss of profit $40 000 ($200 000x20%) of Product C should also be considered. This will result in a loss of $53 000 ($547 000 – $600 000). (1) Product P should not be made. (1)
Q2 · X Limited is currently making Product C which consistently generates an annual profit of…
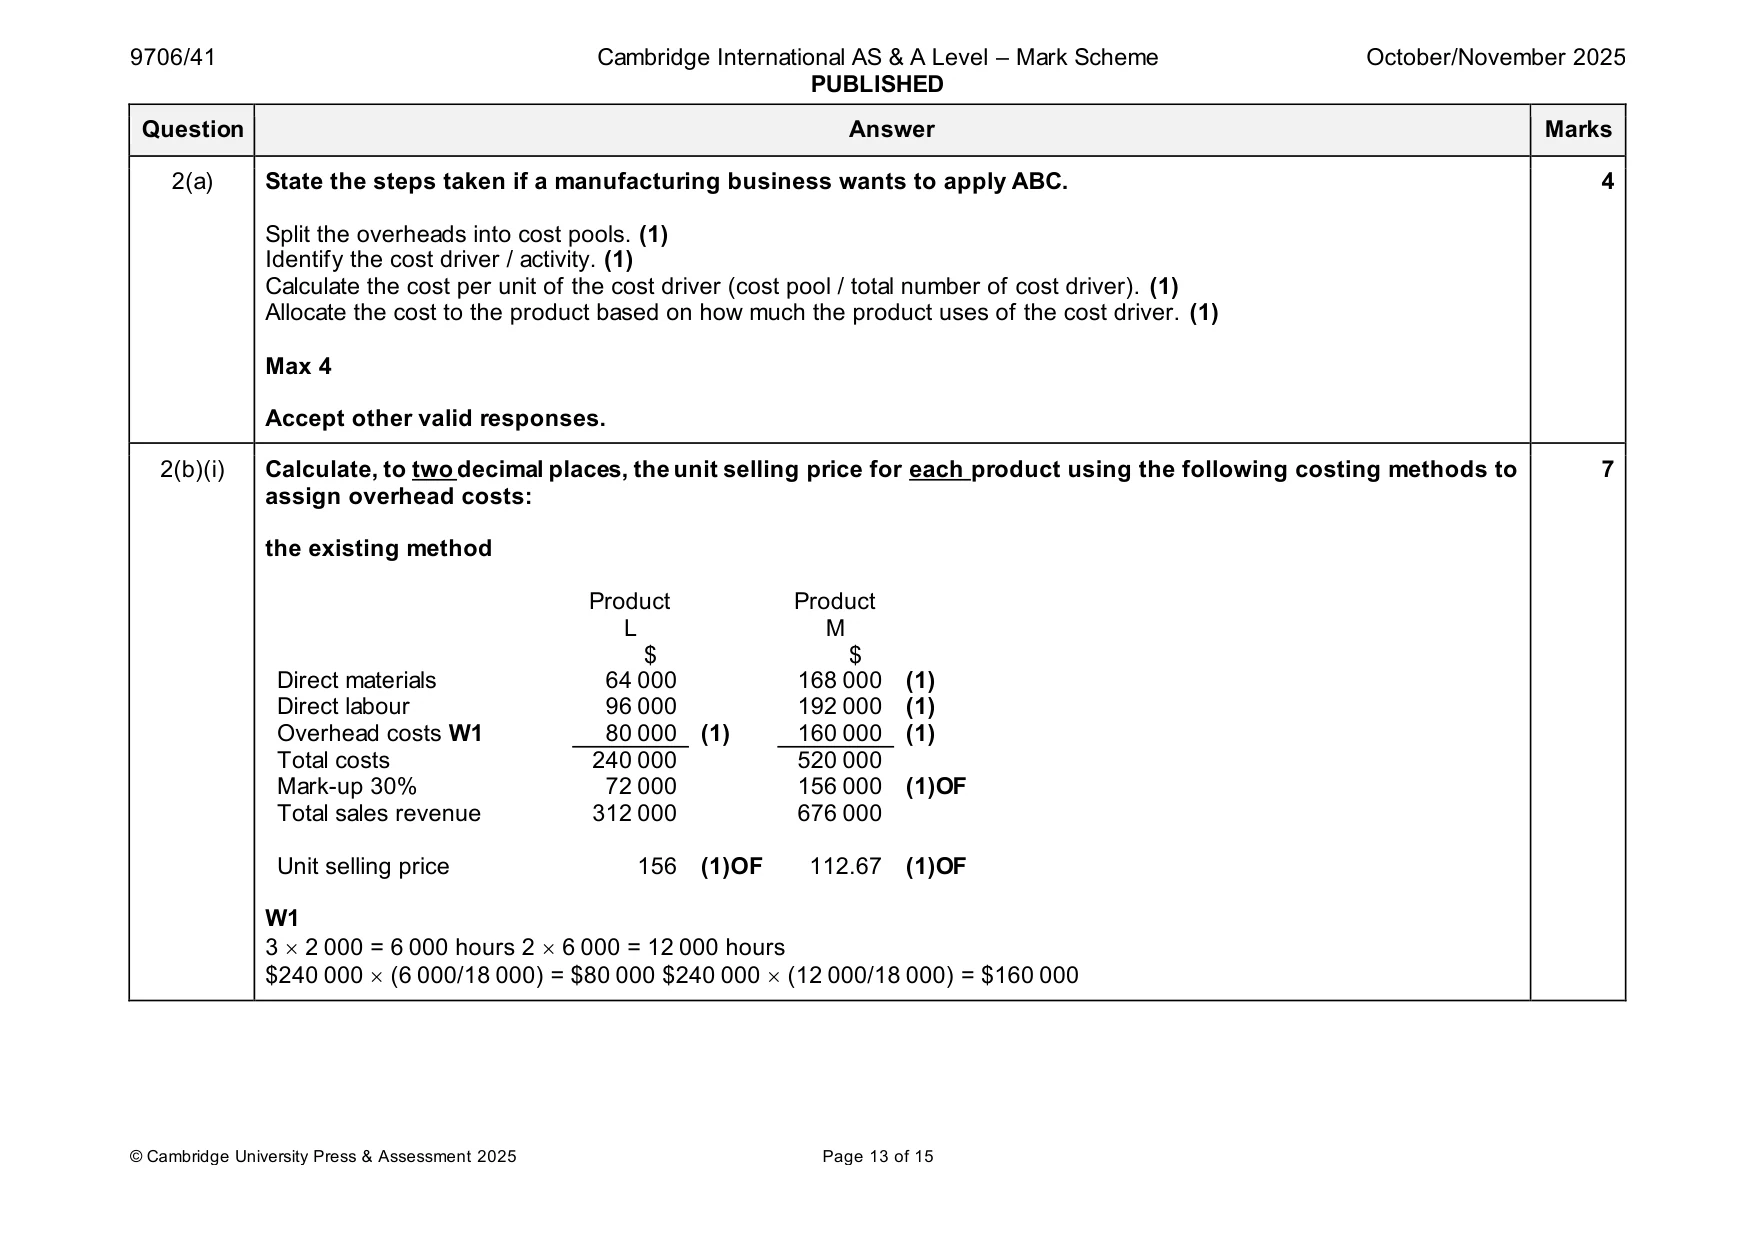
2 X Limited is currently making Product C which consistently generates an annual profit of $200 000. If the directors decide to make Product P, 20% of the production capacity of Product C will need to be used for Product P. (d) Assess the impact on the directors’ decision to make Product P if these two issues are addressed. Support your answer with calculations. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [6] [Total: 25] 2 Read Source B in the insert. (a) State the steps taken if a manufacturing business wants to apply ABC. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] (b) Calculate, to two decimal places, the unit selling price for each product using the following costing methods to assign overhead costs: (i) the existing method ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... Workings:
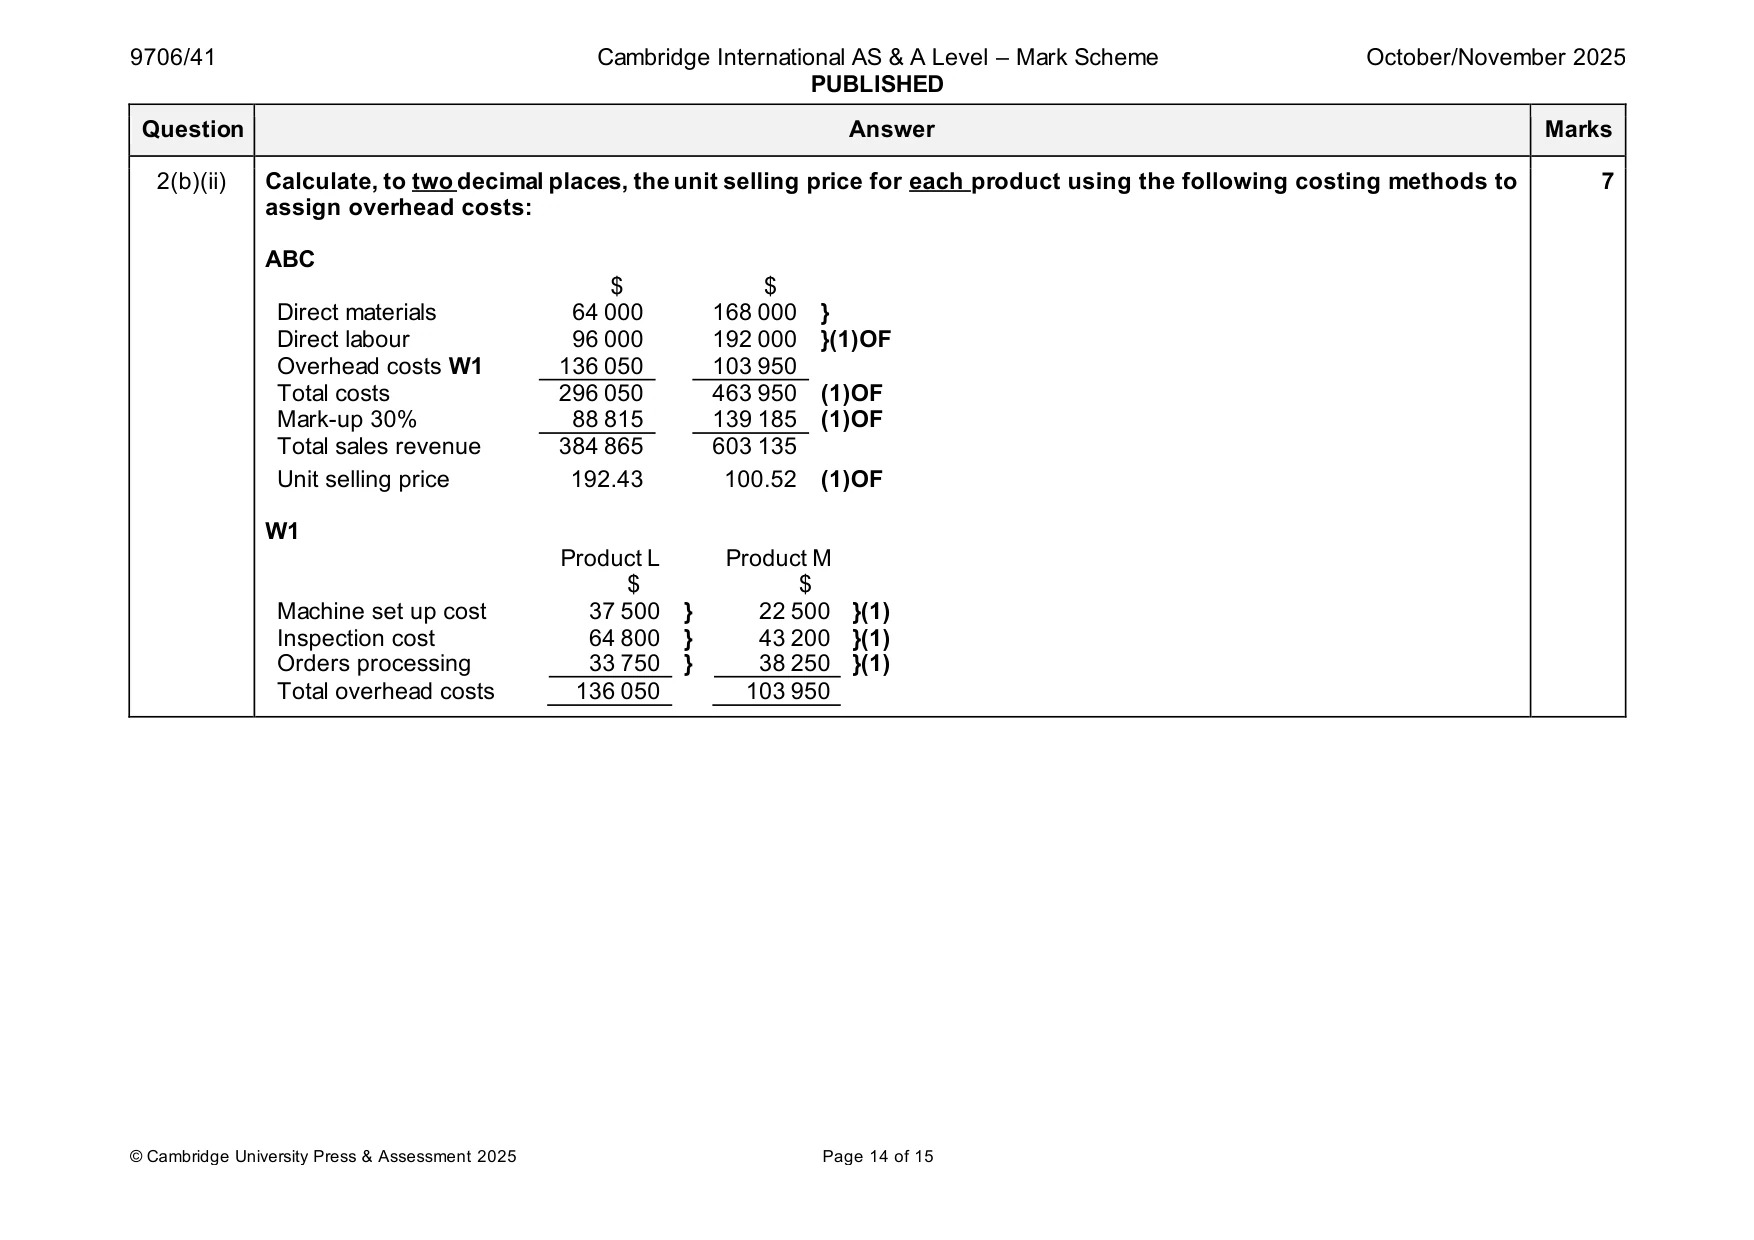
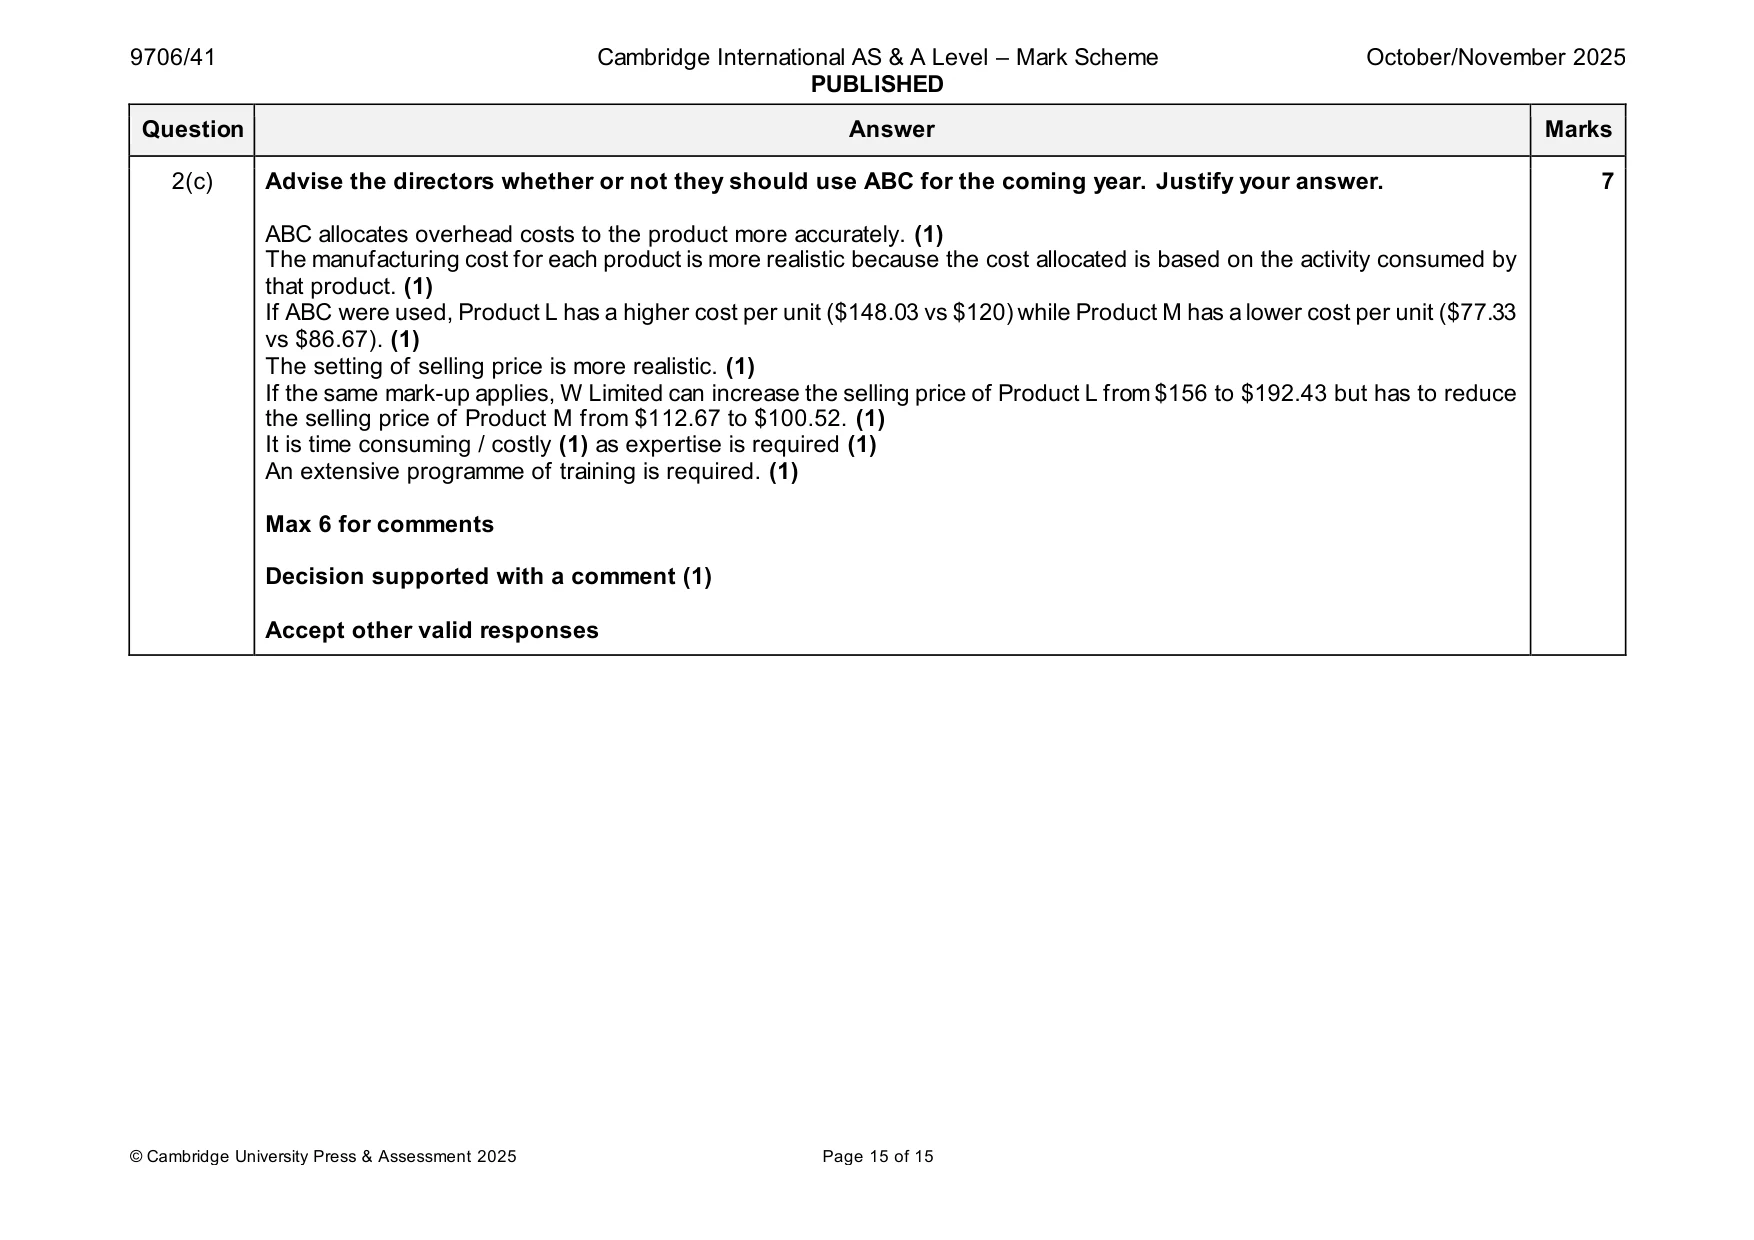
Mark scheme: 2(a) State the steps taken if a manufacturing business wants to apply ABC. 4 Split the overheads into cost pools. (1) Identify the cost driver / activity. (1) Calculate the cost per unit of the cost driver (cost pool / total number of cost driver). (1) Allocate the cost to the product based on how much the product uses of the cost driver. (1) Max 4 Accept other valid responses. 2(b)(i) Calculate, to two decimal places, the unit selling price for each product using the following costing methods to 7 assign overhead costs: the existing method Product Product L M $ $ Direct materials 64 000 168 000 (1) Direct labour 96 000 192 000 (1) Overhead costs W1 80 000 (1) 160 000 (1) Total costs 240 000 520 000 Mark-up 30% 72 000 156 000 (1)OF Total sales revenue 312 000 676 000 Unit selling price 156 (1)OF 112.67 (1)OF W1 3 2 000 = 6 000 hours 2 6 000 = 12 000 hours $240 000 (6 000/18 000) = $80 000 $240 000 (12 000/18 000) = $160 000 2(b)(ii) Calculate, to two decimal places, the unit selling price for each product using the following costing methods to 7 assign overhead costs: ABC $ $ Direct materials 64 000 168 000 } Direct labour 96 000 192 000 }(1)OF Overhead costs W1 136 050 103 950 Total costs 296 050 463 950 (1)OF Mark-up 30% 88 815 139 185 (1)OF Total sales revenue 384 865 603 135 Unit selling price 192.43 100.52 (1)OF W1 Product L Product M $ $ Machine set up cost 37 500 } 22 500 }(1) Inspection cost 64 800 } 43 200 }(1) Orders processing 33 750 } 38 250 }(1) Total overhead costs 136 050 103 950 2(c) Advise the directors whether or not they should use ABC for the coming year. Justify your answer. 7 ABC allocates overhead costs to the product more accurately. (1) The manufacturing cost for each product is more realistic because the cost allocated is based on the activity consumed by that product. (1) If ABC were used, Product L has a higher cost per unit ($148.03 vs $120) while Product M has a lower cost per unit ($77.33 vs $86.67). (1) The setting of selling price is more realistic. (1) If the same mark-up applies, W Limited can increase the selling price of Product L from $156 to $192.43 but has to reduce the selling price of Product M from $112.67 to $100.52. (1) It is time consuming / costly (1) as expertise is required (1) An extensive programme of training is required. (1) Max 6 for comments Decision supported with a comment (1) Accept other valid responses
What was in this paper
The subtopics covered by these 2 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2025 Oct/Nov, Paper 4 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.