Cambridge A Level Accounting 9706 — 2023 Feb/March Paper 2 · Variant 2
9706/22/F/M/23 · 6 questions · 90 marks · ≈101 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme16 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Nibras and Raif are in partnership
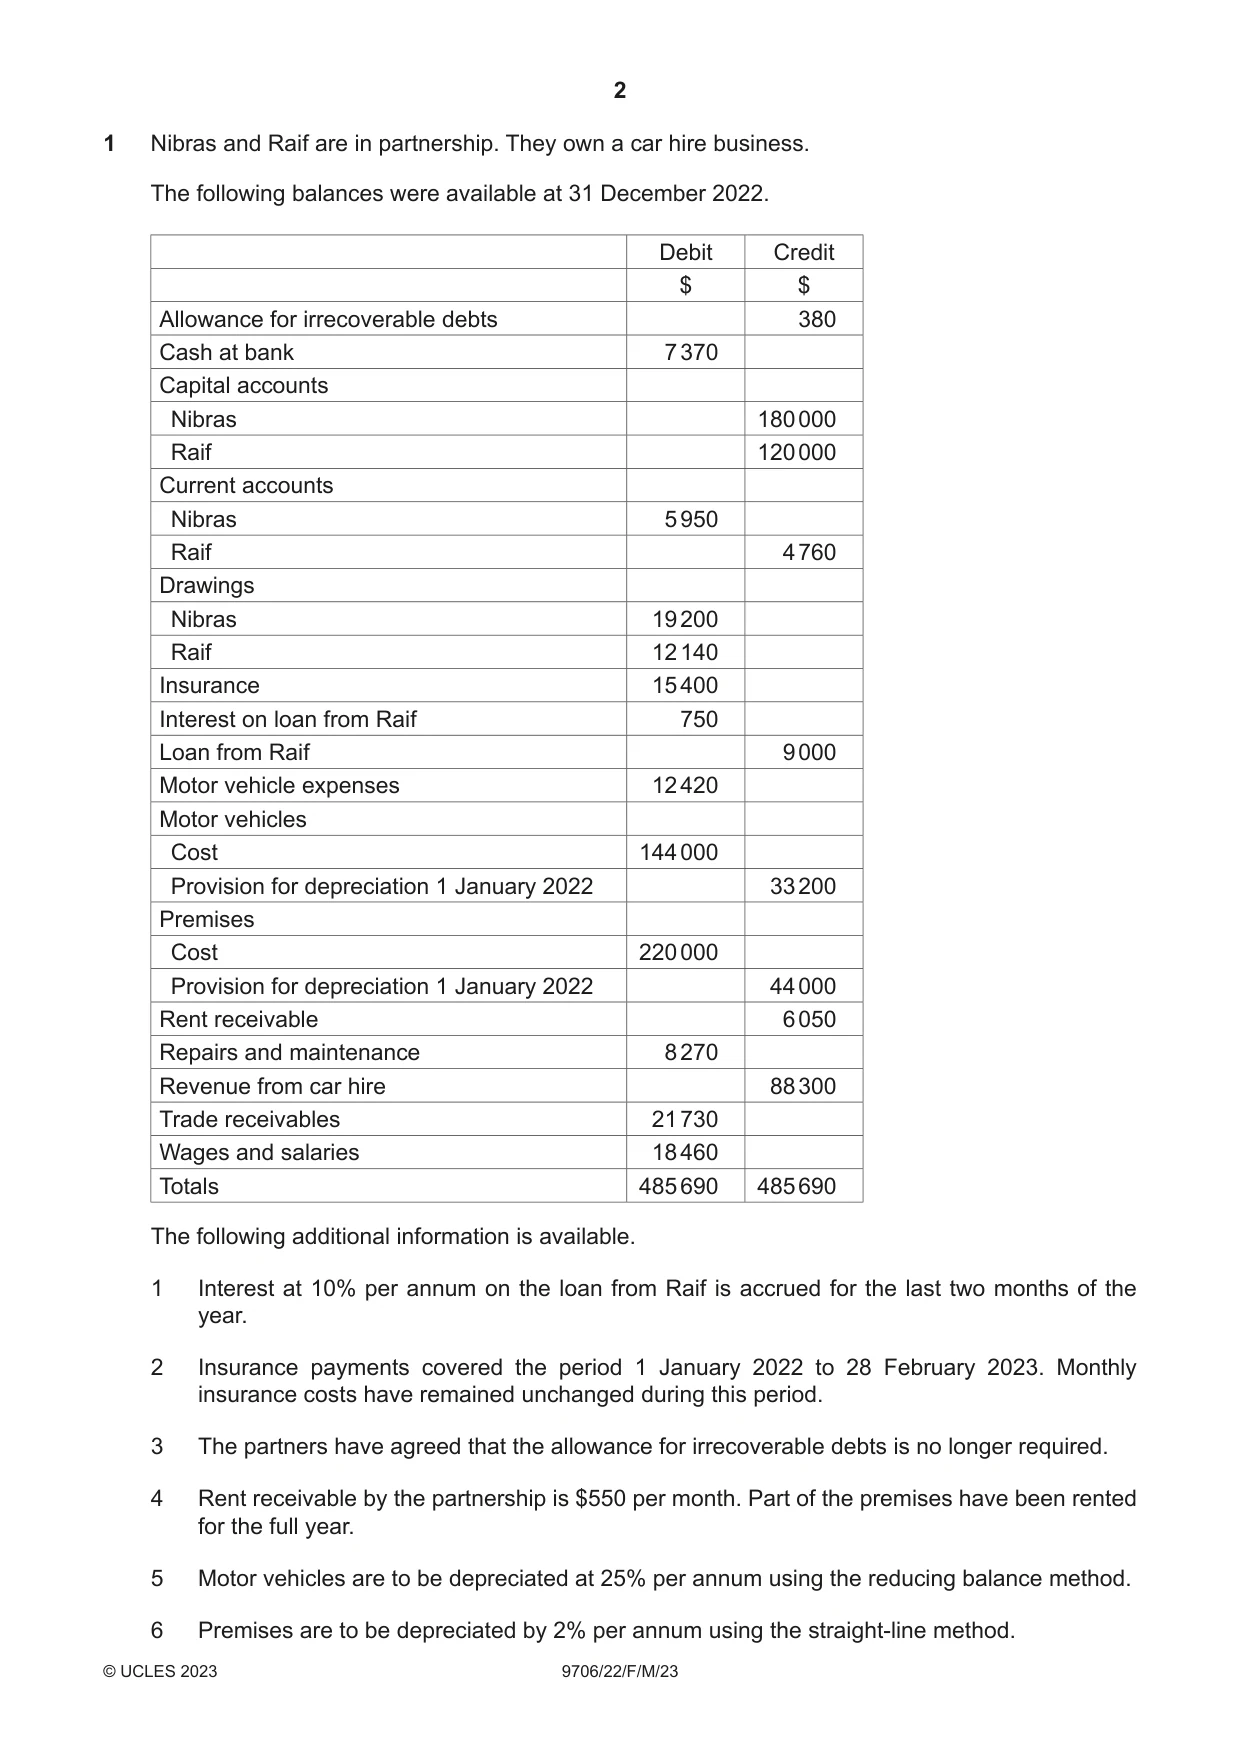
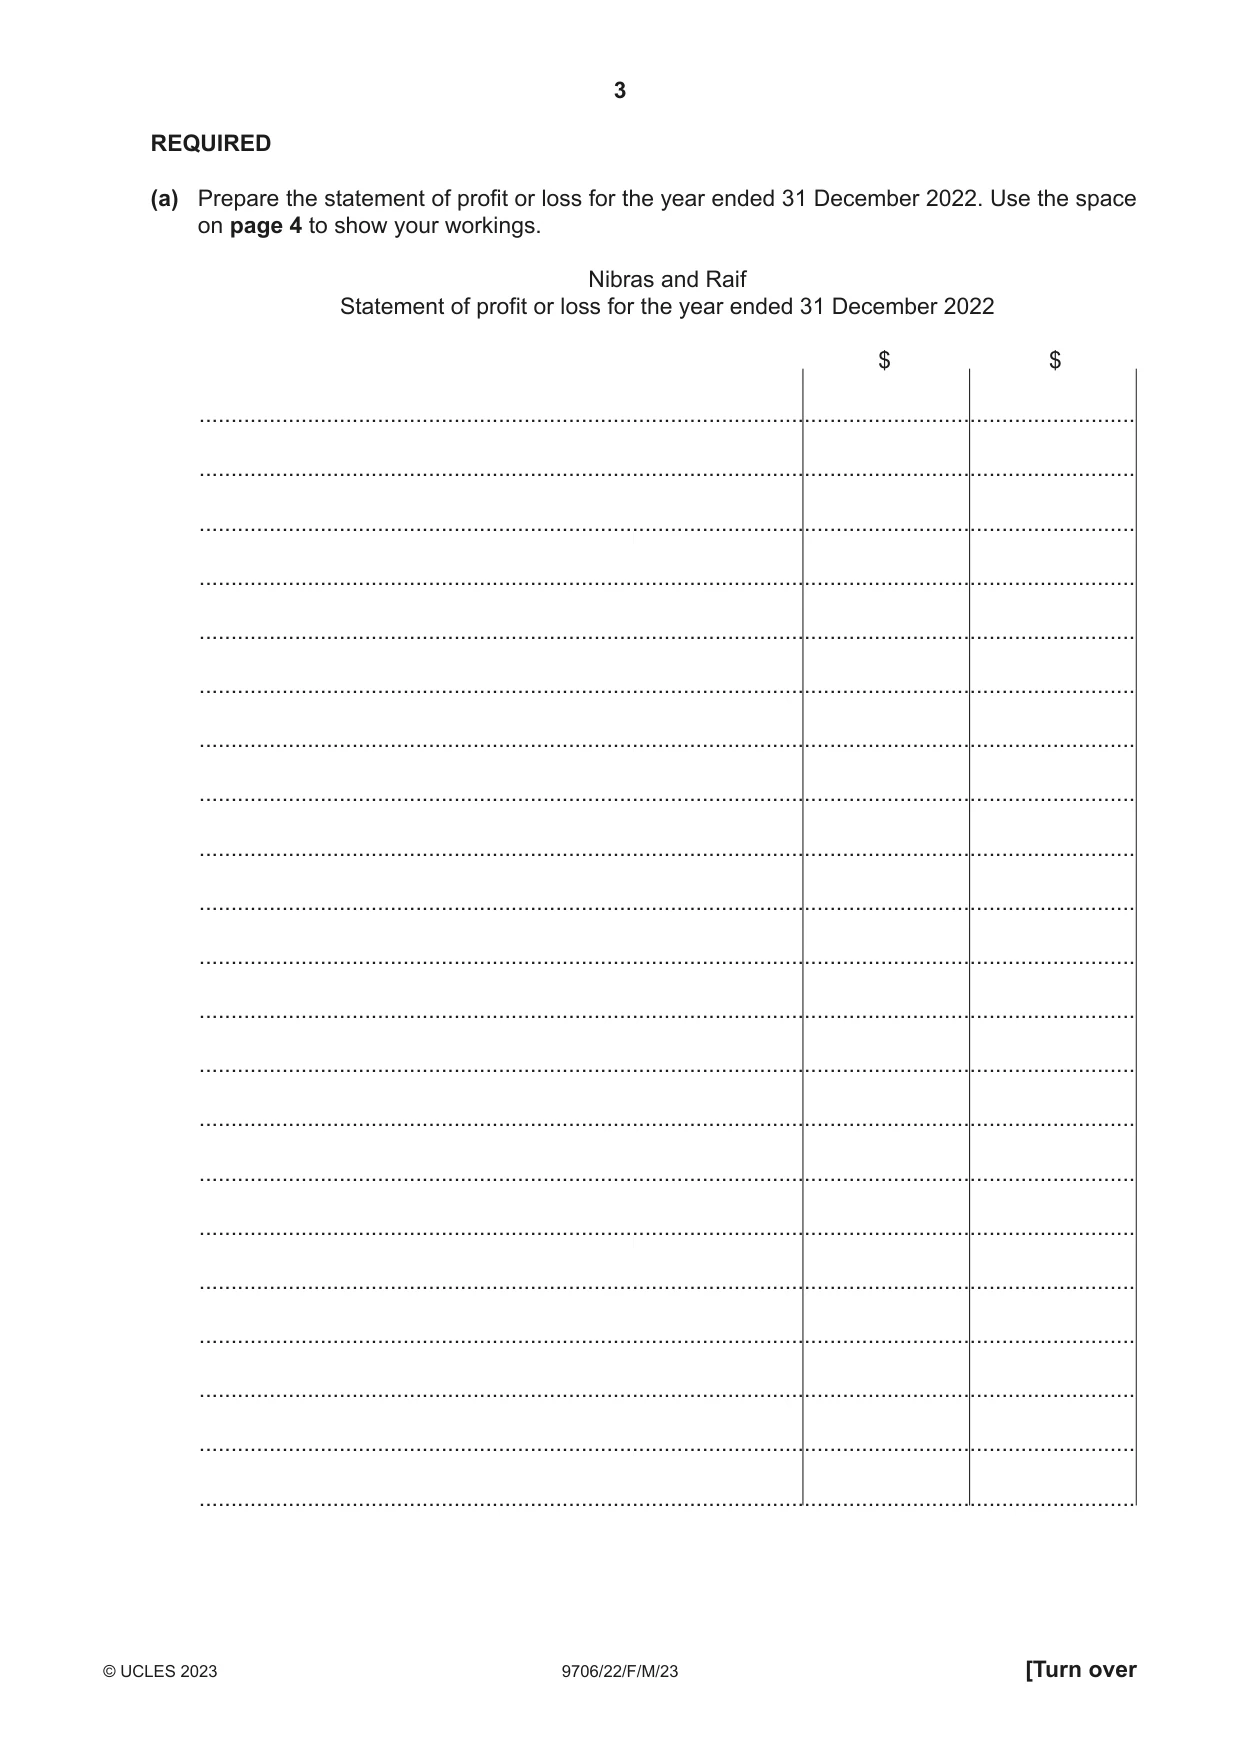
1 Nibras and Raif are in partnership. They own a car hire business. The following balances were available at 31 December 2022. Debit Credit $ $ Allowance for irrecoverable debts 380 Cash at bank 7 370 Capital accounts Nibras 180 000 Raif 120 000 Current accounts Nibras 5 950 Raif 4 760 Drawings Nibras 19 200 Raif 12 140 Insurance 15 400 Interest on loan from Raif 750 Loan from Raif 9 000 Motor vehicle expenses 12 420 Motor vehicles Cost 144 000 Provision for depreciation 1 January 2022 33 200 Premises Cost 220 000 Provision for depreciation 1 January 2022 44 000 Rent receivable 6 050 Repairs and maintenance 8 270 Revenue from car hire 88 300 Trade receivables 21 730 Wages and salaries 18 460 Totals 485 690 485 690 The following additional information is available. 1 Interest at 10% per annum on the loan from Raif is accrued for the last two months of the year. 2 Insurance payments covered the period 1 January 2022 to 28 February 2023. Monthly insurance costs have remained unchanged during this period. 3 The partners have agreed that the allowance for irrecoverable debts is no longer required. 4 Rent receivable by the partnership is $550 per month. Part of the premises have been rented for the full year. 5 Motor vehicles are to be depreciated at 25% per annum using the reducing balance method. 6 Premises are to be depreciated by 2% per annum using the straight-line method. REQUIRED (a) Prepare the statement of profit or loss for the year ended 3 on page 4 to show your workings. Nibras and Raif Statement of profit or loss for the year ended .............................................................................................. .............................................................................................. .............................................................................................. .............................................................................................. .............................................................................................. .............................................................................................. .............................................................................................. .............................................................................................. .............................................................................................. .............................................................................................. .............................................................................................. .............................................................................................. .............................................................................................. .............................................................................................. .............................................................................................. .............................................................................................. .............................................................................................. .............................................................................................. .............................................................................................. .............................................................................................. .............................................................................................. Workings: [9] Additional information Nibras and Raif agreed the following terms for the appropriation of profits and losses. 1 Interest on capital to be 10% per annum.
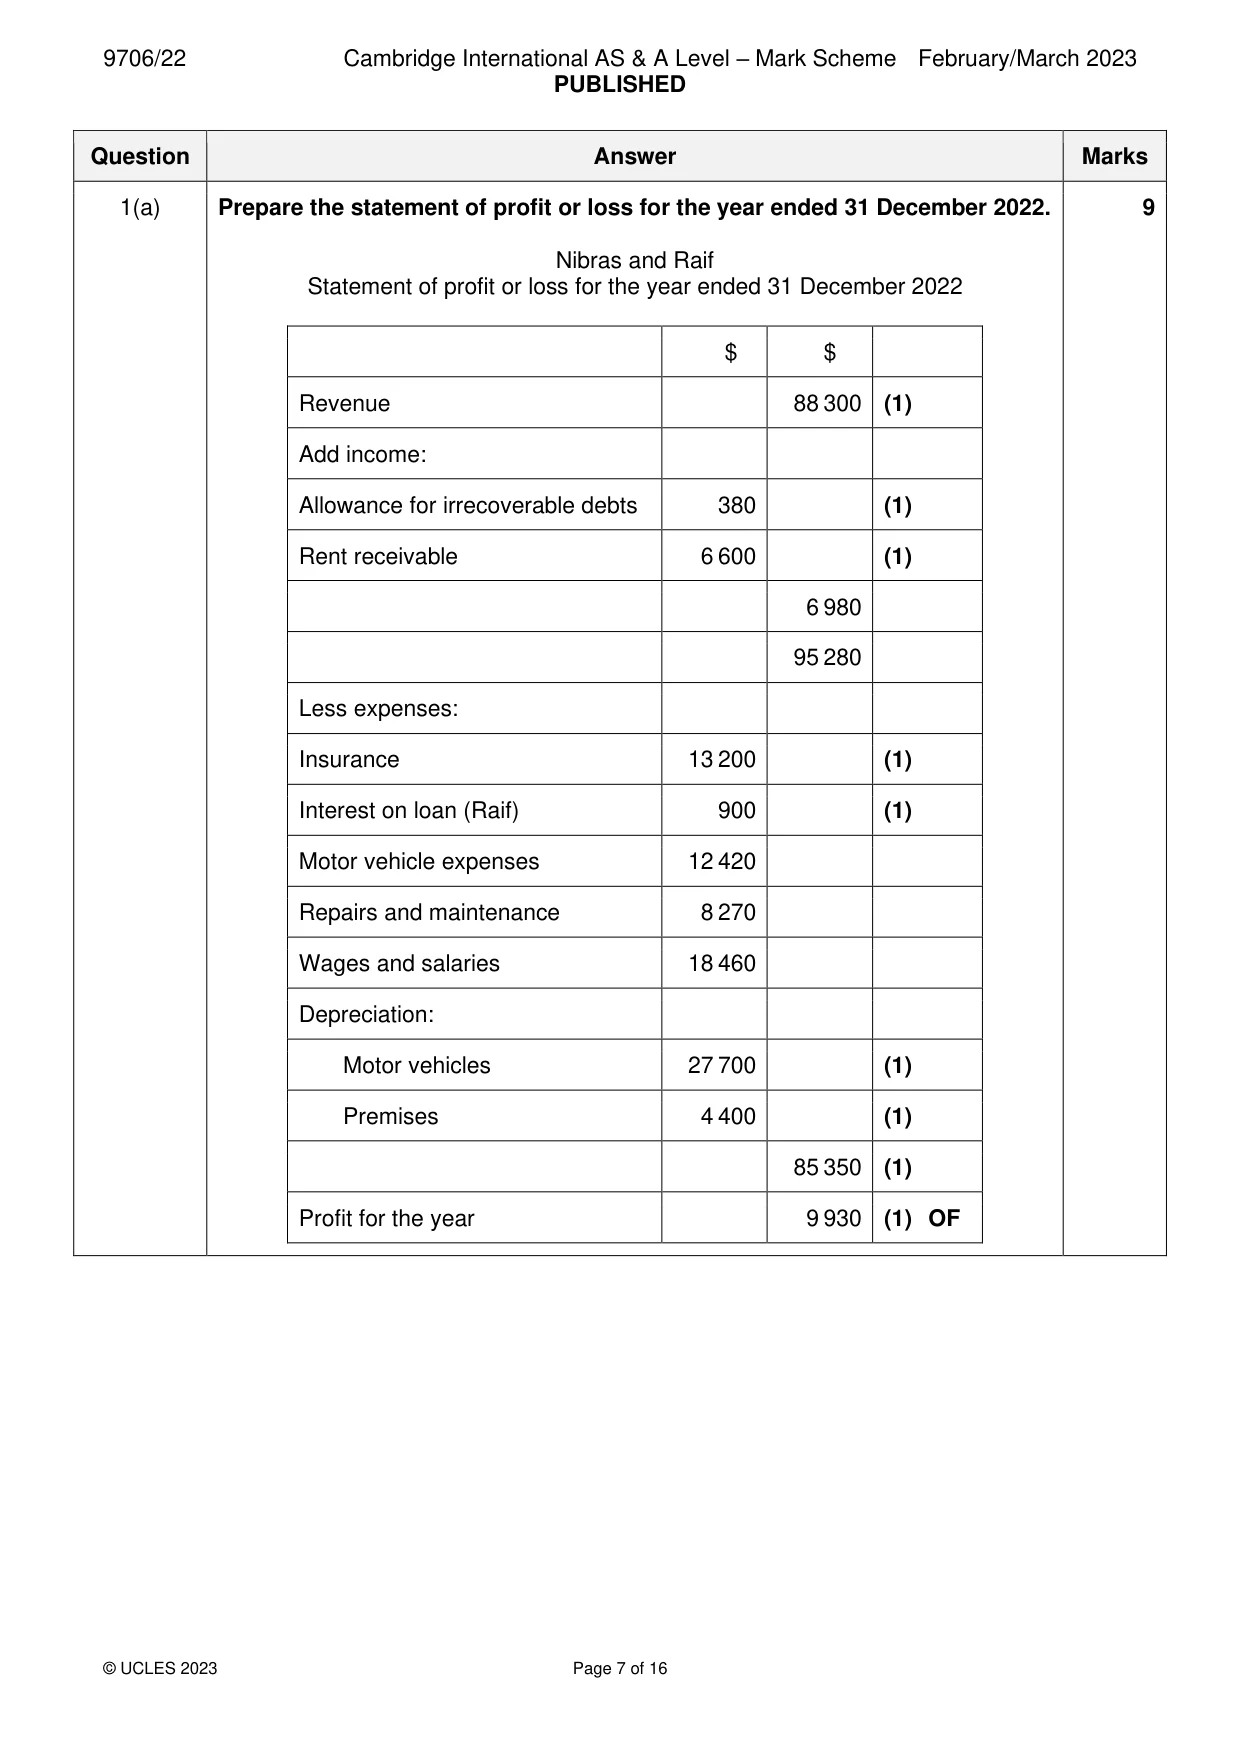
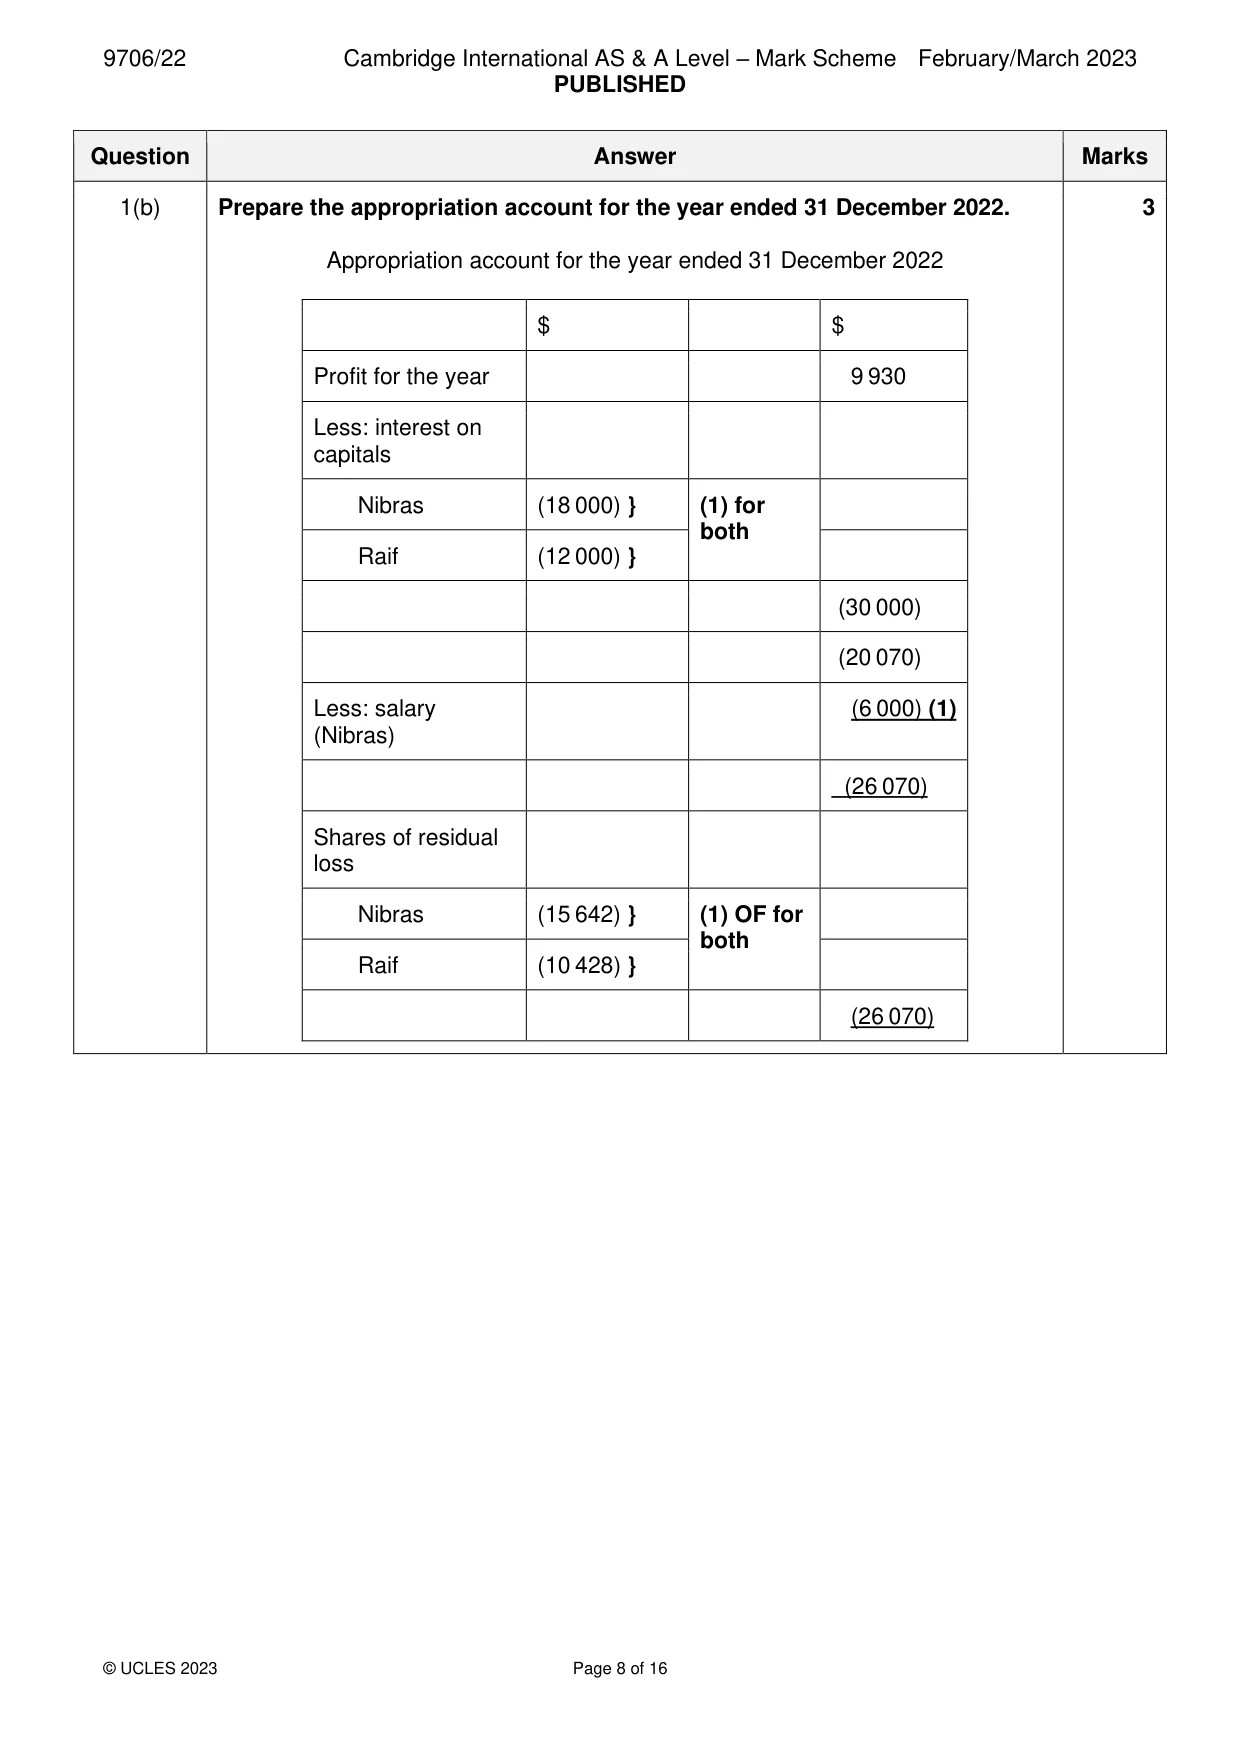
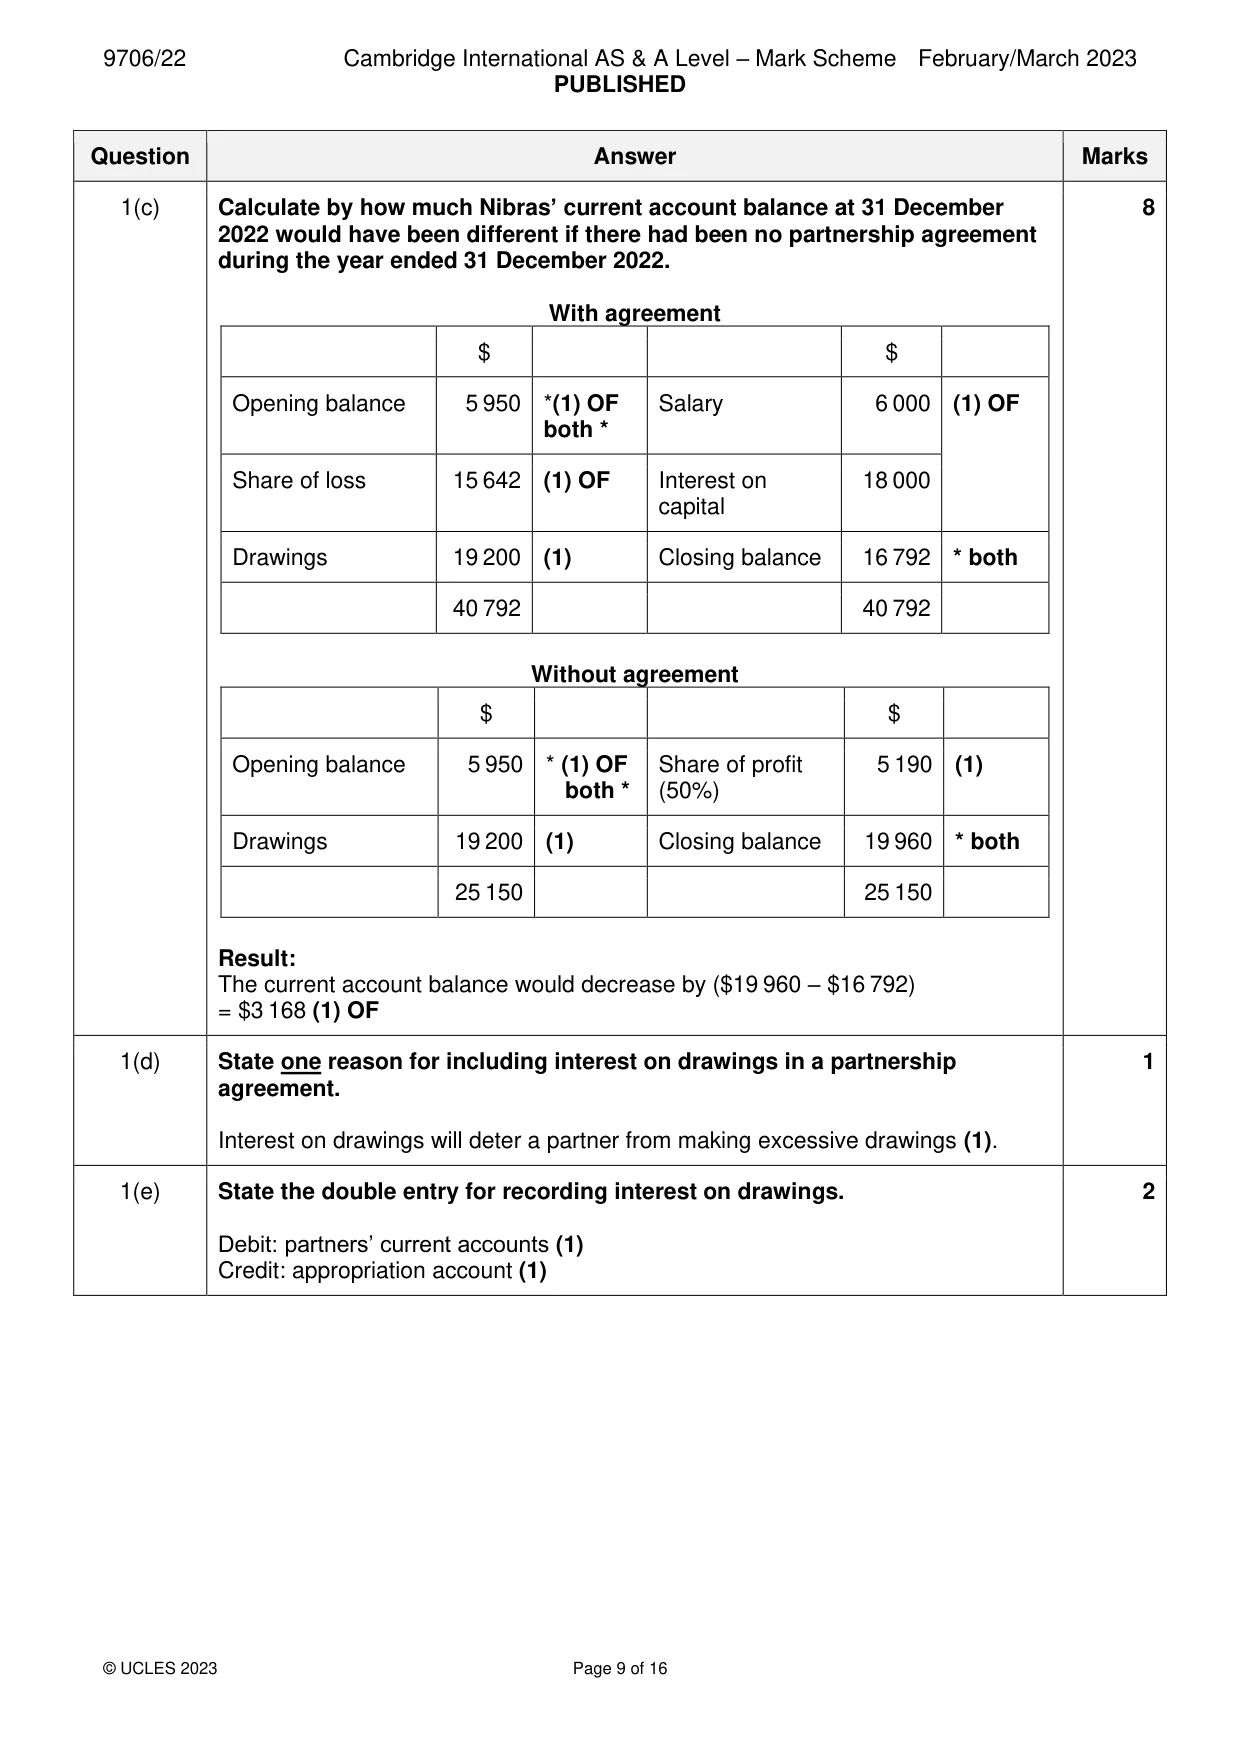
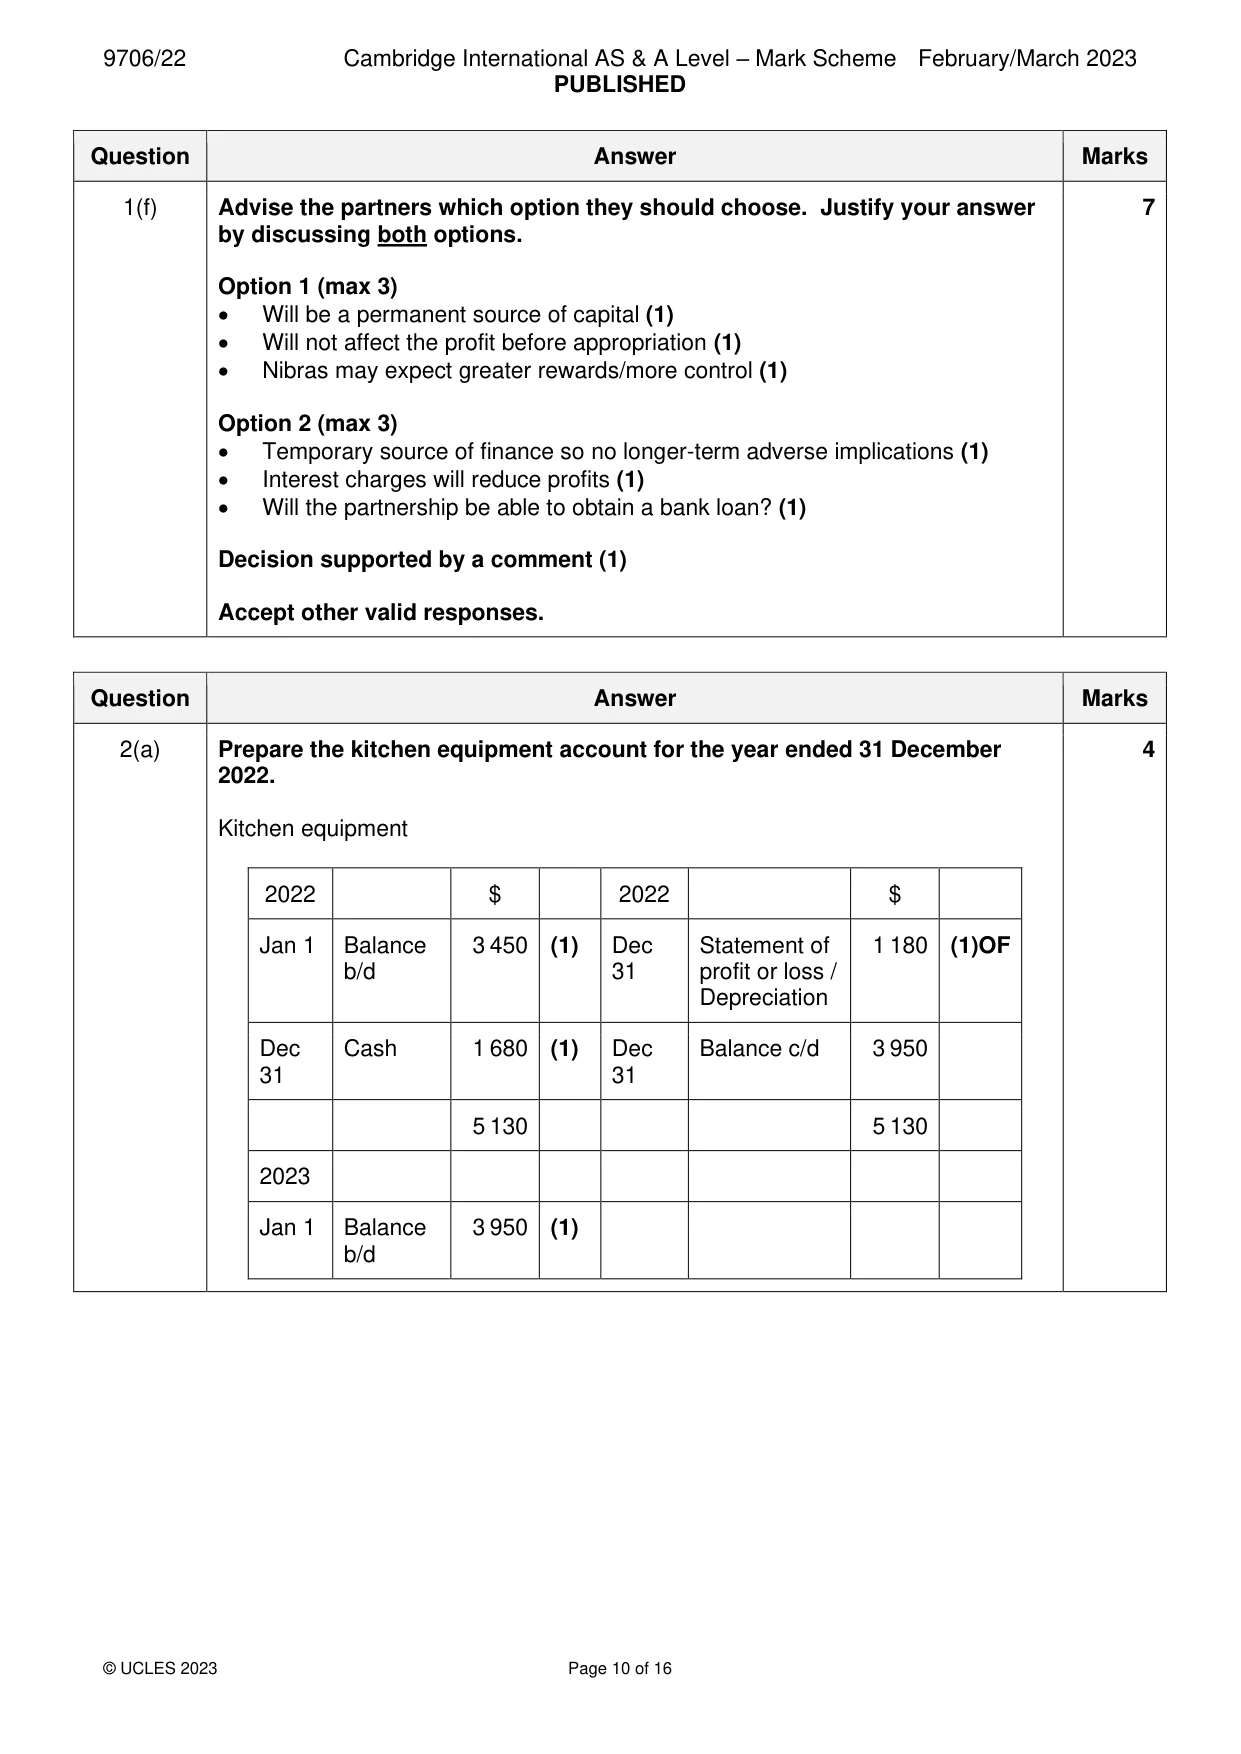
Mark scheme: Question Answer Marks 1(a) Prepare the statement of profit or loss for the year ended 31 December 2022. 9 Nibras and Raif Statement of profit or loss for the year ended 31 December 2022 $ $ Revenue 88 300 (1) Add income: Allowance for irrecoverable debts 380 (1) Rent receivable 6 600 (1) 6 980 95 280 Less expenses: Insurance 13 200 (1) Interest on loan (Raif) 900 (1) Motor vehicle expenses 12 420 Repairs and maintenance 8 270 Wages and salaries 18 460 Depreciation: Motor vehicles 27 700 (1) Premises 4 400 (1) 85 350 (1) Profit for the year 9 930 (1) OF 1(b) Prepare the appropriation account for the year ended 31 December 2022. 3 Appropriation account for the year ended 31 December 2022 $ $ Profit for the year 9 930 Less: interest on capitals Nibras (18 000) } (1) for both Raif (12 000) } (30 000) (20 070) Less: salary (6 000) (1) (Nibras) (26 070) Shares of residual loss Nibras (15 642) } (1) OF for both Raif (10 428) } (26 070) 1(c) Calculate by how much Nibras’ current account balance at 31 December 8 2022 would have been different if there had been no partnership agreement during the year ended 31 December 2022. With agreement $ $ Opening balance 5 950 *(1) OF Salary 6 000 (1) OF both * Share of loss 15 642 (1) OF Interest on 18 000 capital Drawings 19 200 (1) Closing balance 16 792 * both 40 792 40 792 Without agreement $ $ Opening balance 5 950 * (1) OF Share of profit 5 190 (1) both * (50%) Drawings 19 200 (1) Closing balance 19 960 * both 25 150 25 150 Result: The current account balance would decrease by ($19 960 – $16 792) = $3 168 (1) OF 1(d) State one reason for including interest on drawings in a partnership 1 agreement. Interest on drawings will deter a partner from making excessive drawings (1). 1(e) State the double entry for recording interest on drawings. 2 Debit: partners’ current accounts (1) Credit: appropriation account (1) 1(f) Advise the partners which option they should choose. Justify your answer 7 by discussing both options. Option 1 (max 3) • Will be a permanent source of capital (1) • Will not affect the profit before appropriation (1) • Nibras may expect greater rewards/more control (1) Option 2 (max 3) • Temporary source of finance so no longer-term adverse implications (1) • Interest charges will reduce profits (1) • Will the partnership be able to obtain a bank loan? (1) Decision supported by a comment (1) Accept other valid responses.
Q2 · Jakoub owns a restaurant
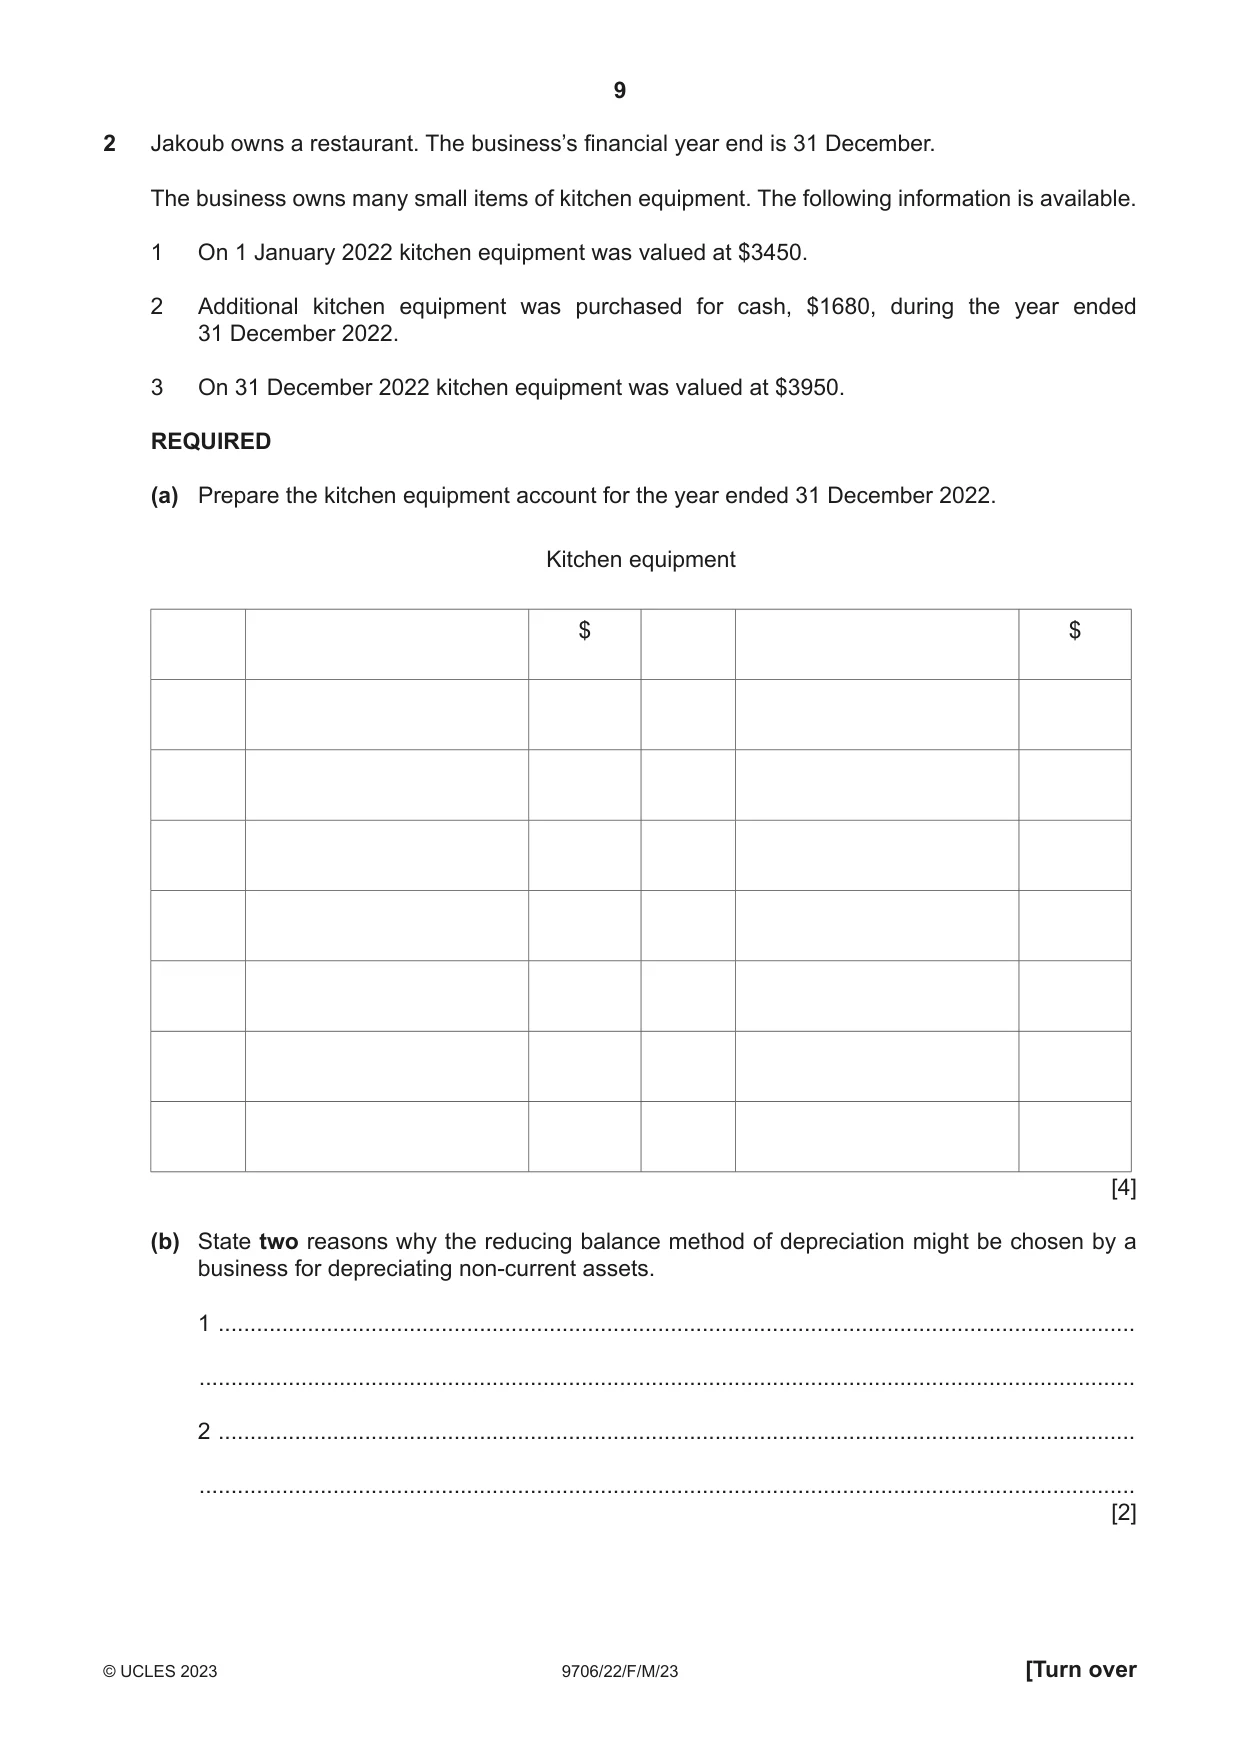
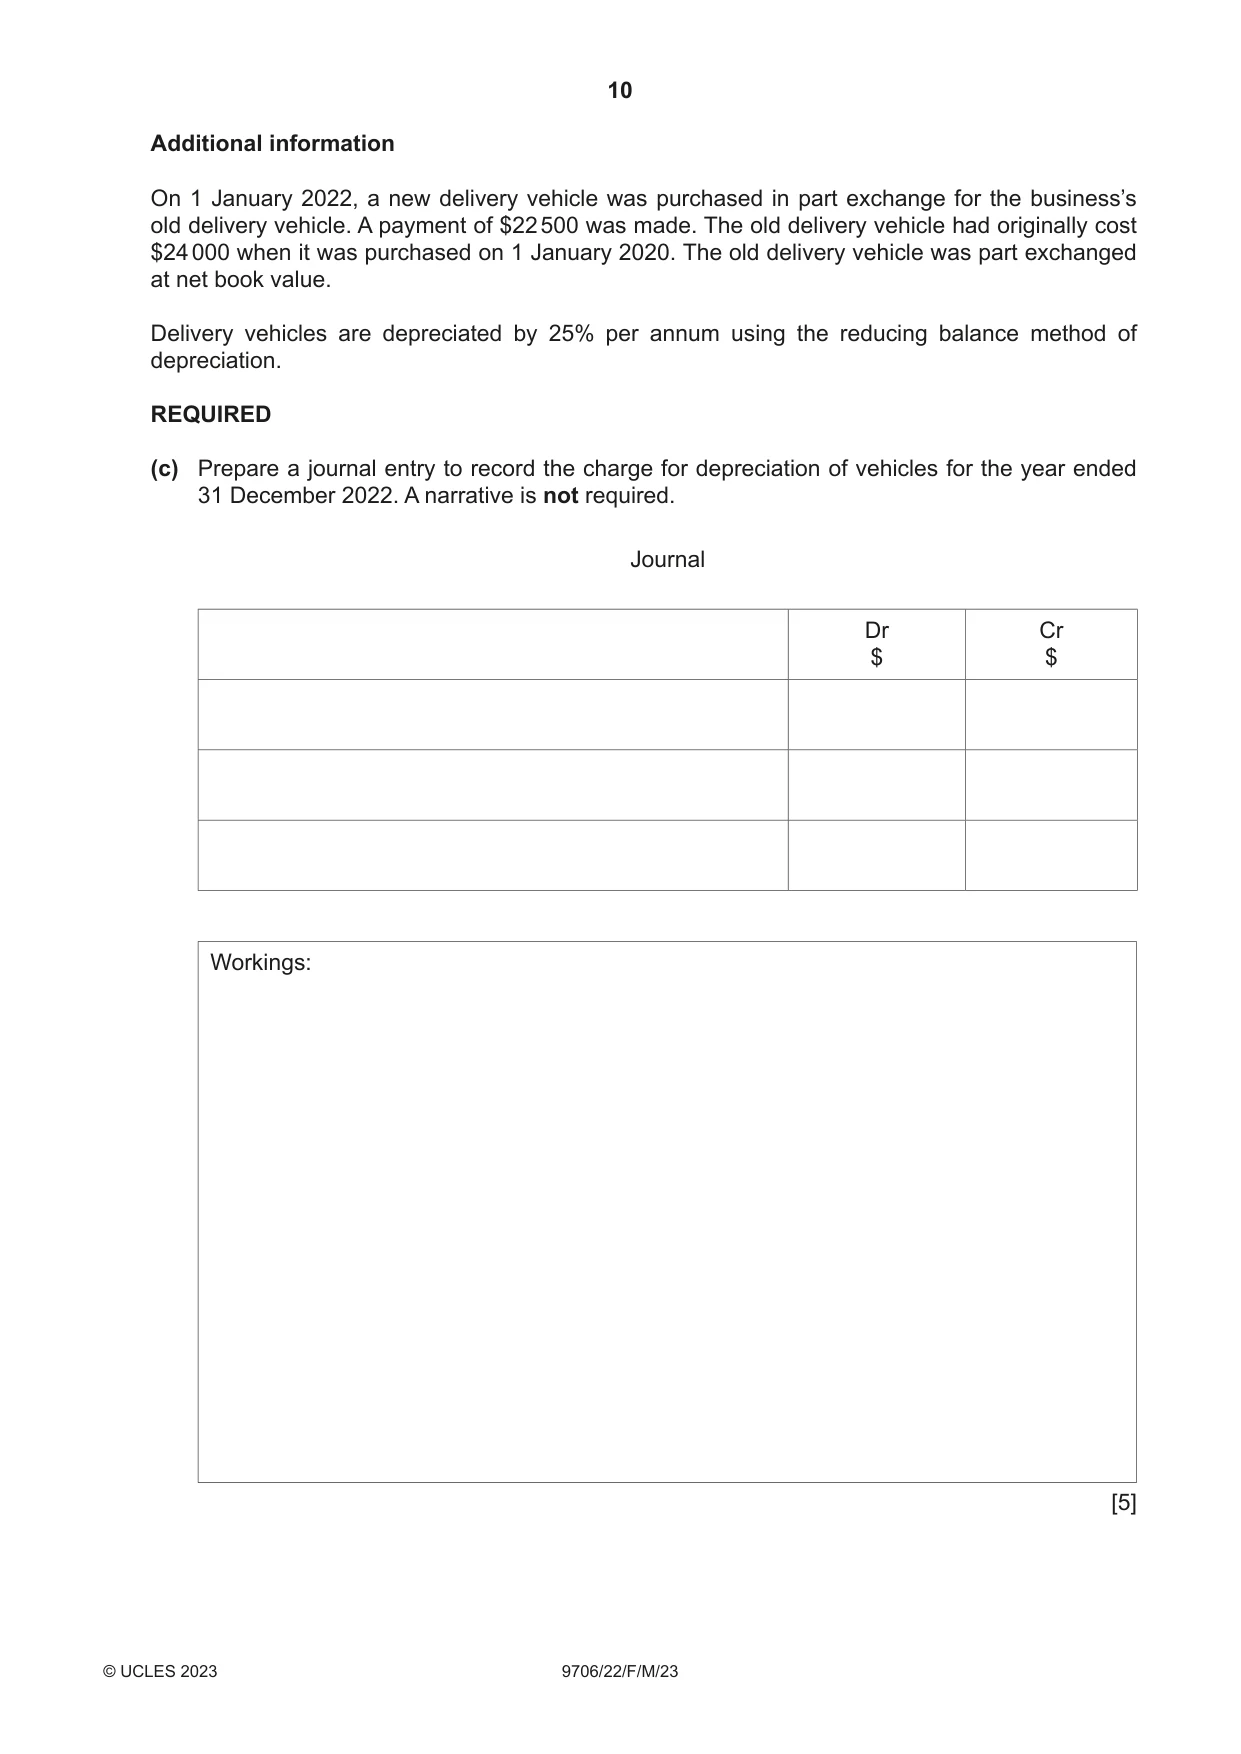
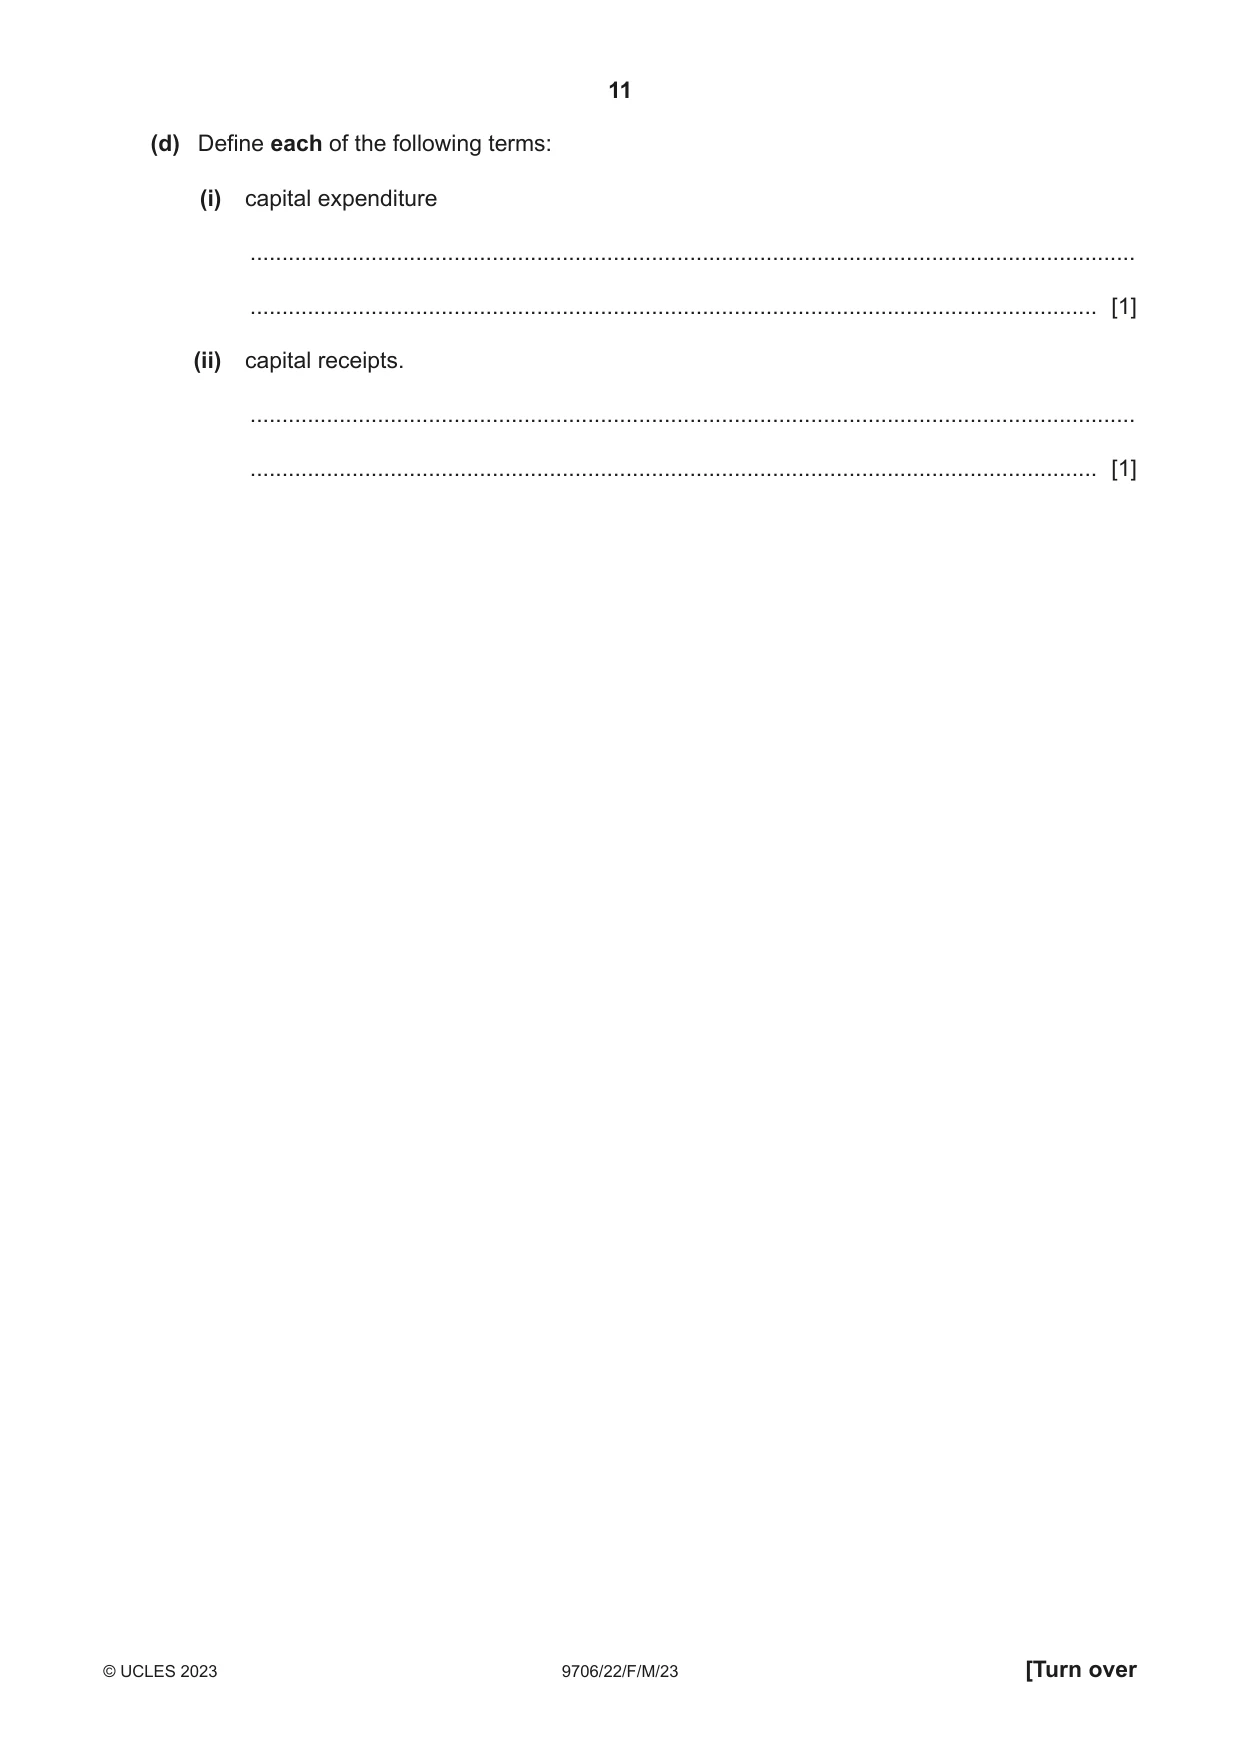
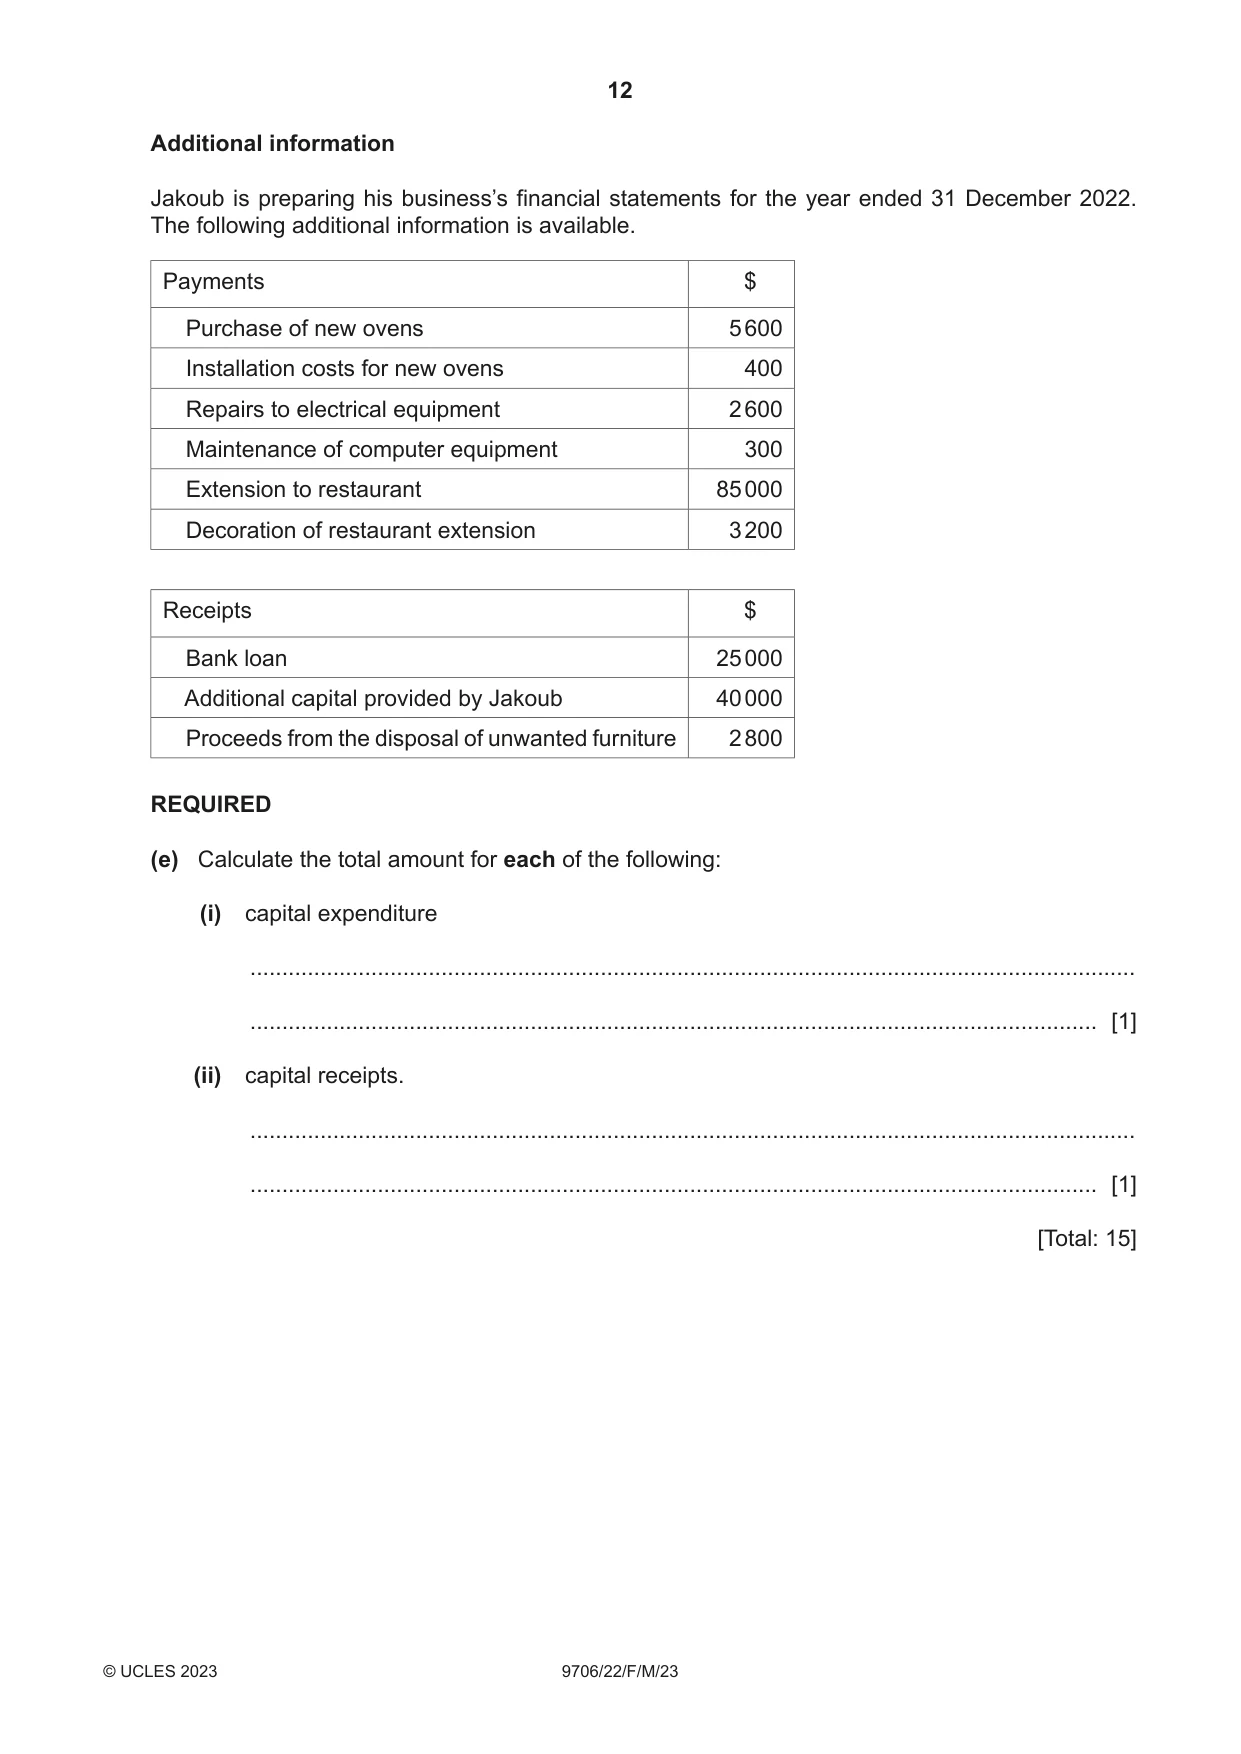
2 Jakoub owns a restaurant. The business’s financial year end is 31 December. The business owns many small items of kitchen equipment. The following information is available. 1 On 1 January 2022 kitchen equipment was valued at $3450. 2 Additional kitchen equipment was purchased for cash, $1680, during the year ended 31 December 2022. 3 On 31 December 2022 kitchen equipment was valued at $3950. REQUIRED (a) Prepare the kitchen equipment account for the year ended 31 December 2022. Kitchen equipment $ $ [4] (b) State two reasons why the reducing balance method of depreciation might be chosen by a business for depreciating non-current assets. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] Additional information On 1 January 2022, a new delivery vehicle was purchased in part exchange for the business’s old delivery vehicle. A payment of $22 500 was made. The old delivery vehicle had originally cost $24 000 when it was purchased on 1 January 2020. The old delivery vehicle was part exchanged at net book value. Delivery vehicles are depreciated by 25% per annum using the reducing balance method of depreciation. REQUIRED (c) Prepare a journal entry to record the charge for depreciation of vehicles for the year ended 31 December 2022. A narrative is not required. Journal Dr Cr $ $ Workings: [5] (d) Define each of the following terms: (i) capital expenditure ........................................................................................................................................... ..................................................................................................................................... [1] (ii) capital receipts. ........................................................................................................................................... ..................................................................................................................................... [1] Additional information Jakoub is preparing his business’s financial statements for the year ended 31 December 2022. The following additional information is available. Payments $ Purchase of new ovens 5 600 Installation costs for new ovens 400 Repairs to electrical equipment 2 600 Maintenance of computer equipment 300 Extension to restaurant 85 000 Decoration of restaurant extension 3 200 Receipts $ Bank loan 25 000 Additional capital provided by Jakoub 40 000 Proceeds from the disposal of unwanted furniture 2 800 REQUIRED (e) Calculate the total amount for each of the following: (i) capital expenditure ........................................................................................................................................... ..................................................................................................................................... [1] (ii) capital receipts. ........................................................................................................................................... ..................................................................................................................................... [1] [Total: 15]
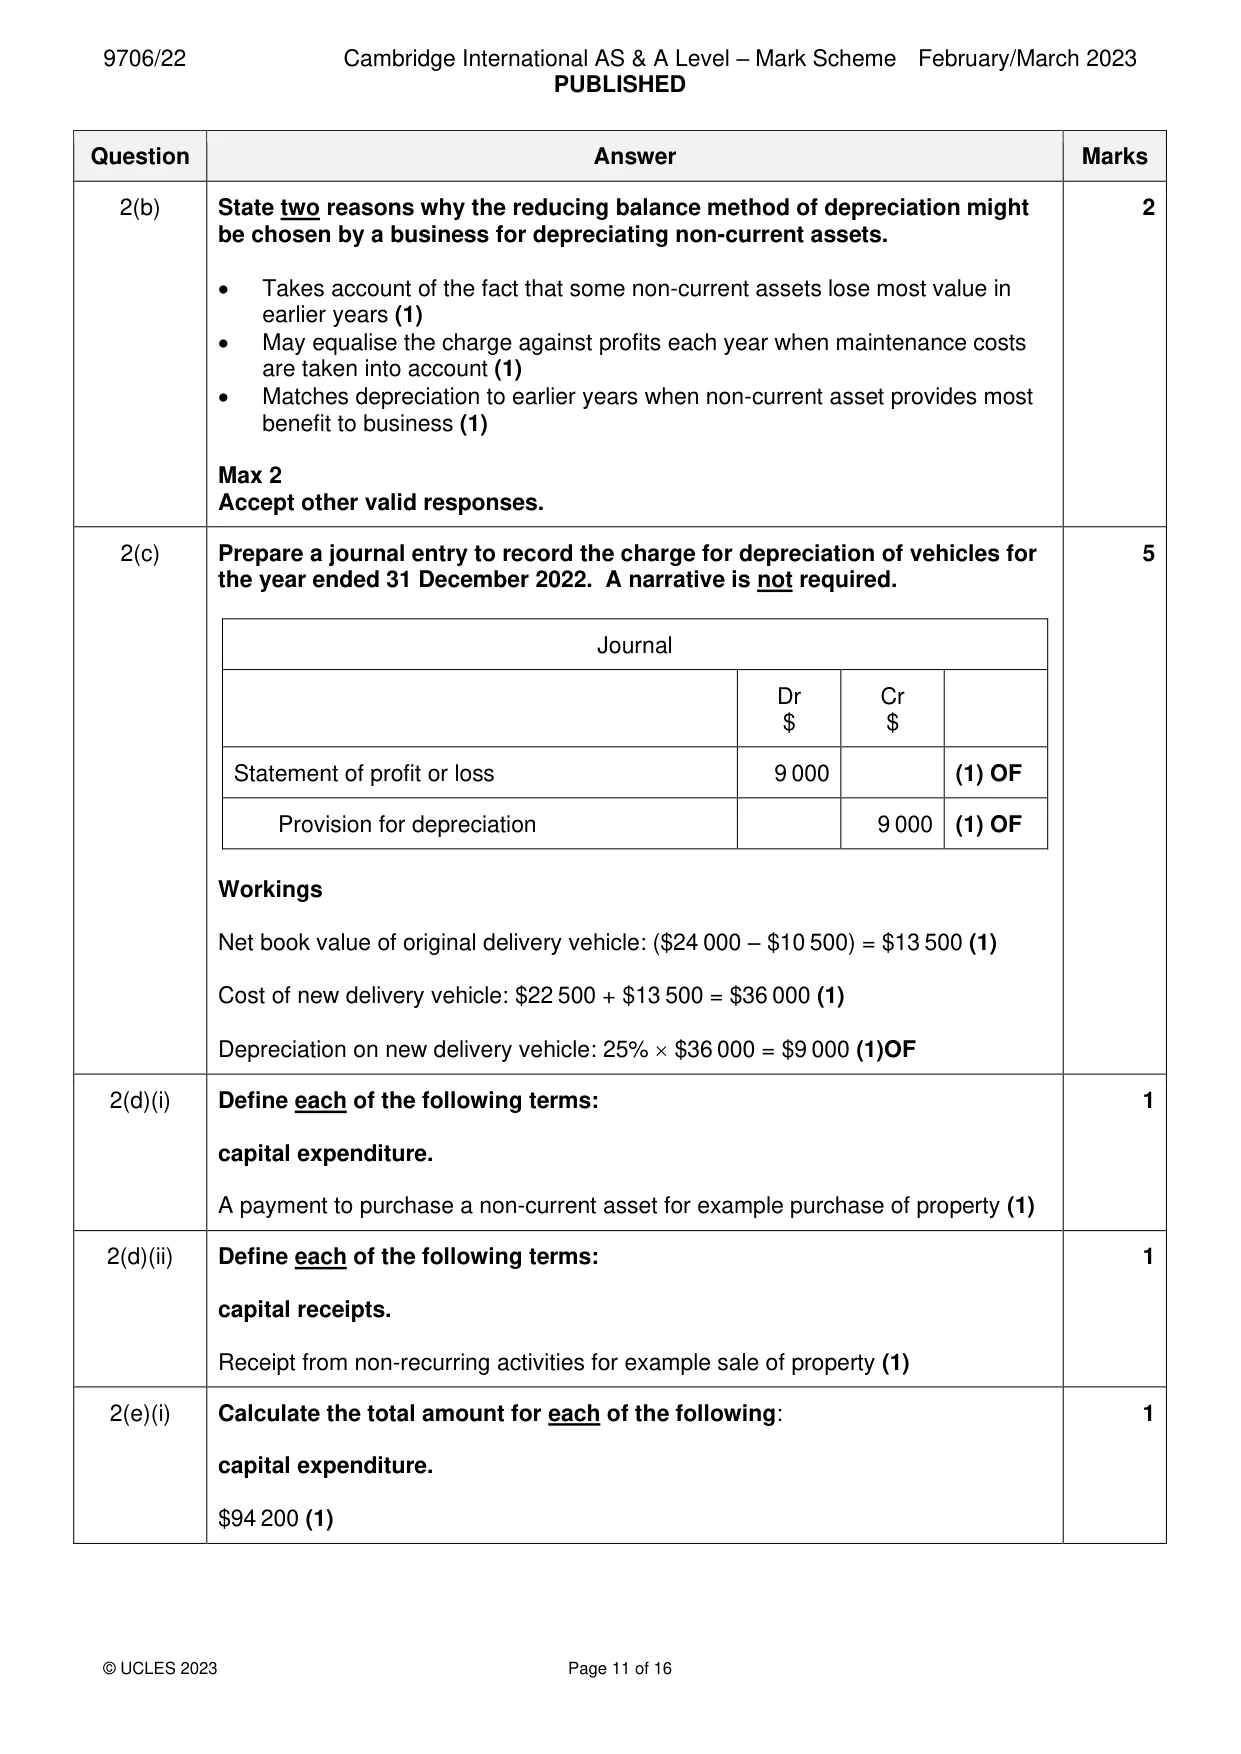
Mark scheme: Question Answer Marks 2(a) Prepare the kitchen equipment account for the year ended 31 December 4 2022. Kitchen equipment 2022 $ 2022 $ Jan 1 Balance 3 450 (1) Dec Statement of 1 180 (1)OF b/d 31 profit or loss / Depreciation Dec Cash 1 680 (1) Dec Balance c/d 3 950 31 31 5 130 5 130 2023 Jan 1 Balance 3 950 (1) b/d 2(b) State two reasons why the reducing balance method of depreciation might 2 be chosen by a business for depreciating non-current assets. • Takes account of the fact that some non-current assets lose most value in earlier years (1) • May equalise the charge against profits each year when maintenance costs are taken into account (1) • Matches depreciation to earlier years when non-current asset provides most benefit to business (1) Max 2 Accept other valid responses. 2(c) Prepare a journal entry to record the charge for depreciation of vehicles for 5 the year ended 31 December 2022. A narrative is not required. Journal Dr Cr $ $ Statement of profit or loss 9 000 (1) OF Provision for depreciation 9 000 (1) OF Workings Net book value of original delivery vehicle: ($24 000 – $10 500) = $13 500 (1) Cost of new delivery vehicle: $22 500 + $13 500 = $36 000 (1) Depreciation on new delivery vehicle: 25% $36 000 = $9 000 (1)OF 2(d)(i) Define each of the following terms: 1 capital expenditure. A payment to purchase a non-current asset for example purchase of property (1) 2(d)(ii) Define each of the following terms: 1 capital receipts. Receipt from non-recurring activities for example sale of property (1) 2(e)(i) Calculate the total amount for each of the following: 1 capital expenditure. $94 200 (1) 2(e)(ii) Calculate the total amount for each of the following: 1 capital receipts. $67 800 (1)
Q3 · Remaining profits and losses to be shared in the ratio Nibras:Raif, 3:2
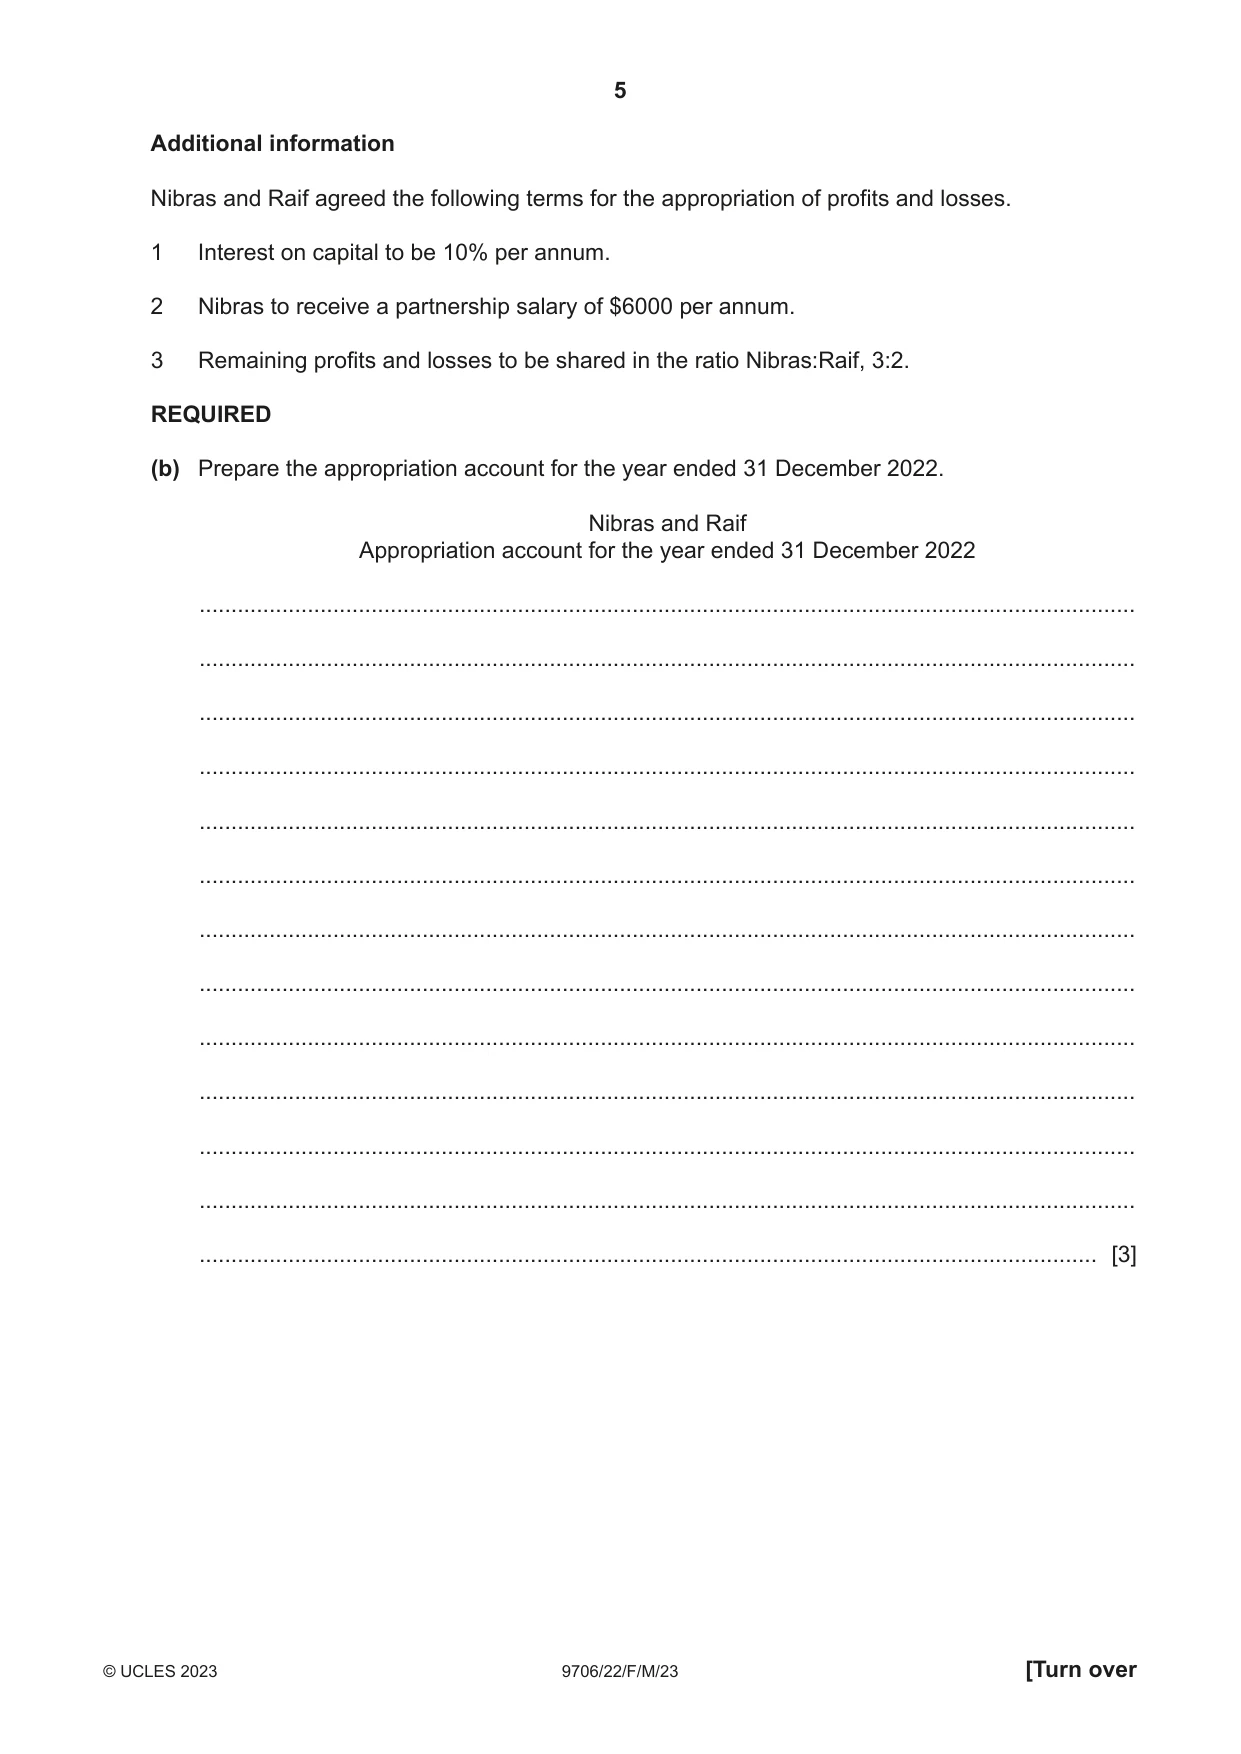
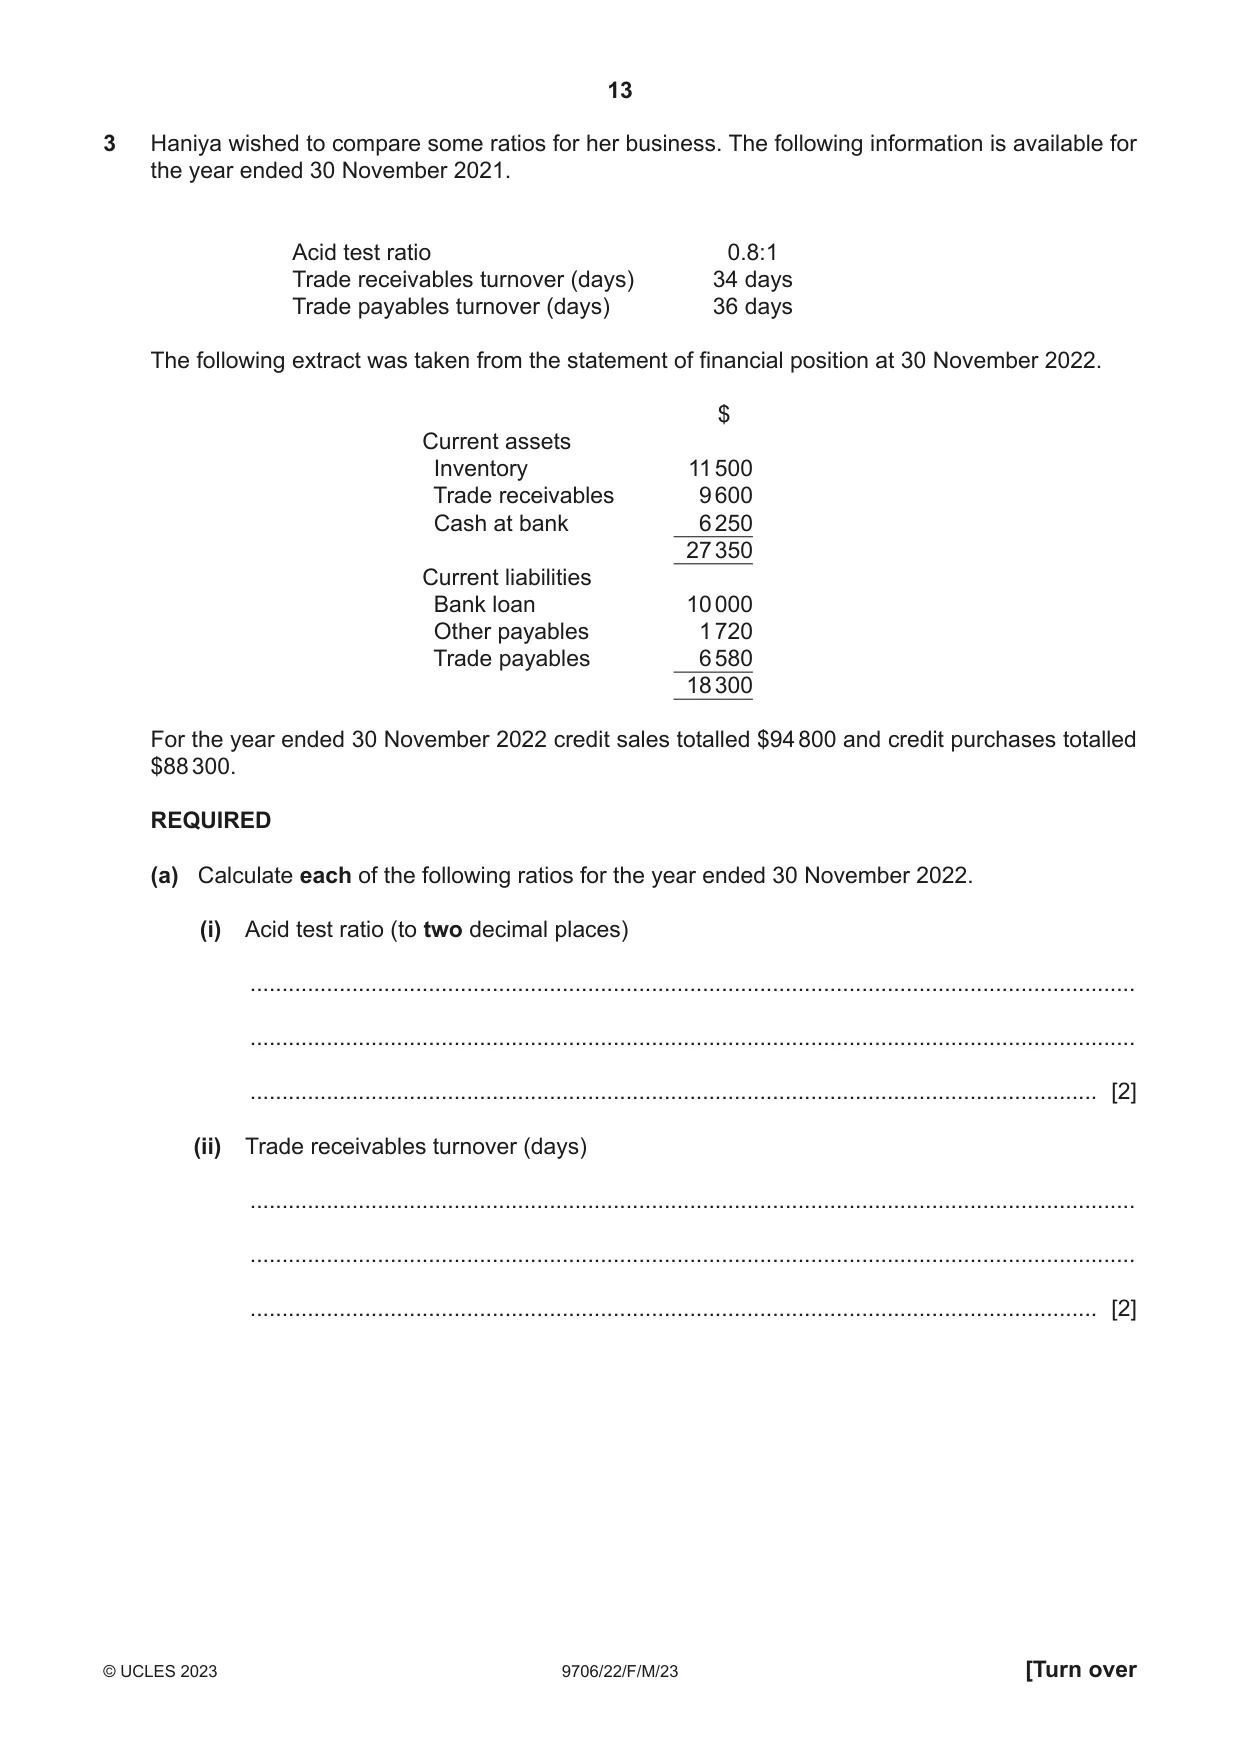
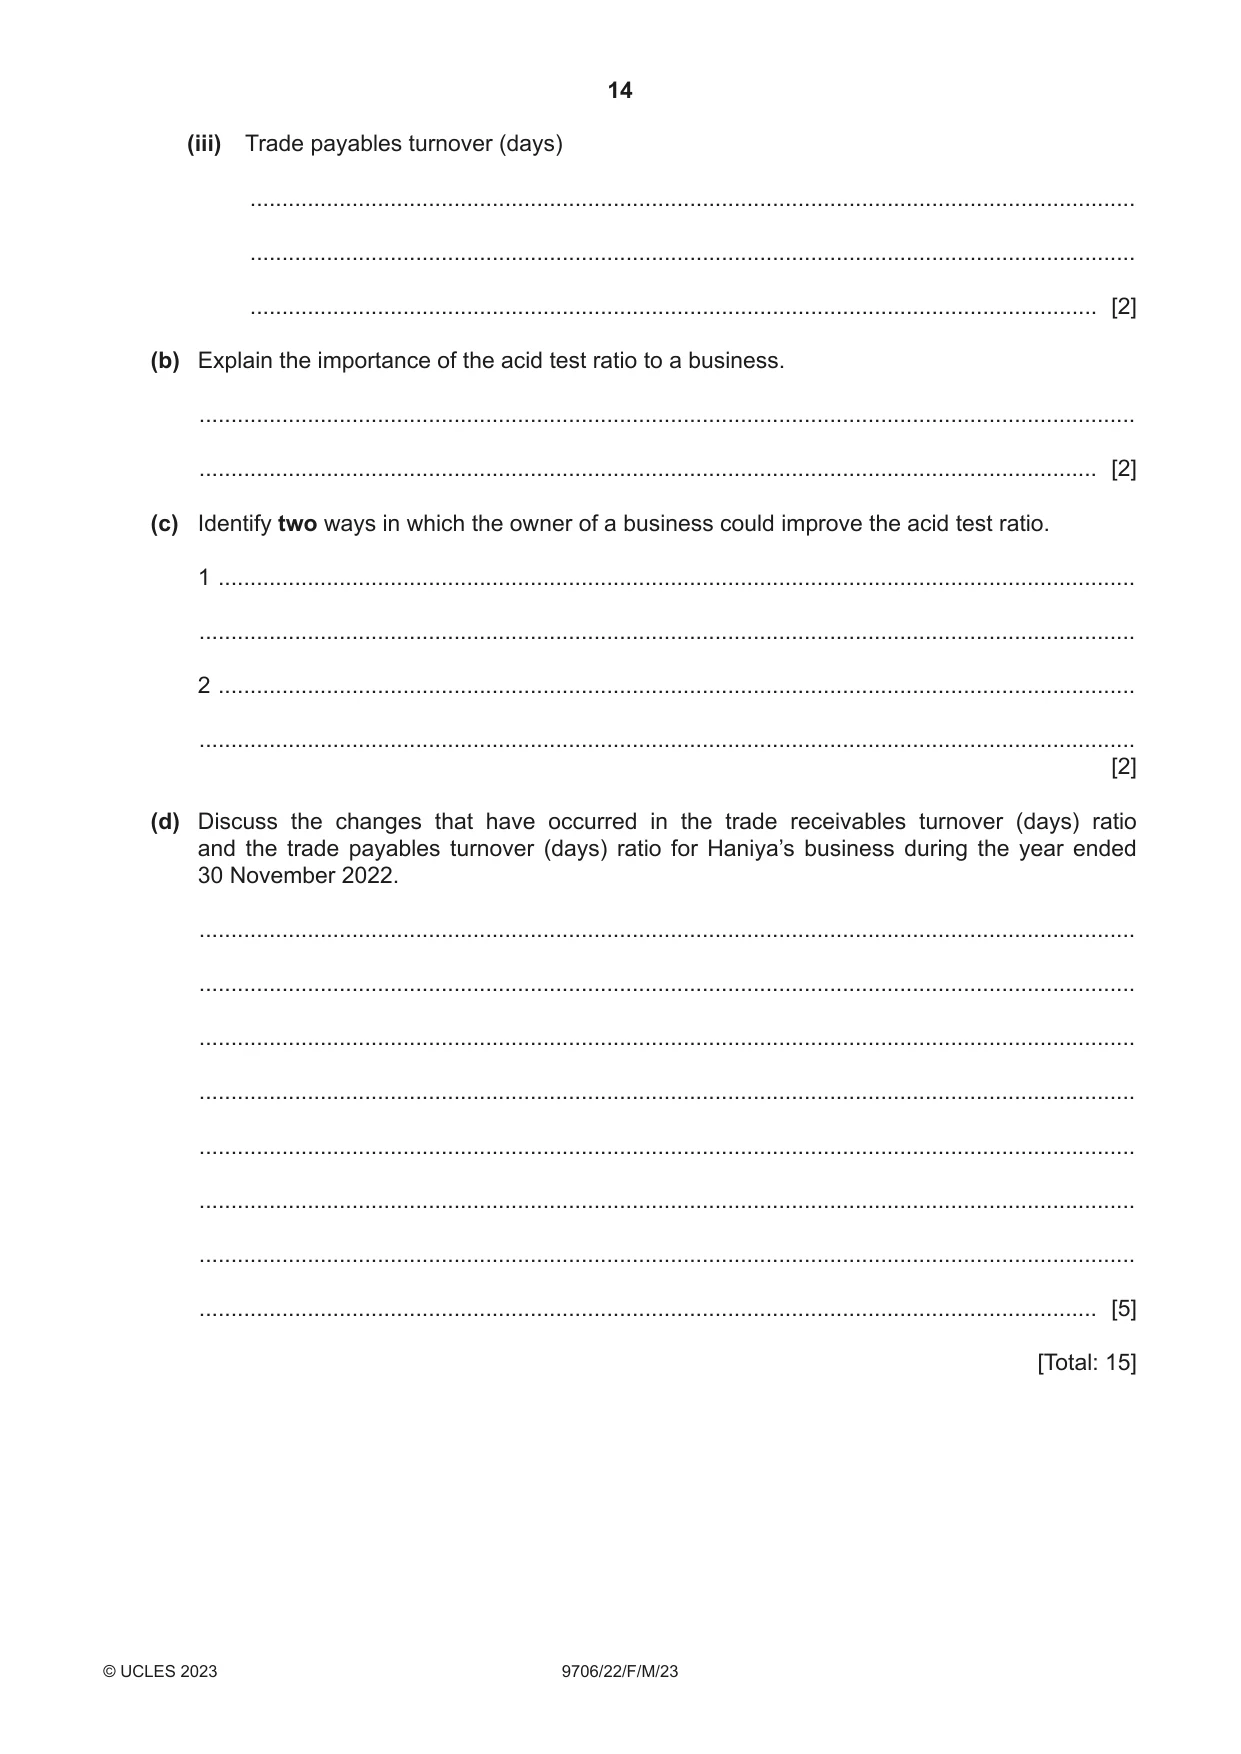
3 Remaining profits and losses to be shared in the ratio Nibras:Raif, 3:2. REQUIRED (b) Prepare the appropriation account for the year ended 31 December 2022. Nibras and Raif Appropriation account for the year ended 31 December 2022 ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] Additional information The partners would like to know what difference it would have made if they had operated without a partnership agreement during the year ended 31 December 2022. REQUIRED (c) Calculate by how much Nibras’ current account balance at 31 December 2022 would have been different if there had been no partnership agreement during the year ended 31 December 2022. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [8] Additional information The partners had considered charging interest on drawings as part of their agreement. REQUIRED (d) State one reason for including interest on drawings in a partnership agreement. ................................................................................................................................................... ............................................................................................................................................. [1] (e) State the double entry for recording interest on drawings. Debit ......................................................................................................................................... Credit ........................................................................................................................................ [2] Additional information Nibras and Raif would like to expand their business but they require additional finance. They have considered two options: Option 1: Nibras to introduce additional capital by selling some personal investments Option 2: Arrange a bank loan REQUIRED (f) Advise the partners which option they should choose. Justify your answer by discussing both options. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [7] [Total: 30] 2 Jakoub owns a restaurant. The business’s financial year end is 31 December. The business owns many small items of kitchen equipment. The following information is available. 1 On 1 January 2022 kitchen equipment was valued at $3450. 2 Additional kitchen equipment was purchased for cash, $1680, during the year ended 31 December 2022. 3 On 31 December 2022 kitchen equipment was valued at $3950. REQUIRED (a) Prepare the kitchen equipment account for the year ended 31 December 2022. Kitchen equipment $ $ [4] (b) State two reasons why the reducing balance method of depreciation might be chosen by a business for depreciating non-current assets. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] Additional information On 1 January 2022, a new delivery vehicle was purchased in part exchange for the business’s old delivery vehicle. A payment of $22 500 was made. The old delivery vehicle had originally cost $24 000 when it was purchased on 1 January 2020. The old delivery vehicle was part exchanged at net book value. Delivery vehicles are depreciated by 25% per annum using the reducing balance method of depreciation. REQUIRED (c) Prepare a journal entry to record the charge for depreciation of vehicles for the year ended 31 December 2022. A narrative is not required. Journal Dr Cr $ $ Workings: [5] (d) Define each of the following terms: (i) capital expenditure ........................................................................................................................................... ..................................................................................................................................... [1] (ii) capital receipts. ........................................................................................................................................... ..................................................................................................................................... [1] Additional information Jakoub is preparing his business’s financial statements for the year ended 31 December 2022. The following additional information is available. Payments $ Purchase of new ovens 5 600 Installation costs for new ovens 400 Repairs to electrical equipment 2 600 Maintenance of computer equipment 300 Extension to restaurant 85 000 Decoration of restaurant extension 3 200 Receipts $ Bank loan 25 000 Additional capital provided by Jakoub 40 000 Proceeds from the disposal of unwanted furniture 2 800 REQUIRED (e) Calculate the total amount for each of the following: (i) capital expenditure ........................................................................................................................................... ..................................................................................................................................... [1] (ii) capital receipts. ........................................................................................................................................... ..................................................................................................................................... [1] [Total: 15] 3 Haniya wished to compare some ratios for her business. The following information is available for the year ended 30 November 2021. Acid test ratio 0.8:1 Trade receivables turnover (days) 34 days Trade payables turnover (days) 36 days The following extract was taken from the statement of financial position at 30 November 2022. $ Current assets Inventory 11 500 Trade receivables 9 600 Cash at bank 6 250 27 350 Current liabilities Bank loan 10 000 Other payables 1 720 Trade payables 6 580 18 300 For the year ended 30 November 2022 credit sales totalled $94 800 and credit purchases totalled $88 300. REQUIRED (a) Calculate each of the following ratios for the year ended 30 November 2022. (i) Acid test ratio (to two decimal places) ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] (ii) Trade receivables turnover (days) ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] (iii) Trade payables turnover (days) ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] (b) Explain the importance of the acid test ratio to a business. ................................................................................................................................................... ............................................................................................................................................. [2] (c) Identify two ways in which the owner of a business could improve the acid test ratio. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] (d) Discuss the changes that have occurred in the trade receivables turnover (days) ratio and the trade payables turnover (days) ratio for Haniya’s business during the year ended 30 November 2022. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 15]
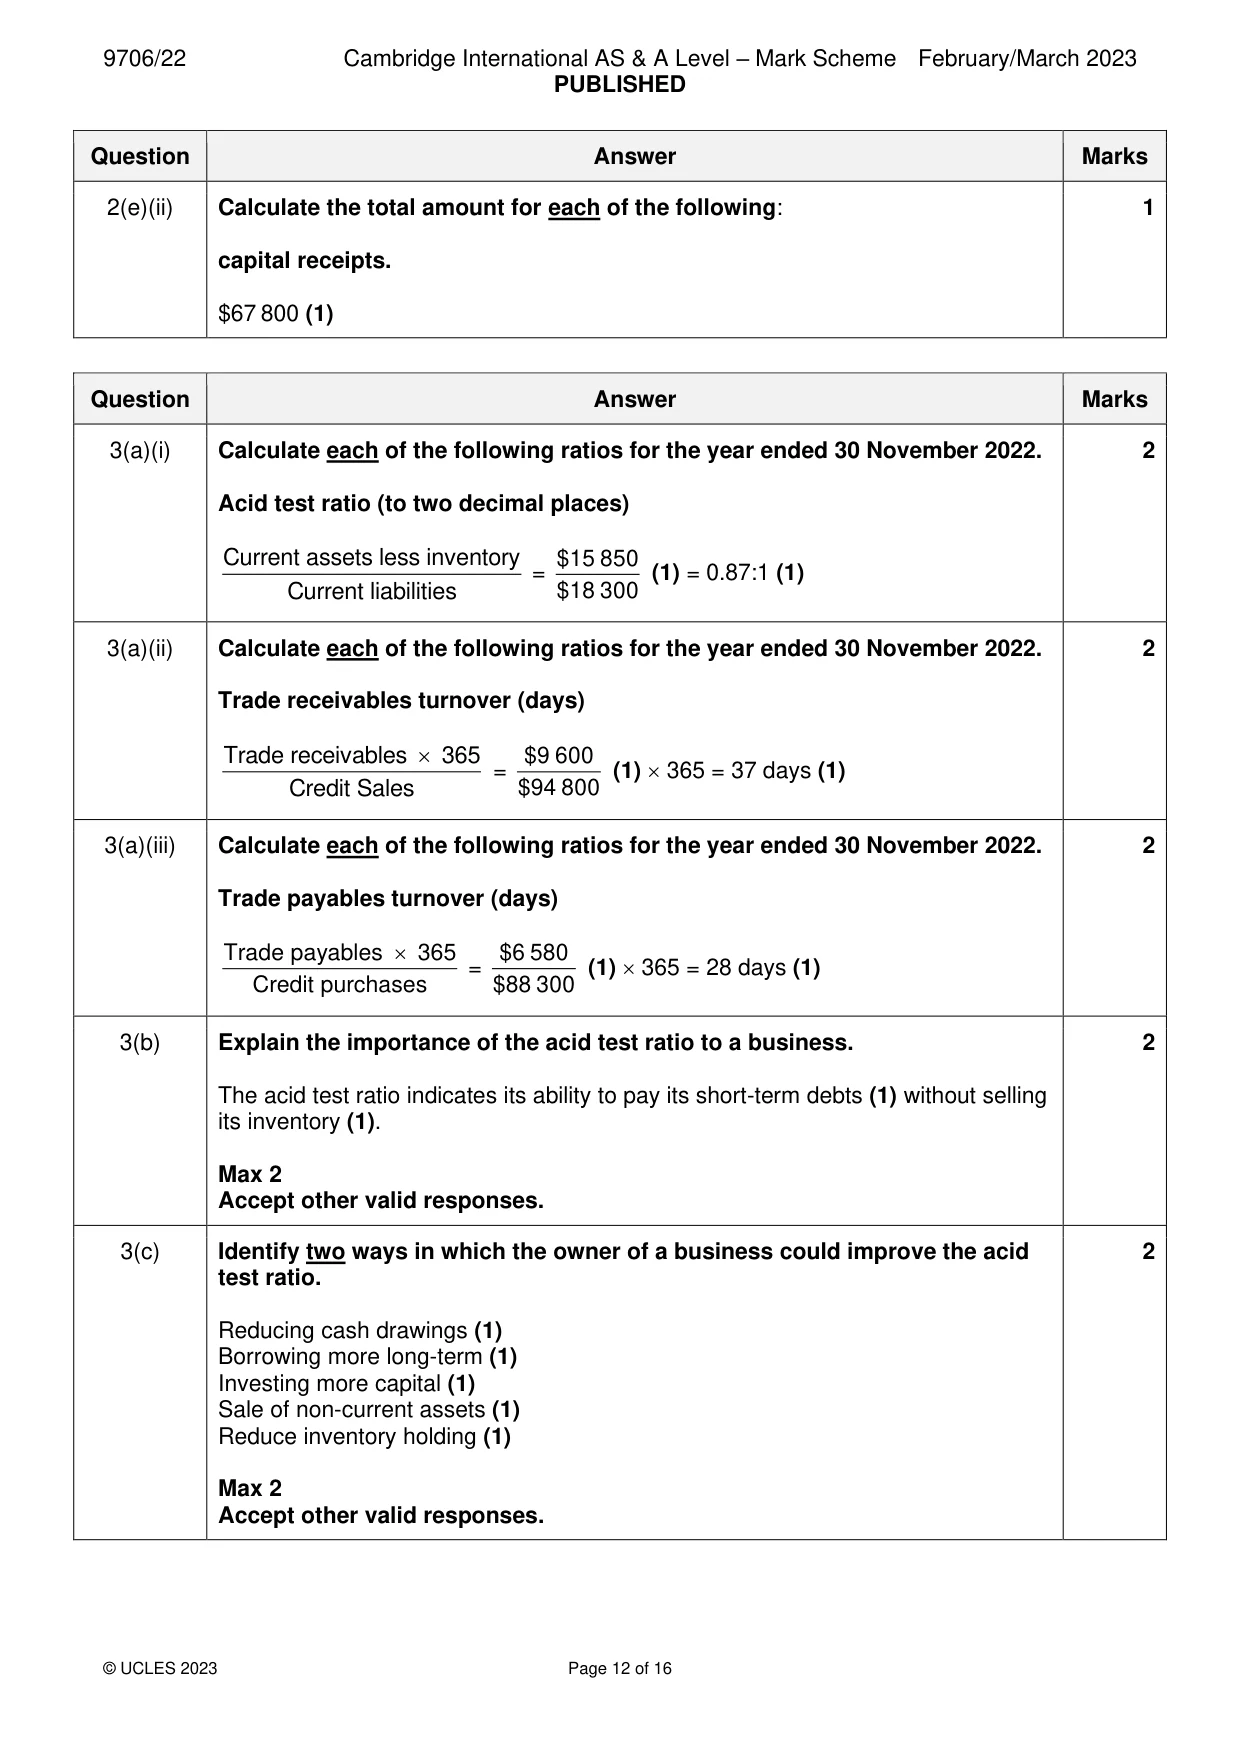
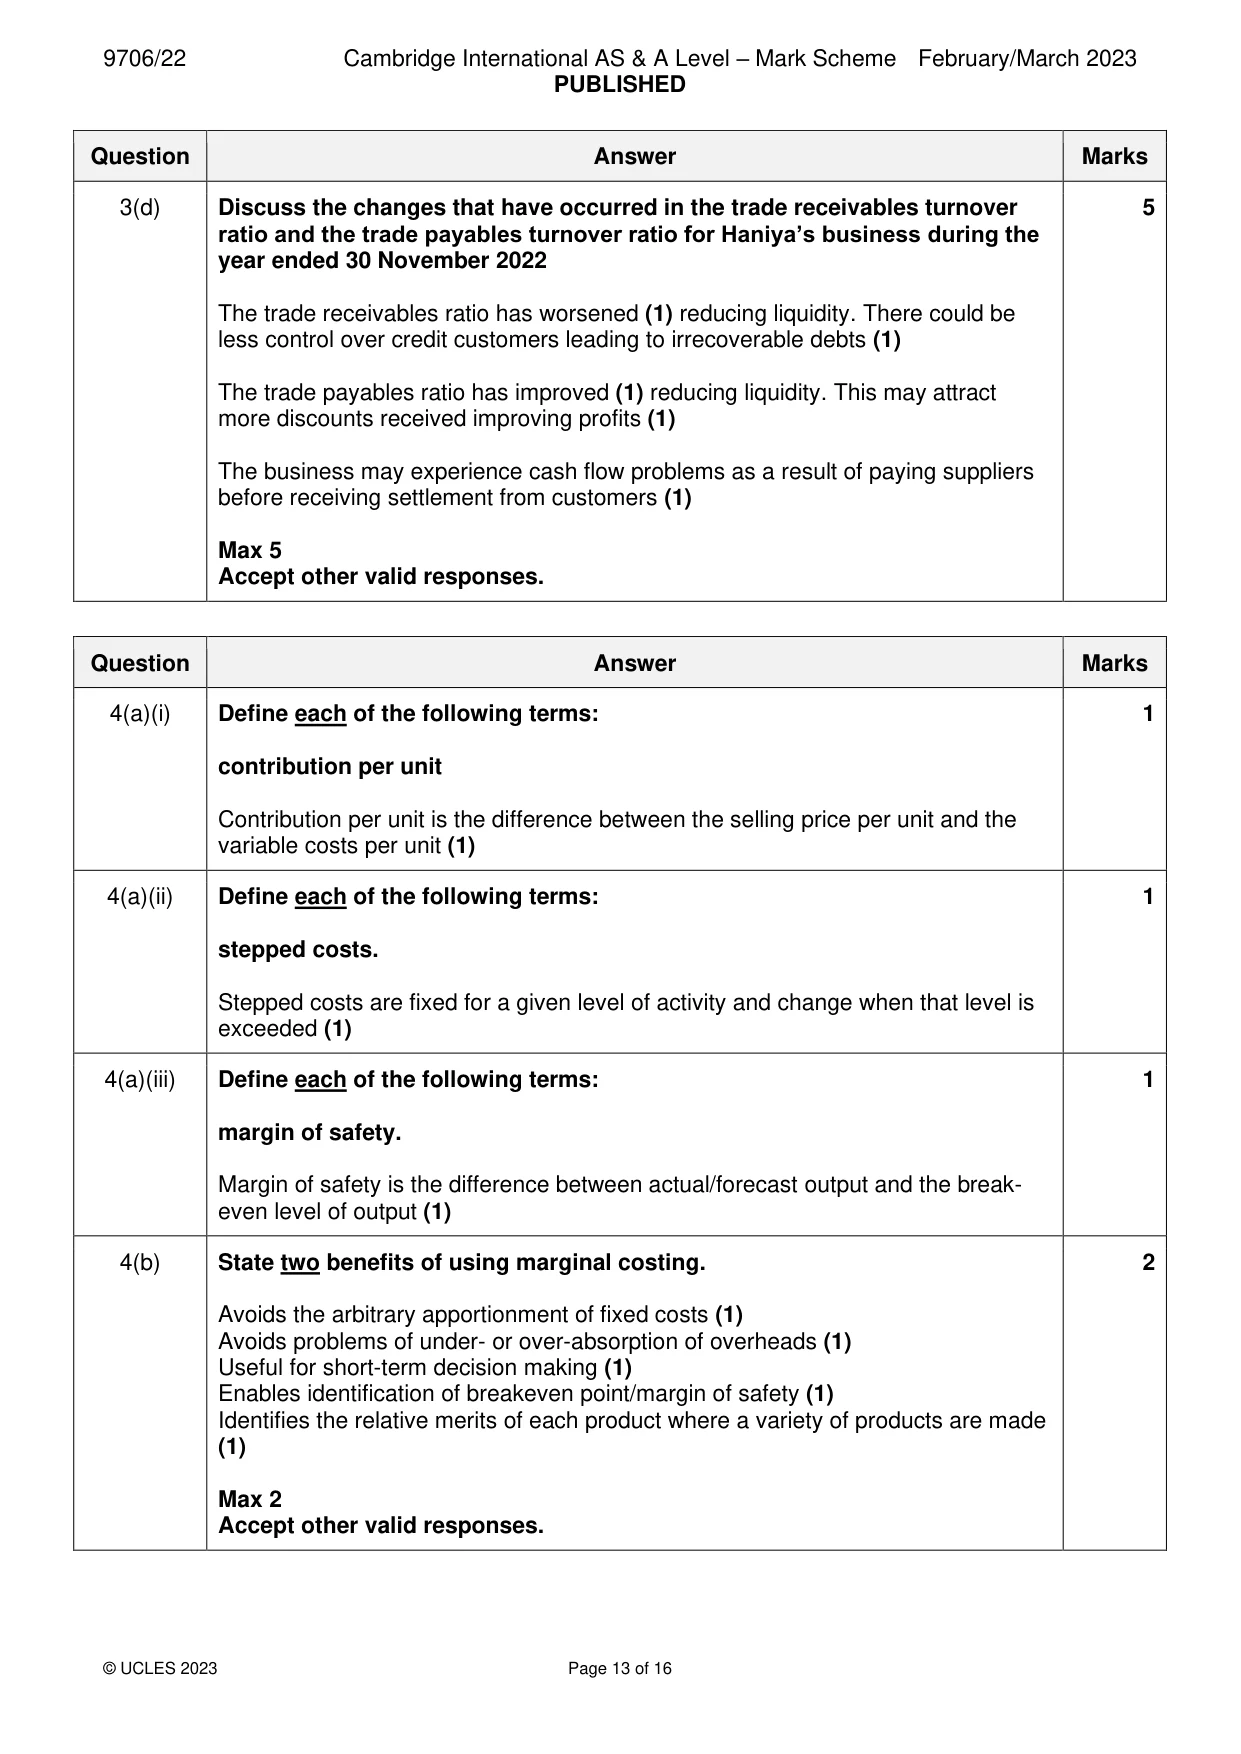
Mark scheme: 3(a)(i) Calculate each of the following ratios for the year ended 30 November 2022. 2 Acid test ratio (to two decimal places) Current assets less inventory $15 850 = (1) = 0.87:1 (1) Current liabilities $18 300 3(a)(ii) Calculate each of the following ratios for the year ended 30 November 2022. 2 Trade receivables turnover (days) Trade receivables 365 $9 600 = (1) 365 = 37 days (1) Credit Sales $94 800 3(a)(iii) Calculate each of the following ratios for the year ended 30 November 2022. 2 Trade payables turnover (days) Trade payables 365 $6 580 = (1) 365 = 28 days (1) Credit purchases $88 300 3(b) Explain the importance of the acid test ratio to a business. 2 The acid test ratio indicates its ability to pay its short-term debts (1) without selling its inventory (1). Max 2 Accept other valid responses. 3(c) Identify two ways in which the owner of a business could improve the acid 2 test ratio. Reducing cash drawings (1) Borrowing more long-term (1) Investing more capital (1) Sale of non-current assets (1) Reduce inventory holding (1) Max 2 Accept other valid responses. 3(d) Discuss the changes that have occurred in the trade receivables turnover 5 ratio and the trade payables turnover ratio for Haniya’s business during the year ended 30 November 2022 The trade receivables ratio has worsened (1) reducing liquidity. There could be less control over credit customers leading to irrecoverable debts (1) The trade payables ratio has improved (1) reducing liquidity. This may attract more discounts received improving profits (1) The business may experience cash flow problems as a result of paying suppliers before receiving settlement from customers (1) Max 5 Accept other valid responses.
More questions on Analysis and communication of accounting information
Q4 · G Limited manufactures a single product type at one of its factories
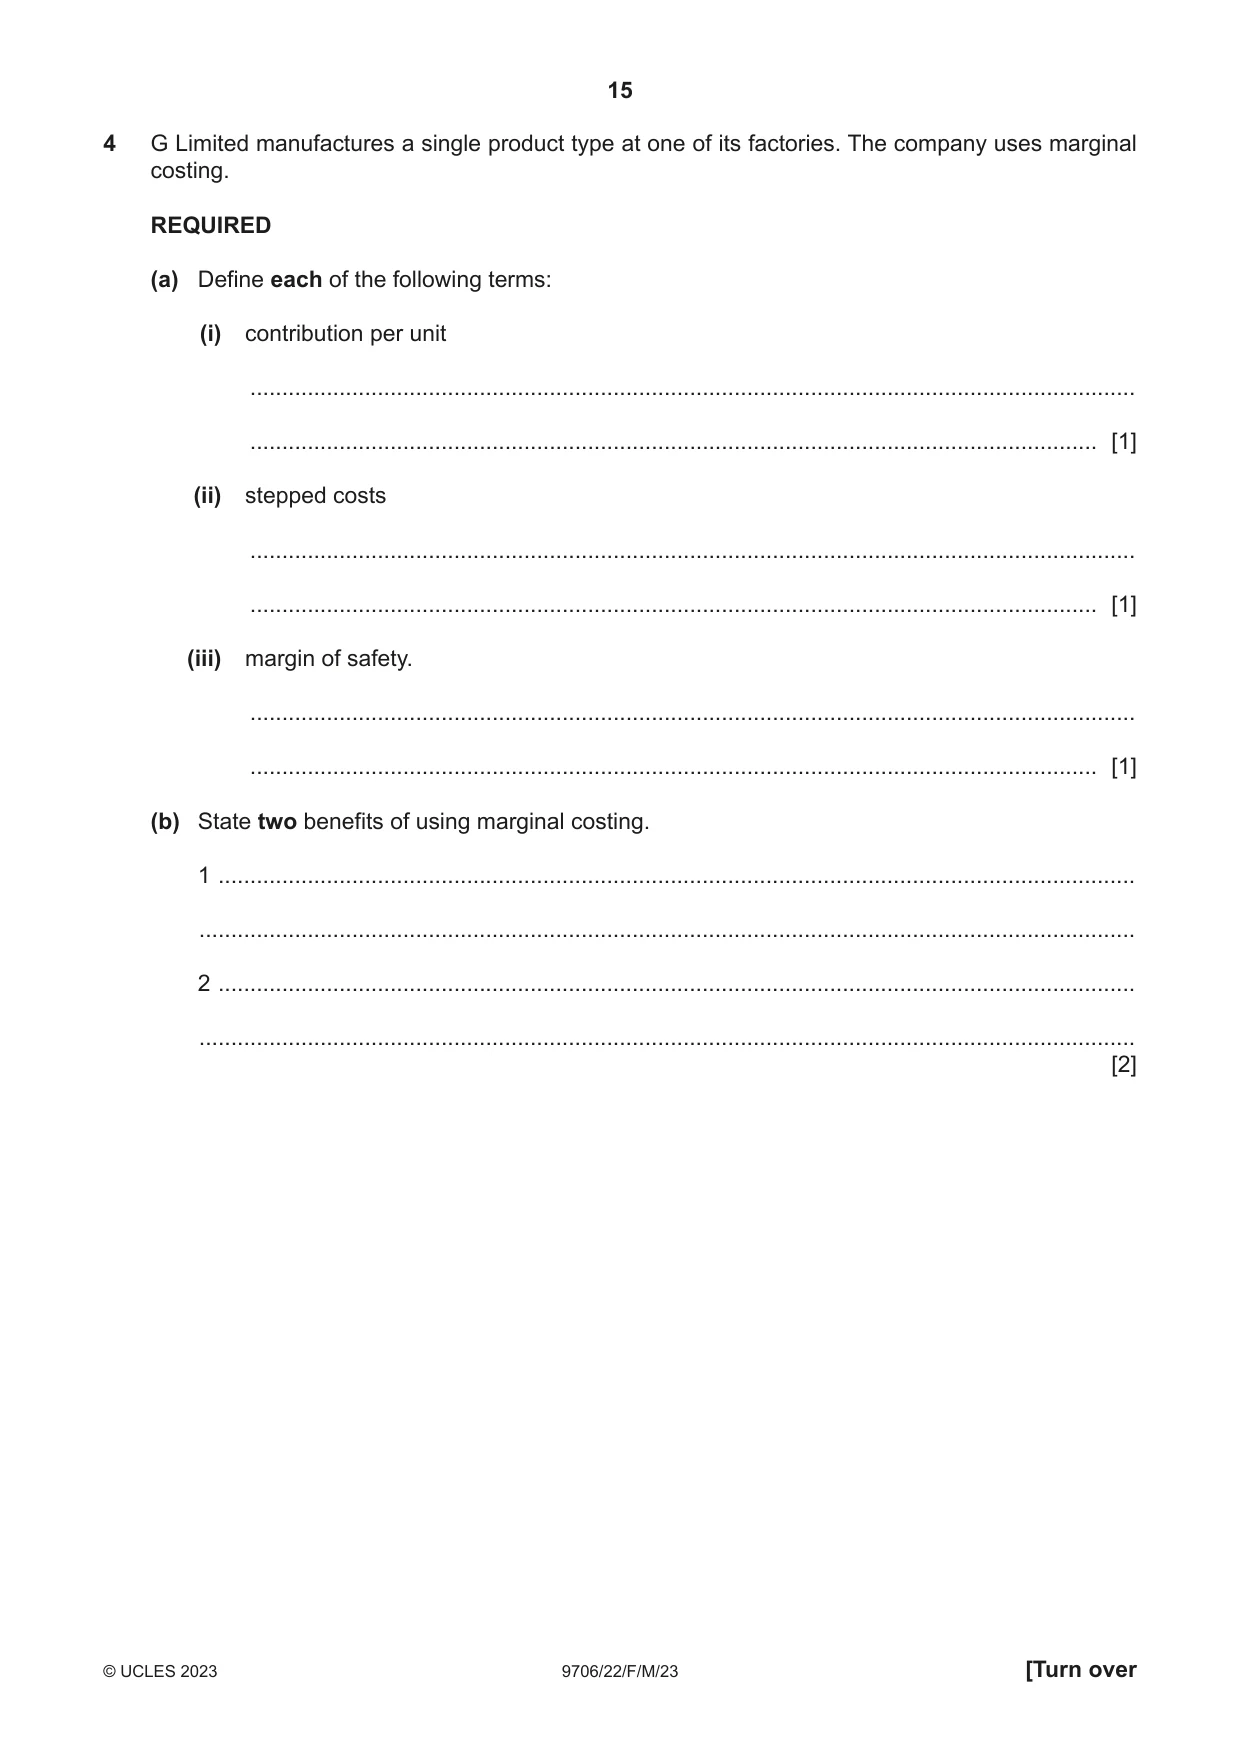
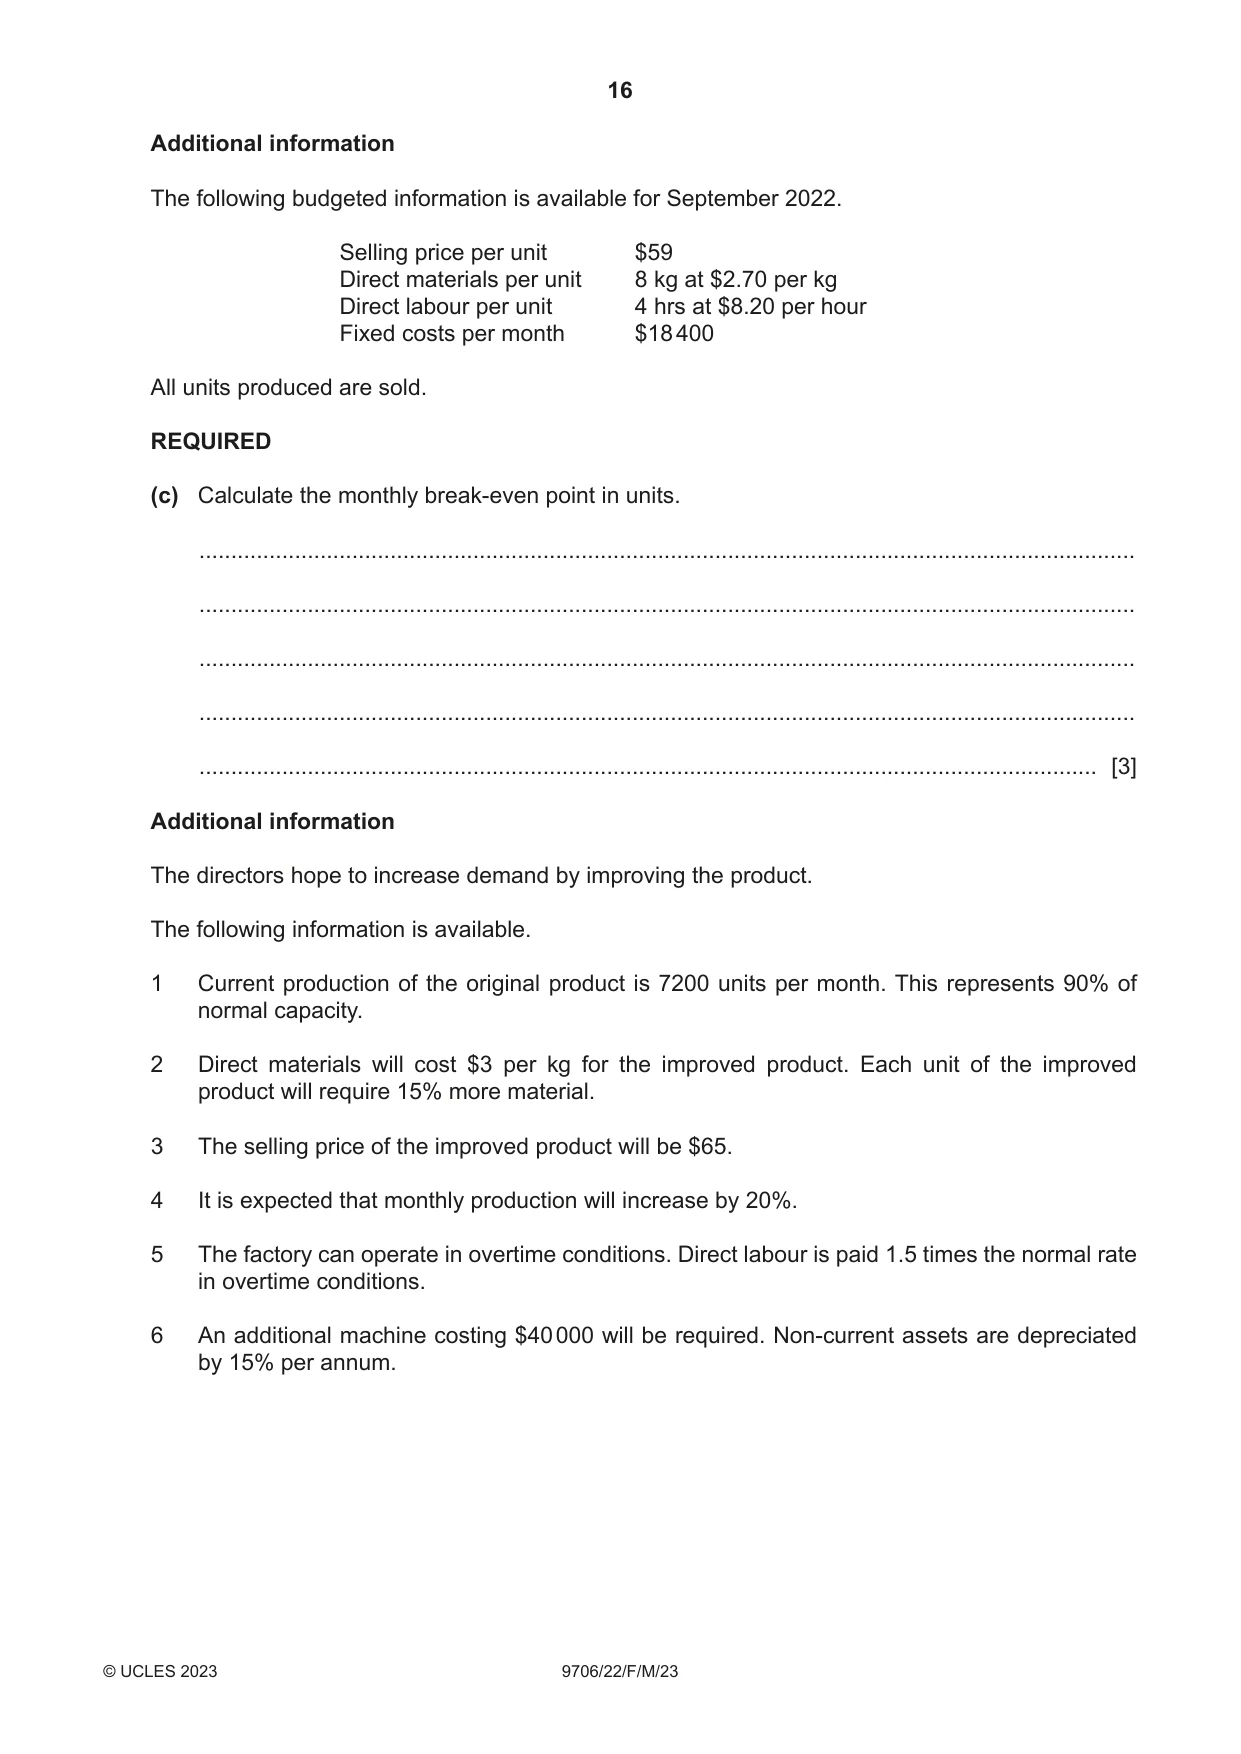
4 G Limited manufactures a single product type at one of its factories. The company uses marginal costing. REQUIRED (a) Define each of the following terms: (i) contribution per unit ........................................................................................................................................... ..................................................................................................................................... [1] (ii) stepped costs ........................................................................................................................................... ..................................................................................................................................... [1] (iii) margin of safety. ........................................................................................................................................... ..................................................................................................................................... [1] (b) State two benefits of using marginal costing. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] Additional information The following budgeted information is available for September 2022. Selling price per unit $59 Direct materials per unit 8 kg at $2.70 per kg Direct labour per unit 4 hrs at $8.20 per hour Fixed costs per month $18 400 All units produced are sold. REQUIRED (c) Calculate the monthly break-even point in units. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] Additional information The directors hope to increase demand by improving the product. The following information is available. 1 Current production of the original product is 7200 units per month. This represents 90% of normal capacity. 2 Direct materials will cost $3 per kg for the improved product. Each unit of the improved product will require 15% more material. 3 The selling price of the improved product will be $65. 4 It is expected that monthly production will increase by 20%.
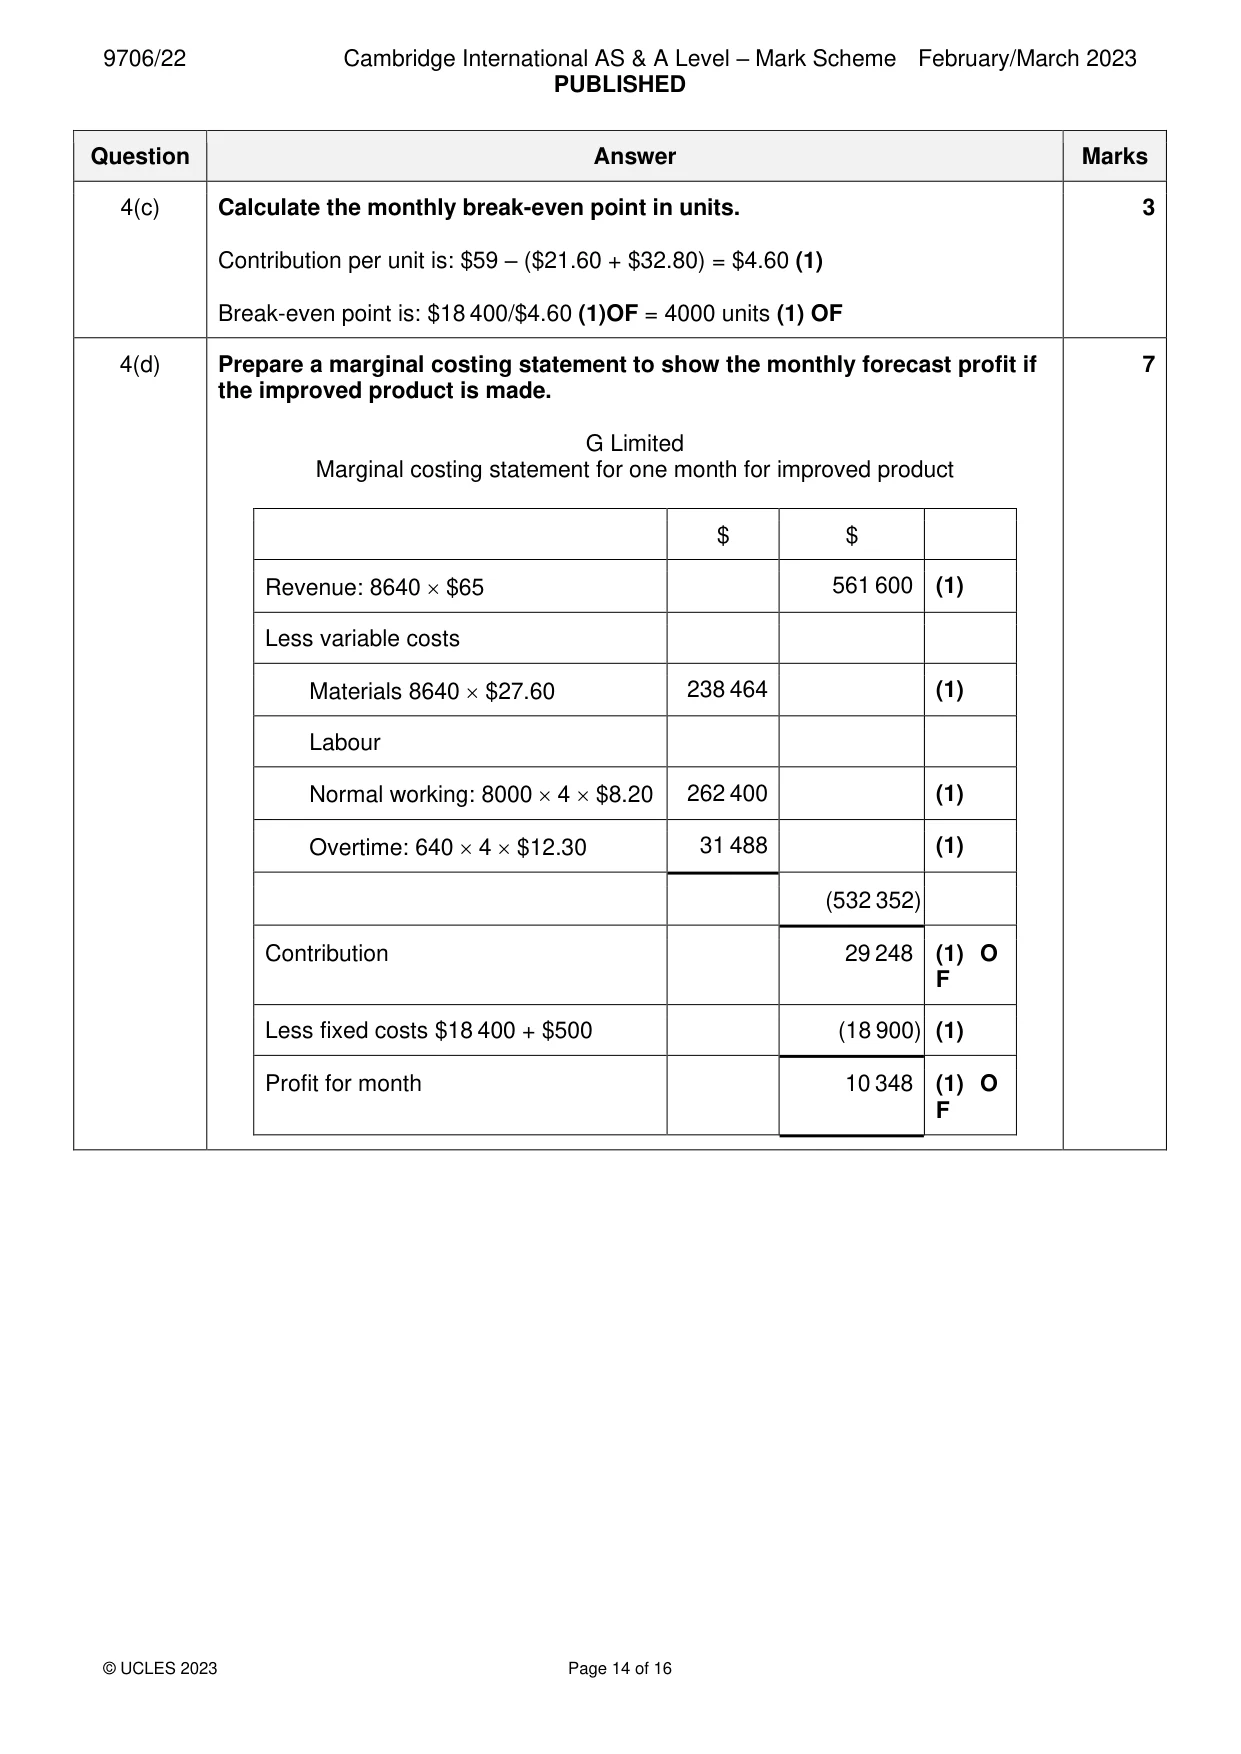
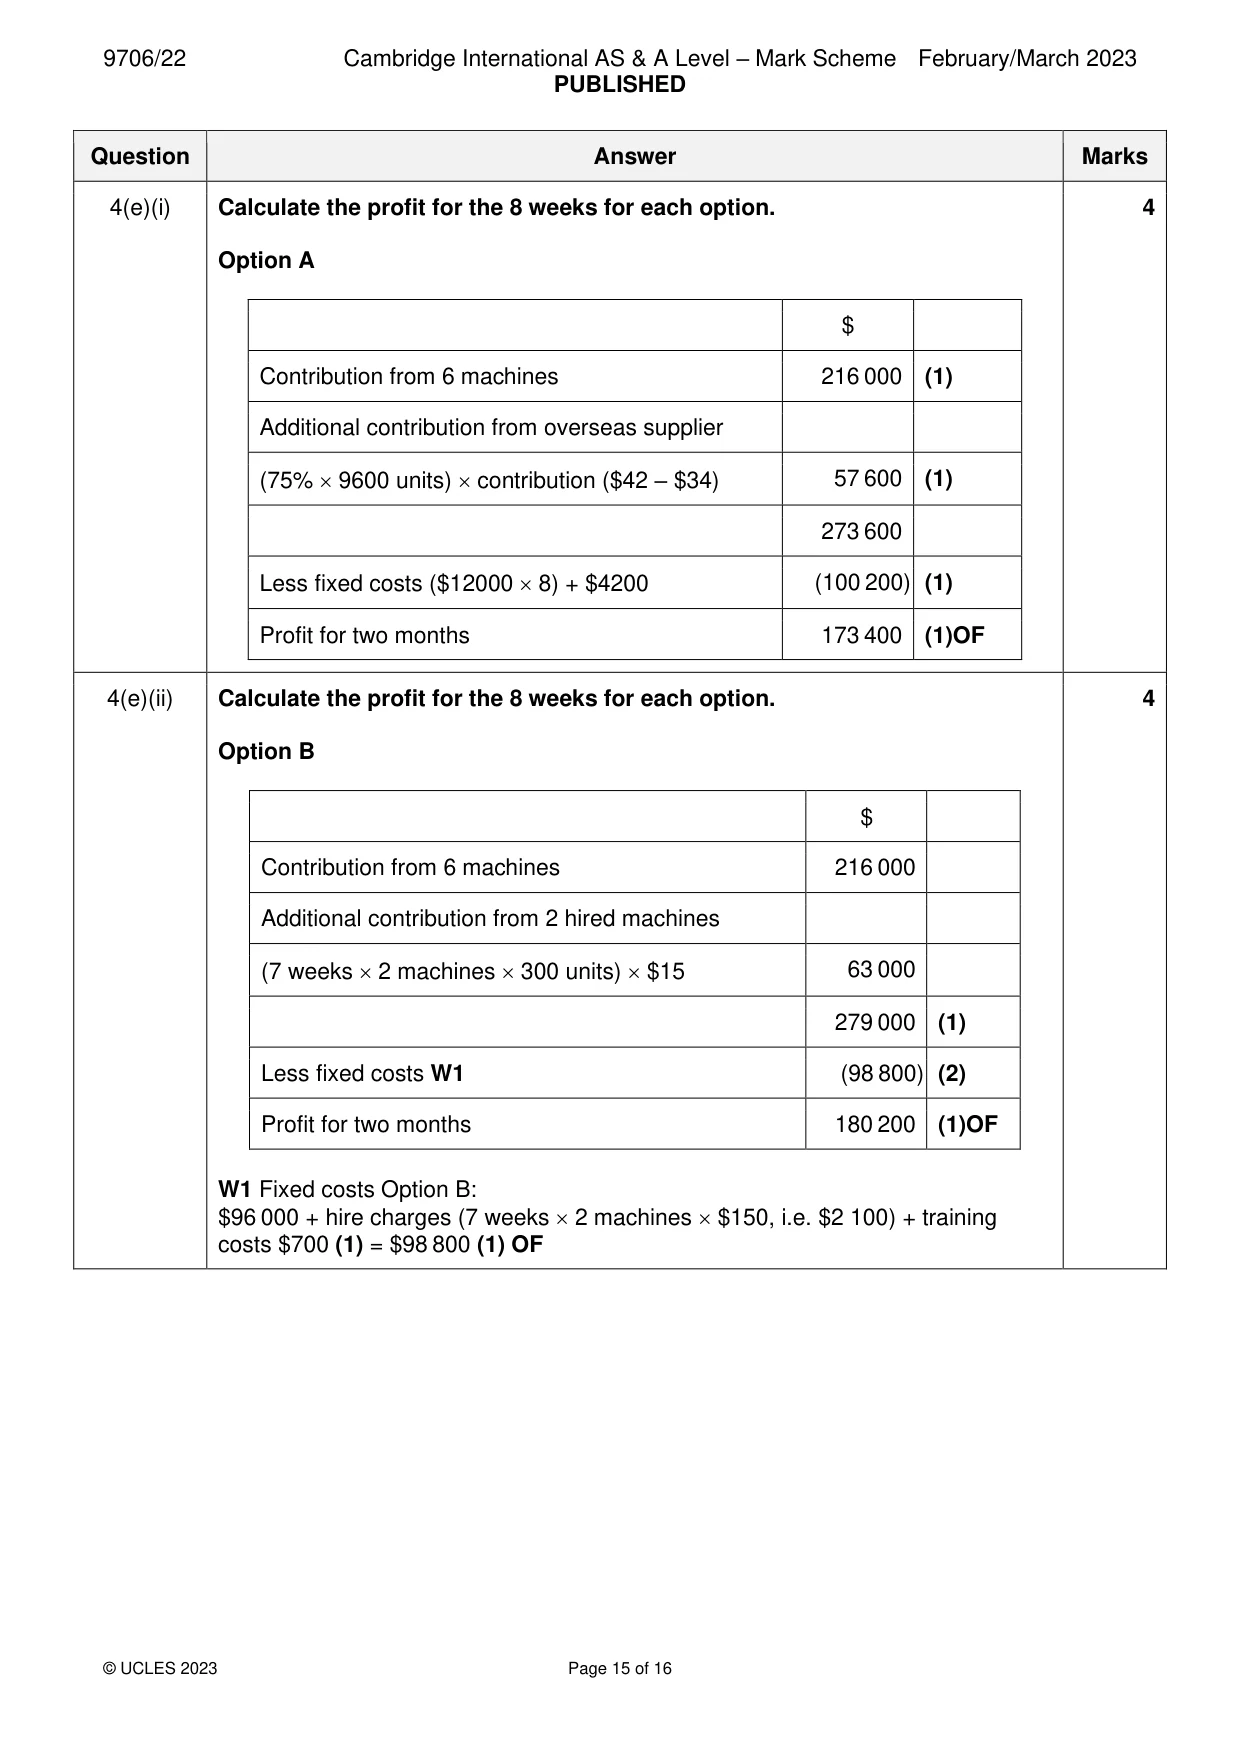
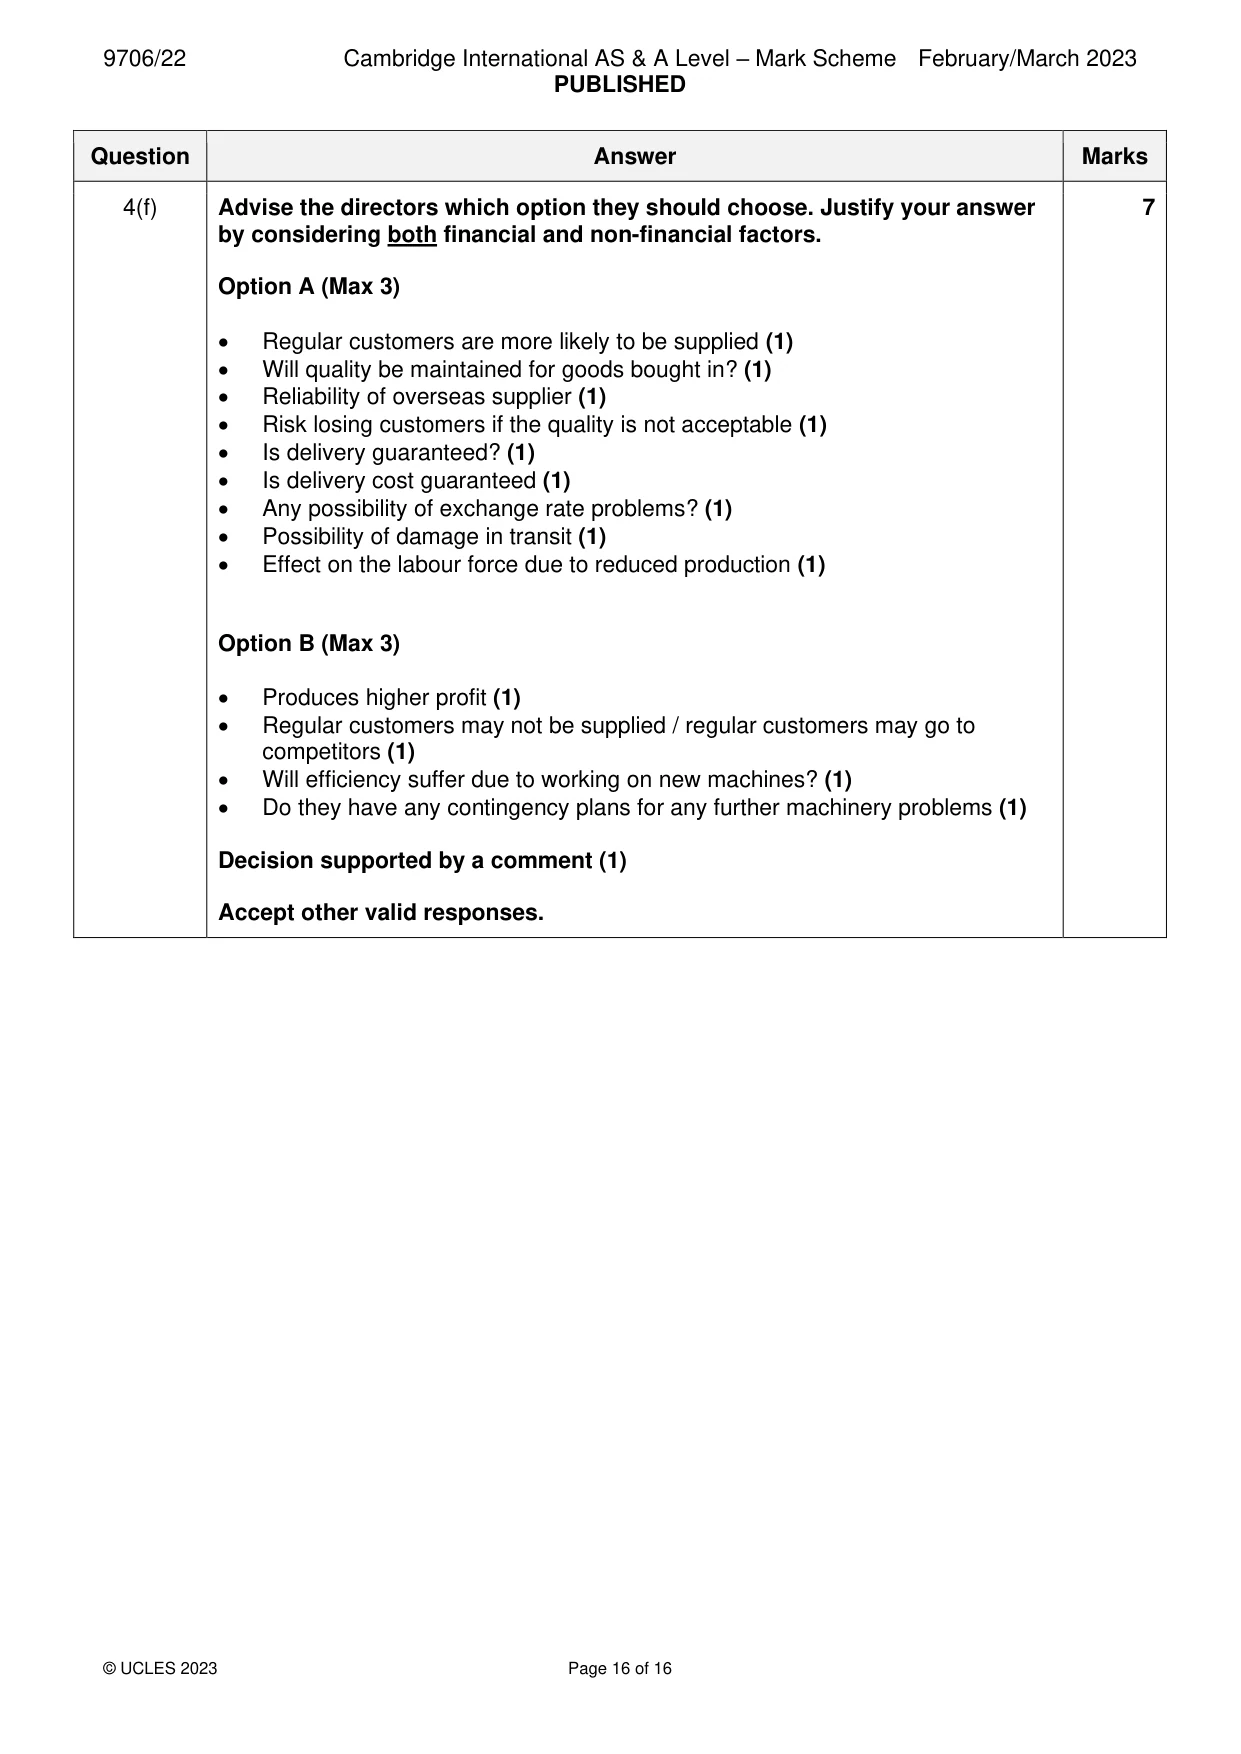
Mark scheme: 4(a)(i) Define each of the following terms: 1 contribution per unit Contribution per unit is the difference between the selling price per unit and the variable costs per unit (1) 4(a)(ii) Define each of the following terms: 1 stepped costs. Stepped costs are fixed for a given level of activity and change when that level is exceeded (1) 4(a)(iii) Define each of the following terms: 1 margin of safety. Margin of safety is the difference between actual/forecast output and the break- even level of output (1) 4(b) State two benefits of using marginal costing. 2 Avoids the arbitrary apportionment of fixed costs (1) Avoids problems of under- or over-absorption of overheads (1) Useful for short-term decision making (1) Enables identification of breakeven point/margin of safety (1) Identifies the relative merits of each product where a variety of products are made (1) Max 2 Accept other valid responses. 4(c) Calculate the monthly break-even point in units. 3 Contribution per unit is: $59 – ($21.60 + $32.80) = $4.60 (1) Break-even point is: $18 400/$4.60 (1)OF = 4000 units (1) OF 4(d) Prepare a marginal costing statement to show the monthly forecast profit if 7 the improved product is made. G Limited Marginal costing statement for one month for improved product $ $ Revenue: 8640 $65 561 600 (1) Less variable costs Materials 8640 $27.60 238 464 (1) Labour Normal working: 8000 4 $8.20 262 400 (1) Overtime: 640 4 $12.30 31 488 (1) (532 352) Contribution 29 248 (1) O F Less fixed costs $18 400 + $500 (18 900) (1) Profit for month 10 348 (1) O F 4(e)(i) Calculate the profit for the 8 weeks for each option. 4 Option A $ Contribution from 6 machines 216 000 (1) Additional contribution from overseas supplier (75% 9600 units) contribution ($42 – $34) 57 600 (1) 273 600 Less fixed costs ($12000 8) + $4200 (100 200) (1) Profit for two months 173 400 (1)OF 4(e)(ii) Calculate the profit for the 8 weeks for each option. 4 Option B $ Contribution from 6 machines 216 000 Additional contribution from 2 hired machines (7 weeks 2 machines 300 units) $15 63 000 279 000 (1) Less fixed costs W1 (98 800) (2) Profit for two months 180 200 (1)OF W1 Fixed costs Option B: $96 000 + hire charges (7 weeks 2 machines $150, i.e. $2 100) + training costs $700 (1) = $98 800 (1) OF 4(f) Advise the directors which option they should choose. Justify your answer 7 by considering both financial and non-financial factors. Option A (Max 3) • Regular customers are more likely to be supplied (1) • Will quality be maintained for goods bought in? (1) • Reliability of overseas supplier (1) • Risk losing customers if the quality is not acceptable (1) • Is delivery guaranteed? (1) • Is delivery cost guaranteed (1) • Any possibility of exchange rate problems? (1) • Possibility of damage in transit (1) • Effect on the labour force due to reduced production (1) Option B (Max 3) • Produces higher profit (1) • Regular customers may not be supplied / regular customers may go to competitors (1) • Will efficiency suffer due to working on new machines? (1) • Do they have any contingency plans for any further machinery problems (1) Decision supported by a comment (1) Accept other valid responses.
Q5 · The factory can operate in overtime conditions
5 The factory can operate in overtime conditions. Direct labour is paid 1.5 times the normal rate in overtime conditions.
Q6 · An additional machine costing $40 000 will be required
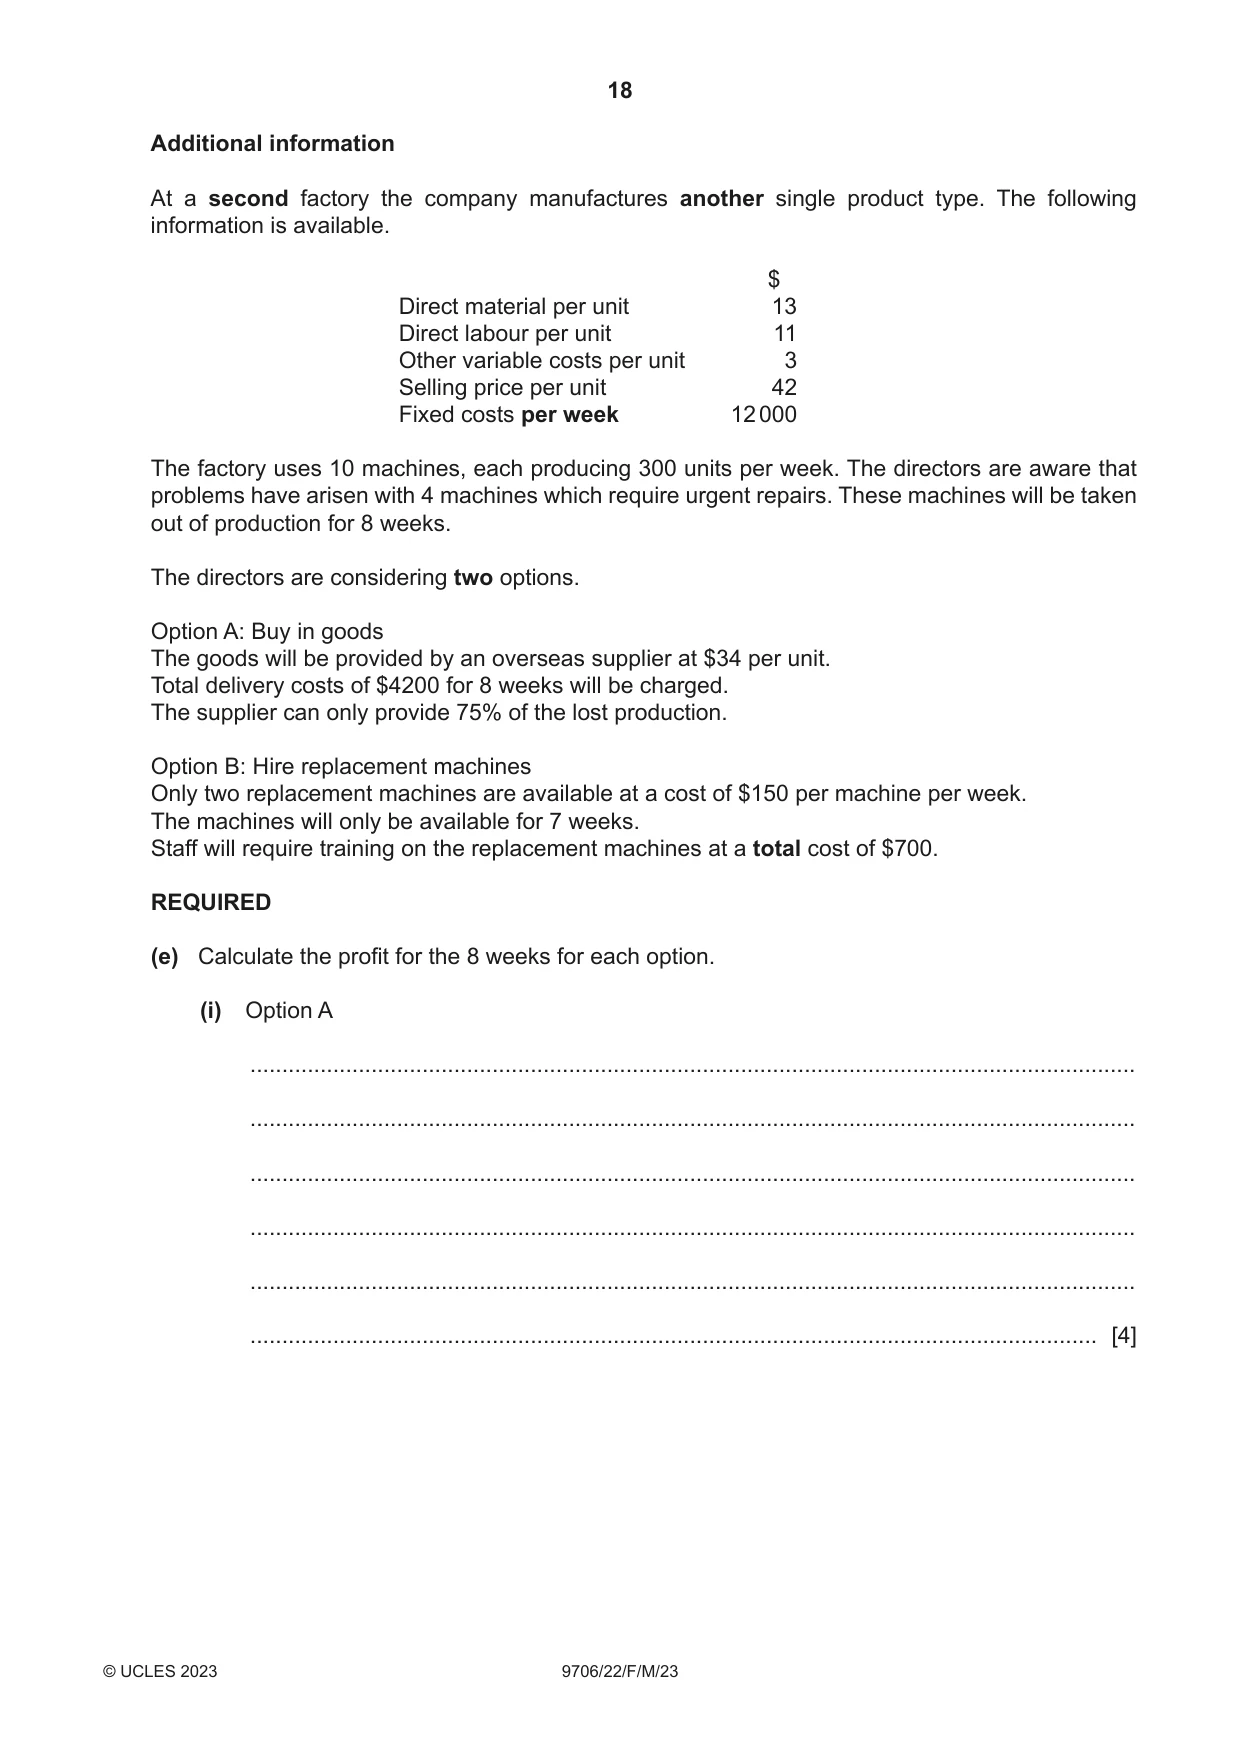
6 An additional machine costing $40 000 will be required. Non-current assets are depreciated by 15% per annum. REQUIRED (d) Prepare a marginal costing statement to show the monthly forecast profit if the improved product is made. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [7] Additional information At a second factory the company manufactures another single product type. The following information is available. $ Direct material per unit 13 Direct labour per unit 11 Other variable costs per unit 3 Selling price per unit 42 Fixed costs per week 12 000 The factory uses 10 machines, each producing 300 units per week. The directors are aware that problems have arisen with 4 machines which require urgent repairs. These machines will be taken out of production for 8 weeks. The directors are considering two options. Option A: Buy in goods The goods will be provided by an overseas supplier at $34 per unit. Total delivery costs of $4200 for 8 weeks will be charged. The supplier can only provide 75% of the lost production. Option B: Hire replacement machines Only two replacement machines are available at a cost of $150 per machine per week. The machines will only be available for 7 weeks. Staff will require training on the replacement machines at a total cost of $700. REQUIRED (e) Calculate the profit for the 8 weeks for each option. (i) Option A ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [4]
What was in this paper
The subtopics covered by these 6 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2023 Feb/March, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.