Cambridge A Level Accounting 9706 — 2022 Feb/March Paper 2 · Variant 2
9706/22/F/M/22 · 6 questions · 90 marks · ≈101 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme19 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Rafiq owns a retail business
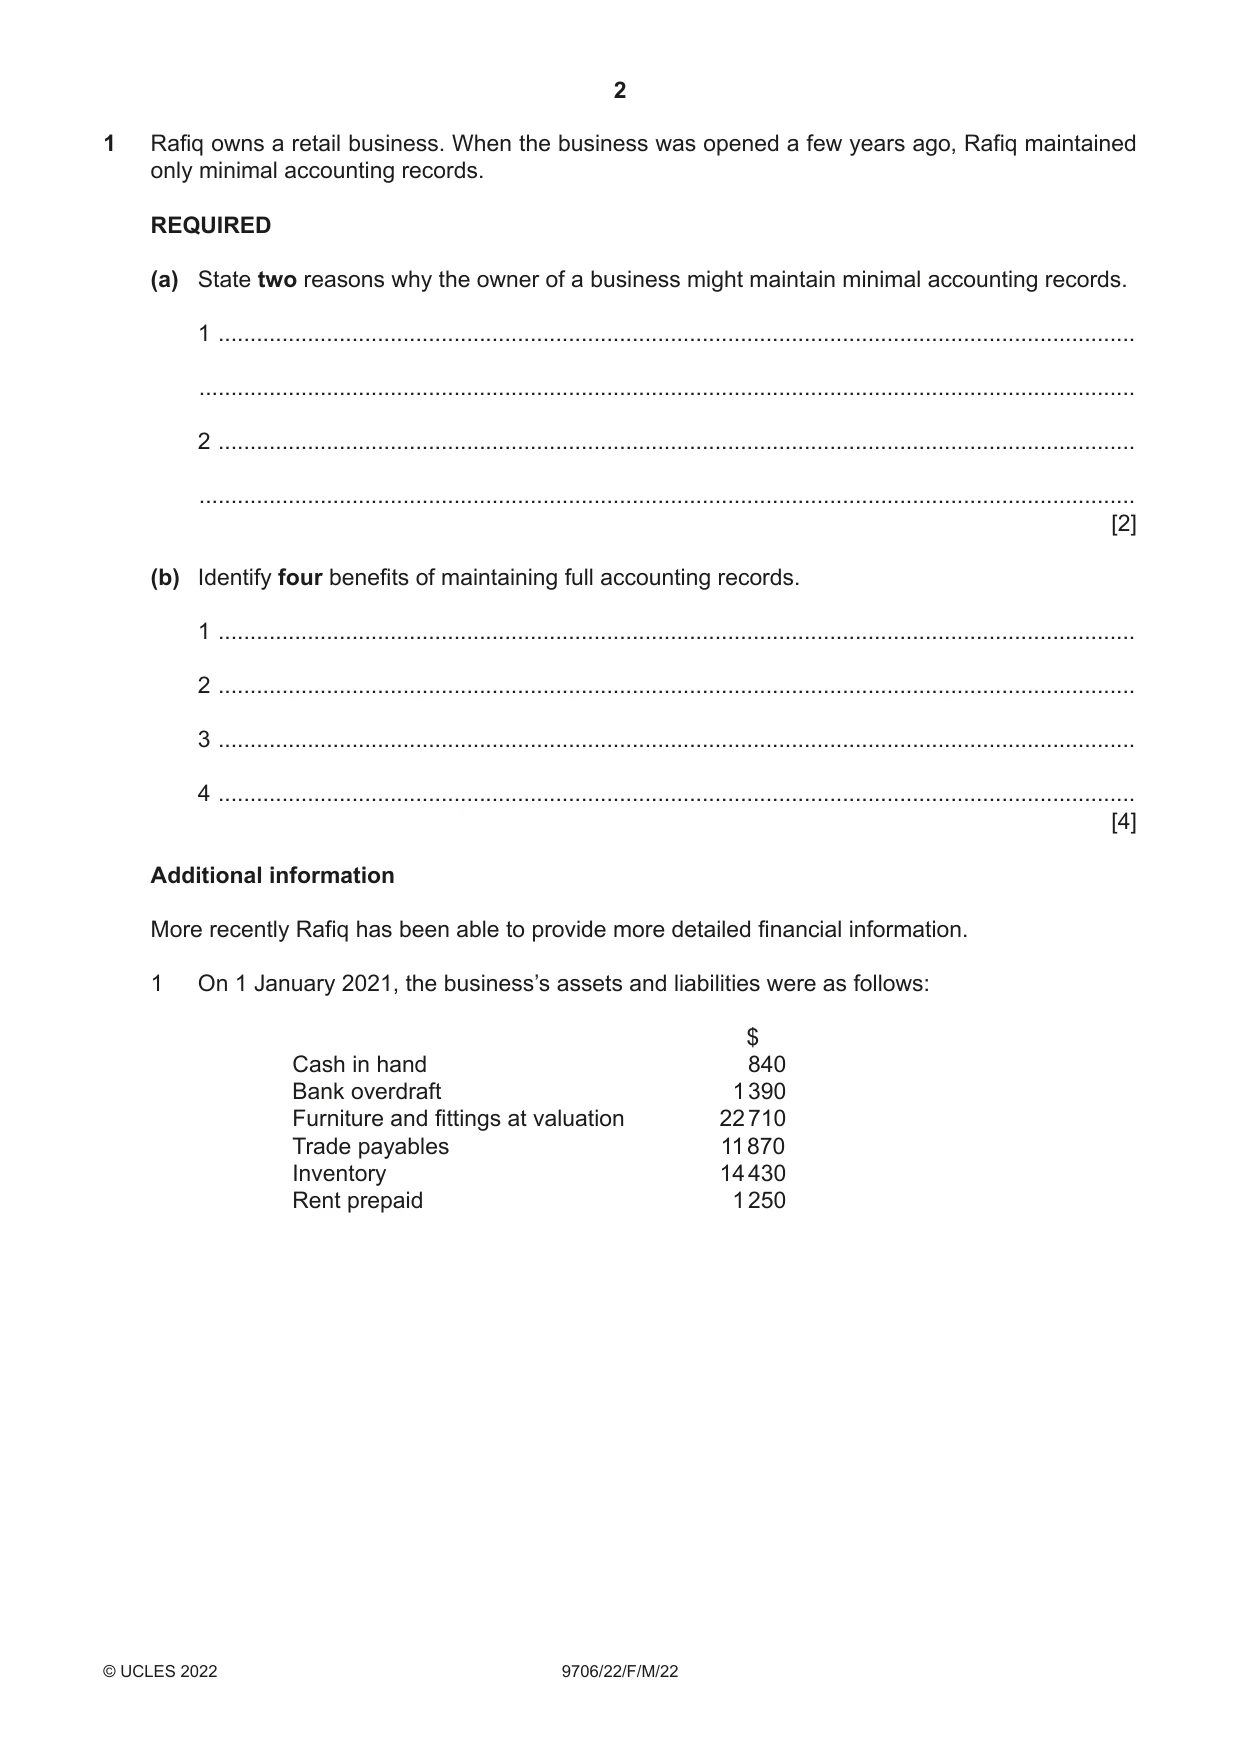
1 Rafiq owns a retail business. When the business was opened a few years ago, Rafiq maintained only minimal accounting records. REQUIRED (a) State two reasons why the owner of a business might maintain minimal accounting records. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] (b) Identify four benefits of maintaining full accounting records. 1 ................................................................................................................................................ 2 ................................................................................................................................................ 3 ................................................................................................................................................ 4 ................................................................................................................................................ [4] Additional information More recently Rafiq has been able to provide more detailed financial information. 1 On 1 January 2021, the business’s assets and liabilities were as follows: $ Cash in hand 840 Bank overdraft 1 390 Furniture and fittings at valuation 22 710 Trade payables 11 870 Inventory 14 430 Rent prepaid 1 250
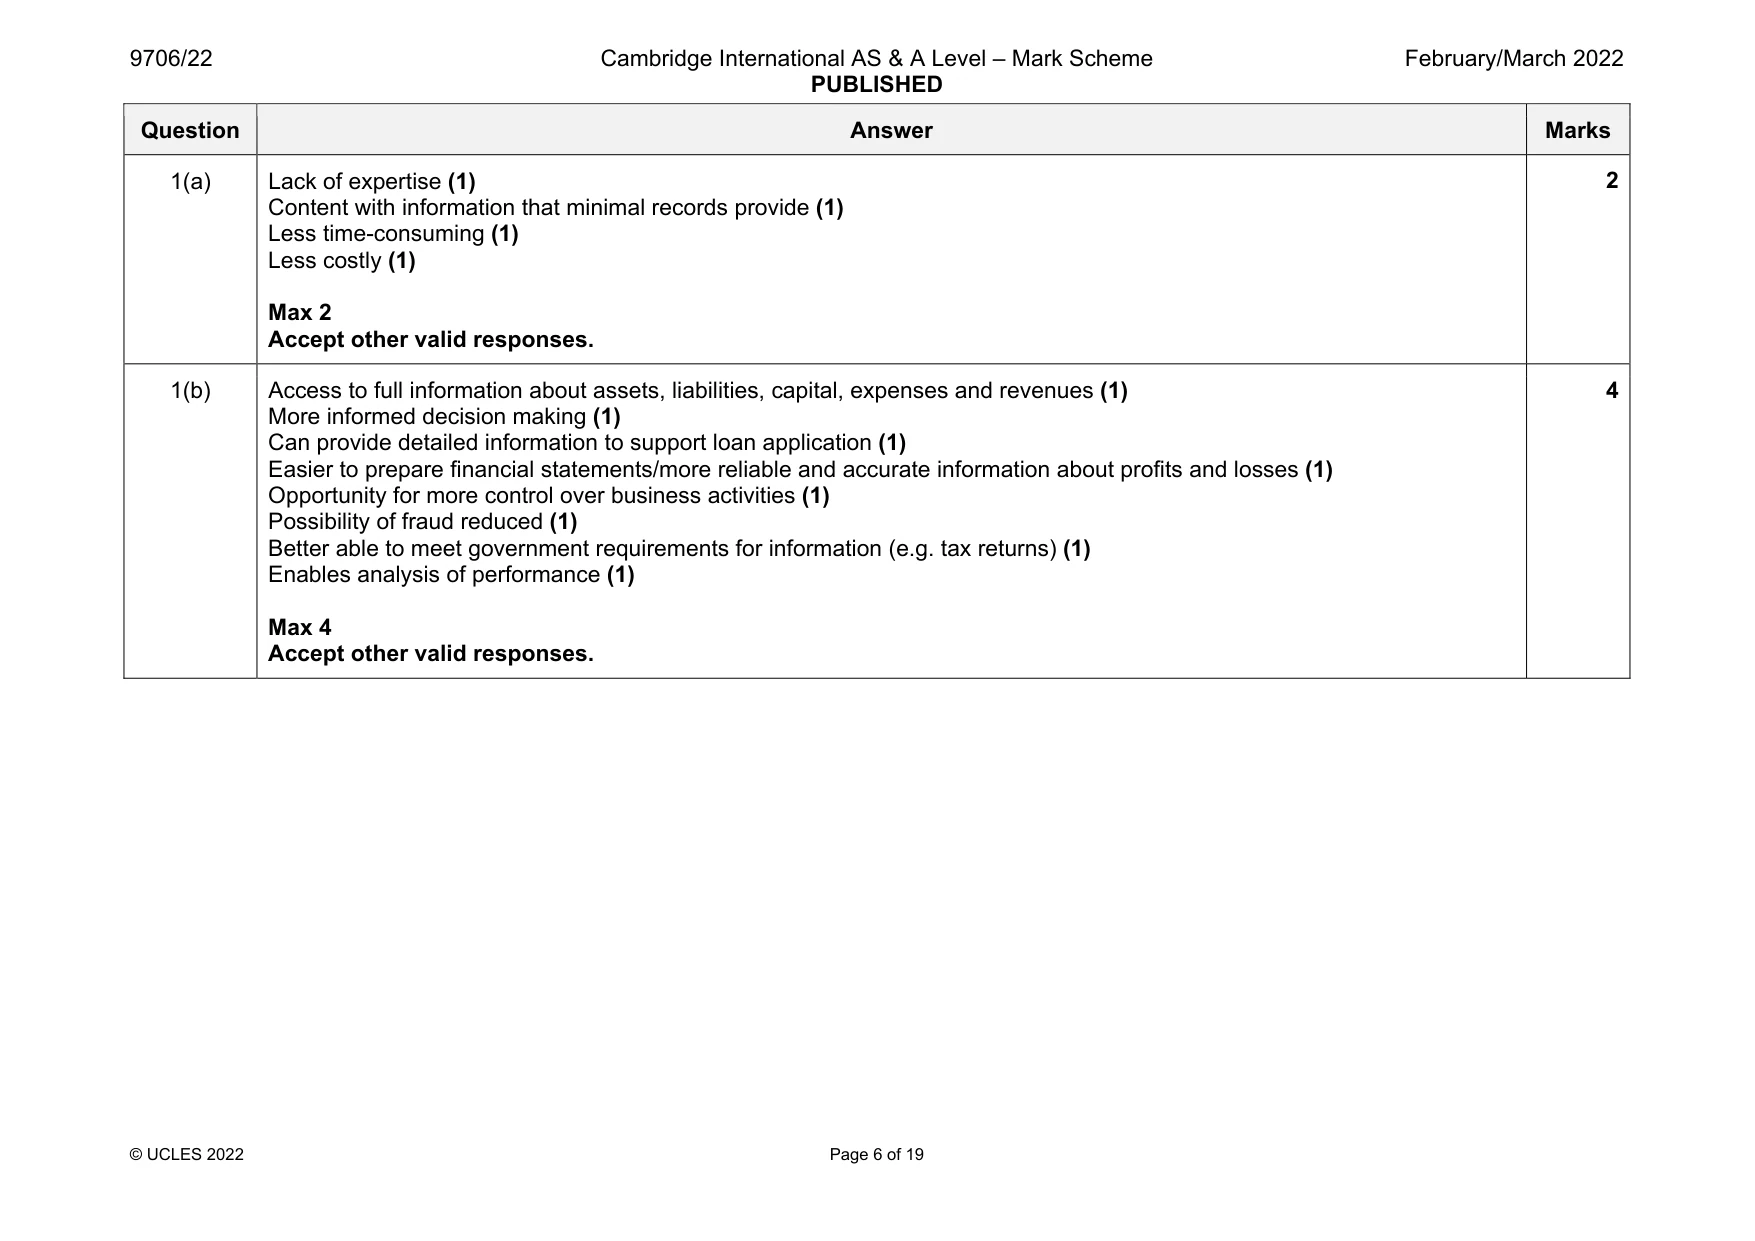
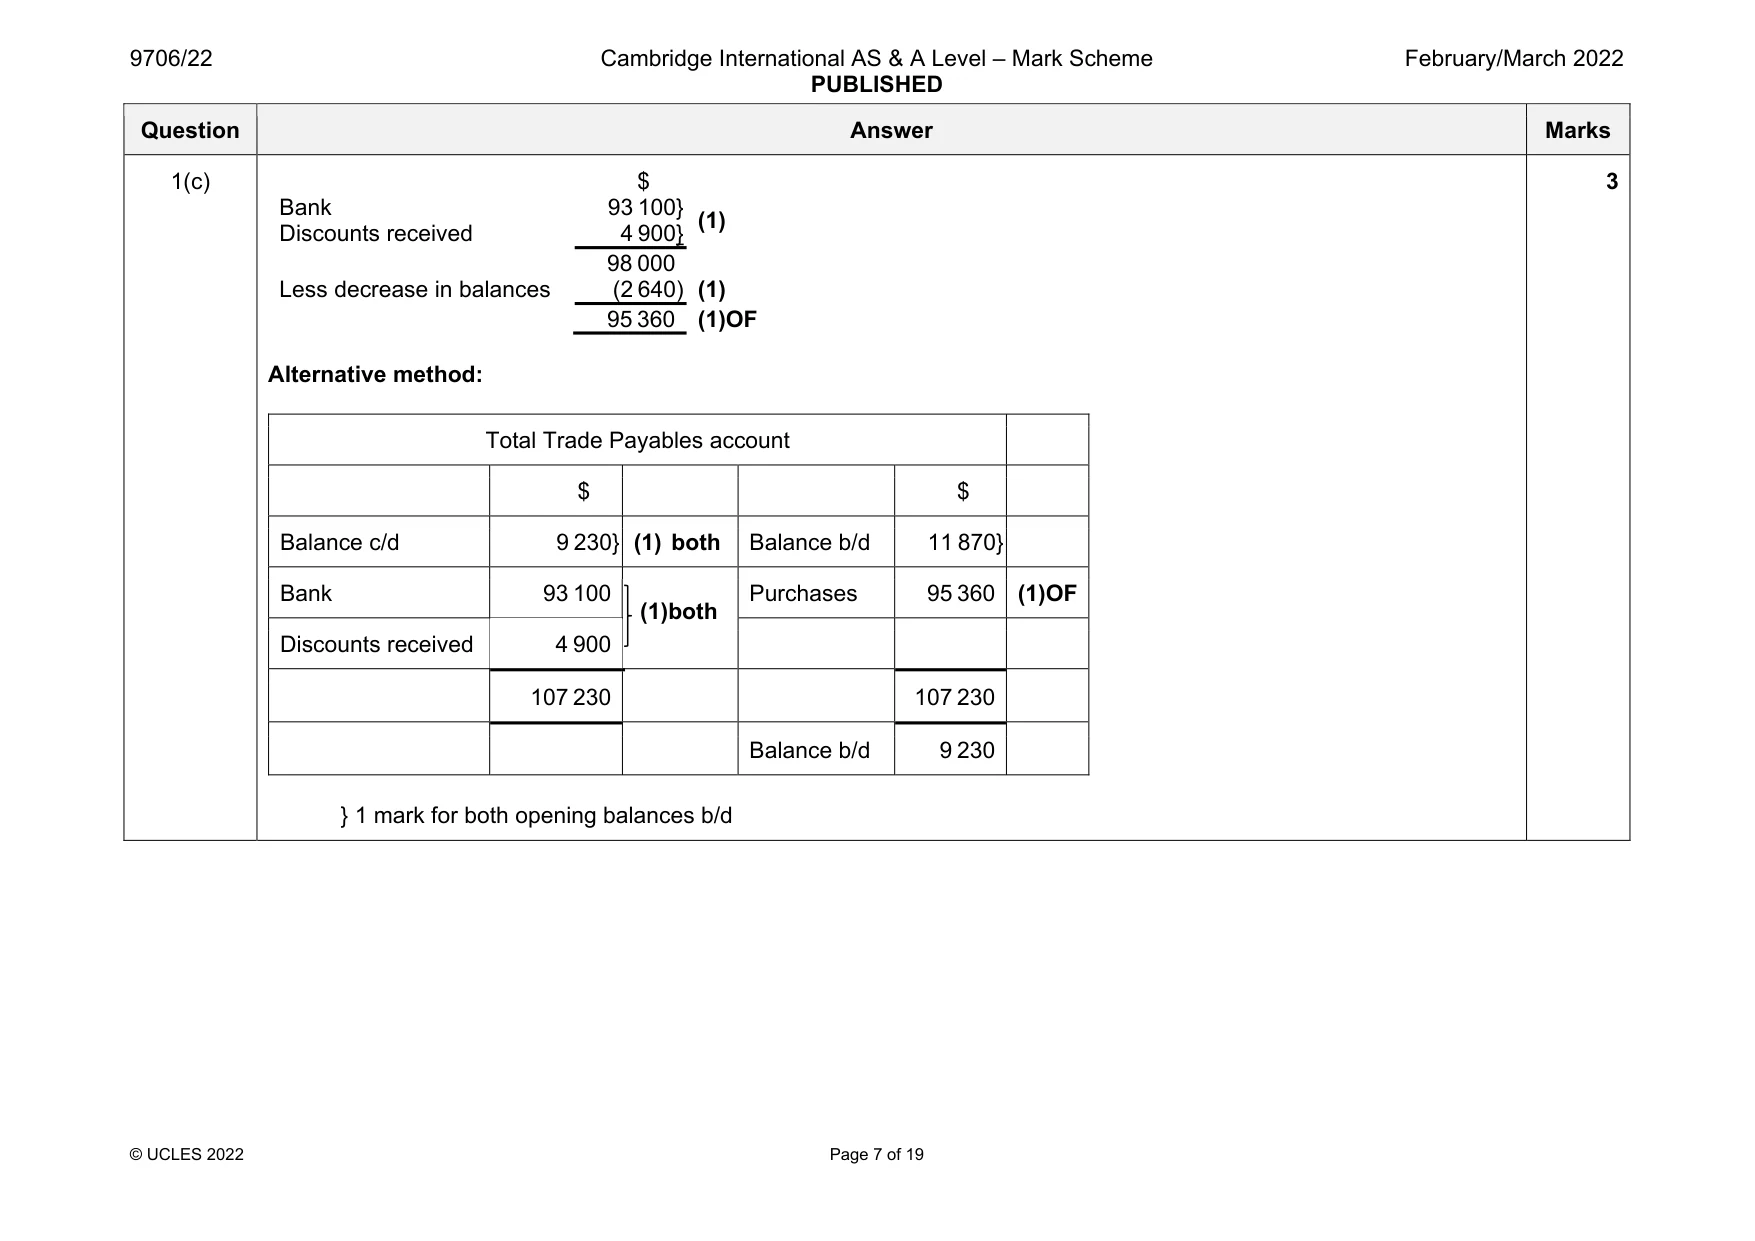
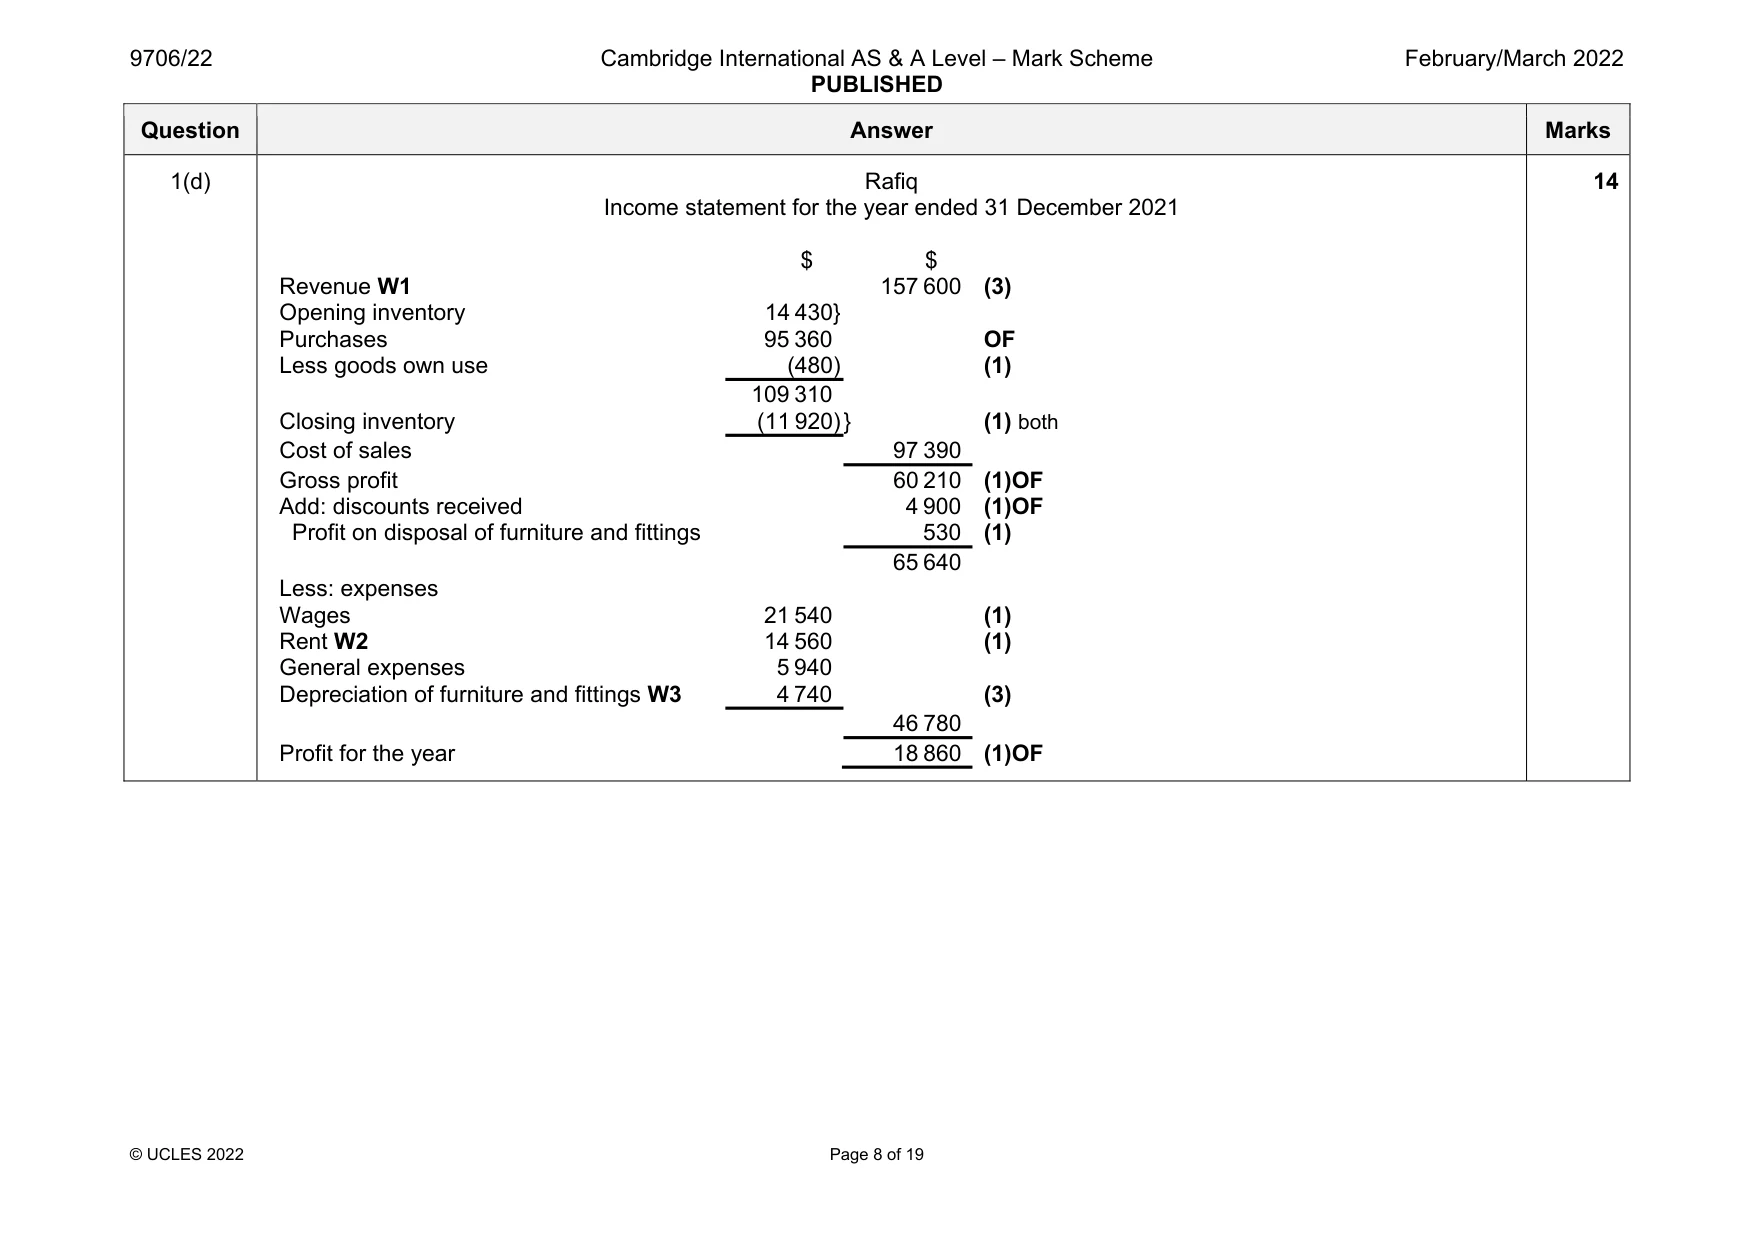
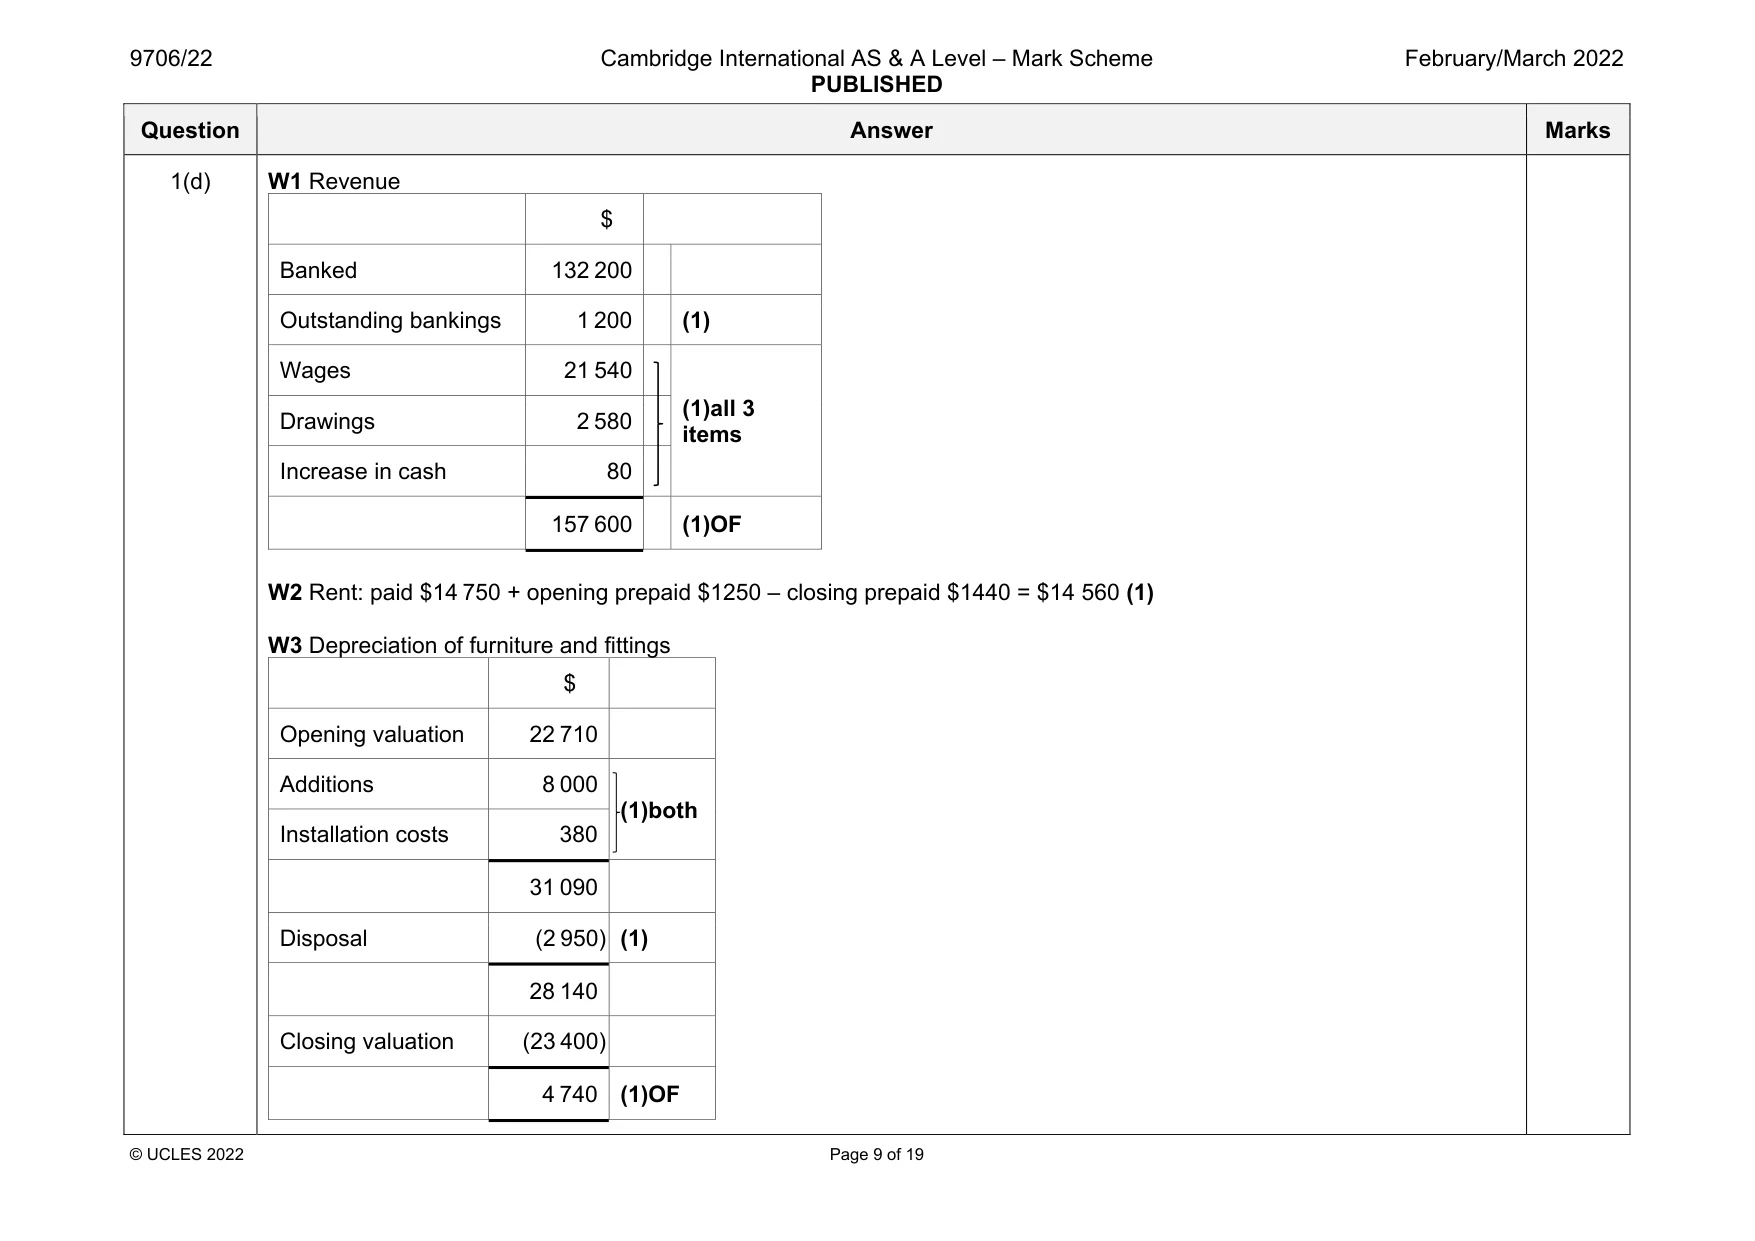
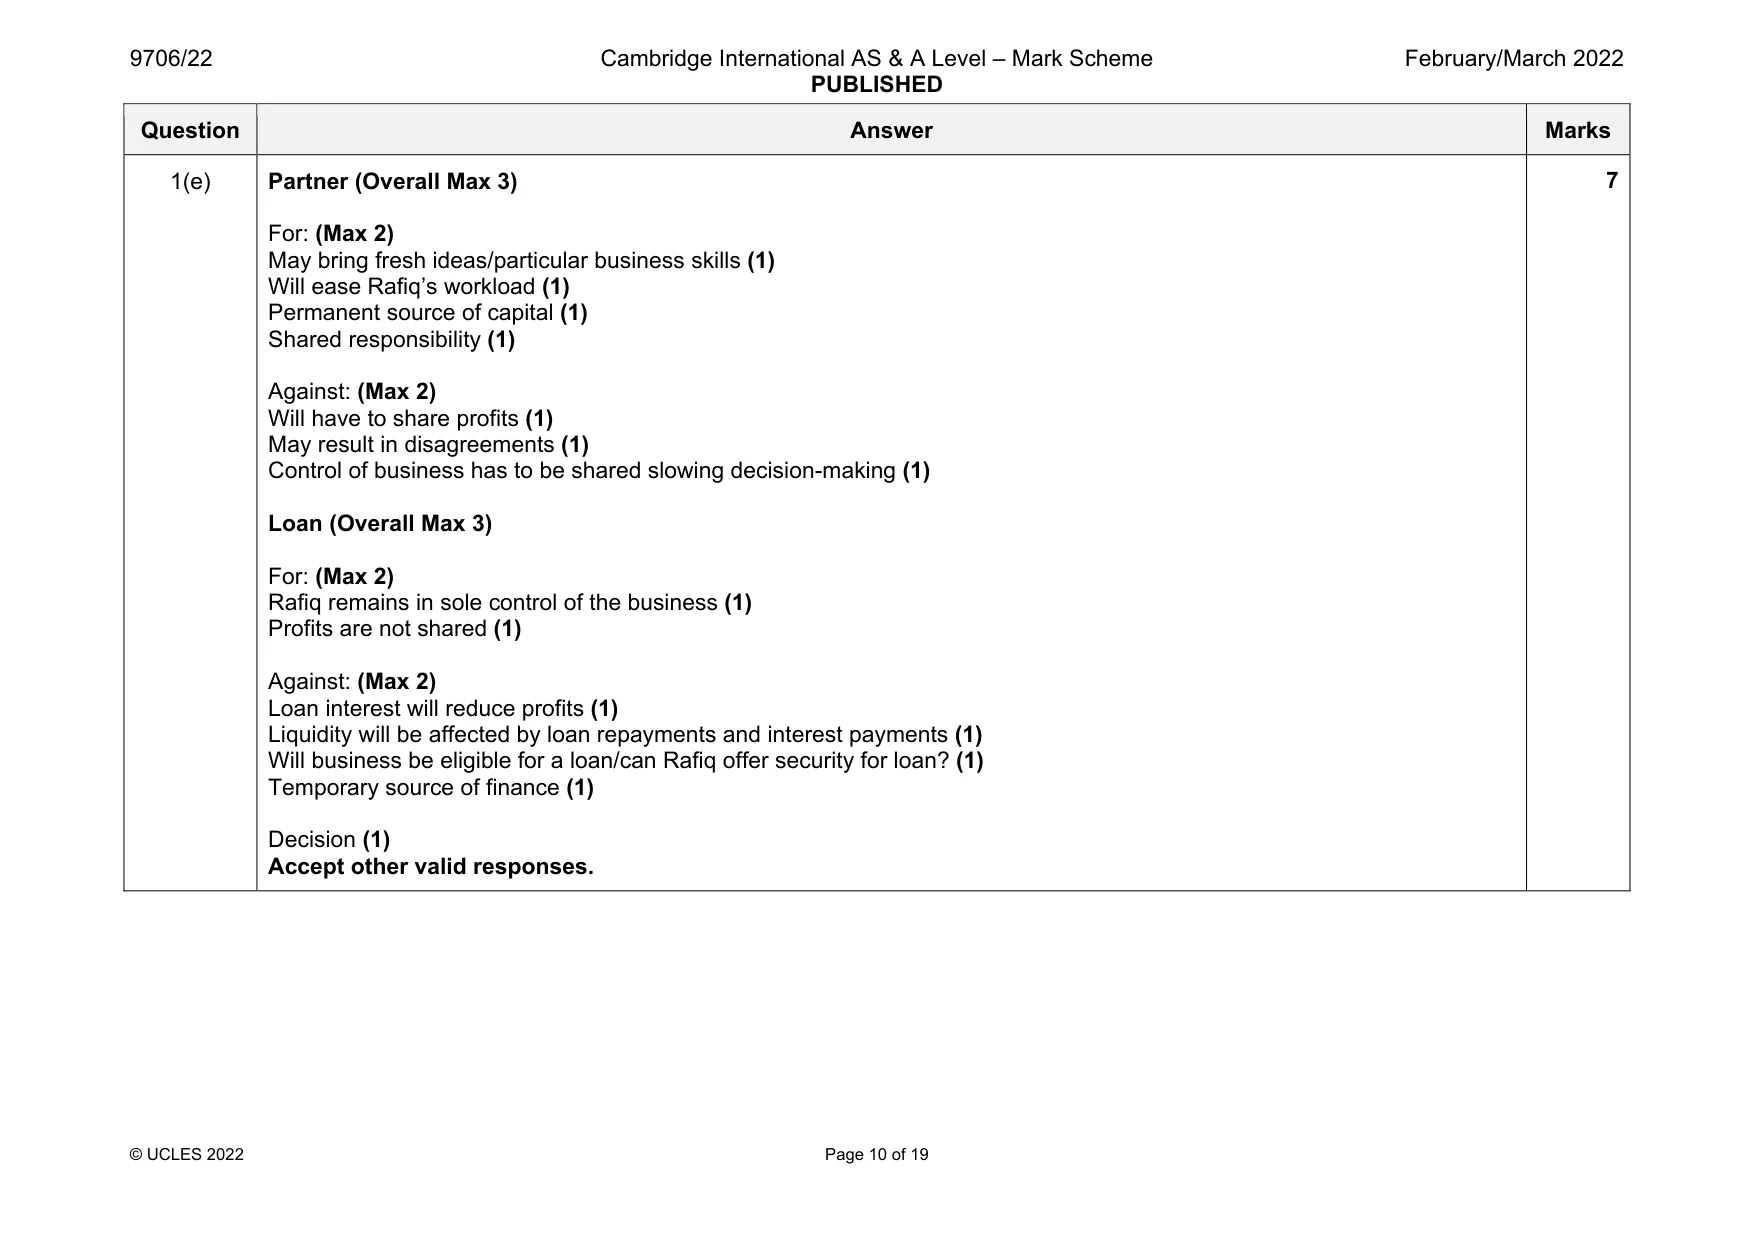
Mark scheme: 1(a) Lack of expertise (1) Content with information that minimal records provide (1) Less time-consuming (1) Less costly (1) Max 2 Accept other valid responses. 1(b) Access to full information about assets, liabilities, capital, expenses and revenues (1) More informed decision making (1) Can provide detailed information to support loan application (1) Easier to prepare financial statements/more reliable and accurate information about profits and losses (1) Opportunity for more control over business activities (1) Possibility of fraud reduced (1) Better able to meet government requirements for information (e.g. tax returns) (1) Enables analysis of performance (1) Max 4 Accept other valid responses. 4 Question Answer Marks 1(c) $ Bank 93 100} (1) Discounts received 4 900} 98 000 Less decrease in balances (2 640) (1) 95 360 (1)OF Alternative method: Total Trade Payables account $ $ Balance c/d 9 230} (1) both Balance b/d 11 870} Bank 93 100 (1)both Purchases 95 360 (1)OF Discounts received 4 900 107 230 107 230 Balance b/d 9 230 } 1 mark for both opening balances b/d 3 Question Answer Marks 1(d) Rafiq Income statement for the year ended 31 December 2021 $ $ Revenue W1 157 600 (3) Opening inventory 14 430} Purchases 95 360 OF Less goods own use (480) (1) 109 310 Closing inventory (11 920) } (1) both Cost of sales 97 390 Gross profit 60 210 (1)OF Add: discounts received 4 900 (1)OF Profit on disposal of furniture and fittings 530 (1) 65 640 Less: expenses Wages 21 540 (1) Rent W2 14 560 (1) General expenses 5 940 Depreciation of furniture and fittings W3 4 740 (3) 46 780 Profit for the year 18 860 (1)OF 14 Question Answer Marks 1(d) W1 Revenue $ Banked 132 200 Outstanding bankings 1 200 (1) Wages 21 540 (1)all 3 items Drawings 2 580 Increase in cash 80 157 600 (1)OF W2 Rent: paid $14 750 + opening prepaid $1250 – closing prepaid $1440 = $14 560 (1) W3 Depreciation of furniture and fittings $ Opening valuation 22 710 Additions 8 000 (1)both Installation costs 380 31 090 Disposal (2 950) (1) 28 140 Closing valuation (23 400) 4 740 (1)OF Question Answer Marks 1(e) Partner (Overall Max 3) For: (Max 2) May bring fresh ideas/particular business skills (1) Will ease Rafiq’s workload (1) Permanent source of capital (1) Shared responsibility (1) Against: (Max 2) Will have to share profits (1) May result in disagreements (1) Control of business has to be shared slowing decision-making (1) Loan (Overall Max 3) For: (Max 2) Rafiq remains in sole control of the business (1) Profits are not shared (1) Against: (Max 2) Loan interest will reduce profits (1) Liquidity will be affected by loan repayments and interest payments (1) Will business be eligible for a loan/can Rafiq offer security for loan? (1) Temporary source of finance (1) Decision (1) Accept other valid responses. 7
Q2 · The following summary of receipts and payments for the year ended 31 December 2021 has…
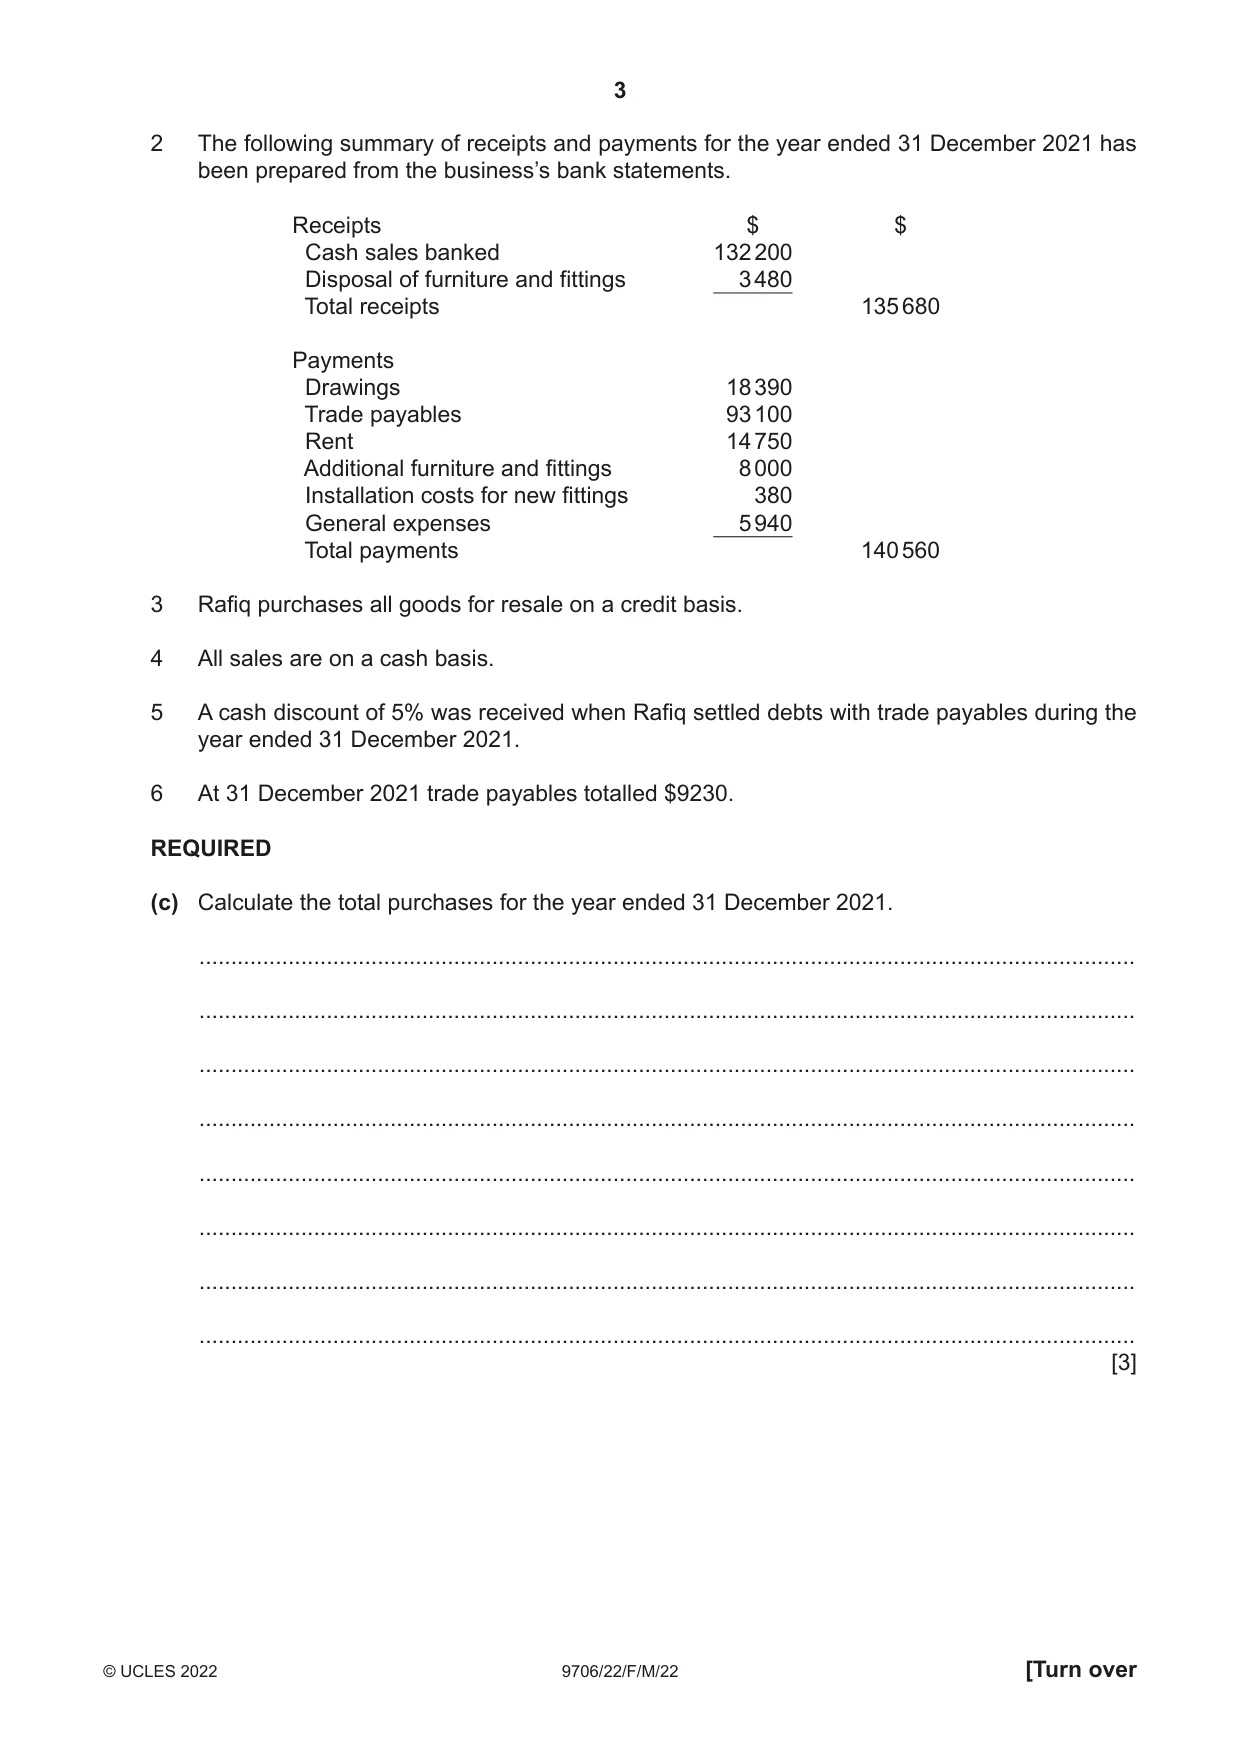
2 The following summary of receipts and payments for the year ended 31 December 2021 has been prepared from the business’s bank statements. Receipts $ $ Cash sales banked 132 200 Disposal of furniture and fittings 3 480 Total receipts 135 680 Payments Drawings 18 390 Trade payables 93 100 Rent 14 750 Additional furniture and fittings 8 000 Installation costs for new fittings 380 General expenses 5 940 Total payments 140 560
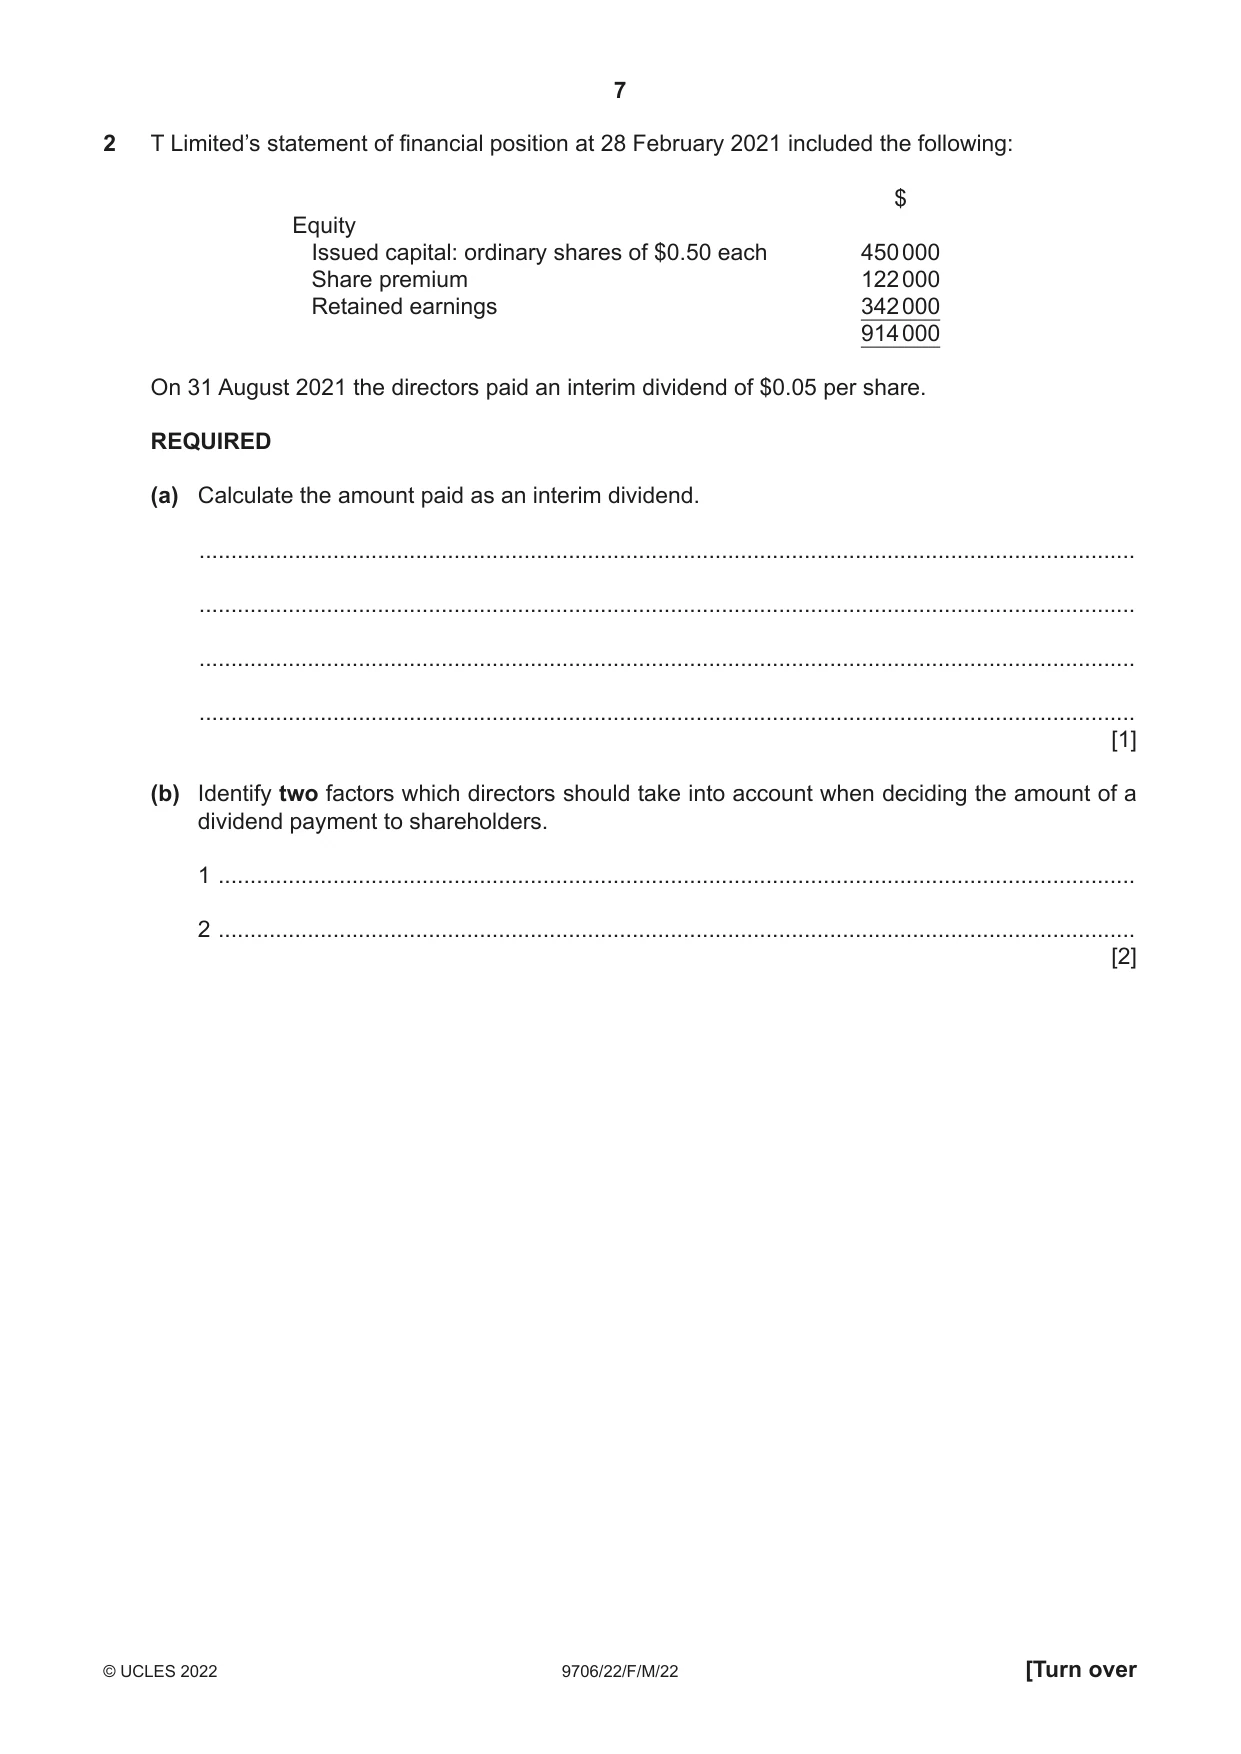
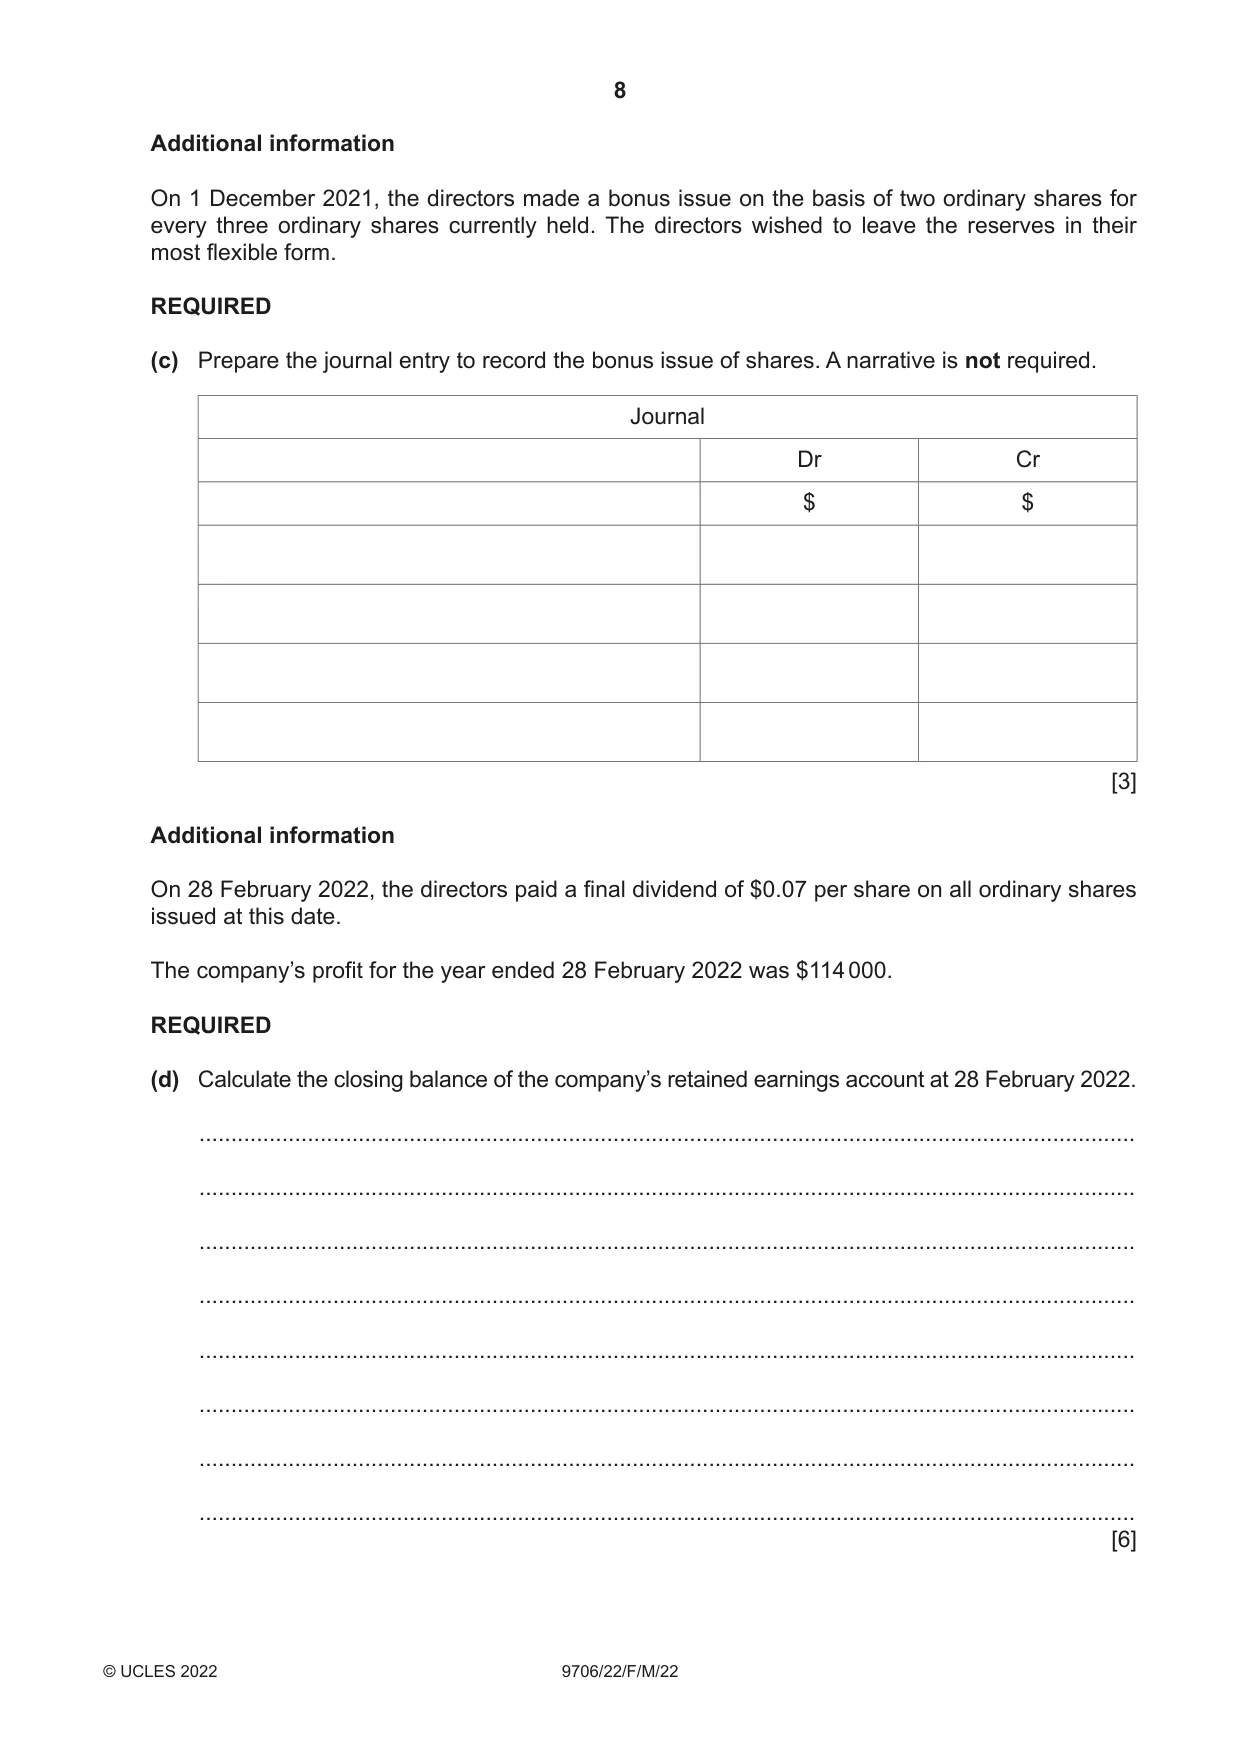
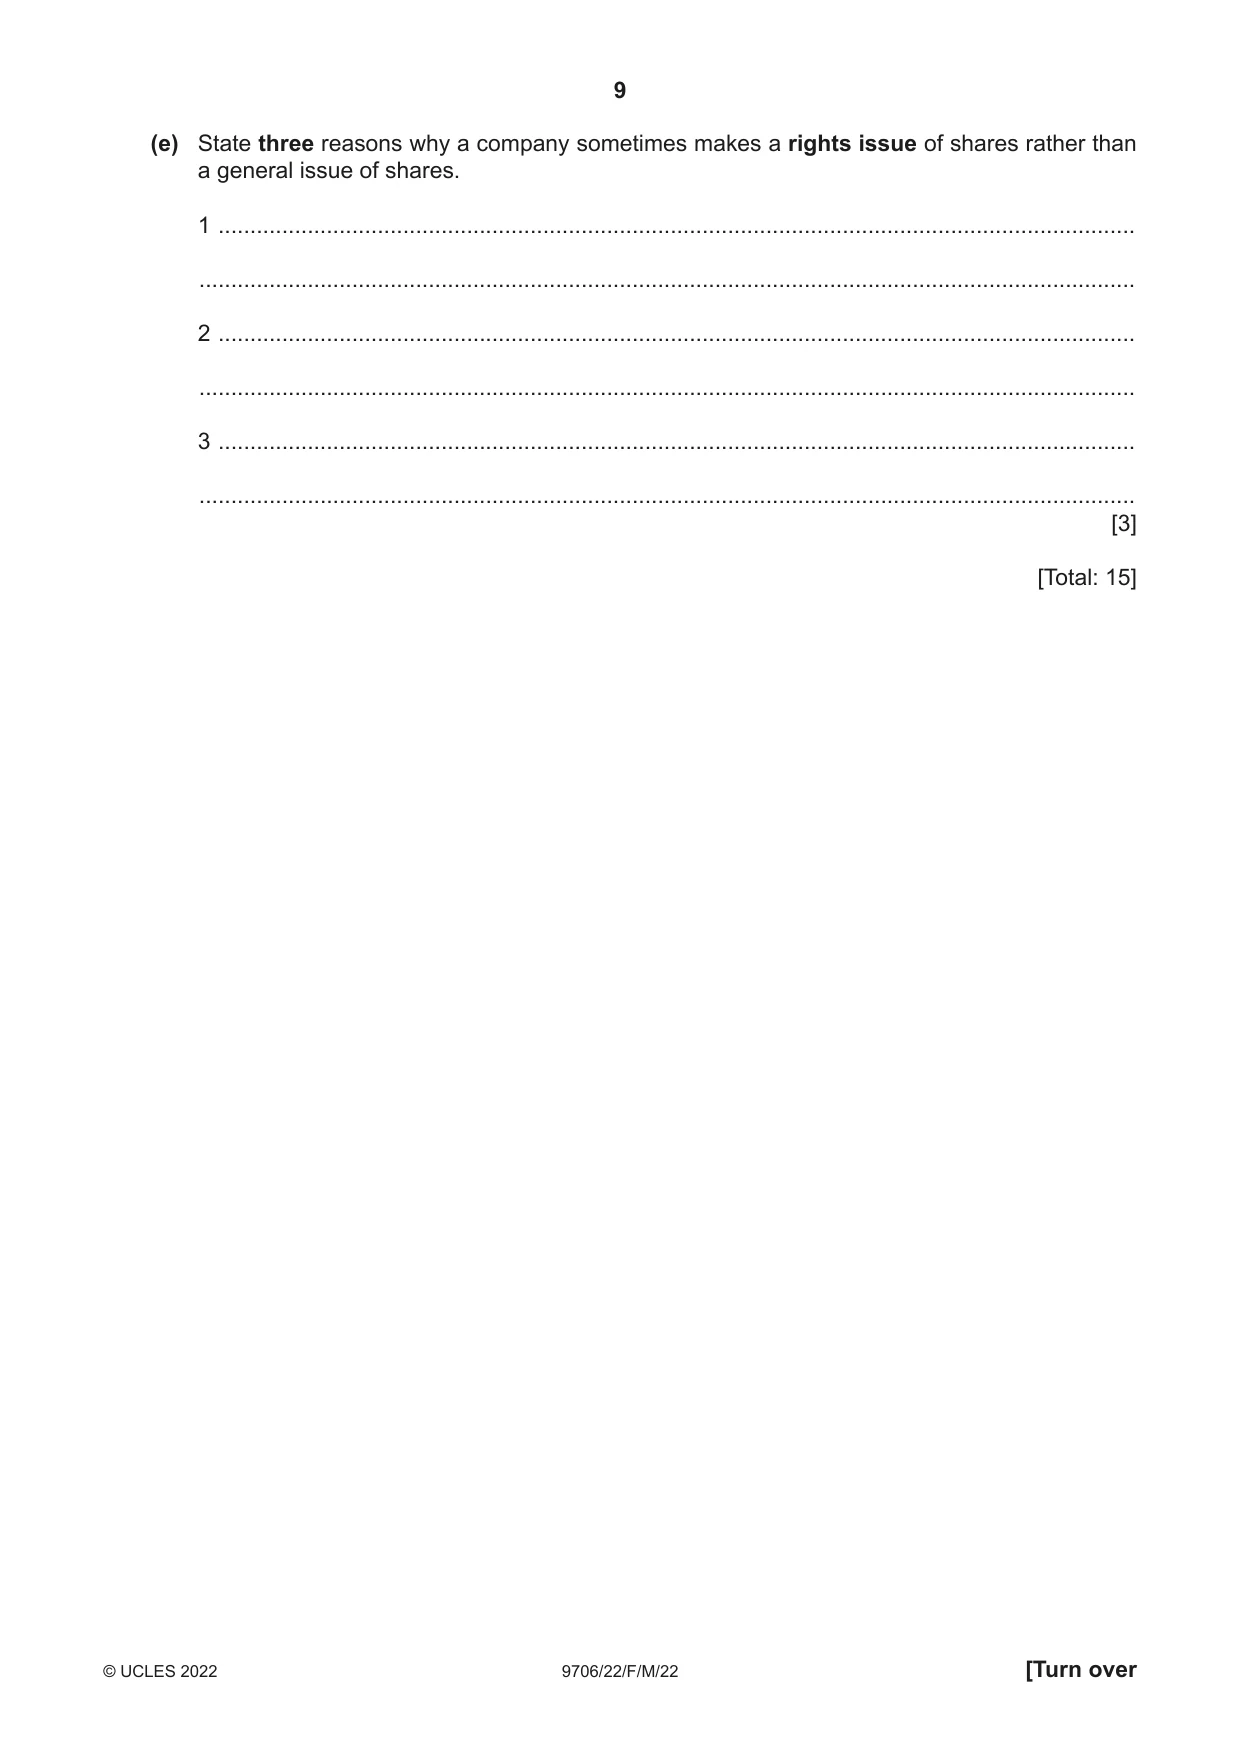
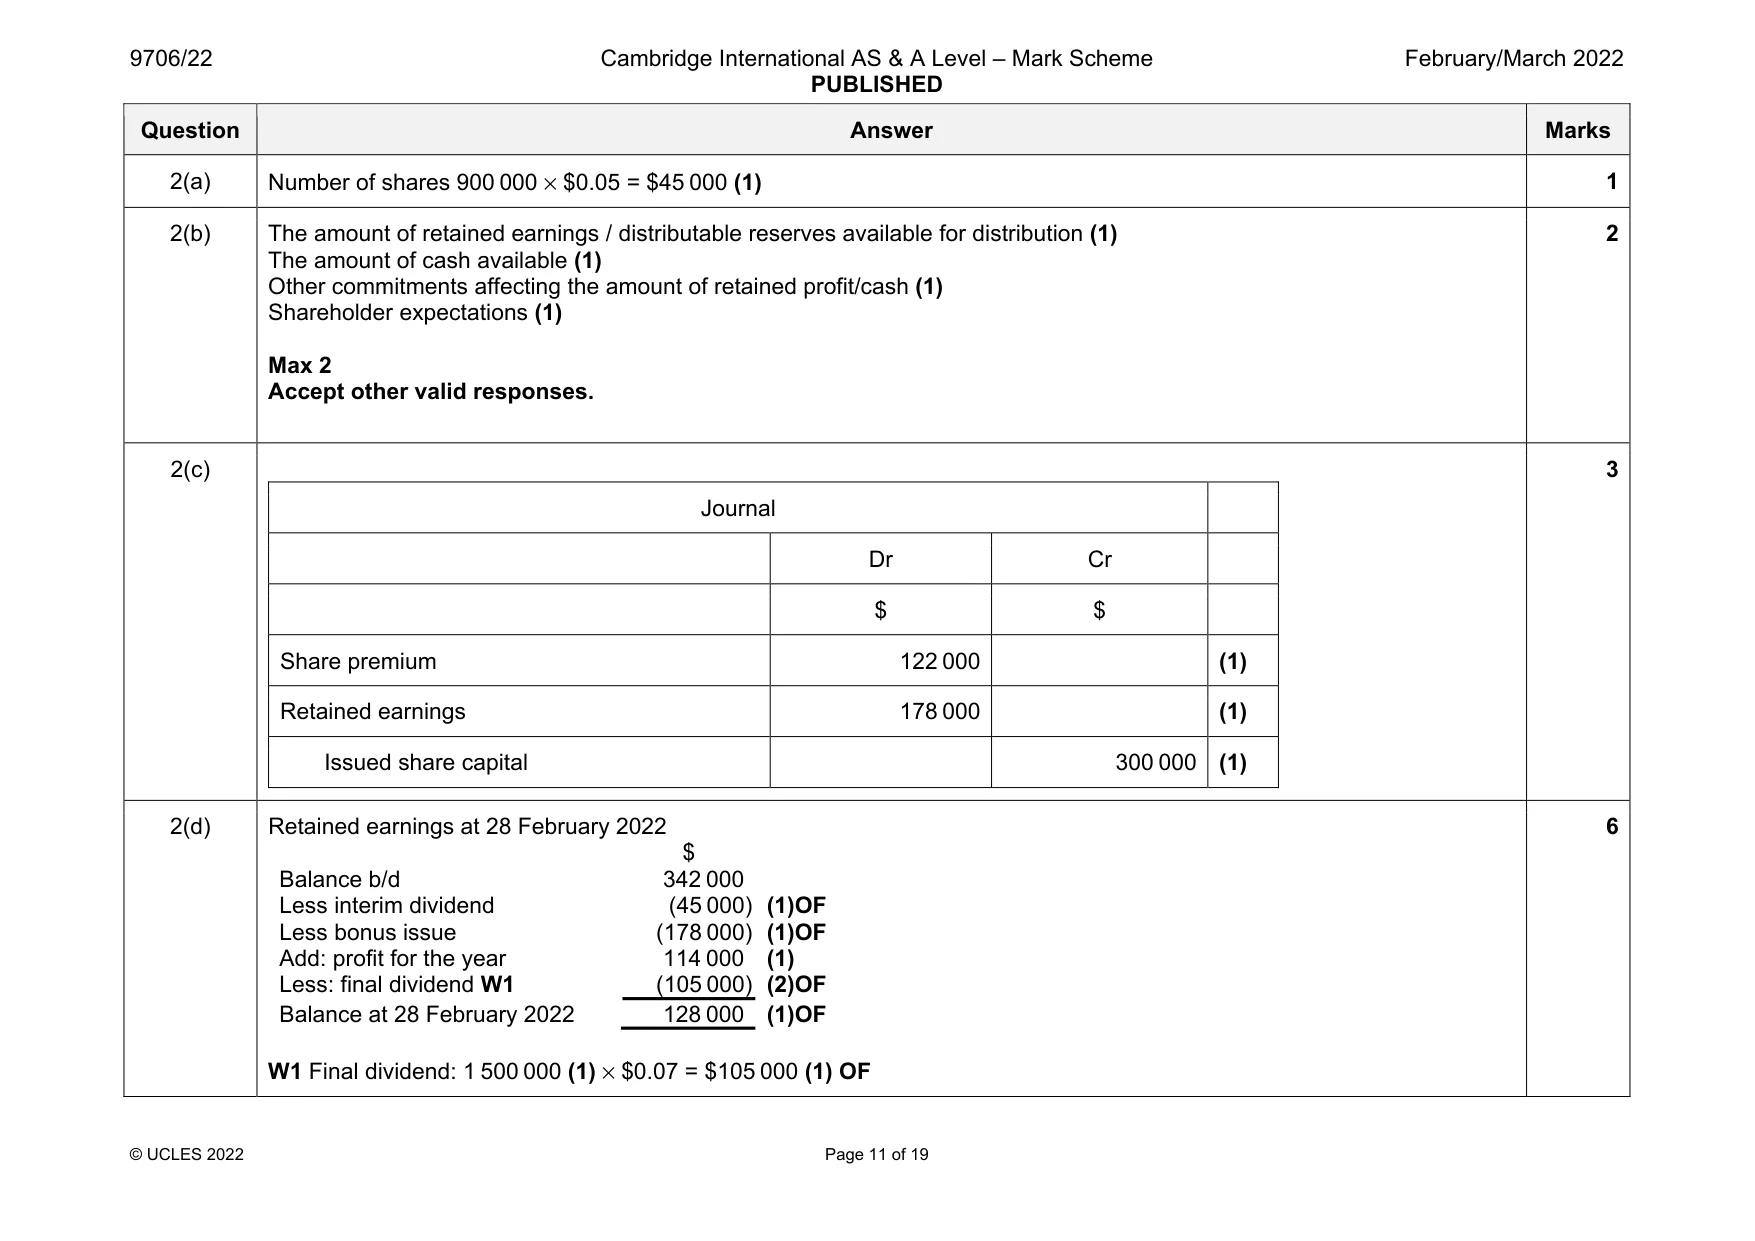
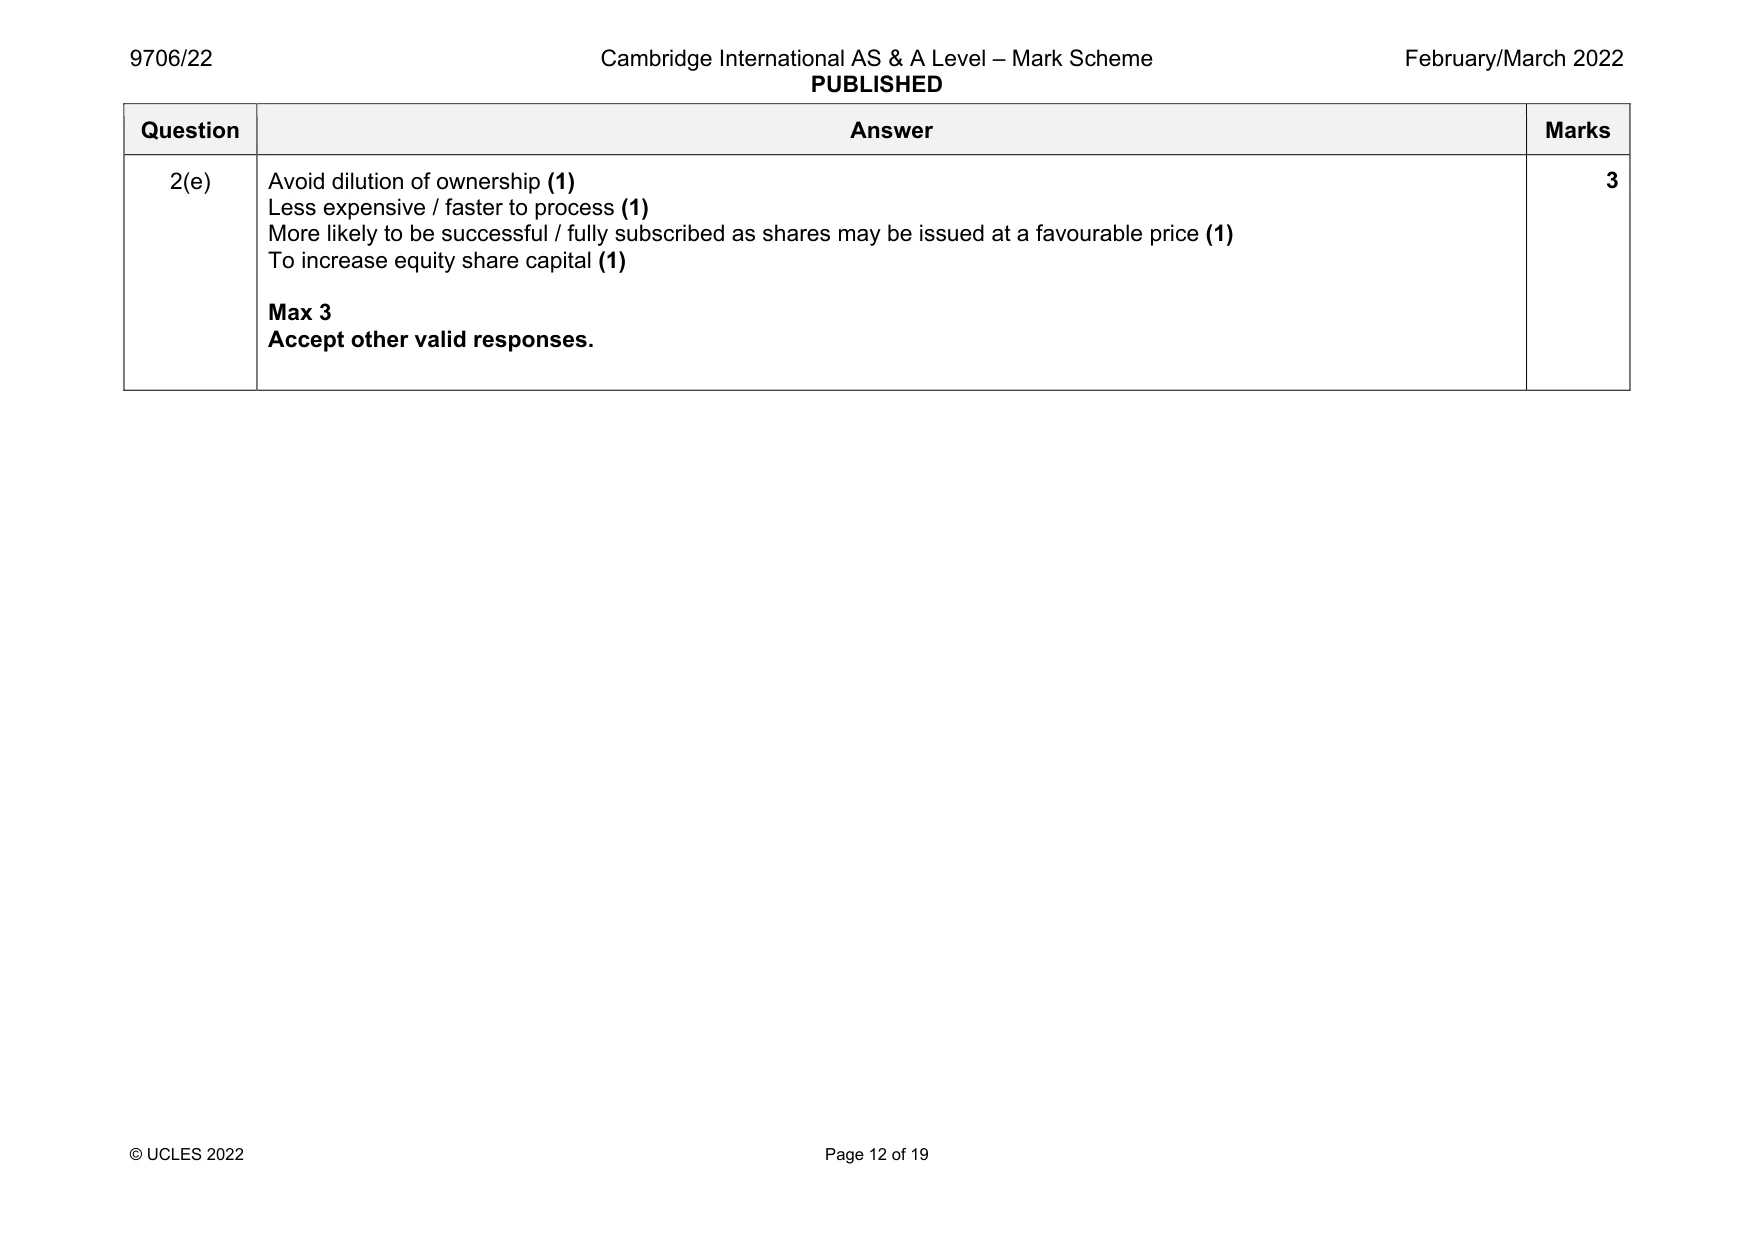
Mark scheme: 2(a) Number of shares 900 000 × $0.05 = $45 000 (1) 1 2(b) The amount of retained earnings / distributable reserves available for distribution (1) The amount of cash available (1) Other commitments affecting the amount of retained profit/cash (1) Shareholder expectations (1) Max 2 Accept other valid responses. 2 2(c) Journal Dr Cr $ $ Share premium 122 000 (1) Retained earnings 178 000 (1) Issued share capital 300 000 (1) 3 2(d) Retained earnings at 28 February 2022 $ Balance b/d 342 000 Less interim dividend (45 000) (1)OF Less bonus issue (178 000) (1)OF Add: profit for the year 114 000 (1) Less: final dividend W1 (105 000) (2)OF Balance at 28 February 2022 128 000 (1)OF W1 Final dividend: 1 500 000 (1) × $0.07 = $105 000 (1) OF 6 Question Answer Marks 2(e) Avoid dilution of ownership (1) Less expensive / faster to process (1) More likely to be successful / fully subscribed as shares may be issued at a favourable price (1) To increase equity share capital (1) Max 3 Accept other valid responses. 3
Q3 · Bipin, Feroz and Neeru have been in partnership for many years sharing profits and losses…
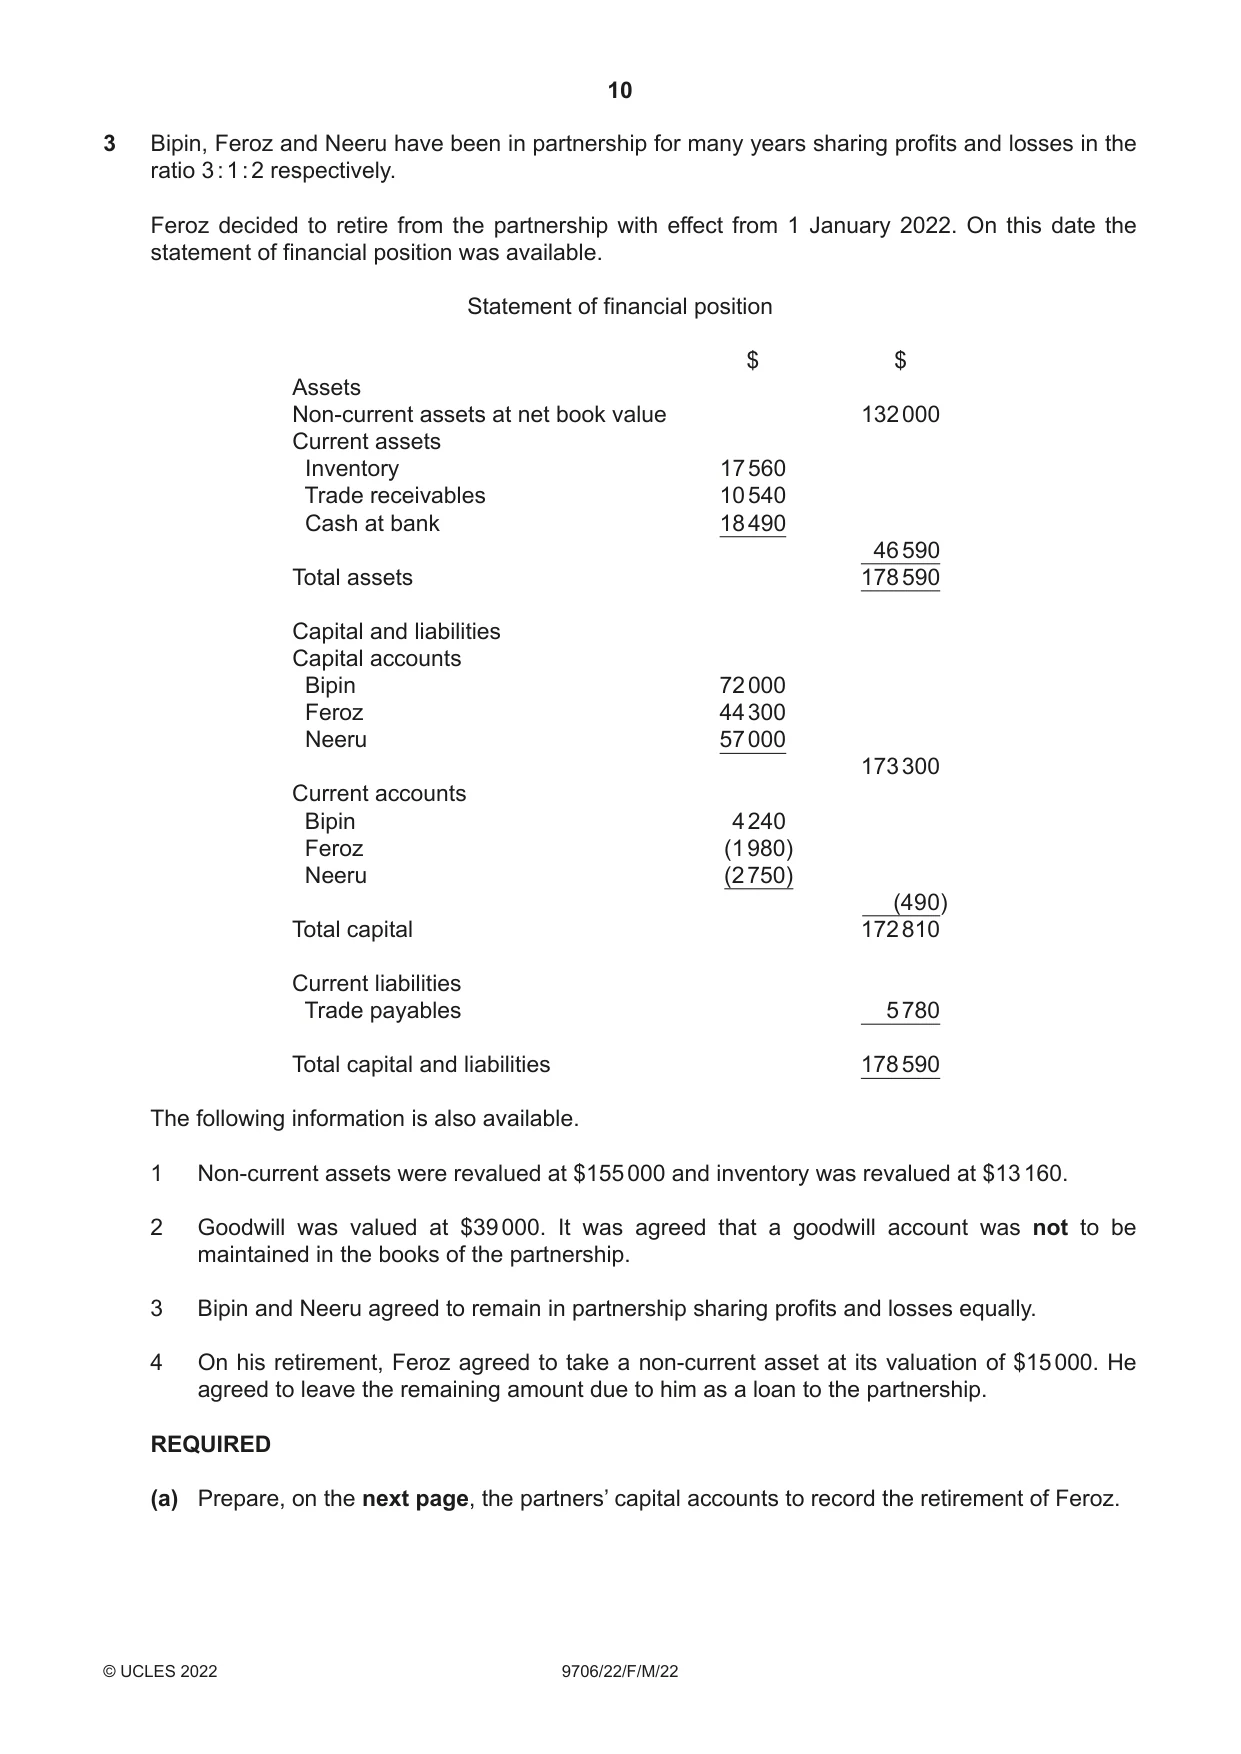
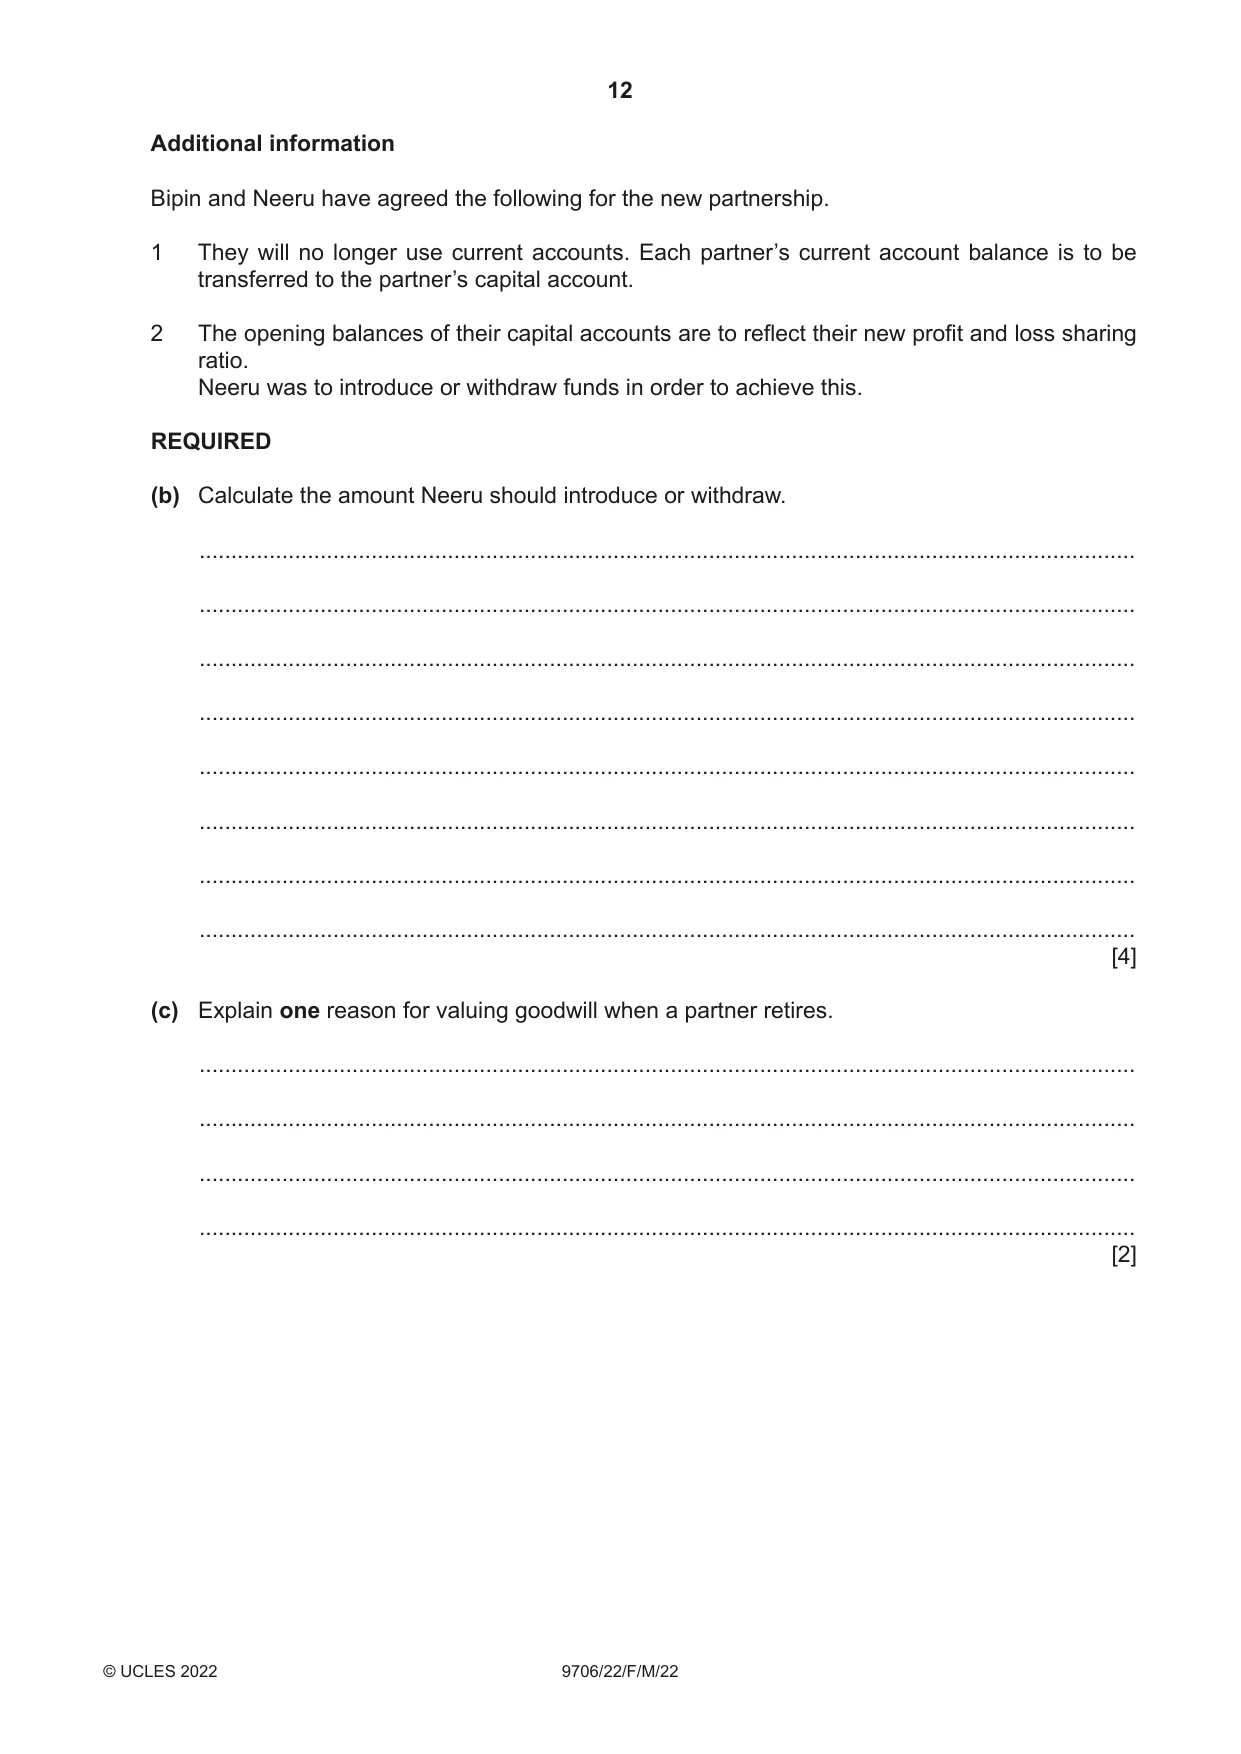
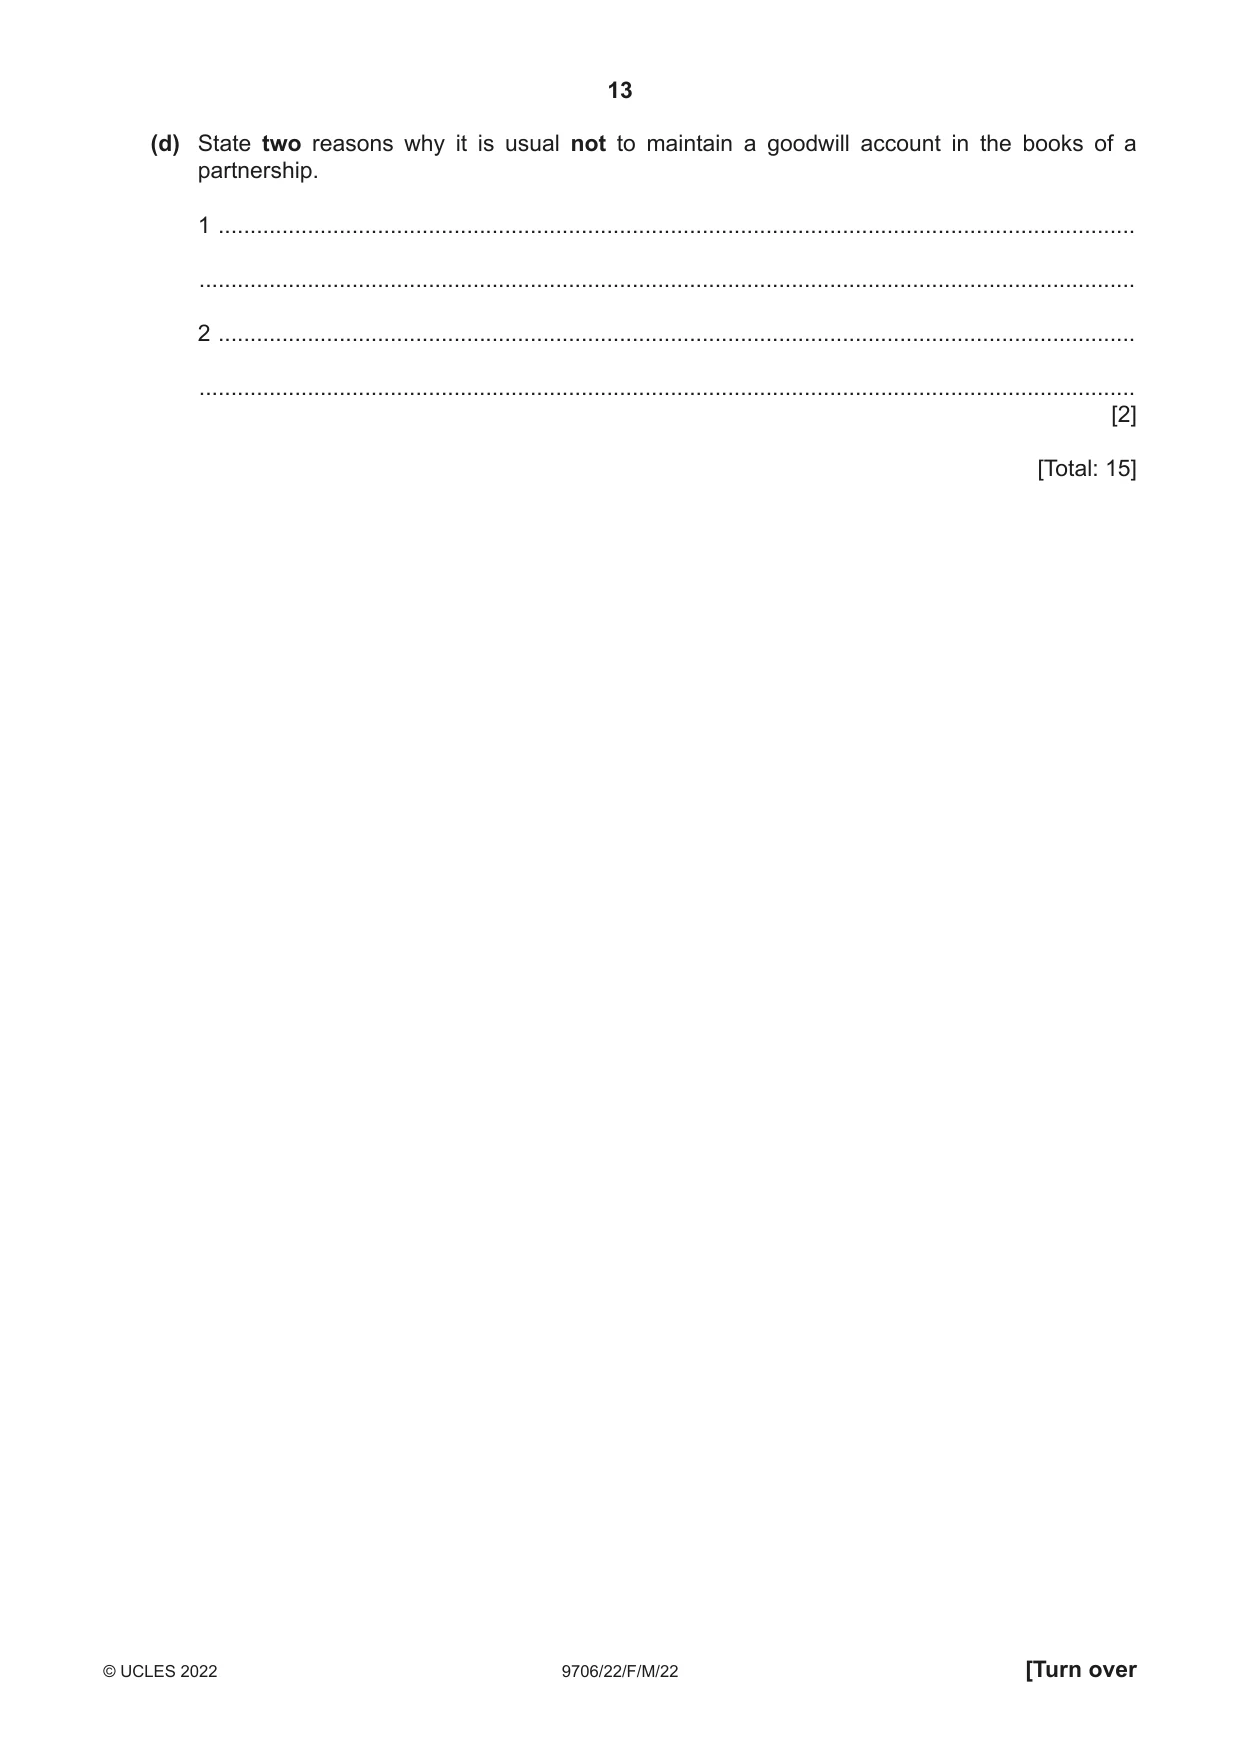
3 Bipin, Feroz and Neeru have been in partnership for many years sharing profits and losses in the ratio 3 : 1 : 2 respectively. Feroz decided to retire from the partnership with effect from 1 January 2022. On this date the statement of financial position was available. Statement of financial position $ $ Assets Non-current assets at net book value 132 000 Current assets Inventory 17 560 Trade receivables 10 540 Cash at bank 18 490 46 590 Total assets 178 590 Capital and liabilities Capital accounts Bipin 72 000 Feroz 44 300 Neeru 57 000 173 300 Current accounts Bipin 4 240 Feroz (1 980) Neeru (2 750) (490) Total capital 172 810 Current liabilities Trade payables 5 780 Total capital and liabilities 178 590 The following information is also available. 1 Non-current assets were revalued at $155 000 and inventory was revalued at $13 160. 2 Goodwill was valued at $39 000. It was agreed that a goodwill account was not to be maintained in the books of the partnership. 3 Bipin and Neeru agreed to remain in partnership sharing profits and losses equally. 4 On his retirement, Feroz agreed to take a non-current asset at its valuation of $15 000. He agreed to leave the remaining amount due to him as a loan to the partnership. REQUIRED (a) Prepare, on the next page, the partners’ capital accounts to record the retirement of Feroz. [7] Additional information Bipin and Neeru have agreed the following for the new partnership. 1 They will no longer use current accounts. Each partner’s current account balance is to be transferred to the partner’s capital account. 2 The opening balances of their capital accounts are to reflect their new profit and loss sharing ratio. Neeru was to introduce or withdraw funds in order to achieve this. REQUIRED (b) Calculate the amount Neeru should introduce or withdraw. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... [4] (c) Explain one reason for valuing goodwill when a partner retires. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... [2] (d) State two reasons why it is usual not to maintain a goodwill account in the books of a partnership. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] [Total: 15]
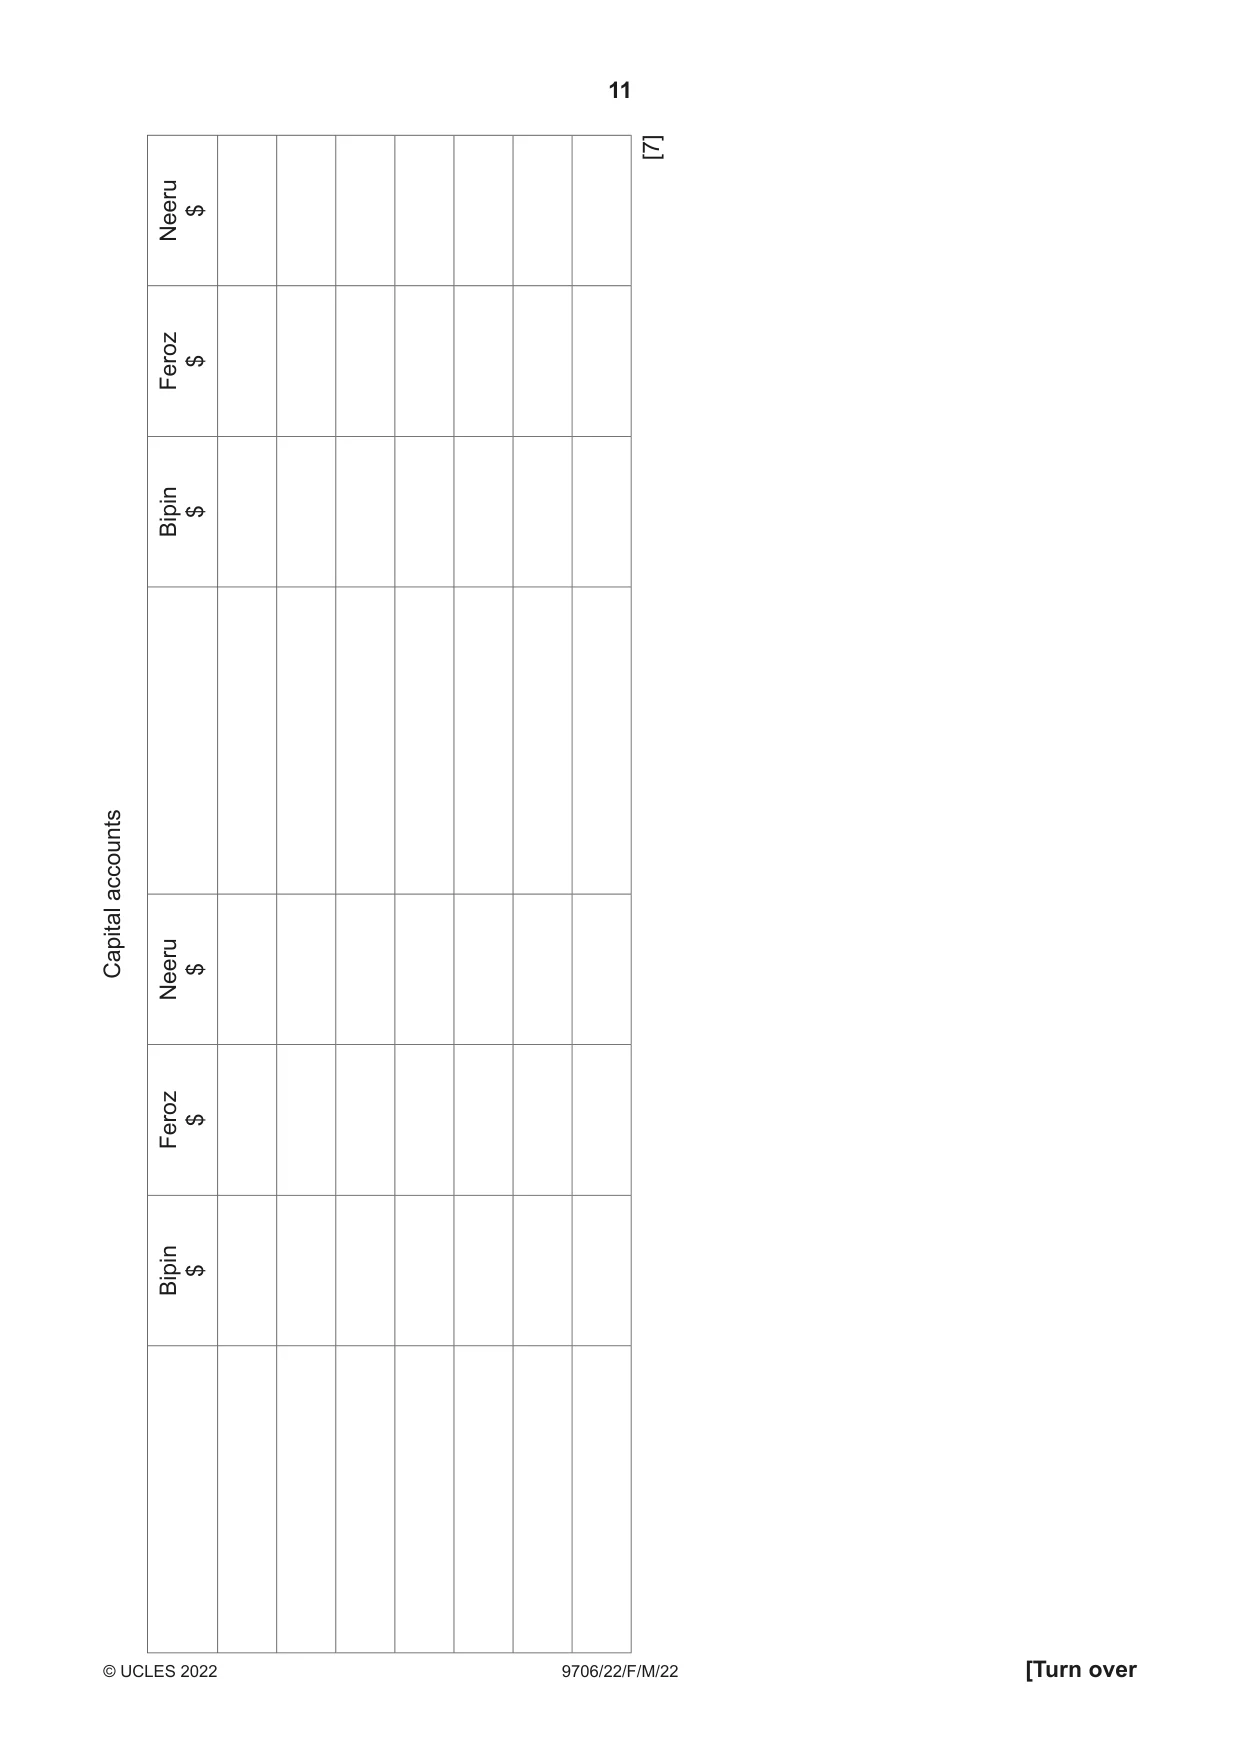
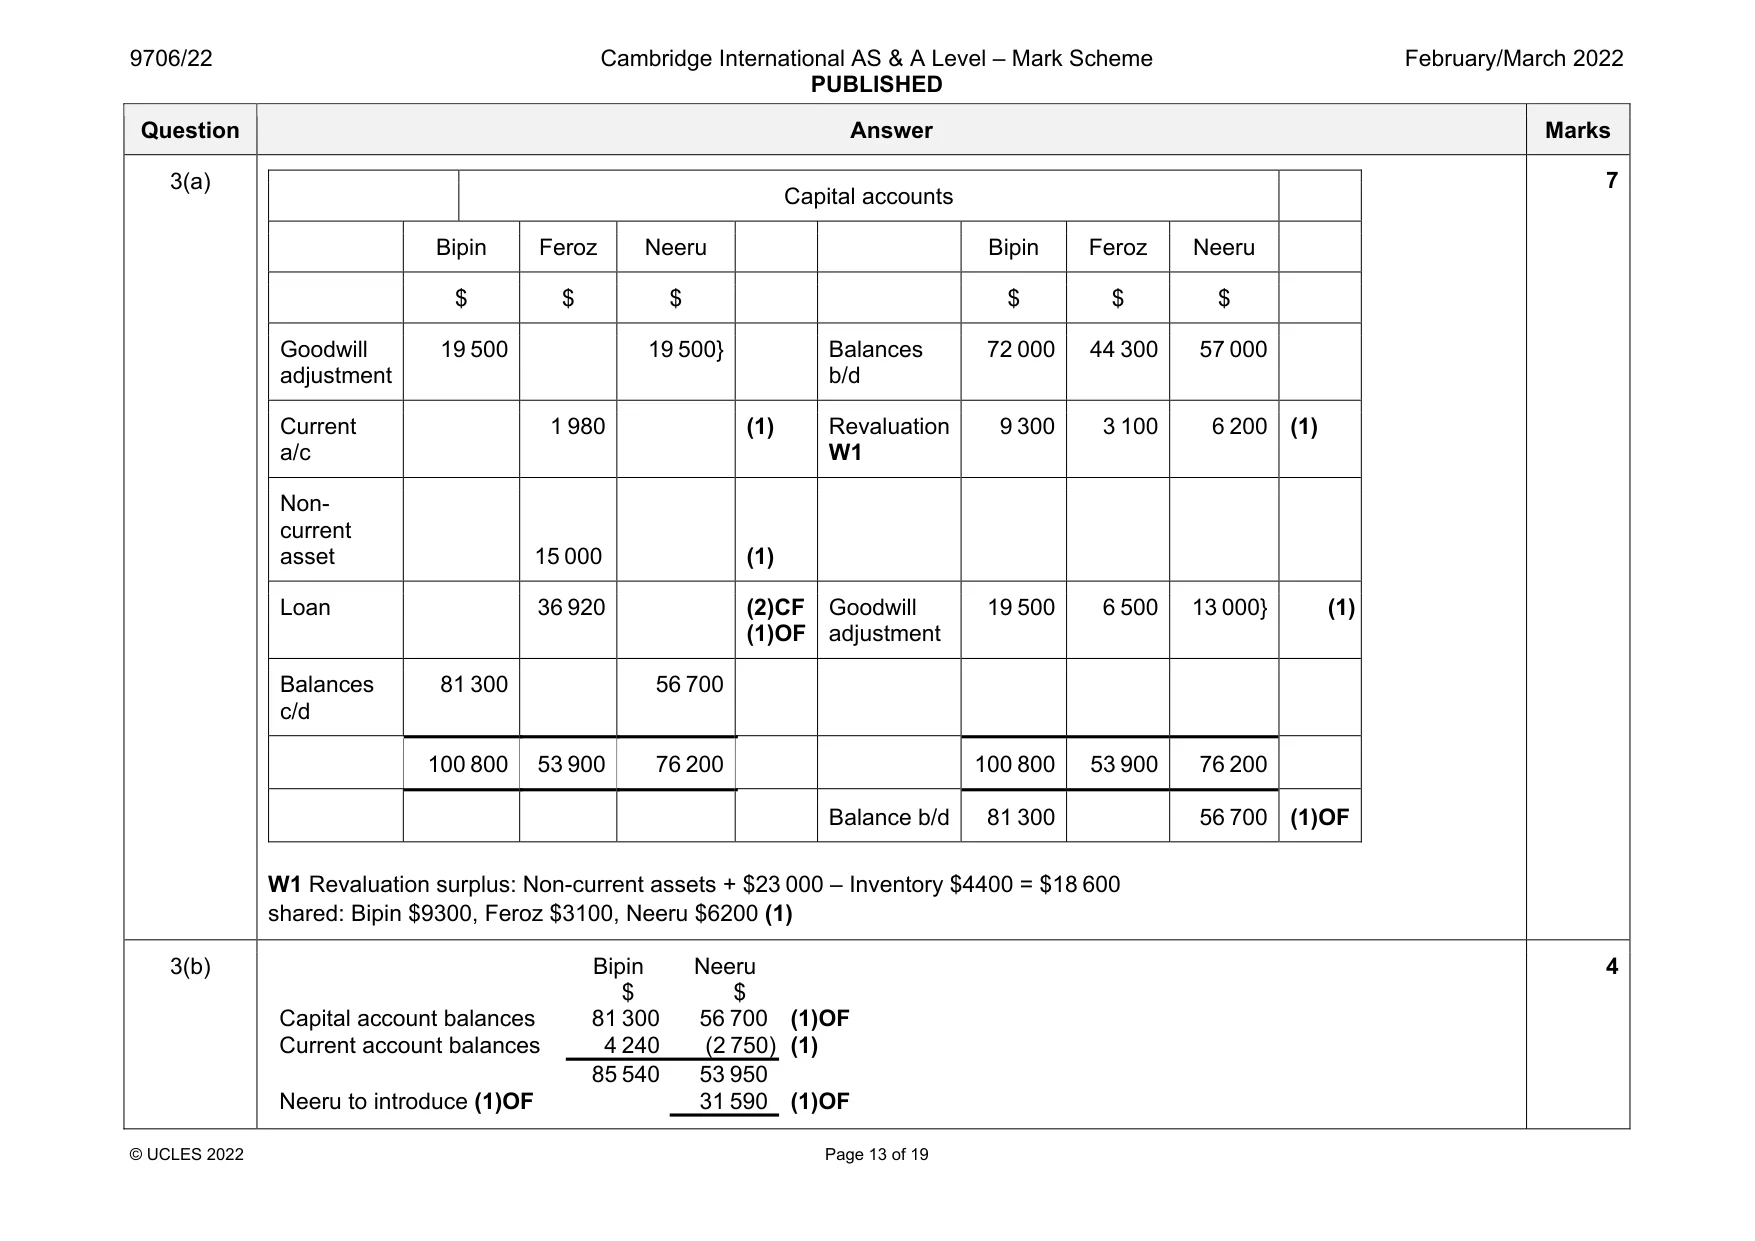
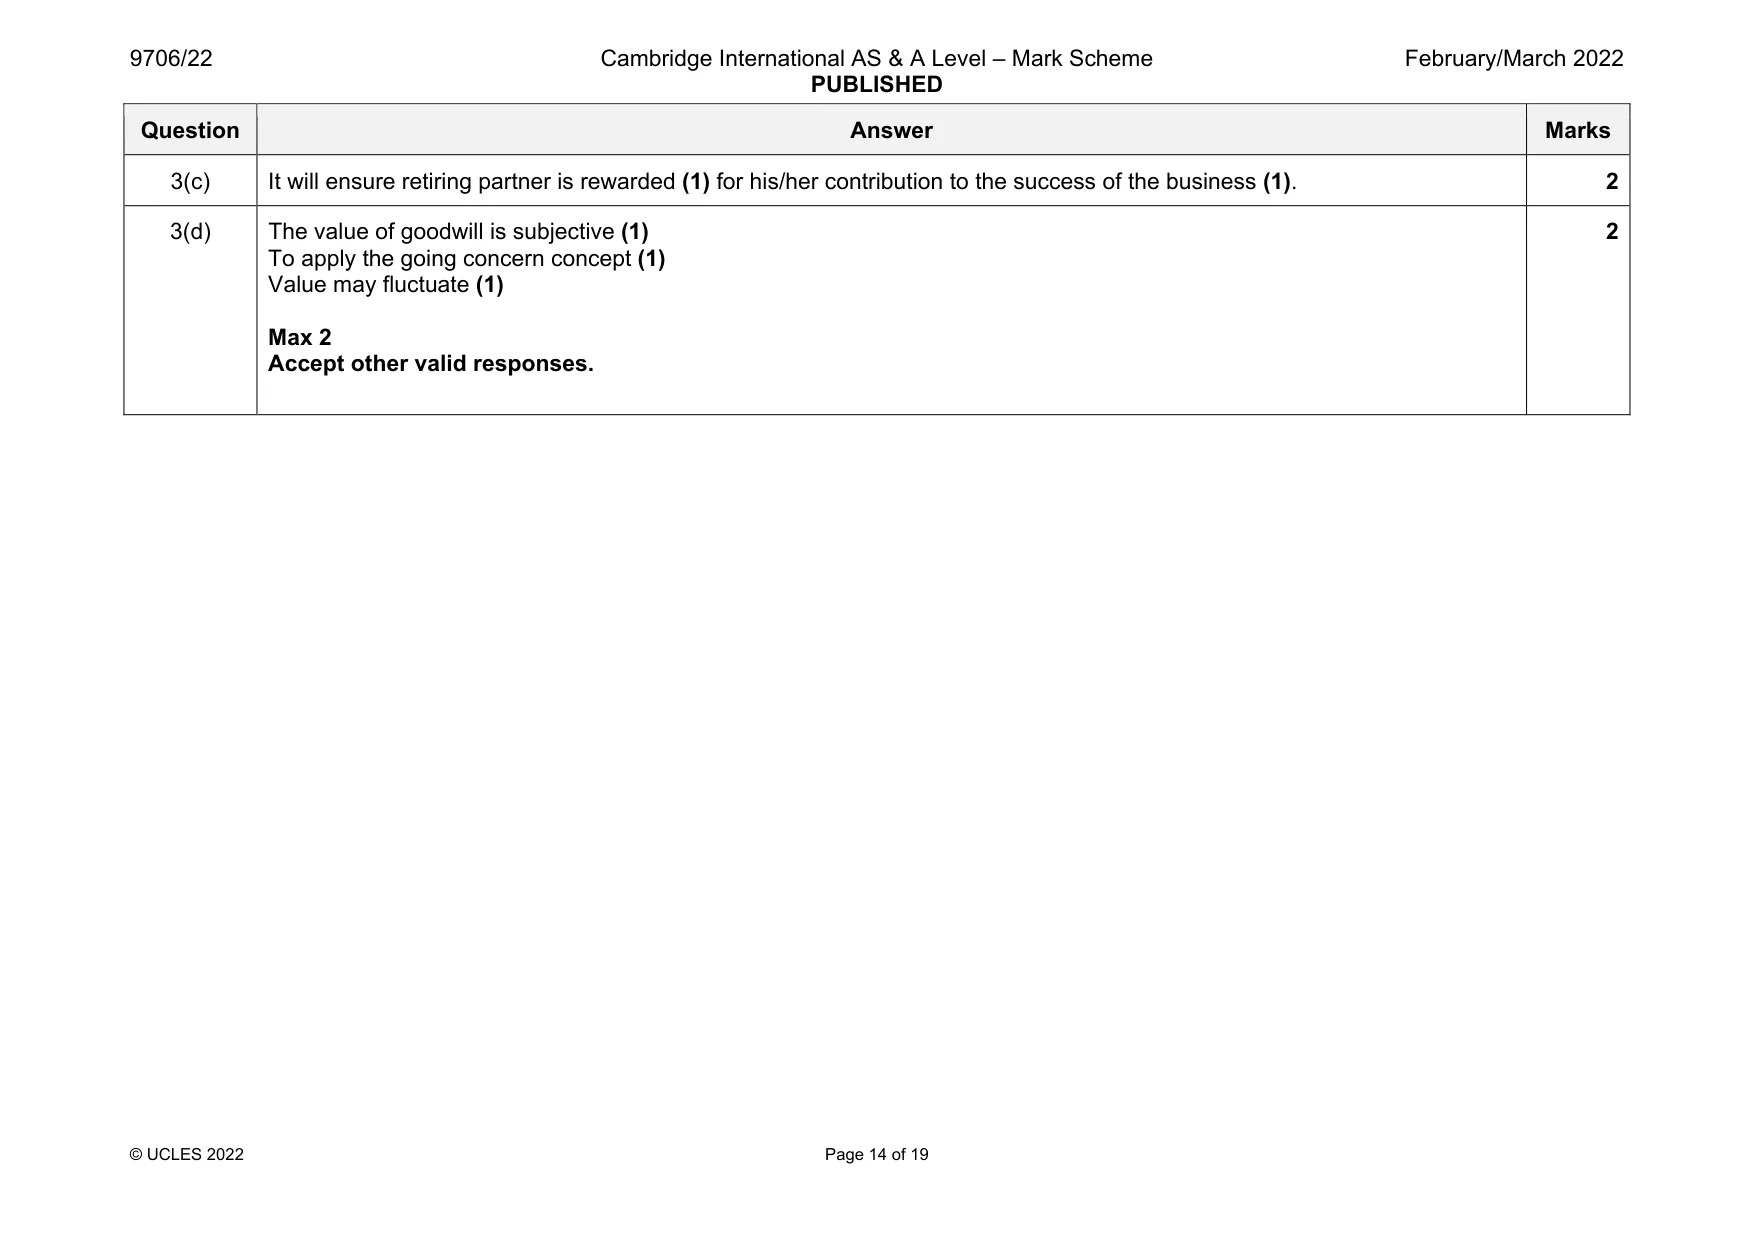
Mark scheme: 3(a) Capital accounts Bipin Feroz Neeru Bipin Feroz Neeru $ $ $ $ $ $ Goodwill adjustment 19 500 19 500} Balances b/d 72 000 44 300 57 000 Current a/c 1 980 (1) Revaluation W1 9 300 3 100 6 200 (1) Non- current asset 15 000 (1) Loan 36 920 (2)CF (1)OF Goodwill adjustment 19 500 6 500 13 000} (1) Balances c/d 81 300 56 700 100 800 53 900 76 200 100 800 53 900 76 200 Balance b/d 81 300 56 700 (1)OF W1 Revaluation surplus: Non-current assets + $23 000 – Inventory $4400 = $18 600 shared: Bipin $9300, Feroz $3100, Neeru $6200 (1) 3(b) Bipin Neeru $ $ Capital account balances 81 300 56 700 (1)OF Current account balances 4 240 (2 750) (1) 85 540 53 950 Neeru to introduce (1)OF 31 590 (1)OF 4 Question Answer Marks 3(c) It will ensure retiring partner is rewarded (1) for his/her contribution to the success of the business (1). 2 3(d) The value of goodwill is subjective (1) To apply the going concern concept (1) Value may fluctuate (1) Max 2 Accept other valid responses. 2
Q4 · R Limited uses absorption costing at one of its factories
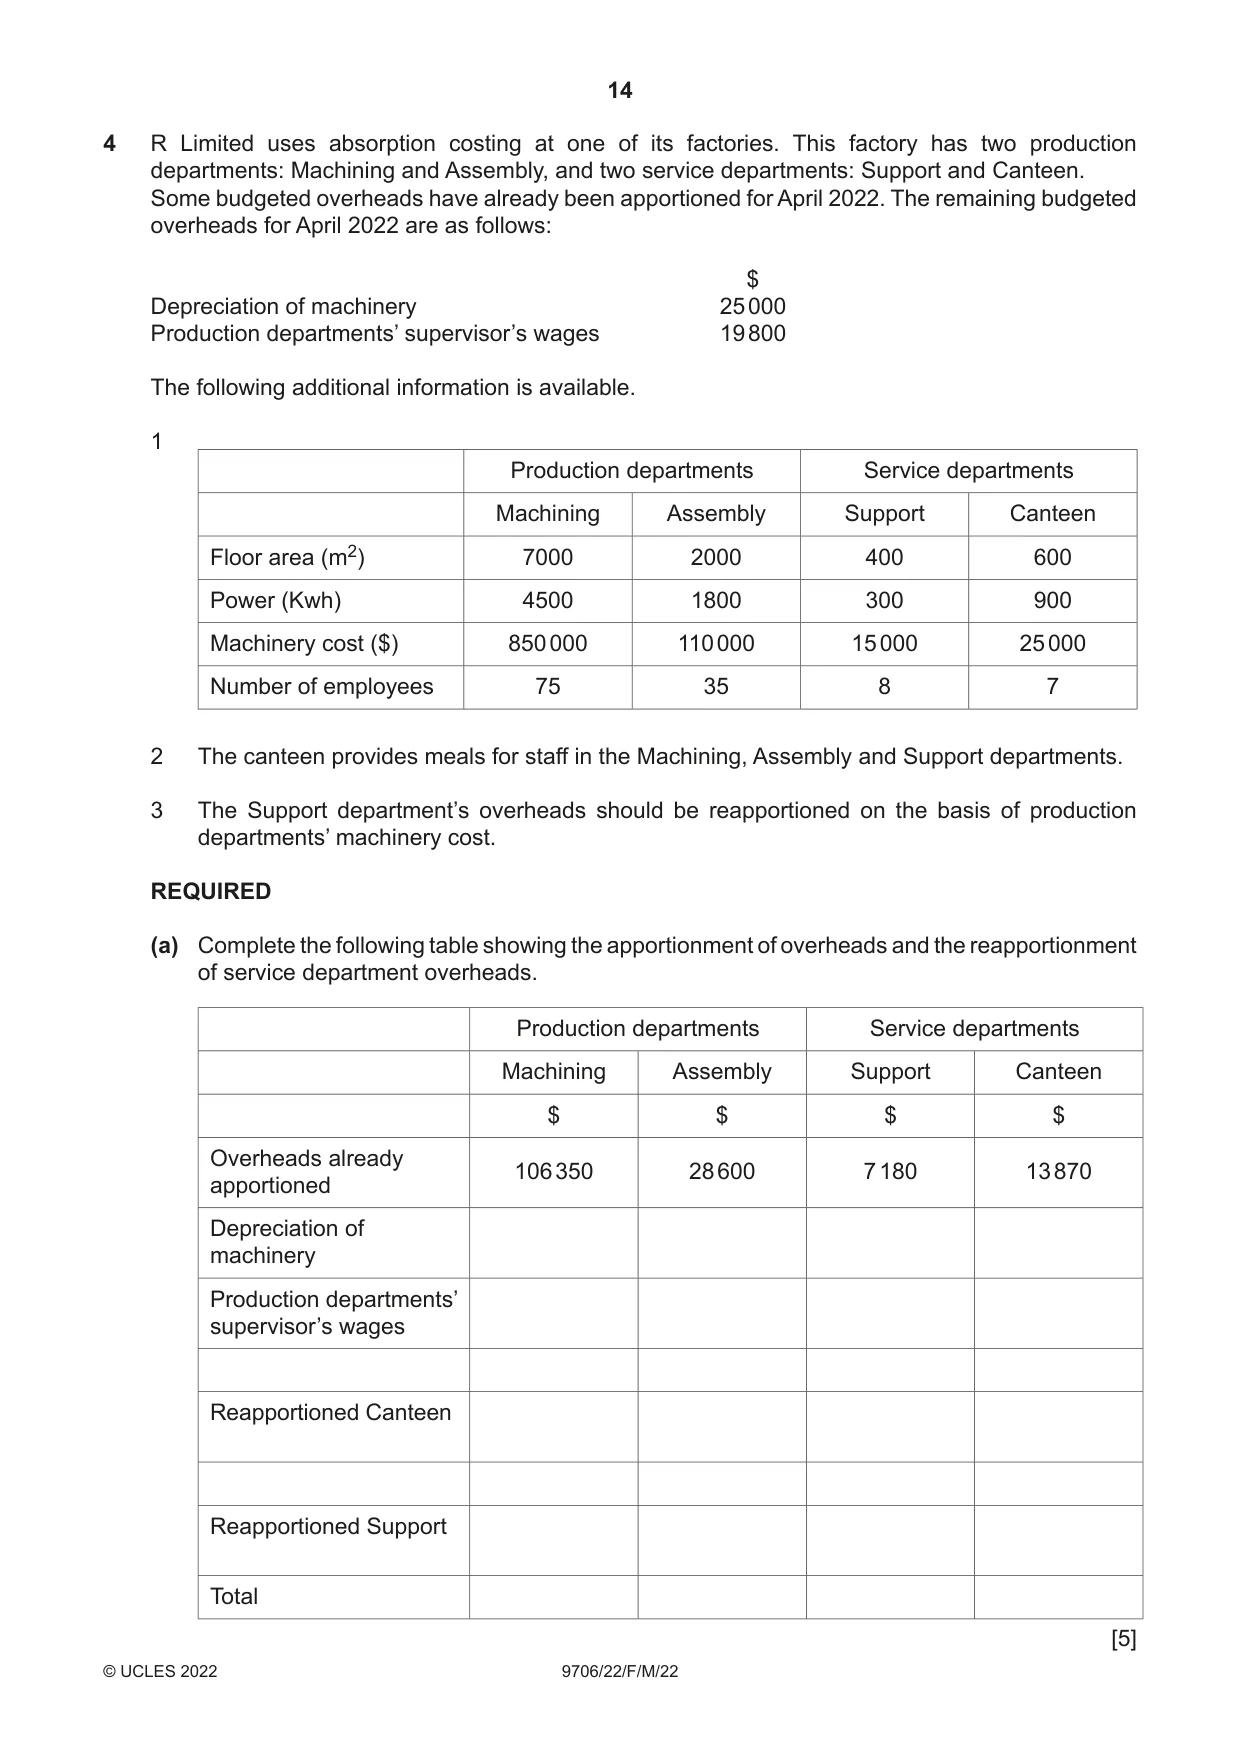
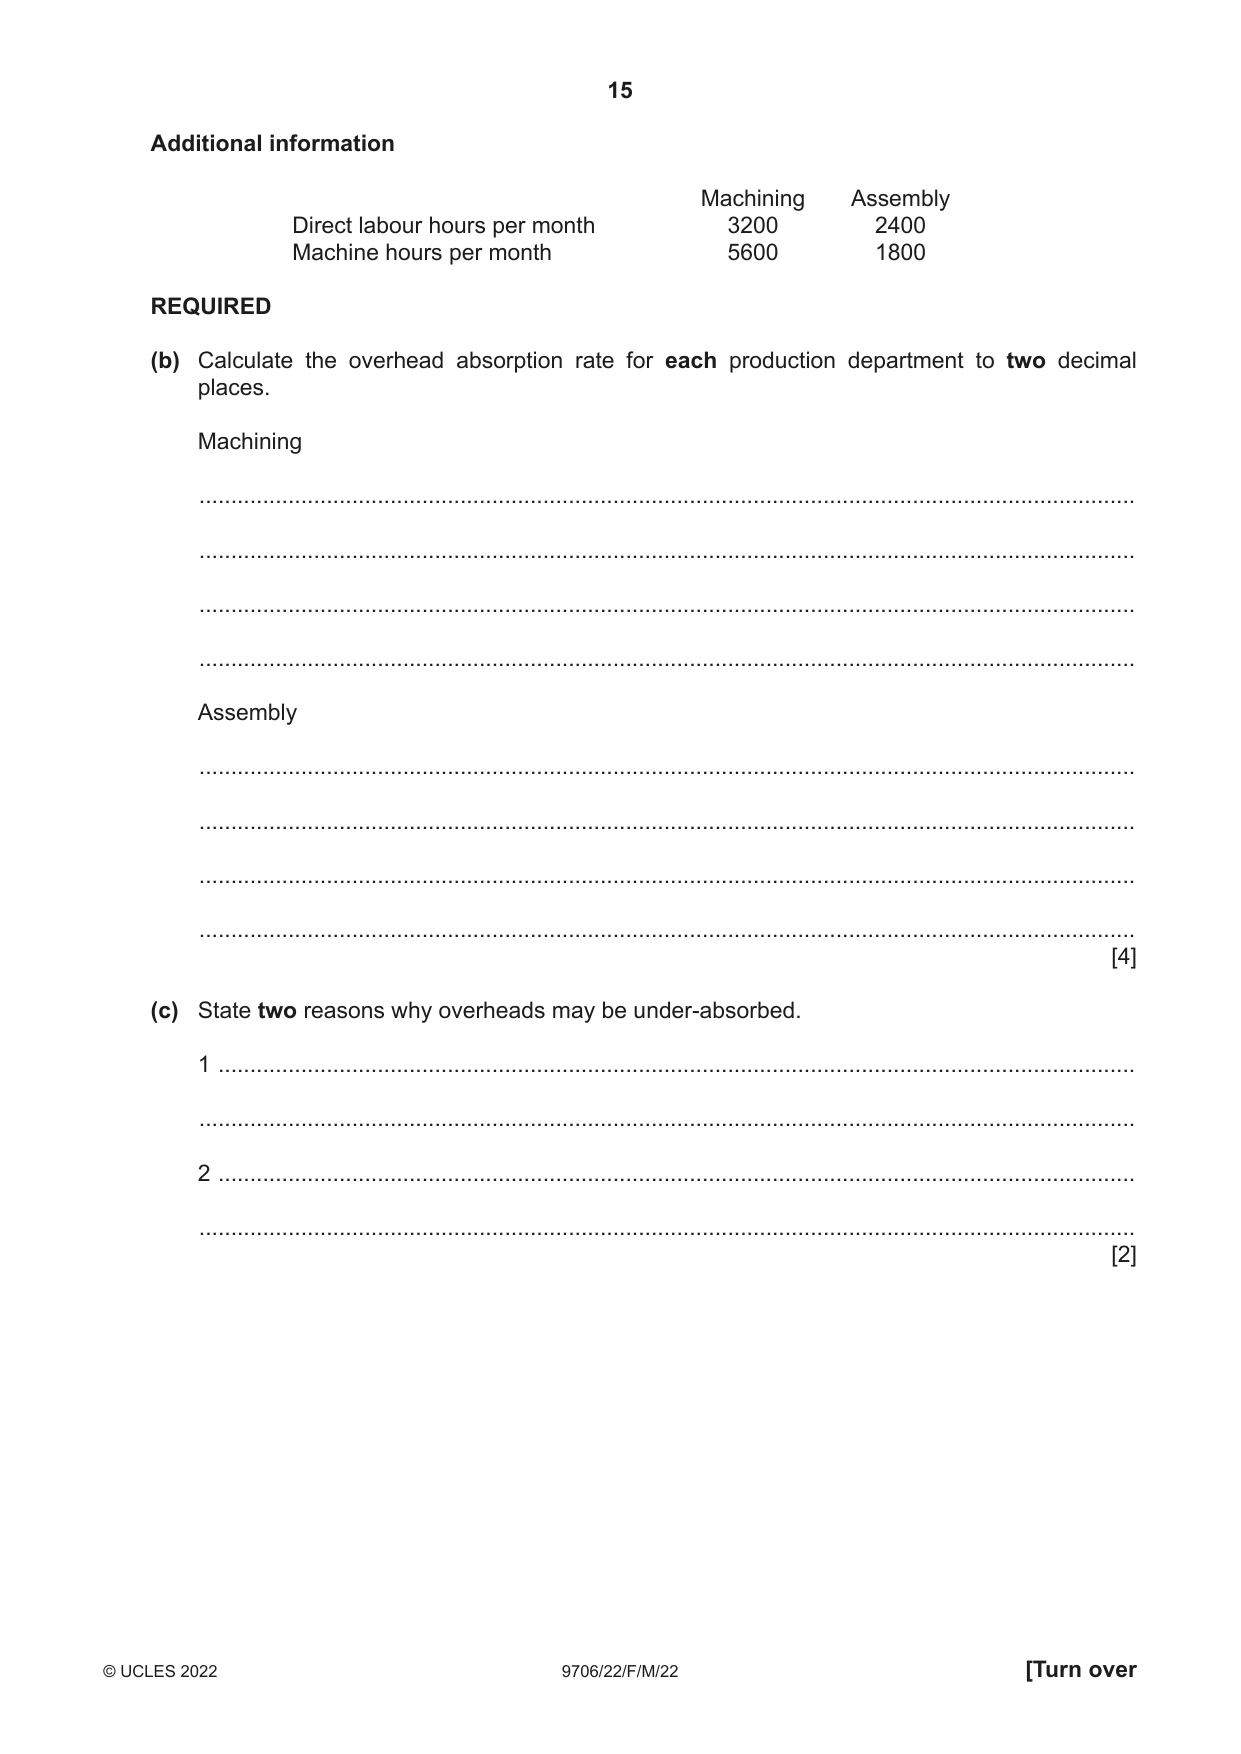
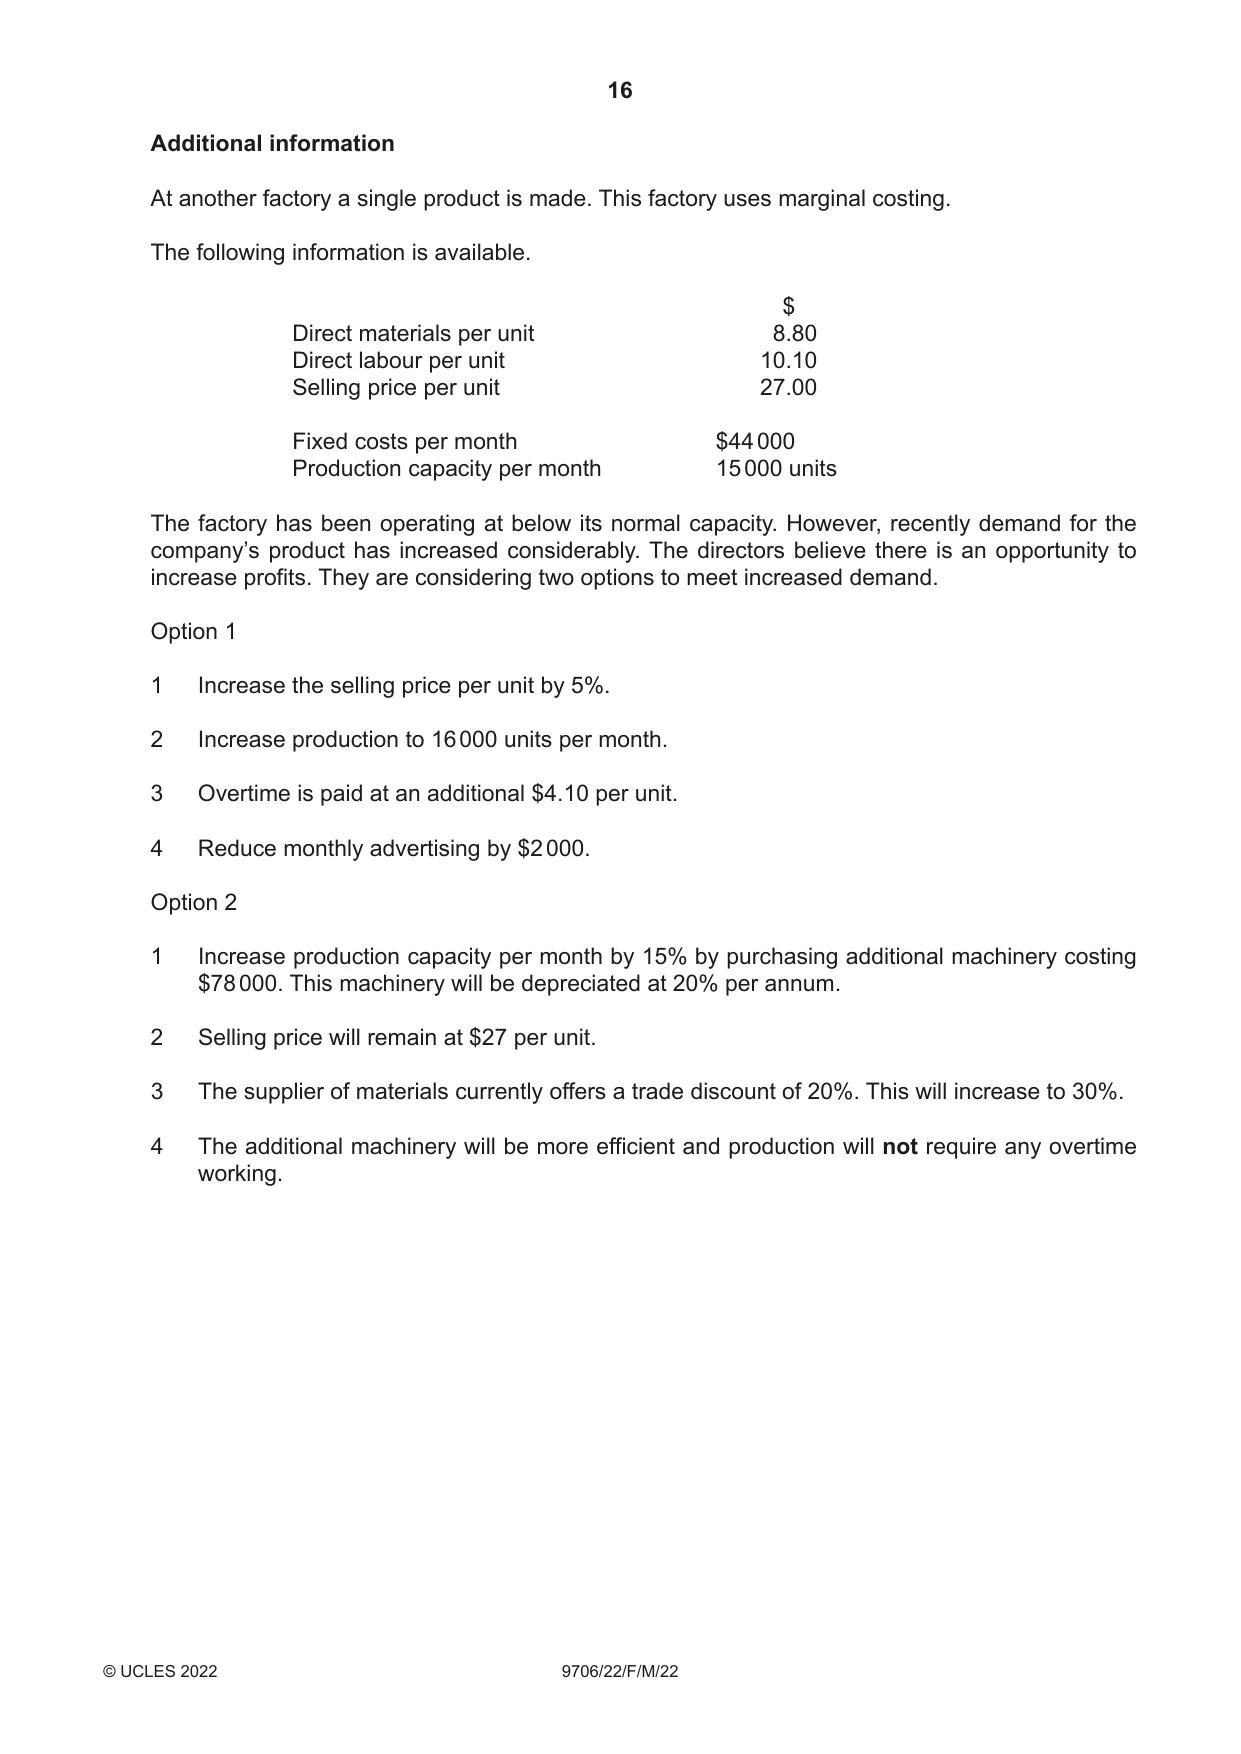
4 R Limited uses absorption costing at one of its factories. This factory has two production departments: Machining and Assembly, and two service departments: Support and Canteen. Some budgeted overheads have already been apportioned for April 2022. The remaining budgeted overheads for April 2022 are as follows: $ Depreciation of machinery 25 000 Production departments’ supervisor’s wages 19 800 The following additional information is available. 1 Production departments Service departments Machining Assembly Support Canteen Floor area (m2) 7000 2000 400 600 Power (Kwh) 4500 1800 300 900 Machinery cost ($) 850 000 110 000 15 000 25 000 Number of employees 75 35 8 7 2 The canteen provides meals for staff in the Machining, Assembly and Support departments. 3 The Support department’s overheads should be reapportioned on the basis of production departments’ machinery cost. REQUIRED (a) Complete the following table showing the apportionment of overheads and the reapportionment of service department overheads. Production departments Service departments Machining Assembly Support Canteen $ $ $ $ Overheads already 106 350 28 600 7 180 13 870 apportioned Depreciation of machinery Production departments’ supervisor’s wages Reapportioned Canteen Reapportioned Support Total [5] Additional information Machining Assembly Direct labour hours per month 3200 2400 Machine hours per month 5600 1800 REQUIRED (b) Calculate the overhead absorption rate for each production department to two decimal places. Machining ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Assembly ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... [4] (c) State two reasons why overheads may be under-absorbed. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] Additional information At another factory a single product is made. This factory uses marginal costing. The following information is available. $ Direct materials per unit 8.80 Direct labour per unit 10.10 Selling price per unit 27.00 Fixed costs per month $44 000 Production capacity per month 15 000 units The factory has been operating at below its normal capacity. However, recently demand for the company’s product has increased considerably. The directors believe there is an opportunity to increase profits. They are considering two options to meet increased demand. Option 1 1 Increase the selling price per unit by 5%. 2 Increase production to 16 000 units per month. 3 Overtime is paid at an additional $4.10 per unit. 4 Reduce monthly advertising by $2 000. Option 2 1 Increase production capacity per month by 15% by purchasing additional machinery costing $78 000. This machinery will be depreciated at 20% per annum. 2 Selling price will remain at $27 per unit. 3 The supplier of materials currently offers a trade discount of 20%. This will increase to 30%. 4 The additional machinery will be more efficient and production will not require any overtime working.
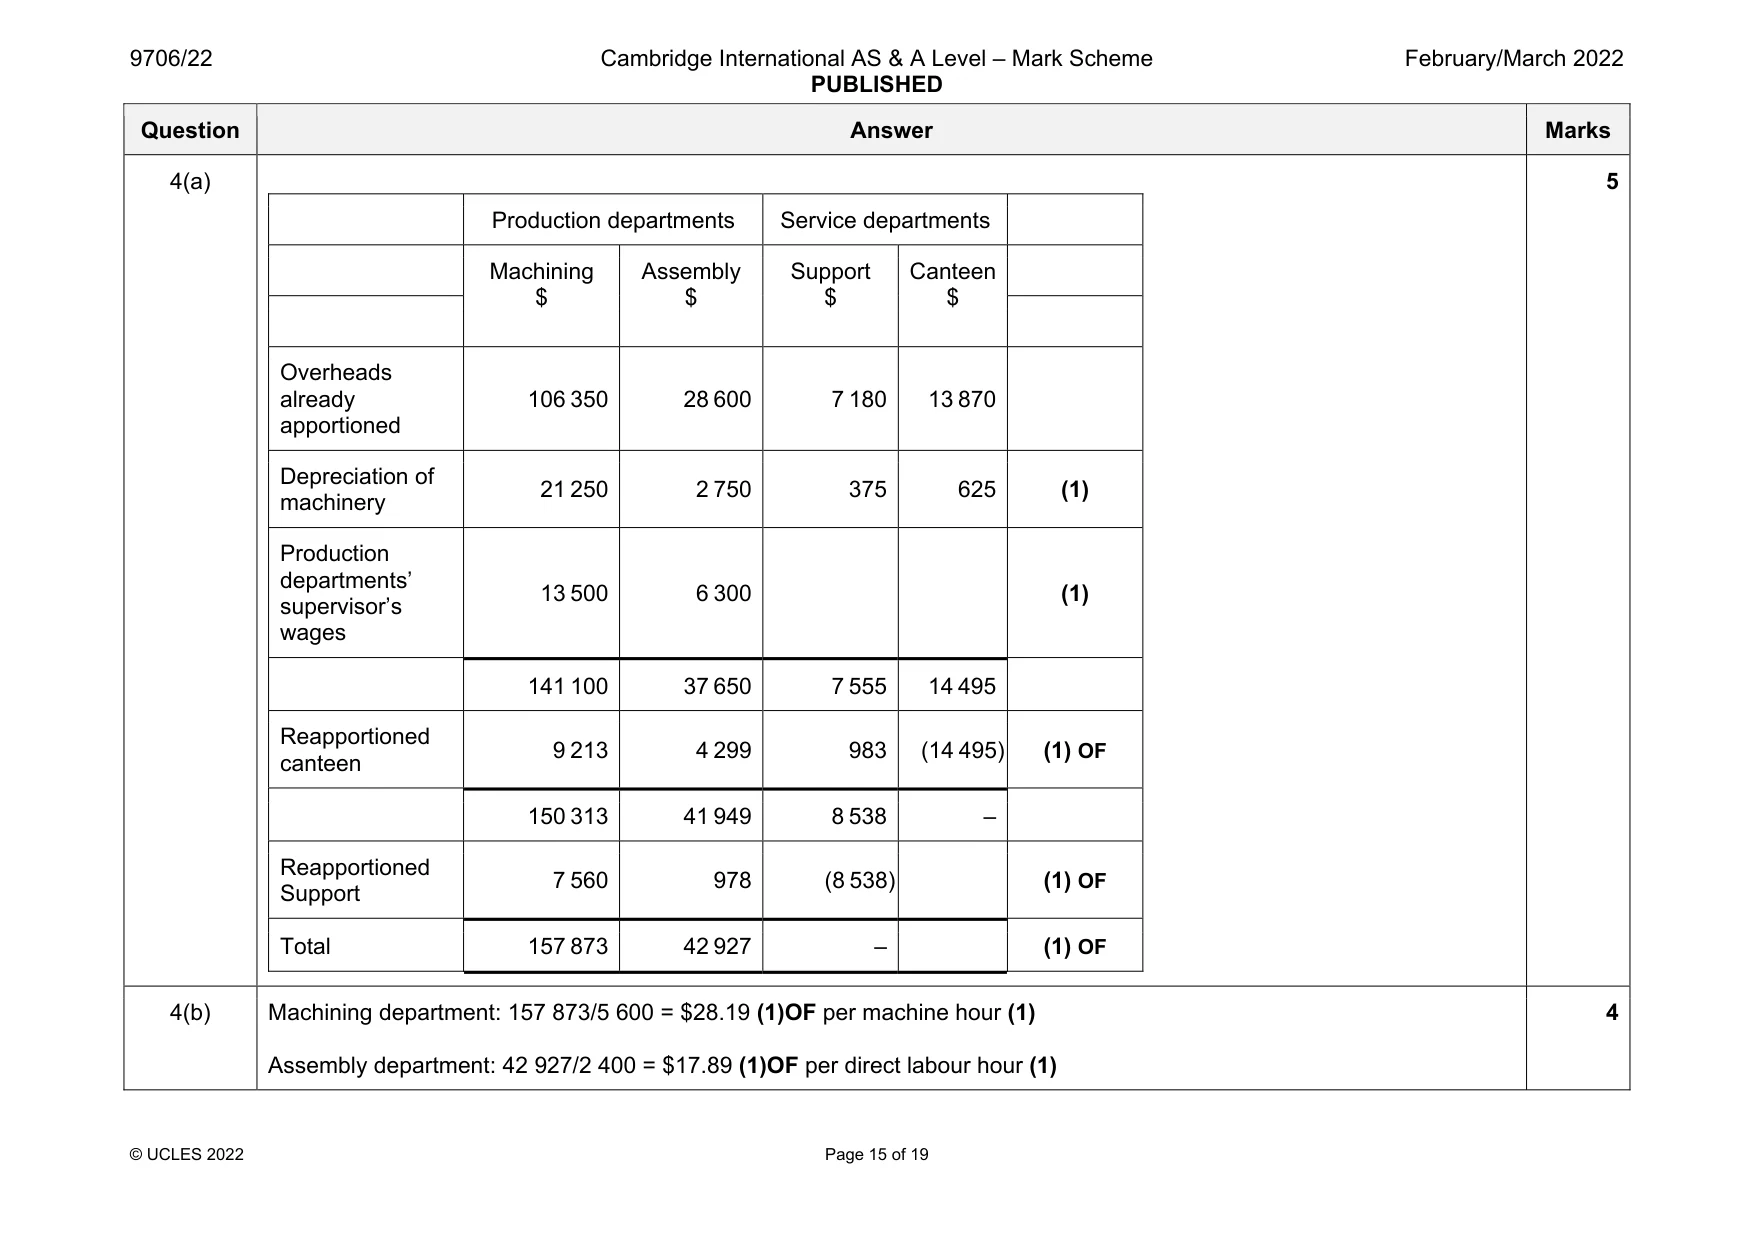
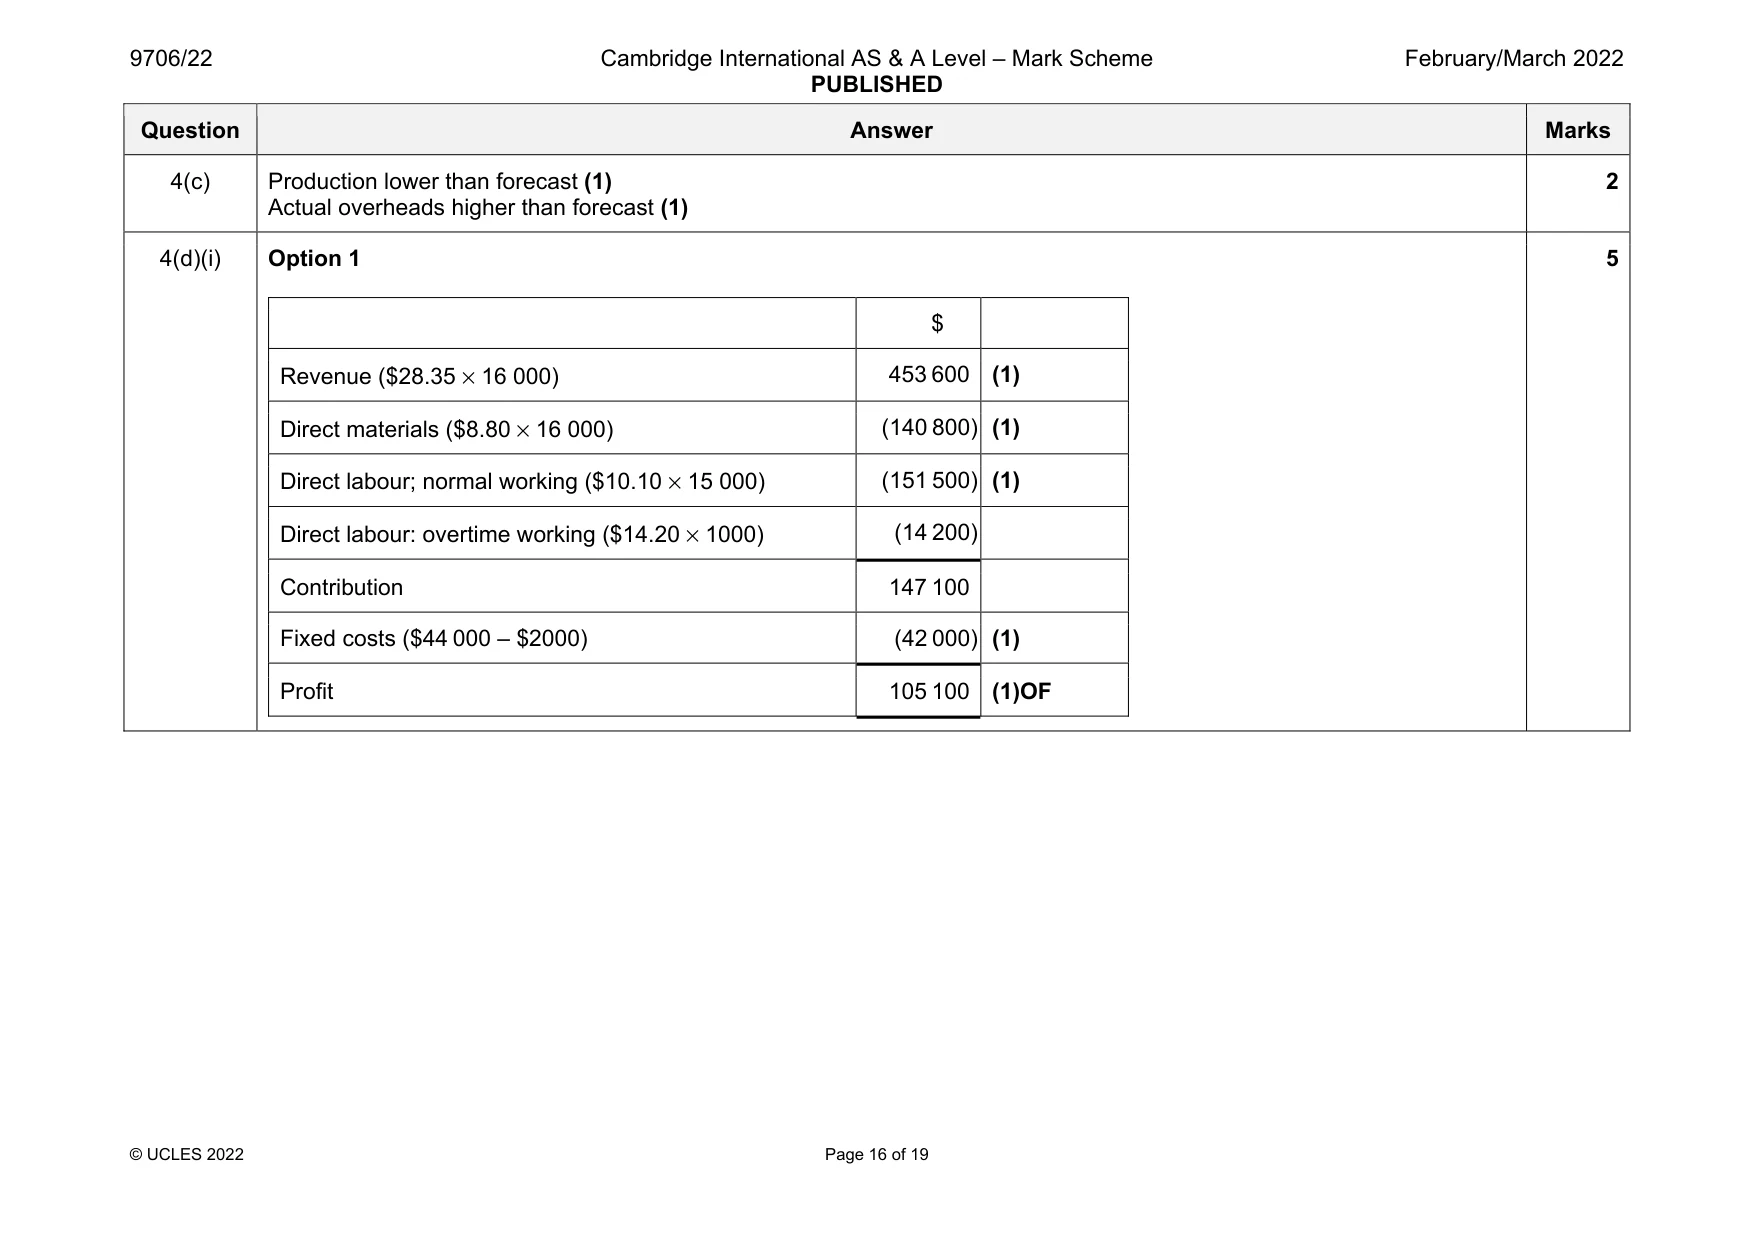
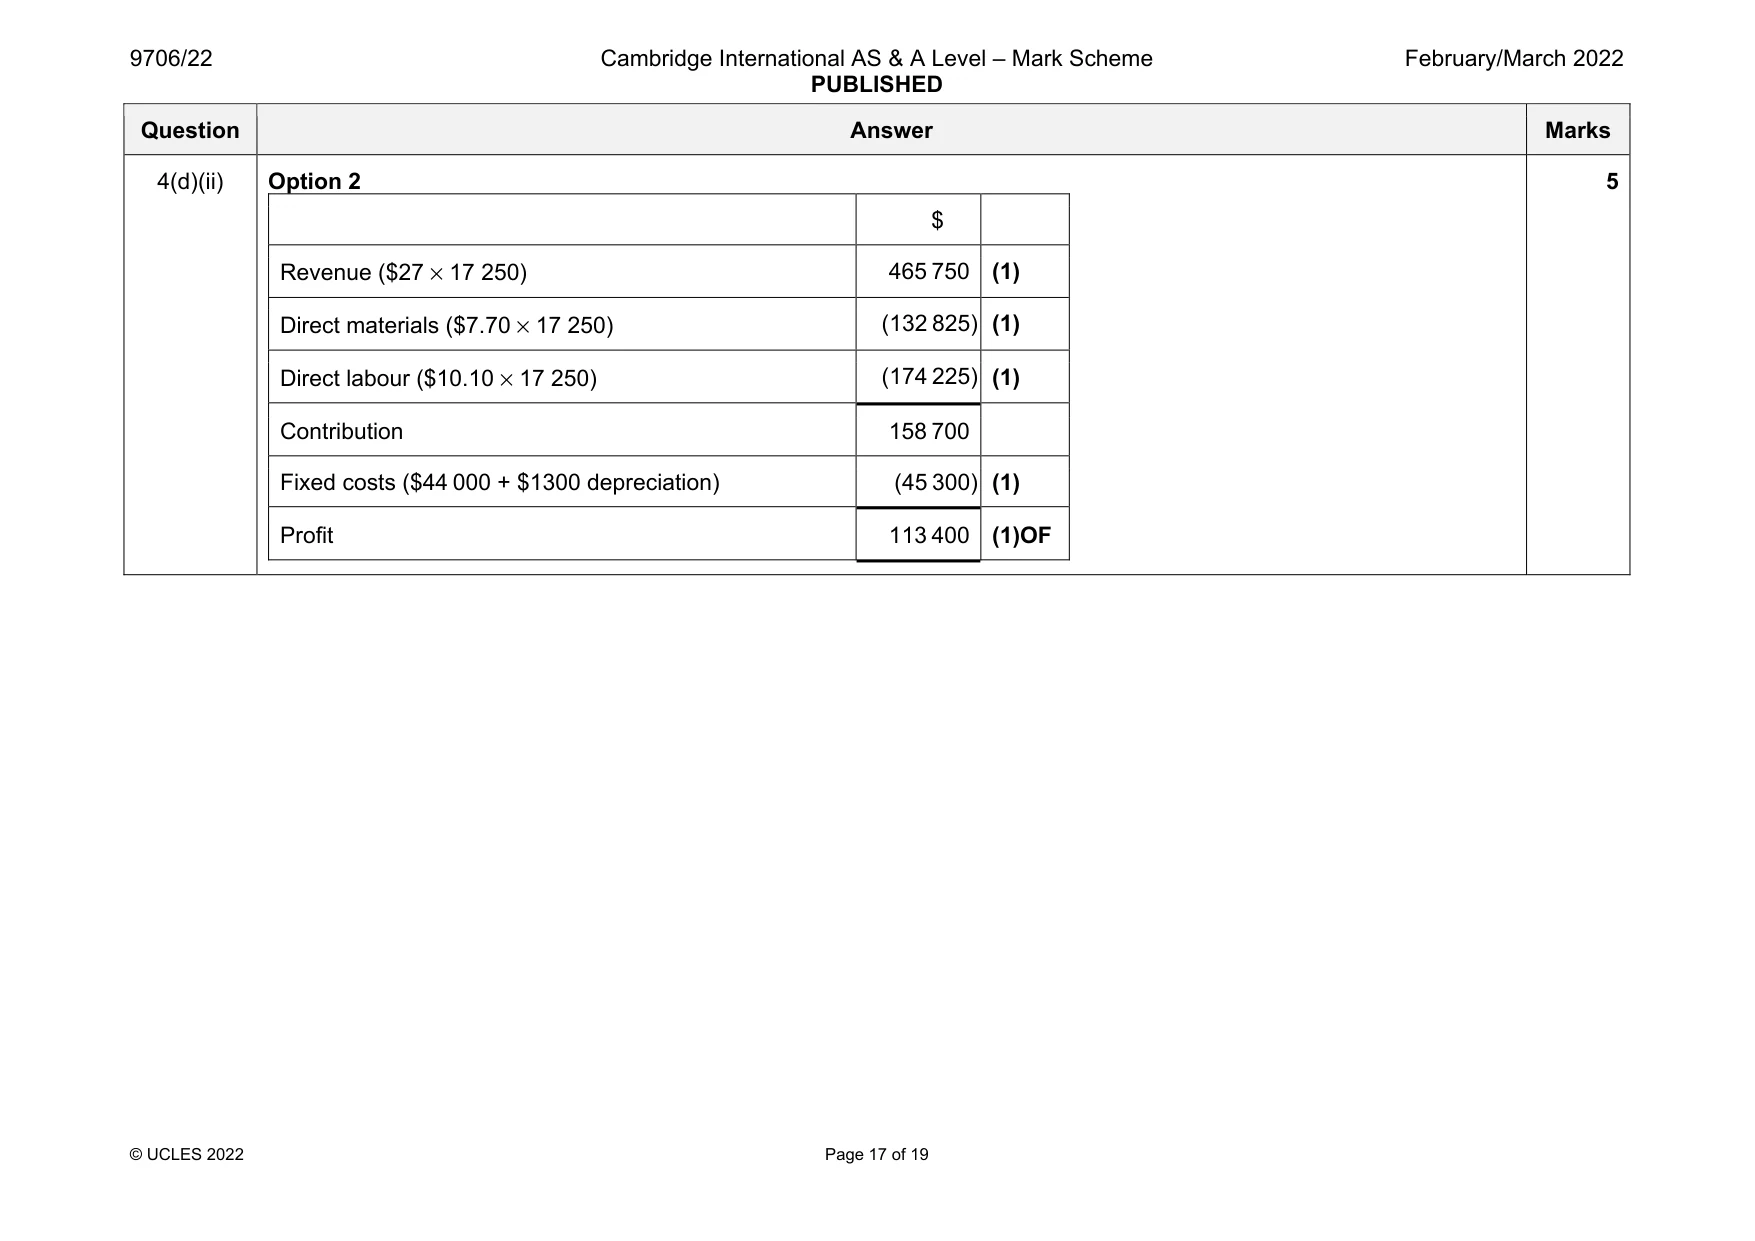
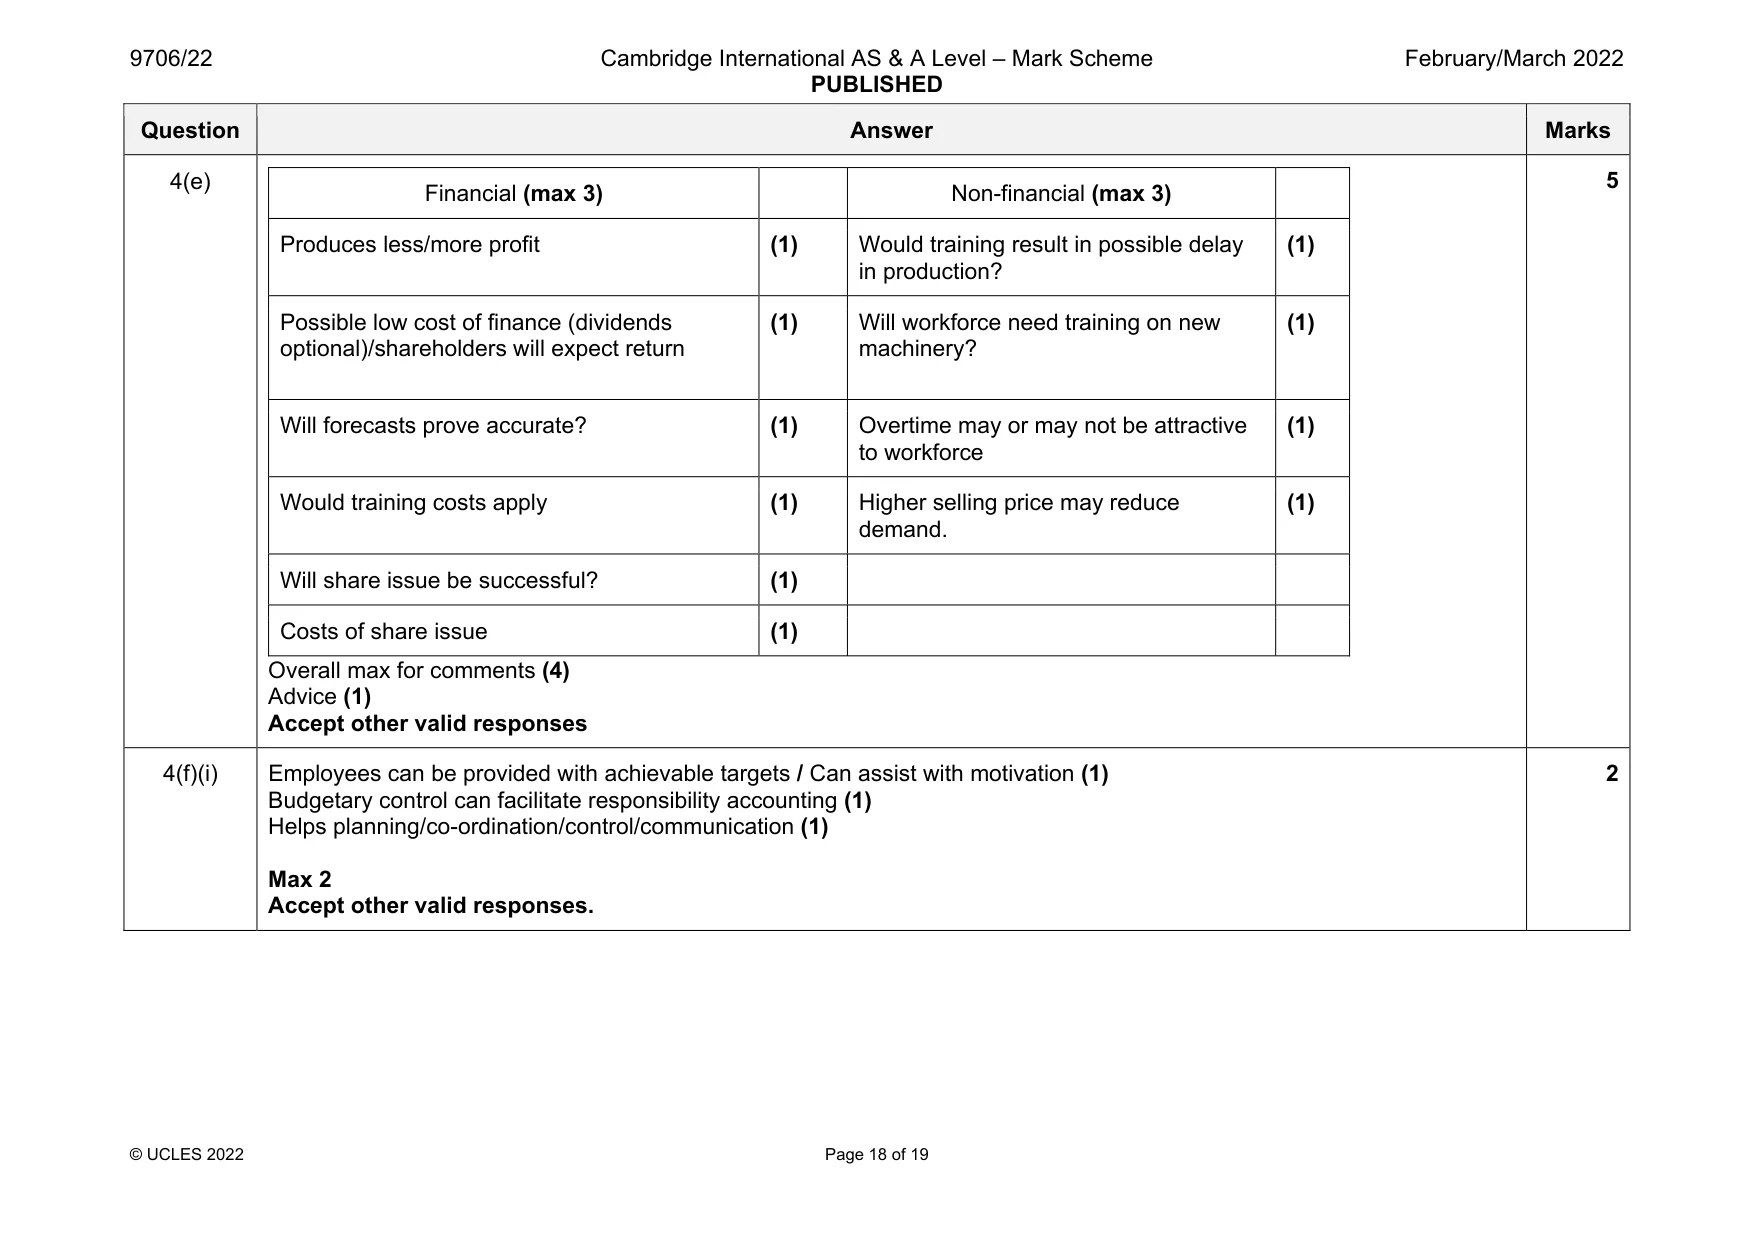
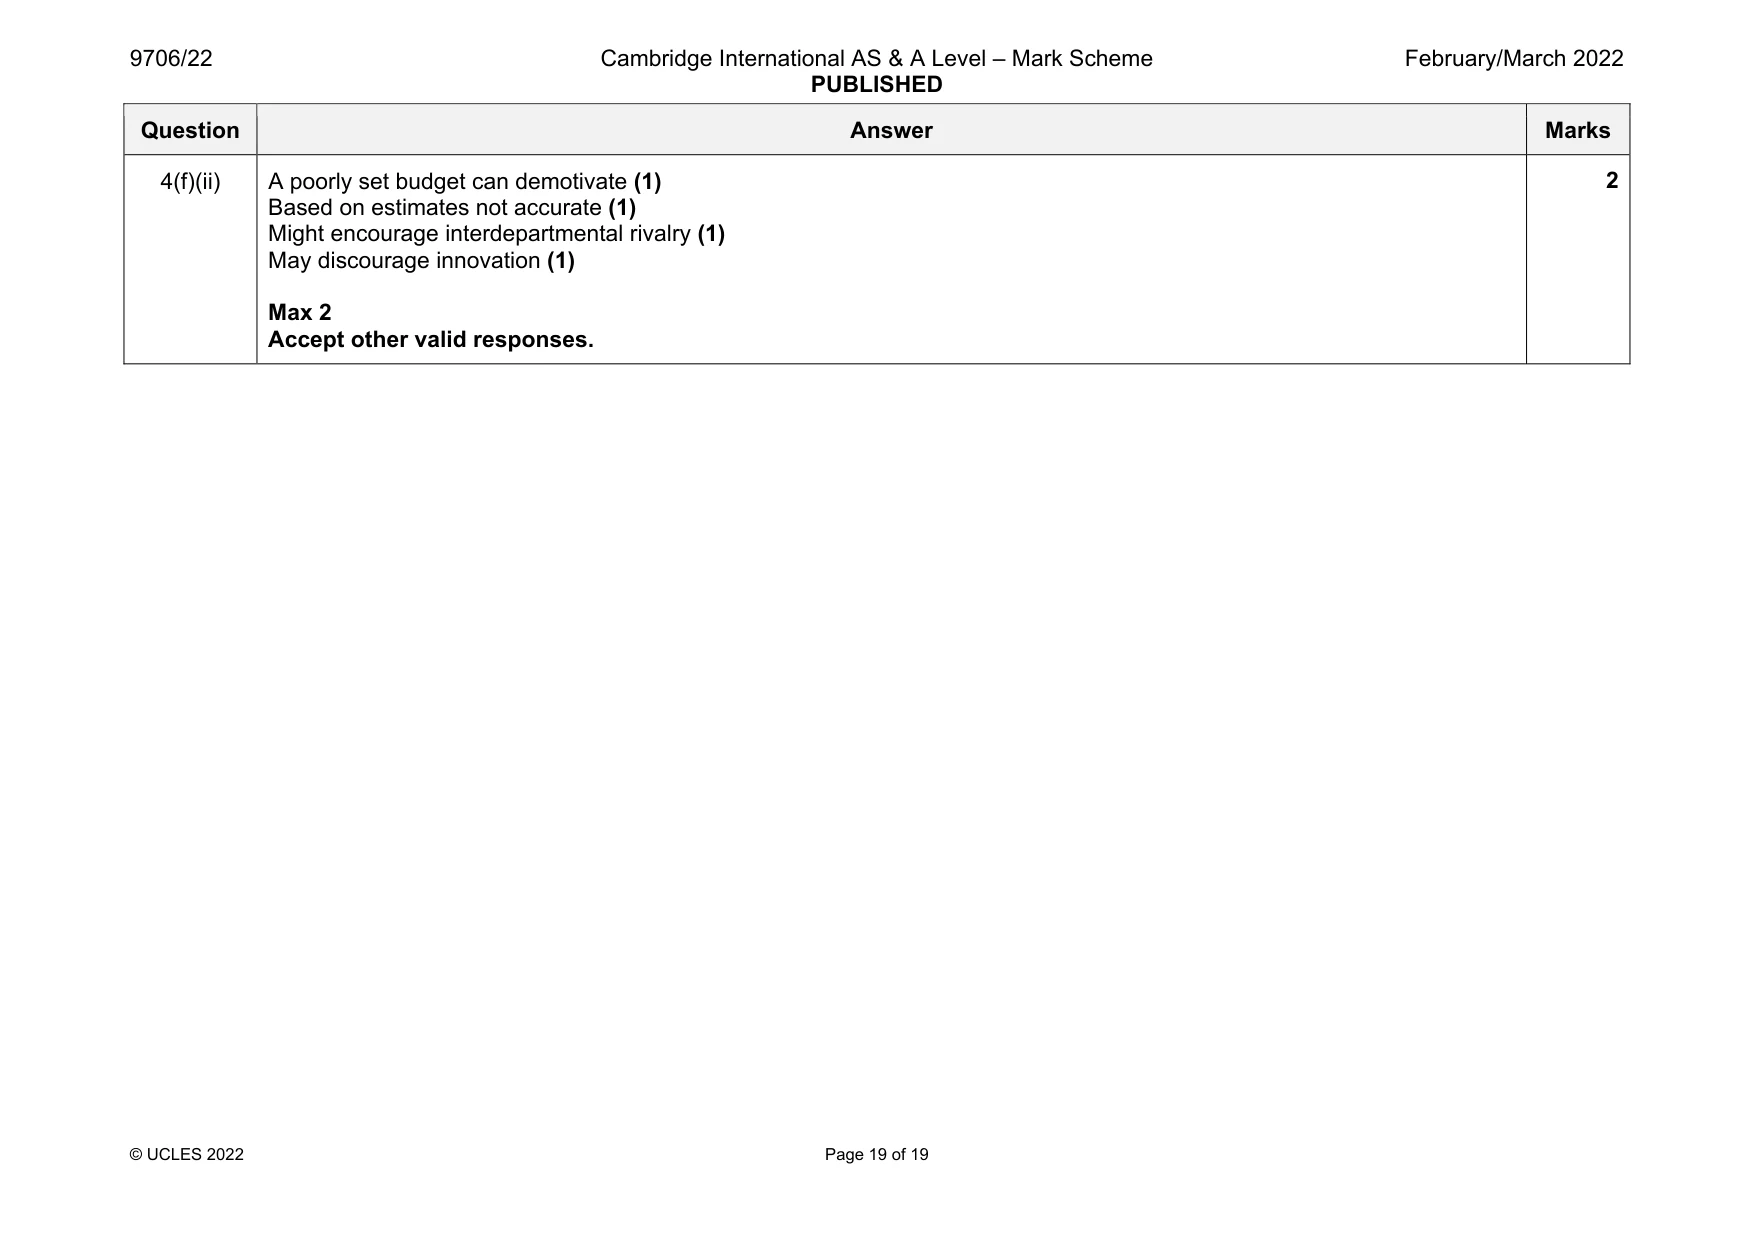
Mark scheme: 4(a) Production departments Service departments Machining $ Assembly $ Support $ Canteen $ Overheads already apportioned 106 350 28 600 7 180 13 870 Depreciation of machinery 21 250 2 750 375 625 (1) Production departments’ supervisor’s wages 13 500 6 300 (1) 141 100 37 650 7 555 14 495 Reapportioned canteen 9 213 4 299 983 (14 495) (1) OF 150 313 41 949 8 538 – Reapportioned Support 7 560 978 (8 538) (1) OF Total 157 873 42 927 – (1) OF 5 4(b) Machining department: 157 873/5 600 = $28.19 (1)OF per machine hour (1) Assembly department: 42 927/2 400 = $17.89 (1)OF per direct labour hour (1) 4 Question Answer Marks 4(c) Production lower than forecast (1) Actual overheads higher than forecast (1) 2 4(d)(i) Option 1 $ Revenue ($28.35 × 16 000) 453 600 (1) Direct materials ($8.80 × 16 000) (140 800) (1) Direct labour; normal working ($10.10 × 15 000) (151 500) (1) Direct labour: overtime working ($14.20 × 1000) (14 200) Contribution 147 100 Fixed costs ($44 000 – $2000) (42 000) (1) Profit 105 100 (1)OF 5 Question Answer Marks 4(d)(ii) Option 2 $ Revenue ($27 × 17 250) 465 750 (1) Direct materials ($7.70 × 17 250) (132 825) (1) Direct labour ($10.10 × 17 250) (174 225) (1) Contribution 158 700 Fixed costs ($44 000 + $1300 depreciation) (45 300) (1) Profit 113 400 (1)OF 5 Question Answer Marks 4(e) Financial (max 3) Non-financial (max 3) Produces less/more profit (1) Would training result in possible delay in production? (1) Possible low cost of finance (dividends optional)/shareholders will expect return (1) Will workforce need training on new machinery? (1) Will forecasts prove accurate? (1) Overtime may or may not be attractive to workforce (1) Would training costs apply (1) Higher selling price may reduce demand. (1) Will share issue be successful? (1) Costs of share issue (1) Overall max for comments (4) Advice (1) Accept other valid responses 5 4(f)(i) Employees can be provided with achievable targets / Can assist with motivation (1) Budgetary control can facilitate responsibility accounting (1) Helps planning/co-ordination/control/communication (1) Max 2 Accept other valid responses. 2 Question Answer Marks 4(f)(ii) A poorly set budget can demotivate (1) Based on estimates not accurate (1) Might encourage interdepartmental rivalry (1) May discourage innovation (1) Max 2 Accept other valid responses. 2
Q5 · A cash discount of 5% was received when Rafiq settled debts with trade payables during…
5 A cash discount of 5% was received when Rafiq settled debts with trade payables during the year ended 31 December 2021.
Q6 · At 31 December 2021 trade payables totalled $9230
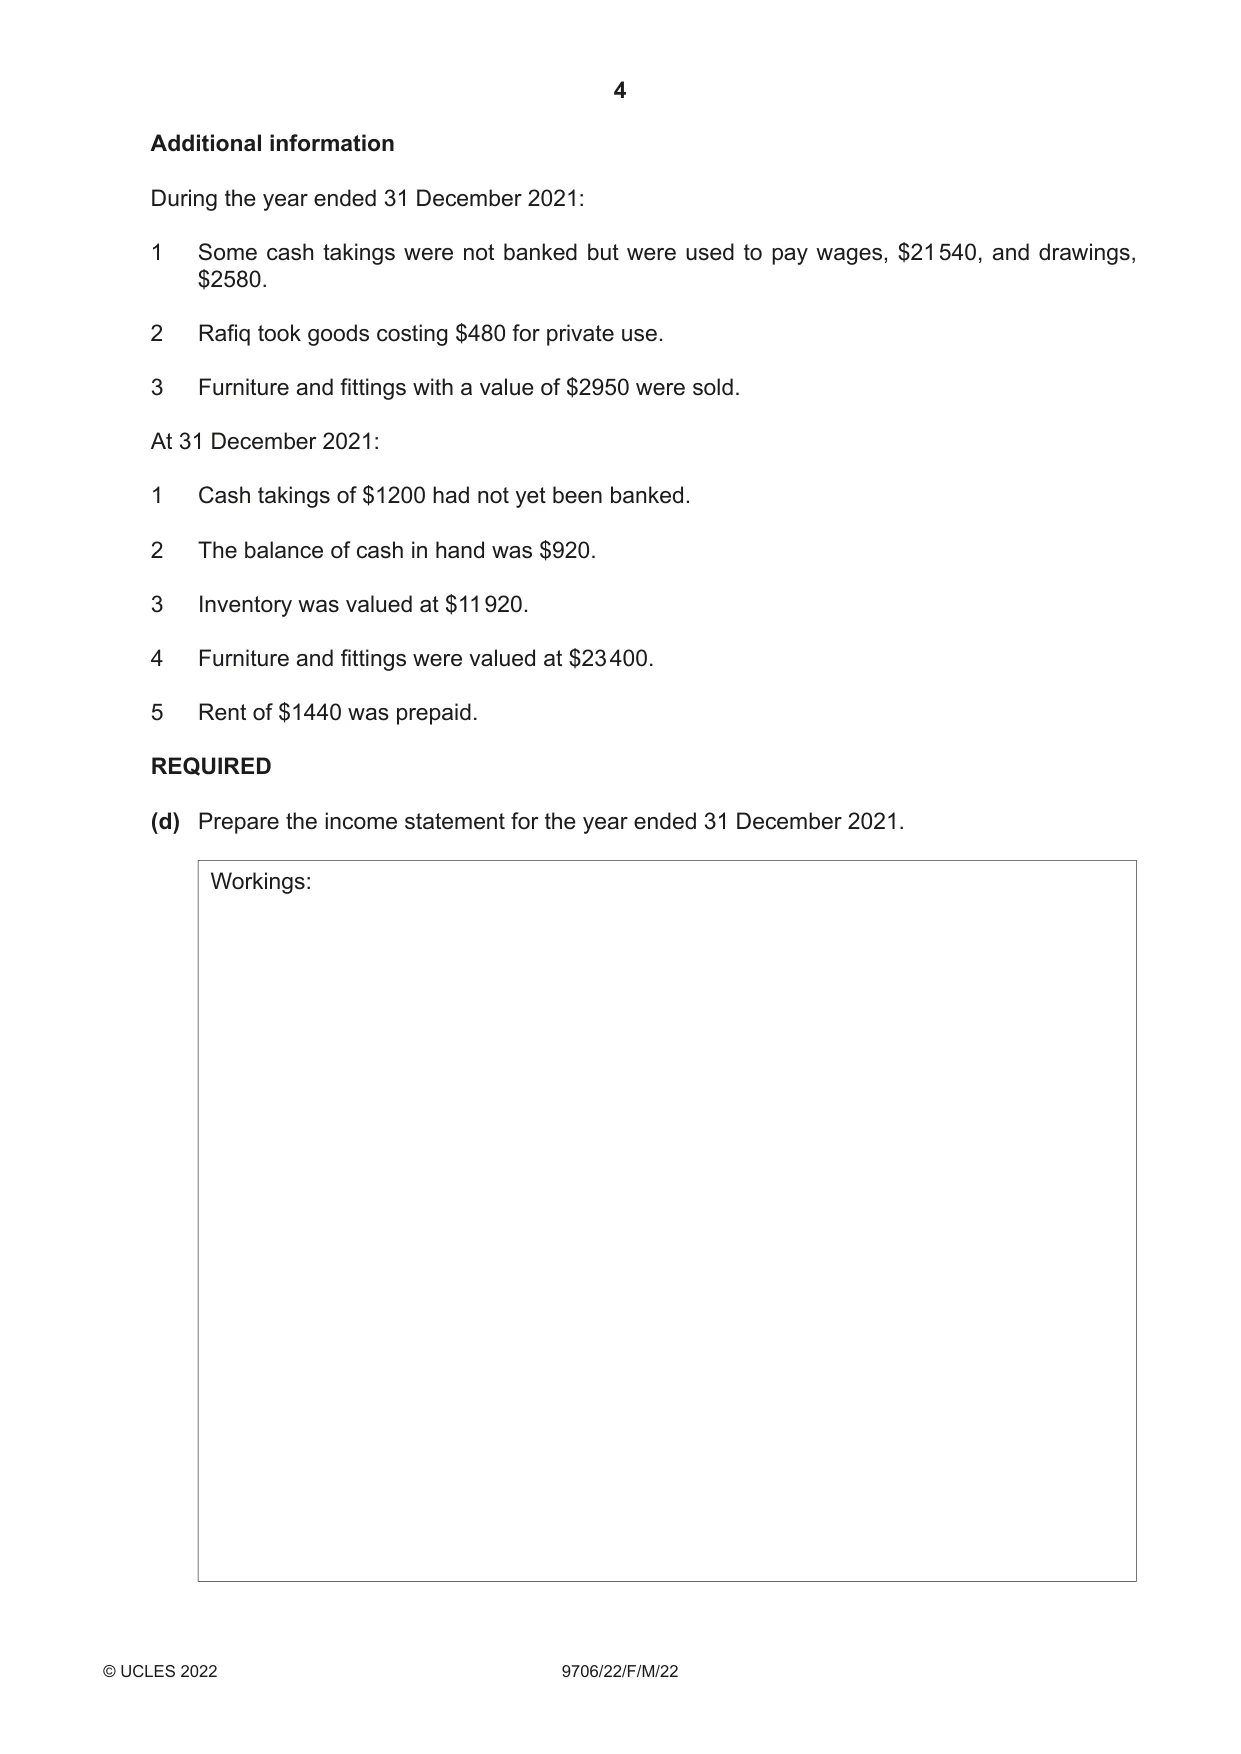
6 At 31 December 2021 trade payables totalled $9230. REQUIRED (c) Calculate the total purchases for the year ended 31 December 2021. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... [3] Additional information During the year ended 31 December 2021: 1 Some cash takings were not banked but were used to pay wages, $21 540, and drawings, $2580. 2 Rafiq took goods costing $480 for private use. 3 Furniture and fittings with a value of $2950 were sold. At 31 December 2021: 1 Cash takings of $1200 had not yet been banked. 2 The balance of cash in hand was $920. 3 Inventory was valued at $11 920. 4 Furniture and fittings were valued at $23 400. 5 Rent of $1440 was prepaid. REQUIRED (d) Prepare the income statement for the year ended 31 December 2021. Workings: Rafiq Income statement for the year ended 31 December 2021 ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... [14]
What was in this paper
The subtopics covered by these 6 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2022 Feb/March, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.