Cambridge A Level Accounting 9706 — 2020 Oct/Nov Paper 2 · Variant 1
9706/21/O/N/20 · 5 questions · 90 marks · ≈101 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper16 pages
Mark scheme10 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Ismail opened a retail business on 1 January 2019 with the following assets and…
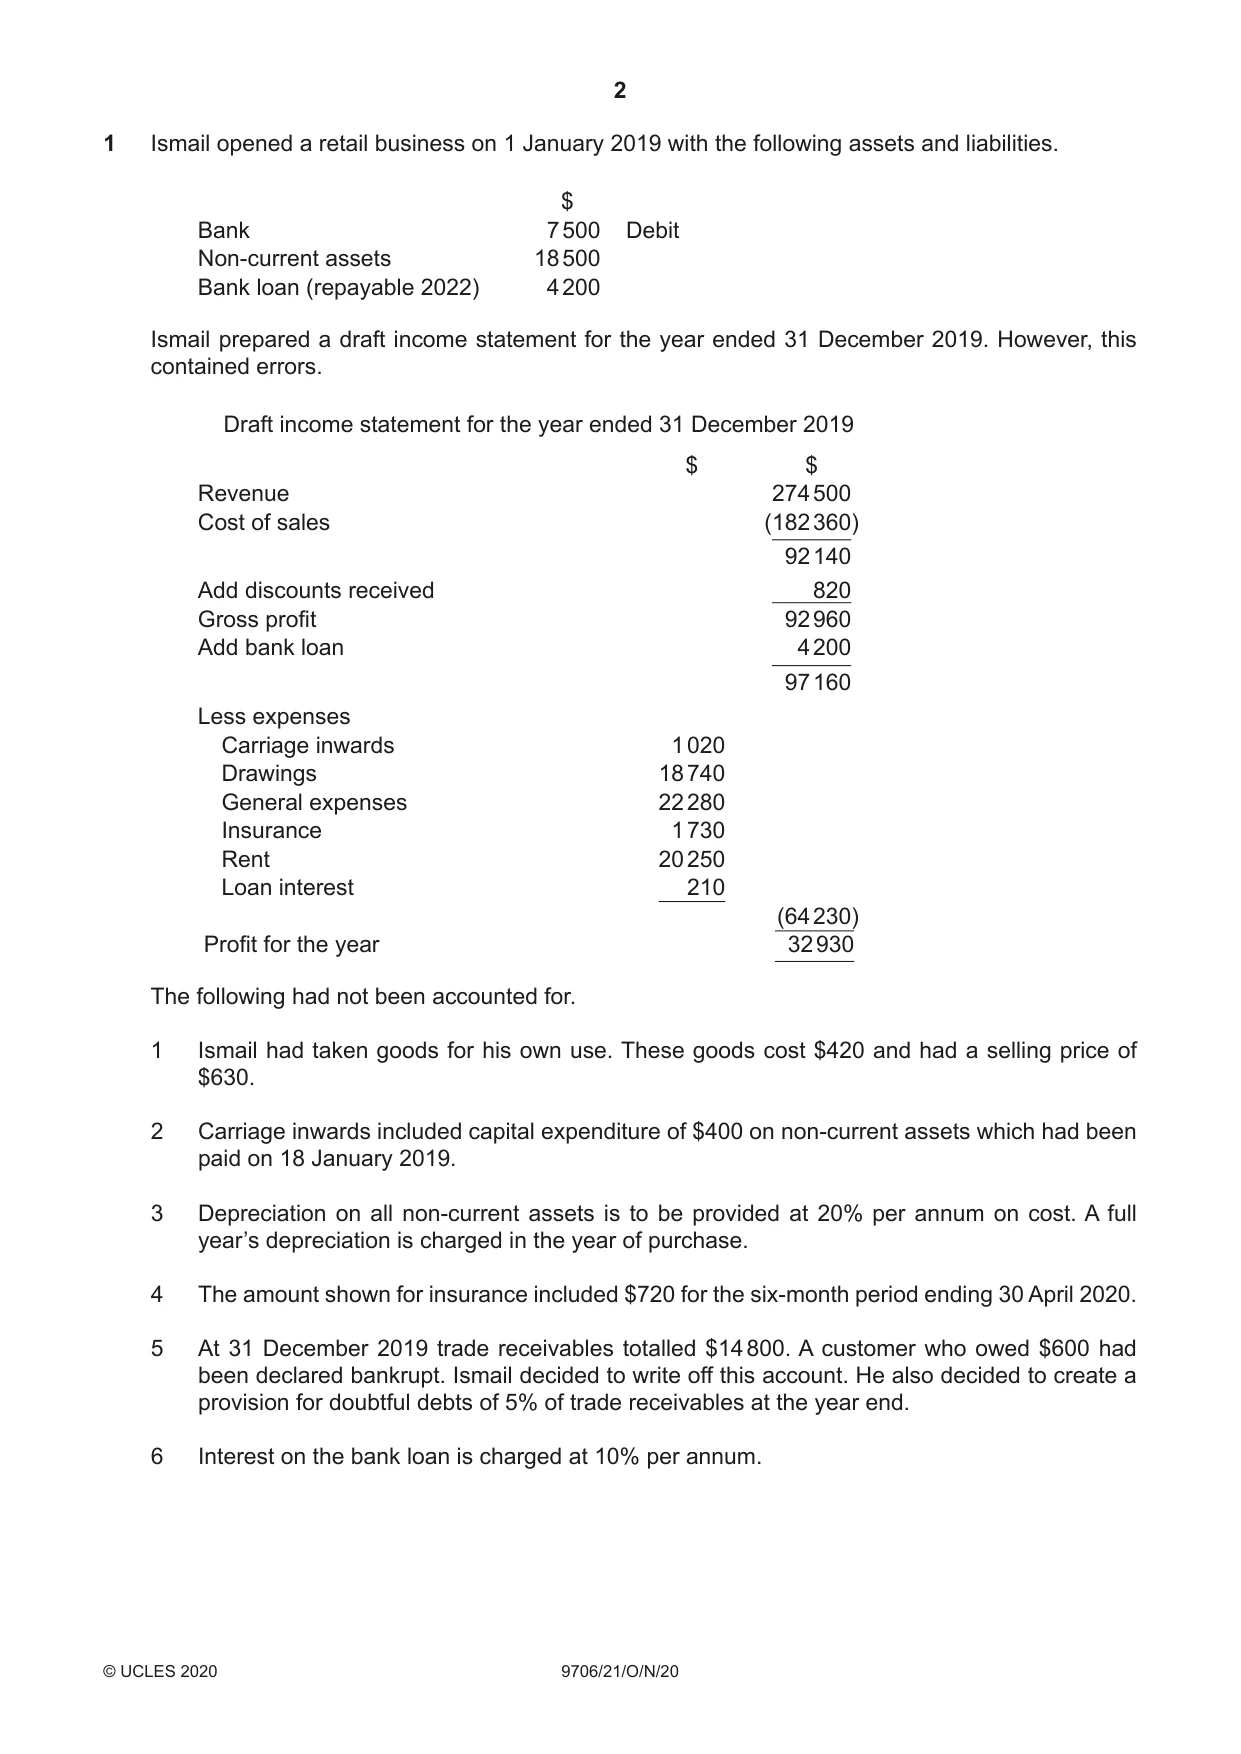
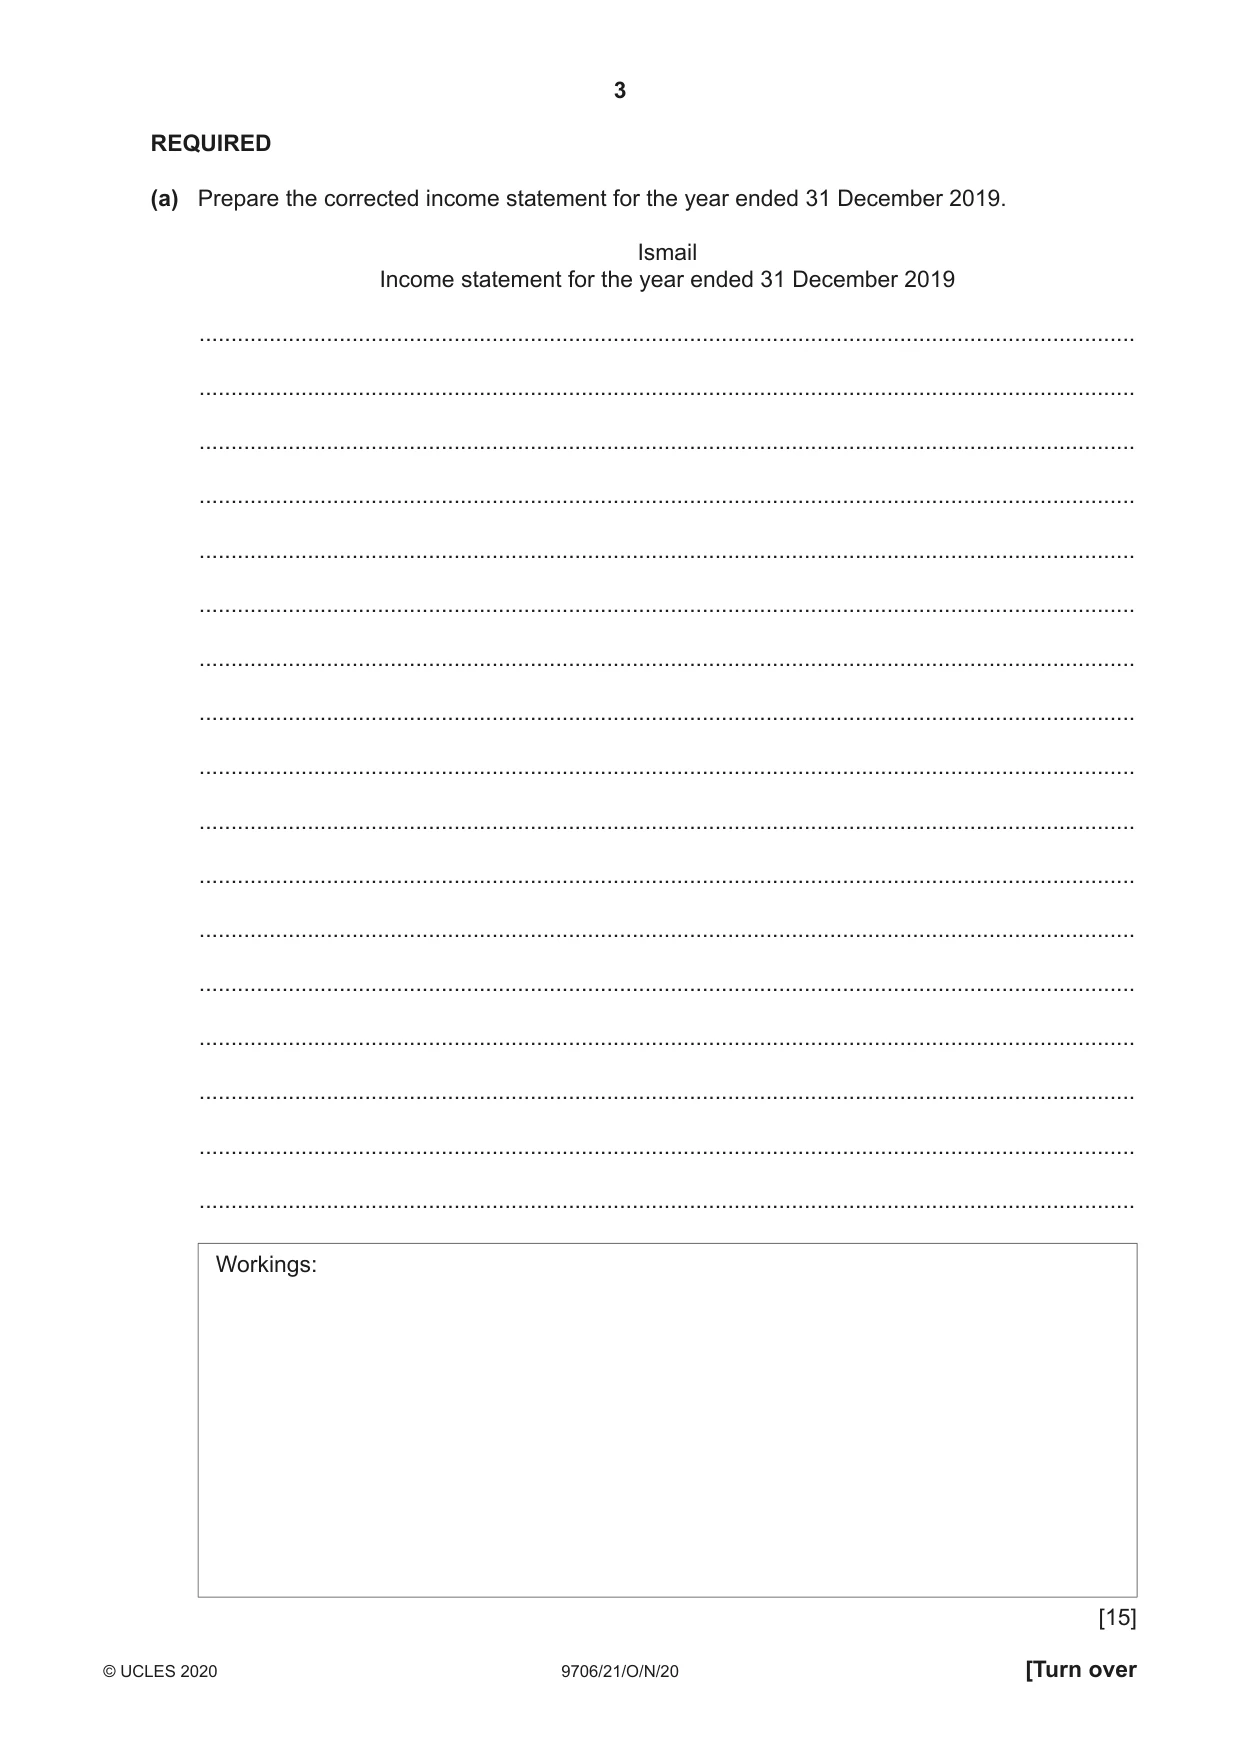
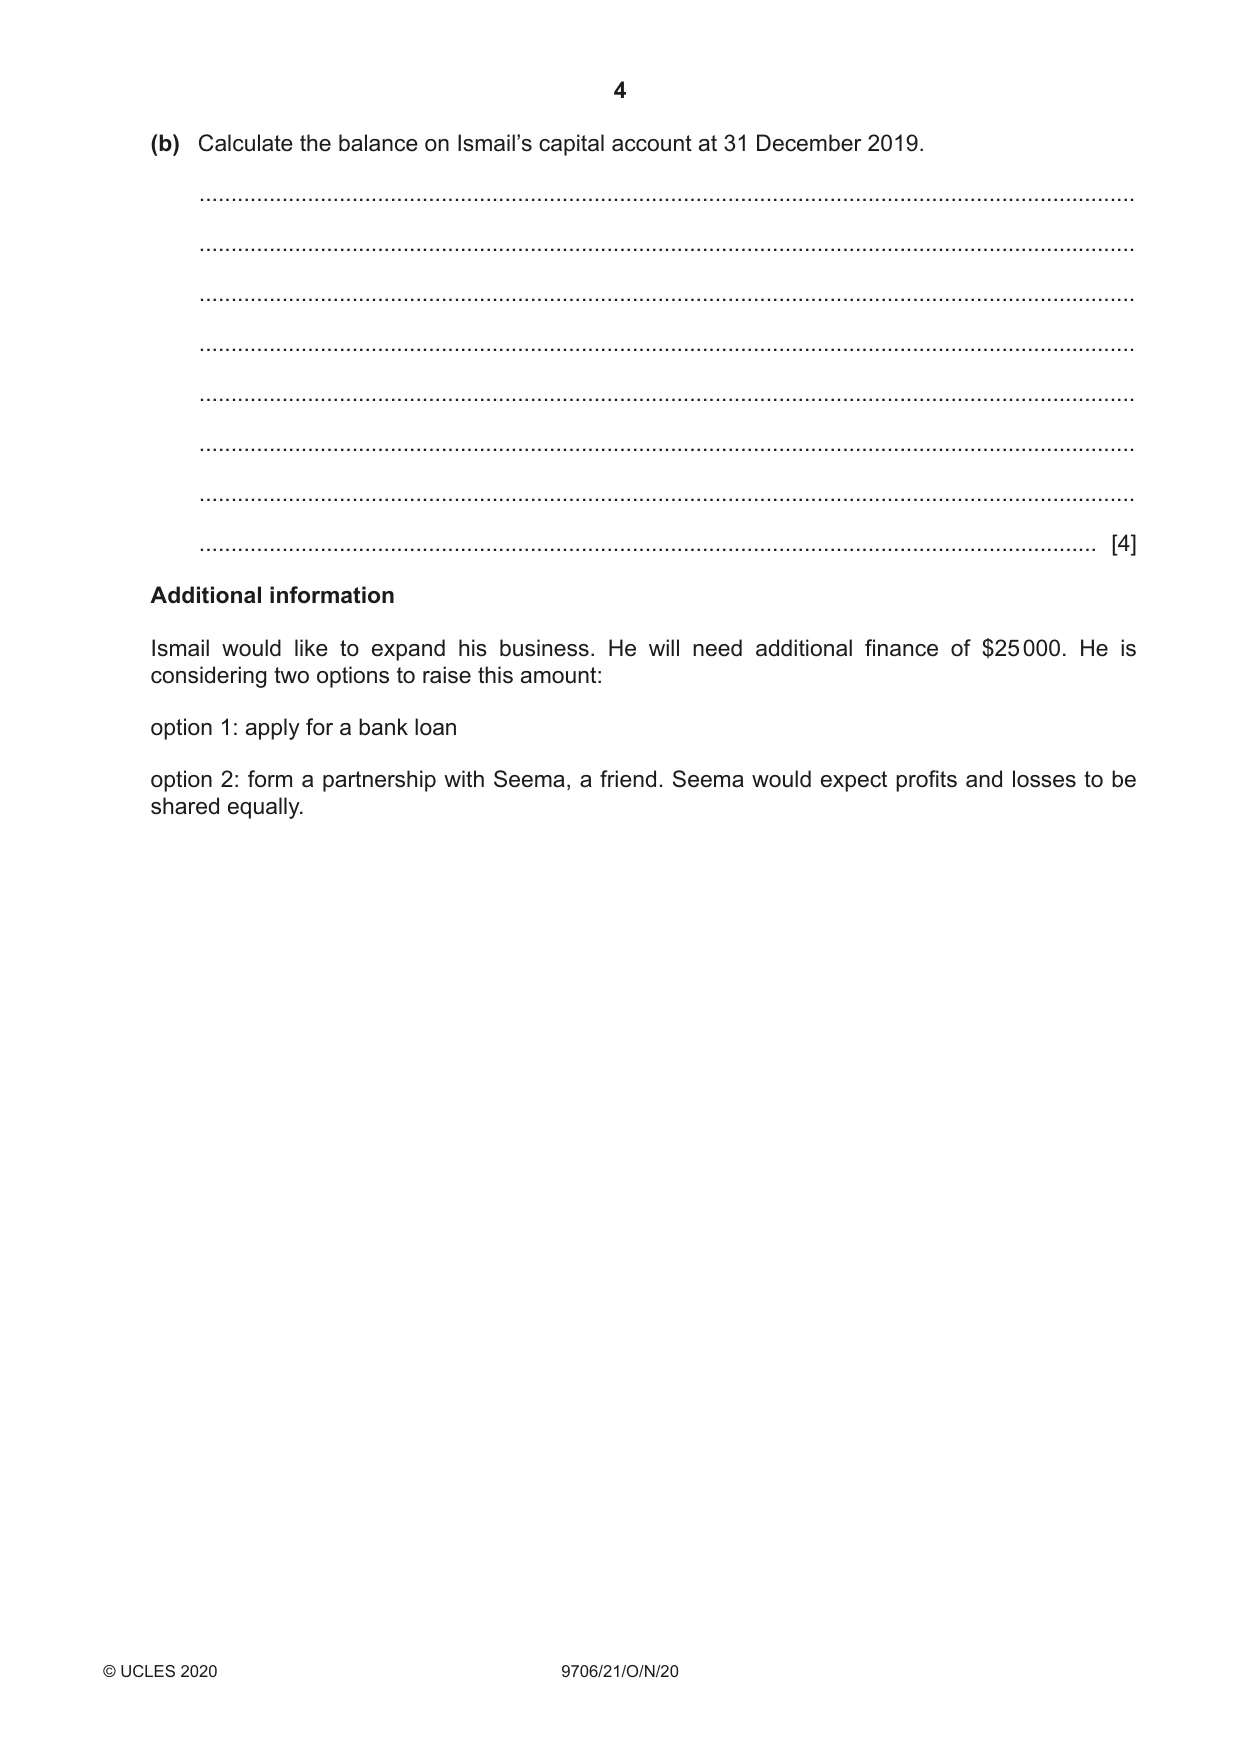
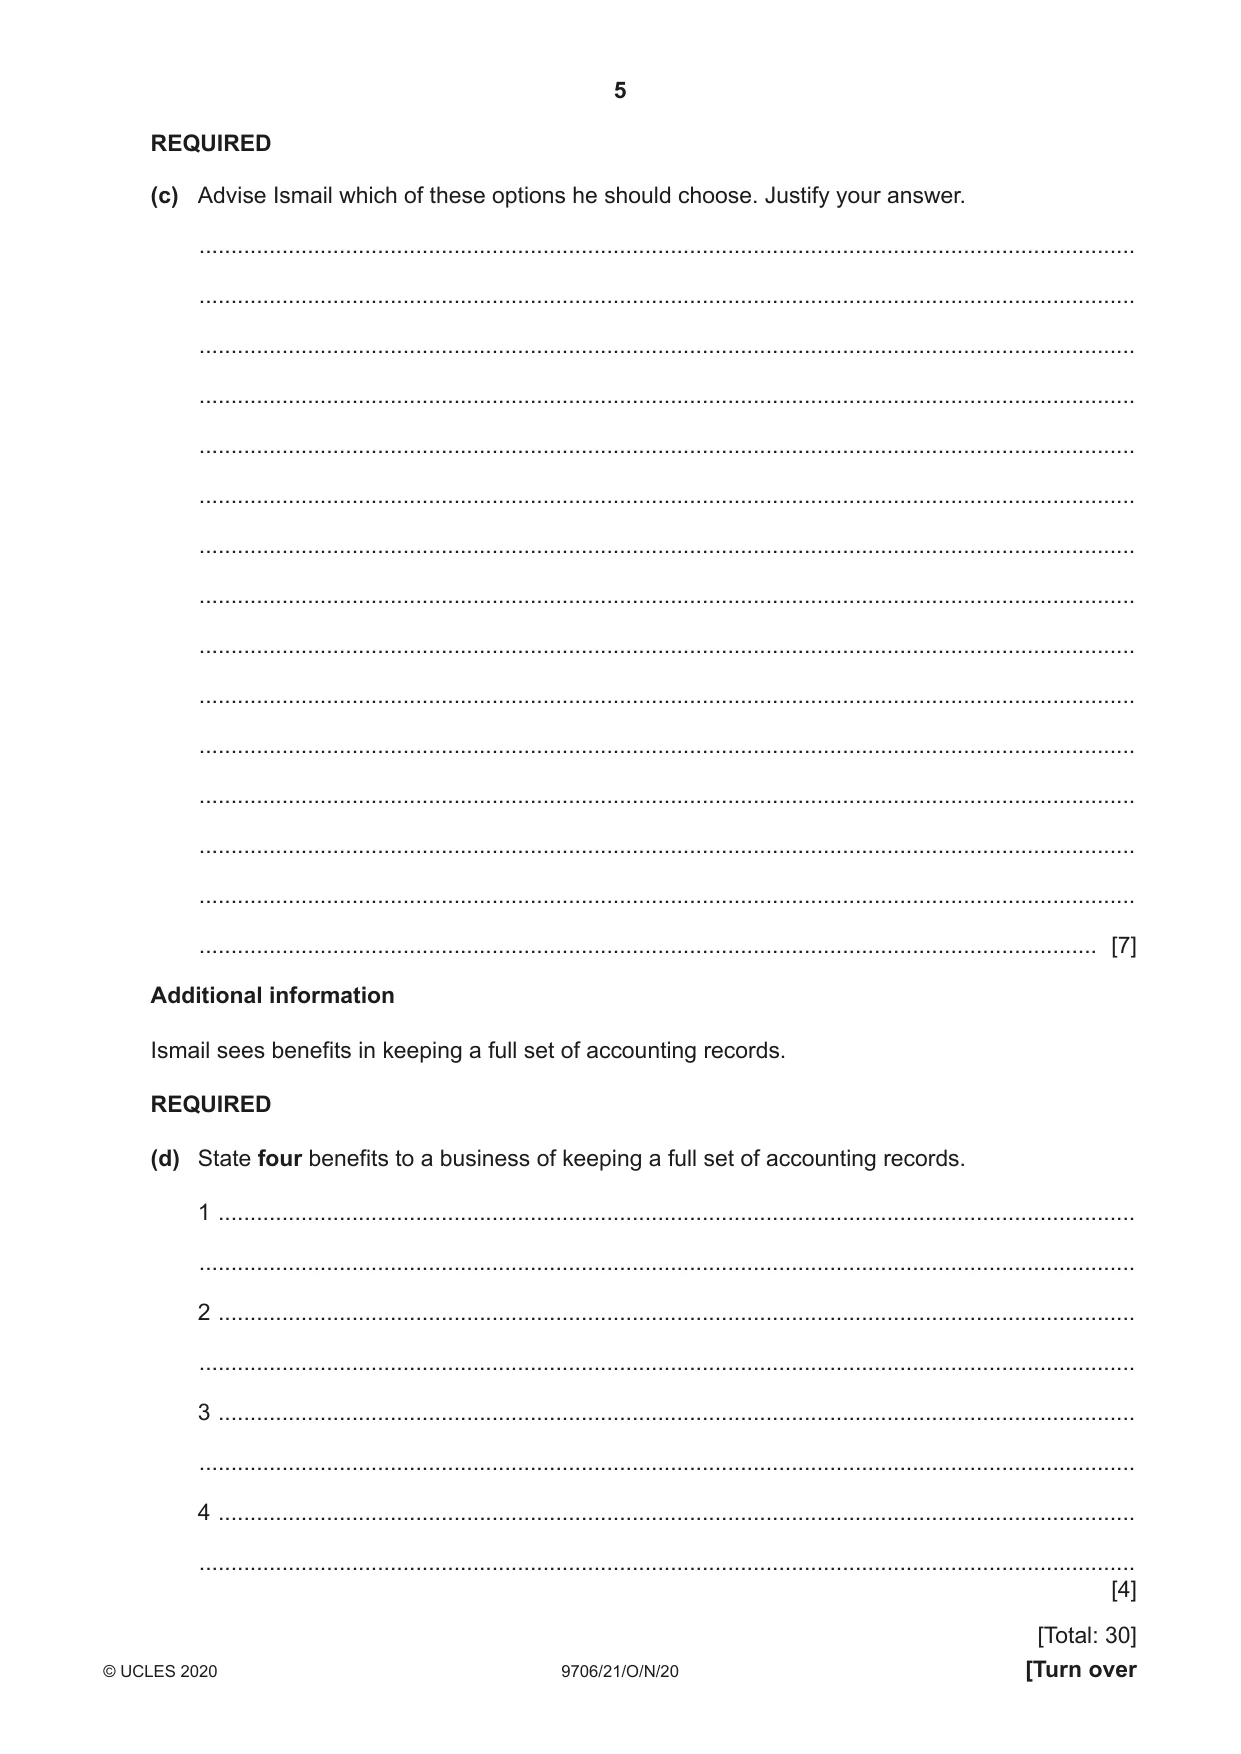
1 Ismail opened a retail business on 1 January 2019 with the following assets and liabilities. $ Bank 7 500 Debit Non-current assets 18 500 Bank loan (repayable 2022) 4 200 Ismail prepared a draft income statement for the year ended 31 December 2019. However, this contained errors. Draft income statement for the year ended 31 December 2019 $ $ Revenue 274 500 Cost of sales (182 360) 92 140 Add discounts received 820 Gross profit 92 960 Add bank loan 4 200 97 160 Less expenses Carriage inwards 1 020 Drawings 18 740 General expenses 22 280 Insurance 1 730 Rent 20 250 Loan interest 210 (64 230) Profit for the year 32 930 The following had not been accounted for. 1 Ismail had taken goods for his own use. These goods cost $420 and had a selling price of $630. 2 Carriage inwards included capital expenditure of $400 on non-current assets which had been paid on 18 January 2019. 3 Depreciation on all non-current assets is to be provided at 20% per annum on cost. A full year’s depreciation is charged in the year of purchase. 4 The amount shown for insurance included $720 for the six-month period ending 30 April 2020. 5 At 31 December 2019 trade receivables totalled $14 800. A customer who owed $600 had been declared bankrupt. Ismail decided to write off this account. He also decided to create a provision for doubtful debts of 5% of trade receivables at the year end. 6 Interest on the bank loan is charged at 10% per annum. REQUIRED (a) Prepare the corrected income statement for the year ended 31 December 2019. Ismail Income statement for the year ended 31 December 2019 ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Workings: [15] (b) Calculate the balance on Ismail’s capital account at 31 December 2019. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] Additional information Ismail would like to expand his business. He will need additional finance of $25 000. He is considering two options to raise this amount: option 1: apply for a bank loan option 2: form a partnership with Seema, a friend. Seema would expect profits and losses to be shared equally. REQUIRED (c) Advise Ismail which of these options he should choose. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [7] Additional information Ismail sees benefits in keeping a full set of accounting records. REQUIRED (d) State four benefits to a business of keeping a full set of accounting records. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... 3 ................................................................................................................................................ ................................................................................................................................................... 4 ................................................................................................................................................ ................................................................................................................................................... [4] [Total: 30]
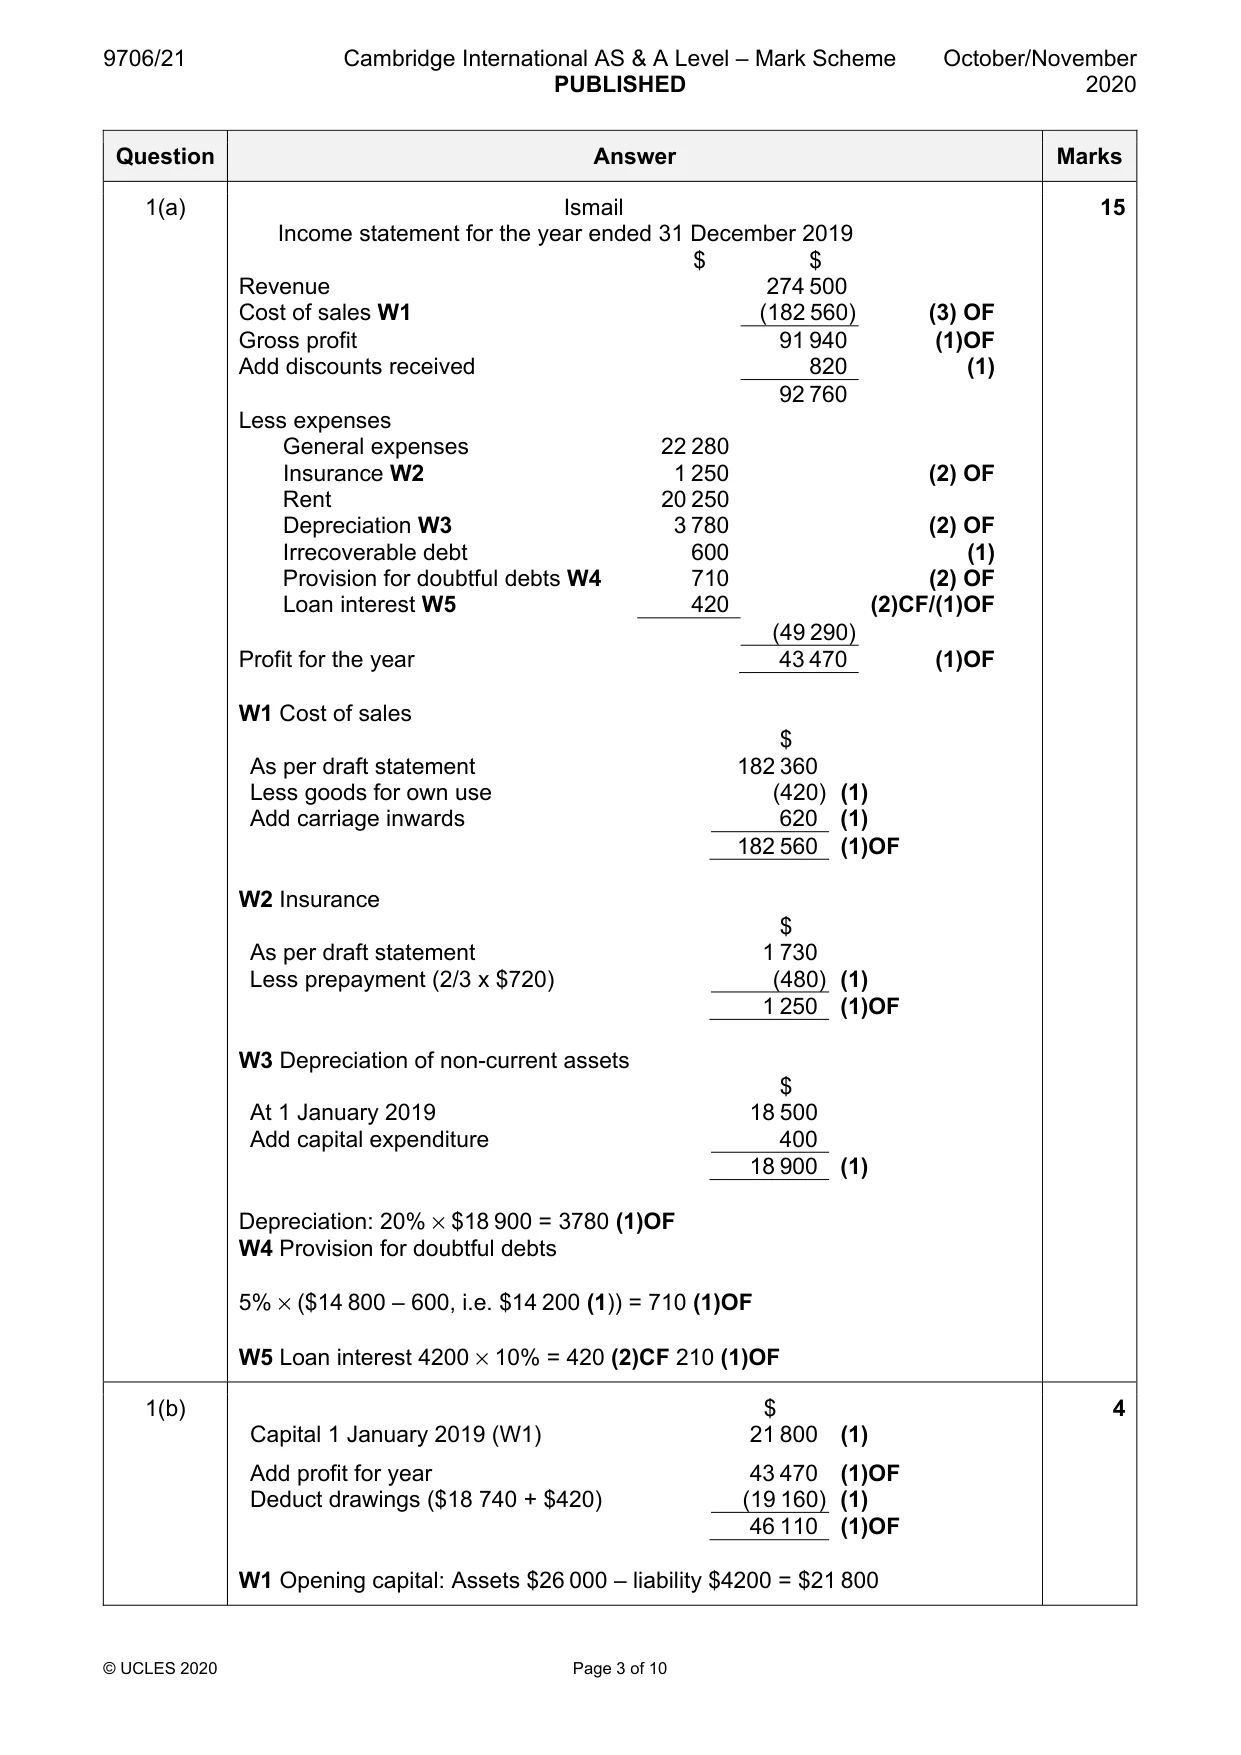
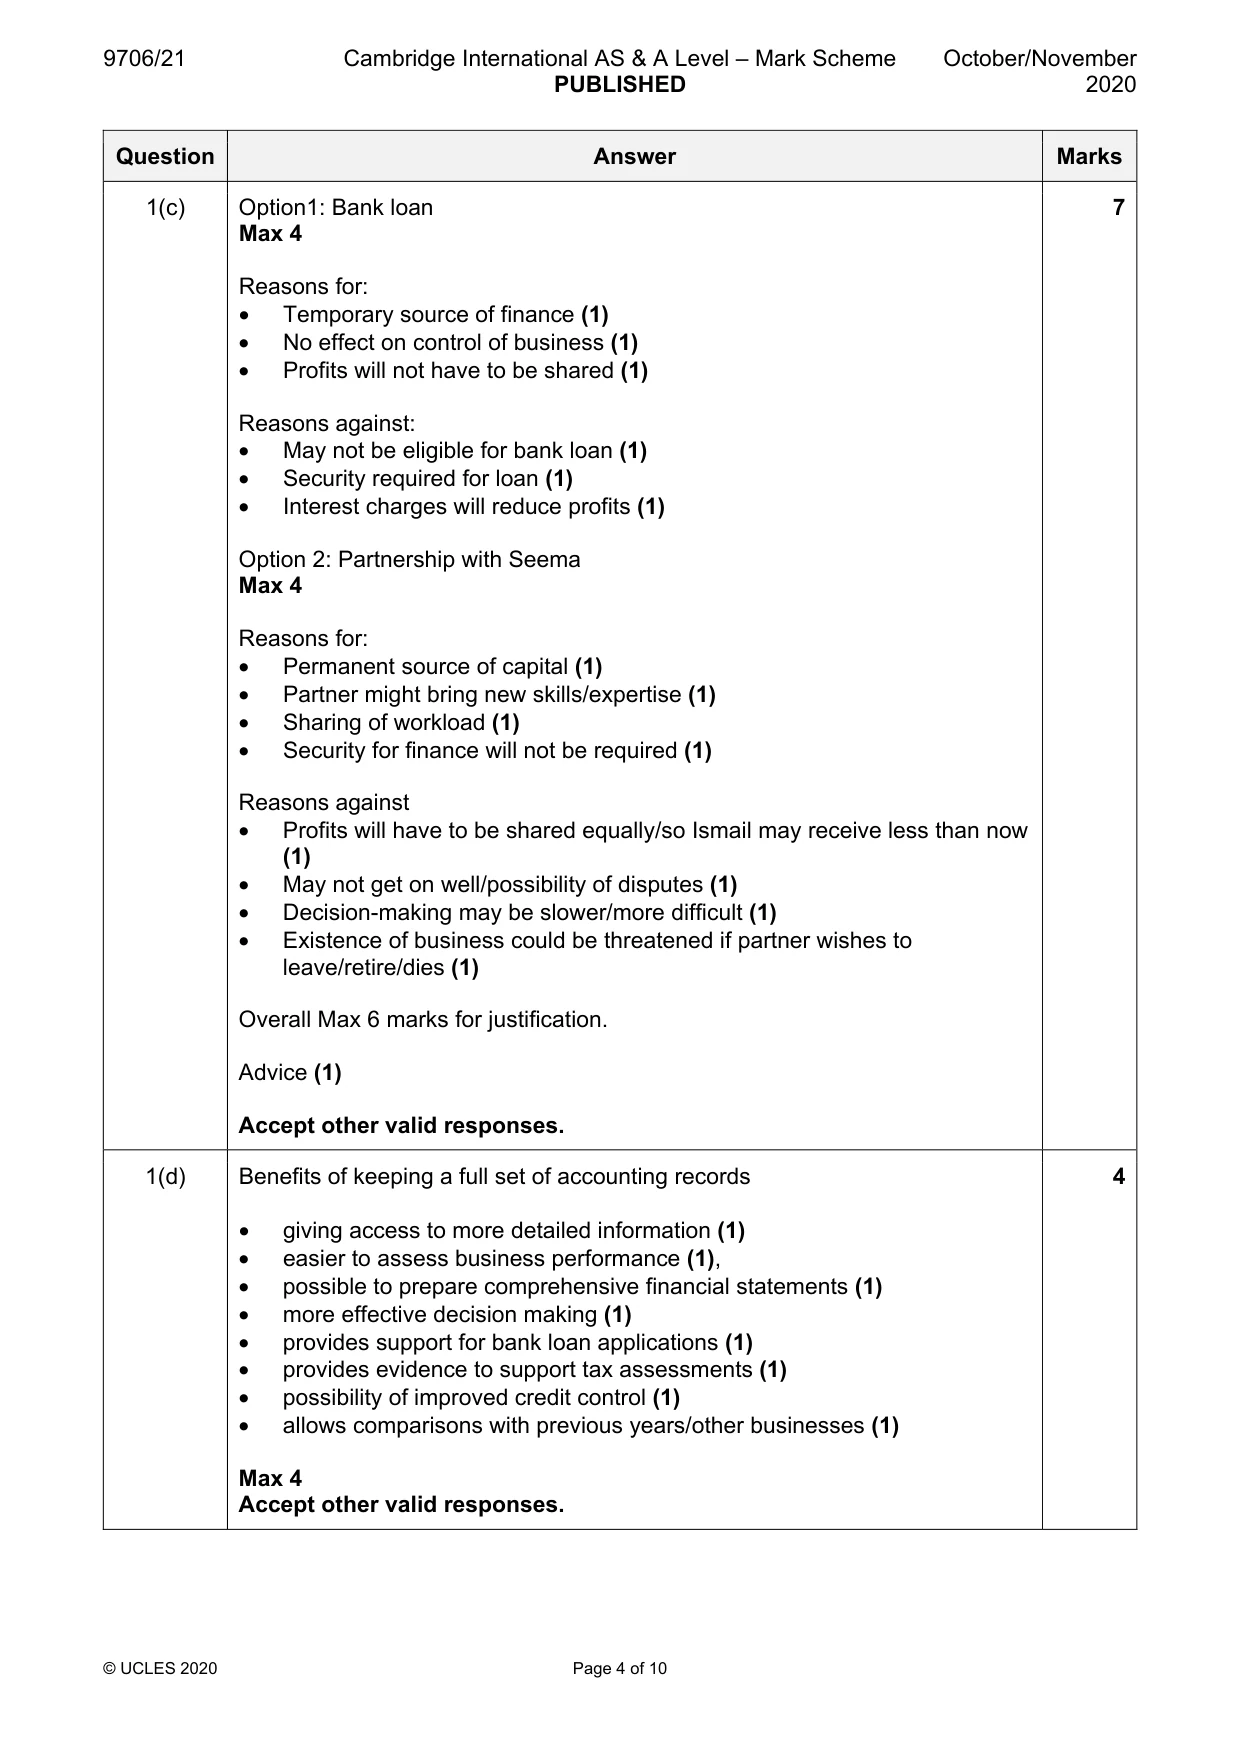
Mark scheme: Question Answer Marks 1(a) Ismail 15 Income statement for the year ended 31 December 2019 $ $ Revenue 274 500 Cost of sales W1 (182 560) (3) OF Gross profit 91 940 (1)OF Add discounts received 820 (1) 92 760 Less expenses General expenses 22 280 Insurance W2 1 250 (2) OF Rent 20 250 Depreciation W3 3 780 (2) OF Irrecoverable debt 600 (1) Provision for doubtful debts W4 710 (2) OF Loan interest W5 420 (2)CF/(1)OF (49 290) Profit for the year 43 470 (1)OF W1 Cost of sales $ As per draft statement 182 360 Less goods for own use (420) (1) Add carriage inwards 620 (1) 182 560 (1)OF W2 Insurance $ As per draft statement 1 730 Less prepayment (2/3 x $720) (480) (1) 1 250 (1)OF W3 Depreciation of non-current assets $ At 1 January 2019 18 500 Add capital expenditure 400 18 900 (1) Depreciation: 20% × $18 900 = 3780 (1)OF W4 Provision for doubtful debts 5% × ($14 800 – 600, i.e. $14 200 (1)) = 710 (1)OF W5 Loan interest 4200 × 10% = 420 (2)CF 210 (1)OF 1(b) $ 4 Capital 1 January 2019 (W1) 21 800 (1) Add profit for year 43 470 (1)OF Deduct drawings ($18 740 + $420) (19 160) (1) 46 110 (1)OF W1 Opening capital: Assets $26 000 – liability $4200 = $21 800 1(c) Option1: Bank loan 7 Max 4 Reasons for: • Temporary source of finance (1) • No effect on control of business (1) • Profits will not have to be shared (1) Reasons against: • May not be eligible for bank loan (1) • Security required for loan (1) • Interest charges will reduce profits (1) Option 2: Partnership with Seema Max 4 Reasons for: • Permanent source of capital (1) • Partner might bring new skills/expertise (1) • Sharing of workload (1) • Security for finance will not be required (1) Reasons against • Profits will have to be shared equally/so Ismail may receive less than now (1) • May not get on well/possibility of disputes (1) • Decision-making may be slower/more difficult (1) • Existence of business could be threatened if partner wishes to leave/retire/dies (1) Overall Max 6 marks for justification. Advice (1) Accept other valid responses. 1(d) Benefits of keeping a full set of accounting records 4 • giving access to more detailed information (1) • easier to assess business performance (1), • possible to prepare comprehensive financial statements (1) • more effective decision making (1) • provides support for bank loan applications (1) • provides evidence to support tax assessments (1) • possibility of improved credit control (1) • allows comparisons with previous years/other businesses (1) Max 4 Accept other valid responses.
Q2 · Noor, a sole trader, prepares bank reconciliation statements at the end of each month
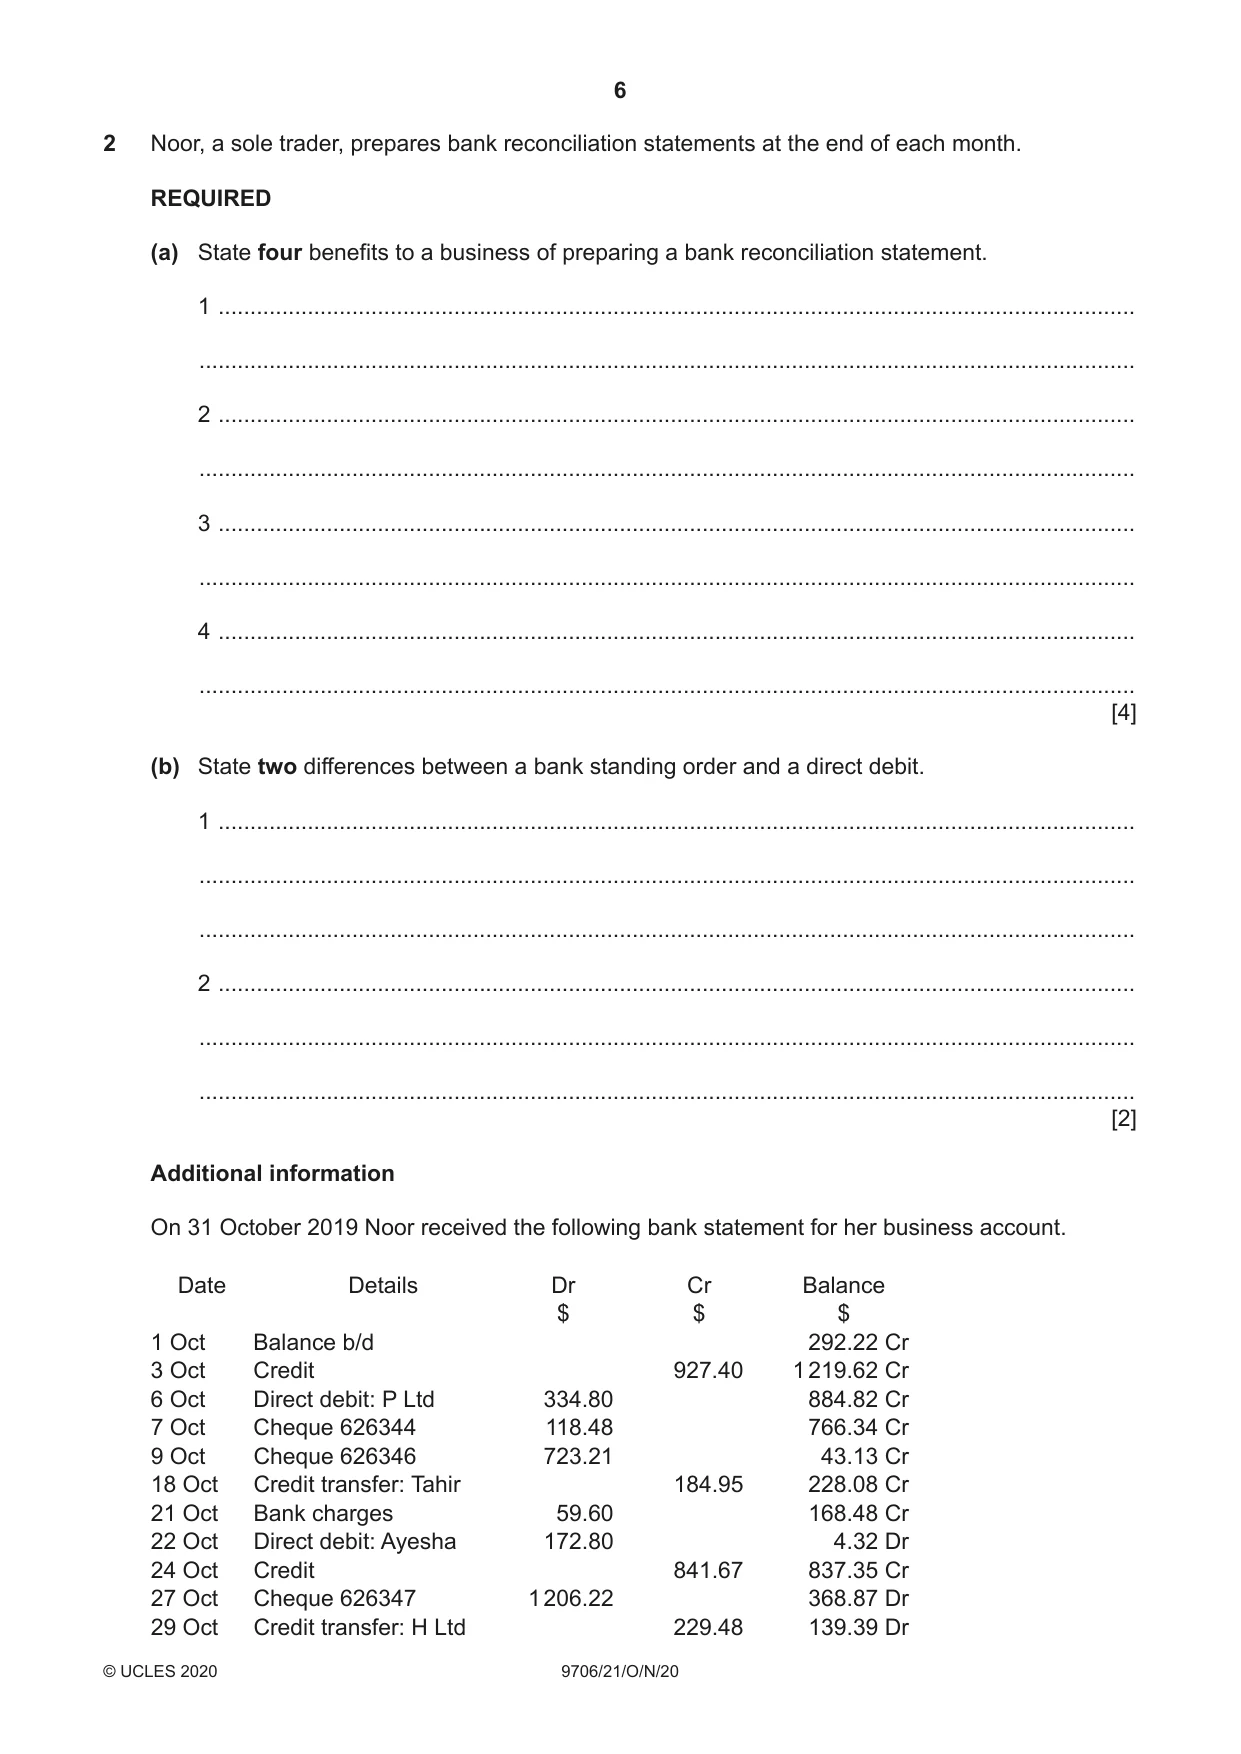
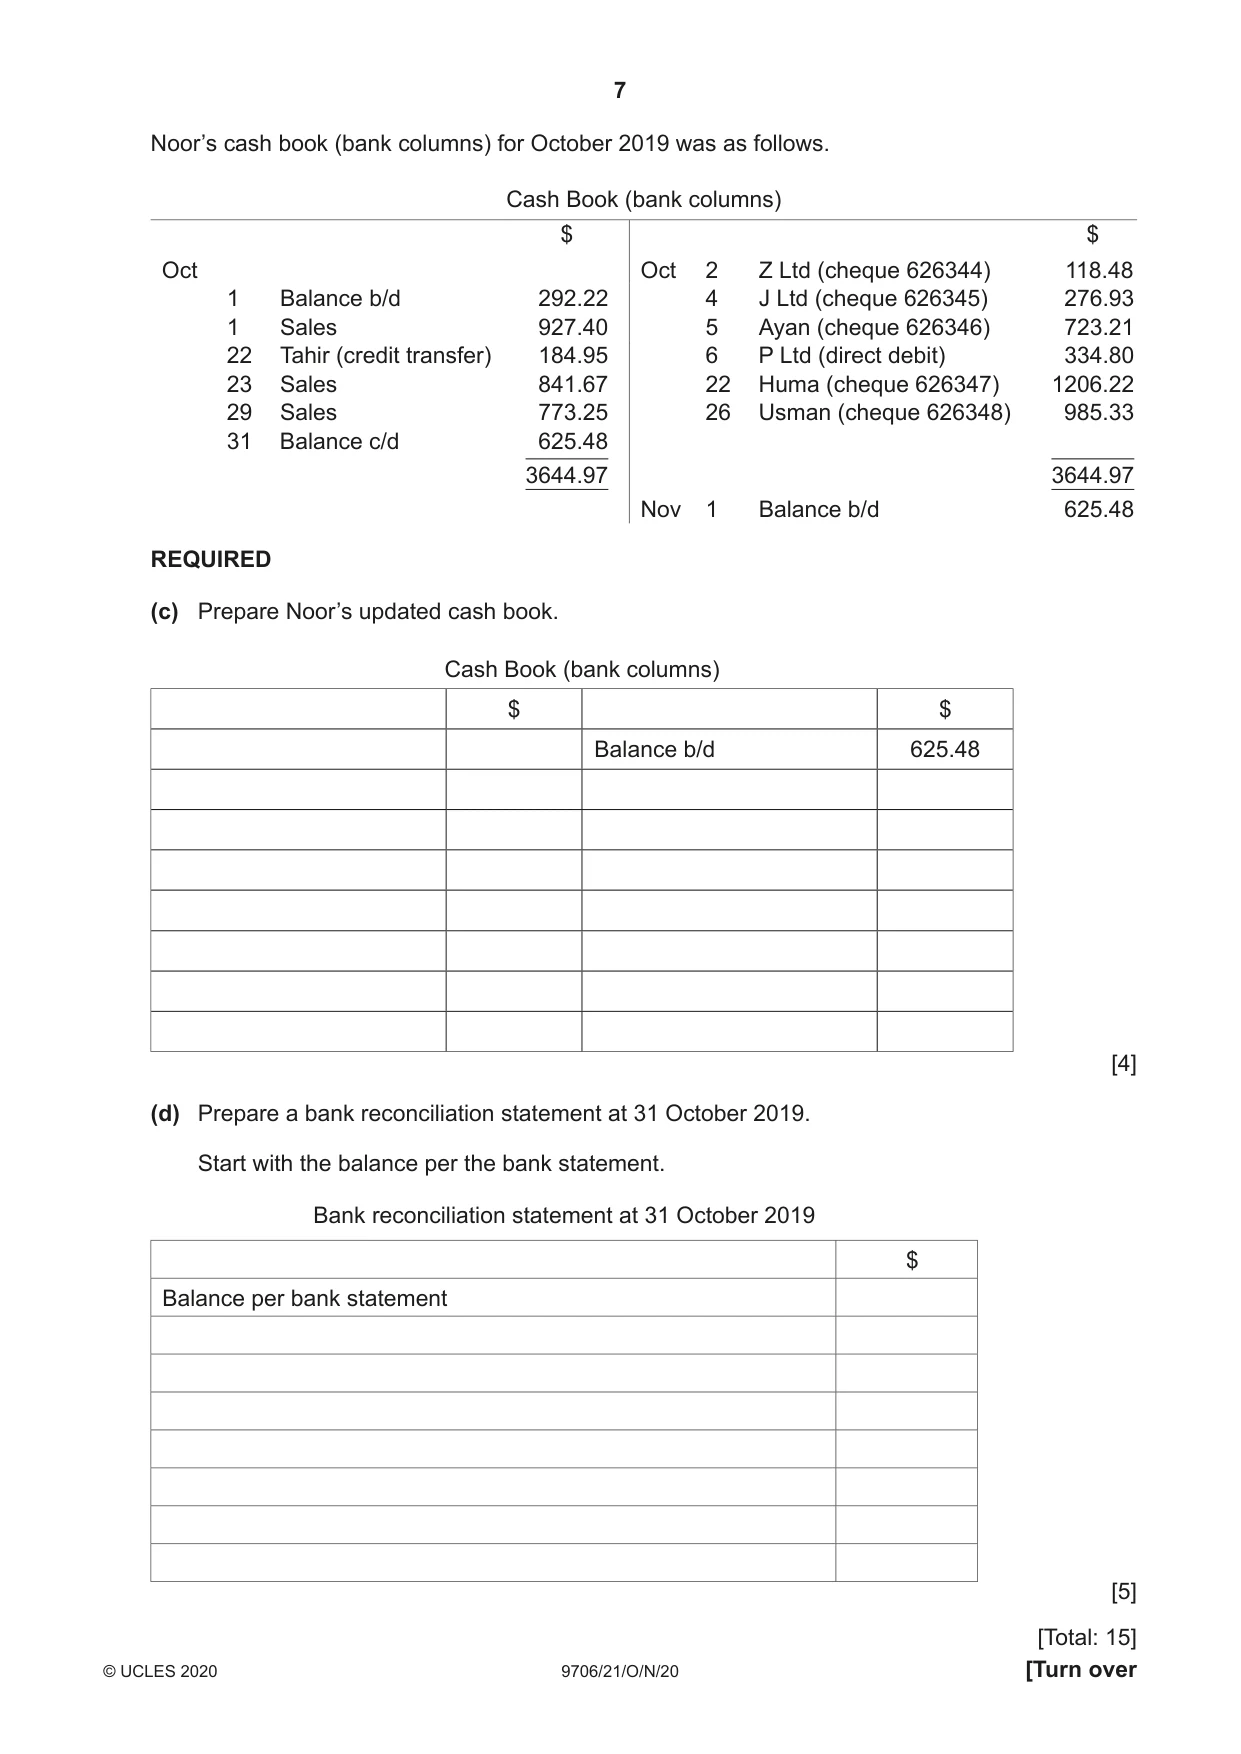
2 Noor, a sole trader, prepares bank reconciliation statements at the end of each month. REQUIRED (a) State four benefits to a business of preparing a bank reconciliation statement. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... 3 ................................................................................................................................................ ................................................................................................................................................... 4 ................................................................................................................................................ ................................................................................................................................................... [4] (b) State two differences between a bank standing order and a direct debit. 1 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... [2] Additional information On 31 October 2019 Noor received the following bank statement for her business account. Date Details Dr Cr Balance $ $ $ 1 Oct Balance b/d 292.22 Cr 3 Oct Credit 927.40 1 219.62 Cr 6 Oct Direct debit: P Ltd 334.80 884.82 Cr 7 Oct Cheque 626344 118.48 766.34 Cr 9 Oct Cheque 626346 723.21 43.13 Cr 18 Oct Credit transfer: Tahir 184.95 228.08 Cr 21 Oct Bank charges 59.60 168.48 Cr 22 Oct Direct debit: Ayesha 172.80 4.32 Dr 24 Oct Credit 841.67 837.35 Cr 27 Oct Cheque 626347 1 206.22 368.87 Dr 29 Oct Credit transfer: H Ltd 229.48 139.39 Dr Noor’s cash book (bank columns) for October 2019 was as follows. Cash Book (bank columns) $ $ Oct Oct 2 Z Ltd (cheque 626344) 118.48 1 Balance b/d 292.22 4 J Ltd (cheque 626345) 276.93 1 Sales 927.40 5 Ayan (cheque 626346) 723.21 22 Tahir (credit transfer) 184.95 6 P Ltd (direct debit) 334.80 23 Sales 841.67 22 Huma (cheque 626347) 1206.22 29 Sales 773.25 26 Usman (cheque 626348) 985.33 31 Balance c/d 625.48 3644.97 3644.97 Nov 1 Balance b/d 625.48 REQUIRED (c) Prepare Noor’s updated cash book. Cash Book (bank columns) $ $ Balance b/d 625.48 [4] (d) Prepare a bank reconciliation statement at 31 October 2019. Start with the balance per the bank statement. Bank reconciliation statement at 31 October 2019 $ Balance per bank statement [5] [Total: 15]
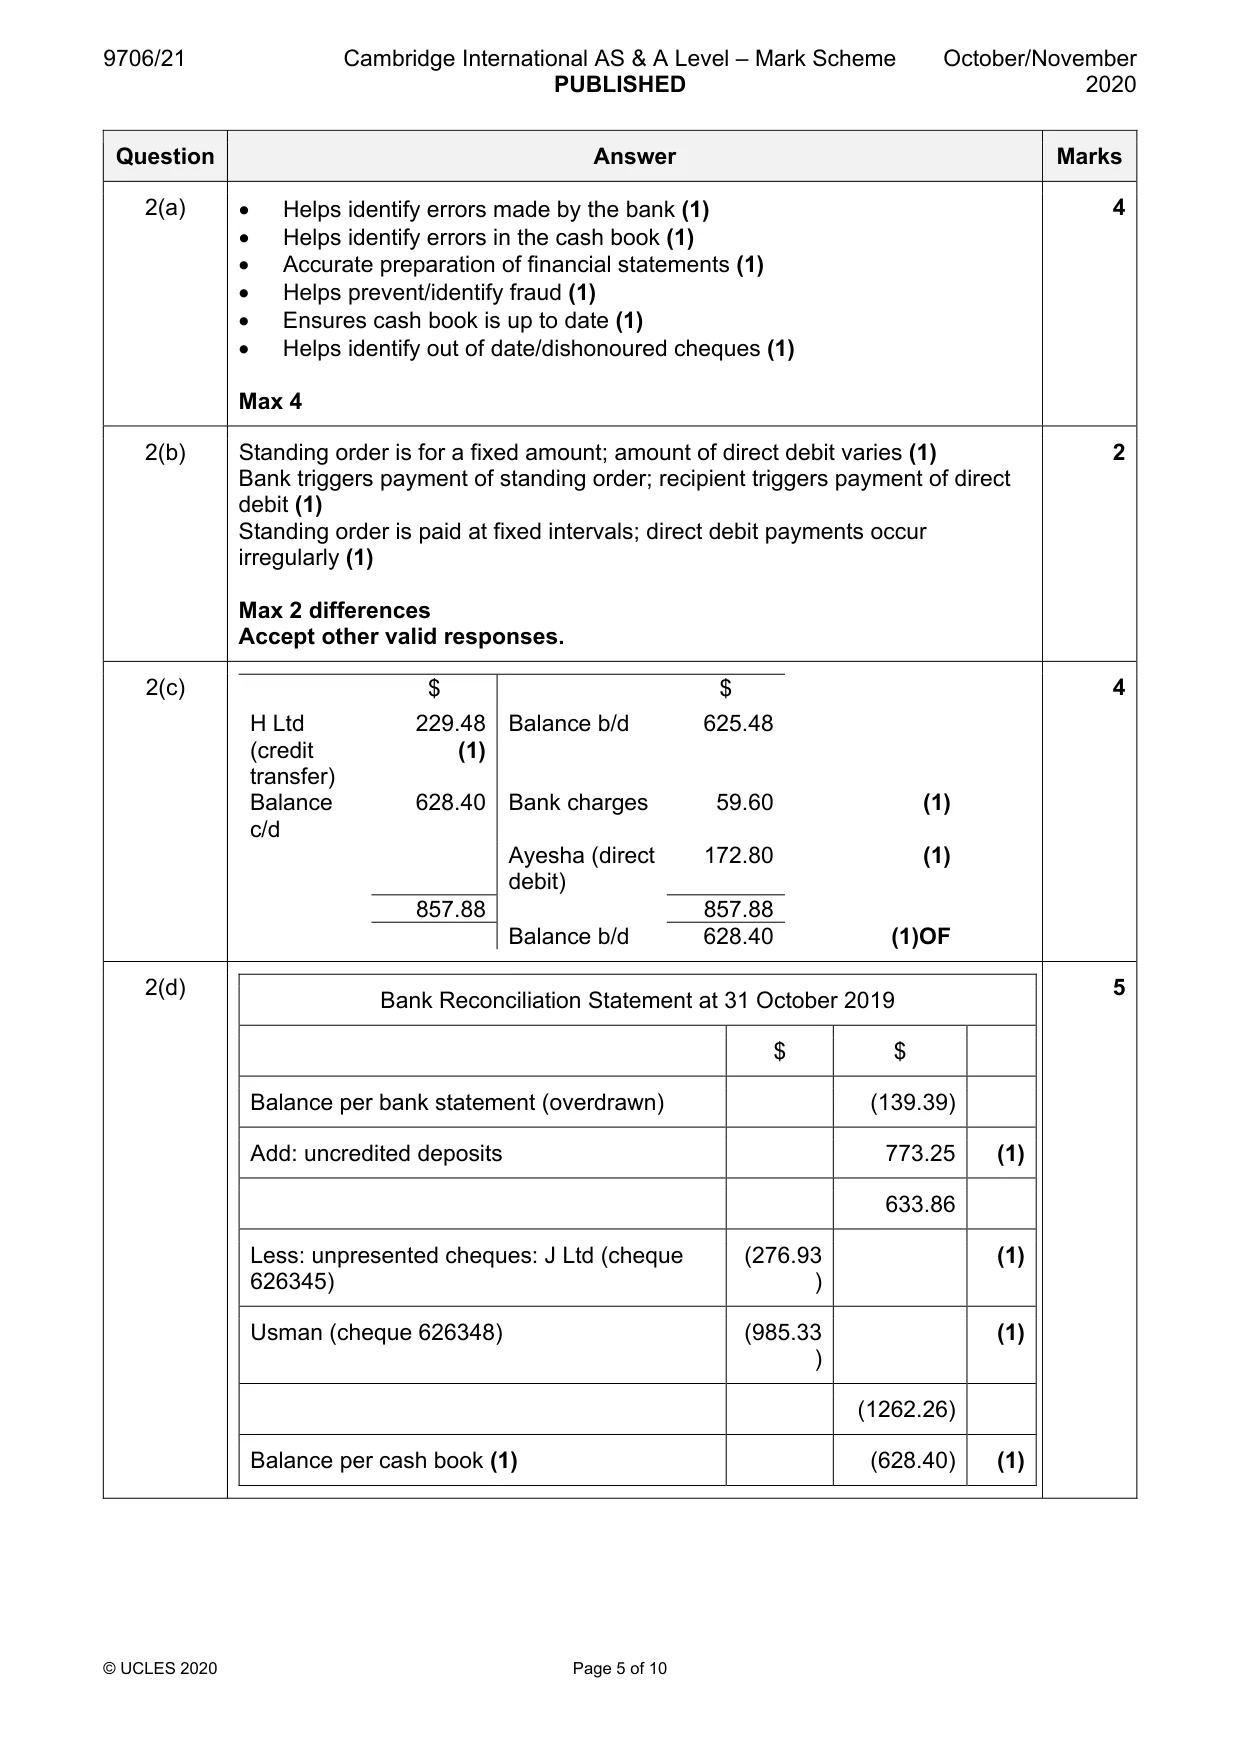
Mark scheme: 2(a) • Helps identify errors made by the bank (1) 4 • Helps identify errors in the cash book (1) • Accurate preparation of financial statements (1) • Helps prevent/identify fraud (1) • Ensures cash book is up to date (1) • Helps identify out of date/dishonoured cheques (1) Max 4 2(b) Standing order is for a fixed amount; amount of direct debit varies (1) 2 Bank triggers payment of standing order; recipient triggers payment of direct debit (1) Standing order is paid at fixed intervals; direct debit payments occur irregularly (1) Max 2 differences Accept other valid responses. 2(c) $ $ 4 H Ltd 229.48 Balance b/d 625.48 (credit (1) transfer) Balance 628.40 Bank charges 59.60 (1) c/d Ayesha (direct 172.80 (1) debit) 857.88 857.88 Balance b/d 628.40 (1)OF 2(d) 5 Bank Reconciliation Statement at 31 October 2019 $ $ Balance per bank statement (overdrawn) (139.39) Add: uncredited deposits 773.25 (1) 633.86 Less: unpresented cheques: J Ltd (cheque (276.93 (1) 626345) ) Usman (cheque 626348) (985.33 (1) ) (1262.26) Balance per cash book (1) (628.40) (1)
Q3 · M Limited was formed five years ago
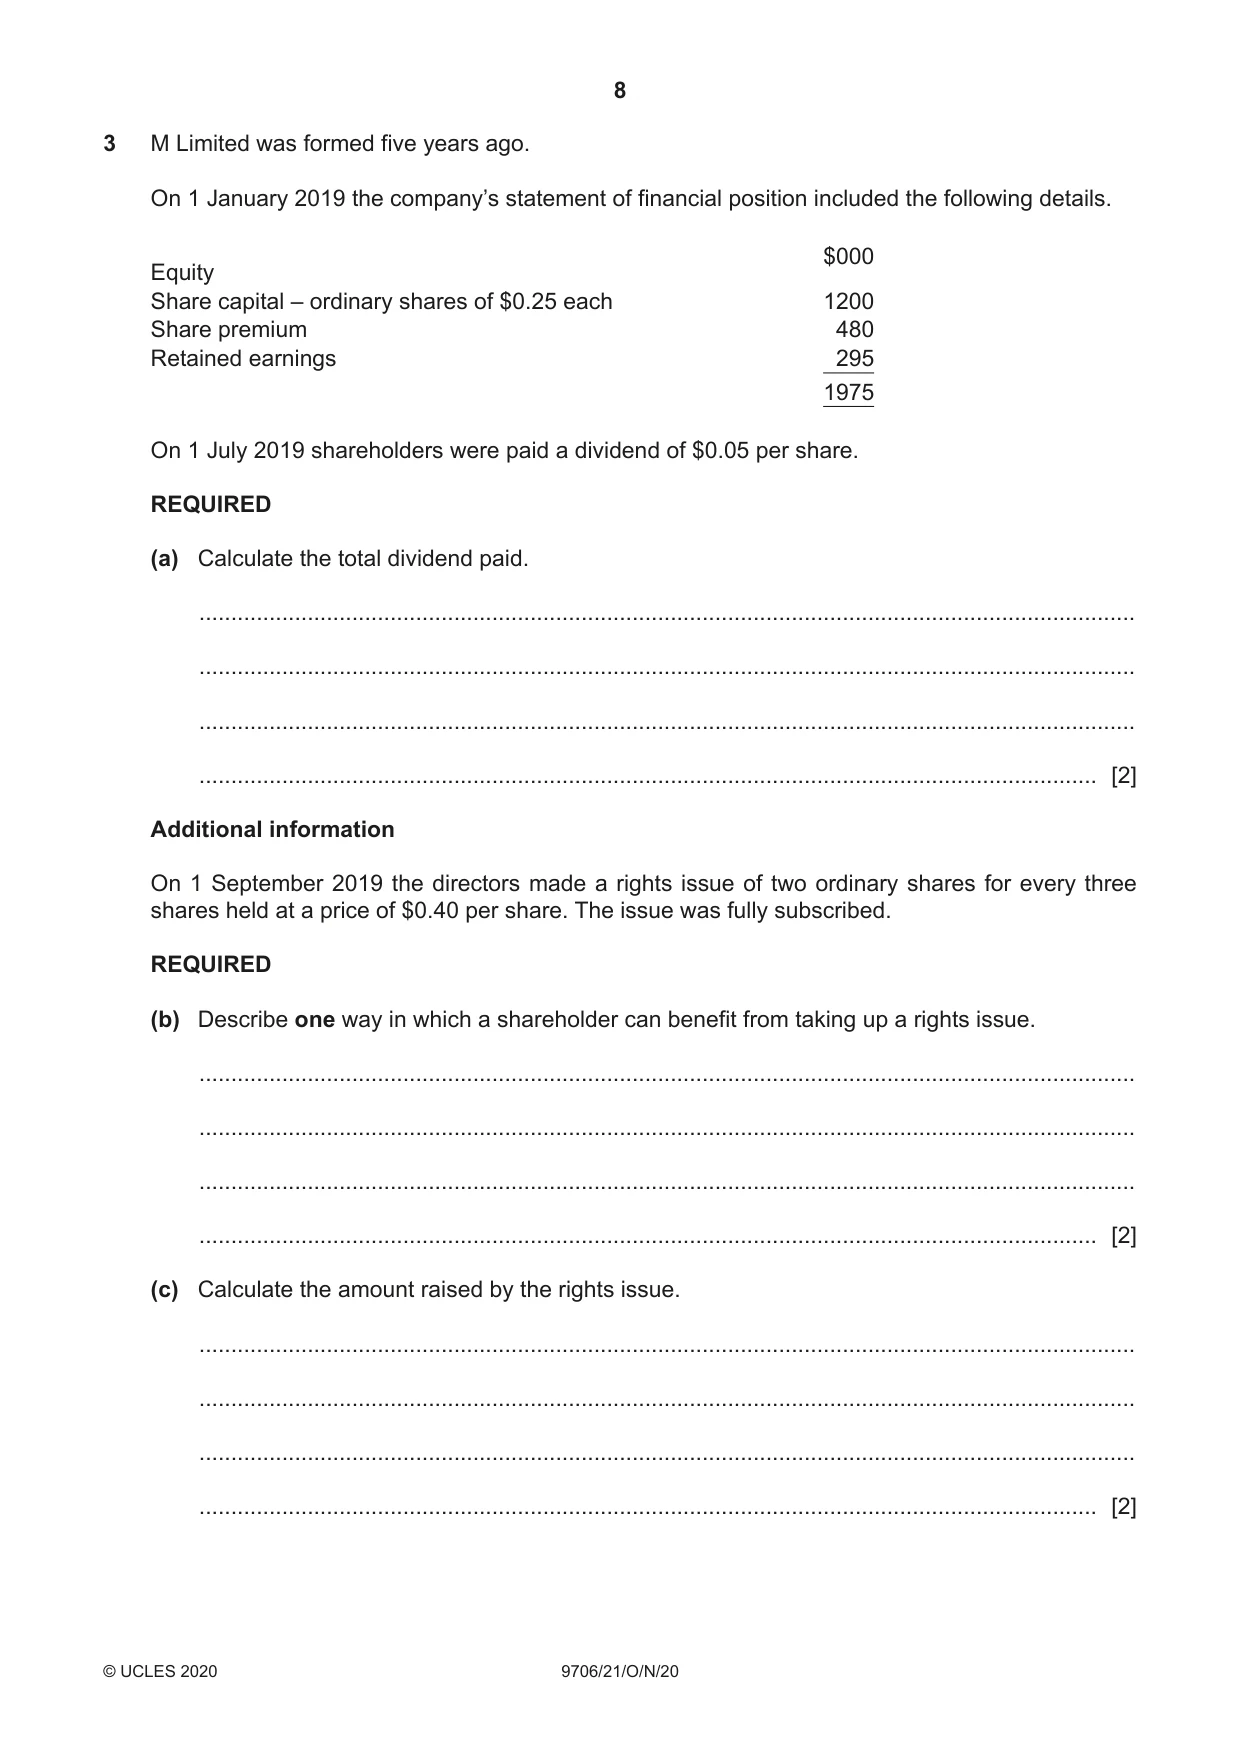
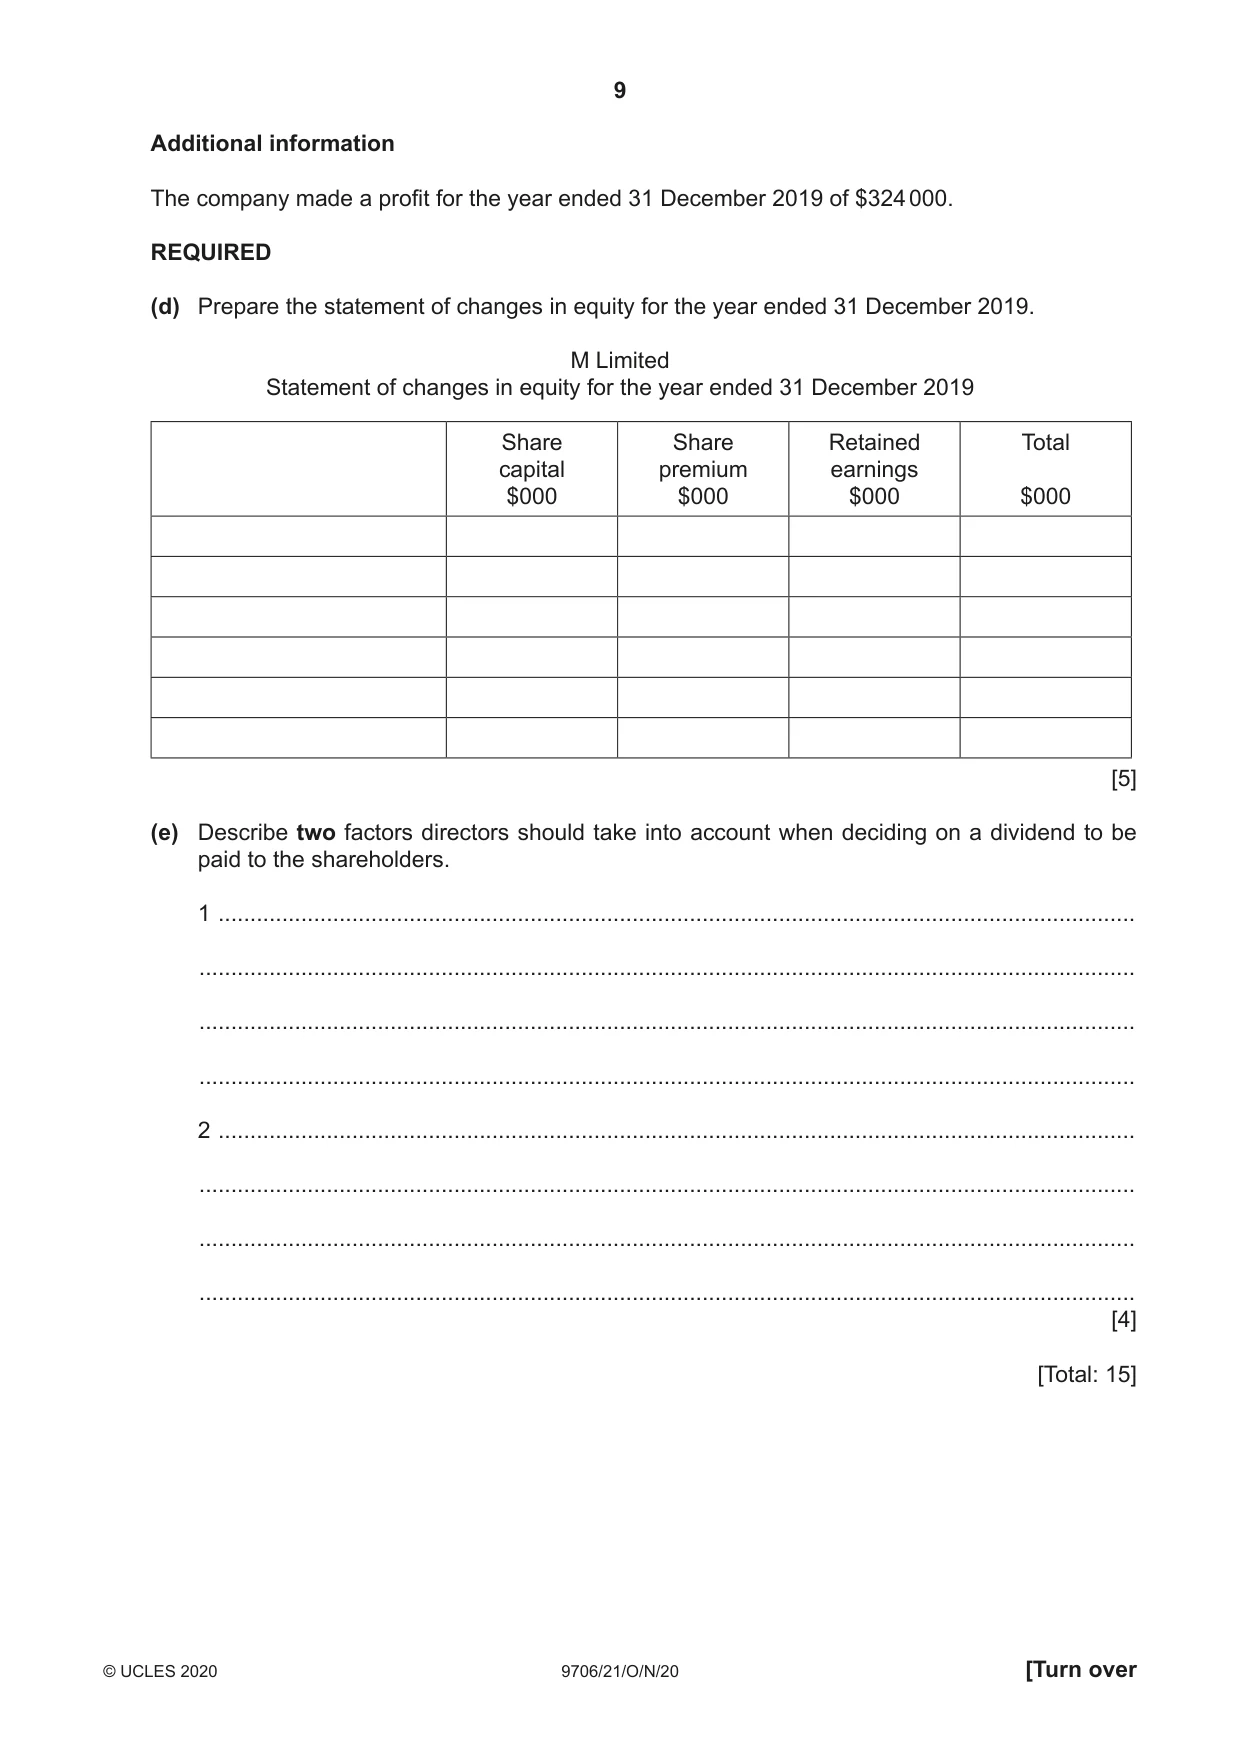
3 M Limited was formed five years ago. On 1 January 2019 the company’s statement of financial position included the following details. $000 Equity Share capital – ordinary shares of $0.25 each 1200 Share premium 480 Retained earnings 295 1975 On 1 July 2019 shareholders were paid a dividend of $0.05 per share. REQUIRED (a) Calculate the total dividend paid. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] Additional information On 1 September 2019 the directors made a rights issue of two ordinary shares for every three shares held at a price of $0.40 per share. The issue was fully subscribed. REQUIRED (b) Describe one way in which a shareholder can benefit from taking up a rights issue. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] (c) Calculate the amount raised by the rights issue. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] Additional information The company made a profit for the year ended 31 December 2019 of $324 000. REQUIRED (d) Prepare the statement of changes in equity for the year ended 31 December 2019. M Limited Statement of changes in equity for the year ended 31 December 2019 Share Share Retained Total capital premium earnings $000 $000 $000 $000 [5] (e) Describe two factors directors should take into account when deciding on a dividend to be paid to the shareholders. 1 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... [4] [Total: 15]
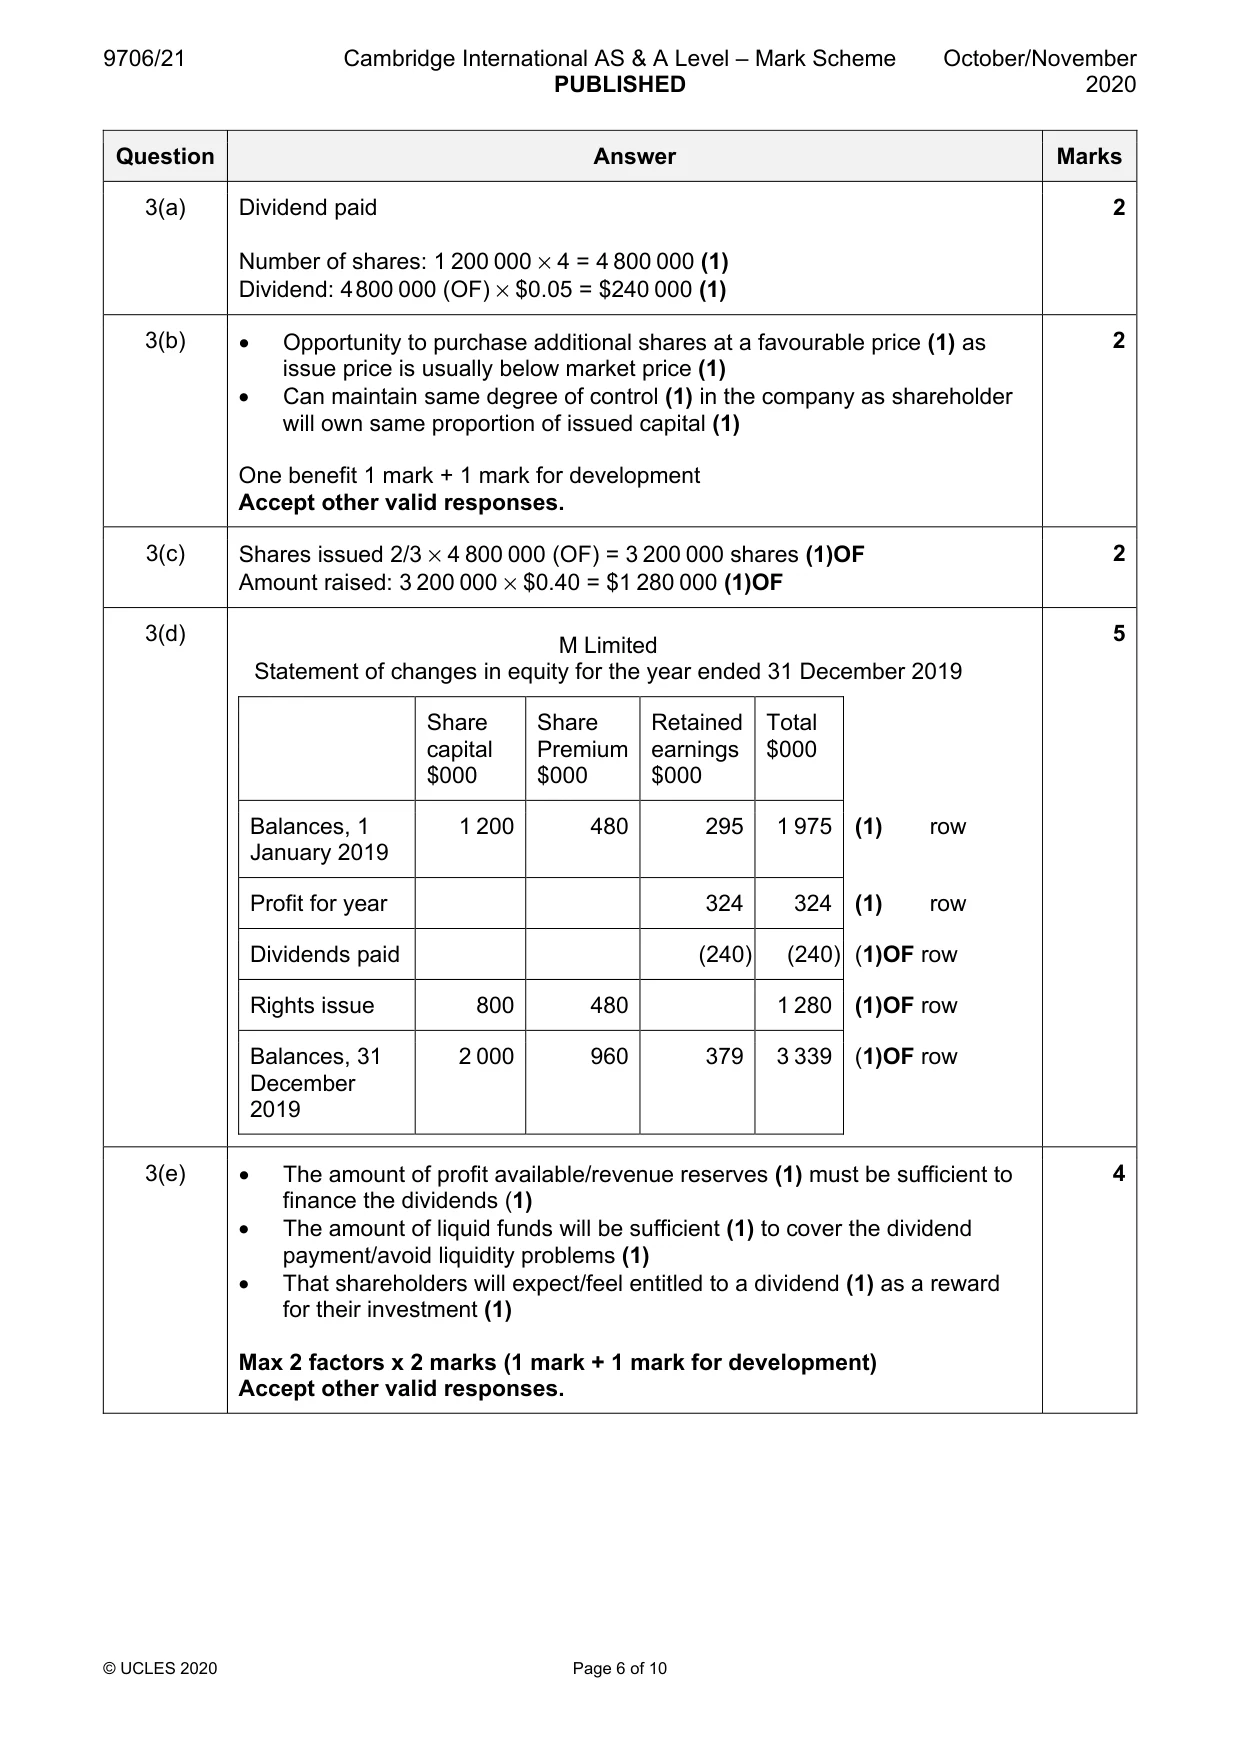
Mark scheme: 3(a) Dividend paid 2 Number of shares: 1 200 000 × 4 = 4 800 000 (1) Dividend: 4 800 000 (OF) × $0.05 = $240 000 (1) 3(b) • Opportunity to purchase additional shares at a favourable price (1) as 2 issue price is usually below market price (1) • Can maintain same degree of control (1) in the company as shareholder will own same proportion of issued capital (1) One benefit 1 mark + 1 mark for development Accept other valid responses. 3(c) Shares issued 2/3 × 4 800 000 (OF) = 3 200 000 shares (1)OF 2 Amount raised: 3 200 000 × $0.40 = $1 280 000 (1)OF 3(d) 5 M Limited Statement of changes in equity for the year ended 31 December 2019 Share Share Retained Total capital Premium earnings $000 $000 $000 $000 Balances, 1 1 200 480 295 1 975 (1) row January 2019 Profit for year 324 324 (1) row Dividends paid (240) (240) (1)OF row Rights issue 800 480 1 280 (1)OF row Balances, 31 2 000 960 379 3 339 (1)OF row December 2019 3(e) • The amount of profit available/revenue reserves (1) must be sufficient to 4 finance the dividends (1) • The amount of liquid funds will be sufficient (1) to cover the dividend payment/avoid liquidity problems (1) • That shareholders will expect/feel entitled to a dividend (1) as a reward for their investment (1) Max 2 factors x 2 marks (1 mark + 1 mark for development) Accept other valid responses.
Q4 · Y Limited is a furniture manufacturer
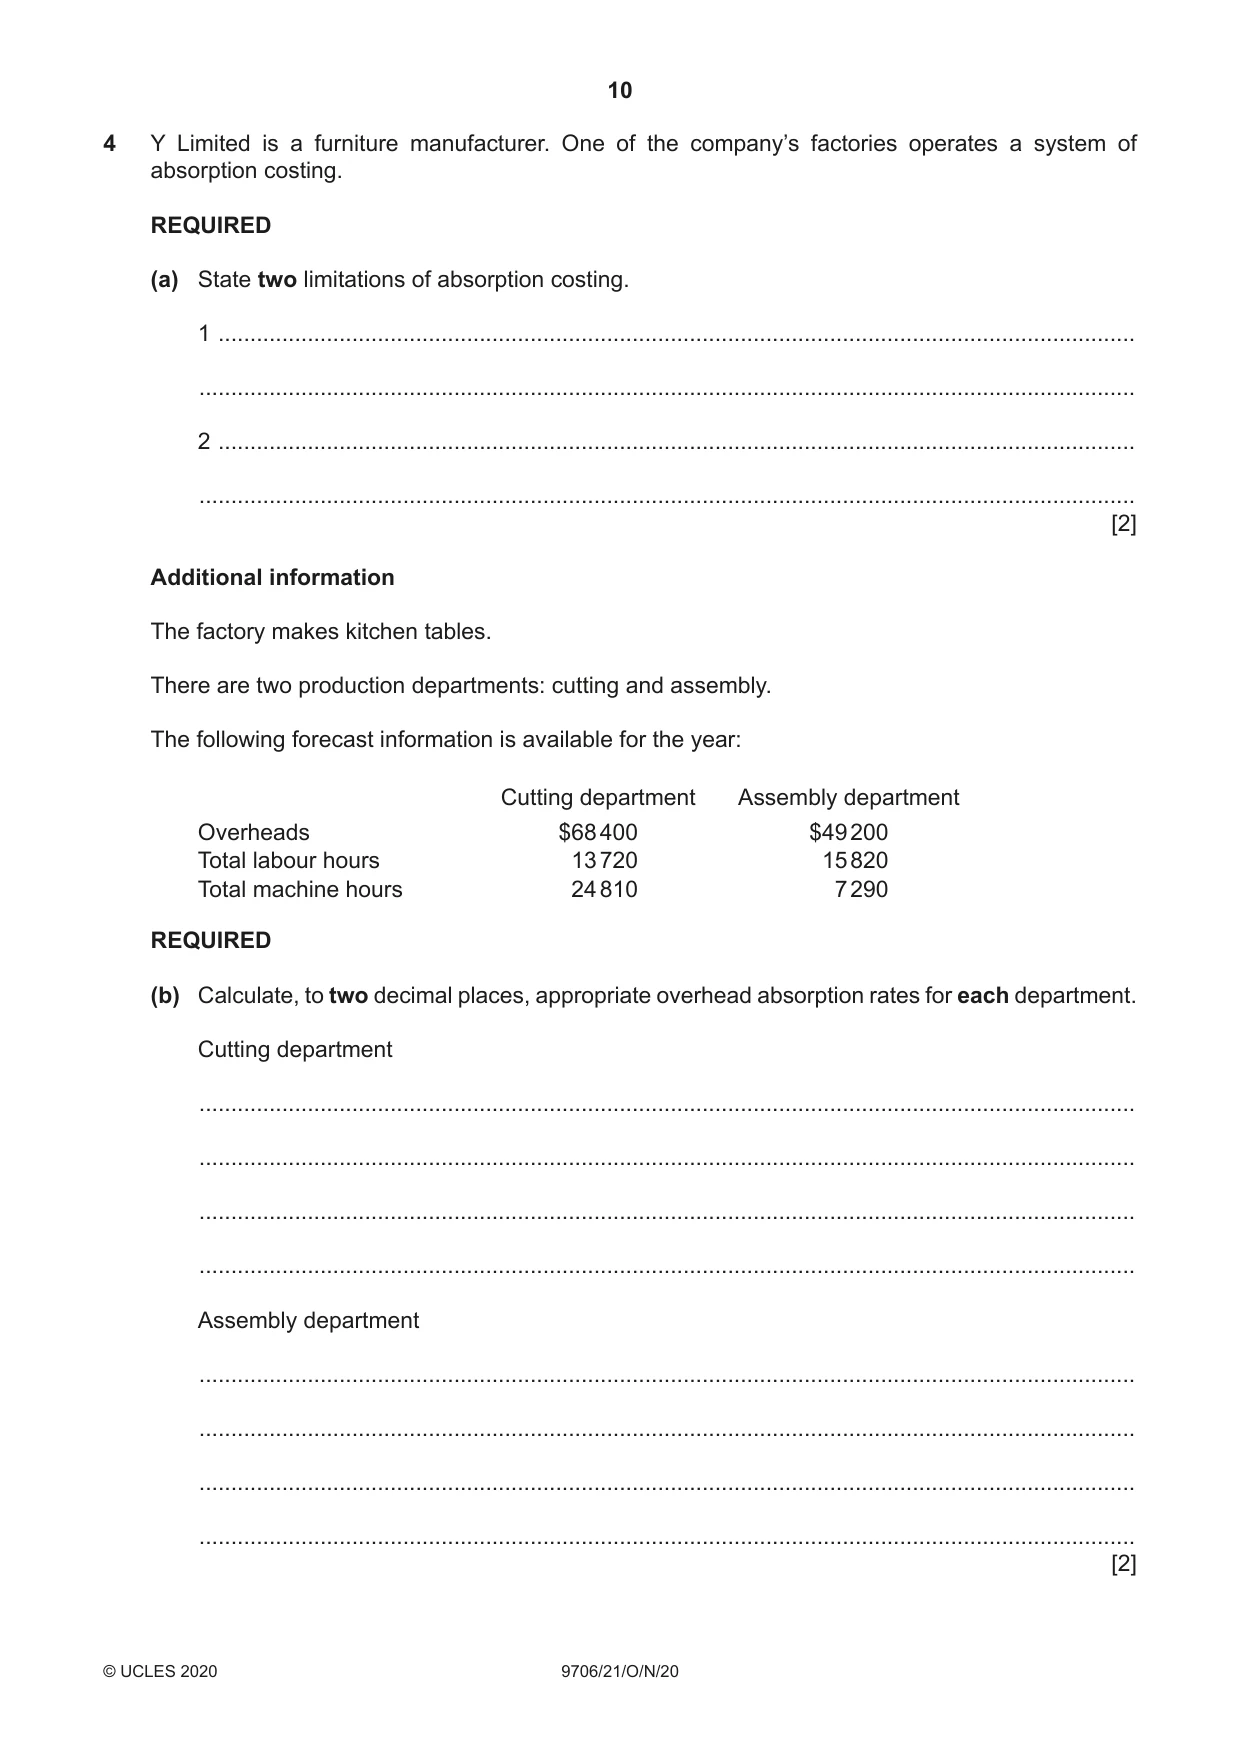
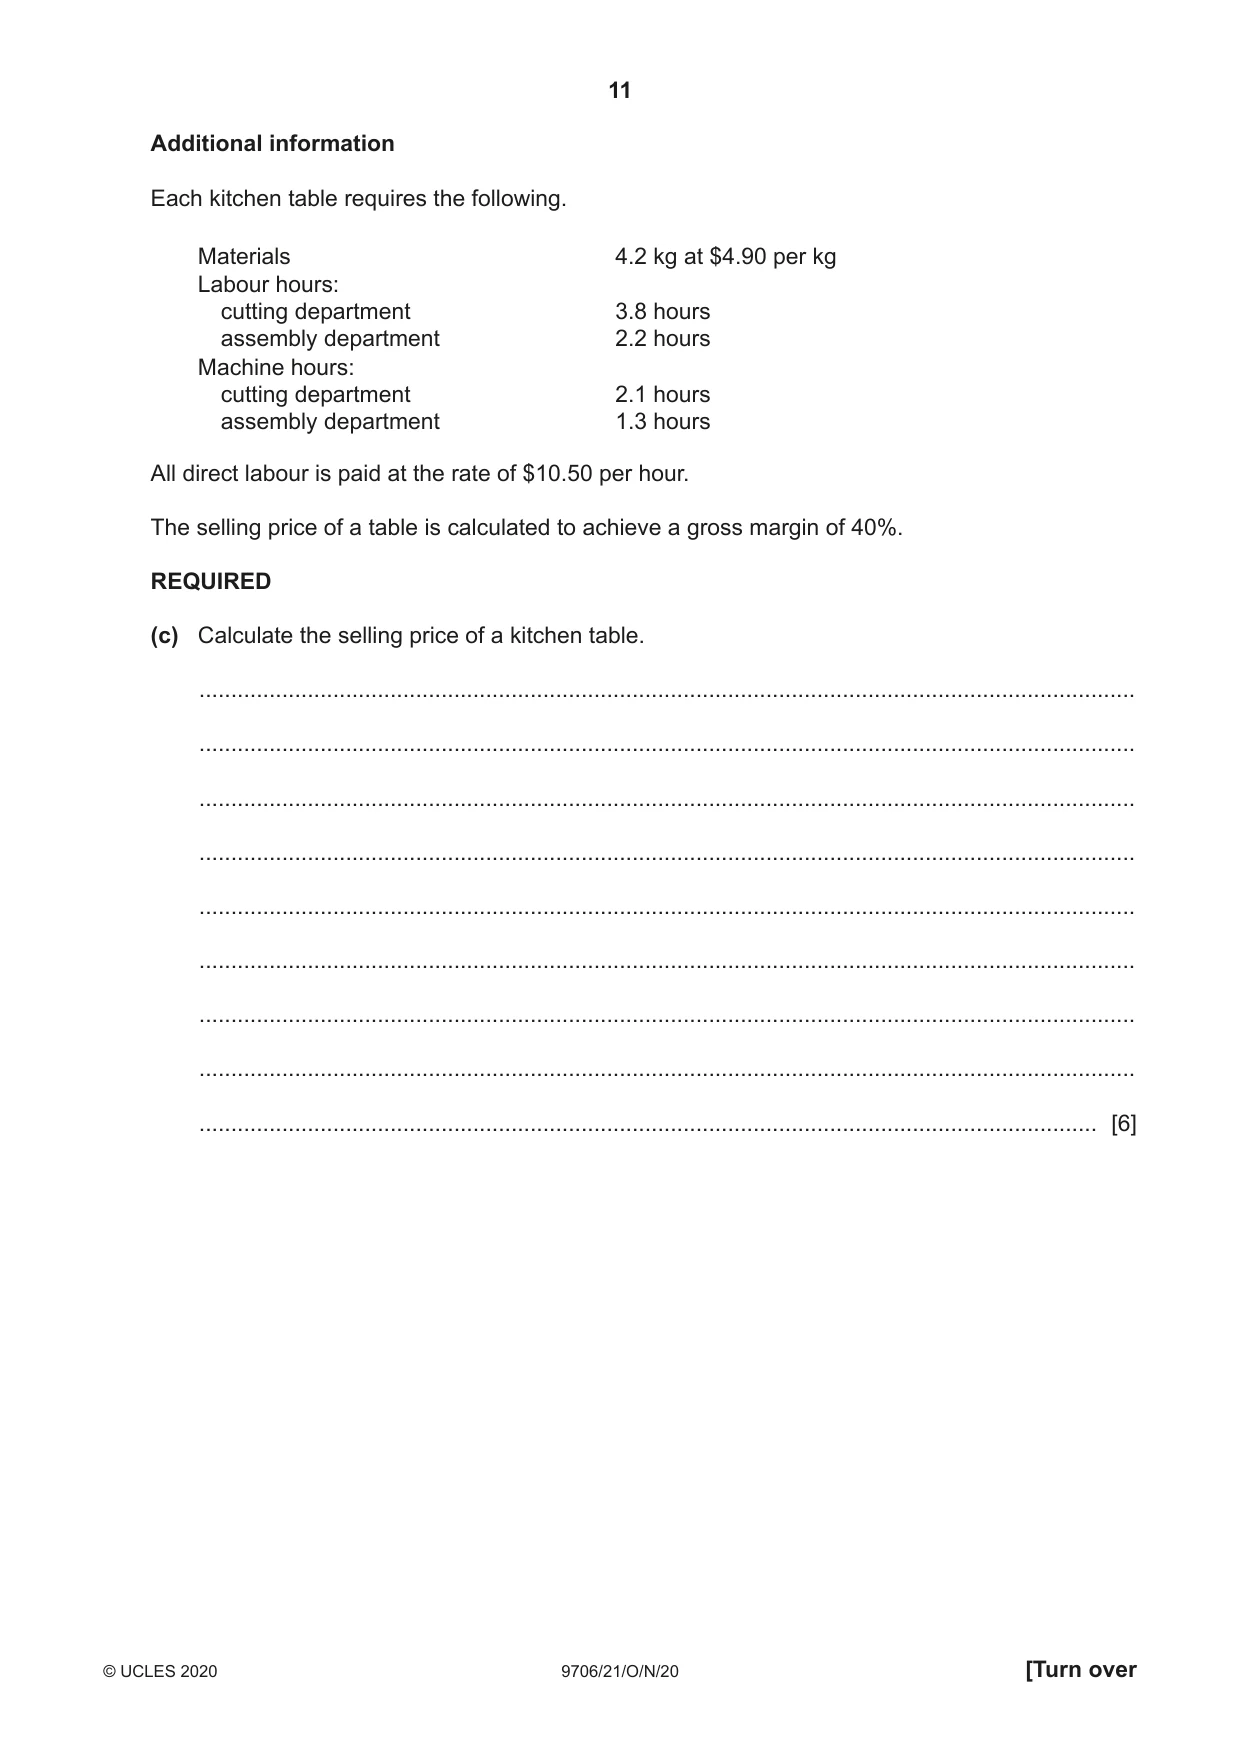
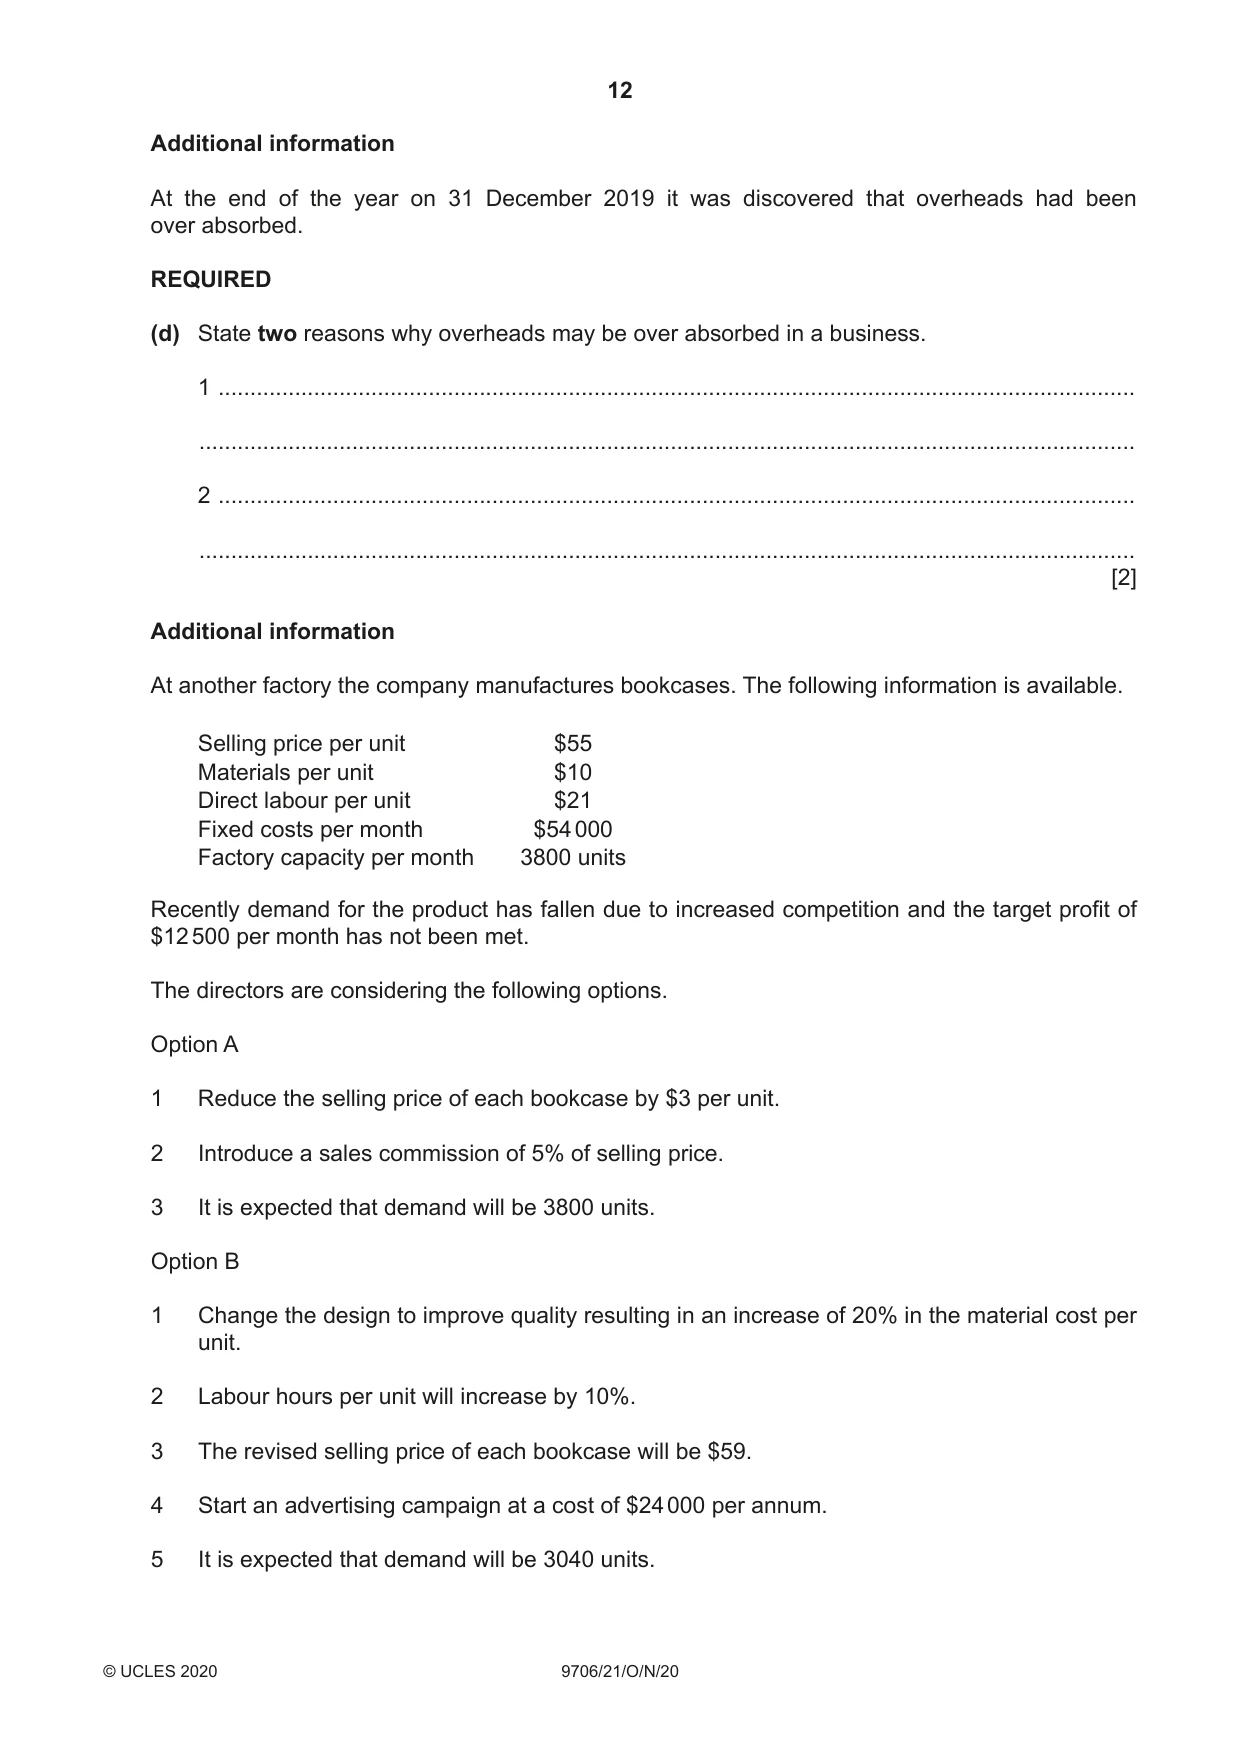
4 Y Limited is a furniture manufacturer. One of the company’s factories operates a system of absorption costing. REQUIRED (a) State two limitations of absorption costing. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] Additional information The factory makes kitchen tables. There are two production departments: cutting and assembly. The following forecast information is available for the year: Cutting department Assembly department Overheads $68 400 $49 200 Total labour hours 13 720 15 820 Total machine hours 24 810 7 290 REQUIRED (b) Calculate, to two decimal places, appropriate overhead absorption rates for each department. Cutting department ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... Assembly department ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... [2] Additional information Each kitchen table requires the following. Materials 4.2 kg at $4.90 per kg Labour hours: cutting department 3.8 hours assembly department 2.2 hours Machine hours: cutting department 2.1 hours assembly department 1.3 hours All direct labour is paid at the rate of $10.50 per hour. The selling price of a table is calculated to achieve a gross margin of 40%. REQUIRED (c) Calculate the selling price of a kitchen table. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [6] Additional information At the end of the year on 31 December 2019 it was discovered that overheads had been over absorbed. REQUIRED (d) State two reasons why overheads may be over absorbed in a business. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] Additional information At another factory the company manufactures bookcases. The following information is available. Selling price per unit $55 Materials per unit $10 Direct labour per unit $21 Fixed costs per month $54 000 Factory capacity per month 3800 units Recently demand for the product has fallen due to increased competition and the target profit of $12 500 per month has not been met. The directors are considering the following options. Option A 1 Reduce the selling price of each bookcase by $3 per unit. 2 Introduce a sales commission of 5% of selling price. 3 It is expected that demand will be 3800 units. Option B 1 Change the design to improve quality resulting in an increase of 20% in the material cost per unit. 2 Labour hours per unit will increase by 10%. 3 The revised selling price of each bookcase will be $59. 4 Start an advertising campaign at a cost of $24 000 per annum.
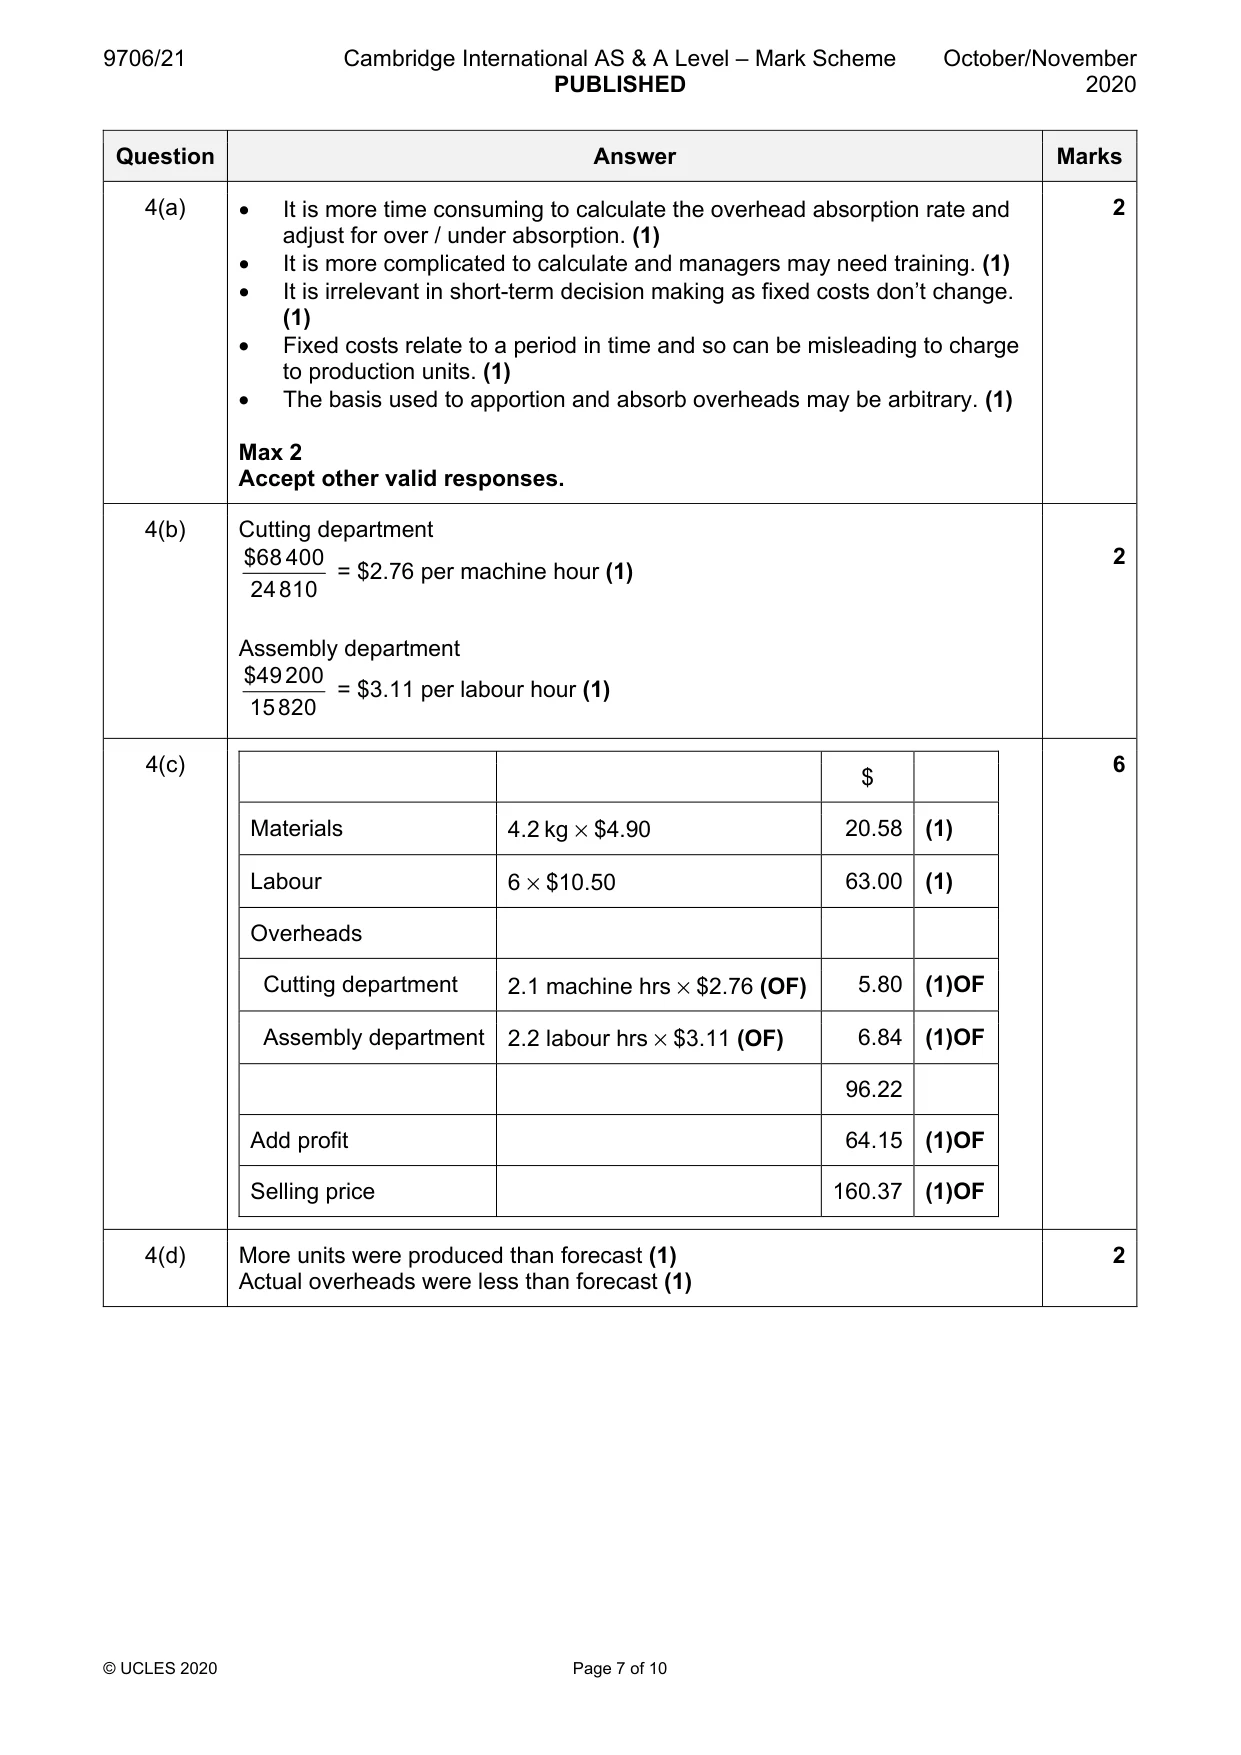
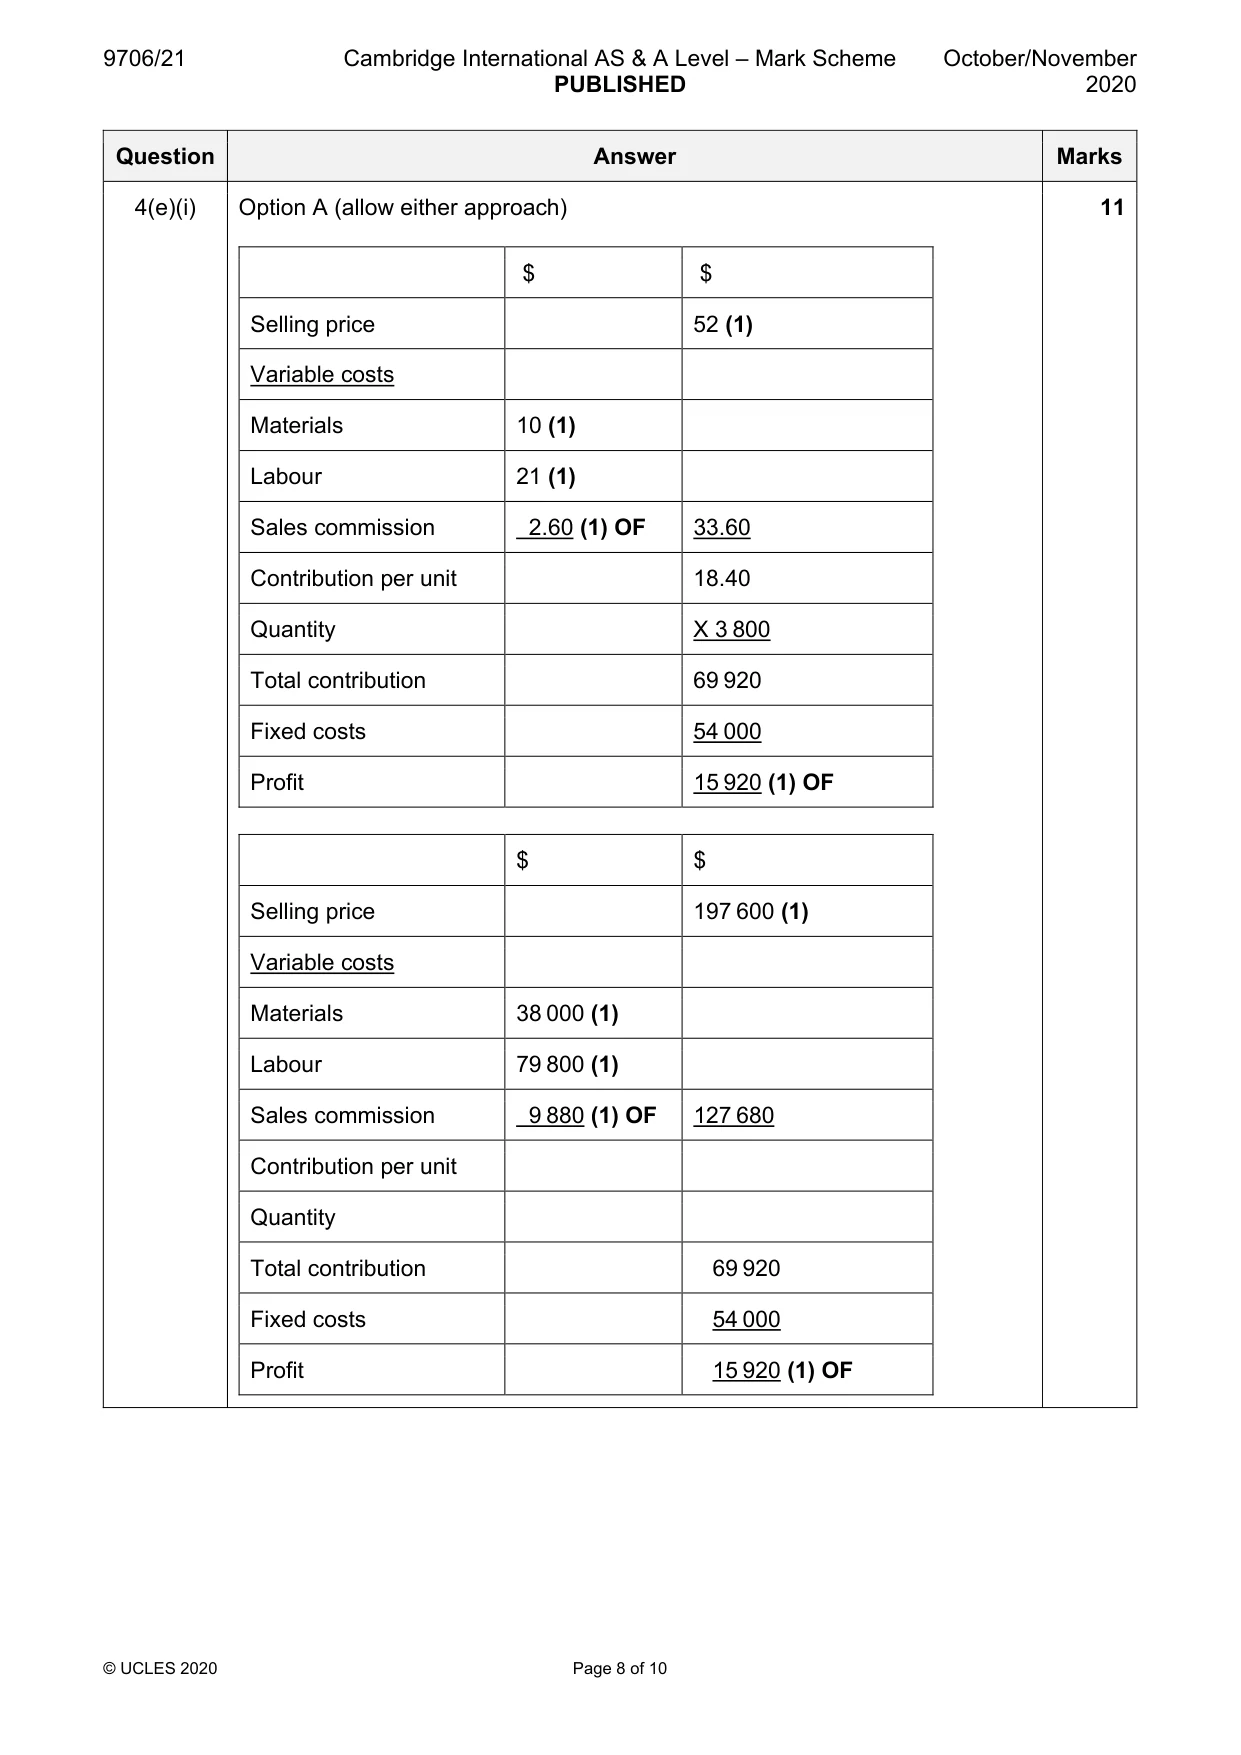
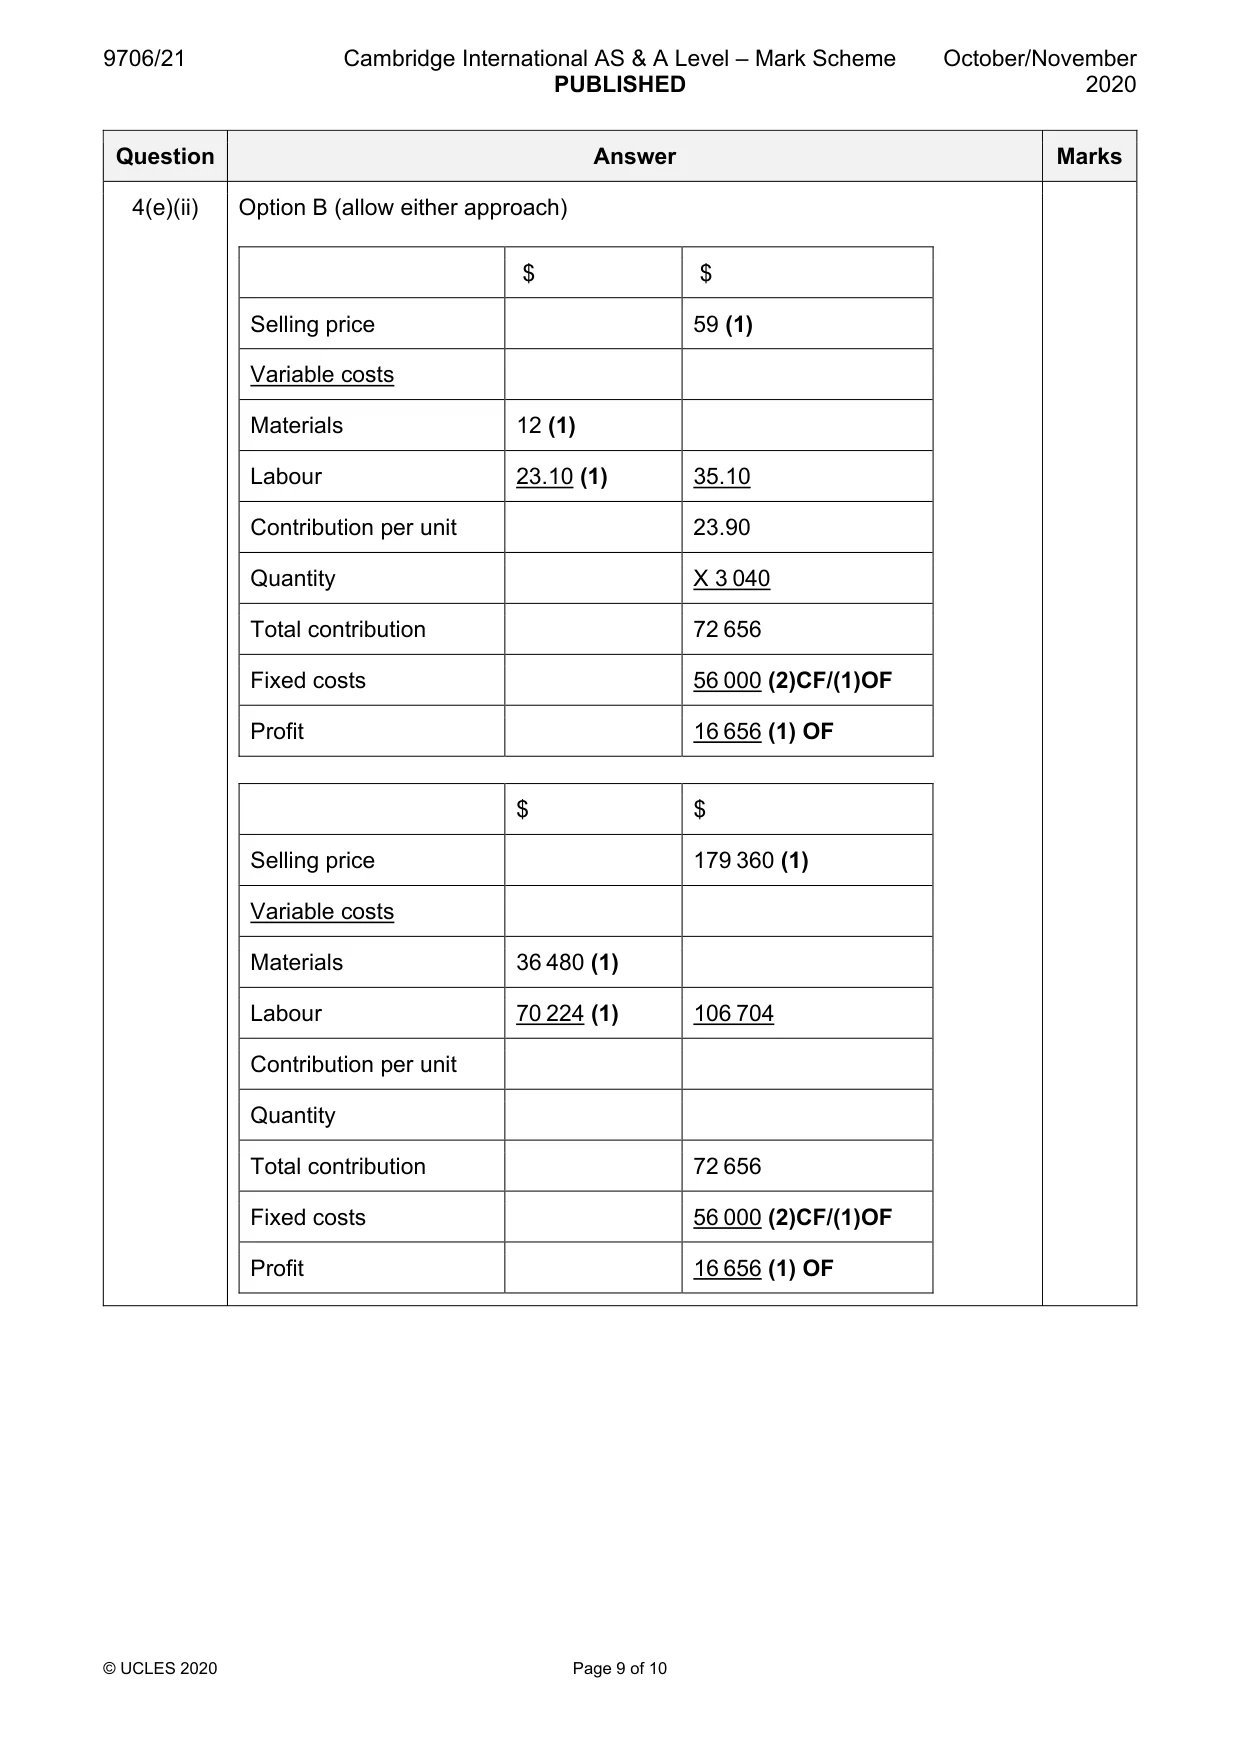
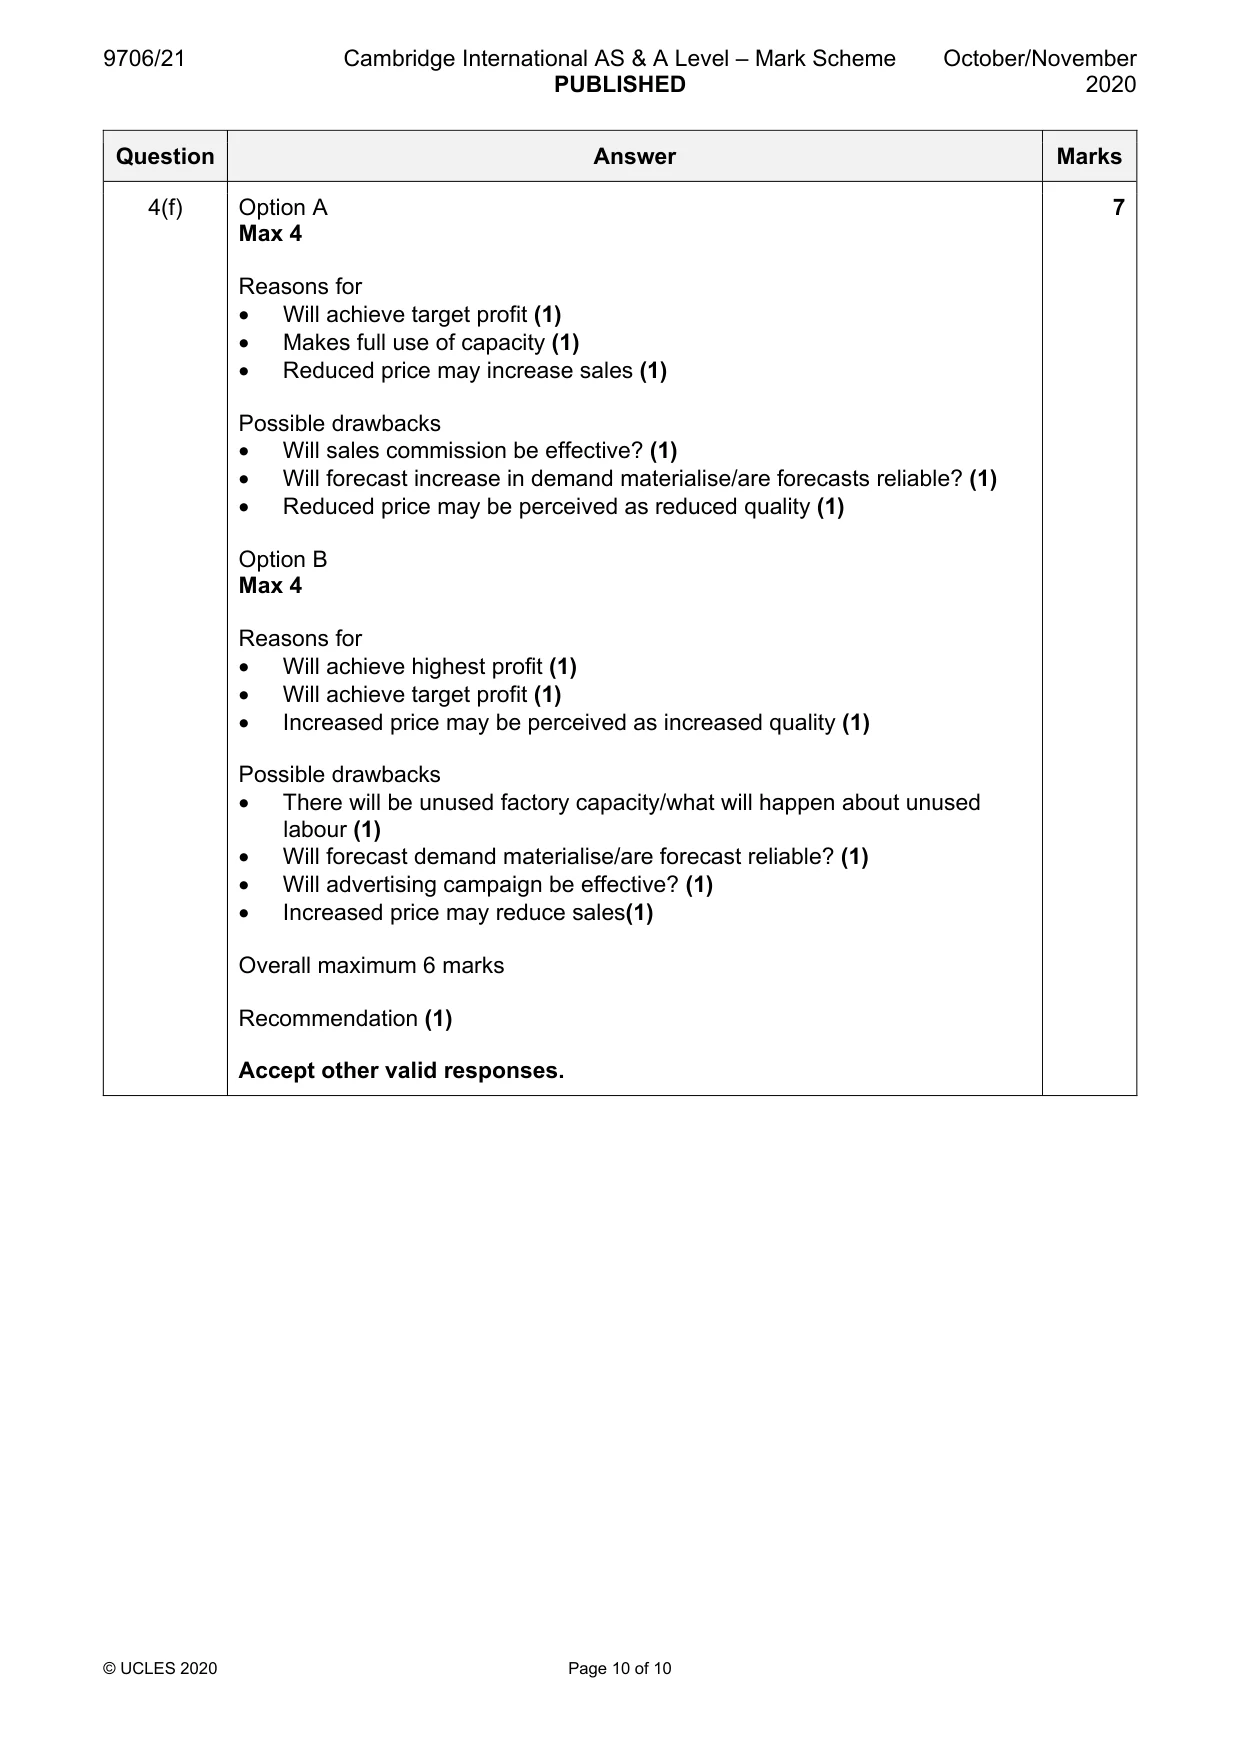
Mark scheme: 4(a) • It is more time consuming to calculate the overhead absorption rate and 2 adjust for over / under absorption. (1) • It is more complicated to calculate and managers may need training. (1) • It is irrelevant in short-term decision making as fixed costs don’t change. (1) • Fixed costs relate to a period in time and so can be misleading to charge to production units. (1) • The basis used to apportion and absorb overheads may be arbitrary. (1) Max 2 Accept other valid responses. 4(b) Cutting department $68 400 2 = $2.76 per machine hour (1) 24810 Assembly department $49200 = $3.11 per labour hour (1) 15820 4(c) 6 $ Materials 4.2 kg × $4.90 20.58 (1) Labour 6 × $10.50 63.00 (1) Overheads Cutting department 2.1 machine hrs × $2.76 (OF) 5.80 (1)OF Assembly department 2.2 labour hrs × $3.11 (OF) 6.84 (1)OF 96.22 Add profit 64.15 (1)OF Selling price 160.37 (1)OF 4(d) More units were produced than forecast (1) 2 Actual overheads were less than forecast (1) 4(e)(i) Option A (allow either approach) 11 $ $ Selling price 52 (1) Variable costs Materials 10 (1) Labour 21 (1) Sales commission 2.60 (1) OF 33.60 Contribution per unit 18.40 Quantity X 3 800 Total contribution 69 920 Fixed costs 54 000 Profit 15 920 (1) OF $ $ Selling price 197 600 (1) Variable costs Materials 38 000 (1) Labour 79 800 (1) Sales commission 9 880 (1) OF 127 680 Contribution per unit Quantity Total contribution 69 920 Fixed costs 54 000 Profit 15 920 (1) OF 4(e)(ii) Option B (allow either approach) $ $ Selling price 59 (1) Variable costs Materials 12 (1) Labour 23.10 (1) 35.10 Contribution per unit 23.90 Quantity X 3 040 Total contribution 72 656 Fixed costs 56 000 (2)CF/(1)OF Profit 16 656 (1) OF $ $ Selling price 179 360 (1) Variable costs Materials 36 480 (1) Labour 70 224 (1) 106 704 Contribution per unit Quantity Total contribution 72 656 Fixed costs 56 000 (2)CF/(1)OF Profit 16 656 (1) OF 4(f) Option A 7 Max 4 Reasons for • Will achieve target profit (1) • Makes full use of capacity (1) • Reduced price may increase sales (1) Possible drawbacks • Will sales commission be effective? (1) • Will forecast increase in demand materialise/are forecasts reliable? (1) • Reduced price may be perceived as reduced quality (1) Option B Max 4 Reasons for • Will achieve highest profit (1) • Will achieve target profit (1) • Increased price may be perceived as increased quality (1) Possible drawbacks • There will be unused factory capacity/what will happen about unused labour (1) • Will forecast demand materialise/are forecast reliable? (1) • Will advertising campaign be effective? (1) • Increased price may reduce sales(1) Overall maximum 6 marks Recommendation (1) Accept other valid responses.
Q5 · REQUIRED (e) Calculate the forecast profit per month for: (i) Option A…
REQUIRED (e) Calculate the forecast profit per month for: (i) Option A ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... (ii) Option B ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... [11] (f) Recommend which option the directors should choose. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [7] [Total: 30]
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2020 Oct/Nov, Paper 2 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.