Cambridge A Level Accounting 9706 — 2015 Oct/Nov Paper 4 · Variant 3
9706/43/O/N/15 · 120 marks · ≈135 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper8 pages
Mark scheme
No mark scheme is in the library for this paper.
Paper as text
Question paper, page 1
This document consists of 6 printed pages, 2 blank pages and 1 insert. IB15 11_9706_43/6RP © UCLES 2015 [Turn over *7711591124* Cambridge International Examinations Cambridge International Advanced Subsidiary and Advanced Level ACCOUNTING 9706/43 Paper 4 Problem Solving (Supplementary Topics) October/November 2015 2 hours No Additional Materials are required. READ THESE INSTRUCTIONS FIRST An answer booklet is provided inside this question paper. You should follow the instructions on the front cover of the answer booklet. If you need additional answer paper ask the invigilator for a continuation booklet. Answer all questions. All accounting statements are to be presented in good style. International accounting terms and formats should be used as appropriate. Workings should be shown. You may use a calculator. The number of marks is given in brackets [ ] at the end of each question or part question.
Question paper, page 2
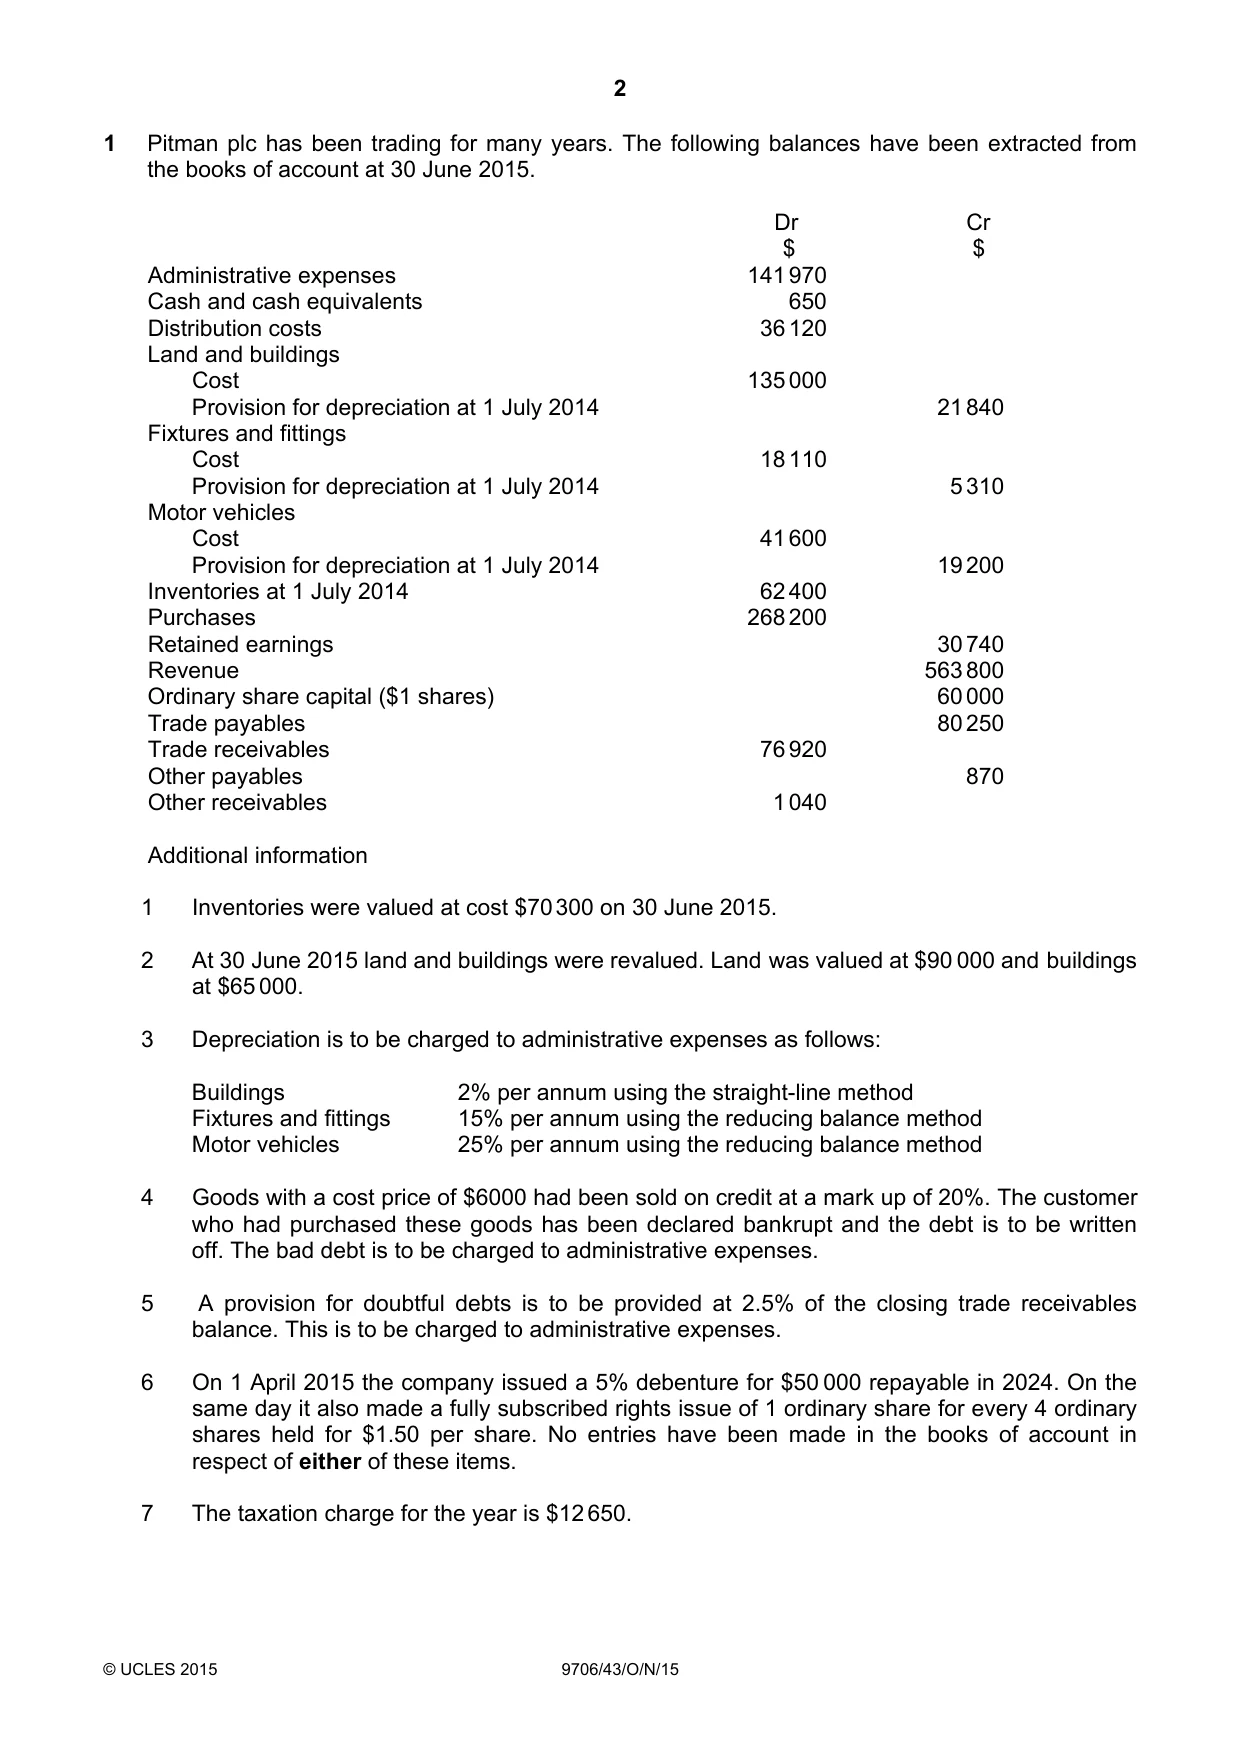
2 © UCLES 2015 9706/43/O/N/15 1 Pitman plc has been trading for many years. The following balances have been extracted from the books of account at 30 June 2015. Dr Cr $ $ Administrative expenses 141 970 Cash and cash equivalents 650 Distribution costs 36 120 Land and buildings Cost 135 000 Provision for depreciation at 1 July 2014 21 840 Fixtures and fittings Cost 18 110 Provision for depreciation at 1 July 2014 5 310 Motor vehicles Cost 41 600 Provision for depreciation at 1 July 2014 19 200 Inventories at 1 July 2014 62 400 Purchases 268 200 Retained earnings 30 740 Revenue 563 800 Ordinary share capital ($1 shares) 60 000 Trade payables 80 250 Trade receivables 76 920 Other payables 870 Other receivables 1 040 Additional information 1 Inventories were valued at cost $70 300 on 30 June 2015. 2 At 30 June 2015 land and buildings were revalued. Land was valued at $90 000 and buildings at $65 000. 3 Depreciation is to be charged to administrative expenses as follows: Buildings 2% per annum using the straight-line method Fixtures and fittings 15% per annum using the reducing balance method Motor vehicles 25% per annum using the reducing balance method 4 Goods with a cost price of $6000 had been sold on credit at a mark up of 20%. The customer who had purchased these goods has been declared bankrupt and the debt is to be written off. The bad debt is to be charged to administrative expenses. 5 A provision for doubtful debts is to be provided at 2.5% of the closing trade receivables balance. This is to be charged to administrative expenses. 6 On 1 April 2015 the company issued a 5% debenture for $50 000 repayable in 2024. On the same day it also made a fully subscribed rights issue of 1 ordinary share for every 4 ordinary shares held for $1.50 per share. No entries have been made in the books of account in respect of either of these items. 7 The taxation charge for the year is $12 650.
Question paper, page 3
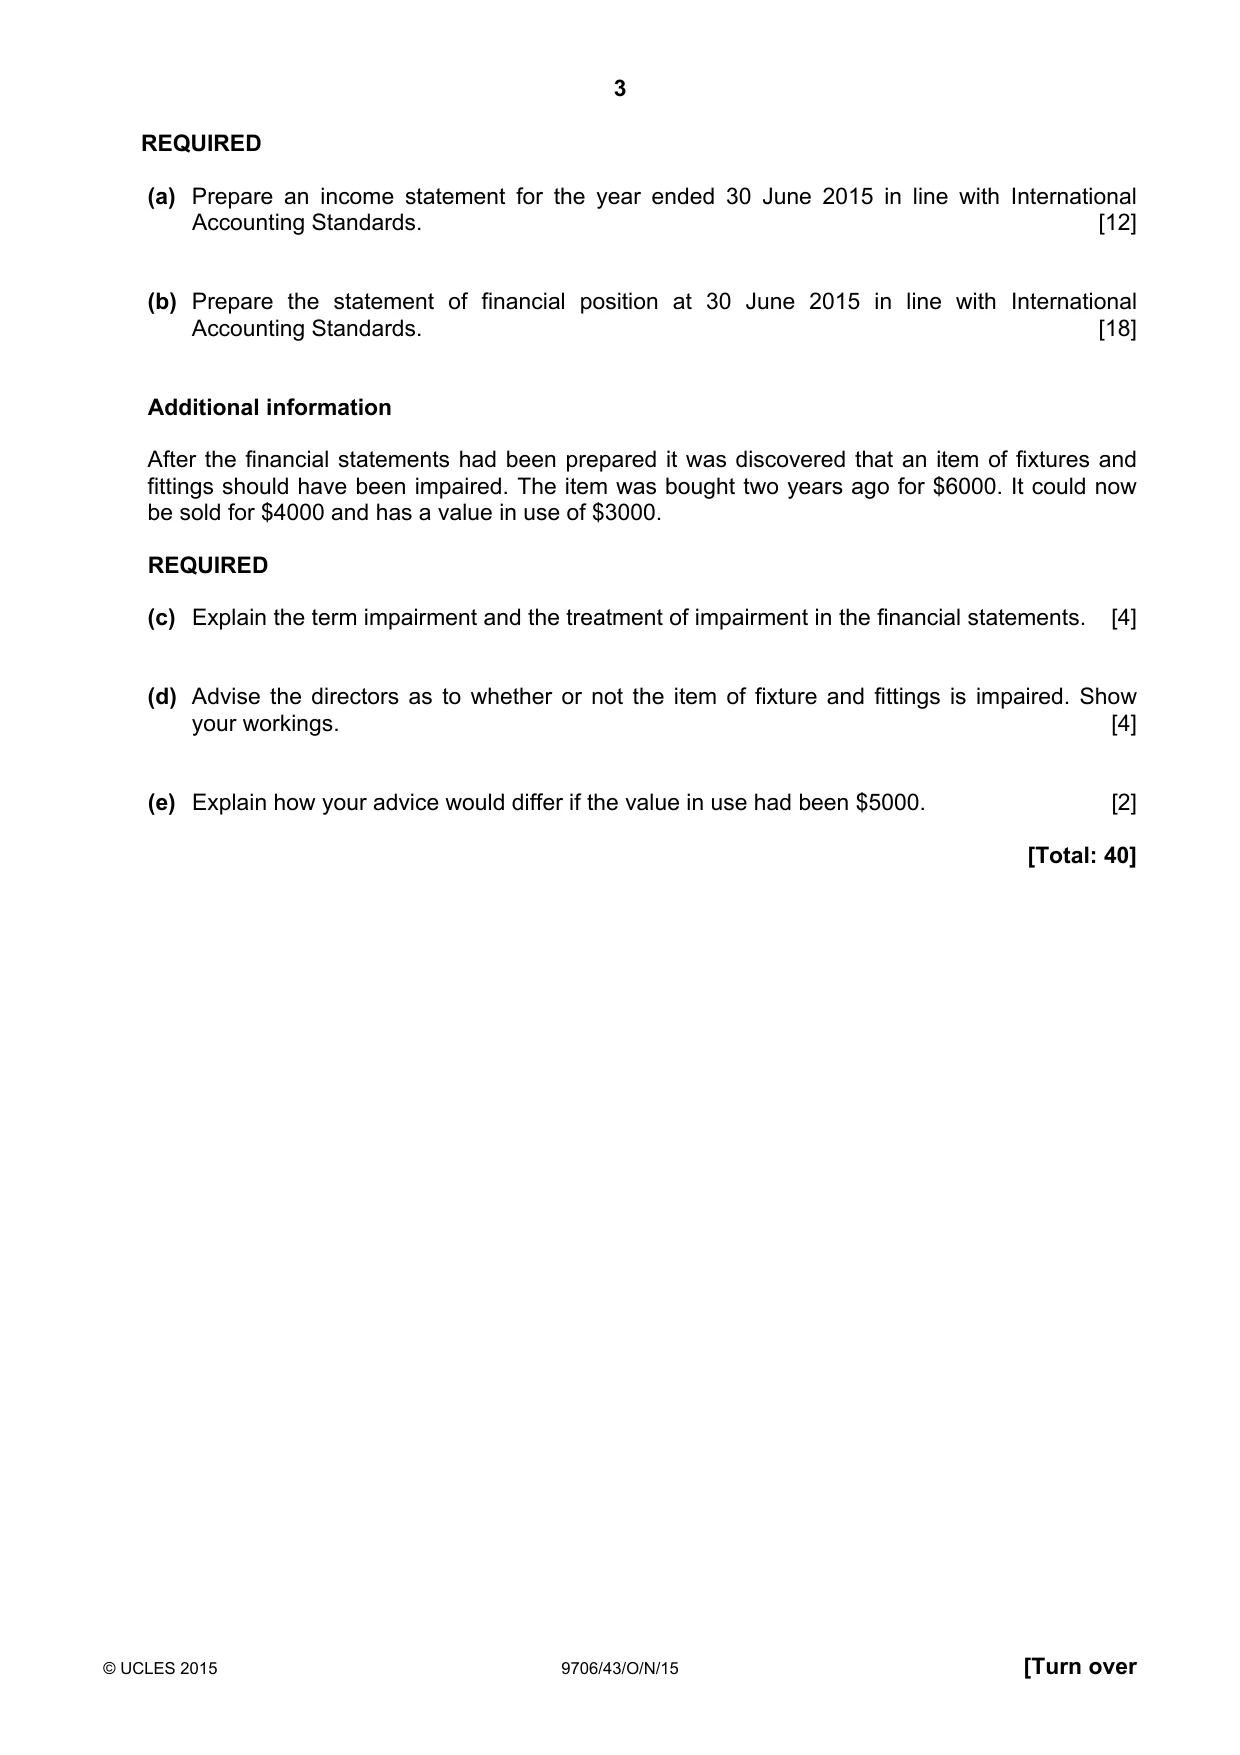
3 © UCLES 2015 9706/43/O/N/15 [Turn over REQUIRED (a) Prepare an income statement for the year ended 30 June 2015 in line with International Accounting Standards. [12] (b) Prepare the statement of financial position at 30 June 2015 in line with International Accounting Standards. [18] Additional information After the financial statements had been prepared it was discovered that an item of fixtures and fittings should have been impaired. The item was bought two years ago for $6000. It could now be sold for $4000 and has a value in use of $3000. REQUIRED (c) Explain the term impairment and the treatment of impairment in the financial statements. [4] (d) Advise the directors as to whether or not the item of fixture and fittings is impaired. Show your workings. [4] (e) Explain how your advice would differ if the value in use had been $5000. [2] [Total: 40]
Question paper, page 4
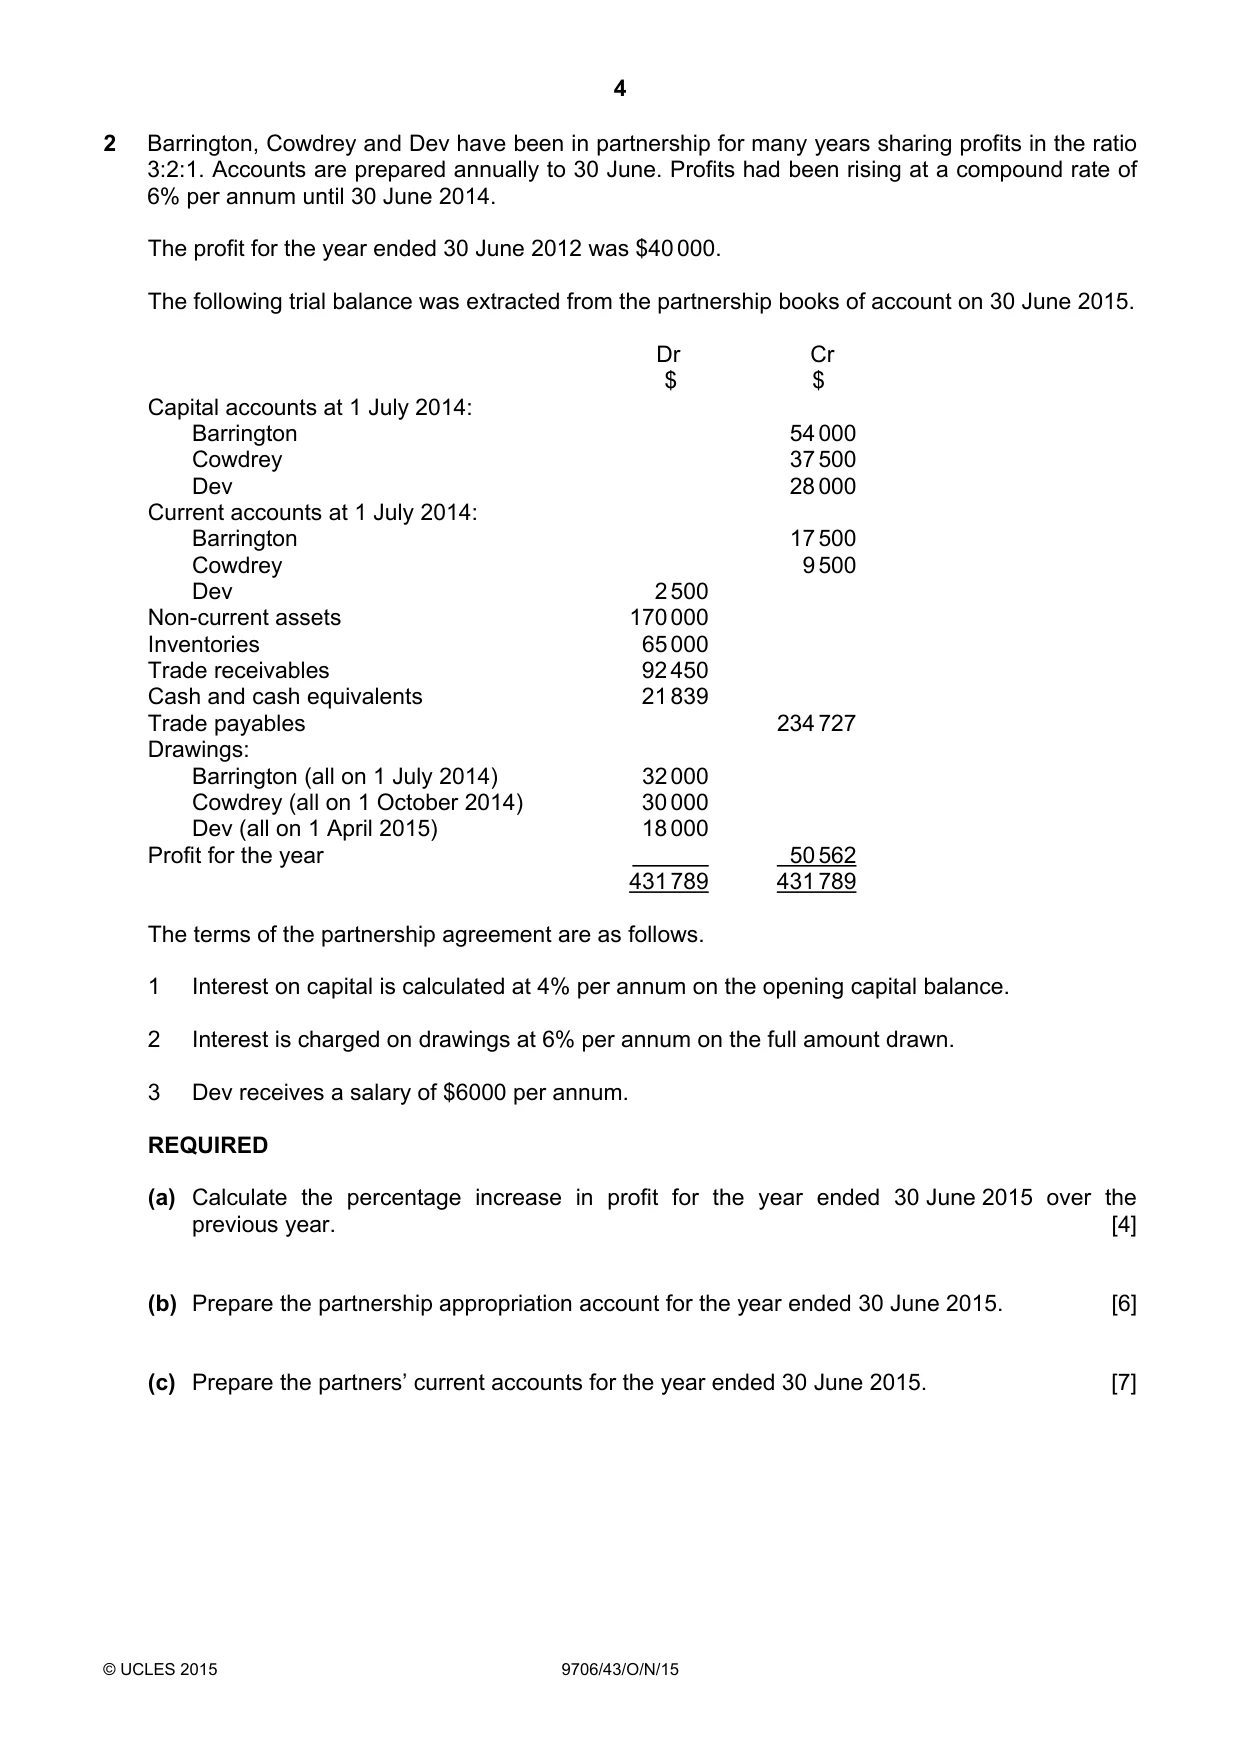
4 © UCLES 2015 9706/43/O/N/15 2 Barrington, Cowdrey and Dev have been in partnership for many years sharing profits in the ratio 3:2:1. Accounts are prepared annually to 30 June. Profits had been rising at a compound rate of 6% per annum until 30 June 2014. The profit for the year ended 30 June 2012 was $40 000. The following trial balance was extracted from the partnership books of account on 30 June 2015. Dr Cr $ $ Capital accounts at 1 July 2014: Barrington 54 000 Cowdrey 37 500 Dev 28 000 Current accounts at 1 July 2014: Barrington 17 500 Cowdrey 9 500 Dev 2 500 Non-current assets 170 000 Inventories 65 000 Trade receivables 92 450 Cash and cash equivalents 21 839 Trade payables 234 727 Drawings: Barrington (all on 1 July 2014) 32 000 Cowdrey (all on 1 October 2014) 30 000 Dev (all on 1 April 2015) 18 000 Profit for the year 50 562 431 789 431 789 The terms of the partnership agreement are as follows. 1 Interest on capital is calculated at 4% per annum on the opening capital balance. 2 Interest is charged on drawings at 6% per annum on the full amount drawn. 3 Dev receives a salary of $6000 per annum. REQUIRED (a) Calculate the percentage increase in profit for the year ended 30 June 2015 over the previous year. [4] (b) Prepare the partnership appropriation account for the year ended 30 June 2015. [6] (c) Prepare the partners’ current accounts for the year ended 30 June 2015. [7]
Question paper, page 5
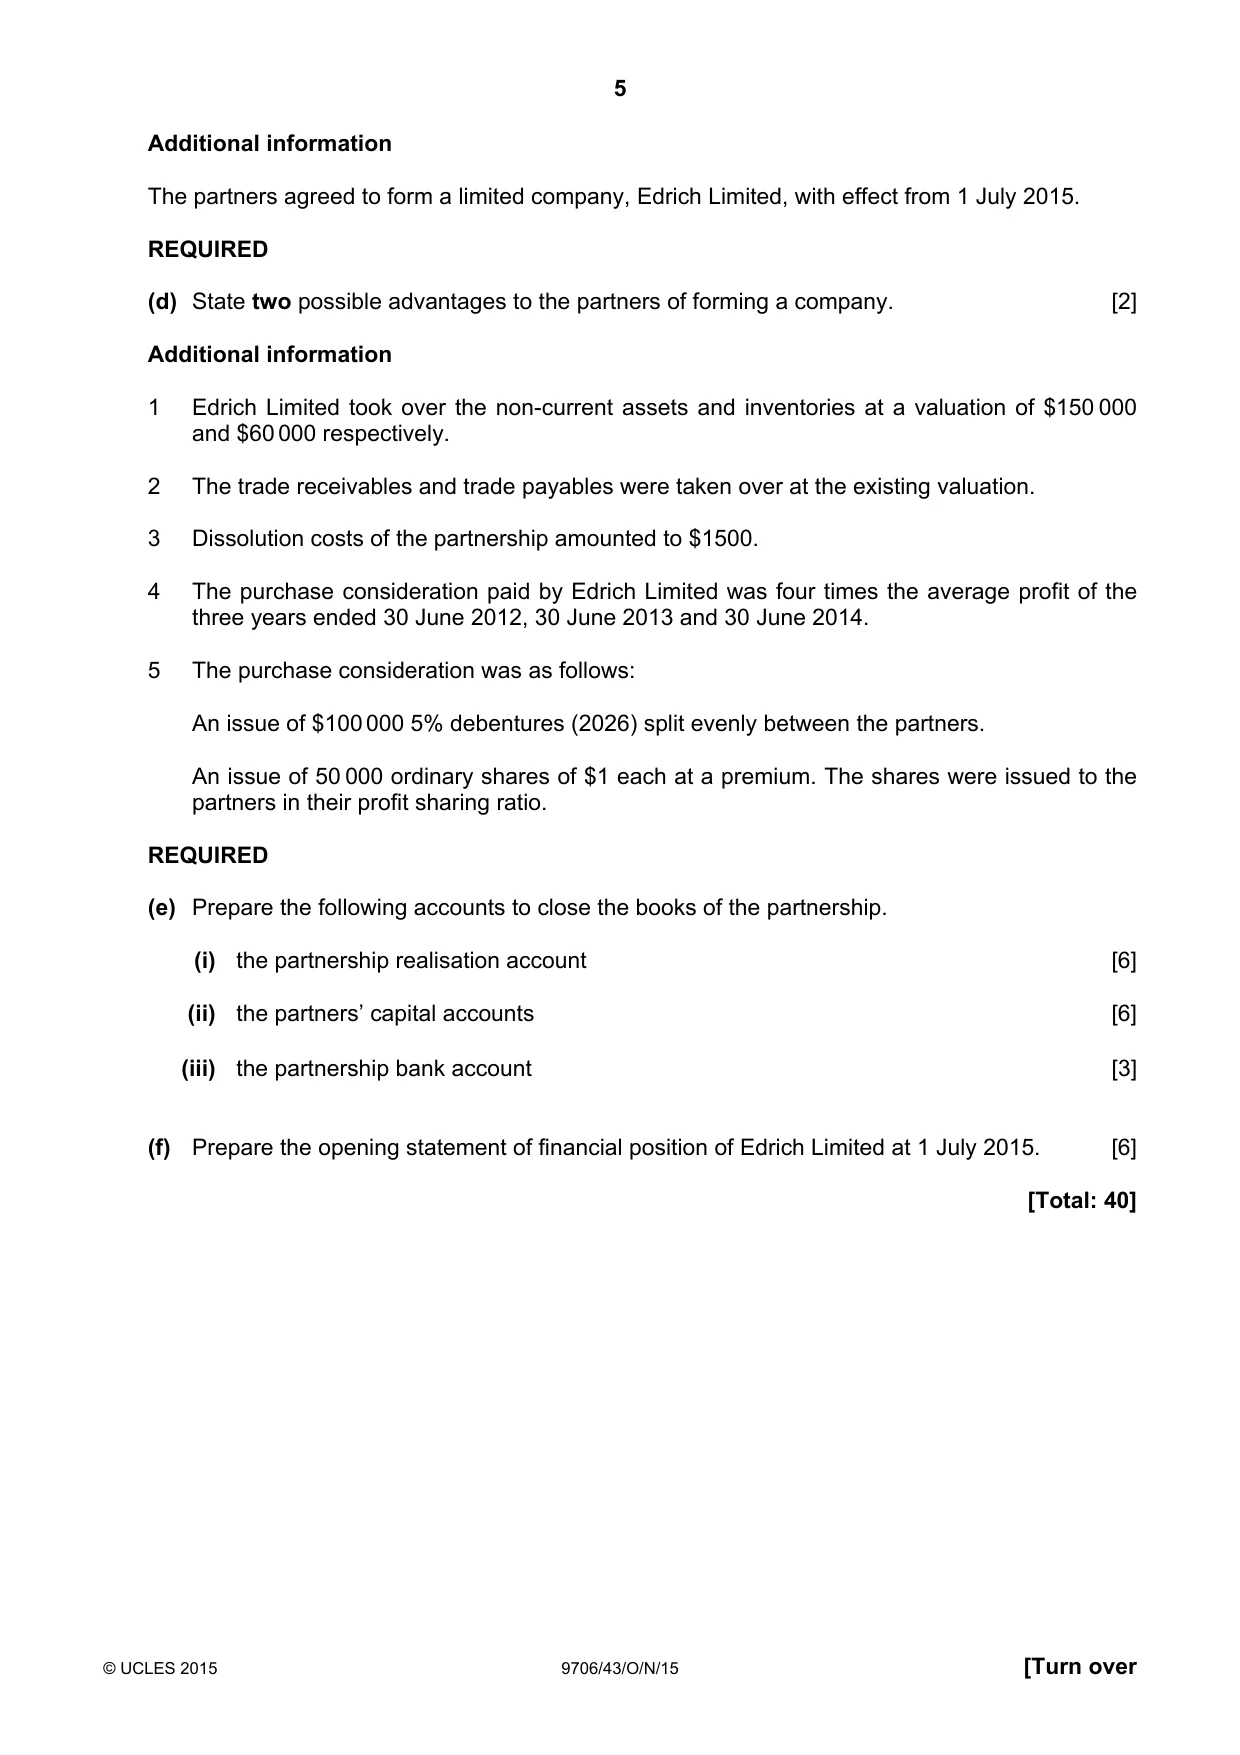
5 © UCLES 2015 9706/43/O/N/15 [Turn over Additional information The partners agreed to form a limited company, Edrich Limited, with effect from 1 July 2015. REQUIRED (d) State two possible advantages to the partners of forming a company. [2] Additional information 1 Edrich Limited took over the non-current assets and inventories at a valuation of $150 000 and $60 000 respectively. 2 The trade receivables and trade payables were taken over at the existing valuation. 3 Dissolution costs of the partnership amounted to $1500. 4 The purchase consideration paid by Edrich Limited was four times the average profit of the three years ended 30 June 2012, 30 June 2013 and 30 June 2014. 5 The purchase consideration was as follows: An issue of $100 000 5% debentures (2026) split evenly between the partners. An issue of 50 000 ordinary shares of $1 each at a premium. The shares were issued to the partners in their profit sharing ratio. REQUIRED (e) Prepare the following accounts to close the books of the partnership. (i) the partnership realisation account [6] (ii) the partners’ capital accounts [6] (iii) the partnership bank account [3] (f) Prepare the opening statement of financial position of Edrich Limited at 1 July 2015. [6] [Total: 40]
Question paper, page 6
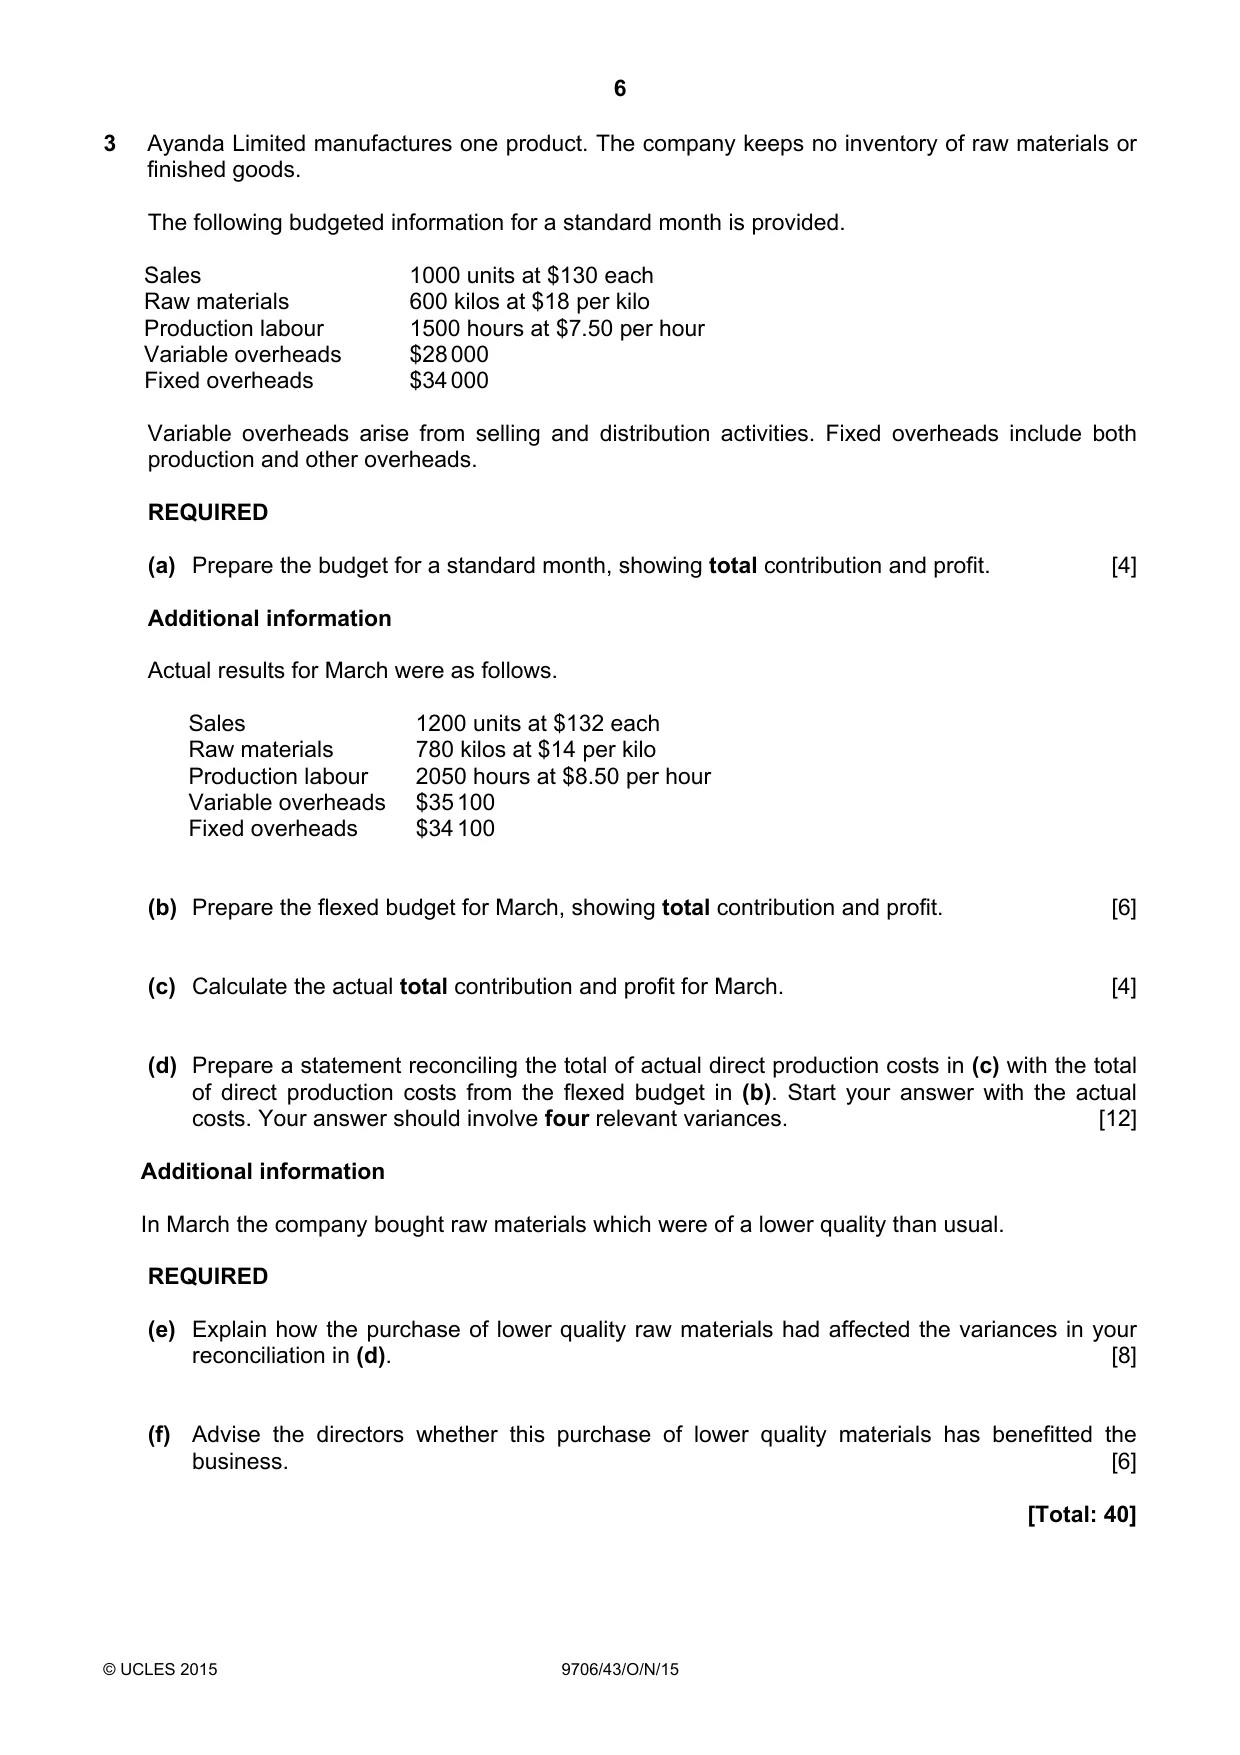
6 © UCLES 2015 9706/43/O/N/15 3 Ayanda Limited manufactures one product. The company keeps no inventory of raw materials or finished goods. The following budgeted information for a standard month is provided. Sales 1000 units at $130 each Raw materials 600 kilos at $18 per kilo Production labour 1500 hours at $7.50 per hour Variable overheads $28 000 Fixed overheads $34 000 Variable overheads arise from selling and distribution activities. Fixed overheads include both production and other overheads. REQUIRED (a) Prepare the budget for a standard month, showing total contribution and profit. [4] Additional information Actual results for March were as follows. Sales 1200 units at $132 each Raw materials 780 kilos at $14 per kilo Production labour 2050 hours at $8.50 per hour Variable overheads $35 100 Fixed overheads $34 100 (b) Prepare the flexed budget for March, showing total contribution and profit. [6] (c) Calculate the actual total contribution and profit for March. [4] (d) Prepare a statement reconciling the total of actual direct production costs in (c) with the total of direct production costs from the flexed budget in (b). Start your answer with the actual costs. Your answer should involve four relevant variances. [12] Additional information In March the company bought raw materials which were of a lower quality than usual. REQUIRED (e) Explain how the purchase of lower quality raw materials had affected the variances in your reconciliation in (d). [8] (f) Advise the directors whether this purchase of lower quality materials has benefitted the business. [6] [Total: 40]
Question paper, page 7
7 © UCLES 2015 9706/43/O/N/15 BLANK PAGE
Question paper, page 8
8 Permission to reproduce items where third-party owned material protected by copyright is included has been sought and cleared where possible. Every reasonable effort has been made by the publisher (UCLES) to trace copyright holders, but if any items requiring clearance have unwittingly been included, the publisher will be pleased to make amends at the earliest possible opportunity. To avoid the issue of disclosure of answer-related information to candidates, all copyright acknowledgements are reproduced online in the Cambridge International Examinations Copyright Acknowledgements Booklet. This is produced for each series of examinations and is freely available to download at www.cie.org.uk after the live examination series. Cambridge International Examinations is part of the Cambridge Assessment Group. Cambridge Assessment is the brand name of University of Cambridge Local Examinations Syndicate (UCLES), which is itself a department of the University of Cambridge. © UCLES 2015 9706/43/O/N/15 BLANK PAGE
What you needed in this session
Cambridge’s own grade thresholds for 2015 Oct/Nov, Paper 4 · Variant 3. A higher threshold means an easier paper — the bar moves with how the cohort did.