Cambridge A Level Accounting 9706 — 2014 Oct/Nov Paper 4 · Variant 1
9706/41/O/N/14 · 120 marks · ≈135 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper8 pages
Mark scheme7 pages
Answers below. Sit the paper first if you are practising.
Paper as text
Question paper, page 1
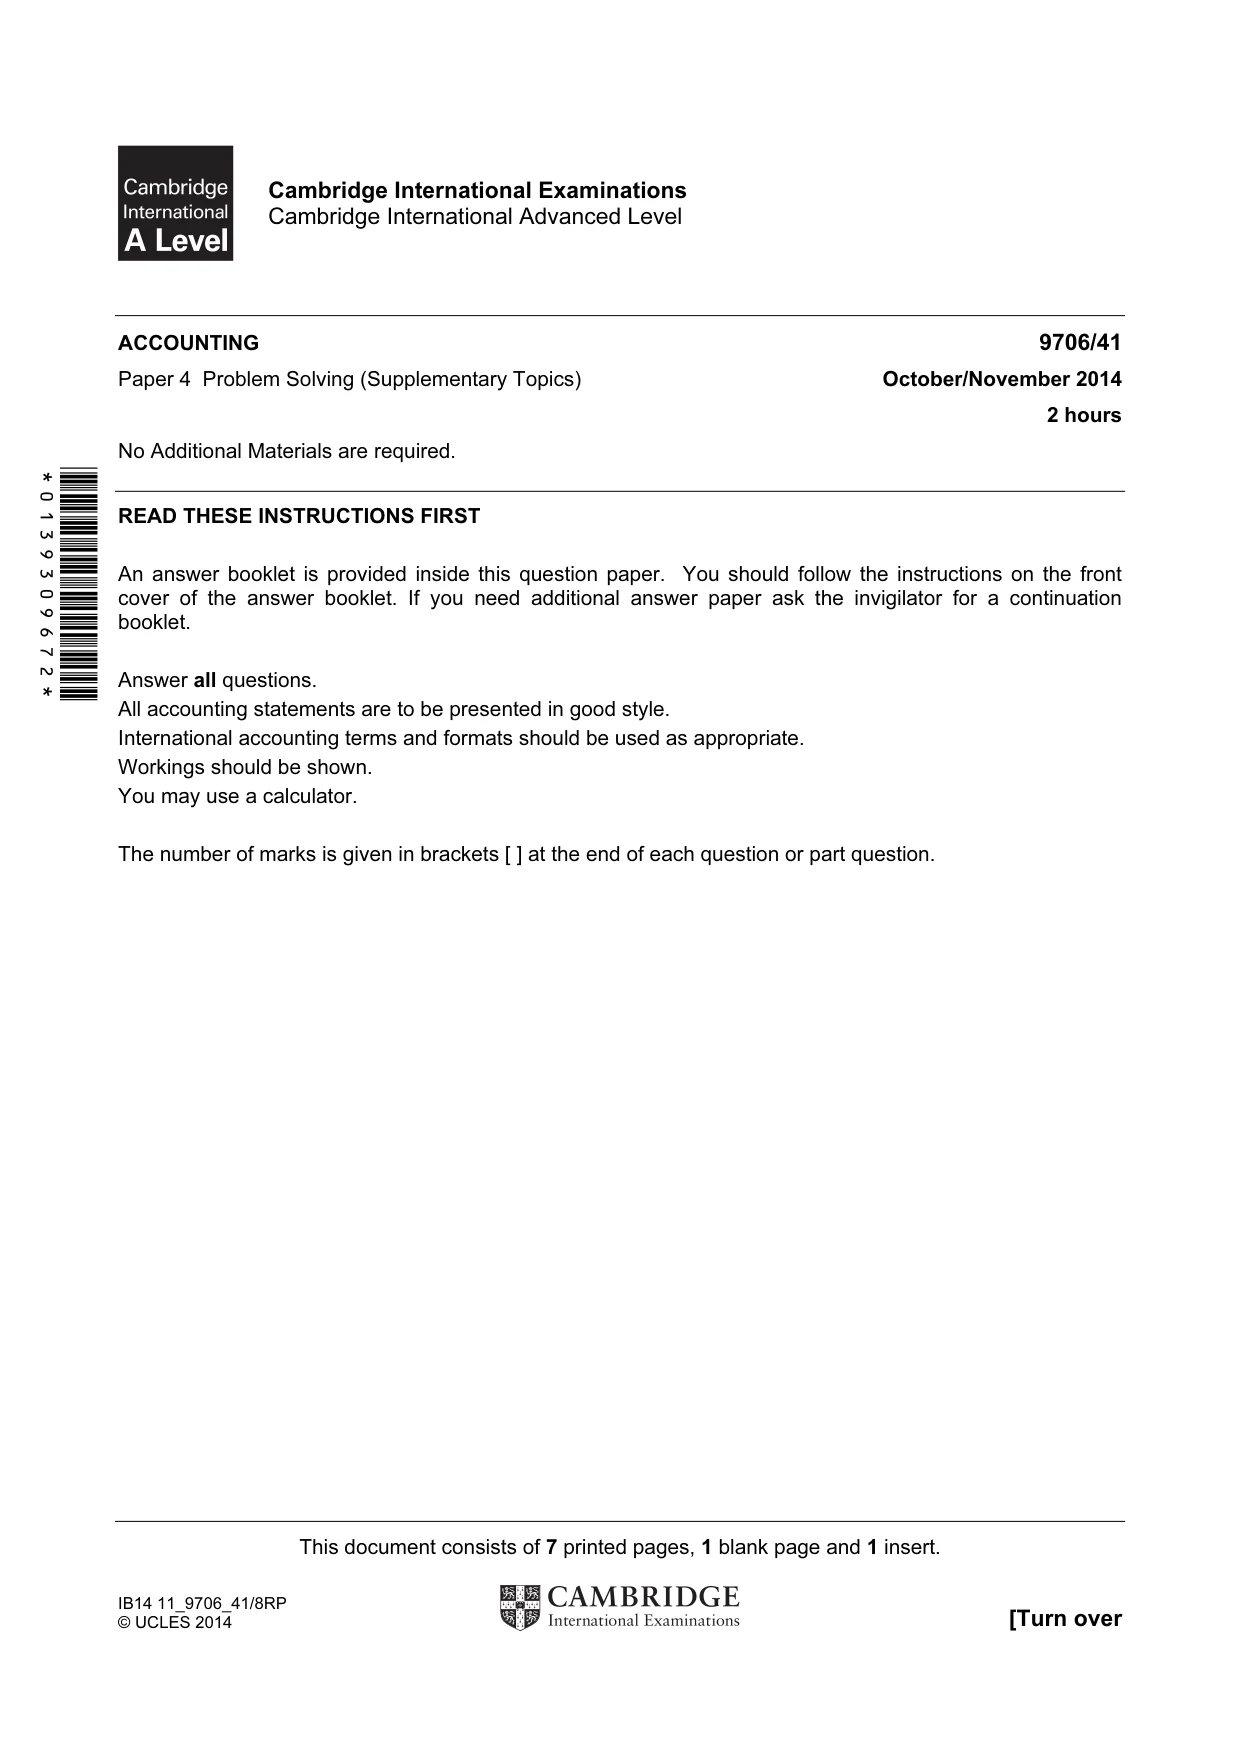
This document consists of 7 printed pages, 1 blank page and 1 insert. IB14 11_9706_41/8RP © UCLES 2014 [Turn over *0139309672* Cambridge International Examinations Cambridge International Advanced Level ACCOUNTING 9706/41 Paper 4 Problem Solving (Supplementary Topics) October/November 2014 2 hours No Additional Materials are required. READ THESE INSTRUCTIONS FIRST An answer booklet is provided inside this question paper. You should follow the instructions on the front cover of the answer booklet. If you need additional answer paper ask the invigilator for a continuation booklet. Answer all questions. All accounting statements are to be presented in good style. International accounting terms and formats should be used as appropriate. Workings should be shown. You may use a calculator. The number of marks is given in brackets [ ] at the end of each question or part question.
Question paper, page 2
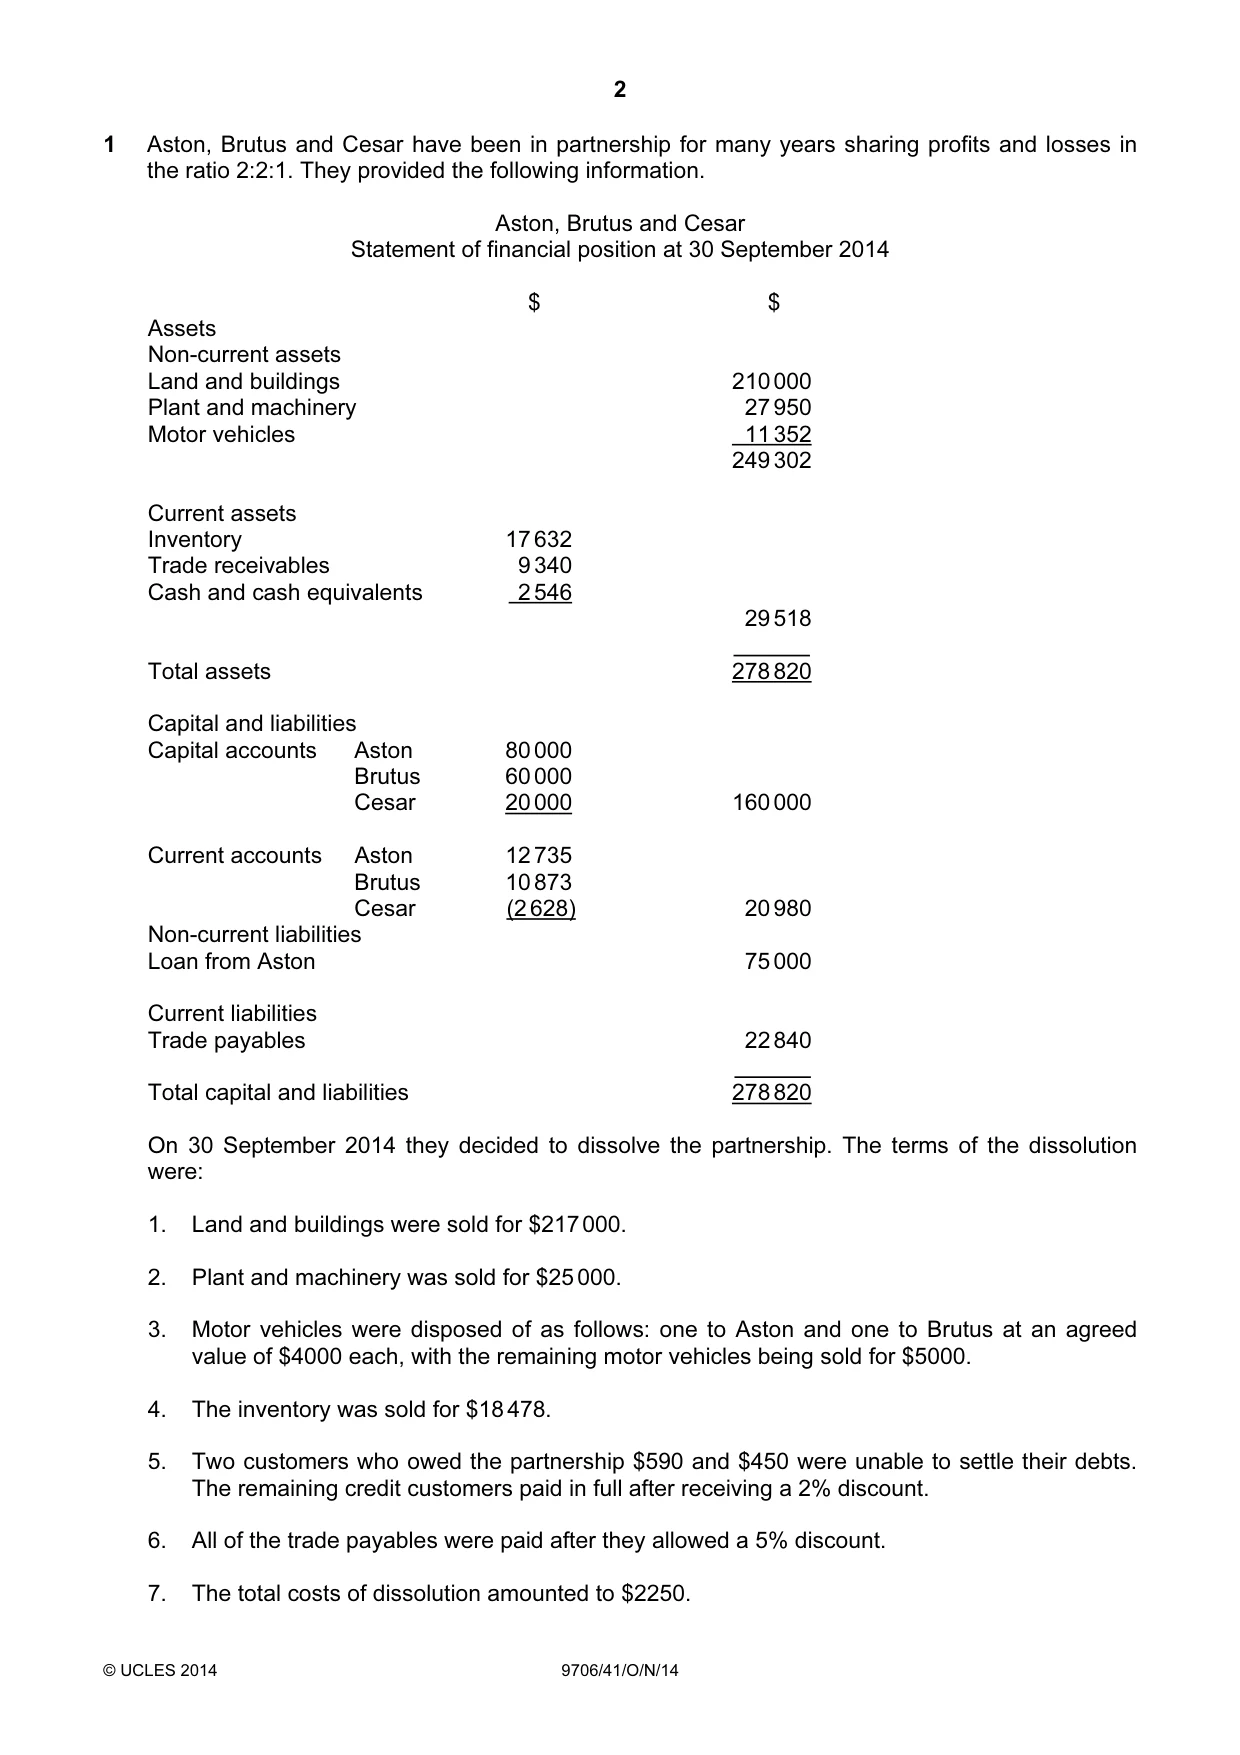
2 © UCLES 2014 9706/41/O/N/14 1 Aston, Brutus and Cesar have been in partnership for many years sharing profits and losses in the ratio 2:2:1. They provided the following information. Aston, Brutus and Cesar Statement of financial position at 30 September 2014 $ $ Assets Non-current assets Land and buildings 210 000 Plant and machinery 27 950 Motor vehicles 11 352 249 302 Current assets Inventory 17 632 Trade receivables 9 340 Cash and cash equivalents 2 546 29 518 Total assets 278 820 Capital and liabilities Capital accounts Aston 80 000 Brutus 60 000 Cesar 20 000 160 000 Current accounts Aston 12 735 Brutus 10 873 Cesar (2 628) 20 980 Non-current liabilities Loan from Aston 75 000 Current liabilities Trade payables 22 840 Total capital and liabilities 278 820 On 30 September 2014 they decided to dissolve the partnership. The terms of the dissolution were: 1. Land and buildings were sold for $217 000. 2. Plant and machinery was sold for $25 000. 3. Motor vehicles were disposed of as follows: one to Aston and one to Brutus at an agreed value of $4000 each, with the remaining motor vehicles being sold for $5000. 4. The inventory was sold for $18 478. 5. Two customers who owed the partnership $590 and $450 were unable to settle their debts. The remaining credit customers paid in full after receiving a 2% discount. 6. All of the trade payables were paid after they allowed a 5% discount. 7. The total costs of dissolution amounted to $2250.
Question paper, page 3
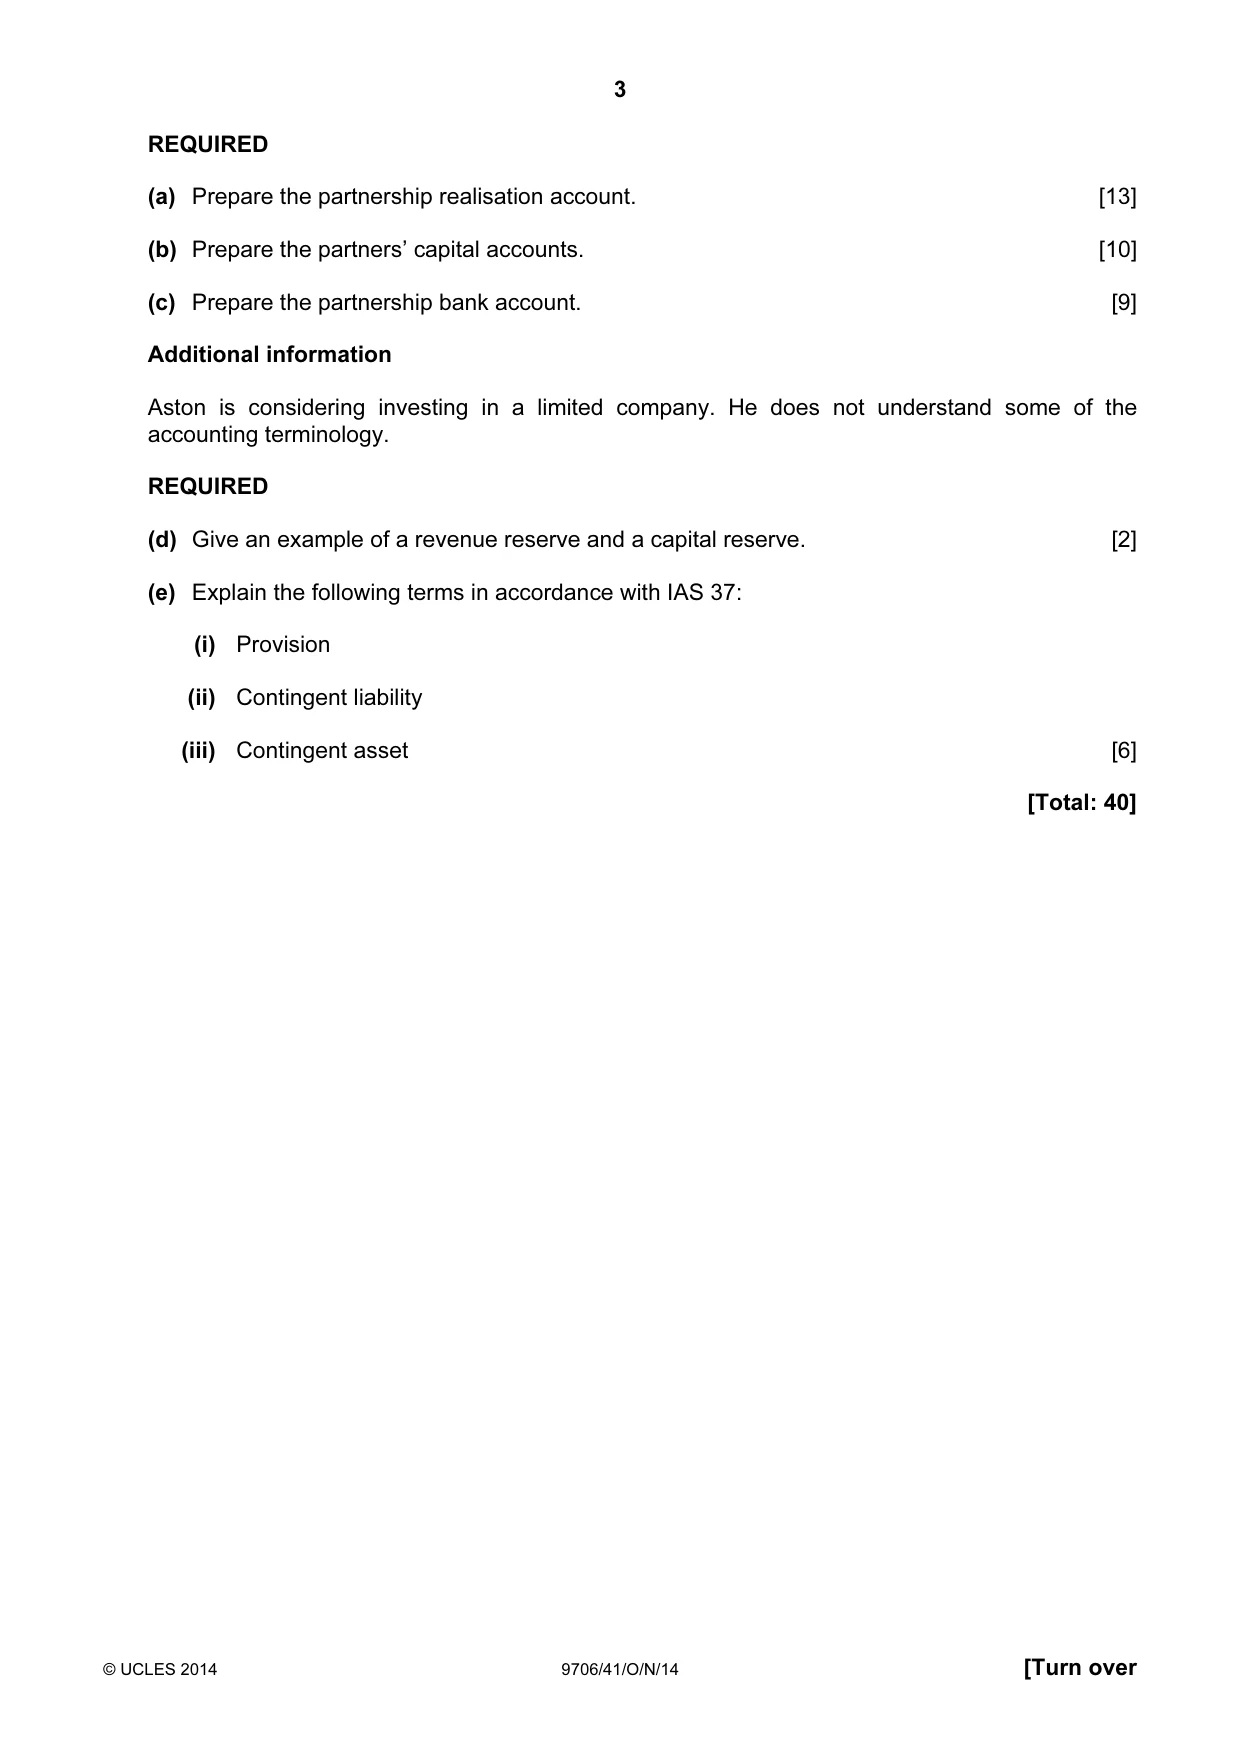
3 © UCLES 2014 9706/41/O/N/14 [Turn over REQUIRED (a) Prepare the partnership realisation account. [13] (b) Prepare the partners’ capital accounts. [10] (c) Prepare the partnership bank account. [9] Additional information Aston is considering investing in a limited company. He does not understand some of the accounting terminology. REQUIRED (d) Give an example of a revenue reserve and a capital reserve. [2] (e) Explain the following terms in accordance with IAS 37: (i) Provision (ii) Contingent liability (iii) Contingent asset [6] [Total: 40]
Question paper, page 4
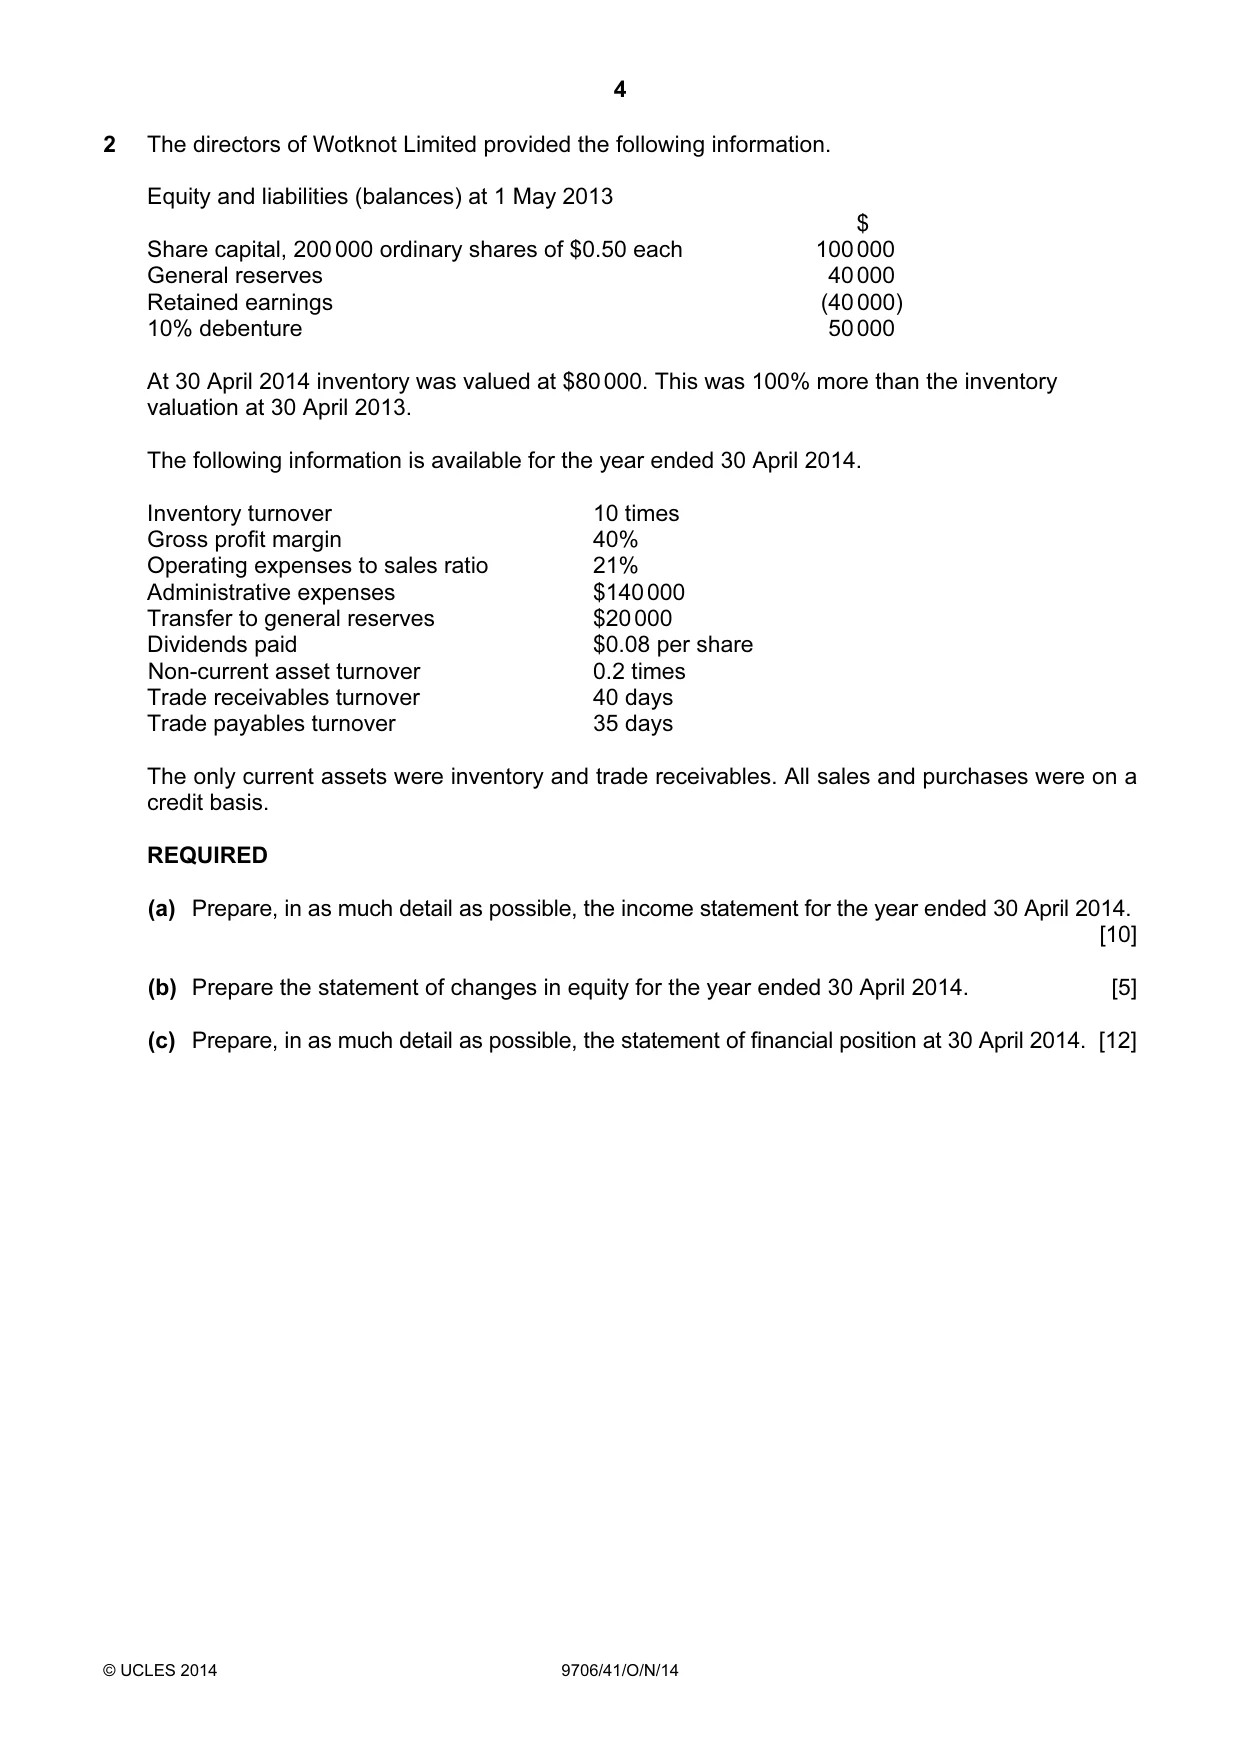
4 © UCLES 2014 9706/41/O/N/14 2 The directors of Wotknot Limited provided the following information. Equity and liabilities (balances) at 1 May 2013 $ Share capital, 200 000 ordinary shares of $0.50 each 100 000 General reserves 40 000 Retained earnings (40 000) 10% debenture 50 000 At 30 April 2014 inventory was valued at $80 000. This was 100% more than the inventory valuation at 30 April 2013. The following information is available for the year ended 30 April 2014. Inventory turnover 10 times Gross profit margin 40% Operating expenses to sales ratio 21% Administrative expenses $140 000 Transfer to general reserves $20 000 Dividends paid $0.08 per share Non-current asset turnover 0.2 times Trade receivables turnover 40 days Trade payables turnover 35 days The only current assets were inventory and trade receivables. All sales and purchases were on a credit basis. REQUIRED (a) Prepare, in as much detail as possible, the income statement for the year ended 30 April 2014. [10] (b) Prepare the statement of changes in equity for the year ended 30 April 2014. [5] (c) Prepare, in as much detail as possible, the statement of financial position at 30 April 2014. [12]
Question paper, page 5
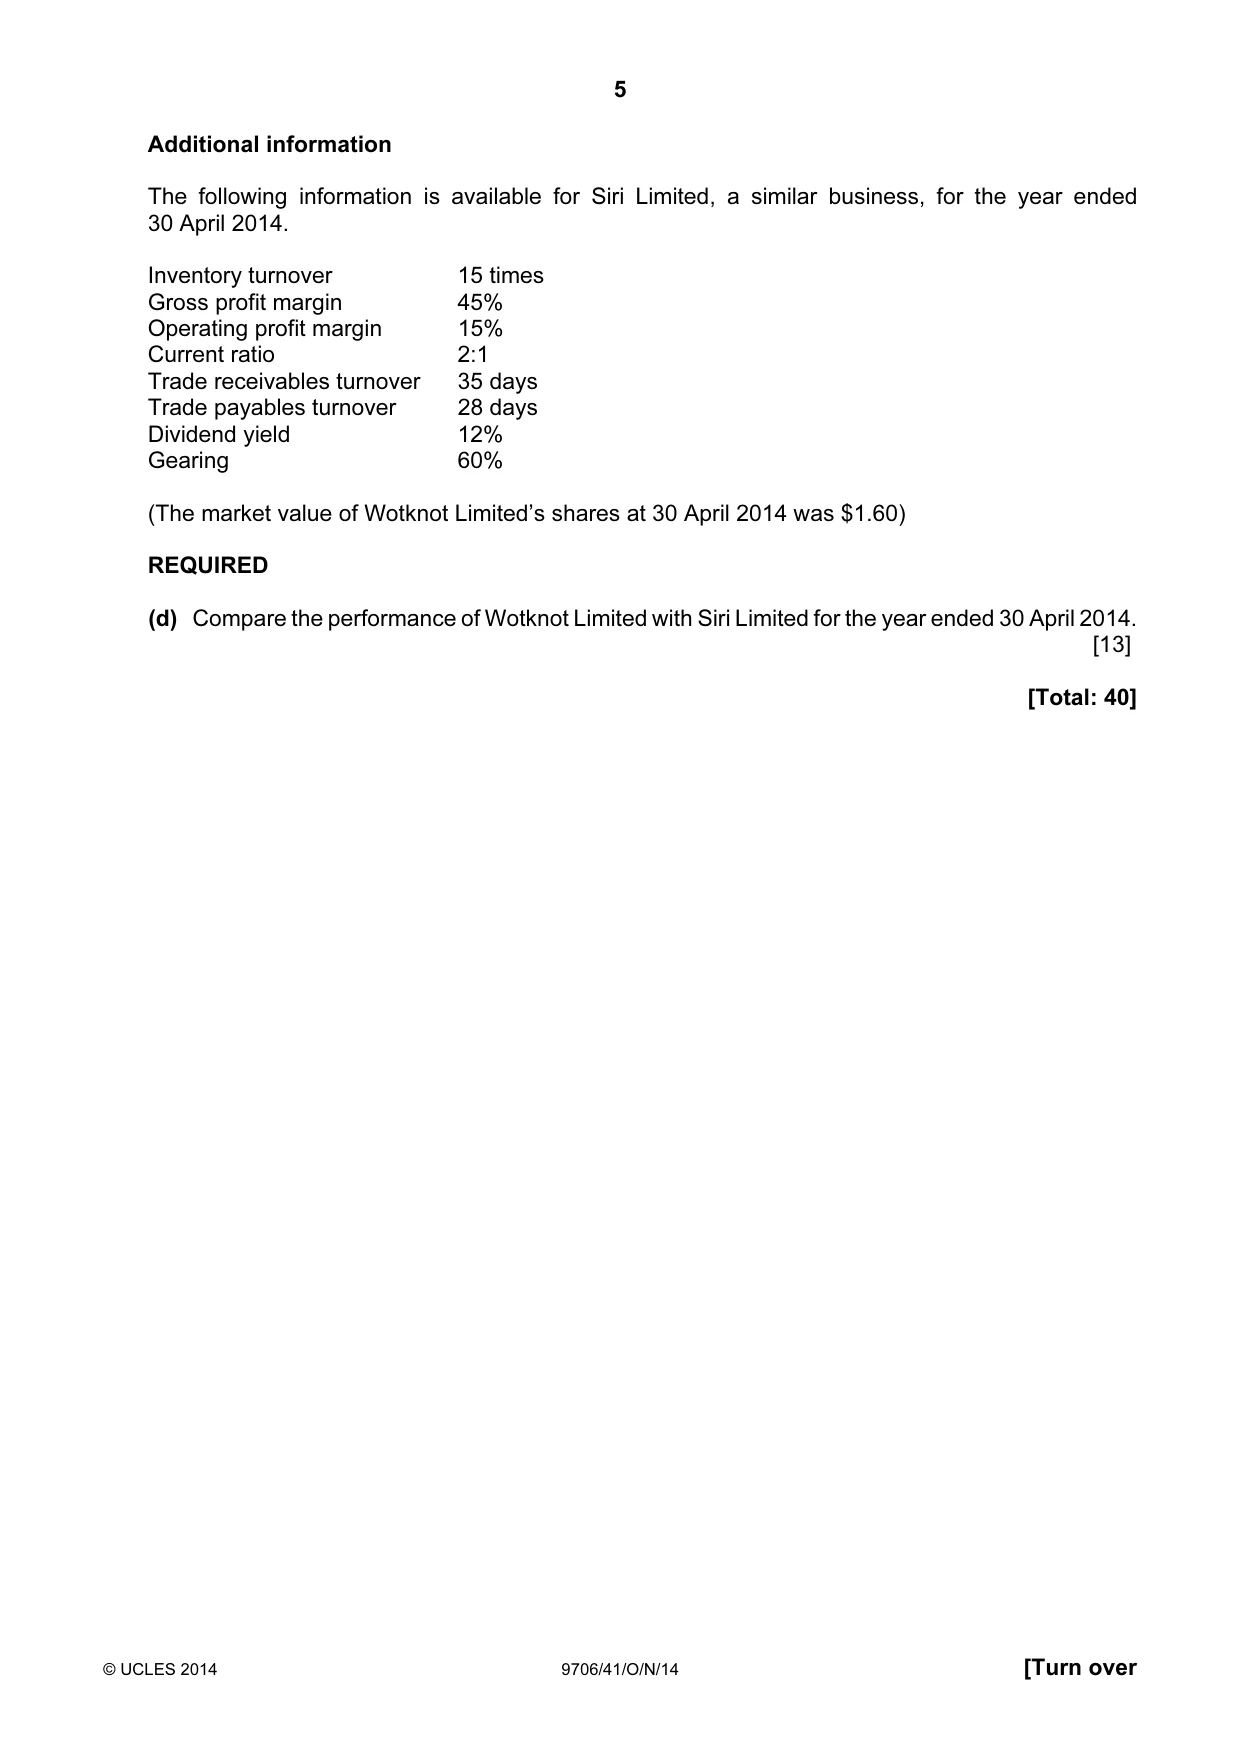
5 © UCLES 2014 9706/41/O/N/14 [Turn over Additional information The following information is available for Siri Limited, a similar business, for the year ended 30 April 2014. Inventory turnover 15 times Gross profit margin 45% Operating profit margin 15% Current ratio 2:1 Trade receivables turnover 35 days Trade payables turnover 28 days Dividend yield 12% Gearing 60% (The market value of Wotknot Limited’s shares at 30 April 2014 was $1.60) REQUIRED (d) Compare the performance of Wotknot Limited with Siri Limited for the year ended 30 April 2014. [13] [Total: 40]
Question paper, page 6
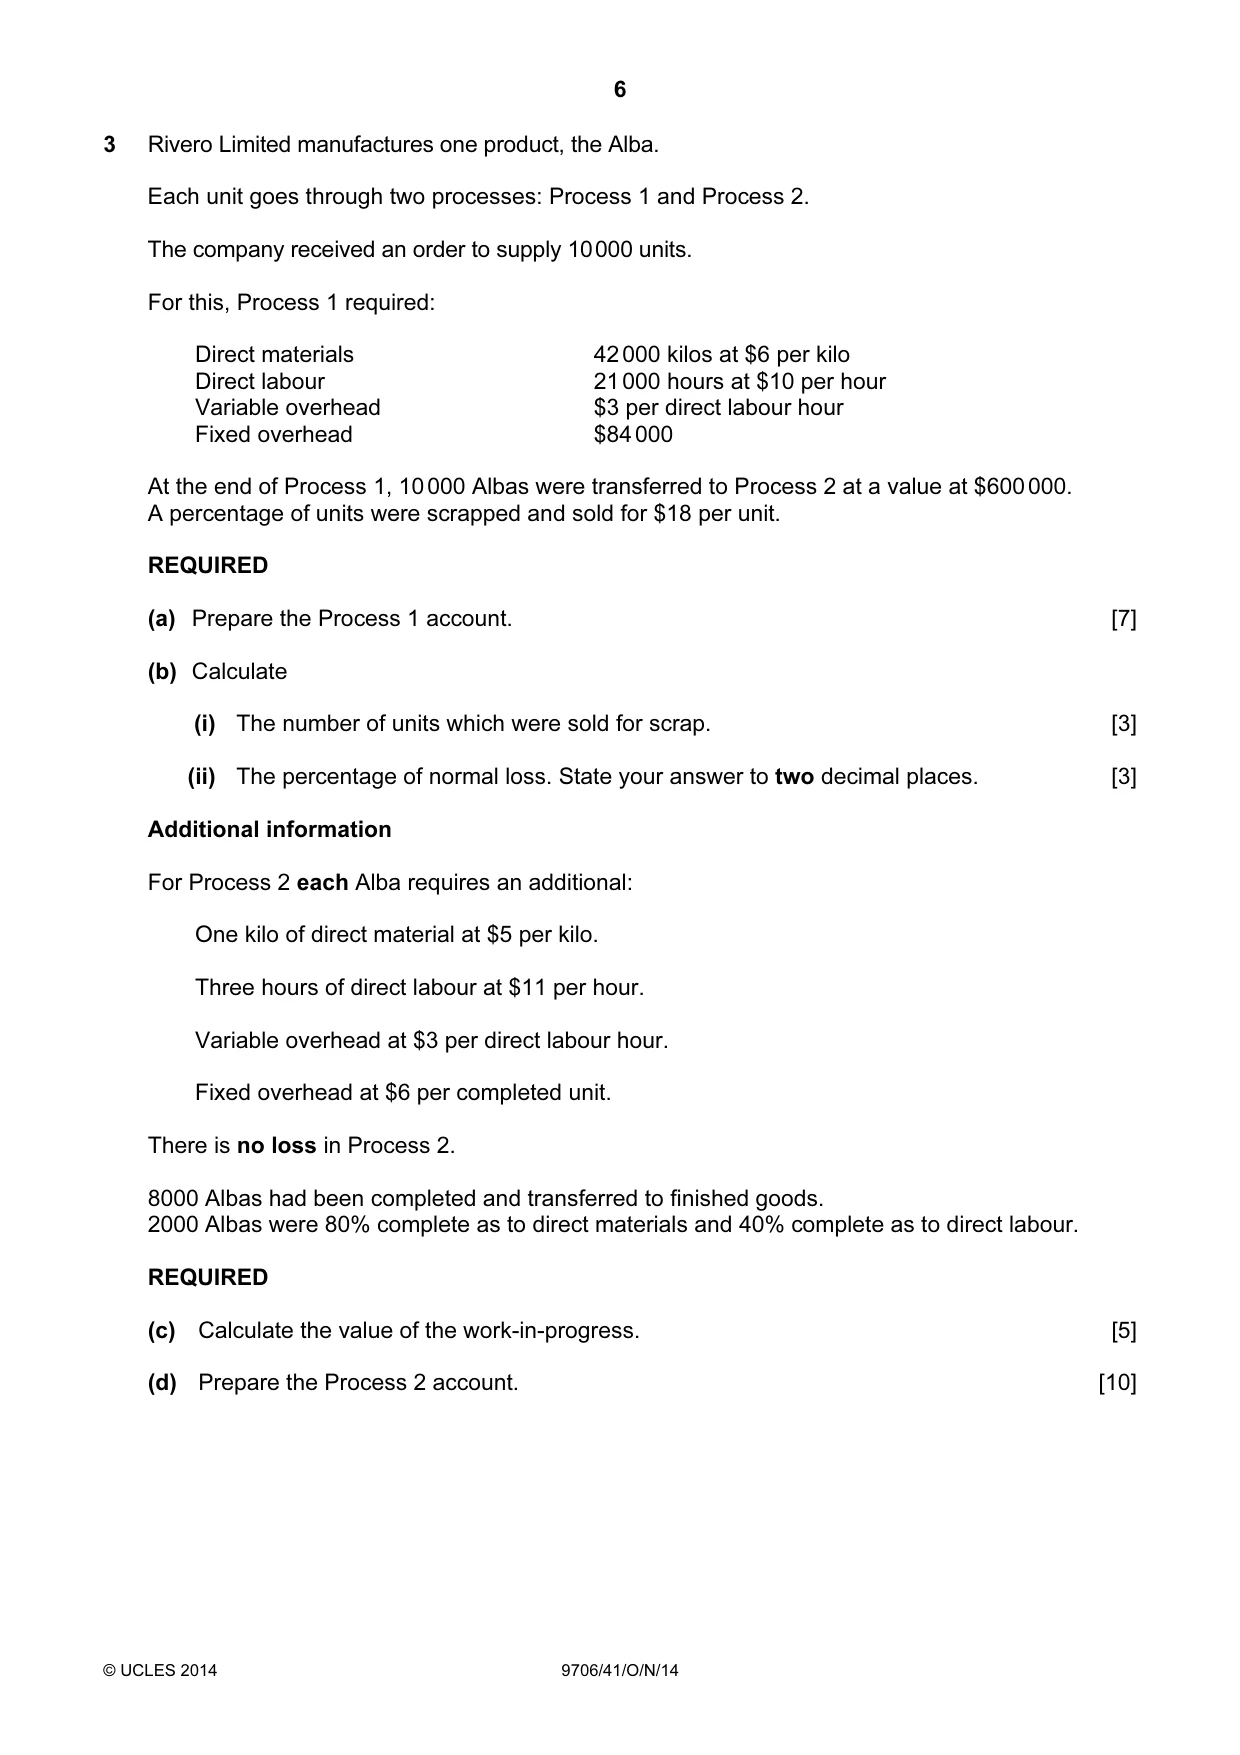
6 © UCLES 2014 9706/41/O/N/14 3 Rivero Limited manufactures one product, the Alba. Each unit goes through two processes: Process 1 and Process 2. The company received an order to supply 10 000 units. For this, Process 1 required: Direct materials 42 000 kilos at $6 per kilo Direct labour 21 000 hours at $10 per hour Variable overhead $3 per direct labour hour Fixed overhead $84 000 At the end of Process 1, 10 000 Albas were transferred to Process 2 at a value at $600 000. A percentage of units were scrapped and sold for $18 per unit. REQUIRED (a) Prepare the Process 1 account. [7] (b) Calculate (i) The number of units which were sold for scrap. [3] (ii) The percentage of normal loss. State your answer to two decimal places. [3] Additional information For Process 2 each Alba requires an additional: One kilo of direct material at $5 per kilo. Three hours of direct labour at $11 per hour. Variable overhead at $3 per direct labour hour. Fixed overhead at $6 per completed unit. There is no loss in Process 2. 8000 Albas had been completed and transferred to finished goods. 2000 Albas were 80% complete as to direct materials and 40% complete as to direct labour. REQUIRED (c) Calculate the value of the work-in-progress. [5] (d) Prepare the Process 2 account. [10]
Question paper, page 7
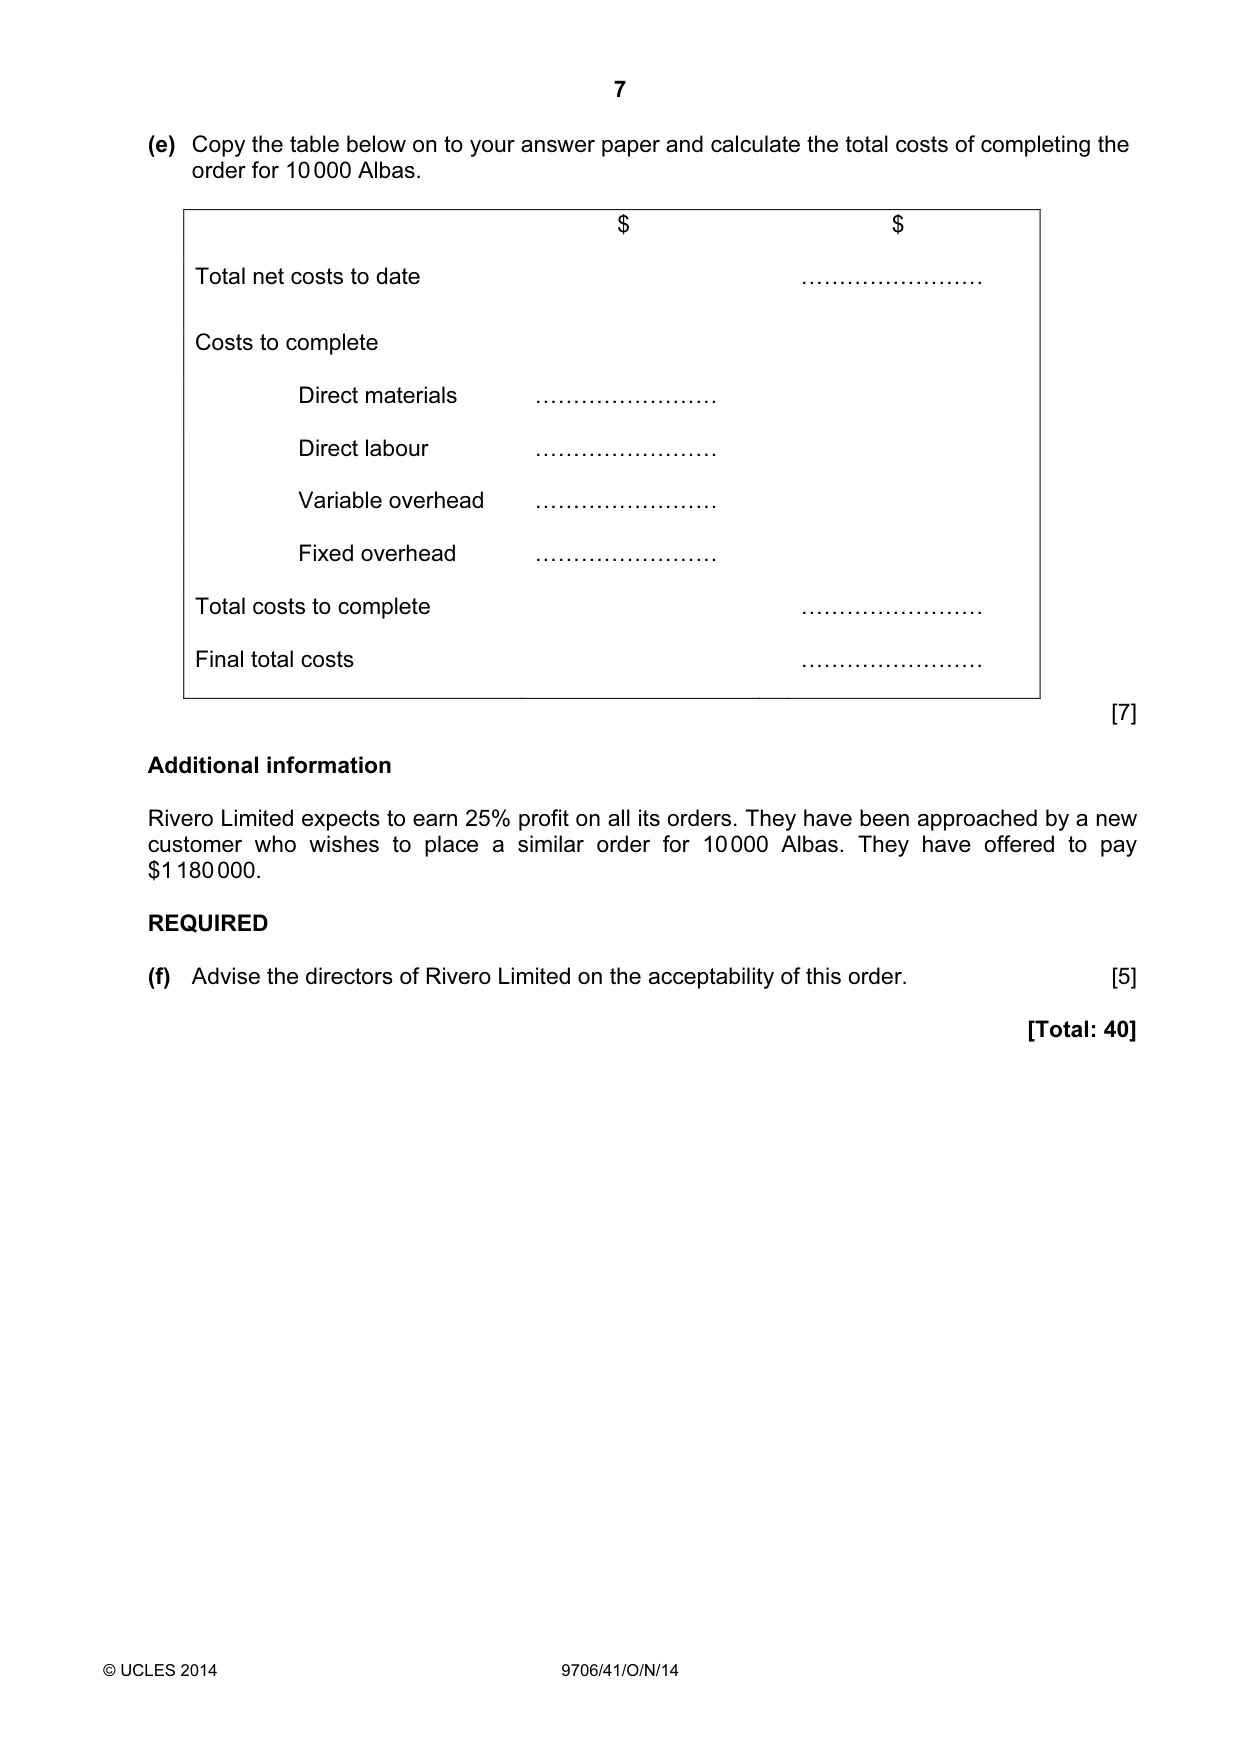
7 © UCLES 2014 9706/41/O/N/14 (e) Copy the table below on to your answer paper and calculate the total costs of completing the order for 10 000 Albas. $ $ Total net costs to date …………………… Costs to complete Direct materials …………………… Direct labour …………………… Variable overhead …………………… Fixed overhead …………………… Total costs to complete …………………… Final total costs …………………… [7] Additional information Rivero Limited expects to earn 25% profit on all its orders. They have been approached by a new customer who wishes to place a similar order for 10 000 Albas. They have offered to pay $1 180 000. REQUIRED (f) Advise the directors of Rivero Limited on the acceptability of this order. [5] [Total: 40]
Question paper, page 8
8 Permission to reproduce items where third-party owned material protected by copyright is included has been sought and cleared where possible. Every reasonable effort has been made by the publisher (UCLES) to trace copyright holders, but if any items requiring clearance have unwittingly been included, the publisher will be pleased to make amends at the earliest possible opportunity. Cambridge International Examinations is part of the Cambridge Assessment Group. Cambridge Assessment is the brand name of University of Cambridge Local Examinations Syndicate (UCLES), which is itself a department of the University of Cambridge. © UCLES 2014 9706/41/O/N/14 BLANK PAGE
Mark scheme, page 1
® IGCSE is the registered trademark of Cambridge International Examinations. CAMBRIDGE INTERNATIONAL EXAMINATIONS Cambridge International Advanced Level MARK SCHEME for the October/November 2014 series 9706 ACCOUNTING 9706/41 Paper 4 (Problem Solving – Supplement), maximum raw mark 120 This mark scheme is published as an aid to teachers and candidates, to indicate the requirements of the examination. It shows the basis on which Examiners were instructed to award marks. It does not indicate the details of the discussions that took place at an Examiners’ meeting before marking began, which would have considered the acceptability of alternative answers. Mark schemes should be read in conjunction with the question paper and the Principal Examiner Report for Teachers. Cambridge will not enter into discussions about these mark schemes. Cambridge is publishing the mark schemes for the October/November 2014 series for most Cambridge IGCSE®, Cambridge International A and AS Level components and some Cambridge O Level components.
Mark scheme, page 2
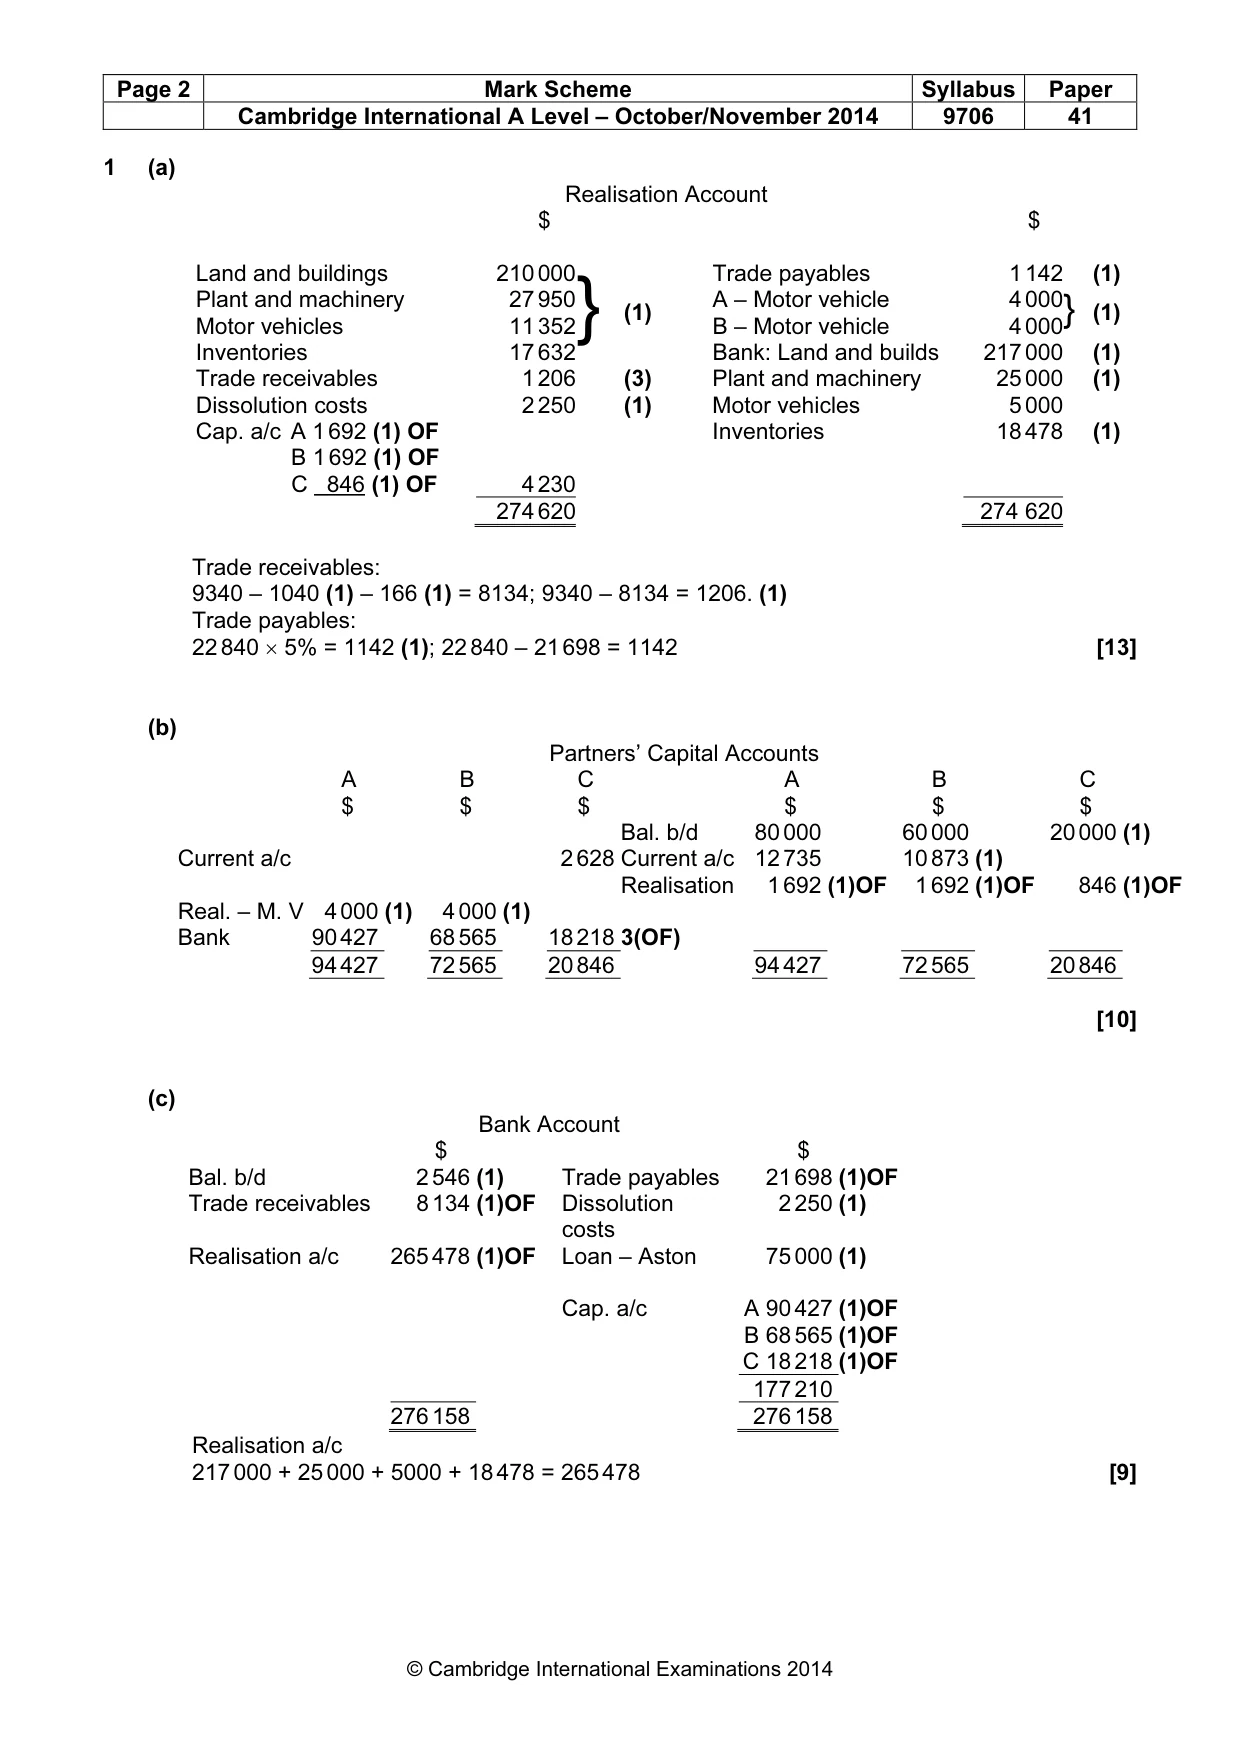
Page 2 Mark Scheme Syllabus Paper Cambridge International A Level – October/November 2014 9706 41 © Cambridge International Examinations 2014 1 (a) Realisation Account $ $ Land and buildings 210 000} (1) Trade payables 1 142 (1) Plant and machinery 27 950 A – Motor vehicle 4 000} (1) Motor vehicles 11 352 B – Motor vehicle 4 000 Inventories 17 632 Bank: Land and builds 217 000 (1) Trade receivables 1 206 (3) Plant and machinery 25 000 (1) Dissolution costs 2 250 (1) Motor vehicles 5 000 Cap. a/c A 1 692 (1) OF Inventories 18 478 (1) B 1 692 (1) OF C 846 (1) OF 4 230 274 620 274 620 Trade receivables: 9340 – 1040 (1) – 166 (1) = 8134; 9340 – 8134 = 1206. (1) Trade payables: 22 840 × 5% = 1142 (1); 22 840 – 21 698 = 1142 [13] (b) Partners’ Capital Accounts A B C A B C $ $ $ $ $ $ Bal. b/d 80 000 60 000 20 000 (1) Current a/c 2 628 Current a/c 12 735 10 873 (1) Realisation 1 692 (1)OF 1 692 (1)OF 846 (1)OF Real. – M. V 4 000 (1) 4 000 (1) Bank 90 427 68 565 18 218 3(OF) 94 427 72 565 20 846 94 427 72 565 20 846 [10] (c) Bank Account $ $ Bal. b/d 2 546 (1) Trade payables 21 698 (1)OF Trade receivables 8 134 (1)OF Dissolution costs 2 250 (1) Realisation a/c 265 478 (1)OF Loan – Aston 75 000 (1) Cap. a/c A 90 427 (1)OF B 68 565 (1)OF C 18 218 (1)OF 177 210 276 158 276 158 Realisation a/c 217 000 + 25 000 + 5000 + 18 478 = 265 478 [9]
Mark scheme, page 3
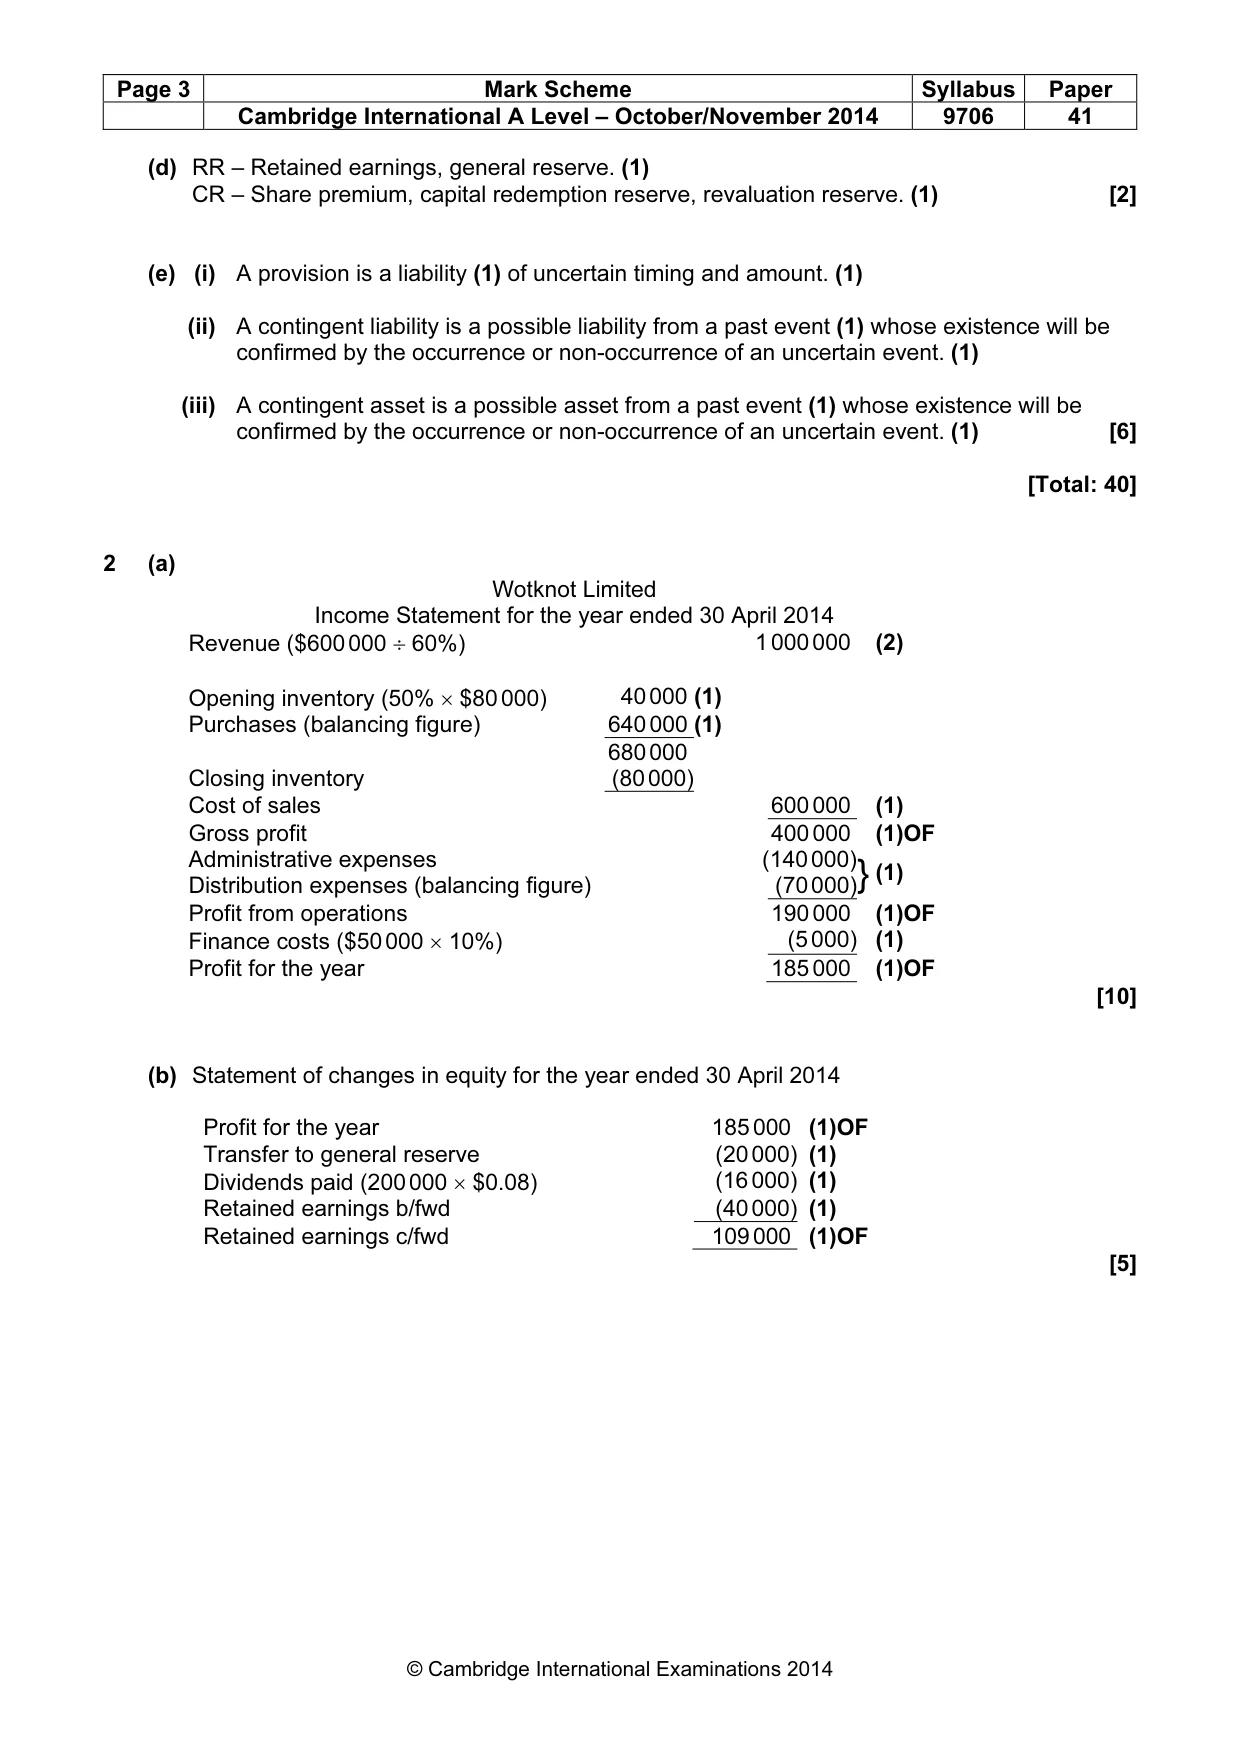
Page 3 Mark Scheme Syllabus Paper Cambridge International A Level – October/November 2014 9706 41 © Cambridge International Examinations 2014 (d) RR – Retained earnings, general reserve. (1) CR – Share premium, capital redemption reserve, revaluation reserve. (1) [2] (e) (i) A provision is a liability (1) of uncertain timing and amount. (1) (ii) A contingent liability is a possible liability from a past event (1) whose existence will be confirmed by the occurrence or non-occurrence of an uncertain event. (1) (iii) A contingent asset is a possible asset from a past event (1) whose existence will be confirmed by the occurrence or non-occurrence of an uncertain event. (1) [6] [Total: 40] 2 (a) Wotknot Limited Income Statement for the year ended 30 April 2014 Revenue ($600 000 ÷ 60%) 1 000 000. (2) Opening inventory (50% × $80 000) 40 000.(1) Purchases (balancing figure) 640 000.(1) 680 000. Closing inventory (80 000) Cost of sales 600 000. (1) Gross profit 400 000. (1)OF Administrative expenses (140 000) } (1) Distribution expenses (balancing figure) (70 000) Profit from operations 190 000. (1)OF Finance costs ($50 000 × 10%) (5 000) (1) Profit for the year 185 000. (1)OF [10] (b) Statement of changes in equity for the year ended 30 April 2014 Profit for the year 185 000. (1)OF Transfer to general reserve (20 000) (1) Dividends paid (200 000 × $0.08) (16 000) (1) Retained earnings b/fwd (40 000) (1) Retained earnings c/fwd 109 000. (1)OF [5]
Mark scheme, page 4
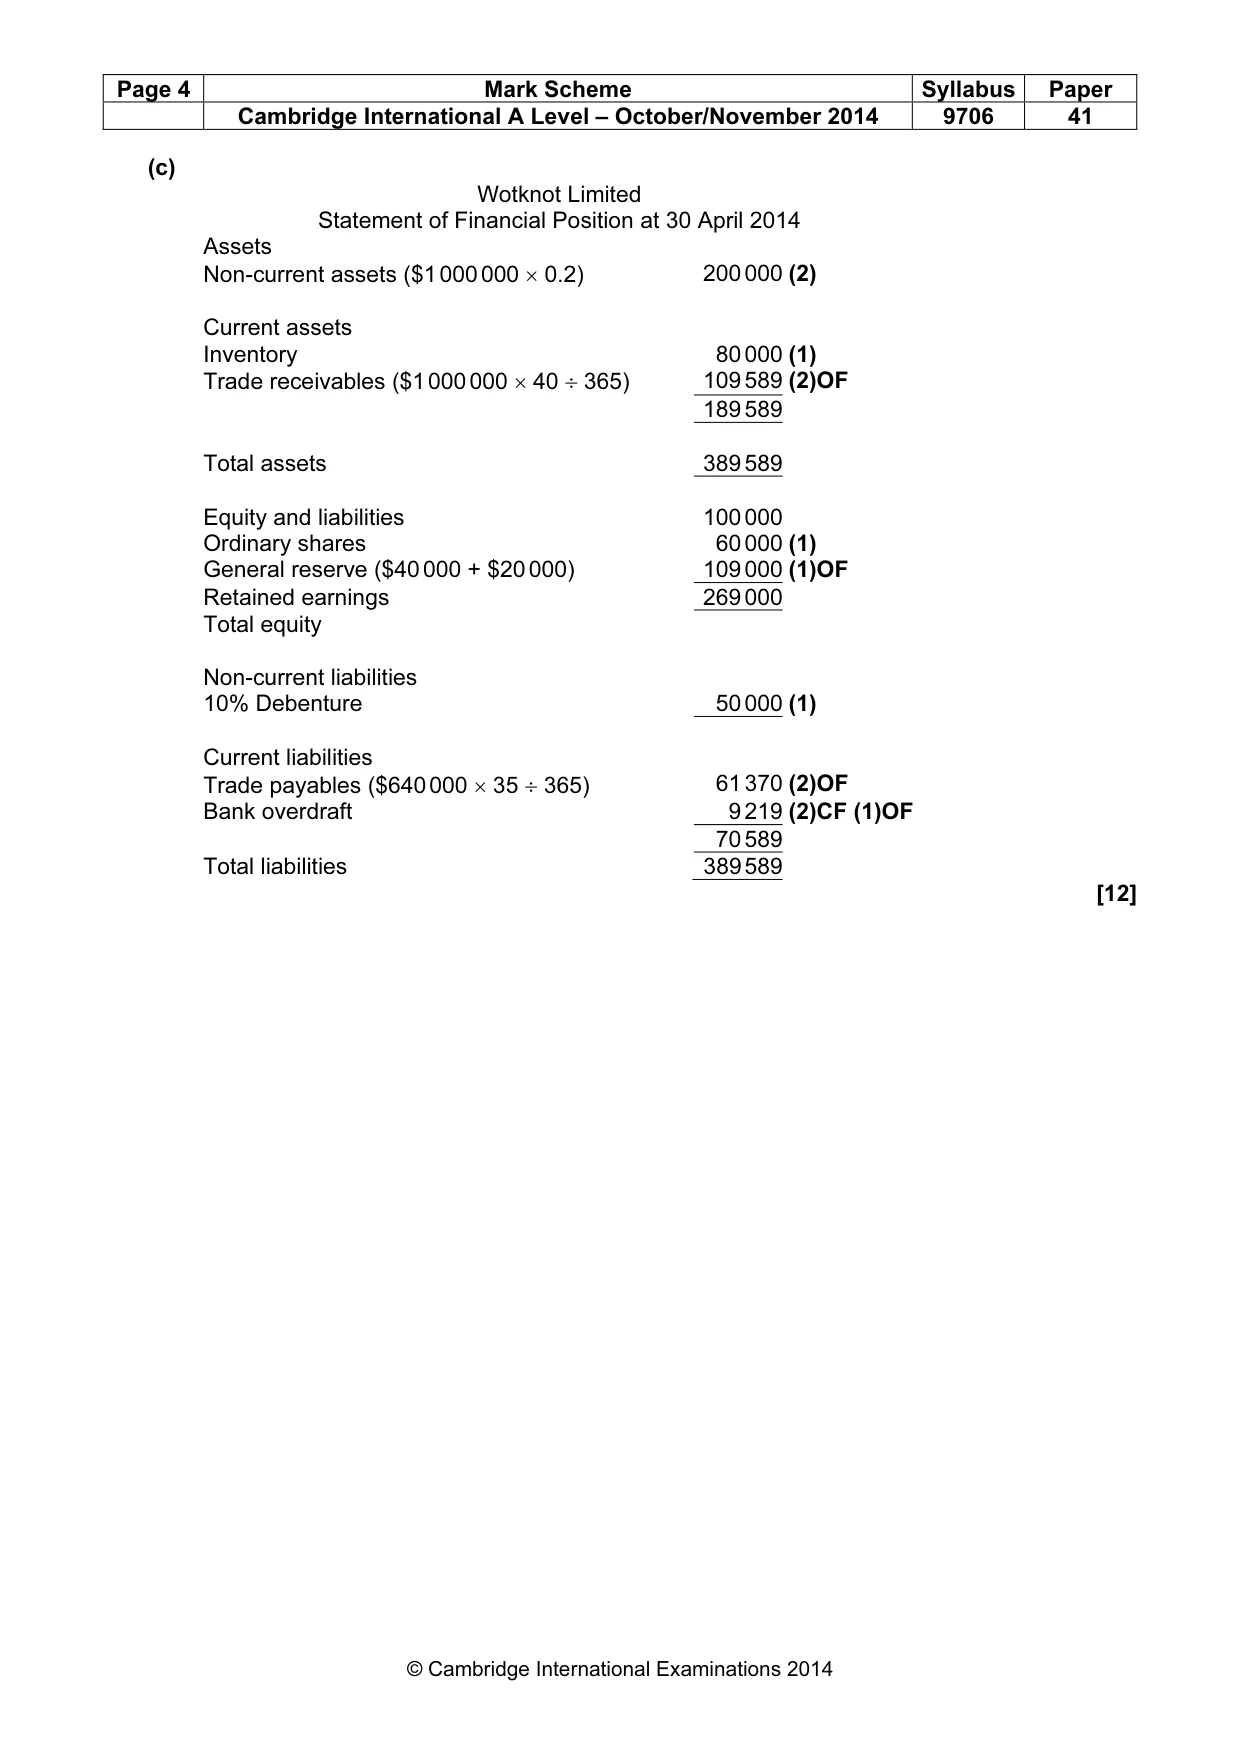
Page 4 Mark Scheme Syllabus Paper Cambridge International A Level – October/November 2014 9706 41 © Cambridge International Examinations 2014 (c) Wotknot Limited Statement of Financial Position at 30 April 2014 Assets Non-current assets ($1 000 000 × 0.2) 200 000 (2) Current assets Inventory 80 000 (1) Trade receivables ($1 000 000 × 40 ÷ 365) 109 589 (2)OF 189 589 Total assets 389 589 Equity and liabilities 100 000 Ordinary shares 60 000 (1) General reserve ($40 000 + $20 000) 109 000 (1)OF Retained earnings 269 000 Total equity Non-current liabilities 10% Debenture 50 000 (1) Current liabilities Trade payables ($640 000 × 35 ÷ 365) 61 370 (2)OF Bank overdraft 9 219 (2)CF (1)OF 70 589 Total liabilities 389 589 [12]
Mark scheme, page 5
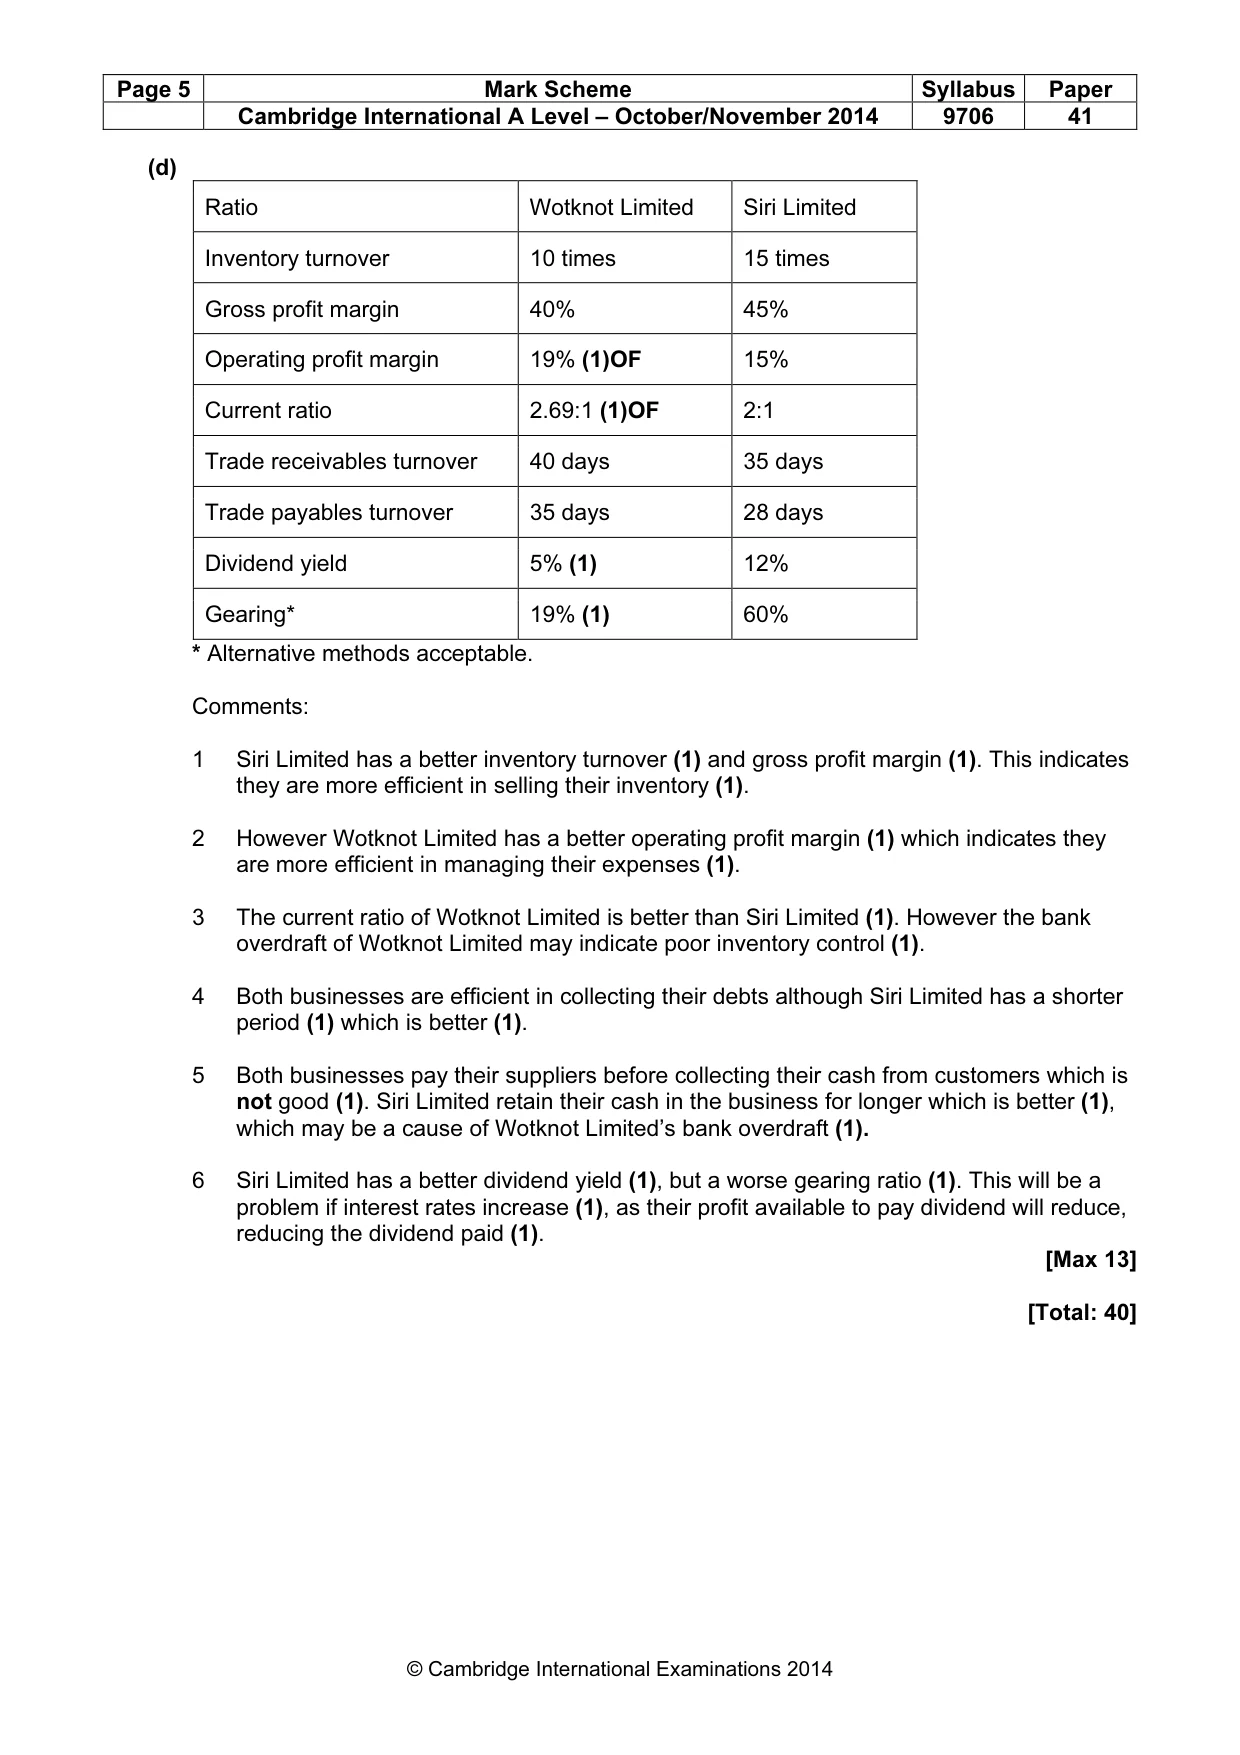
Page 5 Mark Scheme Syllabus Paper Cambridge International A Level – October/November 2014 9706 41 © Cambridge International Examinations 2014 (d) Ratio Wotknot Limited Siri Limited Inventory turnover 10 times 15 times Gross profit margin 40% 45% Operating profit margin 19% (1)OF 15% Current ratio 2.69:1 (1)OF 2:1 Trade receivables turnover 40 days 35 days Trade payables turnover 35 days 28 days Dividend yield 5% (1) 12% Gearing* 19% (1) 60% * Alternative methods acceptable. Comments: 1 Siri Limited has a better inventory turnover (1) and gross profit margin (1). This indicates they are more efficient in selling their inventory (1). 2 However Wotknot Limited has a better operating profit margin (1) which indicates they are more efficient in managing their expenses (1). 3 The current ratio of Wotknot Limited is better than Siri Limited (1). However the bank overdraft of Wotknot Limited may indicate poor inventory control (1). 4 Both businesses are efficient in collecting their debts although Siri Limited has a shorter period (1) which is better (1). 5 Both businesses pay their suppliers before collecting their cash from customers which is not good (1). Siri Limited retain their cash in the business for longer which is better (1), which may be a cause of Wotknot Limited’s bank overdraft (1). 6 Siri Limited has a better dividend yield (1), but a worse gearing ratio (1). This will be a problem if interest rates increase (1), as their profit available to pay dividend will reduce, reducing the dividend paid (1). [Max 13] [Total: 40]
Mark scheme, page 6
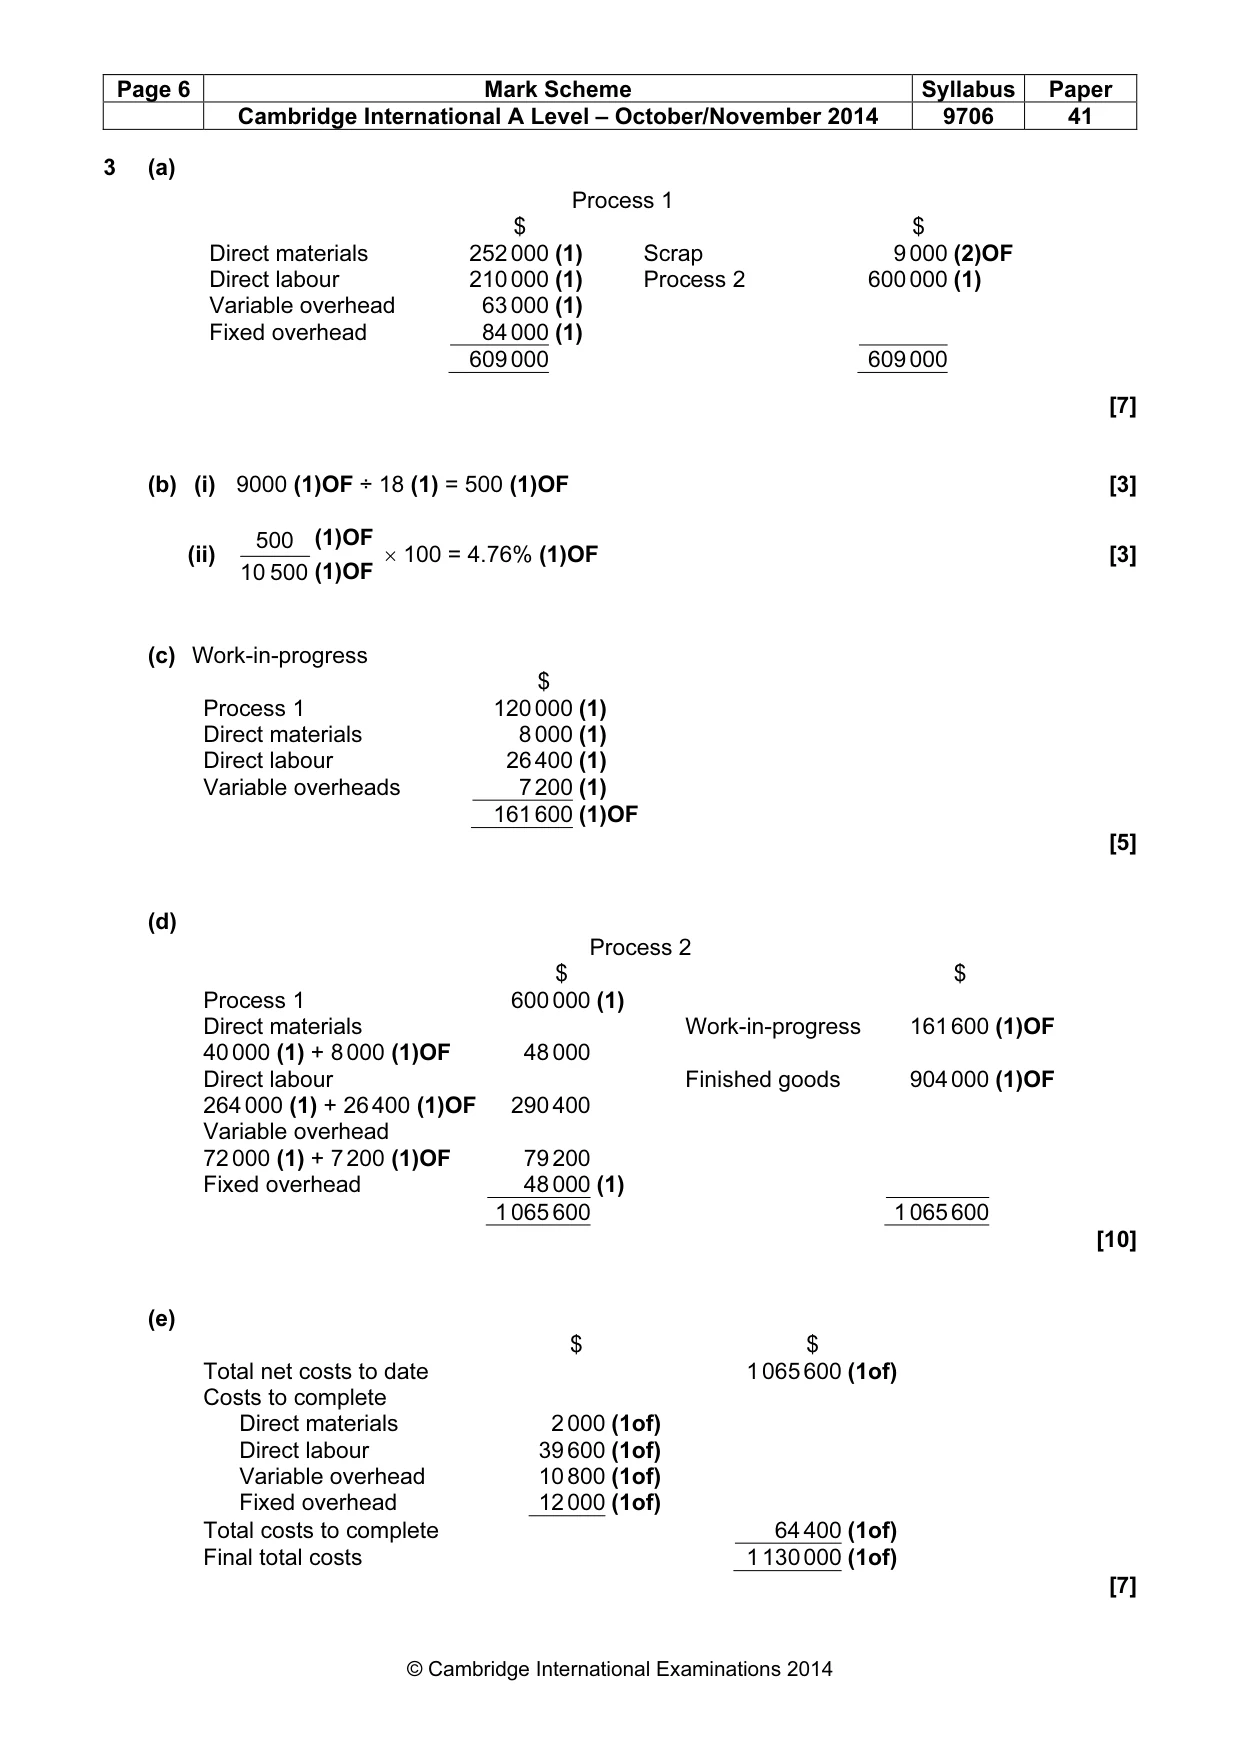
Page 6 Mark Scheme Syllabus Paper Cambridge International A Level – October/November 2014 9706 41 © Cambridge International Examinations 2014 3 (a) [7] (b) (i) 9000 (1)OF ÷ 18 (1) = 500 (1)OF [3] (ii) (1)OF (1)OF 500 10 500 × 100 = 4.76% (1)OF [3] (c) Work-in-progress $ Process 1 120 000 (1) Direct materials 8 000 (1) Direct labour 26 400 (1) Variable overheads 7 200 (1) 161 600 (1)OF [5] (d) Process 2 $ $ Process 1 600 000 (1) Direct materials Work-in-progress 161 600 (1)OF 40 000 (1) + 8 000 (1)OF 48 000 Direct labour Finished goods 904 000 (1)OF 264 000 (1) + 26 400 (1)OF 290 400 Variable overhead 72 000 (1) + 7 200 (1)OF 79 200 Fixed overhead 48 000 (1) 1 065 600 1 065 600 [10] (e) $ $ Total net costs to date 1 065 600 (1of) Costs to complete Direct materials 2 000 (1of) Direct labour 39 600 (1of) Variable overhead 10 800 (1of) Fixed overhead 12 000 (1of) Total costs to complete 64 400 (1of) Final total costs 1 130 000 (1of) [7] Process 1 $ $ Direct materials 252 000 (1) Scrap 9 000 (2)OF Direct labour 210 000 (1) Process 2 600 000 (1) Variable overhead 63 000 (1) Fixed overhead 84 000 (1) 609 000 609 000
Mark scheme, page 7
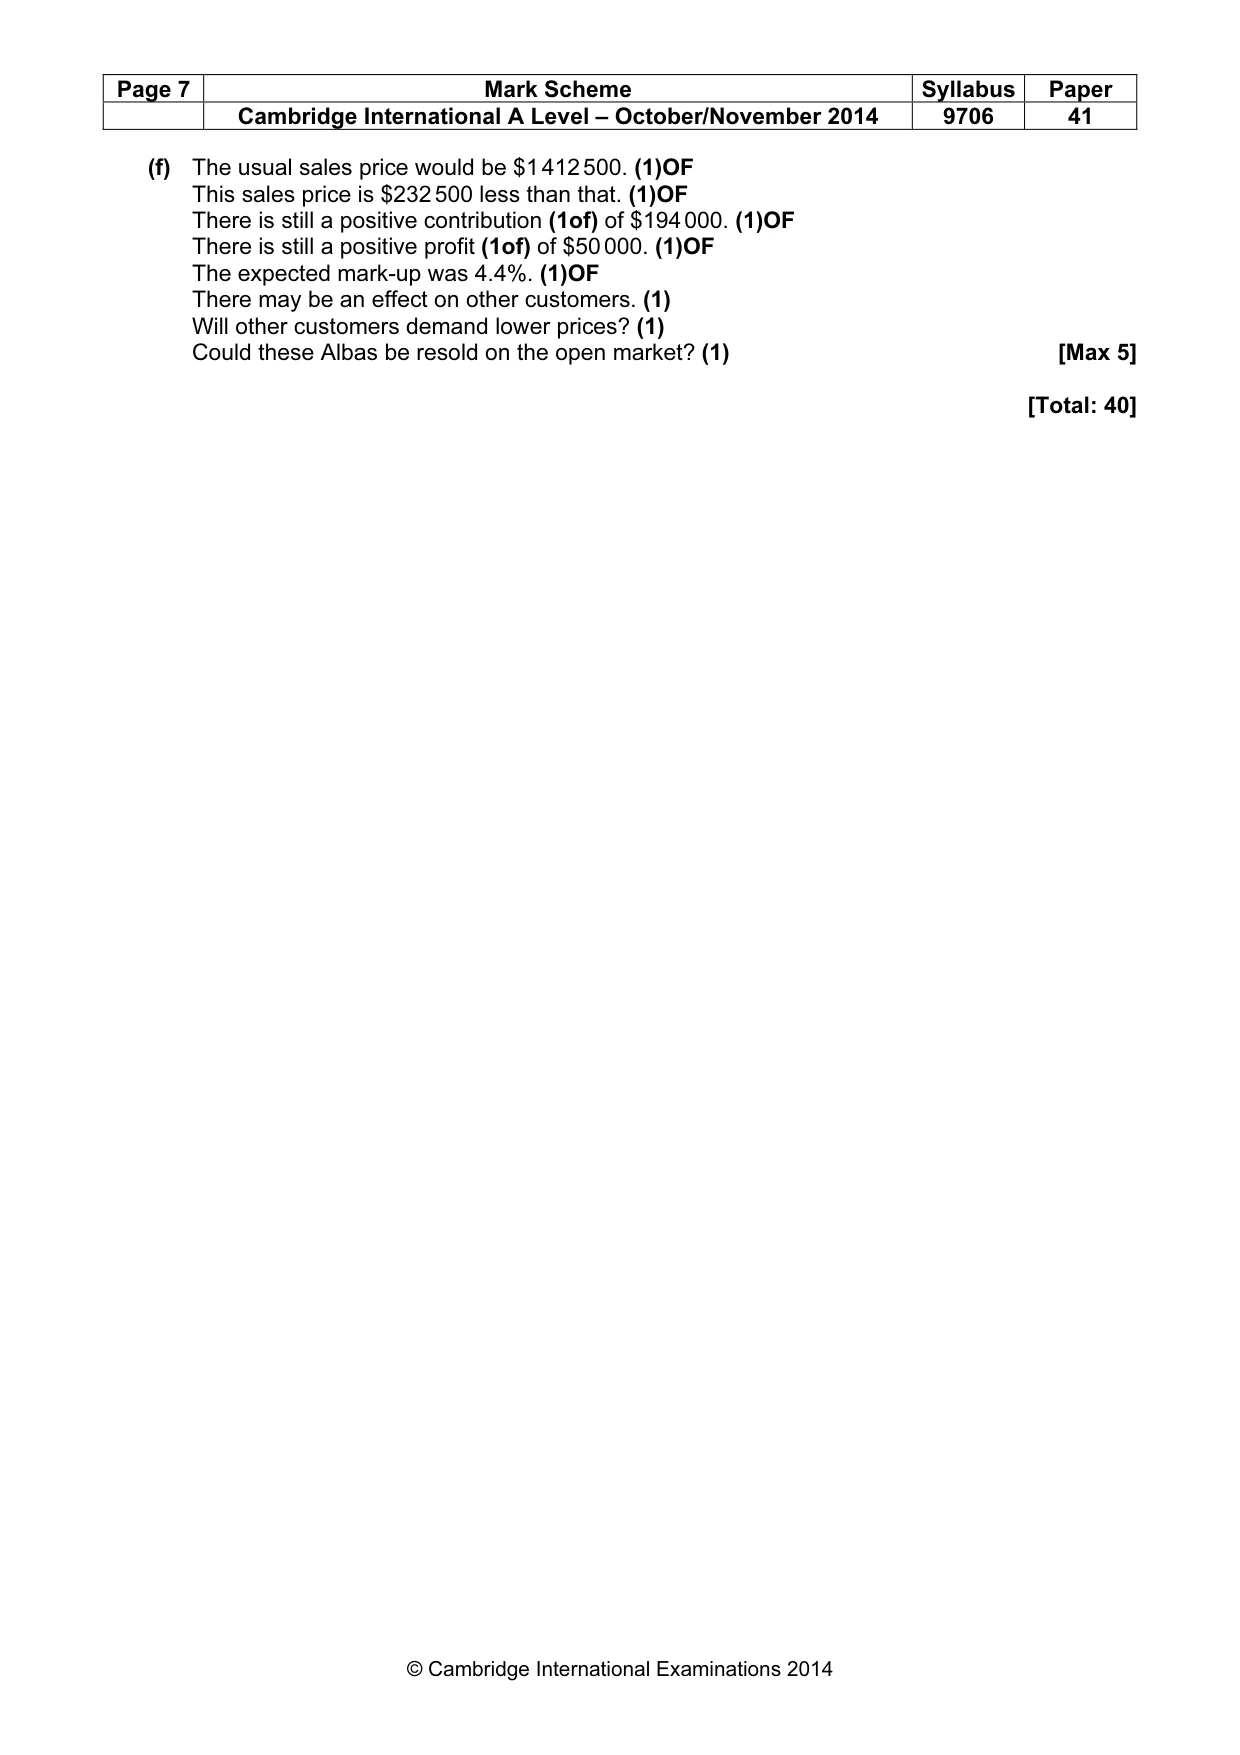
Page 7 Mark Scheme Syllabus Paper Cambridge International A Level – October/November 2014 9706 41 © Cambridge International Examinations 2014 (f) The usual sales price would be $1 412 500. (1)OF This sales price is $232 500 less than that. (1)OF There is still a positive contribution (1of) of $194 000. (1)OF There is still a positive profit (1of) of $50 000. (1)OF The expected mark-up was 4.4%. (1)OF There may be an effect on other customers. (1) Will other customers demand lower prices? (1) Could these Albas be resold on the open market? (1) [Max 5] [Total: 40]
What you needed in this session
Cambridge’s own grade thresholds for 2014 Oct/Nov, Paper 4 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.