Questions as text
Q1 · Rashid’s financial year ends on 31 December 0985/11 May/June 2020
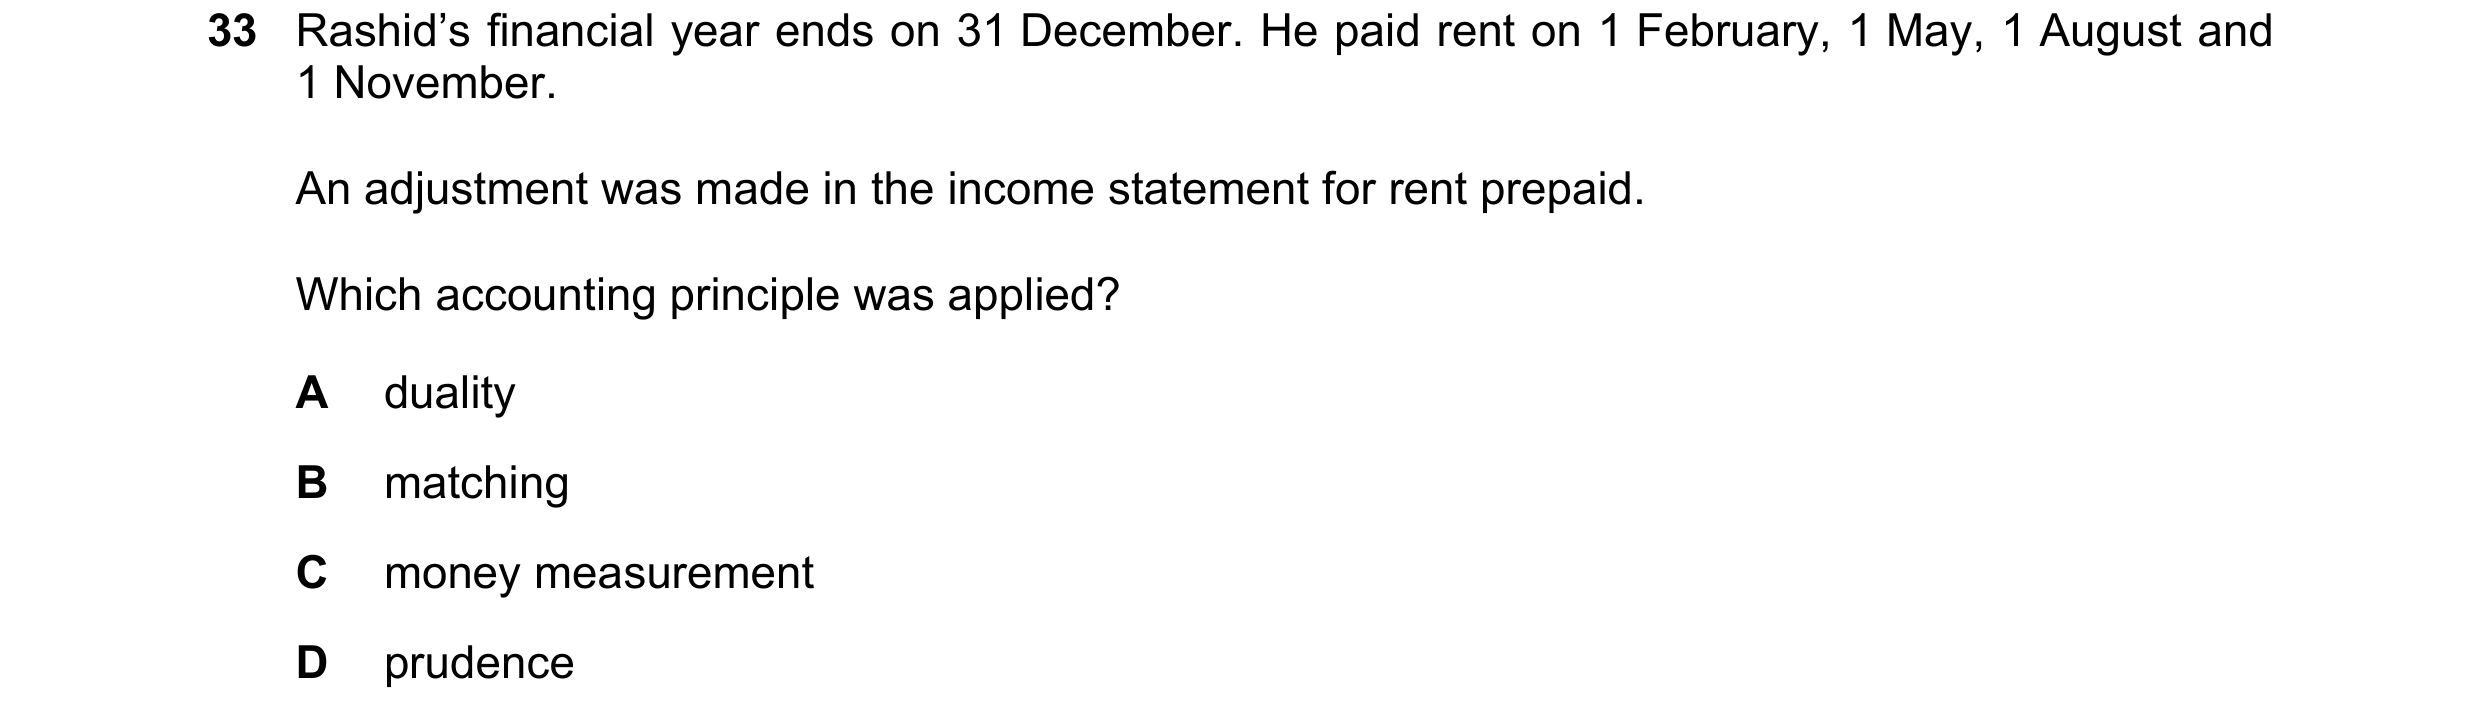
33 Rashid’s financial year ends on 31 December. He paid rent on 1 February, 1 May, 1 August and 1 November. An adjustment was made in the income statement for rent prepaid. Which accounting principle was applied? A duality B matching C money measurement D prudence
1 marks
Answer: B
This question in 0985/11 May/June 2020
Q2 · Which statement describes the going concern principle? 0985/11 May/June 2020
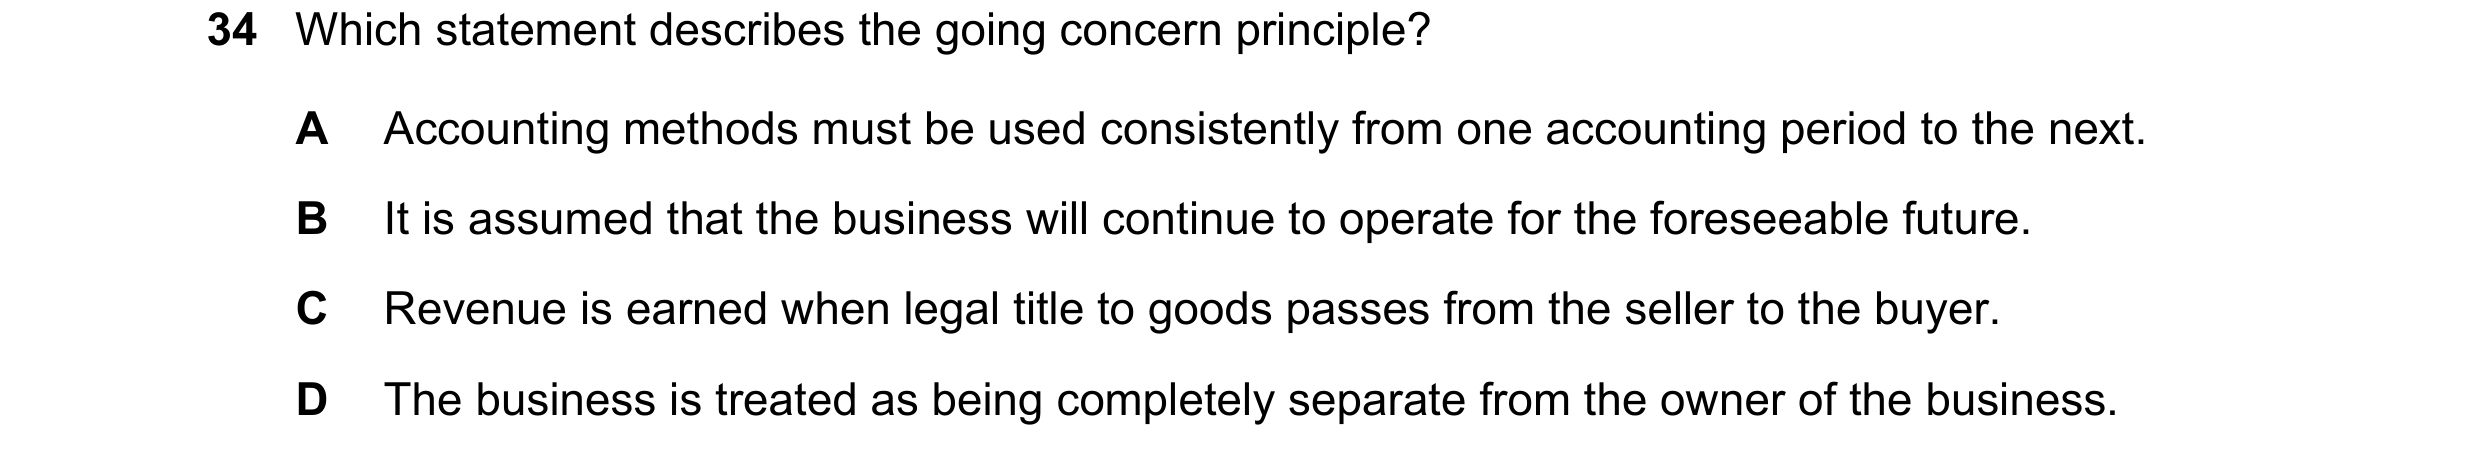
34 Which statement describes the going concern principle? A Accounting methods must be used consistently from one accounting period to the next. B It is assumed that the business will continue to operate for the foreseeable future. C Revenue is earned when legal title to goods passes from the seller to the buyer. D The business is treated as being completely separate from the owner of the business.
1 marks
Answer: B
This question in 0985/11 May/June 2020
Q3 · Brad purchased a machine for $1000 on 1 January 2019 0985/11 May/June 2020
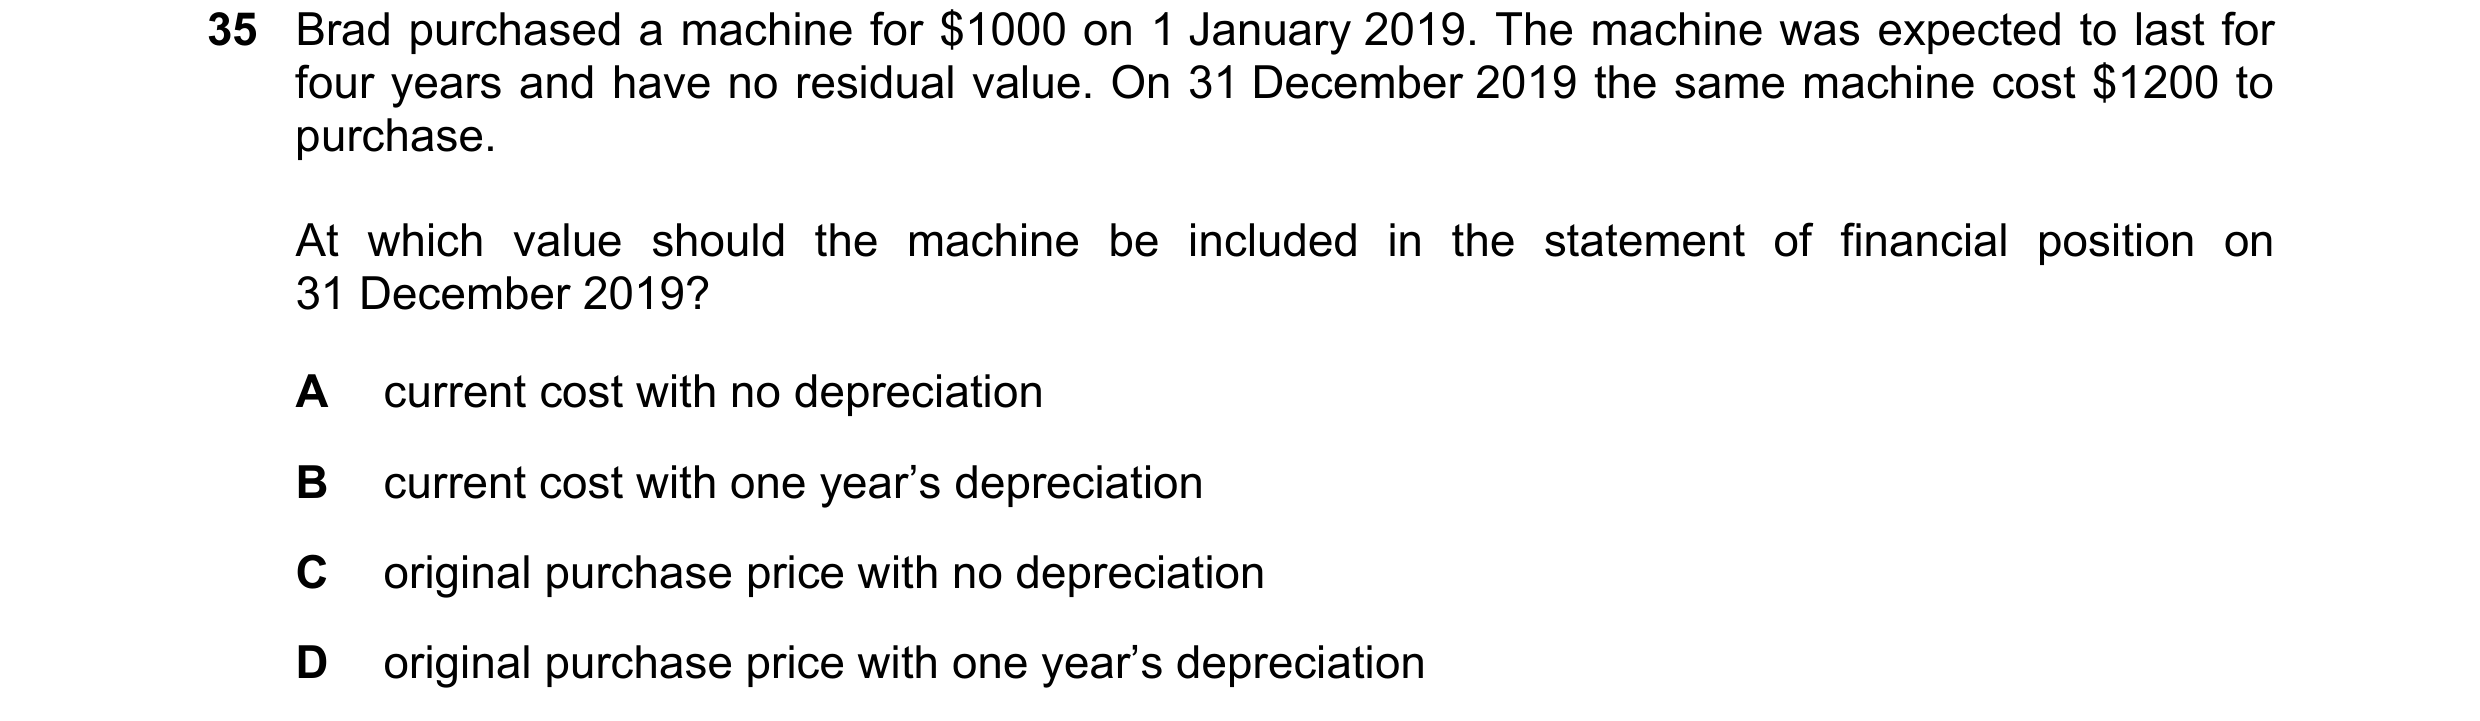
35 Brad purchased a machine for $1000 on 1 January 2019. The machine was expected to last for four years and have no residual value. On 31 December 2019 the same machine cost $1200 to purchase. At which value should the machine be included in the statement of financial position on 31 December 2019? A current cost with no depreciation B current cost with one year’s depreciation C original purchase price with no depreciation D original purchase price with one year’s depreciation
1 marks
Answer: D
This question in 0985/11 May/June 2020
Q4 · At the end of the financial year, a company did not account for the unused stationary… 0985/12 May/June 2020
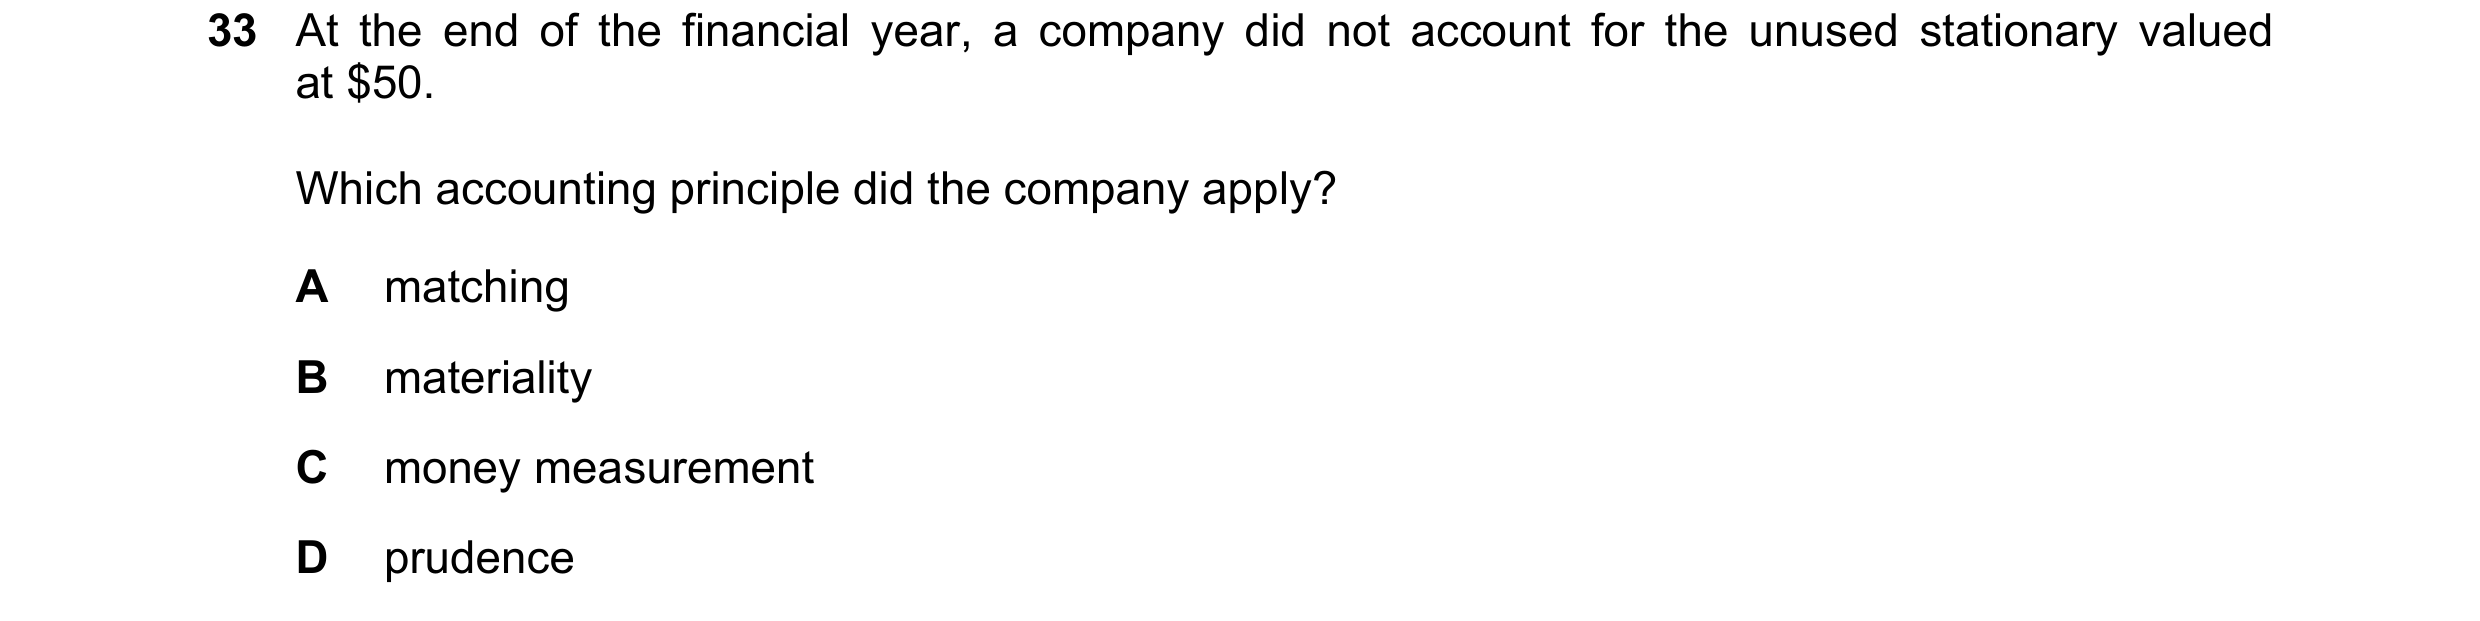
33 At the end of the financial year, a company did not account for the unused stationary valued at $50. Which accounting principle did the company apply? A matching B materiality C money measurement D prudence
1 marks
Answer: B
This question in 0985/12 May/June 2020
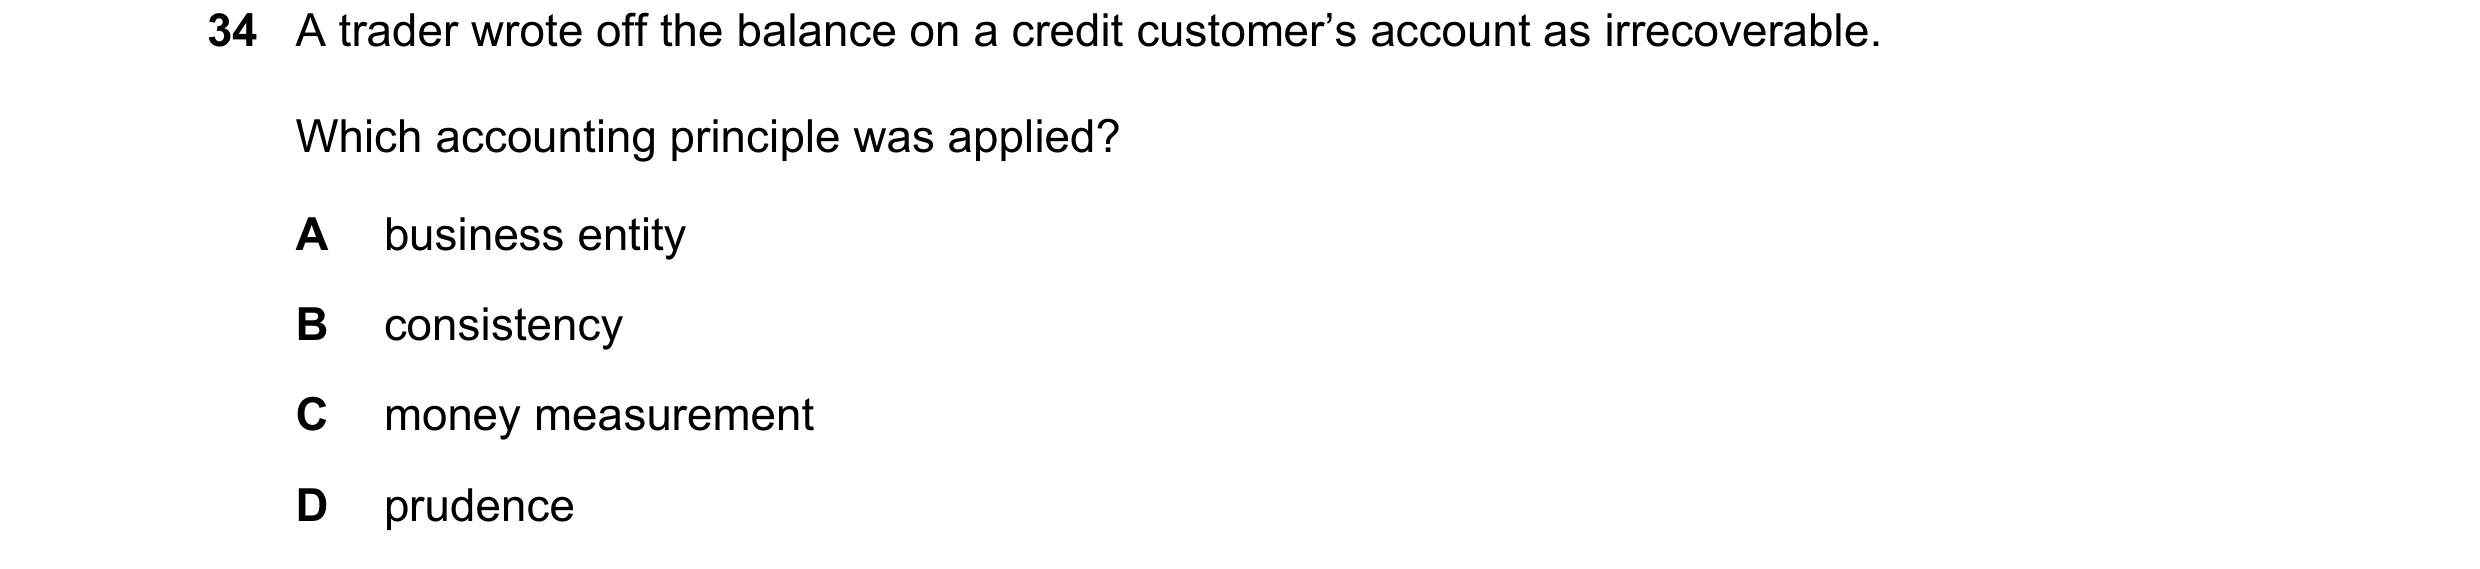
Q5 · A trader wrote off the balance on a credit customer’s account as irrecoverable 0985/12 May/June 2020
34 A trader wrote off the balance on a credit customer’s account as irrecoverable. Which accounting principle was applied? A business entity B consistency C money measurement D prudence
1 marks
Answer: D
This question in 0985/12 May/June 2020
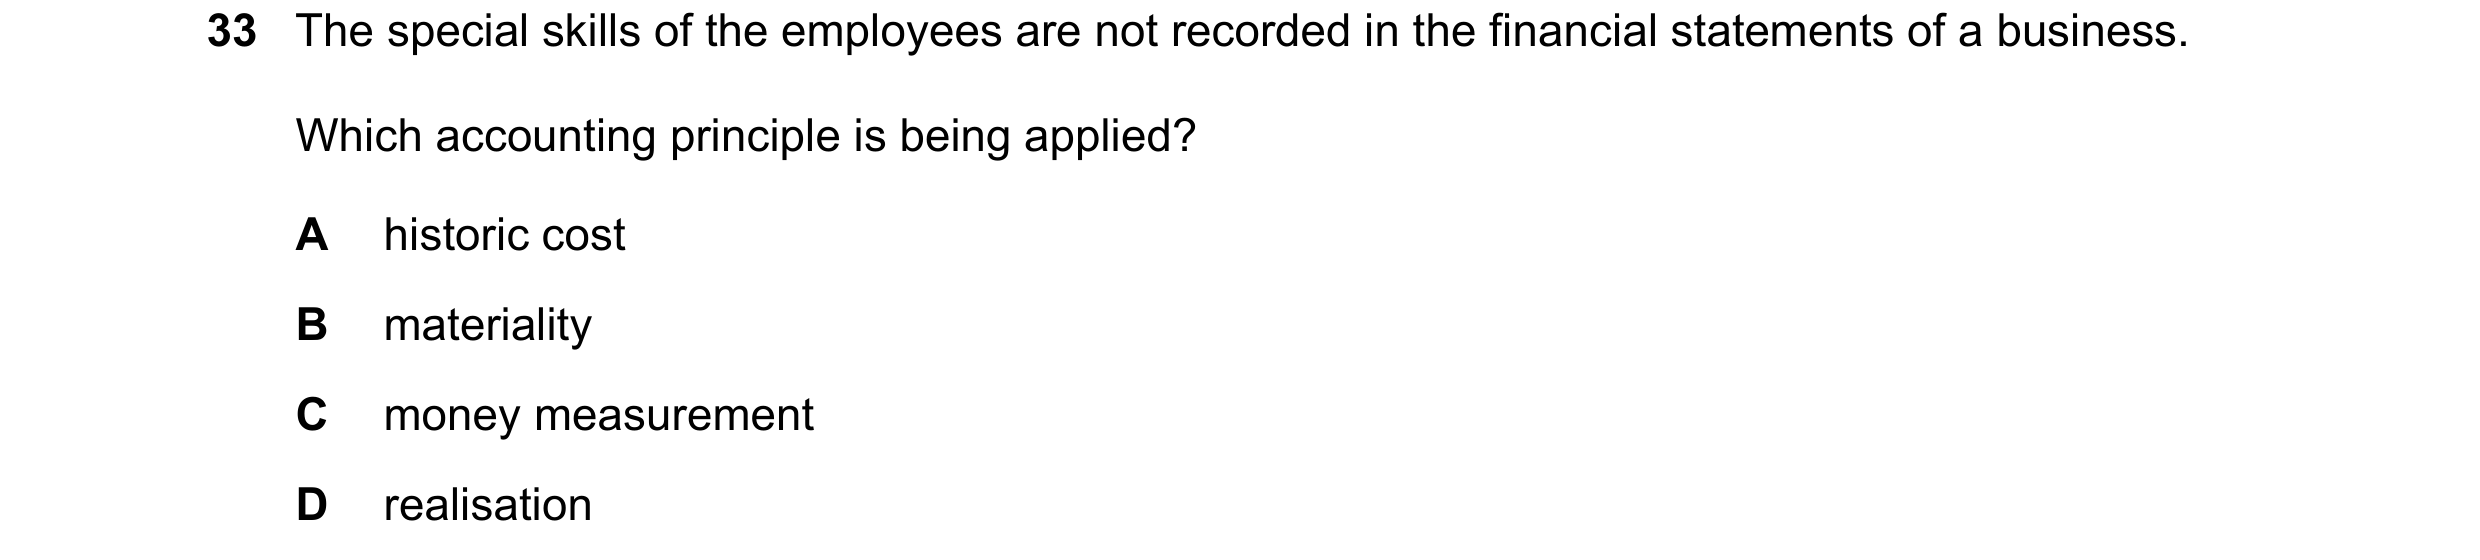
Q6 · The special skills of the employees are not recorded in the financial statements of a… 0985/12 Oct/Nov 2020
33 The special skills of the employees are not recorded in the financial statements of a business. Which accounting principle is being applied? A historic cost B materiality C money measurement D realisation
1 marks
Answer: C
This question in 0985/12 Oct/Nov 2020
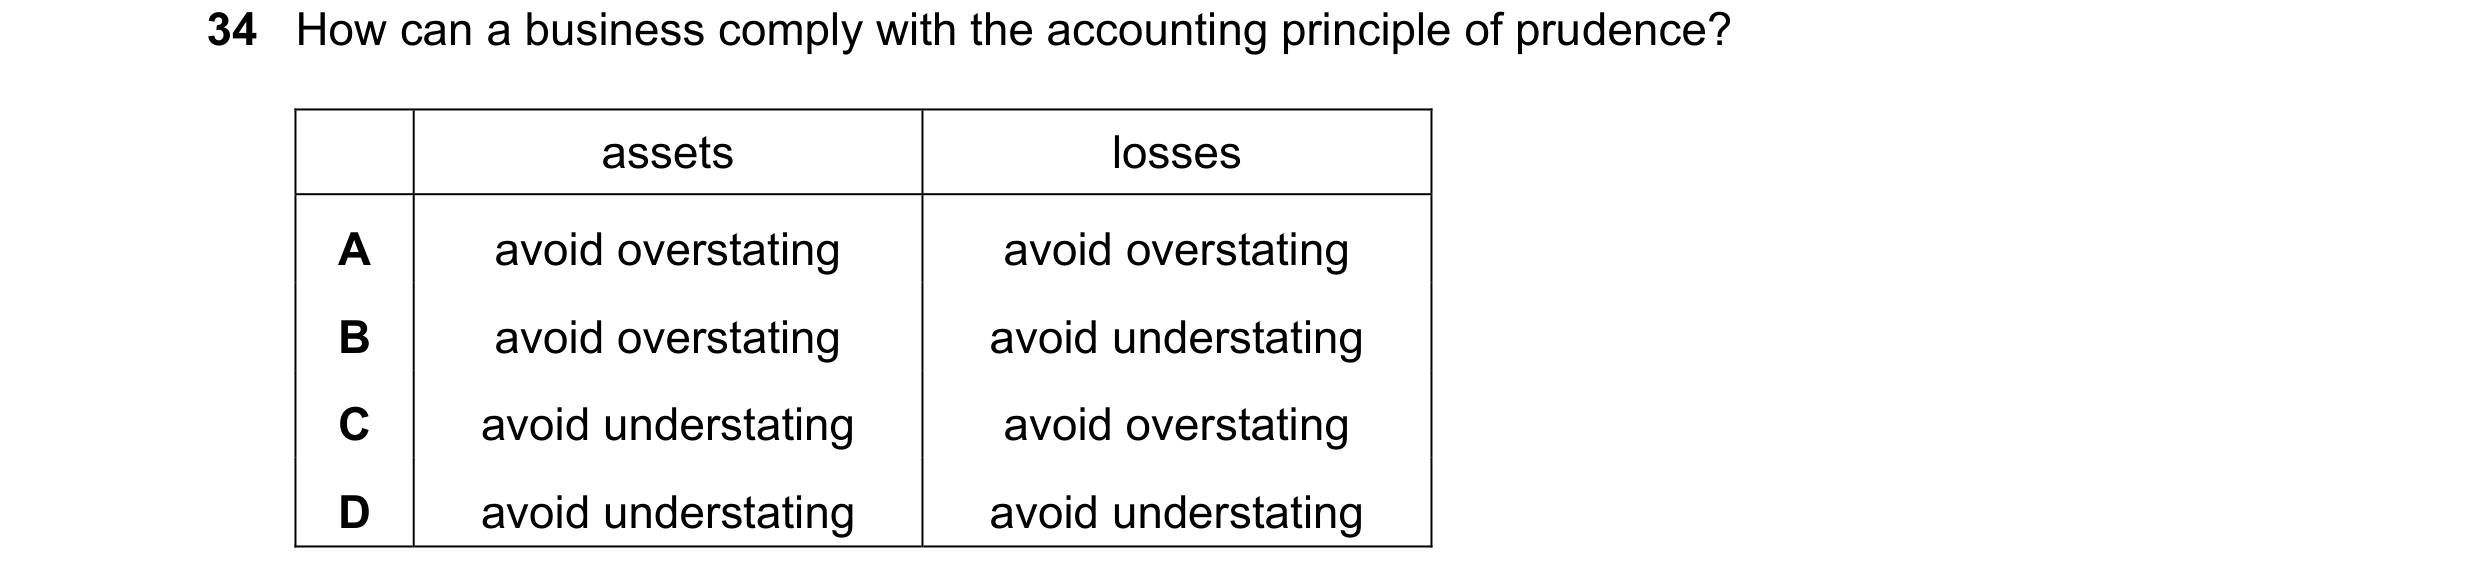
Q7 · How can a business comply with the accounting principle of prudence? 0985/12 Oct/Nov 2020
34 How can a business comply with the accounting principle of prudence? assets losses A avoid overstating avoid overstating B avoid overstating avoid understating C avoid understating avoid overstating D avoid understating avoid understating
1 marks
Answer: B
This question in 0985/12 Oct/Nov 2020
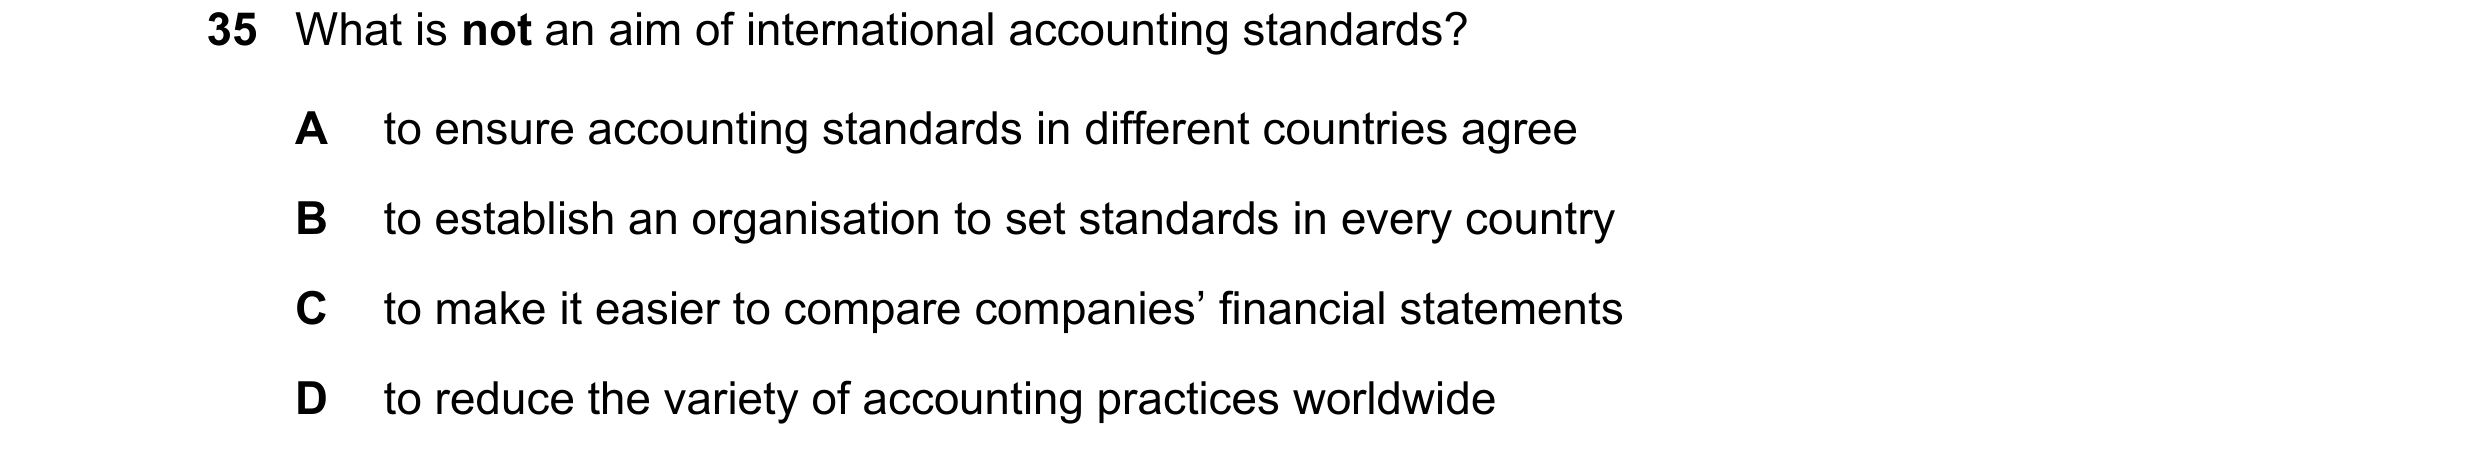
Q8 · What is not an aim of international accounting standards? 0985/12 Oct/Nov 2020
35 What is not an aim of international accounting standards? A to ensure accounting standards in different countries agree B to establish an organisation to set standards in every country C to make it easier to compare companies’ financial statements D to reduce the variety of accounting practices worldwide
1 marks
Answer: B
This question in 0985/12 Oct/Nov 2020
Q9 · Why does a business provide for depreciation on non-current assets? 0985/11 May/June 2021
12 Why does a business provide for depreciation on non-current assets? A to charge the cost of non-current assets against profit in the year of purchase B to ensure that non-current assets appear at book value in the statement of financial position C to ensure that the matching principle is applied when preparing financial statements D to retain cash in the business for replacement of non-current assets
1 marks
Answer: C
This question in 0985/11 May/June 2021
Q10 · Why does a business maintain a provision for doubtful debts account? 0985/11 May/June 2021
15 Why does a business maintain a provision for doubtful debts account? A to apply the accounting principle of prudence B to avoid profit for the year being understated C to have an accurate forecast of debts which will be uncollectible D to reduce the expense of irrecoverable debts in the future
1 marks
Answer: A
This question in 0985/11 May/June 2021
Q11 · How should inventory be valued? 0985/11 May/June 2021
16 How should inventory be valued? A cost B higher of cost and net realisable value C lower of cost and net realisable value D net realisable value
1 marks
Answer: C
This question in 0985/11 May/June 2021
Q12 · Sabeena runs a retail business 0985/11 May/June 2021
33 Sabeena runs a retail business. She plans to close her business in a few weeks’ time. How should her fixtures and fittings be valued in the statement of financial position? A at book value B at expected sales value C at original cost D at replacement cost
1 marks
Answer: B
This question in 0985/11 May/June 2021
Q13 · Why should a trader match his costs for a financial year with the revenues for the same… 0985/11 May/June 2021
34 Why should a trader match his costs for a financial year with the revenues for the same period? A to account for all liabilities B to account for money that has been paid in advance C to make sure outstanding income is included D to show the correct profit figure
1 marks
Answer: D
This question in 0985/11 May/June 2021
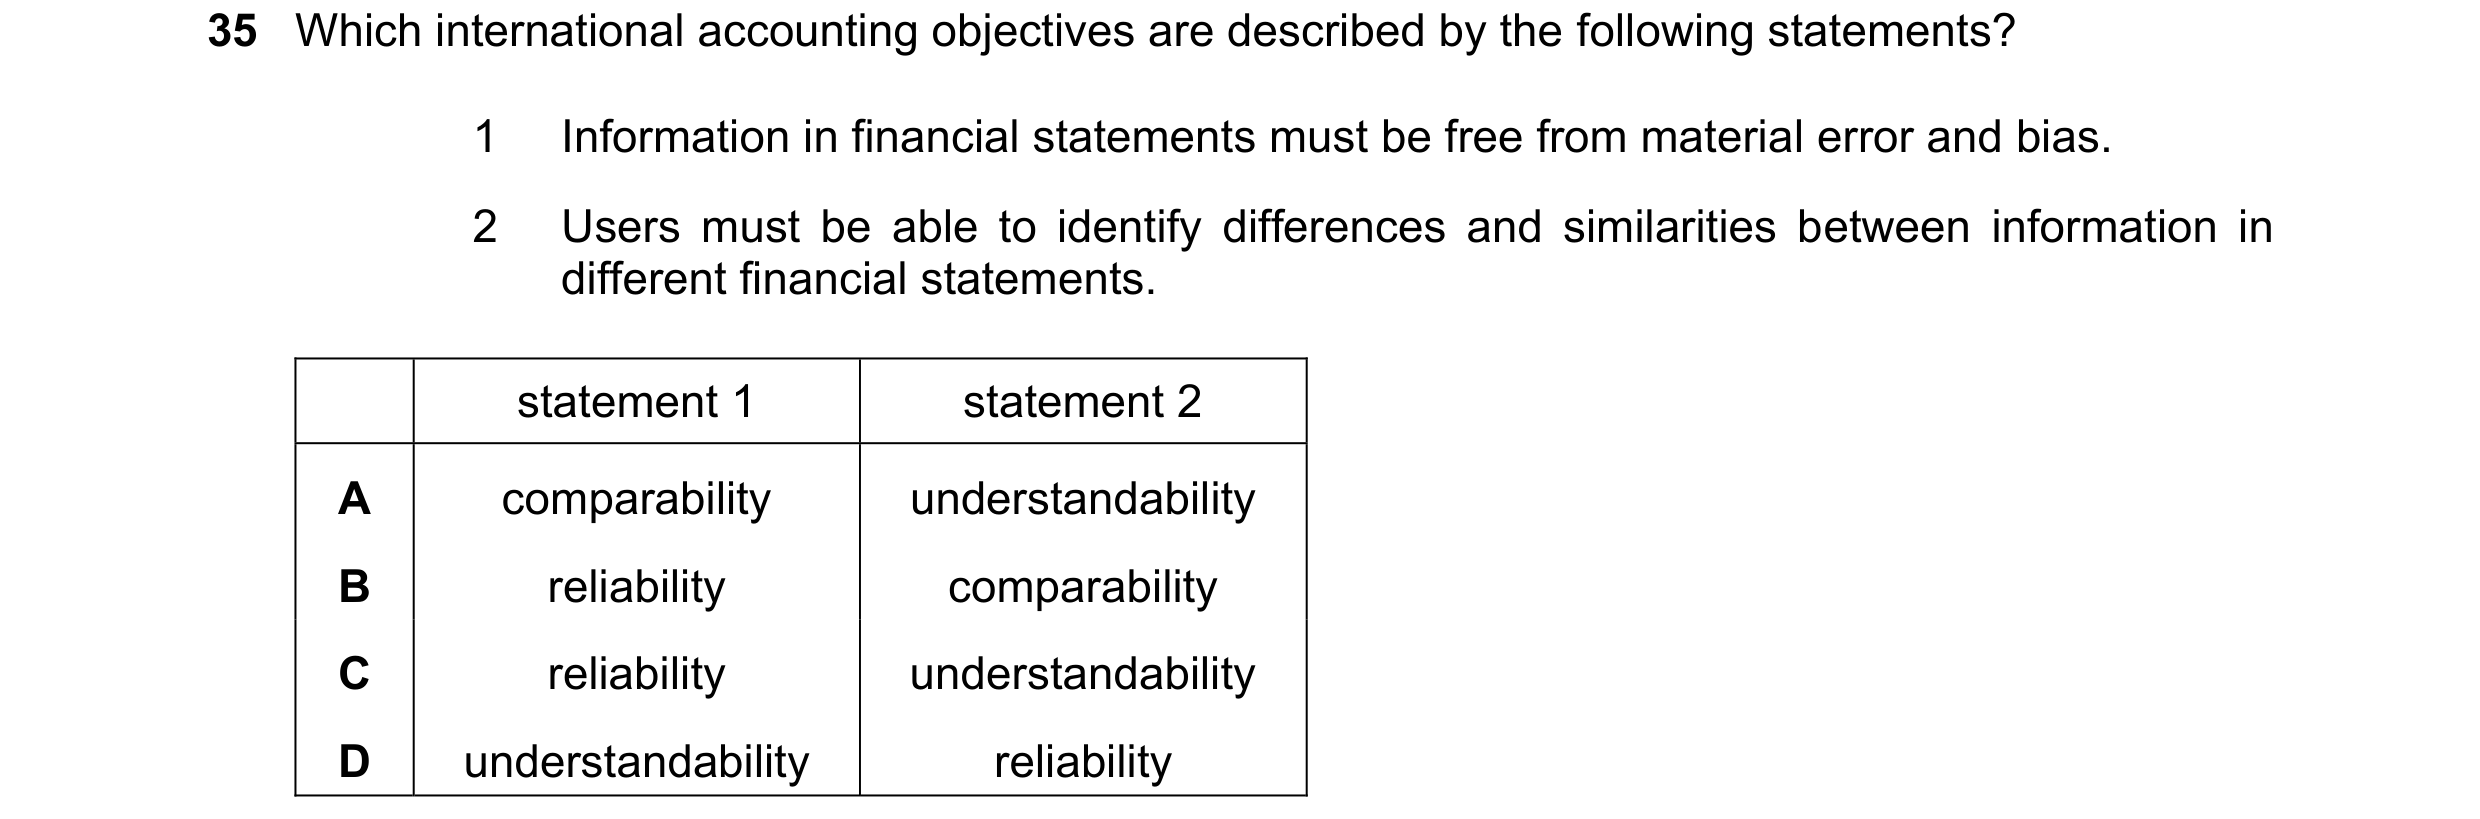
Q14 · Which international accounting objectives are described by the following statements? 0985/11 May/June 2021
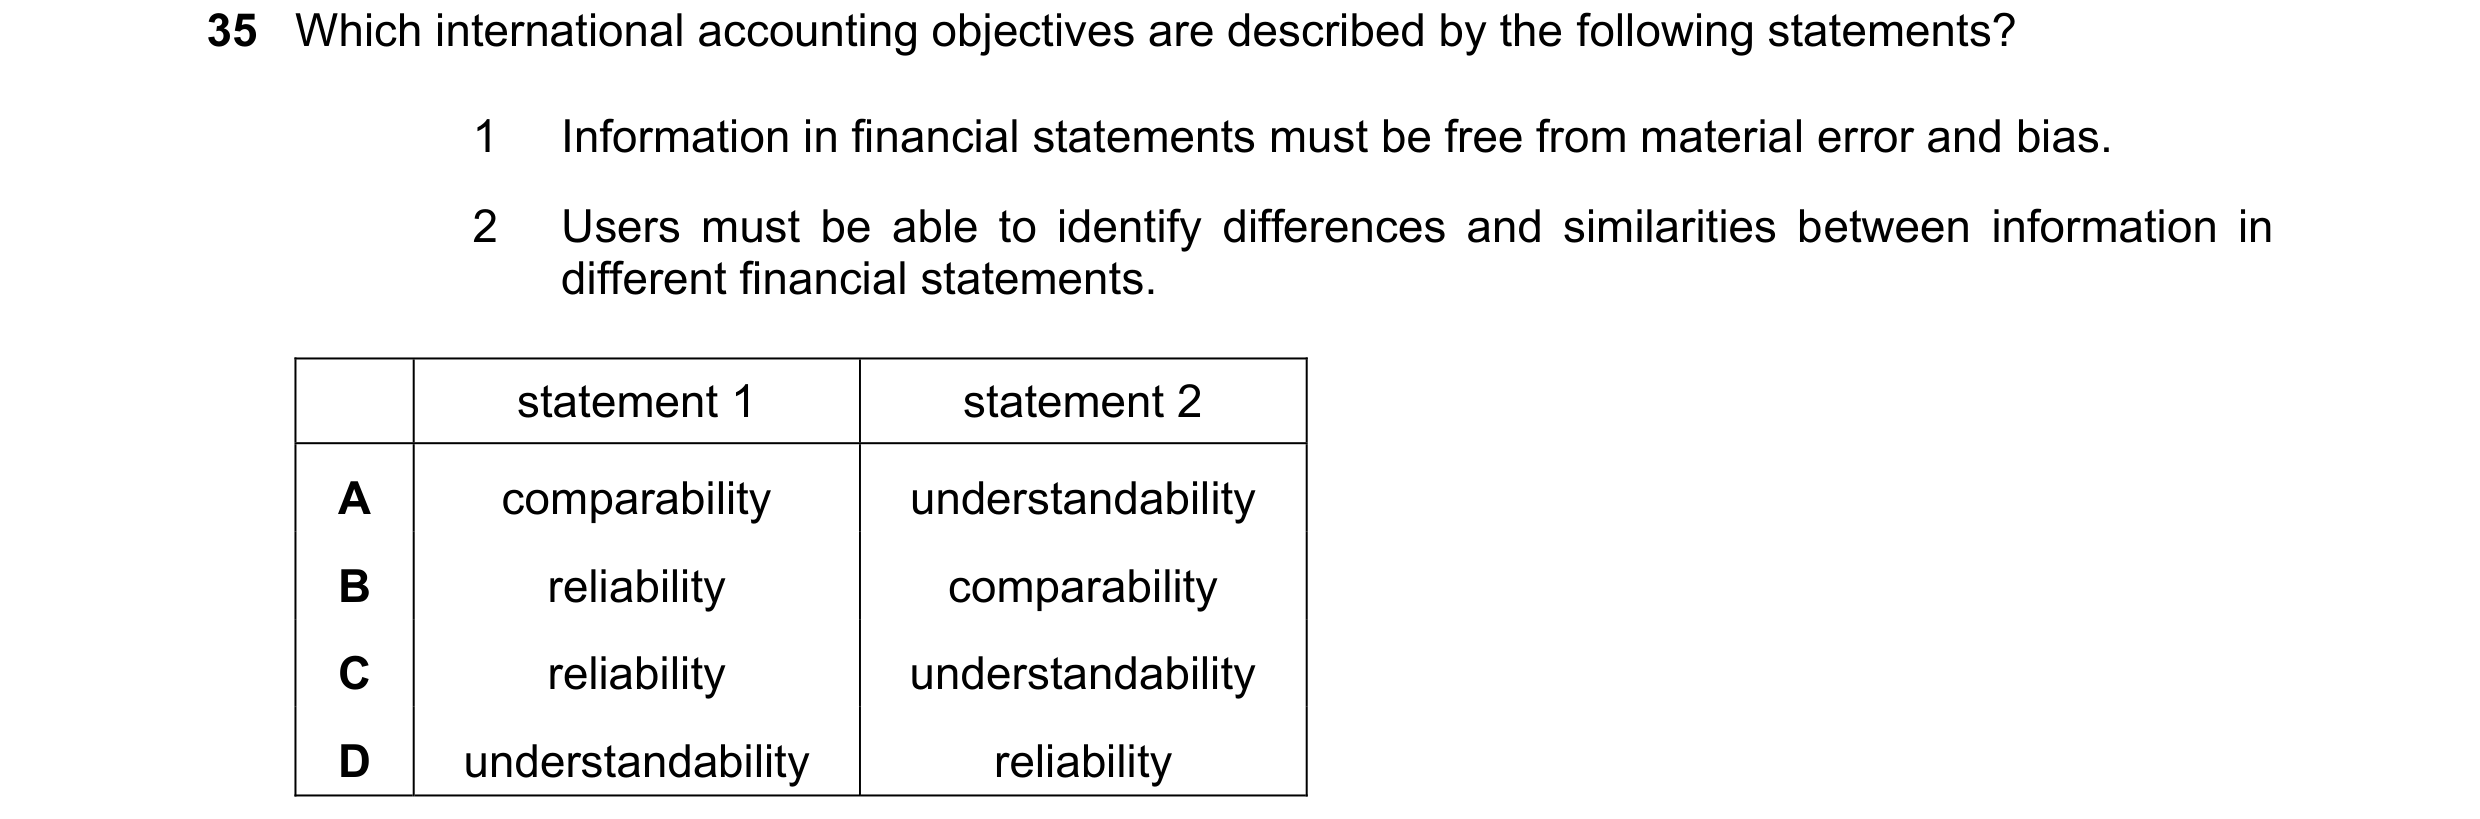
35 Which international accounting objectives are described by the following statements? 1 Information in financial statements must be free from material error and bias. 2 Users must be able to identify differences and similarities between information in different financial statements. statement 1 statement 2 A comparability understandability B reliability comparability C reliability understandability D understandability reliability
1 marks
Answer: B
This question in 0985/11 May/June 2021
Q15 · Why does a business provide for depreciation on non-current assets? 0985/12 May/June 2021
17 Why does a business provide for depreciation on non-current assets? A to charge the cost of non-current assets against profit in the year of purchase B to ensure that non-current assets appear at book value in the statement of financial position C to ensure that the matching principle is applied when preparing financial statements D to retain cash in the business for replacement of non-current assets
1 marks
Answer: C
This question in 0985/12 May/June 2021
Q16 · Why would a bakery business not include a value for inventory of stationery in the… 0985/12 May/June 2021
19 Why would a bakery business not include a value for inventory of stationery in the statement of financial position? A It was expected it would be used in the next few months. B It was purchased regularly and paid for in cash. C It was not for resale. D It was of very low value.
1 marks
Answer: D
This question in 0985/12 May/June 2021
Q17 · How should inventory be valued? 0985/12 May/June 2021
21 How should inventory be valued? A cost B higher of cost and net realisable value C lower of cost and net realisable value D net realisable value
1 marks
Answer: C
This question in 0985/12 May/June 2021
Q18 · Which international accounting objectives are described by the following statements? 0985/12 May/June 2021
35 Which international accounting objectives are described by the following statements? 1 Information in financial statements must be free from material error and bias. 2 Users must be able to identify differences and similarities between information in different financial statements. statement 1 statement 2 A comparability understandability B reliability comparability C reliability understandability D understandability reliability
1 marks
Answer: B
This question in 0985/12 May/June 2021
Q19 · Charlie is a car dealer 0985/12 Oct/Nov 2021
34 Charlie is a car dealer. Joe wanted a new car and went to Charlie’s car showroom. On Monday Joe took a car for a test drive and decided to buy it. On Tuesday Joe arranged to pay for the car by cheque. On Wednesday Joe collected the car and received an invoice. On Thursday Joe’s cheque was cleared by the bank. On which day was Charlie able to account for the profit on the sale? A Monday B Tuesday C Wednesday D Thursday
1 marks
Answer: C
This question in 0985/12 Oct/Nov 2021
Q20 · Which accounting objective requires that financial information is provided in time for a… 0985/12 Oct/Nov 2021
35 Which accounting objective requires that financial information is provided in time for a decision to be made? A comparability B relevance C reliability D understandability
1 marks
Answer: B
This question in 0985/12 Oct/Nov 2021
Q21 · Which accounting policy requires that the information in financial statements is free… 0985/11 May/June 2022
35 Which accounting policy requires that the information in financial statements is free from significant errors and bias? A comparability B consistency C reliability D understandability
1 marks
Answer: C
This question in 0985/11 May/June 2022
Q22 · ‘Revenue should only be regarded as earned when the legal title of goods and services… 0985/12 May/June 2022
34 ‘Revenue should only be regarded as earned when the legal title of goods and services passes from the seller to the buyer.’ To which accounting principle does this statement refer? A going concern B matching C money measurement D realisation
1 marks
Answer: D
This question in 0985/12 May/June 2022
Q23 · ‘The information provided in financial statements should be capable of being… 0985/12 May/June 2022
35 ‘The information provided in financial statements should be capable of being independently verified.’ To which accounting policy does this statement refer? A comparability B relevance C reliability D understandability
1 marks
Answer: C
This question in 0985/12 May/June 2022
Q24 · Why should inventory be valued at the lower of cost and net realisable value? 0985/12 Oct/Nov 2022
17 Why should inventory be valued at the lower of cost and net realisable value? A to avoid undervaluing the inventory B to comply with the historic cost principle C to comply with the principle of materiality D to ensure that profits are not overstated
1 marks
Answer: D
This question in 0985/12 Oct/Nov 2022
Q25 · A business renewed an insurance policy 0985/12 Oct/Nov 2022
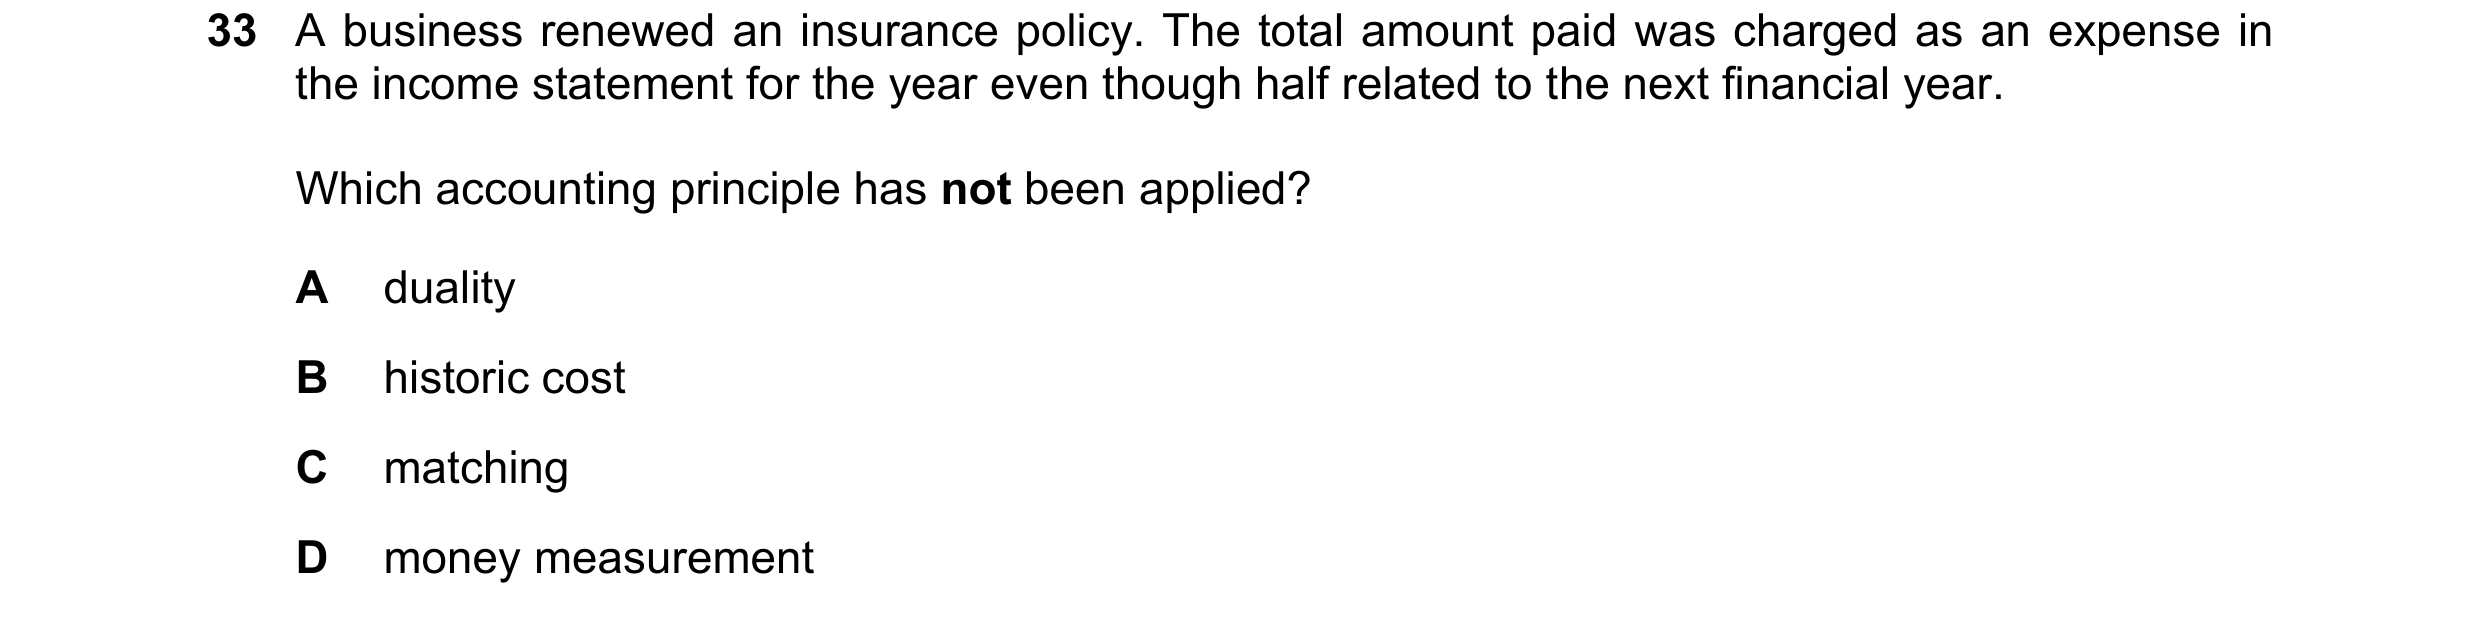
33 A business renewed an insurance policy. The total amount paid was charged as an expense in the income statement for the year even though half related to the next financial year. Which accounting principle has not been applied? A duality B historic cost C matching D money measurement
1 marks
Answer: C
This question in 0985/12 Oct/Nov 2022
Q26 · What is meant by the business entity principle? 0985/12 Oct/Nov 2022
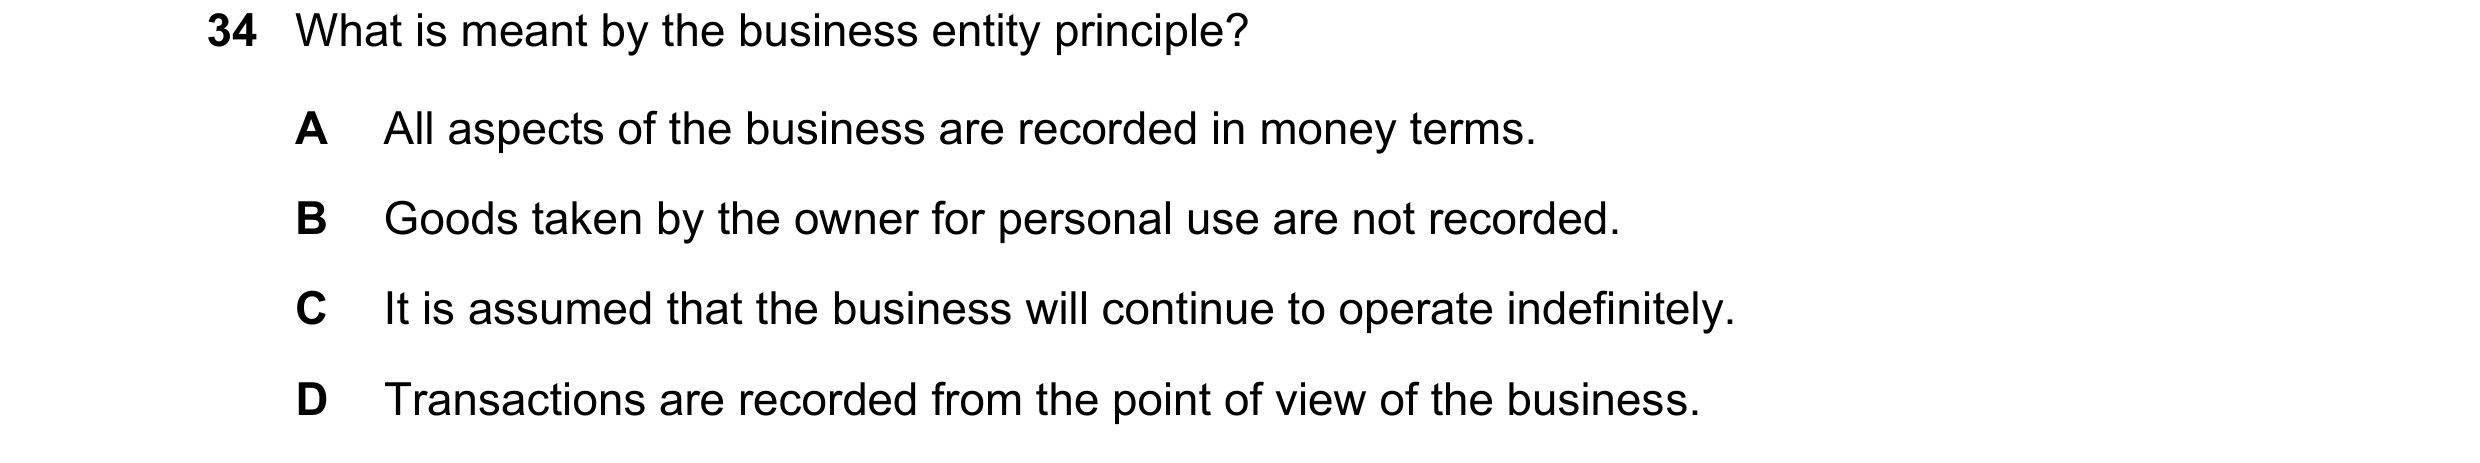
34 What is meant by the business entity principle? A All aspects of the business are recorded in money terms. B Goods taken by the owner for personal use are not recorded. C It is assumed that the business will continue to operate indefinitely. D Transactions are recorded from the point of view of the business.
1 marks
Answer: D
This question in 0985/12 Oct/Nov 2022
Q27 · Which statement is not correct about reasons for using international accounting standards? 0985/12 Oct/Nov 2022
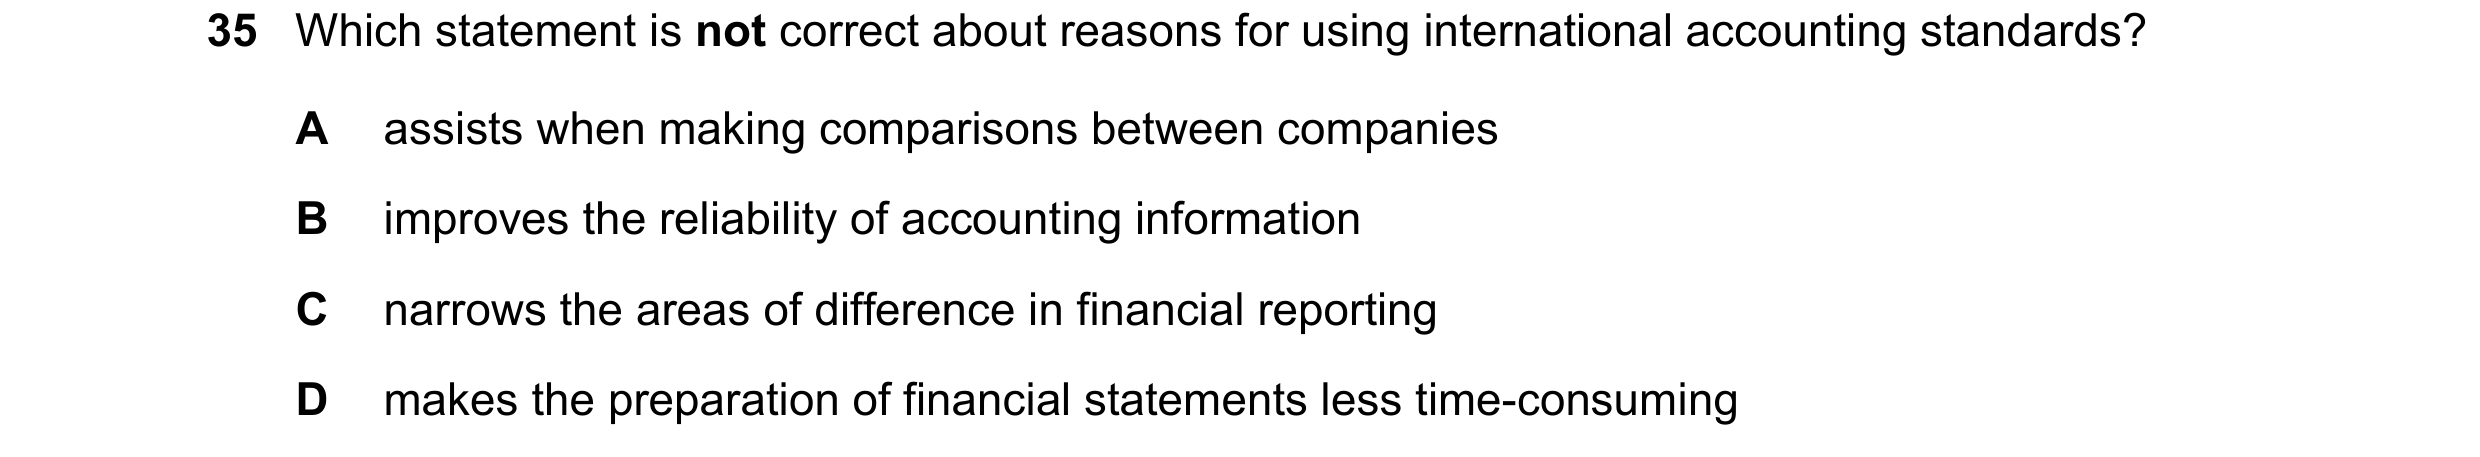
35 Which statement is not correct about reasons for using international accounting standards? A assists when making comparisons between companies B improves the reliability of accounting information C narrows the areas of difference in financial reporting D makes the preparation of financial statements less time-consuming
1 marks
Answer: D
This question in 0985/12 Oct/Nov 2022
Q28 · Manvinder started a business and paid a cheque for $1000 into a business bank account 0985/11 May/June 2023
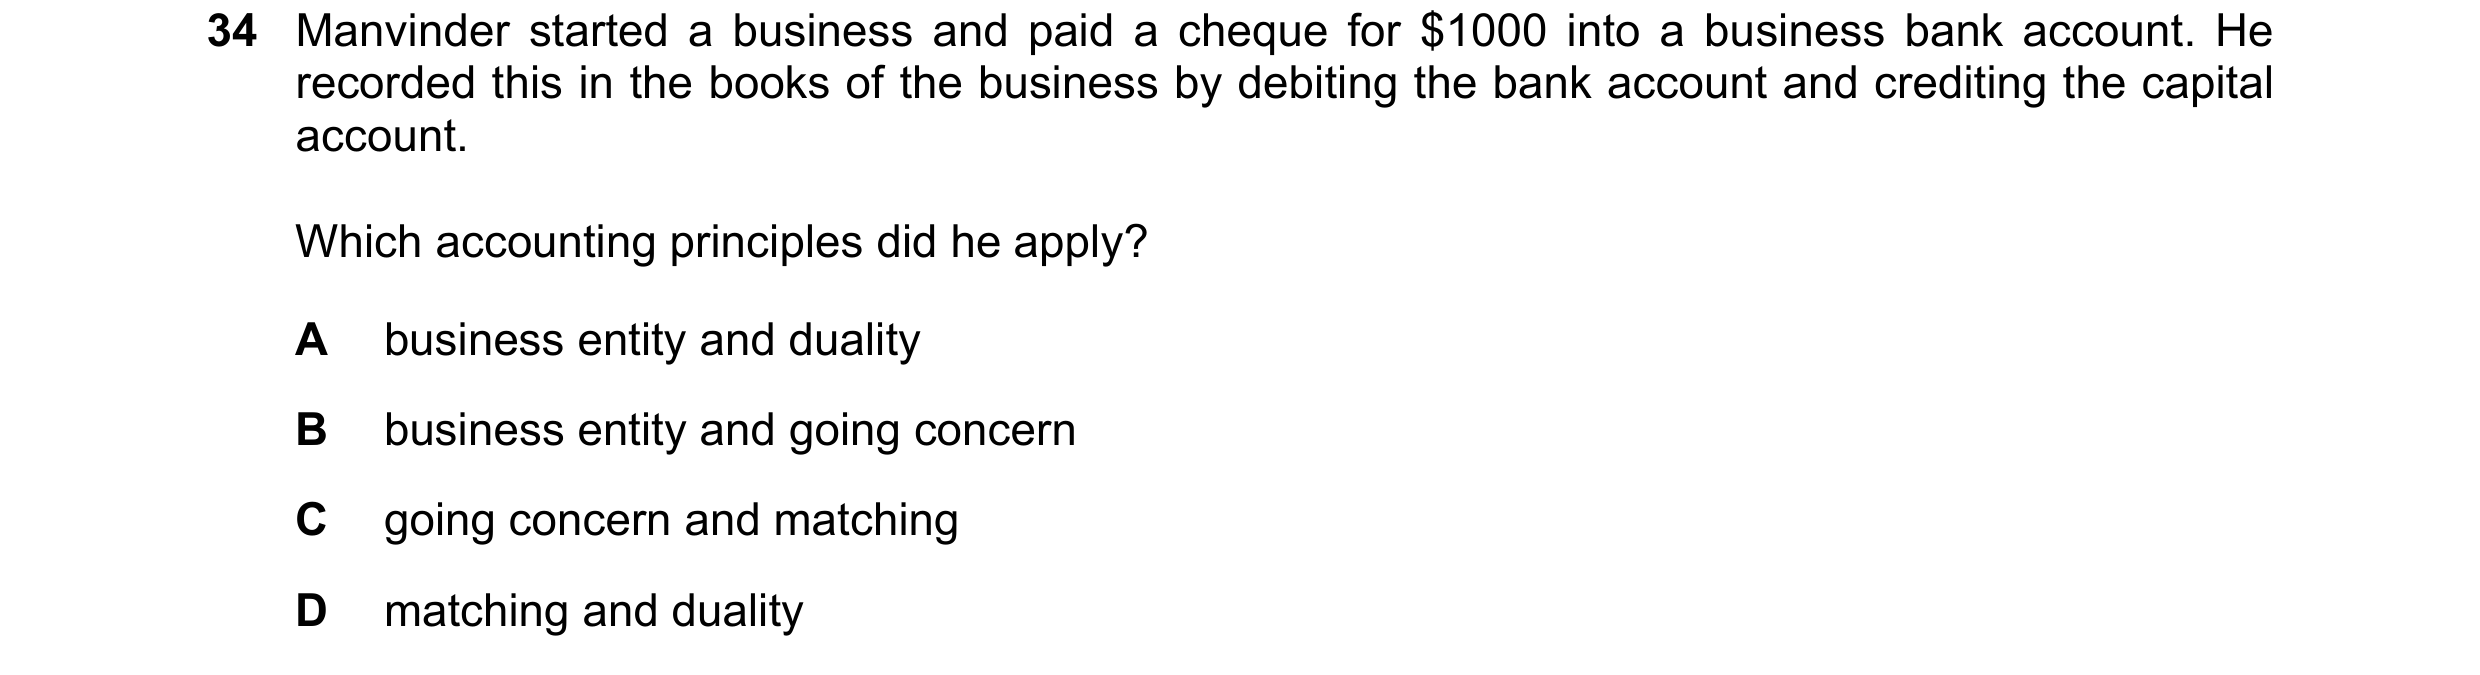
34 Manvinder started a business and paid a cheque for $1000 into a business bank account. He recorded this in the books of the business by debiting the bank account and crediting the capital account. Which accounting principles did he apply? A business entity and duality B business entity and going concern C going concern and matching D matching and duality
1 marks
Answer: A
This question in 0985/11 May/June 2023
Q29 · A trader always records assets and expenses in his ledger at the price he paid for them 0985/11 May/June 2023
35 A trader always records assets and expenses in his ledger at the price he paid for them. Which accounting principle is he applying? A business entity B historic cost C prudence D realisation
1 marks
Answer: B
This question in 0985/11 May/June 2023
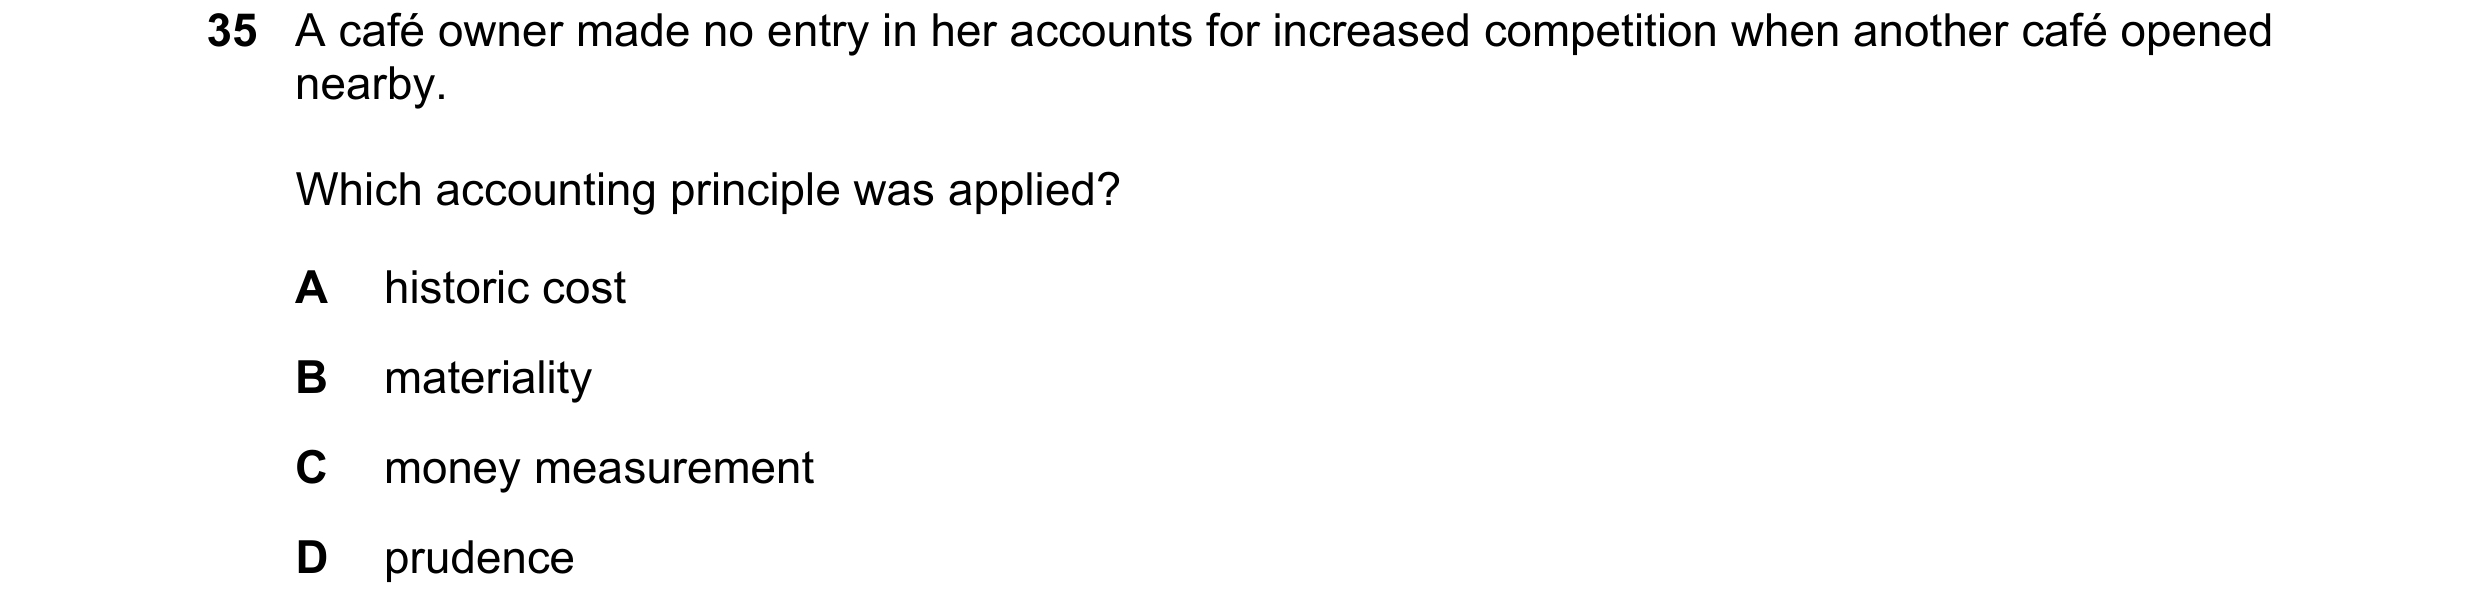
Q30 · A café owner made no entry in her accounts for increased competition when another café… 0985/12 May/June 2023
35 A café owner made no entry in her accounts for increased competition when another café opened nearby. Which accounting principle was applied? A historic cost B materiality C money measurement D prudence
1 marks
Answer: C
This question in 0985/12 May/June 2023
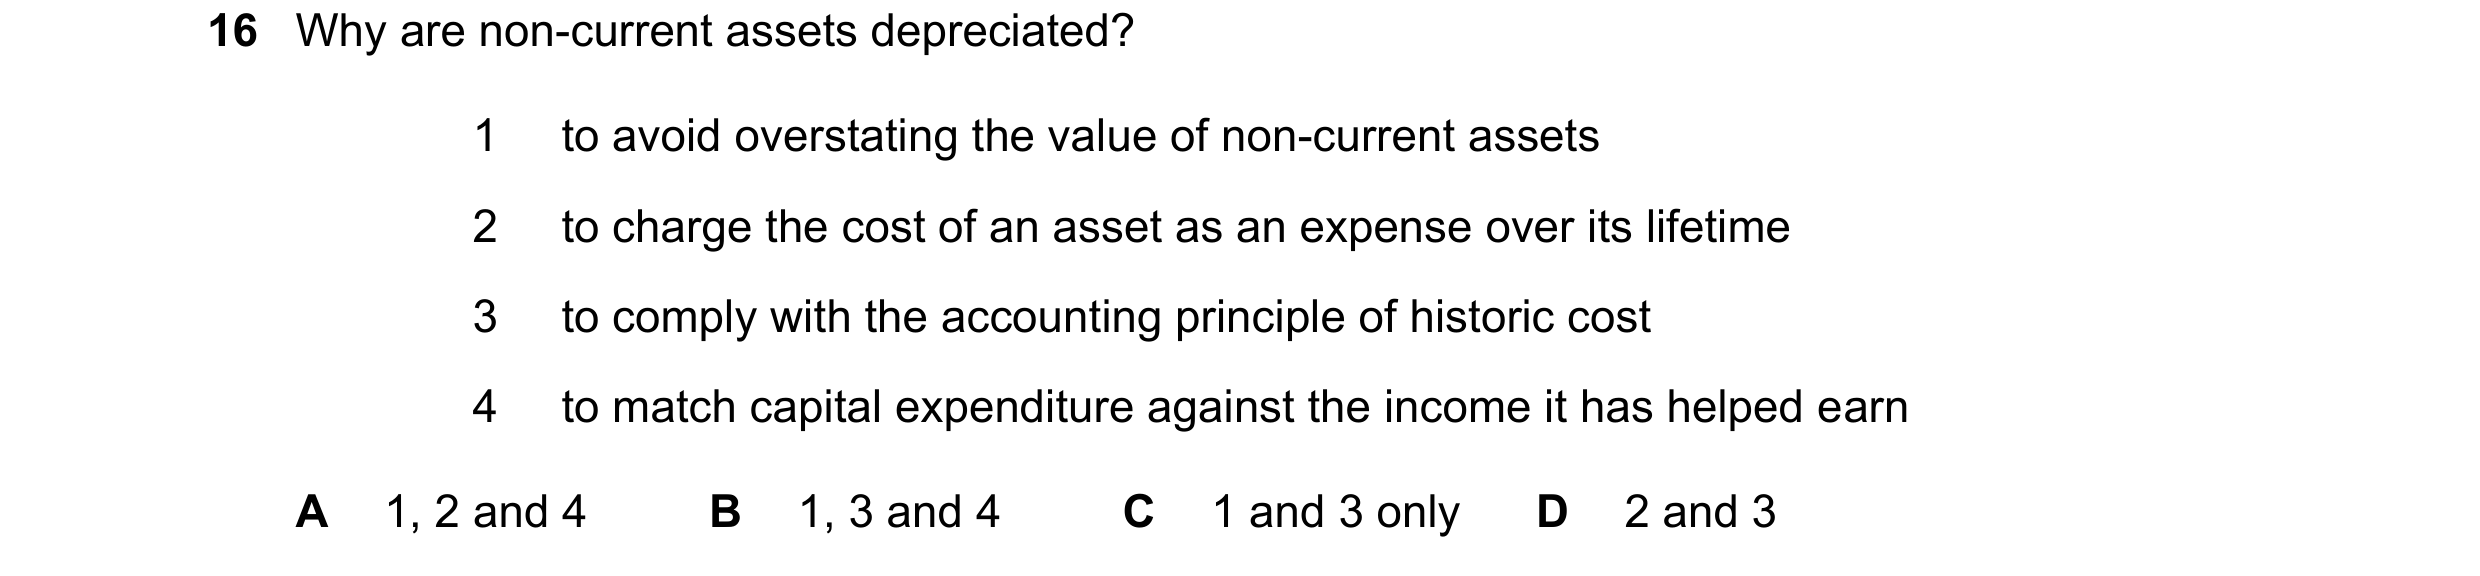
Q31 · Why are non-current assets depreciated? 0985/12 Oct/Nov 2023
16 Why are non-current assets depreciated? 1 to avoid overstating the value of non-current assets 2 to charge the cost of an asset as an expense over its lifetime 3 to comply with the accounting principle of historic cost 4 to match capital expenditure against the income it has helped earn A 1, 2 and 4 B 1, 3 and 4 C 1 and 3 only D 2 and 3
1 marks
Answer: A
This question in 0985/12 Oct/Nov 2023
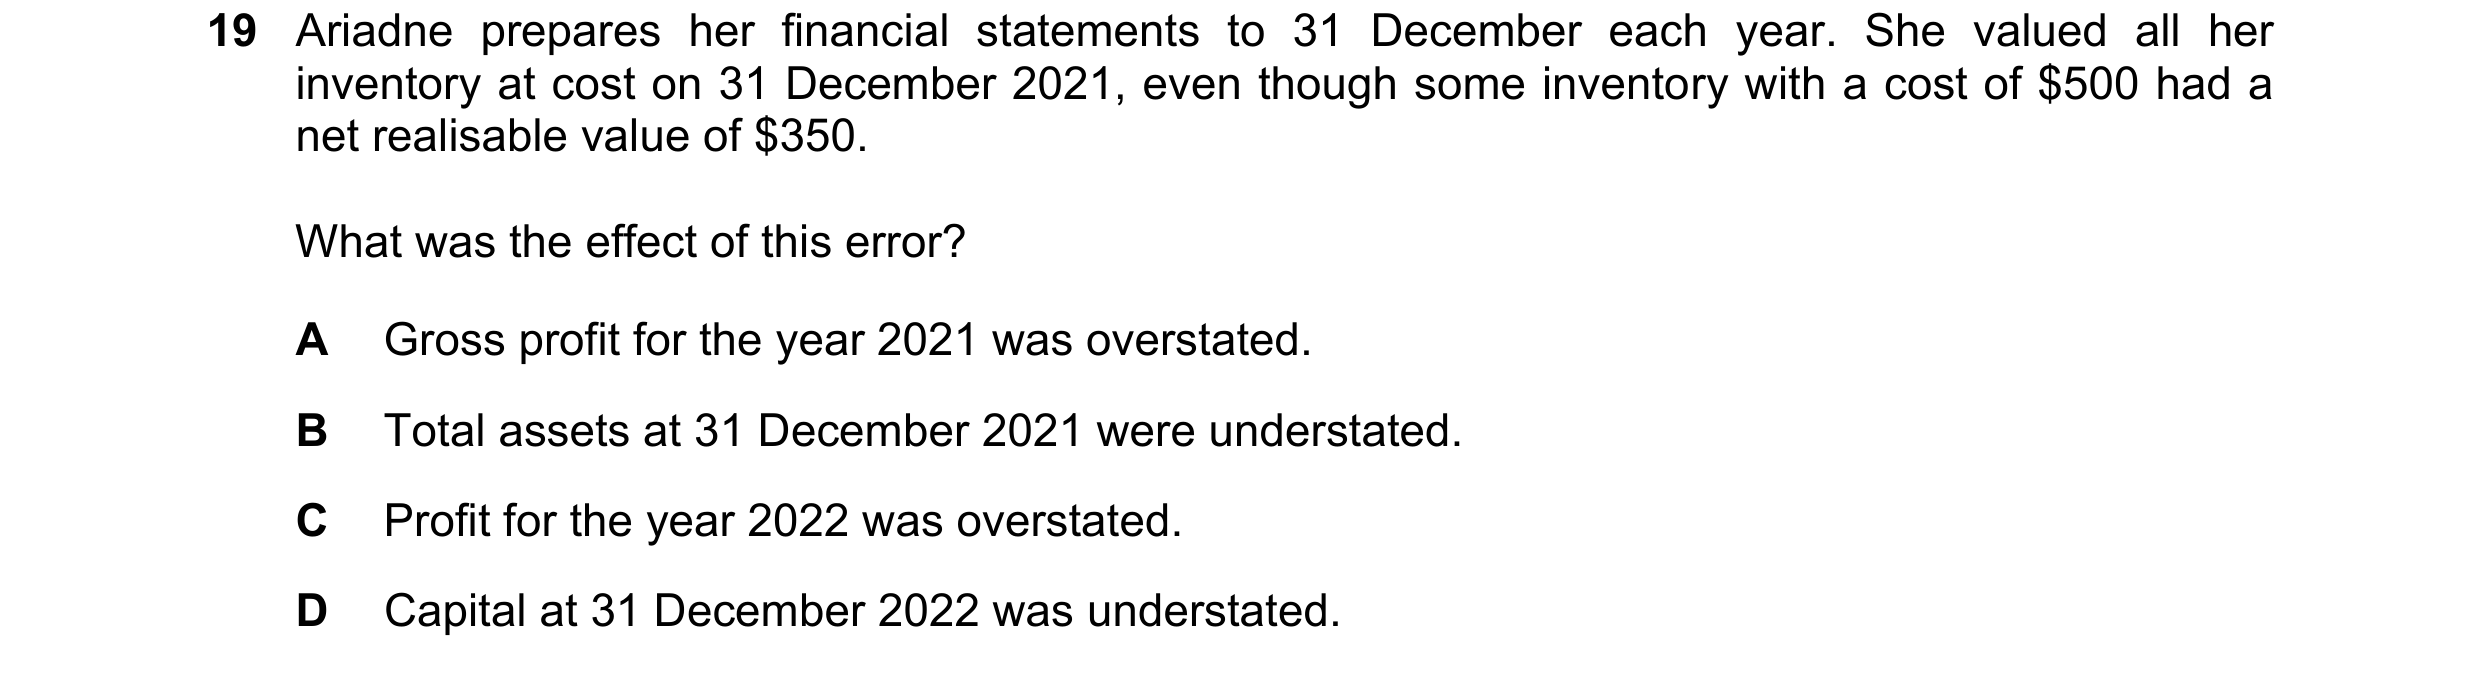
Q32 · Ariadne prepares her financial statements to 31 December each year 0985/12 Oct/Nov 2023
19 Ariadne prepares her financial statements to 31 December each year. She valued all her inventory at cost on 31 December 2021, even though some inventory with a cost of $500 had a net realisable value of $350. What was the effect of this error? A Gross profit for the year 2021 was overstated. B Total assets at 31 December 2021 were understated. C Profit for the year 2022 was overstated. D Capital at 31 December 2022 was understated.
1 marks
Answer: A
This question in 0985/12 Oct/Nov 2023
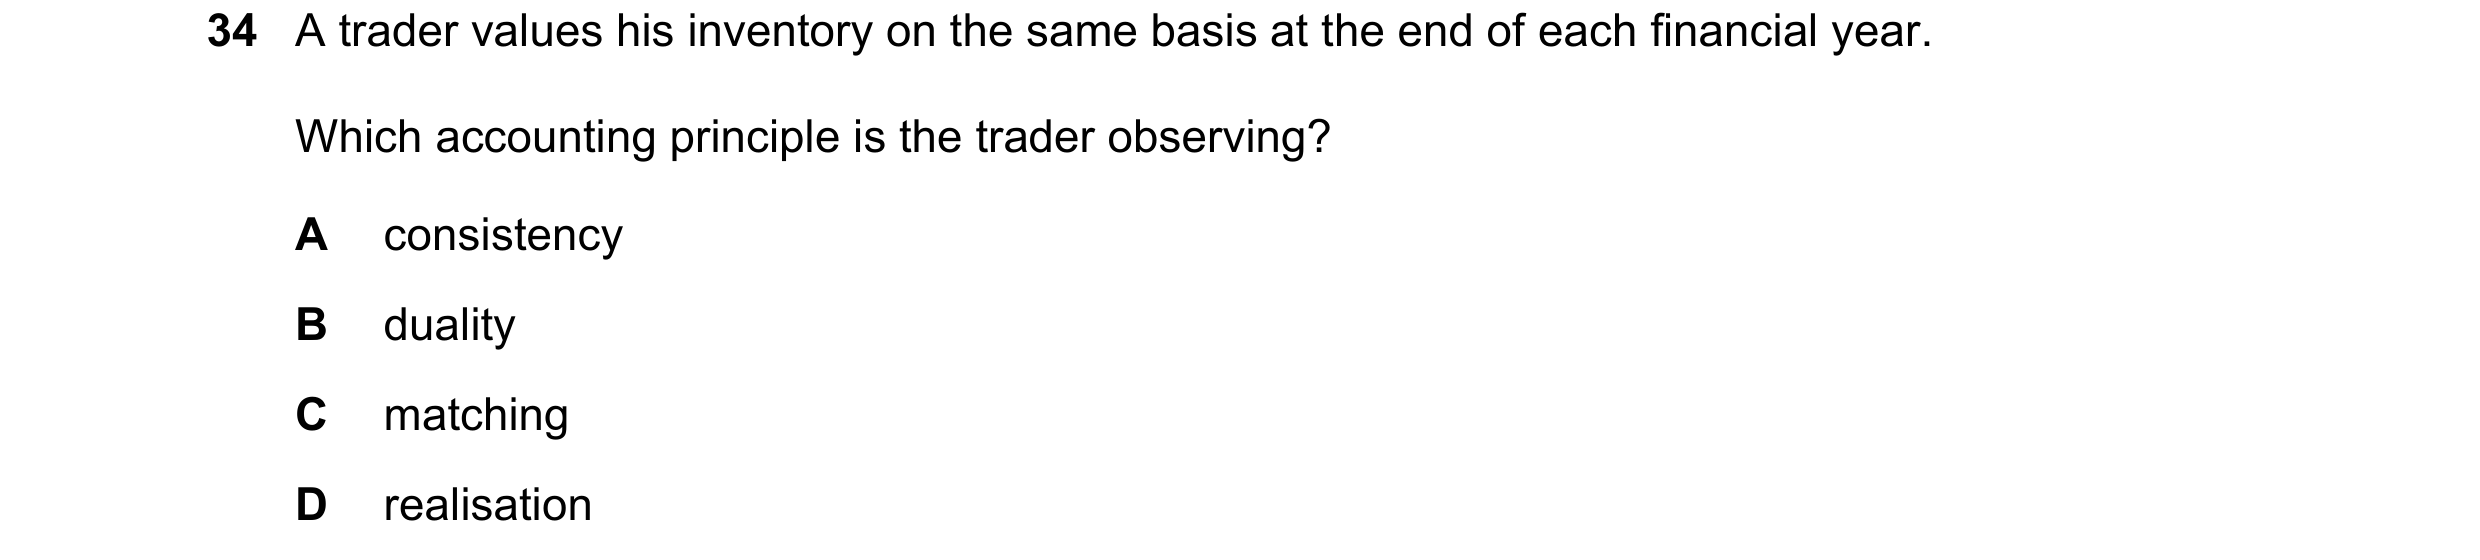
Q33 · A trader values his inventory on the same basis at the end of each financial year 0985/12 Oct/Nov 2023
34 A trader values his inventory on the same basis at the end of each financial year. Which accounting principle is the trader observing? A consistency B duality C matching D realisation
1 marks
Answer: A
This question in 0985/12 Oct/Nov 2023
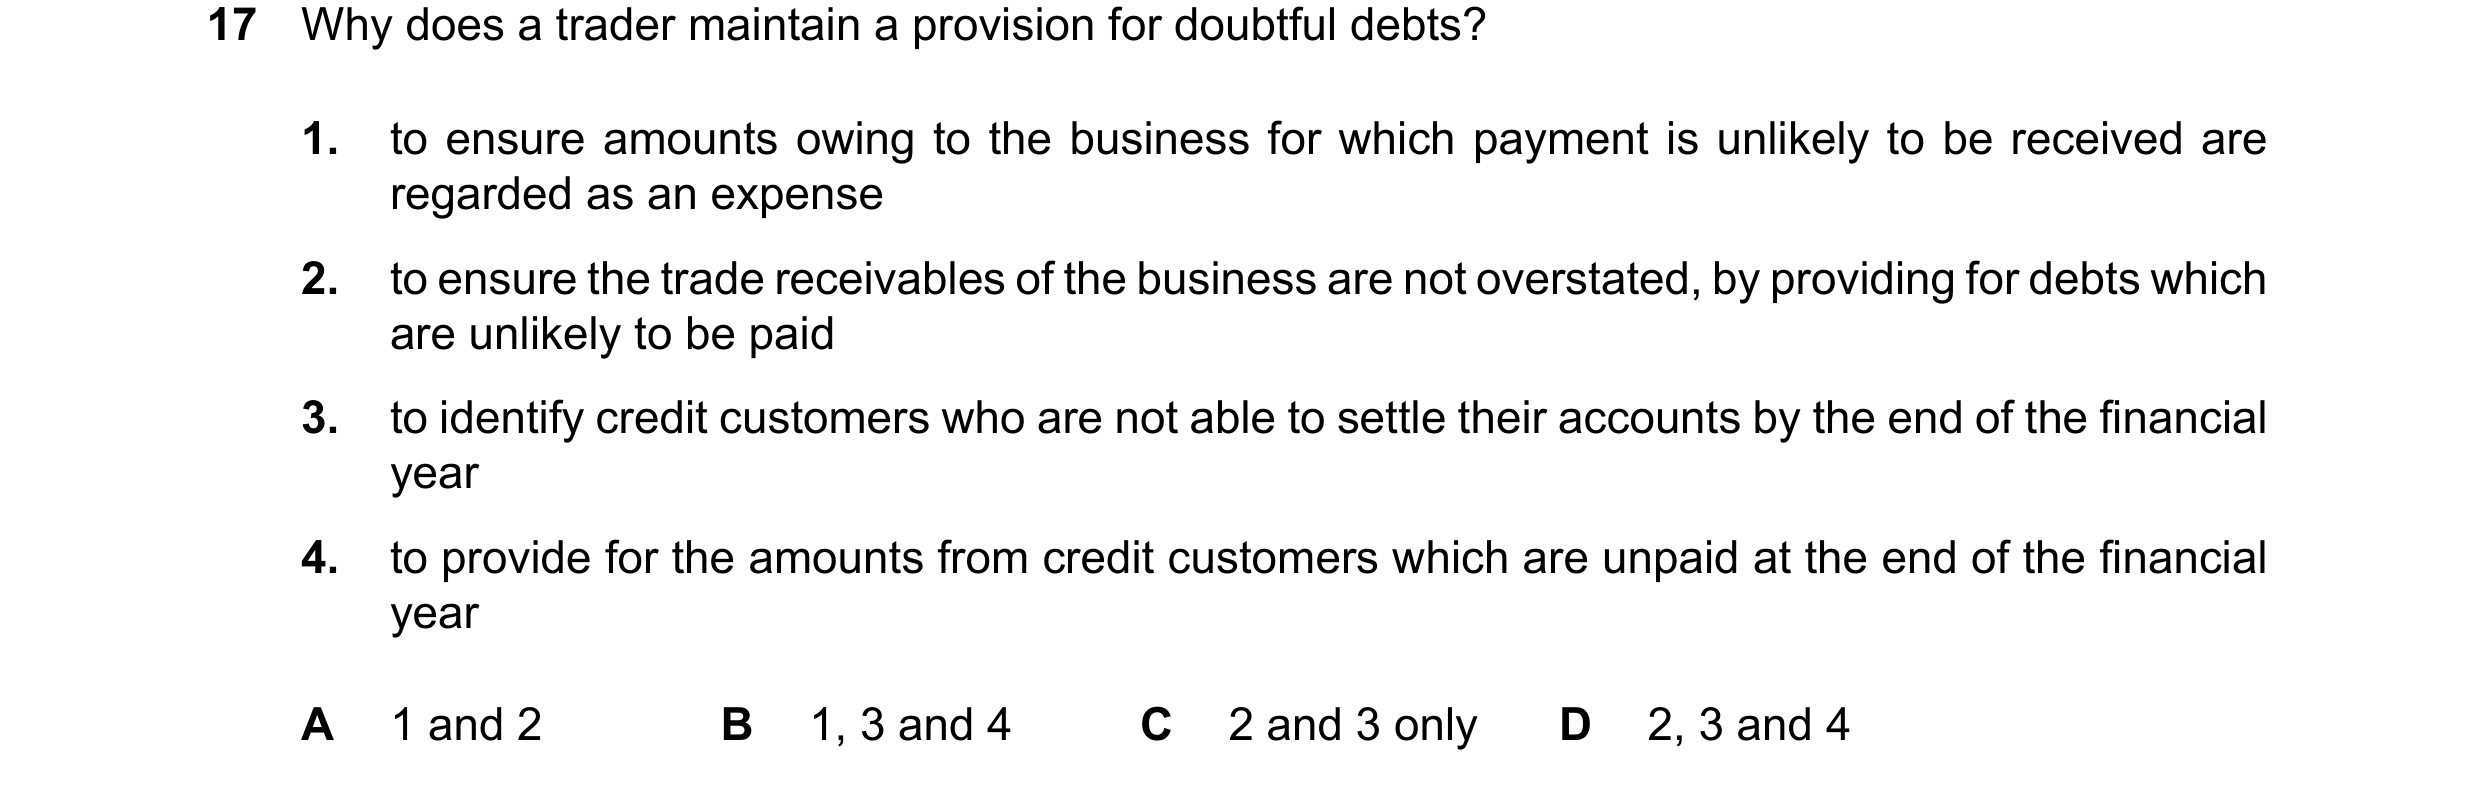
Q34 · Why does a trader maintain a provision for doubtful debts? 0985/11 May/June 2024
17 Why does a trader maintain a provision for doubtful debts? 1. to ensure amounts owing to the business for which payment is unlikely to be received are regarded as an expense 2. to ensure the trade receivables of the business are not overstated, by providing for debts which are unlikely to be paid 3. to identify credit customers who are not able to settle their accounts by the end of the financial year 4. to provide for the amounts from credit customers which are unpaid at the end of the financial year A 1 and 2 B 1, 3 and 4 C 2 and 3 only D 2, 3 and 4
1 marks
Answer: A
This question in 0985/11 May/June 2024
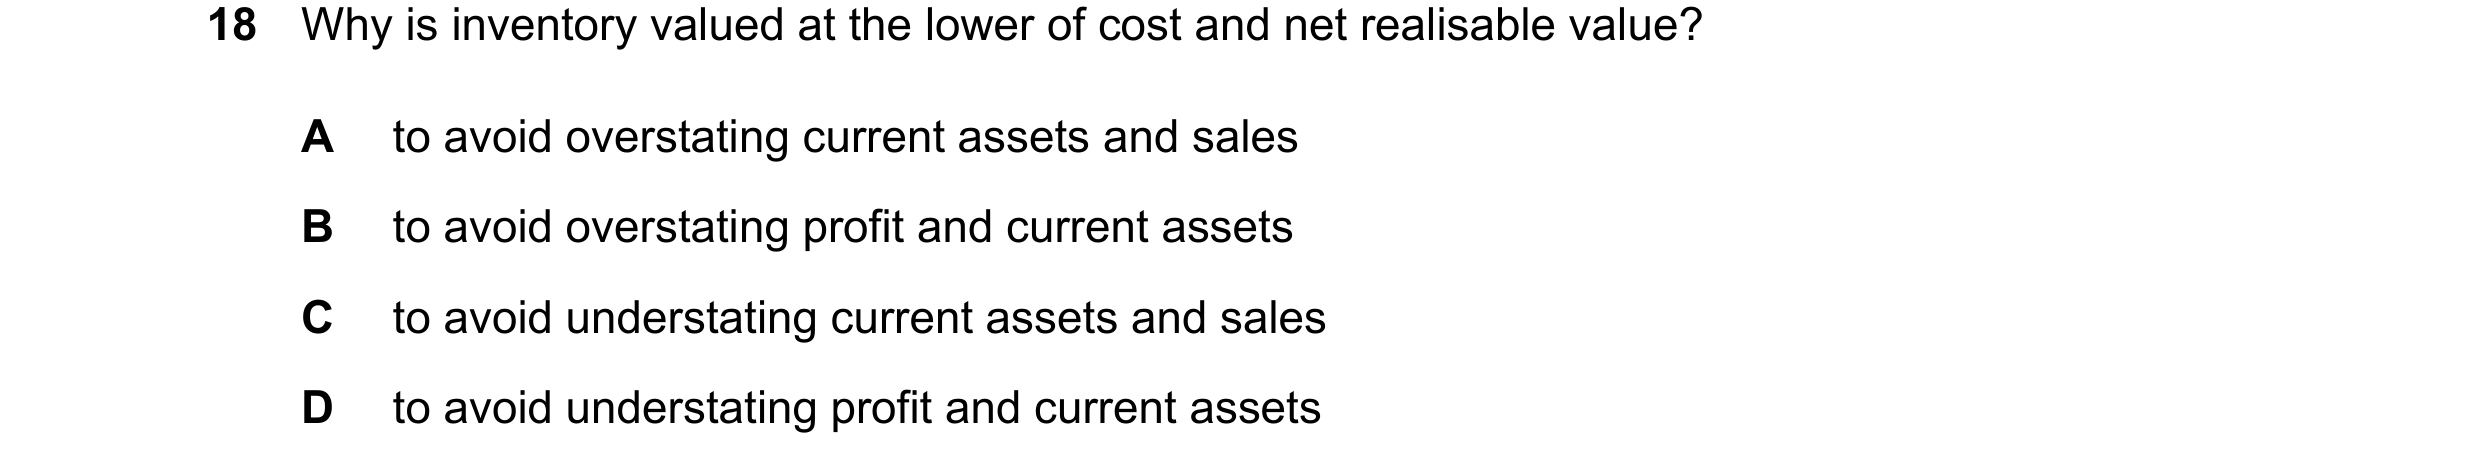
Q35 · Why is inventory valued at the lower of cost and net realisable value? 0985/11 May/June 2024
18 Why is inventory valued at the lower of cost and net realisable value? A to avoid overstating current assets and sales B to avoid overstating profit and current assets C to avoid understating current assets and sales D to avoid understating profit and current assets
1 marks
Answer: B
This question in 0985/11 May/June 2024
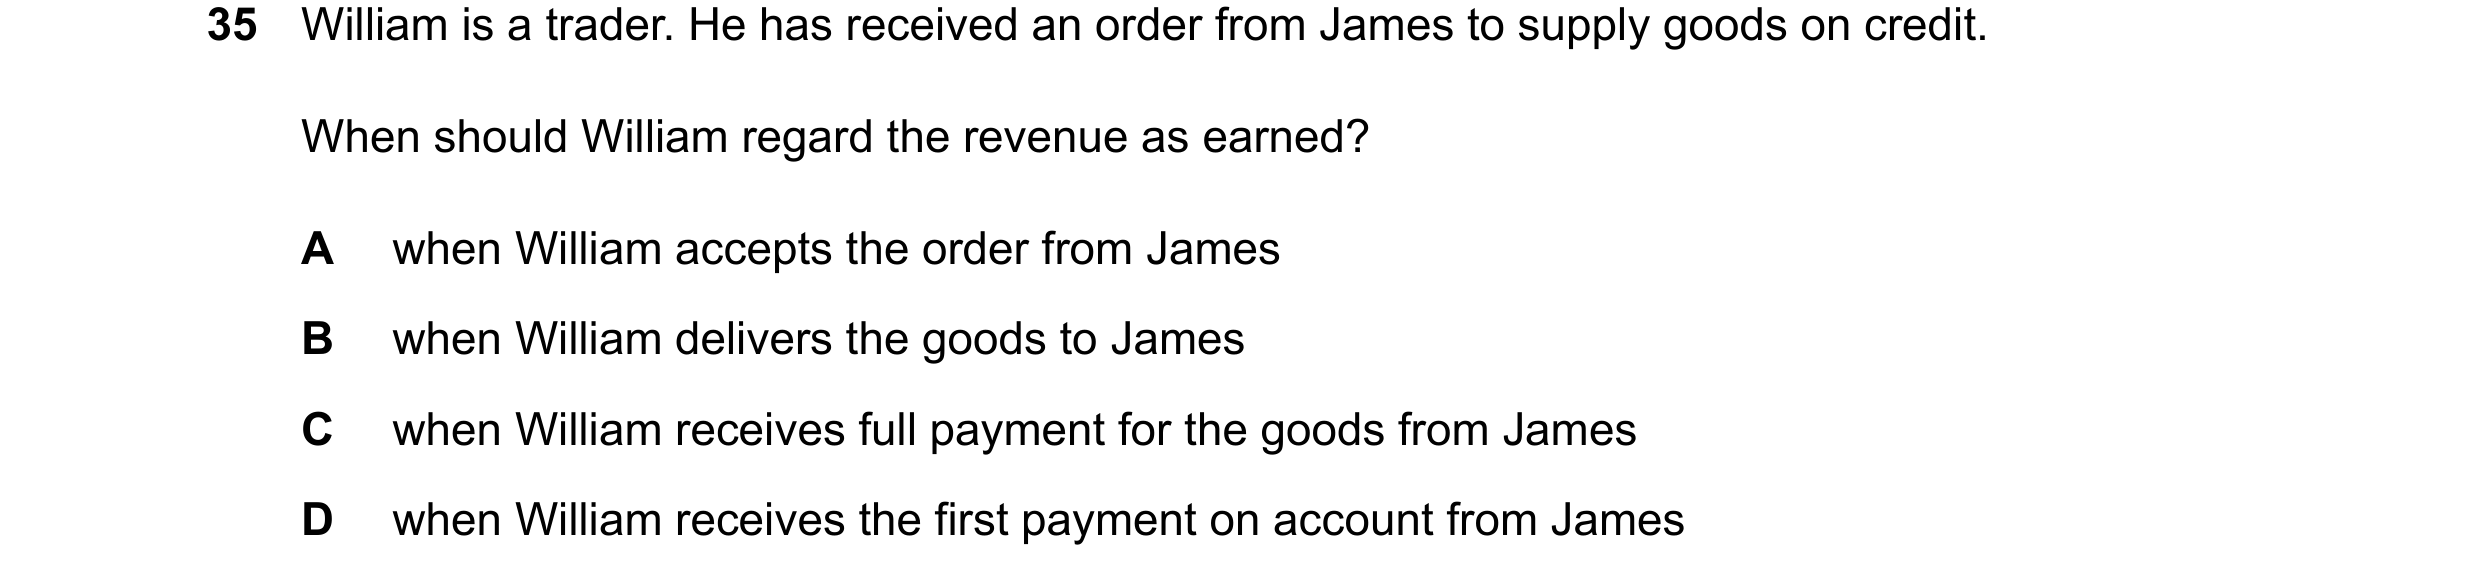
Q36 · William is a trader 0985/11 May/June 2024
35 William is a trader. He has received an order from James to supply goods on credit. When should William regard the revenue as earned? A when William accepts the order from James B when William delivers the goods to James C when William receives full payment for the goods from James D when William receives the first payment on account from James
1 marks
Answer: B
This question in 0985/11 May/June 2024
Q37 · Why is it important to match costs and revenues? 0985/12 May/June 2024
17 Why is it important to match costs and revenues? A so that every debit entry has a corresponding credit entry B so that the business does not incur any losses C to enable a better comparison of profit from year to year D to ensure that the bank balance is accurate
1 marks
Answer: C
This question in 0985/12 May/June 2024
Q38 · Which statement correctly describes the principle of realisation? 0985/12 May/June 2024
35 Which statement correctly describes the principle of realisation? A Profit is earned when a cheque is received from a customer in payment for goods supplied. B Profit is earned when a cheque received from a customer is paid into the business bank account. C Profit is earned when the goods are supplied, and ownership passes to the customer. D Profit is earned when the customer places an order for the goods.
1 marks
Answer: C
This question in 0985/12 May/June 2024
Q39 · Which accounting principle is the accounting equation based on? 0985/12 Oct/Nov 2024
34 Which accounting principle is the accounting equation based on? A duality B going concern C materiality D realisation
1 marks
Answer: A
This question in 0985/12 Oct/Nov 2024
Q40 · Which qualitative factor requires that financial information is provided in a timely… 0985/12 Oct/Nov 2024
35 Which qualitative factor requires that financial information is provided in a timely manner so that it can be used for decision making? A comparability B relevance C reliability D understandability
1 marks
Answer: B
This question in 0985/12 Oct/Nov 2024
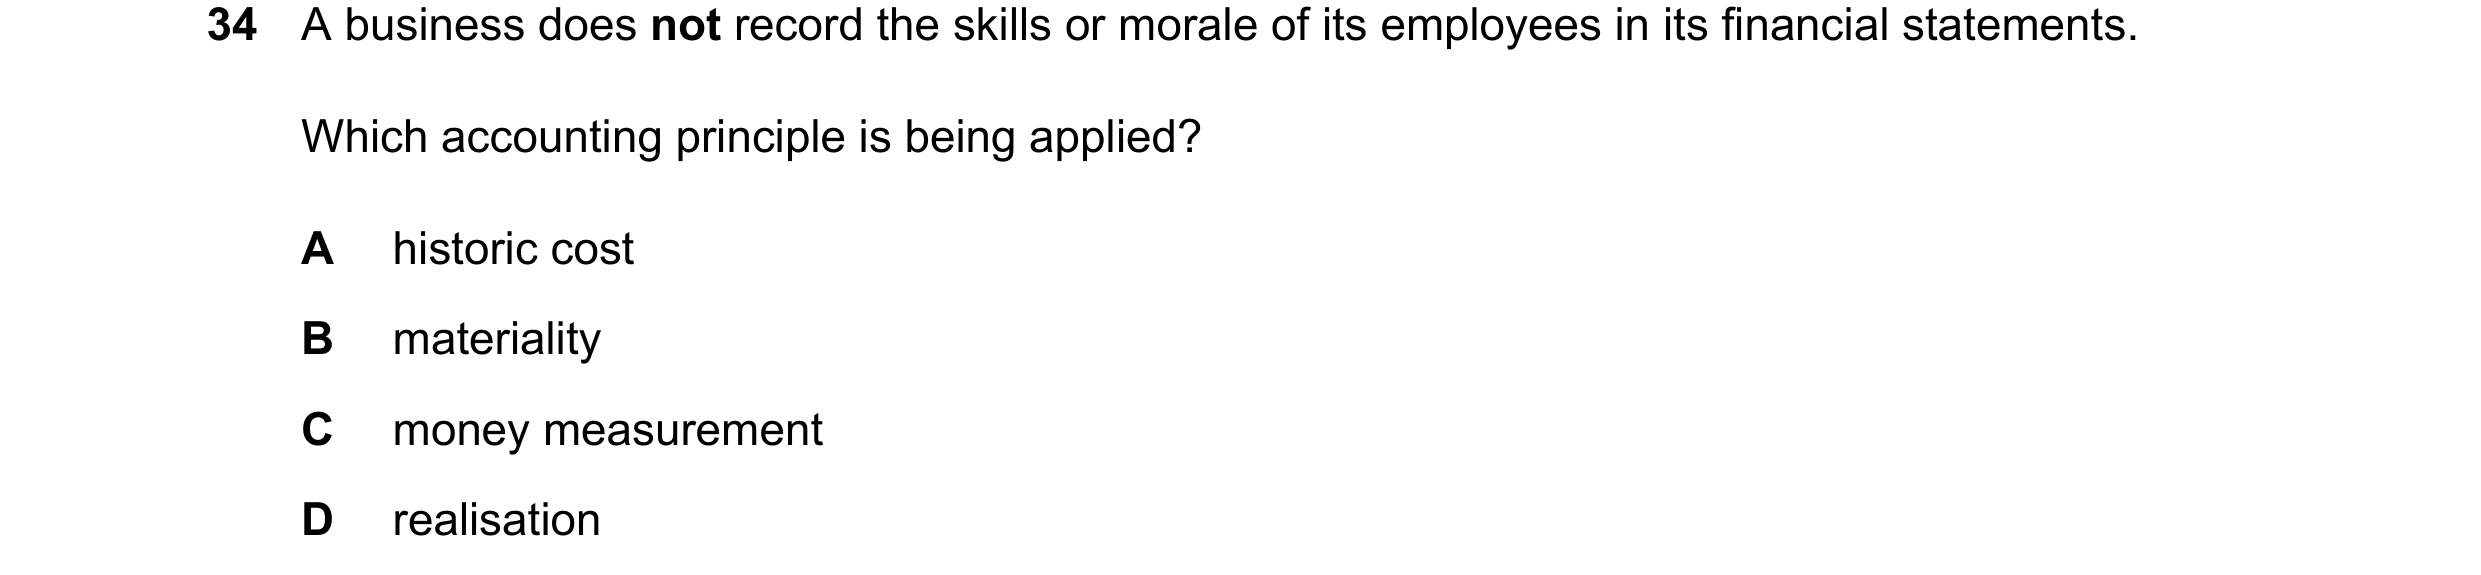
Q41 · A business does not record the skills or morale of its employees in its financial… 0985/11 May/June 2025
34 A business does not record the skills or morale of its employees in its financial statements. Which accounting principle is being applied? A historic cost B materiality C money measurement D realisation
1 marks
Answer: C
This question in 0985/11 May/June 2025
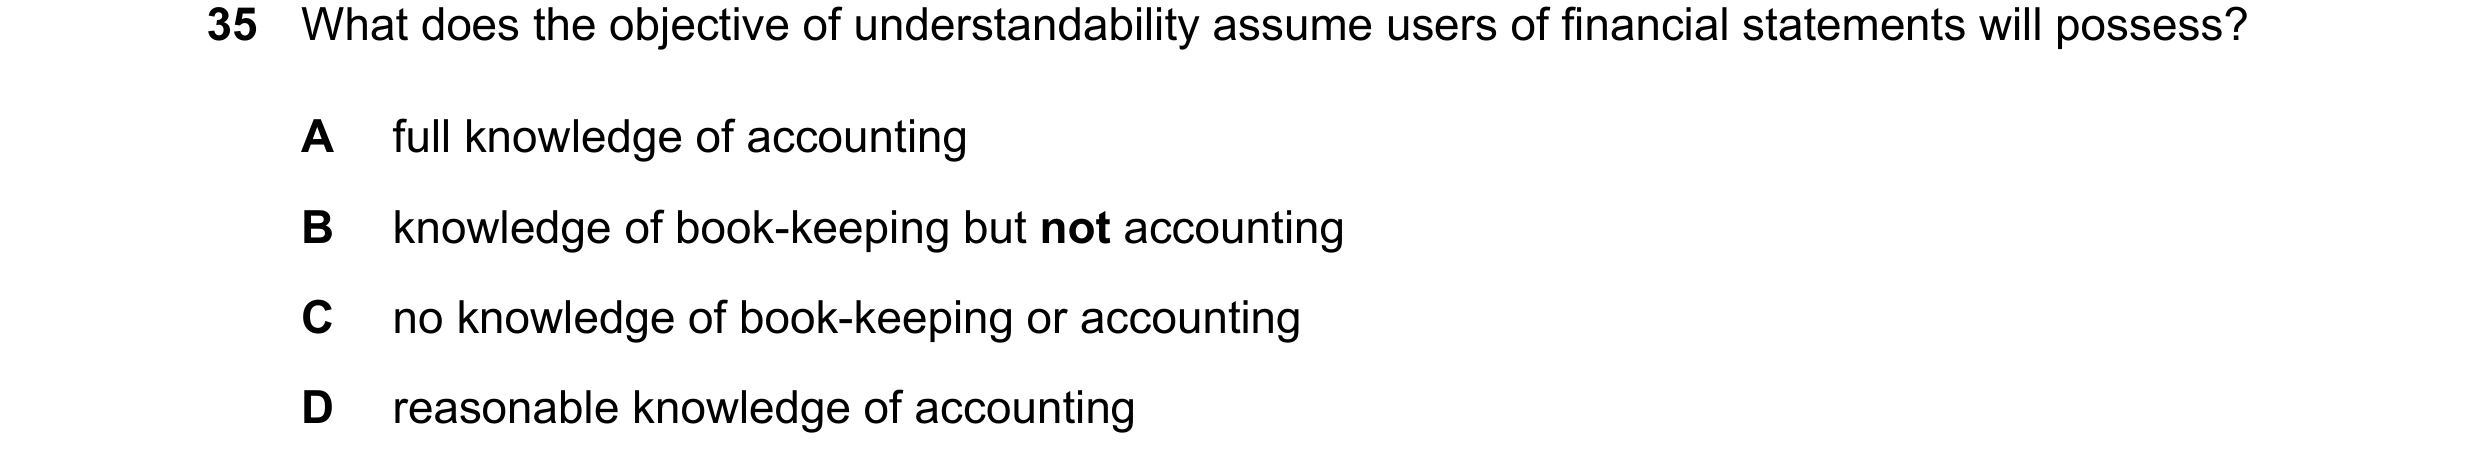
Q42 · What does the objective of understandability assume users of financial statements will… 0985/11 May/June 2025
35 What does the objective of understandability assume users of financial statements will possess? A full knowledge of accounting B knowledge of book-keeping but not accounting C no knowledge of book-keeping or accounting D reasonable knowledge of accounting
1 marks
Answer: D
This question in 0985/11 May/June 2025
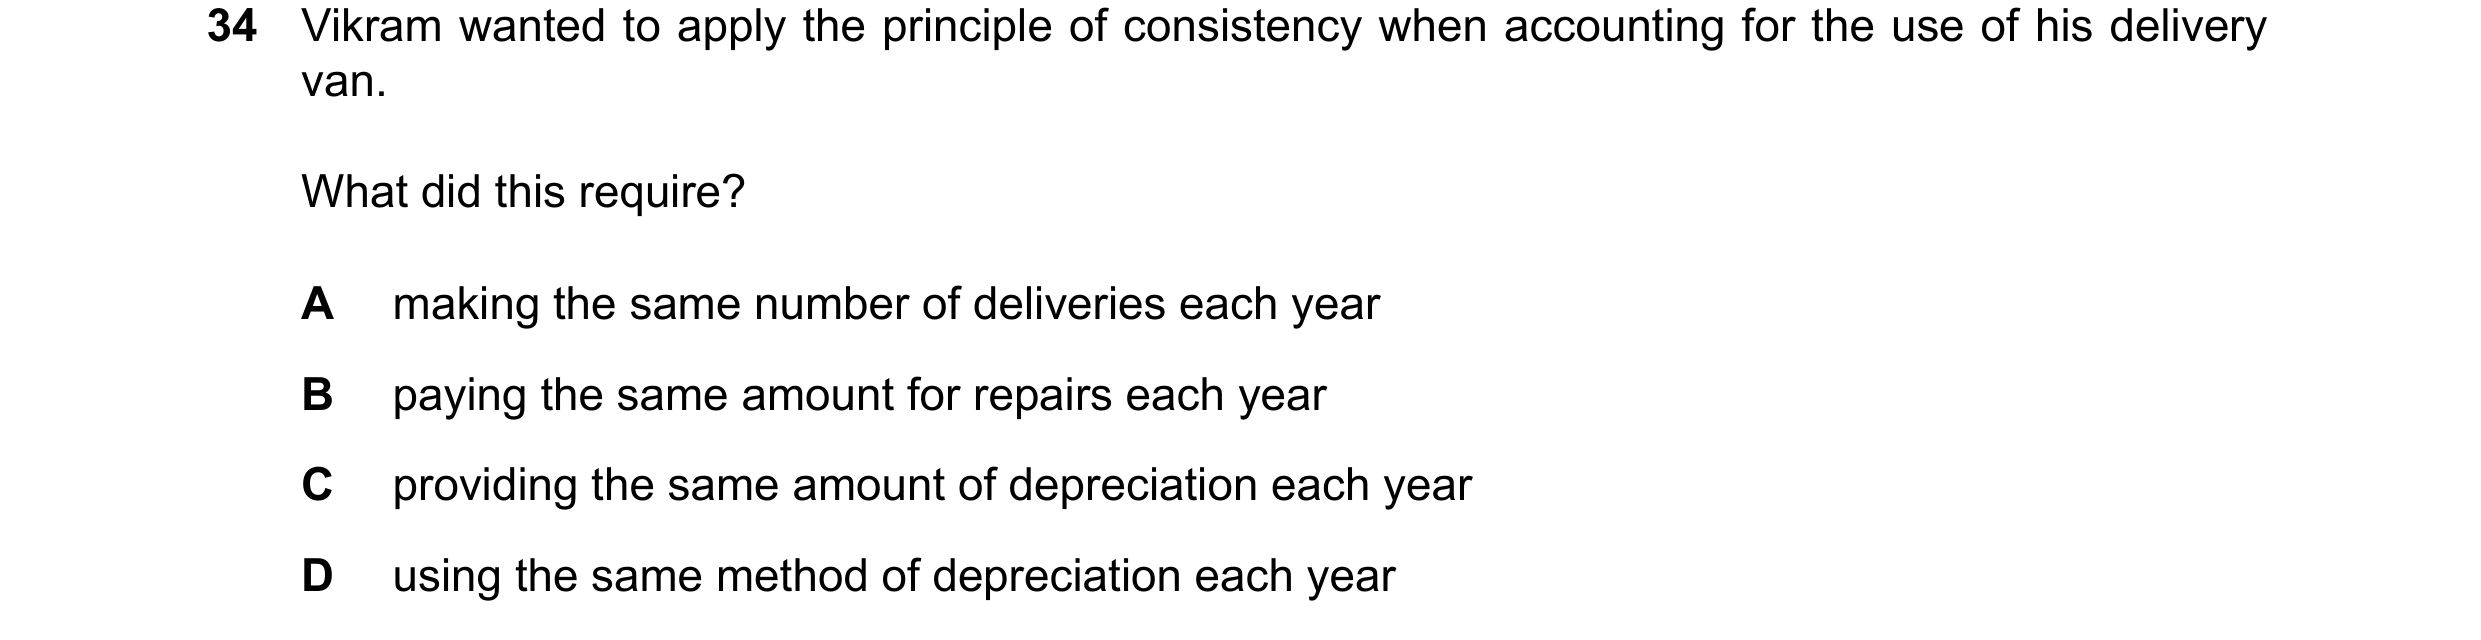
Q43 · Vikram wanted to apply the principle of consistency when accounting for the use of his… 0985/12 May/June 2025
34 Vikram wanted to apply the principle of consistency when accounting for the use of his delivery van. What did this require? A making the same number of deliveries each year B paying the same amount for repairs each year C providing the same amount of depreciation each year D using the same method of depreciation each year
1 marks
Answer: D
This question in 0985/12 May/June 2025
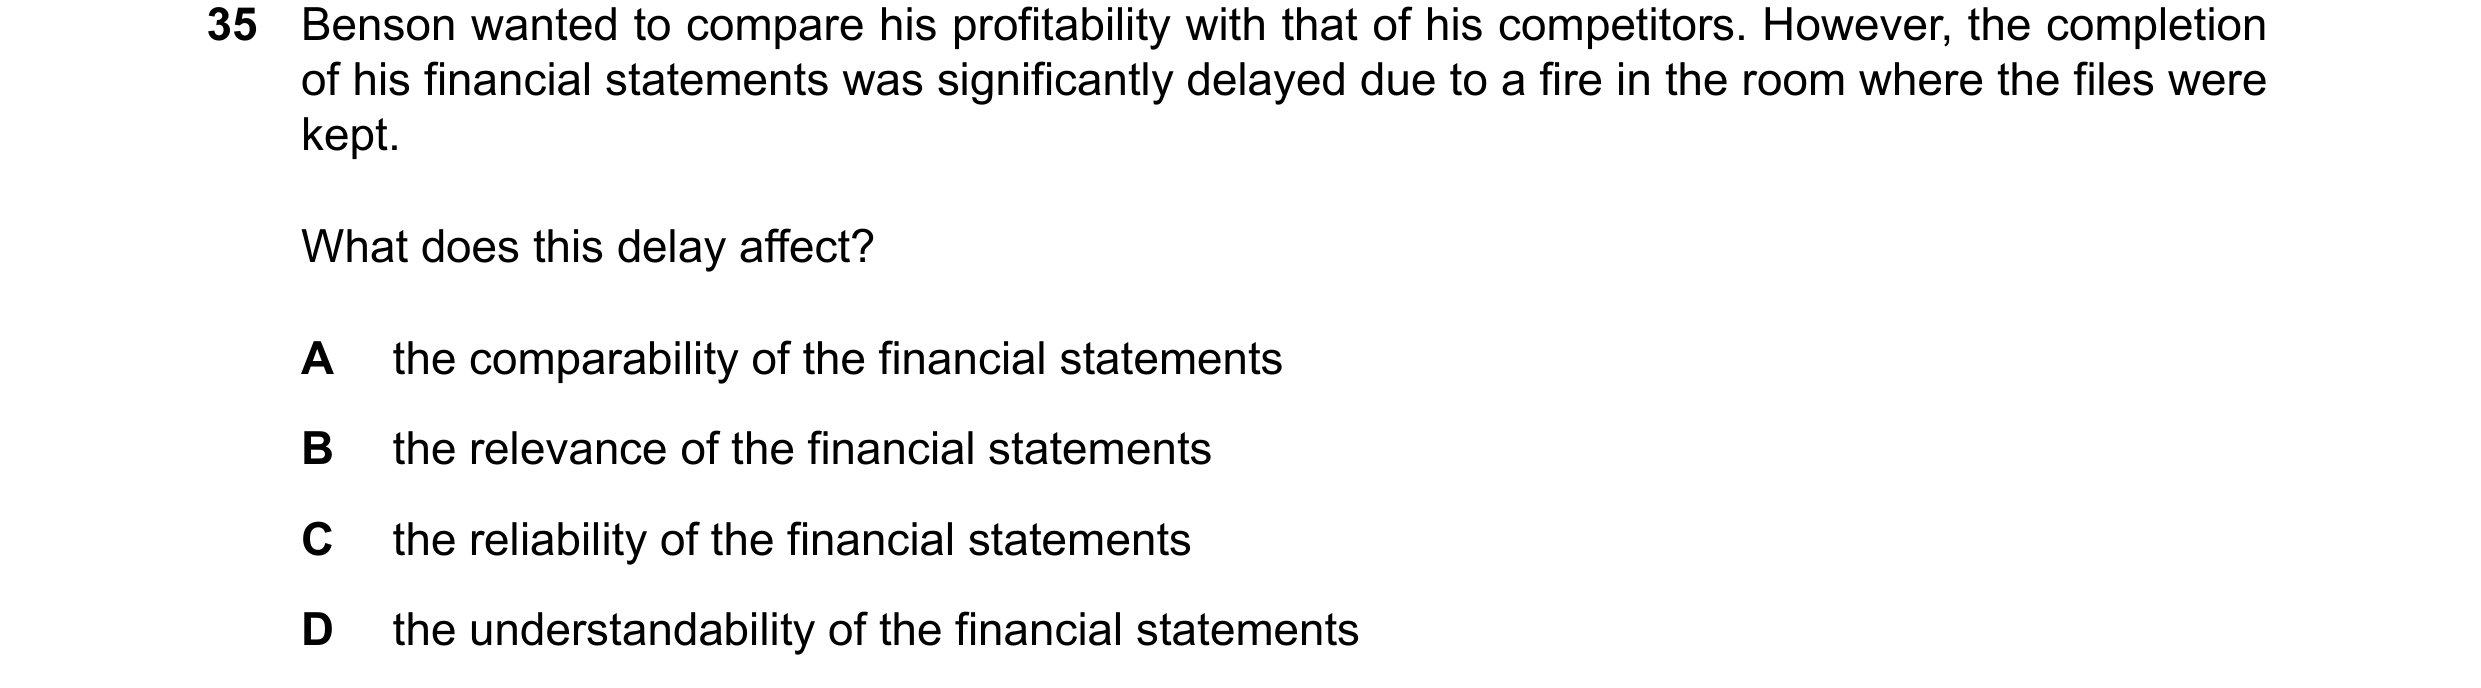
Q44 · Benson wanted to compare his profitability with that of his competitors 0985/12 May/June 2025
35 Benson wanted to compare his profitability with that of his competitors. However, the completion of his financial statements was significantly delayed due to a fire in the room where the files were kept. What does this delay affect? A the comparability of the financial statements B the relevance of the financial statements C the reliability of the financial statements D the understandability of the financial statements
1 marks
Answer: B
This question in 0985/12 May/June 2025
 1 / 9
 2 / 9
 3 / 9
 4 / 9
 5 / 9
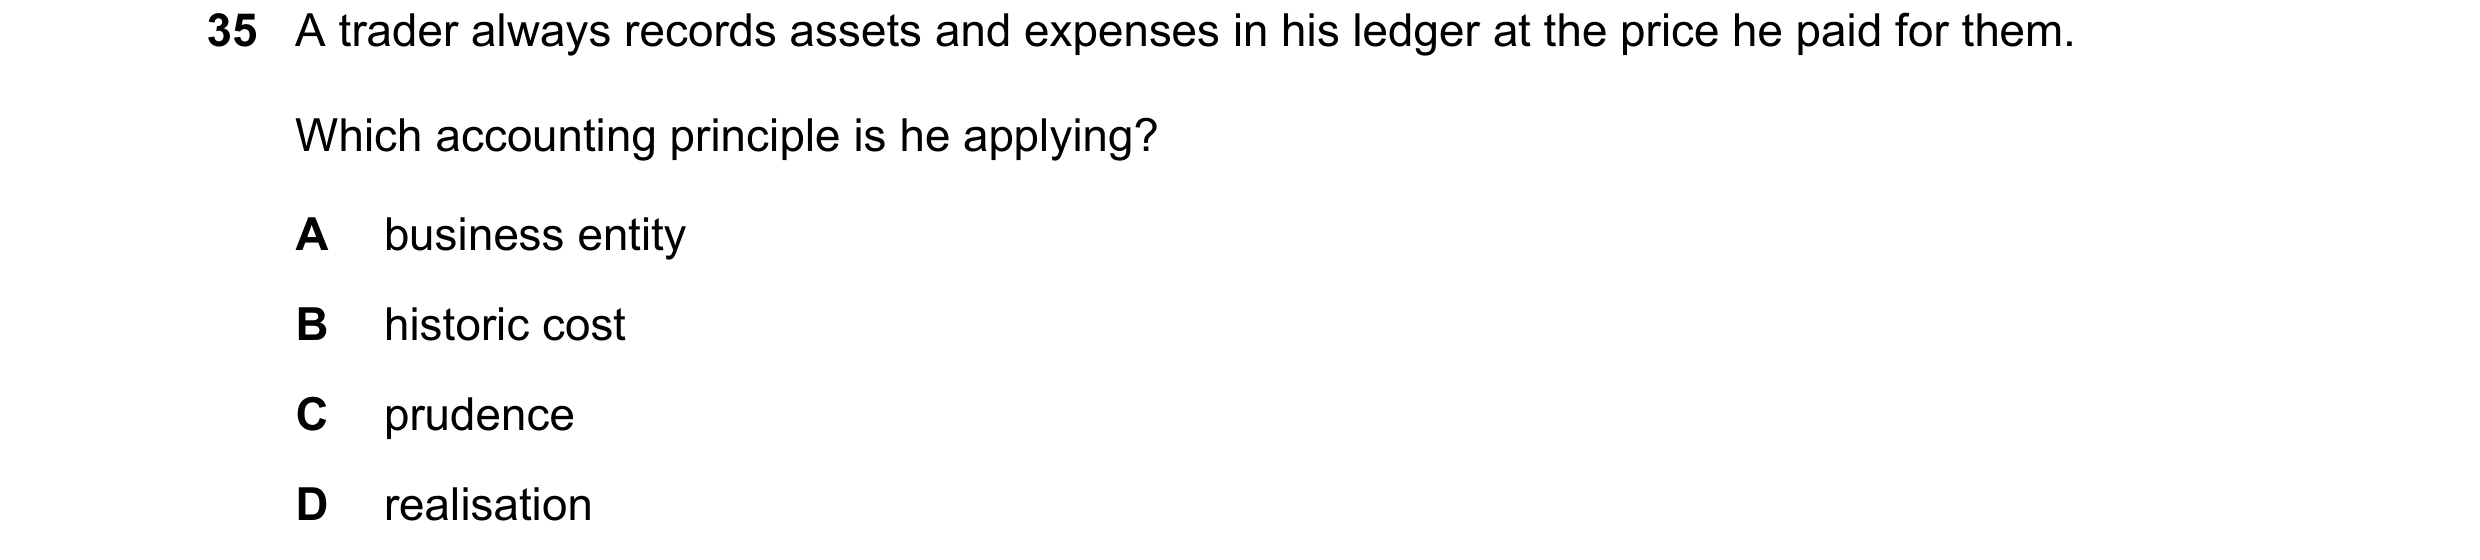
 6 / 9
 7 / 9
 8 / 9
 9 / 9