Cambridge IGCSE Accounting (9-1) 0985 — 2020 Oct/Nov Paper 1 · Variant 2
0985/12/O/N/20 · 35 questions · 35 marks · ≈39 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
Mark scheme3 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · A trader prepares financial statements each year
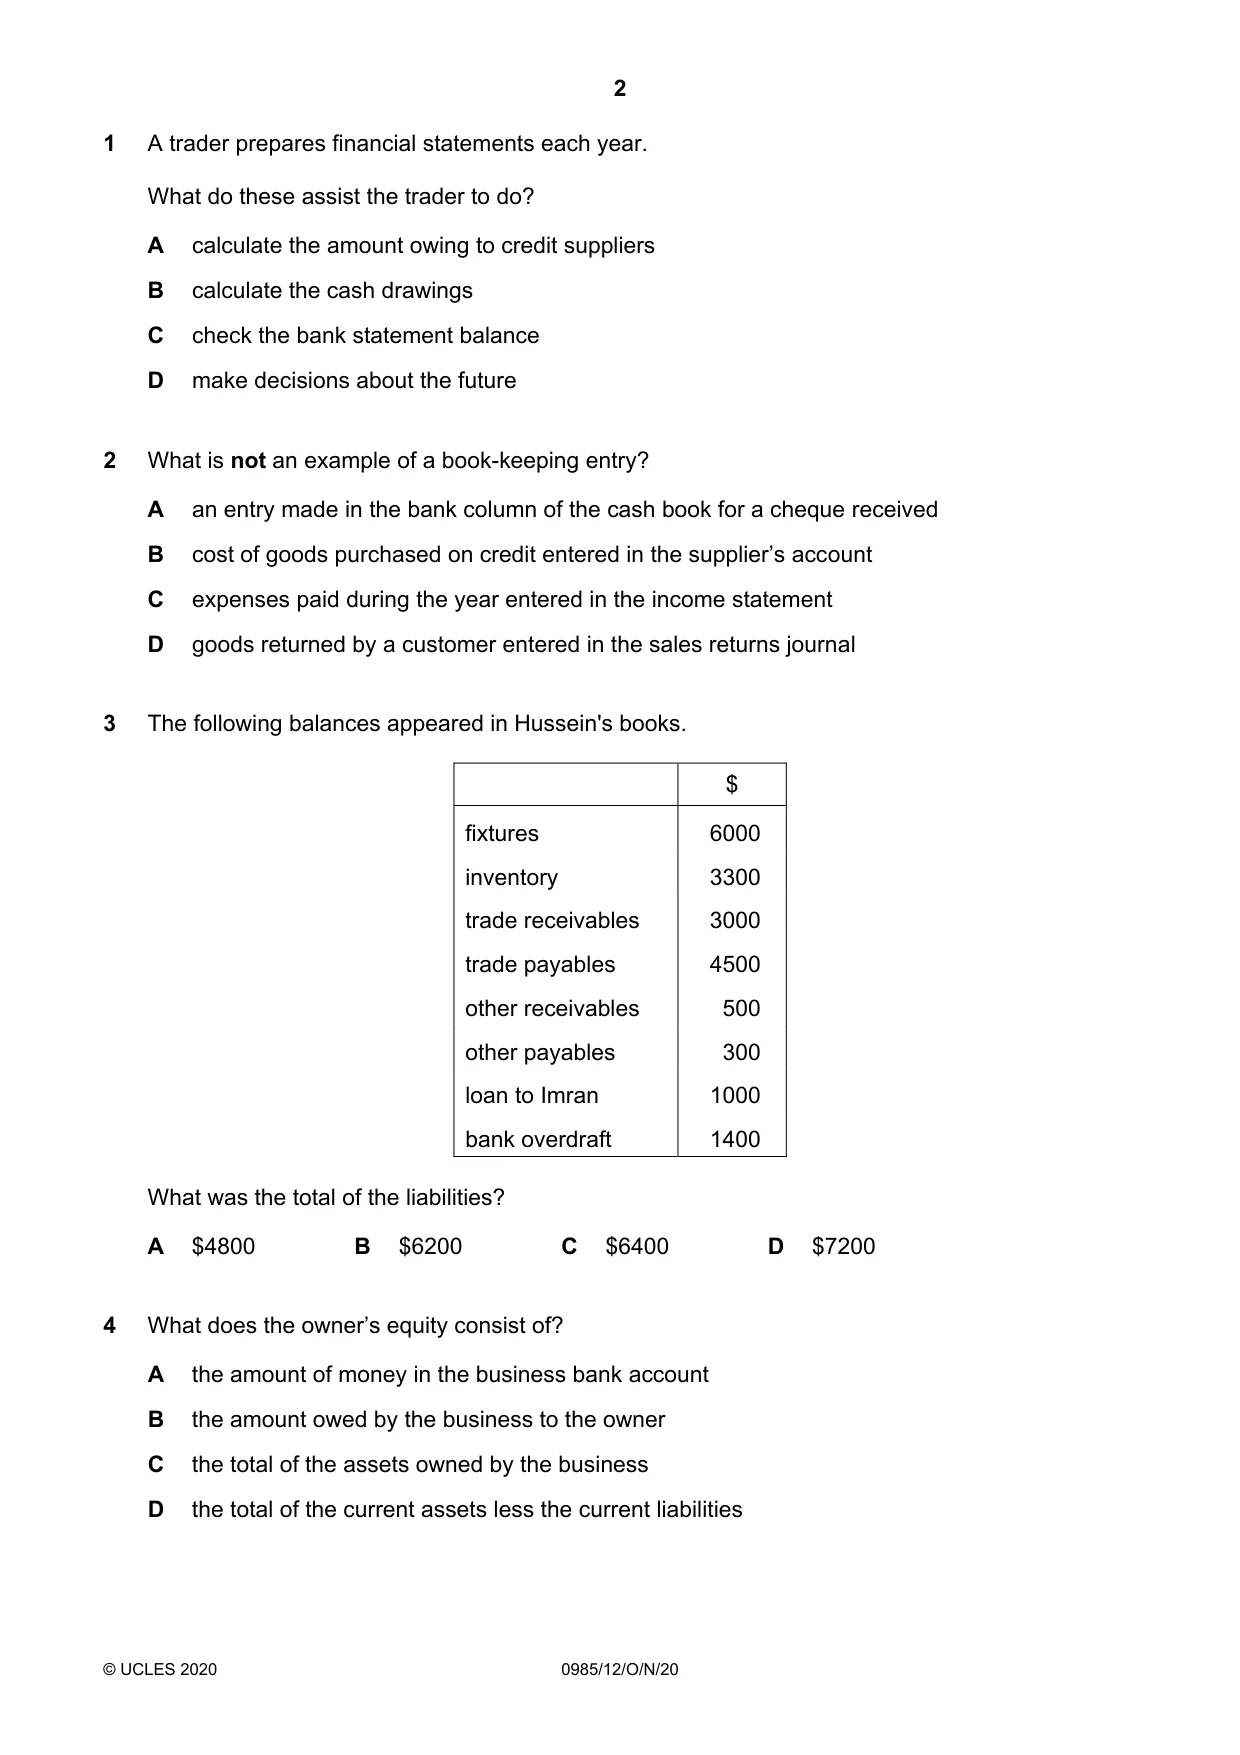
1 A trader prepares financial statements each year. What do these assist the trader to do? A calculate the amount owing to credit suppliers B calculate the cash drawings C check the bank statement balance D make decisions about the future
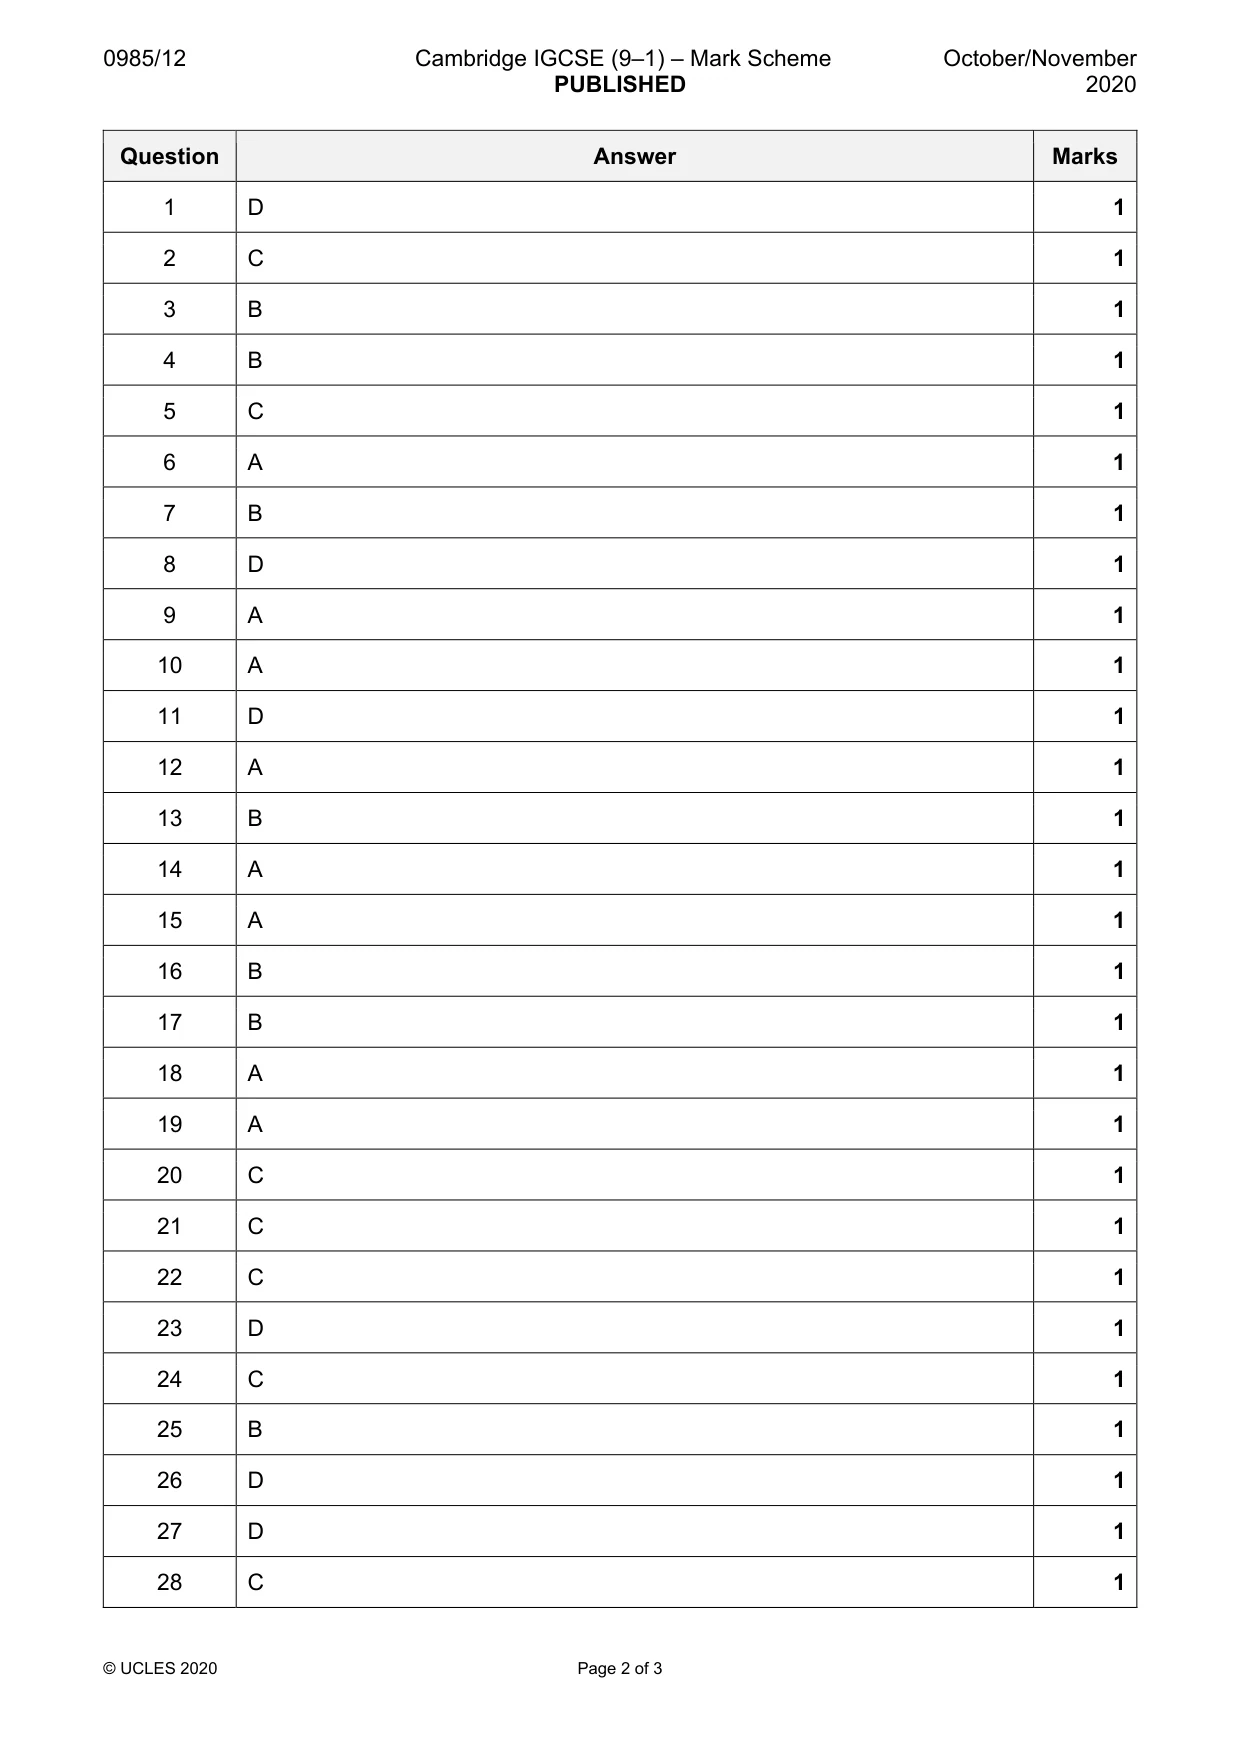
Mark scheme: D
Q2 · What is not an example of a book-keeping entry?
2 What is not an example of a book-keeping entry? A an entry made in the bank column of the cash book for a cheque received B cost of goods purchased on credit entered in the supplier’s account C expenses paid during the year entered in the income statement D goods returned by a customer entered in the sales returns journal
Mark scheme: C
Q3 · The following balances appeared in Hussein's books
3 The following balances appeared in Hussein's books. $ fixtures 6000 inventory 3300 trade receivables 3000 trade payables 4500 other receivables 500 other payables 300 loan to Imran 1000 bank overdraft 1400 What was the total of the liabilities? A $4800 B $6200 C $6400 D $7200
Mark scheme: B
Q4 · What does the owner’s equity consist of?
4 What does the owner’s equity consist of? A the amount of money in the business bank account B the amount owed by the business to the owner C the total of the assets owned by the business D the total of the current assets less the current liabilities
Mark scheme: B
Q5 · Which entries did Sally make to record the following transaction?
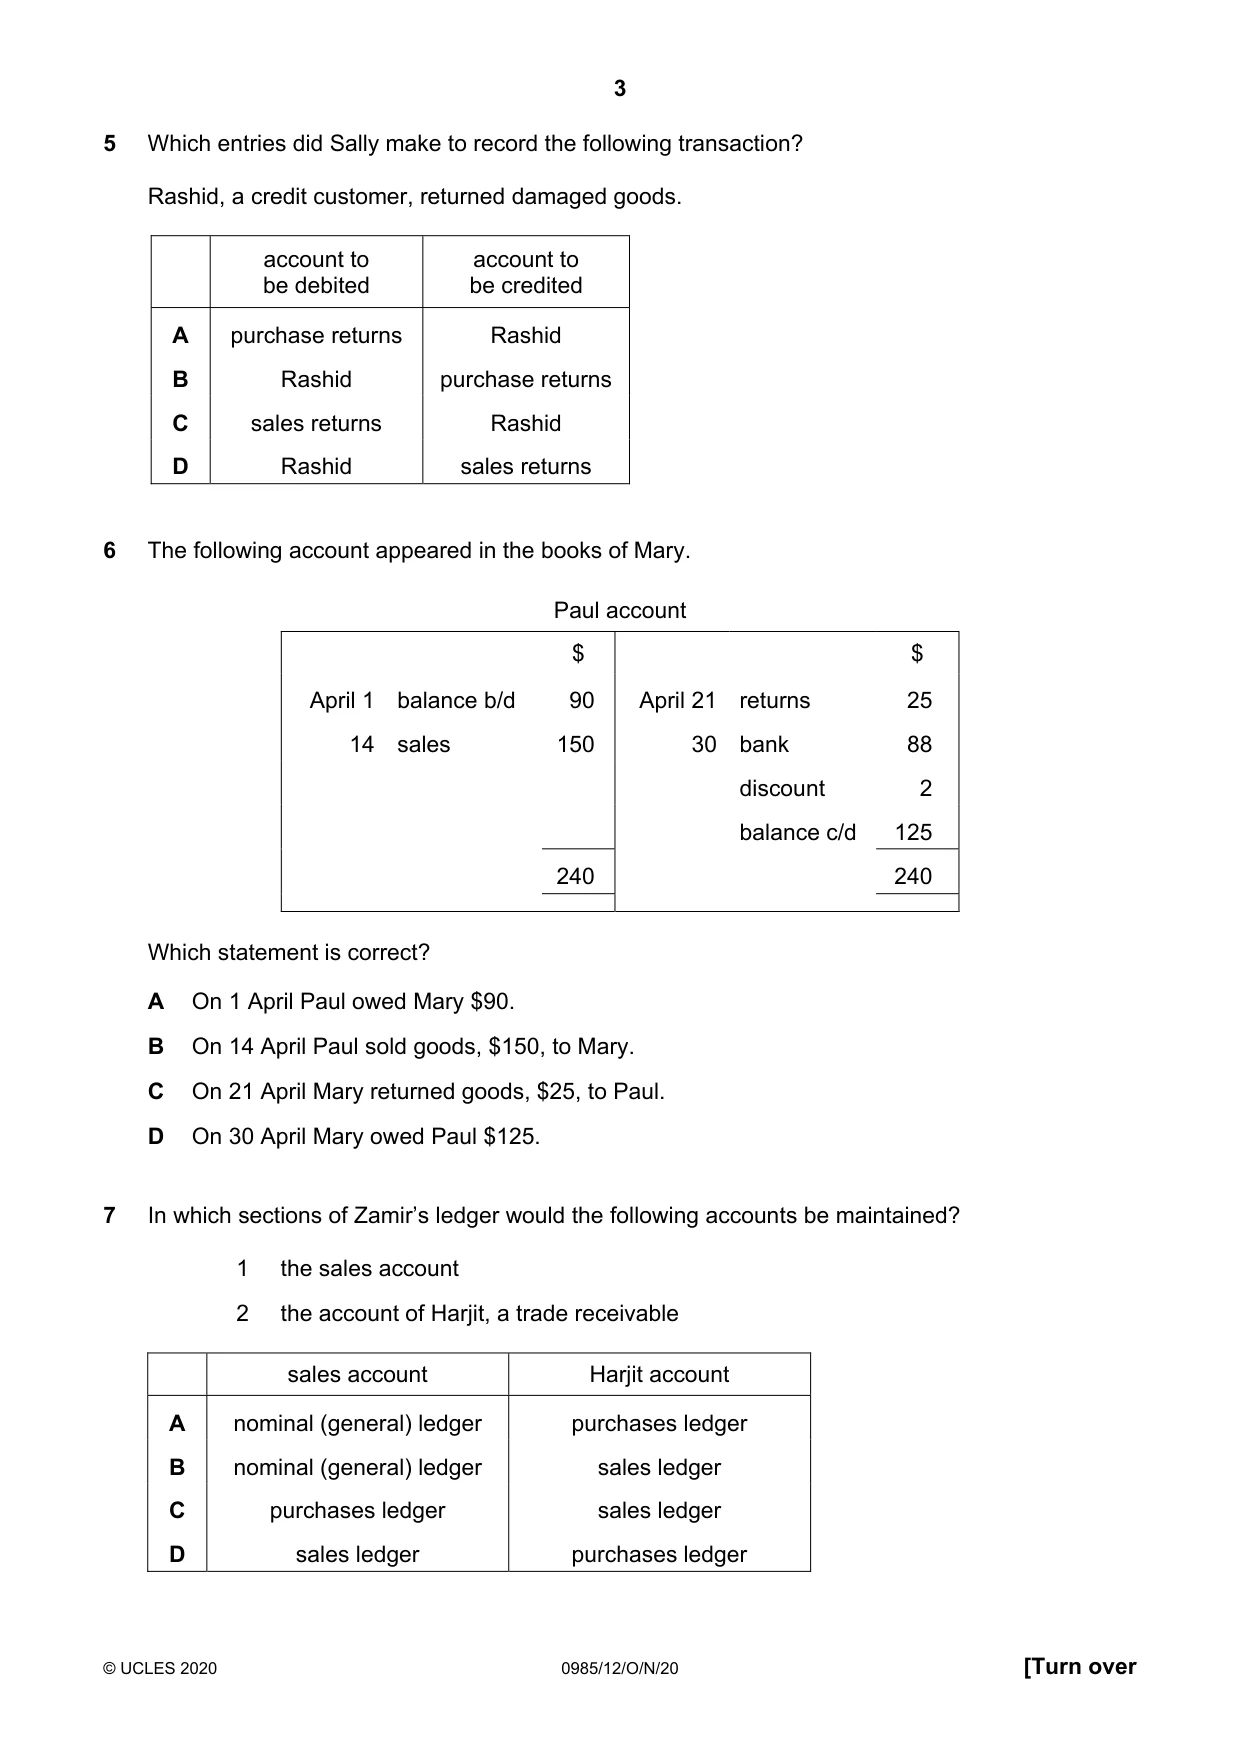
5 Which entries did Sally make to record the following transaction? Rashid, a credit customer, returned damaged goods. account to account to be debited be credited A purchase returns Rashid B Rashid purchase returns C sales returns Rashid D Rashid sales returns
Mark scheme: C
Q6 · The following account appeared in the books of Mary
6 The following account appeared in the books of Mary. Paul account $ $ April 1 balance b/d 90 April 21 returns 25 14 sales 150 30 bank 88 discount 2 balance c/d 125 240 240 Which statement is correct? A On 1 April Paul owed Mary $90. B On 14 April Paul sold goods, $150, to Mary. C On 21 April Mary returned goods, $25, to Paul. D On 30 April Mary owed Paul $125.
Mark scheme: A
Q7 · In which sections of Zamir’s ledger would the following accounts be maintained?
7 In which sections of Zamir’s ledger would the following accounts be maintained? 1 the sales account 2 the account of Harjit, a trade receivable sales account Harjit account A nominal (general) ledger purchases ledger B nominal (general) ledger sales ledger C purchases ledger sales ledger D sales ledger purchases ledger
Mark scheme: B
Q8 · Sue allows 2% cash discount to credit customers who settle their account within 28 days
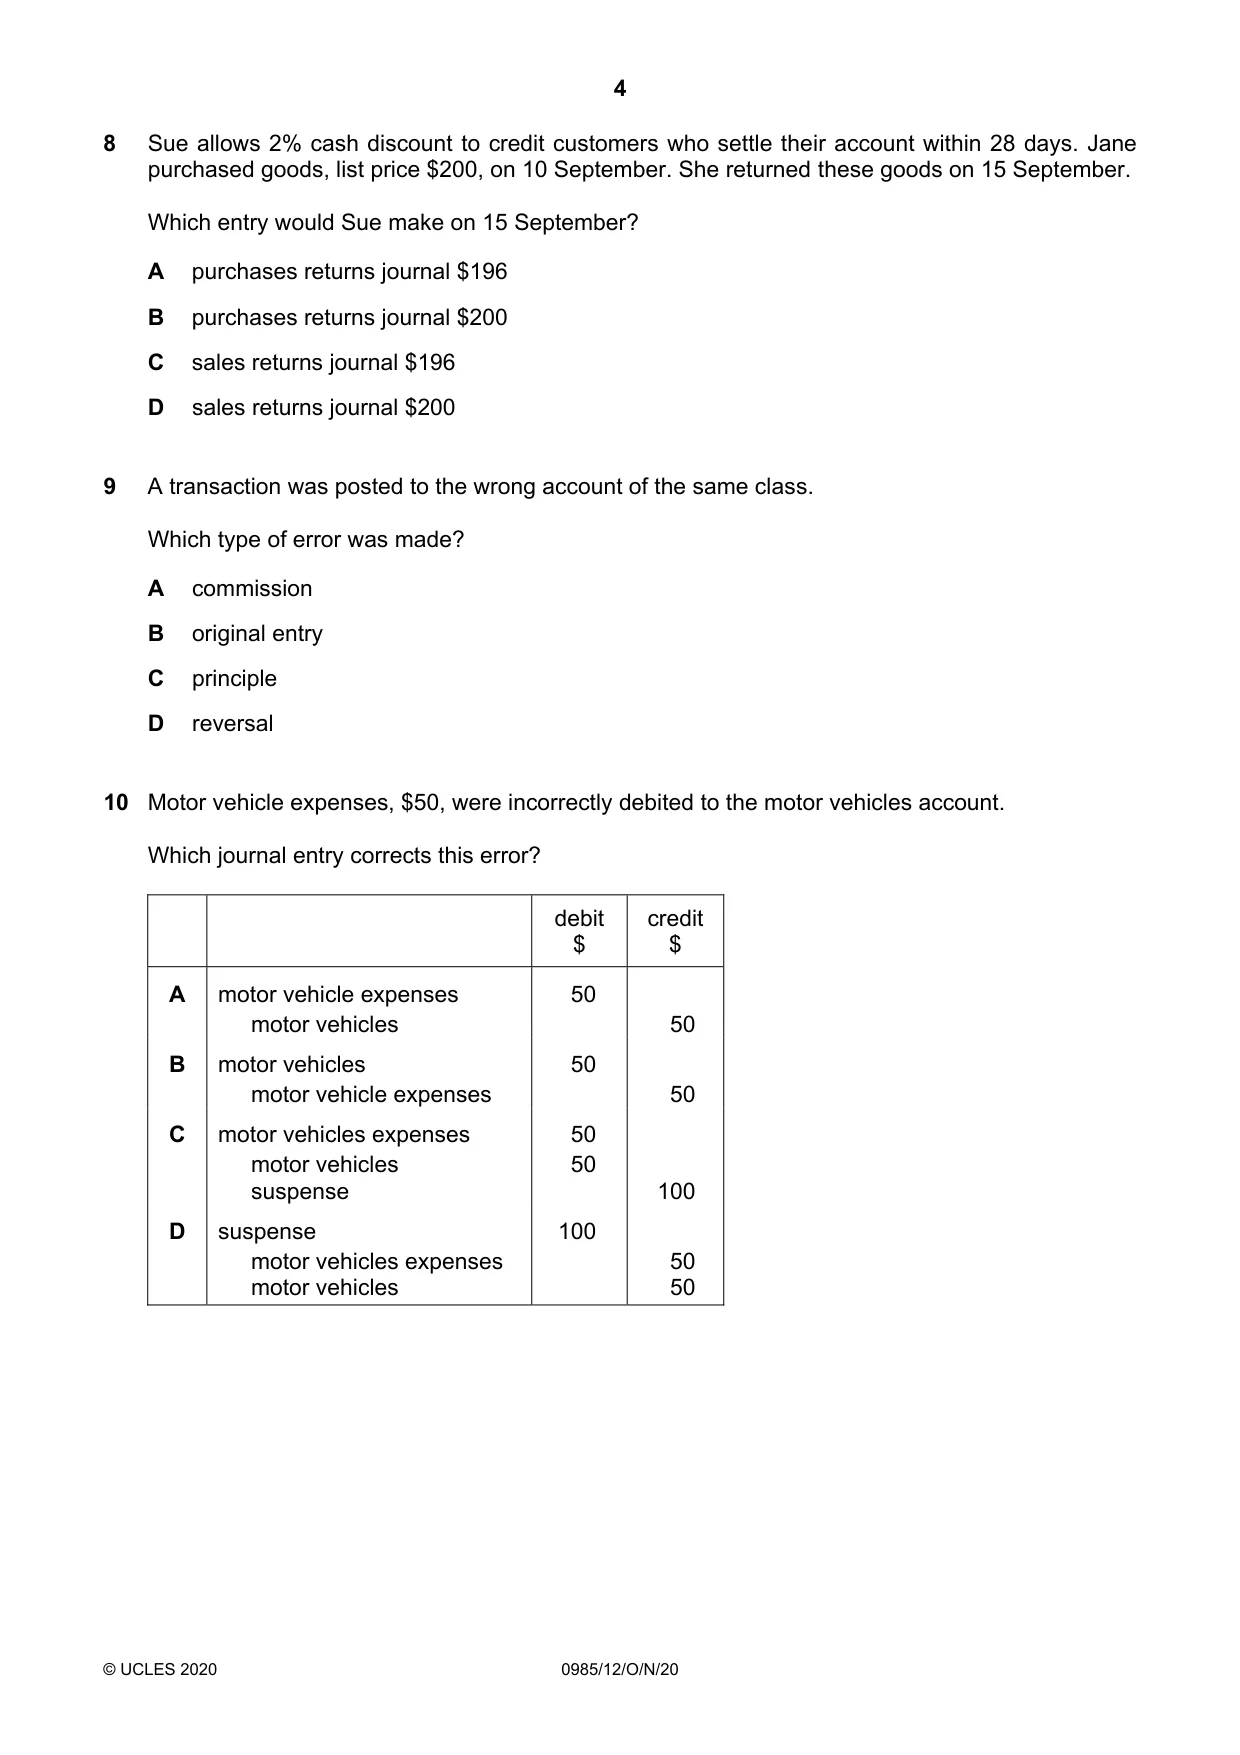
8 Sue allows 2% cash discount to credit customers who settle their account within 28 days. Jane purchased goods, list price $200, on 10 September. She returned these goods on 15 September. Which entry would Sue make on 15 September? A purchases returns journal $196 B purchases returns journal $200 C sales returns journal $196 D sales returns journal $200
Mark scheme: D
Q9 · A transaction was posted to the wrong account of the same class
9 A transaction was posted to the wrong account of the same class. Which type of error was made? A commission B original entry C principle D reversal
Mark scheme: A
Q10 · Motor vehicle expenses, $50, were incorrectly debited to the motor vehicles account
10 Motor vehicle expenses, $50, were incorrectly debited to the motor vehicles account. Which journal entry corrects this error? debit credit $ $ A motor vehicle expenses 50 motor vehicles 50 B motor vehicles 50 motor vehicle expenses 50 C motor vehicles expenses 50 motor vehicles 50 suspense 100 D suspense 100 motor vehicles expenses 50 motor vehicles 50
Mark scheme: A
Q11 · Kate calculated her draft profit for the year at $28 400
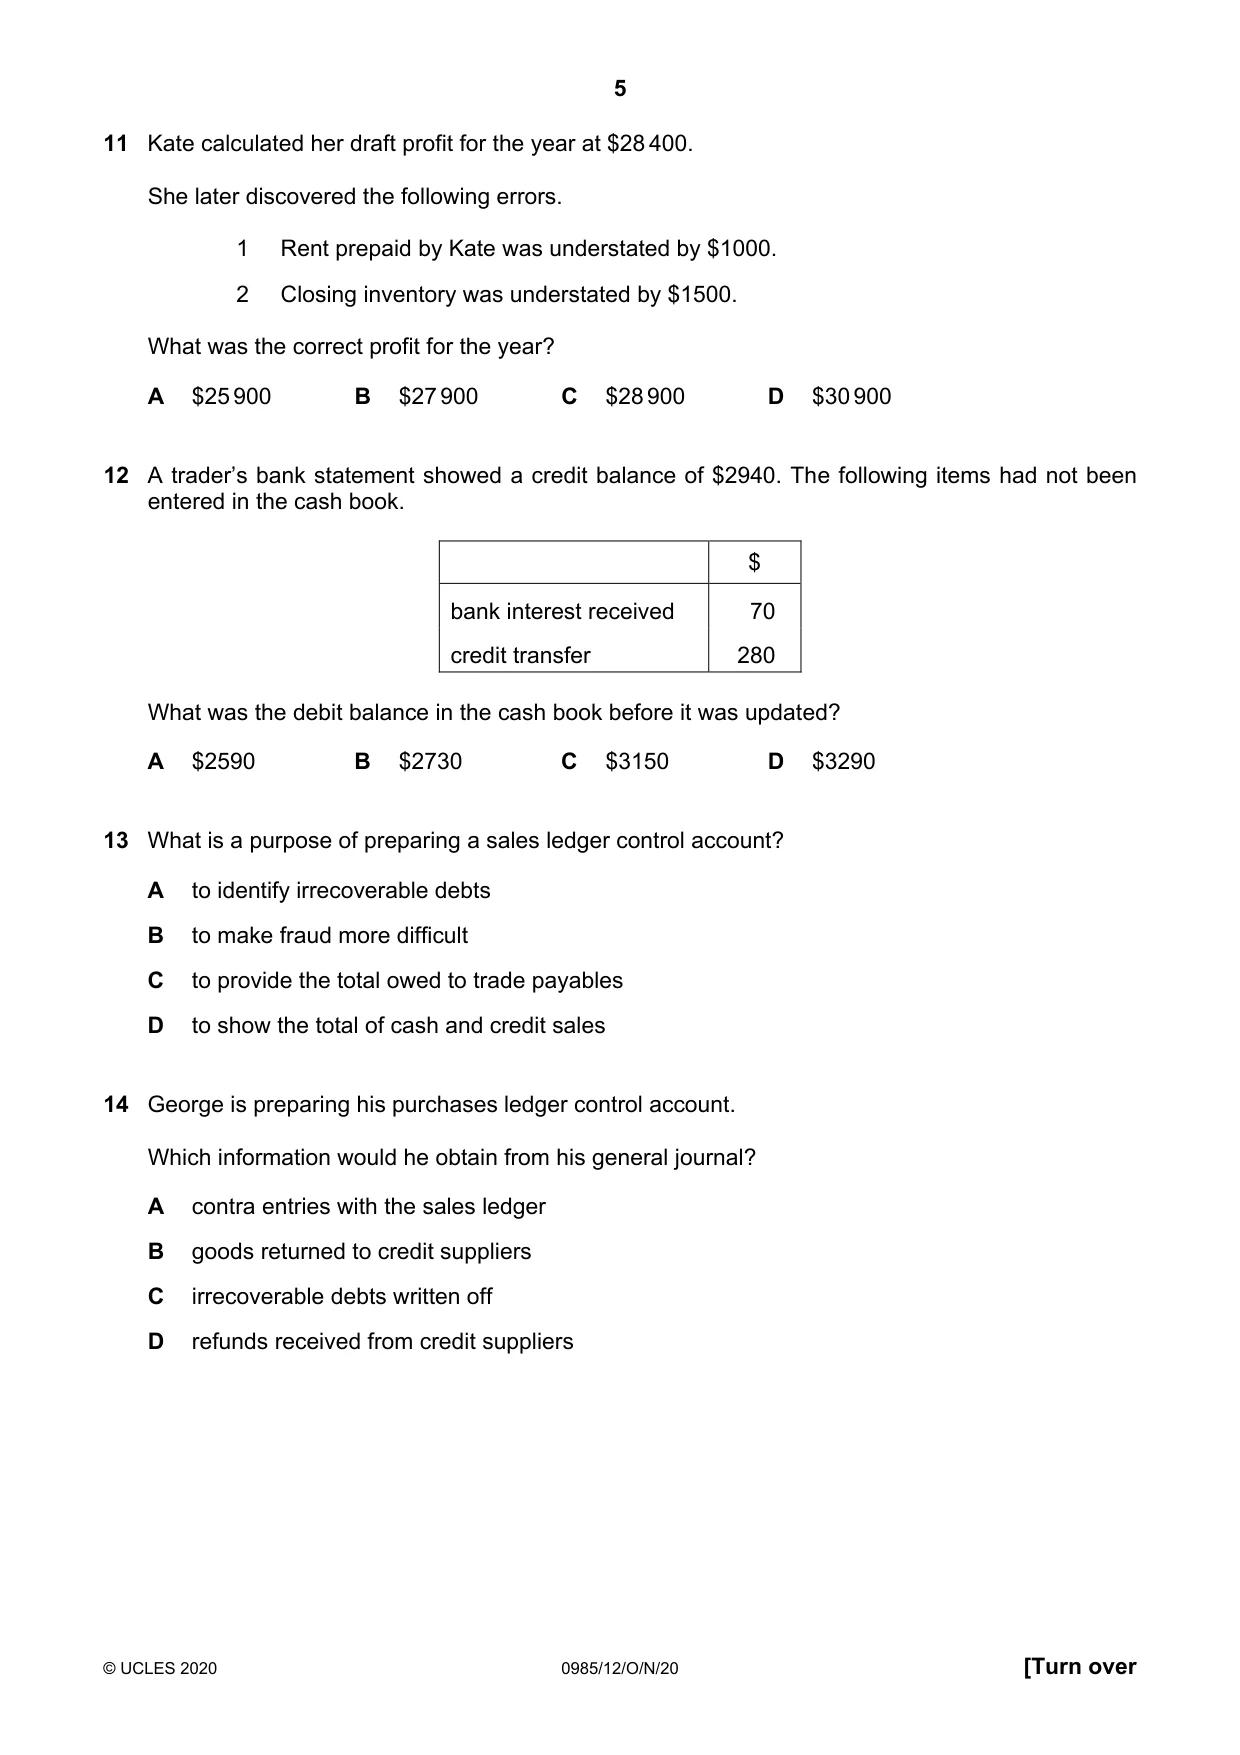
11 Kate calculated her draft profit for the year at $28 400. She later discovered the following errors. 1 Rent prepaid by Kate was understated by $1000. 2 Closing inventory was understated by $1500. What was the correct profit for the year? A $25 900 B $27 900 C $28 900 D $30 900
Mark scheme: D
Q12 · A trader’s bank statement showed a credit balance of $2940
12 A trader’s bank statement showed a credit balance of $2940. The following items had not been entered in the cash book. $ bank interest received 70 credit transfer 280 What was the debit balance in the cash book before it was updated? A $2590 B $2730 C $3150 D $3290
Mark scheme: A
Q13 · What is a purpose of preparing a sales ledger control account?
13 What is a purpose of preparing a sales ledger control account? A to identify irrecoverable debts B to make fraud more difficult C to provide the total owed to trade payables D to show the total of cash and credit sales
Mark scheme: B
Q14 · George is preparing his purchases ledger control account
14 George is preparing his purchases ledger control account. Which information would he obtain from his general journal? A contra entries with the sales ledger B goods returned to credit suppliers C irrecoverable debts written off D refunds received from credit suppliers
Mark scheme: A
Q15 · A trader debited the cost of repairing office equipment to the office equipment account
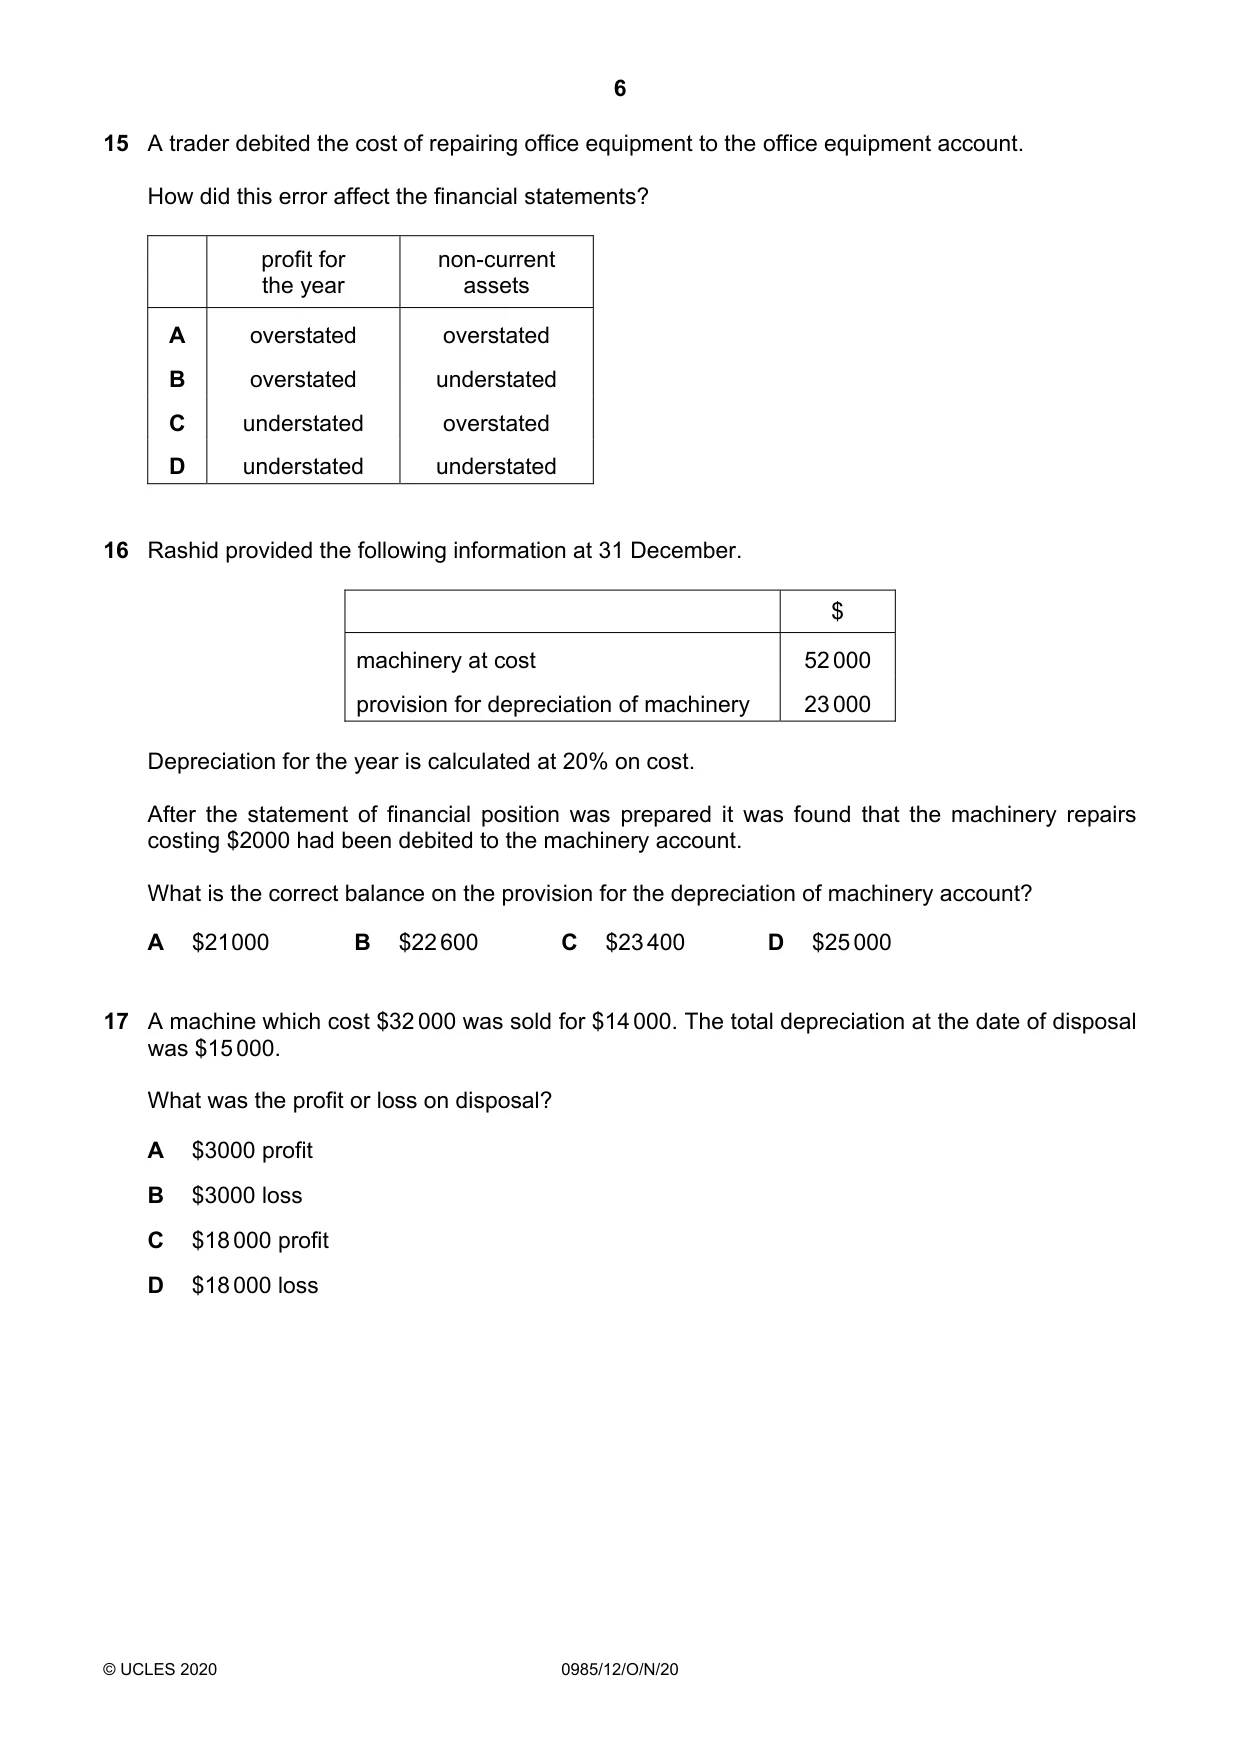
15 A trader debited the cost of repairing office equipment to the office equipment account. How did this error affect the financial statements? profit for non-current the year assets A overstated overstated B overstated understated C understated overstated D understated understated
Mark scheme: A
More questions on Capital and revenue expenditure and receipts
Q16 · Rashid provided the following information at 31 December
16 Rashid provided the following information at 31 December. $ machinery at cost 52 000 provision for depreciation of machinery 23 000 Depreciation for the year is calculated at 20% on cost. After the statement of financial position was prepared it was found that the machinery repairs costing $2000 had been debited to the machinery account. What is the correct balance on the provision for the depreciation of machinery account? A $21 000 B $22 600 C $23 400 D $25 000
Mark scheme: B
More questions on Accounting for depreciation and disposal of non-current assets
Q17 · A machine which cost $32 000 was sold for $14 000
17 A machine which cost $32 000 was sold for $14 000. The total depreciation at the date of disposal was $15 000. What was the profit or loss on disposal? A $3000 profit B $3000 loss C $18 000 profit D $18 000 loss
Mark scheme: B
More questions on Accounting for depreciation and disposal of non-current assets
Q18 · Beena maintains a provision for doubtful debts of 3% of the trade receivables at the end…
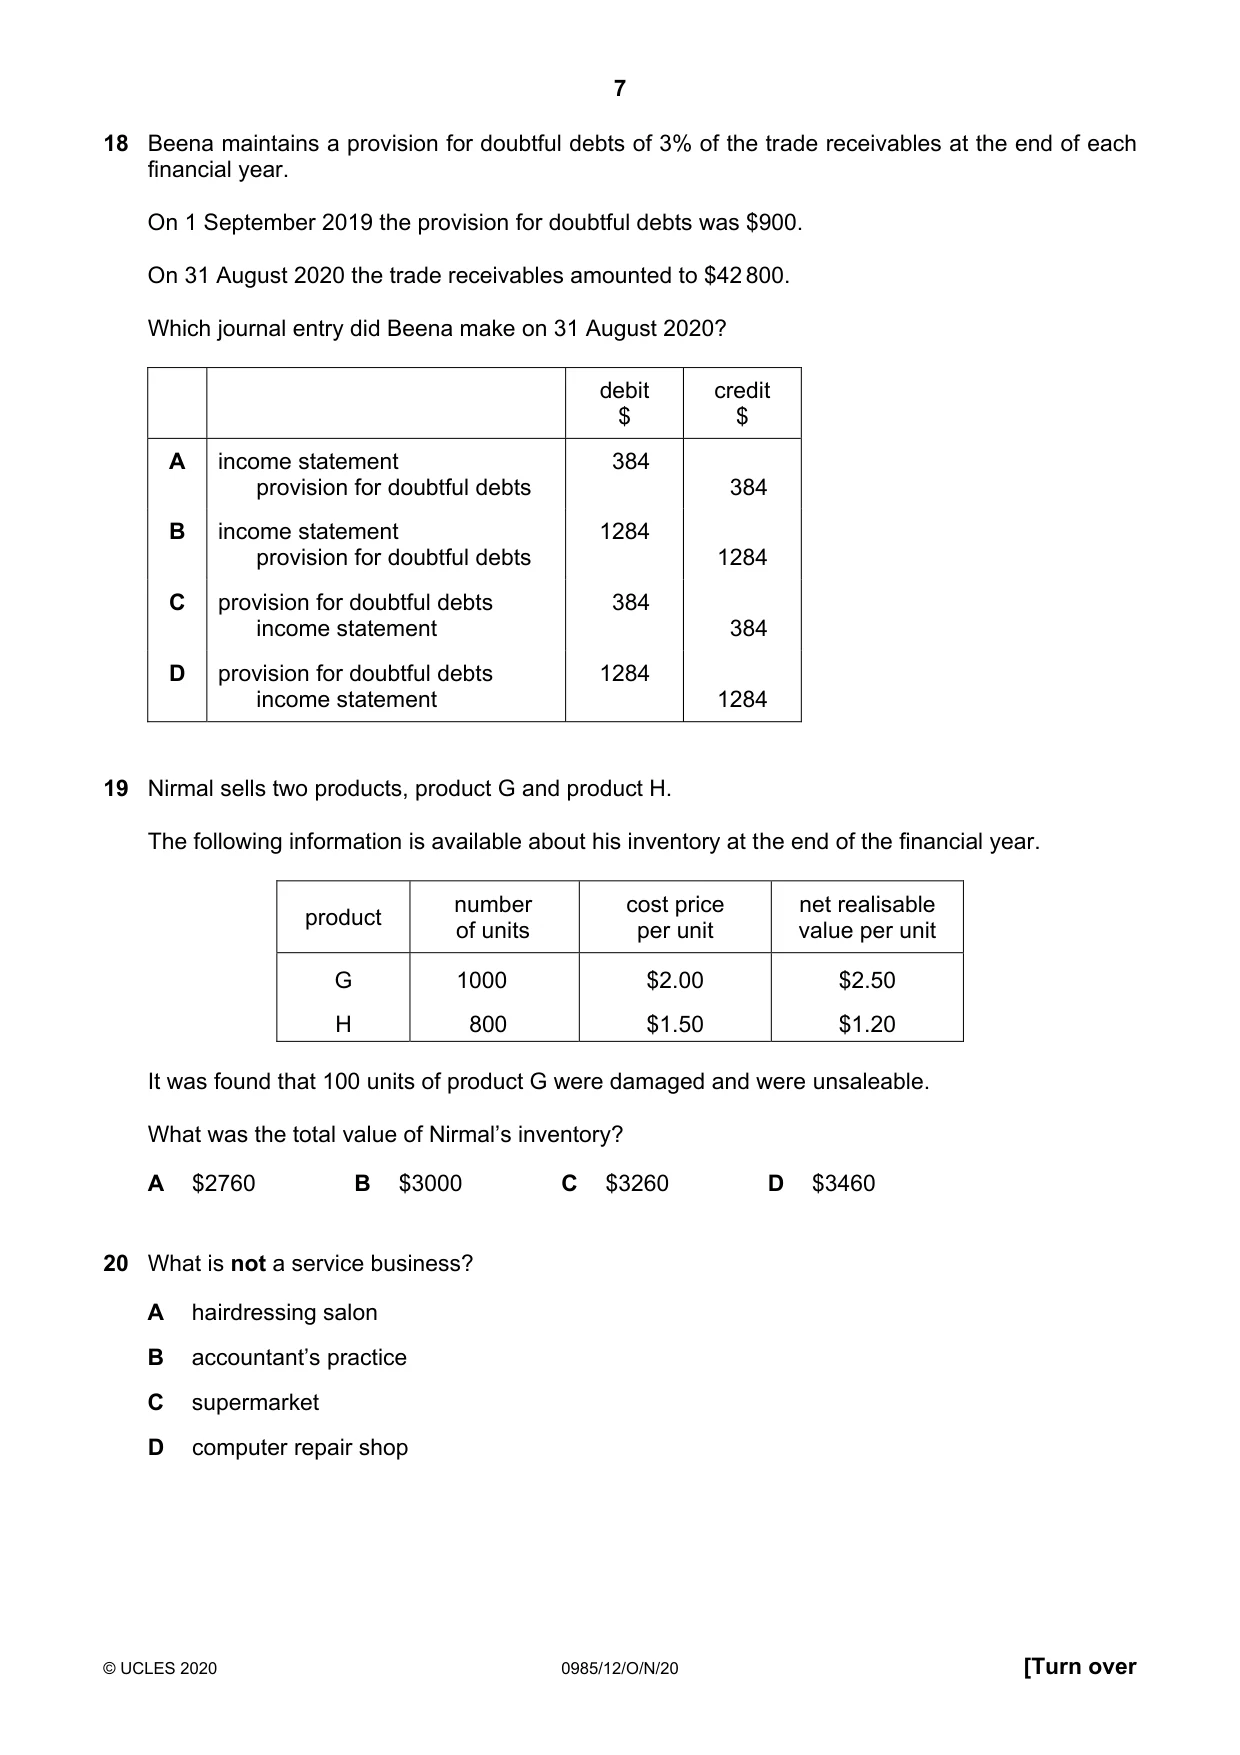
18 Beena maintains a provision for doubtful debts of 3% of the trade receivables at the end of each financial year. On 1 September 2019 the provision for doubtful debts was $900. On 31 August 2020 the trade receivables amounted to $42 800. Which journal entry did Beena make on 31 August 2020? debit credit $ $ A income statement 384 provision for doubtful debts 384 B income statement 1284 provision for doubtful debts 1284 C provision for doubtful debts 384 income statement 384 D provision for doubtful debts 1284 income statement 1284
Mark scheme: A
More questions on Irrecoverable debts and allowance for irrecoverable debts
Q19 · Nirmal sells two products, product G and product H
19 Nirmal sells two products, product G and product H. The following information is available about his inventory at the end of the financial year. number cost price net realisable product of units per unit value per unit G 1000 $2.00 $2.50 H 800 $1.50 $1.20 It was found that 100 units of product G were damaged and were unsaleable. What was the total value of Nirmal’s inventory? A $2760 B $3000 C $3260 D $3460
Mark scheme: A
Q20 · What is not a service business?
20 What is not a service business? A hairdressing salon B accountant’s practice C supermarket D computer repair shop
Mark scheme: C
Q21 · The financial year of Peter ends on 30 September
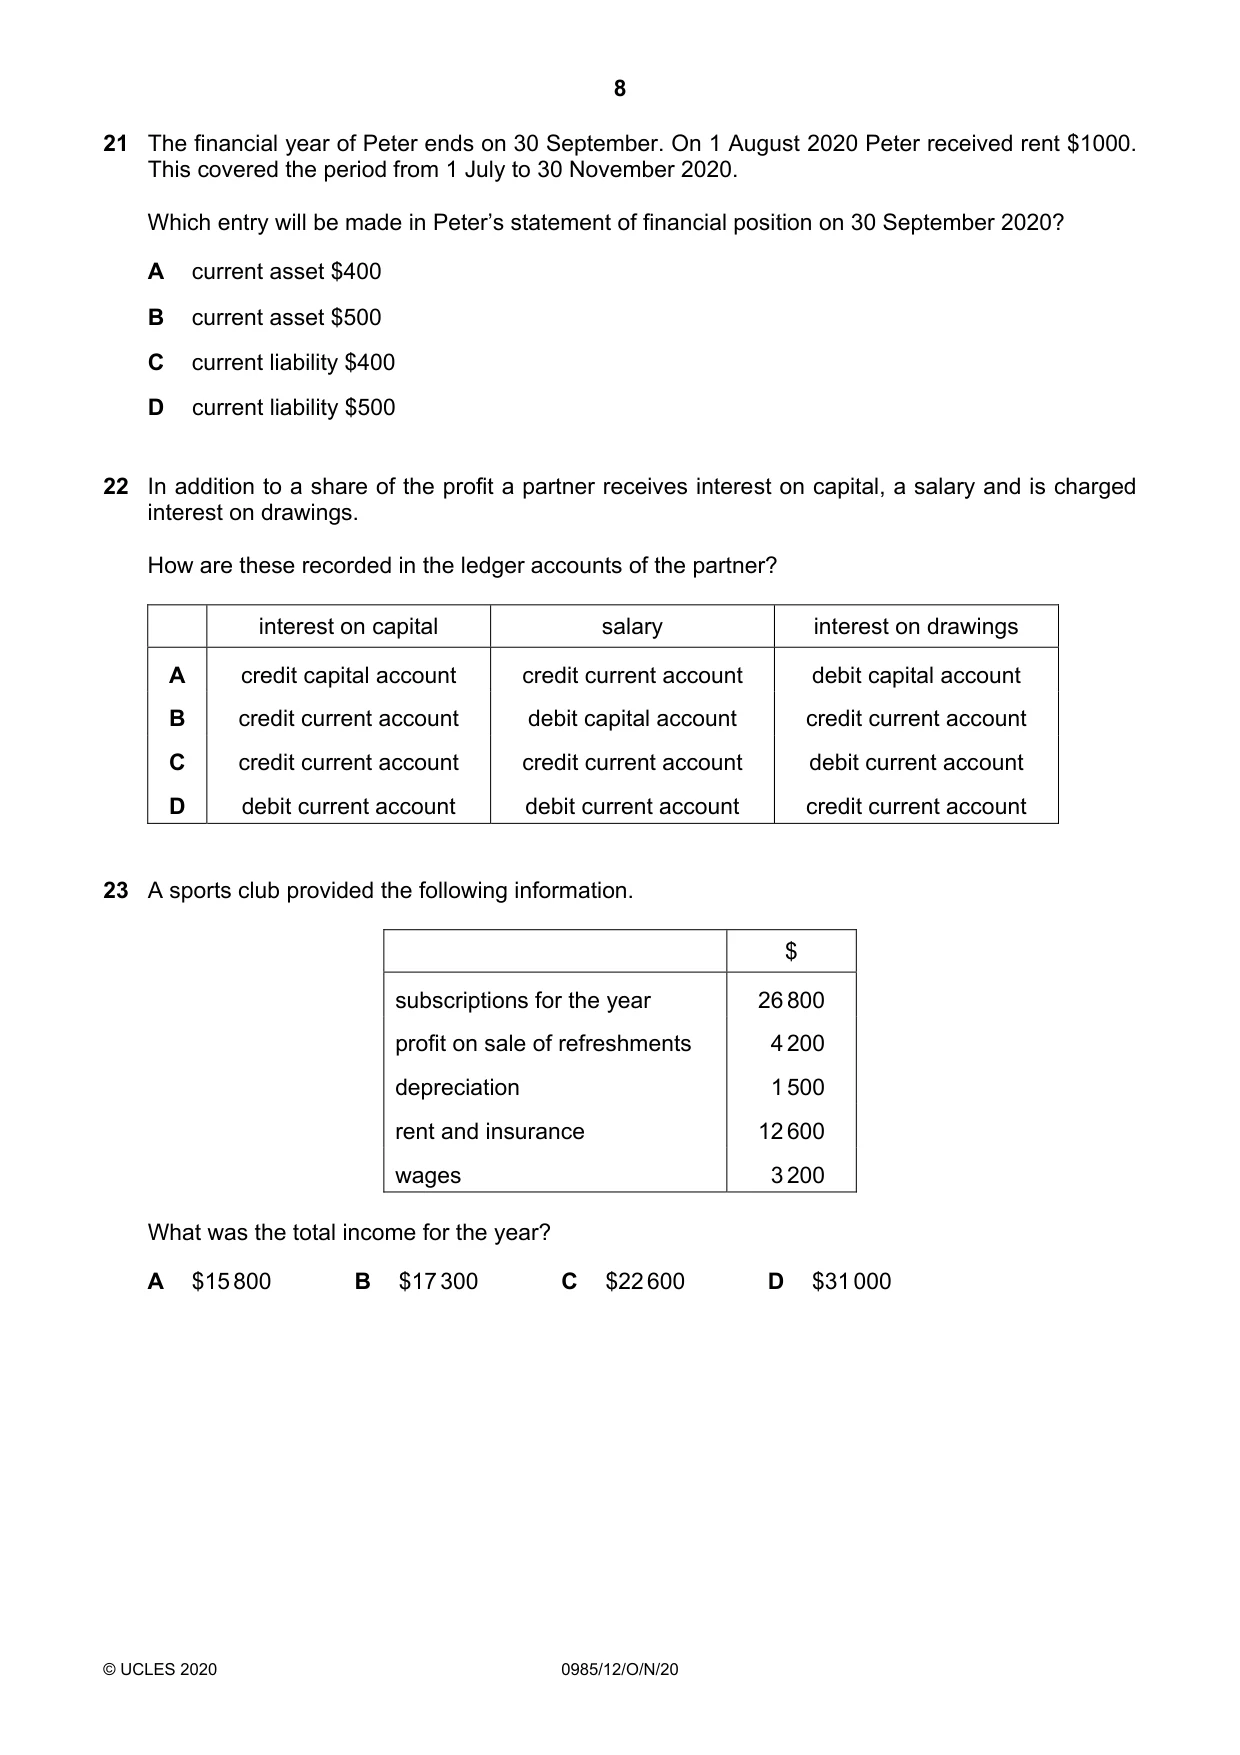
21 The financial year of Peter ends on 30 September. On 1 August 2020 Peter received rent $1000. This covered the period from 1 July to 30 November 2020. Which entry will be made in Peter’s statement of financial position on 30 September 2020? A current asset $400 B current asset $500 C current liability $400 D current liability $500
Mark scheme: C
Q22 · In addition to a share of the profit a partner receives interest on capital, a salary and…
22 In addition to a share of the profit a partner receives interest on capital, a salary and is charged interest on drawings. How are these recorded in the ledger accounts of the partner? interest on capital salary interest on drawings A credit capital account credit current account debit capital account B credit current account debit capital account credit current account C credit current account credit current account debit current account D debit current account debit current account credit current account
Mark scheme: C
Q23 · A sports club provided the following information
23 A sports club provided the following information. $ subscriptions for the year 26 800 profit on sale of refreshments 4 200 depreciation 1 500 rent and insurance 12 600 wages 3 200 What was the total income for the year? A $15 800 B $17 300 C $22 600 D $31 000
Mark scheme: D
Q24 · A club was formed on 1 July 2019
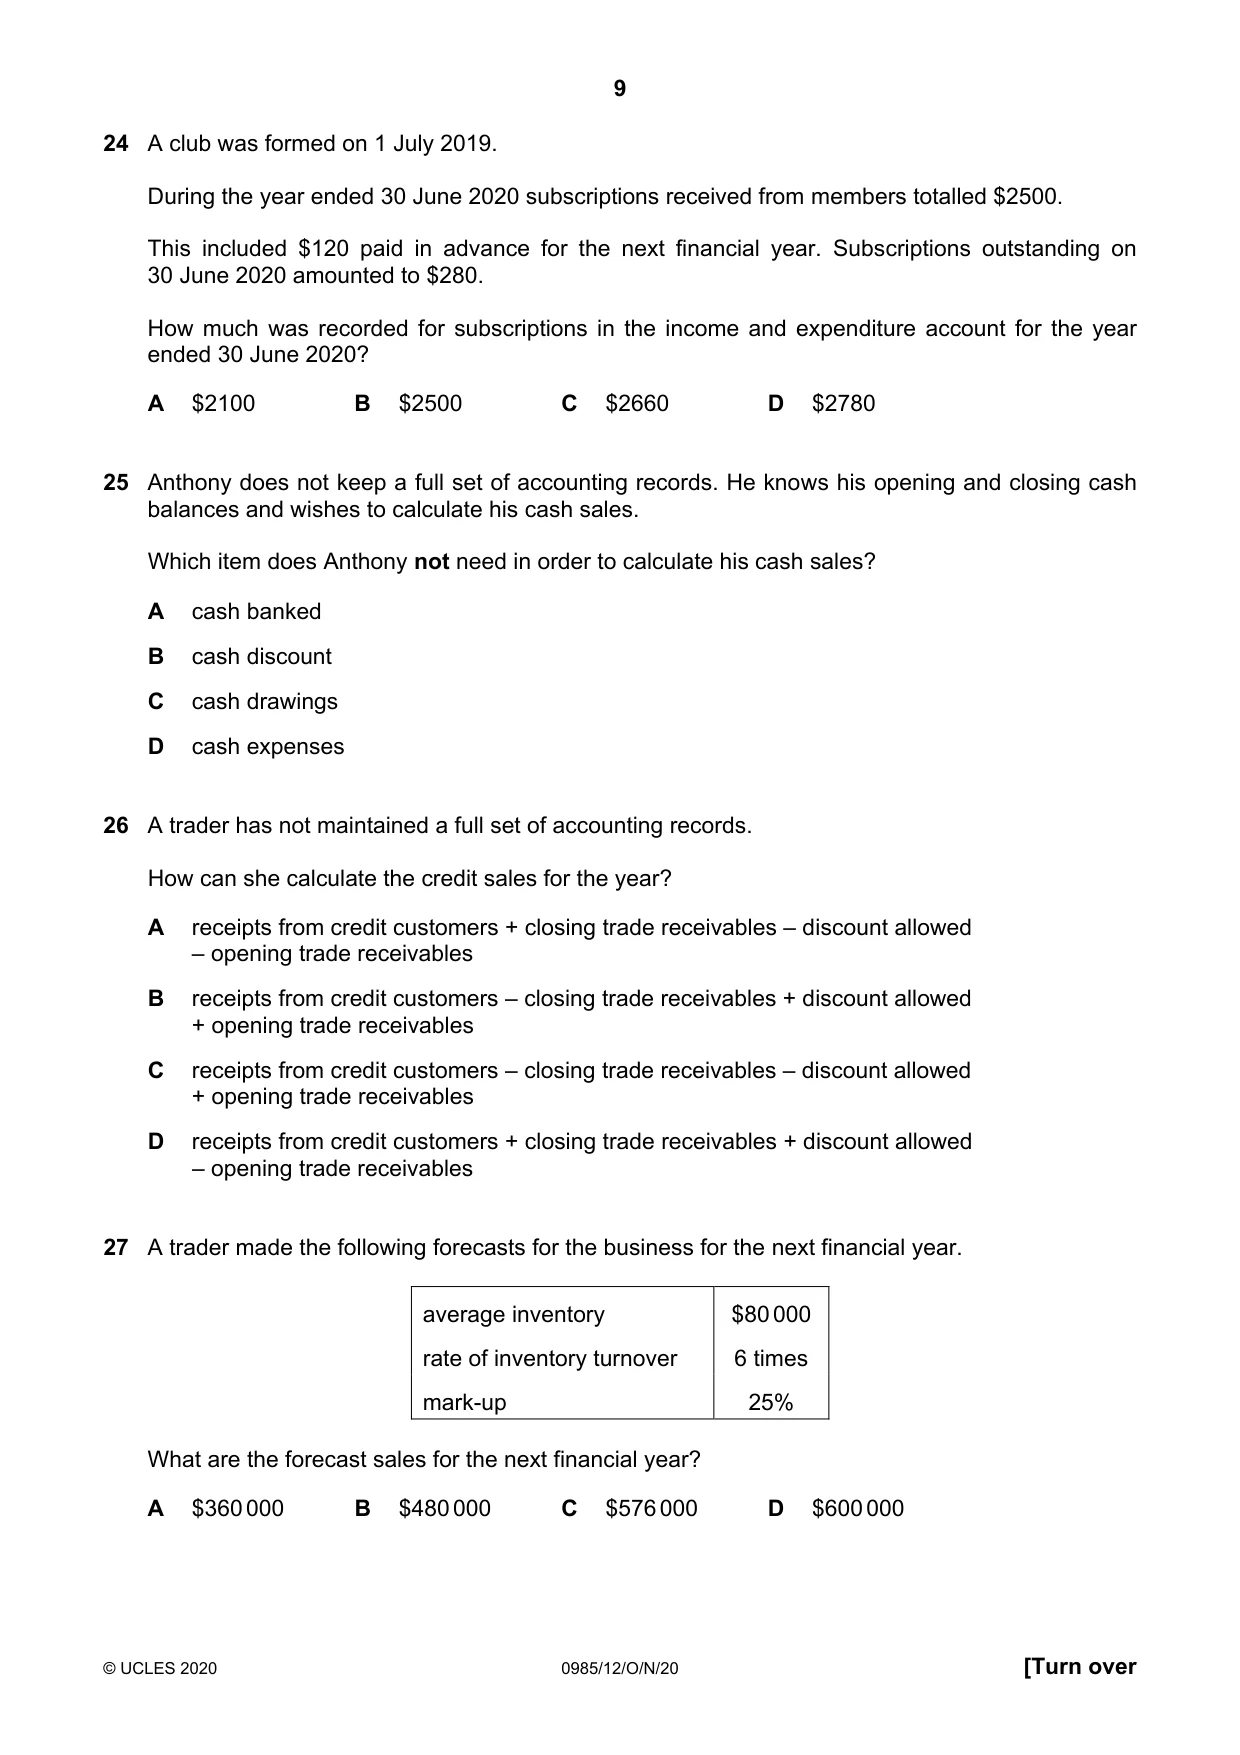
24 A club was formed on 1 July 2019. During the year ended 30 June 2020 subscriptions received from members totalled $2500. This included $120 paid in advance for the next financial year. Subscriptions outstanding on 30 June 2020 amounted to $280. How much was recorded for subscriptions in the income and expenditure account for the year ended 30 June 2020? A $2100 B $2500 C $2660 D $2780
Mark scheme: C
Q25 · Anthony does not keep a full set of accounting records
25 Anthony does not keep a full set of accounting records. He knows his opening and closing cash balances and wishes to calculate his cash sales. Which item does Anthony not need in order to calculate his cash sales? A cash banked B cash discount C cash drawings D cash expenses
Mark scheme: B
Q26 · A trader has not maintained a full set of accounting records
26 A trader has not maintained a full set of accounting records. How can she calculate the credit sales for the year? A receipts from credit customers + closing trade receivables – discount allowed – opening trade receivables B receipts from credit customers – closing trade receivables + discount allowed + opening trade receivables C receipts from credit customers – closing trade receivables – discount allowed + opening trade receivables D receipts from credit customers + closing trade receivables + discount allowed – opening trade receivables
Mark scheme: D
Q27 · A trader made the following forecasts for the business for the next financial year
27 A trader made the following forecasts for the business for the next financial year. average inventory $80 000 rate of inventory turnover 6 times mark-up 25% What are the forecast sales for the next financial year? A $360 000 B $480 000 C $576 000 D $600 000
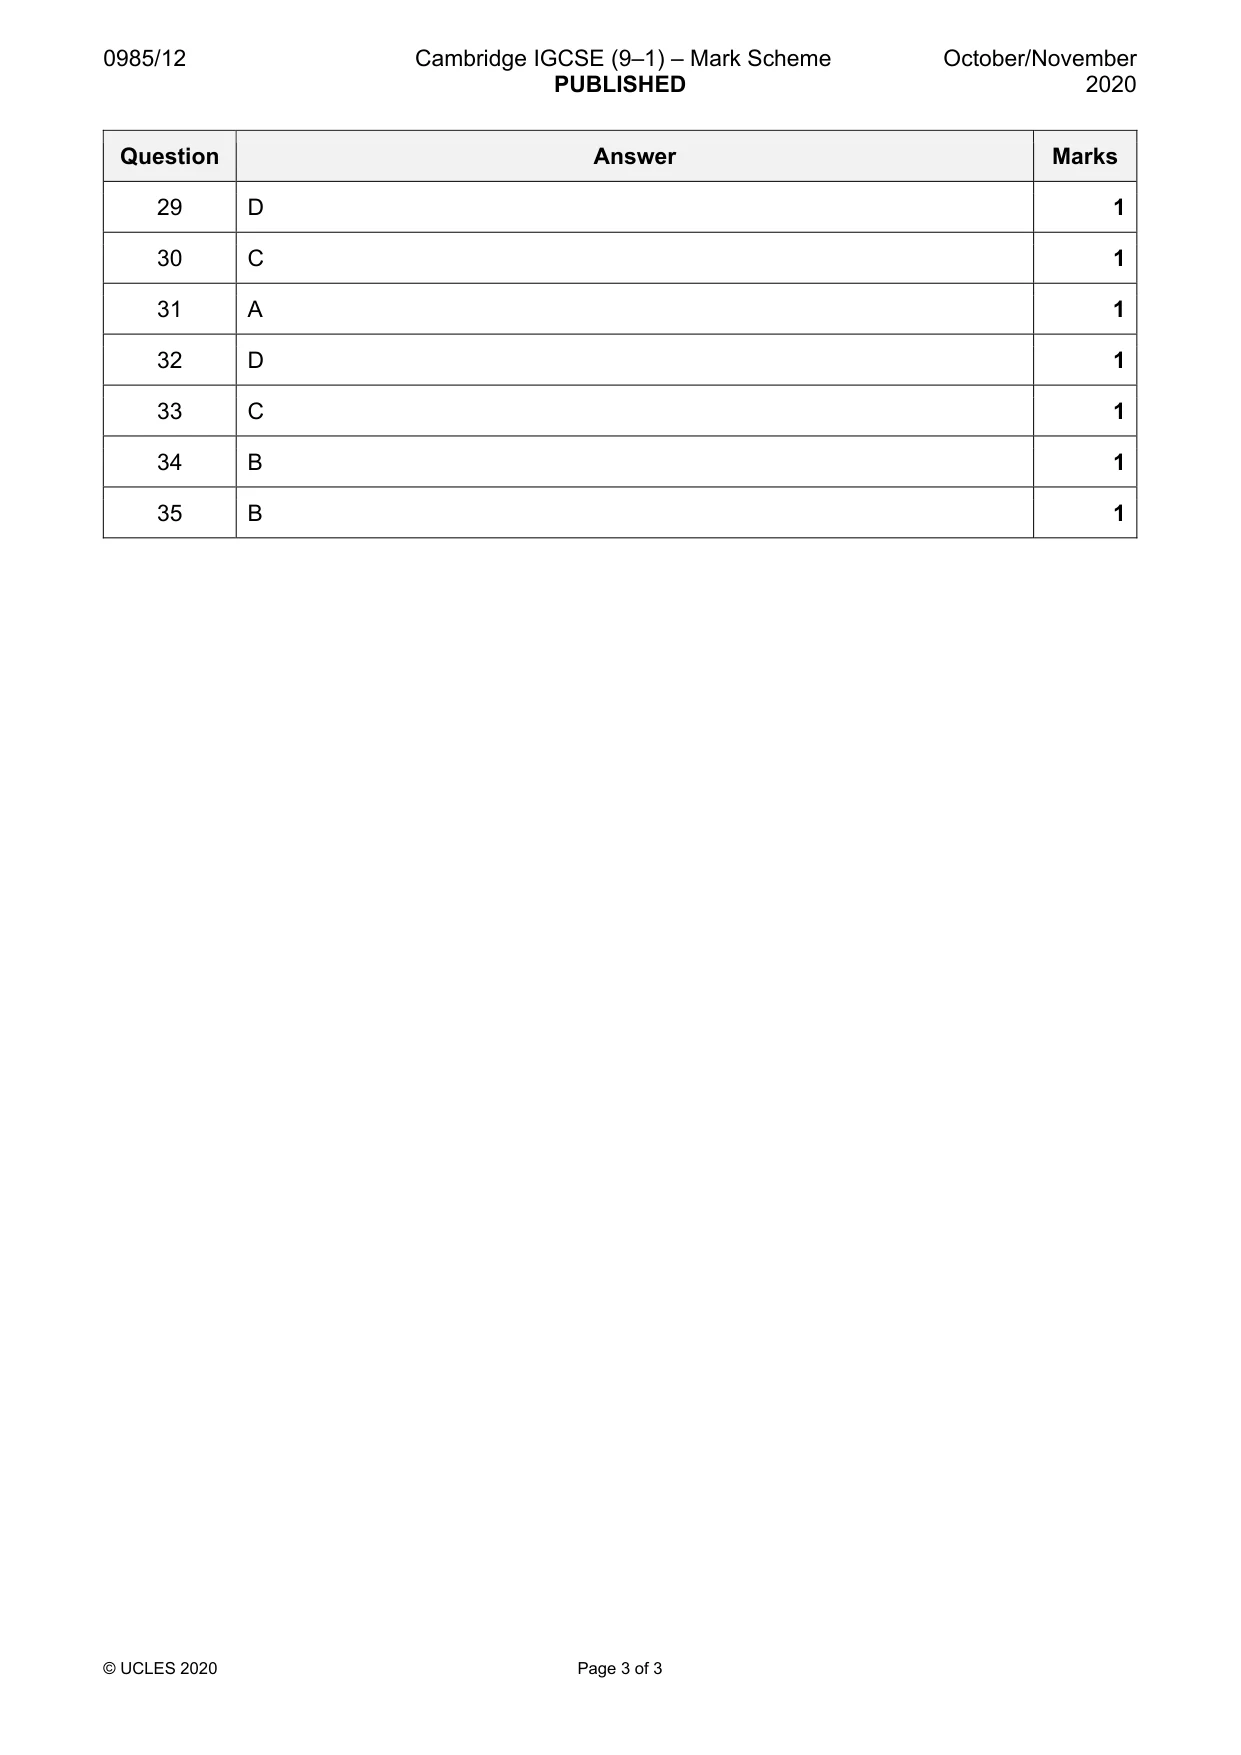
Mark scheme: D
More questions on Calculation and understanding of accounting ratios
Q28 · A company provided the following information about its current ratio
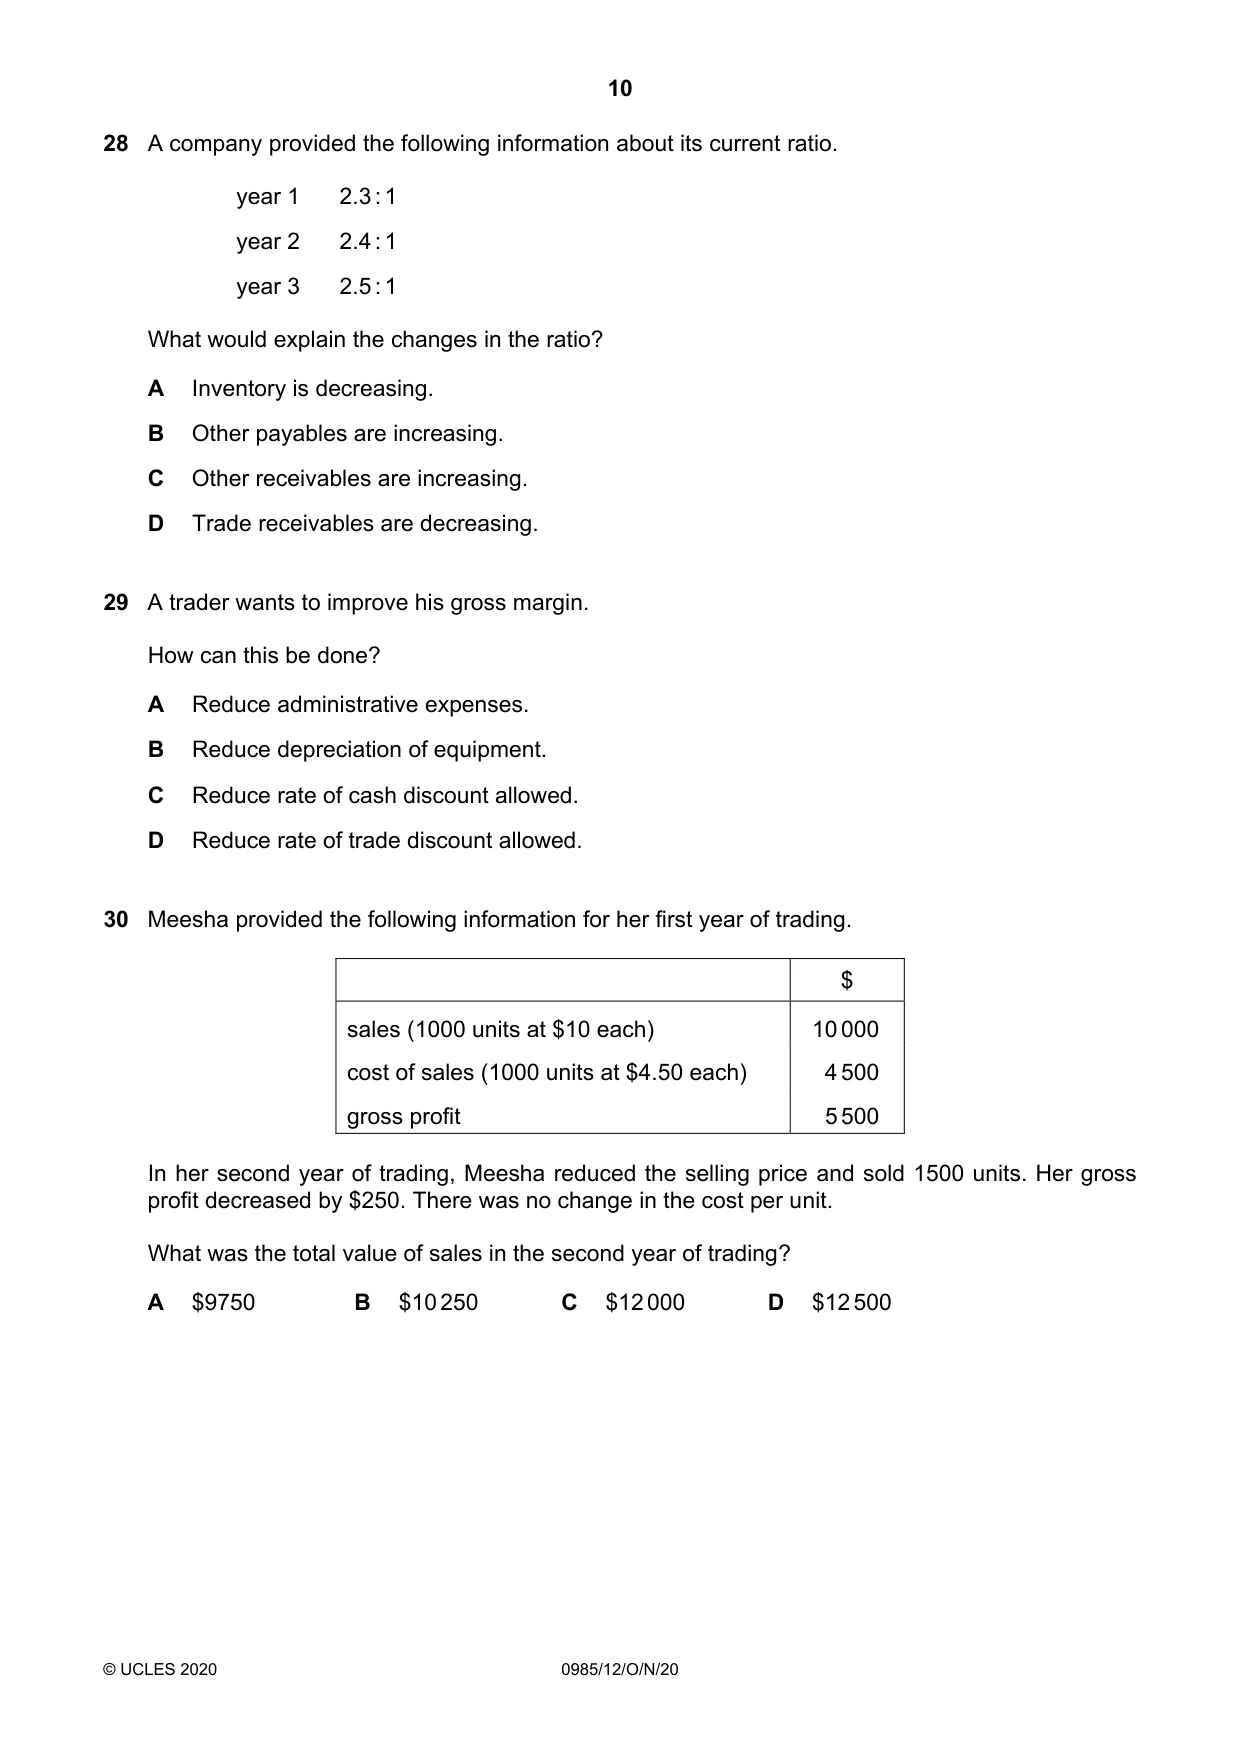
28 A company provided the following information about its current ratio. year 1 2.3 : 1 year 2 2.4 : 1 year 3 2.5 : 1 What would explain the changes in the ratio? A Inventory is decreasing. B Other payables are increasing. C Other receivables are increasing. D Trade receivables are decreasing.
Mark scheme: C
Q29 · A trader wants to improve his gross margin
29 A trader wants to improve his gross margin. How can this be done? A Reduce administrative expenses. B Reduce depreciation of equipment. C Reduce rate of cash discount allowed. D Reduce rate of trade discount allowed.
Mark scheme: D
More questions on Calculation and understanding of accounting ratios
Q30 · Meesha provided the following information for her first year of trading
30 Meesha provided the following information for her first year of trading. $ sales (1000 units at $10 each) 10 000 cost of sales (1000 units at $4.50 each) 4 500 gross profit 5 500 In her second year of trading, Meesha reduced the selling price and sold 1500 units. Her gross profit decreased by $250. There was no change in the cost per unit. What was the total value of sales in the second year of trading? A $9750 B $10 250 C $12 000 D $12 500
Mark scheme: C
More questions on Calculation and understanding of accounting ratios
Q31 · AB Limited and CD Limited both started business on 1 January 2019 with an ordinary share…
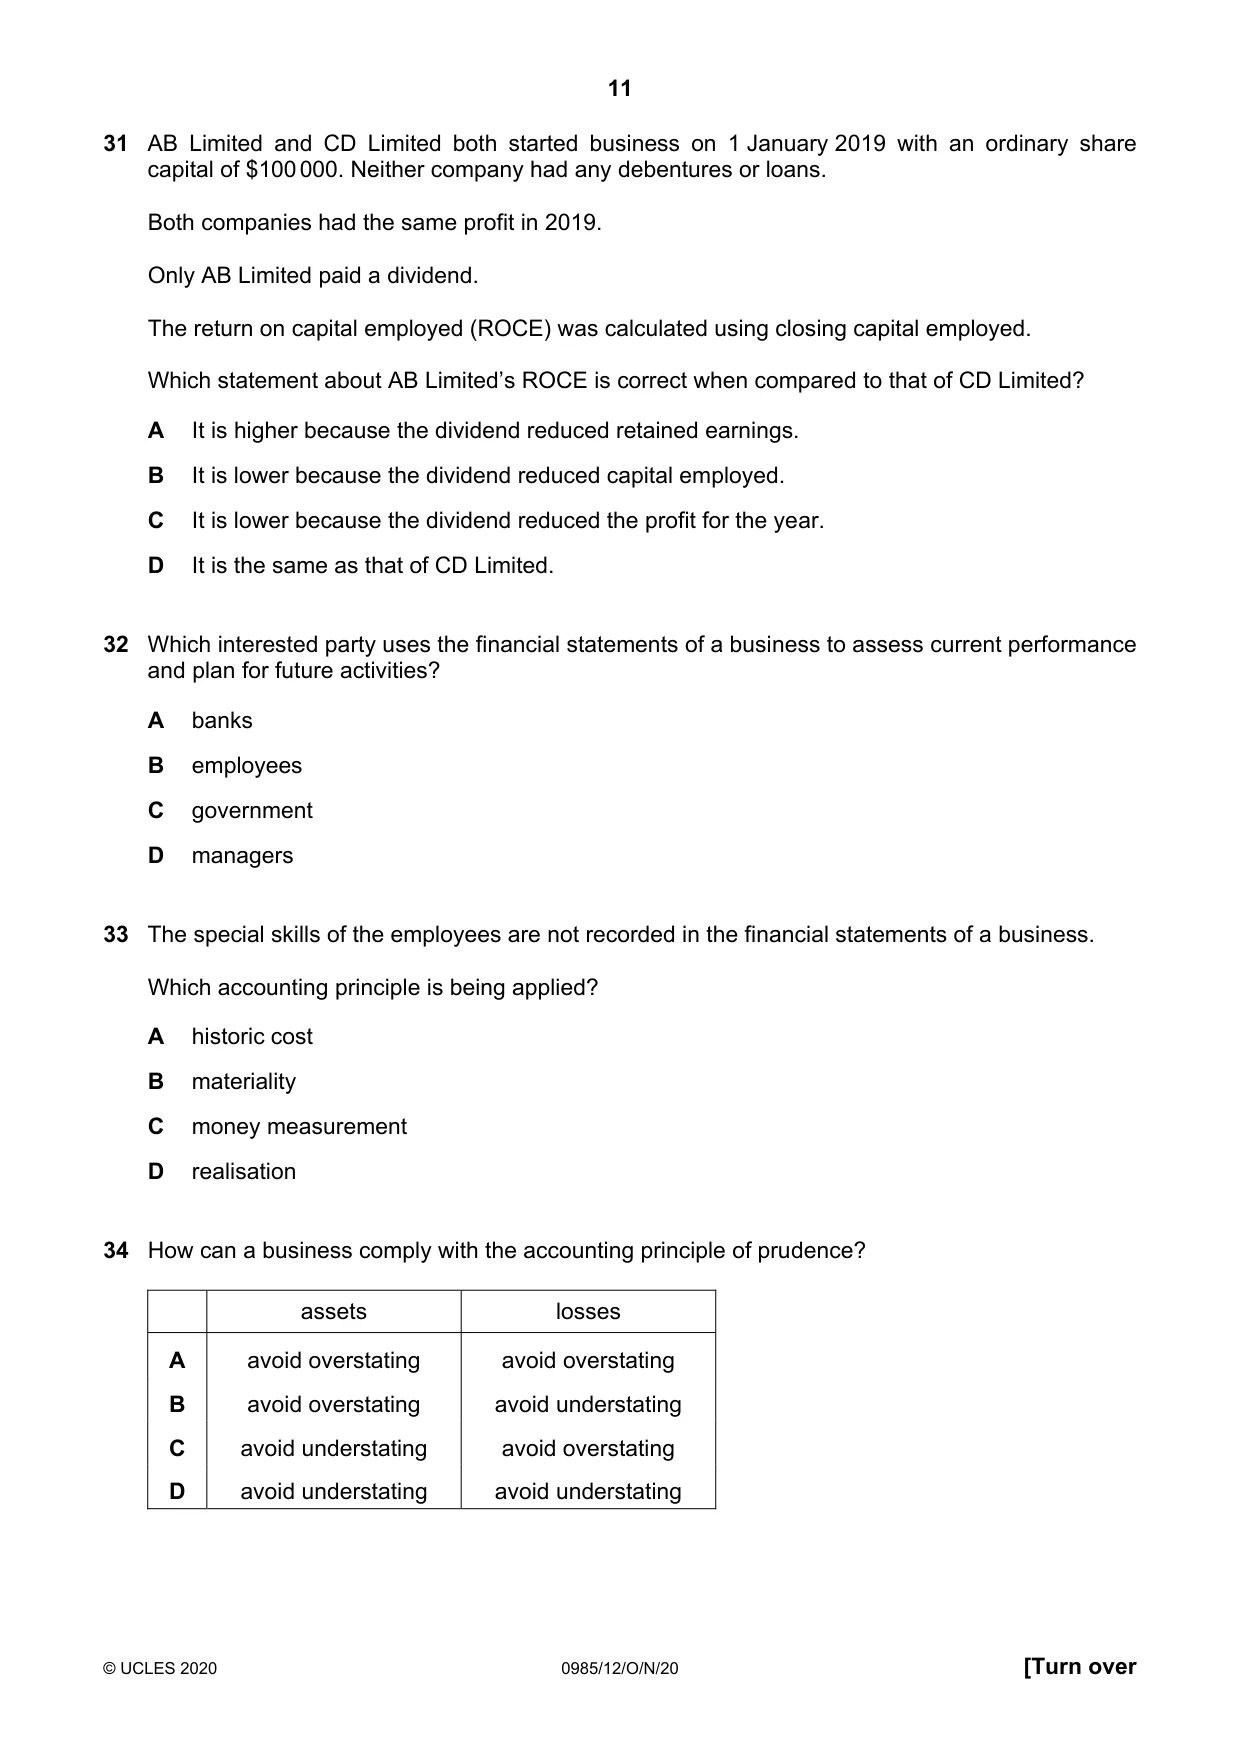
31 AB Limited and CD Limited both started business on 1 January 2019 with an ordinary share capital of $100 000. Neither company had any debentures or loans. Both companies had the same profit in 2019. Only AB Limited paid a dividend. The return on capital employed (ROCE) was calculated using closing capital employed. Which statement about AB Limited’s ROCE is correct when compared to that of CD Limited? A It is higher because the dividend reduced retained earnings. B It is lower because the dividend reduced capital employed. C It is lower because the dividend reduced the profit for the year. D It is the same as that of CD Limited.
Mark scheme: A
More questions on Calculation and understanding of accounting ratios
Q32 · Which interested party uses the financial statements of a business to assess current…
32 Which interested party uses the financial statements of a business to assess current performance and plan for future activities? A banks B employees C government D managers
Mark scheme: D
Q33 · The special skills of the employees are not recorded in the financial statements of a…
33 The special skills of the employees are not recorded in the financial statements of a business. Which accounting principle is being applied? A historic cost B materiality C money measurement D realisation
Mark scheme: C
Q34 · How can a business comply with the accounting principle of prudence?
34 How can a business comply with the accounting principle of prudence? assets losses A avoid overstating avoid overstating B avoid overstating avoid understating C avoid understating avoid overstating D avoid understating avoid understating
Mark scheme: B
Q35 · What is not an aim of international accounting standards?
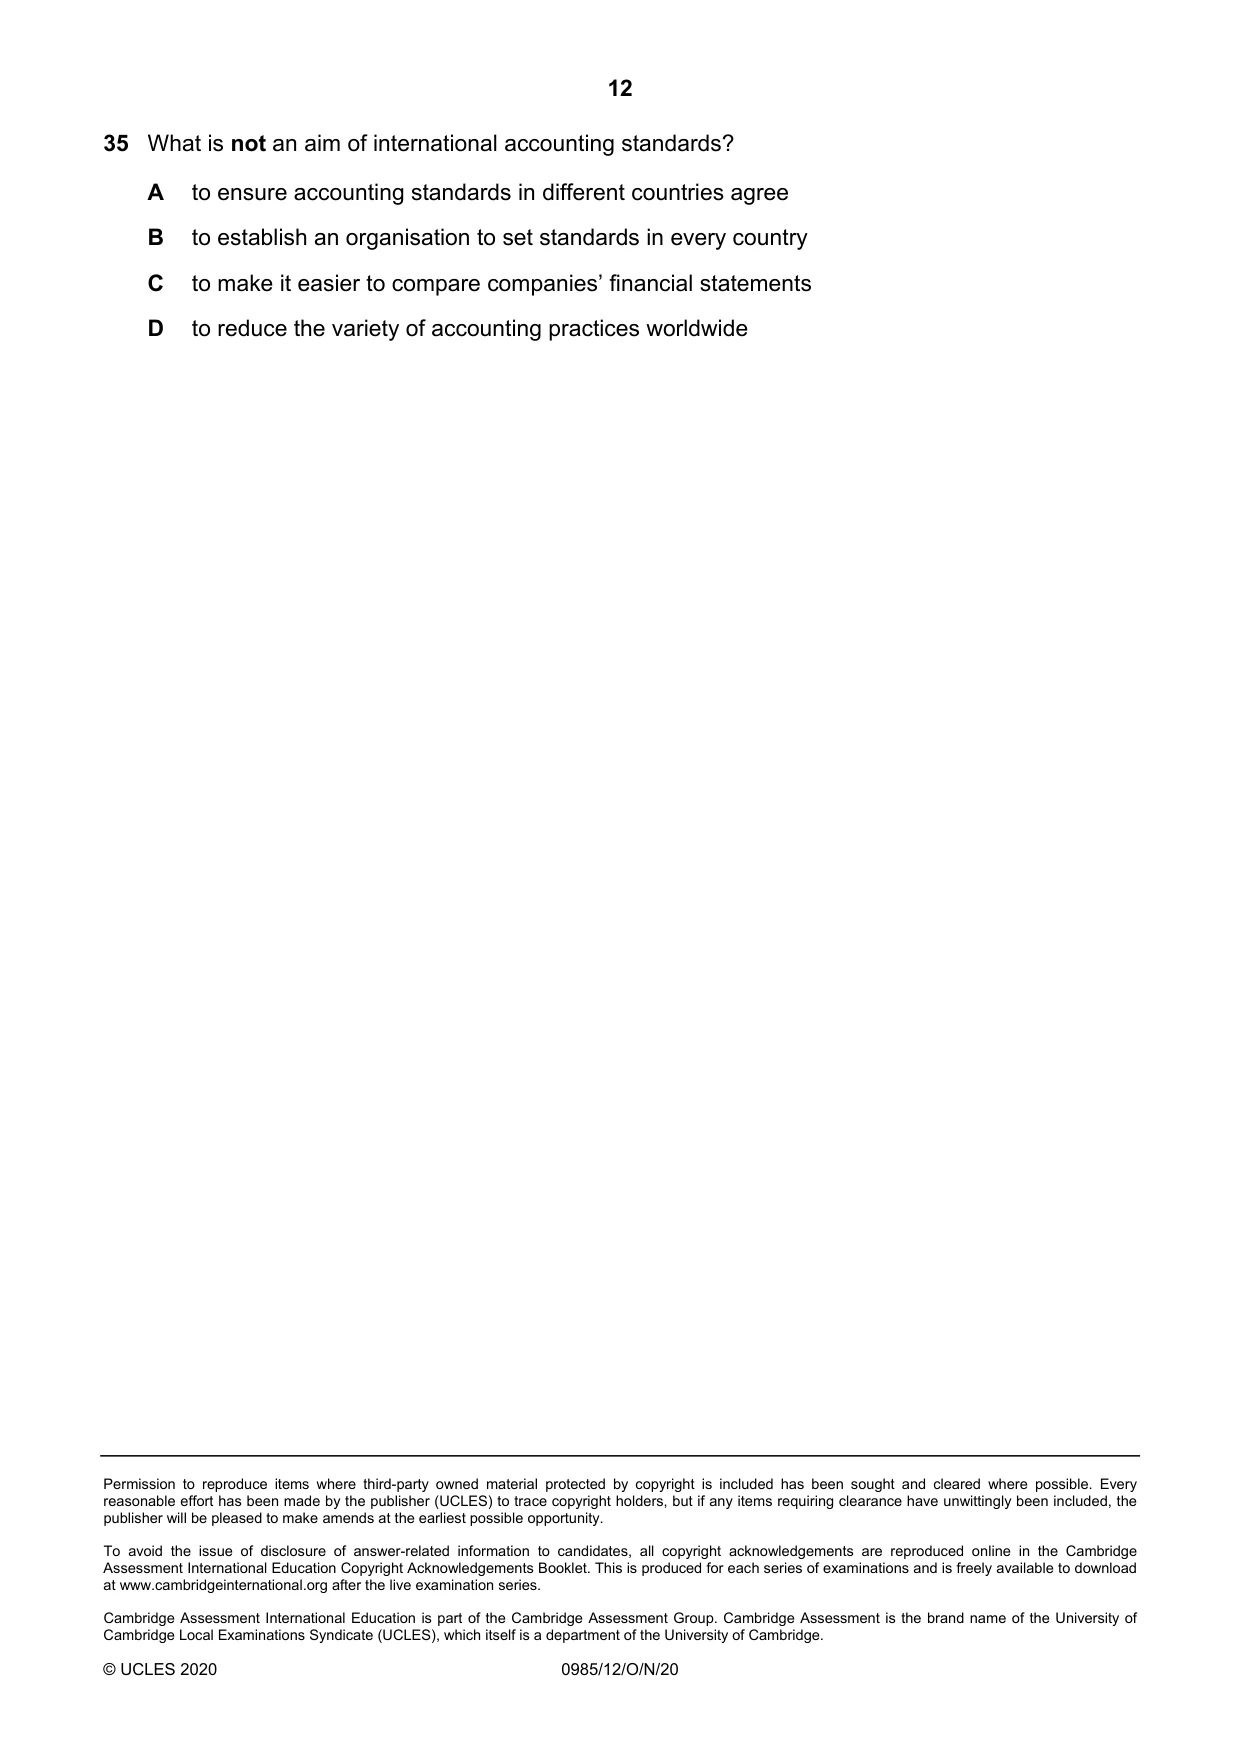
35 What is not an aim of international accounting standards? A to ensure accounting standards in different countries agree B to establish an organisation to set standards in every country C to make it easier to compare companies’ financial statements D to reduce the variety of accounting practices worldwide
Mark scheme: B
What was in this paper
The subtopics covered by these 35 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
4The double entry system of book-keeping4Accounting concepts3Corrections of errors3Accounting for depreciation and disposal of non-current assets2Clubs and societies2Control accounts2Incomplete records2The accounting equation2The purpose of accounting2Bank reconciliation1Books of prime entry1Capital and revenue expenditure and receipts1Interested parties1Interpretation of accounting ratios1Irrecoverable debts and allowance for irrecoverable debts1Other payables and other receivables1Partnerships1Valuation of inventory1What you needed in this session
Cambridge’s own grade thresholds for 2020 Oct/Nov, Paper 1 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.