Questions as text
Q1 · Gordon provided the following information for the year 0985/11 May/June 2020
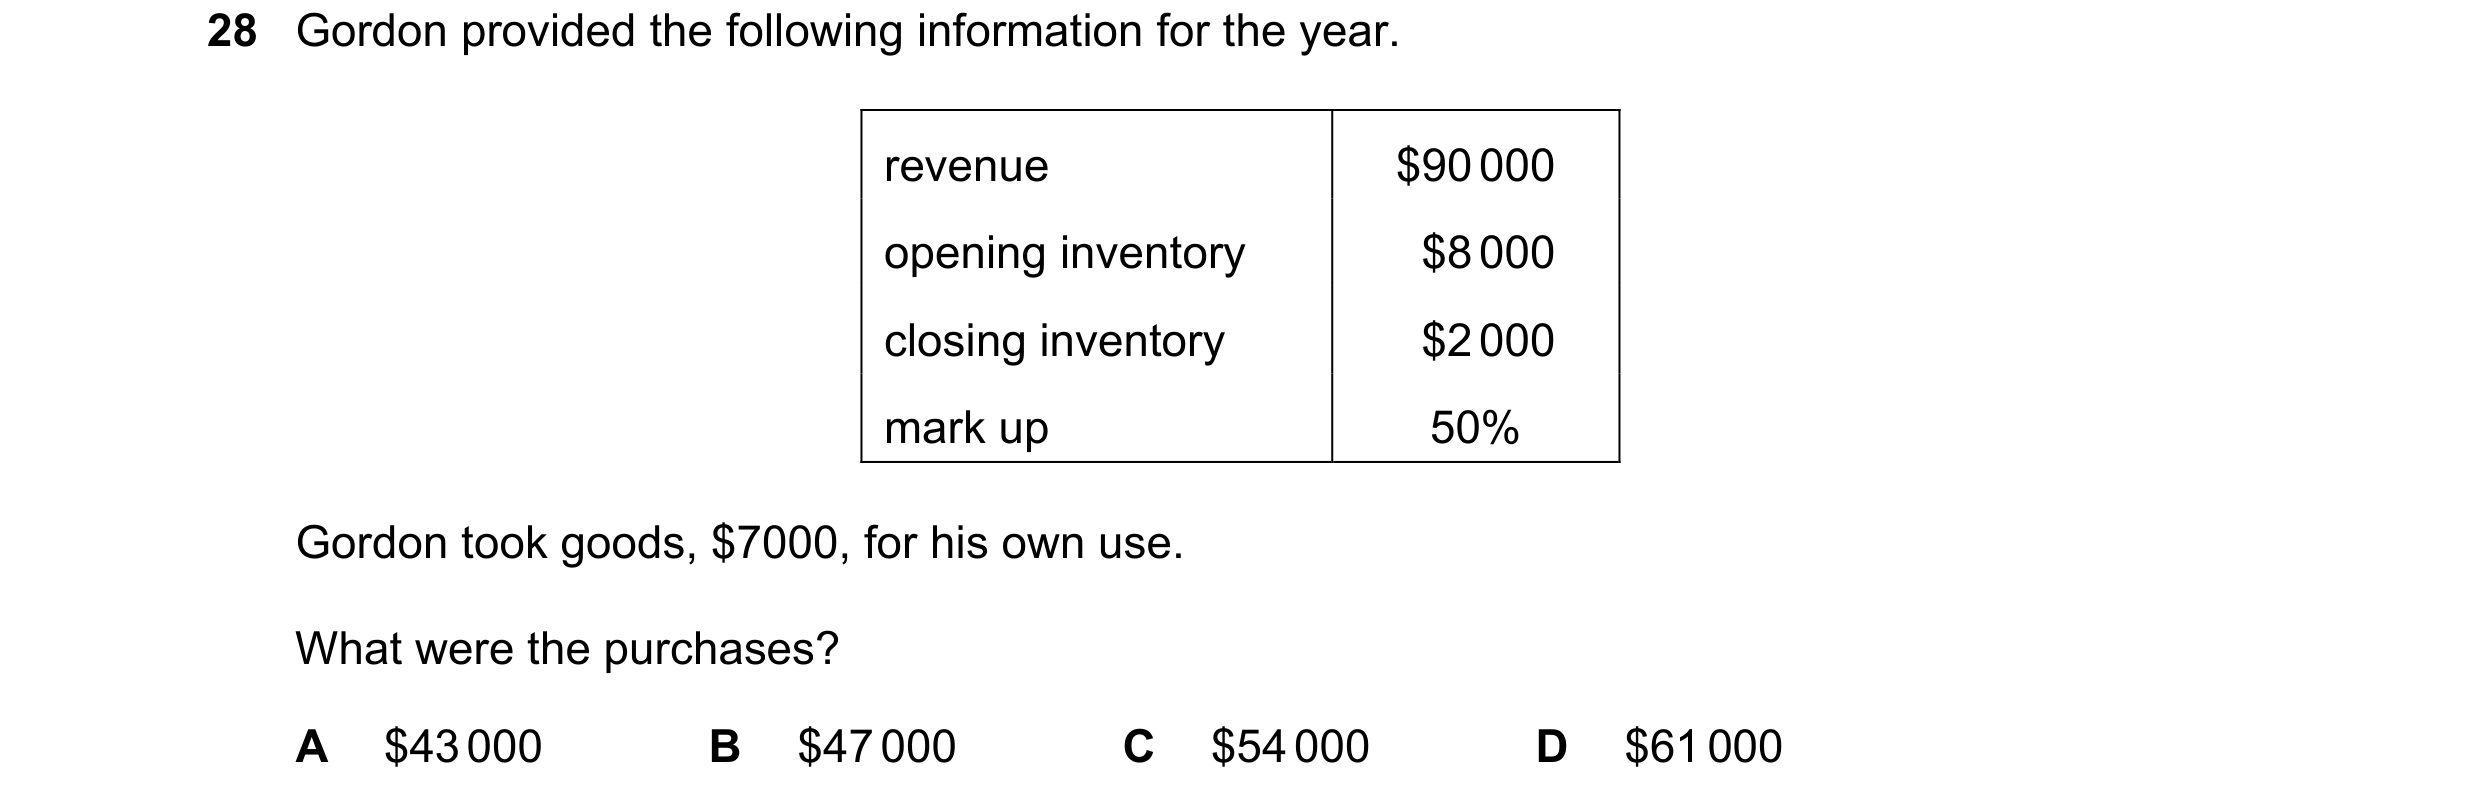
28 Gordon provided the following information for the year. revenue $90 000 opening inventory $8 000 closing inventory $2 000 mark up 50% Gordon took goods, $7000, for his own use. What were the purchases? A $43 000 B $47 000 C $54 000 D $61 000
1 marks
Answer: D
This question in 0985/11 May/June 2020
Q2 · Joel’s inventory on 31 December 2019 was valued at $4800 0985/12 May/June 2020
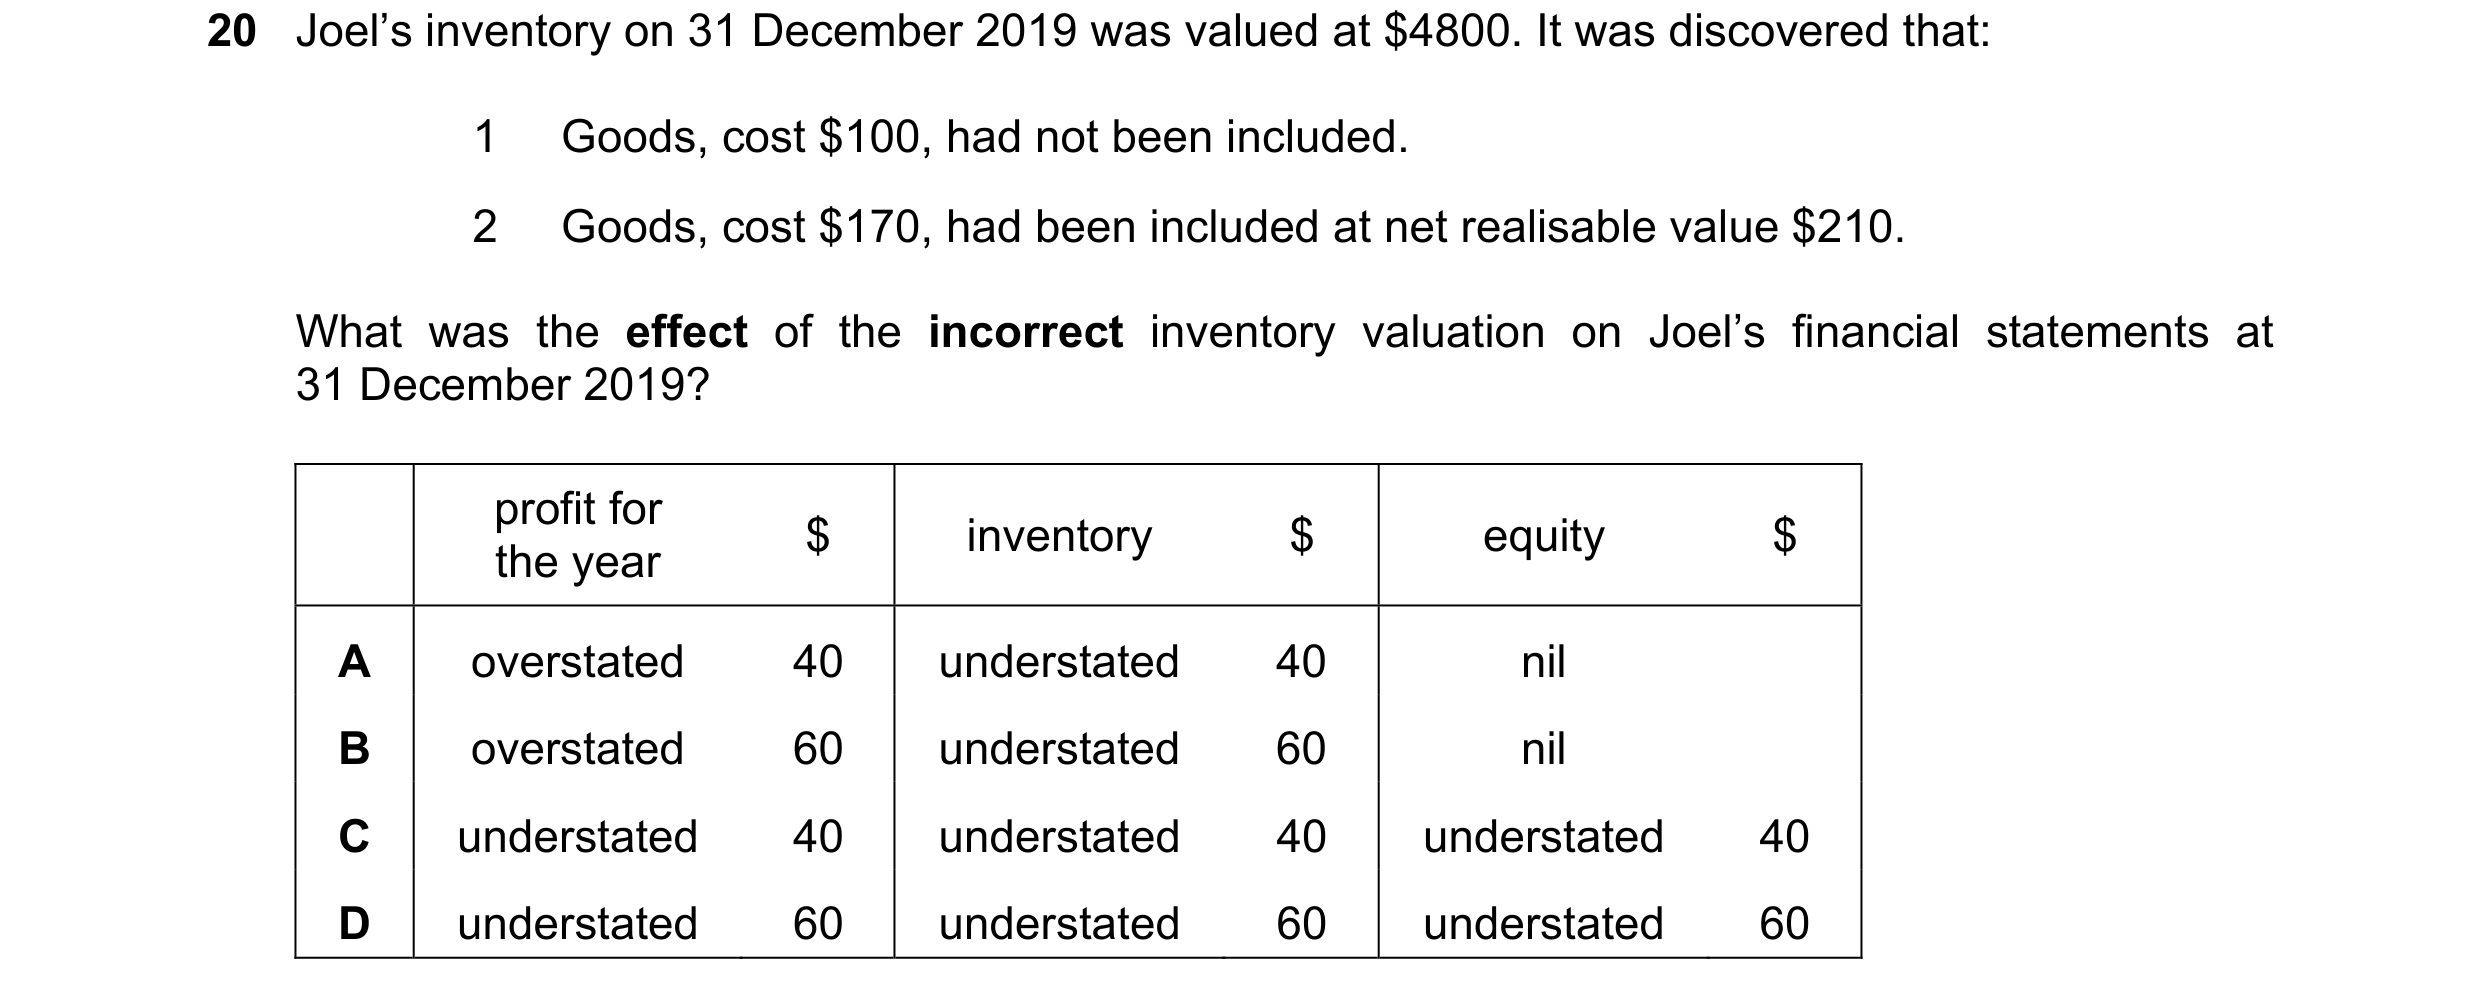
20 Joel’s inventory on 31 December 2019 was valued at $4800. It was discovered that: 1 Goods, cost $100, had not been included. 2 Goods, cost $170, had been included at net realisable value $210. What was the effect of the incorrect inventory valuation on Joel’s financial statements at 31 December 2019? profit for $ inventory $ equity $ the year A overstated 40 understated 40 nil B overstated 60 understated 60 nil C understated 40 understated 40 understated 40 D understated 60 understated 60 understated 60
1 marks
Answer: D
This question in 0985/12 May/June 2020
Q3 · Gordon provided the following information for the year 0985/12 May/June 2020
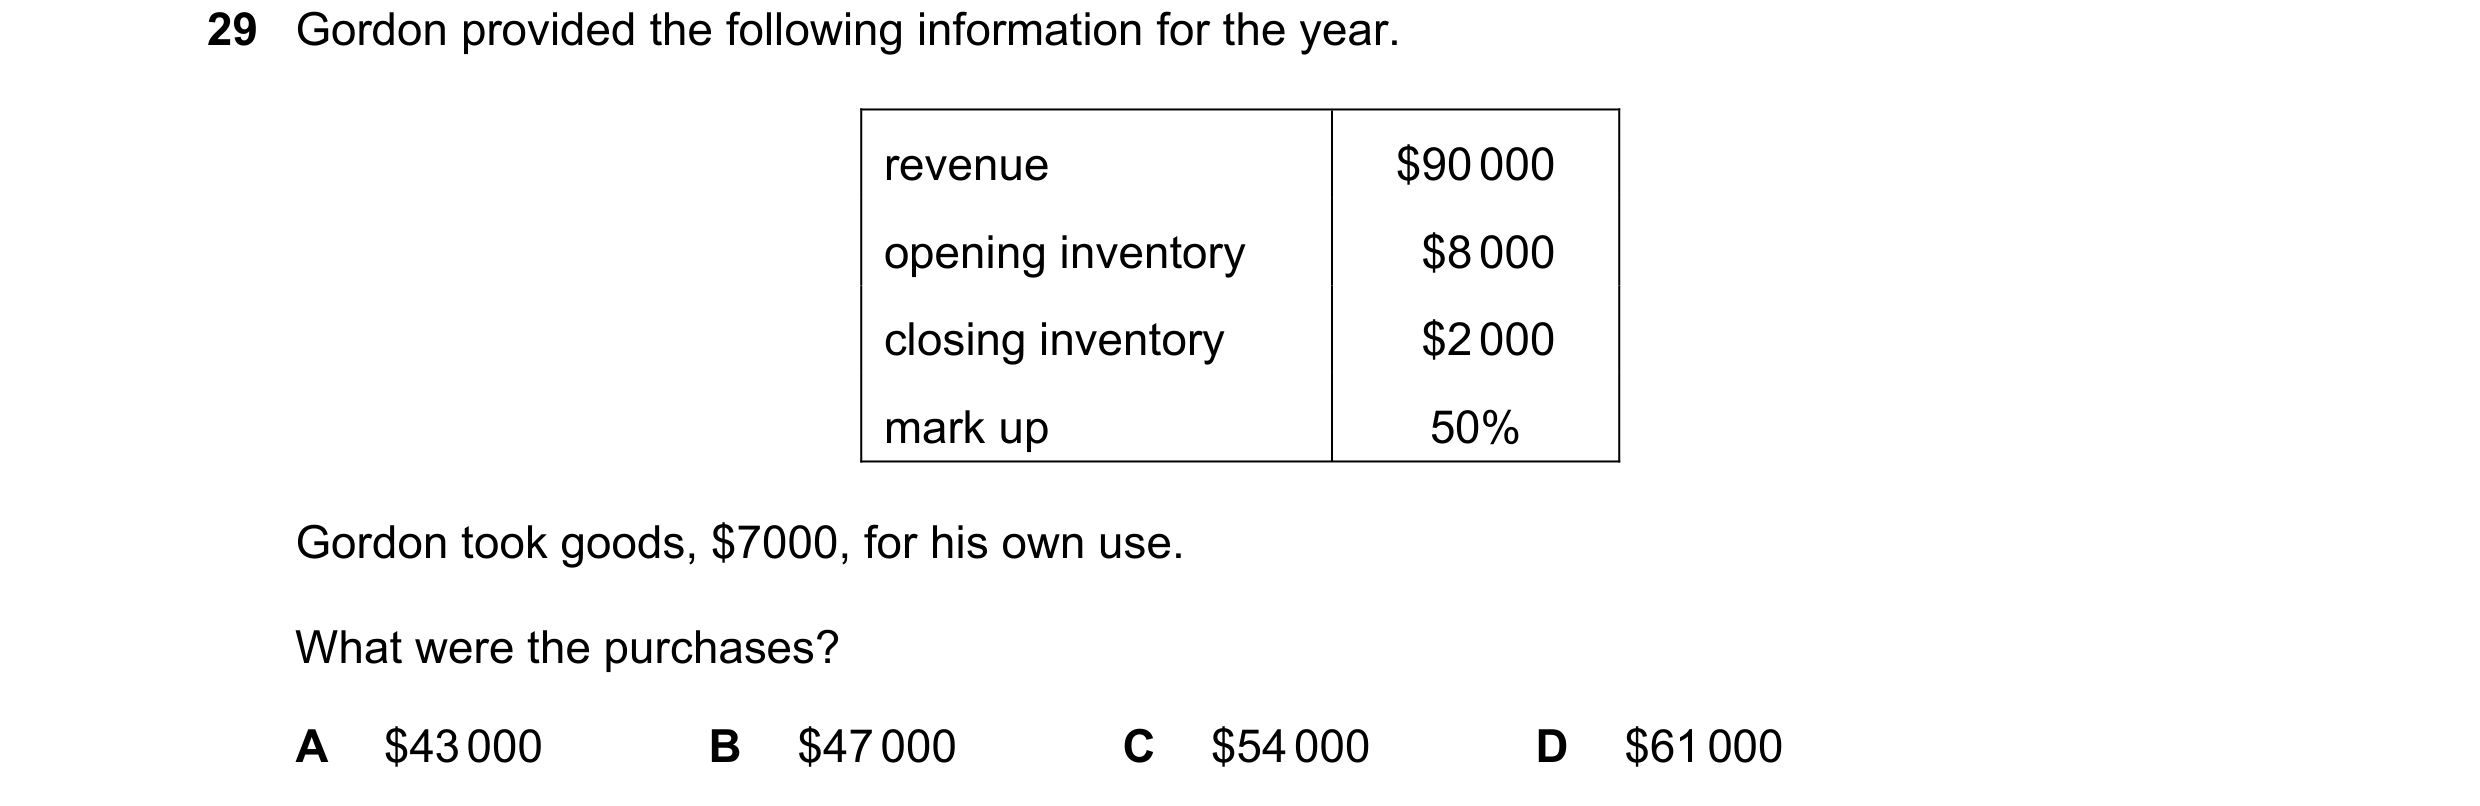
29 Gordon provided the following information for the year. revenue $90 000 opening inventory $8 000 closing inventory $2 000 mark up 50% Gordon took goods, $7000, for his own use. What were the purchases? A $43 000 B $47 000 C $54 000 D $61 000
1 marks
Answer: D
This question in 0985/12 May/June 2020
Q4 · Nirmal sells two products, product G and product H 0985/12 Oct/Nov 2020
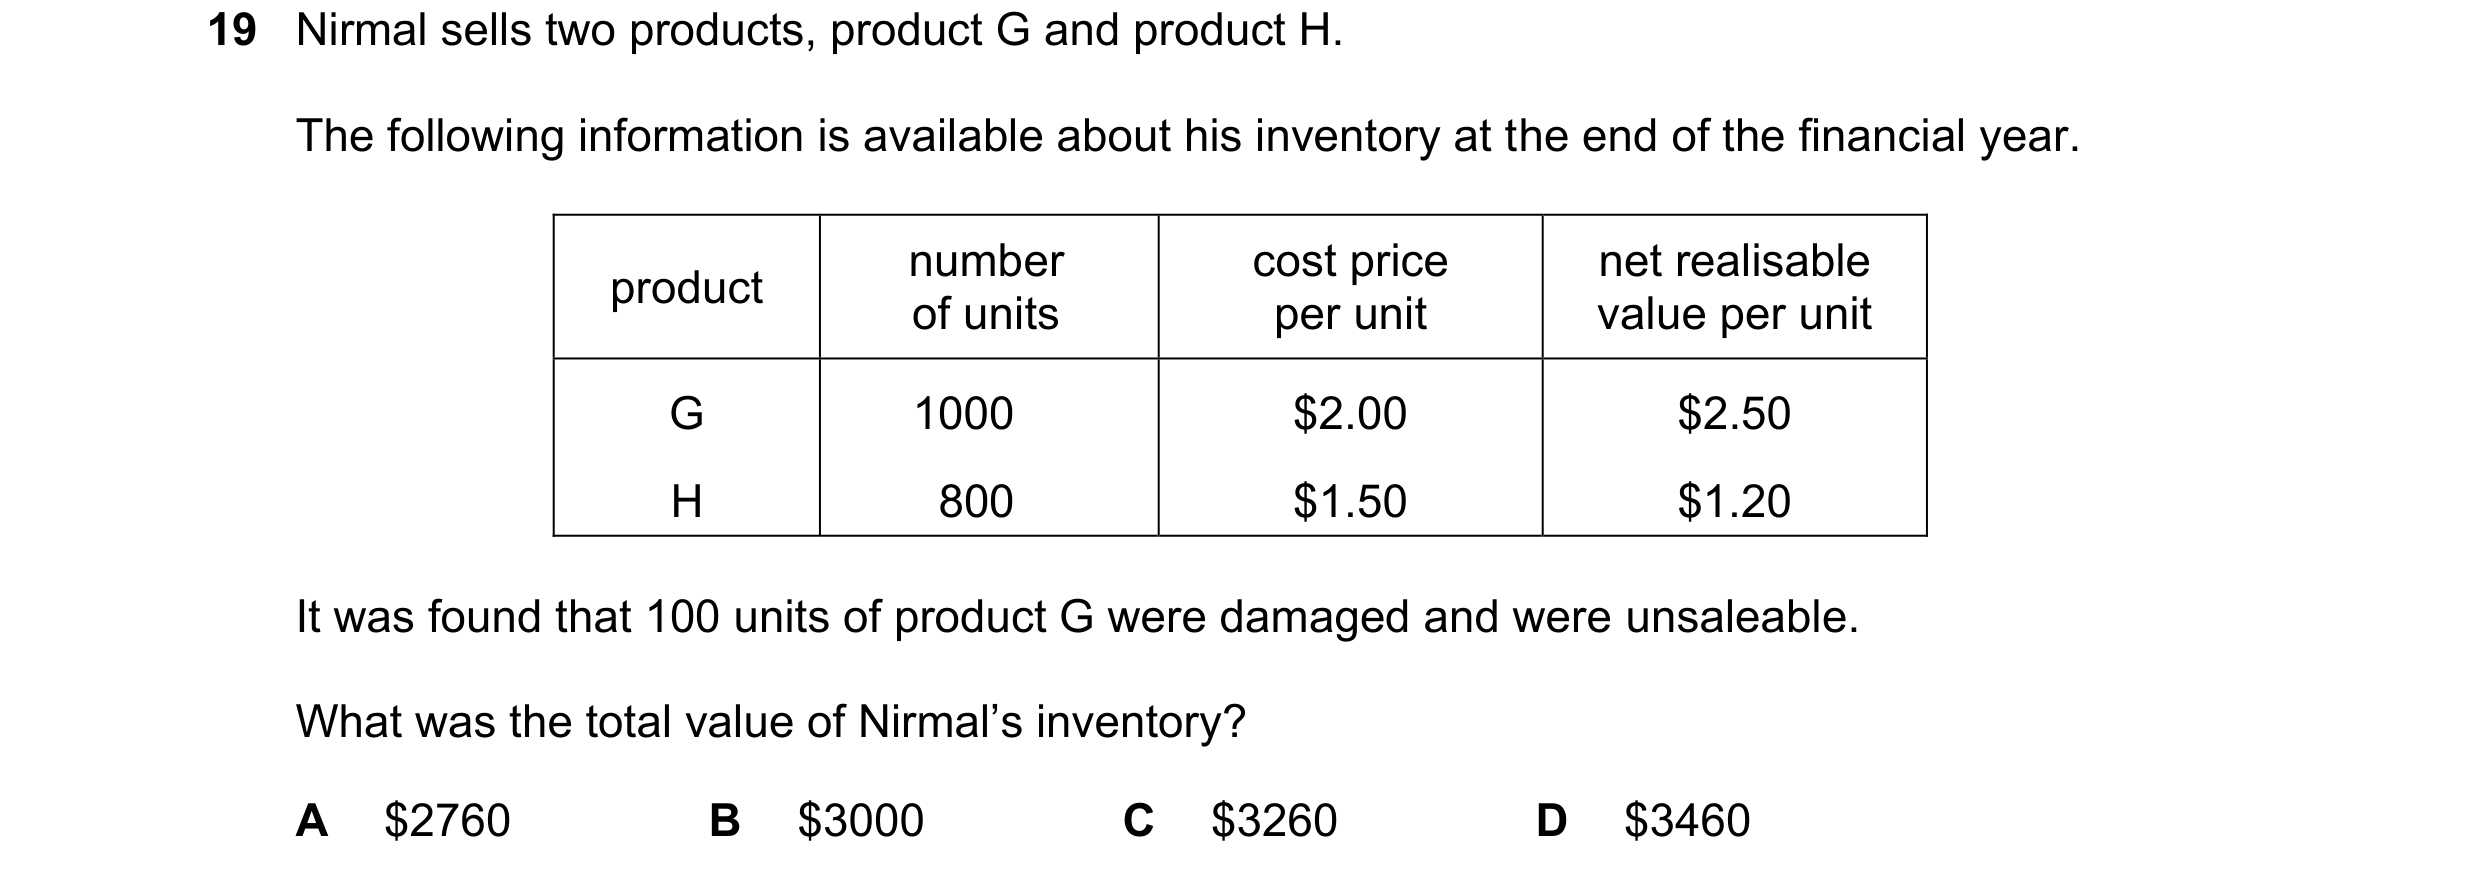
19 Nirmal sells two products, product G and product H. The following information is available about his inventory at the end of the financial year. number cost price net realisable product of units per unit value per unit G 1000 $2.00 $2.50 H 800 $1.50 $1.20 It was found that 100 units of product G were damaged and were unsaleable. What was the total value of Nirmal’s inventory? A $2760 B $3000 C $3260 D $3460
1 marks
Answer: A
This question in 0985/12 Oct/Nov 2020
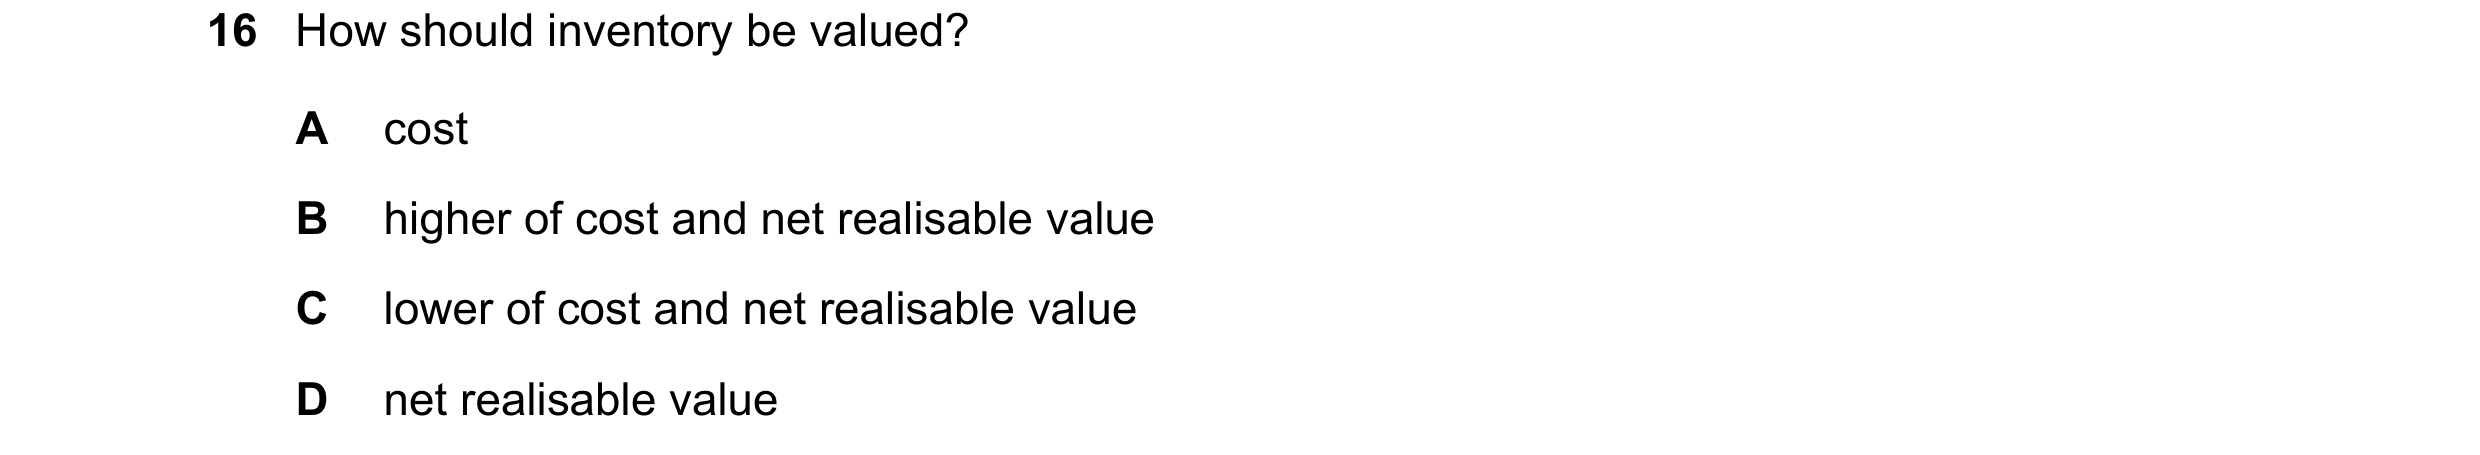
Q5 · How should inventory be valued? 0985/11 May/June 2021
16 How should inventory be valued? A cost B higher of cost and net realisable value C lower of cost and net realisable value D net realisable value
1 marks
Answer: C
This question in 0985/11 May/June 2021
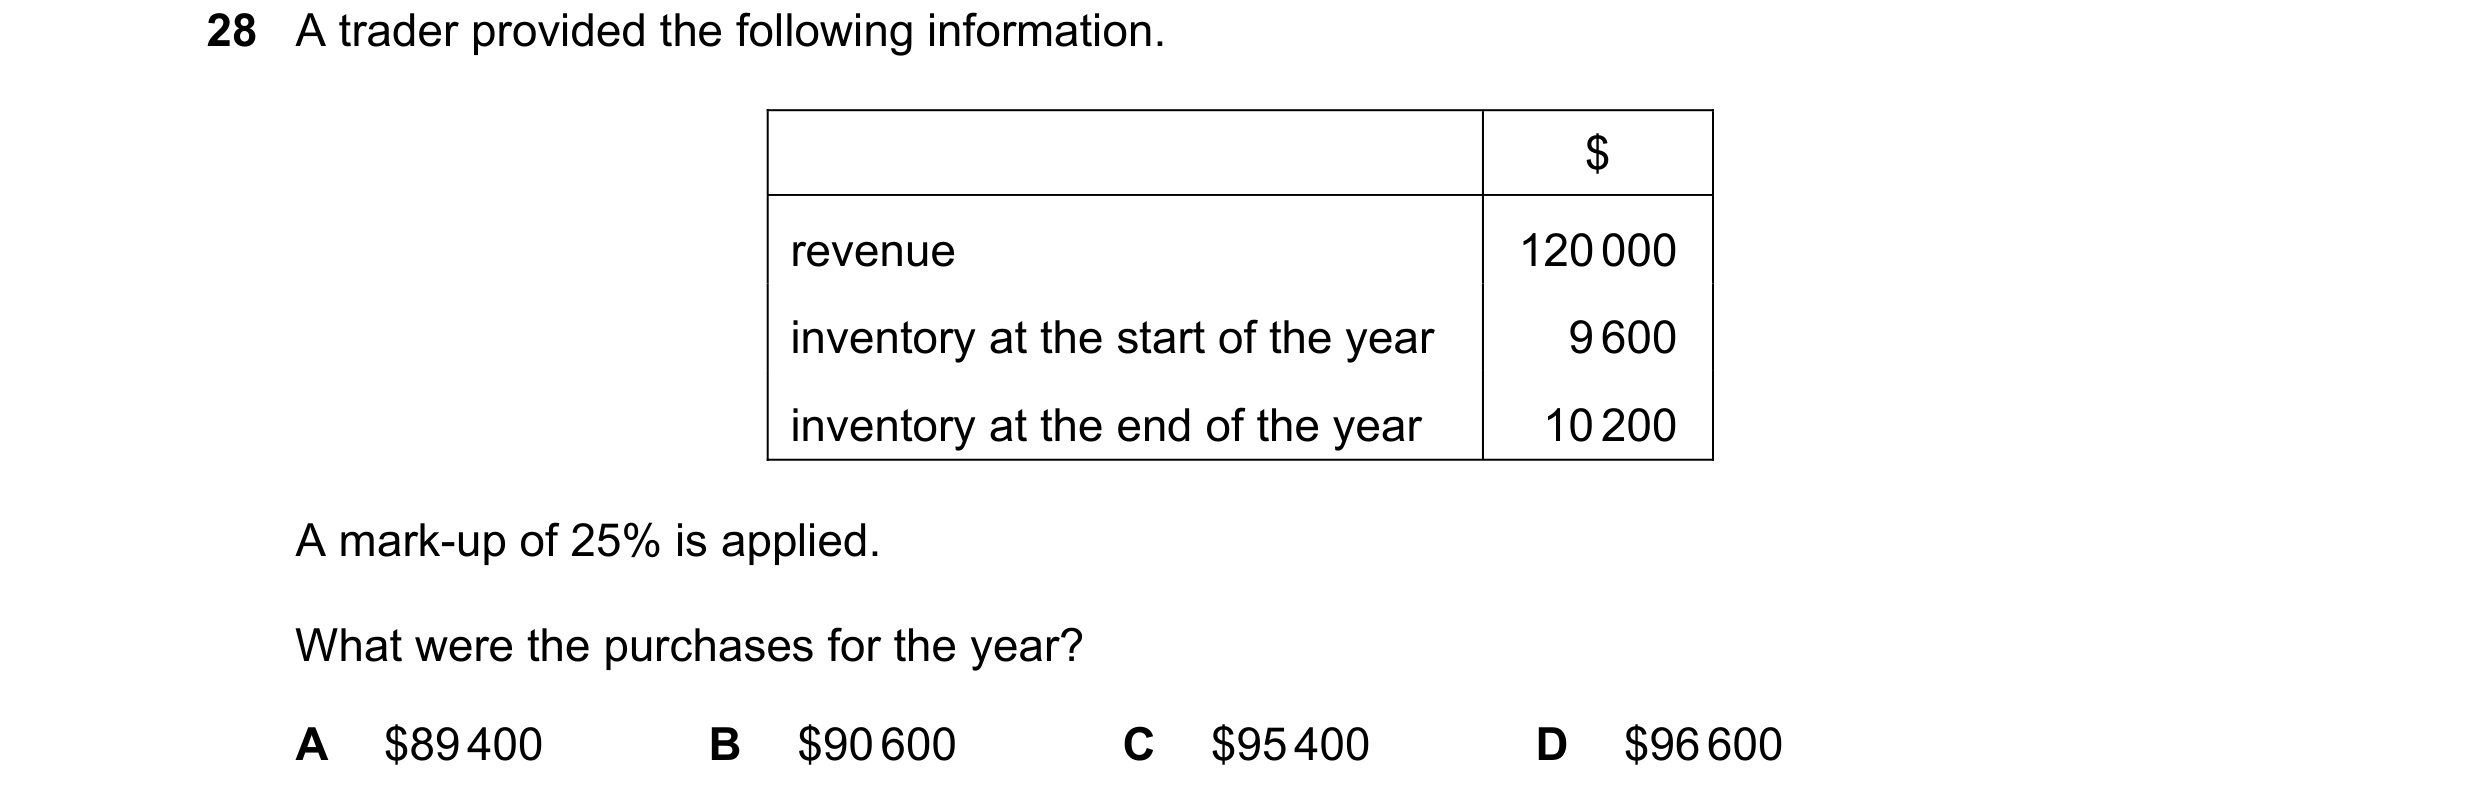
Q6 · A trader provided the following information 0985/11 May/June 2021
28 A trader provided the following information. $ revenue 120 000 inventory at the start of the year 9 600 inventory at the end of the year 10 200 A mark-up of 25% is applied. What were the purchases for the year? A $89 400 B $90 600 C $95 400 D $96 600
1 marks
Answer: D
This question in 0985/11 May/June 2021
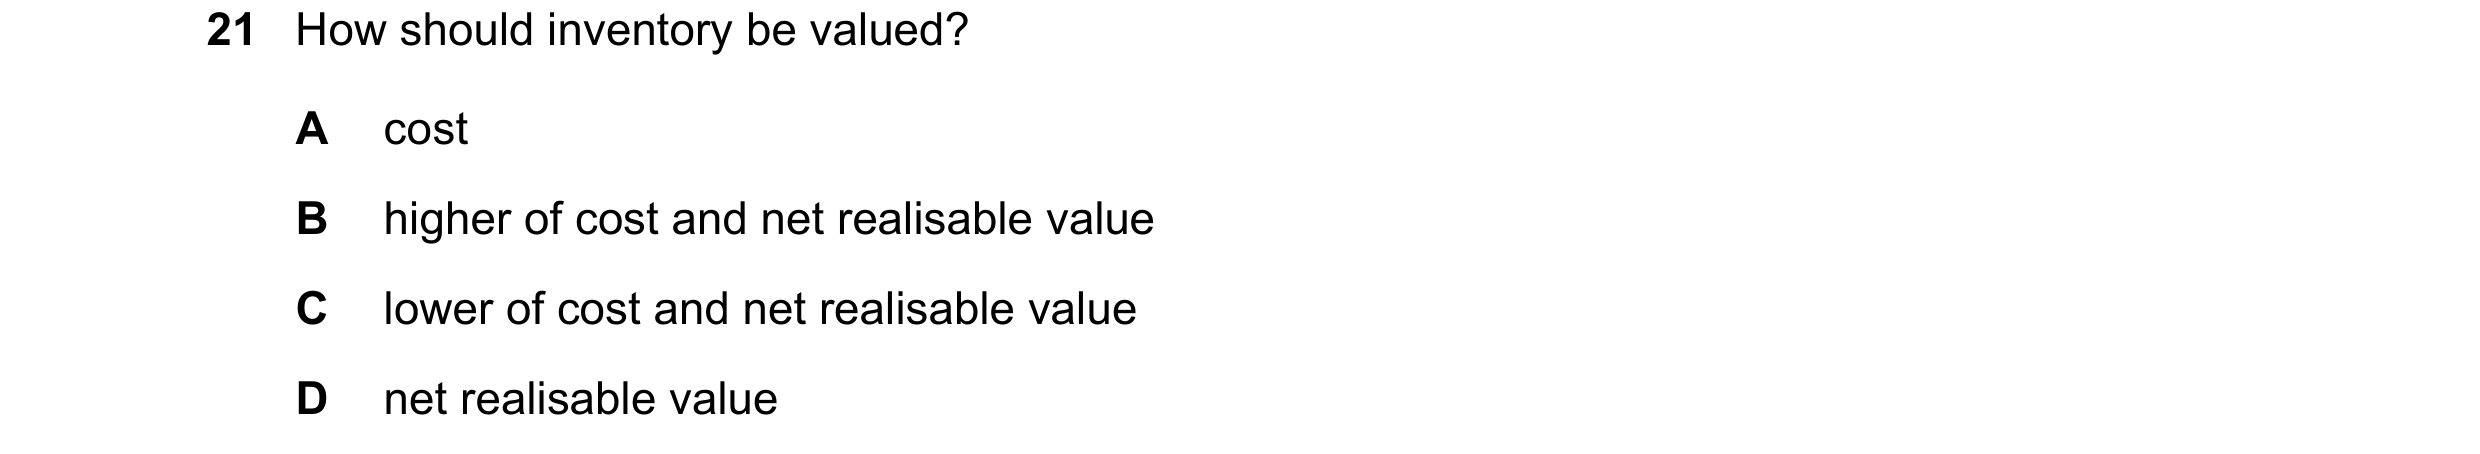
Q7 · How should inventory be valued? 0985/12 May/June 2021
21 How should inventory be valued? A cost B higher of cost and net realisable value C lower of cost and net realisable value D net realisable value
1 marks
Answer: C
This question in 0985/12 May/June 2021
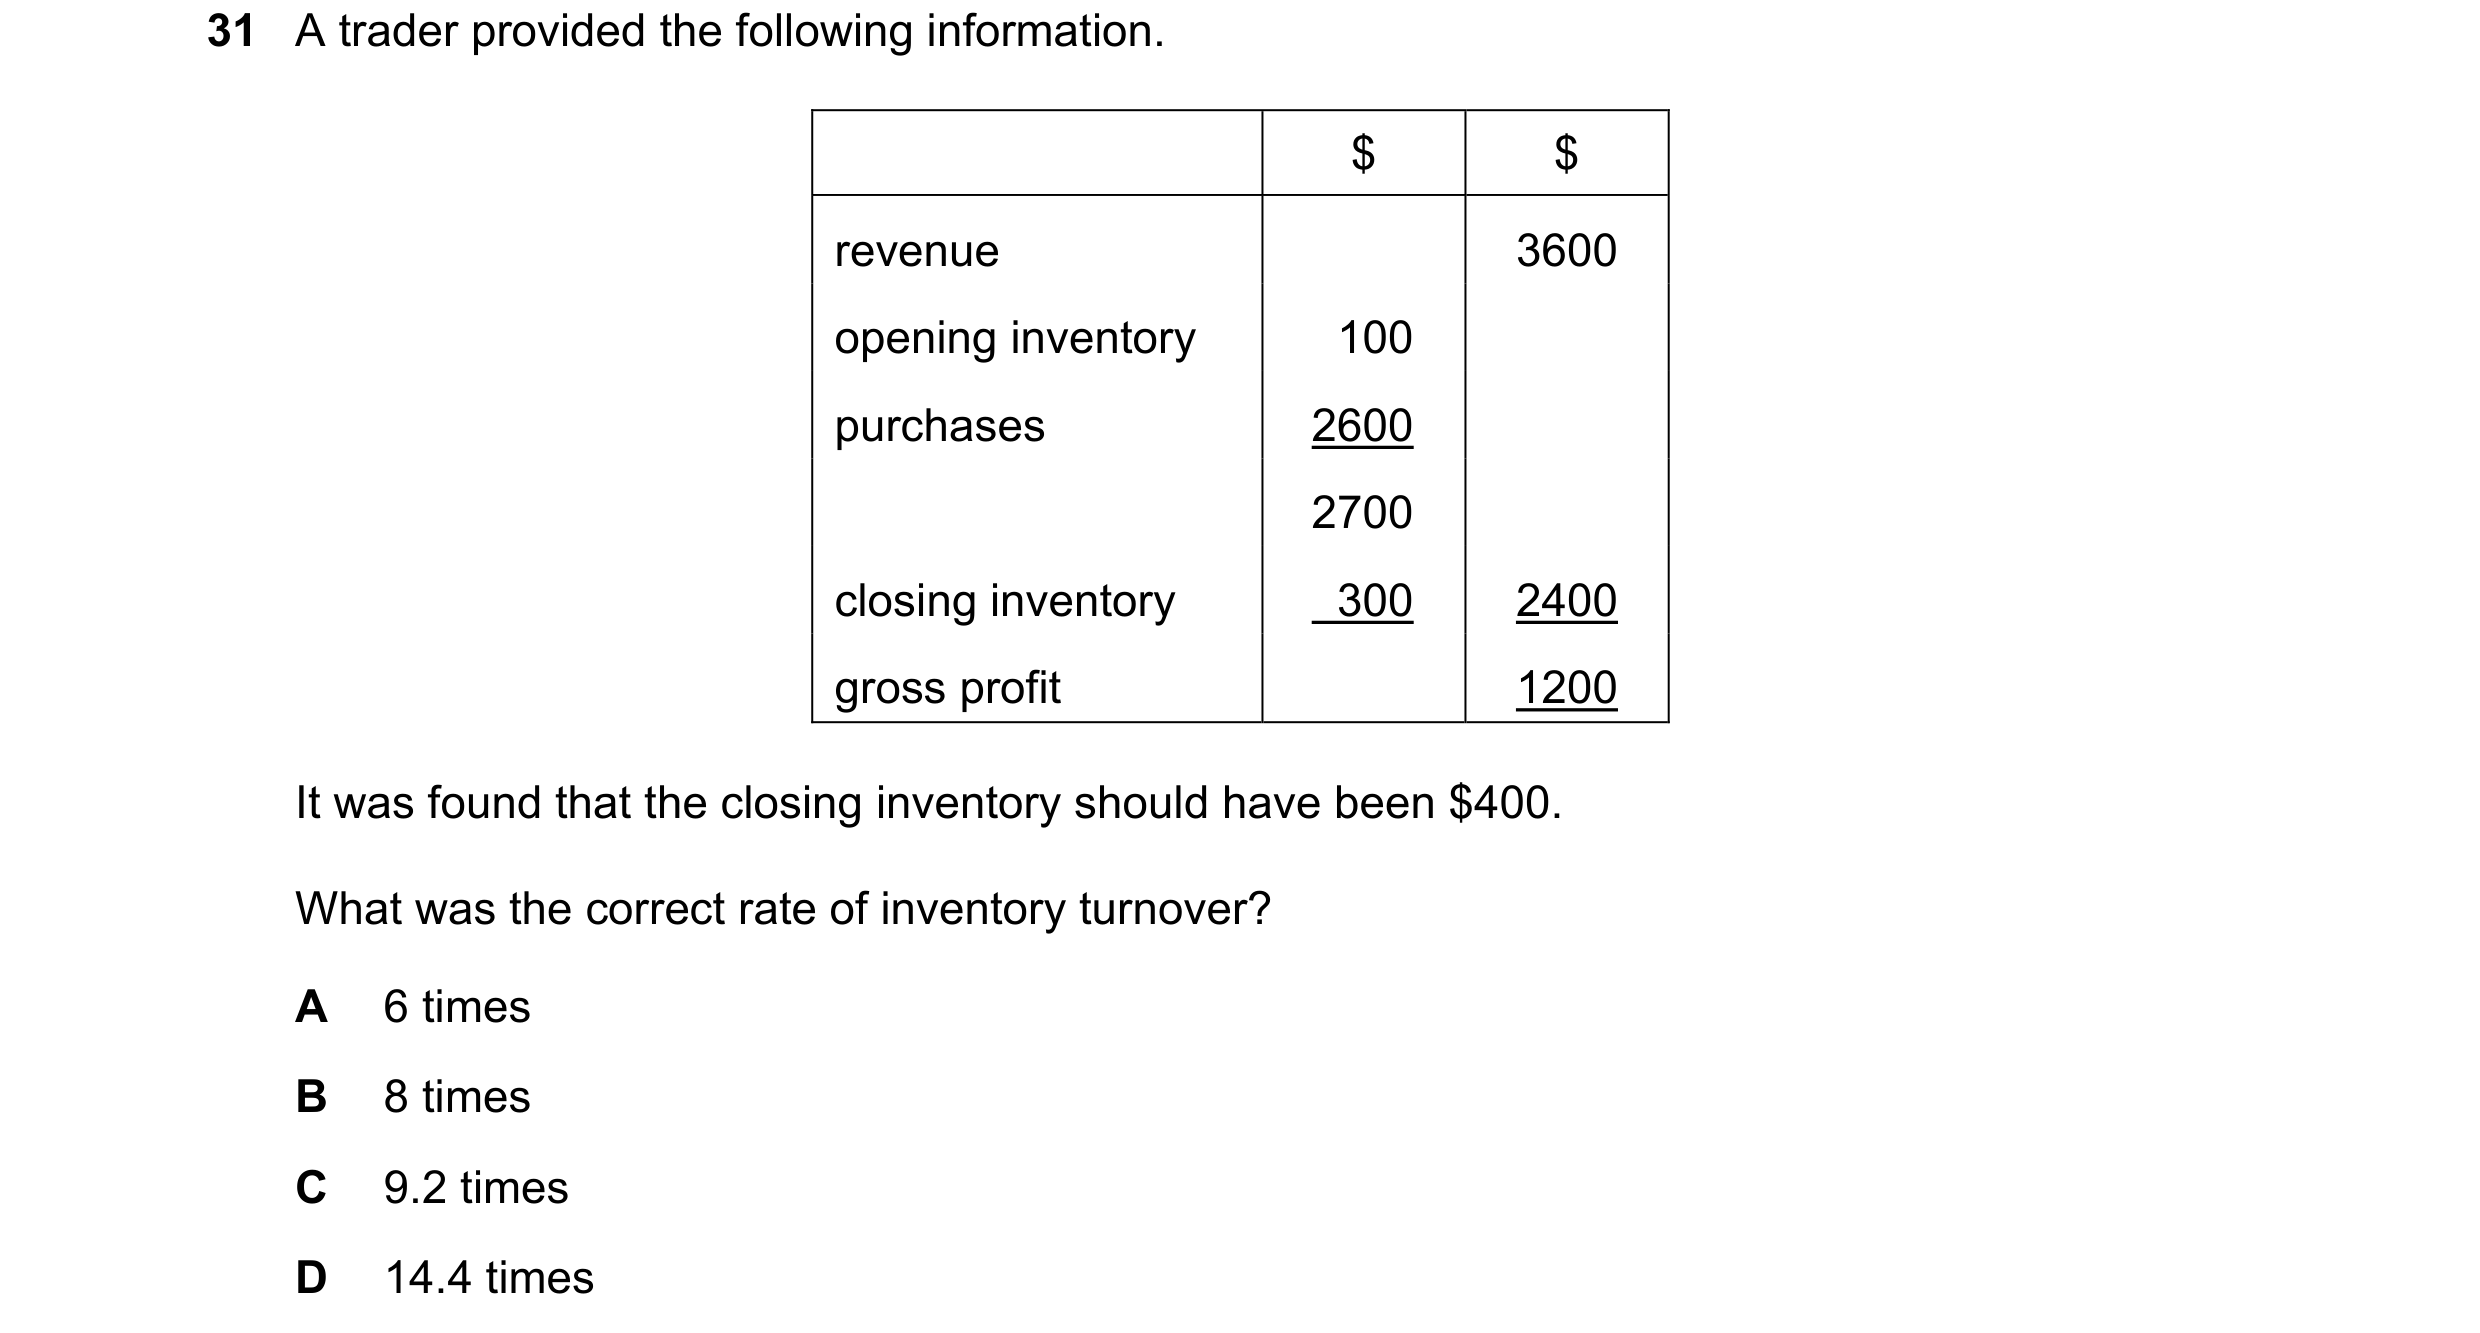
Q8 · A trader provided the following information 0985/12 May/June 2021
31 A trader provided the following information. $ $ revenue 3600 opening inventory 100 purchases 2600 2700 closing inventory 300 2400 gross profit 1200 It was found that the closing inventory should have been $400. What was the correct rate of inventory turnover? A 6 times B 8 times C 9.2 times D 14.4 times
1 marks
Answer: C
This question in 0985/12 May/June 2021
Q9 · After preparing draft financial statements at the end of her first year of trading, Lucy… 0985/12 Oct/Nov 2021
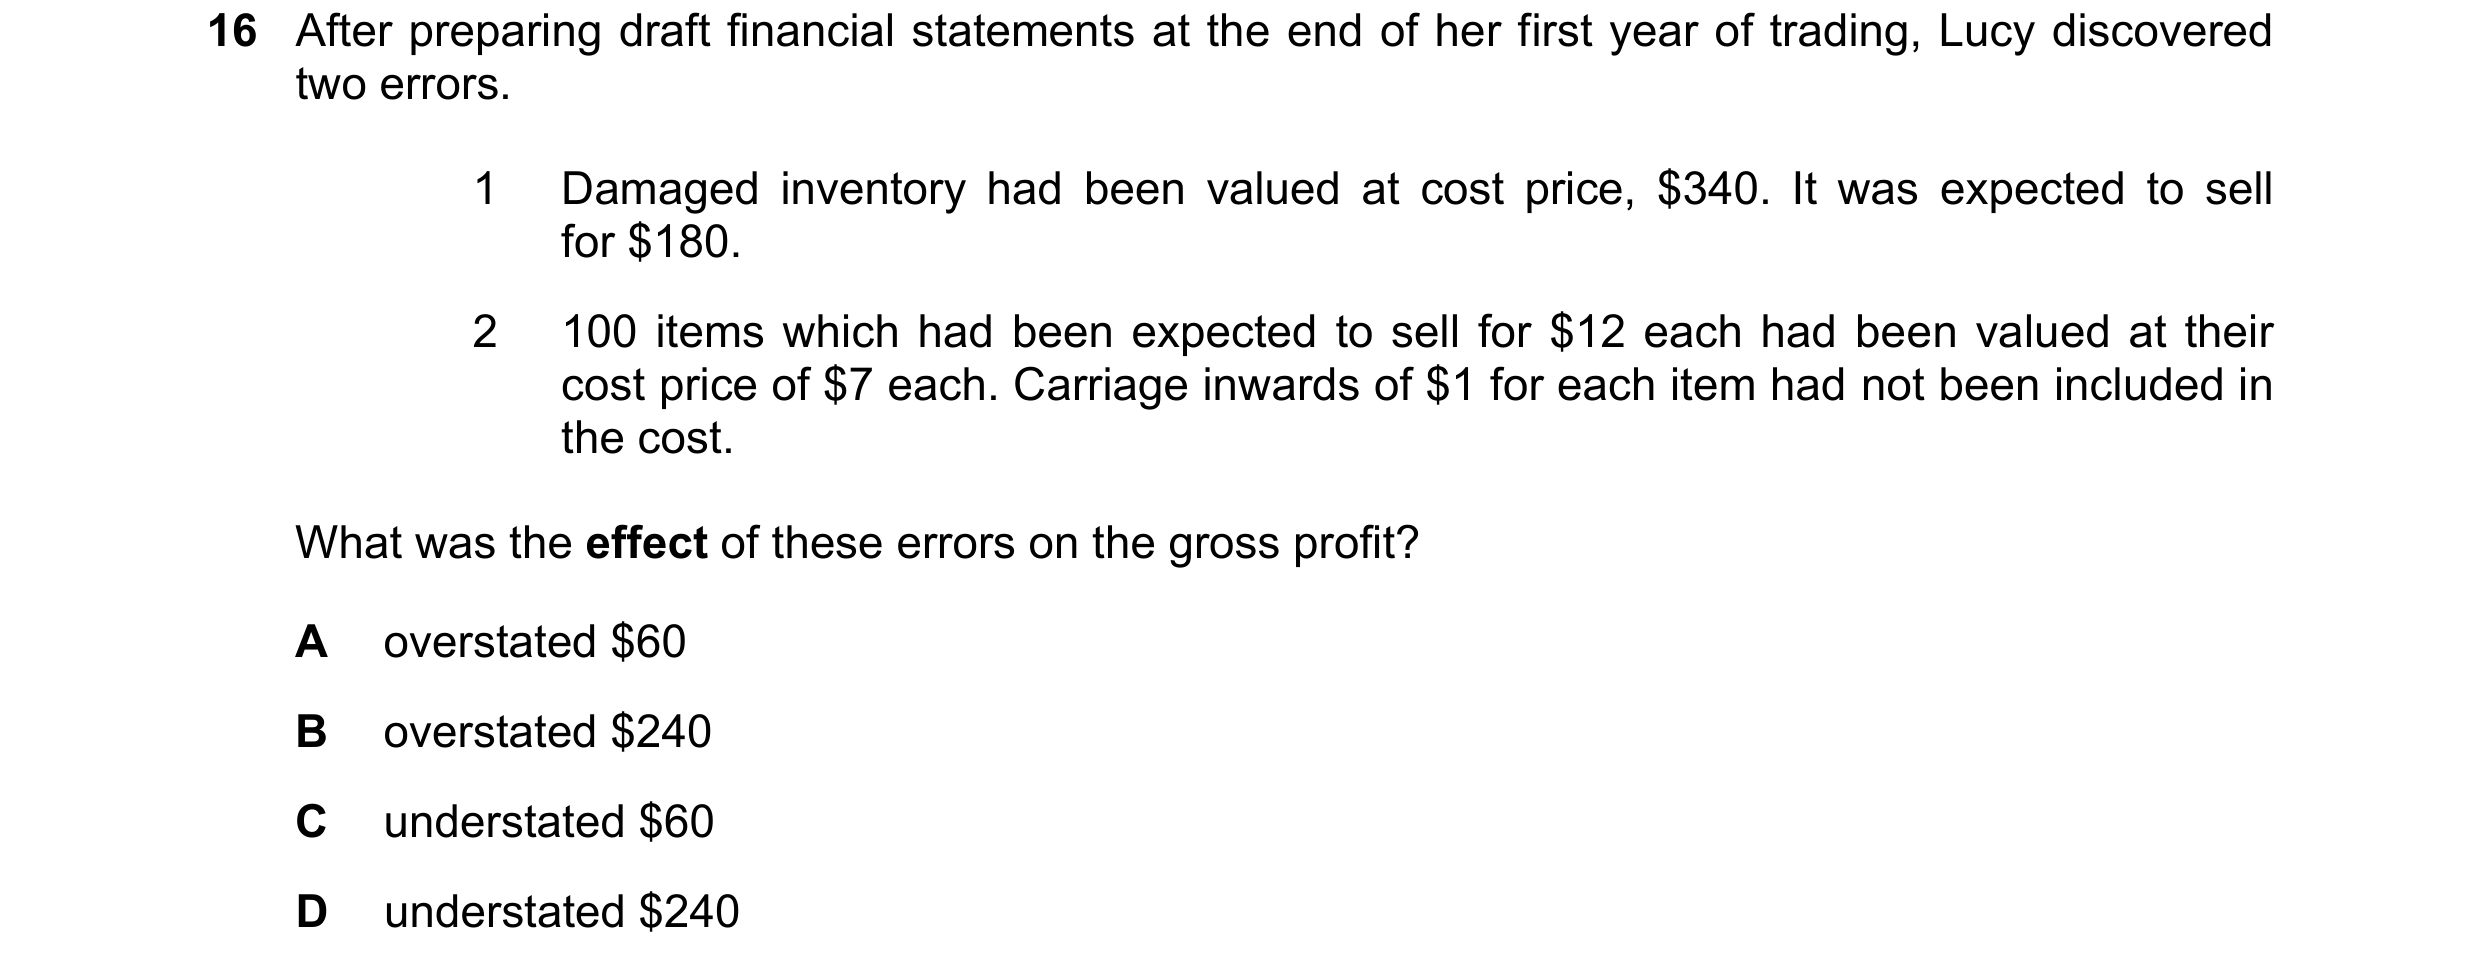
16 After preparing draft financial statements at the end of her first year of trading, Lucy discovered two errors. 1 Damaged inventory had been valued at cost price, $340. It was expected to sell for $180. 2 100 items which had been expected to sell for $12 each had been valued at their cost price of $7 each. Carriage inwards of $1 for each item had not been included in the cost. What was the effect of these errors on the gross profit? A overstated $60 B overstated $240 C understated $60 D understated $240
1 marks
Answer: A
This question in 0985/12 Oct/Nov 2021
Q10 · When preparing his financial statements, a trader valued his inventory at cost 0985/11 May/June 2022
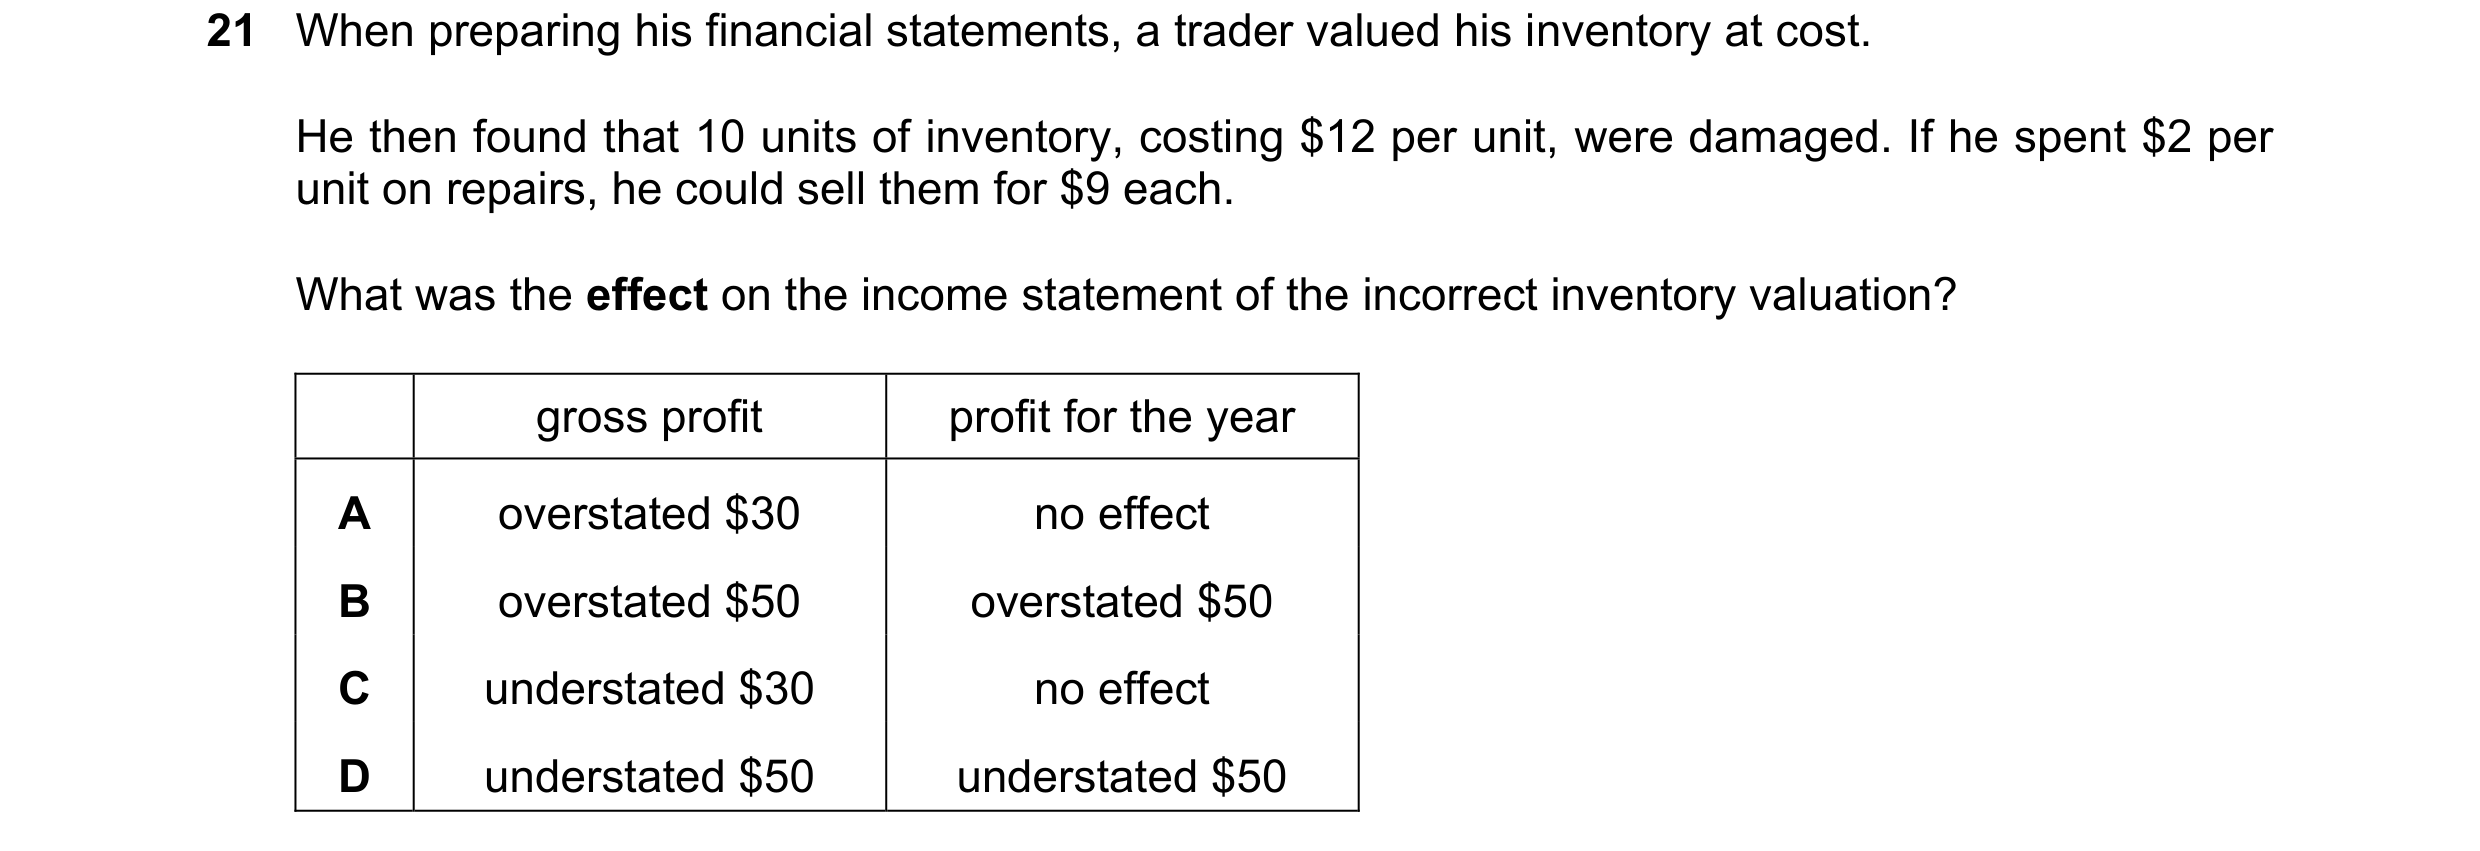
21 When preparing his financial statements, a trader valued his inventory at cost. He then found that 10 units of inventory, costing $12 per unit, were damaged. If he spent $2 per unit on repairs, he could sell them for $9 each. What was the effect on the income statement of the incorrect inventory valuation? gross profit profit for the year A overstated $30 no effect B overstated $50 overstated $50 C understated $30 no effect D understated $50 understated $50
1 marks
Answer: B
This question in 0985/11 May/June 2022
Q11 · Jerry started his business on 1 January 2022 with no opening inventory 0985/11 May/June 2022
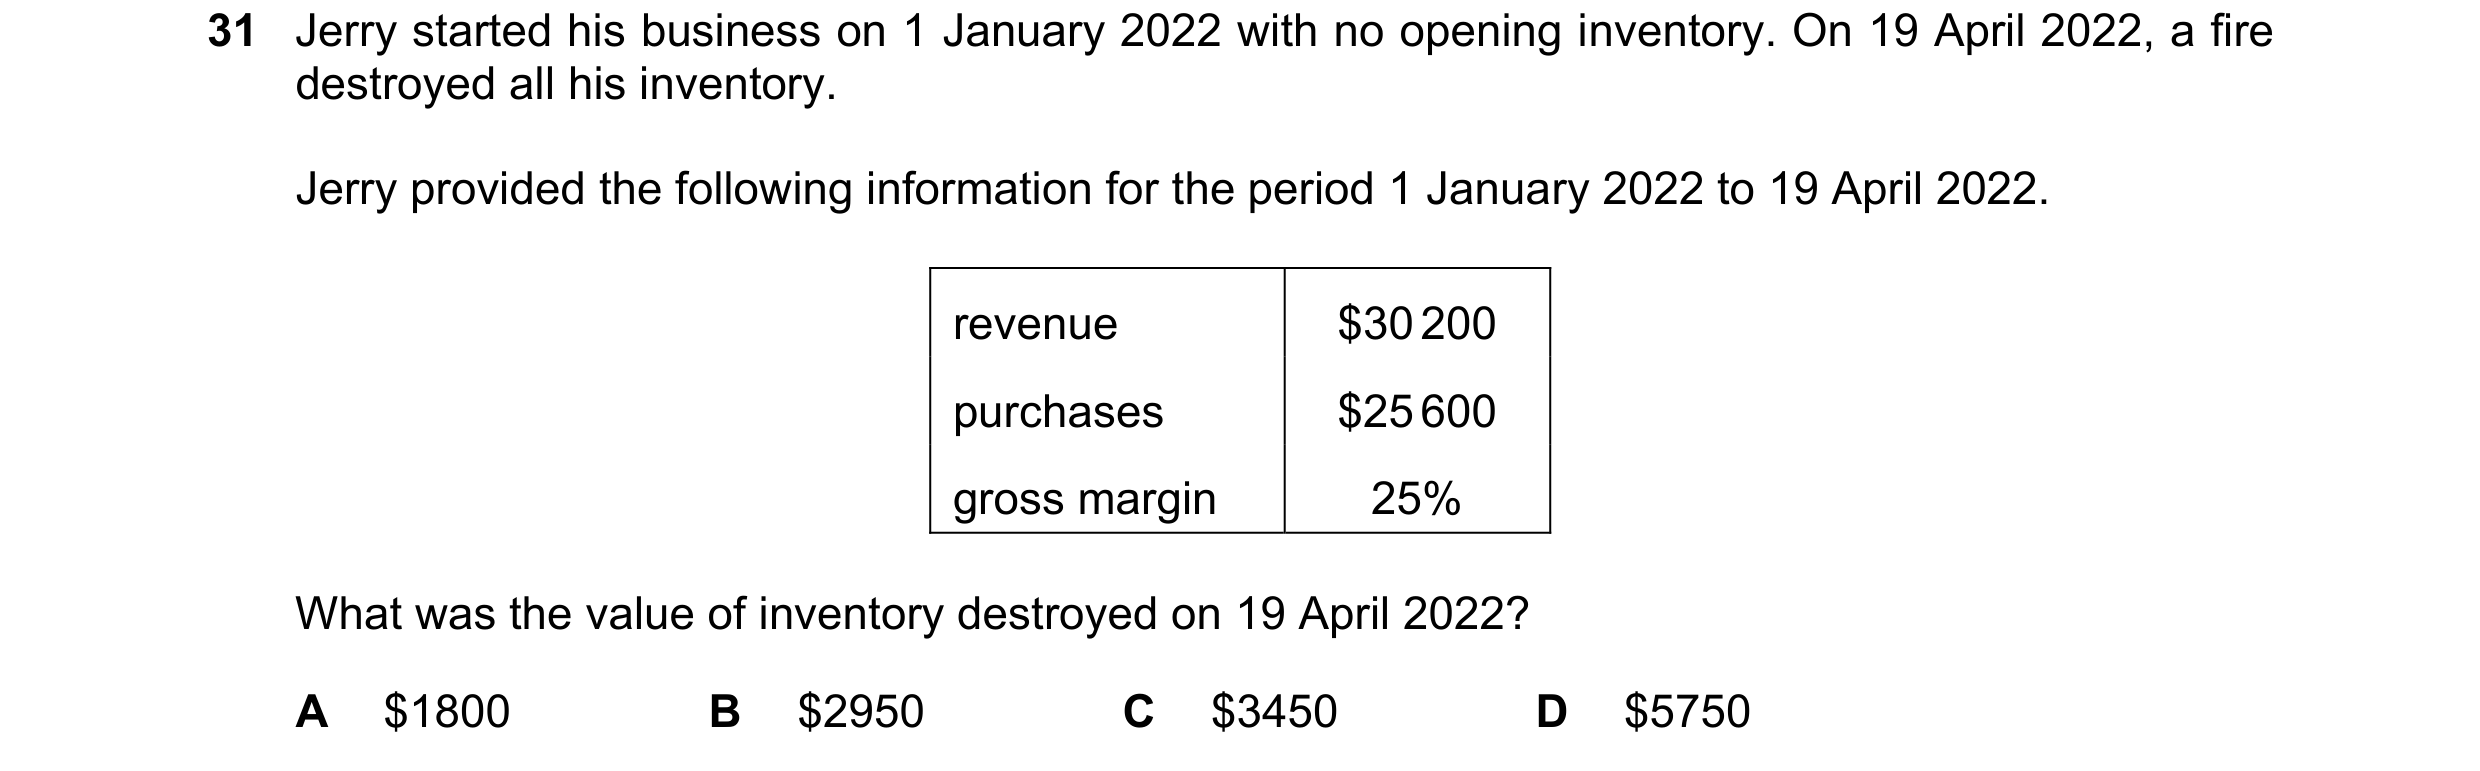
31 Jerry started his business on 1 January 2022 with no opening inventory. On 19 April 2022, a fire destroyed all his inventory. Jerry provided the following information for the period 1 January 2022 to 19 April 2022. revenue $30 200 purchases $25 600 gross margin 25% What was the value of inventory destroyed on 19 April 2022? A $1800 B $2950 C $3450 D $5750
1 marks
Answer: B
This question in 0985/11 May/June 2022
Q12 · After the financial statements for the year ended 30 April 2022 had been prepared, a… 0985/12 May/June 2022
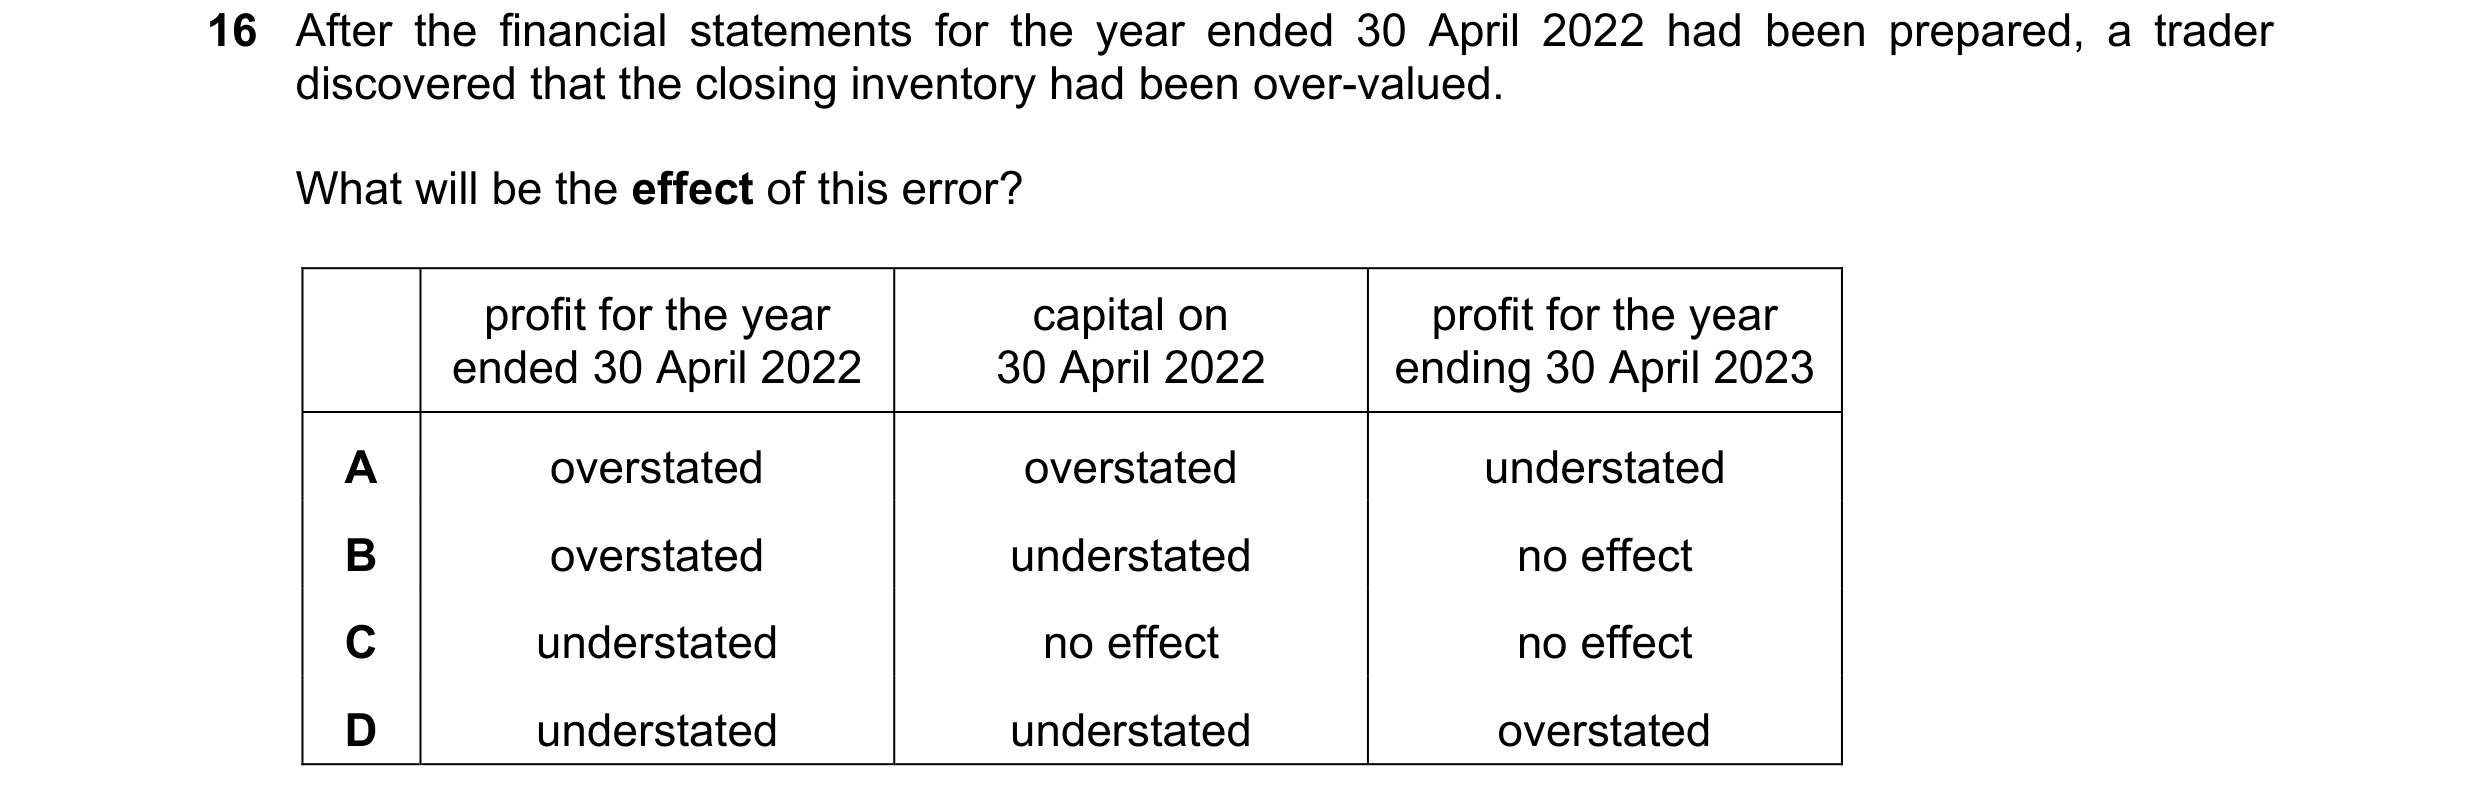
16 After the financial statements for the year ended 30 April 2022 had been prepared, a trader discovered that the closing inventory had been over-valued. What will be the effect of this error? profit for the year capital on profit for the year ended 30 April 2022 30 April 2022 ending 30 April 2023 A overstated overstated understated B overstated understated no effect C understated no effect no effect D understated understated overstated
1 marks
Answer: A
This question in 0985/12 May/June 2022
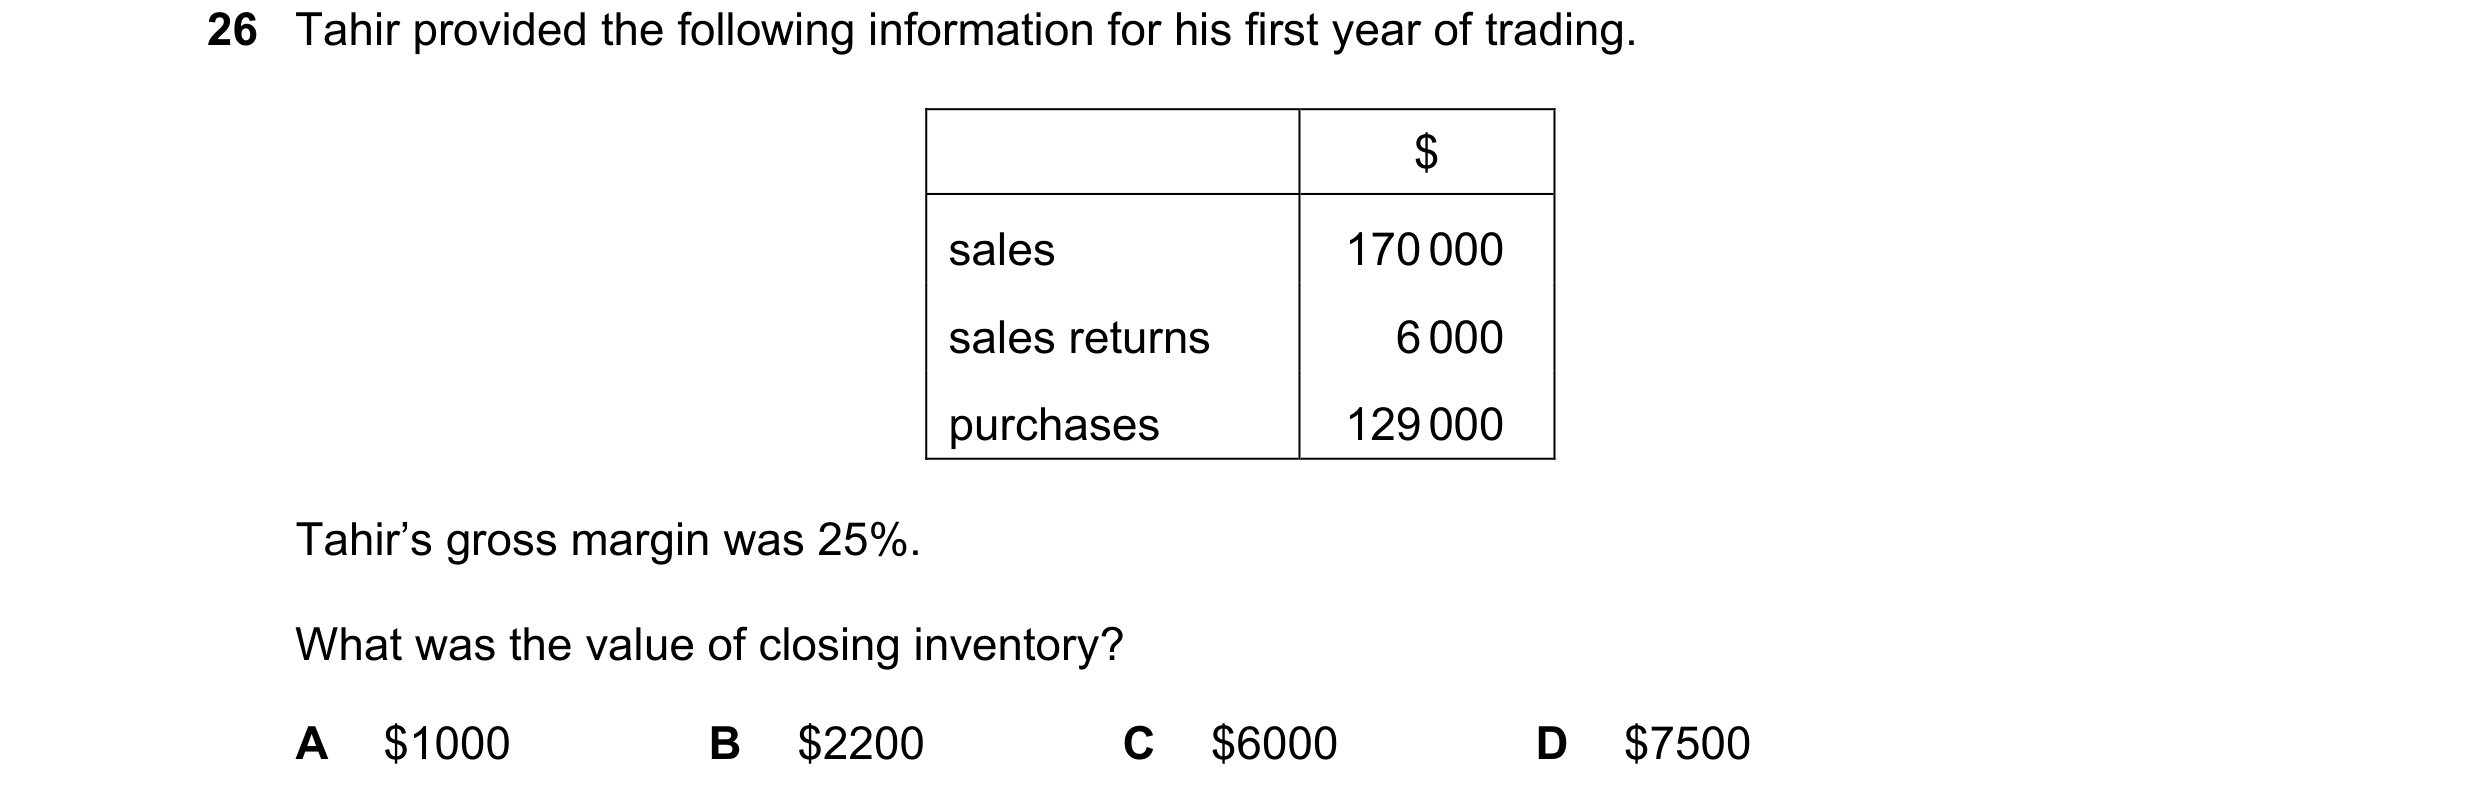
Q13 · Tahir provided the following information for his first year of trading 0985/12 May/June 2022
26 Tahir provided the following information for his first year of trading. $ sales 170 000 sales returns 6 000 purchases 129 000 Tahir’s gross margin was 25%. What was the value of closing inventory? A $1000 B $2200 C $6000 D $7500
1 marks
Answer: C
This question in 0985/12 May/June 2022
Q14 · Why should inventory be valued at the lower of cost and net realisable value? 0985/12 Oct/Nov 2022
17 Why should inventory be valued at the lower of cost and net realisable value? A to avoid undervaluing the inventory B to comply with the historic cost principle C to comply with the principle of materiality D to ensure that profits are not overstated
1 marks
Answer: D
This question in 0985/12 Oct/Nov 2022
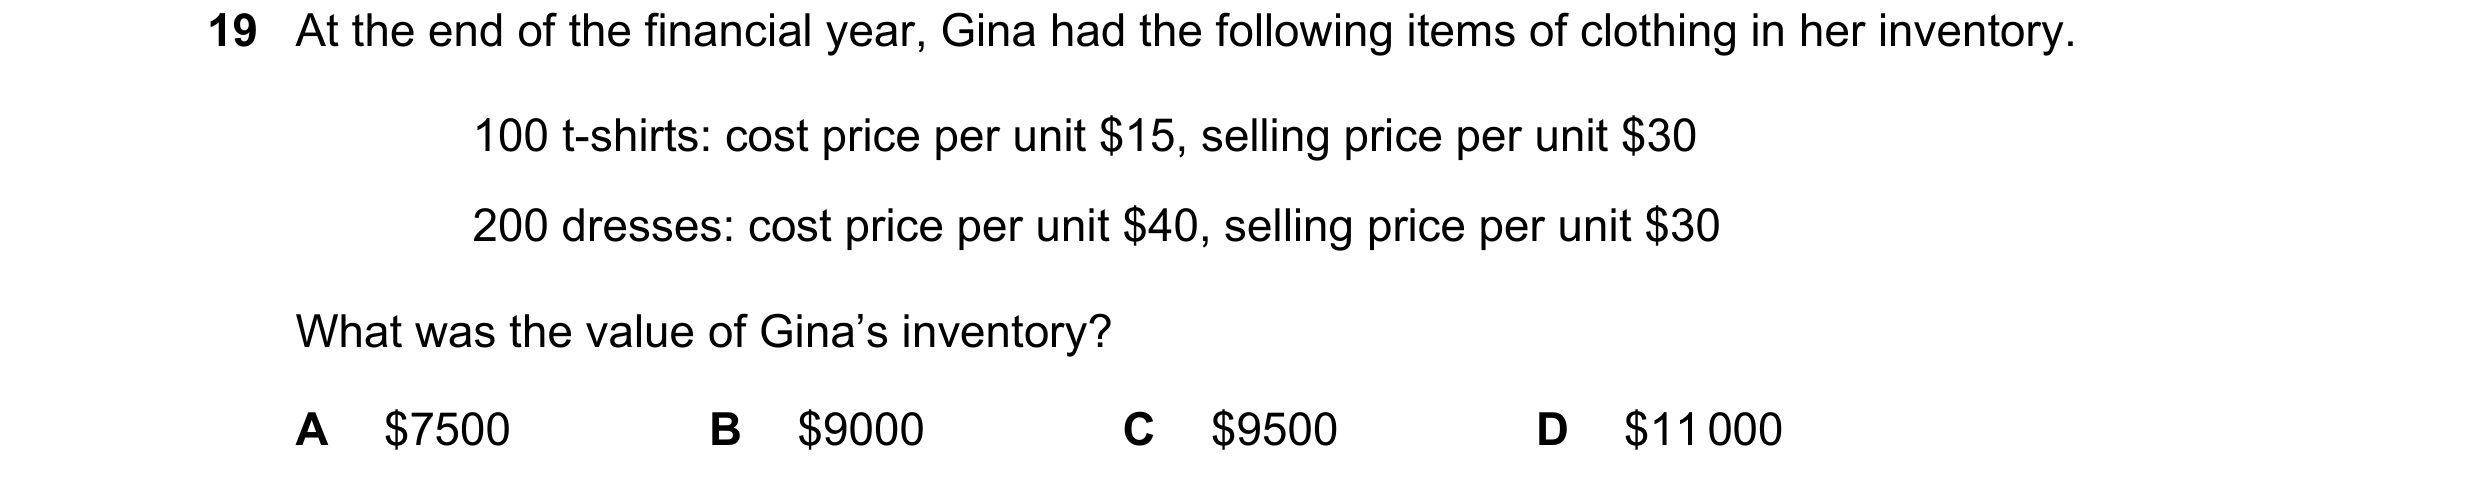
Q15 · At the end of the financial year, Gina had the following items of clothing in her… 0985/11 May/June 2023
19 At the end of the financial year, Gina had the following items of clothing in her inventory. 100 t-shirts: cost price per unit $15, selling price per unit $30 200 dresses: cost price per unit $40, selling price per unit $30 What was the value of Gina’s inventory? A $7500 B $9000 C $9500 D $11 000
1 marks
Answer: A
This question in 0985/11 May/June 2023
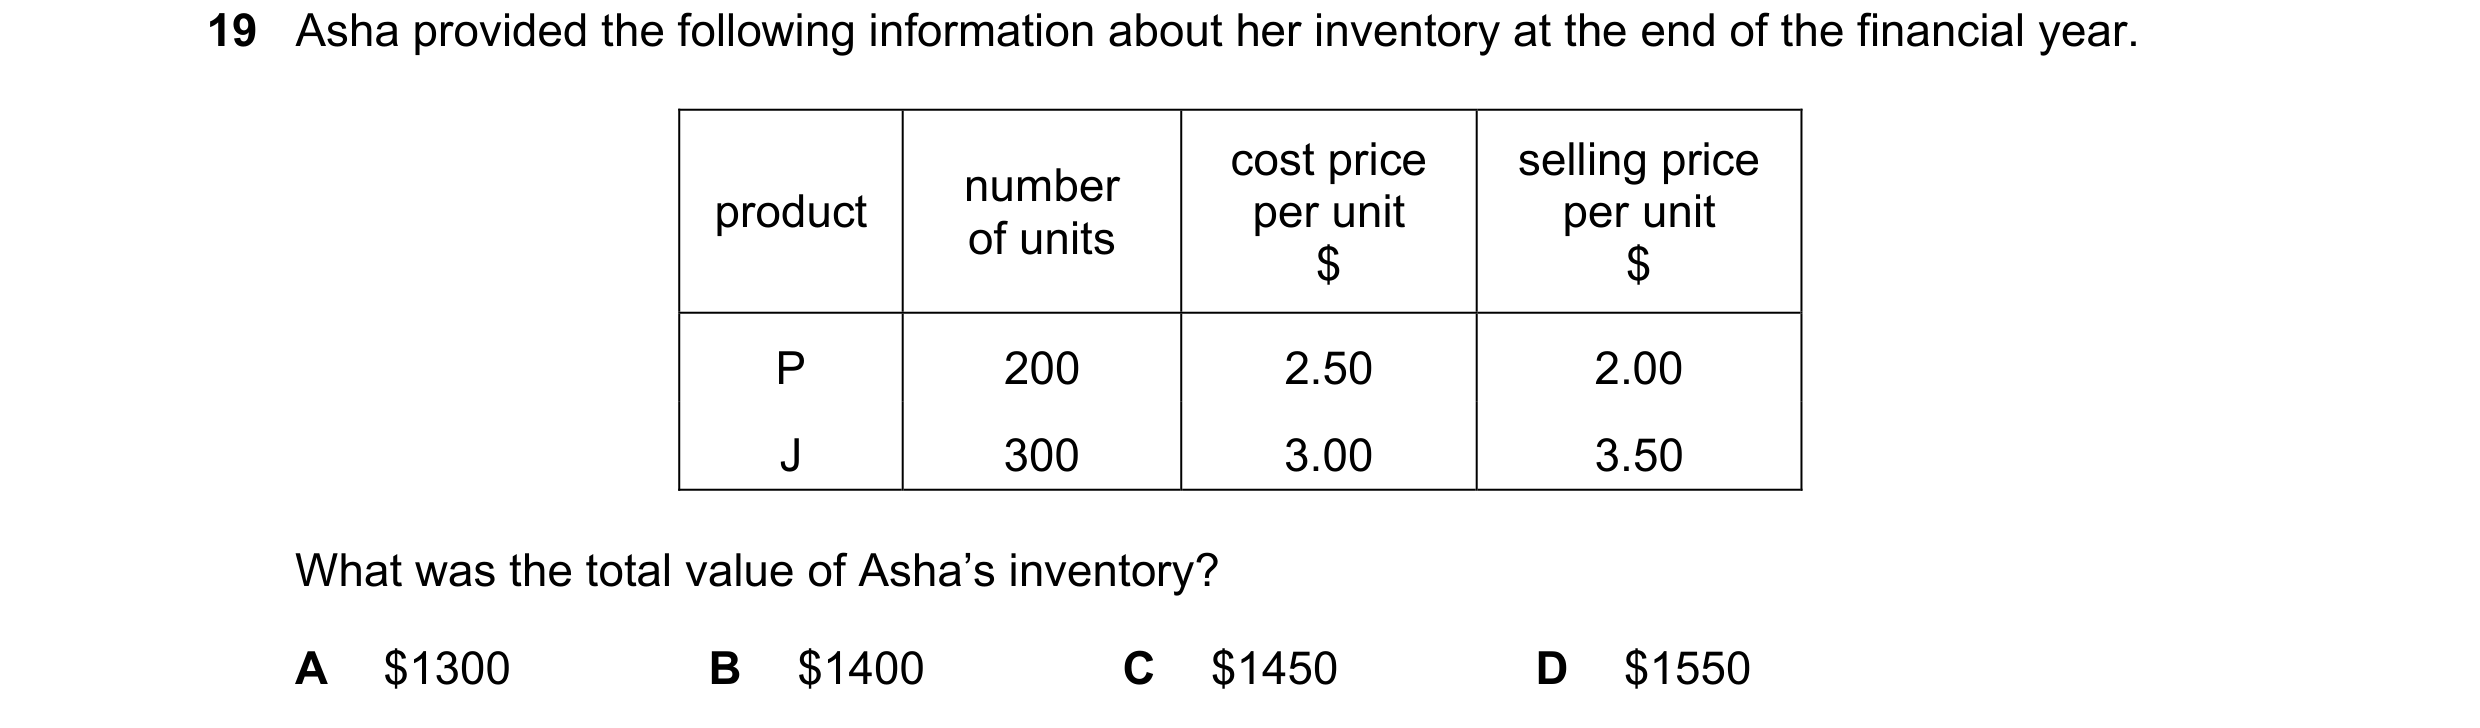
Q16 · Asha provided the following information about her inventory at the end of the financial… 0985/12 May/June 2023
19 Asha provided the following information about her inventory at the end of the financial year. cost price selling price number product per unit per unit of units $ $ P 200 2.50 2.00 J 300 3.00 3.50 What was the total value of Asha’s inventory? A $1300 B $1400 C $1450 D $1550
1 marks
Answer: A
This question in 0985/12 May/June 2023
Q17 · Ariadne prepares her financial statements to 31 December each year 0985/12 Oct/Nov 2023
19 Ariadne prepares her financial statements to 31 December each year. She valued all her inventory at cost on 31 December 2021, even though some inventory with a cost of $500 had a net realisable value of $350. What was the effect of this error? A Gross profit for the year 2021 was overstated. B Total assets at 31 December 2021 were understated. C Profit for the year 2022 was overstated. D Capital at 31 December 2022 was understated.
1 marks
Answer: A
This question in 0985/12 Oct/Nov 2023
Q18 · Why is inventory valued at the lower of cost and net realisable value? 0985/11 May/June 2024
18 Why is inventory valued at the lower of cost and net realisable value? A to avoid overstating current assets and sales B to avoid overstating profit and current assets C to avoid understating current assets and sales D to avoid understating profit and current assets
1 marks
Answer: B
This question in 0985/11 May/June 2024
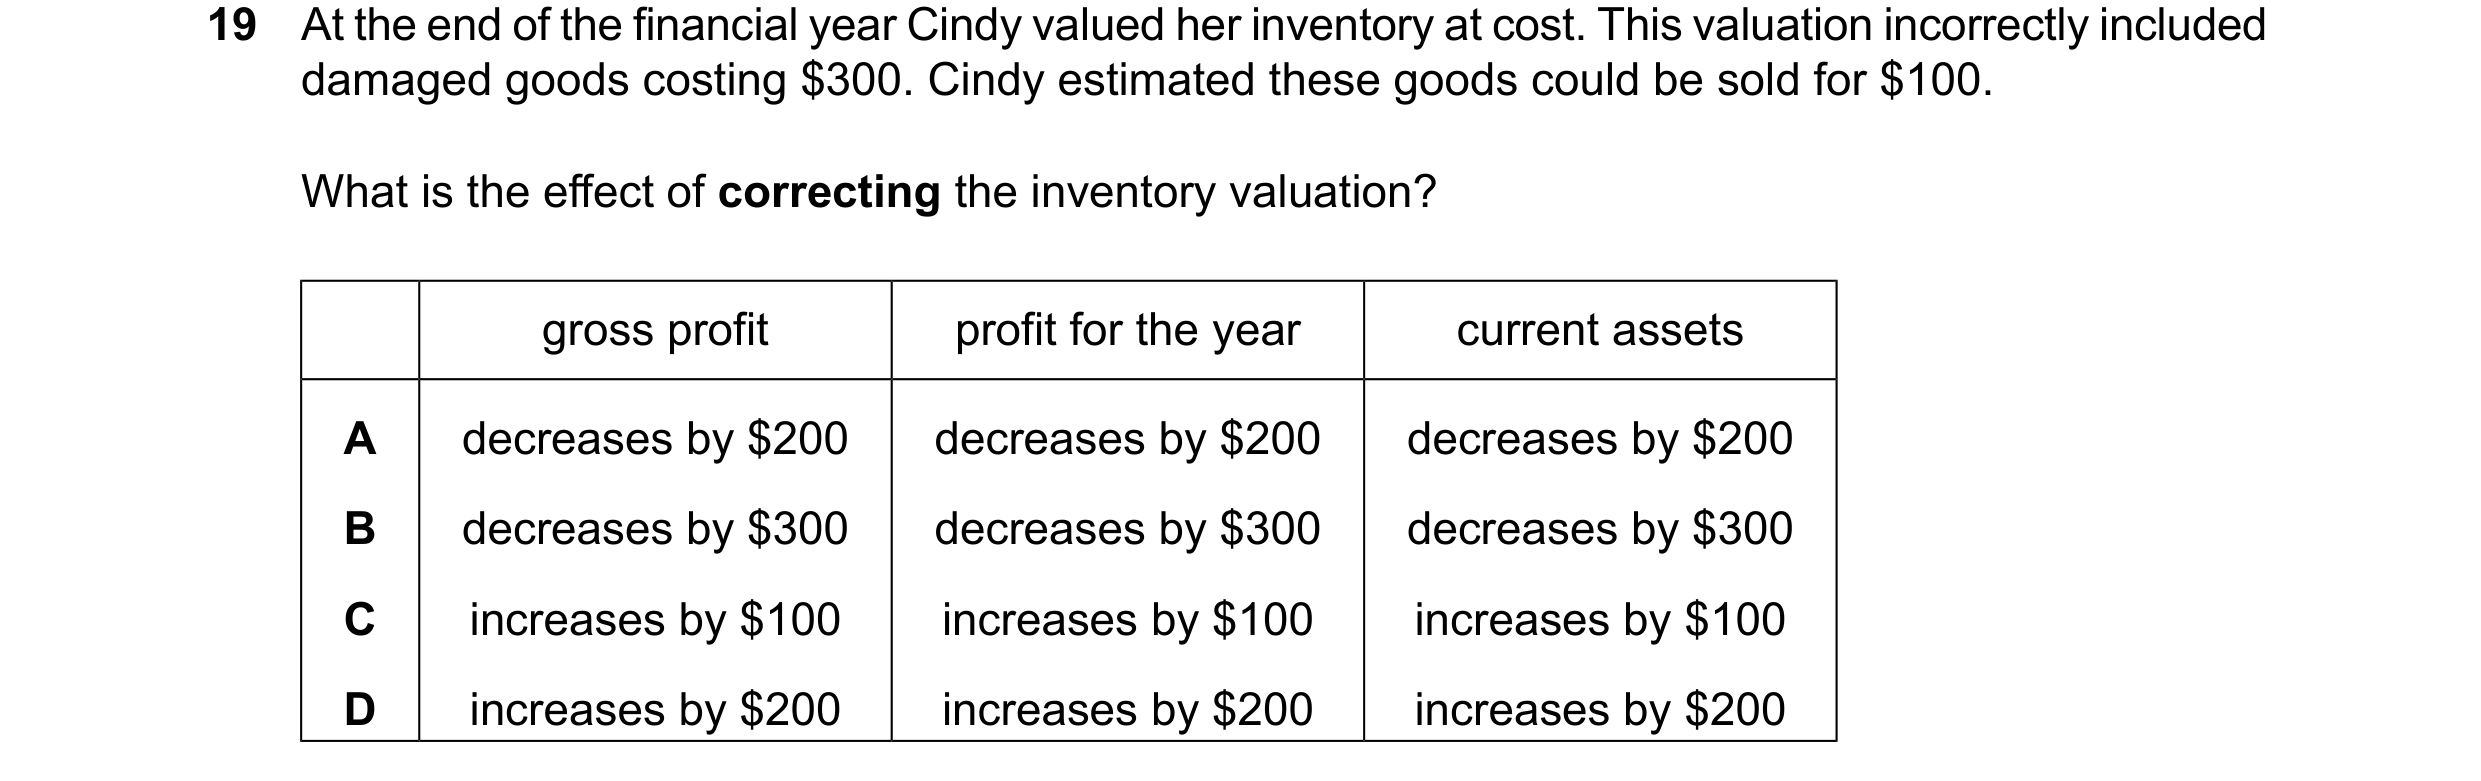
Q19 · At the end of the financial year Cindy valued her inventory at cost 0985/11 May/June 2024
19 At the end of the financial year Cindy valued her inventory at cost. This valuation incorrectly included damaged goods costing $300. Cindy estimated these goods could be sold for $100. What is the effect of correcting the inventory valuation? gross profit profit for the year current assets A decreases by $200 decreases by $200 decreases by $200 B decreases by $300 decreases by $300 decreases by $300 C increases by $100 increases by $100 increases by $100 D increases by $200 increases by $200 increases by $200
1 marks
Answer: A
This question in 0985/11 May/June 2024
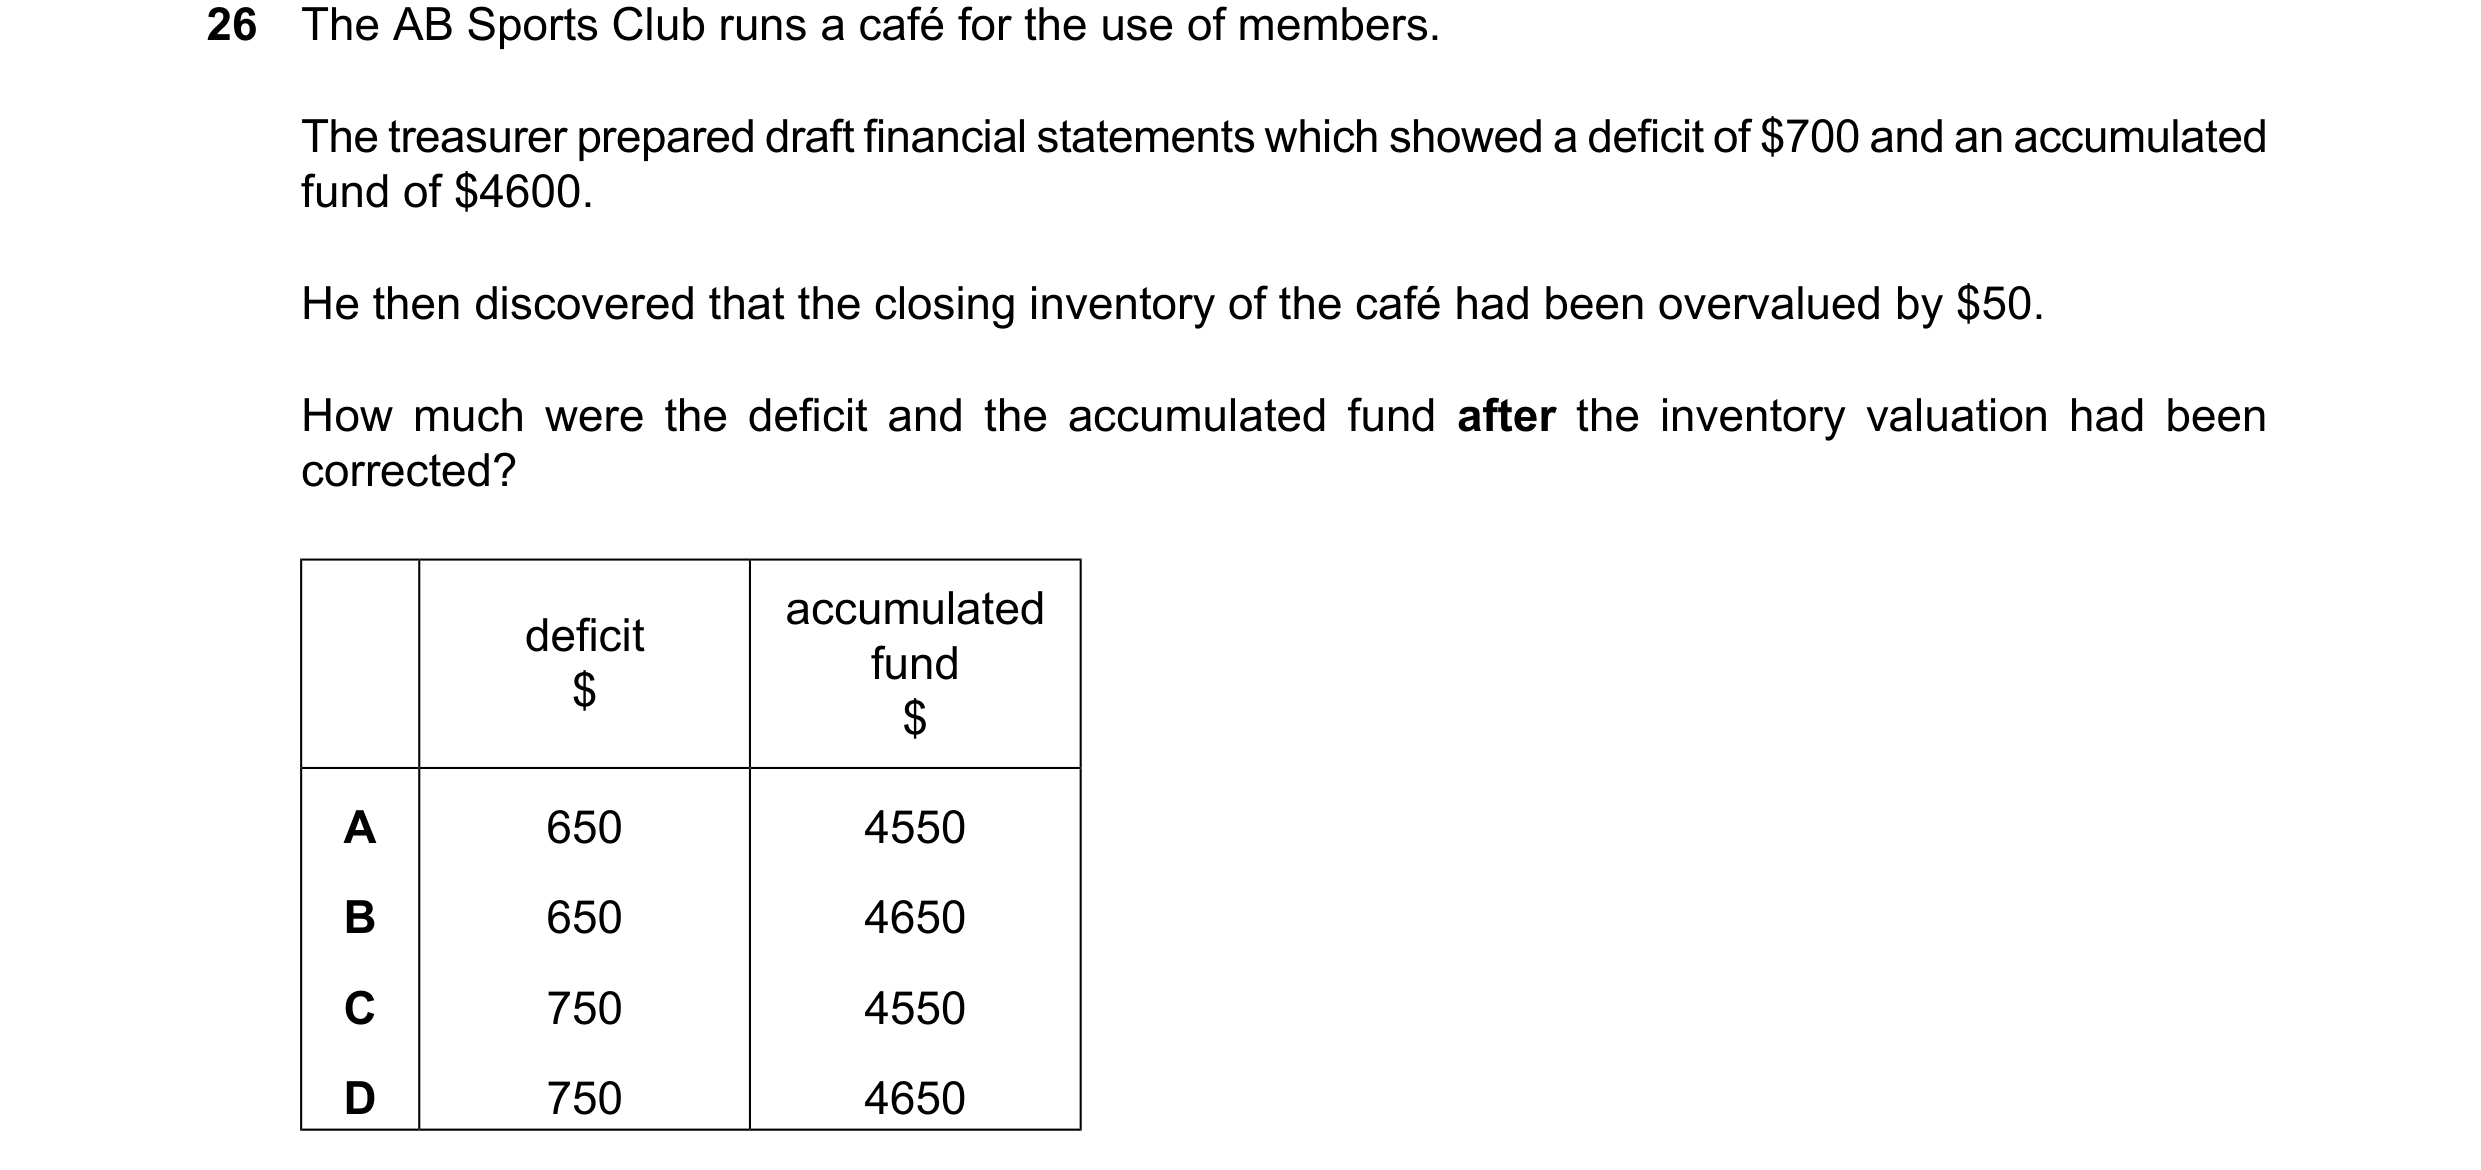
Q20 · The AB Sports Club runs a café for the use of members 0985/11 May/June 2024
26 The AB Sports Club runs a café for the use of members. The treasurer prepared draft financial statements which showed a deficit of $700 and an accumulated fund of $4600. He then discovered that the closing inventory of the café had been overvalued by $50. How much were the deficit and the accumulated fund after the inventory valuation had been corrected? accumulated deficit fund $ $ A 650 4550 B 650 4650 C 750 4550 D 750 4650
1 marks
Answer: C
This question in 0985/11 May/June 2024
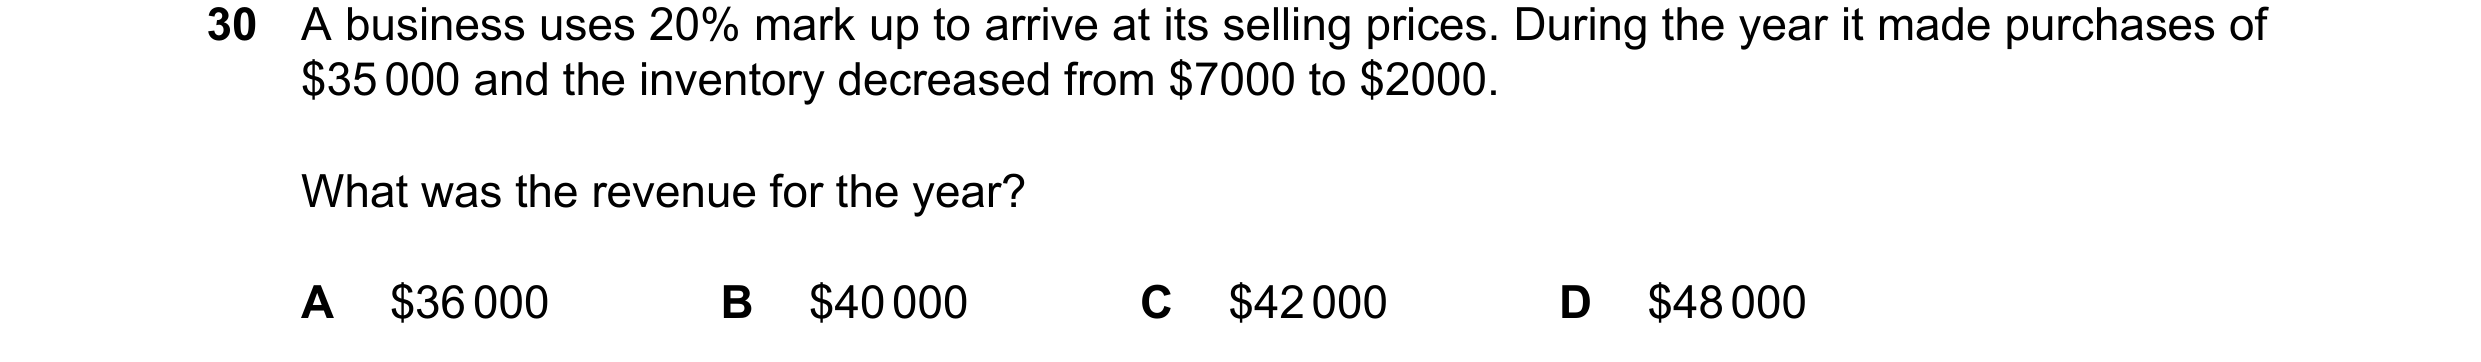
Q21 · A business uses 20% mark up to arrive at its selling prices 0985/11 May/June 2024
30 A business uses 20% mark up to arrive at its selling prices. During the year it made purchases of $35000 and the inventory decreased from $7000 to $2000. What was the revenue for the year? A $36000 B $40000 C $42000 D $48000
1 marks
Answer: D
This question in 0985/11 May/June 2024
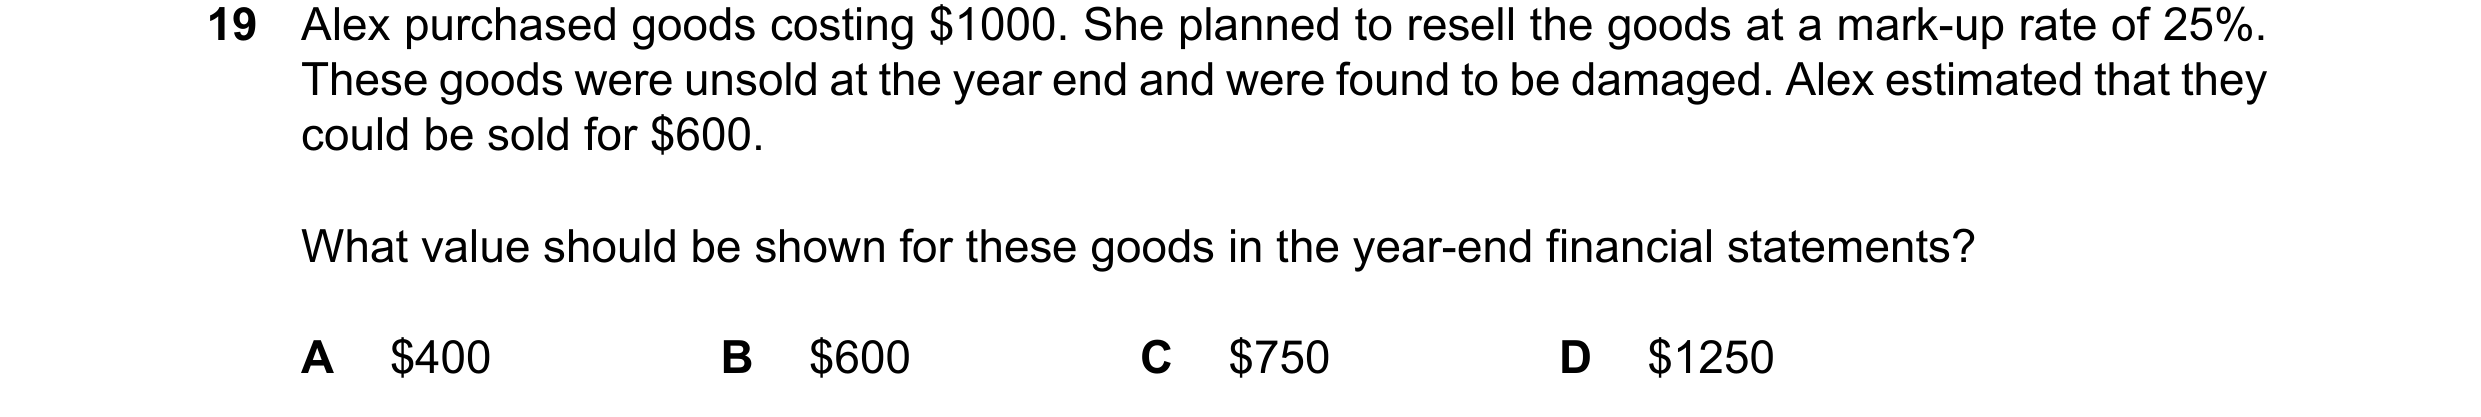
Q22 · Alex purchased goods costing $1000 0985/12 May/June 2024
19 Alex purchased goods costing $1000. She planned to resell the goods at a mark-up rate of 25%. These goods were unsold at the year end and were found to be damaged. Alex estimated that they could be sold for $600. What value should be shown for these goods in the year-end financial statements? A $400 B $600 C $750 D $1250
1 marks
Answer: B
This question in 0985/12 May/June 2024
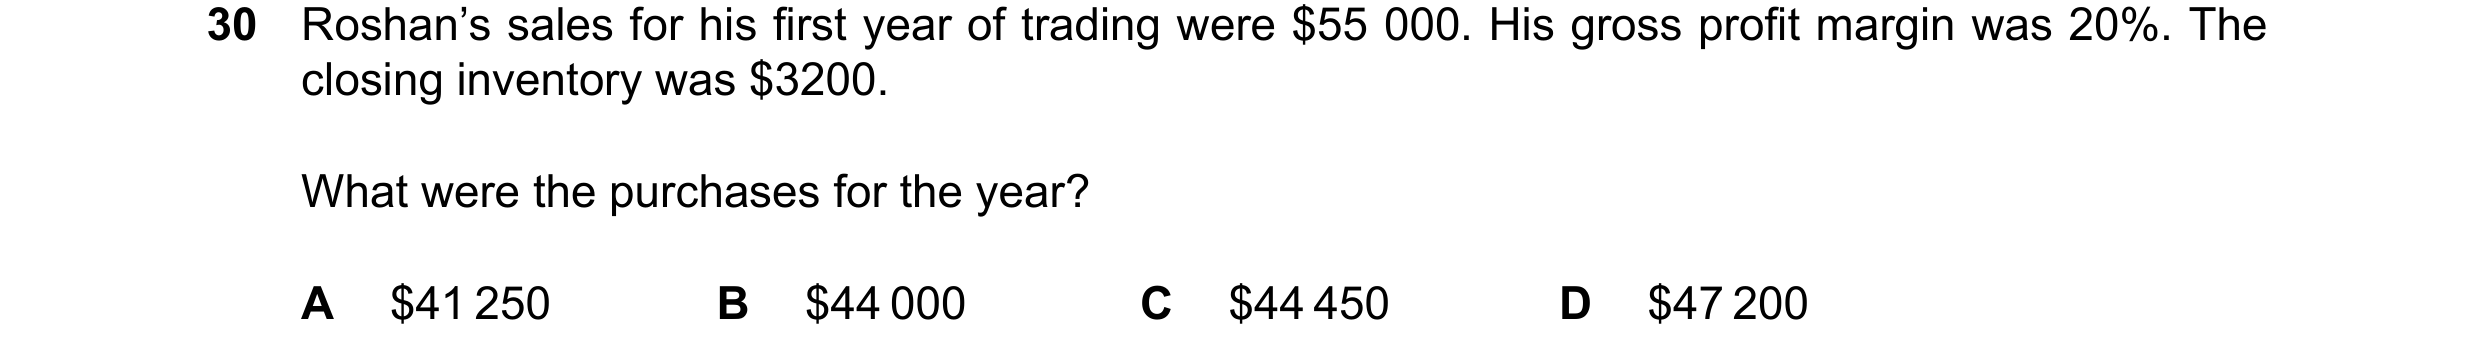
Q23 · Roshan’s sales for his first year of trading were $55 000 0985/12 May/June 2024
30 Roshan’s sales for his first year of trading were $55 000. His gross profit margin was 20%. The closing inventory was $3200. What were the purchases for the year? A $41 250 B $44 000 C $44 450 D $47 200
1 marks
Answer: D
This question in 0985/12 May/June 2024
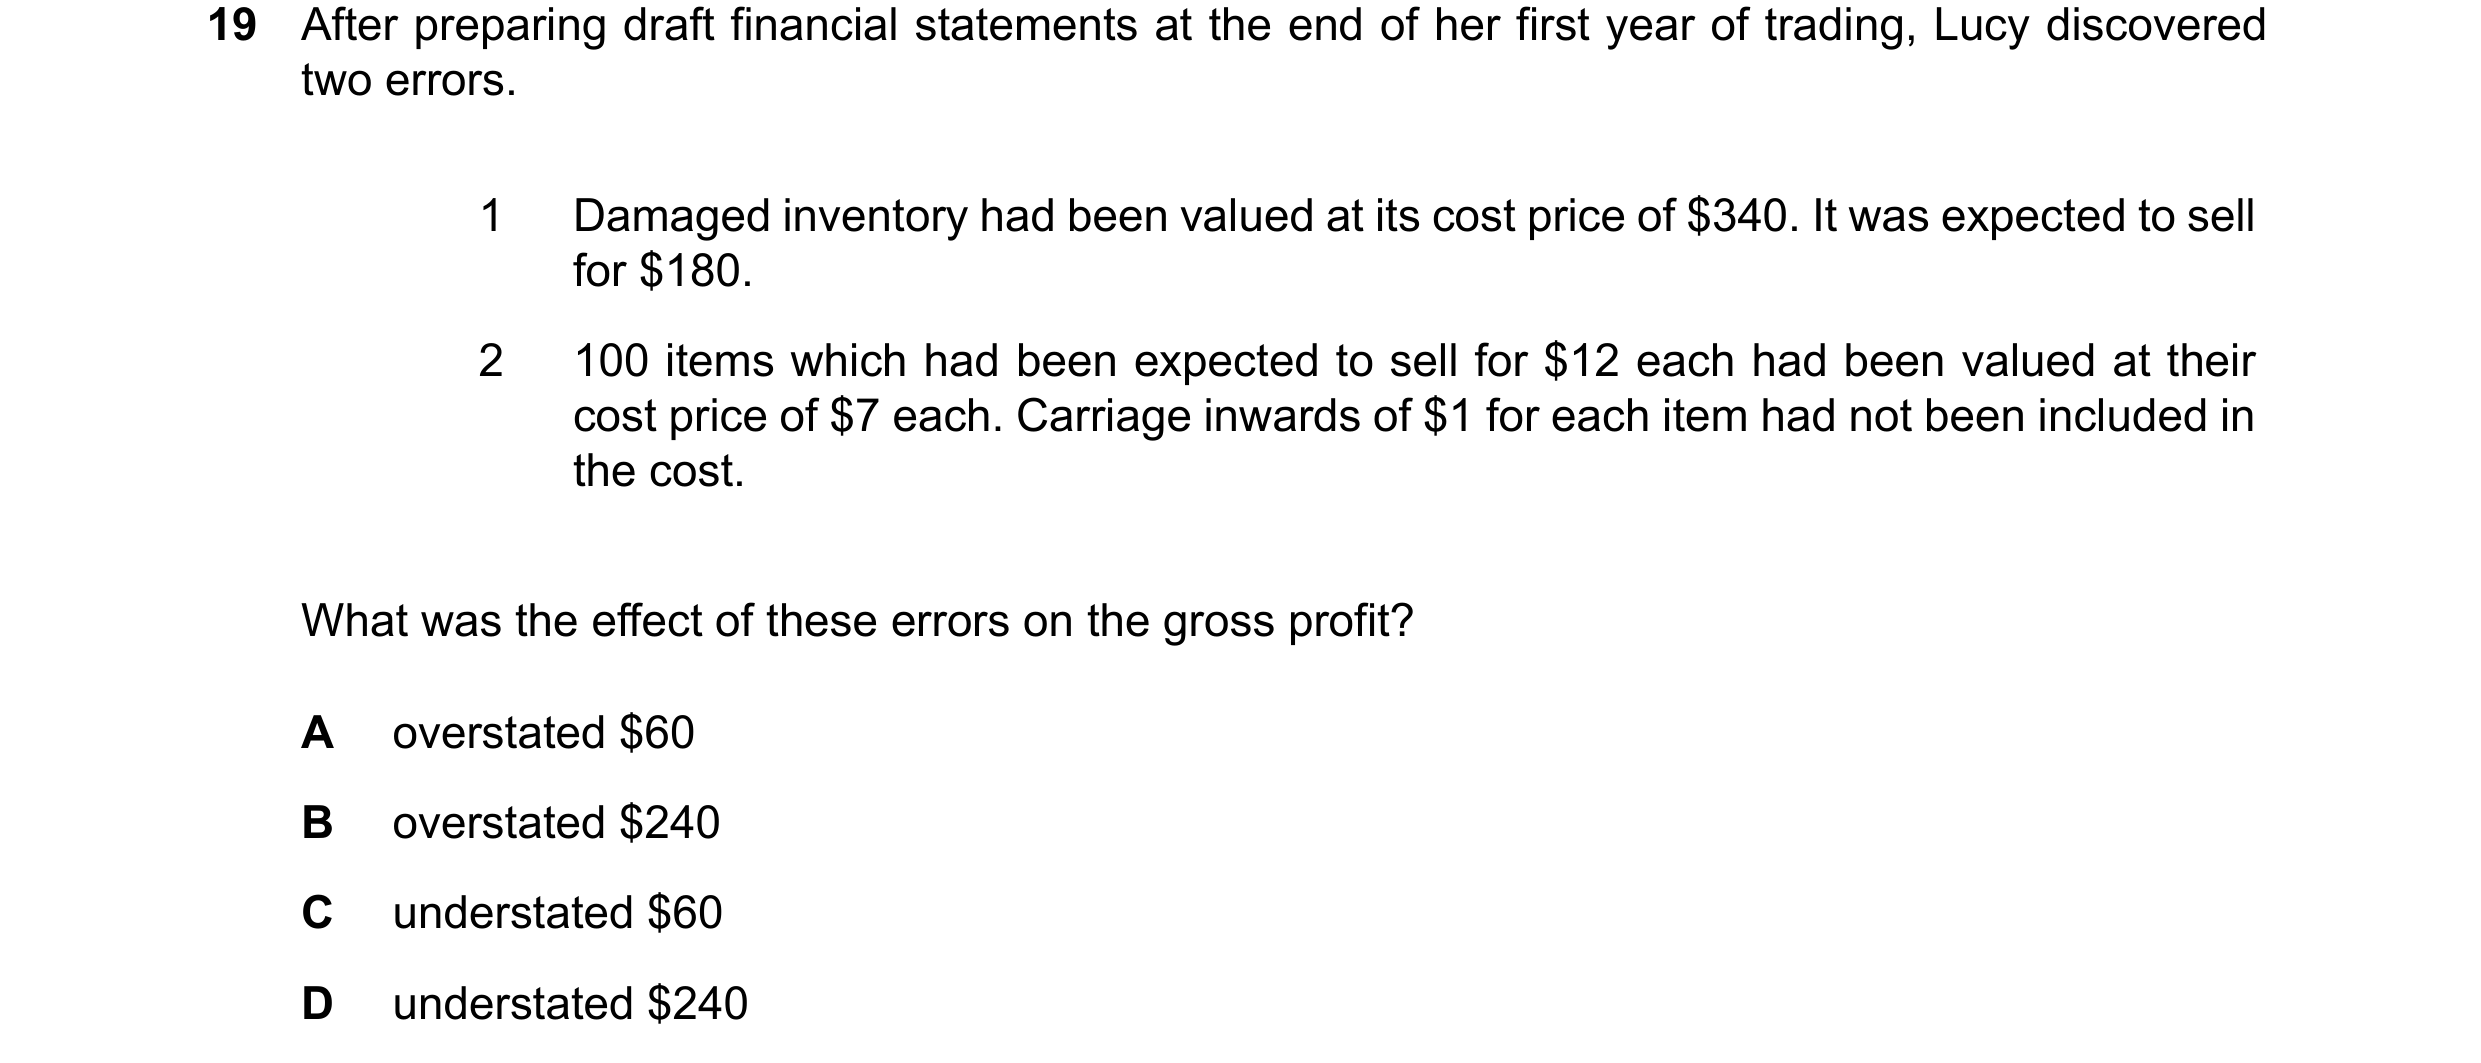
Q24 · After preparing draft financial statements at the end of her first year of trading, Lucy… 0985/12 Oct/Nov 2024
19 After preparing draft financial statements at the end of her first year of trading, Lucy discovered two errors. 1 Damaged inventory had been valued at its cost price of $340. It was expected to sell for $180. 2 100 items which had been expected to sell for $12 each had been valued at their cost price of $7 each. Carriage inwards of $1 for each item had not been included in the cost. What was the effect of these errors on the gross profit? A overstated $60 B overstated $240 C understated $60 D understated $240
1 marks
Answer: A
This question in 0985/12 Oct/Nov 2024
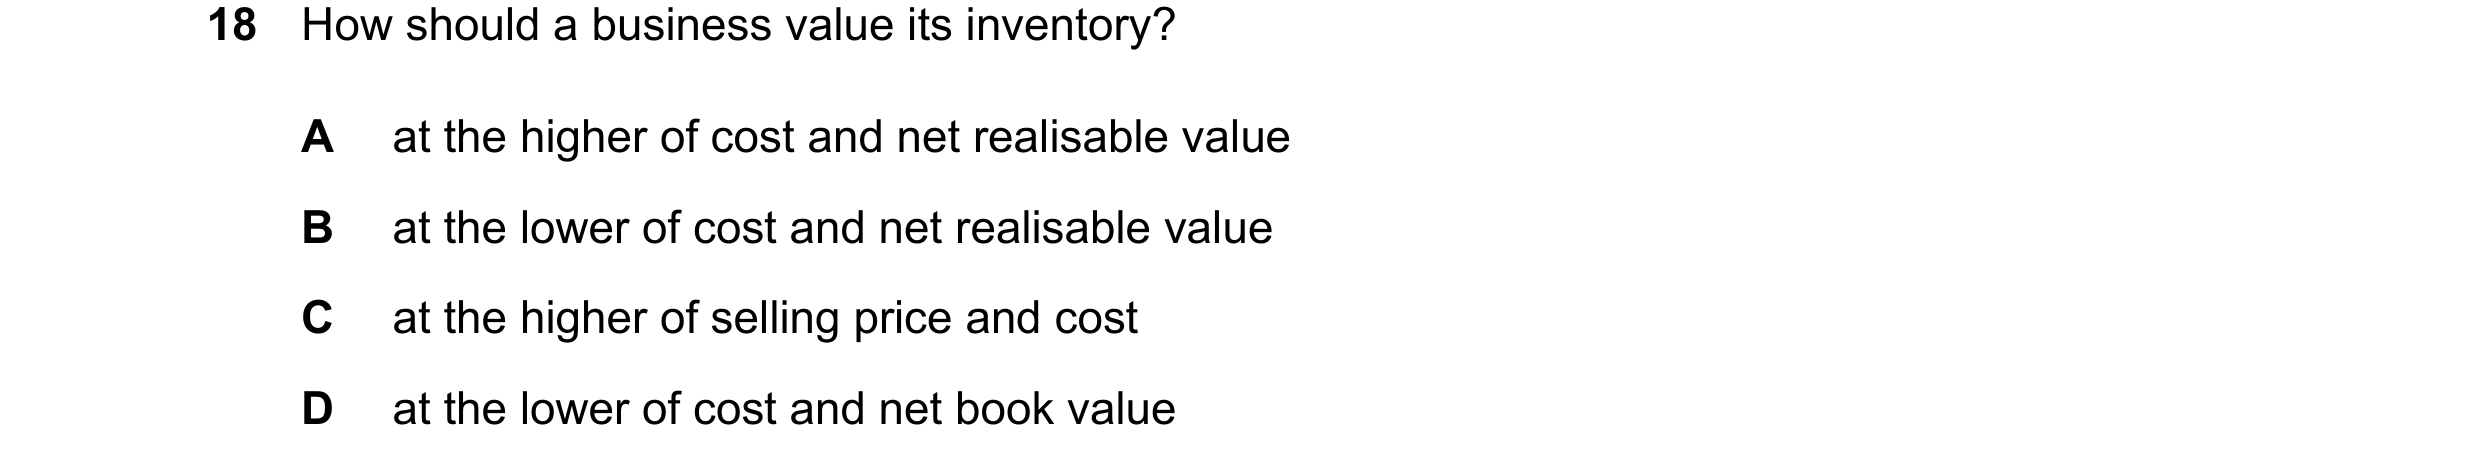
Q25 · How should a business value its inventory? 0985/11 May/June 2025
18 How should a business value its inventory? A at the higher of cost and net realisable value B at the lower of cost and net realisable value C at the higher of selling price and cost D at the lower of cost and net book value
1 marks
Answer: B
This question in 0985/11 May/June 2025
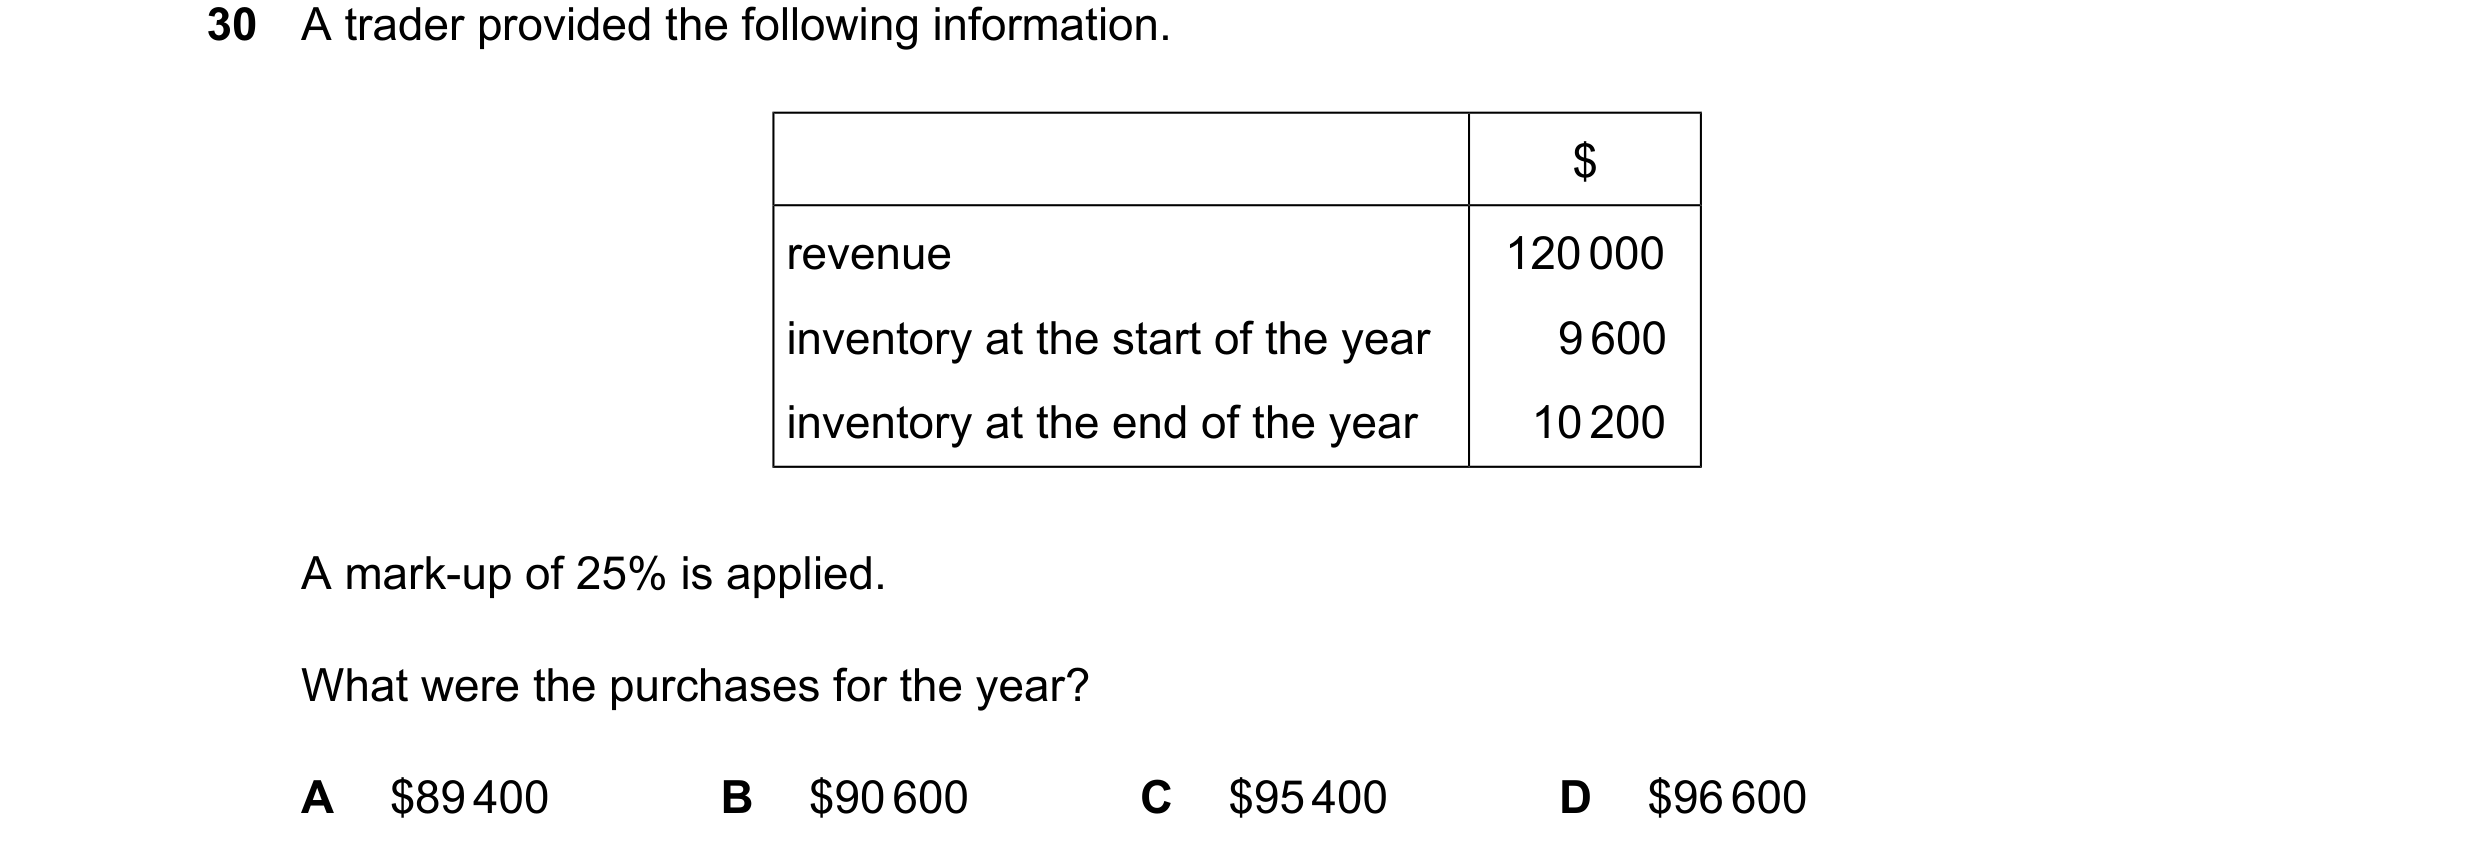
Q26 · A trader provided the following information 0985/11 May/June 2025
30 A trader provided the following information. $ revenue 120000 inventory at the start of the year 9600 inventory at the end of the year 10200 A mark-up of 25% is applied. What were the purchases for the year? A $89400 B $90600 C $95400 D $96600
1 marks
Answer: D
This question in 0985/11 May/June 2025
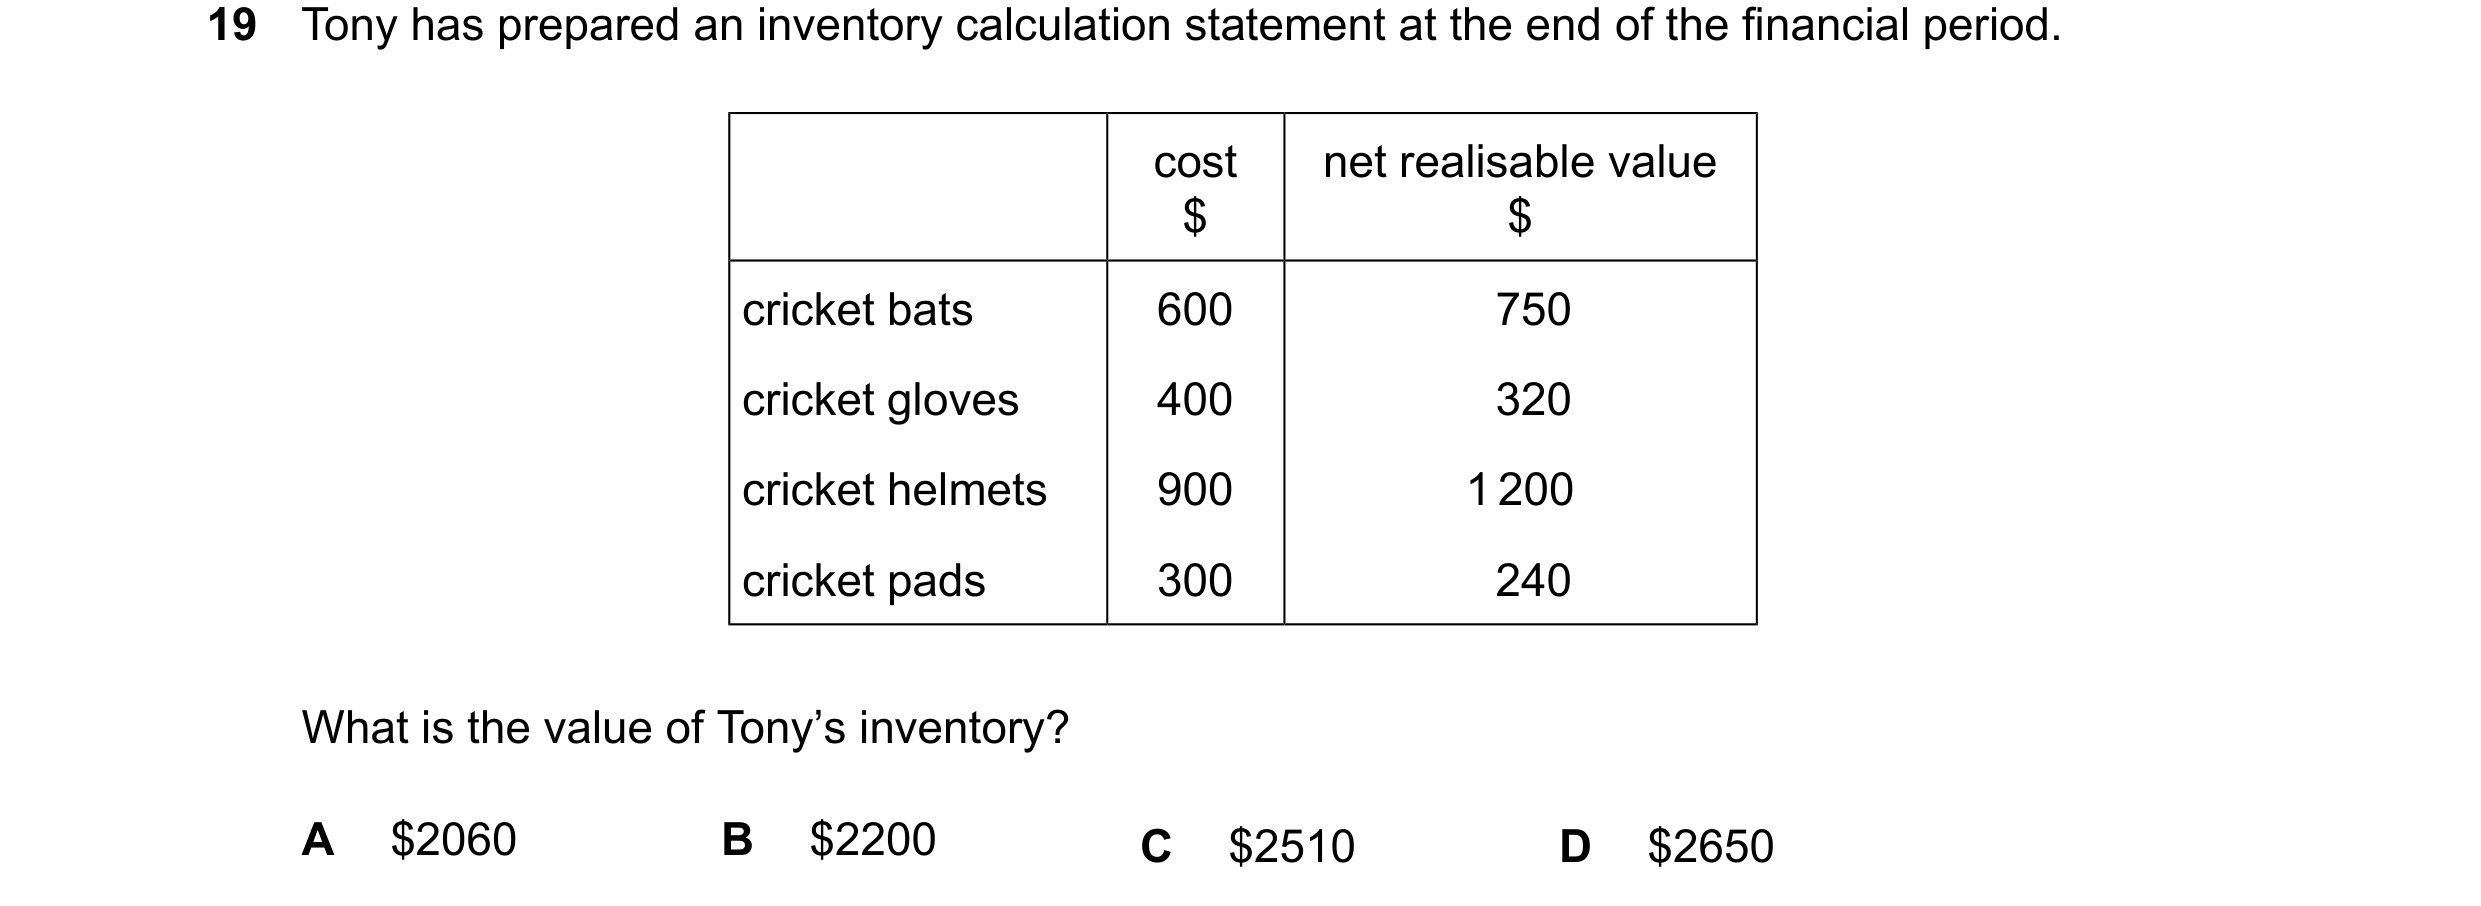
Q27 · Tony has prepared an inventory calculation statement at the end of the financial period 0985/12 May/June 2025
19 Tony has prepared an inventory calculation statement at the end of the financial period. cost net realisable value $ $ cricket bats 600 750 cricket gloves 400 320 cricket helmets 900 1200 cricket pads 300 240 What is the value of Tony’s inventory? A $2060 B $2200 C $2510 D $2650
1 marks
Answer: A
This question in 0985/12 May/June 2025
 1 / 7
 2 / 7
 3 / 7
 4 / 7
 5 / 7
 6 / 7
 7 / 7