Cambridge IGCSE Accounting 0452 — 2013 Oct/Nov Paper 2 · Variant 3
0452/23/O/N/13 · 120 marks · ≈135 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme9 pages
Answers below. Sit the paper first if you are practising.
Paper as text
Question paper, page 1
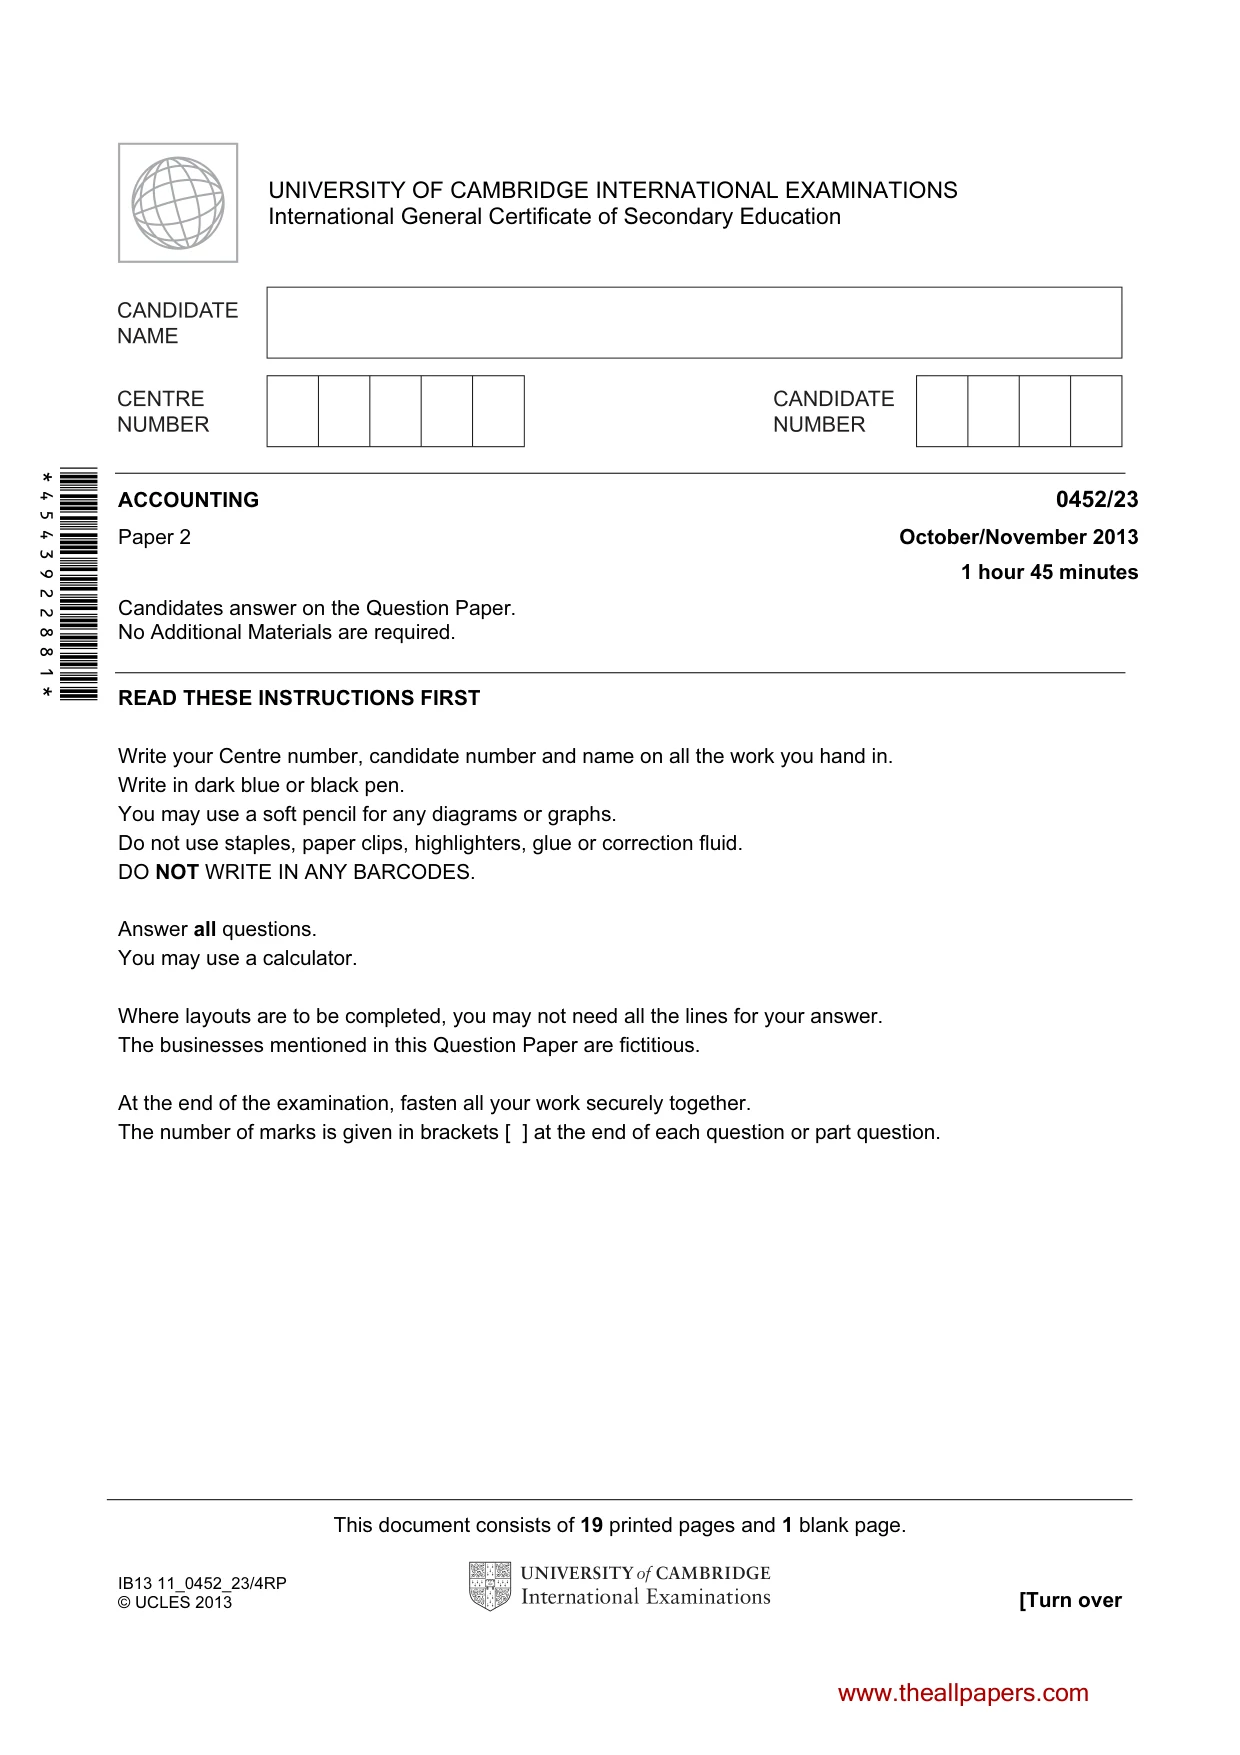
This document consists of 19 printed pages and 1 blank page. IB13 11_0452_23/4RP © UCLES 2013 [Turn over *4543922881* UNIVERSITY OF CAMBRIDGE INTERNATIONAL EXAMINATIONS International General Certificate of Secondary Education ACCOUNTING 0452/23 Paper 2 October/November 2013 1 hour 45 minutes Candidates answer on the Question Paper. No Additional Materials are required. READ THESE INSTRUCTIONS FIRST Write your Centre number, candidate number and name on all the work you hand in. Write in dark blue or black pen. You may use a soft pencil for any diagrams or graphs. Do not use staples, paper clips, highlighters, glue or correction fluid. DO NOT WRITE IN ANY BARCODES. Answer all questions. You may use a calculator. Where layouts are to be completed, you may not need all the lines for your answer. The businesses mentioned in this Question Paper are fictitious. At the end of the examination, fasten all your work securely together. The number of marks is given in brackets [ ] at the end of each question or part question. www.theallpapers.com
Question paper, page 2
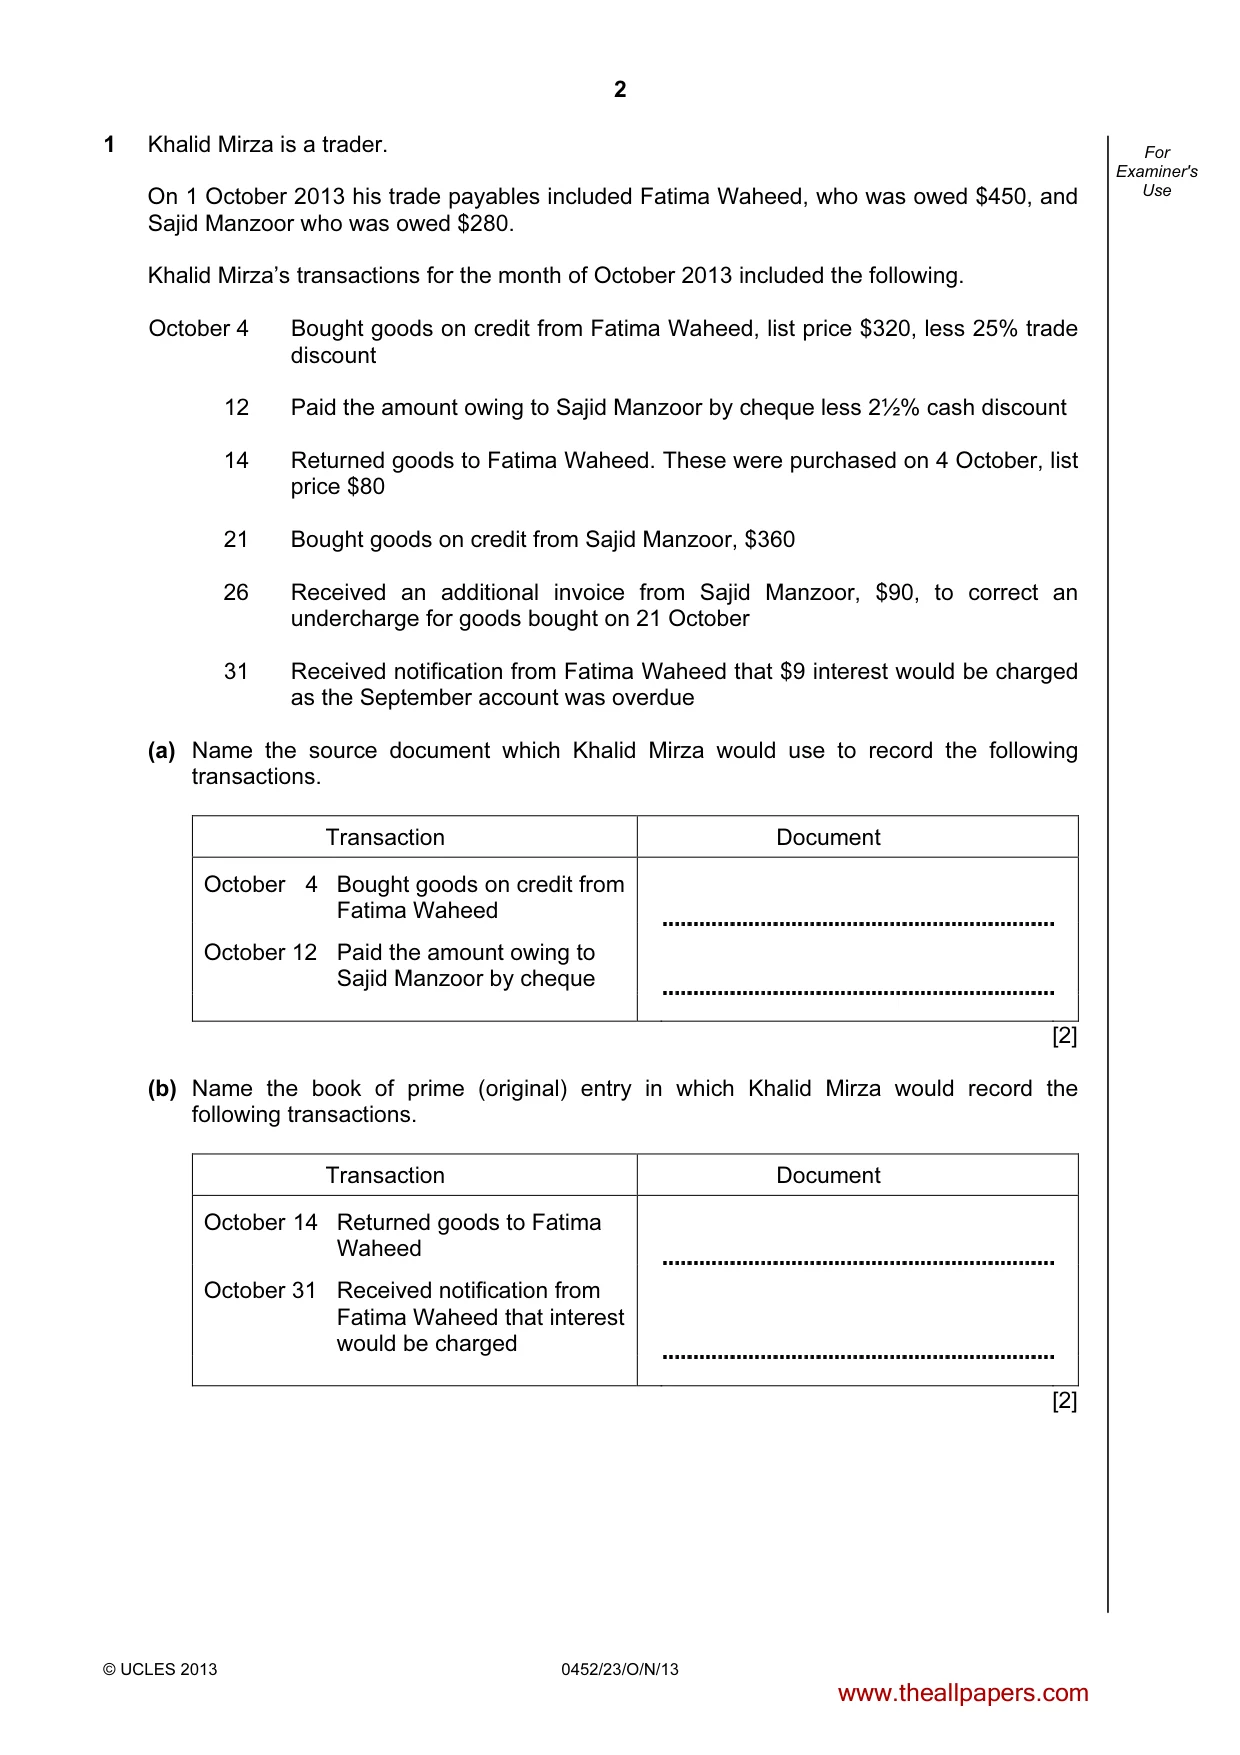
2 © UCLES 2013 0452/23/O/N/13 For Examiner's Use 1 Khalid Mirza is a trader. On 1 October 2013 his trade payables included Fatima Waheed, who was owed $450, and Sajid Manzoor who was owed $280. Khalid Mirza’s transactions for the month of October 2013 included the following. October 4 Bought goods on credit from Fatima Waheed, list price $320, less 25% trade discount 12 Paid the amount owing to Sajid Manzoor by cheque less 2½% cash discount 14 Returned goods to Fatima Waheed. These were purchased on 4 October, list price $80 21 Bought goods on credit from Sajid Manzoor, $360 26 Received an additional invoice from Sajid Manzoor, $90, to correct an undercharge for goods bought on 21 October 31 Received notification from Fatima Waheed that $9 interest would be charged as the September account was overdue (a) Name the source document which Khalid Mirza would use to record the following transactions. Transaction Document October 4 Bought goods on credit from Fatima Waheed October 12 Paid the amount owing to Sajid Manzoor by cheque [2] (b) Name the book of prime (original) entry in which Khalid Mirza would record the following transactions. Transaction Document October 14 Returned goods to Fatima Waheed October 31 Received notification from Fatima Waheed that interest would be charged [2] www.theallpapers.com
Question paper, page 3
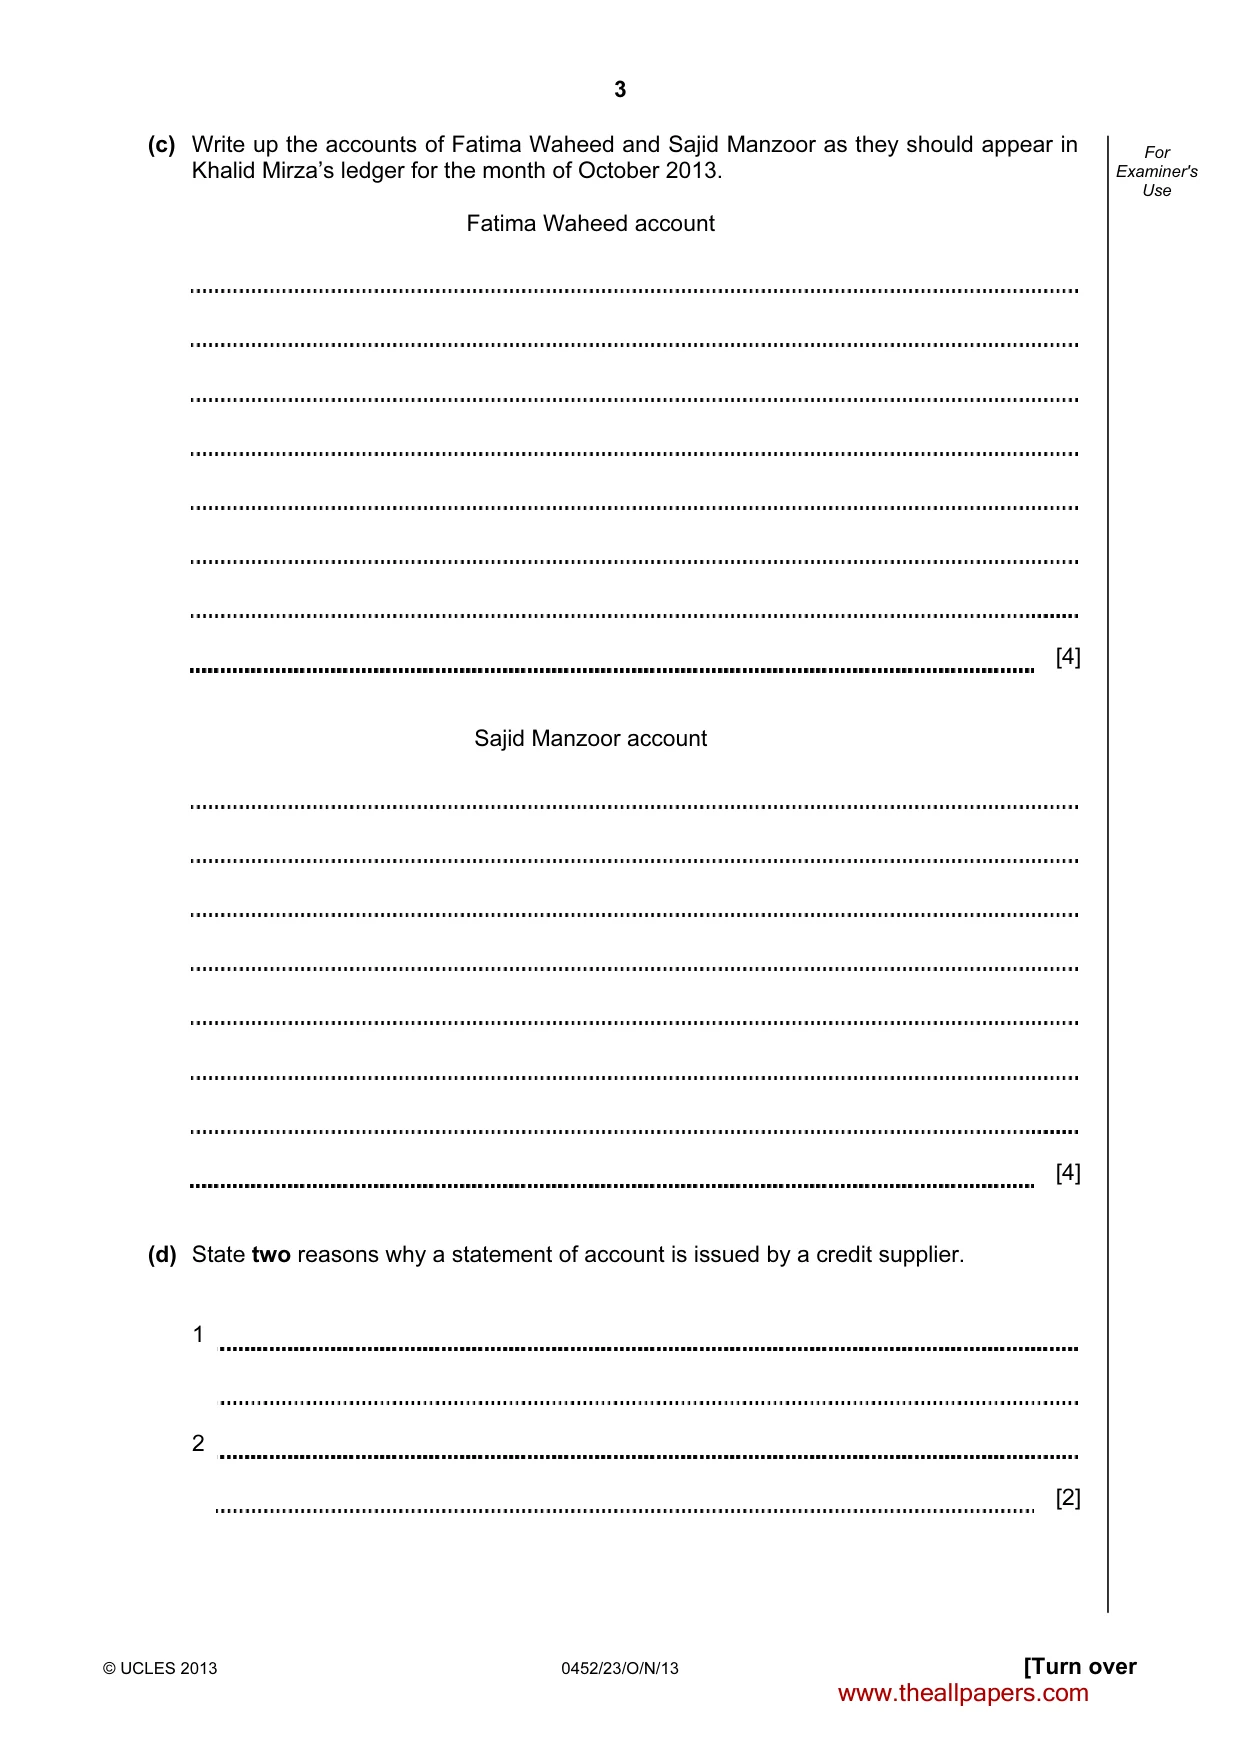
3 © UCLES 2013 0452/23/O/N/13 [Turn over For Examiner's Use (c) Write up the accounts of Fatima Waheed and Sajid Manzoor as they should appear in Khalid Mirza’s ledger for the month of October 2013. Fatima Waheed account [4] Sajid Manzoor account [4] (d) State two reasons why a statement of account is issued by a credit supplier. 1 2 [2] www.theallpapers.com
Question paper, page 4
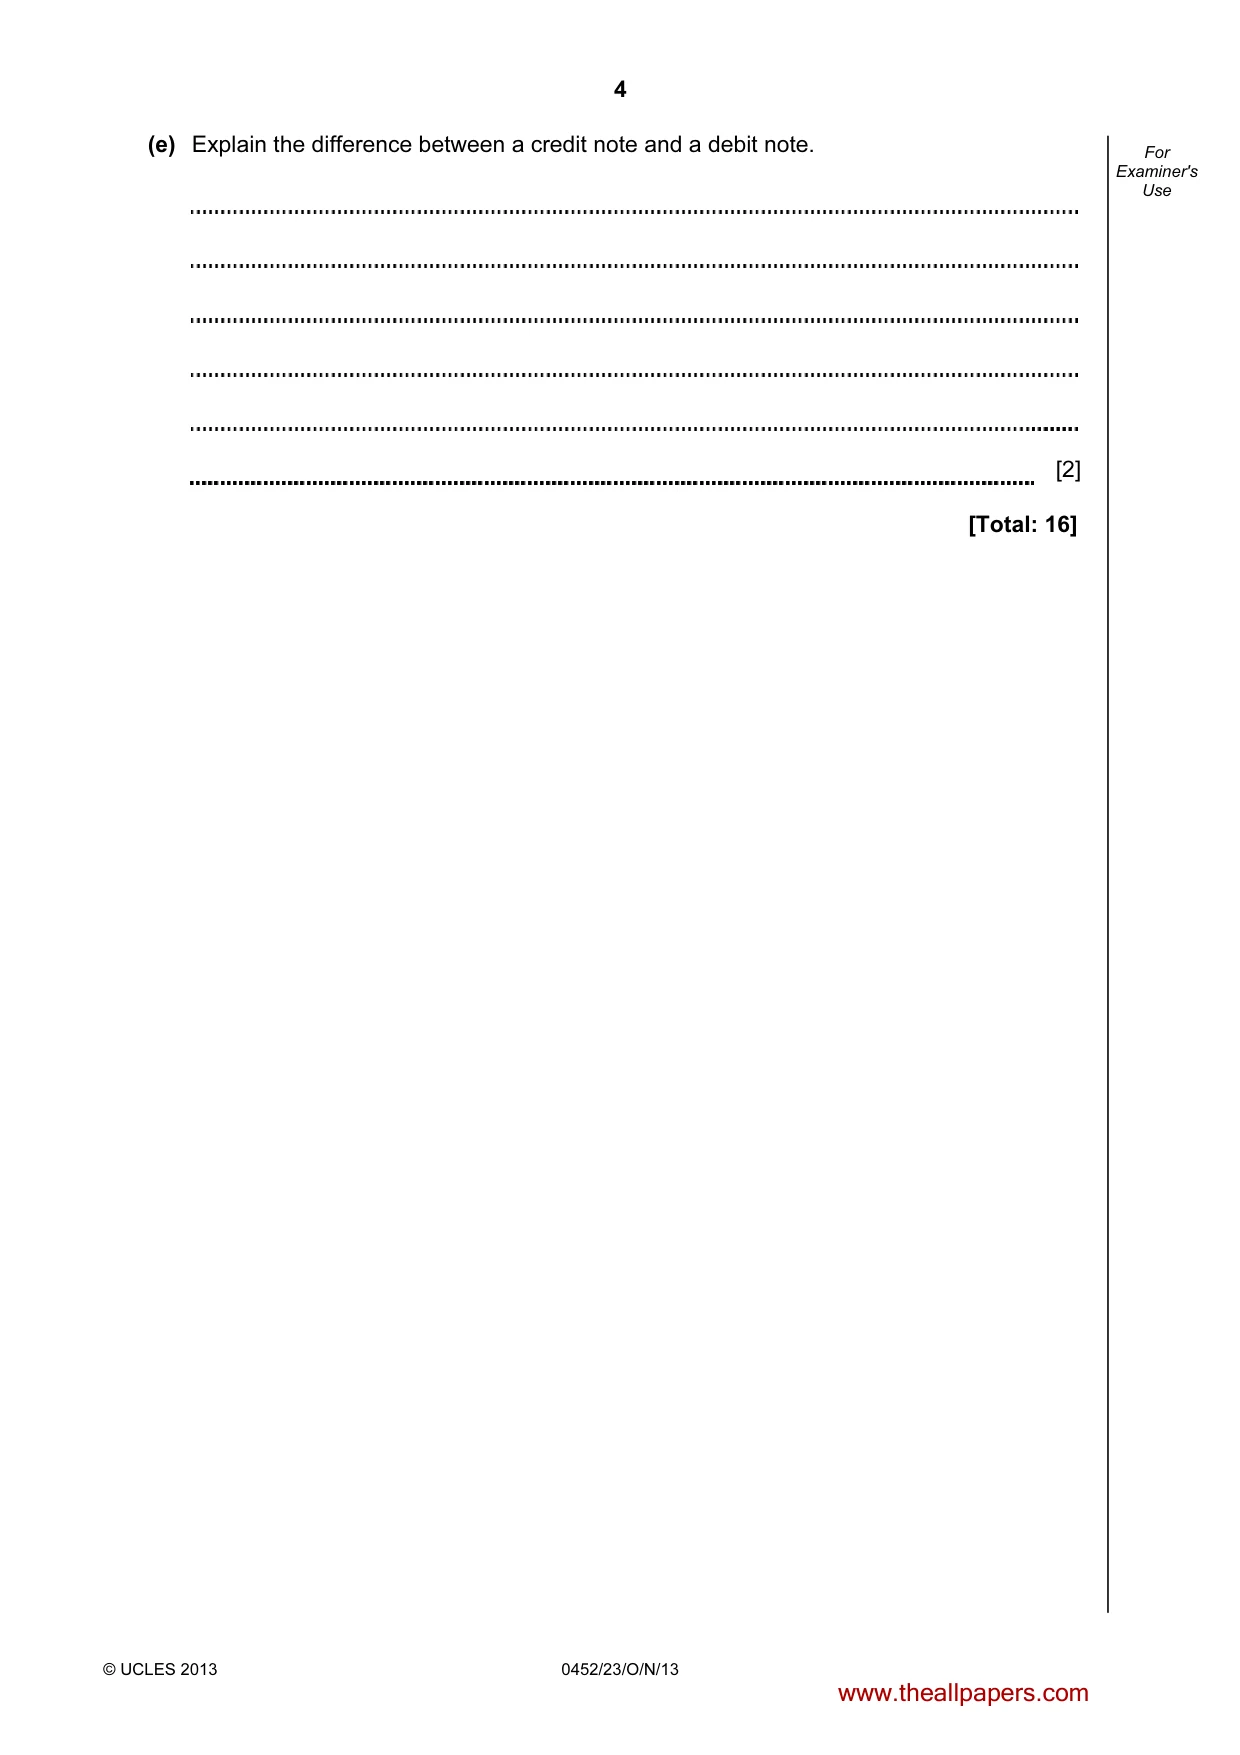
4 © UCLES 2013 0452/23/O/N/13 For Examiner's Use (e) Explain the difference between a credit note and a debit note. [2] [Total: 16] www.theallpapers.com
Question paper, page 5
5 © UCLES 2013 0452/23/O/N/13 [Turn over Question 2 is on the next page. www.theallpapers.com
Question paper, page 6
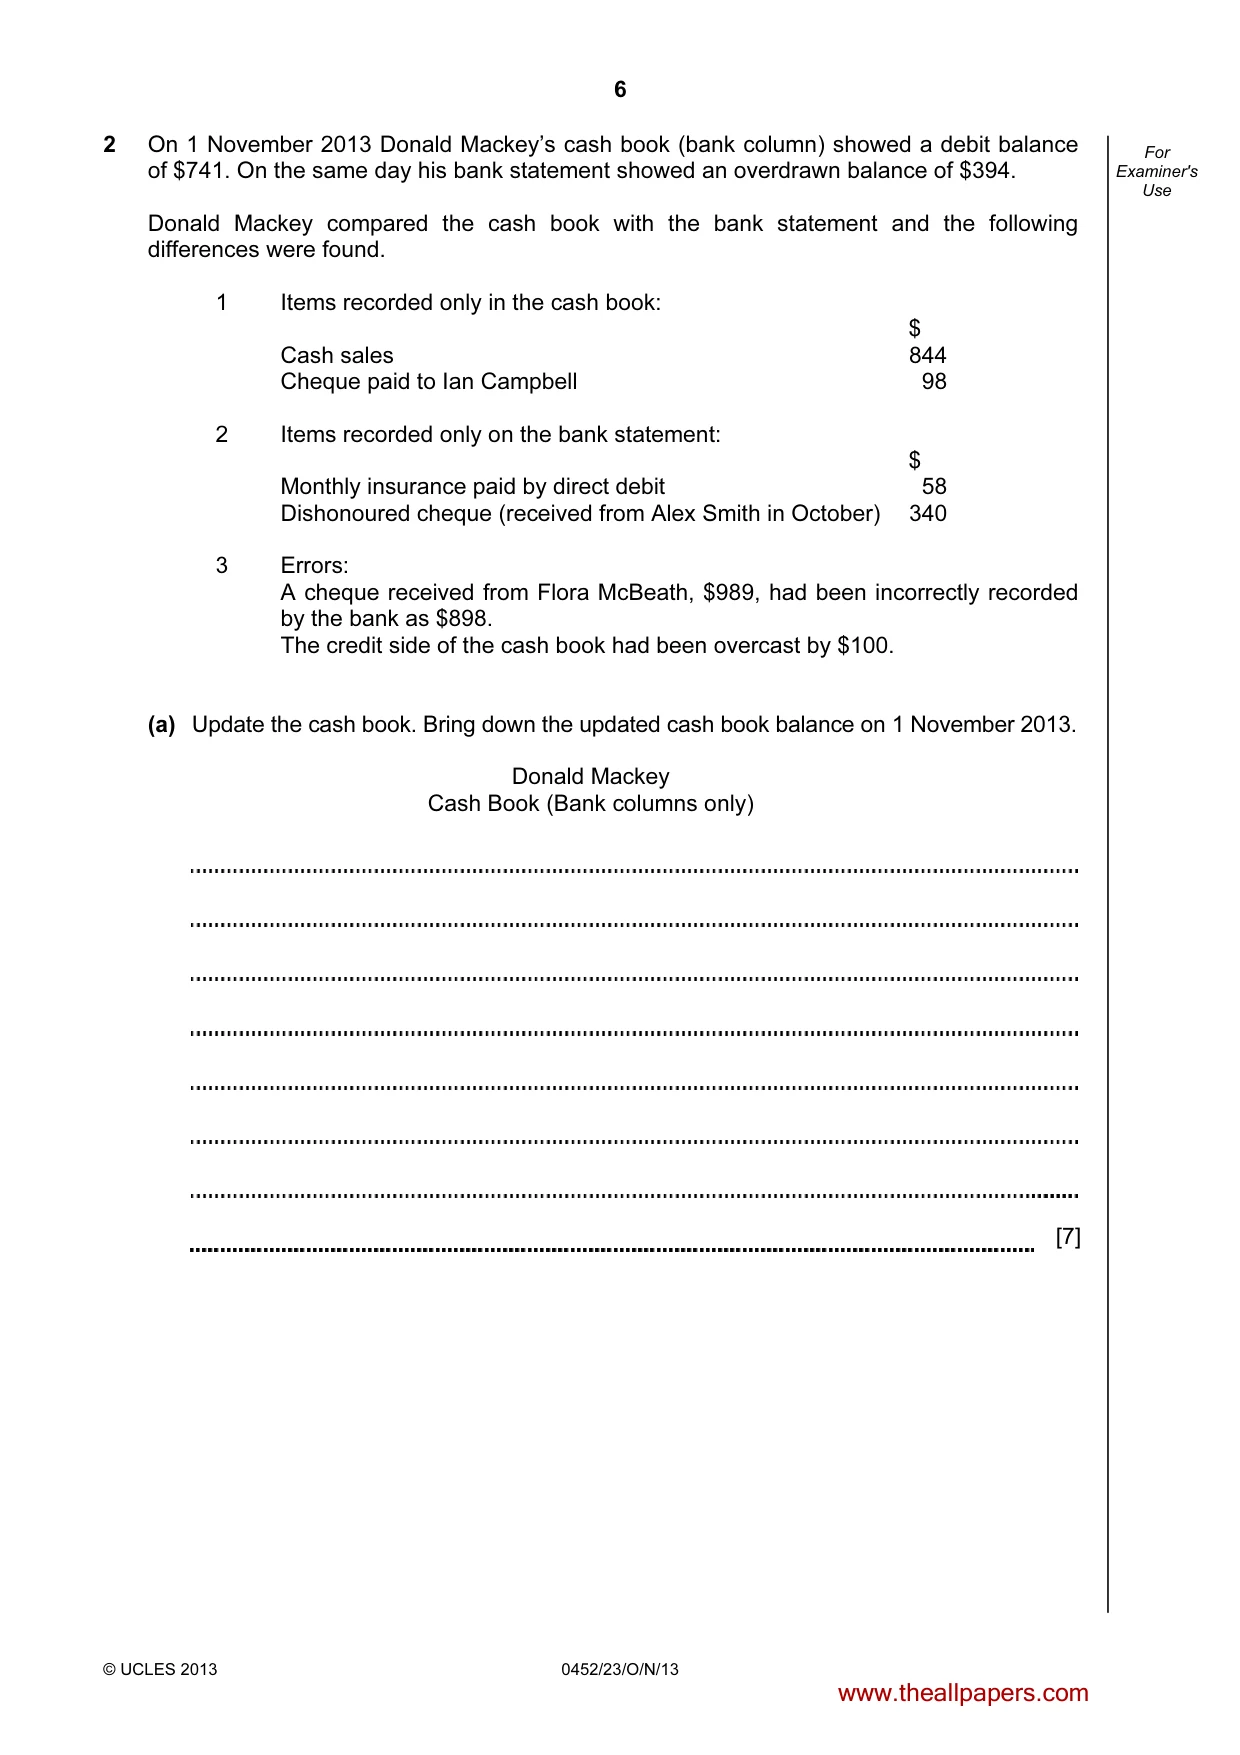
6 © UCLES 2013 0452/23/O/N/13 For Examiner's Use 2 On 1 November 2013 Donald Mackey’s cash book (bank column) showed a debit balance of $741. On the same day his bank statement showed an overdrawn balance of $394. Donald Mackey compared the cash book with the bank statement and the following differences were found. 1 Items recorded only in the cash book: $ Cash sales 844 Cheque paid to Ian Campbell 98 2 Items recorded only on the bank statement: $ Monthly insurance paid by direct debit 58 Dishonoured cheque (received from Alex Smith in October) 340 3 Errors: A cheque received from Flora McBeath, $989, had been incorrectly recorded by the bank as $898. The credit side of the cash book had been overcast by $100. (a) Update the cash book. Bring down the updated cash book balance on 1 November 2013. Donald Mackey Cash Book (Bank columns only) [7] www.theallpapers.com
Question paper, page 7
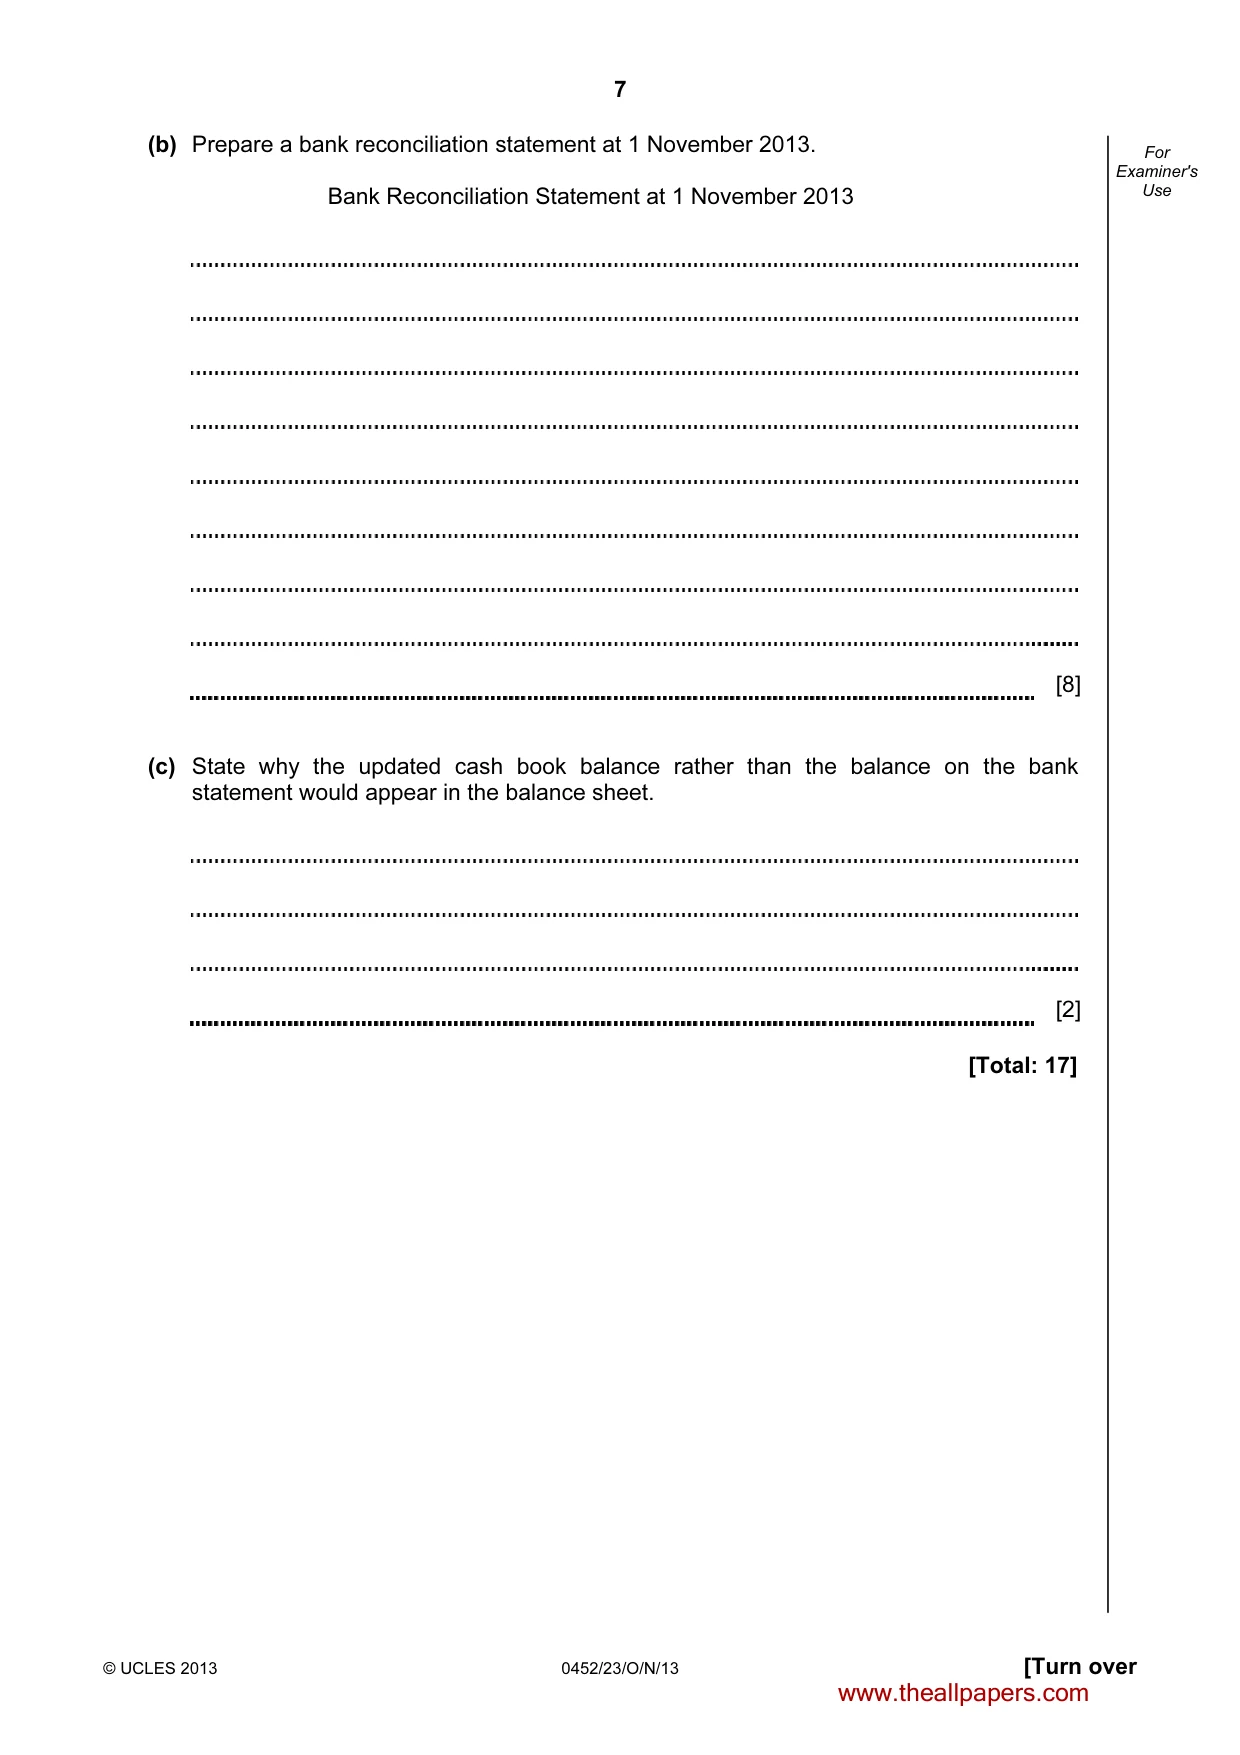
7 © UCLES 2013 0452/23/O/N/13 [Turn over For Examiner's Use (b) Prepare a bank reconciliation statement at 1 November 2013. Bank Reconciliation Statement at 1 November 2013 [8] (c) State why the updated cash book balance rather than the balance on the bank statement would appear in the balance sheet. [2] [Total: 17] www.theallpapers.com
Question paper, page 8
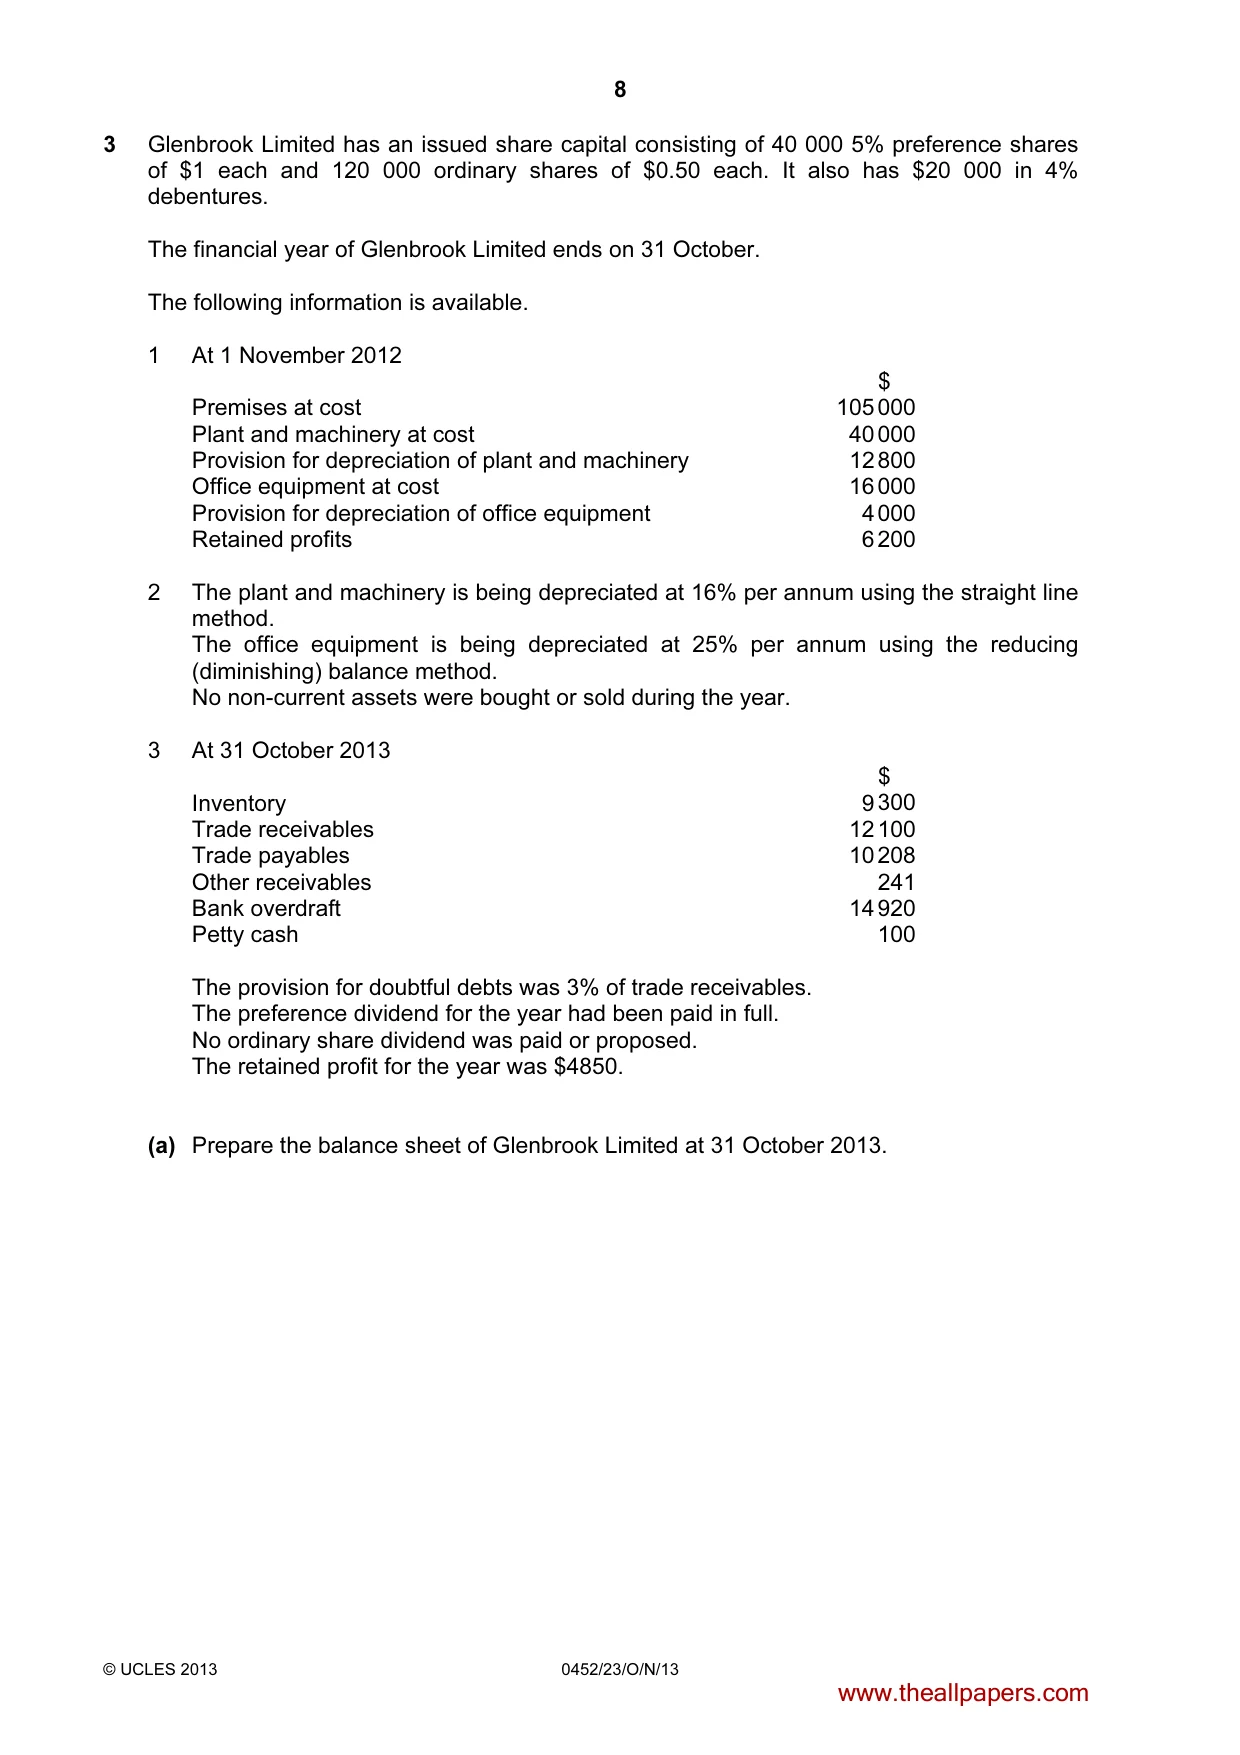
8 © UCLES 2013 0452/23/O/N/13 3 Glenbrook Limited has an issued share capital consisting of 40 000 5% preference shares of $1 each and 120 000 ordinary shares of $0.50 each. It also has $20 000 in 4% debentures. The financial year of Glenbrook Limited ends on 31 October. The following information is available. 1 At 1 November 2012 $ Premises at cost 105 000 Plant and machinery at cost 40 000 Provision for depreciation of plant and machinery 12 800 Office equipment at cost 16 000 Provision for depreciation of office equipment 4 000 Retained profits 6 200 2 The plant and machinery is being depreciated at 16% per annum using the straight line method. The office equipment is being depreciated at 25% per annum using the reducing (diminishing) balance method. No non-current assets were bought or sold during the year. 3 At 31 October 2013 $ Inventory 9 300 Trade receivables 12 100 Trade payables 10 208 Other receivables 241 Bank overdraft 14 920 Petty cash 100 The provision for doubtful debts was 3% of trade receivables. The preference dividend for the year had been paid in full. No ordinary share dividend was paid or proposed. The retained profit for the year was $4850. (a) Prepare the balance sheet of Glenbrook Limited at 31 October 2013. www.theallpapers.com
Question paper, page 9
9 © UCLES 2013 0452/23/O/N/13 [Turn over For Examiner's Use Glenbrook Limited Balance Sheet at 31 October 2013 [16] www.theallpapers.com
Question paper, page 10
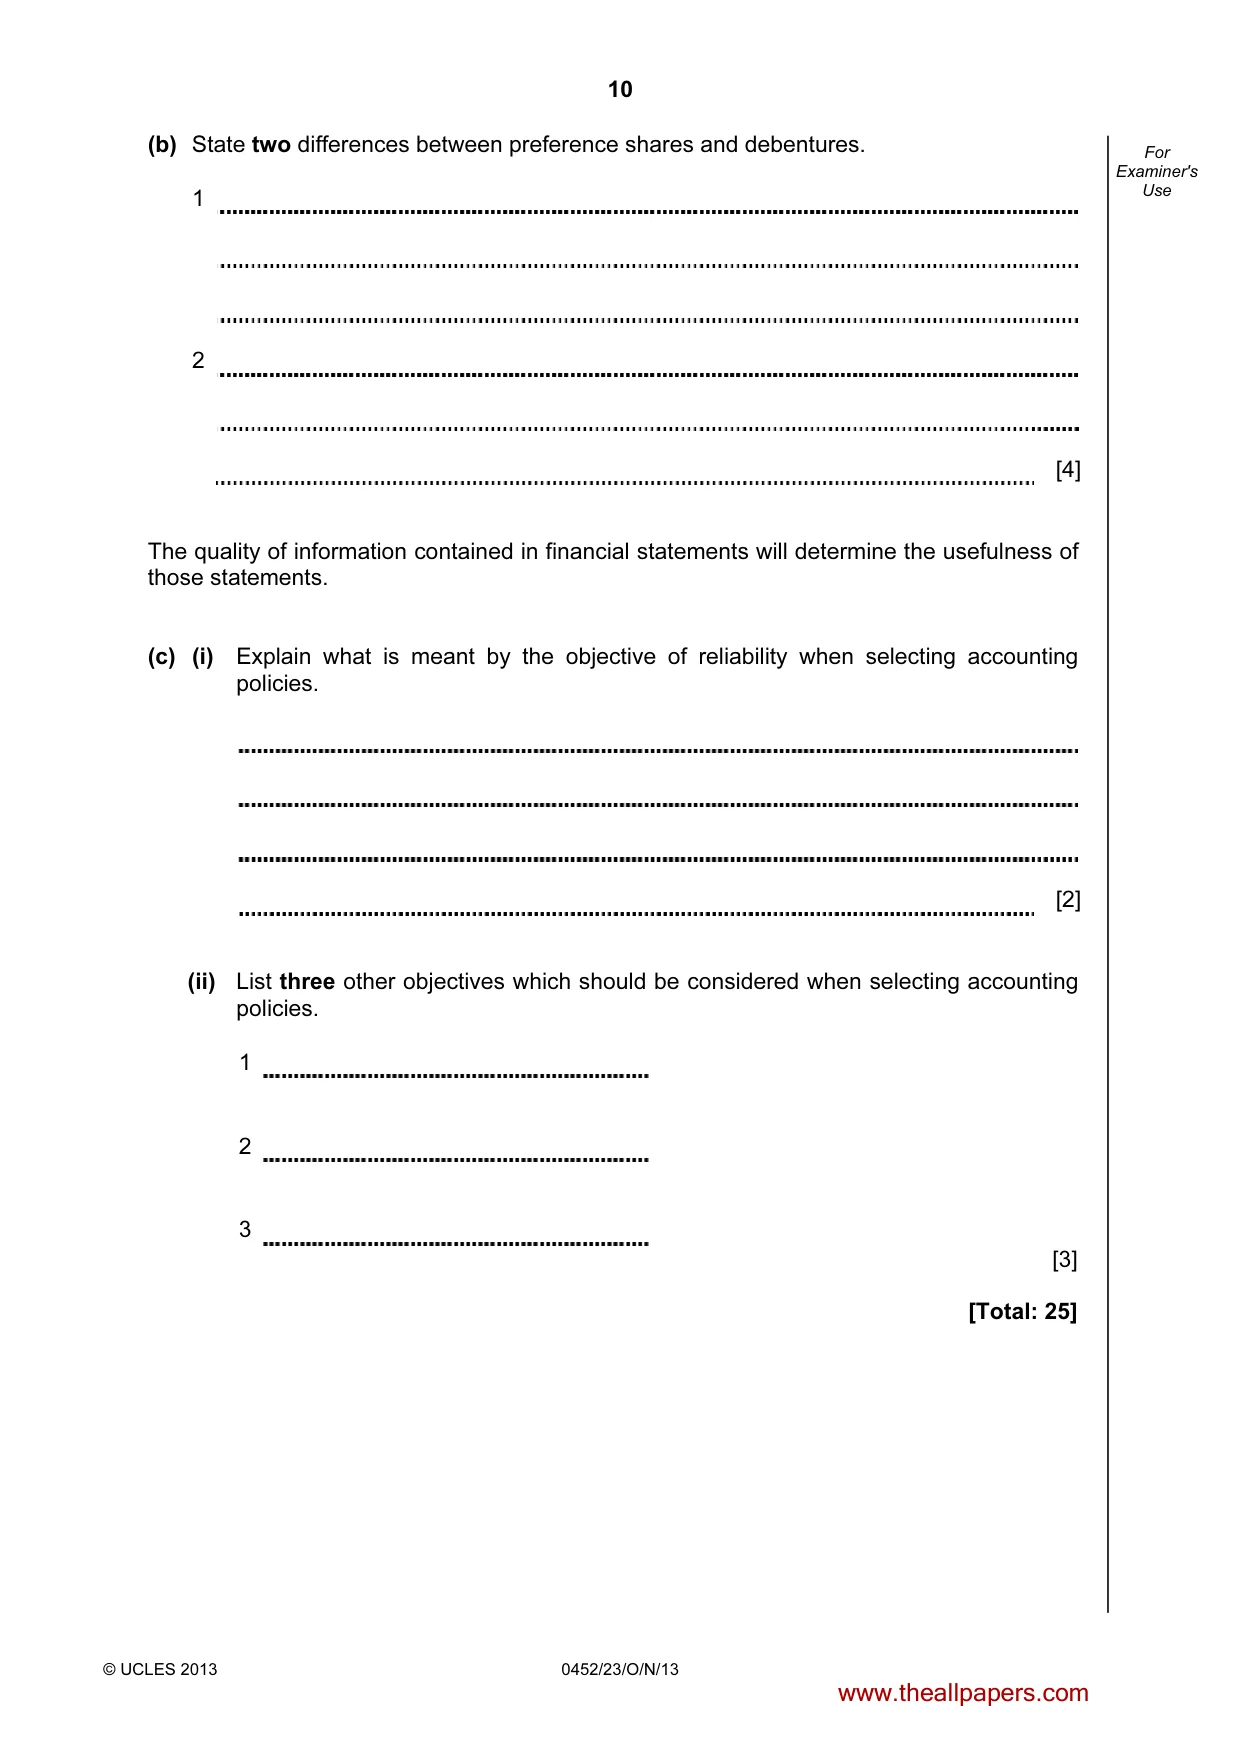
10 © UCLES 2013 0452/23/O/N/13 For Examiner's Use (b) State two differences between preference shares and debentures. 1 2 [4] The quality of information contained in financial statements will determine the usefulness of those statements. (c) (i) Explain what is meant by the objective of reliability when selecting accounting policies. [2] (ii) List three other objectives which should be considered when selecting accounting policies. 1 2 3 [3] [Total: 25] www.theallpapers.com
Question paper, page 11
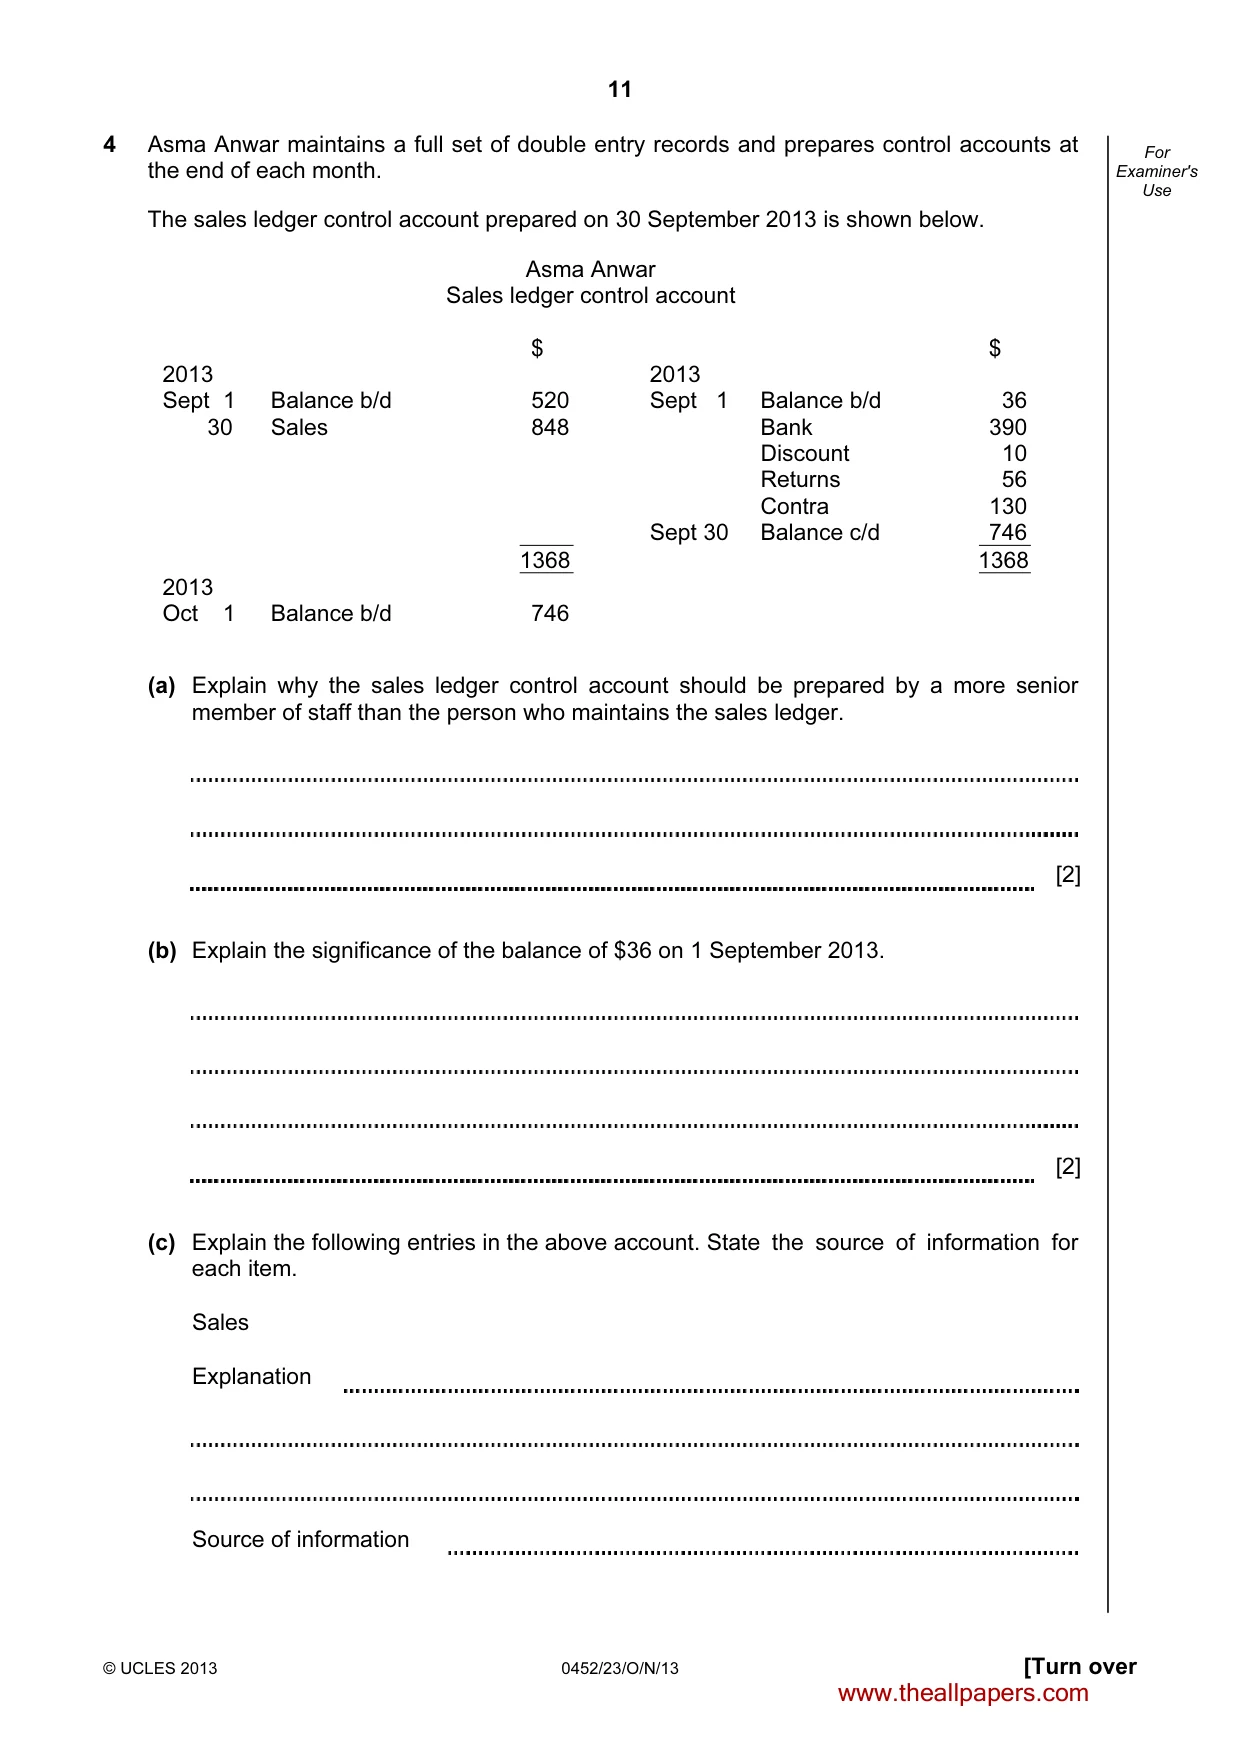
11 © UCLES 2013 0452/23/O/N/13 [Turn over For Examiner's Use 4 Asma Anwar maintains a full set of double entry records and prepares control accounts at the end of each month. The sales ledger control account prepared on 30 September 2013 is shown below. Asma Anwar Sales ledger control account $ $ 2013 2013 Sept 1 Balance b/d 520 Sept 1 Balance b/d 36 30 Sales 848 Bank 390 Discount 10 Returns 56 Contra 130 Sept 30 Balance c/d 746 1368 1368 2013 Oct 1 Balance b/d 746 (a) Explain why the sales ledger control account should be prepared by a more senior member of staff than the person who maintains the sales ledger. [2] (b) Explain the significance of the balance of $36 on 1 September 2013. [2] (c) Explain the following entries in the above account. State the source of information for each item. Sales Explanation Source of information www.theallpapers.com
Question paper, page 12
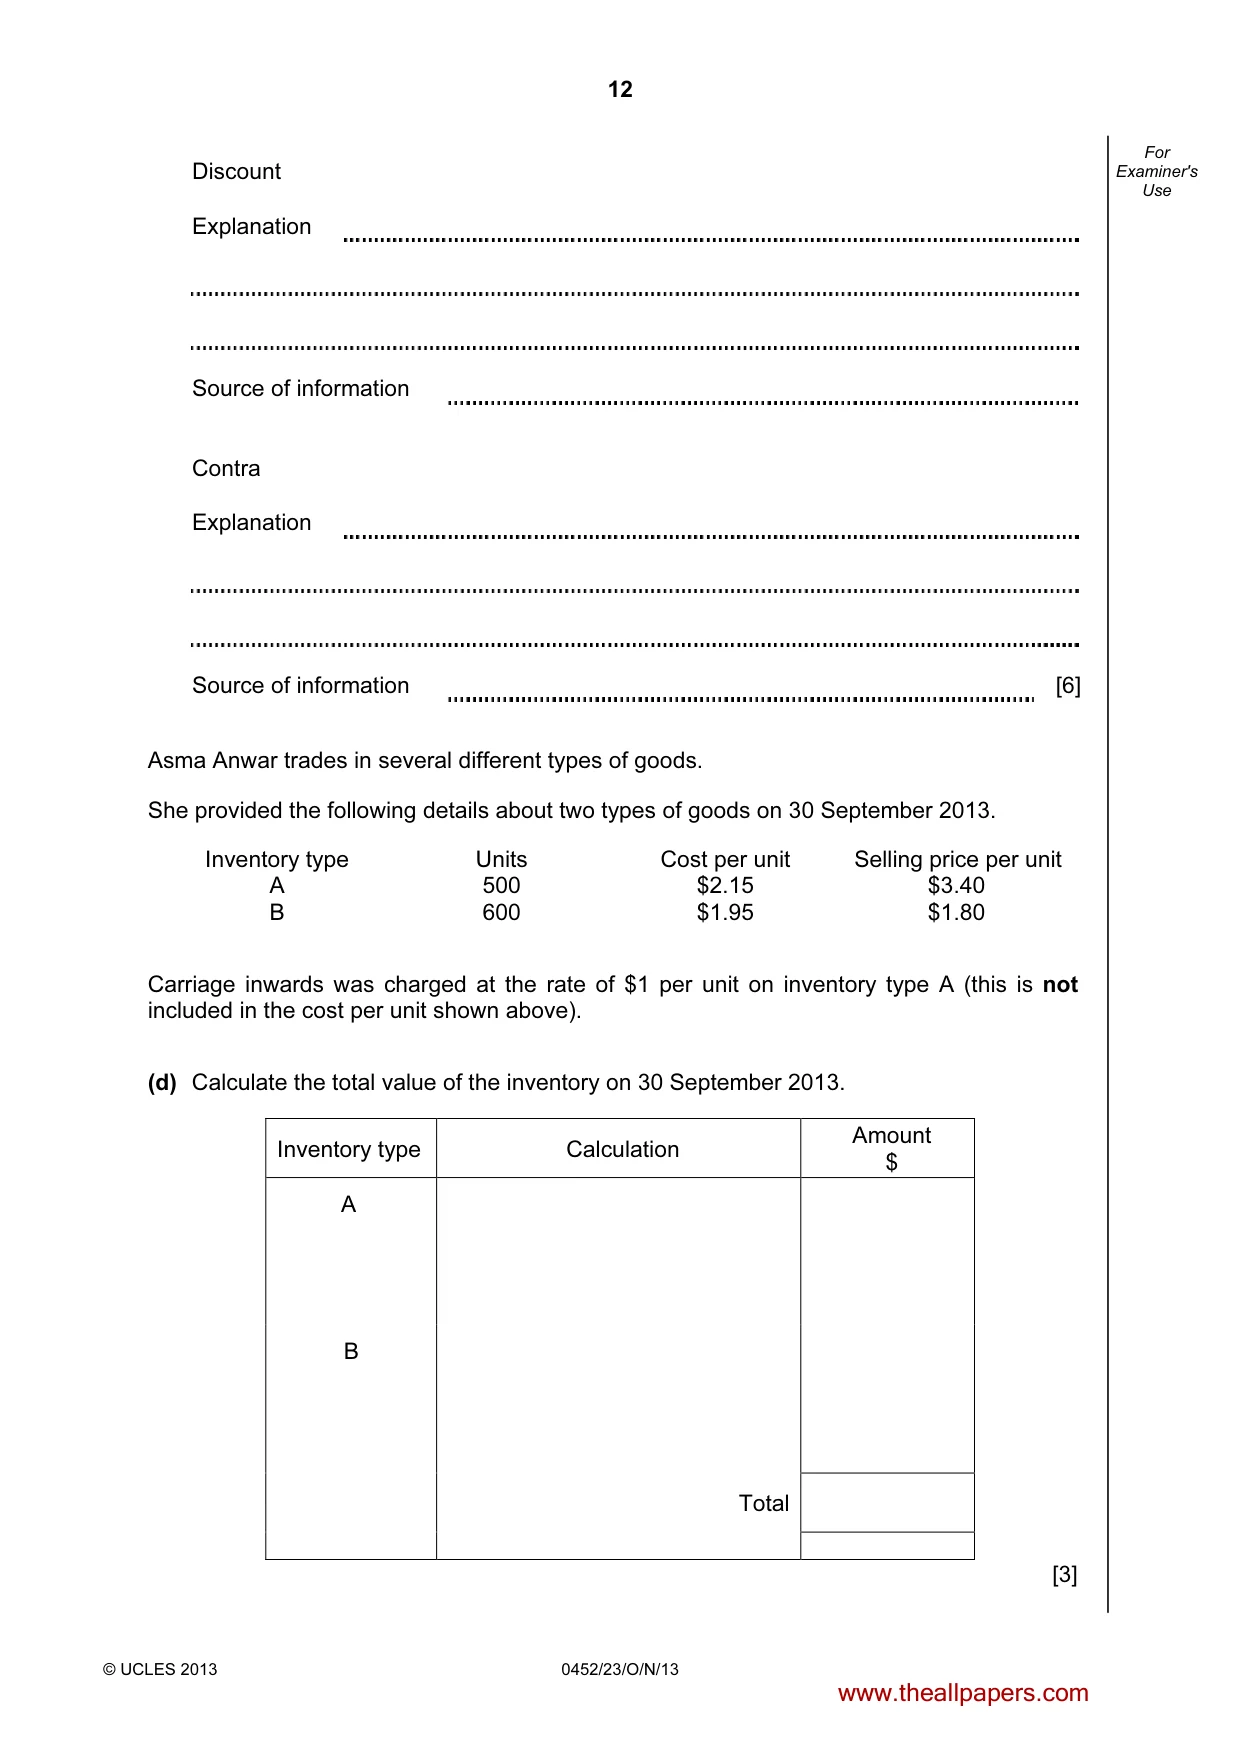
12 © UCLES 2013 0452/23/O/N/13 For Examiner's Use Discount Explanation Source of information Contra Explanation Source of information [6] Asma Anwar trades in several different types of goods. She provided the following details about two types of goods on 30 September 2013. Inventory type Units Cost per unit Selling price per unit A 500 $2.15 $3.40 B 600 $1.95 $1.80 Carriage inwards was charged at the rate of $1 per unit on inventory type A (this is not included in the cost per unit shown above). (d) Calculate the total value of the inventory on 30 September 2013. Inventory type Calculation Amount $ A B Total [3] www.theallpapers.com
Question paper, page 13
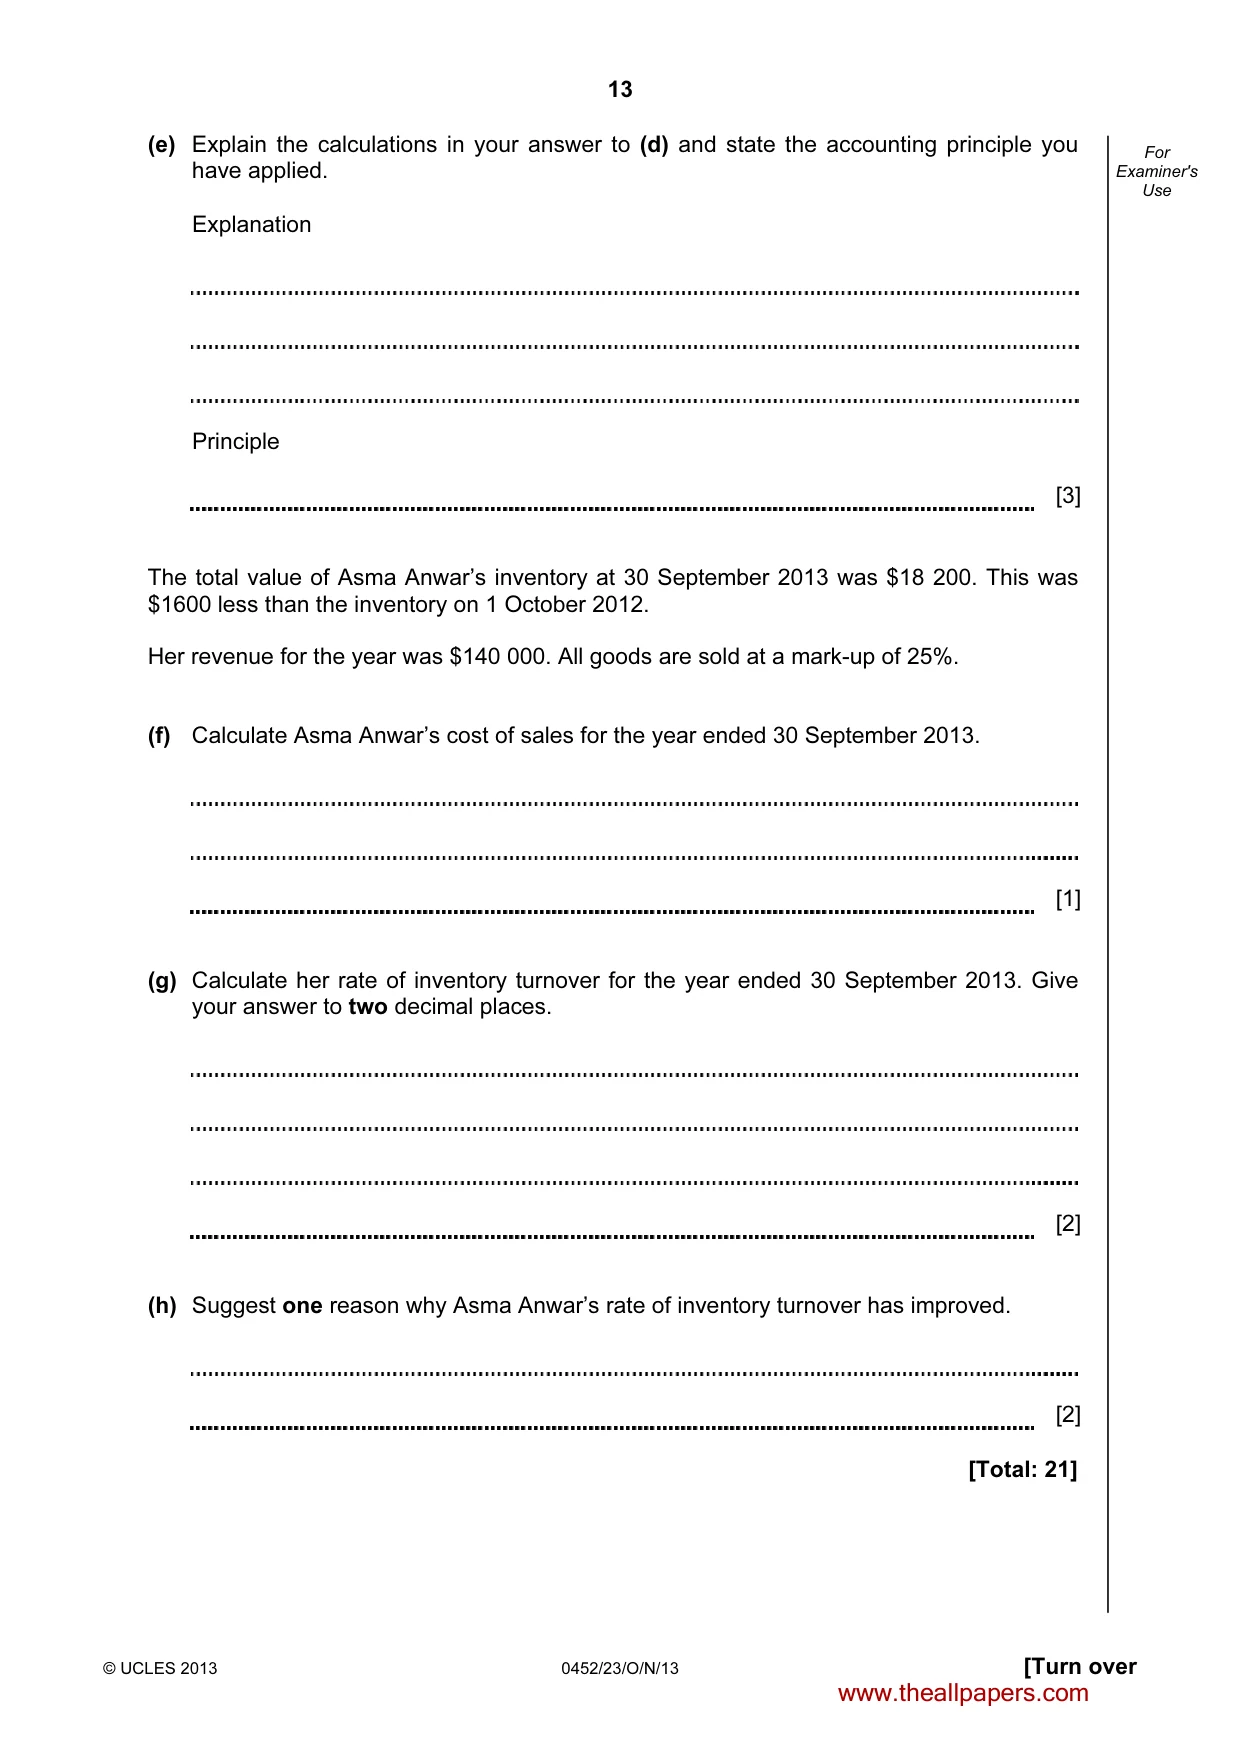
13 © UCLES 2013 0452/23/O/N/13 [Turn over For Examiner's Use (e) Explain the calculations in your answer to (d) and state the accounting principle you have applied. Explanation Principle [3] The total value of Asma Anwar’s inventory at 30 September 2013 was $18 200. This was $1600 less than the inventory on 1 October 2012. Her revenue for the year was $140 000. All goods are sold at a mark-up of 25%. (f) Calculate Asma Anwar’s cost of sales for the year ended 30 September 2013. [1] (g) Calculate her rate of inventory turnover for the year ended 30 September 2013. Give your answer to two decimal places. [2] (h) Suggest one reason why Asma Anwar’s rate of inventory turnover has improved. [2] [Total: 21] www.theallpapers.com
Question paper, page 14
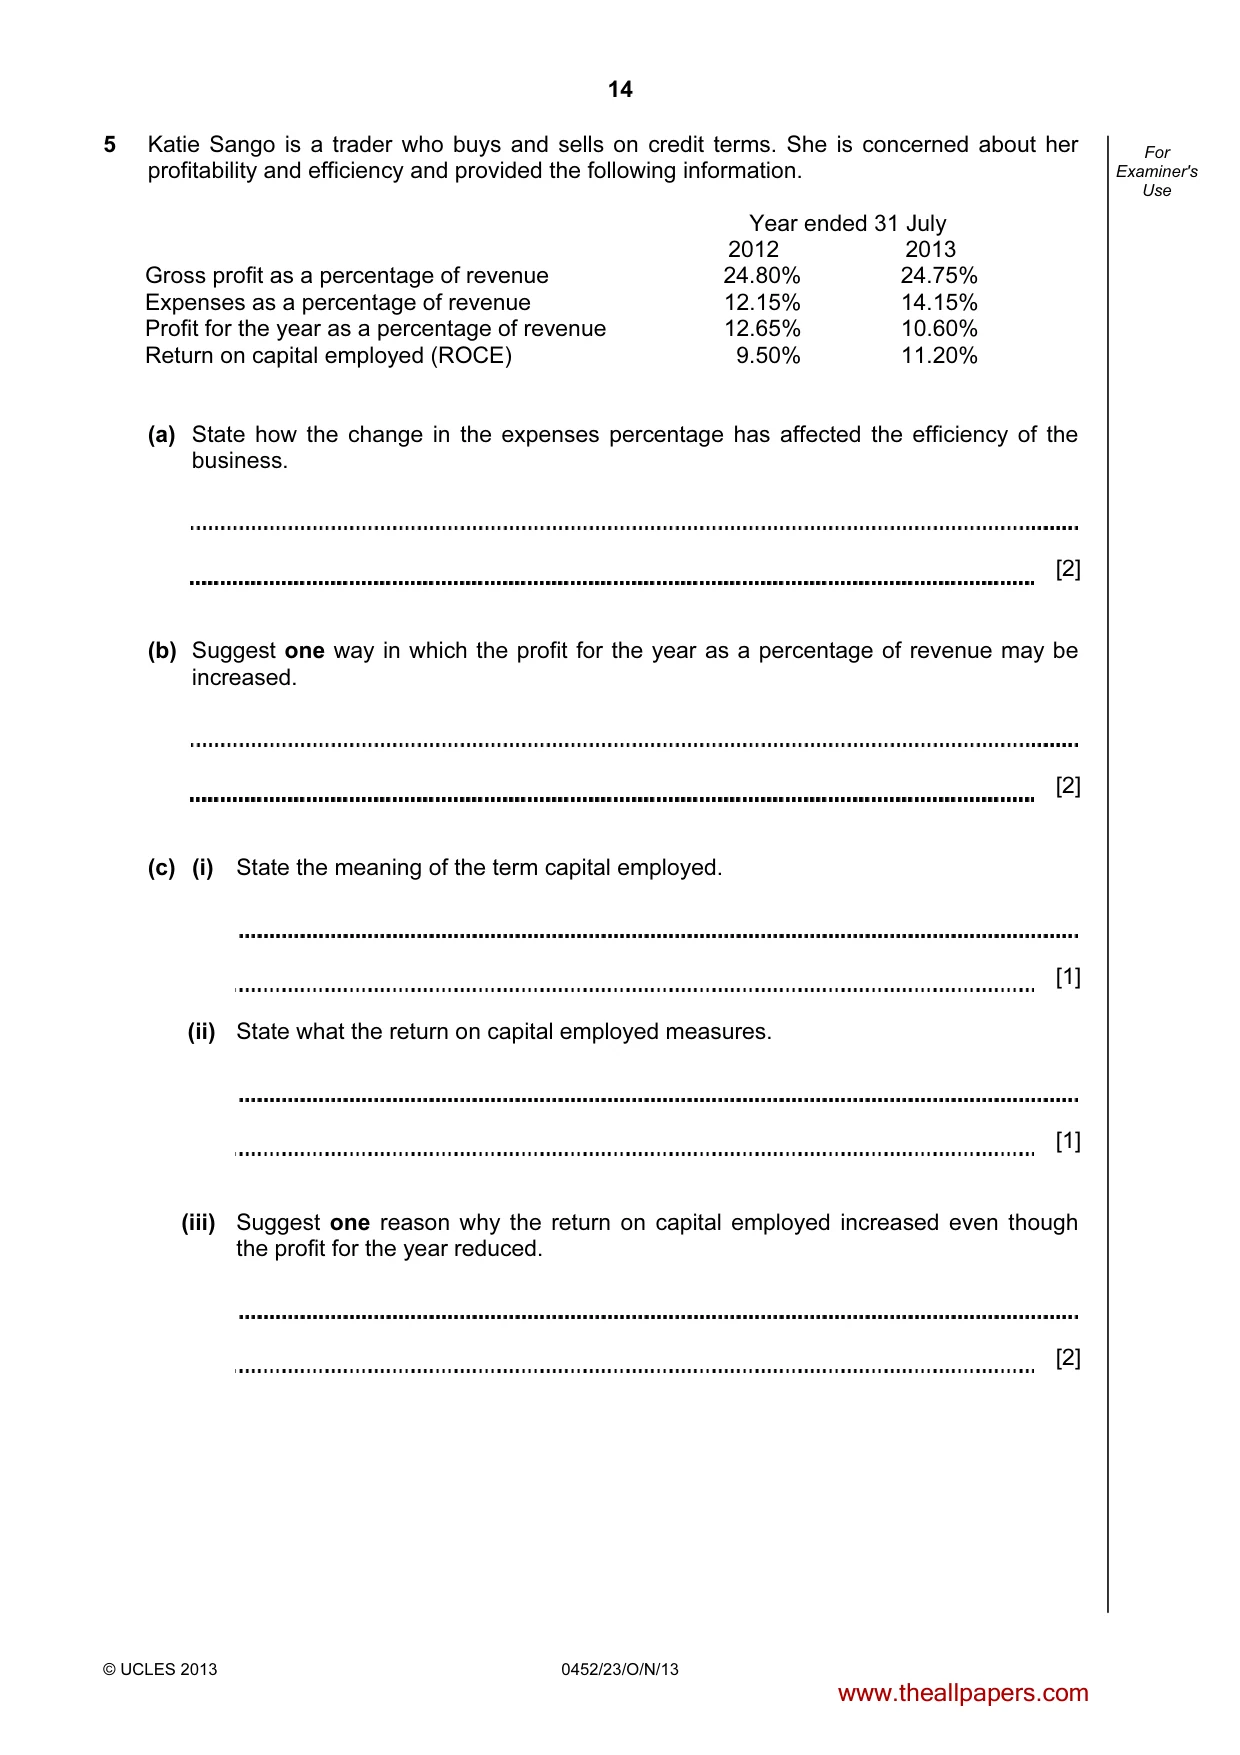
14 © UCLES 2013 0452/23/O/N/13 For Examiner's Use 5 Katie Sango is a trader who buys and sells on credit terms. She is concerned about her profitability and efficiency and provided the following information. Year ended 31 July 2012 2013 Gross profit as a percentage of revenue 24.80% 24.75% Expenses as a percentage of revenue 12.15% 14.15% Profit for the year as a percentage of revenue 12.65% 10.60% Return on capital employed (ROCE) 9.50% 11.20% (a) State how the change in the expenses percentage has affected the efficiency of the business. [2] (b) Suggest one way in which the profit for the year as a percentage of revenue may be increased. [2] (c) (i) State the meaning of the term capital employed. [1] (ii) State what the return on capital employed measures. [1] (iii) Suggest one reason why the return on capital employed increased even though the profit for the year reduced. [2] www.theallpapers.com
Question paper, page 15
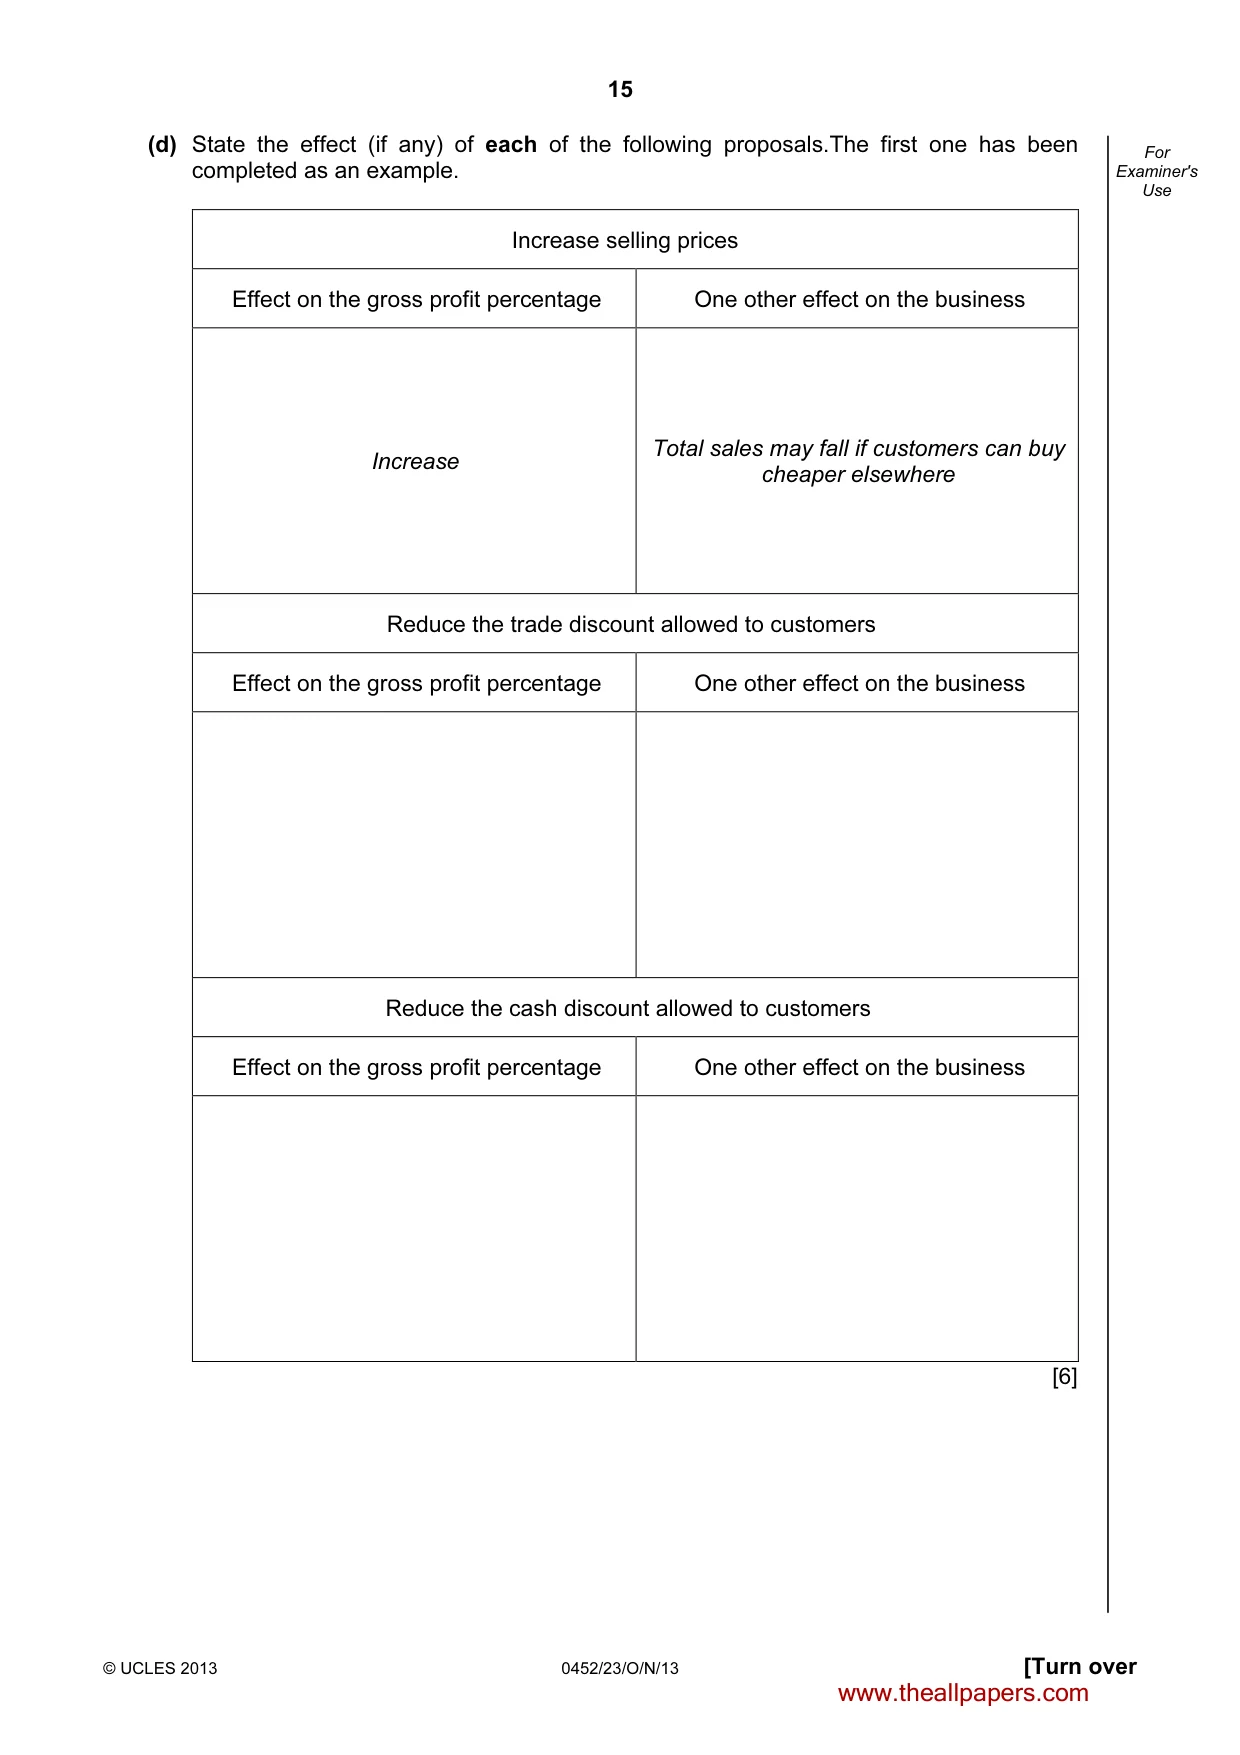
15 © UCLES 2013 0452/23/O/N/13 [Turn over For Examiner's Use (d) State the effect (if any) of each of the following proposals.The first one has been completed as an example. Increase selling prices Effect on the gross profit percentage One other effect on the business Increase Total sales may fall if customers can buy cheaper elsewhere Reduce the trade discount allowed to customers Effect on the gross profit percentage One other effect on the business Reduce the cash discount allowed to customers Effect on the gross profit percentage One other effect on the business [6] www.theallpapers.com
Question paper, page 16
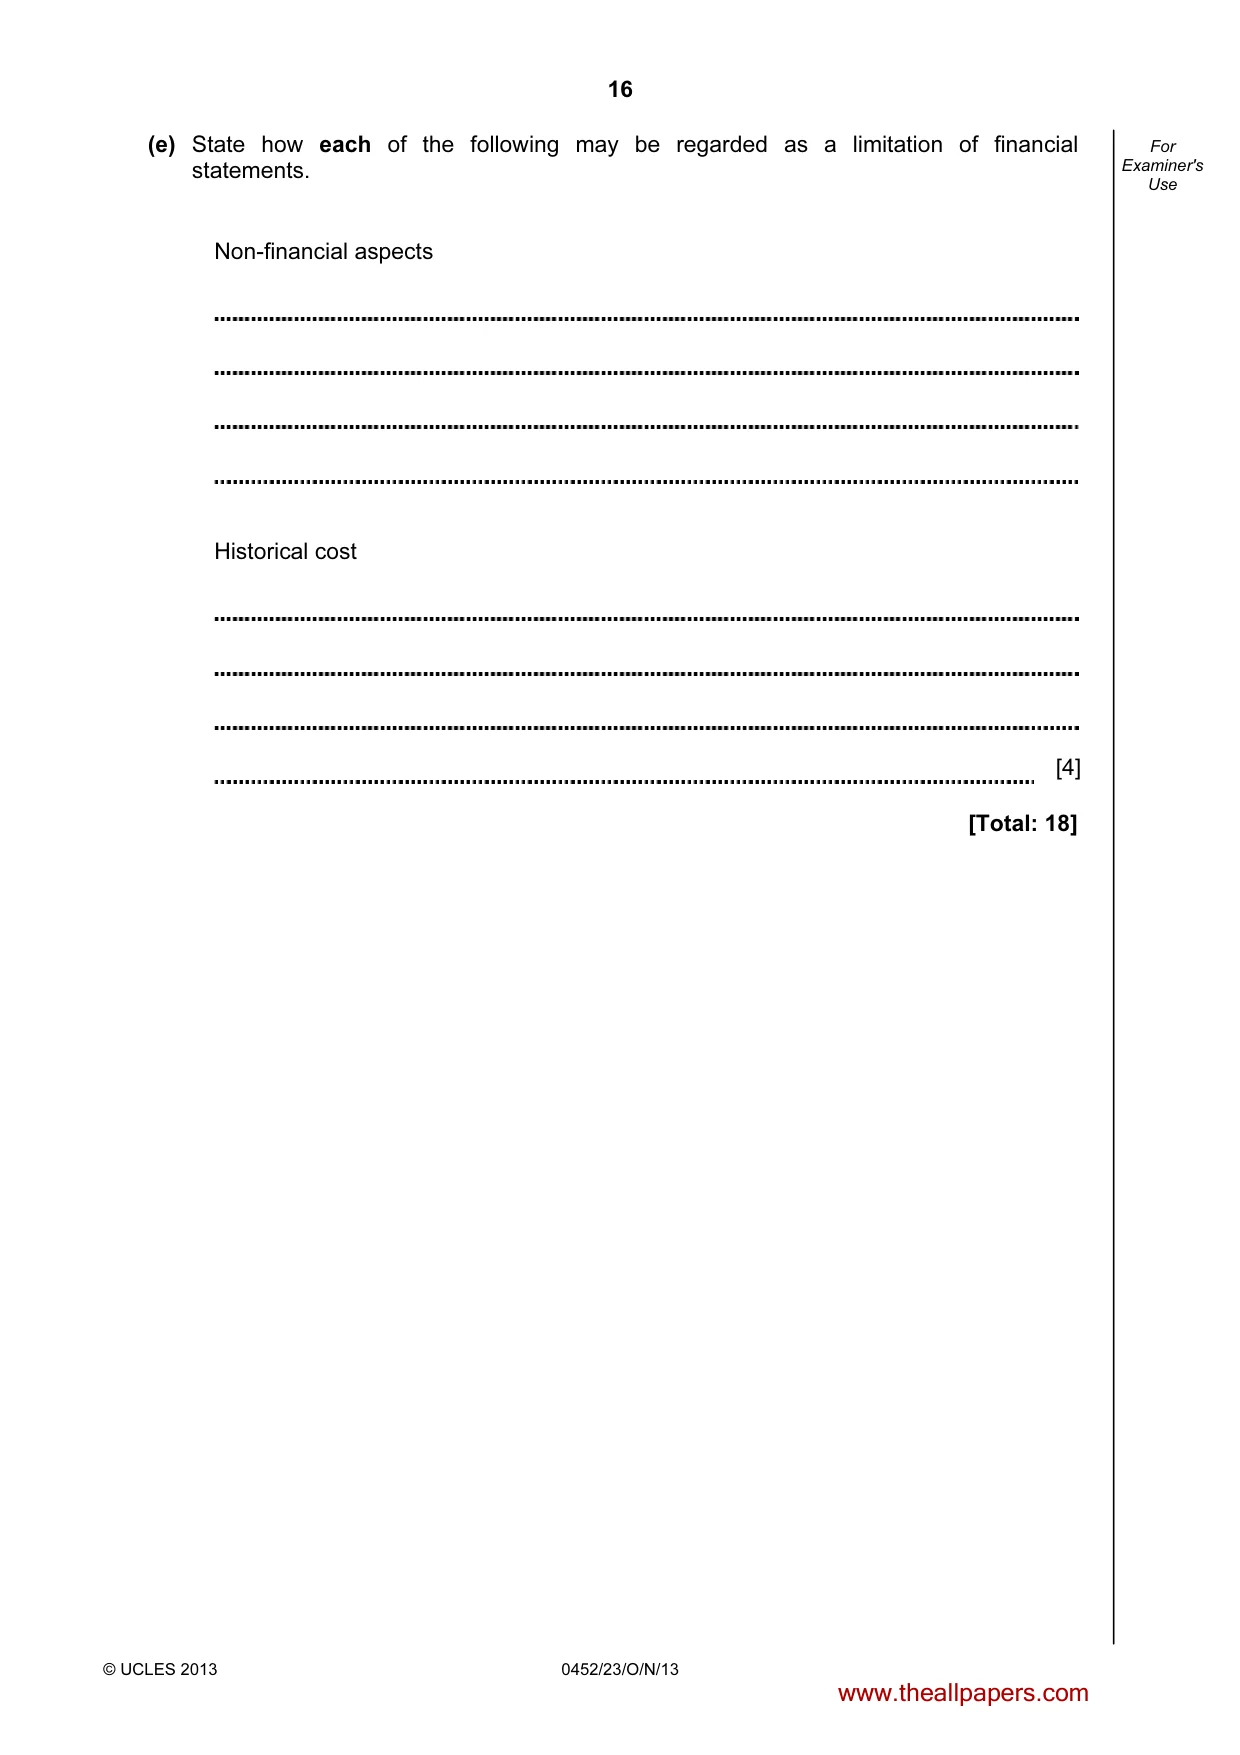
16 © UCLES 2013 0452/23/O/N/13 For Examiner's Use (e) State how each of the following may be regarded as a limitation of financial statements. Non-financial aspects Historical cost [4] [Total: 18] www.theallpapers.com
Question paper, page 17
17 © UCLES 2013 0452/23/O/N/13 [Turn over Question 6 is on the next page. www.theallpapers.com
Question paper, page 18
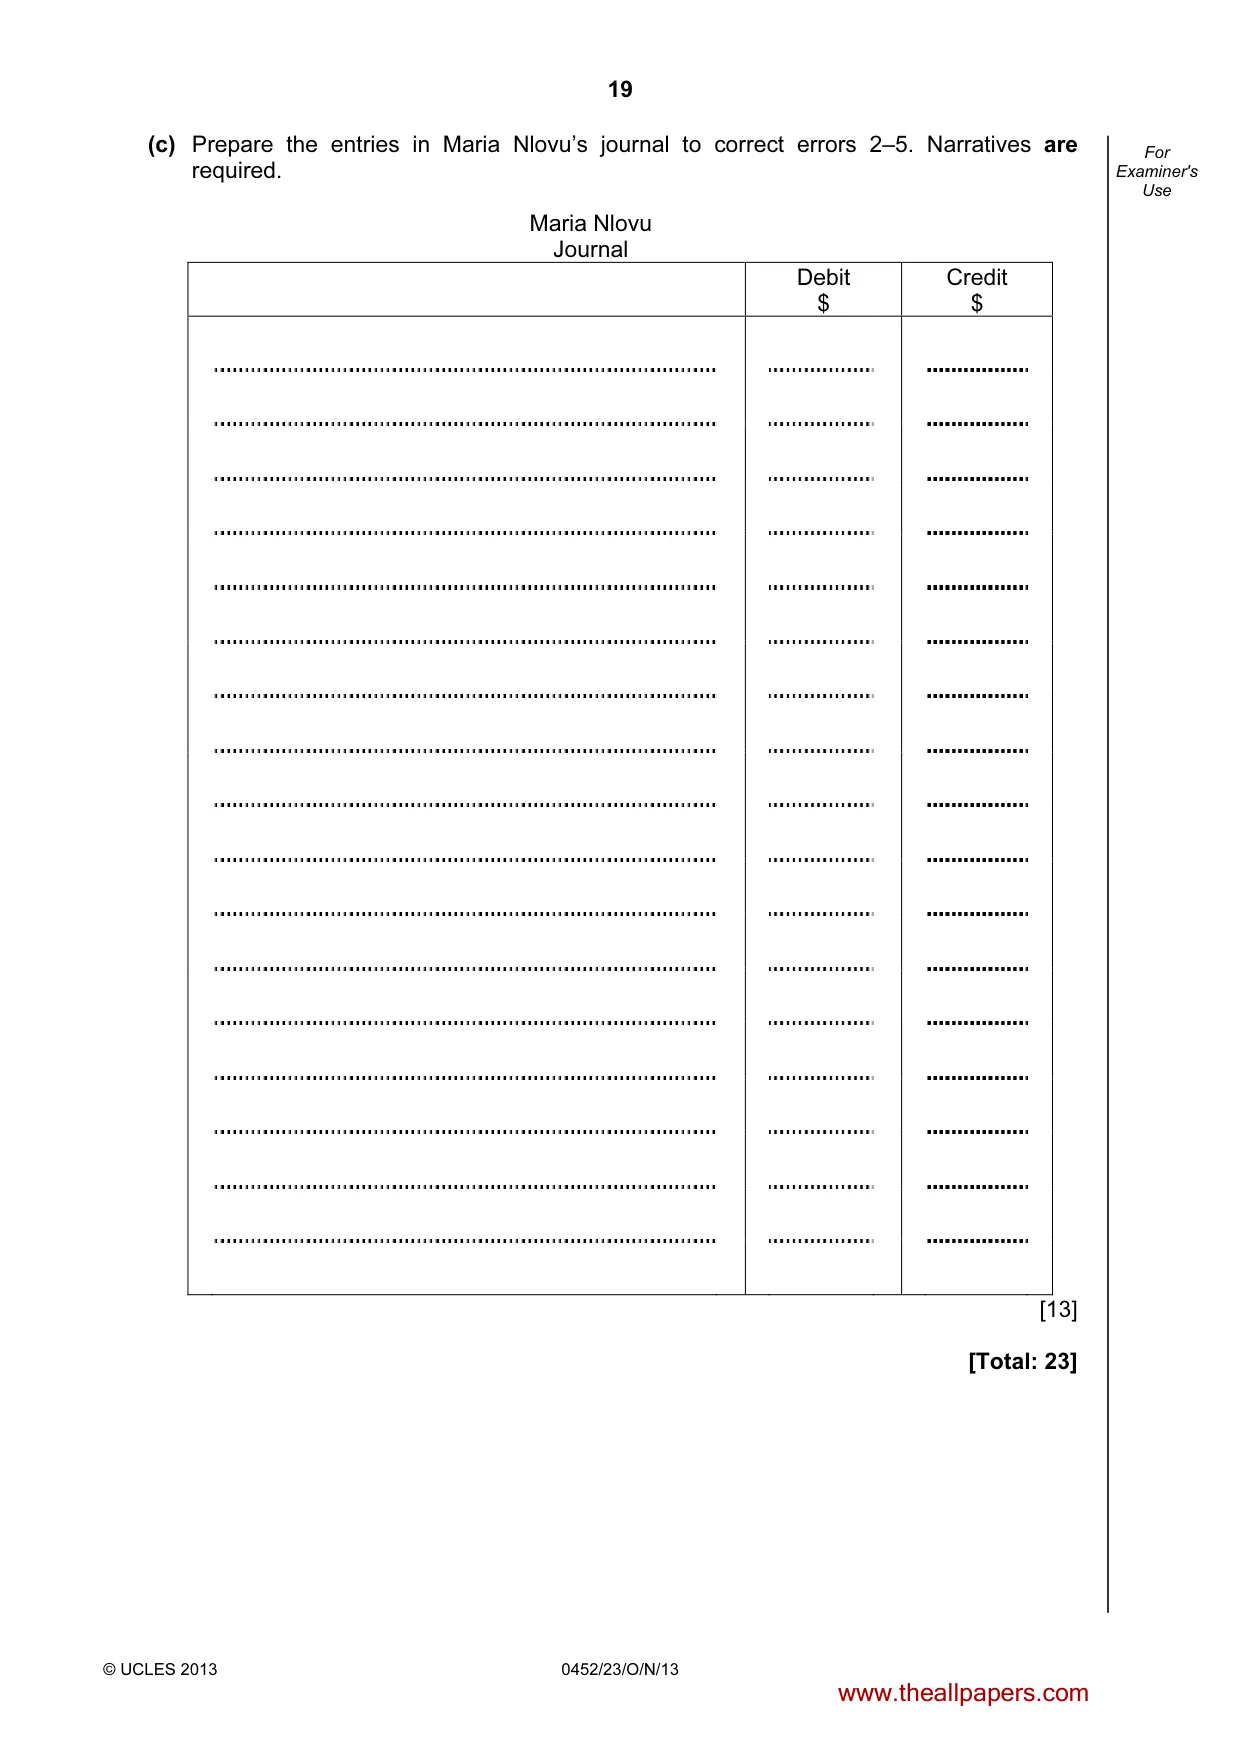
18 © UCLES 2013 0452/23/O/N/13 For Examiner's Use 6 Maria Nlovu is a trader. Her financial year ends on 31 August. The trial balance prepared on 31 August 2013 failed to agree and the difference was entered in a suspense account. Maria Nlovu then prepared a draft income statement. The following errors were later discovered. 1 The purchases account had been overcast by $1000. 2 Carriage inwards, $111, had been debited to the carriage outwards account. 3 Repairs to motor vehicles, $315, had been included in the motor vehicles account. 4 Rent paid, $350, had been credited to the rent received account. 5 Goods, $45, returned to Helmut, a supplier, had been entered on the wrong side of his account. (a) Complete the table below to show what effect each of the above errors had on the profit for the year ended 31 August 2013. The first one has been completed as an example. Effect on profit for the year Error Overstated $ Understated $ No effect 1 1000 2 3 4 5 [8] (b) Name the type of error made in: Error number 2 Error number 3. [2] www.theallpapers.com
Question paper, page 19
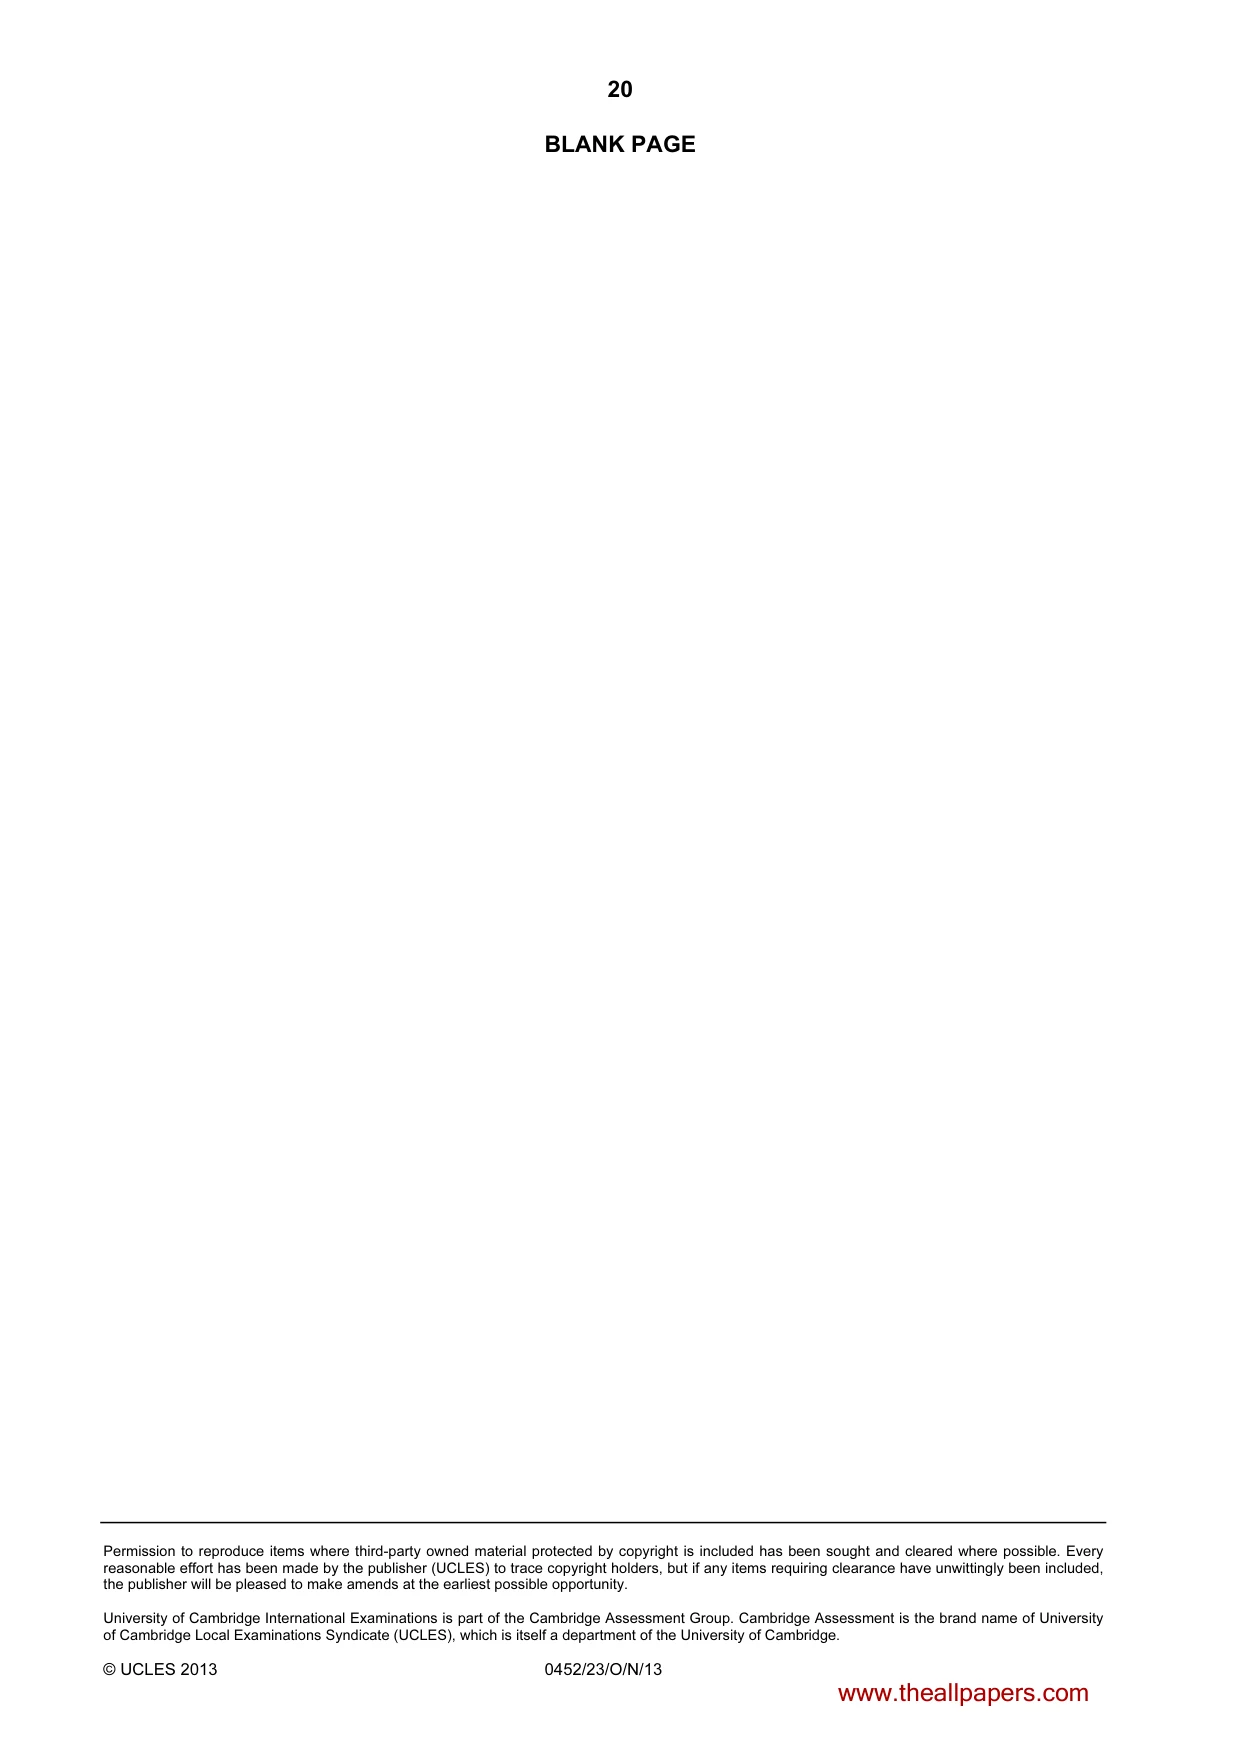
19 © UCLES 2013 0452/23/O/N/13 For Examiner's Use (c) Prepare the entries in Maria Nlovu’s journal to correct errors 2–5. Narratives are required. Maria Nlovu Journal Debit $ Credit $ [13] [Total: 23] www.theallpapers.com
Question paper, page 20
20 Permission to reproduce items where third-party owned material protected by copyright is included has been sought and cleared where possible. Every reasonable effort has been made by the publisher (UCLES) to trace copyright holders, but if any items requiring clearance have unwittingly been included, the publisher will be pleased to make amends at the earliest possible opportunity. University of Cambridge International Examinations is part of the Cambridge Assessment Group. Cambridge Assessment is the brand name of University of Cambridge Local Examinations Syndicate (UCLES), which is itself a department of the University of Cambridge. © UCLES 2013 0452/23/O/N/13 BLANK PAGE www.theallpapers.com
Mark scheme, page 1
CAMBRIDGE INTERNATIONAL EXAMINATIONS International General Certificate of Secondary Education MARK SCHEME for the October/November 2013 series 0452 ACCOUNTING 0452/23 Paper 2, maximum raw mark 120 This mark scheme is published as an aid to teachers and candidates, to indicate the requirements of the examination. It shows the basis on which Examiners were instructed to award marks. It does not indicate the details of the discussions that took place at an Examiners’ meeting before marking began, which would have considered the acceptability of alternative answers. Mark schemes should be read in conjunction with the question paper and the Principal Examiner Report for Teachers. Cambridge will not enter into discussions about these mark schemes. Cambridge is publishing the mark schemes for the October/November 2013 series for most IGCSE, GCE Advanced Level and Advanced Subsidiary Level components and some Ordinary Level components.
Mark scheme, page 2
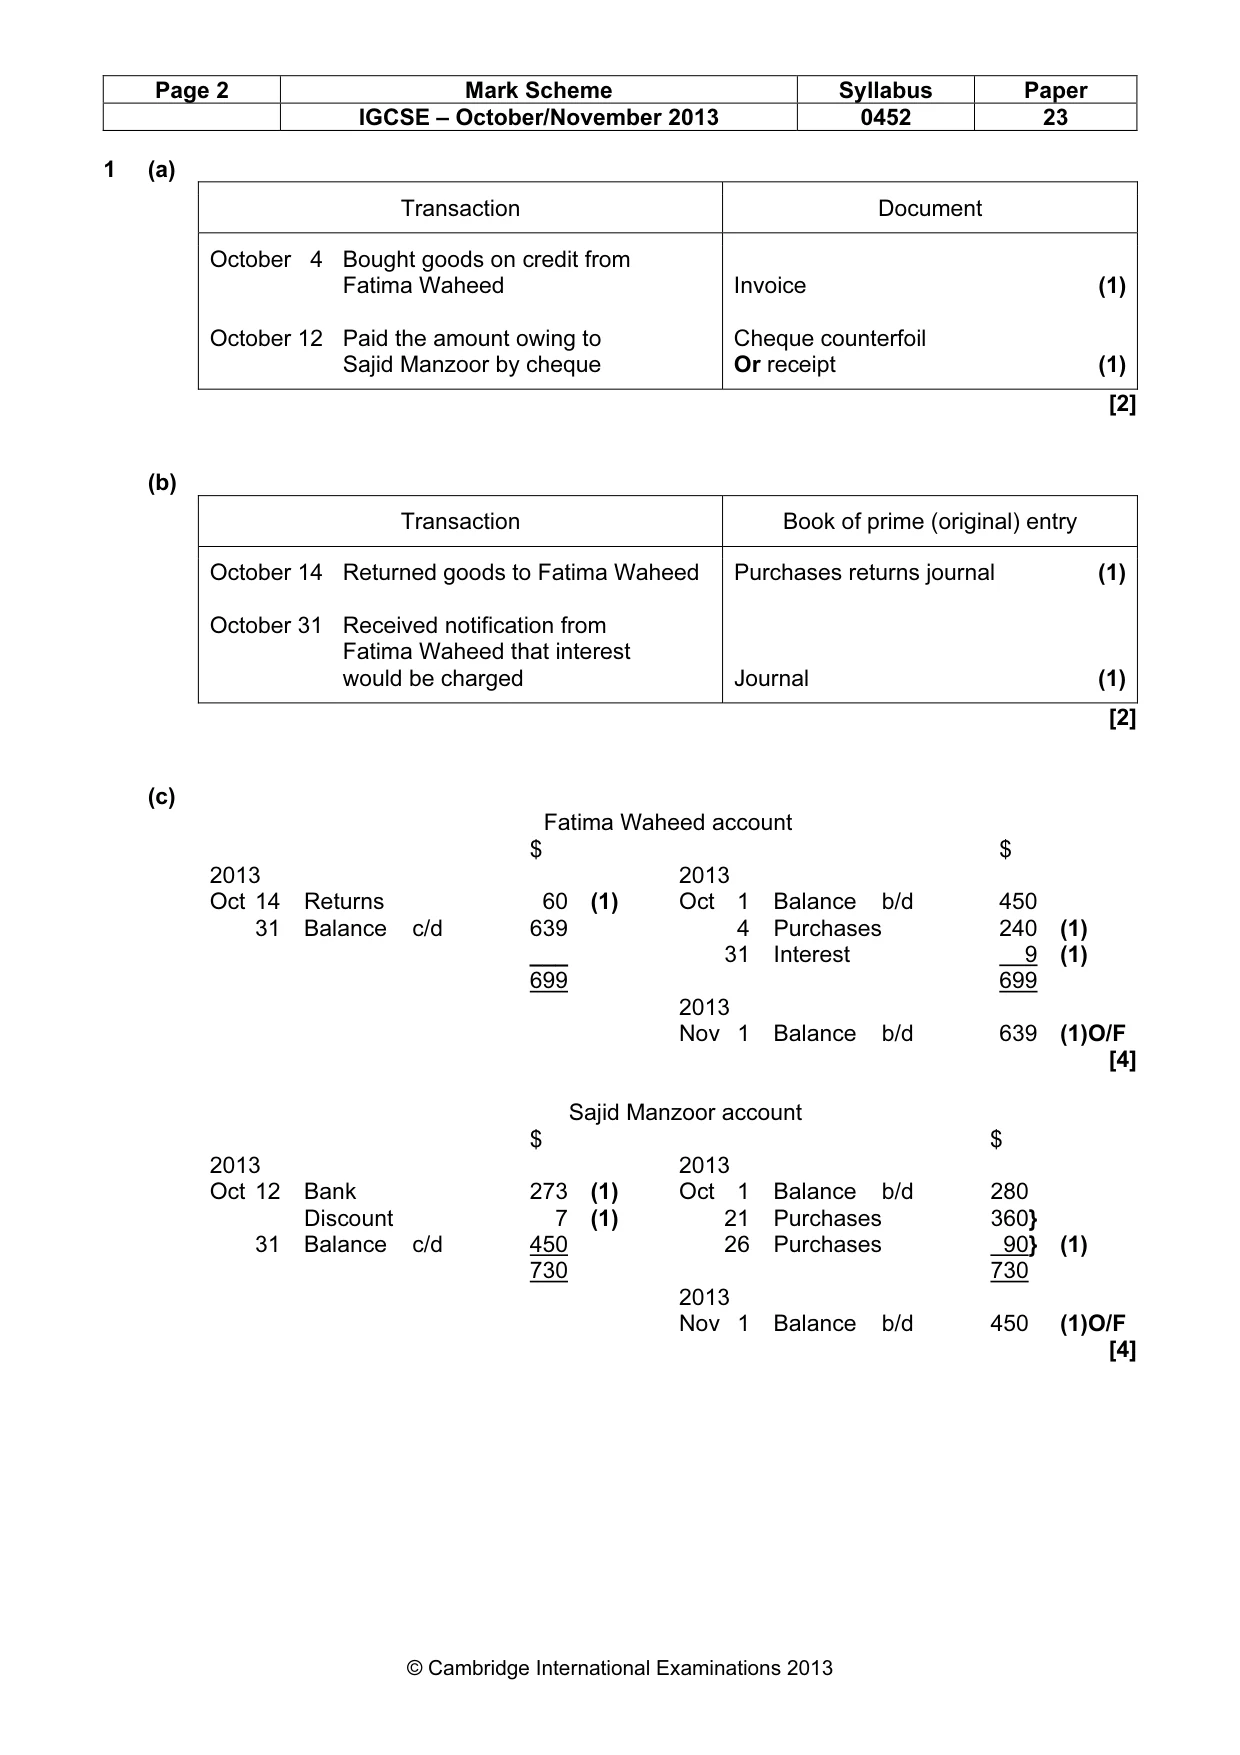
Page 2 Mark Scheme Syllabus Paper IGCSE – October/November 2013 0452 23 © Cambridge International Examinations 2013 1 (a) Transaction Document October 4 Bought goods on credit from Fatima Waheed October 12 Paid the amount owing to Sajid Manzoor by cheque Invoice (1) Cheque counterfoil Or receipt (1) [2] (b) Transaction Book of prime (original) entry October 14 Returned goods to Fatima Waheed October 31 Received notification from Fatima Waheed that interest would be charged Purchases returns journal (1) Journal (1) [2] (c) Fatima Waheed account $ $ 2013 2013 Oct 14 Returns 60 (1) Oct 1 Balance b/d 450 31 Balance c/d 639 4 Purchases 240 (1) ___ 31 Interest 9 (1) 699 699 2013 Nov 1 Balance b/d 639 (1)O/F [4] Sajid Manzoor account $ $ 2013 2013 Oct 12 Bank 273 (1) Oct 1 Balance b/d 280 Discount 7 (1) 21 Purchases 360} 31 Balance c/d 450 26 Purchases 90} (1) 730 730 2013 Nov 1 Balance b/d 450 (1)O/F [4]
Mark scheme, page 3
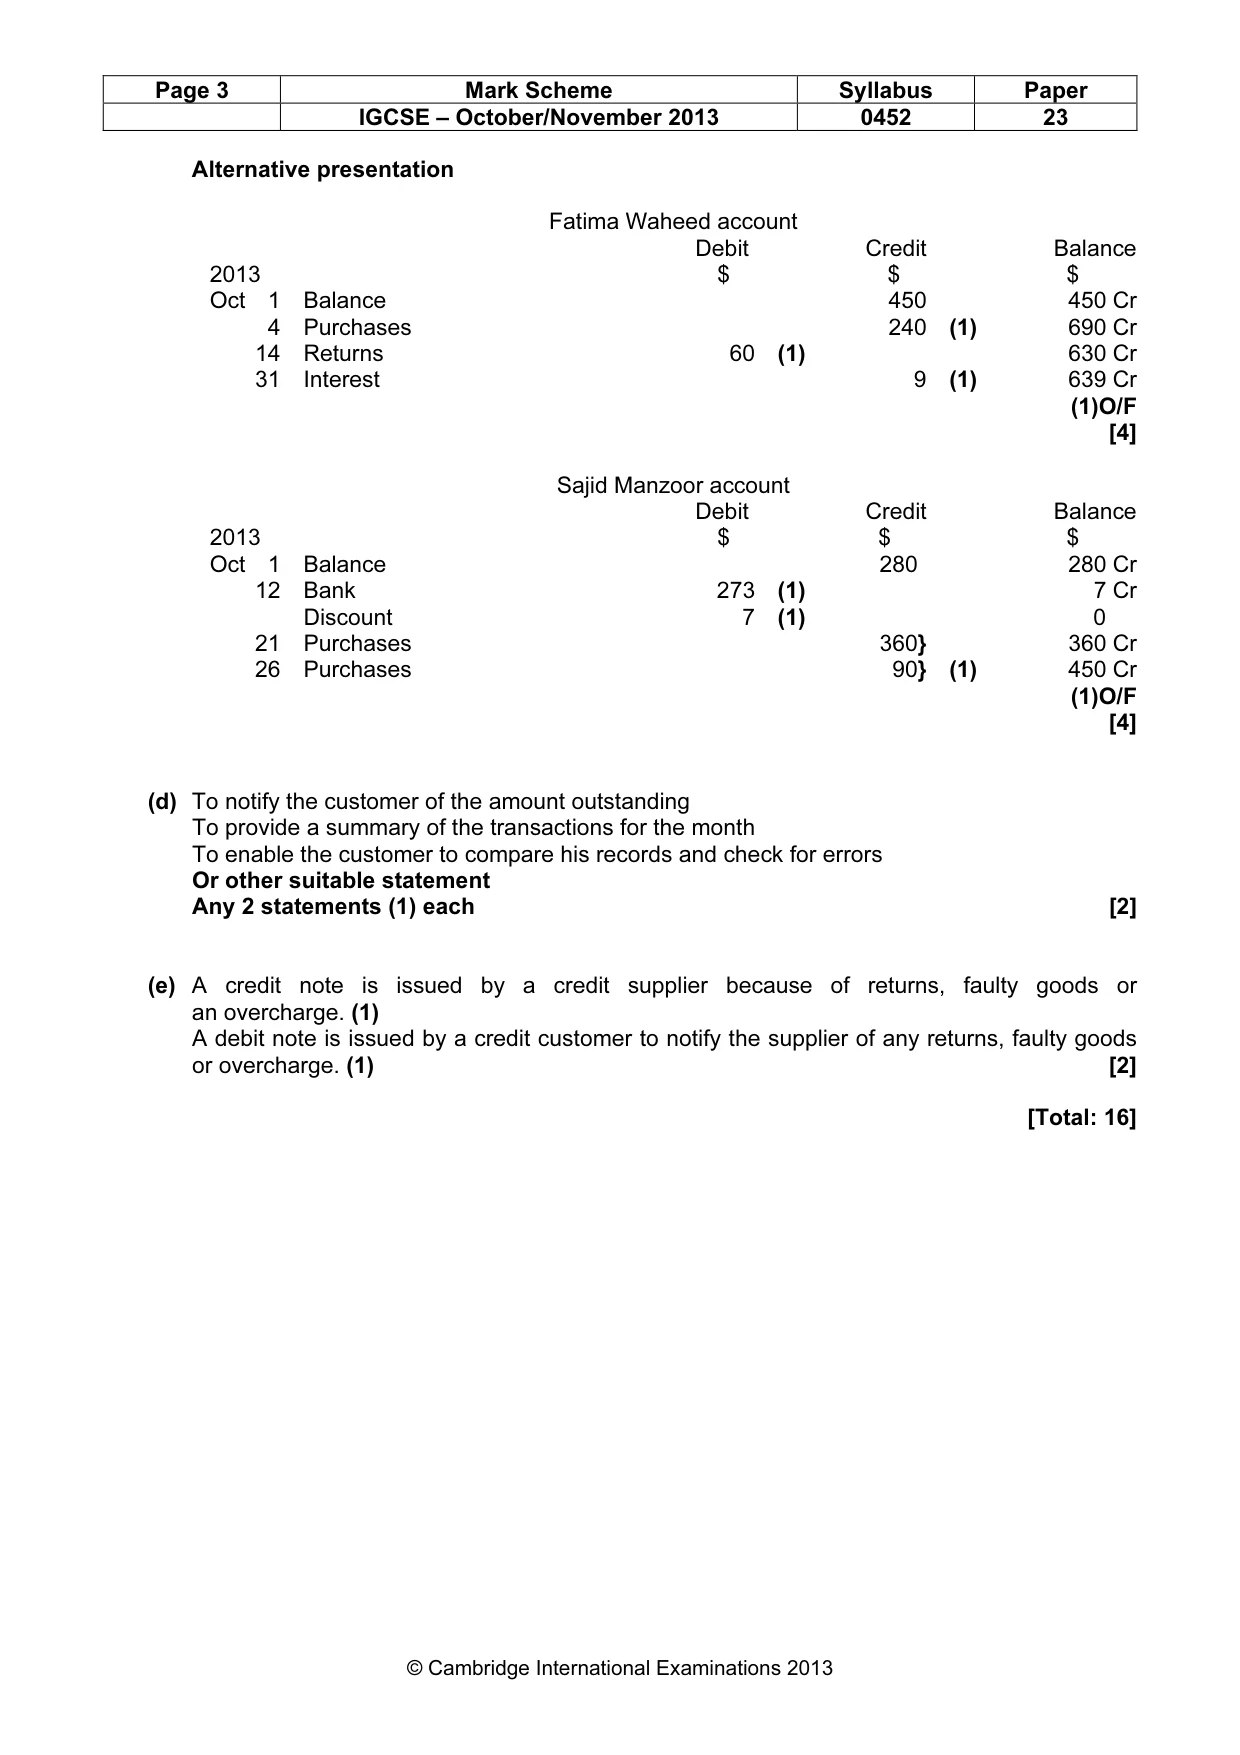
Page 3 Mark Scheme Syllabus Paper IGCSE – October/November 2013 0452 23 © Cambridge International Examinations 2013 Alternative presentation Fatima Waheed account Debit Credit Balance 2013 $ $ $ Oct 1 Balance 450 450 Cr 4 Purchases 240 (1) 690 Cr 14 Returns 60 (1) 630 Cr 31 Interest 9 (1) 639 Cr (1)O/F [4] Sajid Manzoor account Debit Credit Balance 2013 $ $ $ Oct 1 Balance 280 280 Cr 12 Bank 273 (1) 7 Cr Discount 7 (1) 0 21 Purchases 360} 360 Cr 26 Purchases 90} (1) 450 Cr (1)O/F [4] (d) To notify the customer of the amount outstanding To provide a summary of the transactions for the month To enable the customer to compare his records and check for errors Or other suitable statement Any 2 statements (1) each [2] (e) A credit note is issued by a credit supplier because of returns, faulty goods or an overcharge. (1) A debit note is issued by a credit customer to notify the supplier of any returns, faulty goods or overcharge. (1) [2] [Total: 16]
Mark scheme, page 4
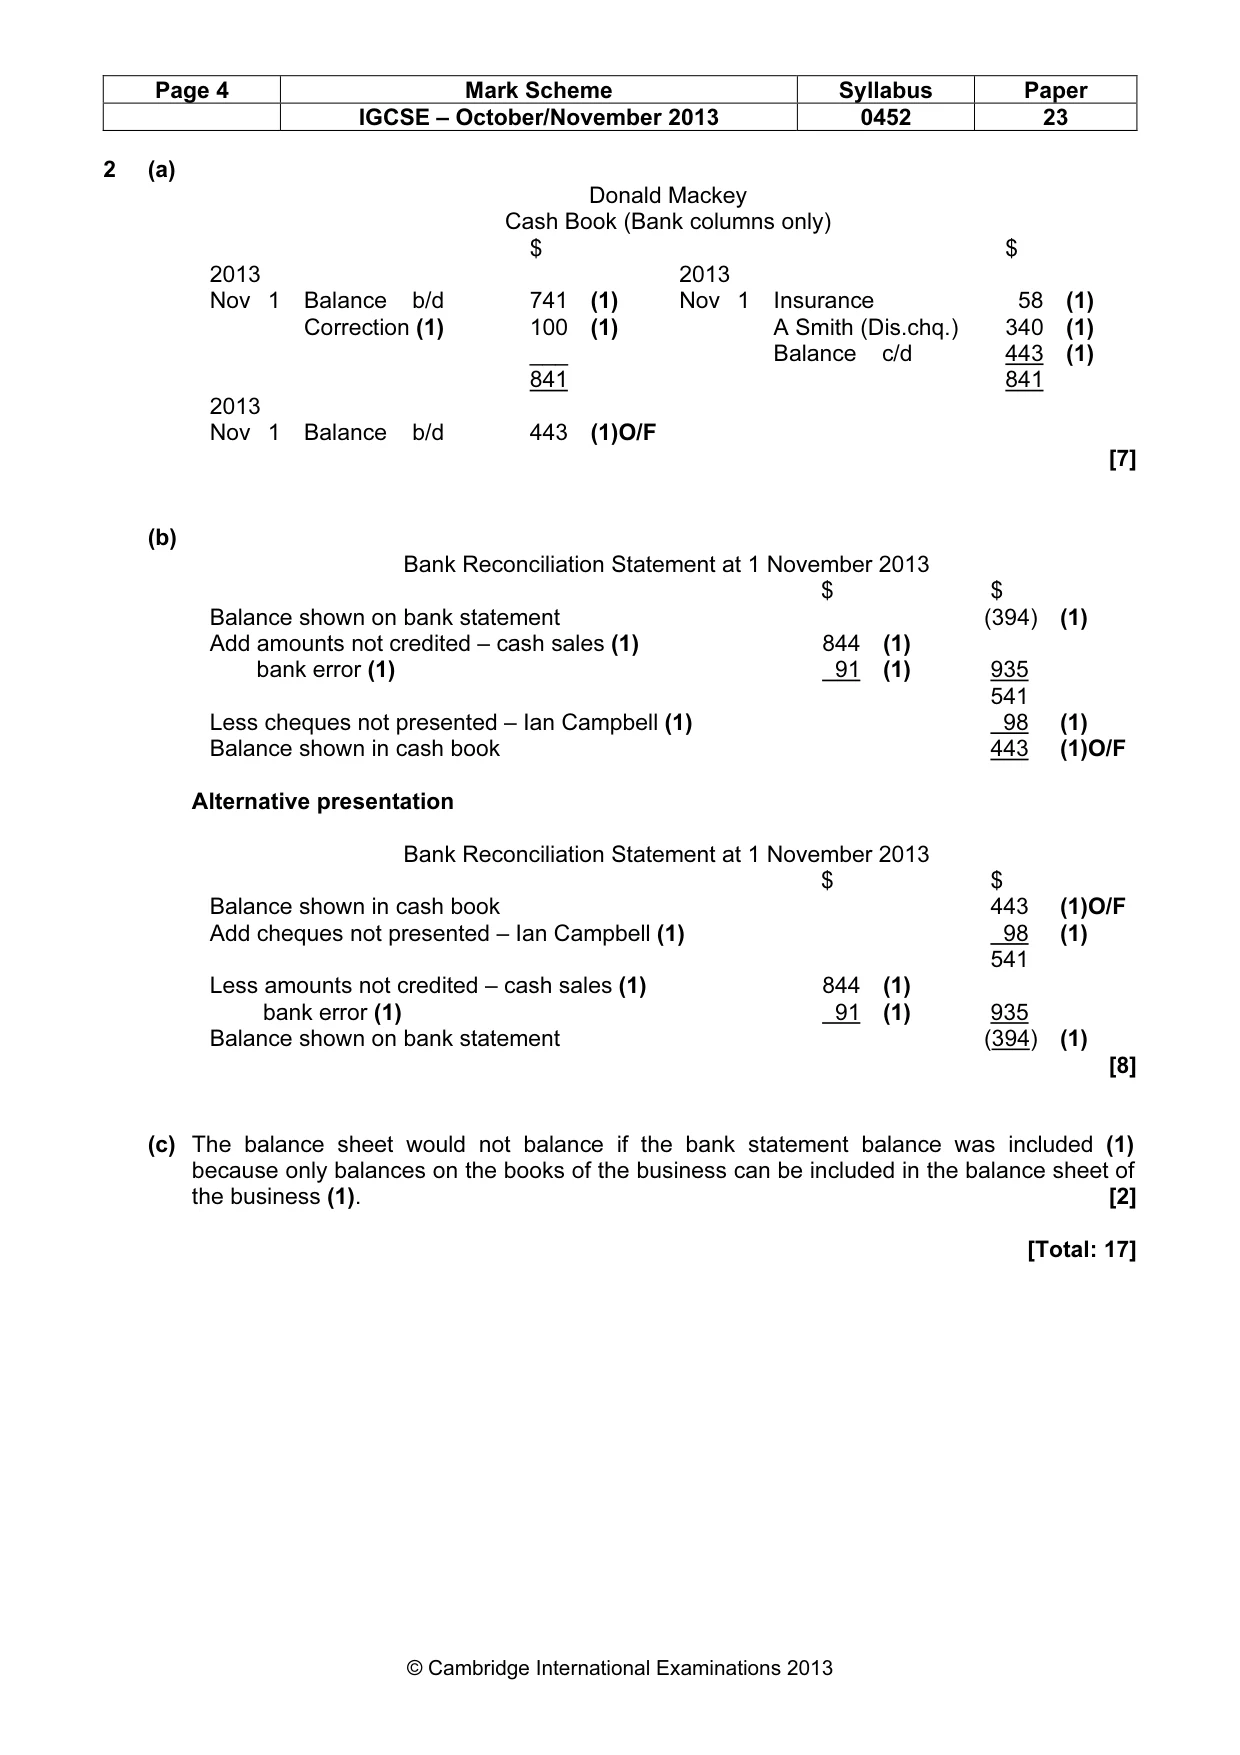
Page 4 Mark Scheme Syllabus Paper IGCSE – October/November 2013 0452 23 © Cambridge International Examinations 2013 2 (a) Donald Mackey Cash Book (Bank columns only) $ $ 2013 2013 Nov 1 Balance b/d 741 (1) Nov 1 Insurance 58 (1) Correction (1) 100 (1) A Smith (Dis.chq.) 340 (1) ___ Balance c/d 443 (1) 841 841 2013 Nov 1 Balance b/d 443 (1)O/F [7] (b) Bank Reconciliation Statement at 1 November 2013 $ $ Balance shown on bank statement (394) (1) Add amounts not credited – cash sales (1) 844 (1) bank error (1) 91 (1) 935 541 Less cheques not presented – Ian Campbell (1) 98 (1) Balance shown in cash book 443 (1)O/F Alternative presentation Bank Reconciliation Statement at 1 November 2013 $ $ Balance shown in cash book 443 (1)O/F Add cheques not presented – Ian Campbell (1) 98 (1) 541 Less amounts not credited – cash sales (1) 844 (1) bank error (1) 91 (1) 935 Balance shown on bank statement (394) (1) [8] (c) The balance sheet would not balance if the bank statement balance was included (1) because only balances on the books of the business can be included in the balance sheet of the business (1). [2] [Total: 17]
Mark scheme, page 5
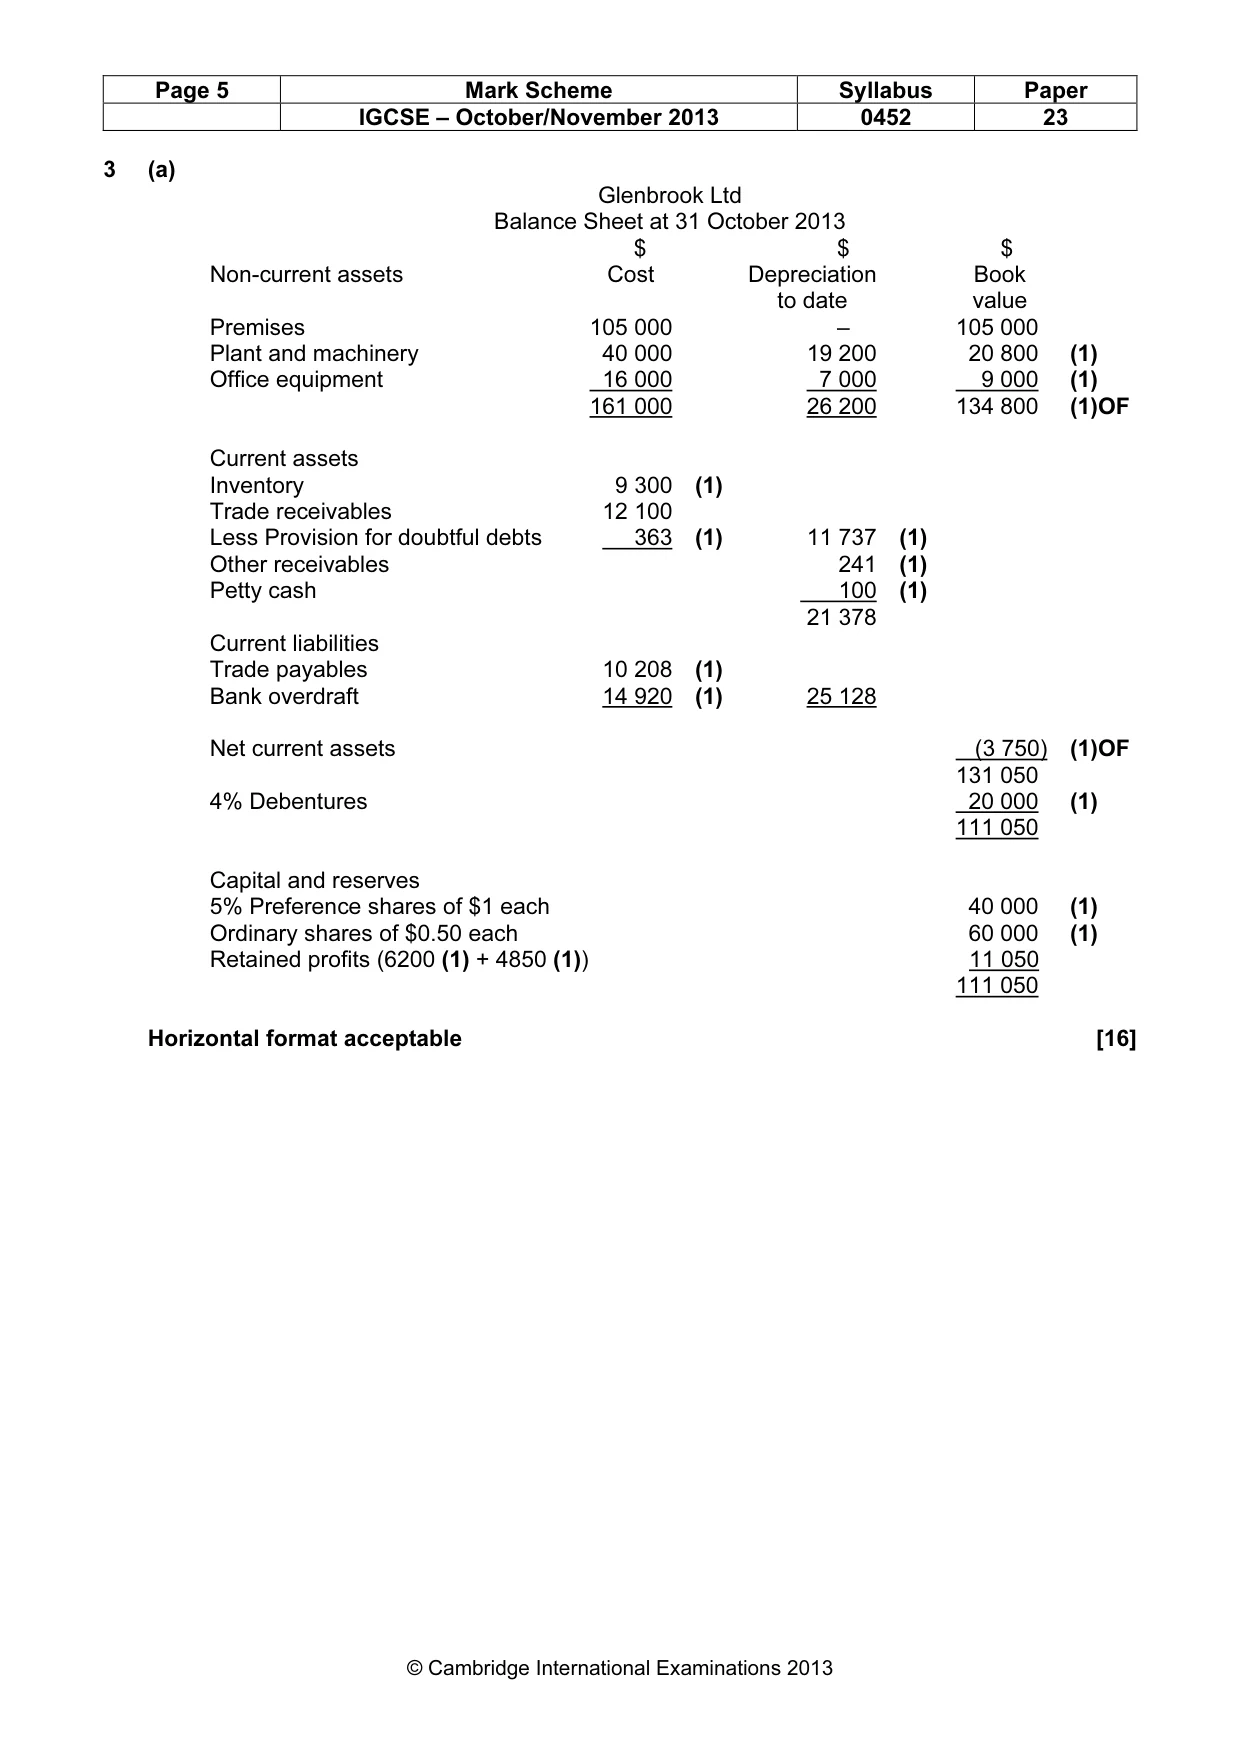
Page 5 Mark Scheme Syllabus Paper IGCSE – October/November 2013 0452 23 © Cambridge International Examinations 2013 3 (a) Glenbrook Ltd Balance Sheet at 31 October 2013 $ $ $ Non-current assets Cost Depreciation to date Book value Premises 105 000 – 105 000 Plant and machinery 40 000 19 200 20 800 (1) Office equipment 16 000 7 000 9 000 (1) 161 000 26 200 134 800 (1)OF Current assets Inventory 9 300 (1) Trade receivables 12 100 Less Provision for doubtful debts 363 (1) 11 737 (1) Other receivables 241 (1) Petty cash 100 (1) 21 378 Current liabilities Trade payables 10 208 (1) Bank overdraft 14 920 (1) 25 128 Net current assets (3 750) (1)OF 131 050 4% Debentures 20 000 (1) 111 050 Capital and reserves 5% Preference shares of $1 each 40 000 (1) Ordinary shares of $0.50 each 60 000 (1) Retained profits (6200 (1) + 4850 (1)) 11 050 111 050 Horizontal format acceptable [16]
Mark scheme, page 6
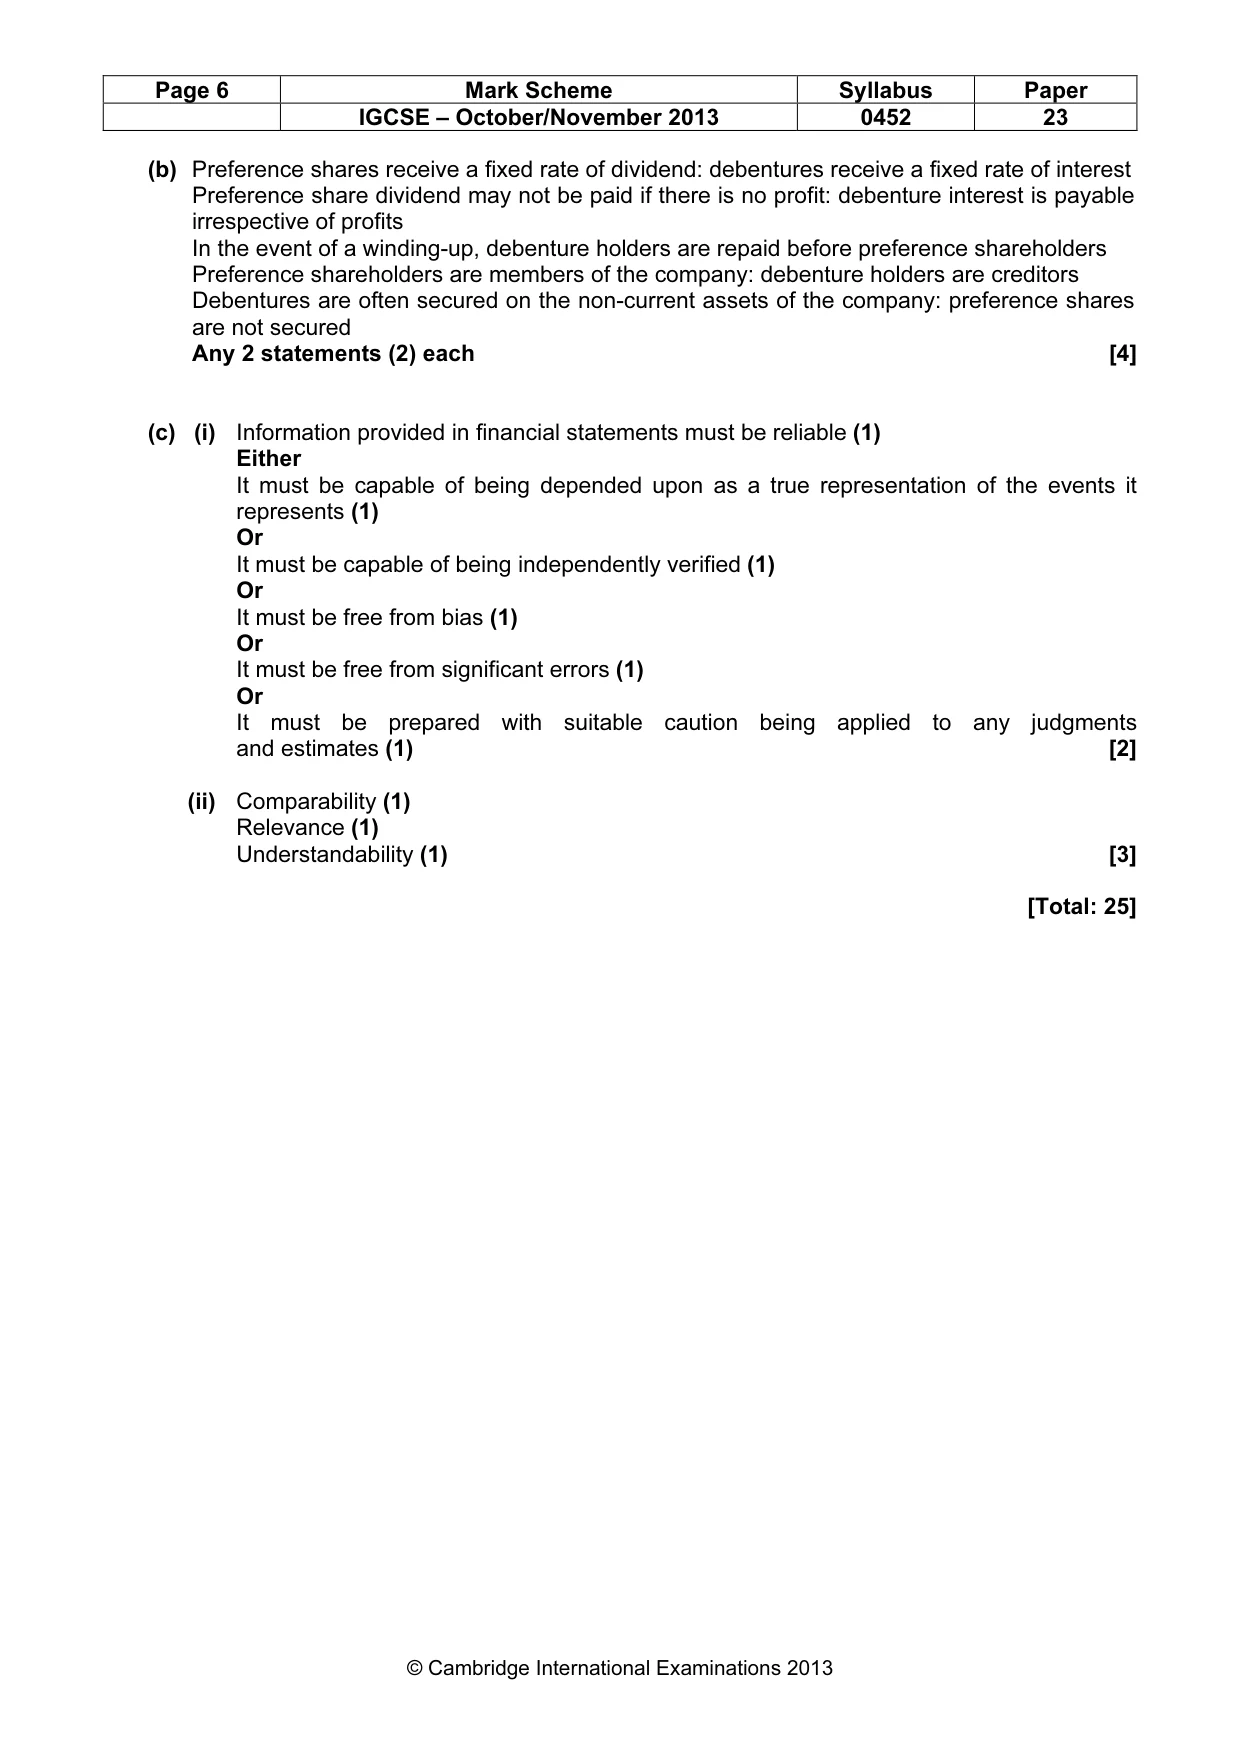
Page 6 Mark Scheme Syllabus Paper IGCSE – October/November 2013 0452 23 © Cambridge International Examinations 2013 (b) Preference shares receive a fixed rate of dividend: debentures receive a fixed rate of interest Preference share dividend may not be paid if there is no profit: debenture interest is payable irrespective of profits In the event of a winding-up, debenture holders are repaid before preference shareholders Preference shareholders are members of the company: debenture holders are creditors Debentures are often secured on the non-current assets of the company: preference shares are not secured Any 2 statements (2) each [4] (c) (i) Information provided in financial statements must be reliable (1) Either It must be capable of being depended upon as a true representation of the events it represents (1) Or It must be capable of being independently verified (1) Or It must be free from bias (1) Or It must be free from significant errors (1) Or It must be prepared with suitable caution being applied to any judgments and estimates (1) [2] (ii) Comparability (1) Relevance (1) Understandability (1) [3] [Total: 25]
Mark scheme, page 7
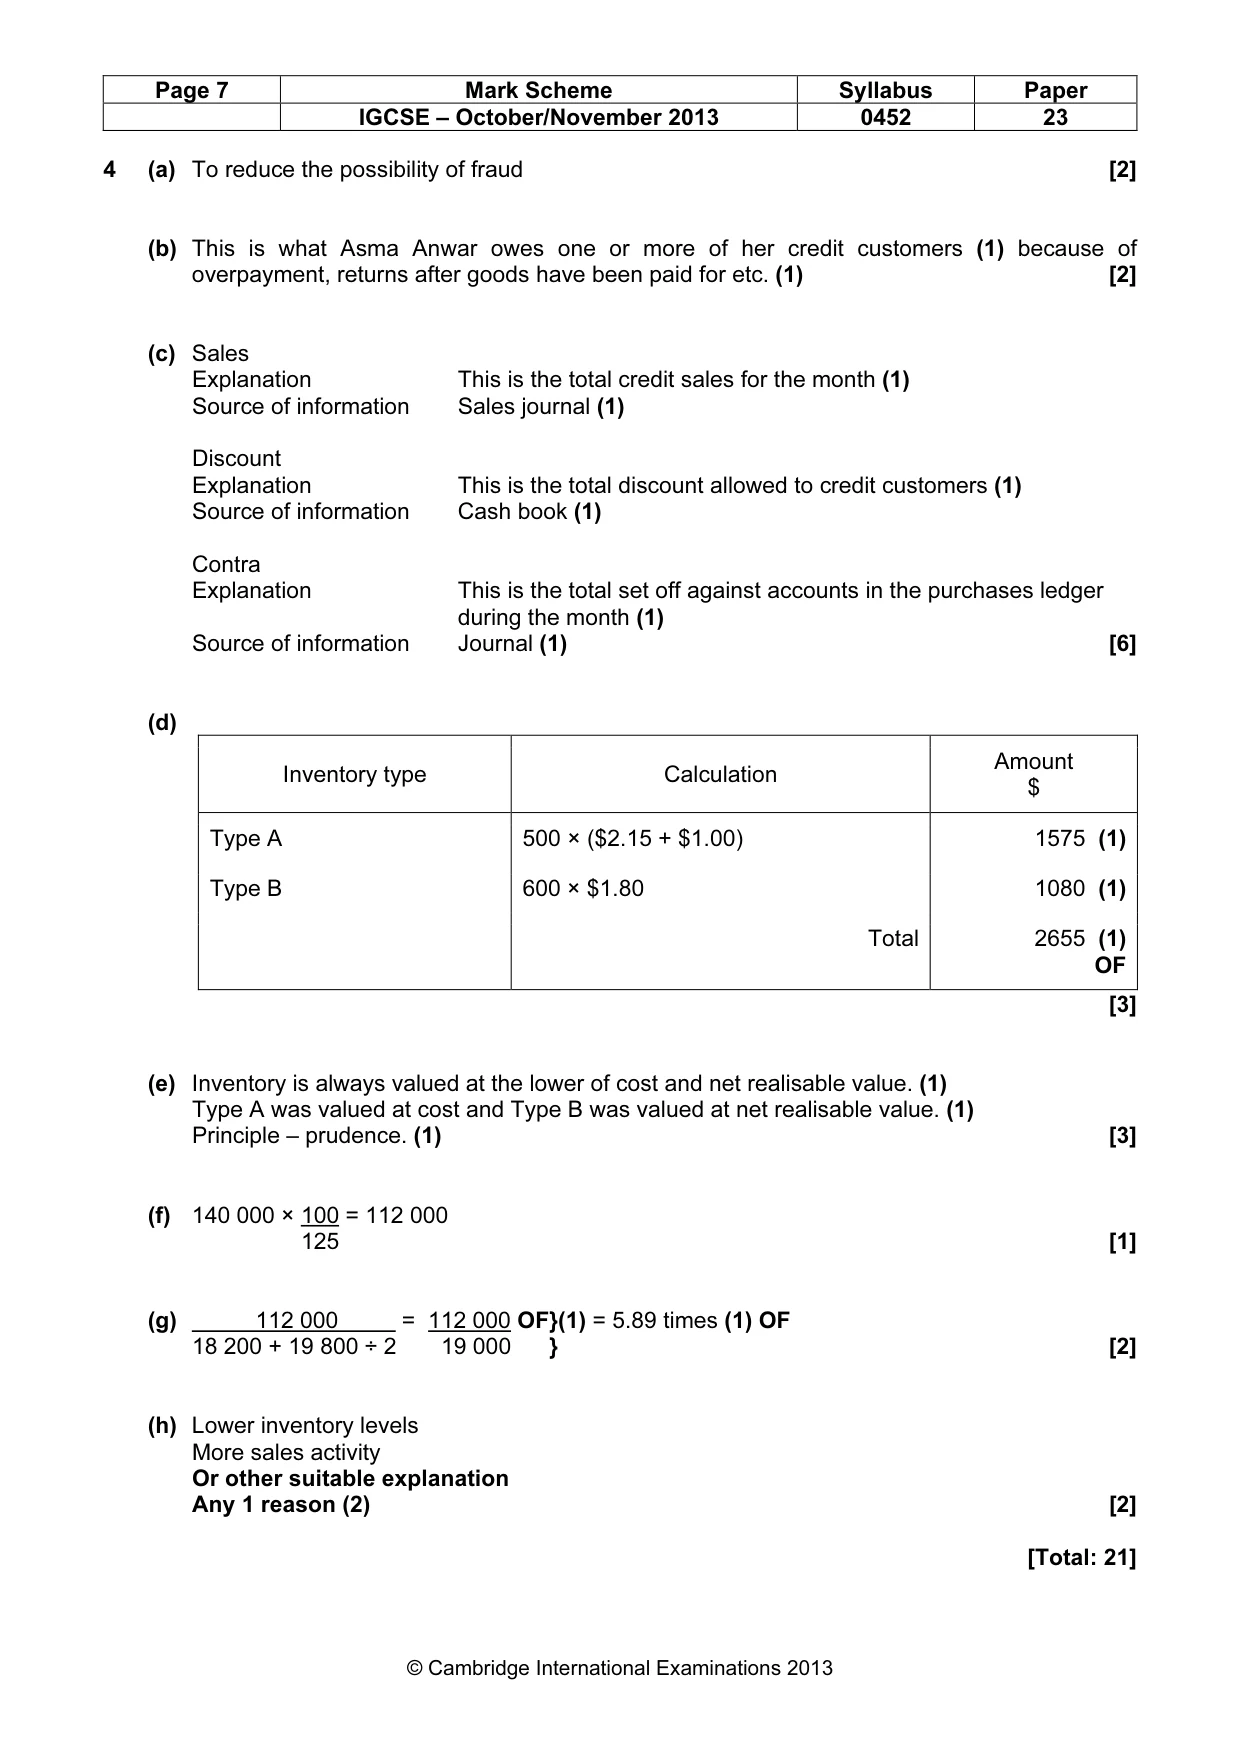
Page 7 Mark Scheme Syllabus Paper IGCSE – October/November 2013 0452 23 © Cambridge International Examinations 2013 4 (a) To reduce the possibility of fraud [2] (b) This is what Asma Anwar owes one or more of her credit customers (1) because of overpayment, returns after goods have been paid for etc. (1) [2] (c) Sales Explanation This is the total credit sales for the month (1) Source of information Sales journal (1) Discount Explanation This is the total discount allowed to credit customers (1) Source of information Cash book (1) Contra Explanation This is the total set off against accounts in the purchases ledger during the month (1) Source of information Journal (1) [6] (d) Inventory type Calculation Amount $ Type A 500 × ($2.15 + $1.00) 1575 (1) Type B 600 × $1.80 1080 (1) Total 2655 (1) OF [3] (e) Inventory is always valued at the lower of cost and net realisable value. (1) Type A was valued at cost and Type B was valued at net realisable value. (1) Principle – prudence. (1) [3] (f) 140 000 × 100 = 112 000 125 [1] (g) 112 000 = 112 000 OF}(1) = 5.89 times (1) OF 18 200 + 19 800 ÷ 2 19 000 } [2] (h) Lower inventory levels More sales activity Or other suitable explanation Any 1 reason (2) [2] [Total: 21]
Mark scheme, page 8
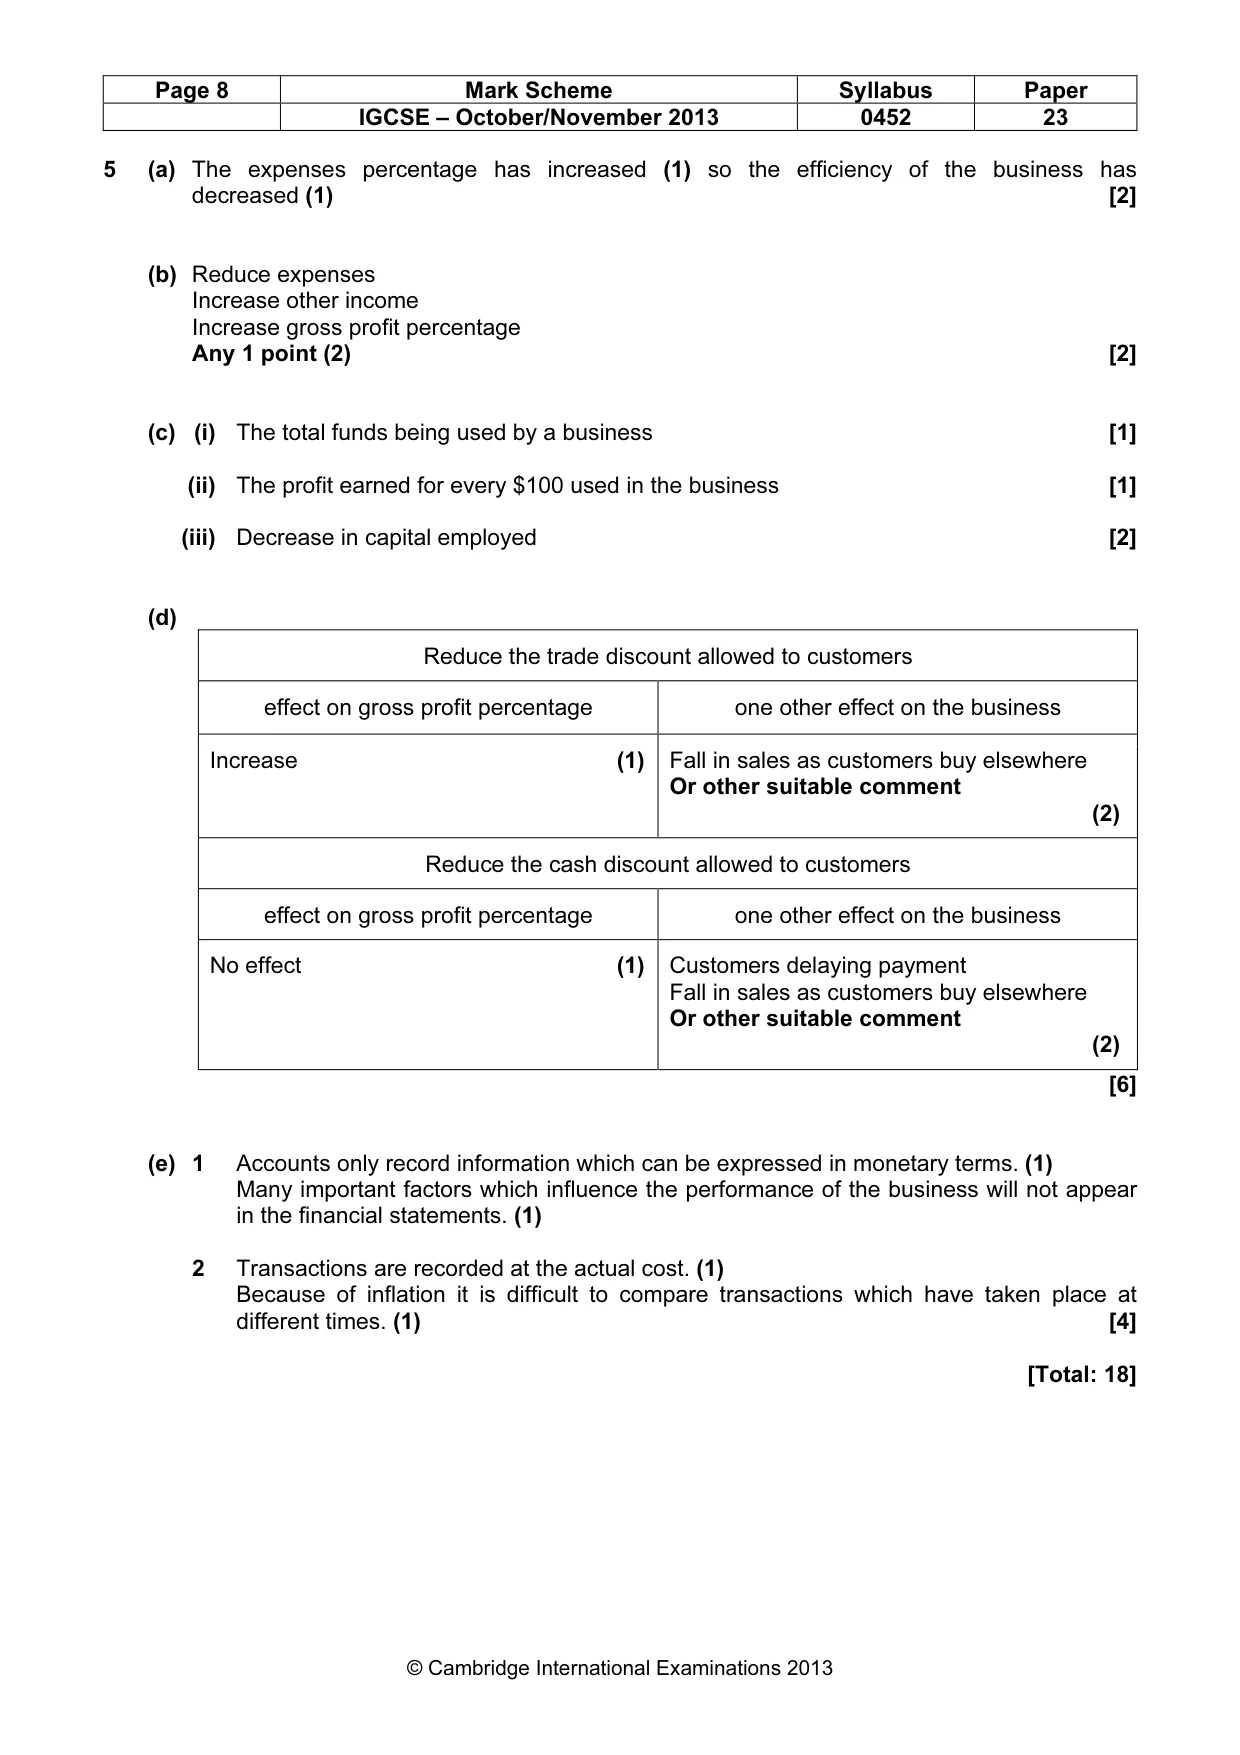
Page 8 Mark Scheme Syllabus Paper IGCSE – October/November 2013 0452 23 © Cambridge International Examinations 2013 5 (a) The expenses percentage has increased (1) so the efficiency of the business has decreased (1) [2] (b) Reduce expenses Increase other income Increase gross profit percentage Any 1 point (2) [2] (c) (i) The total funds being used by a business [1] (ii) The profit earned for every $100 used in the business [1] (iii) Decrease in capital employed [2] (d) Reduce the trade discount allowed to customers effect on gross profit percentage one other effect on the business Increase (1) Fall in sales as customers buy elsewhere Or other suitable comment (2) Reduce the cash discount allowed to customers effect on gross profit percentage one other effect on the business No effect (1) Customers delaying payment Fall in sales as customers buy elsewhere Or other suitable comment (2) [6] (e) 1 Accounts only record information which can be expressed in monetary terms. (1) Many important factors which influence the performance of the business will not appear in the financial statements. (1) 2 Transactions are recorded at the actual cost. (1) Because of inflation it is difficult to compare transactions which have taken place at different times. (1) [4] [Total: 18]
Mark scheme, page 9
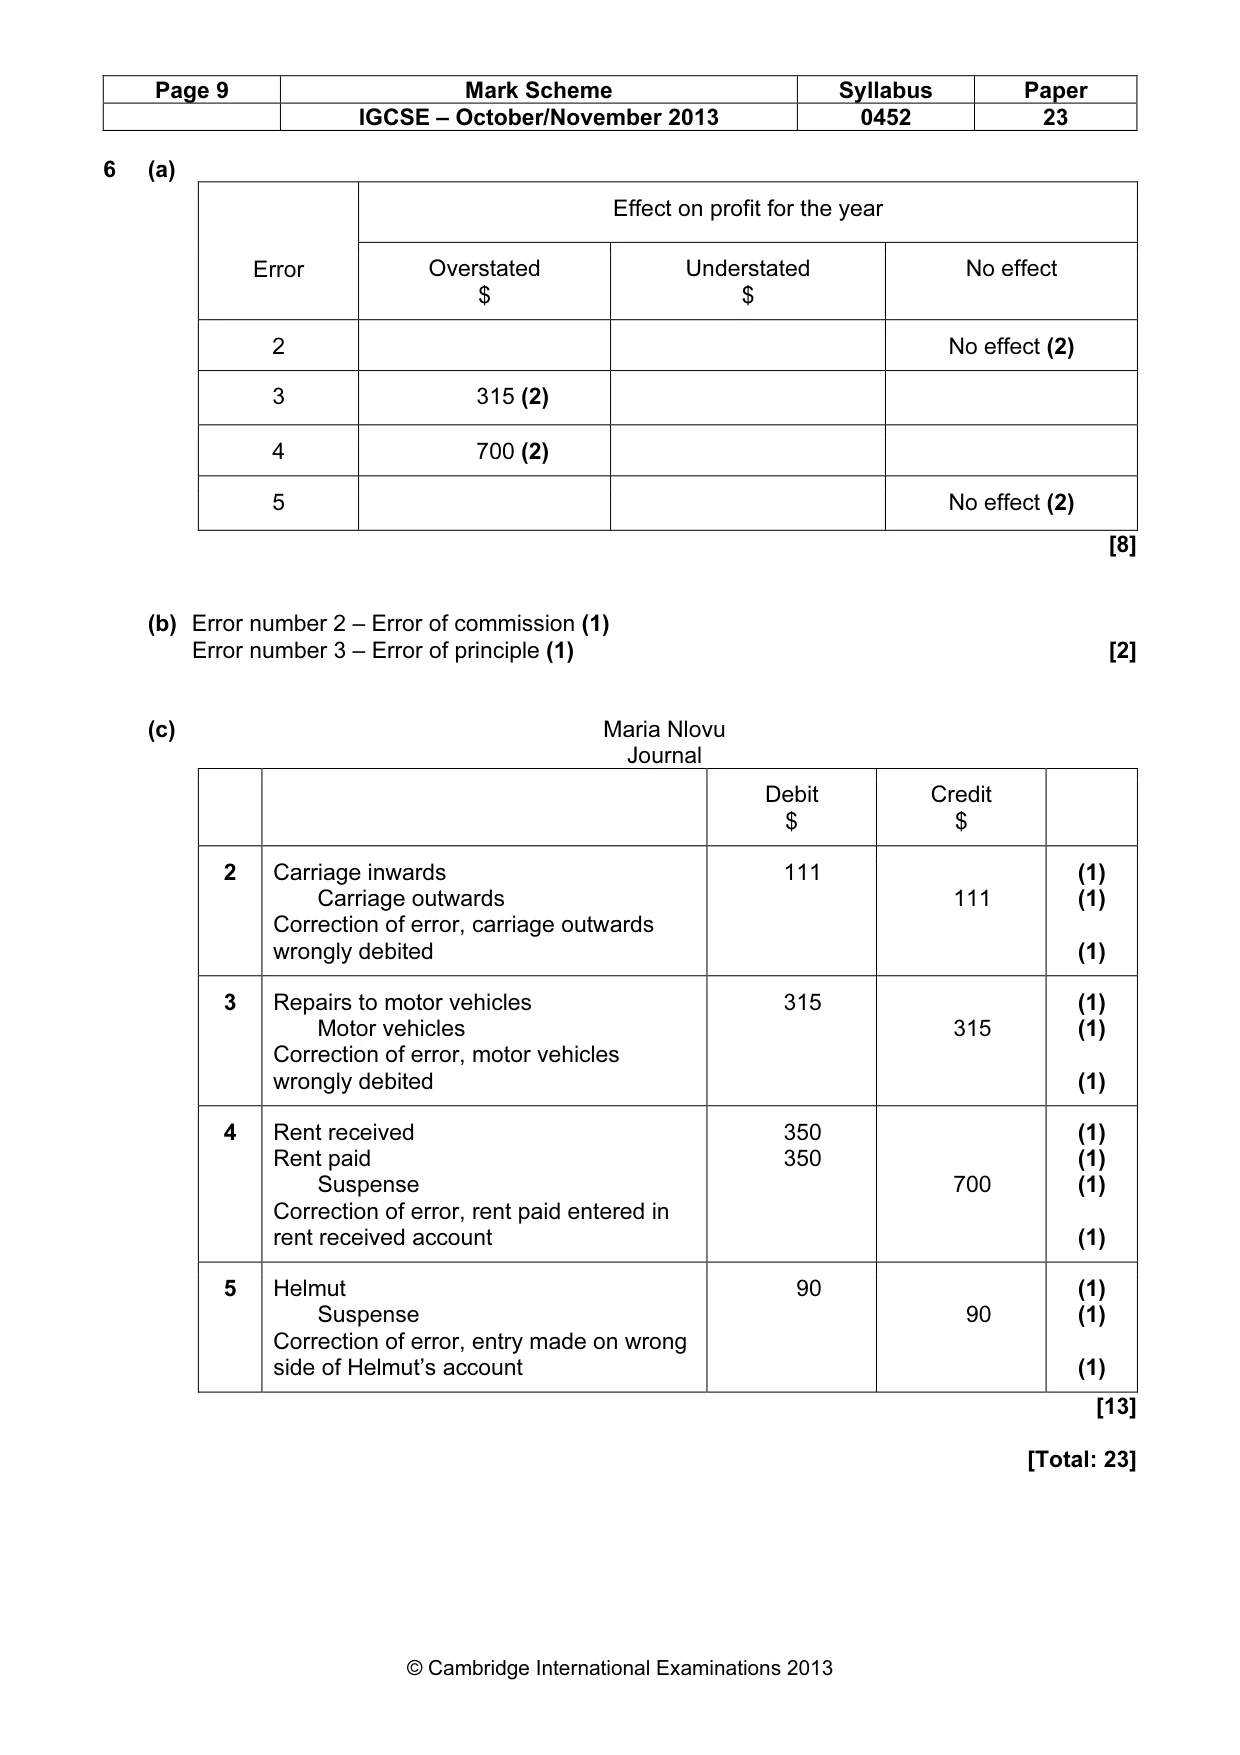
Page 9 Mark Scheme Syllabus Paper IGCSE – October/November 2013 0452 23 © Cambridge International Examinations 2013 6 (a) Error Effect on profit for the year Overstated $ Understated $ No effect 2 No effect (2) 3 315 (2) 4 700 (2) 5 No effect (2) [8] (b) Error number 2 – Error of commission (1) Error number 3 – Error of principle (1) [2] (c) Maria Nlovu Journal Debit $ Credit $ 2 Carriage inwards Carriage outwards Correction of error, carriage outwards wrongly debited 111 111 (1) (1) (1) 3 Repairs to motor vehicles Motor vehicles Correction of error, motor vehicles wrongly debited 315 315 (1) (1) (1) 4 Rent received Rent paid Suspense Correction of error, rent paid entered in rent received account 350 350 700 (1) (1) (1) (1) 5 Helmut Suspense Correction of error, entry made on wrong side of Helmut’s account 90 90 (1) (1) (1) [13] [Total: 23]
What you needed in this session
Cambridge’s own grade thresholds for 2013 Oct/Nov, Paper 2 · Variant 3. A higher threshold means an easier paper — the bar moves with how the cohort did.