Cambridge IGCSE Accounting 0452 — 2023 Oct/Nov Paper 2 · Variant 3
0452/23/O/N/23 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper24 pages
Mark scheme15 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Shakir started trading in the year ended 31 August 2023 but did not keep proper books of…
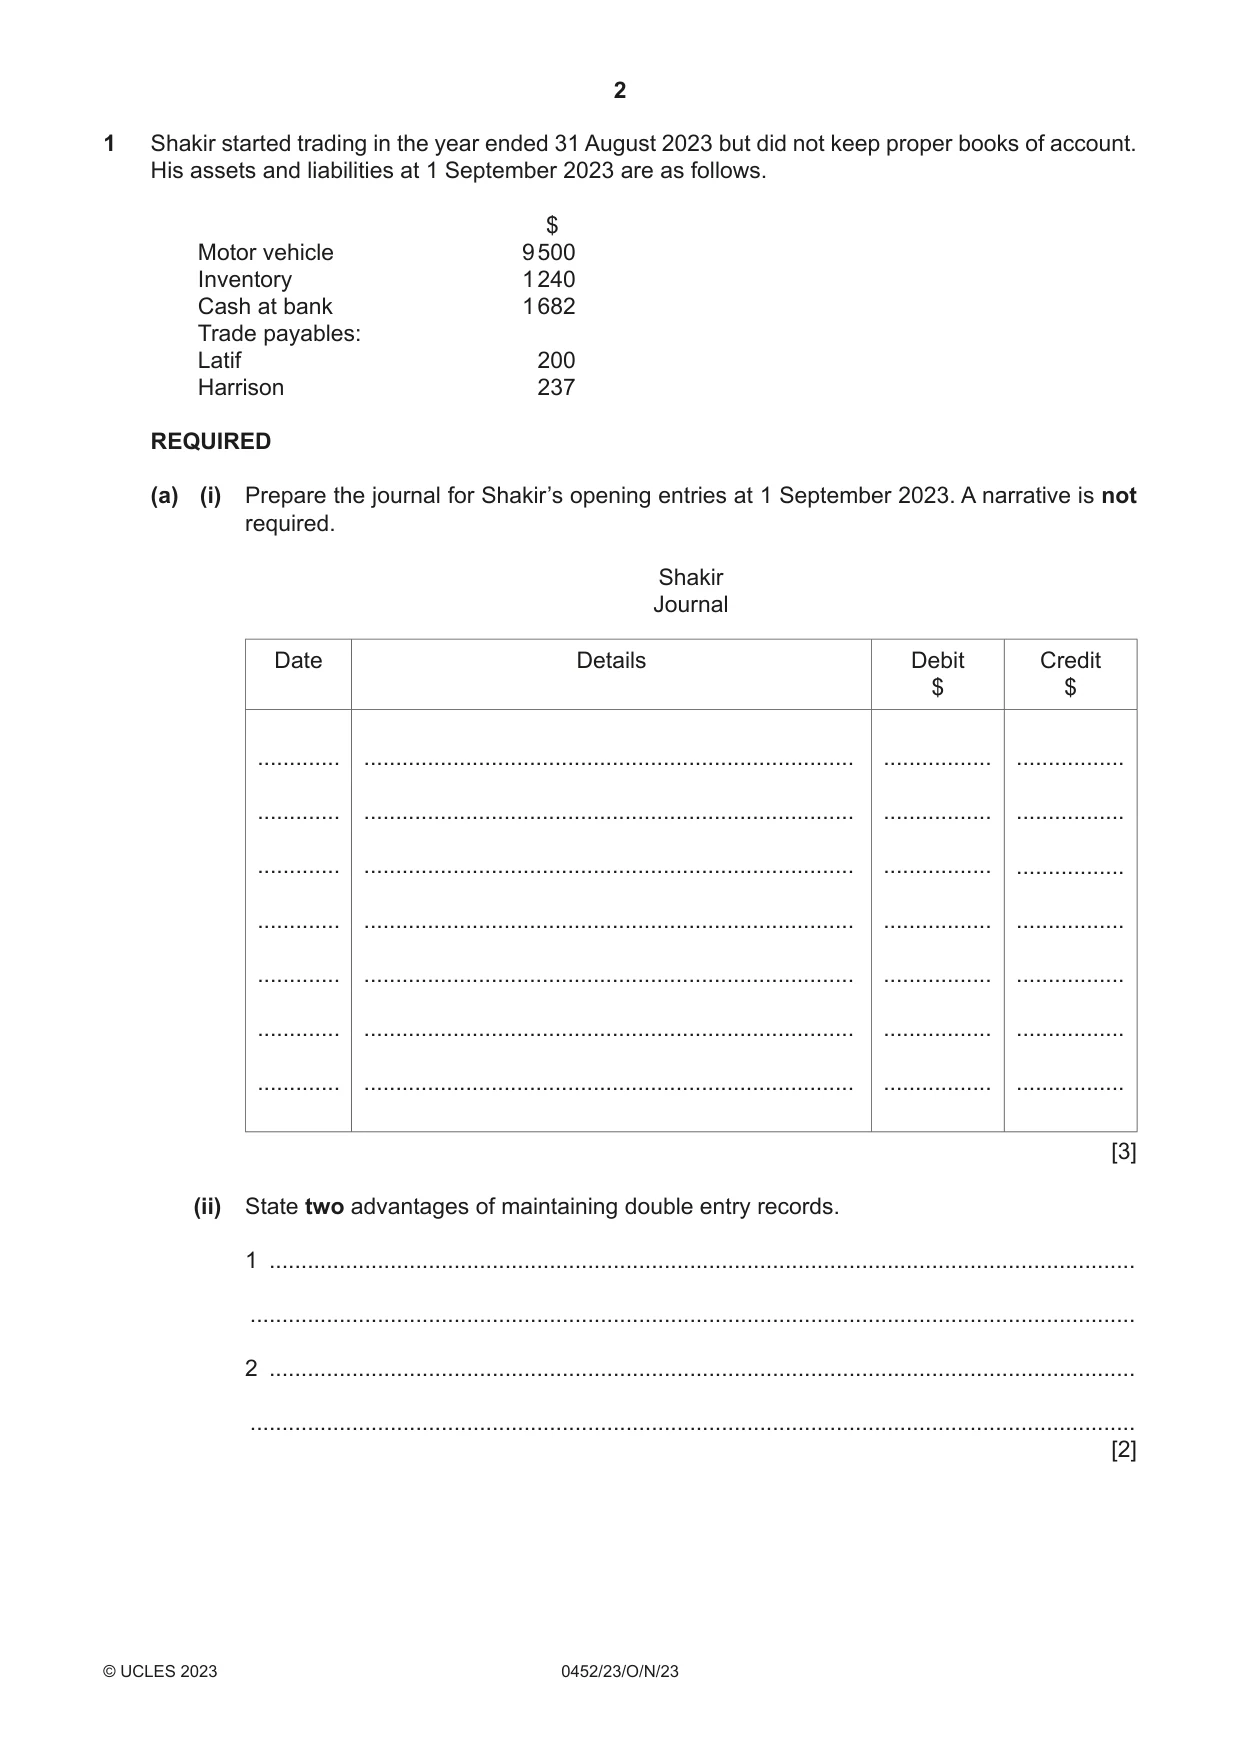
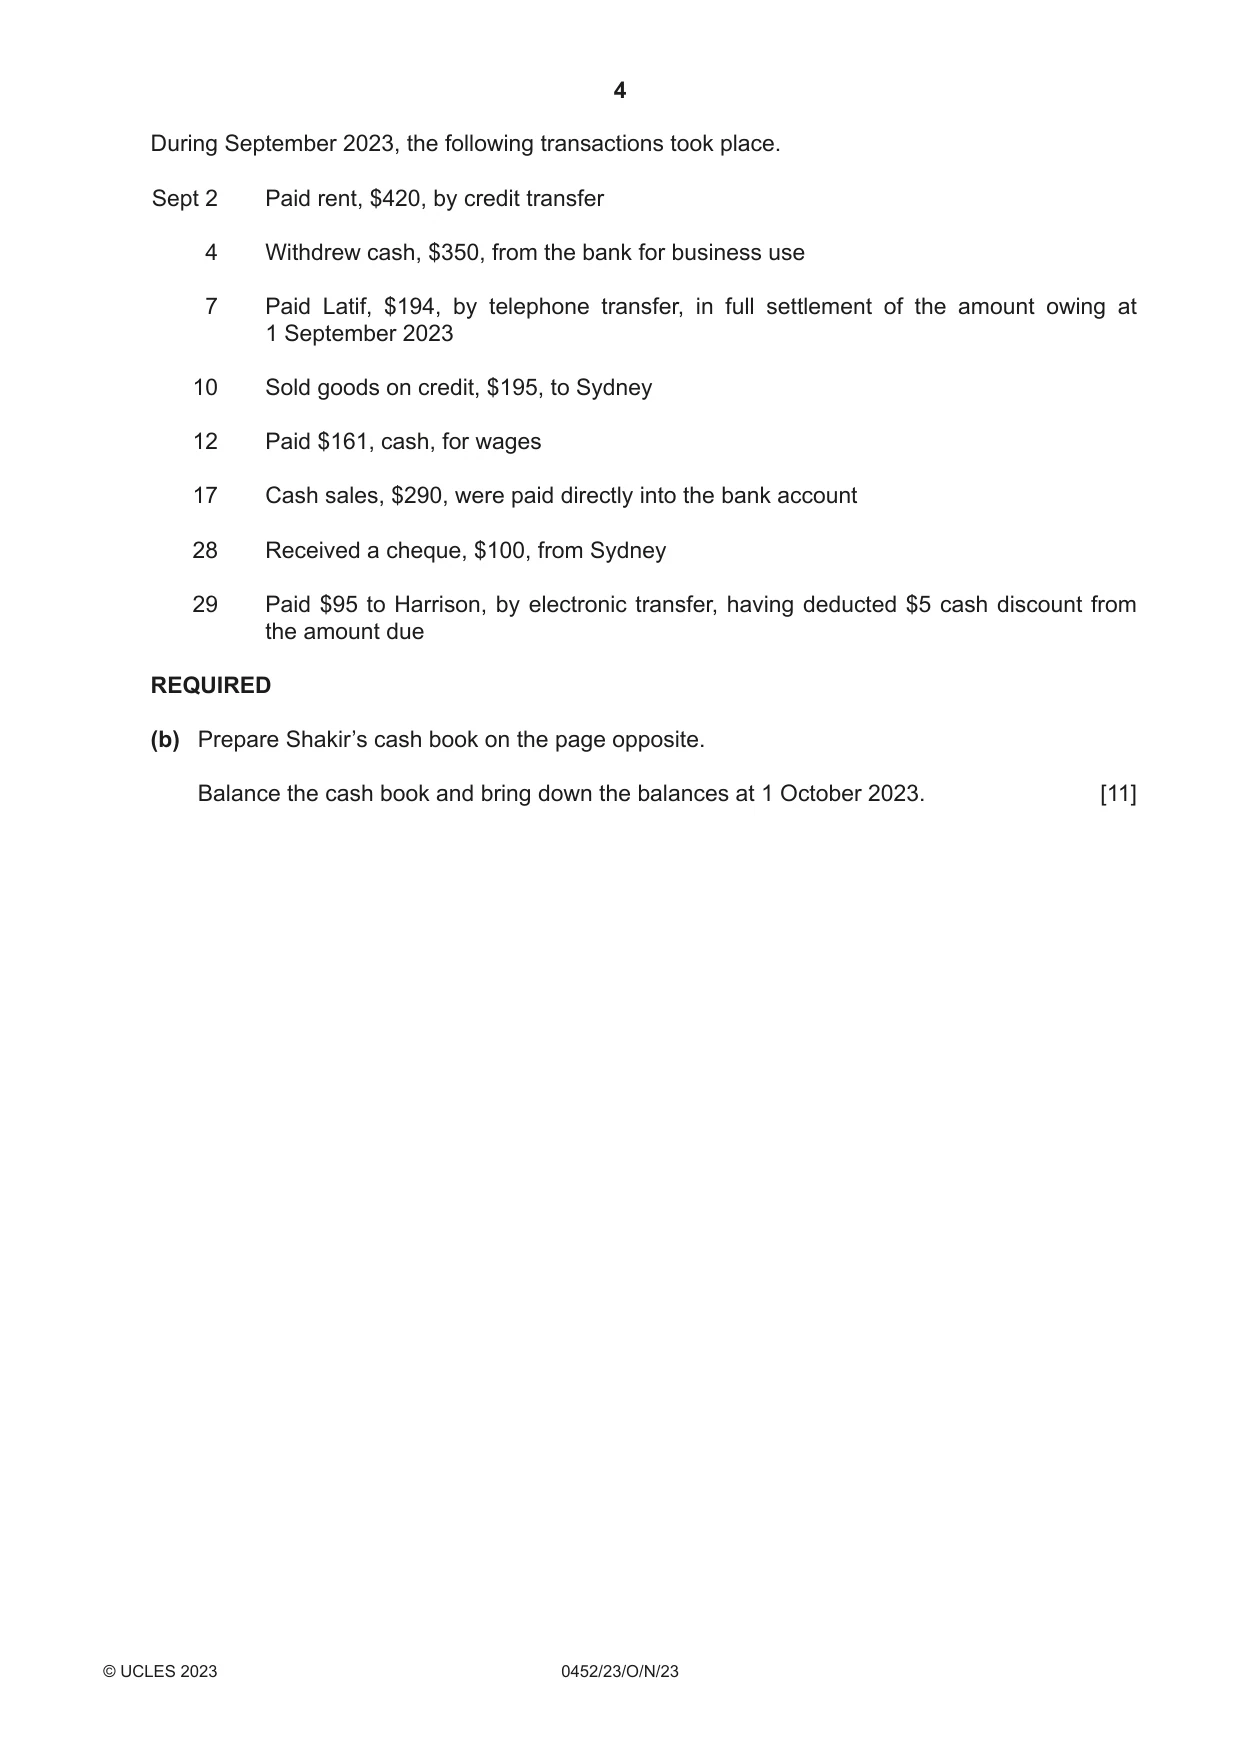
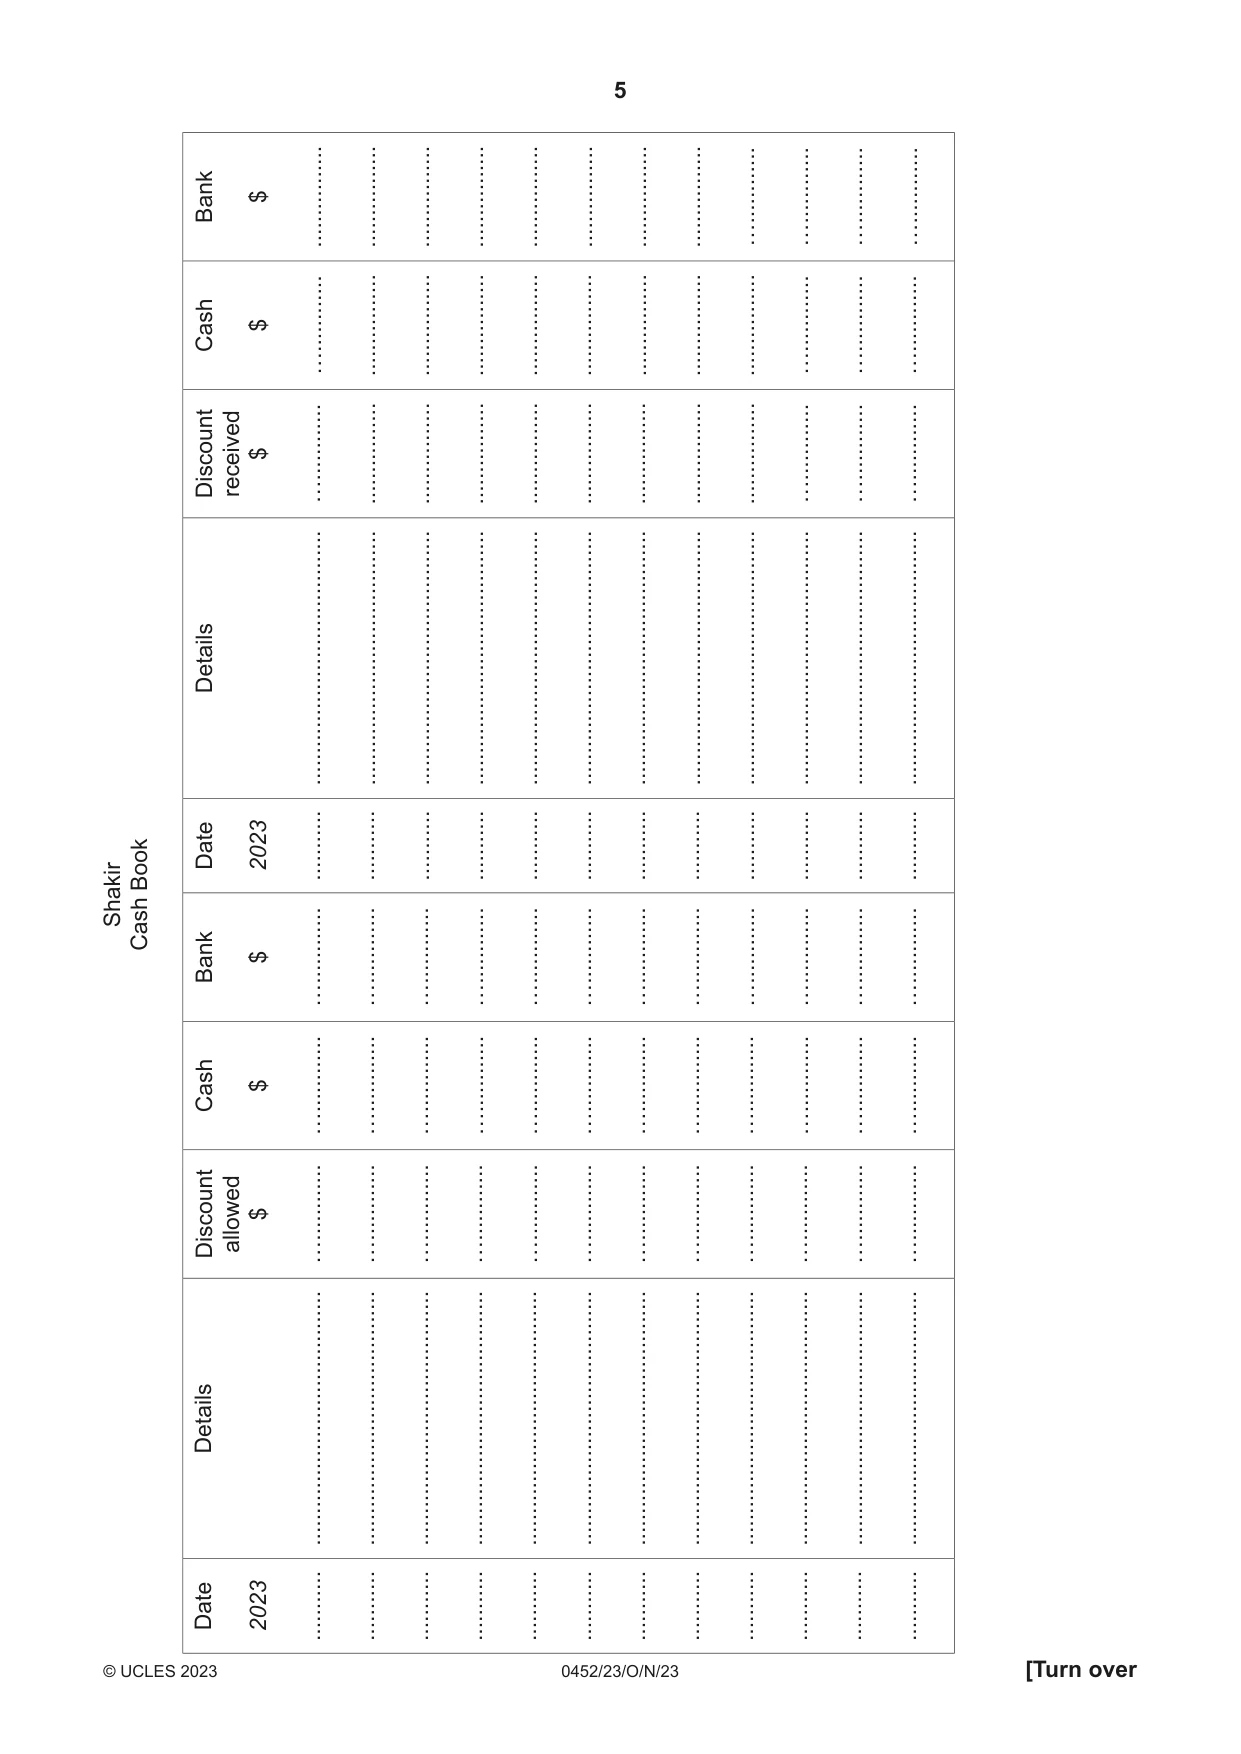
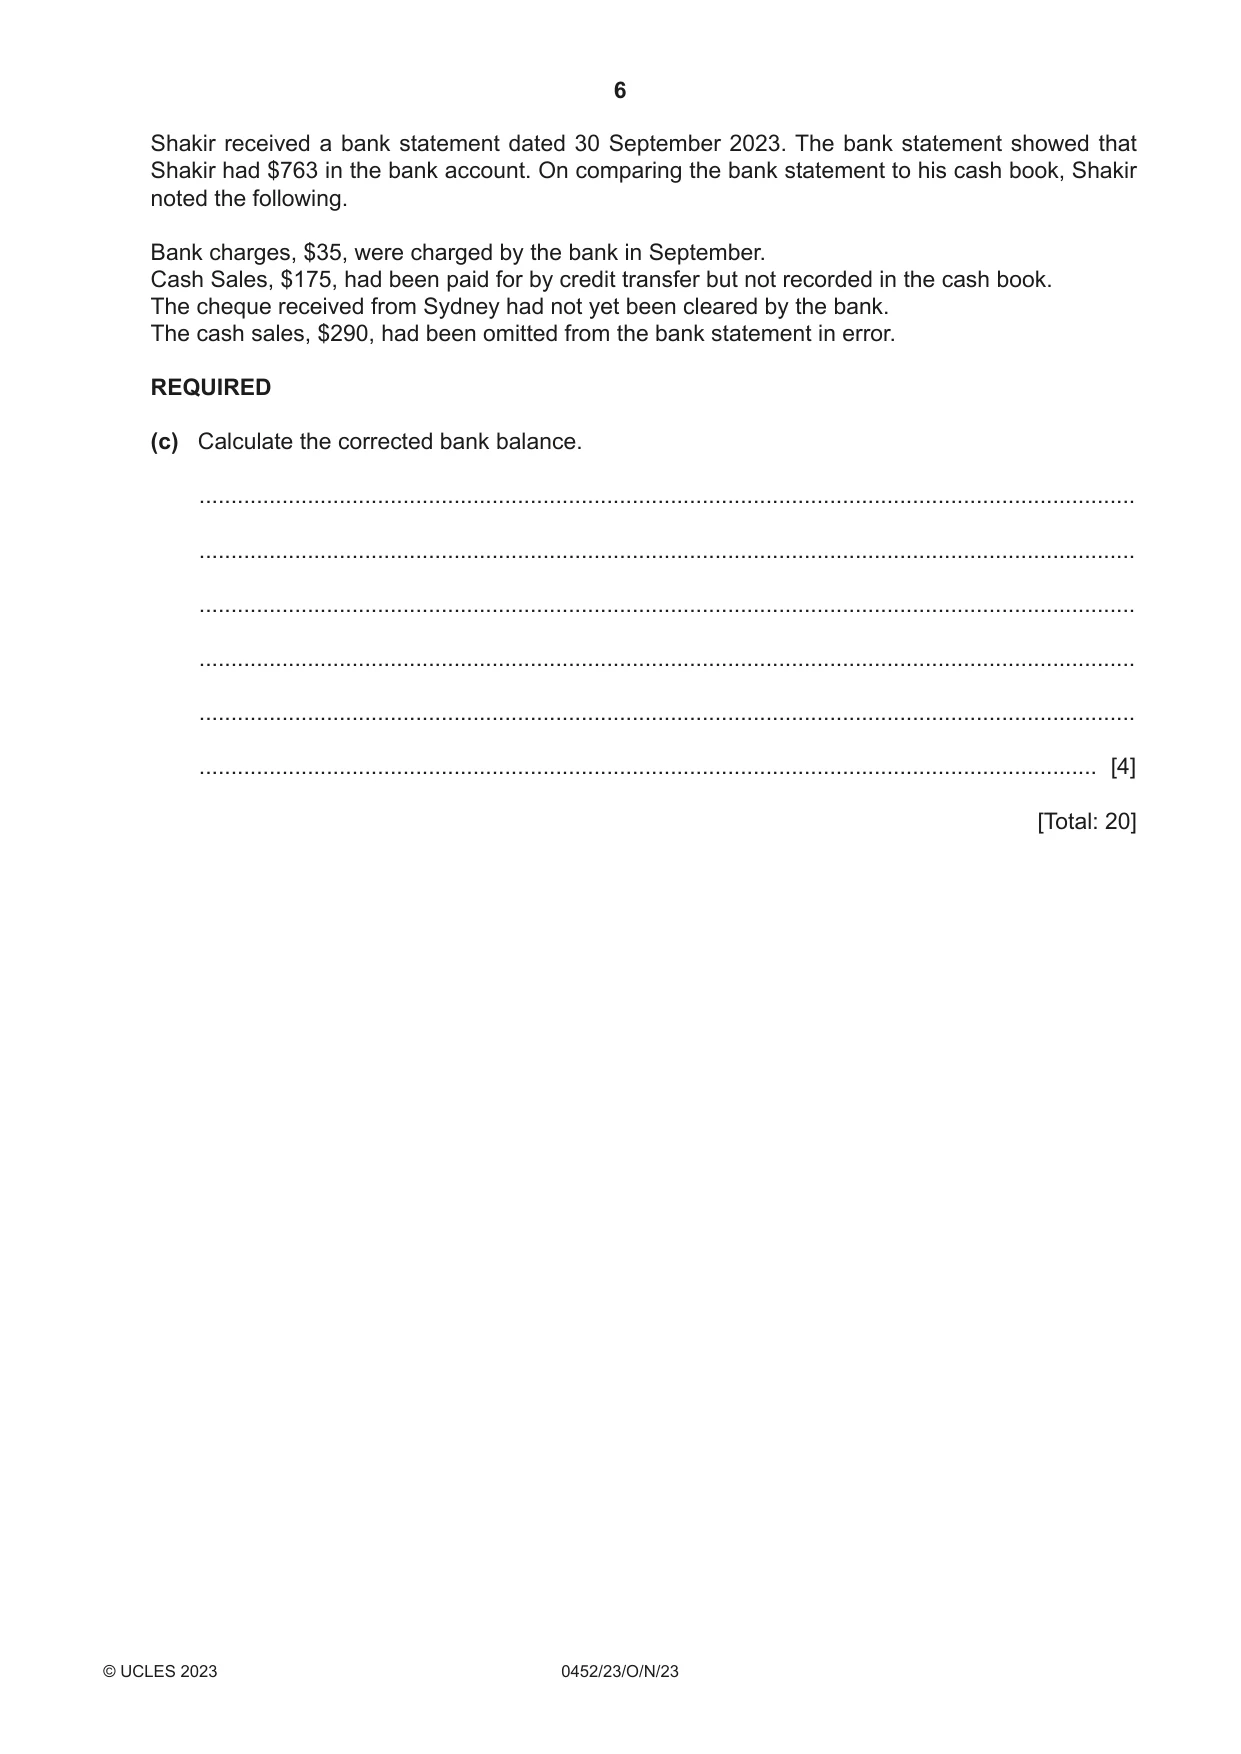
1 Shakir started trading in the year ended 31 August 2023 but did not keep proper books of account. His assets and liabilities at 1 September 2023 are as follows. $ Motor vehicle 9 500 Inventory 1 240 Cash at bank 1 682 Trade payables: Latif 200 Harrison 237 REQUIRED (a) (i) Prepare the journal for Shakir’s opening entries at 1 September 2023. A narrative is not required. Shakir Journal Date Details Debit Credit $ $ ............. ............................................................................. ................. ................. ............. ............................................................................. ................. ................. ............. ............................................................................. ................. ................. ............. ............................................................................. ................. ................. ............. ............................................................................. ................. ................. ............. ............................................................................. ................. ................. ............. ............................................................................. ................. ................. [3] (ii) State two advantages of maintaining double entry records. 1 ........................................................................................................................................ ........................................................................................................................................... 2 ........................................................................................................................................ ........................................................................................................................................... [2] During September 2023, the following transactions took place. Sept 2 Paid rent, $420, by credit transfer 4 Withdrew cash, $350, from the bank for business use 7 Paid Latif, $194, by telephone transfer, in full settlement of the amount owing at 1 September 2023 10 Sold goods on credit, $195, to Sydney 12 Paid $161, cash, for wages 17 Cash sales, $290, were paid directly into the bank account 28 Received a cheque, $100, from Sydney 29 Paid $95 to Harrison, by electronic transfer, having deducted $5 cash discount from the amount due REQUIRED (b) Prepare Shakir’s cash book on the page opposite. Balance the cash book and bring down the balances at 1 October 2023. [11] $ Bank ................ ................ ................ ................ ................ ................ ................ ................ …............ …............ …............ …............ $ Cash …............ ................ ................ ................ ................ ................ ................ ................ ................ …............ …............ …............ $ Discountreceived …............ ................ ................ ................ ................ ................ ................ ................ ................ …............ …............ …............ Details ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ Date 2023 ........... ........... ........... ........... ........... ........... ........... ........... ........... ........... ........... ........... Book Shakir Cash $ Bank …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ $ Cash …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ $ Discountallowed …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ …............ Details ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ Shakir received a bank statement dated 30 September 2023. The bank statement showed that Shakir had $763 in the bank account. On comparing the bank statement to his cash book, Shakir noted the following. Bank charges, $35, were charged by the bank in September. Cash Sales, $175, had been paid for by credit transfer but not recorded in the cash book. The cheque received from Sydney had not yet been cleared by the bank. The cash sales, $290, had been omitted from the bank statement in error. REQUIRED (c) Calculate the corrected bank balance. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] [Total: 20]
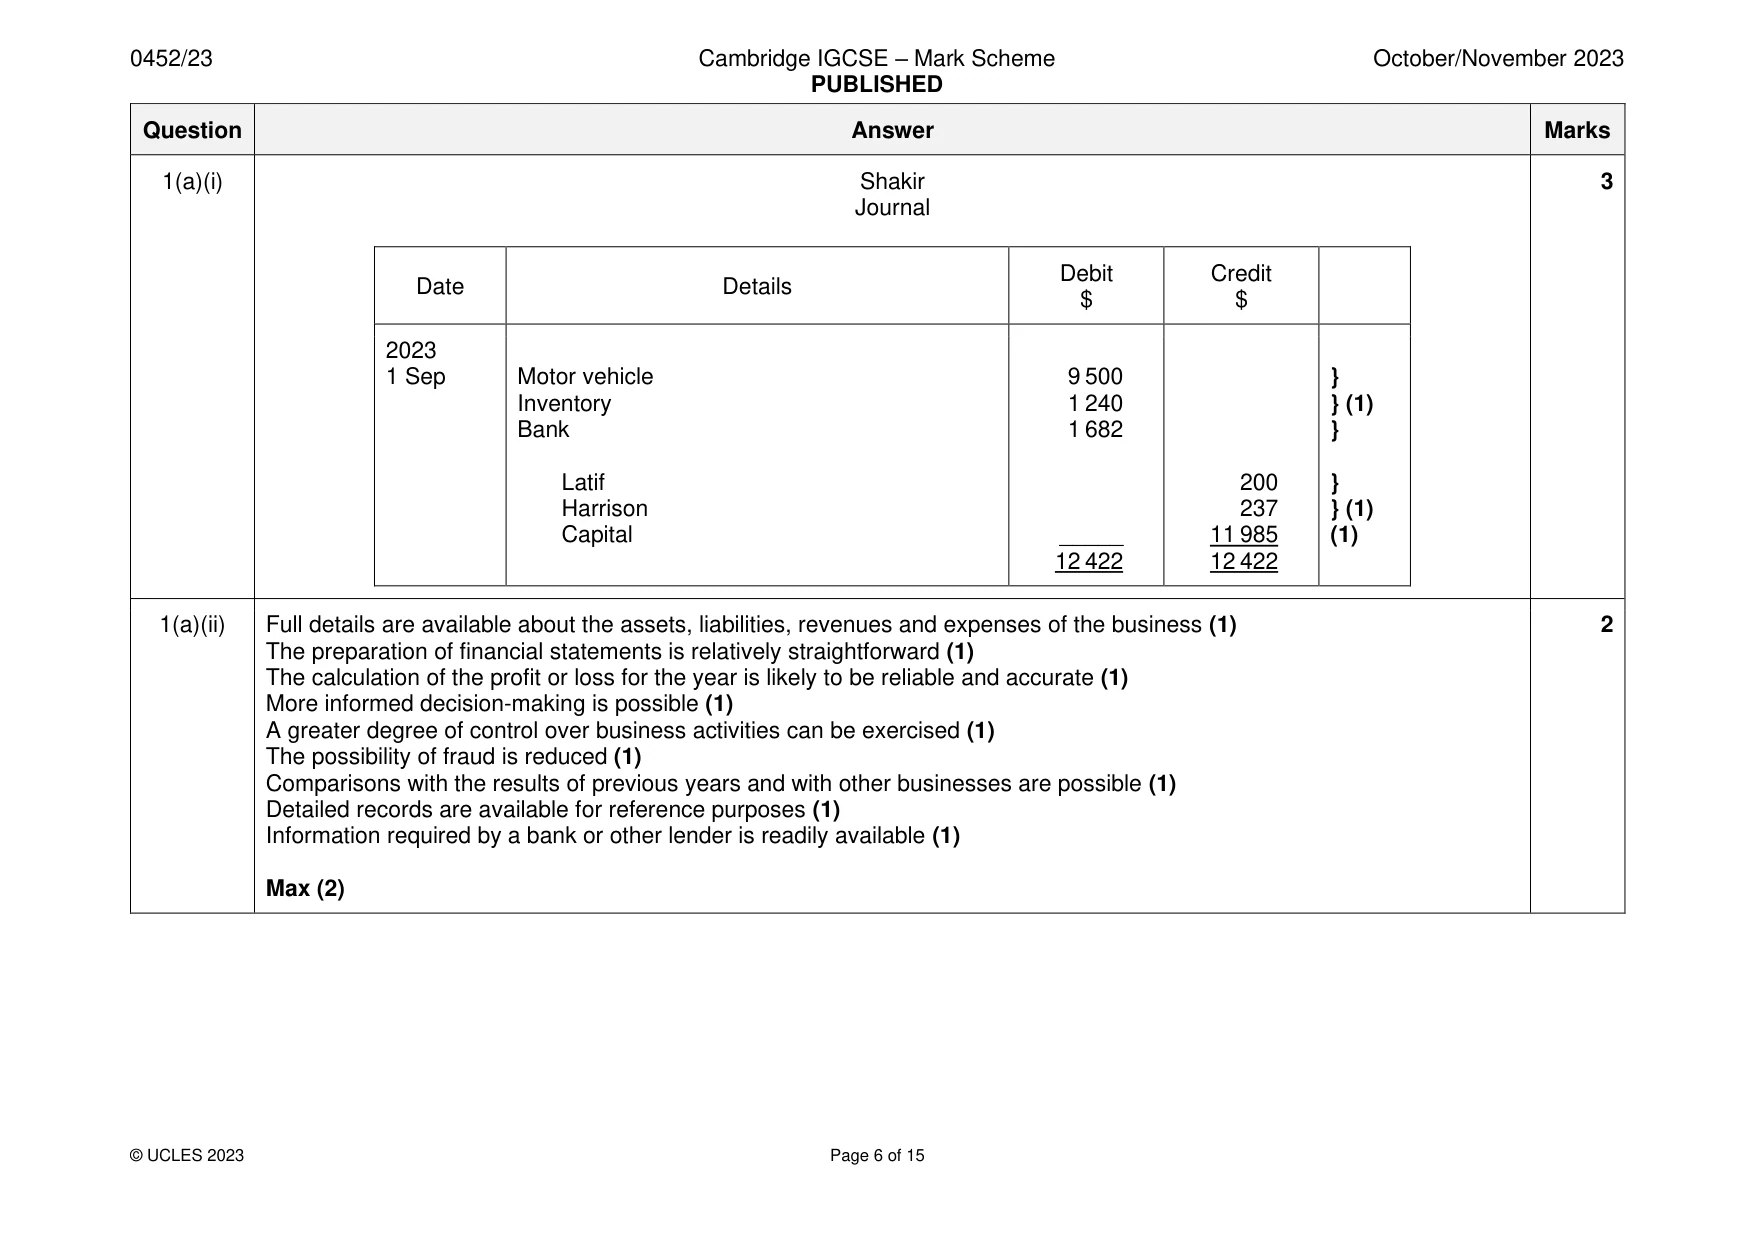
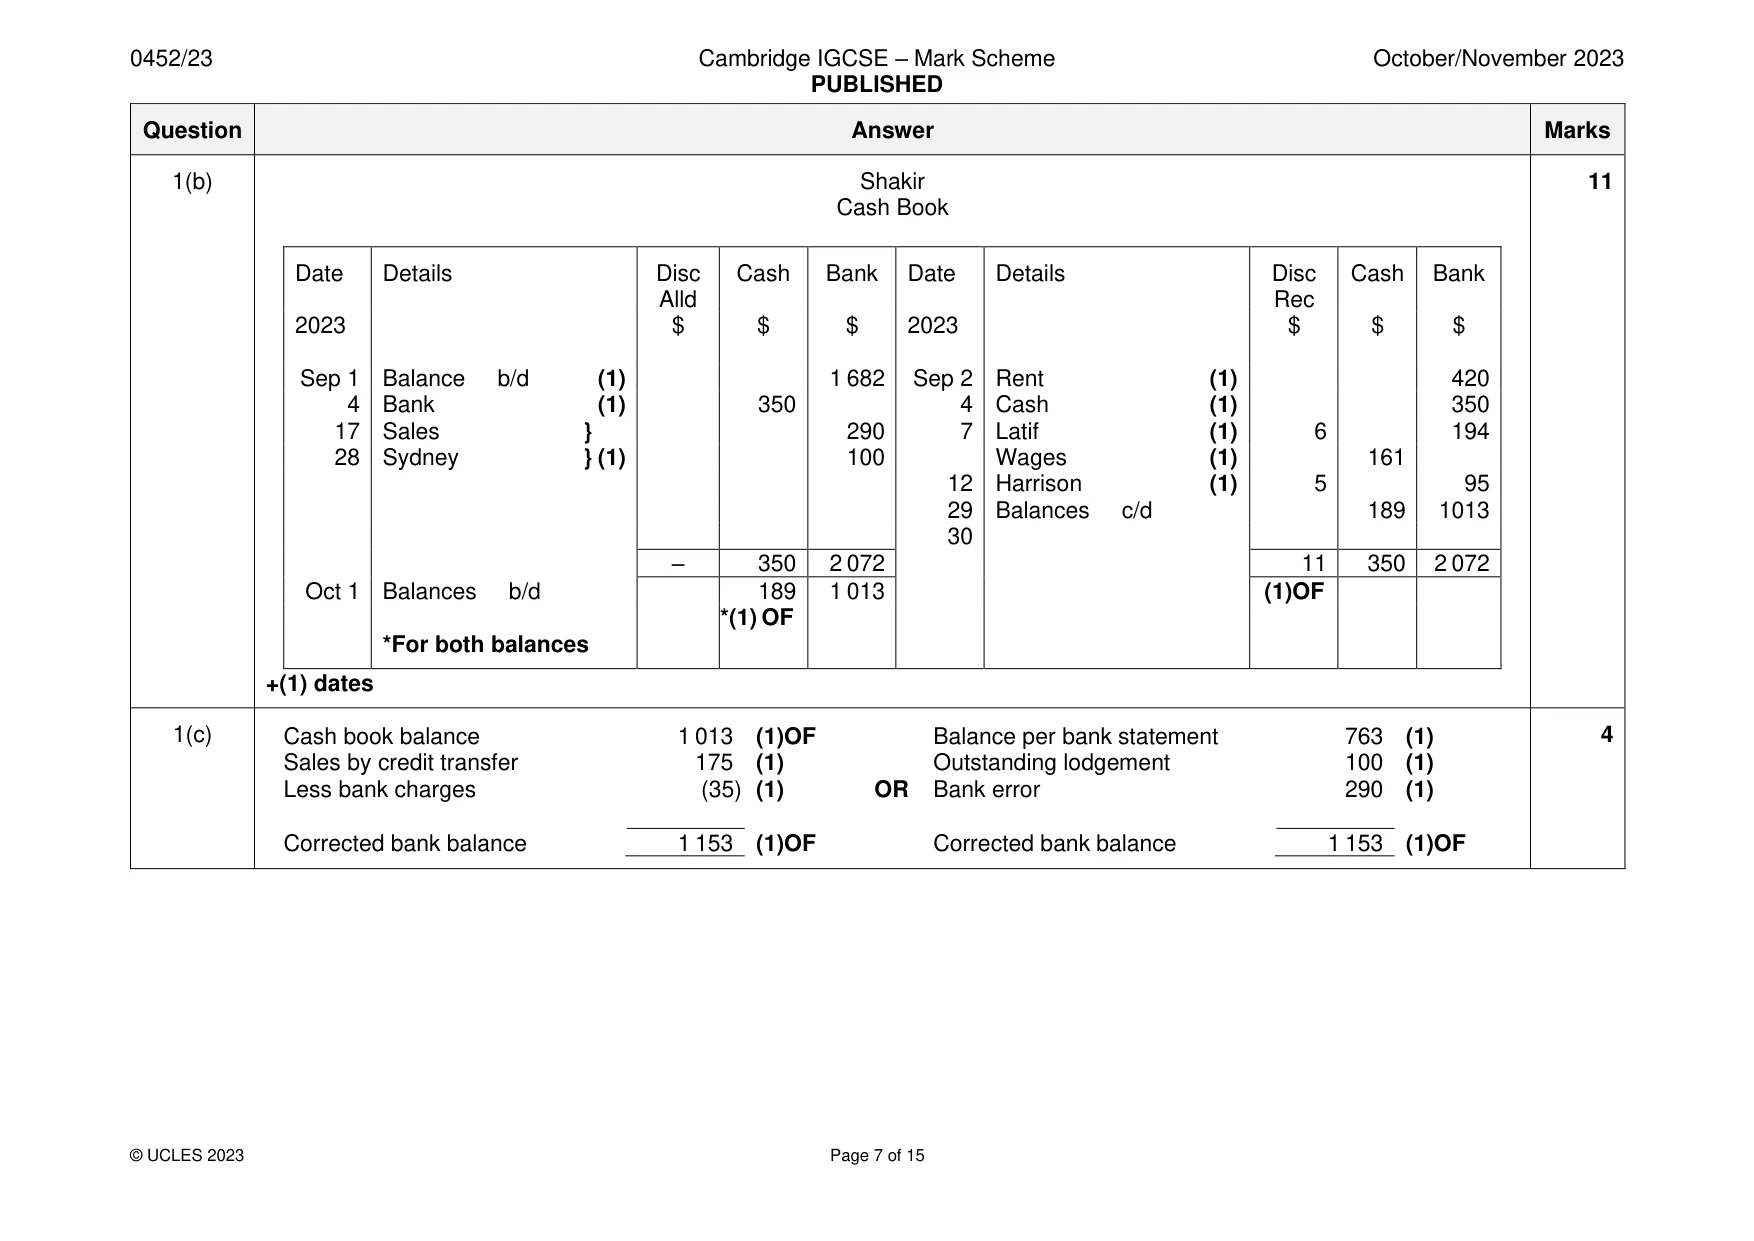
Mark scheme: Question Answer Marks 1(a)(i) Shakir 3 Journal Debit Credit Date Details $ $ 2023 1 Sep Motor vehicle 9 500 } Inventory 1 240 } (1) Bank 1 682 } Latif 200 } Harrison 237 } (1) Capital _____ 11 985 (1)} 12 422 12 422 }}}} 1(a)(ii) Full details are available about the assets, liabilities, revenues and expenses of the business (1) 2 The preparation of financial statements is relatively straightforward (1) The calculation of the profit or loss for the year is likely to be reliable and accurate (1) More informed decision-making is possible (1) A greater degree of control over business activities can be exercised (1) The possibility of fraud is reduced (1) Comparisons with the results of previous years and with other businesses are possible (1) Detailed records are available for reference purposes (1) Information required by a bank or other lender is readily available (1) Max (2) 1(b) Shakir 11 Cash Book Date Details Disc Cash Bank Date Details Disc Cash Bank Alld Rec 2023 $ $ $ 2023 $ $ $ Sep 1 Balance b/d (1) 1 682 Sep 2 Rent (1) 420 4 Bank (1) 350 4 Cash (1) 350 17 Sales } 290 7 Latif (1) 6 194 28 Sydney } (1) 100 Wages (1) 161 12 Harrison (1) 5 95 29 Balances c/d 189 1013 30 – 350 2 072 11 350 2 072 Oct 1 Balances b/d 189 1 013 (1)OF *(1) OF *For both balances +(1) dates 1(c) Cash book balance 1 013 (1)OF Balance per bank statement 763 (1) 4 Sales by credit transfer 175 (1) Outstanding lodgement 100 (1) Less bank charges (35) (1) OR Bank error 290 (1) Corrected bank balance 1 153 (1)OF Corrected bank balance 1 153 (1)OF
Q2 · Hilary owns a manufacturing business
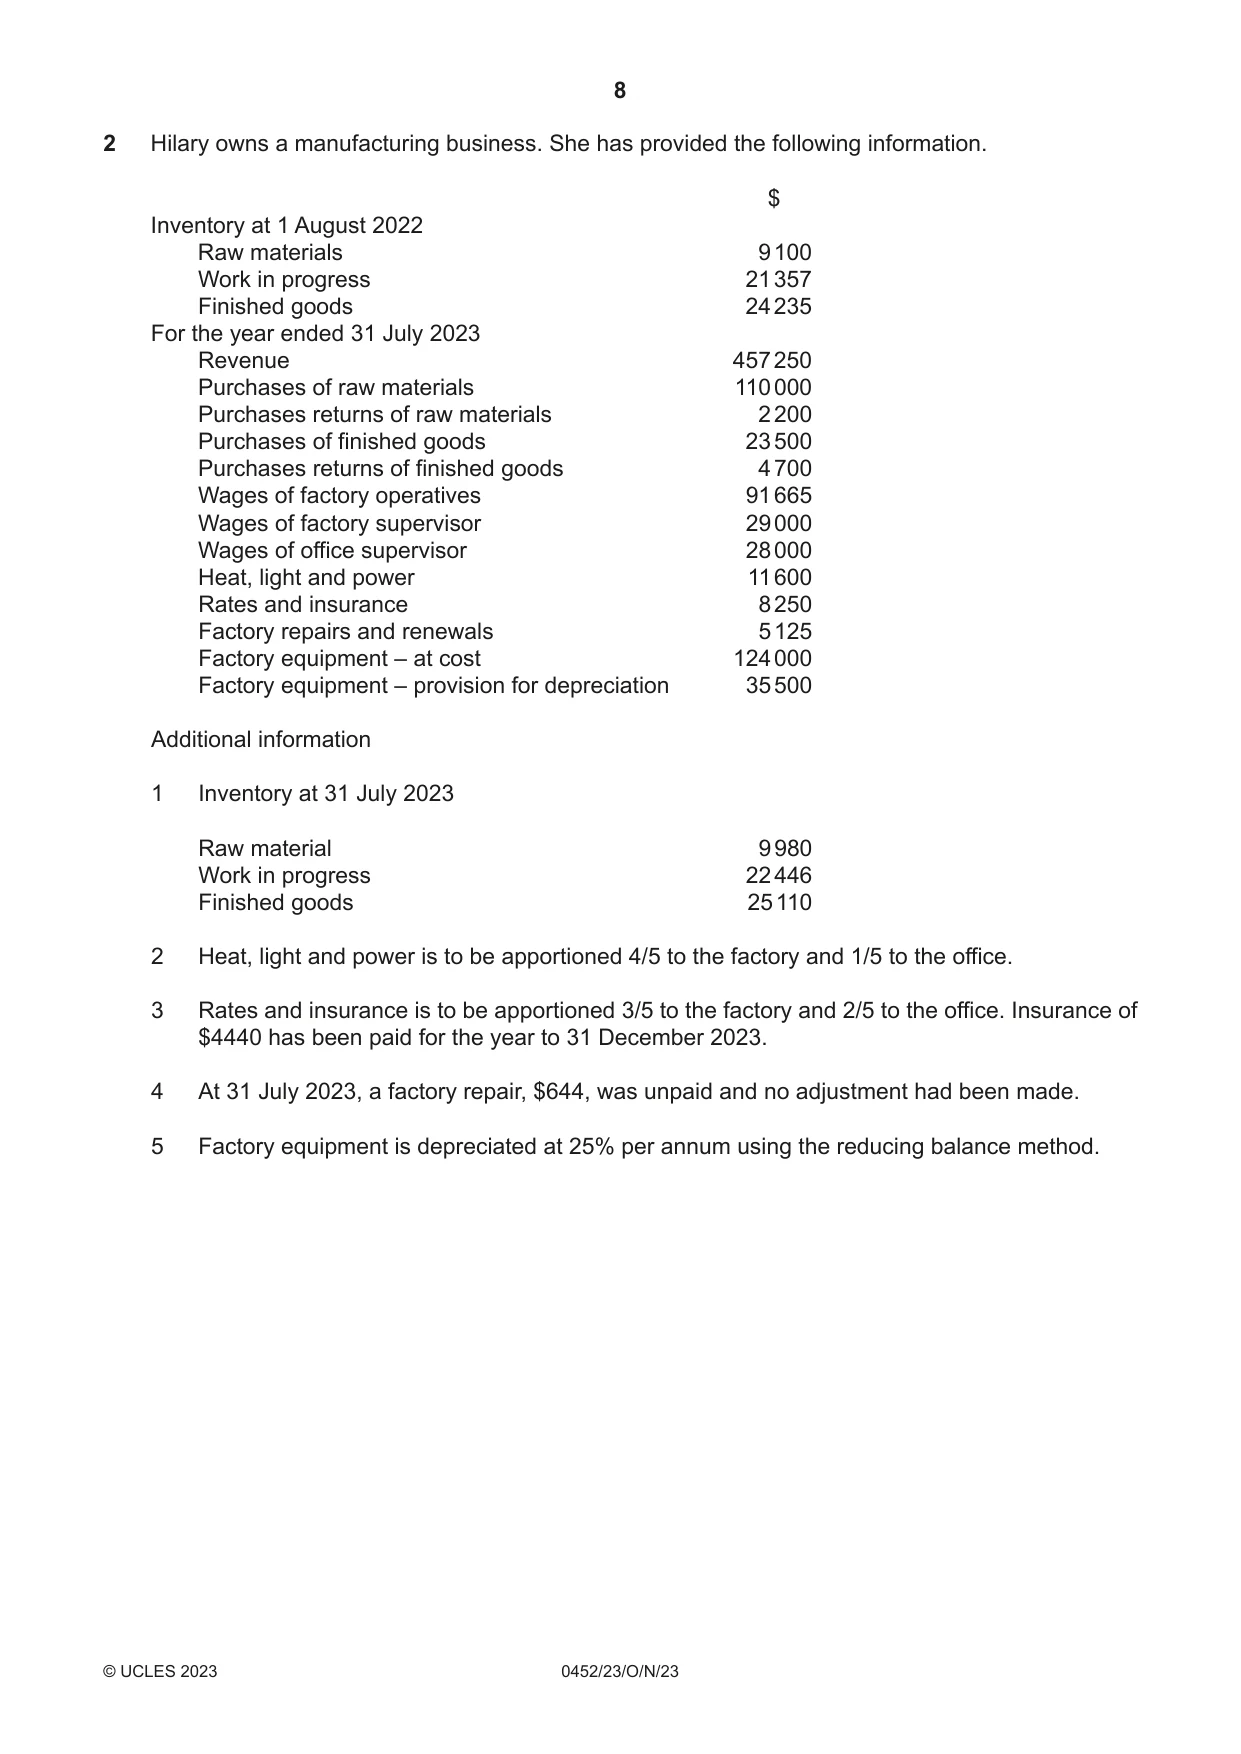
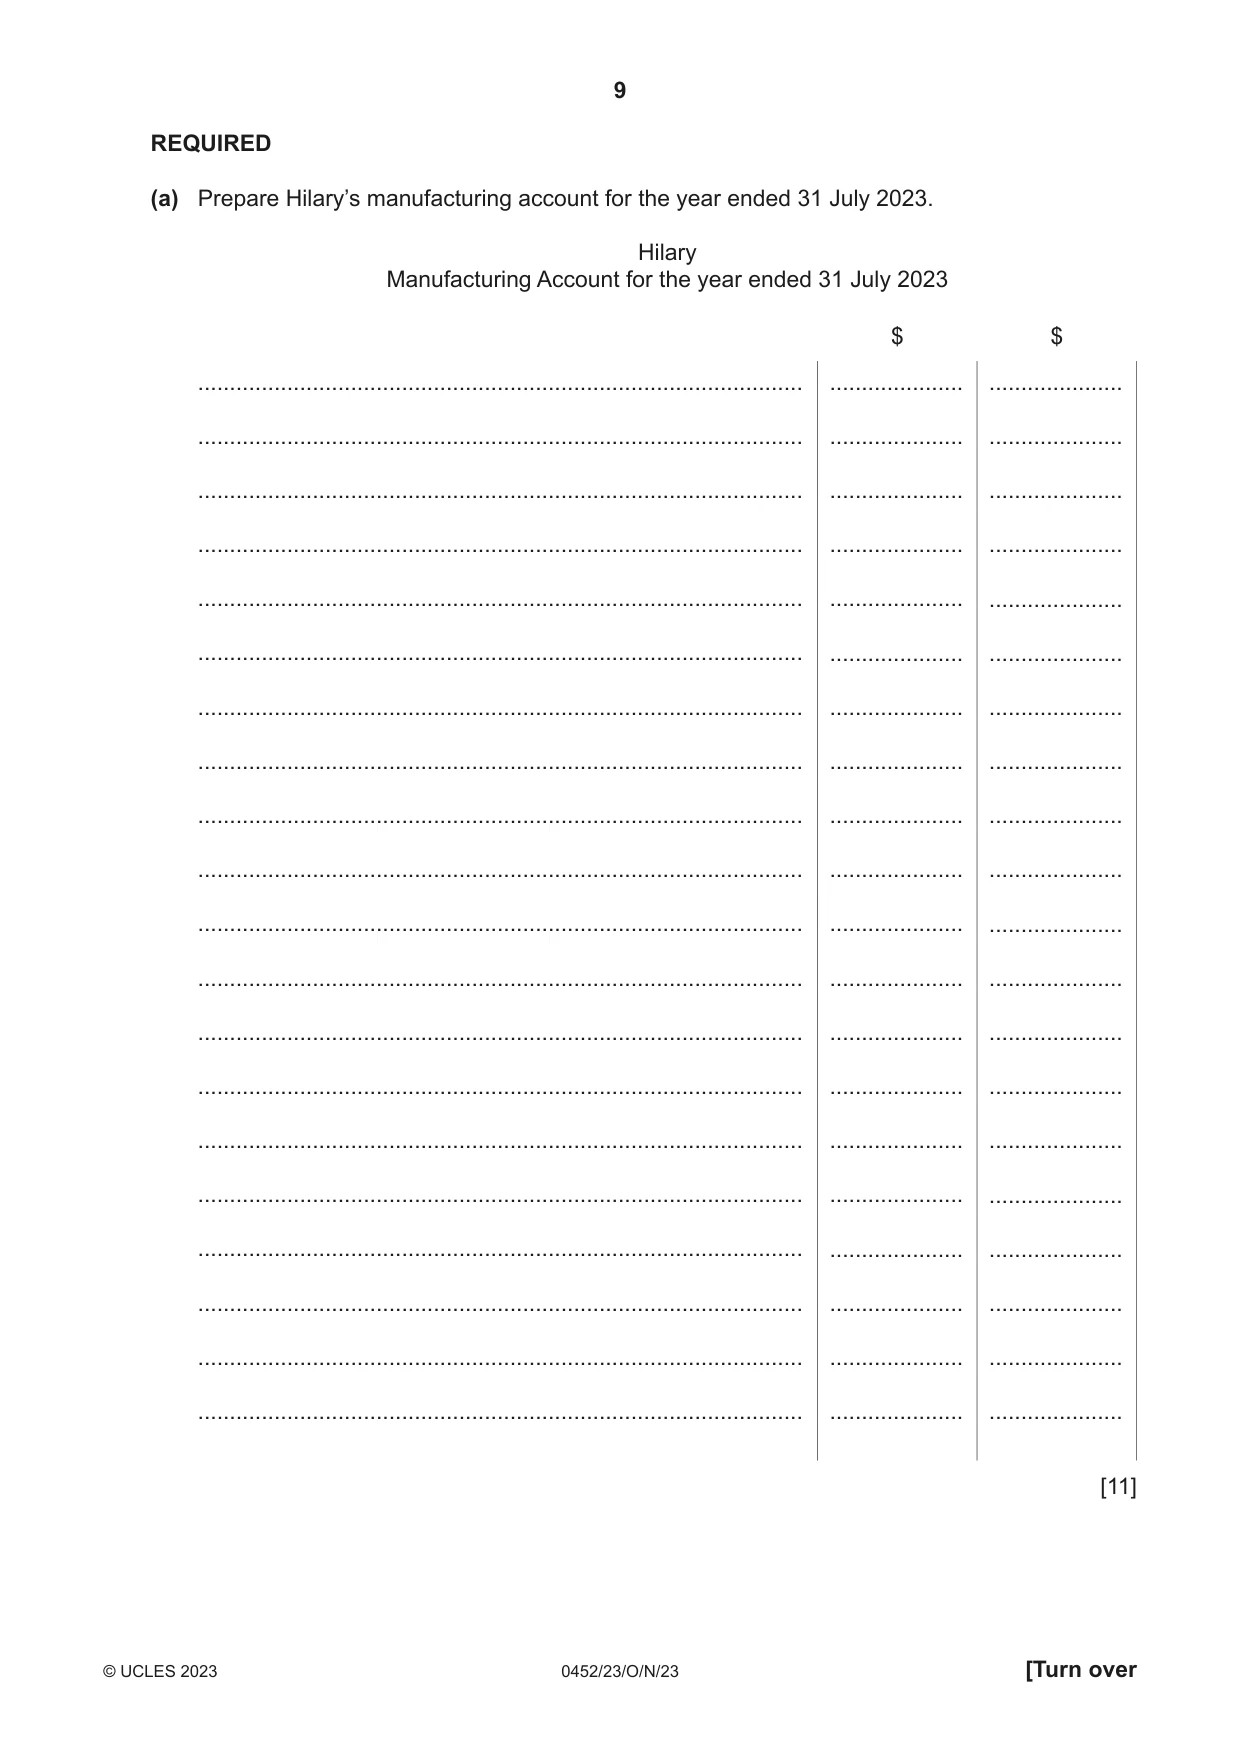
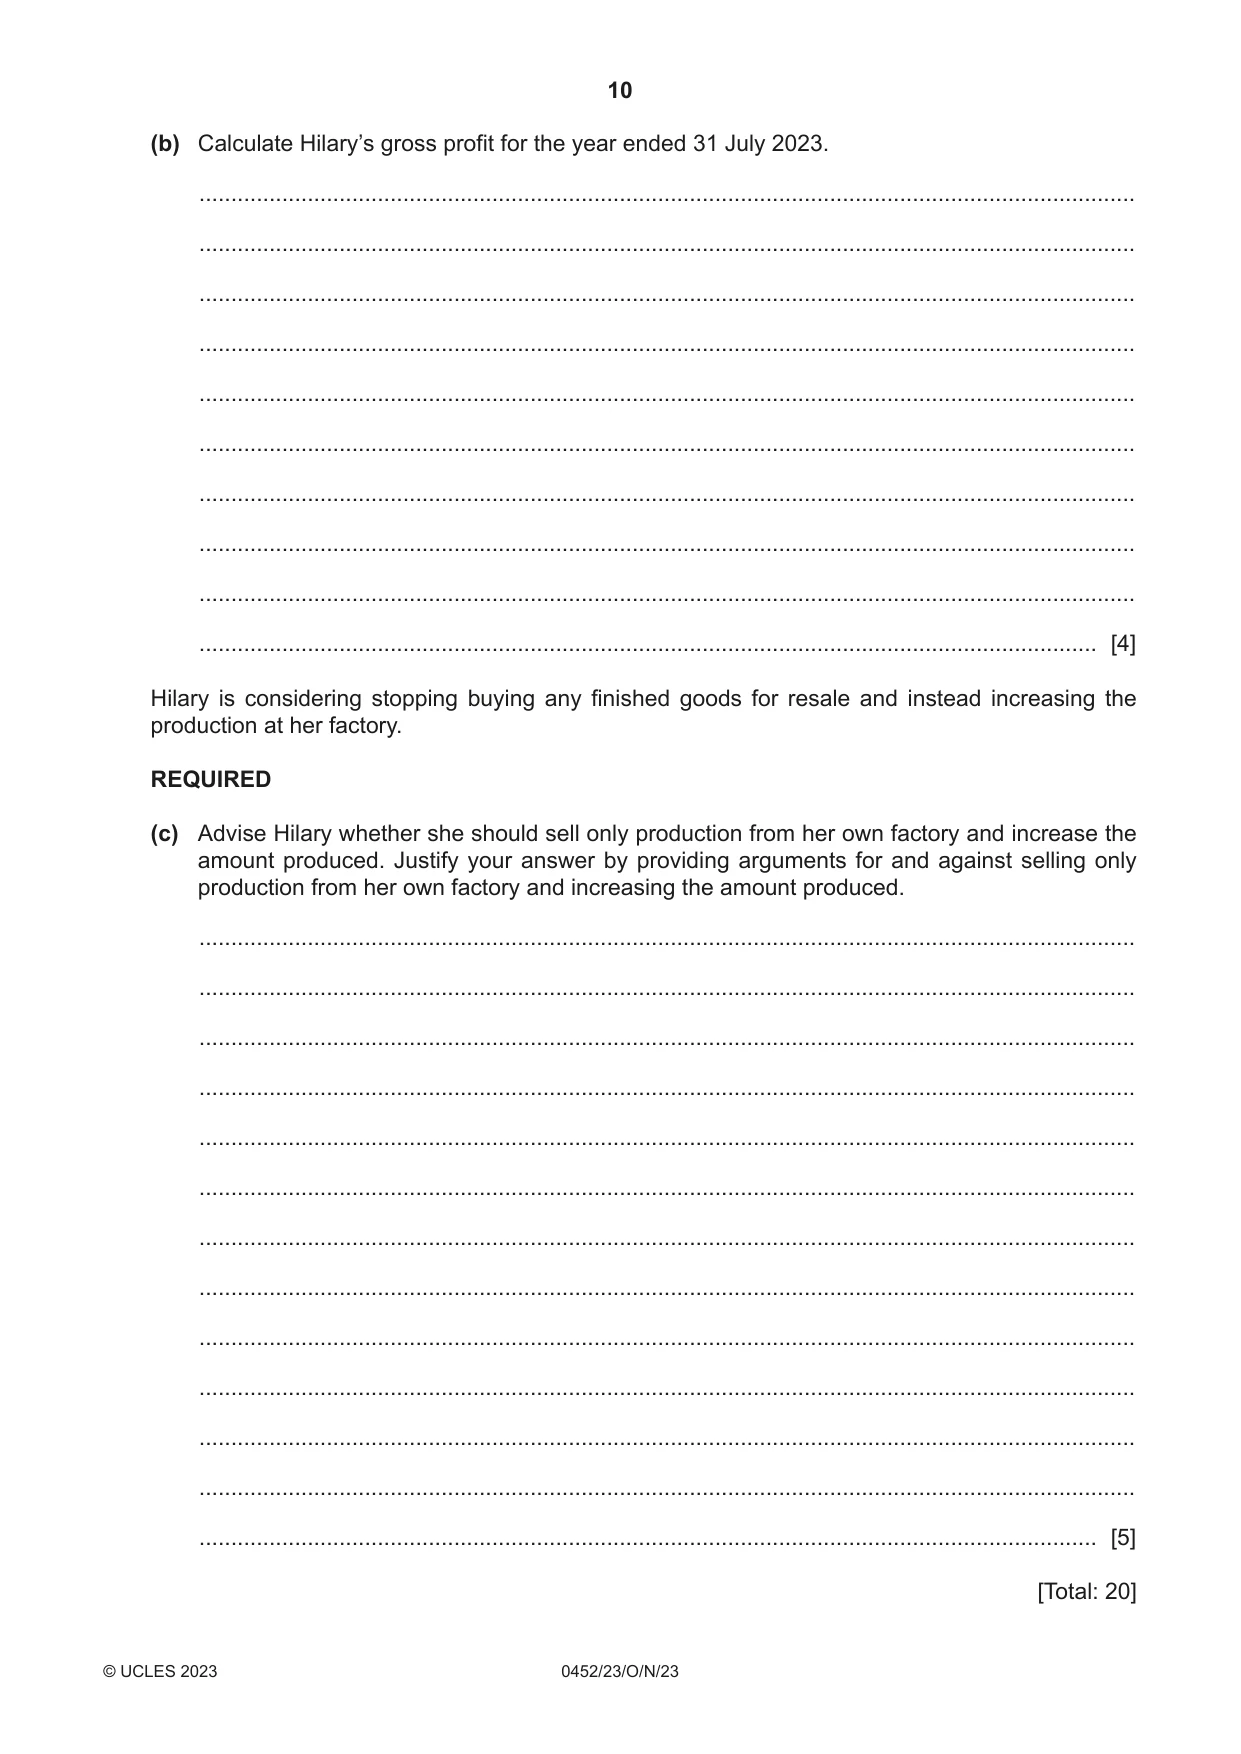
2 Hilary owns a manufacturing business. She has provided the following information. $ Inventory at 1 August 2022 Raw materials 9 100 Work in progress 21 357 Finished goods 24 235 For the year ended 31 July 2023 Revenue 457 250 Purchases of raw materials 110 000 Purchases returns of raw materials 2 200 Purchases of finished goods 23 500 Purchases returns of finished goods 4 700 Wages of factory operatives 91 665 Wages of factory supervisor 29 000 Wages of office supervisor 28 000 Heat, light and power 11 600 Rates and insurance 8 250 Factory repairs and renewals 5 125 Factory equipment – at cost 124 000 Factory equipment – provision for depreciation 35 500 Additional information 1 Inventory at 31 July 2023 Raw material 9 980 Work in progress 22 446 Finished goods 25 110 2 Heat, light and power is to be apportioned 4/5 to the factory and 1/5 to the office. 3 Rates and insurance is to be apportioned 3/5 to the factory and 2/5 to the office. Insurance of $4440 has been paid for the year to 31 December 2023. 4 At 31 July 2023, a factory repair, $644, was unpaid and no adjustment had been made. 5 Factory equipment is depreciated at 25% per annum using the reducing balance method. REQUIRED (a) Prepare Hilary’s manufacturing account for the year ended 3 Hilary Manufacturing Account for the year ended ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... (b) Calculate Hilary’s gross profit for the year ended 31 July 2023. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] Hilary is considering stopping buying any finished goods for resale and instead increasing the production at her factory. REQUIRED (c) Advise Hilary whether she should sell only production from her own factory and increase the amount produced. Justify your answer by providing arguments for and against selling only production from her own factory and increasing the amount produced. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
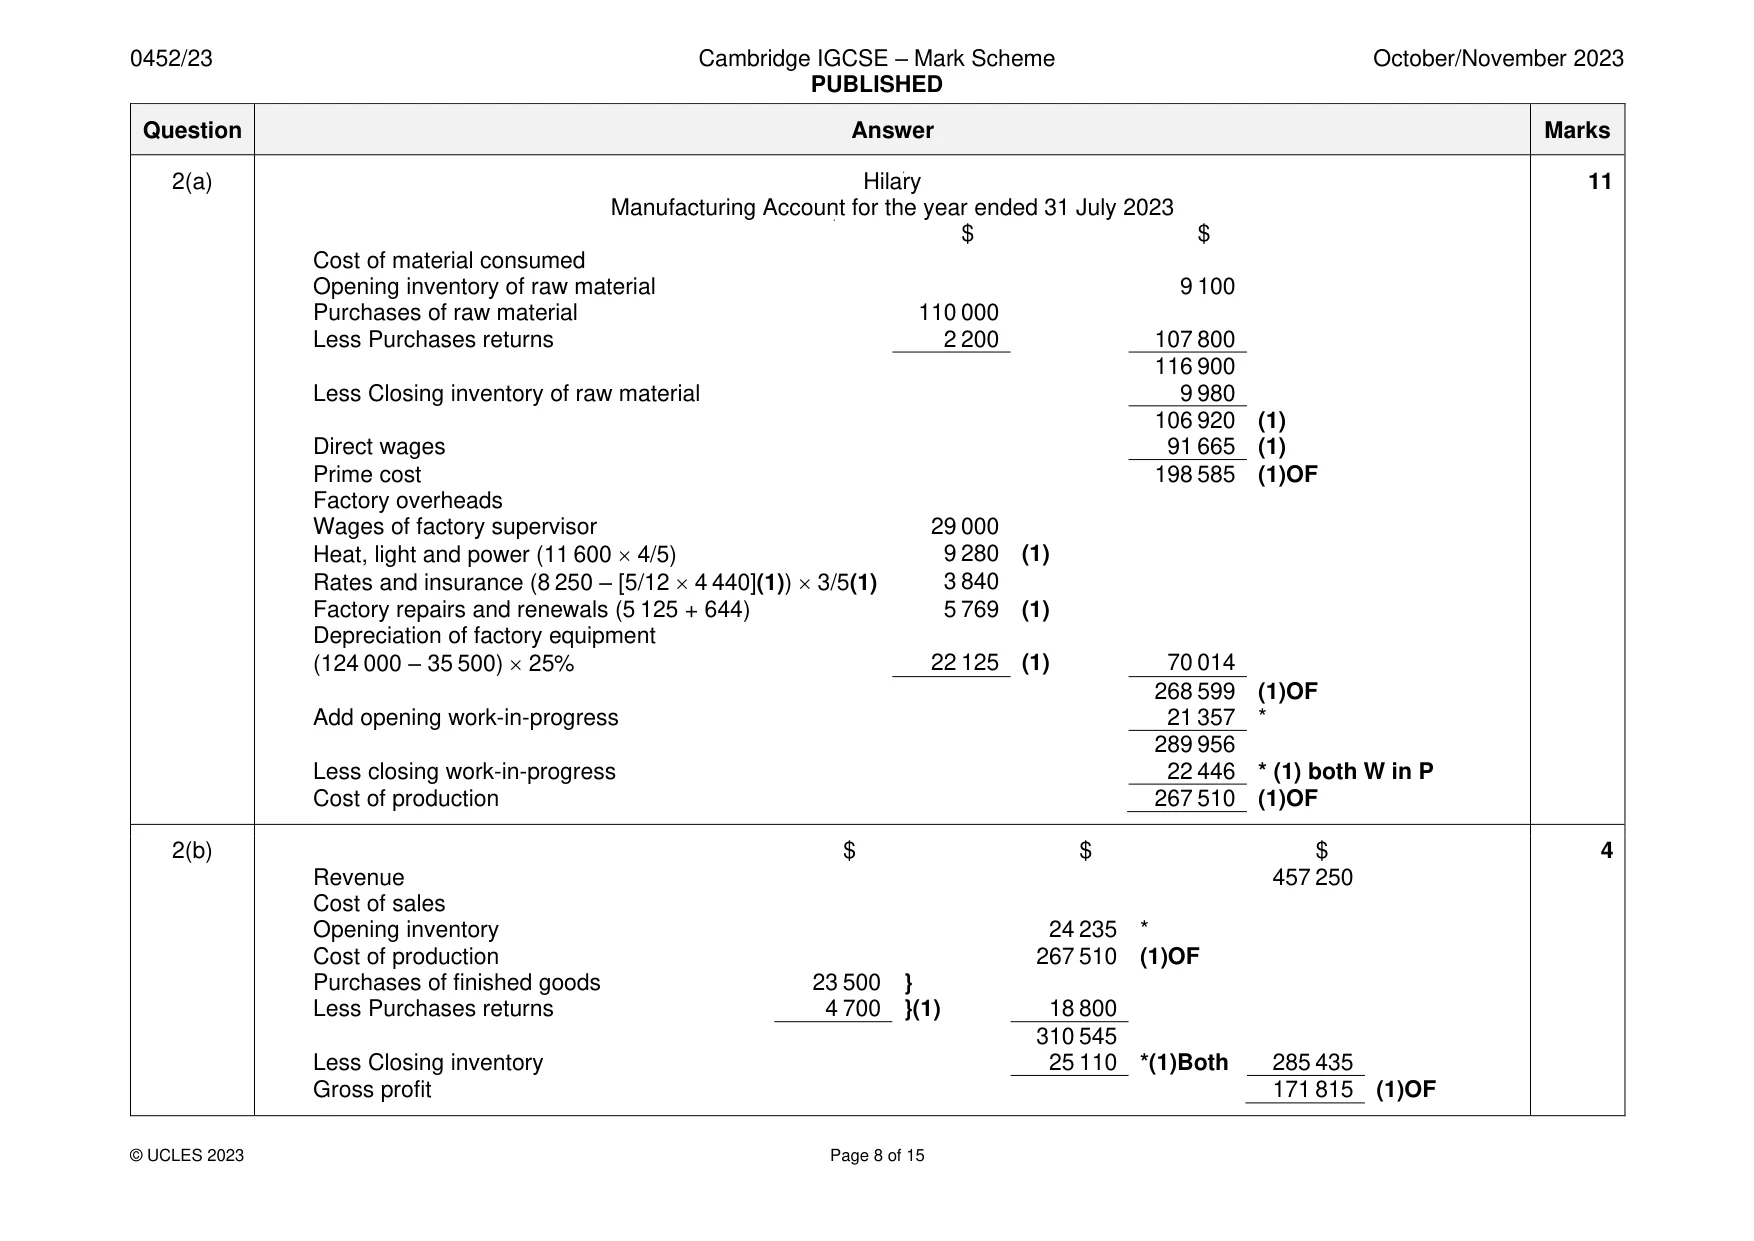
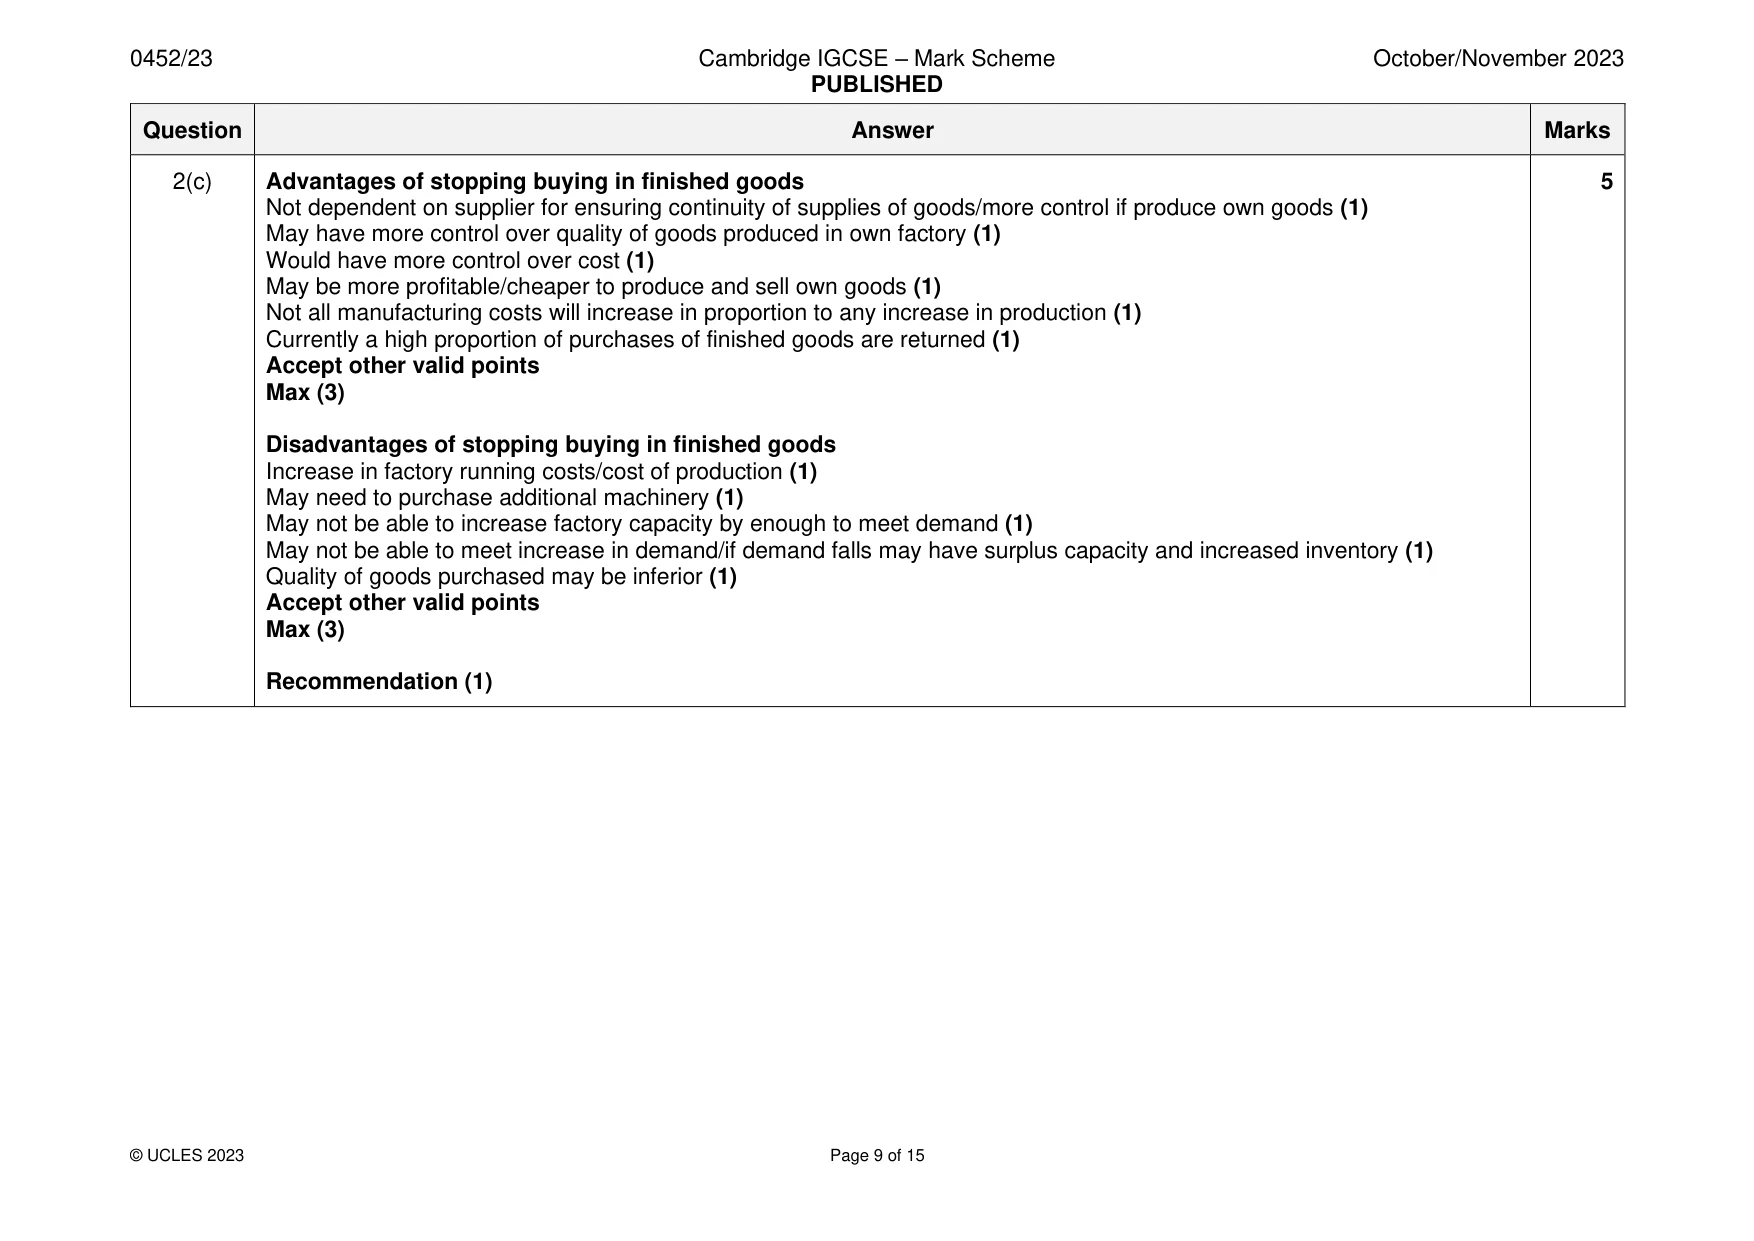
Mark scheme: 2(a) Hilary 11 Manufacturing Account for the year ended 31 July 2023 $ $ Cost of material consumed Opening inventory of raw material 9 100 Purchases of raw material 110 000 Less Purchases returns 2 200 107 800 116 900 Less Closing inventory of raw material 9 980 106 920 (1) Direct wages 91 665 (1) Prime cost 198 585 (1)OF Factory overheads Wages of factory supervisor 29 000 Heat, light and power (11 600 4/5) 9 280 (1) Rates and insurance (8 250 – [5/12 4 440](1)) 3/5(1) 3 840 Factory repairs and renewals (5 125 + 644) 5 769 (1) Depreciation of factory equipment (124 000 – 35 500) 25% 22 125 (1) 70 014 268 599 (1)OF Add opening work-in-progress 21 357 * 289 956 Less closing work-in-progress 22 446 * (1) both W in P Cost of production 267 510 (1)OF 2(b) $ $ $ 4 Revenue 457 250 Cost of sales Opening inventory 24 235 * Cost of production 267 510 (1)OF Purchases of finished goods 23 500 } Less Purchases returns 4 700 }(1) 18 800 310 545 Less Closing inventory 25 110 *(1)Both 285 435 Gross profit 171 815 (1)OF 2(c) Advantages of stopping buying in finished goods 5 Not dependent on supplier for ensuring continuity of supplies of goods/more control if produce own goods (1) May have more control over quality of goods produced in own factory (1) Would have more control over cost (1) May be more profitable/cheaper to produce and sell own goods (1) Not all manufacturing costs will increase in proportion to any increase in production (1) Currently a high proportion of purchases of finished goods are returned (1) Accept other valid points Max (3) Disadvantages of stopping buying in finished goods Increase in factory running costs/cost of production (1) May need to purchase additional machinery (1) May not be able to increase factory capacity by enough to meet demand (1) May not be able to meet increase in demand/if demand falls may have surplus capacity and increased inventory (1) Quality of goods purchased may be inferior (1) Accept other valid points Max (3) Recommendation (1)
Q3 · Logan is a trader who sells goods on credit
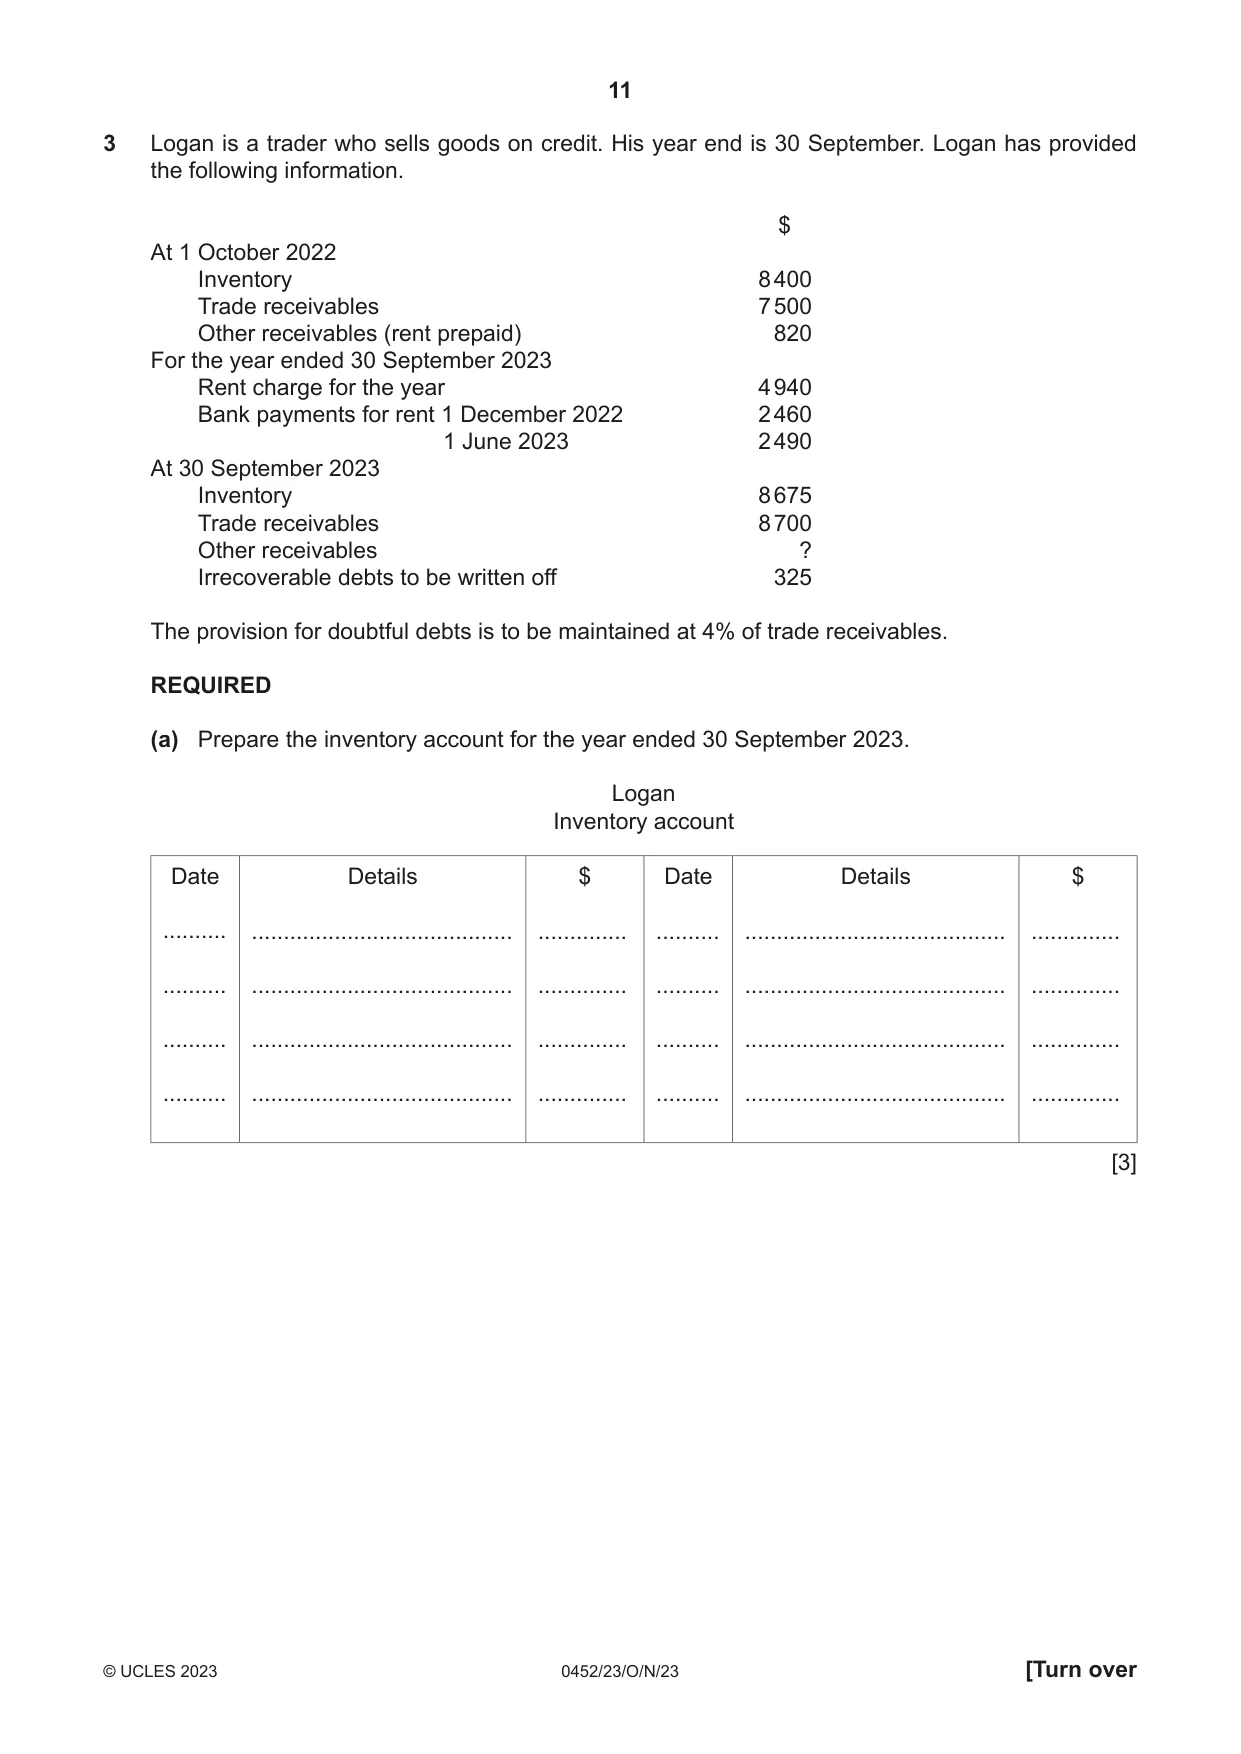
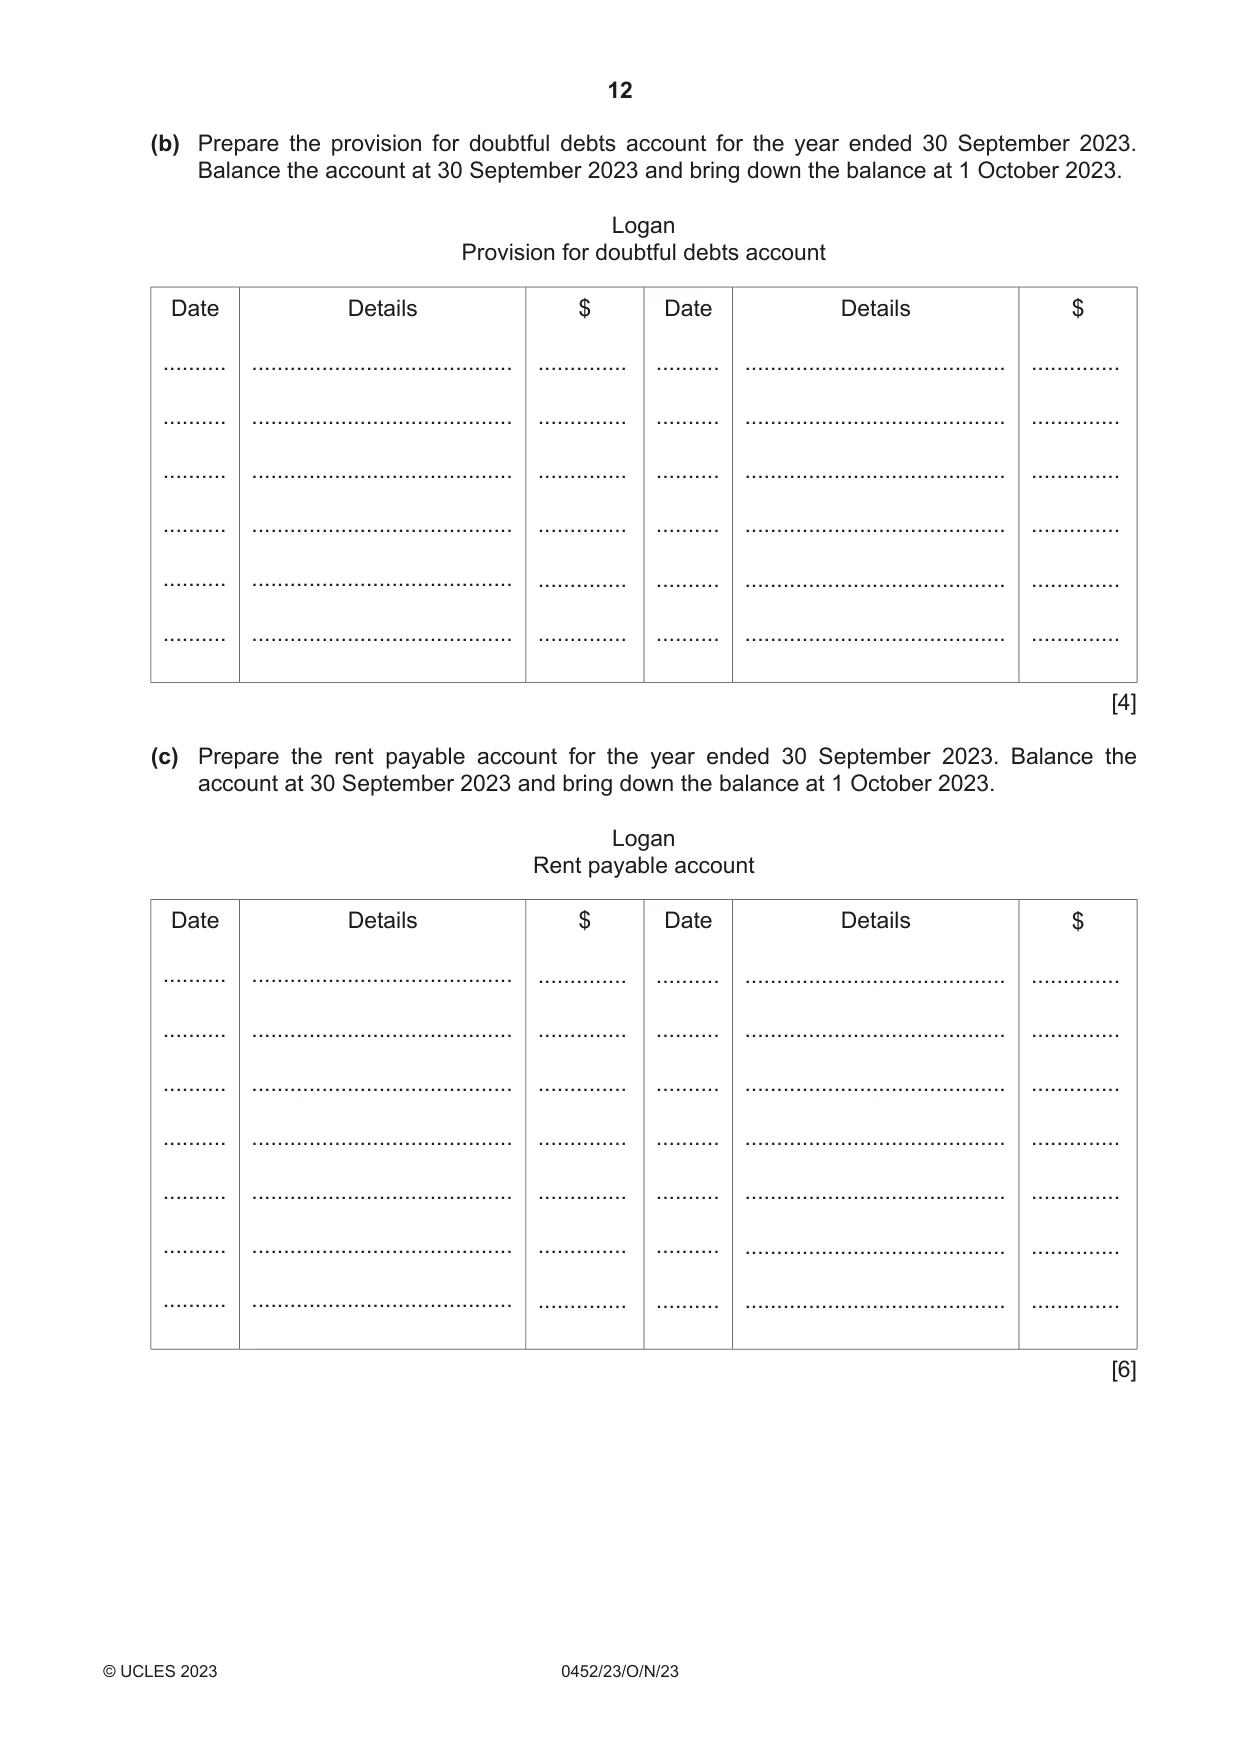
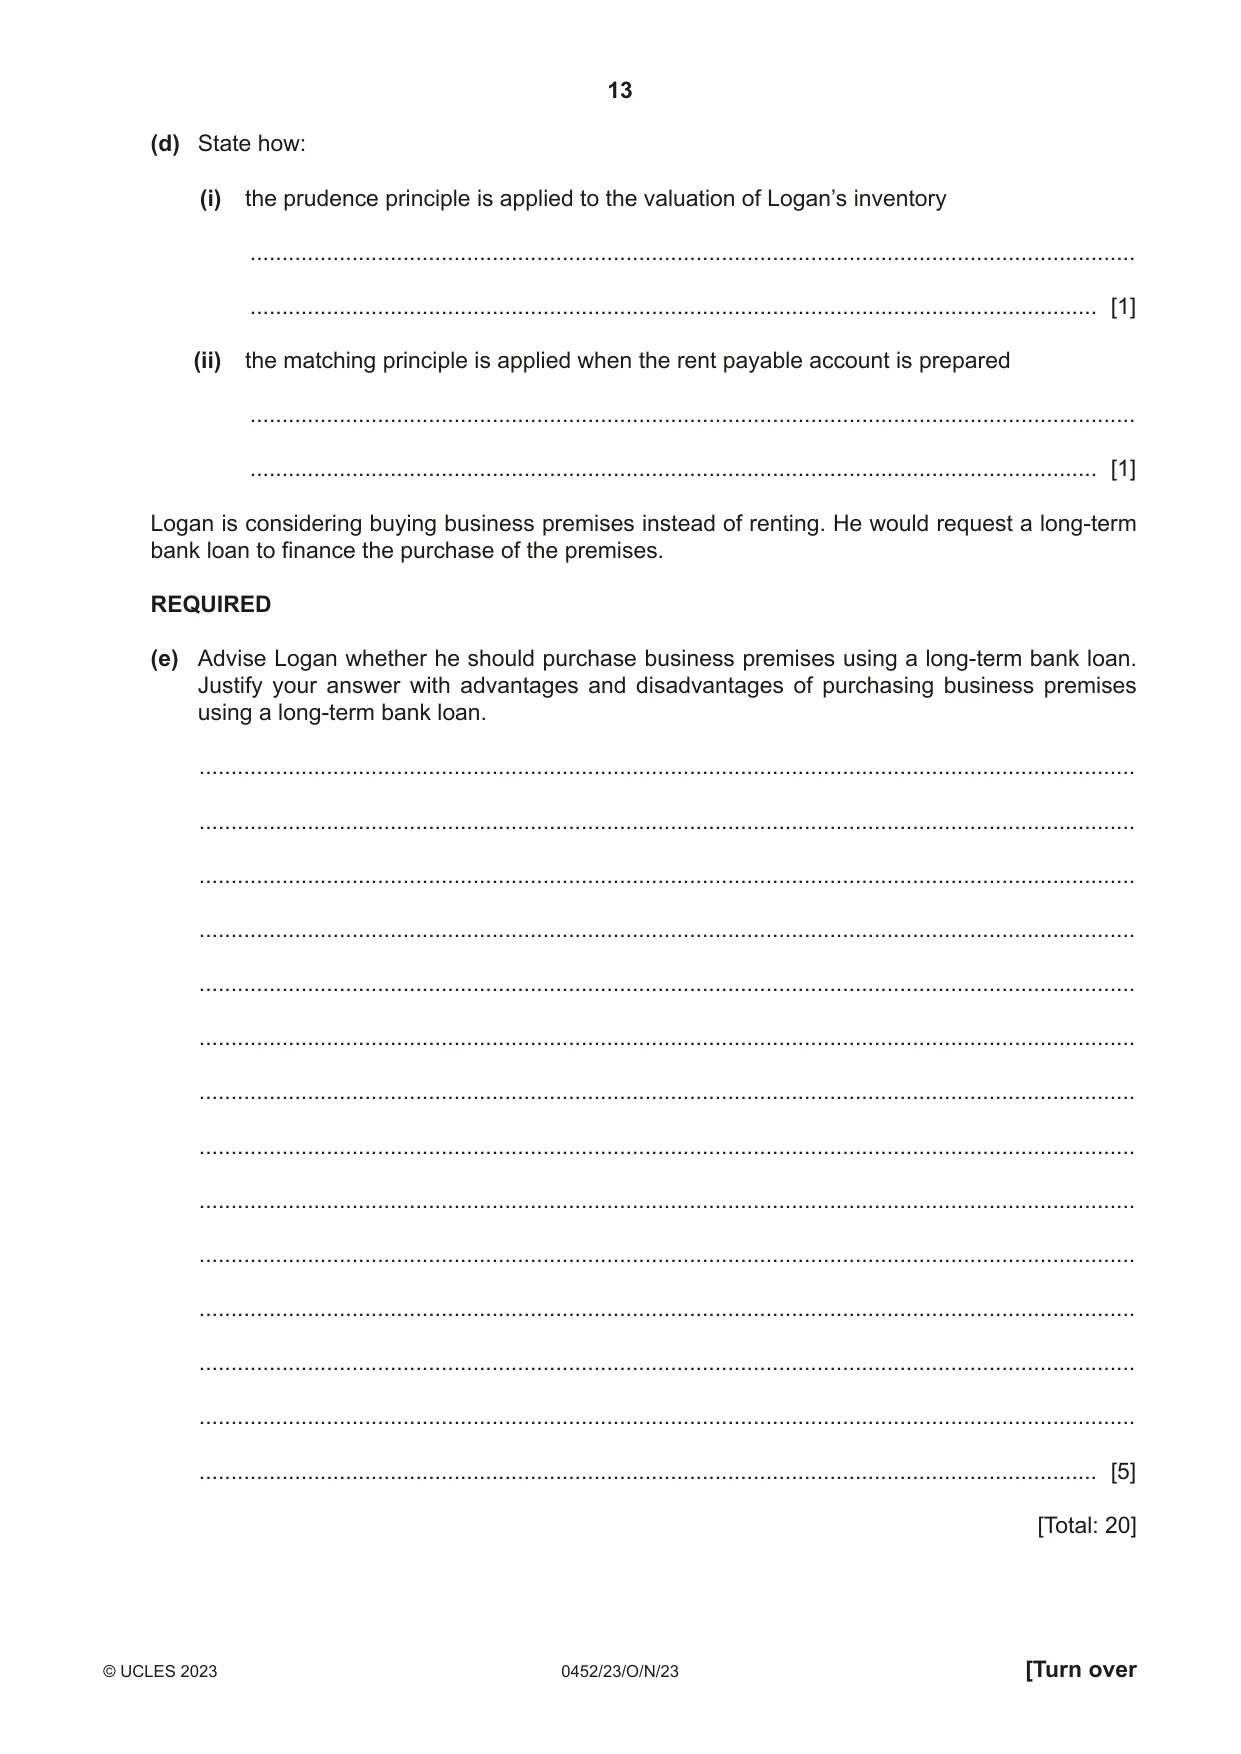
3 Logan is a trader who sells goods on credit. His year end is 30 September. Logan has provided the following information. $ At 1 October 2022 Inventory 8 400 Trade receivables 7 500 Other receivables (rent prepaid) 820 For the year ended 30 September 2023 Rent charge for the year 4 940 Bank payments for rent 1 December 2022 2 460 1 June 2023 2 490 At 30 September 2023 Inventory 8 675 Trade receivables 8 700 Other receivables ? Irrecoverable debts to be written off 325 The provision for doubtful debts is to be maintained at 4% of trade receivables. REQUIRED (a) Prepare the inventory account for the year ended 30 September 2023. Logan Inventory account Date Details $ Date Details $ .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. [3] (b) Prepare the provision for doubtful debts account for the year ended 30 September 2023. Balance the account at 30 September 2023 and bring down the balance at 1 October 2023. Logan Provision for doubtful debts account Date Details $ Date Details $ .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. [4] (c) Prepare the rent payable account for the year ended 30 September 2023. Balance the account at 30 September 2023 and bring down the balance at 1 October 2023. Logan Rent payable account Date Details $ Date Details $ .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. [6] (d) State how: (i) the prudence principle is applied to the valuation of Logan’s inventory ........................................................................................................................................... ..................................................................................................................................... [1] (ii) the matching principle is applied when the rent payable account is prepared ........................................................................................................................................... ..................................................................................................................................... [1] Logan is considering buying business premises instead of renting. He would request a long-term bank loan to finance the purchase of the premises. REQUIRED (e) Advise Logan whether he should purchase business premises using a long-term bank loan. Justify your answer with advantages and disadvantages of purchasing business premises using a long-term bank loan. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
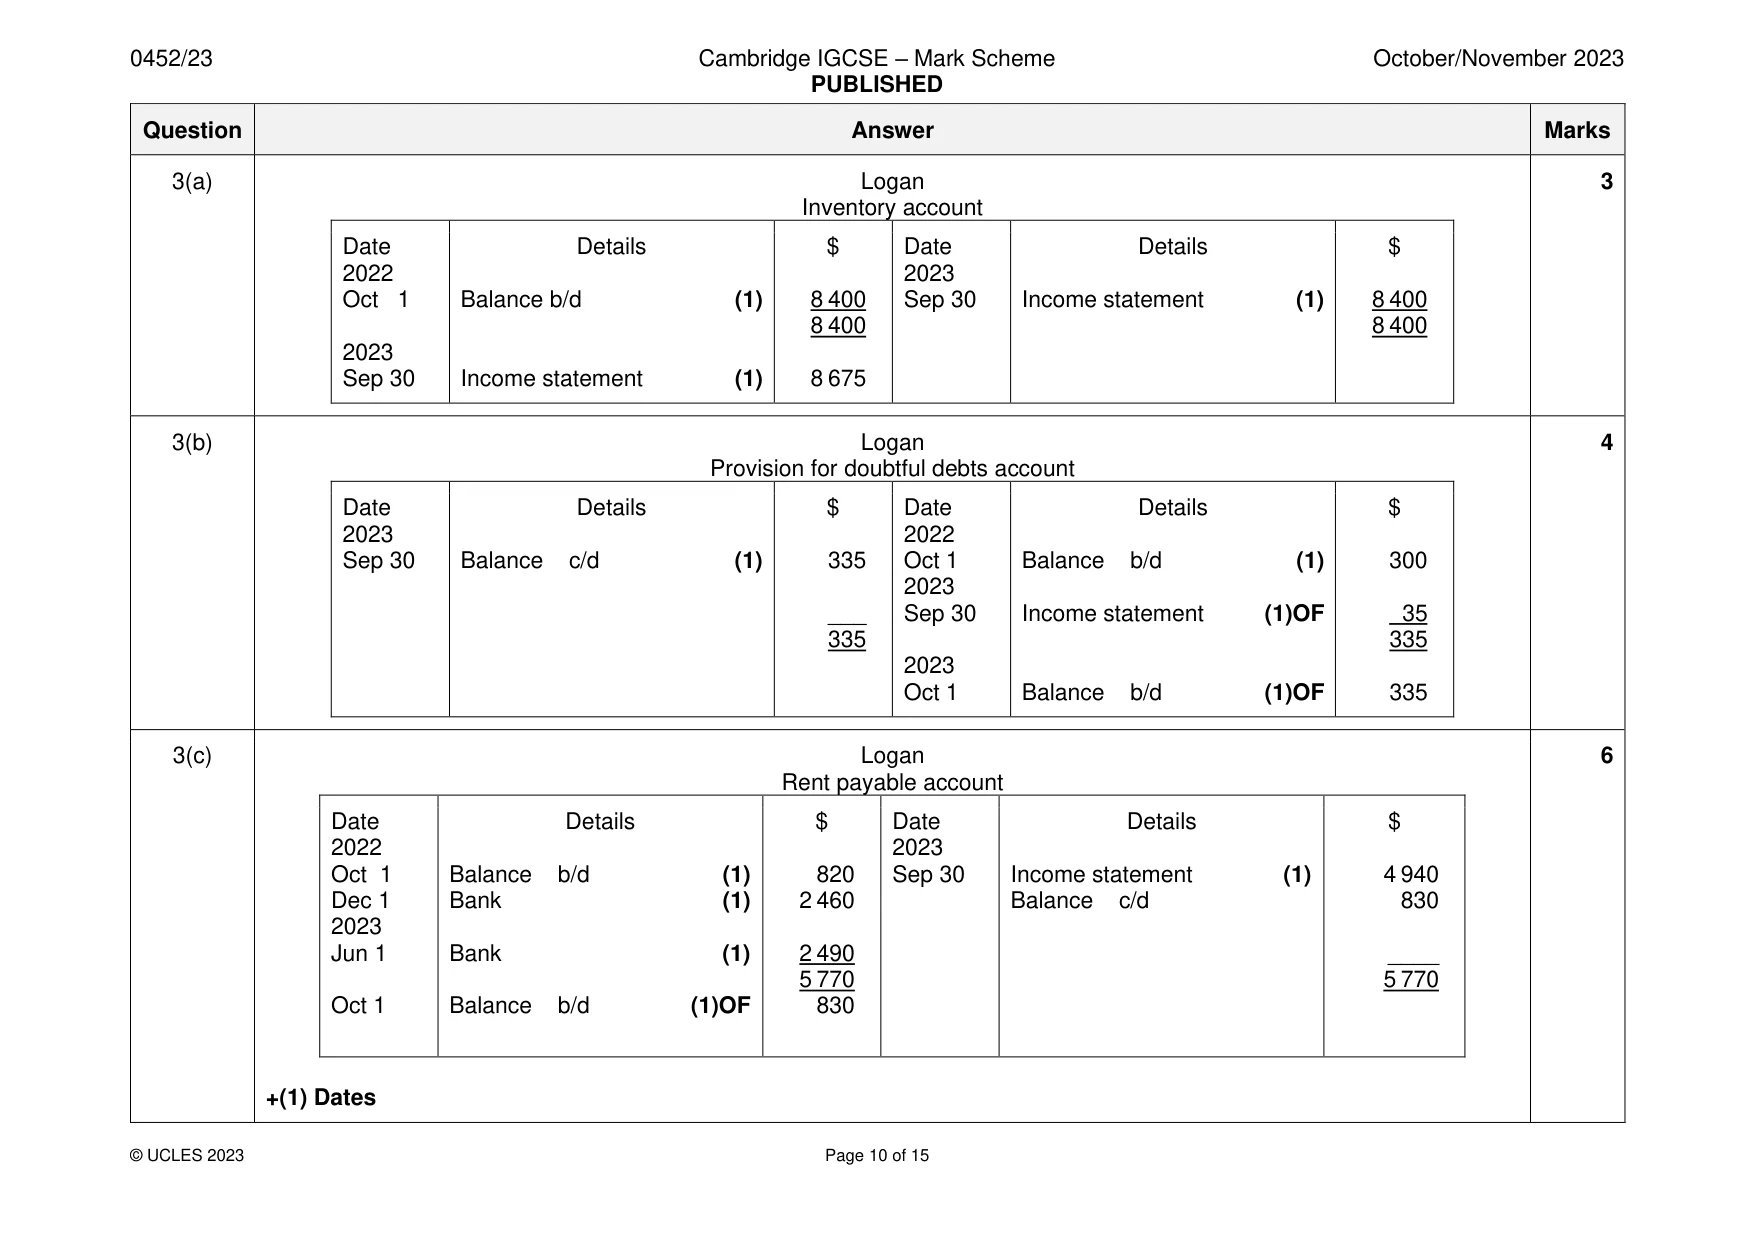
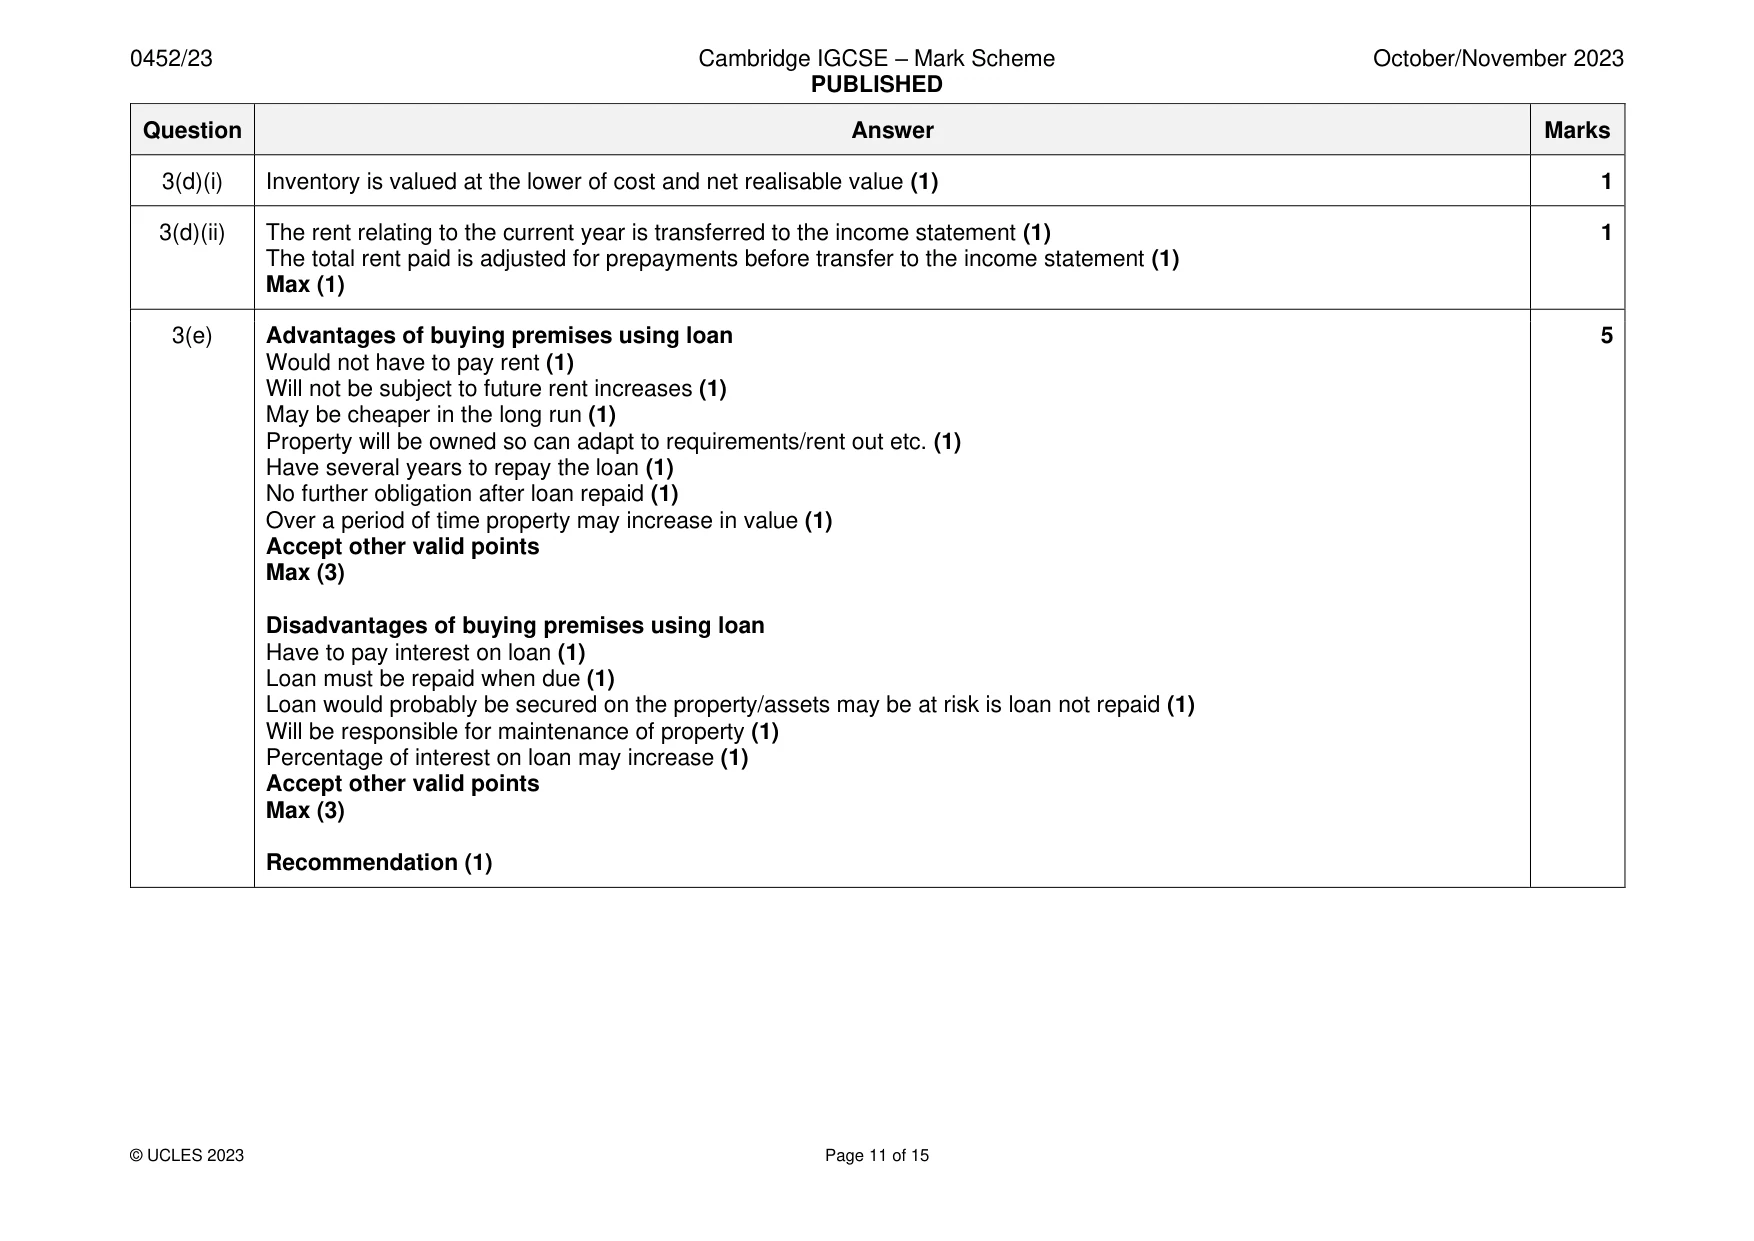
Mark scheme: 3(a) Logan 3 Inventory account Date Details $ Date Details $ 2022 2023 Oct 1 Balance b/d (1) 8 400 Sep 30 Income statement (1) 8 400 8 400 8 400 2023 Sep 30 Income statement (1) 8 675 3(b) Logan 4 Provision for doubtful debts account Date Details $ Date Details $ 2023 2022 Sep 30 Balance c/d (1) 335 Oct 1 Balance b/d (1) 300 2023 ___ Sep 30 Income statement (1)OF 35 335 335 2023 Oct 1 Balance b/d (1)OF 335 3(c) Logan 6 Rent payable account Date Details $ Date Details $ 2022 2023 Oct 1 Balance b/d (1) 820 Sep 30 Income statement (1) 4 940 Dec 1 Bank (1) 2 460 Balance c/d 830 2023 Jun 1 Bank (1) 2 490 ____ 5 770 5 770 Oct 1 Balance b/d (1)OF 830 +(1) Dates 3(d)(i) Inventory is valued at the lower of cost and net realisable value (1) 1 3(d)(ii) The rent relating to the current year is transferred to the income statement (1) 1 The total rent paid is adjusted for prepayments before transfer to the income statement (1) Max (1) 3(e) Advantages of buying premises using loan 5 Would not have to pay rent (1) Will not be subject to future rent increases (1) May be cheaper in the long run (1) Property will be owned so can adapt to requirements/rent out etc. (1) Have several years to repay the loan (1) No further obligation after loan repaid (1) Over a period of time property may increase in value (1) Accept other valid points Max (3) Disadvantages of buying premises using loan Have to pay interest on loan (1) Loan must be repaid when due (1) Loan would probably be secured on the property/assets may be at risk is loan not repaid (1) Will be responsible for maintenance of property (1) Percentage of interest on loan may increase (1) Accept other valid points Max (3) Recommendation (1)
Q4 · Asia is a trader
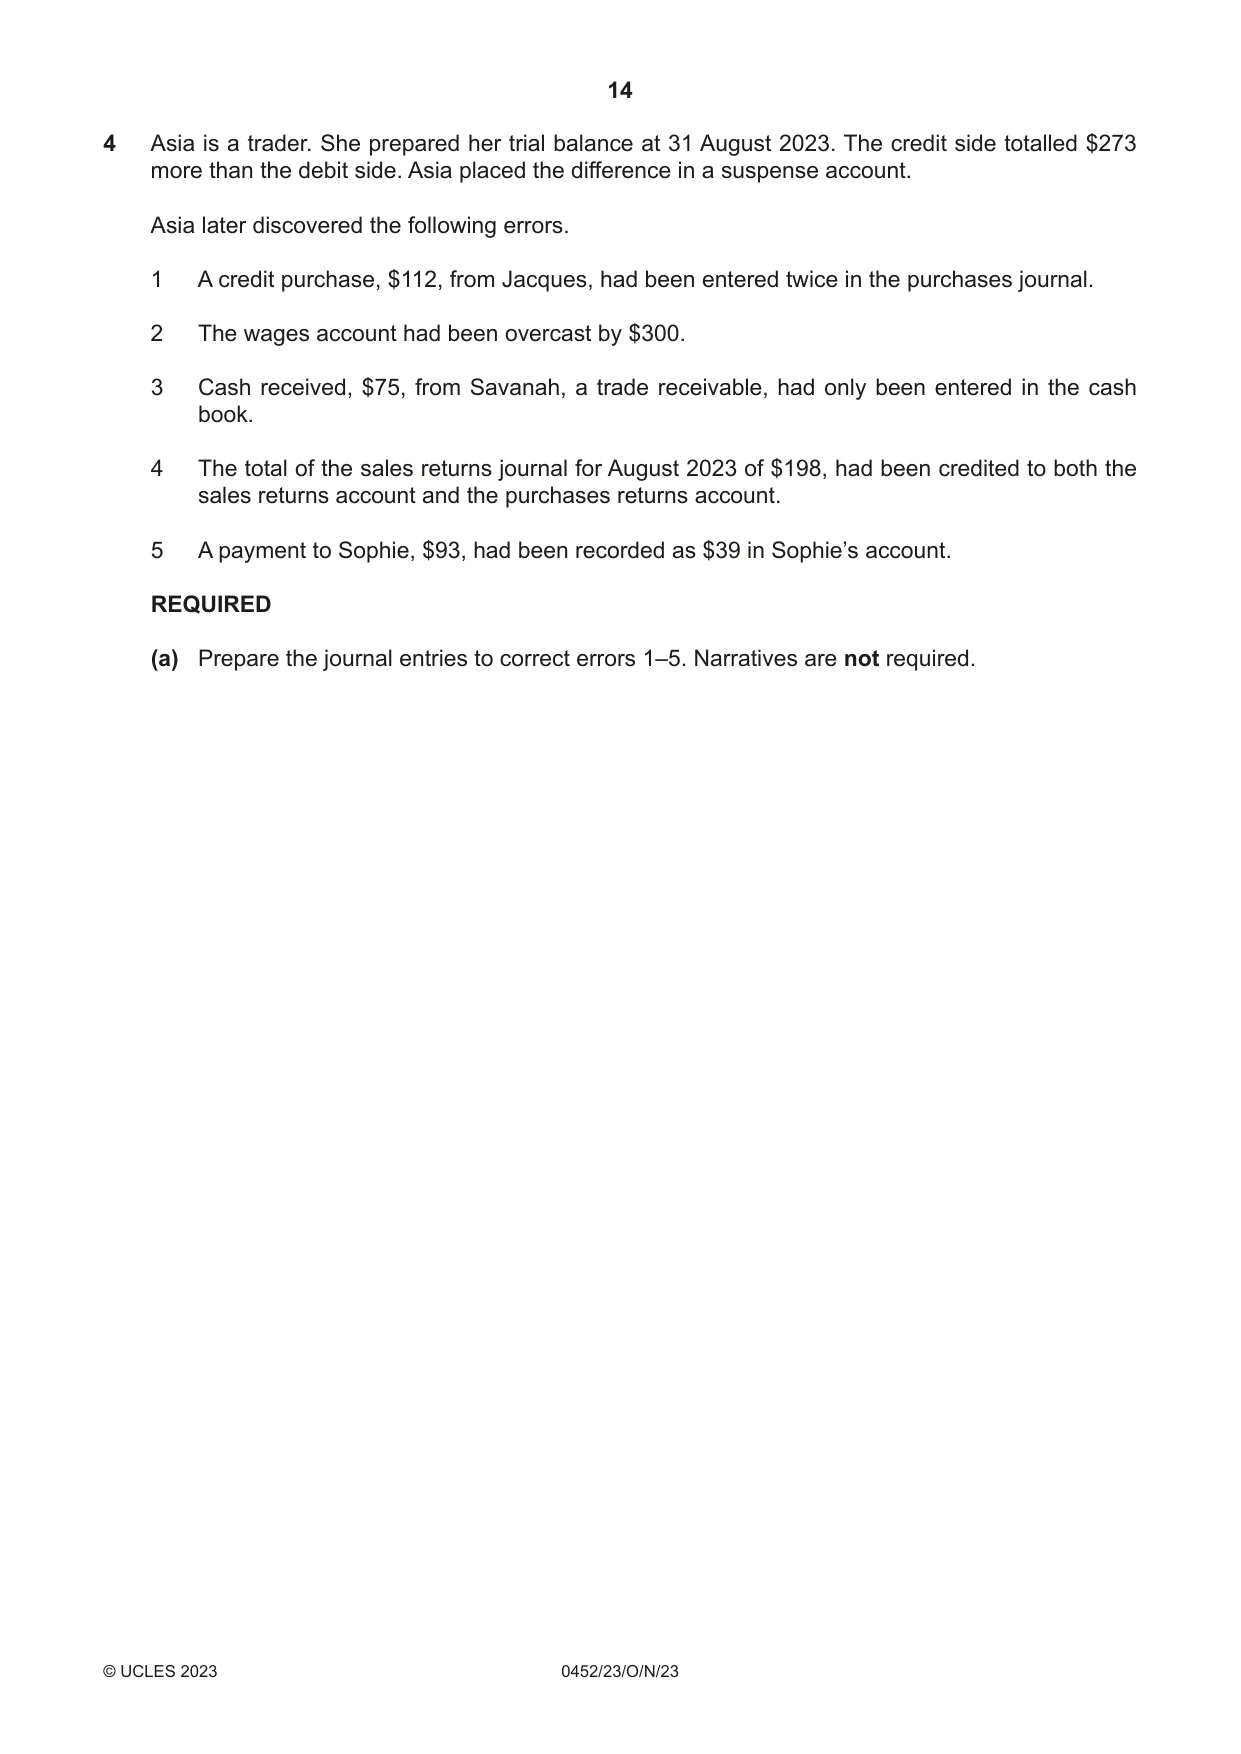
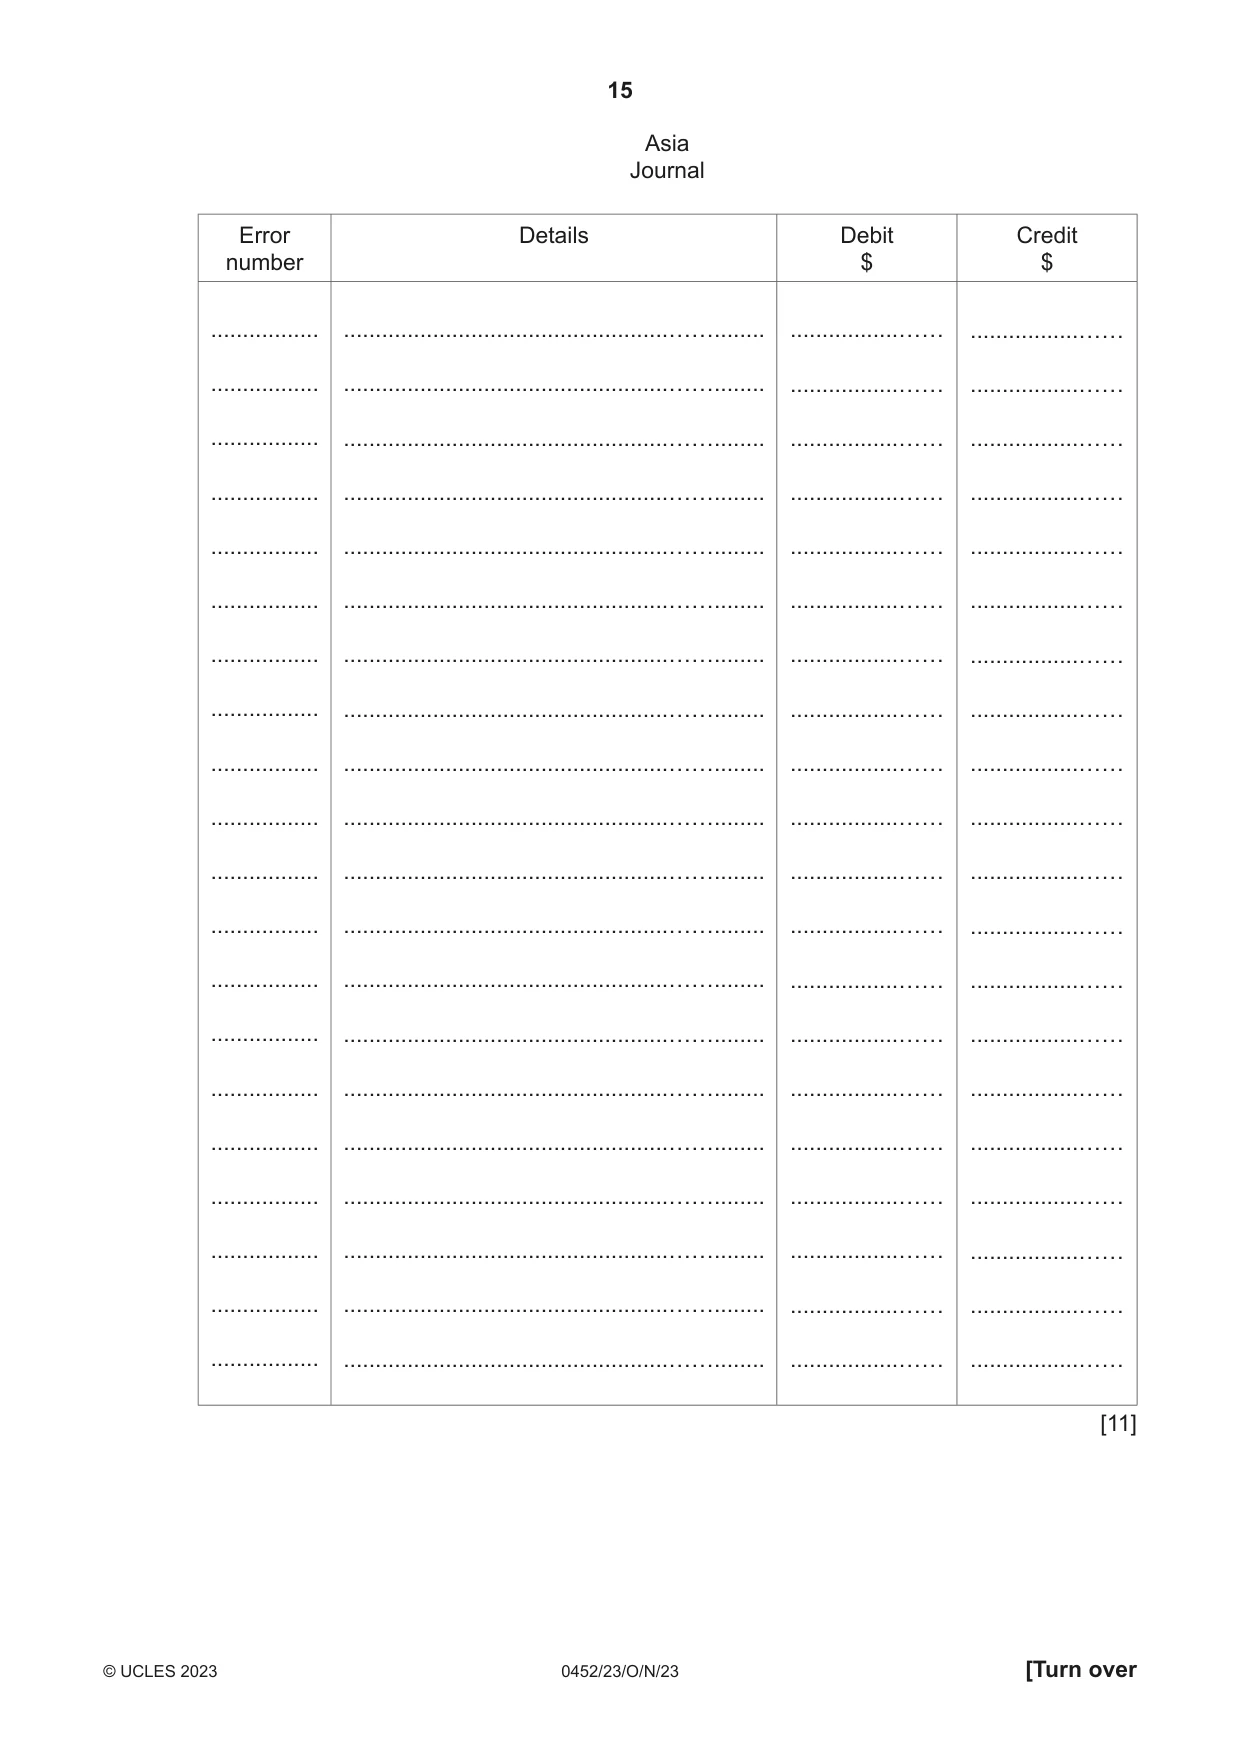
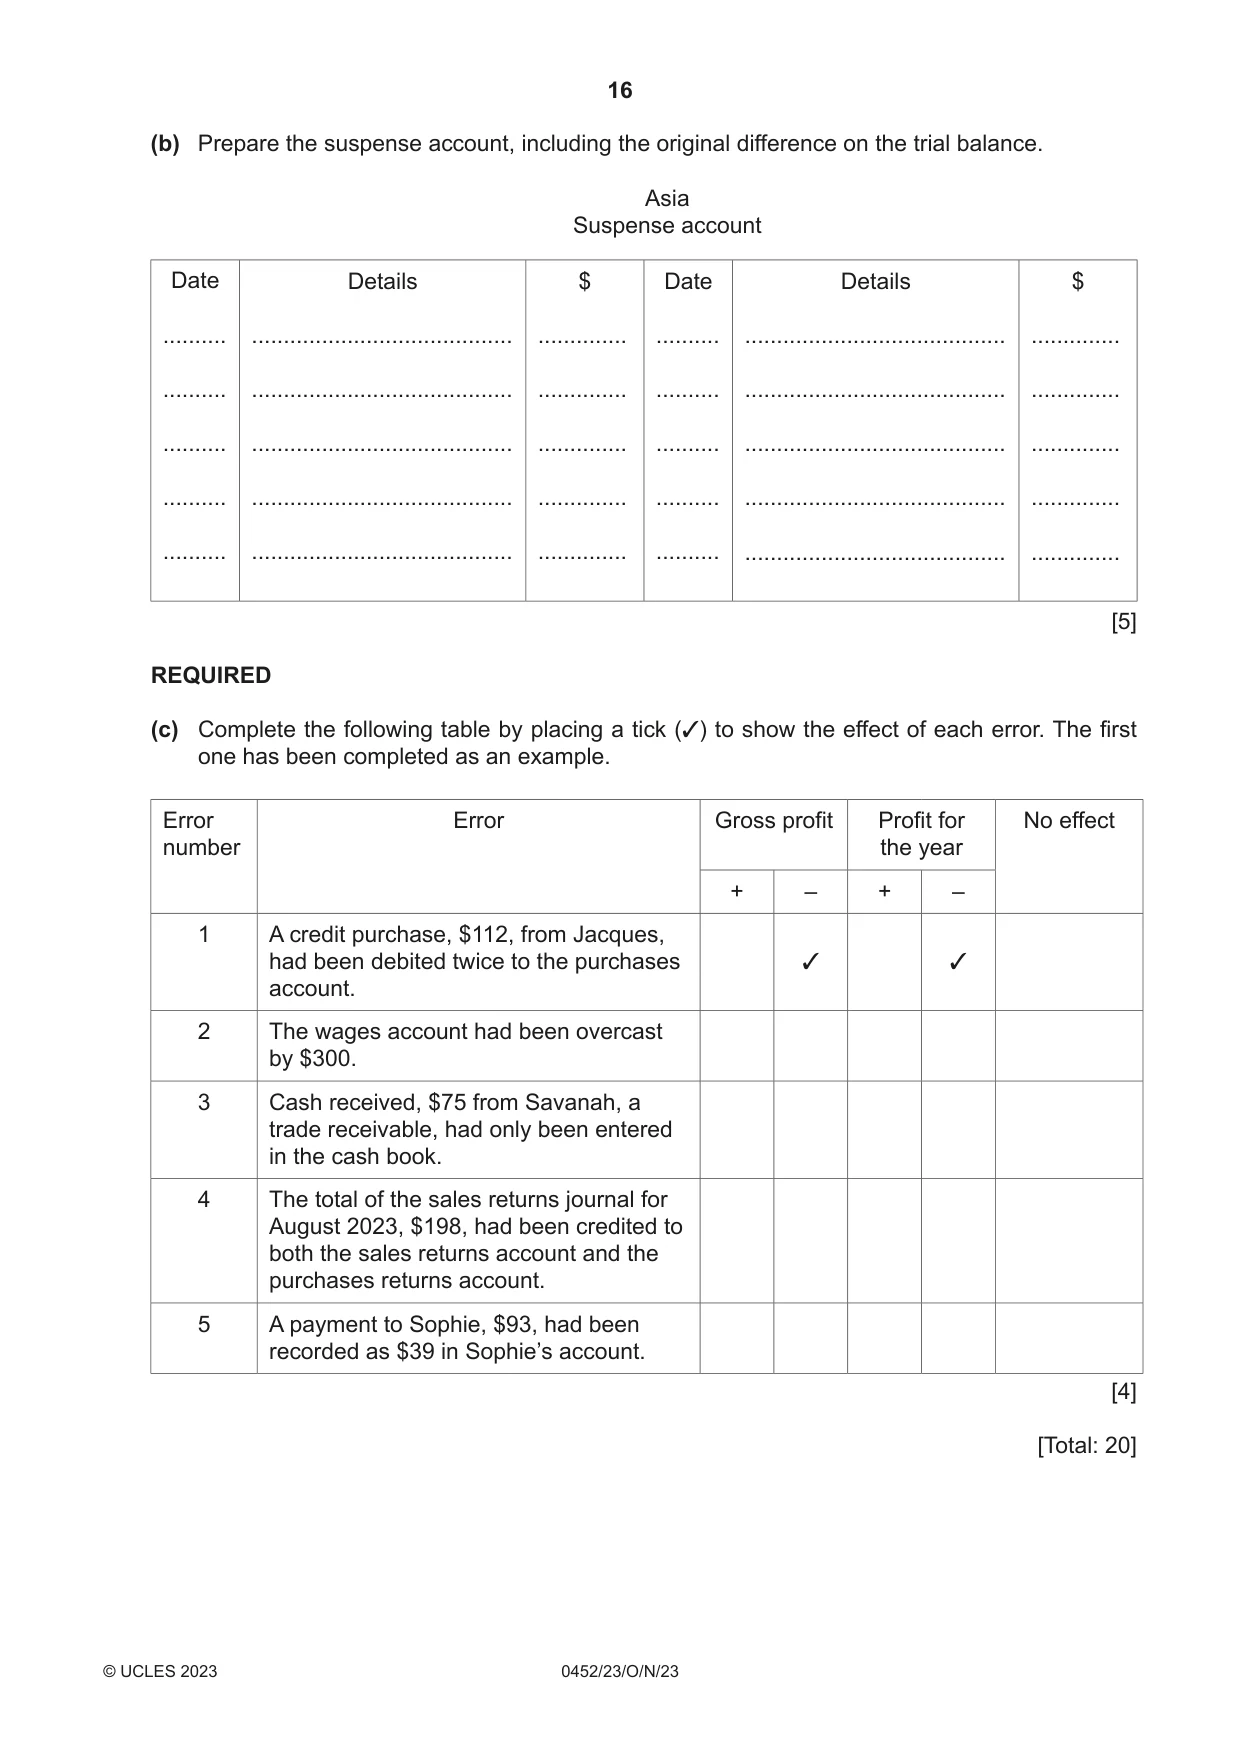
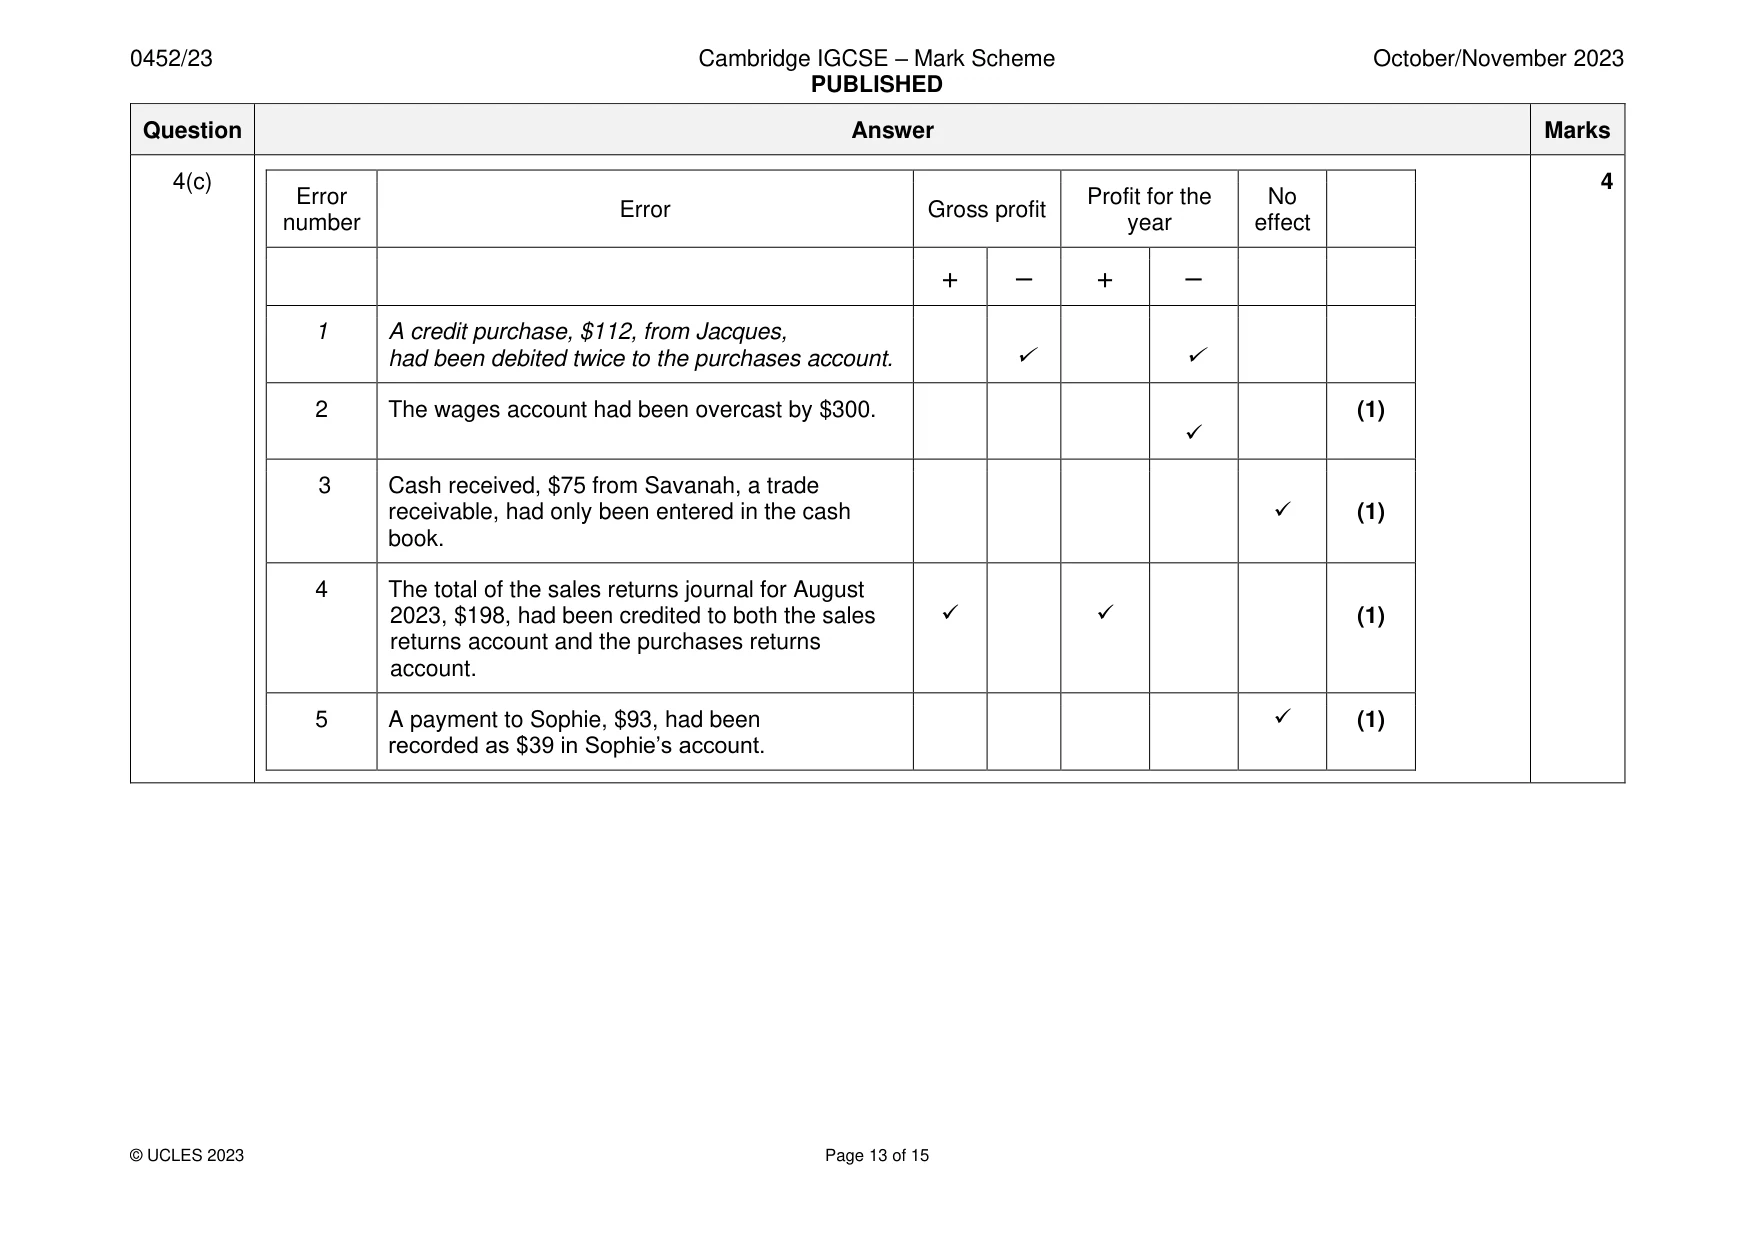
4 Asia is a trader. She prepared her trial balance at 31 August 2023. The credit side totalled $273 more than the debit side. Asia placed the difference in a suspense account. Asia later discovered the following errors. 1 A credit purchase, $112, from Jacques, had been entered twice in the purchases journal. 2 The wages account had been overcast by $300. 3 Cash received, $75, from Savanah, a trade receivable, had only been entered in the cash book. 4 The total of the sales returns journal for August 2023 of $198, had been credited to both the sales returns account and the purchases returns account. 5 A payment to Sophie, $93, had been recorded as $39 in Sophie’s account. REQUIRED (a) Prepare the journal entries to correct errors 1–5. Narratives are not required. Asia Journal Details ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ ...................................................……........ (b) Prepare the suspense account, including the original difference on the trial balance. Asia Suspense account Date Details $ Date Details $ .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. [5] REQUIRED (c) Complete the following table by placing a tick (3) to show the effect of each error. The first one has been completed as an example. Error Error Gross profit Profit for No effect number the year + – + – 1 A credit purchase, $112, from Jacques, had been debited twice to the purchases 3 3 account. 2 The wages account had been overcast by $300. 3 Cash received, $75 from Savanah, a trade receivable, had only been entered in the cash book. 4 The total of the sales returns journal for August 2023, $198, had been credited to both the sales returns account and the purchases returns account. 5 A payment to Sophie, $93, had been recorded as $39 in Sophie’s account. [4] [Total: 20]
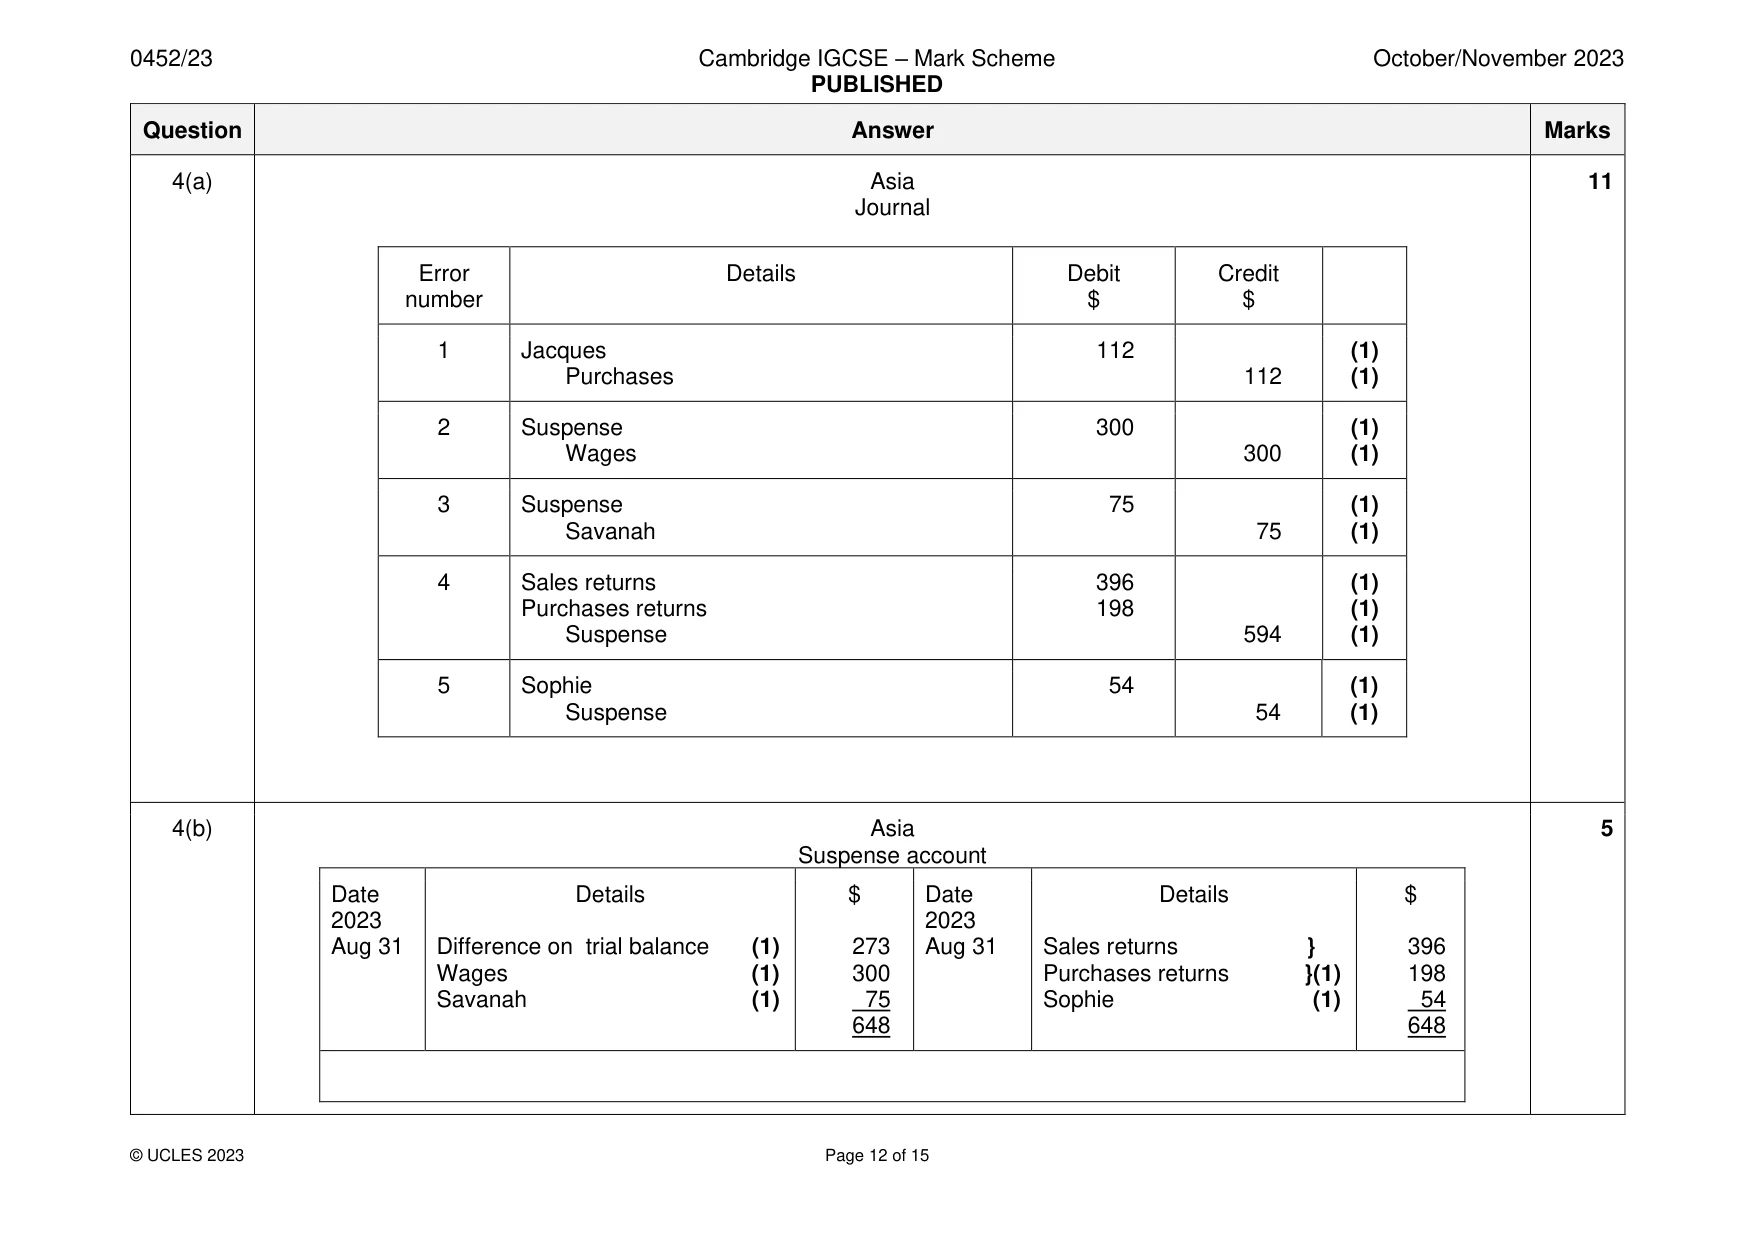
Mark scheme: 4(a) Asia 11 Journal Error Details Debit Credit number $ $ 1 Jacques 112 (1) Purchases 112 (1) 2 Suspense 300 (1) Wages 300 (1) 3 Suspense 75 (1) Savanah 75 (1) 4 Sales returns 396 (1) Purchases returns 198 (1) Suspense 594 (1) 5 Sophie 54 (1) Suspense 54 (1) 4(b) Asia 5 Suspense account Date Details $ Date Details $ 2023 2023 Aug 31 Difference on trial balance (1) 273 Aug 31 Sales returns } 396 Wages (1) 300 Purchases returns }(1) 198 Savanah (1) 75 Sophie (1) 54 648 648 4(c) 4 Error Profit for the No Error Gross profit number year effect + – + – 1 A credit purchase, $112, from Jacques, had been debited twice to the purchases account. ✓ ✓ 2 The wages account had been overcast by $300. (1) ✓ 3 Cash received, $75 from Savanah, a trade receivable, had only been entered in the cash ✓ (1) book. 4 The total of the sales returns journal for August 2023, $198, had been credited to both the sales ✓ ✓ (1) returns account and the purchases returns account. 5 A payment to Sophie, $93, had been ✓ (1) recorded as $39 in Sophie’s account.
Q5 · B Limited provides cleaning services to client offices and factories
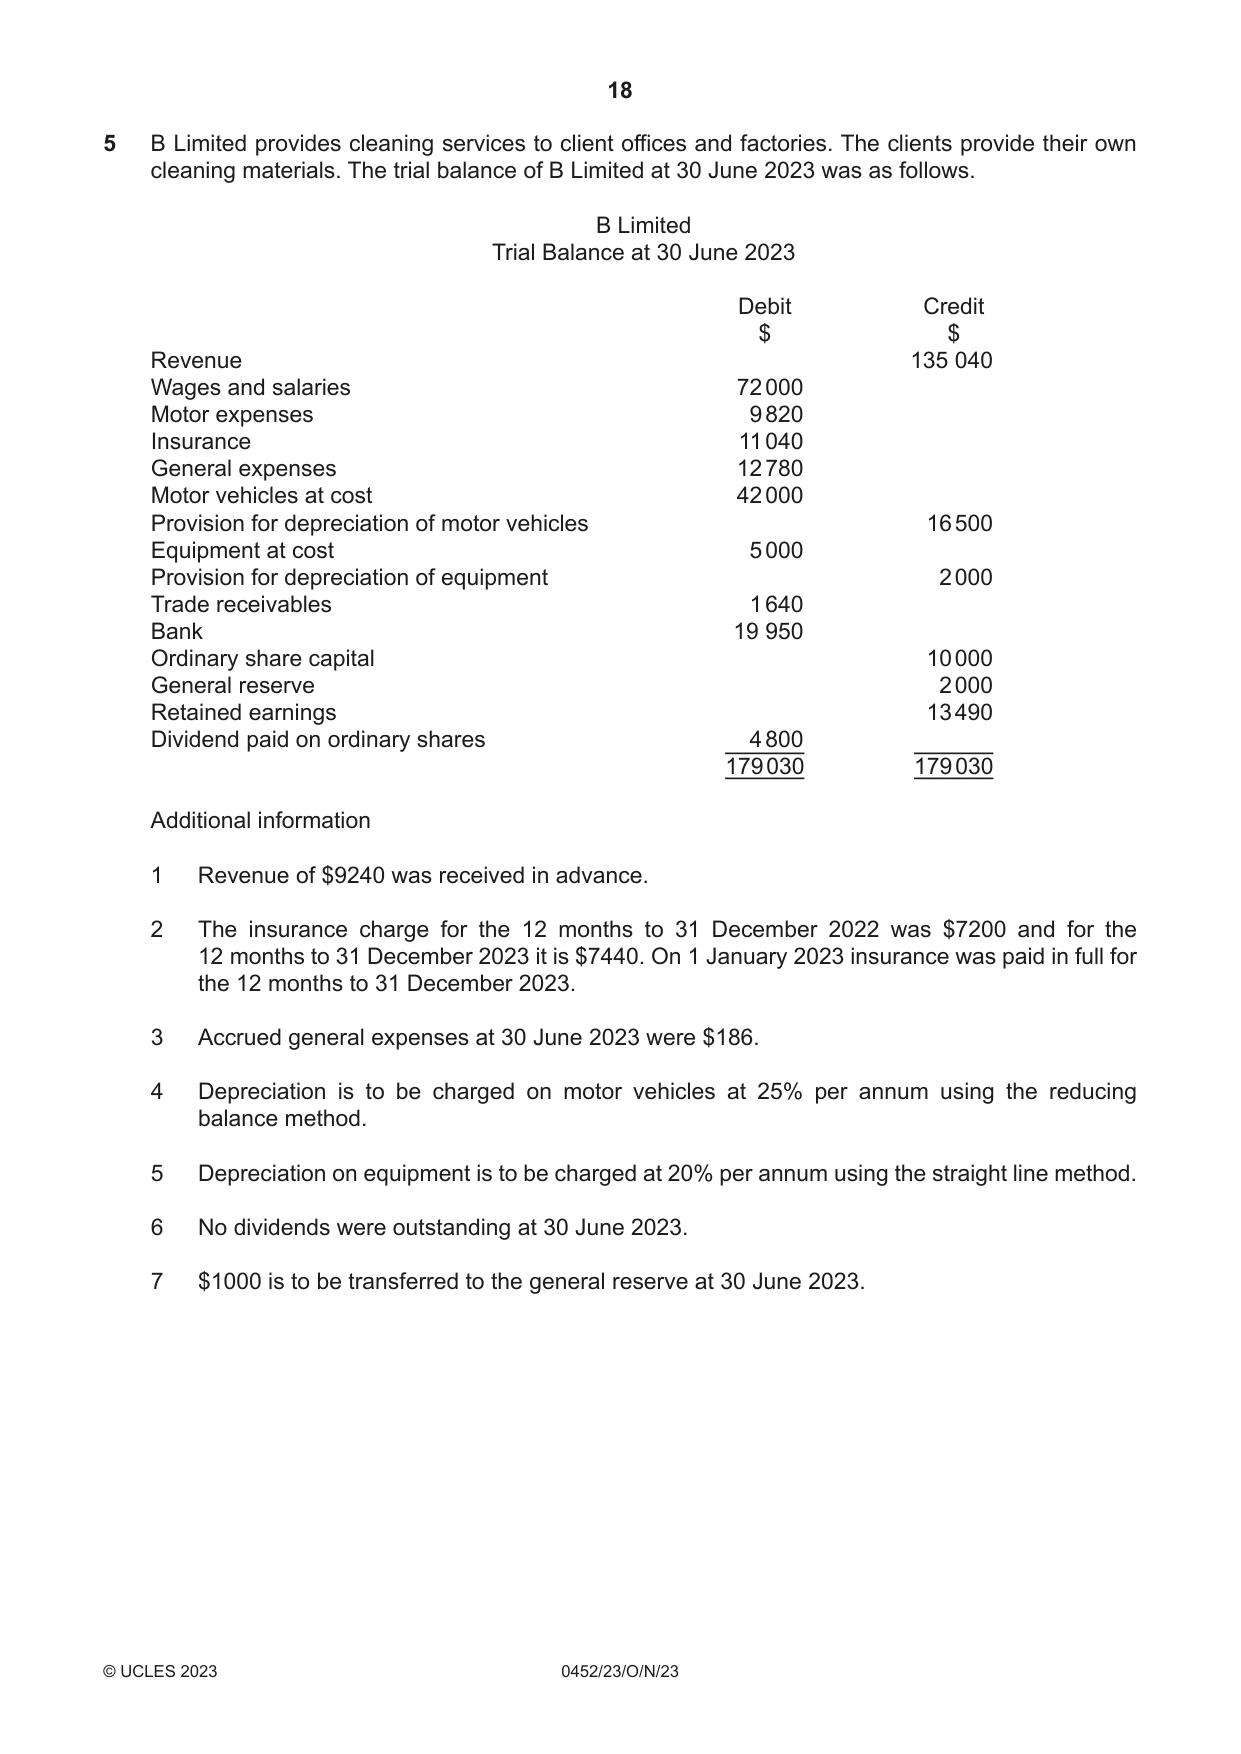
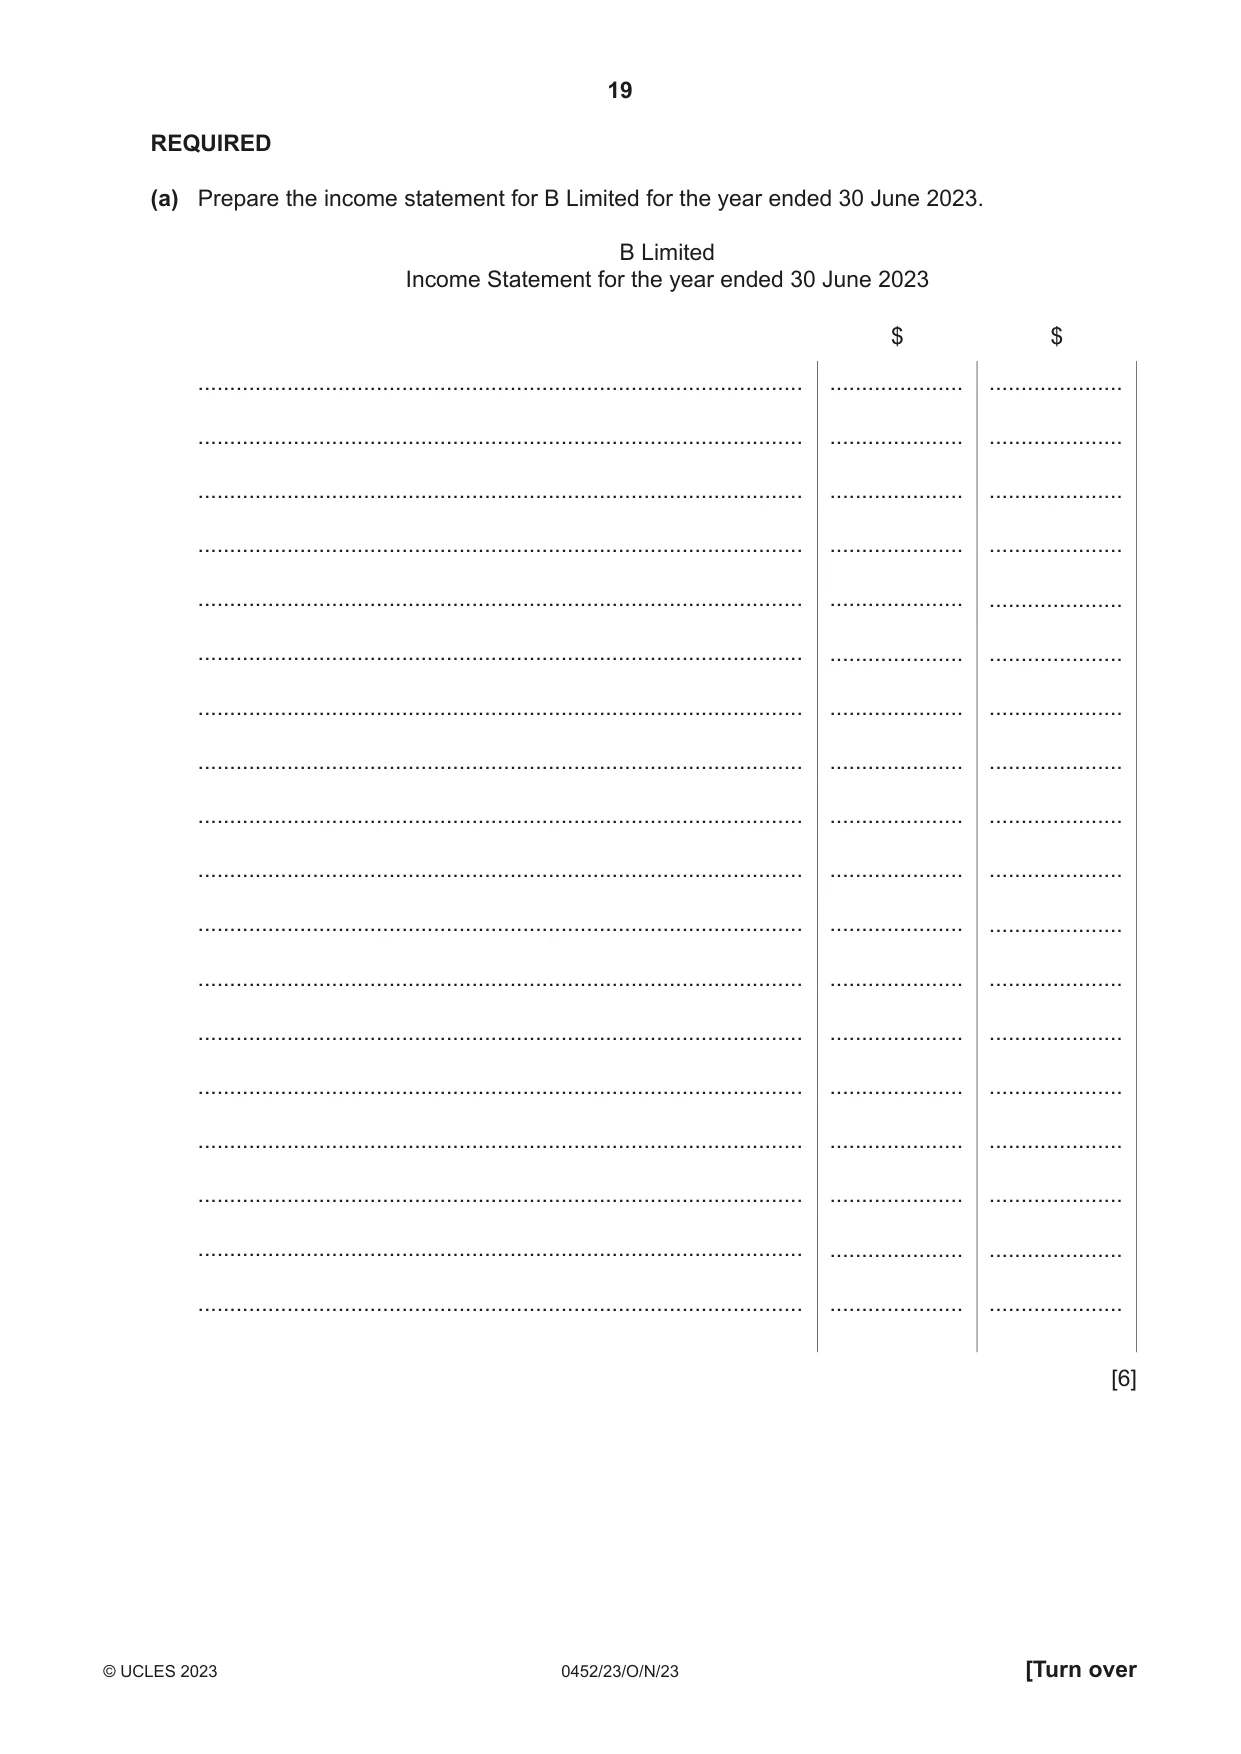
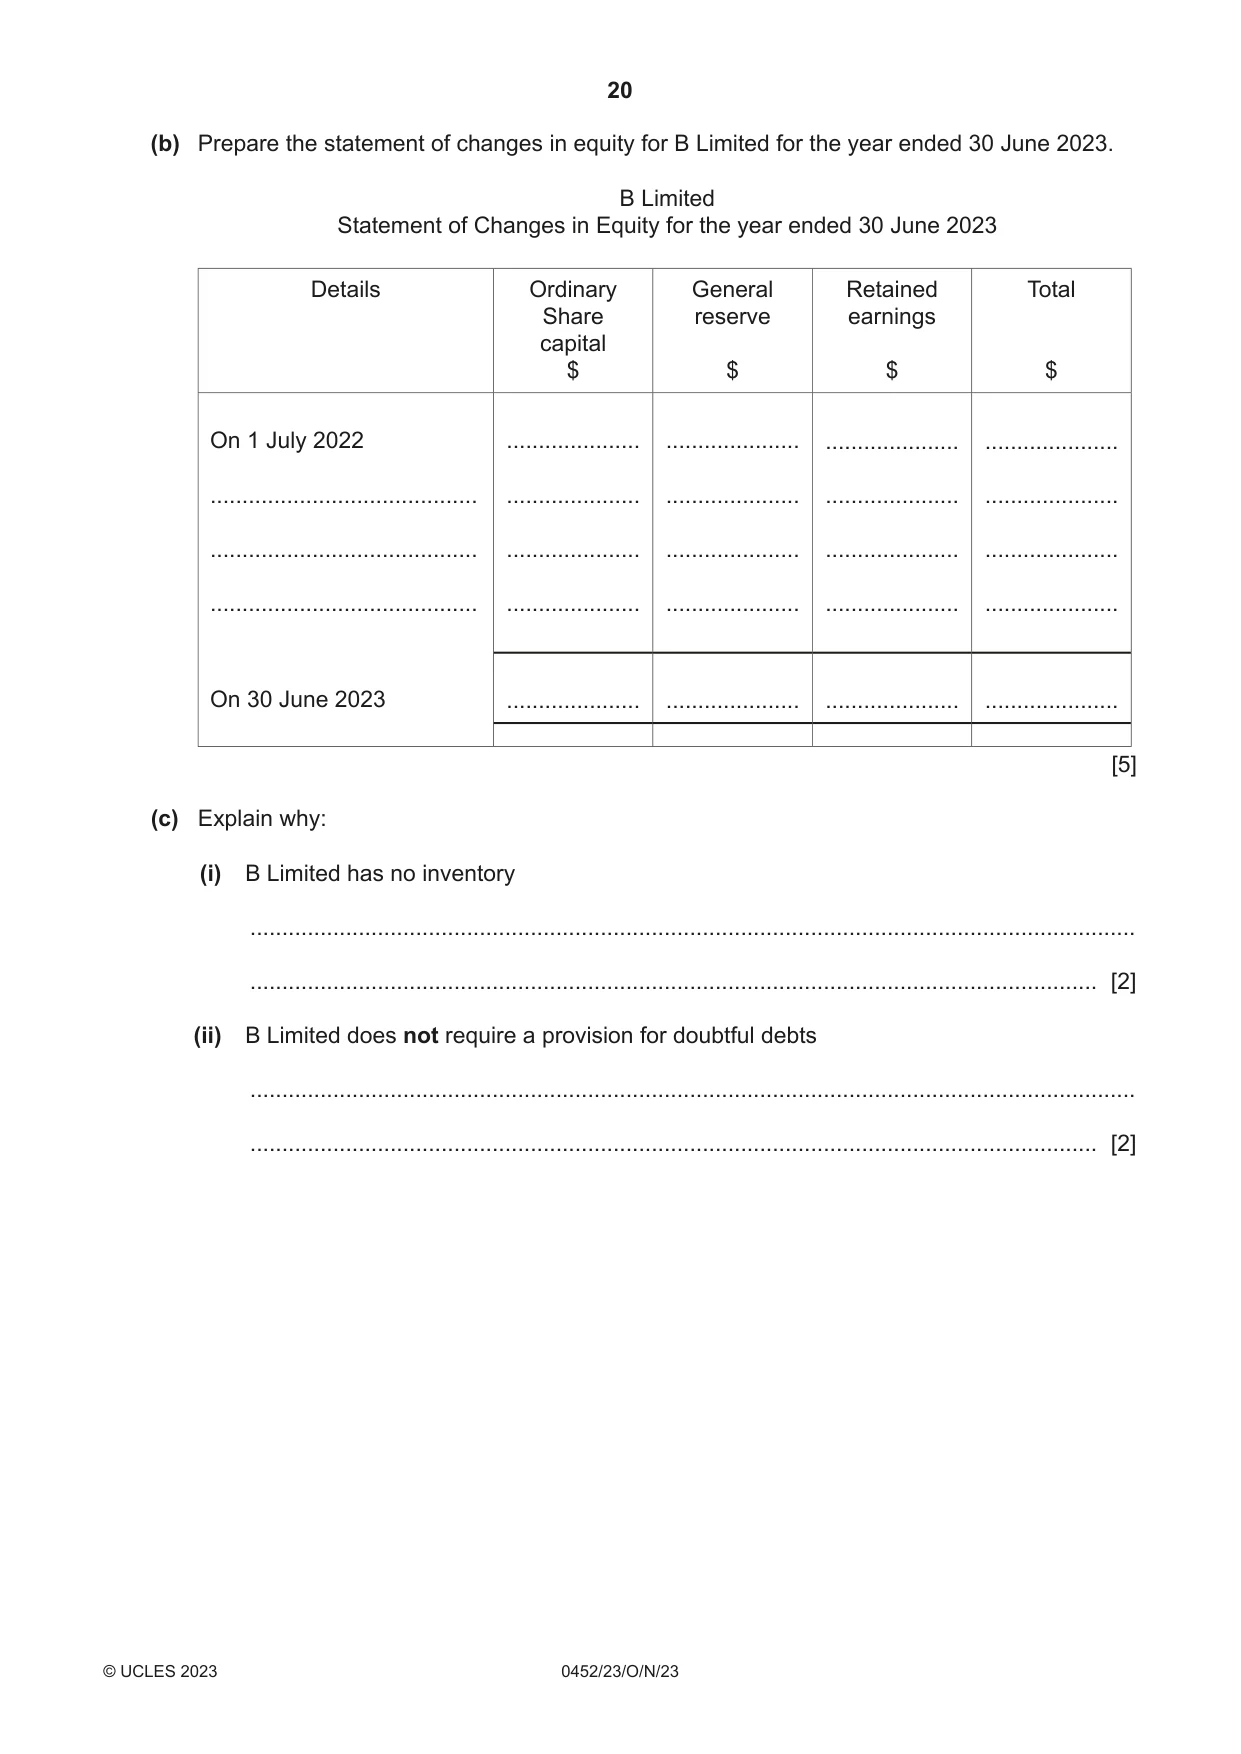
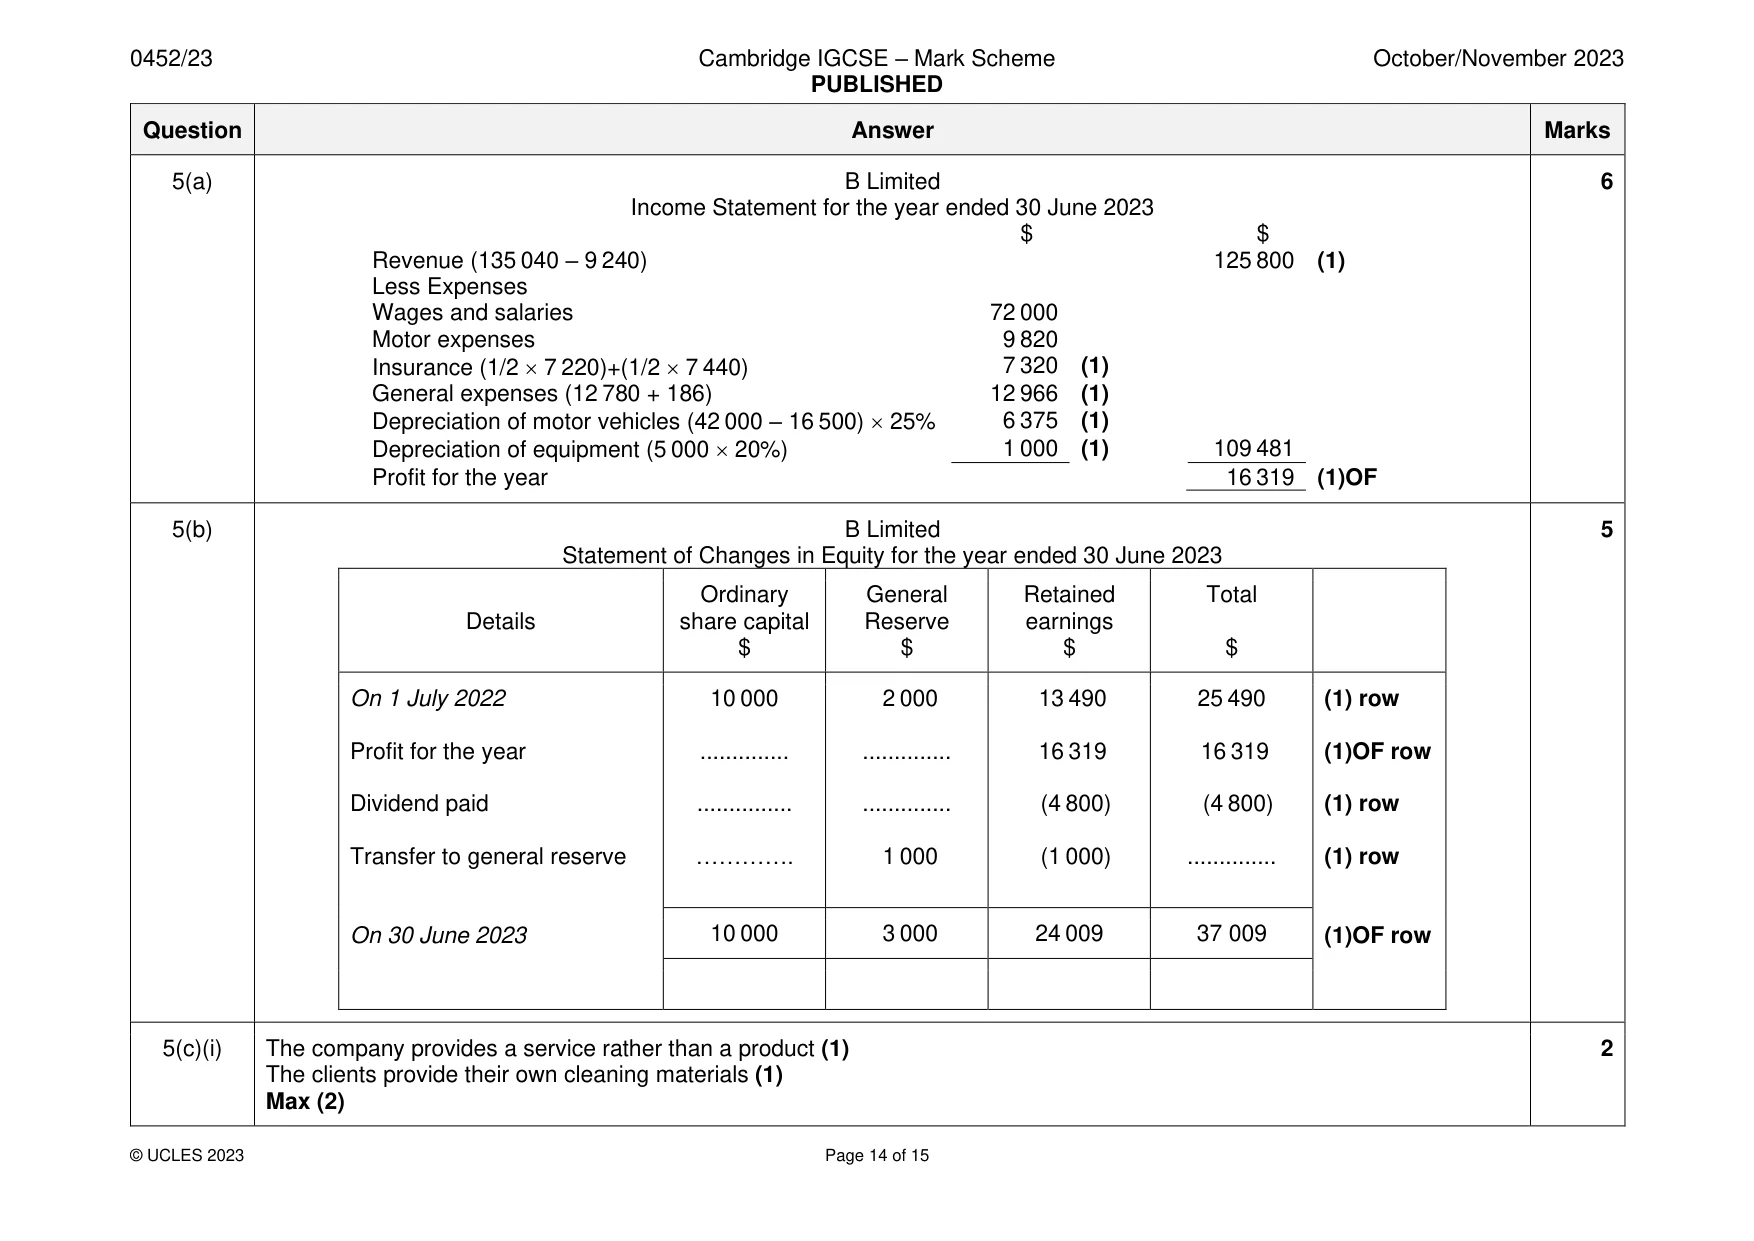
5 B Limited provides cleaning services to client offices and factories. The clients provide their own cleaning materials. The trial balance of B Limited at 30 June 2023 was as follows. B Limited Trial Balance at 30 June 2023 Debit Credit $ $ Revenue 135 040 Wages and salaries 72 000 Motor expenses 9 820 Insurance 11 040 General expenses 12 780 Motor vehicles at cost 42 000 Provision for depreciation of motor vehicles 16 500 Equipment at cost 5 000 Provision for depreciation of equipment 2 000 Trade receivables 1 640 Bank 19 950 Ordinary share capital 10 000 General reserve 2 000 Retained earnings 13 490 Dividend paid on ordinary shares 4 800 179 030 179 030 Additional information 1 Revenue of $9240 was received in advance. 2 The insurance charge for the 12 months to 31 December 2022 was $7200 and for the 12 months to 31 December 2023 it is $7440. On 1 January 2023 insurance was paid in full for the 12 months to 31 December 2023. 3 Accrued general expenses at 30 June 2023 were $186. 4 Depreciation is to be charged on motor vehicles at 25% per annum using the reducing balance method. 5 Depreciation on equipment is to be charged at 20% per annum using the straight line method. 6 No dividends were outstanding at 30 June 2023. 7 $1000 is to be transferred to the general reserve at 30 June 2023. REQUIRED (a) Prepare the income statement for B Limited for the year ended 30 June 2023. B Limited Income Statement for the year ended 30 June 2023 $ $ ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... [6] (b) Prepare the statement of changes in equity for B Limited for the year ended 30 June 2023. B Limited Statement of Changes in Equity for the year ended 30 June 2023 Details Ordinary General Retained Total Share reserve earnings capital $ $ $ $ On 1 July 2022 ..................... ..................... ..................... ..................... .......................................... ..................... ..................... ..................... ..................... .......................................... ..................... ..................... ..................... ..................... .......................................... ..................... ..................... ..................... ..................... On 30 June 2023 ..................... ..................... ..................... ..................... [5] (c) Explain why: (i) B Limited has no inventory ........................................................................................................................................... ..................................................................................................................................... [2] (ii) B Limited does not require a provision for doubtful debts ........................................................................................................................................... ..................................................................................................................................... [2]
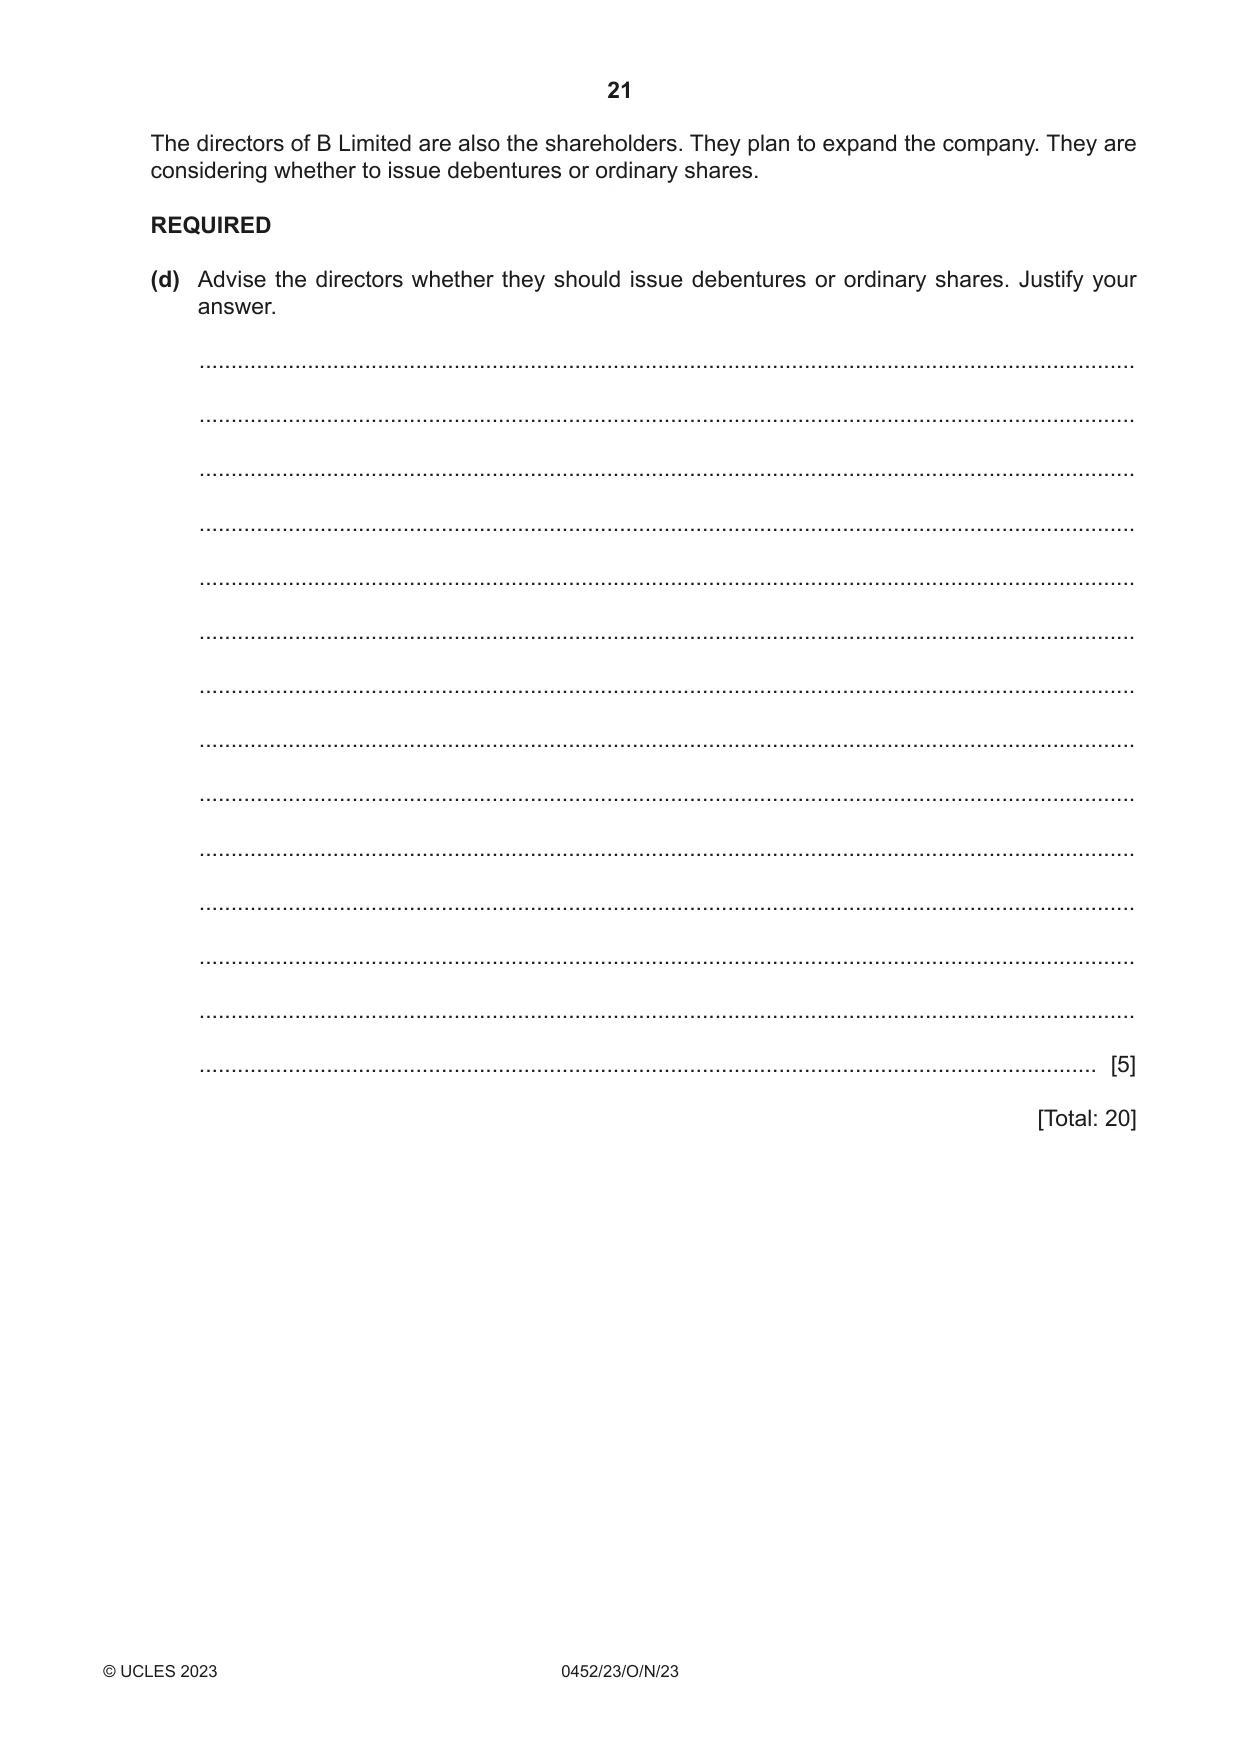
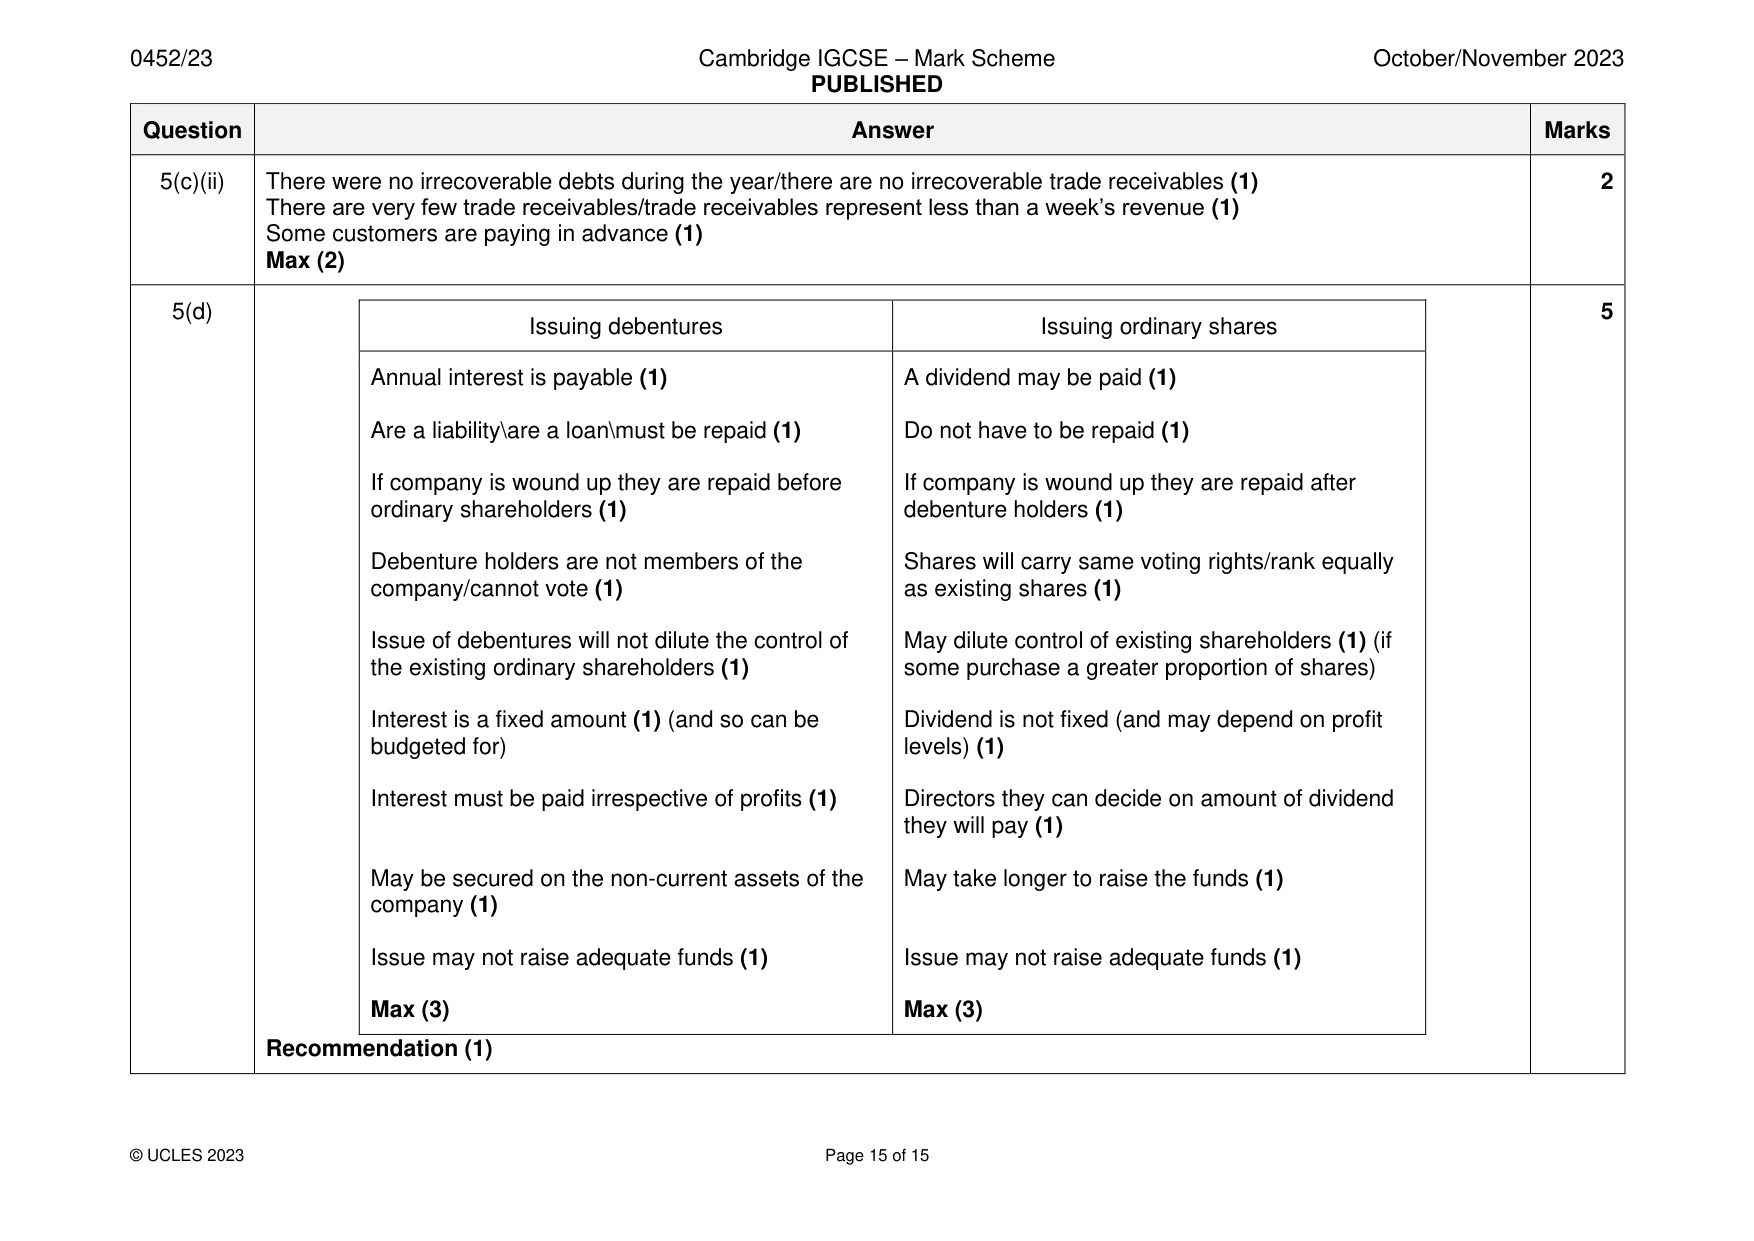
Mark scheme: 5(a) B Limited 6 Income Statement for the year ended 30 June 2023 $ $ Revenue (135 040 – 9 240) 125 800 (1) Less Expenses Wages and salaries 72 000 Motor expenses 9 820 Insurance (1/2 7 220)+(1/2 7 440) 7 320 (1) General expenses (12 780 + 186) 12 966 (1) Depreciation of motor vehicles (42 000 – 16 500) 25% 6 375 (1) Depreciation of equipment (5 000 20%) 1 000 (1) 109 481 Profit for the year 16 319 (1)OF 5(b) B Limited 5 Statement of Changes in Equity for the year ended 30 June 2023 Ordinary General Retained Total Details share capital Reserve earnings $ $ $ $ On 1 July 2022 10 000 2 000 13 490 25 490 (1) row Profit for the year .............. .............. 16 319 16 319 (1)OF row Dividend paid ............... .............. (4 800) (4 800) (1) row Transfer to general reserve …………. 1 000 (1 000) .............. (1) row On 30 June 2023 10 000 3 000 24 009 37 009 (1)OF row 5(c)(i) The company provides a service rather than a product (1) 2 The clients provide their own cleaning materials (1) Max (2) 5(c)(ii) There were no irrecoverable debts during the year/there are no irrecoverable trade receivables (1) 2 There are very few trade receivables/trade receivables represent less than a week’s revenue (1) Some customers are paying in advance (1) Max (2) 5(d) 5 Issuing debentures Issuing ordinary shares Annual interest is payable (1) A dividend may be paid (1) Are a liability\are a loan\must be repaid (1) Do not have to be repaid (1) If company is wound up they are repaid before If company is wound up they are repaid after ordinary shareholders (1) debenture holders (1) Debenture holders are not members of the Shares will carry same voting rights/rank equally company/cannot vote (1) as existing shares (1) Issue of debentures will not dilute the control of May dilute control of existing shareholders (1) (if the existing ordinary shareholders (1) some purchase a greater proportion of shares) Interest is a fixed amount (1) (and so can be Dividend is not fixed (and may depend on profit budgeted for) levels) (1) Interest must be paid irrespective of profits (1) Directors they can decide on amount of dividend they will pay (1) May be secured on the non-current assets of the May take longer to raise the funds (1) company (1) Issue may not raise adequate funds (1) Issue may not raise adequate funds (1) Max (3) Max (3) Recommendation (1)
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2023 Oct/Nov, Paper 2 · Variant 3. A higher threshold means an easier paper — the bar moves with how the cohort did.