Cambridge IGCSE Accounting 0452 — 2025 Oct/Nov Paper 2 · Variant 3
0452/23/O/N/25 · 6 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme17 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Sid owns a business selling cars
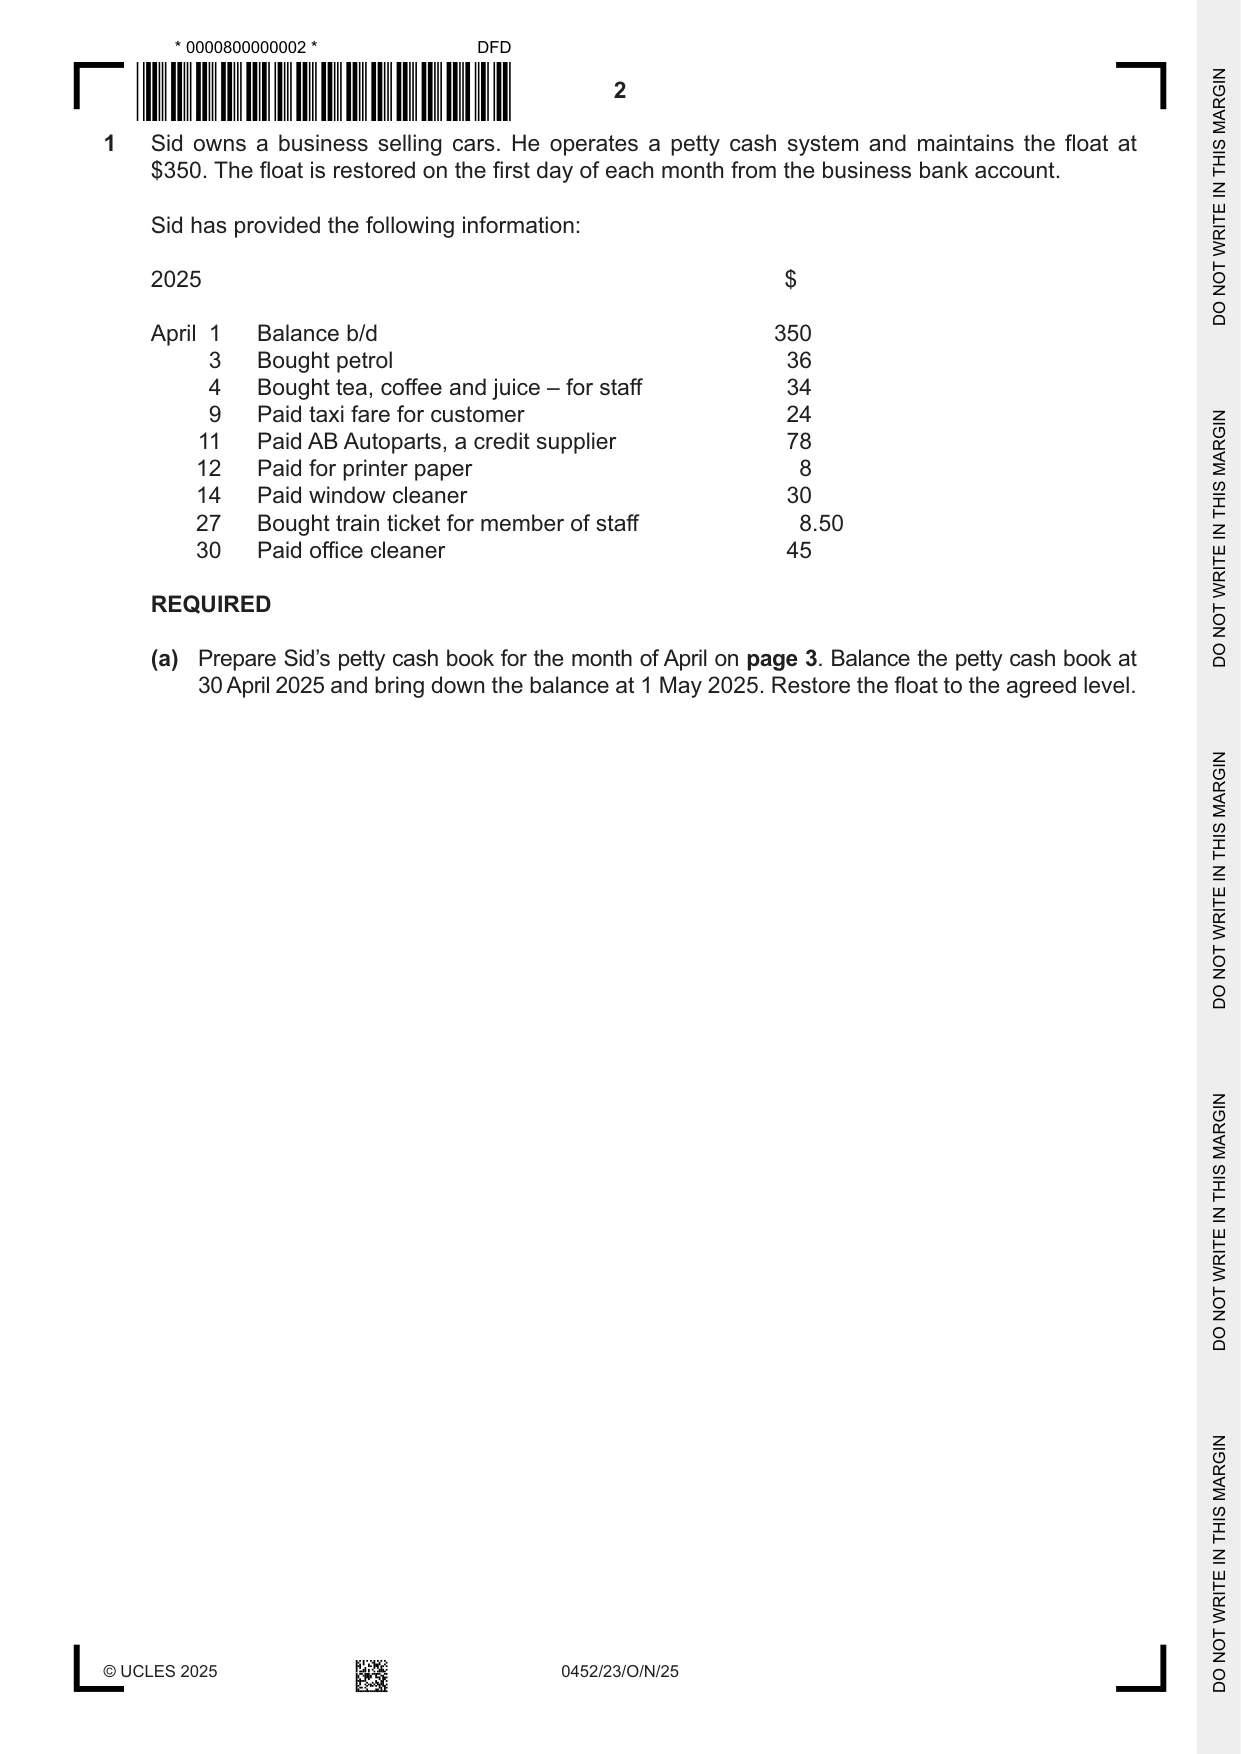
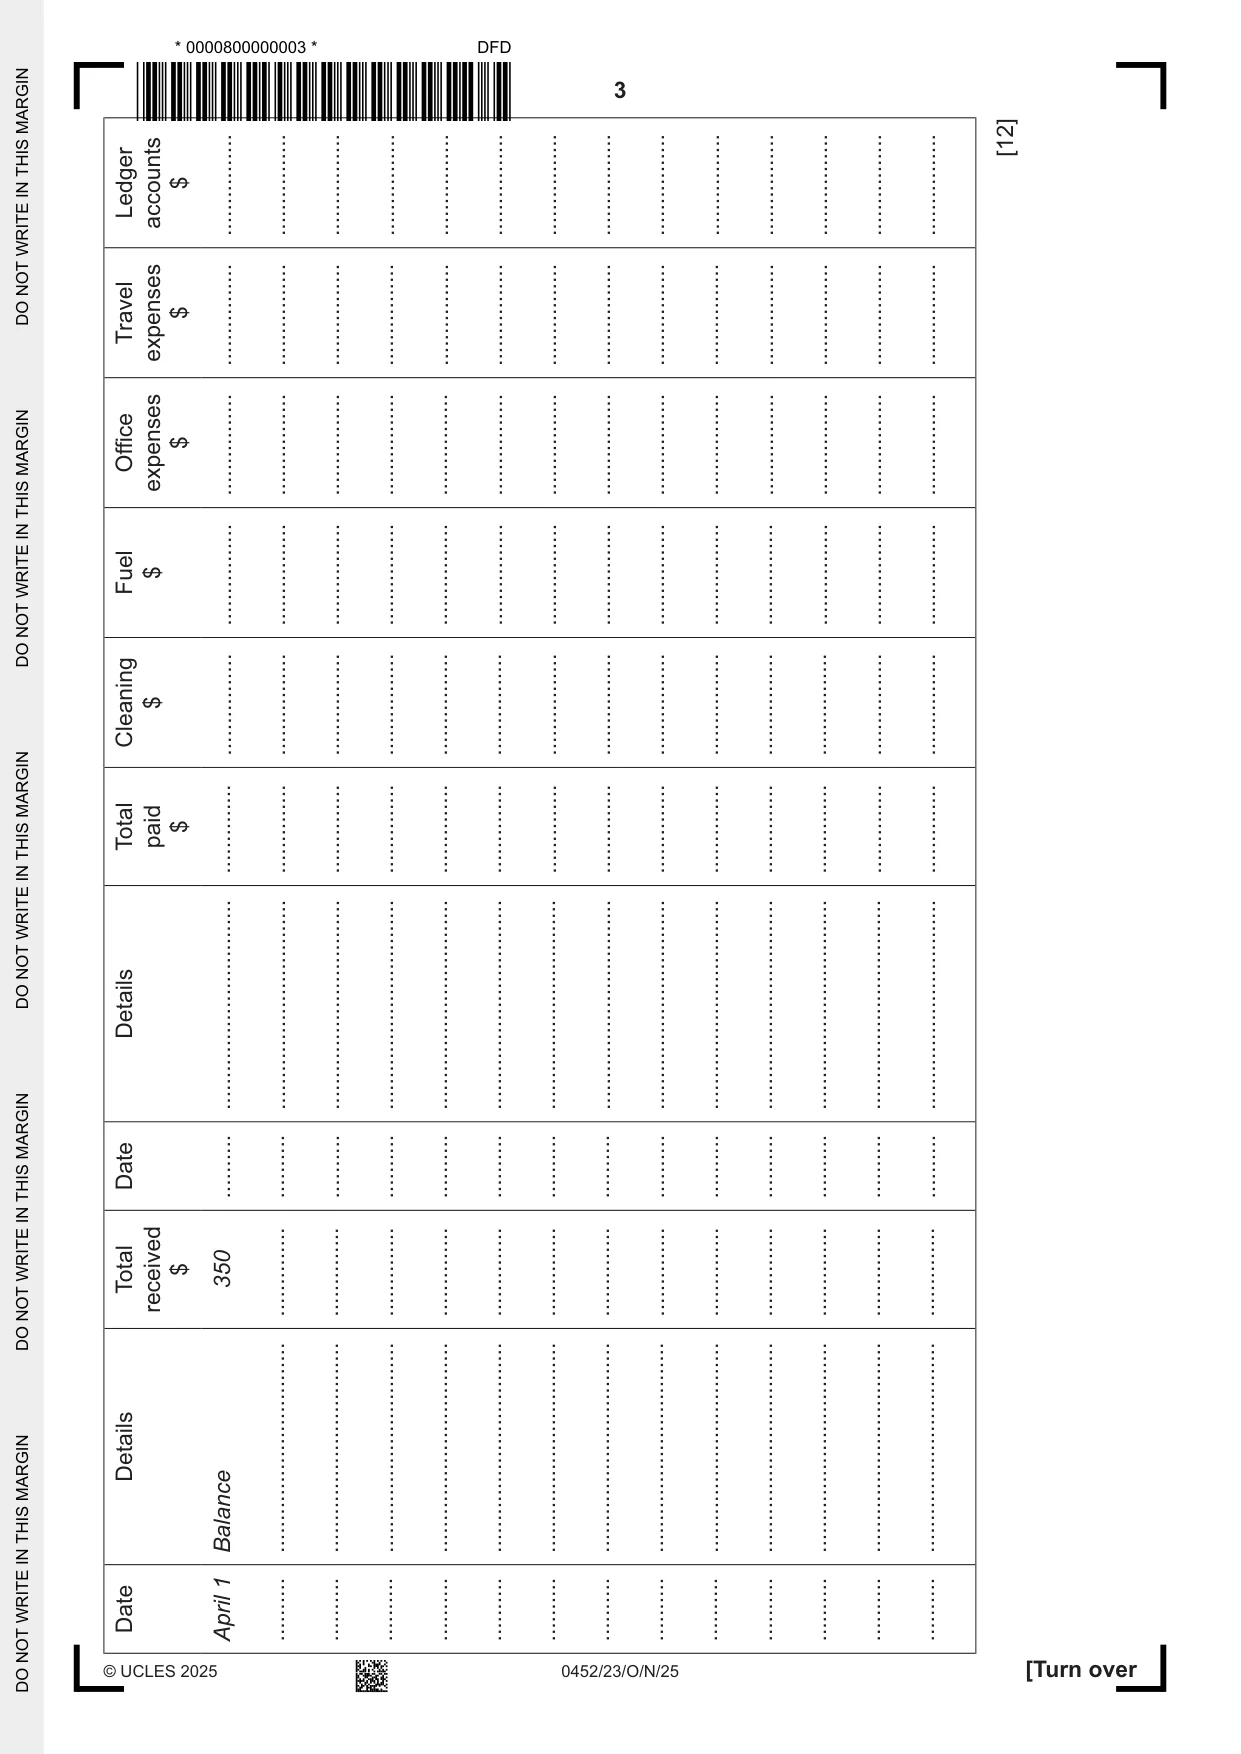
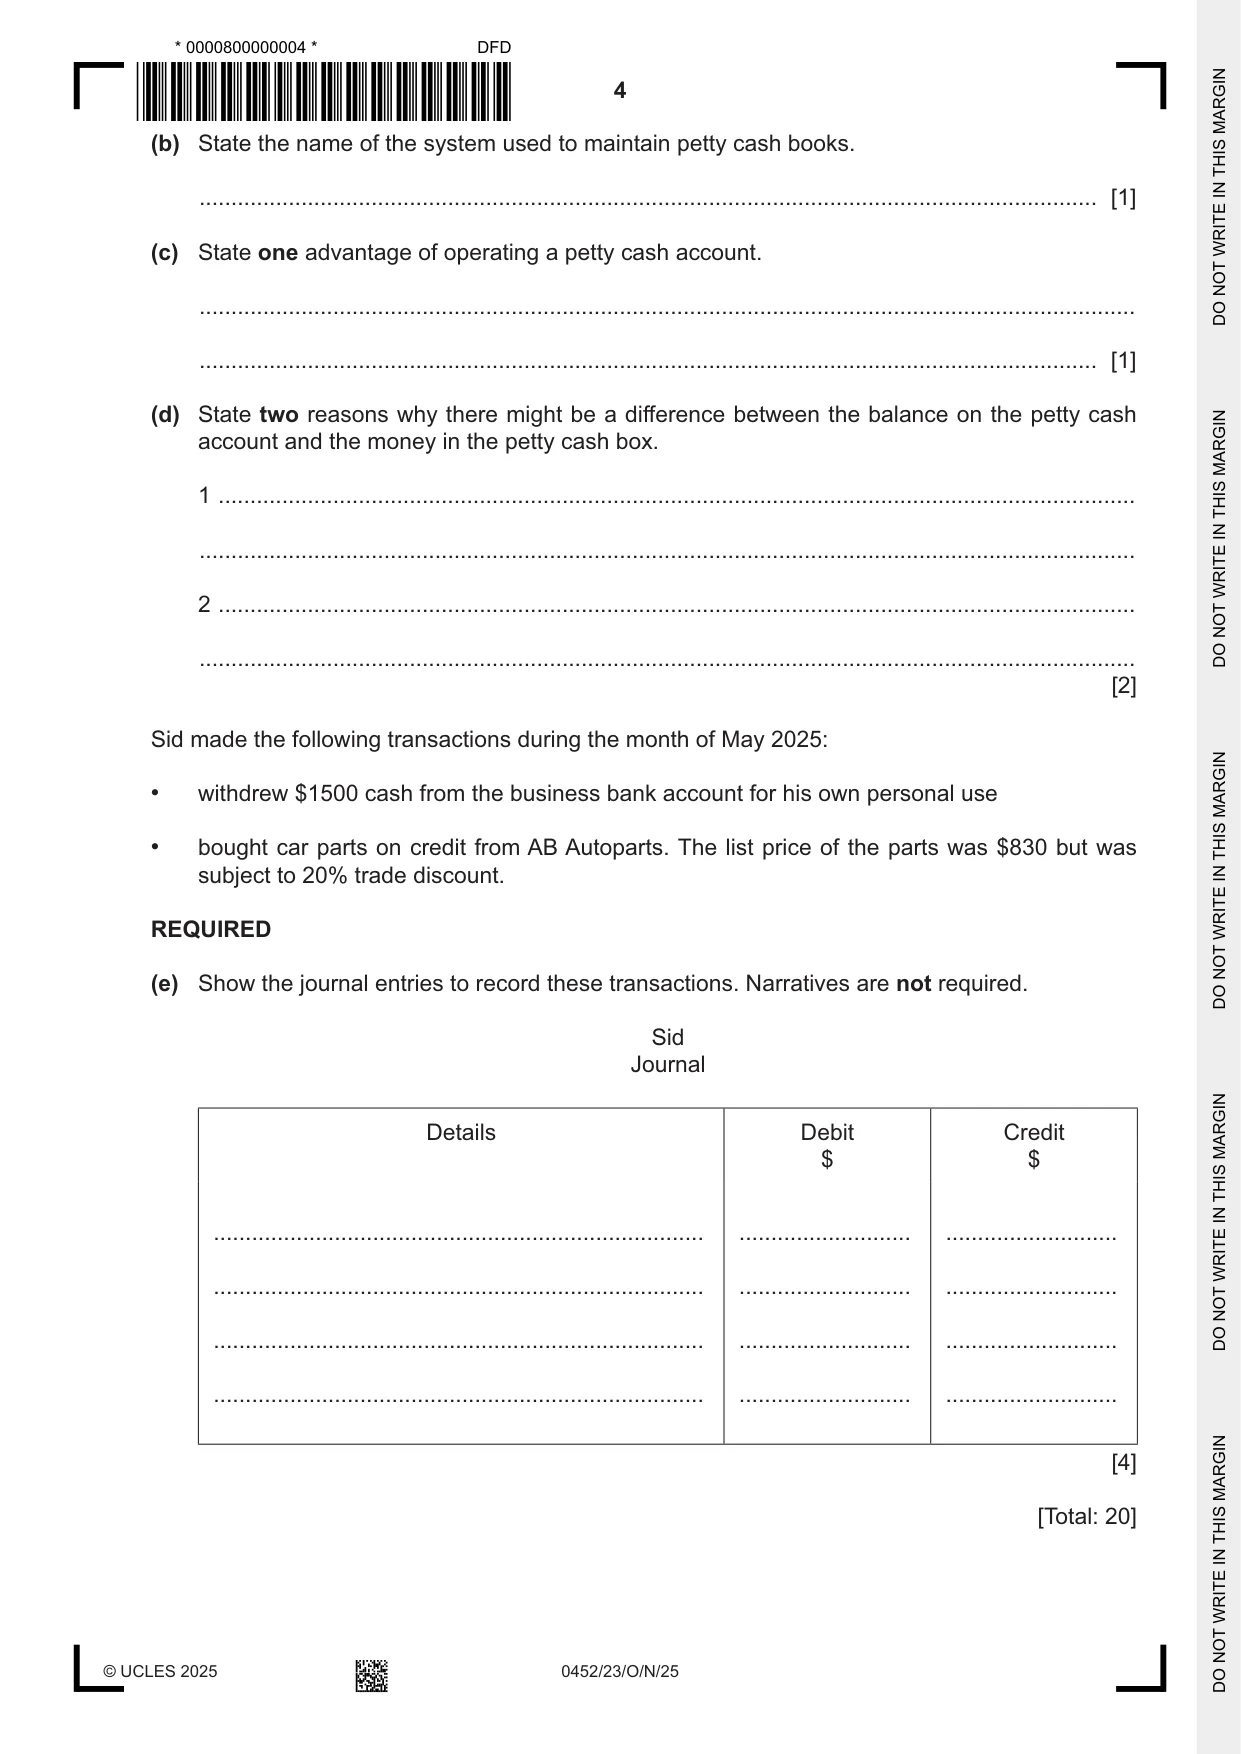
1 Sid owns a business selling cars. He operates a petty cash system and maintains the float at $350. The float is restored on the first day of each month from the business bank account. Sid has provided the following information: 2025 $ April 1 Balance b/d 350 3 Bought petrol 36 4 Bought tea, coffee and juice – for staff 34 9 Paid taxi fare for customer 24 11 Paid AB Autoparts, a credit supplier 78 12 Paid for printer paper 8 14 Paid window cleaner 30 27 Bought train ticket for member of staff 8.50 30 Paid office cleaner 45 REQUIRED (a) Prepare Sid’s petty cash book for the month of April on page 3. Balance the petty cash book at 30 April 2025 and bring down the balance at 1 May 2025. Restore the float to the agreed level. [1 $Ledger accounts ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ $Travel expenses ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ $Office expenses ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ $Fuel ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ $Cleaning ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ $Total paid .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. Details ................................. ................................. ................................. ................................. ................................. ................................. ................................. ................................. ................................. ................................. ................................. ................................. ................................. ................................. Date .......... .......... .......... .......... .......... .......... .......... .......... .......... .......... .......... .......... .......... .......... $Total 350 received .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. Details Balance ................................. ................................. ................................. ................................. ................................. ................................. ................................. ................................. ................................. ................................. ................................. ................................. ................................. (b) State the name of the system used to maintain petty cash books. ............................................................................................................................................. [1] (c) State one advantage of operating a petty cash account. ................................................................................................................................................... ............................................................................................................................................. [1] (d) State two reasons why there might be a difference between the balance on the petty cash account and the money in the petty cash box. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] Sid made the following transactions during the month of May 2025: • withdrew $1500 cash from the business bank account for his own personal use • bought car parts on credit from AB Autoparts. The list price of the parts was $830 but was subject to 20% trade discount. REQUIRED (e) Show the journal entries to record these transactions. Narratives are not required. Sid Journal Details Debit Credit $ $ ............................................................................. ........................... ........................... ............................................................................. ........................... ........................... ............................................................................. ........................... ........................... ............................................................................. ........................... ........................... [4] [Total: 20]
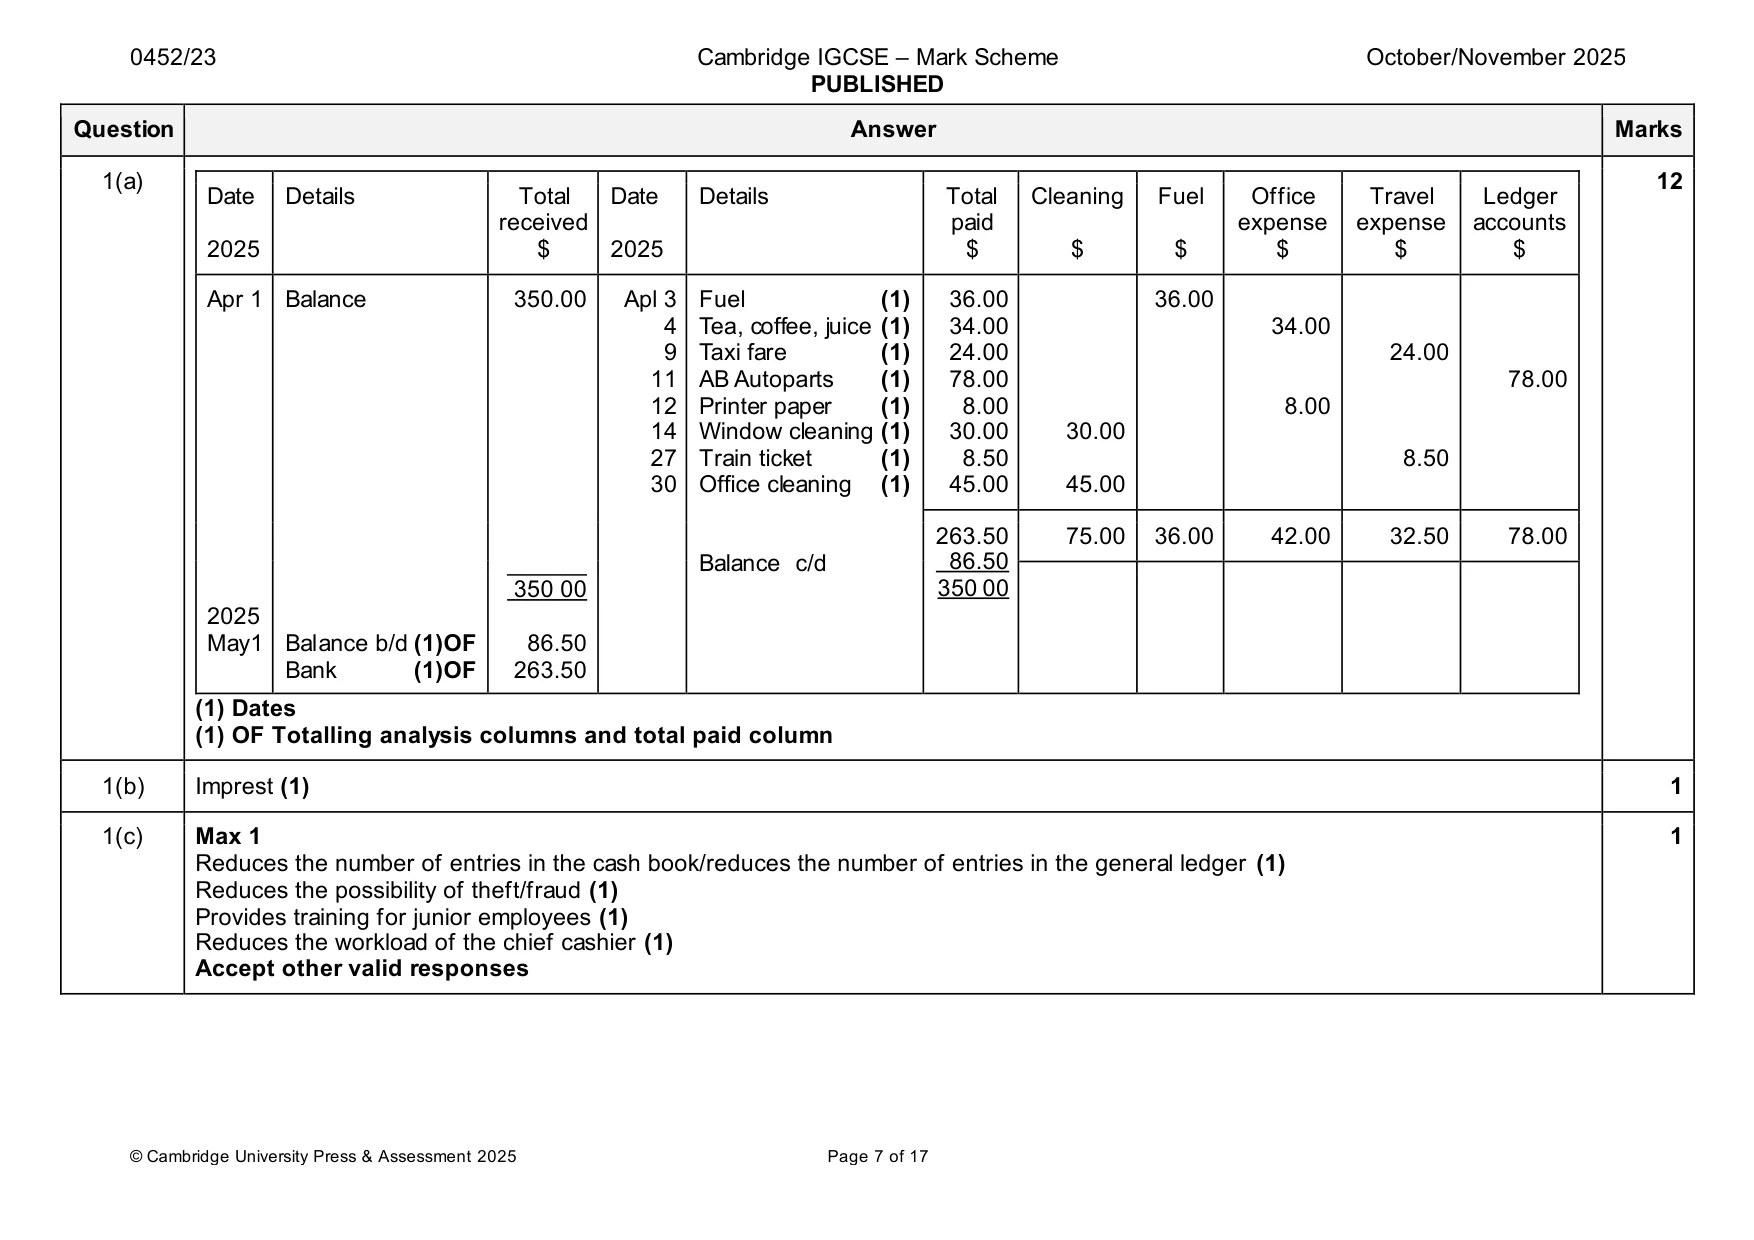
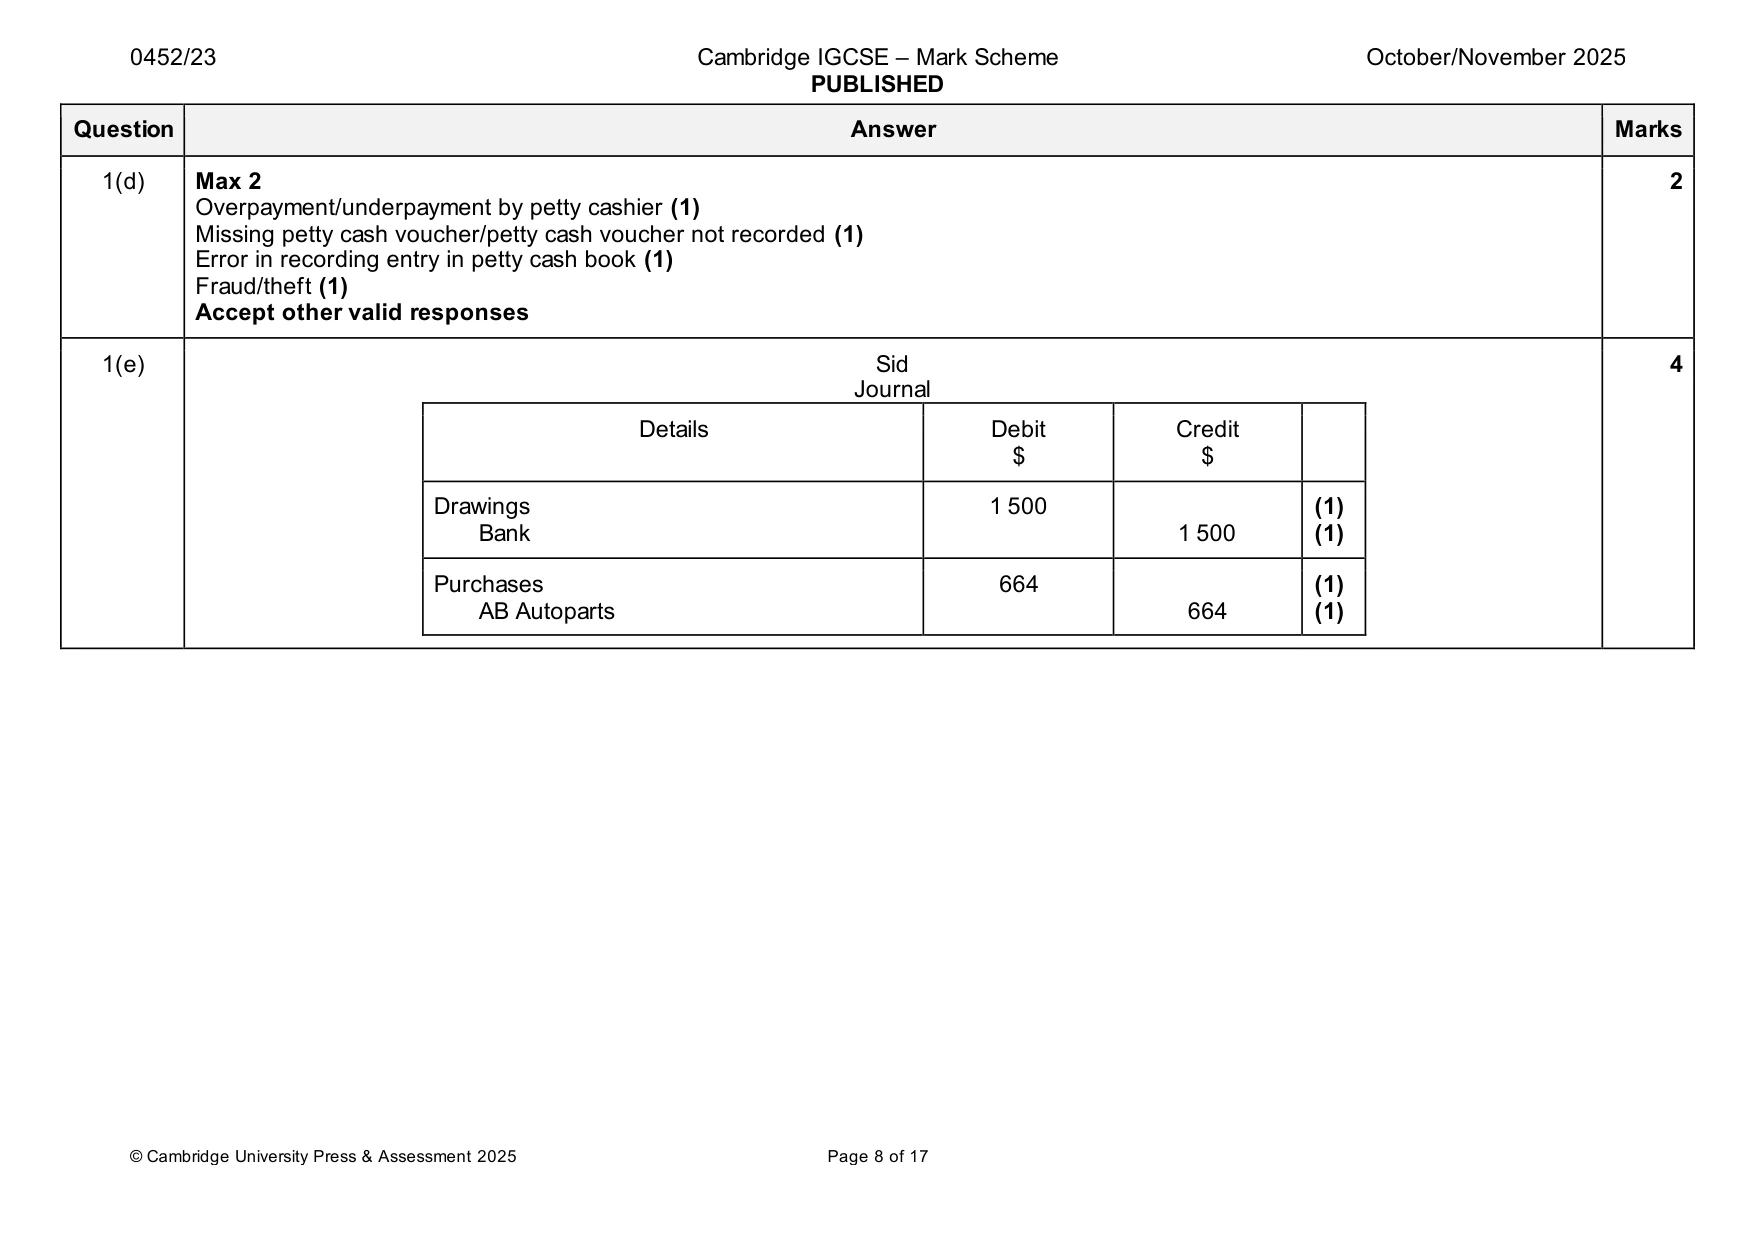
Mark scheme: Question Answer Marks 1(a) 12 Date Details Total Date Details Total Cleaning Fuel Office Travel Ledger received paid expense expense accounts 2025 $ 2025 $ $ $ $ $ $ Apr 1 Balance 350.00 Apl 3 Fuel (1) 36.00 36.00 4 Tea, coffee, juice (1) 34.00 34.00 9 Taxi fare (1) 24.00 24.00 11 AB Autoparts (1) 78.00 78.00 12 Printer paper (1) 8.00 8.00 14 Window cleaning (1) 30.00 30.00 27 Train ticket (1) 8.50 8.50 30 Office cleaning (1) 45.00 45.00 263.50 75.00 36.00 42.00 32.50 78.00 ______ Balance c/d 86.50 350 00 350 00 2025 May1 Balance b/d (1)OF 86.50 Bank (1)OF 263.50 (1) Dates (1) OF Totalling analysis columns and total paid column 1(b) Imprest (1) 1 1(c) Max 1 1 Reduces the number of entries in the cash book/reduces the number of entries in the general ledger (1) Reduces the possibility of theft/fraud (1) Provides training for junior employees (1) Reduces the workload of the chief cashier (1) Accept other valid responses 1(d) Max 2 2 Overpayment/underpayment by petty cashier (1) Missing petty cash voucher/petty cash voucher not recorded (1) Error in recording entry in petty cash book (1) Fraud/theft (1) Accept other valid responses 1(e) Sid 4 Journal Details Debit Credit $ $ Drawings 1 500 (1) Bank 1 500 (1) Purchases 664 (1) AB Autoparts 664 (1)
Q2 · Jenny maintains a full set of accounting records and prepares control accounts at the end…
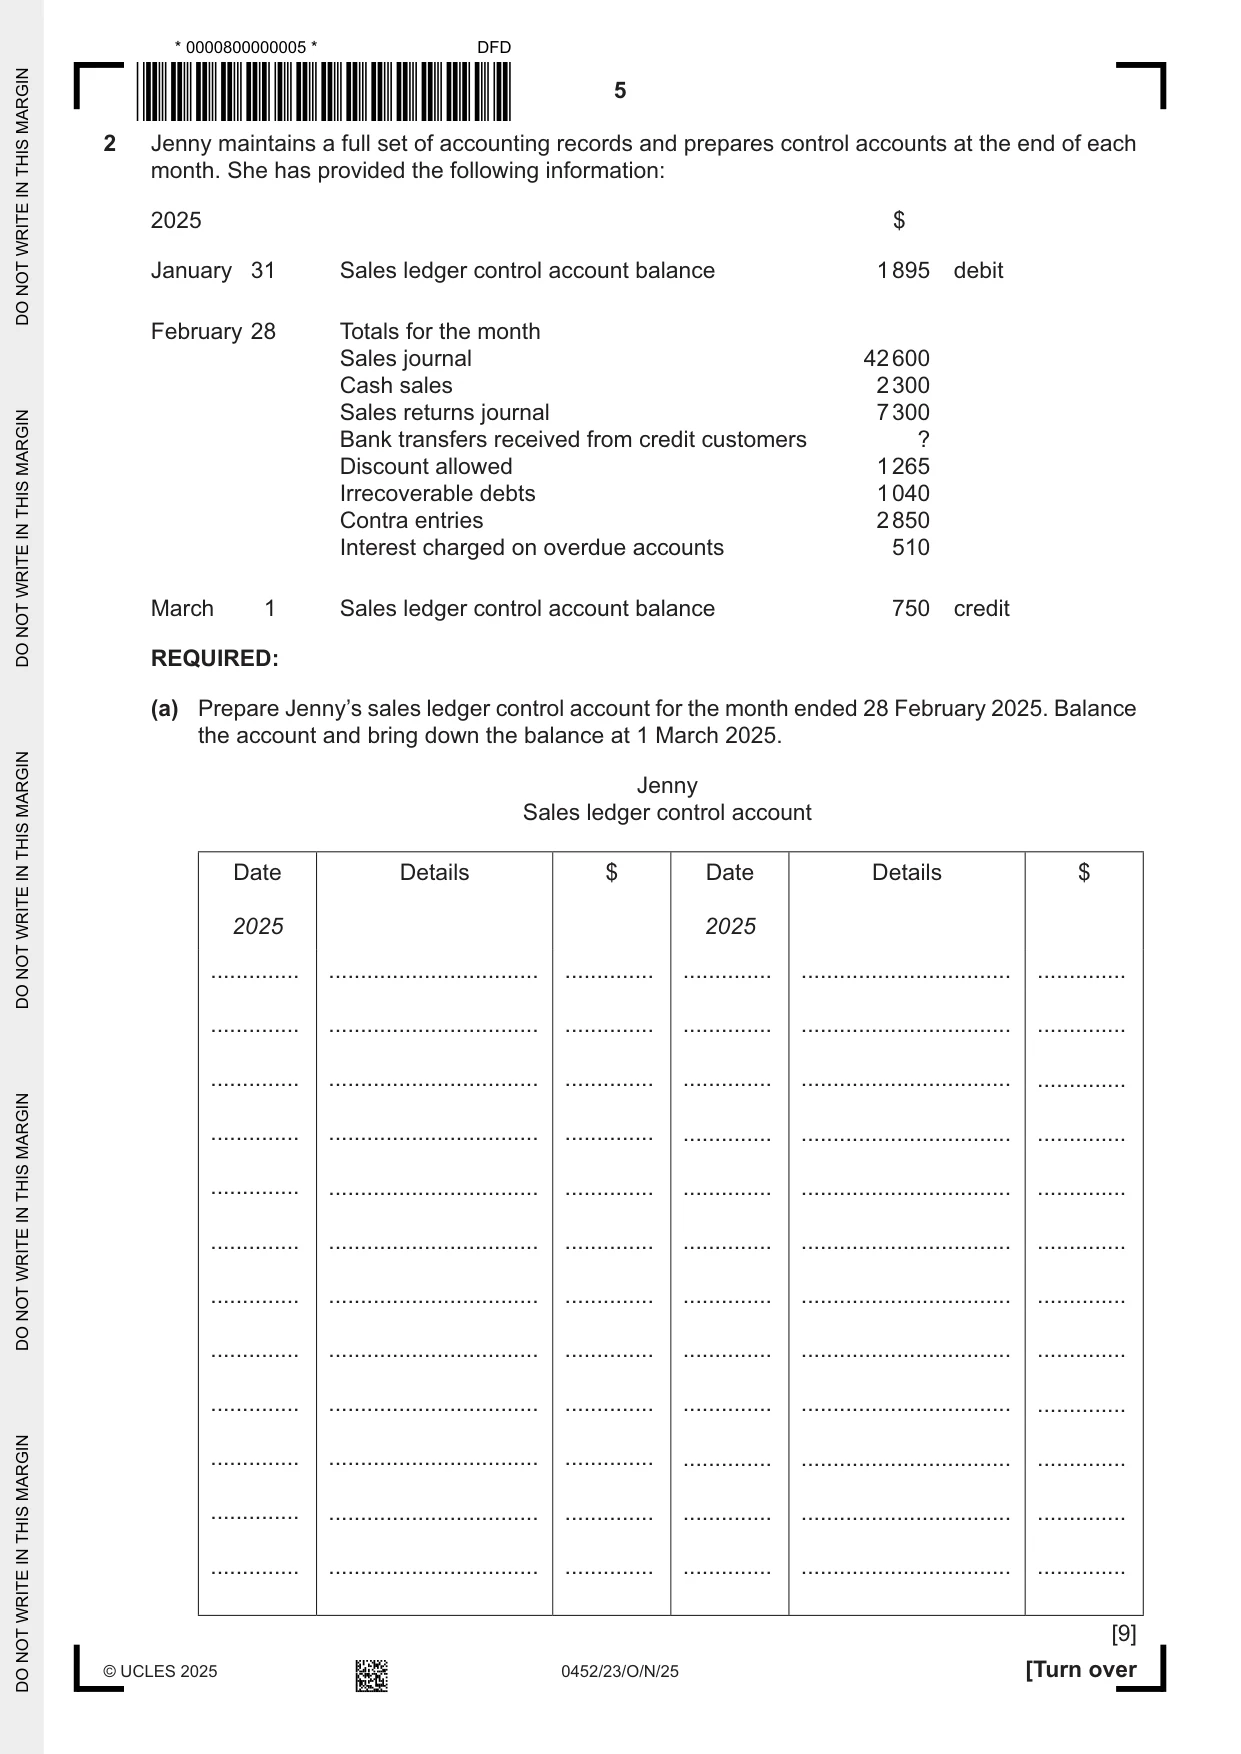
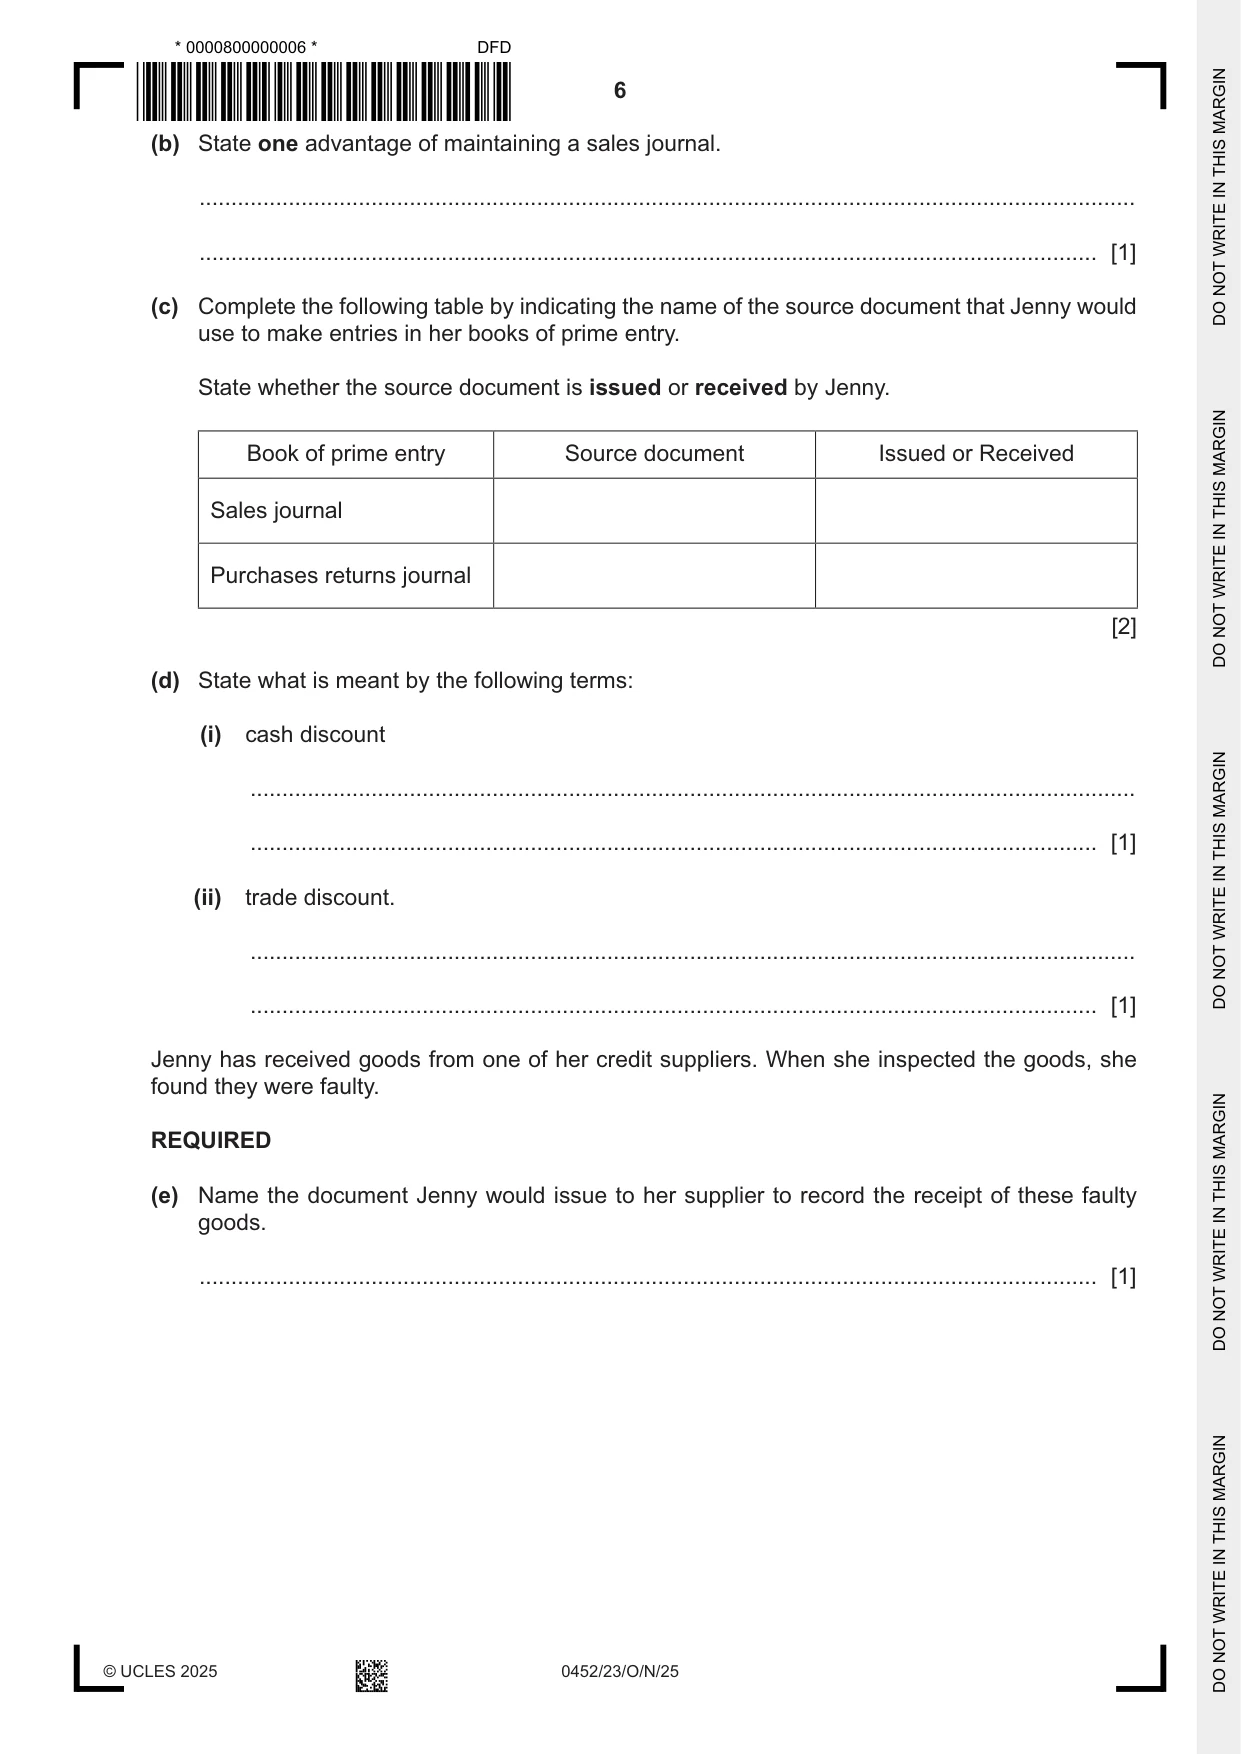
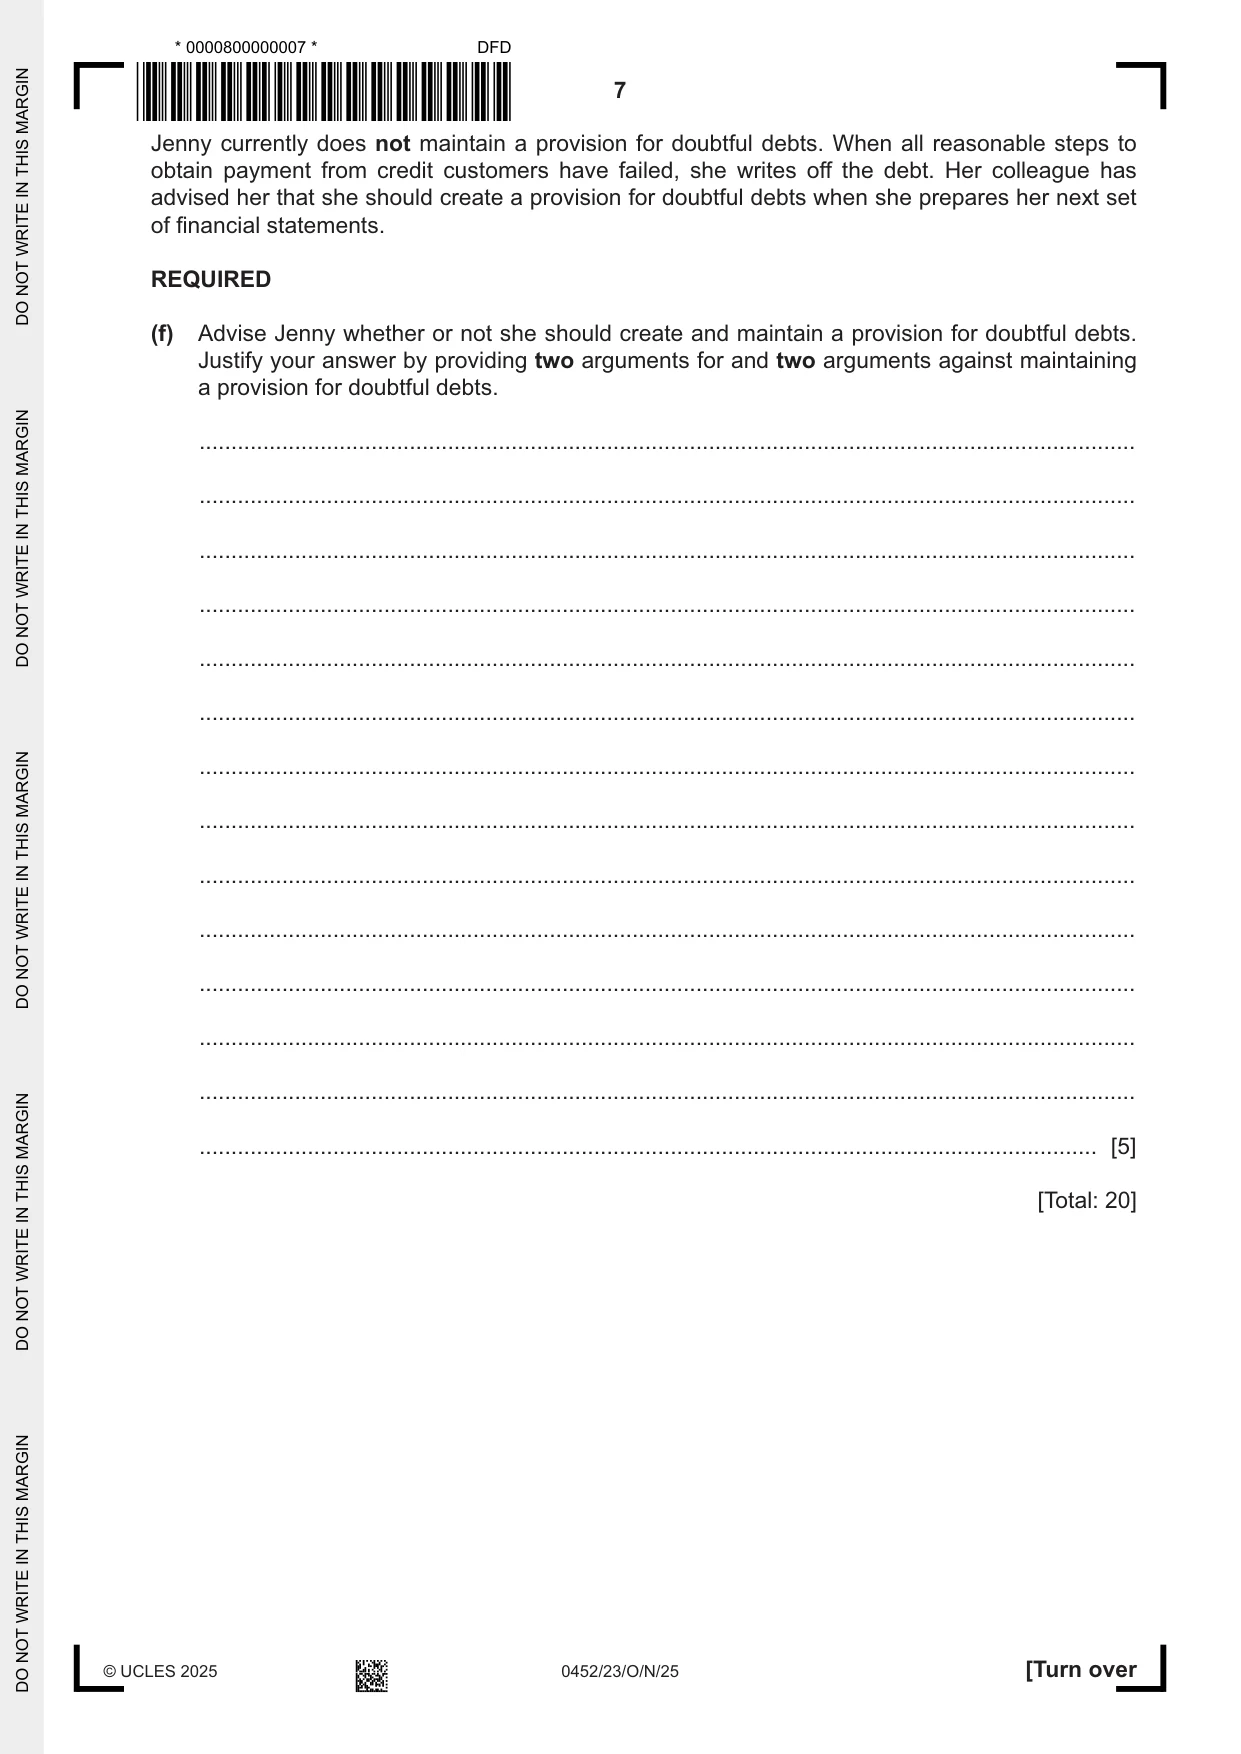
2 Jenny maintains a full set of accounting records and prepares control accounts at the end of each month. She has provided the following information: 2025 $ January 31 Sales ledger control account balance 1 895 debit February 28 Totals for the month Sales journal 42 600 Cash sales 2 300 Sales returns journal 7 300 Bank transfers received from credit customers ? Discount allowed 1 265 Irrecoverable debts 1 040 Contra entries 2 850 Interest charged on overdue accounts 510 March 1 Sales ledger control account balance 750 credit REQUIRED: (a) Prepare Jenny’s sales ledger control account for the month ended 28 February 2025. Balance the account and bring down the balance at 1 March 2025. Jenny Sales ledger control account Date Details $ Date Details $ 2025 2025 .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. .............. ................................. .............. [9] (b) State one advantage of maintaining a sales journal. ................................................................................................................................................... ............................................................................................................................................. [1] (c) Complete the following table by indicating the name of the source document that Jenny would use to make entries in her books of prime entry. State whether the source document is issued or received by Jenny. Book of prime entry Source document Issued or Received Sales journal Purchases returns journal [2] (d) State what is meant by the following terms: (i) cash discount ........................................................................................................................................... ..................................................................................................................................... [1] (ii) trade discount. ........................................................................................................................................... ..................................................................................................................................... [1] Jenny has received goods from one of her credit suppliers. When she inspected the goods, she found they were faulty. REQUIRED (e) Name the document Jenny would issue to her supplier to record the receipt of these faulty goods. ............................................................................................................................................. [1] Jenny currently does not maintain a provision for doubtful debts. When all reasonable steps to obtain payment from credit customers have failed, she writes off the debt. Her colleague has advised her that she should create a provision for doubtful debts when she prepares her next set of financial statements. REQUIRED (f) Advise Jenny whether or not she should create and maintain a provision for doubtful debts. Justify your answer by providing two arguments for and two arguments against maintaining a provision for doubtful debts. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
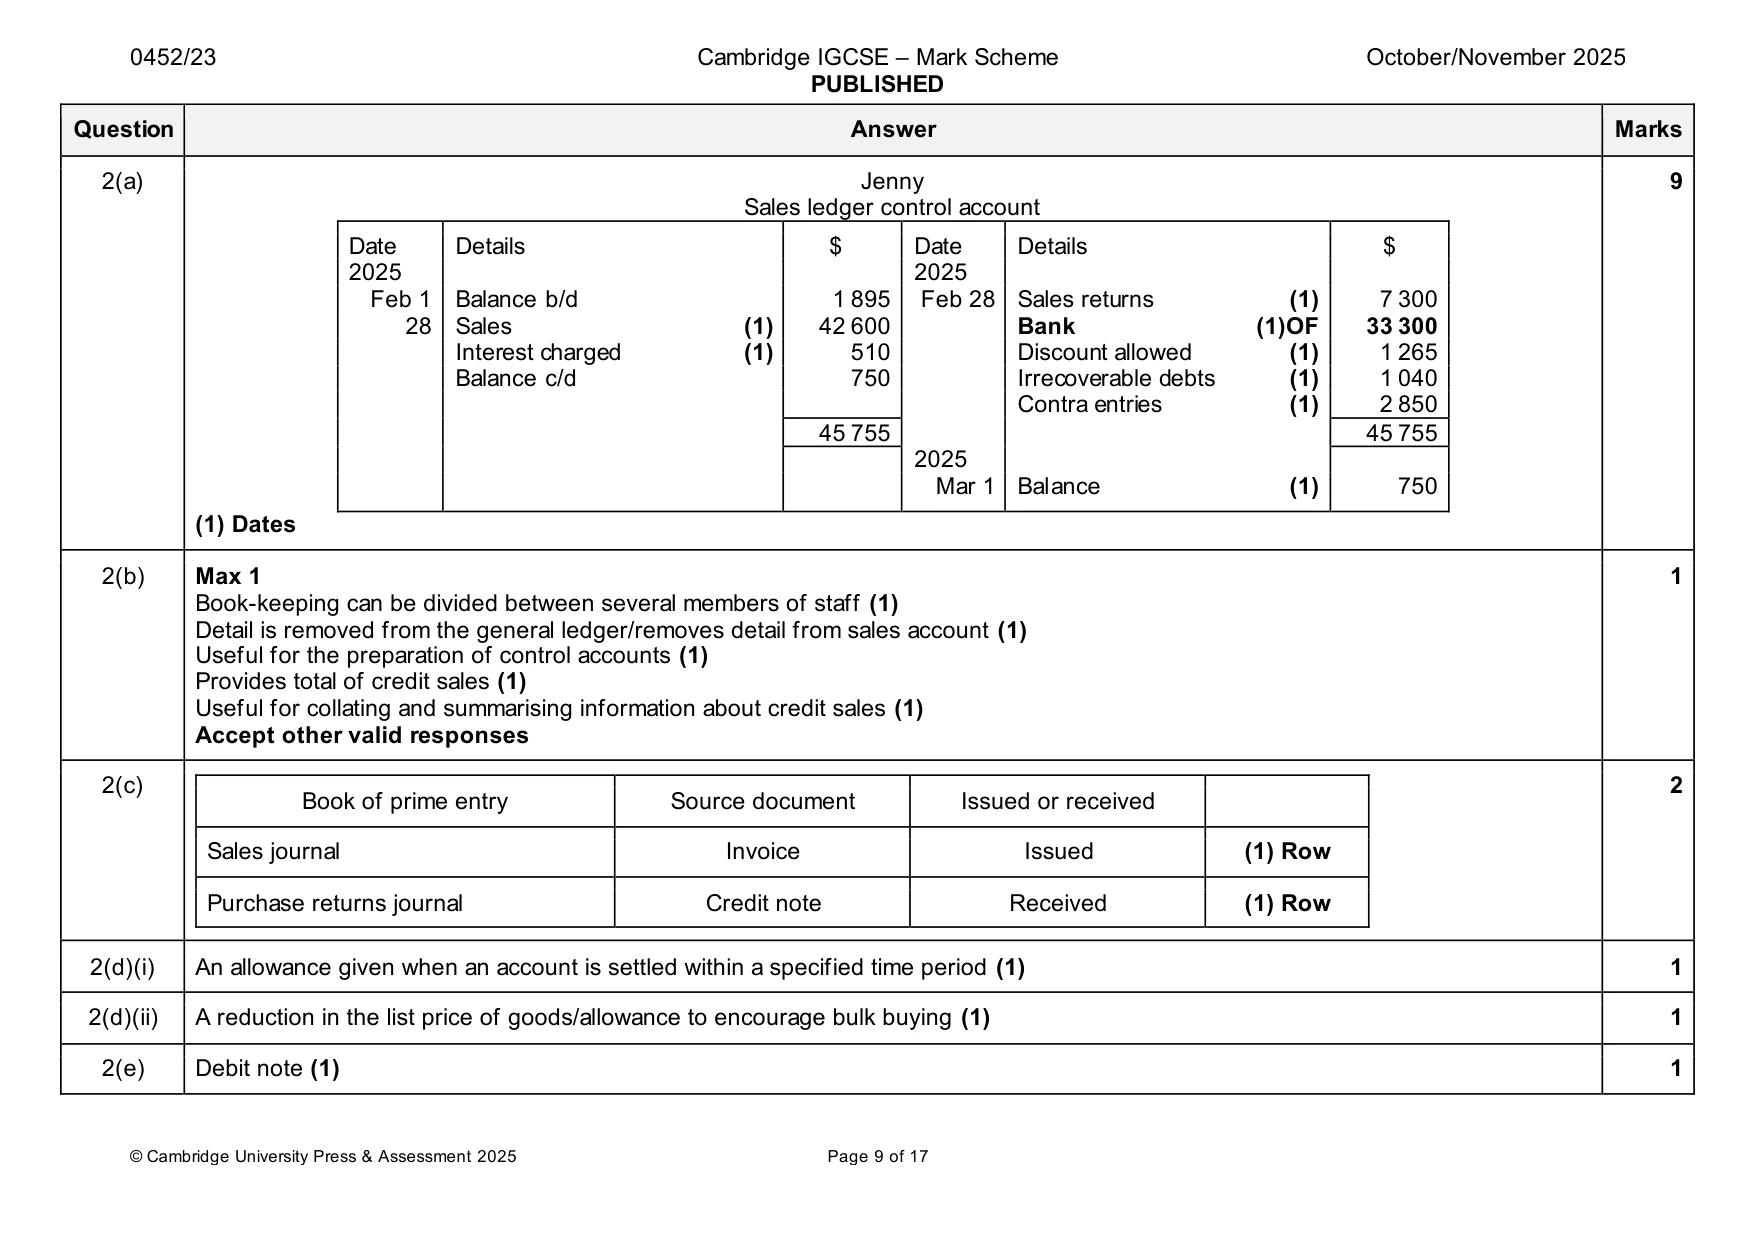
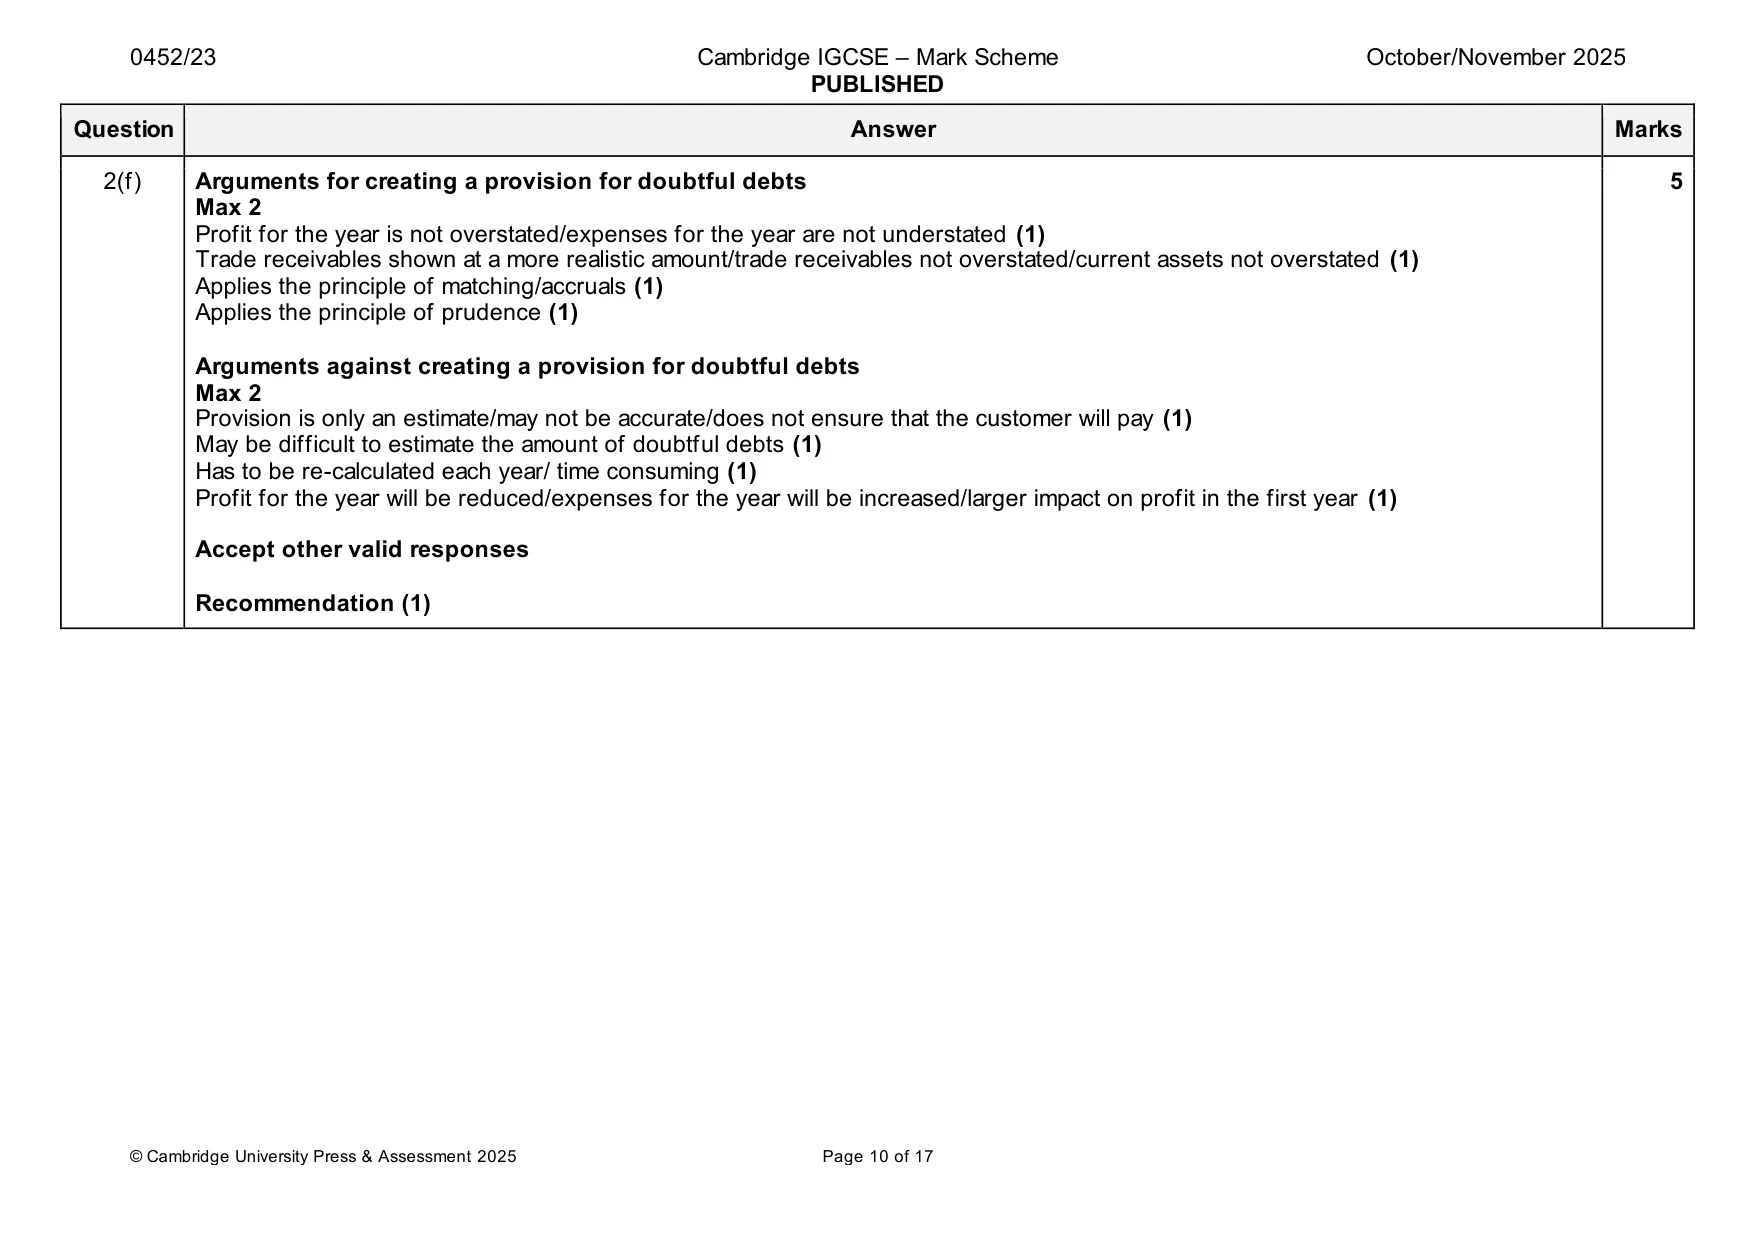
Mark scheme: 2(a) Jenny 9 Sales ledger control account Date Details $ Date Details $ 2025 2025 Feb 1 Balance b/d 1 895 Feb 28 Sales returns (1) 7 300 28 Sales (1) 42 600 Bank (1)OF 33 300 Interest charged (1) 510 Discount allowed (1) 1 265 Balance c/d 750 Irrecoverable debts (1) 1 040 Contra entries (1) 2 850 45 755 45 755 2025 Mar 1 Balance (1) 750 (1) Dates 2(b) Max 1 1 Book-keeping can be divided between several members of staff (1) Detail is removed from the general ledger/removes detail from sales account (1) Useful for the preparation of control accounts (1) Provides total of credit sales (1) Useful for collating and summarising information about credit sales (1) Accept other valid responses 2(c) 2 Book of prime entry Source document Issued or received Sales journal Invoice Issued (1) Row Purchase returns journal Credit note Received (1) Row 2(d)(i) An allowance given when an account is settled within a specified time period (1) 1 2(d)(ii) A reduction in the list price of goods/allowance to encourage bulk buying (1) 1 2(e) Debit note (1) 1 2(f) Arguments for creating a provision for doubtful debts 5 Max 2 Profit for the year is not overstated/expenses for the year are not understated (1) Trade receivables shown at a more realistic amount/trade receivables not overstated/current assets not overstated (1) Applies the principle of matching/accruals (1) Applies the principle of prudence (1) Arguments against creating a provision for doubtful debts Max 2 Provision is only an estimate/may not be accurate/does not ensure that the customer will pay (1) May be difficult to estimate the amount of doubtful debts (1) Has to be re-calculated each year/ time consuming (1) Profit for the year will be reduced/expenses for the year will be increased/larger impact on profit in the first year (1) Accept other valid responses Recommendation (1)
Q3 · Rushil is a trader and has provided his statement of financial position at 30 September…
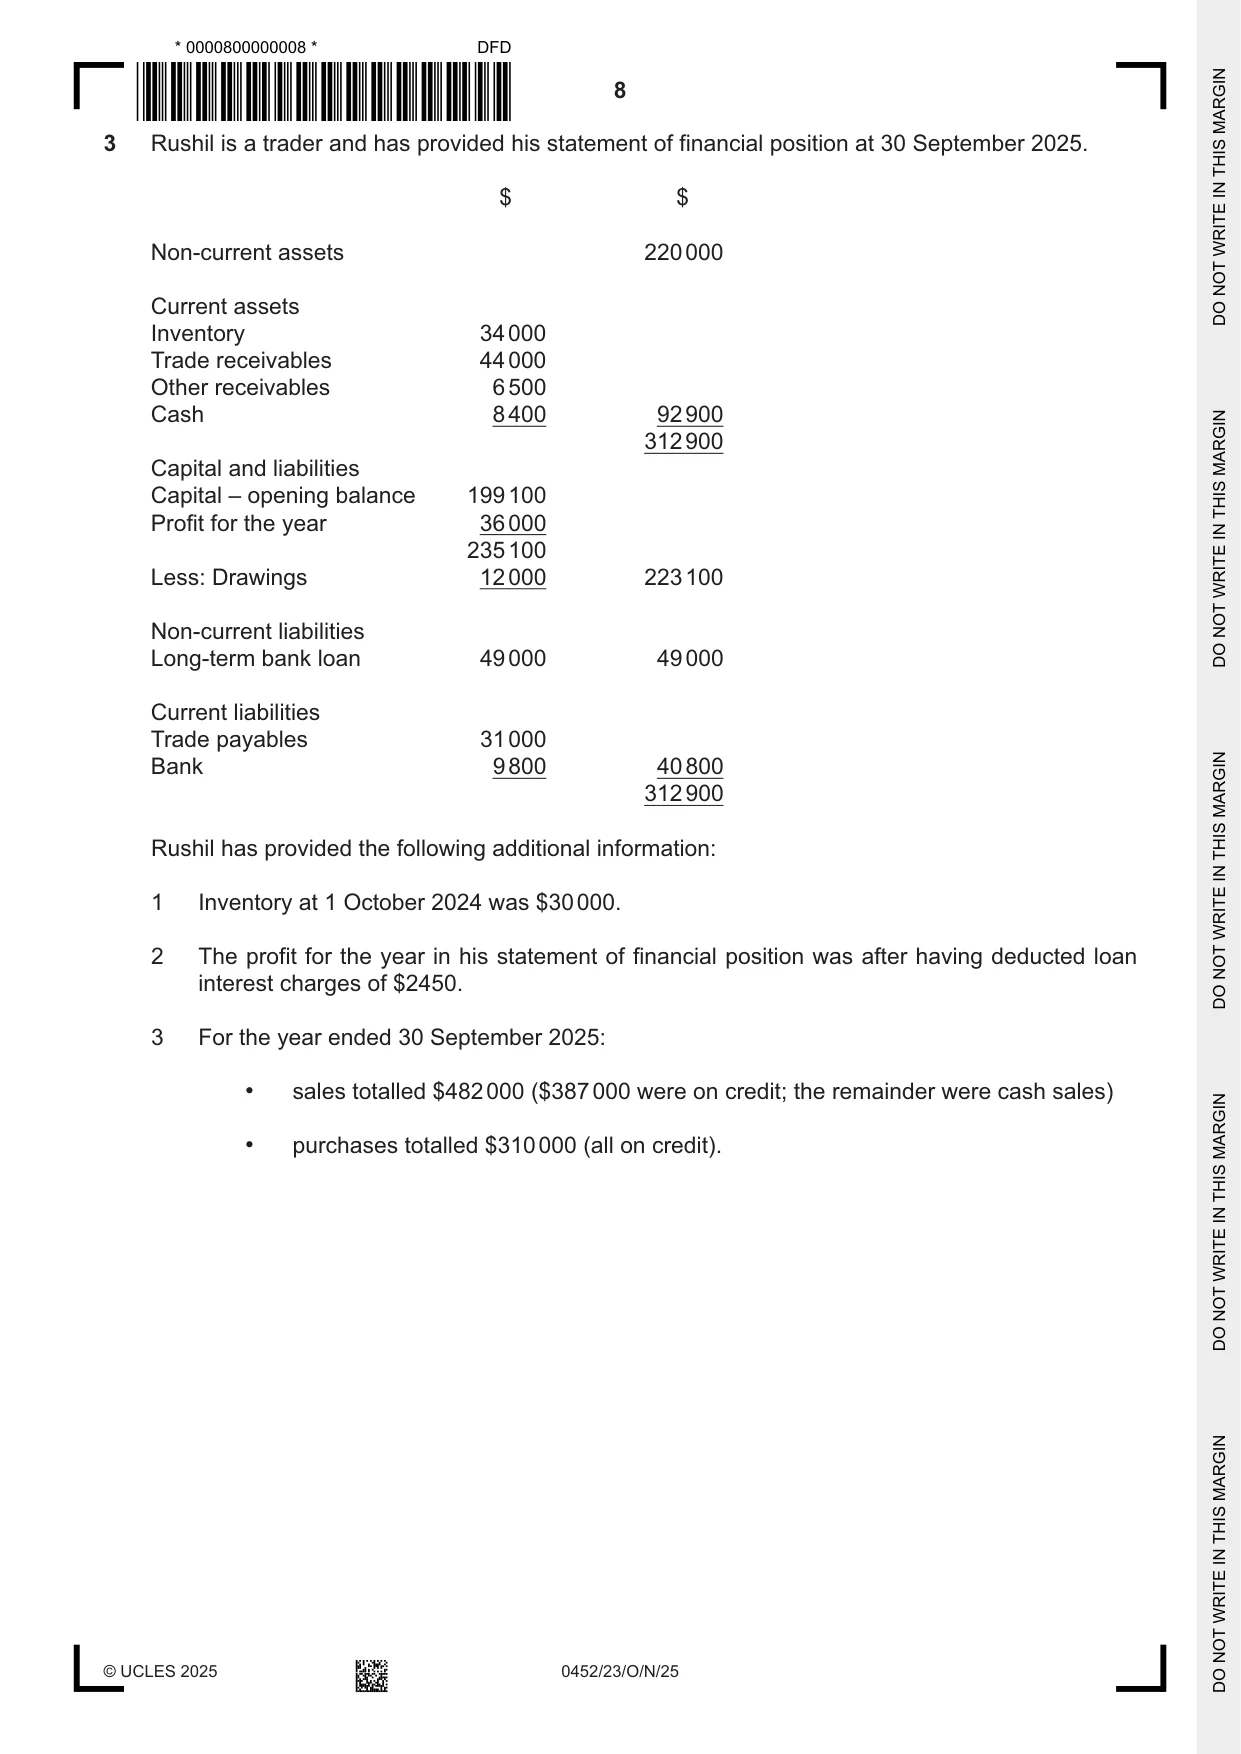
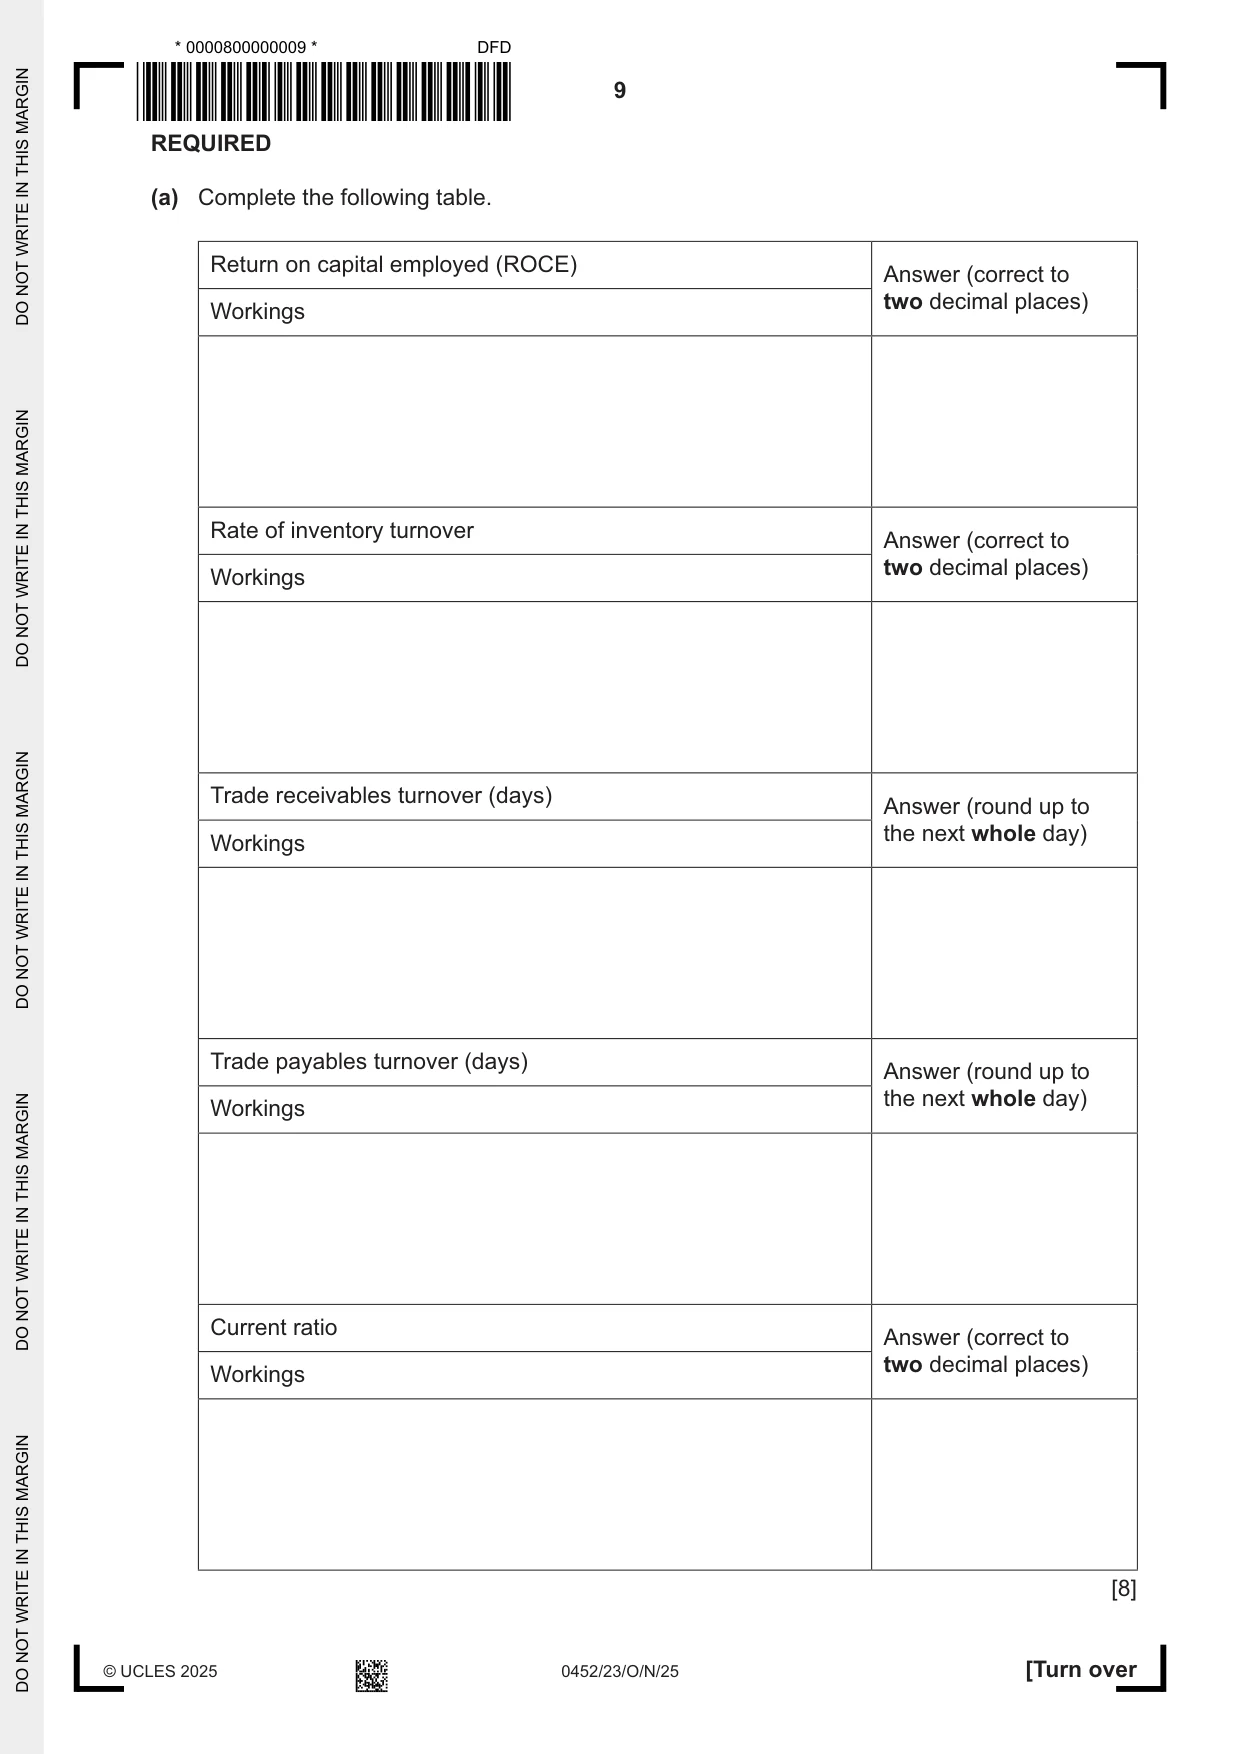
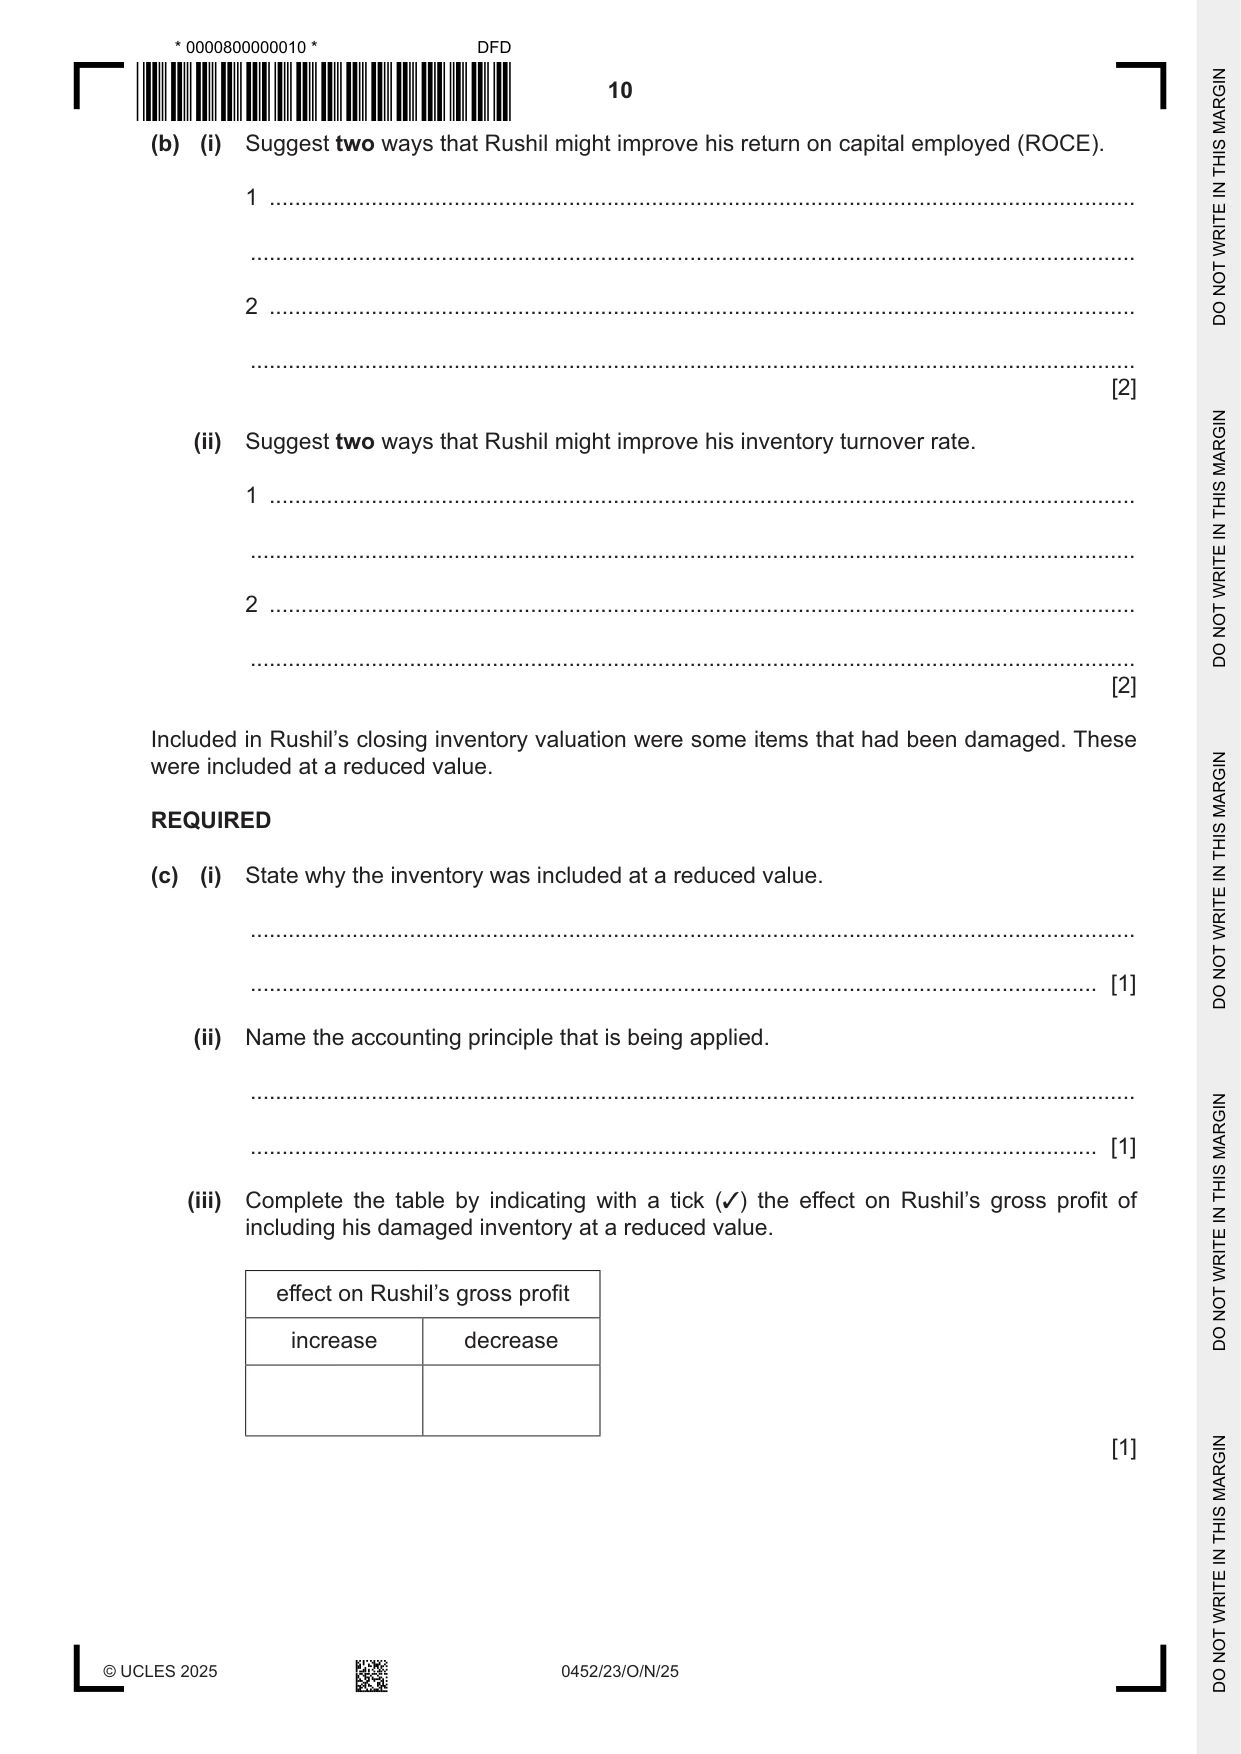
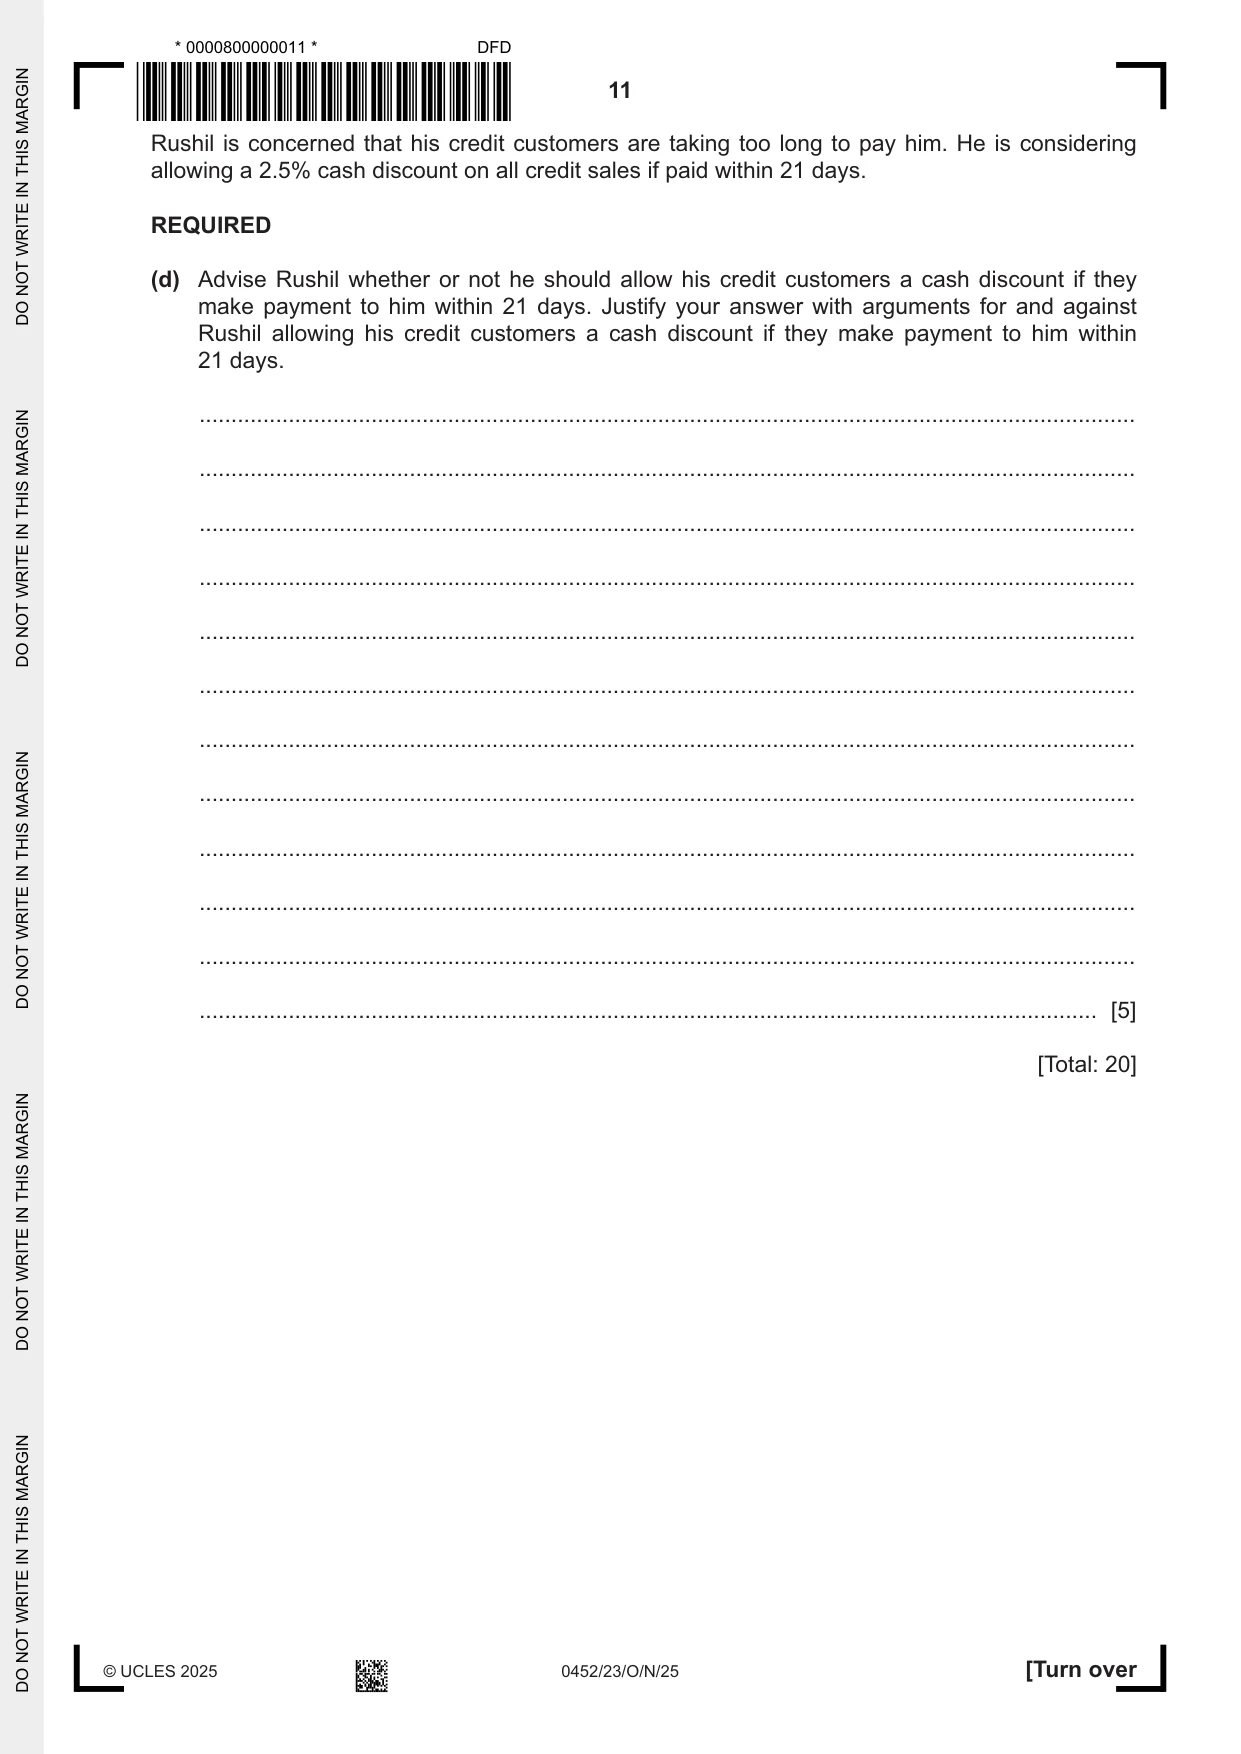
3 Rushil is a trader and has provided his statement of financial position at 30 September 2025. $ $ Non-current assets 220 000 Current assets Inventory 34 000 Trade receivables 44 000 Other receivables 6 500 Cash 8 400 92 900 312 900 Capital and liabilities Capital – opening balance 199 100 Profit for the year 36 000 235 100 Less: Drawings 12 000 223 100 Non-current liabilities Long-term bank loan 49 000 49 000 Current liabilities Trade payables 31 000 Bank 9 800 40 800 312 900 Rushil has provided the following additional information: 1 Inventory at 1 October 2024 was $30 000. 2 The profit for the year in his statement of financial position was after having deducted loan interest charges of $2450. 3 For the year ended 30 September 2025: • sales totalled $482 000 ($387 000 were on credit; the remainder were cash sales) • purchases totalled $310 000 (all on credit). REQUIRED (a) Complete the following table. Return on capital employed (ROCE) Answer (correct to two decimal places) Workings Rate of inventory turnover Answer (correct to two decimal places) Workings Trade receivables turnover (days) Answer (round up to the next whole day) Workings Trade payables turnover (days) Answer (round up to the next whole day) Workings Current ratio Answer (correct to two decimal places) Workings [8] (b) (i) Suggest two ways that Rushil might improve his return on capital employed (ROCE). 1 ........................................................................................................................................ ........................................................................................................................................... 2 ........................................................................................................................................ ........................................................................................................................................... [2] (ii) Suggest two ways that Rushil might improve his inventory turnover rate. 1 ........................................................................................................................................ ........................................................................................................................................... 2 ........................................................................................................................................ ........................................................................................................................................... [2] Included in Rushil’s closing inventory valuation were some items that had been damaged. These were included at a reduced value. REQUIRED (c) (i) State why the inventory was included at a reduced value. ........................................................................................................................................... ..................................................................................................................................... [1] (ii) Name the accounting principle that is being applied. ........................................................................................................................................... ..................................................................................................................................... [1] (iii) Complete the table by indicating with a tick (3) the effect on Rushil’s gross profit of including his damaged inventory at a reduced value. effect on Rushil’s gross profit increase decrease [1] Rushil is concerned that his credit customers are taking too long to pay him. He is considering allowing a 2.5% cash discount on all credit sales if paid within 21 days. REQUIRED (d) Advise Rushil whether or not he should allow his credit customers a cash discount if they make payment to him within 21 days. Justify your answer with arguments for and against Rushil allowing his credit customers a cash discount if they make payment to him within 21 days. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
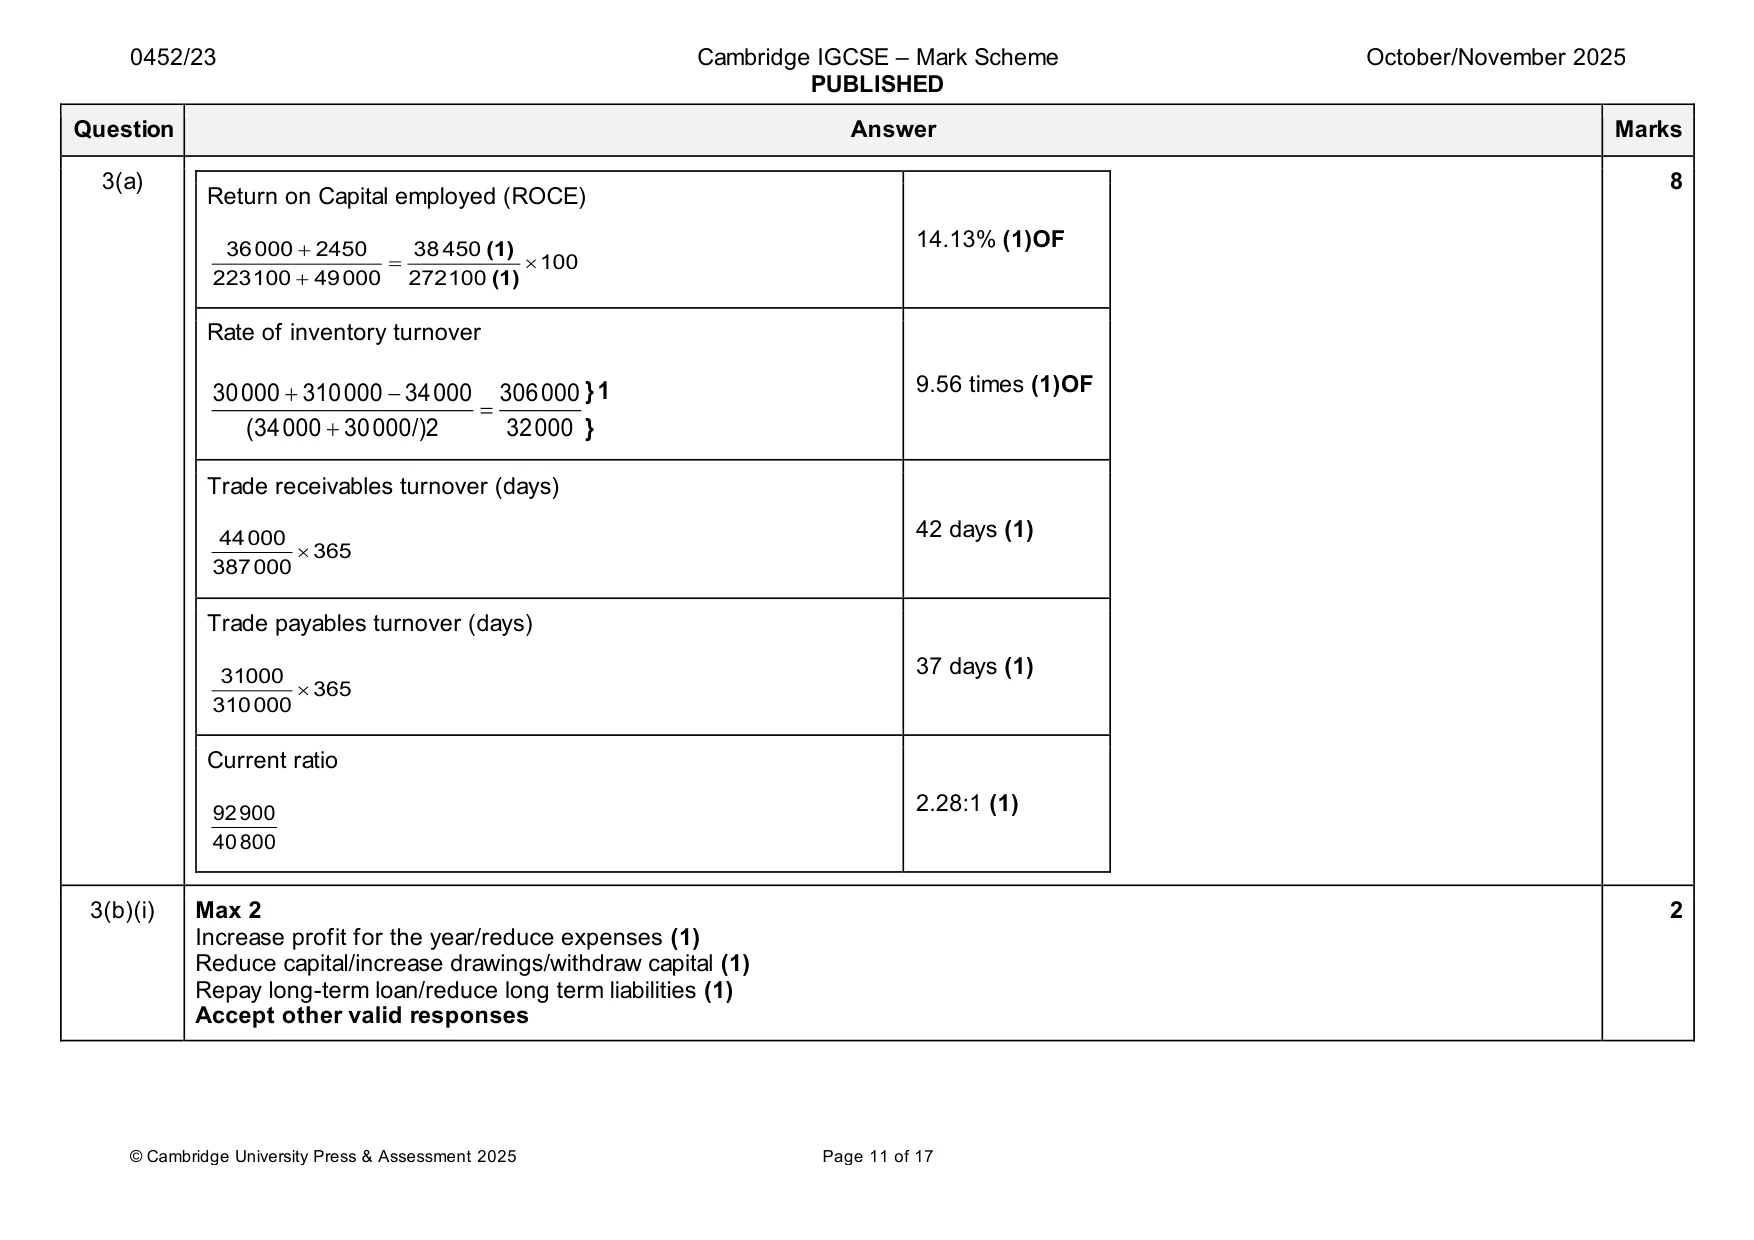
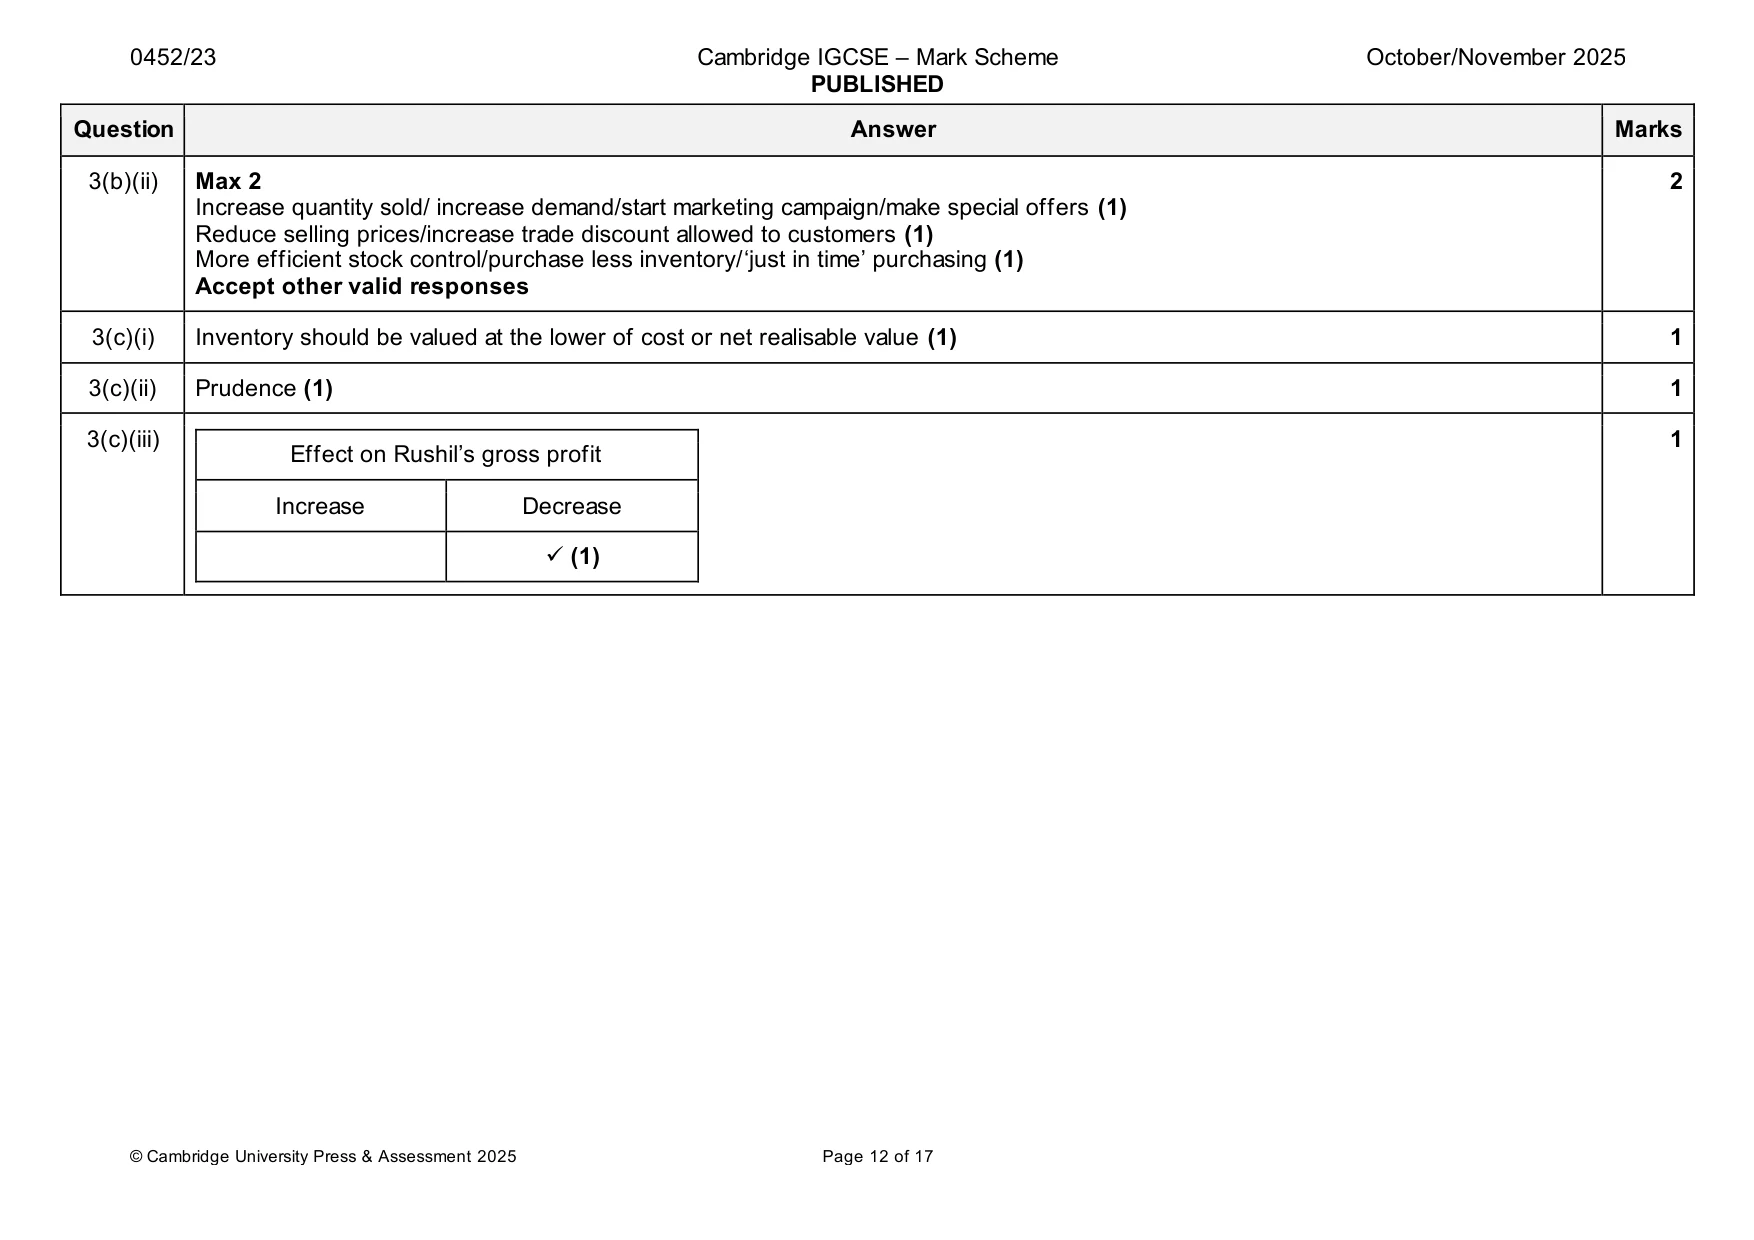
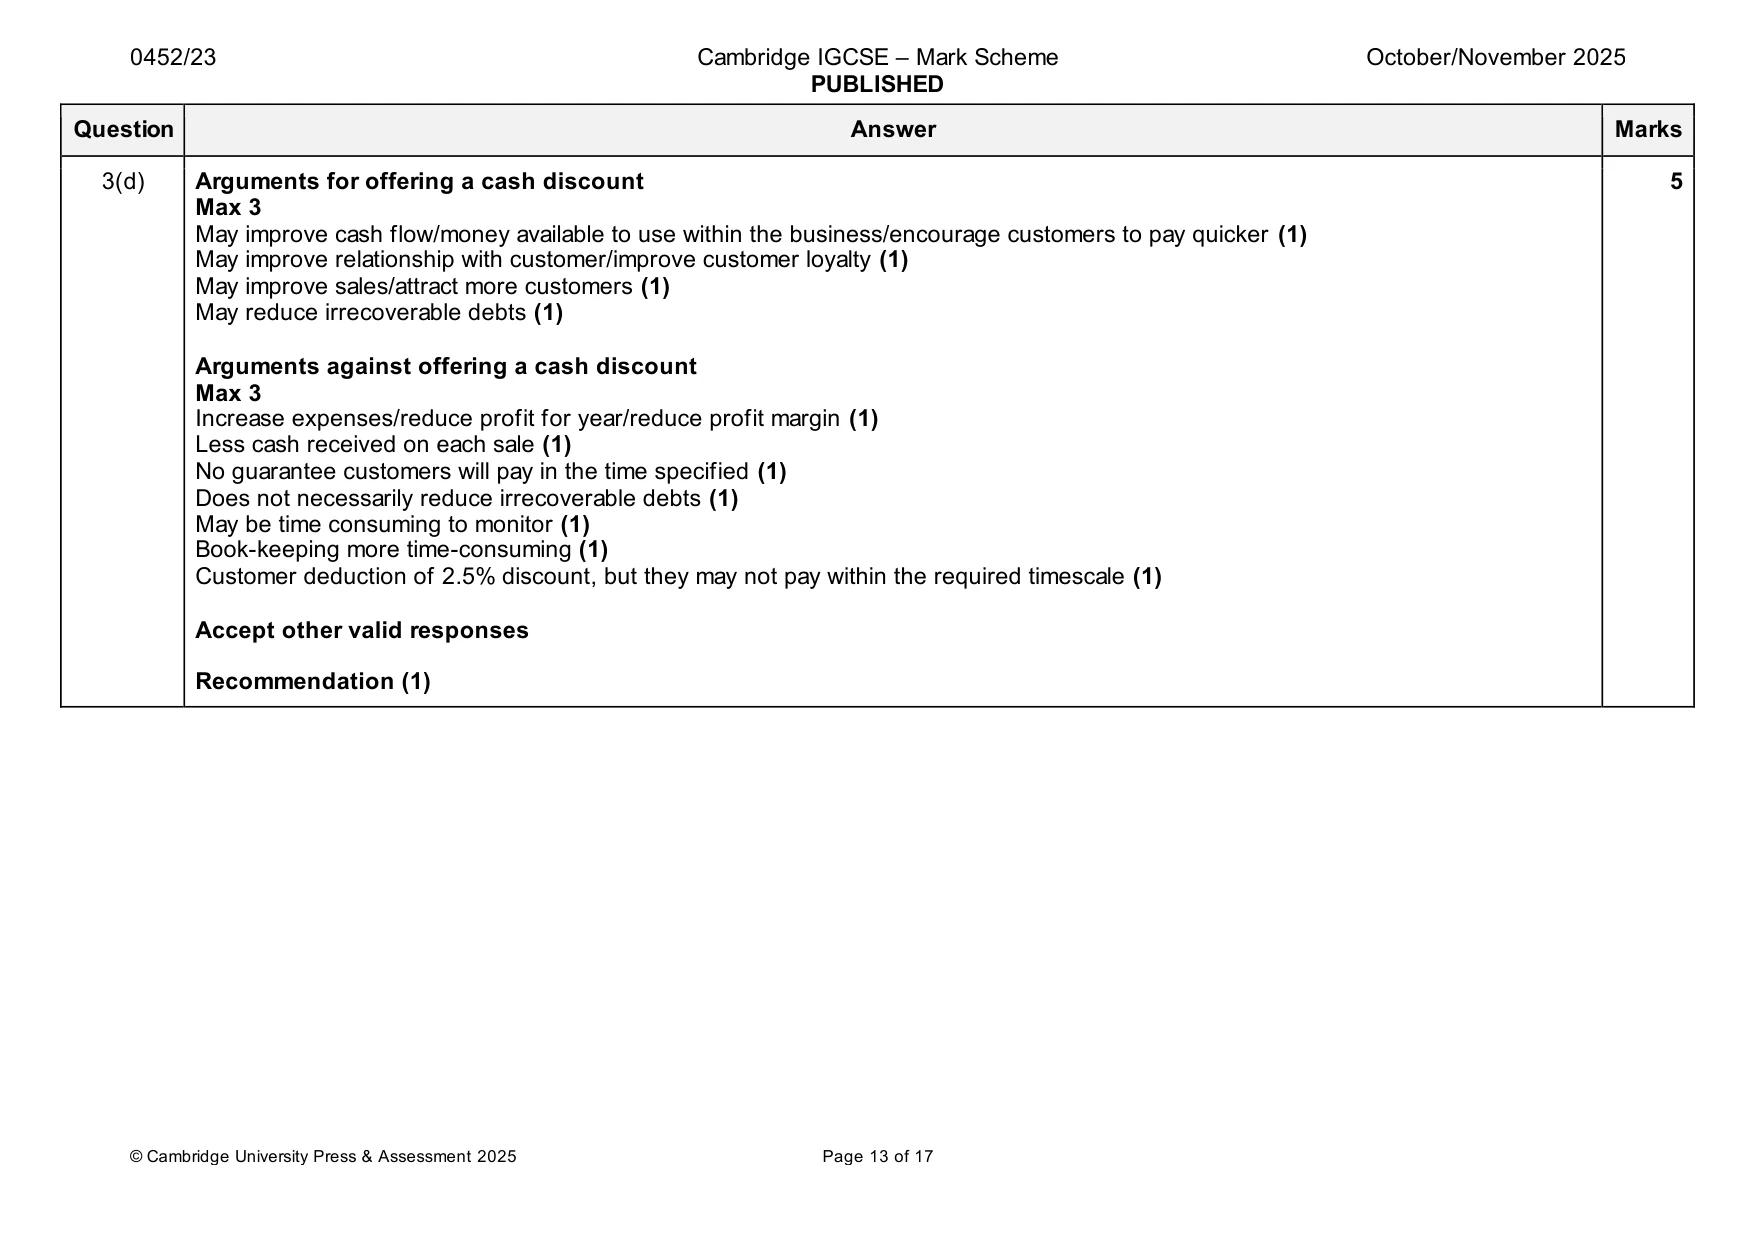
Mark scheme: 3(a) 8 Return on Capital employed (ROCE) 14.13% (1)OF 36000 + 2450 38 450 (1) = 100 223100 + 49000 272100 (1) Rate of inventory turnover 30000 + 310000 − 34000 306000 }1 9.56 times (1)OF = (34000 + 30000/)2 32000 } Trade receivables turnover (days) 42 days (1) 44000 365 387000 Trade payables turnover (days) 37 days (1) 31000 365 310000 Current ratio 2.28:1 (1) 92900 40800 3(b)(i) Max 2 2 Increase profit for the year/reduce expenses (1) Reduce capital/increase drawings/withdraw capital (1) Repay long-term loan/reduce long term liabilities (1) Accept other valid responses 3(b)(ii) Max 2 2 Increase quantity sold/ increase demand/start marketing campaign/make special offers (1) Reduce selling prices/increase trade discount allowed to customers (1) More efficient stock control/purchase less inventory/‘just in time’ purchasing (1) Accept other valid responses 3(c)(i) Inventory should be valued at the lower of cost or net realisable value (1) 1 3(c)(ii) Prudence (1) 1 3(c)(iii) 1 Effect on Rushil’s gross profit Increase Decrease ✓ (1) 3(d) Arguments for offering a cash discount 5 Max 3 May improve cash flow/money available to use within the business/encourage customers to pay quicker (1) May improve relationship with customer/improve customer loyalty (1) May improve sales/attract more customers (1) May reduce irrecoverable debts (1) Arguments against offering a cash discount Max 3 Increase expenses/reduce profit for year/reduce profit margin (1) Less cash received on each sale (1) No guarantee customers will pay in the time specified (1) Does not necessarily reduce irrecoverable debts (1) May be time consuming to monitor (1) Book-keeping more time-consuming (1) Customer deduction of 2.5% discount, but they may not pay within the required timescale (1) Accept other valid responses Recommendation (1)
Q4 · Talula owns a hairdressing salon
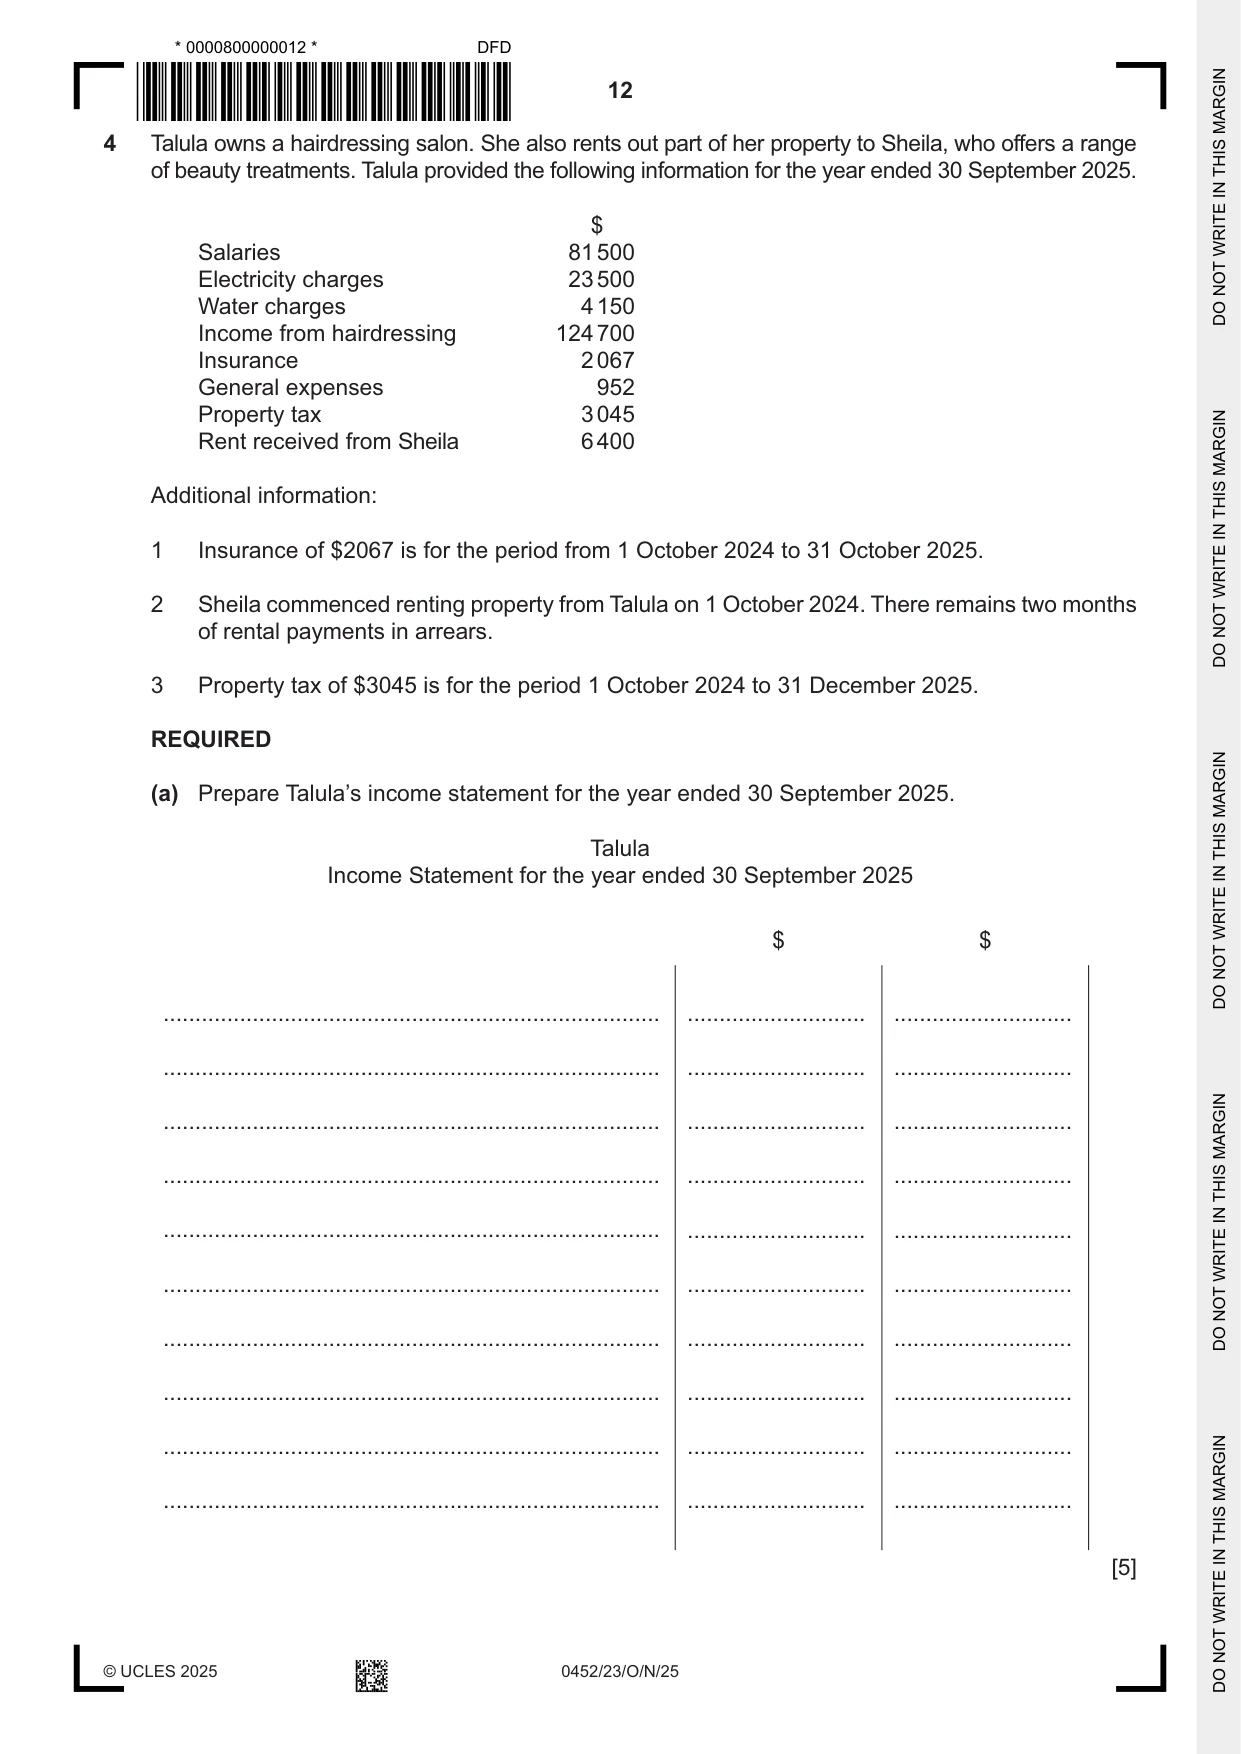
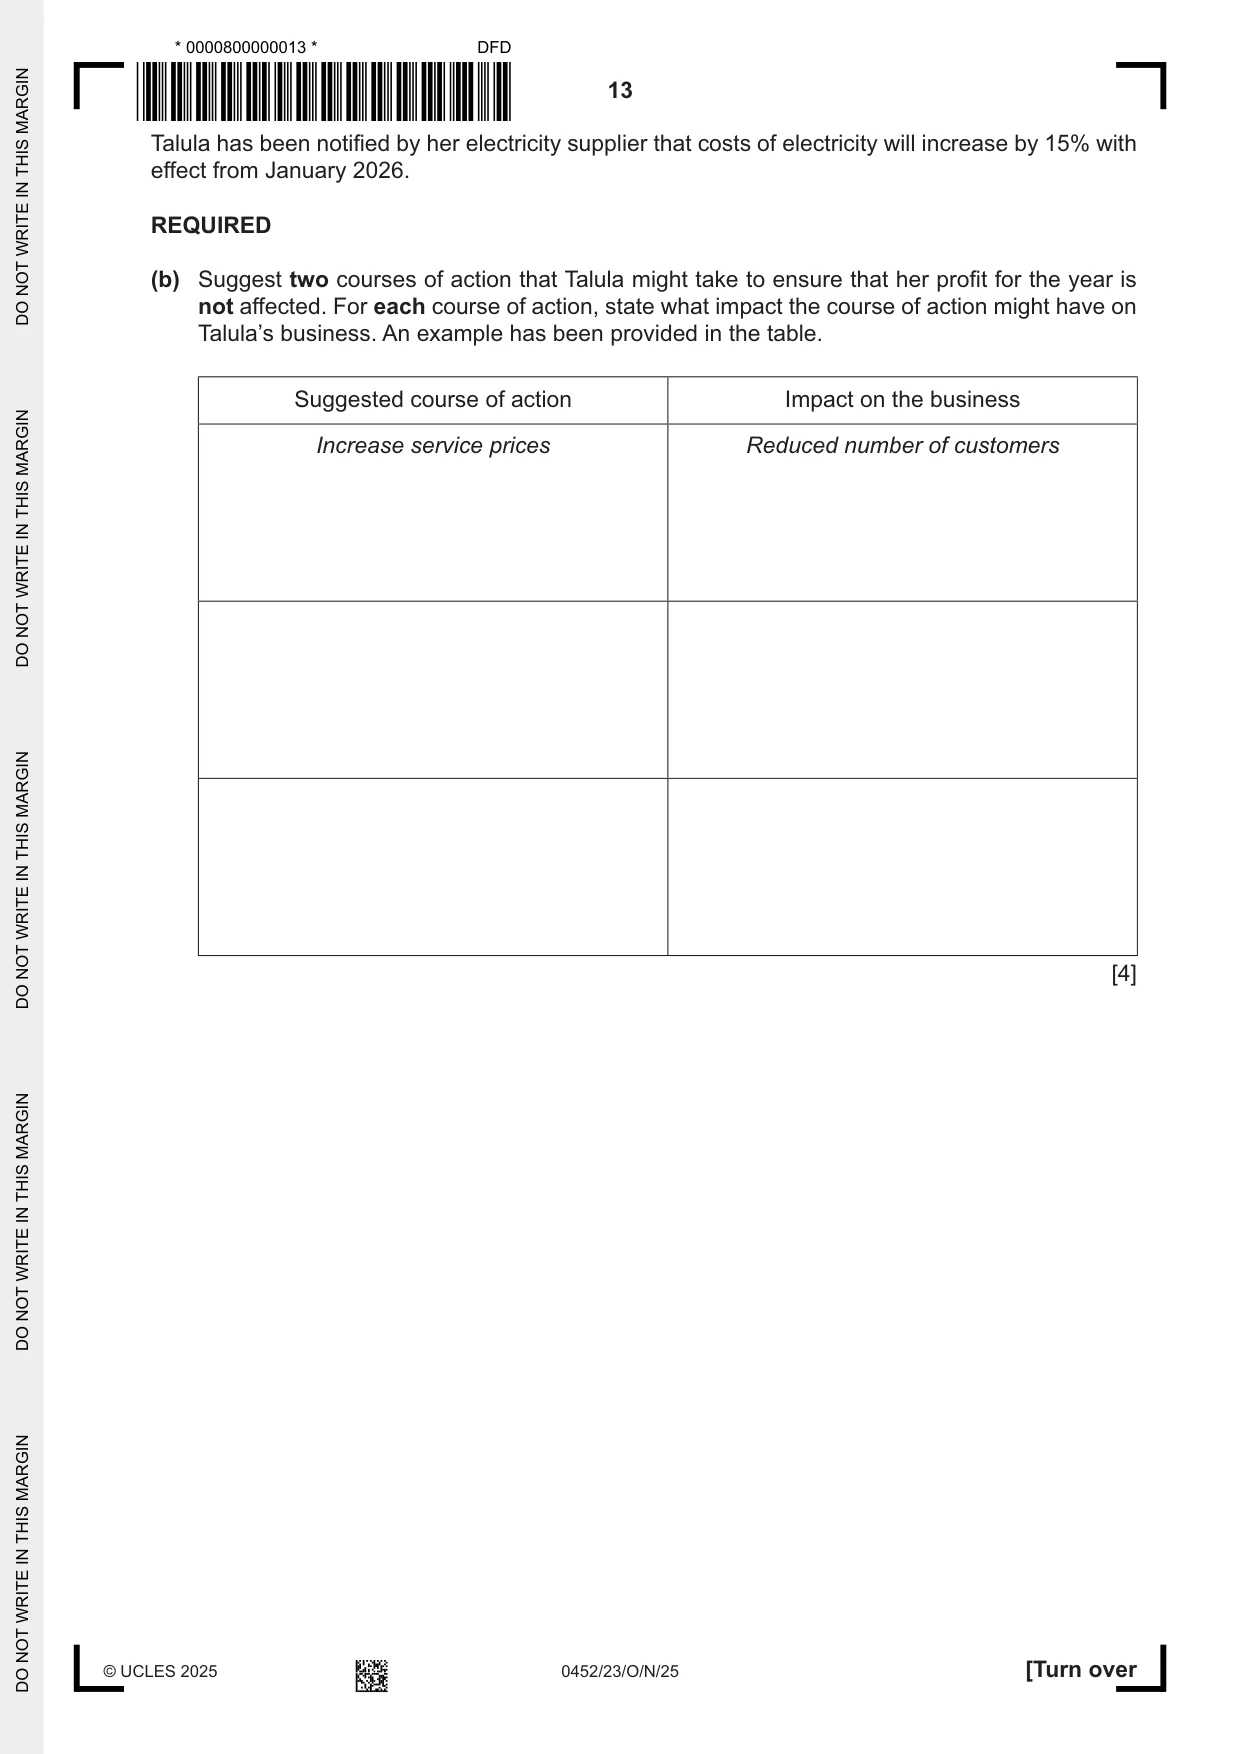
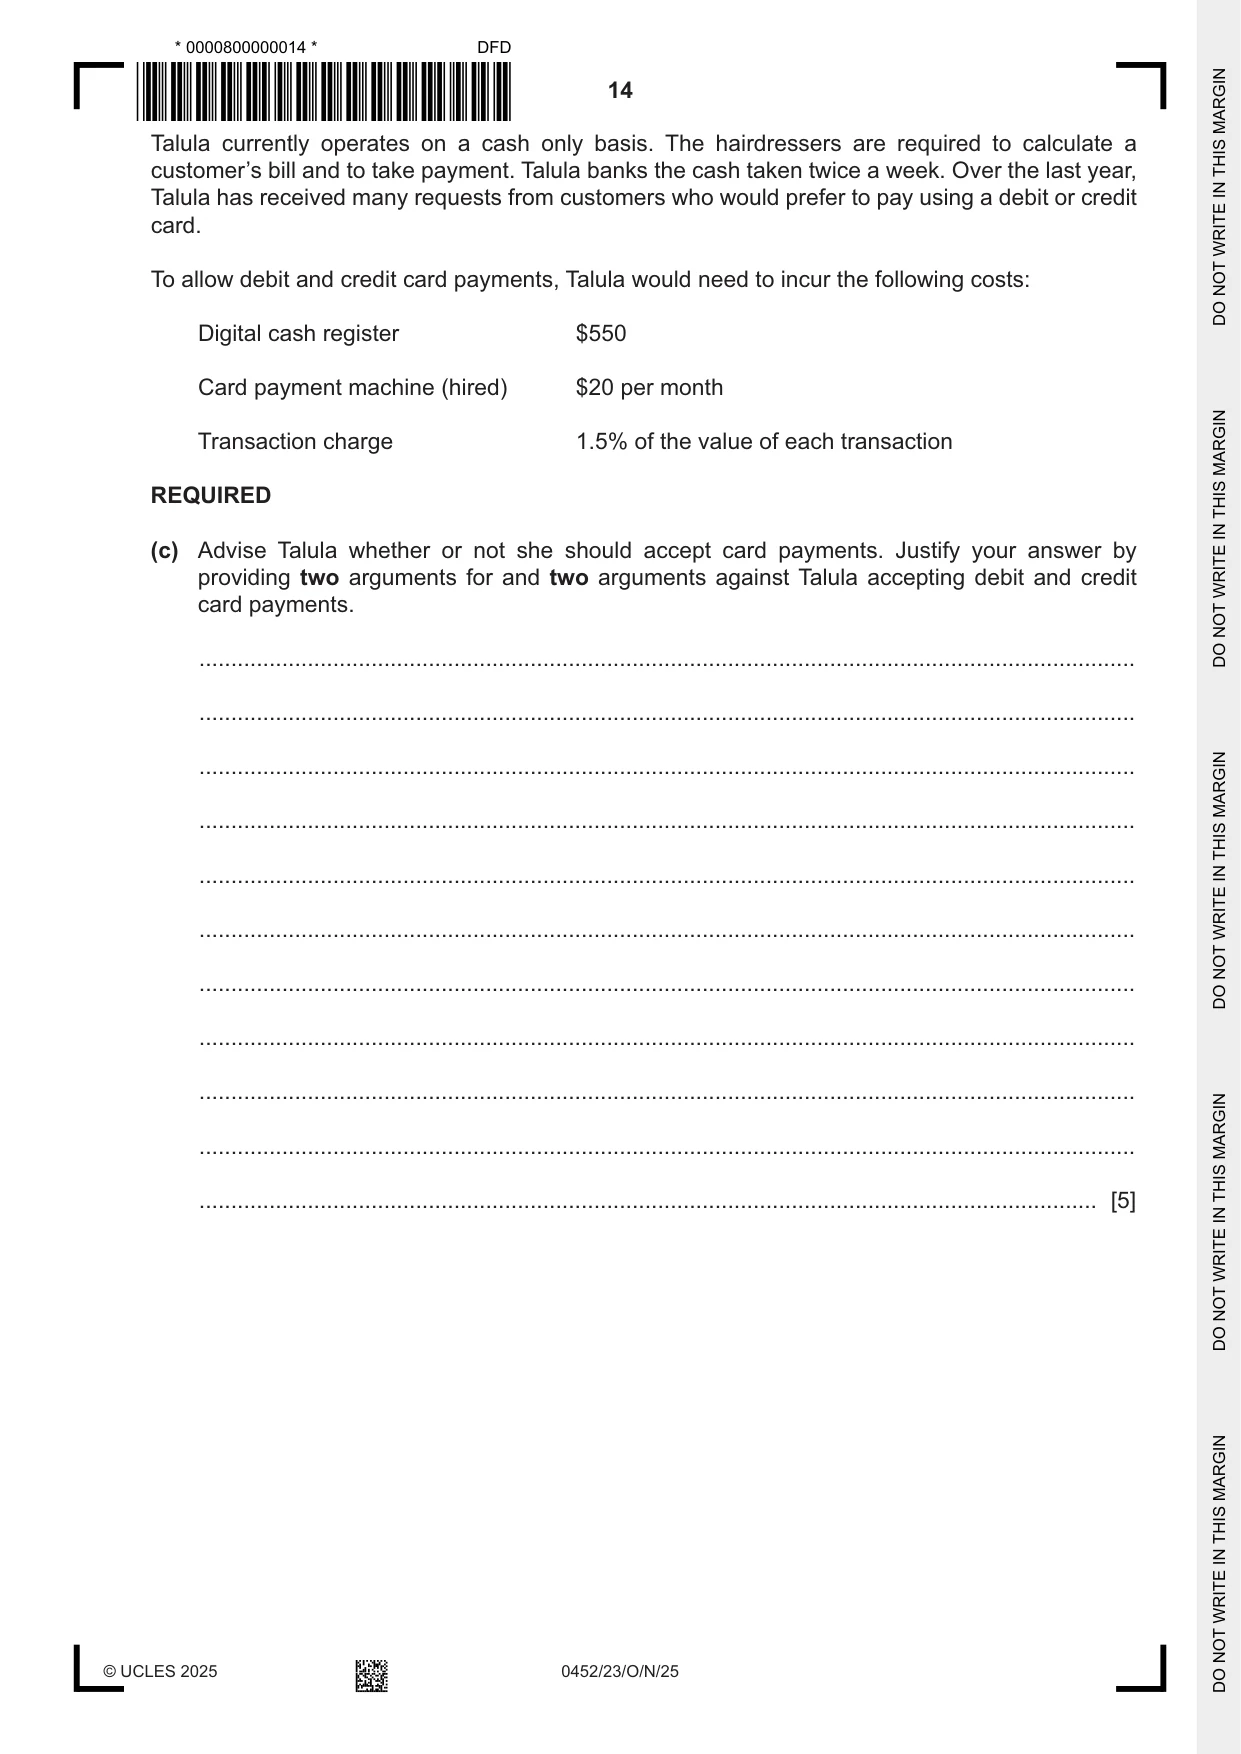
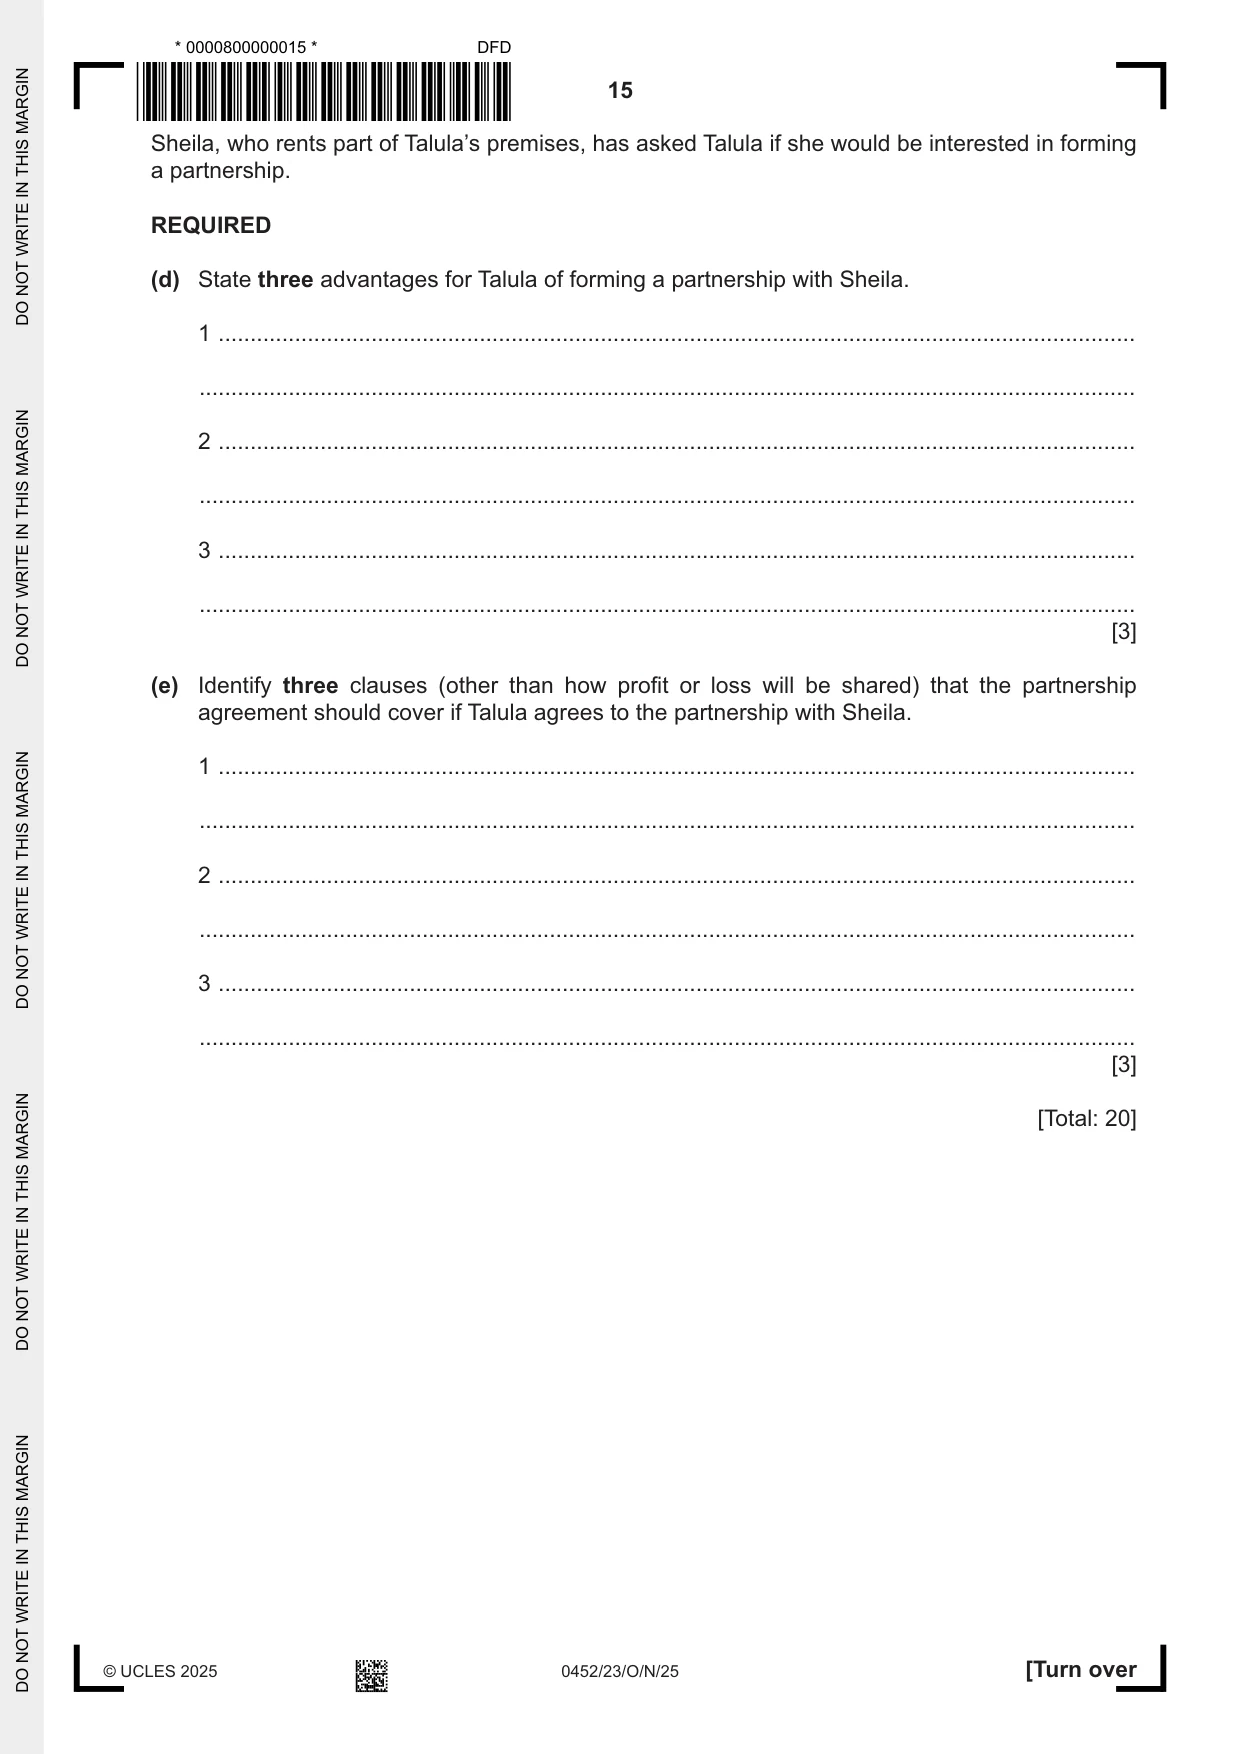
4 Talula owns a hairdressing salon. She also rents out part of her property to Sheila, who offers a range of beauty treatments. Talula provided the following information for the year ended 30 September 2025. $ Salaries 81 500 Electricity charges 23 500 Water charges 4 150 Income from hairdressing 124 700 Insurance 2 067 General expenses 952 Property tax 3 045 Rent received from Sheila 6 400 Additional information: 1 Insurance of $2067 is for the period from 1 October 2024 to 31 October 2025. 2 Sheila commenced renting property from Talula on 1 October 2024. There remains two months of rental payments in arrears. 3 Property tax of $3045 is for the period 1 October 2024 to 31 December 2025. REQUIRED (a) Prepare Talula’s income statement for the year ended 30 September 2025. Talula Income Statement for the year ended 30 September 2025 $ $ .............................................................................. ............................ ............................ .............................................................................. ............................ ............................ .............................................................................. ............................ ............................ .............................................................................. ............................ ............................ .............................................................................. ............................ ............................ .............................................................................. ............................ ............................ .............................................................................. ............................ ............................ .............................................................................. ............................ ............................ .............................................................................. ............................ ............................ .............................................................................. ............................ ............................ [5] Talula has been notified by her electricity supplier that costs of electricity will increase by 15% with effect from January 2026. REQUIRED (b) Suggest two courses of action that Talula might take to ensure that her profit for the year is not affected. For each course of action, state what impact the course of action might have on Talula’s business. An example has been provided in the table. Suggested course of action Impact on the business Increase service prices Reduced number of customers [4] Talula currently operates on a cash only basis. The hairdressers are required to calculate a customer’s bill and to take payment. Talula banks the cash taken twice a week. Over the last year, Talula has received many requests from customers who would prefer to pay using a debit or credit card. To allow debit and credit card payments, Talula would need to incur the following costs: Digital cash register $550 Card payment machine (hired) $20 per month Transaction charge 1.5% of the value of each transaction REQUIRED (c) Advise Talula whether or not she should accept card payments. Justify your answer by providing two arguments for and two arguments against Talula accepting debit and credit card payments. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] Sheila, who rents part of Talula’s premises, has asked Talula if she would be interested in forming a partnership. REQUIRED (d) State three advantages for Talula of forming a partnership with Sheila. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... 3 ................................................................................................................................................ ................................................................................................................................................... [3] (e) Identify three clauses (other than how profit or loss will be shared) that the partnership agreement should cover if Talula agrees to the partnership with Sheila. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... 3 ................................................................................................................................................ ................................................................................................................................................... [3] [Total: 20]
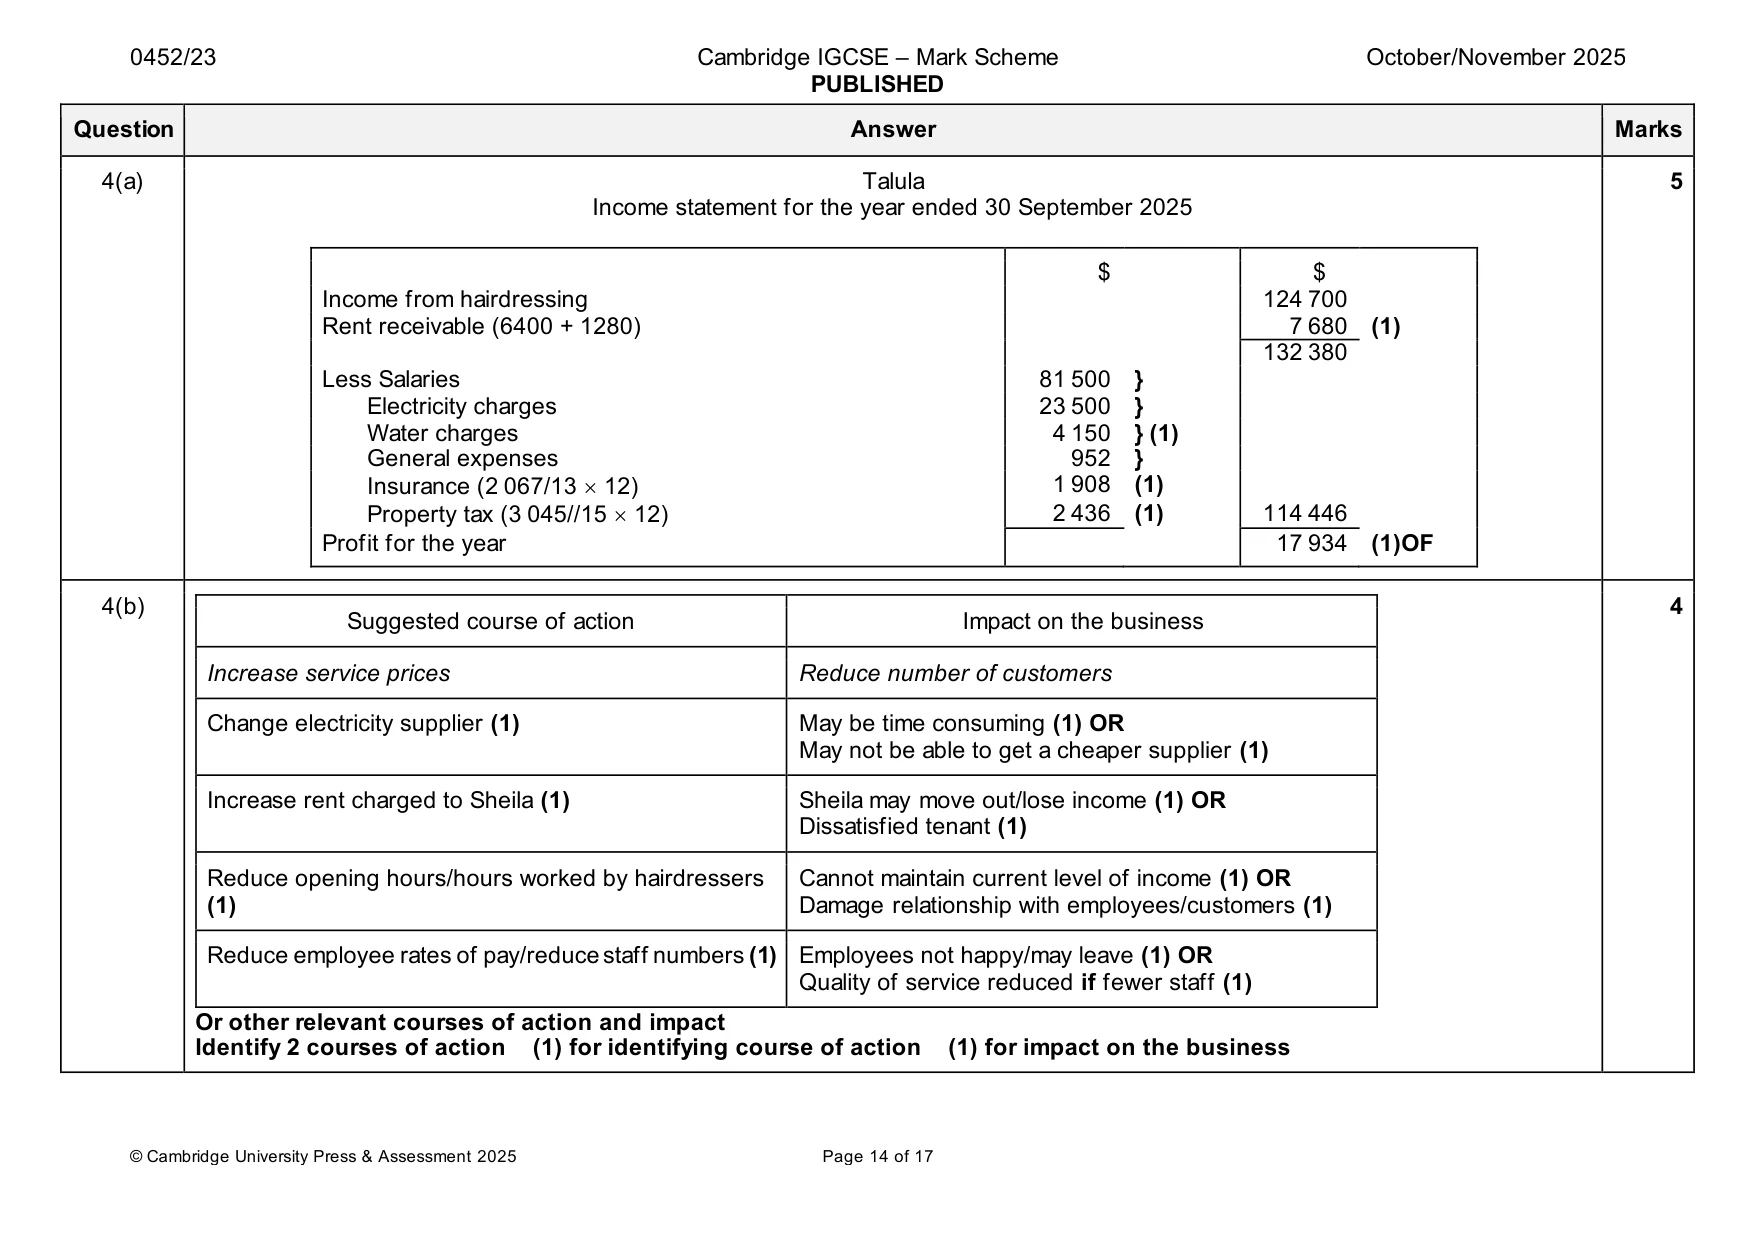
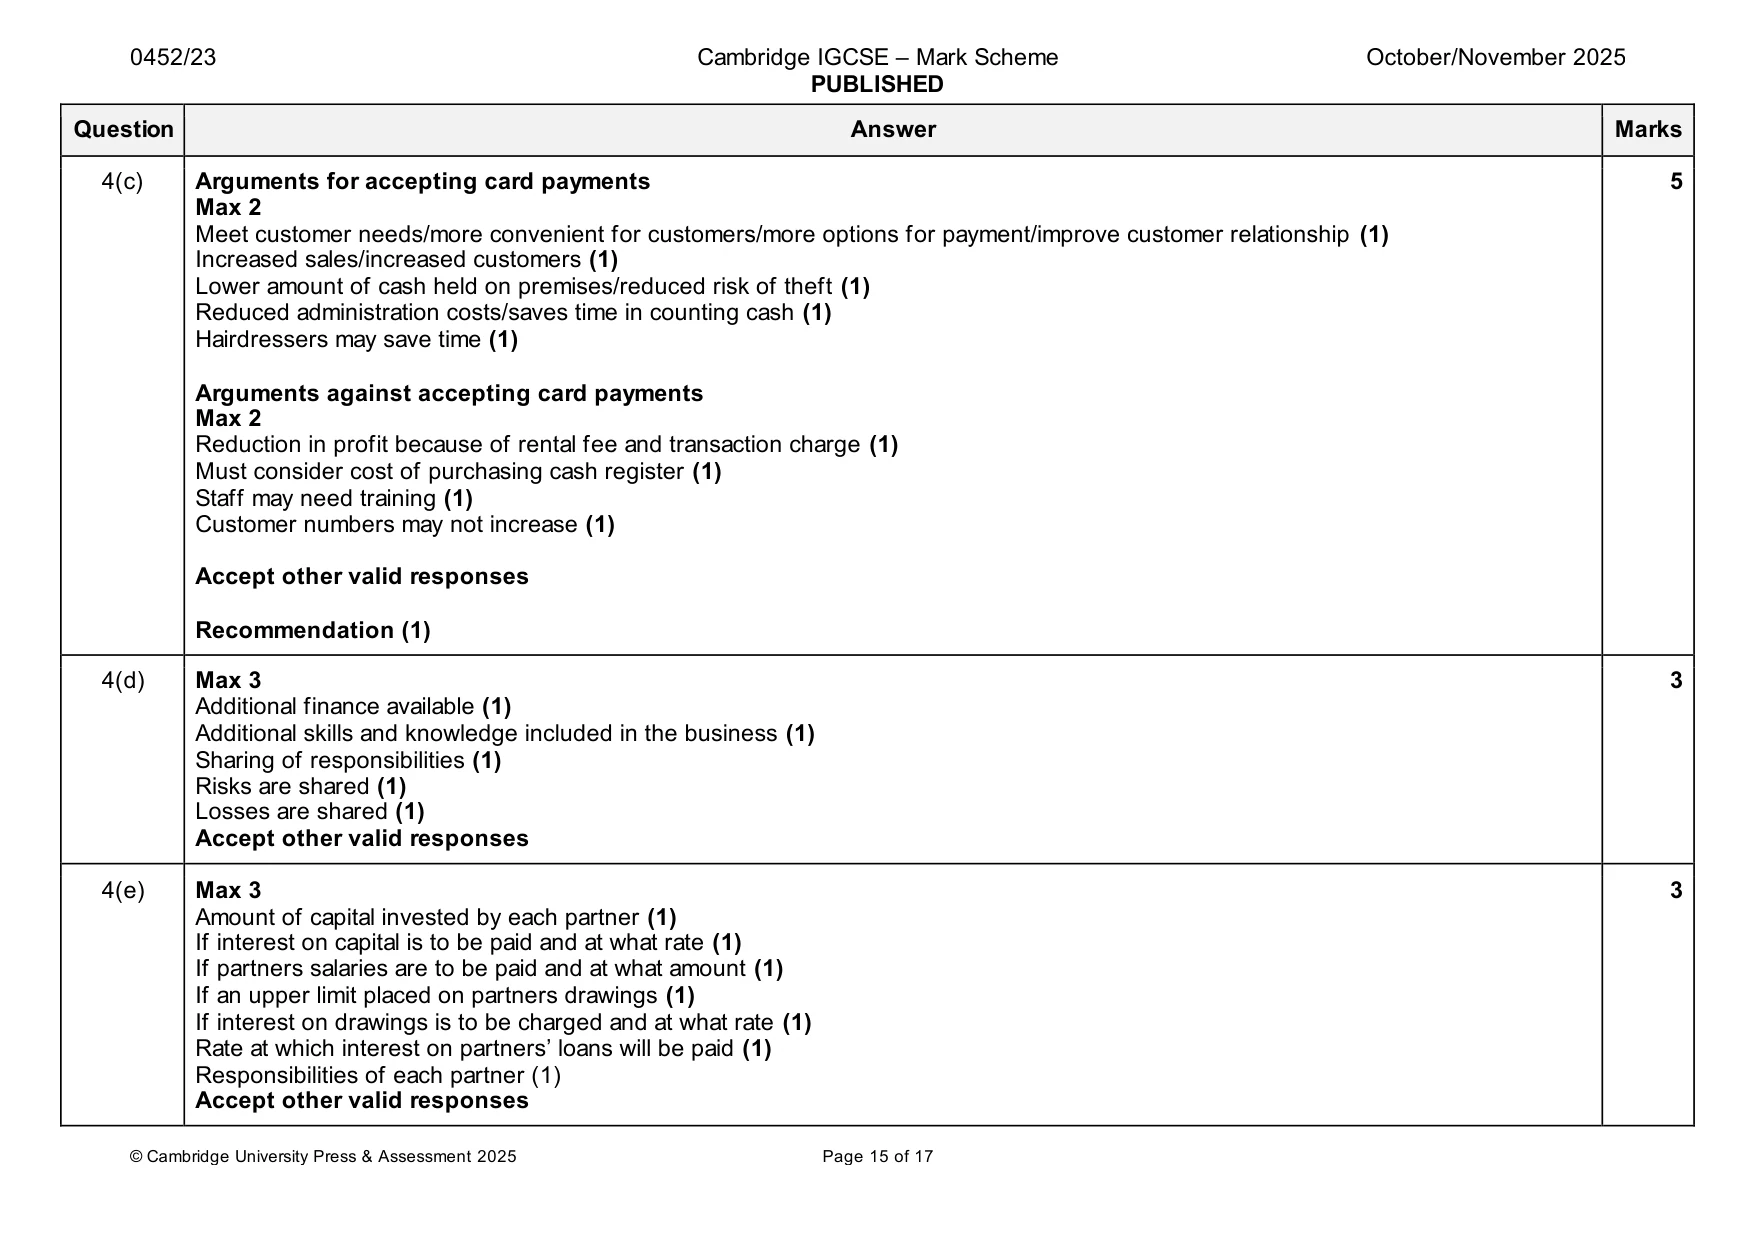
Mark scheme: 4(a) Talula 5 Income statement for the year ended 30 September 2025 $ $ Income from hairdressing 124 700 Rent receivable (6400 + 1280) 7 680 (1) 132 380 Less Salaries 81 500 } Electricity charges 23 500 } Water charges 4 150 } (1) General expenses 952 } Insurance (2 067/13 12) 1 908 (1) Property tax (3 045//15 12) 2 436 (1) 114 446 Profit for the year 17 934 (1)OF 4(b) 4 Suggested course of action Impact on the business Increase service prices Reduce number of customers Change electricity supplier (1) May be time consuming (1) OR May not be able to get a cheaper supplier (1) Increase rent charged to Sheila (1) Sheila may move out/lose income (1) OR Dissatisfied tenant (1) Reduce opening hours/hours worked by hairdressers Cannot maintain current level of income (1) OR (1) Damage relationship with employees/customers (1) Reduce employee rates of pay/reduce staff numbers (1) Employees not happy/may leave (1) OR Quality of service reduced if fewer staff (1) Or other relevant courses of action and impact Identify 2 courses of action (1) for identifying course of action (1) for impact on the business 4(c) Arguments for accepting card payments 5 Max 2 Meet customer needs/more convenient for customers/more options for payment/improve customer relationship (1) Increased sales/increased customers (1) Lower amount of cash held on premises/reduced risk of theft (1) Reduced administration costs/saves time in counting cash (1) Hairdressers may save time (1) Arguments against accepting card payments Max 2 Reduction in profit because of rental fee and transaction charge (1) Must consider cost of purchasing cash register (1) Staff may need training (1) Customer numbers may not increase (1) Accept other valid responses Recommendation (1) 4(d) Max 3 3 Additional finance available (1) Additional skills and knowledge included in the business (1) Sharing of responsibilities (1) Risks are shared (1) Losses are shared (1) Accept other valid responses 4(e) Max 3 3 Amount of capital invested by each partner (1) If interest on capital is to be paid and at what rate (1) If partners salaries are to be paid and at what amount (1) If an upper limit placed on partners drawings (1) If interest on drawings is to be charged and at what rate (1) Rate at which interest on partners’ loans will be paid (1) Responsibilities of each partner (1) Accept other valid responses
Q5 · P Limited is a retail company with a financial year end of 30 June
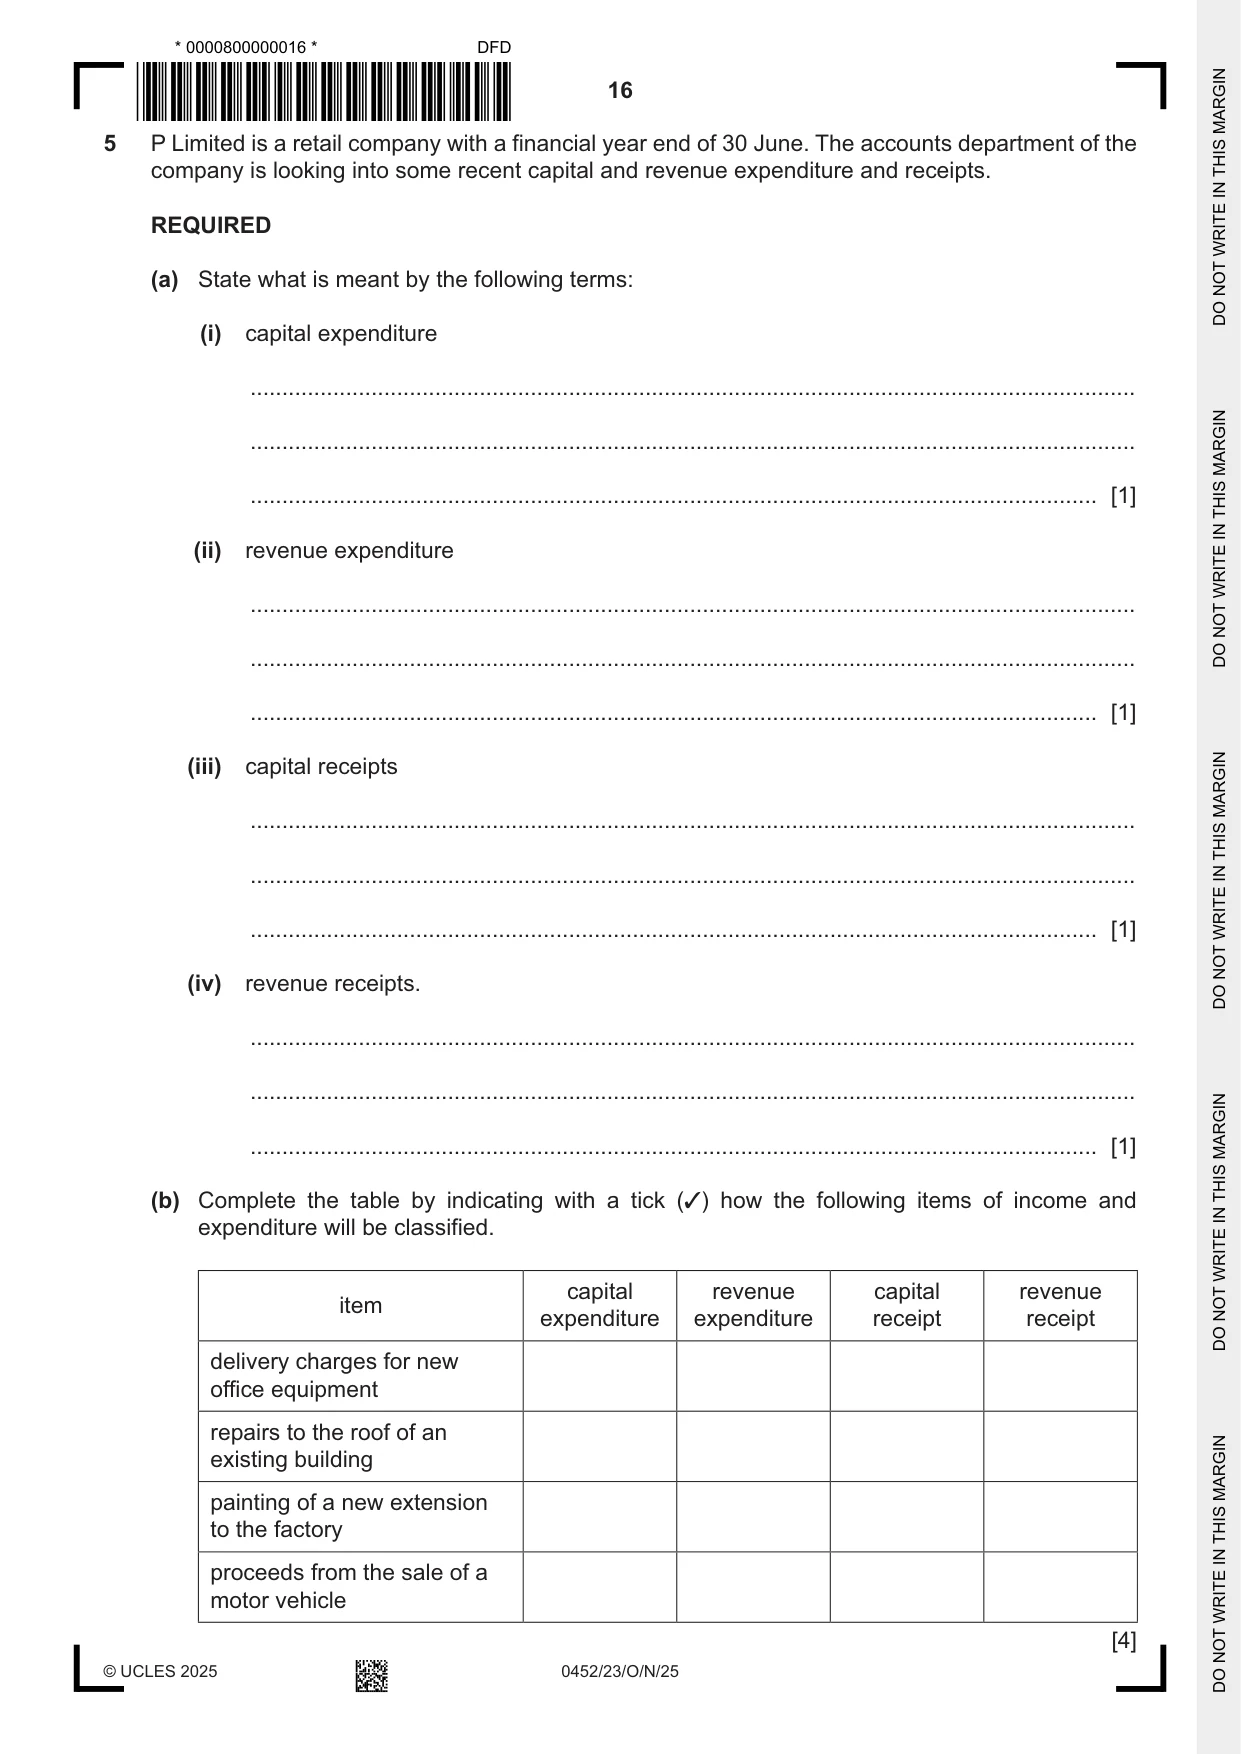
5 P Limited is a retail company with a financial year end of 30 June. The accounts department of the company is looking into some recent capital and revenue expenditure and receipts. REQUIRED (a) State what is meant by the following terms: (i) capital expenditure ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [1] (ii) revenue expenditure ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [1] (iii) capital receipts ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [1] (iv) revenue receipts. ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [1] (b) Complete the table by indicating with a tick (3) how the following items of income and expenditure will be classified. capital revenue capital revenue item expenditure expenditure receipt receipt delivery charges for new office equipment repairs to the roof of an existing building painting of a new extension to the factory proceeds from the sale of a motor vehicle [4]
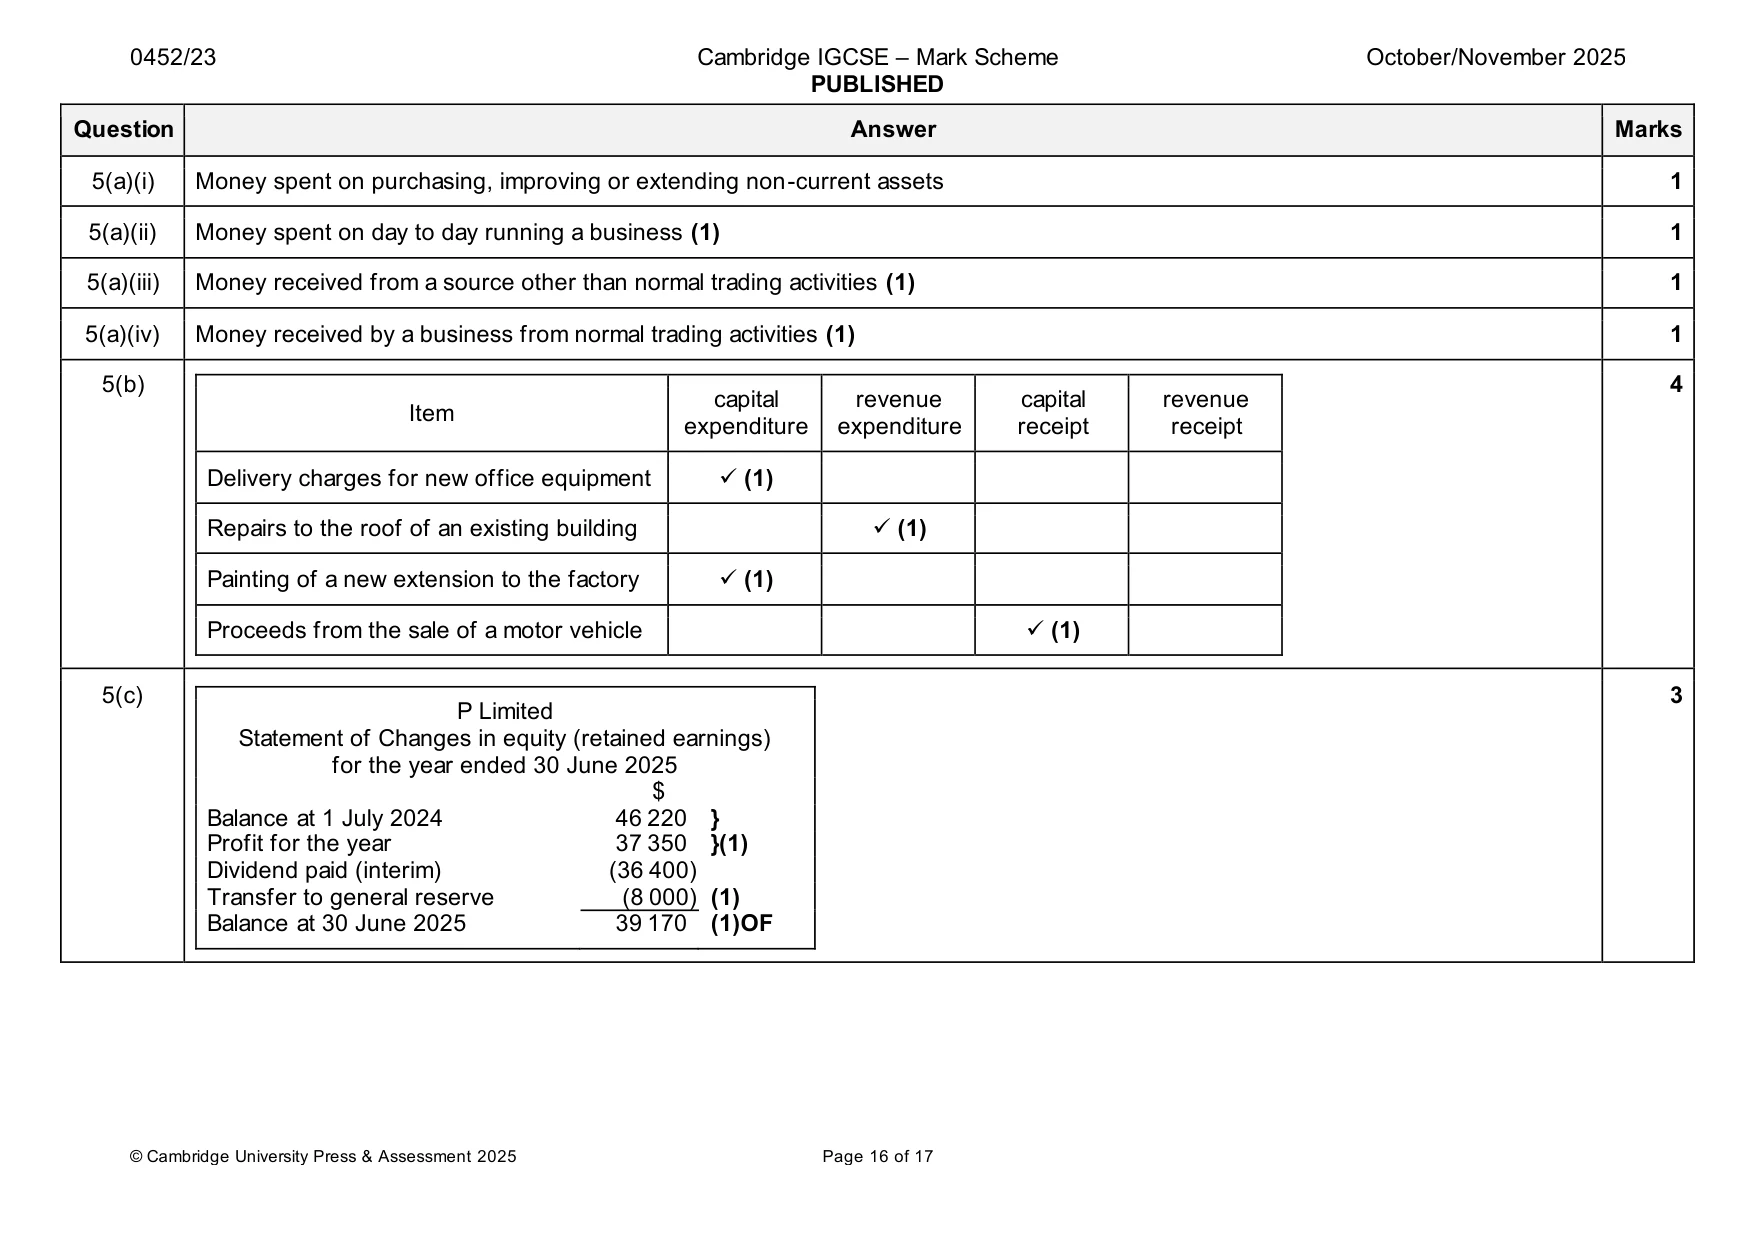
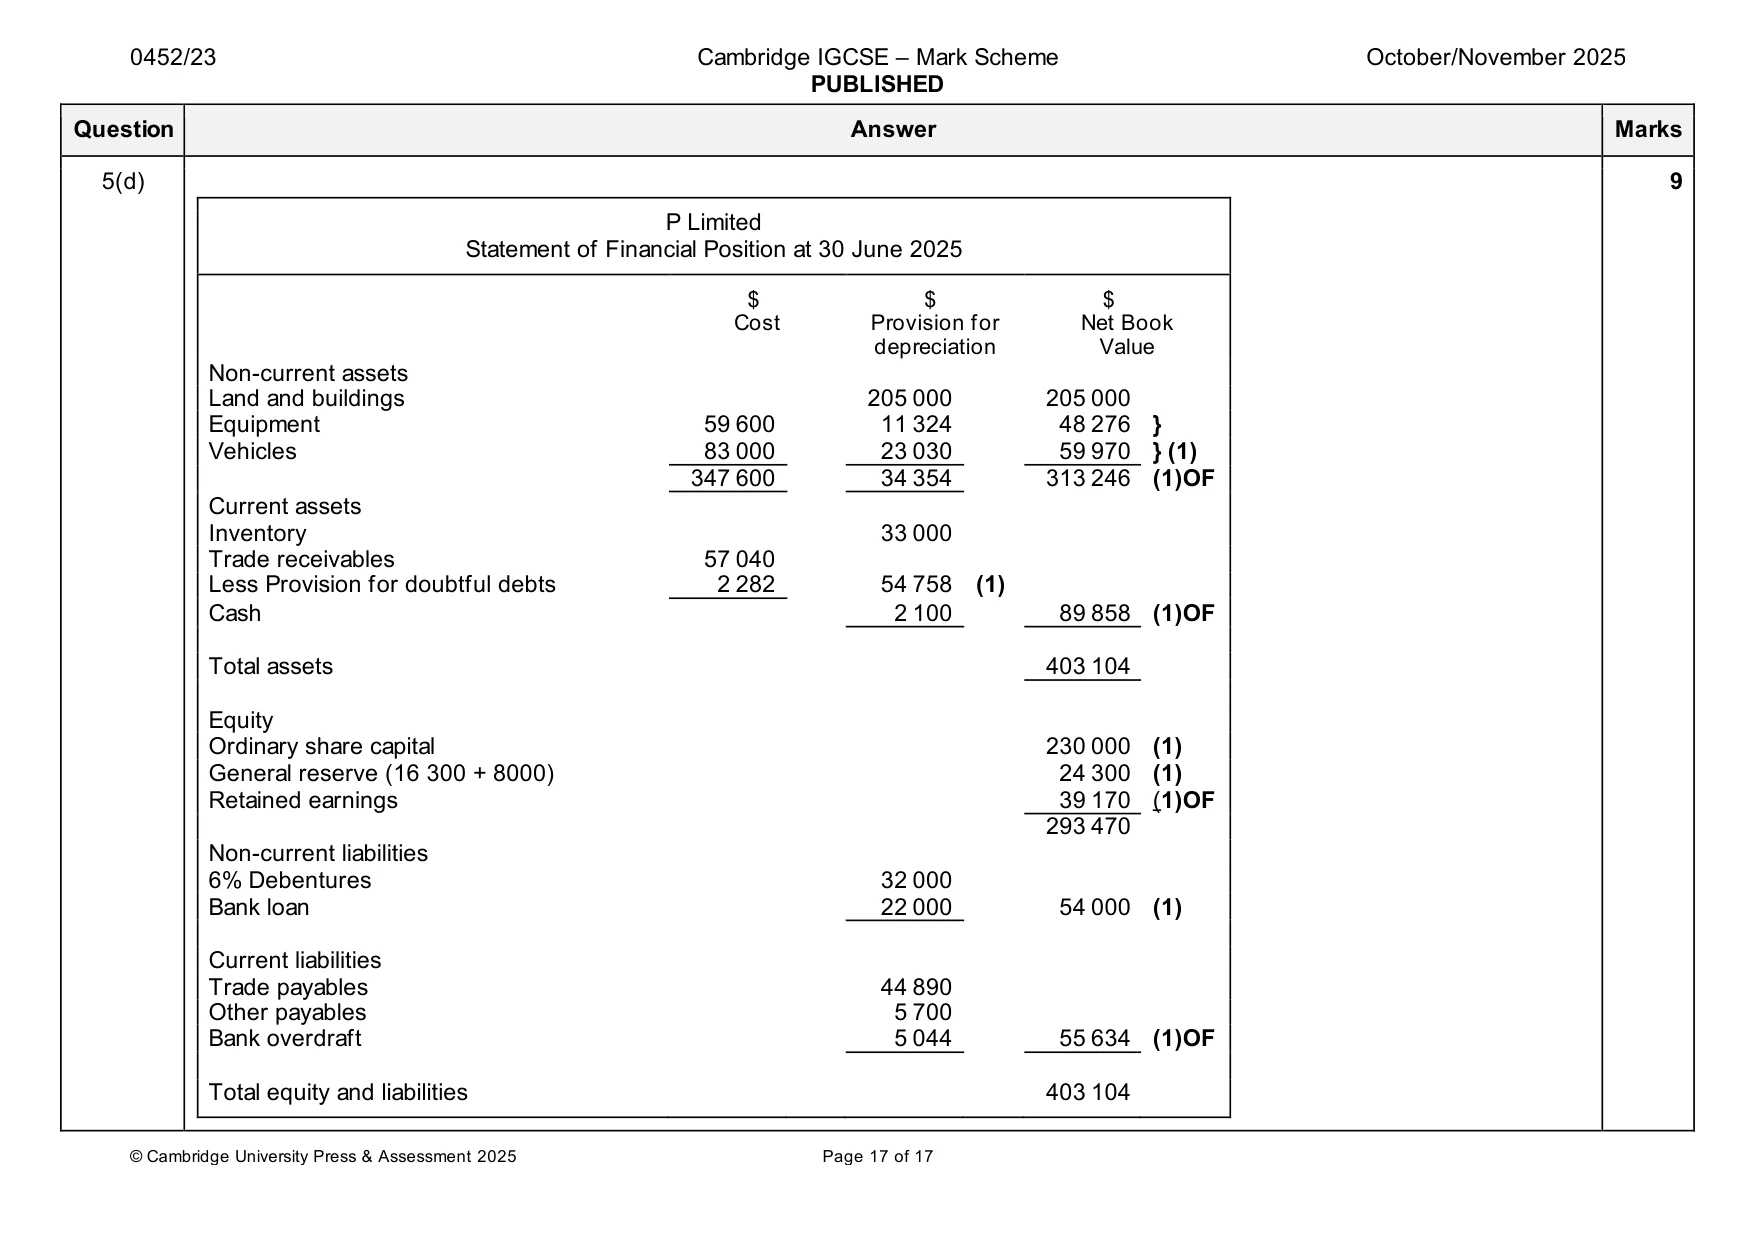
Mark scheme: 5(a)(i) Money spent on purchasing, improving or extending non-current assets 1 5(a)(ii) Money spent on day to day running a business (1) 1 5(a)(iii) Money received from a source other than normal trading activities (1) 1 5(a)(iv) Money received by a business from normal trading activities (1) 1 5(b) 4 capital revenue capital revenue Item expenditure expenditure receipt receipt Delivery charges for new office equipment ✓ (1) Repairs to the roof of an existing building ✓ (1) Painting of a new extension to the factory ✓ (1) Proceeds from the sale of a motor vehicle ✓ (1) 5(c) 3 P Limited Statement of Changes in equity (retained earnings) for the year ended 30 June 2025 $ Balance at 1 July 2024 46 220 } Profit for the year 37 350 }(1) Dividend paid (interim) (36 400) Transfer to general reserve (8 000) (1) Balance at 30 June 2025 39 170 (1)OF 5(d) 9 P Limited Statement of Financial Position at 30 June 2025 $ $ $ Cost Provision for Net Book depreciation Value Non-current assets Land and buildings 205 000 205 000 Equipment 59 600 11 324 48 276 } Vehicles 83 000 23 030 59 970 } (1) 347 600 34 354 313 246 (1)OF Current assets Inventory 33 000 Trade receivables 57 040 Less Provision for doubtful debts 2 282 54 758 (1) Cash 2 100 89 858 (1)OF Total assets 403 104 Equity Ordinary share capital 230 000 (1) General reserve (16 300 + 8000) 24 300 (1) Retained earnings 39 170 (1)OF 293 470 Non-current liabilities 6% Debentures 32 000 Bank loan 22 000 54 000 (1) Current liabilities Trade payables 44 890 Other payables 5 700 Bank overdraft 5 044 55 634 (1)OF Total equity and liabilities 403 104
More questions on Capital and revenue expenditure and receipts
Question 30
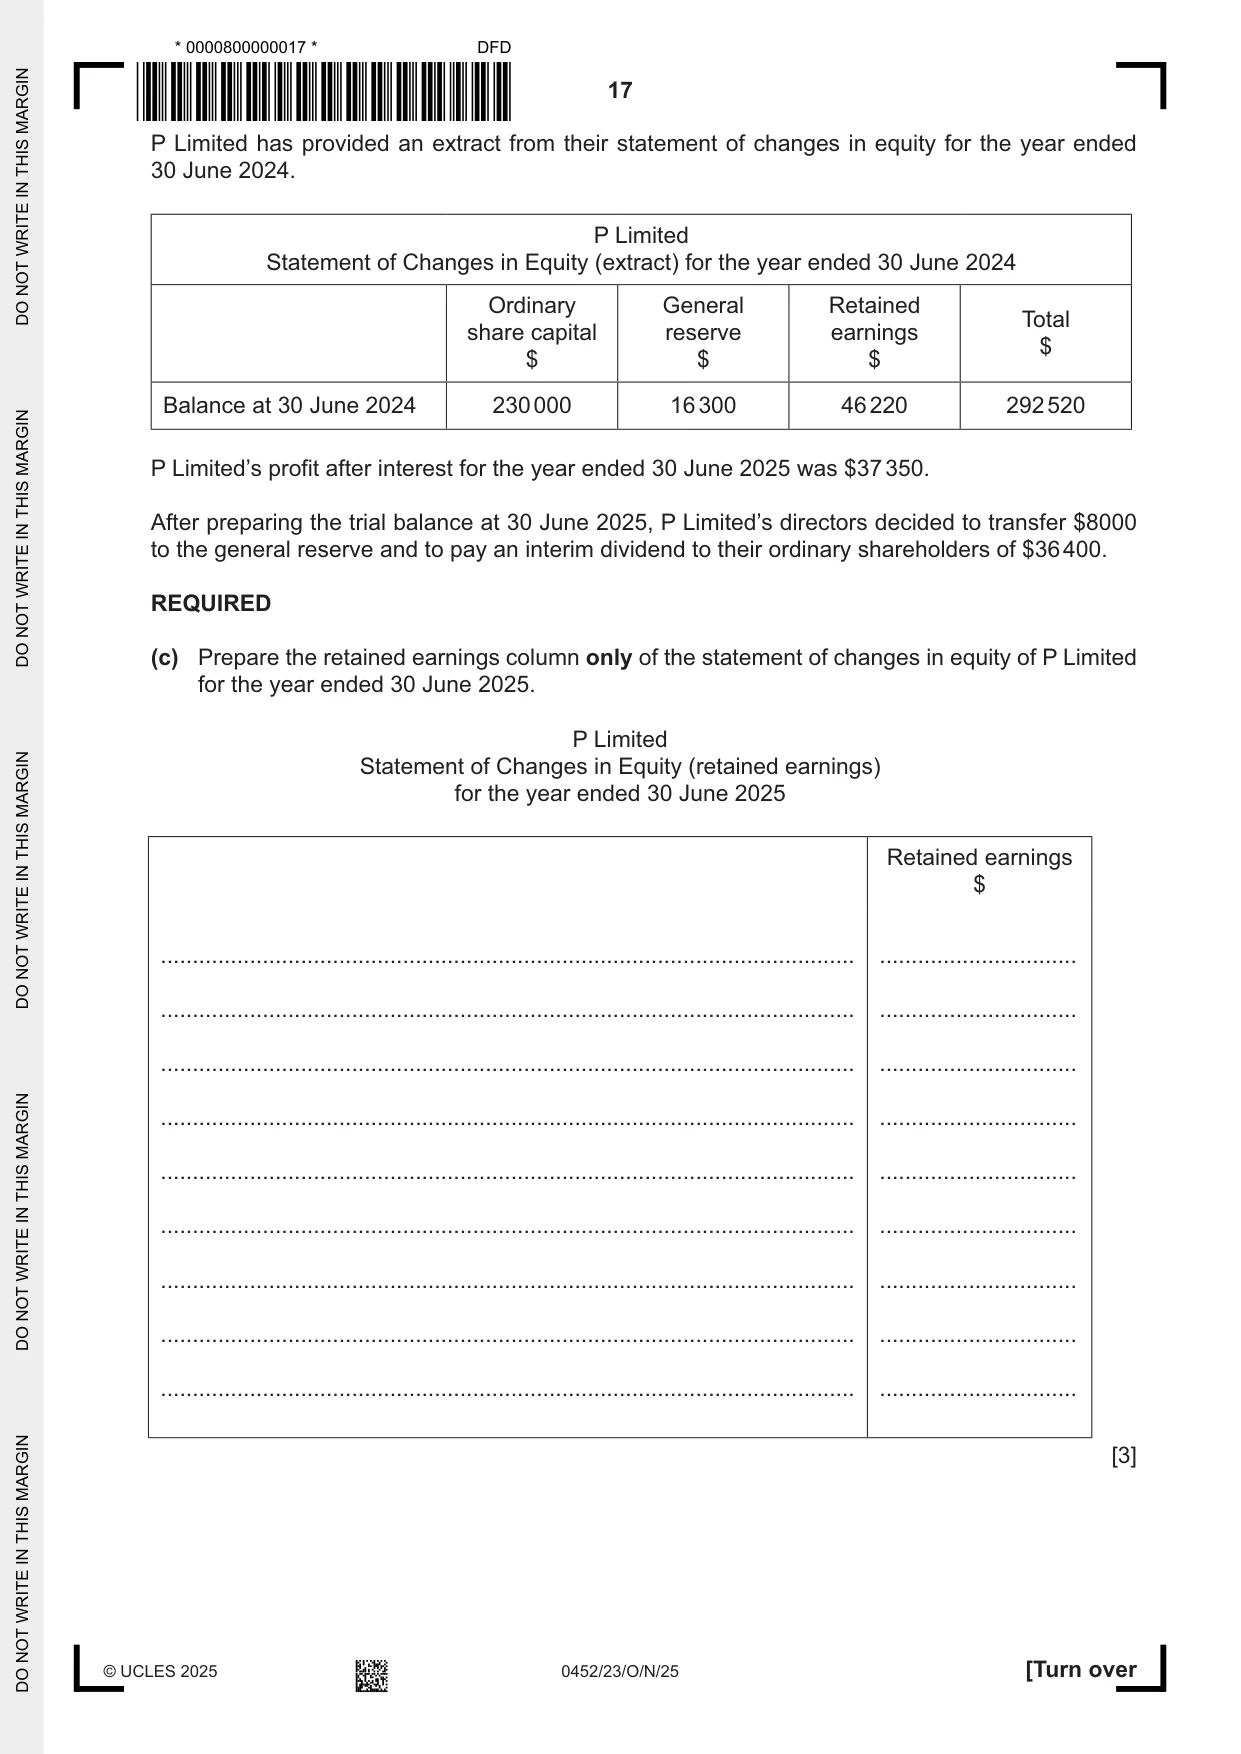
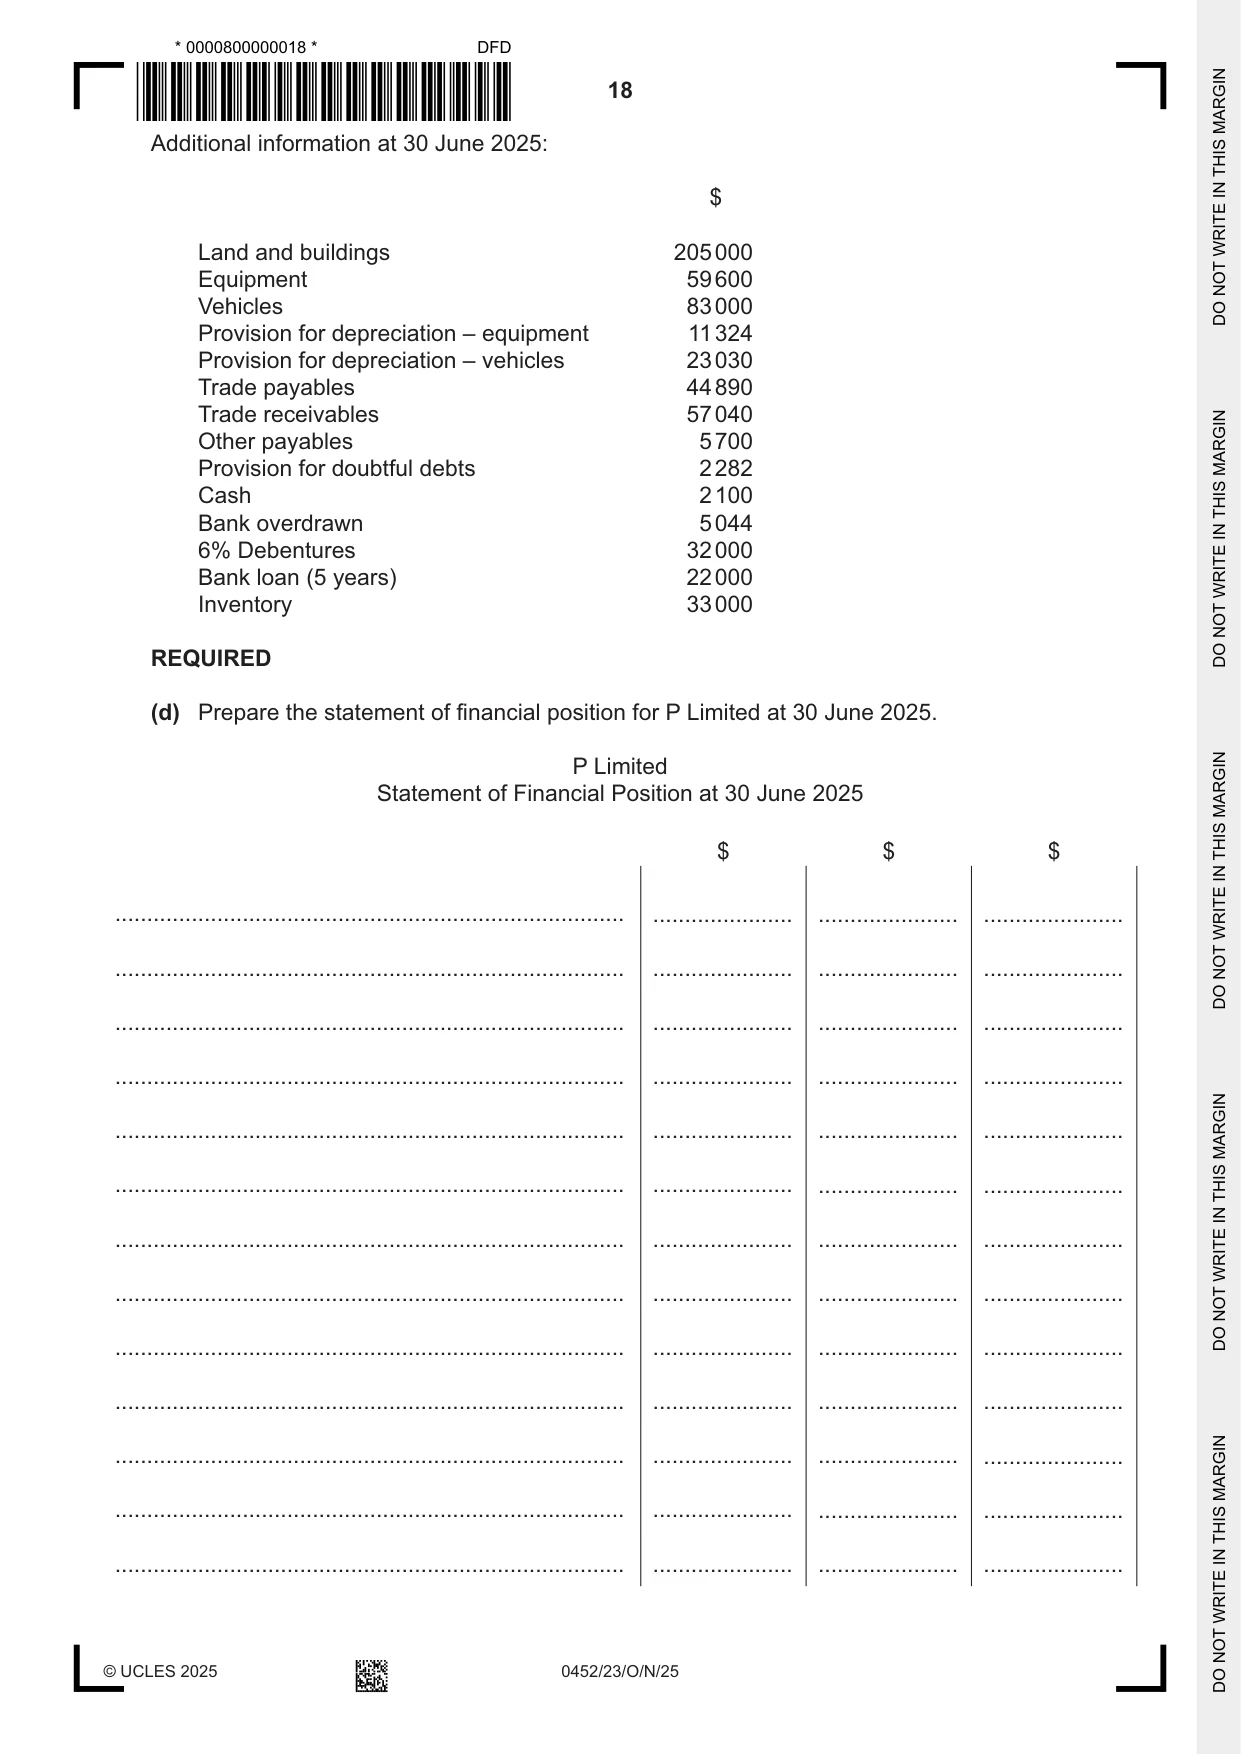
30 June 2024. P Limited Statement of Changes in Equity (extract) for the year ended 30 June 2024 Ordinary General Retained Total share capital reserve earnings $ $ $ $ Balance at 30 June 2024 230 000 16 300 46 220 292 520 P Limited’s profit after interest for the year ended 30 June 2025 was $37 350. After preparing the trial balance at 30 June 2025, P Limited’s directors decided to transfer $8000 to the general reserve and to pay an interim dividend to their ordinary shareholders of $36 400. REQUIRED (c) Prepare the retained earnings column only of the statement of changes in equity of P Limited for the year ended 30 June 2025. P Limited Statement of Changes in Equity (retained earnings) for the year ended 30 June 2025 Retained earnings $ ............................................................................................................. ............................... ............................................................................................................. ............................... ............................................................................................................. ............................... ............................................................................................................. ............................... ............................................................................................................. ............................... ............................................................................................................. ............................... ............................................................................................................. ............................... ............................................................................................................. ............................... ............................................................................................................. ............................... [3] Additional information at 30 June 2025: $ Land and buildings 205 000 Equipment 59 600 Vehicles 83 000 Provision for depreciation – equipment 11 324 Provision for depreciation – vehicles 23 030 Trade payables 44 890 Trade receivables 57 040 Other payables 5 700 Provision for doubtful debts 2 282 Cash 2 100 Bank overdrawn 5 044 6% Debentures 32 000 Bank loan (5 years) 22 000 Inventory 33 000 REQUIRED (d) Prepare the statement of financial position for P Limited at 30 June 2025. P Limited Statement of Financial Position at 30 June 2025 $ $ $ ................................................................................ ...................... ...................... ...................... ................................................................................ ...................... ...................... ...................... ................................................................................ ...................... ...................... ...................... ................................................................................ ...................... ...................... ...................... ................................................................................ ...................... ...................... ...................... ................................................................................ ...................... ...................... ...................... ................................................................................ ...................... ...................... ...................... ................................................................................ ...................... ...................... ...................... ................................................................................ ...................... ...................... ...................... ................................................................................ ...................... ...................... ...................... ................................................................................ ...................... ...................... ...................... ................................................................................ ...................... ...................... ...................... ................................................................................ ...................... ...................... ...................... ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................ ................................................................................
What was in this paper
The subtopics covered by these 6 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2025 Oct/Nov, Paper 2 · Variant 3. A higher threshold means an easier paper — the bar moves with how the cohort did.