Cambridge IGCSE Accounting 0452 — 2024 Oct/Nov Paper 2 · Variant 3
0452/23/O/N/24 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper24 pages
Mark scheme18 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Jenny runs a small trading business
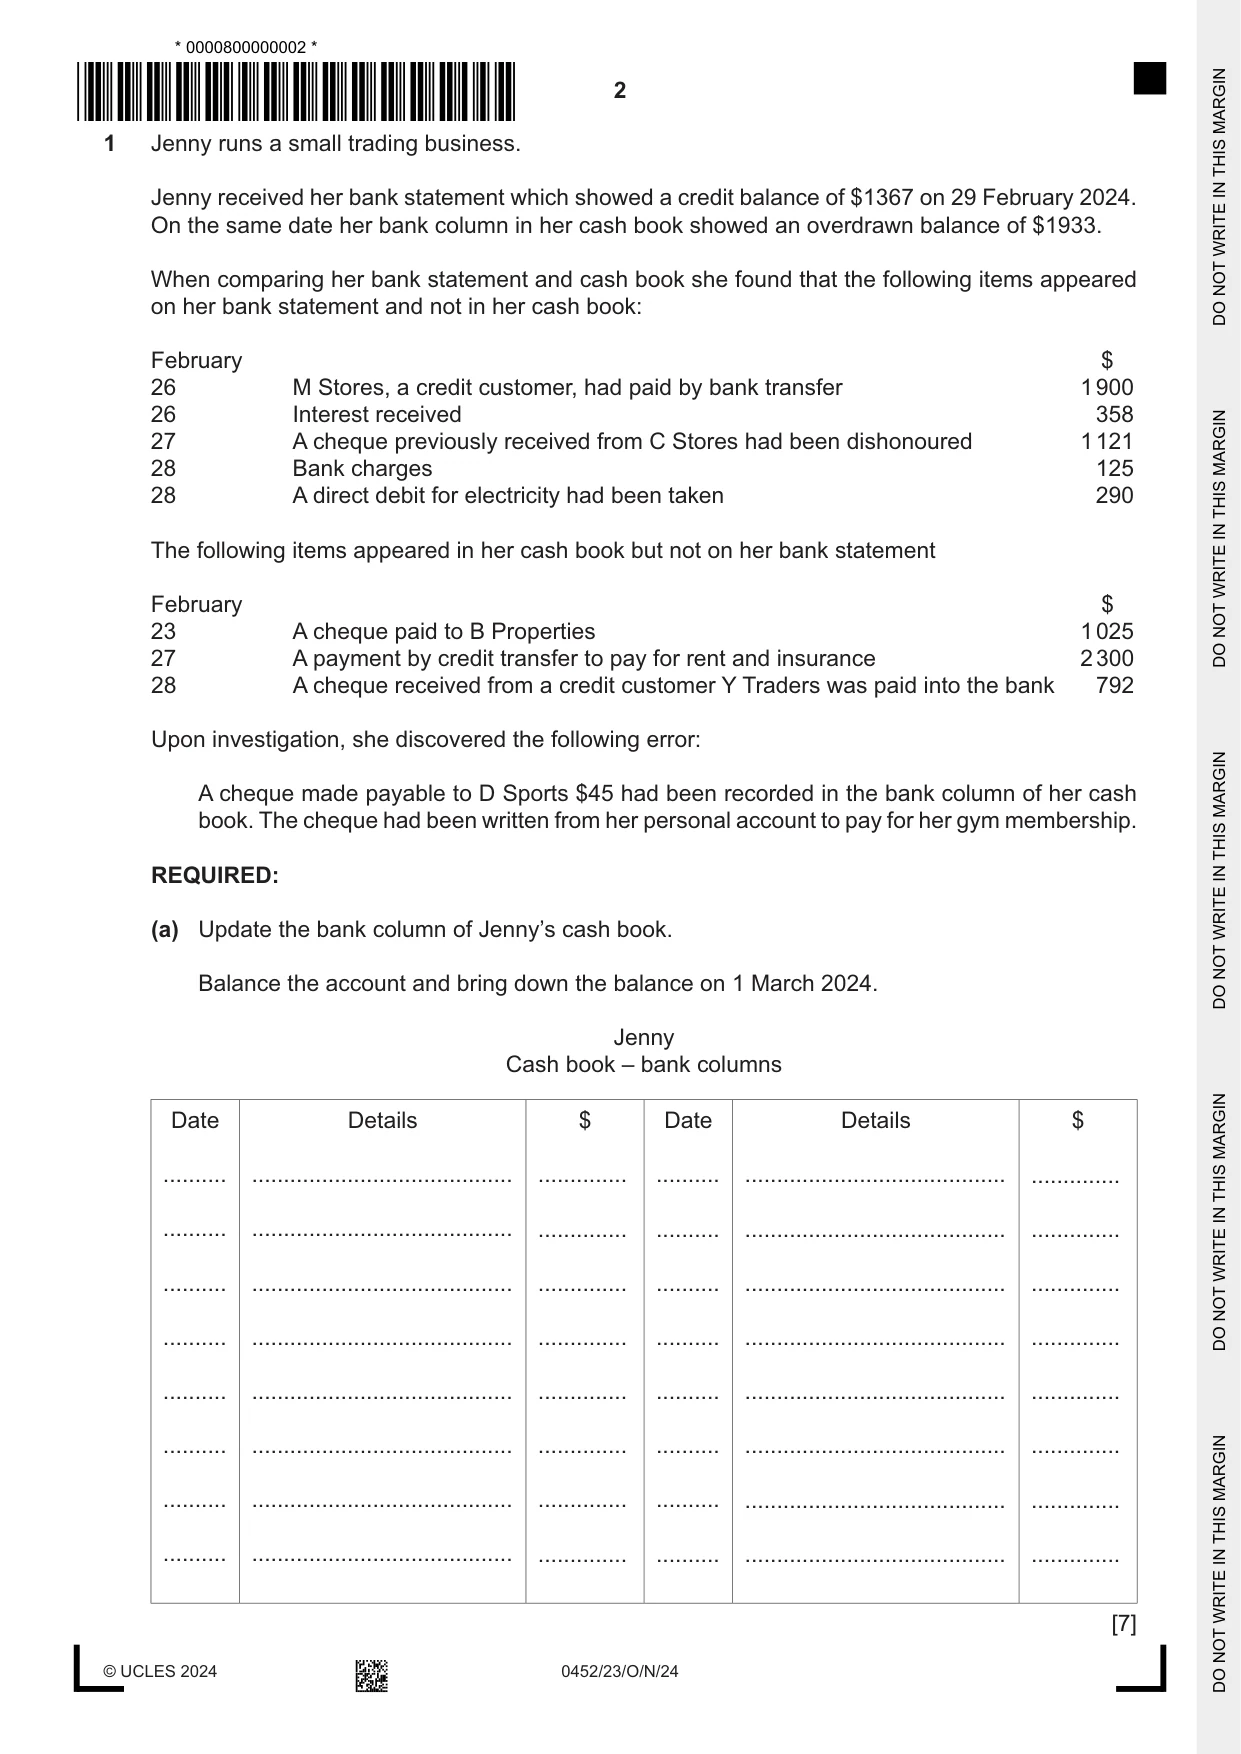
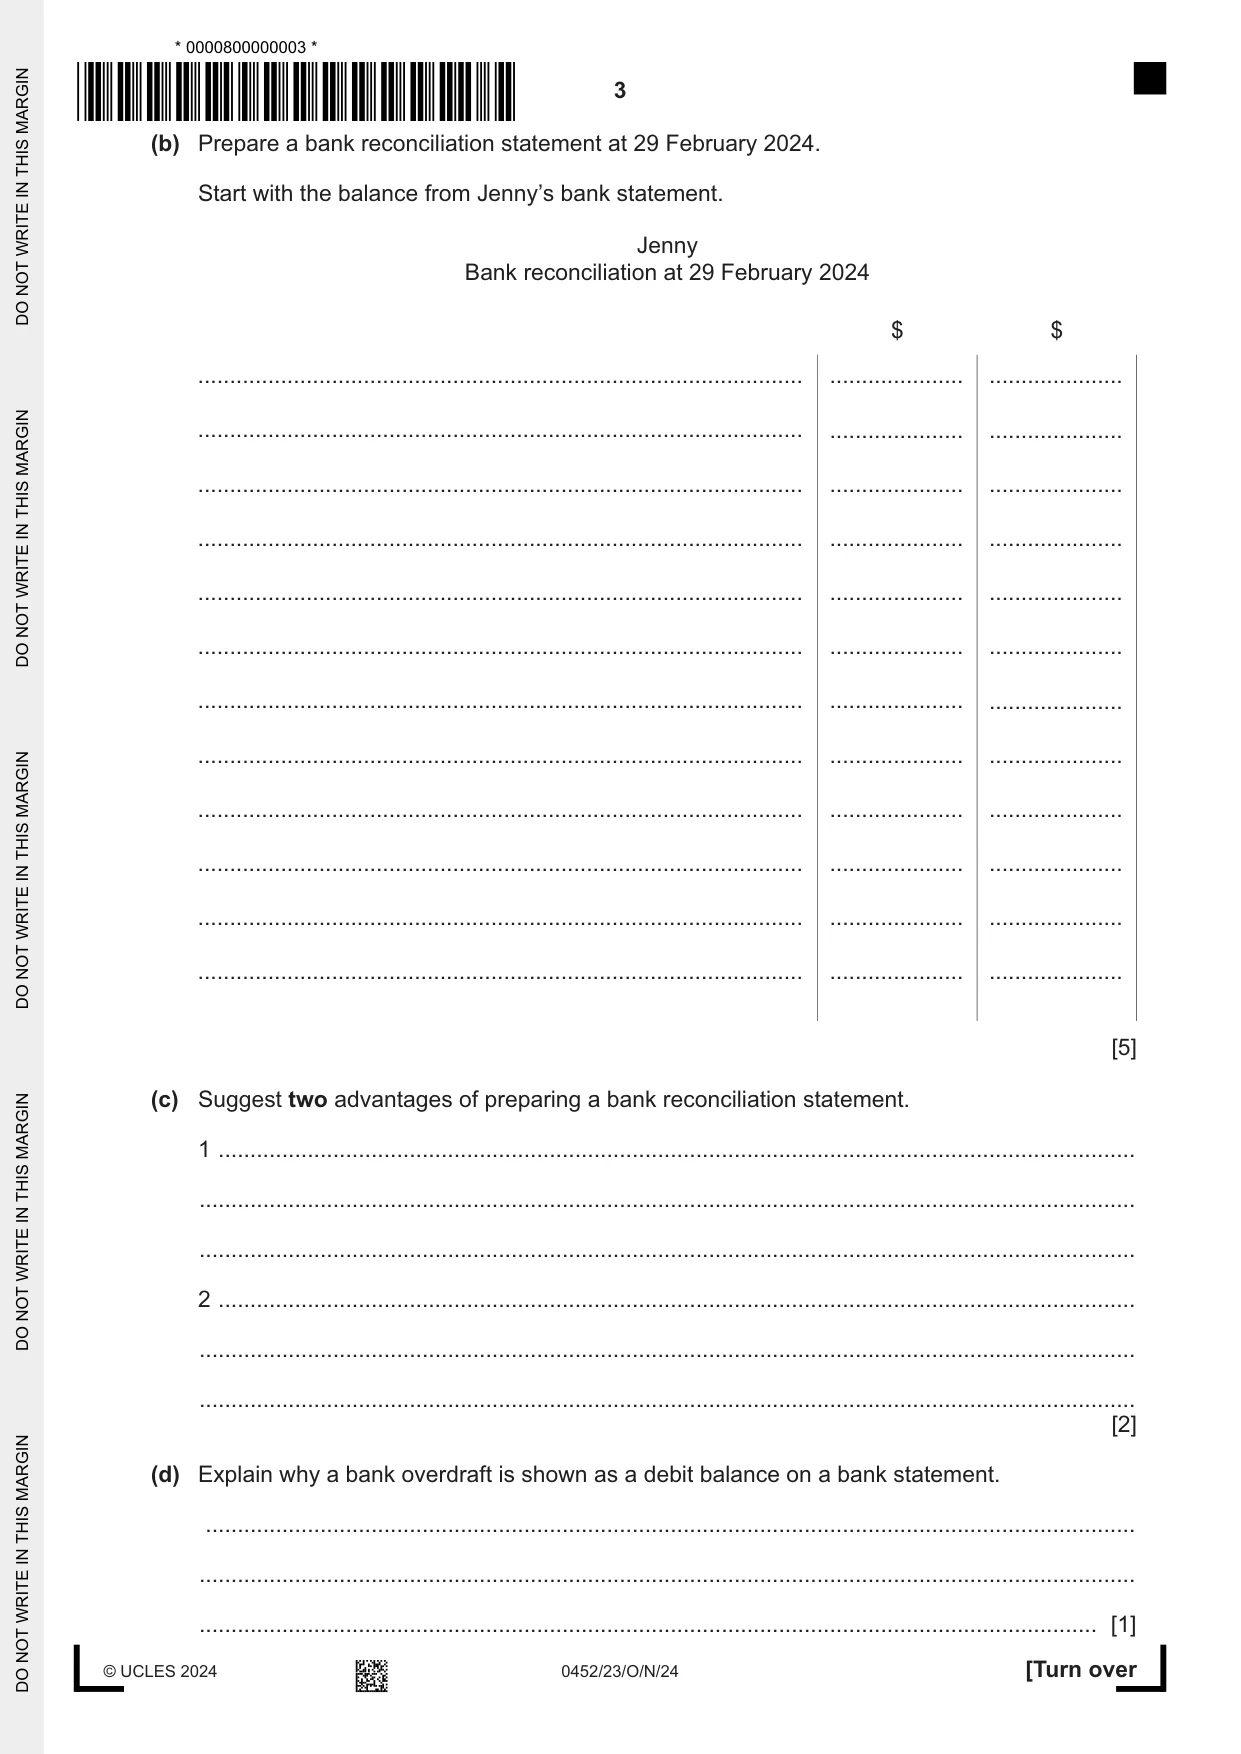
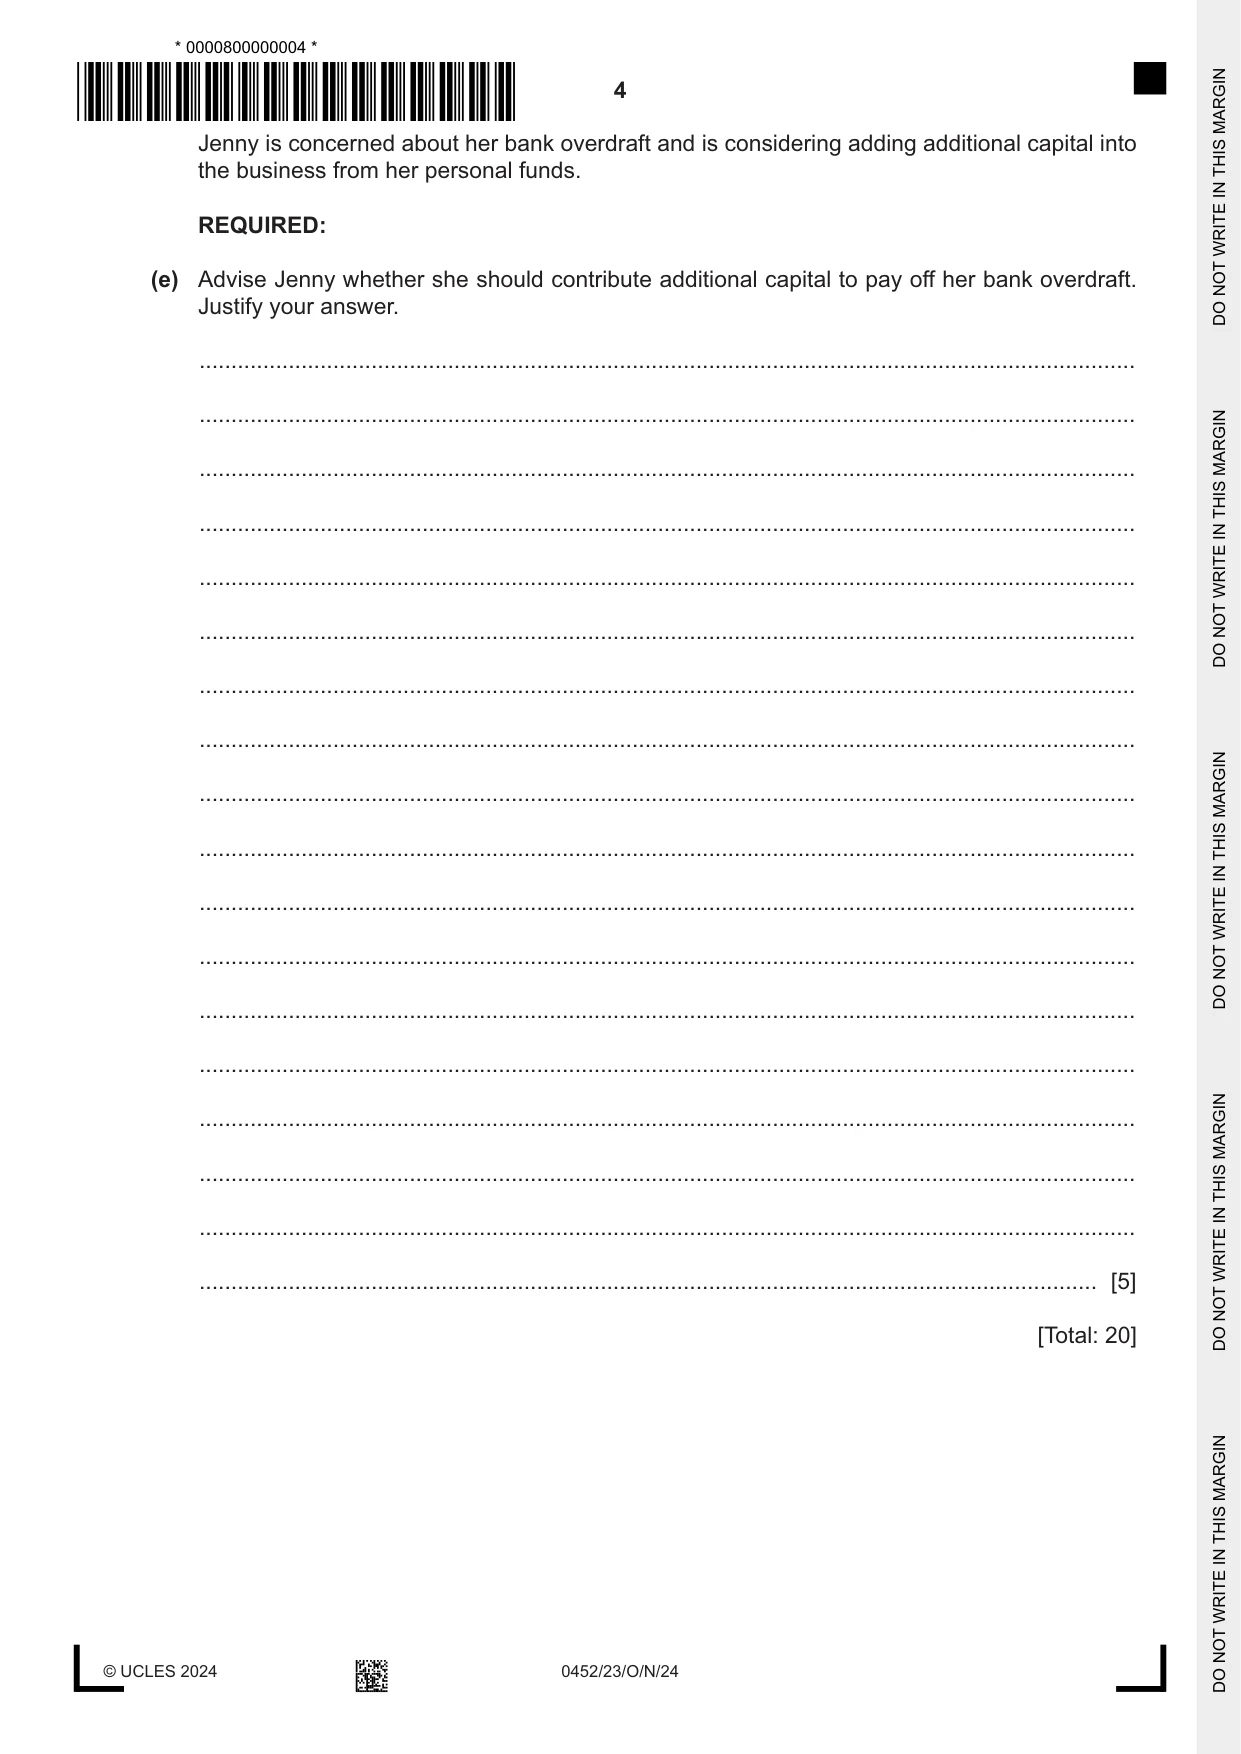
1 Jenny runs a small trading business. Jenny received her bank statement which showed a credit balance of $1367 on 29 February 2024. On the same date her bank column in her cash book showed an overdrawn balance of $1933. When comparing her bank statement and cash book she found that the following items appeared on her bank statement and not in her cash book: February $ 26 M Stores, a credit customer, had paid by bank transfer 1 900 26 Interest received 358 27 A cheque previously received from C Stores had been dishonoured 1 121 28 Bank charges 125 28 A direct debit for electricity had been taken 290 The following items appeared in her cash book but not on her bank statement February $ 23 A cheque paid to B Properties 1 025 27 A payment by credit transfer to pay for rent and insurance 2 300 28 A cheque received from a credit customer Y Traders was paid into the bank 792 Upon investigation, she discovered the following error: A cheque made payable to D Sports $45 had been recorded in the bank column of her cash book. The cheque had been written from her personal account to pay for her gym membership. REQUIRED: (a) Update the bank column of Jenny’s cash book. Balance the account and bring down the balance on 1 March 2024. Jenny Cash book – bank columns Date Details $ Date Details $ .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. [7] (b) Prepare a bank reconciliation statement at 29 February 2024. Start with the balance from Jenny’s bank statement. Jenny Bank reconciliation at 29 February 2024 $ $ ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... [5] (c) Suggest two advantages of preparing a bank reconciliation statement. 1 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... [2] (d) Explain why a bank overdraft is shown as a debit balance on a bank statement. .................................................................................................................................................. ................................................................................................................................................... ............................................................................................................................................. [1] Jenny is concerned about her bank overdraft and is considering adding additional capital into the business from her personal funds. REQUIRED: (e) Advise Jenny whether she should contribute additional capital to pay off her bank overdraft. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20] Question 2 is on page 6.
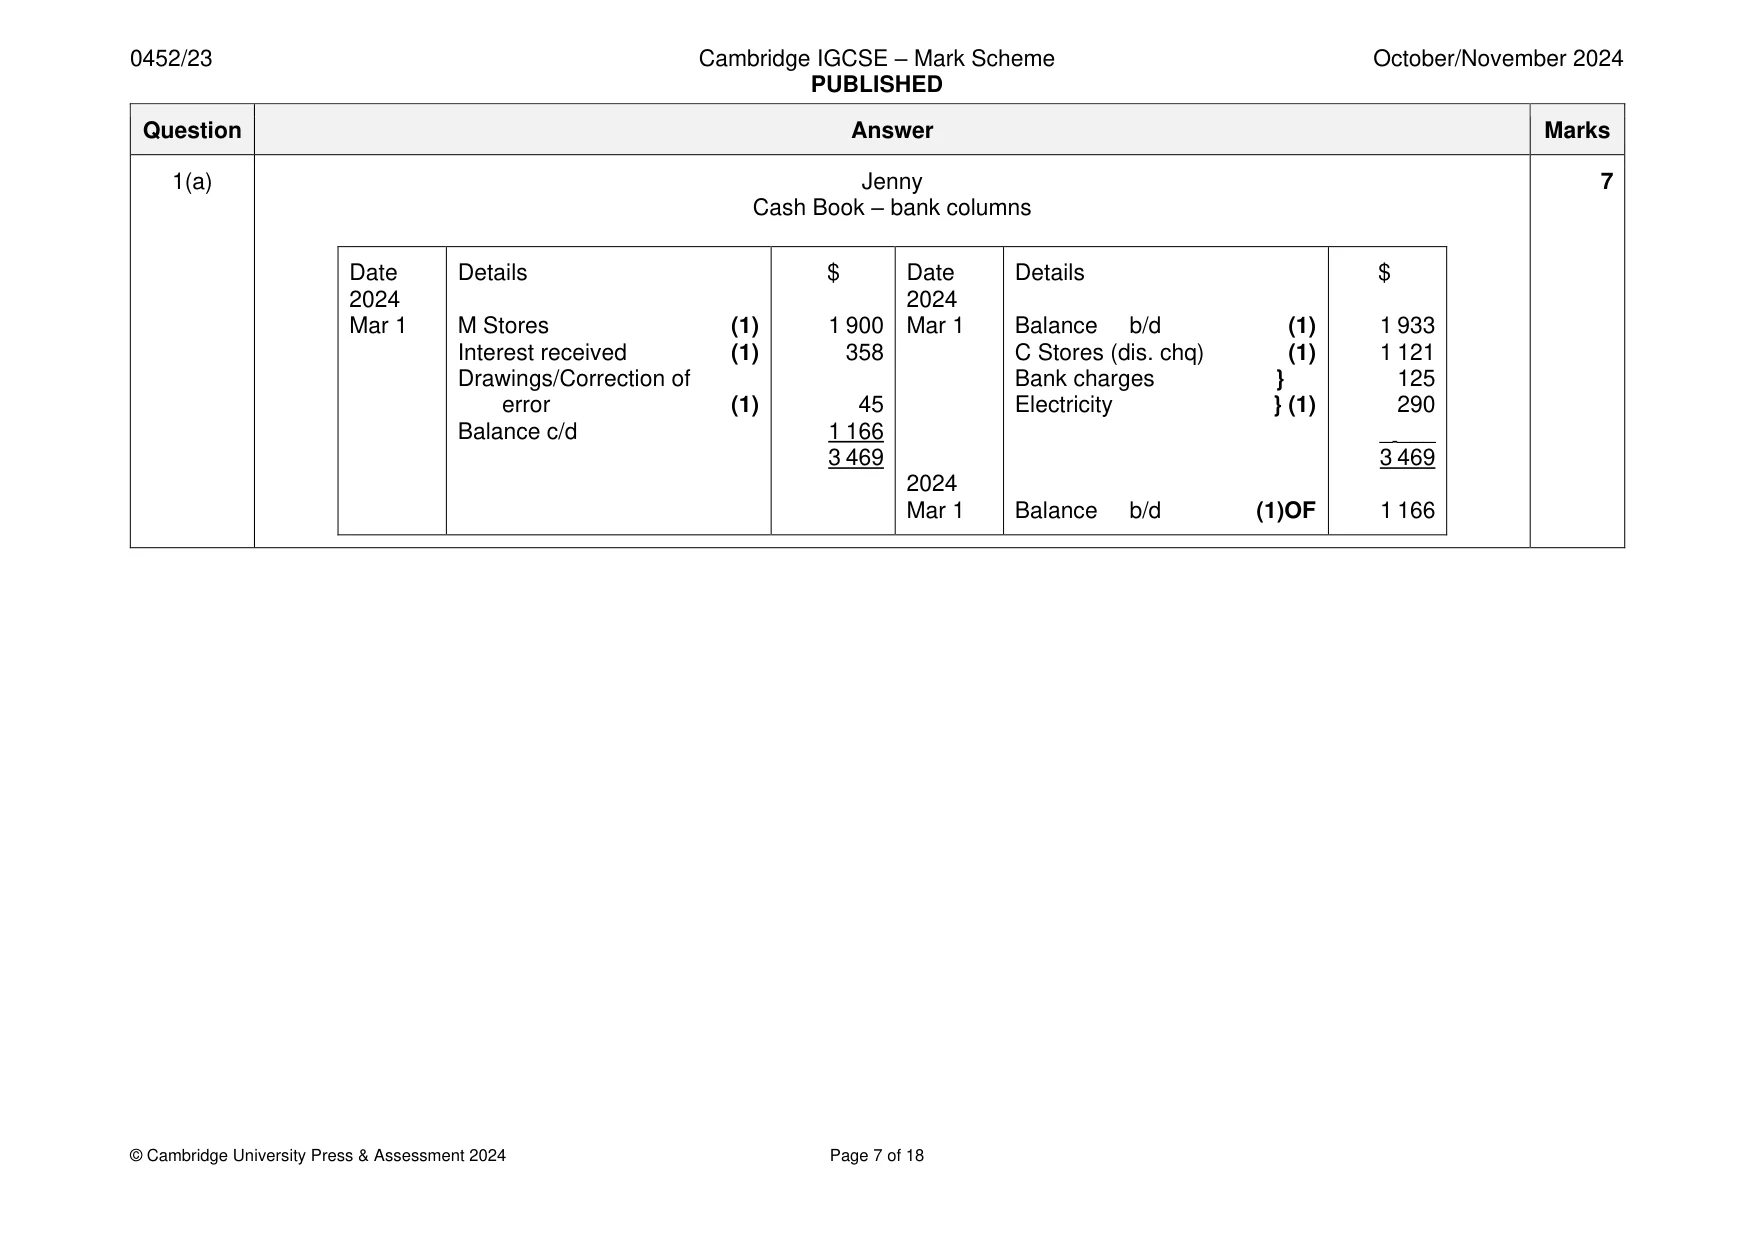
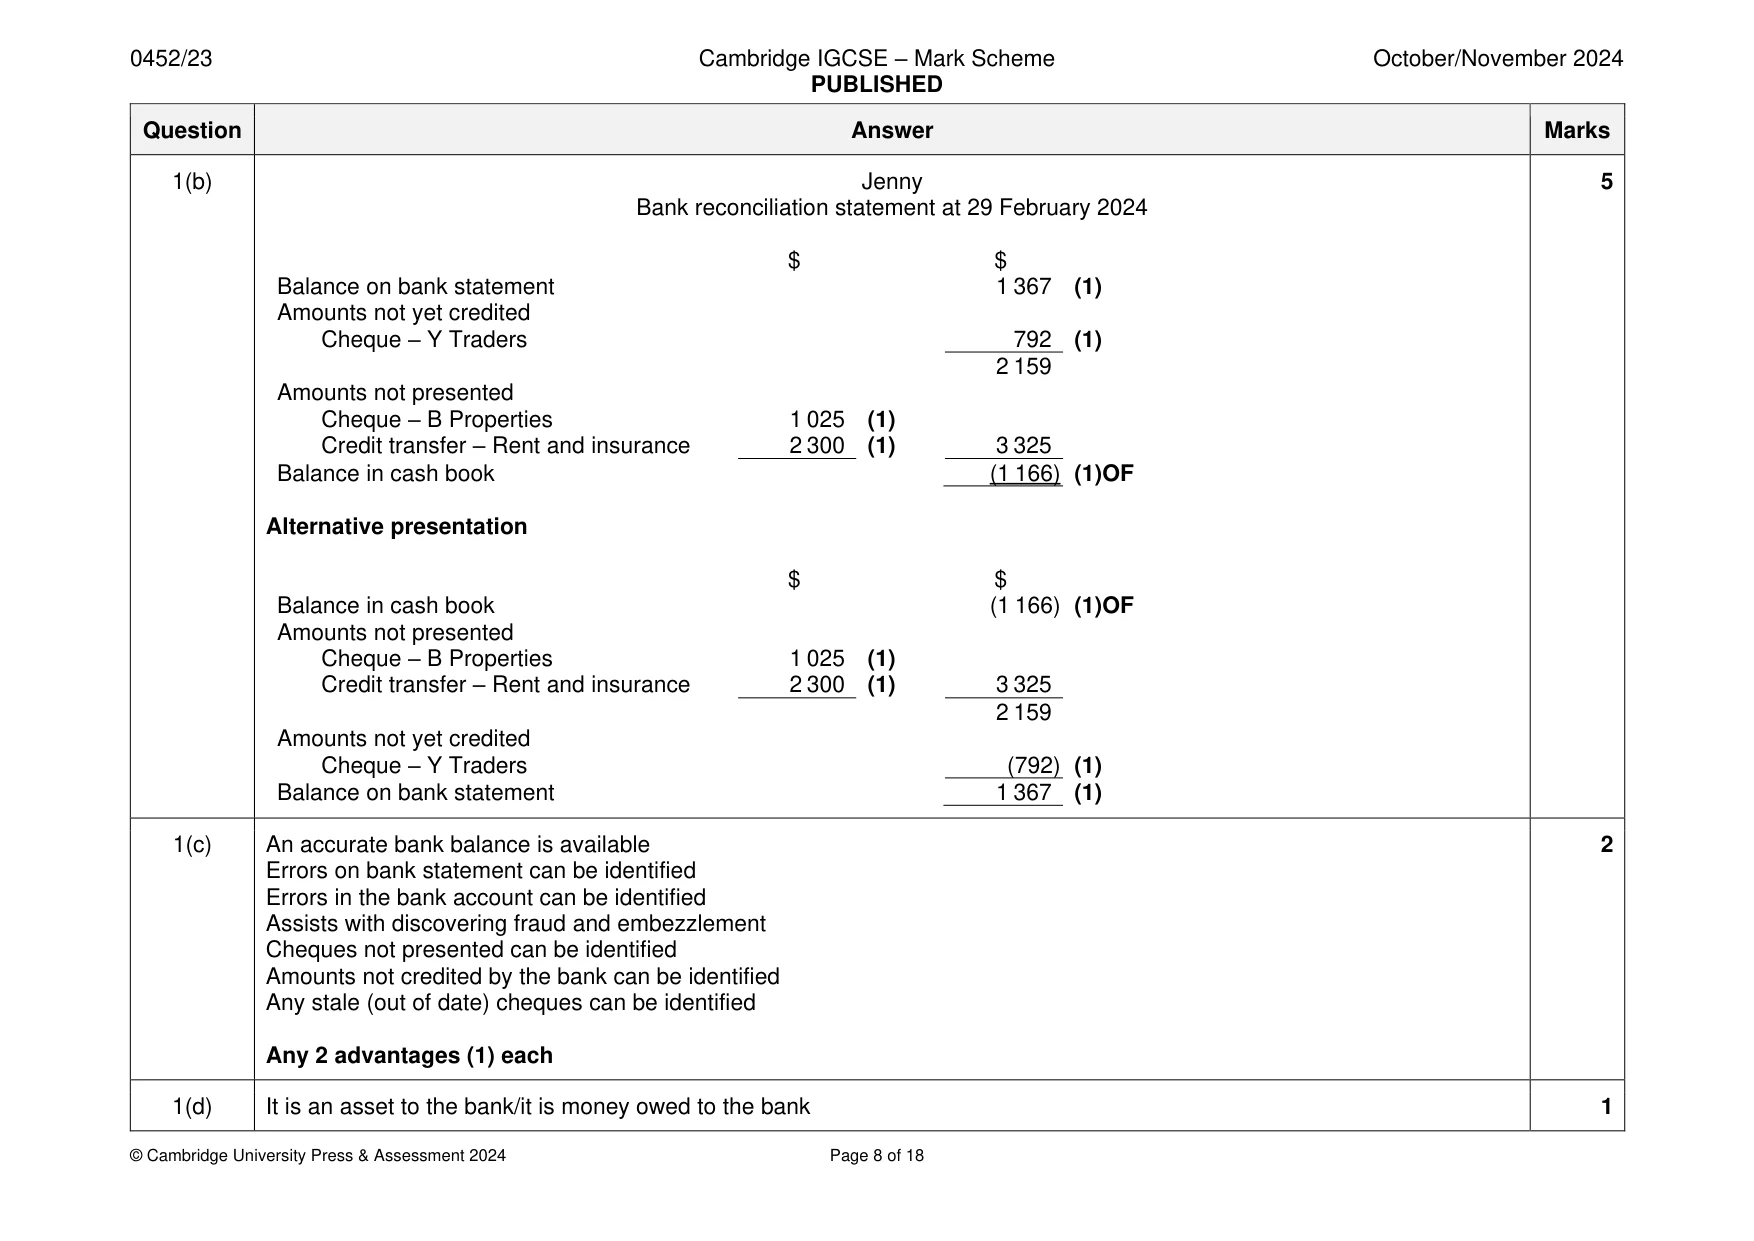
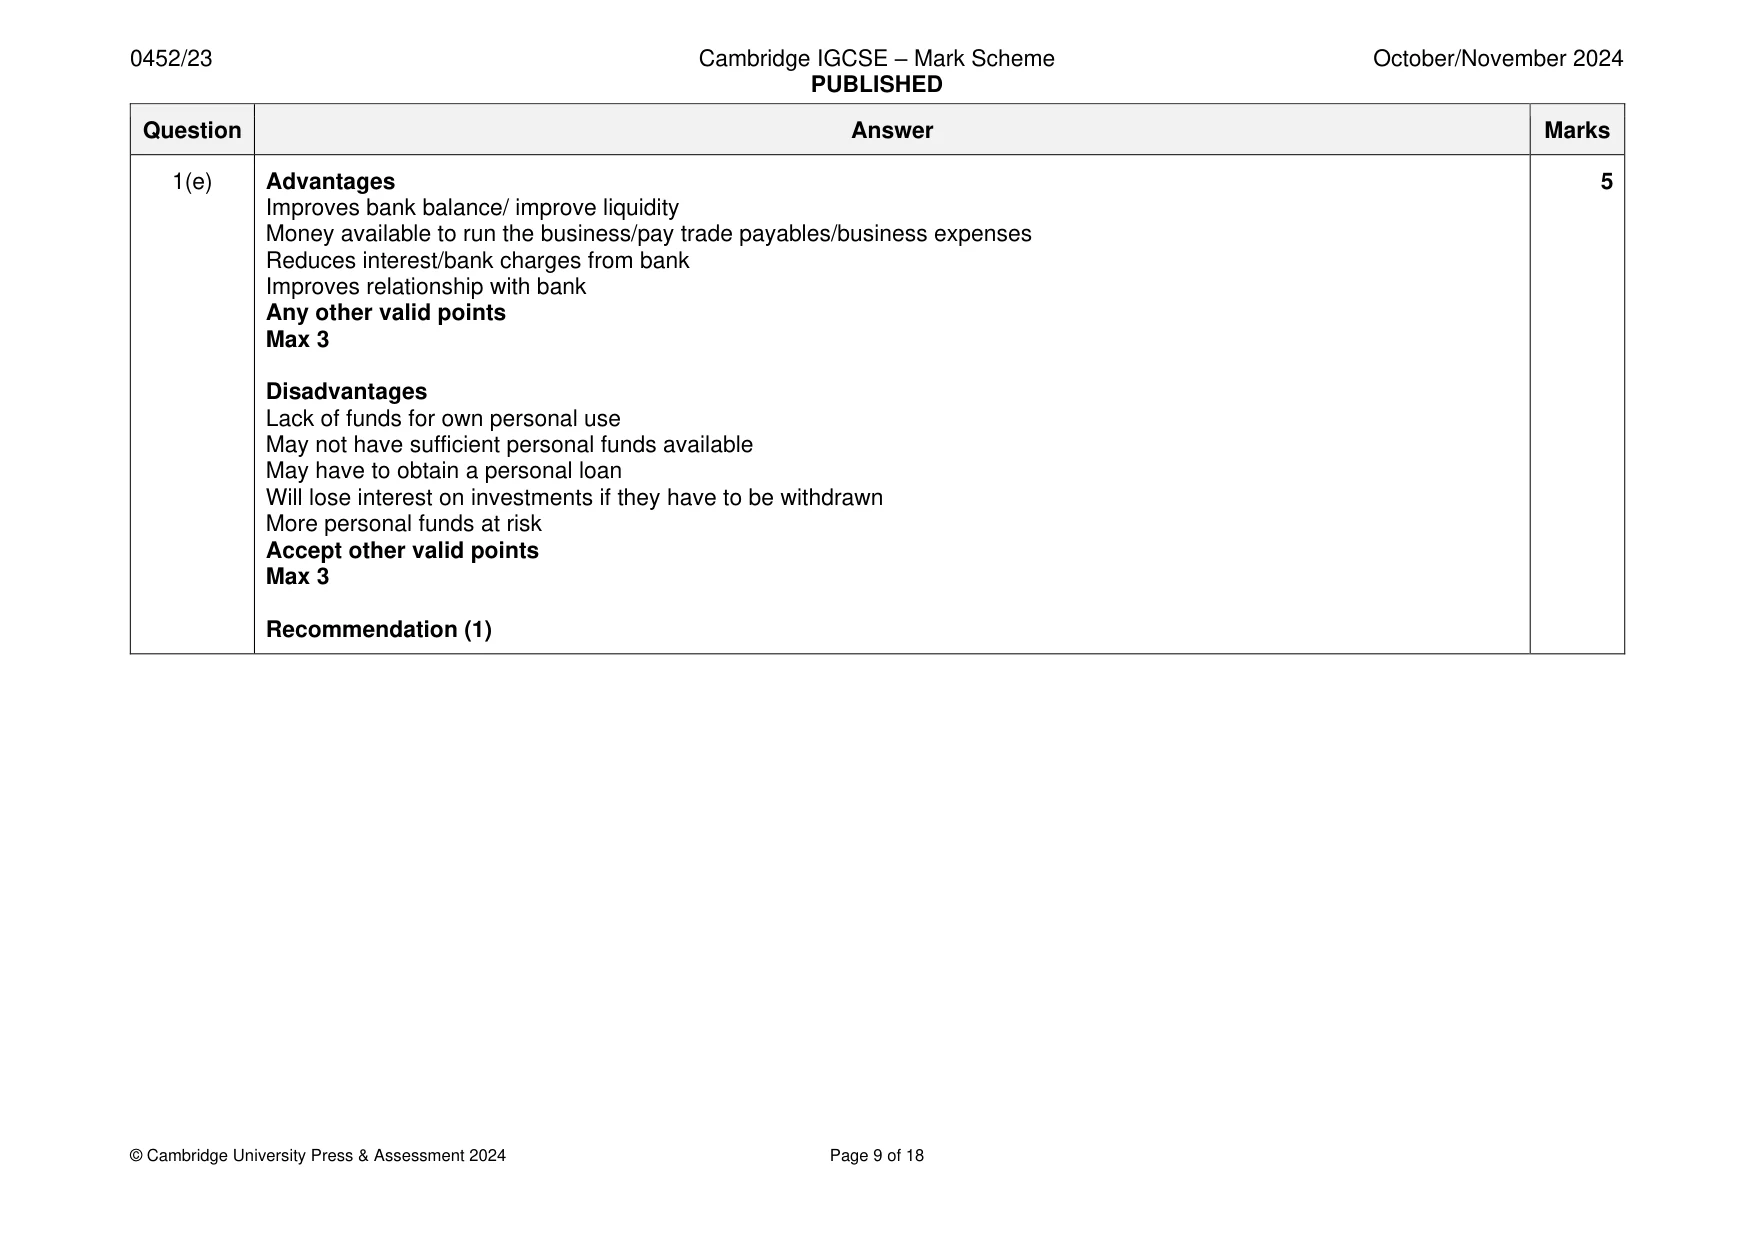
Mark scheme: Question Answer Marks 1(a) Jenny 7 Cash Book – bank columns Date Details $ Date Details $ 2024 2024 Mar 1 M Stores (1) 1 900 Mar 1 Balance b/d (1) 1 933 Interest received (1) 358 C Stores (dis. chq) (1) 1 121 Drawings/Correction of Bank charges } 125 error (1) 45 Electricity } (1) 290 Balance c/d 1 166 _ ___ 3 469 3 469 2024 Mar 1 Balance b/d (1)OF 1 166 1(b) Jenny 5 Bank reconciliation statement at 29 February 2024 $ $ Balance on bank statement 1 367 (1) Amounts not yet credited Cheque – Y Traders 792 (1) 2 159 Amounts not presented Cheque – B Properties 1 025 (1) Credit transfer – Rent and insurance 2 300 (1) 3 325 Balance in cash book (1 166) (1)OF Alternative presentation $ $ Balance in cash book (1 166) (1)OF Amounts not presented Cheque – B Properties 1 025 (1) Credit transfer – Rent and insurance 2 300 (1) 3 325 2 159 Amounts not yet credited Cheque – Y Traders (792) (1) Balance on bank statement 1 367 (1) 1(c) An accurate bank balance is available 2 Errors on bank statement can be identified Errors in the bank account can be identified Assists with discovering fraud and embezzlement Cheques not presented can be identified Amounts not credited by the bank can be identified Any stale (out of date) cheques can be identified Any 2 advantages (1) each 1(d) It is an asset to the bank/it is money owed to the bank 1 1(e) Advantages 5 Improves bank balance/ improve liquidity Money available to run the business/pay trade payables/business expenses Reduces interest/bank charges from bank Improves relationship with bank Any other valid points Max 3 Disadvantages Lack of funds for own personal use May not have sufficient personal funds available May have to obtain a personal loan Will lose interest on investments if they have to be withdrawn More personal funds at risk Accept other valid points Max 3 Recommendation (1)
Q2 · Ali and Sai are in partnership
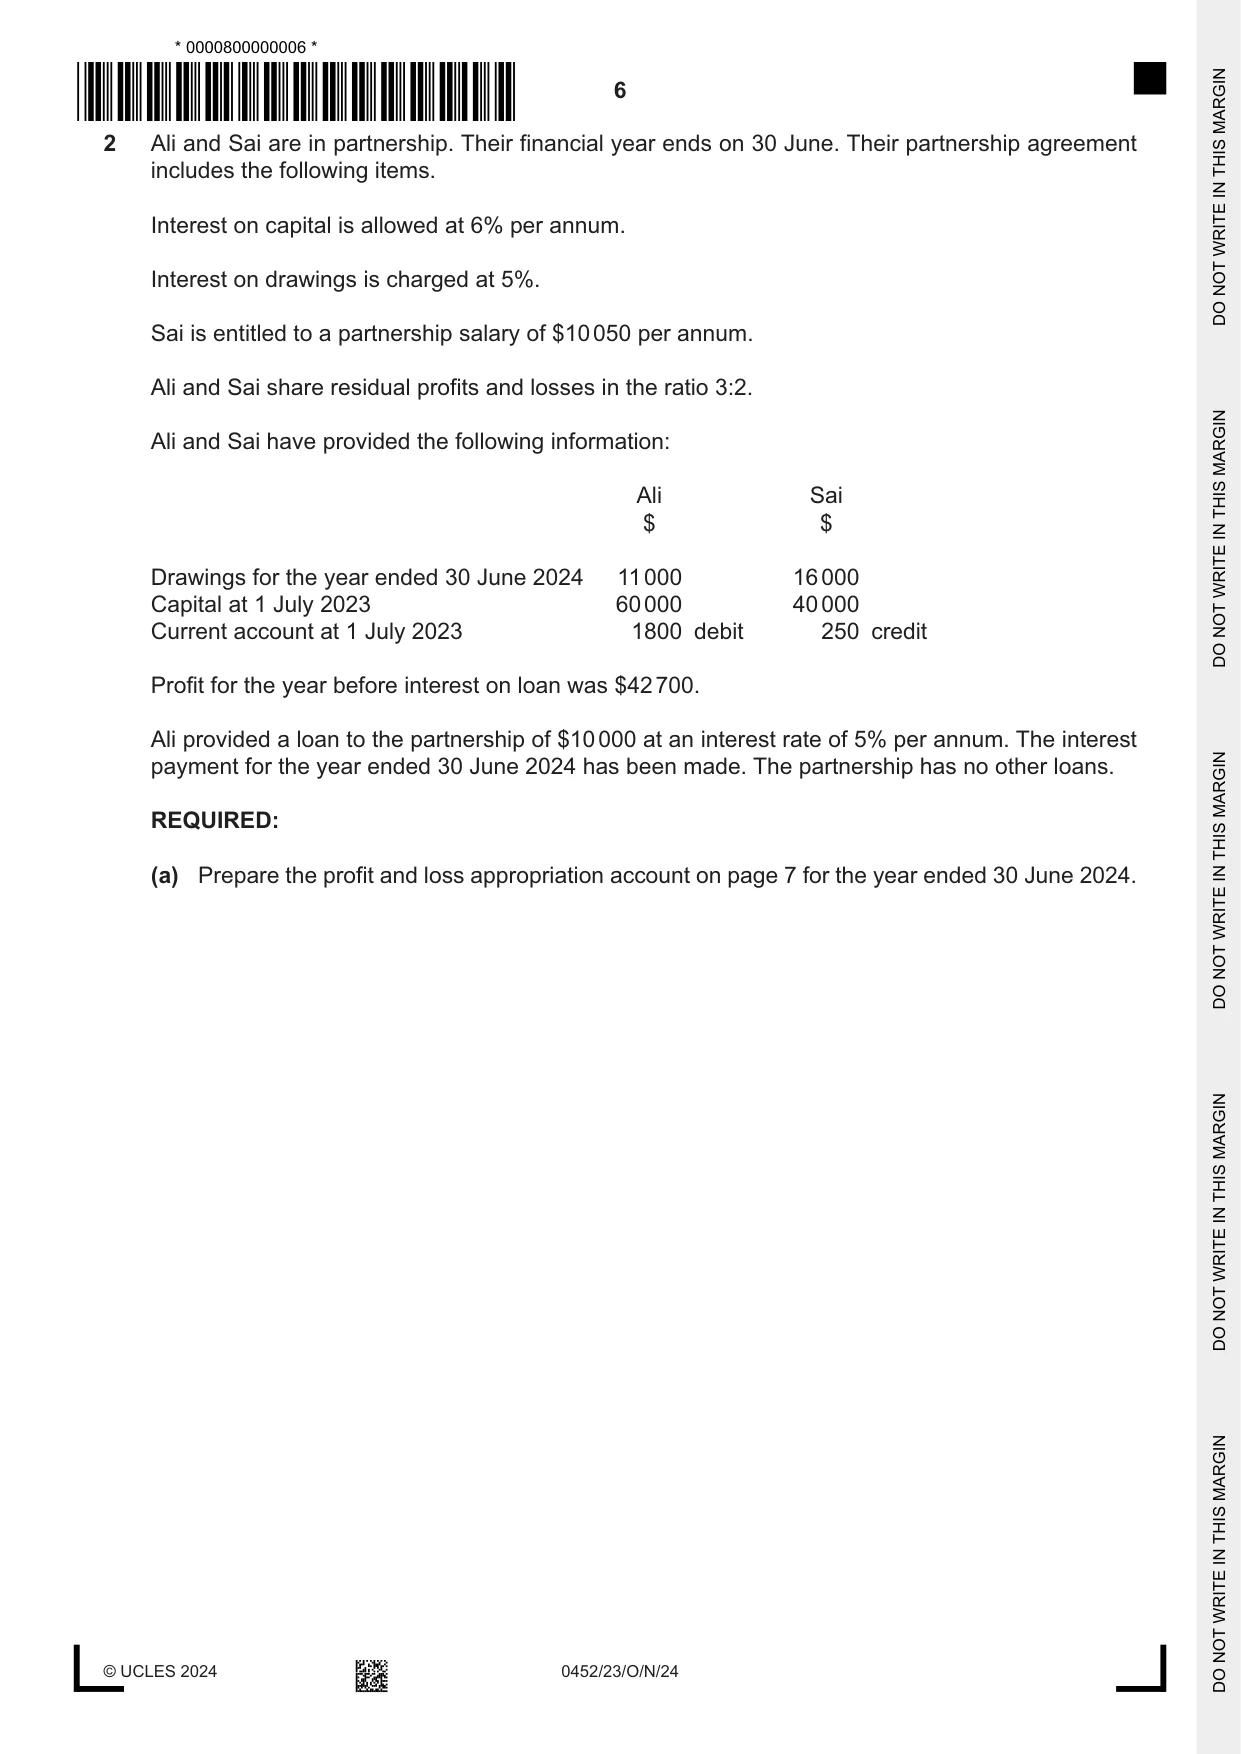
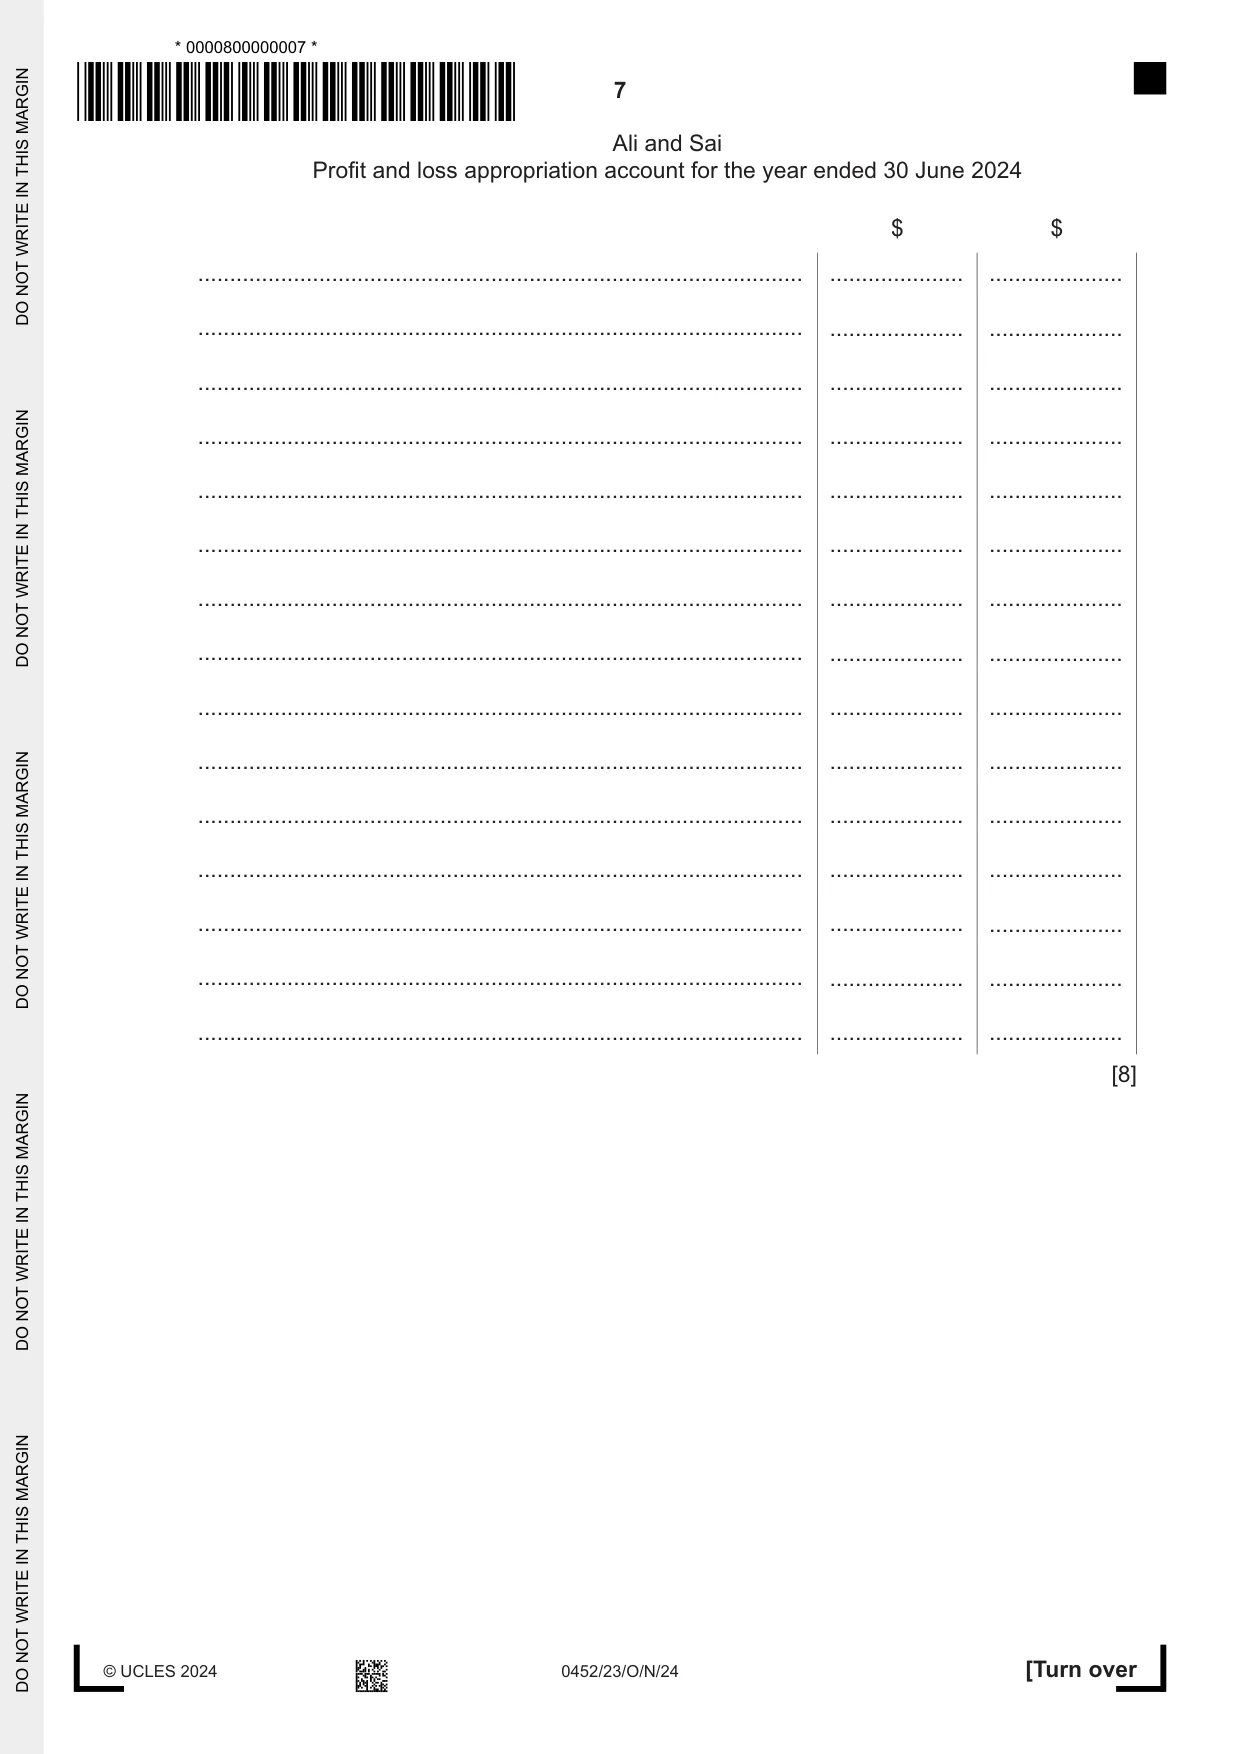
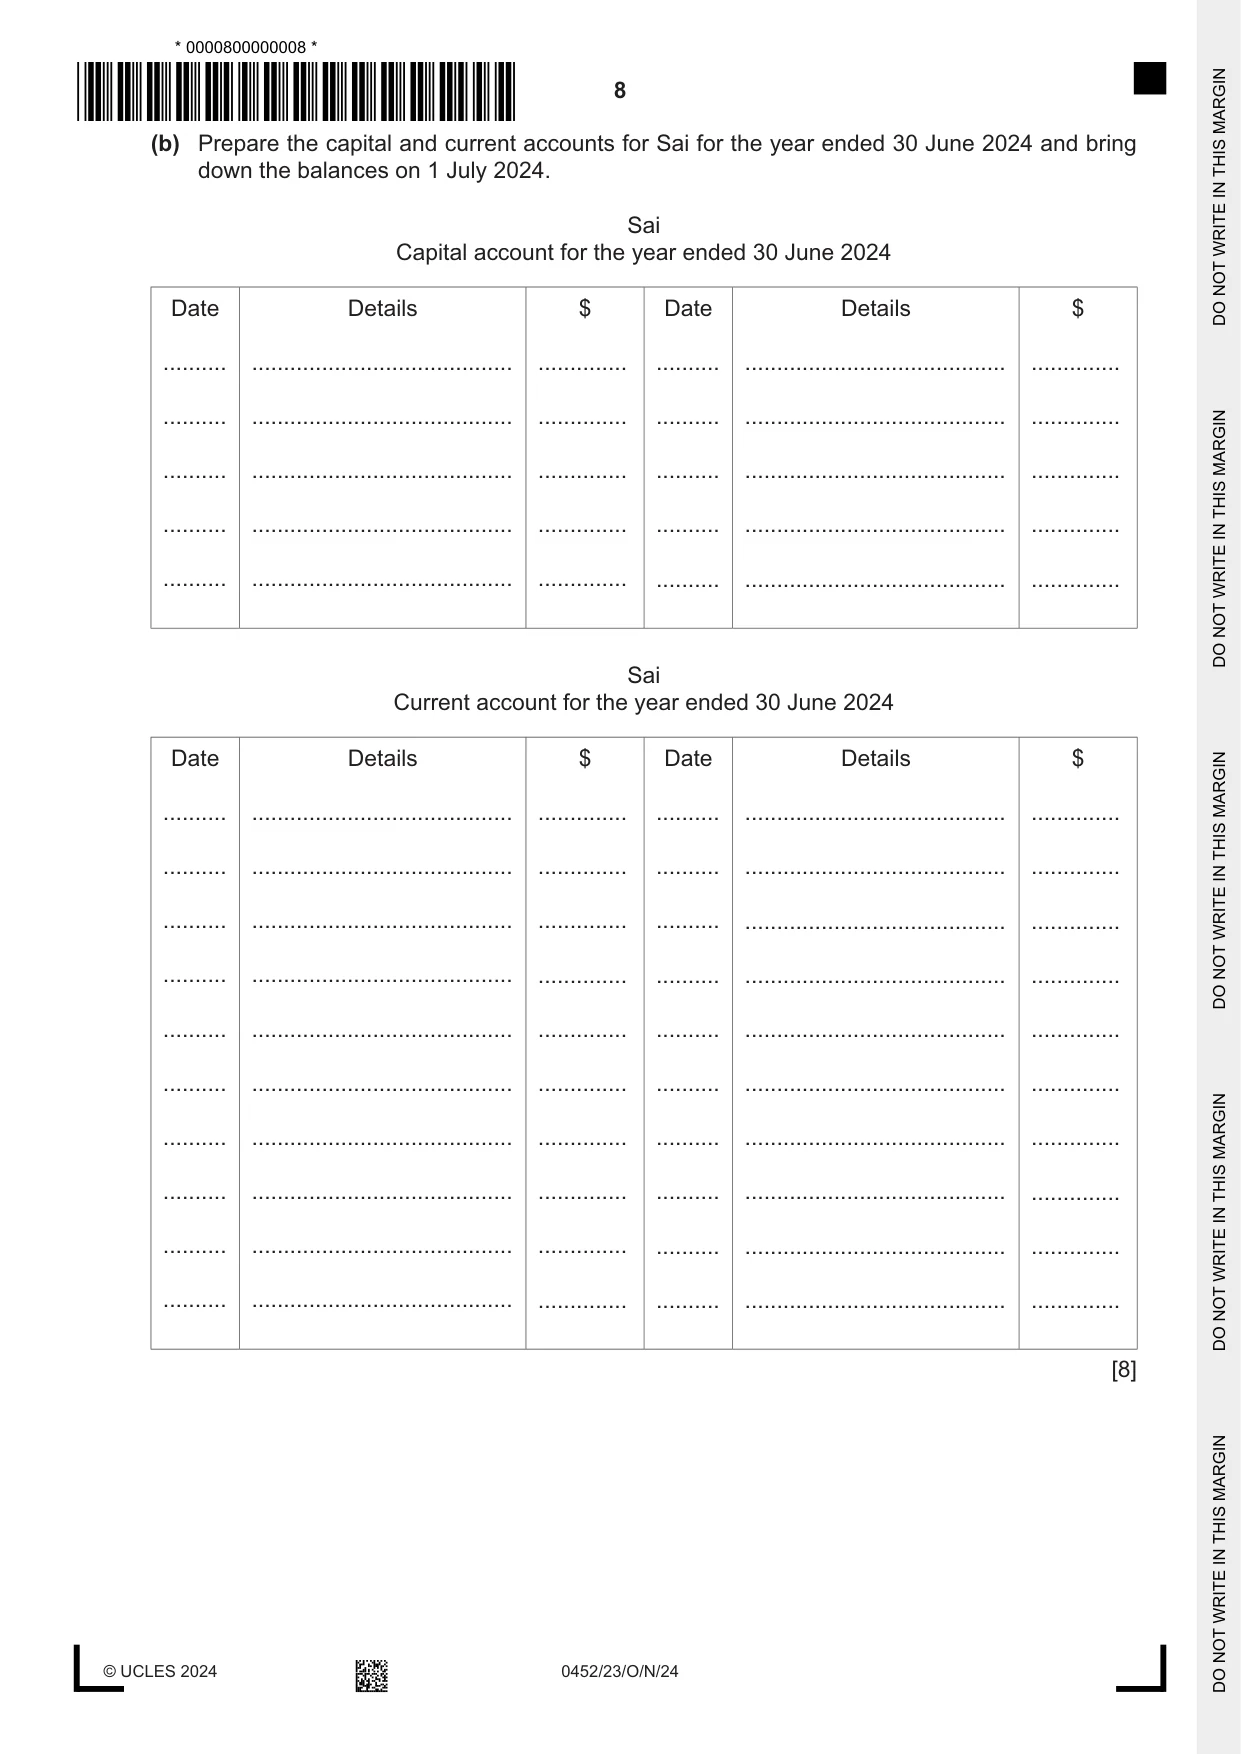
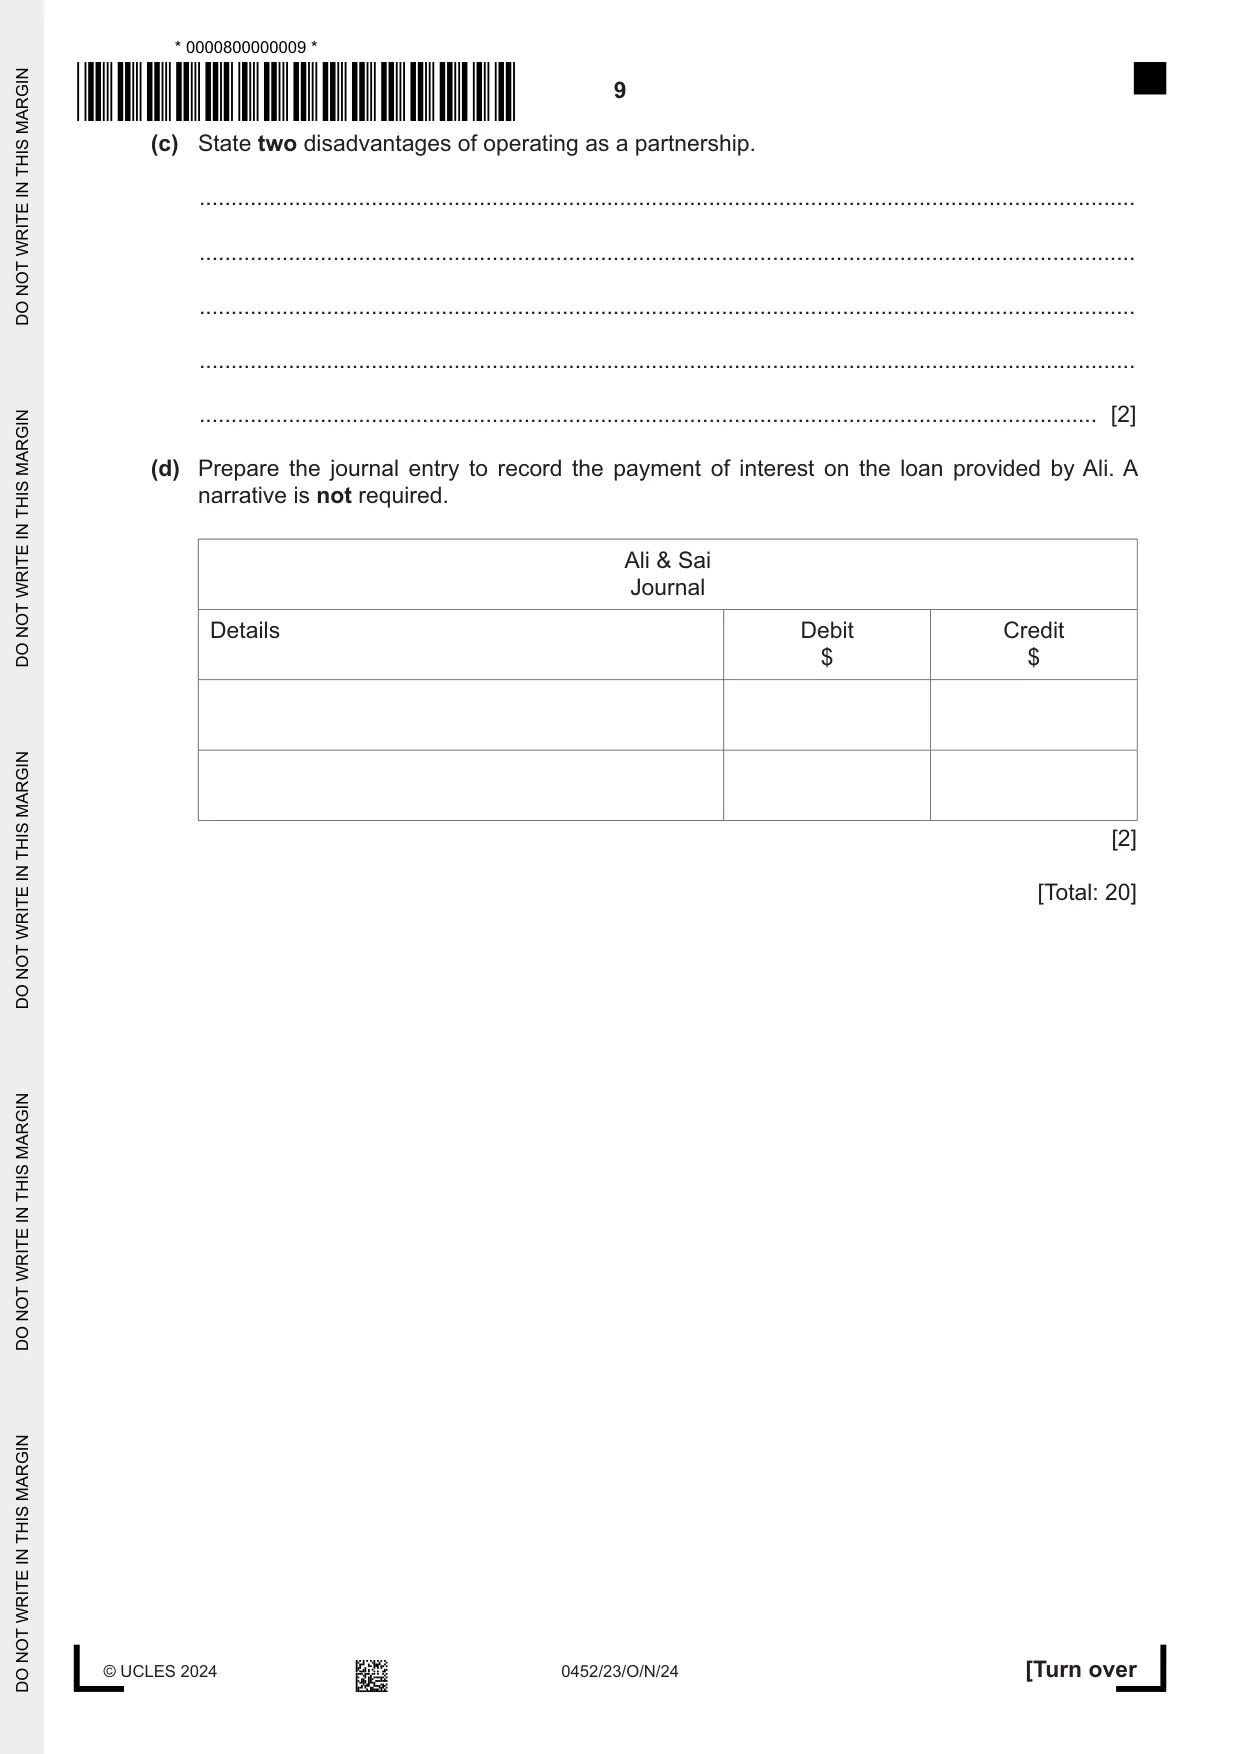
2 Ali and Sai are in partnership. Their financial year ends on 30 June. Their partnership agreement includes the following items. Interest on capital is allowed at 6% per annum. Interest on drawings is charged at 5%. Sai is entitled to a partnership salary of $10 050 per annum. Ali and Sai share residual profits and losses in the ratio 3:2. Ali and Sai have provided the following information: Ali Sai $ $ Drawings for the year ended 30 June 2024 11 000 16 000 Capital at 1 July 2023 60 000 40 000 Current account at 1 July 2023 1800 debit 250 credit Profit for the year before interest on loan was $42 700. Ali provided a loan to the partnership of $10 000 at an interest rate of 5% per annum. The interest payment for the year ended 30 June 2024 has been made. The partnership has no other loans. REQUIRED: (a) Prepare the profit and loss appropriation account on page 7 for the year ended 30 June 2024. Ali and Sai Profit and loss appropriation account for the year ended 30 June 2024 $ $ ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... [8] (b) Prepare the capital and current accounts for Sai for the year ended 30 June 2024 and bring down the balances on 1 July 2024. Sai Capital account for the year ended 30 June 2024 Date Details $ Date Details $ .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. Sai Current account for the year ended 30 June 2024 Date Details $ Date Details $ .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. [8] (c) State two disadvantages of operating as a partnership. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] (d) Prepare the journal entry to record the payment of interest on the loan provided by Ali. A narrative is not required. Ali & Sai Journal Details Debit Credit $ $ [2] [Total: 20]
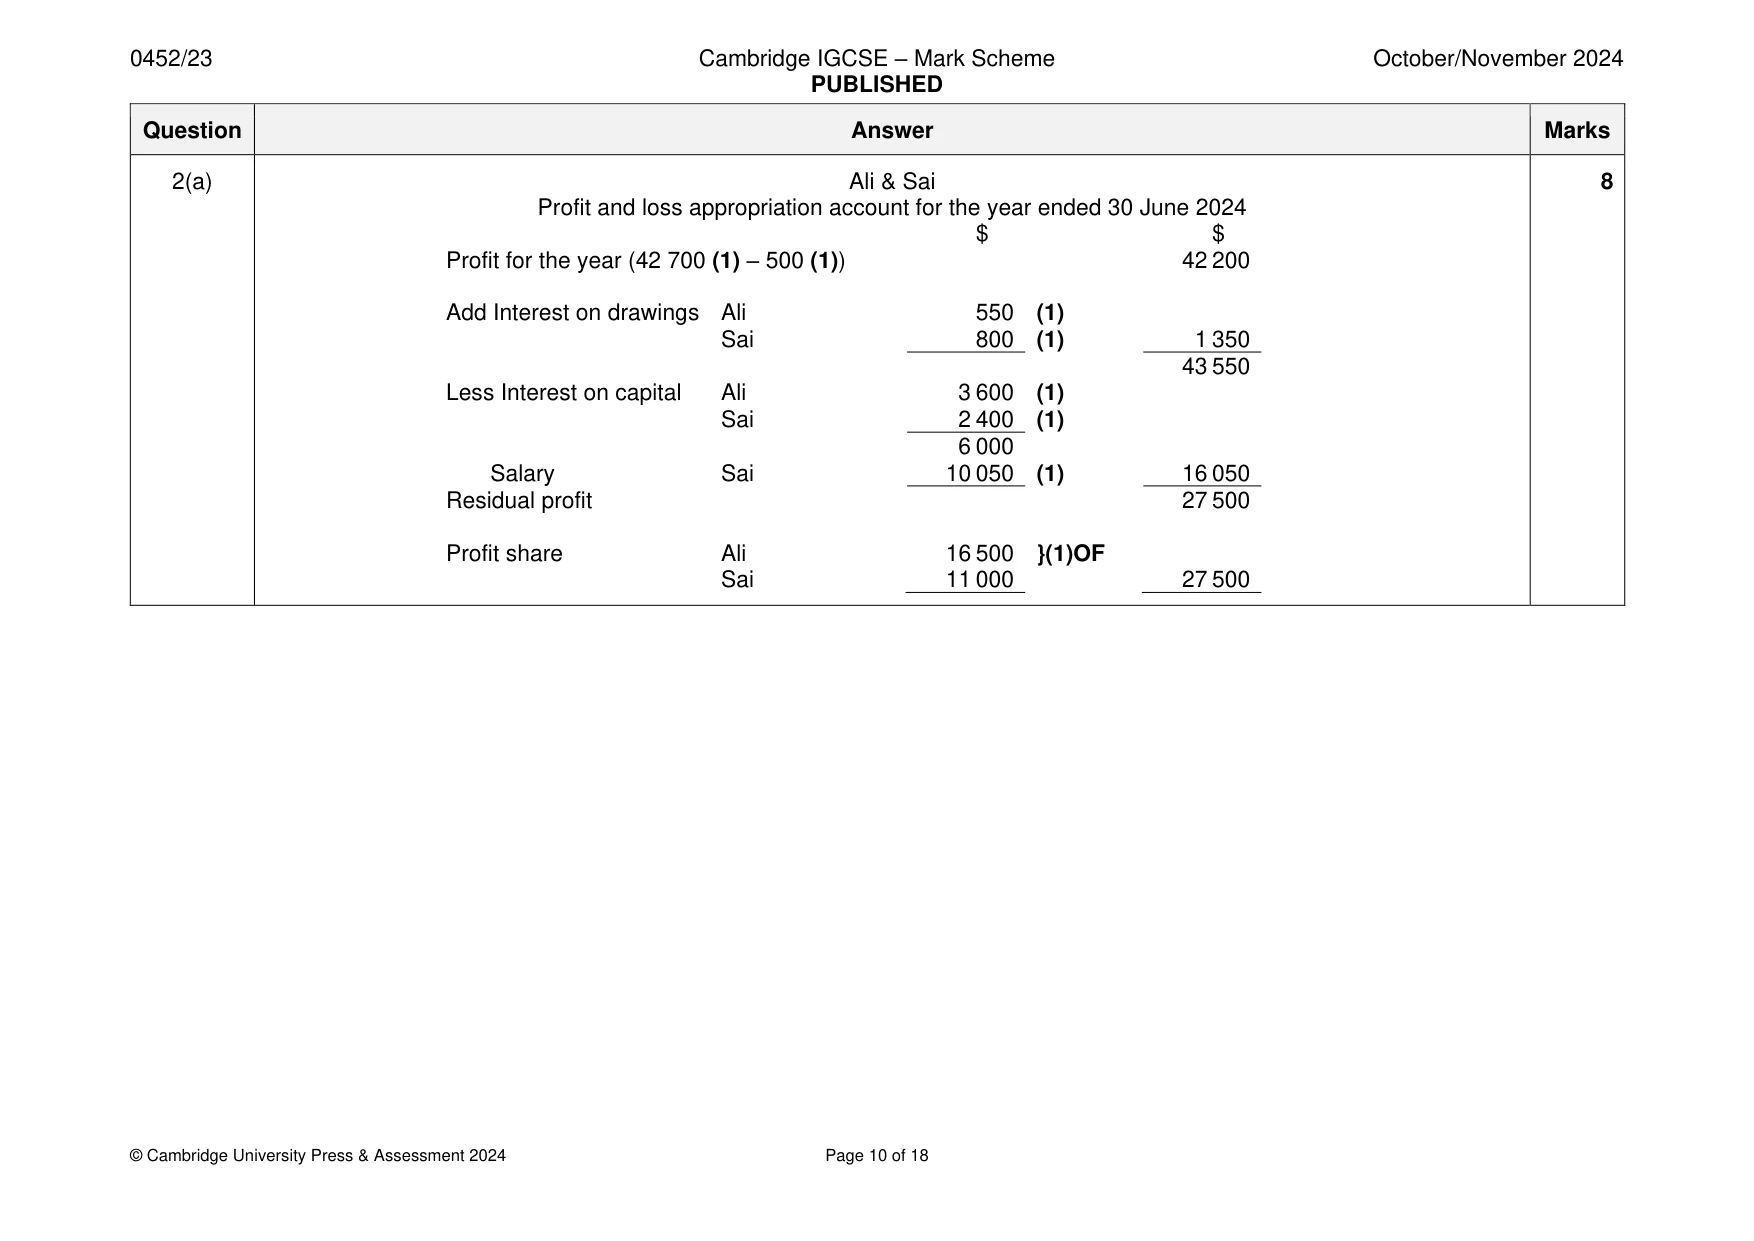
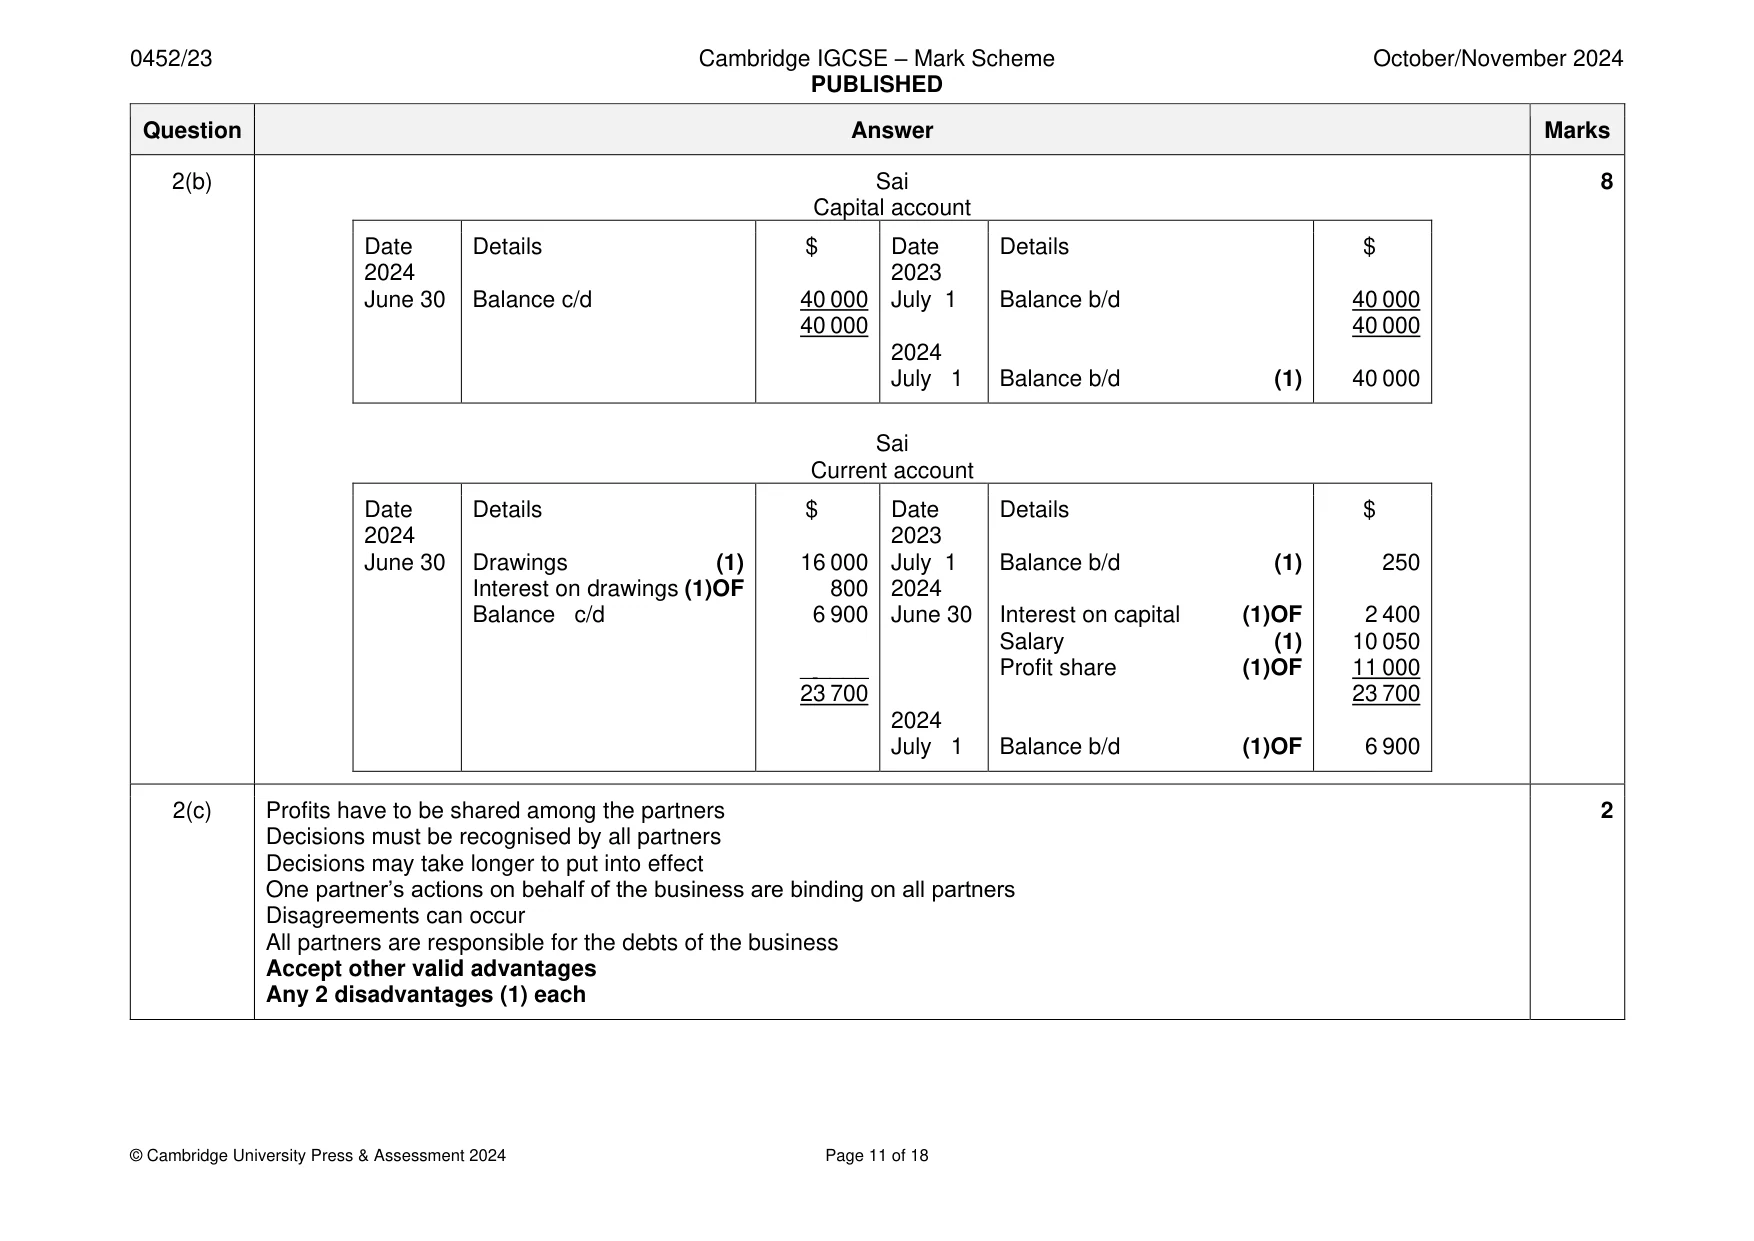
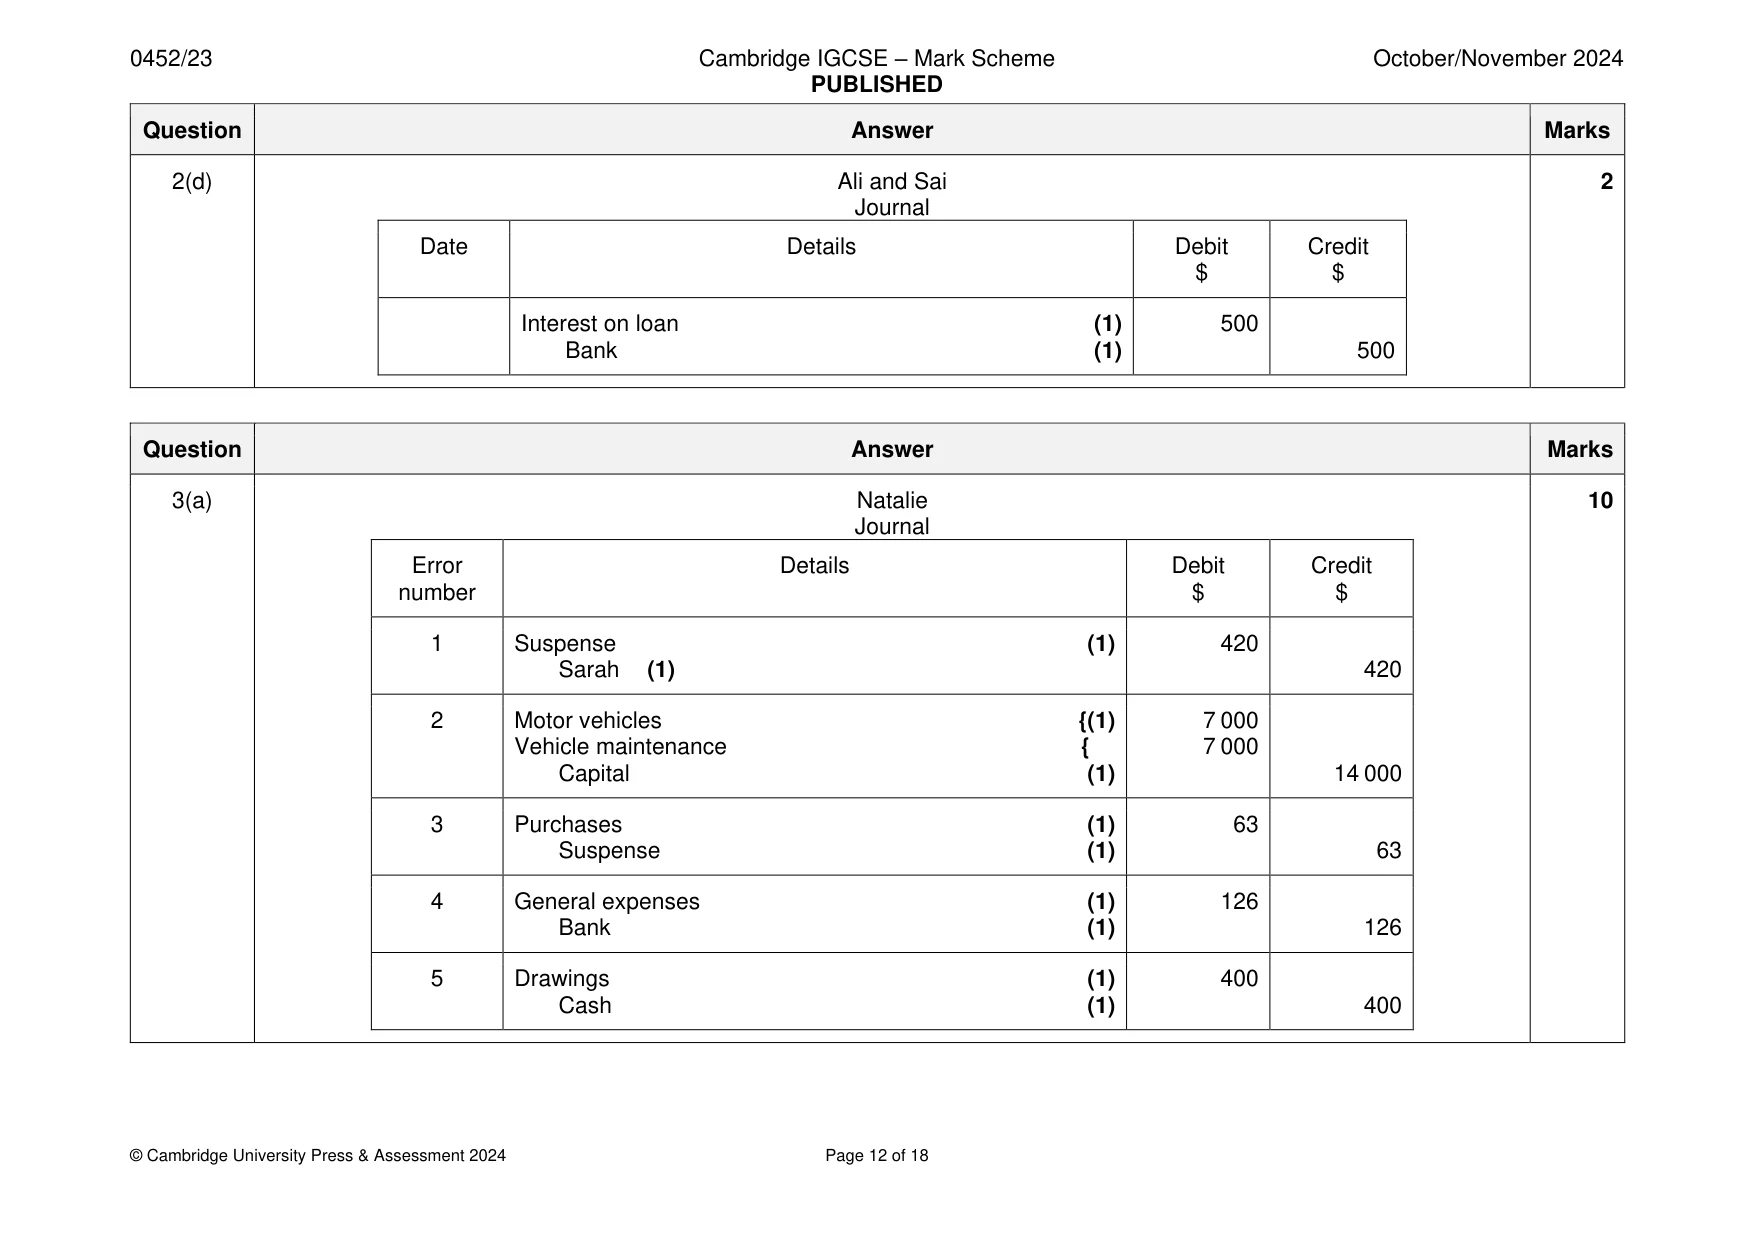
Mark scheme: 2(a) Ali & Sai 8 Profit and loss appropriation account for the year ended 30 June 2024 $ $ Profit for the year (42 700 (1) – 500 (1)) 42 200 Add Interest on drawings Ali 550 (1) Sai 800 (1) 1 350 43 550 Less Interest on capital Ali 3 600 (1) Sai 2 400 (1) 6 000 Salary Sai 10 050 (1) 16 050 Residual profit 27 500 Profit share Ali 16 500 }(1)OF Sai 11 000 27 500 2(b) Sai 8 Capital account Date Details $ Date Details $ 2024 2023 June 30 Balance c/d 40 000 July 1 Balance b/d 40 000 40 000 40 000 2024 July 1 Balance b/d (1) 40 000 Sai Current account Date Details $ Date Details $ 2024 2023 June 30 Drawings (1) 16 000 July 1 Balance b/d (1) 250 Interest on drawings (1)OF 800 2024 Balance c/d 6 900 June 30 Interest on capital (1)OF 2 400 Salary (1) 10 050 _ ____ Profit share (1)OF 11 000 23 700 23 700 2024 July 1 Balance b/d (1)OF 6 900 2(c) Profits have to be shared among the partners 2 Decisions must be recognised by all partners Decisions may take longer to put into effect One partner’s actions on behalf of the business are binding on all partners Disagreements can occur All partners are responsible for the debts of the business Accept other valid advantages Any 2 disadvantages (1) each 2(d) Ali and Sai 2 Journal Date Details Debit Credit $ $ Interest on loan (1) 500 Bank (1) 500
Q3 · Natalie prepared her trial balance at the end of the year 31 March 2024
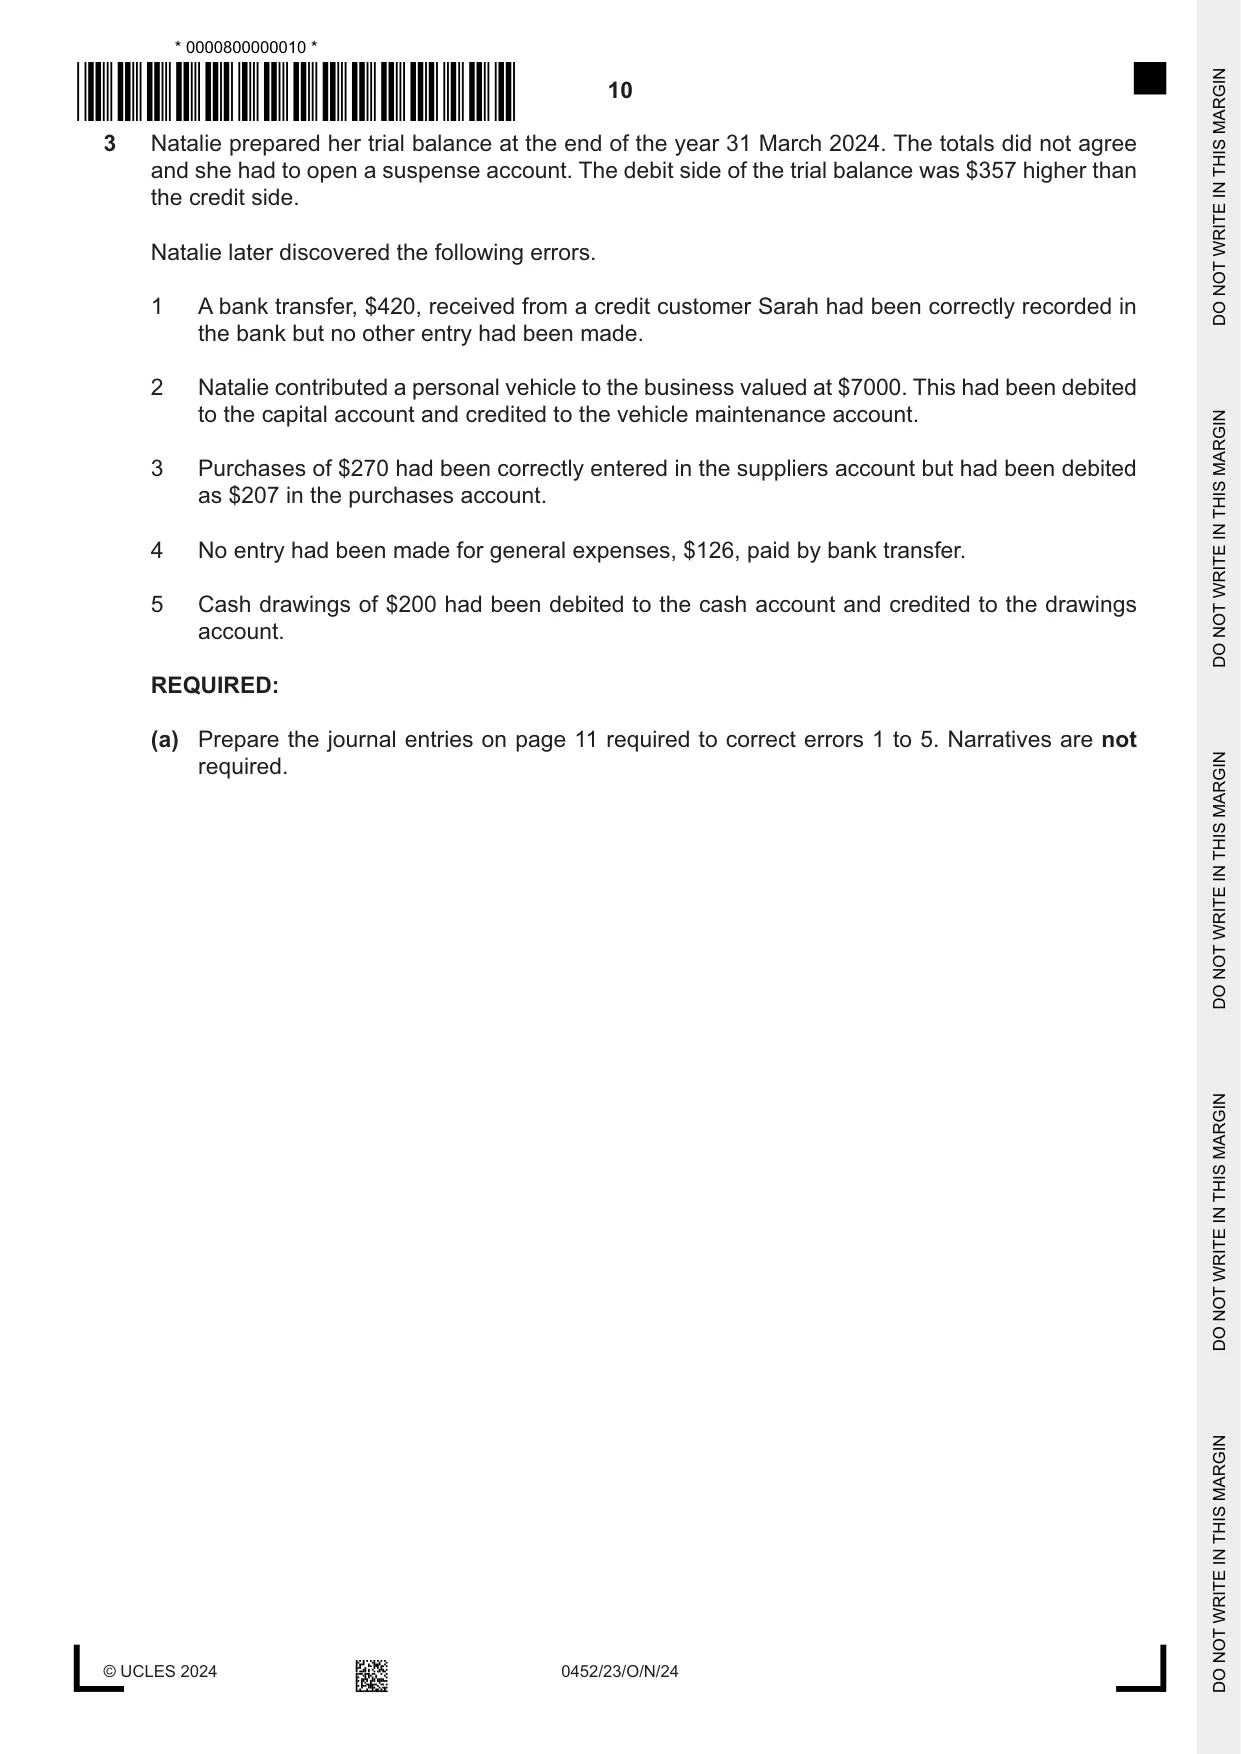
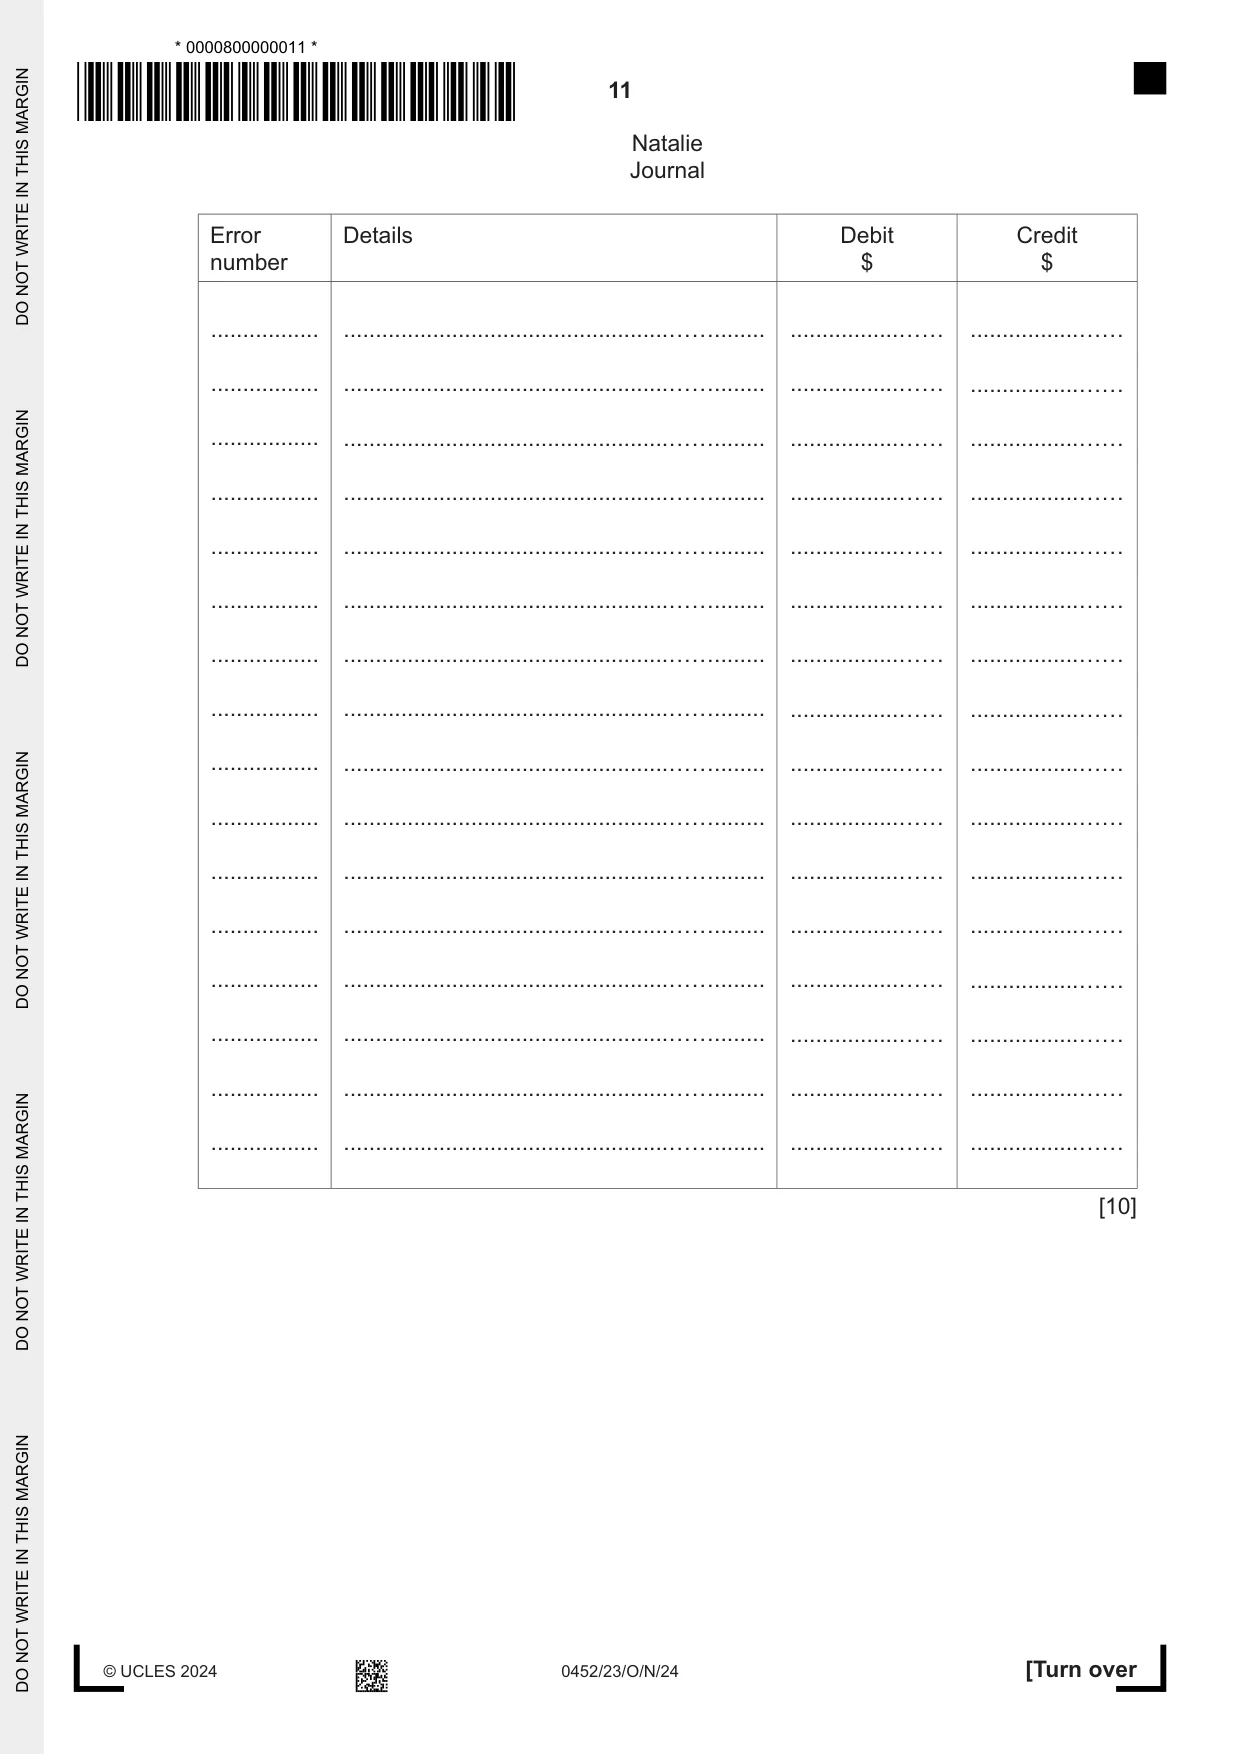
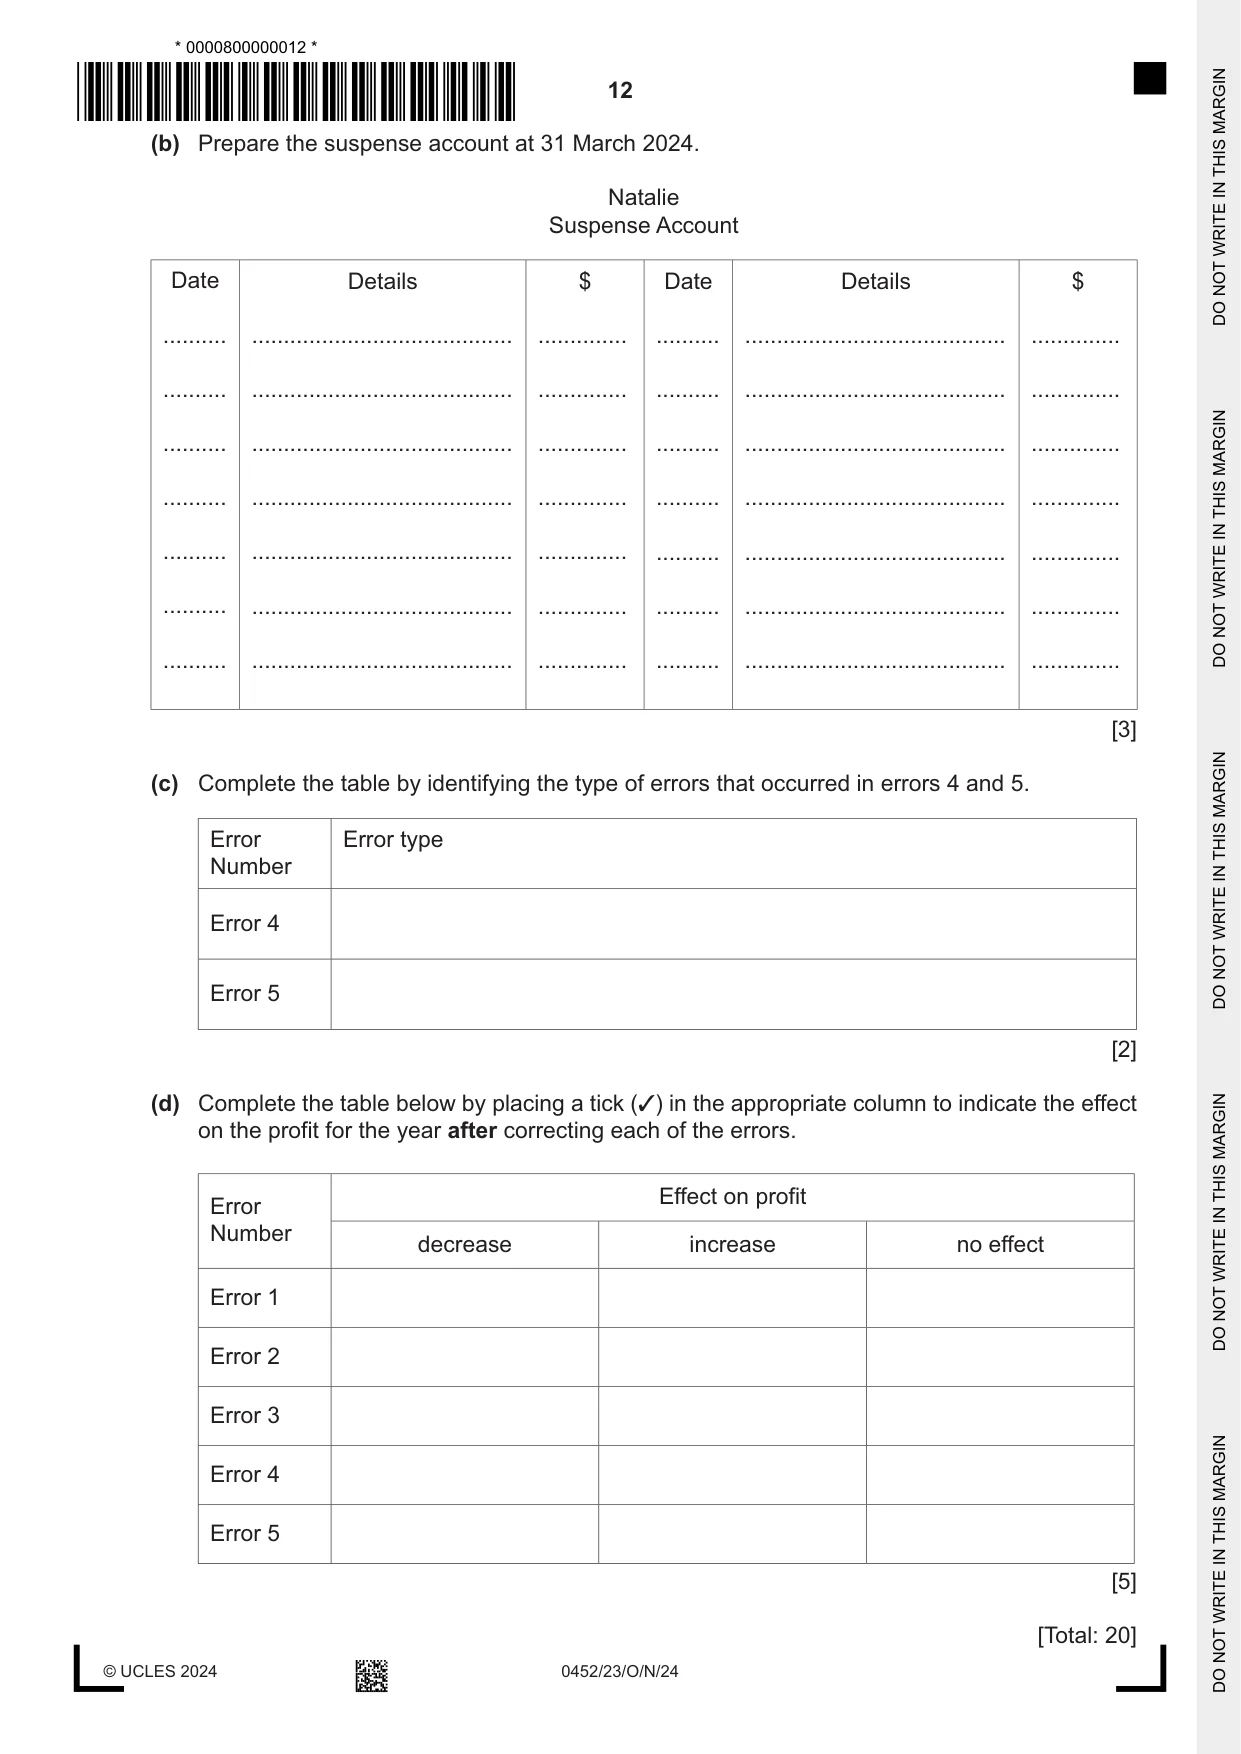
3 Natalie prepared her trial balance at the end of the year 31 March 2024. The totals did not agree and she had to open a suspense account. The debit side of the trial balance was $357 higher than the credit side. Natalie later discovered the following errors. 1 A bank transfer, $420, received from a credit customer Sarah had been correctly recorded in the bank but no other entry had been made. 2 Natalie contributed a personal vehicle to the business valued at $7000. This had been debited to the capital account and credited to the vehicle maintenance account. 3 Purchases of $270 had been correctly entered in the suppliers account but had been debited as $207 in the purchases account. 4 No entry had been made for general expenses, $126, paid by bank transfer. 5 Cash drawings of $200 had been debited to the cash account and credited to the drawings account. REQUIRED: (a) Prepare the journal entries on page 11 required to correct errors 1 to 5. Narratives are not required. Natalie Journal Error Details Debit Credit number $ $ ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… ................. ...................................................……........ .................…… .................…… [10] (b) Prepare the suspense account at 31 March 2024. Natalie Suspense Account Date Details $ Date Details $ .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. [3] (c) Complete the table by identifying the type of errors that occurred in errors 4 and 5. Error Error type Number Error 4 Error 5 [2] (d) Complete the table below by placing a tick (3) in the appropriate column to indicate the effect on the profit for the year after correcting each of the errors. Effect on profit Error Number decrease increase no effect Error 1 Error 2 Error 3 Error 4 Error 5 [5] [Total: 20]
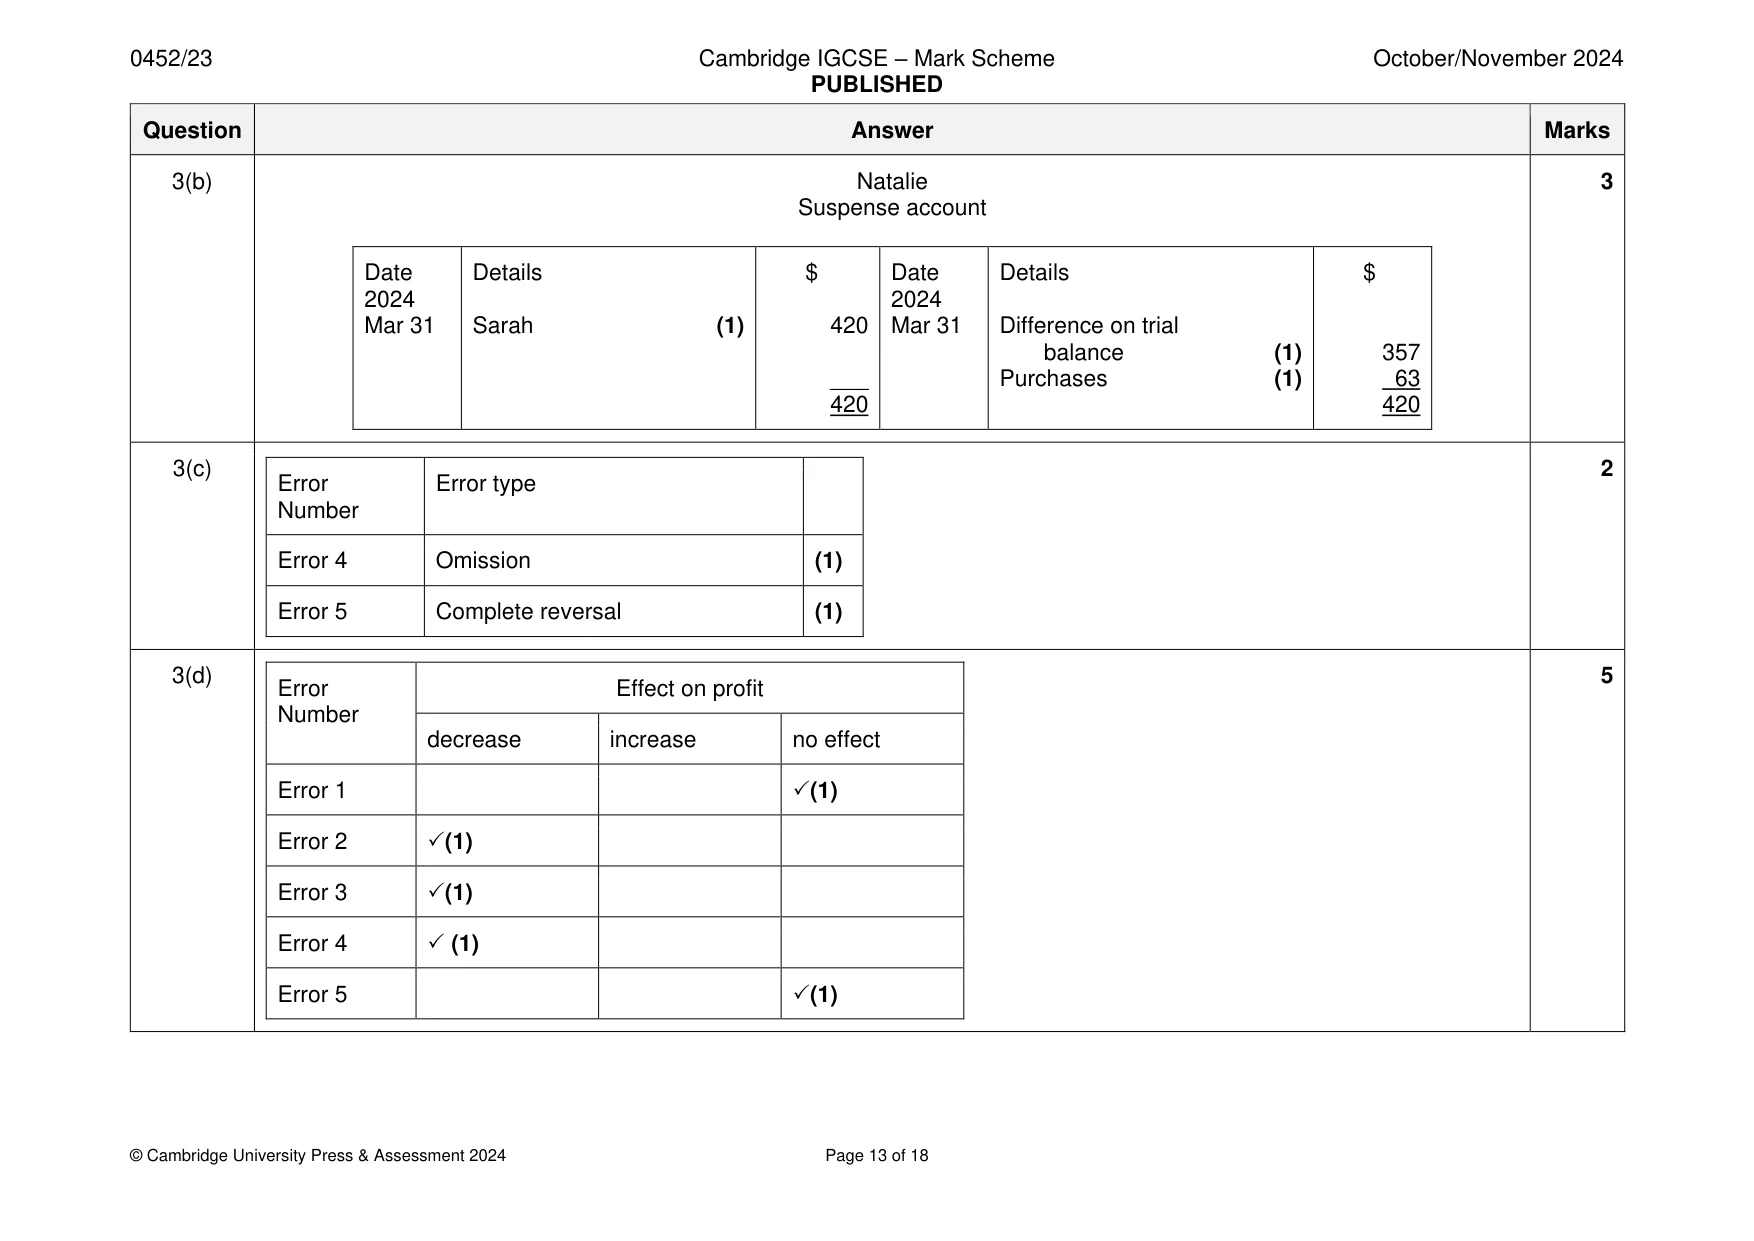
Mark scheme: 3(a) Natalie 10 Journal Error Details Debit Credit number $ $ 1 Suspense (1) 420 Sarah (1) 420 2 Motor vehicles {(1) 7 000 Vehicle maintenance { 7 000 Capital (1) 14 000 3 Purchases (1) 63 Suspense (1) 63 4 General expenses (1) 126 Bank (1) 126 5 Drawings (1) 400 Cash (1) 400 3(b) Natalie 3 Suspense account Date Details $ Date Details $ 2024 2024 Mar 31 Sarah (1) 420 Mar 31 Difference on trial balance (1) 357 ___ Purchases (1) 63 420 420 3(c) 2 Error Error type Number Error 4 Omission (1) Error 5 Complete reversal (1) 3(d) 5 Error Effect on profit Number decrease increase no effect Error 1 (1) Error 2 (1) Error 3 (1) Error 4 (1) Error 5 (1)
Q4 · A company has a fleet of delivery vehicles
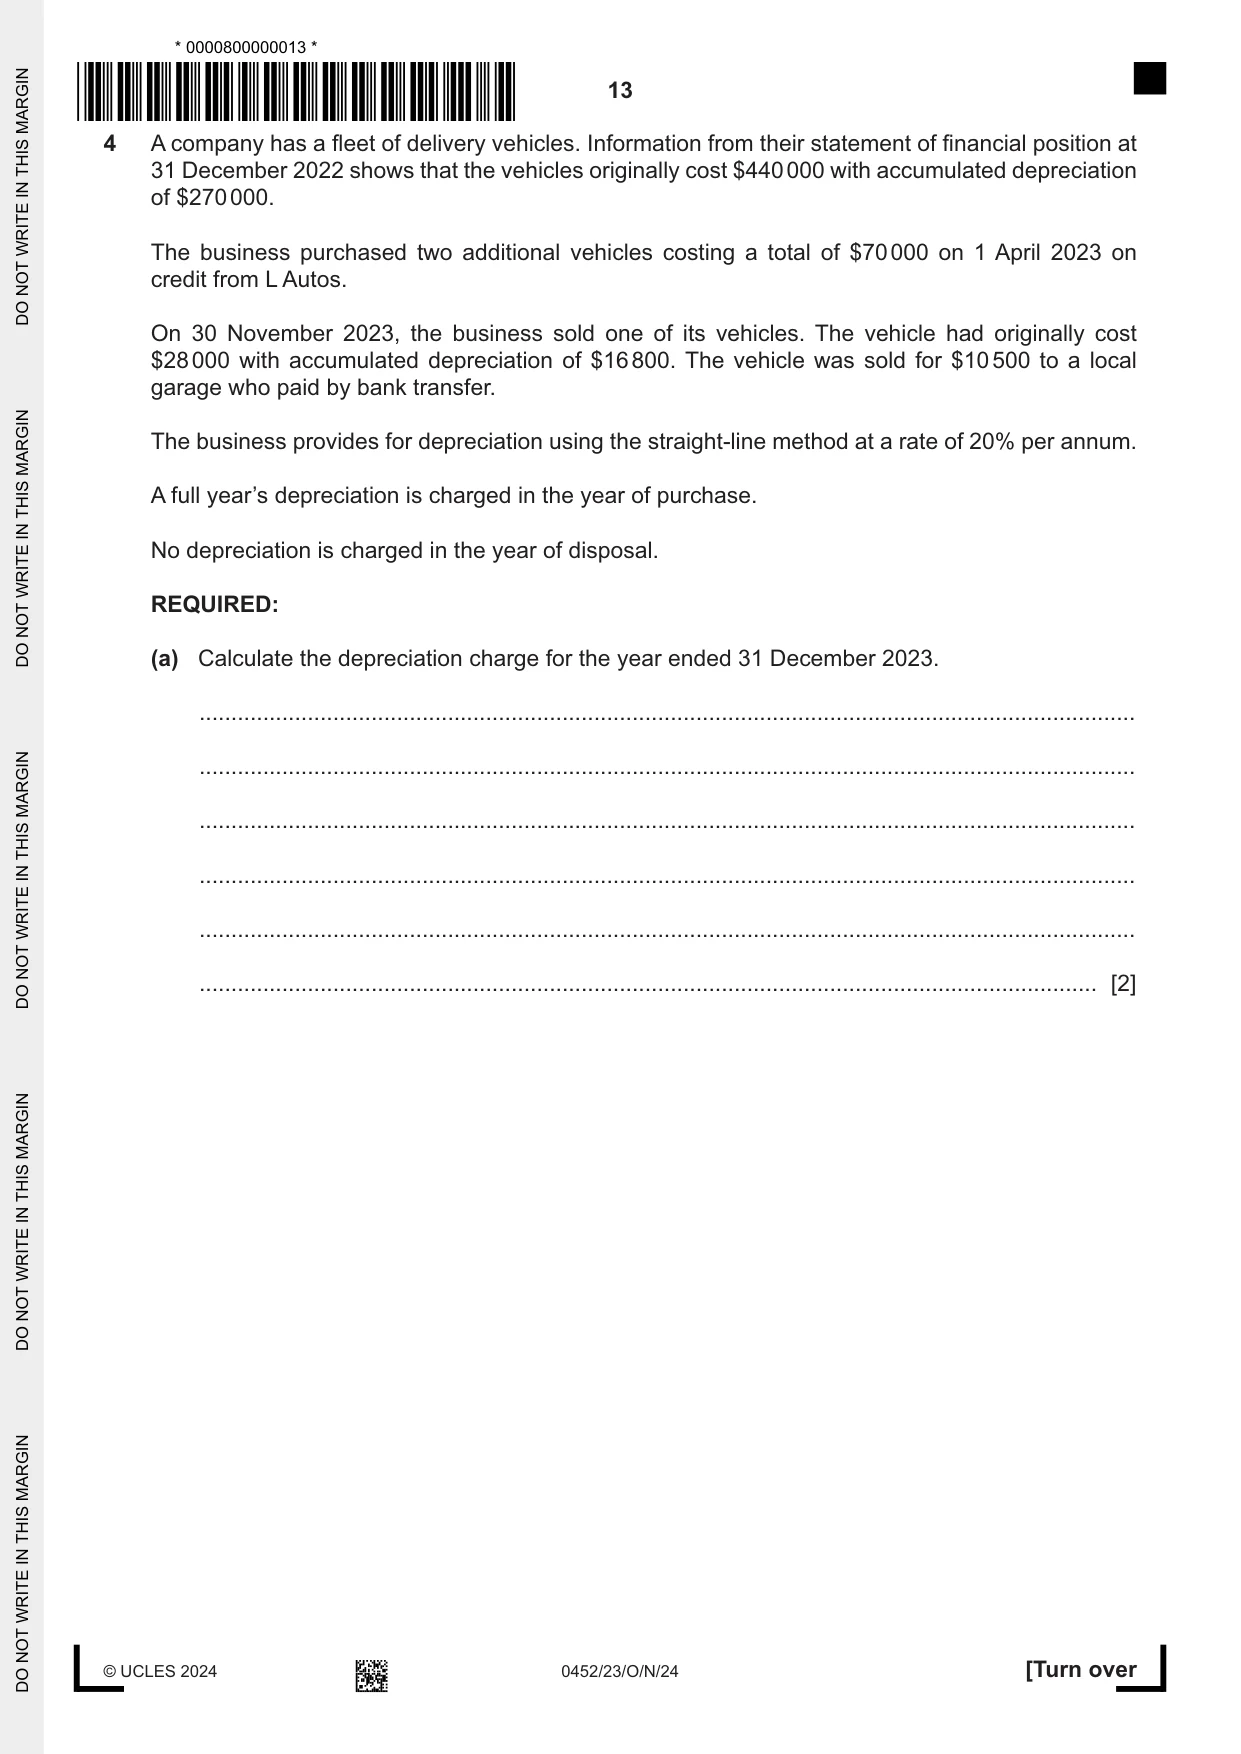
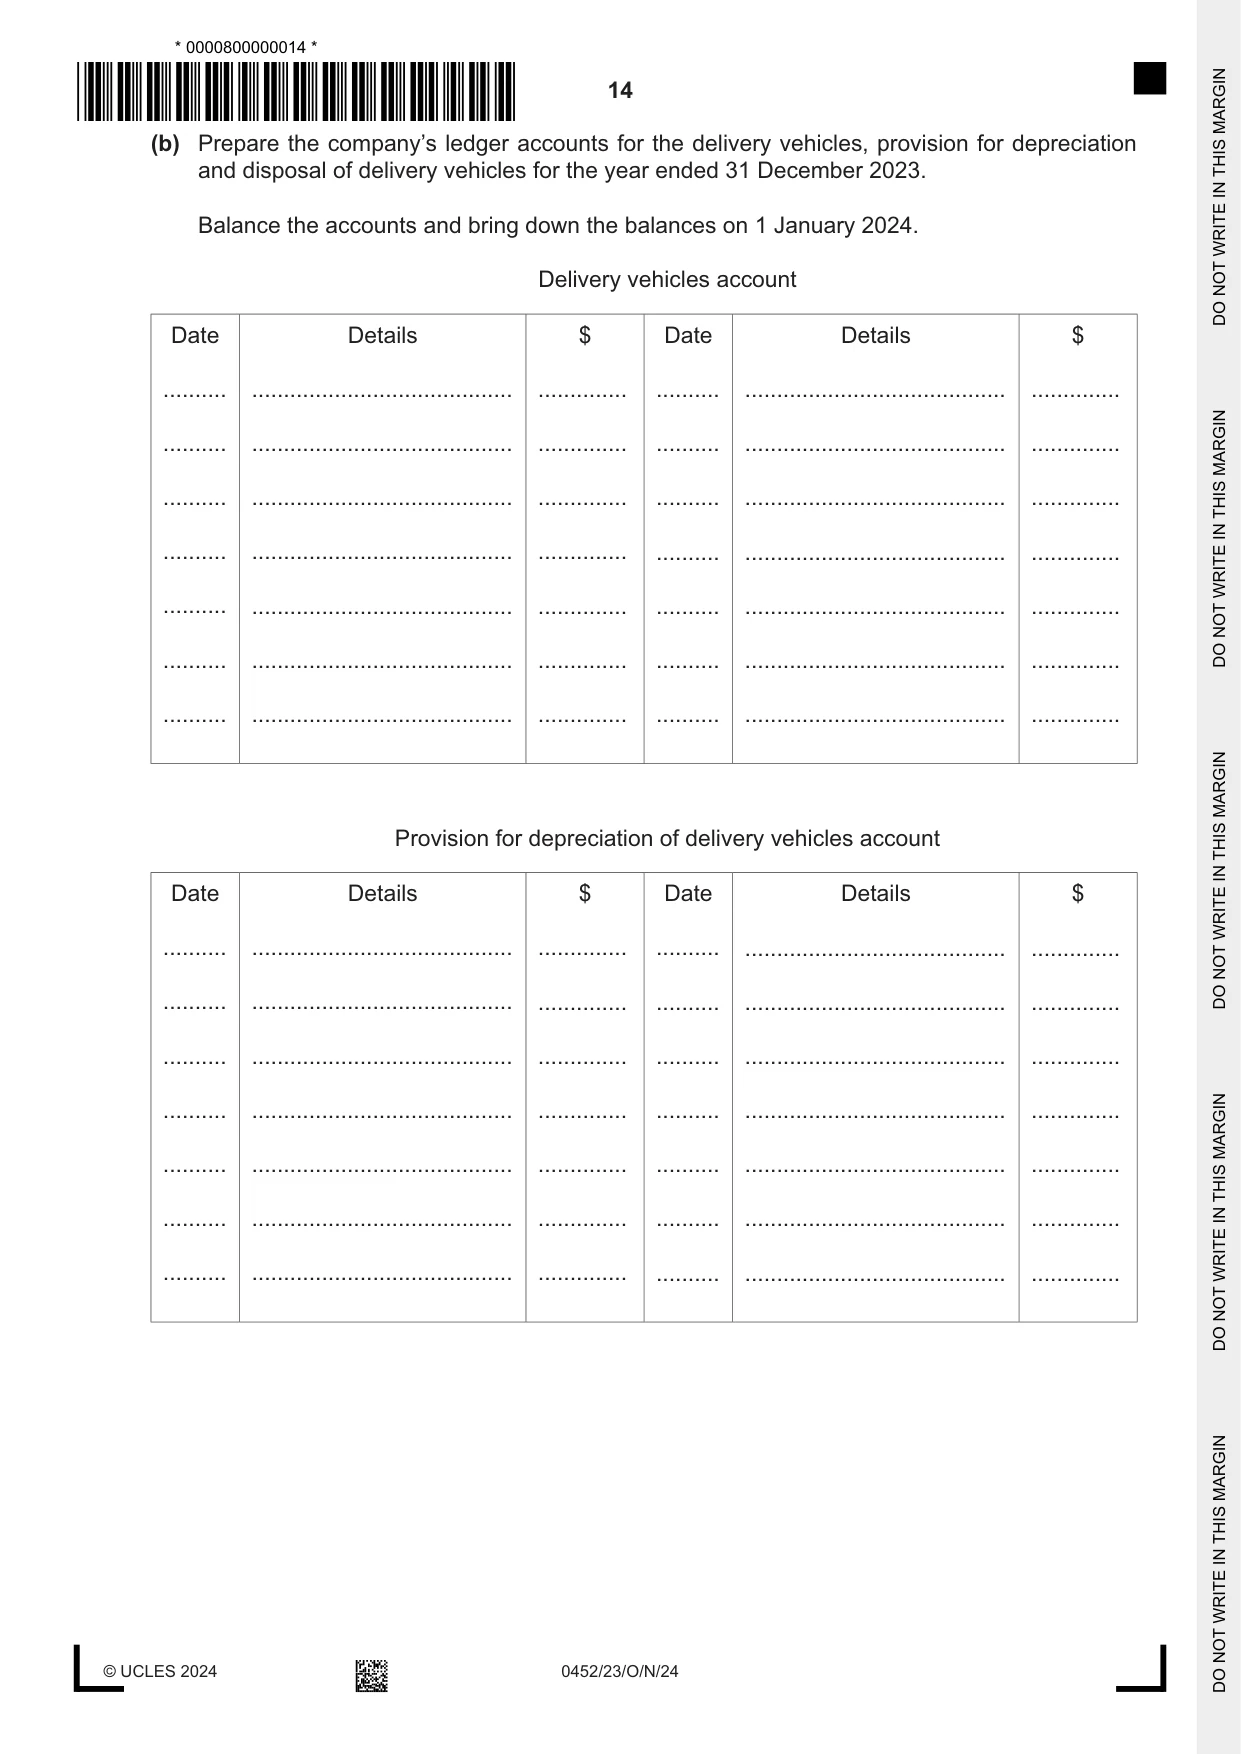
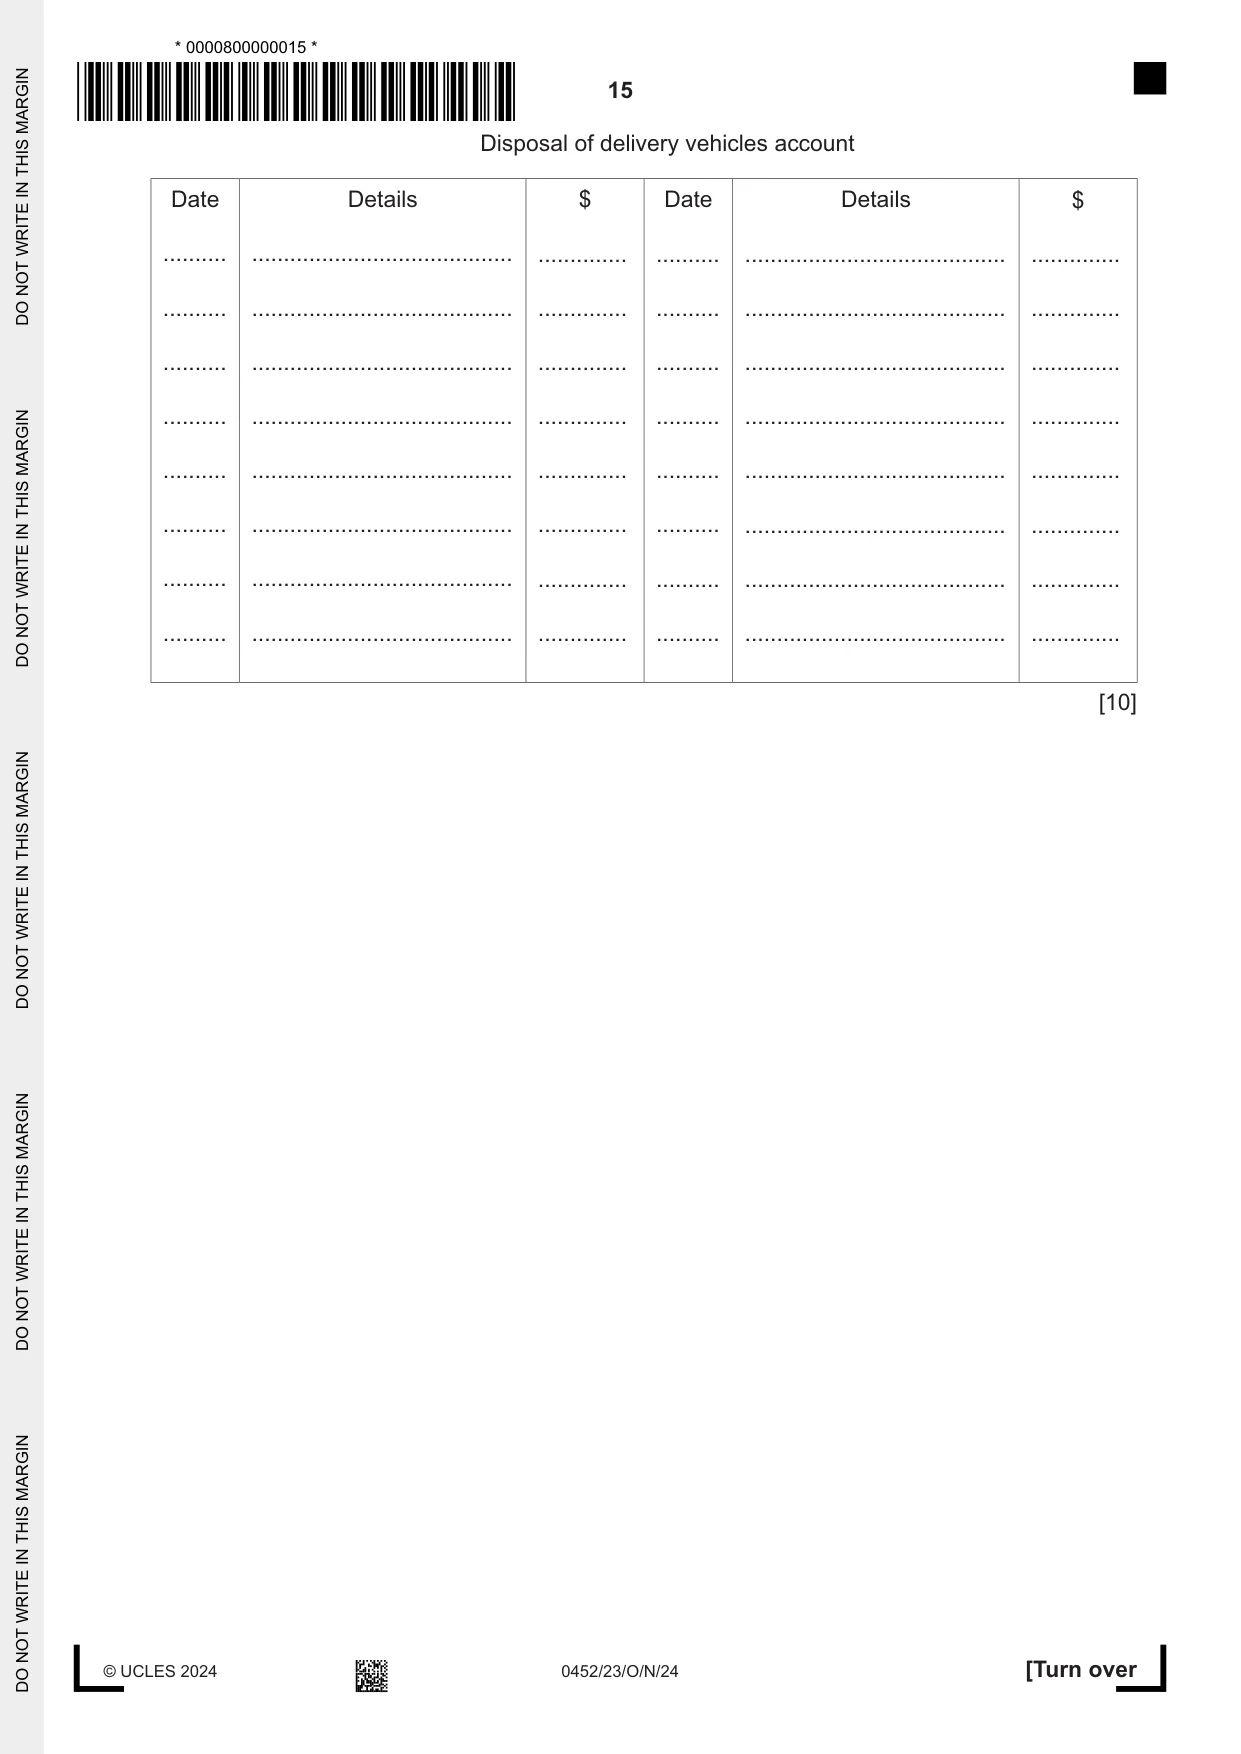
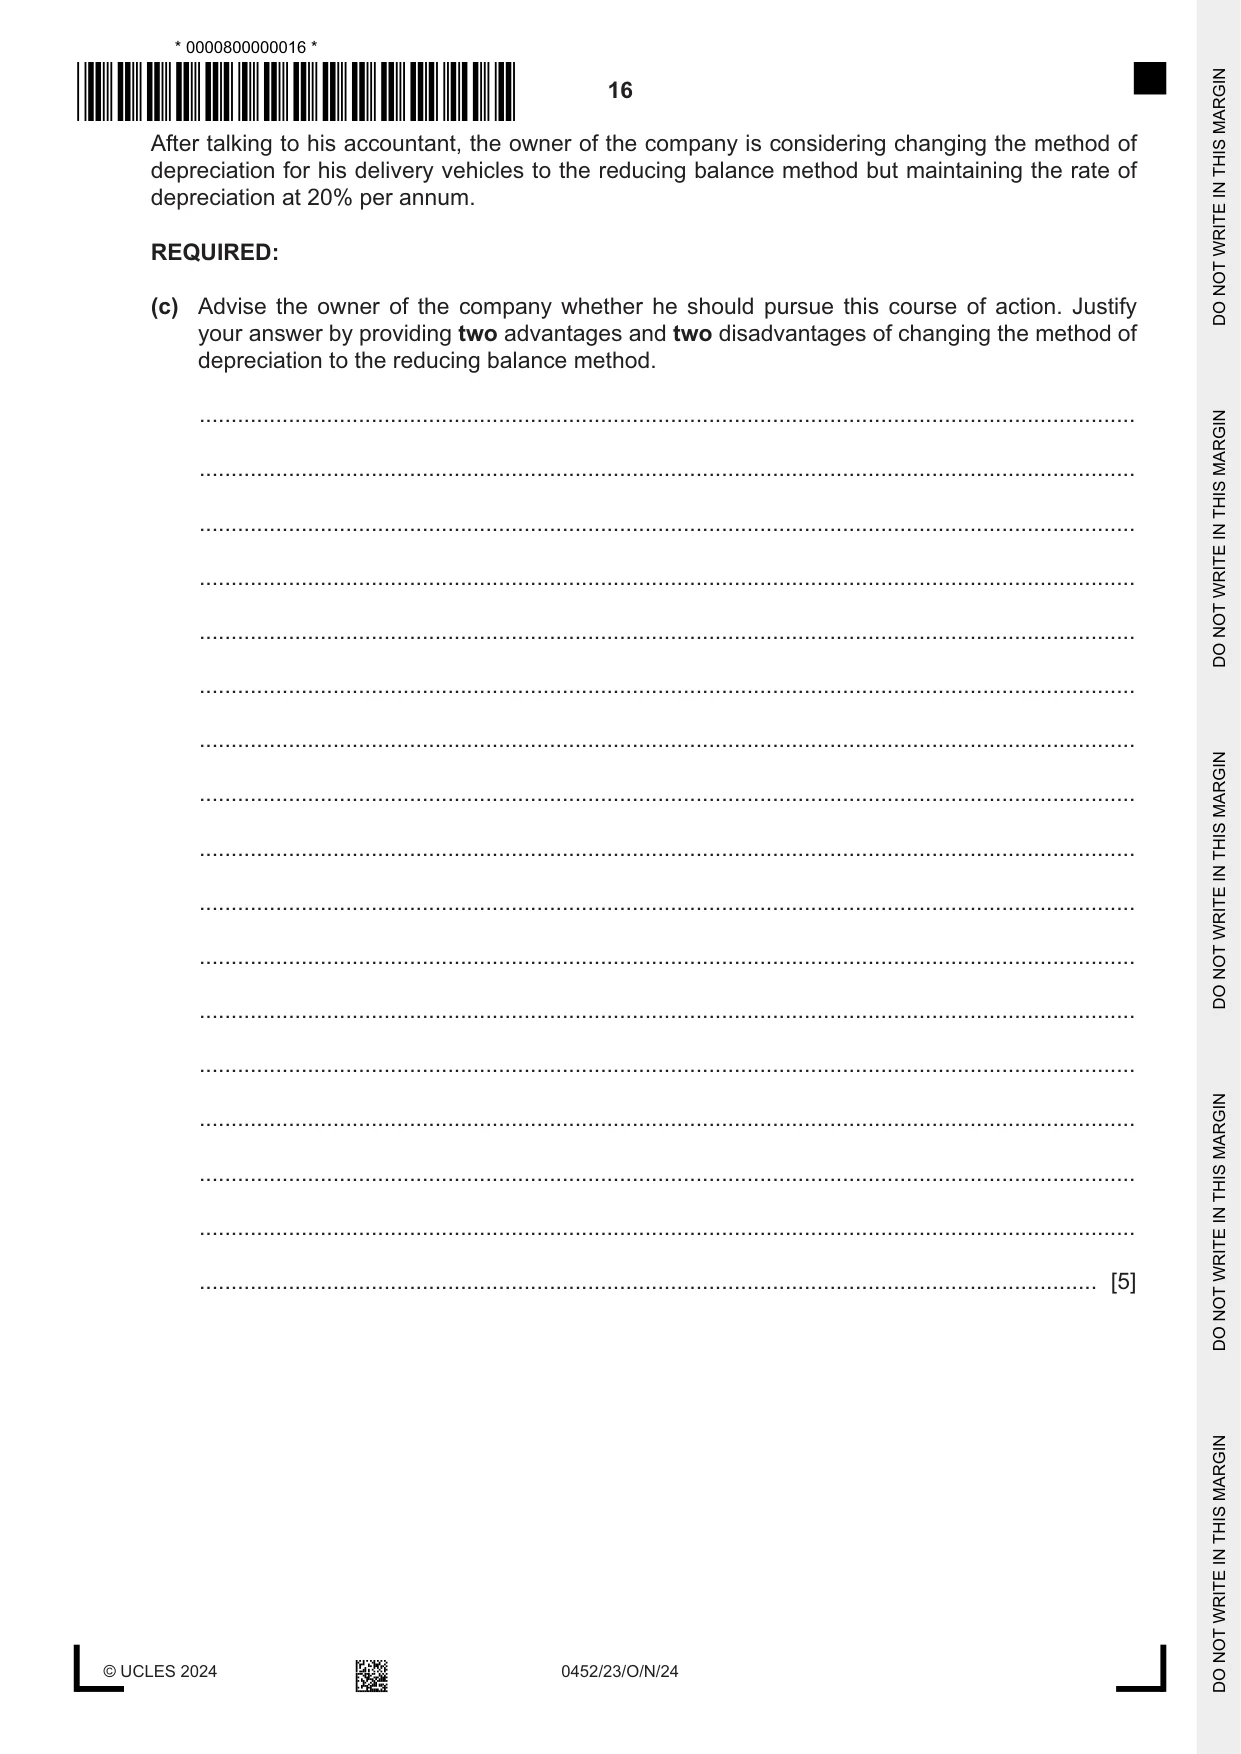
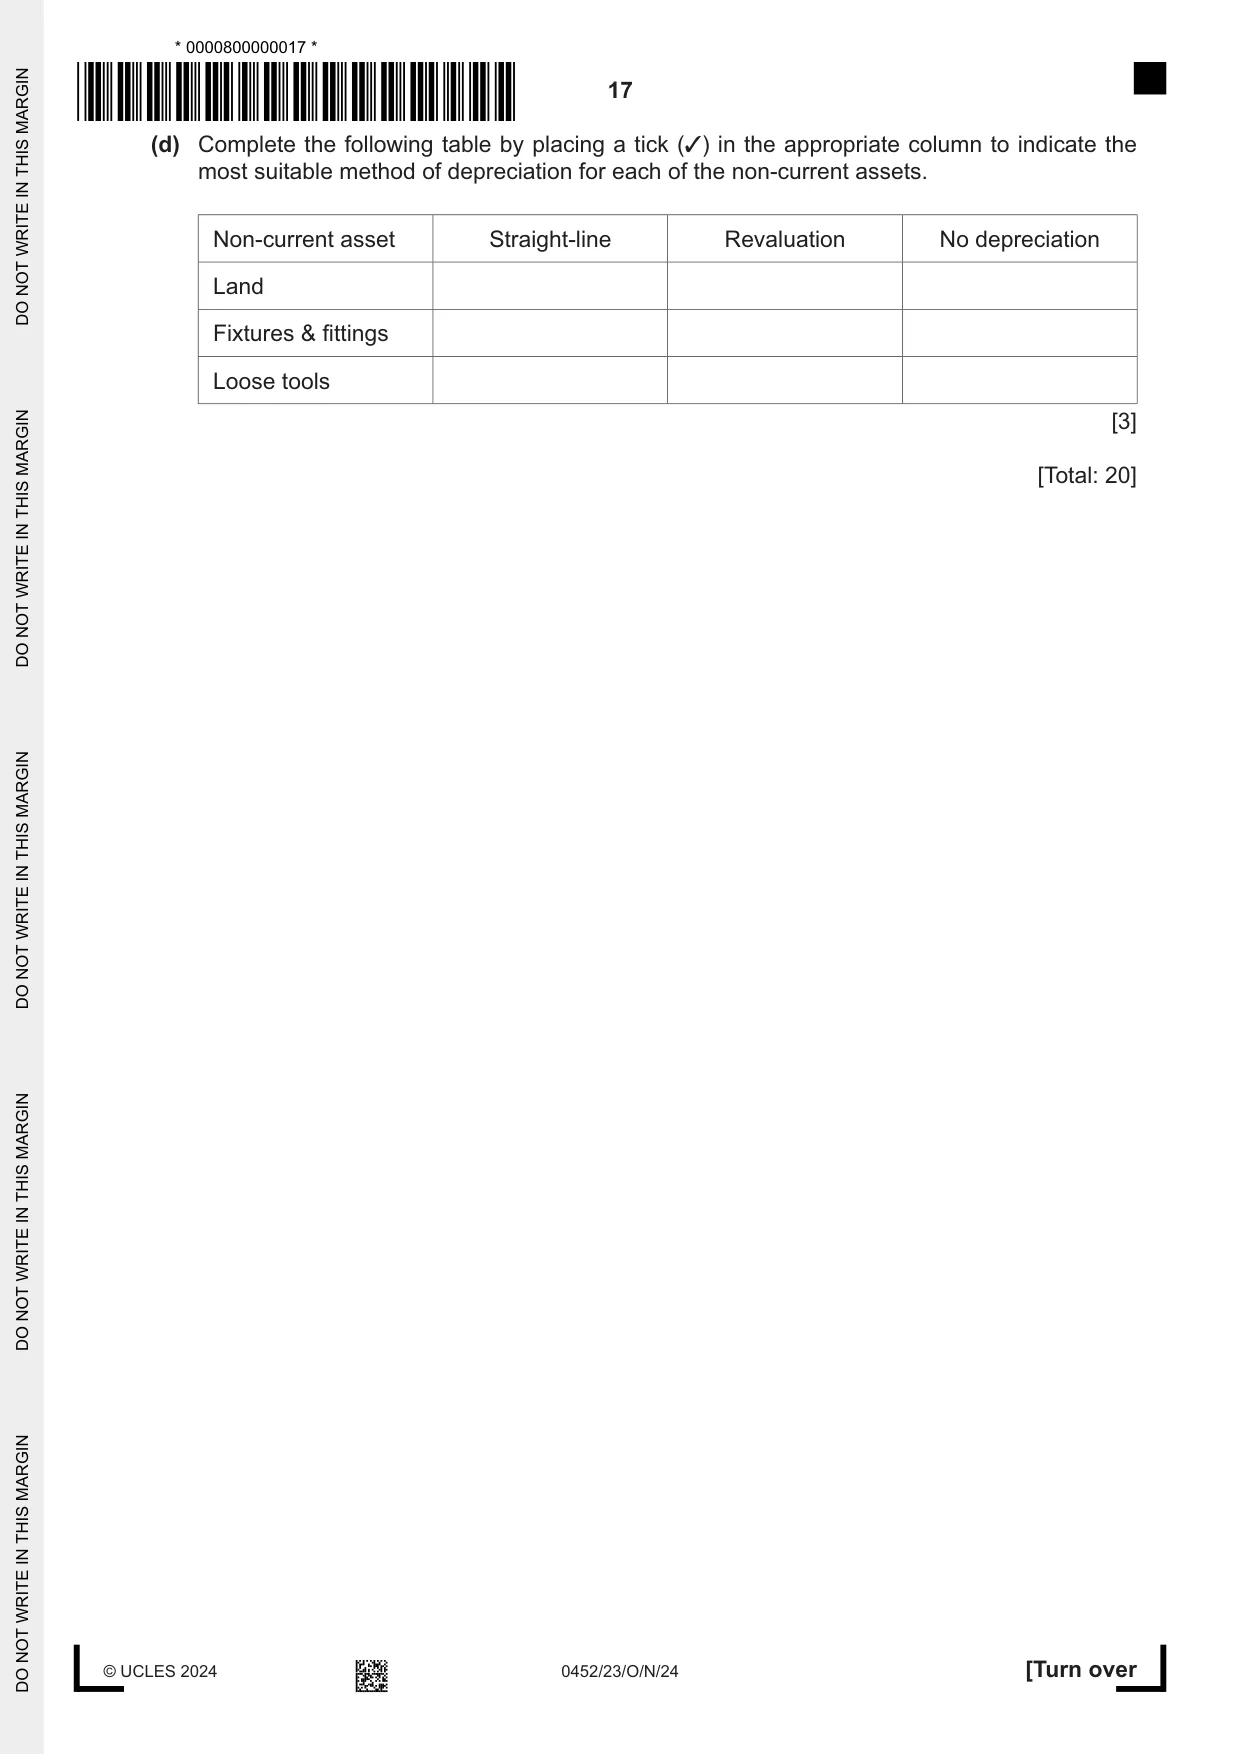
4 A company has a fleet of delivery vehicles. Information from their statement of financial position at 31 December 2022 shows that the vehicles originally cost $440 000 with accumulated depreciation of $270 000. The business purchased two additional vehicles costing a total of $70 000 on 1 April 2023 on credit from L Autos. On 30 November 2023, the business sold one of its vehicles. The vehicle had originally cost $28 000 with accumulated depreciation of $16 800. The vehicle was sold for $10 500 to a local garage who paid by bank transfer. The business provides for depreciation using the straight-line method at a rate of 20% per annum. A full year’s depreciation is charged in the year of purchase. No depreciation is charged in the year of disposal. REQUIRED: (a) Calculate the depreciation charge for the year ended 31 December 2023. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] (b) Prepare the company’s ledger accounts for the delivery vehicles, provision for depreciation and disposal of delivery vehicles for the year ended 31 December 2023. Balance the accounts and bring down the balances on 1 January 2024. Delivery vehicles account Date Details $ Date Details $ .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. Provision for depreciation of delivery vehicles account Date Details $ Date Details $ .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. Disposal of delivery vehicles account Date Details $ Date Details $ .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. [10] After talking to his accountant, the owner of the company is considering changing the method of depreciation for his delivery vehicles to the reducing balance method but maintaining the rate of depreciation at 20% per annum. REQUIRED: (c) Advise the owner of the company whether he should pursue this course of action. Justify your answer by providing two advantages and two disadvantages of changing the method of depreciation to the reducing balance method. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] (d) Complete the following table by placing a tick (3) in the appropriate column to indicate the most suitable method of depreciation for each of the non-current assets. Non-current asset Straight-line Revaluation No depreciation Land Fixtures & fittings Loose tools [3] [Total: 20]
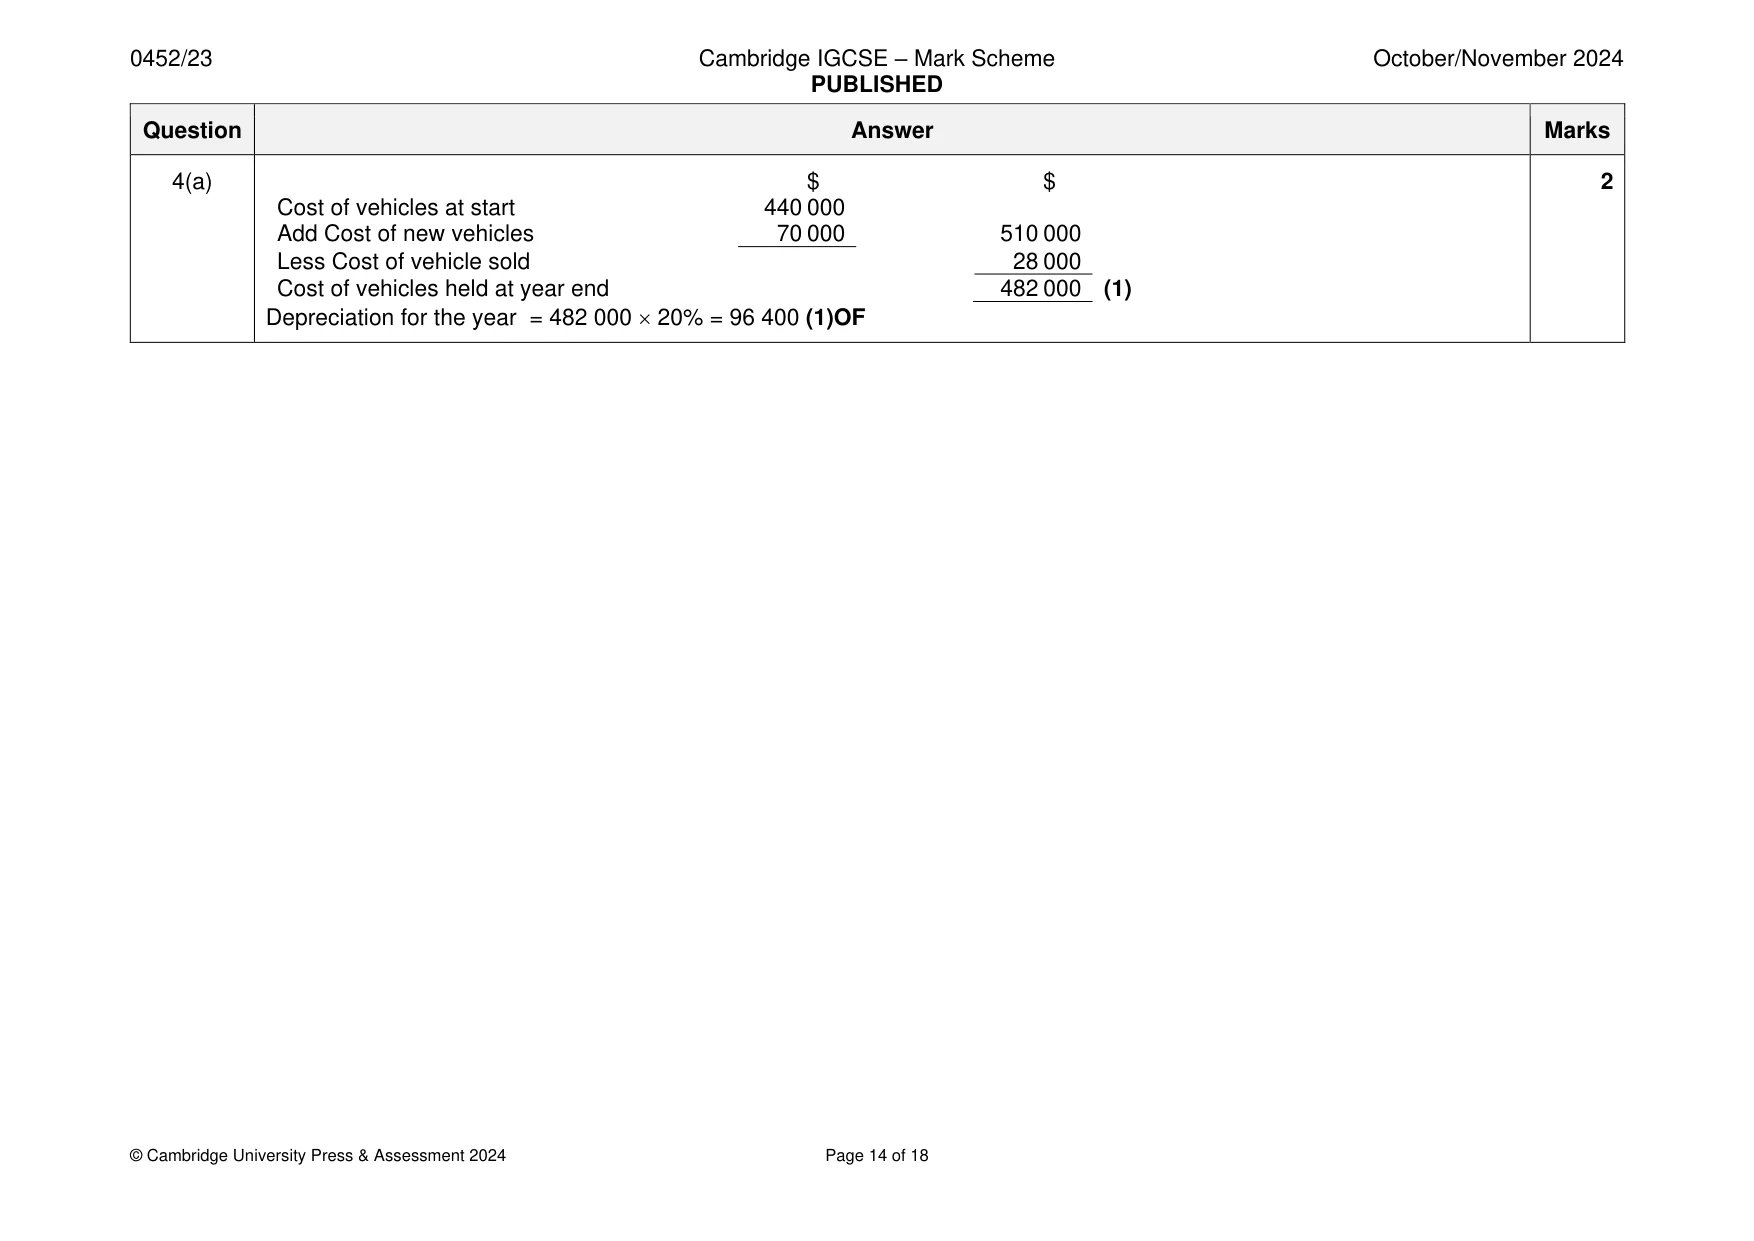
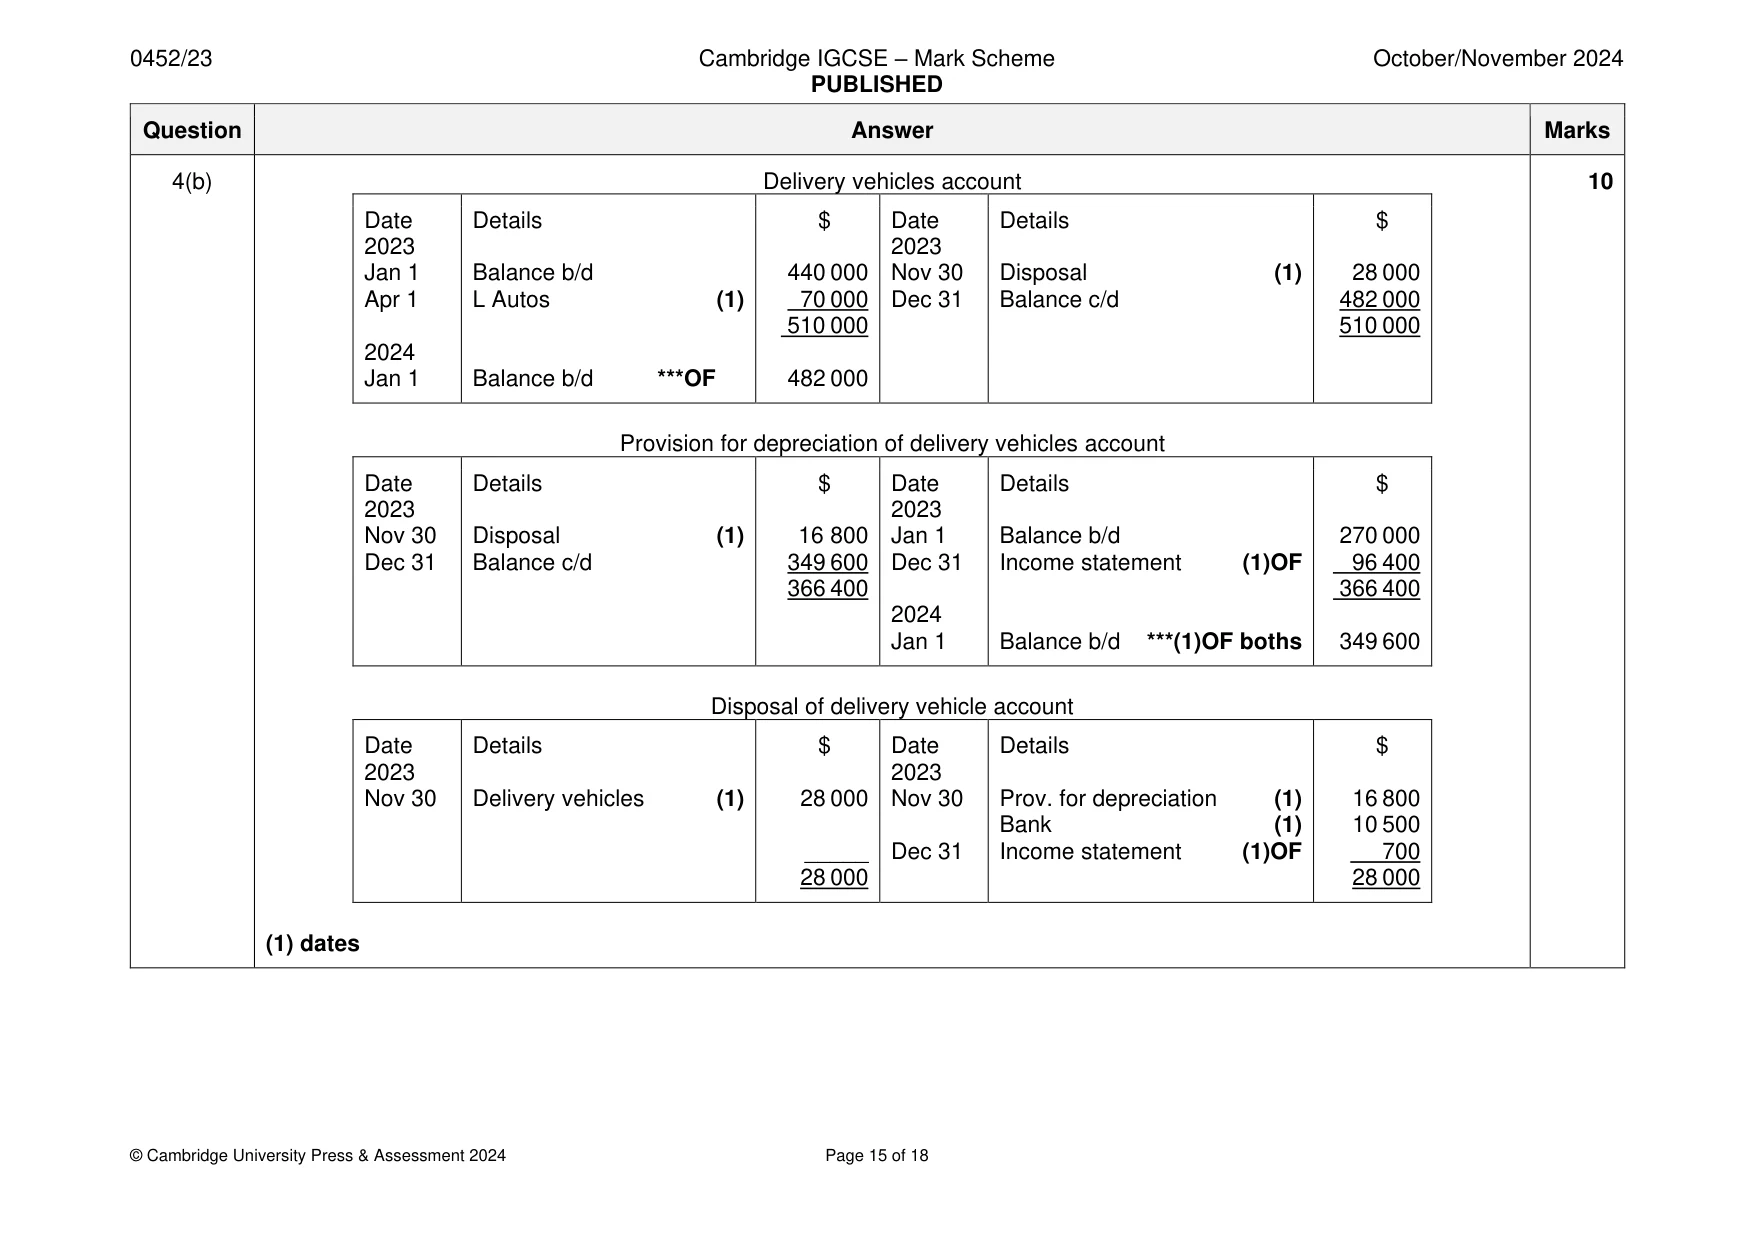
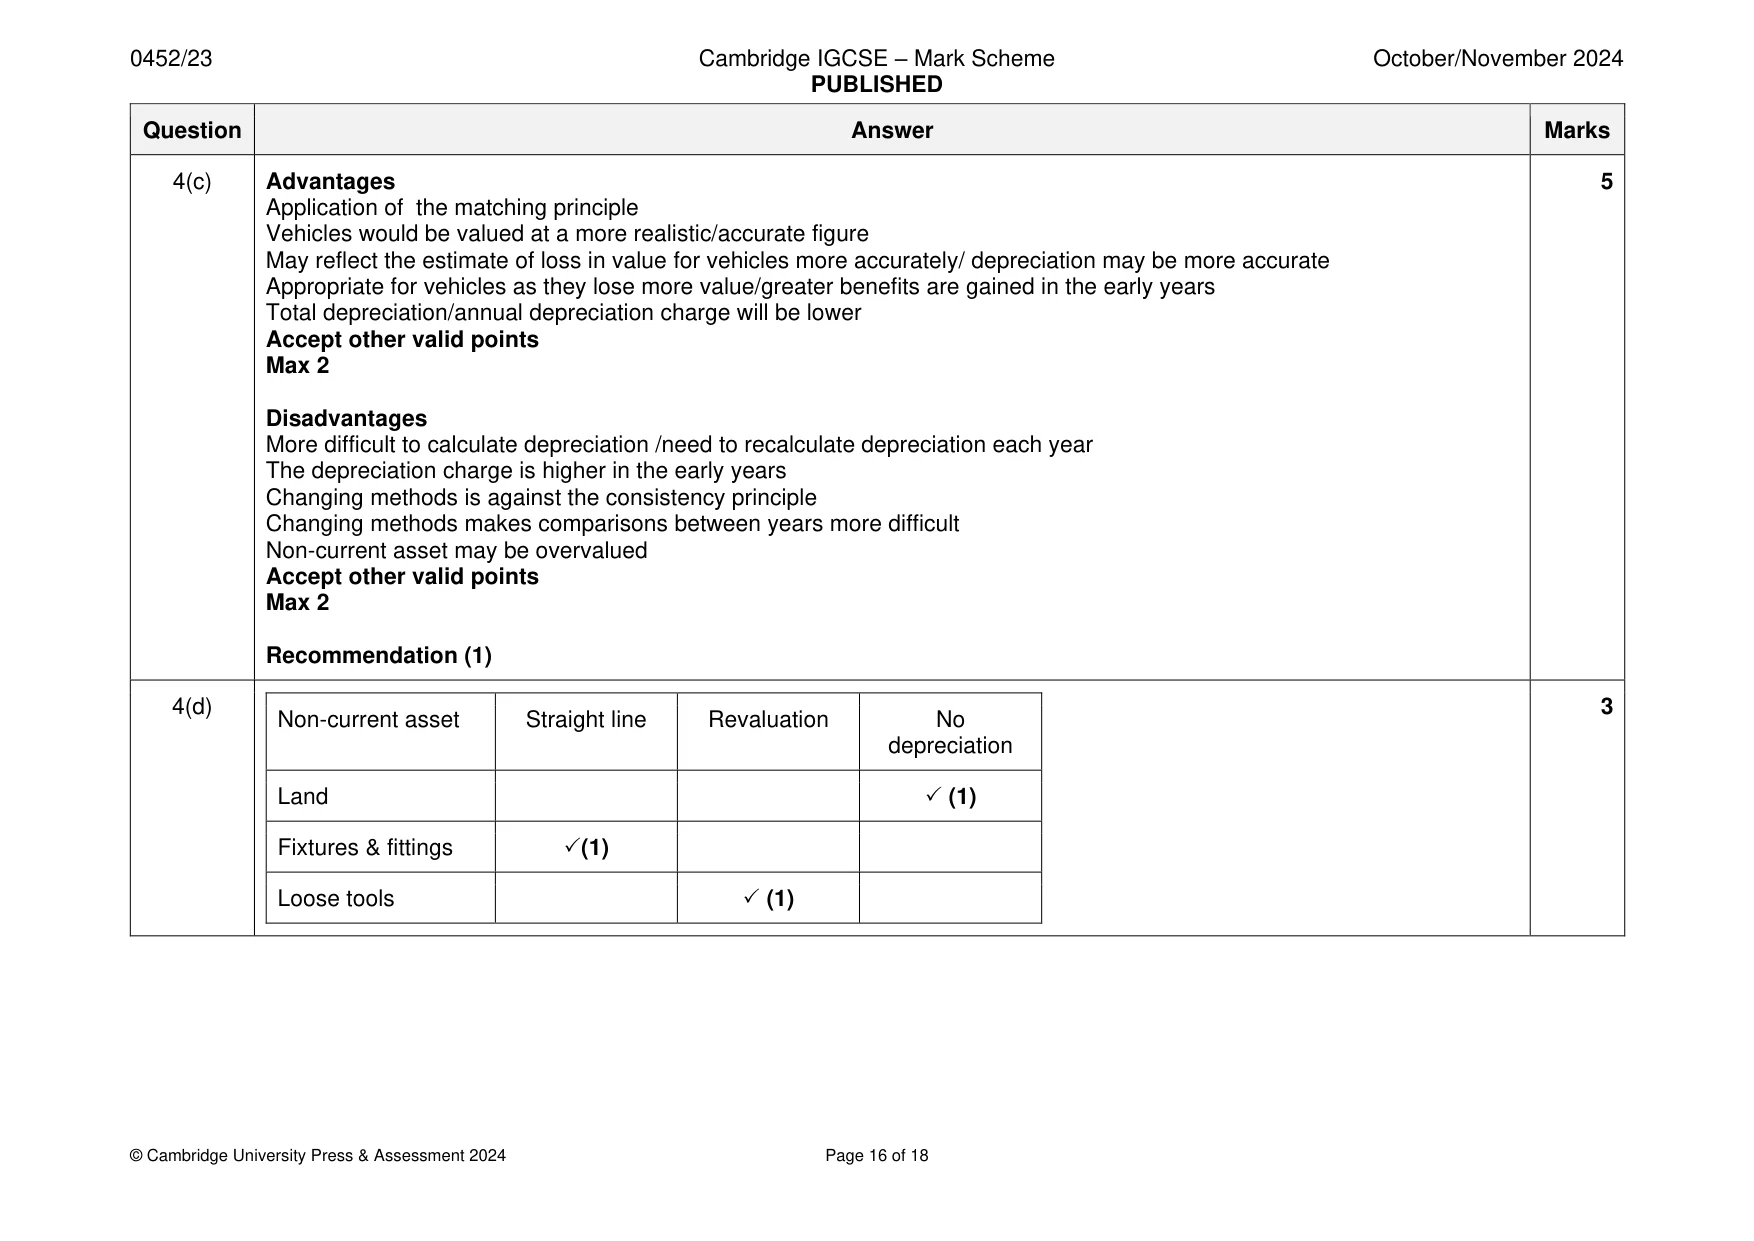
Mark scheme: 4(a) $ $ 2 Cost of vehicles at start 440 000 Add Cost of new vehicles 70 000 510 000 Less Cost of vehicle sold 28 000 Cost of vehicles held at year end 482 000 (1) Depreciation for the year = 482 000 20% = 96 400 (1)OF 4(b) Delivery vehicles account 10 Date Details $ Date Details $ 2023 2023 Jan 1 Balance b/d 440 000 Nov 30 Disposal (1) 28 000 Apr 1 L Autos (1) 70 000 Dec 31 Balance c/d 482 000 510 000 510 000 2024 Jan 1 Balance b/d ***OF 482 000 Provision for depreciation of delivery vehicles account Date Details $ Date Details $ 2023 2023 Nov 30 Disposal (1) 16 800 Jan 1 Balance b/d 270 000 Dec 31 Balance c/d 349 600 Dec 31 Income statement (1)OF 96 400 366 400 366 400 2024 Jan 1 Balance b/d ***(1)OF boths 349 600 Disposal of delivery vehicle account Date Details $ Date Details $ 2023 2023 Nov 30 Delivery vehicles (1) 28 000 Nov 30 Prov. for depreciation (1) 16 800 Bank (1) 10 500 _____ Dec 31 Income statement (1)OF 700 28 000 28 000 (1) dates 4(c) Advantages 5 Application of the matching principle Vehicles would be valued at a more realistic/accurate figure May reflect the estimate of loss in value for vehicles more accurately/ depreciation may be more accurate Appropriate for vehicles as they lose more value/greater benefits are gained in the early years Total depreciation/annual depreciation charge will be lower Accept other valid points Max 2 Disadvantages More difficult to calculate depreciation /need to recalculate depreciation each year The depreciation charge is higher in the early years Changing methods is against the consistency principle Changing methods makes comparisons between years more difficult Non-current asset may be overvalued Accept other valid points Max 2 Recommendation (1) 4(d) 3 Non-current asset Straight line Revaluation No depreciation Land (1) Fixtures & fittings (1) Loose tools (1)
More questions on Accounting for depreciation and disposal of non-current assets
Q5 · The following information was provided by G Limited, a manufacturing company, for the…
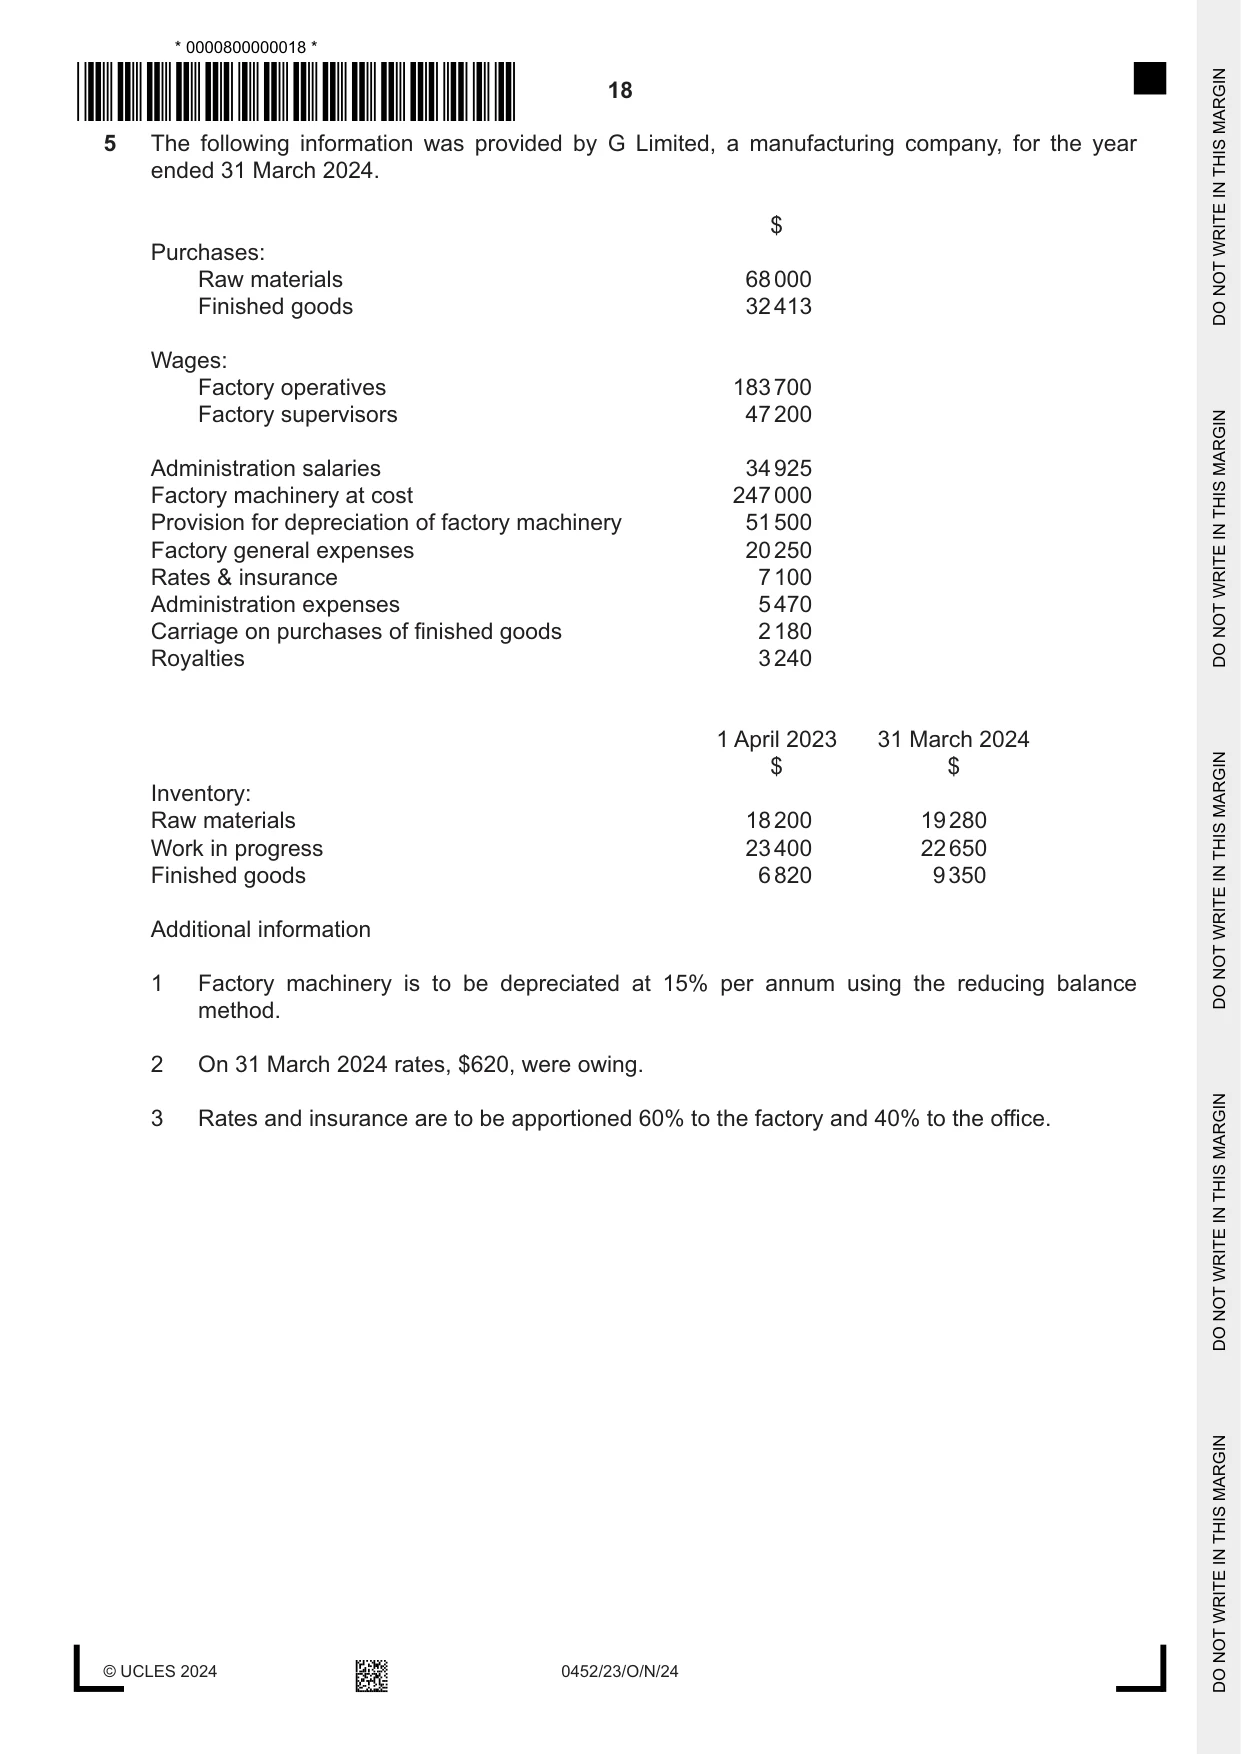
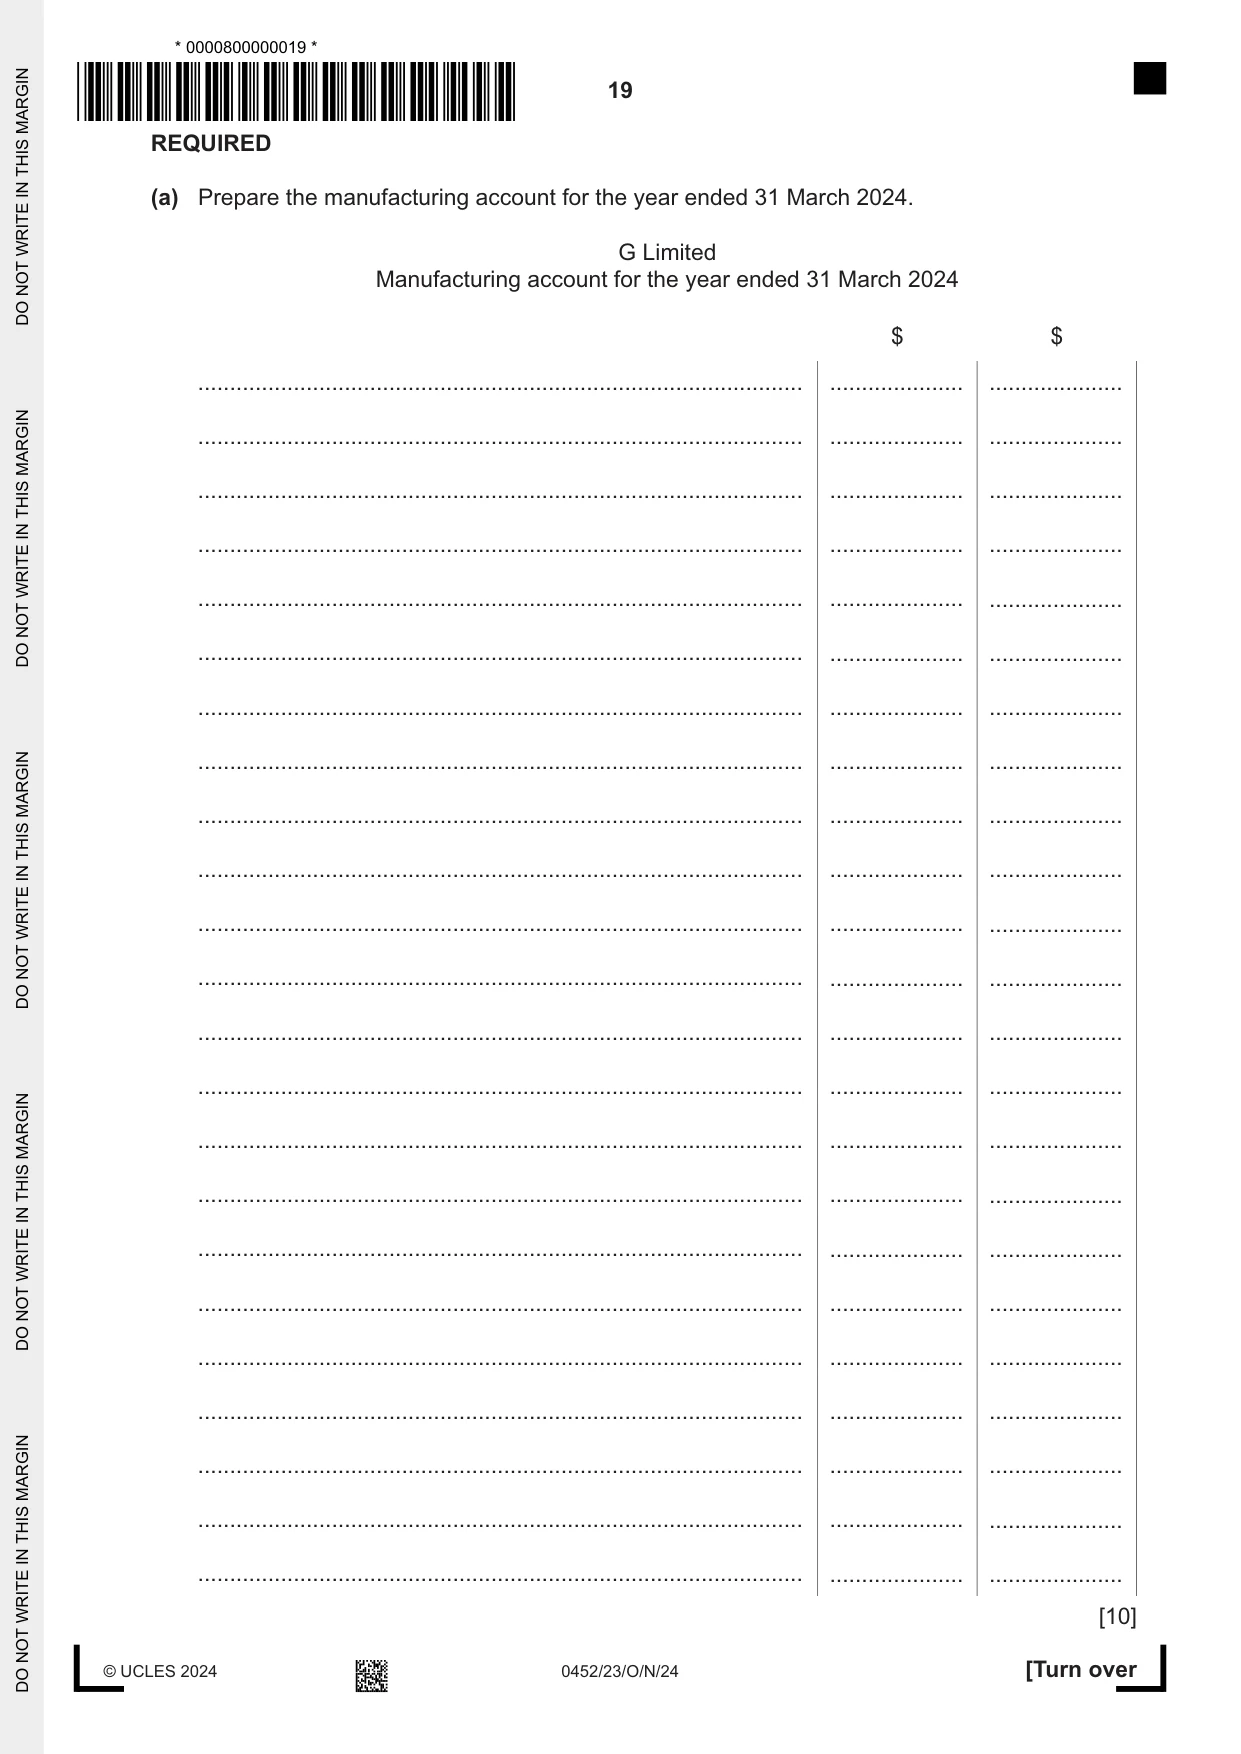
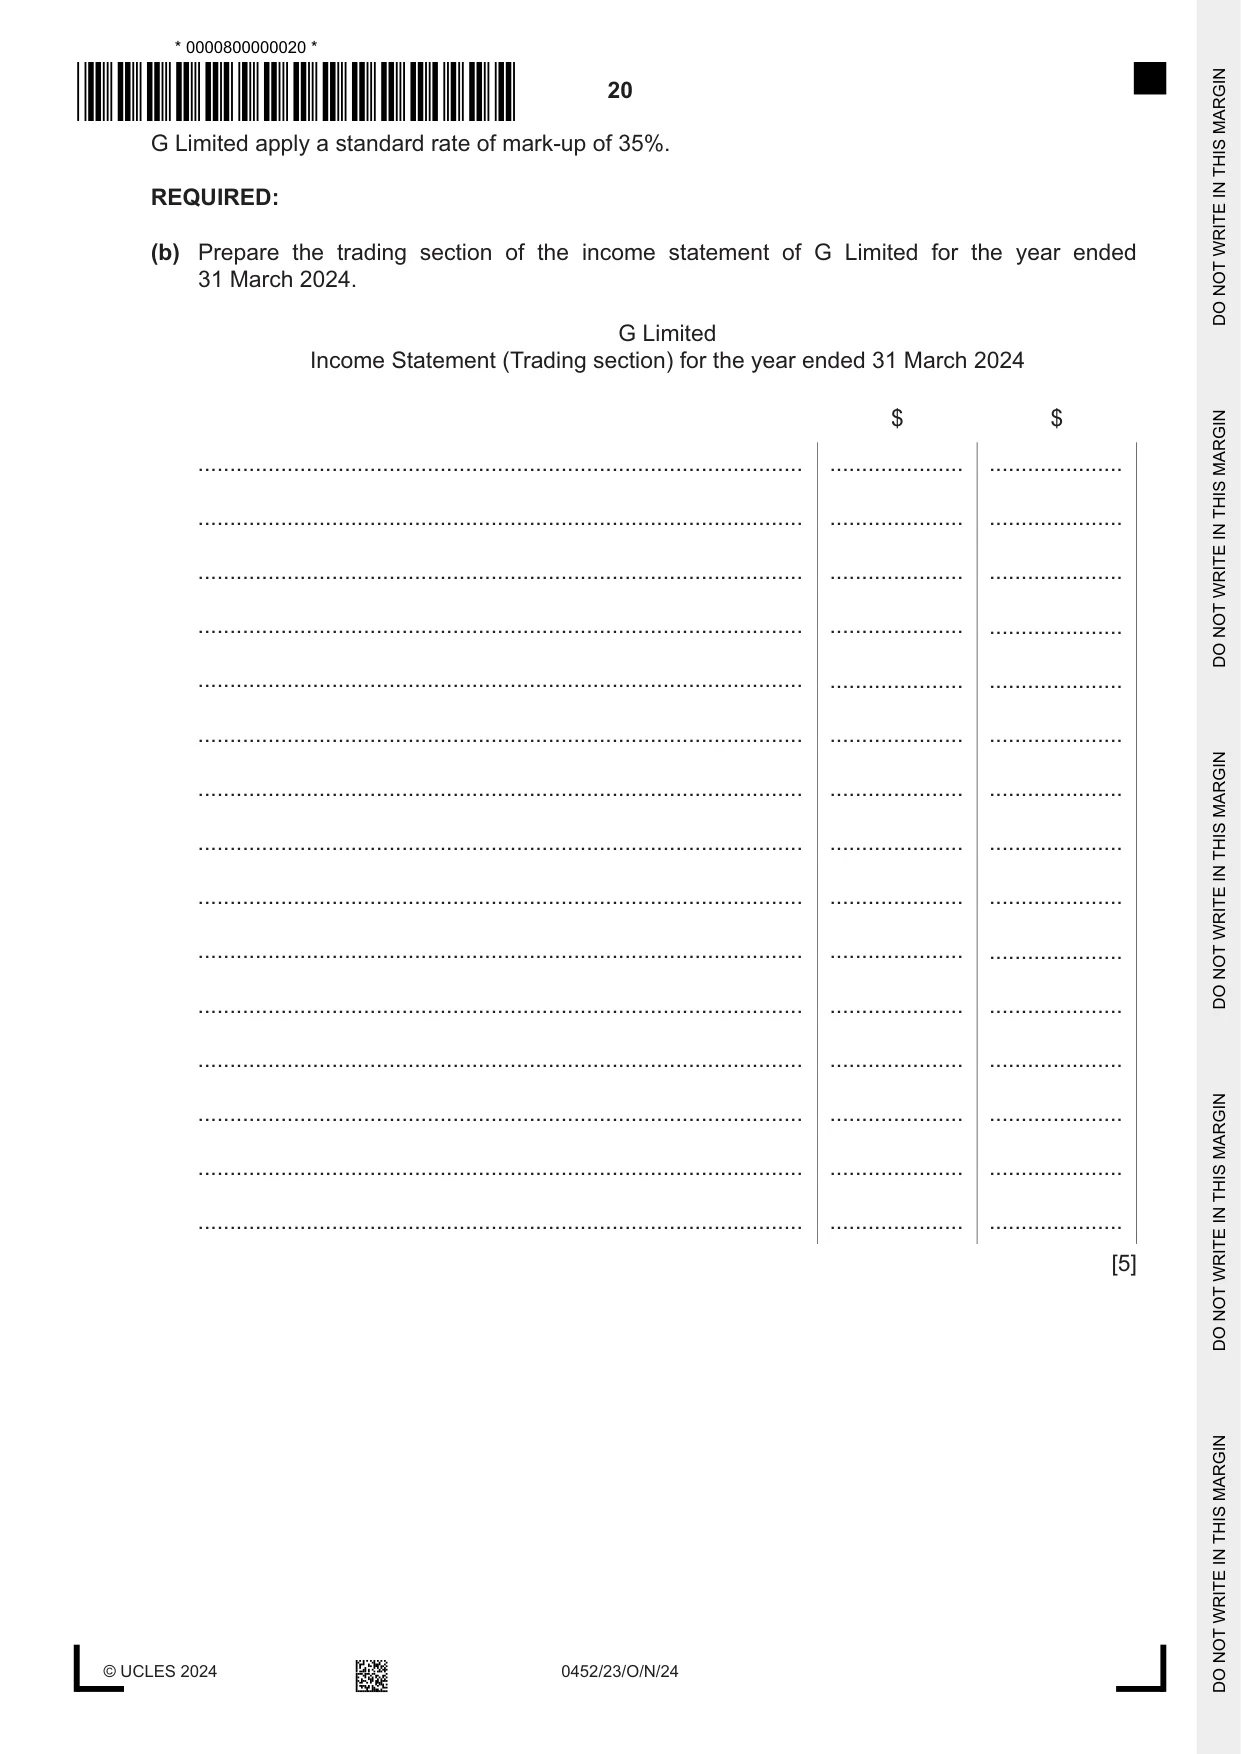
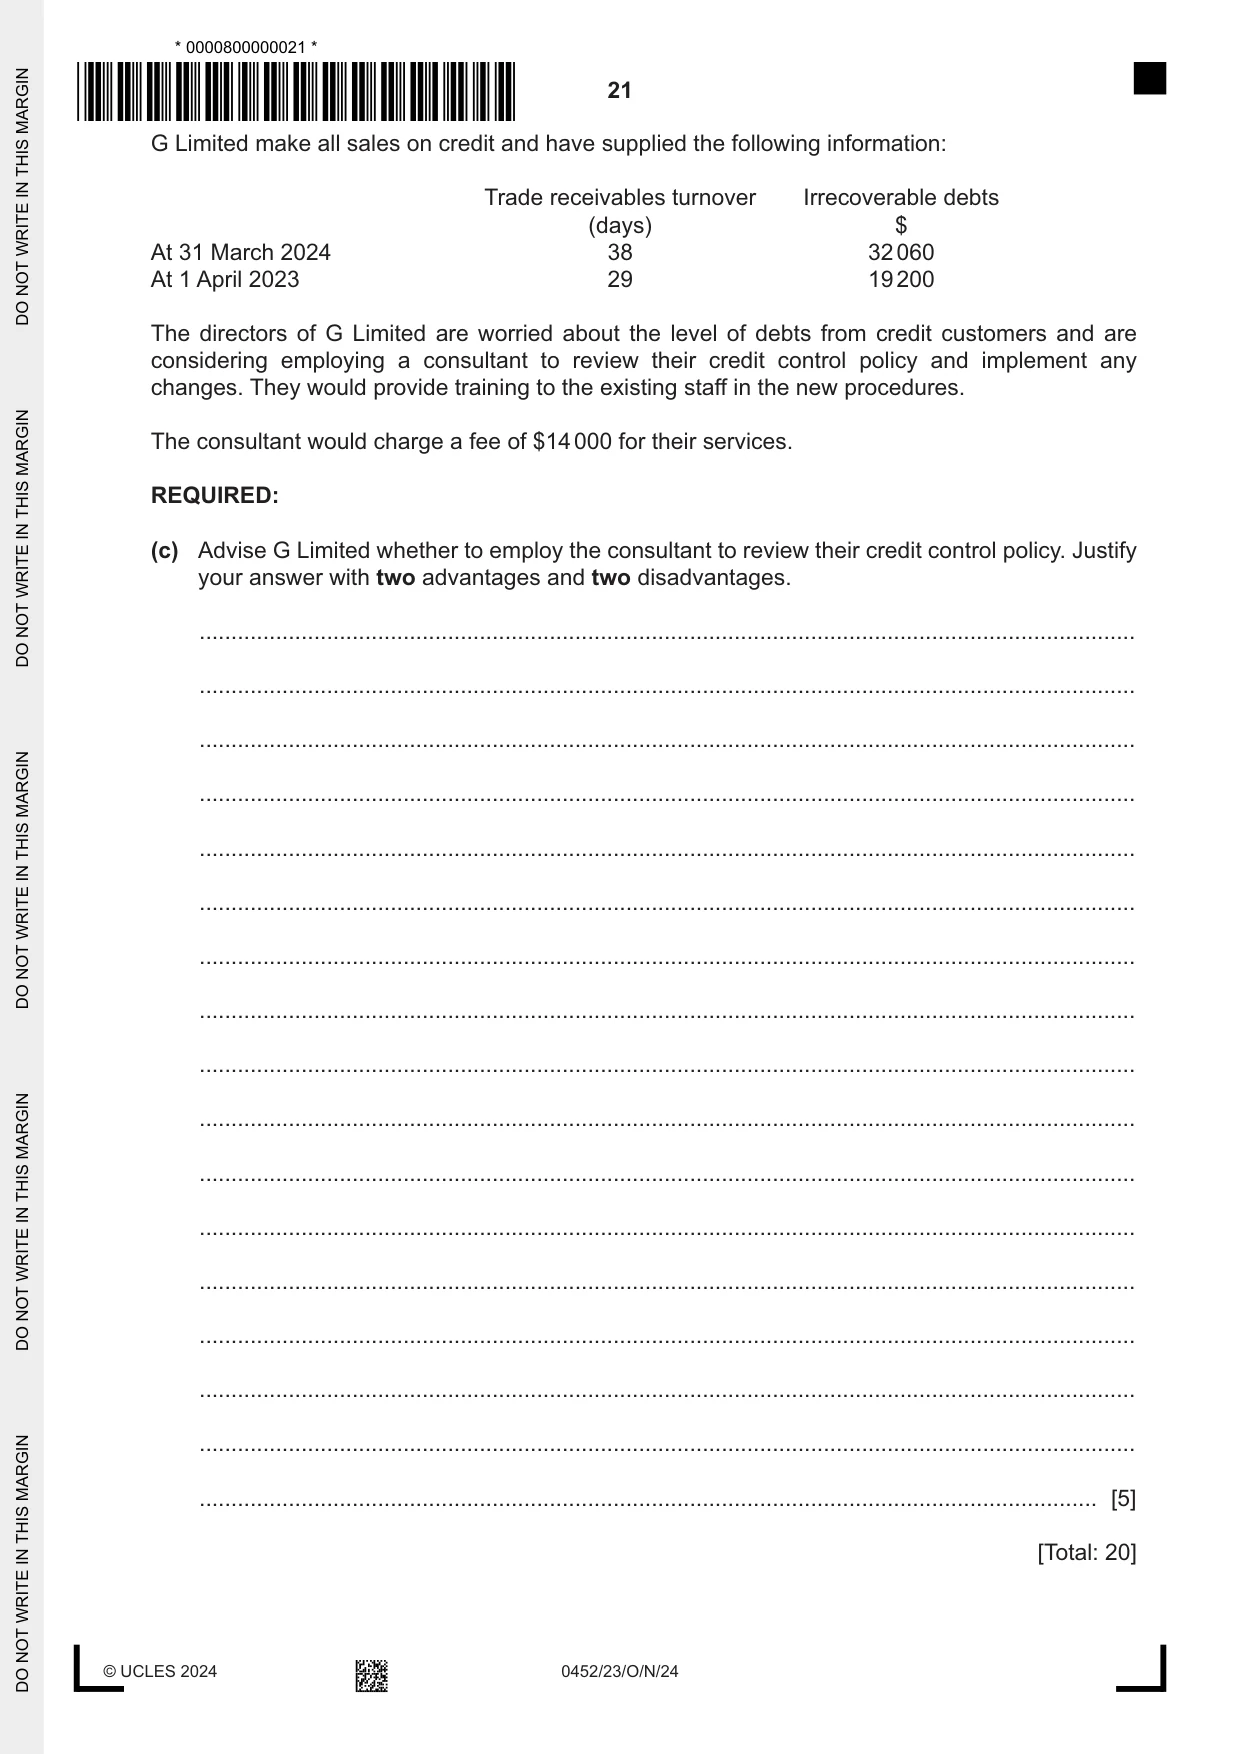
5 The following information was provided by G Limited, a manufacturing company, for the year ended 31 March 2024. $ Purchases: Raw materials 68 000 Finished goods 32 413 Wages: Factory operatives 183 700 Factory supervisors 47 200 Administration salaries 34 925 Factory machinery at cost 247 000 Provision for depreciation of factory machinery 51 500 Factory general expenses 20 250 Rates & insurance 7 100 Administration expenses 5 470 Carriage on purchases of finished goods 2 180 Royalties 3 240 1 April 2023 31 March 2024 $ $ Inventory: Raw materials 18 200 19 280 Work in progress 23 400 22 650 Finished goods 6 820 9 350 Additional information 1 Factory machinery is to be depreciated at 15% per annum using the reducing balance method. 2 On 31 March 2024 rates, $620, were owing. 3 Rates and insurance are to be apportioned 60% to the factory and 40% to the office. REQUIRED (a) Prepare the manufacturing account for the year ended 31 M G Limited Manufacturing account for the year ended ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... G Limited apply a standard rate of mark-up of 35%. REQUIRED: (b) Prepare the trading section of the income statement of G Limited for the year ended 31 March 2024. G Limited Income Statement (Trading section) for the year ended 31 March 2024 $ $ ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... ............................................................................................... ..................... ..................... [5]
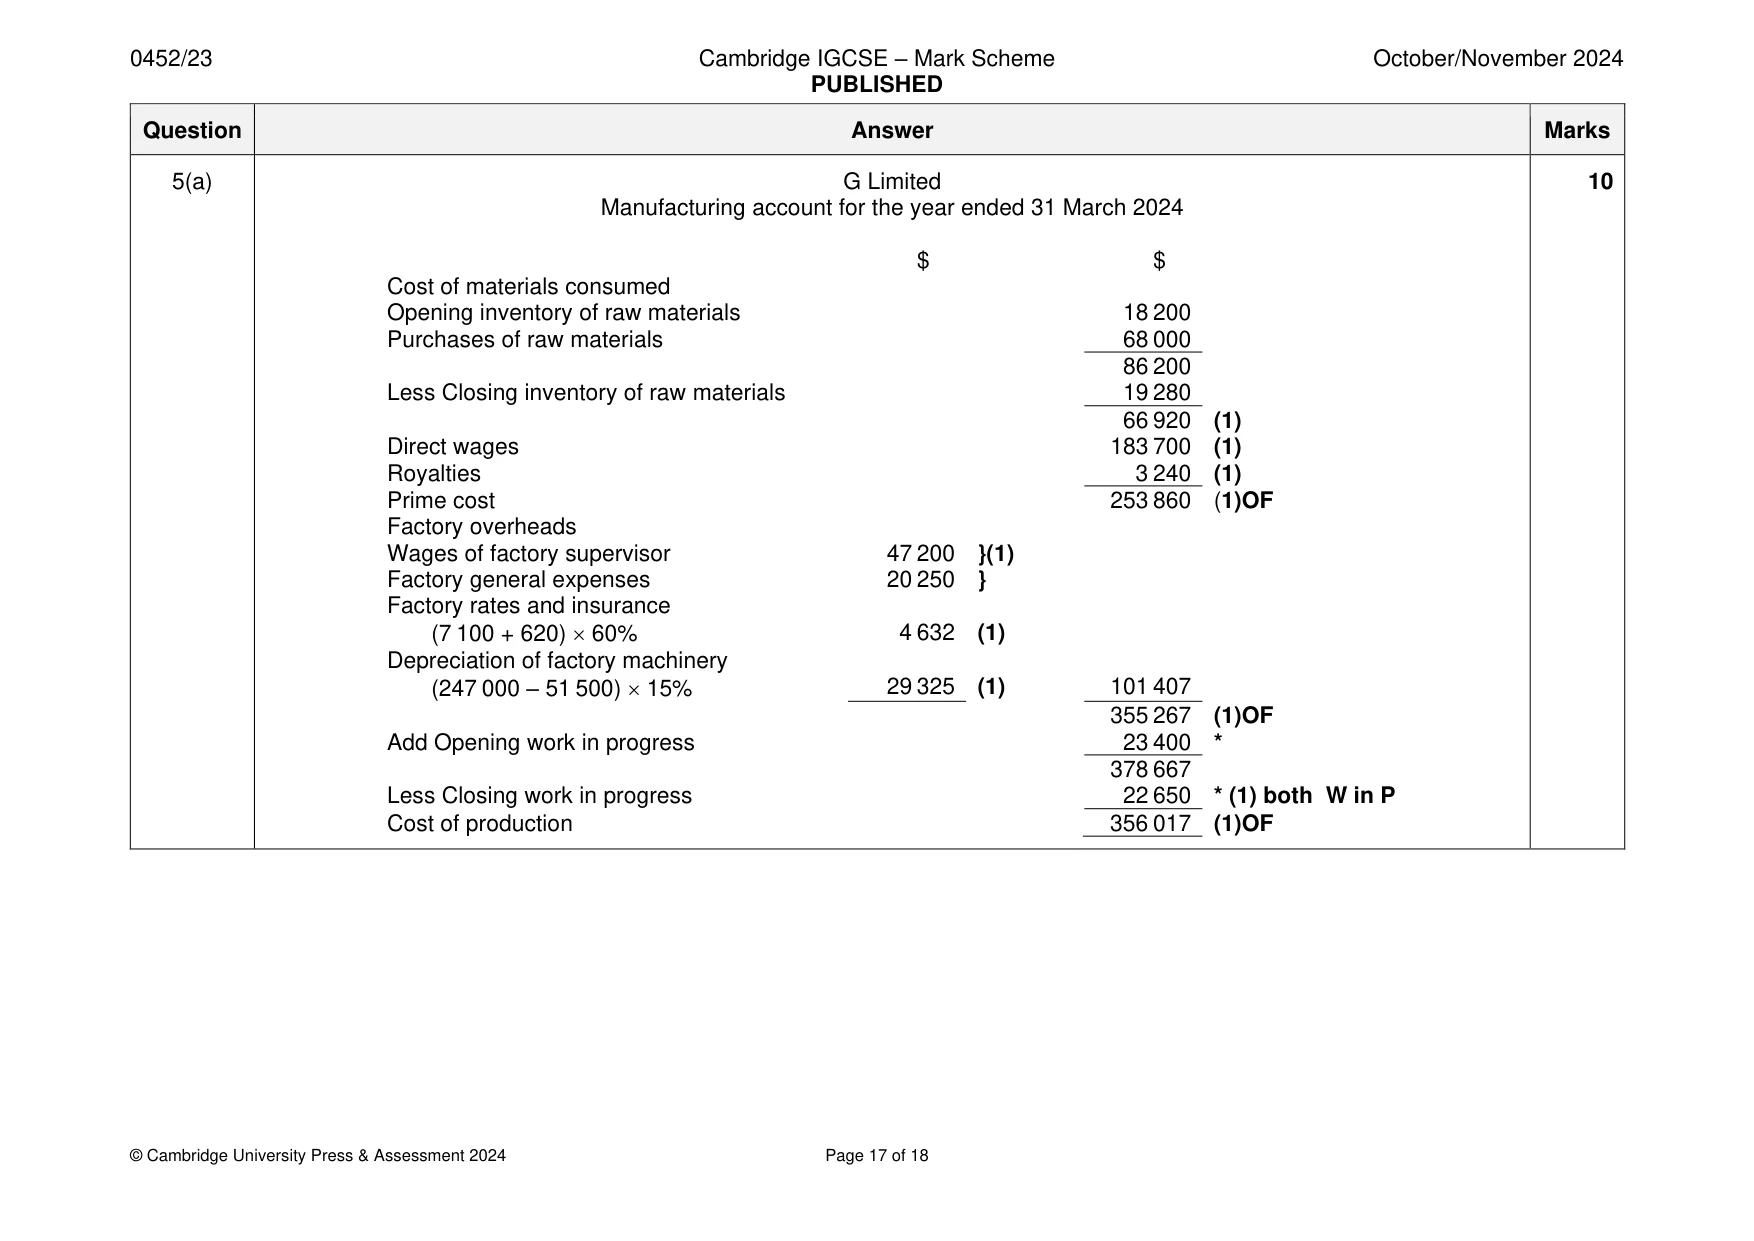
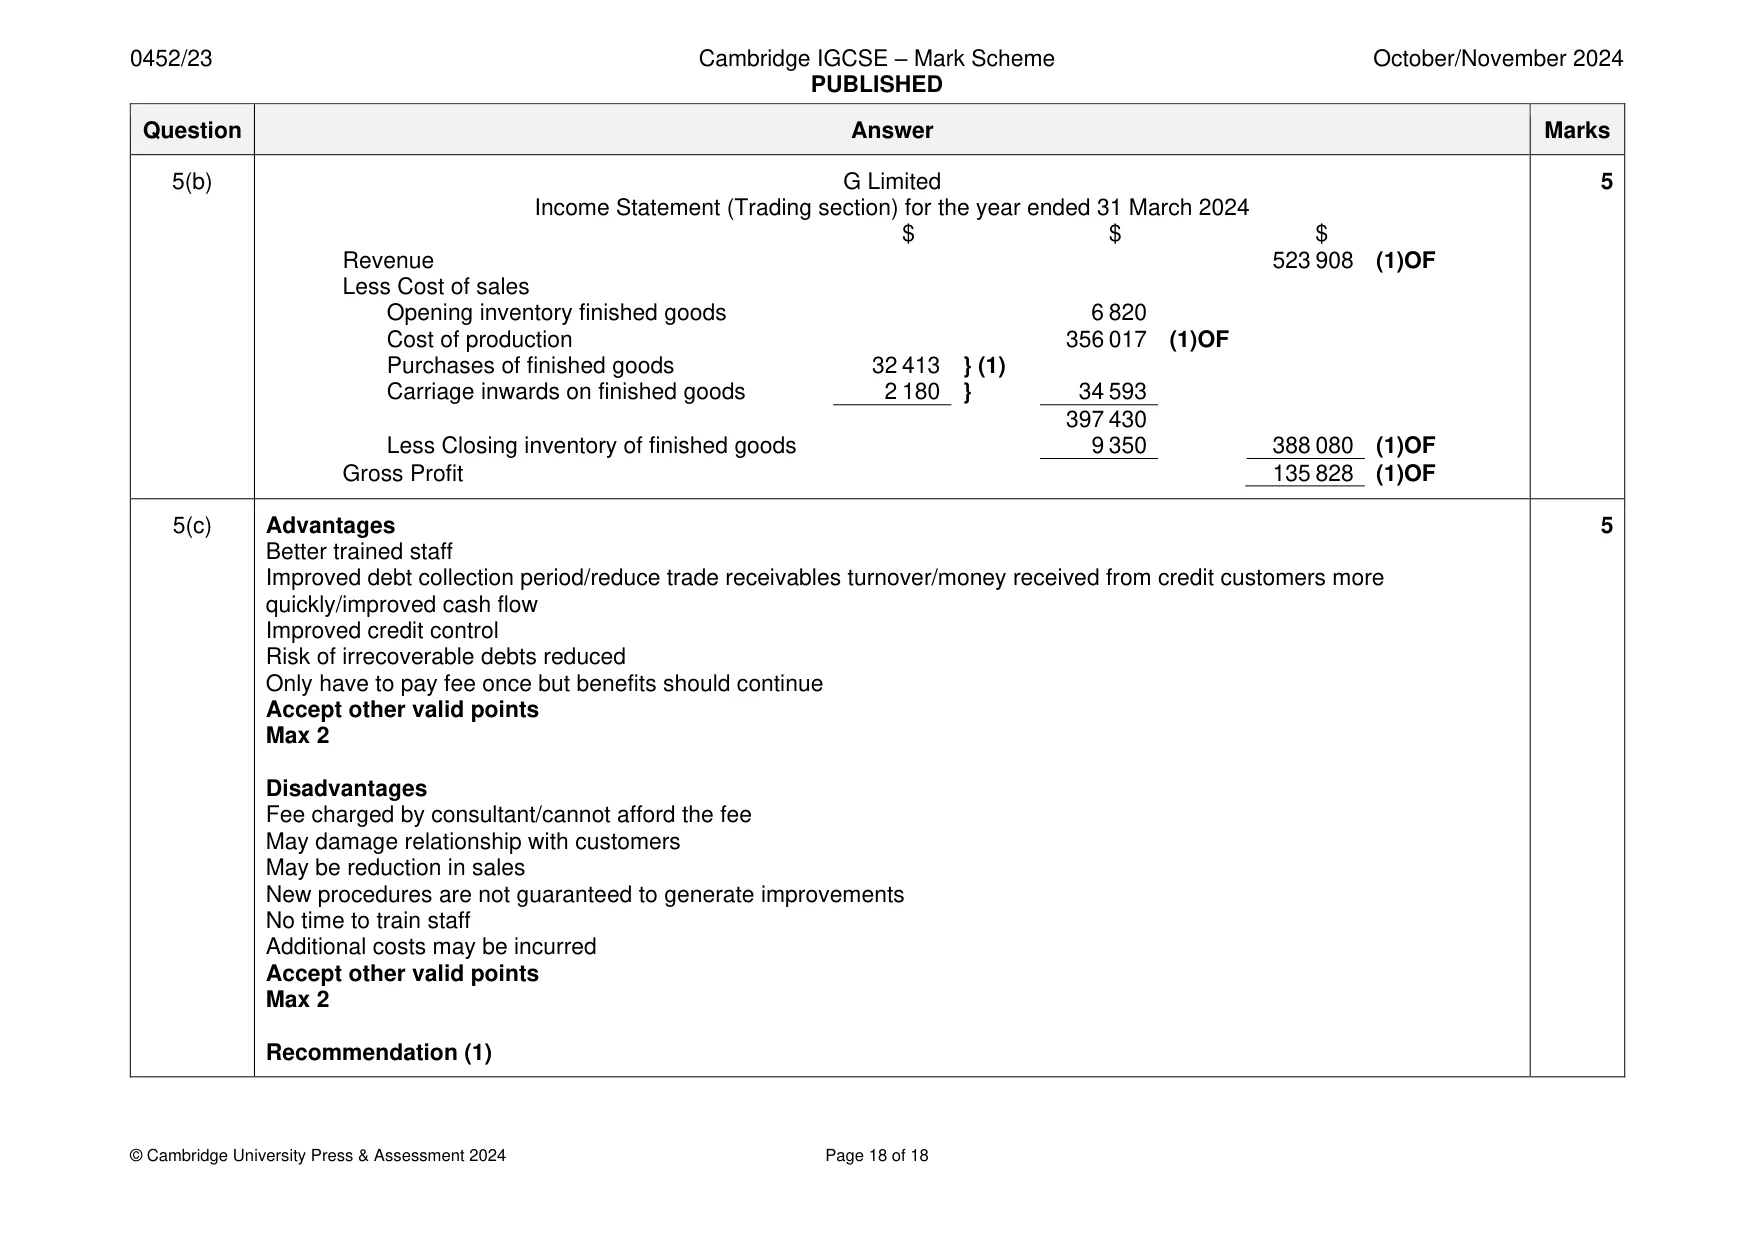
Mark scheme: 5(a) G Limited 10 Manufacturing account for the year ended 31 March 2024 $ $ Cost of materials consumed Opening inventory of raw materials 18 200 Purchases of raw materials 68 000 86 200 Less Closing inventory of raw materials 19 280 66 920 (1) Direct wages 183 700 (1) Royalties 3 240 (1) Prime cost 253 860 (1)OF Factory overheads Wages of factory supervisor 47 200 }(1) Factory general expenses 20 250 } Factory rates and insurance (7 100 + 620) 60% 4 632 (1) Depreciation of factory machinery (247 000 – 51 500) 15% 29 325 (1) 101 407 355 267 (1)OF Add Opening work in progress 23 400 * 378 667 Less Closing work in progress 22 650 * (1) both W in P Cost of production 356 017 (1)OF 5(b) G Limited 5 Income Statement (Trading section) for the year ended 31 March 2024 $ $ $ Revenue 523 908 (1)OF Less Cost of sales Opening inventory finished goods 6 820 Cost of production 356 017 (1)OF Purchases of finished goods 32 413 } (1) Carriage inwards on finished goods 2 180 } 34 593 397 430 Less Closing inventory of finished goods 9 350 388 080 (1)OF Gross Profit 135 828 (1)OF 5(c) Advantages 5 Better trained staff Improved debt collection period/reduce trade receivables turnover/money received from credit customers more quickly/improved cash flow Improved credit control Risk of irrecoverable debts reduced Only have to pay fee once but benefits should continue Accept other valid points Max 2 Disadvantages Fee charged by consultant/cannot afford the fee May damage relationship with customers May be reduction in sales New procedures are not guaranteed to generate improvements No time to train staff Additional costs may be incurred Accept other valid points Max 2 Recommendation (1)
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2024 Oct/Nov, Paper 2 · Variant 3. A higher threshold means an easier paper — the bar moves with how the cohort did.