Cambridge A Level Accounting 9706 — 2007 Oct/Nov Paper 1 · Variant 1
9706/11/O/N/07 · 30 marks · ≈34 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
Mark scheme2 pages
Answers below. Sit the paper first if you are practising.
Paper as text
Question paper, page 1
This document consists of 11 printed pages and 1 blank page. IB07 11_9706_01/3RP © UCLES 2007 [Turn over *0390007796* UNIVERSITY OF CAMBRIDGE INTERNATIONAL EXAMINATIONS General Certificate of Education Advanced Subsidiary Level and Advanced Level ACCOUNTING 9706/01 Paper 1 Multiple Choice October/November 2007 1 hour Additional Materials: Multiple Choice Answer Sheet Soft clean eraser Soft pencil (type B or HB is recommended) READ THESE INSTRUCTIONS FIRST Write in soft pencil. Do not use staples, paper clips, highlighters, glue or correction fluid. Write your name, Centre number and candidate number on the Answer Sheet in the spaces provided unless this has been done for you. There are thirty questions on this paper. Answer all questions. For each question there are four possible answers A, B, C and D. Choose the one you consider correct and record your choice in soft pencil on the separate Answer Sheet. Read the instructions on the Answer Sheet very carefully. Each correct answer will score one mark. A mark will not be deducted for a wrong answer. Any rough working should be done in this booklet. Calculators may be used.
Question paper, page 2
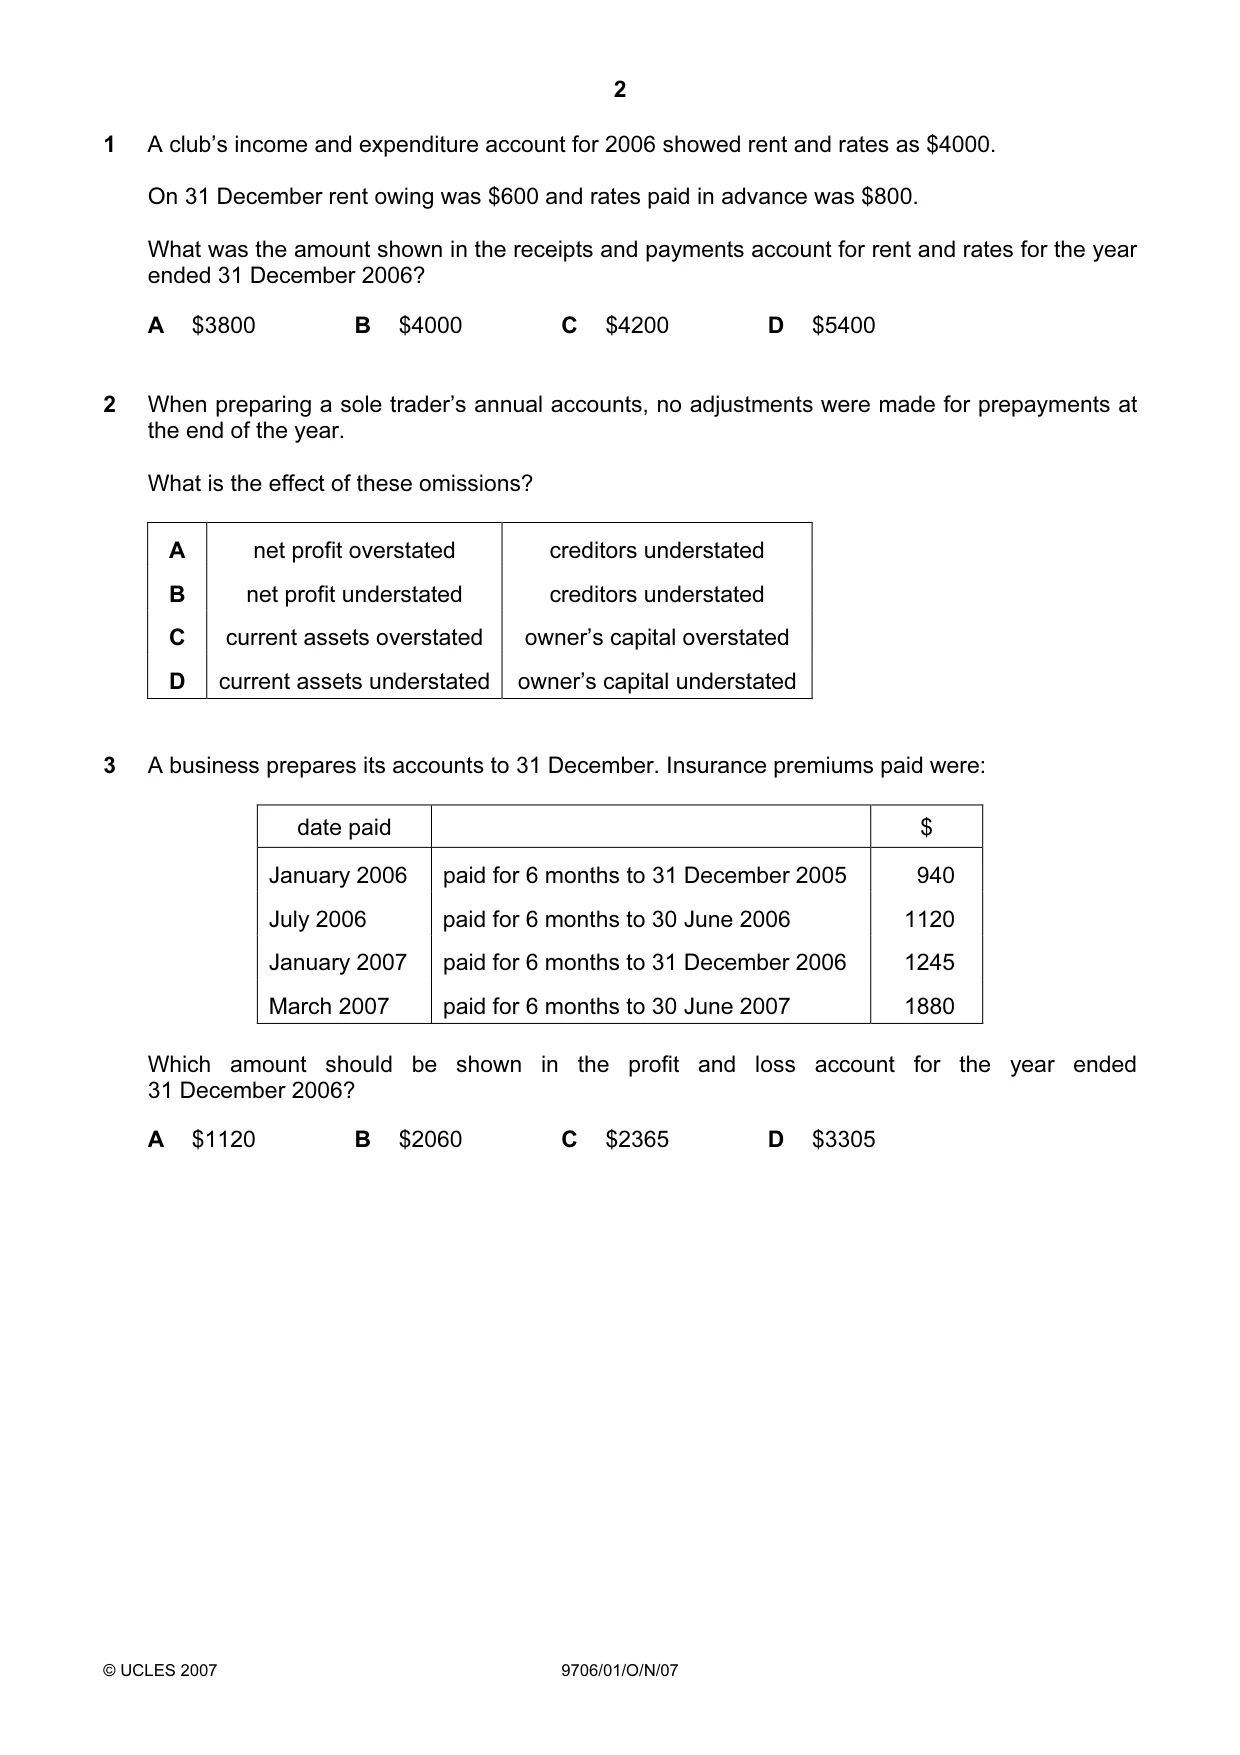
2 © UCLES 2007 9706/01/O/N/07 1 A club’s income and expenditure account for 2006 showed rent and rates as $4000. On 31 December rent owing was $600 and rates paid in advance was $800. What was the amount shown in the receipts and payments account for rent and rates for the year ended 31 December 2006? A $3800 B $4000 C $4200 D $5400 2 When preparing a sole trader’s annual accounts, no adjustments were made for prepayments at the end of the year. What is the effect of these omissions? A net profit overstated creditors understated B net profit understated creditors understated C current assets overstated owner’s capital overstated D current assets understated owner’s capital understated 3 A business prepares its accounts to 31 December. Insurance premiums paid were: date paid $ January 2006 paid for 6 months to 31 December 2005 940 July 2006 paid for 6 months to 30 June 2006 1120 January 2007 paid for 6 months to 31 December 2006 1245 March 2007 paid for 6 months to 30 June 2007 1880 Which amount should be shown in the profit and loss account for the year ended 31 December 2006? A $1120 B $2060 C $2365 D $3305
Question paper, page 3
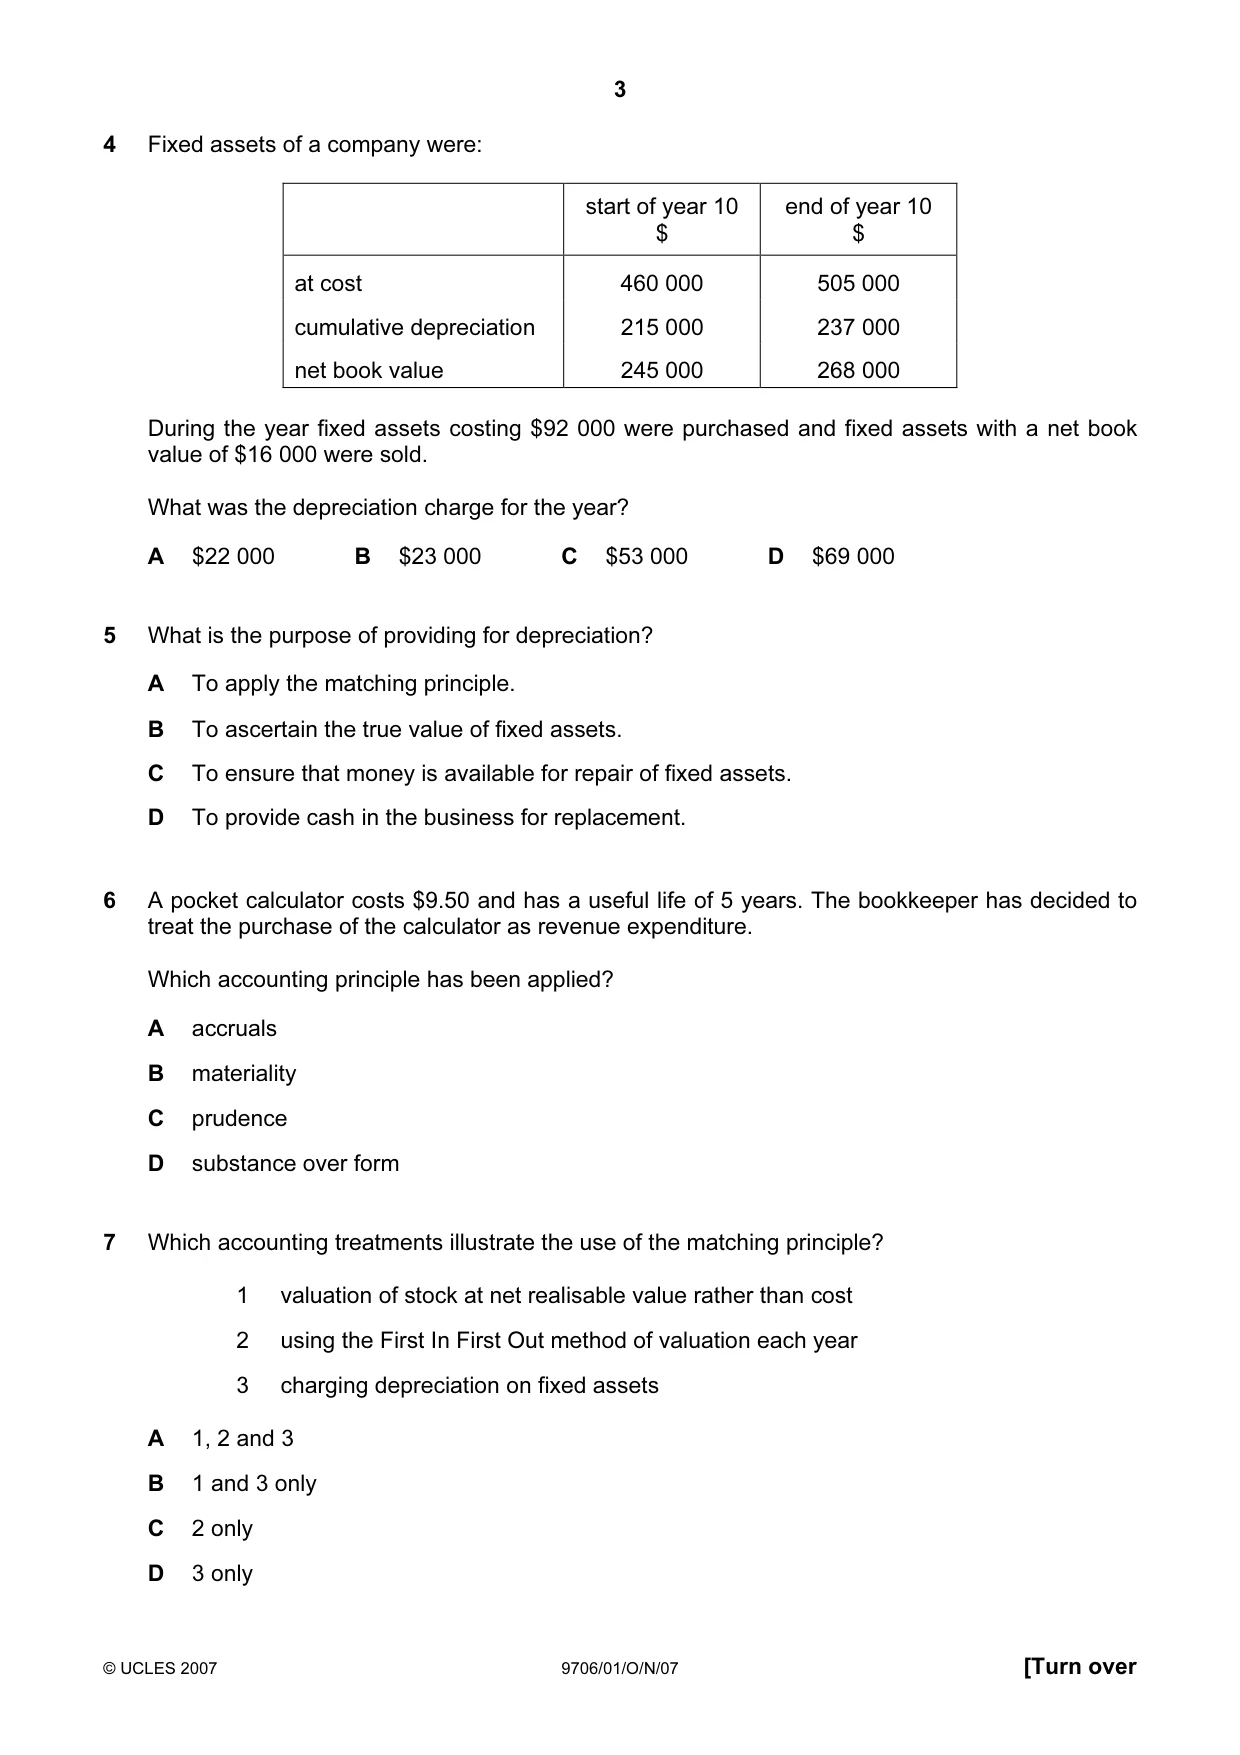
3 © UCLES 2007 9706/01/O/N/07 [Turn over 4 Fixed assets of a company were: start of year 10 $ end of year 10 $ at cost 460 000 505 000 cumulative depreciation 215 000 237 000 net book value 245 000 268 000 During the year fixed assets costing $92 000 were purchased and fixed assets with a net book value of $16 000 were sold. What was the depreciation charge for the year? A $22 000 B $23 000 C $53 000 D $69 000 5 What is the purpose of providing for depreciation? A To apply the matching principle. B To ascertain the true value of fixed assets. C To ensure that money is available for repair of fixed assets. D To provide cash in the business for replacement. 6 A pocket calculator costs $9.50 and has a useful life of 5 years. The bookkeeper has decided to treat the purchase of the calculator as revenue expenditure. Which accounting principle has been applied? A accruals B materiality C prudence D substance over form 7 Which accounting treatments illustrate the use of the matching principle? 1 valuation of stock at net realisable value rather than cost 2 using the First In First Out method of valuation each year 3 charging depreciation on fixed assets A 1, 2 and 3 B 1 and 3 only C 2 only D 3 only
Question paper, page 4
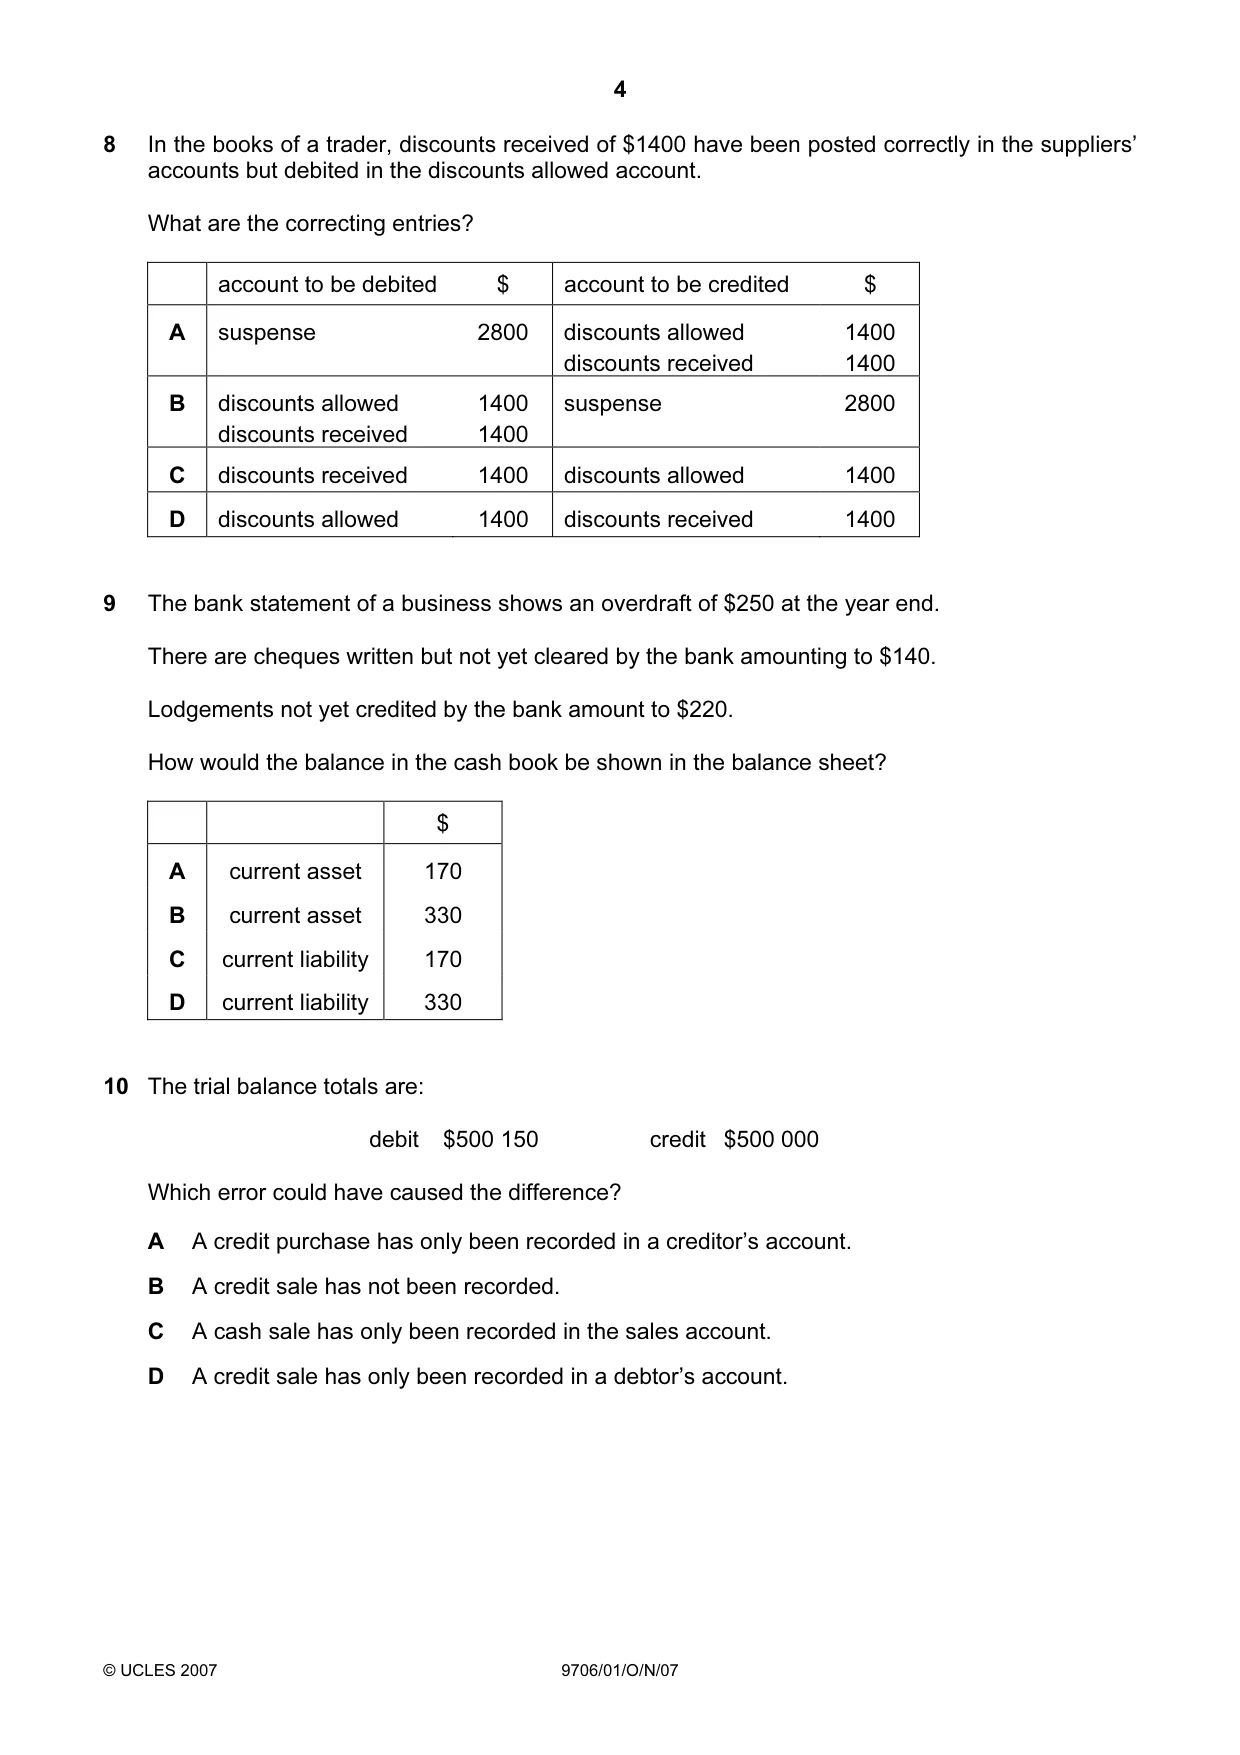
4 © UCLES 2007 9706/01/O/N/07 8 In the books of a trader, discounts received of $1400 have been posted correctly in the suppliers’ accounts but debited in the discounts allowed account. What are the correcting entries? account to be debited $ account to be credited $ A suspense 2800 discounts allowed discounts received 1400 1400 B discounts allowed discounts received 1400 1400 suspense 2800 C discounts received 1400 discounts allowed 1400 D discounts allowed 1400 discounts received 1400 9 The bank statement of a business shows an overdraft of $250 at the year end. There are cheques written but not yet cleared by the bank amounting to $140. Lodgements not yet credited by the bank amount to $220. How would the balance in the cash book be shown in the balance sheet? $ A current asset 170 B current asset 330 C current liability 170 D current liability 330 10 The trial balance totals are: debit $500 150 credit $500 000 Which error could have caused the difference? A A credit purchase has only been recorded in a creditor’s account. B A credit sale has not been recorded. C A cash sale has only been recorded in the sales account. D A credit sale has only been recorded in a debtor’s account.
Question paper, page 5
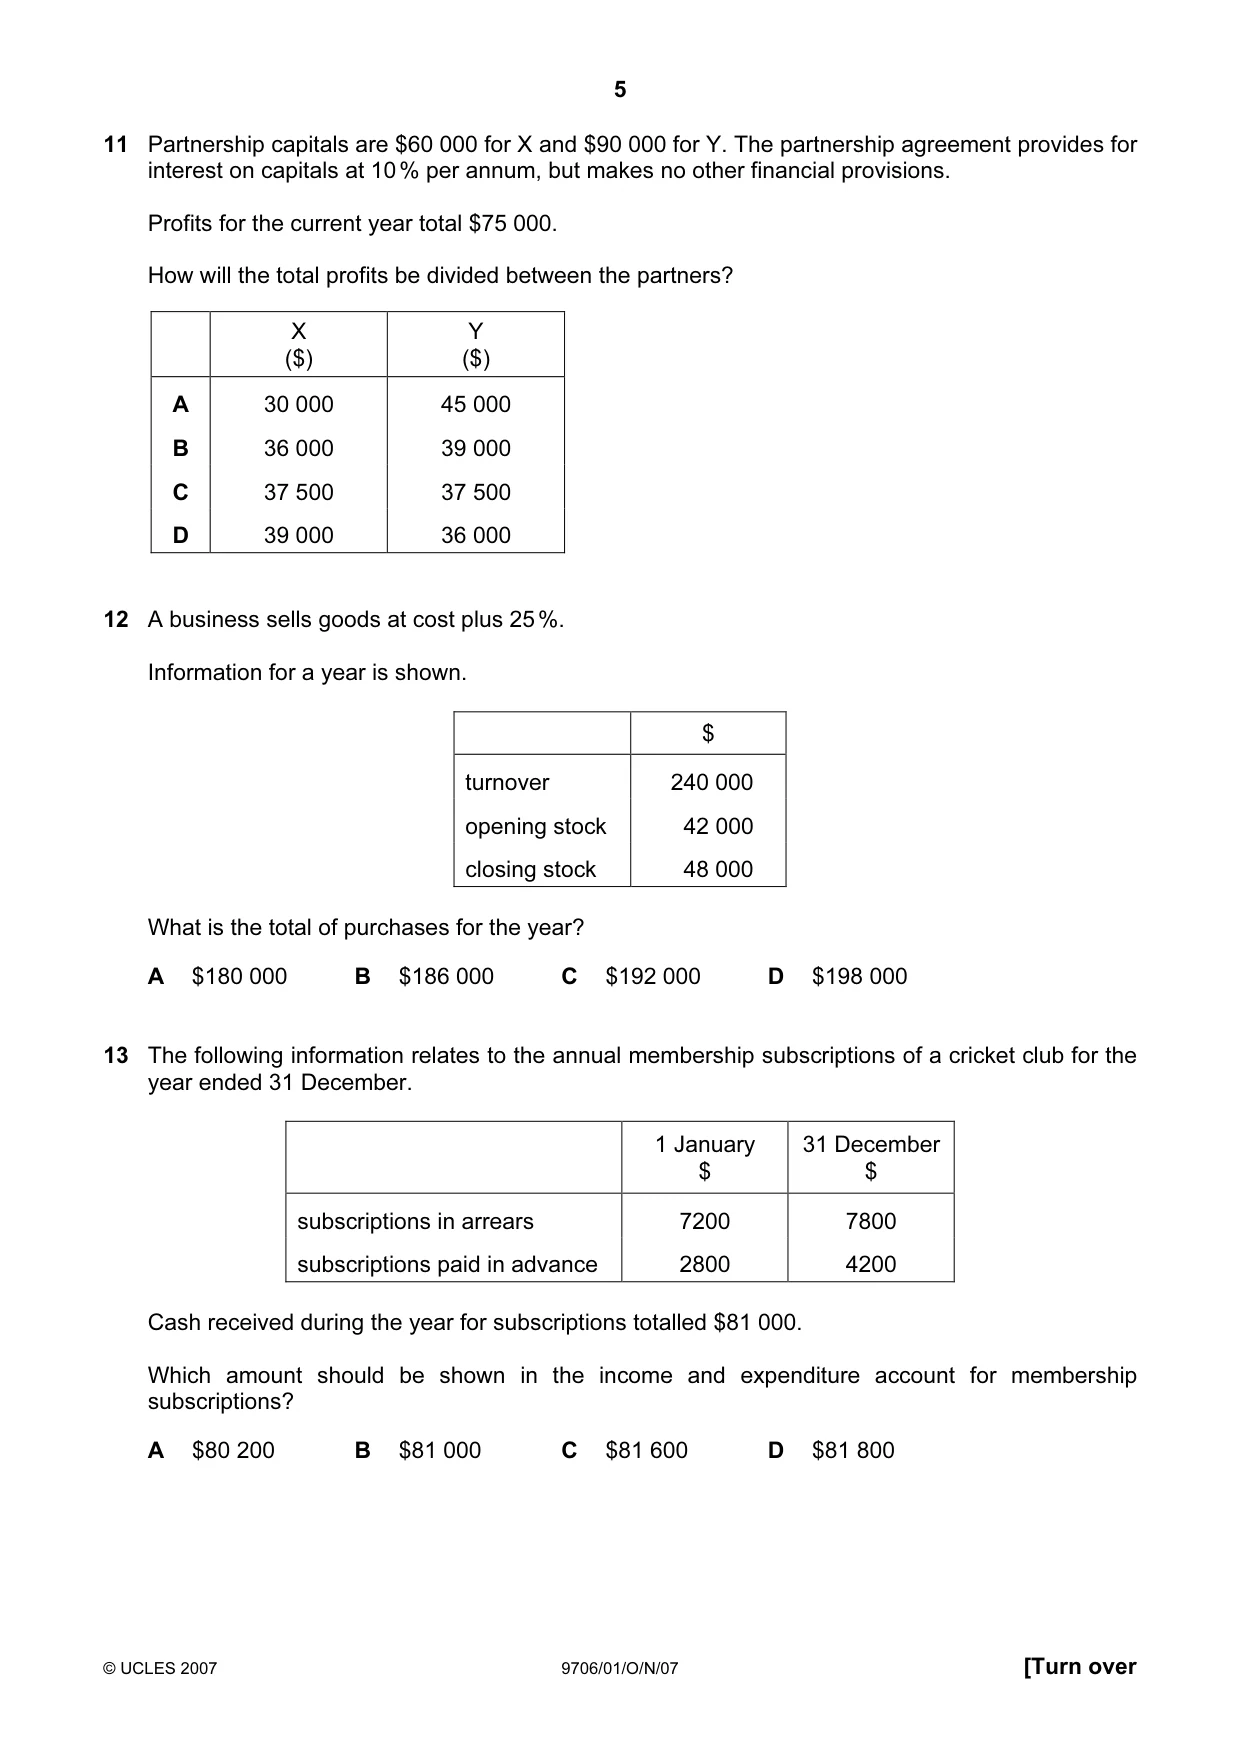
5 © UCLES 2007 9706/01/O/N/07 [Turn over 11 Partnership capitals are $60 000 for X and $90 000 for Y. The partnership agreement provides for interest on capitals at 10 % per annum, but makes no other financial provisions. Profits for the current year total $75 000. How will the total profits be divided between the partners? X ($) Y ($) A 30 000 45 000 B 36 000 39 000 C 37 500 37 500 D 39 000 36 000 12 A business sells goods at cost plus 25 %. Information for a year is shown. $ turnover 240 000 opening stock 42 000 closing stock 48 000 What is the total of purchases for the year? A $180 000 B $186 000 C $192 000 D $198 000 13 The following information relates to the annual membership subscriptions of a cricket club for the year ended 31 December. 1 January $ 31 December $ subscriptions in arrears 7200 7800 subscriptions paid in advance 2800 4200 Cash received during the year for subscriptions totalled $81 000. Which amount should be shown in the income and expenditure account for membership subscriptions? A $80 200 B $81 000 C $81 600 D $81 800
Question paper, page 6
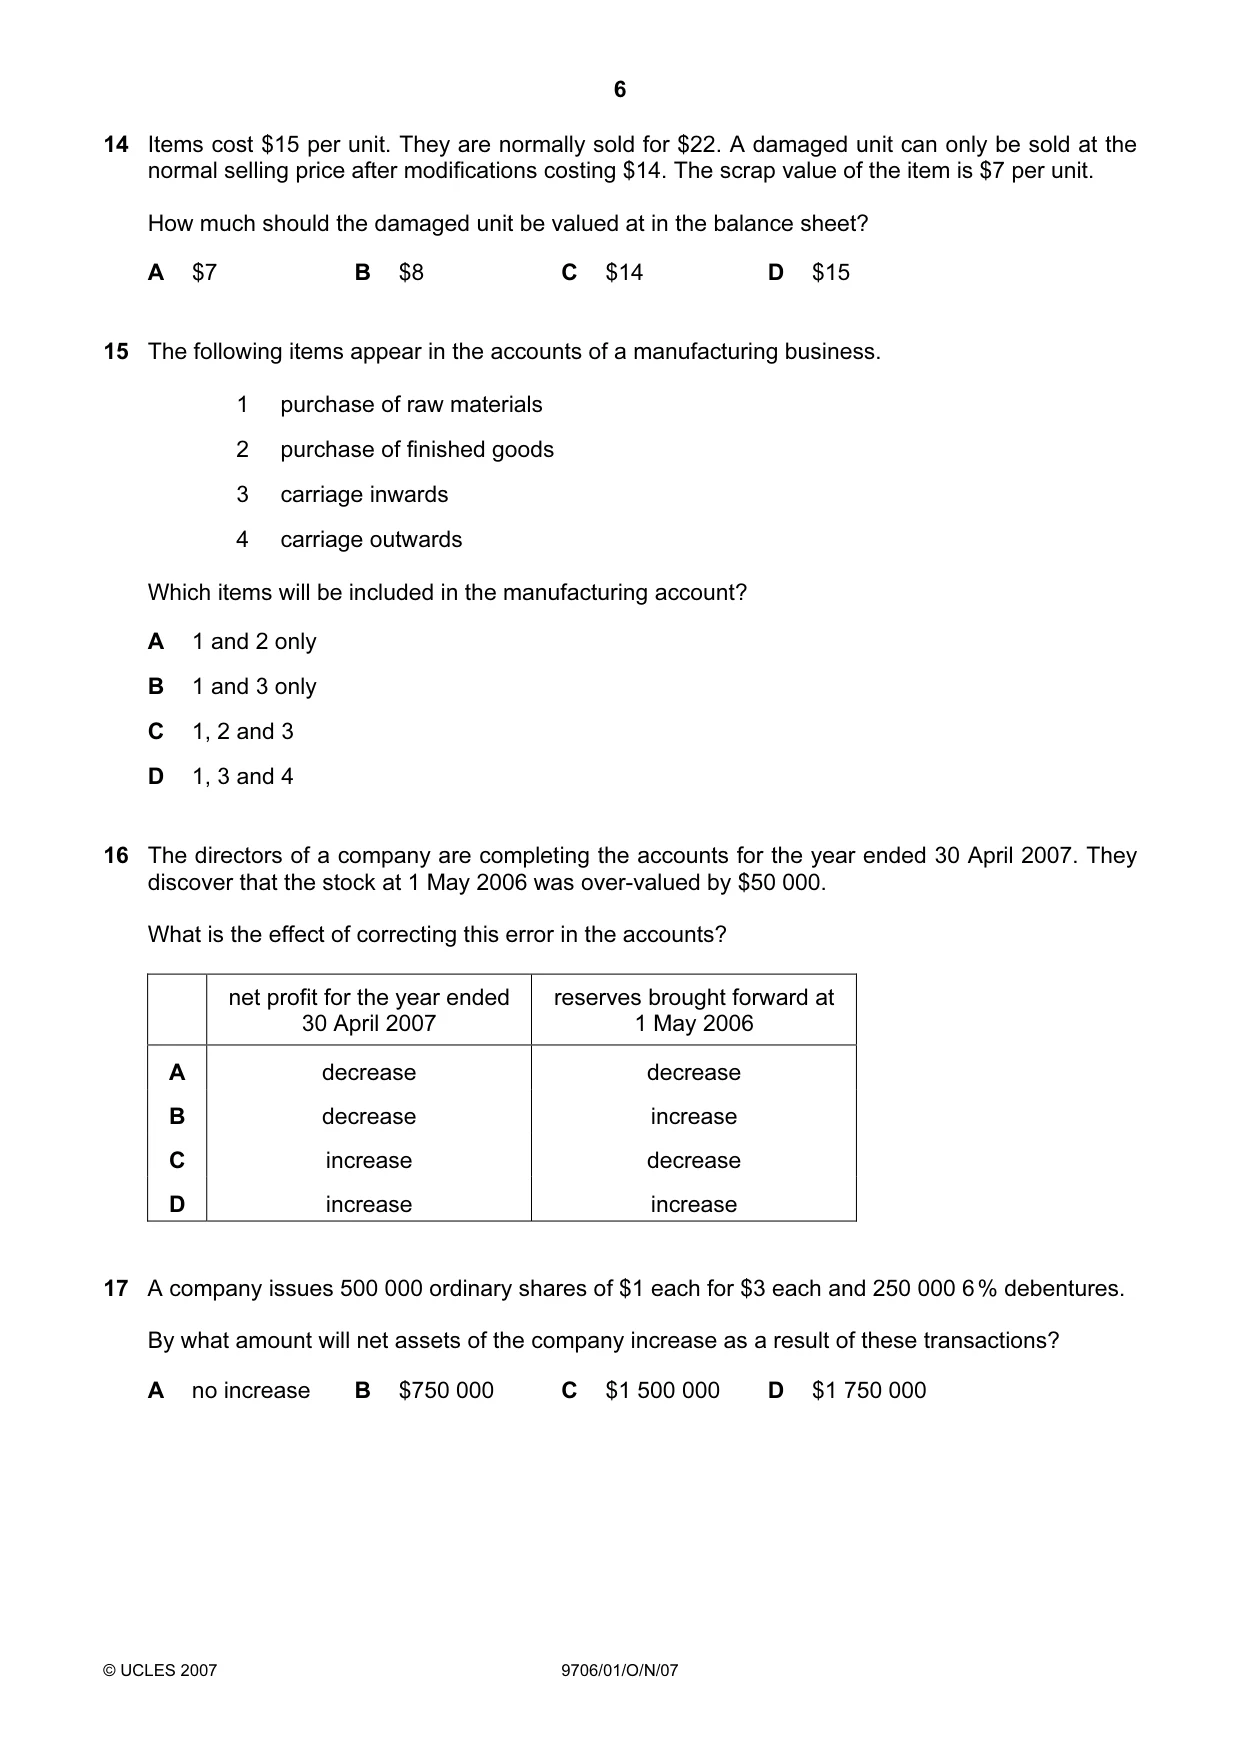
6 © UCLES 2007 9706/01/O/N/07 14 Items cost $15 per unit. They are normally sold for $22. A damaged unit can only be sold at the normal selling price after modifications costing $14. The scrap value of the item is $7 per unit. How much should the damaged unit be valued at in the balance sheet? A $7 B $8 C $14 D $15 15 The following items appear in the accounts of a manufacturing business. 1 purchase of raw materials 2 purchase of finished goods 3 carriage inwards 4 carriage outwards Which items will be included in the manufacturing account? A 1 and 2 only B 1 and 3 only C 1, 2 and 3 D 1, 3 and 4 16 The directors of a company are completing the accounts for the year ended 30 April 2007. They discover that the stock at 1 May 2006 was over-valued by $50 000. What is the effect of correcting this error in the accounts? net profit for the year ended 30 April 2007 reserves brought forward at 1 May 2006 A decrease decrease B decrease increase C increase decrease D increase increase 17 A company issues 500 000 ordinary shares of $1 each for $3 each and 250 000 6 % debentures. By what amount will net assets of the company increase as a result of these transactions? A no increase B $750 000 C $1 500 000 D $1 750 000
Question paper, page 7
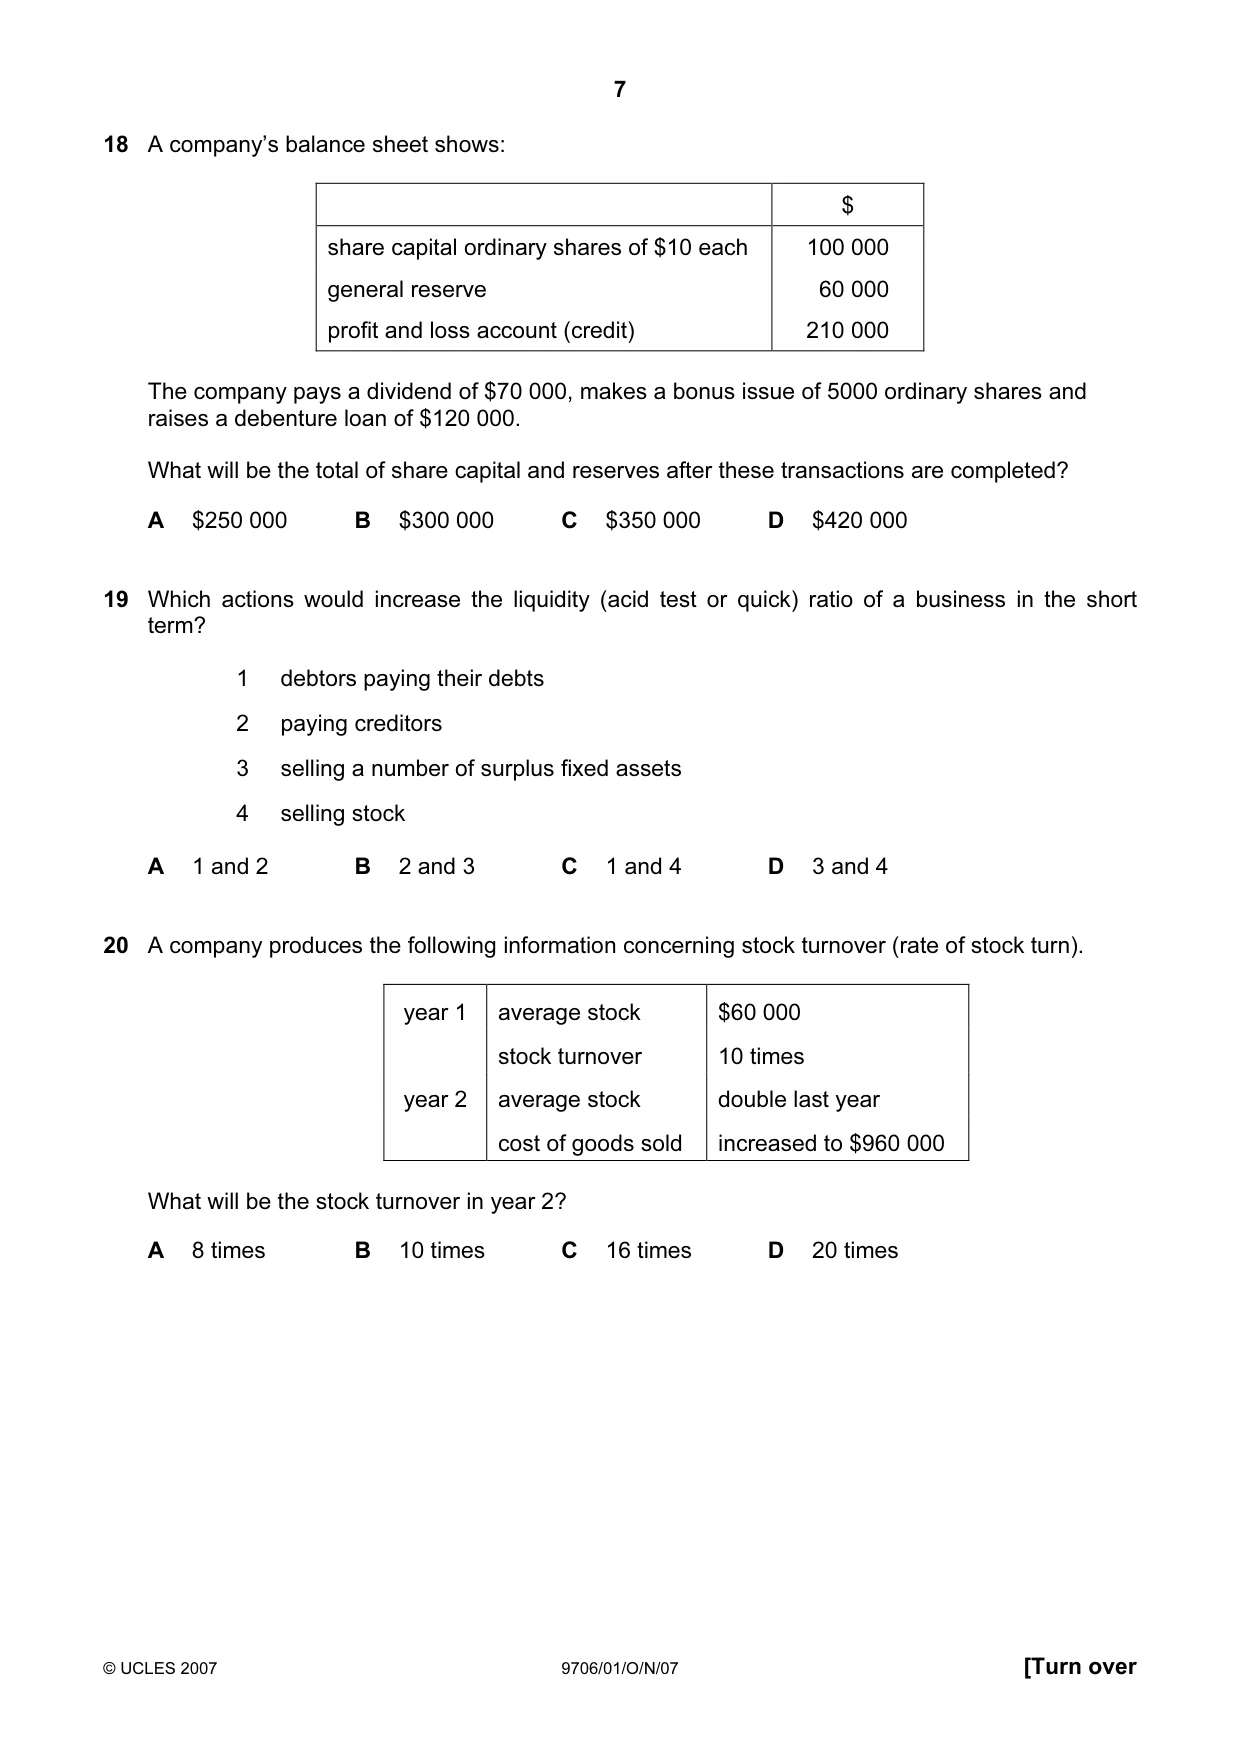
7 © UCLES 2007 9706/01/O/N/07 [Turn over 18 A company’s balance sheet shows: $ share capital ordinary shares of $10 each 100 000 general reserve 60 000 profit and loss account (credit) 210 000 The company pays a dividend of $70 000, makes a bonus issue of 5000 ordinary shares and raises a debenture loan of $120 000. What will be the total of share capital and reserves after these transactions are completed? A $250 000 B $300 000 C $350 000 D $420 000 19 Which actions would increase the liquidity (acid test or quick) ratio of a business in the short term? 1 debtors paying their debts 2 paying creditors 3 selling a number of surplus fixed assets 4 selling stock A 1 and 2 B 2 and 3 C 1 and 4 D 3 and 4 20 A company produces the following information concerning stock turnover (rate of stock turn). year 1 average stock $60 000 stock turnover 10 times year 2 average stock double last year cost of goods sold increased to $960 000 What will be the stock turnover in year 2? A 8 times B 10 times C 16 times D 20 times
Question paper, page 8
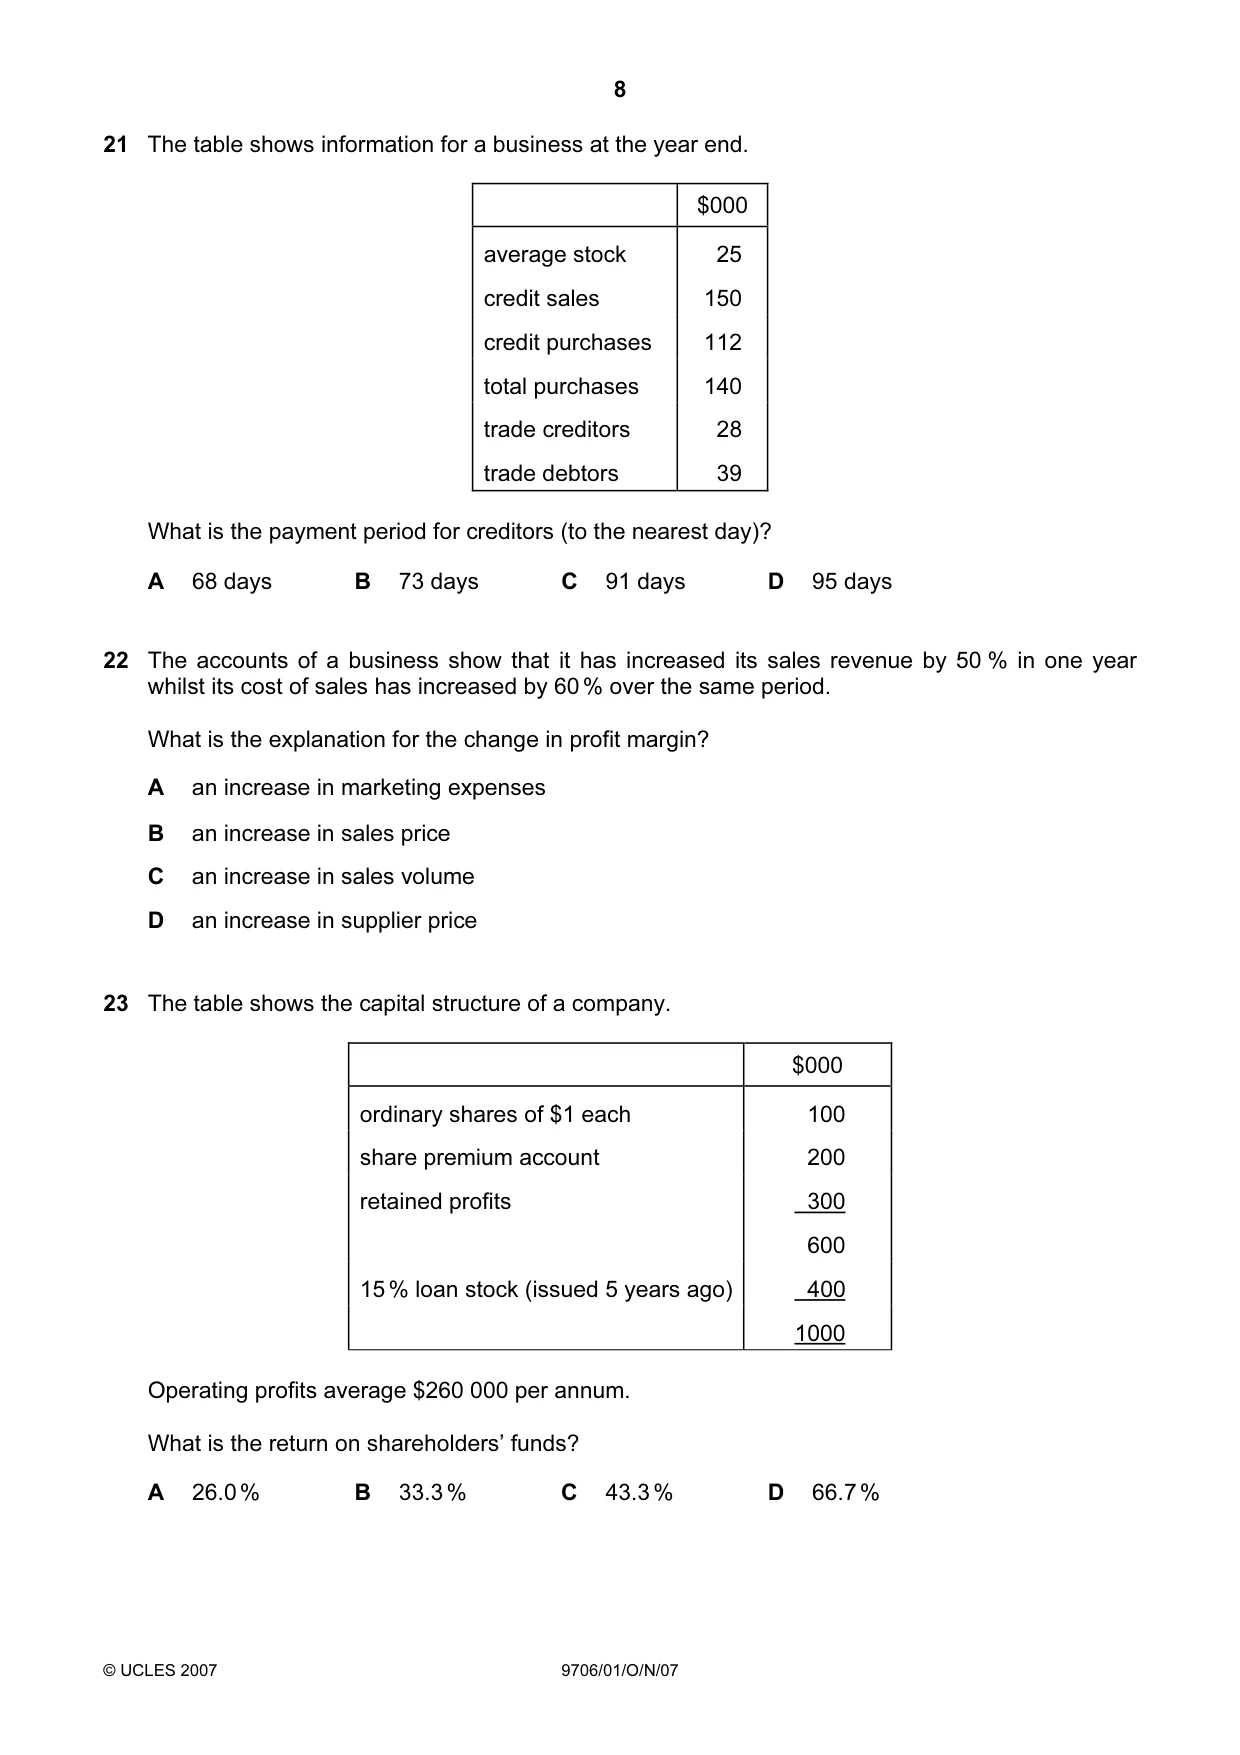
8 © UCLES 2007 9706/01/O/N/07 21 The table shows information for a business at the year end. $000 average stock 25 credit sales 150 credit purchases 112 total purchases 140 trade creditors 28 trade debtors 39 What is the payment period for creditors (to the nearest day)? A 68 days B 73 days C 91 days D 95 days 22 The accounts of a business show that it has increased its sales revenue by 50 % in one year whilst its cost of sales has increased by 60 % over the same period. What is the explanation for the change in profit margin? A an increase in marketing expenses B an increase in sales price C an increase in sales volume D an increase in supplier price 23 The table shows the capital structure of a company. $000 ordinary shares of $1 each 100 share premium account 200 retained profits 300 600 15 % loan stock (issued 5 years ago) 400 1000 Operating profits average $260 000 per annum. What is the return on shareholders’ funds? A 26.0 % B 33.3 % C 43.3 % D 66.7 %
Question paper, page 9
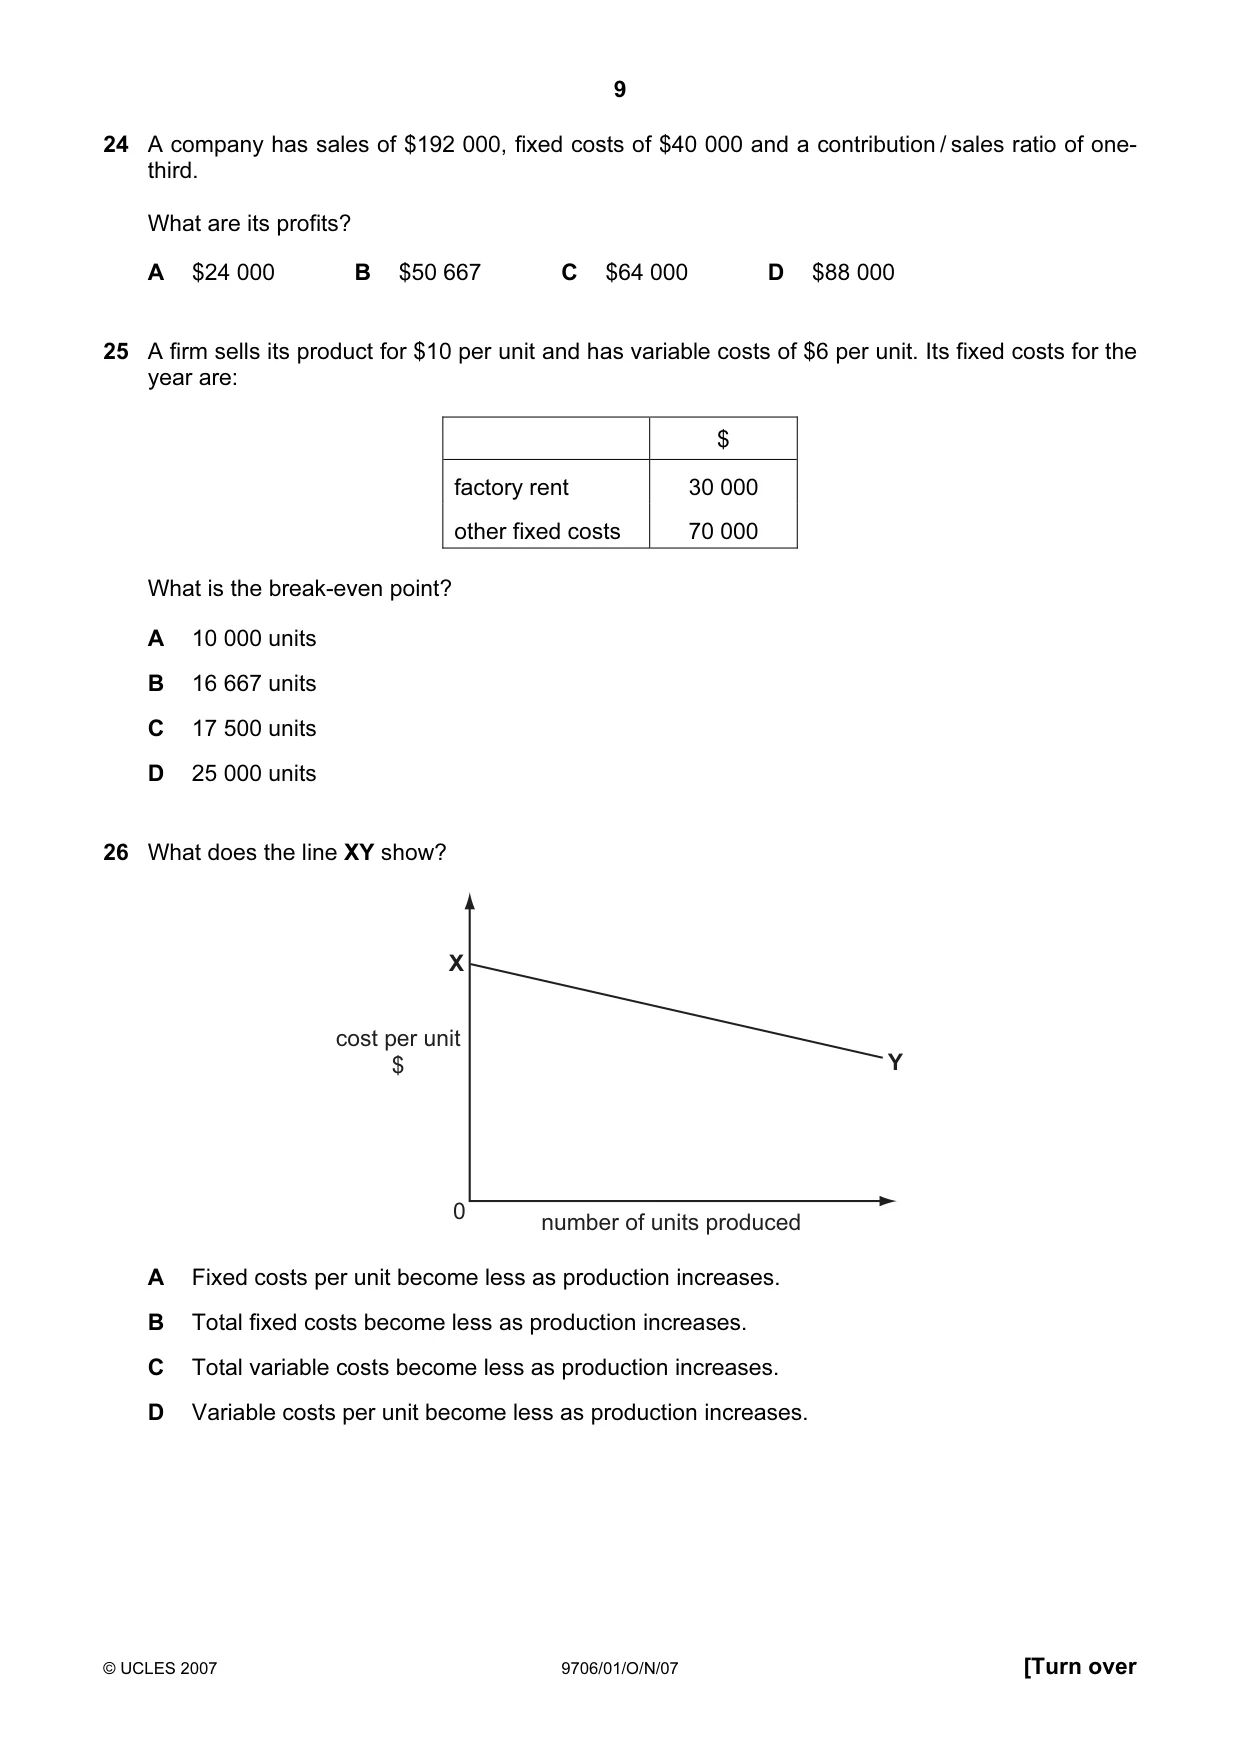
9 © UCLES 2007 9706/01/O/N/07 [Turn over 24 A company has sales of $192 000, fixed costs of $40 000 and a contribution / sales ratio of one- third. What are its profits? A $24 000 B $50 667 C $64 000 D $88 000 25 A firm sells its product for $10 per unit and has variable costs of $6 per unit. Its fixed costs for the year are: $ factory rent 30 000 other fixed costs 70 000 What is the break-even point? A 10 000 units B 16 667 units C 17 500 units D 25 000 units 26 What does the line XY show? 0 number of units produced cost per unit $ X Y A Fixed costs per unit become less as production increases. B Total fixed costs become less as production increases. C Total variable costs become less as production increases. D Variable costs per unit become less as production increases.
Question paper, page 10
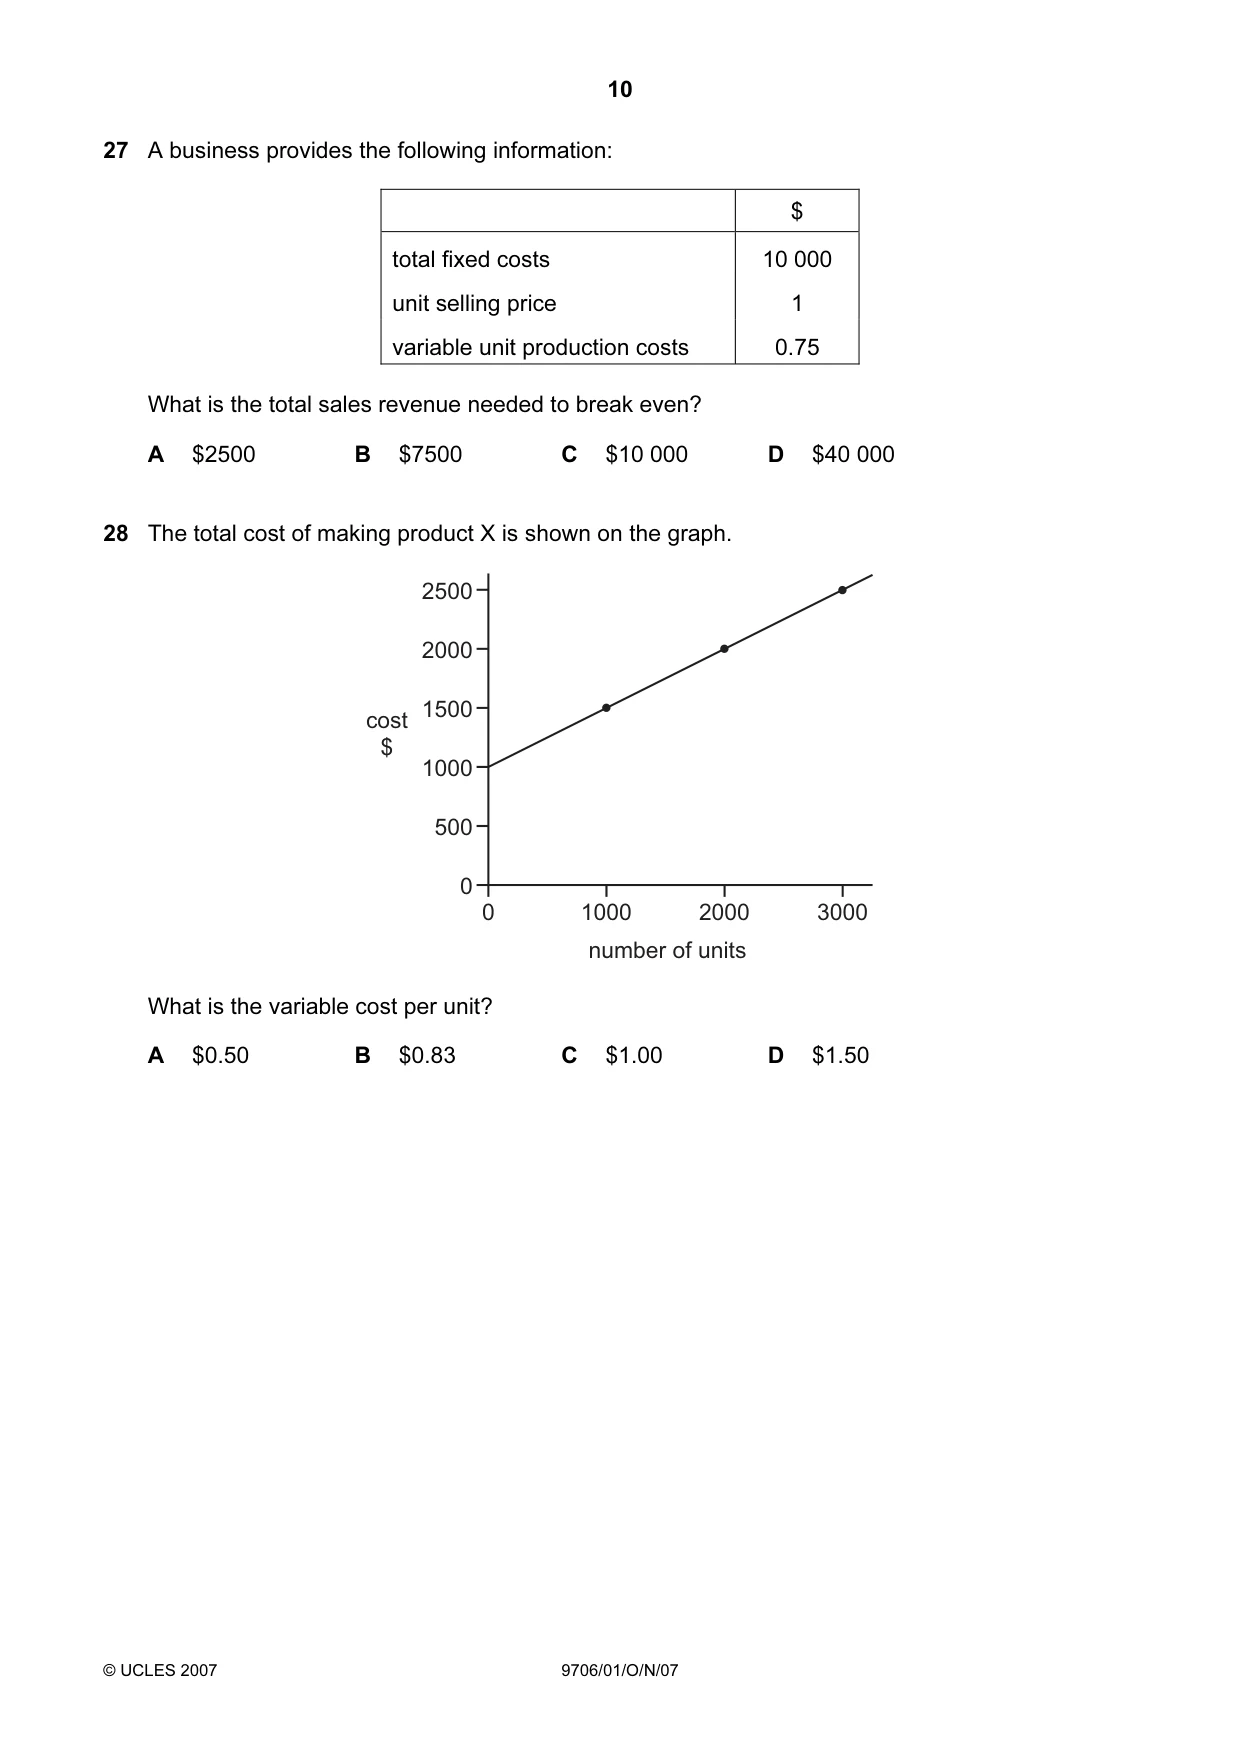
10 © UCLES 2007 9706/01/O/N/07 27 A business provides the following information: $ total fixed costs 10 000 unit selling price 1 variable unit production costs 0.75 What is the total sales revenue needed to break even? A $2500 B $7500 C $10 000 D $40 000 28 The total cost of making product X is shown on the graph. 2500 2000 1500 1000 500 0 0 1000 2000 3000 number of units cost $ What is the variable cost per unit? A $0.50 B $0.83 C $1.00 D $1.50
Question paper, page 11
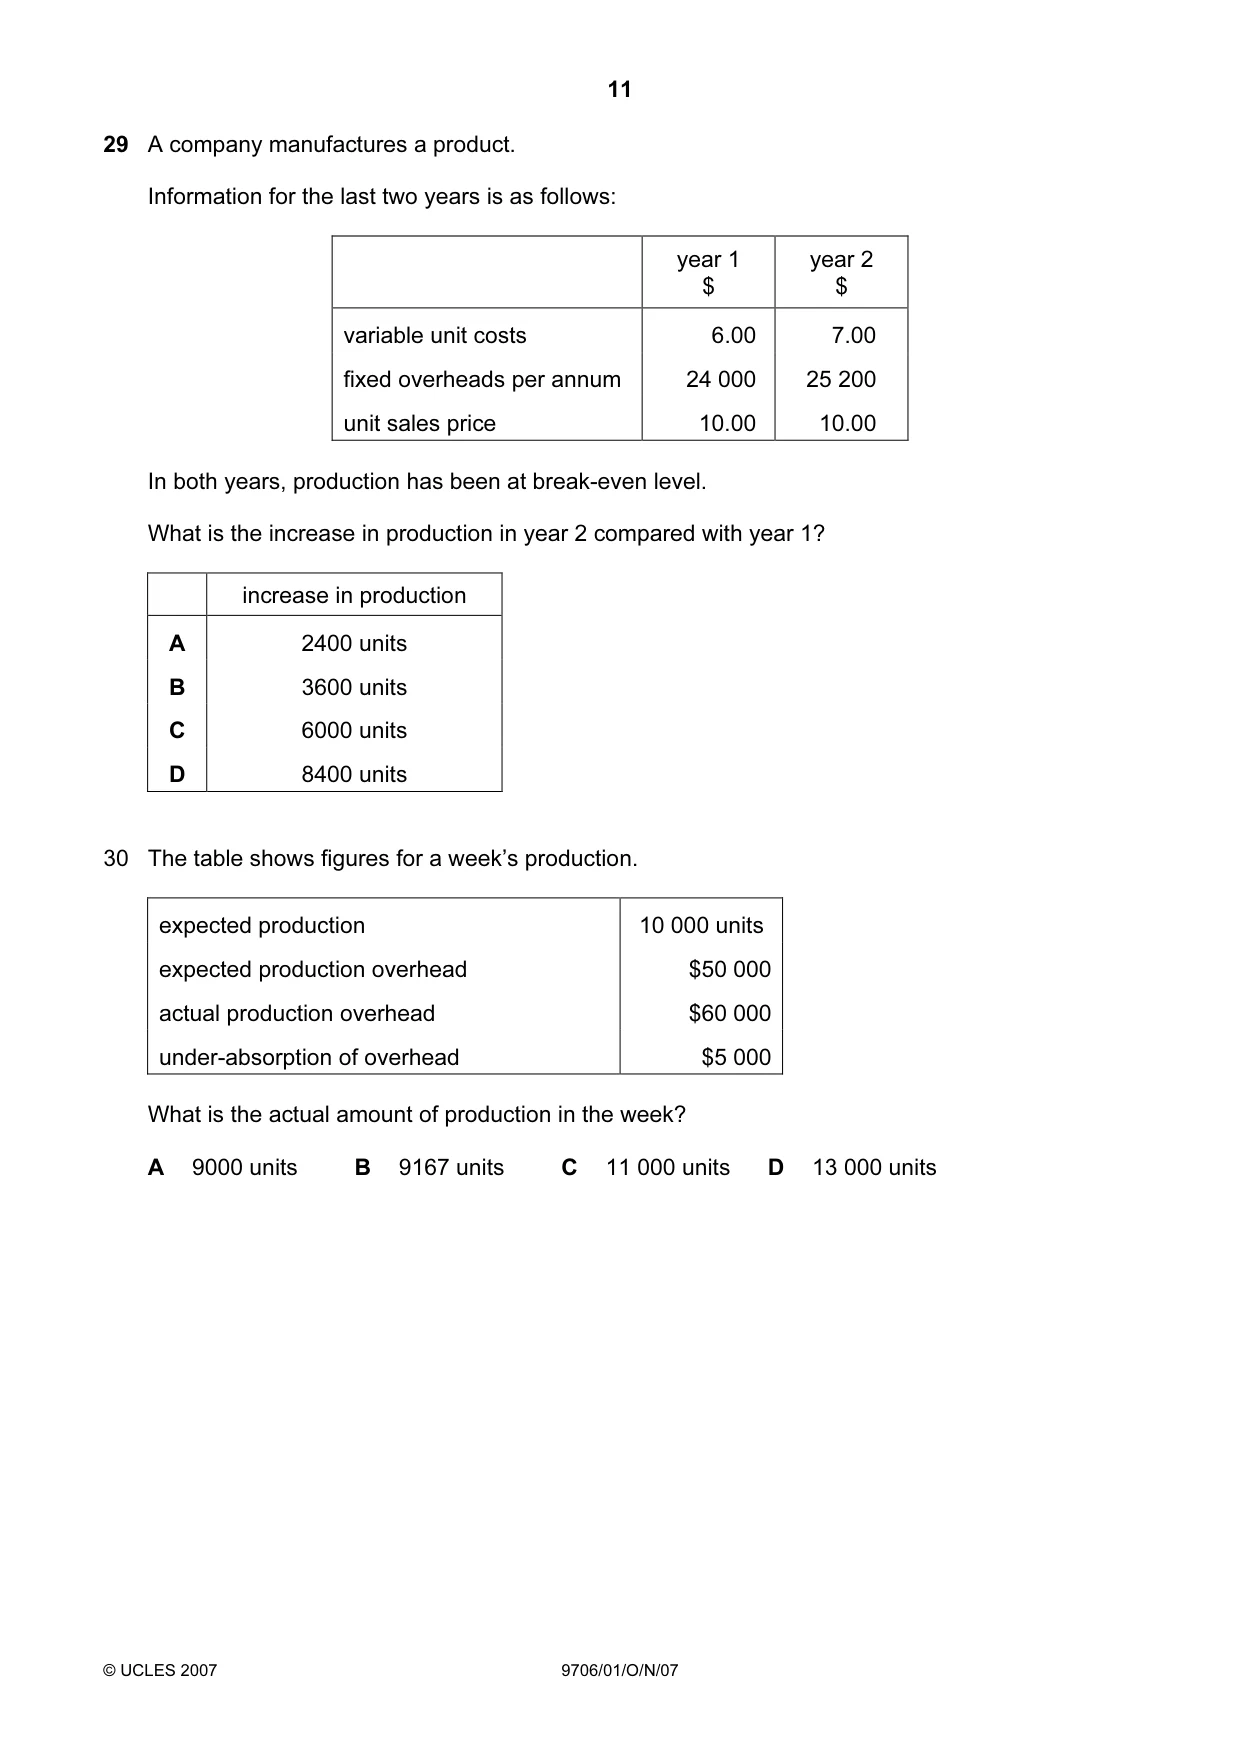
11 © UCLES 2007 9706/01/O/N/07 29 A company manufactures a product. Information for the last two years is as follows: year 1 $ year 2 $ variable unit costs 6.00 7.00 fixed overheads per annum 24 000 25 200 unit sales price 10.00 10.00 In both years, production has been at break-even level. What is the increase in production in year 2 compared with year 1? increase in production A 2400 units B 3600 units C 6000 units D 8400 units 30 The table shows figures for a week’s production. expected production 10 000 units expected production overhead $50 000 actual production overhead $60 000 under-absorption of overhead $5 000 What is the actual amount of production in the week? A 9000 units B 9167 units C 11 000 units D 13 000 units
Question paper, page 12
12 Permission to reproduce items where third-party owned material protected by copyright is included has been sought and cleared where possible. Every reasonable effort has been made by the publisher (UCLES) to trace copyright holders, but if any items requiring clearance have unwittingly been included, the publisher will be pleased to make amends at the earliest possible opportunity. University of Cambridge International Examinations is part of the Cambridge Assessment Group. Cambridge Assessment is the brand name of University of Cambridge Local Examinations Syndicate (UCLES), which is itself a department of the University of Cambridge. 9706/01/O/N/07 BLANK PAGE
Mark scheme, page 1
UNIVERSITY OF CAMBRIDGE INTERNATIONAL EXAMINATIONS GCE Advanced Subsidiary Level and GCE Advanced Level MARK SCHEME for the October/November 2007 question paper 9706 ACCOUNTING 9706/01 Paper 1 (Multiple Choice (Core)), maximum raw mark 30 Mark schemes must be read in conjunction with the question papers and the report on the examination. • CIE will not enter into discussions or correspondence in connection with these mark schemes. CIE is publishing the mark schemes for the October/November 2007 question papers for most IGCSE, GCE Advanced Level and Advanced Subsidiary Level syllabuses and some Ordinary Level syllabuses.
Mark scheme, page 2
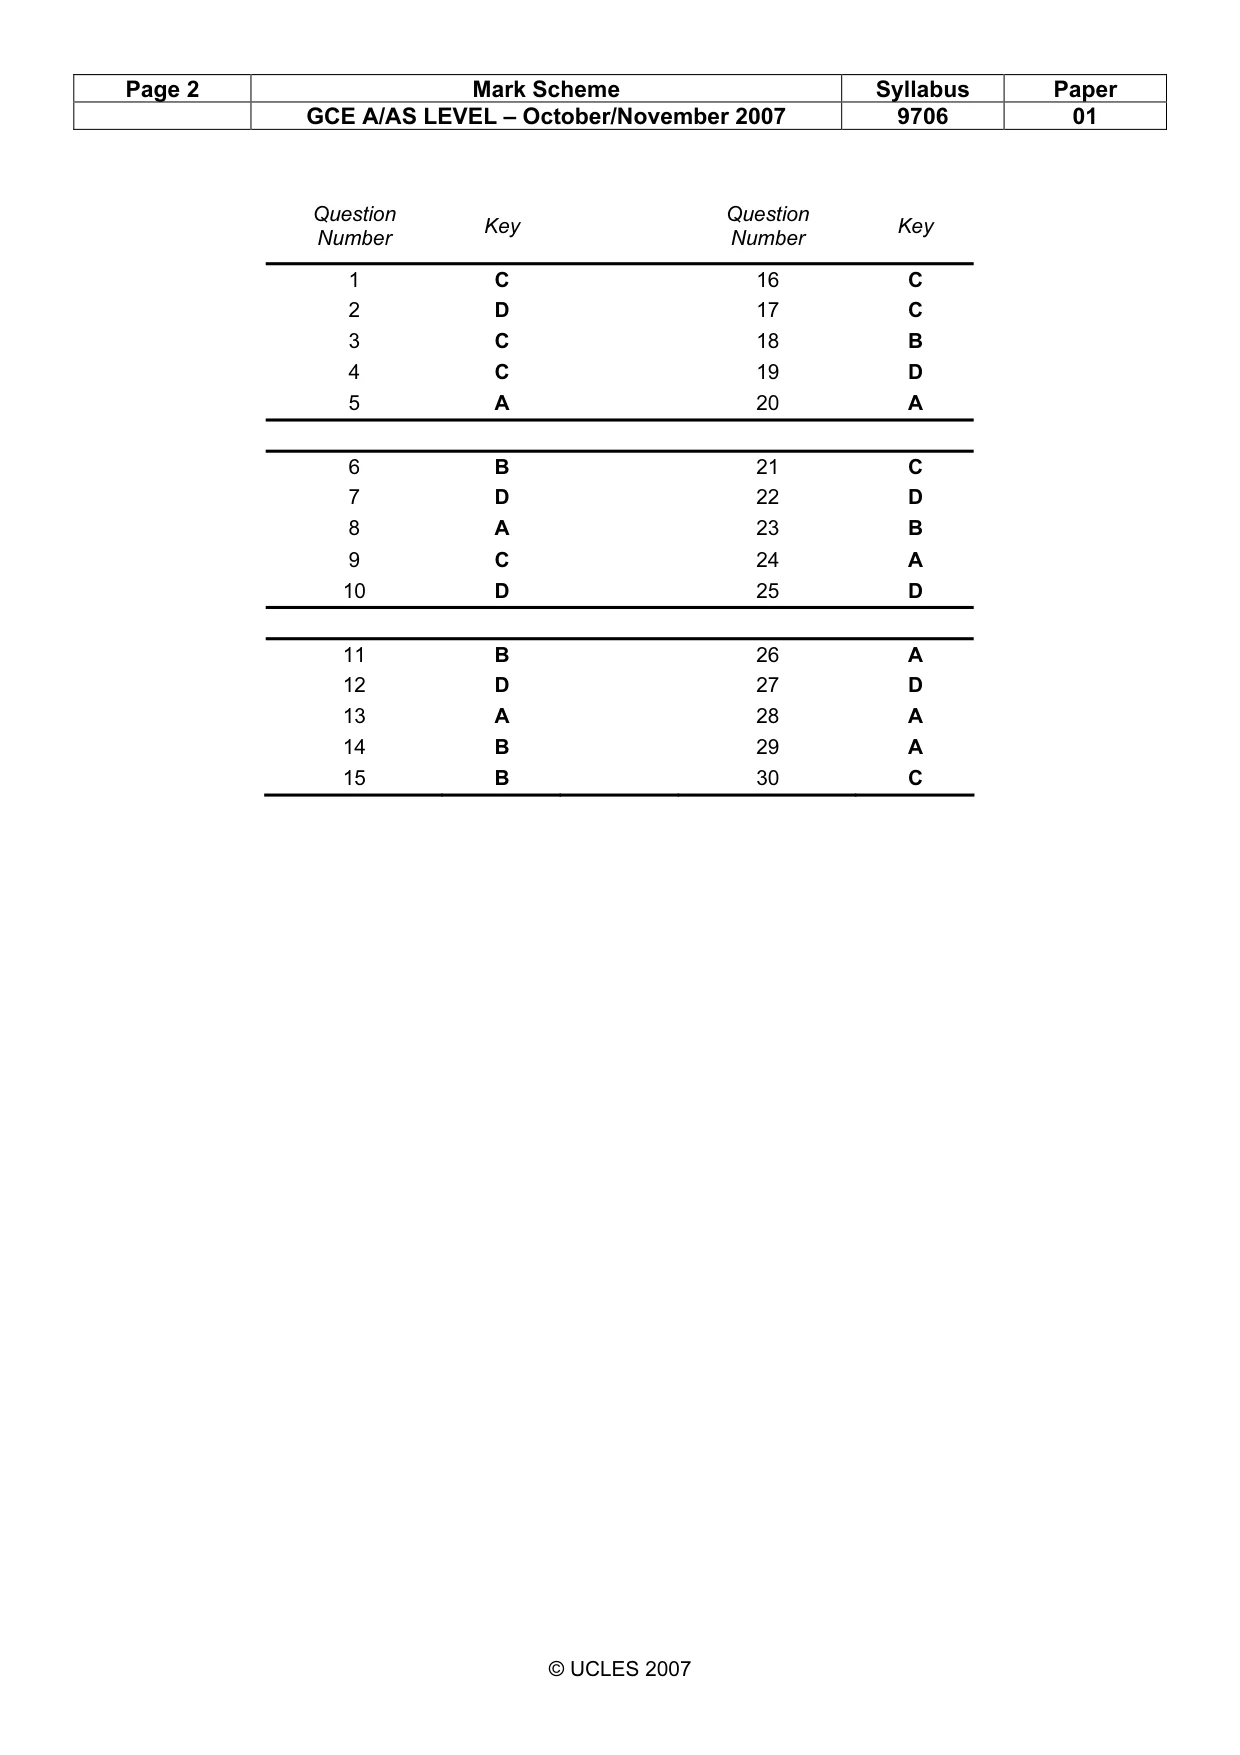
Page 2 Mark Scheme Syllabus Paper GCE A/AS LEVEL – October/November 2007 9706 01 © UCLES 2007 Question Number Key Question Number Key 1 C 16 C 2 D 17 C 3 C 18 B 4 C 19 D 5 A 20 A 6 B 21 C 7 D 22 D 8 A 23 B 9 C 24 A 10 D 25 D 11 B 26 A 12 D 27 D 13 A 28 A 14 B 29 A 15 B 30 C
What you needed in this session
Cambridge’s own grade thresholds for 2007 Oct/Nov, Paper 1 · Variant 1. A higher threshold means an easier paper — the bar moves with how the cohort did.