Cambridge A Level Accounting 9706 — 2005 Oct/Nov Paper 2 · Variant 1
9706/21/O/N/05
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper16 pages
Mark scheme7 pages
Answers below. Sit the paper first if you are practising.
Paper as text
Question paper, page 1
This document consists of 13 printed pages and 3 blank pages. SP (SM) S72510/5 © UCLES 2005 [Turn over UNIVERSITY OF CAMBRIDGE INTERNATIONAL EXAMINATIONS General Certificate of Education Advanced Subsidiary Level and Advanced Level ACCOUNTING 9706/02 Paper 2 Structured Questions October/November 2005 1 hour 30 minutes Candidates answer on the Question Paper. No Additional Materials are required. READ THESE INSTRUCTIONS FIRST Write your Centre number, candidate number and name on all the work you hand in. Write in dark blue or black pen in the spaces provided on the Question Paper. You may use a soft pencil for rough working. Do not use staples, paper clips, highlighters, glue or correction fluid. Answer all questions. At the end of the examination, fasten all your work securely together. The number of marks is given in brackets [ ] at the end of each question or part question. You may use a calculator. Centre Number Candidate Number Name If you have been given a label, look at the details. If any details are incorrect or missing, please fill in your correct details in the space given at the top of this page. Stick your personal label here, if provided. For Examiner’s Use 1 2 3 Total
Question paper, page 2
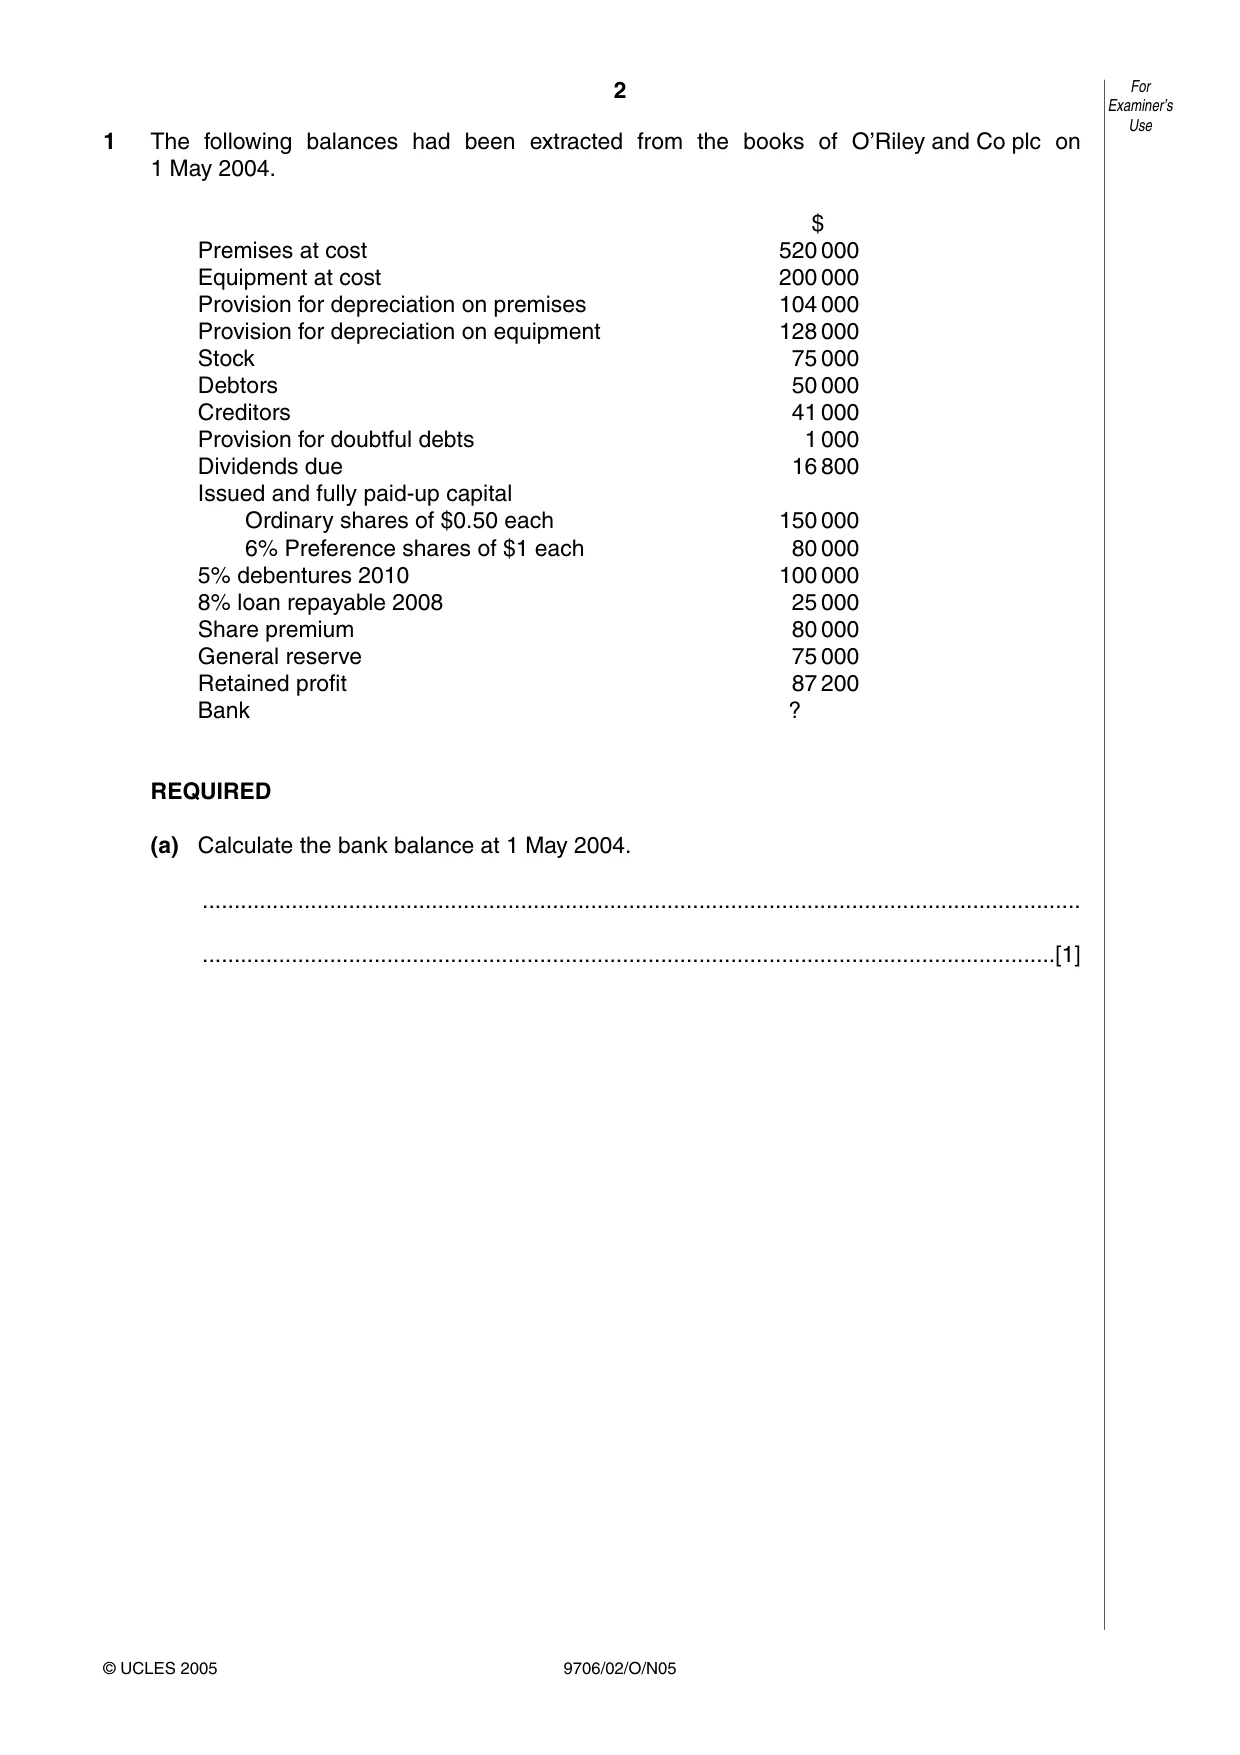
2 9706/02/O/N05 1 The following balances had been extracted from the books of O’Riley and Co plc on 1 May 2004. $ Premises at cost 520 000 Equipment at cost 200 000 Provision for depreciation on premises 104 000 Provision for depreciation on equipment 128 000 Stock 75 000 Debtors 50 000 Creditors 41 000 Provision for doubtful debts 1 000 Dividends due 16 800 Issued and fully paid-up capital Ordinary shares of $0.50 each 150 000 6% Preference shares of $1 each 80 000 5% debentures 2010 100 000 8% loan repayable 2008 25 000 Share premium 80 000 General reserve 75 000 Retained profit 87 200 Bank ? REQUIRED (a) Calculate the bank balance at 1 May 2004. … …[1] For Examiner’s Use © UCLES 2005
Question paper, page 3
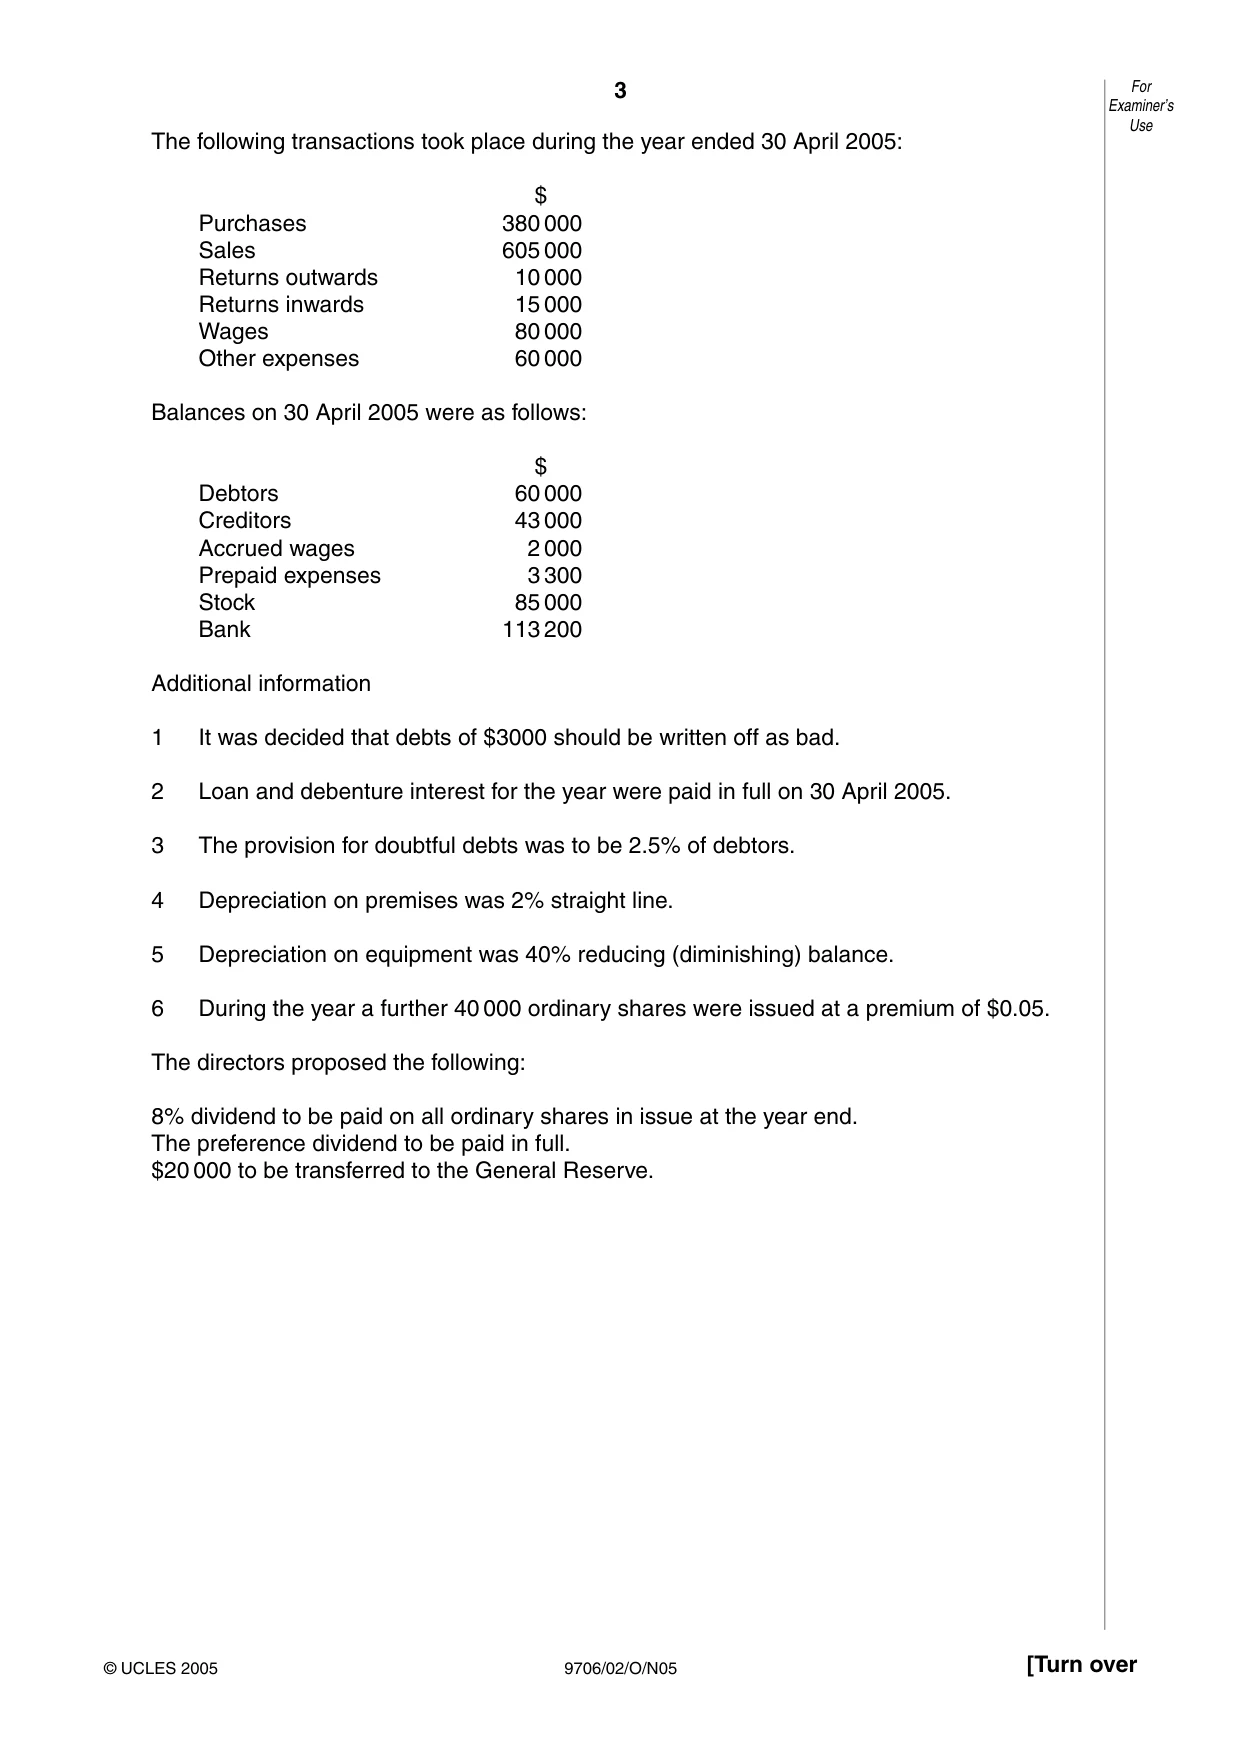
3 9706/02/O/N05 [Turn over The following transactions took place during the year ended 30 April 2005: $ Purchases 380 000 Sales 605 000 Returns outwards 10 000 Returns inwards 15 000 Wages 80 000 Other expenses 60 000 Balances on 30 April 2005 were as follows: $ Debtors 60 000 Creditors 43 000 Accrued wages 2 000 Prepaid expenses 3 300 Stock 85 000 Bank 113 200 Additional information 1 It was decided that debts of $3000 should be written off as bad. 2 Loan and debenture interest for the year were paid in full on 30 April 2005. 3 The provision for doubtful debts was to be 2.5% of debtors. 4 Depreciation on premises was 2% straight line. 5 Depreciation on equipment was 40% reducing (diminishing) balance. 6 During the year a further 40 000 ordinary shares were issued at a premium of $0.05. The directors proposed the following: 8% dividend to be paid on all ordinary shares in issue at the year end. The preference dividend to be paid in full. $20 000 to be transferred to the General Reserve. For Examiner’s Use © UCLES 2005
Question paper, page 4
4 9706/02/O/N05 REQUIRED (b) Prepare O’Riley and Co plc’s Trading, Profit and Loss and Appropriation account for the year ended 30 April 2005. … … … … … … … … … … … … … … … … … … … … … … … … … … For Examiner’s Use © UCLES 2005
Question paper, page 5
5 9706/02/O/N05 [Turn over … … … … … … … … … … … … … … … … … … … … … … … … … … … …[14] For Examiner’s Use © UCLES 2005
Question paper, page 6
6 9706/02/O/N05 (c) Prepare the Balance Sheet at 30 April 2005. … … … … … … … … … … … … … … … … … … … … … … … … … … … For Examiner’s Use © UCLES 2005
Question paper, page 7
7 9706/02/O/N05 [Turn over … … … … … … … … … …[11] (d) Explain share premium and state how it may be used. … … … … … … … …[4] [Total: 30] For Examiner’s Use © UCLES 2005
Question paper, page 8
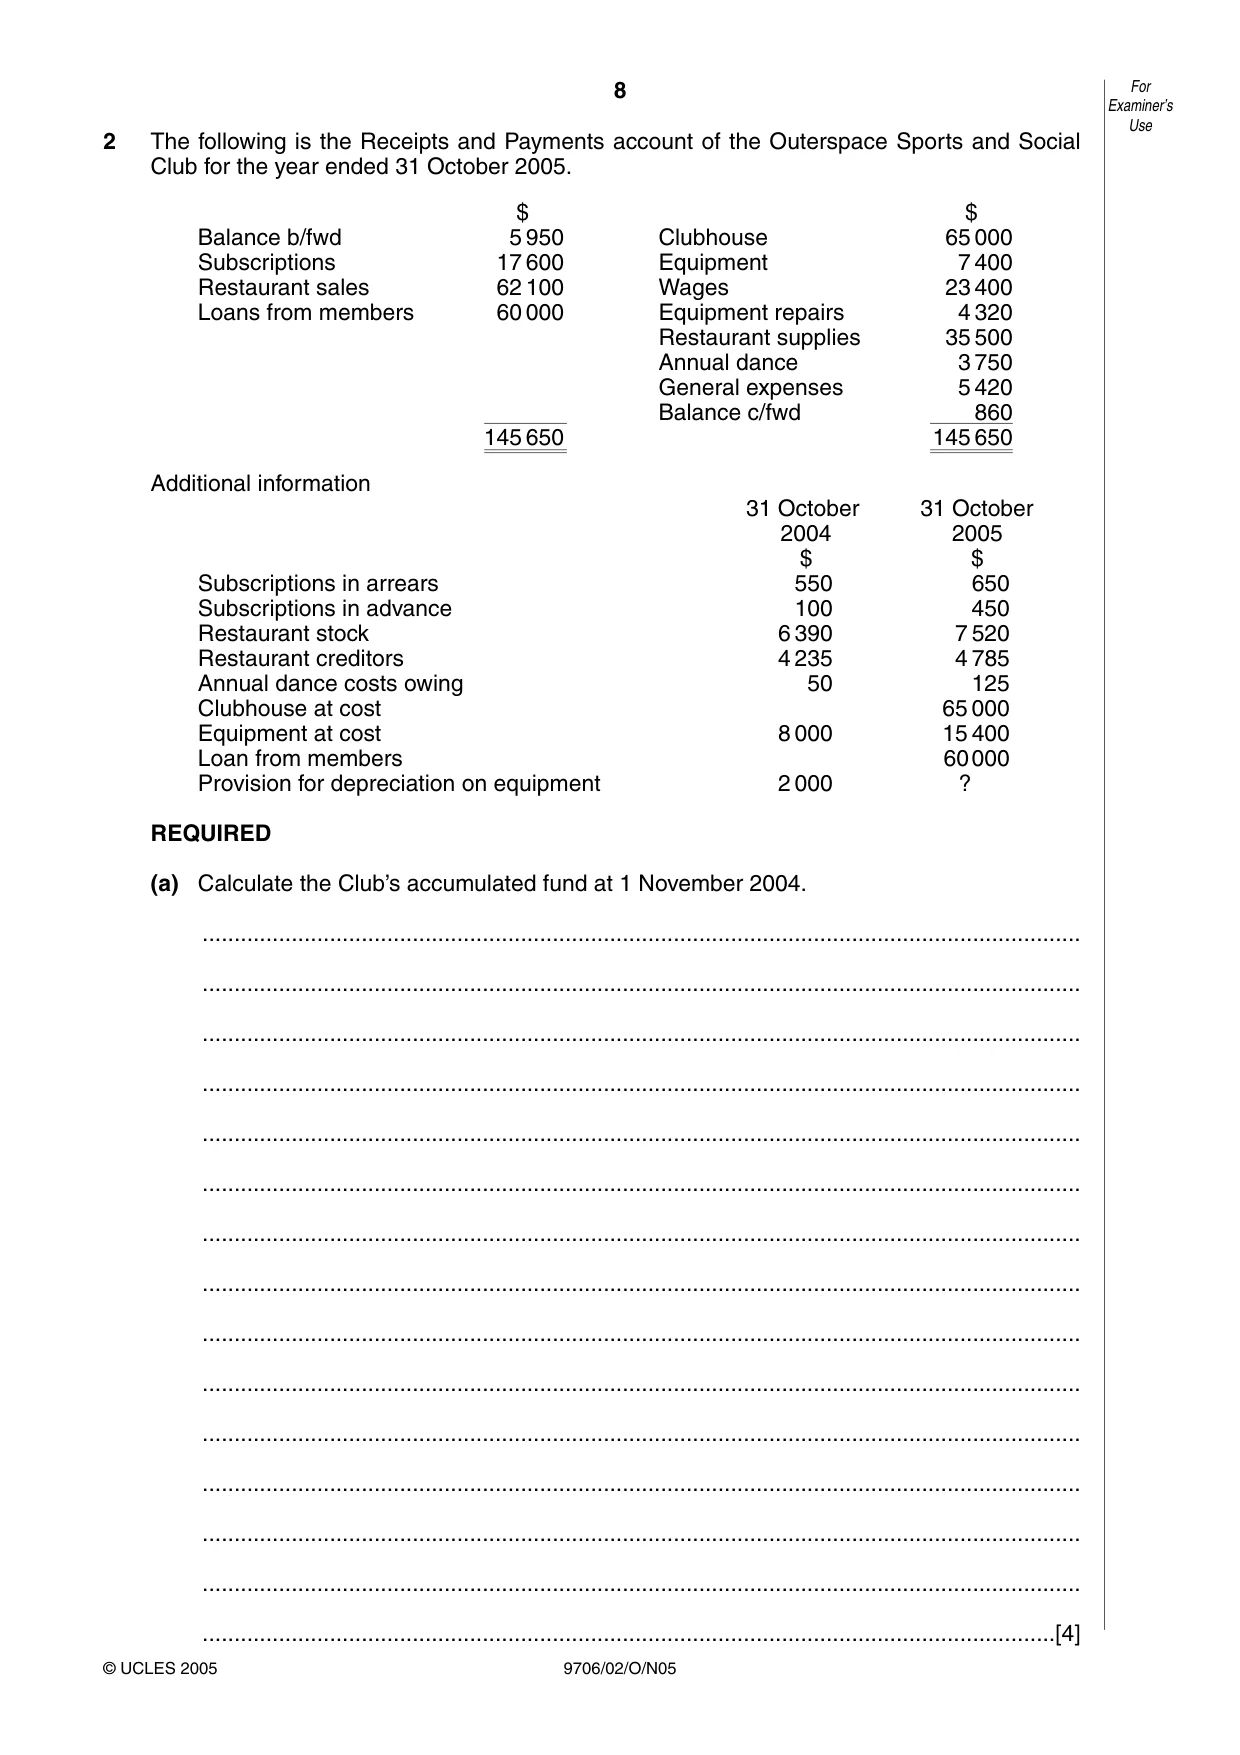
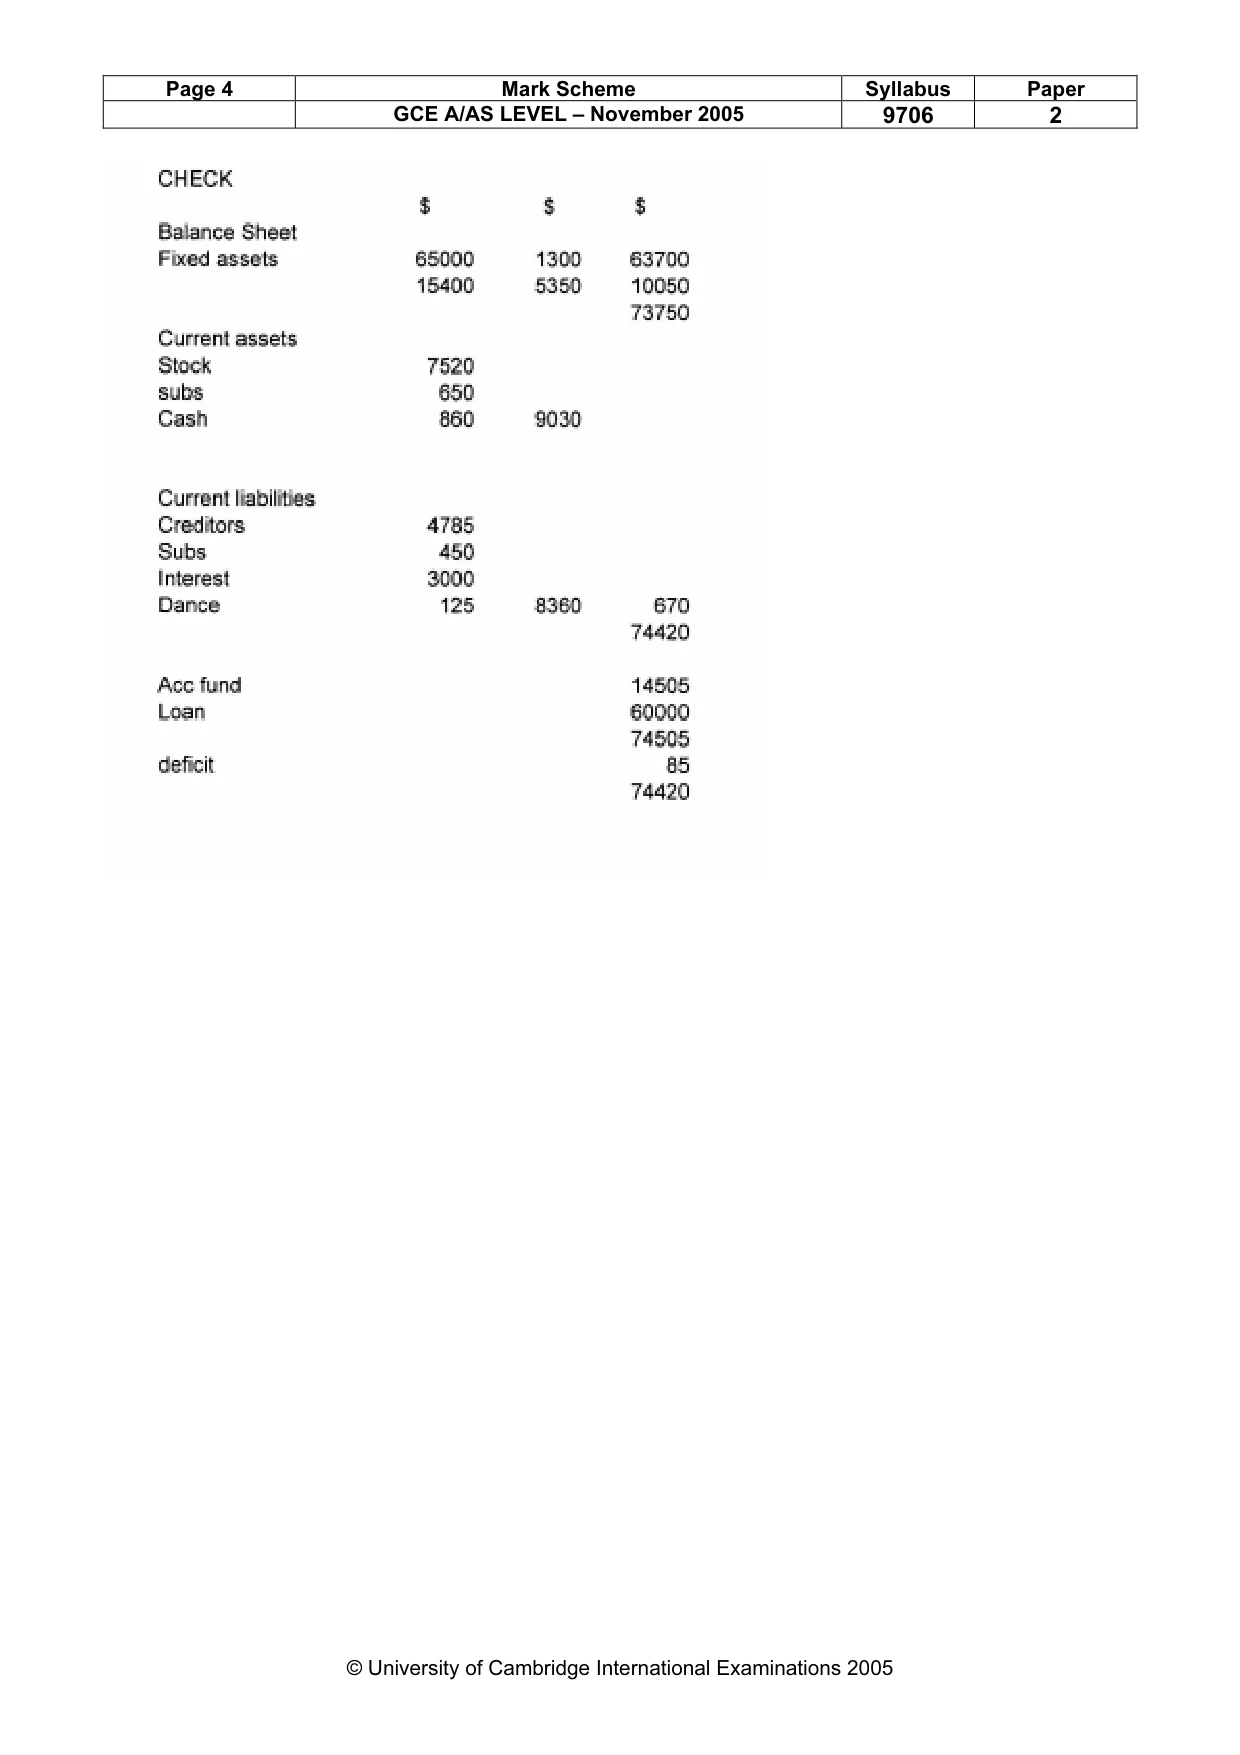
8 9706/02/O/N05 2 The following is the Receipts and Payments account of the Outerspace Sports and Social Club for the year ended 31 October 2005. $ $ Balance b/fwd 5 950 Clubhouse 65 000 Subscriptions 17 600 Equipment 7 400 Restaurant sales 62 100 Wages 23 400 Loans from members 60 000 Equipment repairs 4 320 Restaurant supplies 35 500 Annual dance 3 750 General expenses 5 420 Balance c/fwd 860 145 650 145 650 Additional information 31 October 31 October 2004 2005 $ $ Subscriptions in arrears 550 650 Subscriptions in advance 100 450 Restaurant stock 6 390 7 520 Restaurant creditors 4 235 4 785 Annual dance costs owing 50 125 Clubhouse at cost 65 000 Equipment at cost 8 000 15 400 Loan from members 60000 Provision for depreciation on equipment 2 000 ? REQUIRED (a) Calculate the Club’s accumulated fund at 1 November 2004. … … … … … … … … … … … … … … …[4] For Examiner’s Use © UCLES 2005
Question paper, page 9
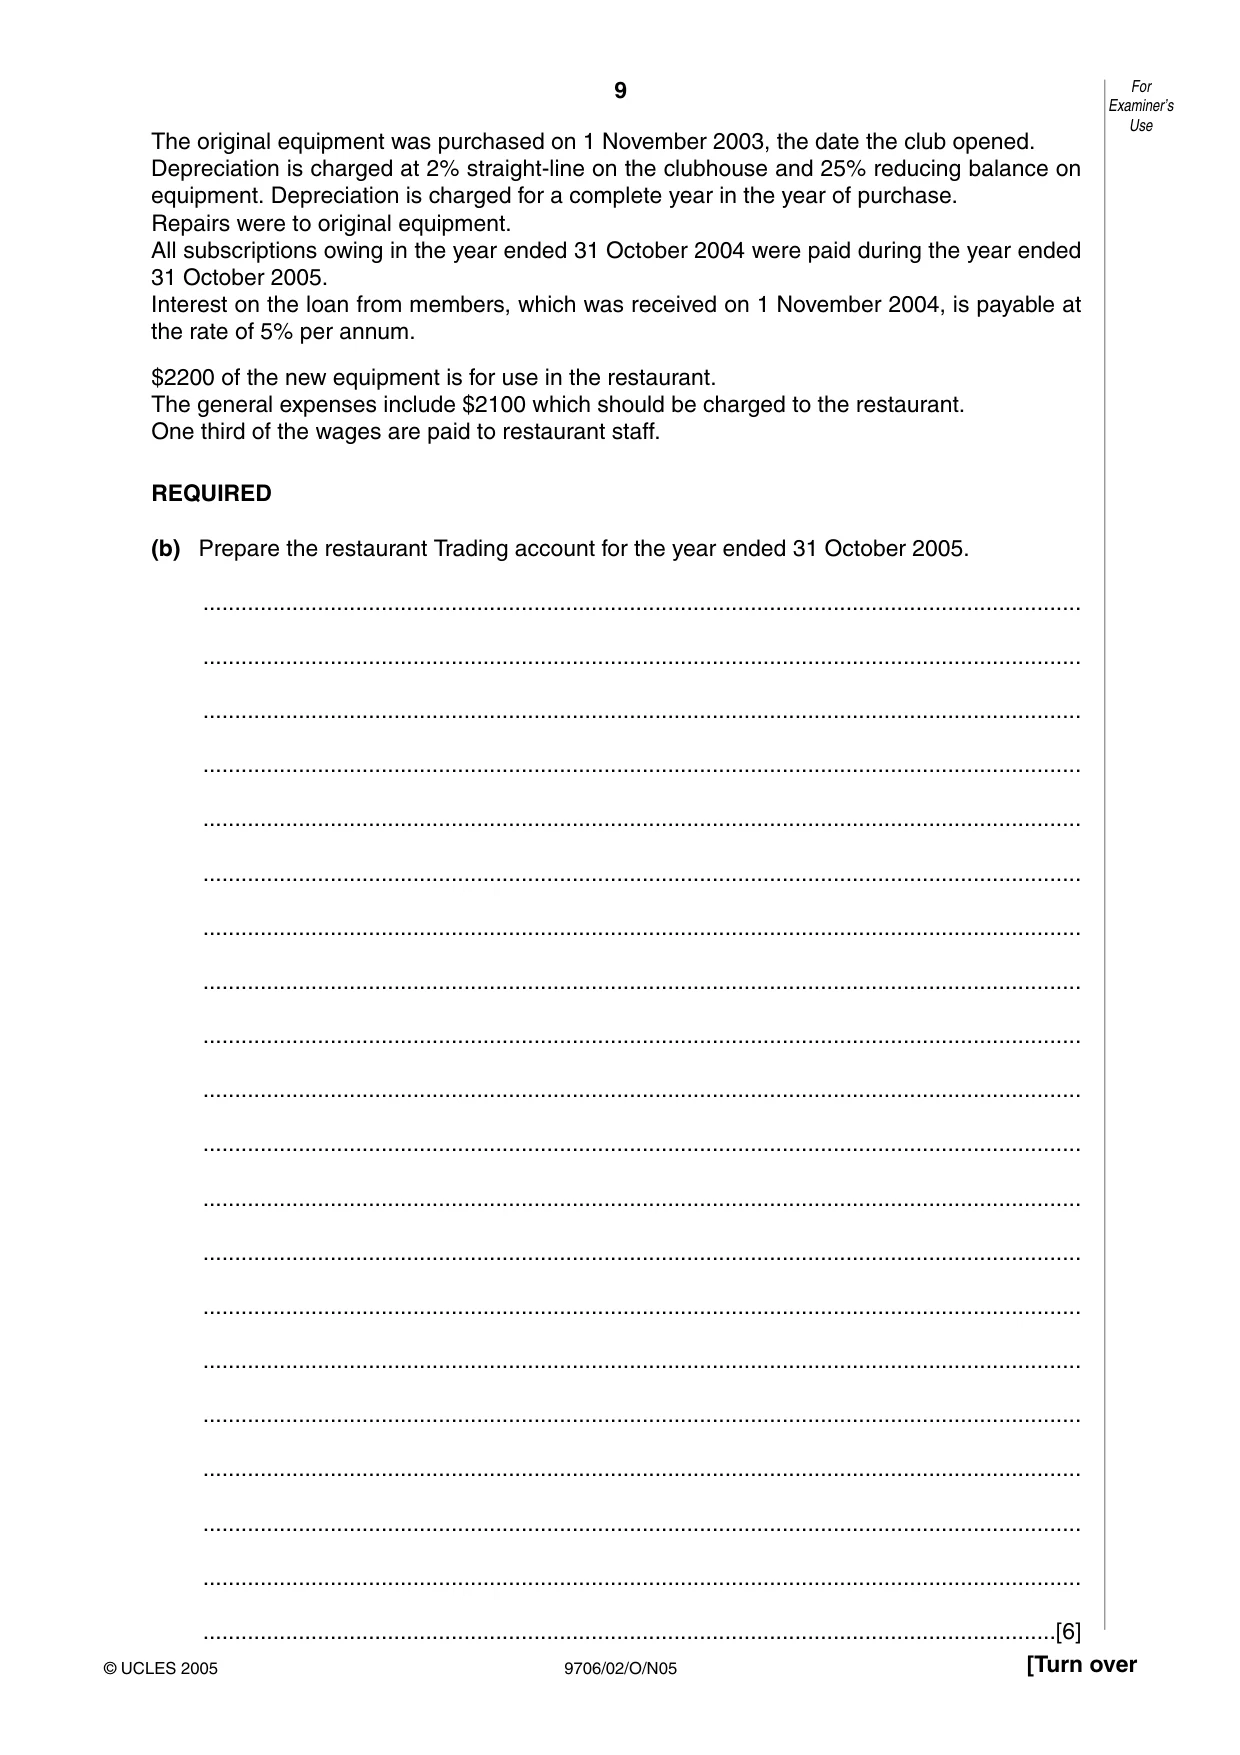
9 9706/02/O/N05 [Turn over The original equipment was purchased on 1 November 2003, the date the club opened. Depreciation is charged at 2% straight-line on the clubhouse and 25% reducing balance on equipment. Depreciation is charged for a complete year in the year of purchase. Repairs were to original equipment. All subscriptions owing in the year ended 31 October 2004 were paid during the year ended 31 October 2005. Interest on the loan from members, which was received on 1 November 2004, is payable at the rate of 5% per annum. $2200 of the new equipment is for use in the restaurant. The general expenses include $2100 which should be charged to the restaurant. One third of the wages are paid to restaurant staff. REQUIRED (b) Prepare the restaurant Trading account for the year ended 31 October 2005. … … … … … … … … … … … … … … … … … … … …[6] For Examiner’s Use © UCLES 2005
Question paper, page 10
10 9706/02/O/N05 (c) Prepare the club’s Income and Expenditure account for the year ended 31 October 2005. … … … … … … … … … … … … … … … … … … … …[20] [Total: 30] For Examiner’s Use © UCLES 2005
Question paper, page 11
11 9706/02/O/N05 [Turn over BLANK PAGE Question 3 is on the next page
Question paper, page 12
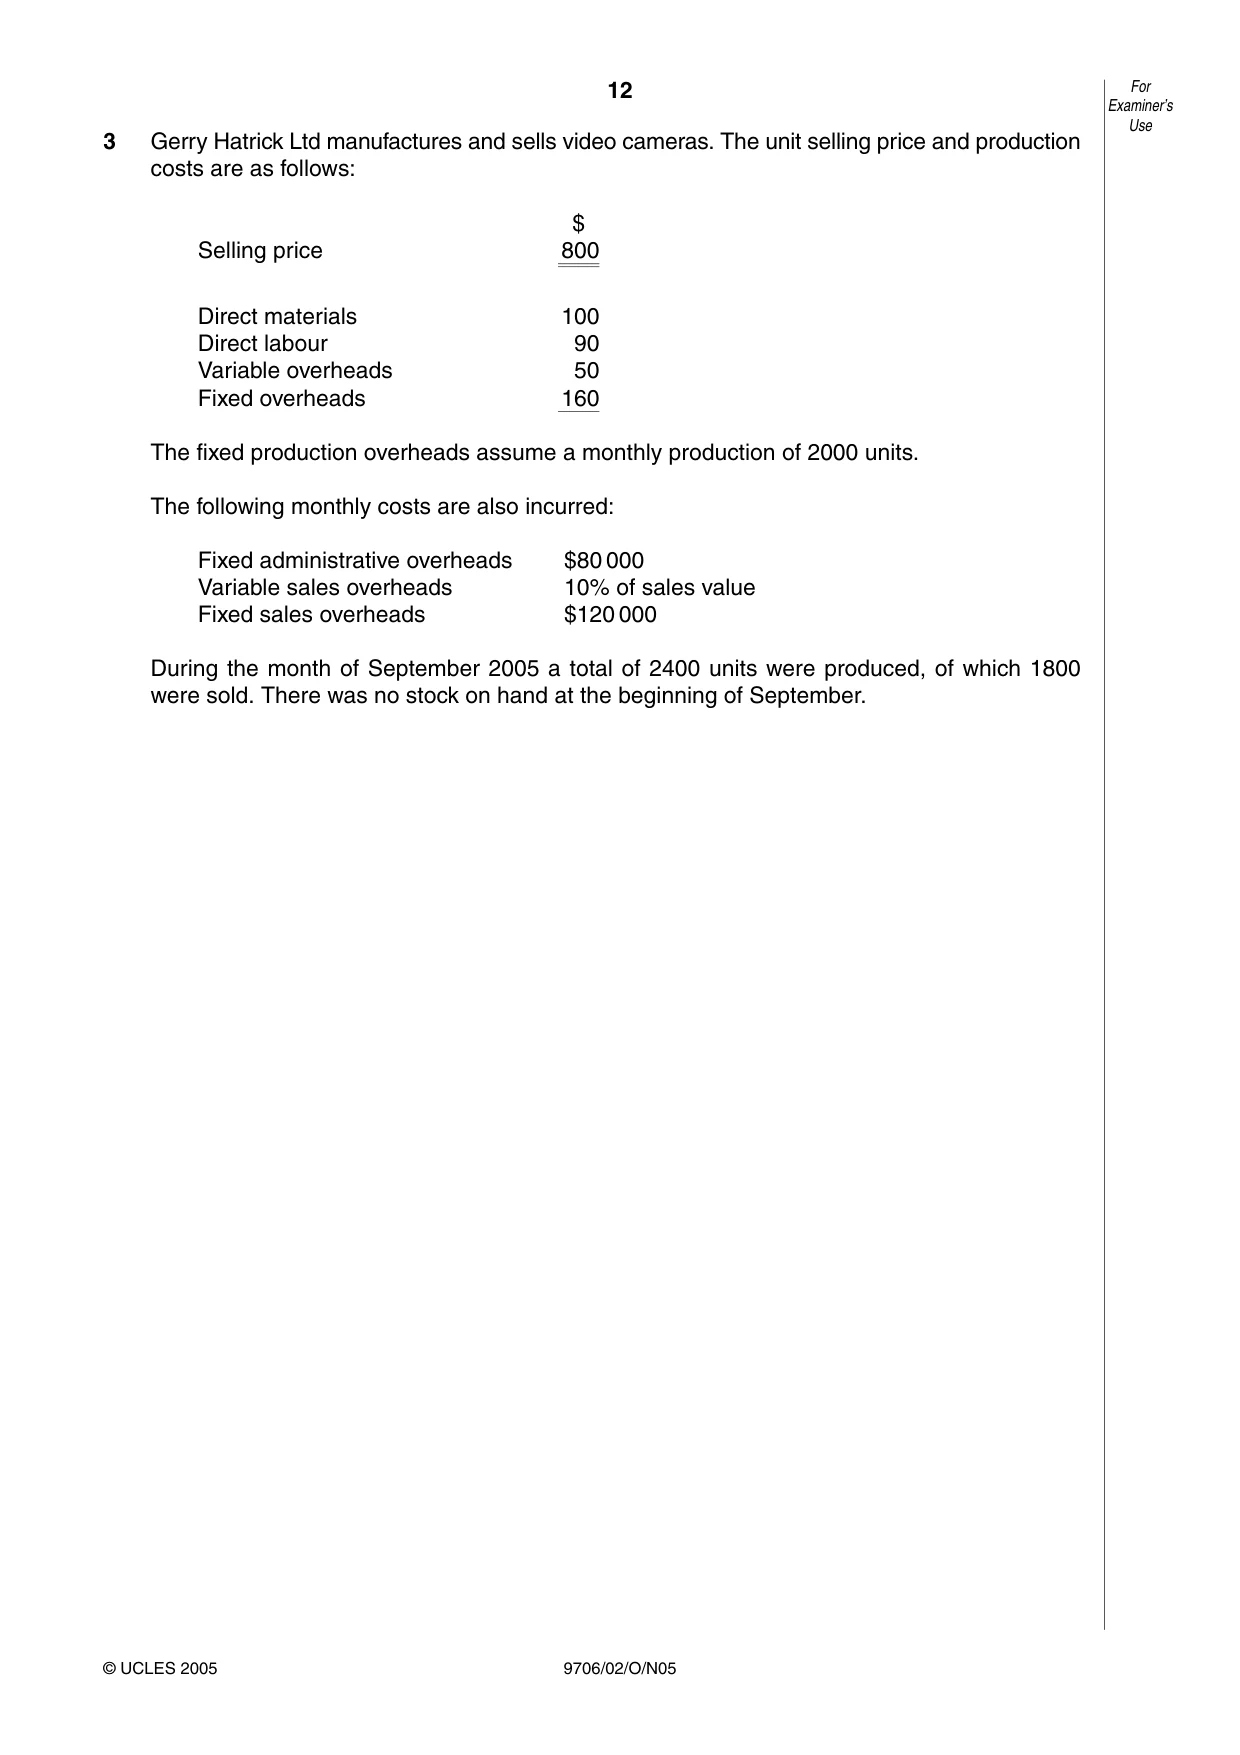
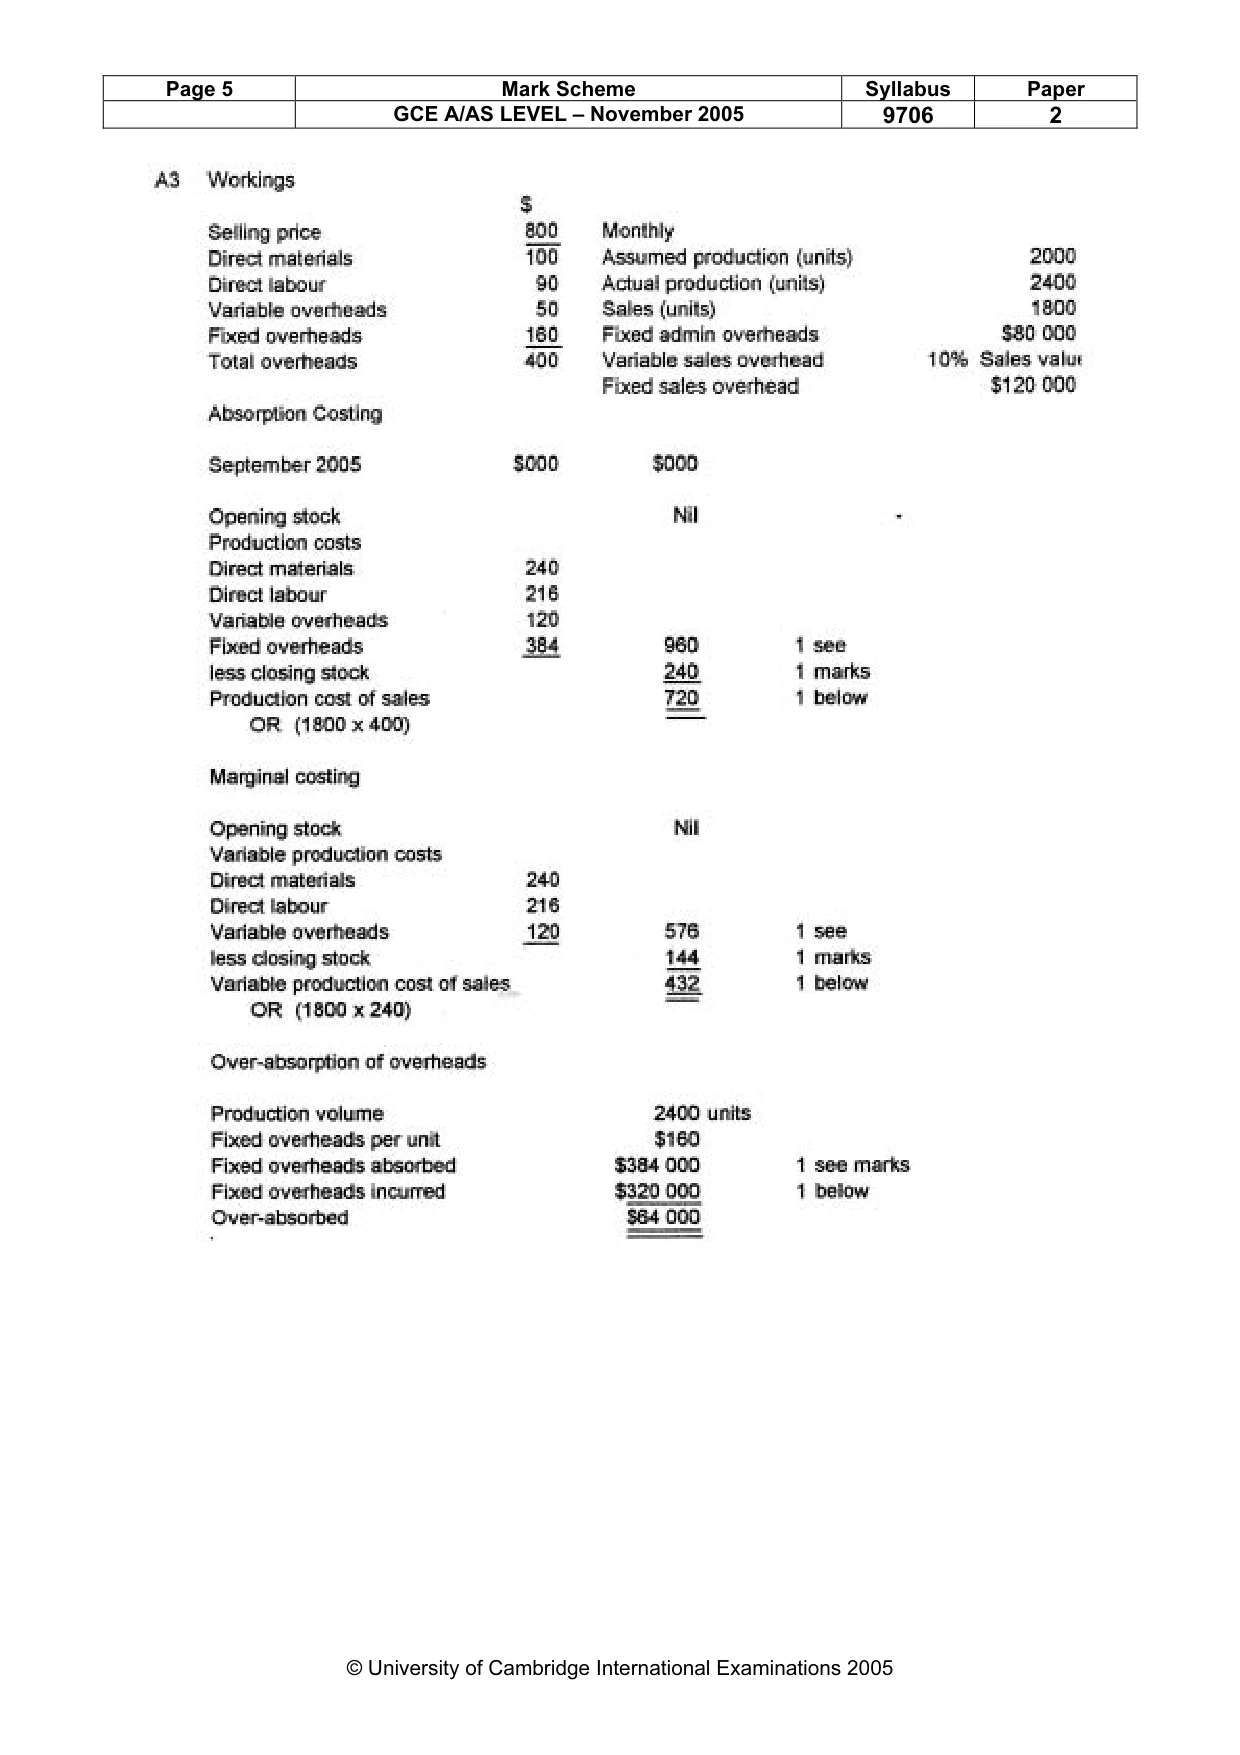
12 9706/02/O/N05 3 Gerry Hatrick Ltd manufactures and sells video cameras. The unit selling price and production costs are as follows: $ Selling price 800 Direct materials 100 Direct labour 90 Variable overheads 50 Fixed overheads 160 The fixed production overheads assume a monthly production of 2000 units. The following monthly costs are also incurred: Fixed administrative overheads $80 000 Variable sales overheads 10% of sales value Fixed sales overheads $120 000 During the month of September 2005 a total of 2400 units were produced, of which 1800 were sold. There was no stock on hand at the beginning of September. For Examiner’s Use © UCLES 2005
Question paper, page 13
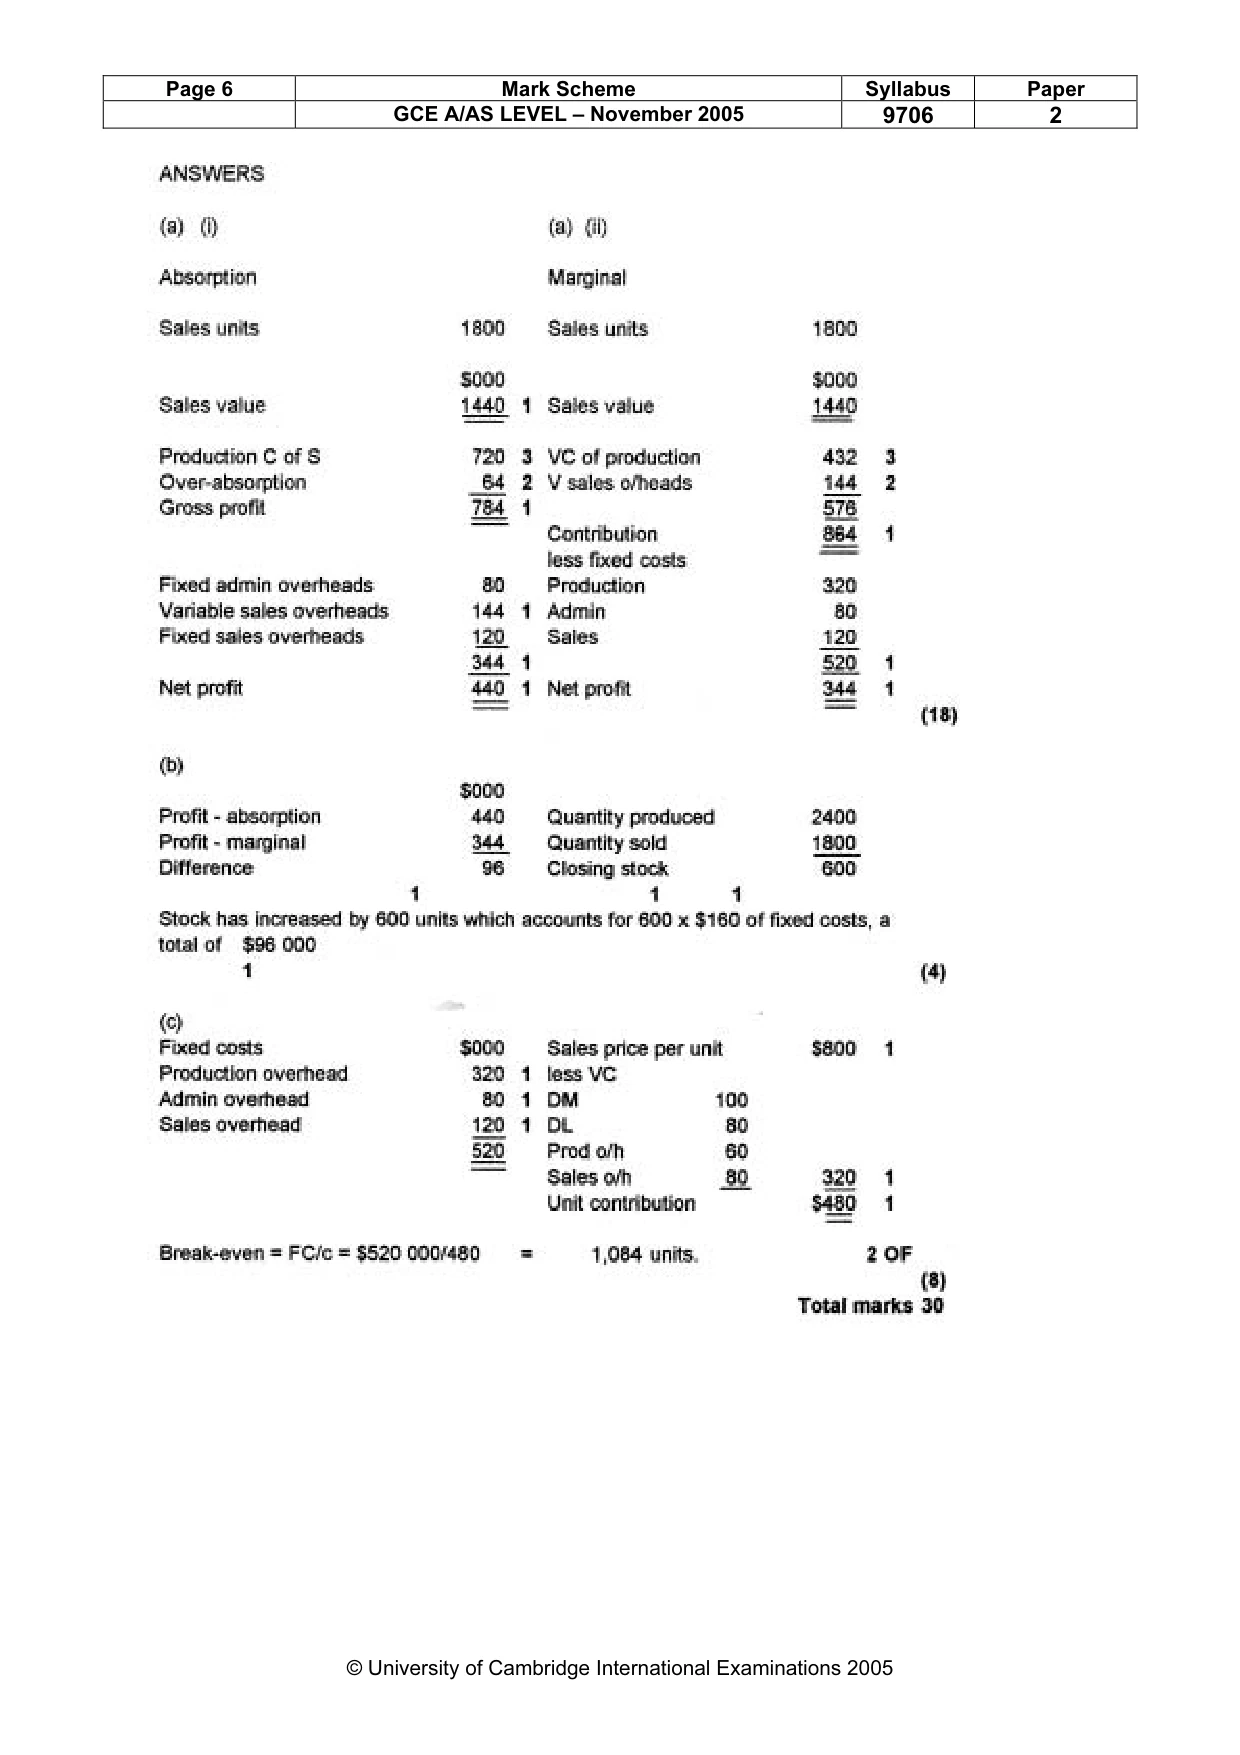
13 9706/02/O/N05 REQUIRED (a) Prepare profit statements for September 2005 using (i) Absorption costing (ii) Marginal costing … … … … … … … … … … … … … … … … … … … …[18] For Examiner’s Use © UCLES 2005 [Turn over
Question paper, page 14
14 9706/02/O/N05 (b) Explain why the profit found when using absorption costing differs from the profit found in marginal costing. … … … … … … …[4] (c) Calculate the break-even point for September 2005 in sales volume. … … … … … … … … … …[8] [Total: 30] For Examiner’s Use © UCLES 2005
Question paper, page 16
16 9706/02/O/N05 BLANK PAGE Permission to reproduce items where third-party owned material protected by copyright is included has been sought and cleared where possible. Every reasonable effort has been made by the publisher (UCLES) to trace copyright holders, but if any items requiring clearance have unwittingly been included, the publisher will be pleased to make amends at the earliest possible opportunity. University of Cambridge International Examinations is part of the University of Cambridge Local Examinations Syndicate (UCLES), which is itself a department of the University of Cambridge.
Mark scheme, page 1
UNIVERSITY OF CAMBRIDGE INTERNATIONAL EXAMINATIONS GCE Advanced/Advanced Subsidiary Level MARK SCHEME for the November 2005 question paper 9706 ACCOUNTING 9706/02 Structured Questions maximum raw mark 90 This mark scheme is published as an aid to teachers and students, to indicate the requirements of the examination. It shows the basis on which Examiners were initially instructed to award marks. It does not indicate the details of the discussions that took place at an Examiners’ meeting before marking began. Any substantial changes to the mark scheme that arose from these discussions will be recorded in the published Report on the Examination. All Examiners are instructed that alternative correct answers and unexpected approaches in candidates’ scripts must be given marks that fairly reflect the relevant knowledge and skills demonstrated. Mark schemes must be read in conjunction with the question papers and the Report on the Examination. The minimum marks in these components needed for various grades were previously published with these mark schemes, but are now instead included in the Report on the Examination for this session. • CIE will not enter into discussion or correspondence in connection with these mark schemes. CIE is publishing the mark schemes for the November 2005 question papers for most IGCSE and GCE Advanced Level and Advanced Subsidiary Level syllabuses and some Ordinary Level syllabuses.
Mark scheme, page 2
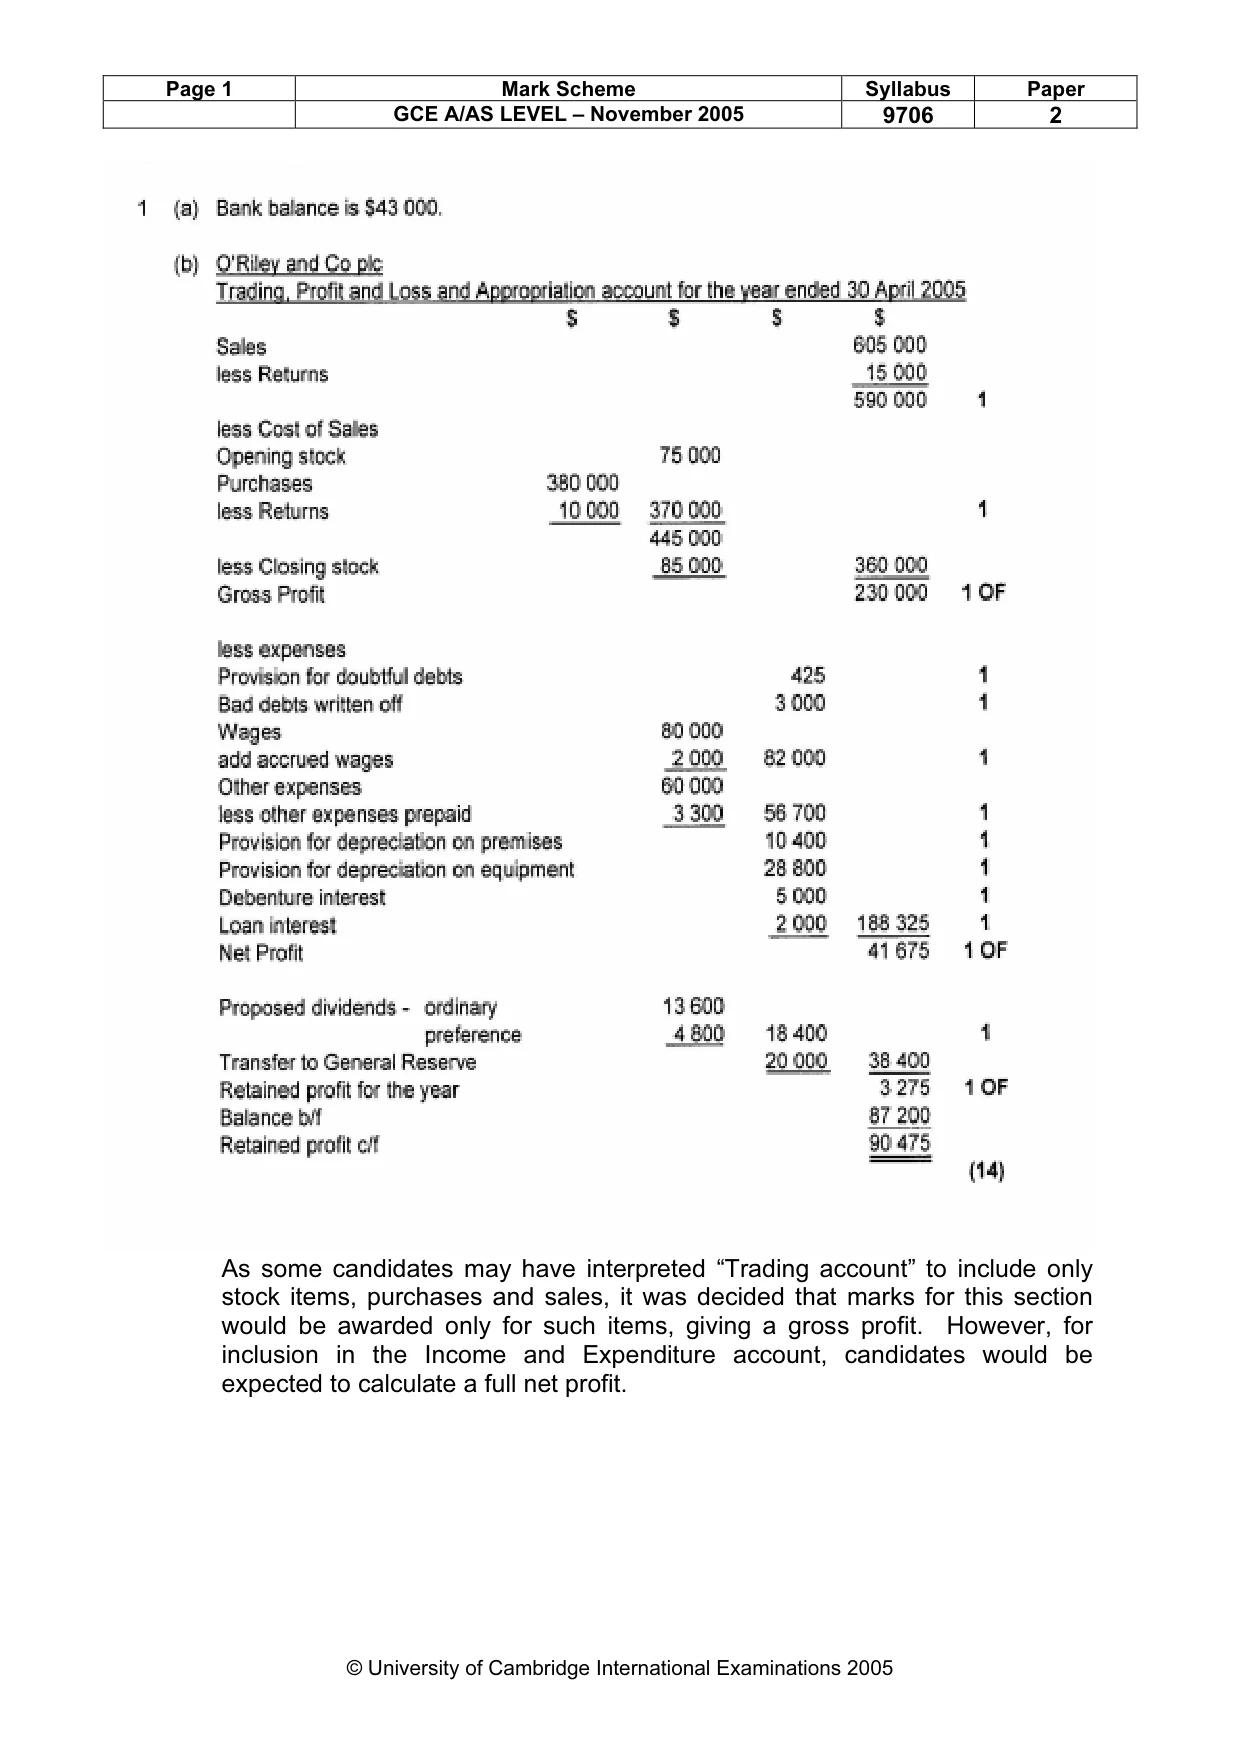
Page 1 Mark Scheme Syllabus Paper GCE A/AS LEVEL – November 2005 9706 2 © University of Cambridge International Examinations 2005 As some candidates may have interpreted “Trading account” to include only stock items, purchases and sales, it was decided that marks for this section would be awarded only for such items, giving a gross profit. However, for inclusion in the Income and Expenditure account, candidates would be expected to calculate a full net profit.
Mark scheme, page 3
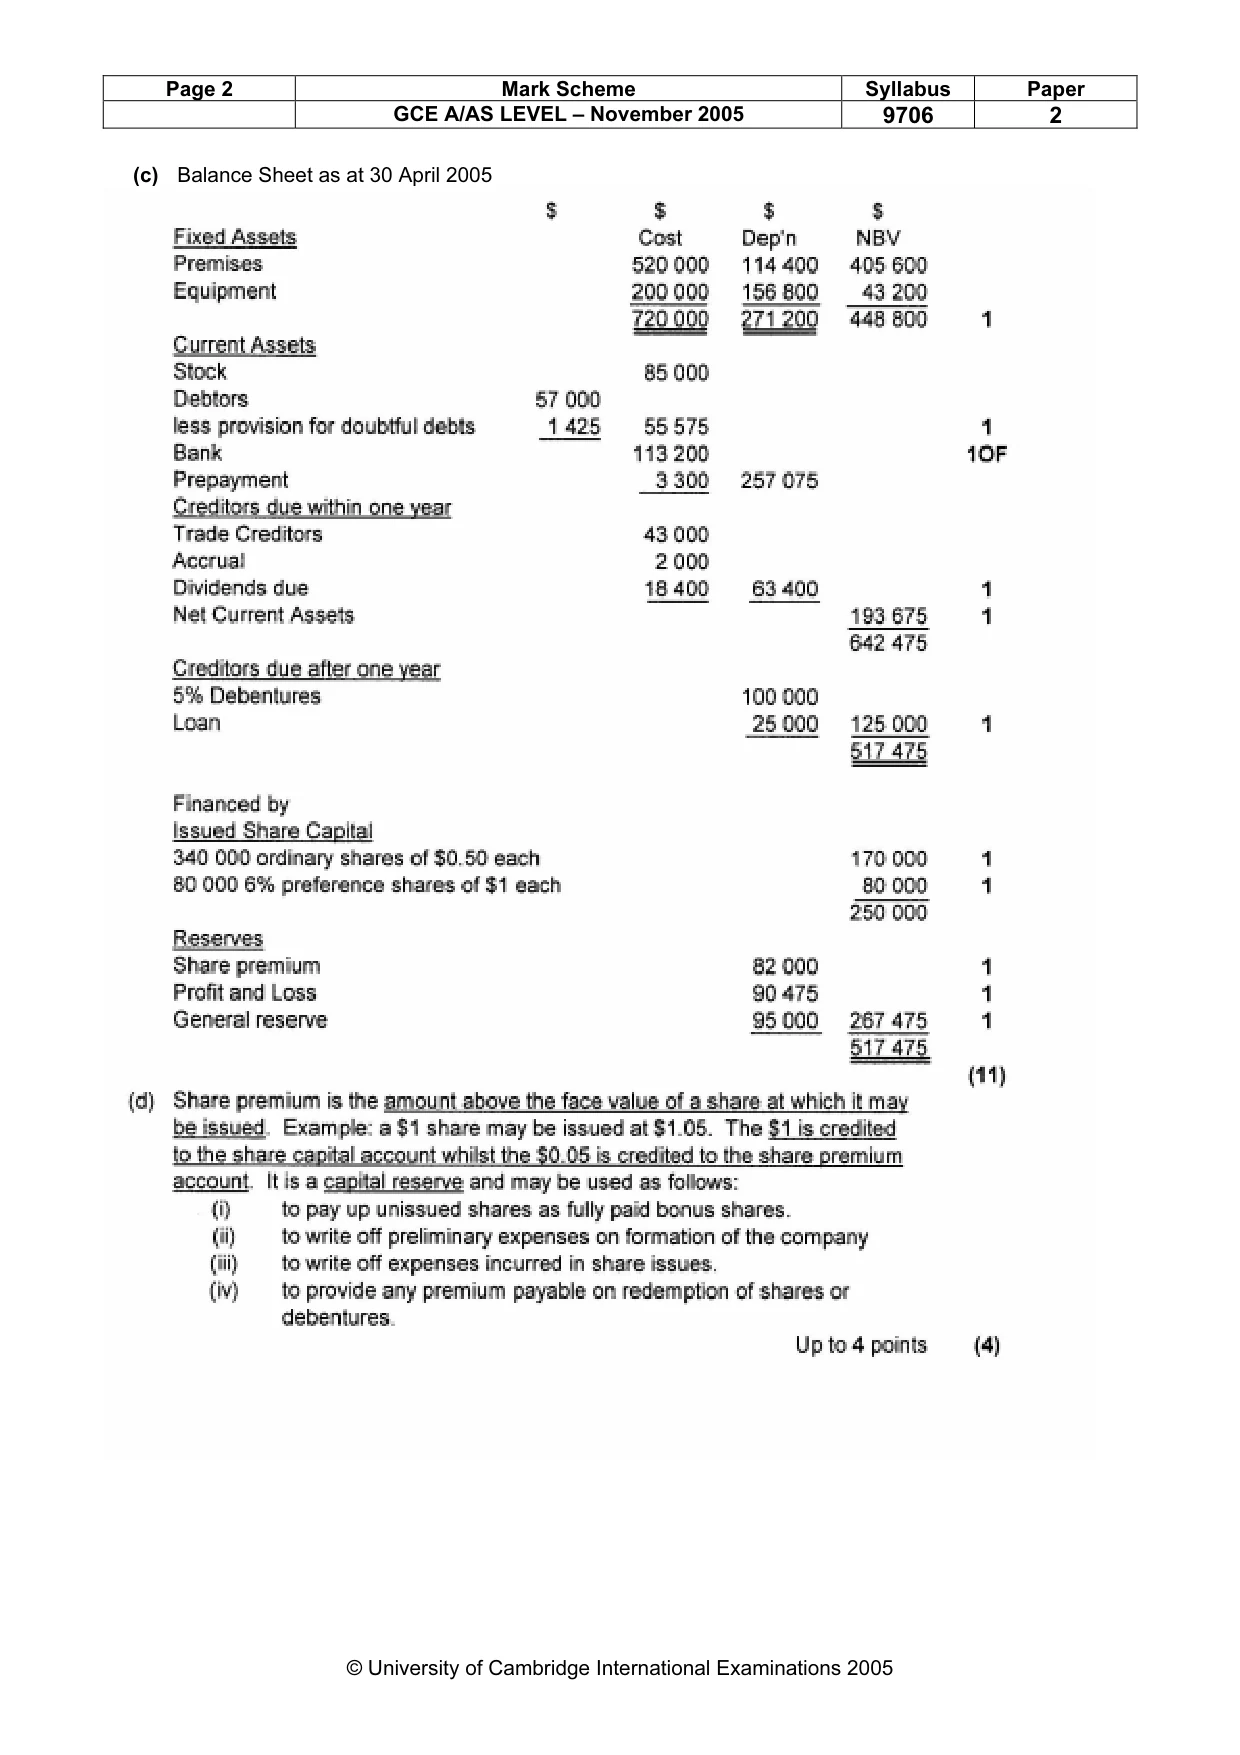
Page 2 Mark Scheme Syllabus Paper GCE A/AS LEVEL – November 2005 9706 2 © University of Cambridge International Examinations 2005 (c) Balance Sheet as at 30 April 2005
Mark scheme, page 4
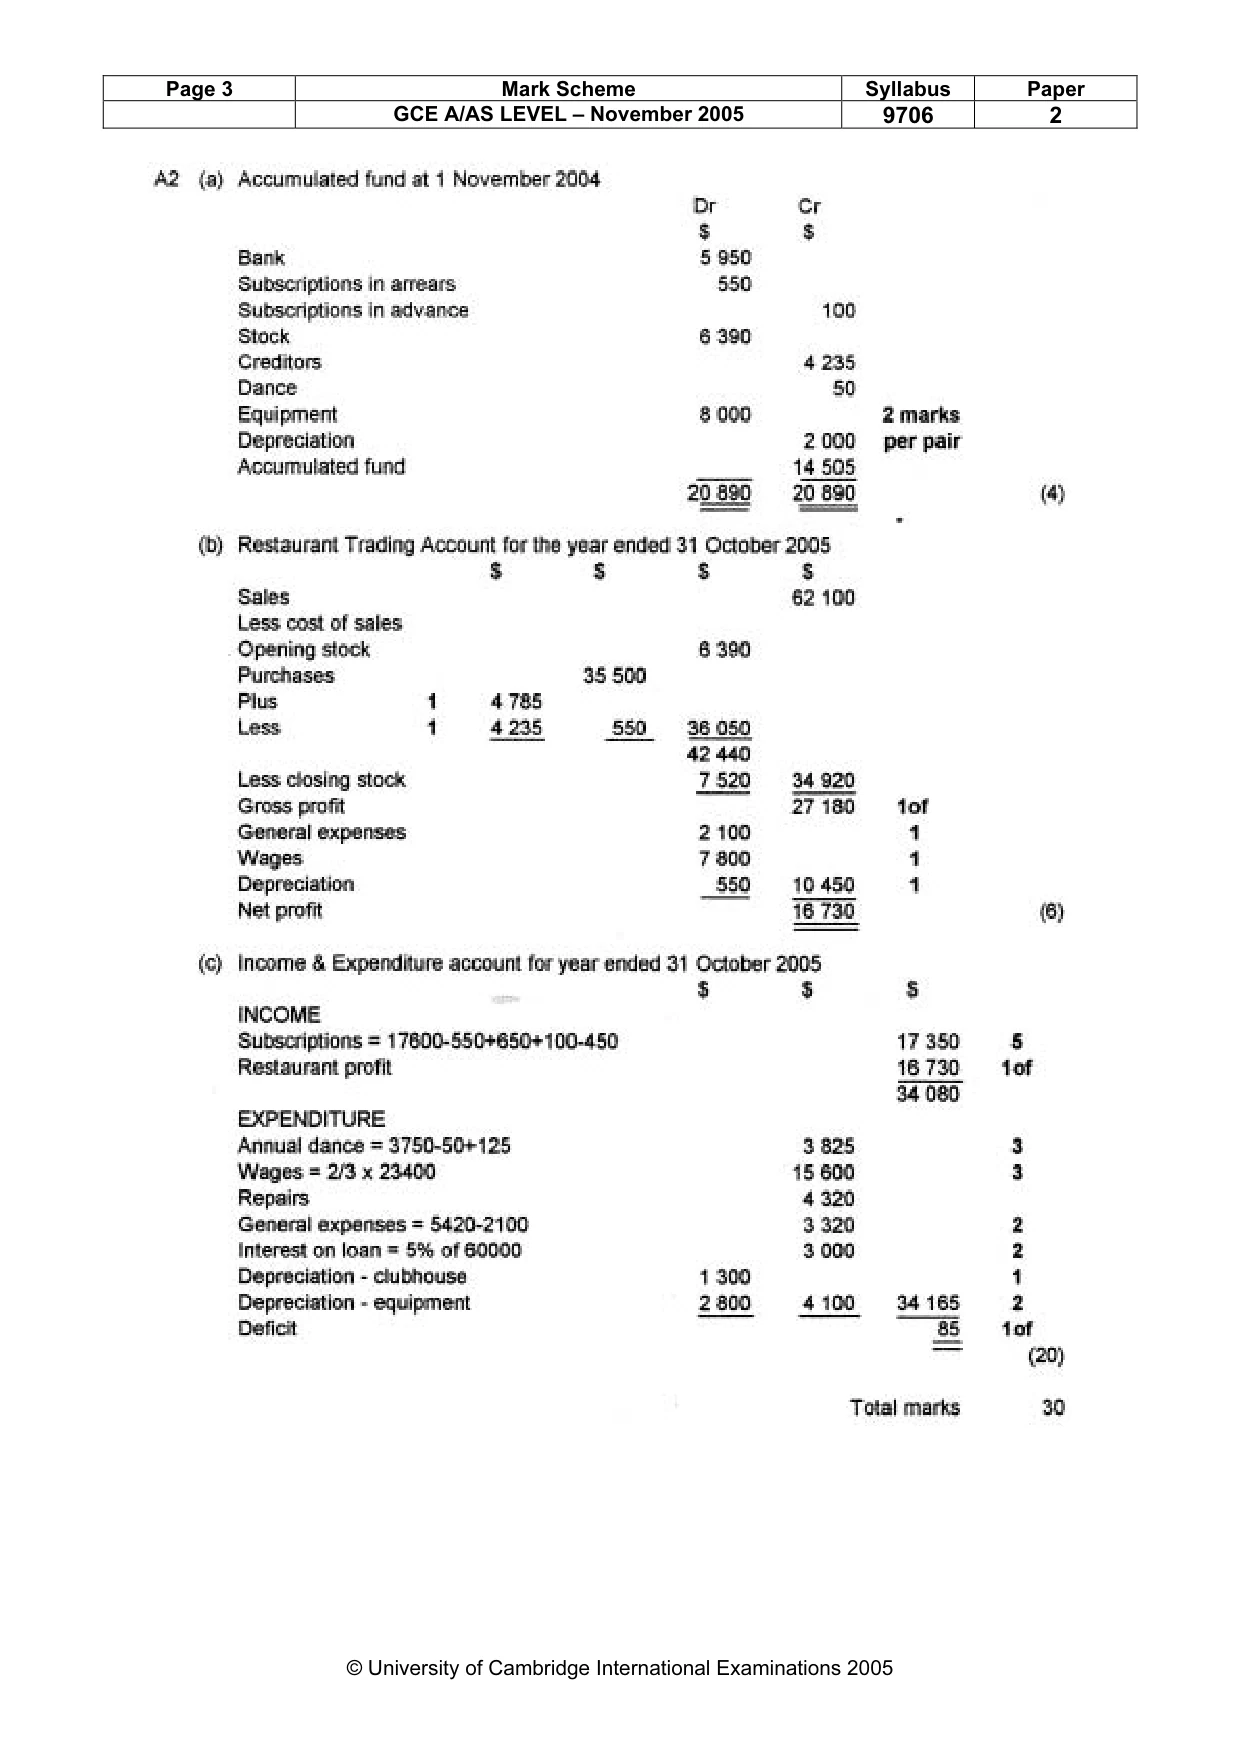
Page 3 Mark Scheme Syllabus Paper GCE A/AS LEVEL – November 2005 9706 2 © University of Cambridge International Examinations 2005
Mark scheme, page 5
Page 4 Mark Scheme Syllabus Paper GCE A/AS LEVEL – November 2005 9706 2 © University of Cambridge International Examinations 2005
Mark scheme, page 6
Page 5 Mark Scheme Syllabus Paper GCE A/AS LEVEL – November 2005 9706 2 © University of Cambridge International Examinations 2005
Mark scheme, page 7
Page 6 Mark Scheme Syllabus Paper GCE A/AS LEVEL – November 2005 9706 2 © University of Cambridge International Examinations 2005