Cambridge A Level Accounting 9706 — 2004 May/June Paper 2 · Variant 1
9706/21/M/J/04
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
Mark scheme
No mark scheme is in the library for this paper.
Paper as text
Question paper, page 1
This document consists of 11 printed pages and 1 blank page. SP (SJF2964) S53066/4 © UCLES 2004 [Turn over UNIVERSITY OF CAMBRIDGE INTERNATIONAL EXAMINATIONS General Certificate of Education Advanced Subsidiary Level and Advanced Level ACCOUNTING 9706/02 Paper 2 Structured Questions May/June 2004 1 hour 30 minutes Candidates answer on the Question Paper. No Additional Materials are required. READ THESE INSTRUCTIONS FIRST Write your Centre number, candidate number and name on all the work you hand in. Write in dark blue or black pen in the spaces provided on the Question Paper. You may use a soft pencil for rough working. Do not use staples, paper clips, highlighters, glue or correction fluid. Answer all questions. At the end of the examination, fasten all your work securely together. The number of marks is given in brackets [ ] at the end of each question or part question. You may use a calculator. Centre Number Candidate Number Name If you have been given a label, look at the details. If any details are incorrect or missing, please fill in your correct details in the space given at the top of this page. Stick your personal label here, if provided. For Examiner’s Use 1 2 3 Total
Question paper, page 2
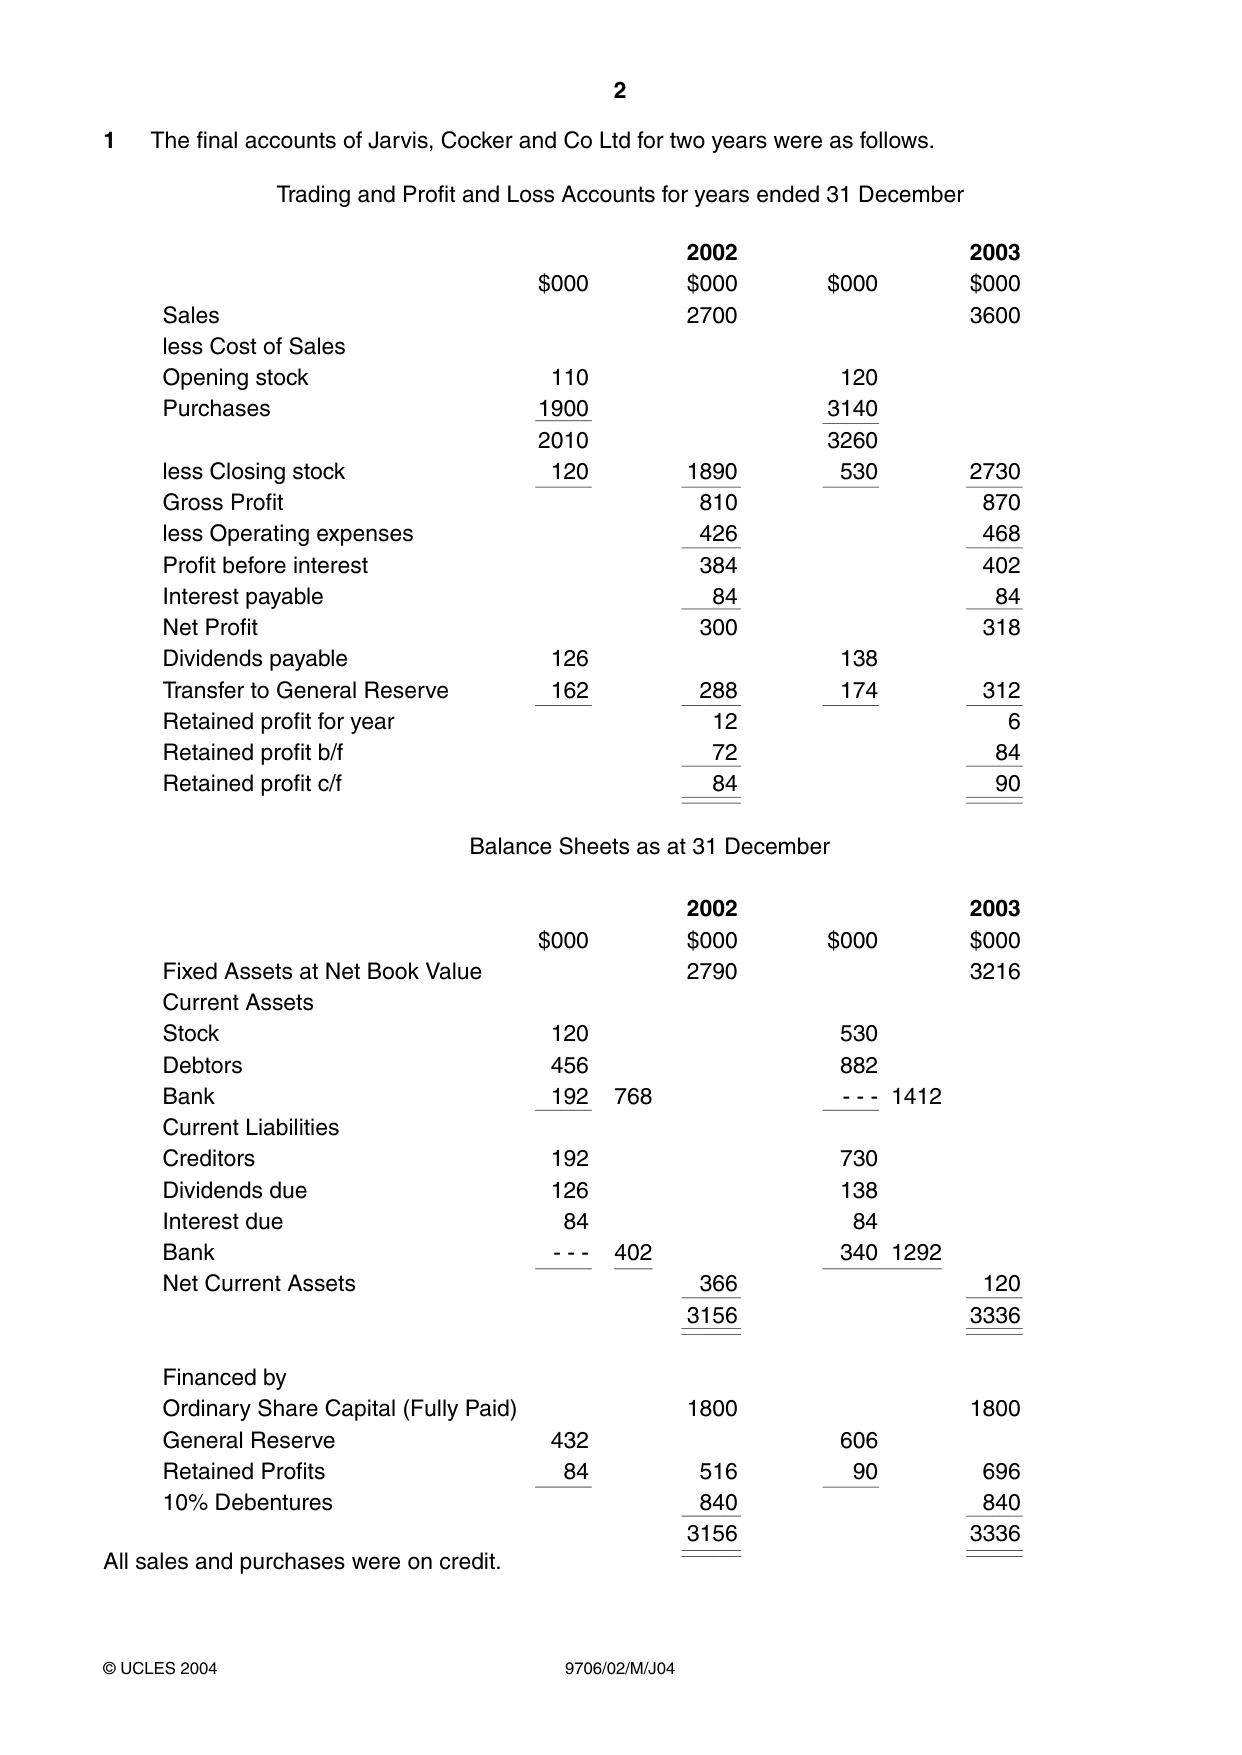
2 9706/02/M/J04 1 The final accounts of Jarvis, Cocker and Co Ltd for two years were as follows. Trading and Profit and Loss Accounts for years ended 31 December 2002 2003 $000 $000 $000 $000 Sales 2700 3600 less Cost of Sales Opening stock 110 120 Purchases 1900 3140 2010 3260 less Closing stock 120 1890 530 2730 Gross Profit 810 870 less Operating expenses 426 468 Profit before interest 384 402 Interest payable 84 84 Net Profit 300 318 Dividends payable 126 138 Transfer to General Reserve 162 288 174 312 Retained profit for year 12 6 Retained profit b/f 72 84 Retained profit c/f 84 90 Balance Sheets as at 31 December 2002 2003 $000 $000 $000 $000 Fixed Assets at Net Book Value 2790 3216 Current Assets Stock 120 530 Debtors 456 882 Bank 192 768 - - - 1412 Current Liabilities Creditors 192 730 Dividends due 126 138 Interest due 84 84 Bank - - - 402 340 1292 Net Current Assets 366 120 3156 3336 Financed by Ordinary Share Capital (Fully Paid) 1800 1800 General Reserve 432 606 Retained Profits 84 516 90 696 10% Debentures 840 840 3156 3336 All sales and purchases were on credit. © UCLES 2004
Question paper, page 3
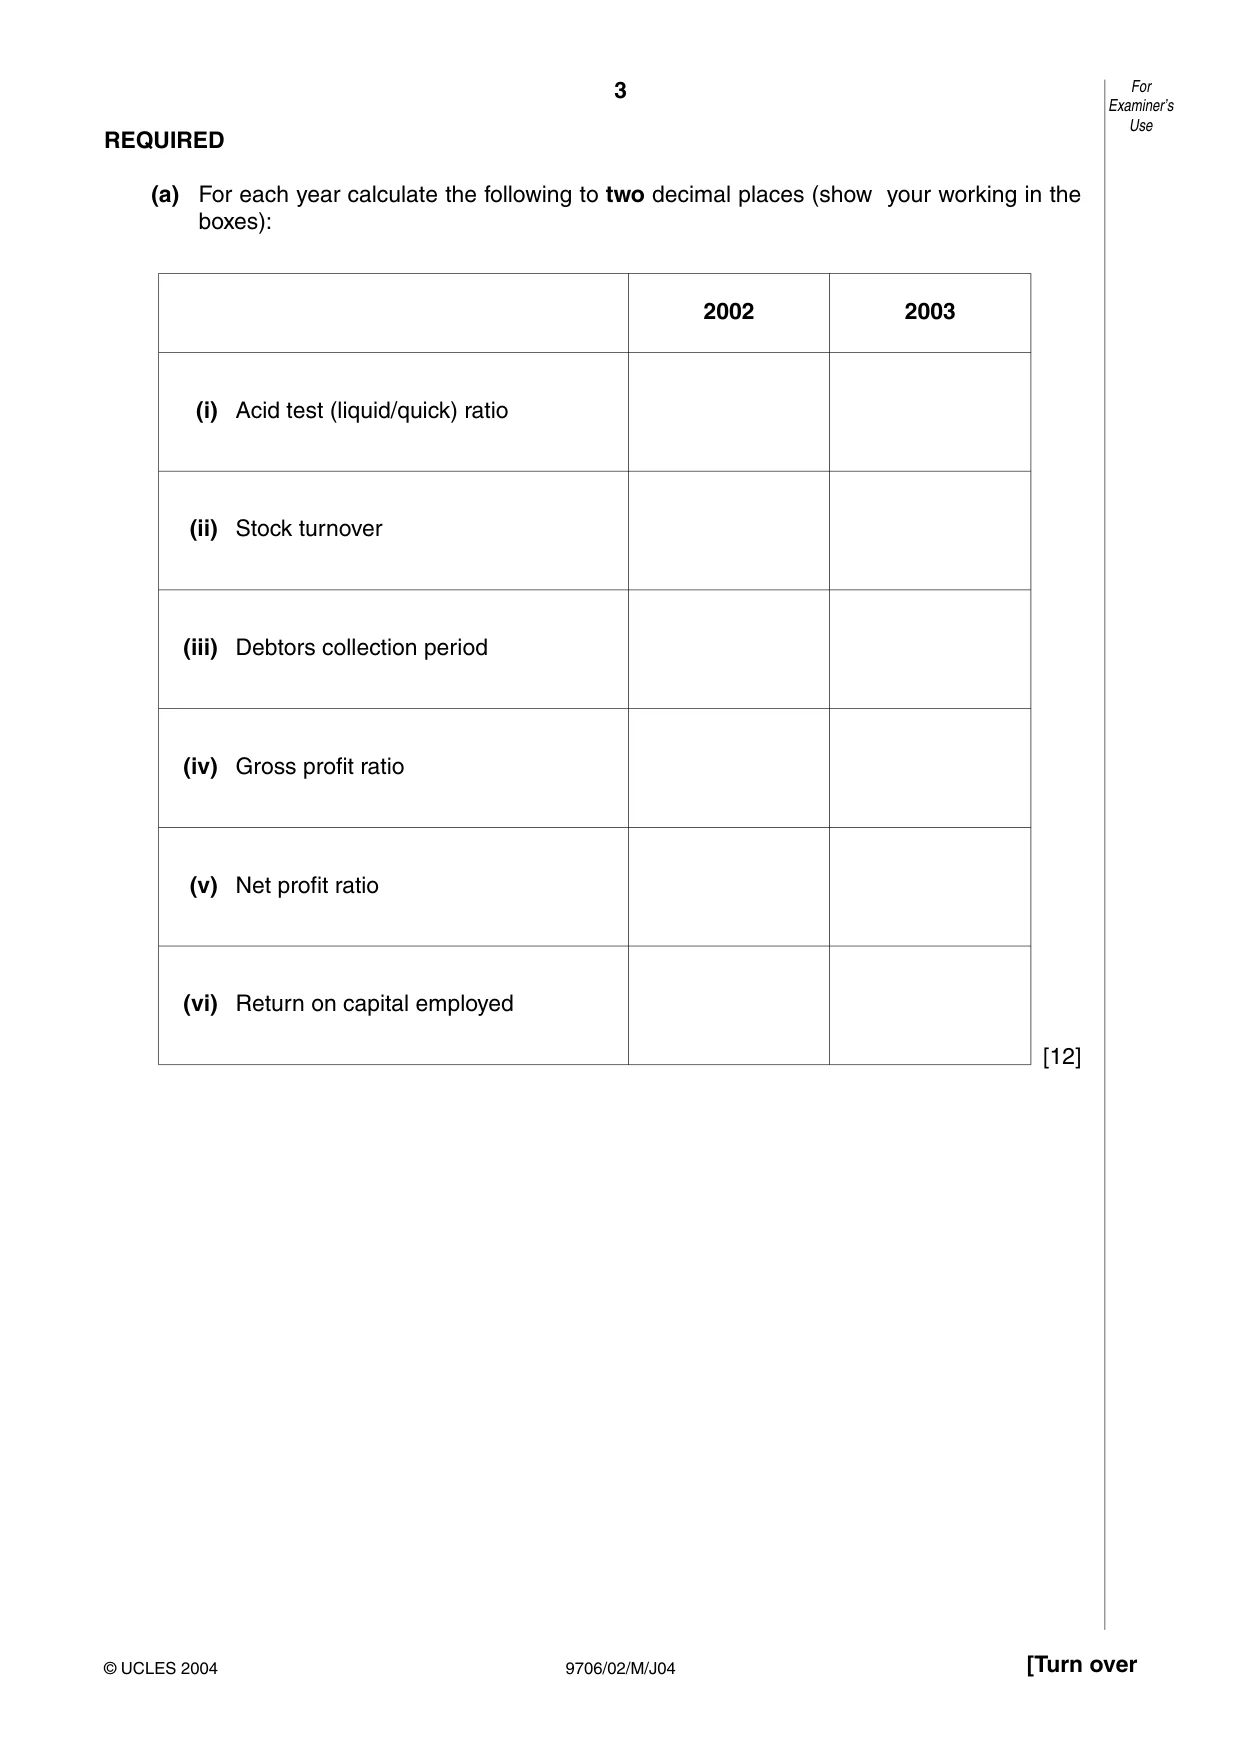
3 9706/02/M/J04 [Turn over REQUIRED (a) For each year calculate the following to two decimal places (show your working in the boxes): [12] For Examiner’s Use © UCLES 2004 (i) Acid test (liquid/quick) ratio (ii) Stock turnover (iii) Debtors collection period (iv) Gross profit ratio (v) Net profit ratio (vi) Return on capital employed 2002 2003
Question paper, page 4
4 9706/02/M/J04 (b) Comment on the changes in the Company from 2002 to 2003, stating for each ratio whether it is better or worse, and why. … … … … … … … … … … … … … … … … … … … … … … … … … … … [12] For Examiner’s Use © UCLES 2004
Question paper, page 5
5 9706/02/M/J04 [Turn over (c) Comment briefly on the advantages and disadvantages of using ratios. … … … … … … … … [6] For Examiner’s Use © UCLES 2004
Question paper, page 6
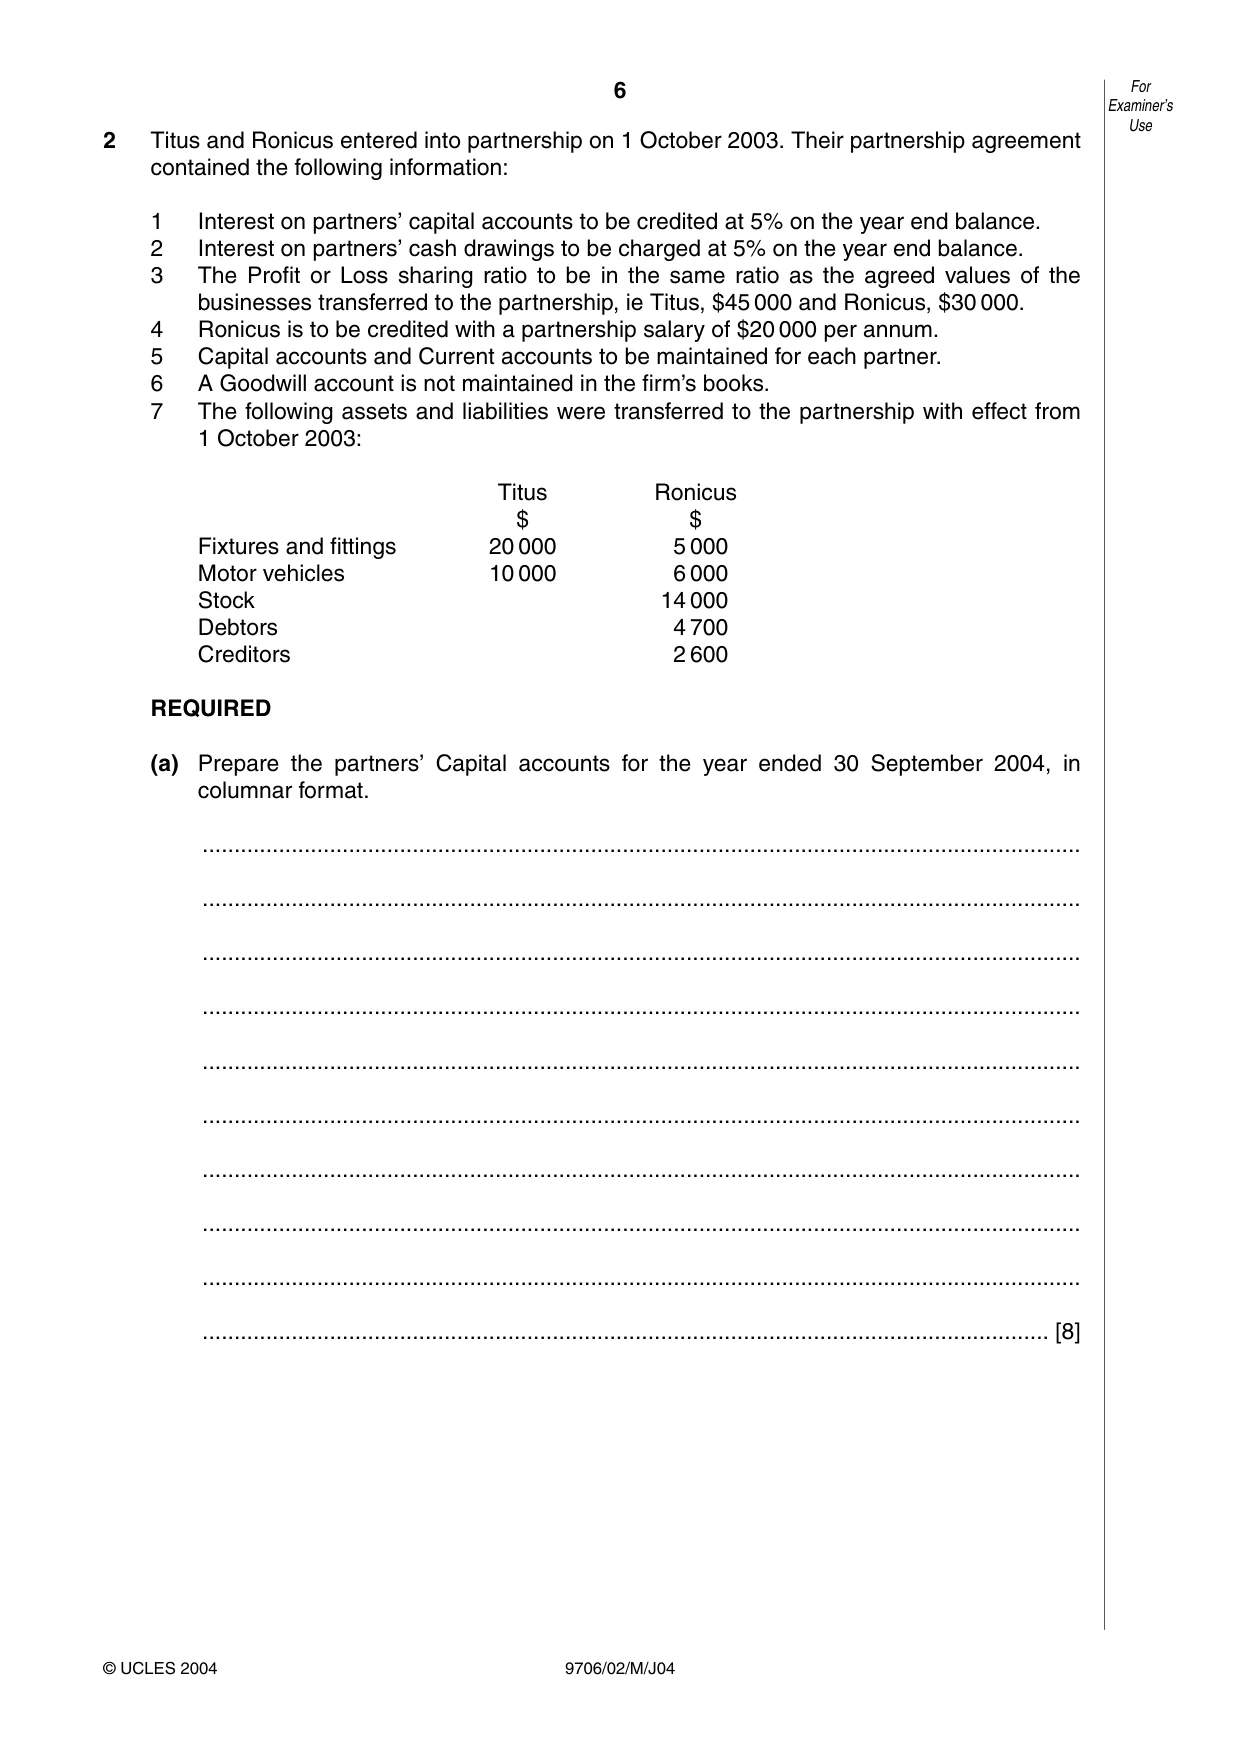
6 9706/02/M/J04 2 Titus and Ronicus entered into partnership on 1 October 2003. Their partnership agreement contained the following information: 1 Interest on partners’ capital accounts to be credited at 5% on the year end balance. 2 Interest on partners’ cash drawings to be charged at 5% on the year end balance. 3 The Profit or Loss sharing ratio to be in the same ratio as the agreed values of the businesses transferred to the partnership, ie Titus, $45 000 and Ronicus, $30 000. 4 Ronicus is to be credited with a partnership salary of $20 000 per annum. 5 Capital accounts and Current accounts to be maintained for each partner. 6 A Goodwill account is not maintained in the firm’s books. 7 The following assets and liabilities were transferred to the partnership with effect from 1 October 2003: Titus Ronicus $ $ Fixtures and fittings 20 000 5 000 Motor vehicles 10 000 6 000 Stock 14 000 Debtors 4 700 Creditors 2 600 REQUIRED (a) Prepare the partners’ Capital accounts for the year ended 30 September 2004, in columnar format. … … … … … … … … … … [8] For Examiner’s Use © UCLES 2004
Question paper, page 7
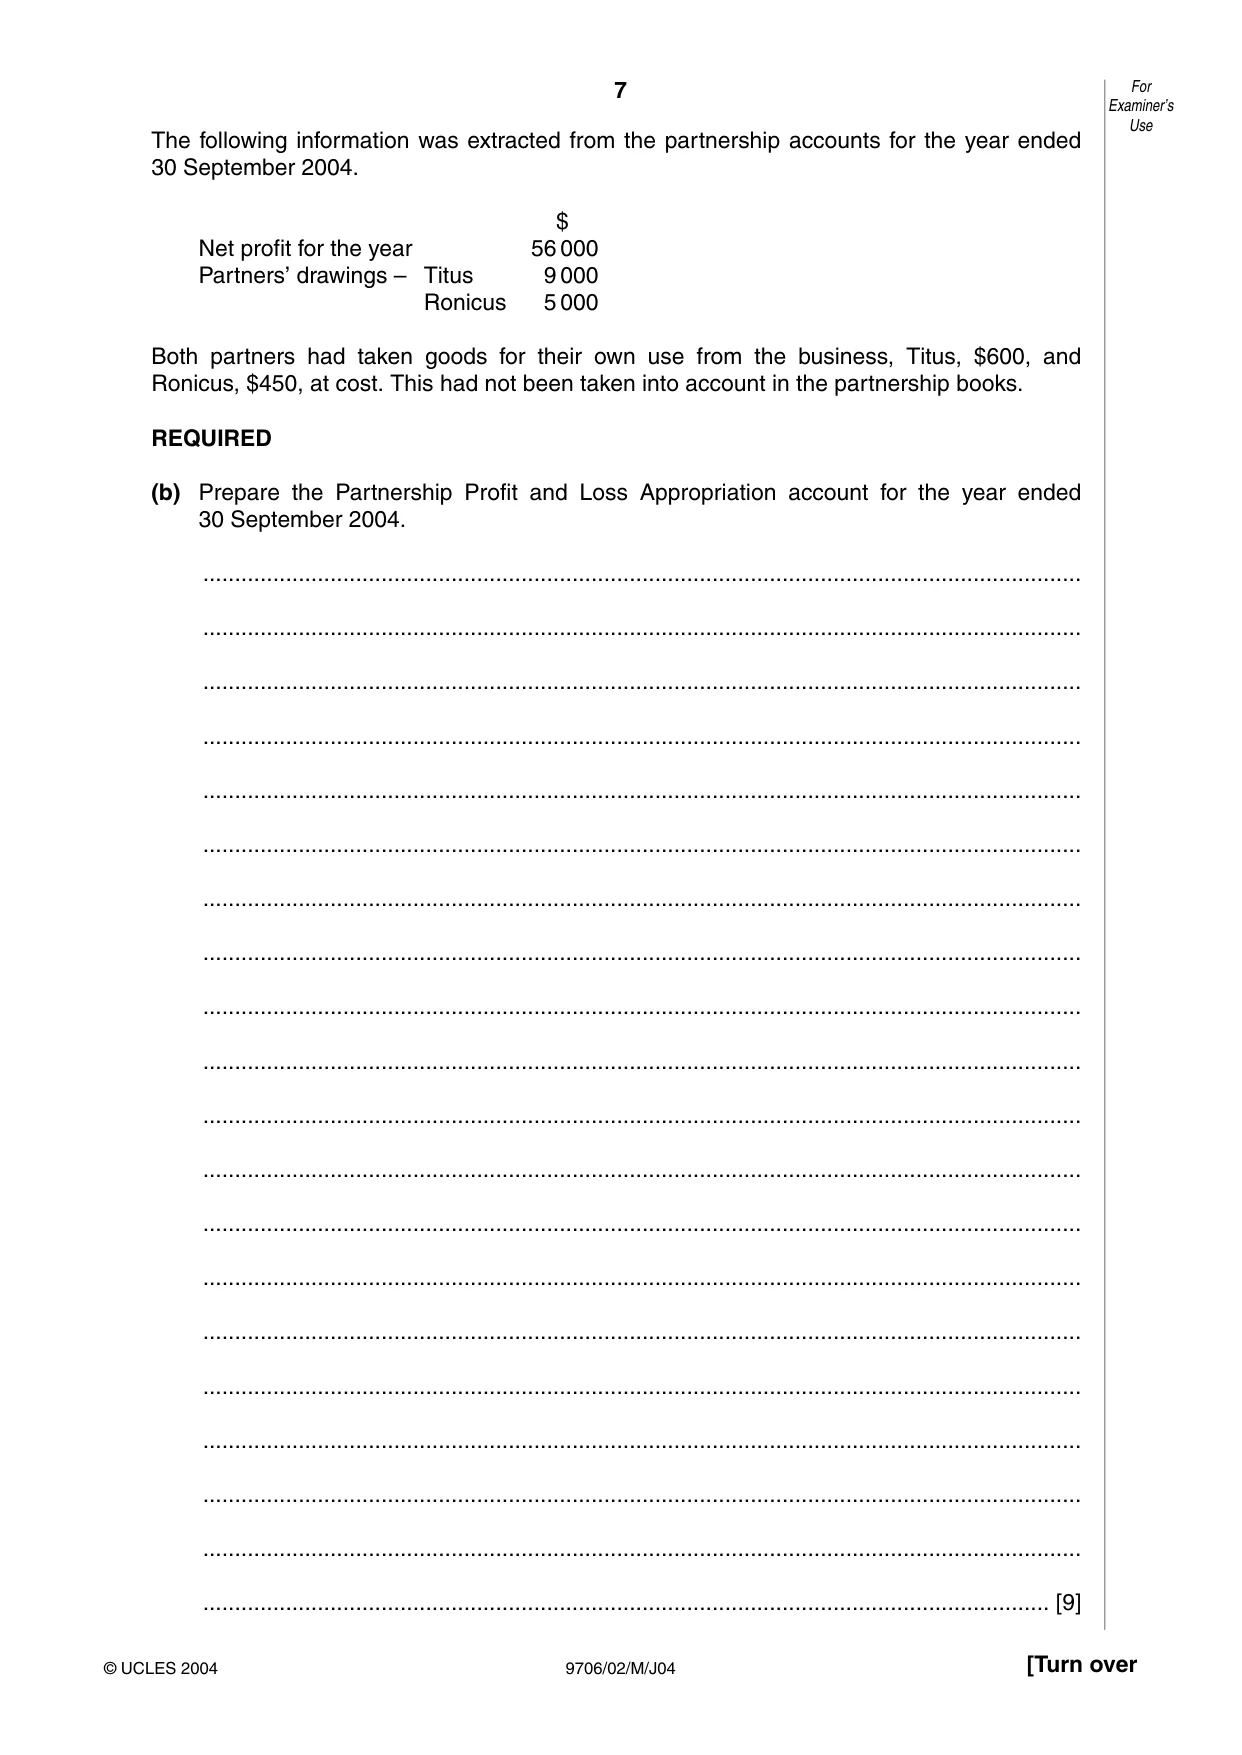
7 9706/02/M/J04 [Turn over The following information was extracted from the partnership accounts for the year ended 30 September 2004. $ Net profit for the year 56 000 Partners’ drawings – Titus 9 000 Ronicus 5 000 Both partners had taken goods for their own use from the business, Titus, $600, and Ronicus, $450, at cost. This had not been taken into account in the partnership books. REQUIRED (b) Prepare the Partnership Profit and Loss Appropriation account for the year ended 30 September 2004. … … … … … … … … … … … … … … … … … … … … [9] For Examiner’s Use © UCLES 2004
Question paper, page 8
8 9706/02/M/J04 (c) Prepare the partners’ Current accounts for the year ended 30 September 2004, in columnar format. … … … … … … … … … … … … [13] For Examiner’s Use © UCLES 2004
Question paper, page 9
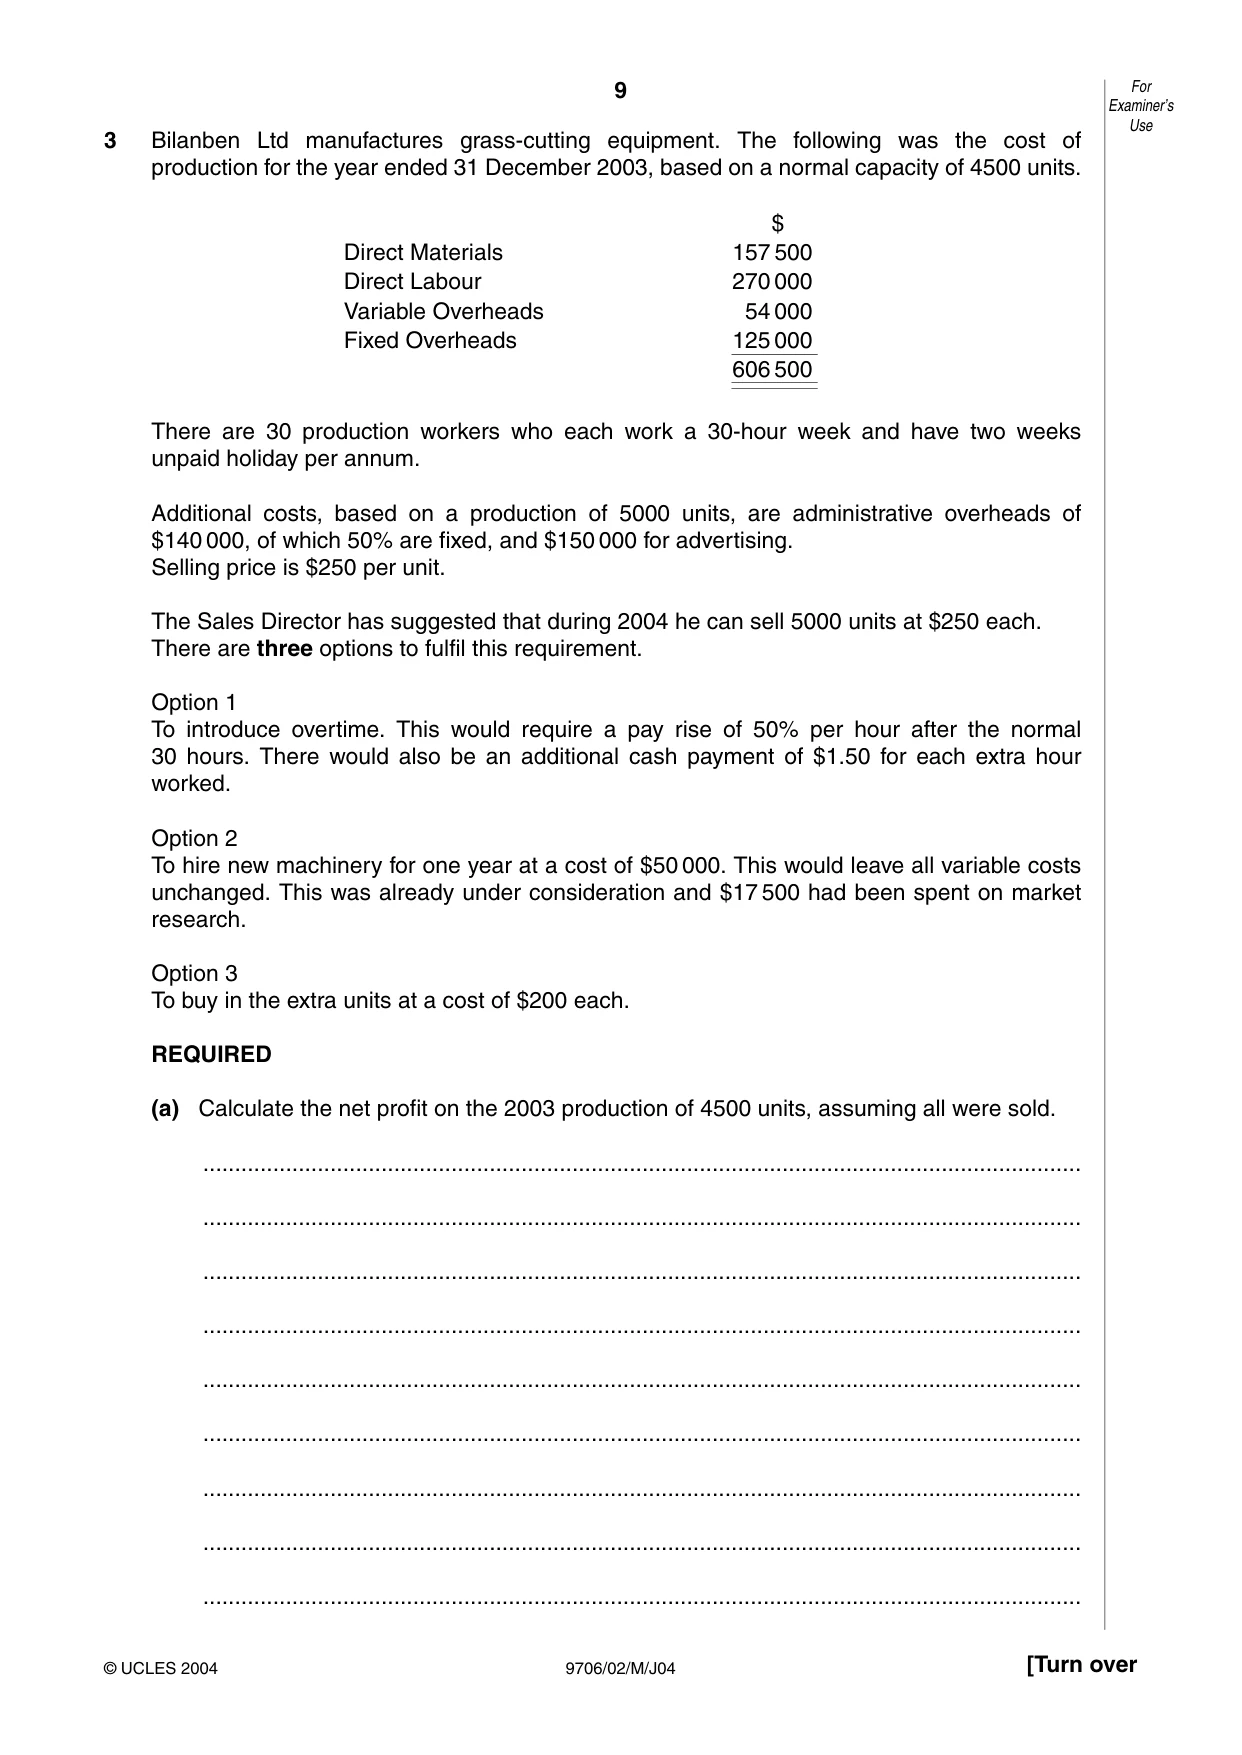
9 9706/02/M/J04 [Turn over 3 Bilanben Ltd manufactures grass-cutting equipment. The following was the cost of production for the year ended 31 December 2003, based on a normal capacity of 4500 units. $ Direct Materials 157 500 Direct Labour 270 000 Variable Overheads 54 000 Fixed Overheads 125 000 606 500 There are 30 production workers who each work a 30-hour week and have two weeks unpaid holiday per annum. Additional costs, based on a production of 5000 units, are administrative overheads of $140 000, of which 50% are fixed, and $150 000 for advertising. Selling price is $250 per unit. The Sales Director has suggested that during 2004 he can sell 5000 units at $250 each. There are three options to fulfil this requirement. Option 1 To introduce overtime. This would require a pay rise of 50% per hour after the normal 30 hours. There would also be an additional cash payment of $1.50 for each extra hour worked. Option 2 To hire new machinery for one year at a cost of $50 000. This would leave all variable costs unchanged. This was already under consideration and $17 500 had been spent on market research. Option 3 To buy in the extra units at a cost of $200 each. REQUIRED (a) Calculate the net profit on the 2003 production of 4500 units, assuming all were sold. … … … … … … … … … For Examiner’s Use © UCLES 2004
Question paper, page 10
10 9706/02/M/J04 … … … … … … … … … … … [10] (b) Prepare statements showing the profitability of each of the three options. … … … … … … … … … … … … … … … … For Examiner’s Use © UCLES 2004
Question paper, page 11
11 9706/02/M/J04 … … … … [17] (c) Write a brief statement comparing the three options. … … … … … … … … … … … … … … … … … [3] For Examiner’s Use © UCLES 2004
Question paper, page 12
12 9706/02/M/J04 BLANK PAGE University of Cambridge International Examinations is part of the University of Cambridge Local Examinations Syndicate (UCLES) which is itself a department of the University of Cambridge.