Cambridge A Level Accounting 9706 — 2003 Oct/Nov Paper 2 · Variant 1
9706/21/O/N/03
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
Mark scheme
No mark scheme is in the library for this paper.
Paper as text
Question paper, page 1
This document consists of 12 printed pages. SP (NF) S42578/2 © CIE 2003 [Turn over CAMBRIDGE INTERNATIONAL EXAMINATIONS General Certificate of Education Advanced Subsidiary Level and Advanced Level ACCOUNTING 9706/02 Paper 2 Structured Questions (Core) October/November 2003 1 hour 30 minutes Candidates answer on the Question Paper. No Additional Materials are required. READ THESE INSTRUCTIONS FIRST Write your Centre number, candidate number and name on all the work you hand in. Write in dark blue or black pen in the spaces provided on the Question Paper. You may use a soft pencil for any diagrams, graphs or rough working. Do not use staples, paper clips, highlighters, glue or correction fluid. Answer all questions. At the end of the examination, fasten all your work securely together. The number of marks is given in brackets [ ] at the end of each question or part question. You may use a calculator. Centre Number Candidate Number Name If you have been given a label, look at the details. If any details are incorrect or missing, please fill in your correct details in the space given at the top of this page. Stick your personal label here, if provided. For Examiner’s Use 1 2 3 Total
Question paper, page 2
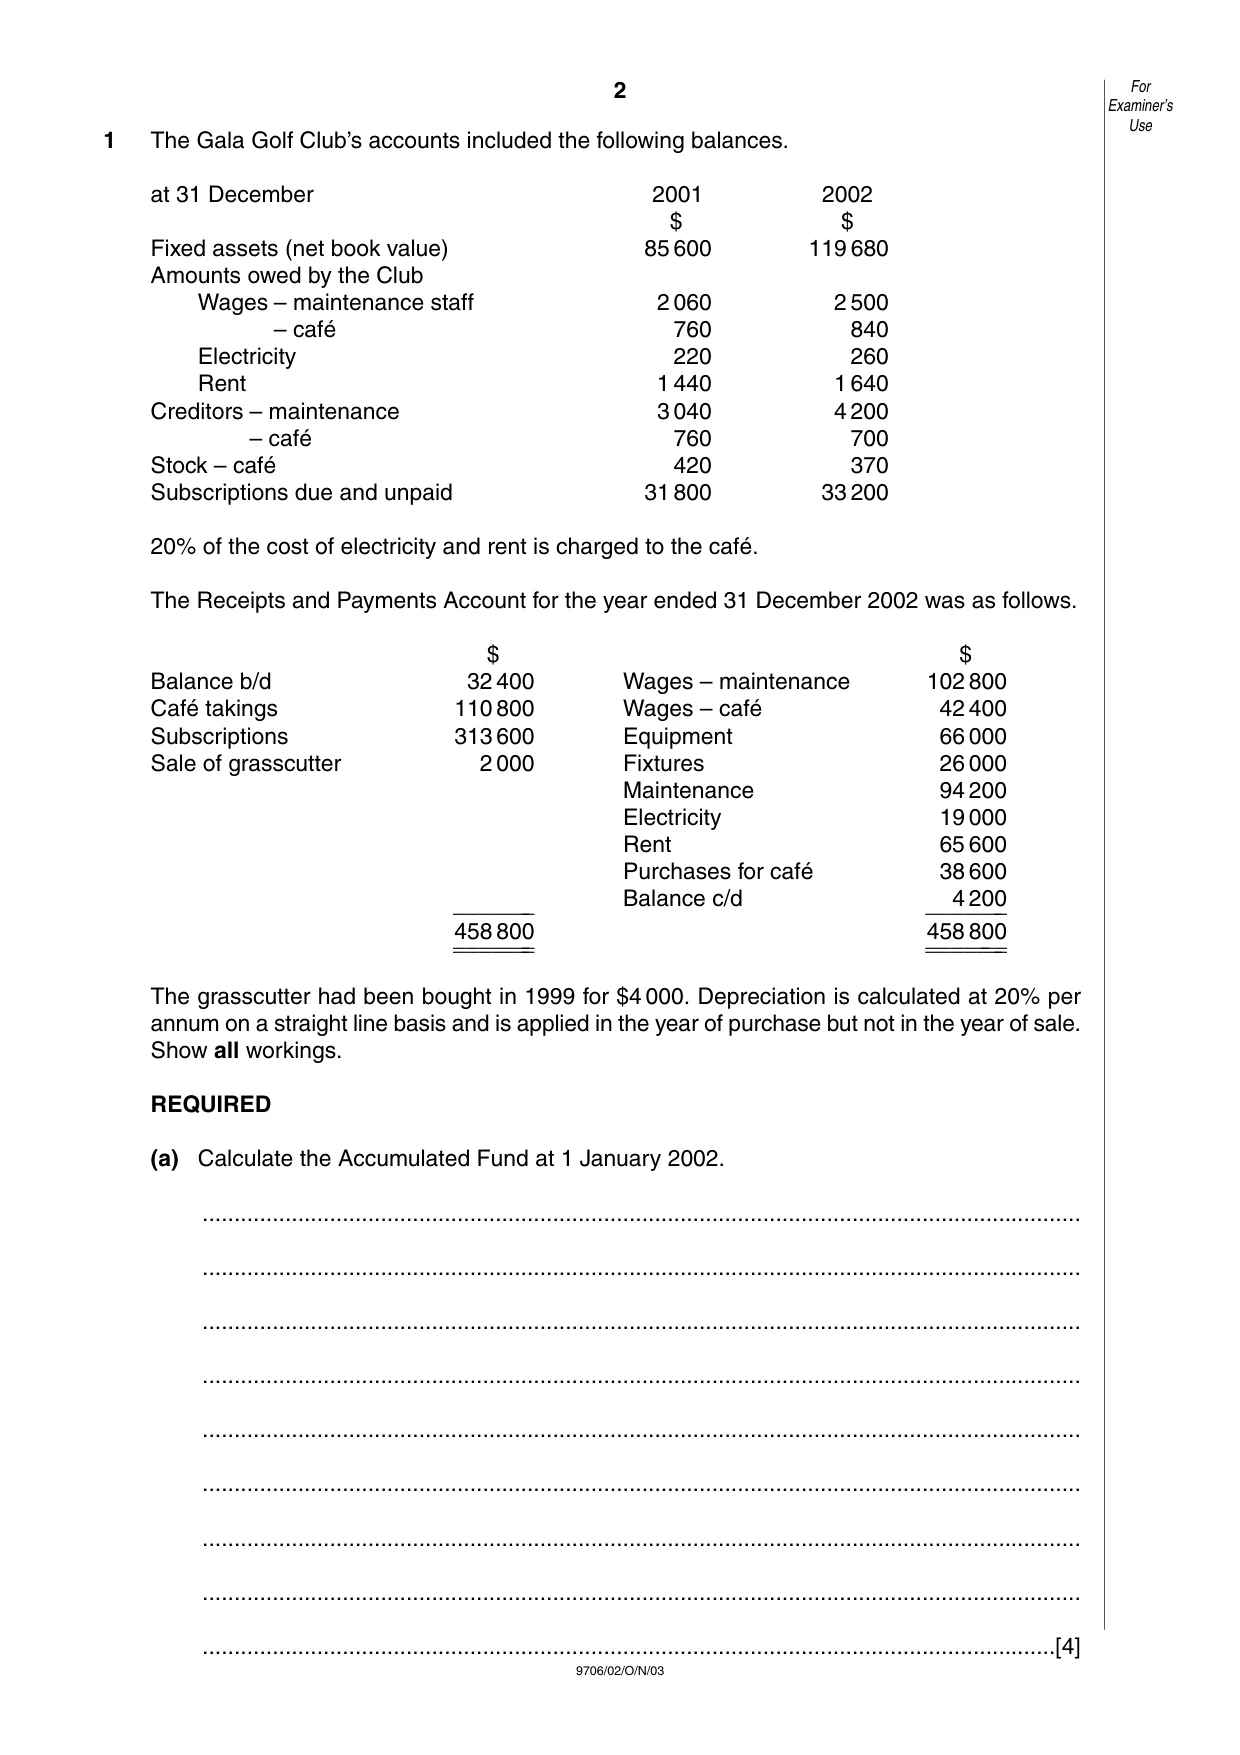
2 9706/02/O/N/03 1 The Gala Golf Club’s accounts included the following balances. at 31 December 2001 2002 $ $ Fixed assets (net book value) 85 600 119 680 Amounts owed by the Club Wages – maintenance staff 2 060 2 500 – café 760 840 Electricity 220 260 Rent 1 440 1 640 Creditors – maintenance 3 040 4 200 – café 760 700 Stock – café 420 370 Subscriptions due and unpaid 31 800 33 200 20% of the cost of electricity and rent is charged to the café. The Receipts and Payments Account for the year ended 31 December 2002 was as follows. $ $ Balance b/d 32 400 Wages – maintenance 102 800 Café takings 110 800 Wages – café 42 400 Subscriptions 313 600 Equipment 66 000 Sale of grasscutter 2 000 Fixtures 26 000 Maintenance 94 200 Electricity 19 000 Rent 65 600 Purchases for café 38 600 Balance c/d 4 200 _______ _______ 458 800 458 800 _______ _______ _______ _______ The grasscutter had been bought in 1999 for $4 000. Depreciation is calculated at 20% per annum on a straight line basis and is applied in the year of purchase but not in the year of sale. Show all workings. REQUIRED (a) Calculate the Accumulated Fund at 1 January 2002. … … … … … … … … …[4] For Examiner’s Use
Question paper, page 3
3 9706/02/O/N/03 [Turn over (b) Prepare the Café Trading Account for the year ended 31 December 2002. … … … … … … … … … … … … … … … … … … … …[4] For Examiner’s Use
Question paper, page 4
4 9706/02/O/N/03 (c) Prepare the Club Income and Expenditure Account for the year ended 31 December 2002. … … … … … … … … … … … … … … … … … … … … … … … … … …[9] For Examiner’s Use
Question paper, page 5
5 9706/02/O/N/03 [Turn over (d) Prepare the Club Balance Sheet as at 31 December 2002. … … … … … … … … … … … … … … … … … … … …[5] (e) (i) State two accounting methods of treating donations received by the Club. … … … … …[4] For Examiner’s Use
Question paper, page 6
6 9706/02/O/N/03 (ii) Distinguish between a Receipts and Payments Account and an Income and Expenditure Account. … … … … … … … … …[4] For Examiner’s Use
Question paper, page 7
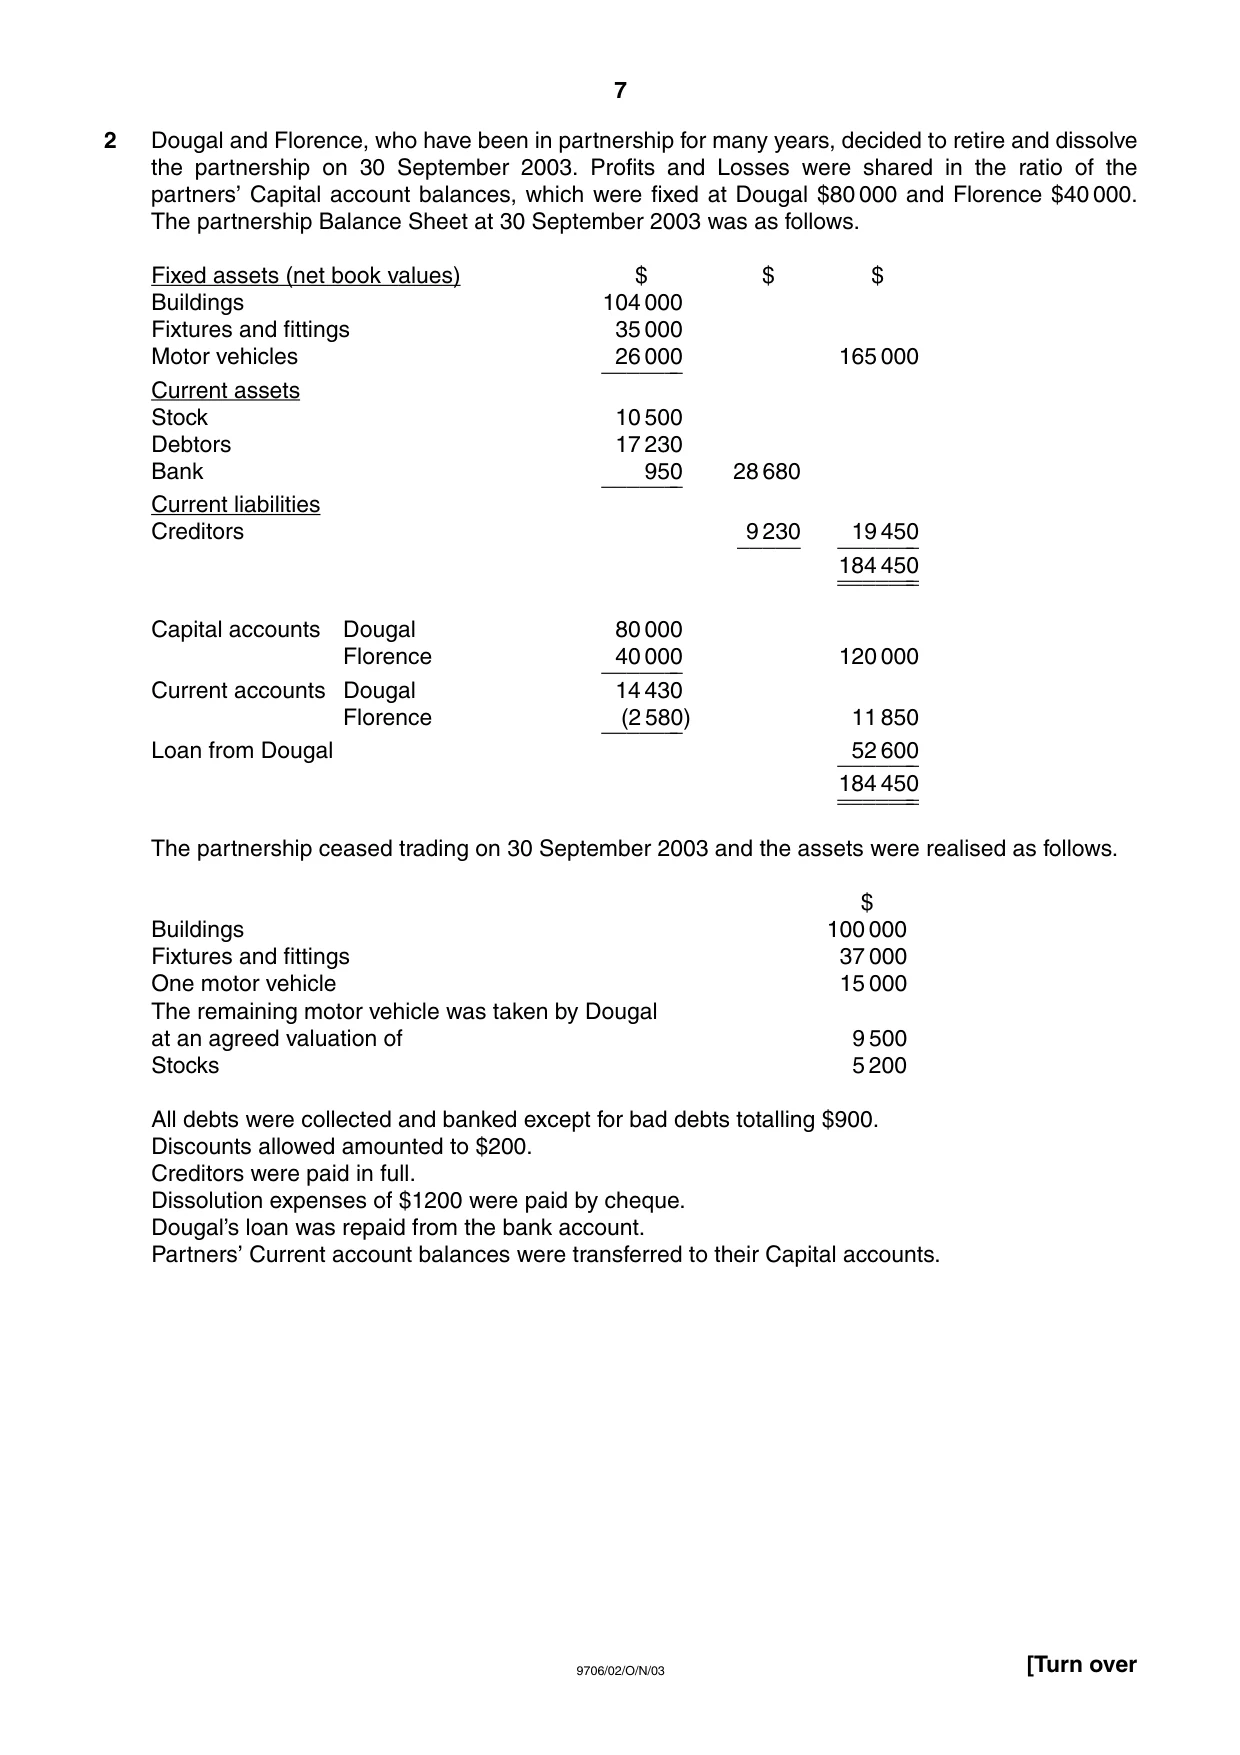
7 9706/02/O/N/03 [Turn over 2 Dougal and Florence, who have been in partnership for many years, decided to retire and dissolve the partnership on 30 September 2003. Profits and Losses were shared in the ratio of the partners’ Capital account balances, which were fixed at Dougal $80 000 and Florence $40 000. The partnership Balance Sheet at 30 September 2003 was as follows. Fixed assets (net book values) $ $ $ Buildings 104 000 Fixtures and fittings 35 000 Motor vehicles 26 000 165 000 _______ Current assets Stock 10 500 Debtors 17 230 Bank 950 28 680 _______ Current liabilities Creditors 9 230 19 450 _____ _______ 184 450 _______ _______ Capital accounts Dougal 80 000 Florence 40 000 120 000 _______ Current accounts Dougal 14 430 Florence (2 580) 11 850 _______ Loan from Dougal 52 600 _______ 184 450 _______ _______ The partnership ceased trading on 30 September 2003 and the assets were realised as follows. $ Buildings 100 000 Fixtures and fittings 37 000 One motor vehicle 15 000 The remaining motor vehicle was taken by Dougal at an agreed valuation of 9 500 Stocks 5 200 All debts were collected and banked except for bad debts totalling $900. Discounts allowed amounted to $200. Creditors were paid in full. Dissolution expenses of $1200 were paid by cheque. Dougal’s loan was repaid from the bank account. Partners’ Current account balances were transferred to their Capital accounts.
Question paper, page 8
8 9706/02/O/N/03 REQUIRED Prepare the following accounts for the month of October 2003. (a) Dissolution (Realisation) account. … … … … … … … … … … … …[8] (b) Partners’ Current accounts, in columnar form. … … … … … … … … … … … …[4] For Examiner’s Use
Question paper, page 9
9 9706/02/O/N/03 [Turn over (c) Partners’ Capital accounts, in columnar form … … … … … … …[4] (d) The partnership Bank account. … … … … … … … …[8] (e) Discuss three problems which may arise in a partnership but would not occur in a limited company. … … … … … … … … …[6] For Examiner’s Use
Question paper, page 10
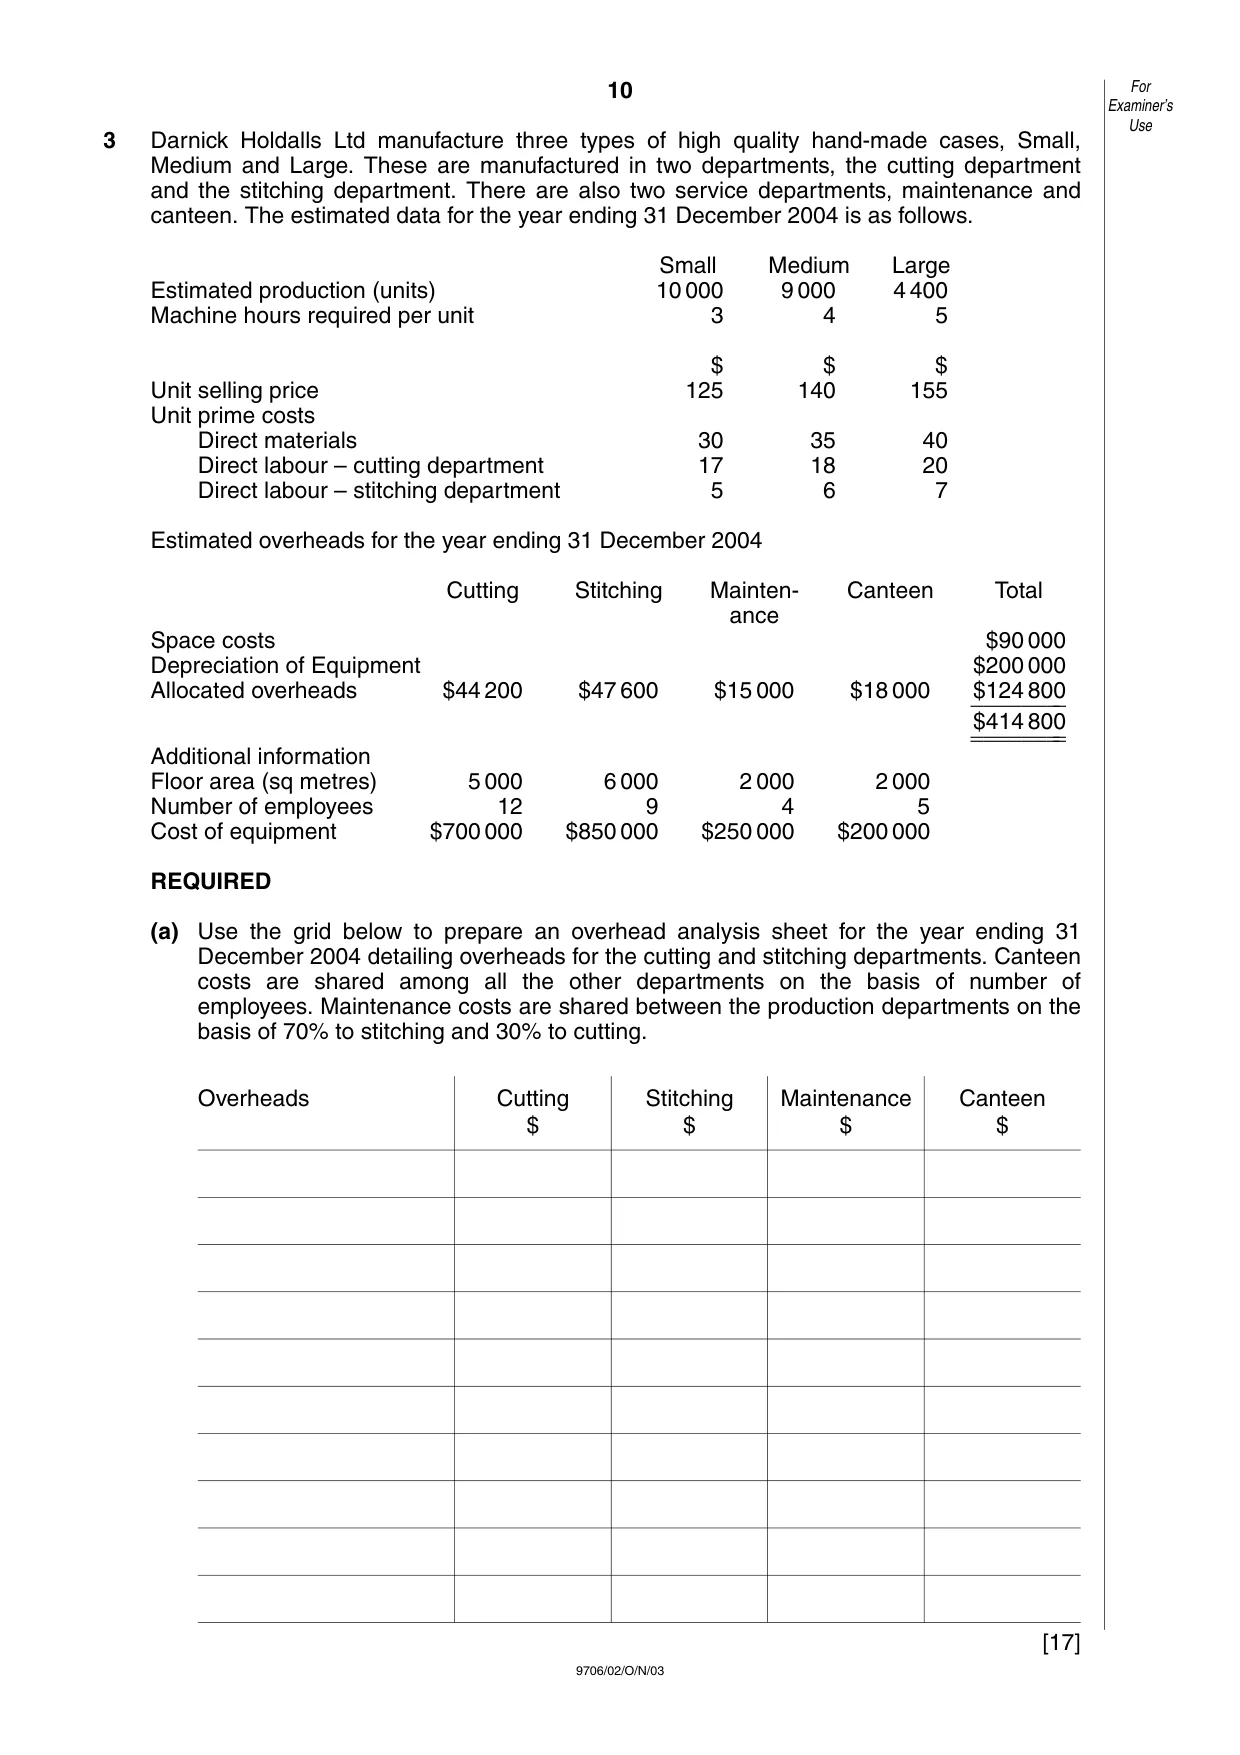
10 9706/02/O/N/03 3 Darnick Holdalls Ltd manufacture three types of high quality hand-made cases, Small, Medium and Large. These are manufactured in two departments, the cutting department and the stitching department. There are also two service departments, maintenance and canteen. The estimated data for the year ending 31 December 2004 is as follows. Small Medium Large Estimated production (units) 10 000 9 000 4 400 Machine hours required per unit 3 4 5 $ $ $ Unit selling price 125 140 155 Unit prime costs Direct materials 30 35 40 Direct labour – cutting department 17 18 20 Direct labour – stitching department 5 6 7 Estimated overheads for the year ending 31 December 2004 Cutting Stitching Mainten- Canteen Total ance Space costs $90 000 Depreciation of Equipment $200 000 Allocated overheads $44 200 $47 600 $15 000 $18 000 $124 800 ________ $414 800 ________ ________ Additional information Floor area (sq metres) 5 000 6 000 2 000 2 000 Number of employees 12 9 4 5 Cost of equipment $700 000 $850 000 $250 000 $200 000 REQUIRED (a) Use the grid below to prepare an overhead analysis sheet for the year ending 31 December 2004 detailing overheads for the cutting and stitching departments. Canteen costs are shared among all the other departments on the basis of number of employees. Maintenance costs are shared between the production departments on the basis of 70% to stitching and 30% to cutting. [17] For Examiner’s Use Overheads Cutting Stitching Maintenance Canteen $ $ $ $
Question paper, page 11
11 9706/02/O/N/03 [Turn over (b) Calculate the overhead recovery rate for (i) the cutting department, based on direct wages; (ii) the stitching department, based on machine hours. Show all workings. … … … … … … … … … … … …[6] (c) Give reasons for the two different methods used in (b). … … … …[2] For Examiner’s Use
Question paper, page 12
12 9706/02/O/N/03 (d) Calculate the total unit cost of one Medium case. … … … … … … … … … …[5] For Examiner’s Use