Cambridge A Level Accounting 9706 — 2003 May/June Paper 2 · Variant 1
9706/21/M/J/03
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper12 pages
Mark scheme
No mark scheme is in the library for this paper.
Paper as text
Question paper, page 1
This document consists of 10 printed pages, 1 lined page and 1 blank page. SJF2731 S39592/4 © CIE 2003 [Turn over CAMBRIDGE INTERNATIONAL EXAMINATIONS General Certificate of Education Advanced Subsidiary Level and Advanced Level ACCOUNTING 9706/02 Paper 2 Structured Questions May/June 2003 1 hour 30 minutes Candidates answer on the Question Paper. No Additional Materials are required. READ THESE INSTRUCTIONS FIRST Write your Centre number, candidate number and name on all the work you hand in. Write in dark blue or black pen in the spaces provided on the Question Paper. You may use a soft pencil for rough working. Do not use staples, paper clips, highlighters, glue or correction fluid. Answer all questions. At the end of the examination, fasten all your work securely together. The number of marks is given in brackets [ ] at the end of each question or part question. You may use a calculator. Centre Number Candidate Number Name If you have been given a label, look at the details. If any details are incorrect or missing, please fill in your correct details in the space given at the top of this page. Stick your personal label here, if provided. For Examiner’s Use 1 2 3 Total
Question paper, page 2
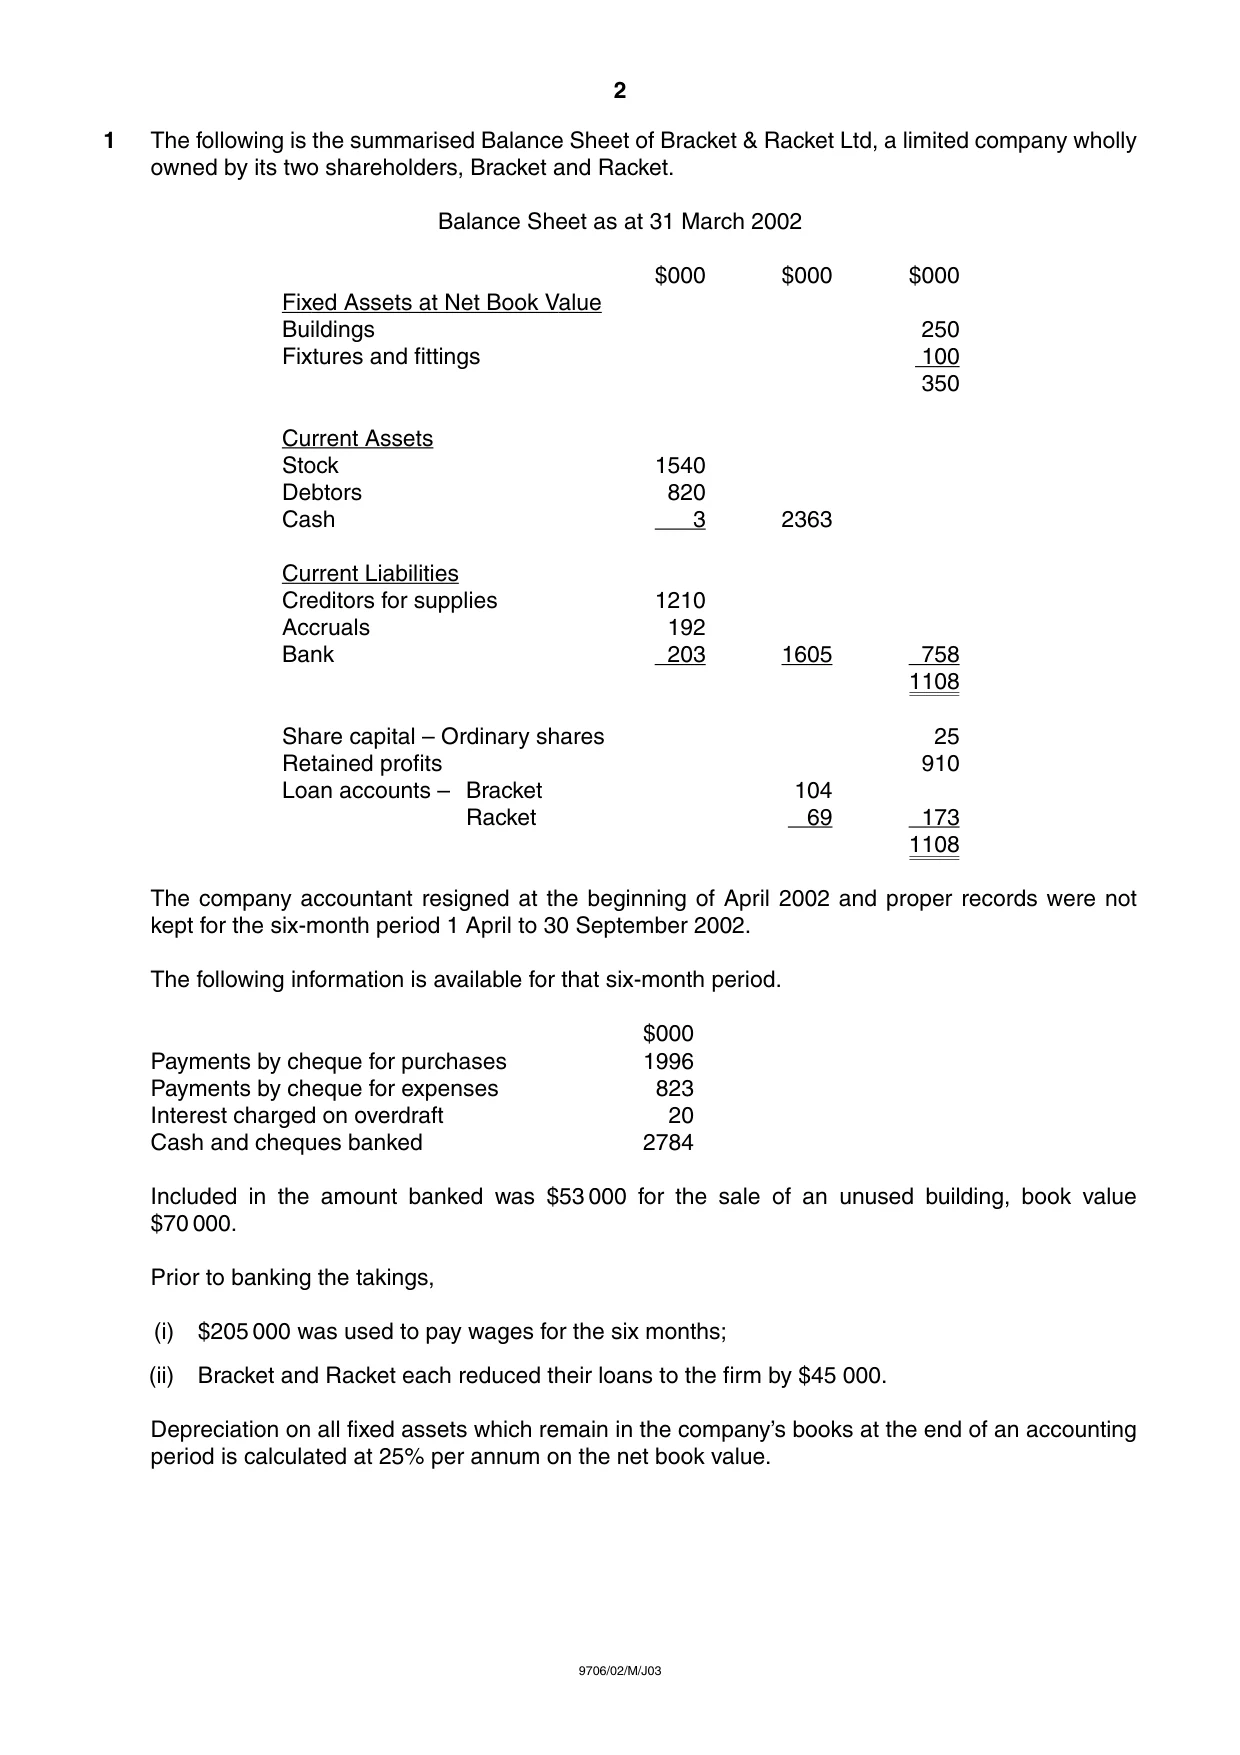
2 9706/02/M/J03 1 The following is the summarised Balance Sheet of Bracket & Racket Ltd, a limited company wholly owned by its two shareholders, Bracket and Racket. Balance Sheet as at 31 March 2002 $000 $000 $000 Fixed Assets at Net Book Value Buildings 250 Fixtures and fittings 100 350 Current Assets Stock 1540 Debtors 820 Cash 3 2363 Current Liabilities Creditors for supplies 1210 Accruals 192 Bank 203 1605 758 1108 Share capital – Ordinary shares 25 Retained profits 910 Loan accounts – Bracket 104 Racket 69 173 1108 The company accountant resigned at the beginning of April 2002 and proper records were not kept for the six-month period 1 April to 30 September 2002. The following information is available for that six-month period. $000 Payments by cheque for purchases 1996 Payments by cheque for expenses 823 Interest charged on overdraft 20 Cash and cheques banked 2784 Included in the amount banked was $53 000 for the sale of an unused building, book value $70 000. Prior to banking the takings, (i) $205 000 was used to pay wages for the six months; (ii) Bracket and Racket each reduced their loans to the firm by $45 000. Depreciation on all fixed assets which remain in the company’s books at the end of an accounting period is calculated at 25% per annum on the net book value.
Question paper, page 3
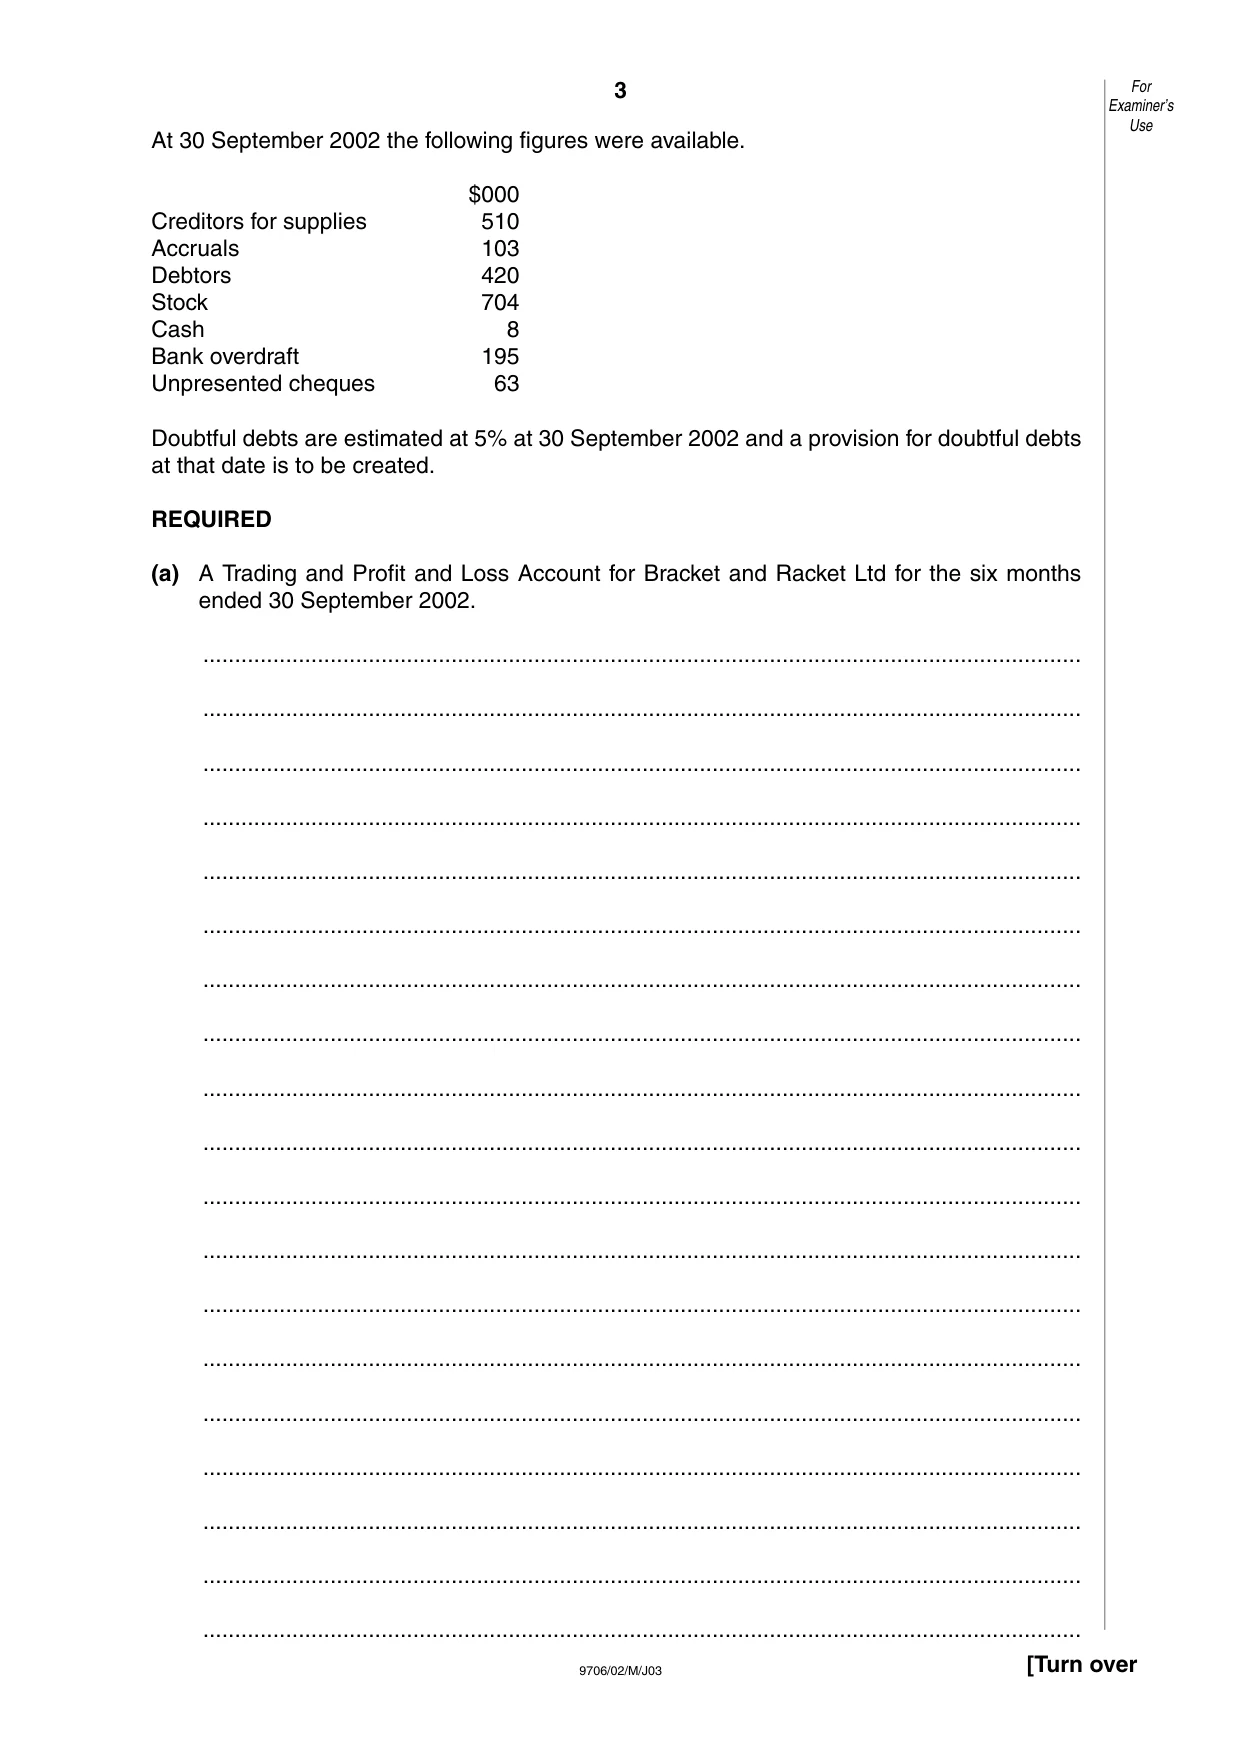
3 9706/02/M/J03 [Turn over At 30 September 2002 the following figures were available. $000 Creditors for supplies 510 Accruals 103 Debtors 420 Stock 704 Cash 8 Bank overdraft 195 Unpresented cheques 63 Doubtful debts are estimated at 5% at 30 September 2002 and a provision for doubtful debts at that date is to be created. REQUIRED (a) A Trading and Profit and Loss Account for Bracket and Racket Ltd for the six months ended 30 September 2002. … … … … … … … … … … … … … … … … … … … For Examiner’s Use
Question paper, page 4
4 9706/02/M/J03 … … … … … … … … … … … … … … … … … … … … … … … … … … … [16] For Examiner’s Use
Question paper, page 5
5 9706/02/M/J03 [Turn over (b) A Balance Sheet for Bracket and Racket Ltd at 30 September 2002. … … … … … … … … … … … … … … … … … … … … … … … … … … … [8] For Examiner’s Use
Question paper, page 6
6 9706/02/M/J03 The Company needs to improve its premises but the bank refuses either to allow a further increase in overdraft or to grant a loan. REQUIRED (c) State six other possible sources of finance. … … … … … … … … … … [6] For Examiner’s Use
Question paper, page 7
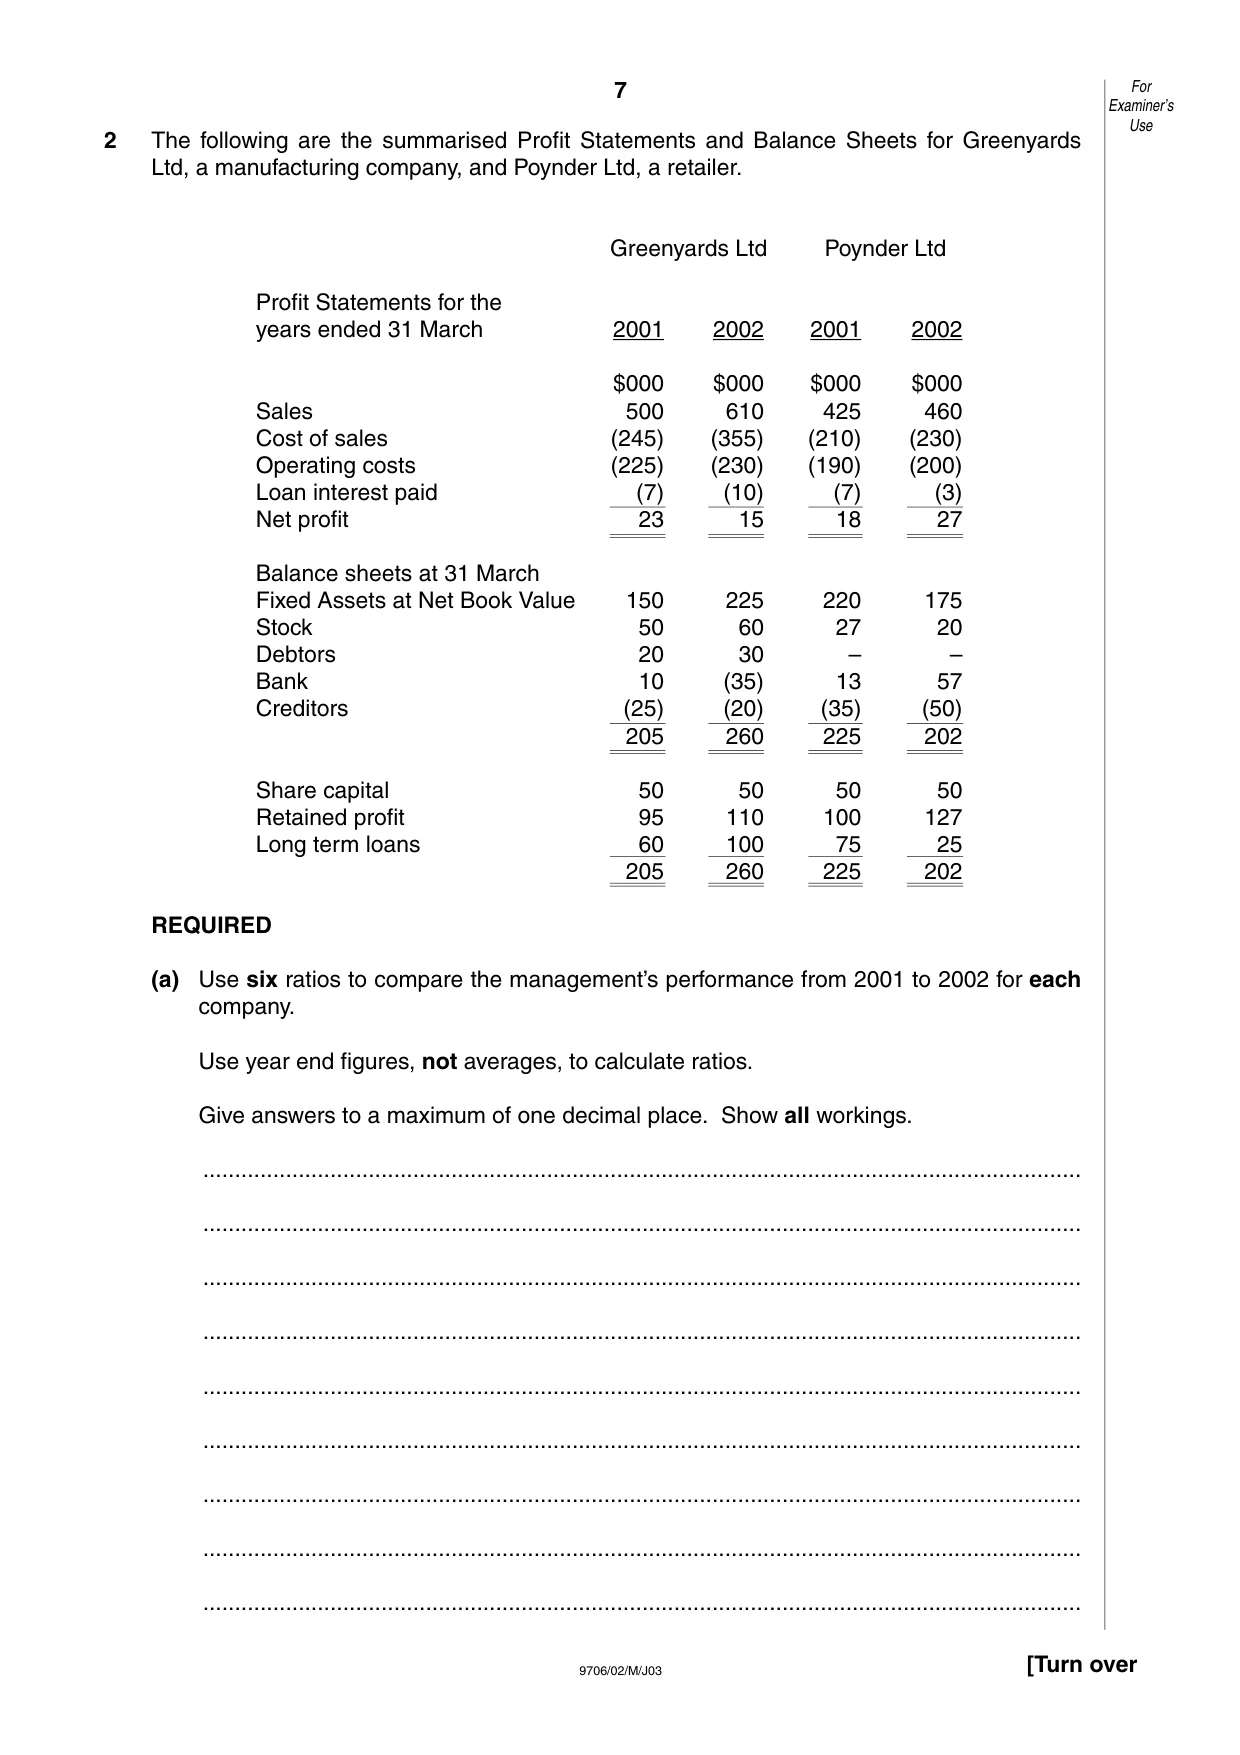
7 9706/02/M/J03 [Turn over 2 The following are the summarised Profit Statements and Balance Sheets for Greenyards Ltd, a manufacturing company, and Poynder Ltd, a retailer. Greenyards Ltd Poynder Ltd Profit Statements for the years ended 31 March 2001 2002 2001 2002 $000 $000 $000 $000 Sales 500 610 425 460 Cost of sales (245) (355) (210) (230) Operating costs (225) (230) (190) (200) Loan interest paid (7) (10) (7) (3) Net profit 23 15 18 27 Balance sheets at 31 March Fixed Assets at Net Book Value 150 225 220 175 Stock 50 60 27 20 Debtors 20 30 – – Bank 10 (35) 13 57 Creditors (25) (20) (35) (50) 205 260 225 202 Share capital 50 50 50 50 Retained profit 95 110 100 127 Long term loans 60 100 75 25 205 260 225 202 REQUIRED (a) Use six ratios to compare the management’s performance from 2001 to 2002 for each company. Use year end figures, not averages, to calculate ratios. Give answers to a maximum of one decimal place. Show all workings. … … … … … … … … … For Examiner’s Use
Question paper, page 8
8 9706/02/M/J03 … … … … … … … … … [12] (b) Comment on your findings. … … … … … … … … … … … … … … … … … … For Examiner’s Use
Question paper, page 9
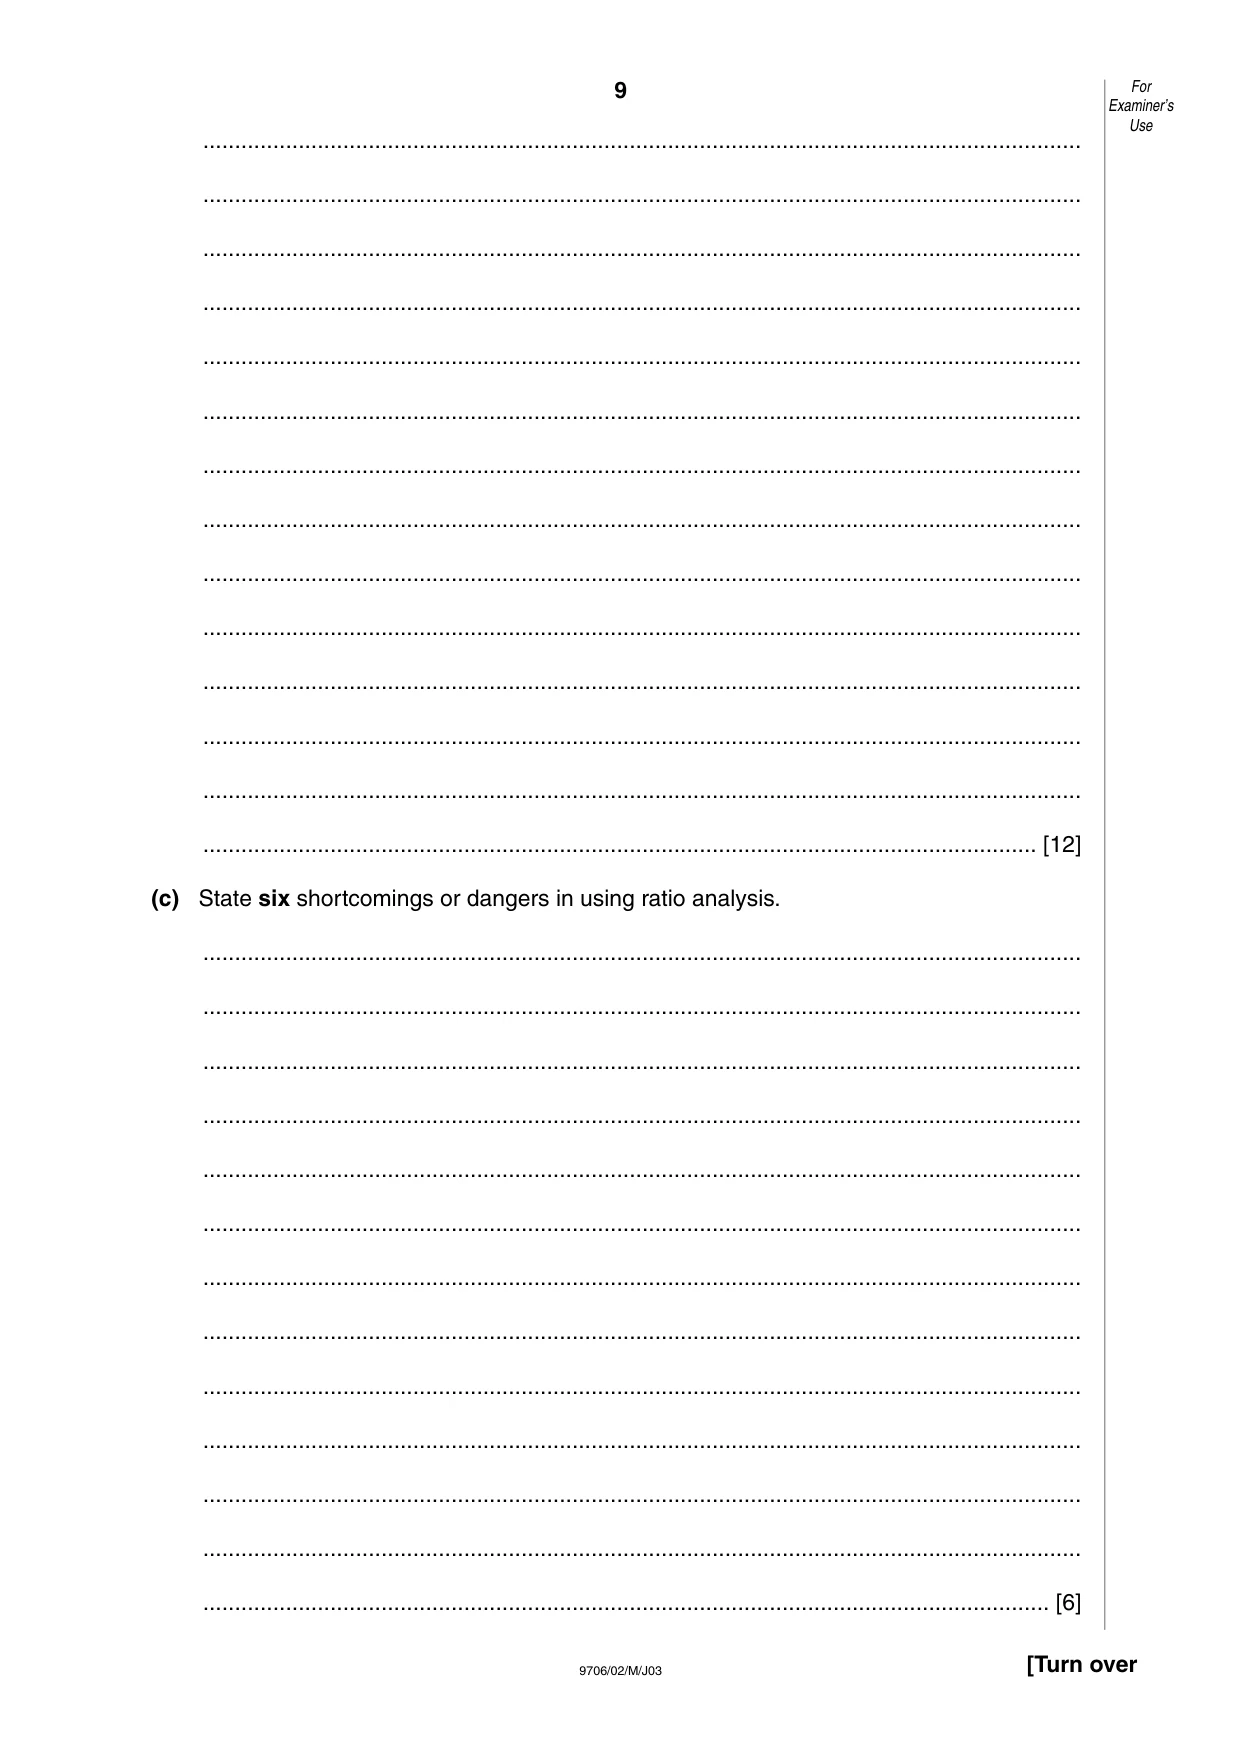
9 9706/02/M/J03 [Turn over … … … … … … … … … … … … … … [12] (c) State six shortcomings or dangers in using ratio analysis. … … … … … … … … … … … … … [6] For Examiner’s Use
Question paper, page 10
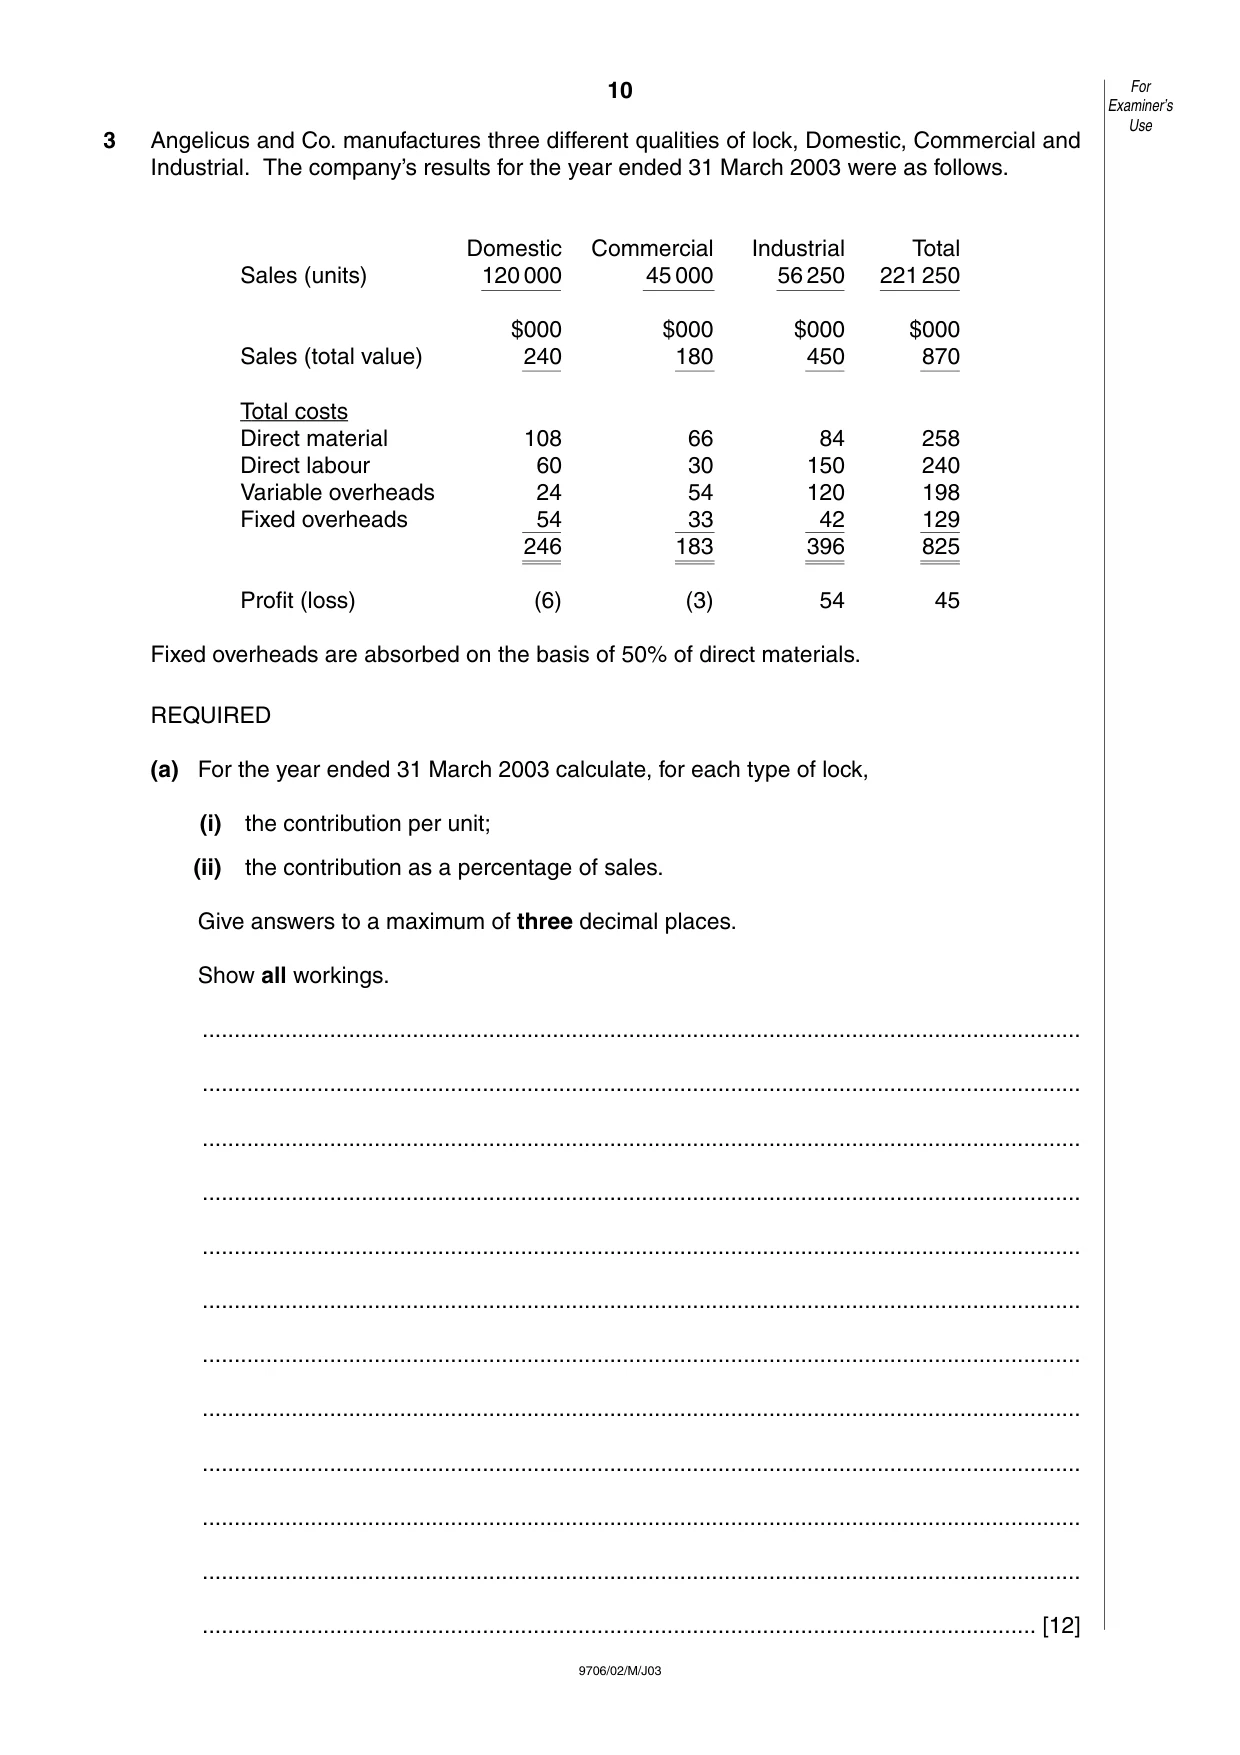
10 9706/02/M/J03 3 Angelicus and Co. manufactures three different qualities of lock, Domestic, Commercial and Industrial. The company’s results for the year ended 31 March 2003 were as follows. Domestic Commercial Industrial Total Sales (units) 120 000 45 000 56 250 221 250 $000 $000 $000 $000 Sales (total value) 240 180 450 870 Total costs Direct material 108 66 84 258 Direct labour 60 30 150 240 Variable overheads 24 54 120 198 Fixed overheads 54 33 42 129 246 183 396 825 Profit (loss) (6) (3) 54 45 Fixed overheads are absorbed on the basis of 50% of direct materials. REQUIRED (a) For the year ended 31 March 2003 calculate, for each type of lock, (i) the contribution per unit; (ii) the contribution as a percentage of sales. Give answers to a maximum of three decimal places. Show all workings. … … … … … … … … … … … … [12] For Examiner’s Use
Question paper, page 11
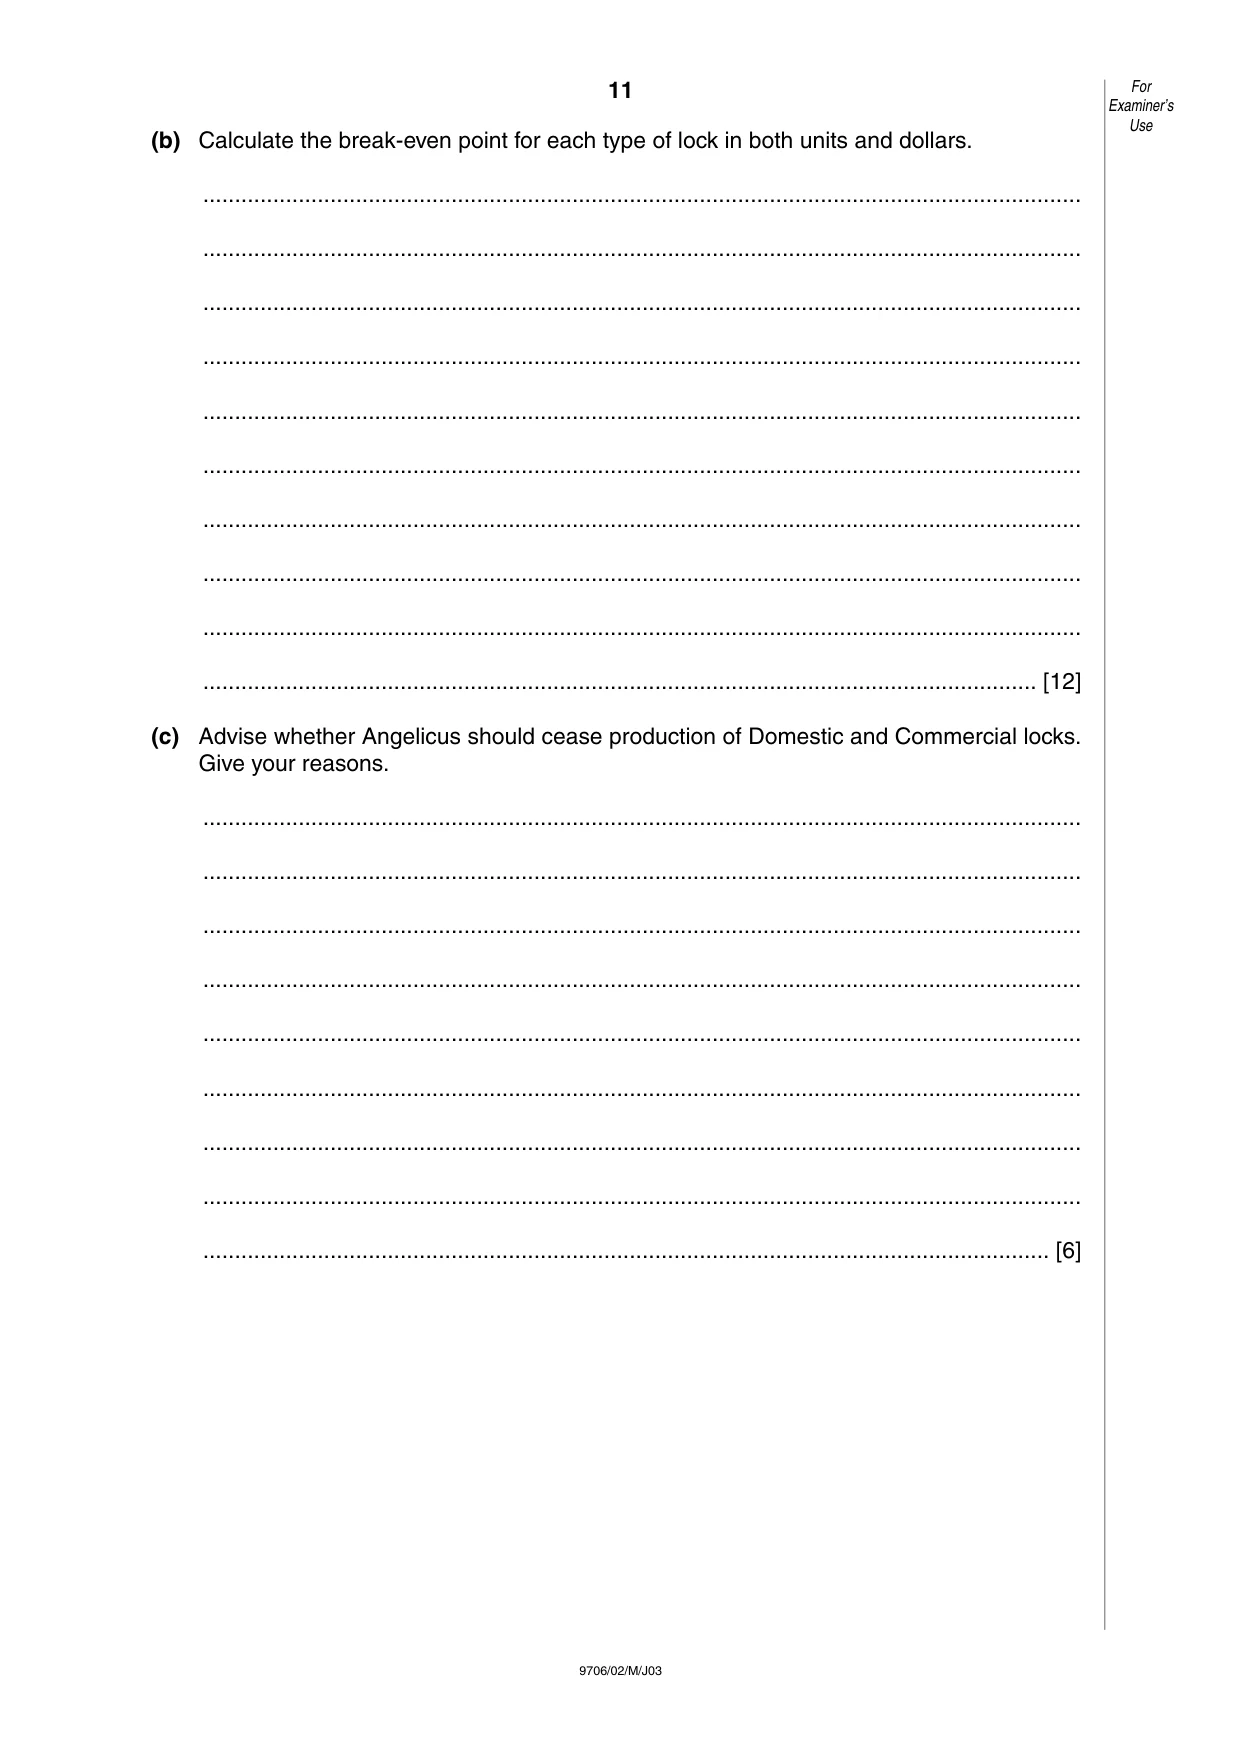
11 9706/02/M/J03 (b) Calculate the break-even point for each type of lock in both units and dollars. … … … … … … … … … … [12] (c) Advise whether Angelicus should cease production of Domestic and Commercial locks. Give your reasons. … … … … … … … … … [6] For Examiner’s Use