Cambridge IGCSE Accounting 0452 — 2025 Oct/Nov Paper 2 · Variant 2
0452/22/O/N/25 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme19 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · On 31 March 2025, Zac’s bank statement showed an overdrawn balance of $1665, but the bank…
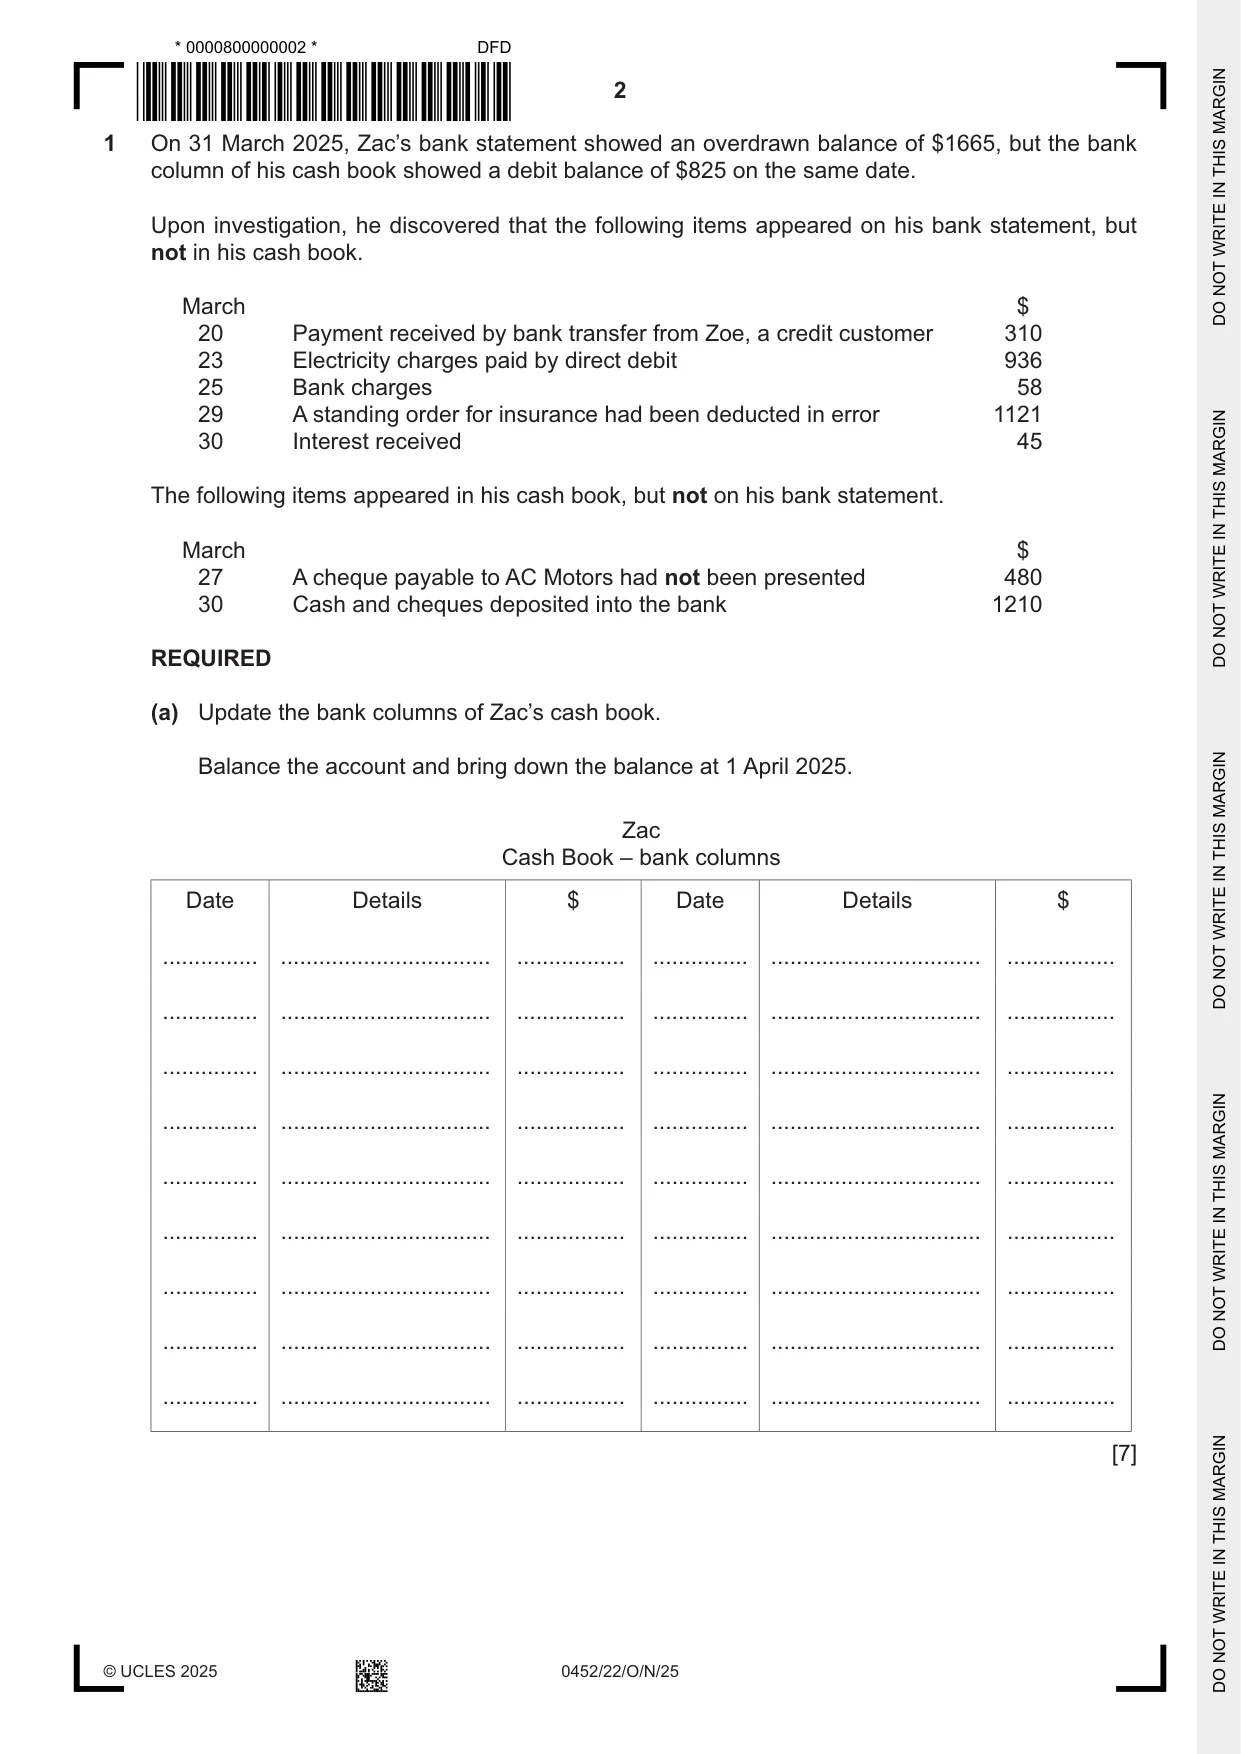
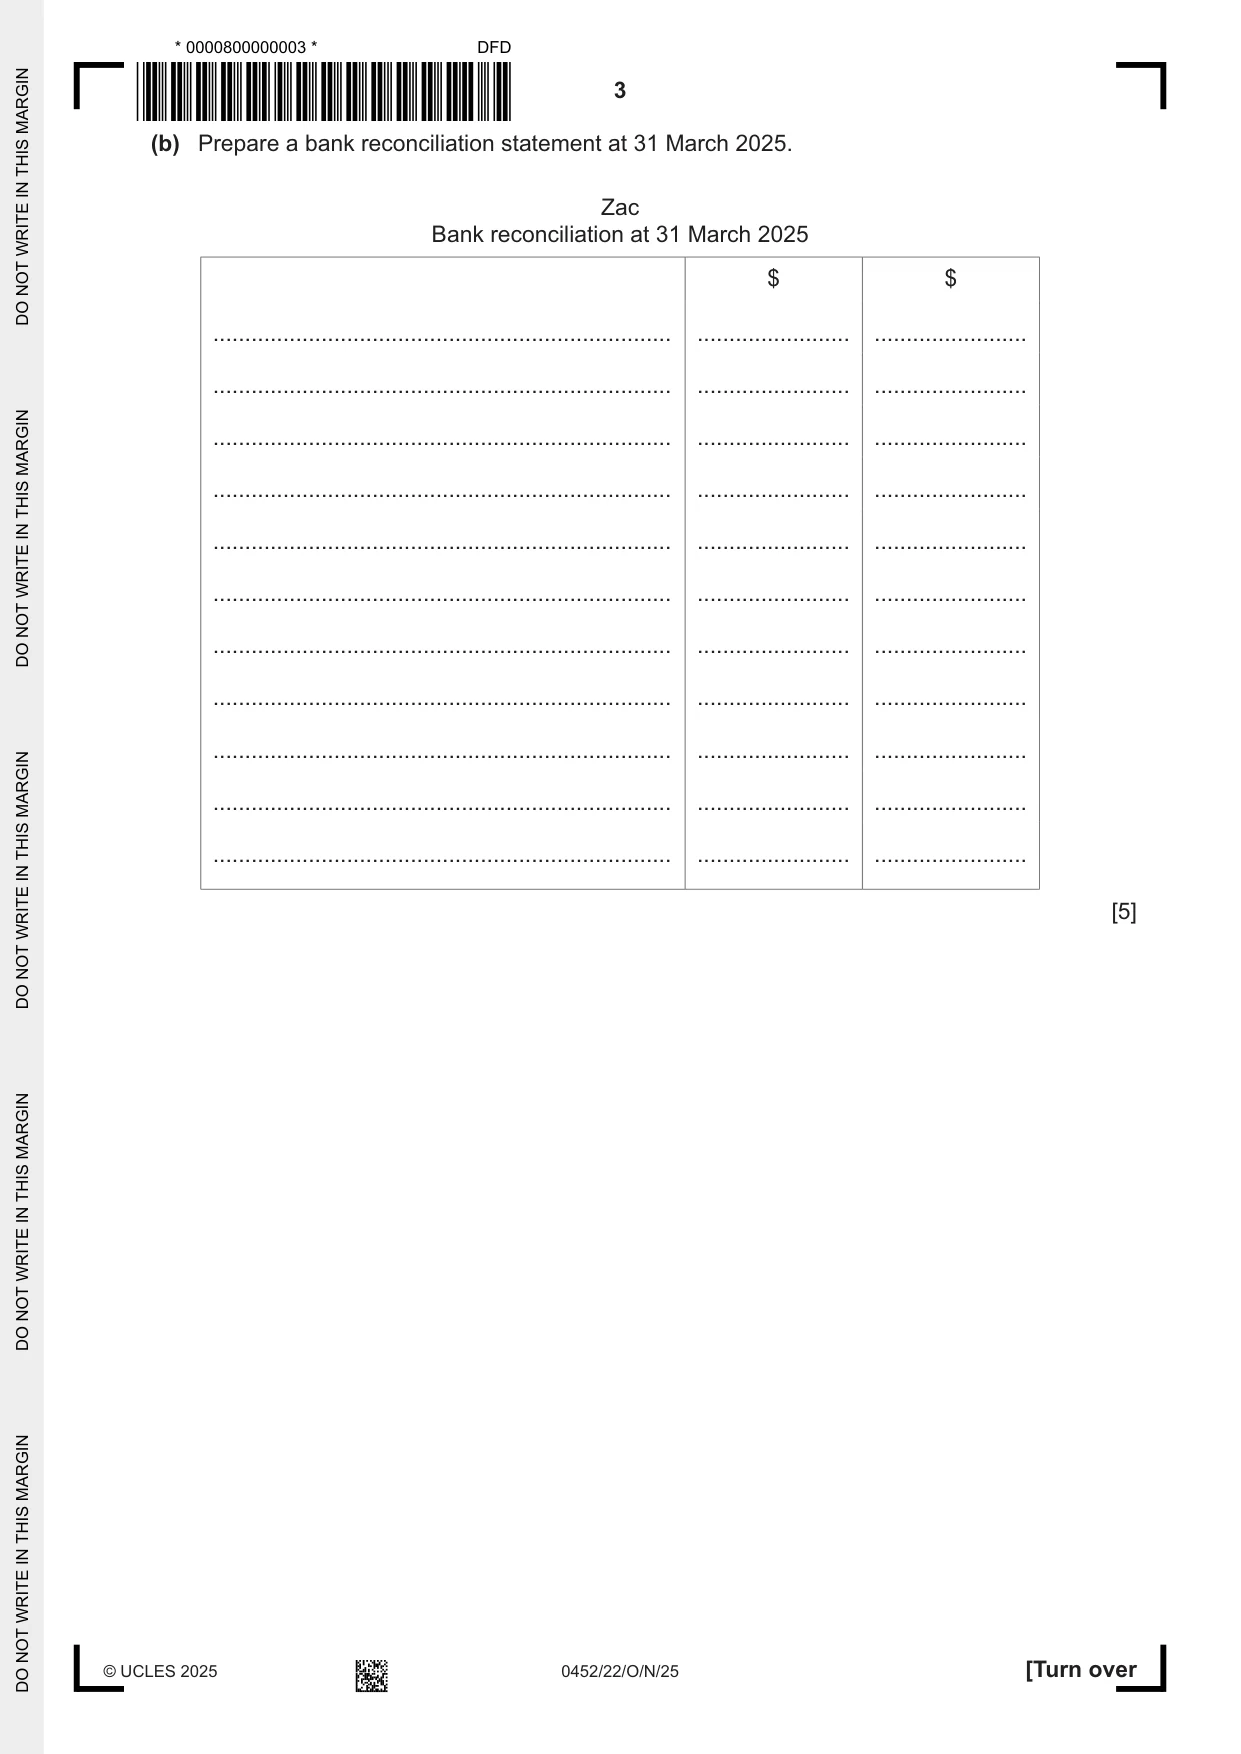
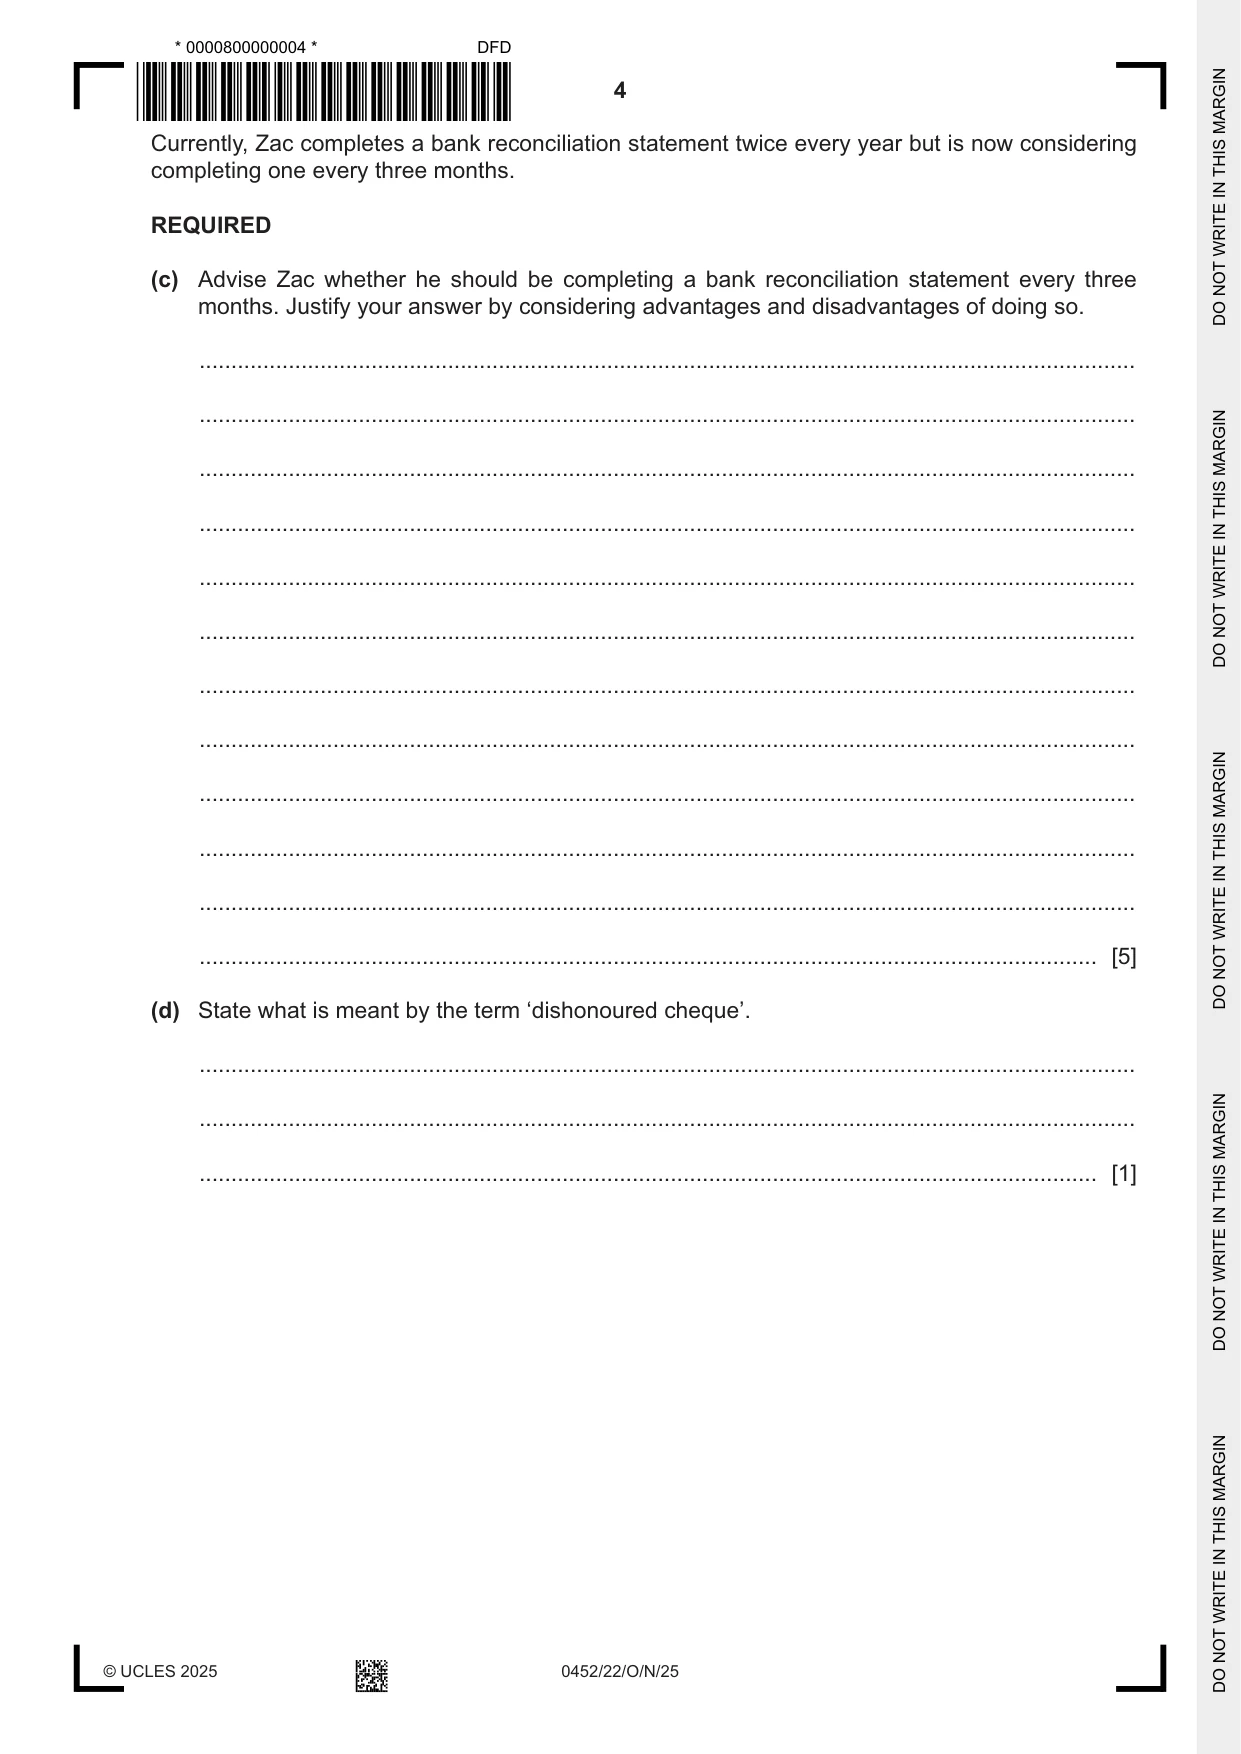
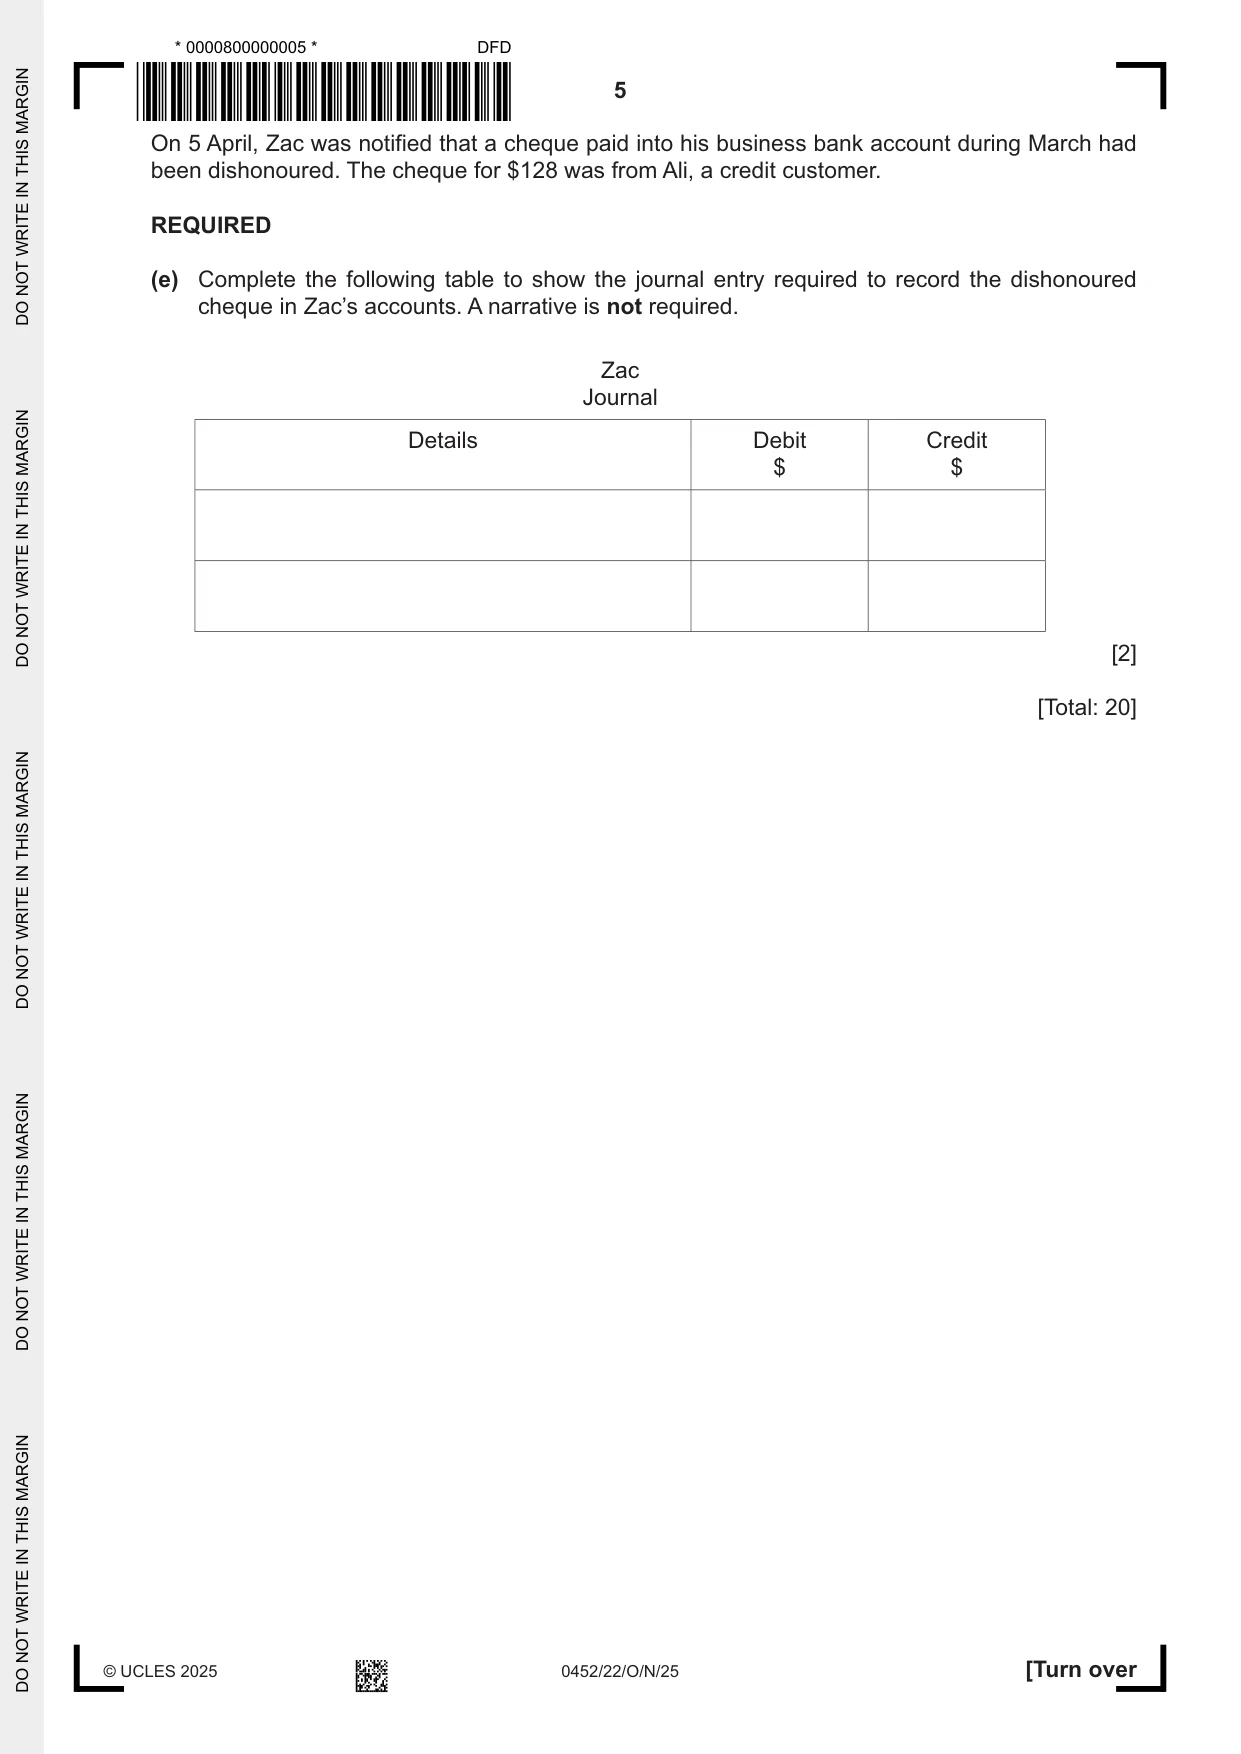
1 On 31 March 2025, Zac’s bank statement showed an overdrawn balance of $1665, but the bank column of his cash book showed a debit balance of $825 on the same date. Upon investigation, he discovered that the following items appeared on his bank statement, but not in his cash book. March $ 20 Payment received by bank transfer from Zoe, a credit customer 310 23 Electricity charges paid by direct debit 936 25 Bank charges 58 29 A standing order for insurance had been deducted in error 1121 30 Interest received 45 The following items appeared in his cash book, but not on his bank statement. March $ 27 A cheque payable to AC Motors had not been presented 480 30 Cash and cheques deposited into the bank 1210 REQUIRED (a) Update the bank columns of Zac’s cash book. Balance the account and bring down the balance at 1 April 2025. Zac Cash Book – bank columns Date Details $ Date Details $ ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. [7] (b) Prepare a bank reconciliation statement at 31 March 2025. Zac Bank reconciliation at 31 March 2025 $ $ ........................................................................ ........................ ........................ ........................................................................ ........................ ........................ ........................................................................ ........................ ........................ ........................................................................ ........................ ........................ ........................................................................ ........................ ........................ ........................................................................ ........................ ........................ ........................................................................ ........................ ........................ ........................................................................ ........................ ........................ ........................................................................ ........................ ........................ ........................................................................ ........................ ........................ ........................................................................ ........................ ........................ [5] Currently, Zac completes a bank reconciliation statement twice every year but is now considering completing one every three months. REQUIRED (c) Advise Zac whether he should be completing a bank reconciliation statement every three months. Justify your answer by considering advantages and disadvantages of doing so. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] (d) State what is meant by the term ‘dishonoured cheque’. ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [1] On 5 April, Zac was notified that a cheque paid into his business bank account during March had been dishonoured. The cheque for $128 was from Ali, a credit customer. REQUIRED (e) Complete the following table to show the journal entry required to record the dishonoured cheque in Zac’s accounts. A narrative is not required. Zac Journal Details Debit Credit $ $ [2] [Total: 20]
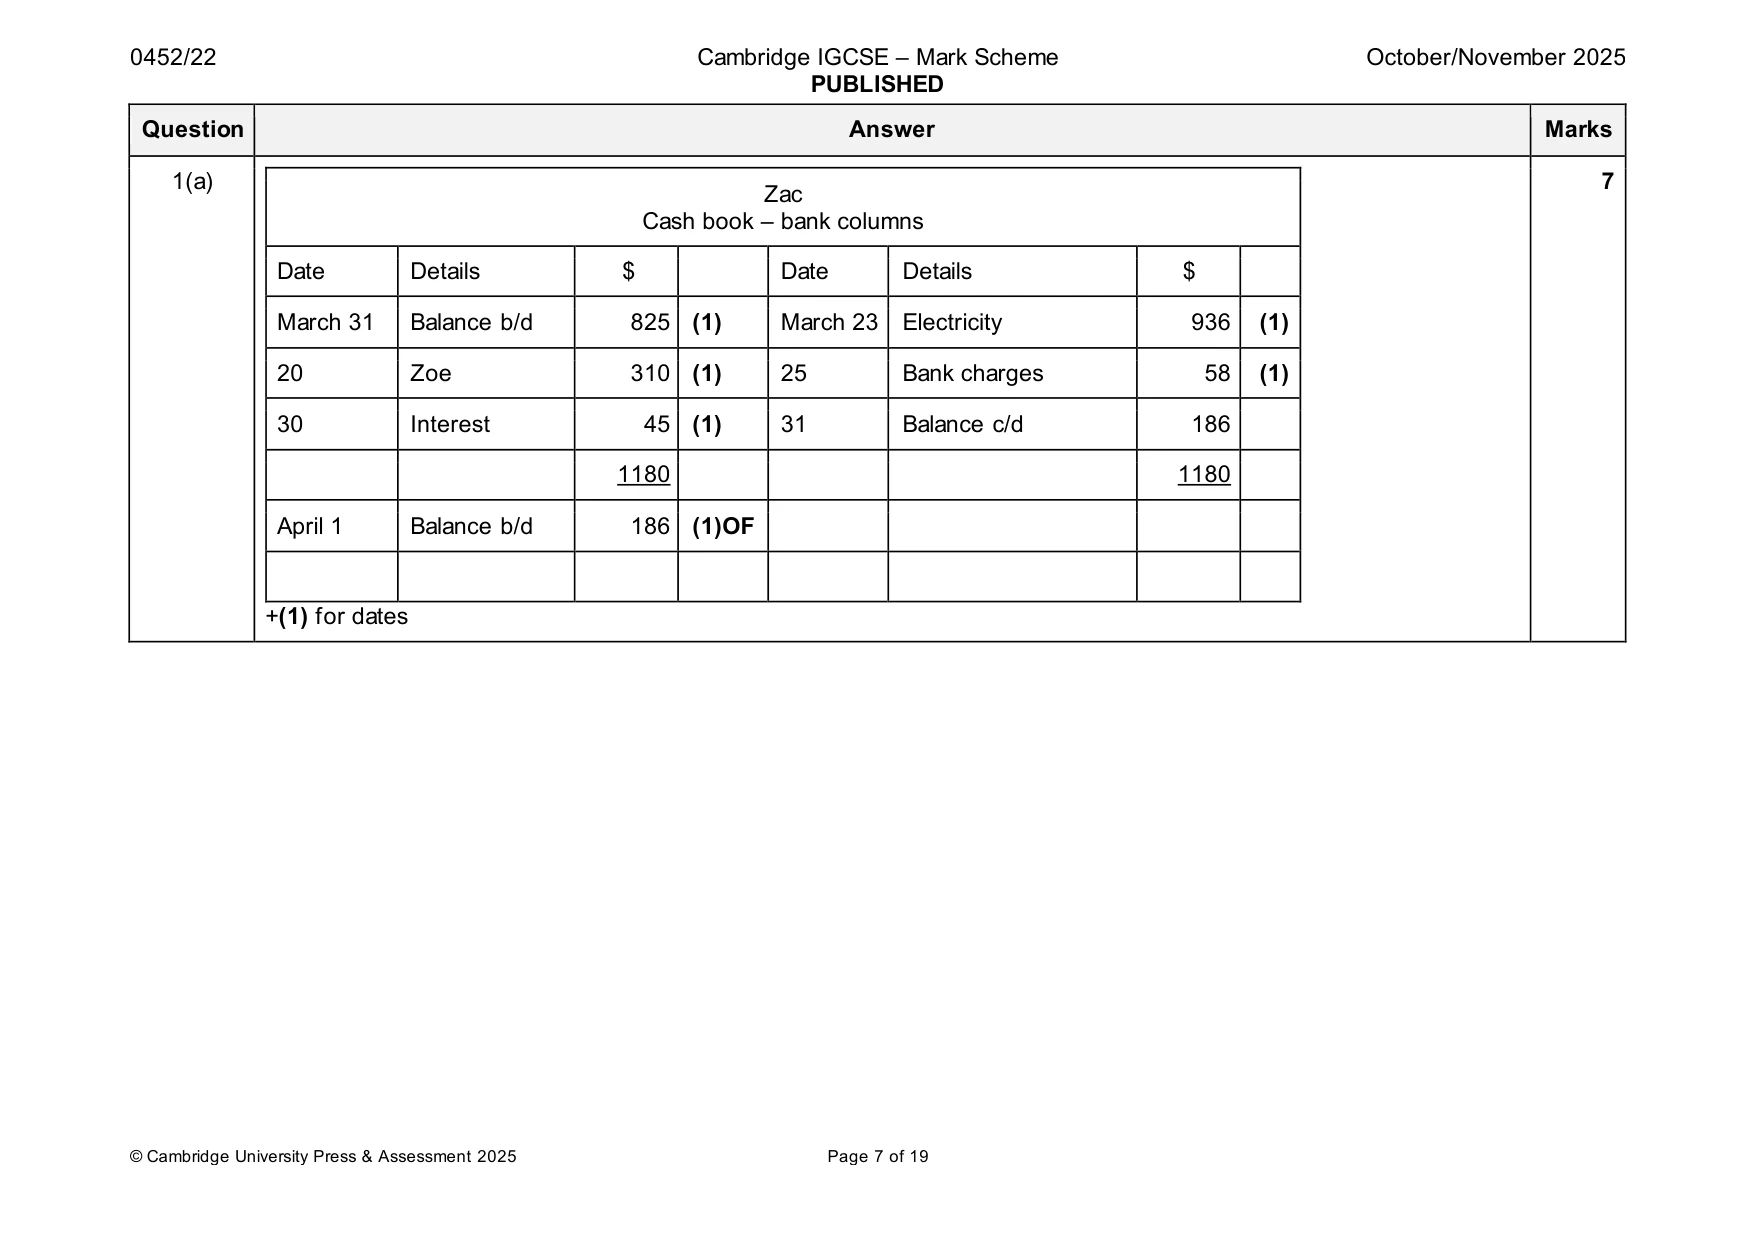
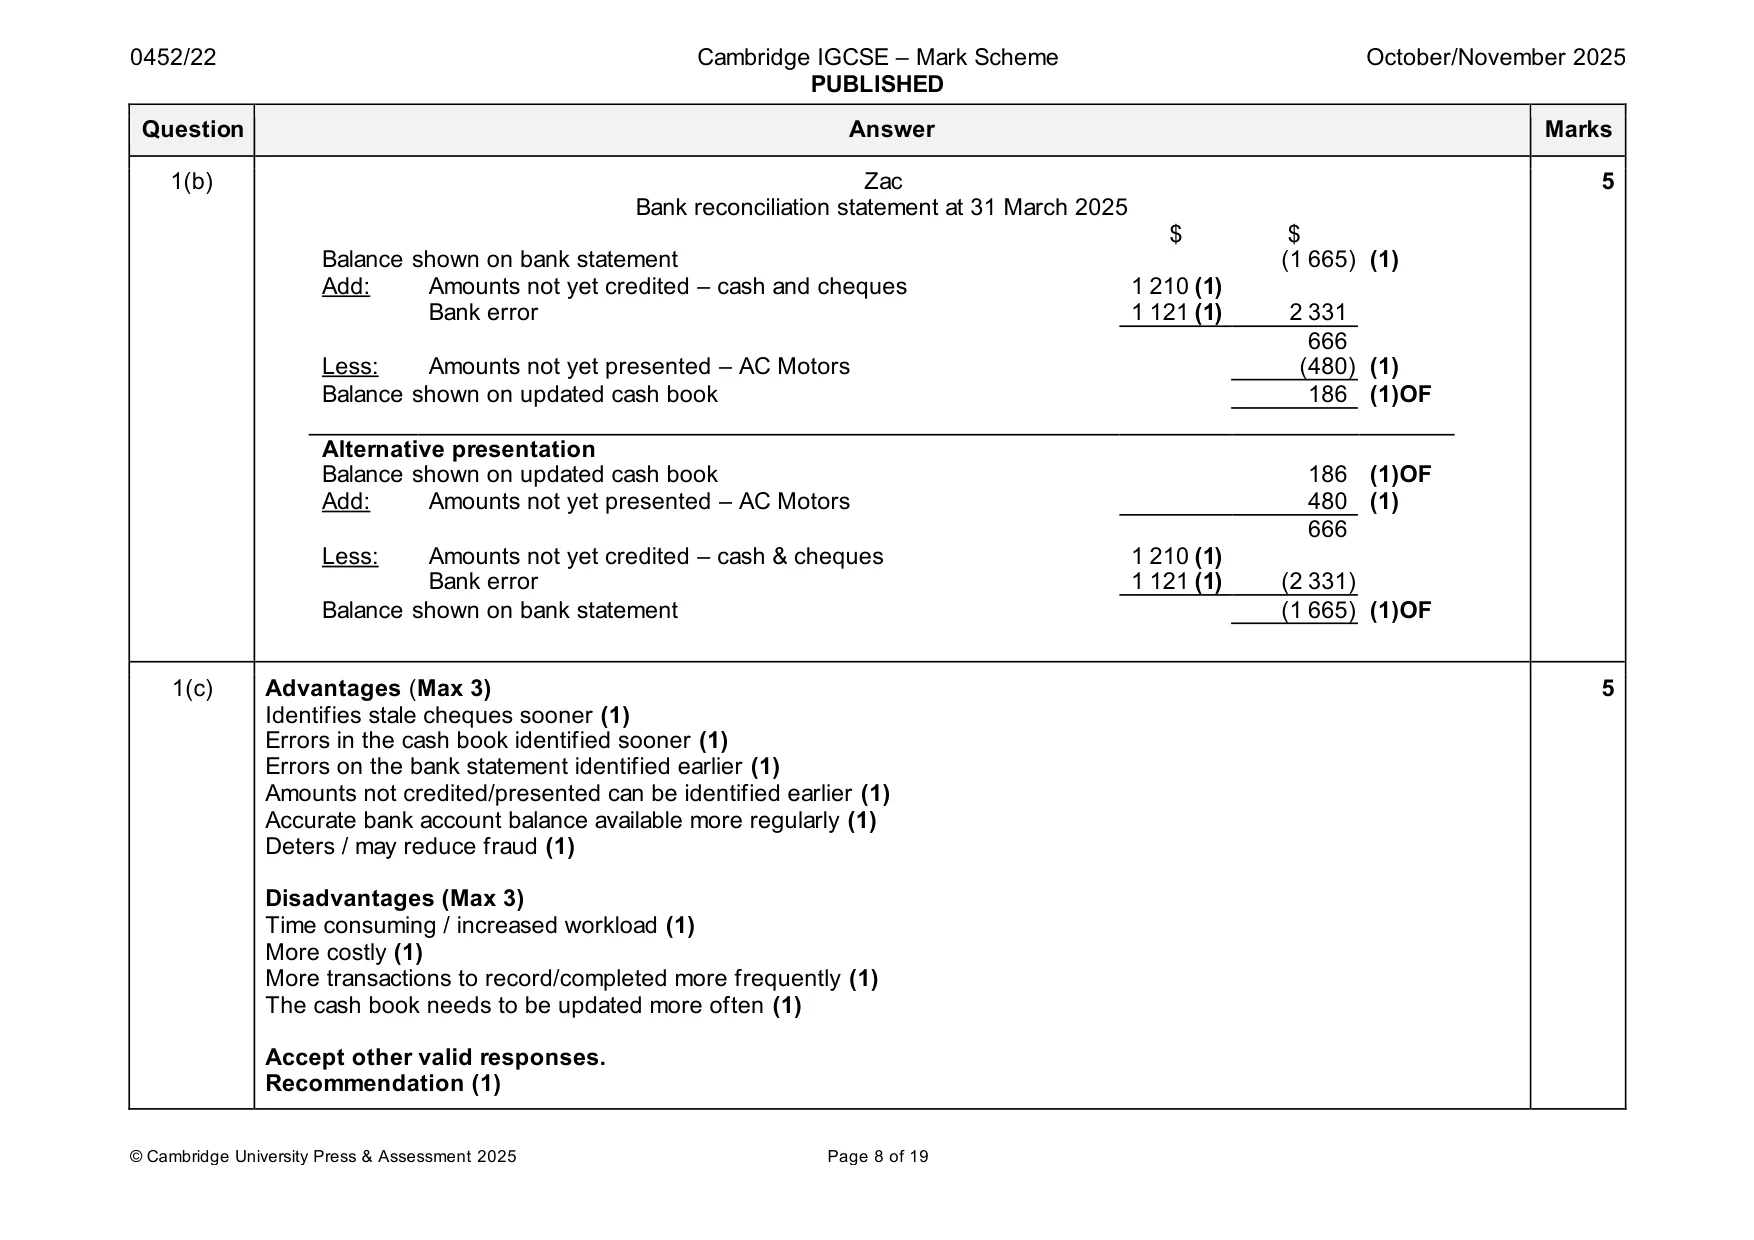
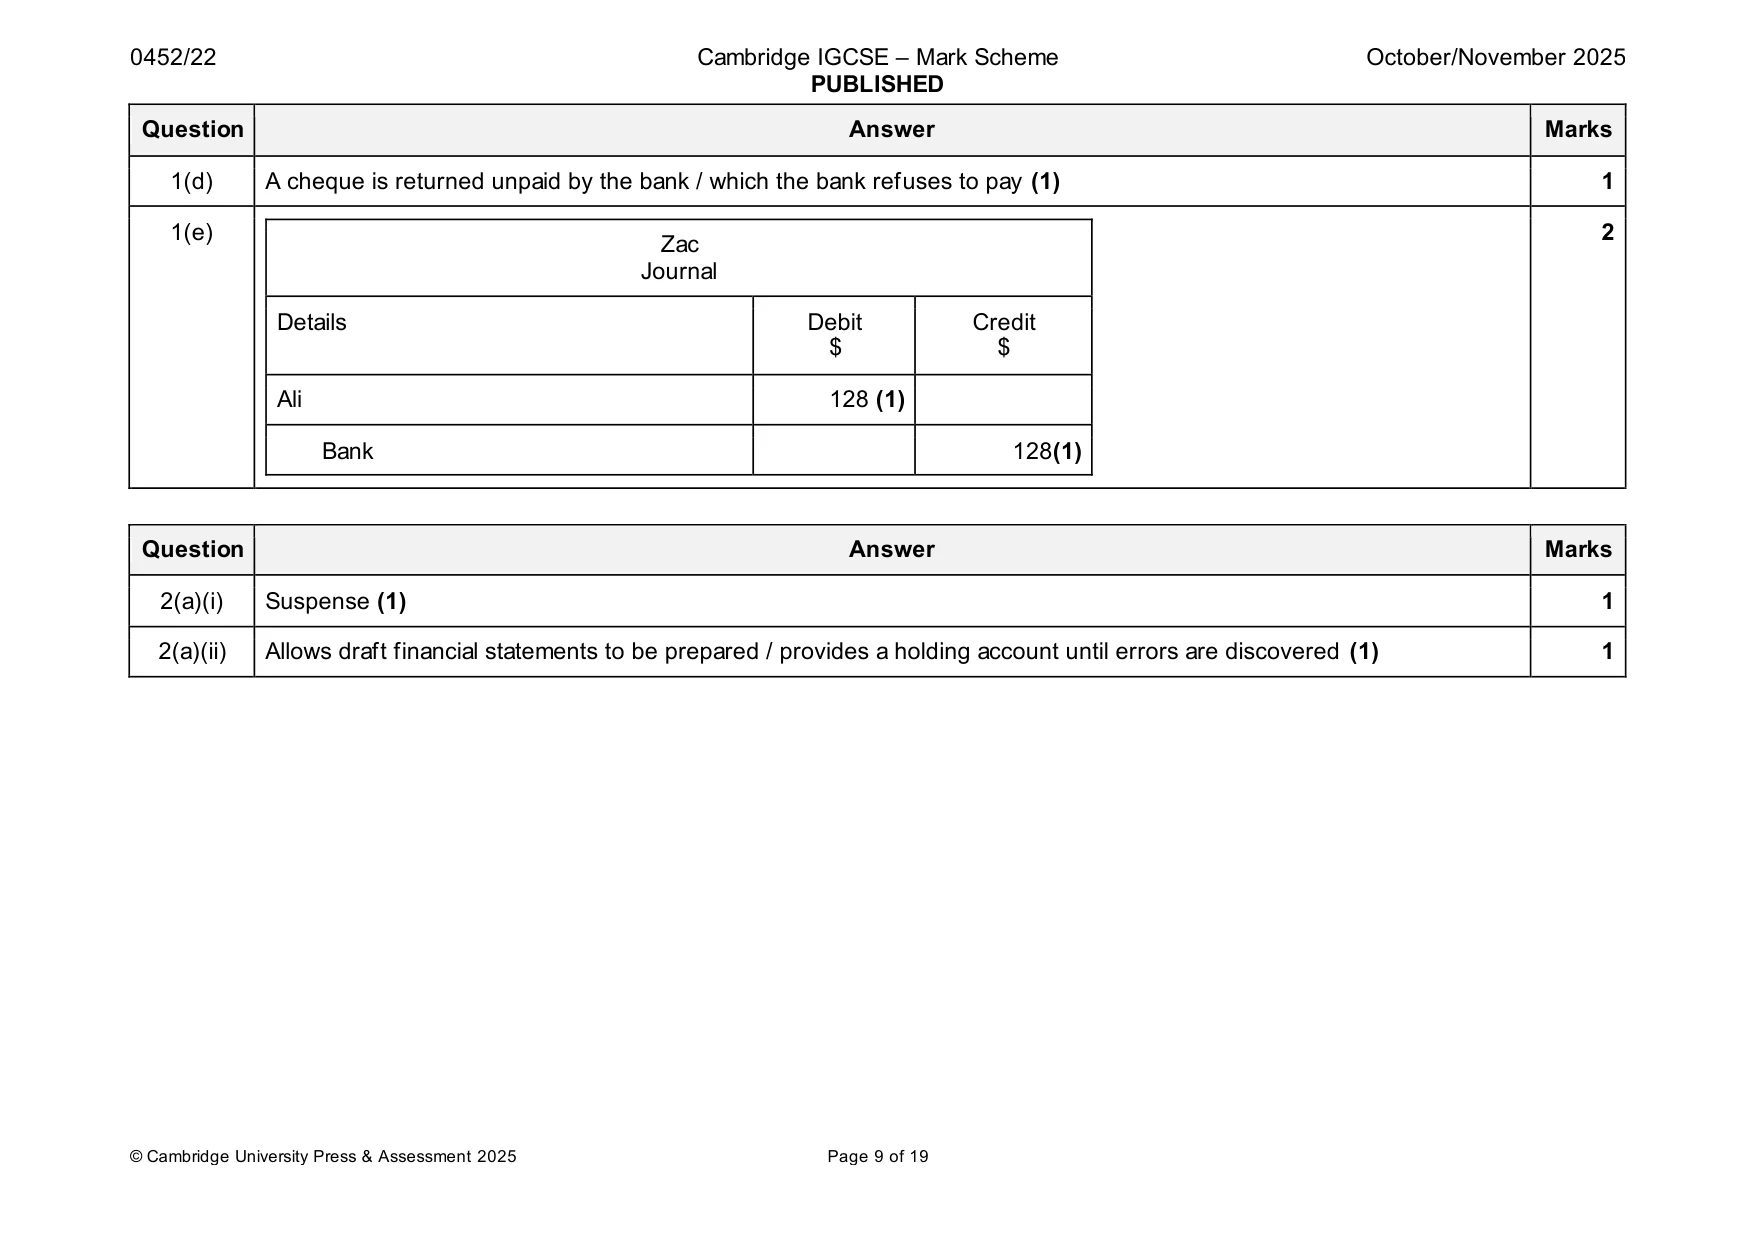
Mark scheme: Question Answer Marks 1(a) 7 Zac Cash book – bank columns Date Details $ Date Details $ March 31 Balance b/d 825 (1) March 23 Electricity 936 (1) 20 Zoe 310 (1) 25 Bank charges 58 (1) 30 Interest 45 (1) 31 Balance c/d 186 1180 1180 April 1 Balance b/d 186 (1)OF +(1) for dates 1(b) Zac 5 Bank reconciliation statement at 31 March 2025 $ $ Balance shown on bank statement (1 665) (1) Add: Amounts not yet credited – cash and cheques 1 210 (1) Bank error 1 121 (1) 2 331 666 Less: Amounts not yet presented – AC Motors (480) (1) Balance shown on updated cash book 186 (1)OF Alternative presentation Balance shown on updated cash book 186 (1)OF Add: Amounts not yet presented – AC Motors 480 (1) 666 Less: Amounts not yet credited – cash & cheques 1 210 (1) Bank error 1 121 (1) (2 331) Balance shown on bank statement (1 665) (1)OF 1(c) Advantages (Max 3) 5 Identifies stale cheques sooner (1) Errors in the cash book identified sooner (1) Errors on the bank statement identified earlier (1) Amounts not credited/presented can be identified earlier (1) Accurate bank account balance available more regularly (1) Deters / may reduce fraud (1) Disadvantages (Max 3) Time consuming / increased workload (1) More costly (1) More transactions to record/completed more frequently (1) The cash book needs to be updated more often (1) Accept other valid responses. Recommendation (1) 1(d) A cheque is returned unpaid by the bank / which the bank refuses to pay (1) 1 1(e) 2 Zac Journal Details Debit Credit $ $ Ali 128 (1) Bank 128(1)
Q2 · Jaya is a trader
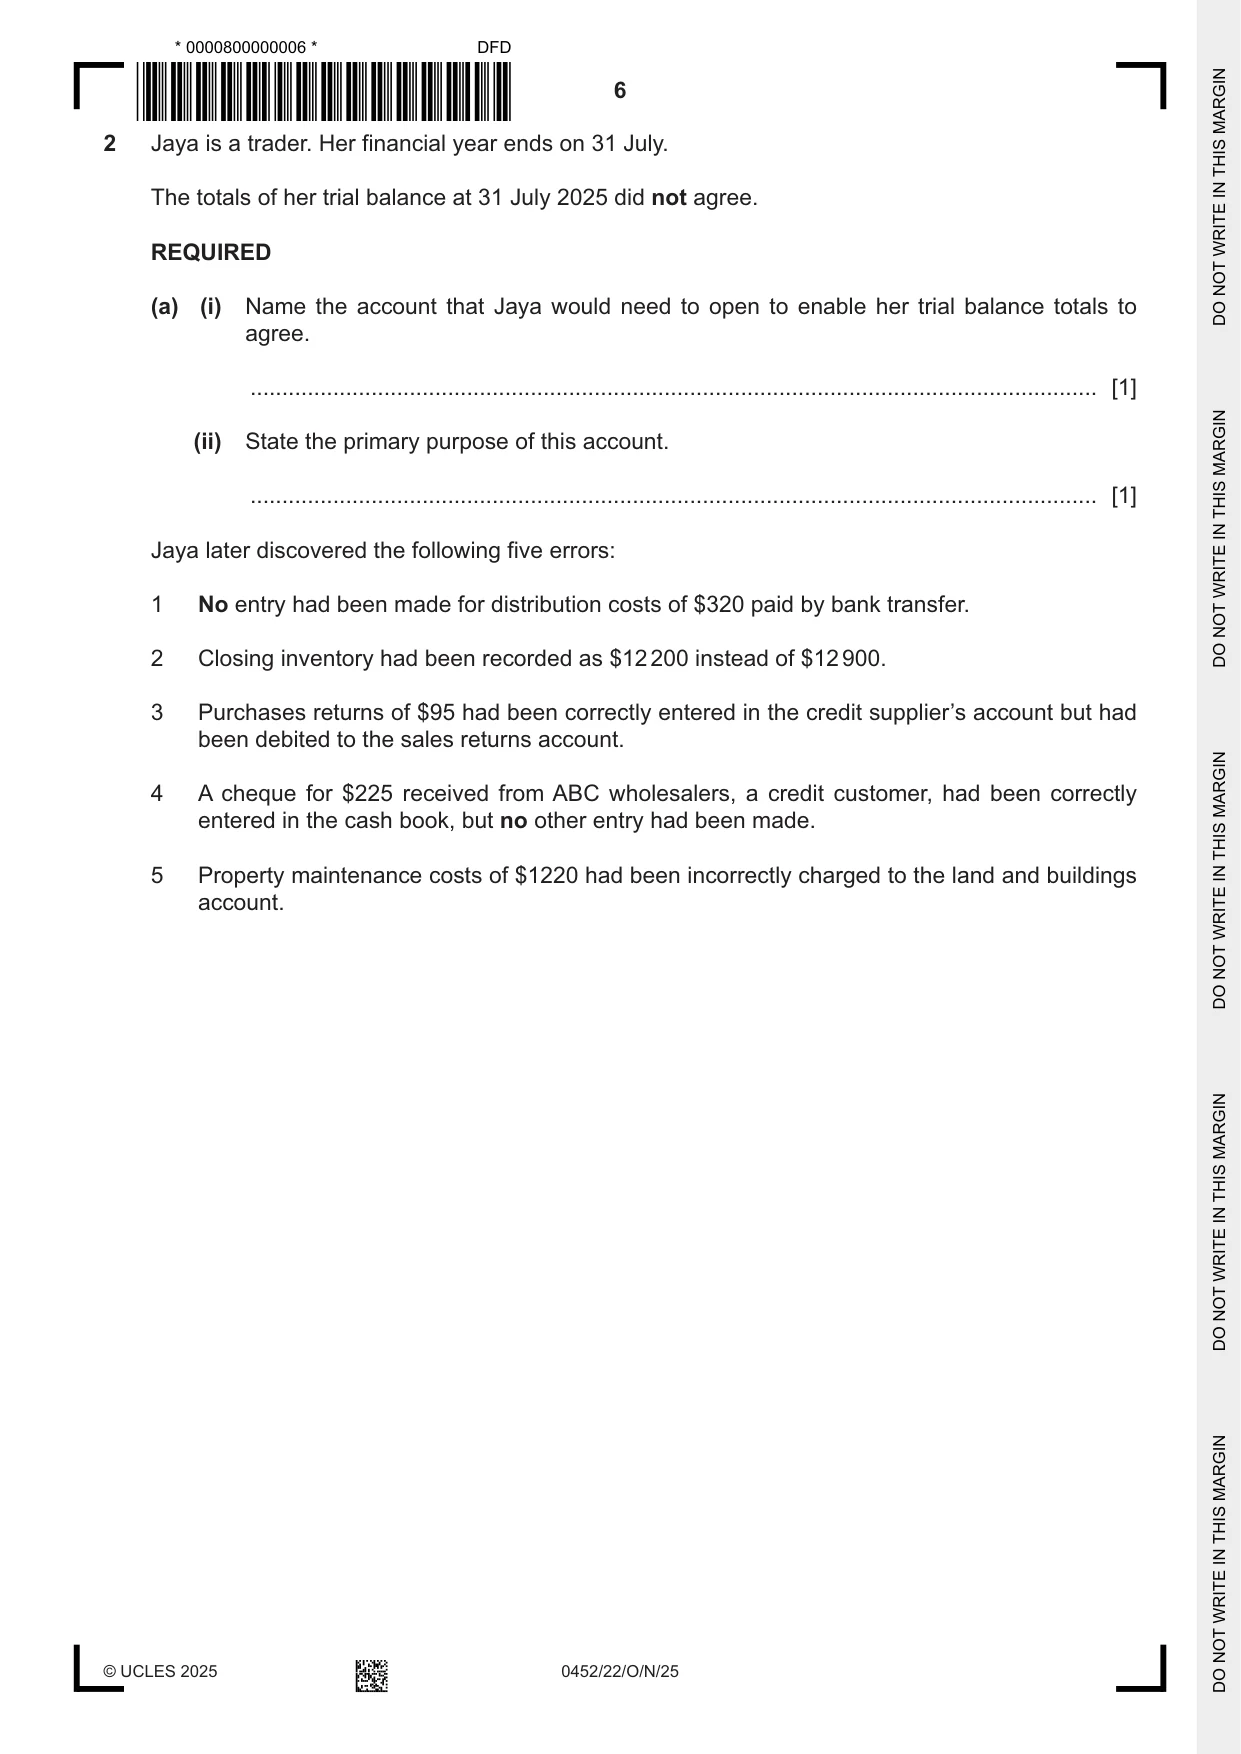
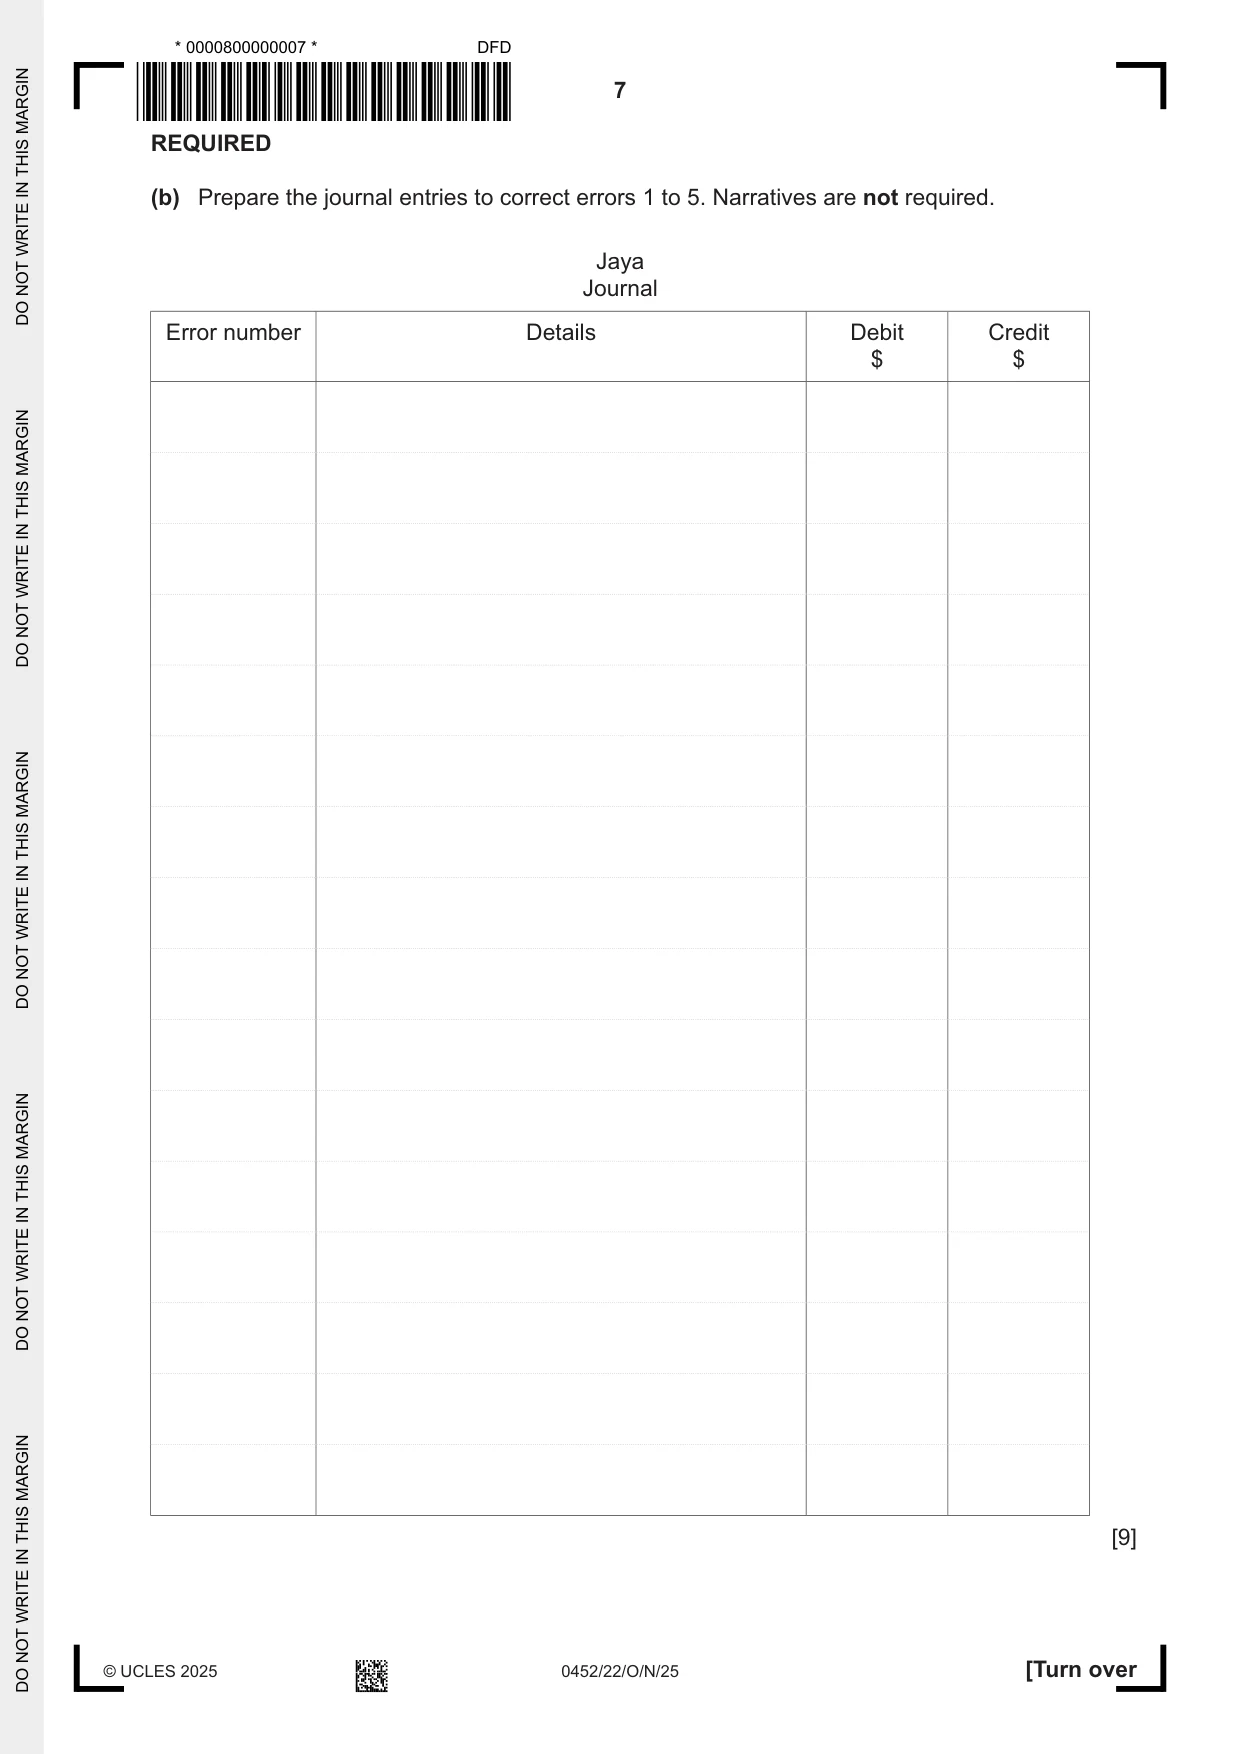
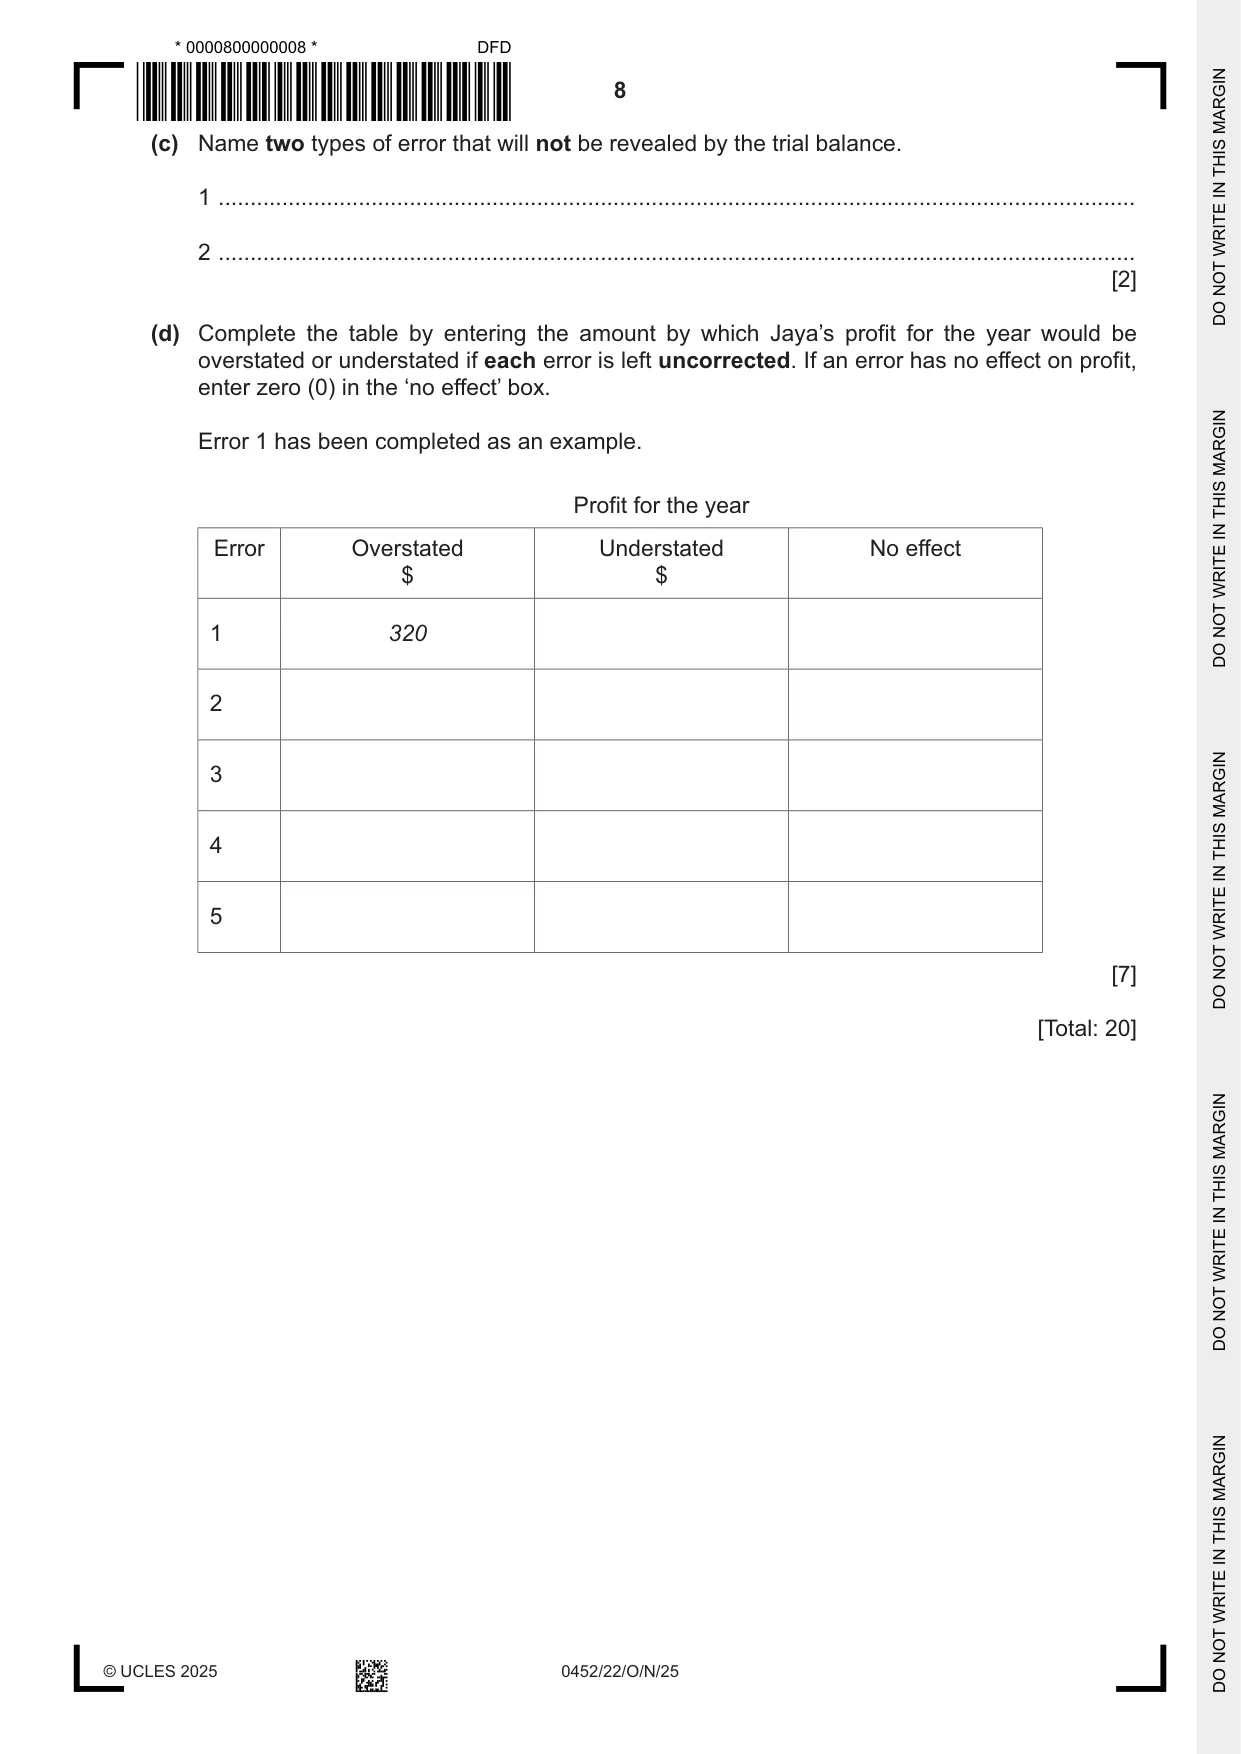
2 Jaya is a trader. Her financial year ends on 31 July. The totals of her trial balance at 31 July 2025 did not agree. REQUIRED (a) (i) Name the account that Jaya would need to open to enable her trial balance totals to agree. ..................................................................................................................................... [1] (ii) State the primary purpose of this account. ..................................................................................................................................... [1] Jaya later discovered the following five errors: 1 No entry had been made for distribution costs of $320 paid by bank transfer. 2 Closing inventory had been recorded as $12 200 instead of $12 900. 3 Purchases returns of $95 had been correctly entered in the credit supplier’s account but had been debited to the sales returns account. 4 A cheque for $225 received from ABC wholesalers, a credit customer, had been correctly entered in the cash book, but no other entry had been made. 5 Property maintenance costs of $1220 had been incorrectly charged to the land and buildings account. REQUIRED (b) Prepare the journal entries to correct errors 1 to 5. Narratives are not required. Jaya Journal Error number Details Debit Credit $ $ [9] (c) Name two types of error that will not be revealed by the trial balance. 1 ................................................................................................................................................ 2 ................................................................................................................................................ [2] (d) Complete the table by entering the amount by which Jaya’s profit for the year would be overstated or understated if each error is left uncorrected. If an error has no effect on profit, enter zero (0) in the ‘no effect’ box. Error 1 has been completed as an example. Profit for the year Error Overstated Understated No effect $ $ 1 320 2 3 4 5 [7] [Total: 20]
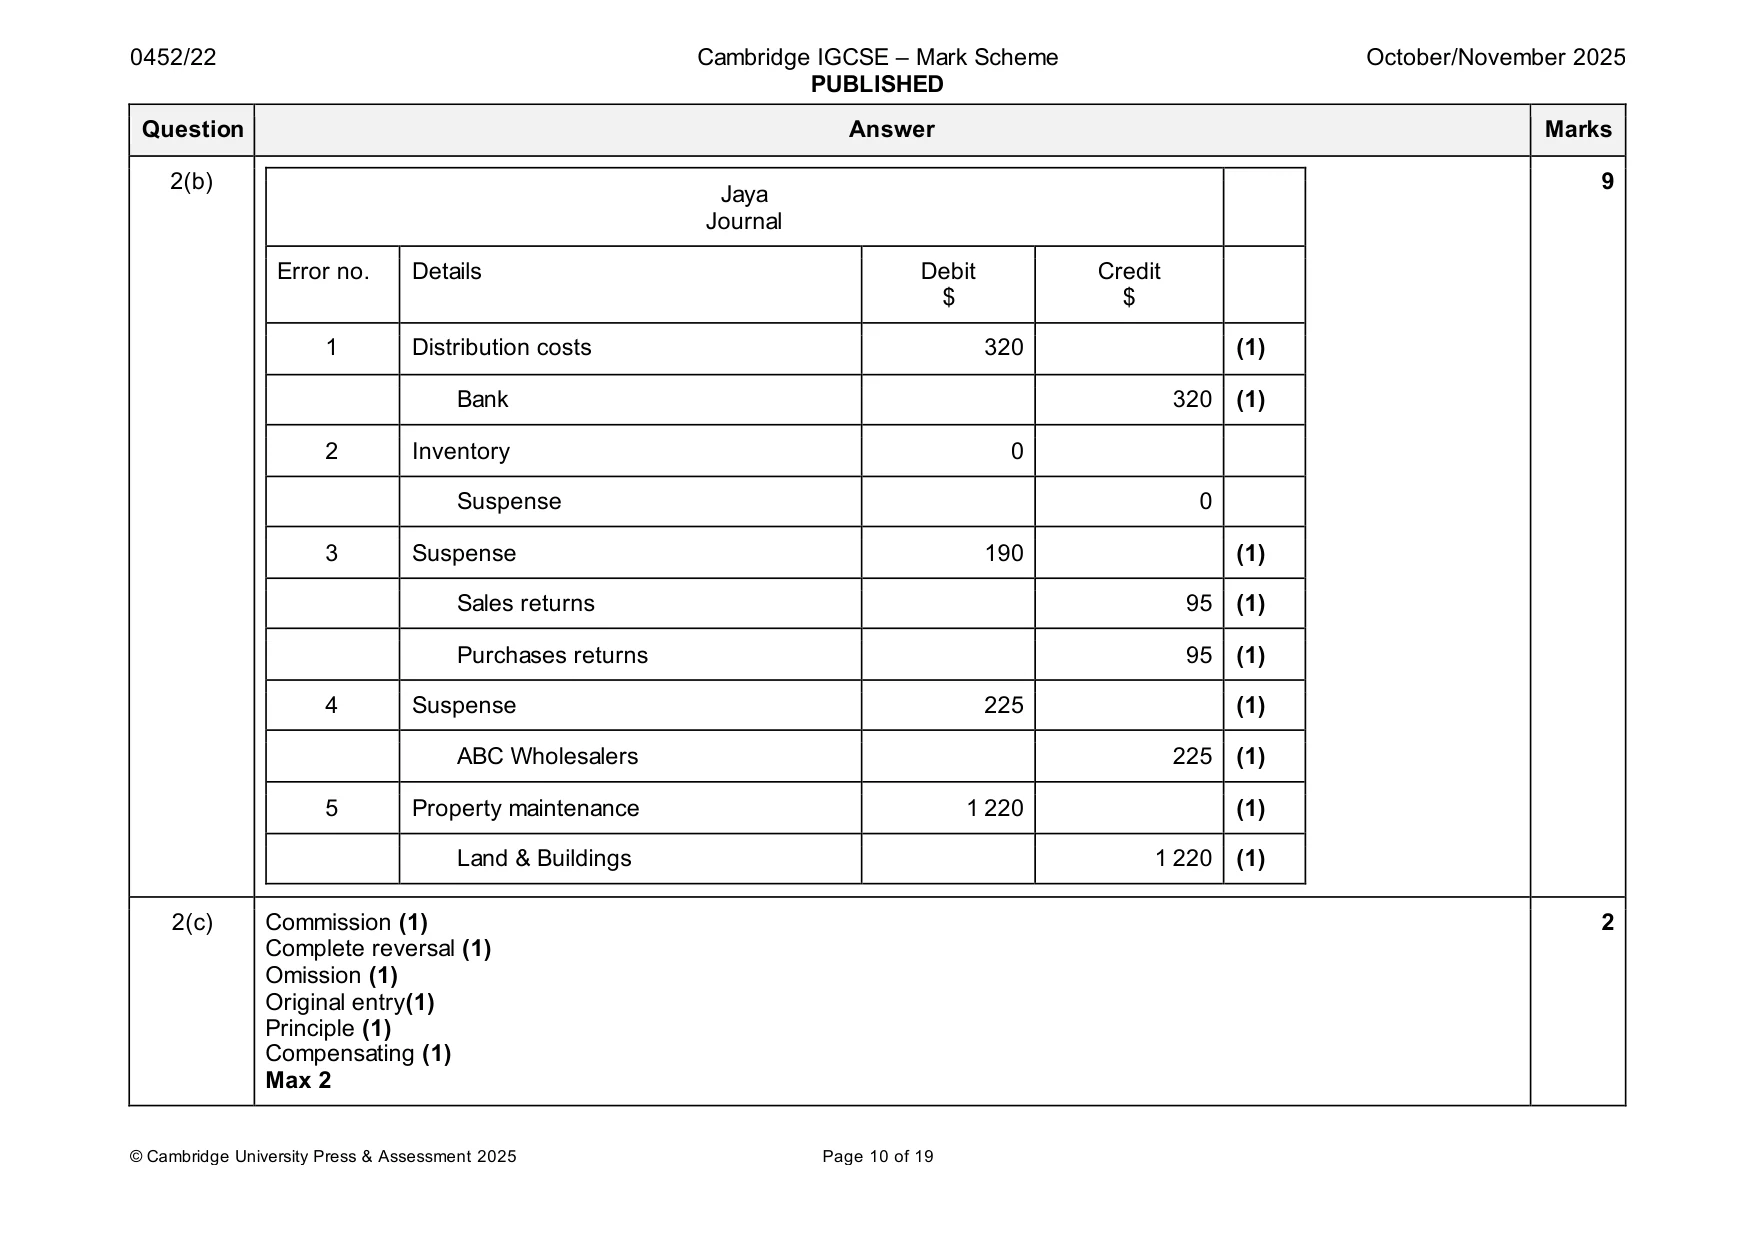
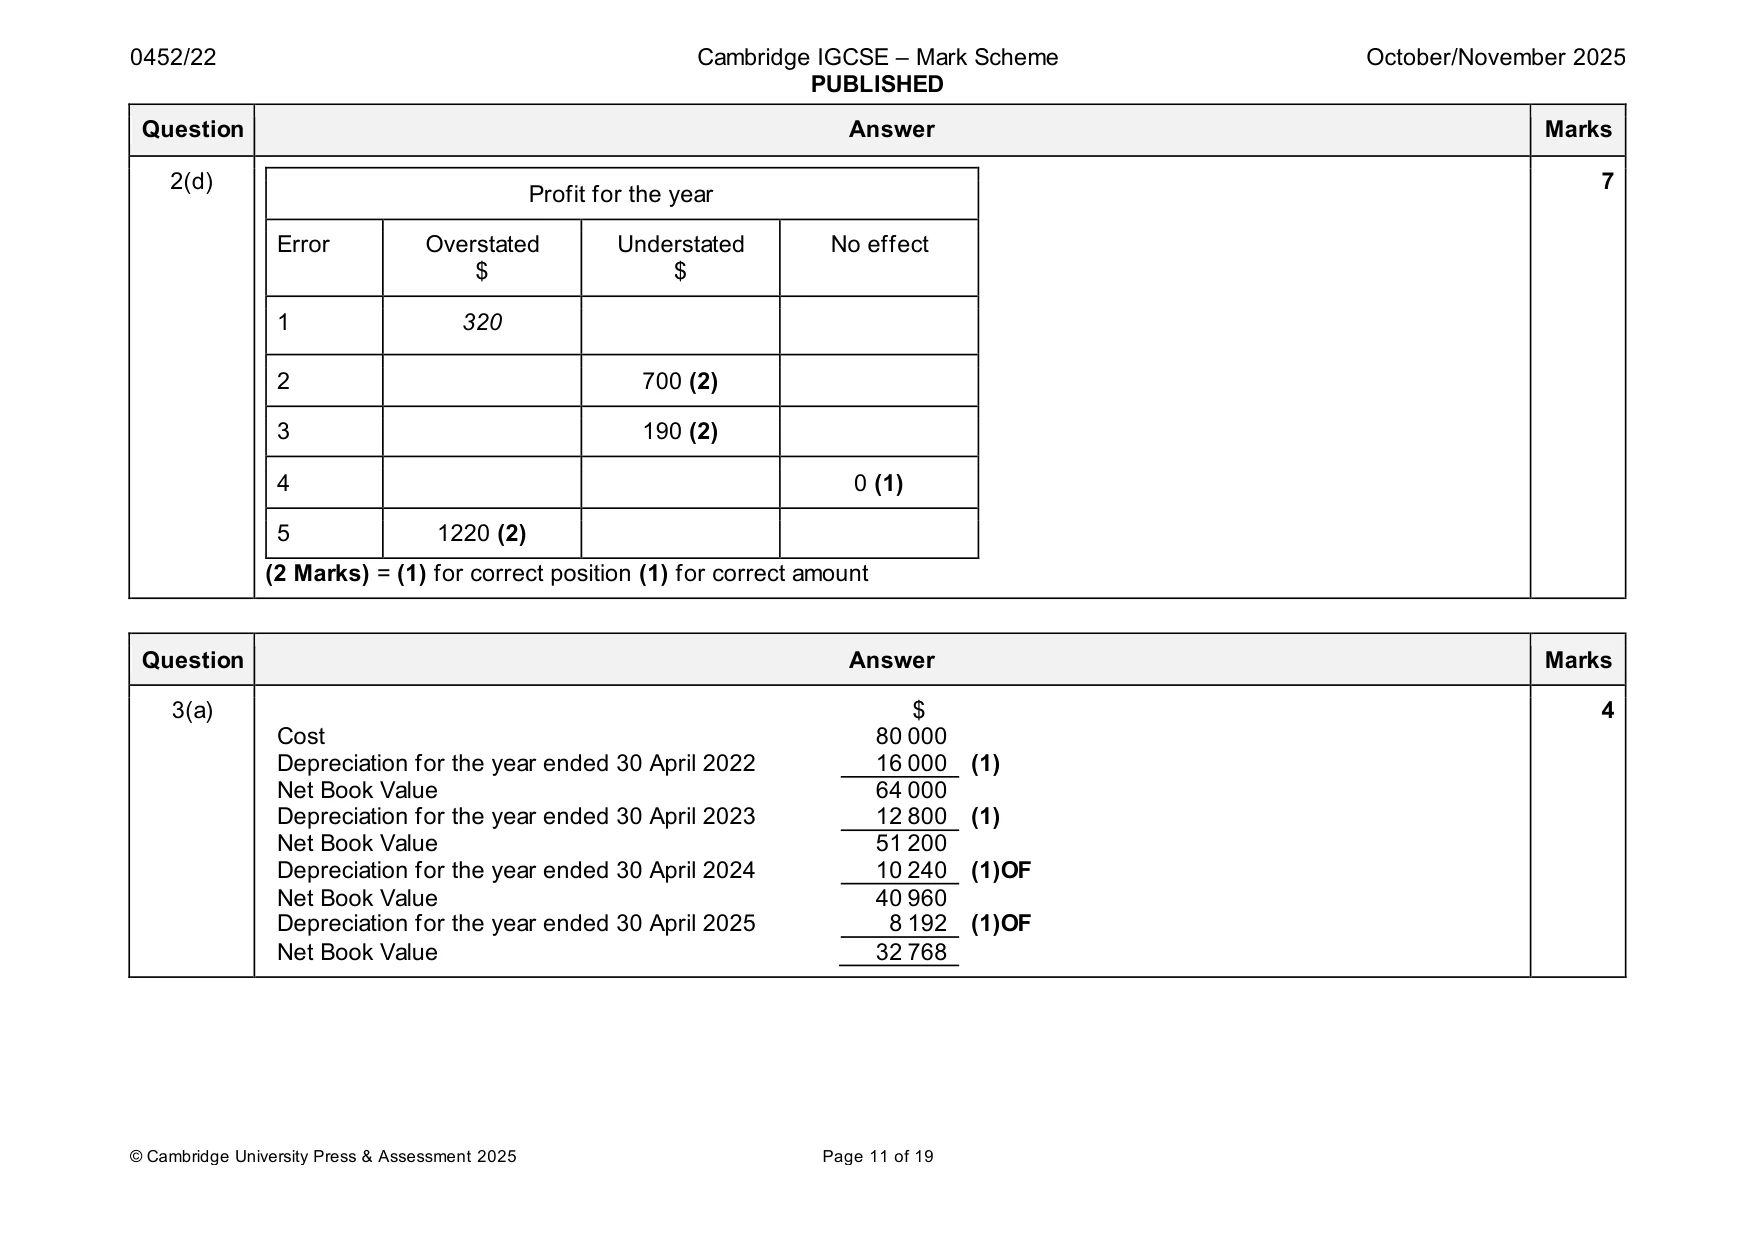
Mark scheme: 2(a)(i) Suspense (1) 1 2(a)(ii) Allows draft financial statements to be prepared / provides a holding account until errors are discovered (1) 1 2(b) 9 Jaya Journal Error no. Details Debit Credit $ $ 1 Distribution costs 320 (1) Bank 320 (1) 2 Inventory 0 Suspense 0 3 Suspense 190 (1) Sales returns 95 (1) Purchases returns 95 (1) 4 Suspense 225 (1) ABC Wholesalers 225 (1) 5 Property maintenance 1 220 (1) Land & Buildings 1 220 (1) 2(c) Commission (1) 2 Complete reversal (1) Omission (1) Original entry(1) Principle (1) Compensating (1) Max 2 2(d) 7 Profit for the year Error Overstated Understated No effect $ $ 1 320 2 700 (2) 3 190 (2) 4 0 (1) 5 1220 (2) (2 Marks) = (1) for correct position (1) for correct amount
Q3 · Ahmed has a vehicle breakdown recovery business
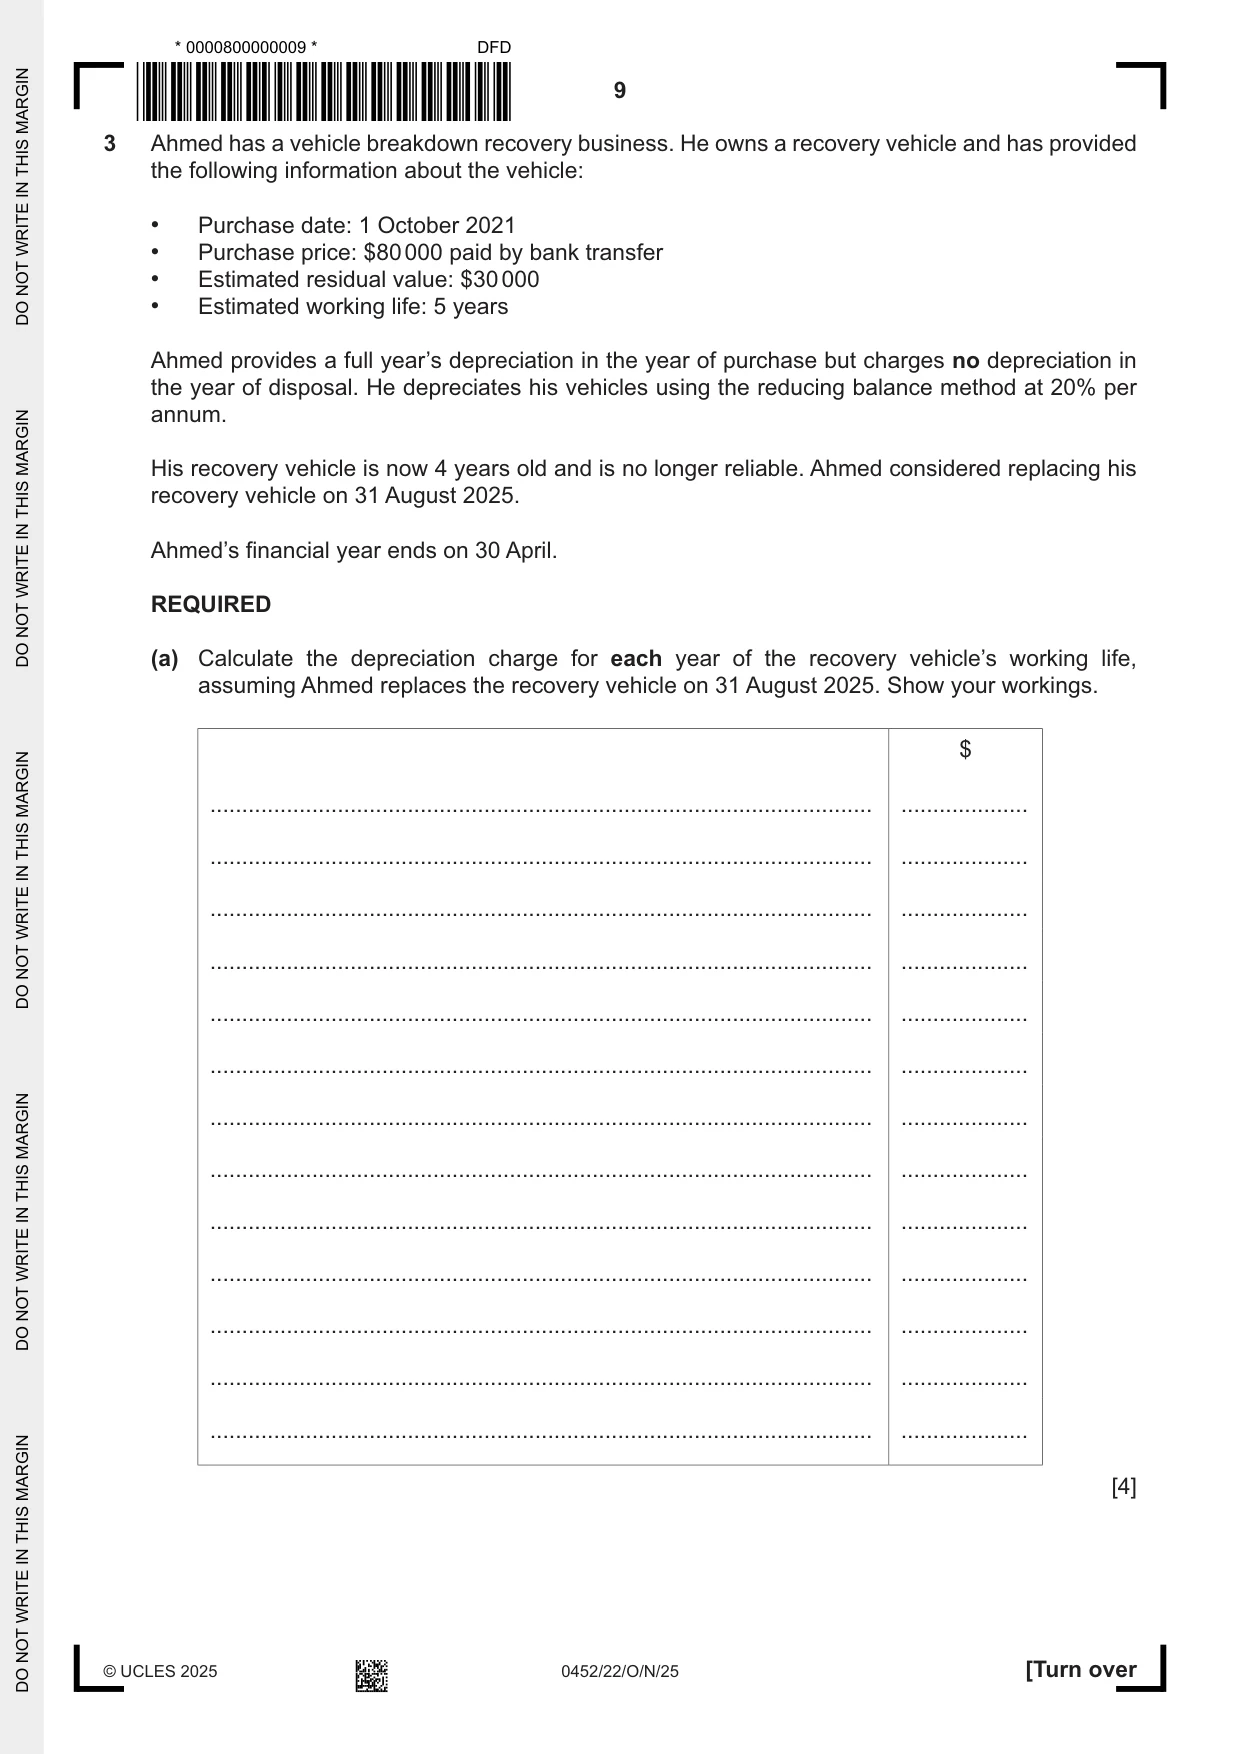
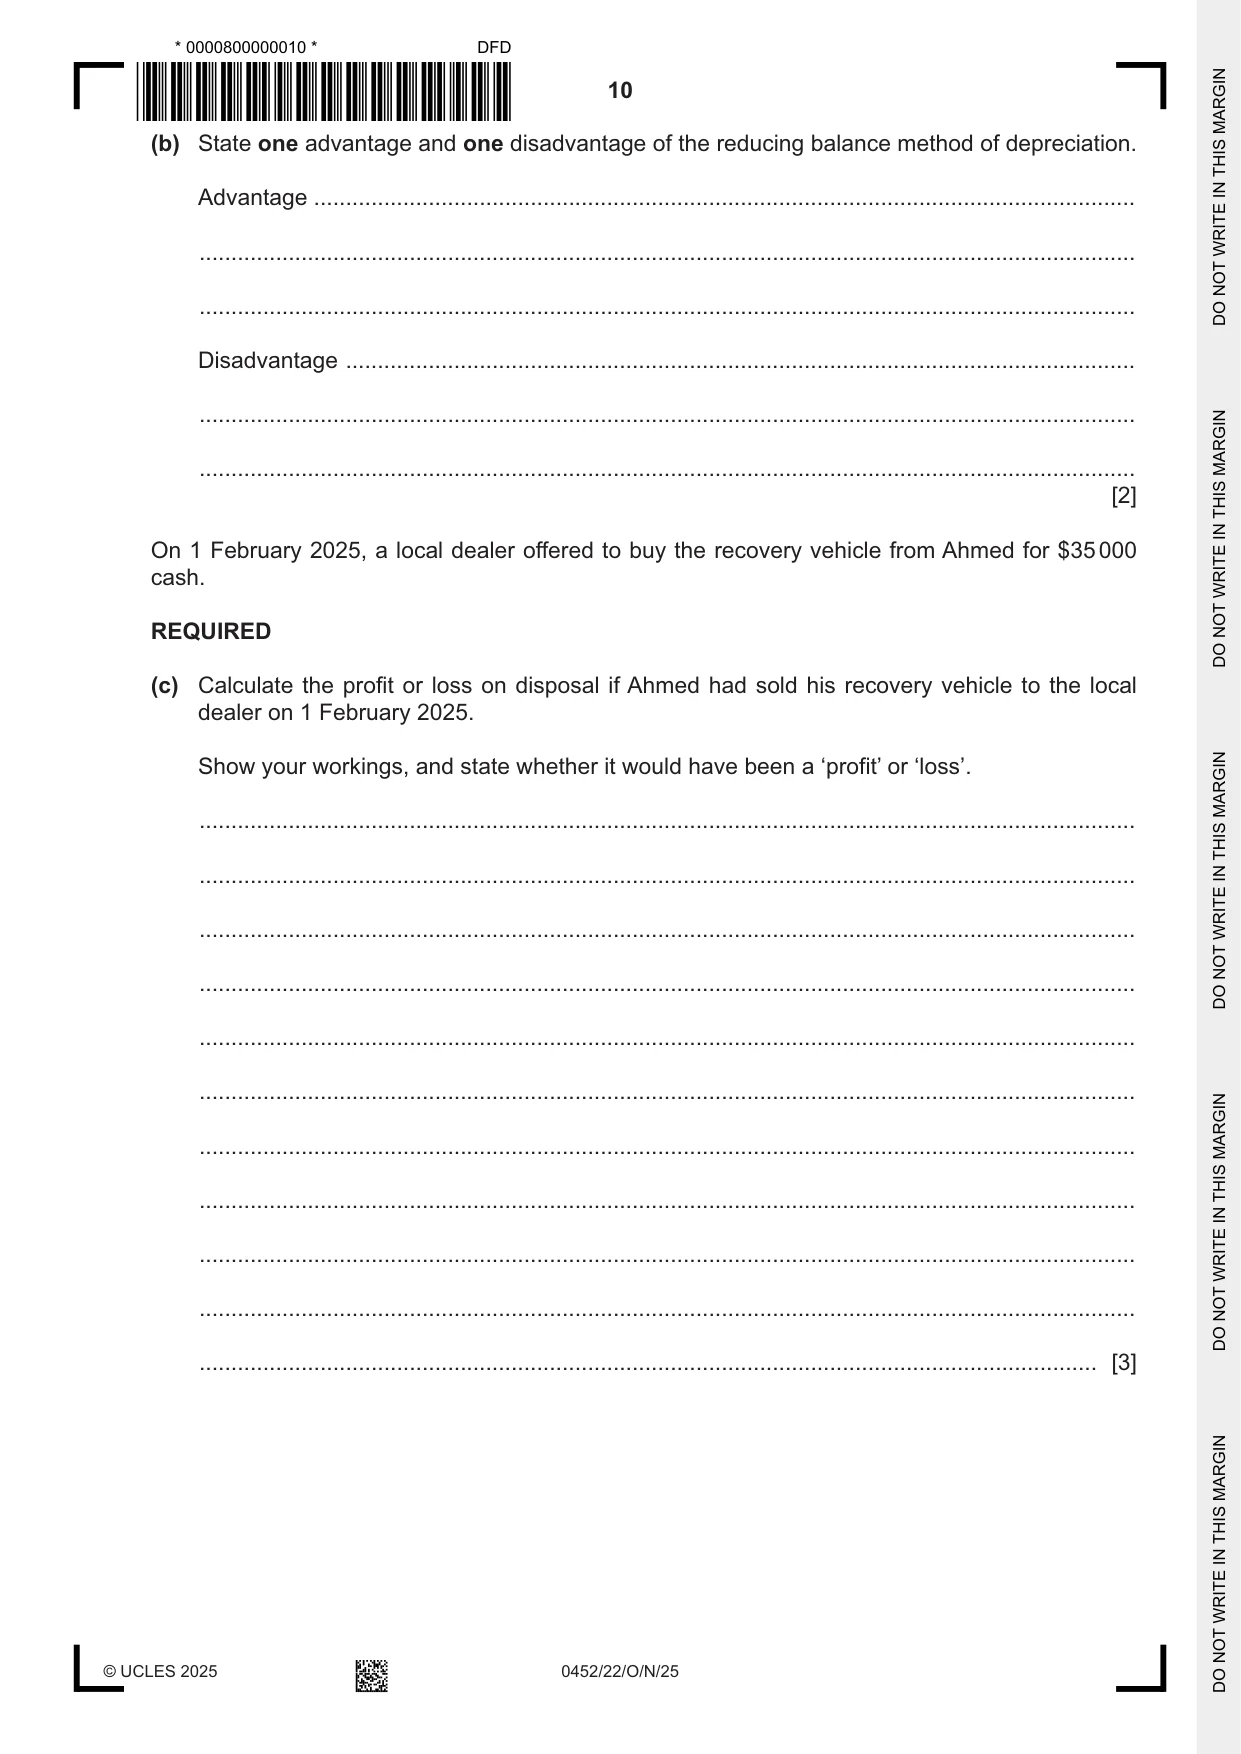
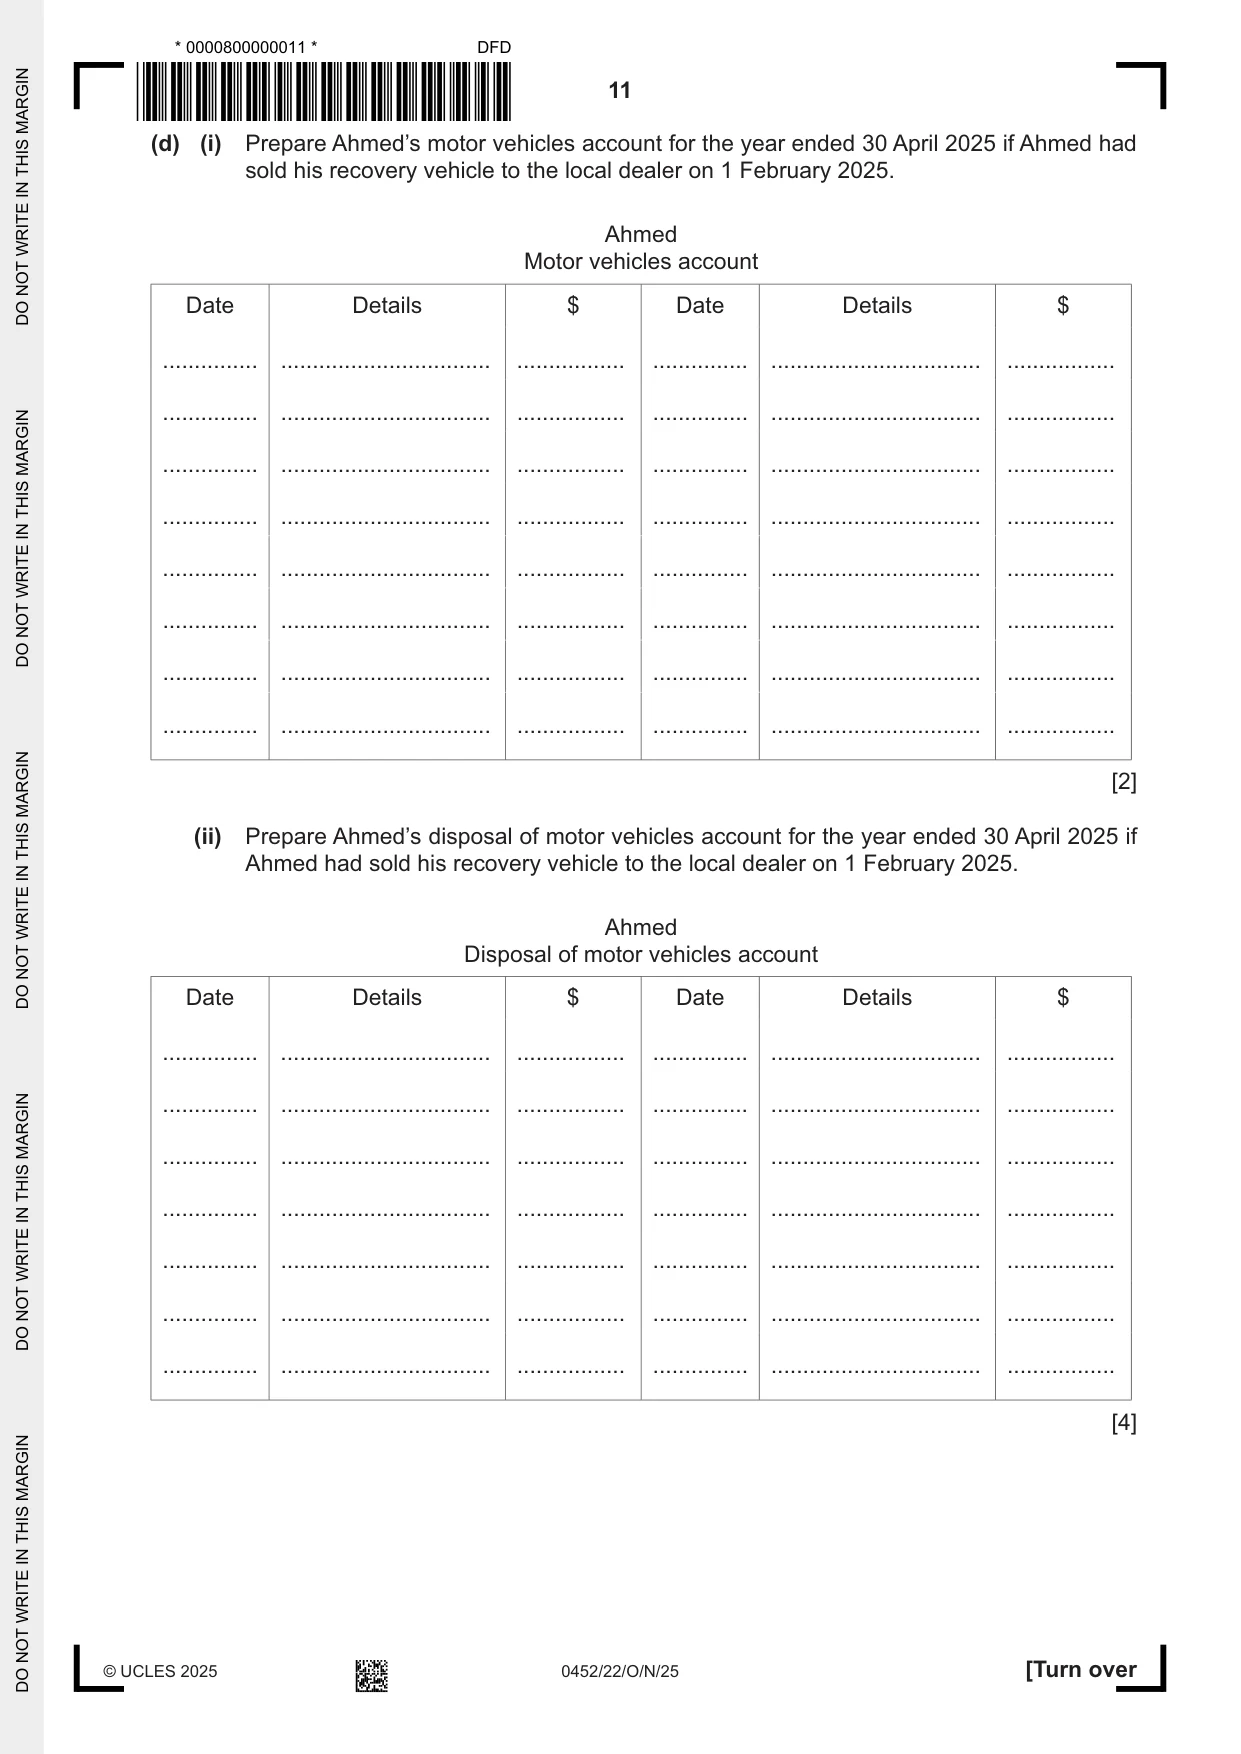
3 Ahmed has a vehicle breakdown recovery business. He owns a recovery vehicle and has provided the following information about the vehicle: • Purchase date: 1 October 2021 • Purchase price: $80 000 paid by bank transfer • Estimated residual value: $30 000 • Estimated working life: 5 years Ahmed provides a full year’s depreciation in the year of purchase but charges no depreciation in the year of disposal. He depreciates his vehicles using the reducing balance method at 20% per annum. His recovery vehicle is now 4 years old and is no longer reliable. Ahmed considered replacing his recovery vehicle on 31 August 2025. Ahmed’s financial year ends on 30 April. REQUIRED (a) Calculate the depreciation charge for each year of the recovery vehicle’s working life, assuming Ahmed replaces the recovery vehicle on 31 August 2025. Show your workings. $ ........................................................................................................ .................... ........................................................................................................ .................... ........................................................................................................ .................... ........................................................................................................ .................... ........................................................................................................ .................... ........................................................................................................ .................... ........................................................................................................ .................... ........................................................................................................ .................... ........................................................................................................ .................... ........................................................................................................ .................... ........................................................................................................ .................... ........................................................................................................ .................... ........................................................................................................ .................... [4] (b) State one advantage and one disadvantage of the reducing balance method of depreciation. Advantage ................................................................................................................................. ................................................................................................................................................... ................................................................................................................................................... Disadvantage ............................................................................................................................ ................................................................................................................................................... ................................................................................................................................................... [2] On 1 February 2025, a local dealer offered to buy the recovery vehicle from Ahmed for $35 000 cash. REQUIRED (c) Calculate the profit or loss on disposal if Ahmed had sold his recovery vehicle to the local dealer on 1 February 2025. Show your workings, and state whether it would have been a ‘profit’ or ‘loss’. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] (d) (i) Prepare Ahmed’s motor vehicles account for the year ended 30 April 2025 if Ahmed had sold his recovery vehicle to the local dealer on 1 February 2025. Ahmed Motor vehicles account Date Details $ Date Details $ ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. [2] (ii) Prepare Ahmed’s disposal of motor vehicles account for the year ended 30 April 2025 if Ahmed had sold his recovery vehicle to the local dealer on 1 February 2025. Ahmed Disposal of motor vehicles account Date Details $ Date Details $ ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. [4] Ahmed sold his recovery vehicle. Since the sale, he has been hiring a recovery vehicle capable of recovering larger vehicles and is now considering buying a similar vehicle. He would finance the purchase of this new vehicle using the money received from selling his old recovery vehicle, and the balance will come from a bank loan repayable in 5 years. Delivery of the new vehicle is estimated to be in 6 months. REQUIRED (e) Advise Ahmed whether he should buy this new recovery vehicle. Justify your answer by providing advantages and disadvantages of buying the new recovery vehicle. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
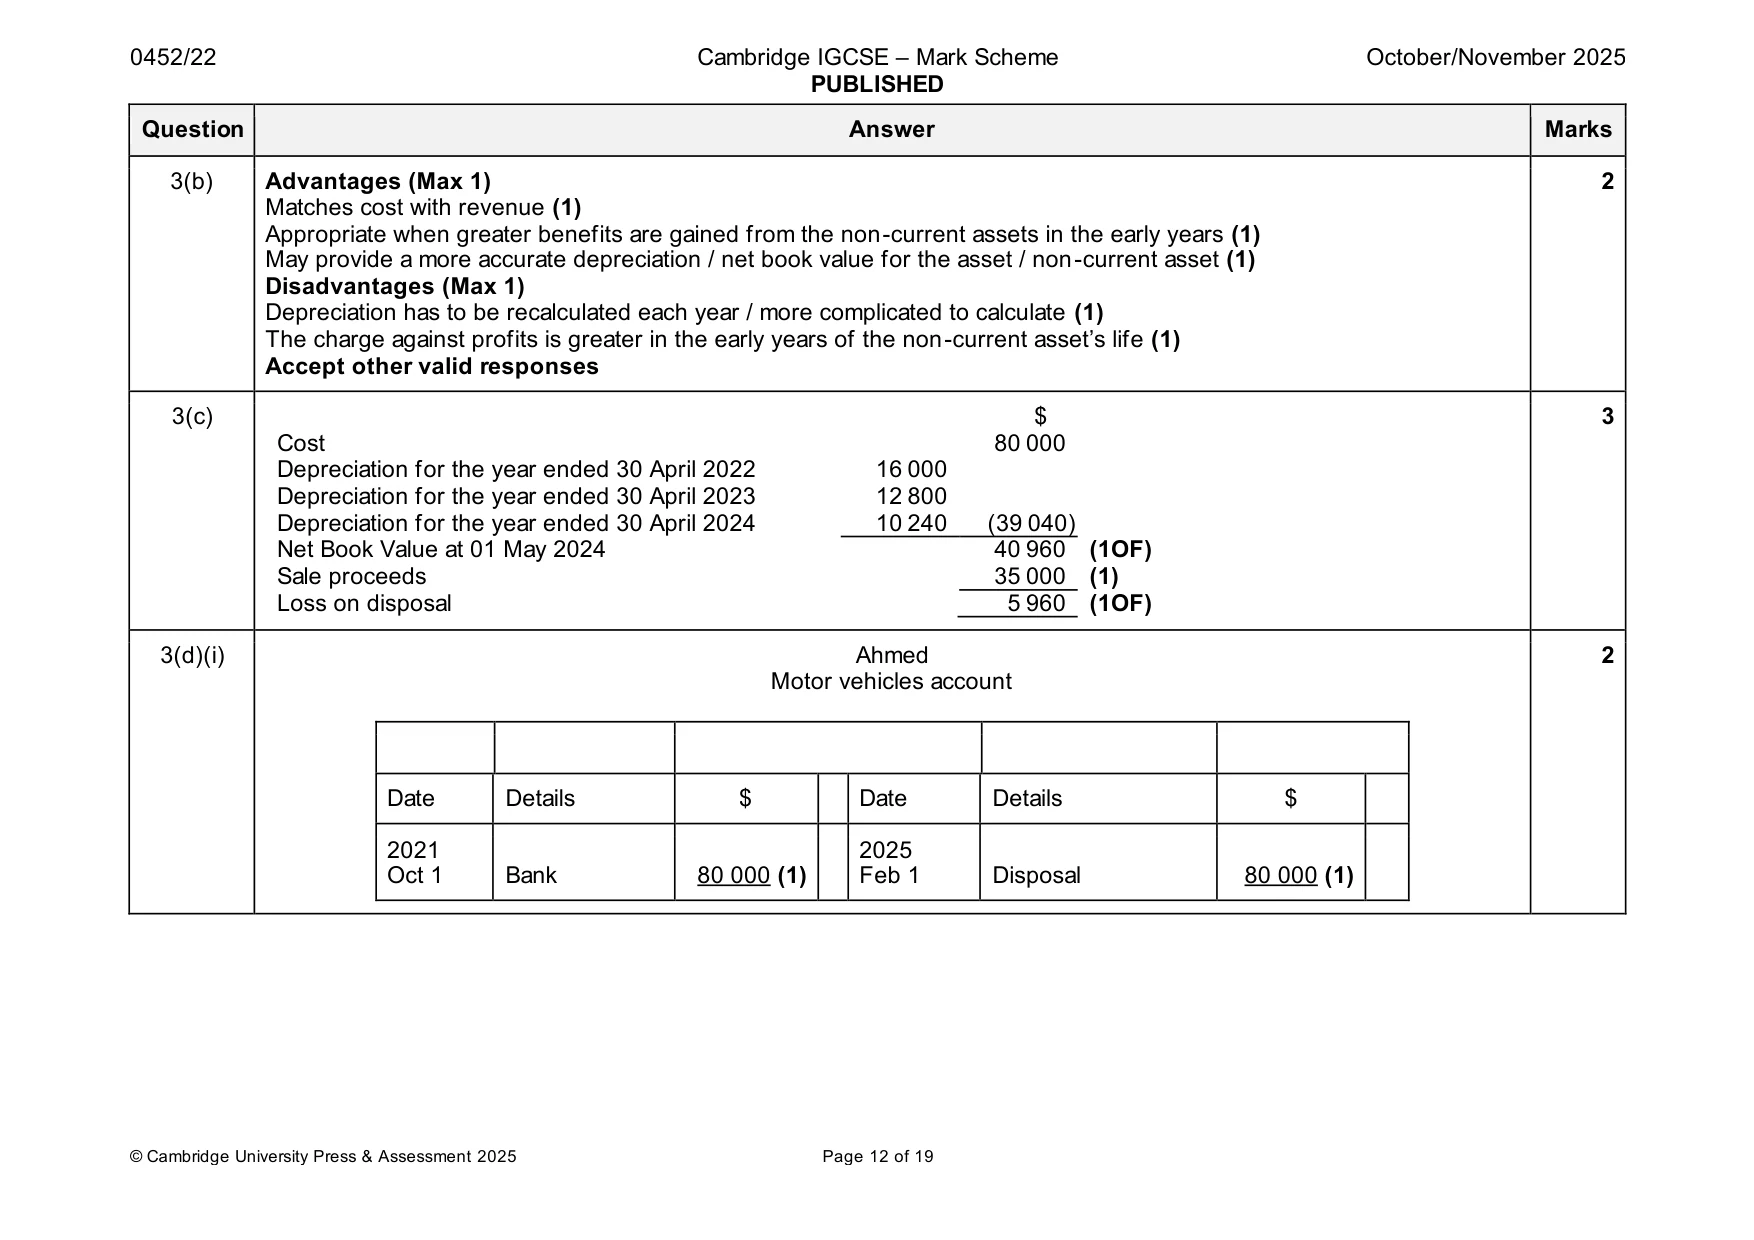
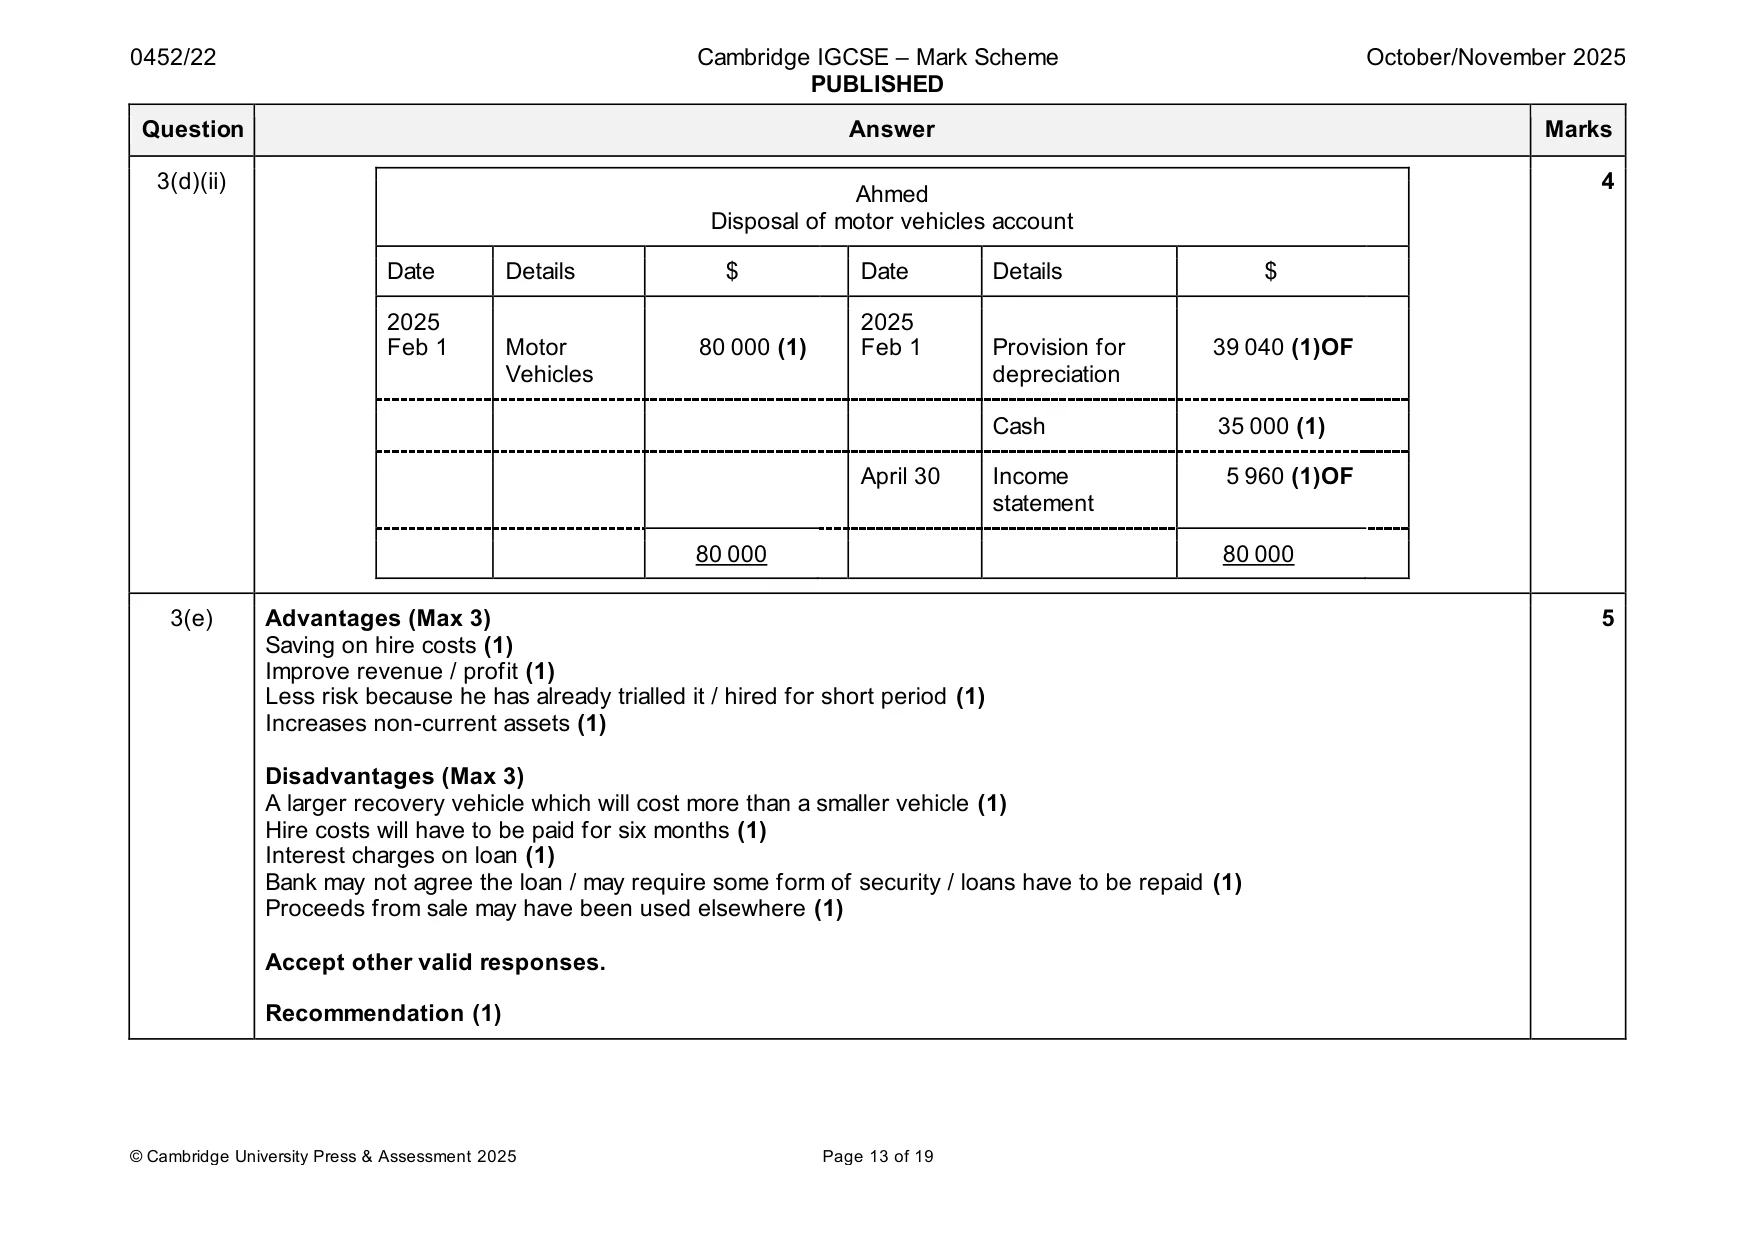
Mark scheme: 3(a) $ 4 Cost 80 000 Depreciation for the year ended 30 April 2022 16 000 (1) Net Book Value 64 000 Depreciation for the year ended 30 April 2023 12 800 (1) Net Book Value 51 200 Depreciation for the year ended 30 April 2024 10 240 (1)OF Net Book Value 40 960 Depreciation for the year ended 30 April 2025 8 192 (1)OF Net Book Value 32 768 3(b) Advantages (Max 1) 2 Matches cost with revenue (1) Appropriate when greater benefits are gained from the non-current assets in the early years (1) May provide a more accurate depreciation / net book value for the asset / non-current asset (1) Disadvantages (Max 1) Depreciation has to be recalculated each year / more complicated to calculate (1) The charge against profits is greater in the early years of the non-current asset’s life (1) Accept other valid responses 3(c) $ 3 Cost 80 000 Depreciation for the year ended 30 April 2022 16 000 Depreciation for the year ended 30 April 2023 12 800 Depreciation for the year ended 30 April 2024 10 240 (39 040) Net Book Value at 01 May 2024 40 960 (1OF) Sale proceeds 35 000 (1) Loss on disposal 5 960 (1OF) 3(d)(i) Ahmed 2 Motor vehicles account Date Details $ Date Details $ 2021 2025 Oct 1 Bank 80 000 (1) Feb 1 Disposal 80 000 (1) 3(d)(ii) 4 Ahmed Disposal of motor vehicles account Date Details $ Date Details $ 2025 2025 Feb 1 Motor 80 000 (1) Feb 1 Provision for 39 040 (1)OF Vehicles depreciation Cash 35 000 (1) April 30 Income 5 960 (1)OF statement 80 000 80 000 3(e) Advantages (Max 3) 5 Saving on hire costs (1) Improve revenue / profit (1) Less risk because he has already trialled it / hired for short period (1) Increases non-current assets (1) Disadvantages (Max 3) A larger recovery vehicle which will cost more than a smaller vehicle (1) Hire costs will have to be paid for six months (1) Interest charges on loan (1) Bank may not agree the loan / may require some form of security / loans have to be repaid (1) Proceeds from sale may have been used elsewhere (1) Accept other valid responses. Recommendation (1)
More questions on Accounting for depreciation and disposal of non-current assets
Q4 · AY Limited has provided the following performance data for the last two years of trading
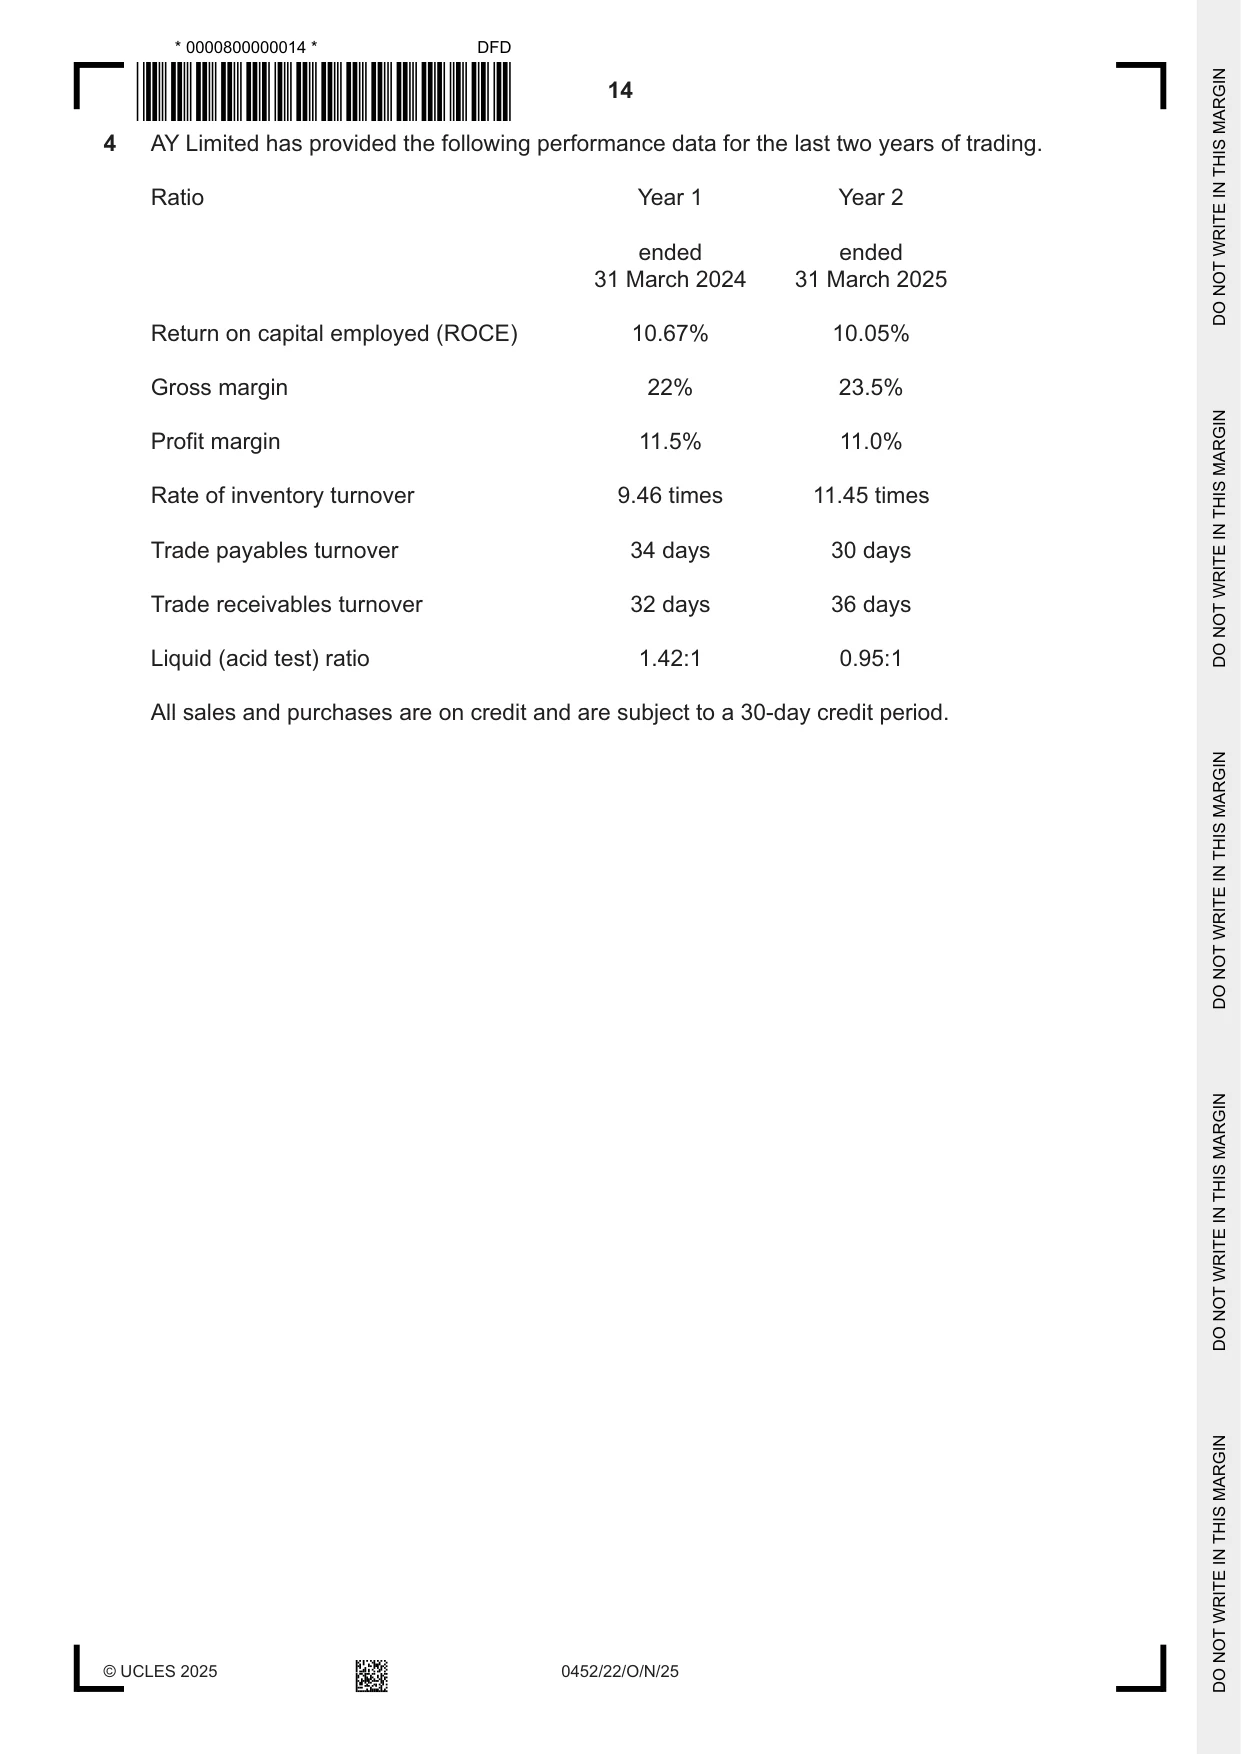
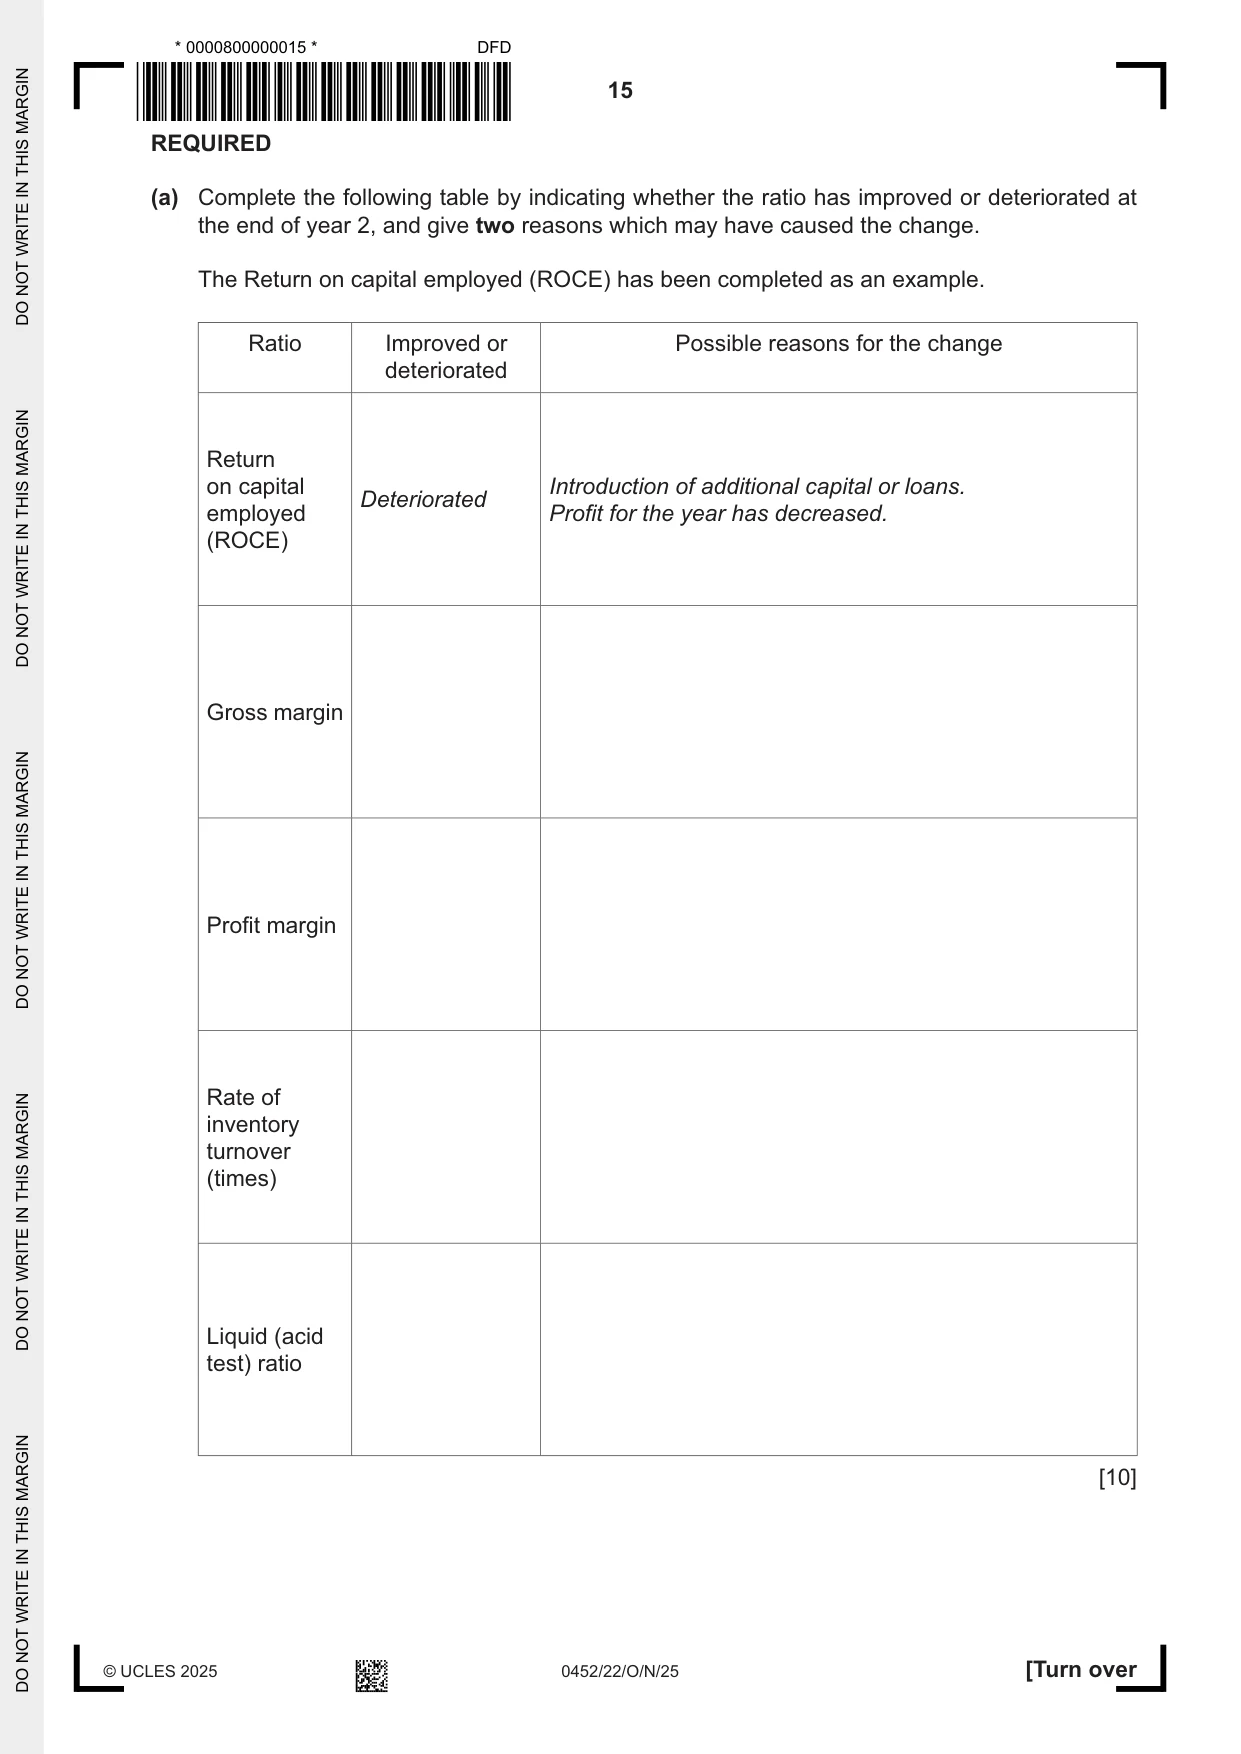
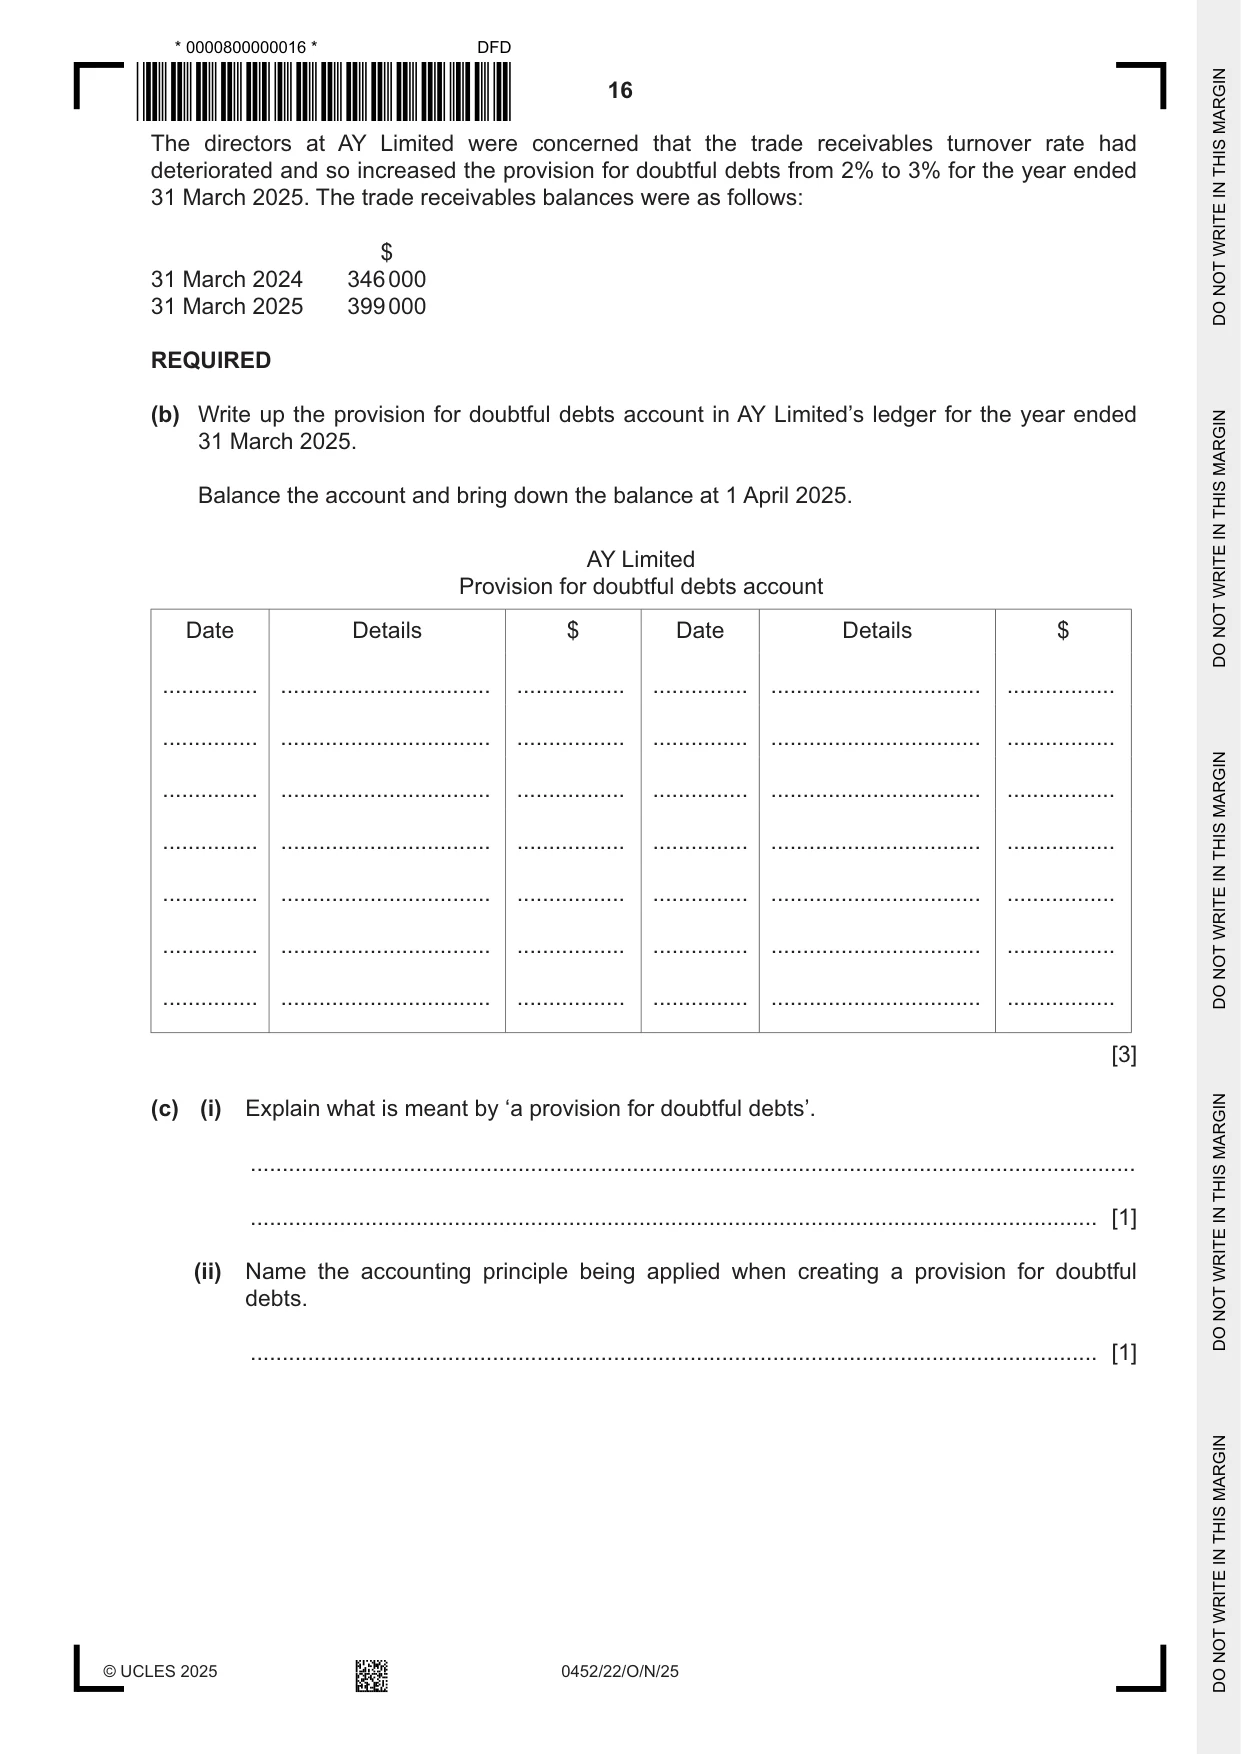
4 AY Limited has provided the following performance data for the last two years of trading. Ratio Year 1 Year 2 ended ended 31 March 2024 31 March 2025 Return on capital employed (ROCE) 10.67% 10.05% Gross margin 22% 23.5% Profit margin 11.5% 11.0% Rate of inventory turnover 9.46 times 11.45 times Trade payables turnover 34 days 30 days Trade receivables turnover 32 days 36 days Liquid (acid test) ratio 1.42:1 0.95:1 All sales and purchases are on credit and are subject to a 30‑day credit period. REQUIRED (a) Complete the following table by indicating whether the ratio has improved or deteriorated at the end of year 2, and give two reasons which may have caused the change. The Return on capital employed (ROCE) has been completed as an example. Ratio Improved or Possible reasons for the change deteriorated Return on capital Introduction of additional capital or loans. Deteriorated employed Profit for the year has decreased. (ROCE) Gross margin Profit margin Rate of inventory turnover (times) Liquid (acid test) ratio [10] The directors at AY Limited were concerned that the trade receivables turnover rate had deteriorated and so increased the provision for doubtful debts from 2% to 3% for the year ended 31 March 2025. The trade receivables balances were as follows: $ 31 March 2024 346 000 31 March 2025 399 000 REQUIRED (b) Write up the provision for doubtful debts account in AY Limited’s ledger for the year ended 31 March 2025. Balance the account and bring down the balance at 1 April 2025. AY Limited Provision for doubtful debts account Date Details $ Date Details $ ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. ............... ................................. ................. [3] (c) (i) Explain what is meant by ‘a provision for doubtful debts’. ........................................................................................................................................... ..................................................................................................................................... [1] (ii) Name the accounting principle being applied when creating a provision for doubtful debts. ..................................................................................................................................... [1] The directors of AY Limited have been considering buying a new piece of equipment costing $75 000. A machinery supplier has approached them, offering a 15% discount on this equipment if they make an immediate purchase. The supplier has indicated that the purchase would need to be on a cash basis. AY Limited’s accountant has suggested that they may be able to finance the purchase of the equipment by delaying payments to their trade payables. REQUIRED (d) Advise the directors of AY Limited whether or not delaying payments to their trade payables would be a good way to secure the purchase of the equipment. Justify your answer by providing points for and against delaying payments to their trade payables. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
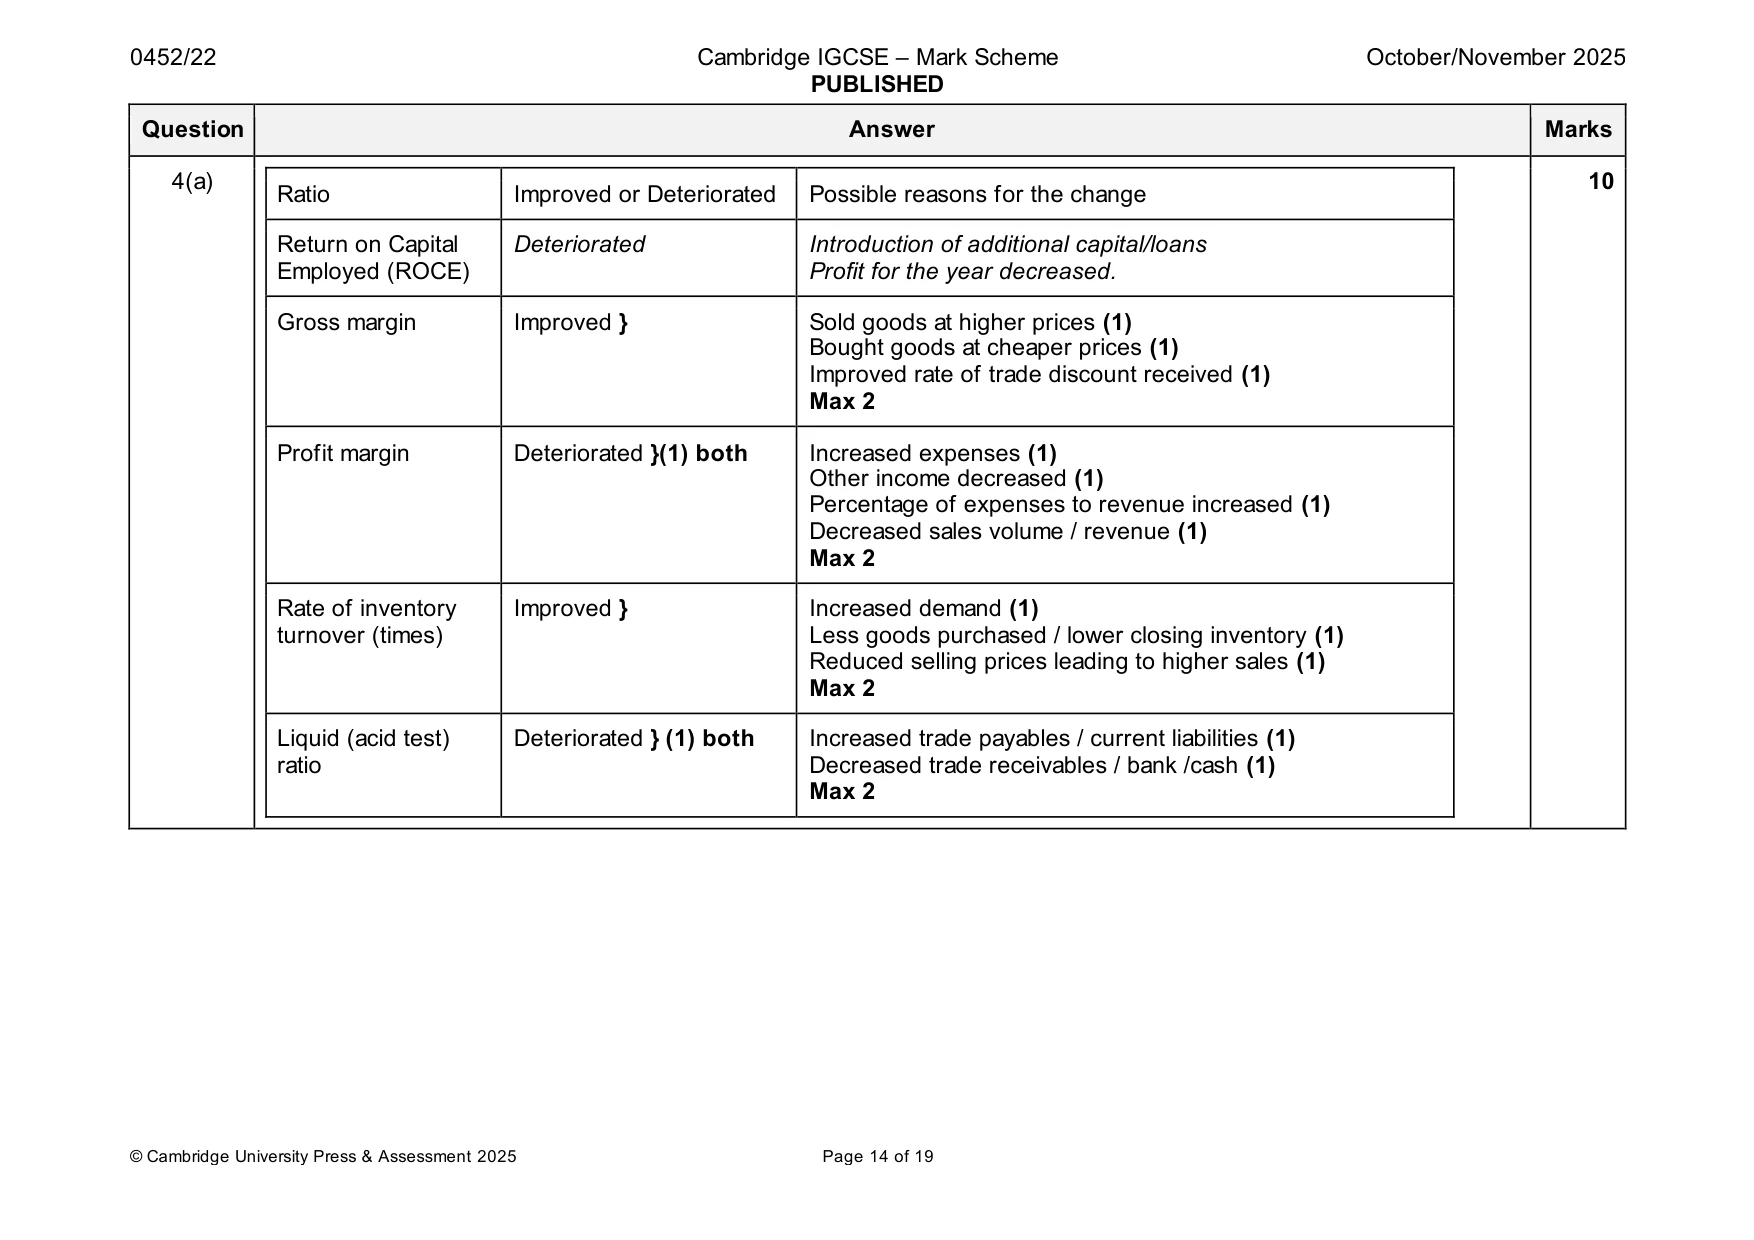
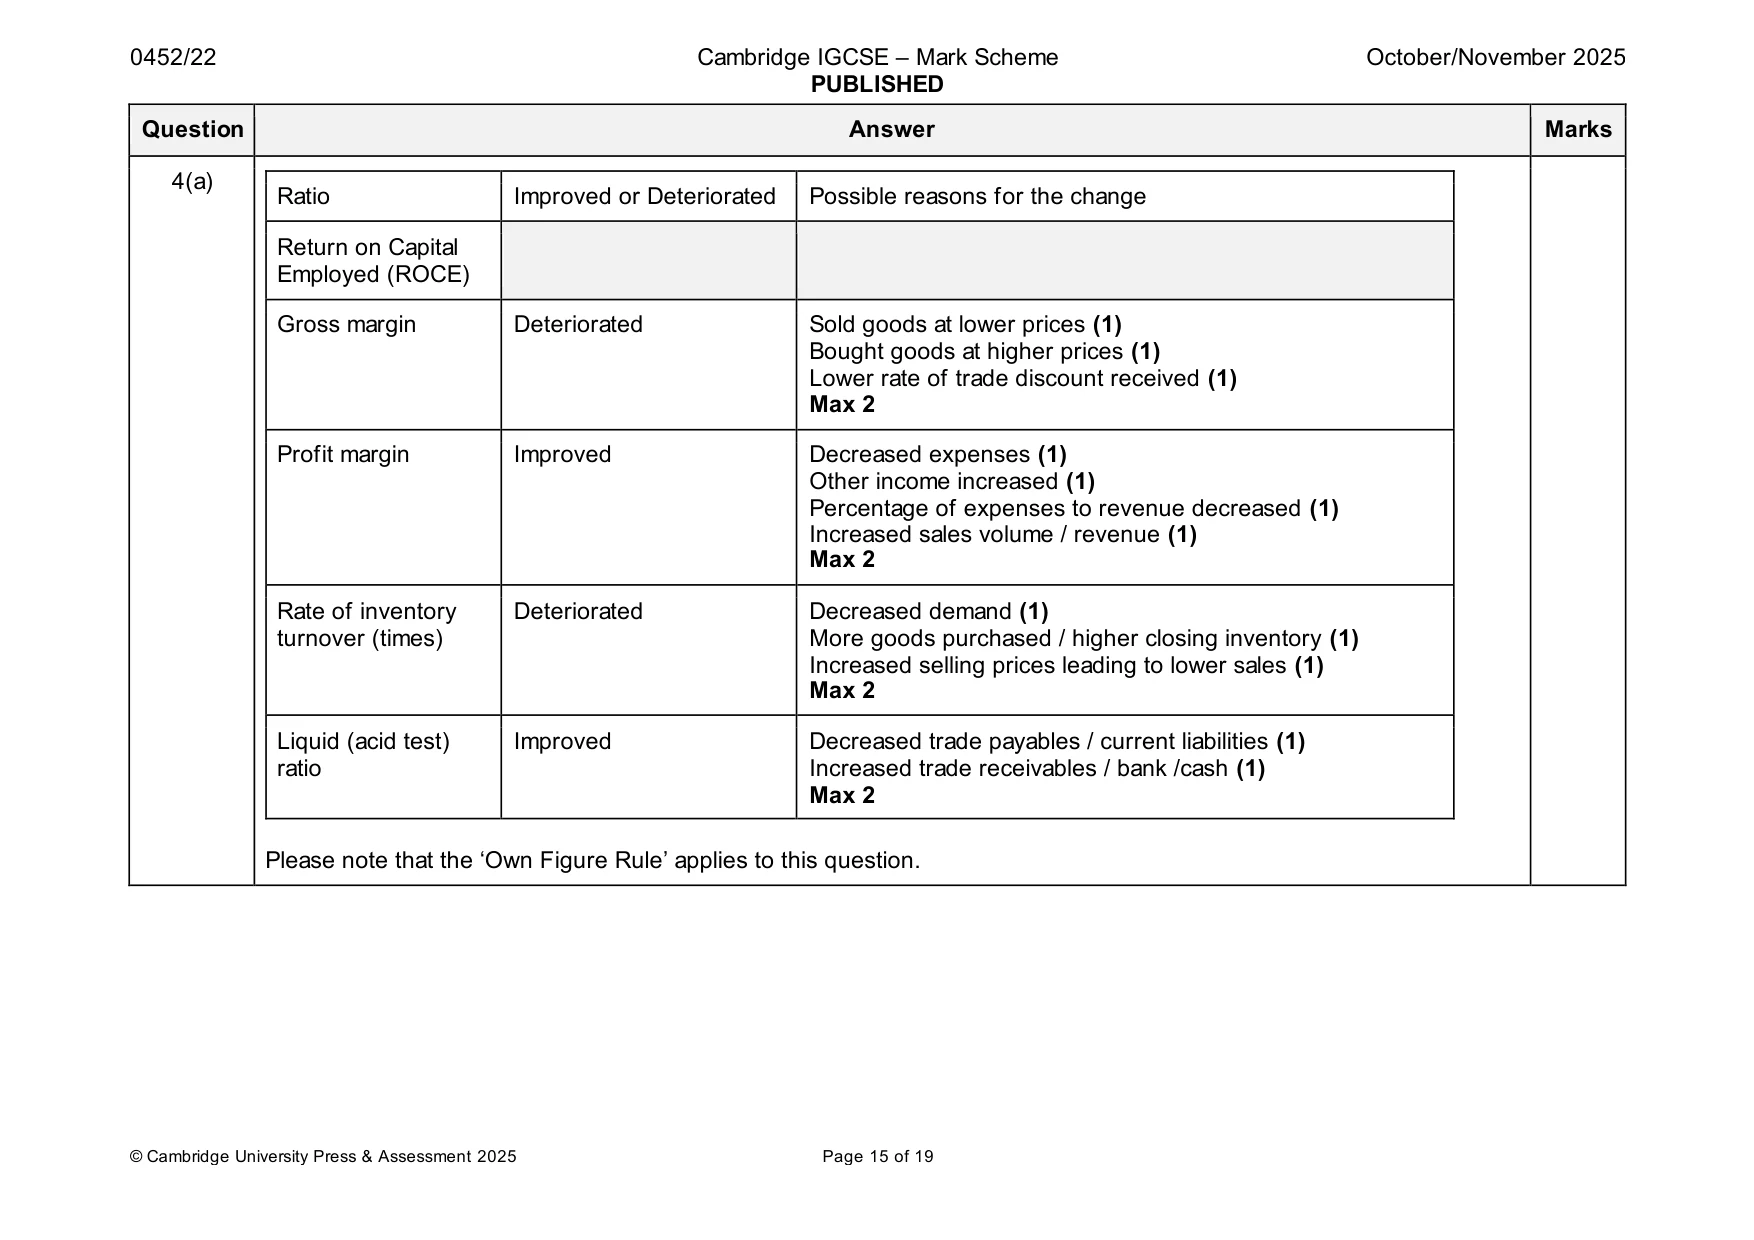
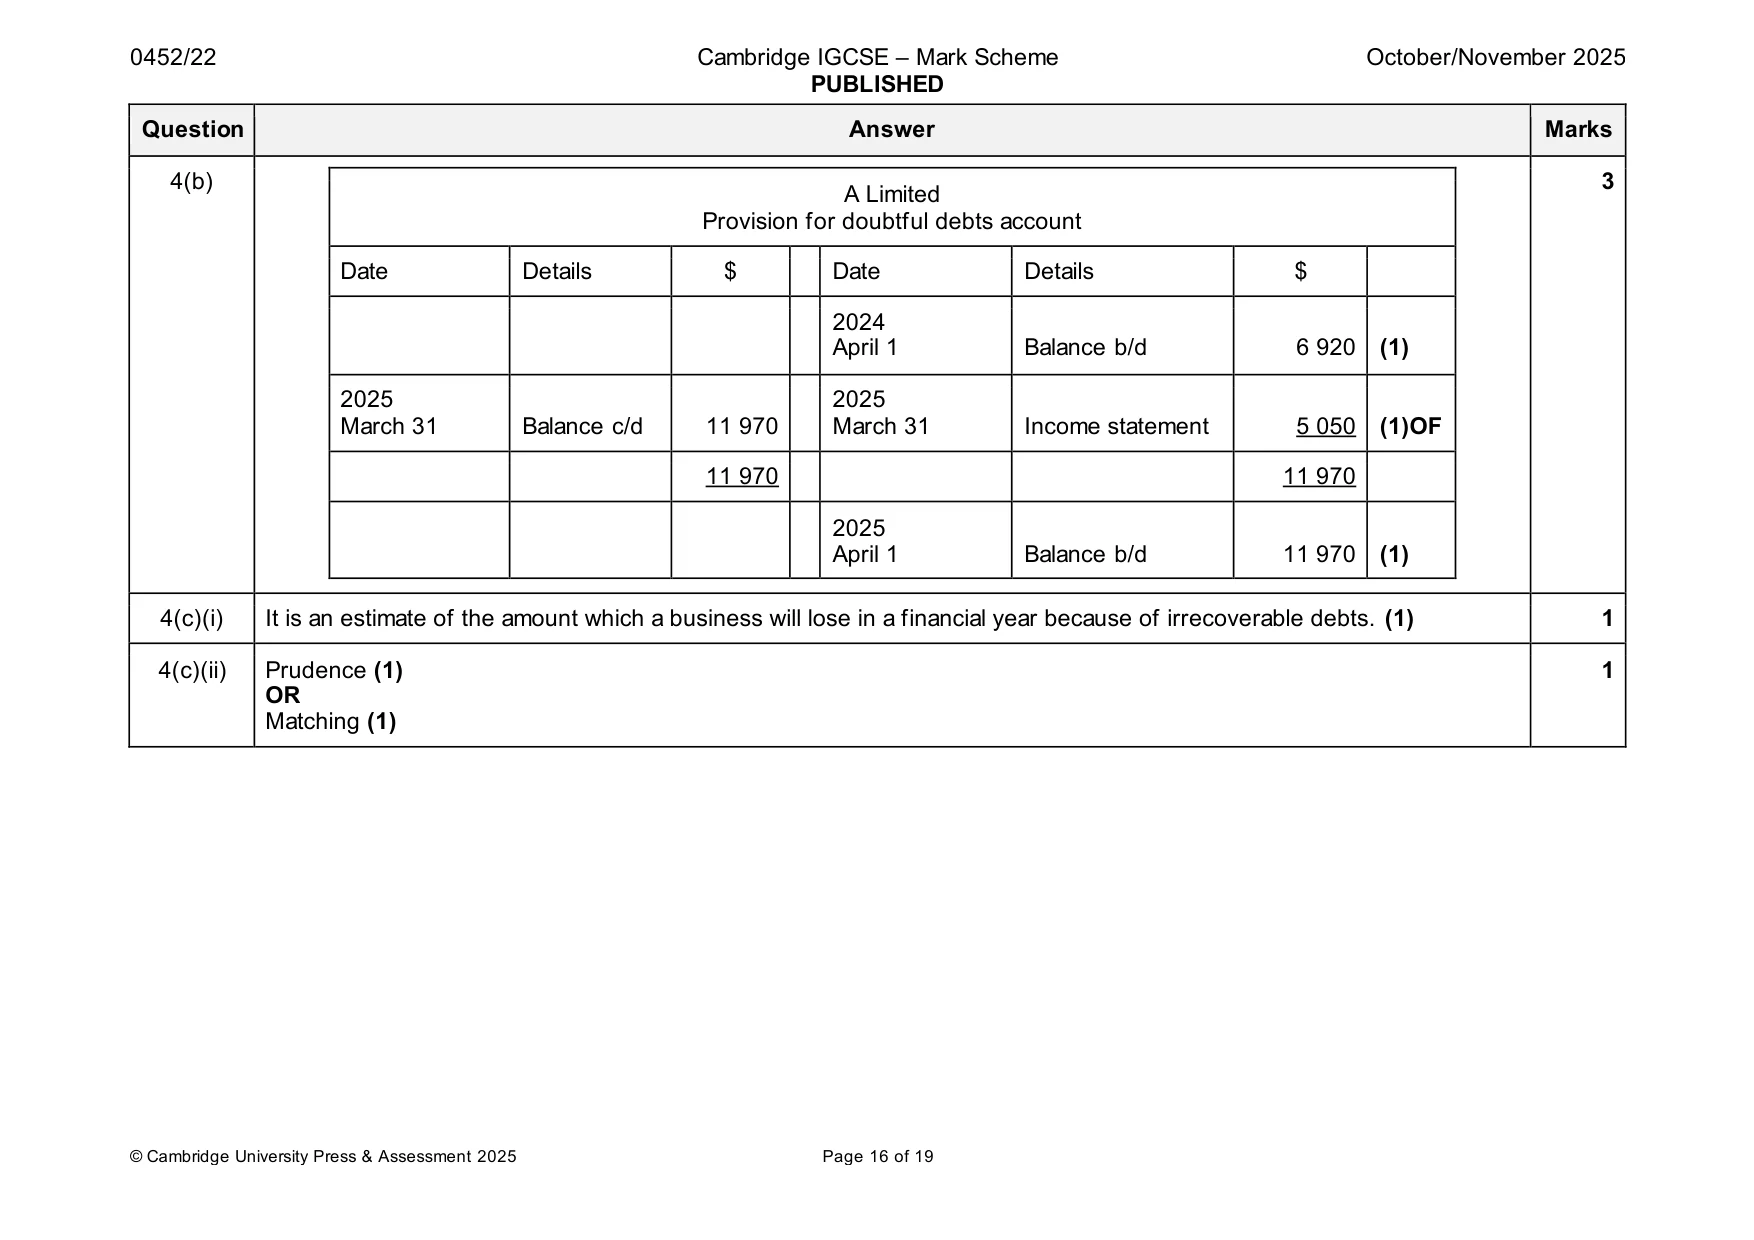
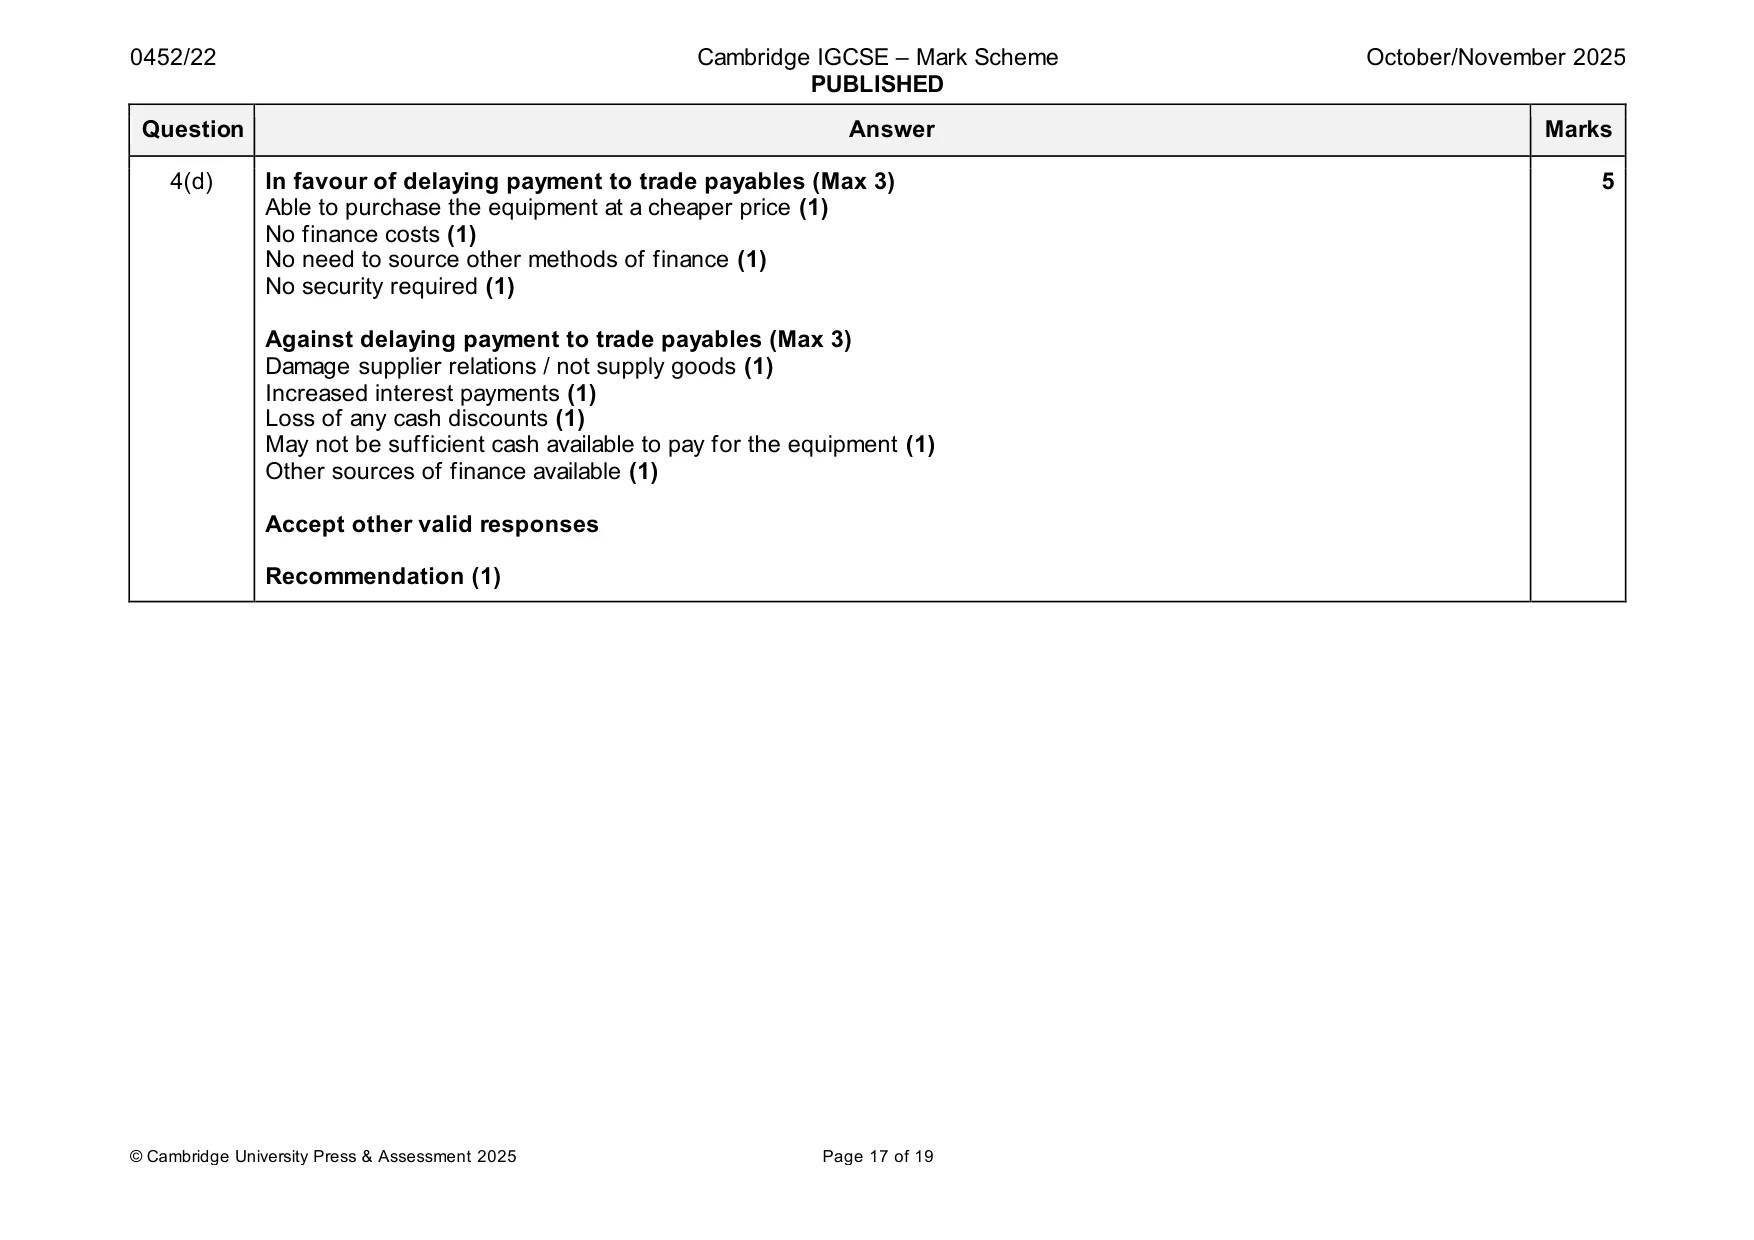
Mark scheme: 4(a) 10 Ratio Improved or Deteriorated Possible reasons for the change Return on Capital Deteriorated Introduction of additional capital/loans Employed (ROCE) Profit for the year decreased. Gross margin Improved } Sold goods at higher prices (1) Bought goods at cheaper prices (1) Improved rate of trade discount received (1) Max 2 Profit margin Deteriorated }(1) both Increased expenses (1) Other income decreased (1) Percentage of expenses to revenue increased (1) Decreased sales volume / revenue (1) Max 2 Rate of inventory Improved } Increased demand (1) turnover (times) Less goods purchased / lower closing inventory (1) Reduced selling prices leading to higher sales (1) Max 2 Liquid (acid test) Deteriorated } (1) both Increased trade payables / current liabilities (1) ratio Decreased trade receivables / bank /cash (1) Max 2 4(a) Ratio Improved or Deteriorated Possible reasons for the change Return on Capital Employed (ROCE) Gross margin Deteriorated Sold goods at lower prices (1) Bought goods at higher prices (1) Lower rate of trade discount received (1) Max 2 Profit margin Improved Decreased expenses (1) Other income increased (1) Percentage of expenses to revenue decreased (1) Increased sales volume / revenue (1) Max 2 Rate of inventory Deteriorated Decreased demand (1) turnover (times) More goods purchased / higher closing inventory (1) Increased selling prices leading to lower sales (1) Max 2 Liquid (acid test) Improved Decreased trade payables / current liabilities (1) ratio Increased trade receivables / bank /cash (1) Max 2 Please note that the ‘Own Figure Rule’ applies to this question. 4(b) 3 A Limited Provision for doubtful debts account Date Details $ Date Details $ 2024 April 1 Balance b/d 6 920 (1) 2025 2025 March 31 Balance c/d 11 970 March 31 Income statement 5 050 (1)OF 11 970 11 970 2025 April 1 Balance b/d 11 970 (1) 4(c)(i) It is an estimate of the amount which a business will lose in a financial year because of irrecoverable debts. (1) 1 4(c)(ii) Prudence (1) 1 OR Matching (1) 4(d) In favour of delaying payment to trade payables (Max 3) 5 Able to purchase the equipment at a cheaper price (1) No finance costs (1) No need to source other methods of finance (1) No security required (1) Against delaying payment to trade payables (Max 3) Damage supplier relations / not supply goods (1) Increased interest payments (1) Loss of any cash discounts (1) May not be sufficient cash available to pay for the equipment (1) Other sources of finance available (1) Accept other valid responses Recommendation (1)
Q5 · GH Company manufactures car parts and has provided the following information relating to…
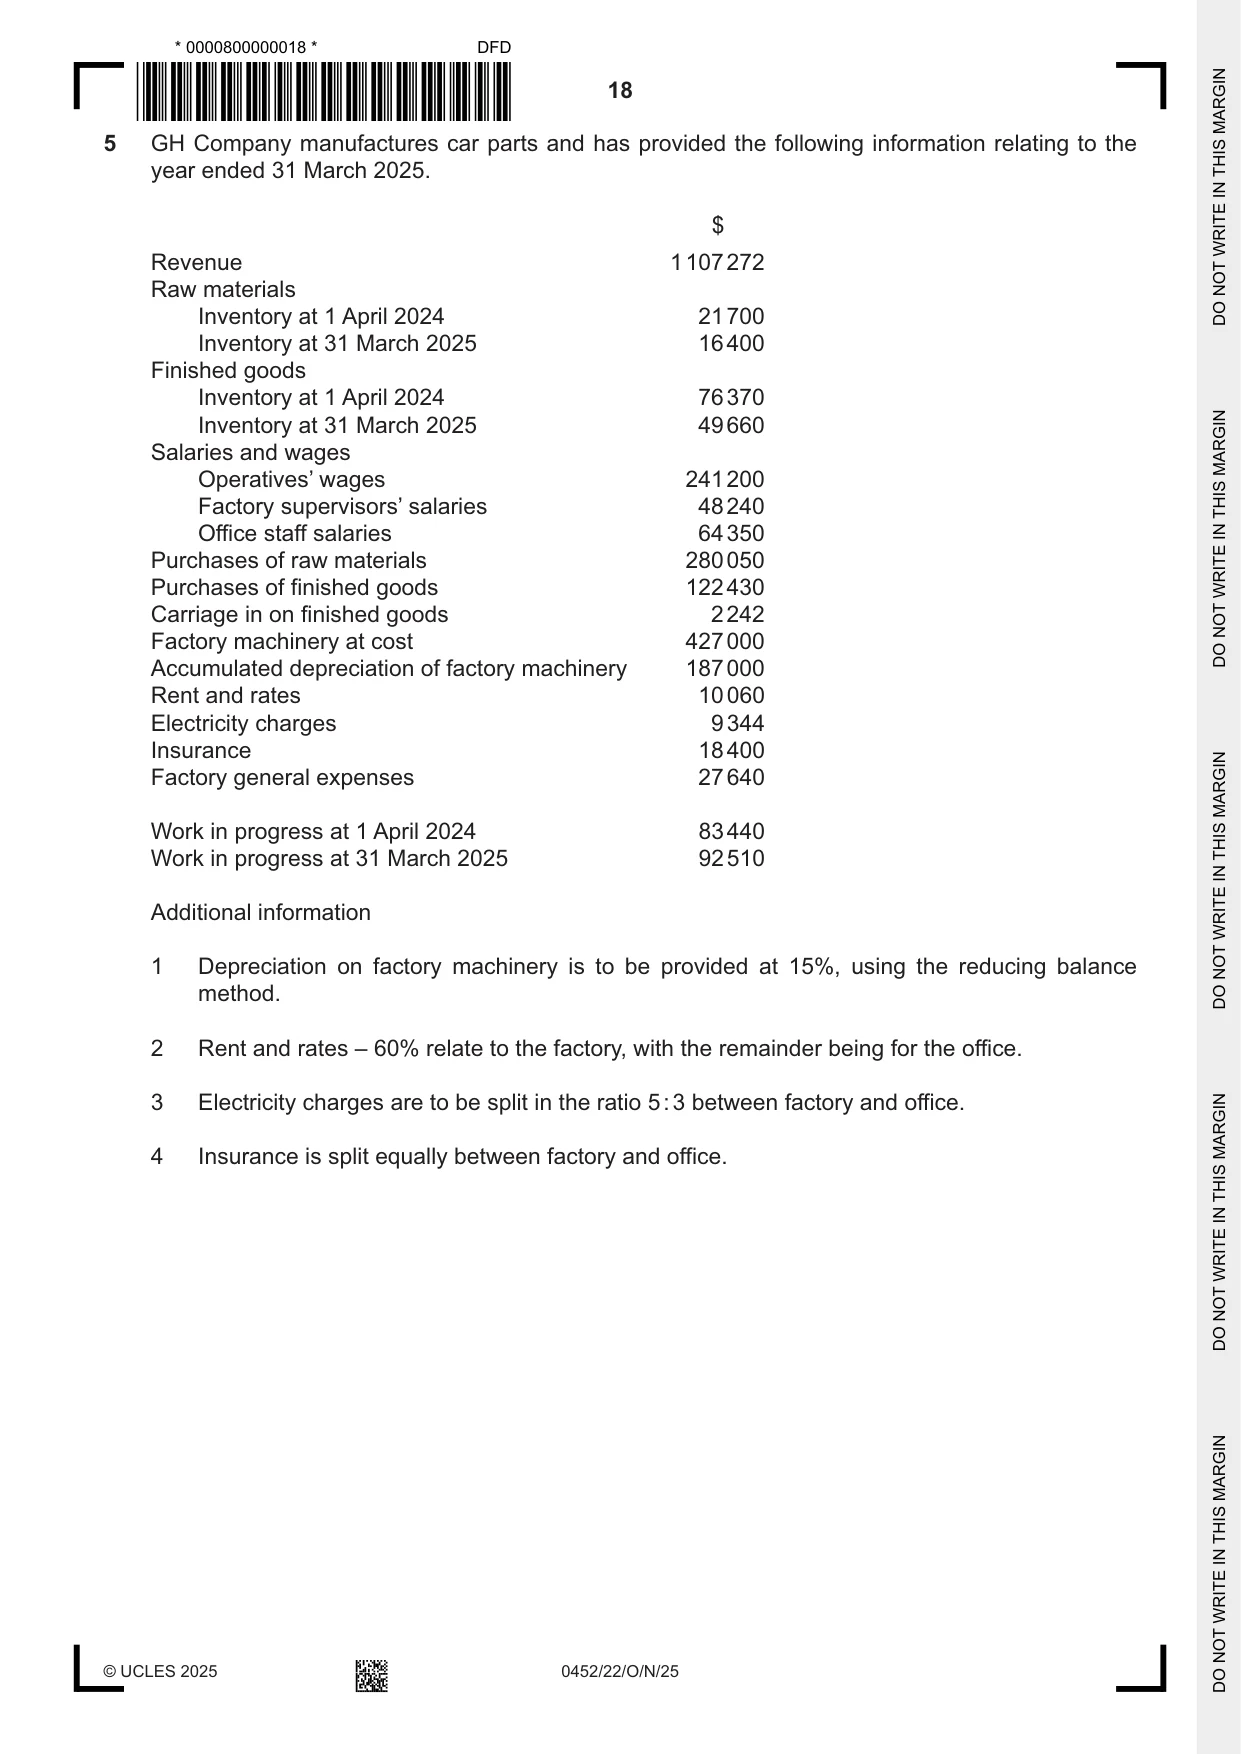
5 GH Company manufactures car parts and has provided the following information relating to the year ended 31 March 2025. $ Revenue 1 107 272 Raw materials Inventory at 1 April 2024 21 700 Inventory at 31 March 2025 16 400 Finished goods Inventory at 1 April 2024 76 370 Inventory at 31 March 2025 49 660 Salaries and wages Operatives’ wages 241 200 Factory supervisors’ salaries 48 240 Office staff salaries 64 350 Purchases of raw materials 280 050 Purchases of finished goods 122 430 Carriage in on finished goods 2 242 Factory machinery at cost 427 000 Accumulated depreciation of factory machinery 187 000 Rent and rates 10 060 Electricity charges 9 344 Insurance 18 400 Factory general expenses 27 640 Work in progress at 1 April 2024 83 440 Work in progress at 31 March 2025 92 510 Additional information 1 Depreciation on factory machinery is to be provided at 15%, using the reducing balance method. 2 Rent and rates – 60% relate to the factory, with the remainder being for the office. 3 Electricity charges are to be split in the ratio 5 : 3 between factory and office. 4 Insurance is split equally between factory and office. REQUIRED (a) Prepare the manufacturing account for GH Company for the year ended 31 March 2025. GH Company Manufacturing Account for the year ended 31 March 2025 $ $ ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... [13] REQUIRED (b) Prepare the trading section of the income statement for GH Company for the year ended 31 March 2025. GH Company Income Statement (Trading section) for the year ended 31 March 2025 $ $ ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... ............................................................................................ ......................... ......................... [7] [Total: 20]
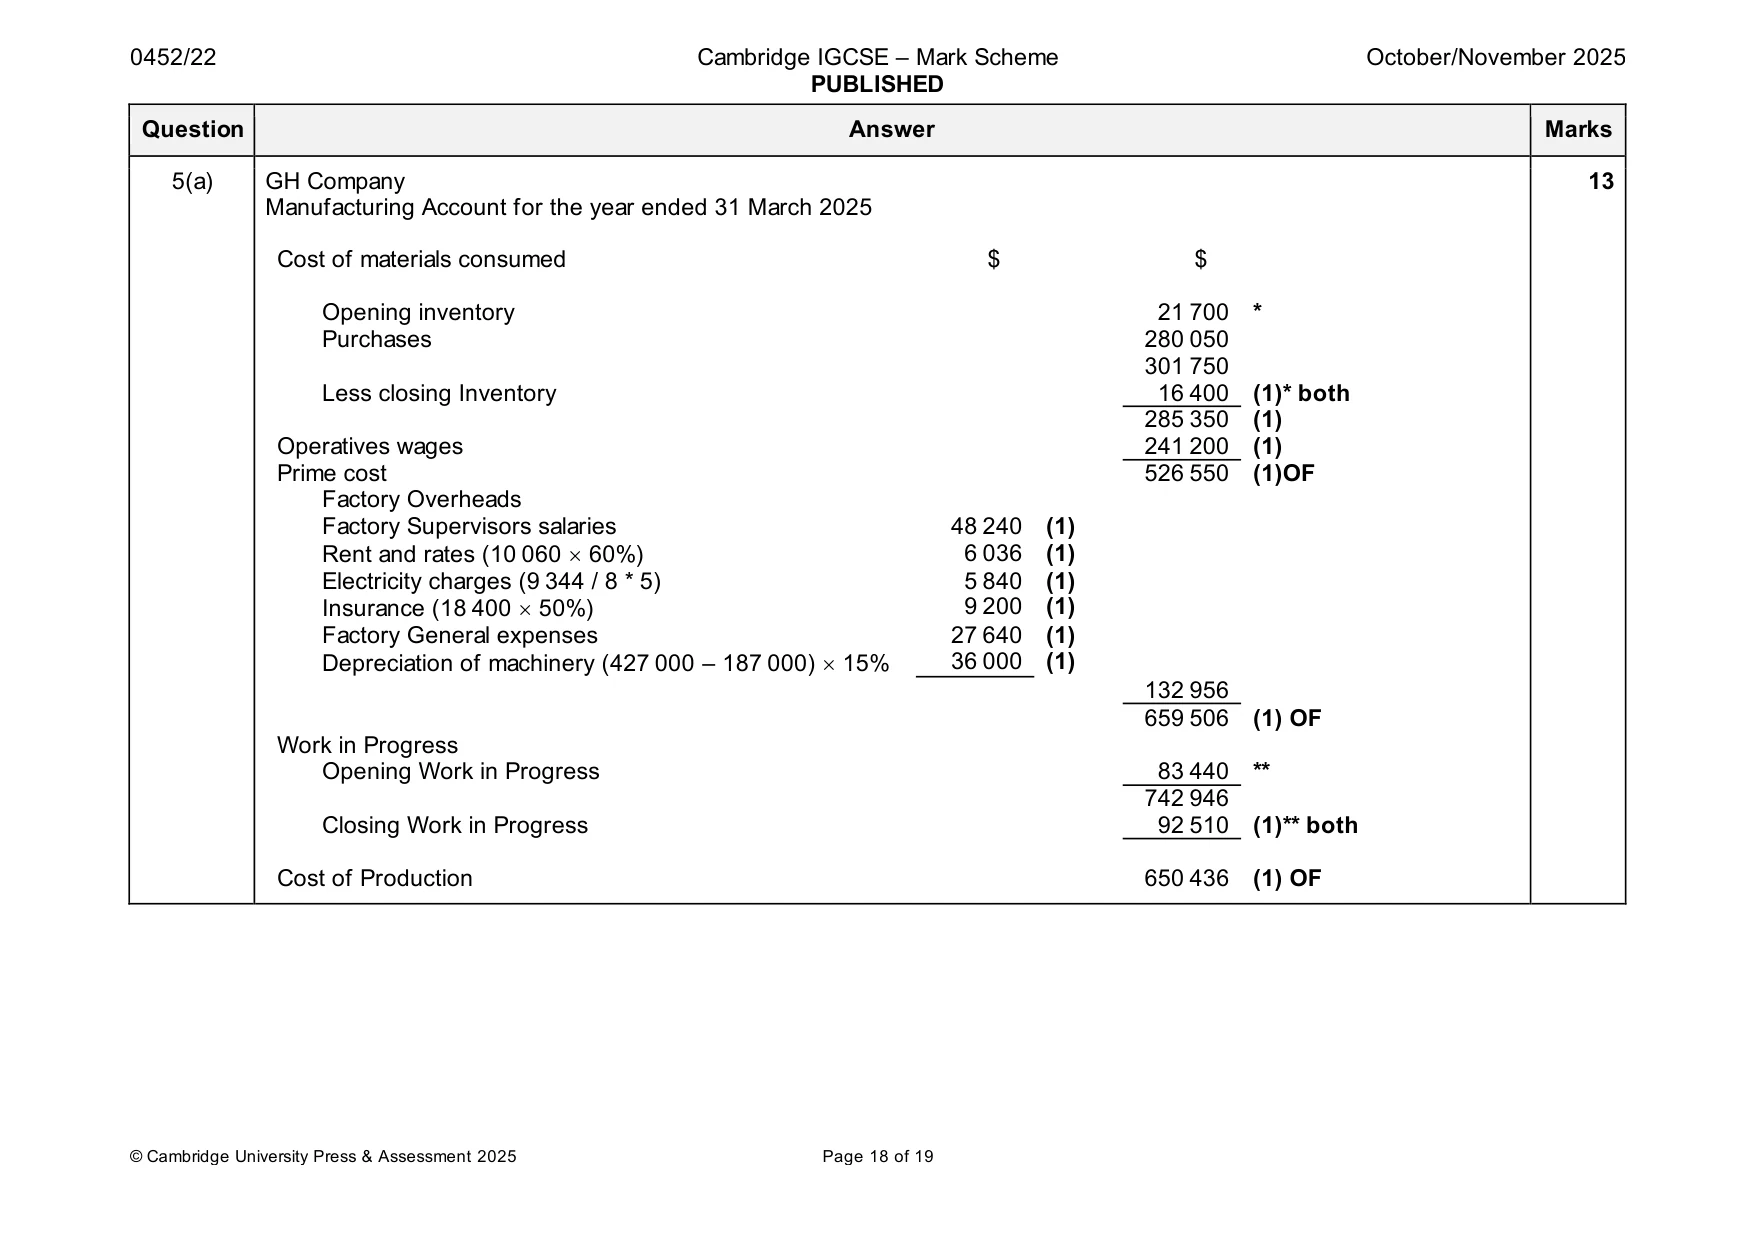
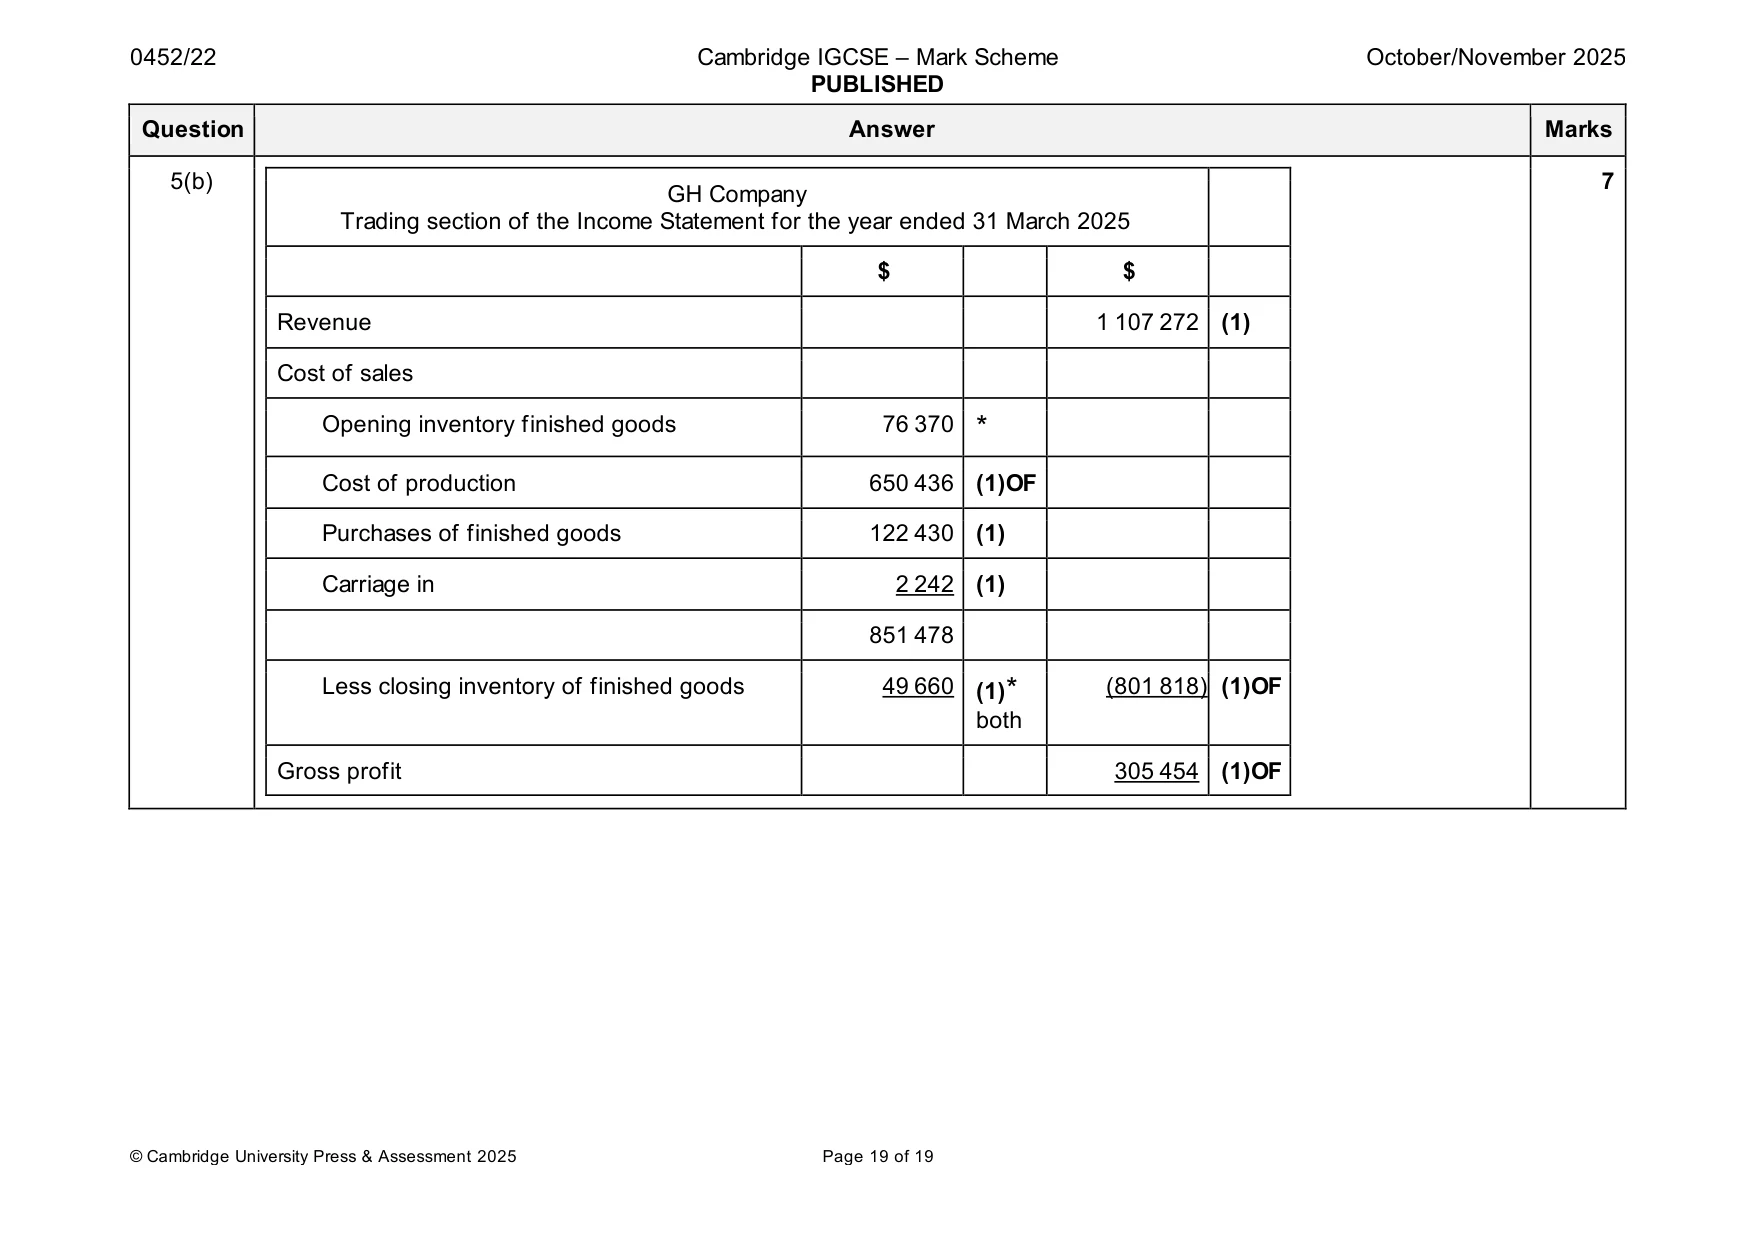
Mark scheme: 5(a) GH Company 13 Manufacturing Account for the year ended 31 March 2025 Cost of materials consumed $ $ Opening inventory 21 700 * Purchases 280 050 301 750 Less closing Inventory 16 400 (1)* both 285 350 (1) Operatives wages 241 200 (1) Prime cost 526 550 (1)OF Factory Overheads Factory Supervisors salaries 48 240 (1) Rent and rates (10 060 60%) 6 036 (1) Electricity charges (9 344 / 8 * 5) 5 840 (1) Insurance (18 400 50%) 9 200 (1) Factory General expenses 27 640 (1) Depreciation of machinery (427 000 – 187 000) 15% 36 000 (1) 132 956 659 506 (1) OF Work in Progress Opening Work in Progress 83 440 ** 742 946 Closing Work in Progress 92 510 (1)** both Cost of Production 650 436 (1) OF 5(b) 7 GH Company Trading section of the Income Statement for the year ended 31 March 2025 $ $ Revenue 1 107 272 (1) Cost of sales Opening inventory finished goods 76 370 * Cost of production 650 436 (1)OF Purchases of finished goods 122 430 (1) Carriage in 2 242 (1) 851 478 Less closing inventory of finished goods 49 660 (1)* (801 818) (1)OF both Gross profit 305 454 (1)OF
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2025 Oct/Nov, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.