Cambridge IGCSE Accounting 0452 — 2023 Feb/March Paper 2 · Variant 2
0452/22/F/M/23 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper24 pages
Mark scheme15 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Saira is a trader
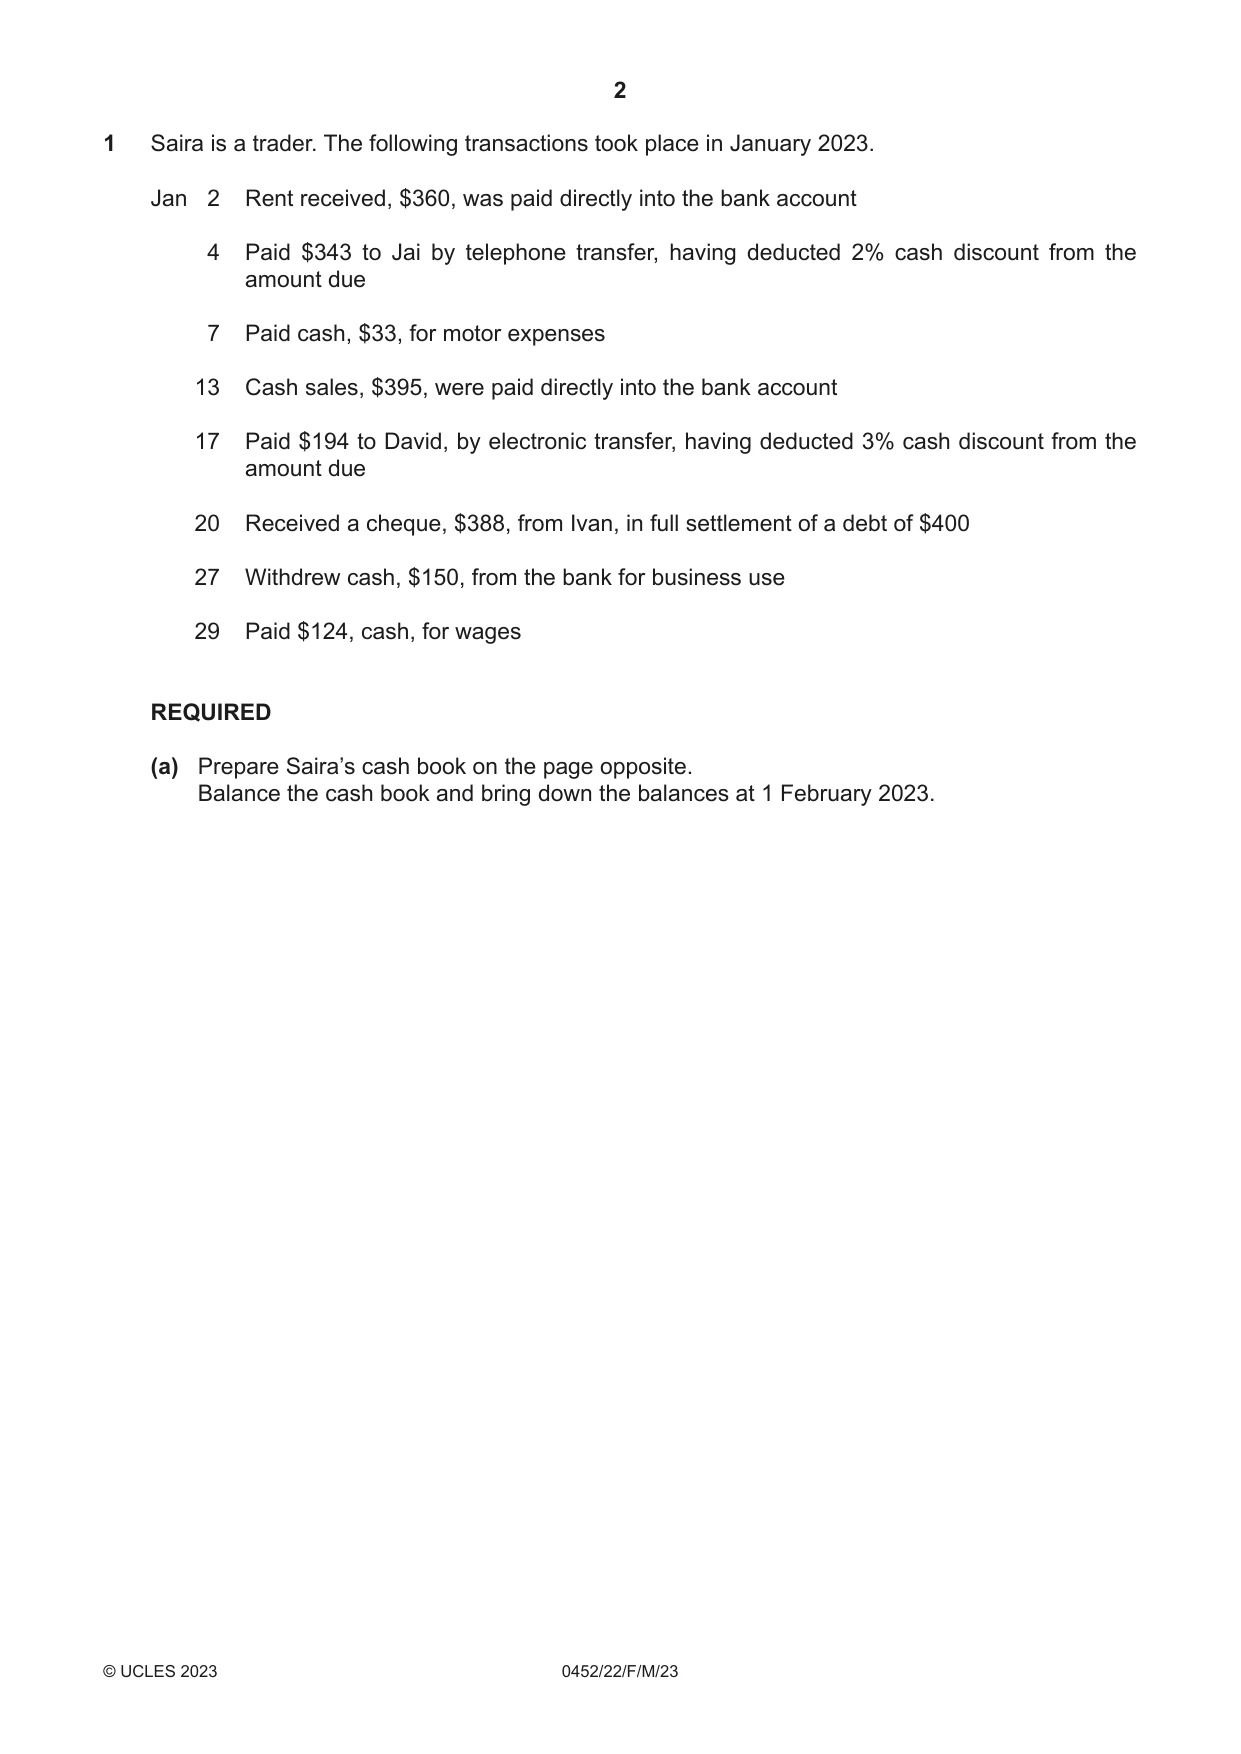
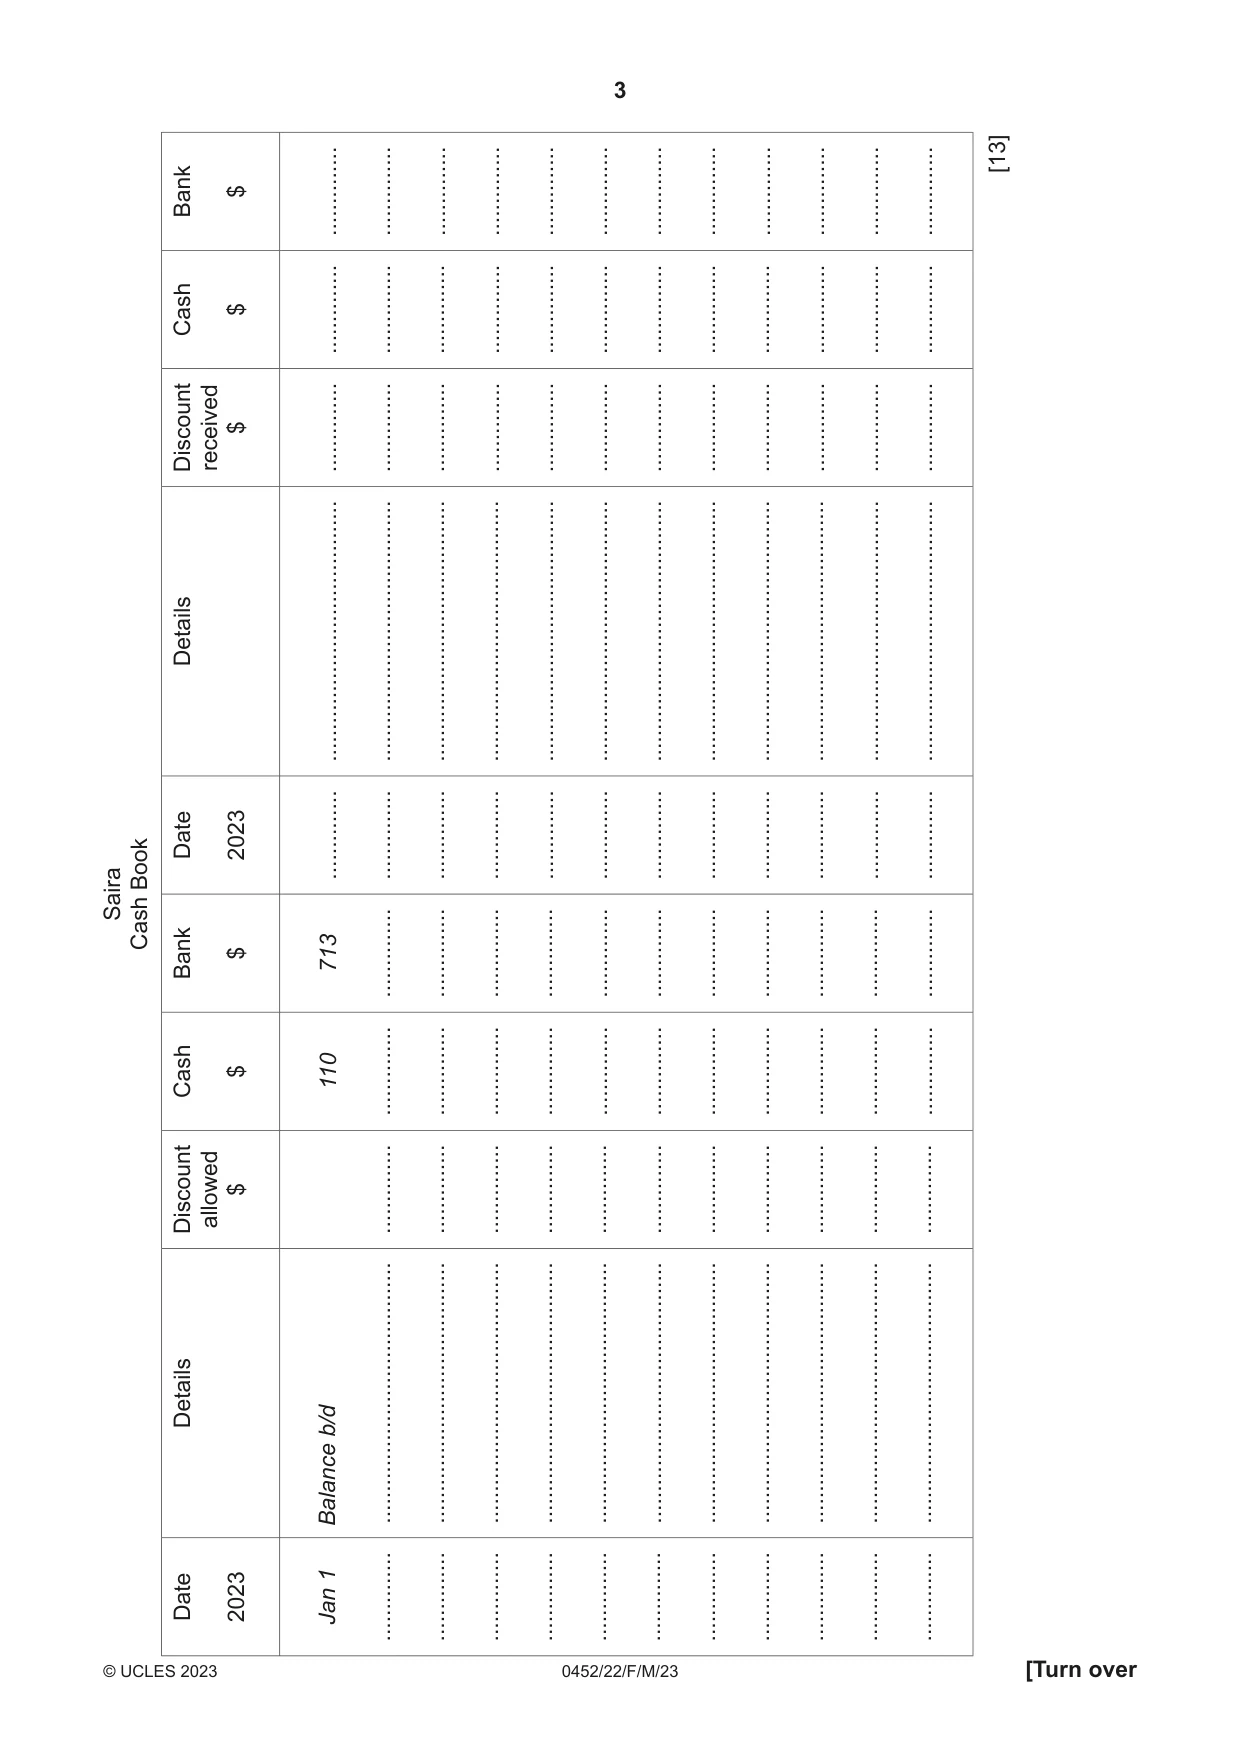
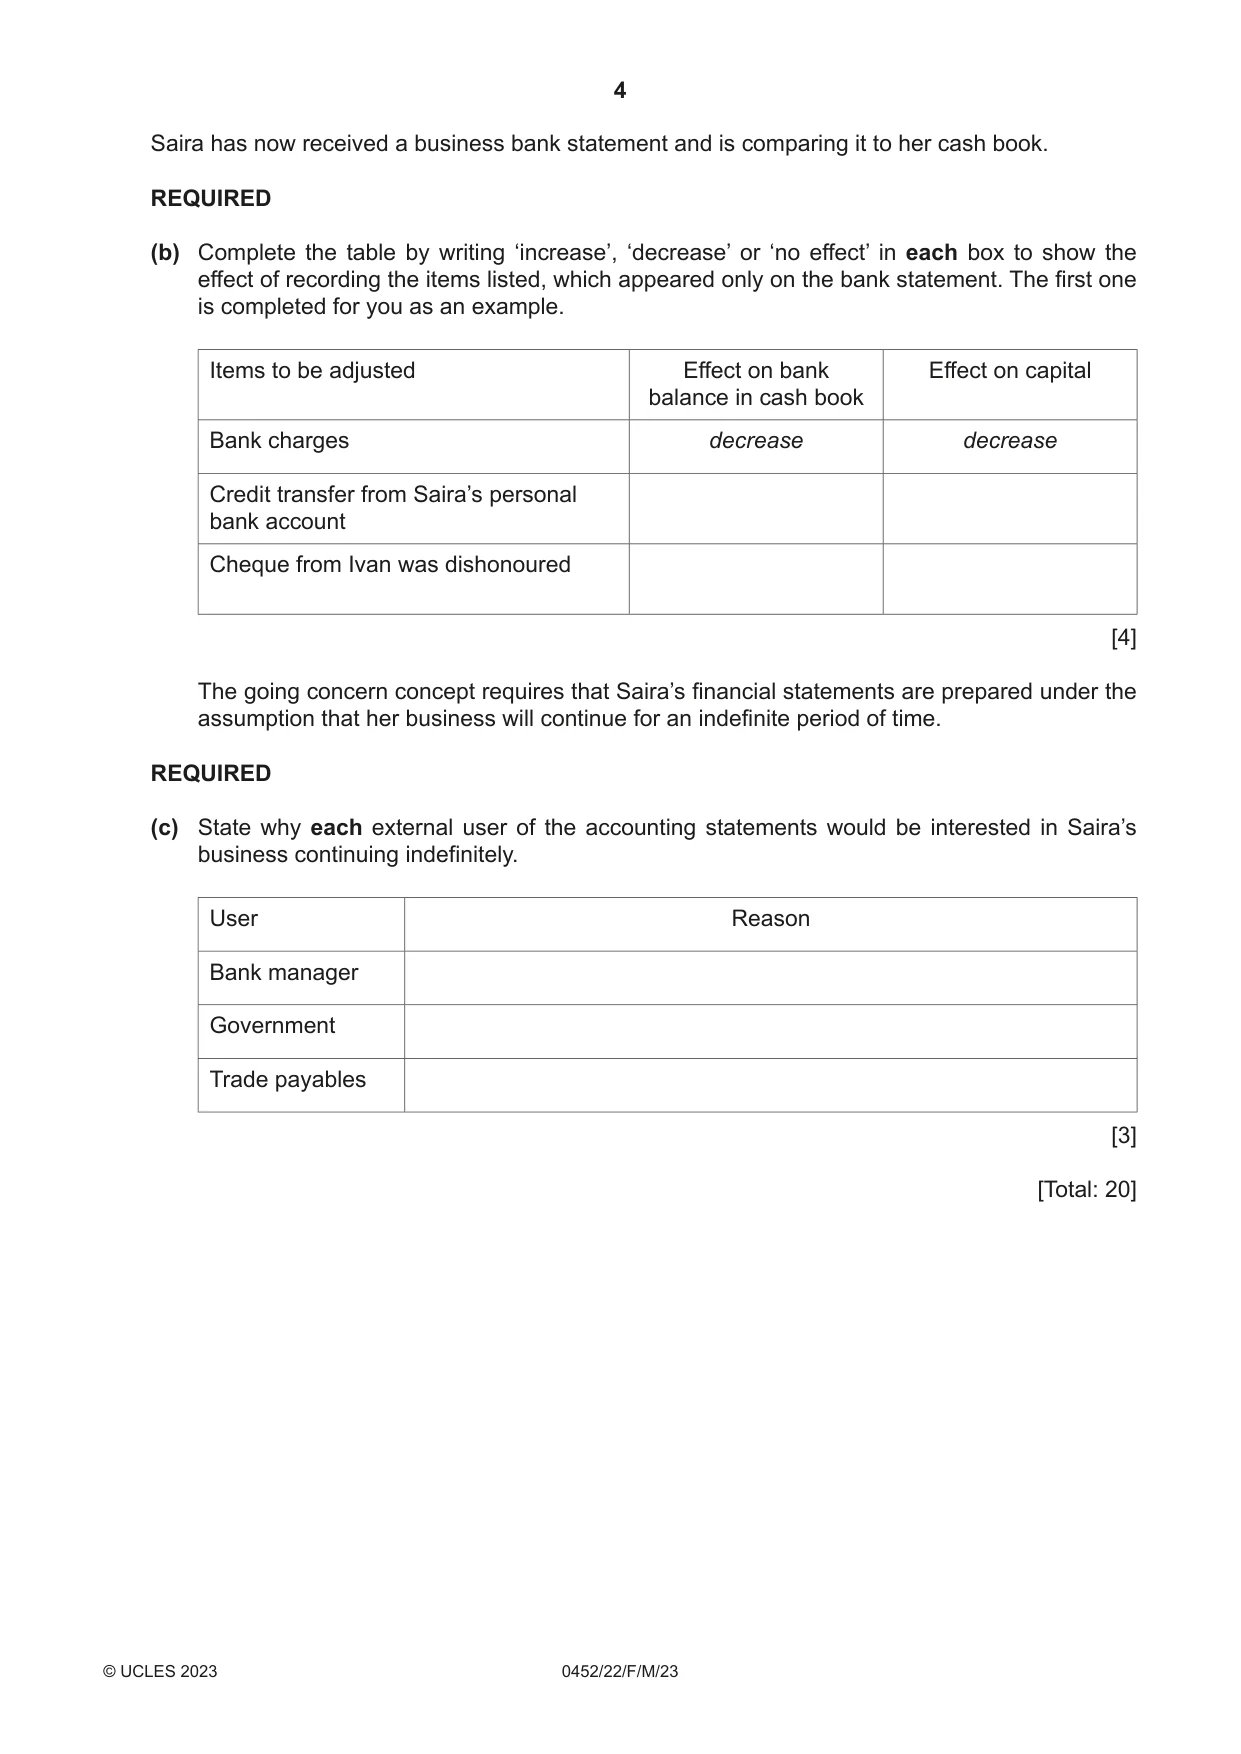
1 Saira is a trader. The following transactions took place in January 2023. Jan 2 Rent received, $360, was paid directly into the bank account 4 Paid $343 to Jai by telephone transfer, having deducted 2% cash discount from the amount due 7 Paid cash, $33, for motor expenses 13 Cash sales, $395, were paid directly into the bank account 17 Paid $194 to David, by electronic transfer, having deducted 3% cash discount from the amount due 20 Received a cheque, $388, from Ivan, in full settlement of a debt of $400 27 Withdrew cash, $150, from the bank for business use 29 Paid $124, cash, for wages REQUIRED (a) Prepare Saira’s cash book on the page opposite. Balance the cash book and bring down the balances at 1 February 2023. [13] $ Bank .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. $ Cash .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. $ Discountreceived .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. Details ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... Date 2023 .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. Book Saira Cash $ 713 Bank .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. $ 110 Cash .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. $ Discountallowed .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. Details b/d Balance ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... Saira has now received a business bank statement and is comparing it to her cash book. REQUIRED (b) Complete the table by writing ‘increase’, ‘decrease’ or ‘no effect’ in each box to show the effect of recording the items listed, which appeared only on the bank statement. The first one is completed for you as an example. Items to be adjusted Effect on bank Effect on capital balance in cash book Bank charges decrease decrease Credit transfer from Saira’s personal bank account Cheque from Ivan was dishonoured [4] The going concern concept requires that Saira’s financial statements are prepared under the assumption that her business will continue for an indefinite period of time. REQUIRED (c) State why each external user of the accounting statements would be interested in Saira’s business continuing indefinitely. User Reason Bank manager Government Trade payables [3] [Total: 20]
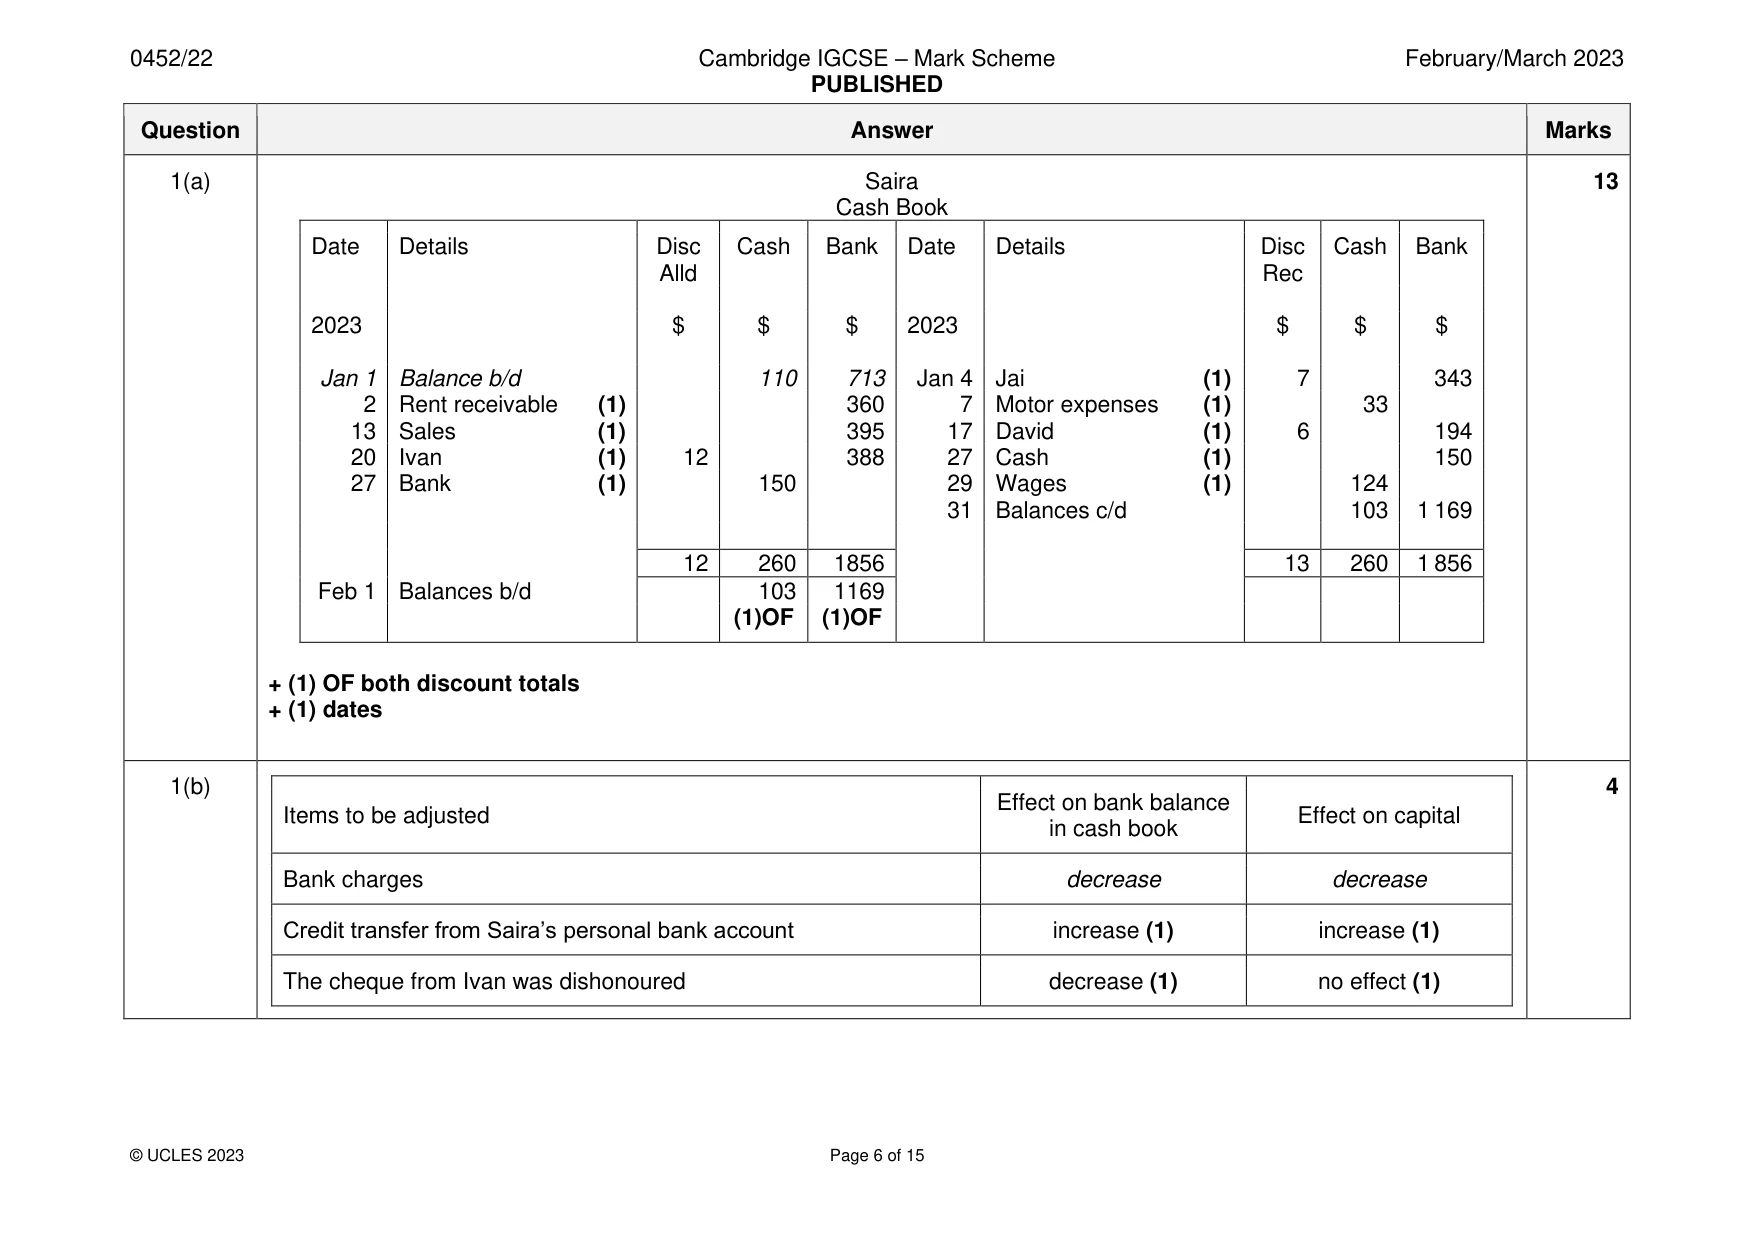
Mark scheme: Question Answer Marks 1(a) Saira 13 Cash Book Date Details Disc Cash Bank Date Details Disc Cash Bank Alld Rec 2023 $ $ $ 2023 $ $ $ Jan 1 Balance b/d 110 713 Jan 4 Jai (1) 7 343 2 Rent receivable (1) 360 7 Motor expenses (1) 33 13 Sales (1) 395 17 David (1) 6 194 20 Ivan (1) 12 388 27 Cash (1) 150 27 Bank (1) 150 29 Wages (1) 124 31 Balances c/d 103 1 169 12 260 1856 13 260 1 856 Feb 1 Balances b/d 103 1169 (1)OF (1)OF + (1) OF both discount totals + (1) dates 1(b) 4 Effect on bank balance Items to be adjusted Effect on capital in cash book Bank charges decrease decrease Credit transfer from Saira’s personal bank account increase (1) increase (1) The cheque from Ivan was dishonoured decrease (1) no effect (1) 1(c) 3 User Reason Bank manager to see if she will be able to repay loan/overdraft/interest (1) Government to see if she will be able to pay any tax which becomes due (1) Trade payables to see if she will be able to pay what she owes/consider whether to allow credit terms (1) Accept other valid points
Q2 · Rai is a trader
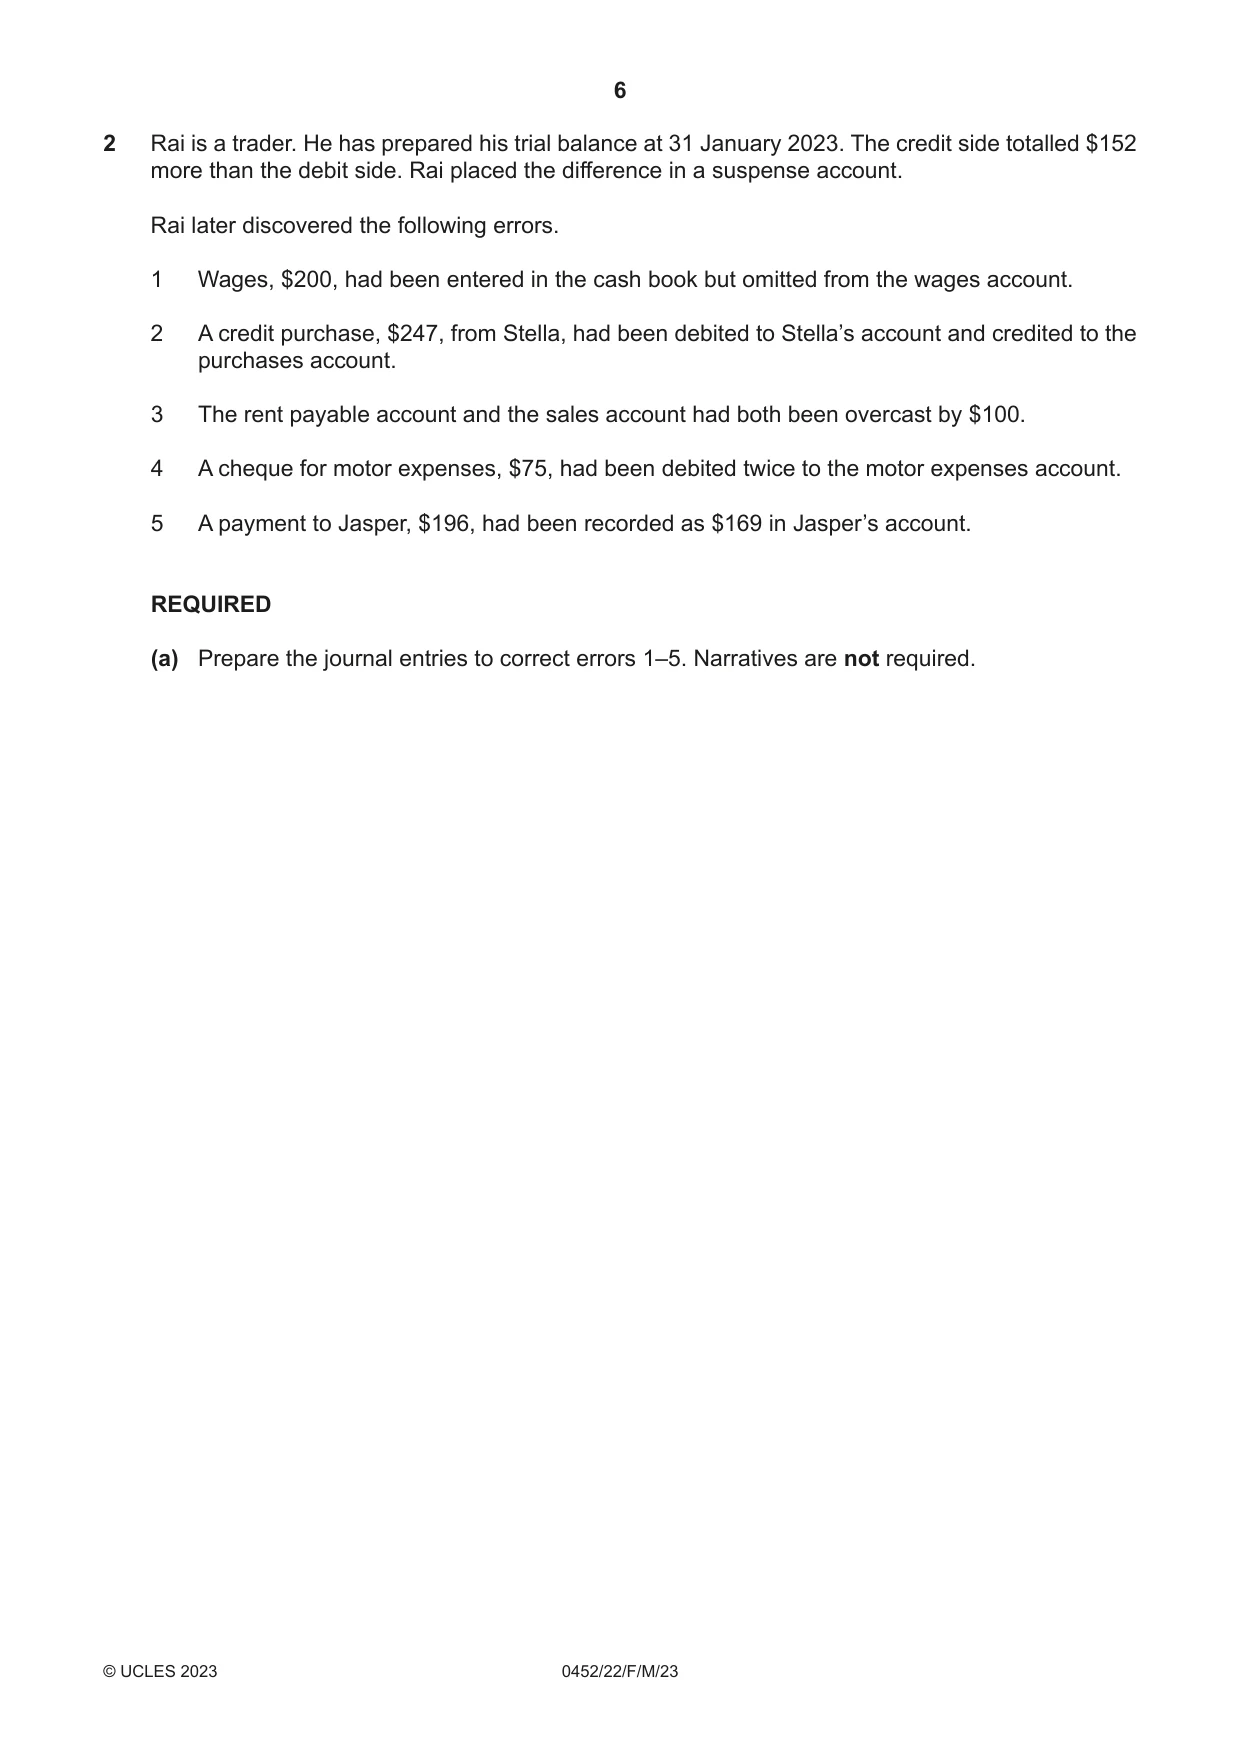
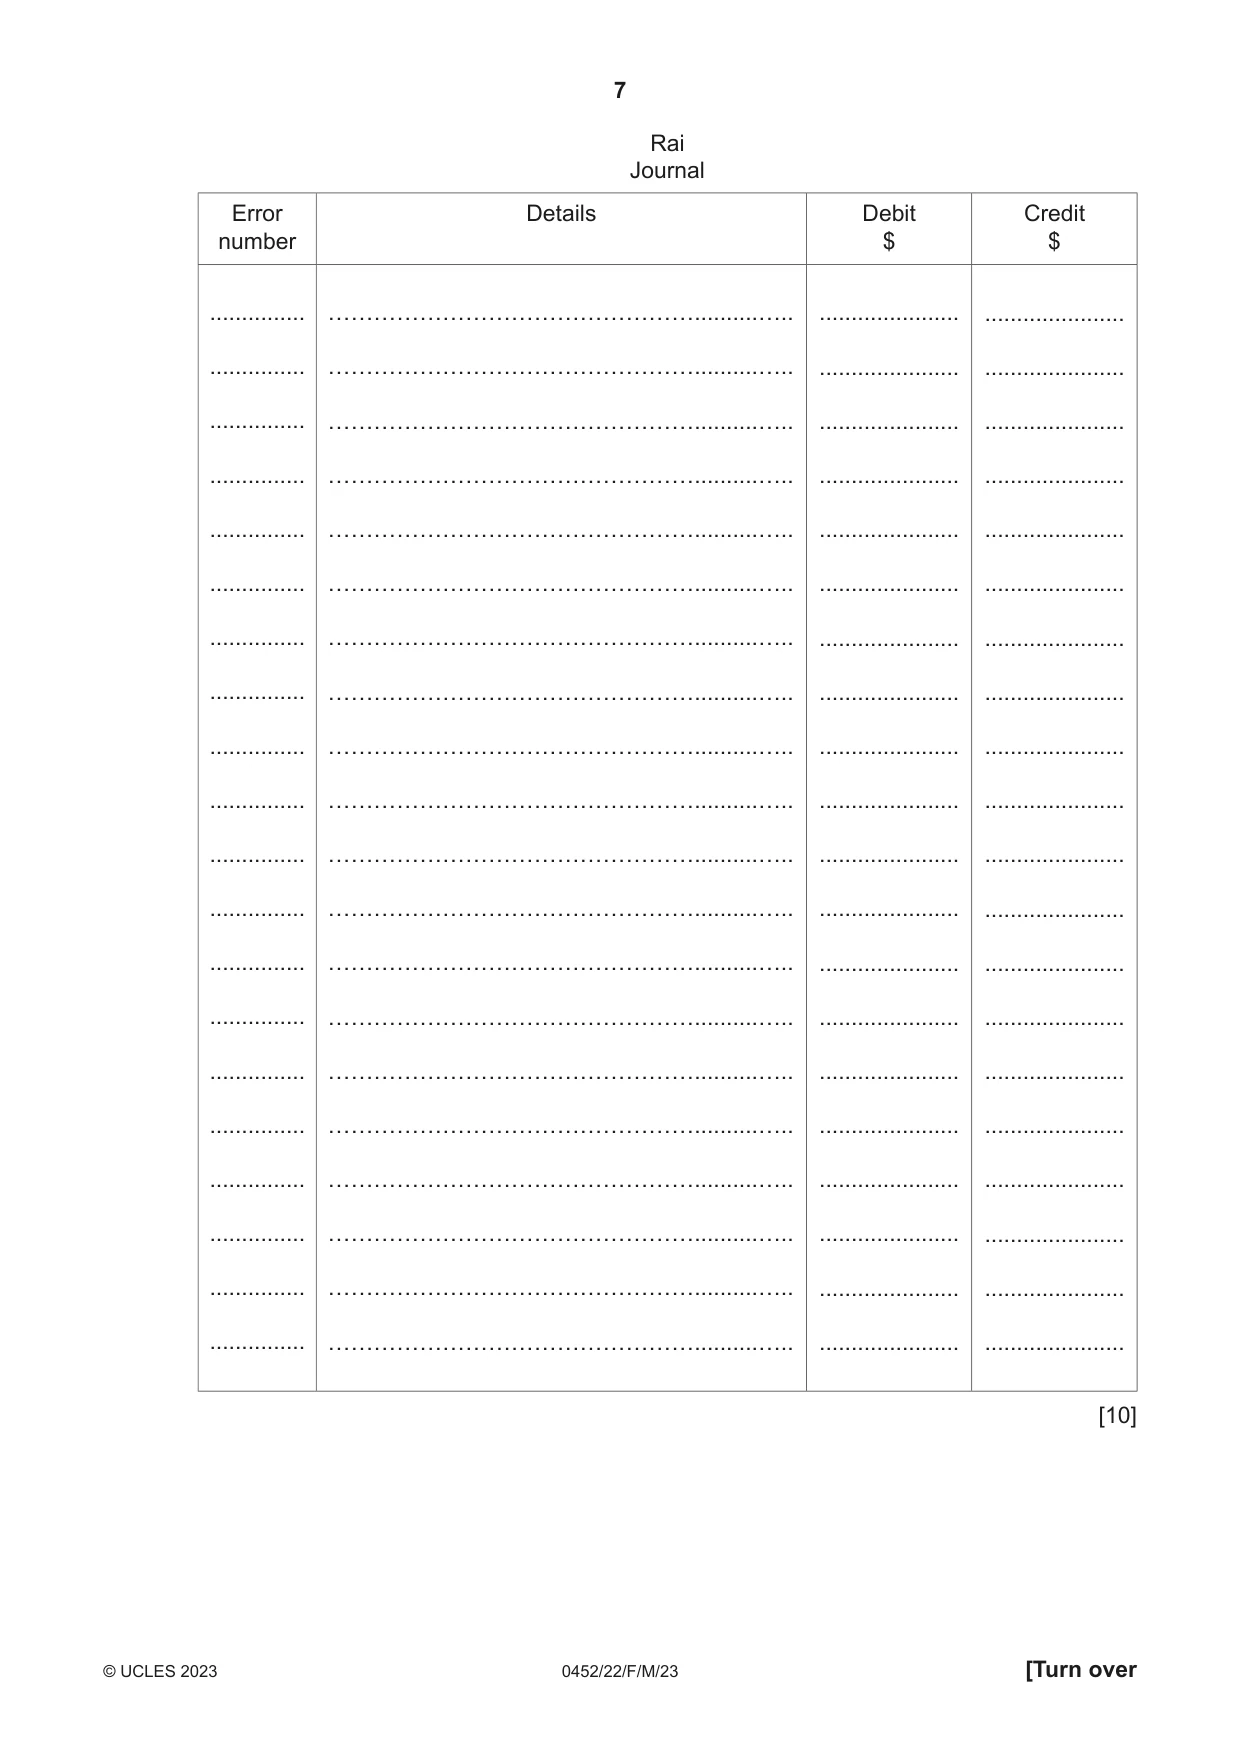
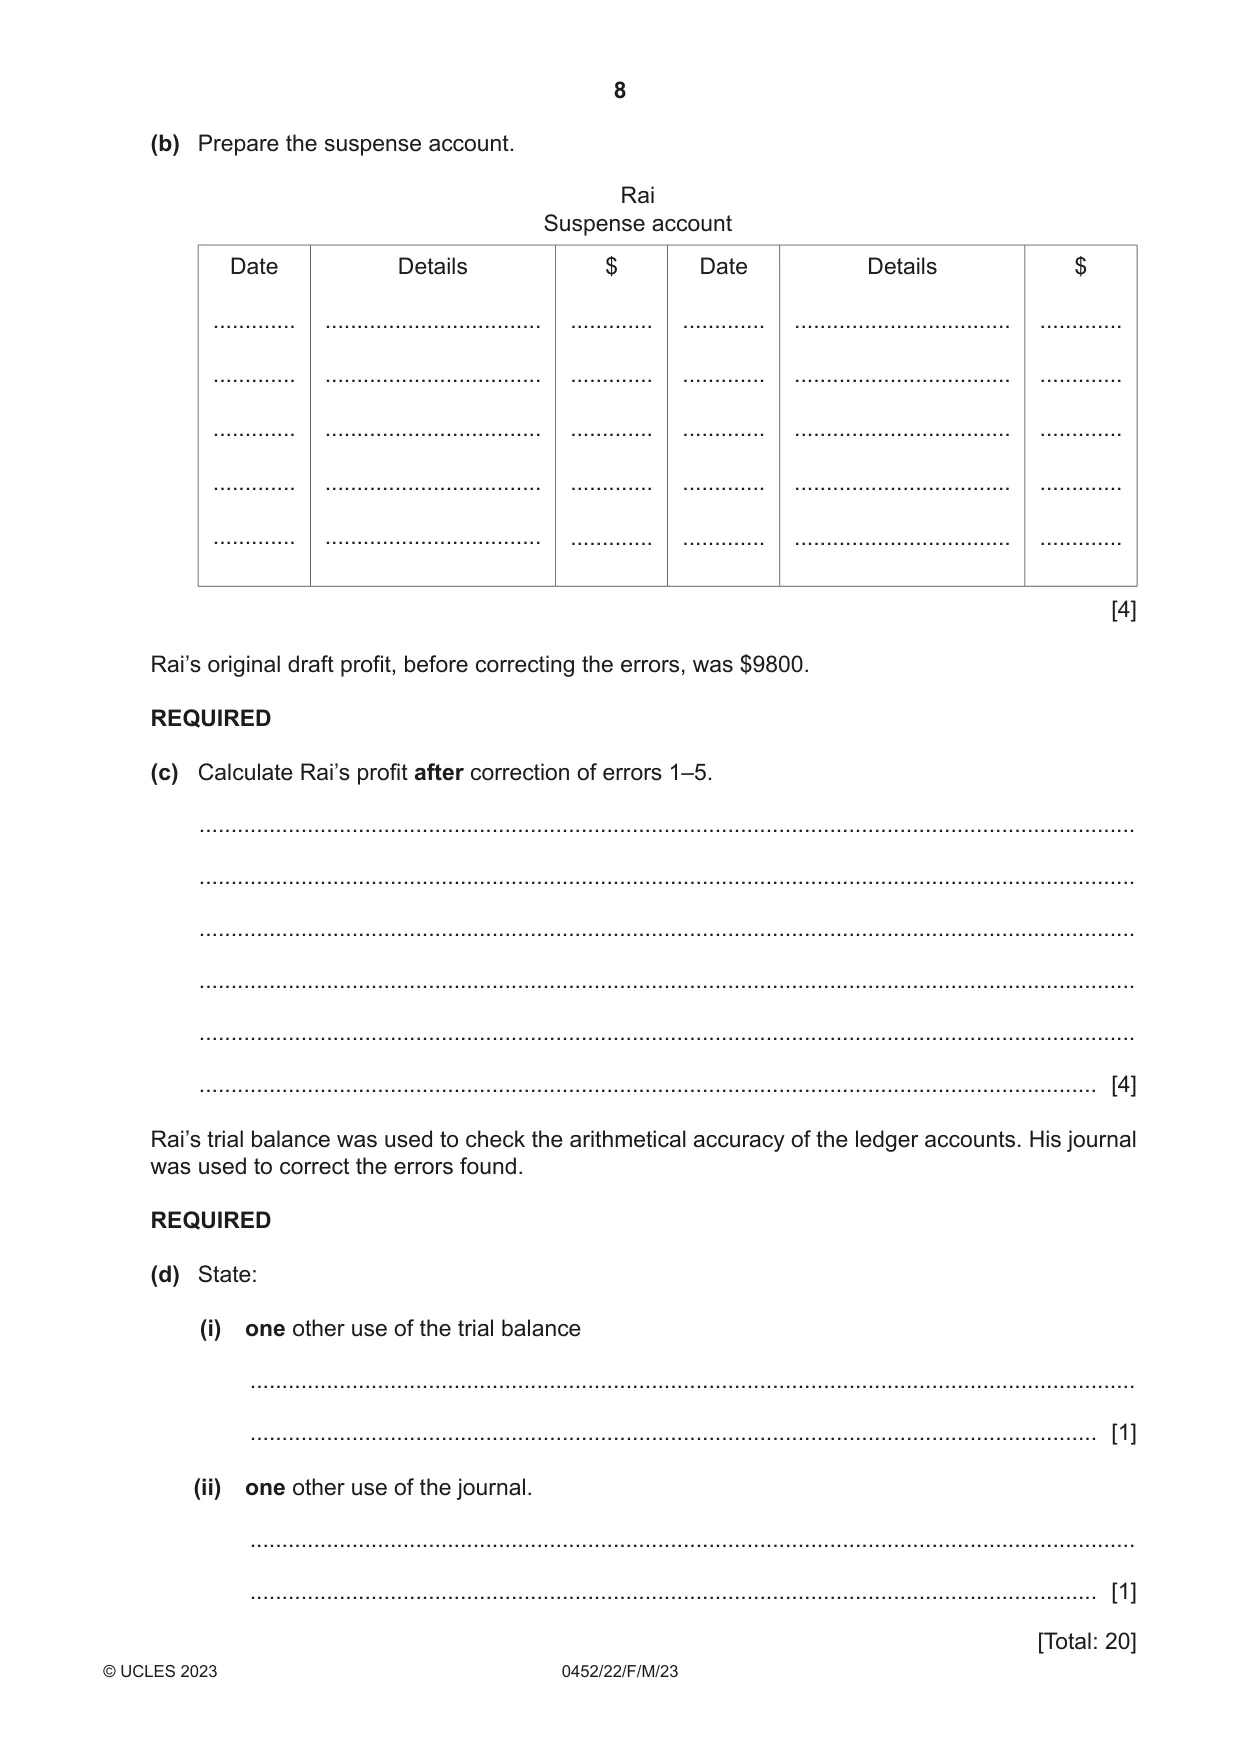
2 Rai is a trader. He has prepared his trial balance at 31 January 2023. The credit side totalled $152 more than the debit side. Rai placed the difference in a suspense account. Rai later discovered the following errors. 1 Wages, $200, had been entered in the cash book but omitted from the wages account. 2 A credit purchase, $247, from Stella, had been debited to Stella’s account and credited to the purchases account. 3 The rent payable account and the sales account had both been overcast by $100. 4 A cheque for motor expenses, $75, had been debited twice to the motor expenses account. 5 A payment to Jasper, $196, had been recorded as $169 in Jasper’s account. REQUIRED (a) Prepare the journal entries to correct errors 1–5. Narratives are not required. Rai Journal Details …………………………………………..........….. …………………………………………..........….. …………………………………………..........….. …………………………………………..........….. …………………………………………..........….. …………………………………………..........….. …………………………………………..........….. …………………………………………..........….. …………………………………………..........….. …………………………………………..........….. …………………………………………..........….. …………………………………………..........….. …………………………………………..........….. …………………………………………..........….. …………………………………………..........….. …………………………………………..........….. …………………………………………..........….. …………………………………………..........….. …………………………………………..........….. …………………………………………..........….. (b) Prepare the suspense account. Rai Suspense account Date Details $ Date Details $ ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. [4] Rai’s original draft profit, before correcting the errors, was $9800. REQUIRED (c) Calculate Rai’s profit after correction of errors 1–5. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] Rai’s trial balance was used to check the arithmetical accuracy of the ledger accounts. His journal was used to correct the errors found. REQUIRED (d) State: (i) one other use of the trial balance ........................................................................................................................................... ..................................................................................................................................... [1] (ii) one other use of the journal. ........................................................................................................................................... ..................................................................................................................................... [1] [Total: 20]
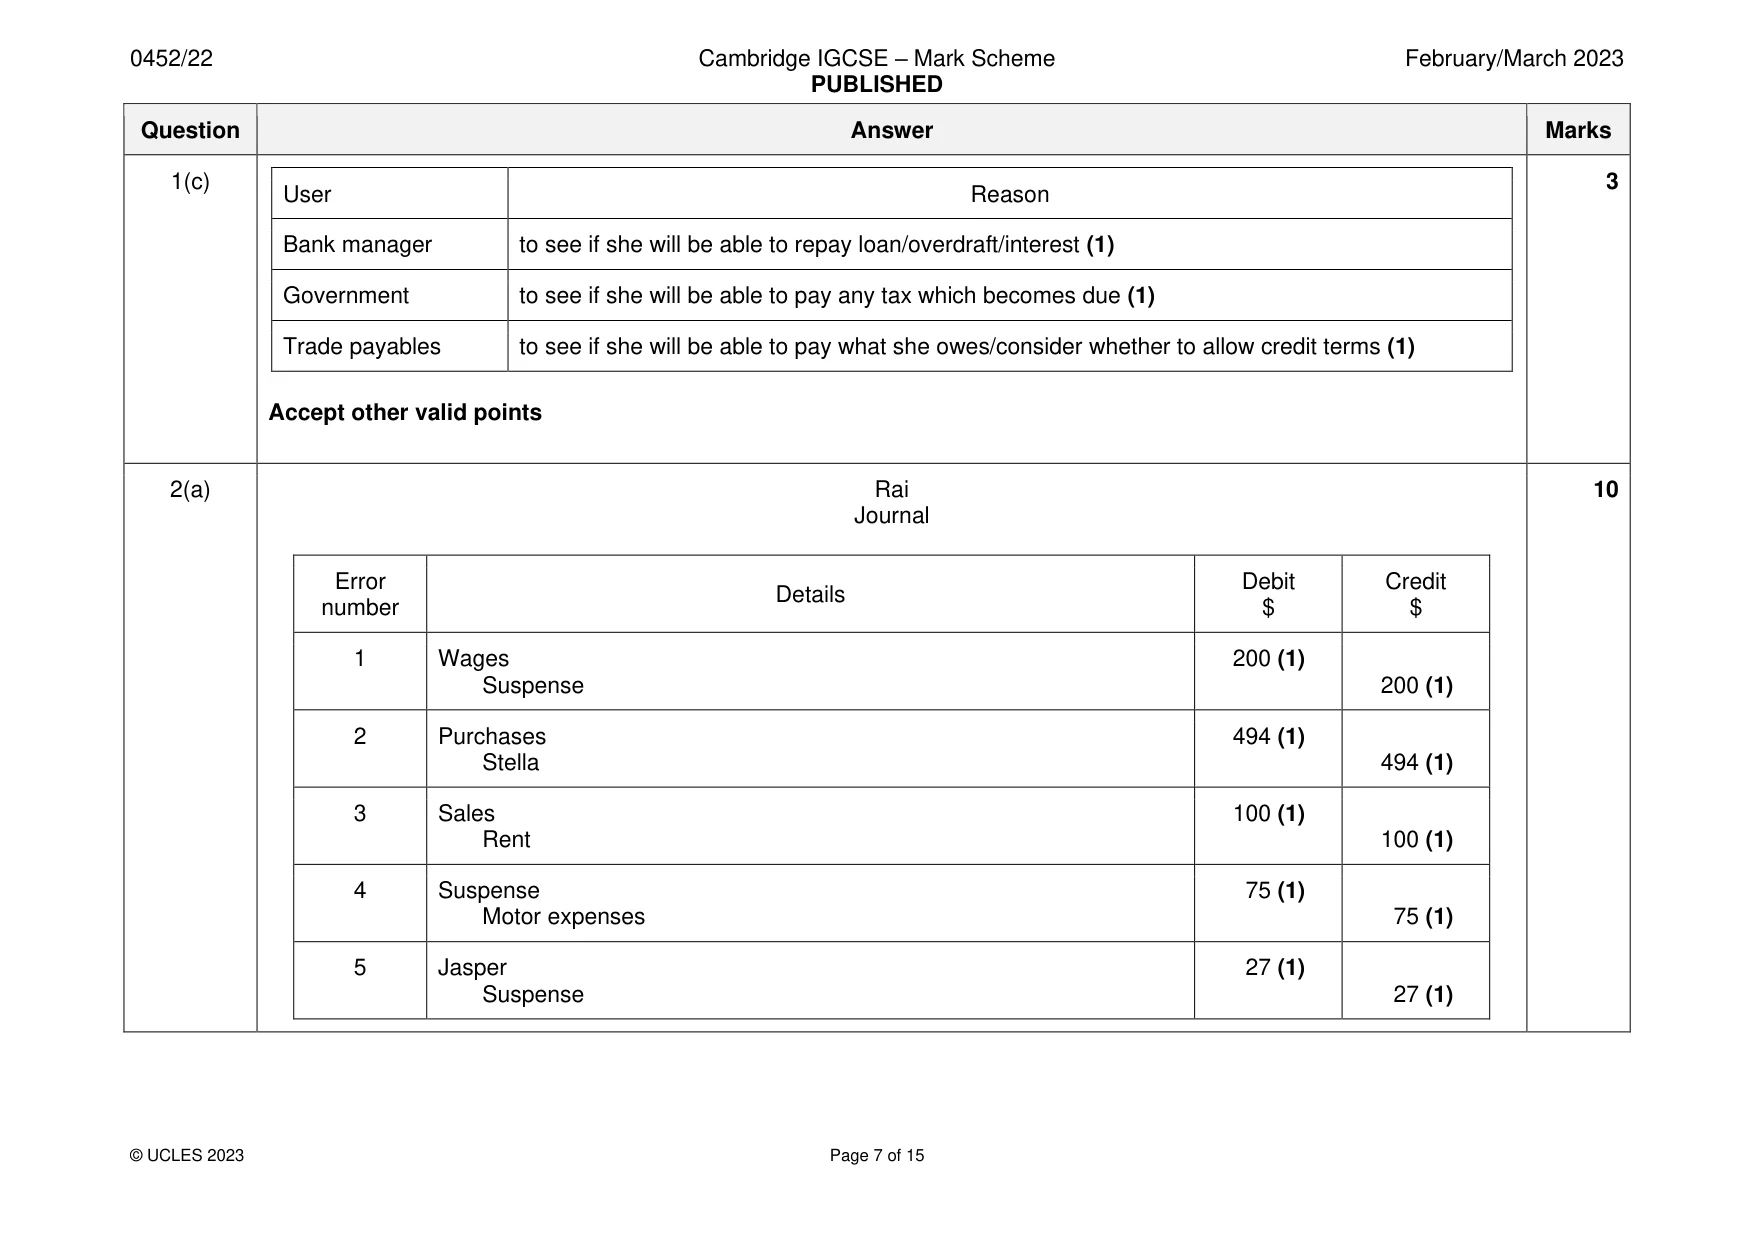
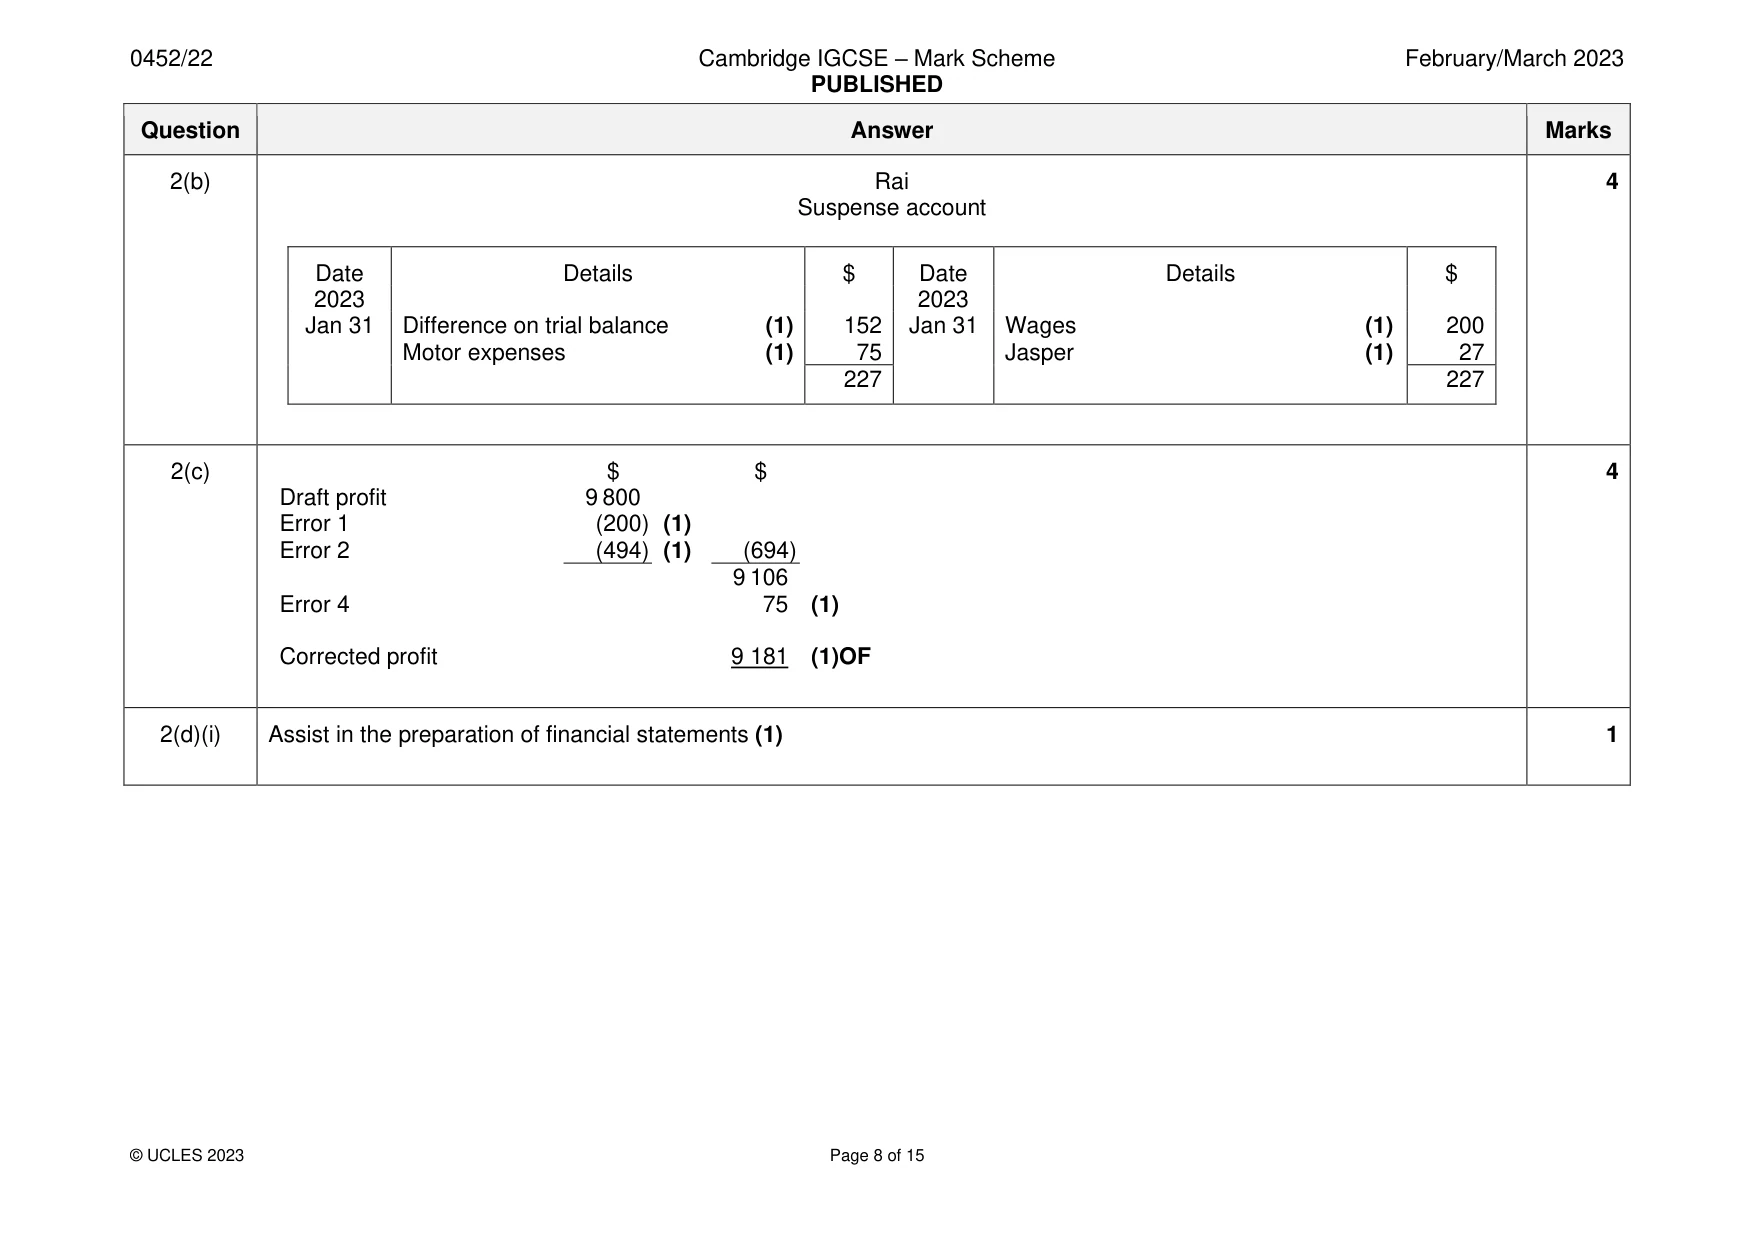
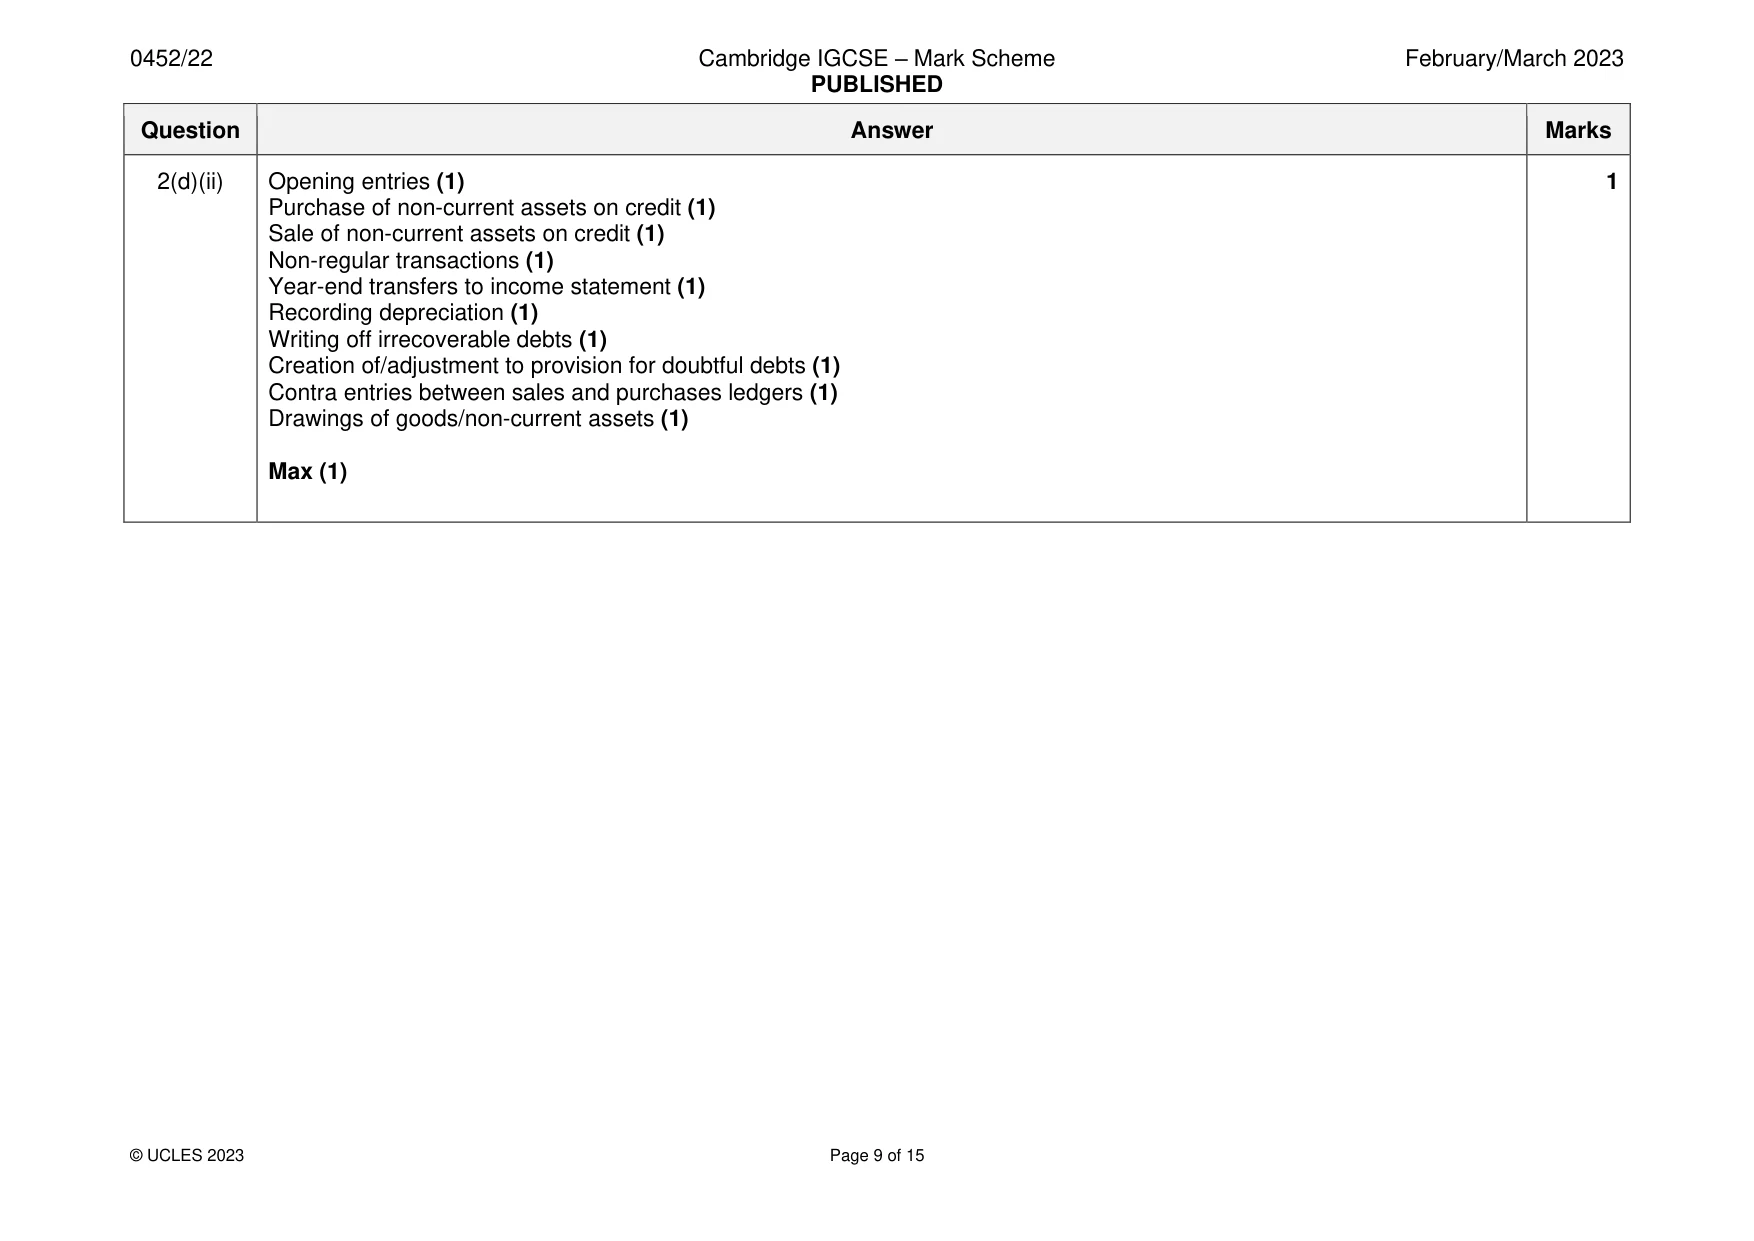
Mark scheme: 2(a) Rai 10 Journal Error Debit Credit Details number $ $ 1 Wages 200 (1) Suspense 200 (1) 2 Purchases 494 (1) Stella 494 (1) 3 Sales 100 (1) Rent 100 (1) 4 Suspense 75 (1) Motor expenses 75 (1) 5 Jasper 27 (1) Suspense 27 (1) 2(b) Rai 4 Suspense account Date Details $ Date Details $ 2023 2023 Jan 31 Difference on trial balance (1) 152 Jan 31 Wages (1) 200 Motor expenses (1) 75 Jasper (1) 27 227 227 2(c) $ $ 4 Draft profit 9 800 Error 1 (200) (1) Error 2 (494) (1) (694) 9 106 Error 4 75 (1) Corrected profit 9 181 (1)OF 2(d)(i) Assist in the preparation of financial statements (1) 1 2(d)(ii) Opening entries (1) 1 Purchase of non-current assets on credit (1) Sale of non-current assets on credit (1) Non-regular transactions (1) Year-end transfers to income statement (1) Recording depreciation (1) Writing off irrecoverable debts (1) Creation of/adjustment to provision for doubtful debts (1) Contra entries between sales and purchases ledgers (1) Drawings of goods/non-current assets (1) Max (1)
Q3 · Lucas is a trader
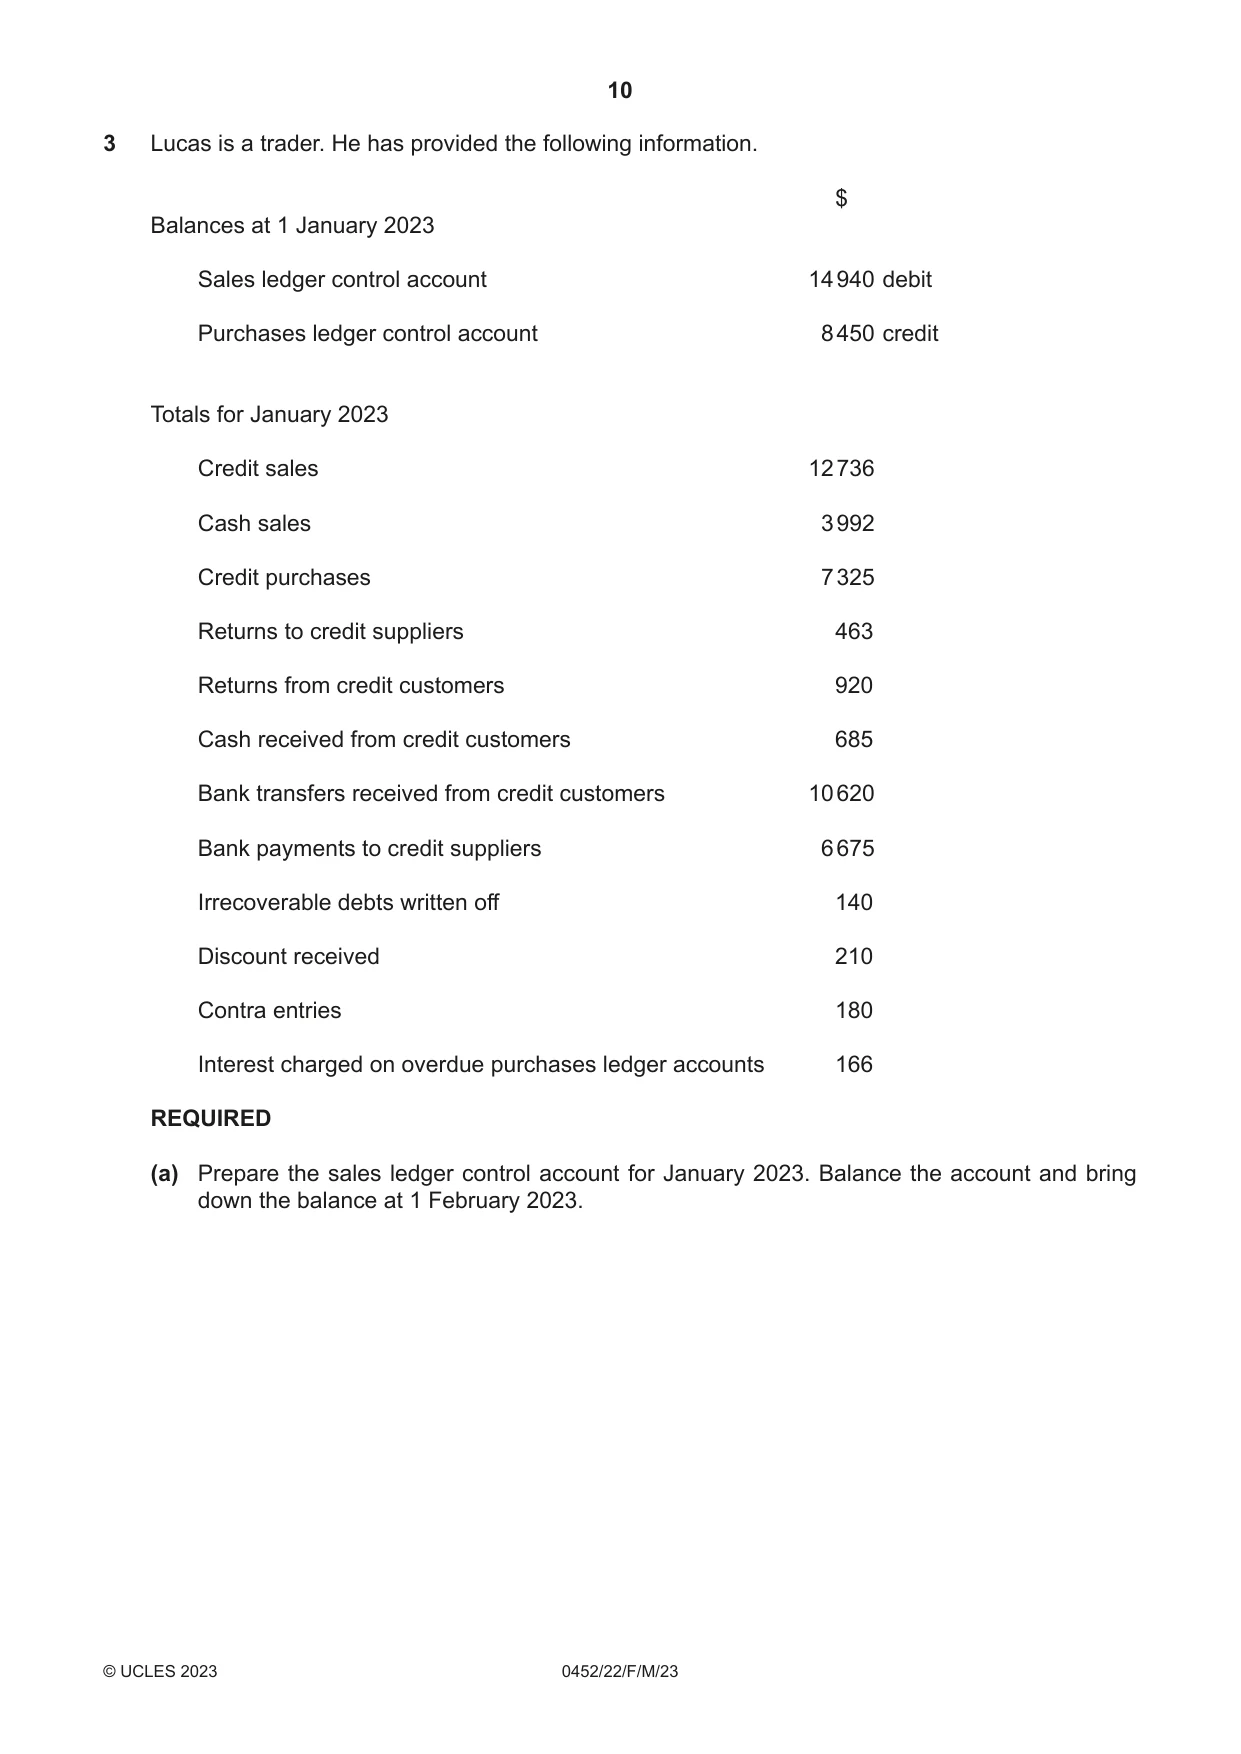
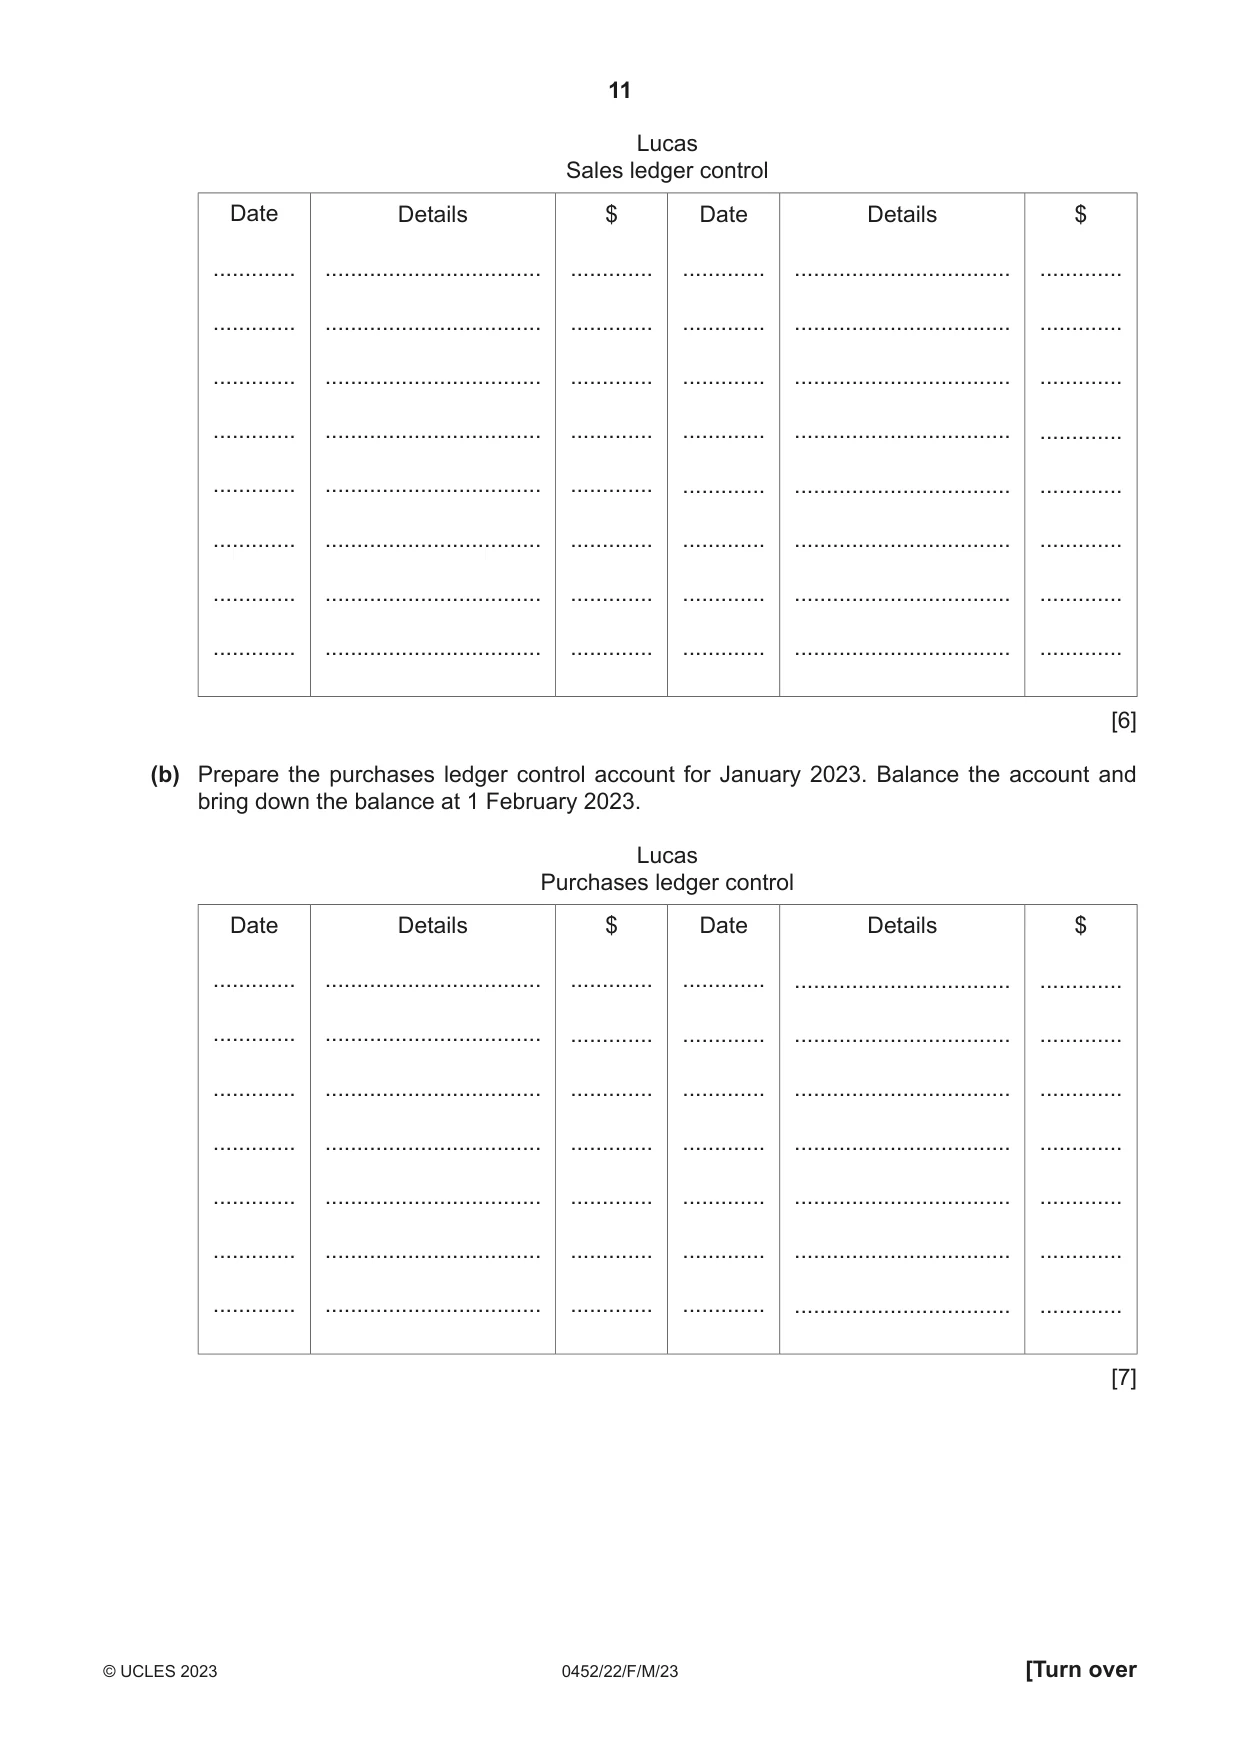
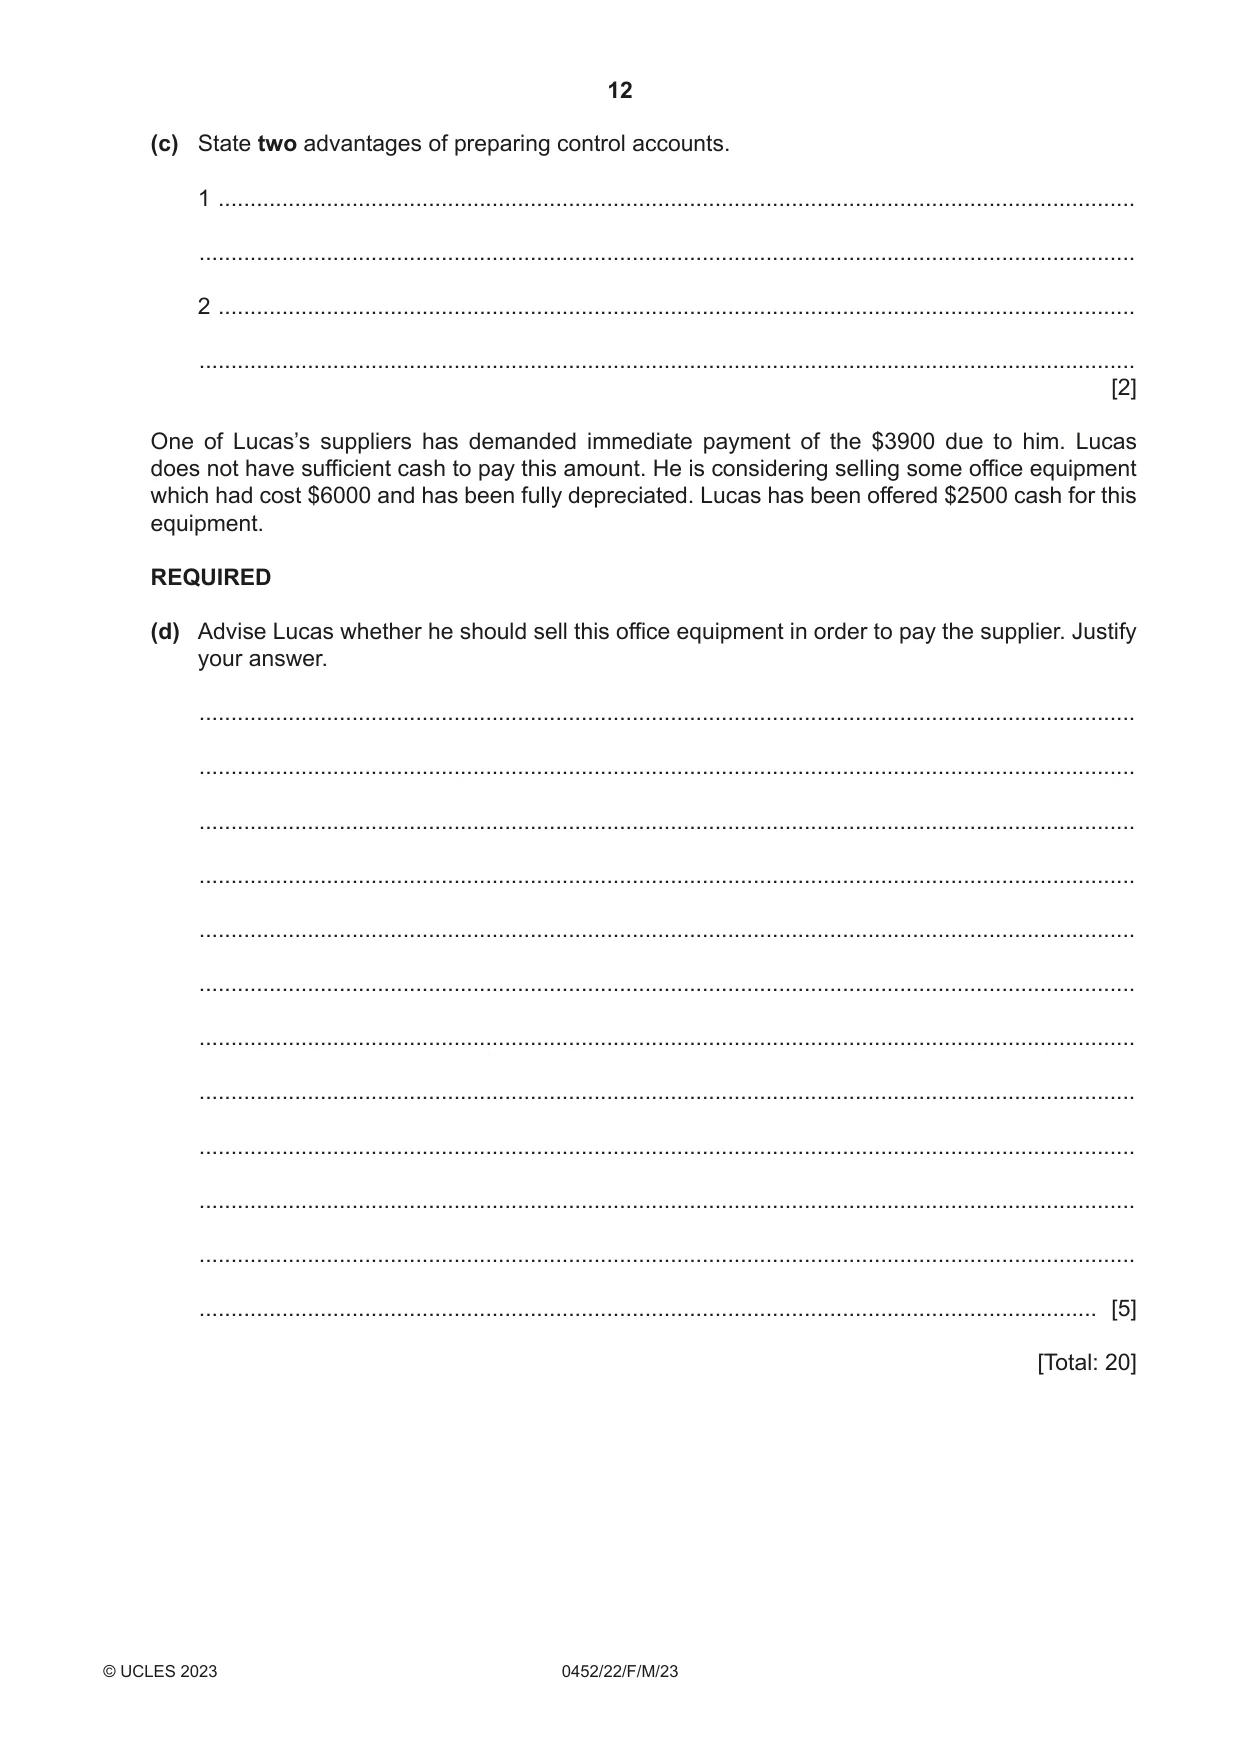
3 Lucas is a trader. He has provided the following information. $ Balances at 1 January 2023 Sales ledger control account 14 940 debit Purchases ledger control account 8 450 credit Totals for January 2023 Credit sales 12 736 Cash sales 3 992 Credit purchases 7 325 Returns to credit suppliers 463 Returns from credit customers 920 Cash received from credit customers 685 Bank transfers received from credit customers 10 620 Bank payments to credit suppliers 6 675 Irrecoverable debts written off 140 Discount received 210 Contra entries 180 Interest charged on overdue purchases ledger accounts 166 REQUIRED (a) Prepare the sales ledger control account for January 2023. Balance the account and bring down the balance at 1 February 2023. Lucas Sales ledger control Date Details $ Date Details $ ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. [6] (b) Prepare the purchases ledger control account for January 2023. Balance the account and bring down the balance at 1 February 2023. Lucas Purchases ledger control Date Details $ Date Details $ ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. [7] (c) State two advantages of preparing control accounts. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] One of Lucas’s suppliers has demanded immediate payment of the $3900 due to him. Lucas does not have sufficient cash to pay this amount. He is considering selling some office equipment which had cost $6000 and has been fully depreciated. Lucas has been offered $2500 cash for this equipment. REQUIRED (d) Advise Lucas whether he should sell this office equipment in order to pay the supplier. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
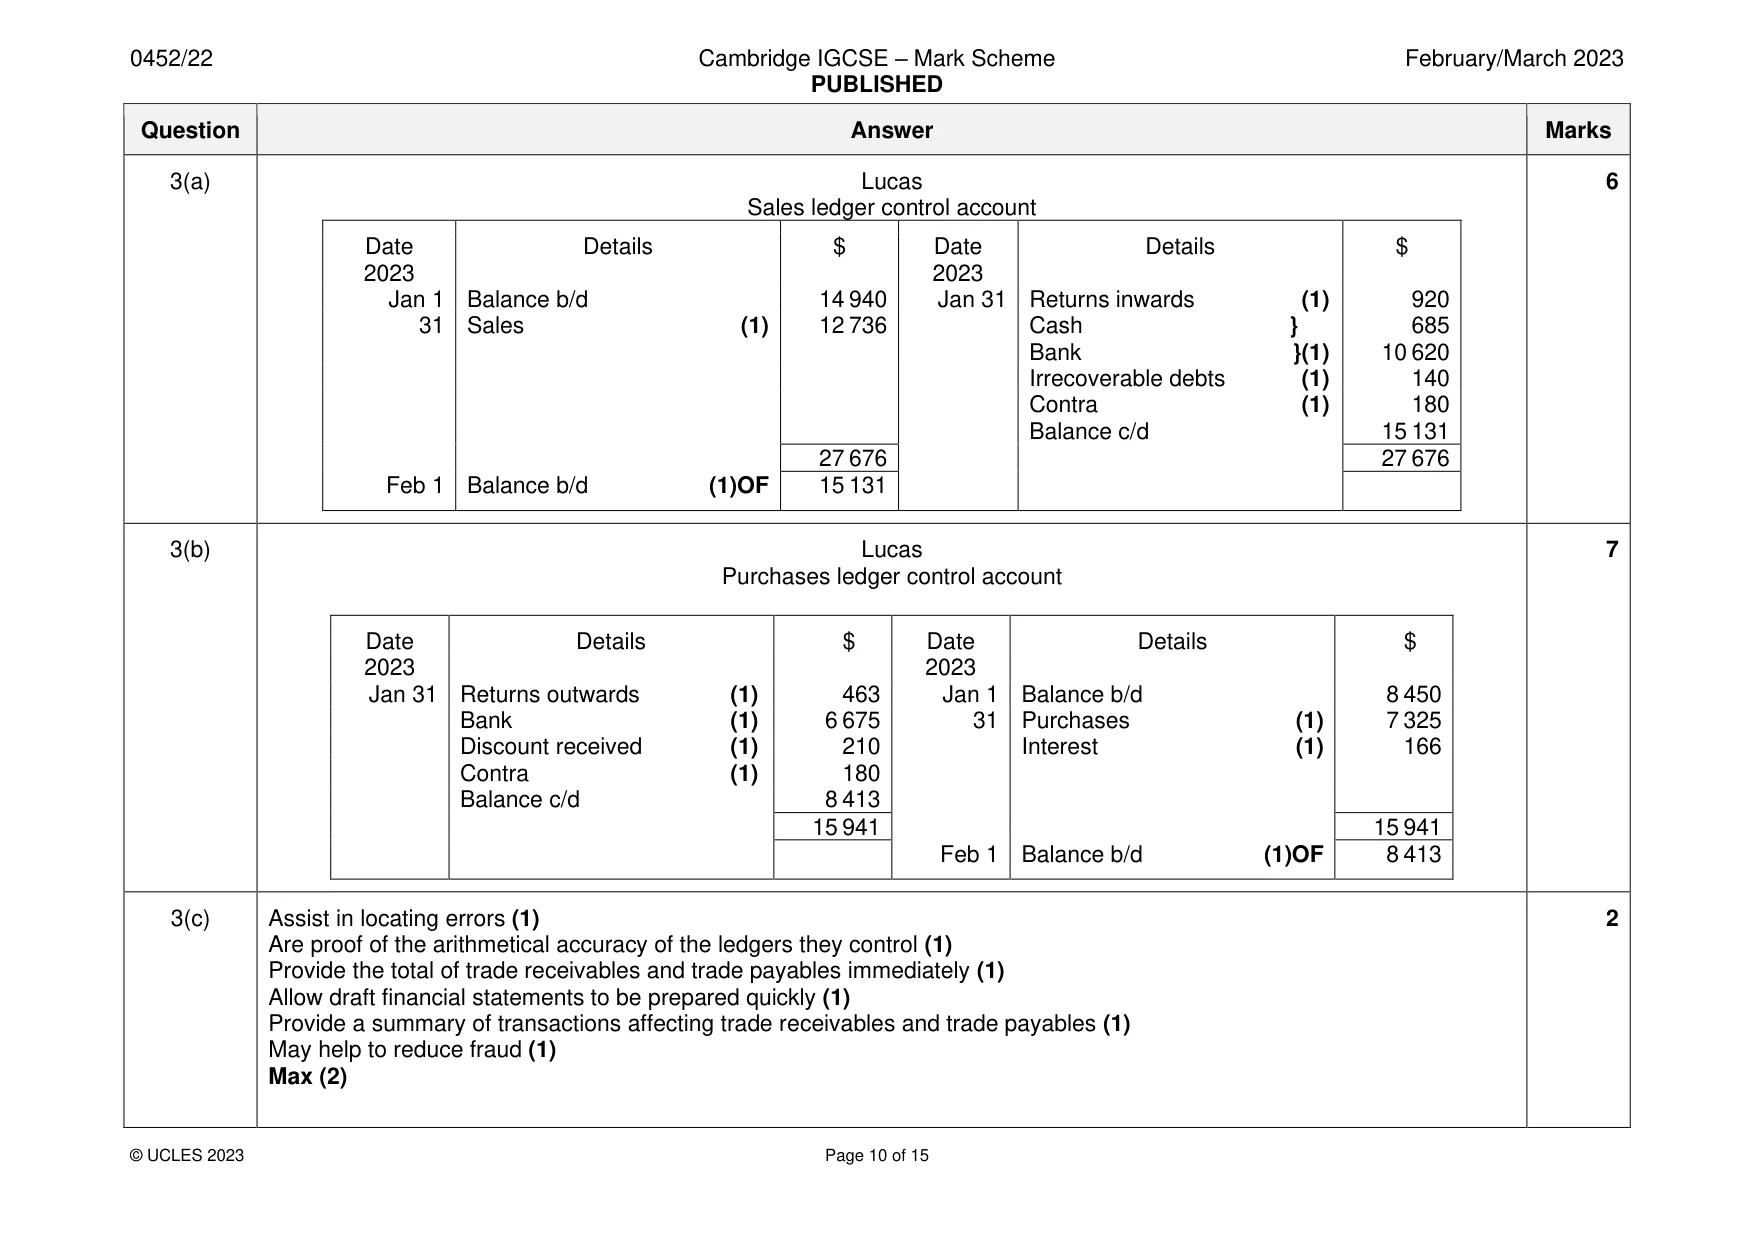
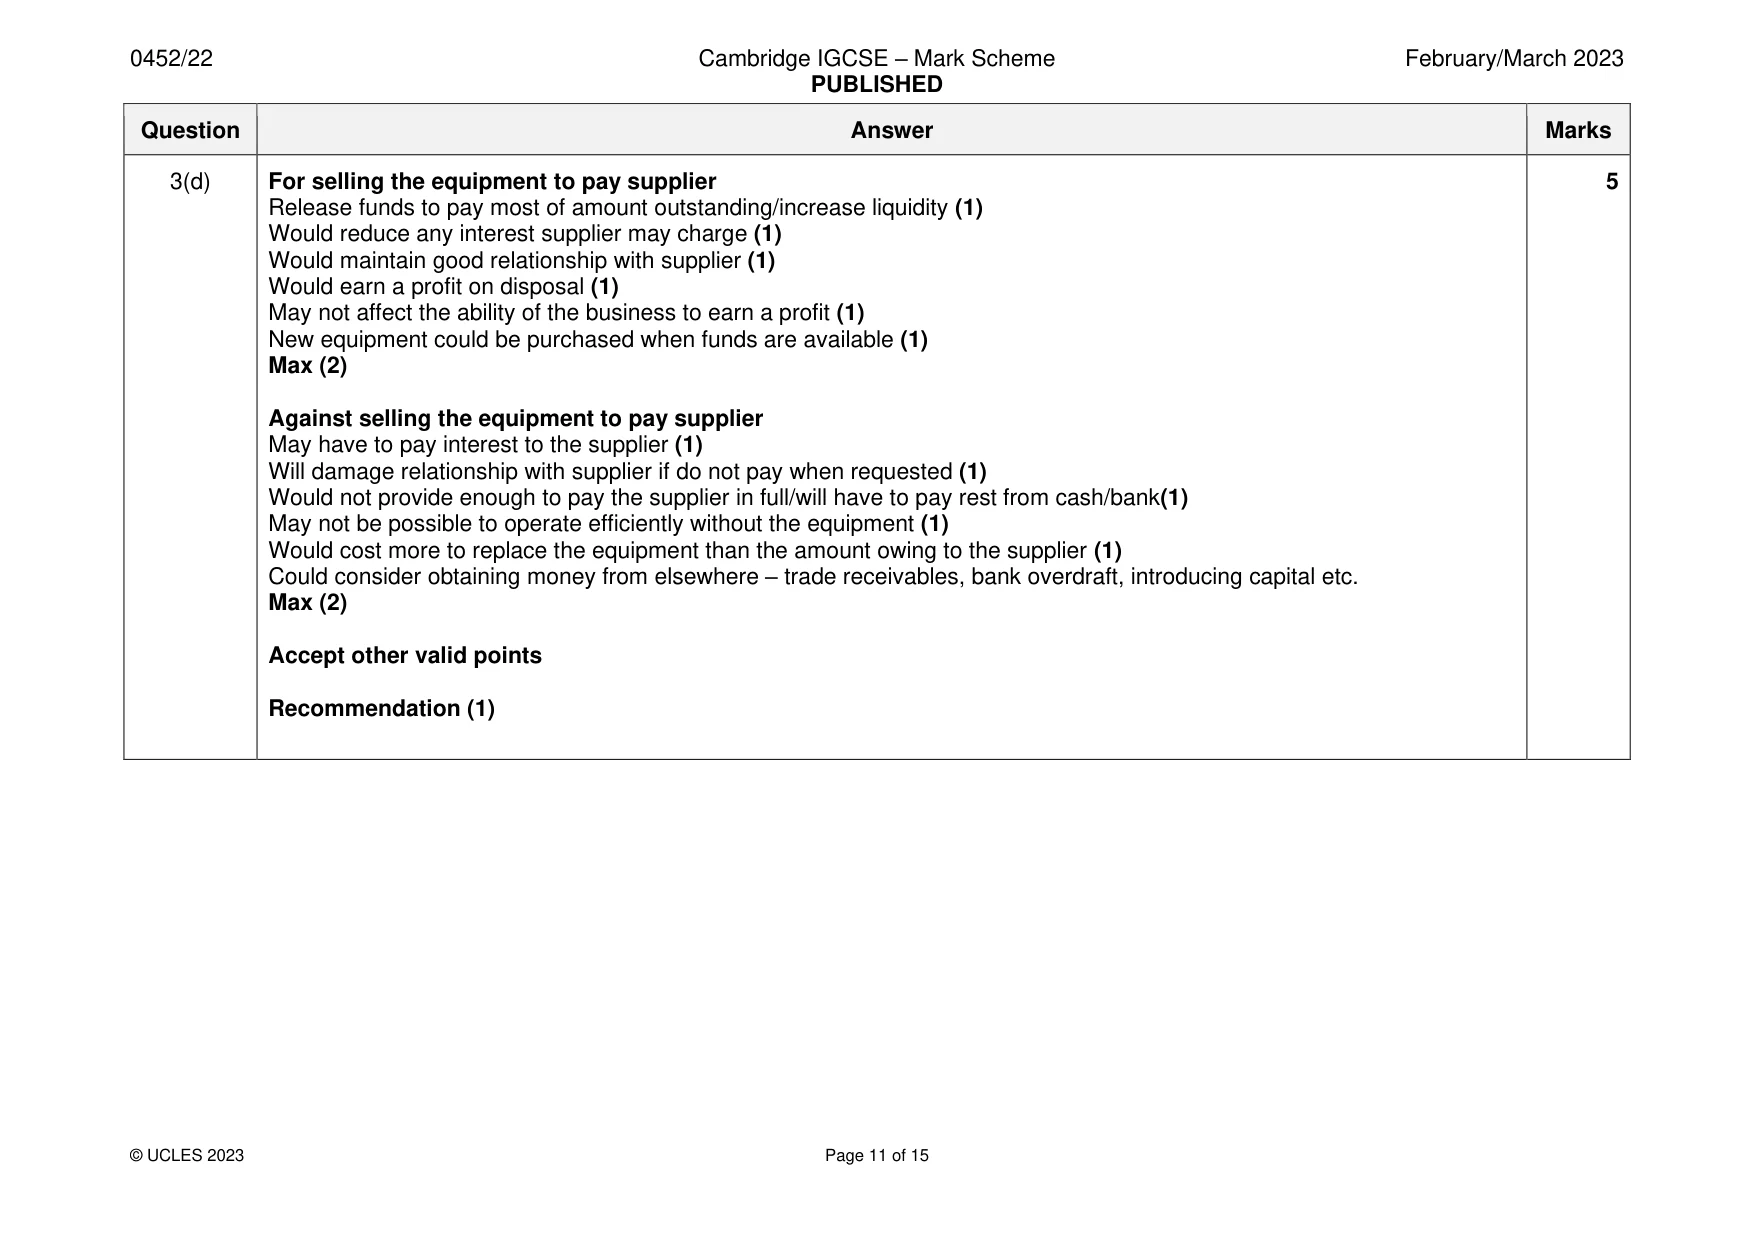
Mark scheme: 3(a) Lucas 6 Sales ledger control account Date Details $ Date Details $ 2023 2023 Jan 1 Balance b/d 14 940 Jan 31 Returns inwards (1) 920 31 Sales (1) 12 736 Cash } 685 Bank }(1) 10 620 Irrecoverable debts (1) 140 Contra (1) 180 Balance c/d 15 131 27 676 27 676 Feb 1 Balance b/d (1)OF 15 131 3(b) Lucas 7 Purchases ledger control account Date Details $ Date Details $ 2023 2023 Jan 31 Returns outwards (1) 463 Jan 1 Balance b/d 8 450 Bank (1) 6 675 31 Purchases (1) 7 325 Discount received (1) 210 Interest (1) 166 Contra (1) 180 Balance c/d 8 413 15 941 15 941 Feb 1 Balance b/d (1)OF 8 413 3(c) Assist in locating errors (1) 2 Are proof of the arithmetical accuracy of the ledgers they control (1) Provide the total of trade receivables and trade payables immediately (1) Allow draft financial statements to be prepared quickly (1) Provide a summary of transactions affecting trade receivables and trade payables (1) May help to reduce fraud (1) Max (2) 3(d) For selling the equipment to pay supplier 5 Release funds to pay most of amount outstanding/increase liquidity (1) Would reduce any interest supplier may charge (1) Would maintain good relationship with supplier (1) Would earn a profit on disposal (1) May not affect the ability of the business to earn a profit (1) New equipment could be purchased when funds are available (1) Max (2) Against selling the equipment to pay supplier May have to pay interest to the supplier (1) Will damage relationship with supplier if do not pay when requested (1) Would not provide enough to pay the supplier in full/will have to pay rest from cash/bank(1) May not be possible to operate efficiently without the equipment (1) Would cost more to replace the equipment than the amount owing to the supplier (1) Could consider obtaining money from elsewhere – trade receivables, bank overdraft, introducing capital etc. Max (2) Accept other valid points Recommendation (1)
Q4 · Adya is a trader
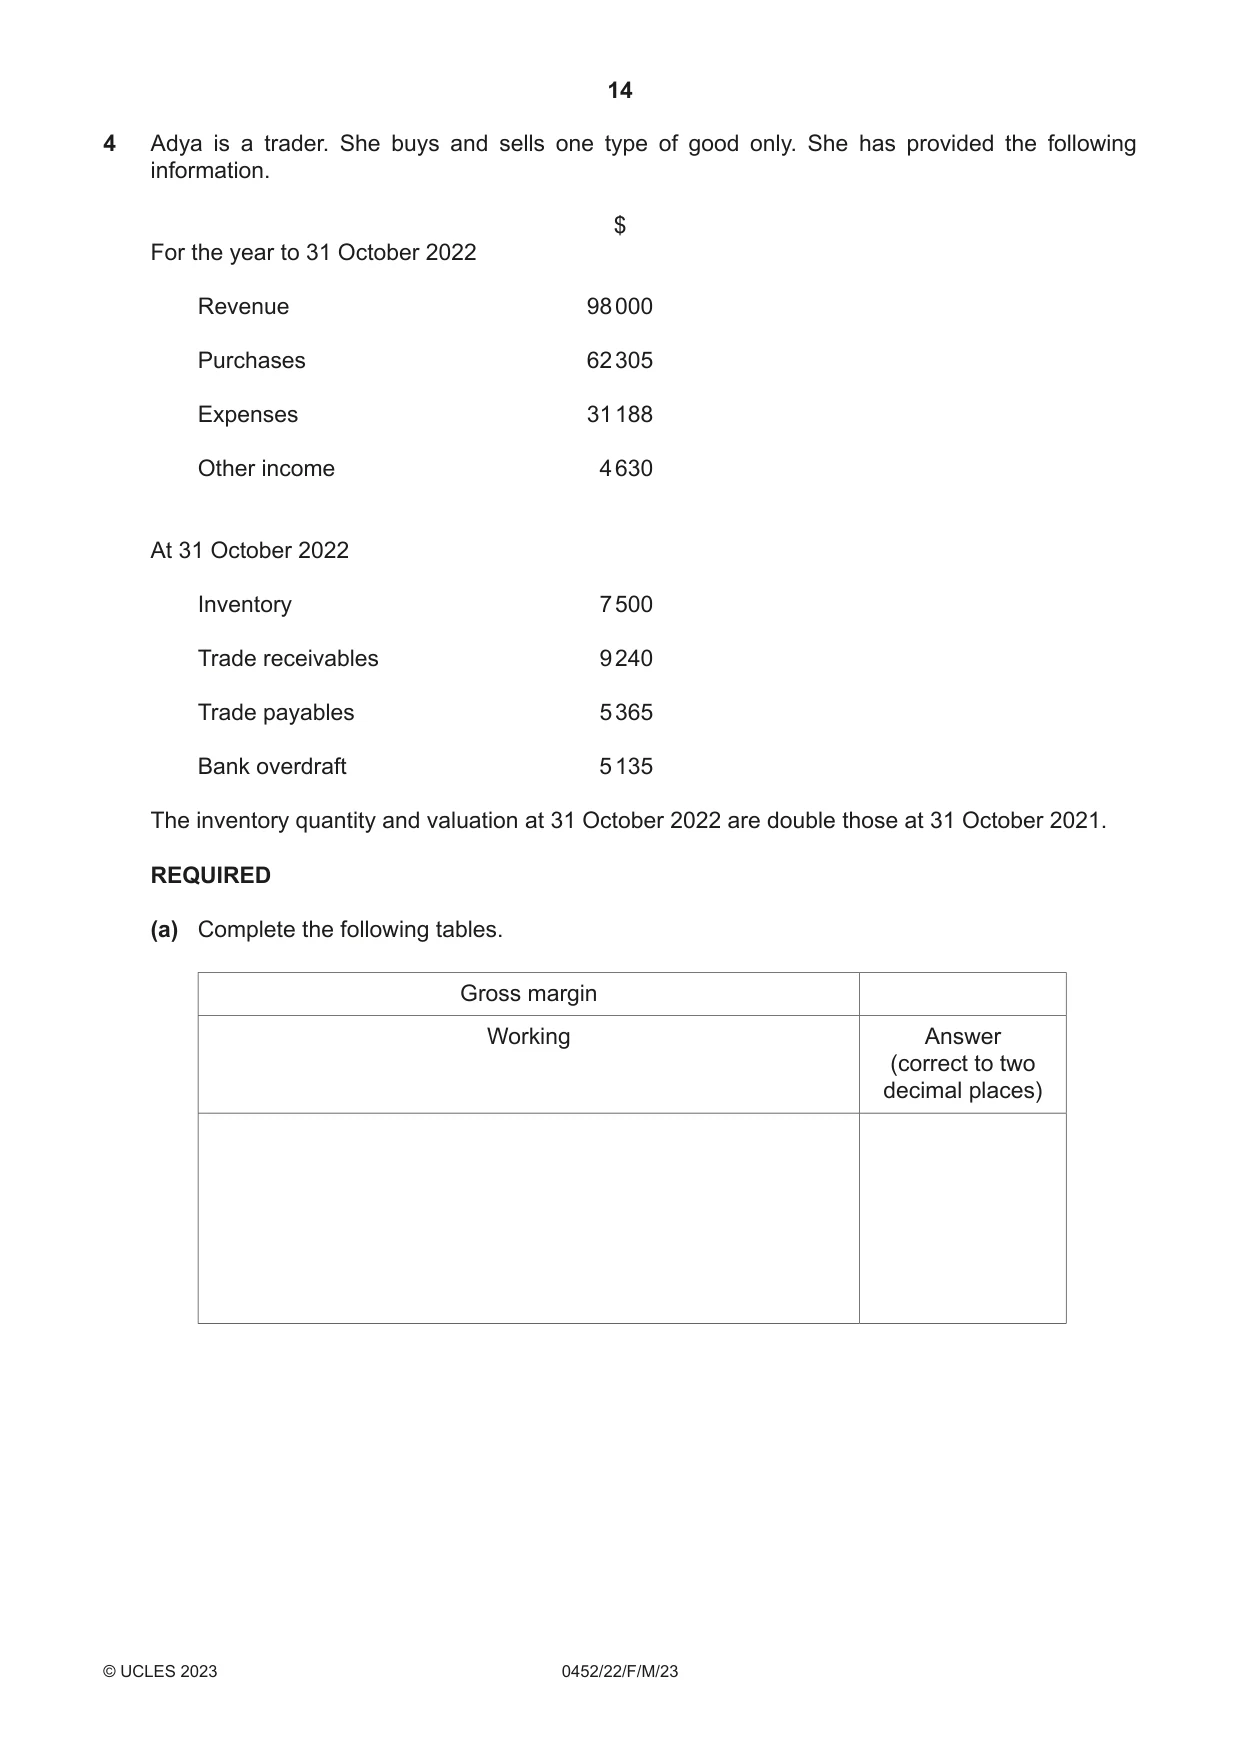
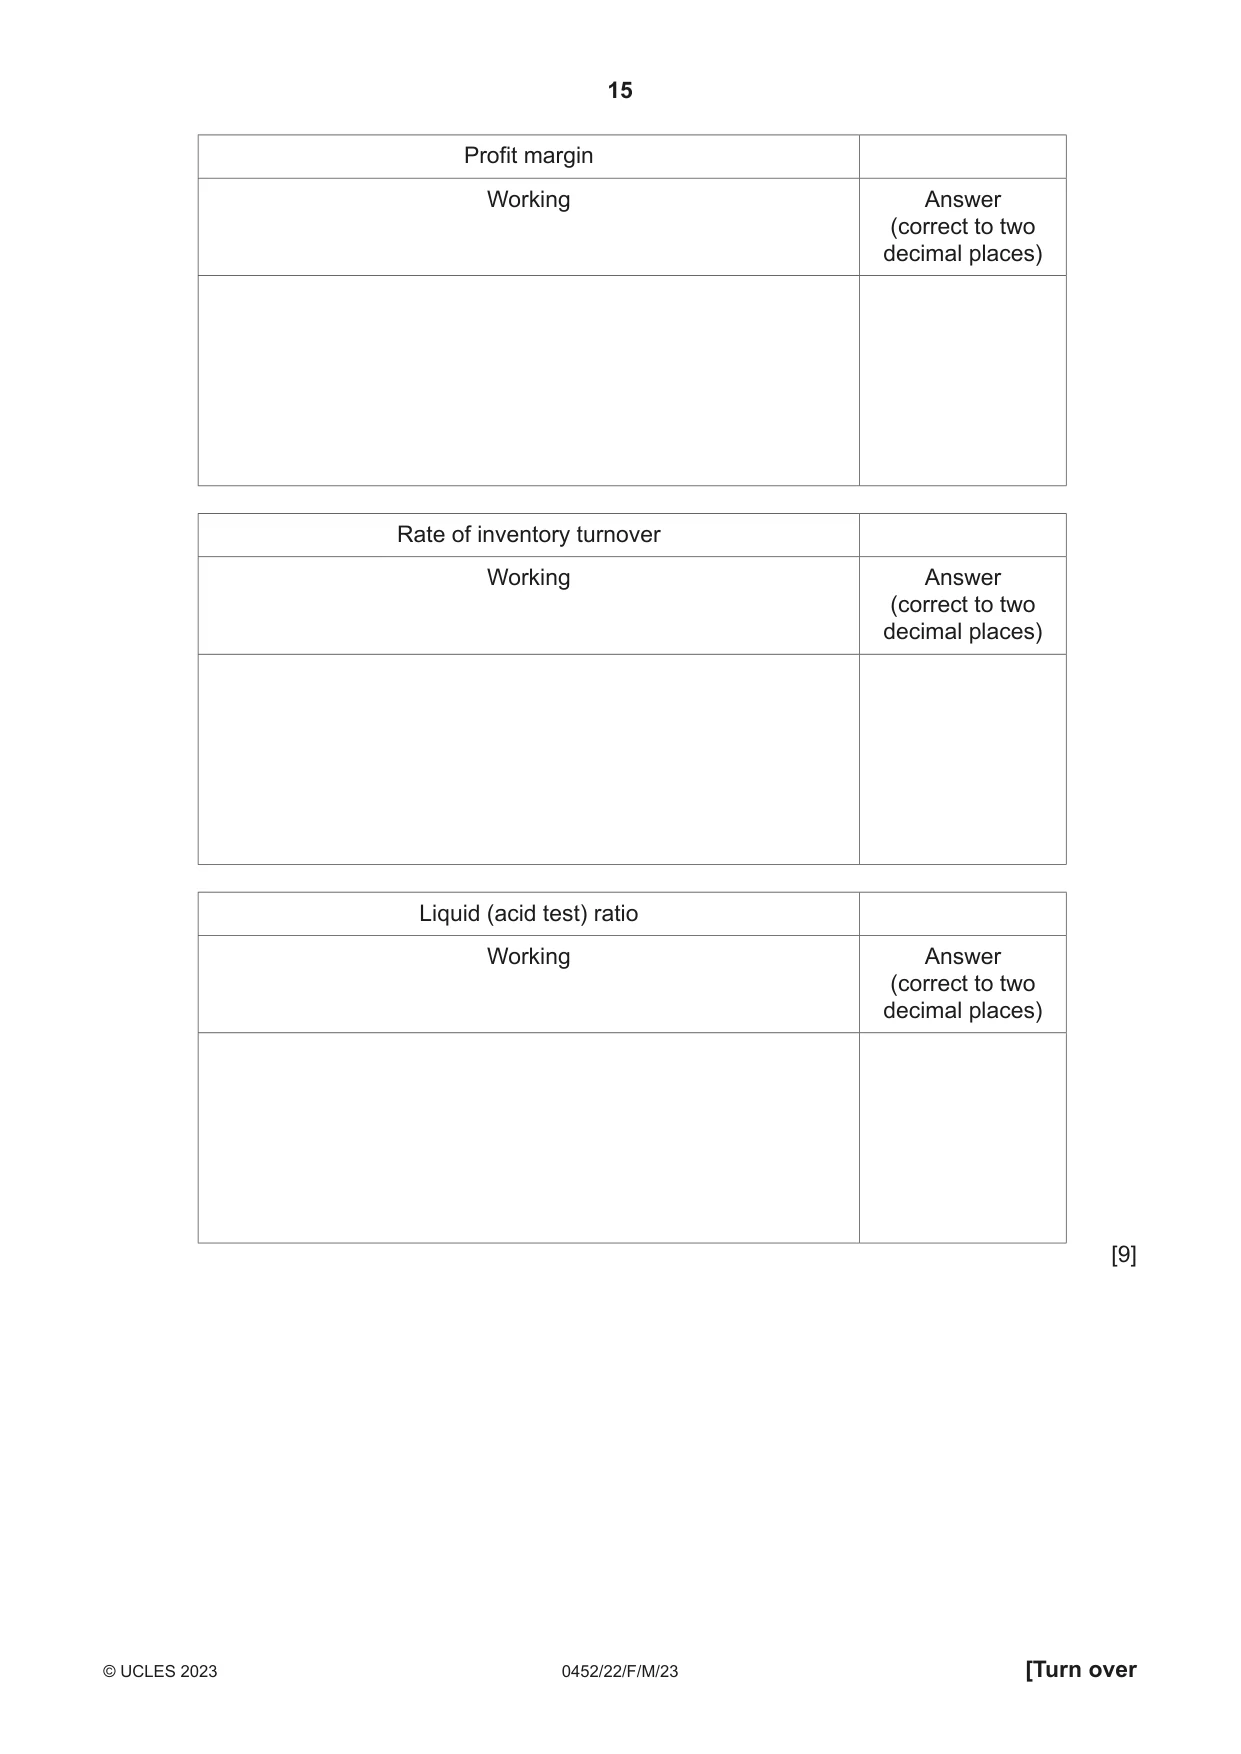
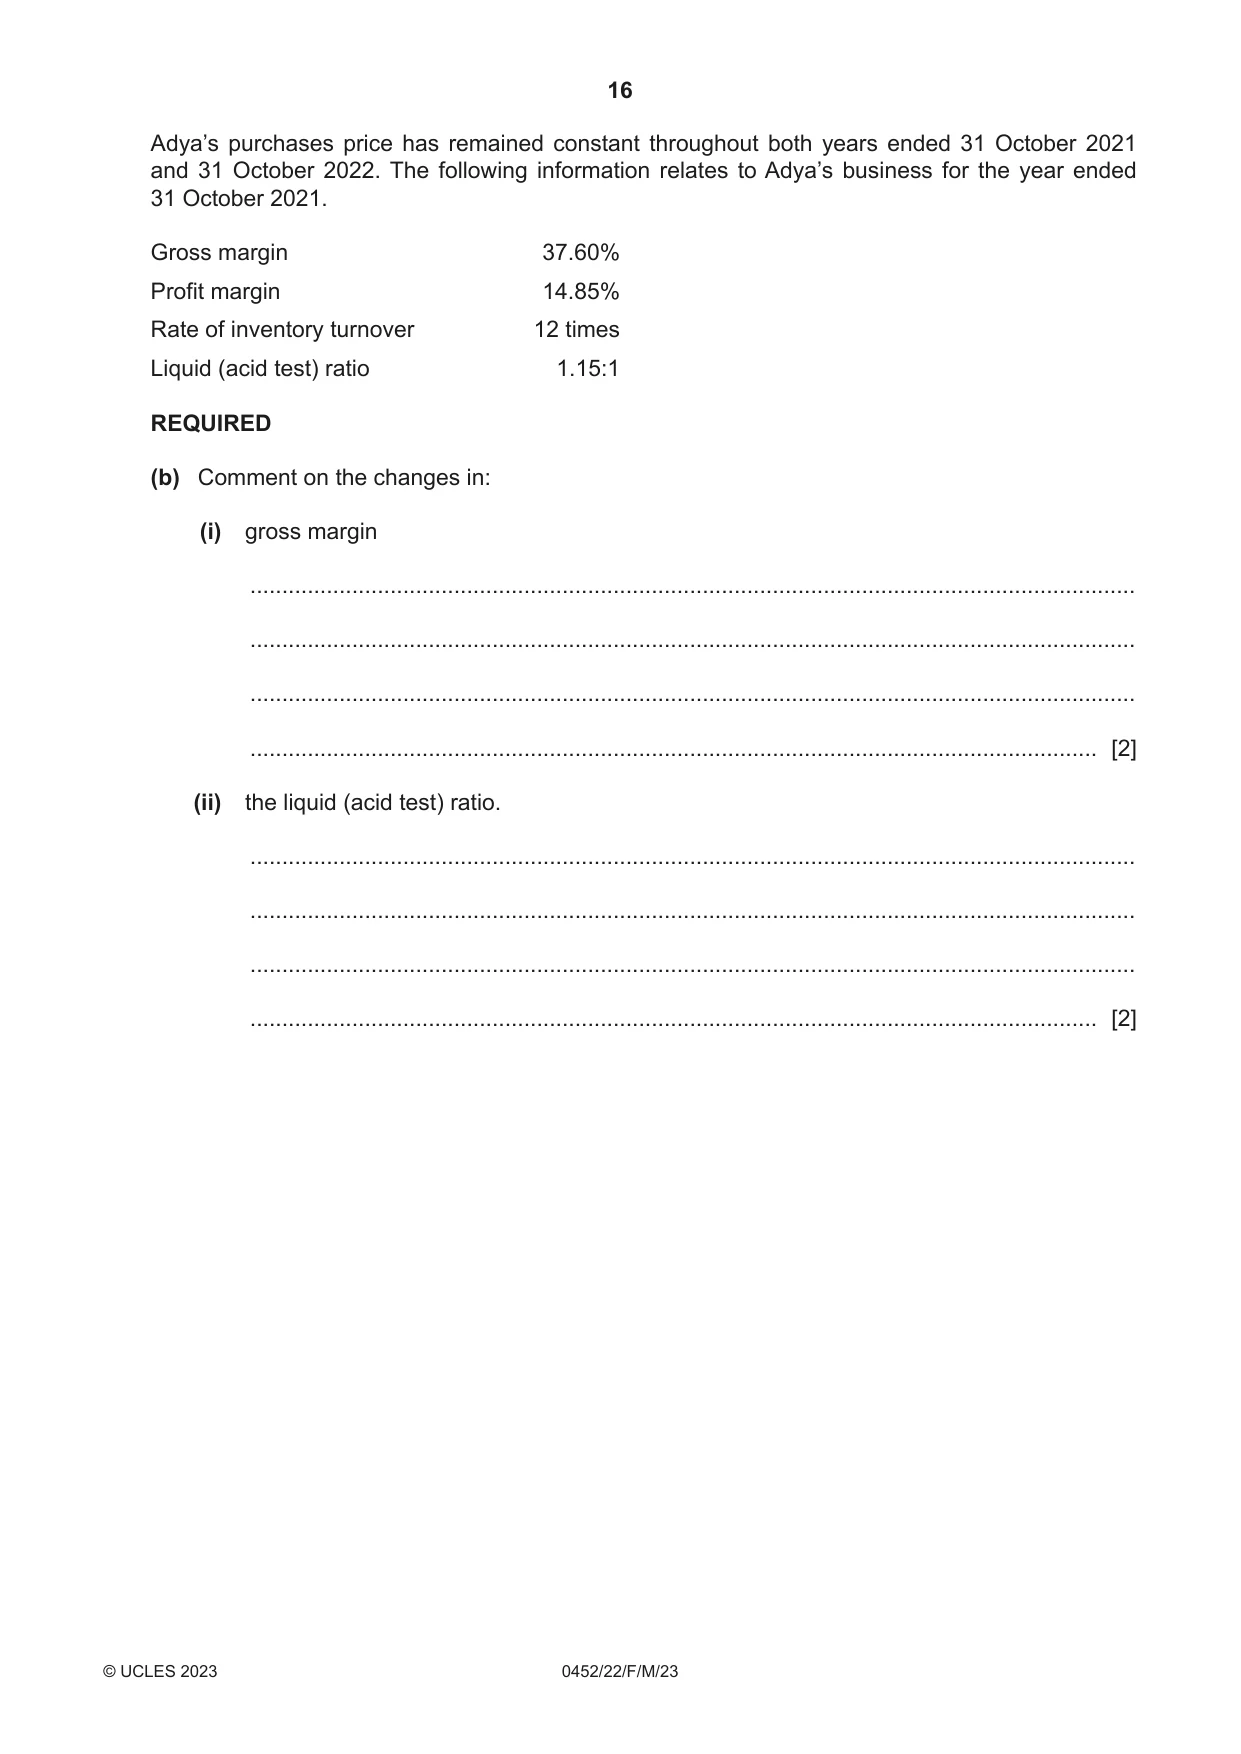
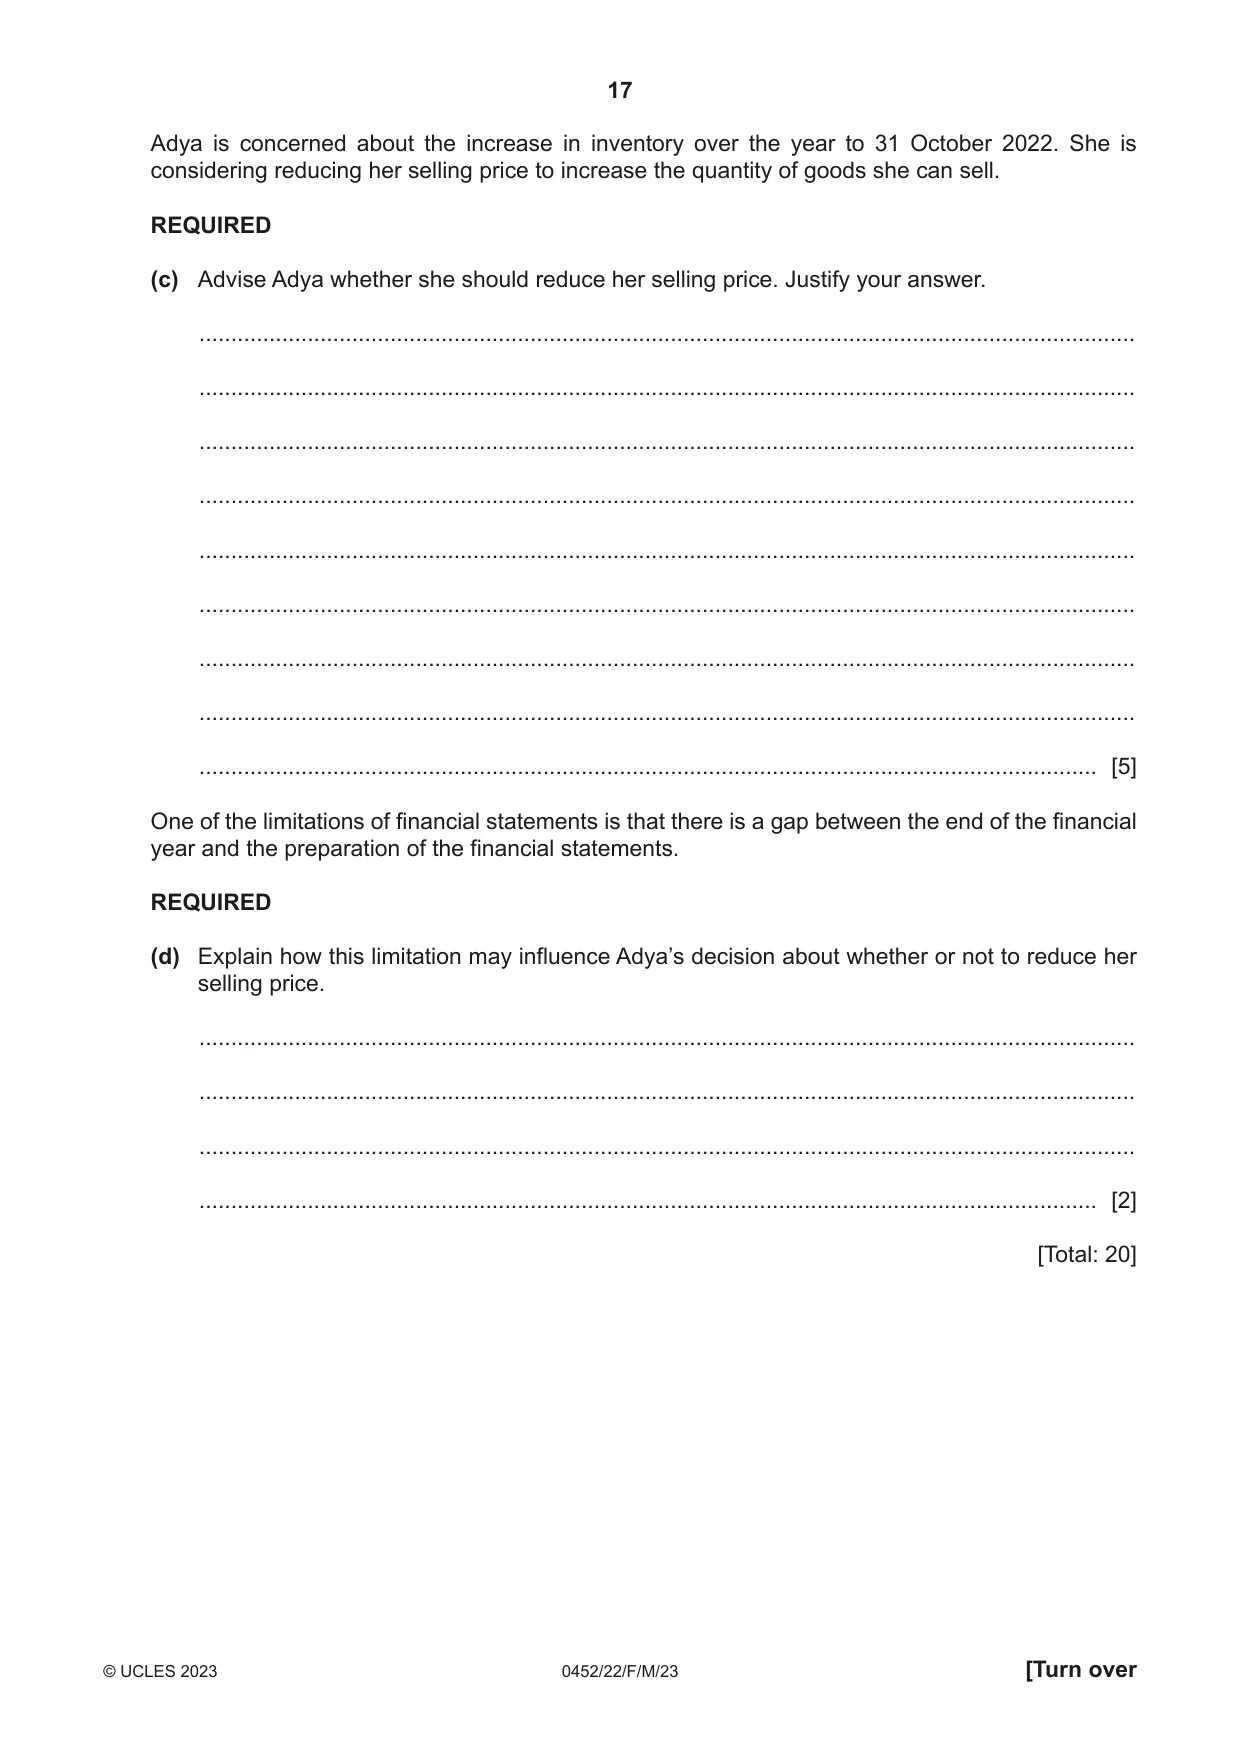
4 Adya is a trader. She buys and sells one type of good only. She has provided the following information. $ For the year to 31 October 2022 Revenue 98 000 Purchases 62 305 Expenses 31 188 Other income 4 630 At 31 October 2022 Inventory 7 500 Trade receivables 9 240 Trade payables 5 365 Bank overdraft 5 135 The inventory quantity and valuation at 31 October 2022 are double those at 31 October 2021. REQUIRED (a) Complete the following tables. Gross margin Working Answer (correct to two decimal places) Profit margin Working Answer (correct to two decimal places) Rate of inventory turnover Working Answer (correct to two decimal places) Liquid (acid test) ratio Working Answer (correct to two decimal places) [9] Adya’s purchases price has remained constant throughout both years ended 31 October 2021 and 31 October 2022. The following information relates to Adya’s business for the year ended 31 October 2021. Gross margin 37.60% Profit margin 14.85% Rate of inventory turnover 12 times Liquid (acid test) ratio 1.15:1 REQUIRED (b) Comment on the changes in: (i) gross margin ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] (ii) the liquid (acid test) ratio. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] Adya is concerned about the increase in inventory over the year to 31 October 2022. She is considering reducing her selling price to increase the quantity of goods she can sell. REQUIRED (c) Advise Adya whether she should reduce her selling price. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] One of the limitations of financial statements is that there is a gap between the end of the financial year and the preparation of the financial statements. REQUIRED (d) Explain how this limitation may influence Adya’s decision about whether or not to reduce her selling price. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] [Total: 20]
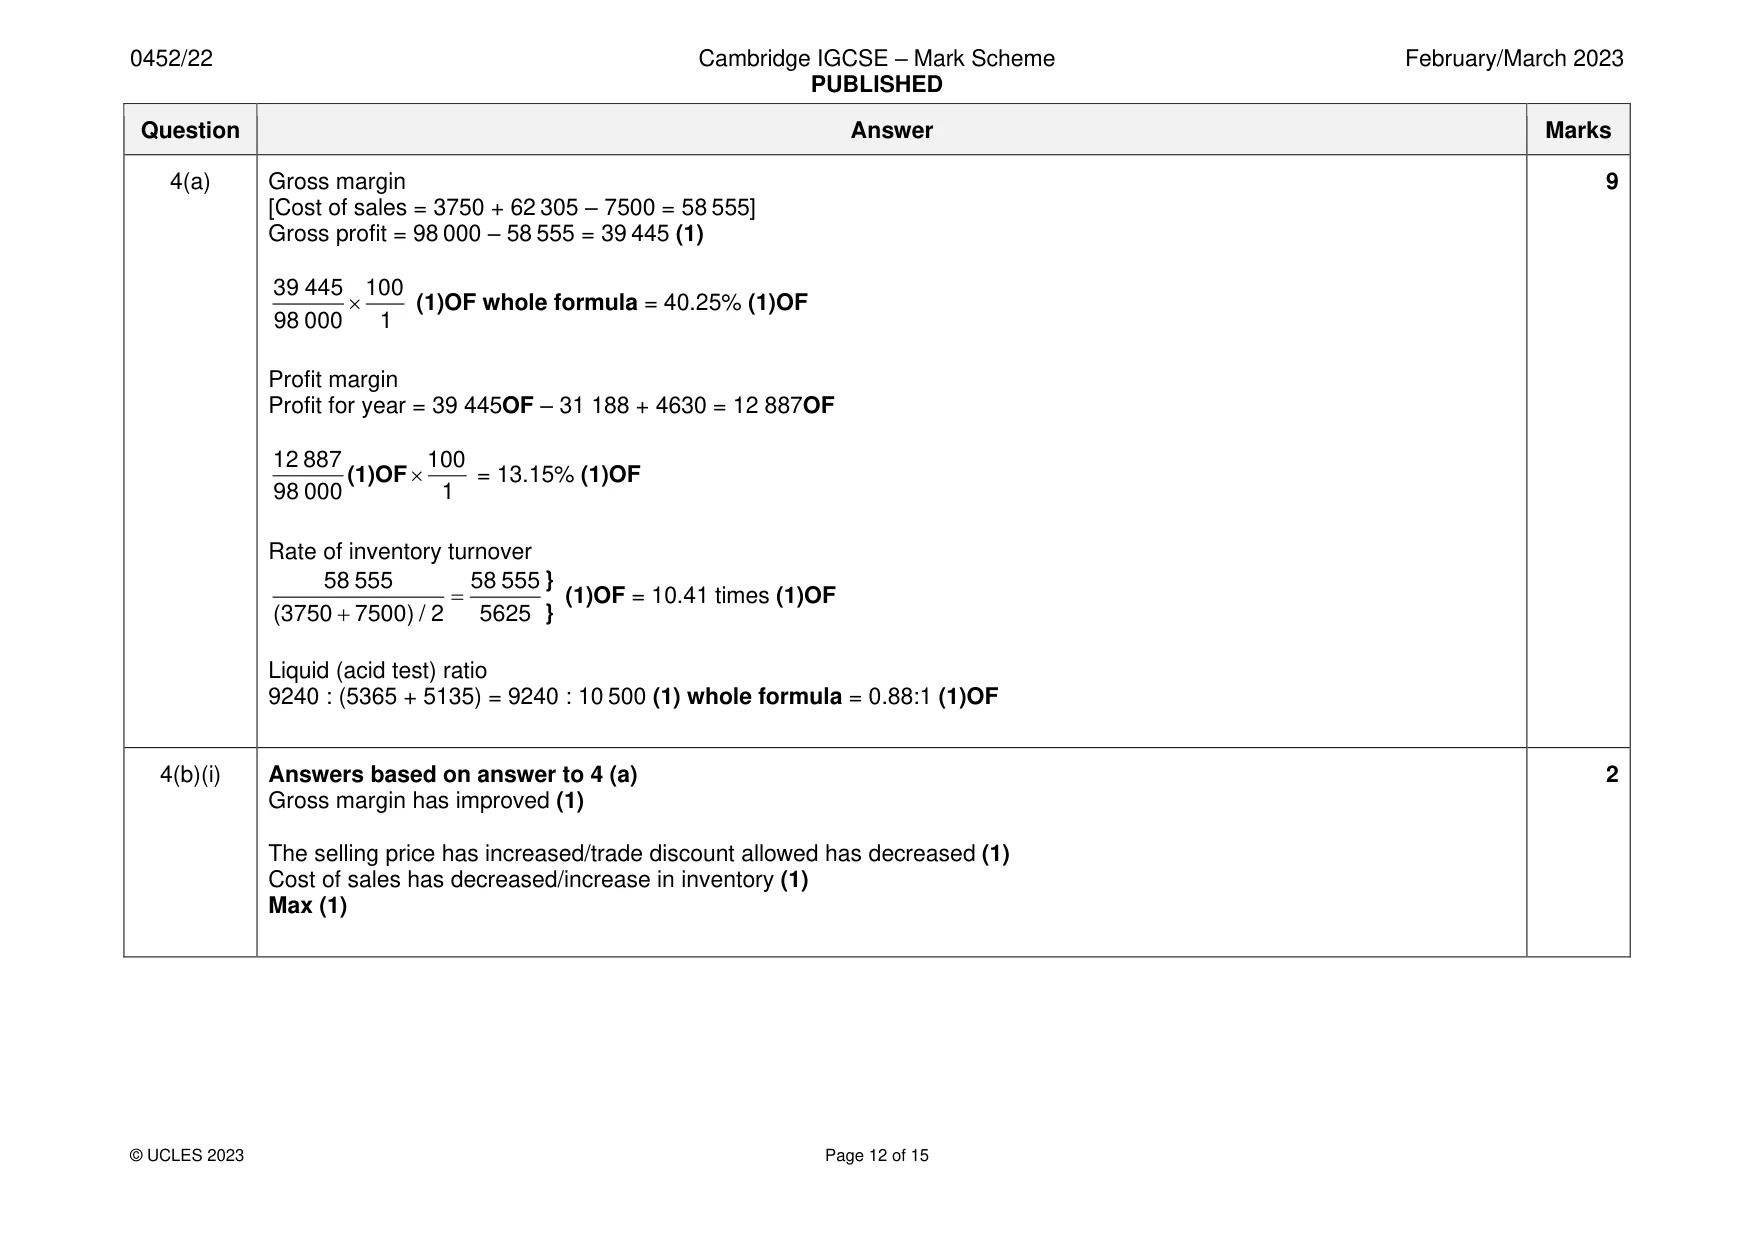
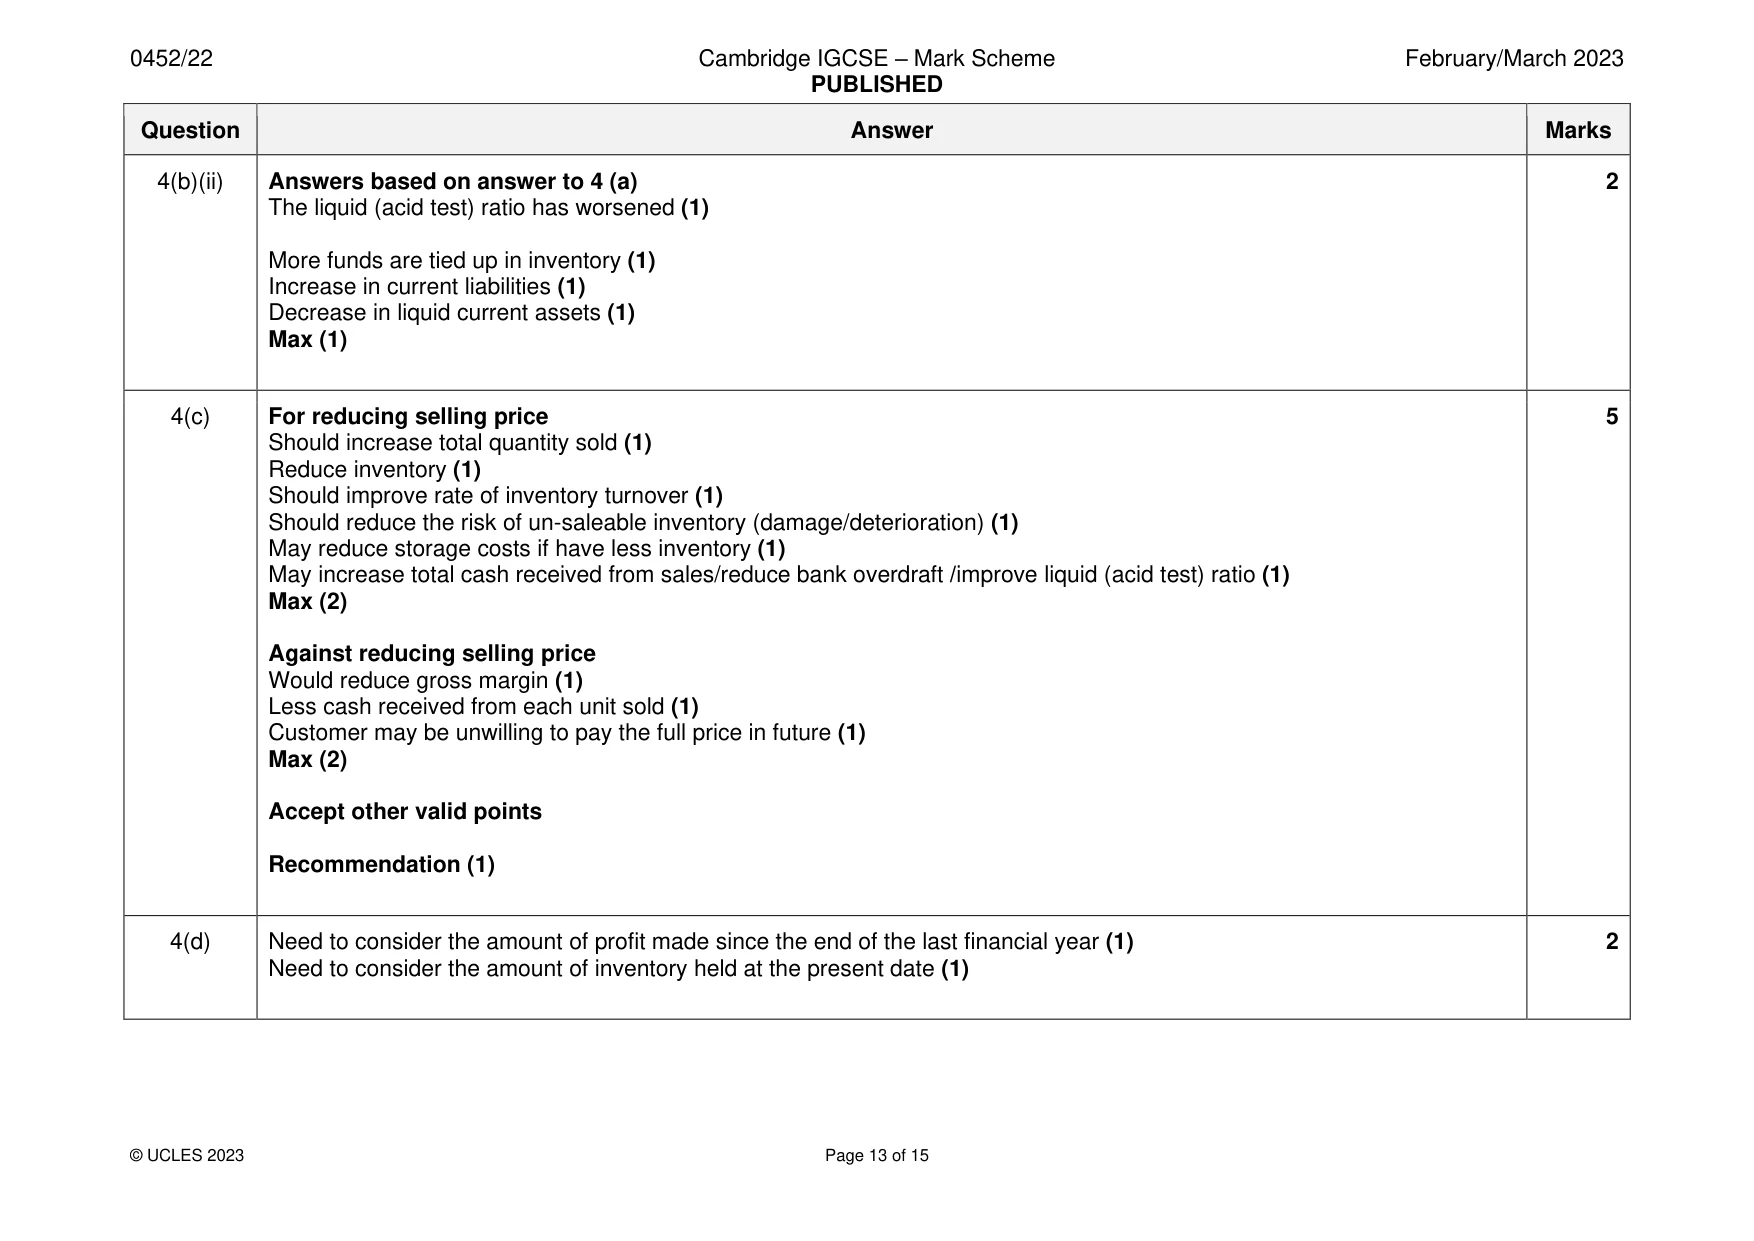
Mark scheme: 4(a) Gross margin 9 [Cost of sales = 3750 + 62 305 – 7500 = 58 555] Gross profit = 98 000 – 58 555 = 39 445 (1) 39 445 100 (1)OF whole formula = 40.25% (1)OF 98 000 1 Profit margin Profit for year = 39 445OF – 31 188 + 4630 = 12 887OF 12 887 100 (1)OF = 13.15% (1)OF 98 000 1 Rate of inventory turnover 58 555 58 555 } = (1)OF = 10.41 times (1)OF (3750 + 7500) / 2 5625 } Liquid (acid test) ratio 9240 : (5365 + 5135) = 9240 : 10 500 (1) whole formula = 0.88:1 (1)OF 4(b)(i) Answers based on answer to 4 (a) 2 Gross margin has improved (1) The selling price has increased/trade discount allowed has decreased (1) Cost of sales has decreased/increase in inventory (1) Max (1) 4(b)(ii) Answers based on answer to 4 (a) 2 The liquid (acid test) ratio has worsened (1) More funds are tied up in inventory (1) Increase in current liabilities (1) Decrease in liquid current assets (1) Max (1) 4(c) For reducing selling price 5 Should increase total quantity sold (1) Reduce inventory (1) Should improve rate of inventory turnover (1) Should reduce the risk of un-saleable inventory (damage/deterioration) (1) May reduce storage costs if have less inventory (1) May increase total cash received from sales/reduce bank overdraft /improve liquid (acid test) ratio (1) Max (2) Against reducing selling price Would reduce gross margin (1) Less cash received from each unit sold (1) Customer may be unwilling to pay the full price in future (1) Max (2) Accept other valid points Recommendation (1) 4(d) Need to consider the amount of profit made since the end of the last financial year (1) 2 Need to consider the amount of inventory held at the present date (1)
More questions on Calculation and understanding of accounting ratios
Q5 · Samir and Punita are in partnership
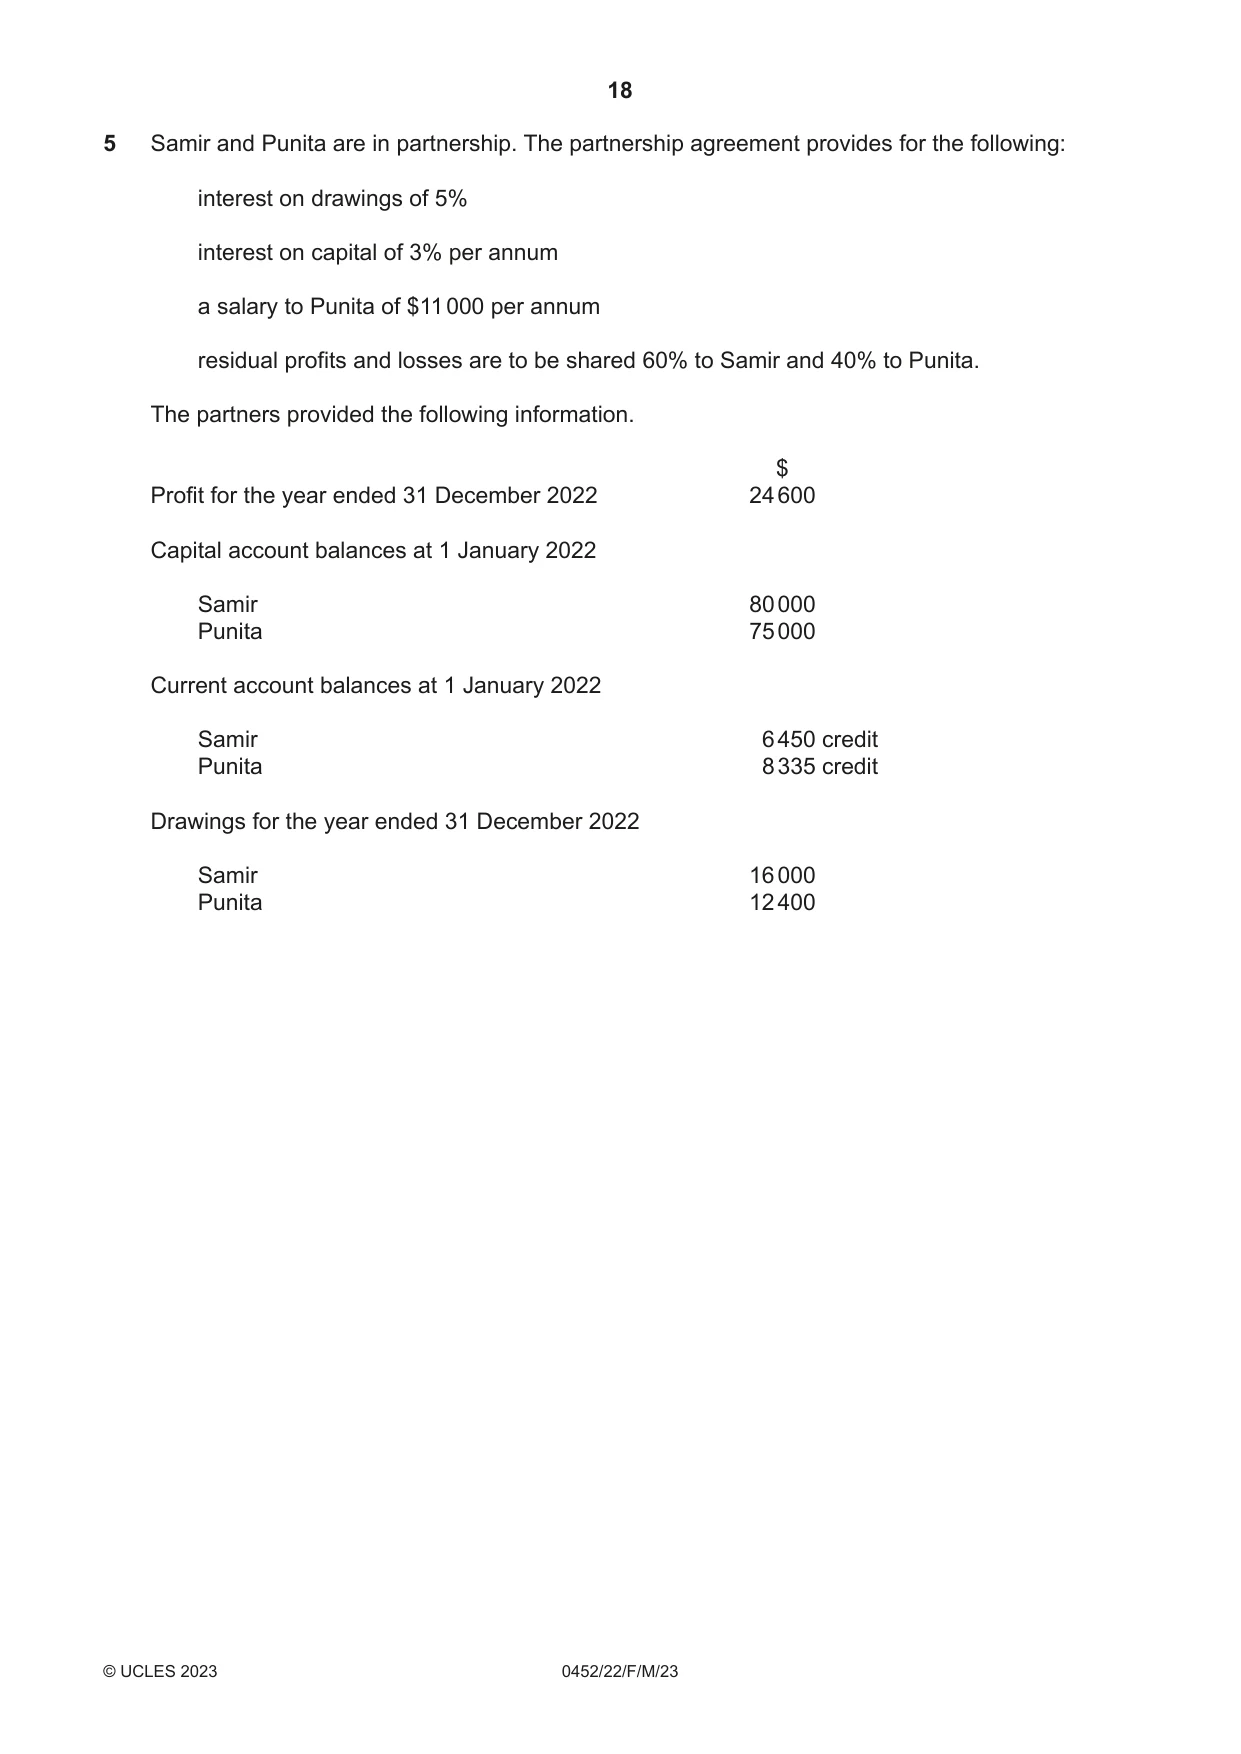
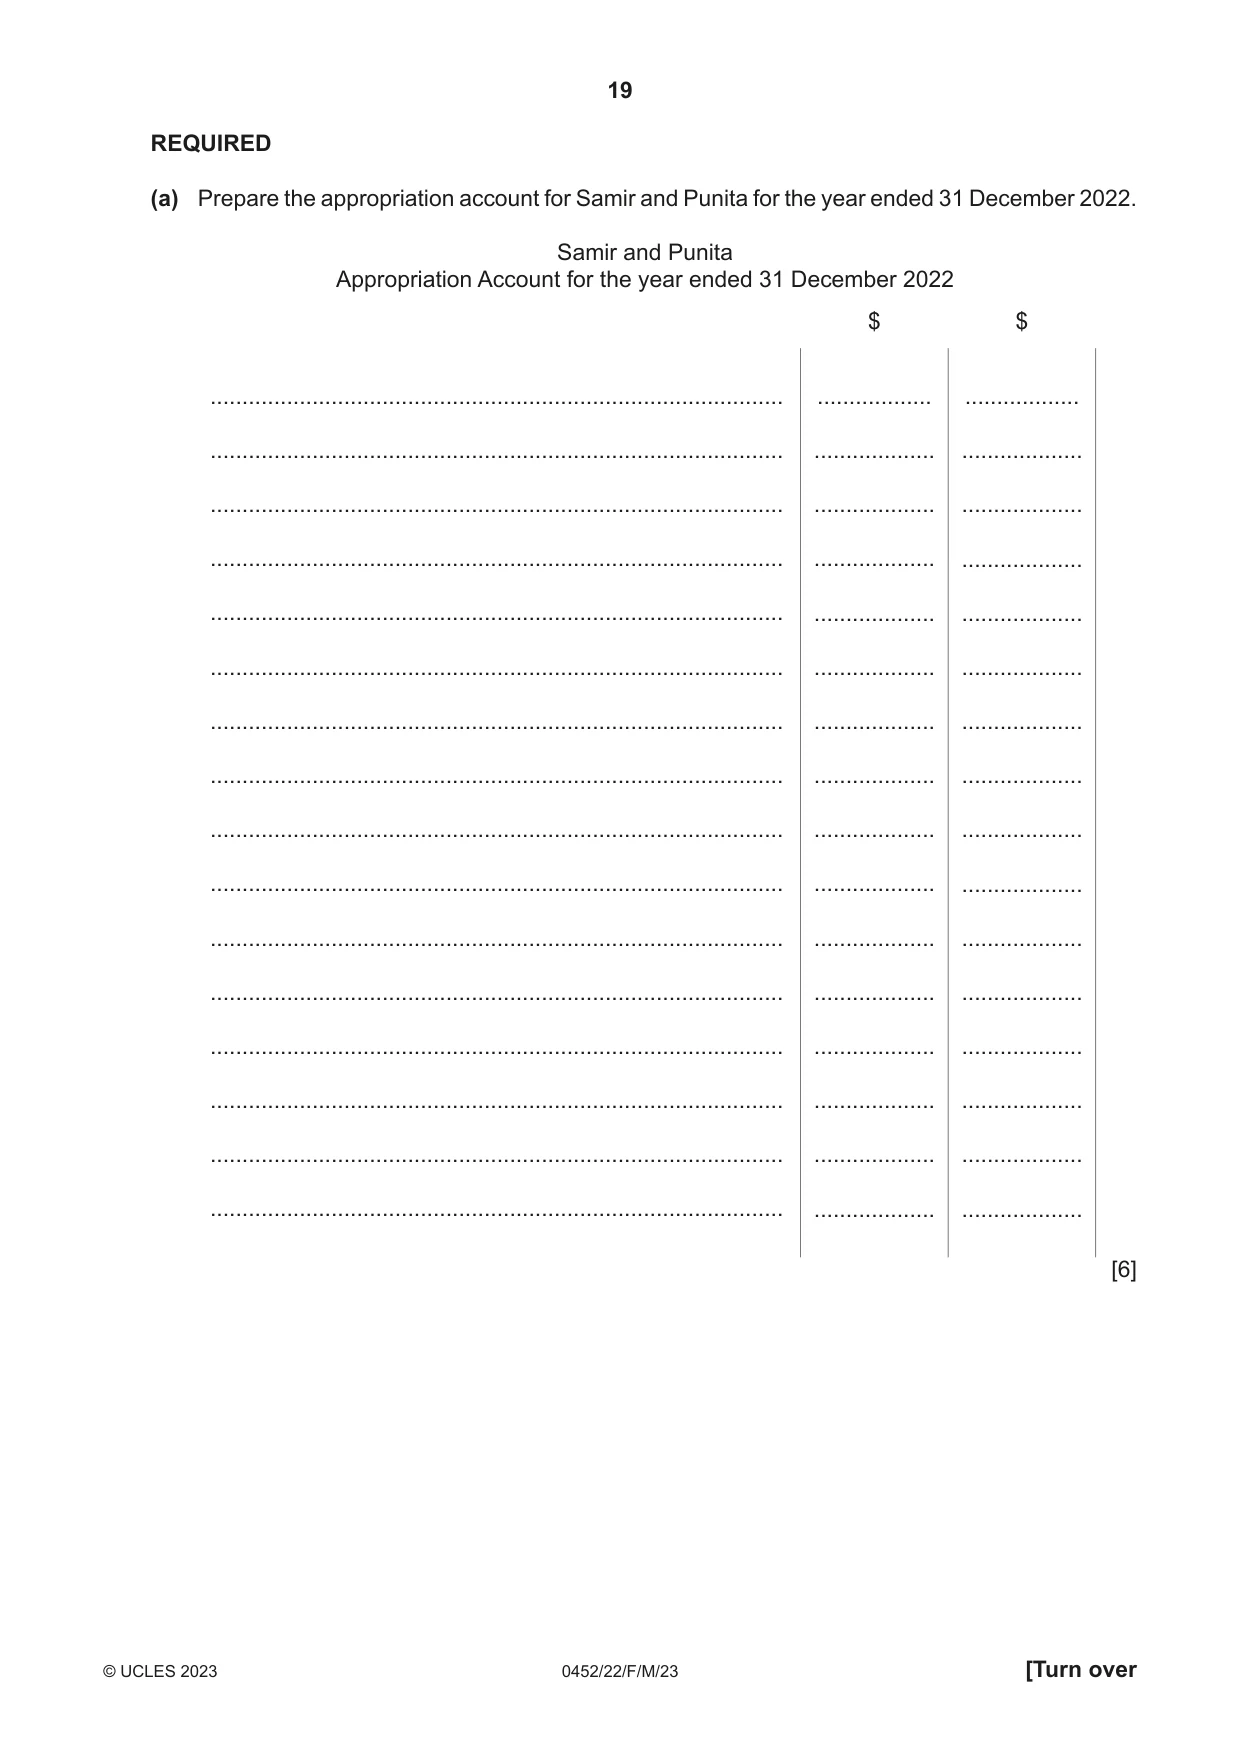
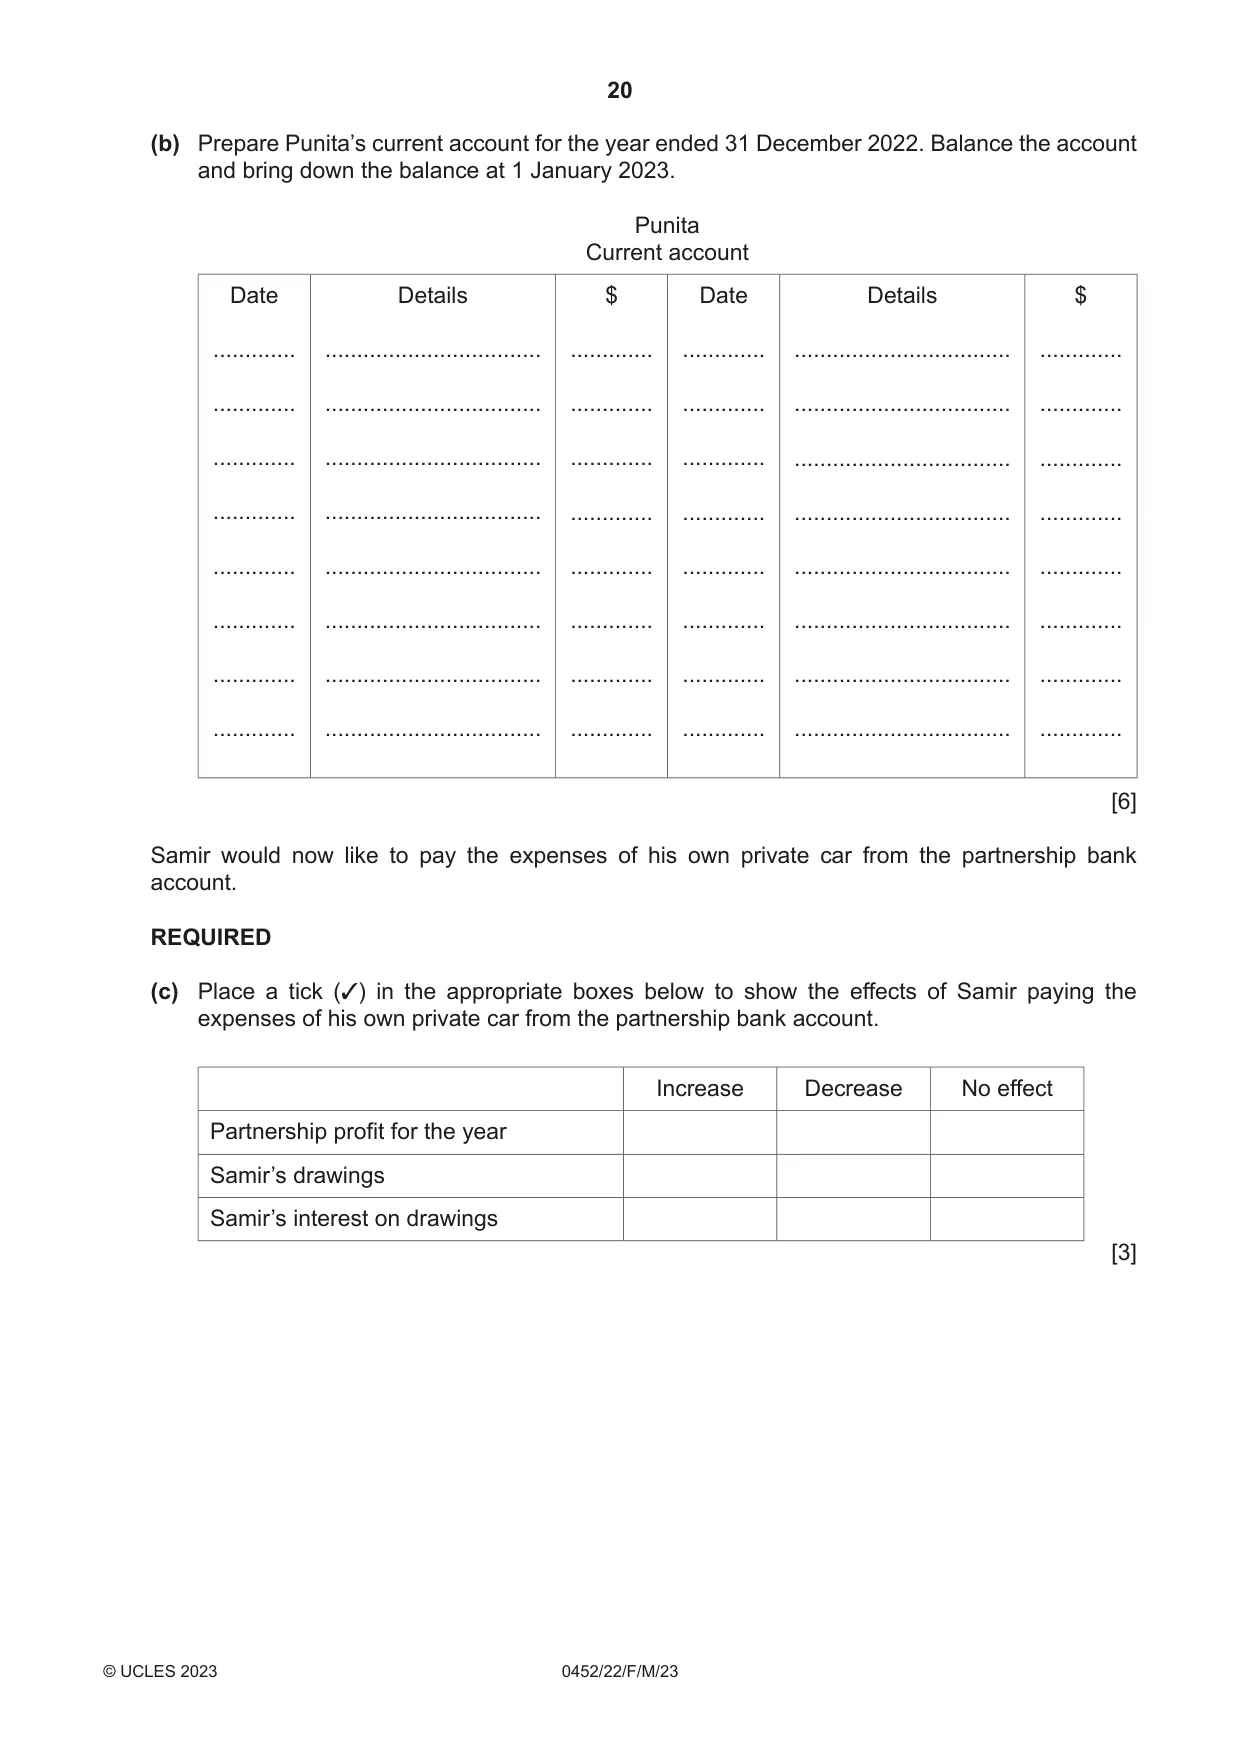
5 Samir and Punita are in partnership. The partnership agreement provides for the following: interest on drawings of 5% interest on capital of 3% per annum a salary to Punita of $11 000 per annum residual profits and losses are to be shared 60% to Samir and 40% to Punita. The partners provided the following information. $ Profit for the year ended 31 December 2022 24 600 Capital account balances at 1 January 2022 Samir 80 000 Punita 75 000 Current account balances at 1 January 2022 Samir 6 450 credit Punita 8 335 credit Drawings for the year ended 31 December 2022 Samir 16 000 Punita 12 400 REQUIRED (a) Prepare the appropriation account for Samir and Punita for the year ended 31 December 2022. Samir and Punita Appropriation Account for the year ended 31 December 2022 $ $ .......................................................................................... .................. .................. .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... .......................................................................................... ................... ................... [6] (b) Prepare Punita’s current account for the year ended 31 December 2022. Balance the account and bring down the balance at 1 January 2023. Punita Current account Date Details $ Date Details $ ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. [6] Samir would now like to pay the expenses of his own private car from the partnership bank account. REQUIRED (c) Place a tick (3) in the appropriate boxes below to show the effects of Samir paying the expenses of his own private car from the partnership bank account. Increase Decrease No effect Partnership profit for the year Samir’s drawings Samir’s interest on drawings [3]
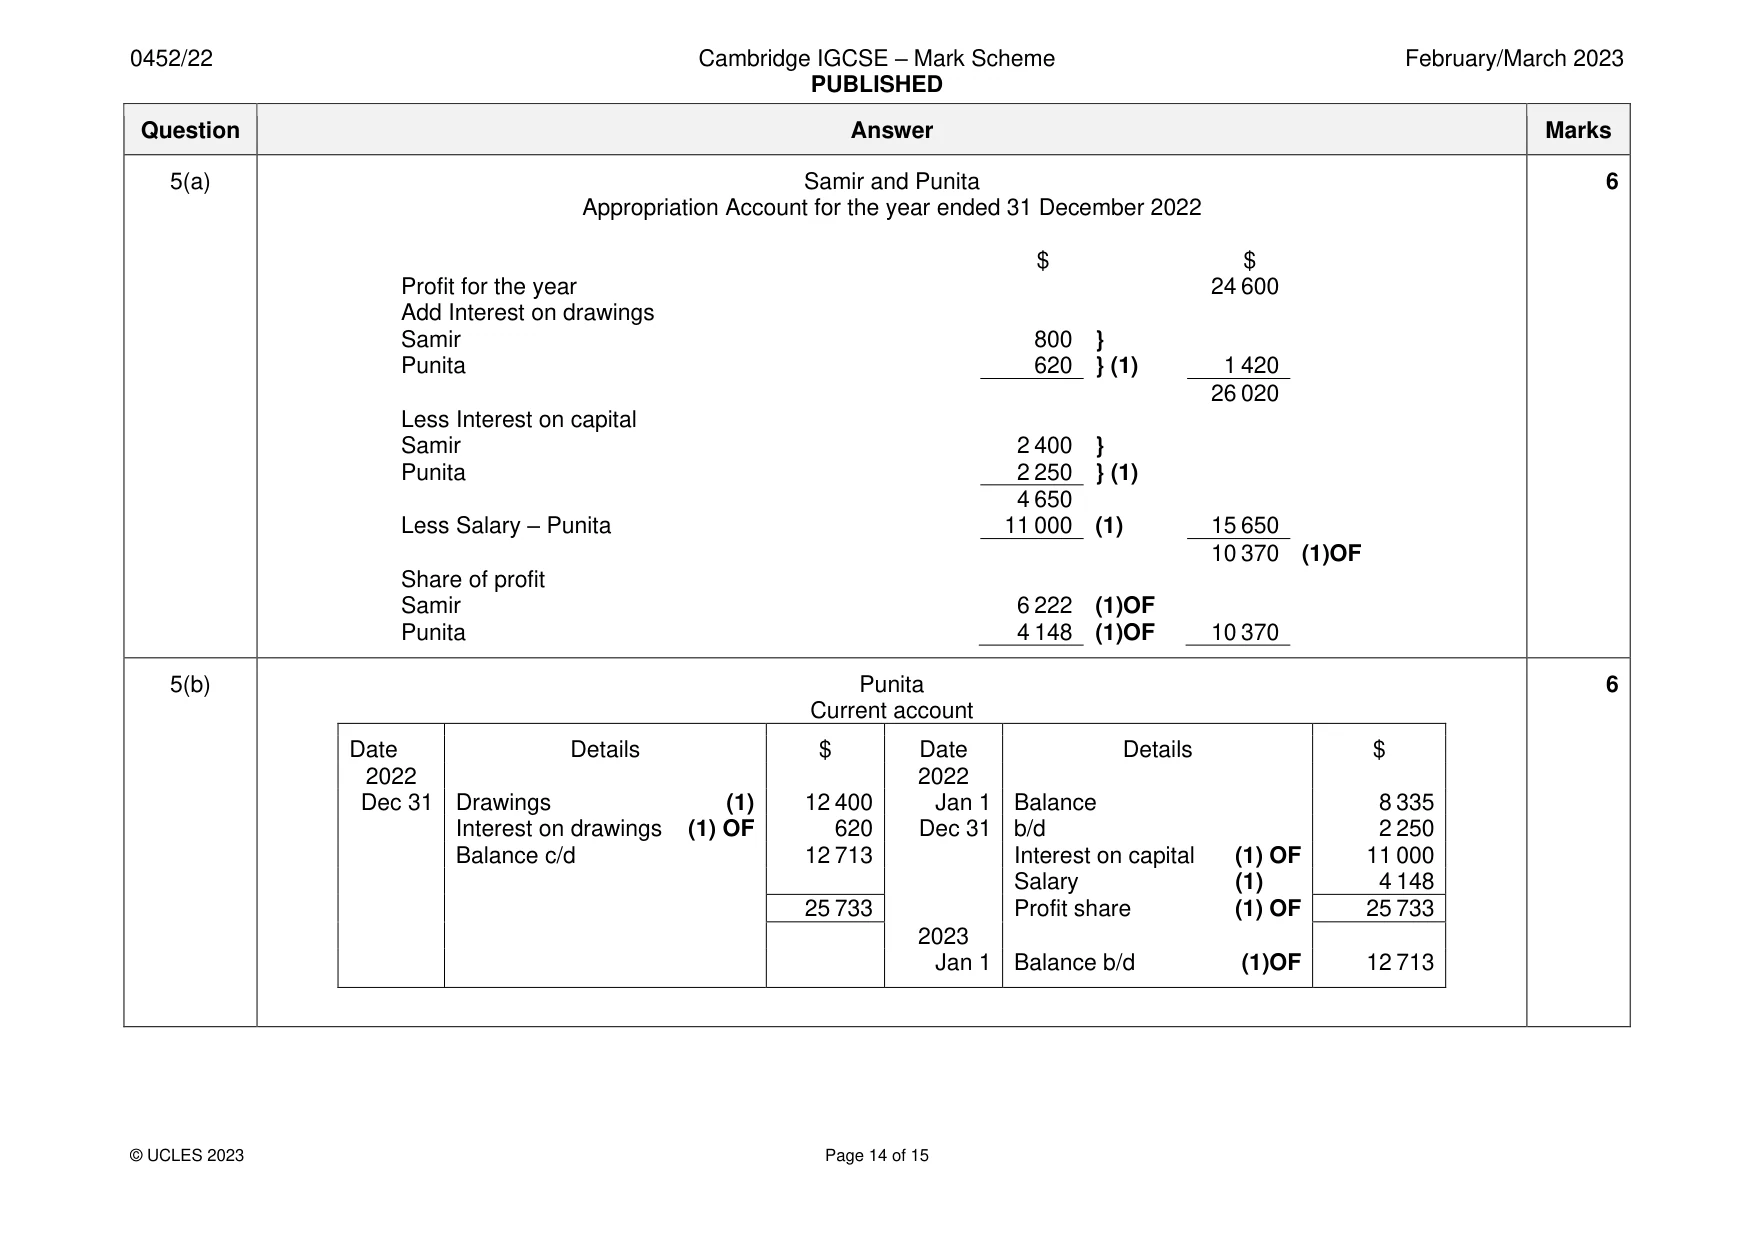
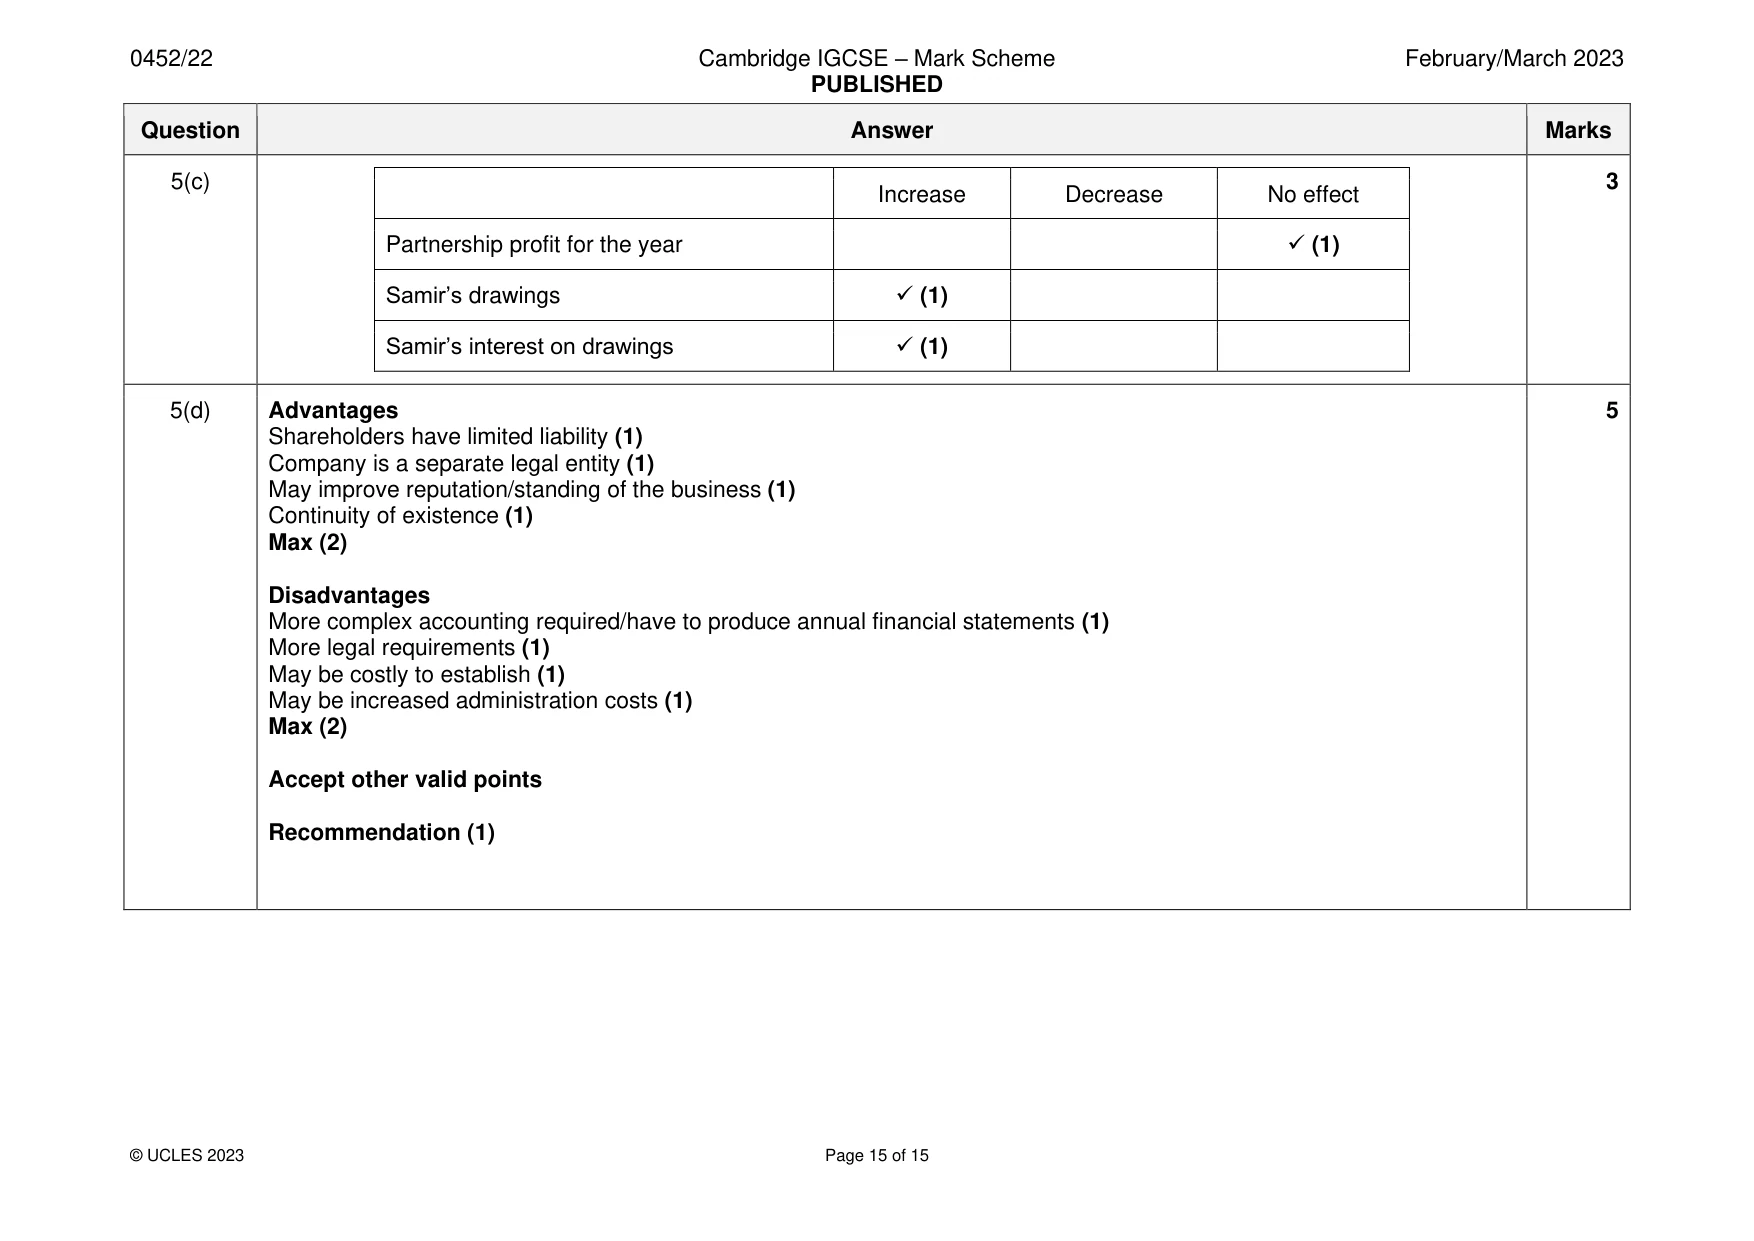
Mark scheme: 5(a) Samir and Punita 6 Appropriation Account for the year ended 31 December 2022 $ $ Profit for the year 24 600 Add Interest on drawings Samir 800 } Punita 620 } (1) 1 420 26 020 Less Interest on capital Samir 2 400 } Punita 2 250 } (1) 4 650 Less Salary – Punita 11 000 (1) 15 650 10 370 (1)OF Share of profit Samir 6 222 (1)OF Punita 4 148 (1)OF 10 370 5(b) Punita 6 Current account Date Details $ Date Details $ 2022 2022 Dec 31 Drawings (1) 12 400 Jan 1 Balance 8 335 Interest on drawings (1) OF 620 Dec 31 b/d 2 250 Balance c/d 12 713 Interest on capital (1) OF 11 000 Salary (1) 4 148 25 733 Profit share (1) OF 25 733 2023 Jan 1 Balance b/d (1)OF 12 713 5(c) 3 Increase Decrease No effect Partnership profit for the year ✓ (1) Samir’s drawings ✓ (1) Samir’s interest on drawings ✓ (1) 5(d) Advantages 5 Shareholders have limited liability (1) Company is a separate legal entity (1) May improve reputation/standing of the business (1) Continuity of existence (1) Max (2) Disadvantages More complex accounting required/have to produce annual financial statements (1) More legal requirements (1) May be costly to establish (1) May be increased administration costs (1) Max (2) Accept other valid points Recommendation (1)
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2023 Feb/March, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.