Cambridge IGCSE Accounting 0452 — 2025 Feb/March Paper 2 · Variant 2
0452/22/F/M/25 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper24 pages
Mark scheme14 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Ria started trading on 1 August 2024
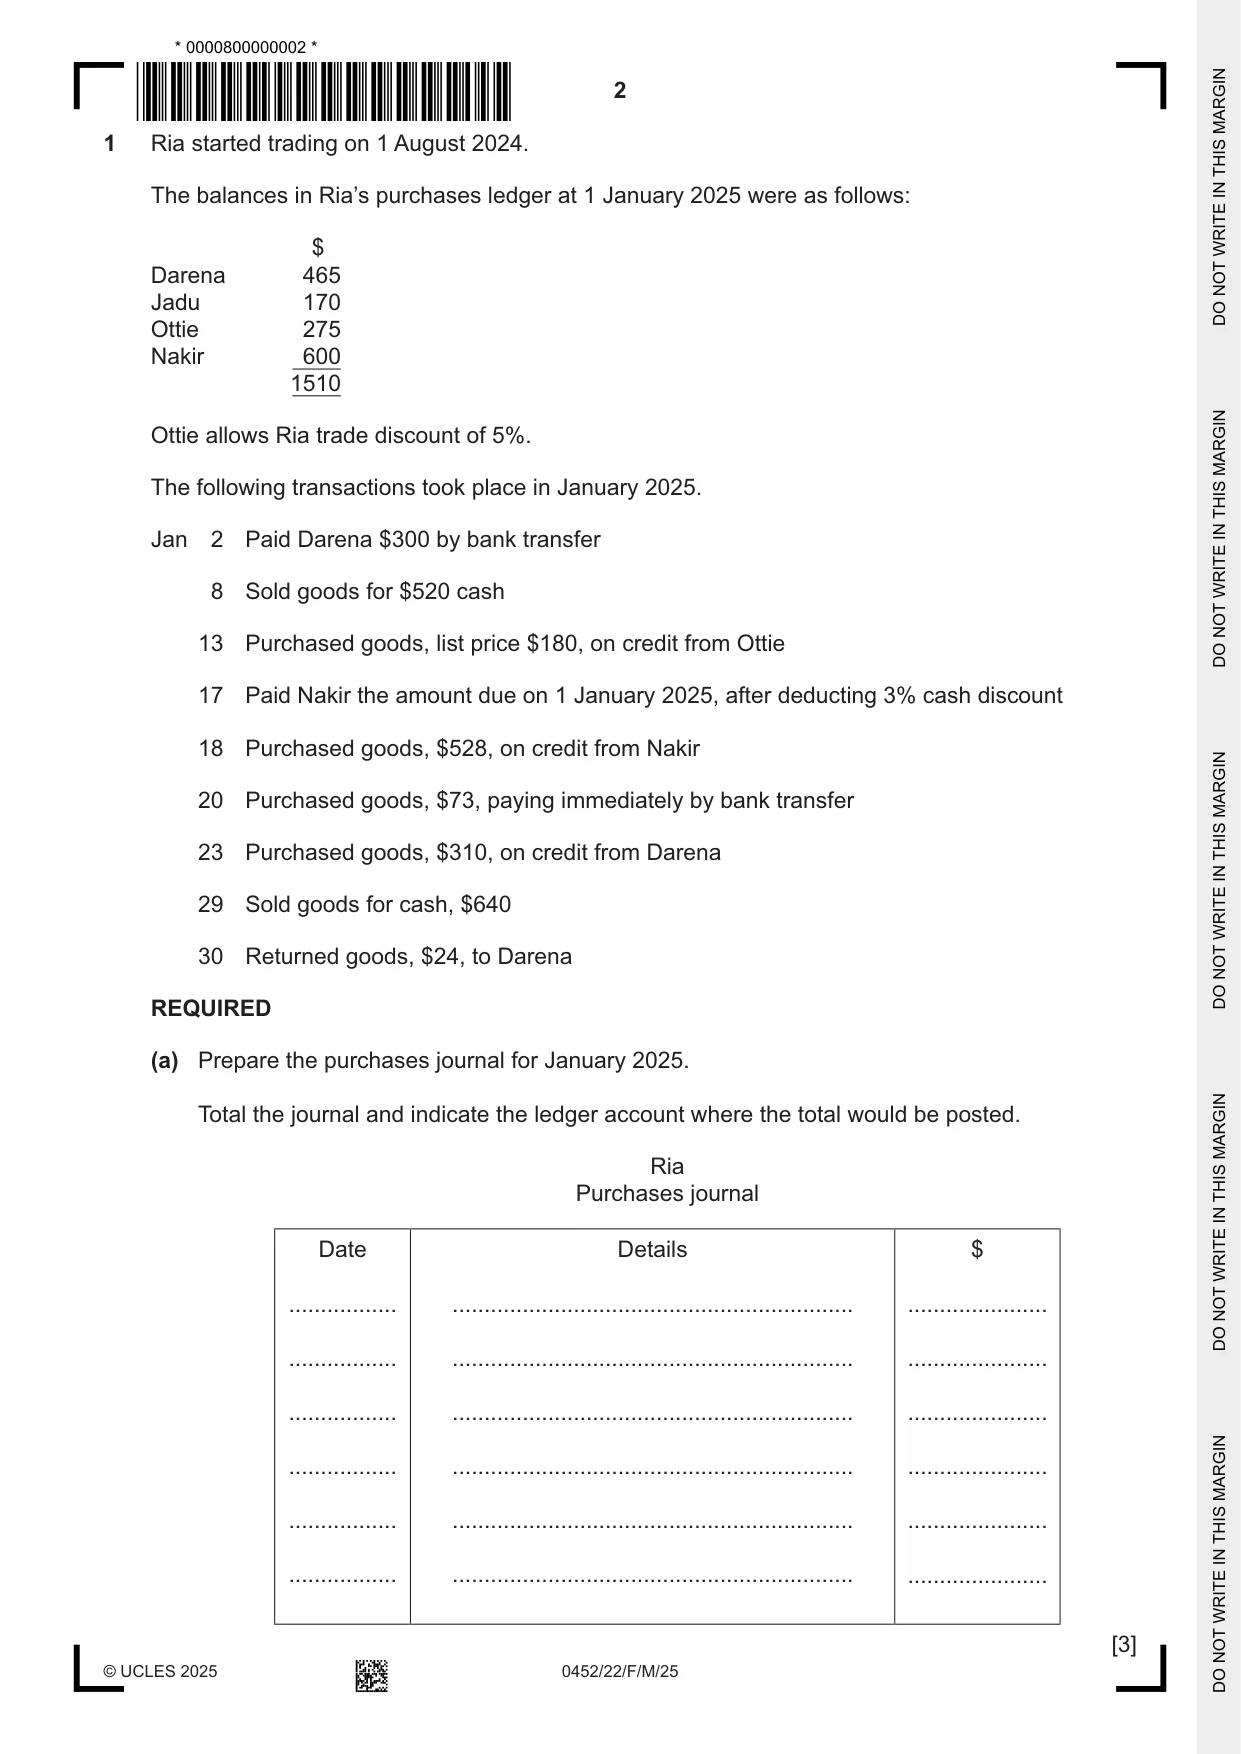
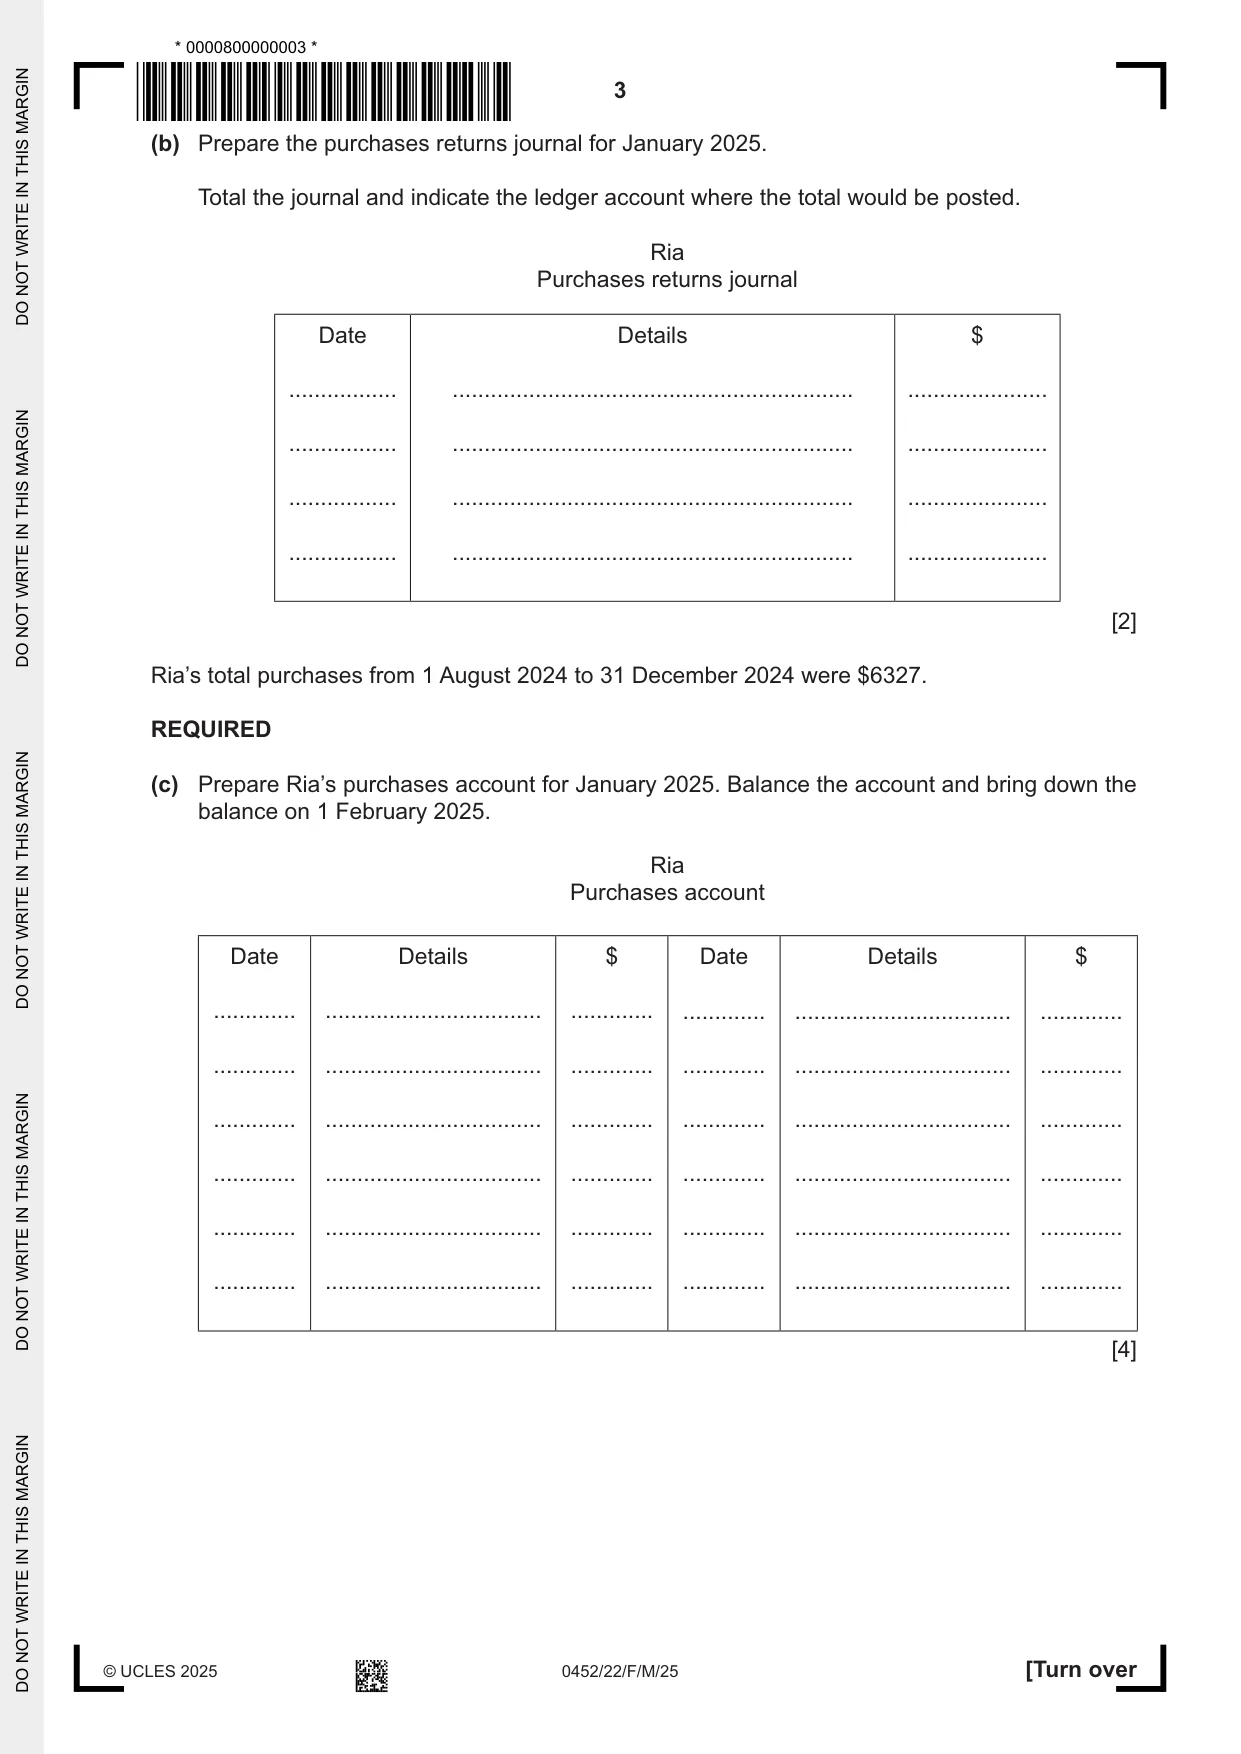
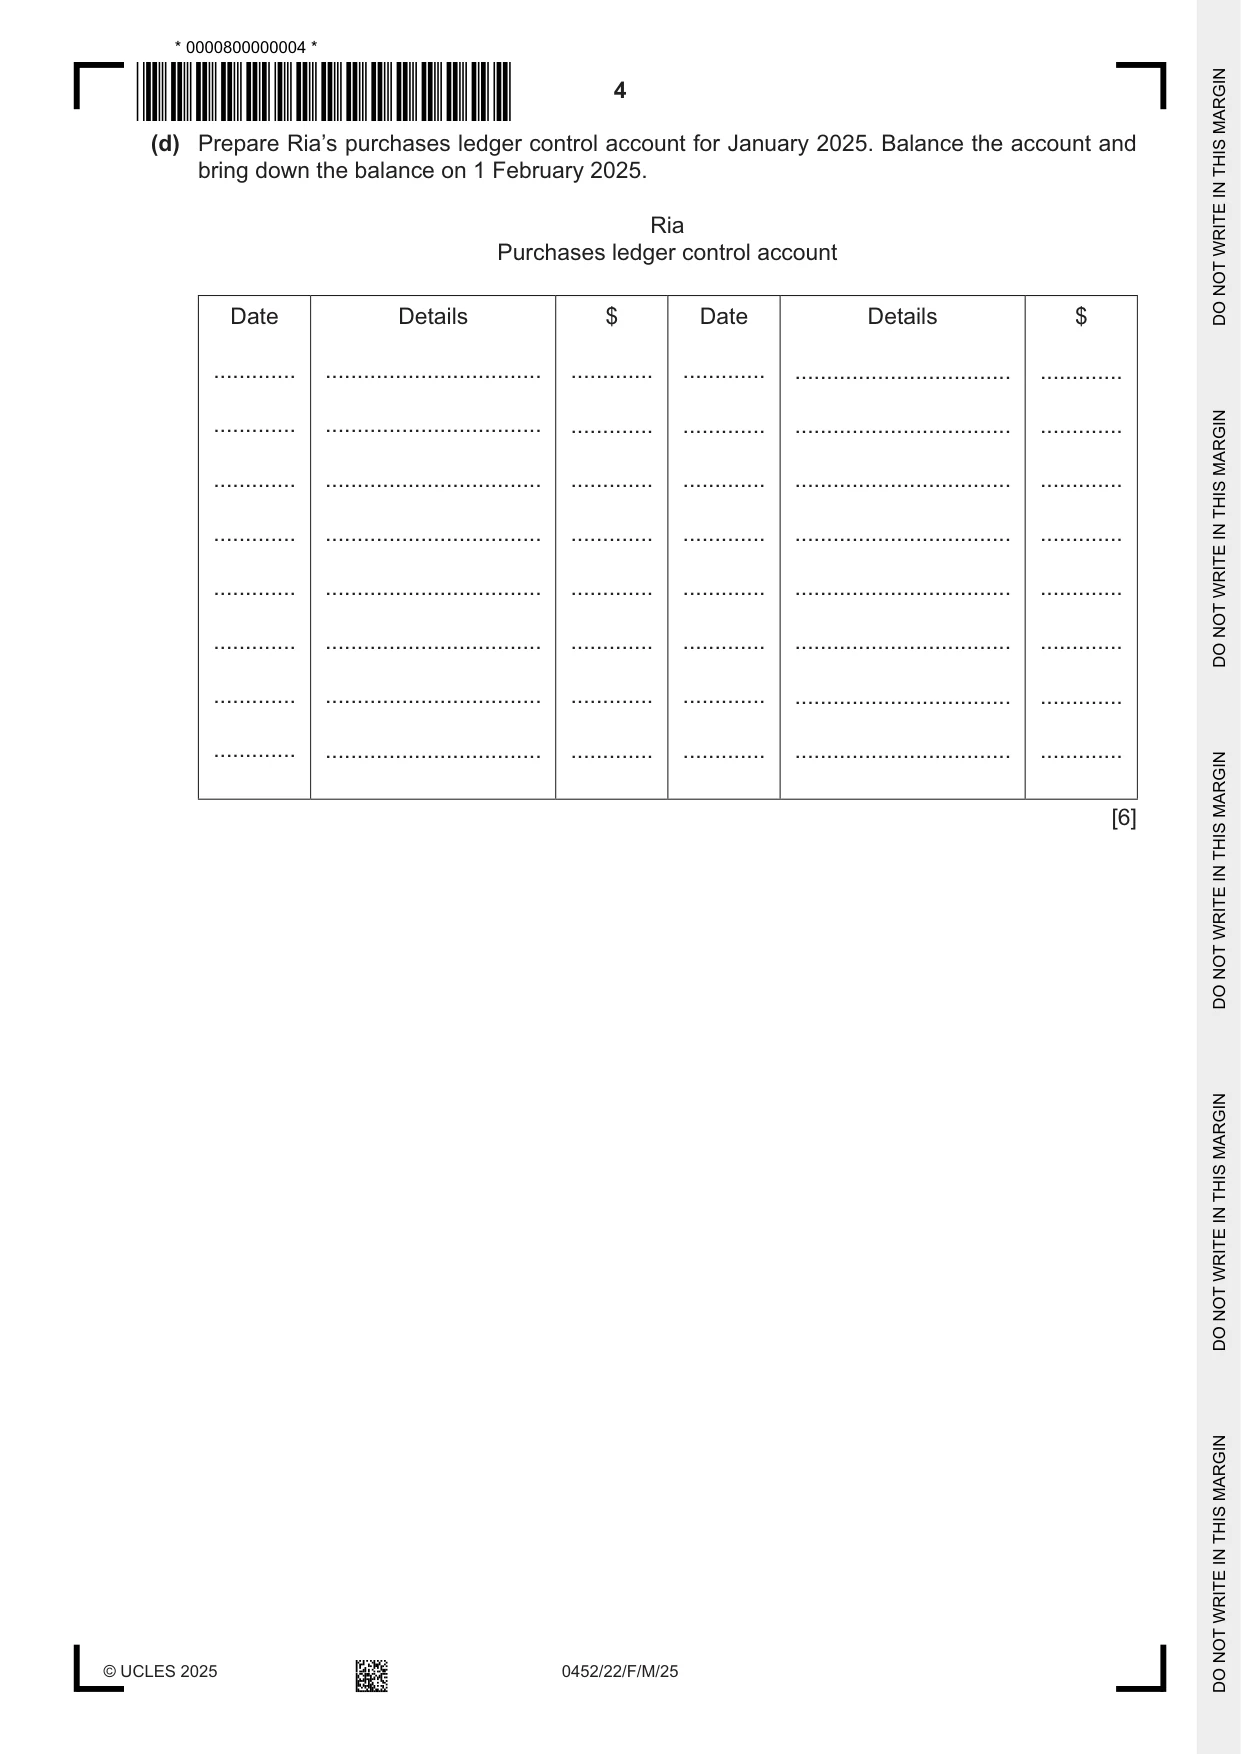
1 Ria started trading on 1 August 2024. The balances in Ria’s purchases ledger at 1 January 2025 were as follows: $ Darena 465 Jadu 170 Ottie 275 Nakir 600 1510 Ottie allows Ria trade discount of 5%. The following transactions took place in January 2025. Jan 2 Paid Darena $300 by bank transfer 8 Sold goods for $520 cash 13 Purchased goods, list price $180, on credit from Ottie 17 Paid Nakir the amount due on 1 January 2025, after deducting 3% cash discount 18 Purchased goods, $528, on credit from Nakir 20 Purchased goods, $73, paying immediately by bank transfer 23 Purchased goods, $310, on credit from Darena 29 Sold goods for cash, $640 30 Returned goods, $24, to Darena REQUIRED (a) Prepare the purchases journal for January 2025. Total the journal and indicate the ledger account where the total would be posted. Ria Purchases journal Date Details $ ................. ............................................................... ...................... ................. ............................................................... ...................... ................. ............................................................... ...................... ................. ............................................................... ...................... ................. ............................................................... ...................... ................. ............................................................... ...................... [3] (b) Prepare the purchases returns journal for January 2025. Total the journal and indicate the ledger account where the total would be posted. Ria Purchases returns journal Date Details $ ................. ............................................................... ...................... ................. ............................................................... ...................... ................. ............................................................... ...................... ................. ............................................................... ...................... [2] Ria’s total purchases from 1 August 2024 to 31 December 2024 were $6327. REQUIRED (c) Prepare Ria’s purchases account for January 2025. Balance the account and bring down the balance on 1 February 2025. Ria Purchases account Date Details $ Date Details $ ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. [4] (d) Prepare Ria’s purchases ledger control account for January 2025. Balance the account and bring down the balance on 1 February 2025. Ria Purchases ledger control account Date Details $ Date Details $ ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. [6] Ria is considering increasing her trade payables payment period to provide her with sufficient cash for an advertising campaign. REQUIRED (e) Advise Ria whether or not she should increase her trade payables payment period to provide her with sufficient cash for an advertising campaign. Justify your answer by providing two advantages and two disadvantages of your advice. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
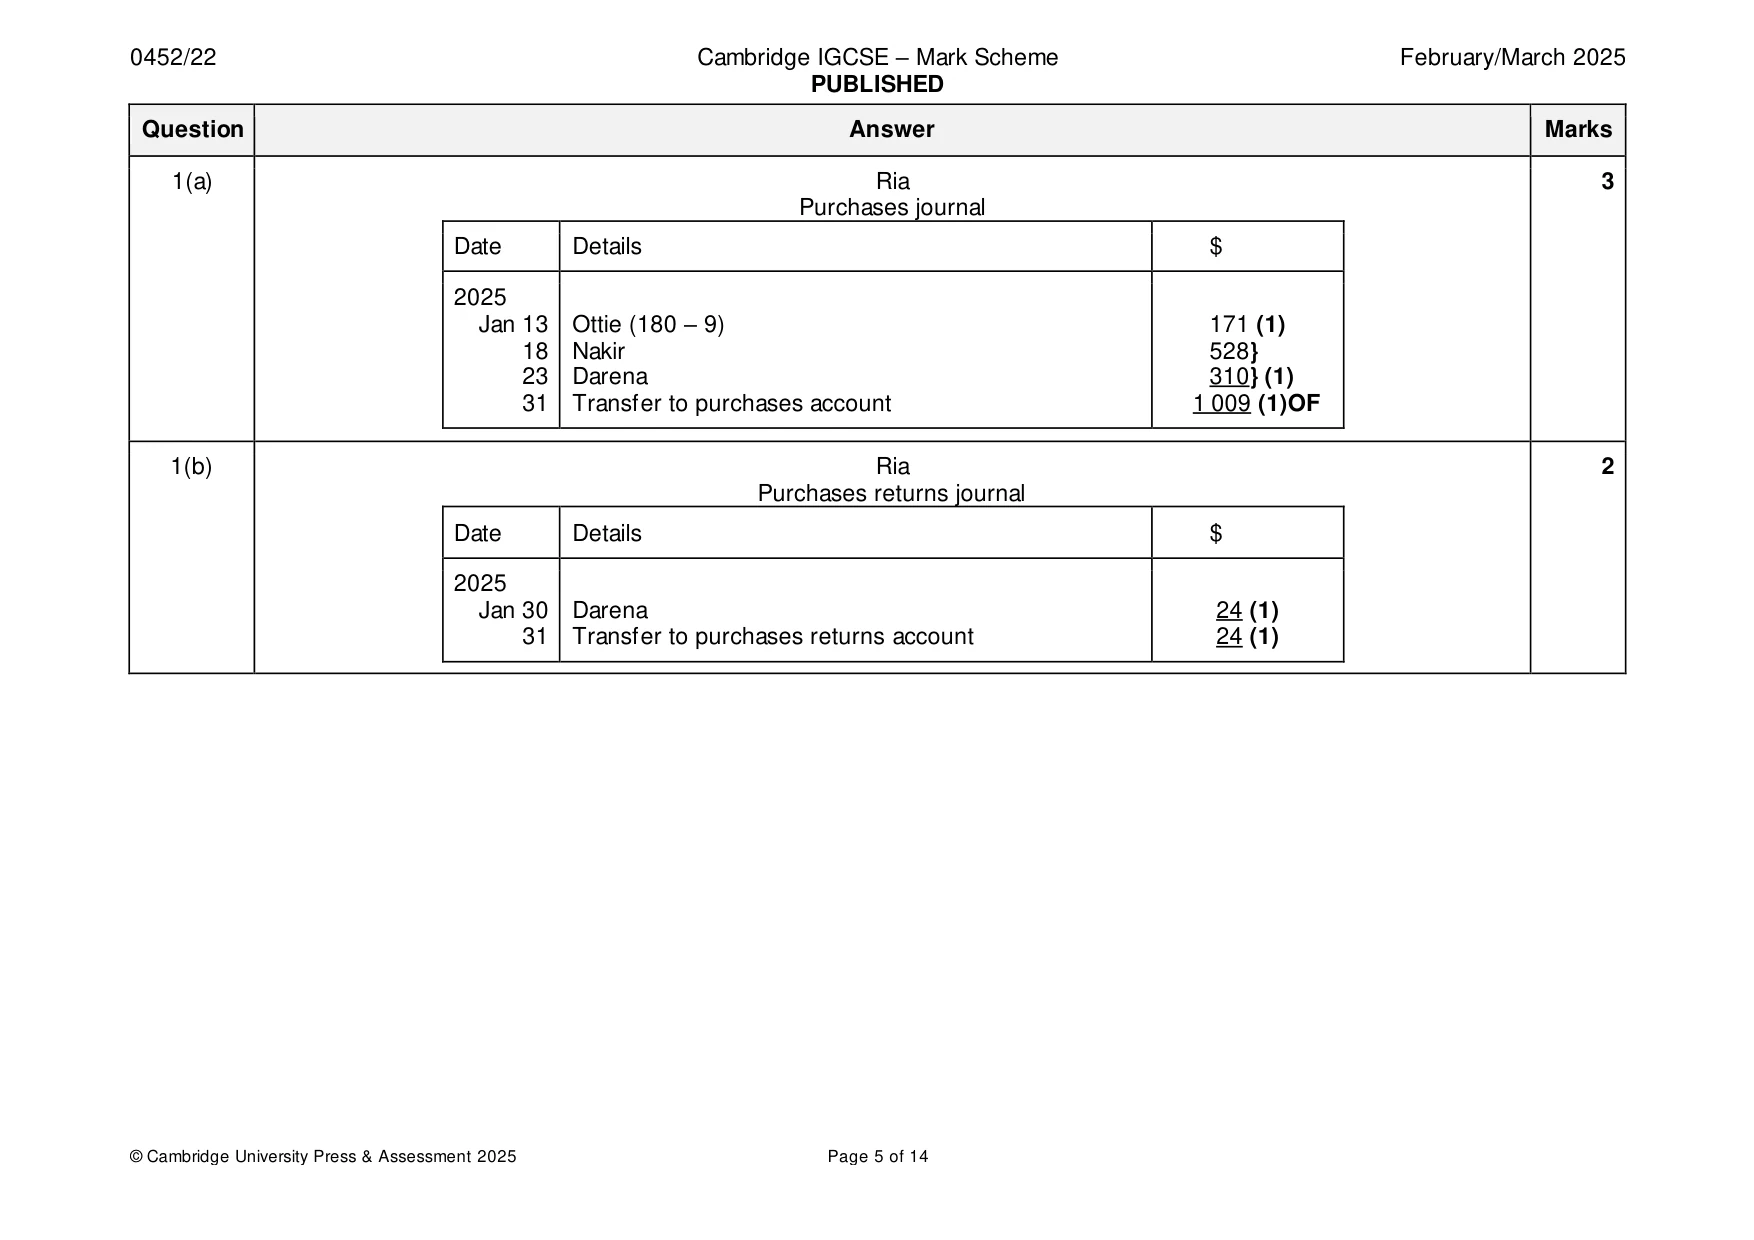
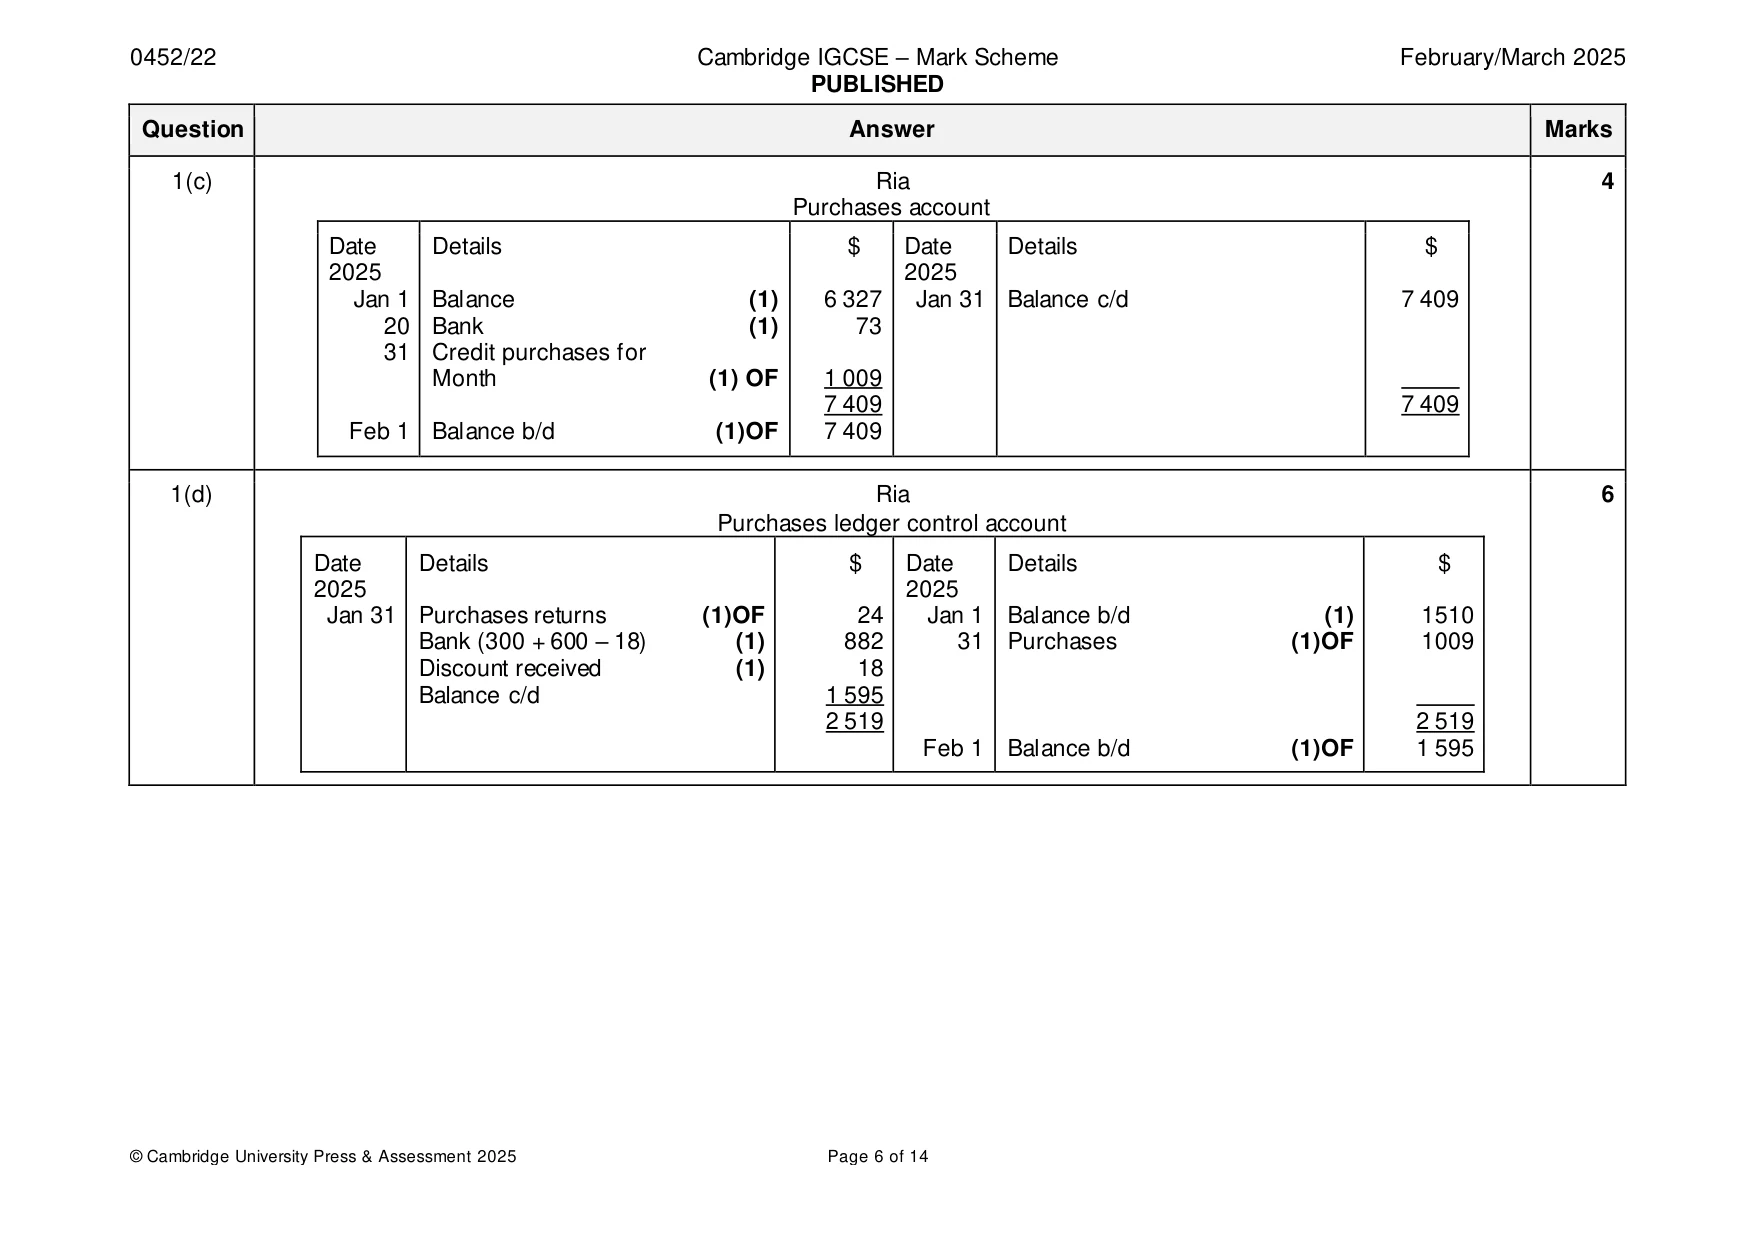
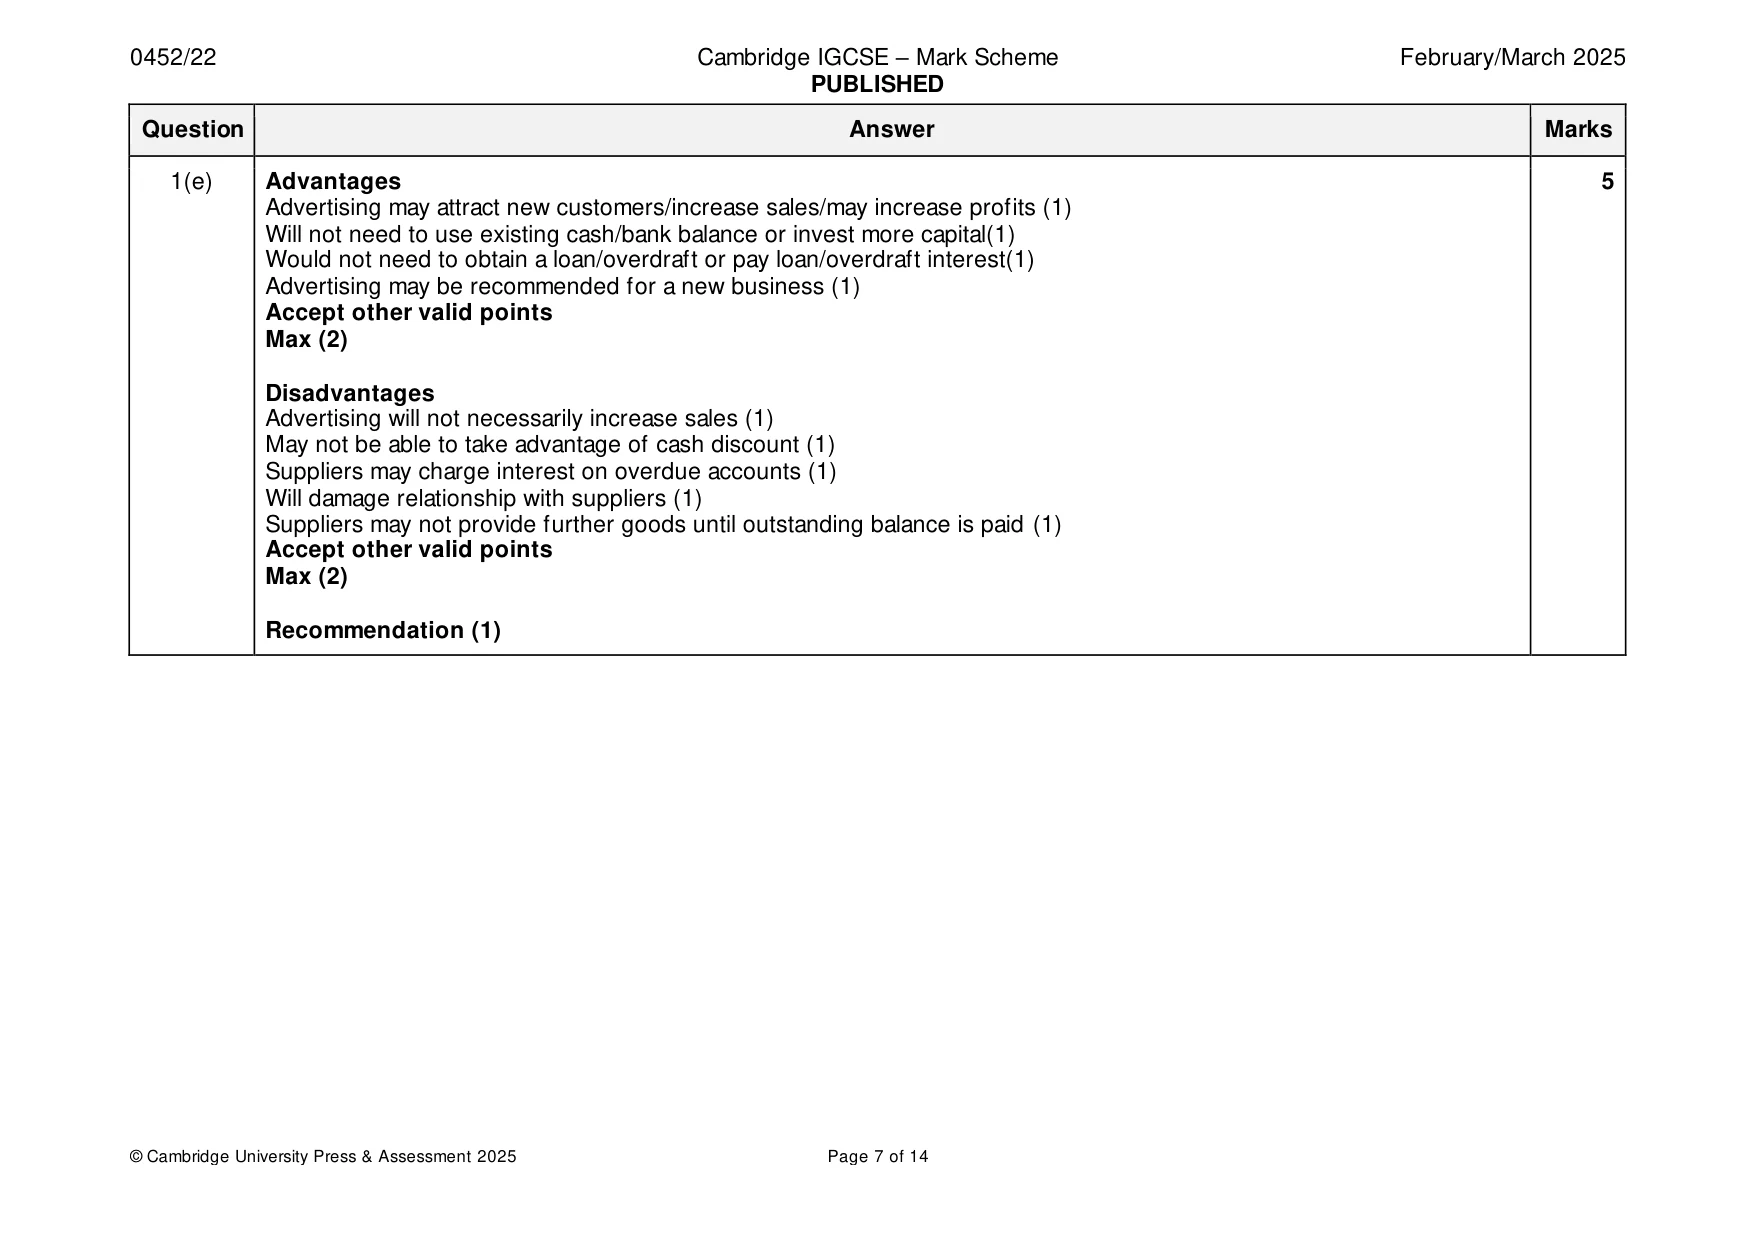
Mark scheme: Question Answer Marks 1(a) Ria 3 Purchases journal Date Details $ 2025 Jan 13 Ottie (180 – 9) 171 (1) 18 Nakir 528} 23 Darena 310} (1) 31 Transfer to purchases account 1 009 (1)OF 1(b) Ria 2 Purchases returns journal Date Details $ 2025 Jan 30 Darena 24 (1) 31 Transfer to purchases returns account 24 (1) 1(c) Ria 4 Purchases account Date Details $ Date Details $ 2025 2025 Jan 1 Balance (1) 6 327 Jan 31 Balance c/d 7 409 20 Bank (1) 73 31 Credit purchases for Month (1) OF 1 009 7 409 7 409 Feb 1 Balance b/d (1)OF 7 409 1(d) Ria 6 Purchases ledger control account Date Details $ Date Details $ 2025 2025 Jan 31 Purchases returns (1)OF 24 Jan 1 Balance b/d (1) 1510 Bank (300 + 600 – 18) (1) 882 31 Purchases (1)OF 1009 Discount received (1) 18 Balance c/d 1 595 2 519 2 519 Feb 1 Balance b/d (1)OF 1 595 1(e) Advantages 5 Advertising may attract new customers/increase sales/may increase profits (1) Will not need to use existing cash/bank balance or invest more capital(1) Would not need to obtain a loan/overdraft or pay loan/overdraft interest(1) Advertising may be recommended for a new business (1) Accept other valid points Max (2) Disadvantages Advertising will not necessarily increase sales (1) May not be able to take advantage of cash discount (1) Suppliers may charge interest on overdue accounts (1) Will damage relationship with suppliers (1) Suppliers may not provide further goods until outstanding balance is paid (1) Accept other valid points Max (2) Recommendation (1)
Q2 · Viraj is a retailer
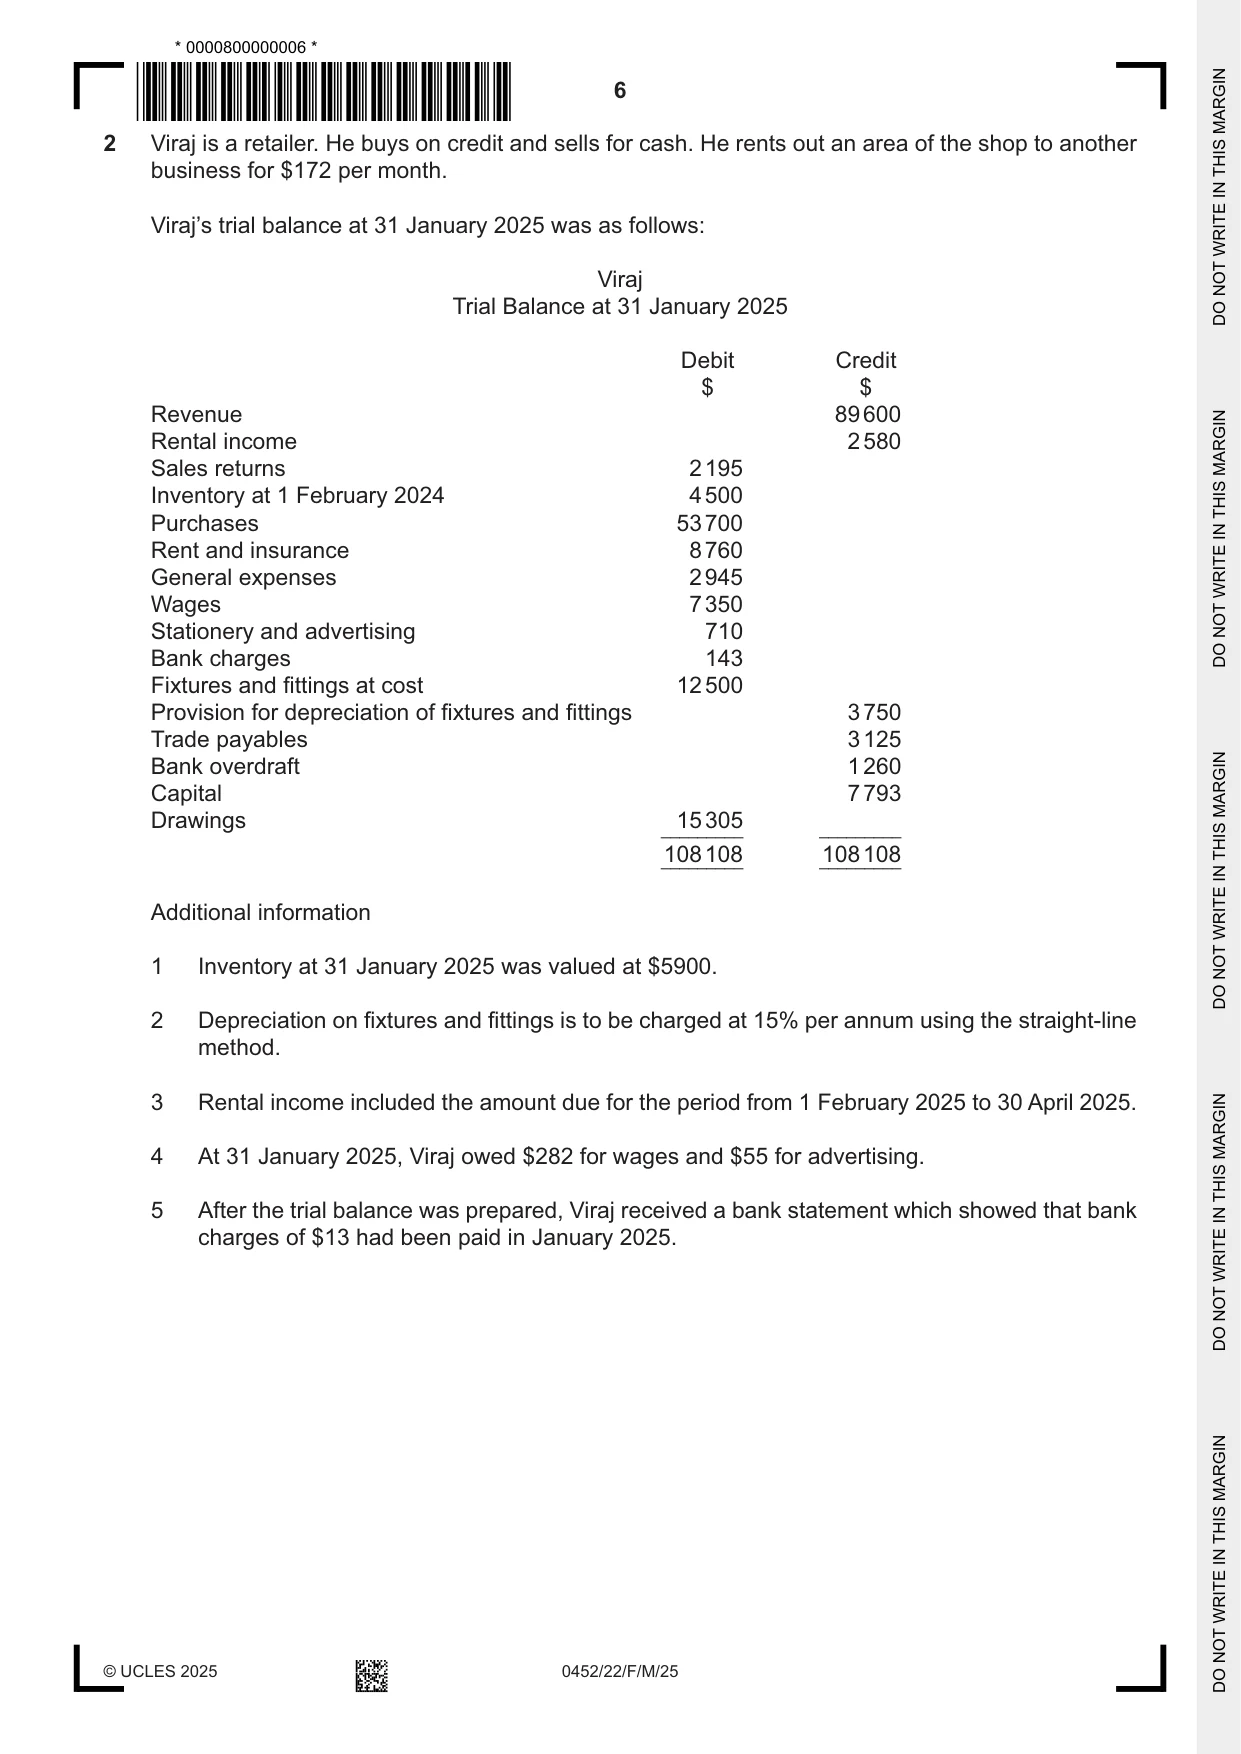
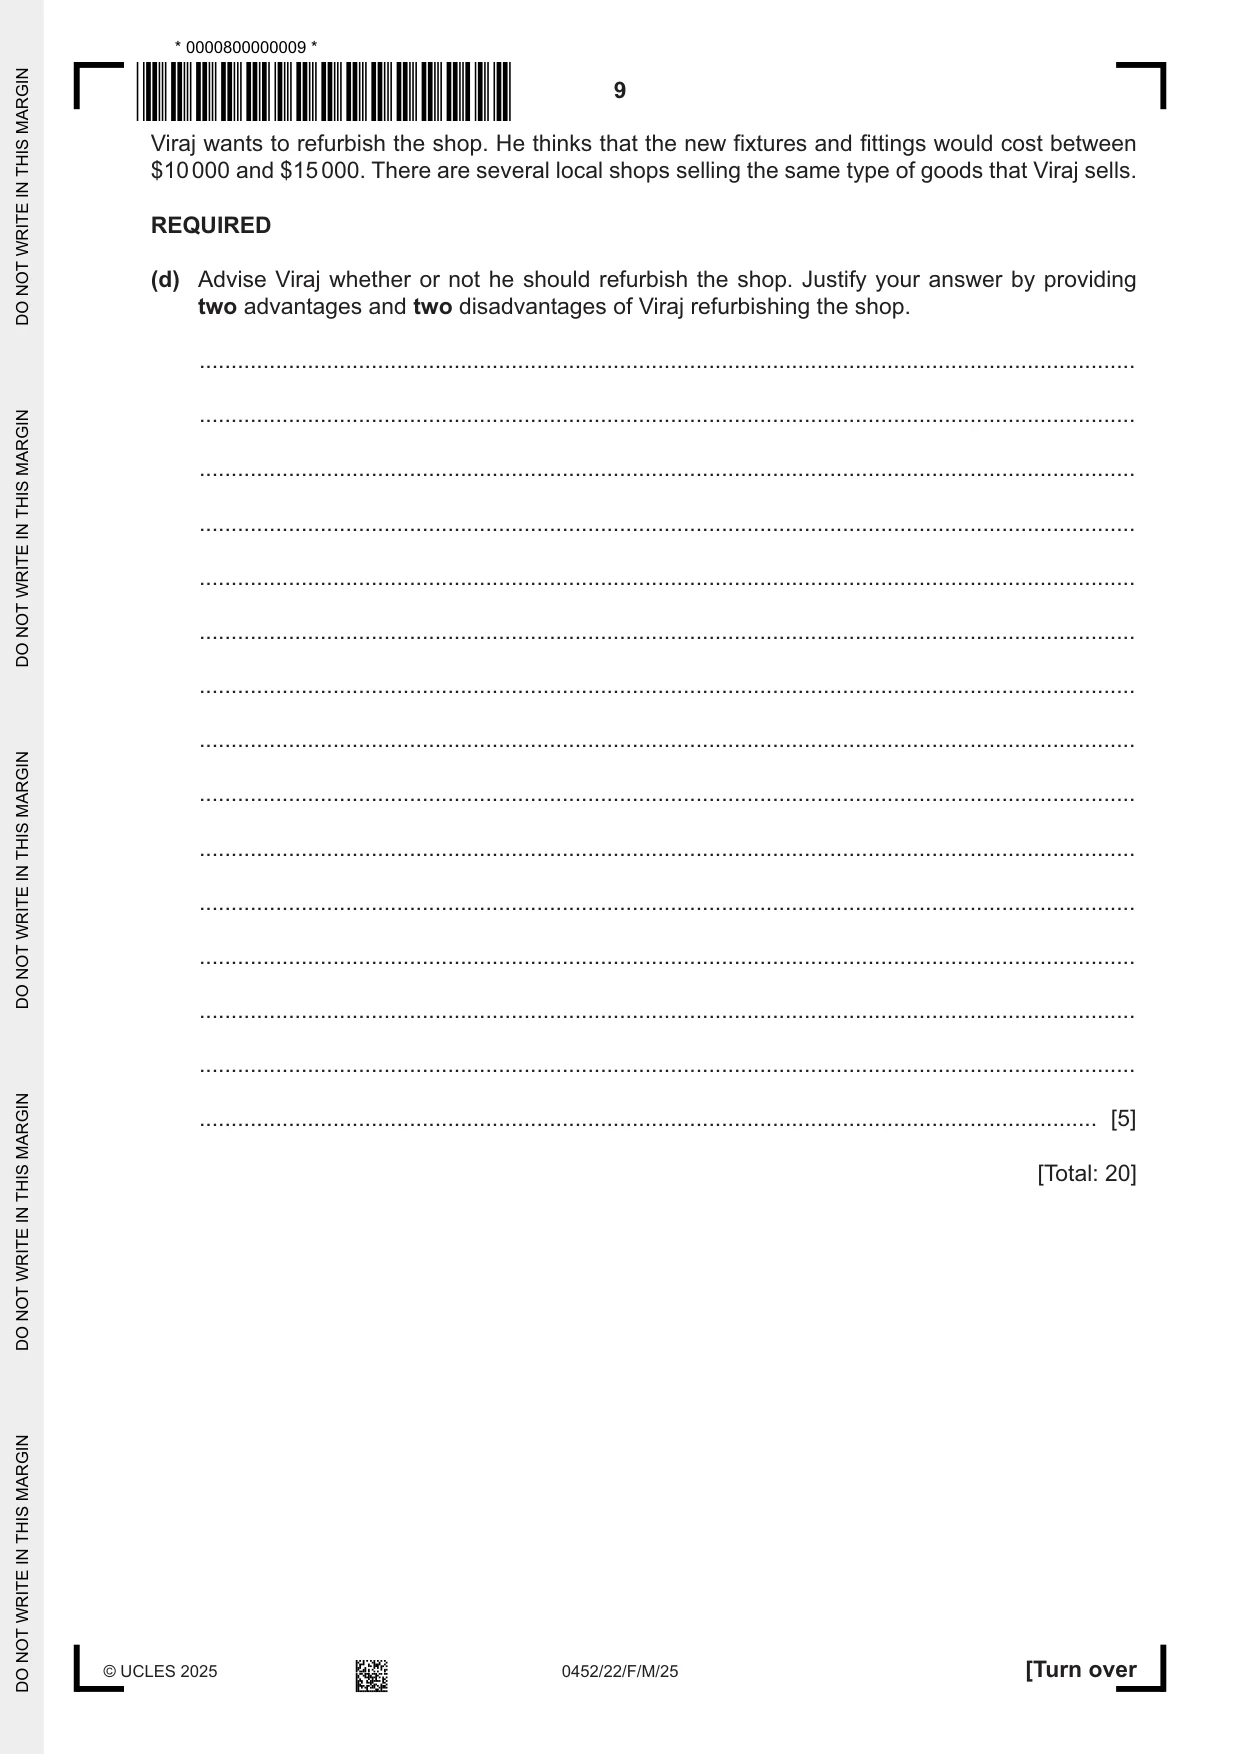
2 Viraj is a retailer. He buys on credit and sells for cash. He rents out an area of the shop to another business for $172 per month. Viraj’s trial balance at 31 January 2025 was as follows: Viraj Trial Balance at 31 January 2025 Debit Credit $ $ Revenue 89 600 Rental income 2 580 Sales returns 2 195 Inventory at 1 February 2024 4 500 Purchases 53 700 Rent and insurance 8 760 General expenses 2 945 Wages 7 350 Stationery and advertising 710 Bank charges 143 Fixtures and fittings at cost 12 500 Provision for depreciation of fixtures and fittings 3 750 Trade payables 3 125 Bank overdraft 1 260 Capital 7 793 Drawings _________15 305 _________ _________108 108 _________108 108 Additional information 1 Inventory at 31 January 2025 was valued at $5900. 2 Depreciation on fixtures and fittings is to be charged at 15% per annum using the straight-line method. 3 Rental income included the amount due for the period from 1 February 2025 to 30 April 2025. 4 At 31 January 2025, Viraj owed $282 for wages and $55 for advertising. 5 After the trial balance was prepared, Viraj received a bank statement which showed that bank charges of $13 had been paid in January 2025. REQUIRED (a) Prepare the income statement for Viraj for the year ended 31 January 2025. Viraj Income Statement for the year ended 31 January 2025 $ $ ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. [9] (b) Prepare the current liabilities section of Viraj’s statement of financial position at 31 January 2025. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] (c) State the accounting principle which Viraj has followed when he did not include a figure in his statement of financial position for: (i) his inventory of price labels ..................................................................................................................................... [1] (ii) his skills as a salesman. ..................................................................................................................................... [1] Viraj wants to refurbish the shop. He thinks that the new fixtures and fittings would cost between $10 000 and $15 000. There are several local shops selling the same type of goods that Viraj sells. REQUIRED (d) Advise Viraj whether or not he should refurbish the shop. Justify your answer by providing two advantages and two disadvantages of Viraj refurbishing the shop. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
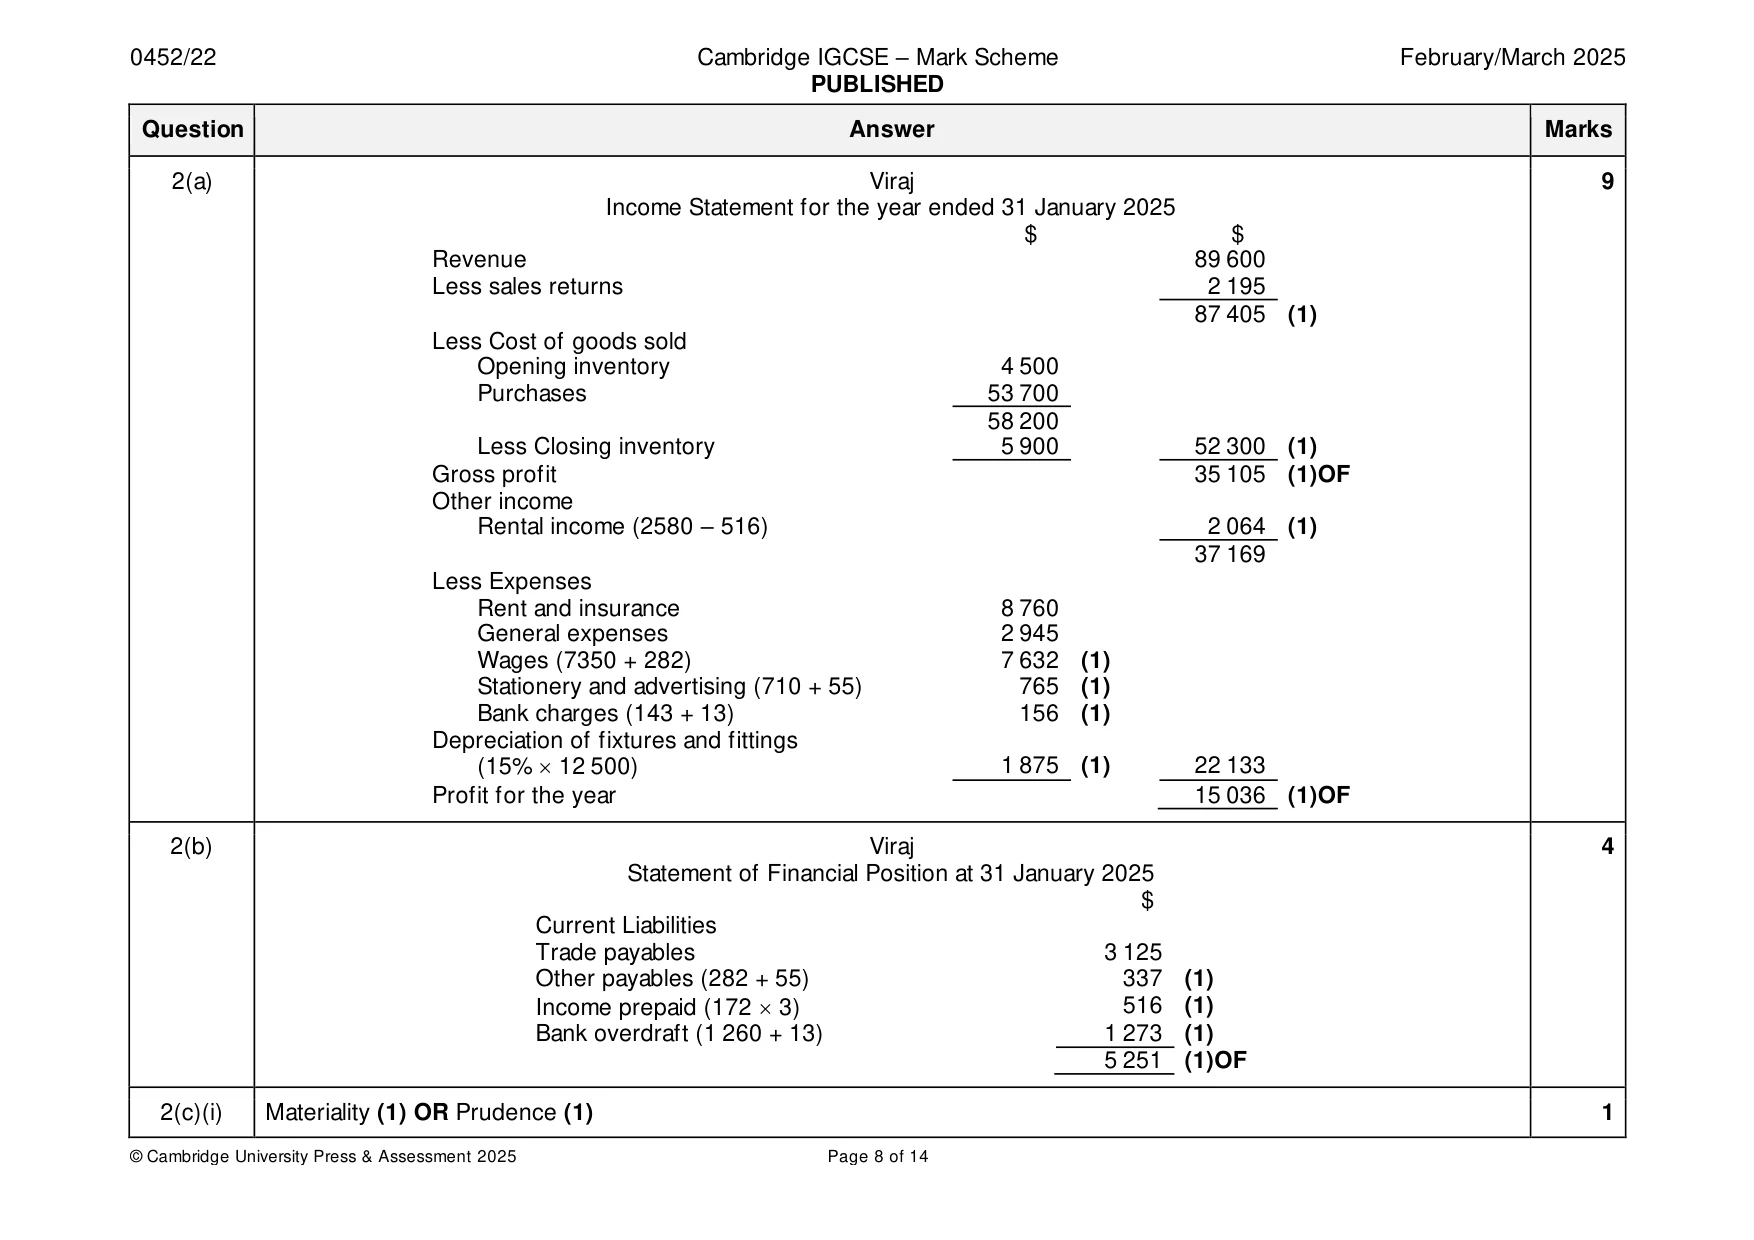
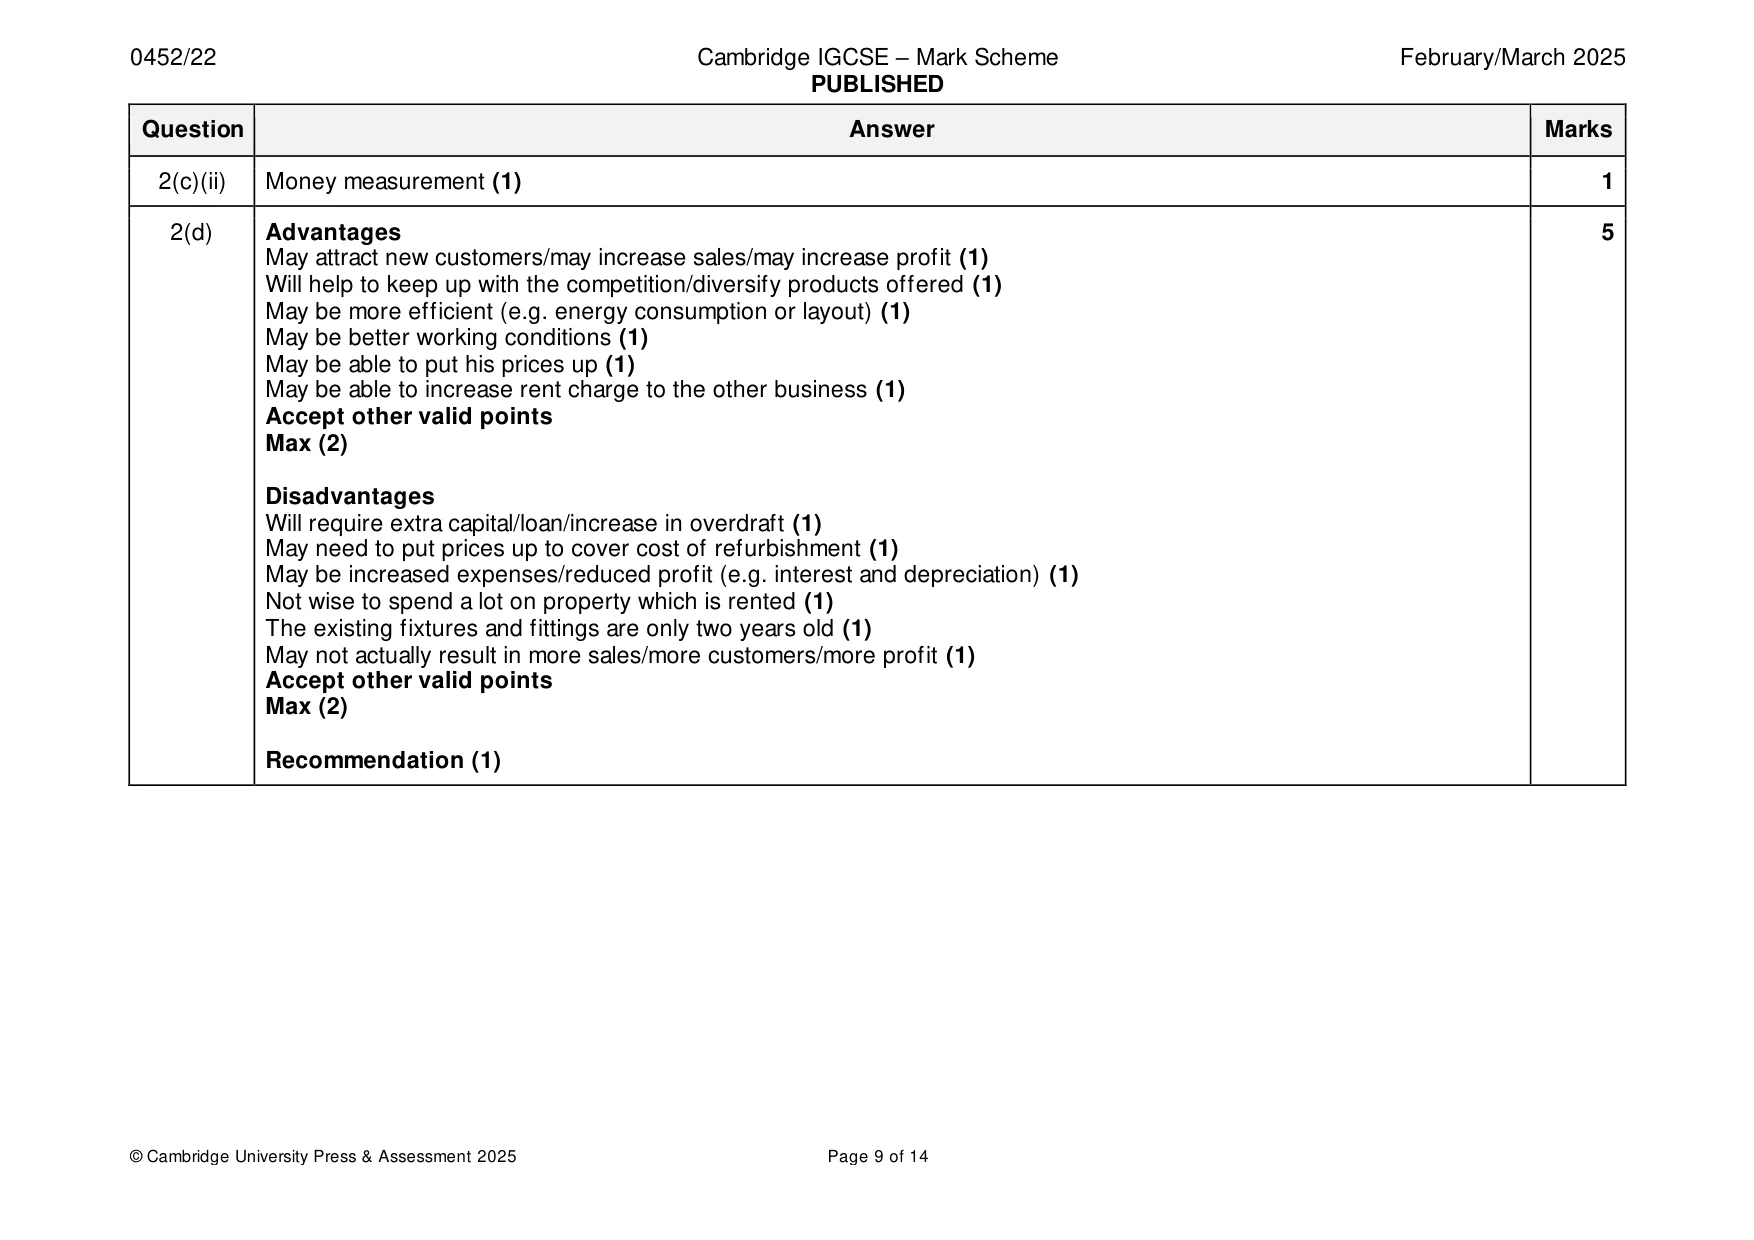
Mark scheme: 2(a) Viraj 9 Income Statement for the year ended 31 January 2025 $ $ Revenue 89 600 Less sales returns 2 195 87 405 (1) Less Cost of goods sold Opening inventory 4 500 Purchases 53 700 58 200 Less Closing inventory 5 900 52 300 (1) Gross profit 35 105 (1)OF Other income Rental income (2580 – 516) 2 064 (1) 37 169 Less Expenses Rent and insurance 8 760 General expenses 2 945 Wages (7350 + 282) 7 632 (1) Stationery and advertising (710 + 55) 765 (1) Bank charges (143 + 13) 156 (1) Depreciation of fixtures and fittings (15% 12 500) 1 875 (1) 22 133 Profit for the year 15 036 (1)OF 2(b) Viraj 4 Statement of Financial Position at 31 January 2025 $ Current Liabilities Trade payables 3 125 Other payables (282 + 55) 337 (1) Income prepaid (172 3) 516 (1) Bank overdraft (1 260 + 13) 1 273 (1) 5 251 (1)OF 2(c)(i) Materiality (1) OR Prudence (1) 1 2(c)(ii) Money measurement (1) 1 2(d) Advantages 5 May attract new customers/may increase sales/may increase profit (1) Will help to keep up with the competition/diversify products offered (1) May be more efficient (e.g. energy consumption or layout) (1) May be better working conditions (1) May be able to put his prices up (1) May be able to increase rent charge to the other business (1) Accept other valid points Max (2) Disadvantages Will require extra capital/loan/increase in overdraft (1) May need to put prices up to cover cost of refurbishment (1) May be increased expenses/reduced profit (e.g. interest and depreciation) (1) Not wise to spend a lot on property which is rented (1) The existing fixtures and fittings are only two years old (1) May not actually result in more sales/more customers/more profit (1) Accept other valid points Max (2) Recommendation (1)
Q3 · Samira has been trading for many years and has a debit bank balance
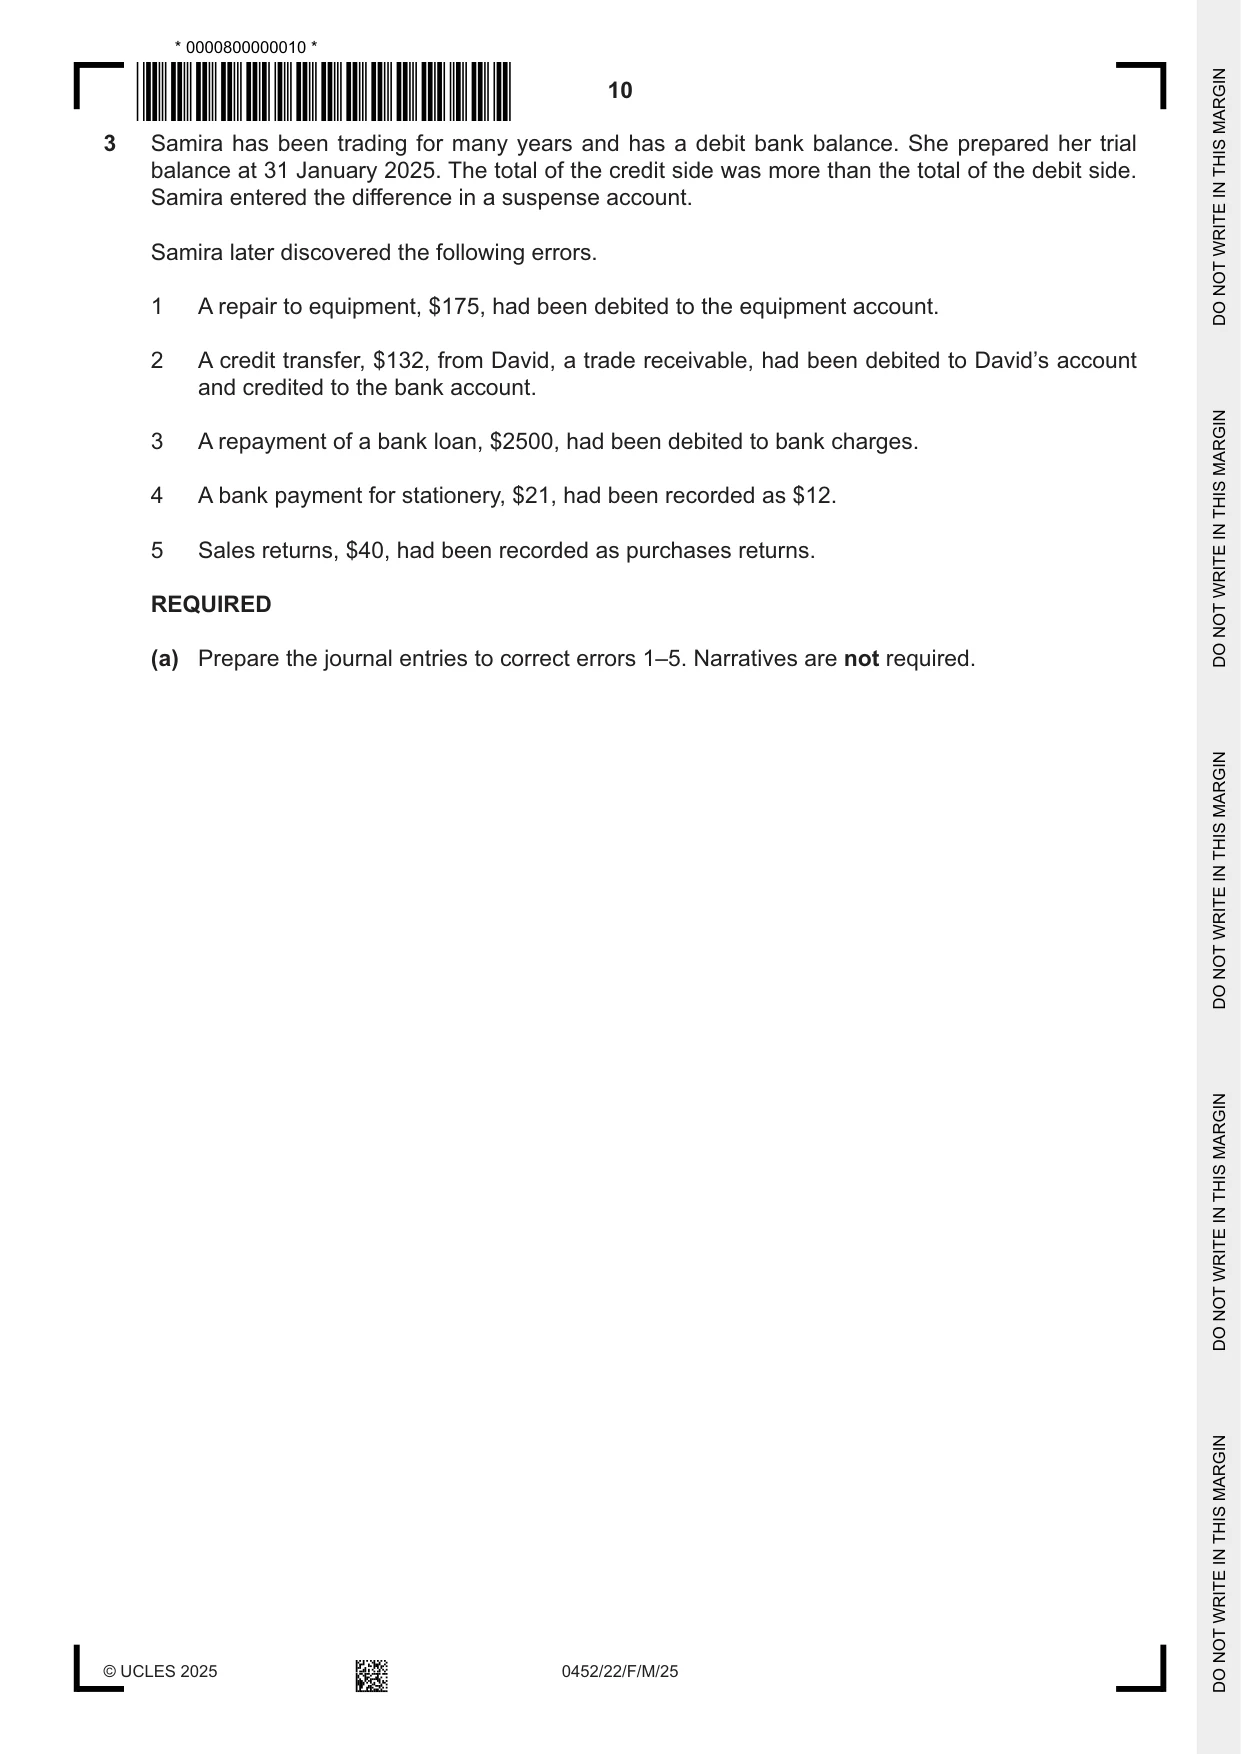
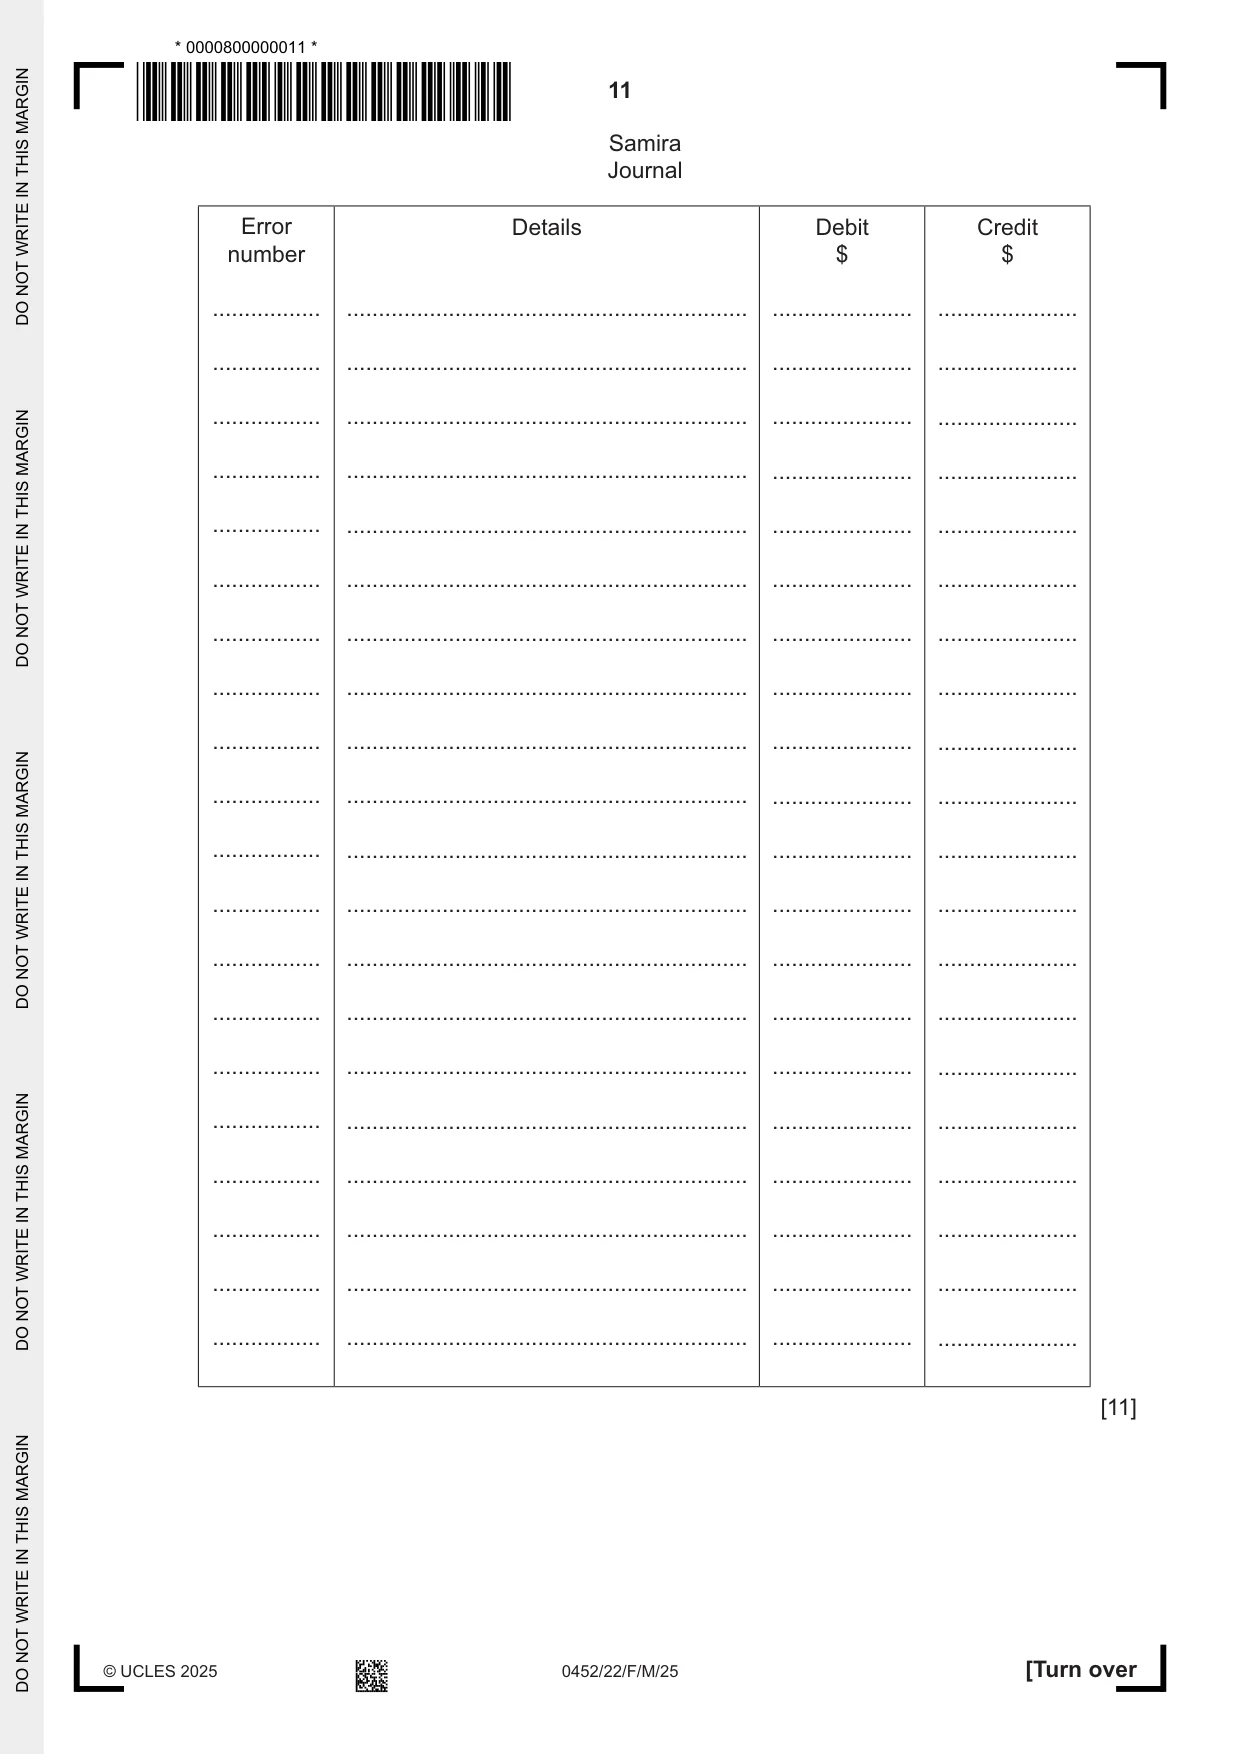
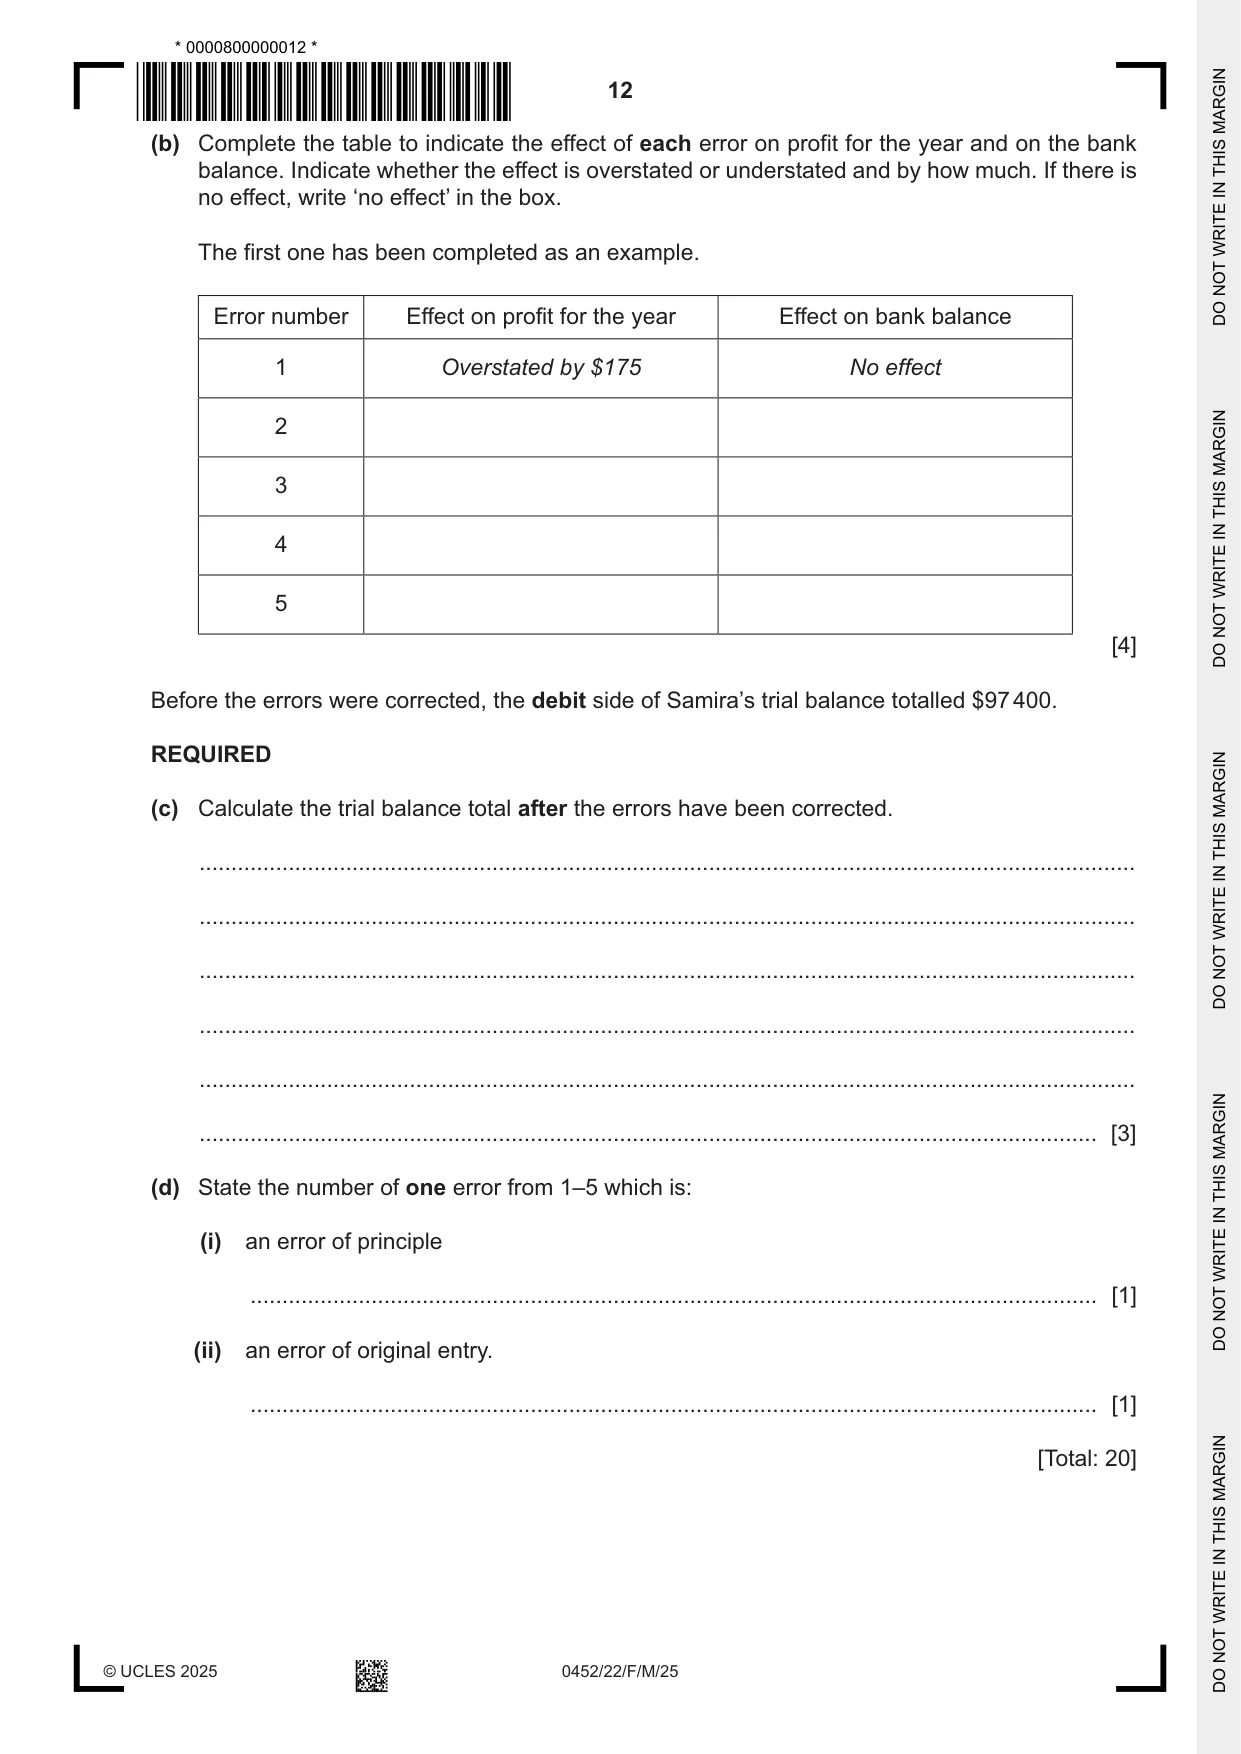
3 Samira has been trading for many years and has a debit bank balance. She prepared her trial balance at 31 January 2025. The total of the credit side was more than the total of the debit side. Samira entered the difference in a suspense account. Samira later discovered the following errors. 1 A repair to equipment, $175, had been debited to the equipment account. 2 A credit transfer, $132, from David, a trade receivable, had been debited to David’s account and credited to the bank account. 3 A repayment of a bank loan, $2500, had been debited to bank charges. 4 A bank payment for stationery, $21, had been recorded as $12. 5 Sales returns, $40, had been recorded as purchases returns. REQUIRED (a) Prepare the journal entries to correct errors 1–5. Narratives are not required. Samira Journal Details ............................................................... ............................................................... ............................................................... ............................................................... ............................................................... ............................................................... ............................................................... ............................................................... ............................................................... ............................................................... ............................................................... ............................................................... ............................................................... ............................................................... ............................................................... ............................................................... ............................................................... ............................................................... ............................................................... ............................................................... (b) Complete the table to indicate the effect of each error on profit for the year and on the bank balance. Indicate whether the effect is overstated or understated and by how much. If there is no effect, write ‘no effect’ in the box. The first one has been completed as an example. Error number Effect on profit for the year Effect on bank balance 1 Overstated by $175 No effect 2 3 4 5 [4] Before the errors were corrected, the debit side of Samira’s trial balance totalled $97 400. REQUIRED (c) Calculate the trial balance total after the errors have been corrected. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] (d) State the number of one error from 1–5 which is: (i) an error of principle ..................................................................................................................................... [1] (ii) an error of original entry. ..................................................................................................................................... [1] [Total: 20]
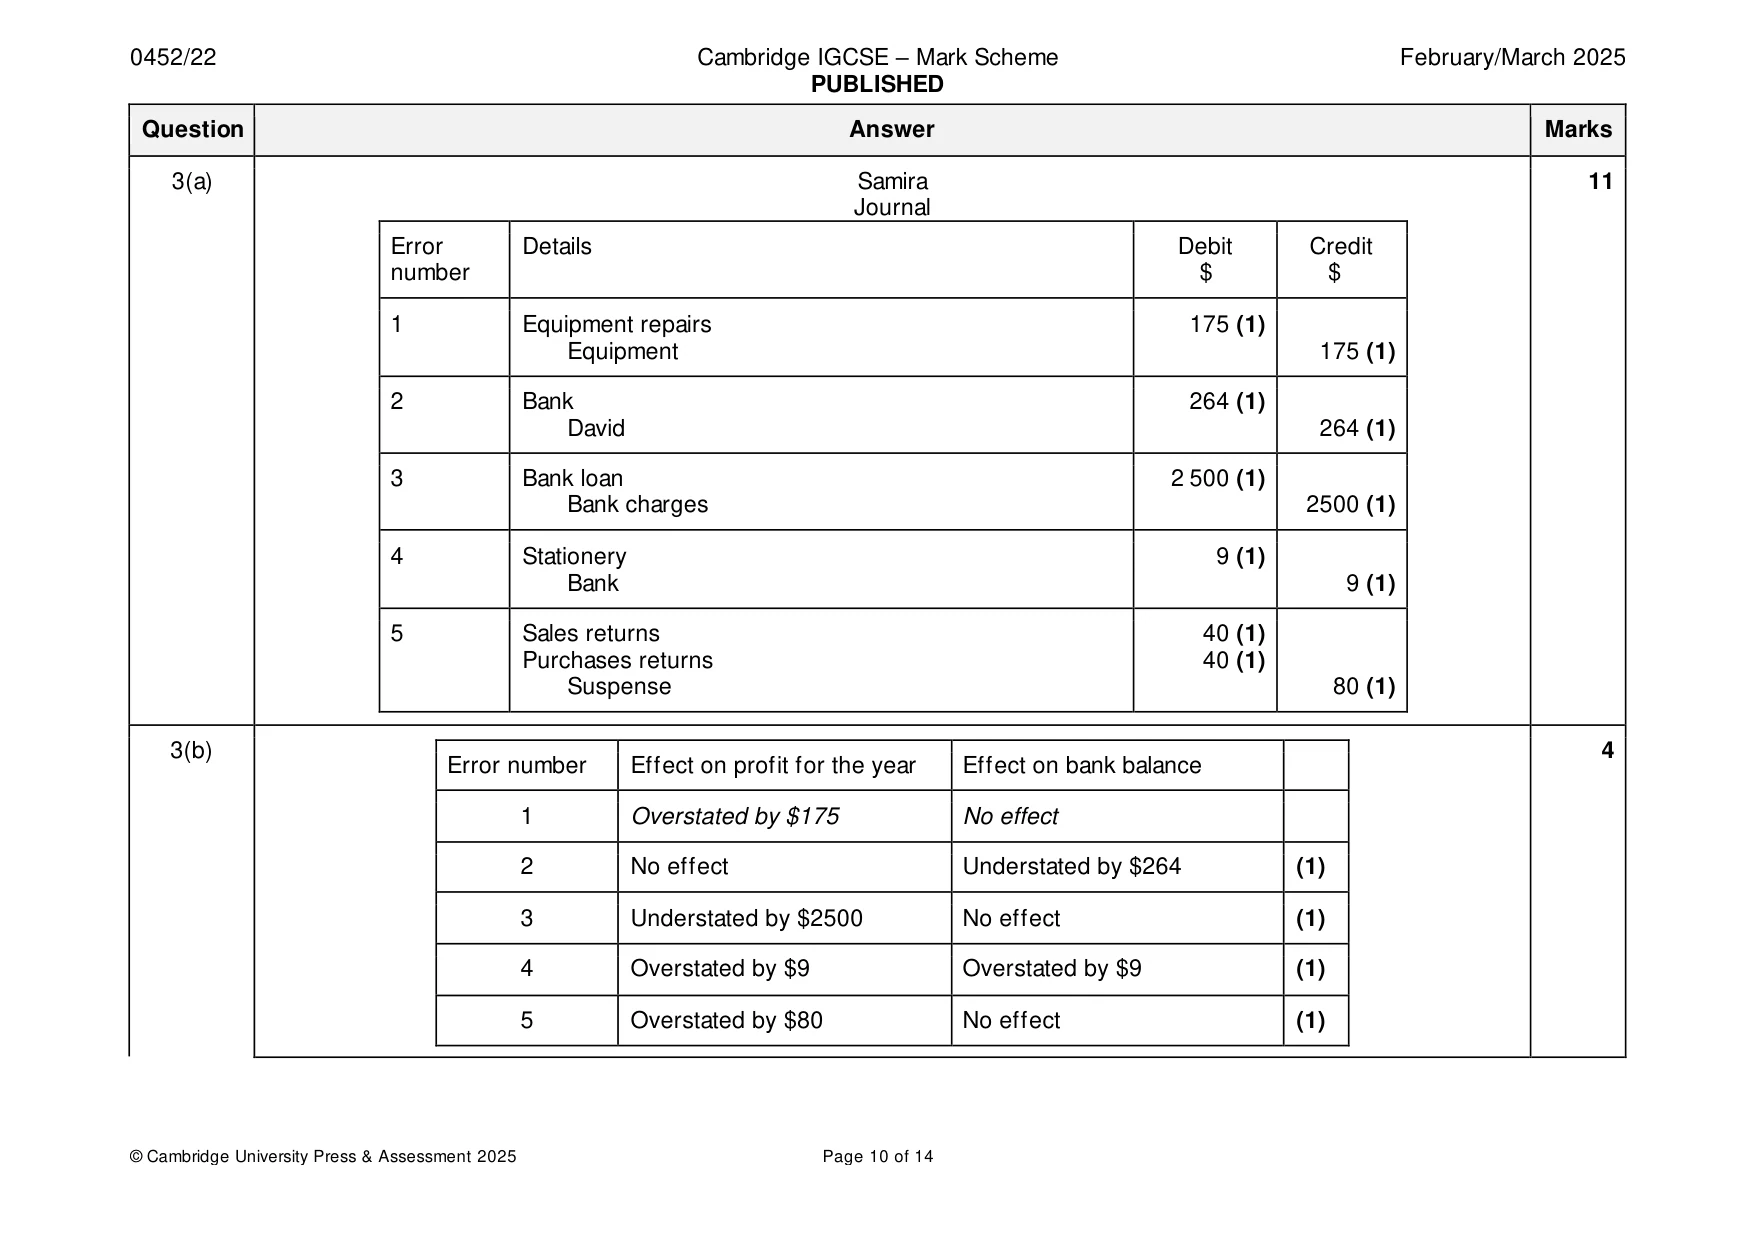
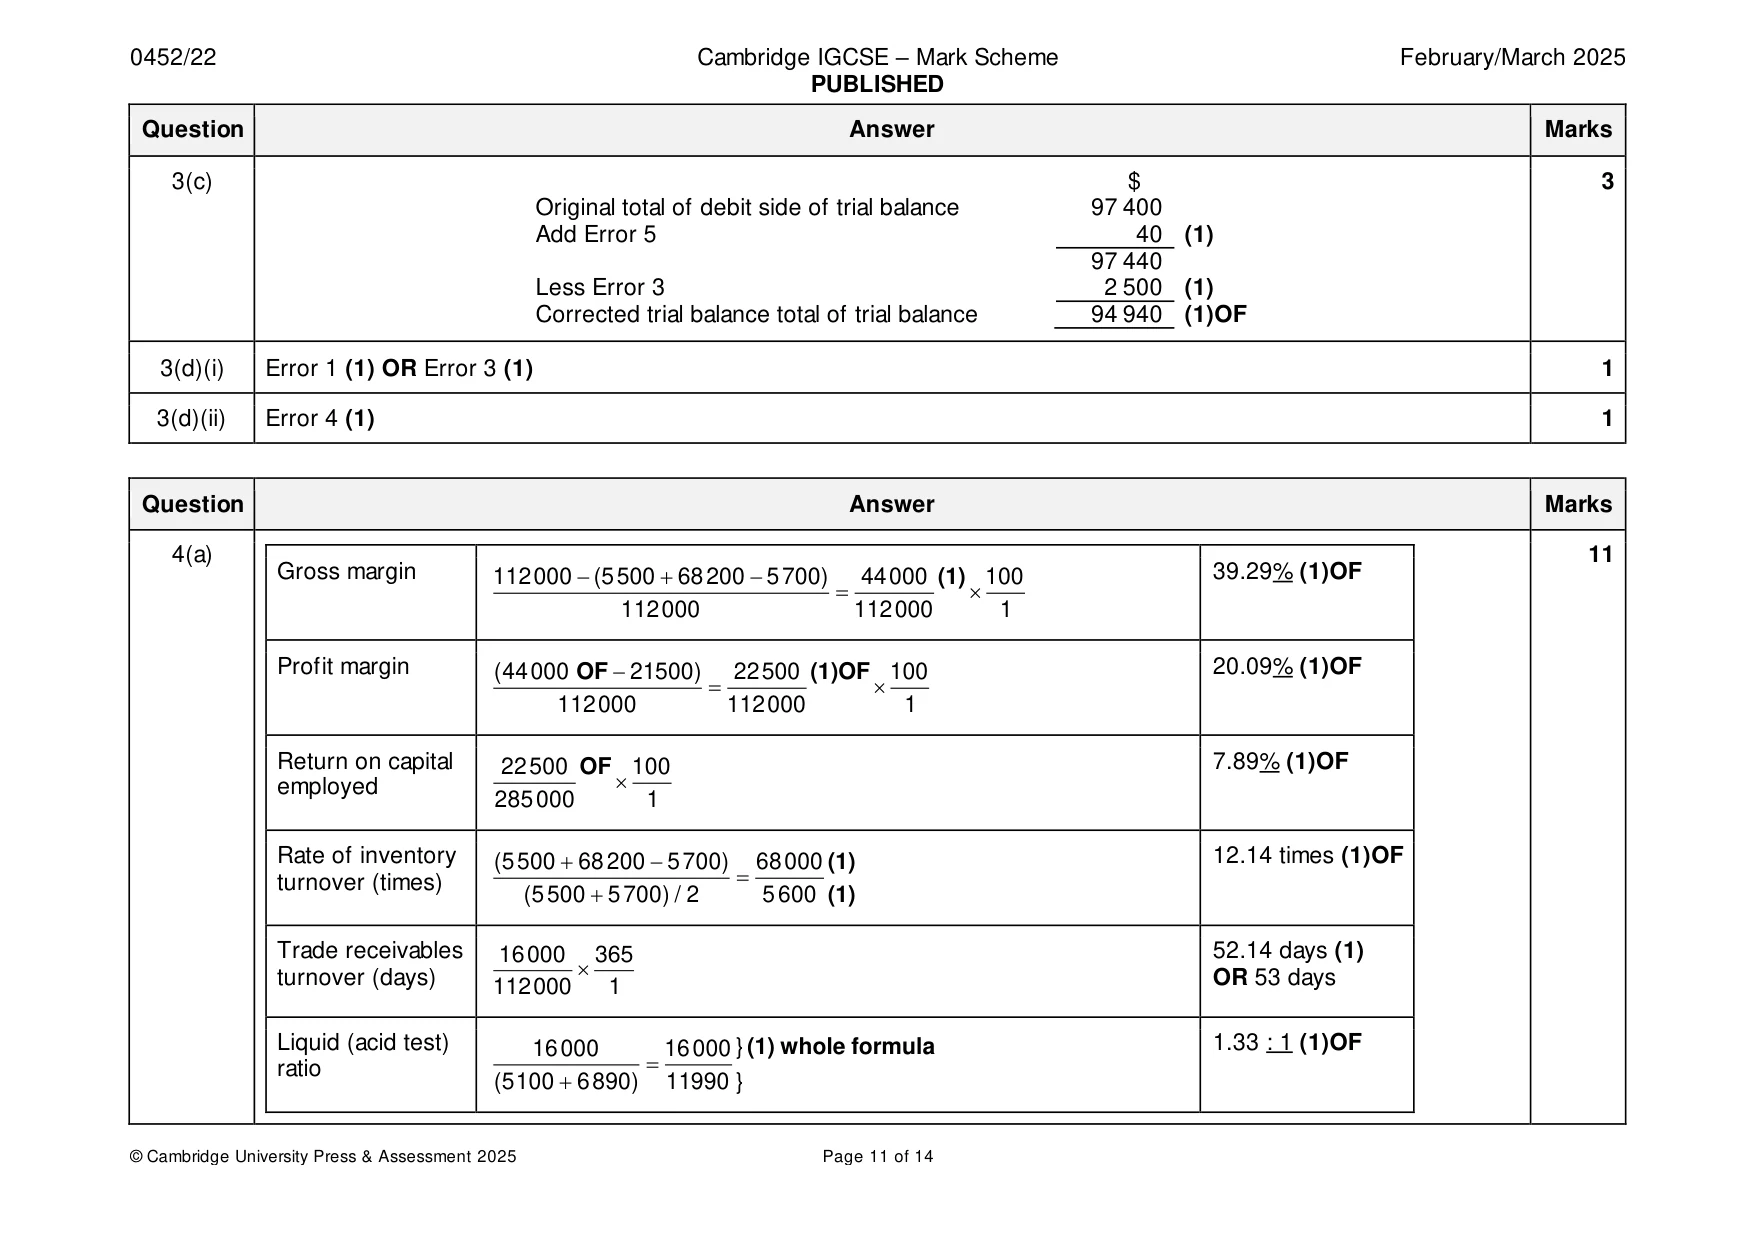
Mark scheme: 3(a) Samira 11 Journal Error Details Debit Credit number $ $ 1 Equipment repairs 175 (1) Equipment 175 (1) 2 Bank 264 (1) David 264 (1) 3 Bank loan 2 500 (1) Bank charges 2500 (1) 4 Stationery 9 (1) Bank 9 (1) 5 Sales returns 40 (1) Purchases returns 40 (1) Suspense 80 (1) 3(b) 4 Error number Effect on profit for the year Effect on bank balance 1 Overstated by $175 No effect 2 No effect Understated by $264 (1) 3 Understated by $2500 No effect (1) 4 Overstated by $9 Overstated by $9 (1) 5 Overstated by $80 No effect (1) 3(c) $ 3 Original total of debit side of trial balance 97 400 Add Error 5 40 (1) 97 440 Less Error 3 2 500 (1) Corrected trial balance total of trial balance 94 940 (1)OF 3(d)(i) Error 1 (1) OR Error 3 (1) 1 3(d)(ii) Error 4 (1) 1
Q4 · Raj is a trader who buys and sells on credit
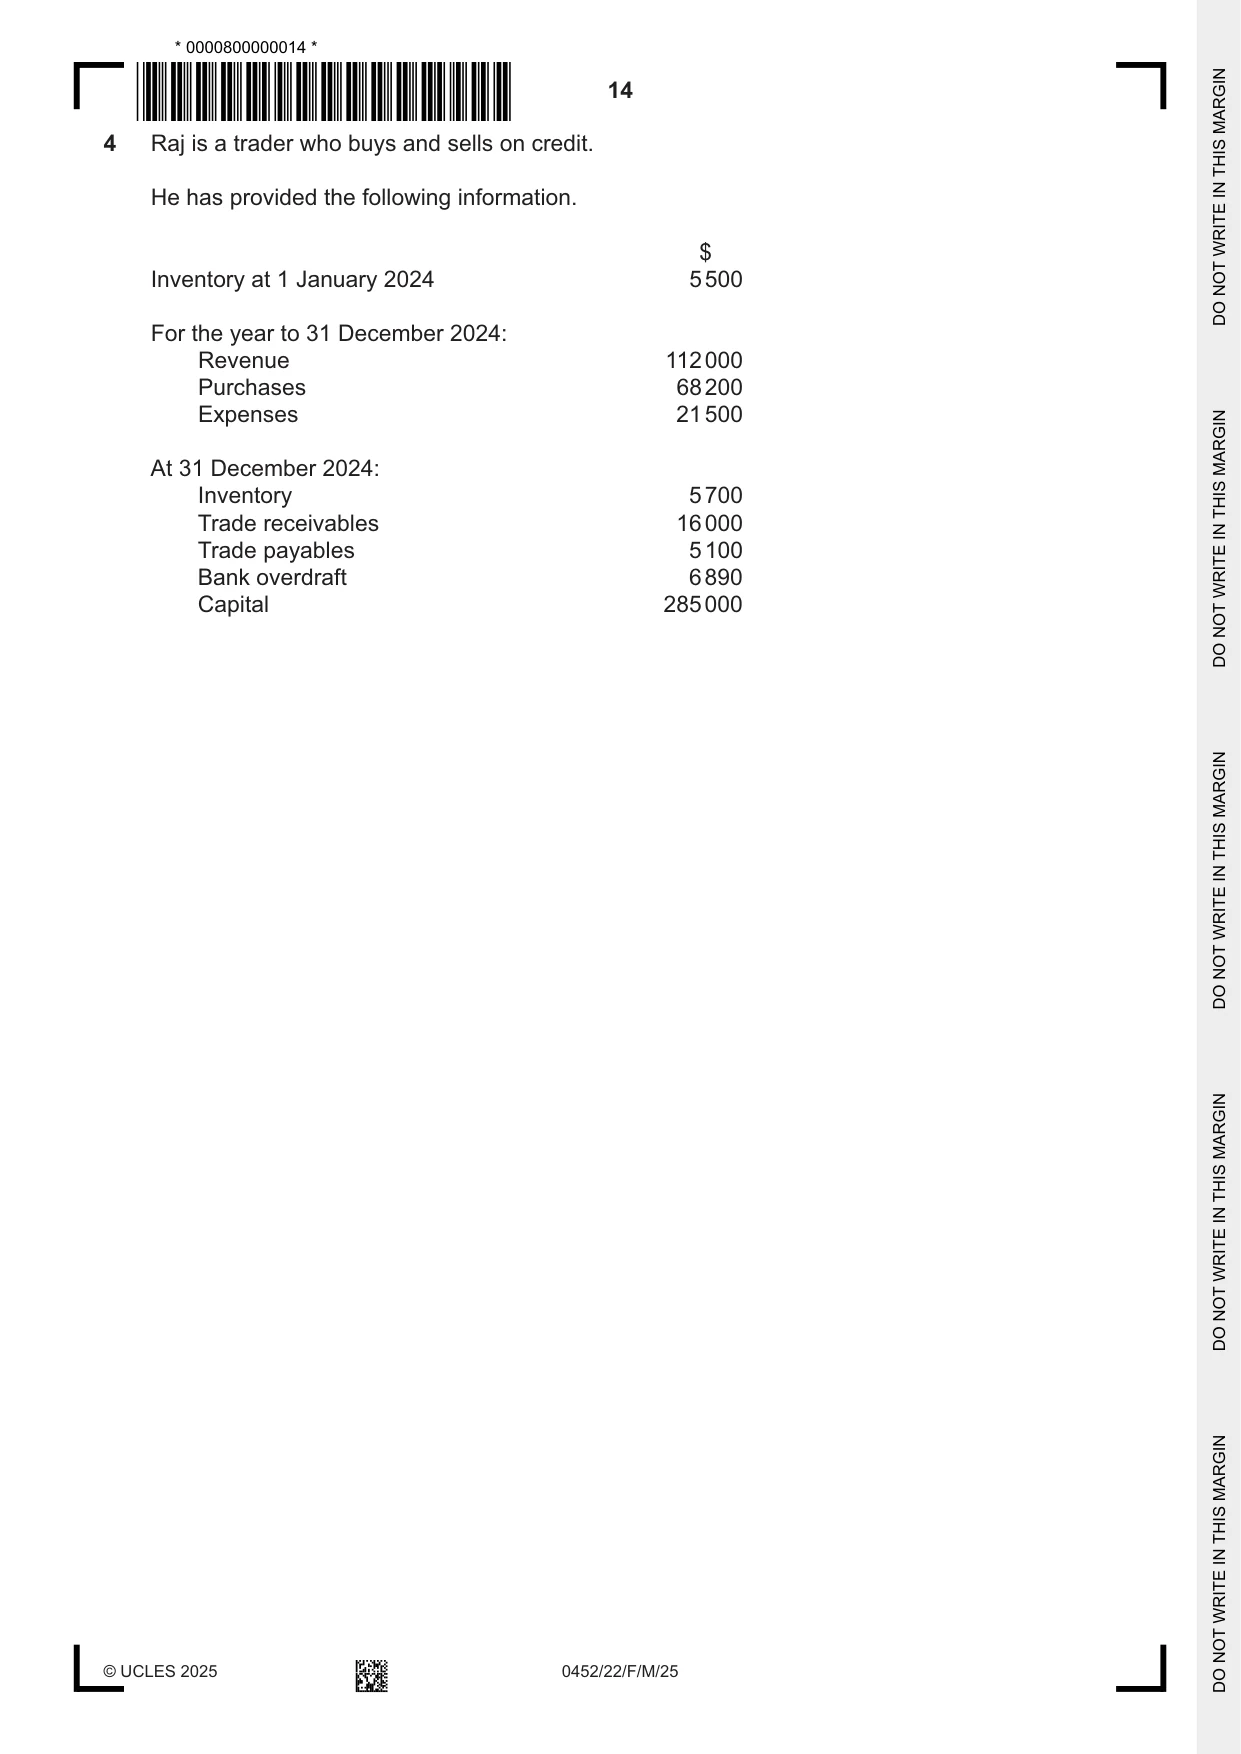
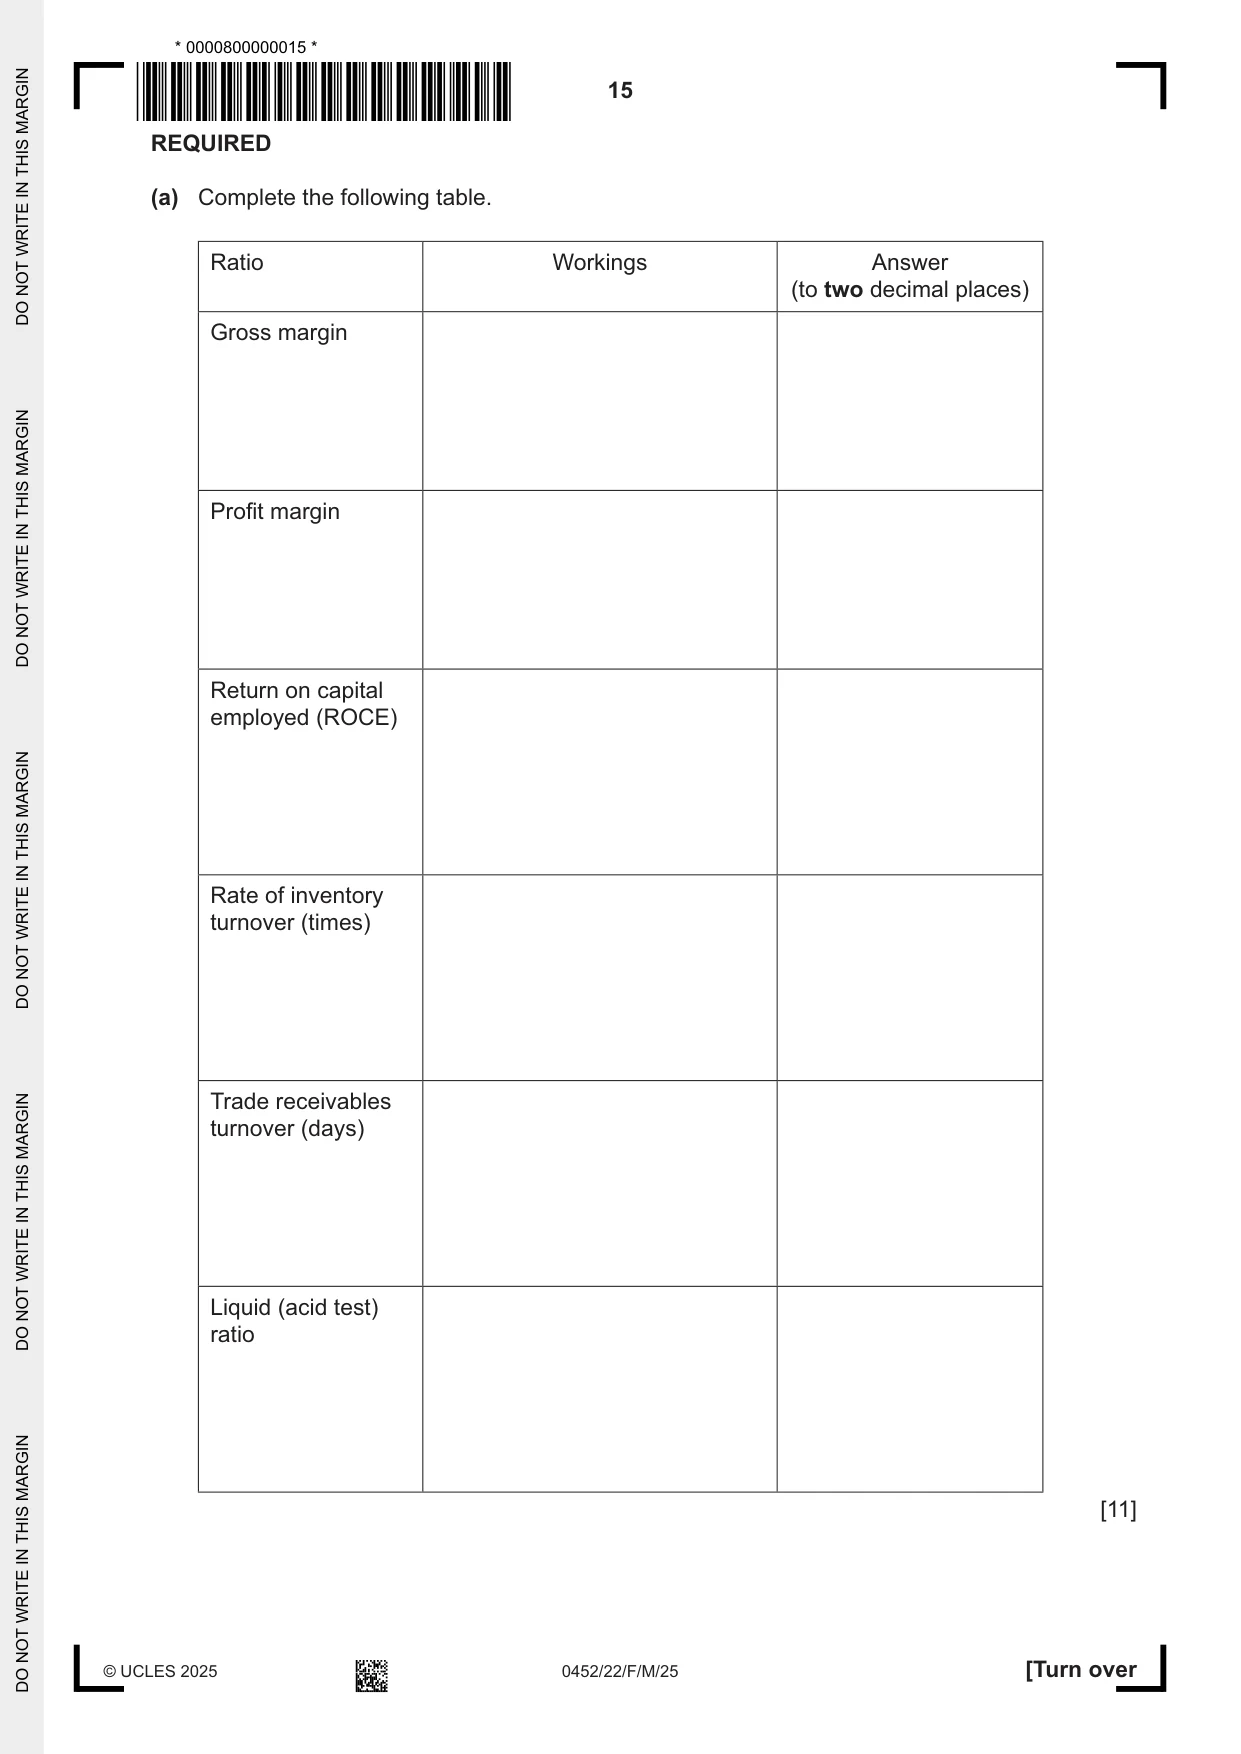
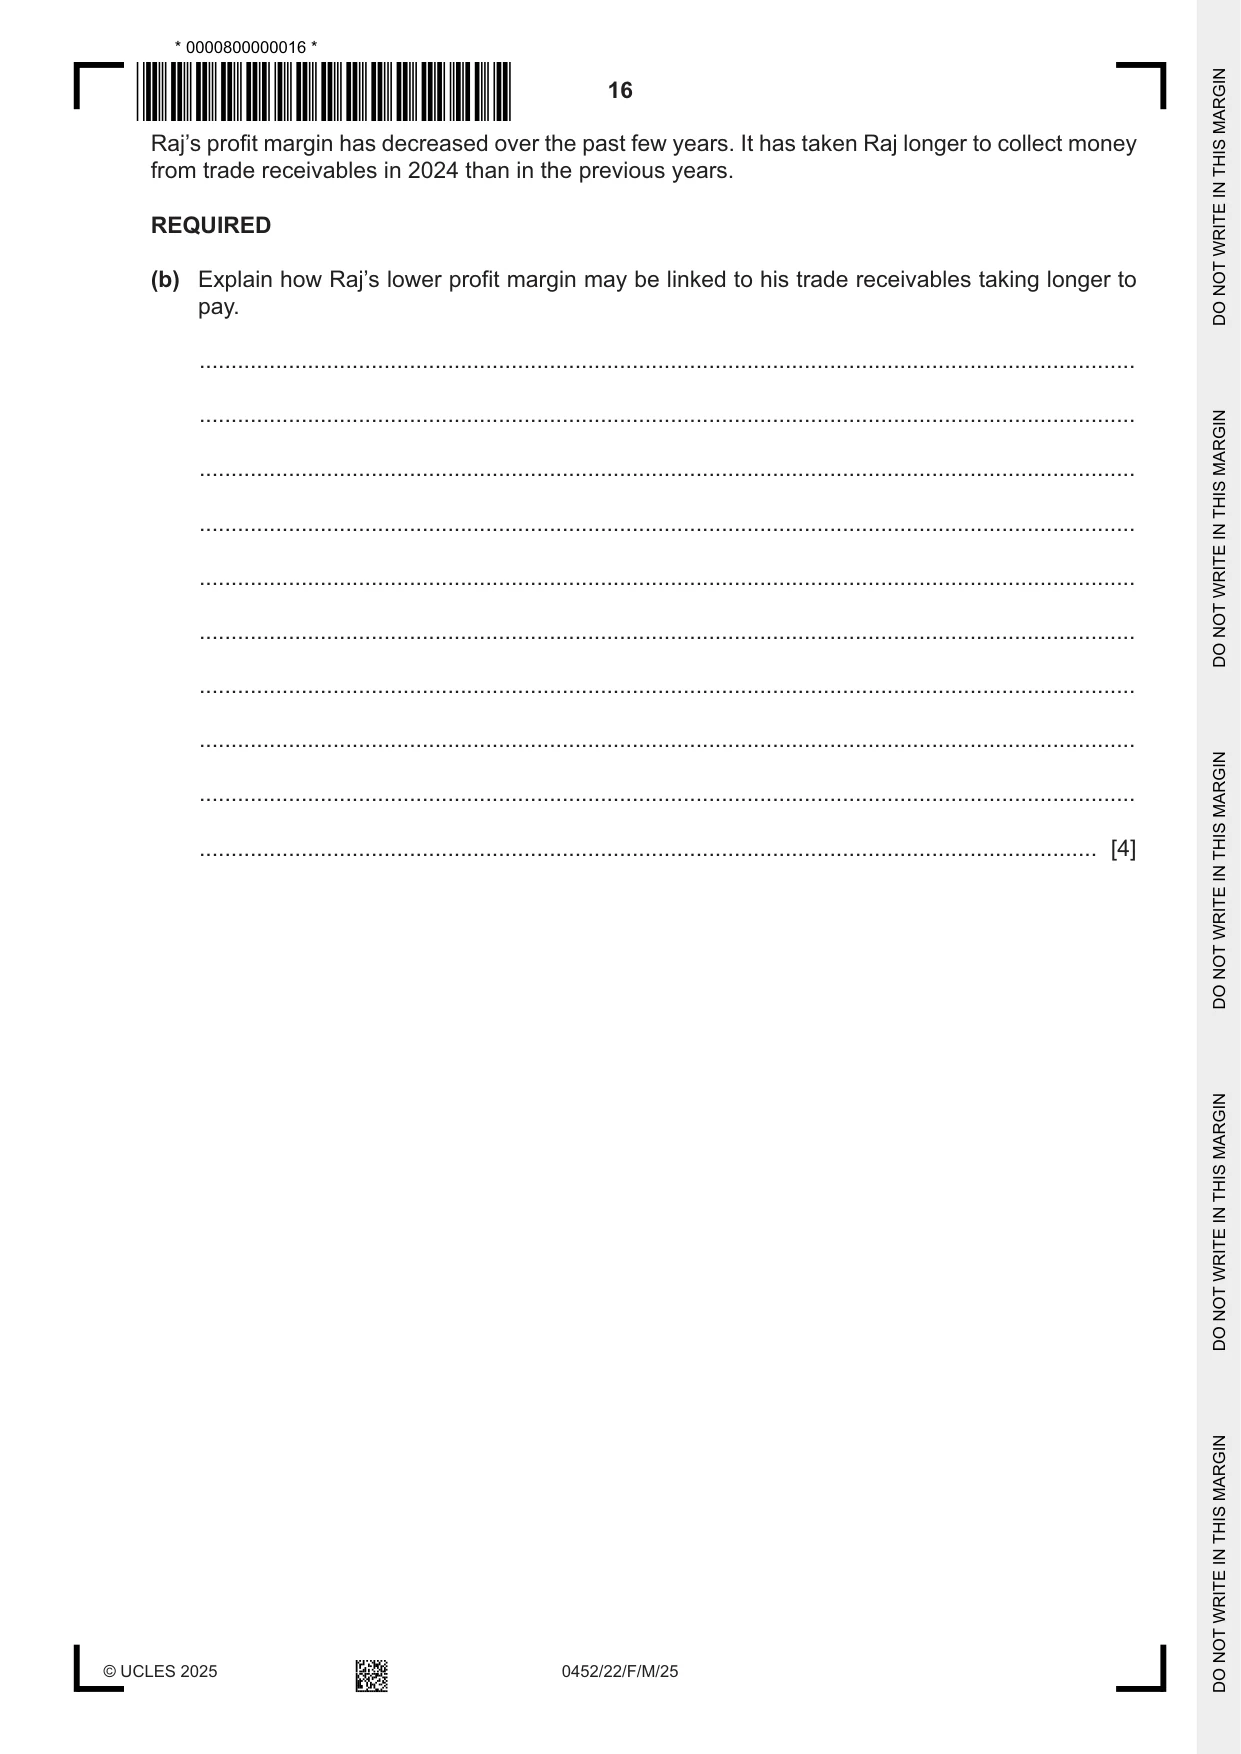
4 Raj is a trader who buys and sells on credit. He has provided the following information. $ Inventory at 1 January 2024 5 500 For the year to 31 December 2024: Revenue 112 000 Purchases 68 200 Expenses 21 500 At 31 December 2024: Inventory 5 700 Trade receivables 16 000 Trade payables 5 100 Bank overdraft 6 890 Capital 285 000 REQUIRED (a) Complete the following table. Ratio Workings Answer (to two decimal places) Gross margin Profit margin Return on capital employed (ROCE) Rate of inventory turnover (times) Trade receivables turnover (days) Liquid (acid test) ratio [11] Raj’s profit margin has decreased over the past few years. It has taken Raj longer to collect money from trade receivables in 2024 than in the previous years. REQUIRED (b) Explain how Raj’s lower profit margin may be linked to his trade receivables taking longer to pay. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] Raj is considering paying more capital into the business to reduce the bank overdraft. REQUIRED (c) Advise Raj whether or not he should pay more capital into the business. Justify your answer by providing points for and against. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
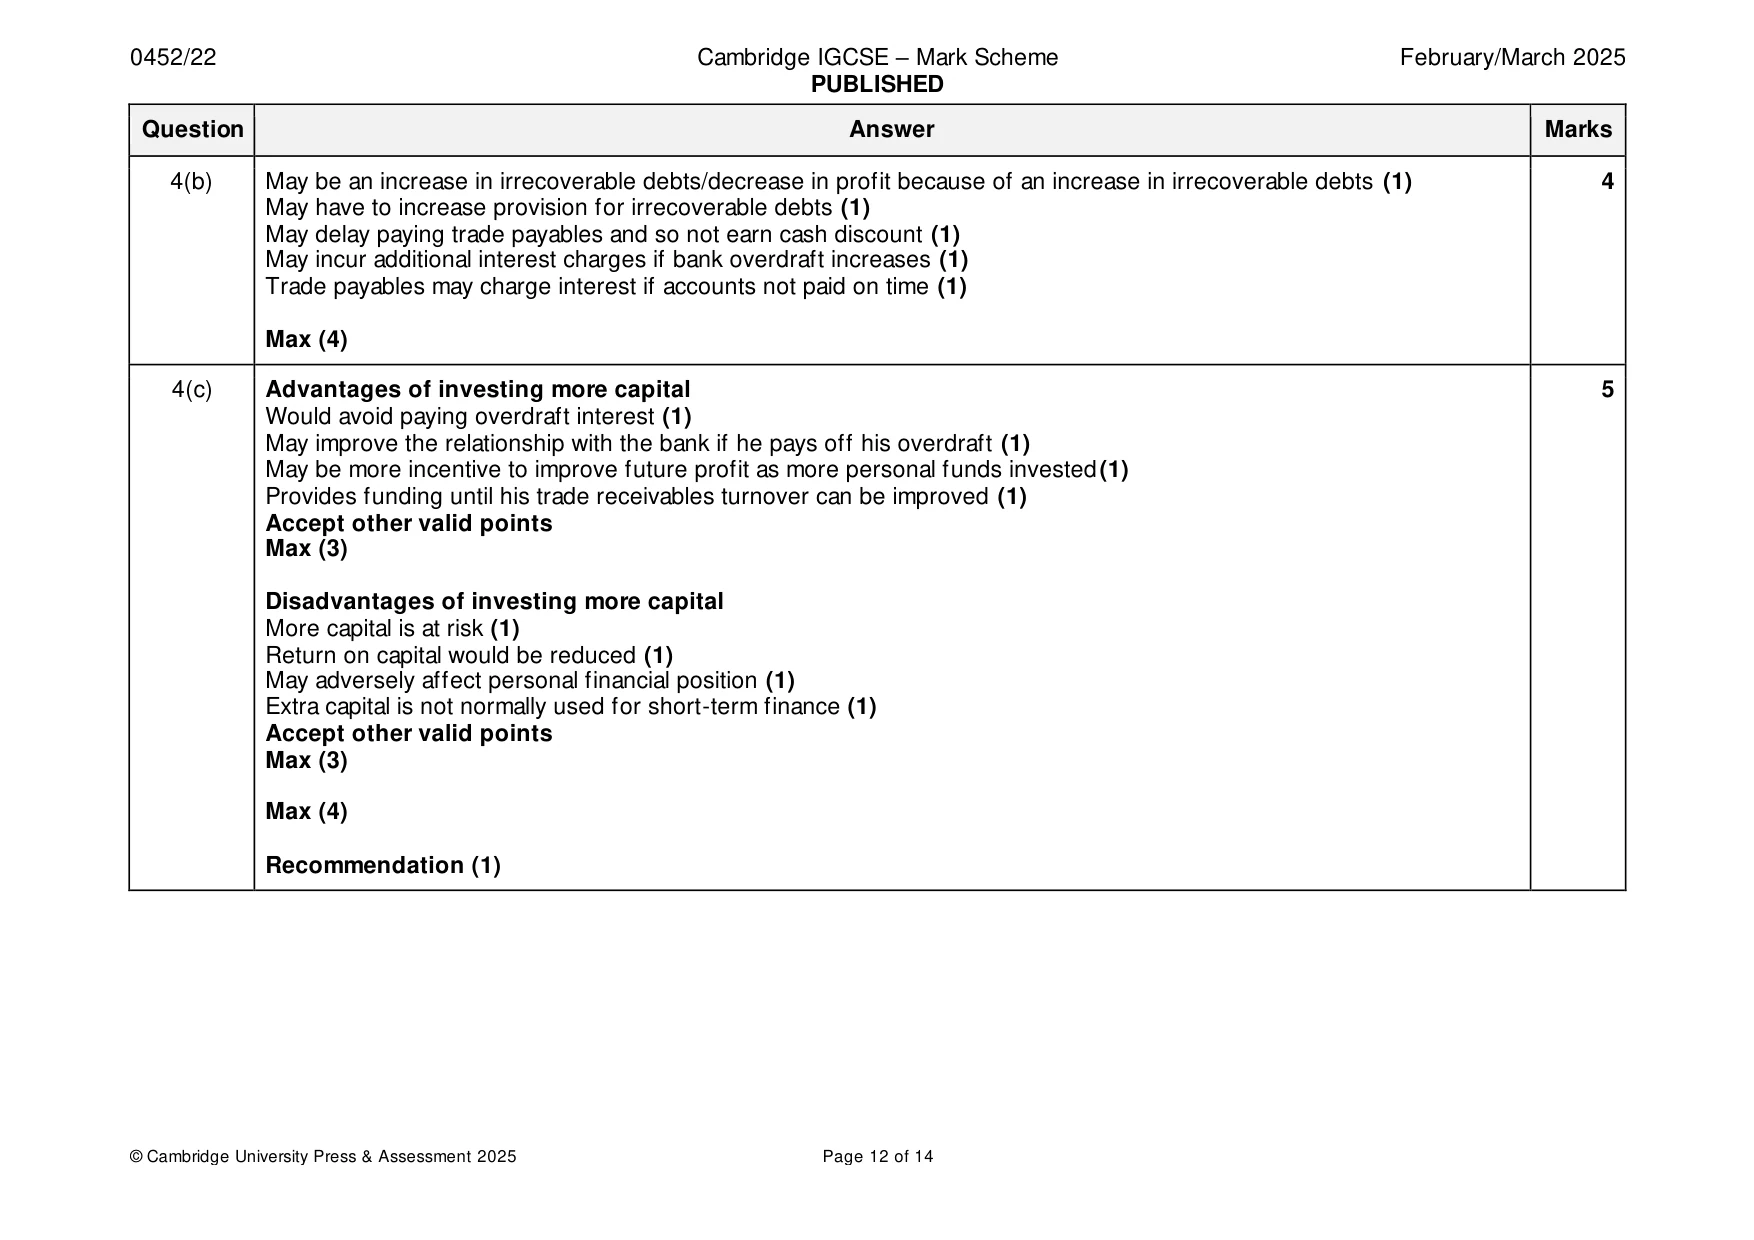
Mark scheme: 4(a) 11 Gross margin 112000 − (5500 + 68200 − 5700) 44000 (1) 100 39.29% (1)OF = 112000 112000 1 Profit margin (44000 OF − 21500) 22500 (1)OF 100 20.09% (1)OF = 112000 112000 1 Return on capital 22500 OF 100 7.89% (1)OF employed 285000 1 Rate of inventory (5500 + 68200 − 5700) 68000 (1) 12.14 times (1)OF turnover (times) = (5500 + 5700) / 2 5600 (1) Trade receivables 16000 365 52.14 days (1) turnover (days) OR 53 days 112000 1 Liquid (acid test) 16000 16000 } (1) whole formula 1.33 : 1 (1)OF ratio = (5100 + 6890) 11990 } 4(b) May be an increase in irrecoverable debts/decrease in profit because of an increase in irrecoverable debts (1) 4 May have to increase provision for irrecoverable debts (1) May delay paying trade payables and so not earn cash discount (1) May incur additional interest charges if bank overdraft increases (1) Trade payables may charge interest if accounts not paid on time (1) Max (4) 4(c) Advantages of investing more capital 5 Would avoid paying overdraft interest (1) May improve the relationship with the bank if he pays off his overdraft (1) May be more incentive to improve future profit as more personal funds invested(1) Provides funding until his trade receivables turnover can be improved (1) Accept other valid points Max (3) Disadvantages of investing more capital More capital is at risk (1) Return on capital would be reduced (1) May adversely affect personal financial position (1) Extra capital is not normally used for short-term finance (1) Accept other valid points Max (3) Max (4) Recommendation (1)
More questions on Calculation and understanding of accounting ratios
Q5 · The ABC Piano Club provides facilities for its members
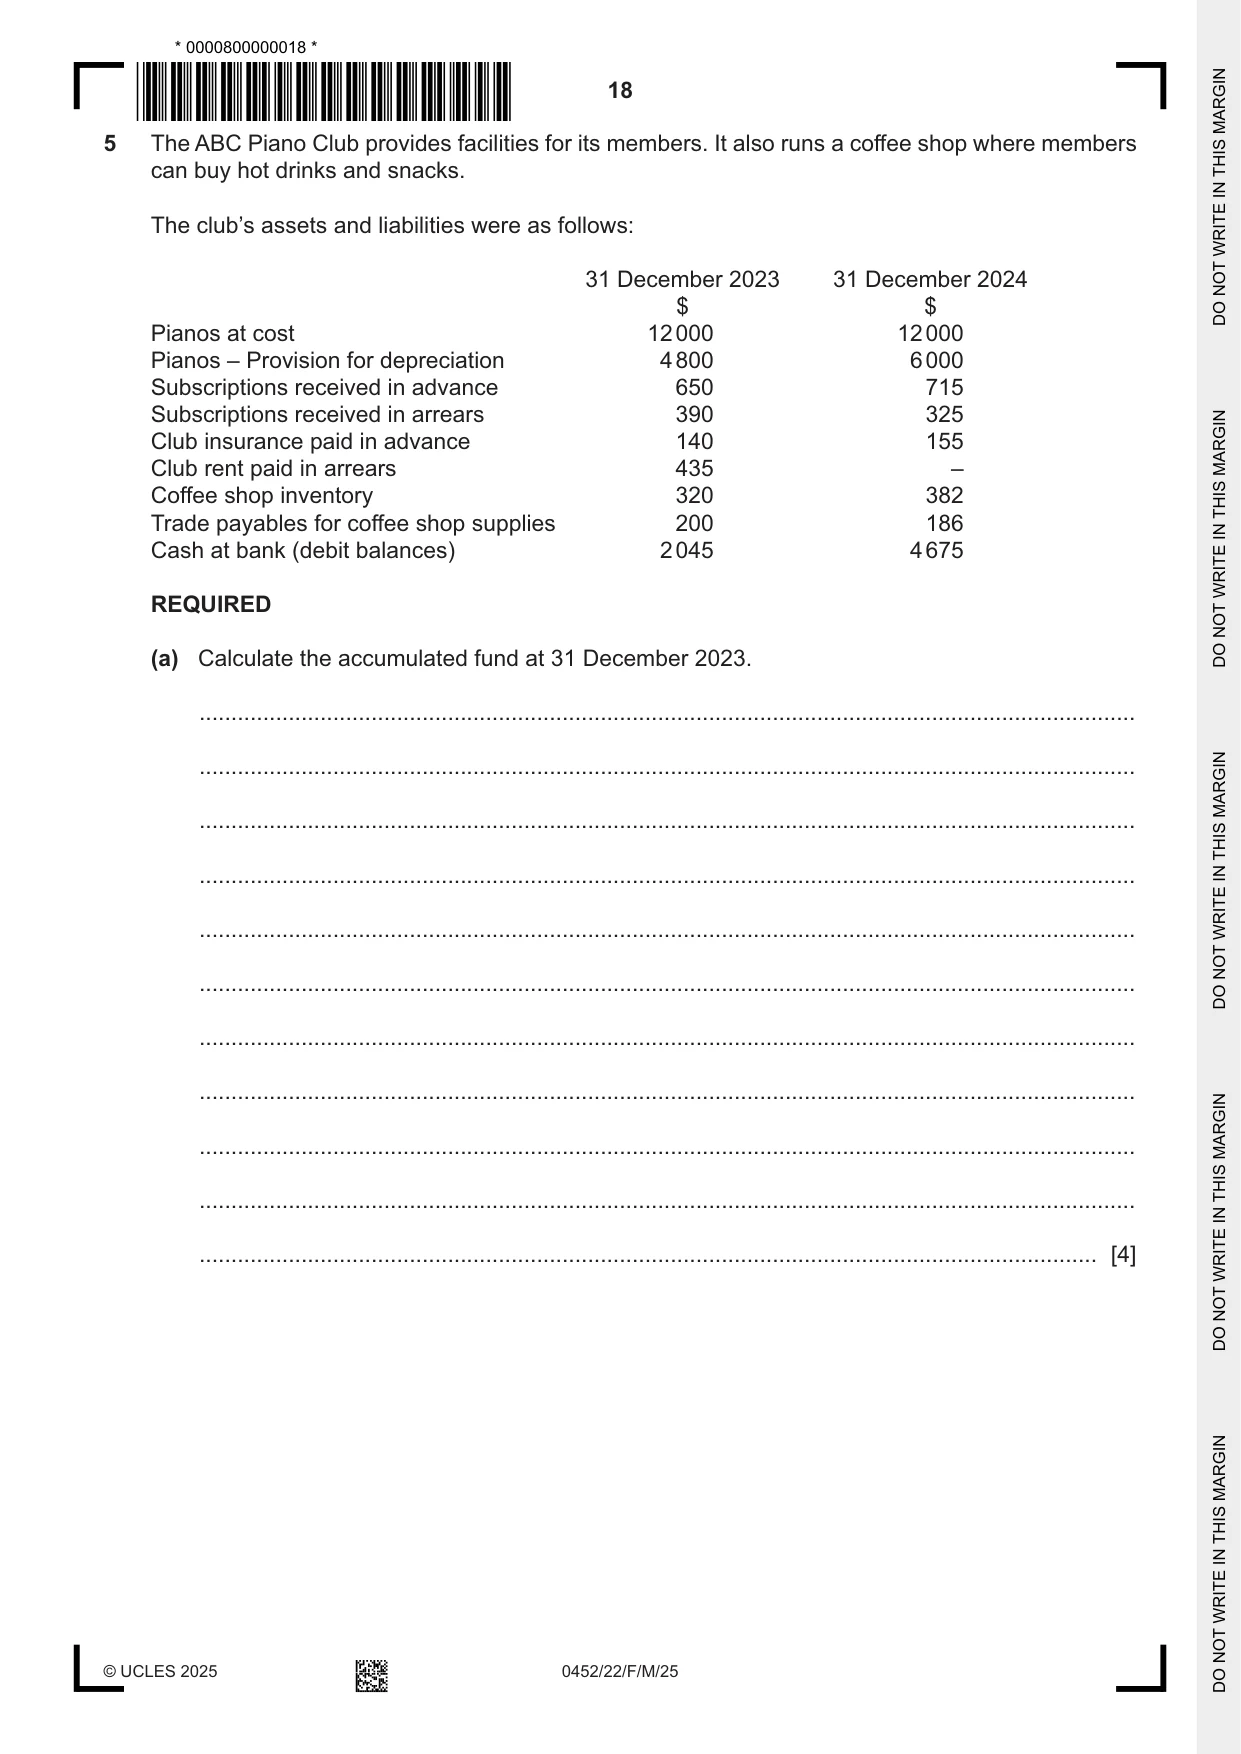
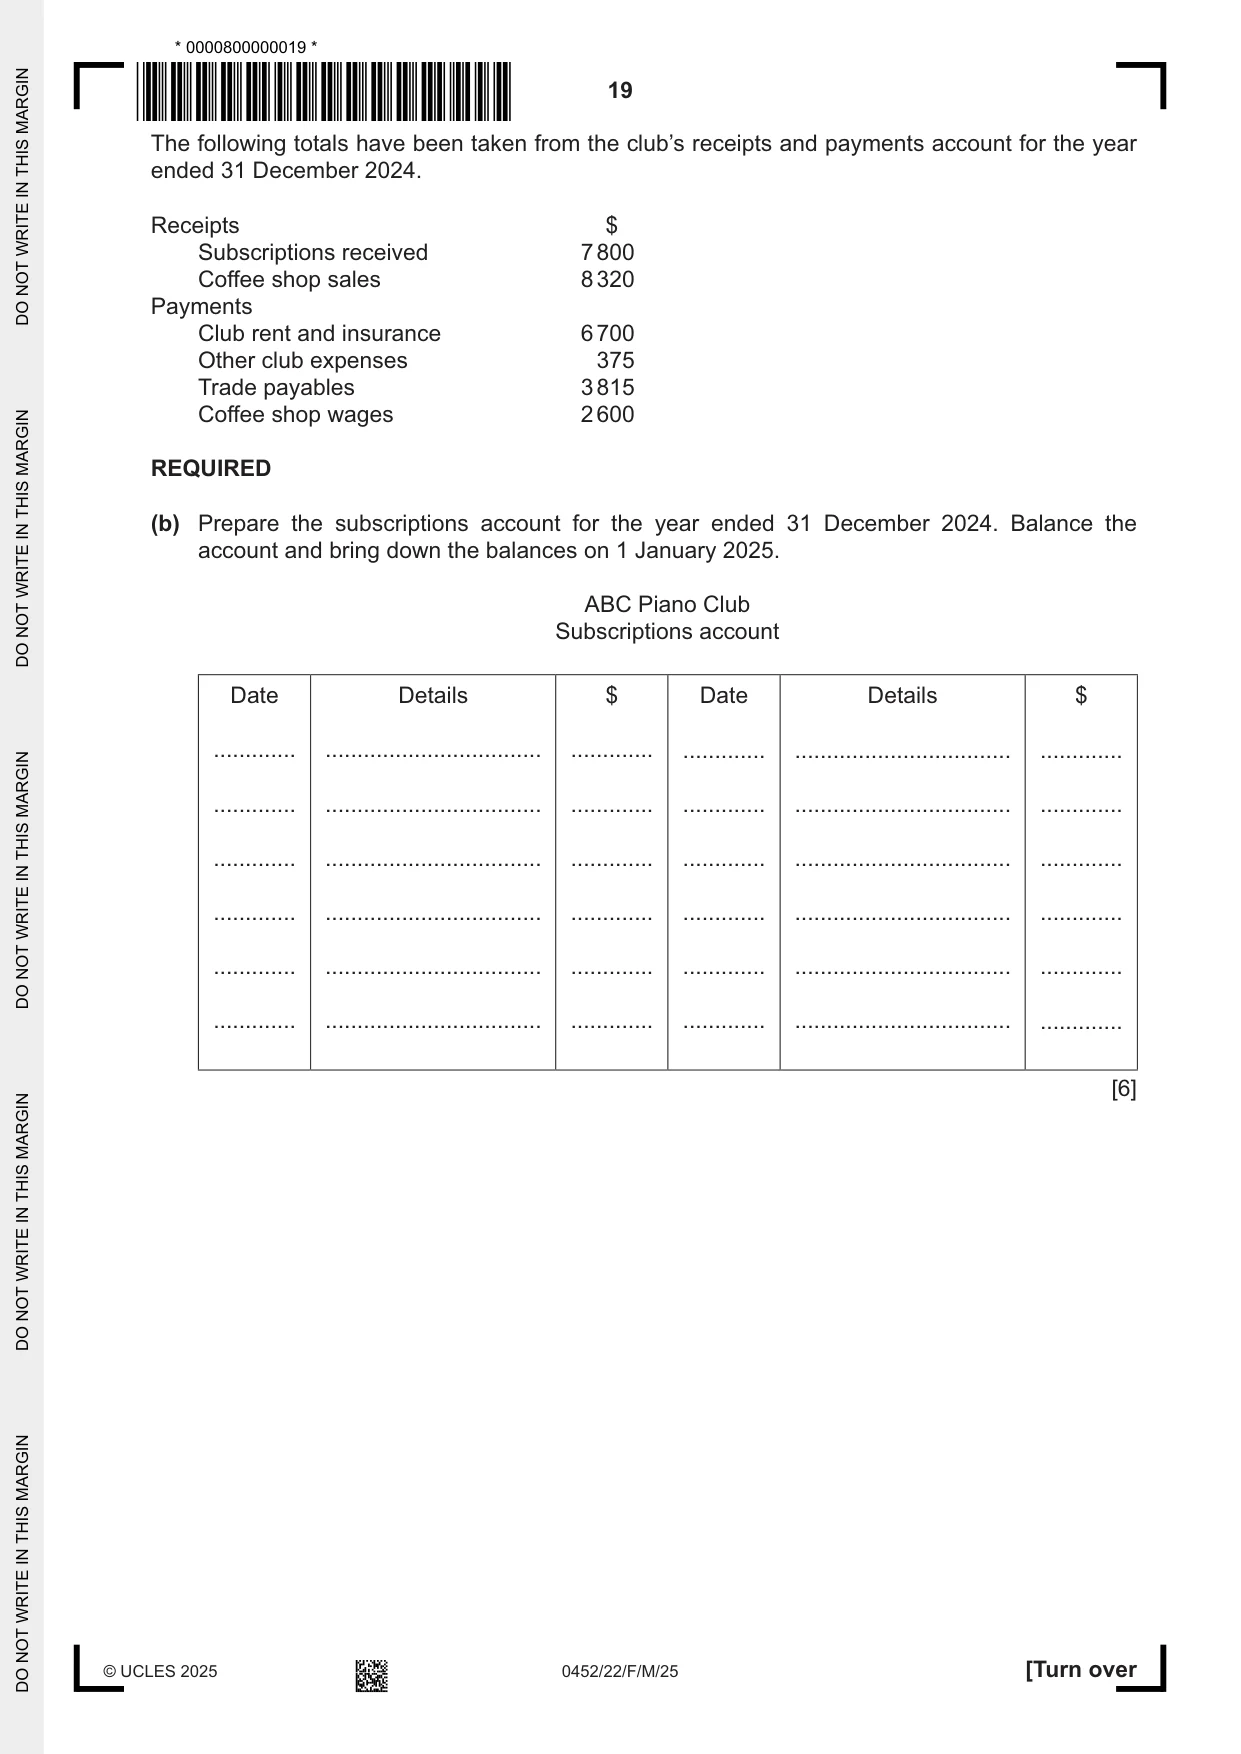
5 The ABC Piano Club provides facilities for its members. It also runs a coffee shop where members can buy hot drinks and snacks. The club’s assets and liabilities were as follows: 31 December 2023 31 December 2024 $ $ Pianos at cost 12 000 12 000 Pianos – Provision for depreciation 4 800 6 000 Subscriptions received in advance 650 715 Subscriptions received in arrears 390 325 Club insurance paid in advance 140 155 Club rent paid in arrears 435 – Coffee shop inventory 320 382 Trade payables for coffee shop supplies 200 186 Cash at bank (debit balances) 2 045 4 675 REQUIRED (a) Calculate the accumulated fund at 31 December 2023. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] The following totals have been taken from the club’s receipts and payments account for the year ended 31 December 2024. Receipts $ Subscriptions received 7 800 Coffee shop sales 8 320 Payments Club rent and insurance 6 700 Other club expenses 375 Trade payables 3 815 Coffee shop wages 2 600 REQUIRED (b) Prepare the subscriptions account for the year ended 31 December 2024. Balance the account and bring down the balances on 1 January 2025. ABC Piano Club Subscriptions account Date Details $ Date Details $ ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. [6] (c) Prepare the Club’s rent and insurance account for the year ended 31 December 2024. Balance the account and bring down the balance on 1 January 2025. ABC Piano Club Club’s rent and insurance account Date Details $ Date Details $ ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. [5]
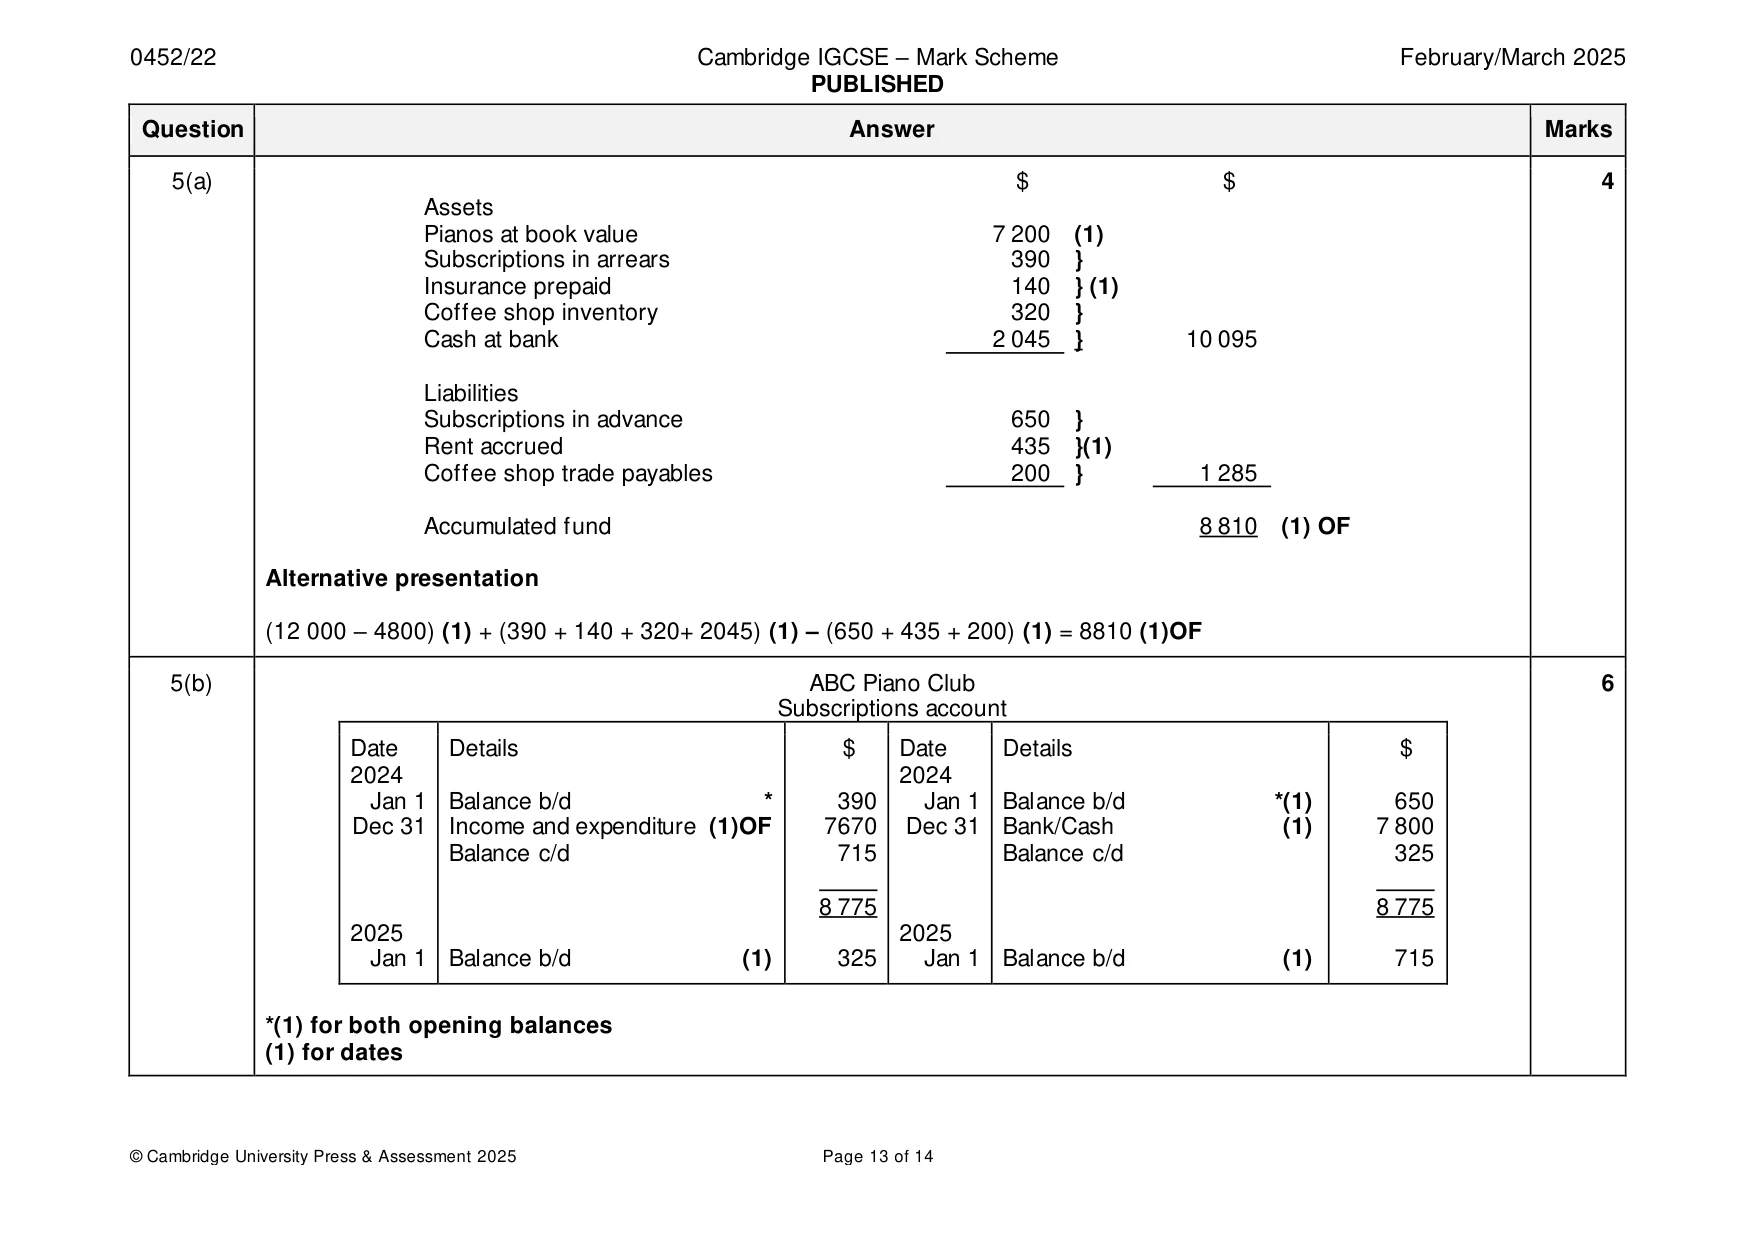
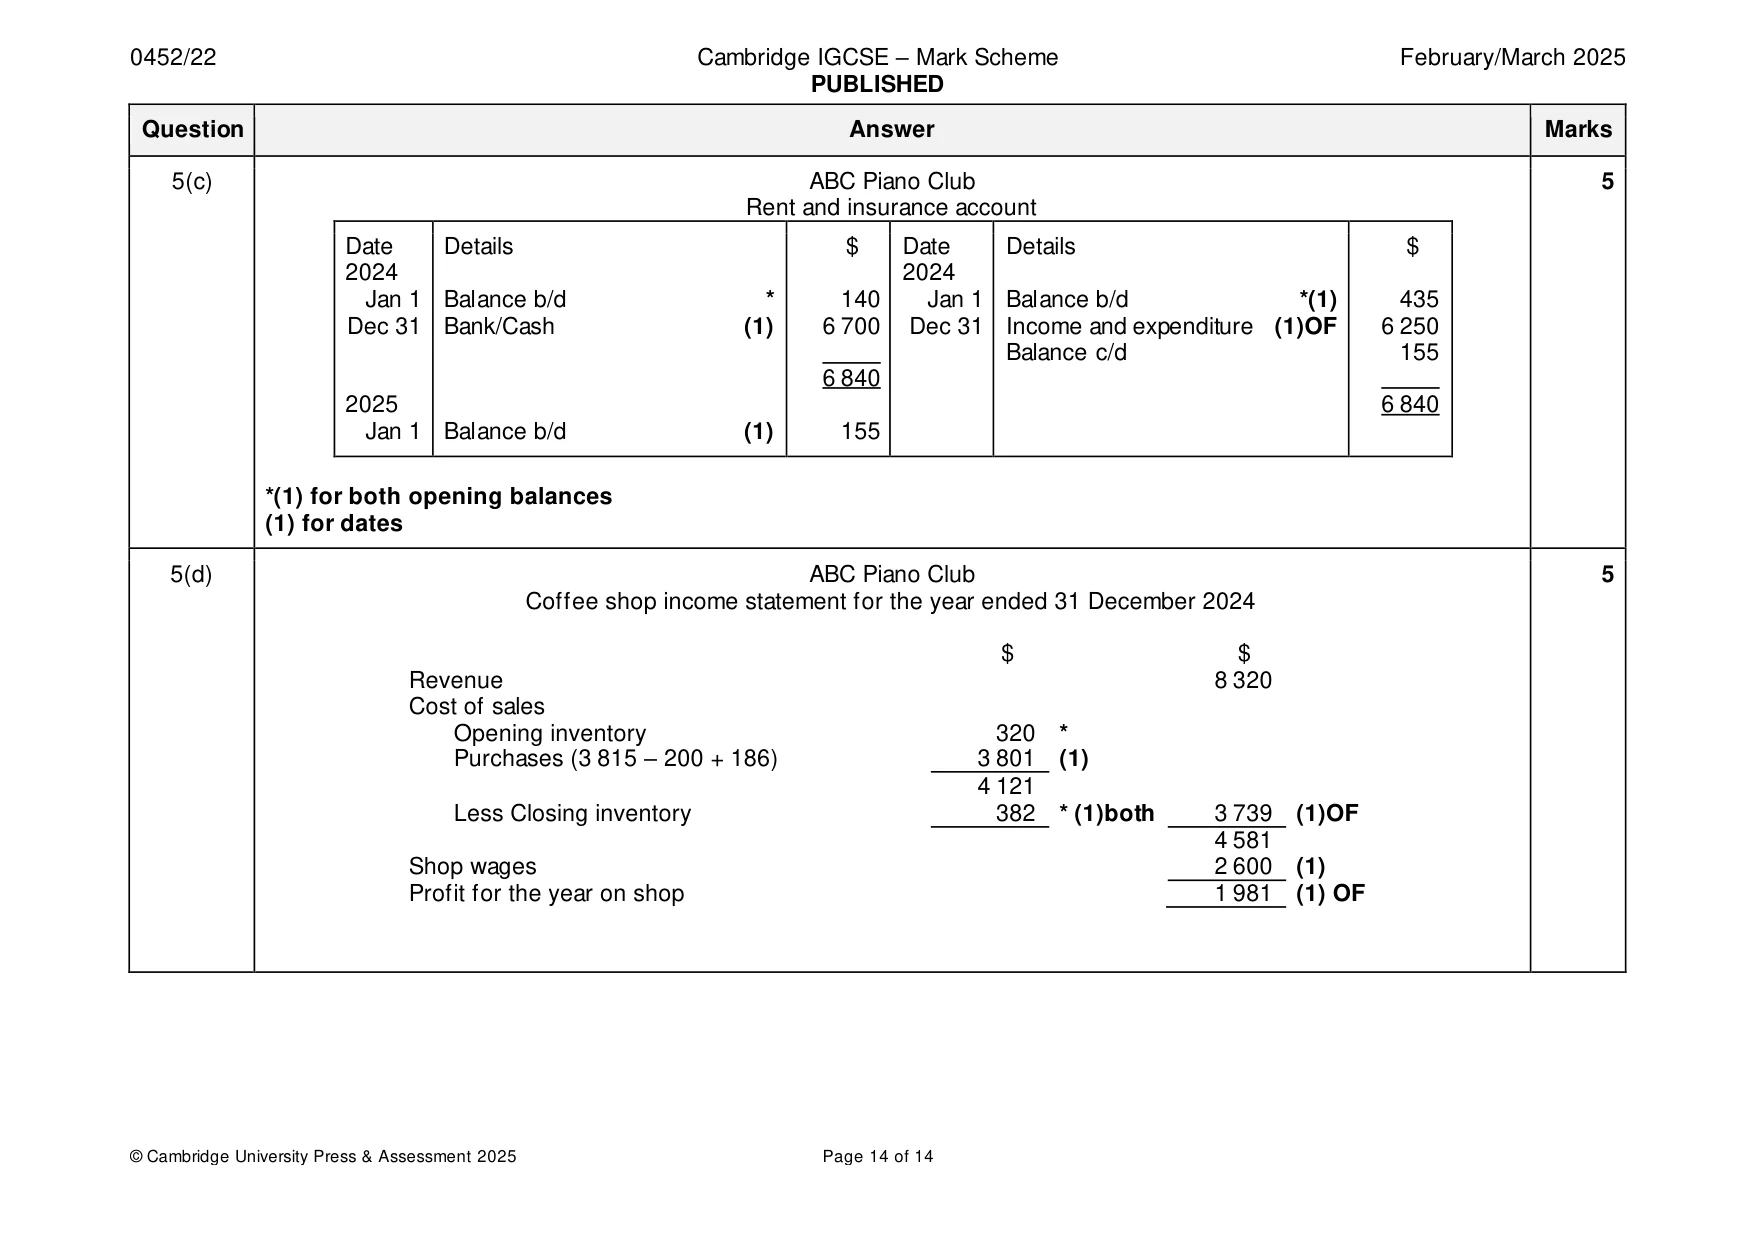
Mark scheme: 5(a) $ $ 4 Assets Pianos at book value 7 200 (1) Subscriptions in arrears 390 } Insurance prepaid 140 } (1) Coffee shop inventory 320 } Cash at bank 2 045 } 10 095 Liabilities Subscriptions in advance 650 } Rent accrued 435 }(1) Coffee shop trade payables 200 } 1 285 Accumulated fund 8 810 (1) OF Alternative presentation (12 000 – 4800) (1) + (390 + 140 + 320+ 2045) (1) – (650 + 435 + 200) (1) = 8810 (1)OF 5(b) ABC Piano Club 6 Subscriptions account Date Details $ Date Details $ 2024 2024 Jan 1 Balance b/d * 390 Jan 1 Balance b/d *(1) 650 Dec 31 Income and expenditure (1)OF 7670 Dec 31 Bank/Cash (1) 7 800 Balance c/d 715 Balance c/d 325 8 775 8 775 2025 2025 Jan 1 Balance b/d (1) 325 Jan 1 Balance b/d (1) 715 *(1) for both opening balances (1) for dates 5(c) ABC Piano Club 5 Rent and insurance account Date Details $ Date Details $ 2024 2024 Jan 1 Balance b/d * 140 Jan 1 Balance b/d *(1) 435 Dec 31 Bank/Cash (1) 6 700 Dec 31 Income and expenditure (1)OF 6 250 Balance c/d 155 6 840 2025 6 840 Jan 1 Balance b/d (1) 155 *(1) for both opening balances (1) for dates 5(d) ABC Piano Club 5 Coffee shop income statement for the year ended 31 December 2024 $ $ Revenue 8 320 Cost of sales Opening inventory 320 * Purchases (3 815 – 200 + 186) 3 801 (1) 4 121 Less Closing inventory 382 * (1)both 3 739 (1)OF 4 581 Shop wages 2 600 (1) Profit for the year on shop 1 981 (1) OF
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2025 Feb/March, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.