Cambridge IGCSE Accounting 0452 — 2024 Feb/March Paper 2 · Variant 2
0452/22/F/M/24 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme17 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Gurjit is a trader
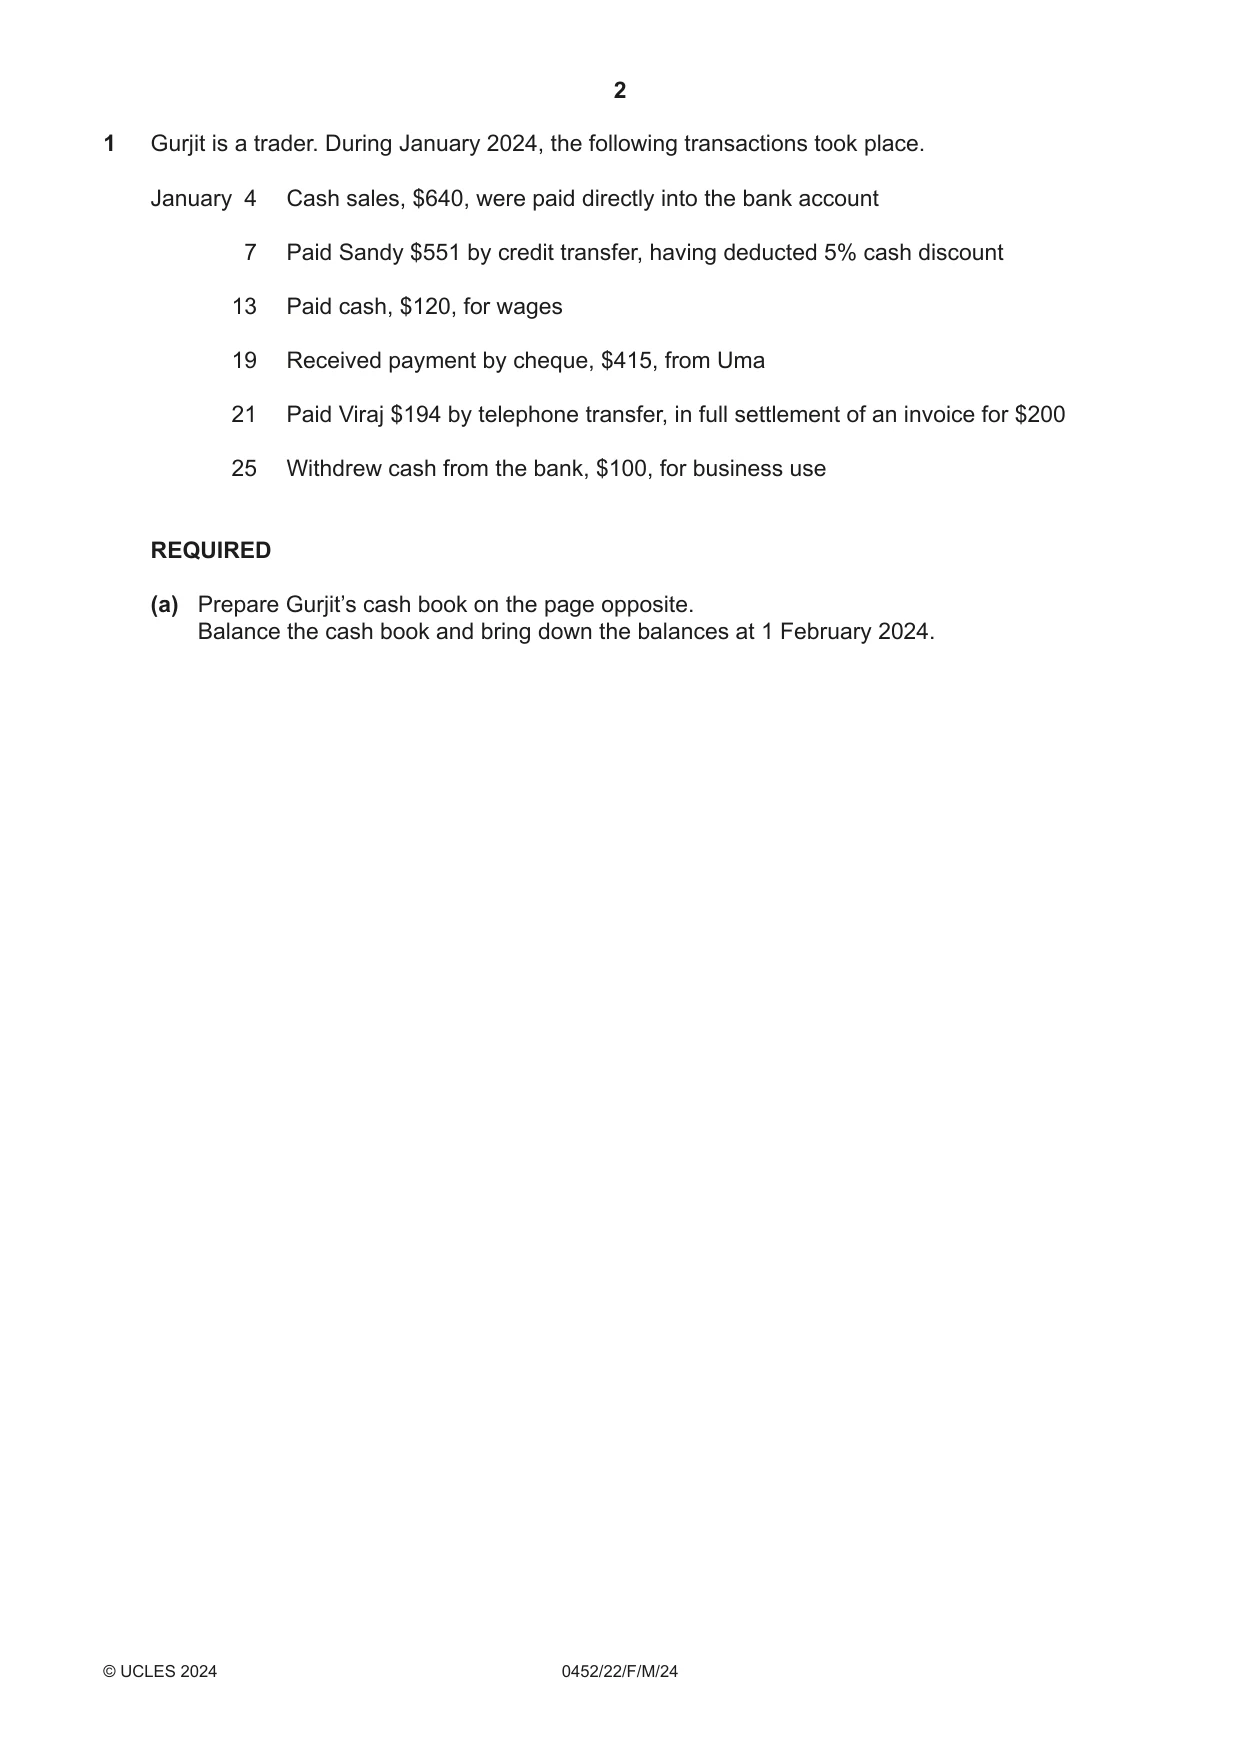
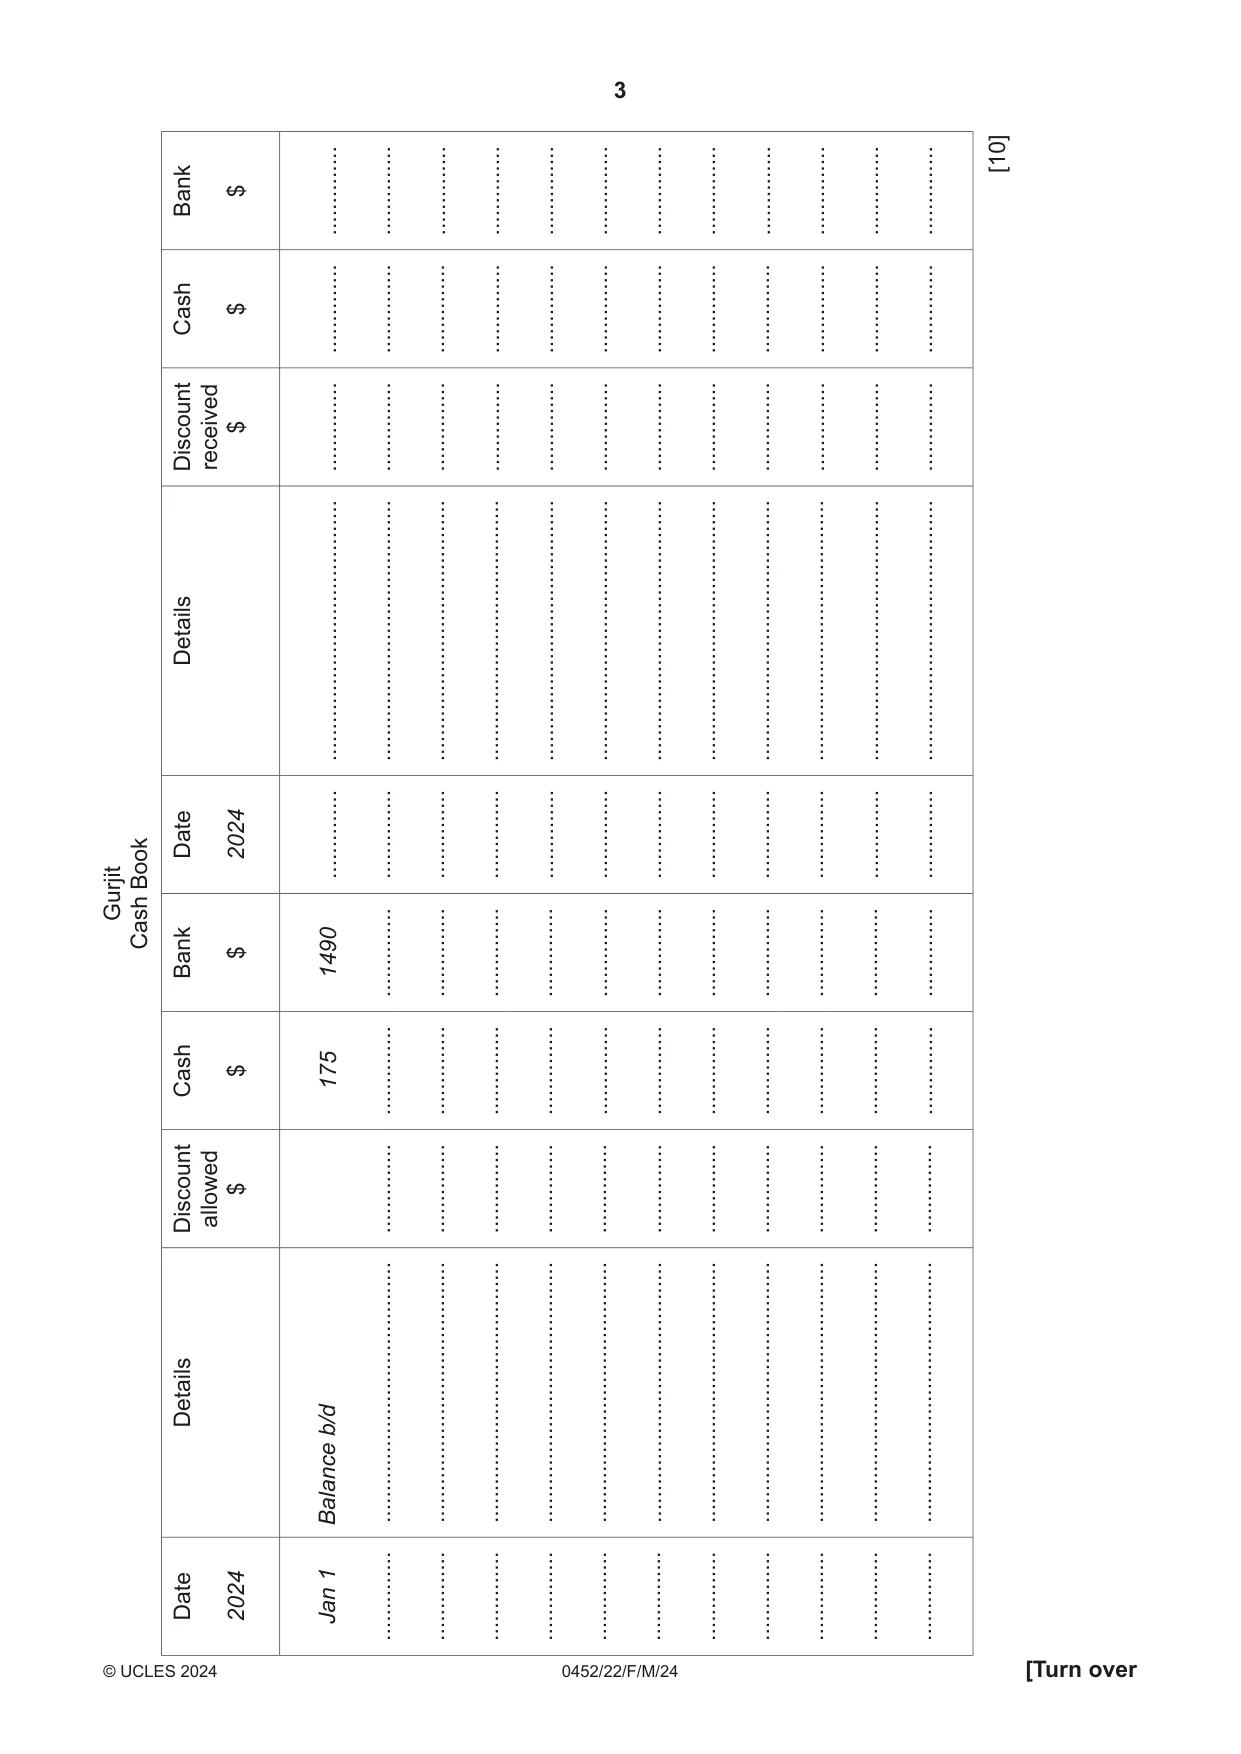
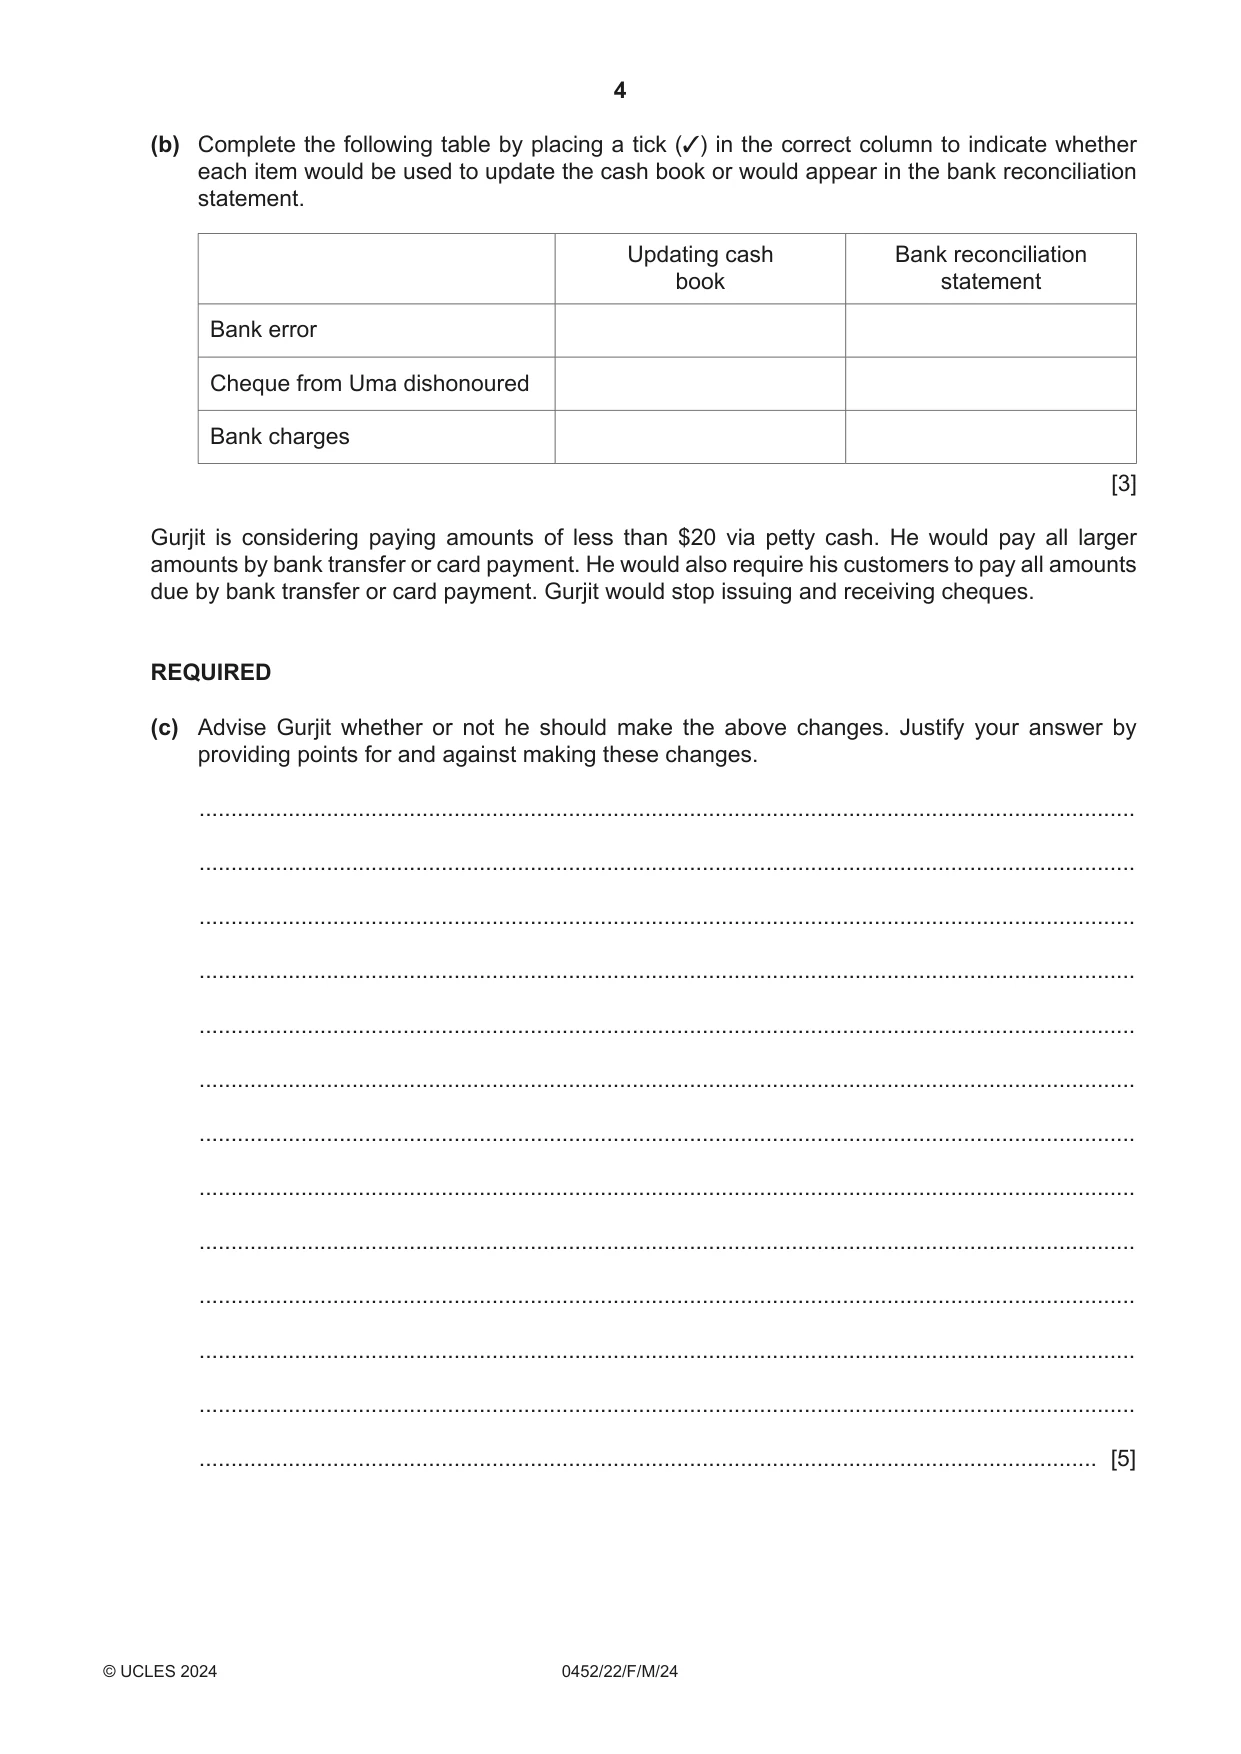
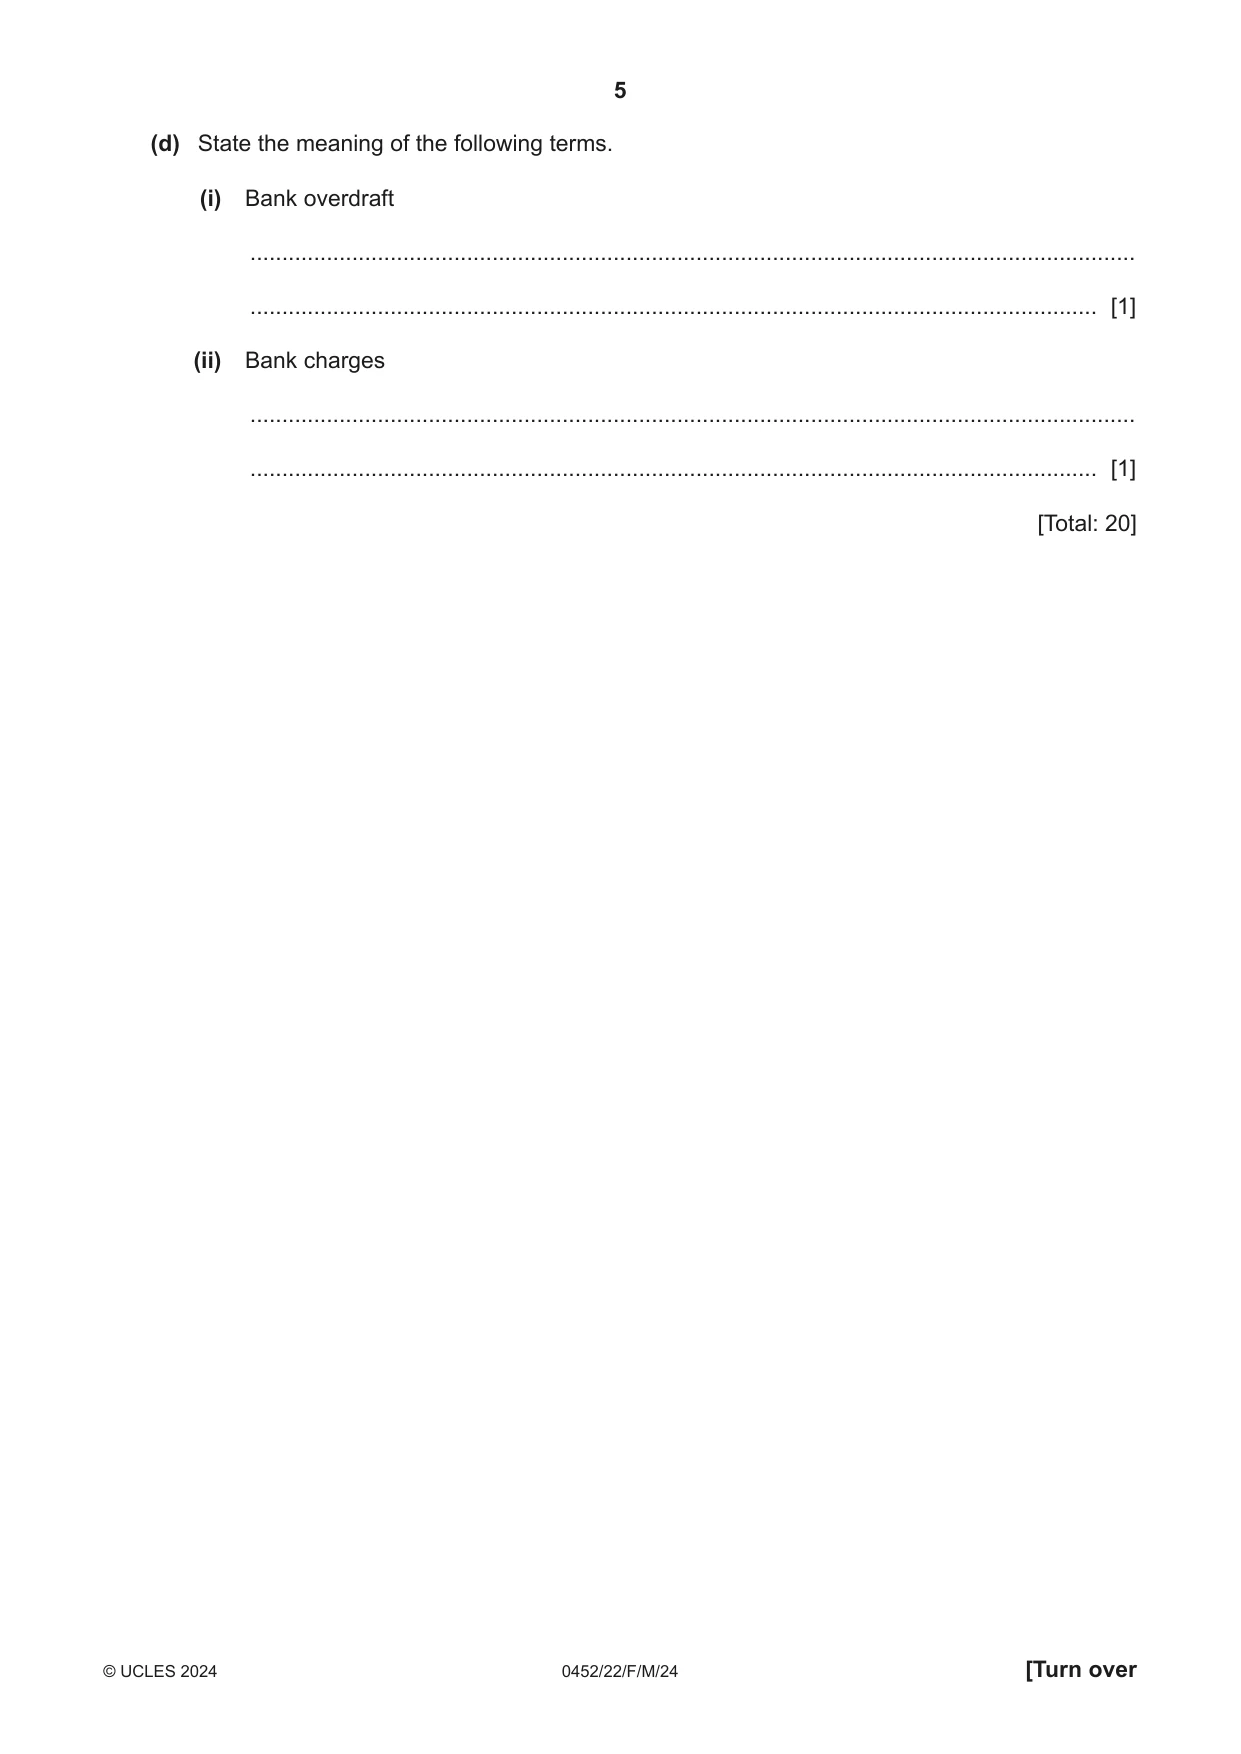
1 Gurjit is a trader. During January 2024, the following transactions took place. January 4 Cash sales, $640, were paid directly into the bank account 7 Paid Sandy $551 by credit transfer, having deducted 5% cash discount 13 Paid cash, $120, for wages 19 Received payment by cheque, $415, from Uma 21 Paid Viraj $194 by telephone transfer, in full settlement of an invoice for $200 25 Withdrew cash from the bank, $100, for business use REQUIRED (a) Prepare Gurjit’s cash book on the page opposite. Balance the cash book and bring down the balances at 1 February 2024. [10] $ Bank .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. $ Cash .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. $ Discountreceived .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. Details ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... Date 2024 .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. Book Gurjit Cash $ Bank 1490 .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. $ 175 Cash .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. $ Discountallowed .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. .............. Details b/d Balance ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... ......................................... (b) Complete the following table by placing a tick (3) in the correct column to indicate whether each item would be used to update the cash book or would appear in the bank reconciliation statement. Updating cash Bank reconciliation book statement Bank error Cheque from Uma dishonoured Bank charges [3] Gurjit is considering paying amounts of less than $20 via petty cash. He would pay all larger amounts by bank transfer or card payment. He would also require his customers to pay all amounts due by bank transfer or card payment. Gurjit would stop issuing and receiving cheques. REQUIRED (c) Advise Gurjit whether or not he should make the above changes. Justify your answer by providing points for and against making these changes. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] (d) State the meaning of the following terms. (i) Bank overdraft ........................................................................................................................................... ..................................................................................................................................... [1] (ii) Bank charges ........................................................................................................................................... ..................................................................................................................................... [1] [Total: 20]
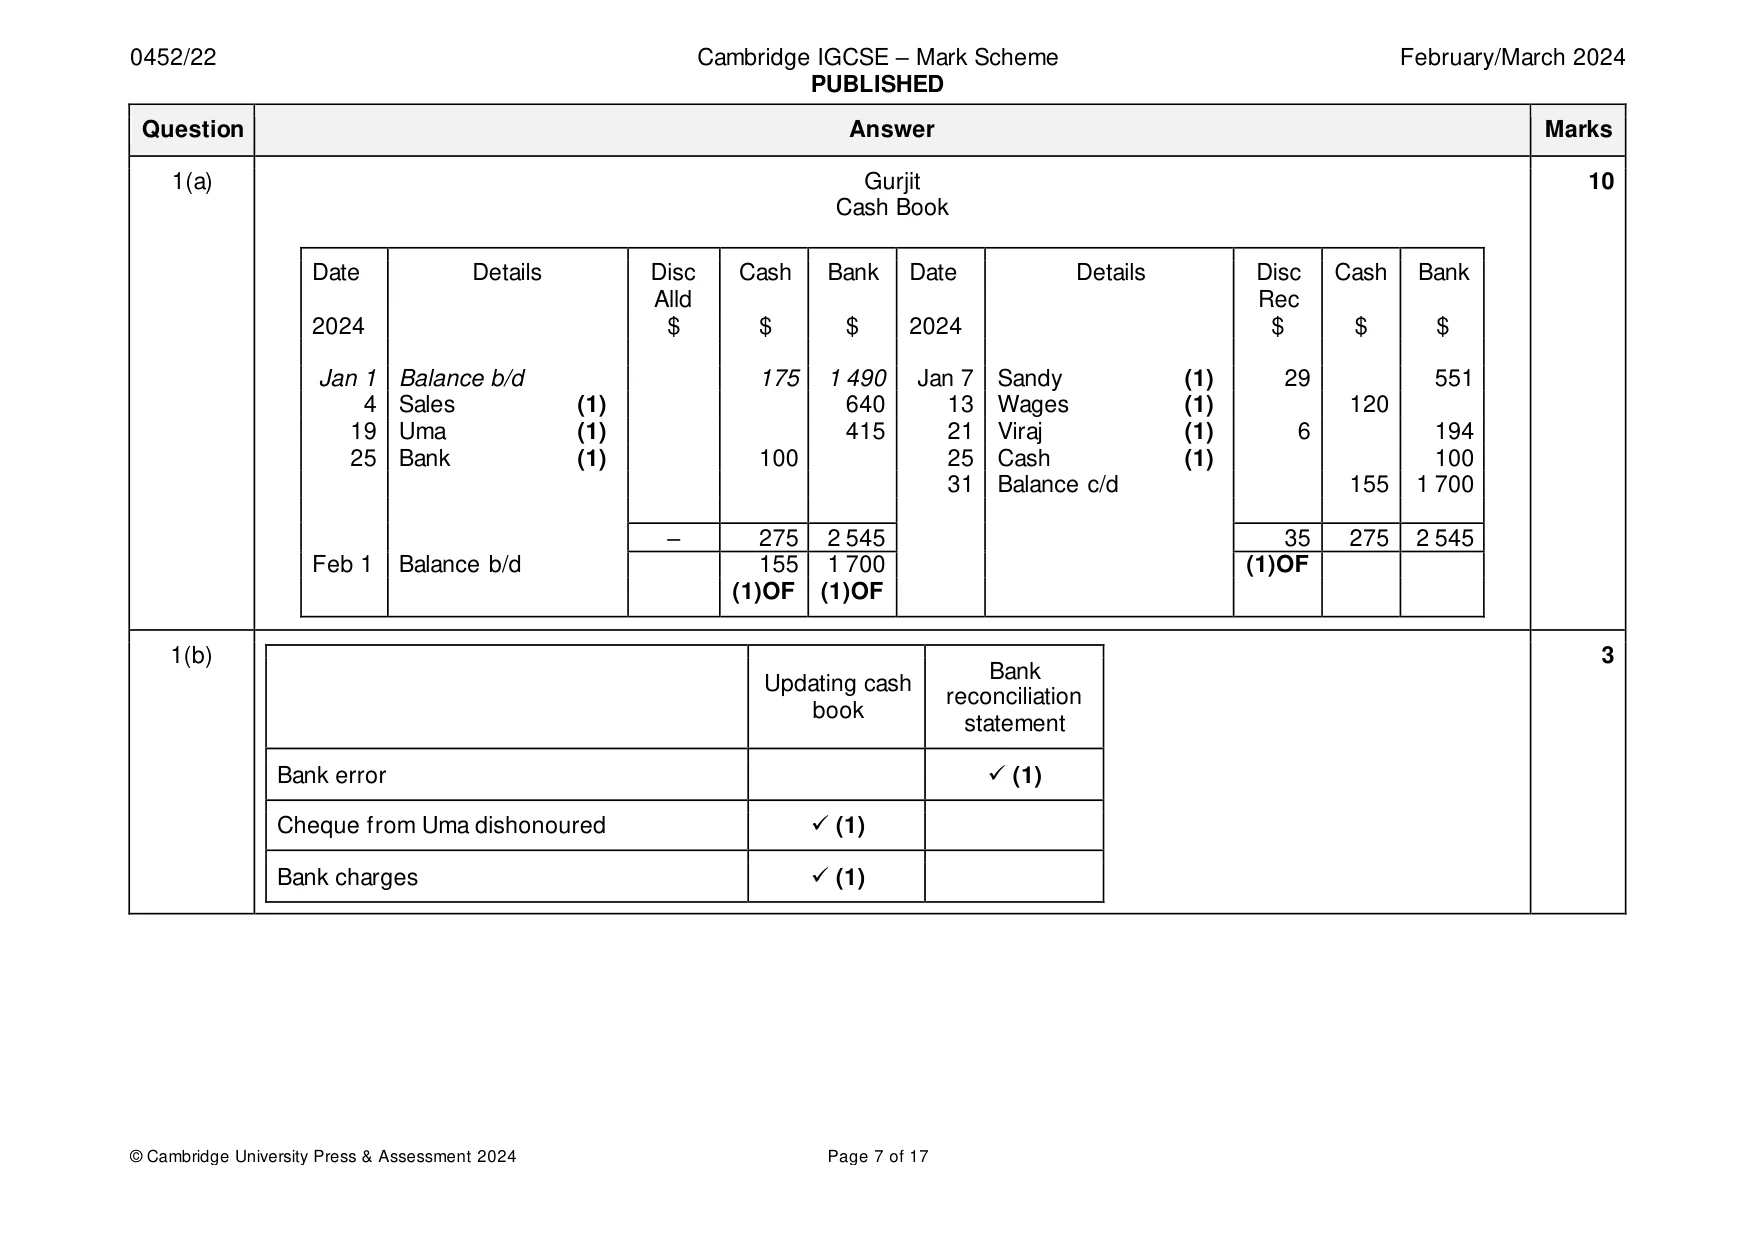
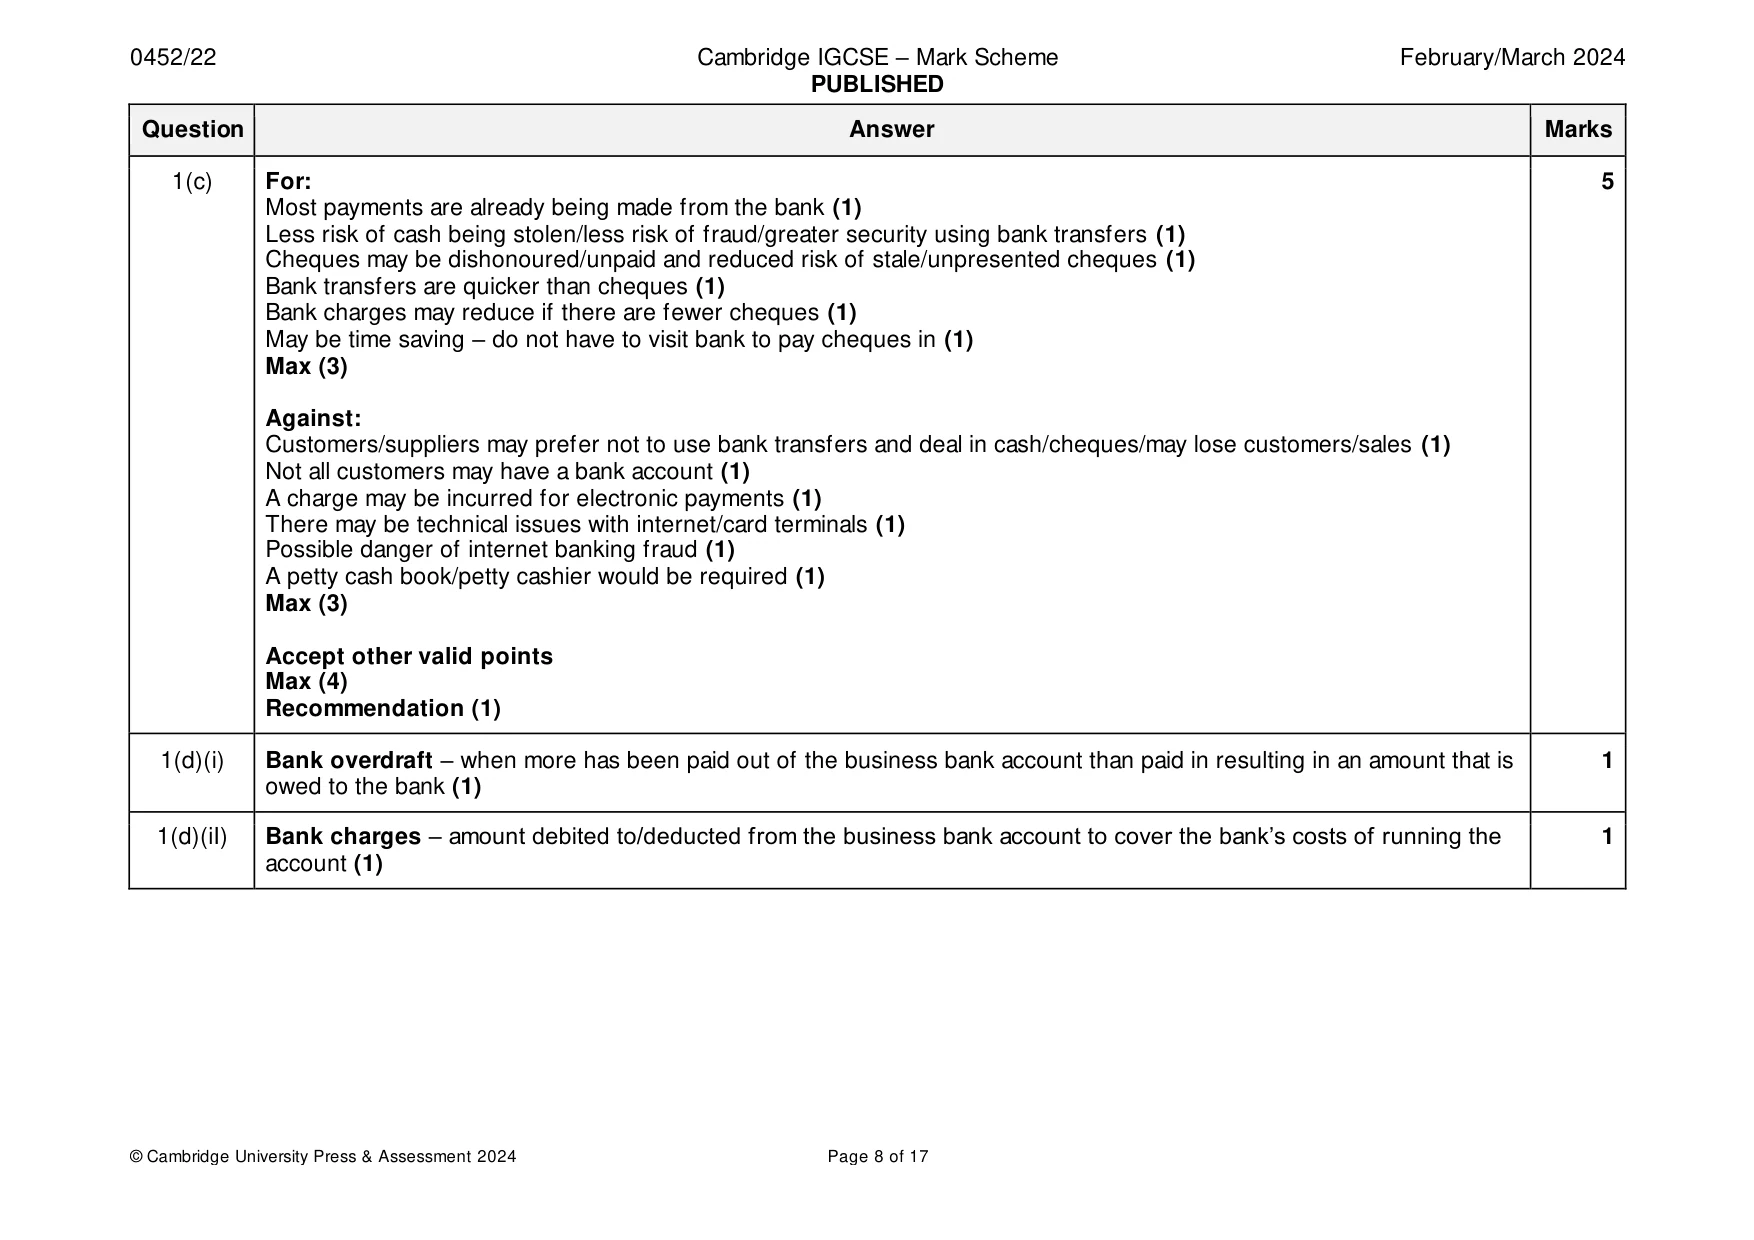
Mark scheme: Question Answer Marks 1(a) Gurjit 10 Cash Book Date Details Disc Cash Bank Date Details Disc Cash Bank Alld Rec 2024 $ $ $ 2024 $ $ $ Jan 1 Balance b/d 175 1 490 Jan 7 Sandy (1) 29 551 4 Sales (1) 640 13 Wages (1) 120 19 Uma (1) 415 21 Viraj (1) 6 194 25 Bank (1) 100 25 Cash (1) 100 31 Balance c/d 155 1 700 – 275 2 545 35 275 2 545 Feb 1 Balance b/d 155 1 700 (1)OF (1)OF (1)OF 1(b) 3 Bank Updating cash reconciliation book statement Bank error ✓ (1) Cheque from Uma dishonoured ✓ (1) Bank charges ✓ (1) 1(c) For: 5 Most payments are already being made from the bank (1) Less risk of cash being stolen/less risk of fraud/greater security using bank transfers (1) Cheques may be dishonoured/unpaid and reduced risk of stale/unpresented cheques (1) Bank transfers are quicker than cheques (1) Bank charges may reduce if there are fewer cheques (1) May be time saving – do not have to visit bank to pay cheques in (1) Max (3) Against: Customers/suppliers may prefer not to use bank transfers and deal in cash/cheques/may lose customers/sales (1) Not all customers may have a bank account (1) A charge may be incurred for electronic payments (1) There may be technical issues with internet/card terminals (1) Possible danger of internet banking fraud (1) A petty cash book/petty cashier would be required (1) Max (3) Accept other valid points Max (4) Recommendation (1) 1(d)(i) Bank overdraft – when more has been paid out of the business bank account than paid in resulting in an amount that is 1 owed to the bank (1) 1(d)(iI) Bank charges – amount debited to/deducted from the business bank account to cover the bank’s costs of running the 1 account (1)
Q2 · Samir buys and sells on credit
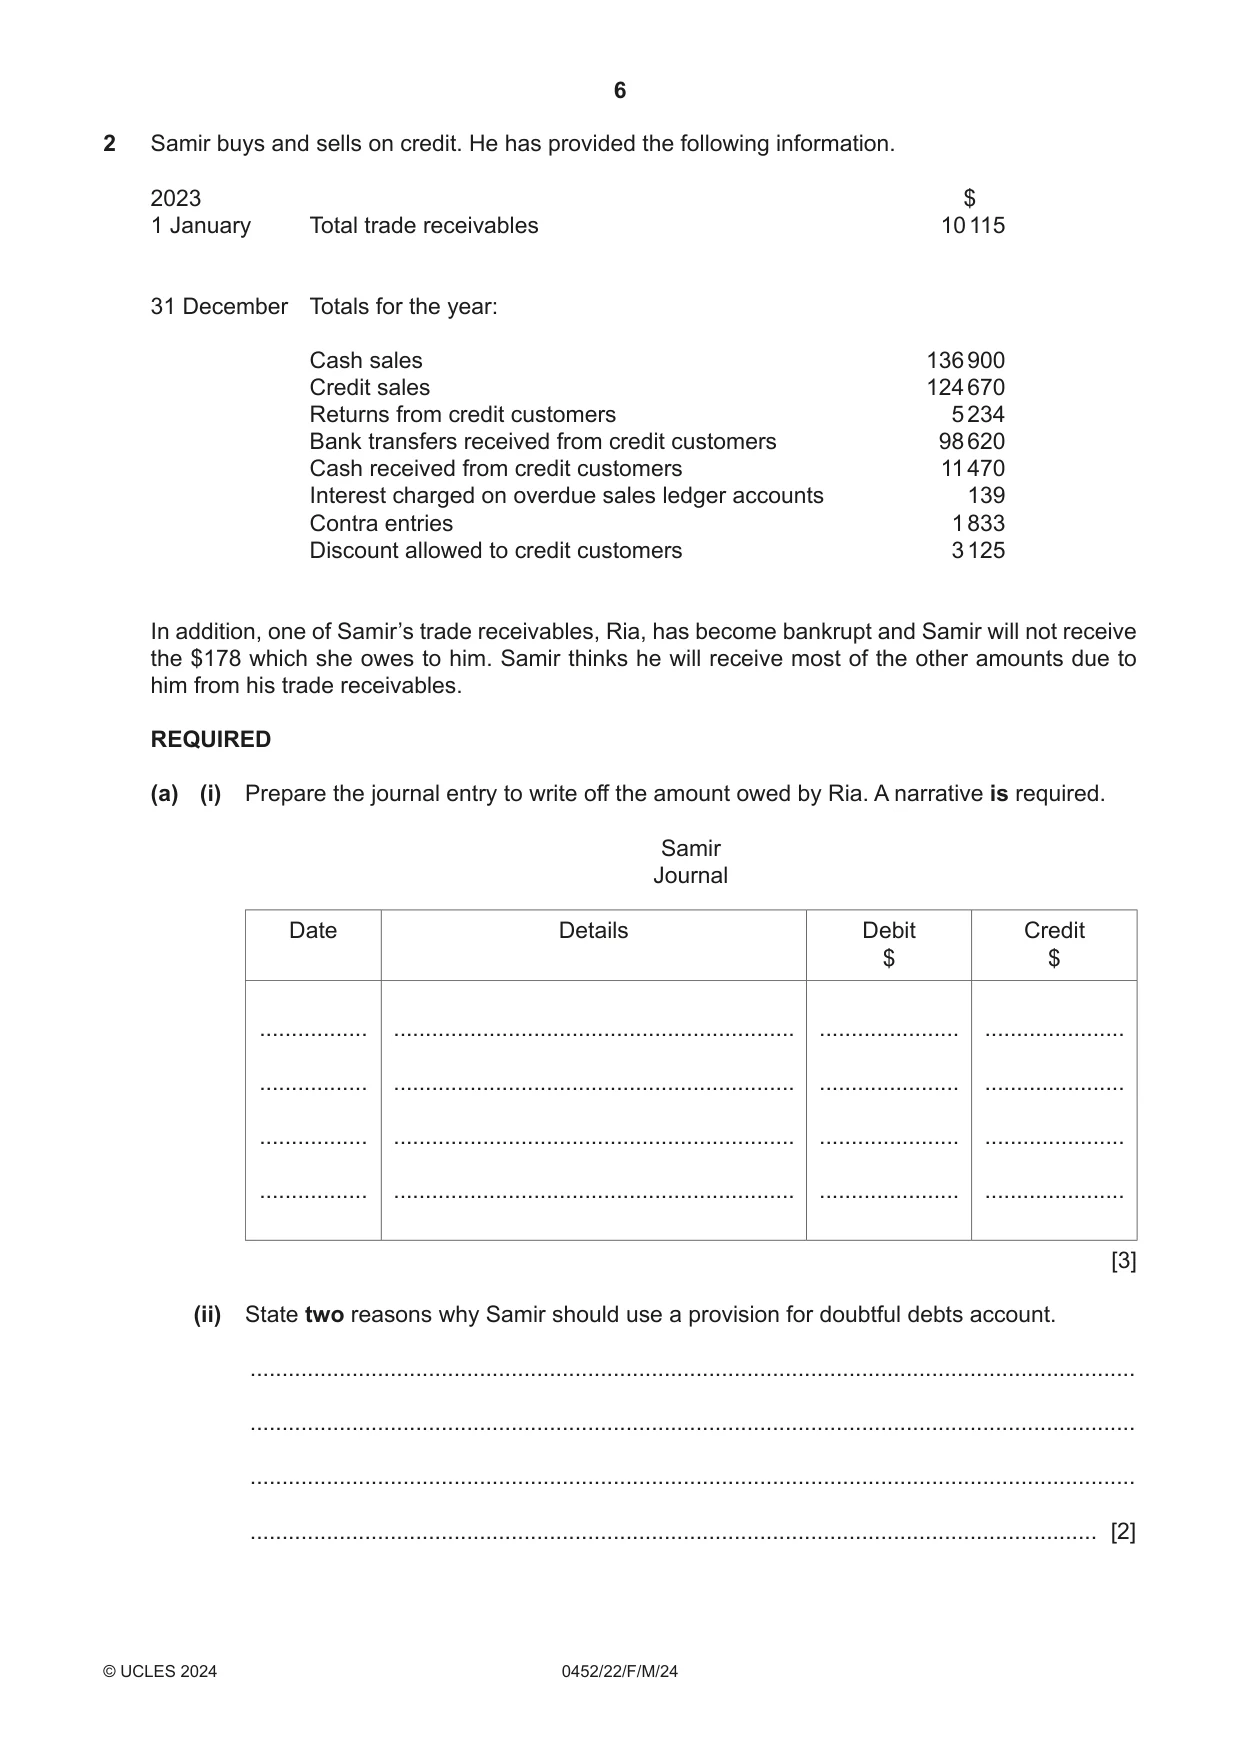
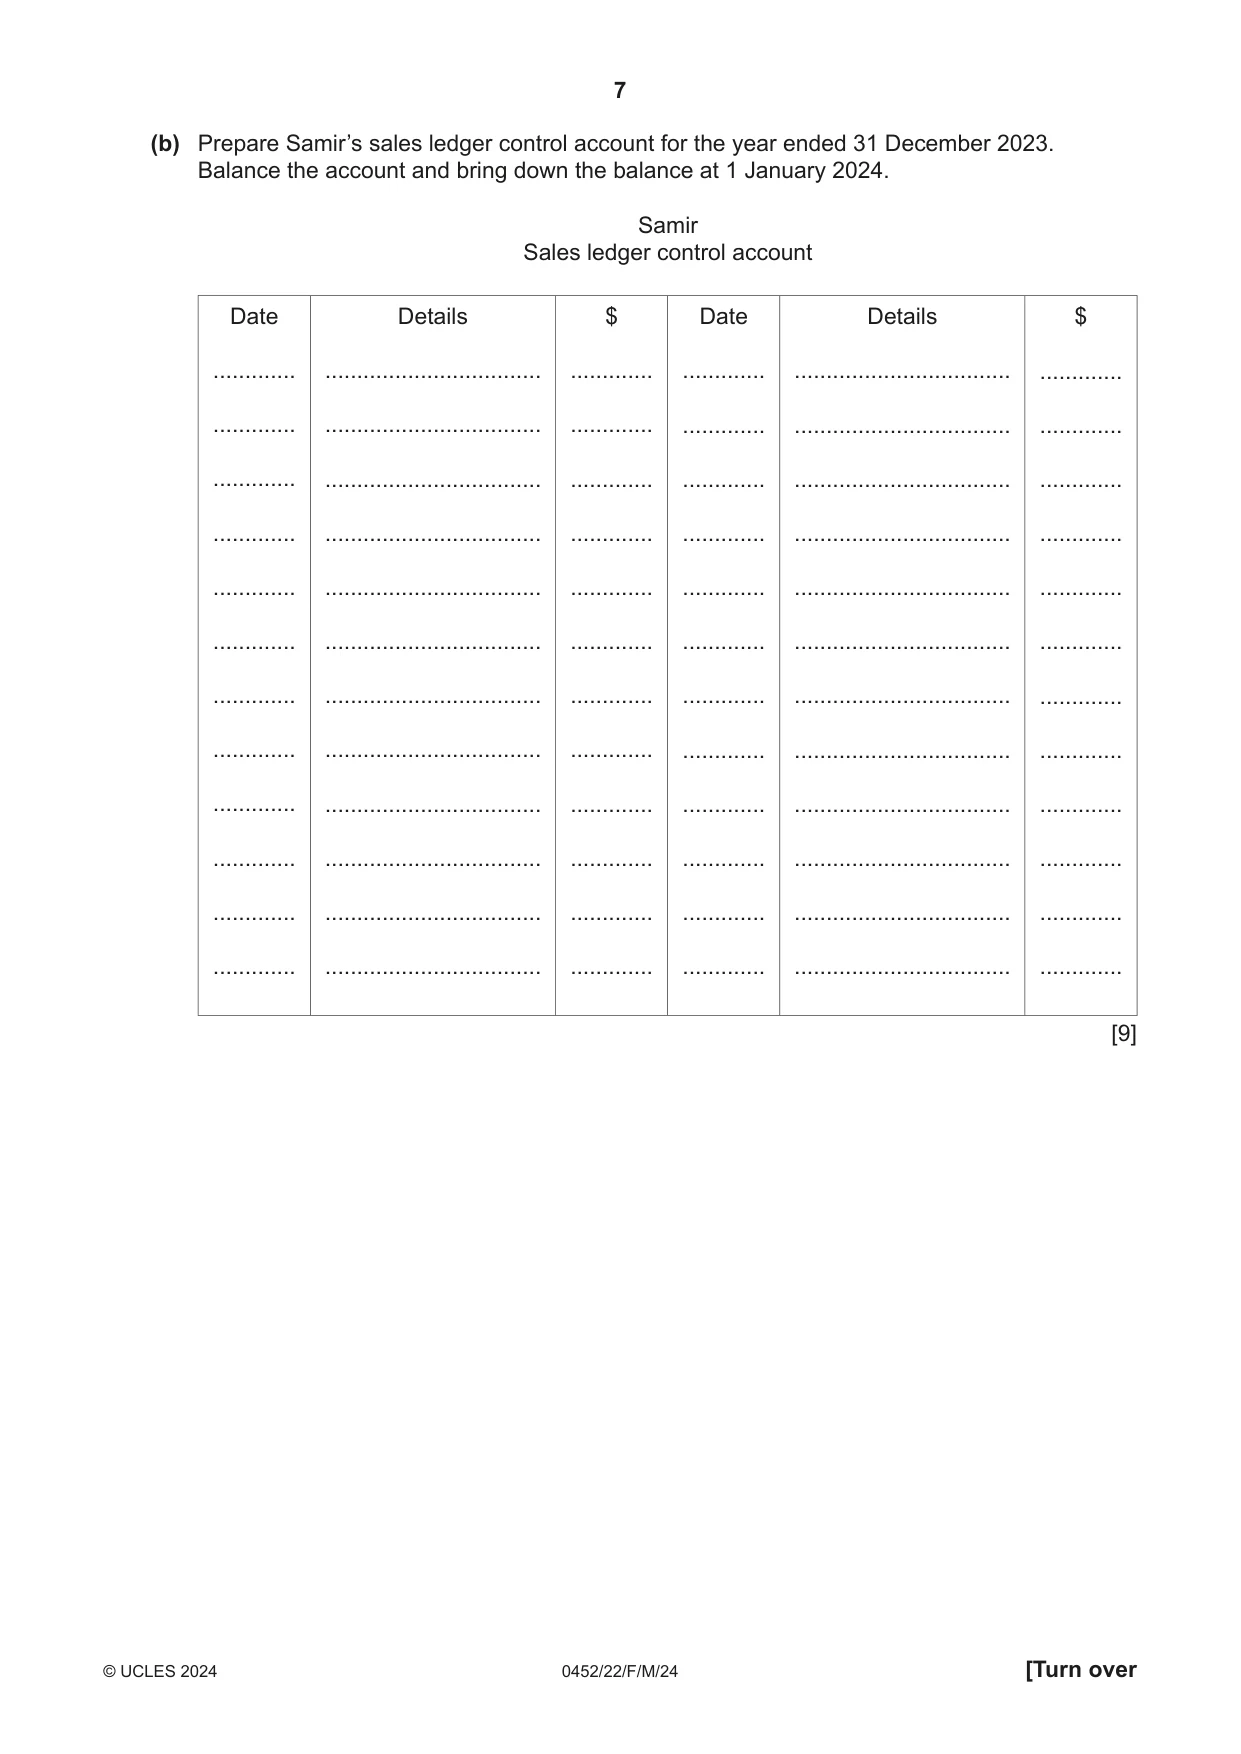
2 Samir buys and sells on credit. He has provided the following information. 2023 $ 1 January Total trade receivables 10 115 31 December Totals for the year: Cash sales 136 900 Credit sales 124 670 Returns from credit customers 5 234 Bank transfers received from credit customers 98 620 Cash received from credit customers 11 470 Interest charged on overdue sales ledger accounts 139 Contra entries 1 833 Discount allowed to credit customers 3 125 In addition, one of Samir’s trade receivables, Ria, has become bankrupt and Samir will not receive the $178 which she owes to him. Samir thinks he will receive most of the other amounts due to him from his trade receivables. REQUIRED (a) (i) Prepare the journal entry to write off the amount owed by Ria. A narrative is required. Samir Journal Date Details Debit Credit $ $ ................. ............................................................... ...................... ...................... ................. ............................................................... ...................... ...................... ................. ............................................................... ...................... ...................... ................. ............................................................... ...................... ...................... [3] (ii) State two reasons why Samir should use a provision for doubtful debts account. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] (b) Prepare Samir’s sales ledger control account for the year ended 31 December 2023. Balance the account and bring down the balance at 1 January 2024. Samir Sales ledger control account Date Details $ Date Details $ ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. [9] Samir is concerned about his ability to pay his trade payables. He is considering whether to stop allowing cash discount to his credit customers so that he will have more cash coming in and can pay his trade payables more easily. REQUIRED (c) (i) Advise Samir whether or not to stop allowing cash discount. Justify your answer by providing advantages and disadvantages of stopping cash discount to his credit customers. ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [5] (ii) Suggest one other action which Samir could take to ensure that he has sufficient cash to pay his trade payables. ........................................................................................................................................... ..................................................................................................................................... [1] [Total: 20]
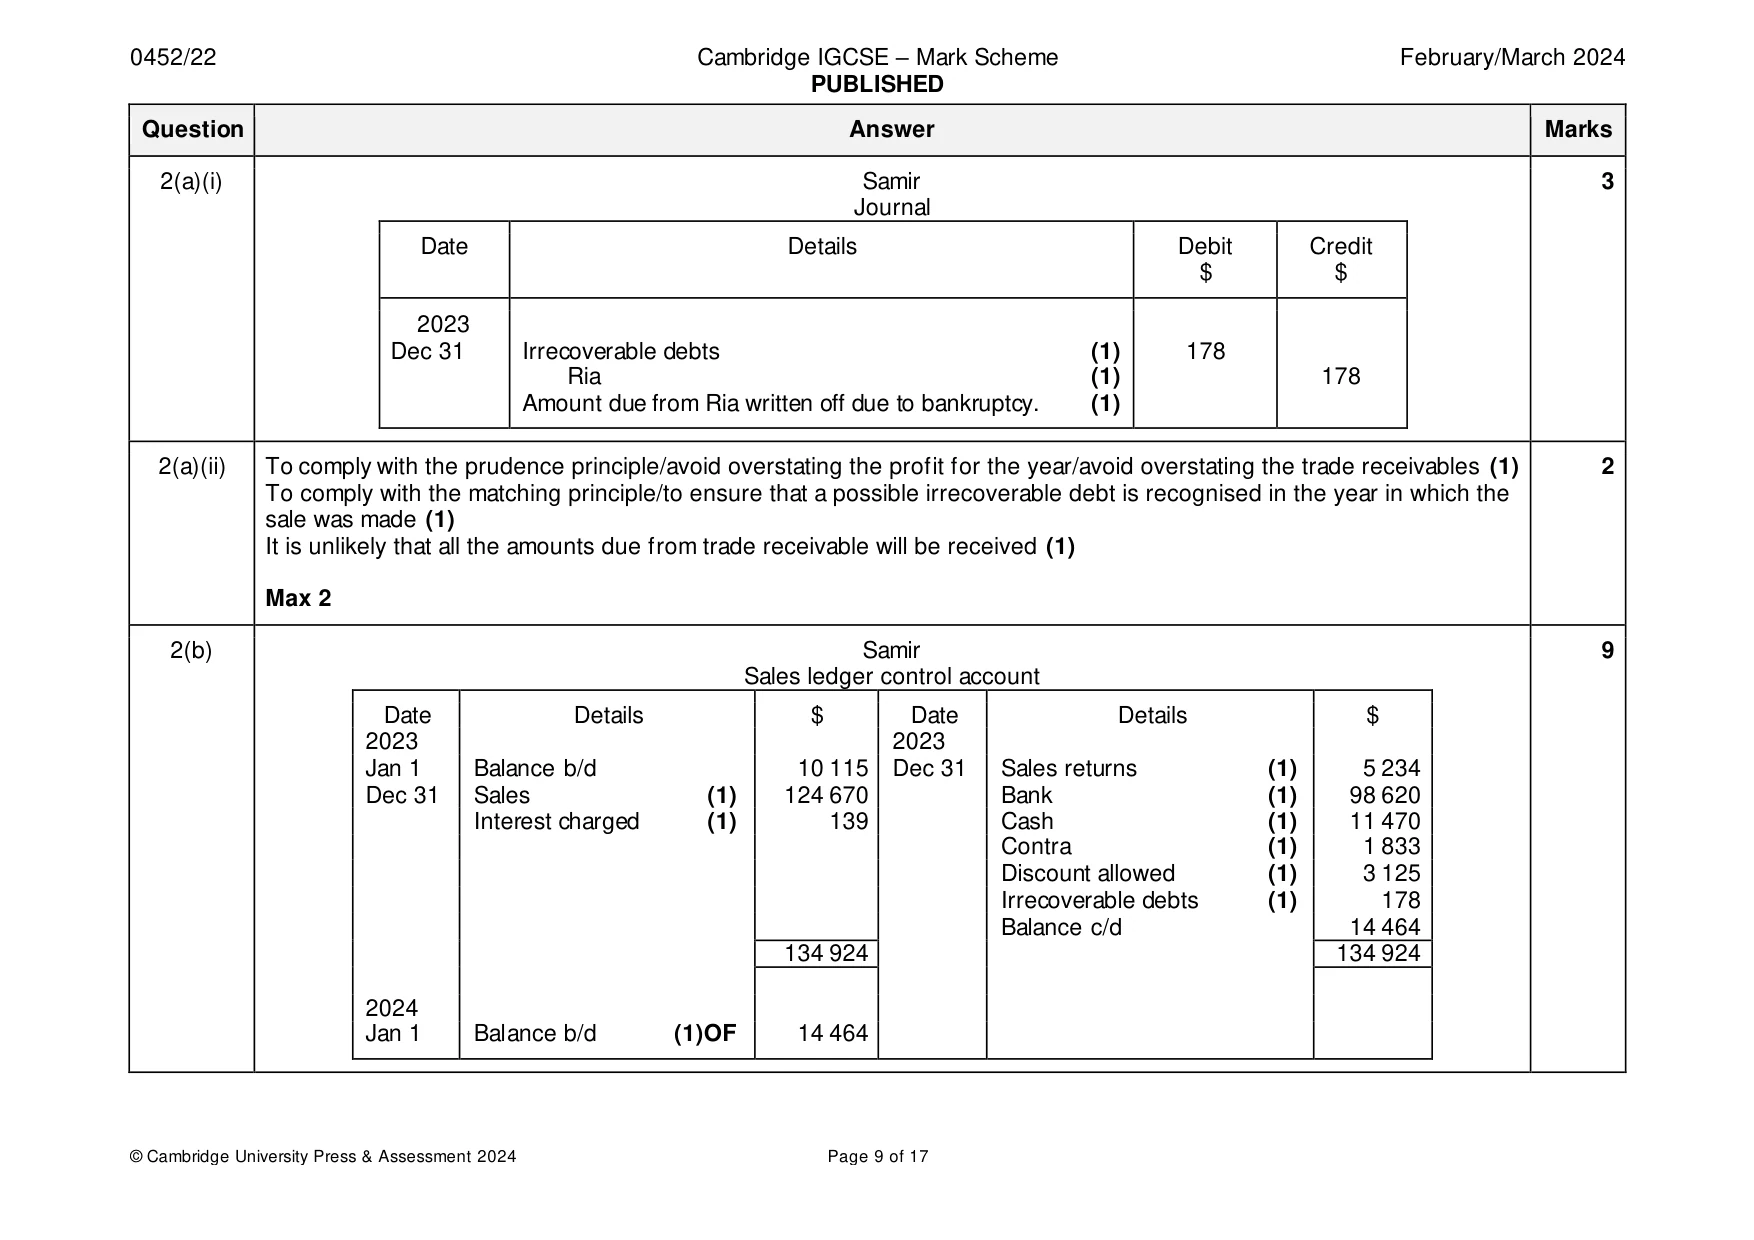
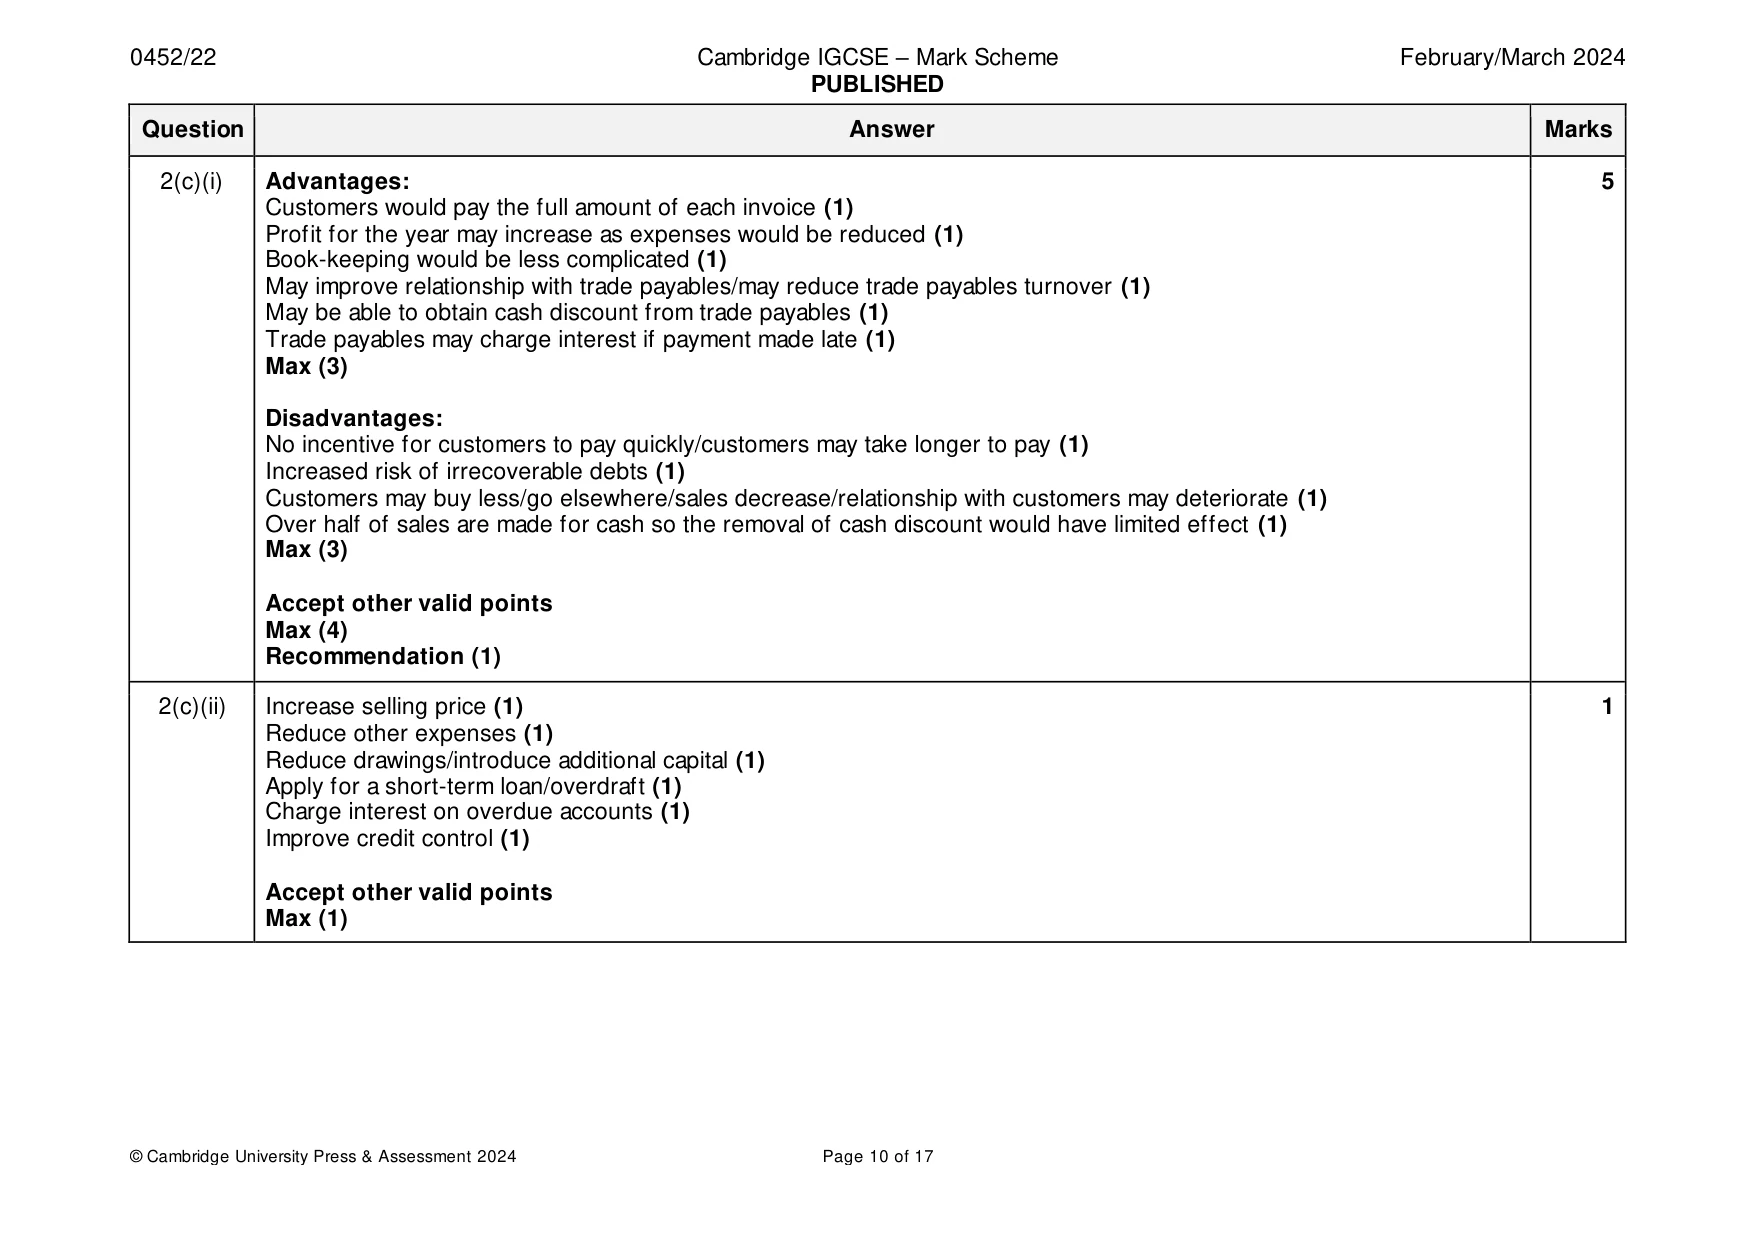
Mark scheme: 2(a)(i) Samir 3 Journal Date Details Debit Credit $ $ 2023 Dec 31 Irrecoverable debts (1) 178 Ria (1) 178 Amount due from Ria written off due to bankruptcy. (1) 2(a)(ii) To comply with the prudence principle/avoid overstating the profit for the year/avoid overstating the trade receivables (1) 2 To comply with the matching principle/to ensure that a possible irrecoverable debt is recognised in the year in which the sale was made (1) It is unlikely that all the amounts due from trade receivable will be received (1) Max 2 2(b) Samir 9 Sales ledger control account Date Details $ Date Details $ 2023 2023 Jan 1 Balance b/d 10 115 Dec 31 Sales returns (1) 5 234 Dec 31 Sales (1) 124 670 Bank (1) 98 620 Interest charged (1) 139 Cash (1) 11 470 Contra (1) 1 833 Discount allowed (1) 3 125 Irrecoverable debts (1) 178 Balance c/d 14 464 134 924 134 924 2024 Jan 1 Balance b/d (1)OF 14 464 2(c)(i) Advantages: 5 Customers would pay the full amount of each invoice (1) Profit for the year may increase as expenses would be reduced (1) Book-keeping would be less complicated (1) May improve relationship with trade payables/may reduce trade payables turnover (1) May be able to obtain cash discount from trade payables (1) Trade payables may charge interest if payment made late (1) Max (3) Disadvantages: No incentive for customers to pay quickly/customers may take longer to pay (1) Increased risk of irrecoverable debts (1) Customers may buy less/go elsewhere/sales decrease/relationship with customers may deteriorate (1) Over half of sales are made for cash so the removal of cash discount would have limited effect (1) Max (3) Accept other valid points Max (4) Recommendation (1) 2(c)(ii) Increase selling price (1) 1 Reduce other expenses (1) Reduce drawings/introduce additional capital (1) Apply for a short-term loan/overdraft (1) Charge interest on overdue accounts (1) Improve credit control (1) Accept other valid points Max (1)
More questions on Irrecoverable debts and allowance for irrecoverable debts
Q3 · The Sporting Excellence Club provides sports facilities for its members
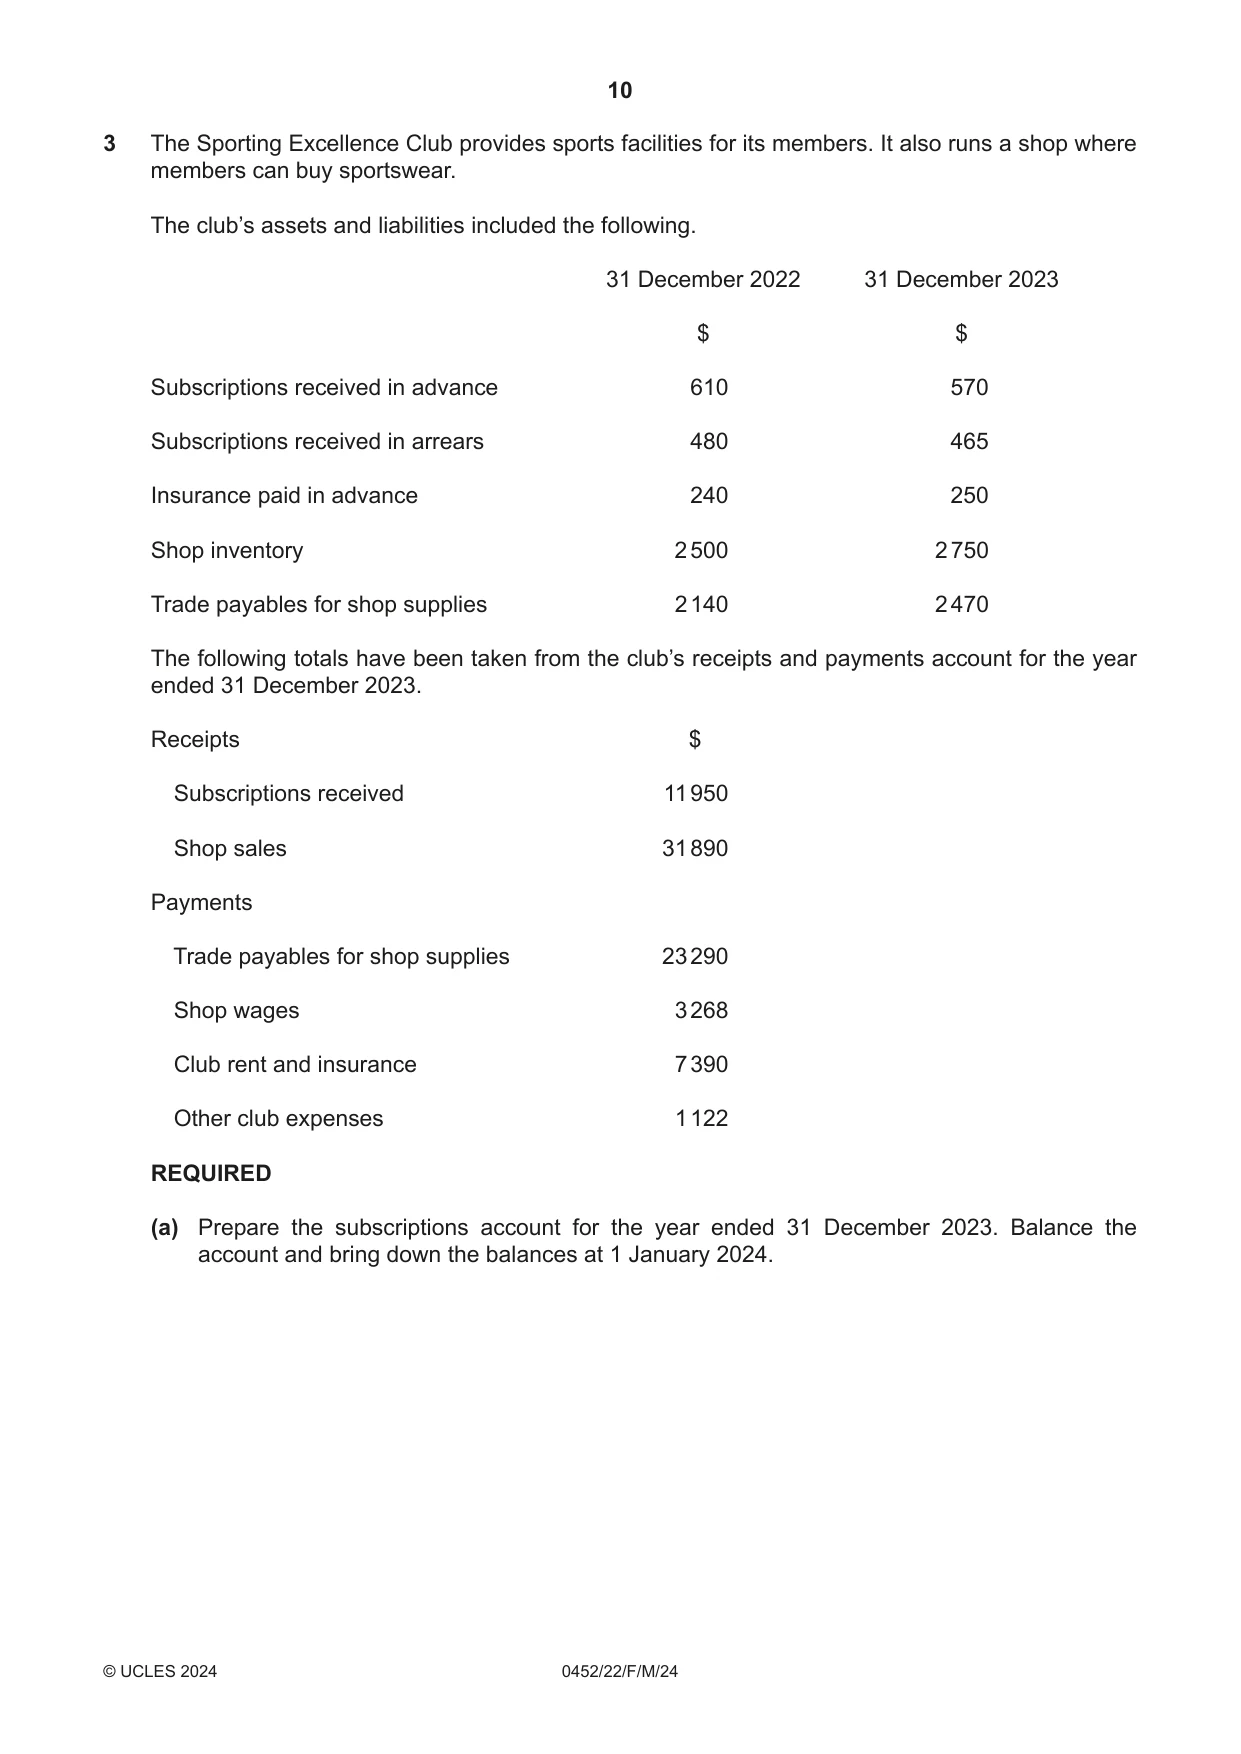
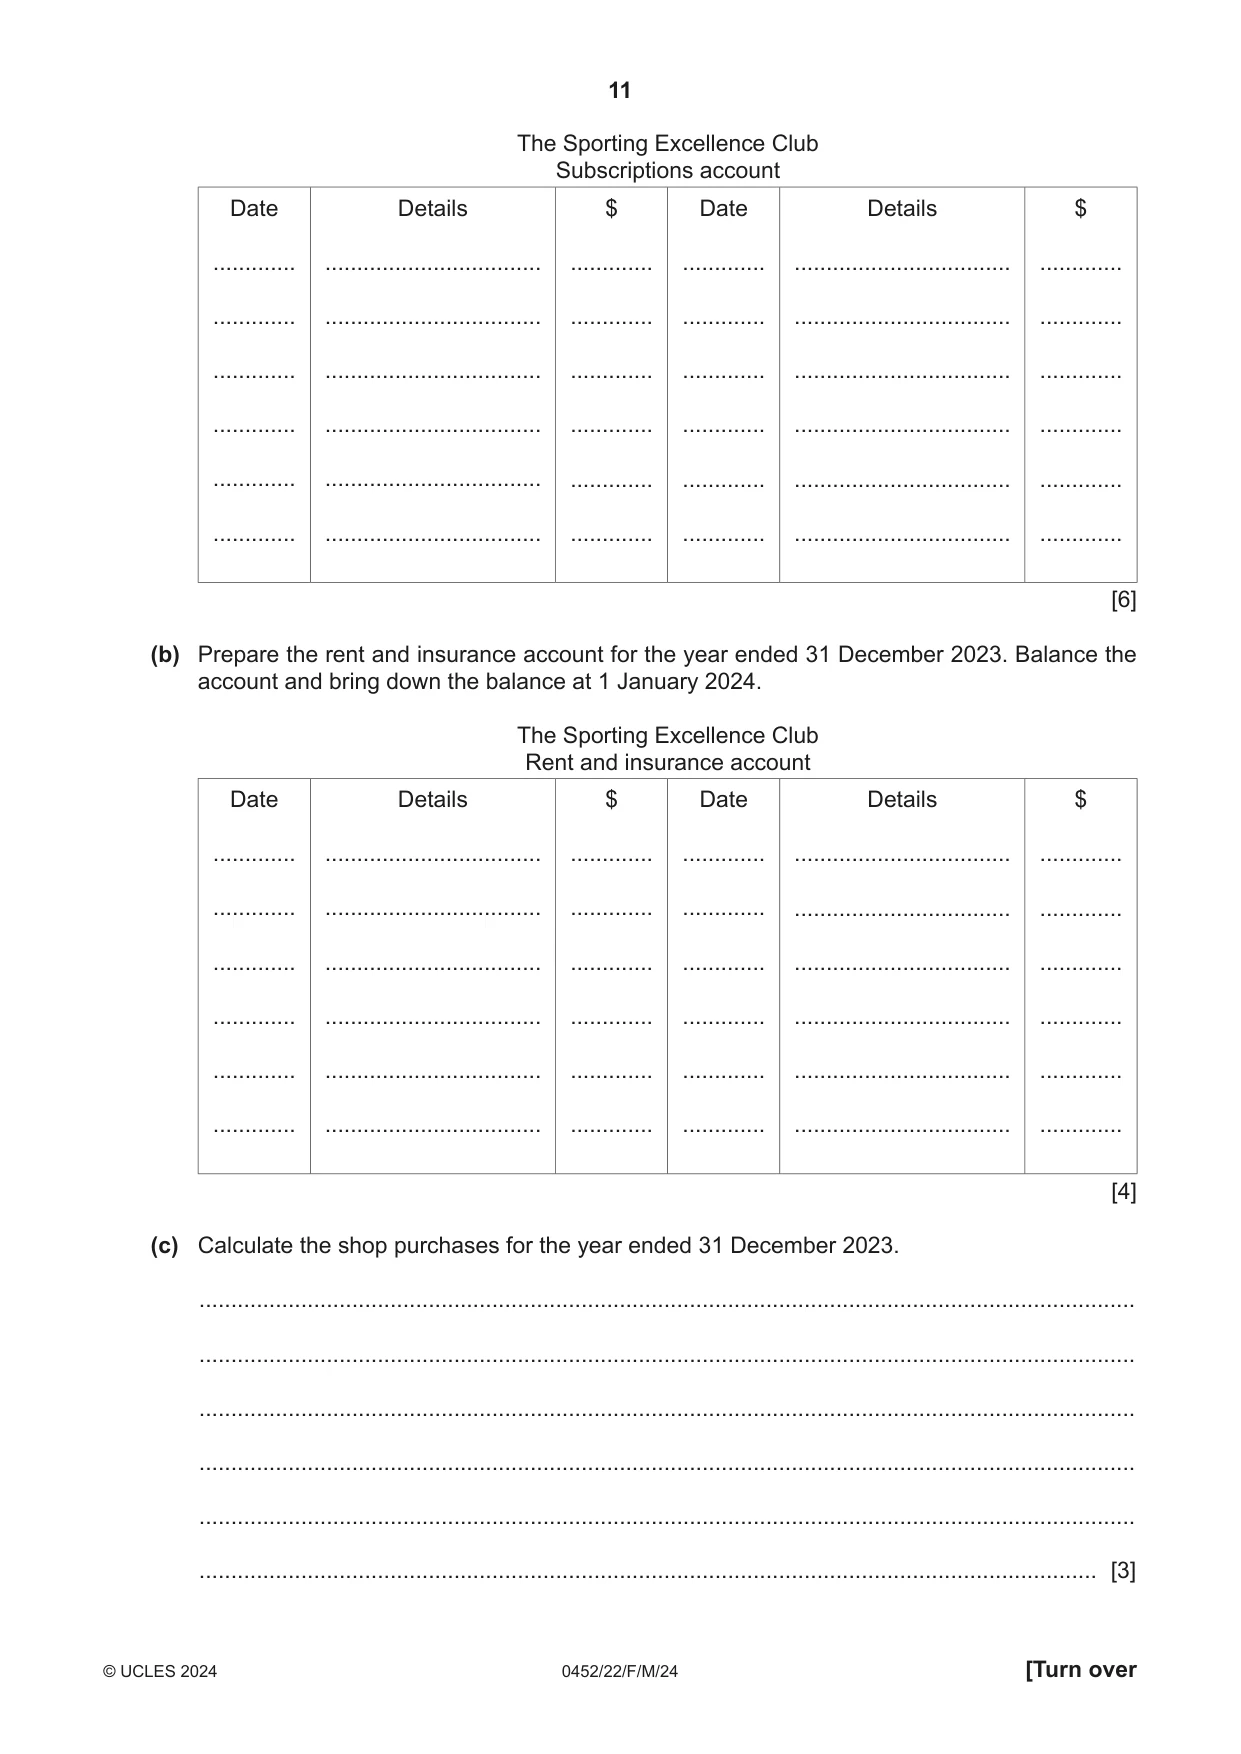
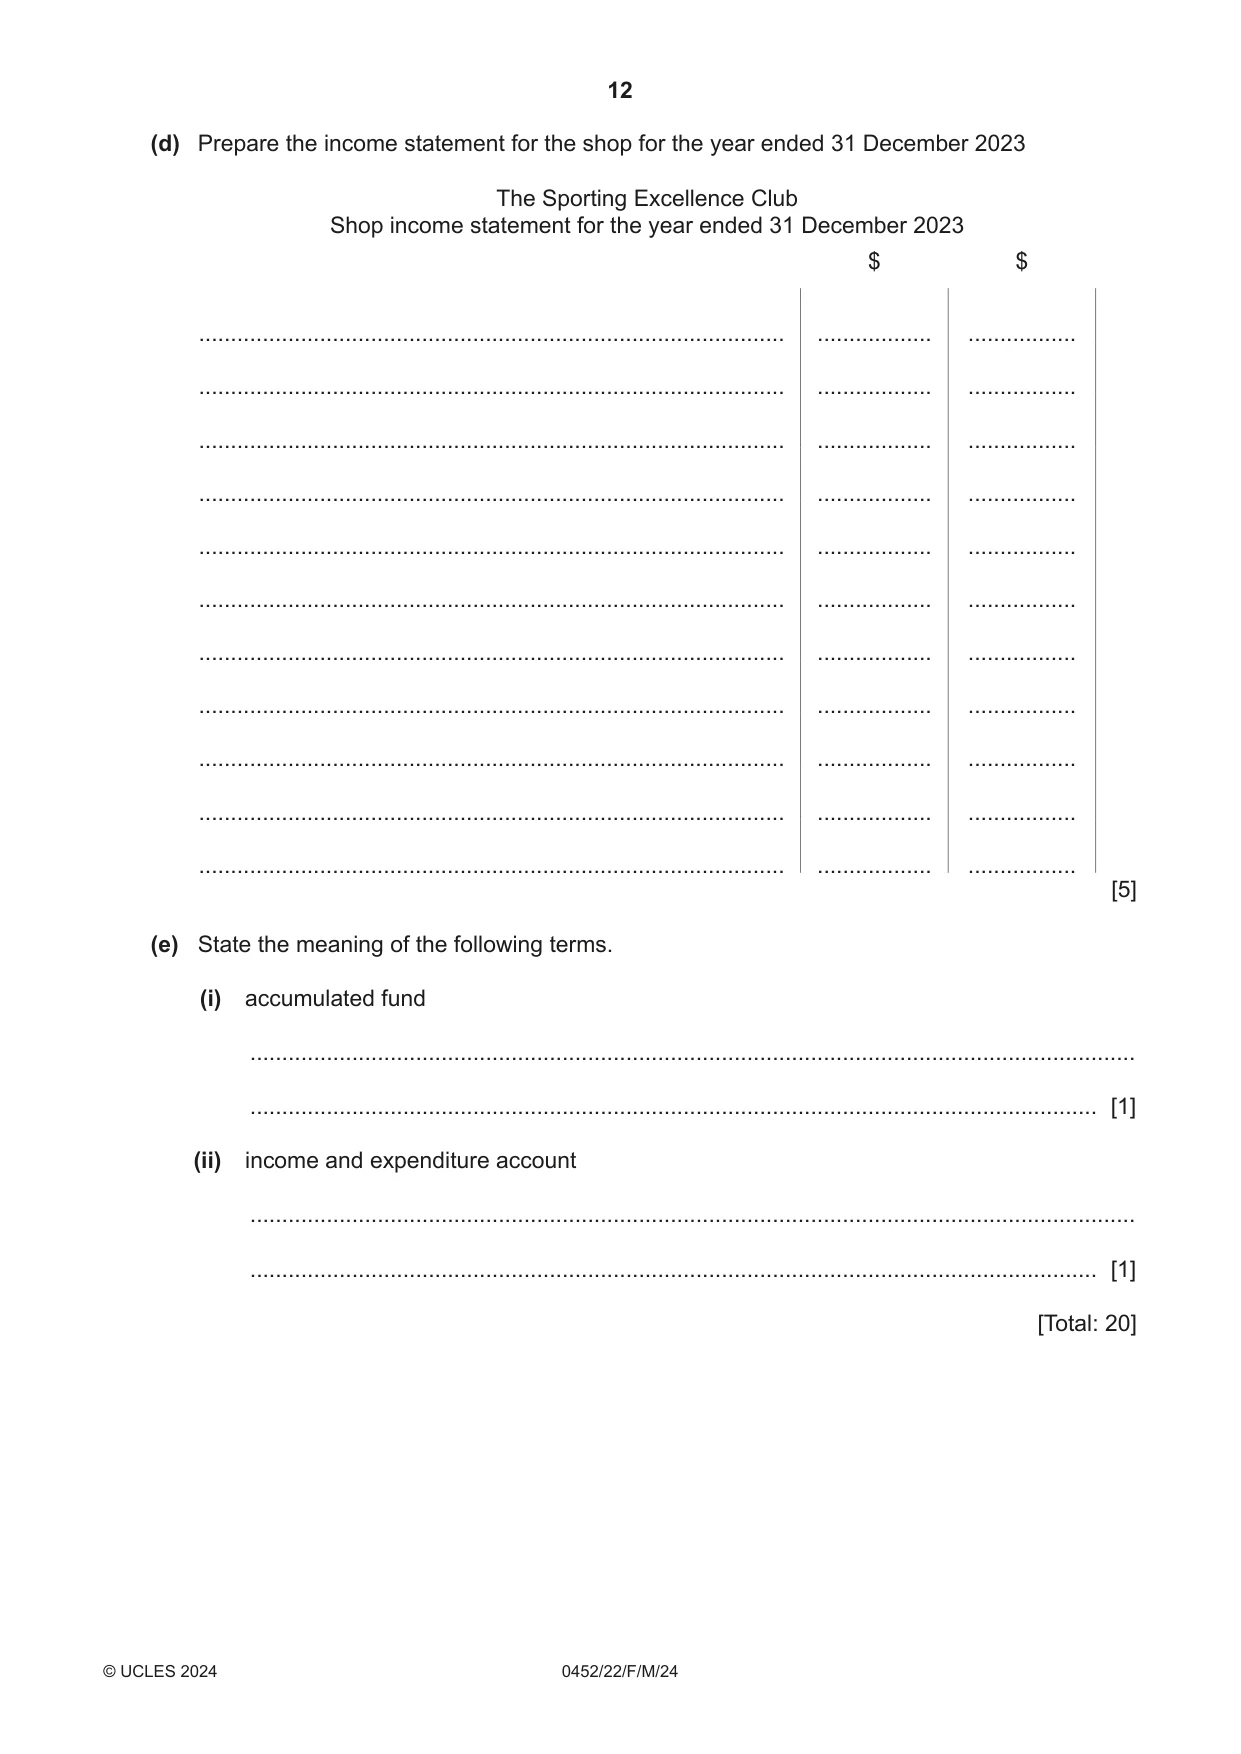
3 The Sporting Excellence Club provides sports facilities for its members. It also runs a shop where members can buy sportswear. The club’s assets and liabilities included the following. 31 December 2022 31 December 2023 $ $ Subscriptions received in advance 610 570 Subscriptions received in arrears 480 465 Insurance paid in advance 240 250 Shop inventory 2 500 2 750 Trade payables for shop supplies 2 140 2 470 The following totals have been taken from the club’s receipts and payments account for the year ended 31 December 2023. Receipts $ Subscriptions received 11 950 Shop sales 31 890 Payments Trade payables for shop supplies 23 290 Shop wages 3 268 Club rent and insurance 7 390 Other club expenses 1 122 REQUIRED (a) Prepare the subscriptions account for the year ended 31 December 2023. Balance the account and bring down the balances at 1 January 2024. The Sporting Excellence Club Subscriptions account Date Details $ Date Details $ ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. [6] (b) Prepare the rent and insurance account for the year ended 31 December 2023. Balance the account and bring down the balance at 1 January 2024. The Sporting Excellence Club Rent and insurance account Date Details $ Date Details $ ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. [4] (c) Calculate the shop purchases for the year ended 31 December 2023. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] (d) Prepare the income statement for the shop for the year ended 31 December 2023 The Sporting Excellence Club Shop income statement for the year ended 31 December 2023 $ $ ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. ............................................................................................ .................. ................. [5] (e) State the meaning of the following terms. (i) accumulated fund ........................................................................................................................................... ..................................................................................................................................... [1] (ii) income and expenditure account ........................................................................................................................................... ..................................................................................................................................... [1] [Total: 20]
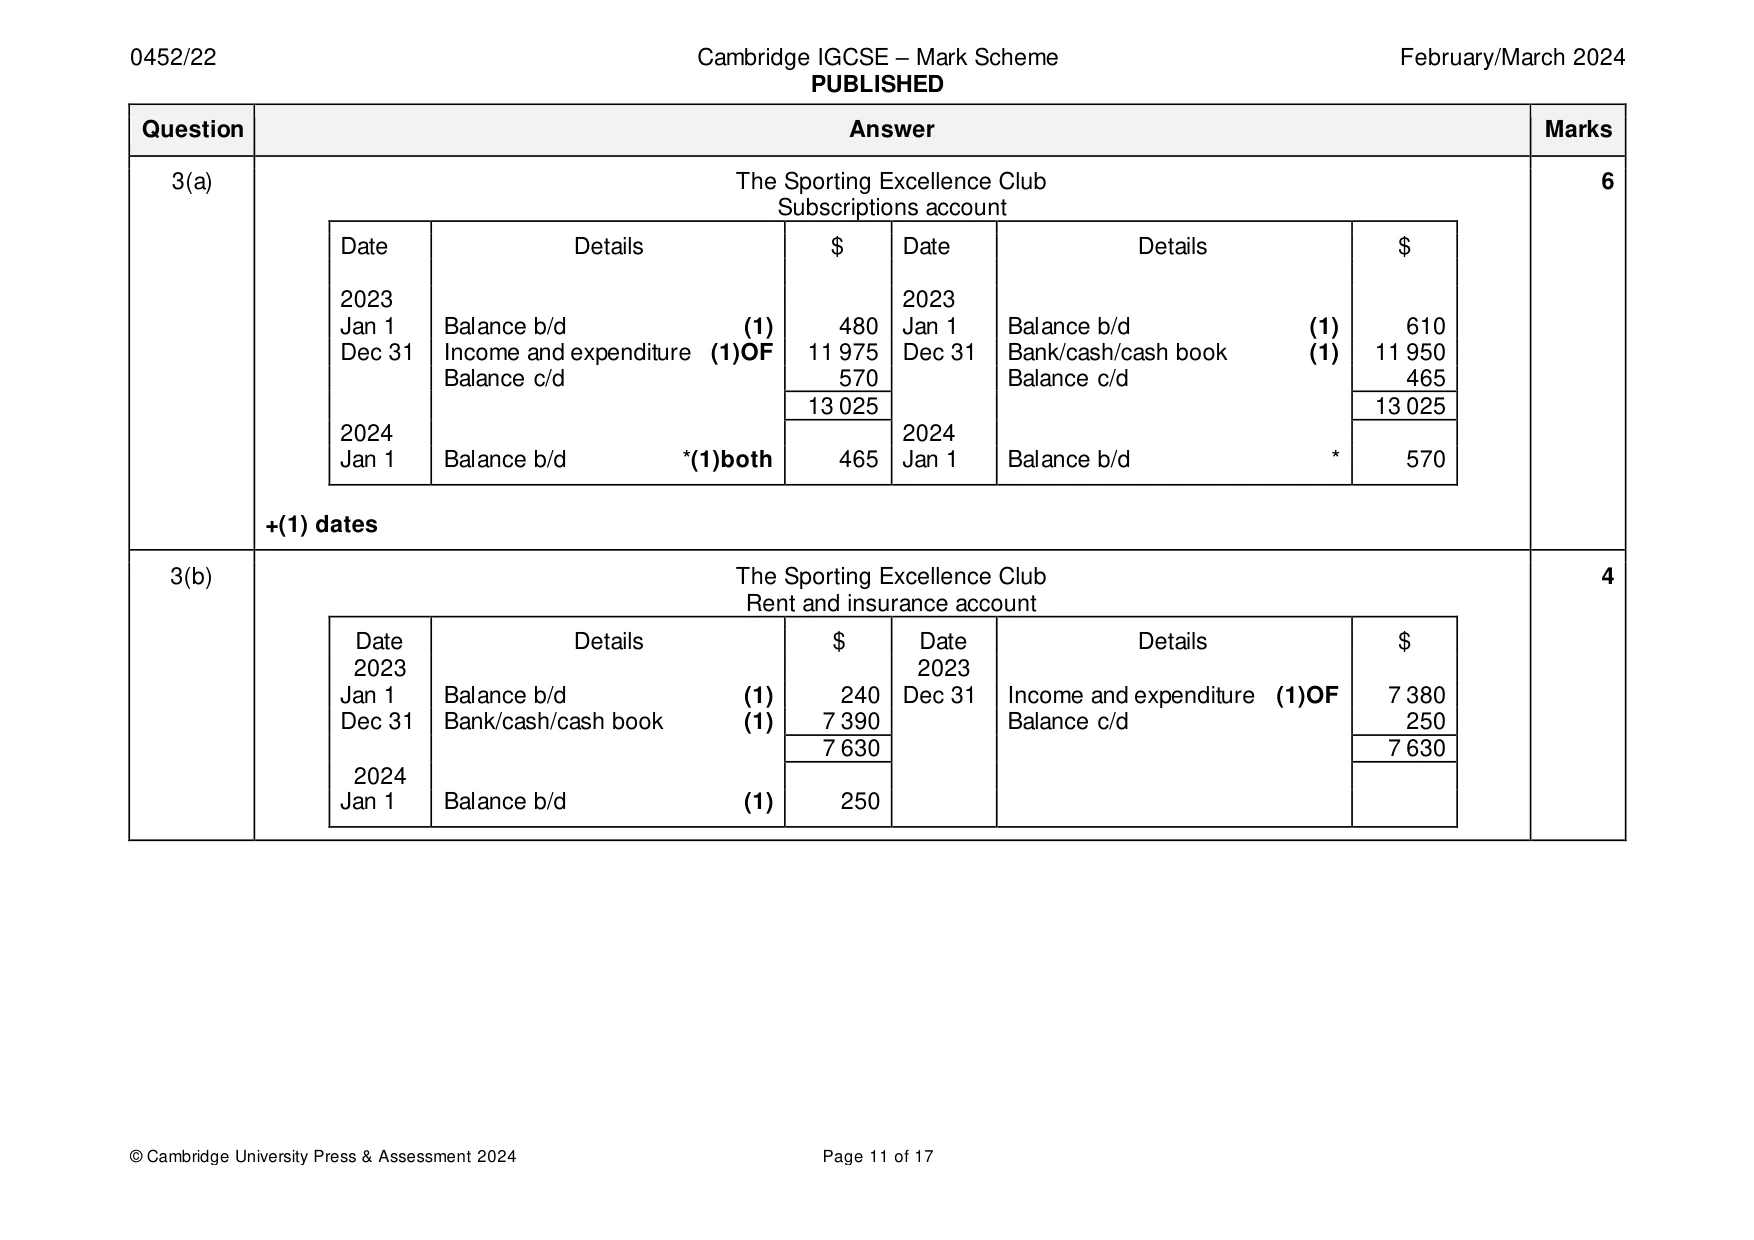
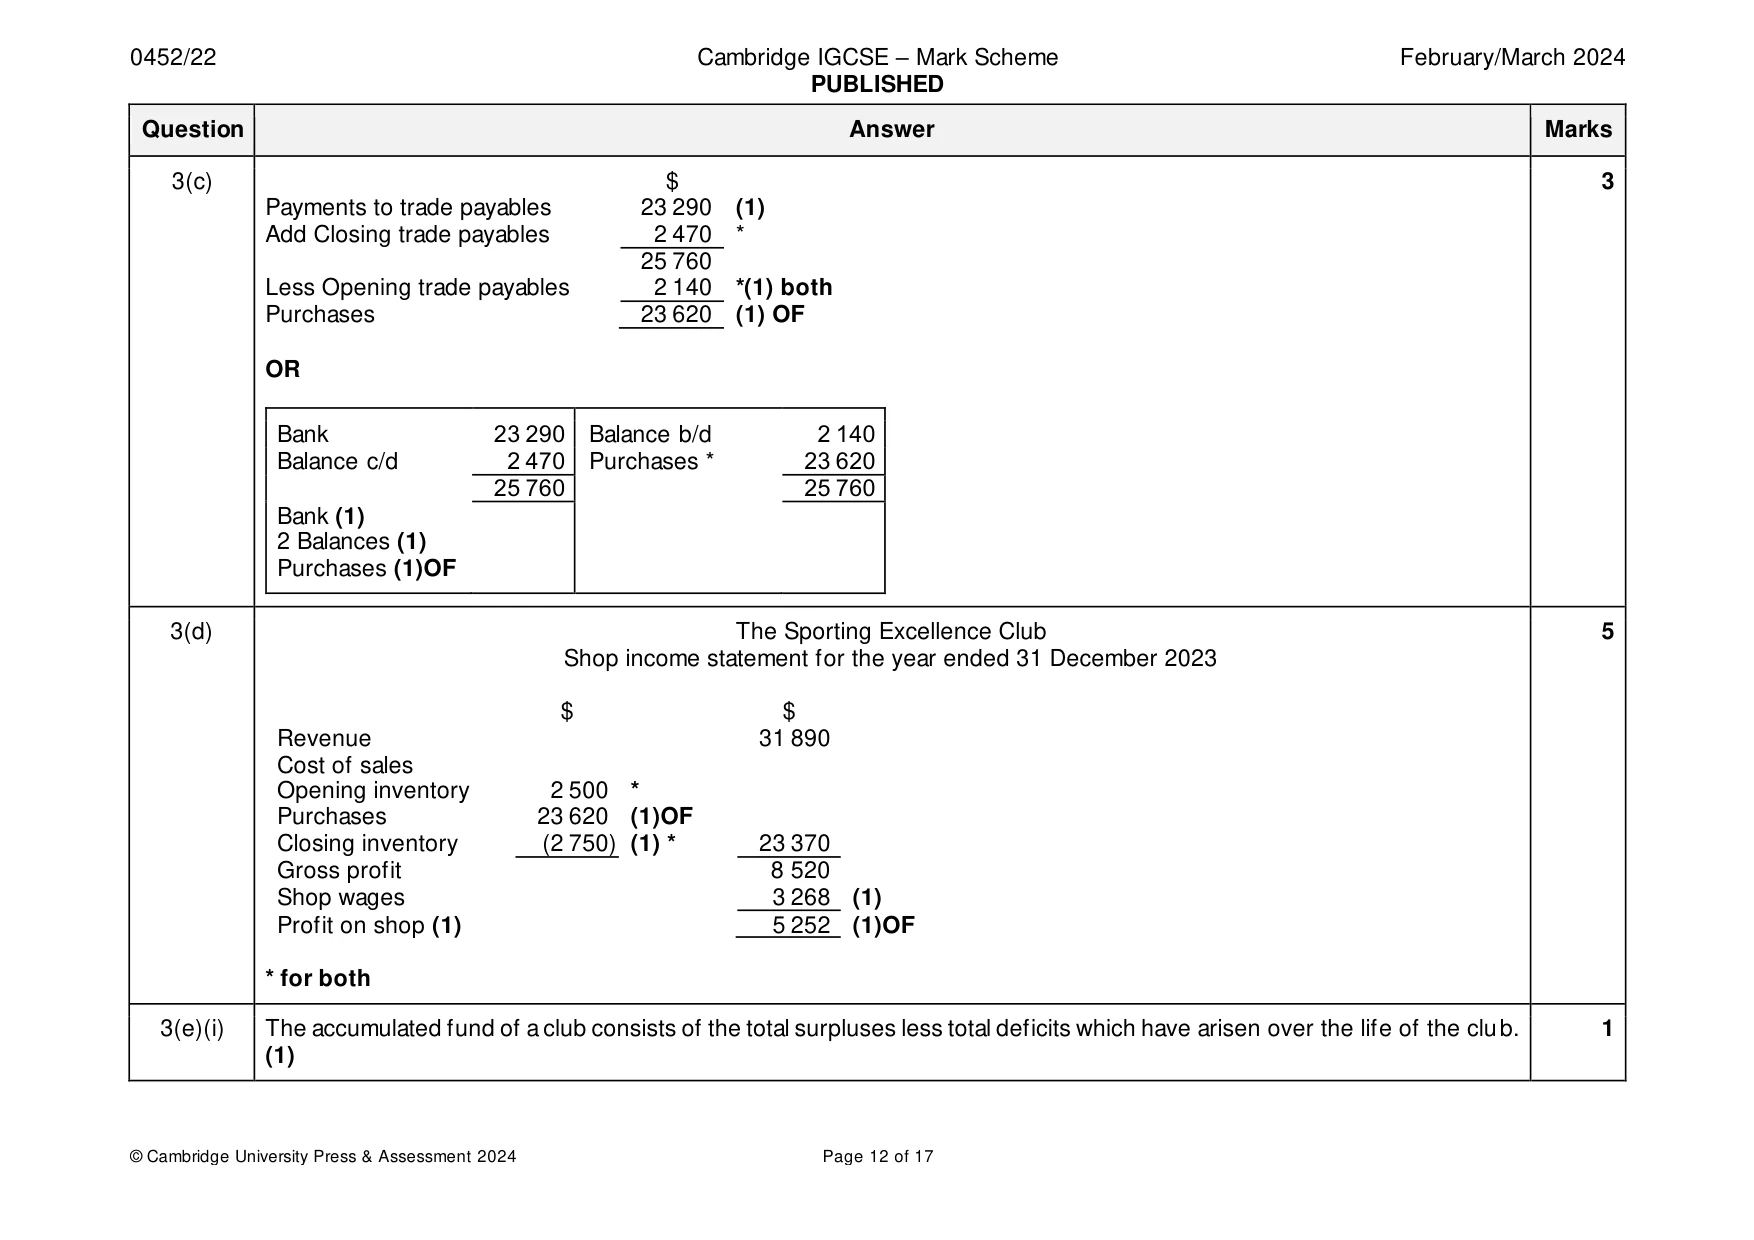
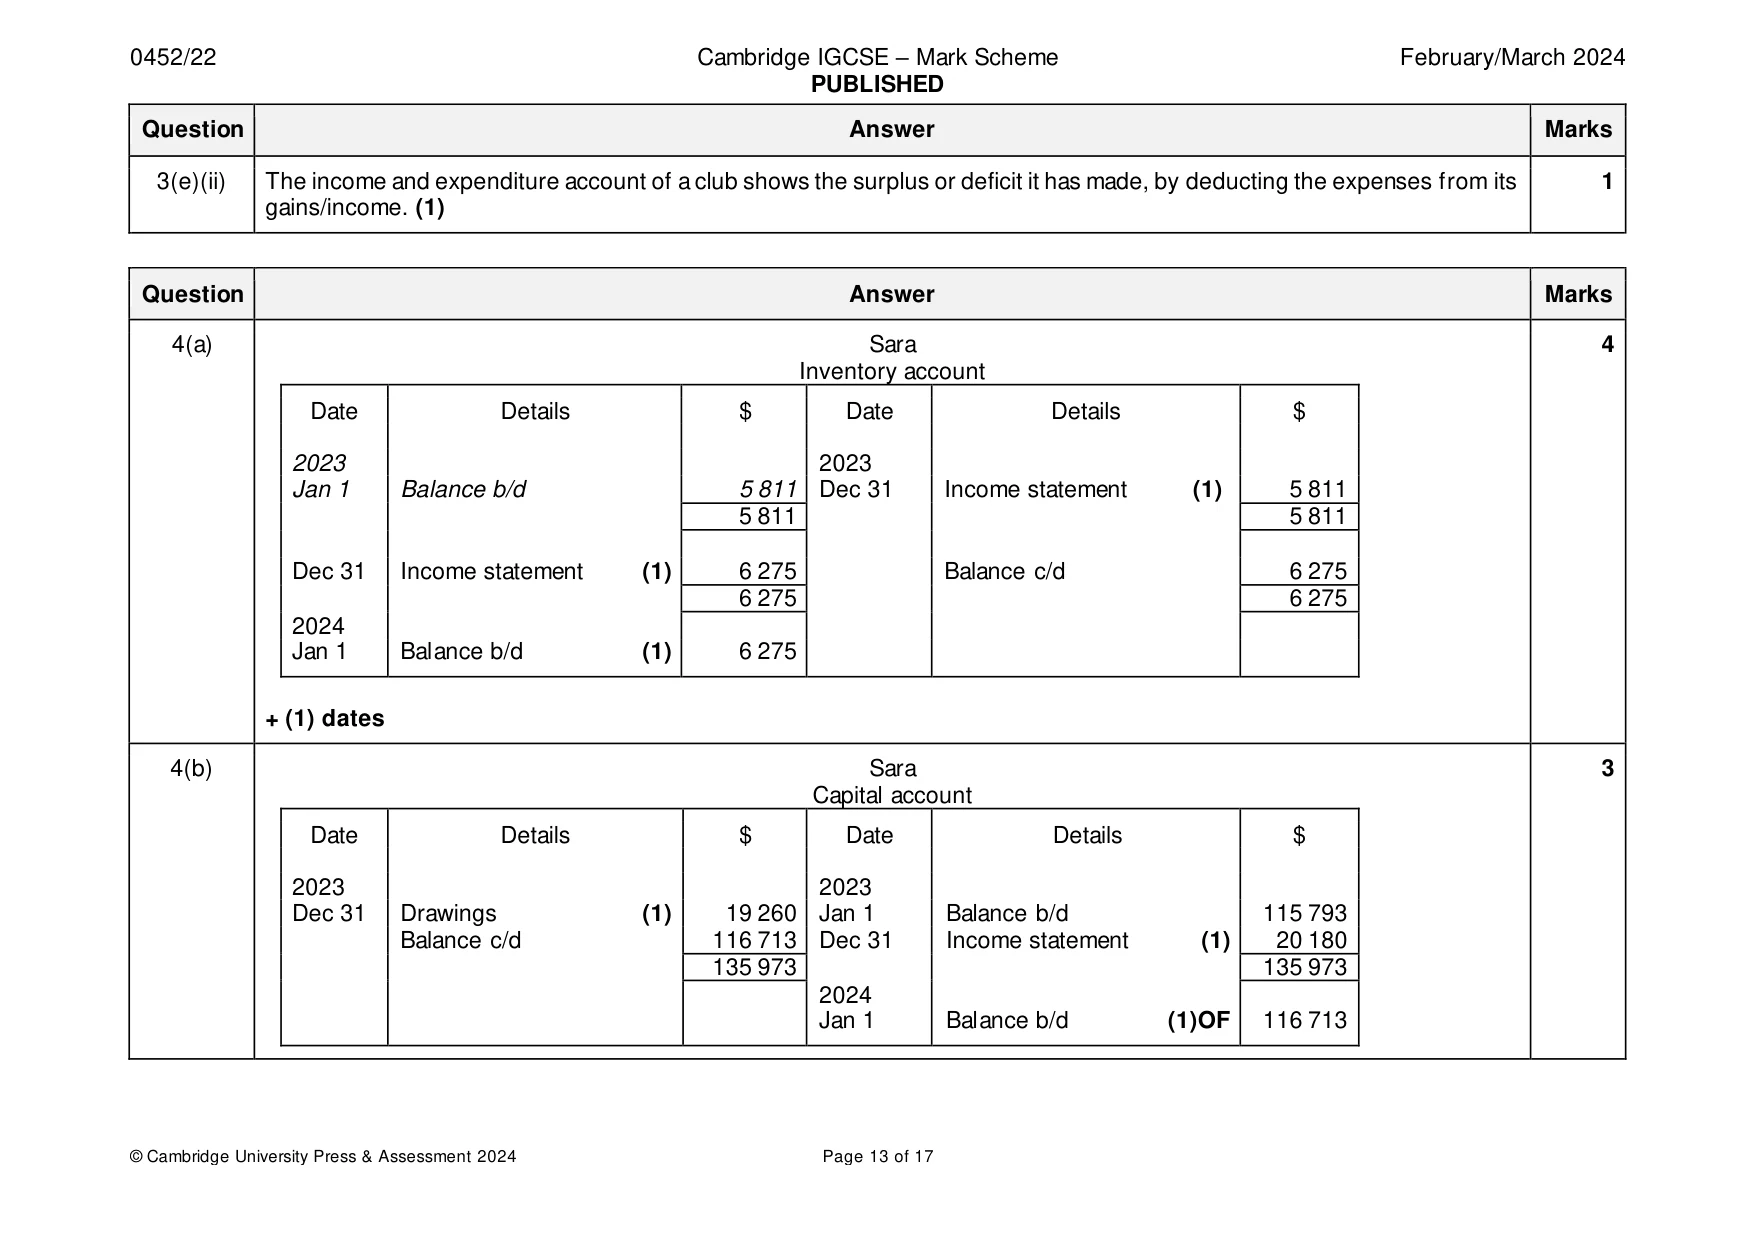
Mark scheme: 3(a) The Sporting Excellence Club 6 Subscriptions account Date Details $ Date Details $ 2023 2023 Jan 1 Balance b/d (1) 480 Jan 1 Balance b/d (1) 610 Dec 31 Income and expenditure (1)OF 11 975 Dec 31 Bank/cash/cash book (1) 11 950 Balance c/d 570 Balance c/d 465 13 025 13 025 2024 2024 Jan 1 Balance b/d *(1)both 465 Jan 1 Balance b/d * 570 +(1) dates 3(b) The Sporting Excellence Club 4 Rent and insurance account Date Details $ Date Details $ 2023 2023 Jan 1 Balance b/d (1) 240 Dec 31 Income and expenditure (1)OF 7 380 Dec 31 Bank/cash/cash book (1) 7 390 Balance c/d 250 7 630 7 630 2024 Jan 1 Balance b/d (1) 250 3(c) $ 3 Payments to trade payables 23 290 (1) Add Closing trade payables 2 470 * 25 760 Less Opening trade payables 2 140 *(1) both Purchases 23 620 (1) OF OR Bank 23 290 Balance b/d 2 140 Balance c/d 2 470 Purchases * 23 620 25 760 25 760 Bank (1) 2 Balances (1) Purchases (1)OF 3(d) The Sporting Excellence Club 5 Shop income statement for the year ended 31 December 2023 $ $ Revenue 31 890 Cost of sales Opening inventory 2 500 * Purchases 23 620 (1)OF Closing inventory (2 750) (1) * 23 370 Gross profit 8 520 Shop wages 3 268 (1) Profit on shop (1) 5 252 (1)OF * for both 3(e)(i) The accumulated fund of a club consists of the total surpluses less total deficits which have arisen over the life of the club. 1 (1) 3(e)(ii) The income and expenditure account of a club shows the surplus or deficit it has made, by deducting the expenses from its 1 gains/income. (1)
Q4 · Sara is a trader
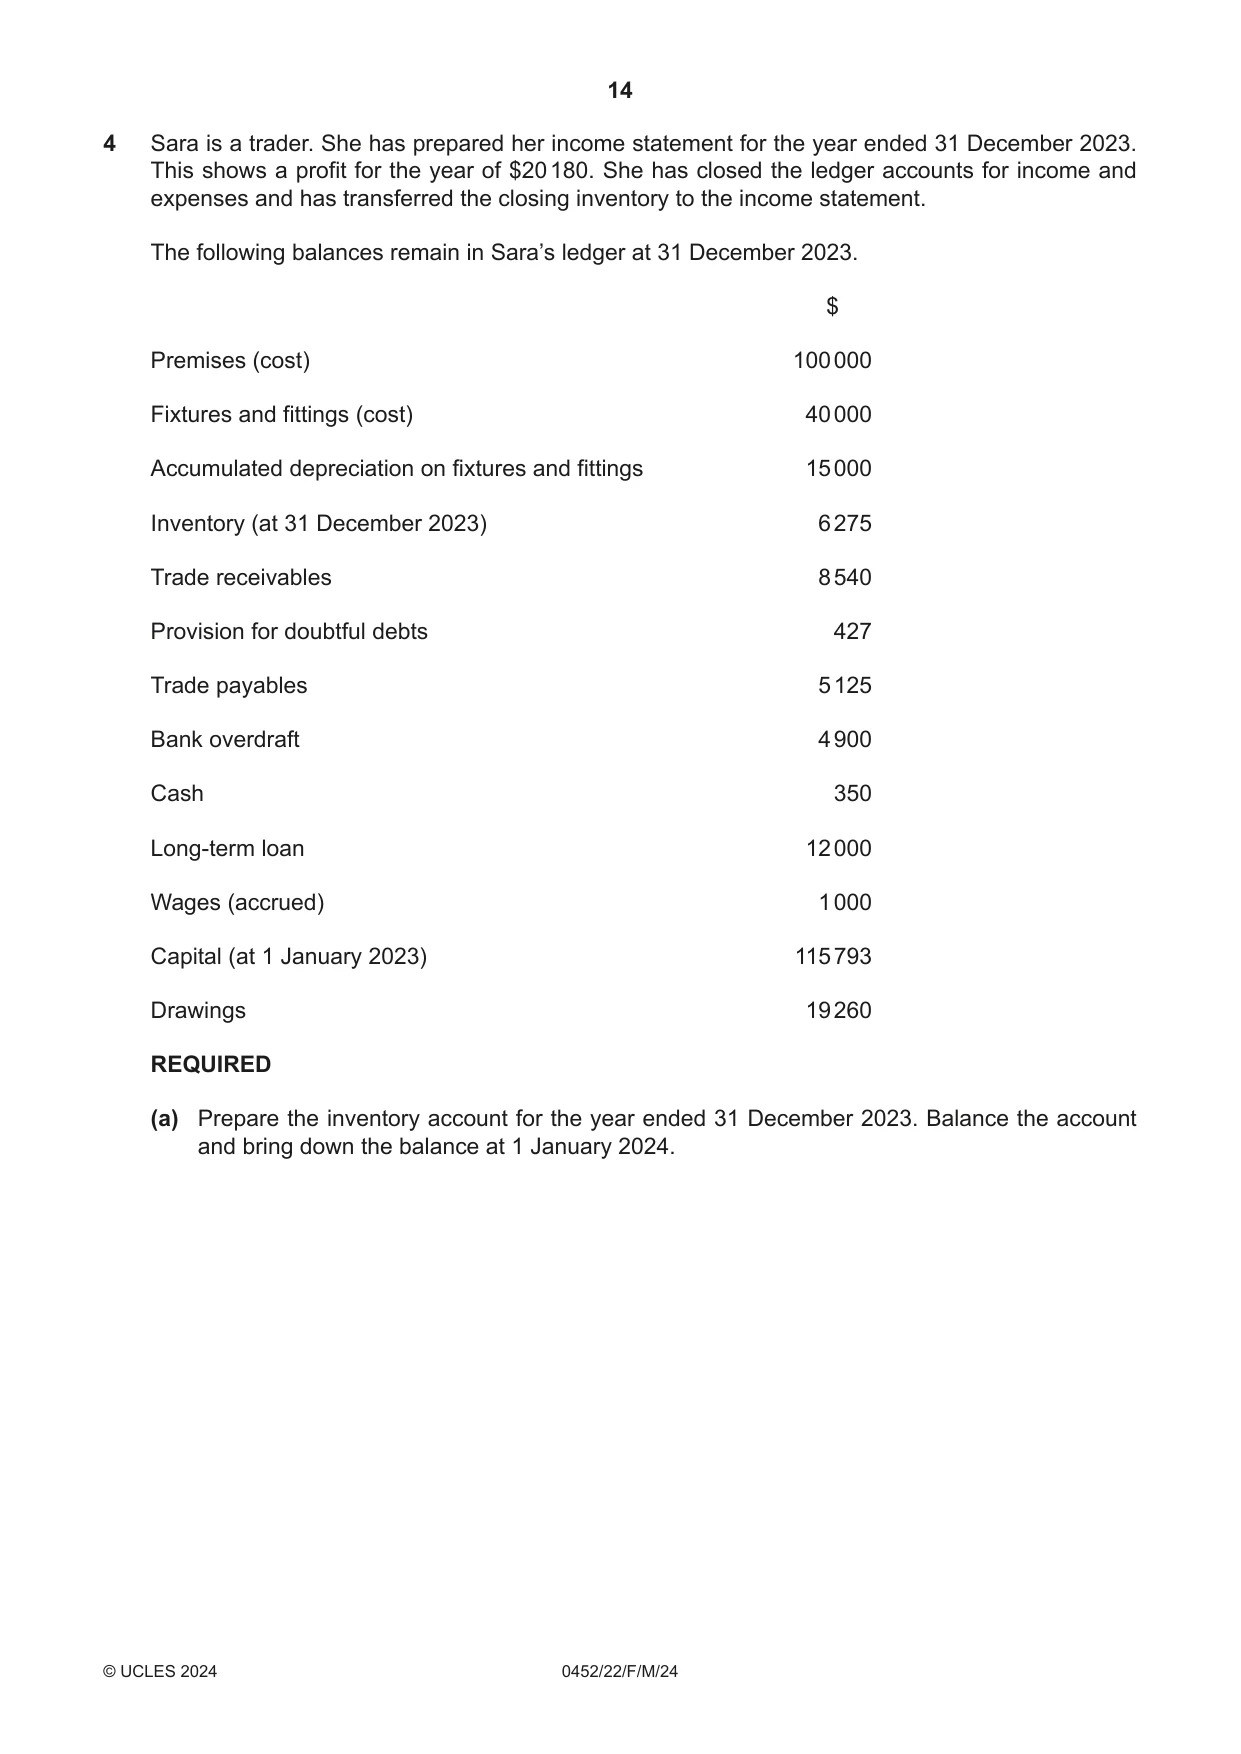
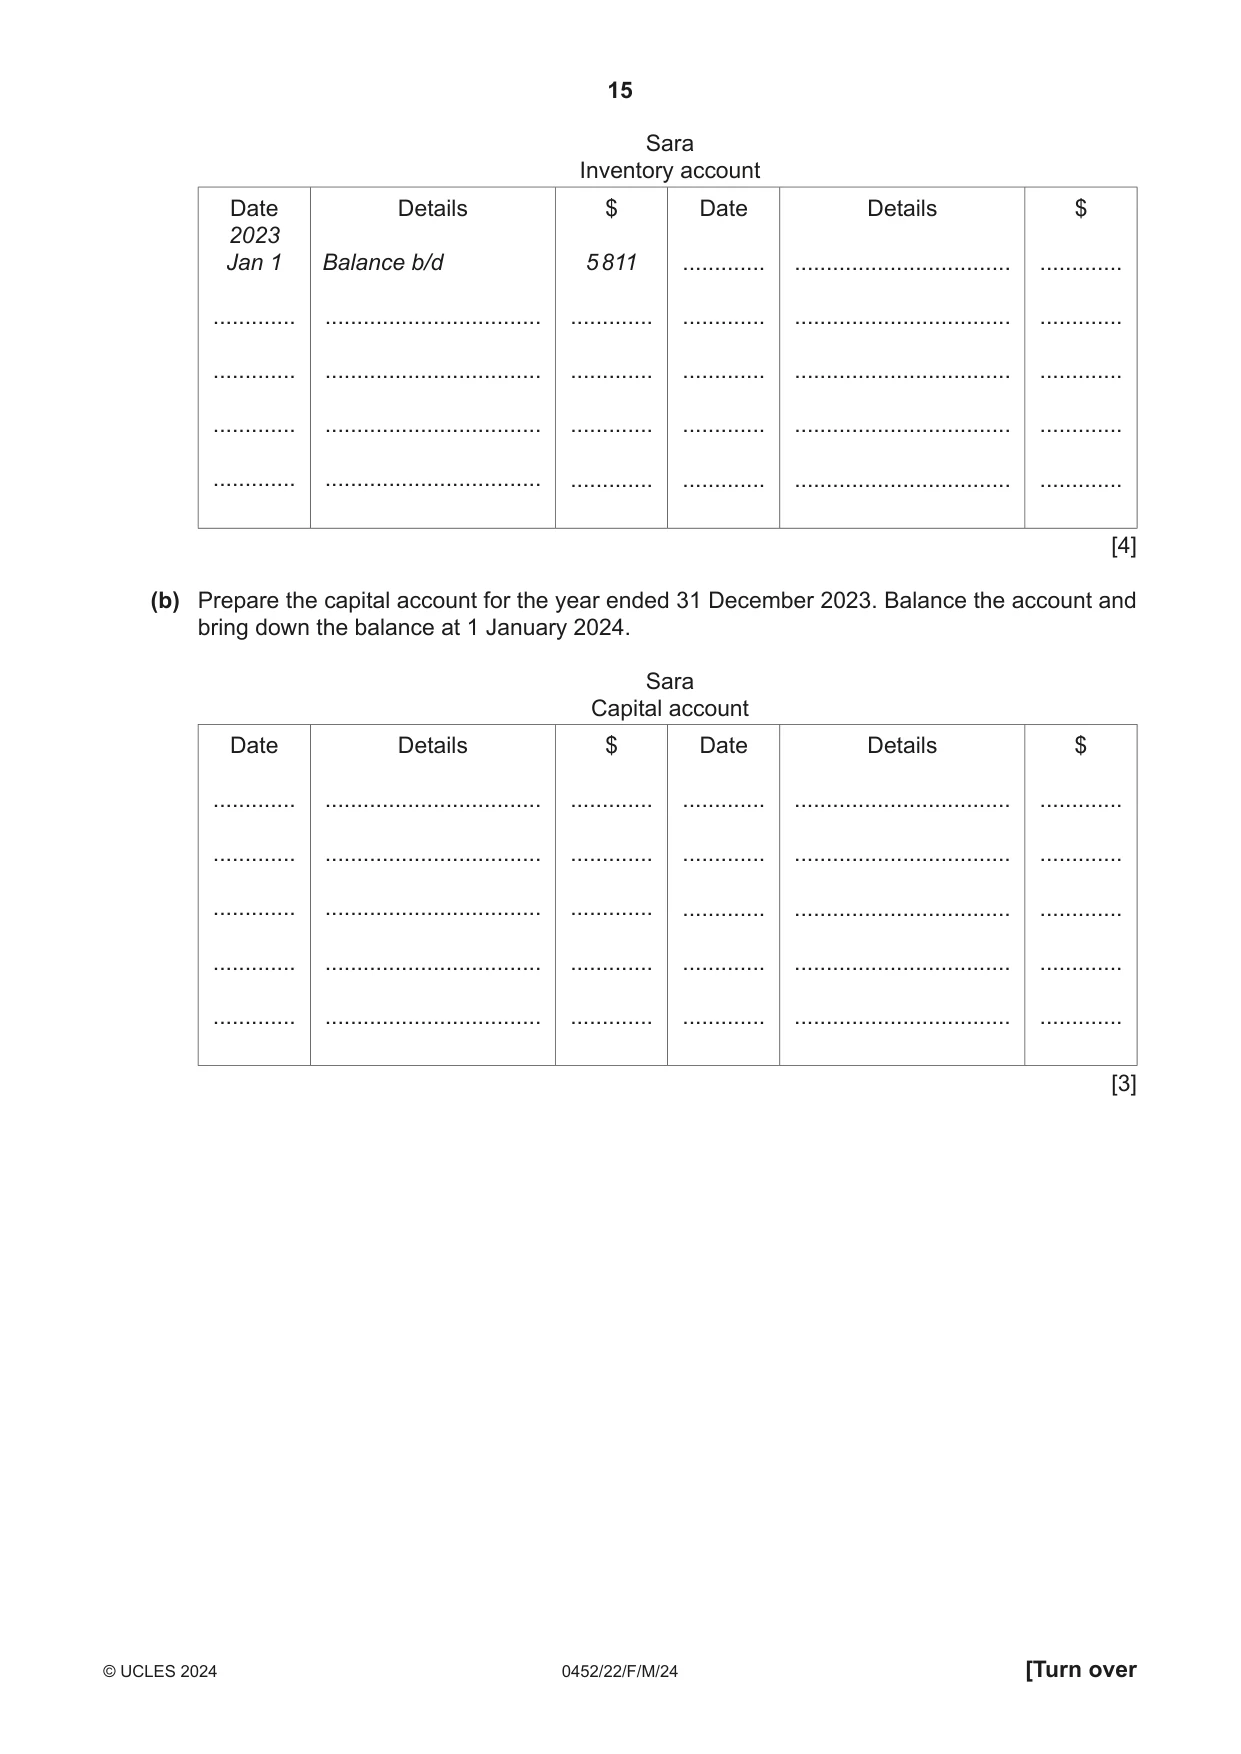
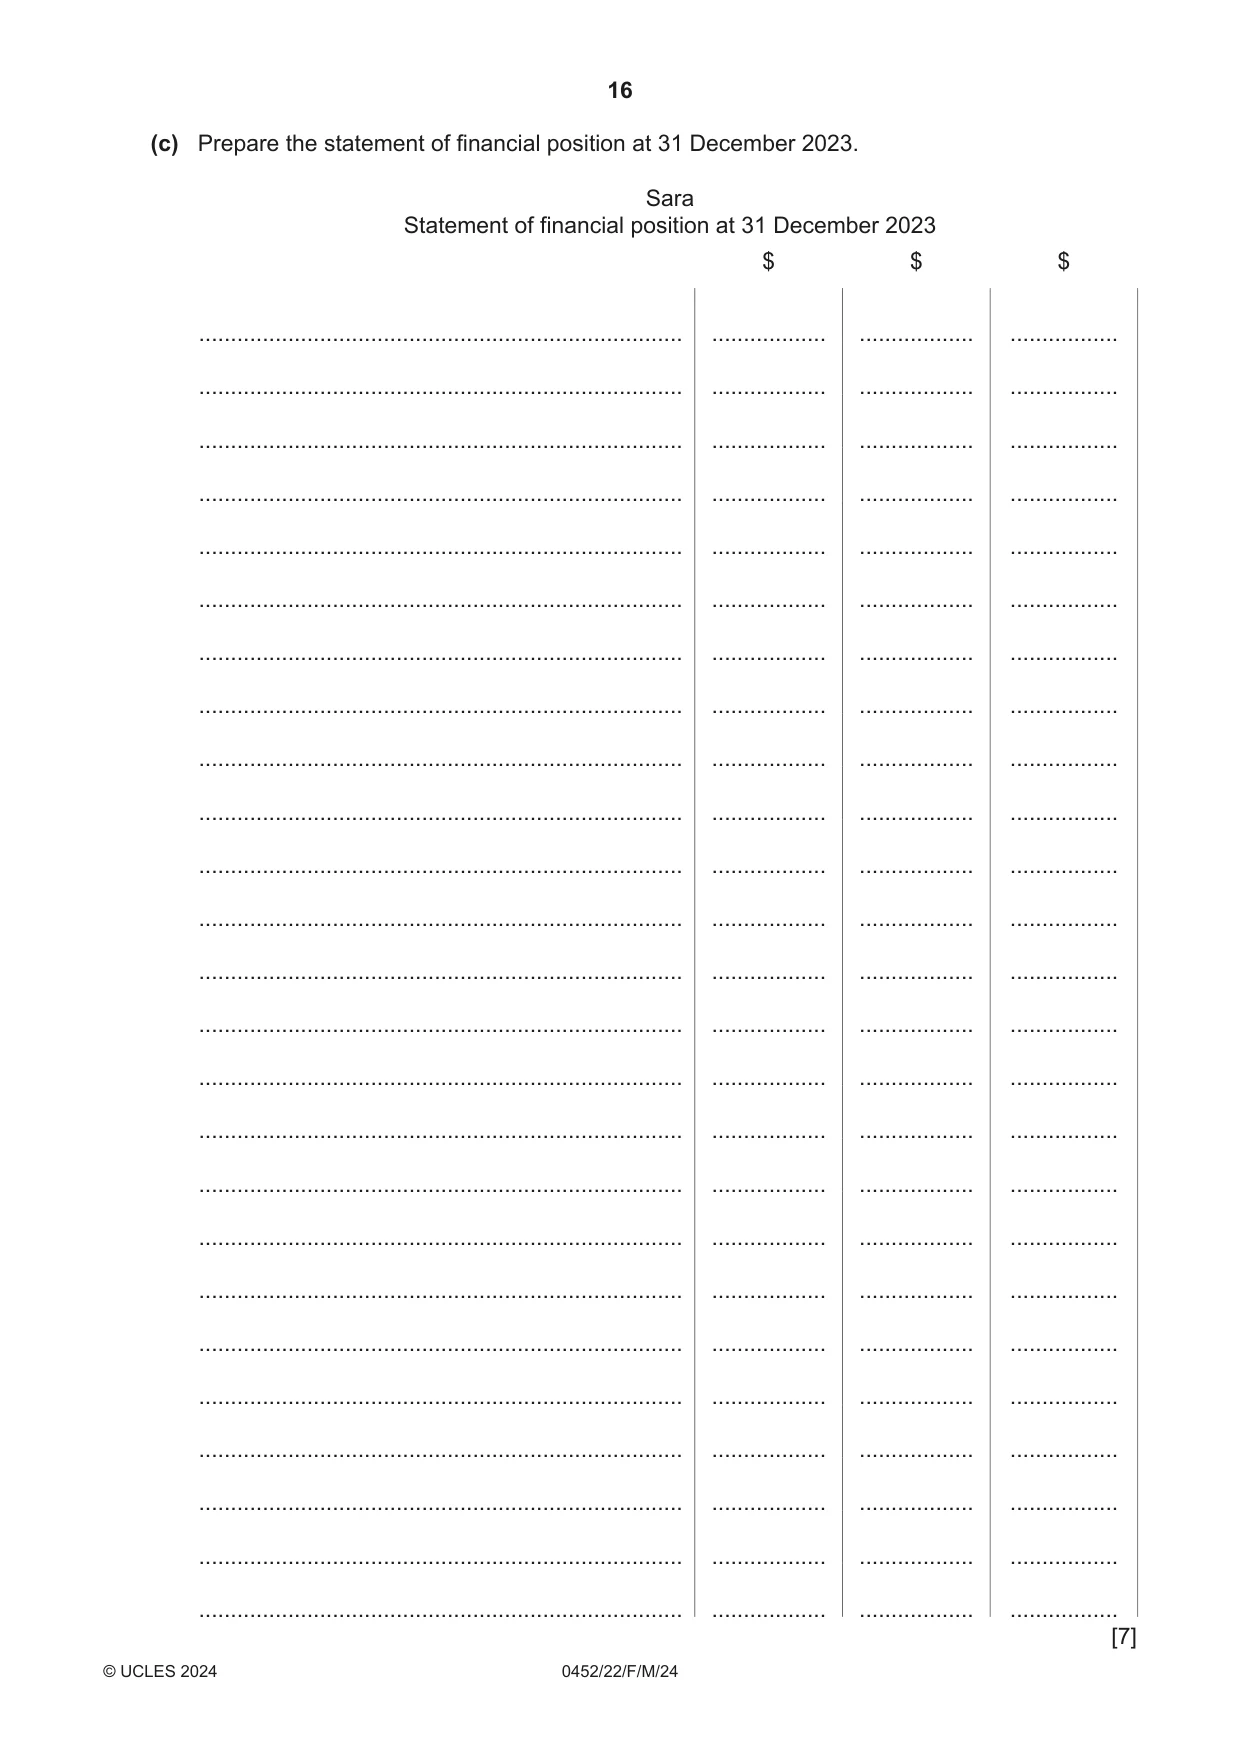
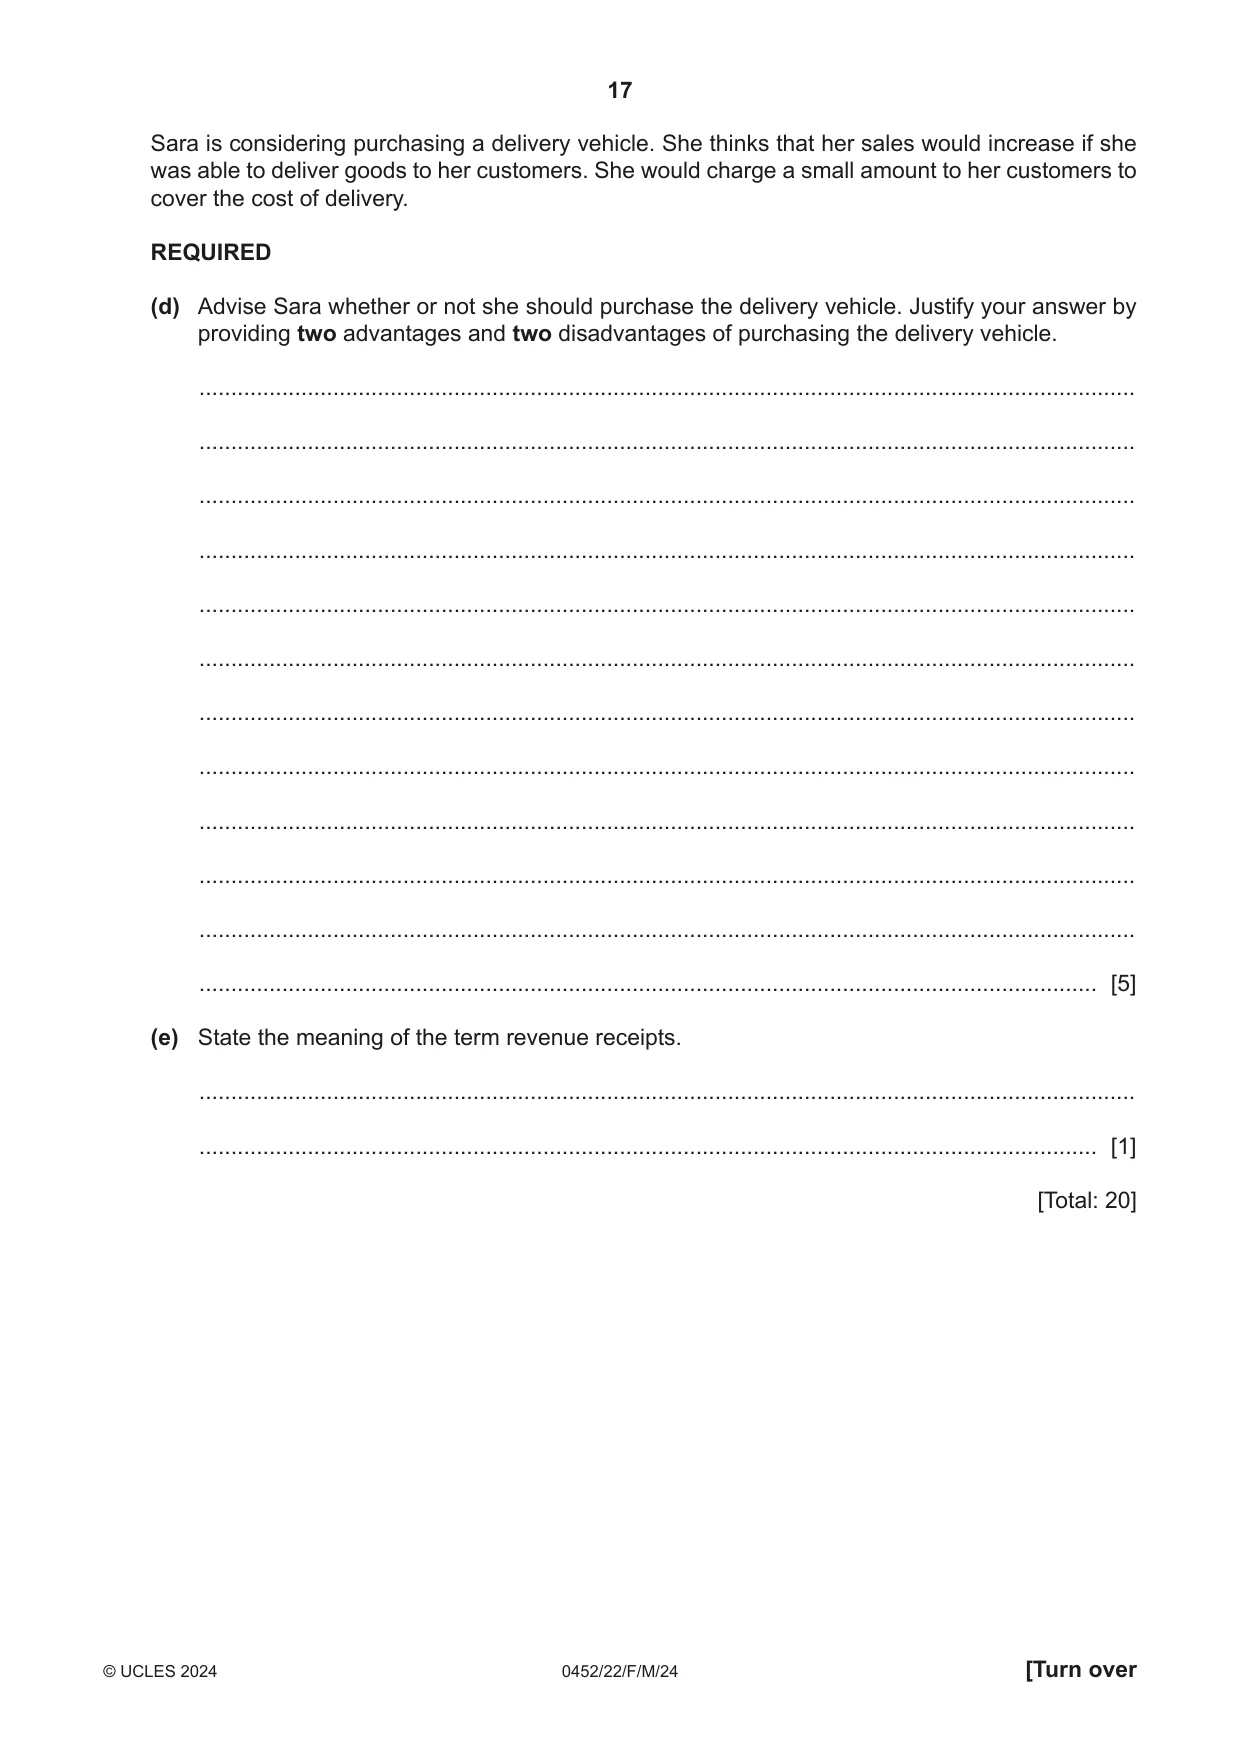
4 Sara is a trader. She has prepared her income statement for the year ended 31 December 2023. This shows a profit for the year of $20 180. She has closed the ledger accounts for income and expenses and has transferred the closing inventory to the income statement. The following balances remain in Sara’s ledger at 31 December 2023. $ Premises (cost) 100 000 Fixtures and fittings (cost) 40 000 Accumulated depreciation on fixtures and fittings 15 000 Inventory (at 31 December 2023) 6 275 Trade receivables 8 540 Provision for doubtful debts 427 Trade payables 5 125 Bank overdraft 4 900 Cash 350 Long-term loan 12 000 Wages (accrued) 1 000 Capital (at 1 January 2023) 115 793 Drawings 19 260 REQUIRED (a) Prepare the inventory account for the year ended 31 December 2023. Balance the account and bring down the balance at 1 January 2024. Sara Inventory account Date Details $ Date Details $ 2023 Jan 1 Balance b/d 5 811 ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. [4] (b) Prepare the capital account for the year ended 31 December 2023. Balance the account and bring down the balance at 1 January 2024. Sara Capital account Date Details $ Date Details $ ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. [3] (c) Prepare the statement of financial position at 31 December 2023. Sara Statement of financial position at 31 December 2023 $ $ $ ............................................................................ .................. .................. ................. ............................................................................ .................. .................. ................. ............................................................................ .................. .................. ................. ............................................................................ .................. .................. ................. ............................................................................ .................. .................. ................. ............................................................................ .................. .................. ................. ............................................................................ .................. .................. ................. ............................................................................ .................. .................. ................. ............................................................................ .................. .................. ................. ............................................................................ .................. .................. ................. ............................................................................ .................. .................. ................. ............................................................................ .................. .................. ................. ............................................................................ .................. .................. ................. ............................................................................ .................. .................. ................. ............................................................................ .................. .................. ................. ............................................................................ .................. .................. ................. ............................................................................ .................. .................. ................. ............................................................................ .................. .................. ................. ............................................................................ .................. .................. ................. ............................................................................ .................. .................. ................. ............................................................................ .................. .................. ................. ............................................................................ .................. .................. ................. ............................................................................ .................. .................. ................. ............................................................................ .................. .................. ................. ............................................................................ .................. .................. ................. [7] Sara is considering purchasing a delivery vehicle. She thinks that her sales would increase if she was able to deliver goods to her customers. She would charge a small amount to her customers to cover the cost of delivery. REQUIRED (d) Advise Sara whether or not she should purchase the delivery vehicle. Justify your answer by providing two advantages and two disadvantages of purchasing the delivery vehicle. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] (e) State the meaning of the term revenue receipts. ................................................................................................................................................... ............................................................................................................................................. [1] [Total: 20]
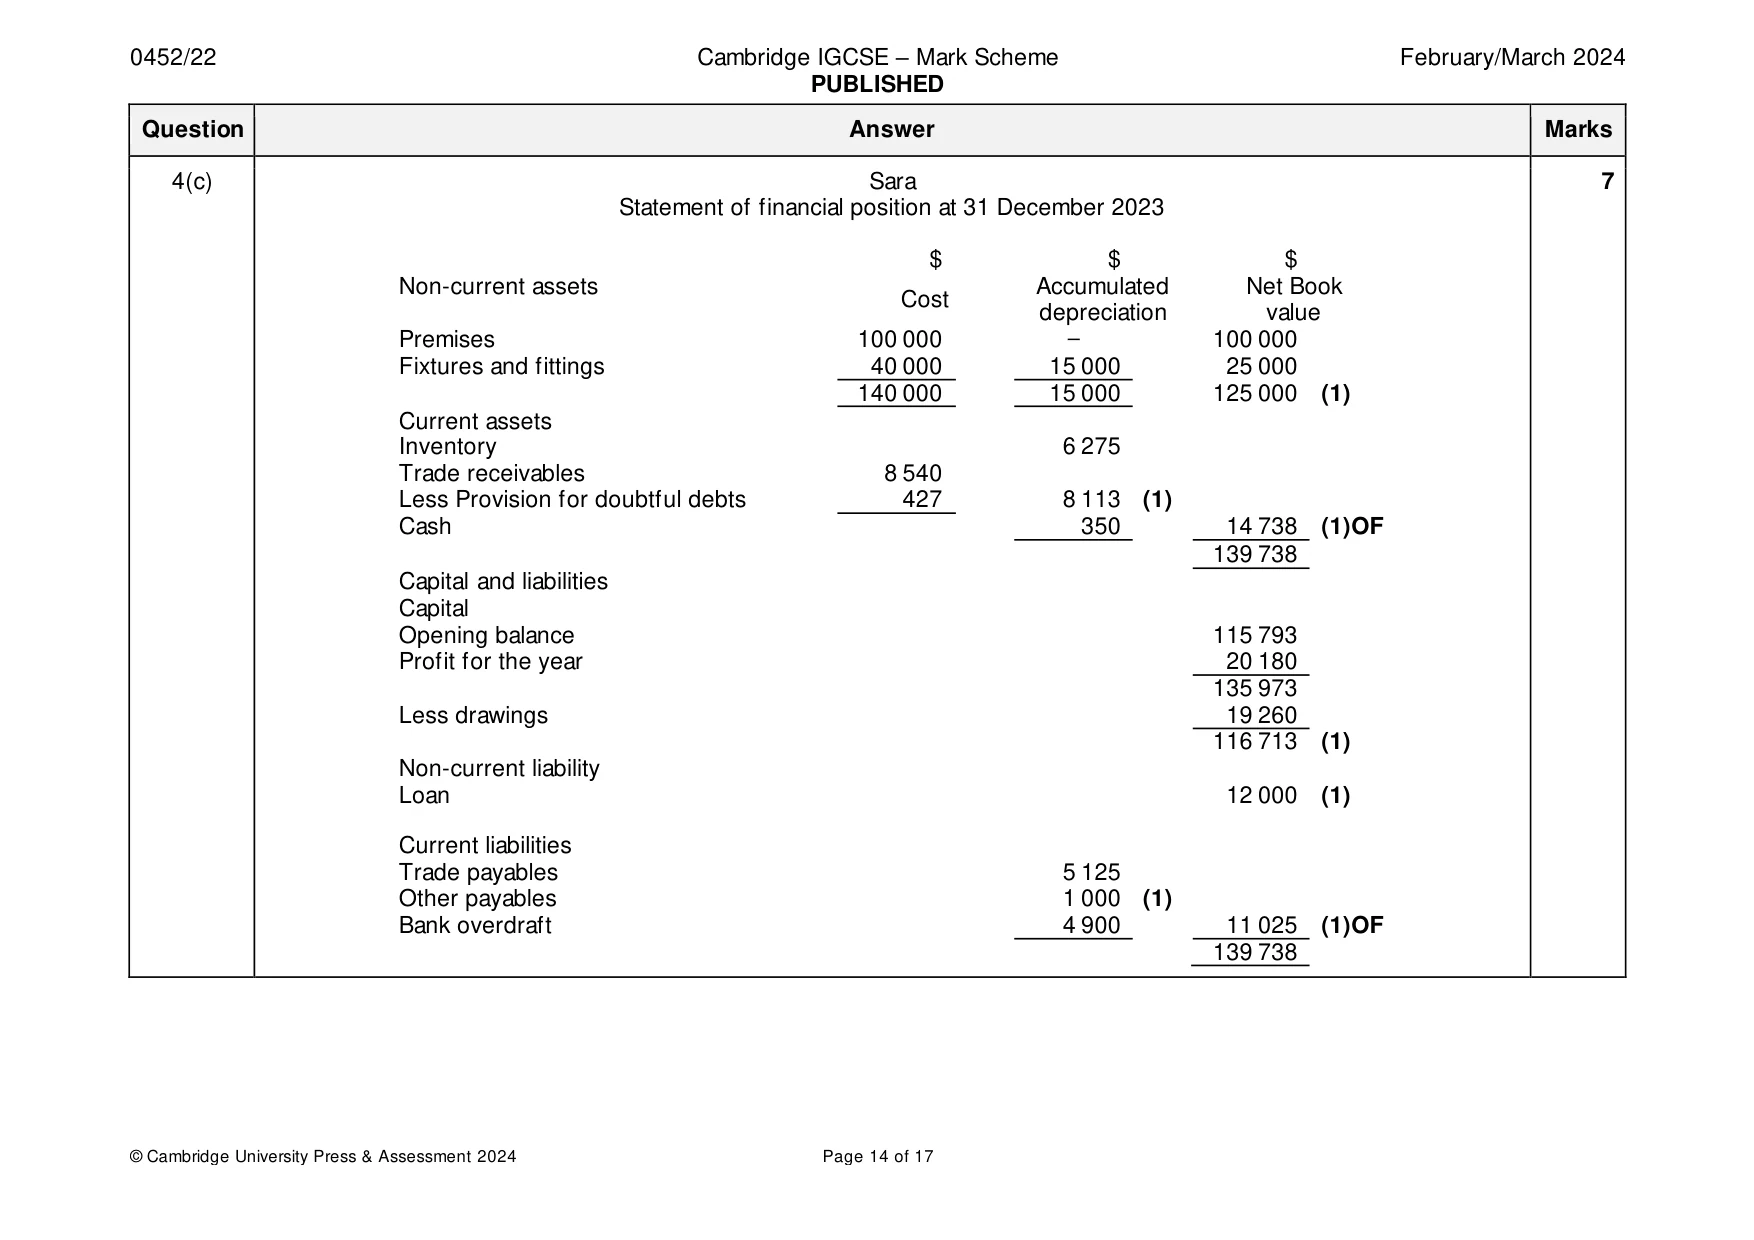
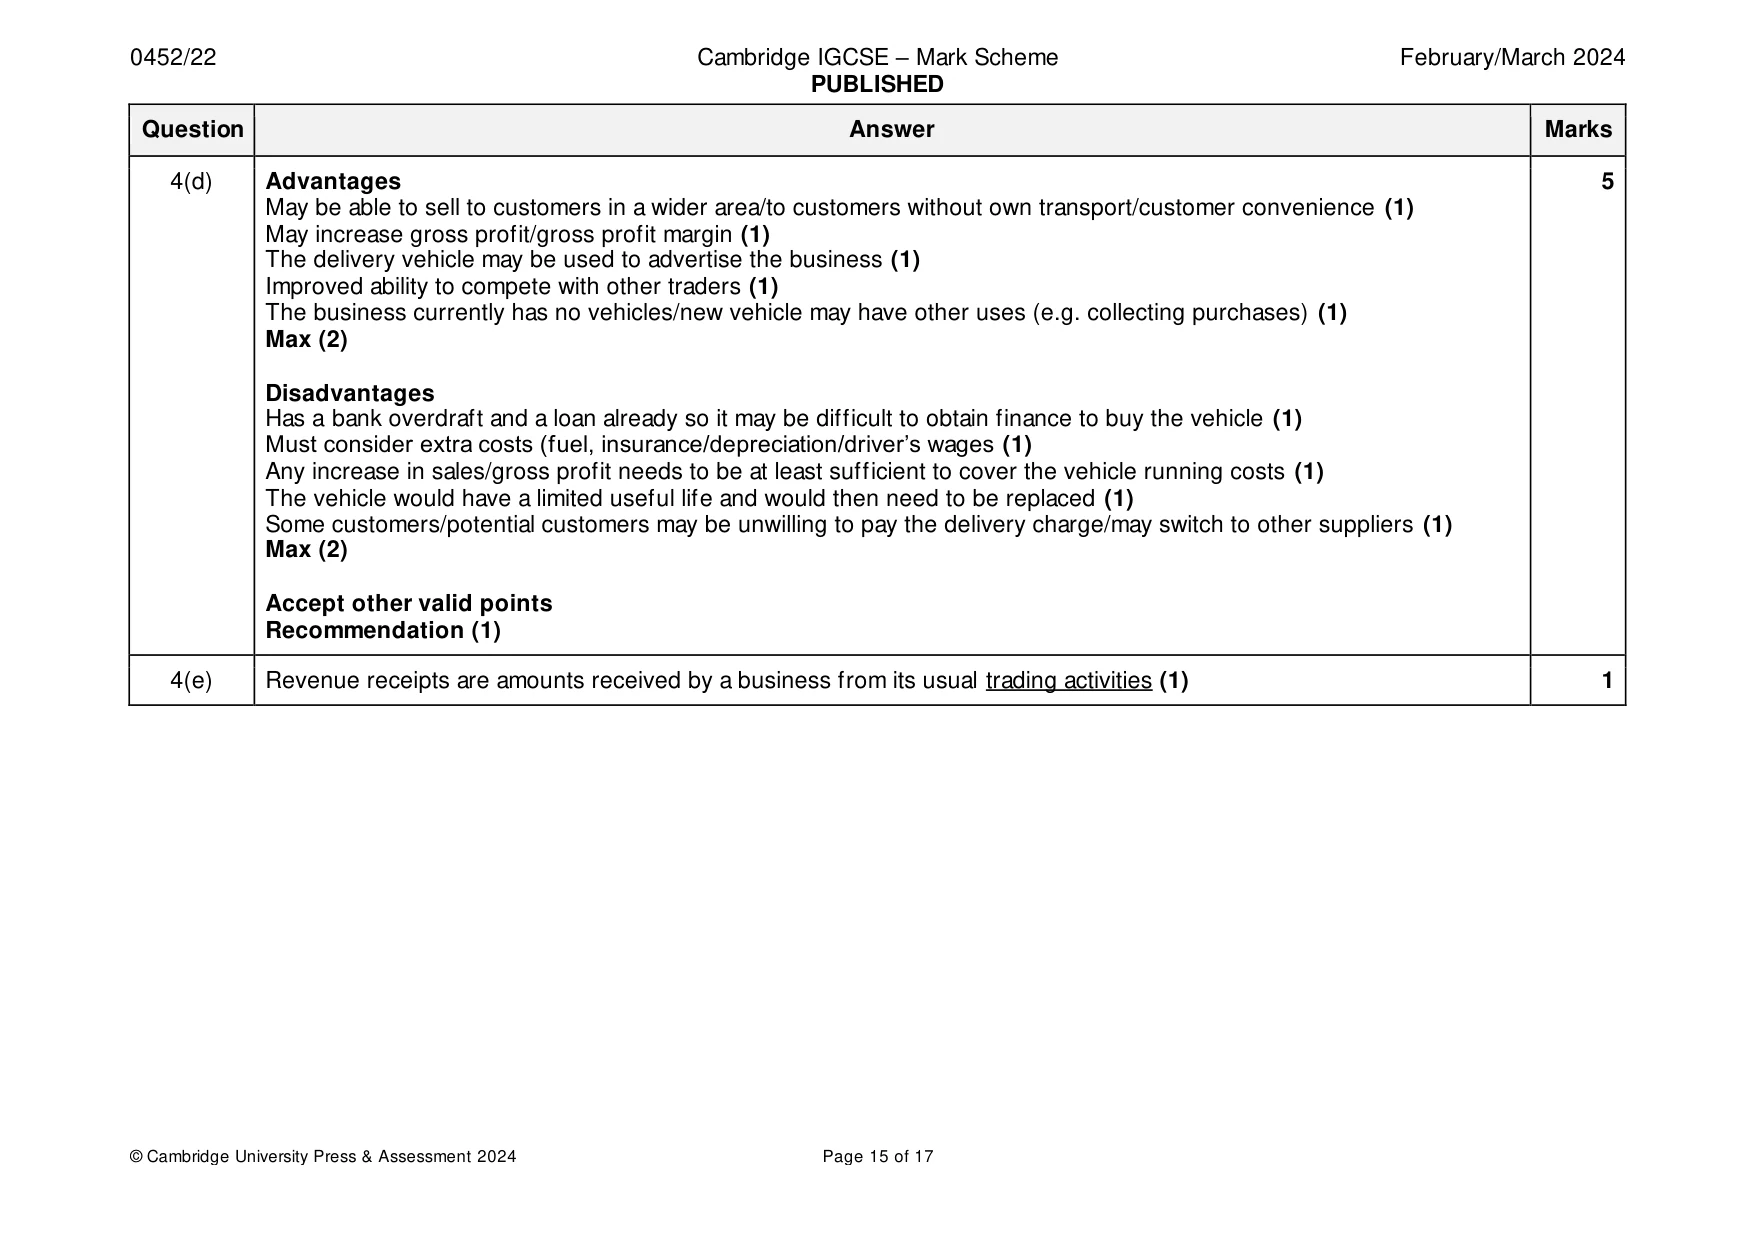
Mark scheme: 4(a) Sara 4 Inventory account Date Details $ Date Details $ 2023 2023 Jan 1 Balance b/d 5 811 Dec 31 Income statement (1) 5 811 5 811 5 811 Dec 31 Income statement (1) 6 275 Balance c/d 6 275 6 275 6 275 2024 Jan 1 Balance b/d (1) 6 275 + (1) dates 4(b) Sara 3 Capital account Date Details $ Date Details $ 2023 2023 Dec 31 Drawings (1) 19 260 Jan 1 Balance b/d 115 793 Balance c/d 116 713 Dec 31 Income statement (1) 20 180 135 973 135 973 2024 Jan 1 Balance b/d (1)OF 116 713 4(c) Sara 7 Statement of financial position at 31 December 2023 $ $ $ Non-current assets Accumulated Net Book Cost depreciation value Premises 100 000 – 100 000 Fixtures and fittings 40 000 15 000 25 000 140 000 15 000 125 000 (1) Current assets Inventory 6 275 Trade receivables 8 540 Less Provision for doubtful debts 427 8 113 (1) Cash 350 14 738 (1)OF 139 738 Capital and liabilities Capital Opening balance 115 793 Profit for the year 20 180 135 973 Less drawings 19 260 116 713 (1) Non-current liability Loan 12 000 (1) Current liabilities Trade payables 5 125 Other payables 1 000 (1) Bank overdraft 4 900 11 025 (1)OF 139 738 4(d) Advantages 5 May be able to sell to customers in a wider area/to customers without own transport/customer convenience (1) May increase gross profit/gross profit margin (1) The delivery vehicle may be used to advertise the business (1) Improved ability to compete with other traders (1) The business currently has no vehicles/new vehicle may have other uses (e.g. collecting purchases) (1) Max (2) Disadvantages Has a bank overdraft and a loan already so it may be difficult to obtain finance to buy the vehicle (1) Must consider extra costs (fuel, insurance/depreciation/driver’s wages (1) Any increase in sales/gross profit needs to be at least sufficient to cover the vehicle running costs (1) The vehicle would have a limited useful life and would then need to be replaced (1) Some customers/potential customers may be unwilling to pay the delivery charge/may switch to other suppliers (1) Max (2) Accept other valid points Recommendation (1) 4(e) Revenue receipts are amounts received by a business from its usual trading activities (1) 1
Q5 · Sunita has prepared a trial balance at 31 December 2023 and a draft income statement for…
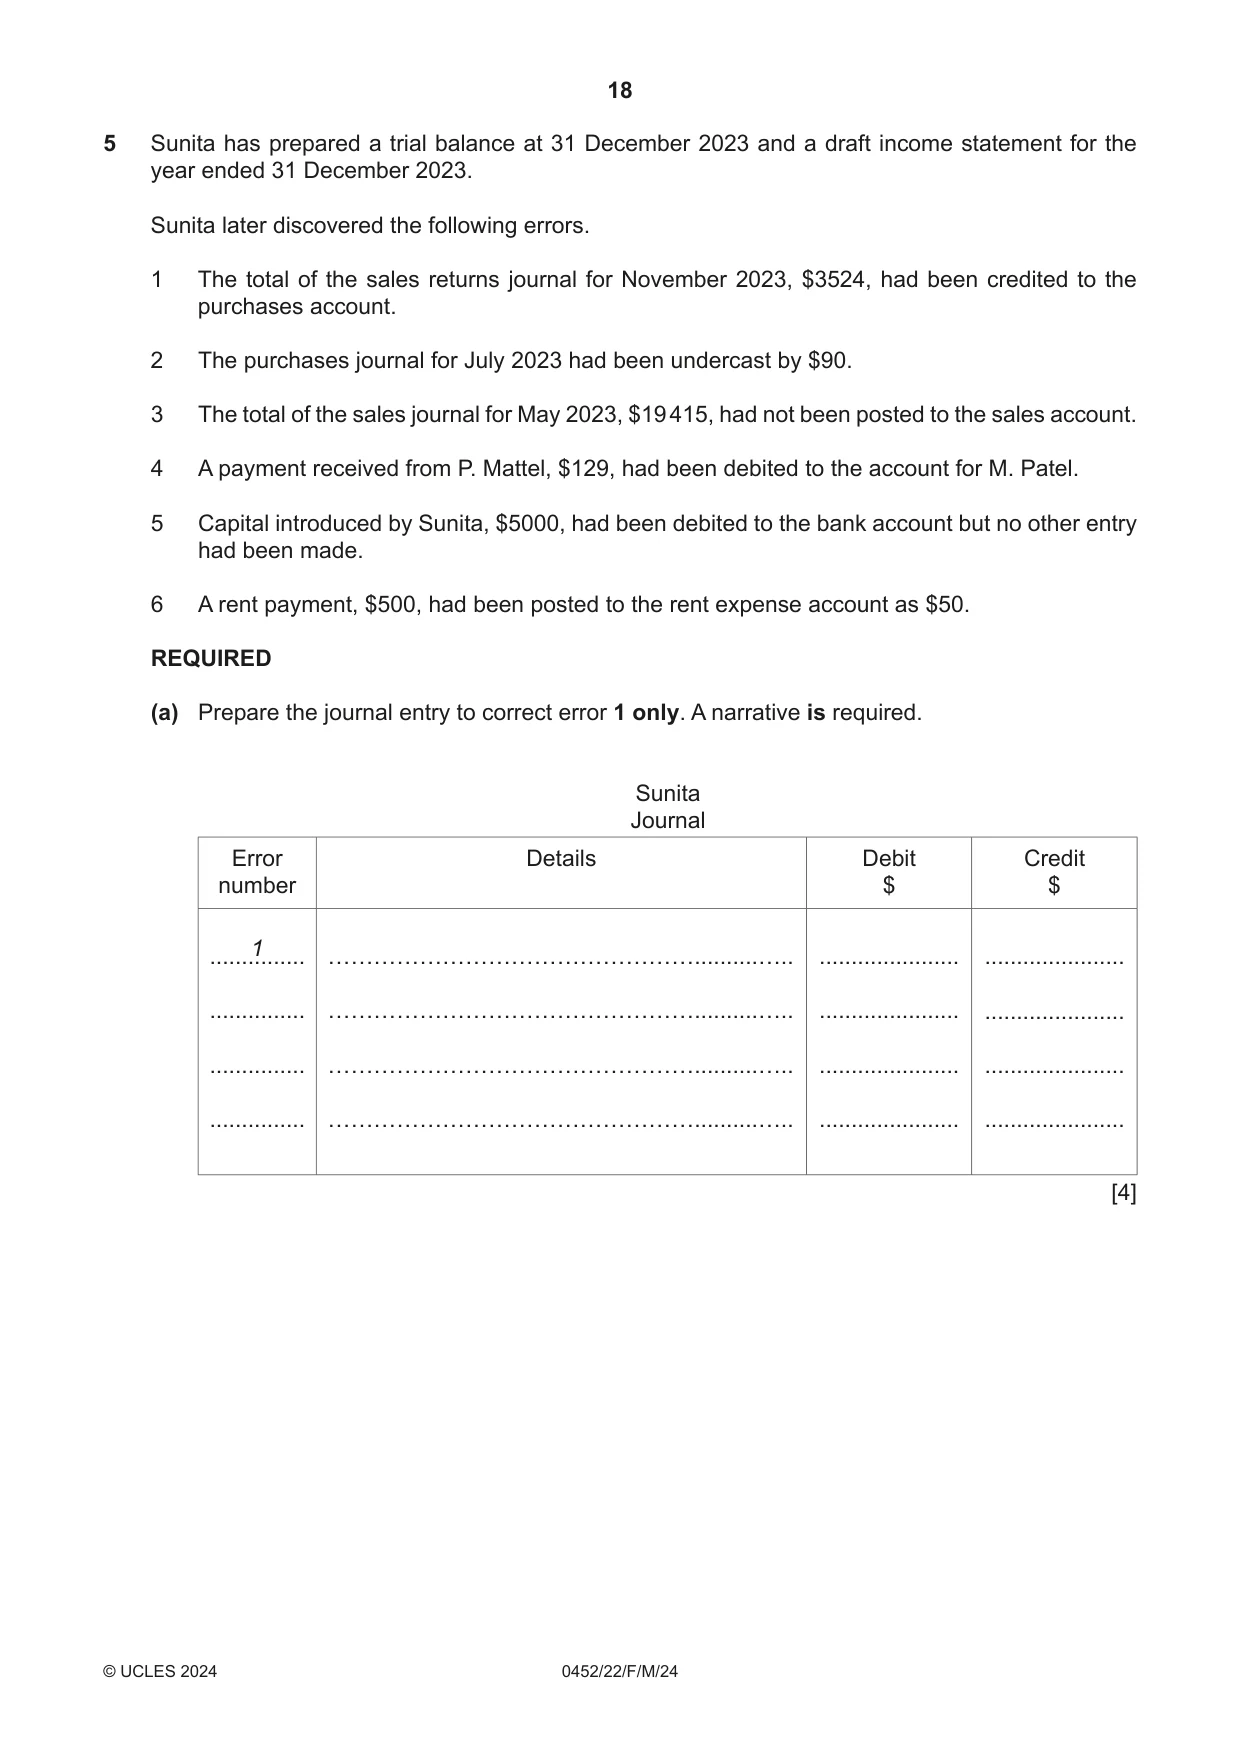
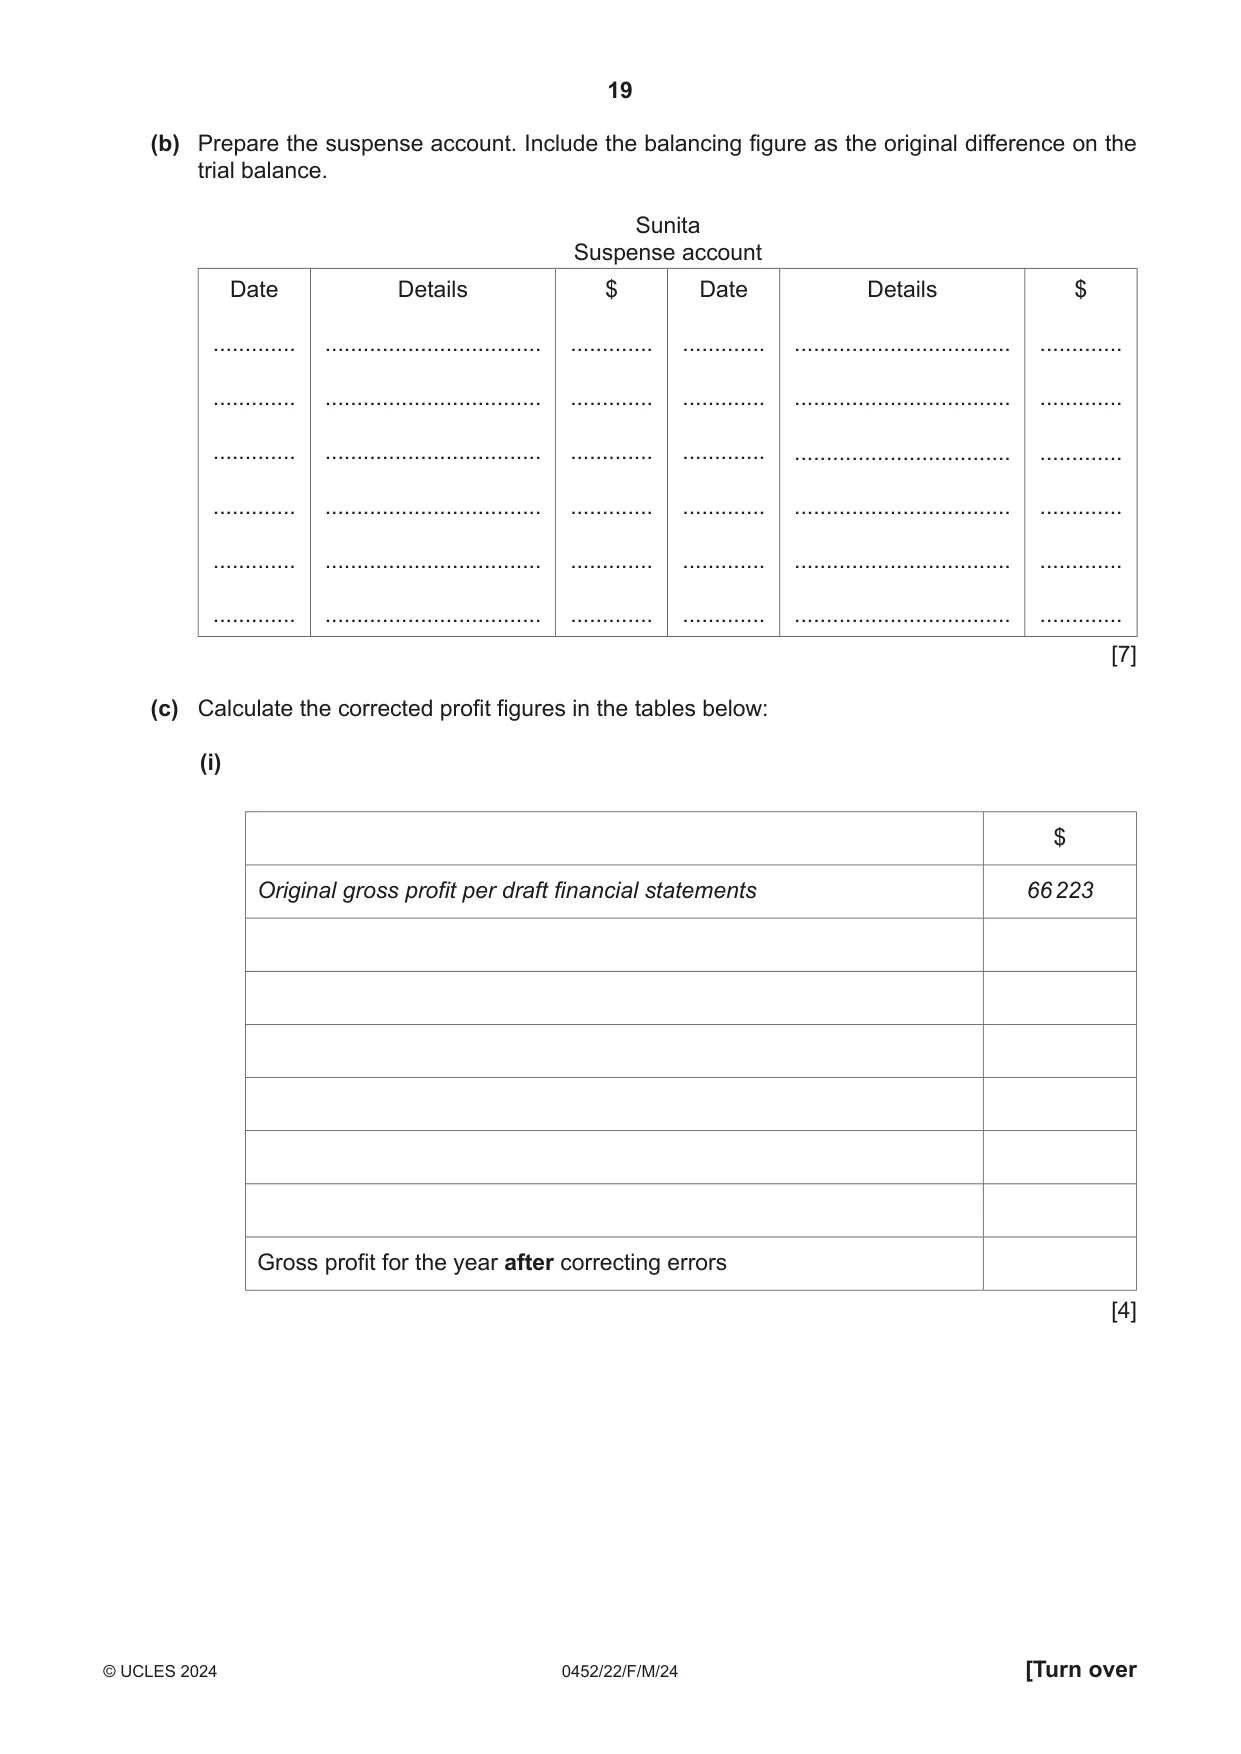
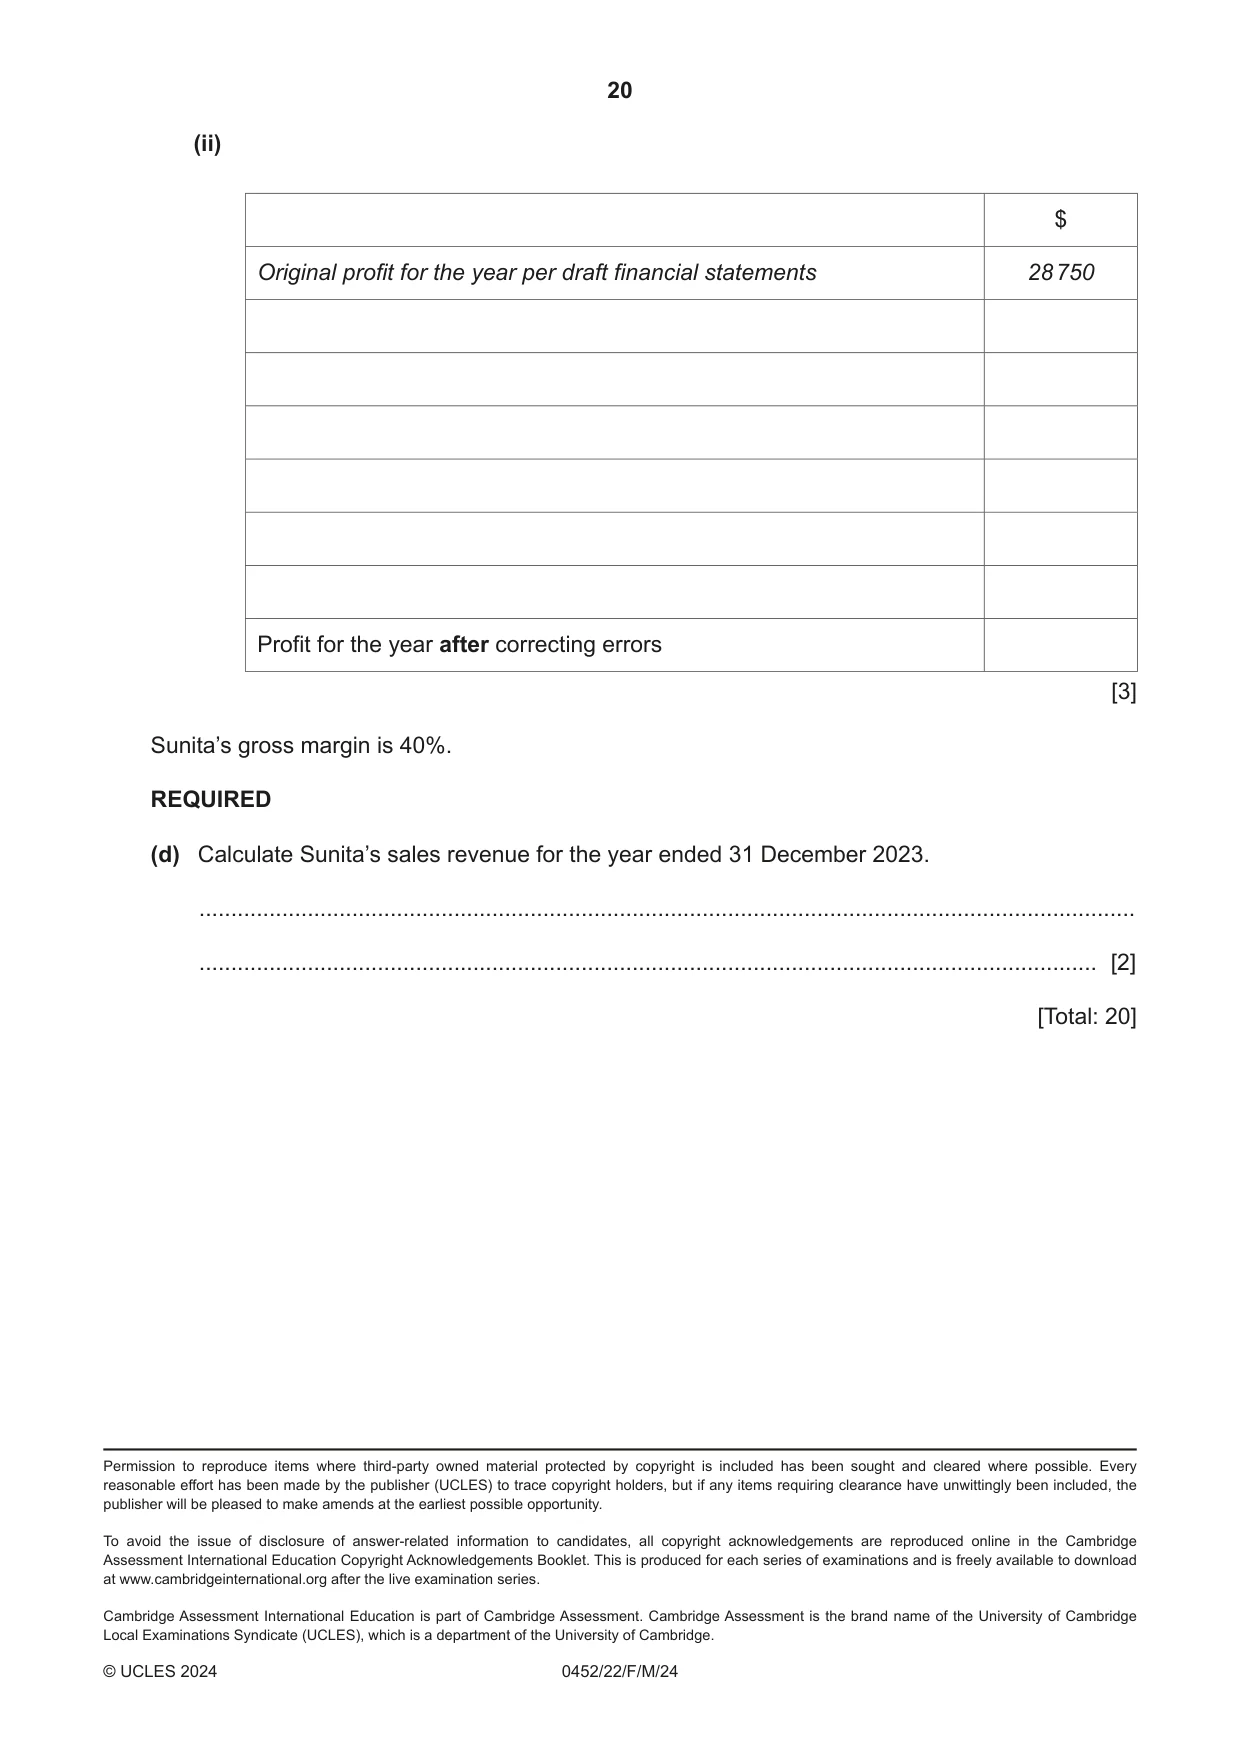
5 Sunita has prepared a trial balance at 31 December 2023 and a draft income statement for the year ended 31 December 2023. Sunita later discovered the following errors. 1 The total of the sales returns journal for November 2023, $3524, had been credited to the purchases account. 2 The purchases journal for July 2023 had been undercast by $90. 3 The total of the sales journal for May 2023, $19 415, had not been posted to the sales account. 4 A payment received from P. Mattel, $129, had been debited to the account for M. Patel. 5 Capital introduced by Sunita, $5000, had been debited to the bank account but no other entry had been made. 6 A rent payment, $500, had been posted to the rent expense account as $50. REQUIRED (a) Prepare the journal entry to correct error 1 only. A narrative is required. Sunita Journal Error Details Debit Credit number $ $ 1 ............... …………………………………………..........….. ...................... ...................... ............... …………………………………………..........….. ...................... ...................... ............... …………………………………………..........….. ...................... ...................... ............... …………………………………………..........….. ...................... ...................... [4] (b) Prepare the suspense account. Include the balancing figure as the original difference on the trial balance. Sunita Suspense account Date Details $ Date Details $ ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. ............. .................................. ............. [7] (c) Calculate the corrected profit figures in the tables below: (i) $ Original gross profit per draft financial statements 66 223 Gross profit for the year after correcting errors [4] (ii) $ Original profit for the year per draft financial statements 28 750 Profit for the year after correcting errors [3] Sunita’s gross margin is 40%. REQUIRED (d) Calculate Sunita’s sales revenue for the year ended 31 December 2023. ................................................................................................................................................... ............................................................................................................................................. [2] [Total: 20]
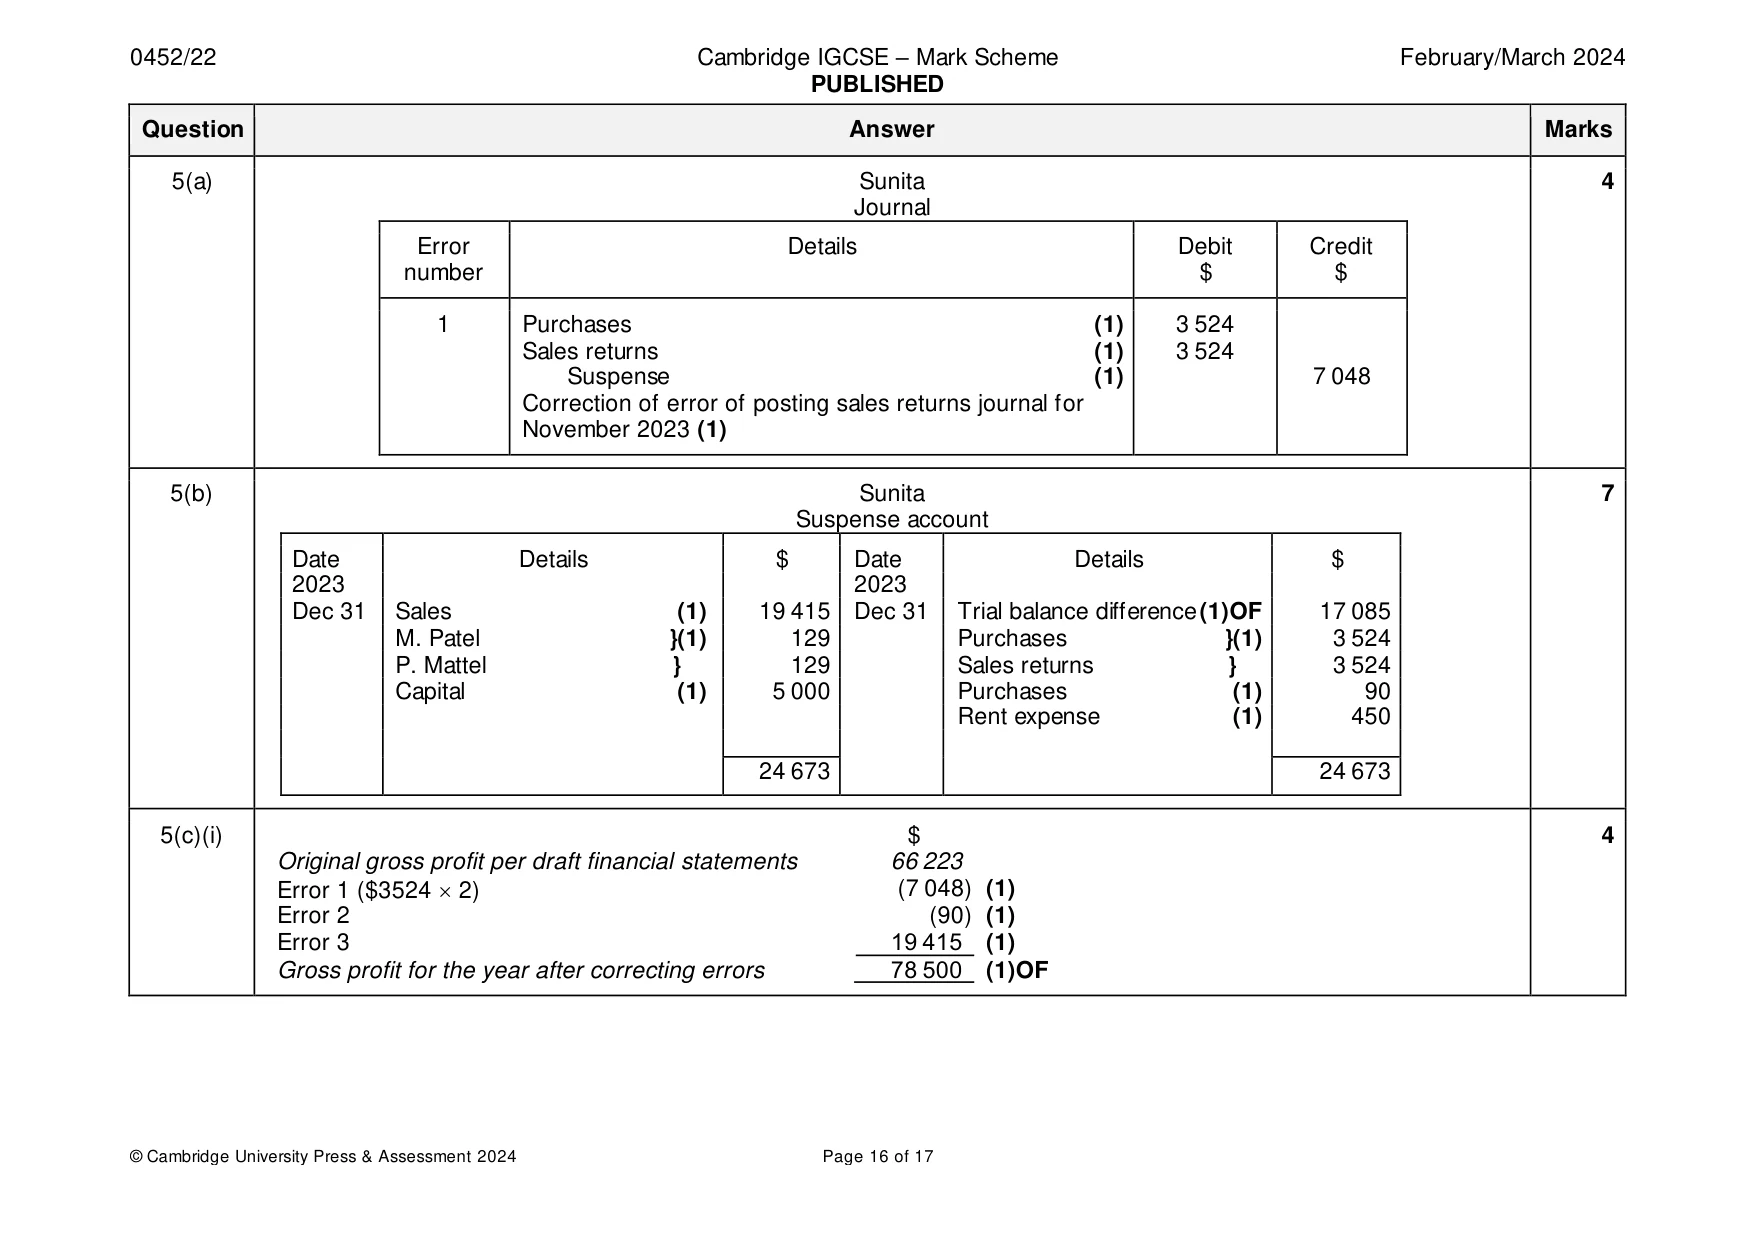
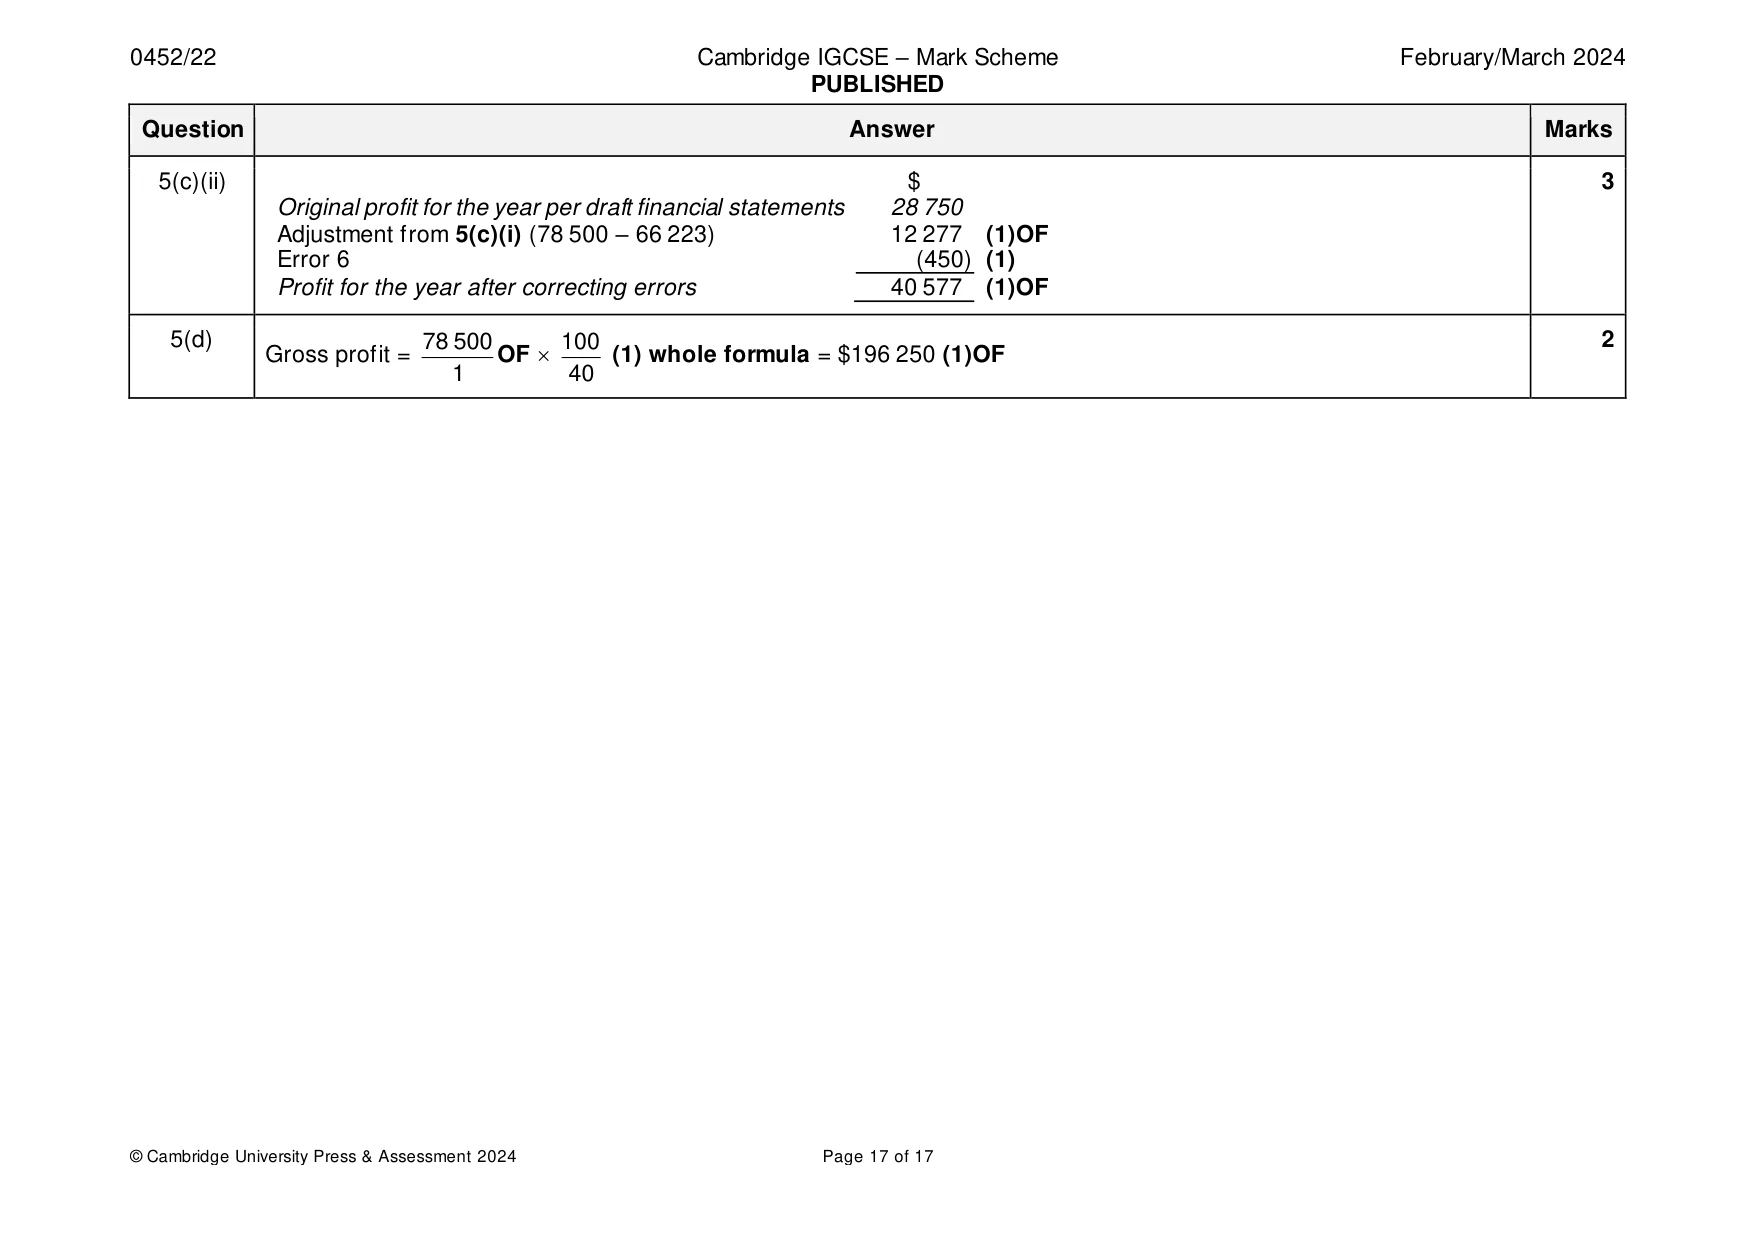
Mark scheme: 5(a) Sunita 4 Journal Error Details Debit Credit number $ $ 1 Purchases (1) 3 524 Sales returns (1) 3 524 Suspense (1) 7 048 Correction of error of posting sales returns journal for November 2023 (1) 5(b) Sunita 7 Suspense account Date Details $ Date Details $ 2023 2023 Dec 31 Sales (1) 19 415 Dec 31 Trial balance difference (1)OF 17 085 M. Patel }(1) 129 Purchases }(1) 3 524 P. Mattel } 129 Sales returns } 3 524 Capital (1) 5 000 Purchases (1) 90 Rent expense (1) 450 24 673 24 673 5(c)(i) $ 4 Original gross profit per draft financial statements 66 223 Error 1 ($3524 2) (7 048) (1) Error 2 (90) (1) Error 3 19 415 (1) Gross profit for the year after correcting errors 78 500 (1)OF 5(c)(ii) $ 3 Original profit for the year per draft financial statements 28 750 Adjustment from 5(c)(i) (78 500 – 66 223) 12 277 (1)OF Error 6 (450) (1) Profit for the year after correcting errors 40 577 (1)OF 5(d) 78 500 100 2 Gross profit = OF (1) whole formula = $196 250 (1)OF 1 40
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2024 Feb/March, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.