Cambridge IGCSE Accounting 0452 — 2023 Oct/Nov Paper 2 · Variant 2
0452/22/O/N/23 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme15 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Seok buys and sells goods on credit
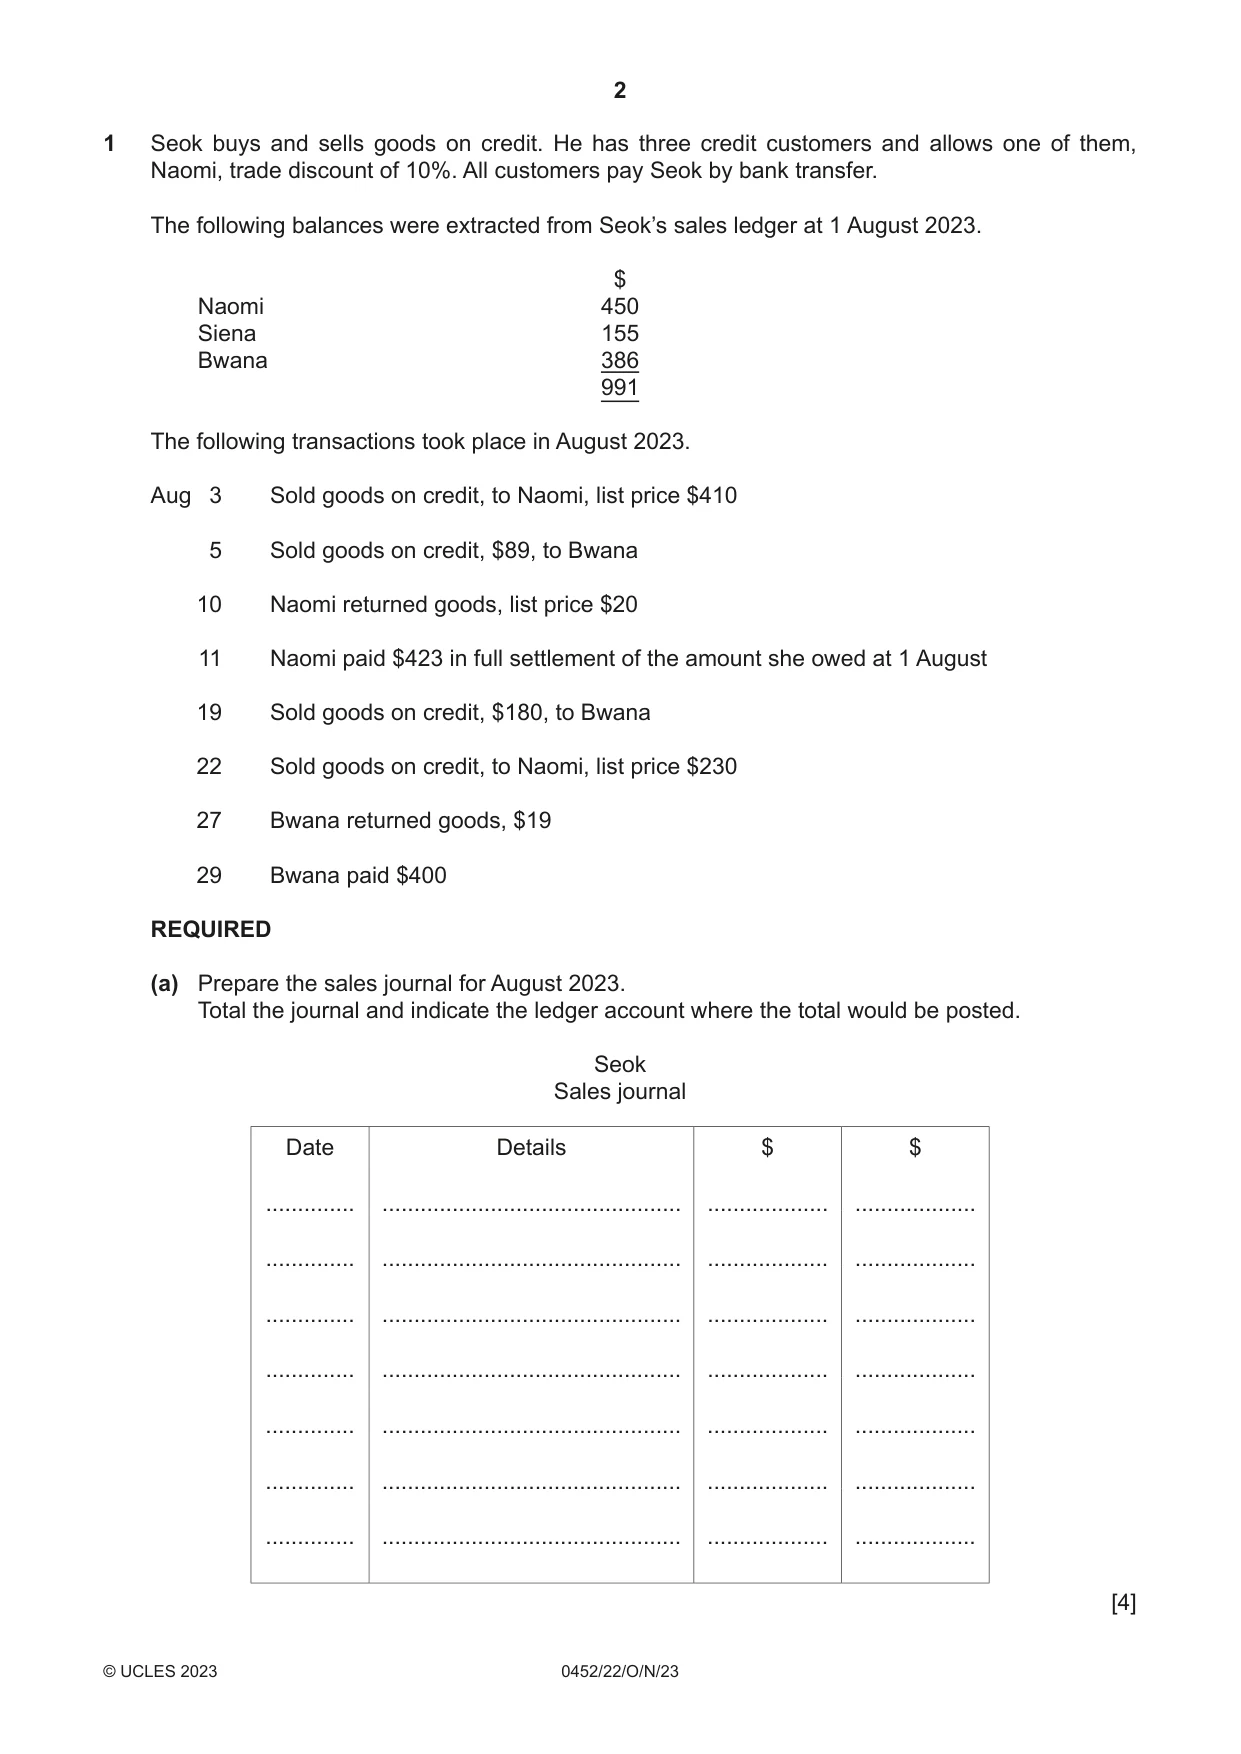
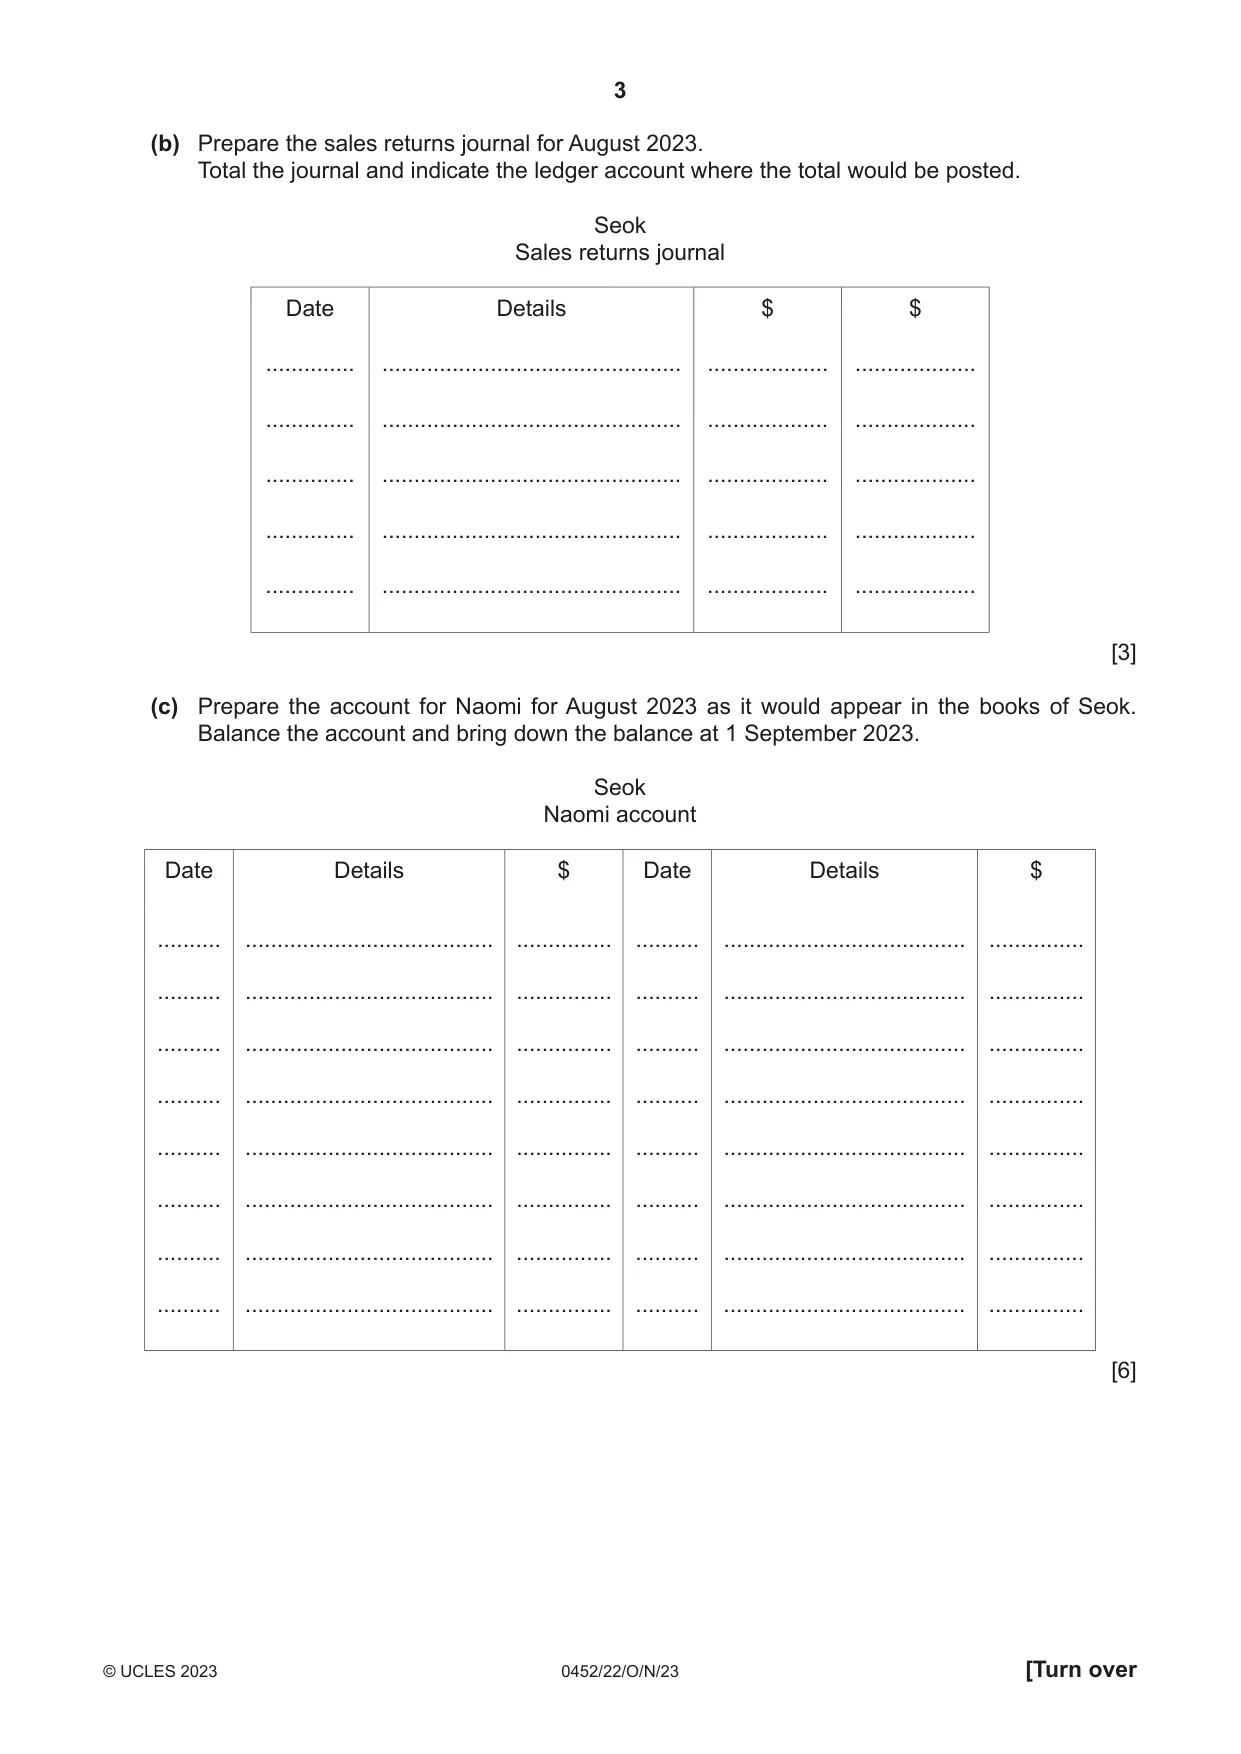
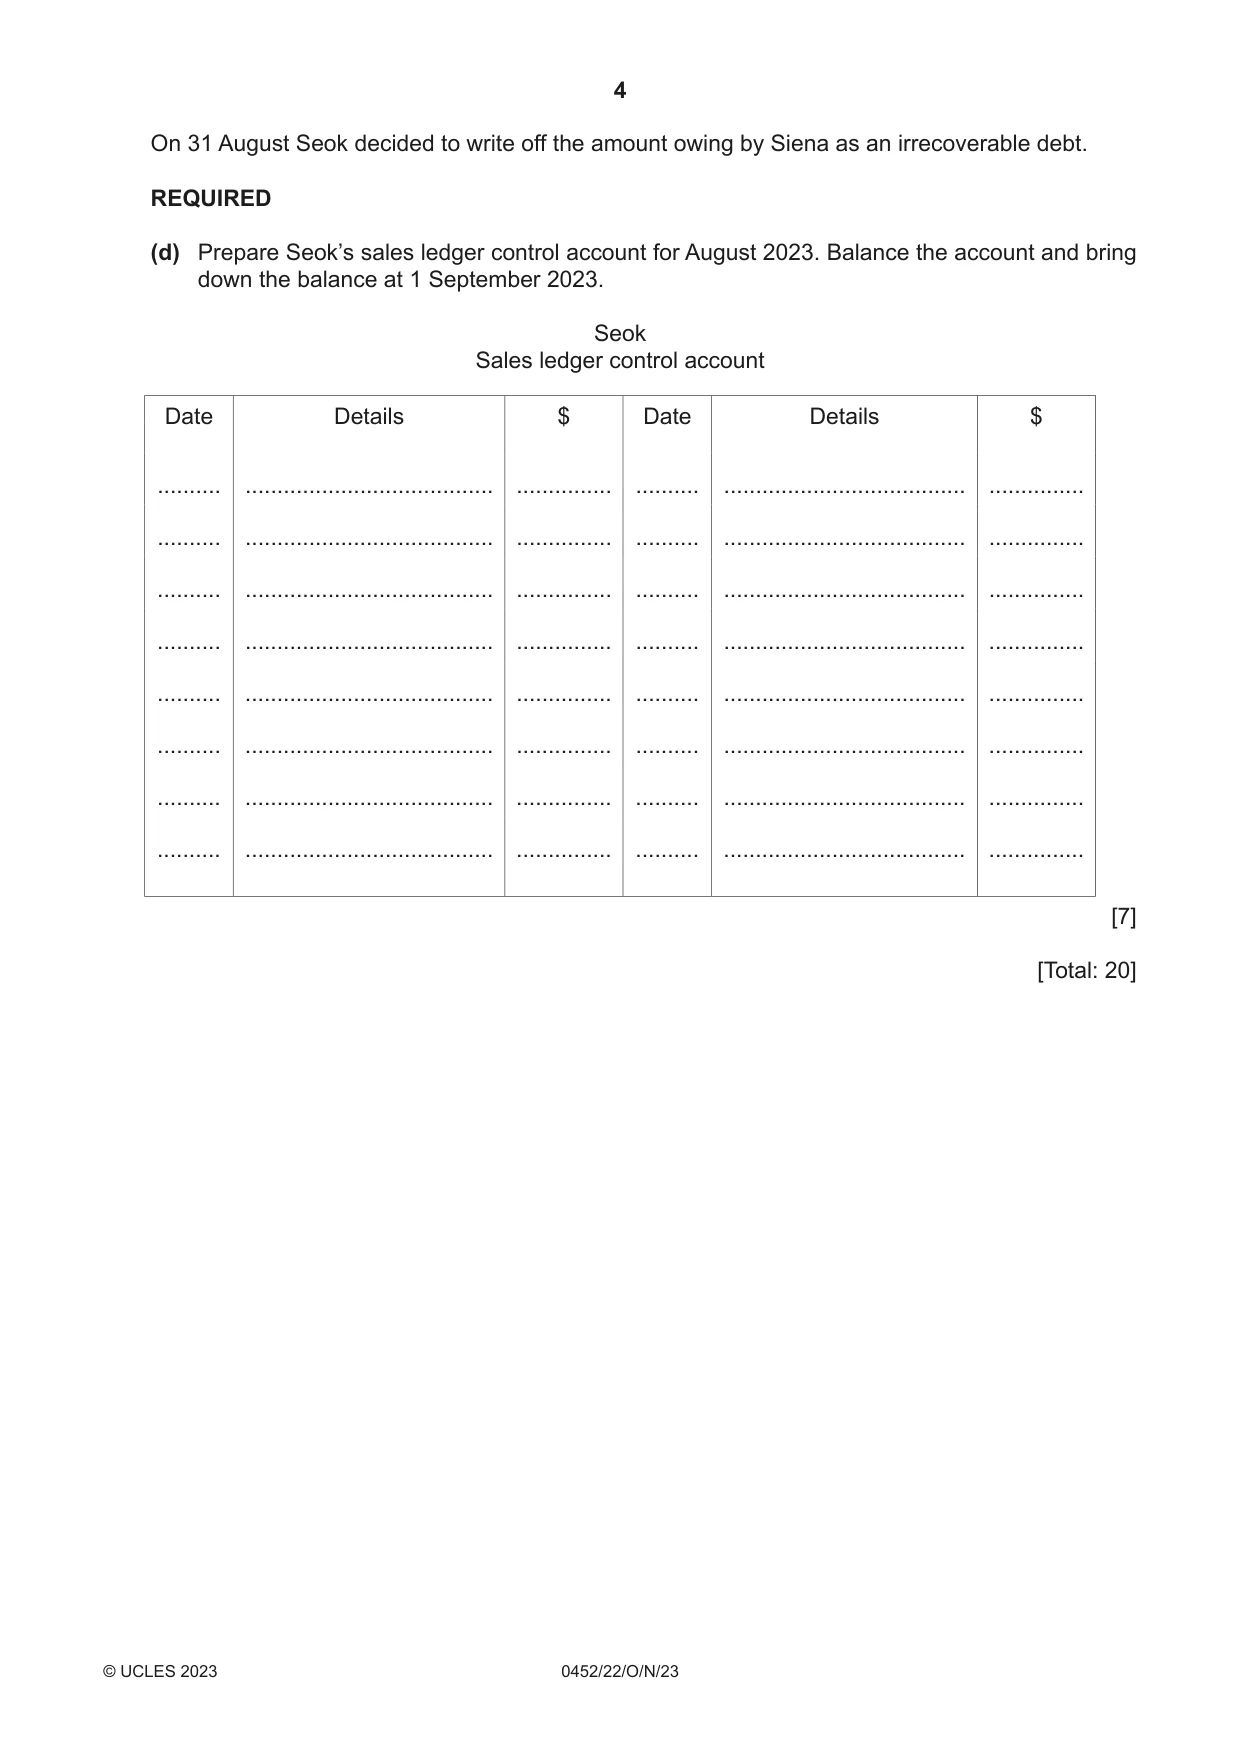
1 Seok buys and sells goods on credit. He has three credit customers and allows one of them, Naomi, trade discount of 10%. All customers pay Seok by bank transfer. The following balances were extracted from Seok’s sales ledger at 1 August 2023. $ Naomi 450 Siena 155 Bwana 386 991 The following transactions took place in August 2023. Aug 3 Sold goods on credit, to Naomi, list price $410 5 Sold goods on credit, $89, to Bwana 10 Naomi returned goods, list price $20 11 Naomi paid $423 in full settlement of the amount she owed at 1 August 19 Sold goods on credit, $180, to Bwana 22 Sold goods on credit, to Naomi, list price $230 27 Bwana returned goods, $19 29 Bwana paid $400 REQUIRED (a) Prepare the sales journal for August 2023. Total the journal and indicate the ledger account where the total would be posted. Seok Sales journal Date Details $ $ .............. ............................................... ................... ................... .............. ............................................... ................... ................... .............. ............................................... ................... ................... .............. ............................................... ................... ................... .............. ............................................... ................... ................... .............. ............................................... ................... ................... .............. ............................................... ................... ................... [4] (b) Prepare the sales returns journal for August 2023. Total the journal and indicate the ledger account where the total would be posted. Seok Sales returns journal Date Details $ $ .............. ............................................... ................... ................... .............. ............................................... ................... ................... .............. ............................................... ................... ................... .............. ............................................... ................... ................... .............. ............................................... ................... ................... [3] (c) Prepare the account for Naomi for August 2023 as it would appear in the books of Seok. Balance the account and bring down the balance at 1 September 2023. Seok Naomi account Date Details $ Date Details $ .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... [6] On 31 August Seok decided to write off the amount owing by Siena as an irrecoverable debt. REQUIRED (d) Prepare Seok’s sales ledger control account for August 2023. Balance the account and bring down the balance at 1 September 2023. Seok Sales ledger control account Date Details $ Date Details $ .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... [7] [Total: 20]
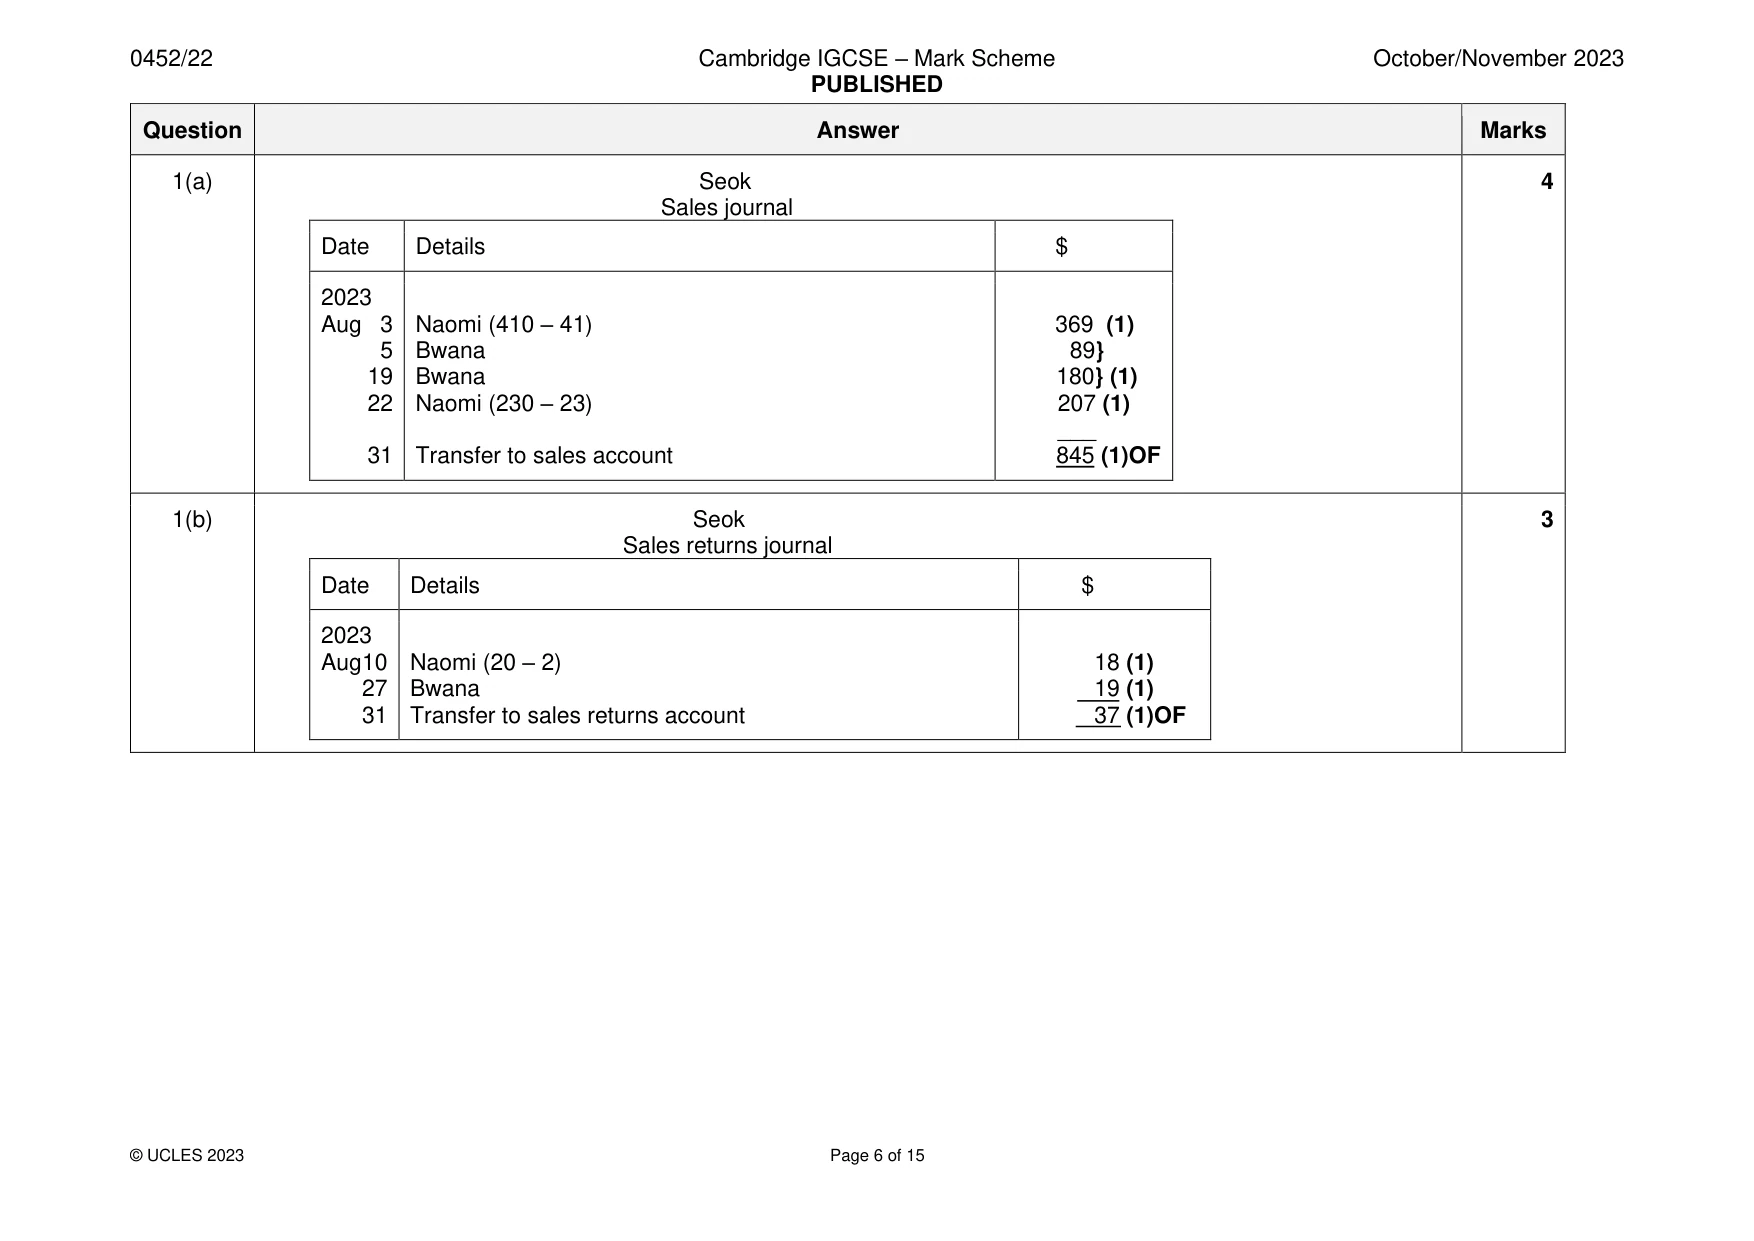
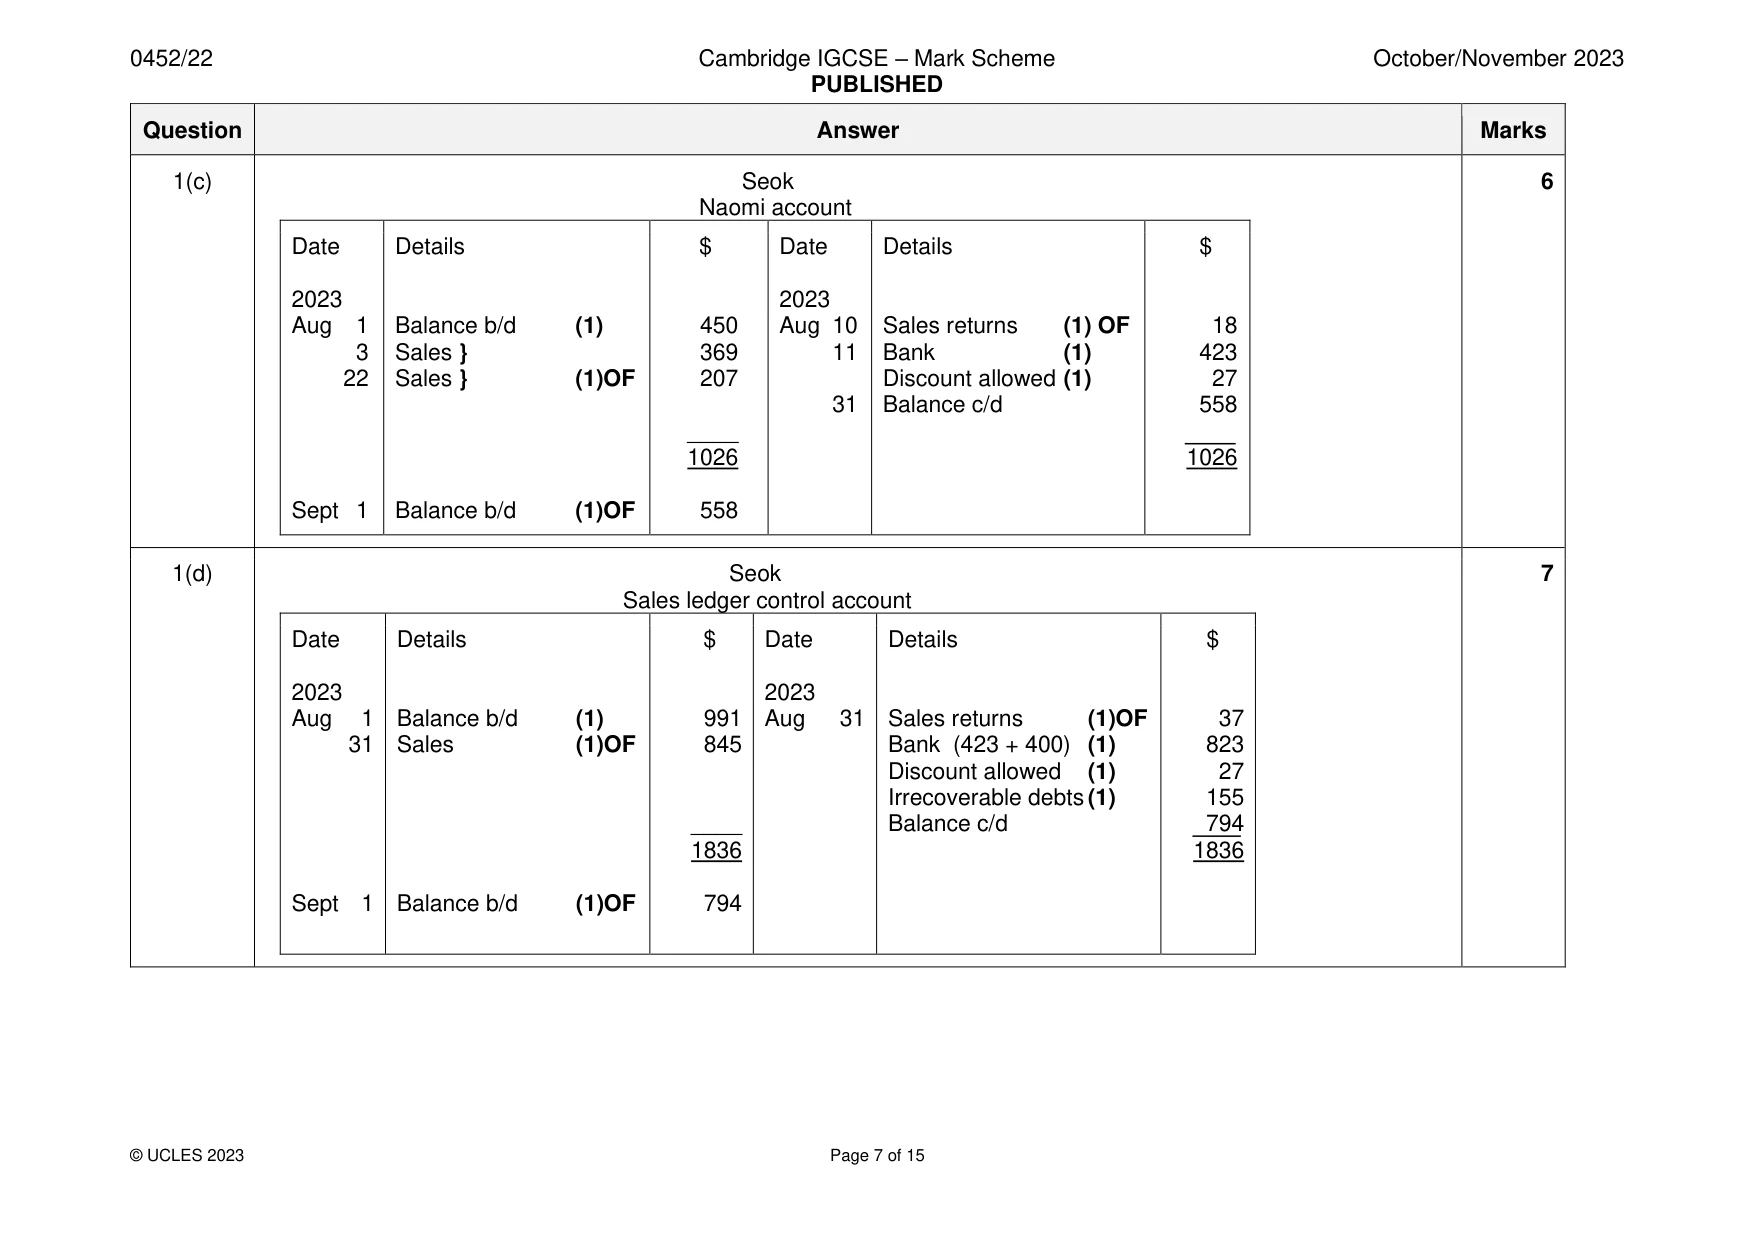
Mark scheme: Question Answer Marks 1(a) Seok 4 Sales journal Date Details $ 2023 Aug 3 Naomi (410 – 41) 369 (1) 5 Bwana 89} 19 Bwana 180} (1) 22 Naomi (230 – 23) 207 (1) ___ 31 Transfer to sales account 845 (1)OF 1(b) Seok 3 Sales returns journal Date Details $ 2023 Aug 10 Naomi (20 – 2) 18 (1) 27 Bwana 19 (1) 31 Transfer to sales returns account 37 (1)OF 1(c) Seok 6 Naomi account Date Details $ Date Details $ 2023 2023 Aug 1 Balance b/d (1) 450 Aug 10 Sales returns (1) OF 18 3 Sales } 369 11 Bank (1) 423 22 Sales } (1)OF 207 Discount allowed (1) 27 31 Balance c/d 558 ____ 1026 1026 Sept 1 Balance b/d (1)OF 558 1(d) Seok 7 Sales ledger control account Date Details $ Date Details $ 2023 2023 Aug 1 Balance b/d (1) 991 Aug 31 Sales returns (1)OF 37 31 Sales (1)OF 845 Bank (423 + 400) (1) 823 Discount allowed (1) 27 Irrecoverable debts (1) 155 ____ Balance c/d 794 1836 1836 Sept 1 Balance b/d (1)OF 794
Q2 · Sara owns a clothing factory
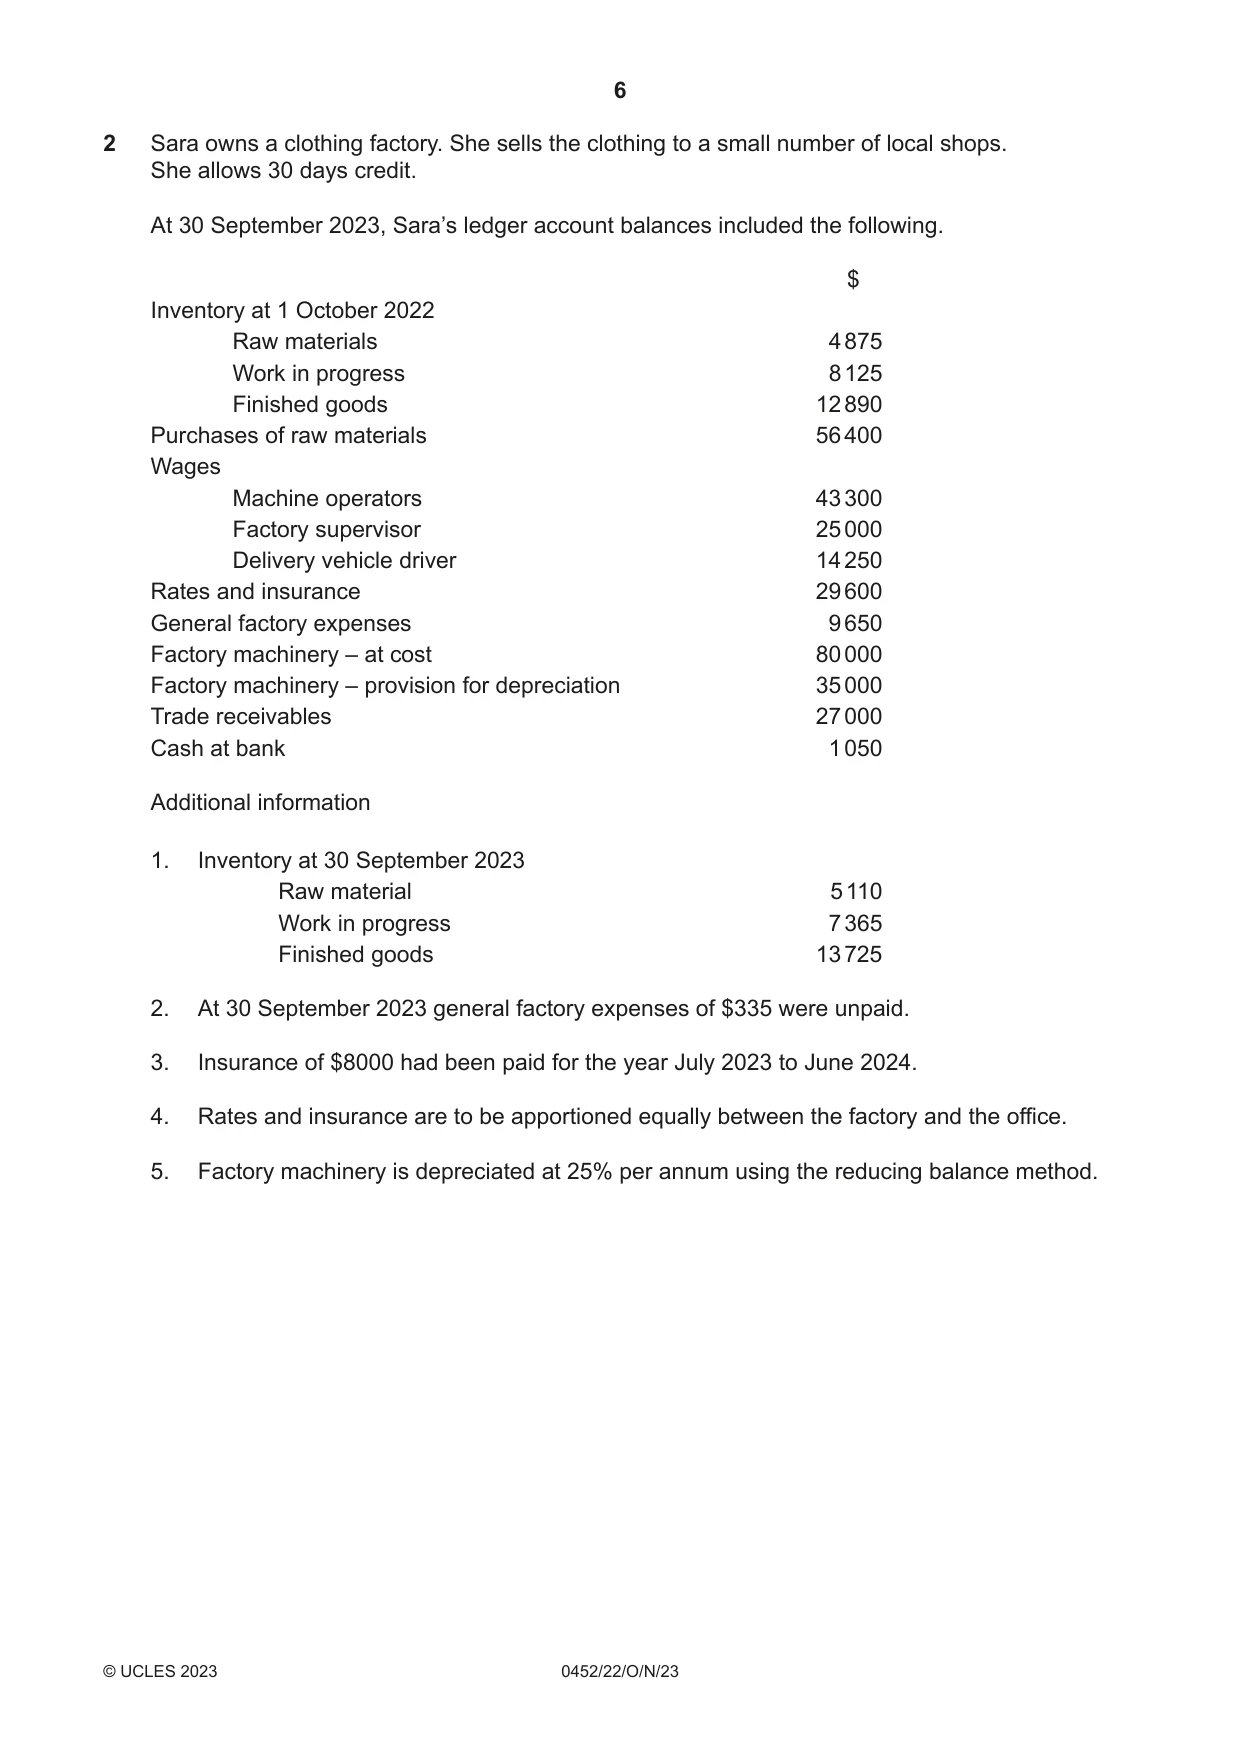
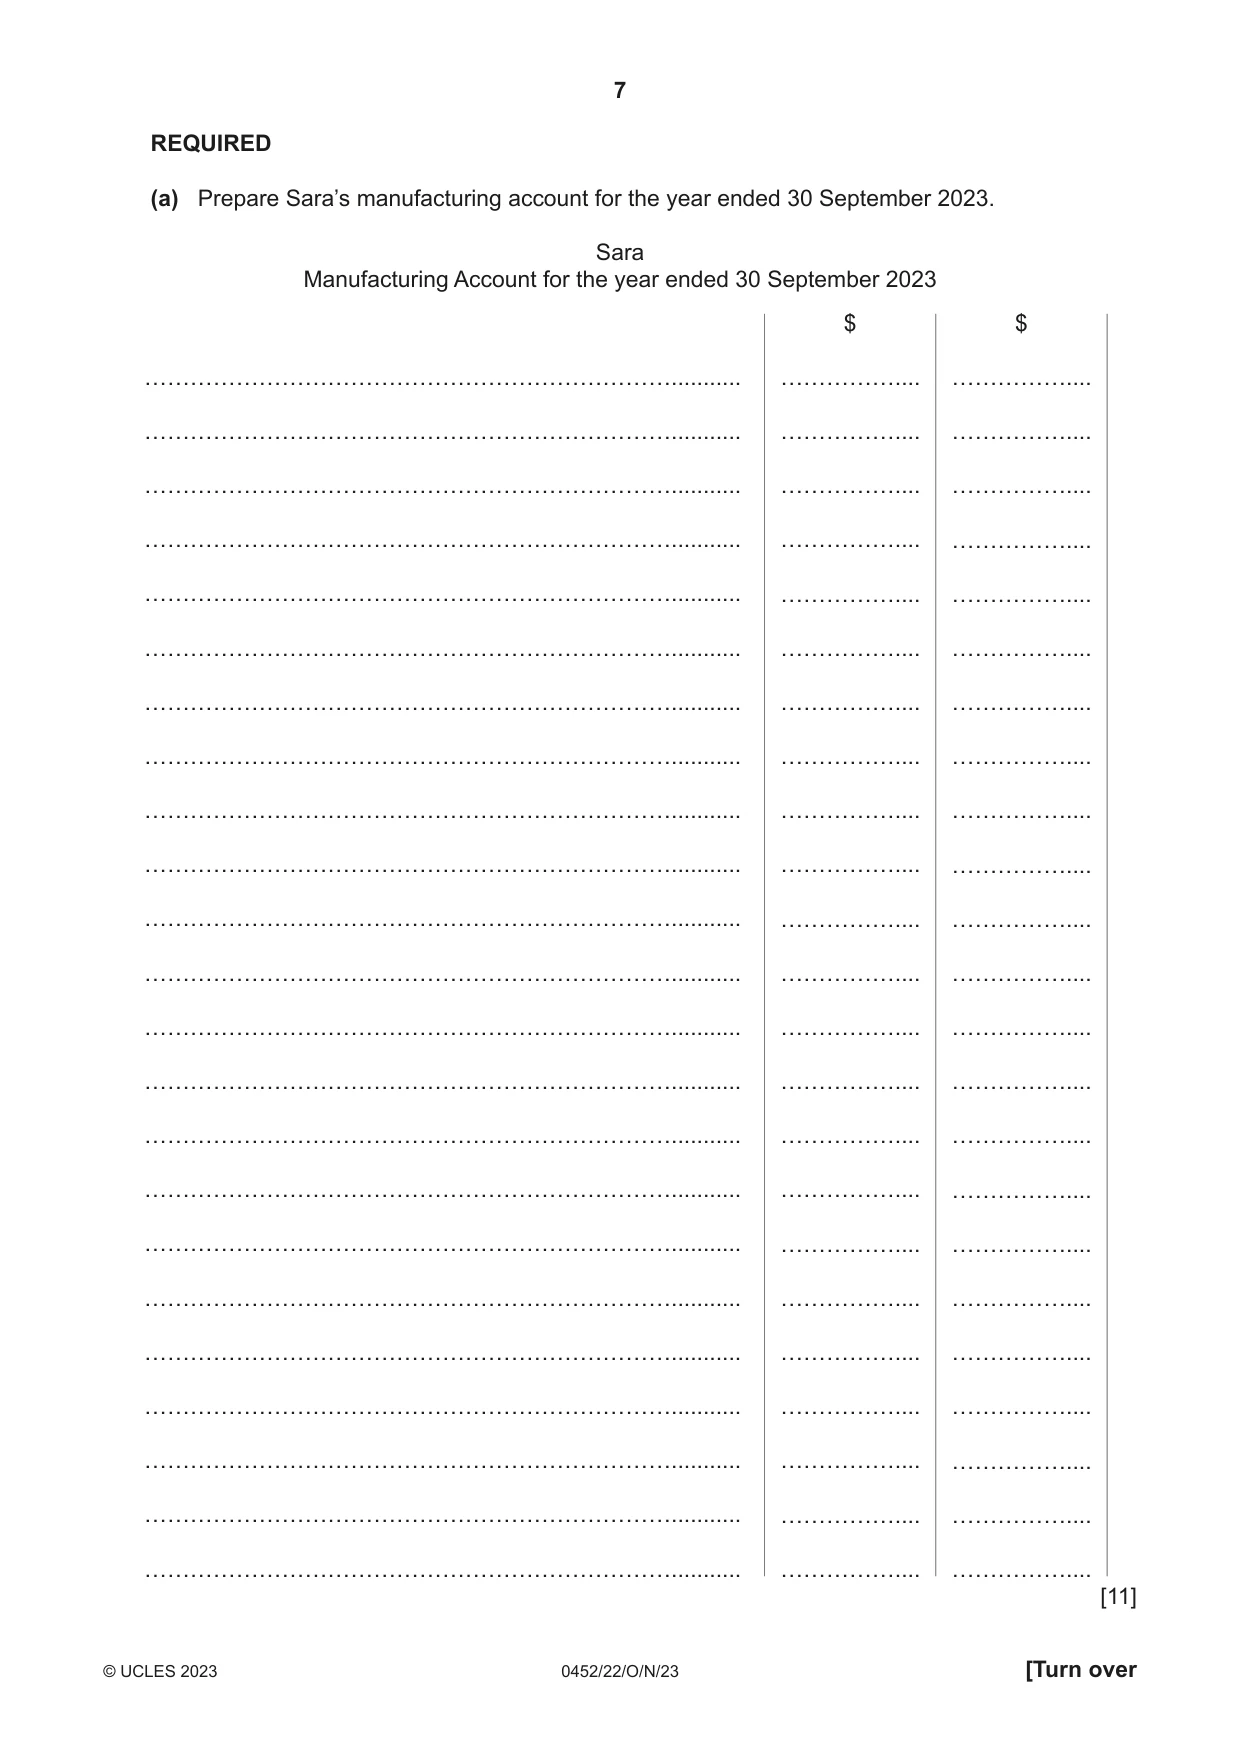
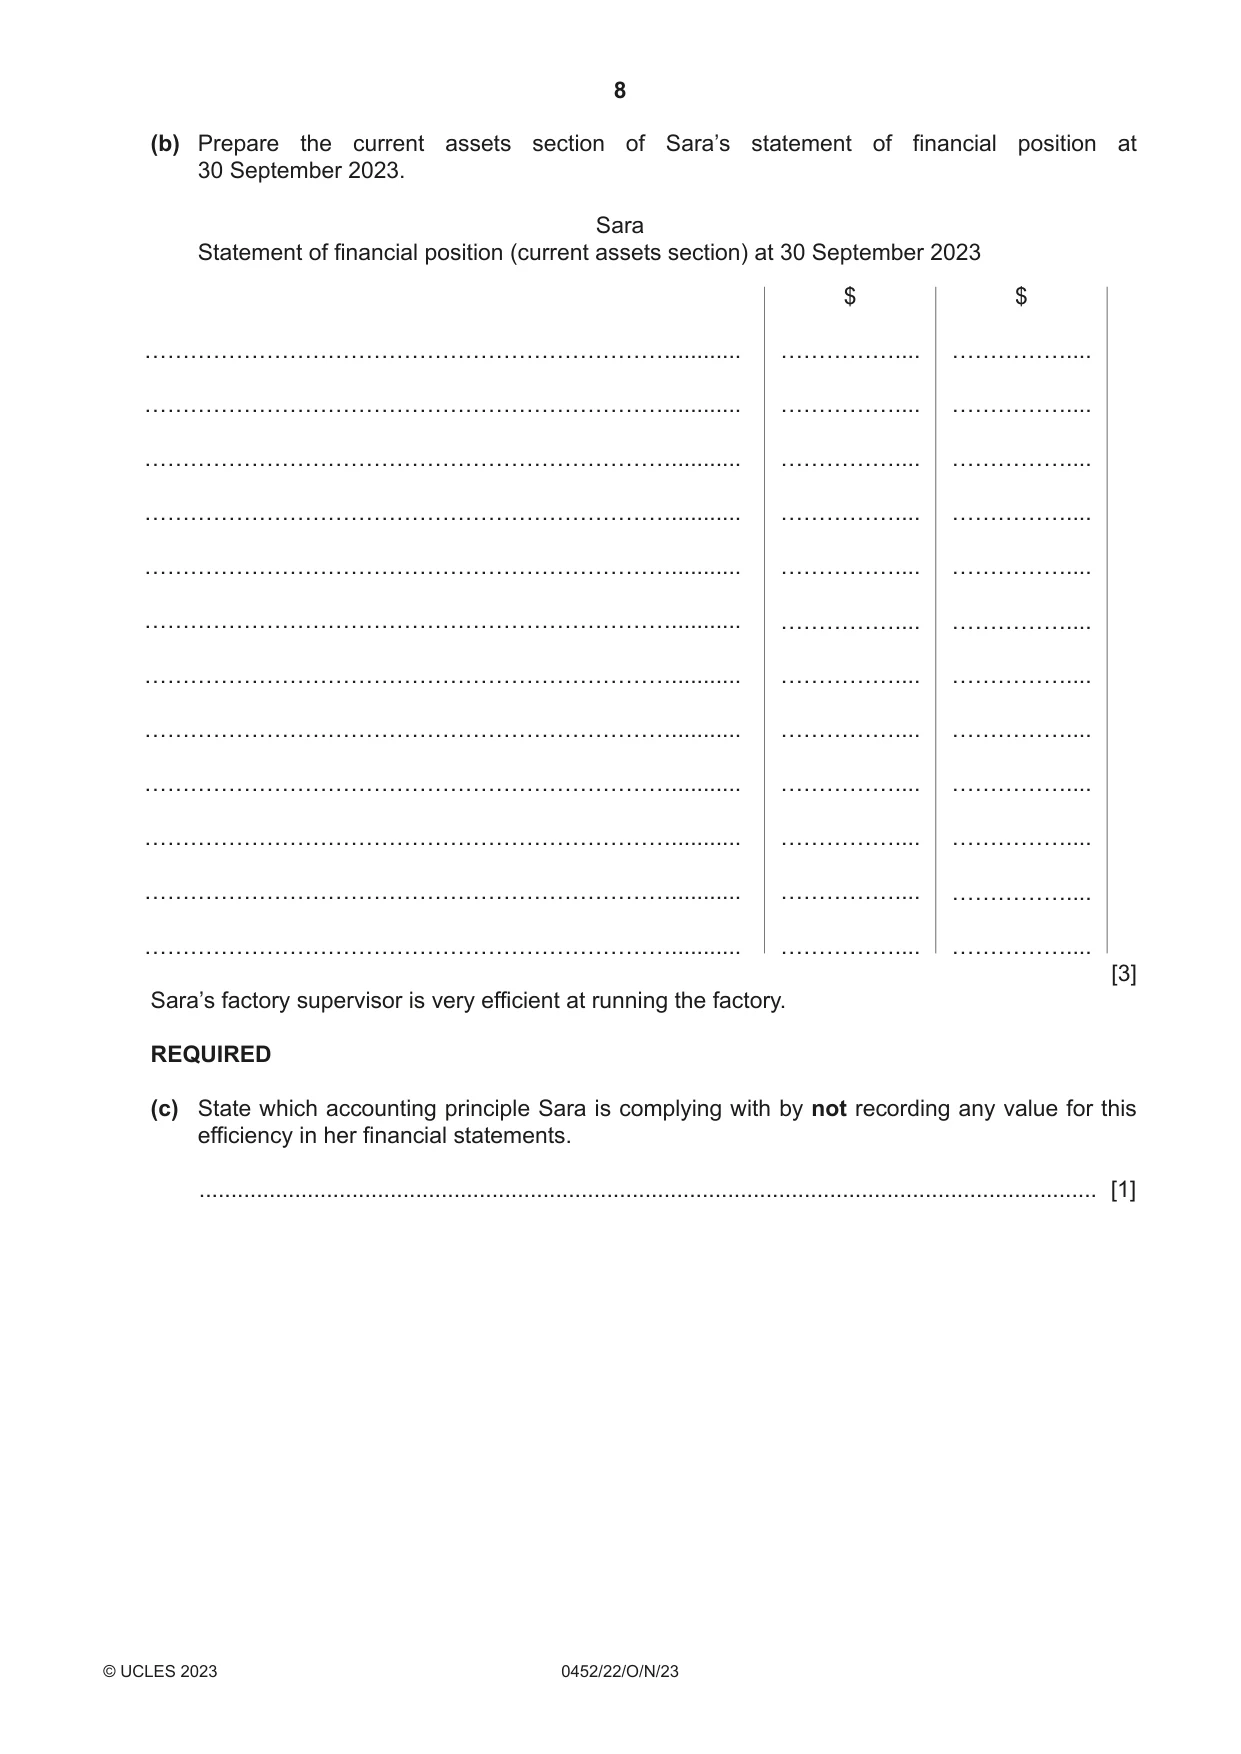
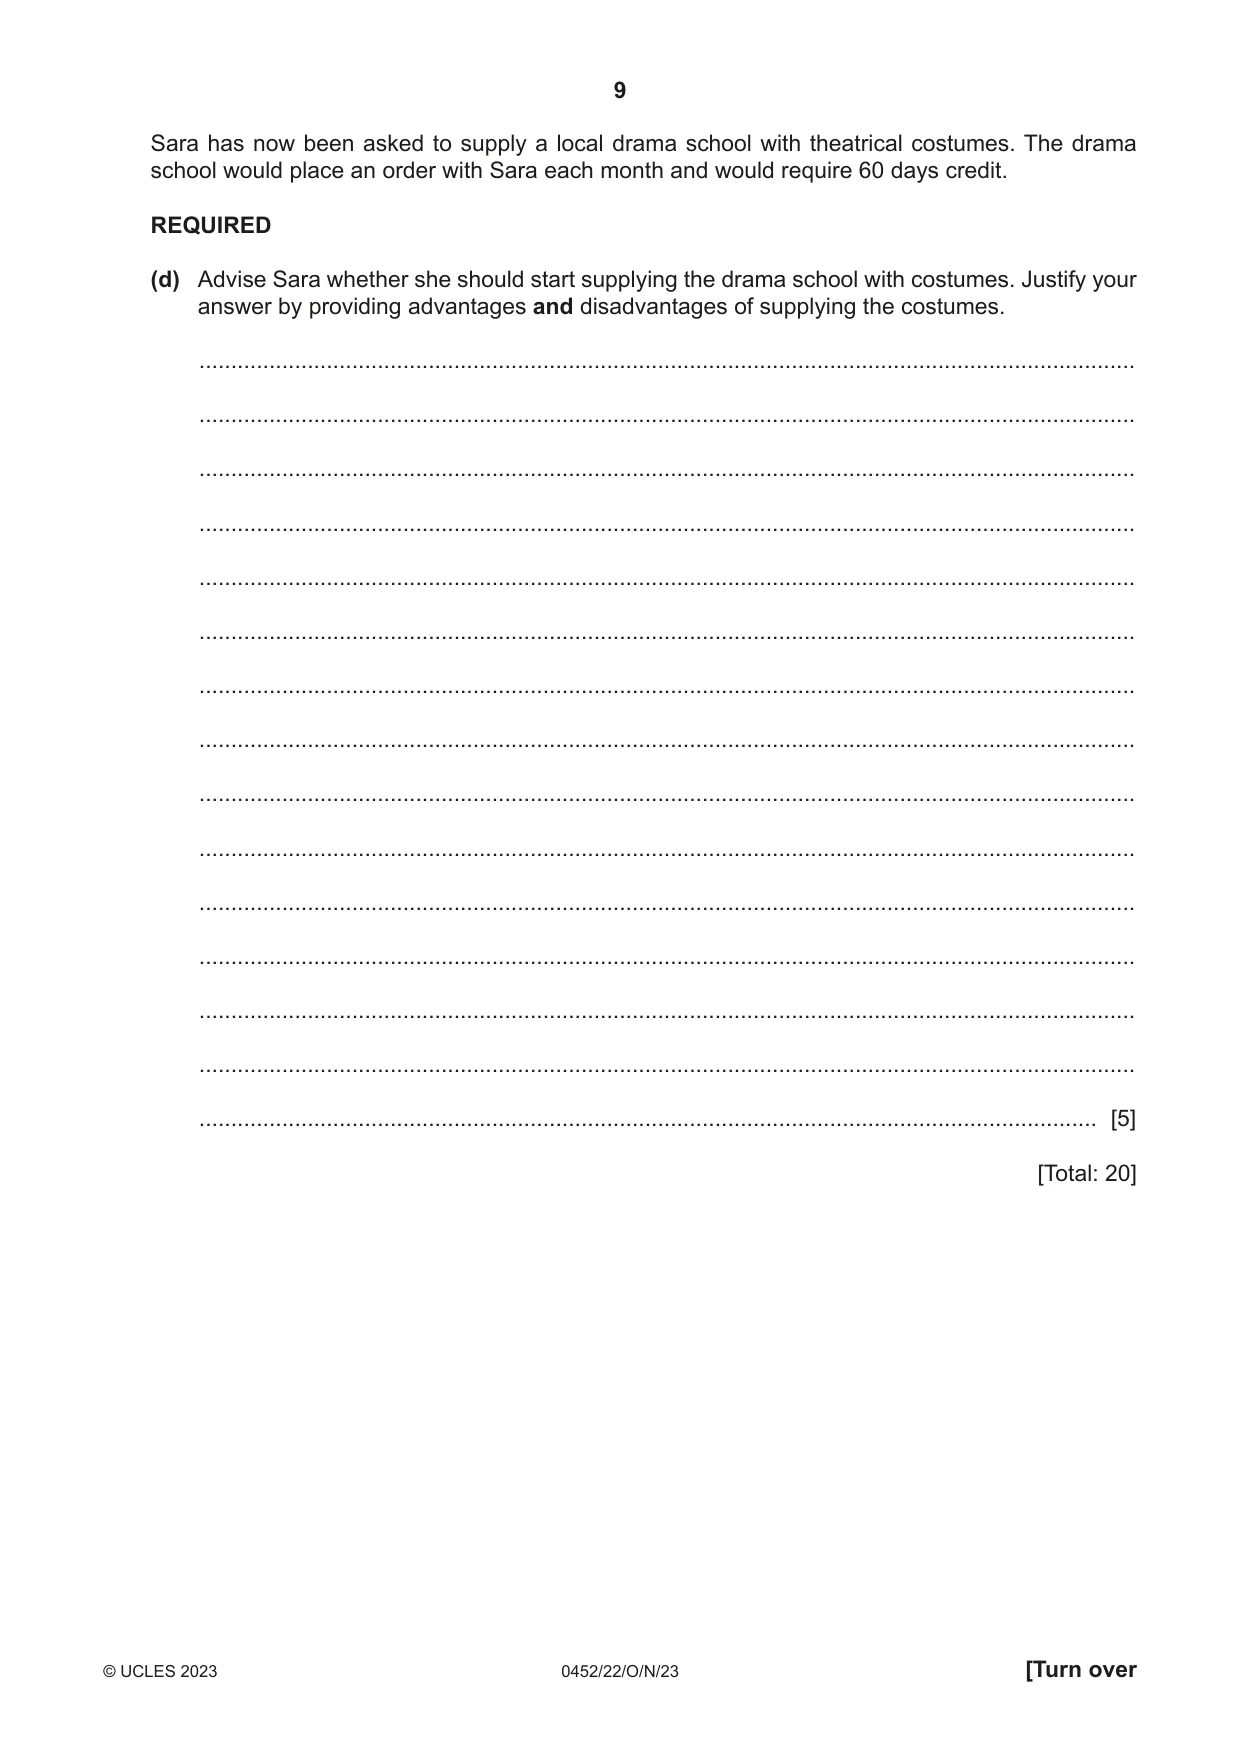
2 Sara owns a clothing factory. She sells the clothing to a small number of local shops. She allows 30 days credit. At 30 September 2023, Sara’s ledger account balances included the following. $ Inventory at 1 October 2022 Raw materials 4 875 Work in progress 8 125 Finished goods 12 890 Purchases of raw materials 56 400 Wages Machine operators 43 300 Factory supervisor 25 000 Delivery vehicle driver 14 250 Rates and insurance 29 600 General factory expenses 9 650 Factory machinery – at cost 80 000 Factory machinery – provision for depreciation 35 000 Trade receivables 27 000 Cash at bank 1 050 Additional information 1. Inventory at 30 September 2023 Raw material 5 110 Work in progress 7 365 Finished goods 13 725 2. At 30 September 2023 general factory expenses of $335 were unpaid. 3. Insurance of $8000 had been paid for the year July 2023 to June 2024. 4. Rates and insurance are to be apportioned equally between the factory and the office. 5. Factory machinery is depreciated at 25% per annum using the reducing balance method. REQUIRED (a) Prepare Sara’s manufacturing account for the year end Sara Manufacturing Account for the year ended 30 ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... (b) Prepare the current assets section of Sara’s statement of financial position at 30 September 2023. Sara Statement of financial position (current assets section) at 30 September 2023 $ $ ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... [3] Sara’s factory supervisor is very efficient at running the factory. REQUIRED (c) State which accounting principle Sara is complying with by not recording any value for this efficiency in her financial statements. ............................................................................................................................................. [1] Sara has now been asked to supply a local drama school with theatrical costumes. The drama school would place an order with Sara each month and would require 60 days credit. REQUIRED (d) Advise Sara whether she should start supplying the drama school with costumes. Justify your answer by providing advantages and disadvantages of supplying the costumes. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
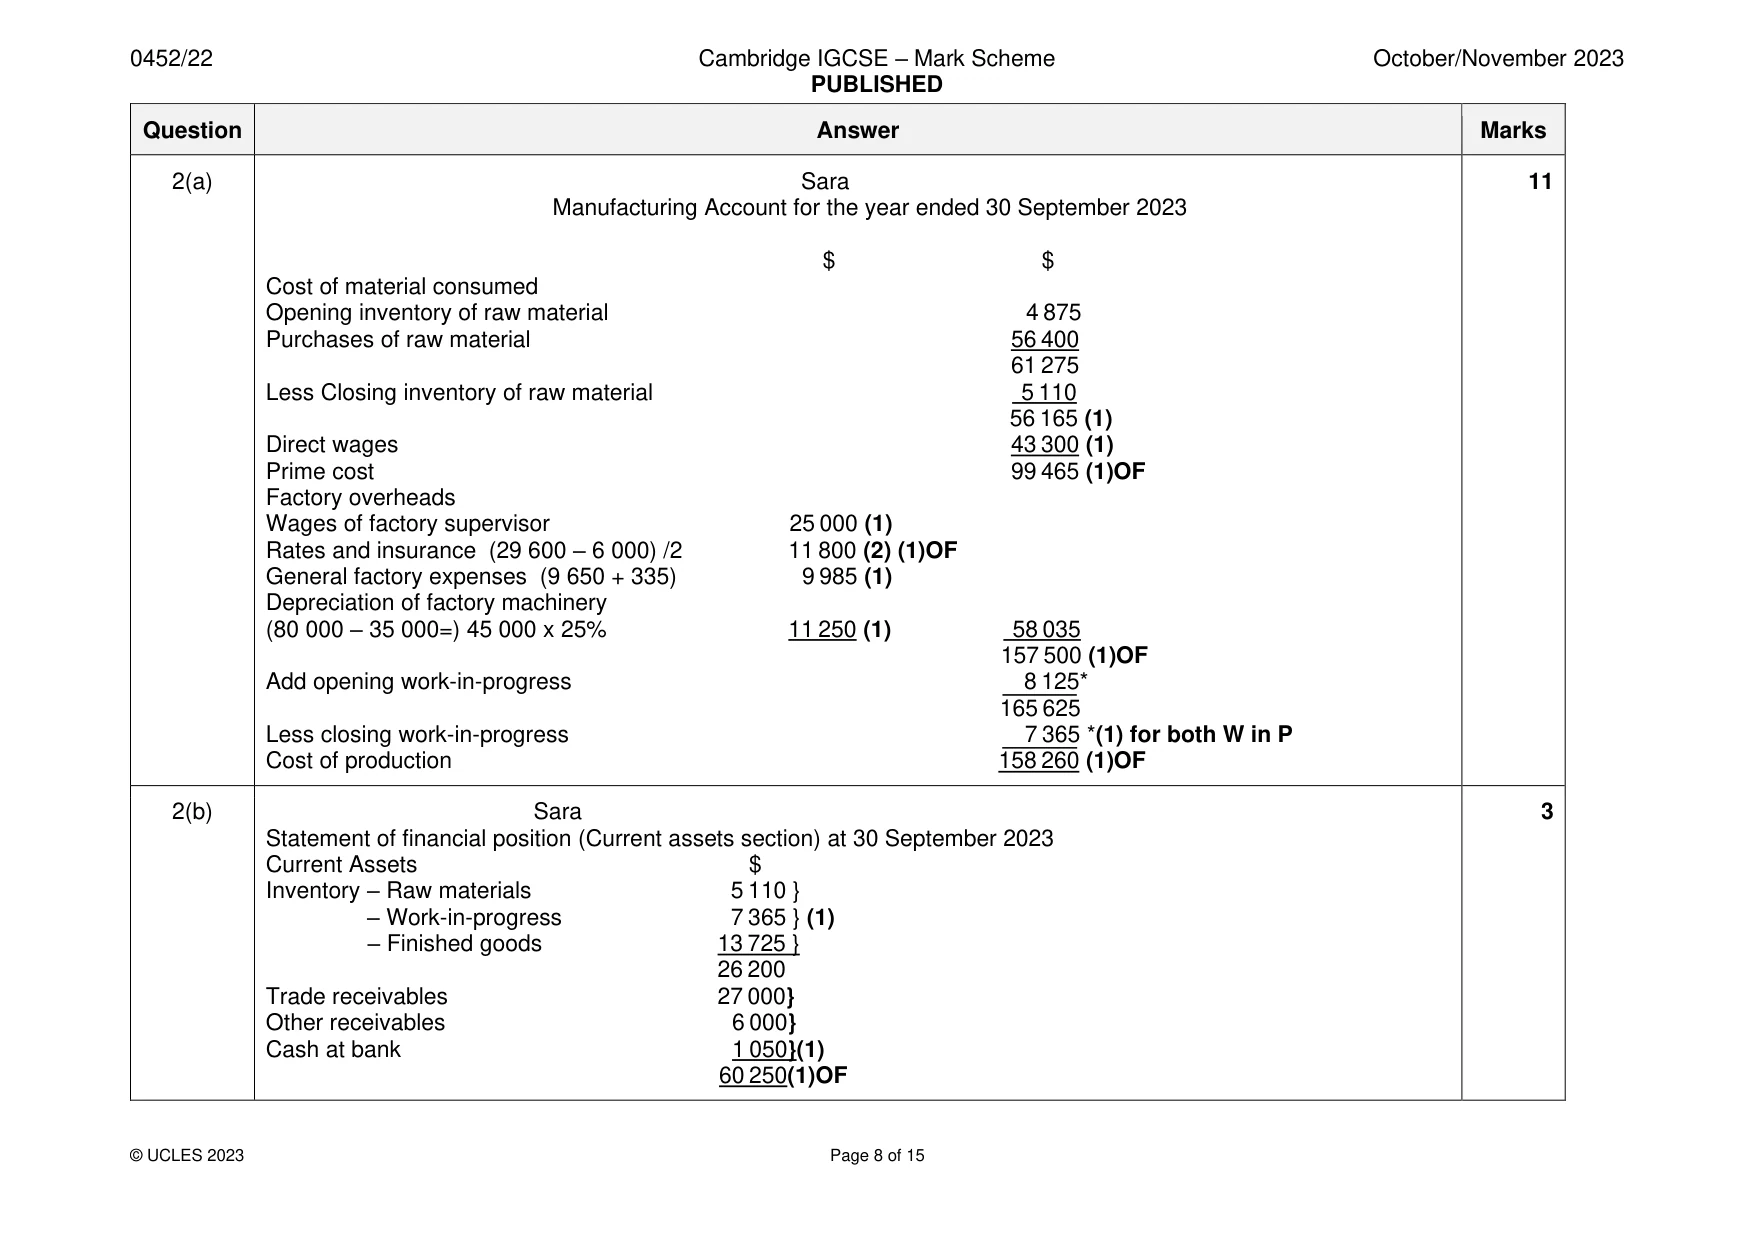
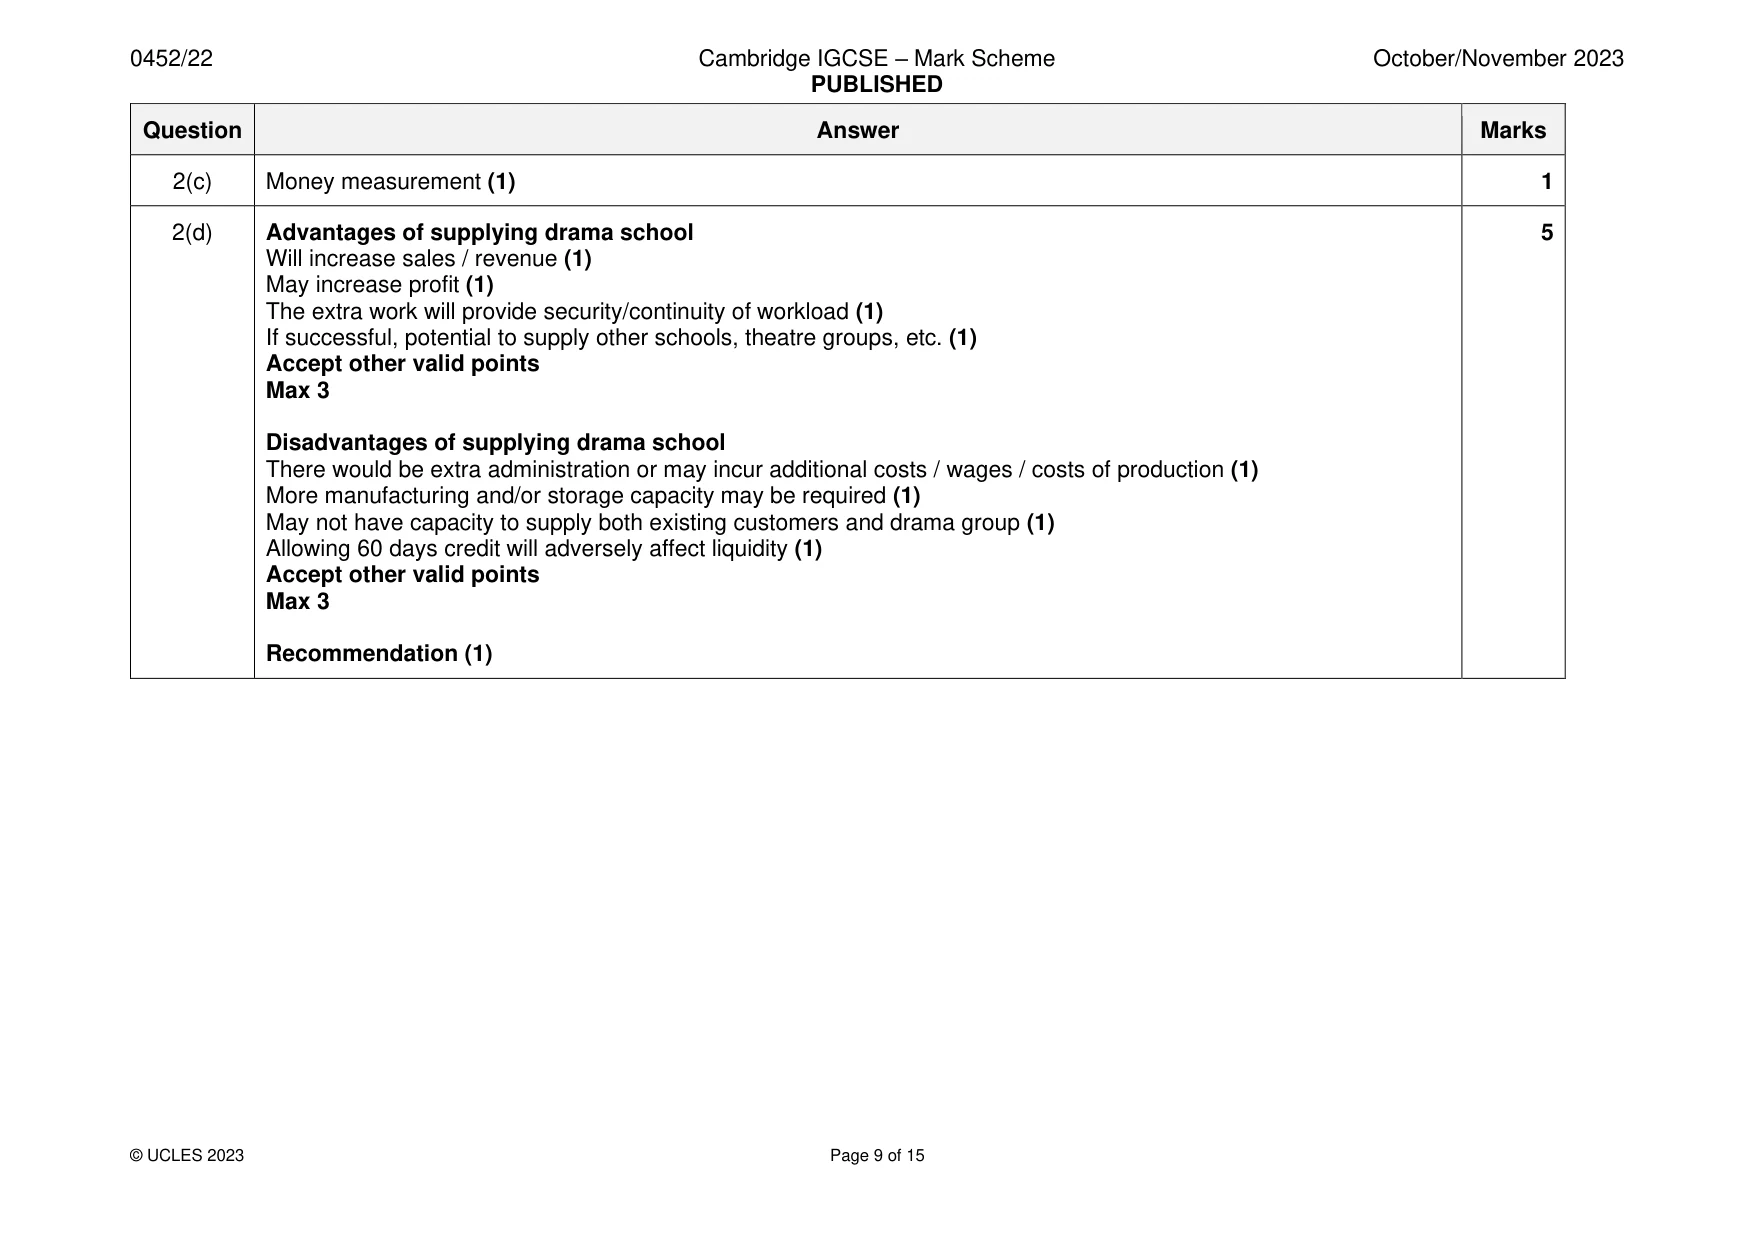
Mark scheme: 2(a) Sara 11 Manufacturing Account for the year ended 30 September 2023 $ $ Cost of material consumed Opening inventory of raw material 4 875 Purchases of raw material 56 400 61 275 Less Closing inventory of raw material 5 110 56 165 (1) Direct wages 43 300 (1) Prime cost 99 465 (1)OF Factory overheads Wages of factory supervisor 25 000 (1) Rates and insurance (29 600 – 6 000) /2 11 800 (2) (1)OF General factory expenses (9 650 + 335) 9 985 (1) Depreciation of factory machinery (80 000 – 35 000=) 45 000 x 25% 11 250 (1) 58 035 157 500 (1)OF Add opening work-in-progress 8 125* 165 625 Less closing work-in-progress 7 365 *(1) for both W in P Cost of production 158 260 (1)OF 2(b) Sara 3 Statement of financial position (Current assets section) at 30 September 2023 Current Assets $ Inventory – Raw materials 5 110 } – Work-in-progress 7 365 } (1) – Finished goods 13 725 } 26 200 Trade receivables 27 000} Other receivables 6 000} Cash at bank 1 050}(1) 60 250(1)OF 2(c) Money measurement (1) 1 2(d) Advantages of supplying drama school 5 Will increase sales / revenue (1) May increase profit (1) The extra work will provide security/continuity of workload (1) If successful, potential to supply other schools, theatre groups, etc. (1) Accept other valid points Max 3 Disadvantages of supplying drama school There would be extra administration or may incur additional costs / wages / costs of production (1) More manufacturing and/or storage capacity may be required (1) May not have capacity to supply both existing customers and drama group (1) Allowing 60 days credit will adversely affect liquidity (1) Accept other valid points Max 3 Recommendation (1)
Q3 · Lionel started trading on 1 July 2022
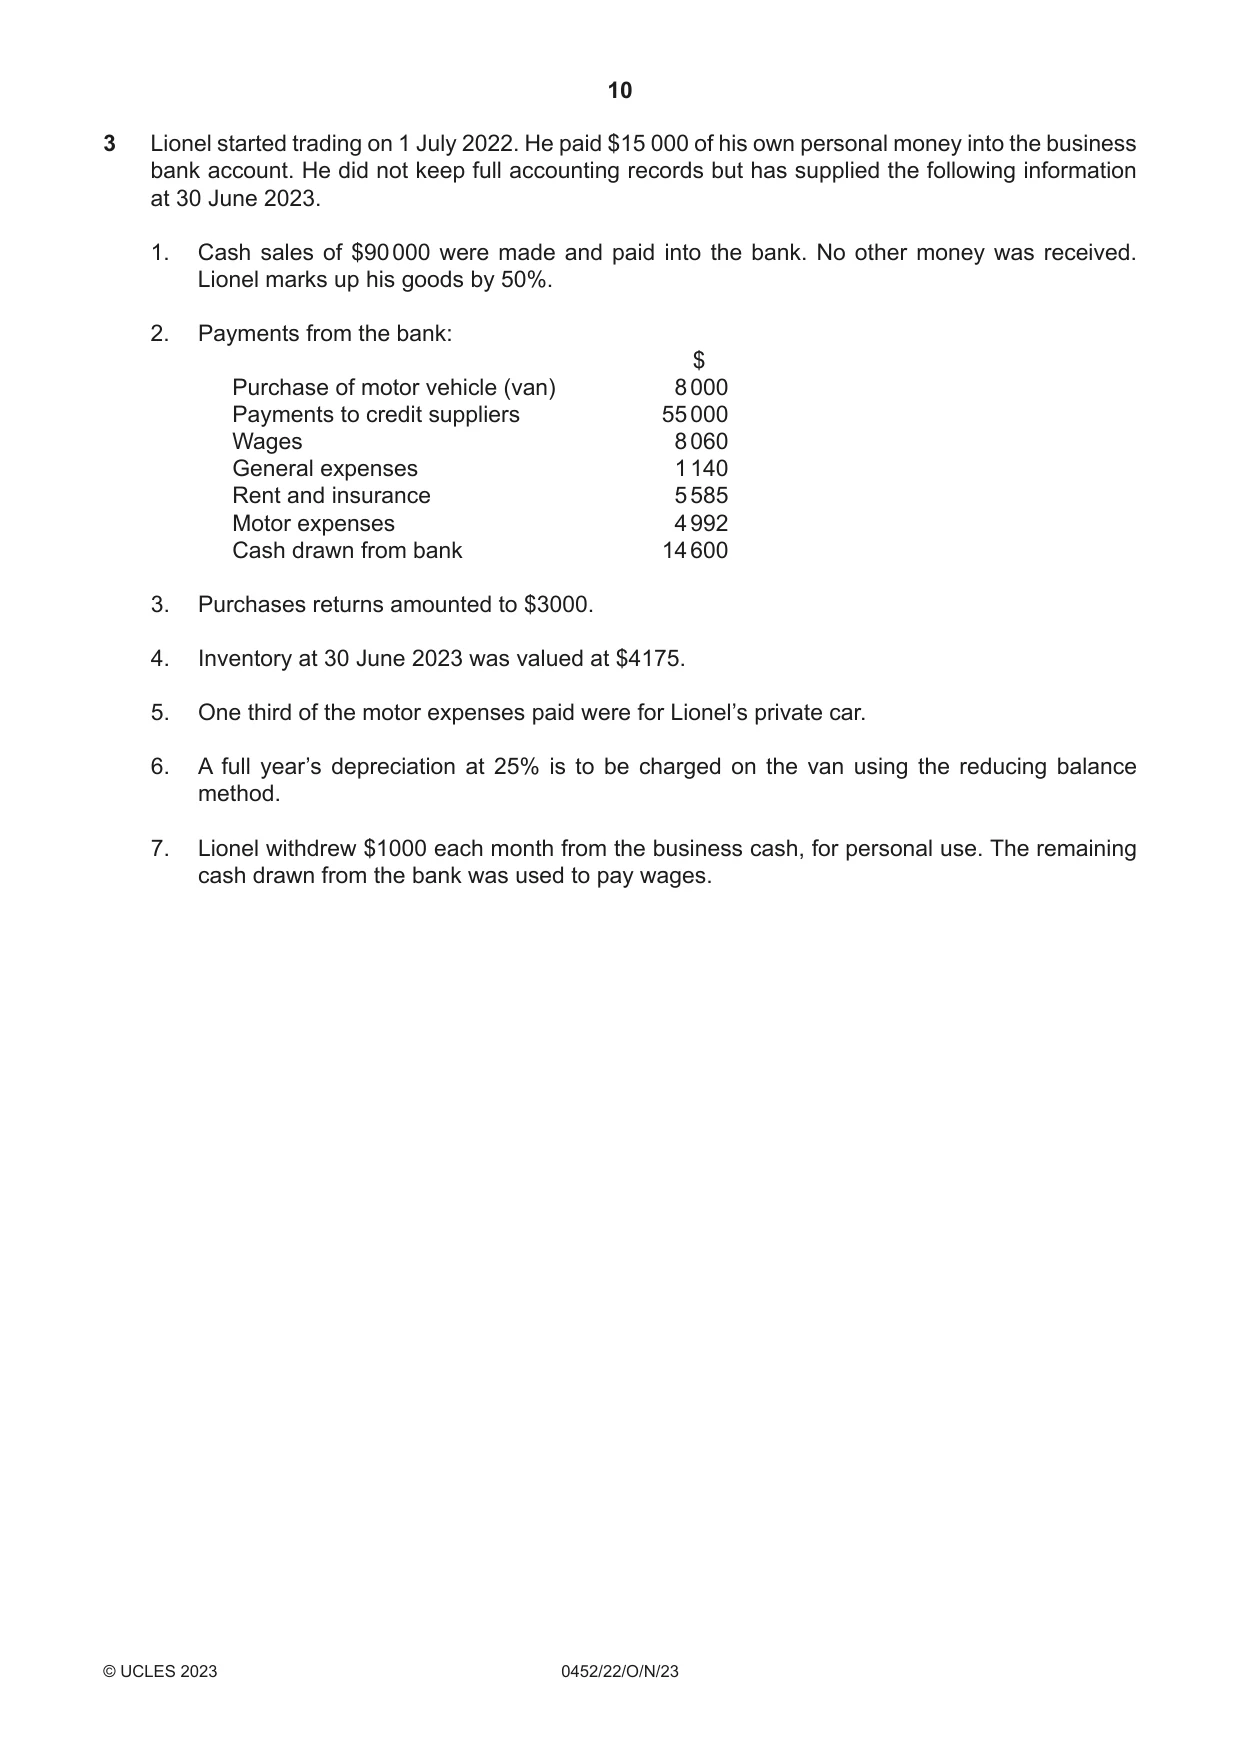
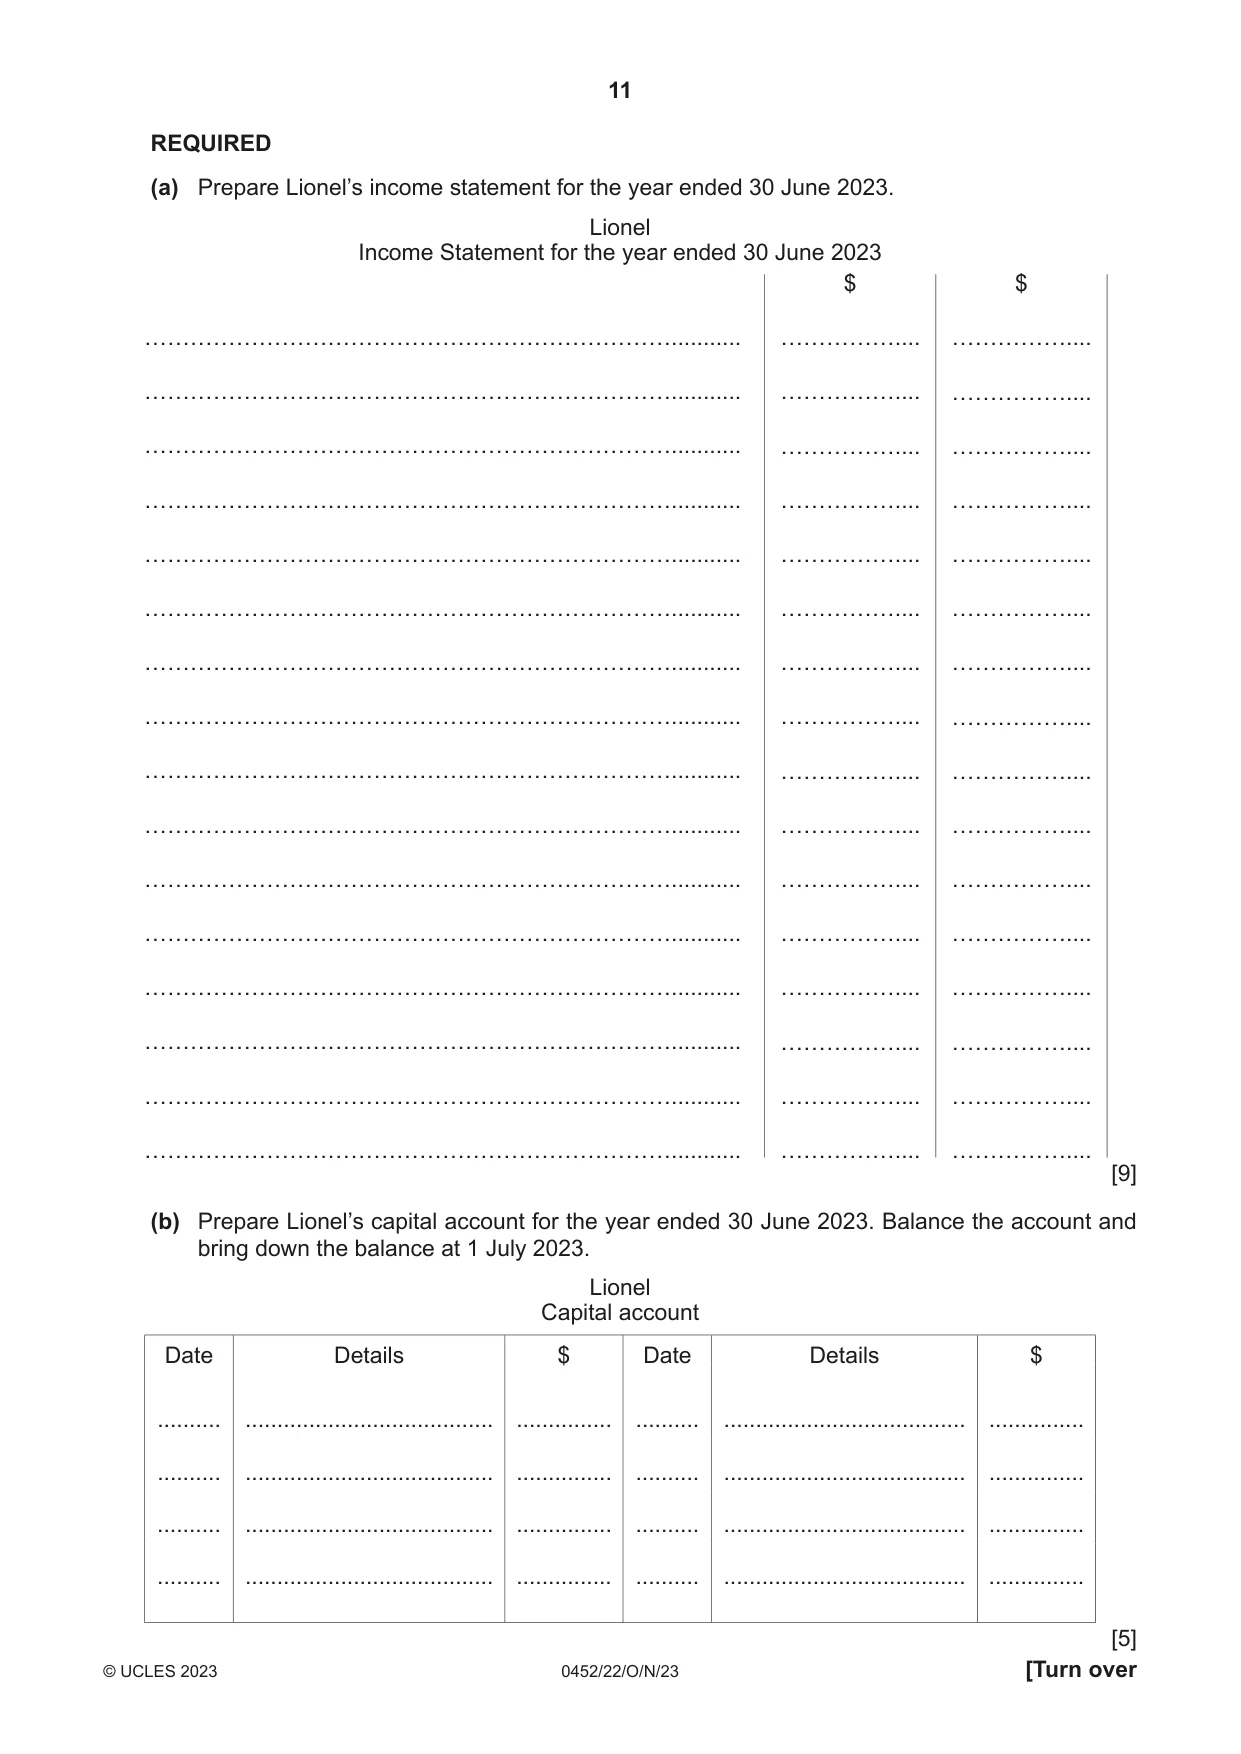
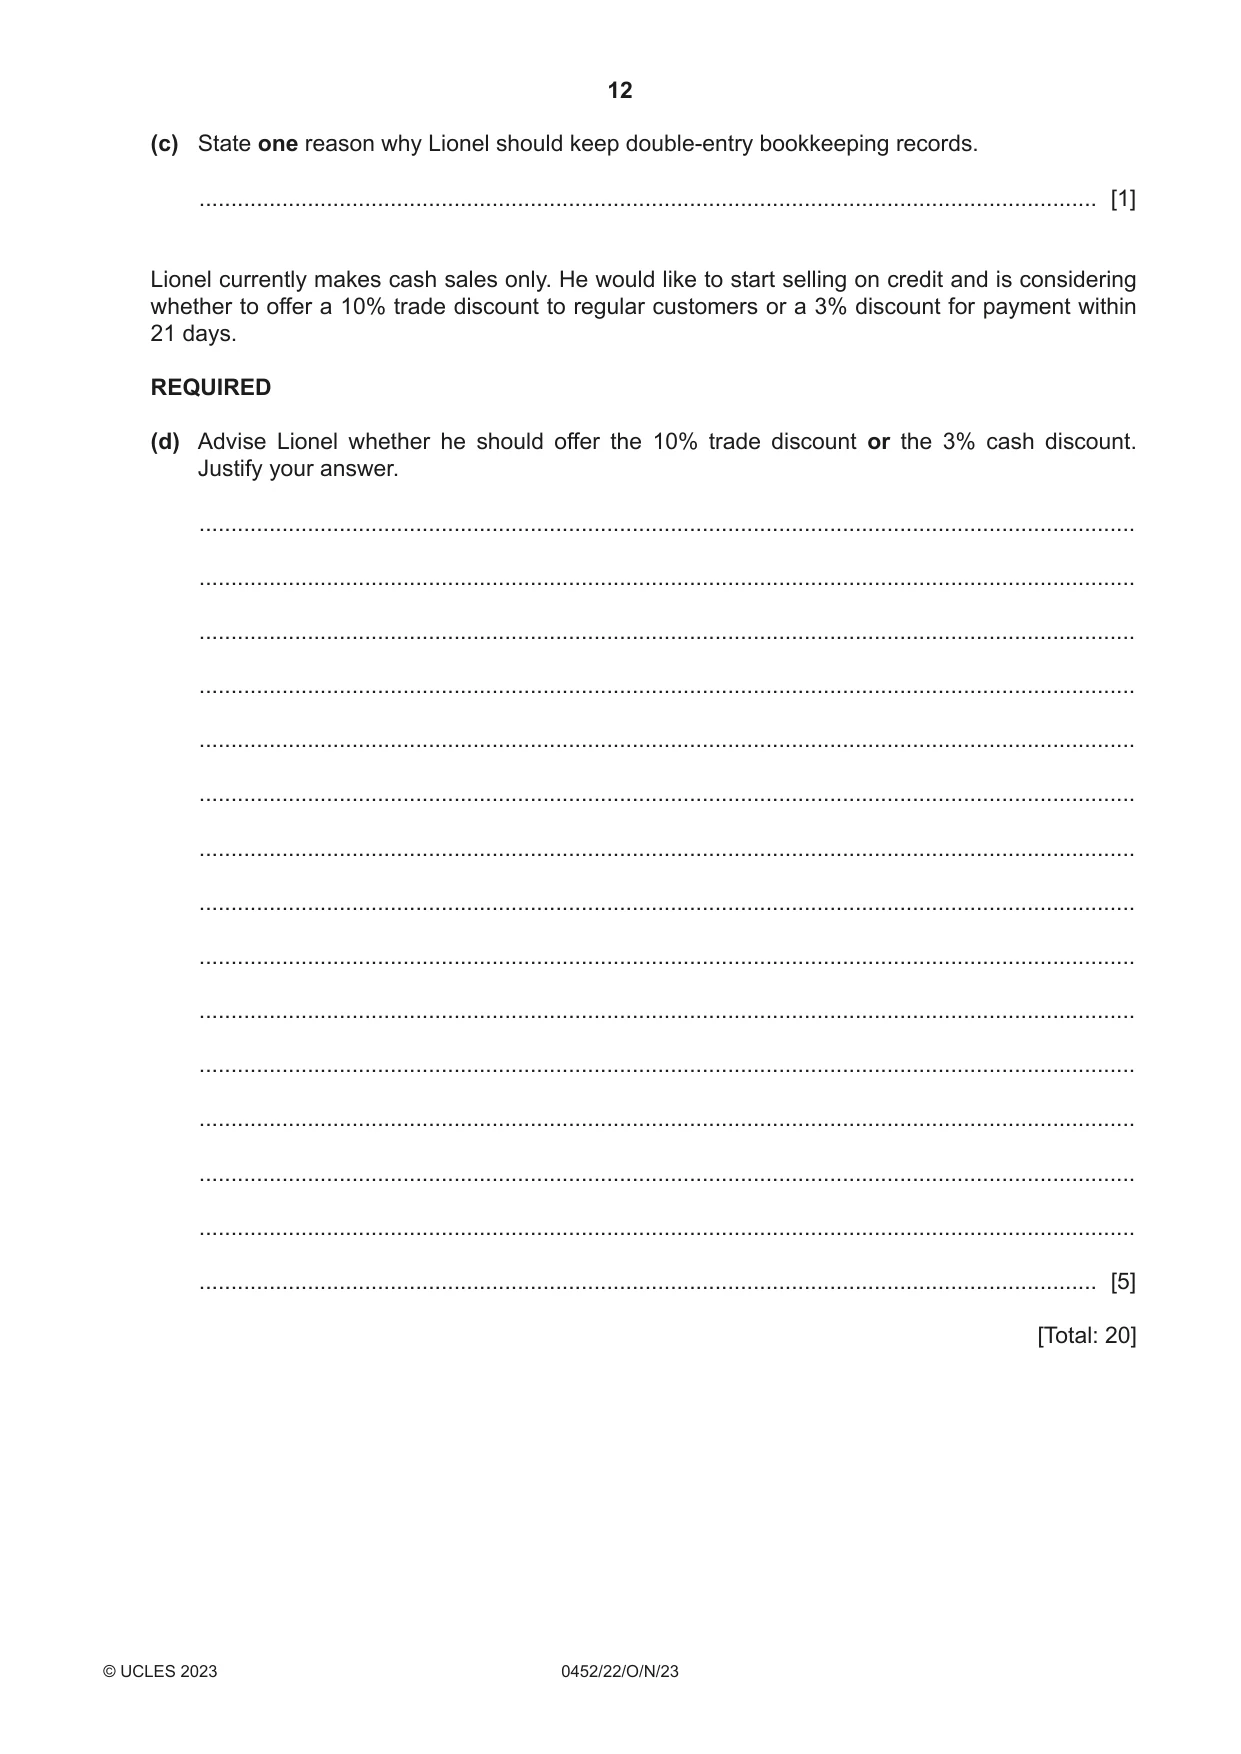
3 Lionel started trading on 1 July 2022. He paid $15 000 of his own personal money into the business bank account. He did not keep full accounting records but has supplied the following information at 30 June 2023. 1. Cash sales of $90 000 were made and paid into the bank. No other money was received. Lionel marks up his goods by 50%. 2. Payments from the bank: $ Purchase of motor vehicle (van) 8 000 Payments to credit suppliers 55 000 Wages 8 060 General expenses 1 140 Rent and insurance 5 585 Motor expenses 4 992 Cash drawn from bank 14 600 3. Purchases returns amounted to $3000. 4. Inventory at 30 June 2023 was valued at $4175. 5. One third of the motor expenses paid were for Lionel’s private car. 6. A full year’s depreciation at 25% is to be charged on the van using the reducing balance method. 7. Lionel withdrew $1000 each month from the business cash, for personal use. The remaining cash drawn from the bank was used to pay wages. REQUIRED (a) Prepare Lionel’s income statement for the year ended 30 June 2023. Lionel Income Statement for the year ended 30 June 2023 $ $ ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... ……………………………………………………………........... …………….... …………….... [9] (b) Prepare Lionel’s capital account for the year ended 30 June 2023. Balance the account and bring down the balance at 1 July 2023. Lionel Capital account Date Details $ Date Details $ .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... [5] (c) State one reason why Lionel should keep double-entry bookkeeping records. ............................................................................................................................................. [1] Lionel currently makes cash sales only. He would like to start selling on credit and is considering whether to offer a 10% trade discount to regular customers or a 3% discount for payment within 21 days. REQUIRED (d) Advise Lionel whether he should offer the 10% trade discount or the 3% cash discount. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
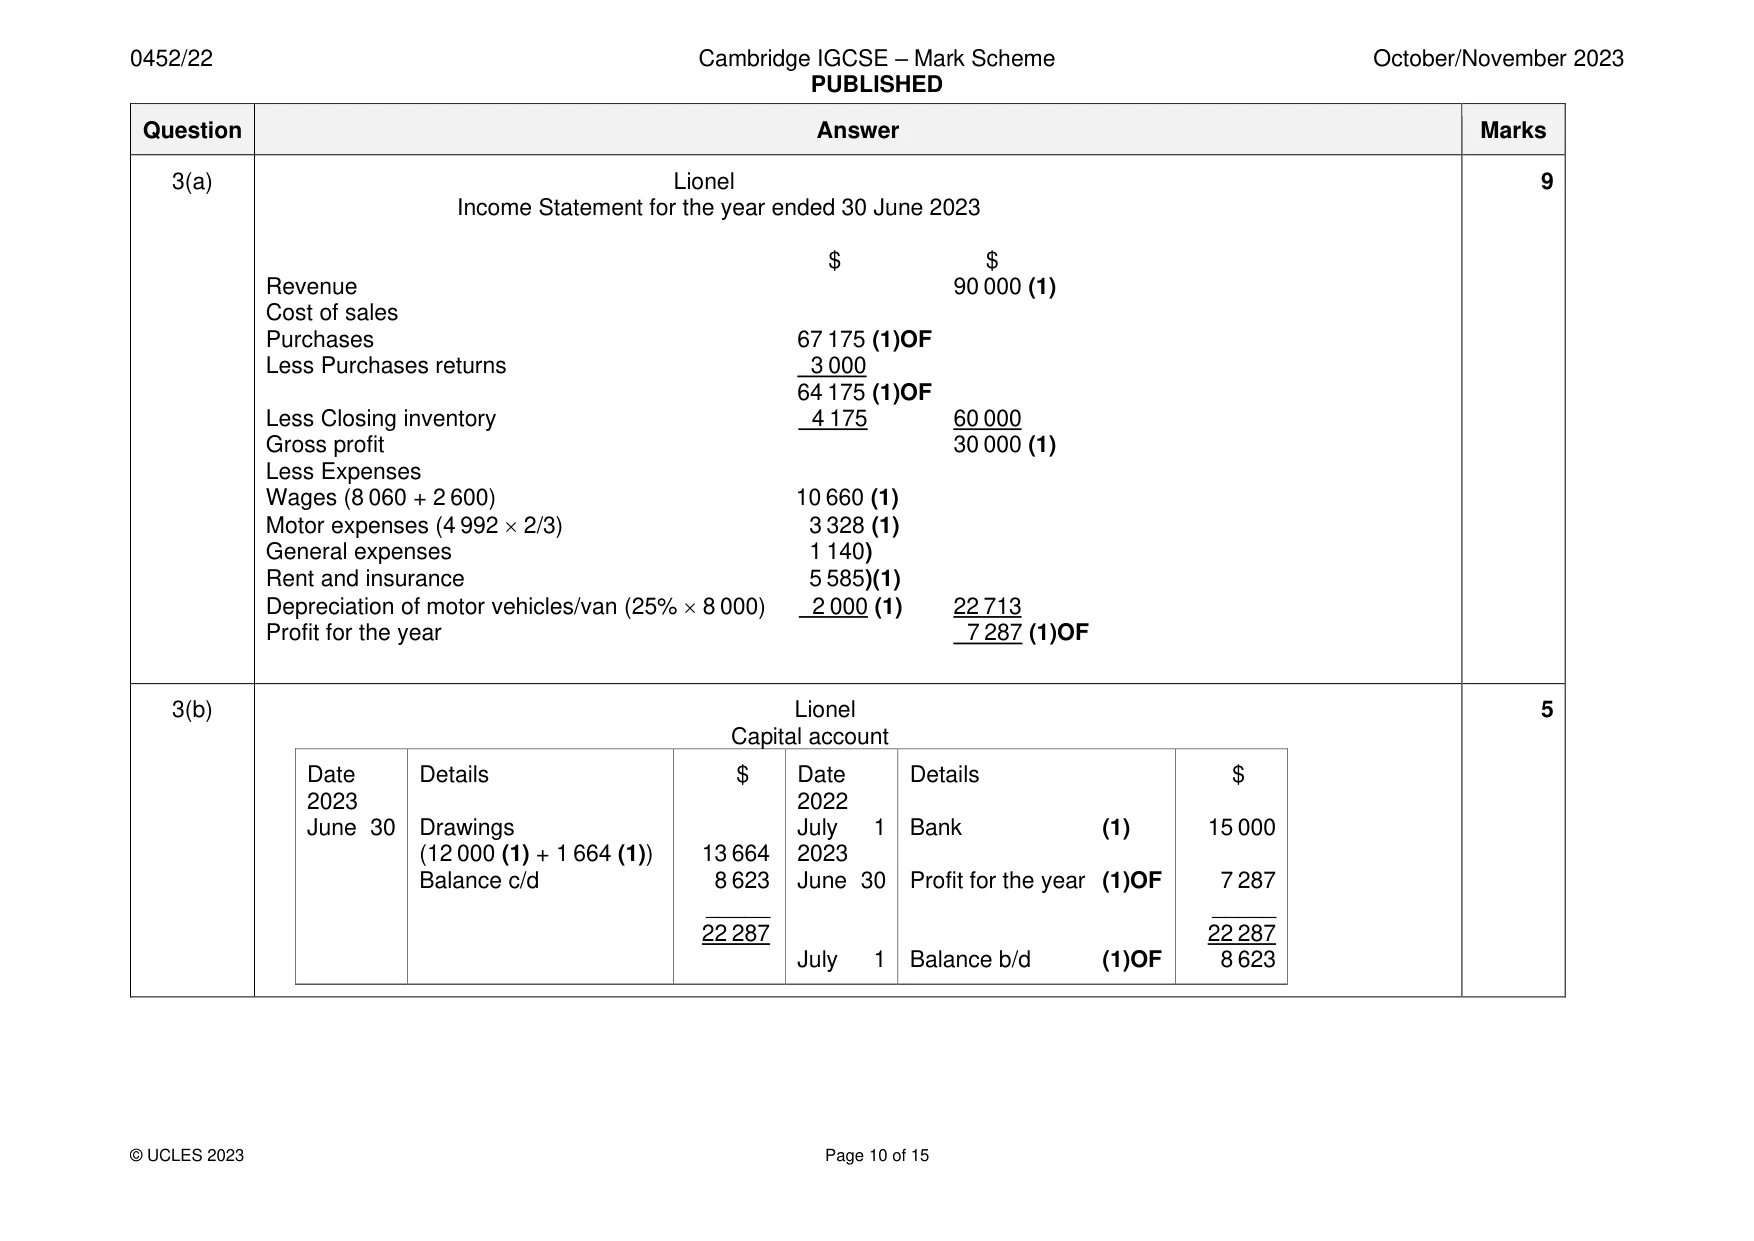
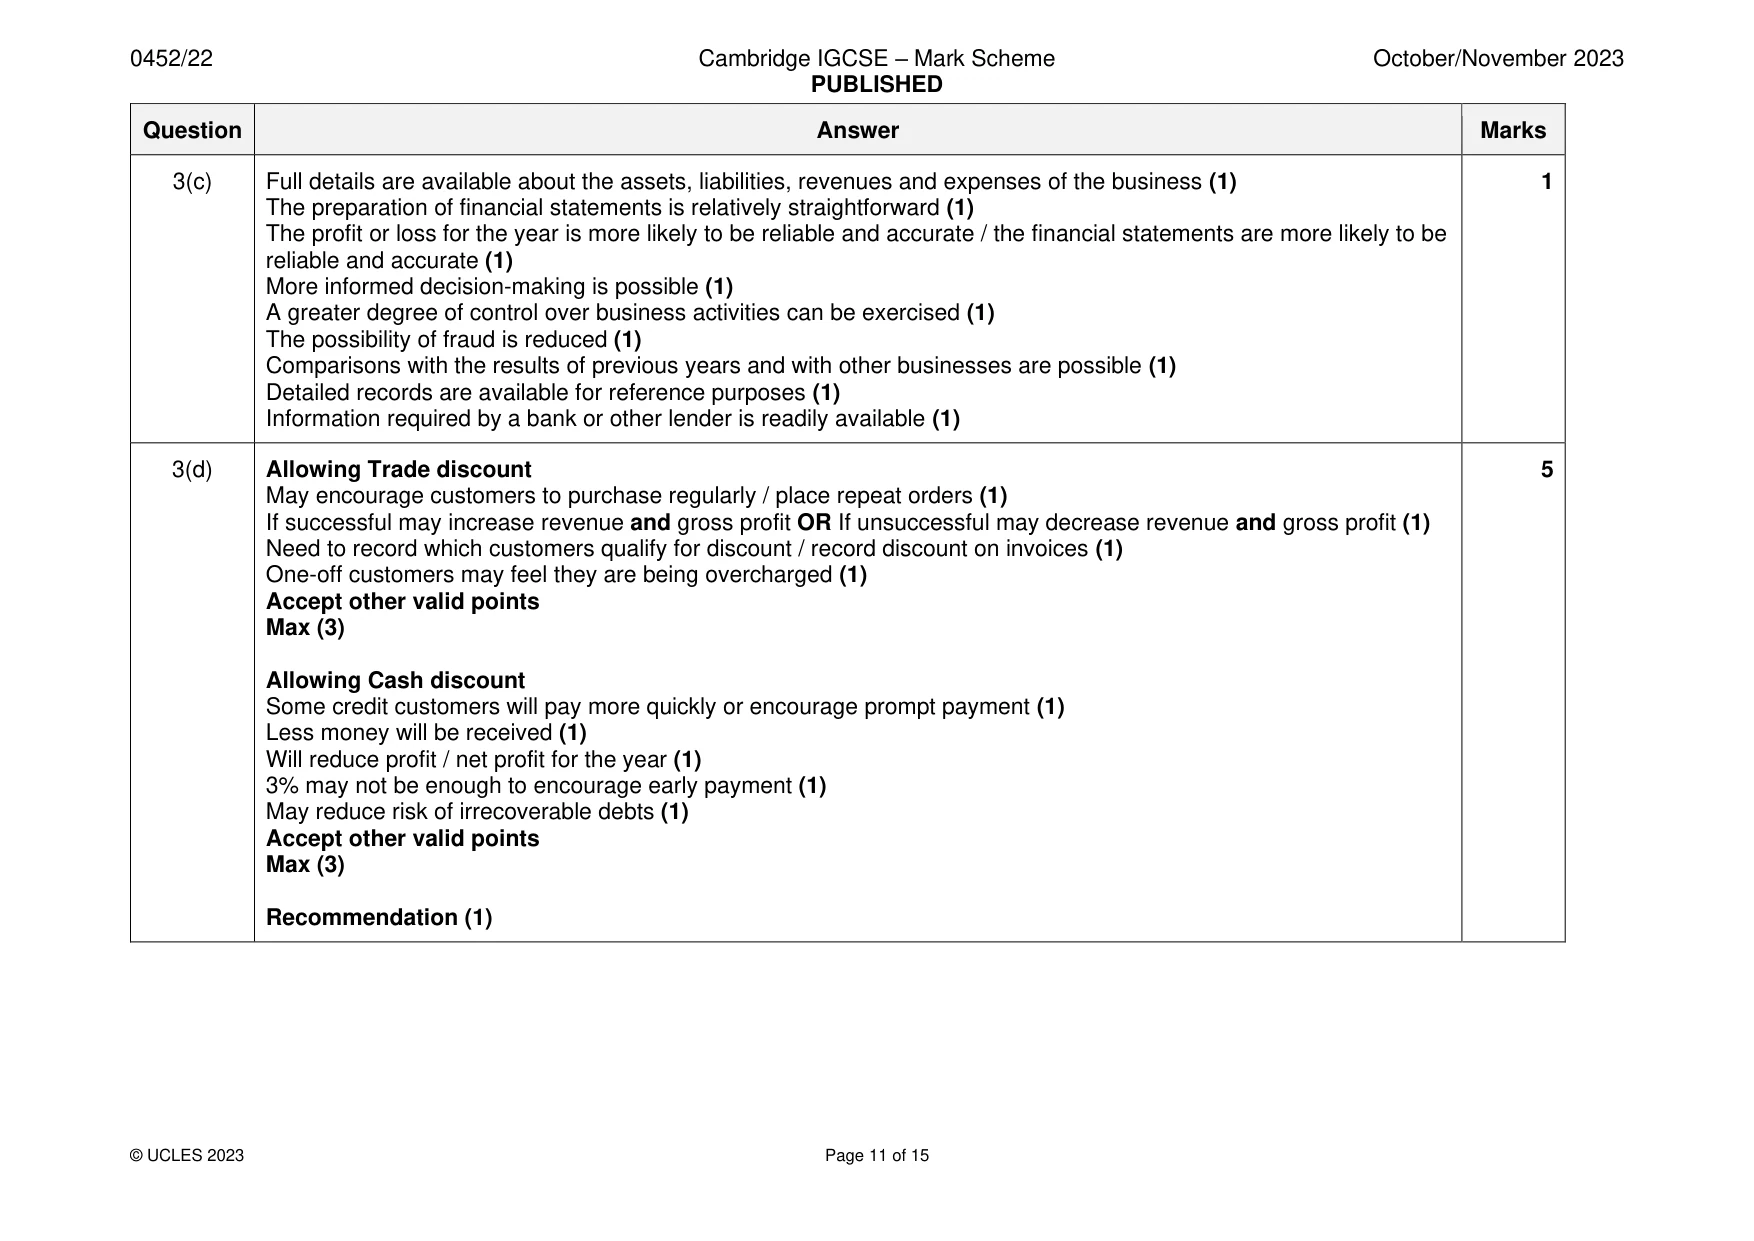
Mark scheme: 3(a) Lionel 9 Income Statement for the year ended 30 June 2023 $ $ Revenue 90 000 (1) Cost of sales Purchases 67 175 (1)OF Less Purchases returns 3 000 64 175 (1)OF Less Closing inventory 4 175 60 000 Gross profit 30 000 (1) Less Expenses Wages (8 060 + 2 600) 10 660 (1) Motor expenses (4 992 2/3) 3 328 (1) General expenses 1 140) Rent and insurance 5 585)(1) Depreciation of motor vehicles/van (25% 8 000) 2 000 (1) 22 713 Profit for the year 7 287 (1)OF 3(b) Lionel 5 Capital account Date Details $ Date Details $ 2023 2022 June 30 Drawings July 1 Bank (1) 15 000 (12 000 (1) + 1 664 (1)) 13 664 2023 Balance c/d 8 623 June 30 Profit for the year (1)OF 7 287 _____ _____ 22 287 22 287 July 1 Balance b/d (1)OF 8 623 3(c) Full details are available about the assets, liabilities, revenues and expenses of the business (1) 1 The preparation of financial statements is relatively straightforward (1) The profit or loss for the year is more likely to be reliable and accurate / the financial statements are more likely to be reliable and accurate (1) More informed decision-making is possible (1) A greater degree of control over business activities can be exercised (1) The possibility of fraud is reduced (1) Comparisons with the results of previous years and with other businesses are possible (1) Detailed records are available for reference purposes (1) Information required by a bank or other lender is readily available (1) 3(d) Allowing Trade discount 5 May encourage customers to purchase regularly / place repeat orders (1) If successful may increase revenue and gross profit OR If unsuccessful may decrease revenue and gross profit (1) Need to record which customers qualify for discount / record discount on invoices (1) One-off customers may feel they are being overcharged (1) Accept other valid points Max (3) Allowing Cash discount Some credit customers will pay more quickly or encourage prompt payment (1) Less money will be received (1) Will reduce profit / net profit for the year (1) 3% may not be enough to encourage early payment (1) May reduce risk of irrecoverable debts (1) Accept other valid points Max (3) Recommendation (1)
Q4 · Rachel is a trader
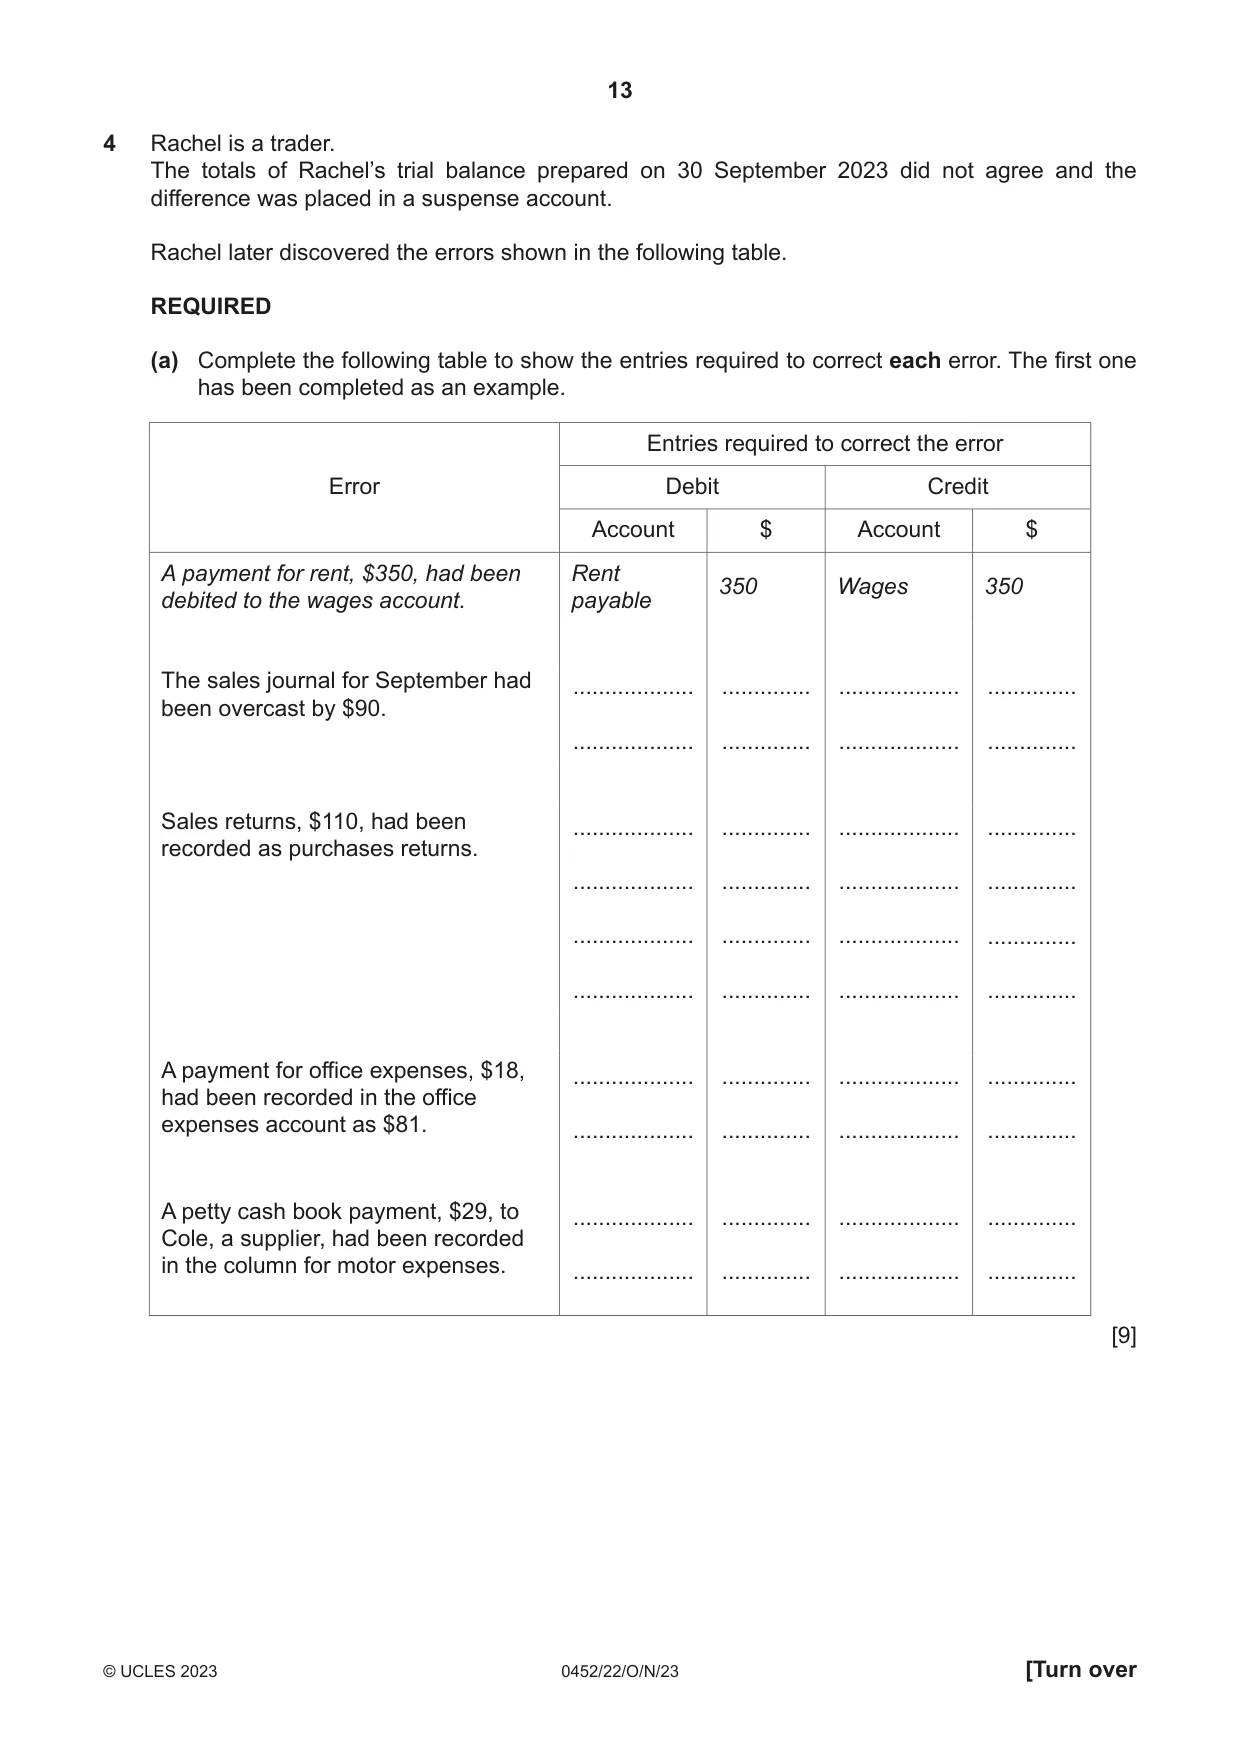
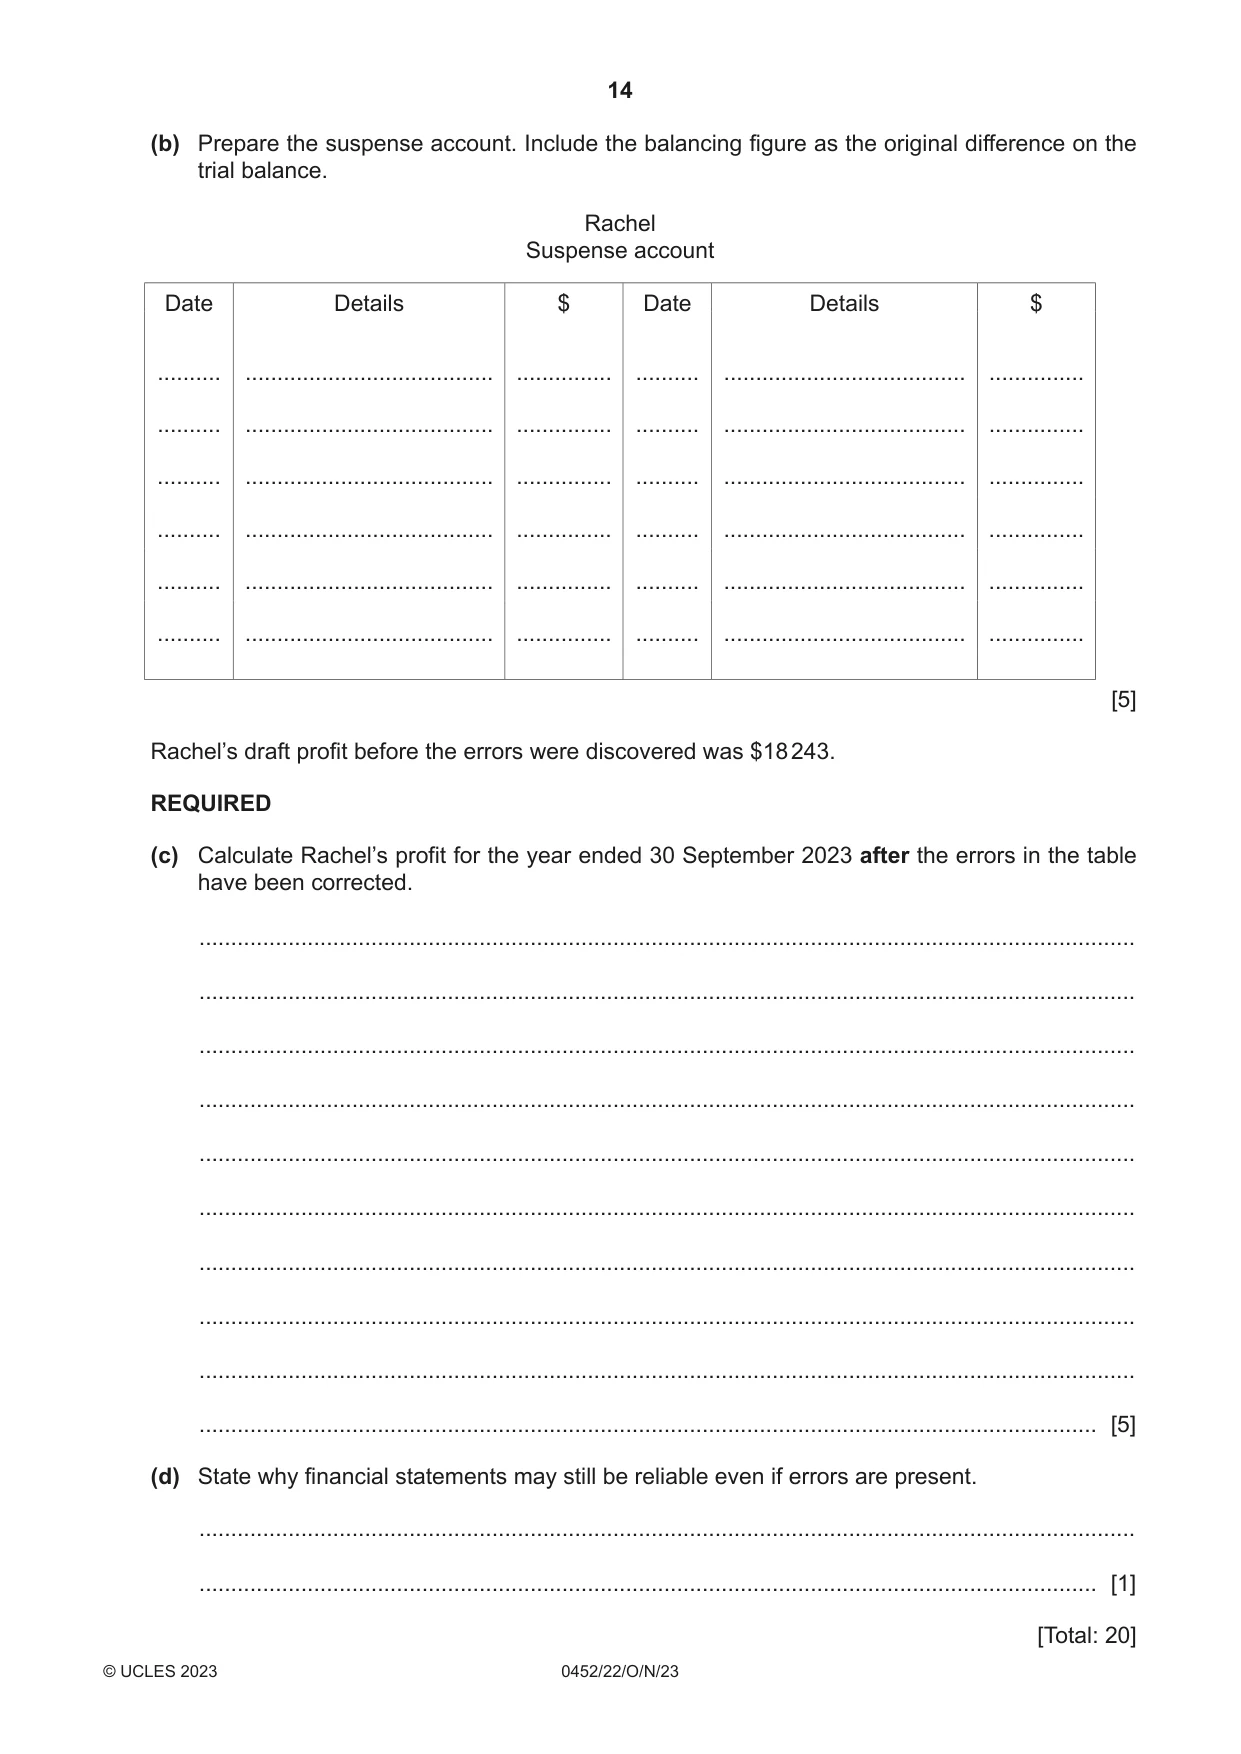
4 Rachel is a trader. The totals of Rachel’s trial balance prepared on 30 September 2023 did not agree and the difference was placed in a suspense account. Rachel later discovered the errors shown in the following table. REQUIRED (a) Complete the following table to show the entries required to correct each error. The first one has been completed as an example. Entries required to correct the error Error Debit Credit Account $ Account $ A payment for rent, $350, had been Rent 350 Wages 350 debited to the wages account. payable The sales journal for September had ................... .............. ................... .............. been overcast by $90. ................... .............. ................... .............. Sales returns, $110, had been ................... .............. ................... .............. recorded as purchases returns. ................... .............. ................... .............. ................... .............. ................... .............. ................... .............. ................... .............. A payment for office expenses, $18, ................... .............. ................... .............. had been recorded in the office expenses account as $81. ................... .............. ................... .............. A petty cash book payment, $29, to ................... .............. ................... .............. Cole, a supplier, had been recorded in the column for motor expenses. ................... .............. ................... .............. [9] (b) Prepare the suspense account. Include the balancing figure as the original difference on the trial balance. Rachel Suspense account Date Details $ Date Details $ .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... .......... ....................................... ............... .......... ...................................... ............... [5] Rachel’s draft profit before the errors were discovered was $18 243. REQUIRED (c) Calculate Rachel’s profit for the year ended 30 September 2023 after the errors in the table have been corrected. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] (d) State why financial statements may still be reliable even if errors are present. ................................................................................................................................................... ............................................................................................................................................. [1] [Total: 20]
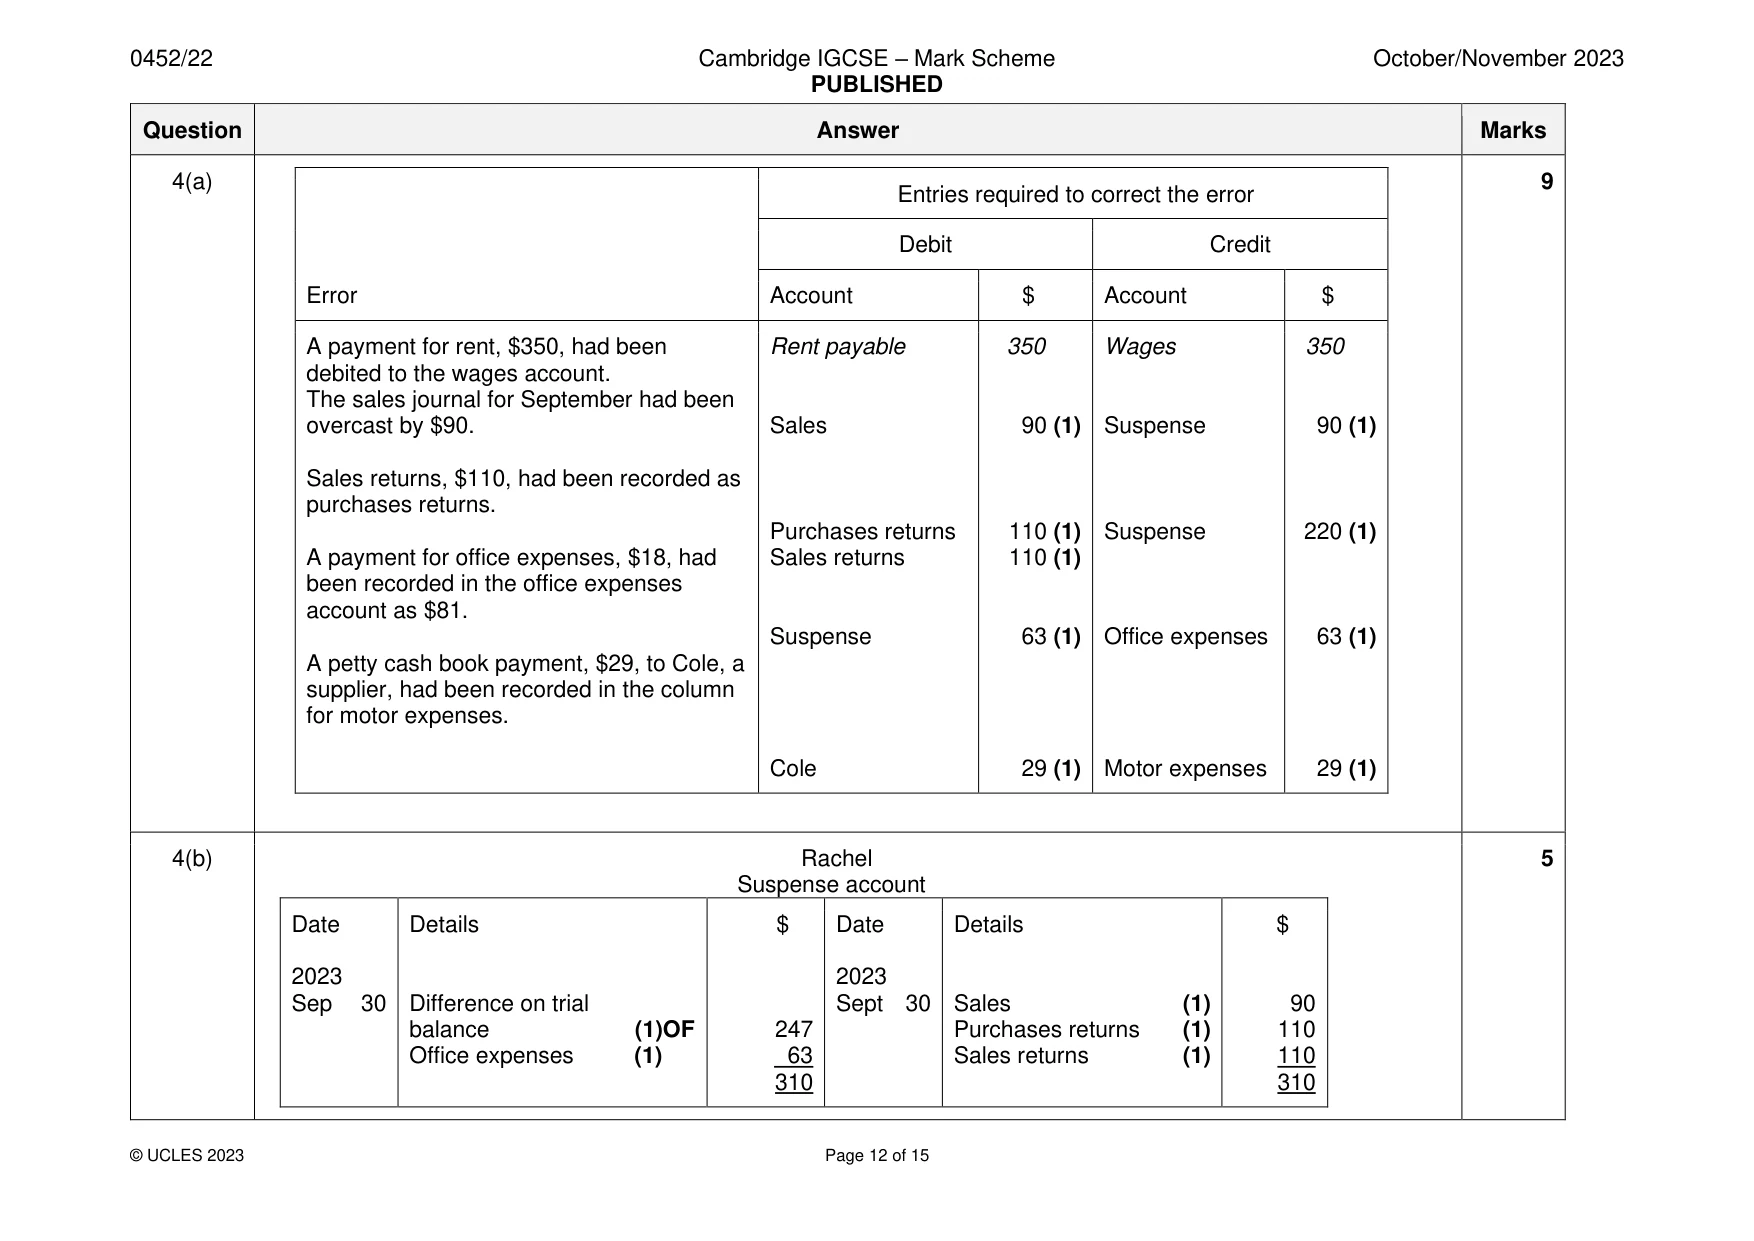
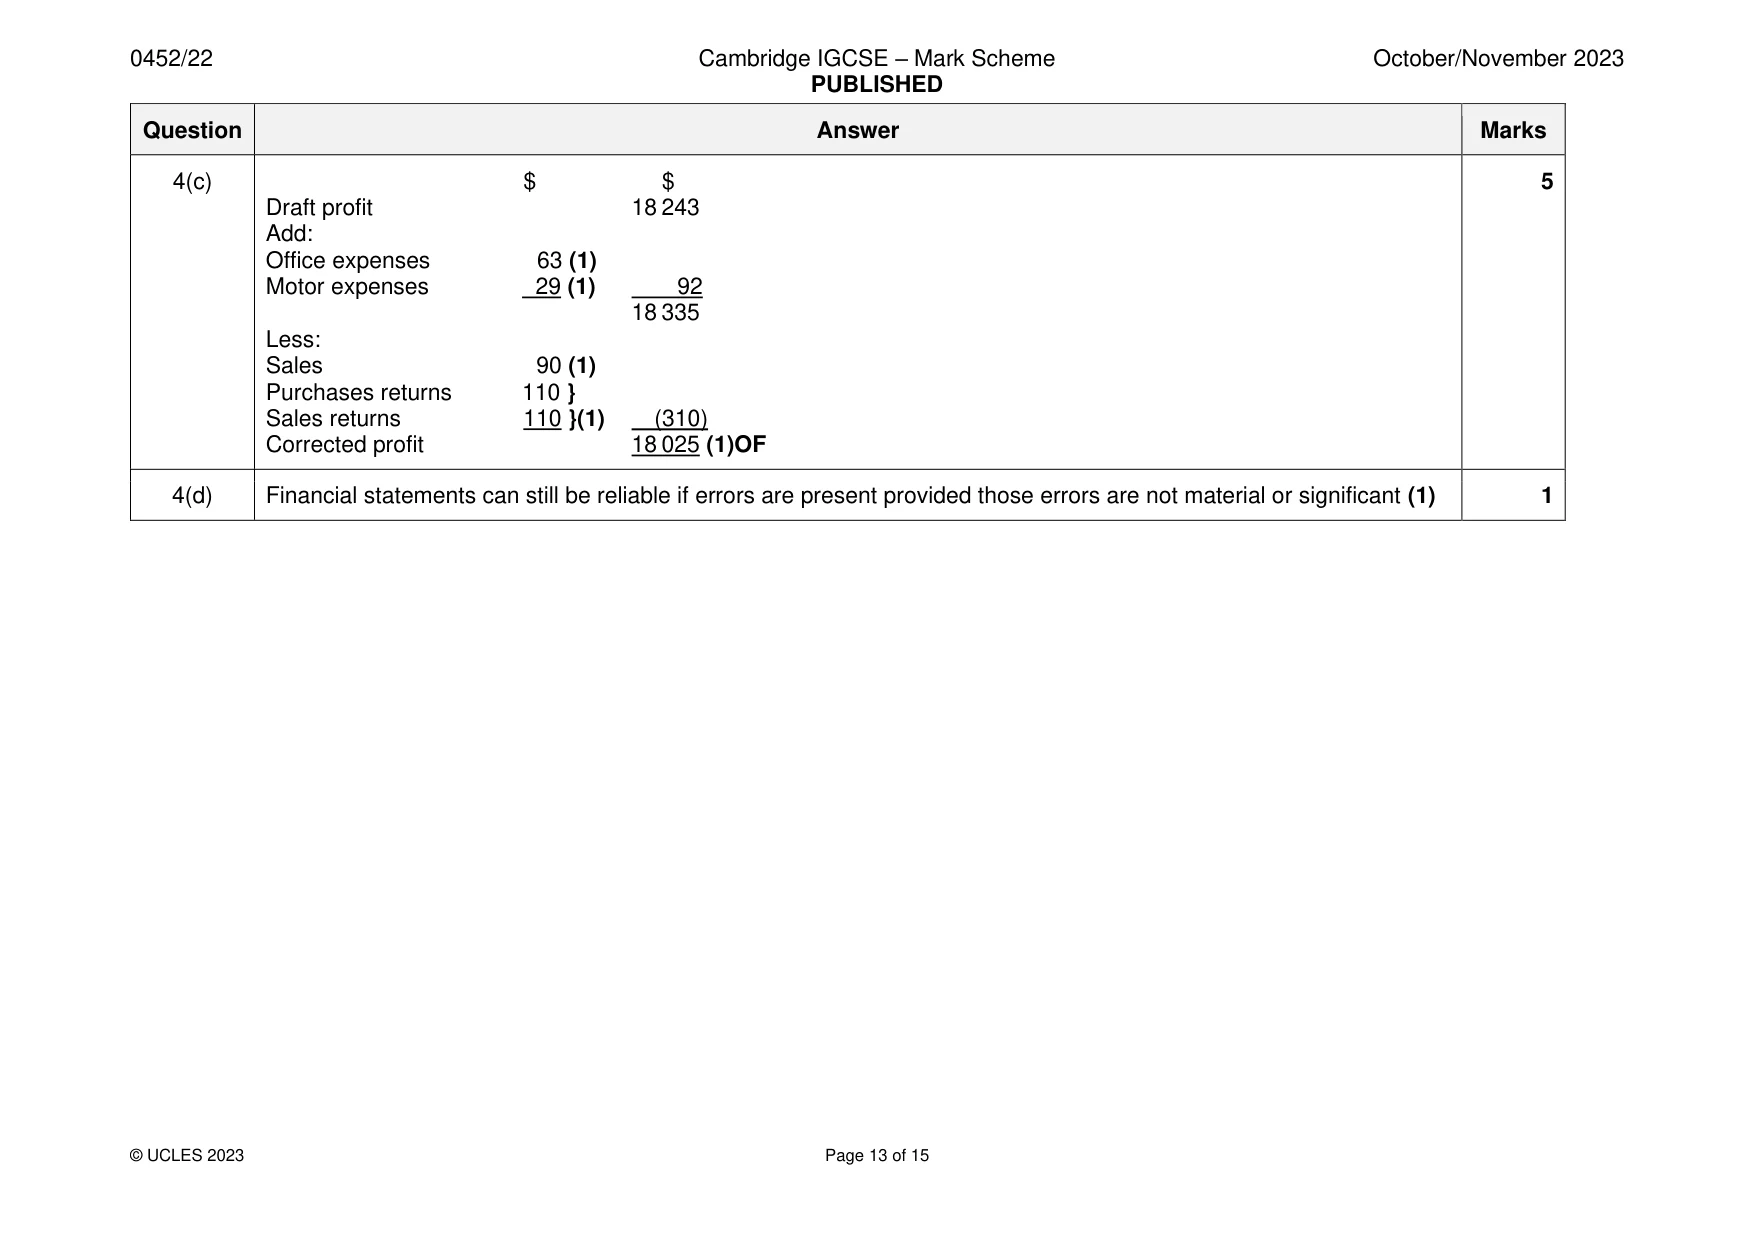
Mark scheme: 4(a) 9 Entries required to correct the error Debit Credit Error Account $ Account $ A payment for rent, $350, had been Rent payable 350 Wages 350 debited to the wages account. The sales journal for September had been overcast by $90. Sales 90 (1) Suspense 90 (1) Sales returns, $110, had been recorded as purchases returns. Purchases returns 110 (1) Suspense 220 (1) A payment for office expenses, $18, had Sales returns 110 (1) been recorded in the office expenses account as $81. Suspense 63 (1) Office expenses 63 (1) A petty cash book payment, $29, to Cole, a supplier, had been recorded in the column for motor expenses. Cole 29 (1) Motor expenses 29 (1) 4(b) Rachel 5 Suspense account Date Details $ Date Details $ 2023 2023 Sep 30 Difference on trial Sept 30 Sales (1) 90 balance (1)OF 247 Purchases returns (1) 110 Office expenses (1) 63 Sales returns (1) 110 310 310 4(c) $ $ 5 Draft profit 18 243 Add: Office expenses 63 (1) Motor expenses 29 (1) 92 18 335 Less: Sales 90 (1) Purchases returns 110 } Sales returns 110 }(1) (310) Corrected profit 18 025 (1)OF 4(d) Financial statements can still be reliable if errors are present provided those errors are not material or significant (1) 1
Q5 · Nala is a retailer who sells toys and games
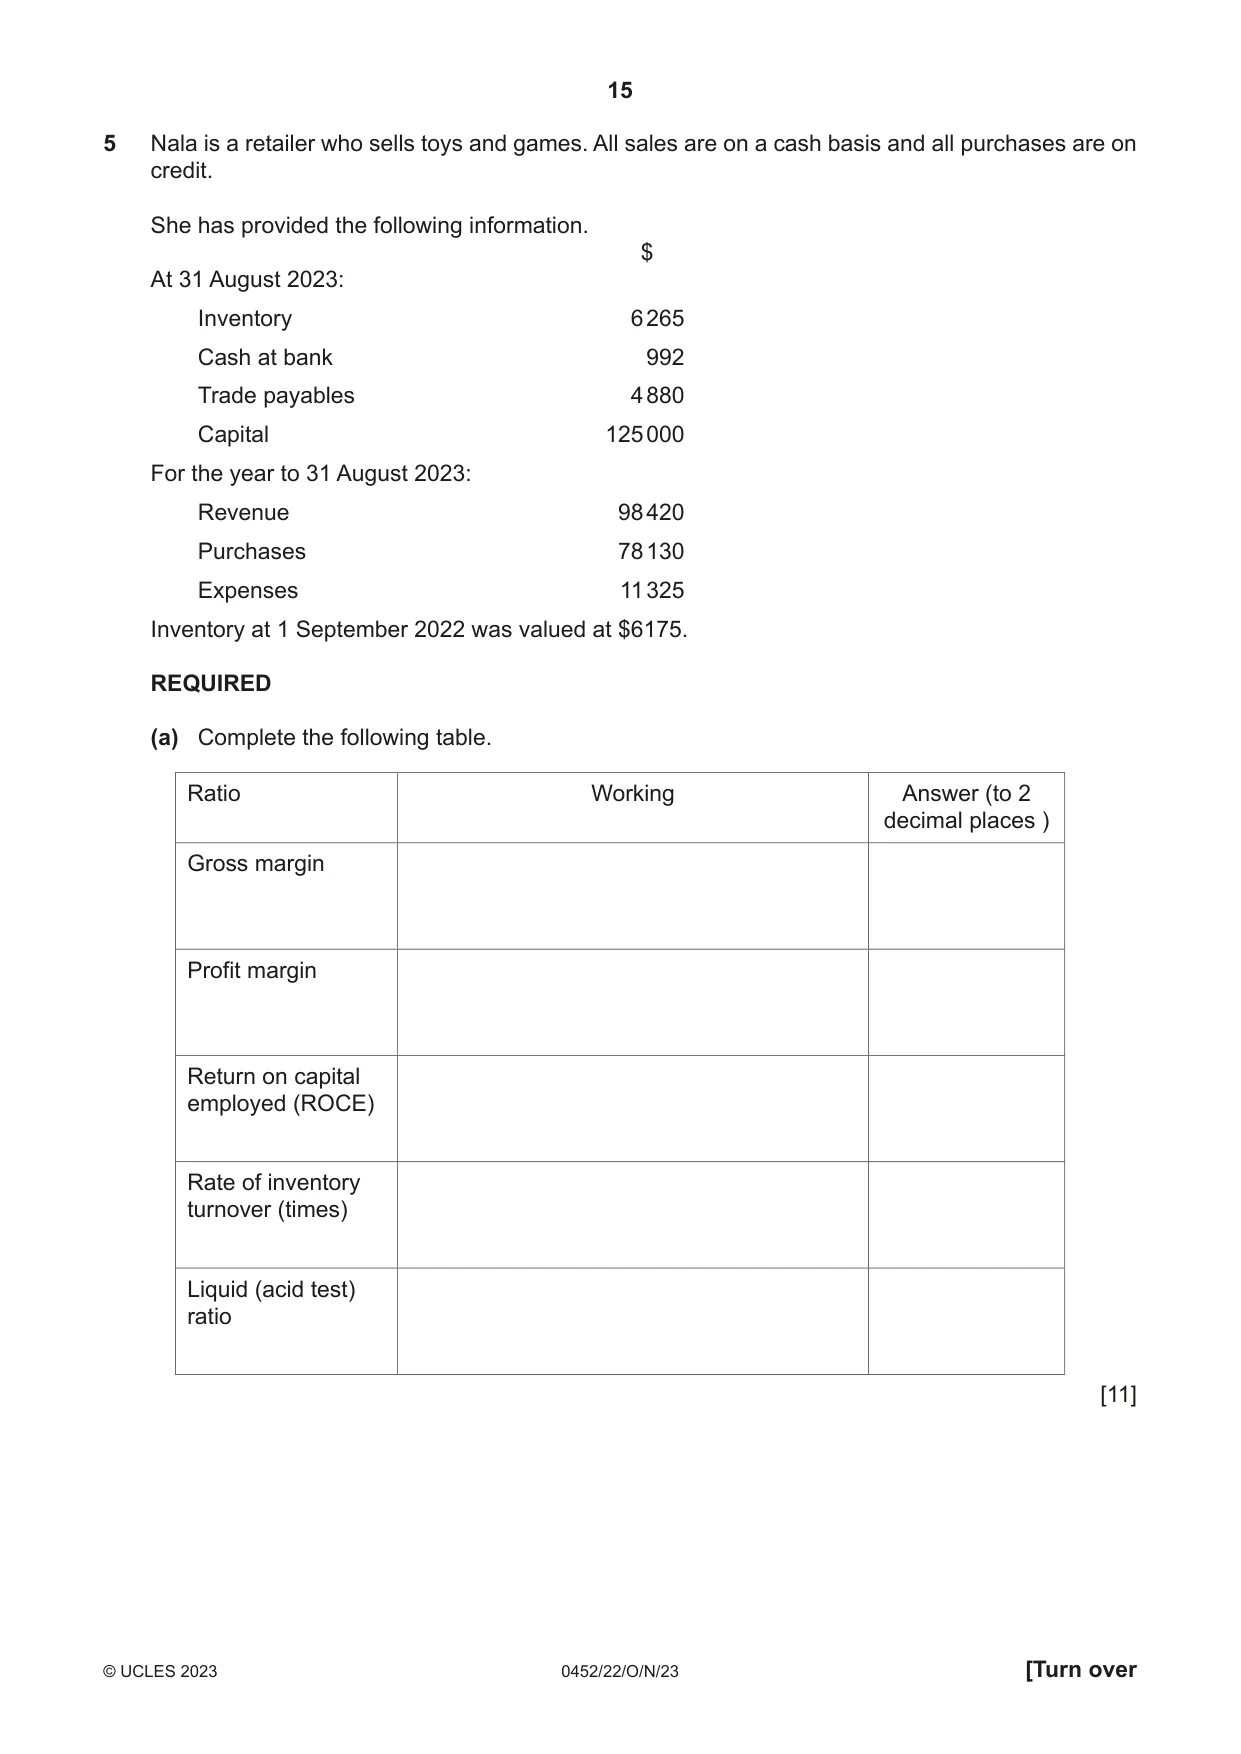
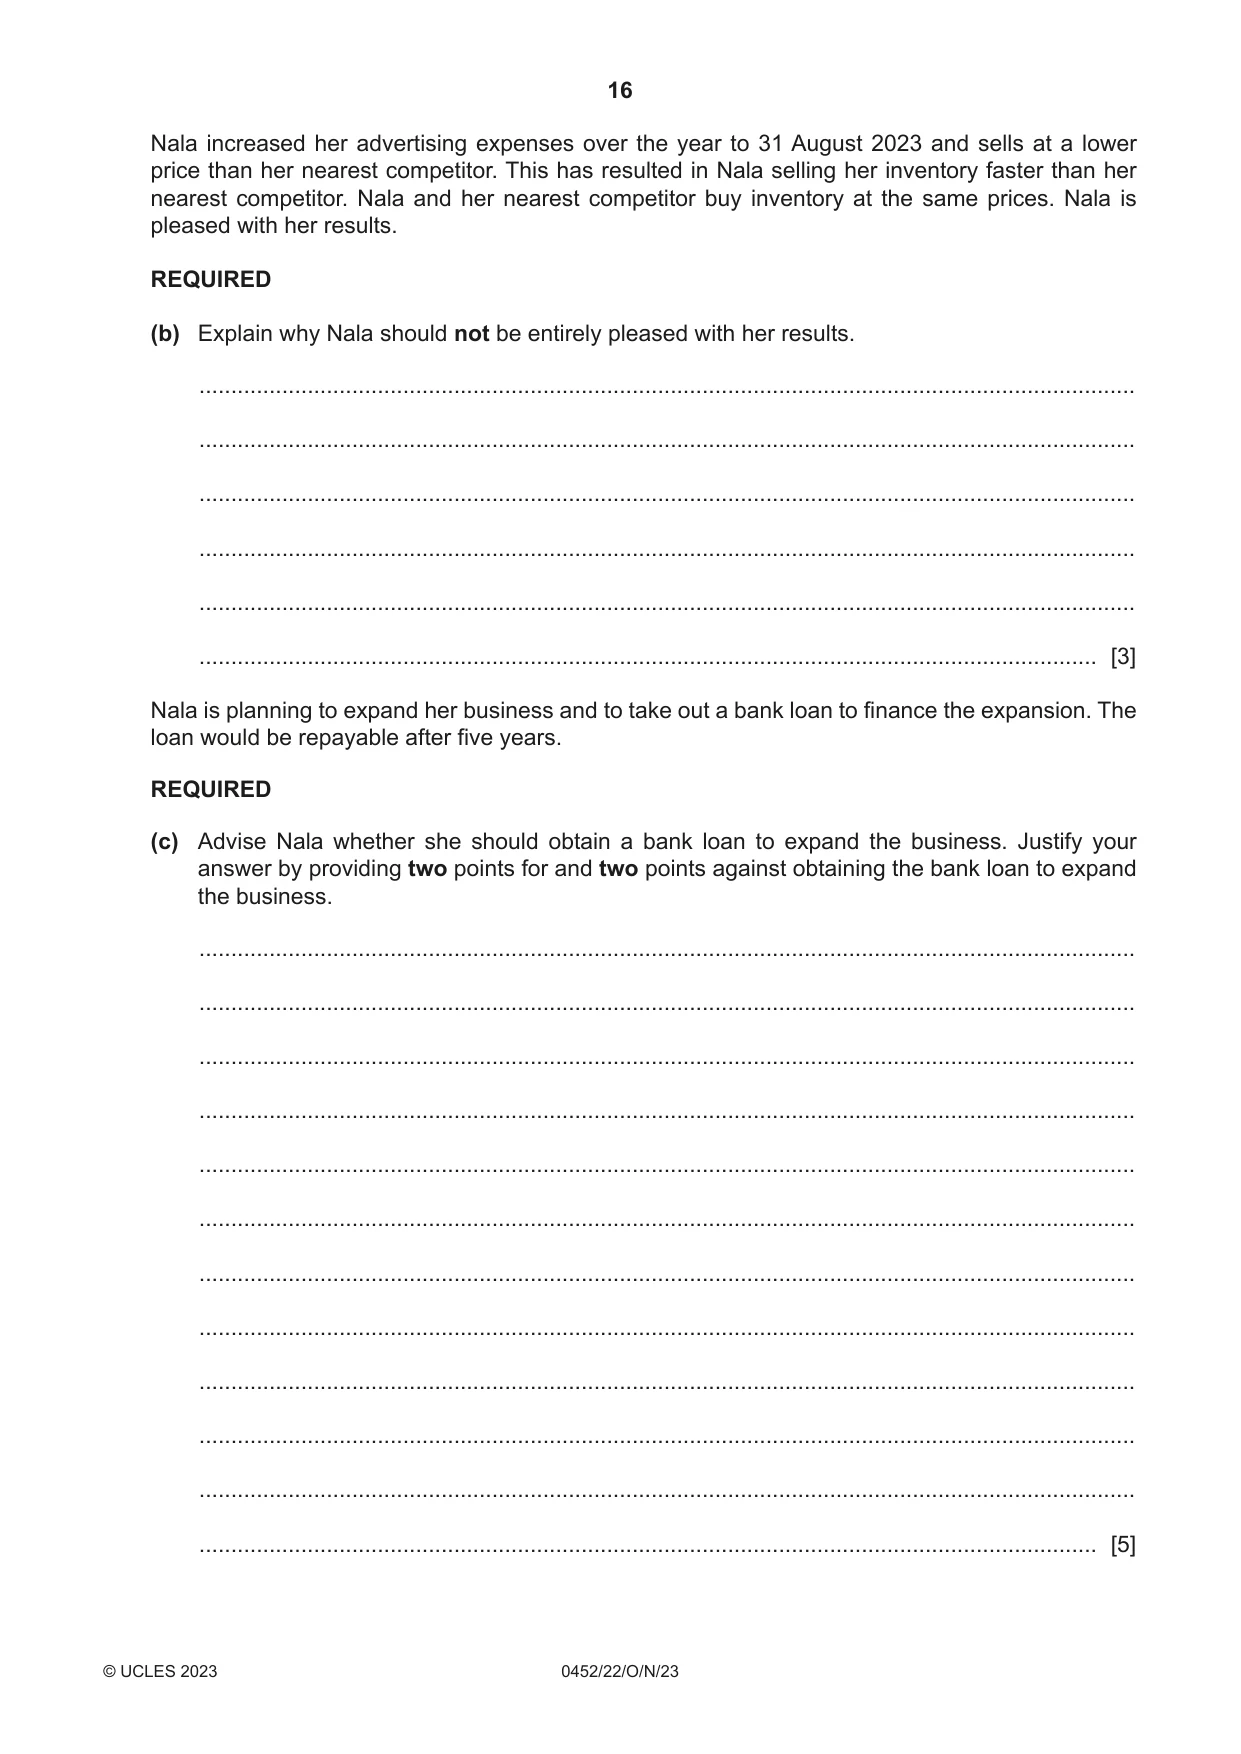
5 Nala is a retailer who sells toys and games. All sales are on a cash basis and all purchases are on credit. She has provided the following information. $ At 31 August 2023: Inventory 6 265 Cash at bank 992 Trade payables 4 880 Capital 125 000 For the year to 31 August 2023: Revenue 98 420 Purchases 78 130 Expenses 11 325 Inventory at 1 September 2022 was valued at $6175. REQUIRED (a) Complete the following table. Ratio Working Answer (to 2 decimal places ) Gross margin Profit margin Return on capital employed (ROCE) Rate of inventory turnover (times) Liquid (acid test) ratio [11] Nala increased her advertising expenses over the year to 31 August 2023 and sells at a lower price than her nearest competitor. This has resulted in Nala selling her inventory faster than her nearest competitor. Nala and her nearest competitor buy inventory at the same prices. Nala is pleased with her results. REQUIRED (b) Explain why Nala should not be entirely pleased with her results. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] Nala is planning to expand her business and to take out a bank loan to finance the expansion. The loan would be repayable after five years. REQUIRED (c) Advise Nala whether she should obtain a bank loan to expand the business. Justify your answer by providing two points for and two points against obtaining the bank loan to expand the business. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] (d) State why Nala’s bank manager would be interested in her financial statements if she requests the loan. ................................................................................................................................................... ............................................................................................................................................. [1] [Total: 20]
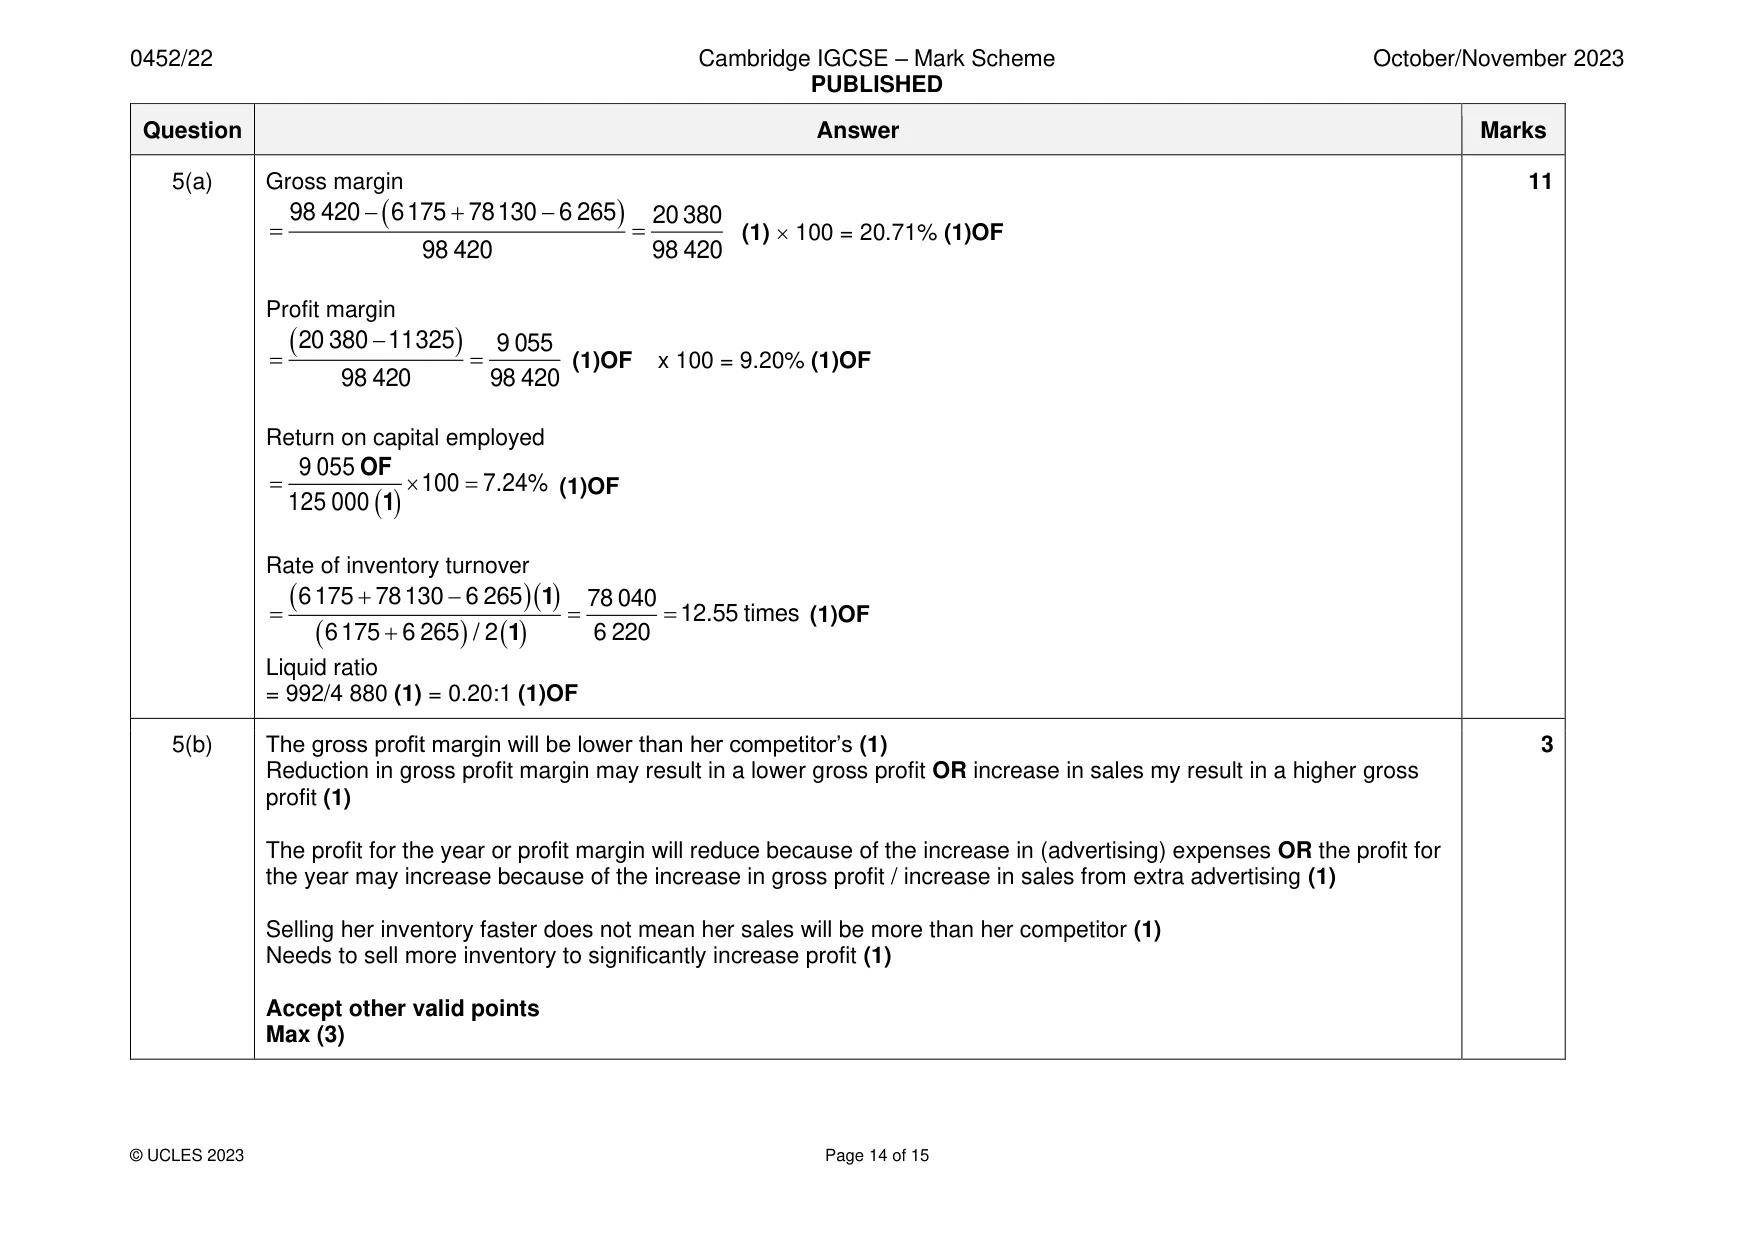
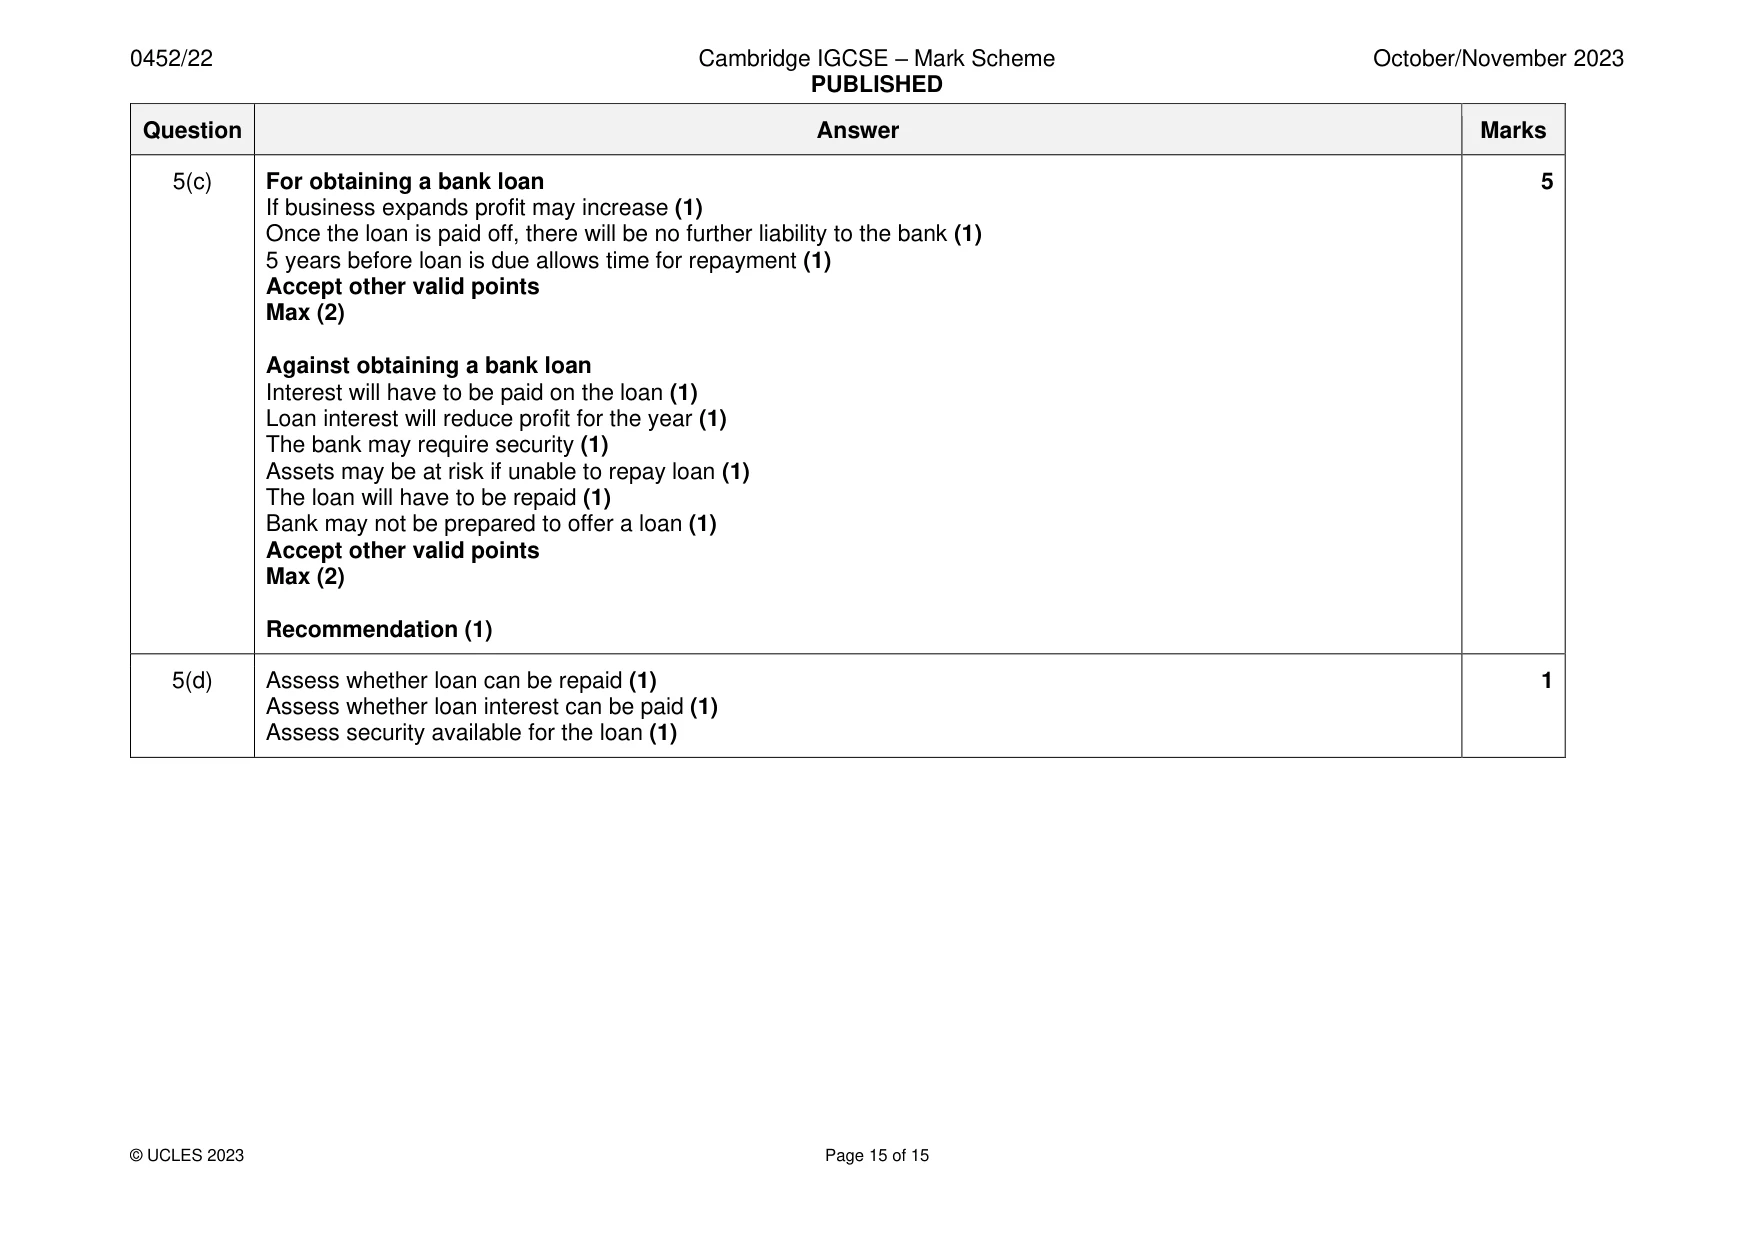
Mark scheme: 5(a) Gross margin 11 98 420 − ( 6175 + 78130 − 6 265 ) 20 380 = = (1) 100 = 20.71% (1)OF 98 420 98 420 Profit margin ( 20 380 − 11325 ) 9 055 = = (1)OF x 100 = 9.20% (1)OF 98 420 98 420 Return on capital employed 9 055 OF = 100 = 7.24% (1)OF 125 000 ( 1) Rate of inventory turnover ( 6175 + 78130 − 6 265 )( 1) 78 040 = = = 12.55 times (1)OF ( 6175 + 6 265 ) / 2 ( 1) 6 220 Liquid ratio = 992/4 880 (1) = 0.20:1 (1)OF 5(b) The gross profit margin will be lower than her competitor’s (1) 3 Reduction in gross profit margin may result in a lower gross profit OR increase in sales my result in a higher gross profit (1) The profit for the year or profit margin will reduce because of the increase in (advertising) expenses OR the profit for the year may increase because of the increase in gross profit / increase in sales from extra advertising (1) Selling her inventory faster does not mean her sales will be more than her competitor (1) Needs to sell more inventory to significantly increase profit (1) Accept other valid points Max (3) 5(c) For obtaining a bank loan 5 If business expands profit may increase (1) Once the loan is paid off, there will be no further liability to the bank (1) 5 years before loan is due allows time for repayment (1) Accept other valid points Max (2) Against obtaining a bank loan Interest will have to be paid on the loan (1) Loan interest will reduce profit for the year (1) The bank may require security (1) Assets may be at risk if unable to repay loan (1) The loan will have to be repaid (1) Bank may not be prepared to offer a loan (1) Accept other valid points Max (2) Recommendation (1) 5(d) Assess whether loan can be repaid (1) 1 Assess whether loan interest can be paid (1) Assess security available for the loan (1)
More questions on Calculation and understanding of accounting ratios
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2023 Oct/Nov, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.