Cambridge IGCSE Accounting 0452 — 2021 Oct/Nov Paper 2 · Variant 3
0452/23/O/N/21 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme17 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Shiv is a trader
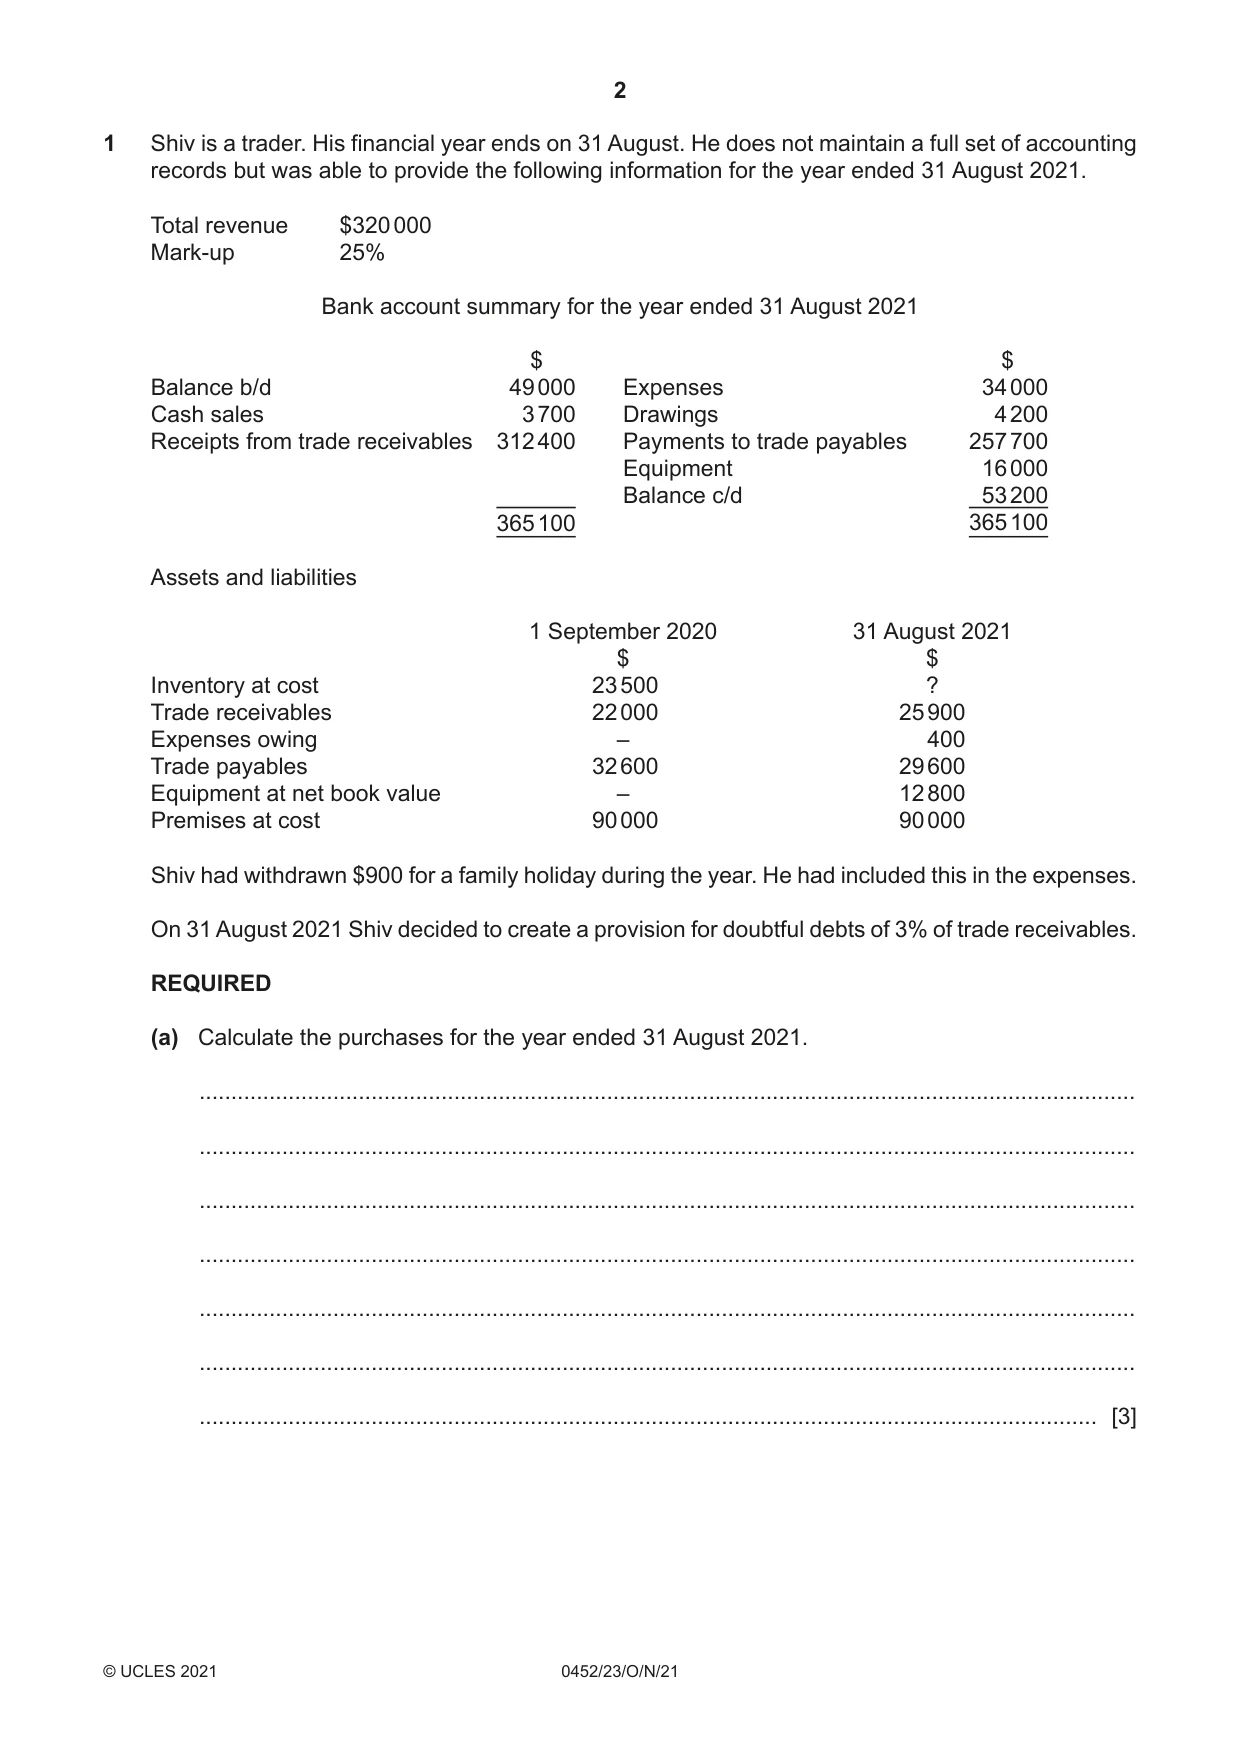
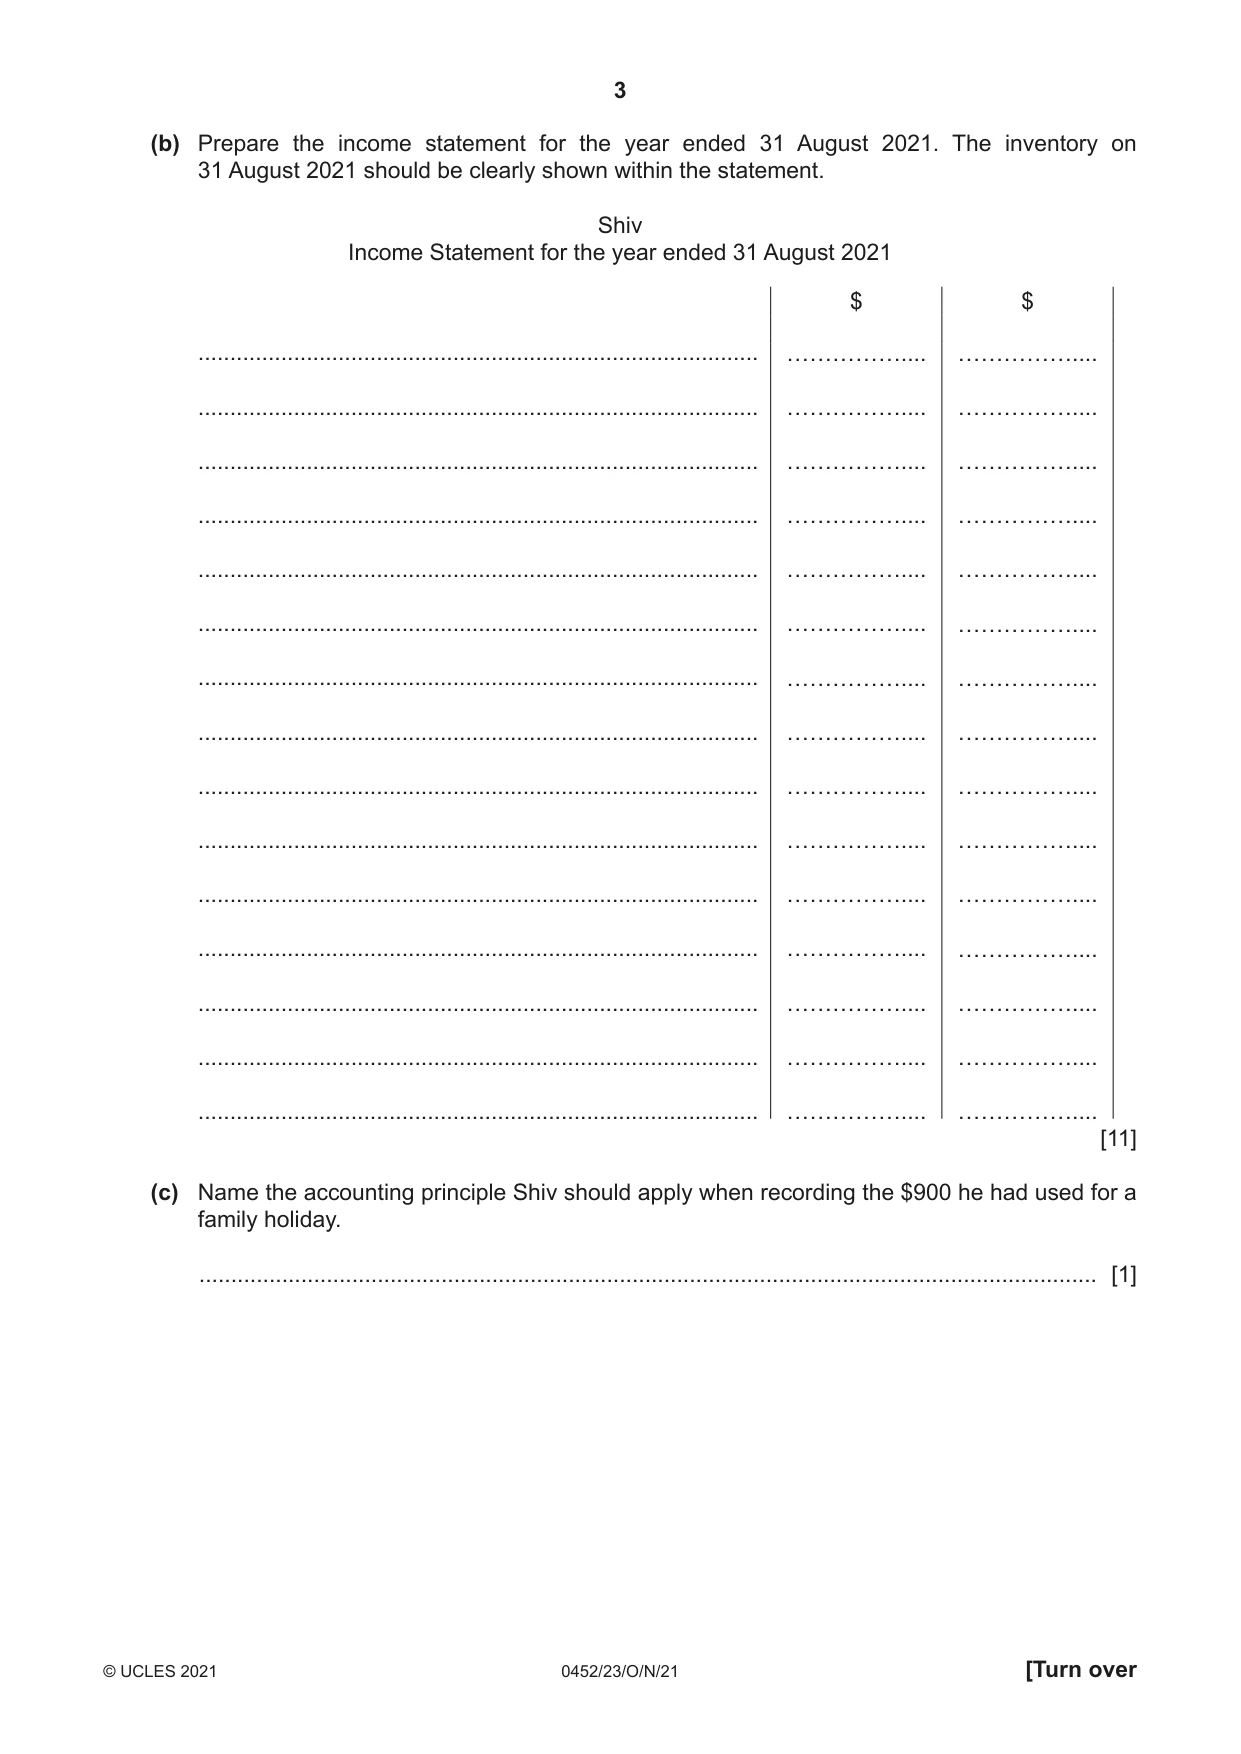
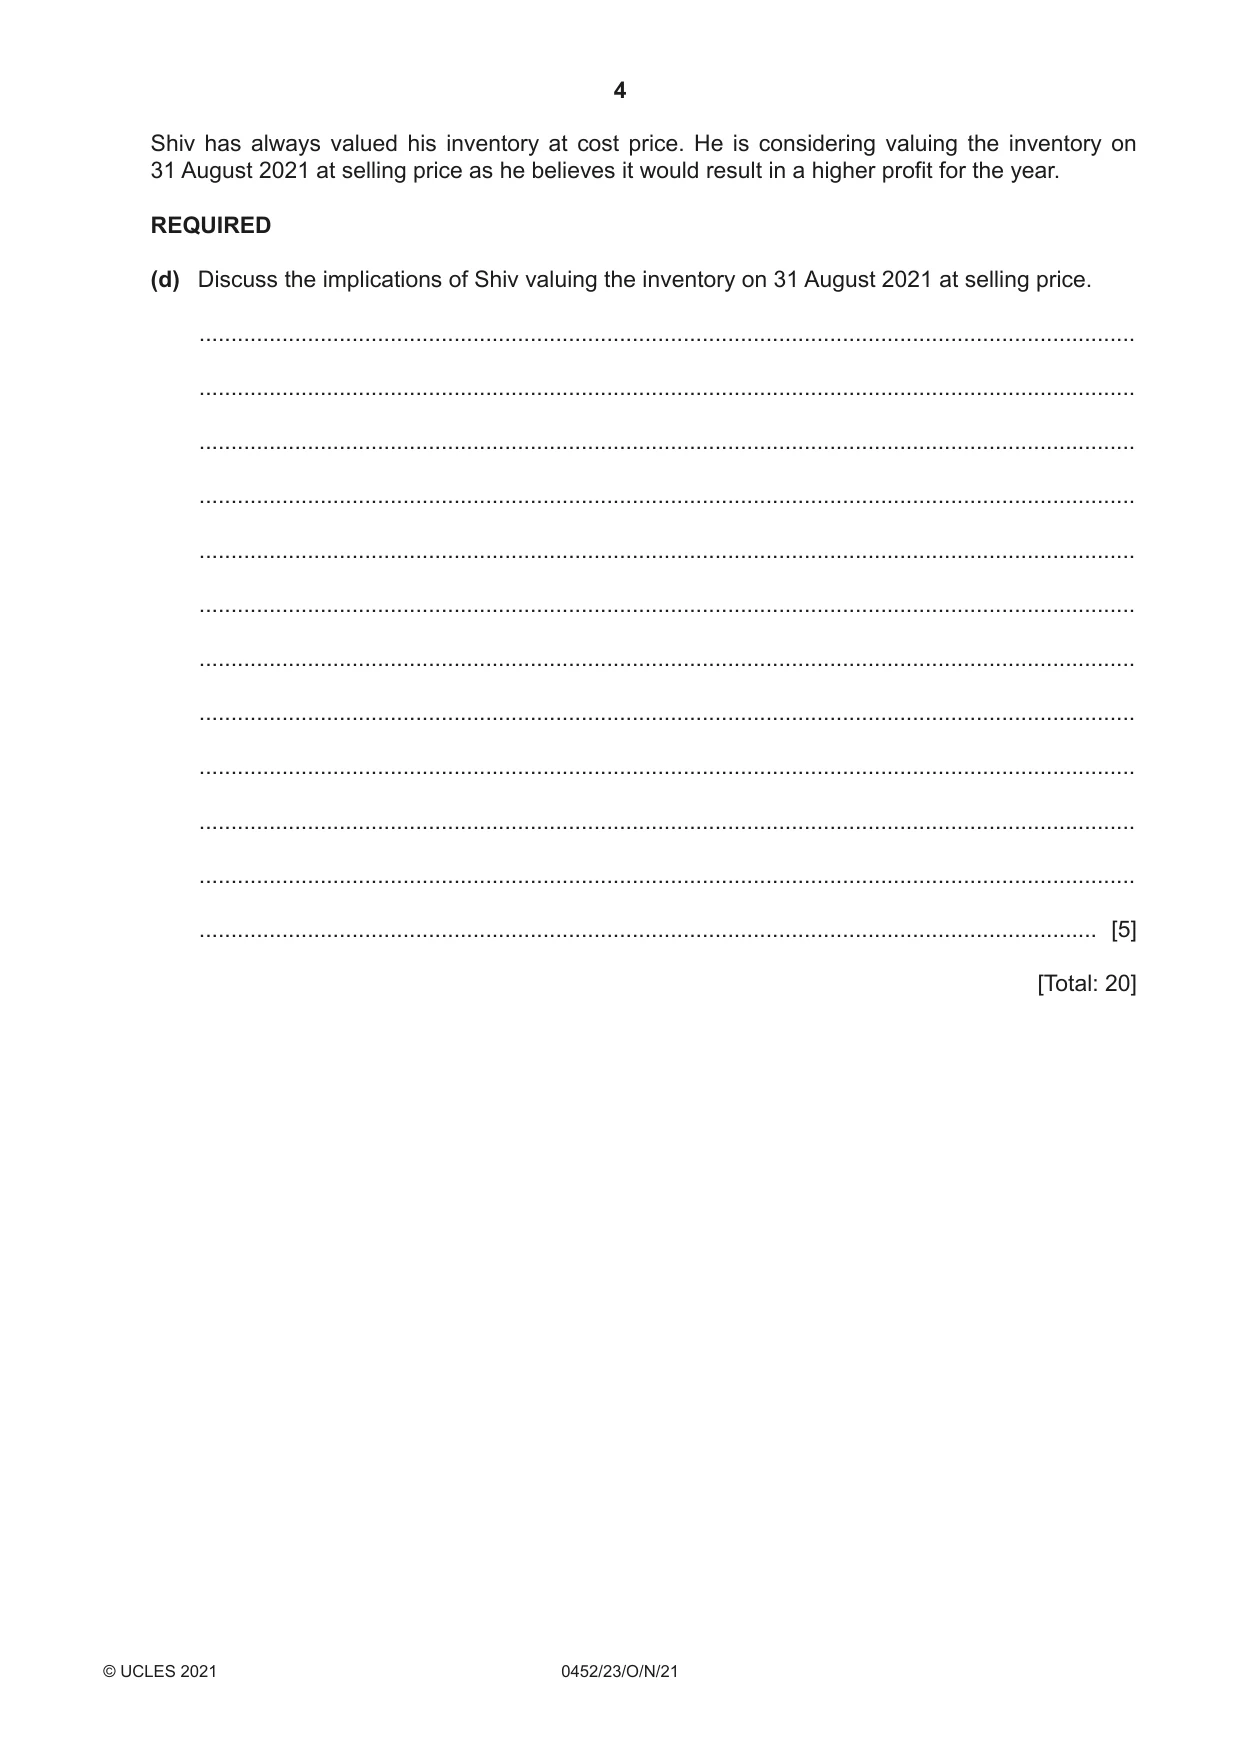
1 Shiv is a trader. His financial year ends on 31 August. He does not maintain a full set of accounting records but was able to provide the following information for the year ended 31 August 2021. Total revenue $320 000 Mark-up 25% Bank account summary for the year ended 31 August 2021 $ $ Balance b/d 49 000 Expenses 34 000 Cash sales 3 700 Drawings 4 200 Receipts from trade receivables 312 400 Payments to trade payables 257 700 Equipment 16 000 Balance c/d 53 200 365 100 365 100 Assets and liabilities 1 September 2020 31 August 2021 $ $ Inventory at cost 23 500 ? Trade receivables 22 000 25 900 Expenses owing – 400 Trade payables 32 600 29 600 Equipment at net book value – 12 800 Premises at cost 90 000 90 000 Shiv had withdrawn $900 for a family holiday during the year. He had included this in the expenses. On 31 August 2021 Shiv decided to create a provision for doubtful debts of 3% of trade receivables. REQUIRED (a) Calculate the purchases for the year ended 31 August 2021. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] (b) Prepare the income statement for the year ended 31 August 2021. The inventory on 31 August 2021 should be clearly shown within the statement. Shiv Income Statement for the year ended 31 August 2021 $ $ ........................................................................................ …………….... …………….... ........................................................................................ …………….... …………….... ........................................................................................ …………….... …………….... ........................................................................................ …………….... …………….... ........................................................................................ …………….... …………….... ........................................................................................ …………….... …………….... ........................................................................................ …………….... …………….... ........................................................................................ …………….... …………….... ........................................................................................ …………….... …………….... ........................................................................................ …………….... …………….... ........................................................................................ …………….... …………….... ........................................................................................ …………….... …………….... ........................................................................................ …………….... …………….... ........................................................................................ …………….... …………….... ........................................................................................ …………….... …………….... [11] (c) Name the accounting principle Shiv should apply when recording the $900 he had used for a family holiday. ............................................................................................................................................. [1] Shiv has always valued his inventory at cost price. He is considering valuing the inventory on 31 August 2021 at selling price as he believes it would result in a higher profit for the year. REQUIRED (d) Discuss the implications of Shiv valuing the inventory on 31 August 2021 at selling price. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20] PLEASE TURN OVER
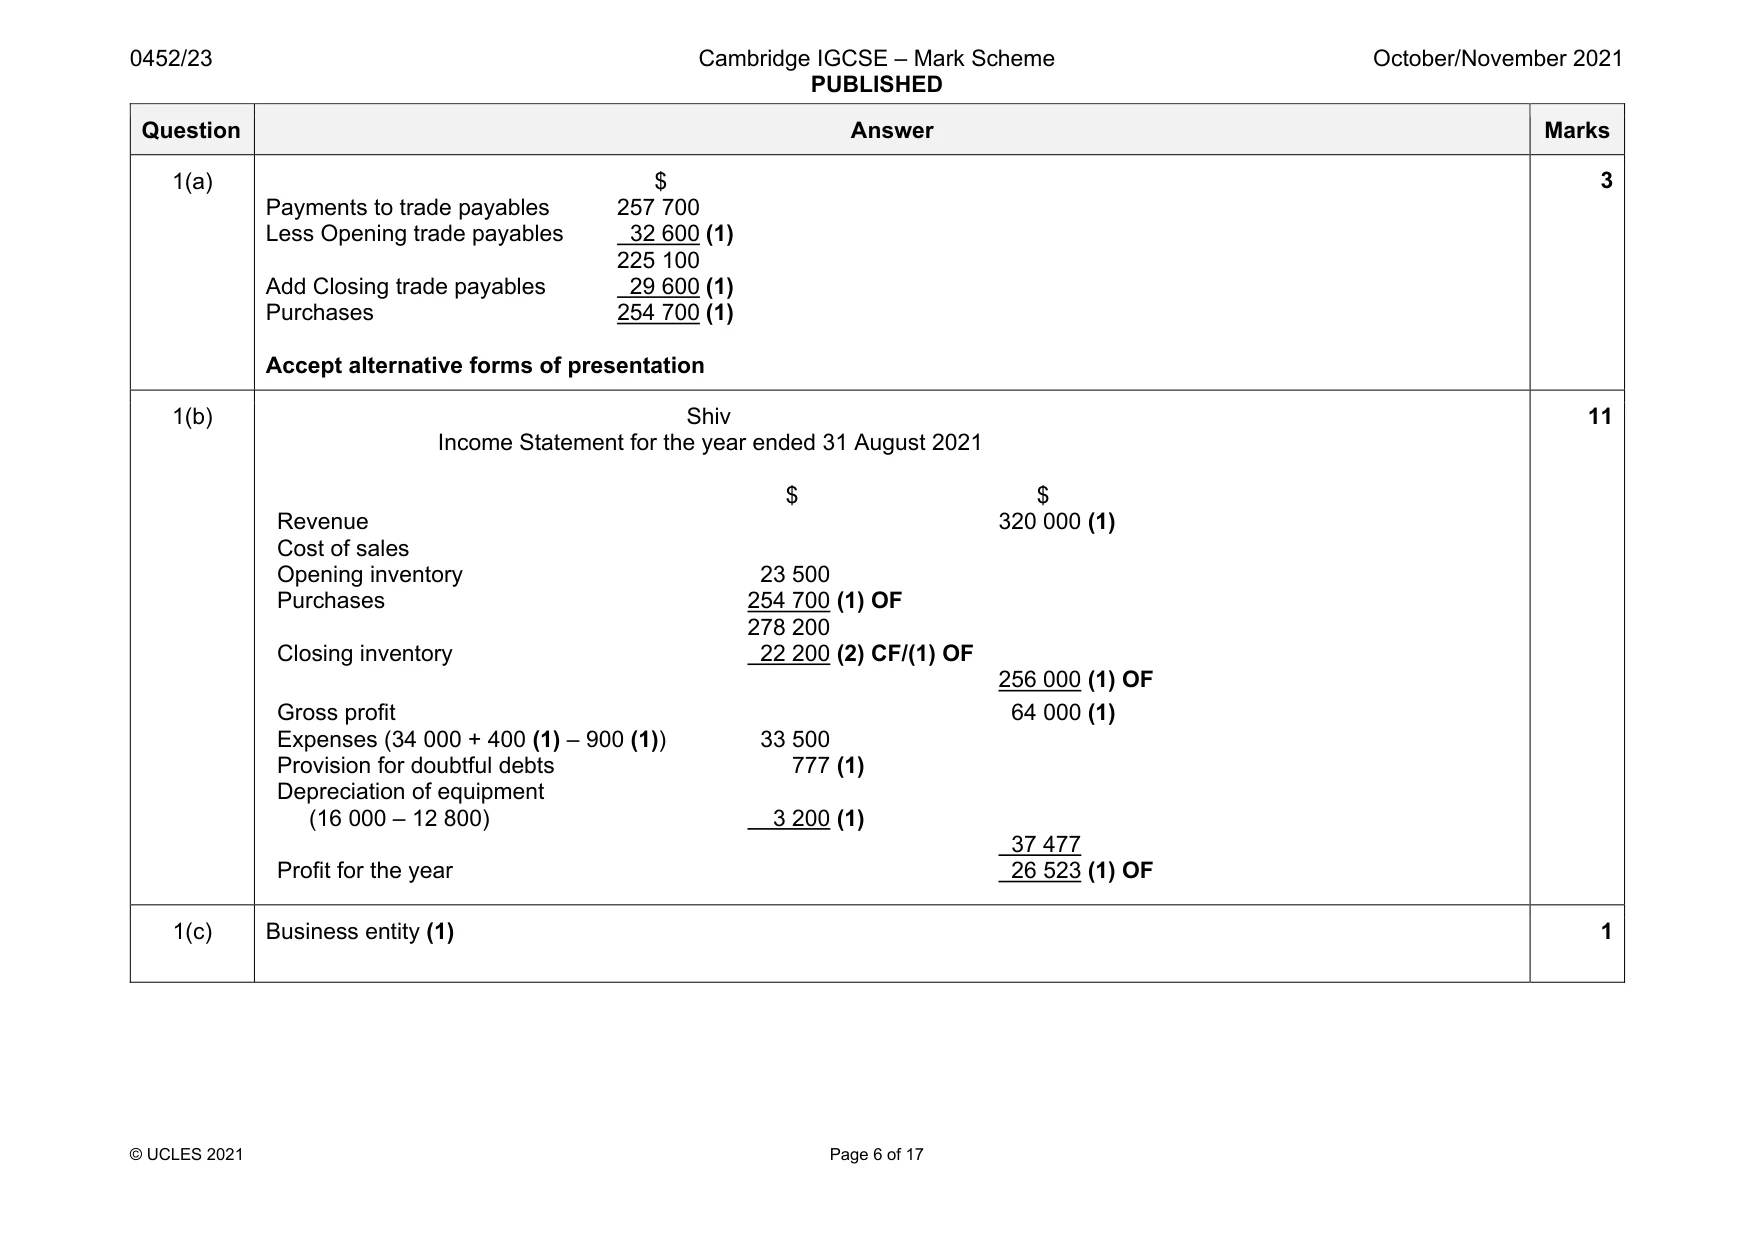
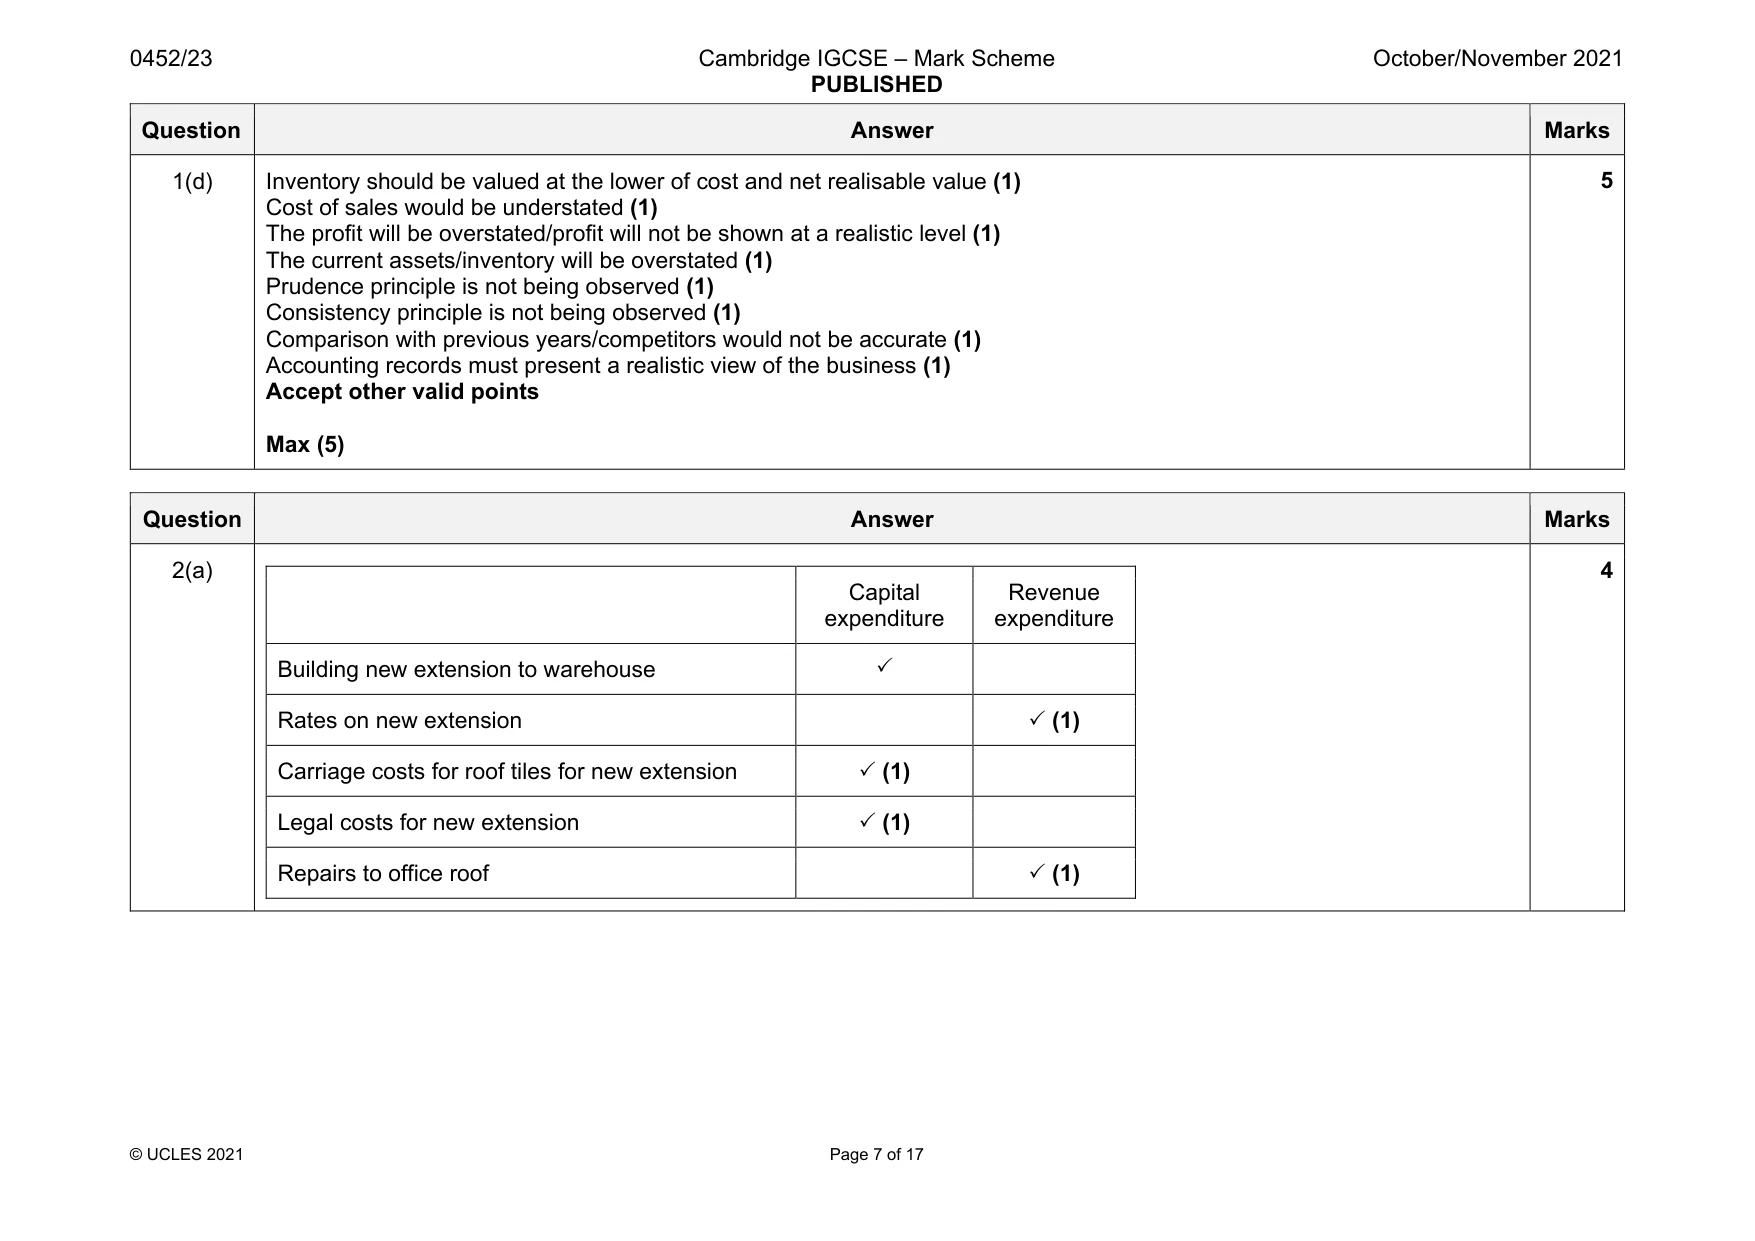
Mark scheme: 1(a) $ Payments to trade payables 257 700 Less Opening trade payables 32 600 (1) 225 100 Add Closing trade payables 29 600 (1) Purchases 254 700 (1) Accept alternative forms of presentation 1(b) Shiv Income Statement for the year ended 31 August 2021 $ $ Revenue 320 000 (1) Cost of sales Opening inventory 23 500 Purchases 254 700 (1) OF 278 200 Closing inventory 22 200 (2) CF/(1) OF 256 000 (1) OF Gross profit 64 000 (1) Expenses (34 000 + 400 (1) – 900 (1)) 33 500 Provision for doubtful debts 777 (1) Depreciation of equipment (16 000 – 12 800) 3 200 (1) 37 477 Profit for the year 26 523 (1) OF 11 1(c) Business entity (1) 1 Question Answer Marks 1(d) Inventory should be valued at the lower of cost and net realisable value (1) Cost of sales would be understated (1) The profit will be overstated/profit will not be shown at a realistic level (1) The current assets/inventory will be overstated (1) Prudence principle is not being observed (1) Consistency principle is not being observed (1) Comparison with previous years/competitors would not be accurate (1) Accounting records must present a realistic view of the business (1) Accept other valid points Max (5) 5
Q2 · Jas owns a printing business and has recently incurred various expenditures relating to…
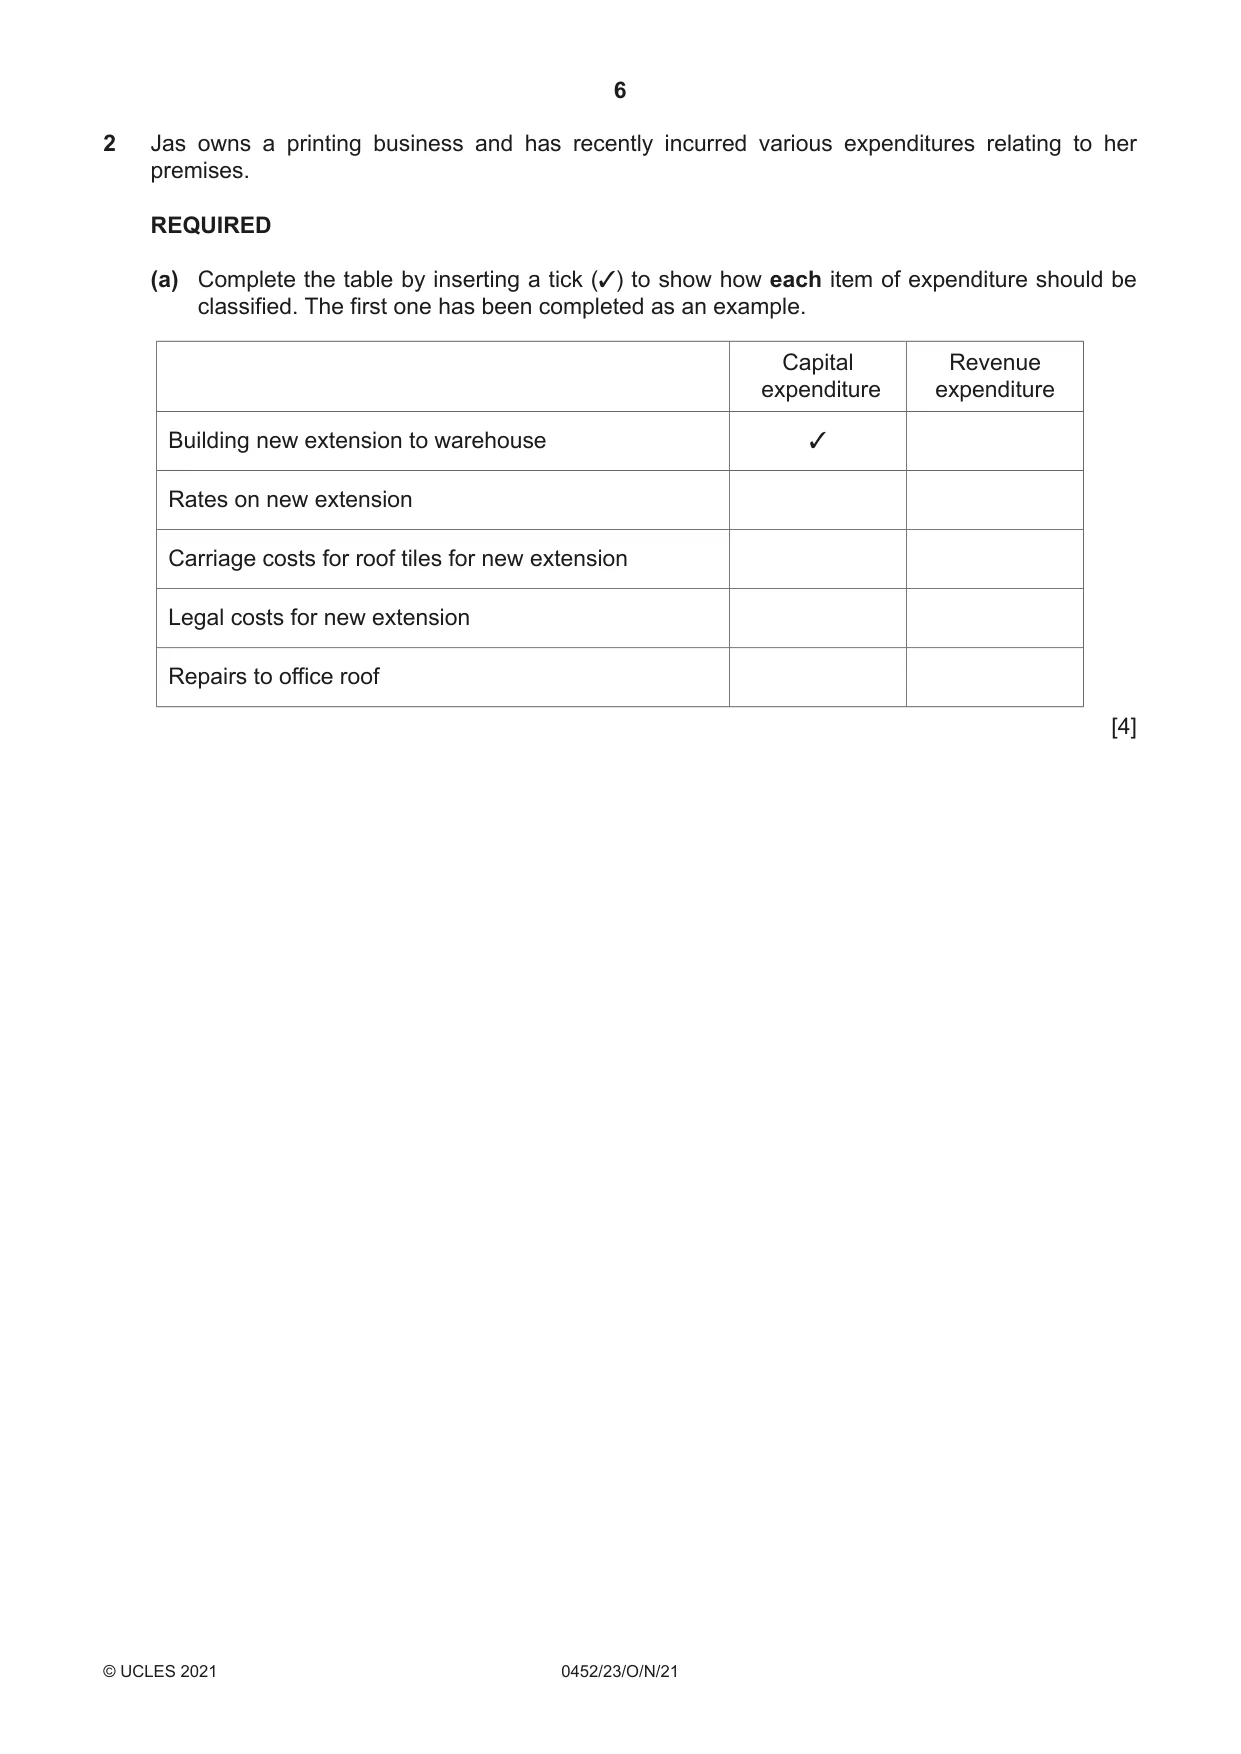
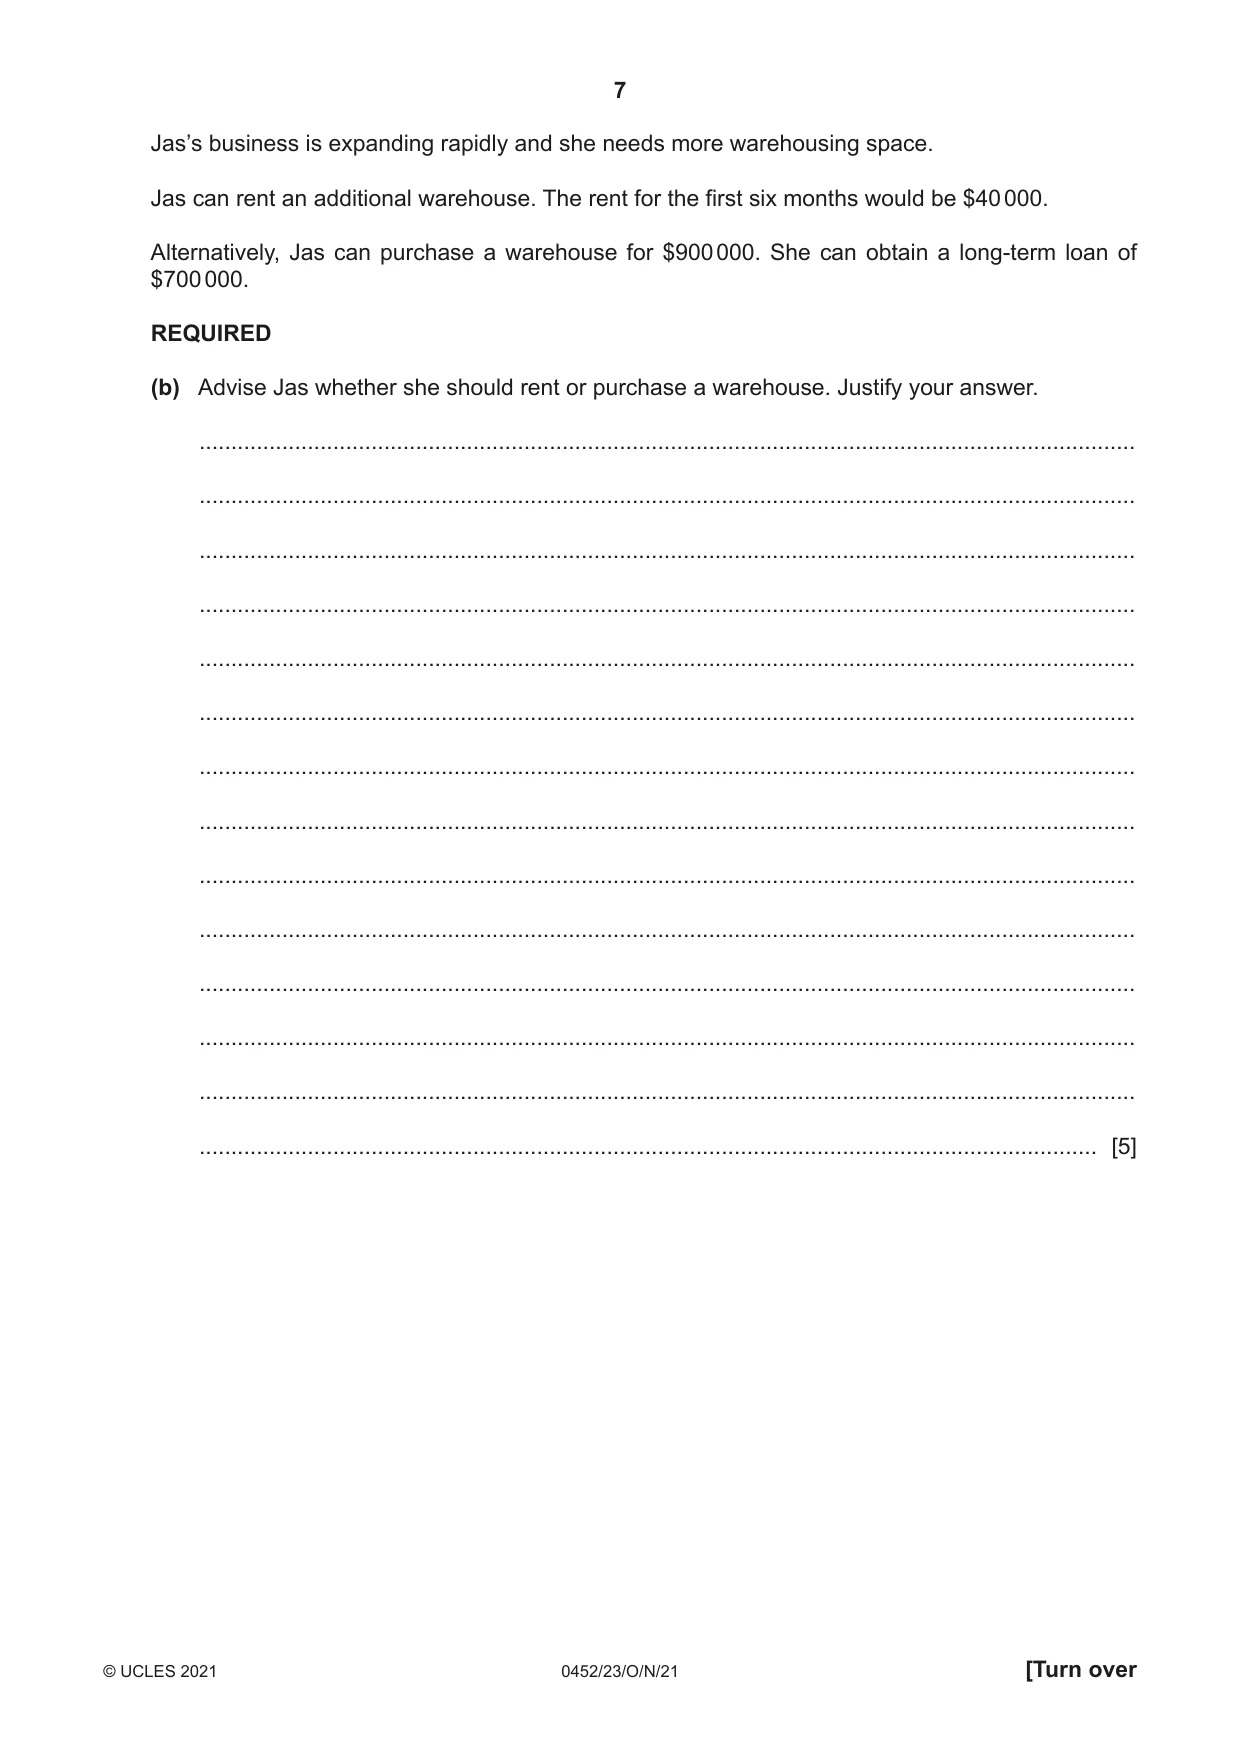
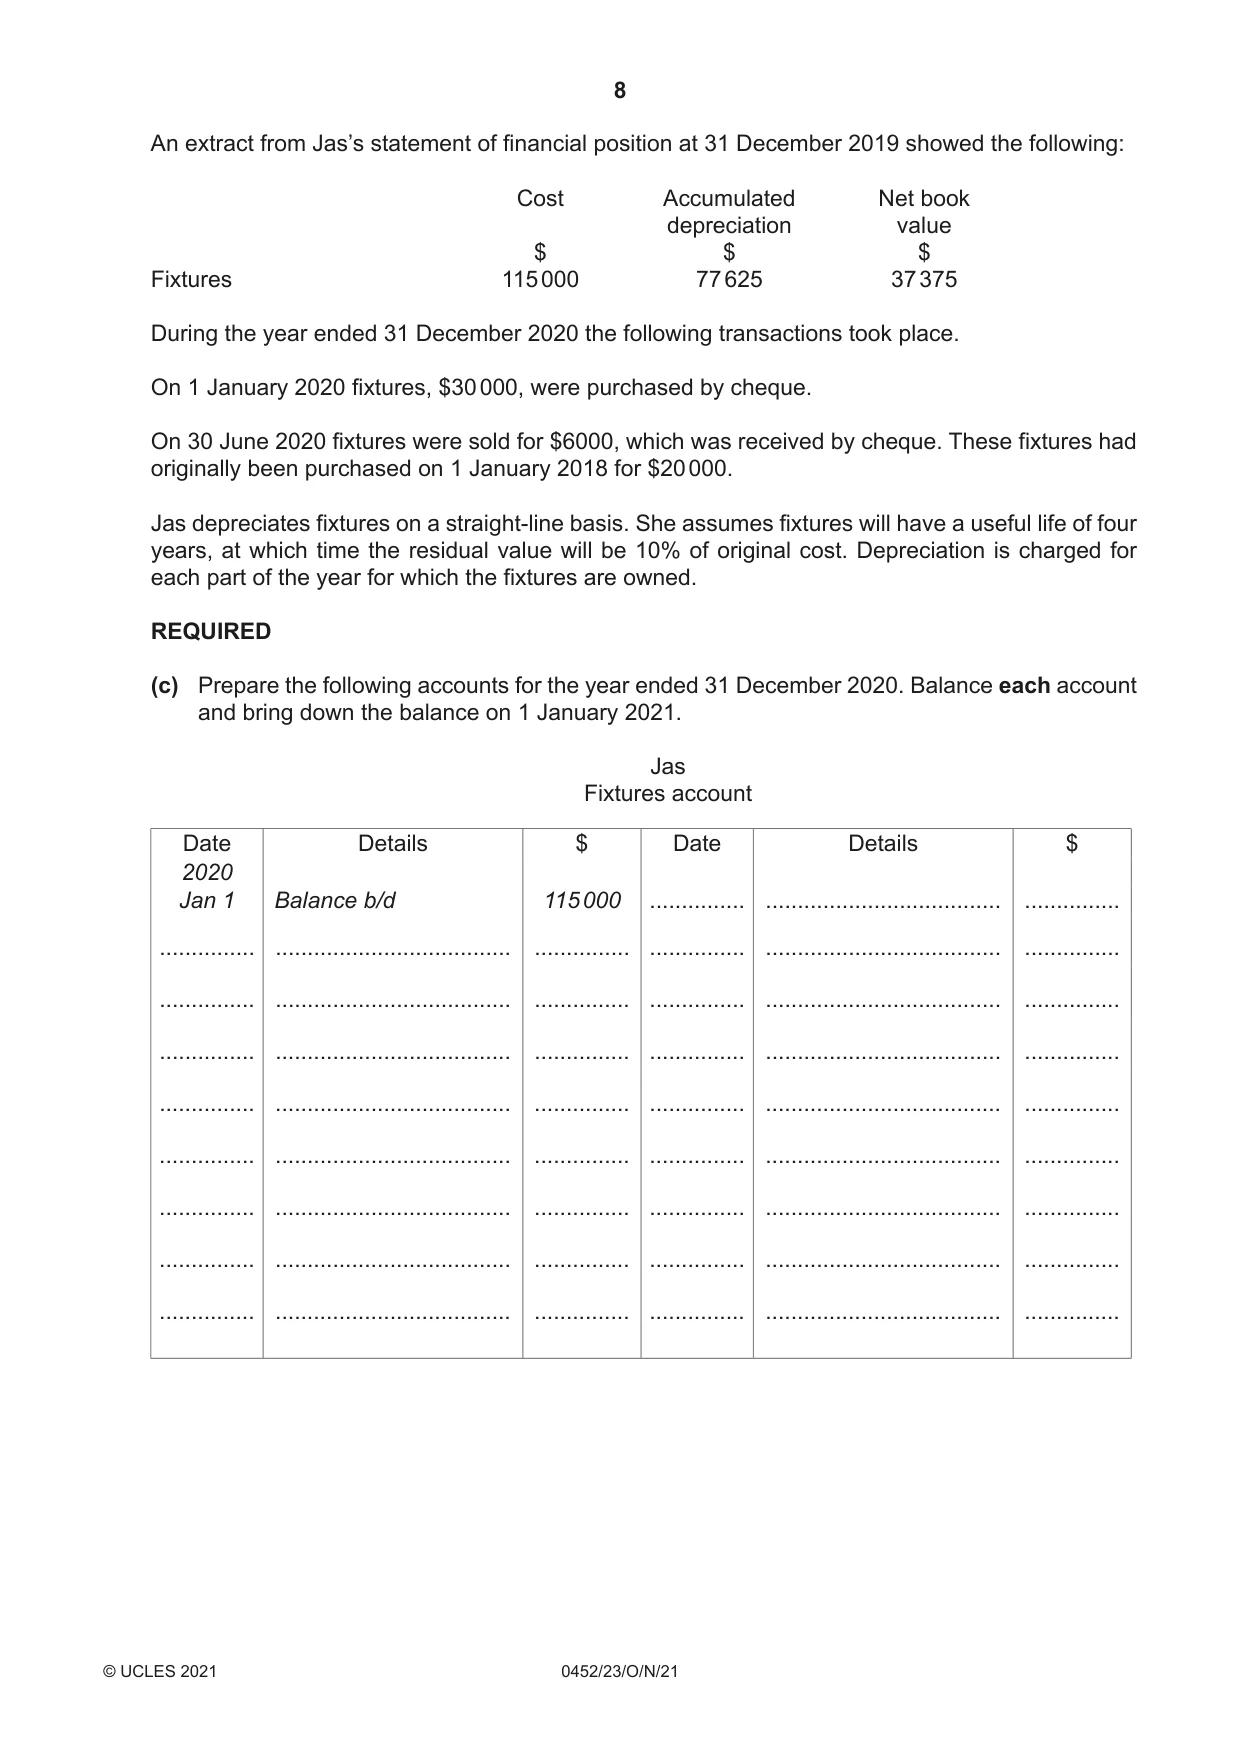
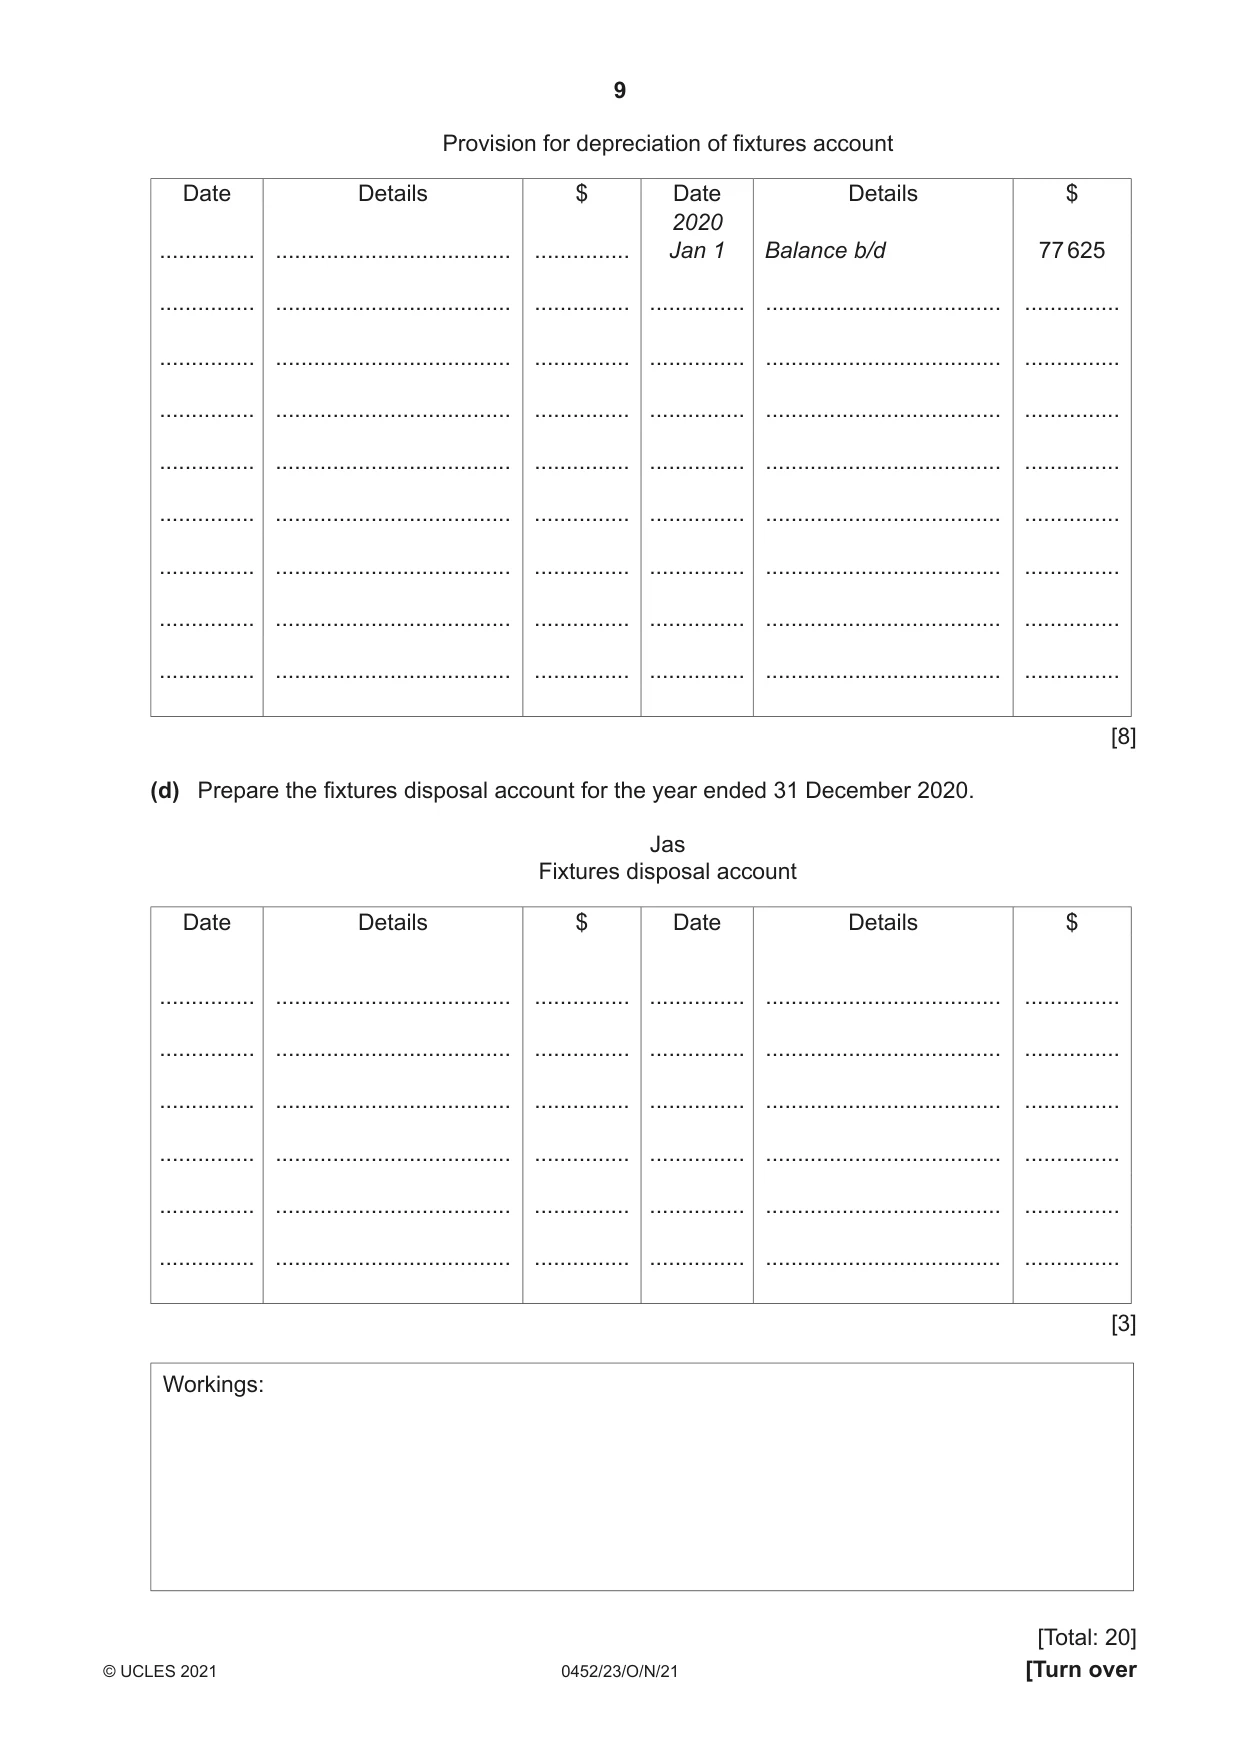
2 Jas owns a printing business and has recently incurred various expenditures relating to her premises. REQUIRED (a) Complete the table by inserting a tick (3) to show how each item of expenditure should be classified. The first one has been completed as an example. Capital Revenue expenditure expenditure Building new extension to warehouse 3 Rates on new extension Carriage costs for roof tiles for new extension Legal costs for new extension Repairs to office roof [4] Jas’s business is expanding rapidly and she needs more warehousing space. Jas can rent an additional warehouse. The rent for the first six months would be $40 000. Alternatively, Jas can purchase a warehouse for $900 000. She can obtain a long-term loan of $700 000. REQUIRED (b) Advise Jas whether she should rent or purchase a warehouse. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] An extract from Jas’s statement of financial position at 31 December 2019 showed the following: Cost Accumulated Net book depreciation value $ $ $ Fixtures 115 000 77 625 37 375 During the year ended 31 December 2020 the following transactions took place. On 1 January 2020 fixtures, $30 000, were purchased by cheque. On 30 June 2020 fixtures were sold for $6000, which was received by cheque. These fixtures had originally been purchased on 1 January 2018 for $20 000. Jas depreciates fixtures on a straight-line basis. She assumes fixtures will have a useful life of four years, at which time the residual value will be 10% of original cost. Depreciation is charged for each part of the year for which the fixtures are owned. REQUIRED (c) Prepare the following accounts for the year ended 31 December 2020. Balance each account and bring down the balance on 1 January 2021. Jas Fixtures account Date Details $ Date Details $ 2020 Jan 1 Balance b/d 115 000 ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... Provision for depreciation of fixtures account Date Details $ Date Details $ 2020 ............... ..................................... ............... Jan 1 Balance b/d 77 625 ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... [8] (d) Prepare the fixtures disposal account for the year ended 31 December 2020. Jas Fixtures disposal account Date Details $ Date Details $ ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... [3] Workings: [Total: 20]
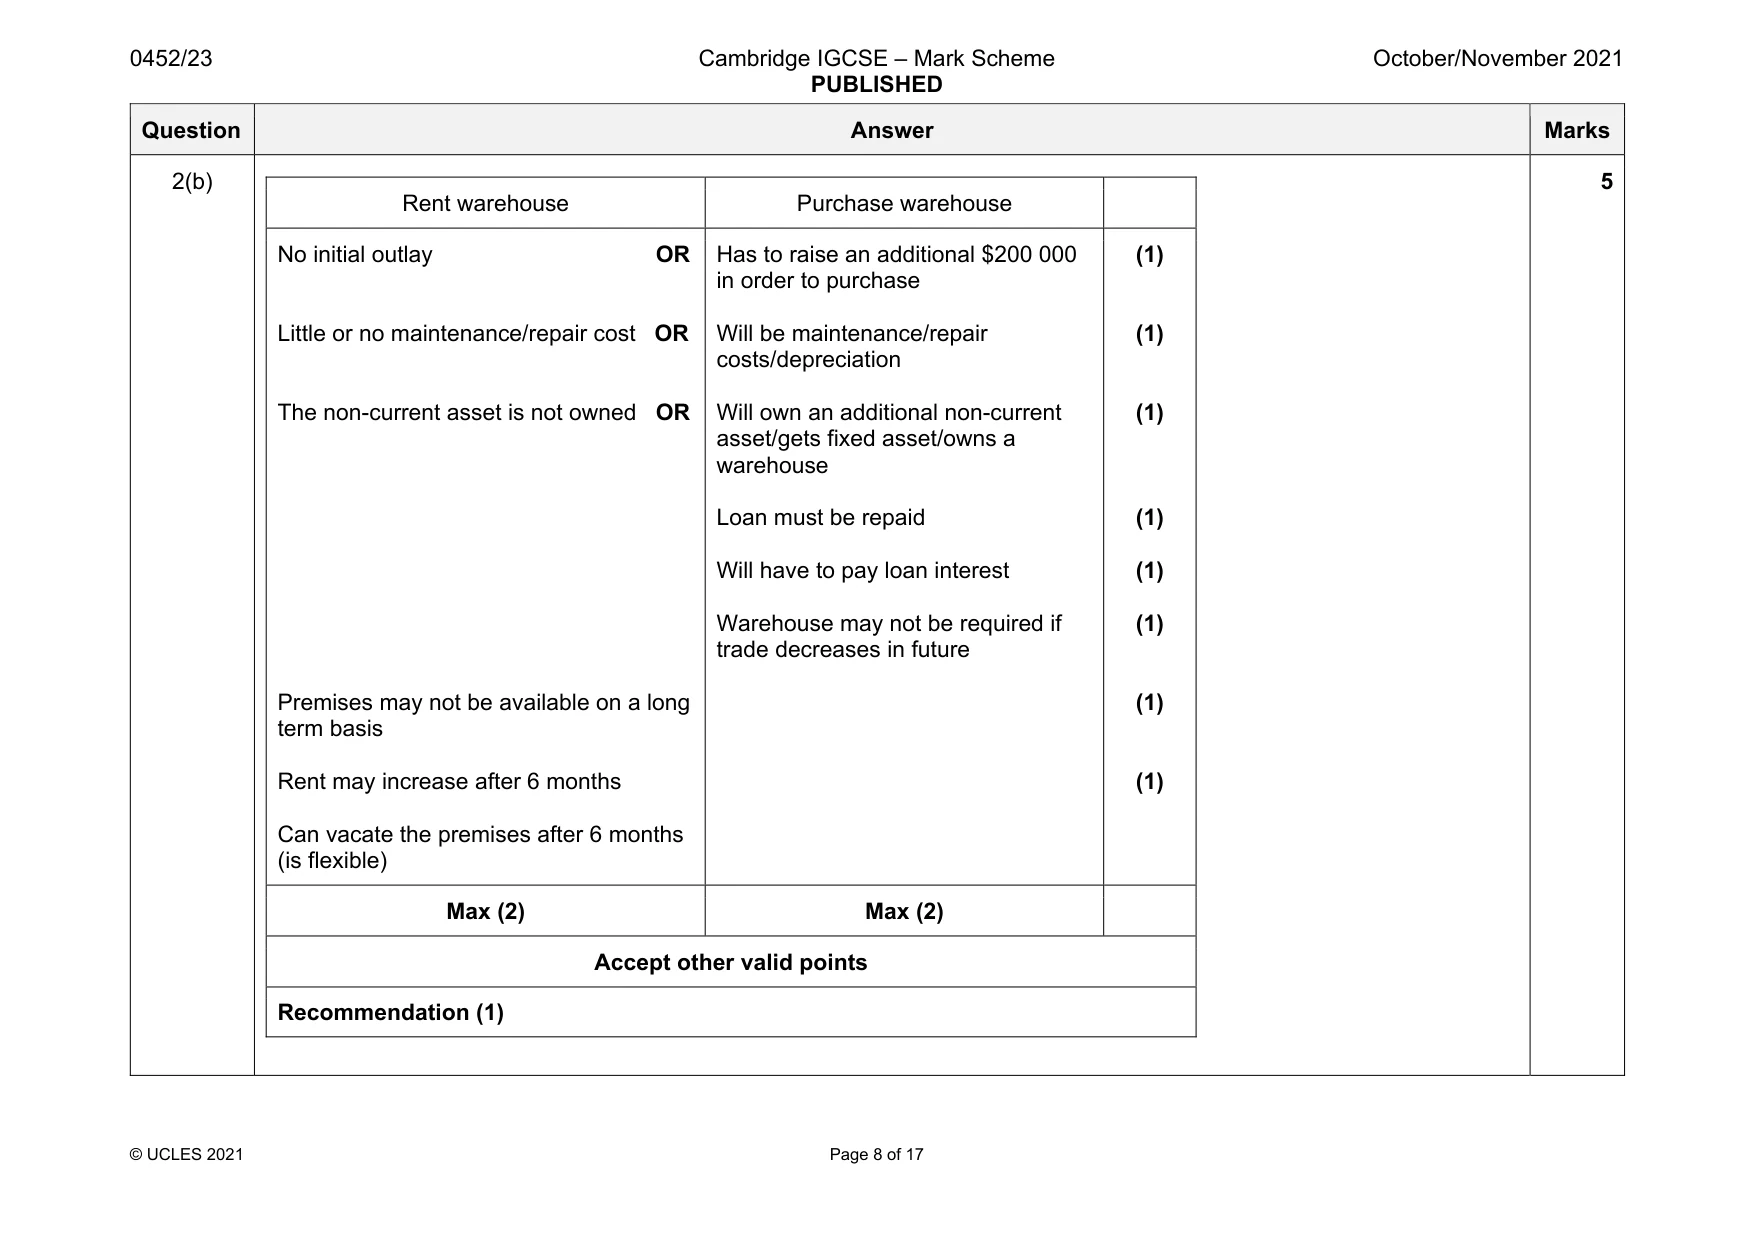
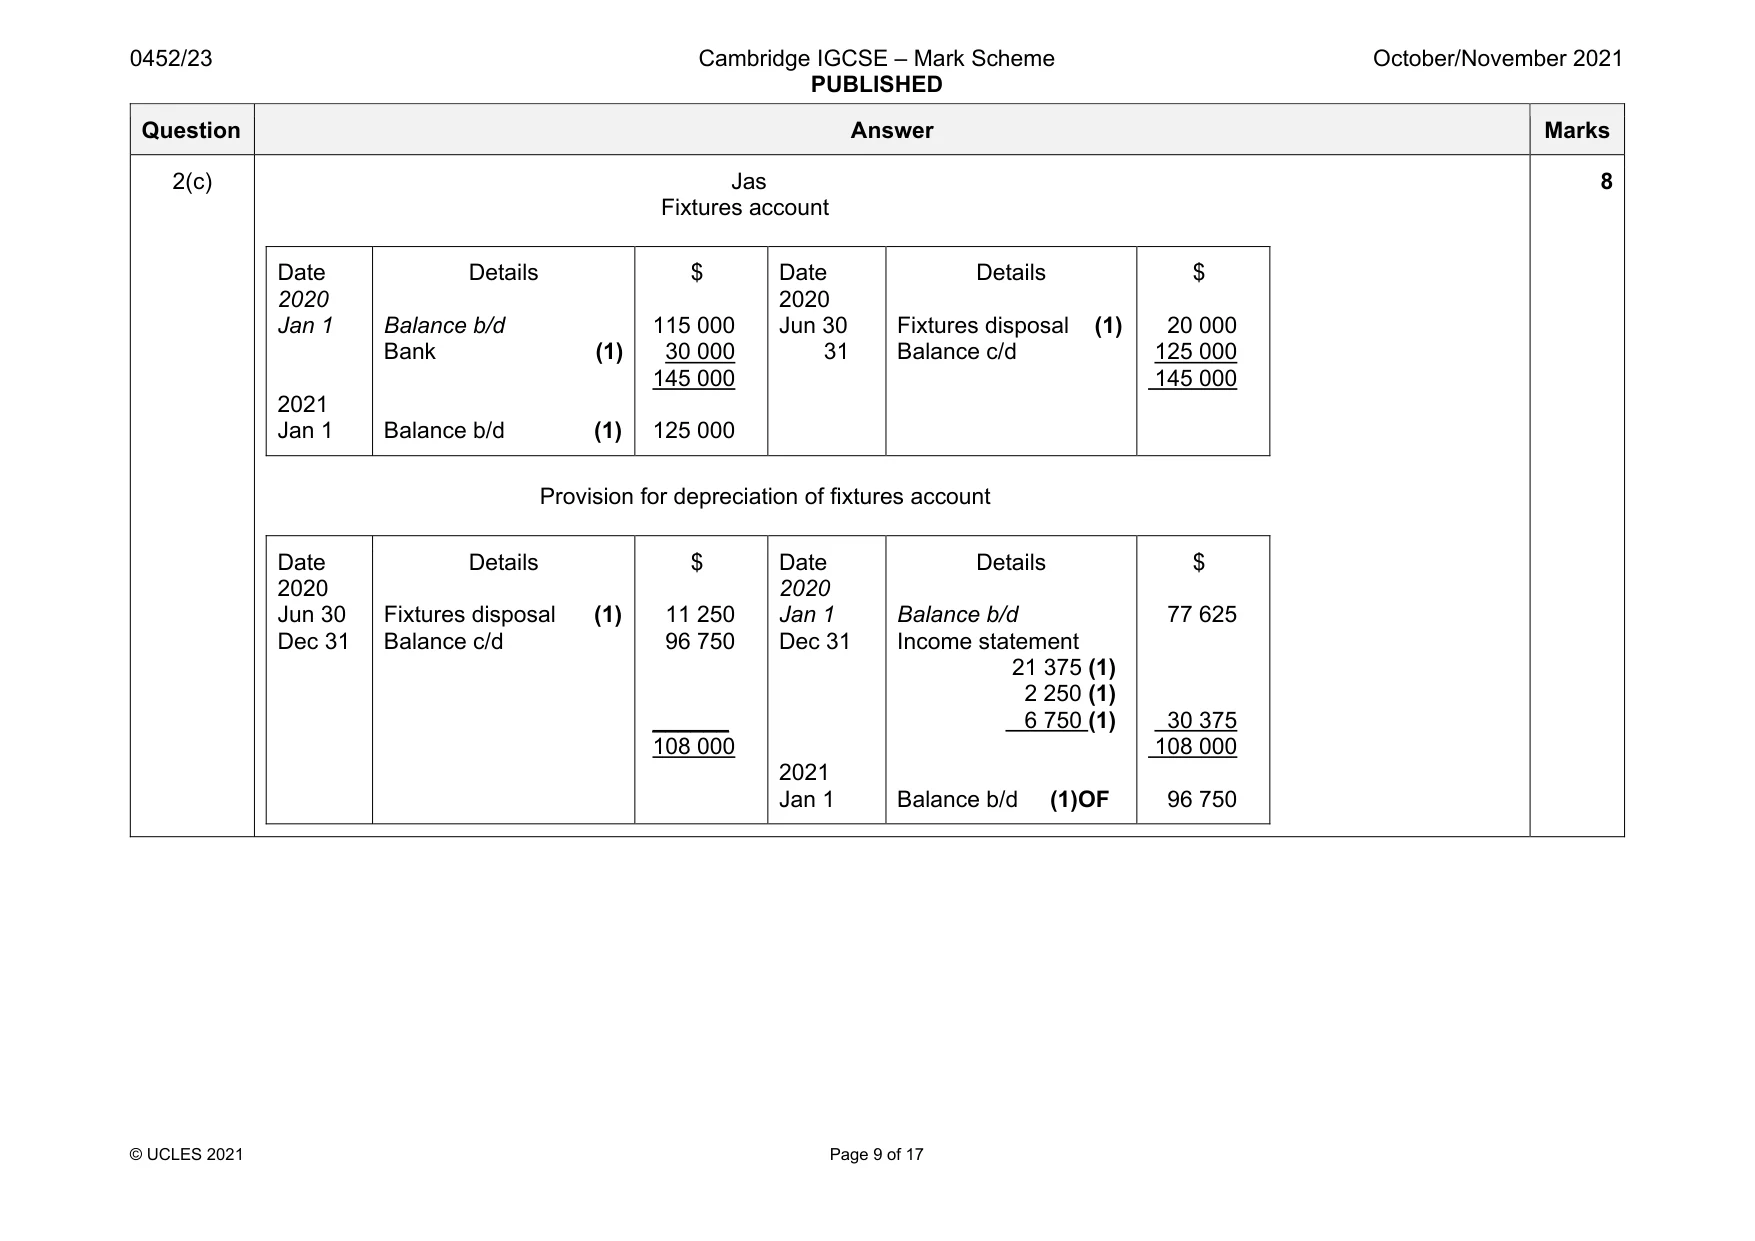
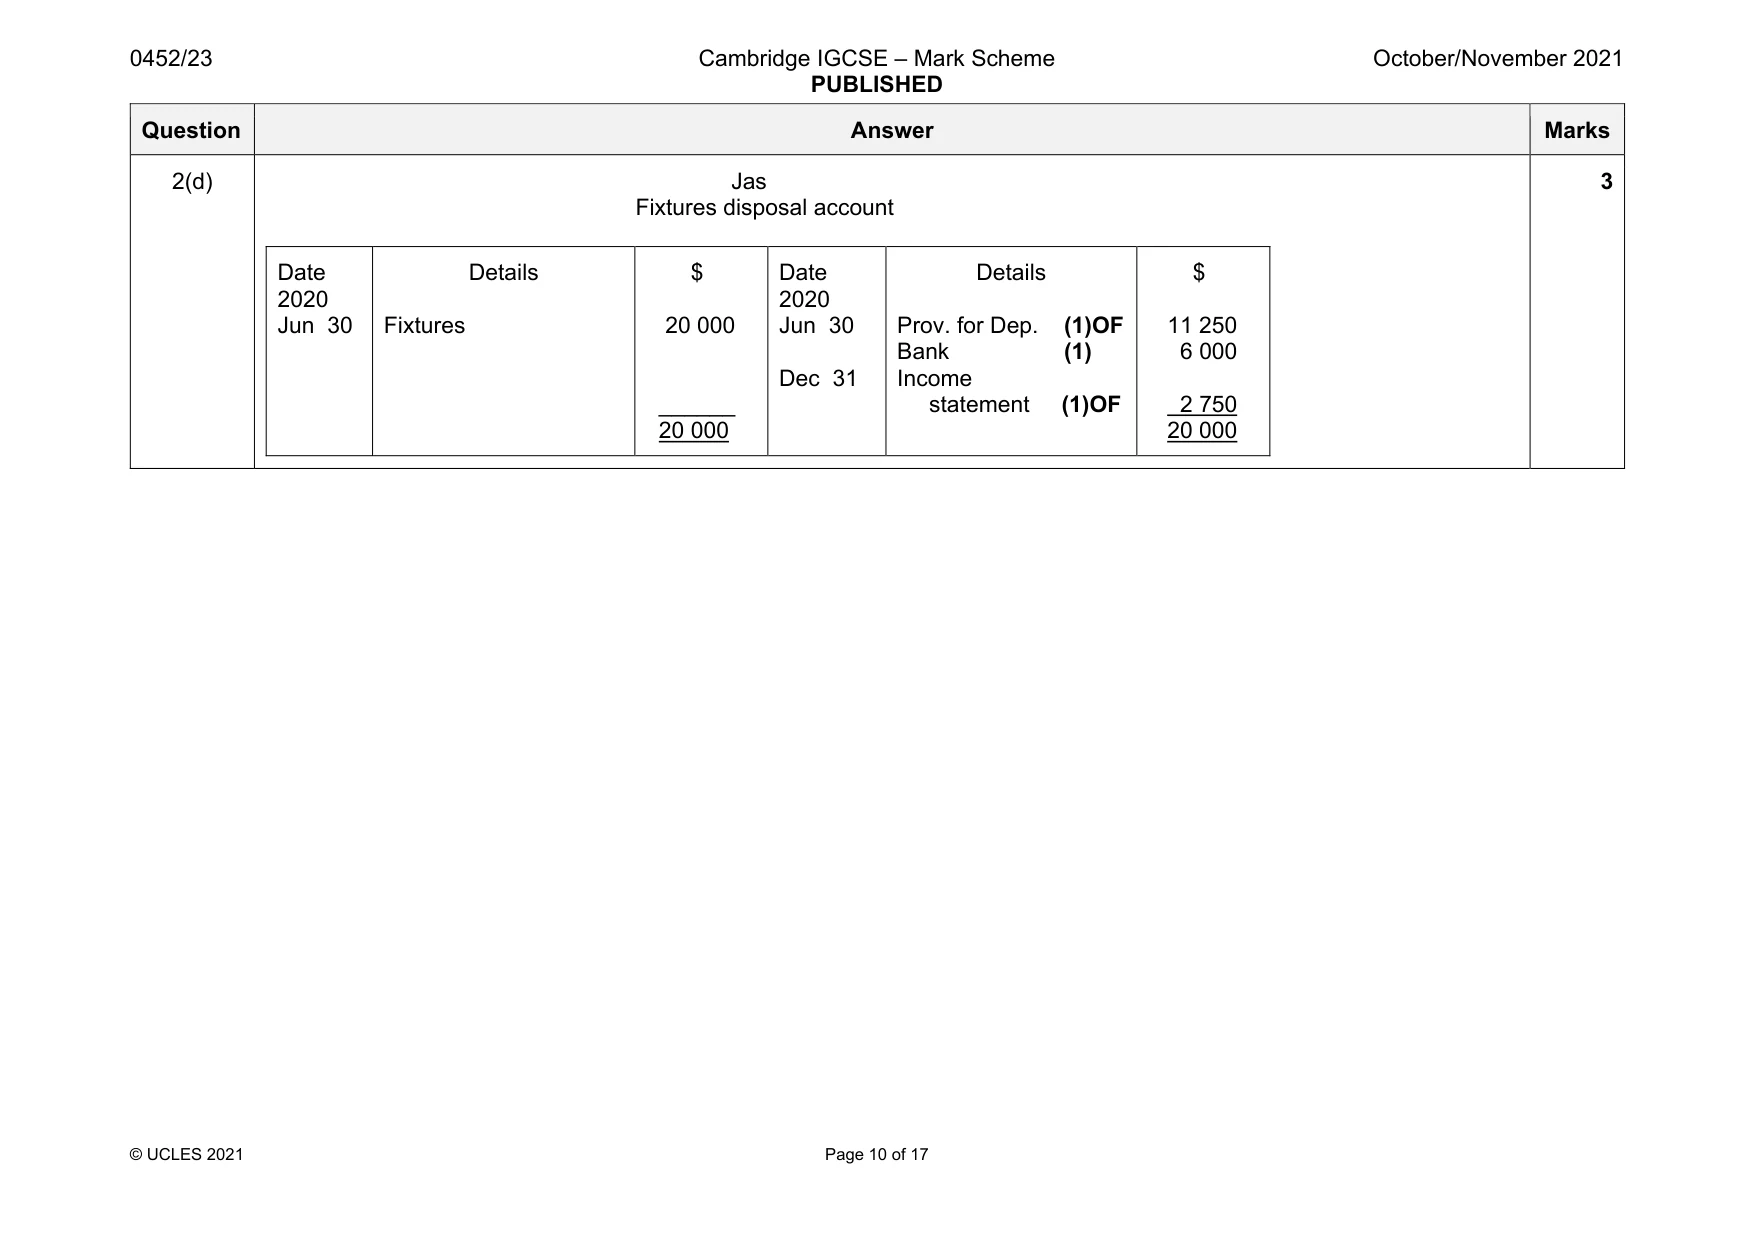
Mark scheme: 2(a) Capital expenditure Revenue expenditure Building new extension to warehouse Rates on new extension (1) Carriage costs for roof tiles for new extension (1) Legal costs for new extension (1) Repairs to office roof (1) 4 Question Answer Marks 2(b) Rent warehouse Purchase warehouse No initial outlay OR Little or no maintenance/repair cost OR The non-current asset is not owned OR Premises may not be available on a long term basis Rent may increase after 6 months Can vacate the premises after 6 months (is flexible) Has to raise an additional $200 000 in order to purchase Will be maintenance/repair costs/depreciation Will own an additional non-current asset/gets fixed asset/owns a warehouse Loan must be repaid Will have to pay loan interest Warehouse may not be required if trade decreases in future (1) (1) (1) (1) (1) (1) (1) (1) Max (2) Max (2) Accept other valid points Recommendation (1) 5 Question Answer Marks 2(c) Jas Fixtures account Date 2020 Jan 1 2021 Jan 1 Details Balance b/d Bank (1) Balance b/d (1) $ 115 000 30 000 145 000 125 000 Date 2020 Jun 30 31 Details Fixtures disposal (1) Balance c/d $ 20 000 125 000 145 000 Provision for depreciation of fixtures account Date 2020 Jun 30 Dec 31 Details Fixtures disposal (1) Balance c/d $ 11 250 96 750 ______ 108 000 Date 2020 Jan 1 Dec 31 2021 Jan 1 Details Balance b/d Income statement 21 375 (1) 2 250 (1) 6 750 (1) Balance b/d (1)OF $ 77 625 30 375 108 000 96 750 8 Question Answer Marks 2(d) Jas Fixtures disposal account Date 2020 Jun 30 Details Fixtures $ 20 000 ______ 20 000 Date 2020 Jun 30 Dec 31 Details Prov. for Dep. (1)OF Bank (1) Income statement (1)OF $ 11 250 6 000 2 750 20 000 3
More questions on Accounting for depreciation and disposal of non-current assets
Q3 · Anil is a trader
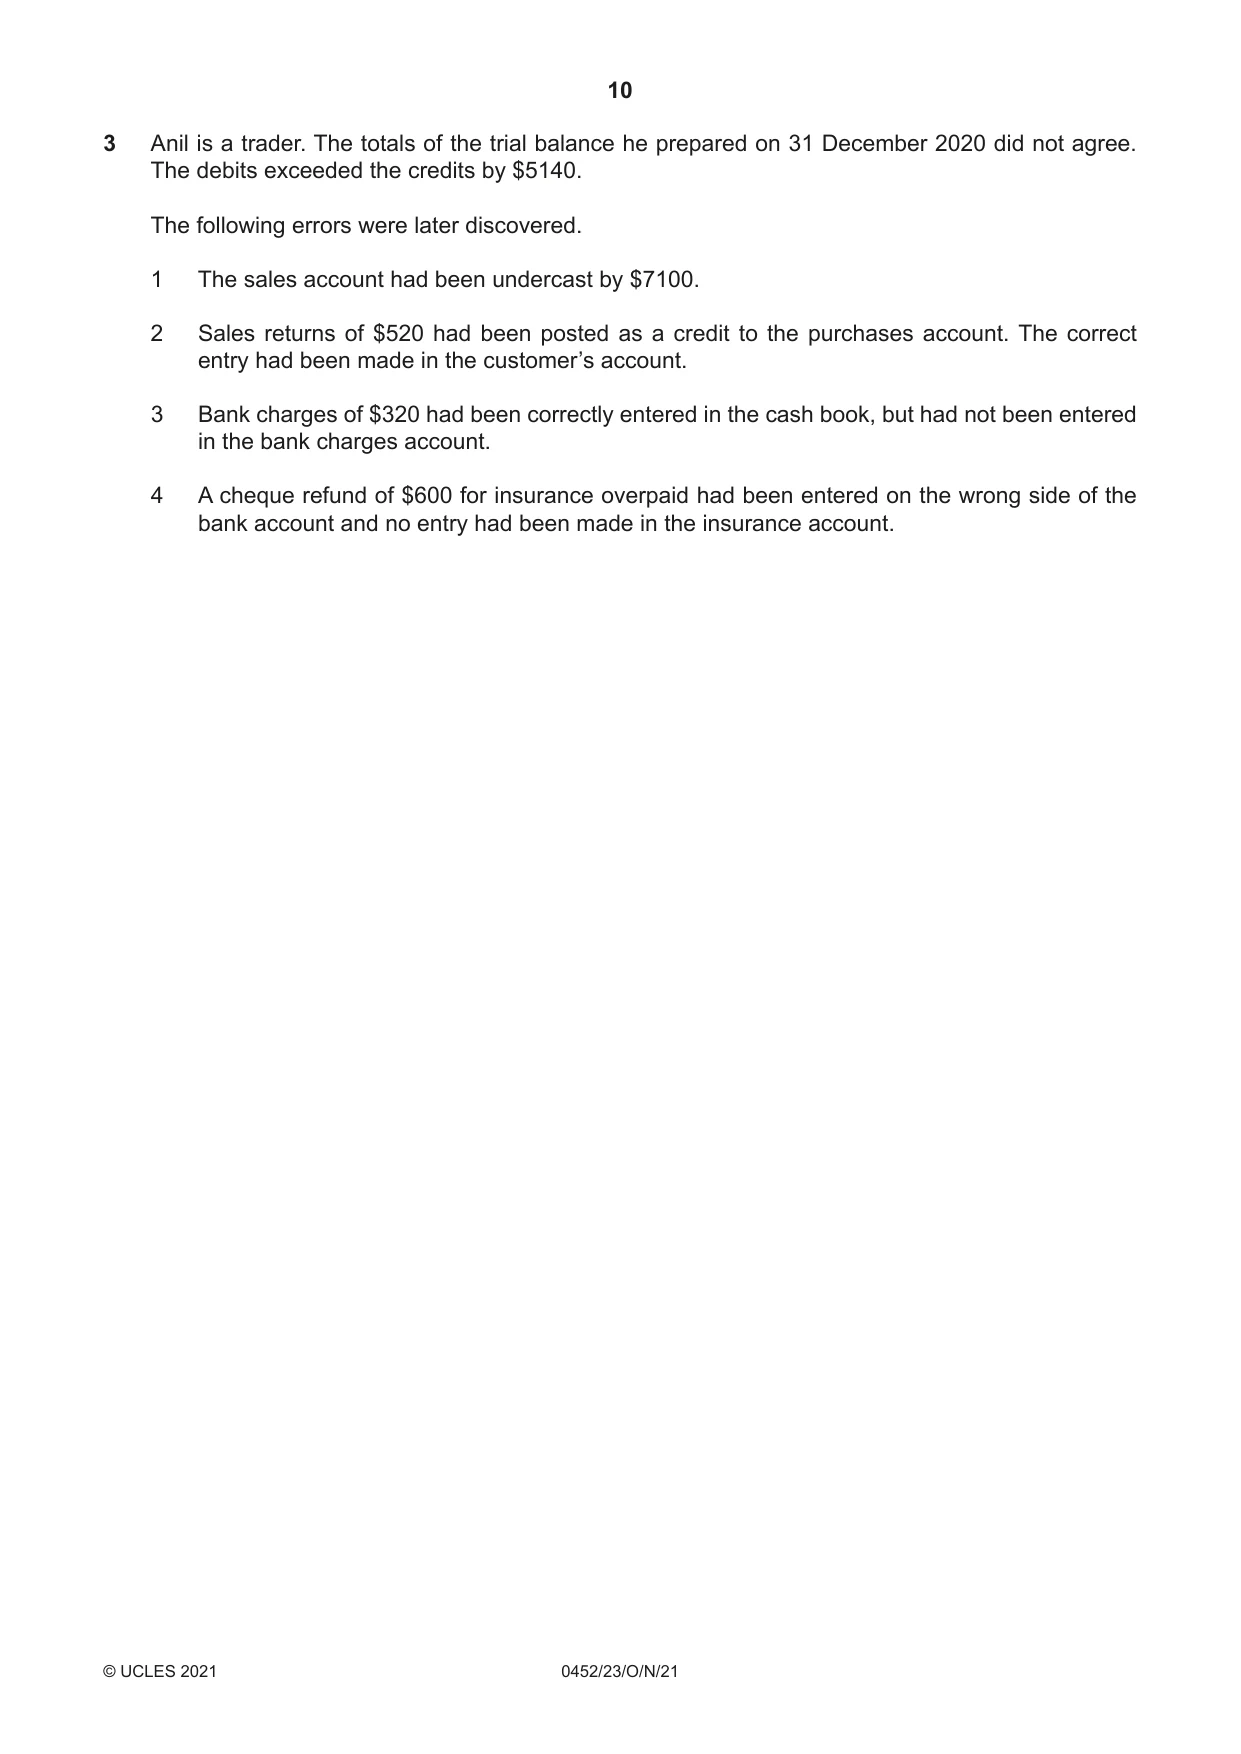
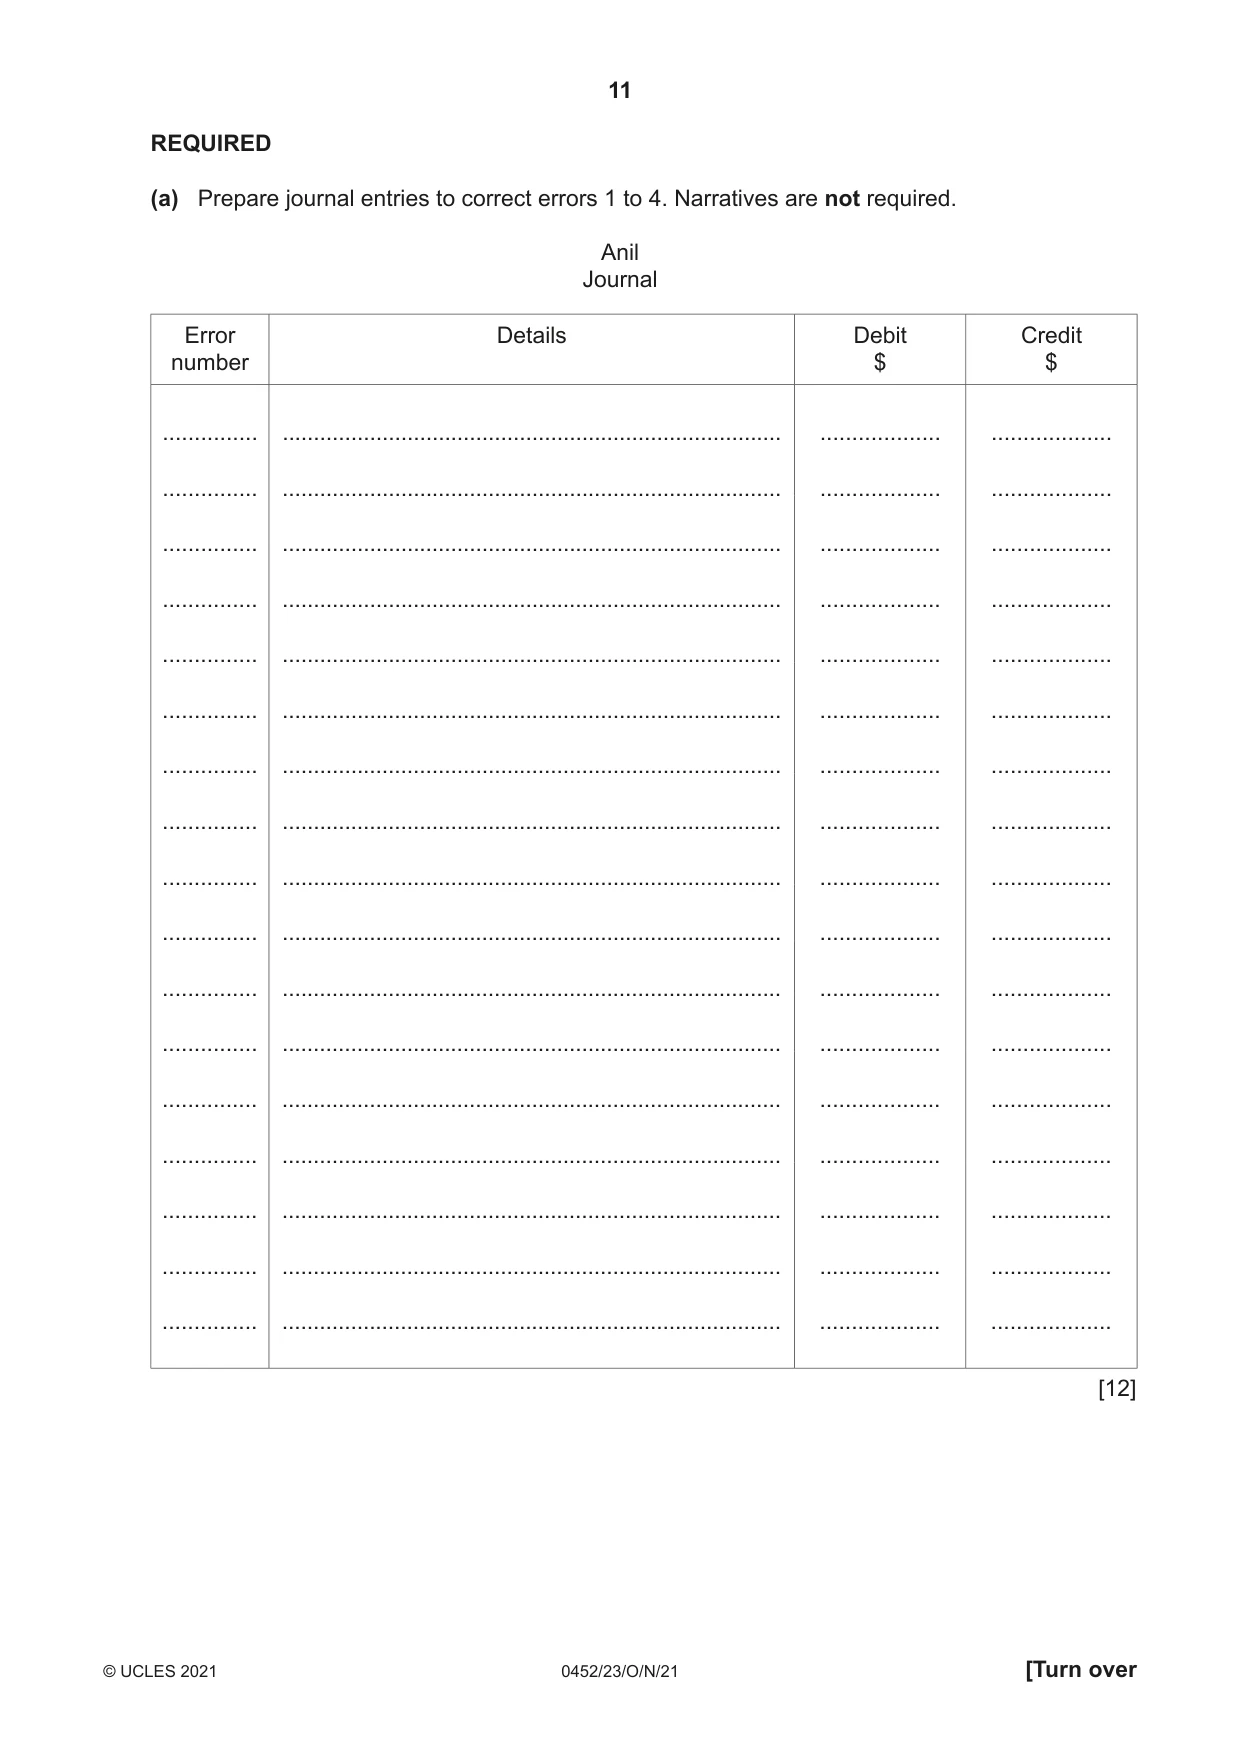
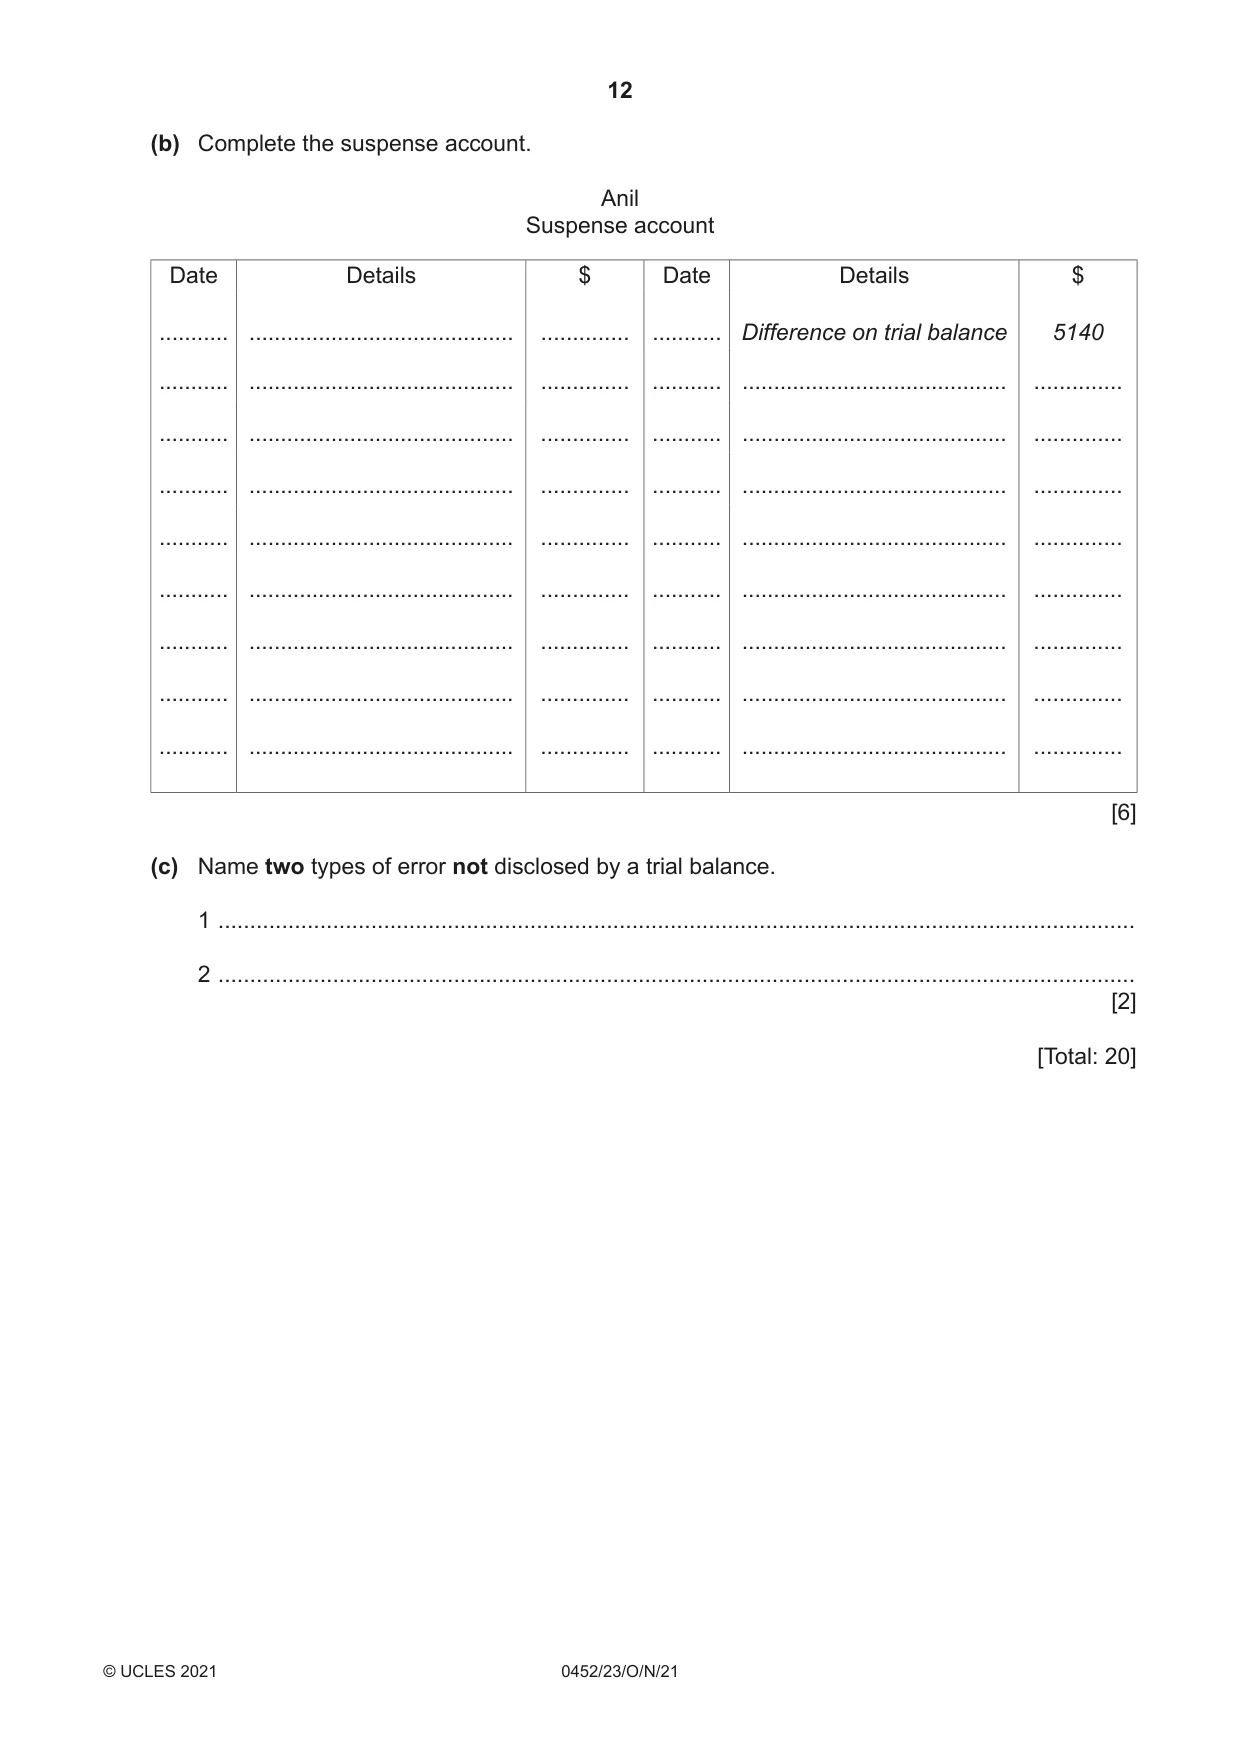
3 Anil is a trader. The totals of the trial balance he prepared on 31 December 2020 did not agree. The debits exceeded the credits by $5140. The following errors were later discovered. 1 The sales account had been undercast by $7100. 2 Sales returns of $520 had been posted as a credit to the purchases account. The correct entry had been made in the customer’s account. 3 Bank charges of $320 had been correctly entered in the cash book, but had not been entered in the bank charges account. 4 A cheque refund of $600 for insurance overpaid had been entered on the wrong side of the bank account and no entry had been made in the insurance account. REQUIRED (a) Prepare journal entries to correct errors 1 to 4. Narratives are not required. Anil Journal Error Details Debit Credit number $ $ ............... ................................................................................ ................... ................... ............... ................................................................................ ................... ................... ............... ................................................................................ ................... ................... ............... ................................................................................ ................... ................... ............... ................................................................................ ................... ................... ............... ................................................................................ ................... ................... ............... ................................................................................ ................... ................... ............... ................................................................................ ................... ................... ............... ................................................................................ ................... ................... ............... ................................................................................ ................... ................... ............... ................................................................................ ................... ................... ............... ................................................................................ ................... ................... ............... ................................................................................ ................... ................... ............... ................................................................................ ................... ................... ............... ................................................................................ ................... ................... ............... ................................................................................ ................... ................... ............... ................................................................................ ................... ................... [12] (b) Complete the suspense account. Anil Suspense account Date Details $ Date Details $ ........... .......................................... .............. ........... Difference on trial balance 5140 ........... .......................................... .............. ........... .......................................... .............. ........... .......................................... .............. ........... .......................................... .............. ........... .......................................... .............. ........... .......................................... .............. ........... .......................................... .............. ........... .......................................... .............. ........... .......................................... .............. ........... .......................................... .............. ........... .......................................... .............. ........... .......................................... .............. ........... .......................................... .............. ........... .......................................... .............. ........... .......................................... .............. ........... .......................................... .............. [6] (c) Name two types of error not disclosed by a trial balance. 1 ................................................................................................................................................ 2 ................................................................................................................................................ [2] [Total: 20] PLEASE TURN OVER
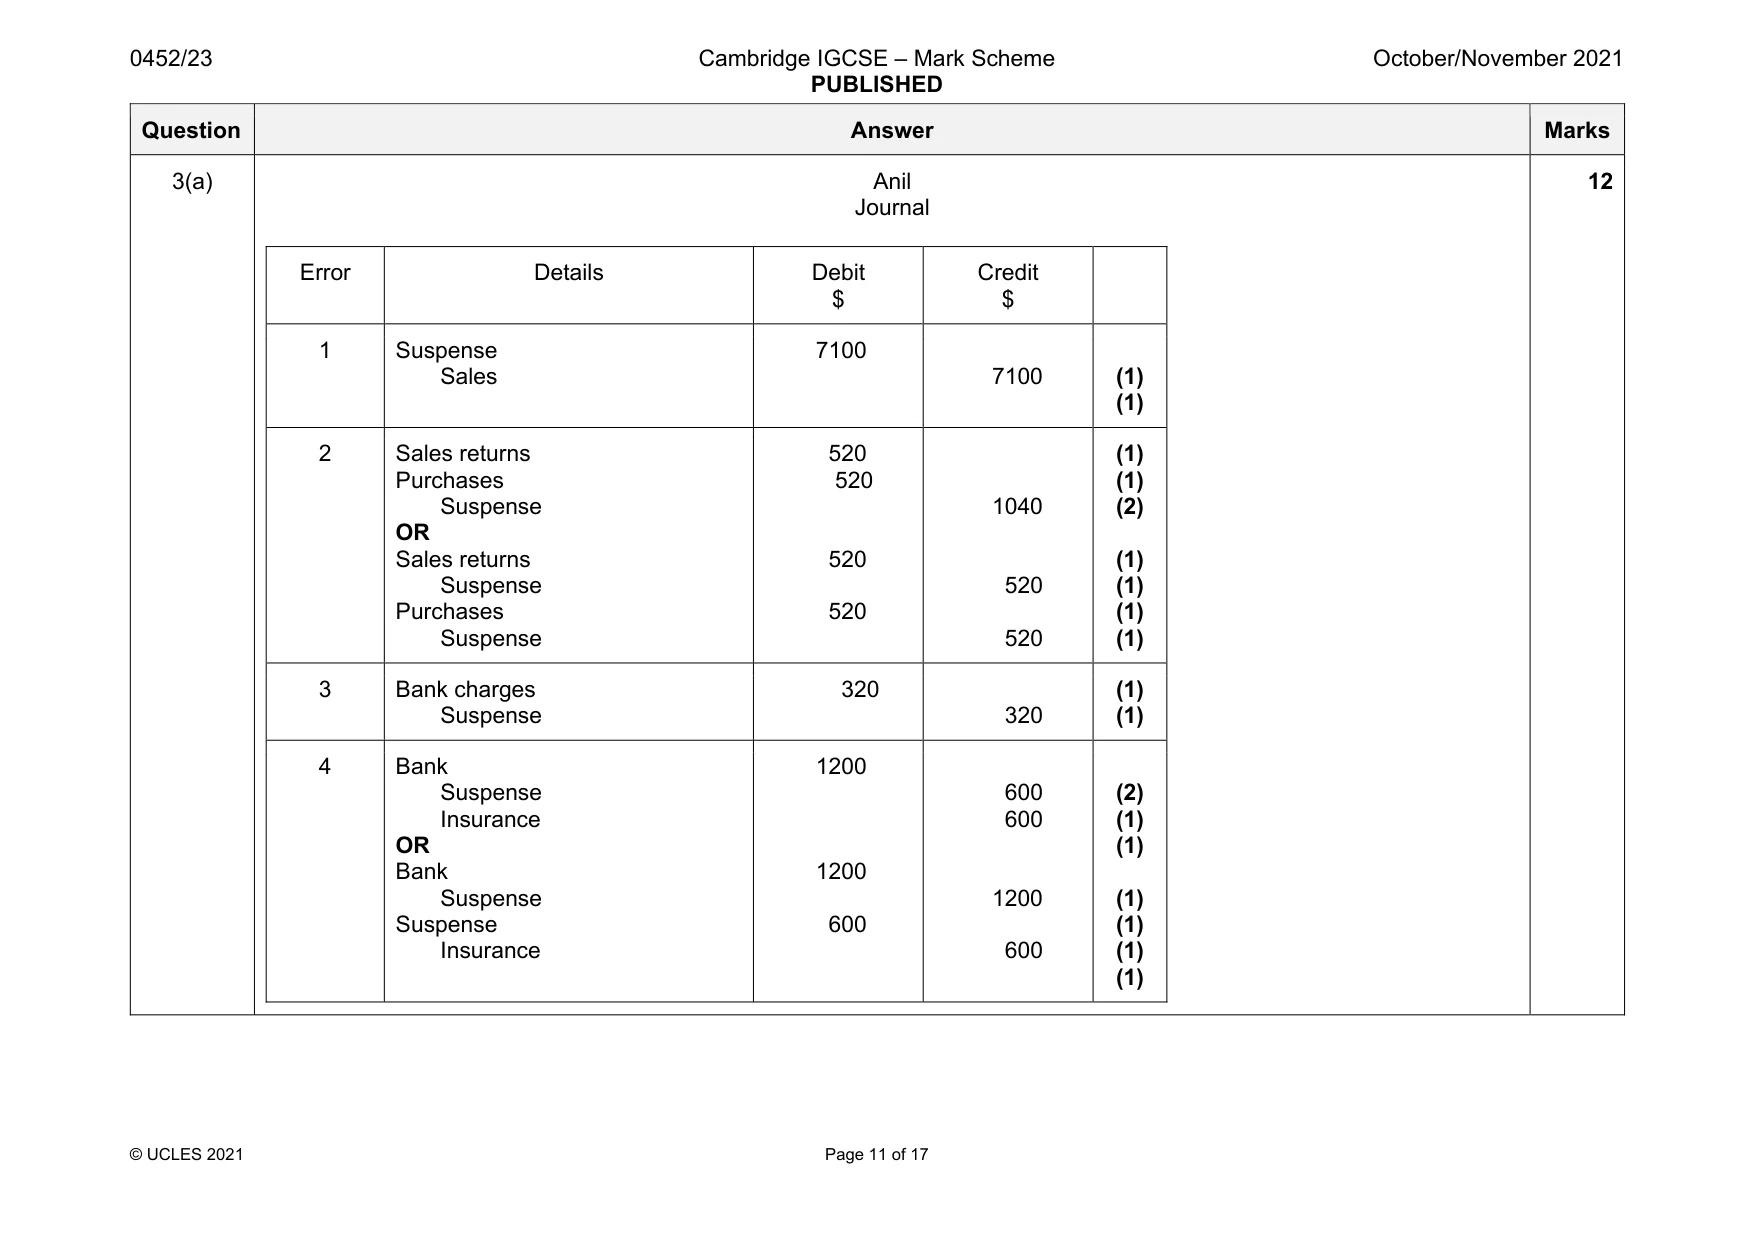
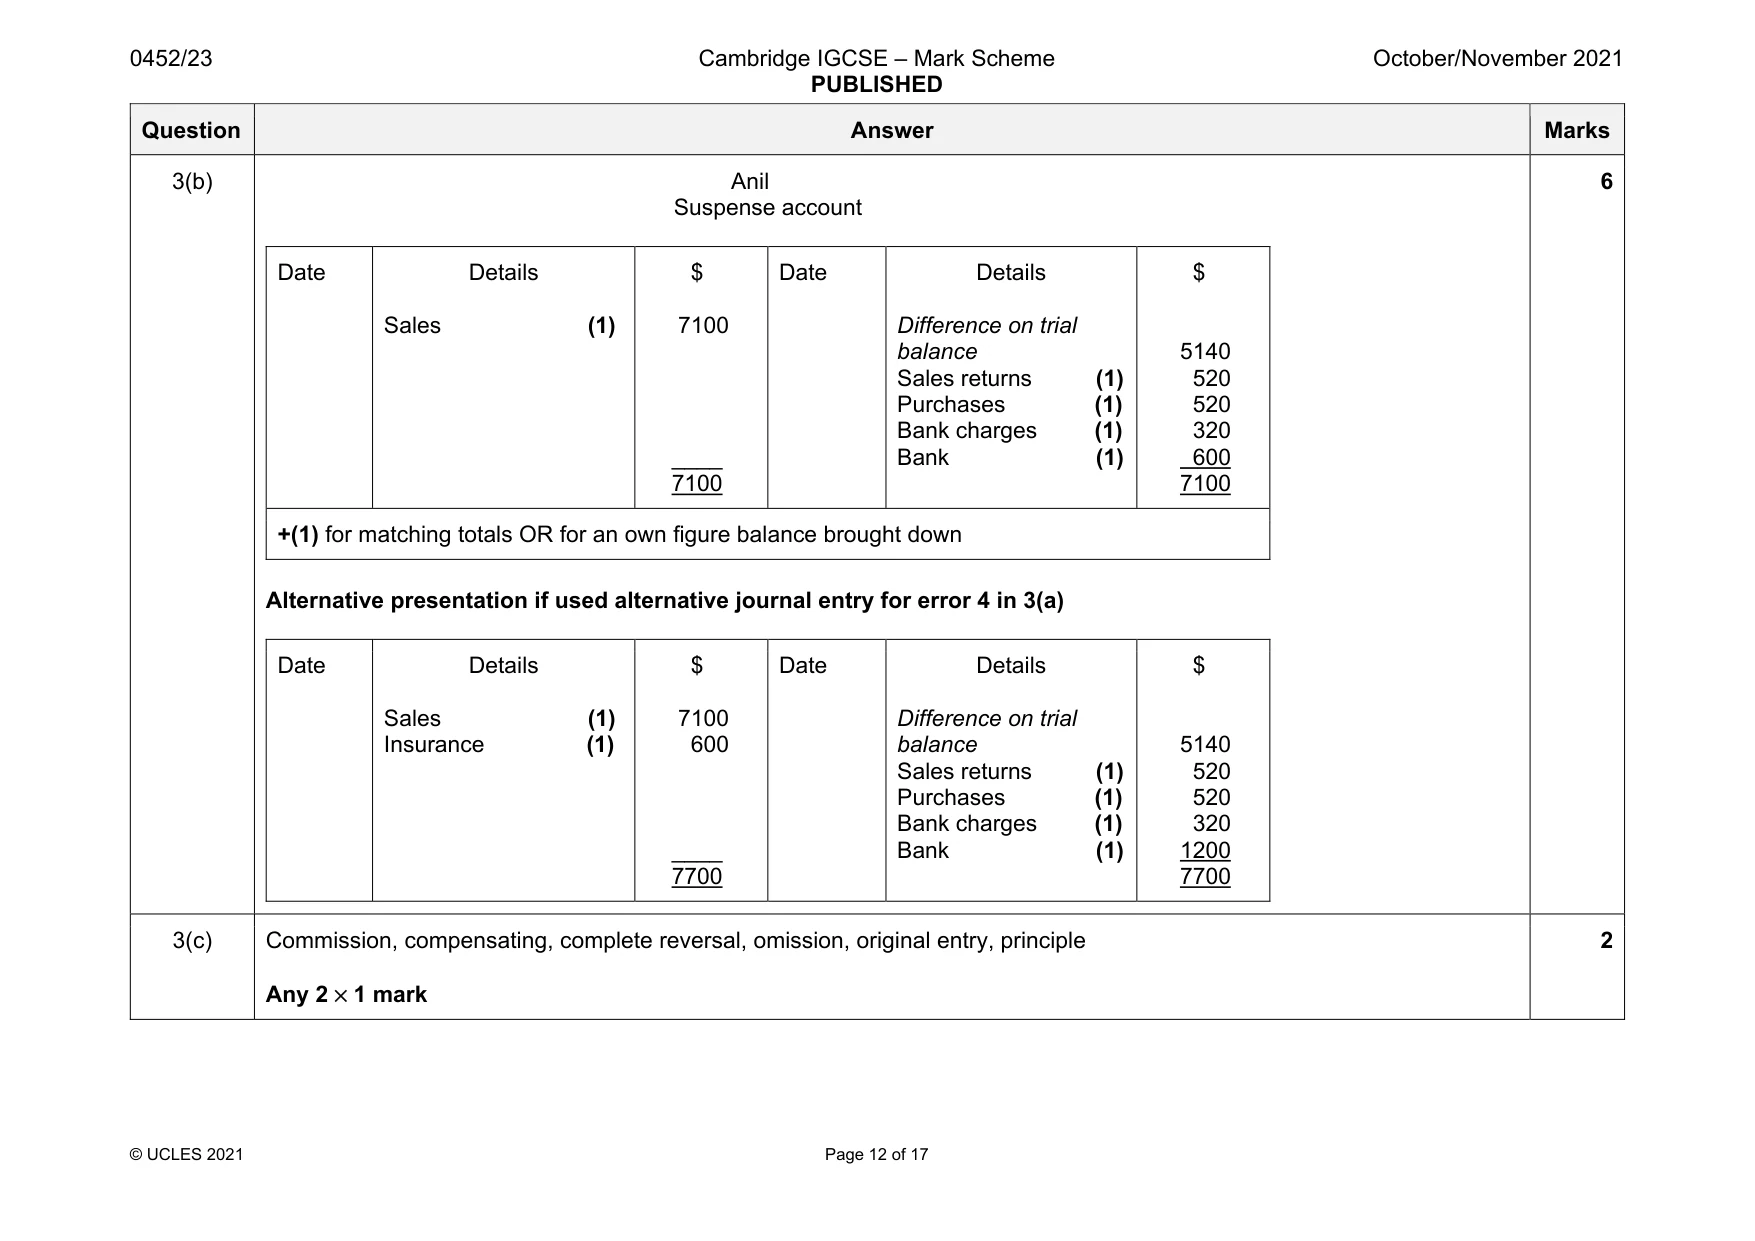
Mark scheme: 3(a) Anil Journal Error Details Debit $ Credit $ 1 Suspense Sales 7100 7100 (1) (1) 2 Sales returns Purchases Suspense OR Sales returns Suspense Purchases Suspense 520 520 520 520 1040 520 520 (1) (1) (2) (1) (1) (1) (1) 3 Bank charges Suspense 320 320 (1) (1) 4 Bank Suspense Insurance OR Bank Suspense Suspense Insurance 1200 1200 600 600 600 1200 600 (2) (1) (1) (1) (1) (1) (1) 12 Question Answer Marks 3(b) Anil Suspense account Date Details Sales (1) $ 7100 ____ 7100 Date Details Difference on trial balance Sales returns (1) Purchases (1) Bank charges (1) Bank (1) $ 5140 520 520 320 600 7100 +(1) for matching totals OR for an own figure balance brought down Alternative presentation if used alternative journal entry for error 4 in 3(a) Date Details Sales (1) Insurance (1) $ 7100 600 ____ 7700 Date Details Difference on trial balance Sales returns (1) Purchases (1) Bank charges (1) Bank (1) $ 5140 520 520 320 1200 7700 6 3(c) Commission, compensating, complete reversal, omission, original entry, principle Any 2 × 1 mark 2
Q4 · Karishma runs her own business
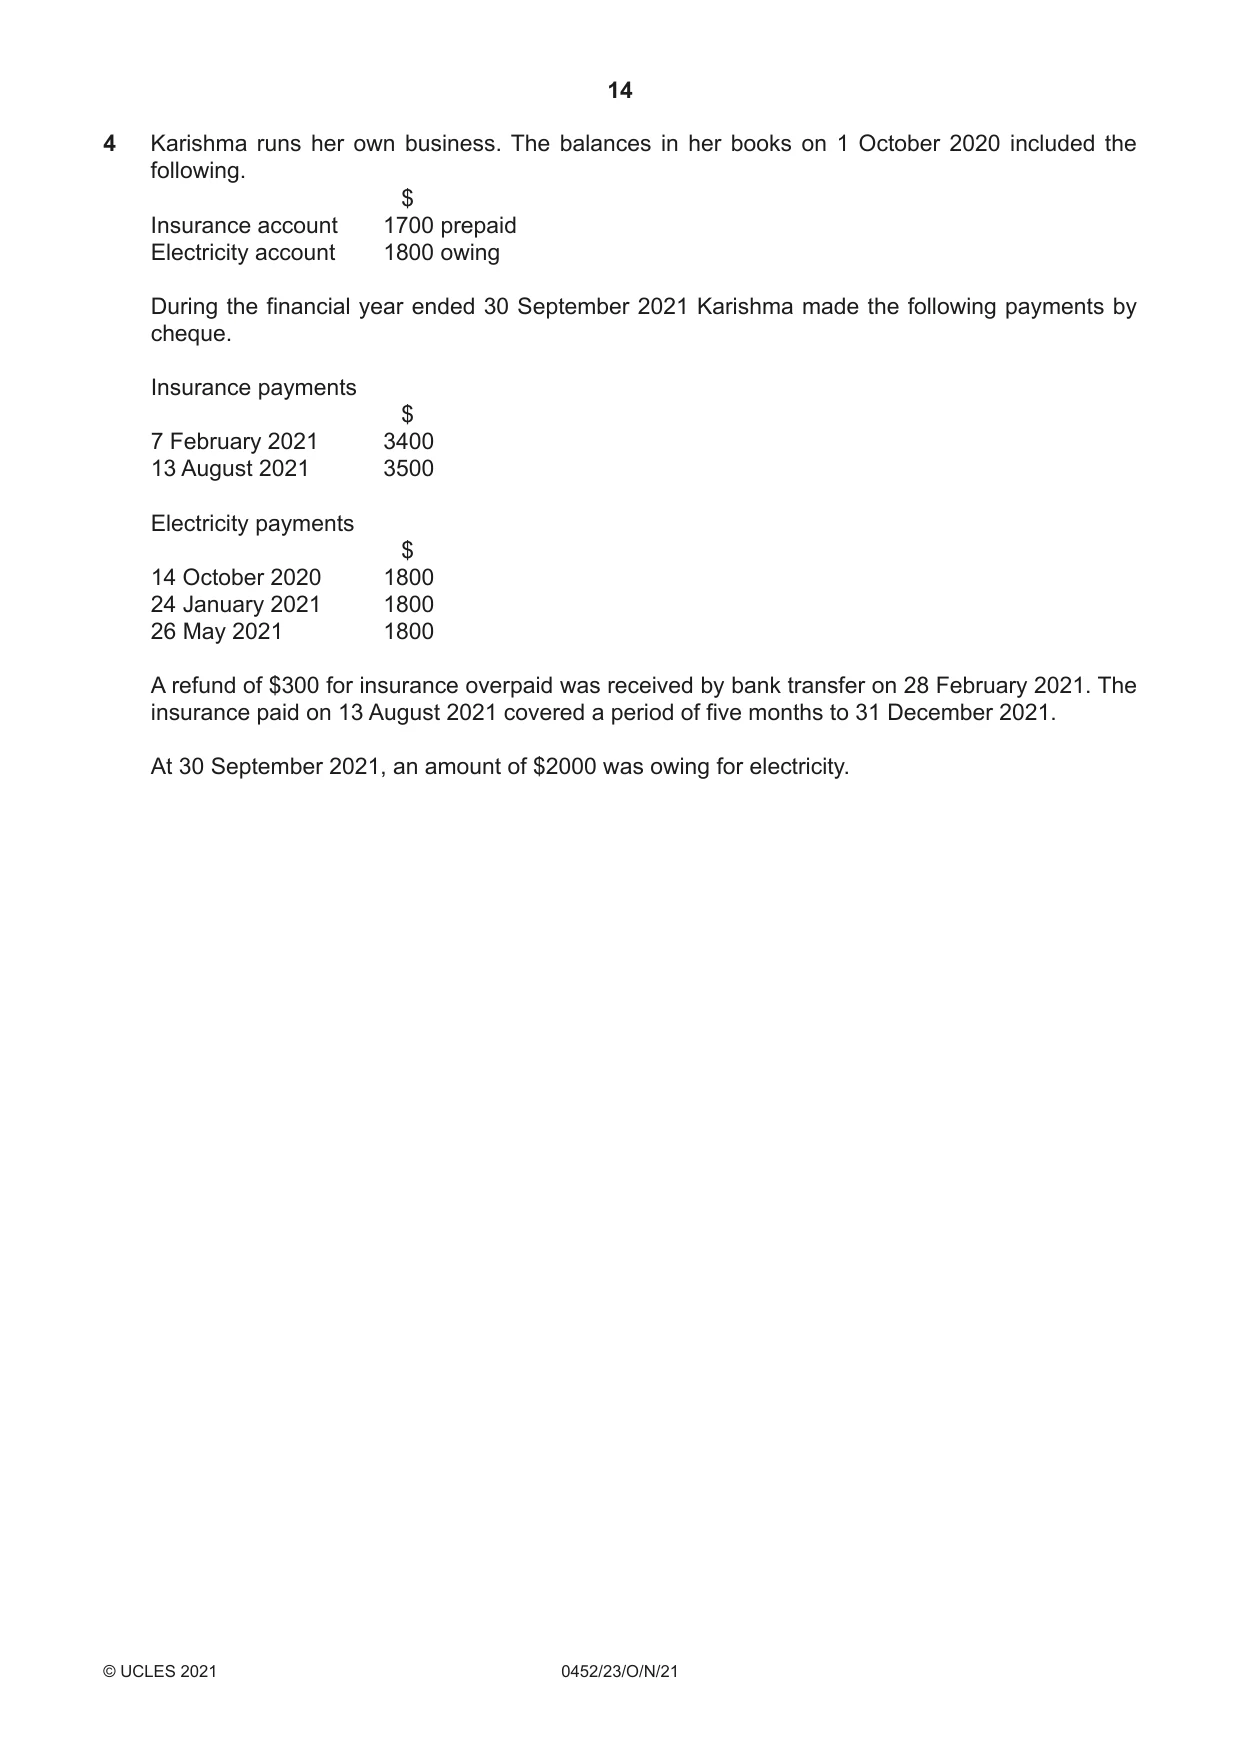
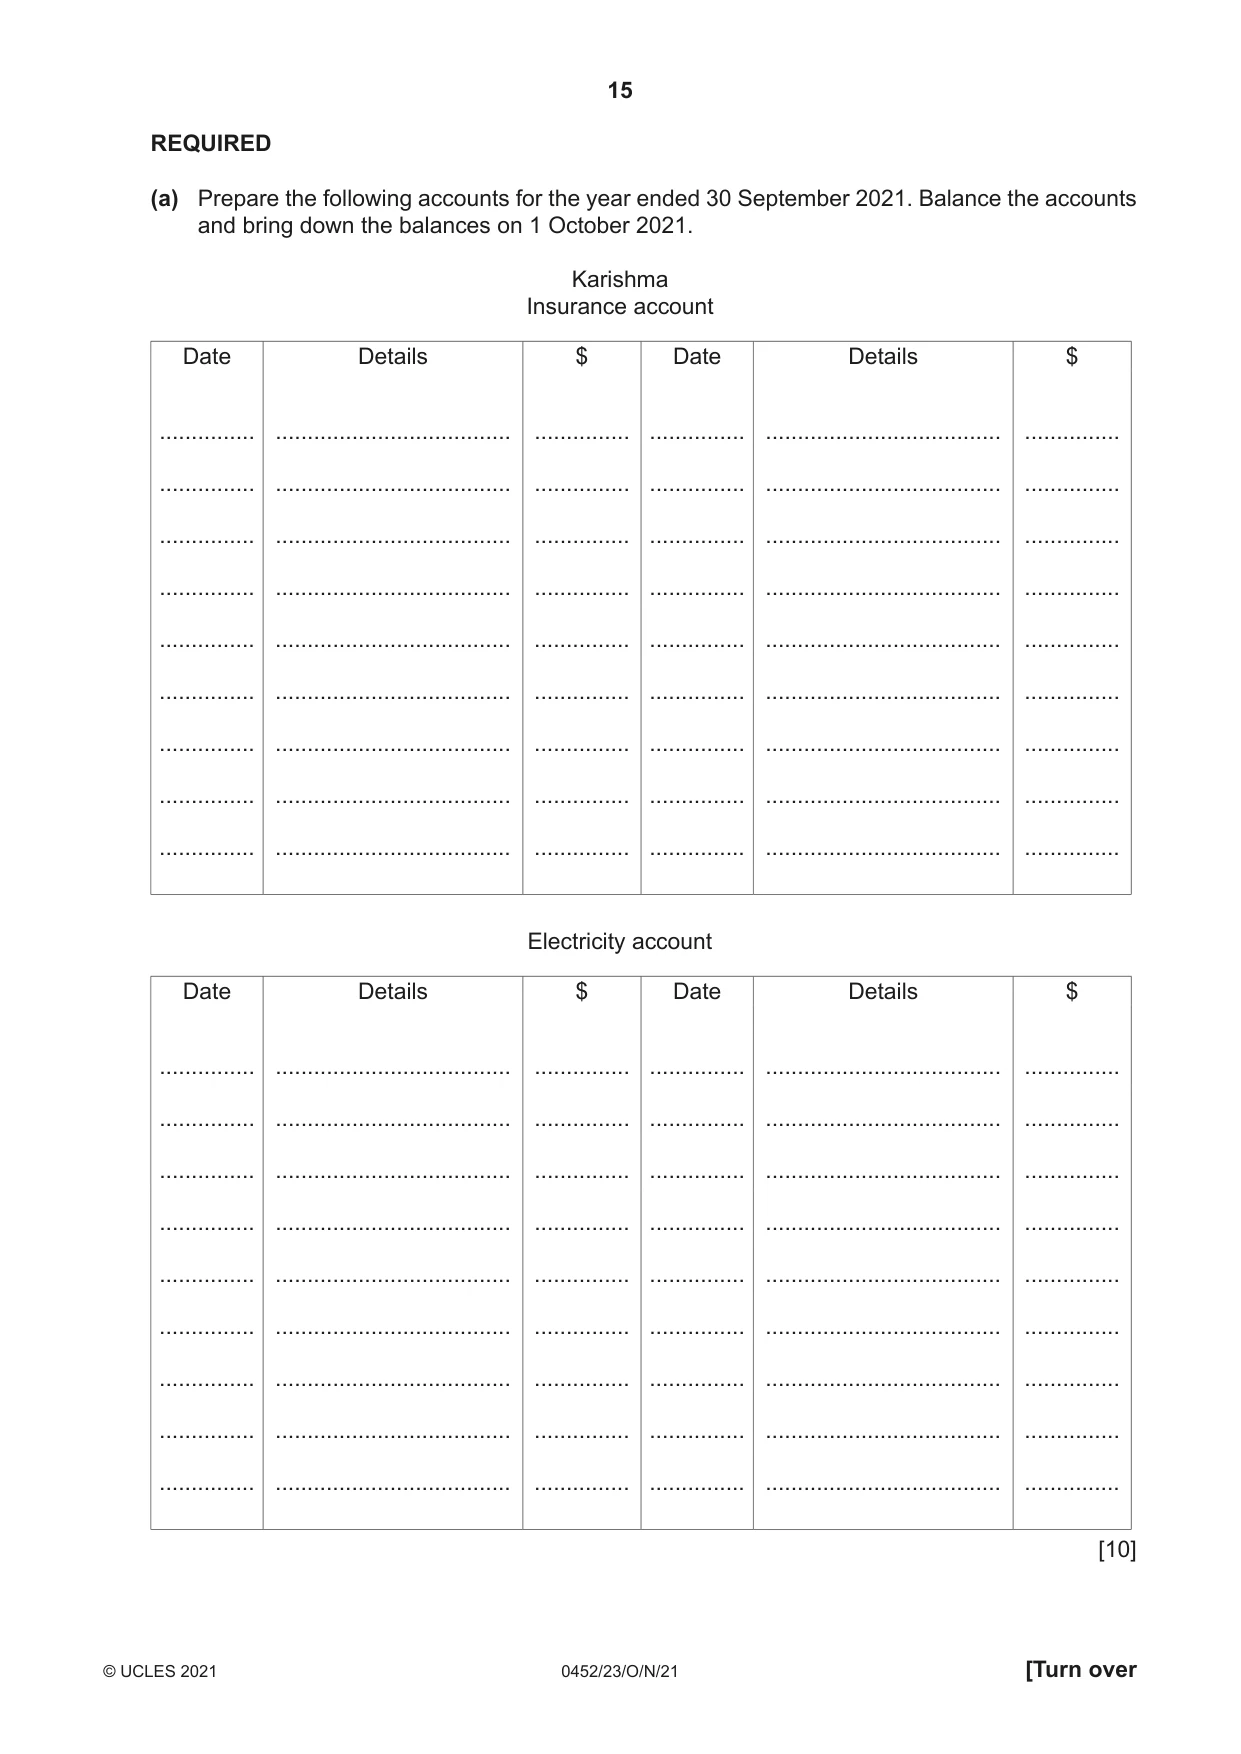
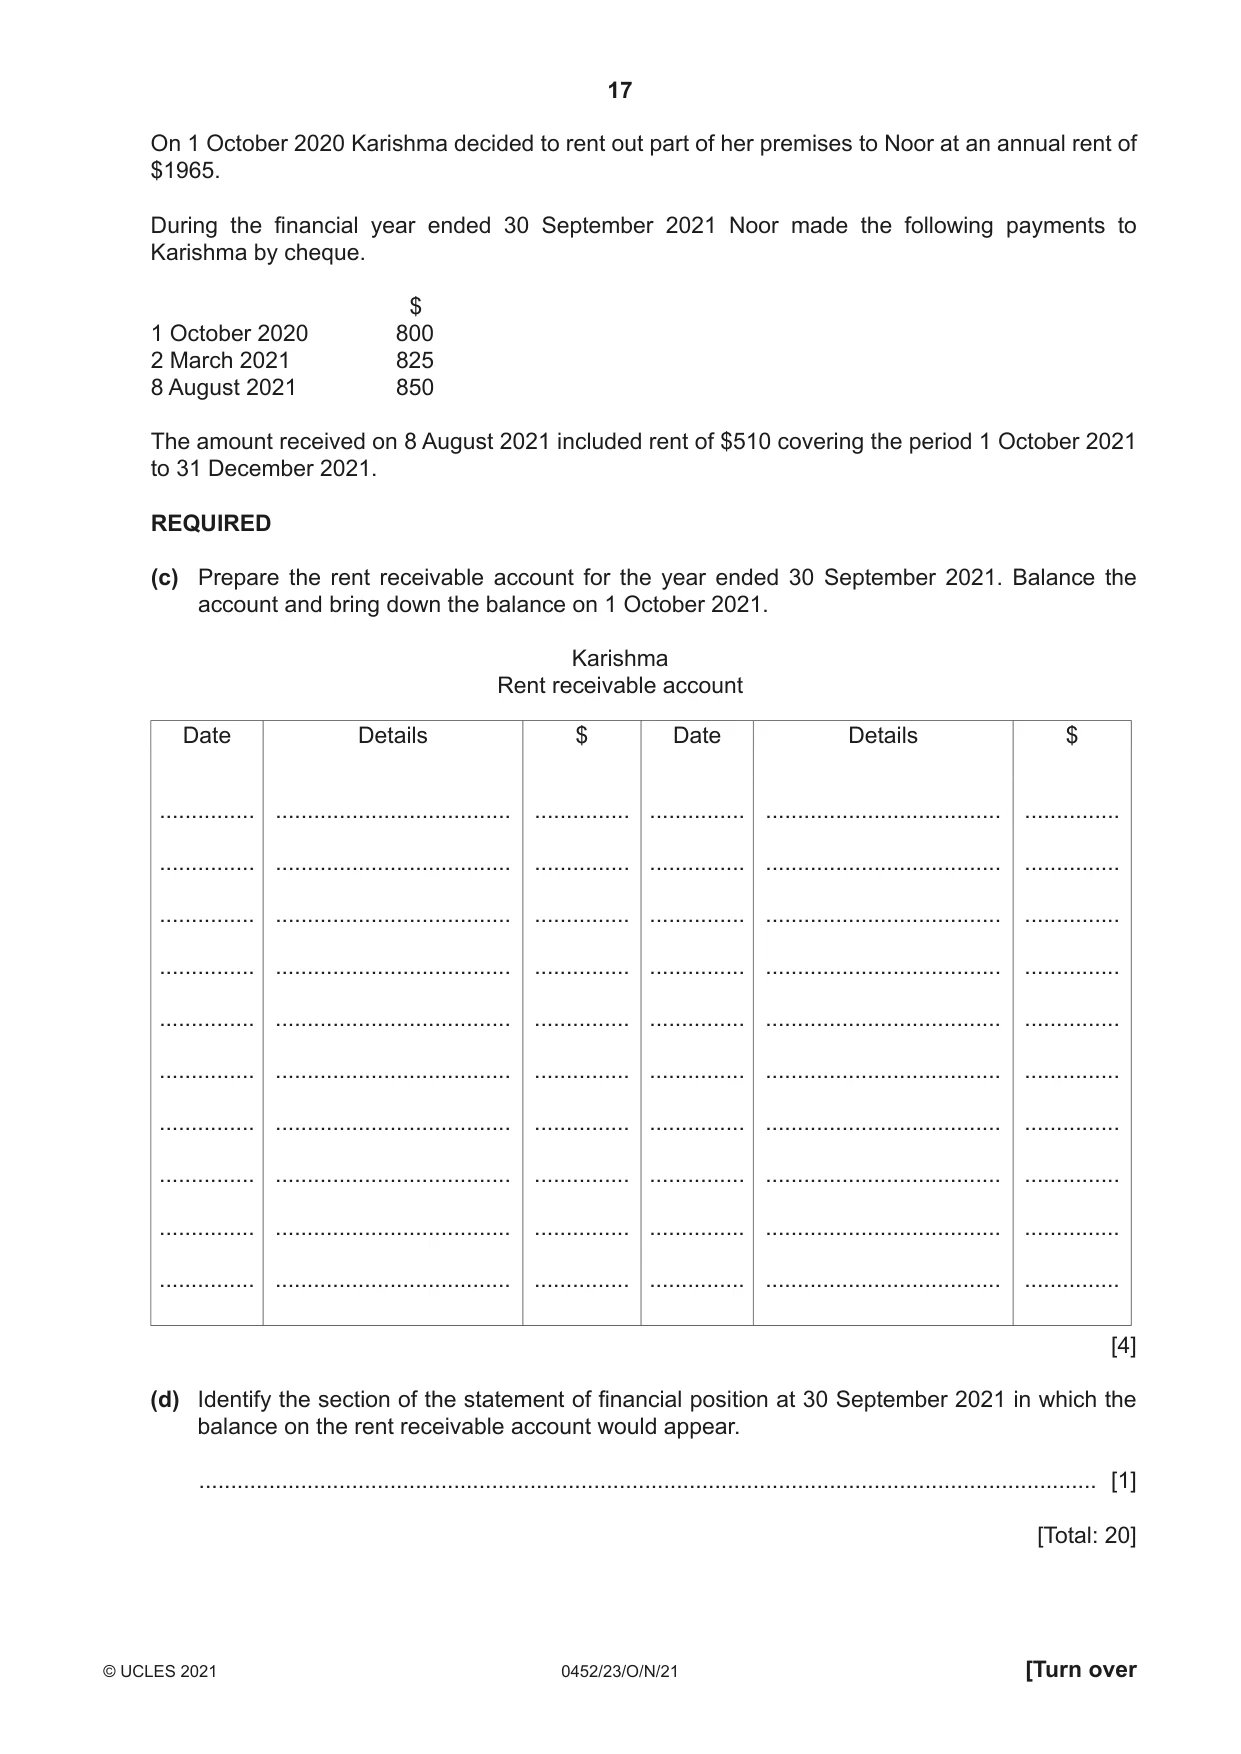
4 Karishma runs her own business. The balances in her books on 1 October 2020 included the following. $ Insurance account 1700 prepaid Electricity account 1800 owing During the financial year ended 30 September 2021 Karishma made the following payments by cheque. Insurance payments $ 7 February 2021 3400 13 August 2021 3500 Electricity payments $ 14 October 2020 1800 24 January 2021 1800 26 May 2021 1800 A refund of $300 for insurance overpaid was received by bank transfer on 28 February 2021. The insurance paid on 13 August 2021 covered a period of five months to 31 December 2021. At 30 September 2021, an amount of $2000 was owing for electricity. REQUIRED (a) Prepare the following accounts for the year ended 30 September 2021. Balance the accounts and bring down the balances on 1 October 2021. Karishma Insurance account Date Details $ Date Details $ ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... Electricity account Date Details $ Date Details $ ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... [10] Karishma is considering changing her electricity supplier. The new supplier has offered Karishma a two-year contract at a fixed monthly amount of $450 payable by direct debit. REQUIRED (b) Advise Karishma whether she should change to the new electricity supplier. Justify your answer with two advantages and two disadvantages of changing supplier. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] On 1 October 2020 Karishma decided to rent out part of her premises to Noor at an annual rent of $1965. During the financial year ended 30 September 2021 Noor made the following payments to Karishma by cheque. $ 1 October 2020 800 2 March 2021 825 8 August 2021 850 The amount received on 8 August 2021 included rent of $510 covering the period 1 October 2021 to 31 December 2021. REQUIRED (c) Prepare the rent receivable account for the year ended 30 September 2021. Balance the account and bring down the balance on 1 October 2021. Karishma Rent receivable account Date Details $ Date Details $ ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... [4] (d) Identify the section of the statement of financial position at 30 September 2021 in which the balance on the rent receivable account would appear. ............................................................................................................................................. [1] [Total: 20]
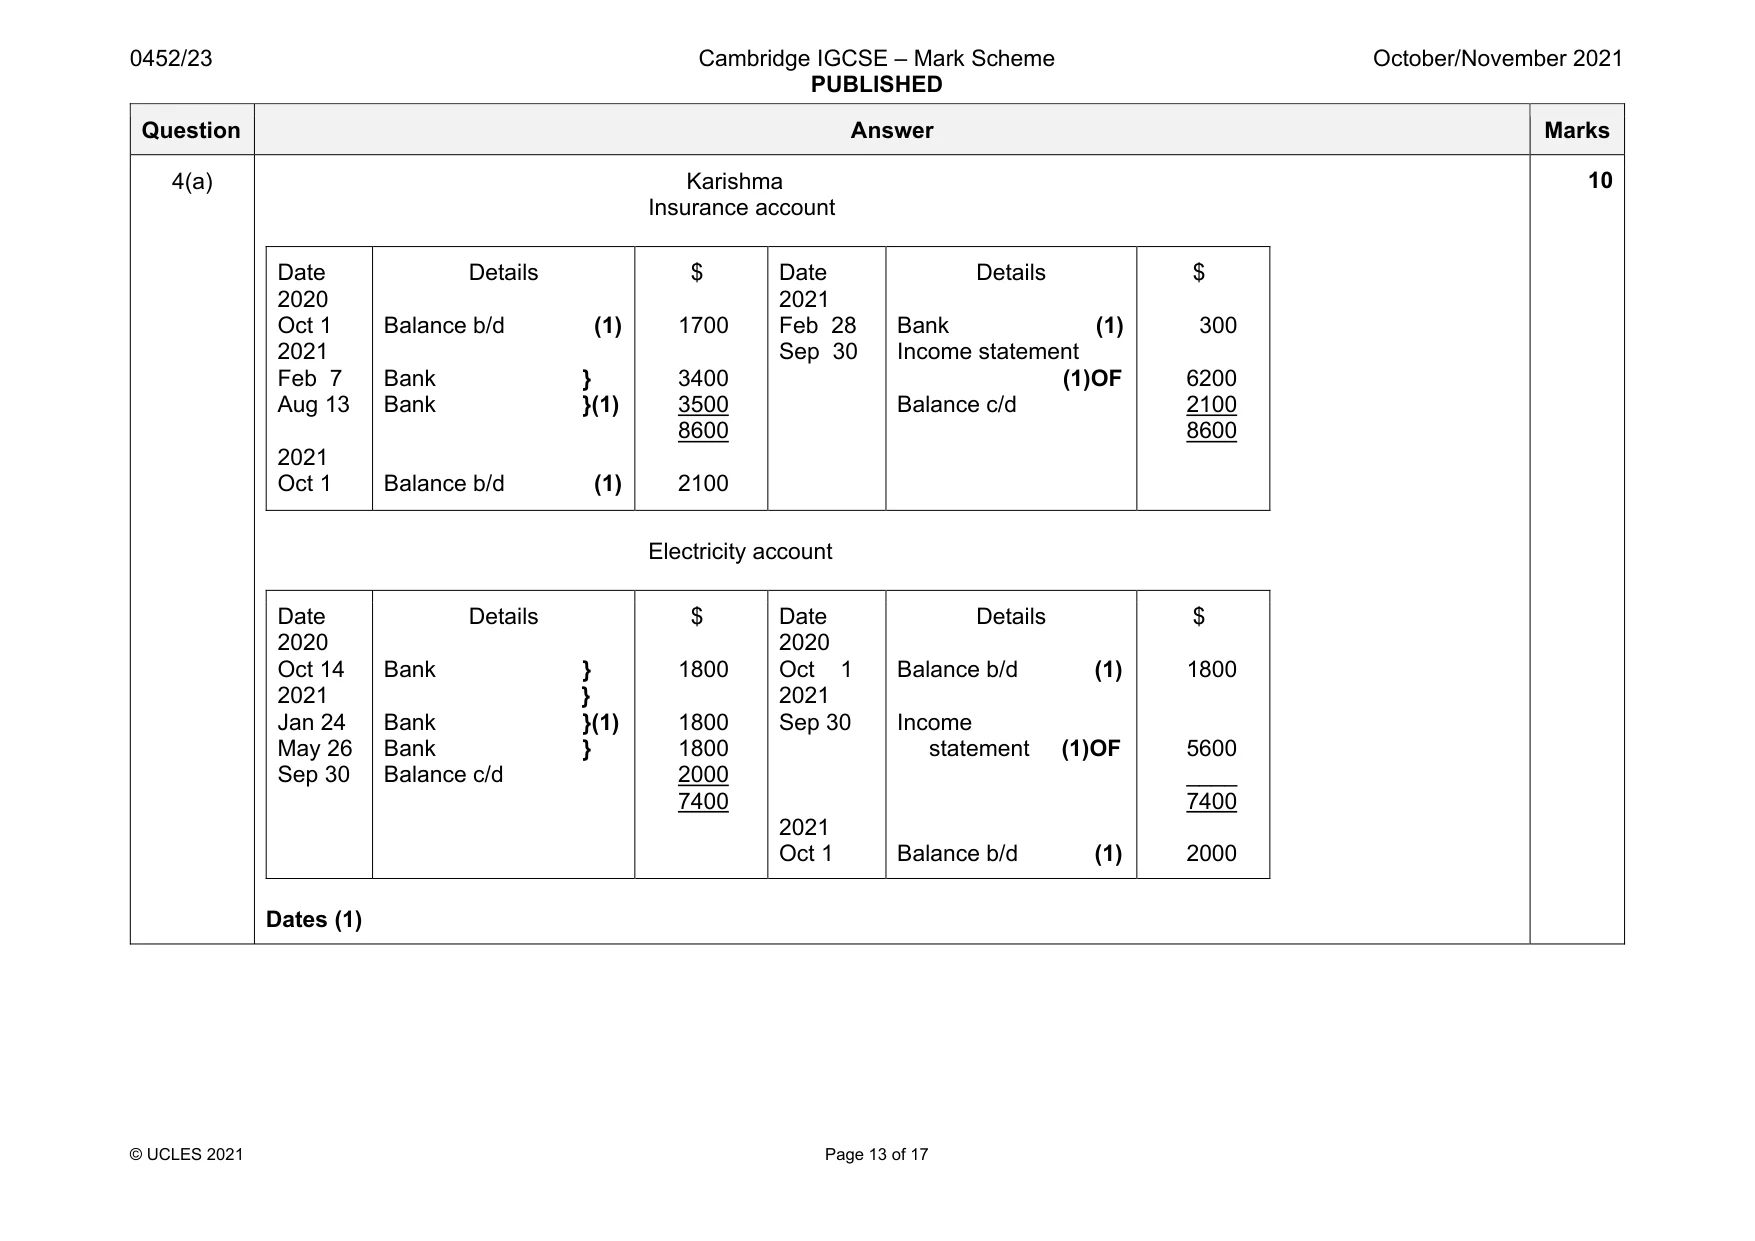
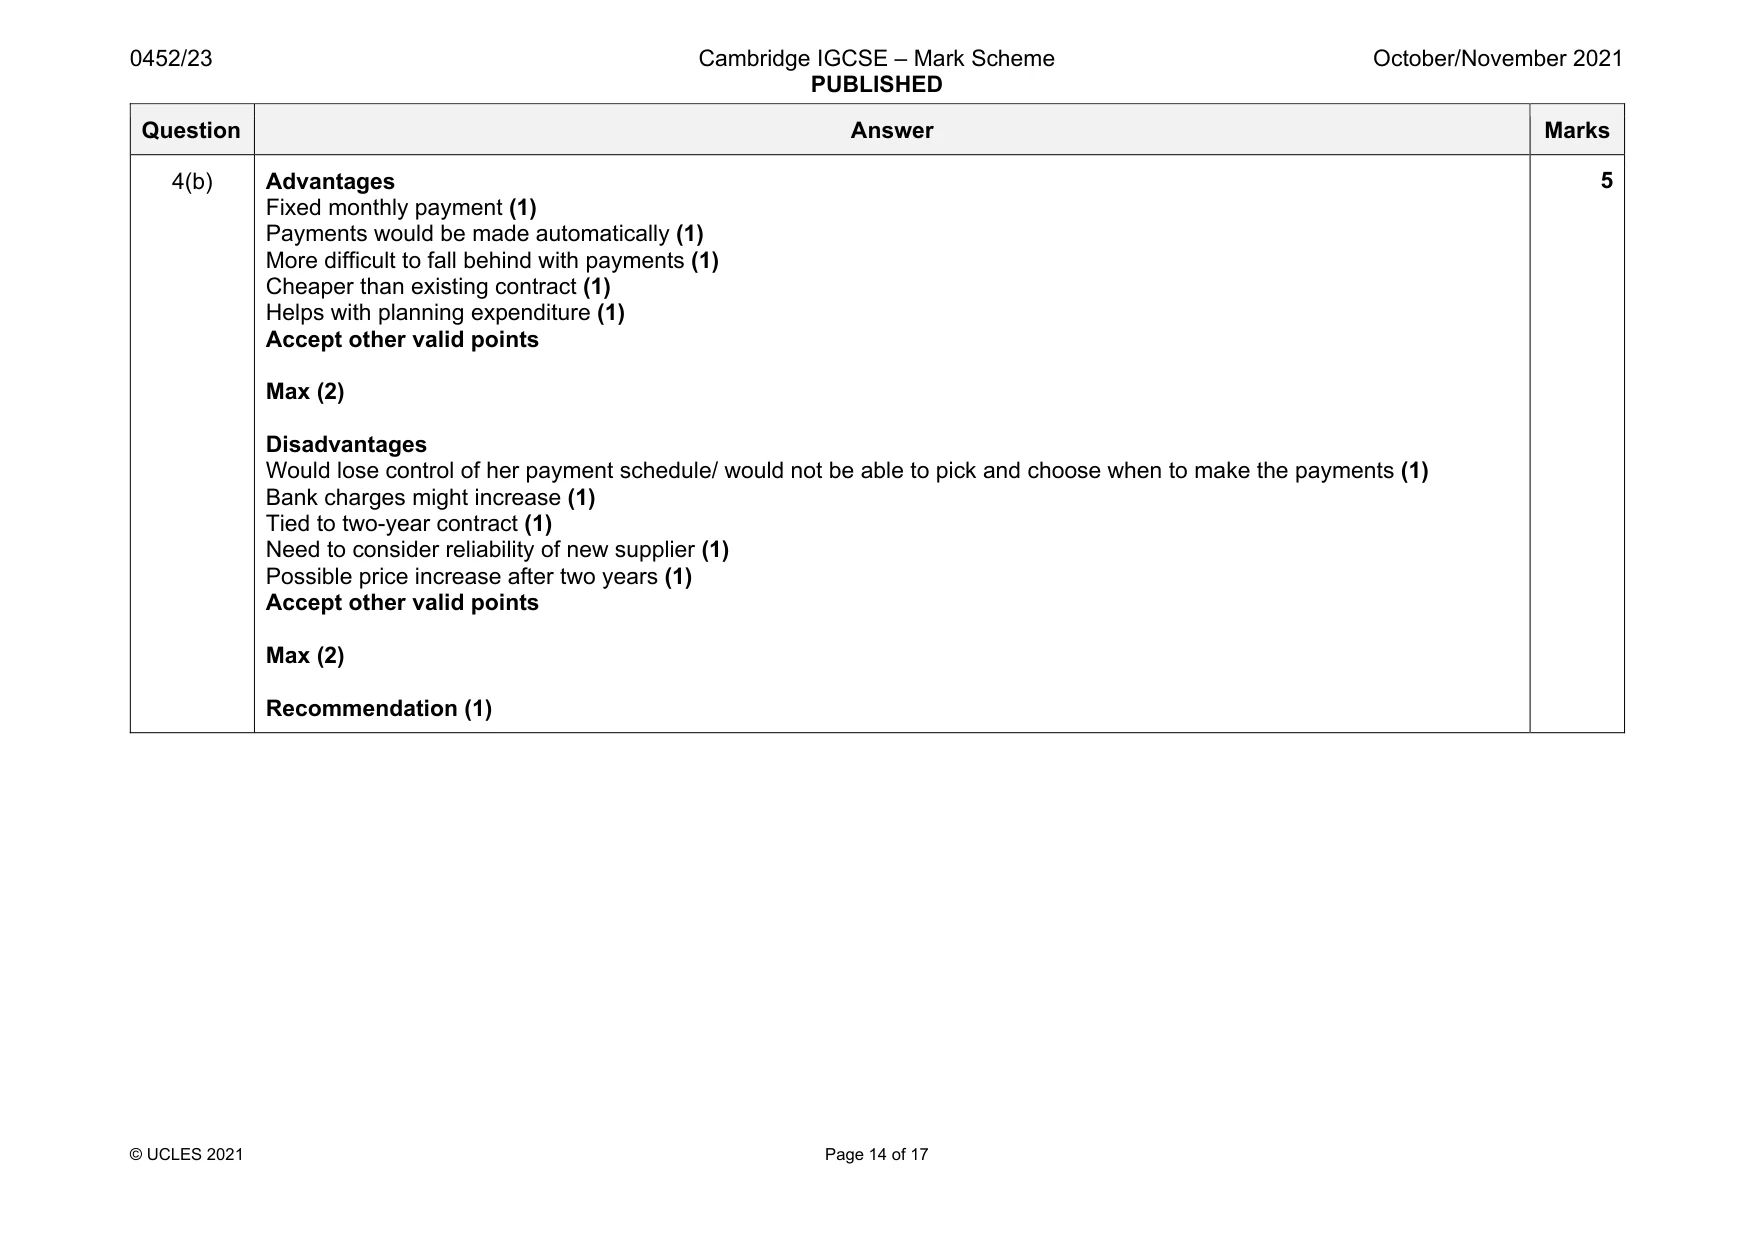
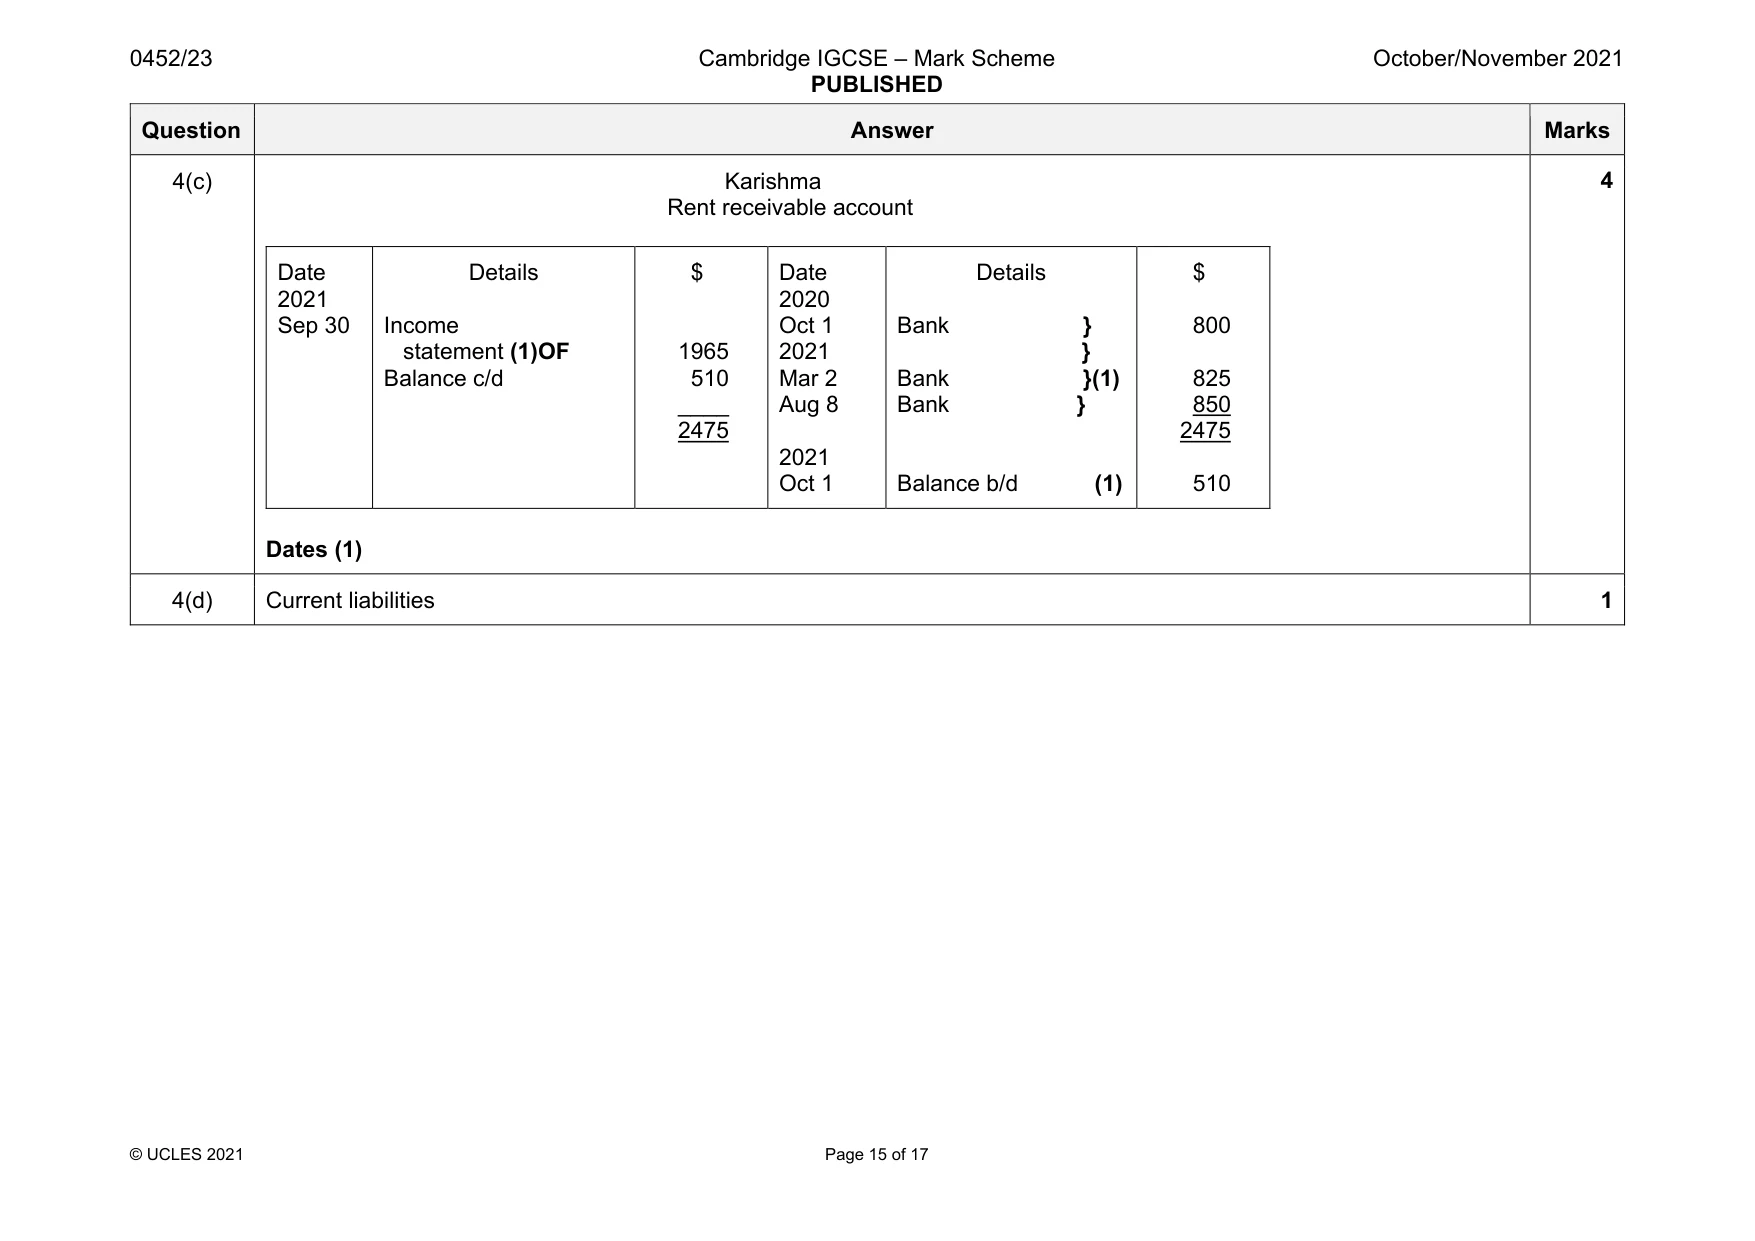
Mark scheme: 4(a) Karishma Insurance account Date 2020 Oct 1 2021 Feb 7 Aug 13 2021 Oct 1 Details Balance b/d (1) Bank } Bank }(1) Balance b/d (1) $ 1700 3400 3500 8600 2100 Date 2021 Feb 28 Sep 30 Details Bank (1) Income statement (1)OF Balance c/d $ 300 6200 2100 8600 Electricity account Date 2020 Oct 14 2021 Jan 24 May 26 Sep 30 Details Bank } } Bank }(1) Bank } Balance c/d $ 1800 1800 1800 2000 7400 Date 2020 Oct 1 2021 Sep 30 2021 Oct 1 Details Balance b/d (1) Income statement (1)OF Balance b/d (1) $ 1800 5600 ____ 7400 2000 Dates (1) Question Answer Marks 4(b) Advantages Fixed monthly payment (1) Payments would be made automatically (1) More difficult to fall behind with payments (1) Cheaper than existing contract (1) Helps with planning expenditure (1) Accept other valid points Max (2) Disadvantages Would lose control of her payment schedule/ would not be able to pick and choose when to make the payments (1) Bank charges might increase (1) Tied to two-year contract (1) Need to consider reliability of new supplier (1) Possible price increase after two years (1) Accept other valid points Max (2) Recommendation (1) 5 Question Answer Marks 4(c) Karishma Rent receivable account Date 2021 Sep 30 Details Income statement (1)OF Balance c/d $ 1965 510 ____ 2475 Date 2020 Oct 1 2021 Mar 2 Aug 8 2021 Oct 1 Details Bank } } Bank }(1) Bank } Balance b/d (1) $ 800 825 850 2475 510 Dates (1) 4 4(d) Current liabilities 1
Q5 · The financial year of VL Sports Club ends on 31 December
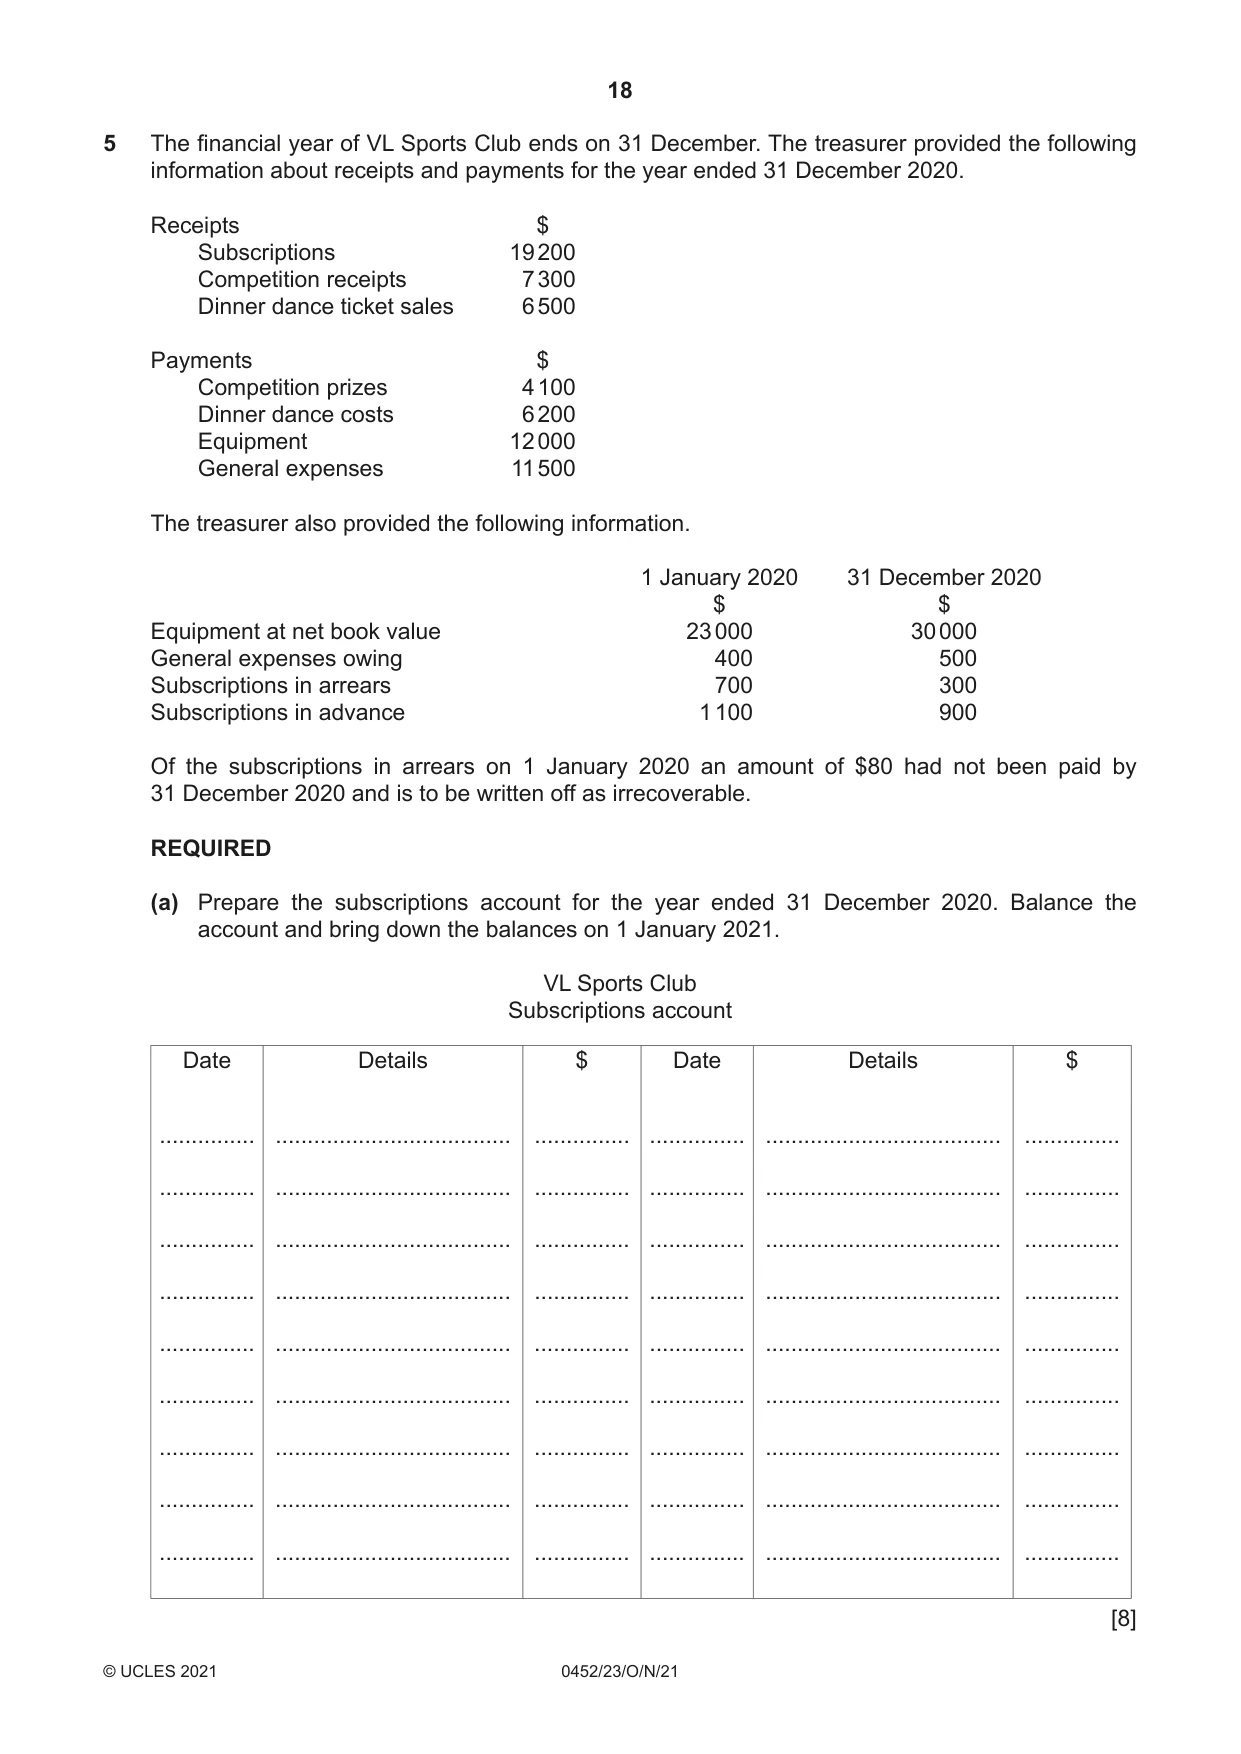
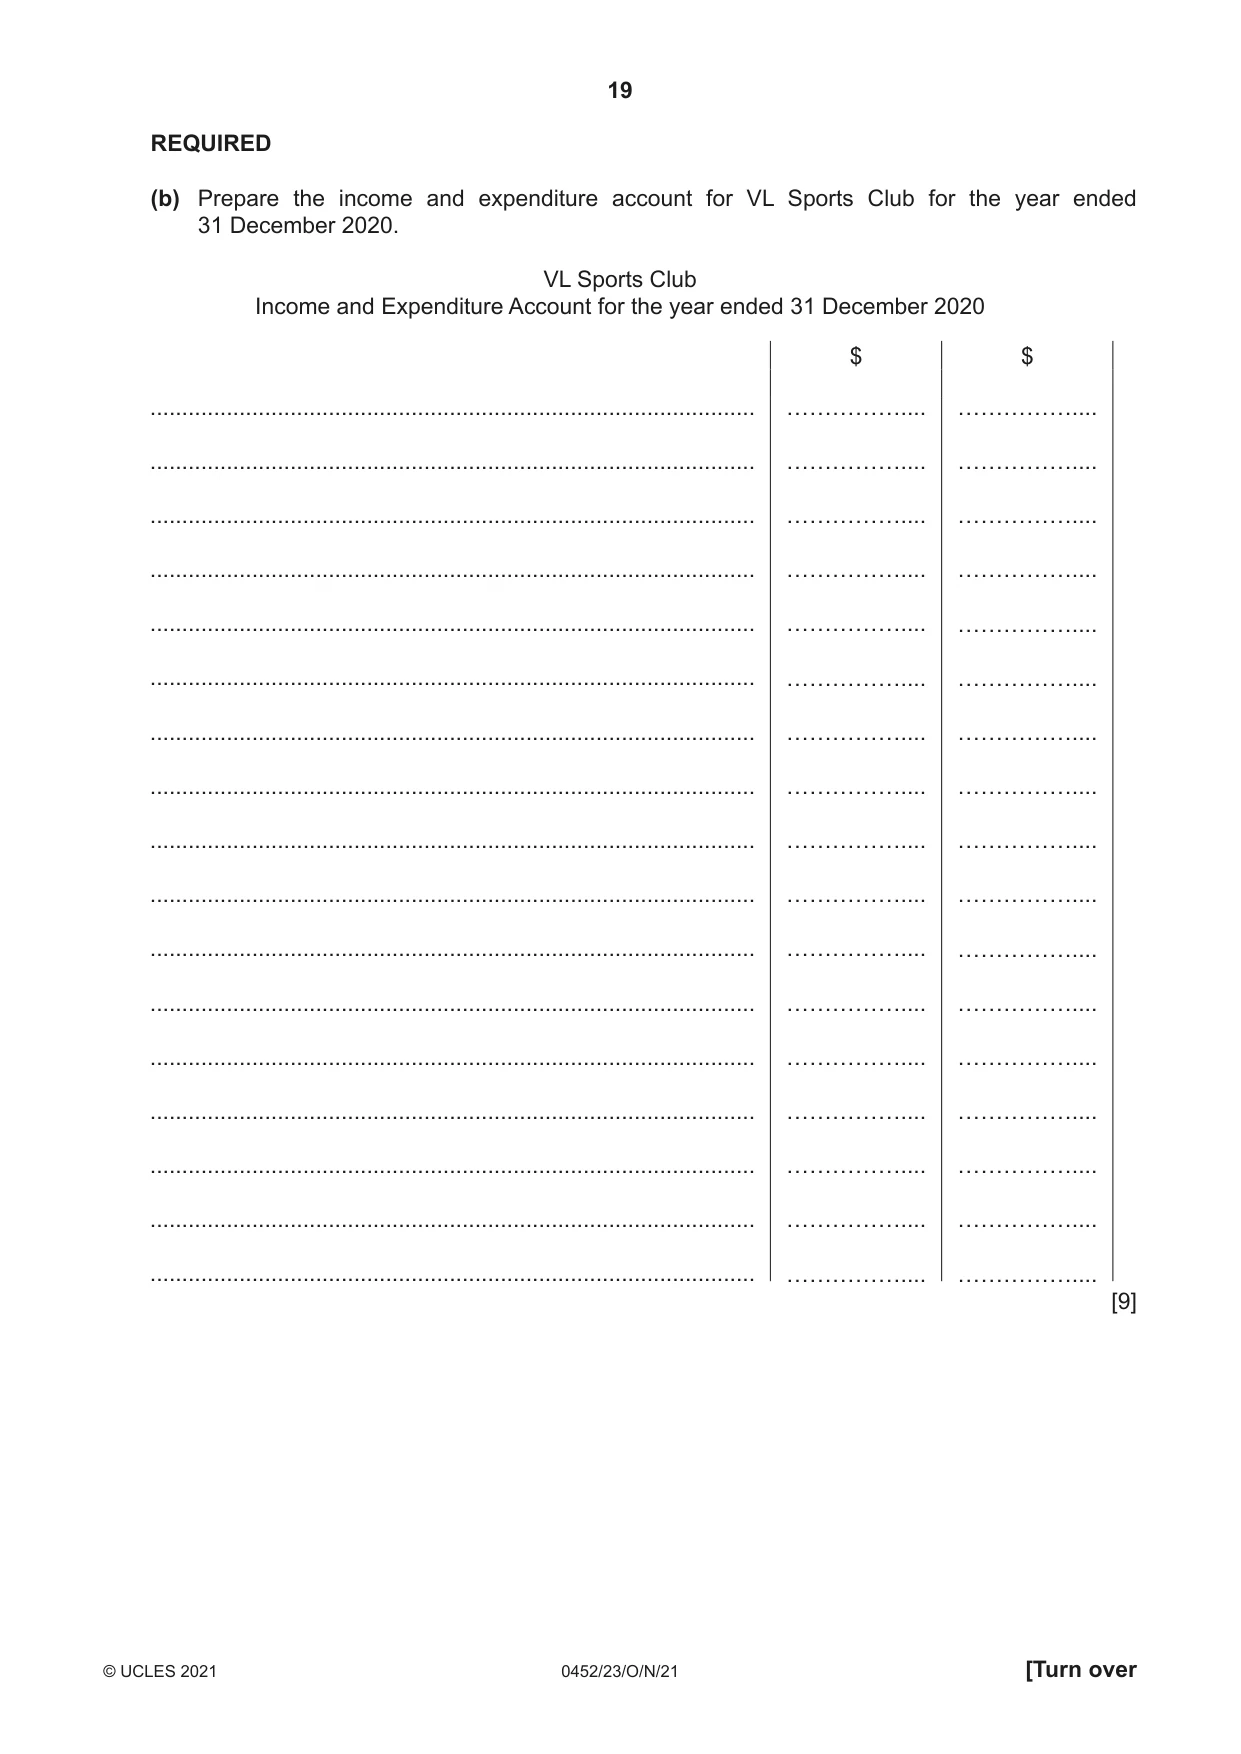
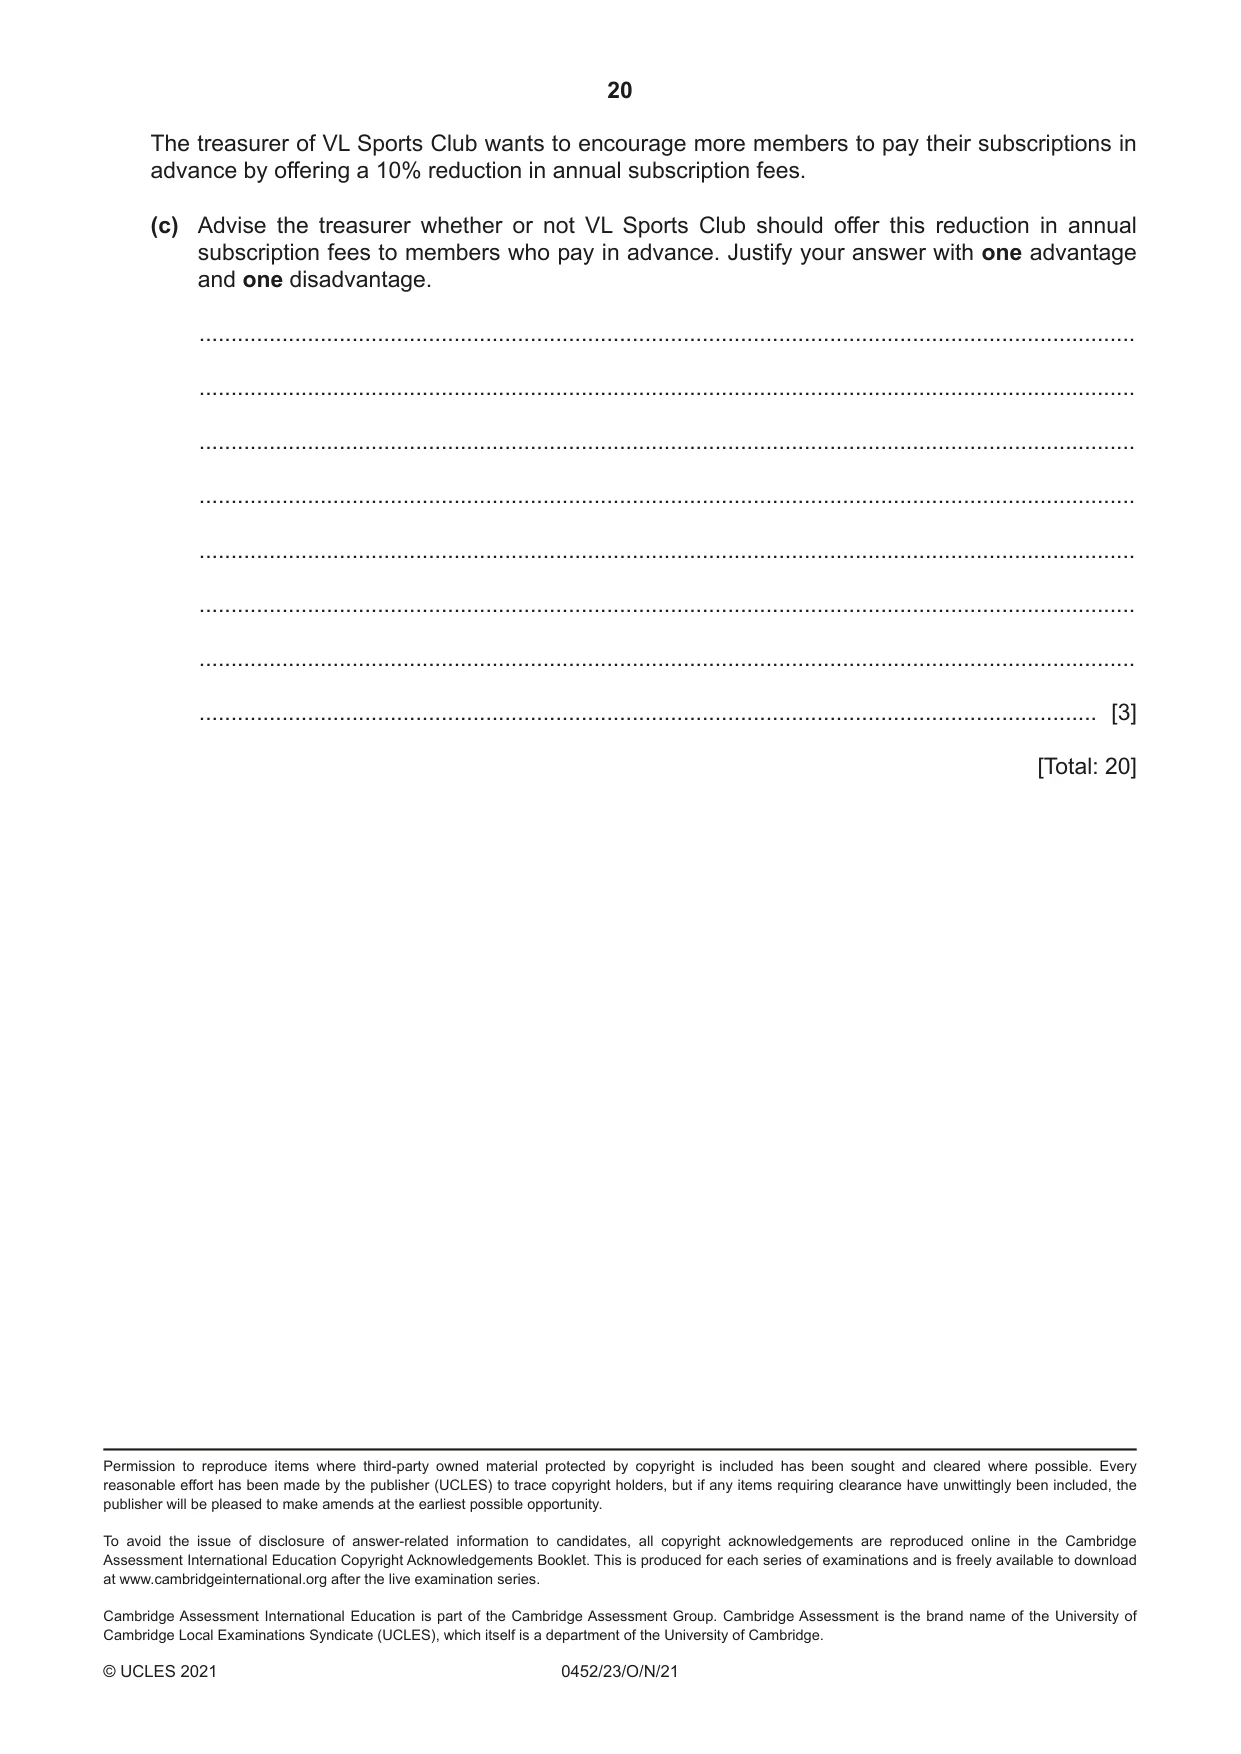
5 The financial year of VL Sports Club ends on 31 December. The treasurer provided the following information about receipts and payments for the year ended 31 December 2020. Receipts $ Subscriptions 19 200 Competition receipts 7 300 Dinner dance ticket sales 6 500 Payments $ Competition prizes 4 100 Dinner dance costs 6 200 Equipment 12 000 General expenses 11 500 The treasurer also provided the following information. 1 January 2020 31 December 2020 $ $ Equipment at net book value 23 000 30 000 General expenses owing 400 500 Subscriptions in arrears 700 300 Subscriptions in advance 1 100 900 Of the subscriptions in arrears on 1 January 2020 an amount of $80 had not been paid by 31 December 2020 and is to be written off as irrecoverable. REQUIRED (a) Prepare the subscriptions account for the year ended 31 December 2020. Balance the account and bring down the balances on 1 January 2021. VL Sports Club Subscriptions account Date Details $ Date Details $ ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... ............... ..................................... ............... [8] REQUIRED (b) Prepare the income and expenditure account for VL Sports Club for the year ended 31 December 2020. VL Sports Club Income and Expenditure Account for the year ended 31 December 2020 $ $ ............................................................................................... …………….... …………….... ............................................................................................... …………….... …………….... ............................................................................................... …………….... …………….... ............................................................................................... …………….... …………….... ............................................................................................... …………….... …………….... ............................................................................................... …………….... …………….... ............................................................................................... …………….... …………….... ............................................................................................... …………….... …………….... ............................................................................................... …………….... …………….... ............................................................................................... …………….... …………….... ............................................................................................... …………….... …………….... ............................................................................................... …………….... …………….... ............................................................................................... …………….... …………….... ............................................................................................... …………….... …………….... ............................................................................................... …………….... …………….... ............................................................................................... …………….... …………….... ............................................................................................... …………….... …………….... [9] The treasurer of VL Sports Club wants to encourage more members to pay their subscriptions in advance by offering a 10% reduction in annual subscription fees. (c) Advise the treasurer whether or not VL Sports Club should offer this reduction in annual subscription fees to members who pay in advance. Justify your answer with one advantage and one disadvantage. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [3] [Total: 20]
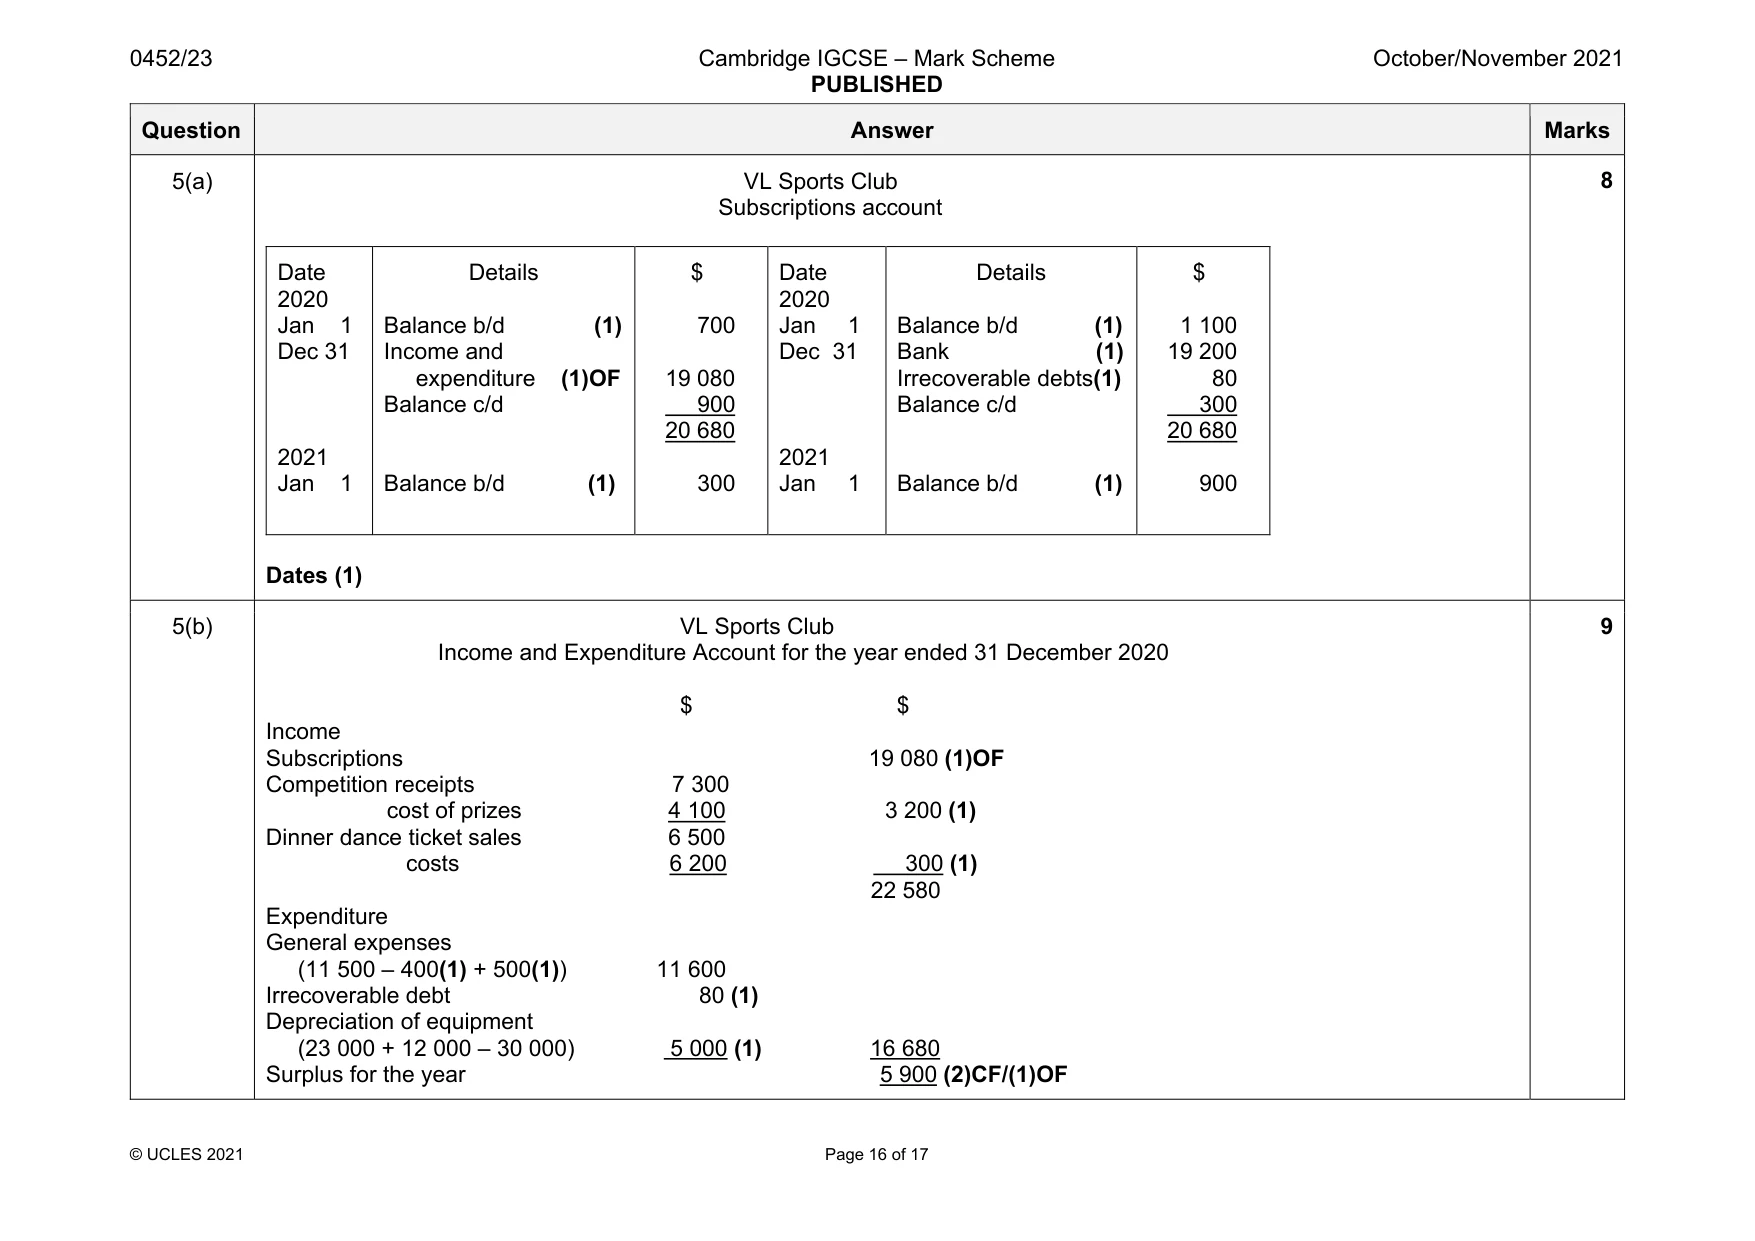
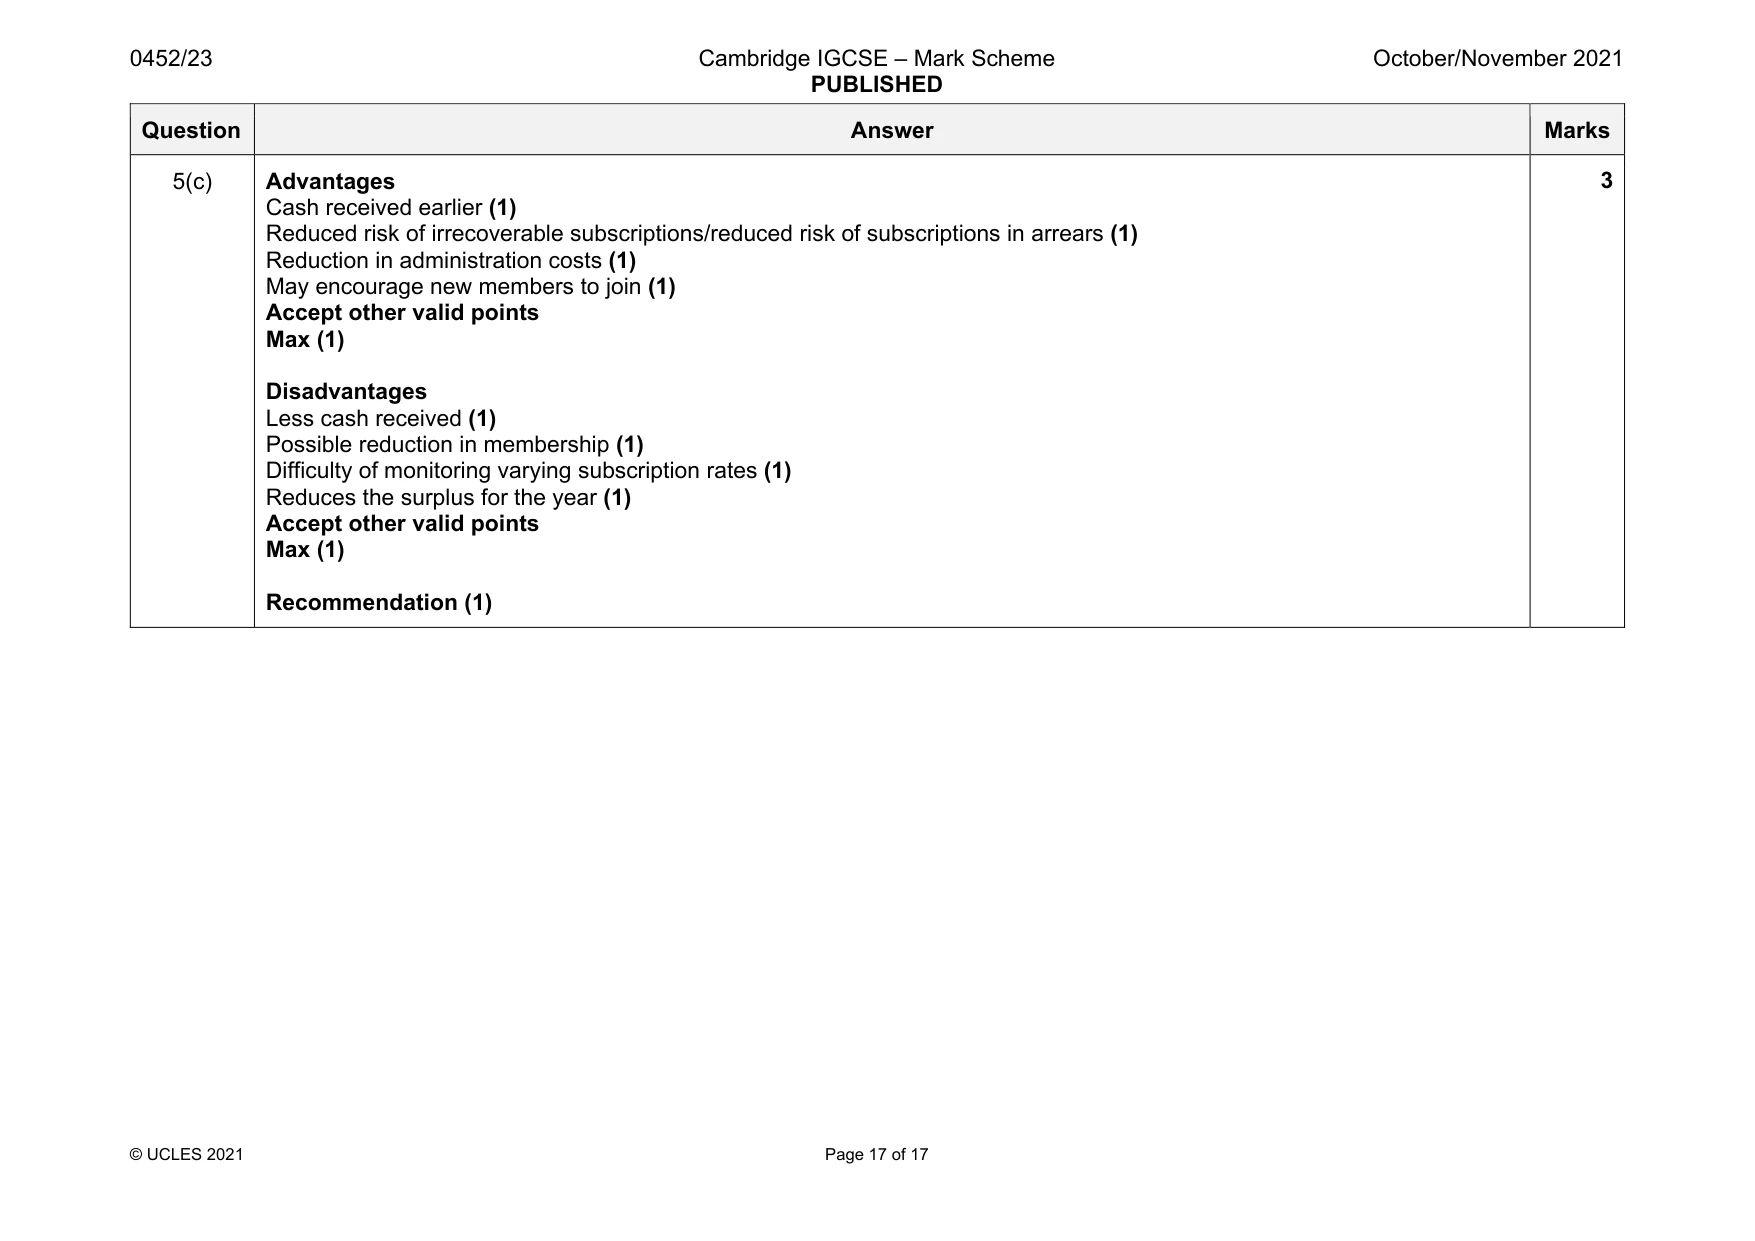
Mark scheme: 5(a) VL Sports Club Subscriptions account Date 2020 Jan 1 Dec 31 2021 Jan 1 Details Balance b/d (1) Income and expenditure (1)OF Balance c/d Balance b/d (1) $ 700 19 080 900 20 680 300 Date 2020 Jan 1 Dec 31 2021 Jan 1 Details Balance b/d (1) Bank (1) Irrecoverable debts(1) Balance c/d Balance b/d (1) $ 1 100 19 200 80 300 20 680 900 Dates (1) 5(b) VL Sports Club Income and Expenditure Account for the year ended 31 December 2020 $ $ Income Subscriptions 19 080 (1)OF Competition receipts 7 300 cost of prizes 4 100 3 200 (1) Dinner dance ticket sales 6 500 costs 6 200 300 (1) 22 580 Expenditure General expenses (11 500 – 400(1) + 500(1)) 11 600 Irrecoverable debt 80 (1) Depreciation of equipment (23 000 + 12 000 – 30 000) 5 000 (1) 16 680 Surplus for the year 5 900 (2)CF/(1)OF 9 Question Answer Marks 5(c) Advantages Cash received earlier (1) Reduced risk of irrecoverable subscriptions/reduced risk of subscriptions in arrears (1) Reduction in administration costs (1) May encourage new members to join (1) Accept other valid points Max (1) Disadvantages Less cash received (1) Possible reduction in membership (1) Difficulty of monitoring varying subscription rates (1) Reduces the surplus for the year (1) Accept other valid points Max (1) Recommendation (1) 3
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2021 Oct/Nov, Paper 2 · Variant 3. A higher threshold means an easier paper — the bar moves with how the cohort did.