Cambridge IGCSE Accounting 0452 — 2021 Oct/Nov Paper 2 · Variant 2
0452/22/O/N/21 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme15 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Ayesha is a trader who maintains a full set of accounting records and prepares control…
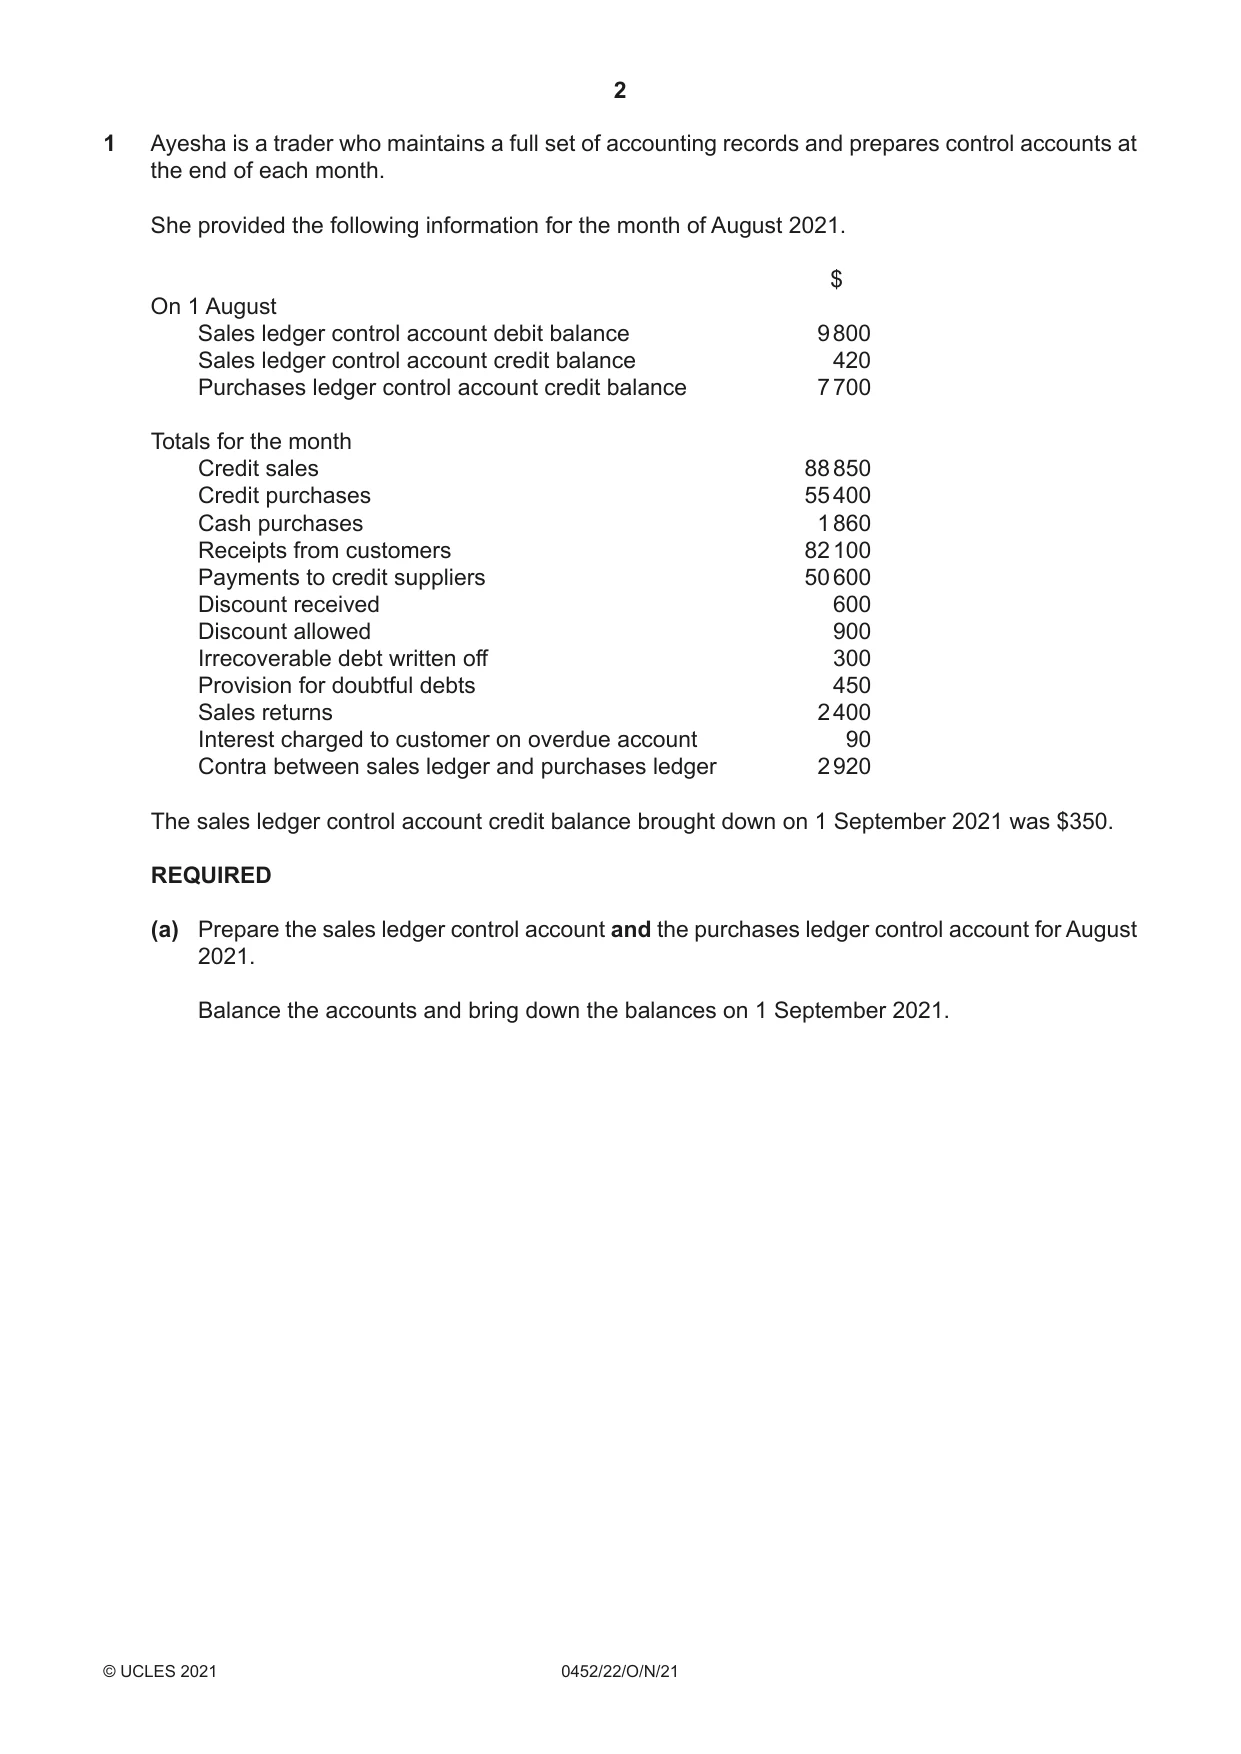
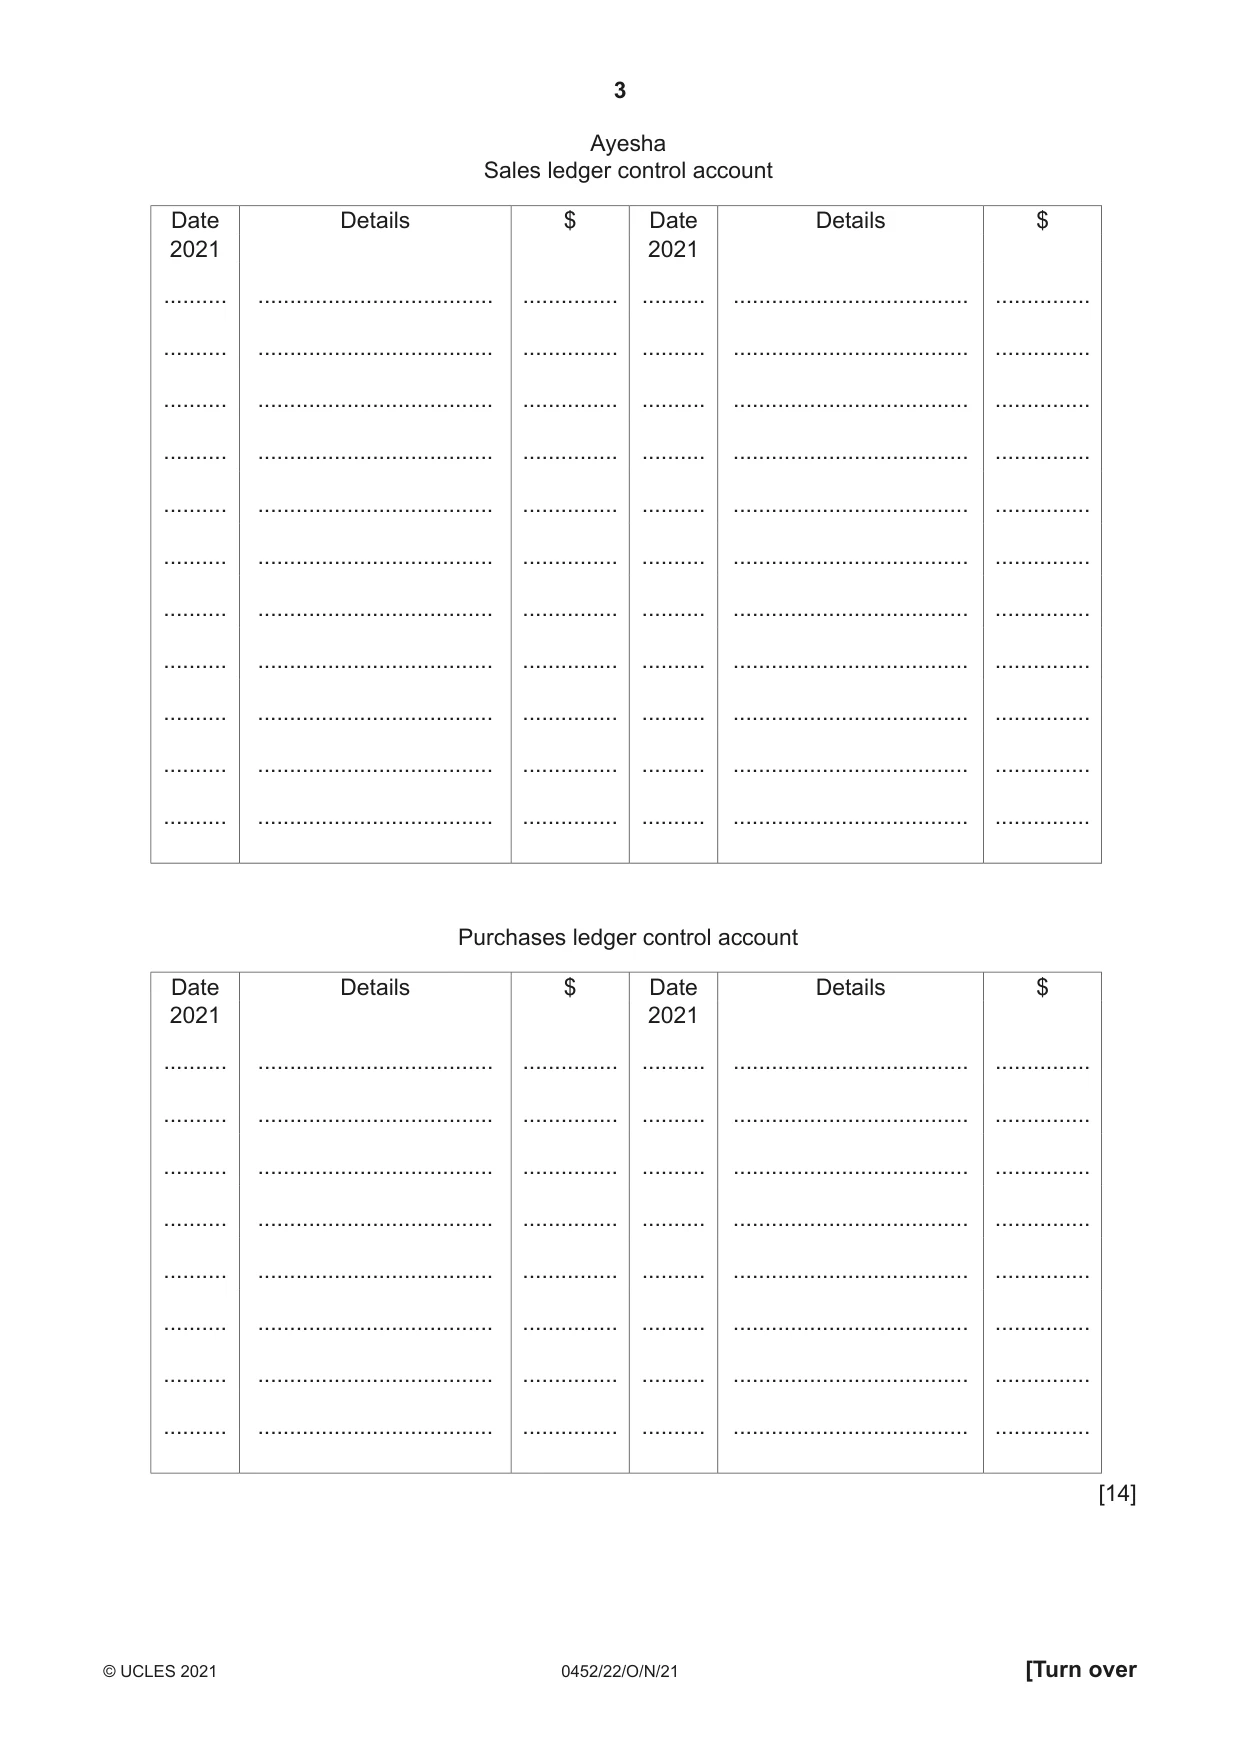
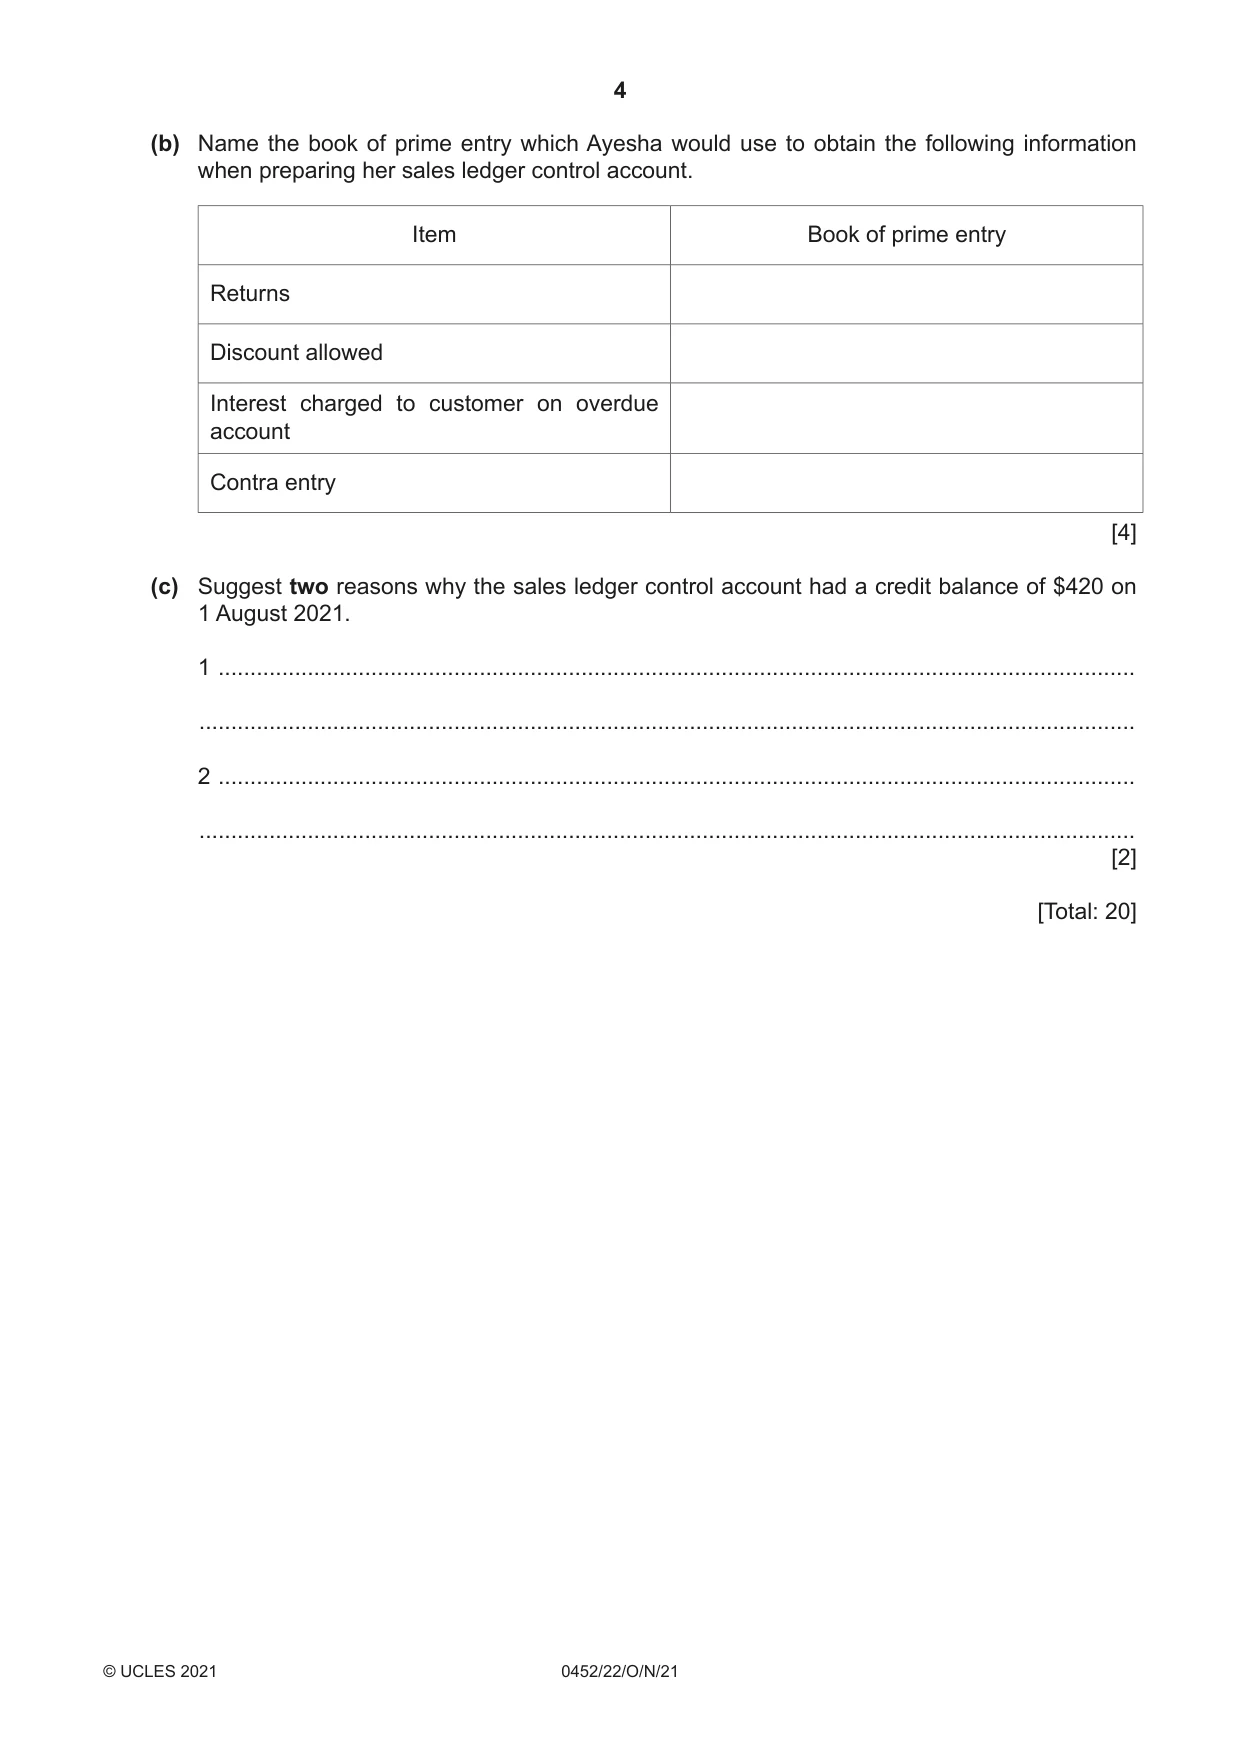
1 Ayesha is a trader who maintains a full set of accounting records and prepares control accounts at the end of each month. She provided the following information for the month of August 2021. $ On 1 August Sales ledger control account debit balance 9 800 Sales ledger control account credit balance 420 Purchases ledger control account credit balance 7 700 Totals for the month Credit sales 88 850 Credit purchases 55 400 Cash purchases 1 860 Receipts from customers 82 100 Payments to credit suppliers 50 600 Discount received 600 Discount allowed 900 Irrecoverable debt written off 300 Provision for doubtful debts 450 Sales returns 2 400 Interest charged to customer on overdue account 90 Contra between sales ledger and purchases ledger 2 920 The sales ledger control account credit balance brought down on 1 September 2021 was $350. REQUIRED (a) Prepare the sales ledger control account and the purchases ledger control account for August 2021. Balance the accounts and bring down the balances on 1 September 2021. Ayesha Sales ledger control account Date Details $ Date Details $ 2021 2021 .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... Purchases ledger control account Date Details $ Date Details $ 2021 2021 .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... .......... ..................................... ............... [14] (b) Name the book of prime entry which Ayesha would use to obtain the following information when preparing her sales ledger control account. Item Book of prime entry Returns Discount allowed Interest charged to customer on overdue account Contra entry [4] (c) Suggest two reasons why the sales ledger control account had a credit balance of $420 on 1 August 2021. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ................................................................................................................................................... [2] [Total: 20]
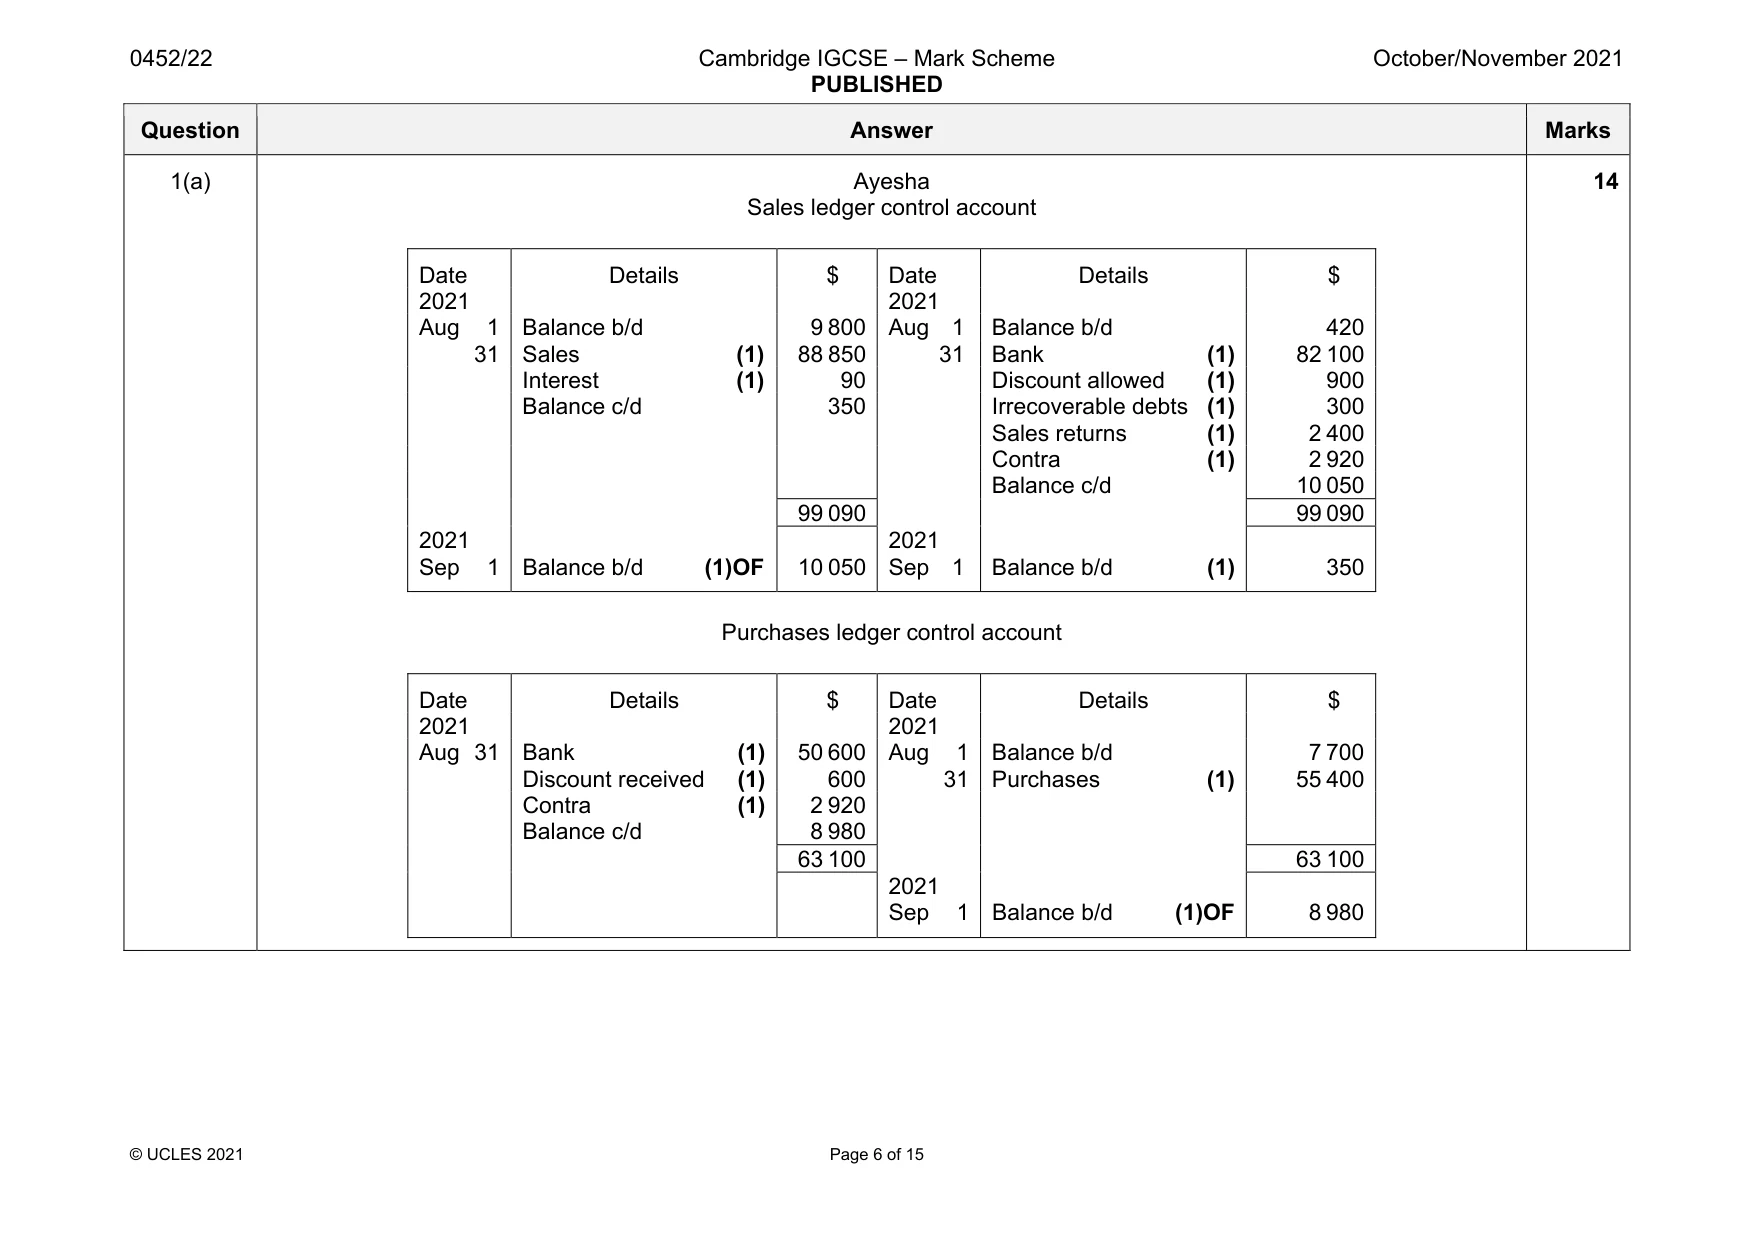
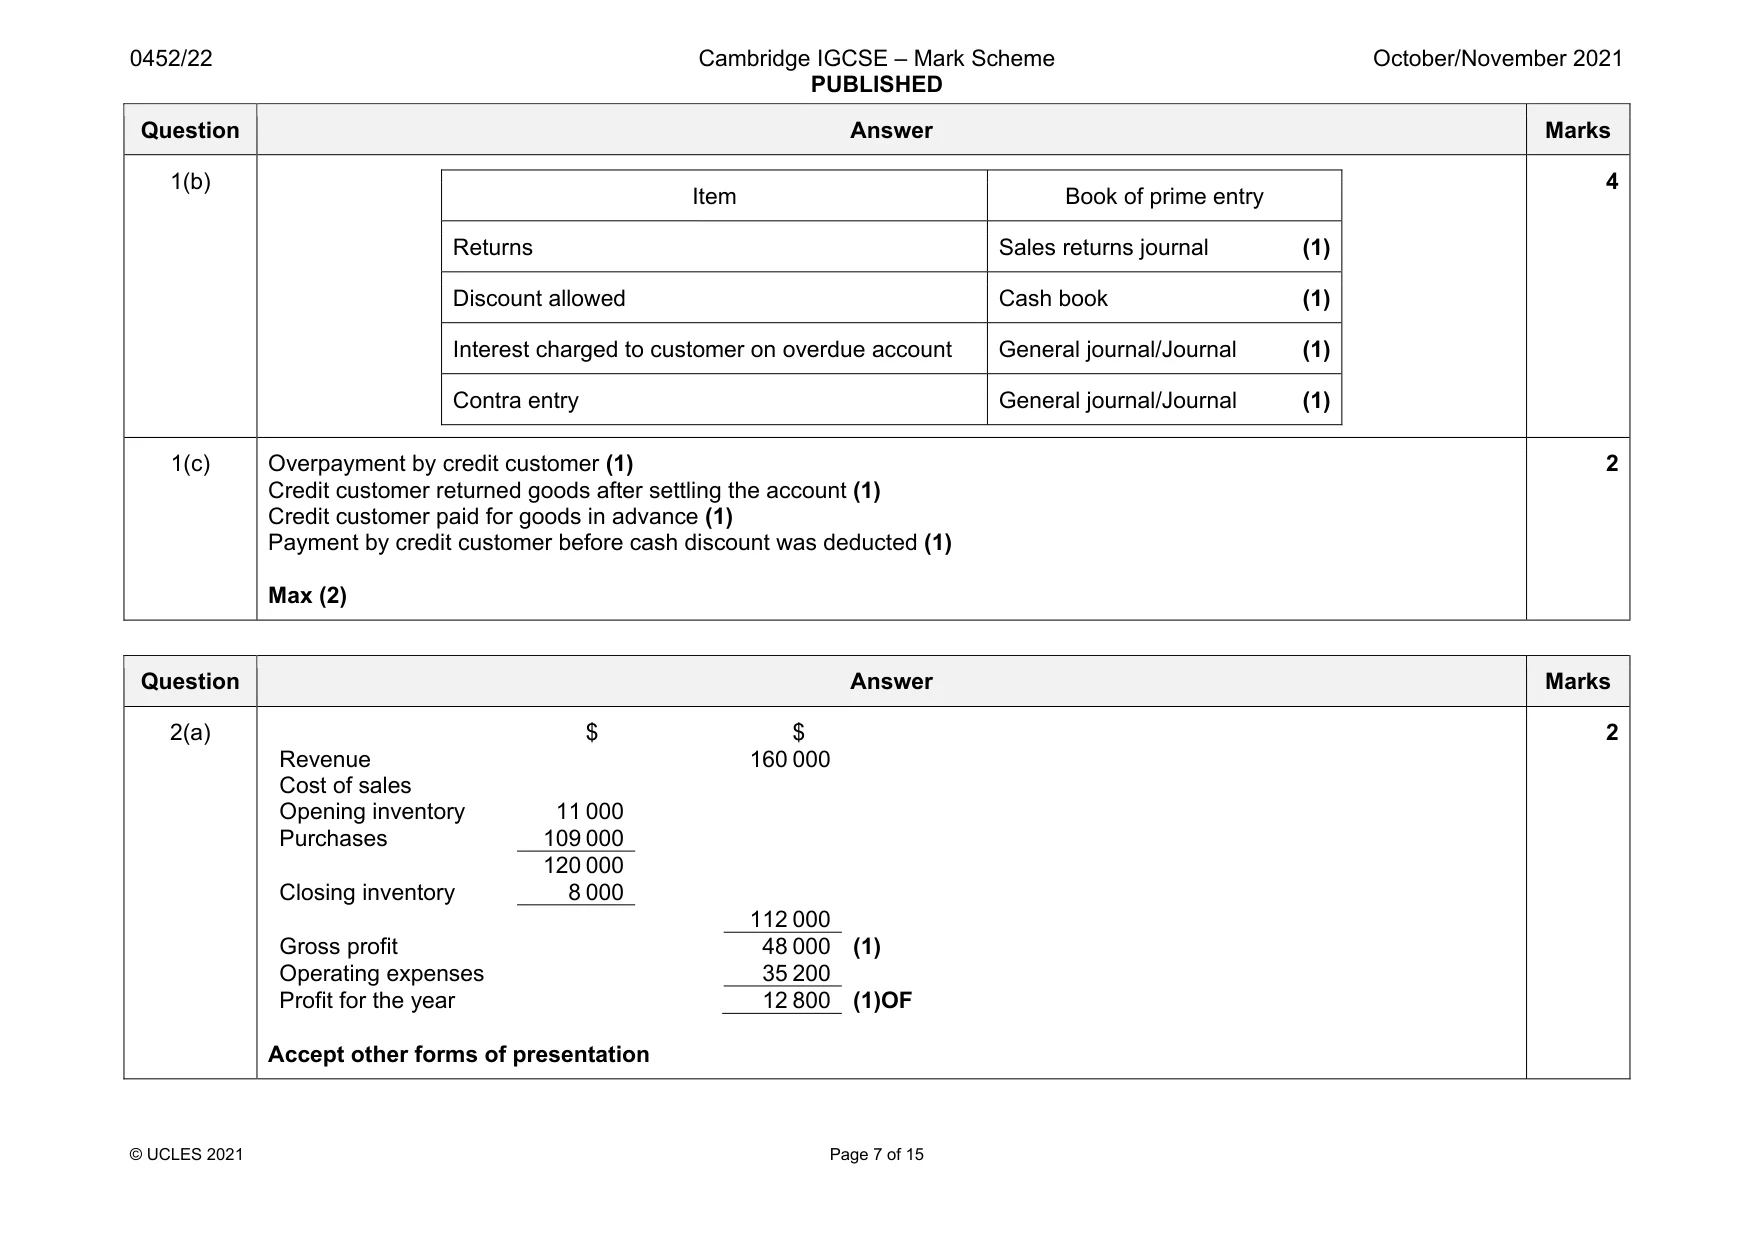
Mark scheme: 1(a) Ayesha Sales ledger control account Date Details $ Date Details $ 2021 2021 Aug 1 Balance b/d 9 800 Aug 1 Balance b/d 420 31 Sales (1) 88 850 31 Bank (1) 82 100 Interest (1) 90 Discount allowed (1) 900 Balance c/d 350 Irrecoverable debts (1) 300 Sales returns (1) 2 400 Contra (1) 2 920 Balance c/d 10 050 99 090 99 090 2021 2021 Sep 1 Balance b/d (1)OF 10 050 Sep 1 Balance b/d (1) 350 Purchases ledger control account Date Details $ Date Details $ 2021 2021 Aug 31 Bank (1) 50 600 Aug 1 Balance b/d 7 700 Discount received (1) 600 31 Purchases (1) 55 400 Contra (1) 2 920 Balance c/d 8 980 63 100 63 100 2021 Sep 1 Balance b/d (1)OF 8 980 14 Question Answer Marks 1(b) Item Book of prime entry Returns Sales returns journal (1) Discount allowed Cash book (1) Interest charged to customer on overdue account General journal/Journal (1) Contra entry General journal/Journal (1) 4 1(c) Overpayment by credit customer (1) Credit customer returned goods after settling the account (1) Credit customer paid for goods in advance (1) Payment by credit customer before cash discount was deducted (1) Max (2) 2
Q2 · Jabir owns an electrical wholesale business
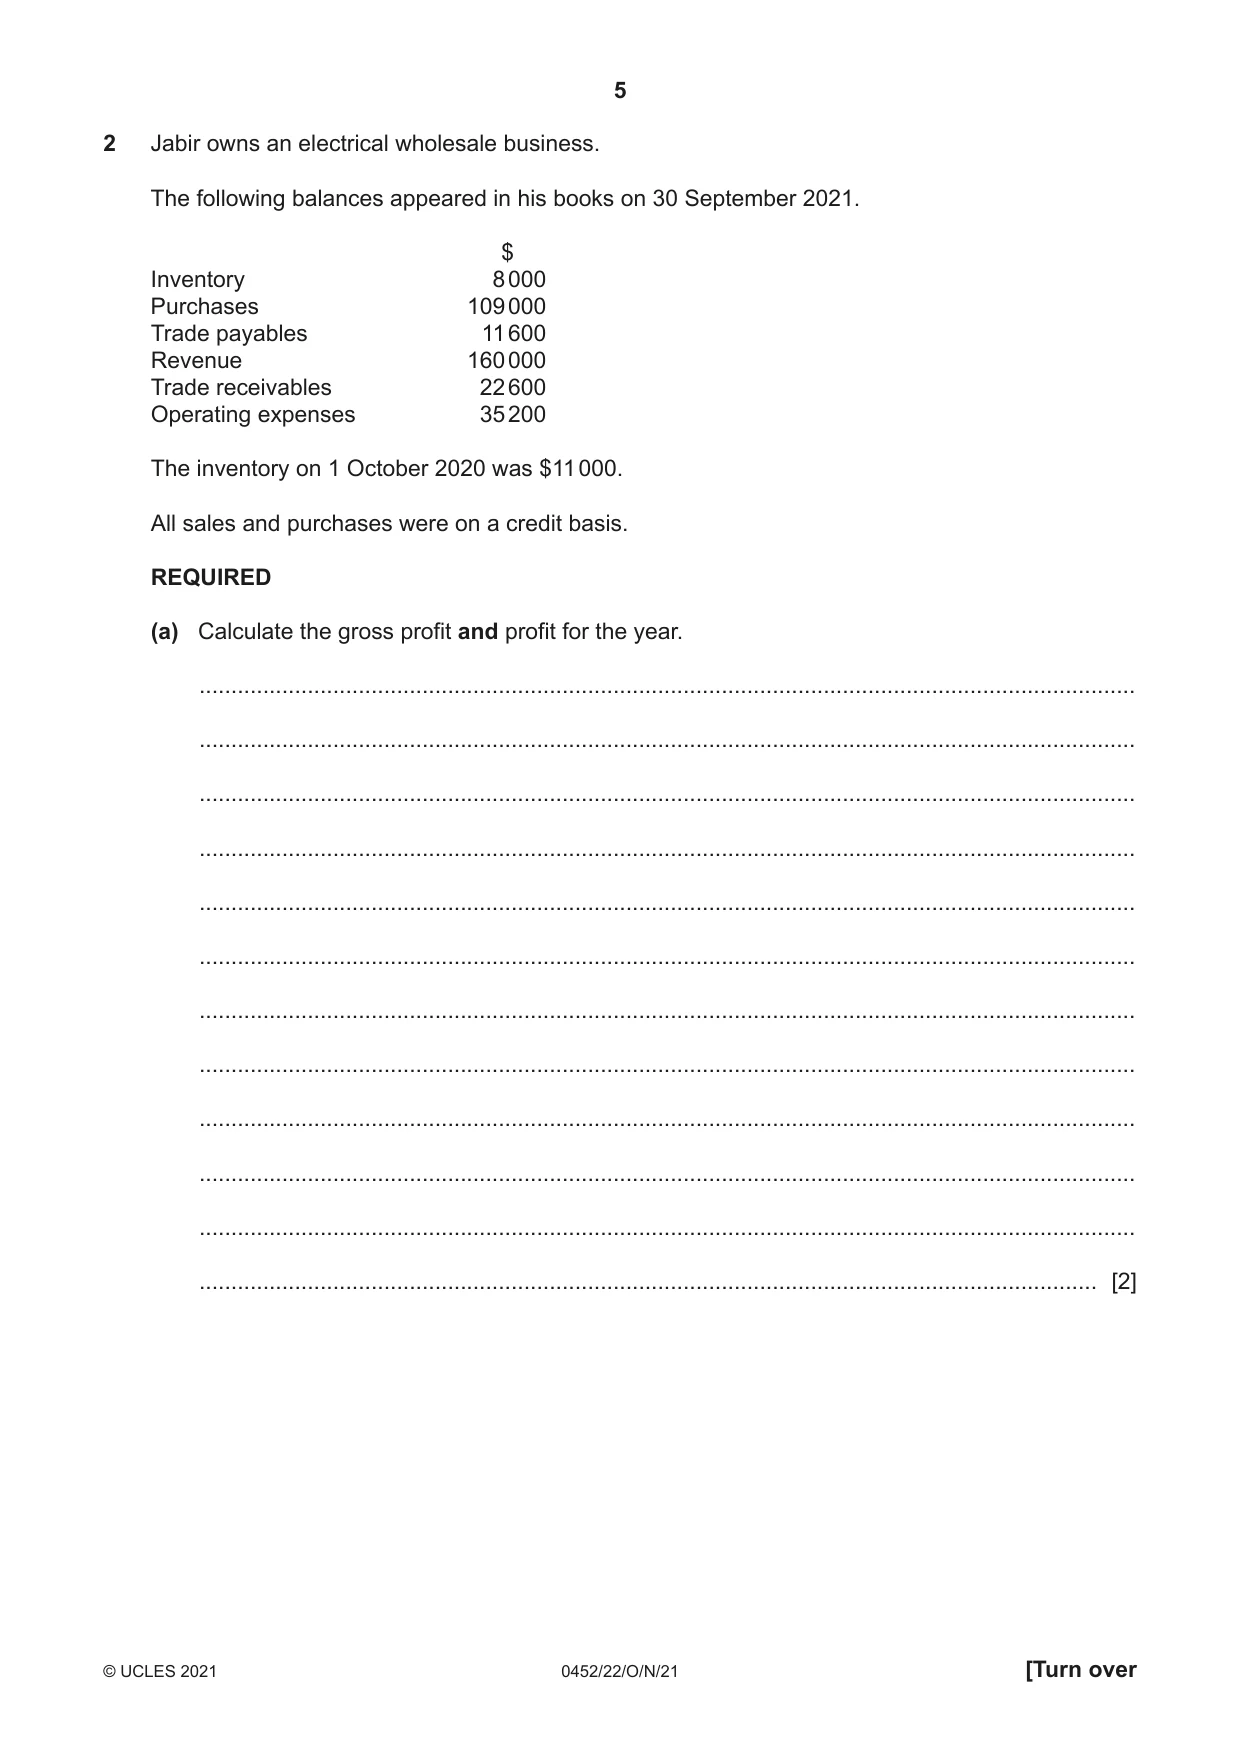
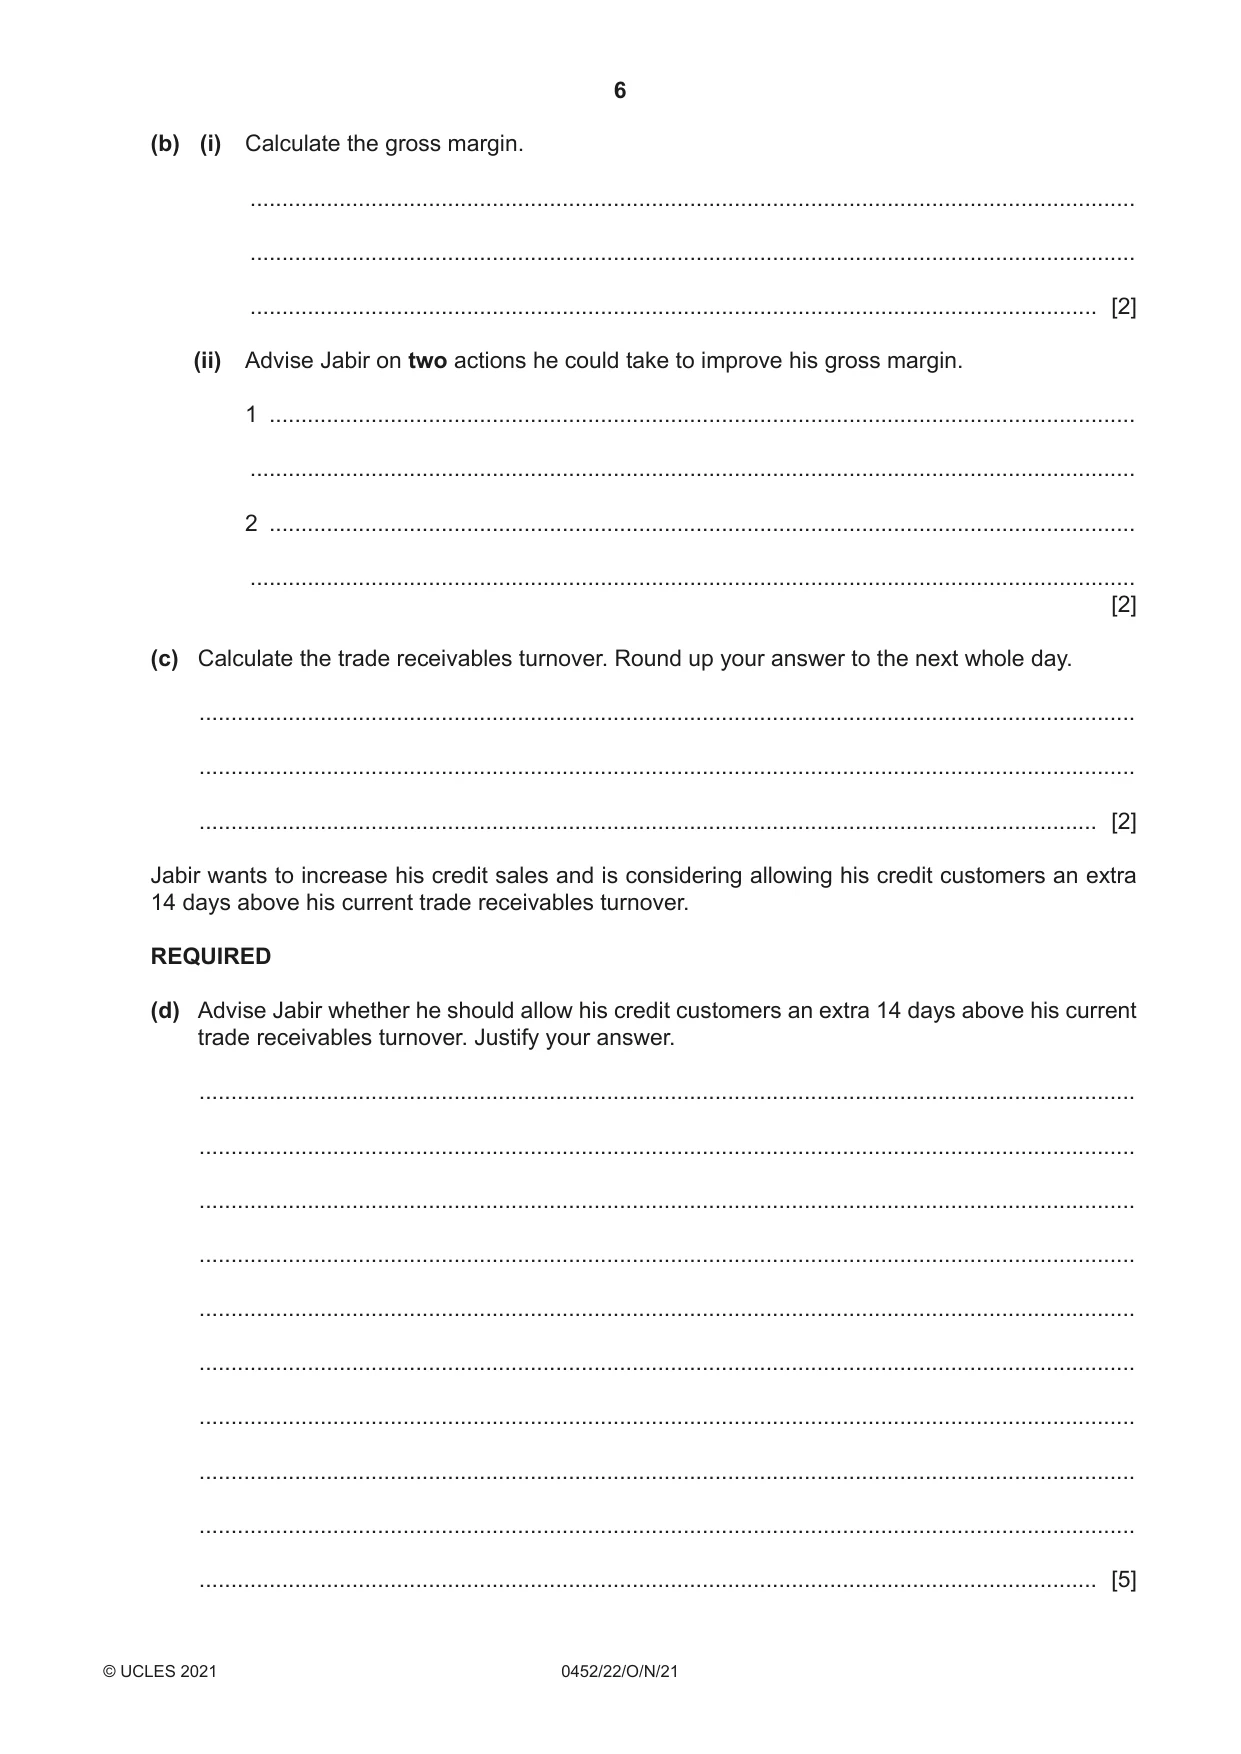
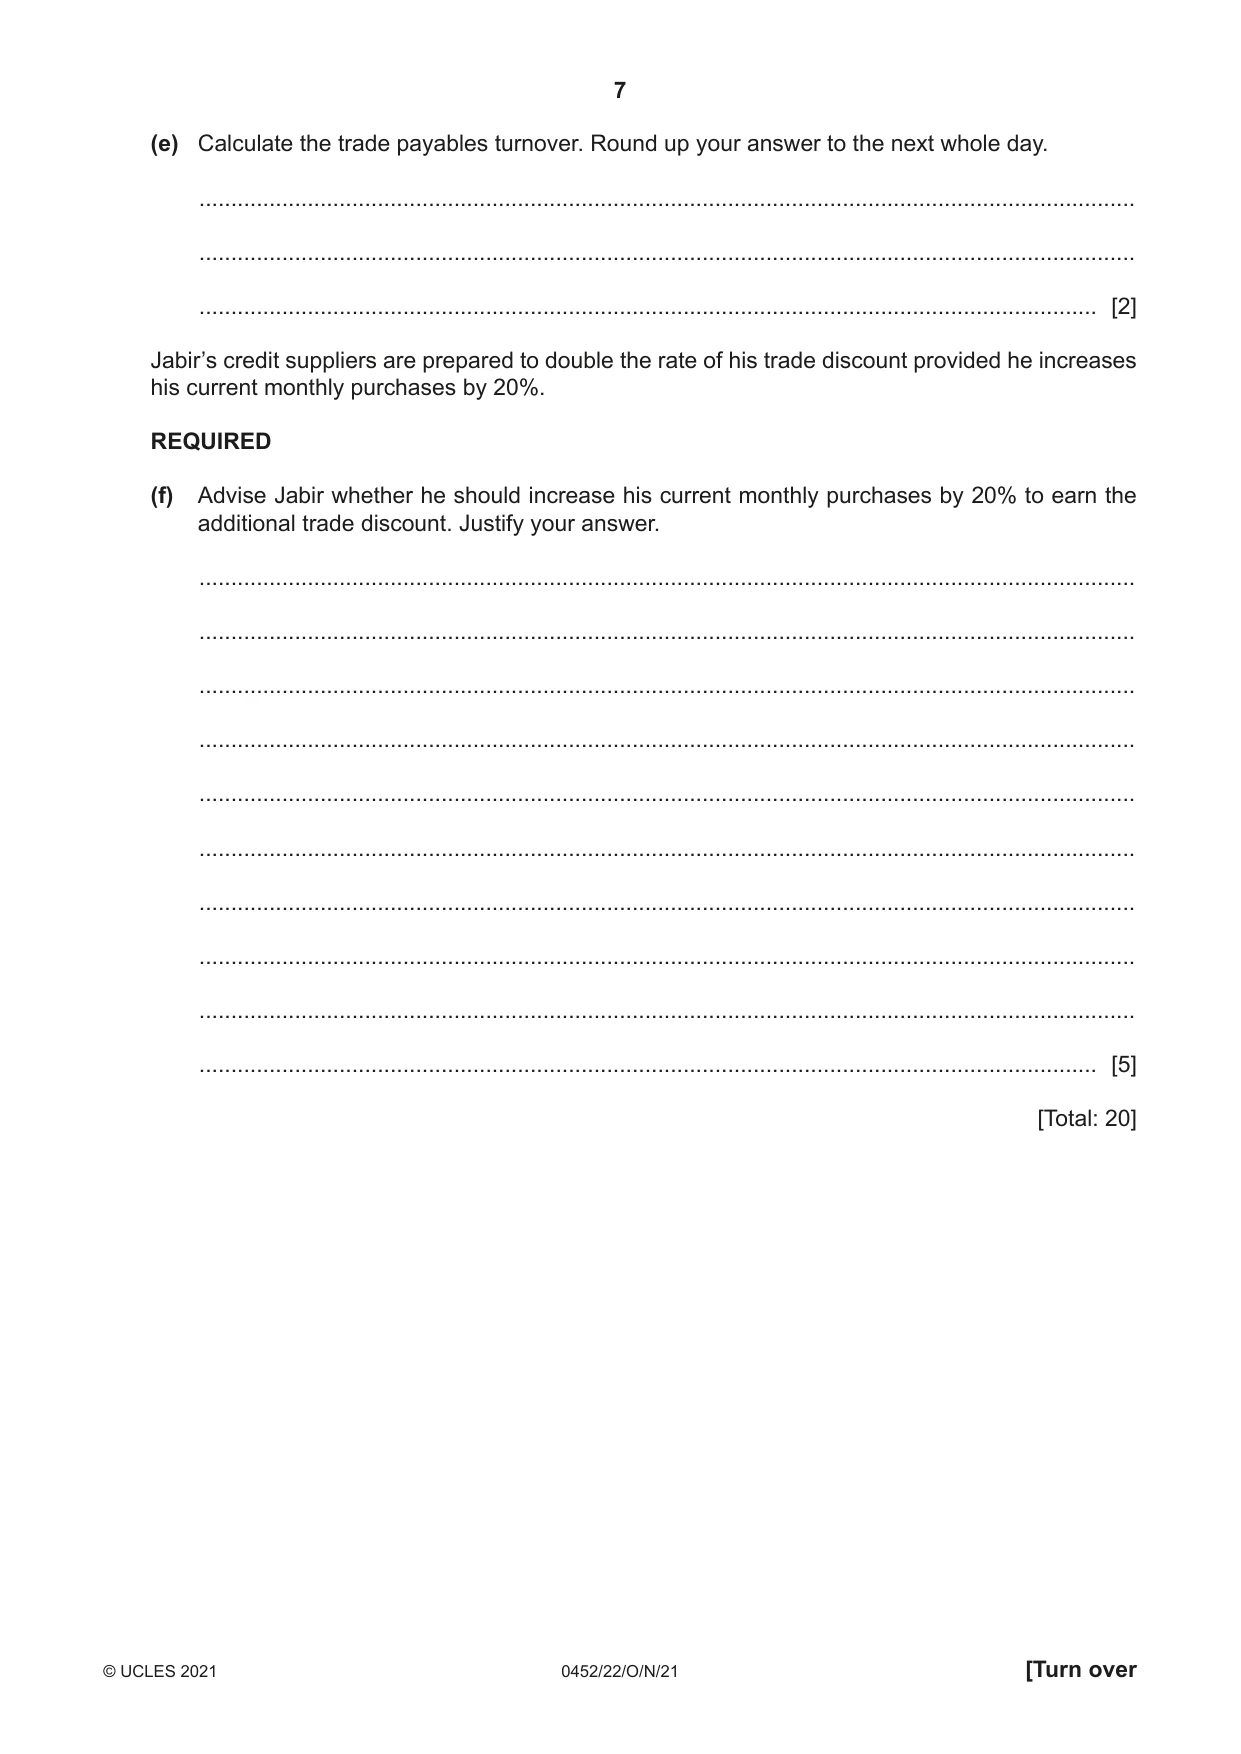
2 Jabir owns an electrical wholesale business. The following balances appeared in his books on 30 September 2021. $ Inventory 8 000 Purchases 109 000 Trade payables 11 600 Revenue 160 000 Trade receivables 22 600 Operating expenses 35 200 The inventory on 1 October 2020 was $11 000. All sales and purchases were on a credit basis. REQUIRED (a) Calculate the gross profit and profit for the year. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] (b) (i) Calculate the gross margin. ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] (ii) Advise Jabir on two actions he could take to improve his gross margin. 1 ........................................................................................................................................ ........................................................................................................................................... 2 ........................................................................................................................................ ........................................................................................................................................... [2] (c) Calculate the trade receivables turnover. Round up your answer to the next whole day. ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] Jabir wants to increase his credit sales and is considering allowing his credit customers an extra 14 days above his current trade receivables turnover. REQUIRED (d) Advise Jabir whether he should allow his credit customers an extra 14 days above his current trade receivables turnover. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] (e) Calculate the trade payables turnover. Round up your answer to the next whole day. ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] Jabir’s credit suppliers are prepared to double the rate of his trade discount provided he increases his current monthly purchases by 20%. REQUIRED (f) Advise Jabir whether he should increase his current monthly purchases by 20% to earn the additional trade discount. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
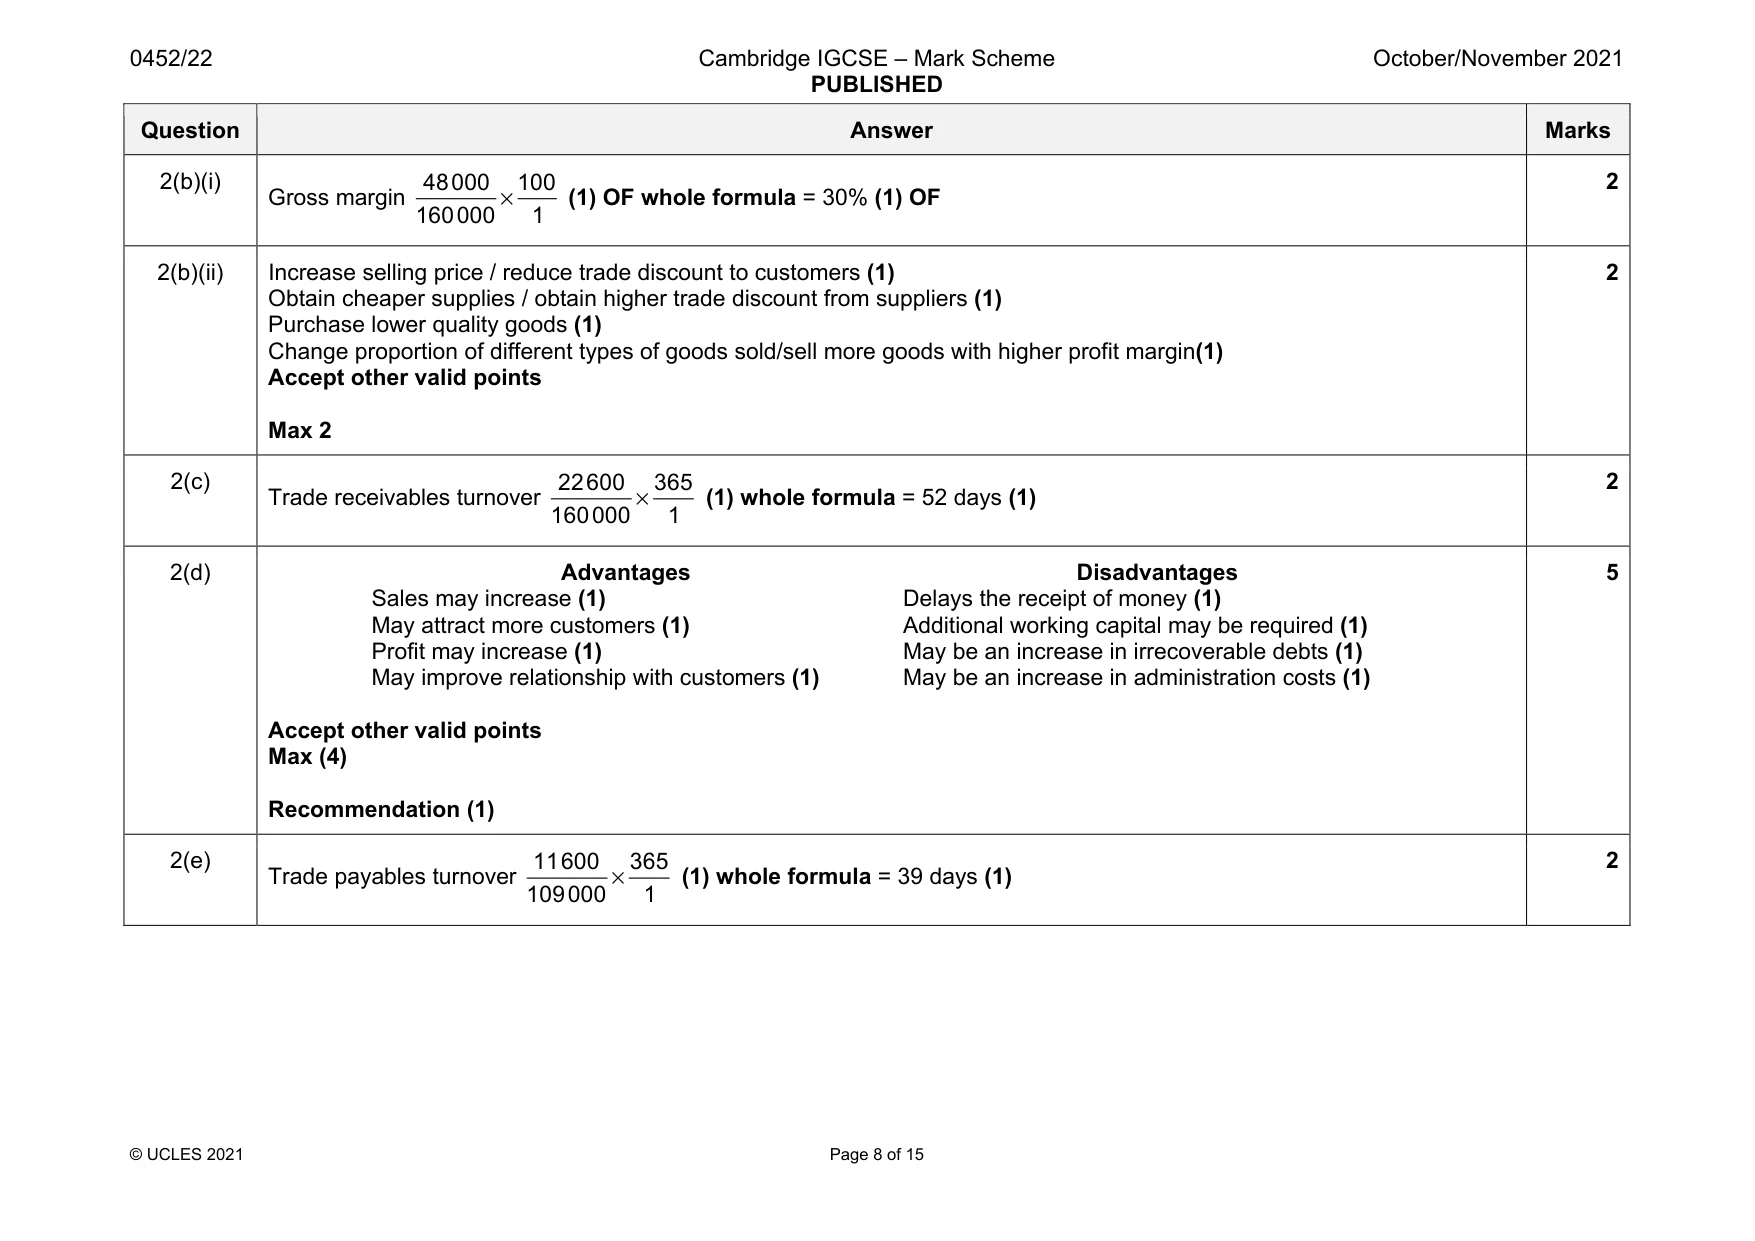
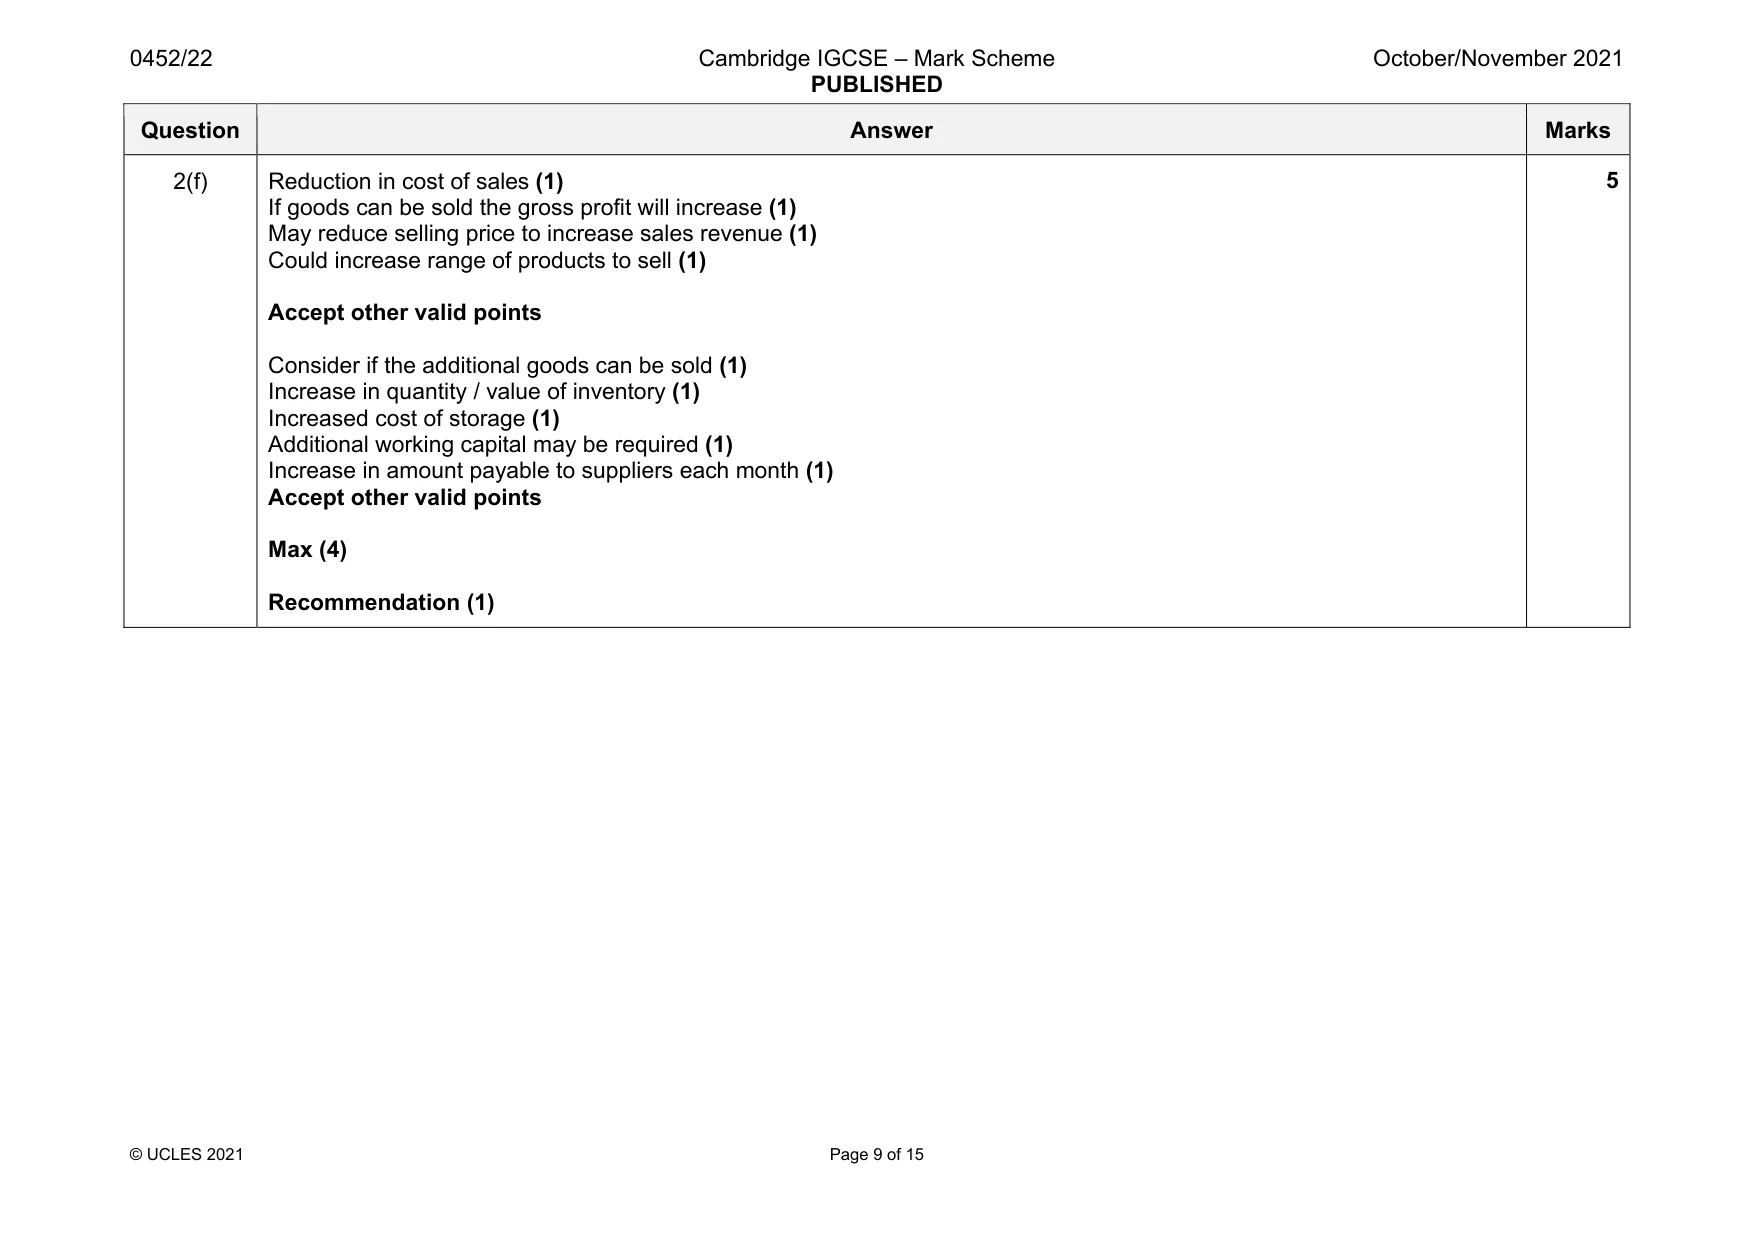
Mark scheme: 2(a) $ $ Revenue 160 000 Cost of sales Opening inventory 11 000 Purchases 109 000 120 000 Closing inventory 8 000 112 000 Gross profit 48 000 (1) Operating expenses 35 200 Profit for the year 12 800 (1)OF Accept other forms of presentation 2 Question Answer Marks 2(b)(i) Gross margin × 48000 100 160000 1 (1) OF whole formula = 30% (1) OF 2 2(b)(ii) Increase selling price / reduce trade discount to customers (1) Obtain cheaper supplies / obtain higher trade discount from suppliers (1) Purchase lower quality goods (1) Change proportion of different types of goods sold/sell more goods with higher profit margin(1) Accept other valid points Max 2 2 2(c) Trade receivables turnover × 22600 365 160000 1 (1) whole formula = 52 days (1) 2 2(d) Advantages Sales may increase (1) May attract more customers (1) Profit may increase (1) May improve relationship with customers (1) Disadvantages Delays the receipt of money (1) Additional working capital may be required (1) May be an increase in irrecoverable debts (1) May be an increase in administration costs (1) Accept other valid points Max (4) Recommendation (1) 5 2(e) Trade payables turnover × 11600 365 109000 1 (1) whole formula = 39 days (1) 2 Question Answer Marks 2(f) Reduction in cost of sales (1) If goods can be sold the gross profit will increase (1) May reduce selling price to increase sales revenue (1) Could increase range of products to sell (1) Accept other valid points Consider if the additional goods can be sold (1) Increase in quantity / value of inventory (1) Increased cost of storage (1) Additional working capital may be required (1) Increase in amount payable to suppliers each month (1) Accept other valid points Max (4) Recommendation (1) 5
More questions on Calculation and understanding of accounting ratios
Q3 · On 31 July 2021 the following information was provided by KA Limited, a manufacturer of…
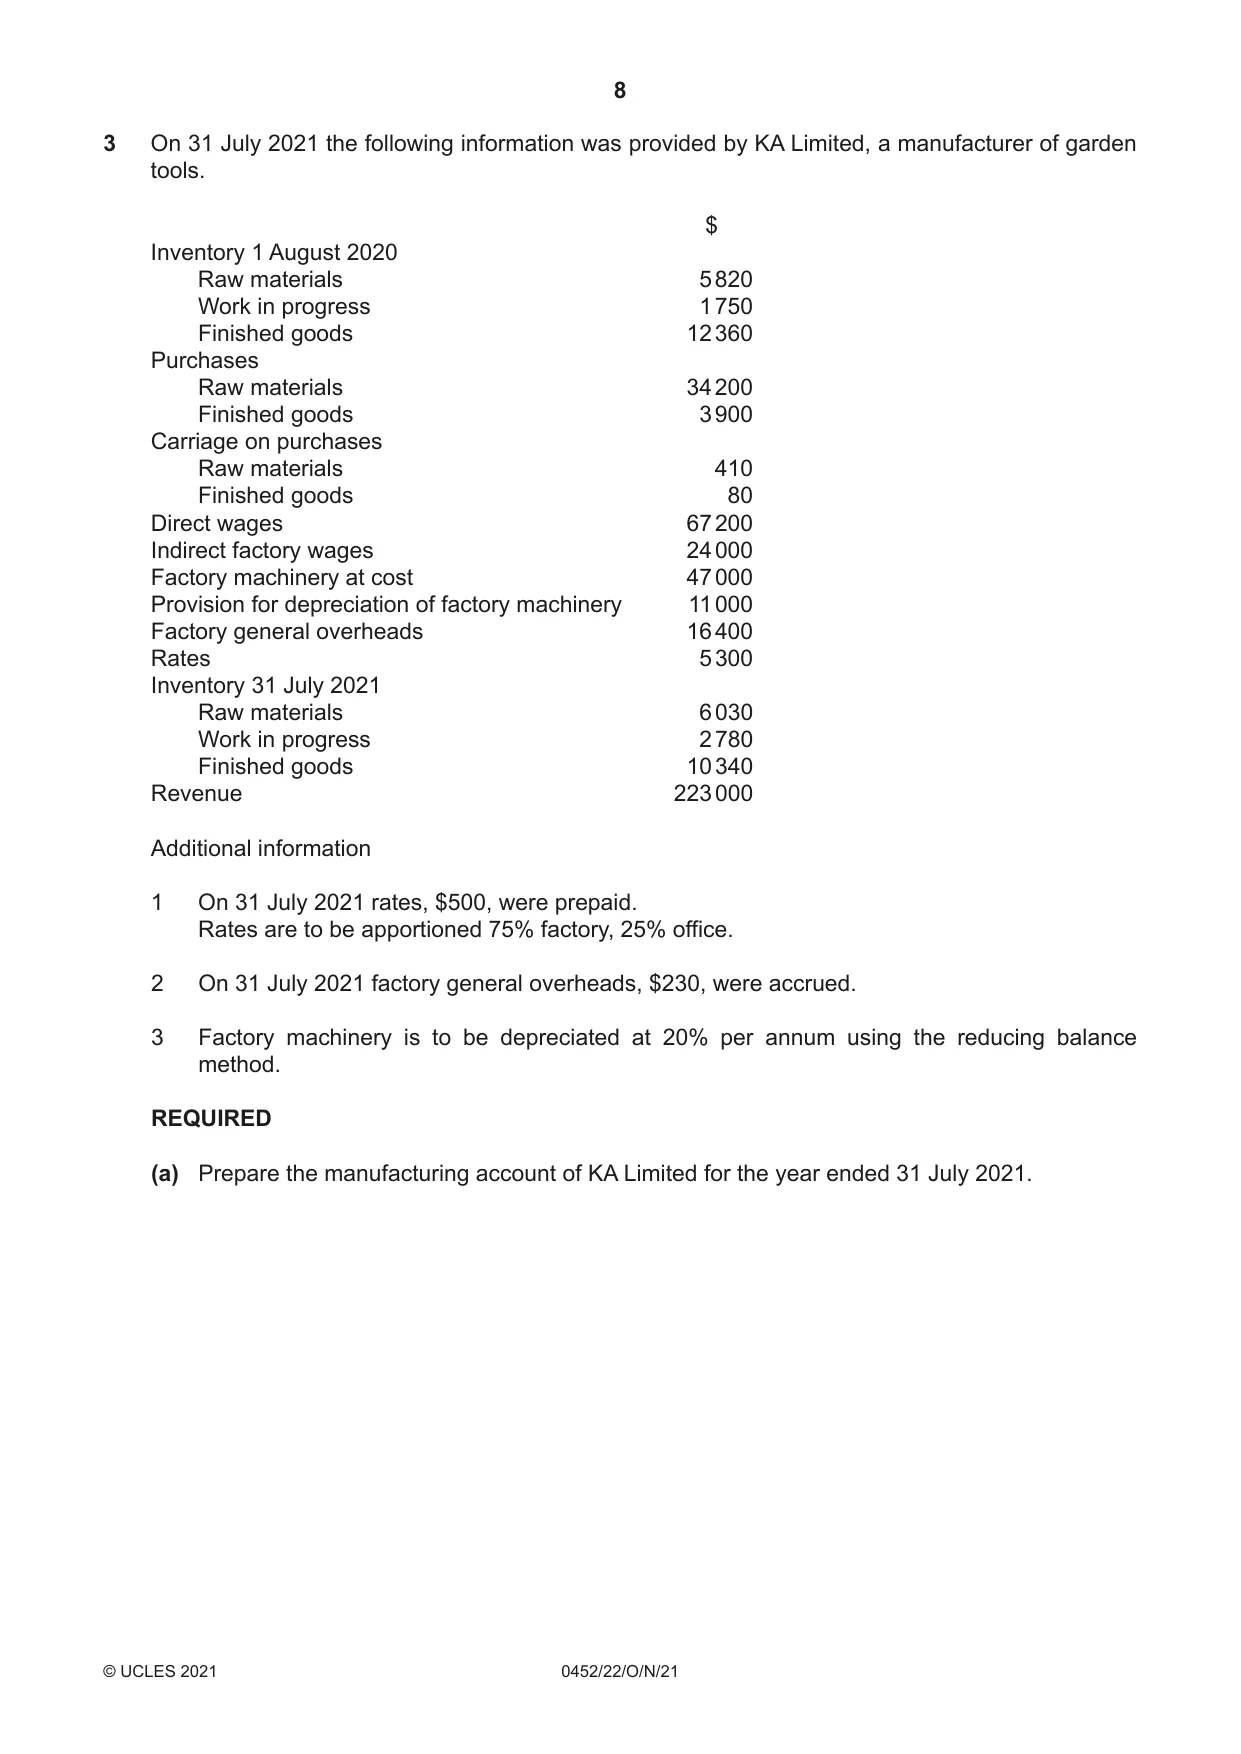
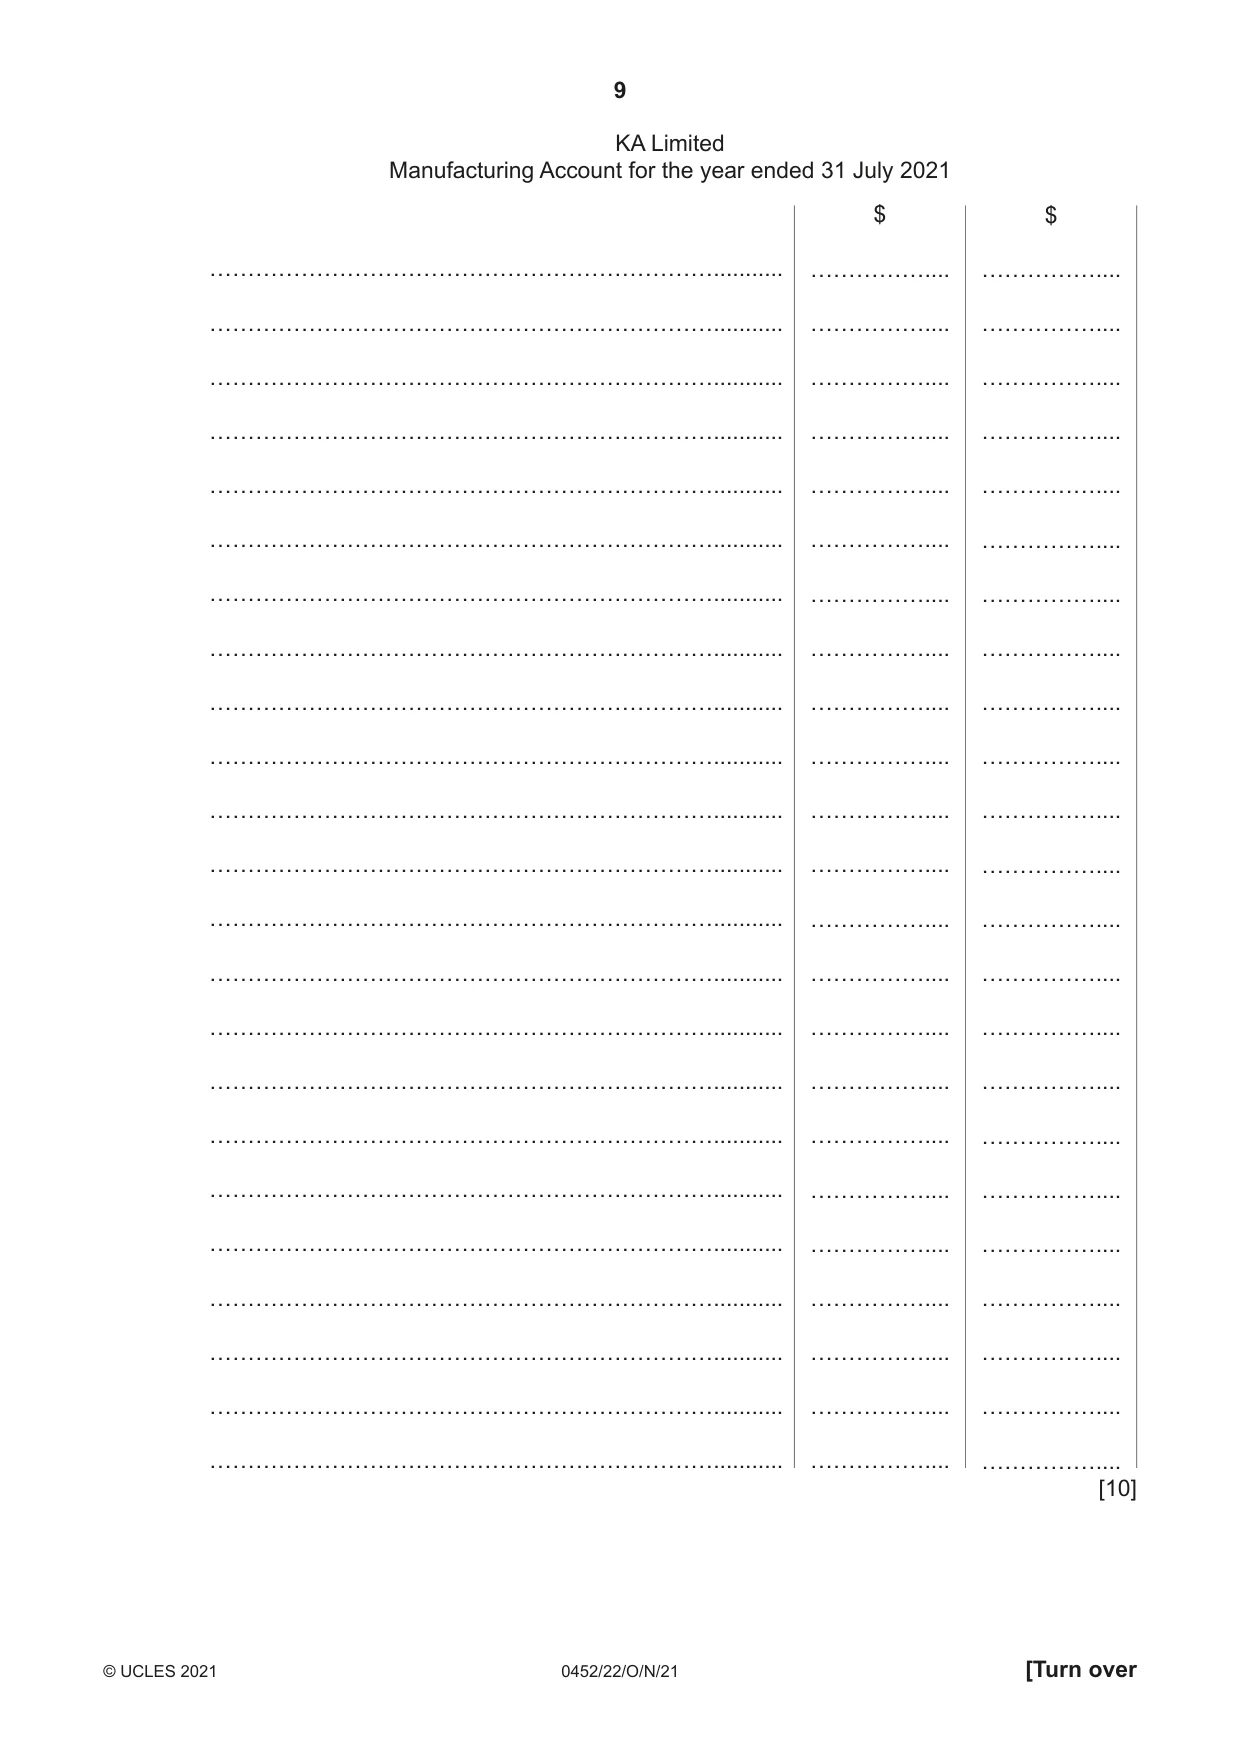
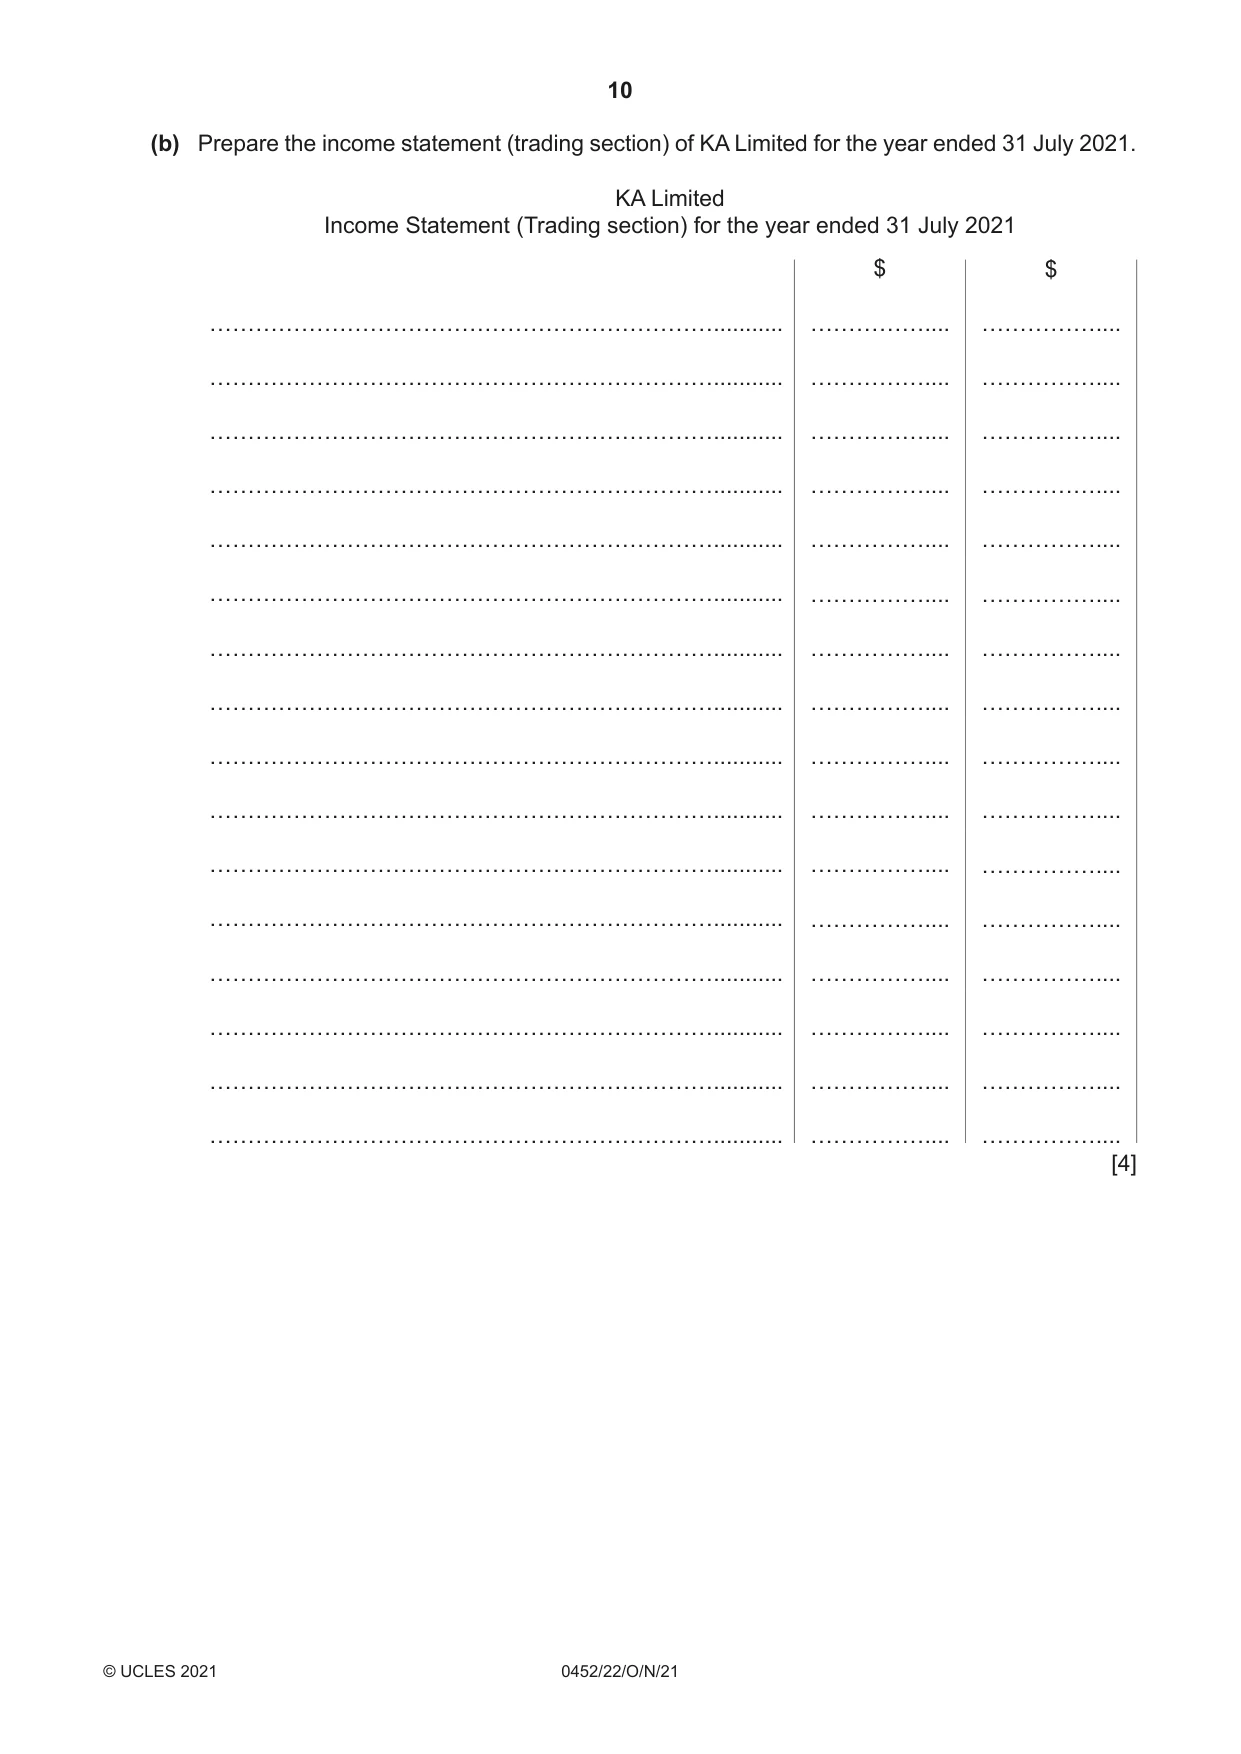
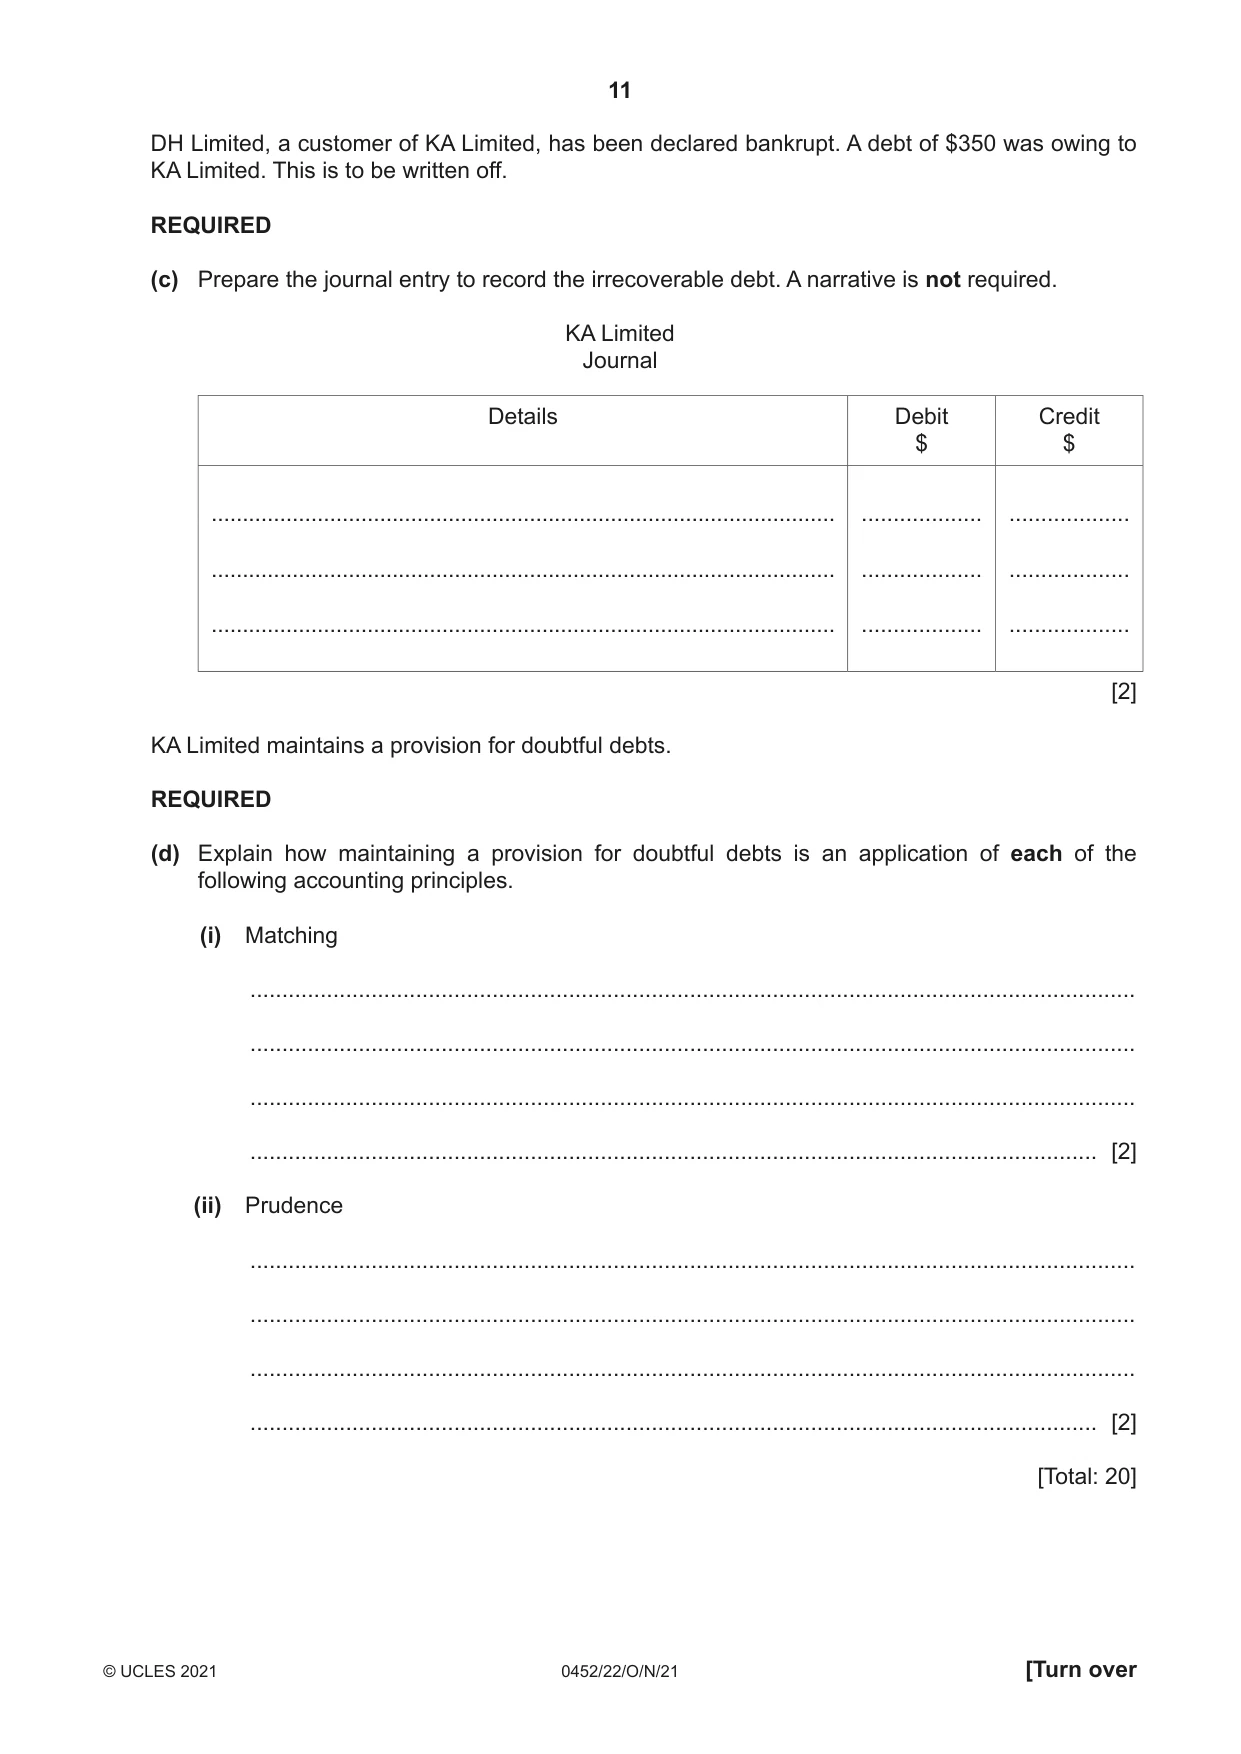
3 On 31 July 2021 the following information was provided by KA Limited, a manufacturer of garden tools. $ Inventory 1 August 2020 Raw materials 5 820 Work in progress 1 750 Finished goods 12 360 Purchases Raw materials 34 200 Finished goods 3 900 Carriage on purchases Raw materials 410 Finished goods 80 Direct wages 67 200 Indirect factory wages 24 000 Factory machinery at cost 47 000 Provision for depreciation of factory machinery 11 000 Factory general overheads 16 400 Rates 5 300 Inventory 31 July 2021 Raw materials 6 030 Work in progress 2 780 Finished goods 10 340 Revenue 223 000 Additional information 1 On 31 July 2021 rates, $500, were prepaid. Rates are to be apportioned 75% factory, 25% office. 2 On 31 July 2021 factory general overheads, $230, were accrued. 3 Factory machinery is to be depreciated at 20% per annum using the reducing balance method. REQUIRED (a) Prepare the manufacturing account of KA Limited for the year ended 31 July 2021. KA Limited Manufacturing Account for the year end …………………………………………………………........... …………………………………………………………........... …………………………………………………………........... …………………………………………………………........... …………………………………………………………........... …………………………………………………………........... …………………………………………………………........... …………………………………………………………........... …………………………………………………………........... …………………………………………………………........... …………………………………………………………........... …………………………………………………………........... …………………………………………………………........... …………………………………………………………........... …………………………………………………………........... …………………………………………………………........... …………………………………………………………........... …………………………………………………………........... …………………………………………………………........... …………………………………………………………........... …………………………………………………………........... …………………………………………………………........... …………………………………………………………........... (b) Prepare the income statement (trading section) of KA Limited for the year ended 31 July 2021. KA Limited Income Statement (Trading section) for the year ended 31 July 2021 $ $ …………………………………………………………........... …………….... …………….... …………………………………………………………........... …………….... …………….... …………………………………………………………........... …………….... …………….... …………………………………………………………........... …………….... …………….... …………………………………………………………........... …………….... …………….... …………………………………………………………........... …………….... …………….... …………………………………………………………........... …………….... …………….... …………………………………………………………........... …………….... …………….... …………………………………………………………........... …………….... …………….... …………………………………………………………........... …………….... …………….... …………………………………………………………........... …………….... …………….... …………………………………………………………........... …………….... …………….... …………………………………………………………........... …………….... …………….... …………………………………………………………........... …………….... …………….... …………………………………………………………........... …………….... …………….... …………………………………………………………........... …………….... …………….... [4] DH Limited, a customer of KA Limited, has been declared bankrupt. A debt of $350 was owing to KA Limited. This is to be written off. REQUIRED (c) Prepare the journal entry to record the irrecoverable debt. A narrative is not required. KA Limited Journal Details Debit Credit $ $ .................................................................................................... ................... ................... .................................................................................................... ................... ................... .................................................................................................... ................... ................... [2] KA Limited maintains a provision for doubtful debts. REQUIRED (d) Explain how maintaining a provision for doubtful debts is an application of each of the following accounting principles. (i) Matching ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] (ii) Prudence ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] [Total: 20]
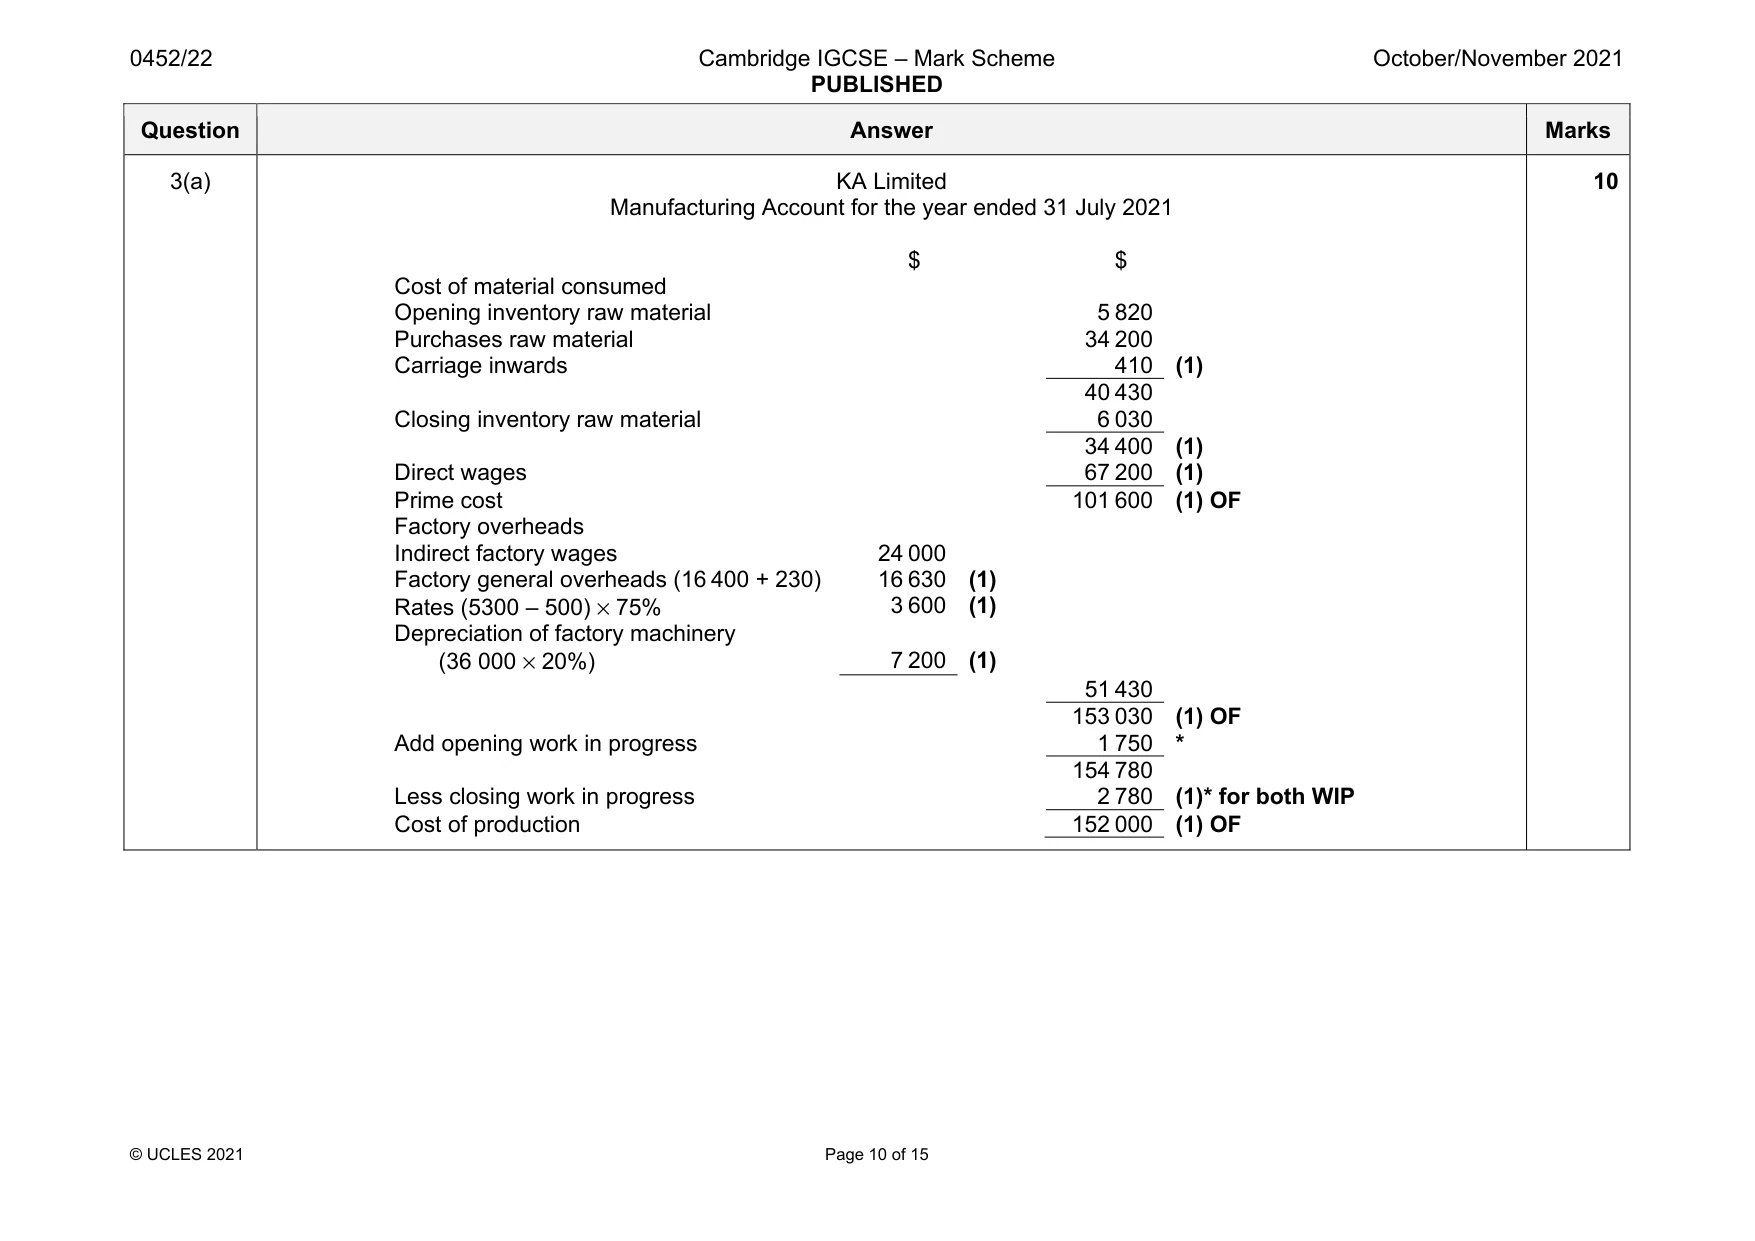
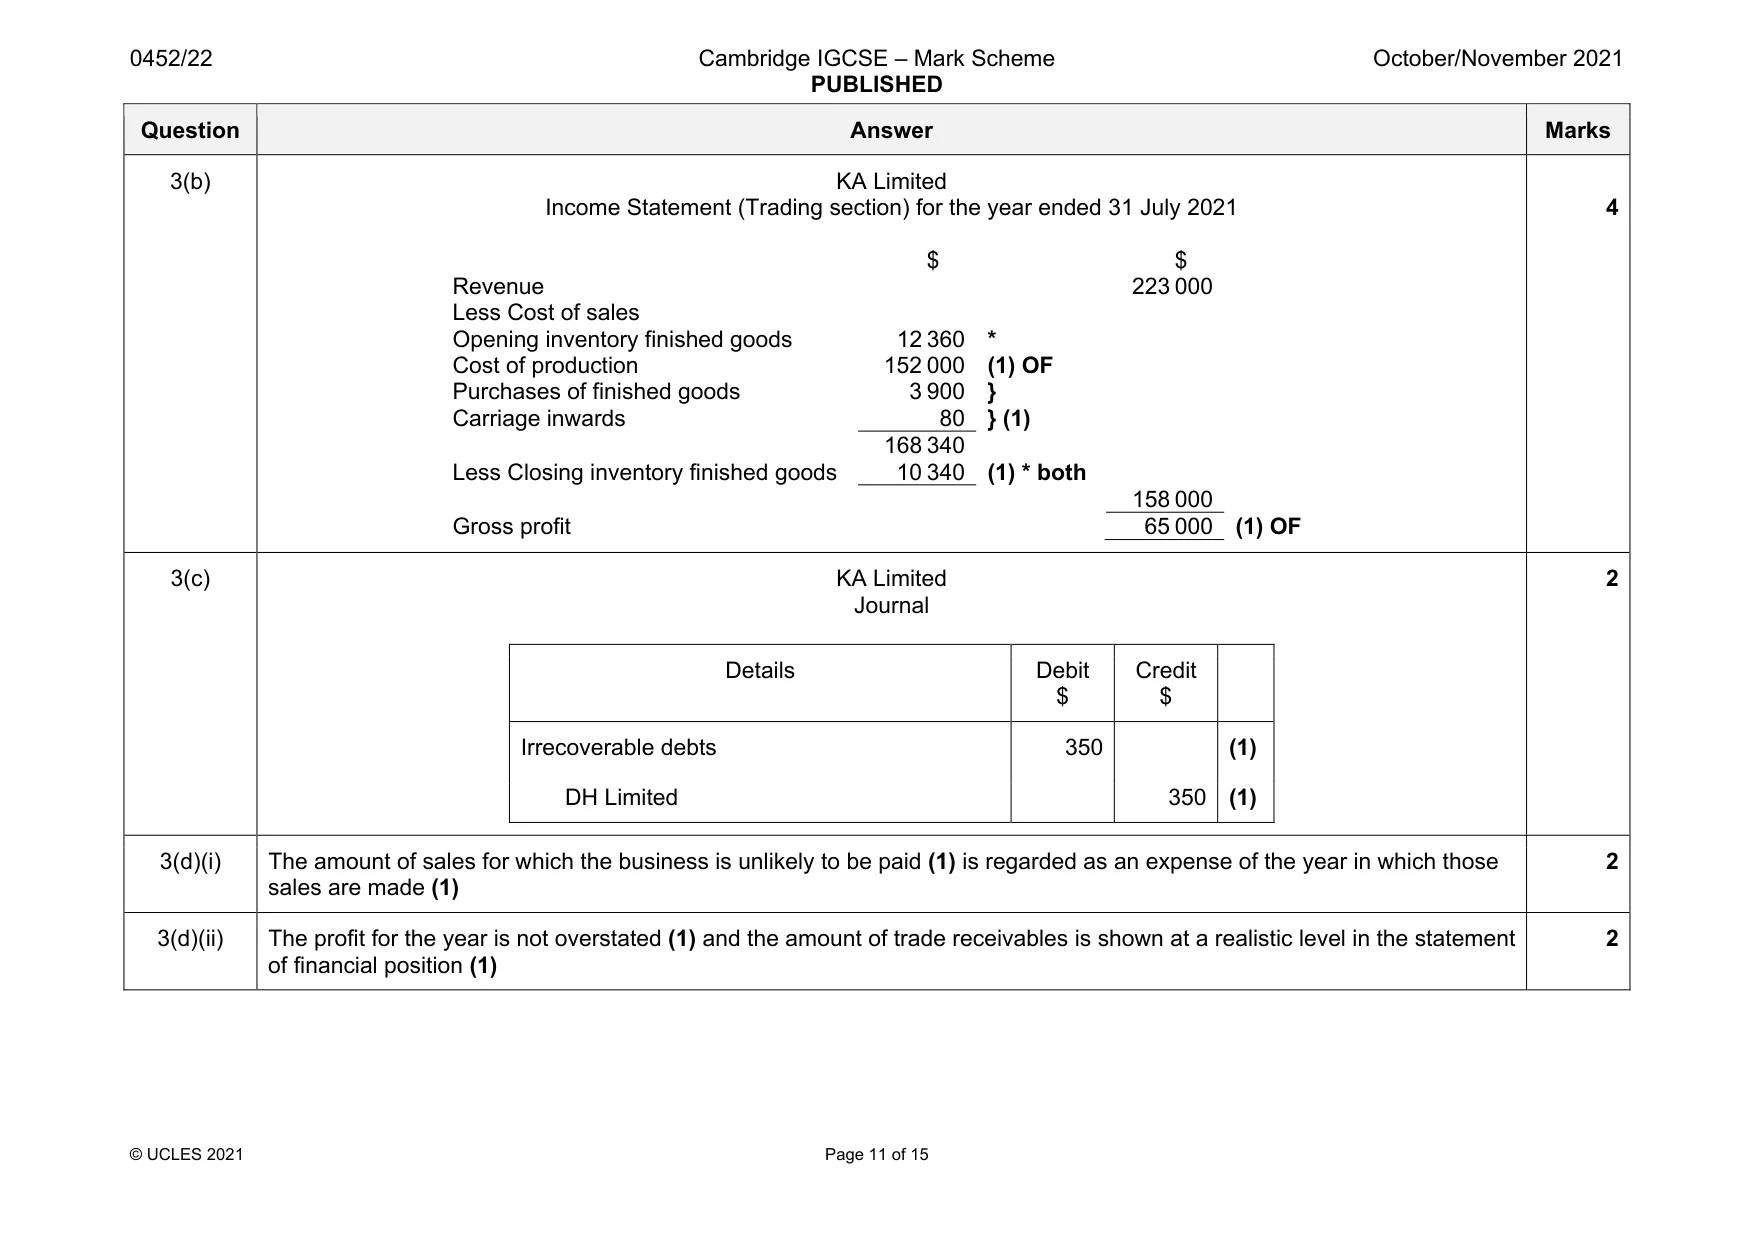
Mark scheme: 3(a) KA Limited Manufacturing Account for the year ended 31 July 2021 $ $ Cost of material consumed Opening inventory raw material 5 820 Purchases raw material 34 200 Carriage inwards 410 (1) 40 430 Closing inventory raw material 6 030 34 400 (1) Direct wages 67 200 (1) Prime cost 101 600 (1) OF Factory overheads Indirect factory wages 24 000 Factory general overheads (16 400 + 230) 16 630 (1) Rates (5300 – 500) × 75% 3 600 (1) Depreciation of factory machinery (36 000 × 20%) 7 200 (1) 51 430 153 030 (1) OF Add opening work in progress 1 750 * 154 780 Less closing work in progress 2 780 (1)* for both WIP Cost of production 152 000 (1) OF 10 Question Answer Marks 3(b) KA Limited Income Statement (Trading section) for the year ended 31 July 2021 $ $ Revenue 223 000 Less Cost of sales Opening inventory finished goods 12 360 * Cost of production 152 000 (1) OF Purchases of finished goods 3 900 } Carriage inwards 80 } (1) 168 340 Less Closing inventory finished goods 10 340 (1) * both 158 000 Gross profit 65 000 (1) OF 4 3(c) KA Limited Journal Details Debit $ Credit $ Irrecoverable debts 350 (1) DH Limited 350 (1) 2 3(d)(i) The amount of sales for which the business is unlikely to be paid (1) is regarded as an expense of the year in which those sales are made (1) 2 3(d)(ii) The profit for the year is not overstated (1) and the amount of trade receivables is shown at a realistic level in the statement of financial position (1) 2
Q4 · Nikita is a trader
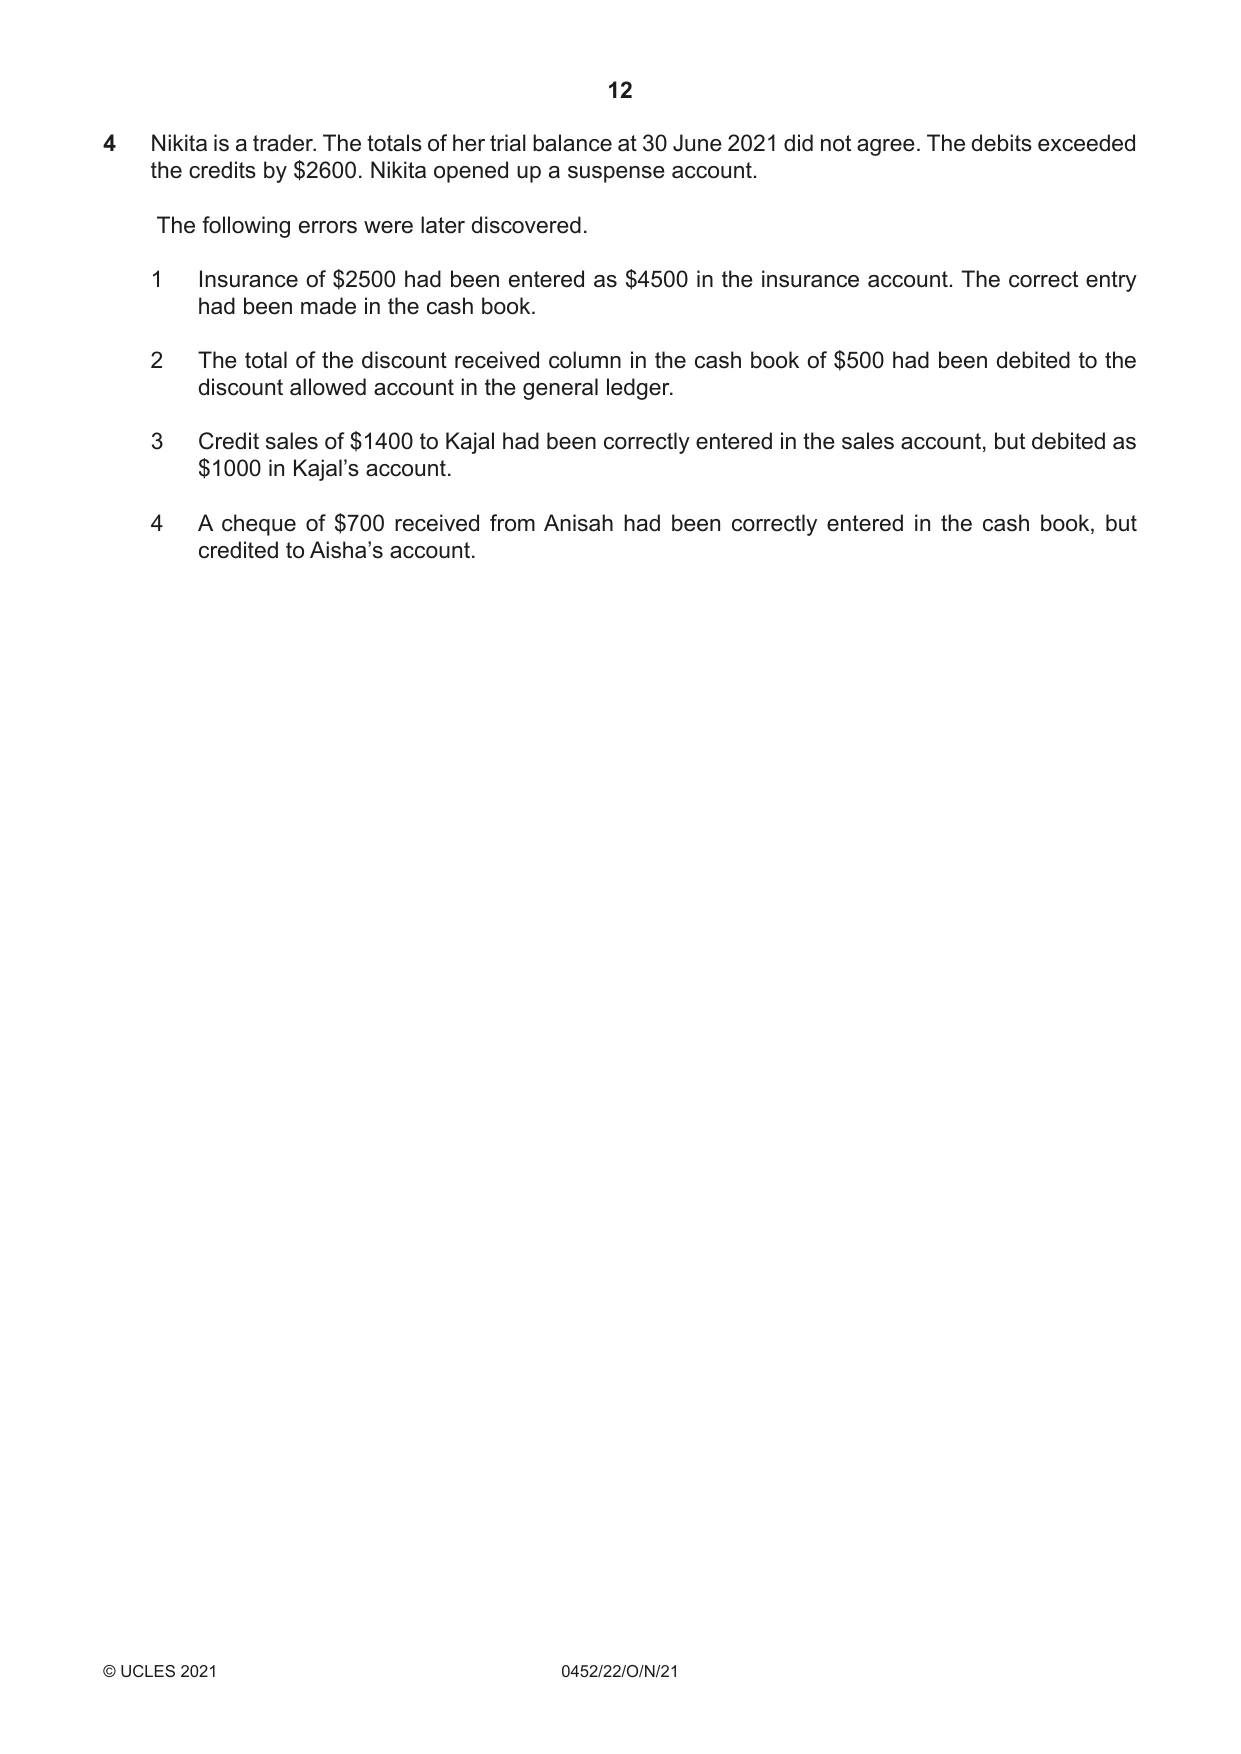
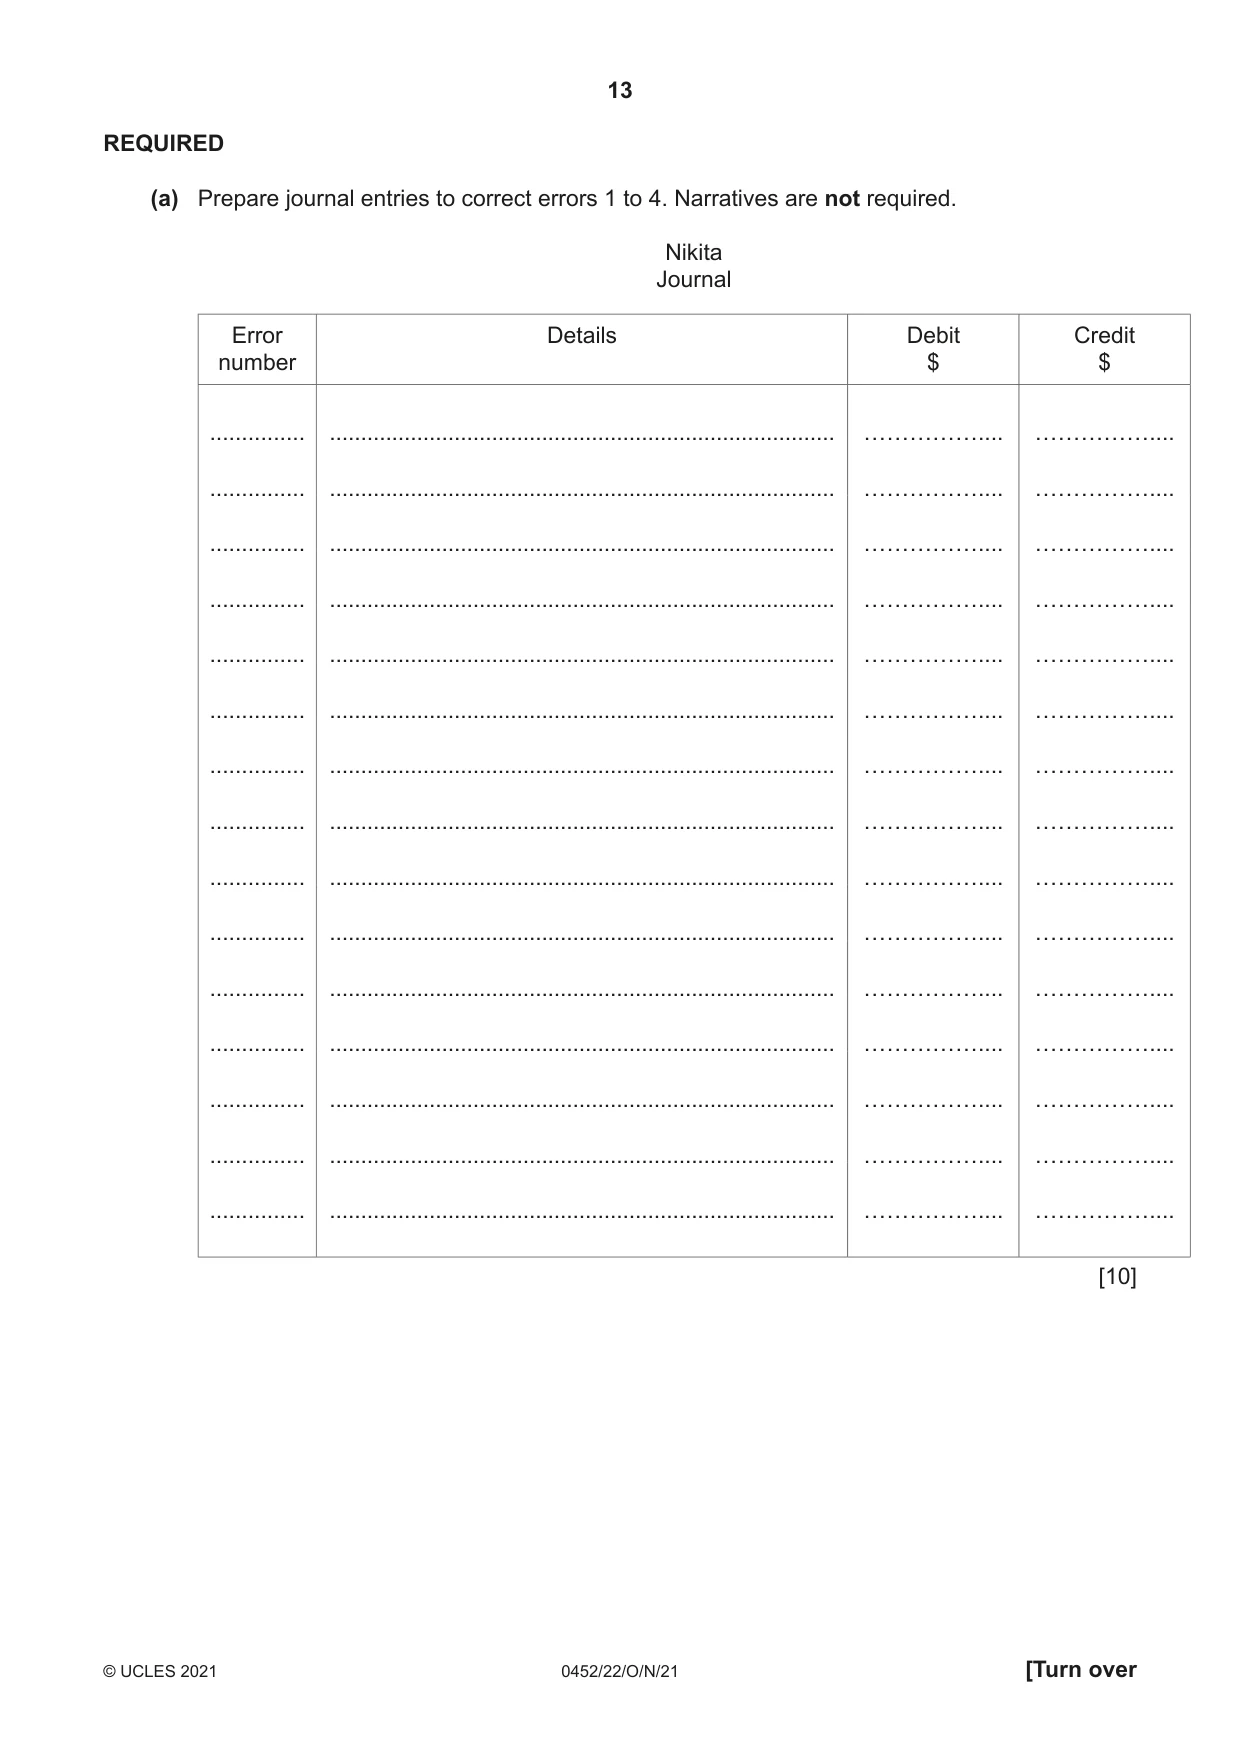
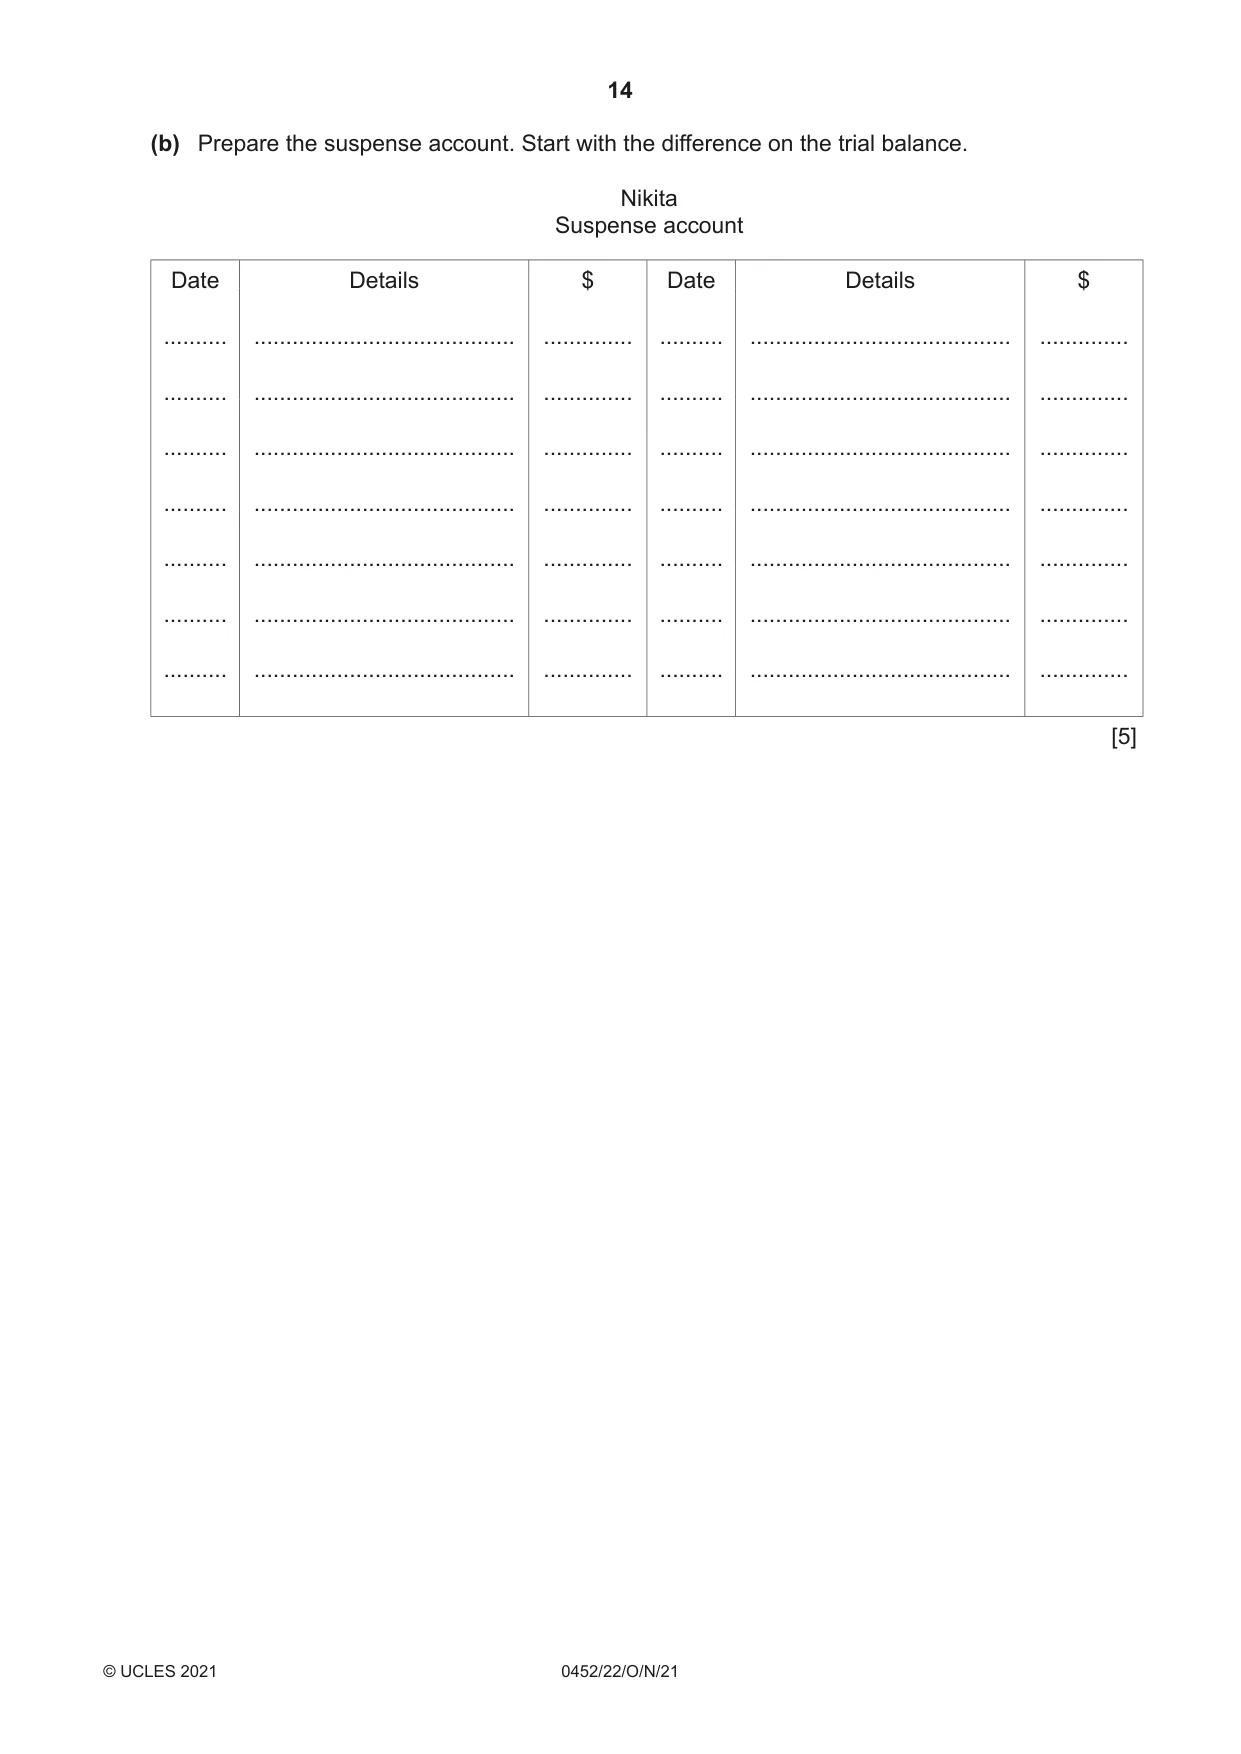
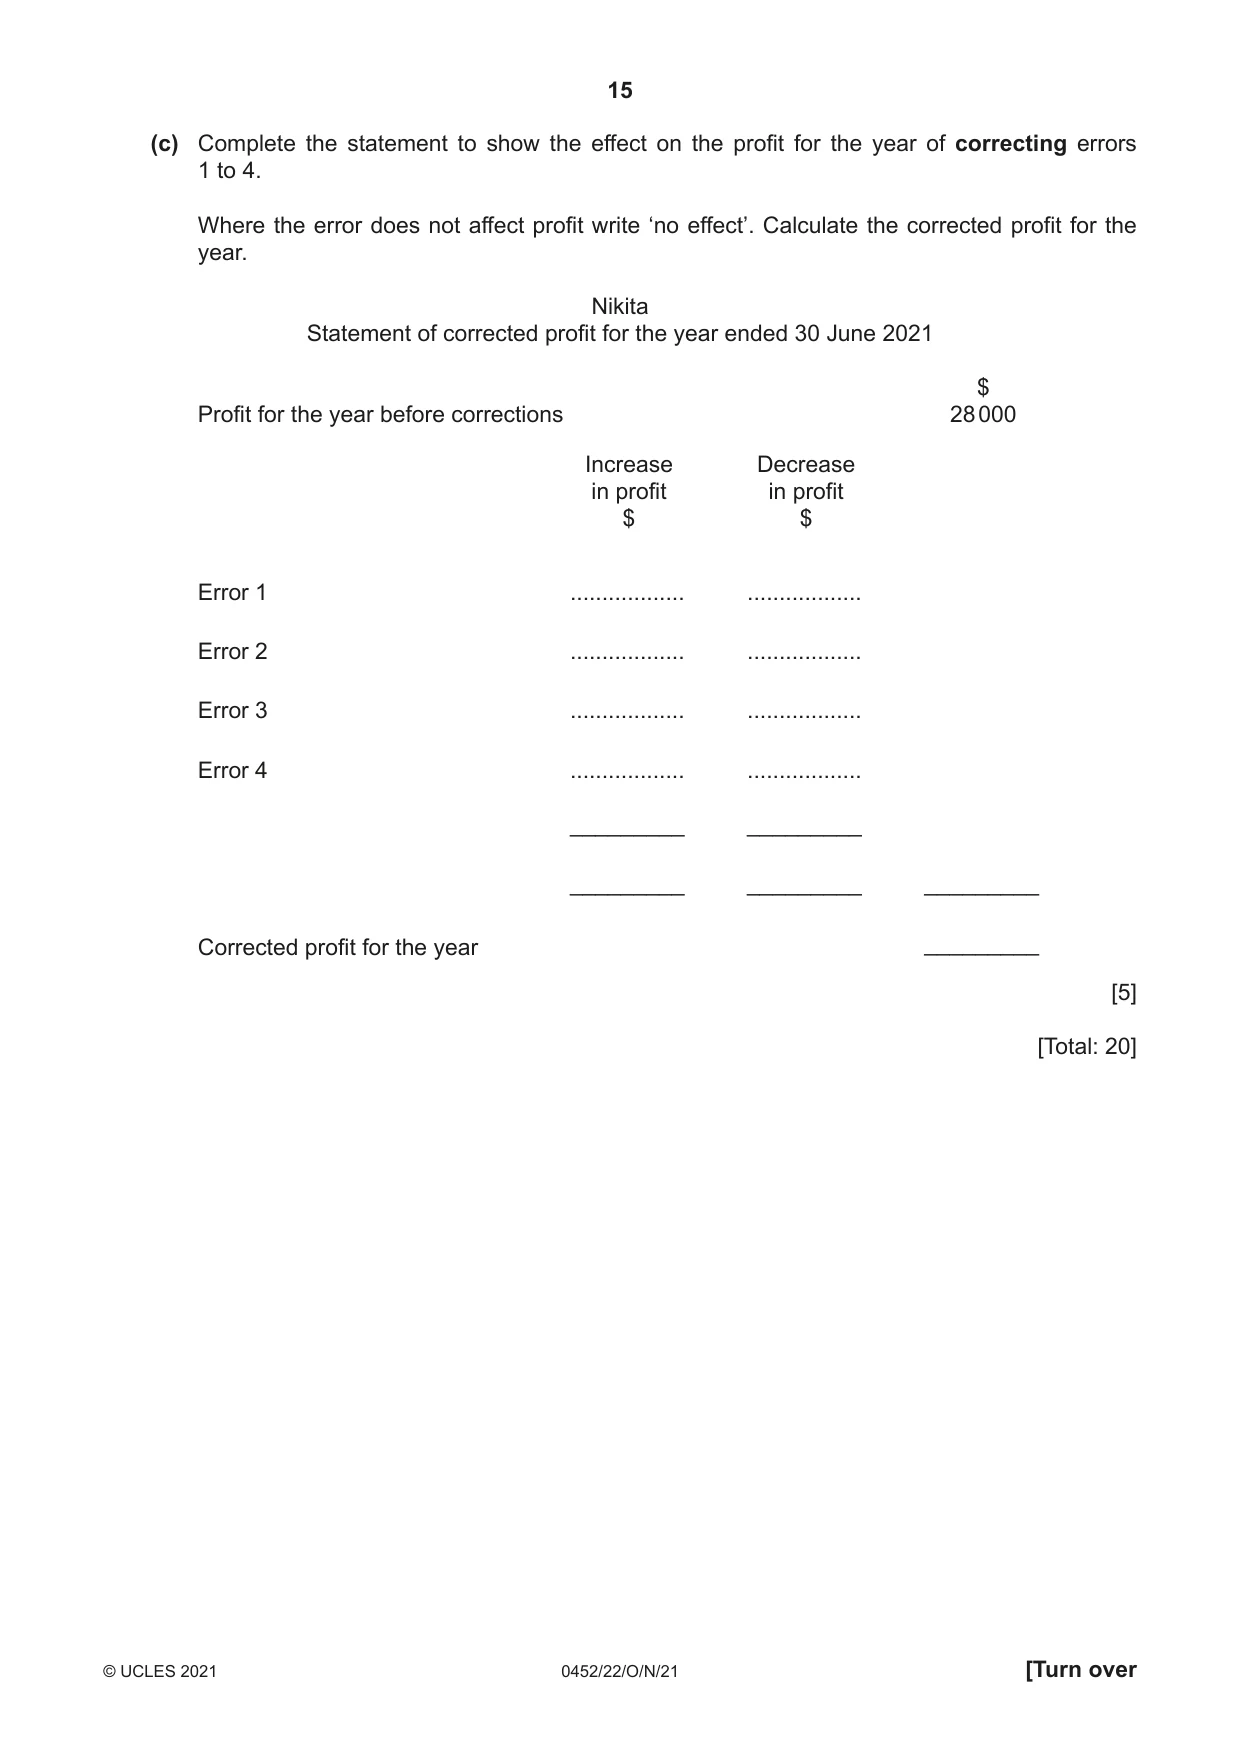
4 Nikita is a trader. The totals of her trial balance at 30 June 2021 did not agree. The debits exceeded the credits by $2600. Nikita opened up a suspense account. The following errors were later discovered. 1 Insurance of $2500 had been entered as $4500 in the insurance account. The correct entry had been made in the cash book. 2 The total of the discount received column in the cash book of $500 had been debited to the discount allowed account in the general ledger. 3 Credit sales of $1400 to Kajal had been correctly entered in the sales account, but debited as $1000 in Kajal’s account. 4 A cheque of $700 received from Anisah had been correctly entered in the cash book, but credited to Aisha’s account. REQUIRED (a) Prepare journal entries to correct errors 1 to 4. Narratives are not required. Nikita Journal Error Details Debit Credit number $ $ ............... ................................................................................. …………….... …………….... ............... ................................................................................. …………….... …………….... ............... ................................................................................. …………….... …………….... ............... ................................................................................. …………….... …………….... ............... ................................................................................. …………….... …………….... ............... ................................................................................. …………….... …………….... ............... ................................................................................. …………….... …………….... ............... ................................................................................. …………….... …………….... ............... ................................................................................. …………….... …………….... ............... ................................................................................. …………….... …………….... ............... ................................................................................. …………….... …………….... ............... ................................................................................. …………….... …………….... ............... ................................................................................. …………….... …………….... ............... ................................................................................. …………….... …………….... ............... ................................................................................. …………….... …………….... [10] (b) Prepare the suspense account. Start with the difference on the trial balance. Nikita Suspense account Date Details $ Date Details $ .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. [5] (c) Complete the statement to show the effect on the profit for the year of correcting errors 1 to 4. Where the error does not affect profit write ‘no effect’. Calculate the corrected profit for the year. Nikita Statement of corrected profit for the year ended 30 June 2021 $ Profit for the year before corrections 28 000 Increase Decrease in profit in profit $ $ Error 1 .................. .................. Error 2 .................. .................. Error 3 .................. .................. Error 4 .................. .................. _________ _________ _________ _________ _________ Corrected profit for the year _________ [5] [Total: 20]
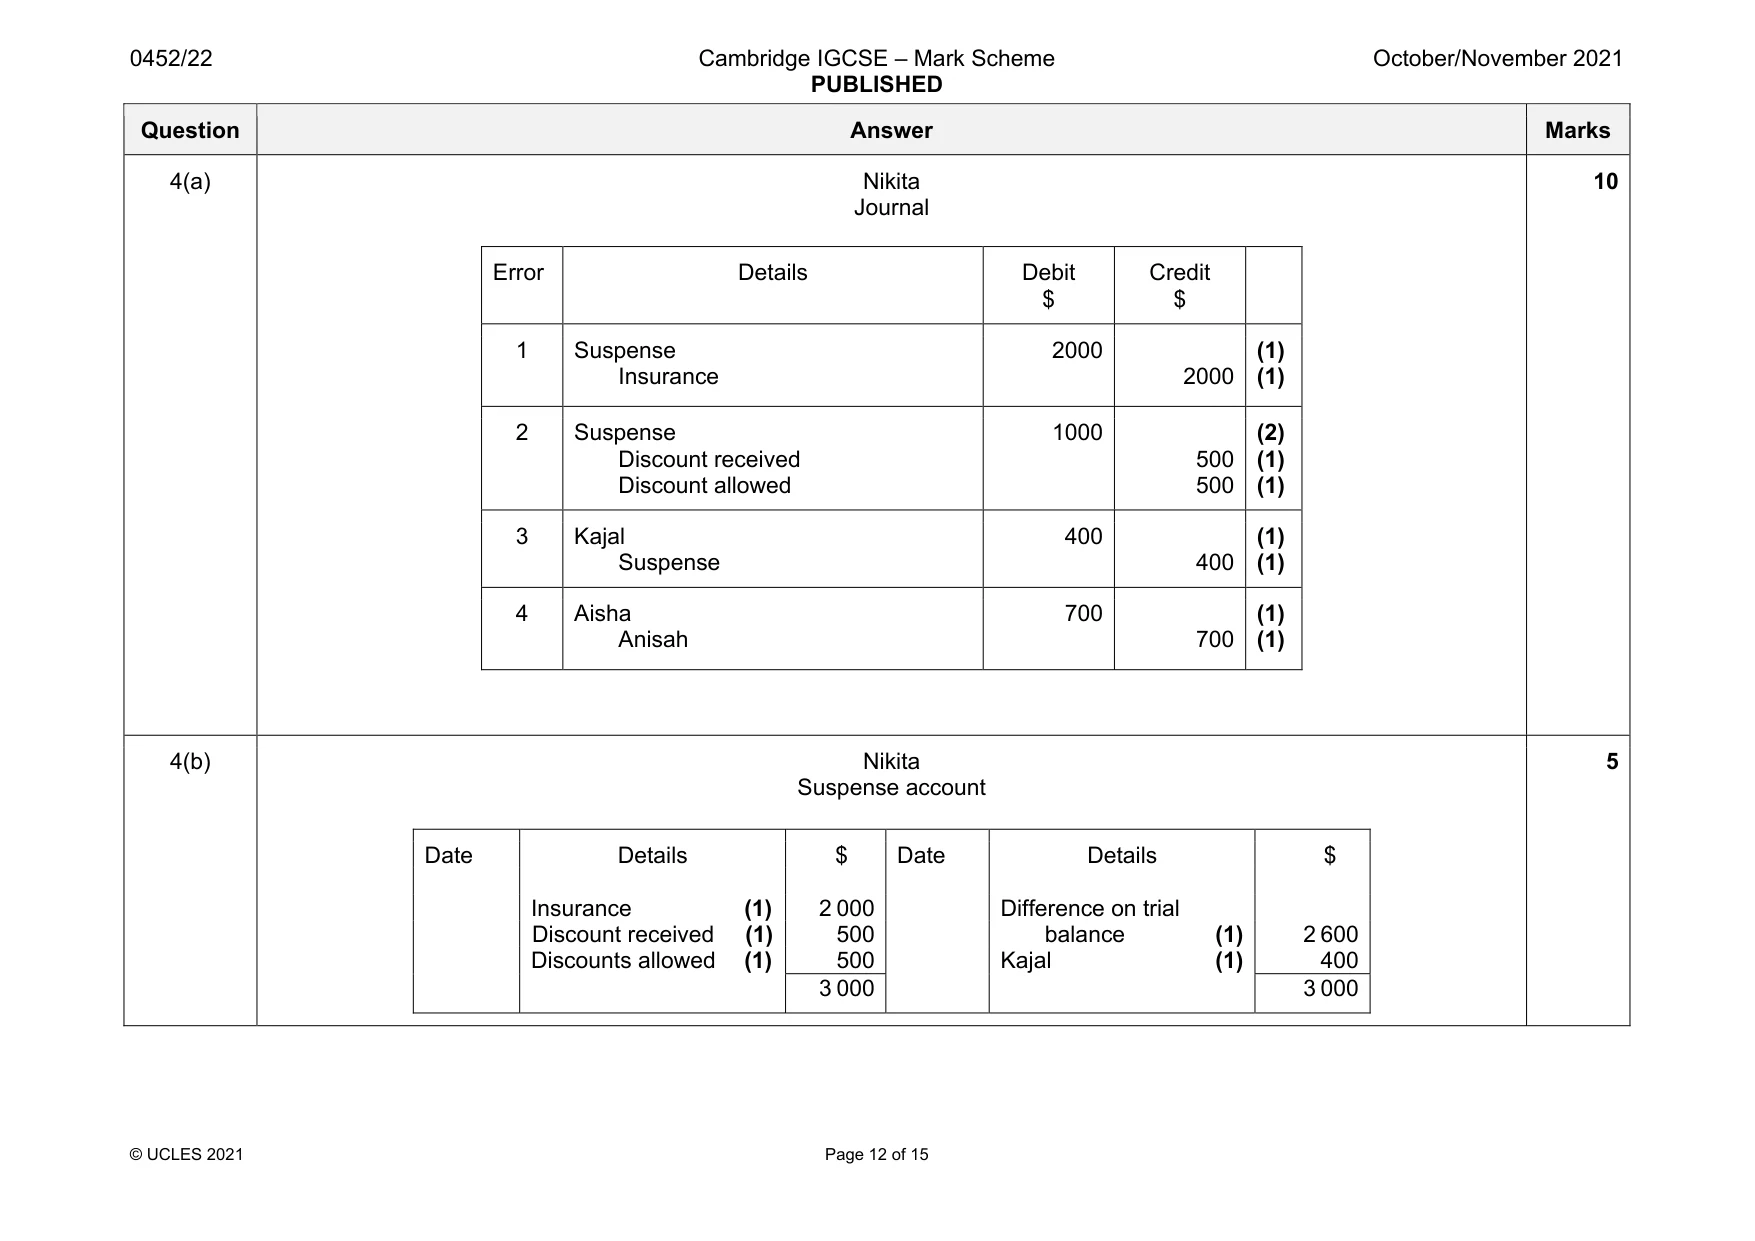
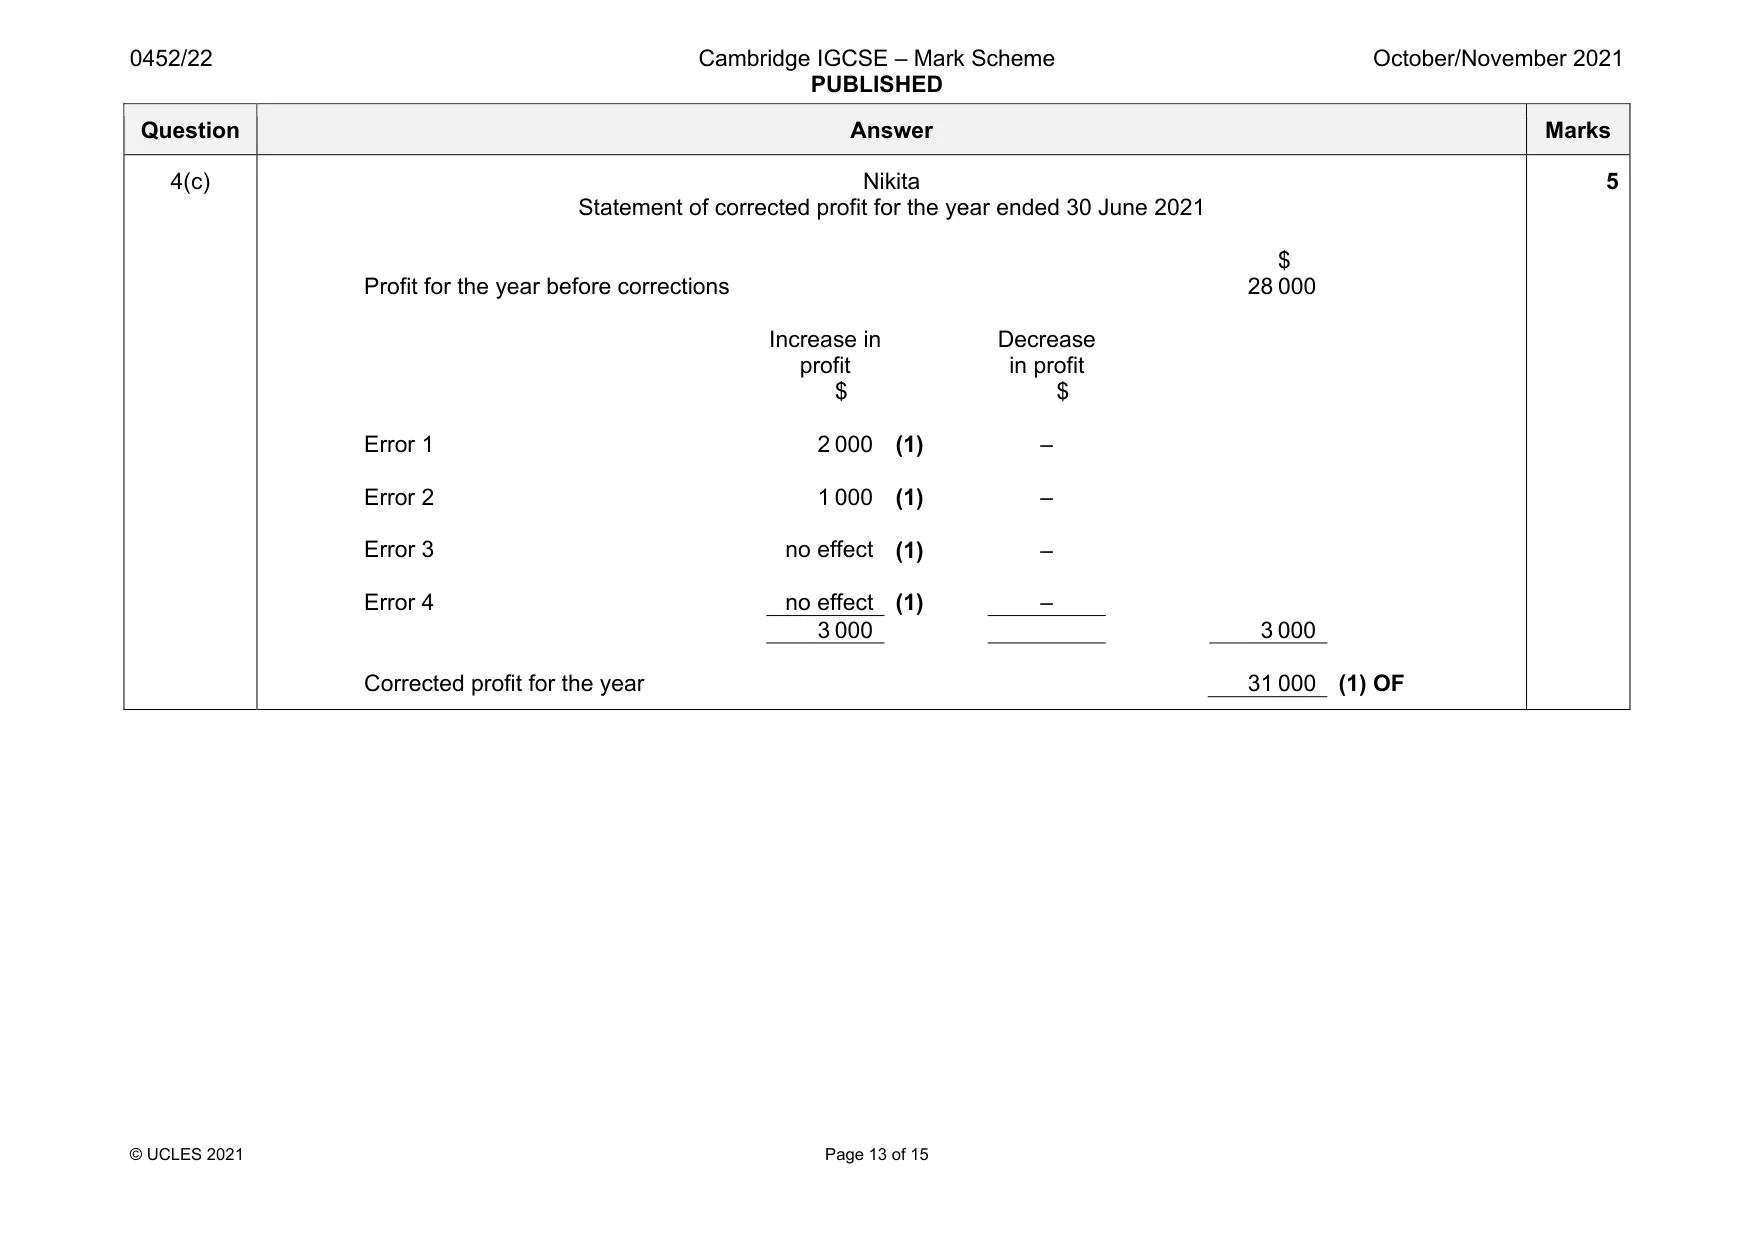
Mark scheme: 4(a) Nikita Journal Error Details Debit $ Credit $ 1 Suspense Insurance 2000 2000 (1) (1) 2 Suspense Discount received Discount allowed 1000 500 500 (2) (1) (1) 3 Kajal Suspense 400 400 (1) (1) 4 Aisha Anisah 700 700 (1) (1) 10 4(b) Nikita Suspense account Date Details $ Date Details $ Insurance (1) 2 000 Difference on trial Discount received (1) 500 balance (1) 2 600 Discounts allowed (1) 500 Kajal (1) 400 3 000 3 000 5 Question Answer Marks 4(c) Nikita Statement of corrected profit for the year ended 30 June 2021 $ Profit for the year before corrections 28 000 Increase in profit Decrease in profit $ $ Error 1 2 000 (1) – Error 2 1 000 (1) – Error 3 no effect (1) – Error 4 no effect (1) – 3 000 3 000 Corrected profit for the year 31 000 (1) OF 5
Q5 · Simon has a business selling office stationery
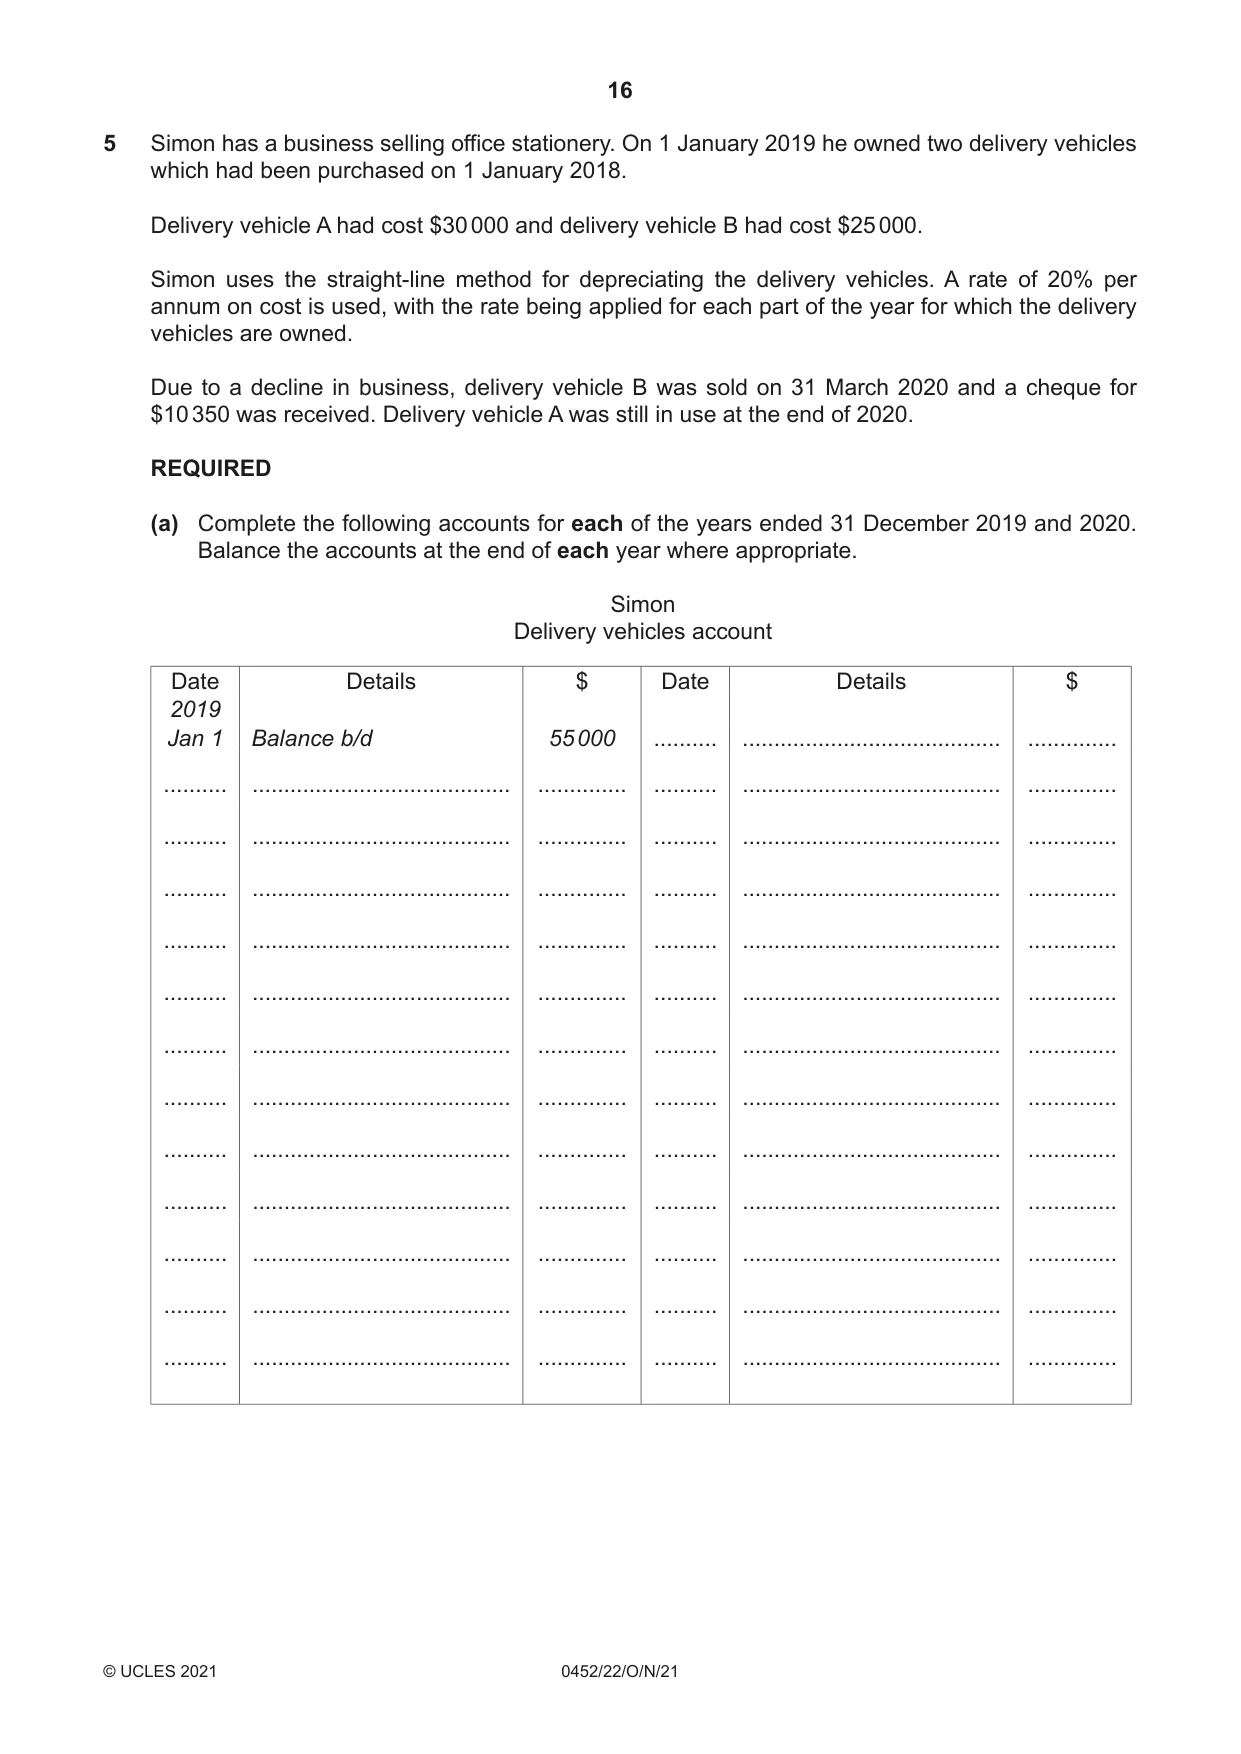
5 Simon has a business selling office stationery. On 1 January 2019 he owned two delivery vehicles which had been purchased on 1 January 2018. Delivery vehicle A had cost $30 000 and delivery vehicle B had cost $25 000. Simon uses the straight-line method for depreciating the delivery vehicles. A rate of 20% per annum on cost is used, with the rate being applied for each part of the year for which the delivery vehicles are owned. Due to a decline in business, delivery vehicle B was sold on 31 March 2020 and a cheque for $10 350 was received. Delivery vehicle A was still in use at the end of 2020. REQUIRED (a) Complete the following accounts for each of the years ended 31 December 2019 and 2020. Balance the accounts at the end of each year where appropriate. Simon Delivery vehicles account Date Details $ Date Details $ 2019 Jan 1 Balance b/d 55 000 .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. Provision for depreciation of delivery vehicles account Date Details $ Date Details $ 2019 .......... ......................................... .............. Jan 1 Balance b/d 11 000 .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. .......... ......................................... .............. Delivery vehicles disposal account Date Details $ Date Details $ .......... ........................................ .............. .......... ........................................ .............. .......... ........................................ .............. .......... ........................................ .............. .......... ........................................ .............. .......... ........................................ .............. .......... ........................................ .............. .......... ........................................ .............. .......... ........................................ .............. .......... ........................................ .............. .......... ........................................ .............. .......... ........................................ .............. .......... ........................................ .............. .......... ........................................ .............. [15] Simon’s sister Yasmin is also in business and depreciates her delivery vehicles by the reducing balance method. Simon is considering whether to apply the reducing balance method of depreciation to his delivery vehicles. REQUIRED (b) Advise Simon whether he should apply the reducing balance method of depreciation. Justify your answer. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5]
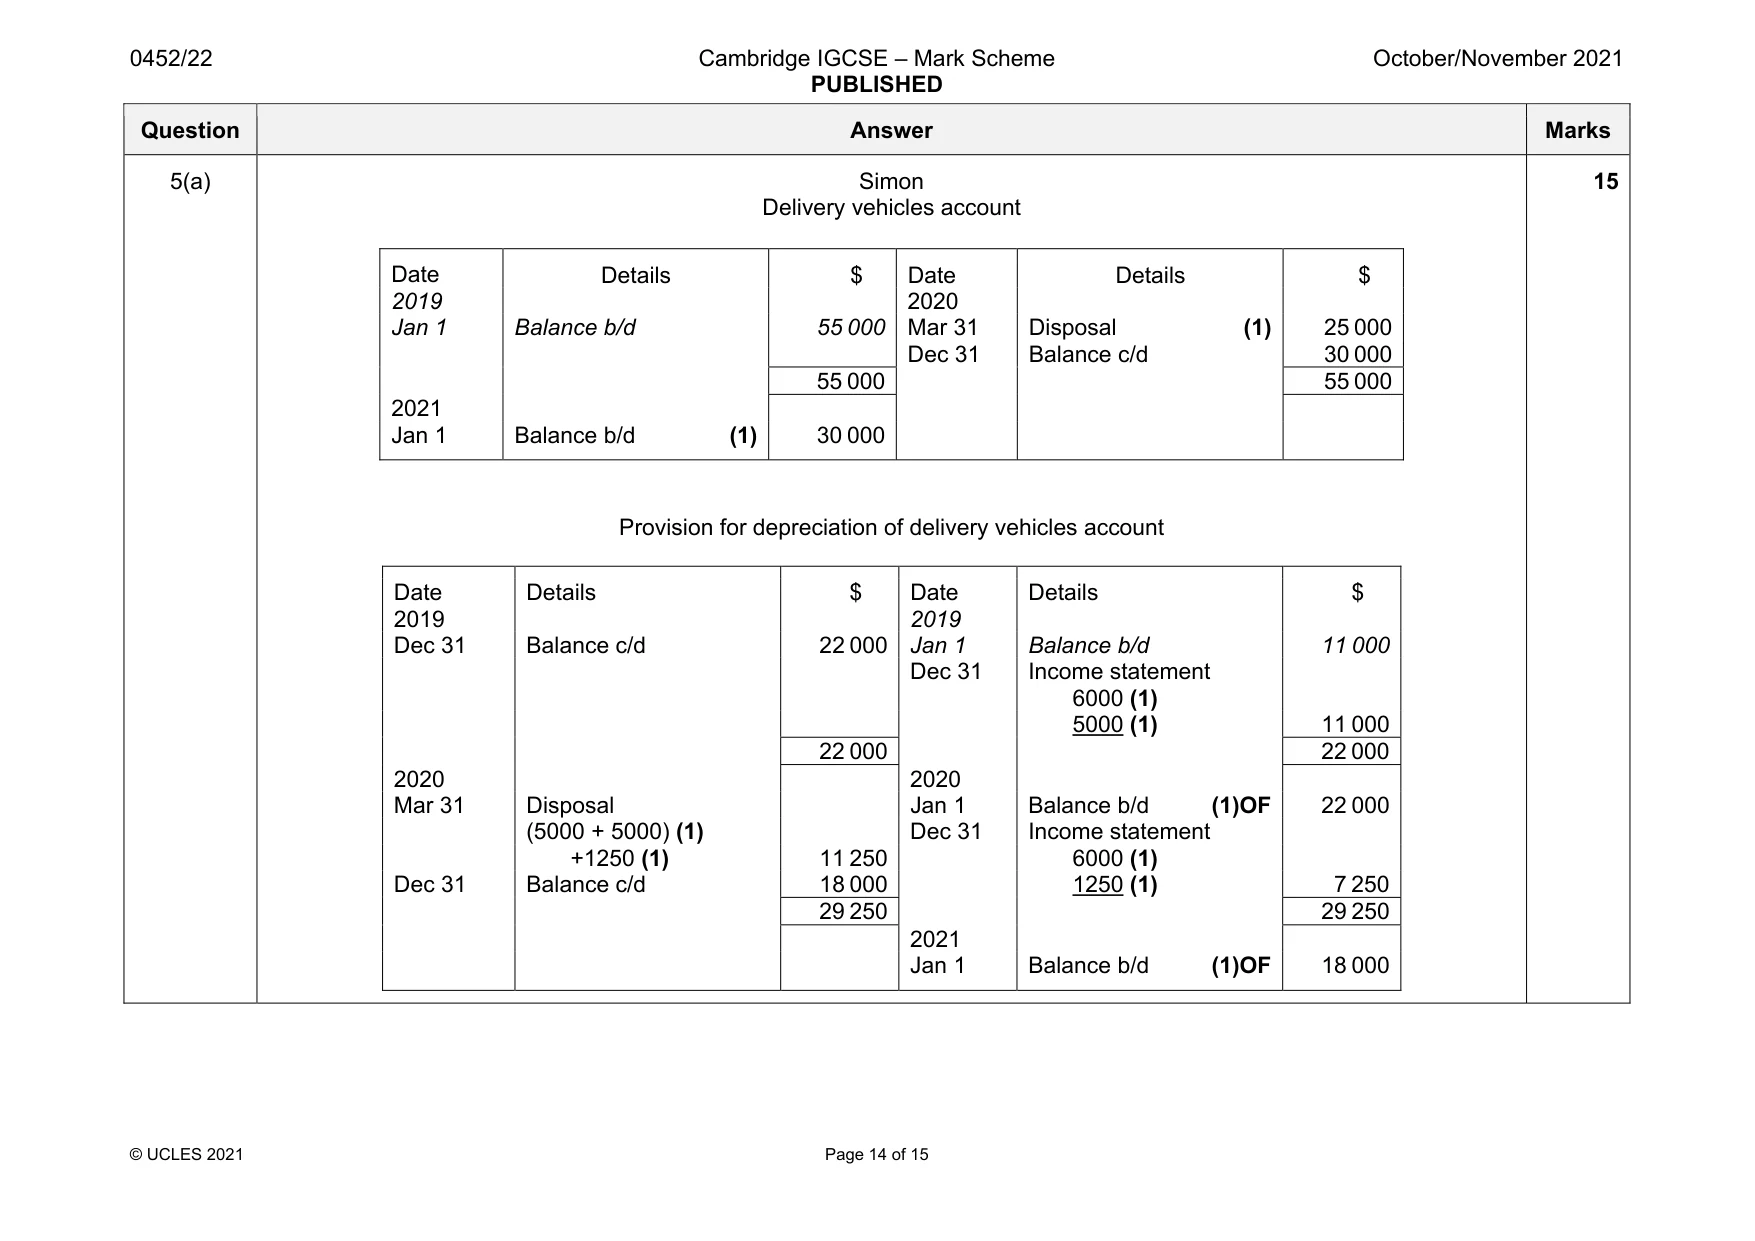
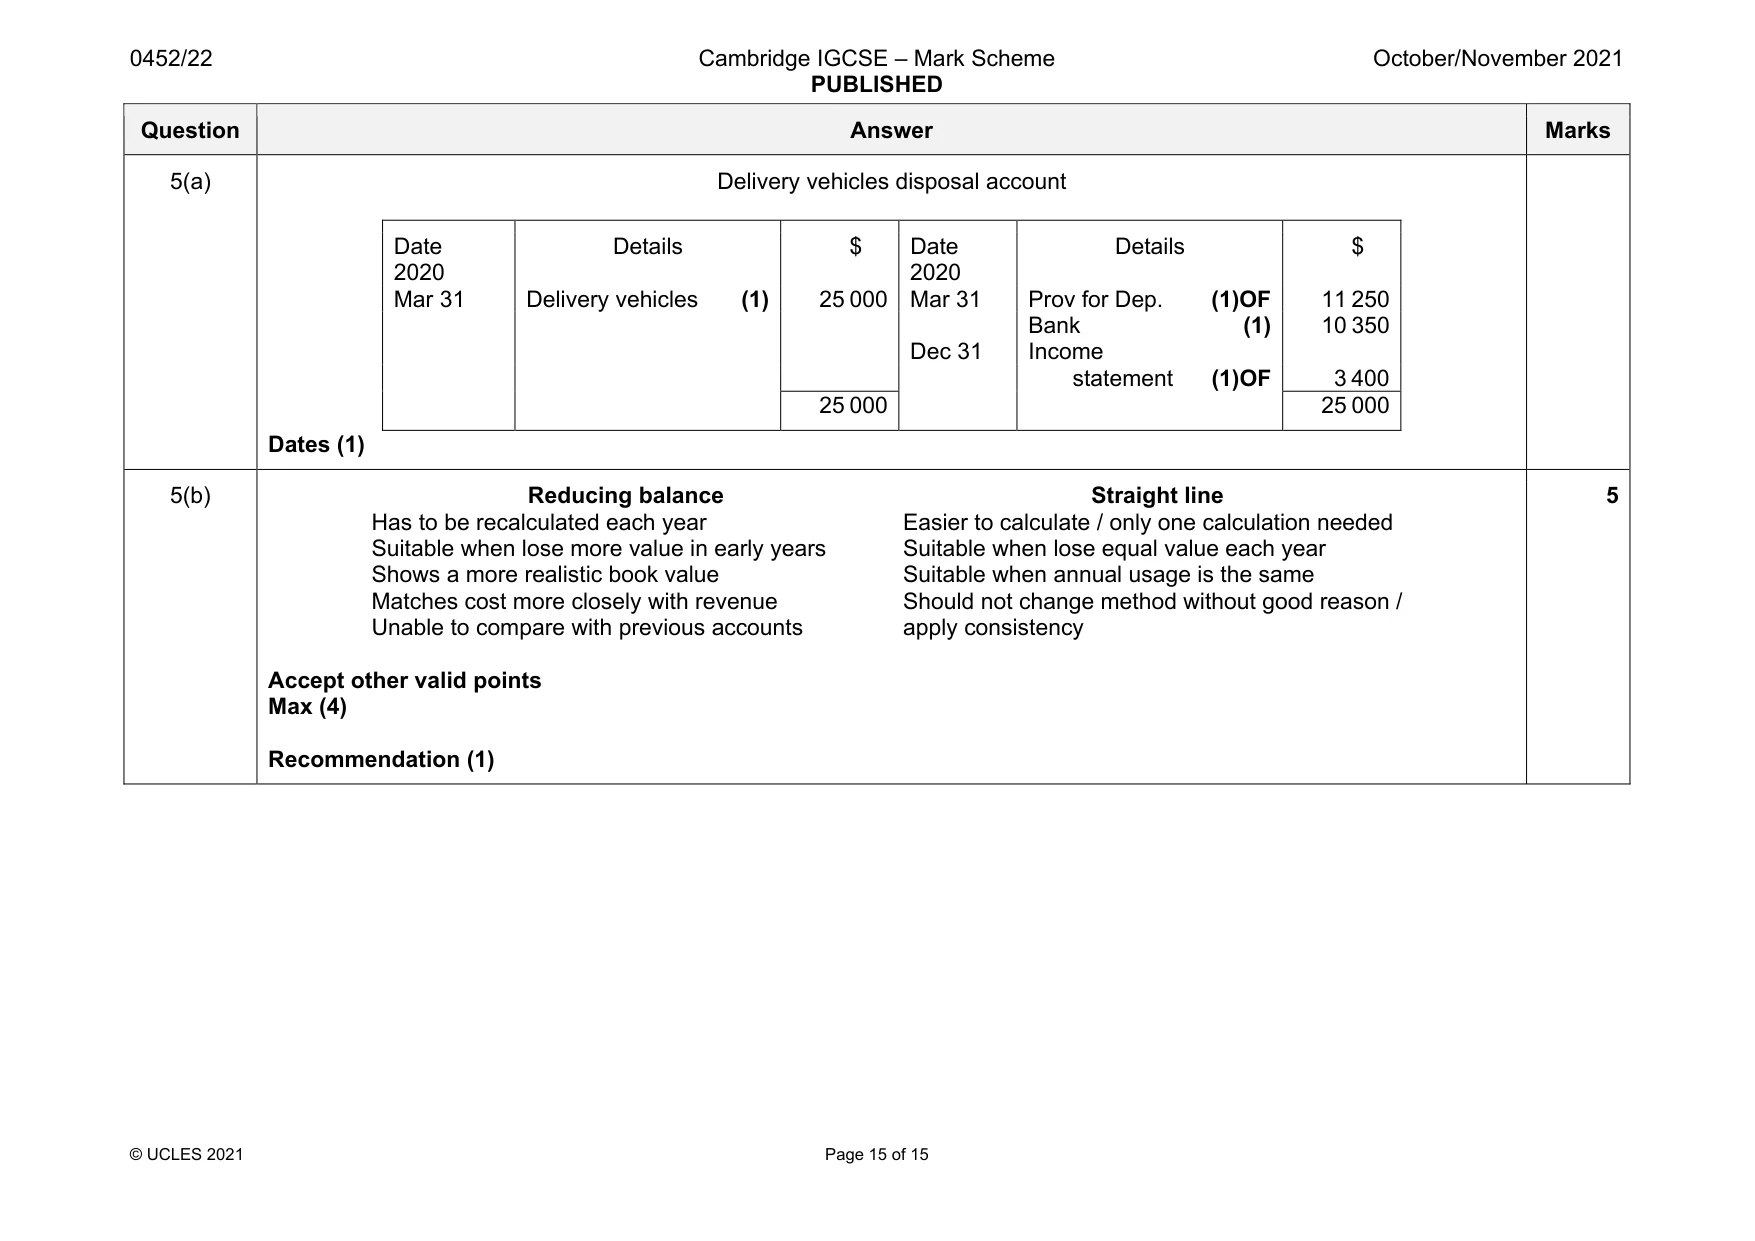
Mark scheme: 5(a) Simon Delivery vehicles account Date Details $ Date Details $ 2019 2020 Jan 1 Balance b/d 55 000 Mar 31 Disposal (1) 25 000 Dec 31 Balance c/d 30 000 55 000 55 000 2021 Jan 1 Balance b/d (1) 30 000 Provision for depreciation of delivery vehicles account Date Details $ Date Details $ 2019 2019 Dec 31 Balance c/d 22 000 Jan 1 Balance b/d 11 000 Dec 31 Income statement 6000 (1) 5000 (1) 11 000 22 000 22 000 2020 2020 Mar 31 Disposal Jan 1 Balance b/d (1)OF 22 000 (5000 + 5000) (1) Dec 31 Income statement +1250 (1) 11 250 6000 (1) Dec 31 Balance c/d 18 000 1250 (1) 7 250 29 250 29 250 2021 Jan 1 Balance b/d (1)OF 18 000 15 Question Answer Marks 5(a) Delivery vehicles disposal account Date Details $ Date Details $ 2020 2020 Mar 31 Delivery vehicles (1) 25 000 Mar 31 Prov for Dep. (1)OF 11 250 Bank (1) 10 350 Dec 31 Income statement (1)OF 3 400 25 000 25 000 Dates (1) 5(b) Reducing balance Has to be recalculated each year Suitable when lose more value in early years Shows a more realistic book value Matches cost more closely with revenue Unable to compare with previous accounts Straight line Easier to calculate / only one calculation needed Suitable when lose equal value each year Suitable when annual usage is the same Should not change method without good reason / apply consistency Accept other valid points Max (4) Recommendation (1) 5
More questions on Accounting for depreciation and disposal of non-current assets
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2021 Oct/Nov, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.