Cambridge IGCSE Accounting 0452 — 2020 Oct/Nov Paper 2 · Variant 3
0452/23/O/N/20 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme14 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Sariah owns a business selling ladies’ clothing
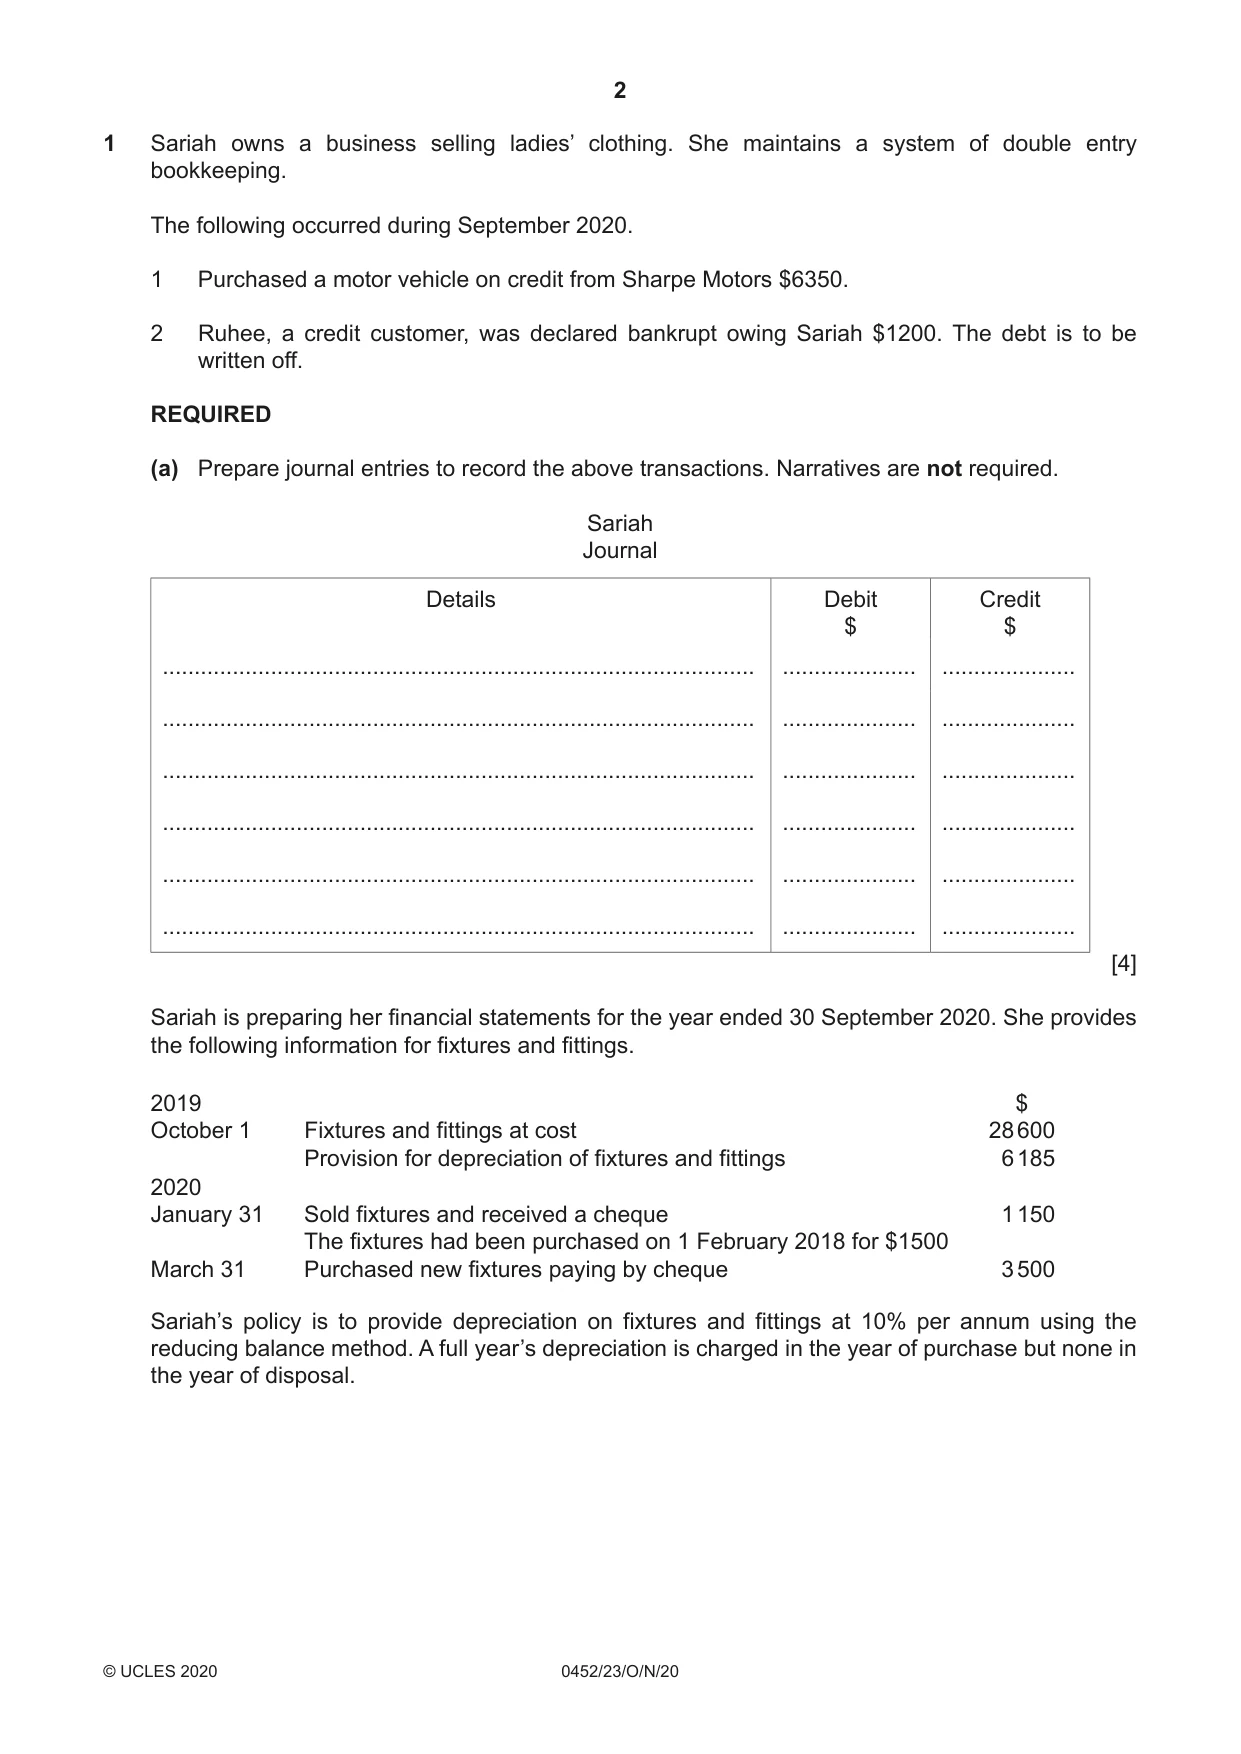
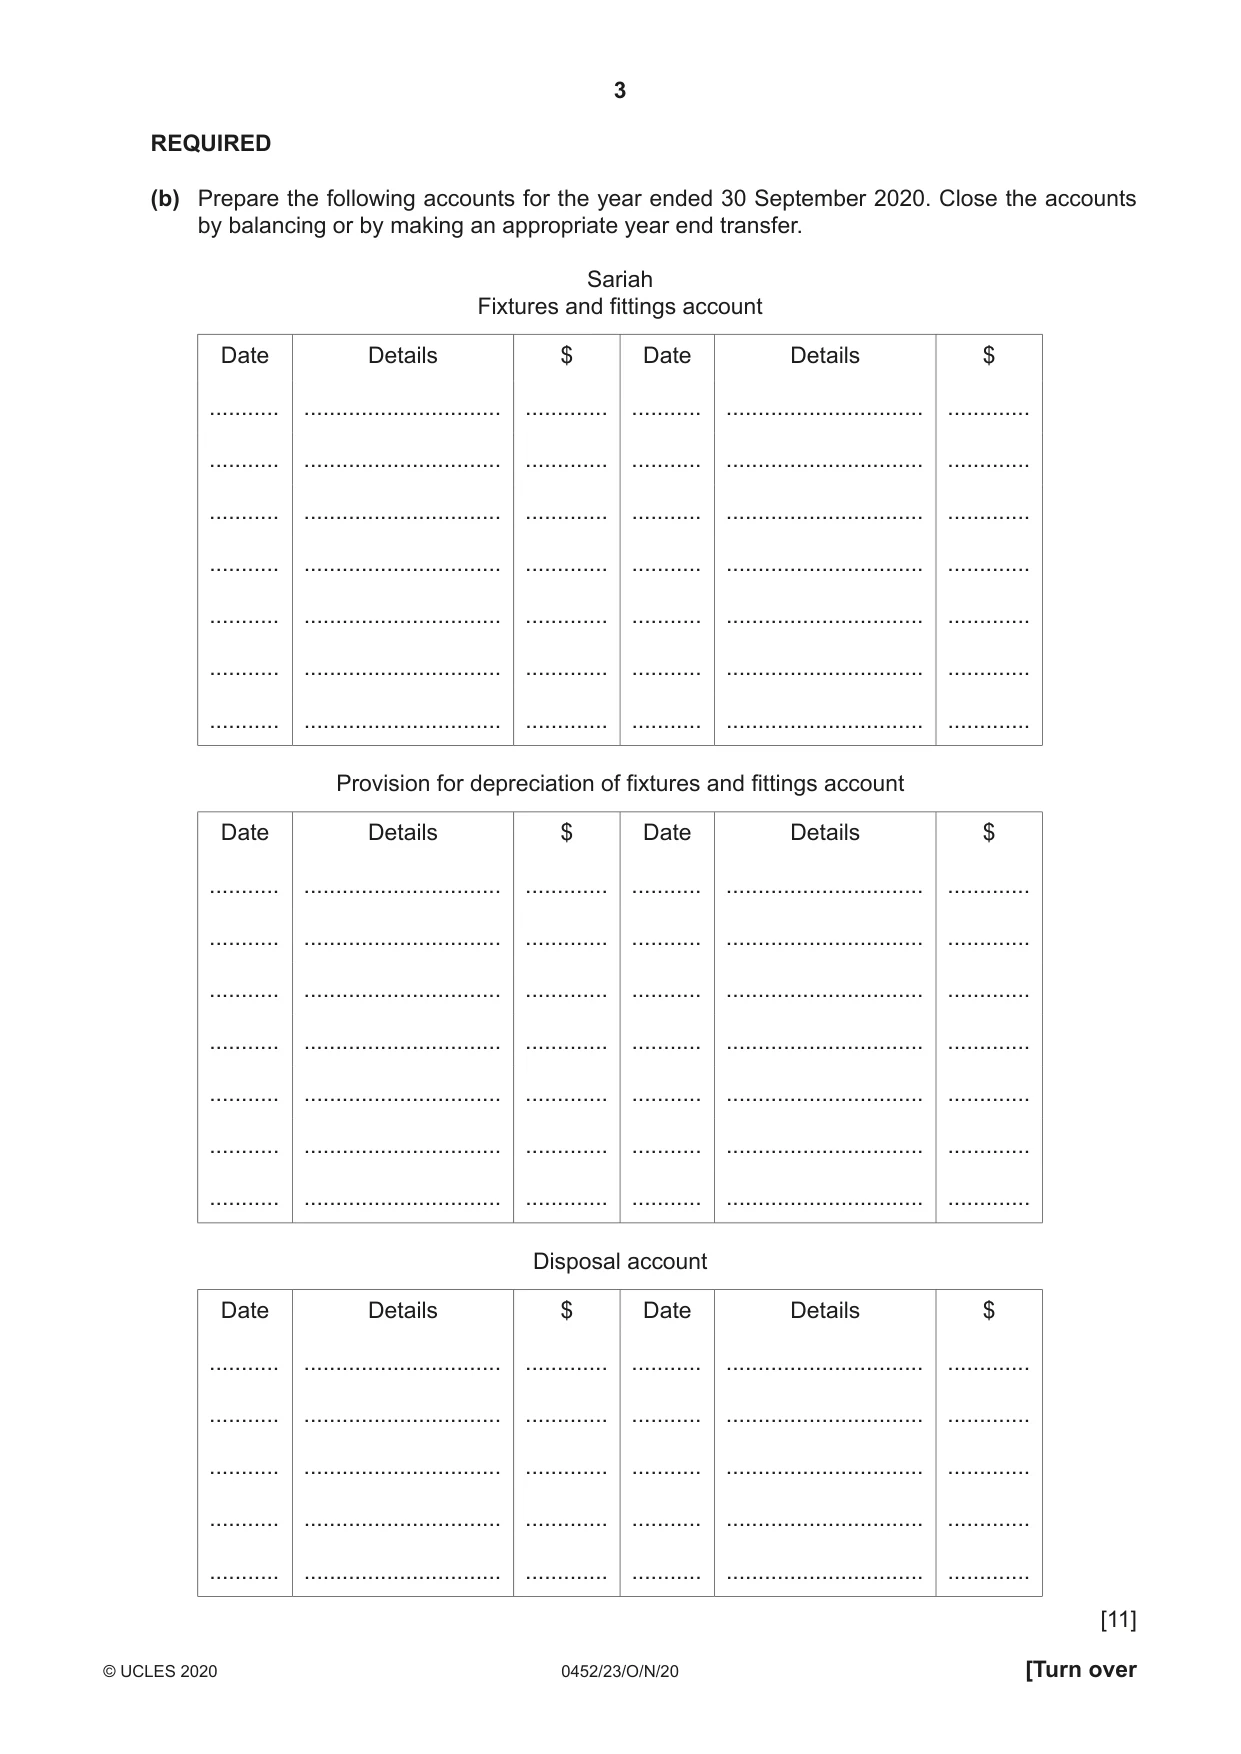
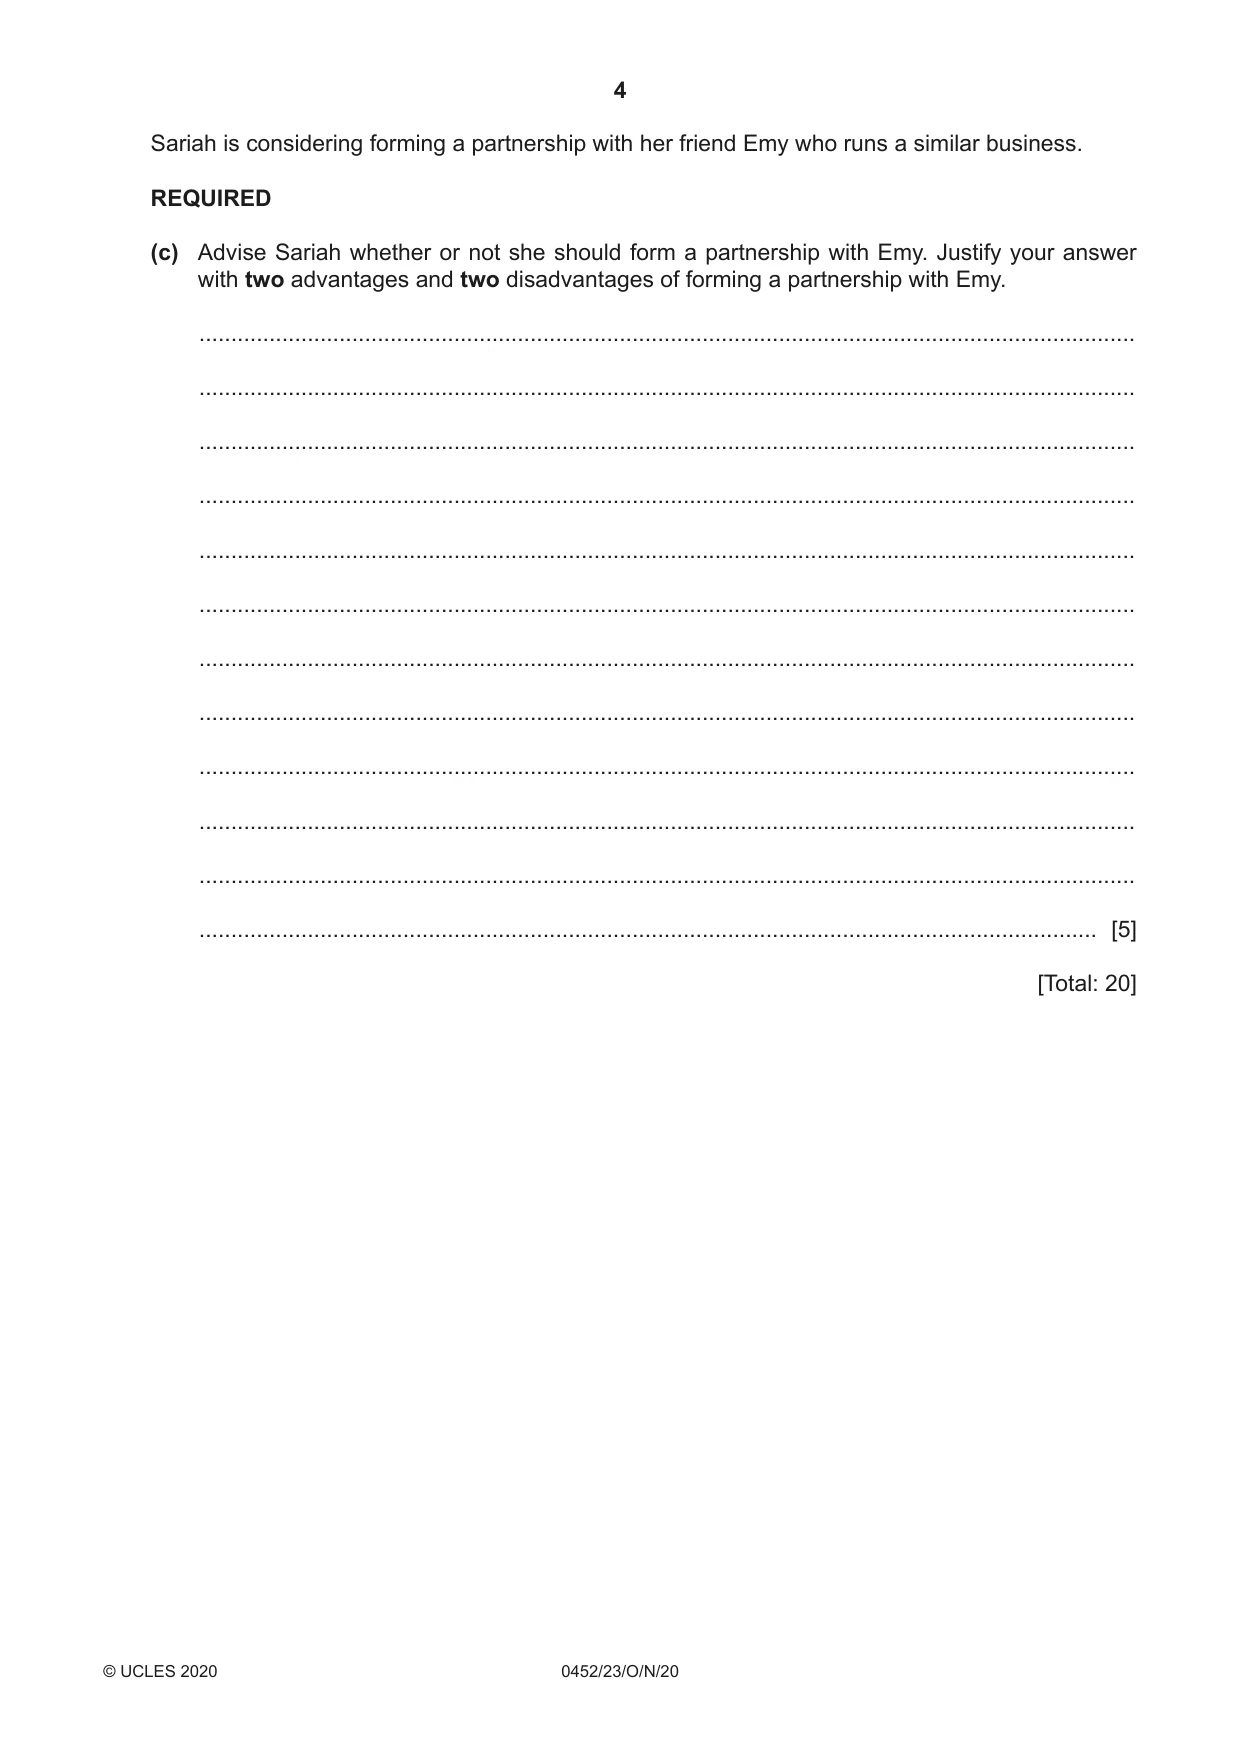
1 Sariah owns a business selling ladies’ clothing. She maintains a system of double entry bookkeeping. The following occurred during September 2020. 1 Purchased a motor vehicle on credit from Sharpe Motors $6350. 2 Ruhee, a credit customer, was declared bankrupt owing Sariah $1200. The debt is to be written off. REQUIRED (a) Prepare journal entries to record the above transactions. Narratives are not required. Sariah Journal Details Debit Credit $ $ ............................................................................................. ..................... ..................... ............................................................................................. ..................... ..................... ............................................................................................. ..................... ..................... ............................................................................................. ..................... ..................... ............................................................................................. ..................... ..................... ............................................................................................. ..................... ..................... [4] Sariah is preparing her financial statements for the year ended 30 September 2020. She provides the following information for fixtures and fittings. 2019 $ October 1 Fixtures and fittings at cost 28 600 Provision for depreciation of fixtures and fittings 6 185 2020 January 31 Sold fixtures and received a cheque 1 150 The fixtures had been purchased on 1 February 2018 for $1500 March 31 Purchased new fixtures paying by cheque 3 500 Sariah’s policy is to provide depreciation on fixtures and fittings at 10% per annum using the reducing balance method. A full year’s depreciation is charged in the year of purchase but none in the year of disposal. REQUIRED (b) Prepare the following accounts for the year ended 30 September 2020. Close the accounts by balancing or by making an appropriate year end transfer. Sariah Fixtures and fittings account Date Details $ Date Details $ ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. Provision for depreciation of fixtures and fittings account Date Details $ Date Details $ ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. Disposal account Date Details $ Date Details $ ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. [11] Sariah is considering forming a partnership with her friend Emy who runs a similar business. REQUIRED (c) Advise Sariah whether or not she should form a partnership with Emy. Justify your answer with two advantages and two disadvantages of forming a partnership with Emy. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20] PLEASE TURN OVER
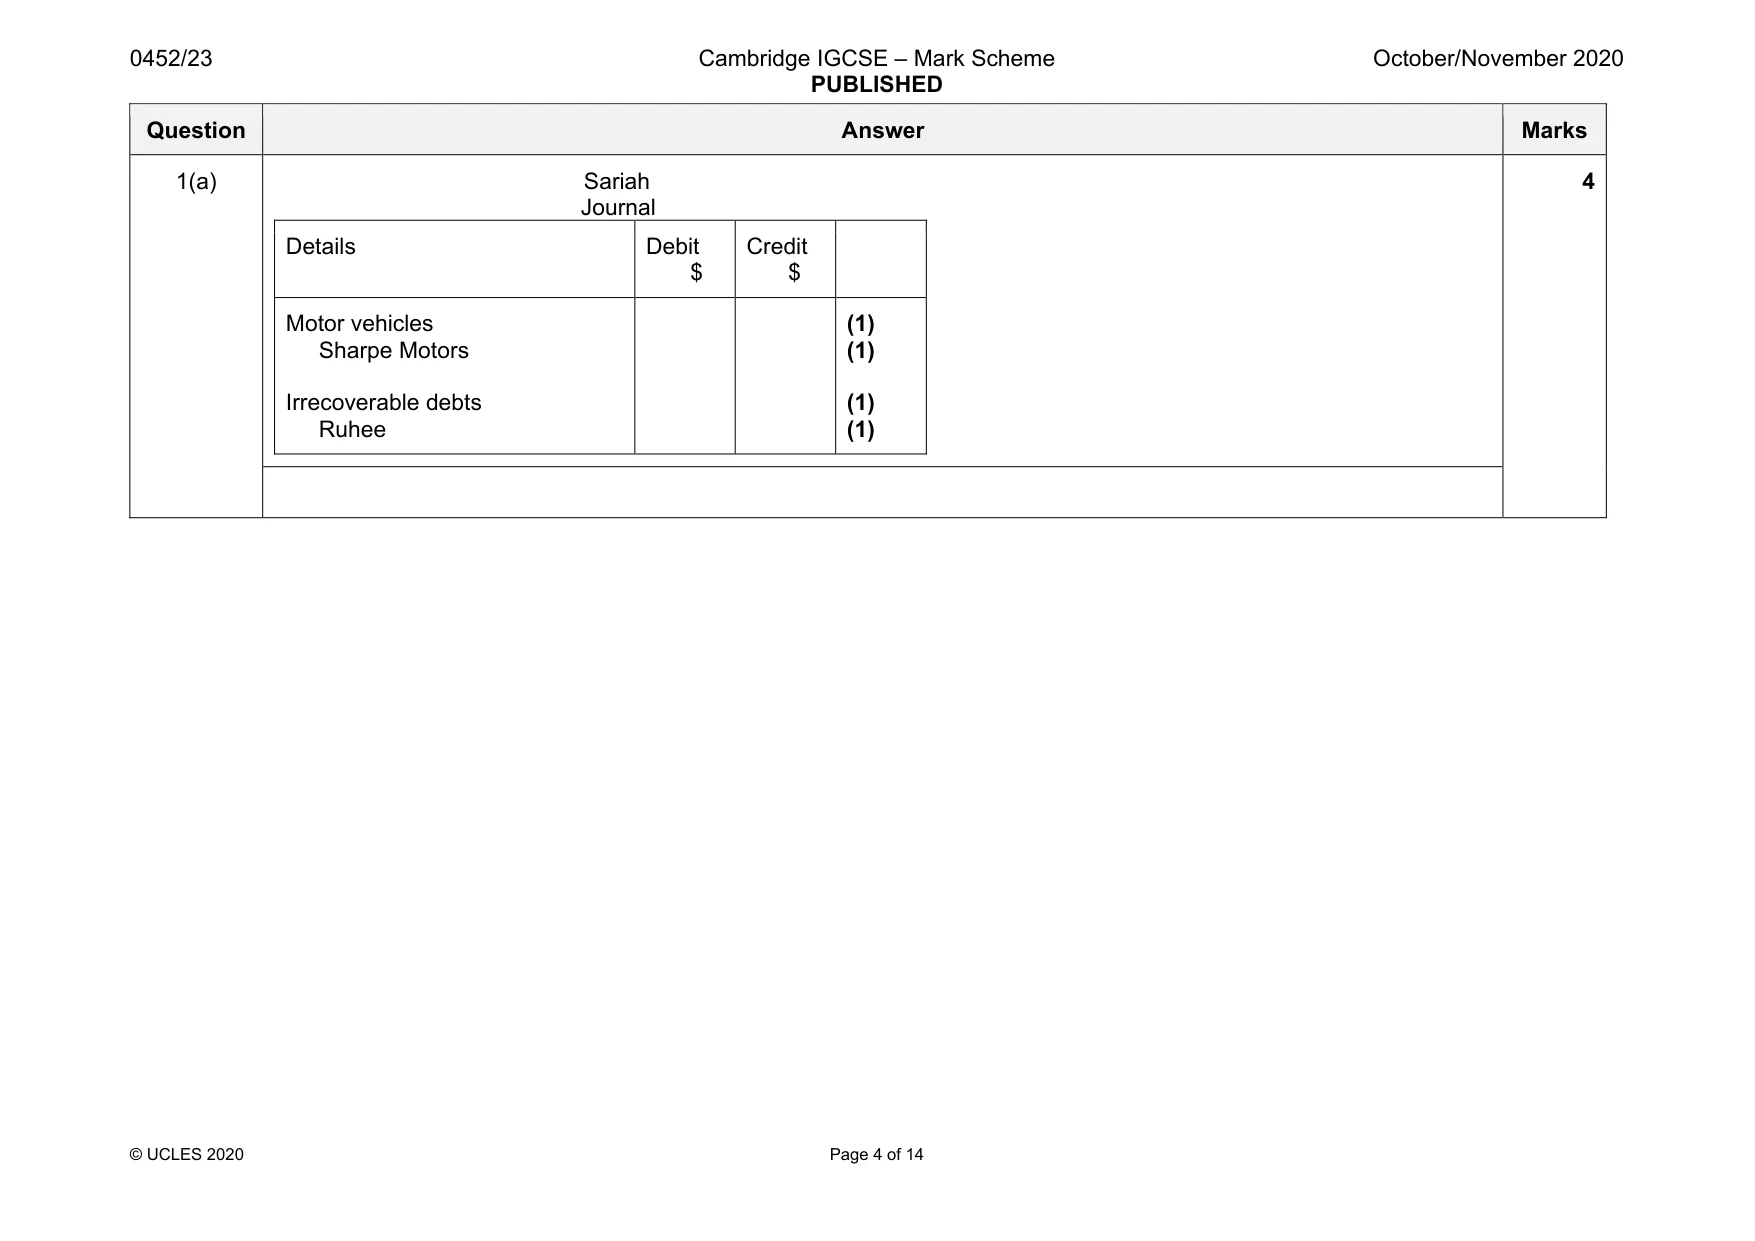
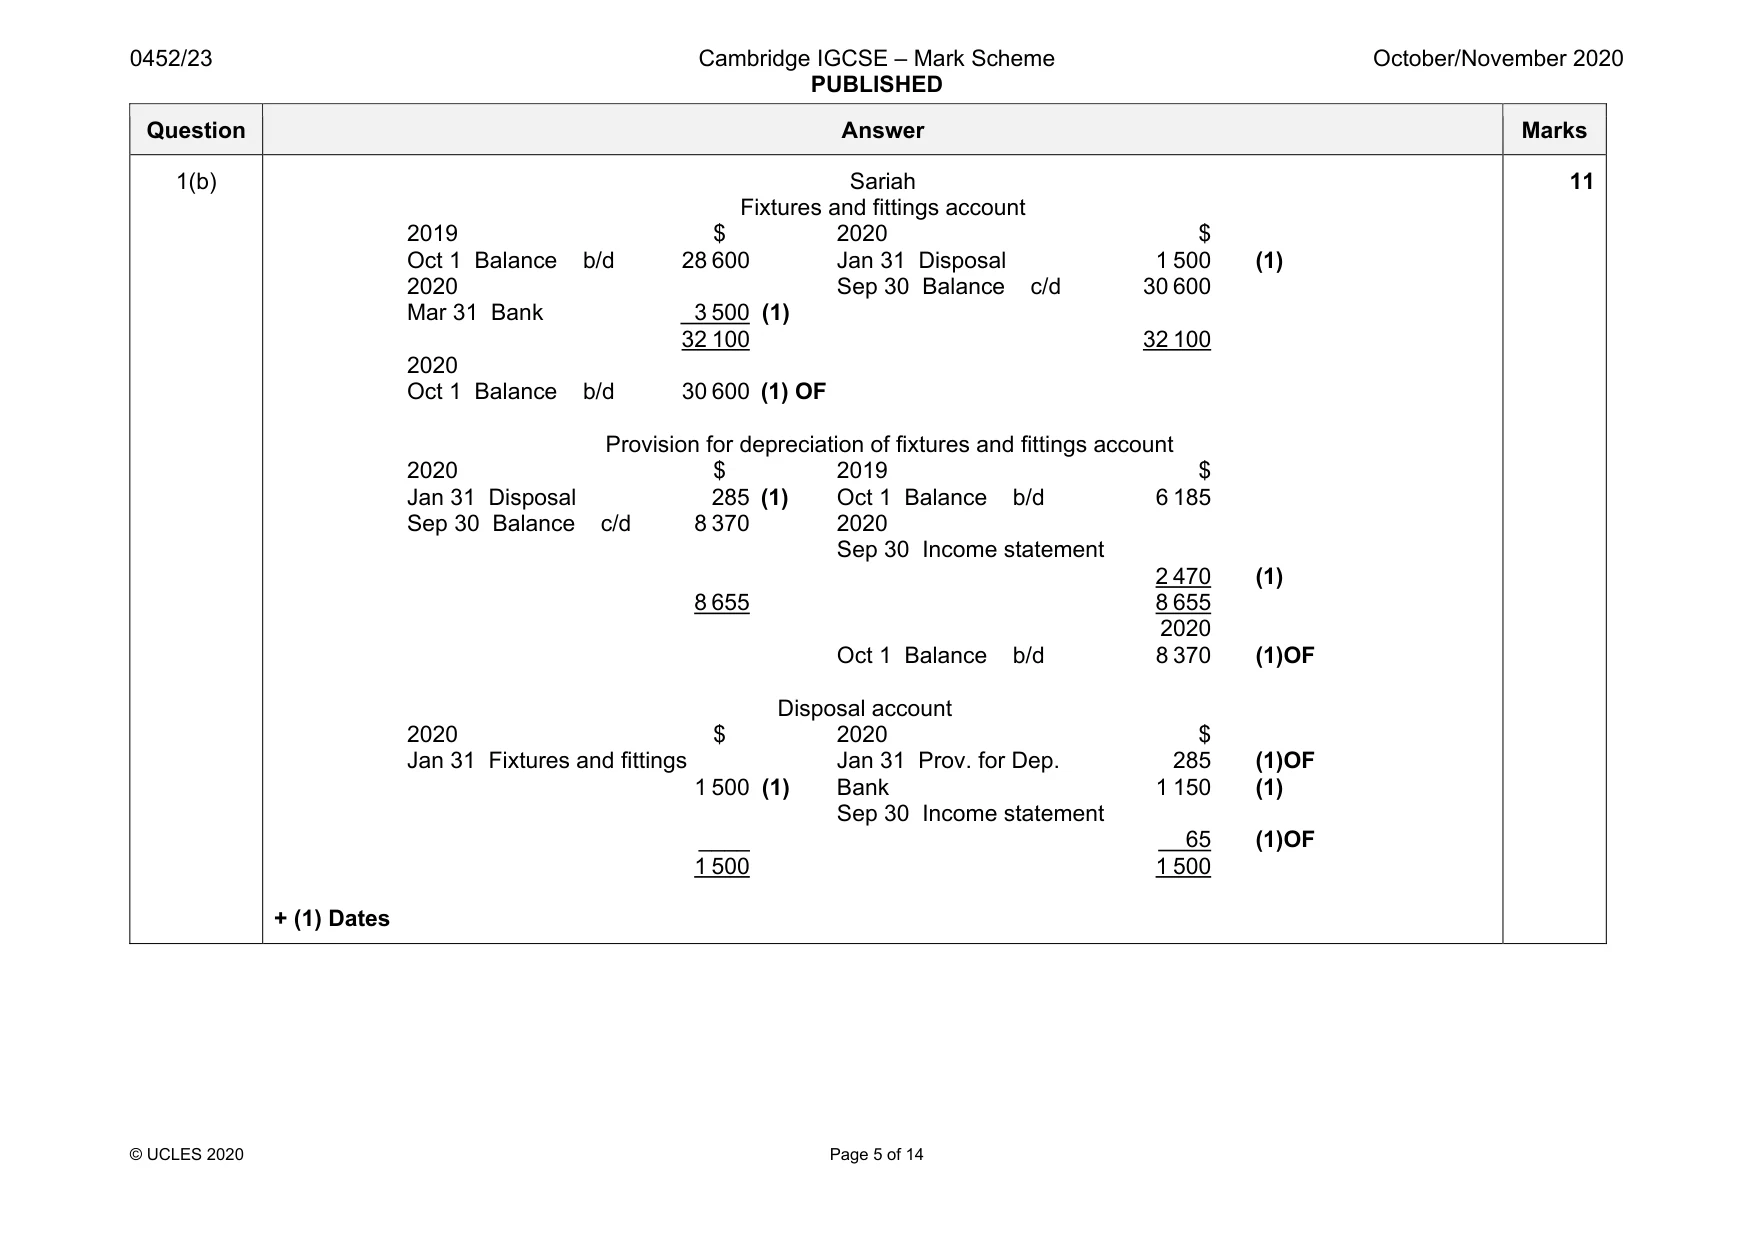
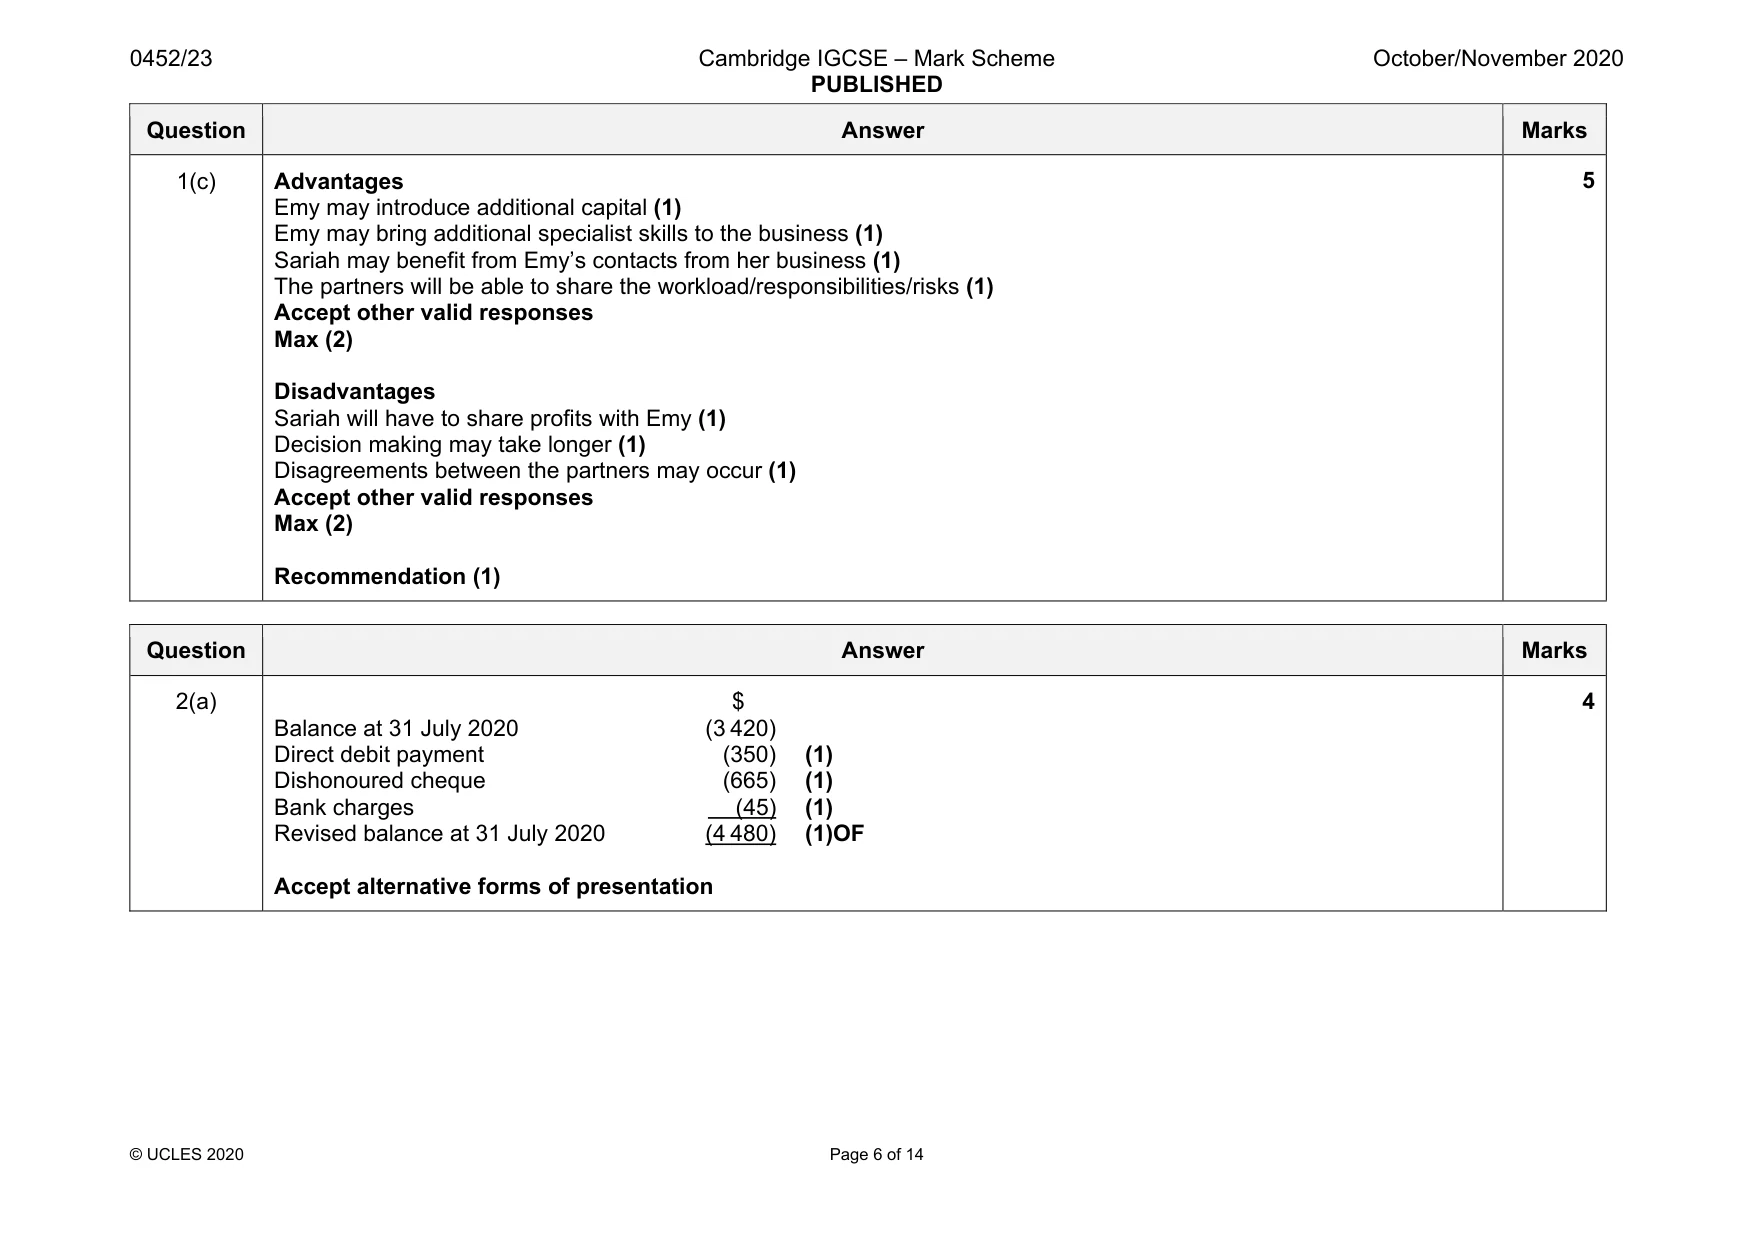
Mark scheme: 1(a) Sariah Journal Details Debit $ Credit $ Motor vehicles Sharpe Motors Irrecoverable debts Ruhee (1) (1) (1) (1) 4 Question Answer Marks 1(b) Sariah Fixtures and fittings account 2019 $ 2020 $ Oct 1 Balance b/d 28 600 Jan 31 Disposal 1 500 (1) 2020 Sep 30 Balance c/d 30 600 Mar 31 Bank 3 500 (1) 32 100 32 100 2020 Oct 1 Balance b/d 30 600 (1) OF Provision for depreciation of fixtures and fittings account 2020 $ 2019 $ Jan 31 Disposal 285 (1) Oct 1 Balance b/d 6 185 Sep 30 Balance c/d 8 370 2020 Sep 30 Income statement 2 470 (1) 8 655 8 655 2020 Oct 1 Balance b/d 8 370 (1)OF Disposal account 2020 $ 2020 $ Jan 31 Fixtures and fittings Jan 31 Prov. for Dep. 285 (1)OF 1 500 (1) Bank 1 150 (1) Sep 30 Income statement ____ 65 (1)OF 1 500 1 500 + (1) Dates 11 Question Answer Marks 1(c) Advantages Emy may introduce additional capital (1) Emy may bring additional specialist skills to the business (1) Sariah may benefit from Emy’s contacts from her business (1) The partners will be able to share the workload/responsibilities/risks (1) Accept other valid responses Max (2) Disadvantages Sariah will have to share profits with Emy (1) Decision making may take longer (1) Disagreements between the partners may occur (1) Accept other valid responses Max (2) Recommendation (1) 5
More questions on Accounting for depreciation and disposal of non-current assets
Q2 · Eniola compared her bank statement for July 2020 with the bank columns of her cash book
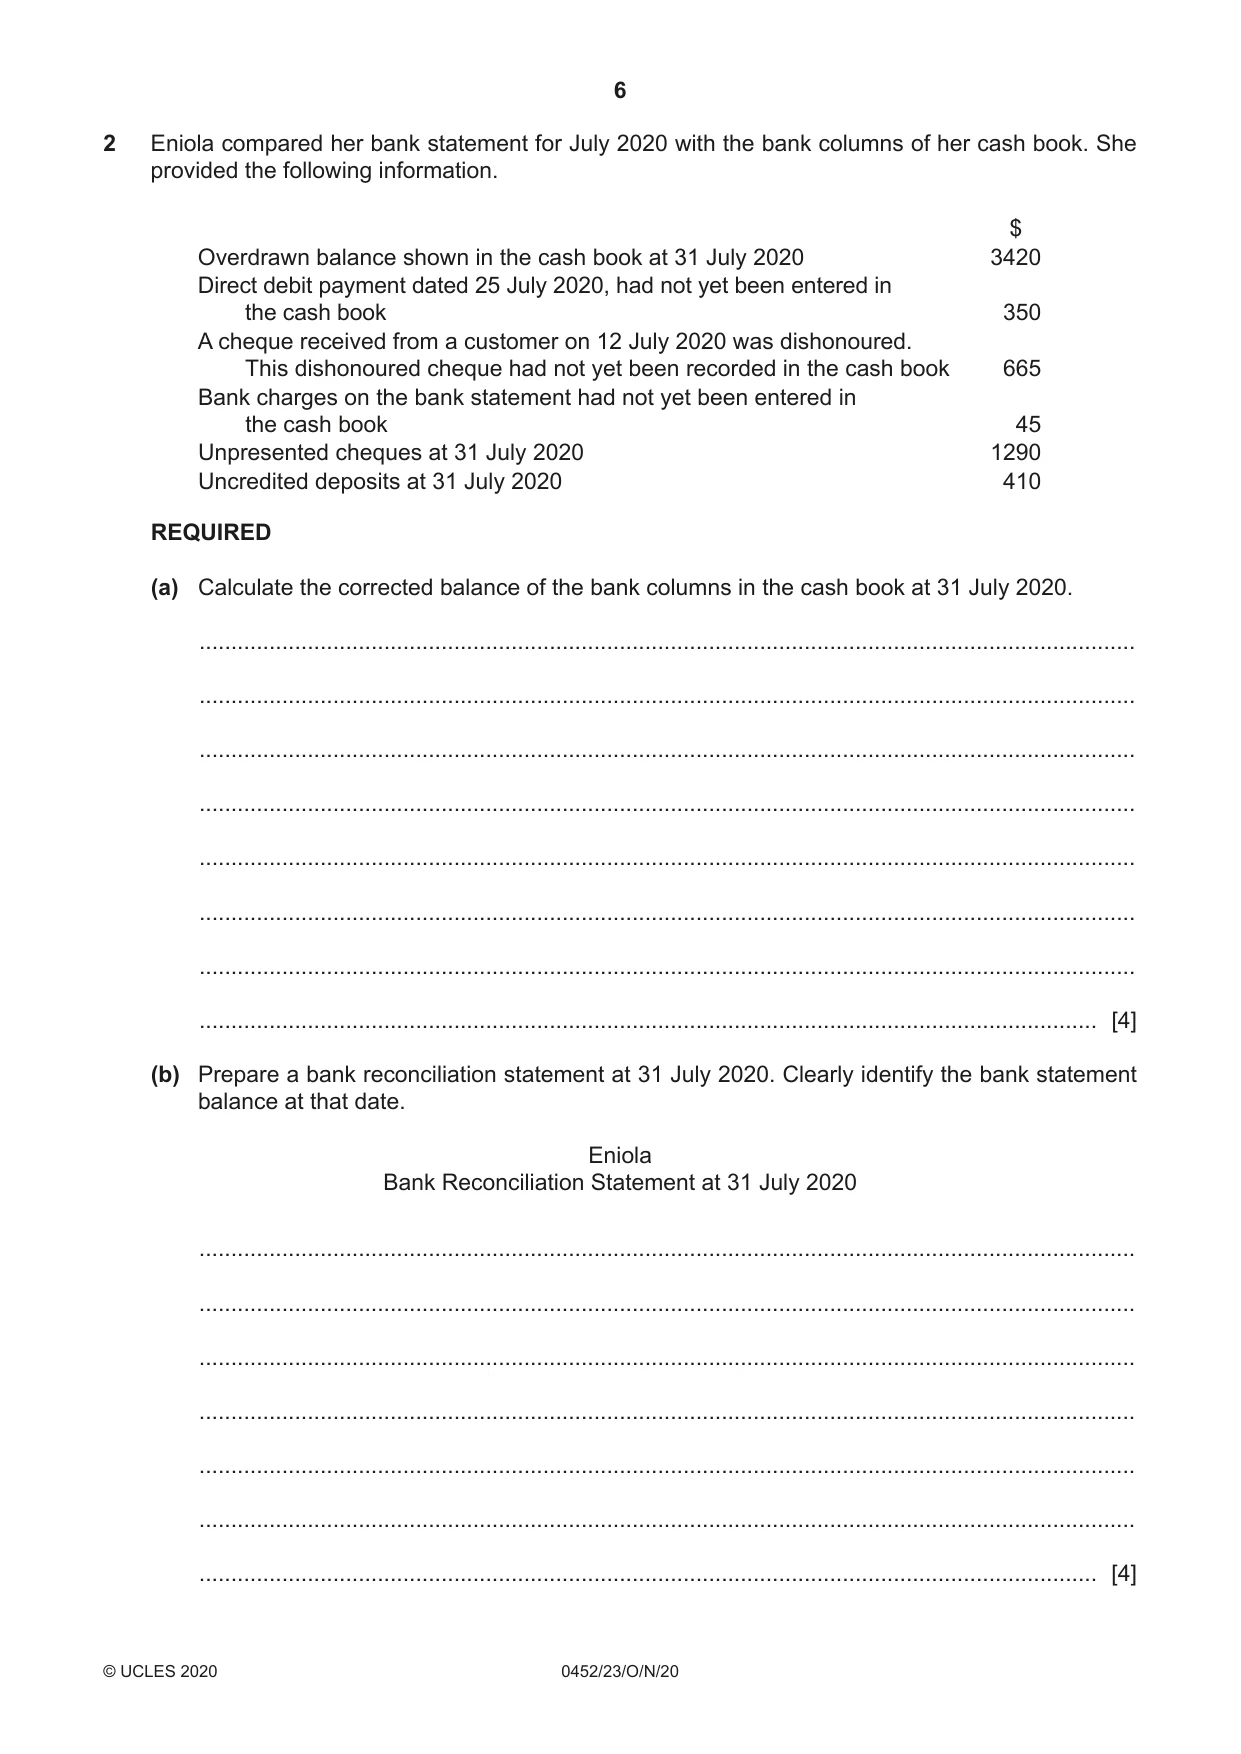
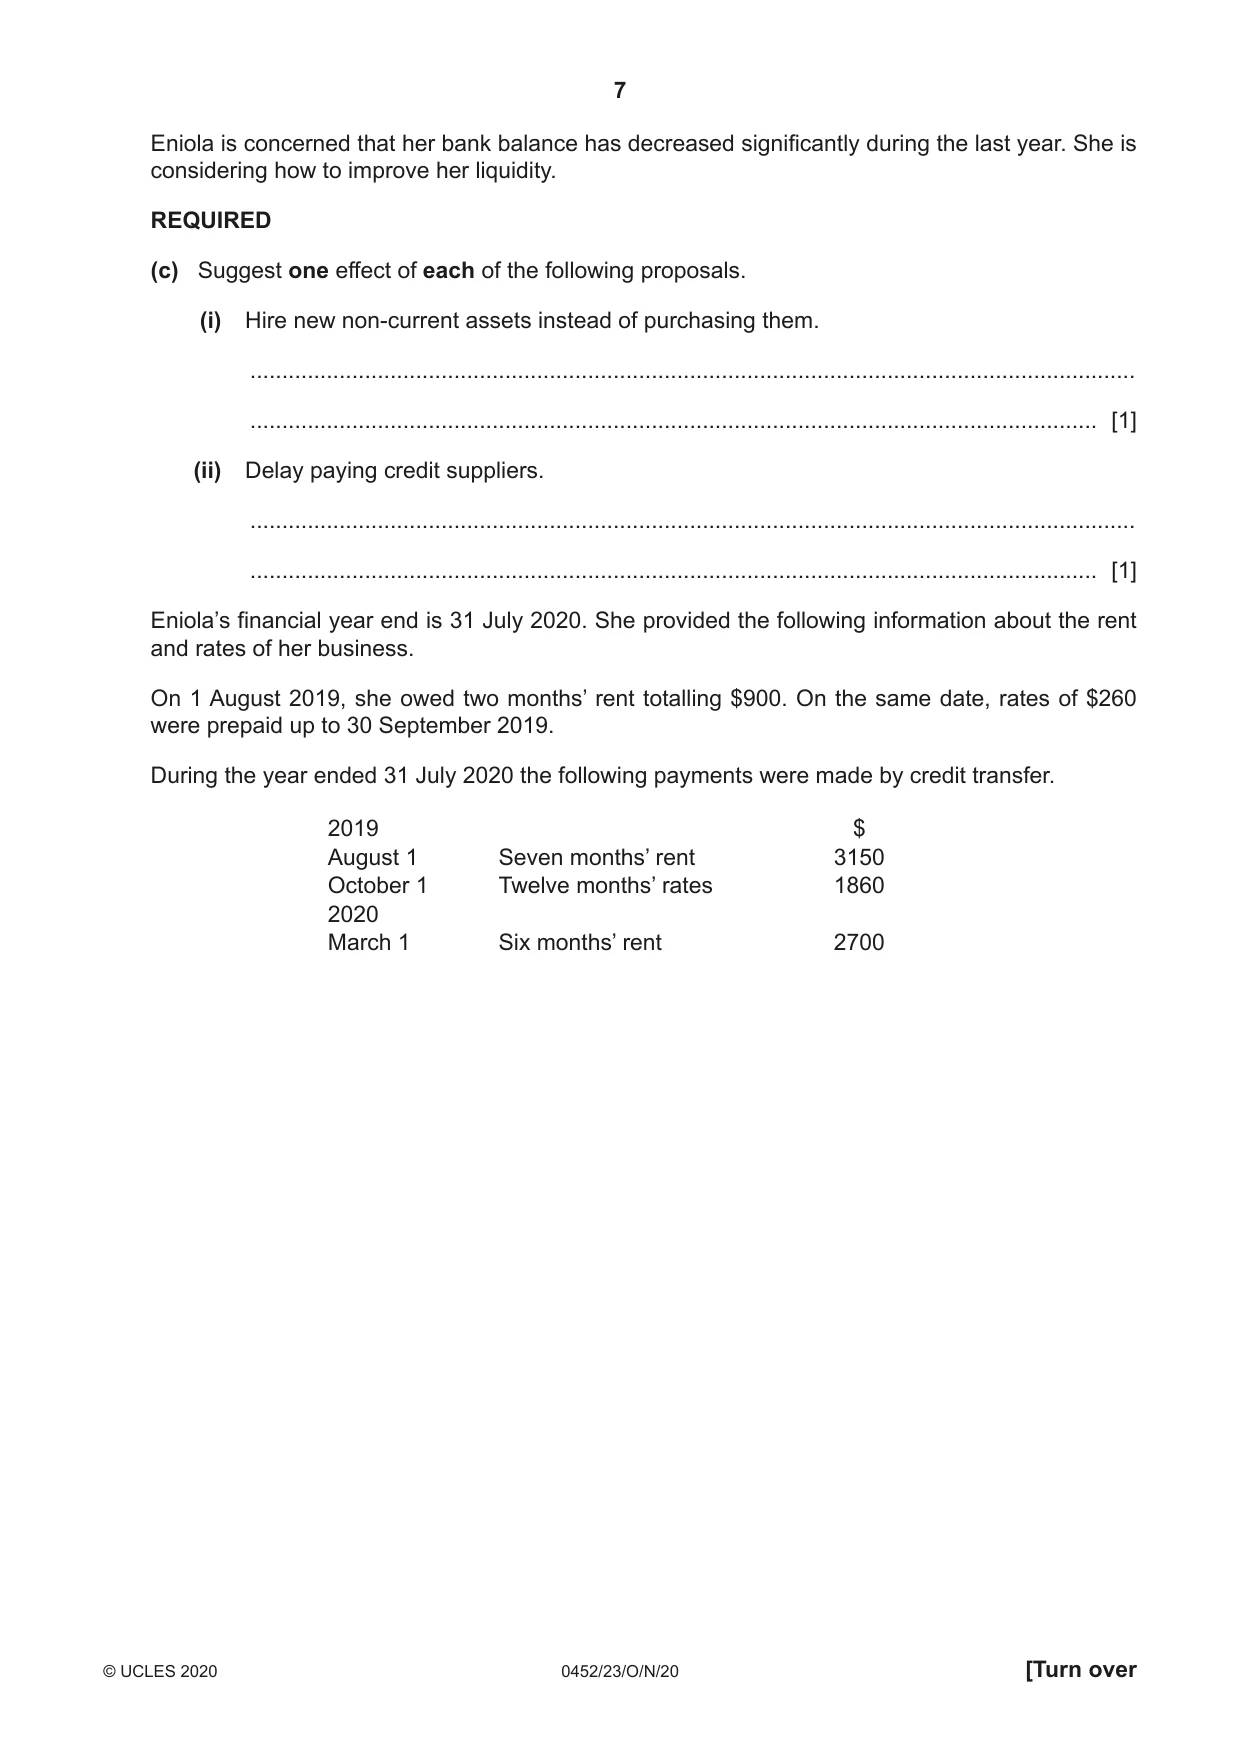
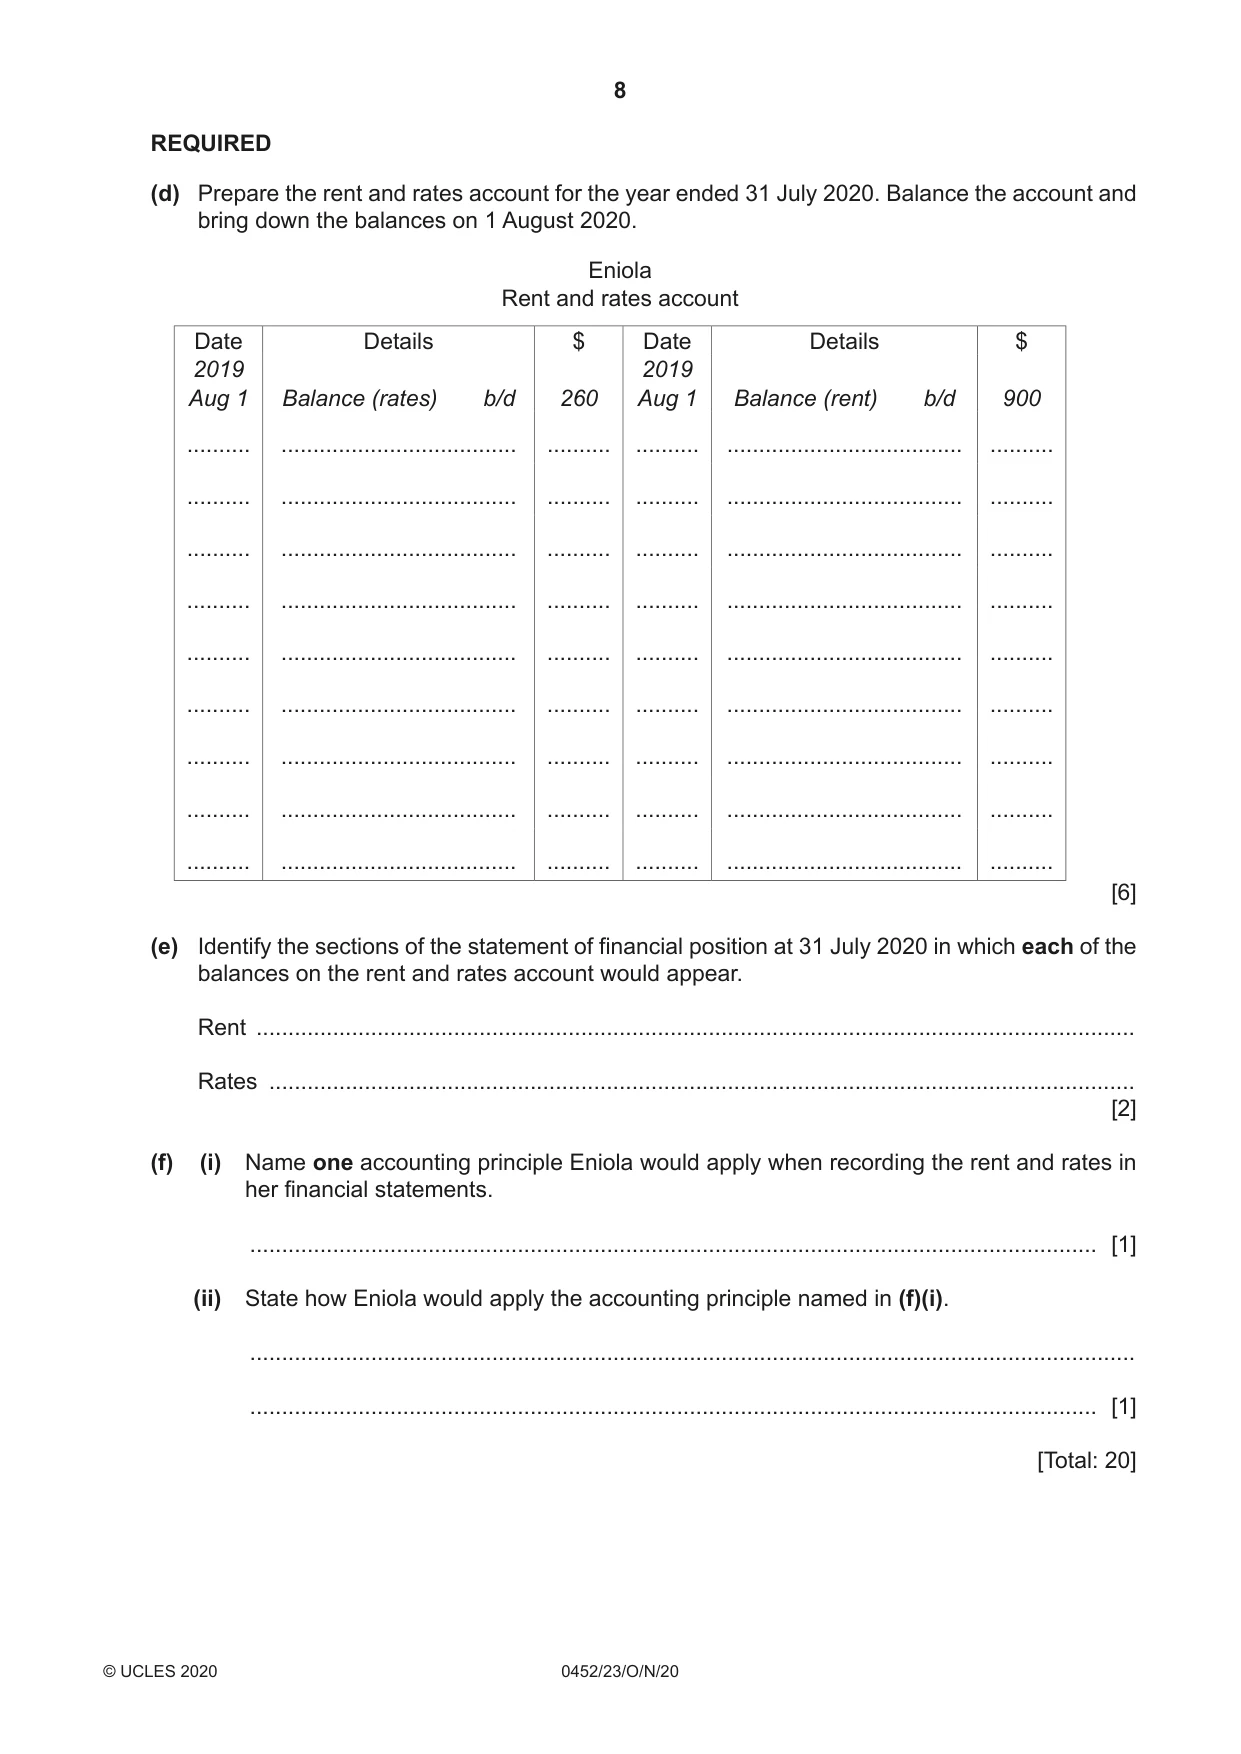
2 Eniola compared her bank statement for July 2020 with the bank columns of her cash book. She provided the following information. $ Overdrawn balance shown in the cash book at 31 July 2020 3420 Direct debit payment dated 25 July 2020, had not yet been entered in the cash book 350 A cheque received from a customer on 12 July 2020 was dishonoured. This dishonoured cheque had not yet been recorded in the cash book 665 Bank charges on the bank statement had not yet been entered in the cash book 45 Unpresented cheques at 31 July 2020 1290 Uncredited deposits at 31 July 2020 410 REQUIRED (a) Calculate the corrected balance of the bank columns in the cash book at 31 July 2020. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] (b) Prepare a bank reconciliation statement at 31 July 2020. Clearly identify the bank statement balance at that date. Eniola Bank Reconciliation Statement at 31 July 2020 ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] Eniola is concerned that her bank balance has decreased significantly during the last year. She is considering how to improve her liquidity. REQUIRED (c) Suggest one effect of each of the following proposals. (i) Hire new non-current assets instead of purchasing them. ........................................................................................................................................... ..................................................................................................................................... [1] (ii) Delay paying credit suppliers. ........................................................................................................................................... ..................................................................................................................................... [1] Eniola’s financial year end is 31 July 2020. She provided the following information about the rent and rates of her business. On 1 August 2019, she owed two months’ rent totalling $900. On the same date, rates of $260 were prepaid up to 30 September 2019. During the year ended 31 July 2020 the following payments were made by credit transfer. 2019 $ August 1 Seven months’ rent 3150 October 1 Twelve months’ rates 1860 2020 March 1 Six months’ rent 2700 REQUIRED (d) Prepare the rent and rates account for the year ended 31 July 2020. Balance the account and bring down the balances on 1 August 2020. Eniola Rent and rates account Date Details $ Date Details $ 2019 2019 Aug 1 Balance (rates) b/d 260 Aug 1 Balance (rent) b/d 900 .......... ..................................... .......... .......... ..................................... .......... .......... ..................................... .......... .......... ..................................... .......... .......... ..................................... .......... .......... ..................................... .......... .......... ..................................... .......... .......... ..................................... .......... .......... ..................................... .......... .......... ..................................... .......... .......... ..................................... .......... .......... ..................................... .......... .......... ..................................... .......... .......... ..................................... .......... .......... ..................................... .......... .......... ..................................... .......... .......... ..................................... .......... .......... ..................................... .......... [6] (e) Identify the sections of the statement of financial position at 31 July 2020 in which each of the balances on the rent and rates account would appear. Rent .......................................................................................................................................... Rates ........................................................................................................................................ [2] (f) (i) Name one accounting principle Eniola would apply when recording the rent and rates in her financial statements. ..................................................................................................................................... [1] (ii) State how Eniola would apply the accounting principle named in (f)(i). ........................................................................................................................................... ..................................................................................................................................... [1] [Total: 20] PLEASE TURN OVER
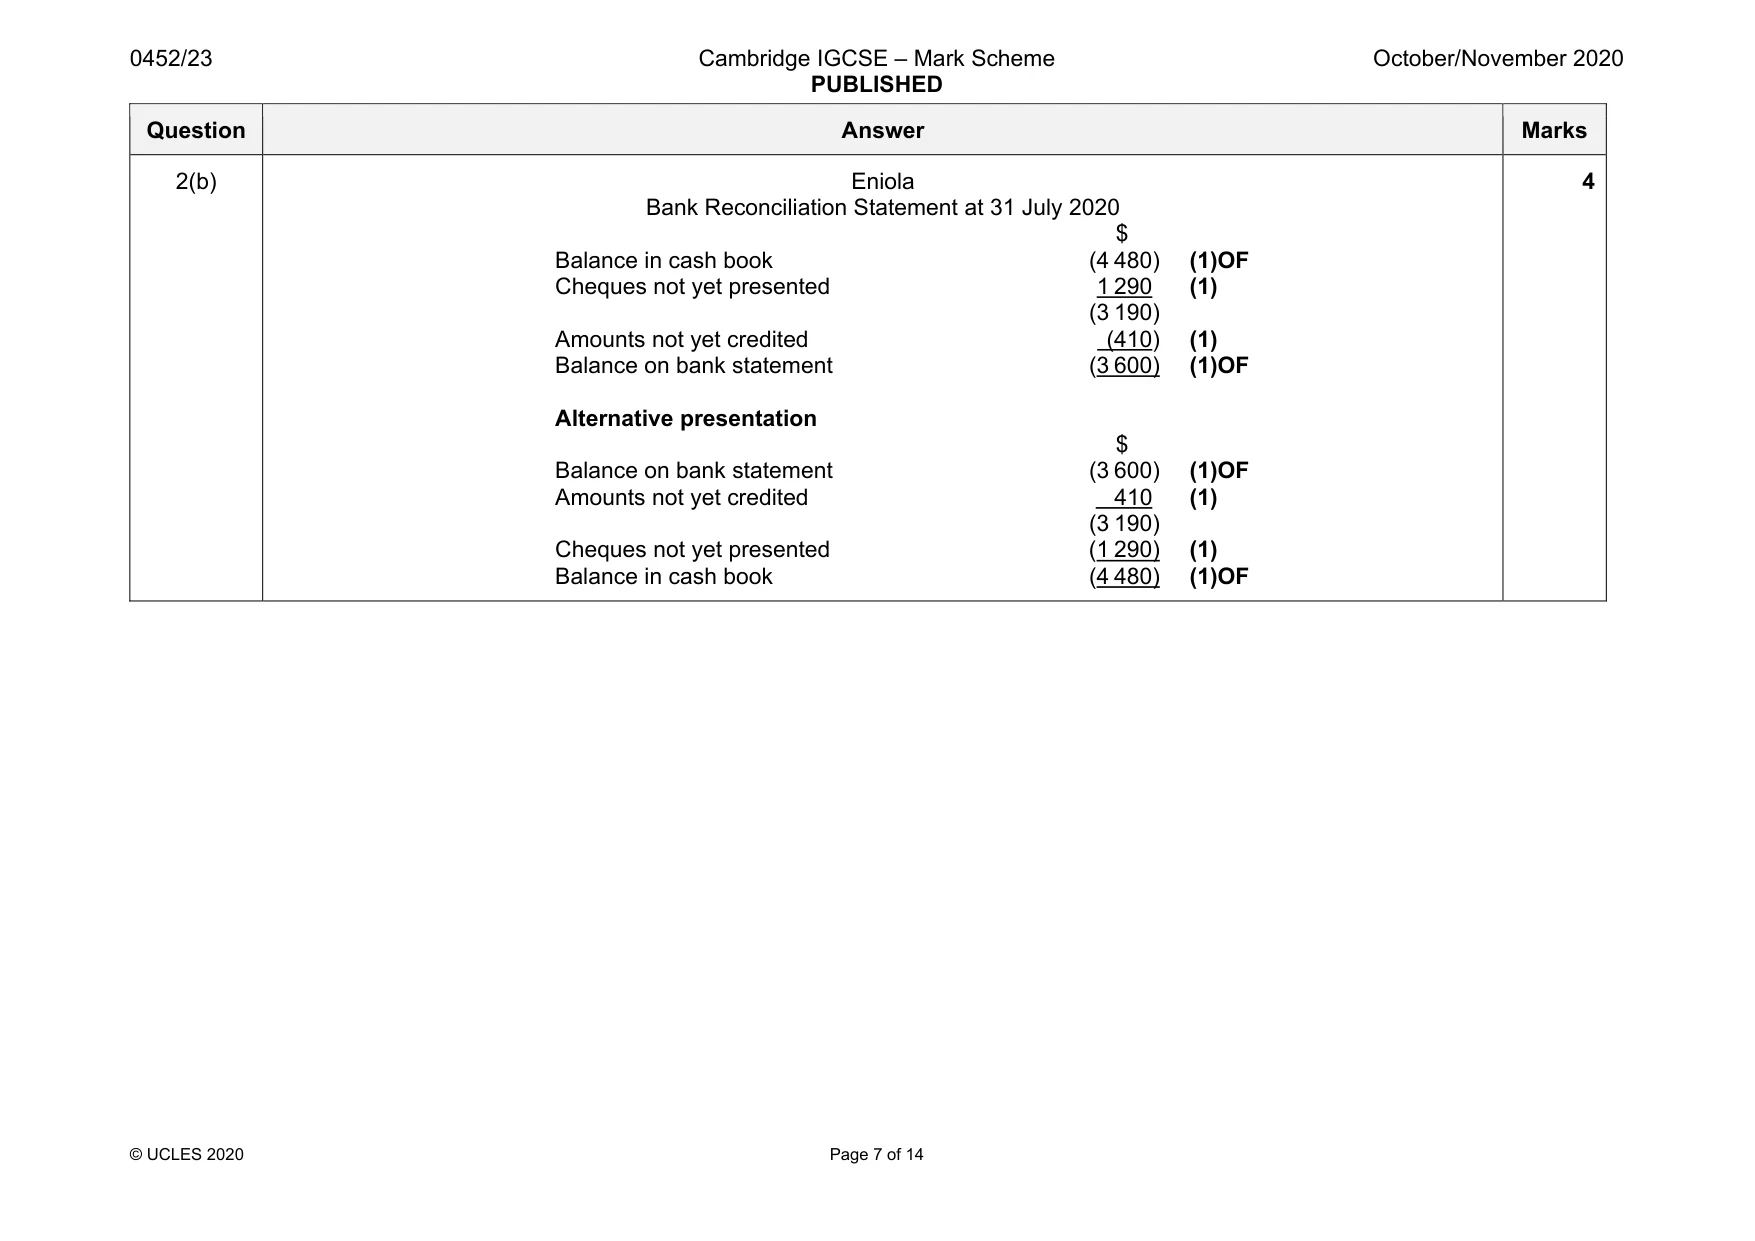
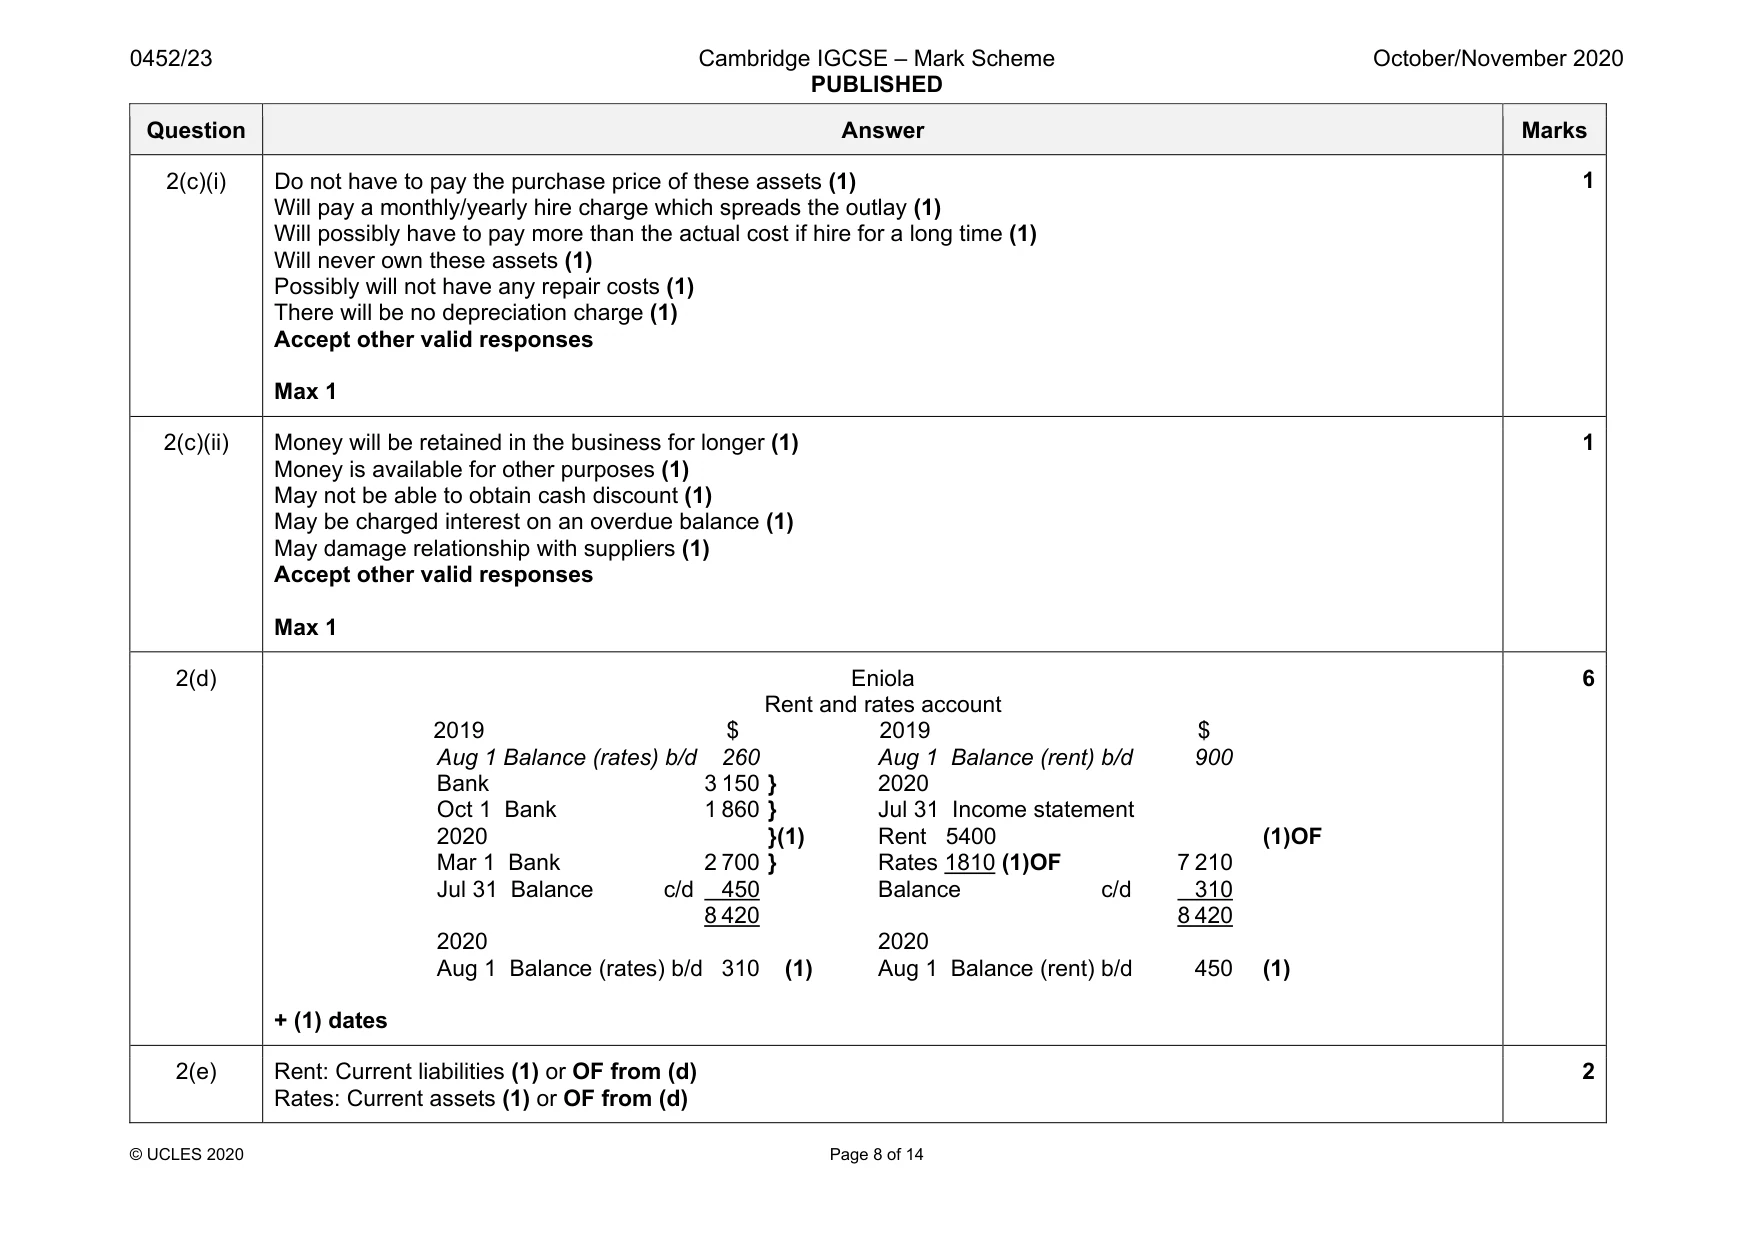
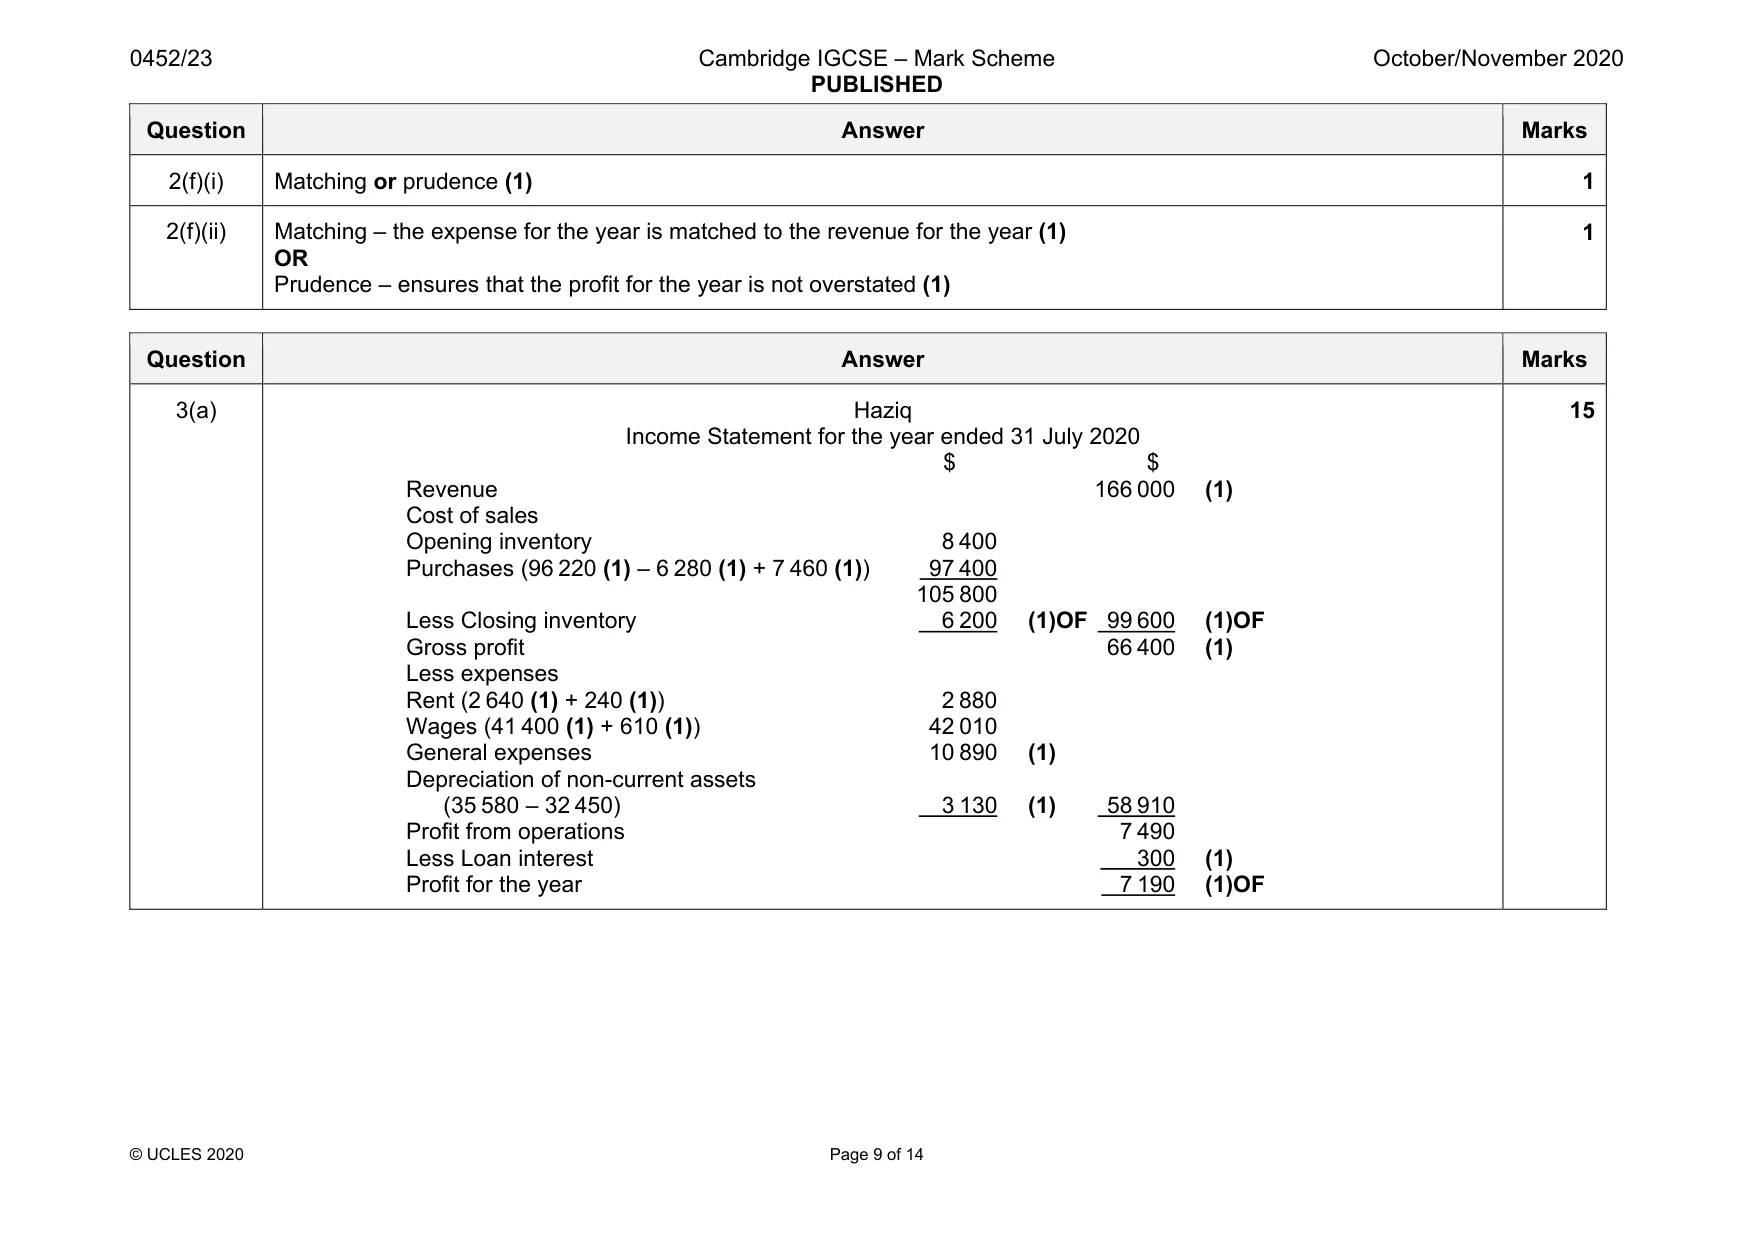
Mark scheme: 2(a) $ Balance at 31 July 2020 (3 420) Direct debit payment (350) (1) Dishonoured cheque (665) (1) Bank charges (45) (1) Revised balance at 31 July 2020 (4 480) (1)OF Accept alternative forms of presentation Question Answer Marks 2(b) Eniola Bank Reconciliation Statement at 31 July 2020 $ Balance in cash book (4 480) (1)OF Cheques not yet presented 1 290 (1) (3 190) Amounts not yet credited (410) (1) Balance on bank statement (3 600) (1)OF Alternative presentation $ Balance on bank statement (3 600) (1)OF Amounts not yet credited 410 (1) (3 190) Cheques not yet presented (1 290) (1) Balance in cash book (4 480) (1)OF 4 Question Answer Marks 2(c)(i) Do not have to pay the purchase price of these assets (1) Will pay a monthly/yearly hire charge which spreads the outlay (1) Will possibly have to pay more than the actual cost if hire for a long time (1) Will never own these assets (1) Possibly will not have any repair costs (1) There will be no depreciation charge (1) Accept other valid responses Max 1 1 2(c)(ii) Money will be retained in the business for longer (1) Money is available for other purposes (1) May not be able to obtain cash discount (1) May be charged interest on an overdue balance (1) May damage relationship with suppliers (1) Accept other valid responses Max 1 1 2(d) Eniola Rent and rates account 2019 $ 2019 $ Aug 1 Balance (rates) b/d 260 Aug 1 Balance (rent) b/d 900 Bank 3 150 } 2020 Oct 1 Bank 1 860 } Jul 31 Income statement 2020 }(1) Rent 5400 (1)OF Mar 1 Bank 2 700 } Rates 1810 (1)OF 7 210 Jul 31 Balance c/d 450 Balance c/d 310 8 420 8 420 2020 2020 Aug 1 Balance (rates) b/d 310 (1) Aug 1 Balance (rent) b/d 450 (1) + (1) dates 6 2(e) Rent: Current liabilities (1) or OF from (d) Rates: Current assets (1) or OF from (d) 2 Question Answer Marks 2(f)(i) Matching or prudence (1) 1 2(f)(ii) Matching – the expense for the year is matched to the revenue for the year (1) OR Prudence – ensures that the profit for the year is not overstated (1) 1
Q3 · Haziq has not maintained full accounting records for his business
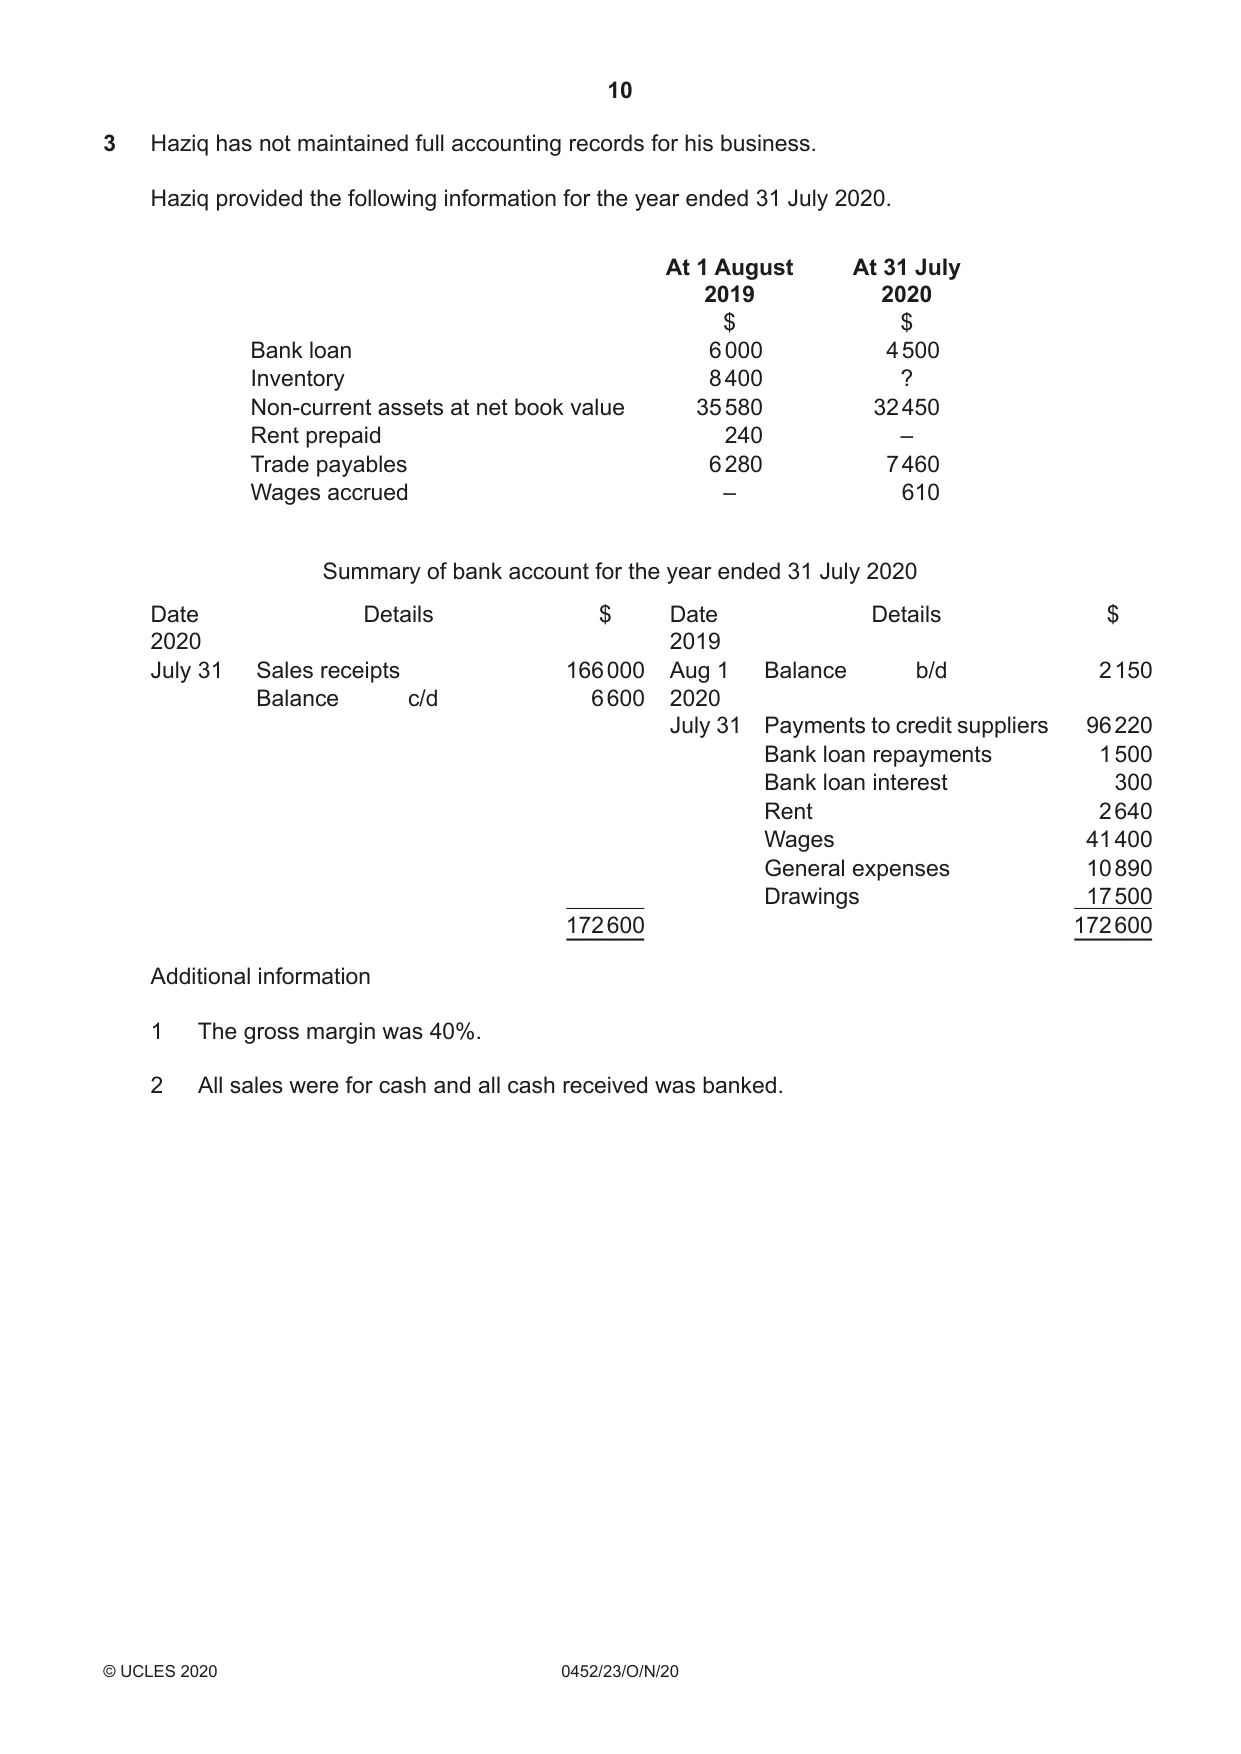
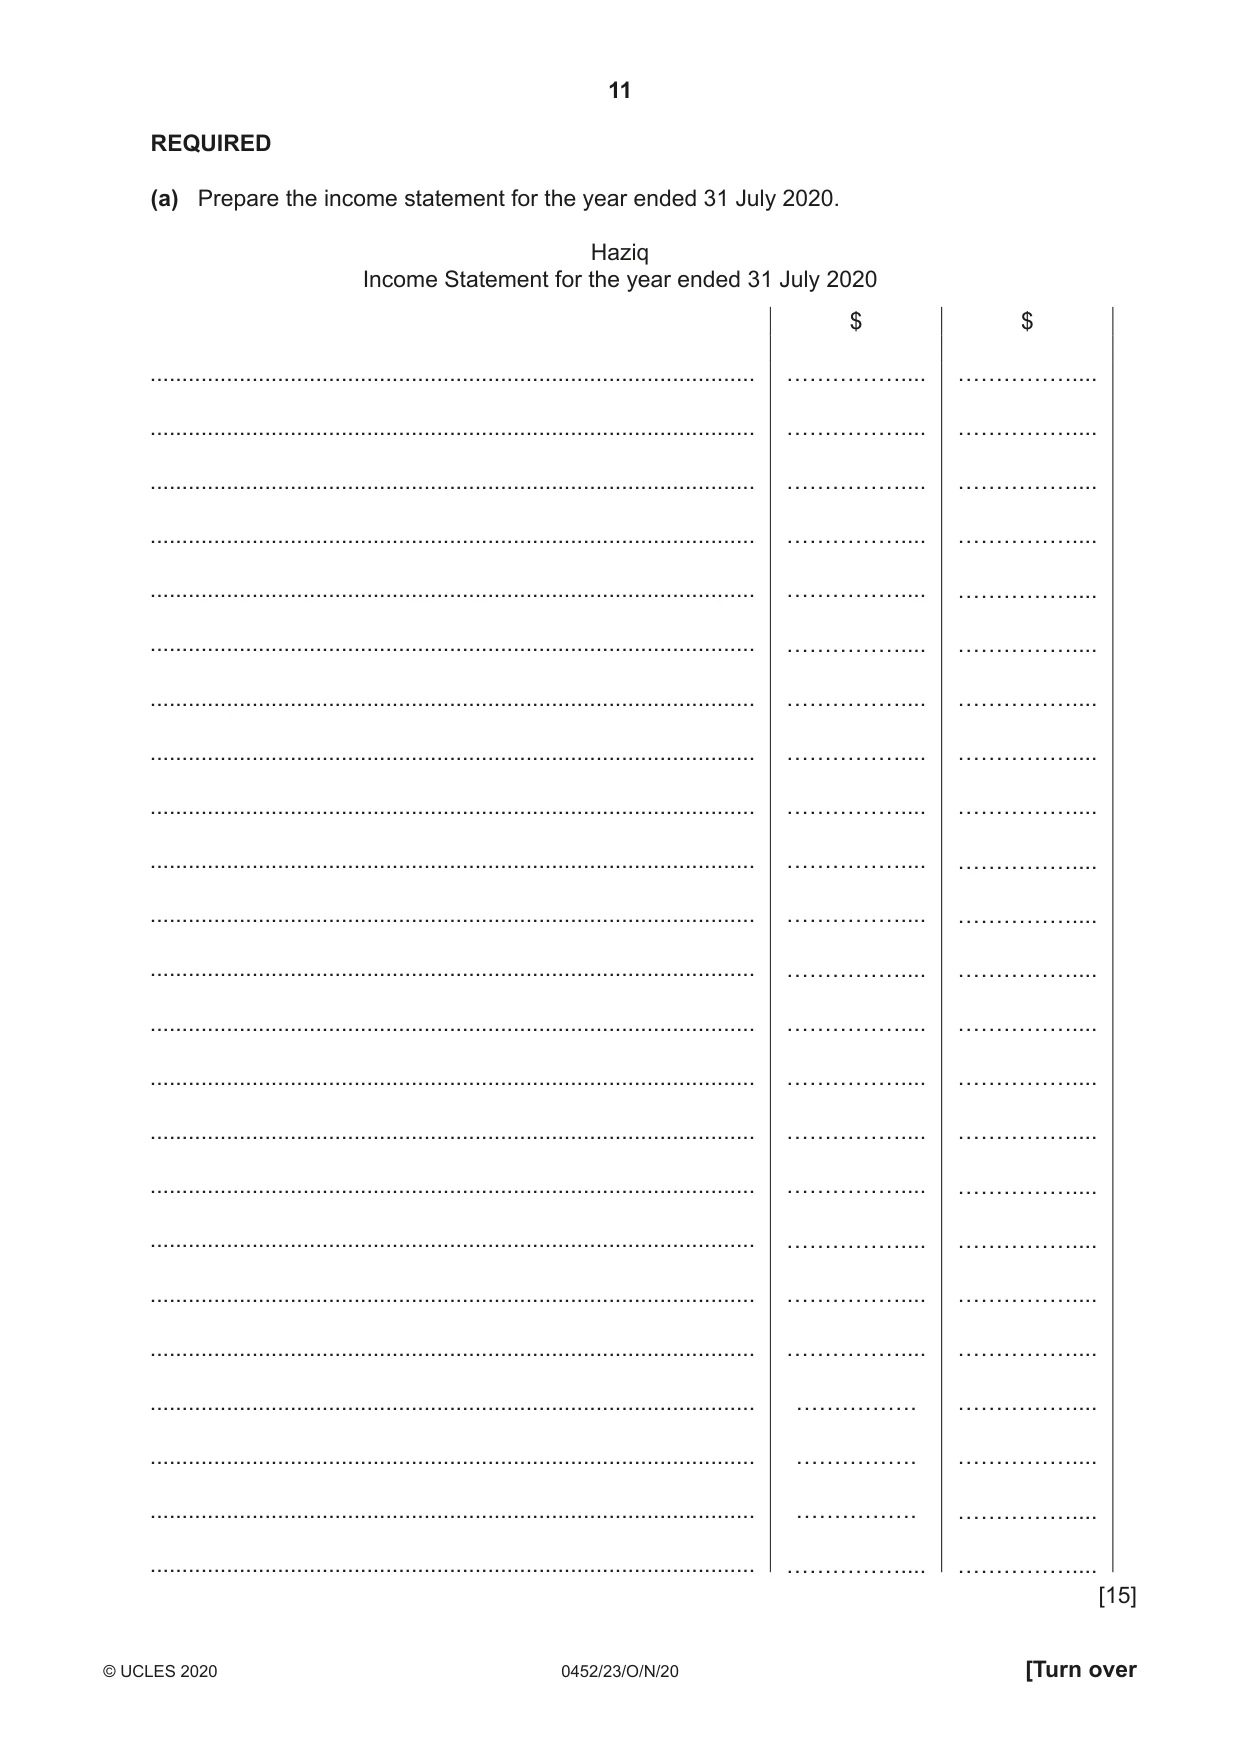
3 Haziq has not maintained full accounting records for his business. Haziq provided the following information for the year ended 31 July 2020. At 1 August At 31 July 2019 2020 $ $ Bank loan 6 000 4 500 Inventory 8 400 ? Non-current assets at net book value 35 580 32 450 Rent prepaid 240 – Trade payables 6 280 7 460 Wages accrued – 610 Summary of bank account for the year ended 31 July 2020 Date Details $ Date Details $ 2020 2019 July 31 Sales receipts 166 000 Aug 1 Balance b/d 2 150 Balance c/d 6 600 2020 July 31 Payments to credit suppliers 96 220 Bank loan repayments 1 500 Bank loan interest 300 Rent 2 640 Wages 41 400 General expenses 10 890 Drawings 17 500 172 600 172 600 Additional information 1 The gross margin was 40%. 2 All sales were for cash and all cash received was banked. REQUIRED (a) Prepare the income statement for the year ended 31 Jul Haziq Income Statement for the year ended 3 ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... ............................................................................................... (b) Advise Haziq whether or not he should maintain a double entry bookkeeping system for his business. Justify your answer with two advantages and two disadvantages. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20] PLEASE TURN OVER
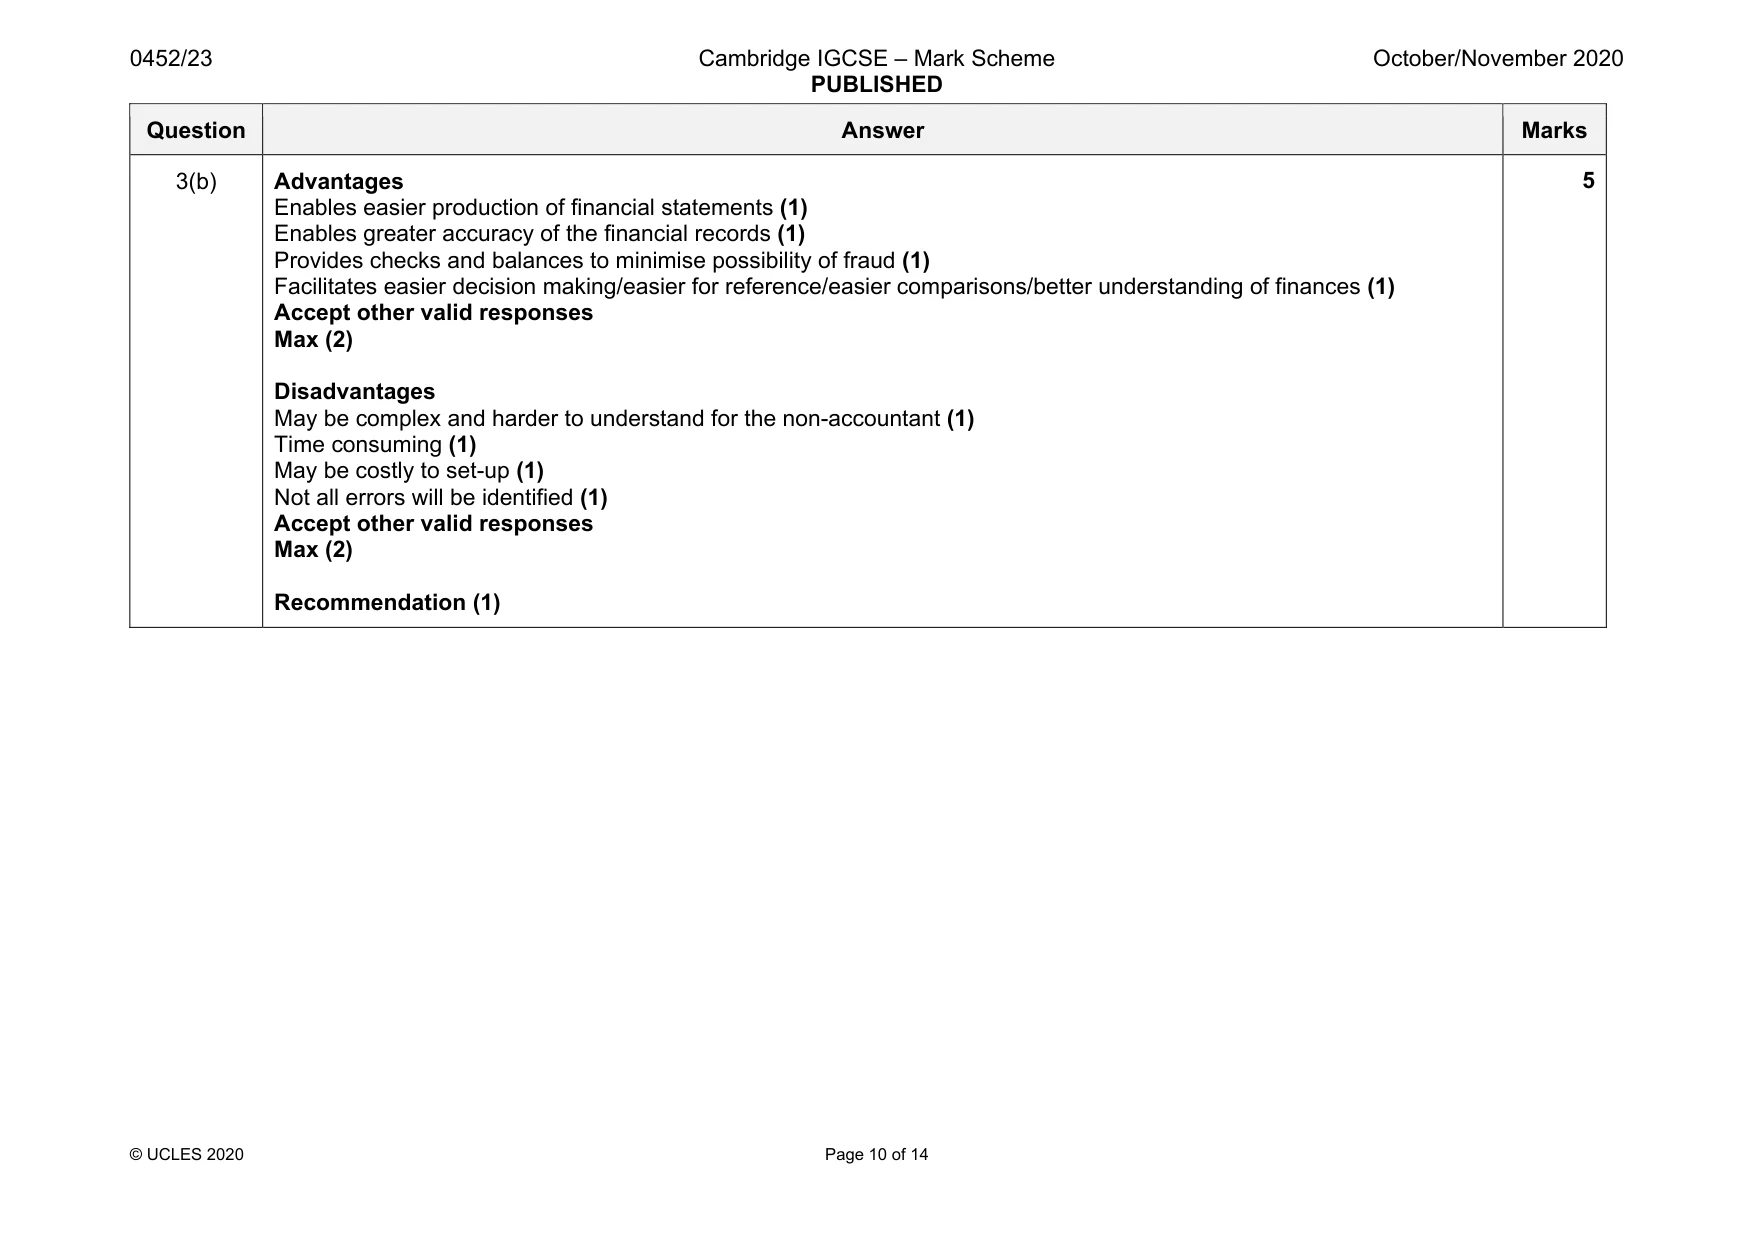
Mark scheme: 3(a) Haziq Income Statement for the year ended 31 July 2020 $ $ Revenue 166 000 (1) Cost of sales Opening inventory 8 400 Purchases (96 220 (1) – 6 280 (1) + 7 460 (1)) 97 400 105 800 Less Closing inventory 6 200 (1)OF 99 600 (1)OF Gross profit 66 400 (1) Less expenses Rent (2 640 (1) + 240 (1)) 2 880 Wages (41 400 (1) + 610 (1)) 42 010 General expenses 10 890 (1) Depreciation of non-current assets (35 580 – 32 450) 3 130 (1) 58 910 Profit from operations 7 490 Less Loan interest 300 (1) Profit for the year 7 190 (1)OF 15 Question Answer Marks 3(b) Advantages Enables easier production of financial statements (1) Enables greater accuracy of the financial records (1) Provides checks and balances to minimise possibility of fraud (1) Facilitates easier decision making/easier for reference/easier comparisons/better understanding of finances (1) Accept other valid responses Max (2) Disadvantages May be complex and harder to understand for the non-accountant (1) Time consuming (1) May be costly to set-up (1) Not all errors will be identified (1) Accept other valid responses Max (2) Recommendation (1) 5
Q4 · The directors of DW Limited provided the following information at 30 September 2020
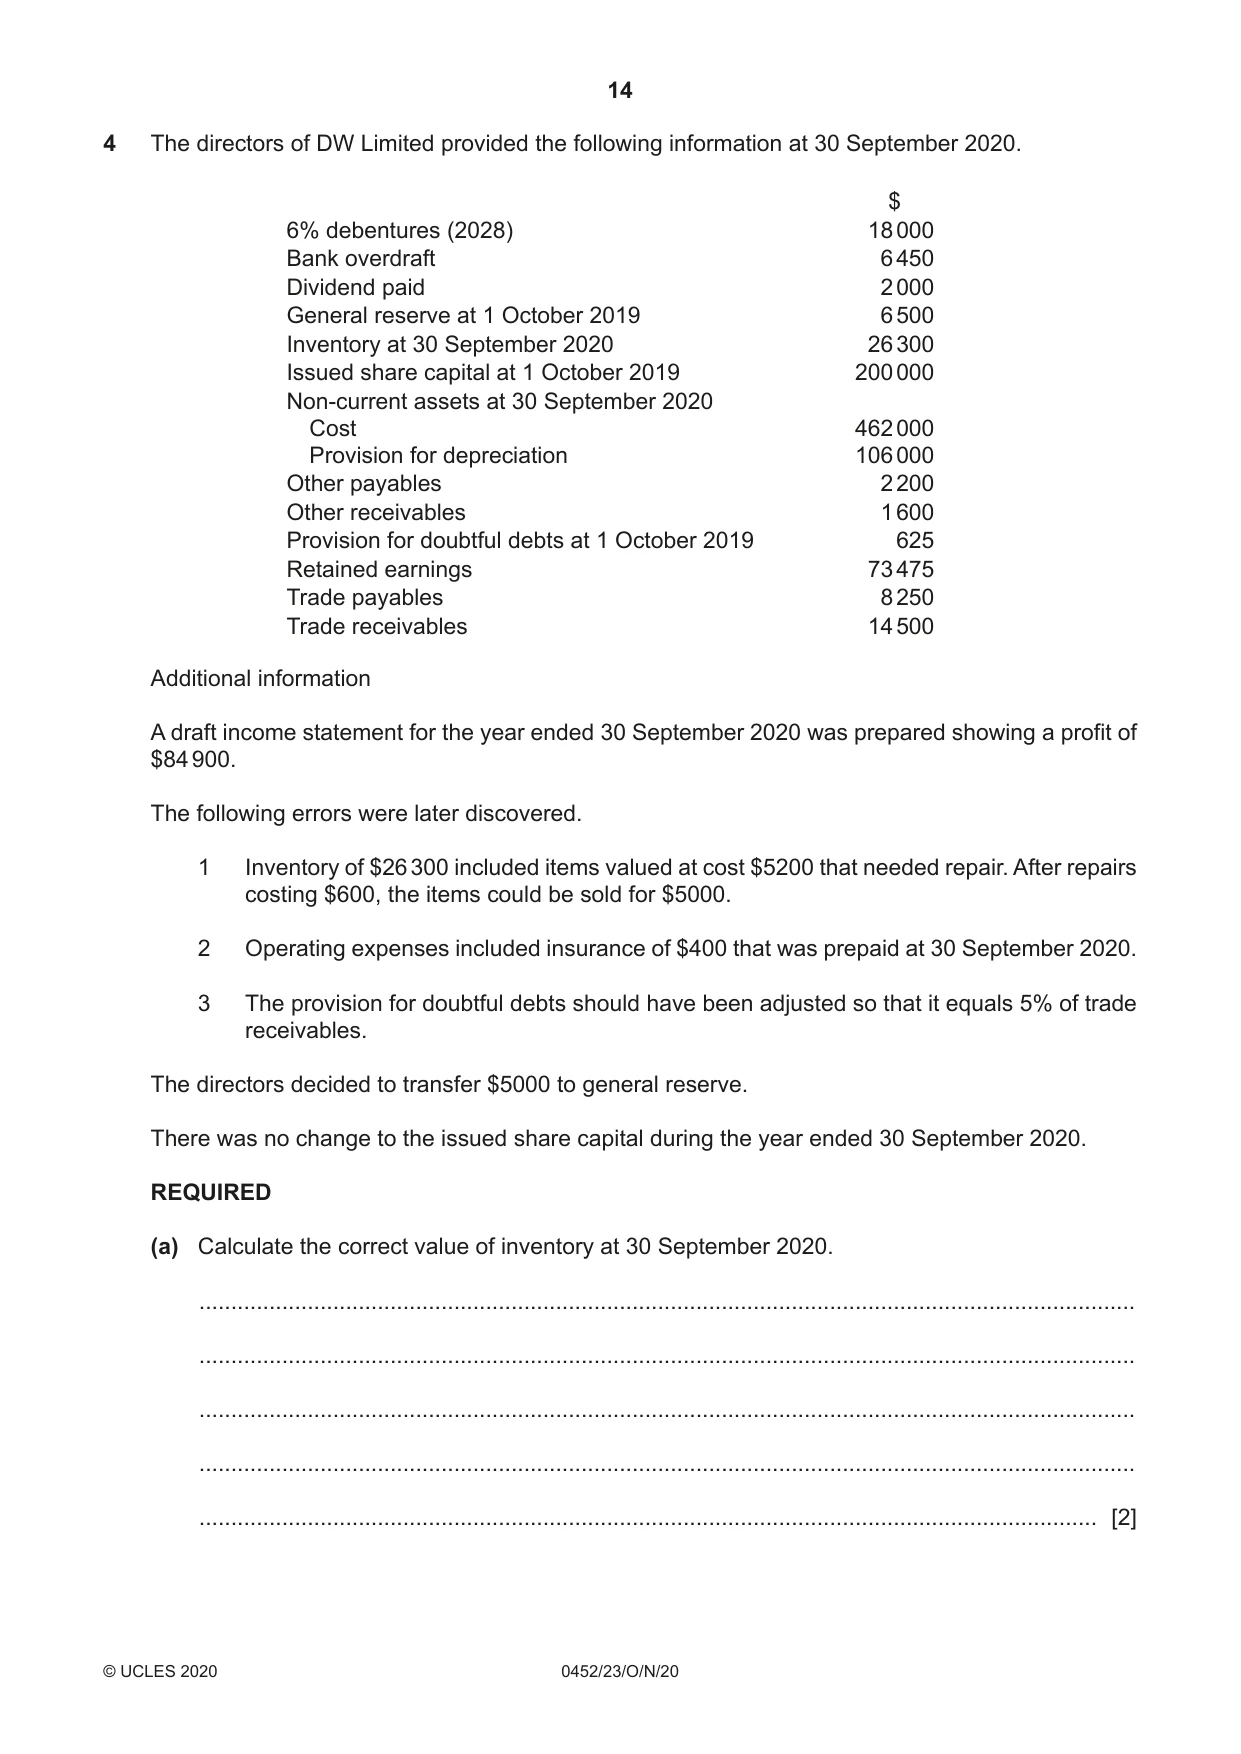
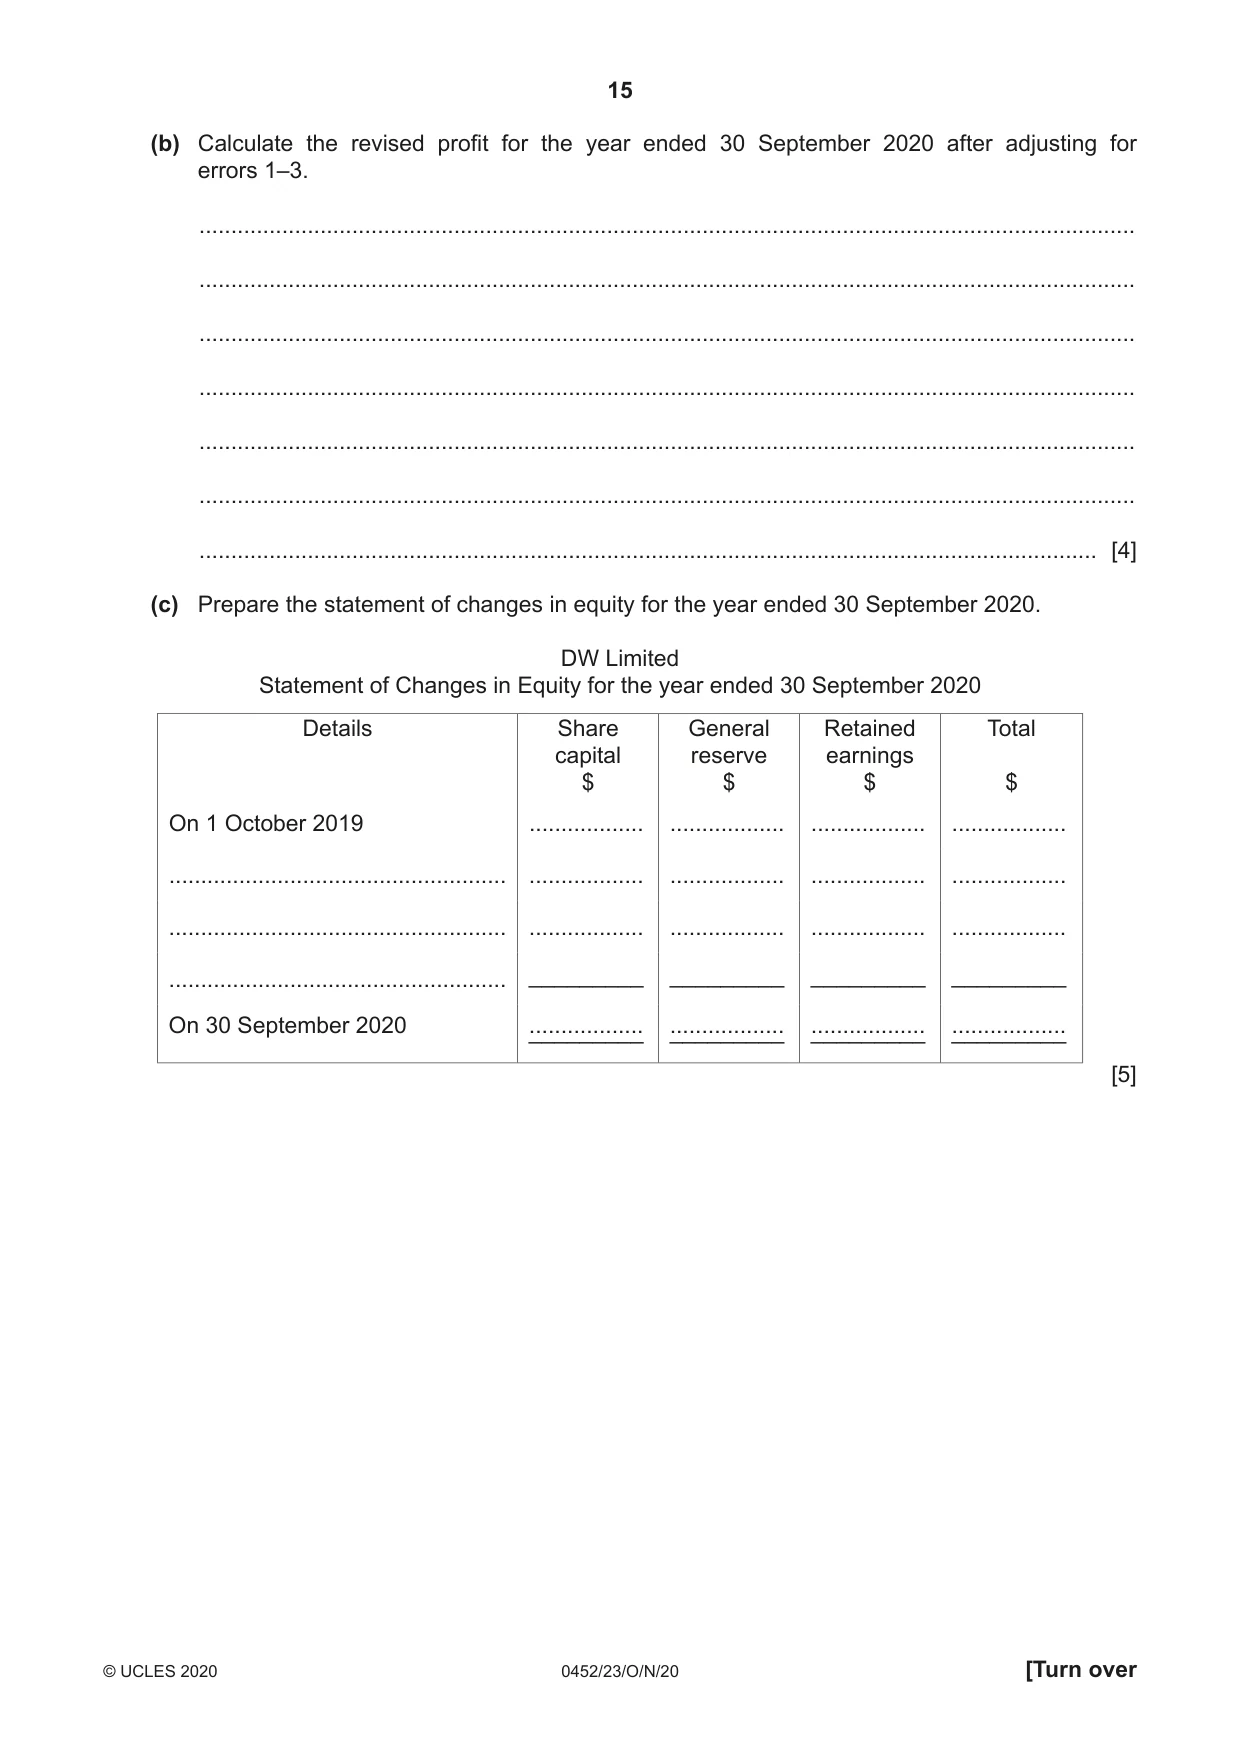
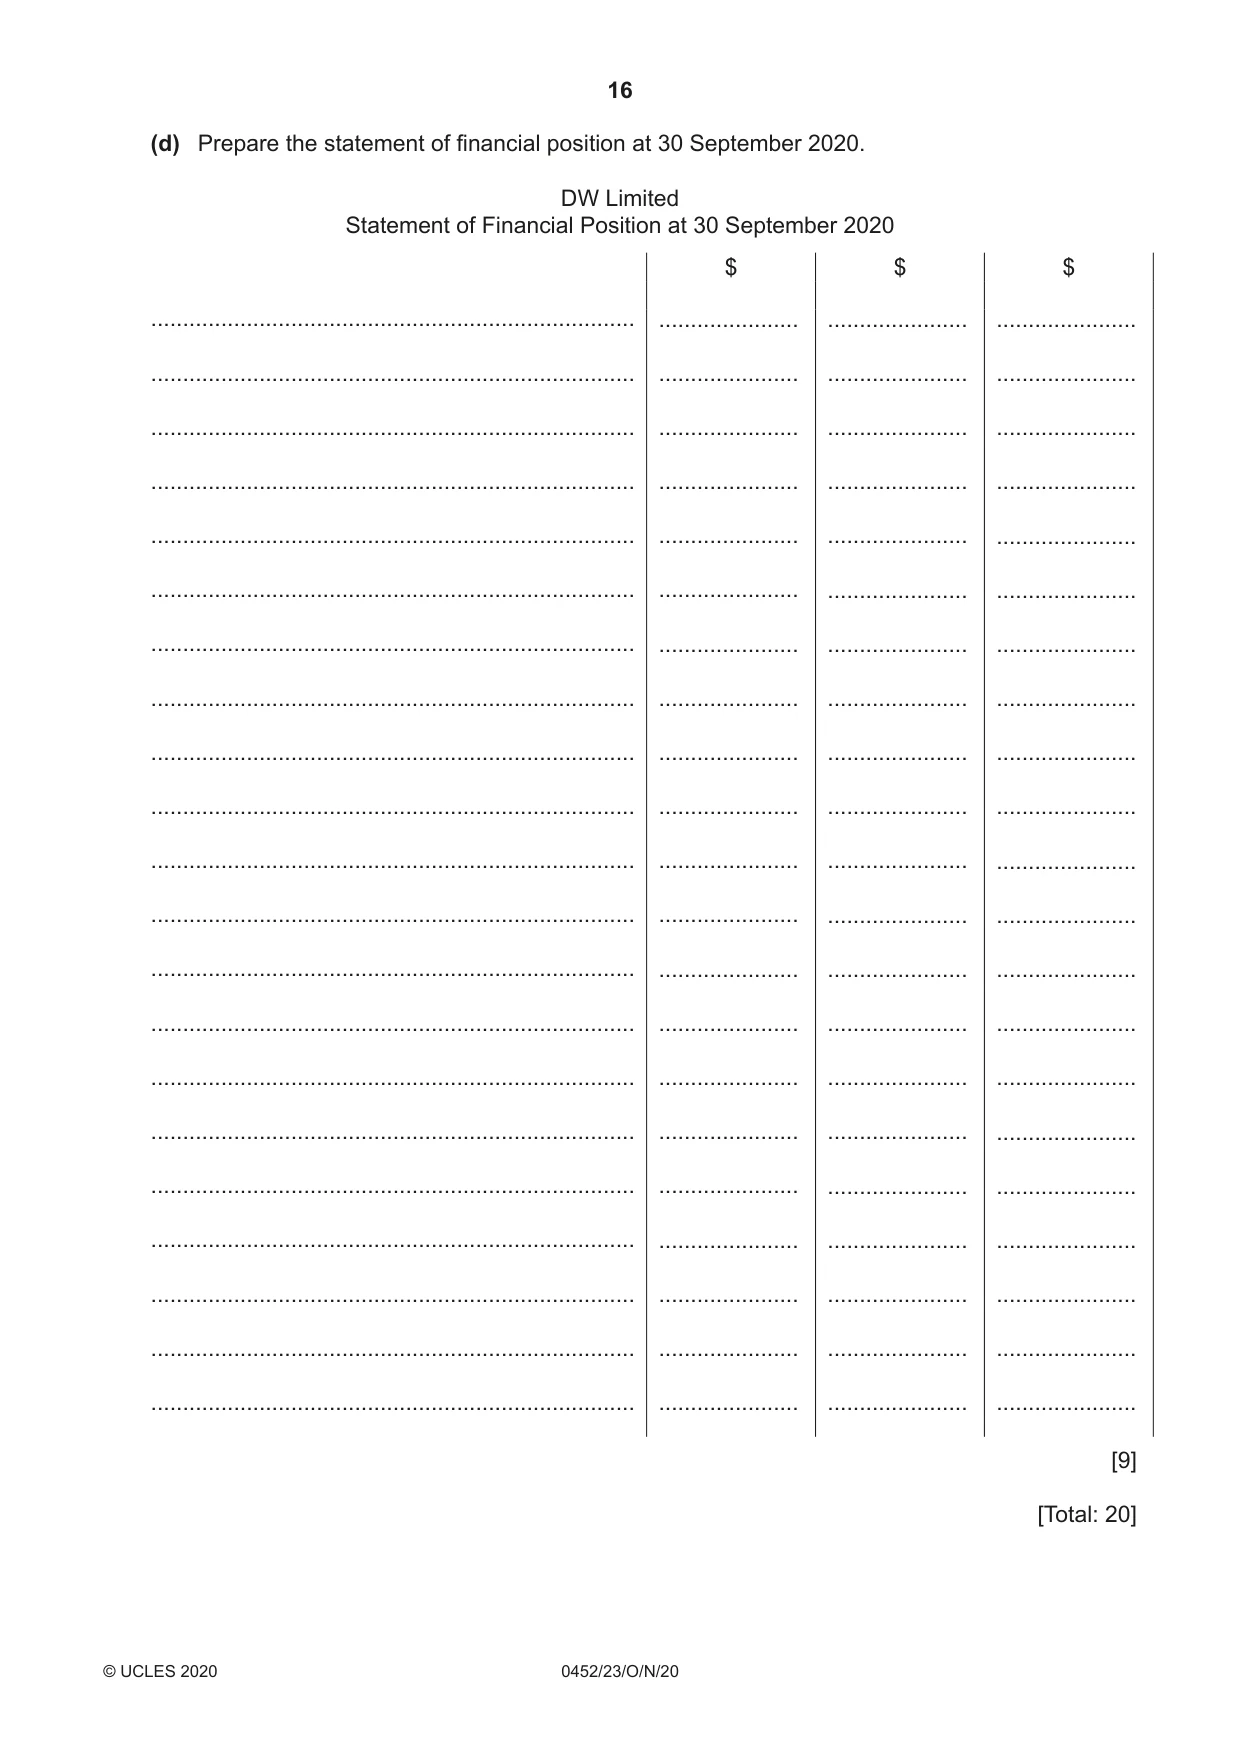
4 The directors of DW Limited provided the following information at 30 September 2020. $ 6% debentures (2028) 18 000 Bank overdraft 6 450 Dividend paid 2 000 General reserve at 1 October 2019 6 500 Inventory at 30 September 2020 26 300 Issued share capital at 1 October 2019 200 000 Non-current assets at 30 September 2020 Cost 462 000 Provision for depreciation 106 000 Other payables 2 200 Other receivables 1 600 Provision for doubtful debts at 1 October 2019 625 Retained earnings 73 475 Trade payables 8 250 Trade receivables 14 500 Additional information A draft income statement for the year ended 30 September 2020 was prepared showing a profit of $84 900. The following errors were later discovered. 1 Inventory of $26 300 included items valued at cost $5200 that needed repair. After repairs costing $600, the items could be sold for $5000. 2 Operating expenses included insurance of $400 that was prepaid at 30 September 2020. 3 The provision for doubtful debts should have been adjusted so that it equals 5% of trade receivables. The directors decided to transfer $5000 to general reserve. There was no change to the issued share capital during the year ended 30 September 2020. REQUIRED (a) Calculate the correct value of inventory at 30 September 2020. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] (b) Calculate the revised profit for the year ended 30 September 2020 after adjusting for errors 1–3. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [4] (c) Prepare the statement of changes in equity for the year ended 30 September 2020. DW Limited Statement of Changes in Equity for the year ended 30 September 2020 Details Share General Retained Total capital reserve earnings $ $ $ $ On 1 October 2019 .................. .................. .................. .................. ..................................................... .................. .................. .................. .................. ..................................................... .................. .................. .................. .................. ..................................................... _________ _________ _________ _________ On 30 September 2020 .................. .................. .................. .................. _________ _________ _________ _________ [5] (d) Prepare the statement of financial position DW Lim Statement of Financial Positi ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ PLEASE TURN OVER
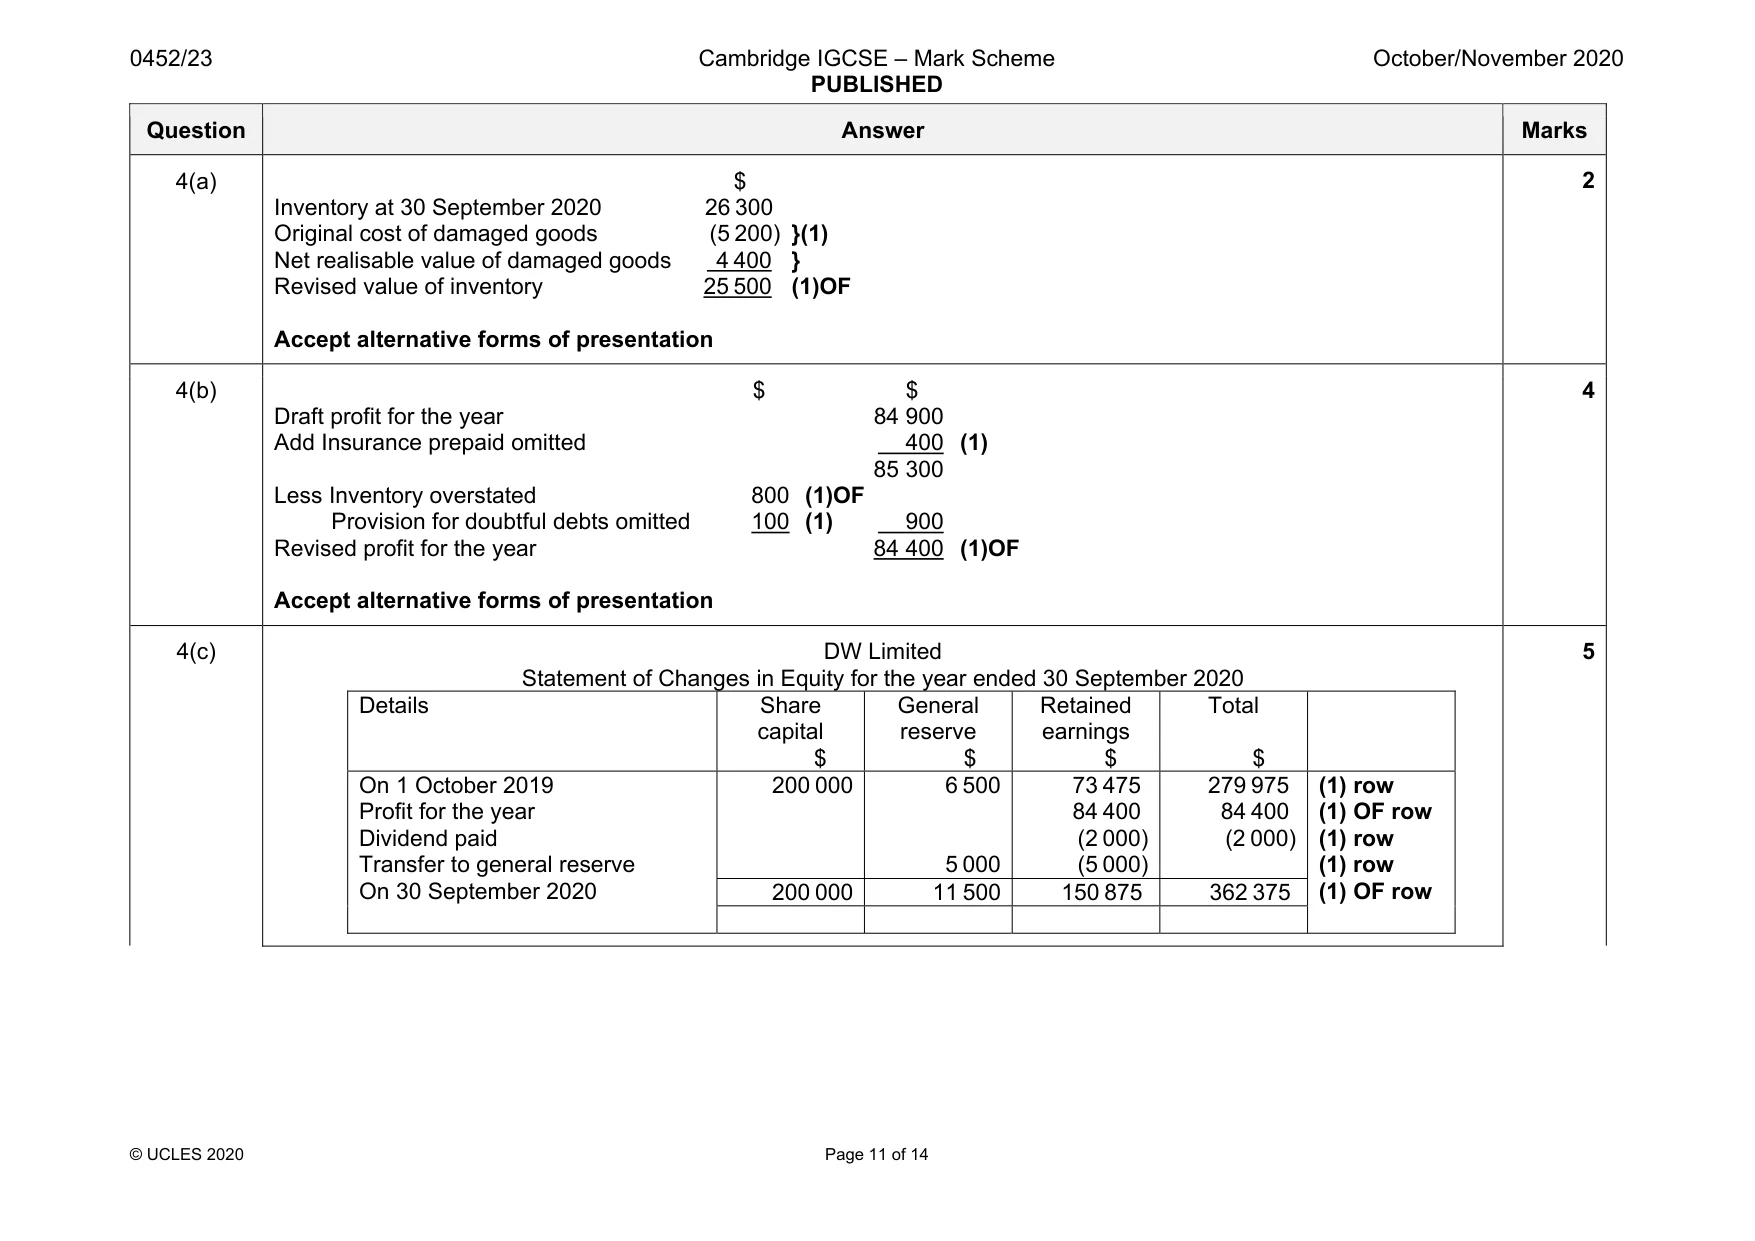
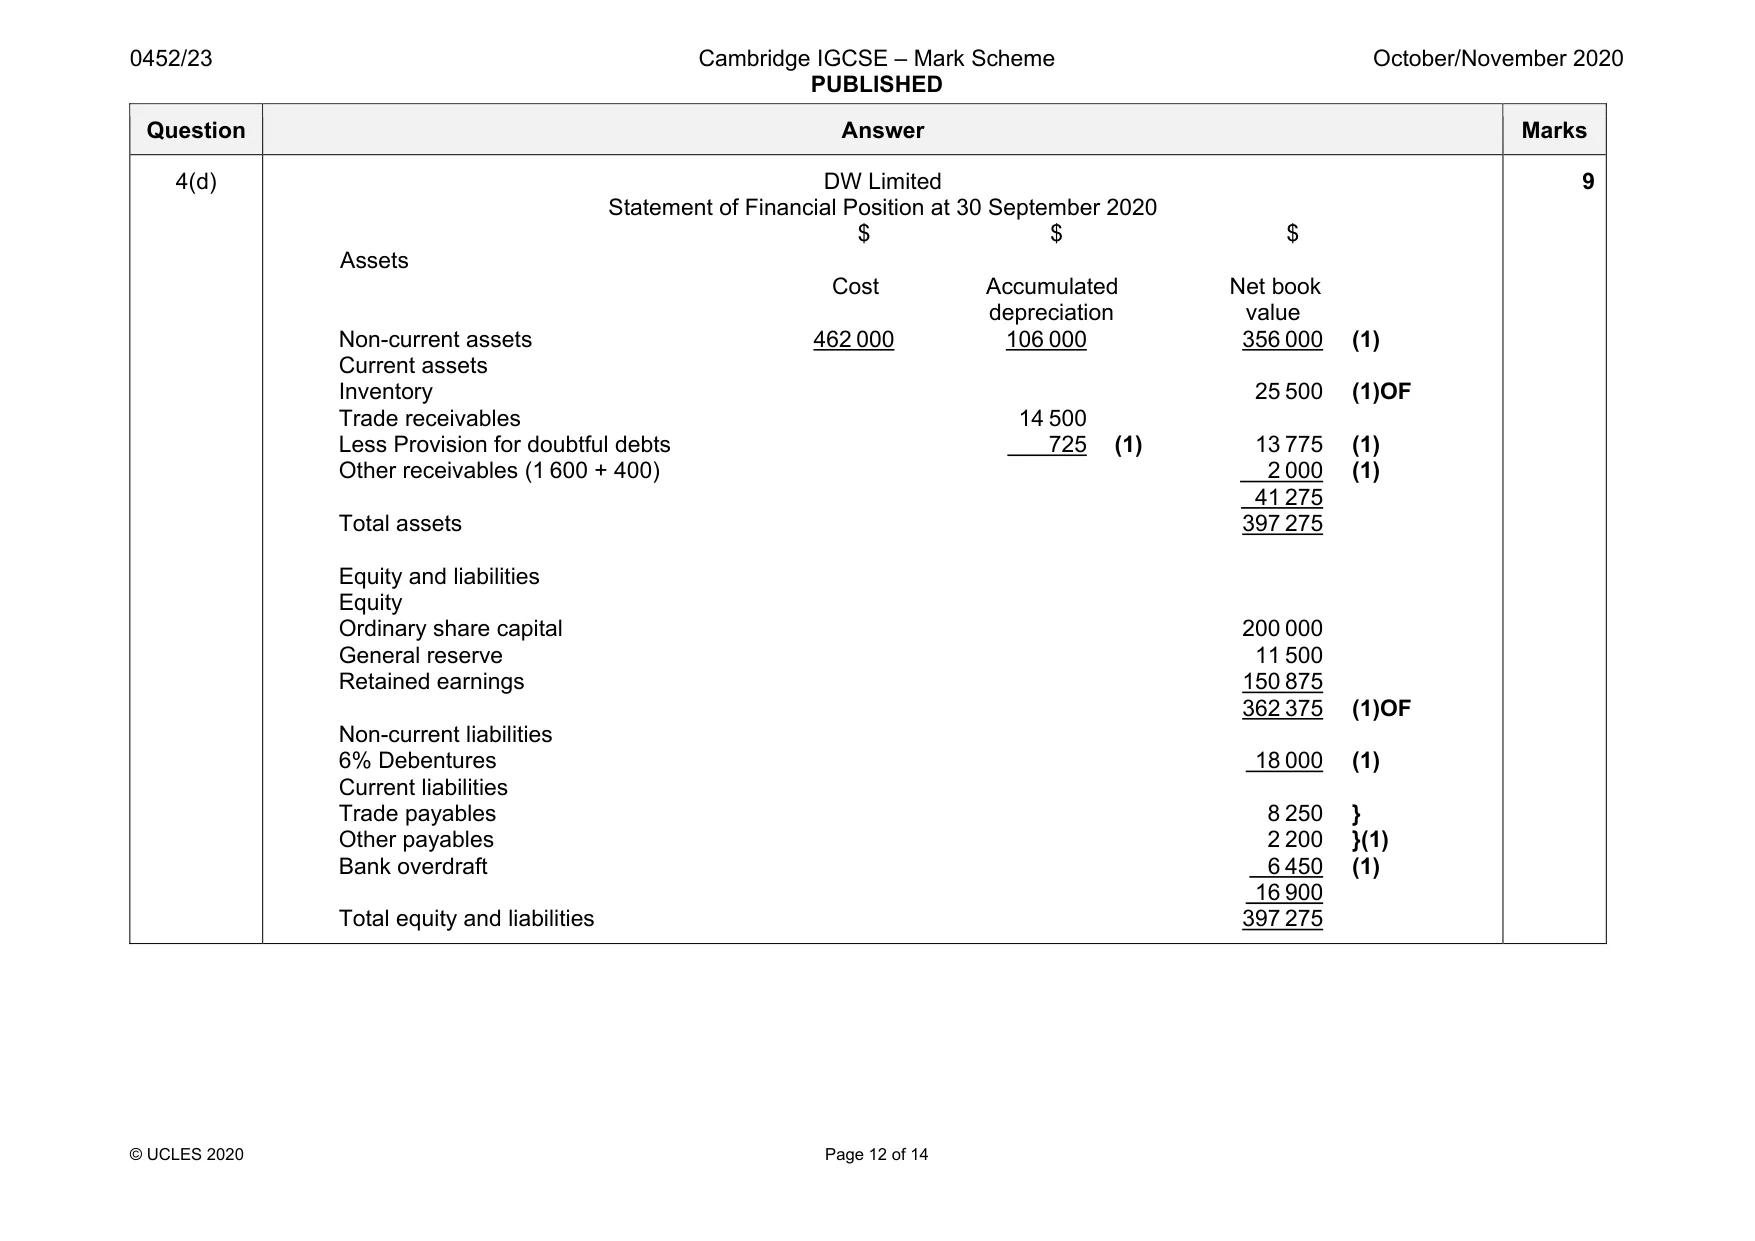
Mark scheme: 4(a) $ Inventory at 30 September 2020 26 300 Original cost of damaged goods (5 200) }(1) Net realisable value of damaged goods 4 400 } Revised value of inventory 25 500 (1)OF Accept alternative forms of presentation 4(b) $ $ Draft profit for the year 84 900 Add Insurance prepaid omitted 400 (1) 85 300 Less Inventory overstated 800 (1)OF Provision for doubtful debts omitted 100 (1) 900 Revised profit for the year 84 400 (1)OF Accept alternative forms of presentation 4 4(c) DW Limited Statement of Changes in Equity for the year ended 30 September 2020 Details Share capital $ General reserve $ Retained earnings $ Total $ On 1 October 2019 Profit for the year Dividend paid Transfer to general reserve On 30 September 2020 200 000 6 500 5 000 73 475 84 400 (2 000) (5 000) 279 975 84 400 (2 000) (1) row (1) OF row (1) row (1) row (1) OF row 200 000 11 500 150 875 362 375 5 Question Answer Marks 4(d) DW Limited Statement of Financial Position at 30 September 2020 $ $ $ Assets Cost Accumulated Net book depreciation value Non-current assets 462 000 106 000 356 000 (1) Current assets Inventory 25 500 (1)OF Trade receivables 14 500 Less Provision for doubtful debts 725 (1) 13 775 (1) Other receivables (1 600 + 400) 2 000 (1) 41 275 Total assets 397 275 Equity and liabilities Equity Ordinary share capital 200 000 General reserve 11 500 Retained earnings 150 875 362 375 (1)OF Non-current liabilities 6% Debentures 18 000 (1) Current liabilities Trade payables 8 250 } Other payables 2 200 }(1) Bank overdraft 6 450 (1) 16 900 Total equity and liabilities 397 275 9
Q5 · Nazim owns a wholesale business and has prepared draft financial statements for the year…
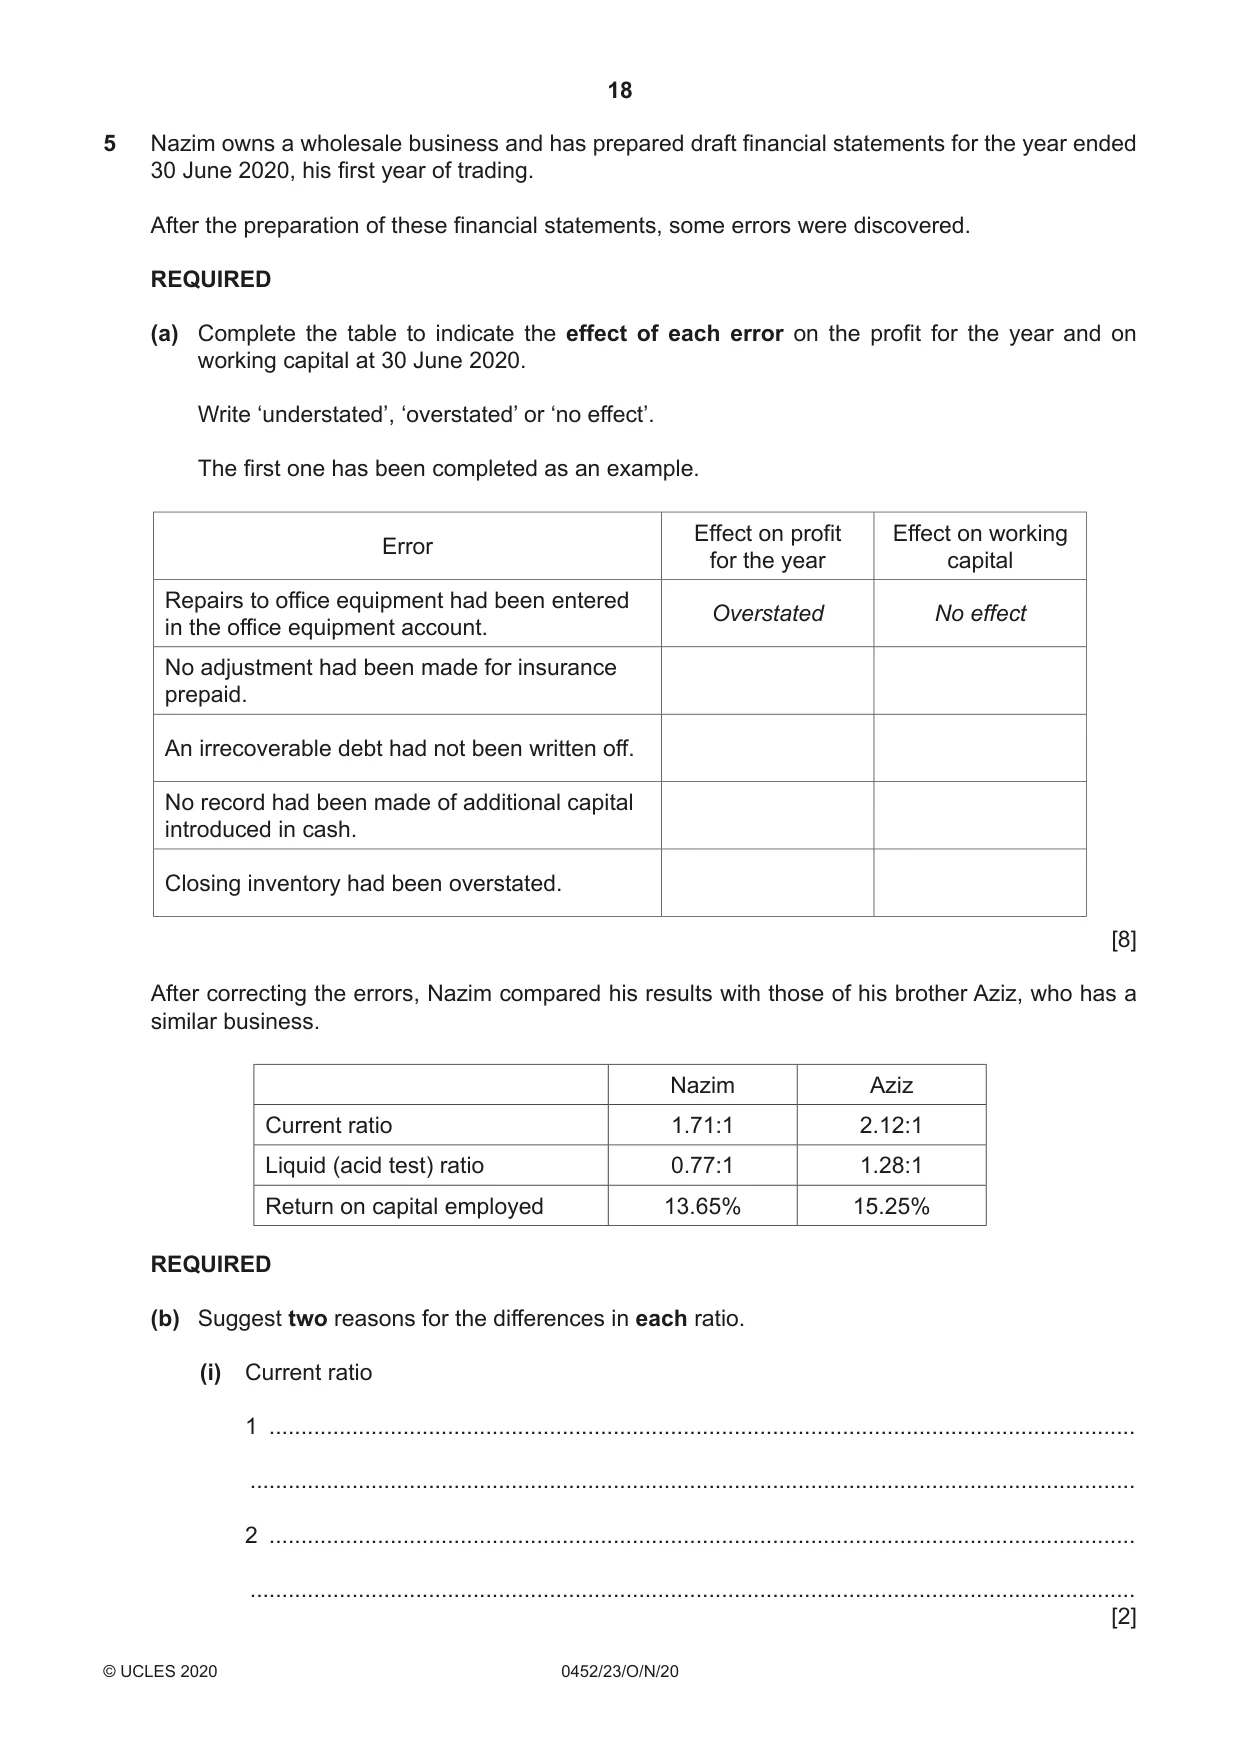
5 Nazim owns a wholesale business and has prepared draft financial statements for the year ended 30 June 2020, his first year of trading. After the preparation of these financial statements, some errors were discovered. REQUIRED (a) Complete the table to indicate the effect of each error on the profit for the year and on working capital at 30 June 2020. Write ‘understated’, ‘overstated’ or ‘no effect’. The first one has been completed as an example. Effect on profit Effect on working Error for the year capital Repairs to office equipment had been entered Overstated No effect in the office equipment account. No adjustment had been made for insurance prepaid. An irrecoverable debt had not been written off. No record had been made of additional capital introduced in cash. Closing inventory had been overstated. [8] After correcting the errors, Nazim compared his results with those of his brother Aziz, who has a similar business. Nazim Aziz Current ratio 1.71:1 2.12:1 Liquid (acid test) ratio 0.77:1 1.28:1 Return on capital employed 13.65% 15.25% REQUIRED (b) Suggest two reasons for the differences in each ratio. (i) Current ratio 1 ........................................................................................................................................ ........................................................................................................................................... 2 ........................................................................................................................................ ........................................................................................................................................... [2] (ii) Liquid (acid test) ratio 1 ........................................................................................................................................ ........................................................................................................................................... 2 ........................................................................................................................................ ........................................................................................................................................... [2] (iii) Return on capital employed (ROCE) 1 ........................................................................................................................................ ........................................................................................................................................... 2 ........................................................................................................................................ ........................................................................................................................................... [2] Nazim discovered that his rate of inventory turnover (times) was also lower than that of Aziz. REQUIRED (c) Suggest one reason for this difference. ................................................................................................................................................... ............................................................................................................................................. [1] Nazim is concerned about the length of time his credit customers are taking to pay their accounts. He is considering operating a strict credit control policy requiring customers to pay within 30 days. REQUIRED (d) Advise Nazim whether or not he should introduce this strict credit control policy. Justify your answer by providing two advantages and two disadvantages. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] [Total: 20]
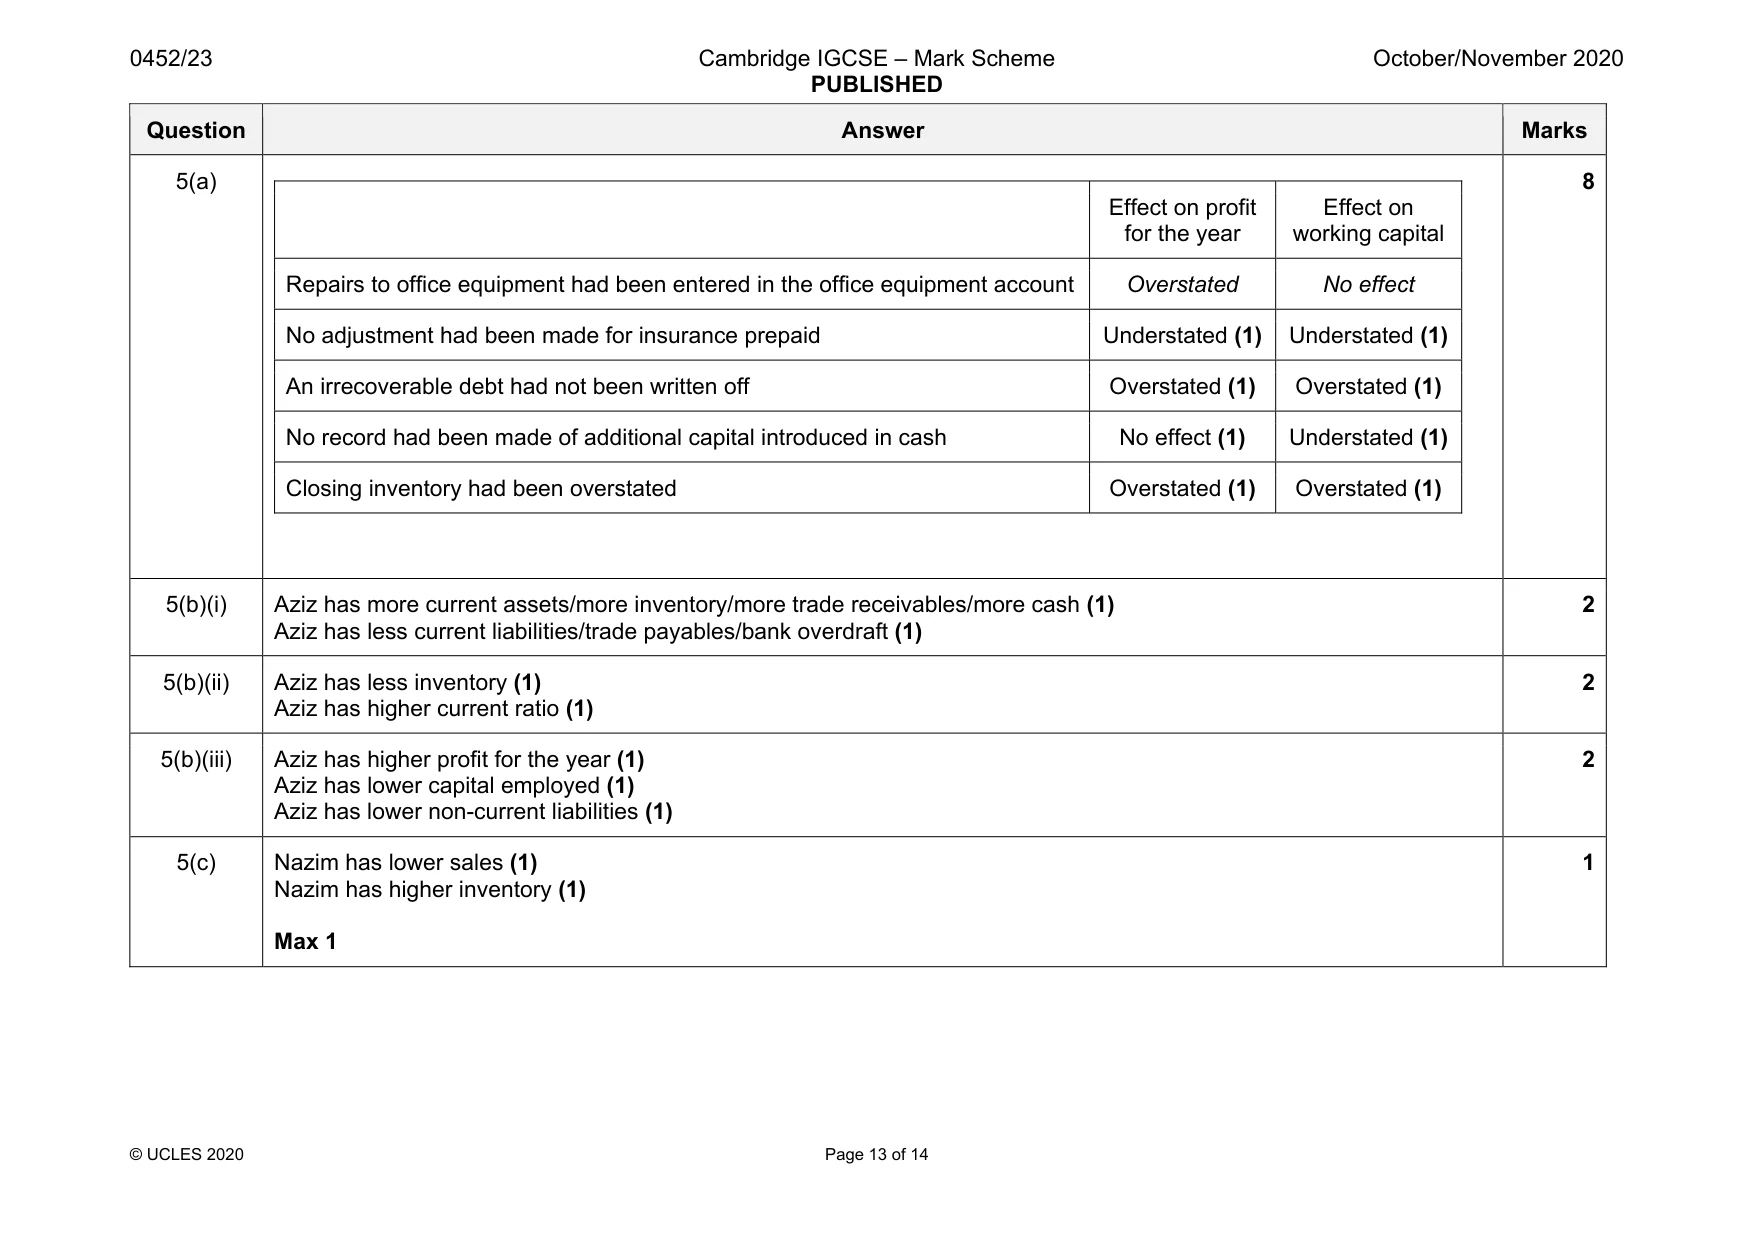
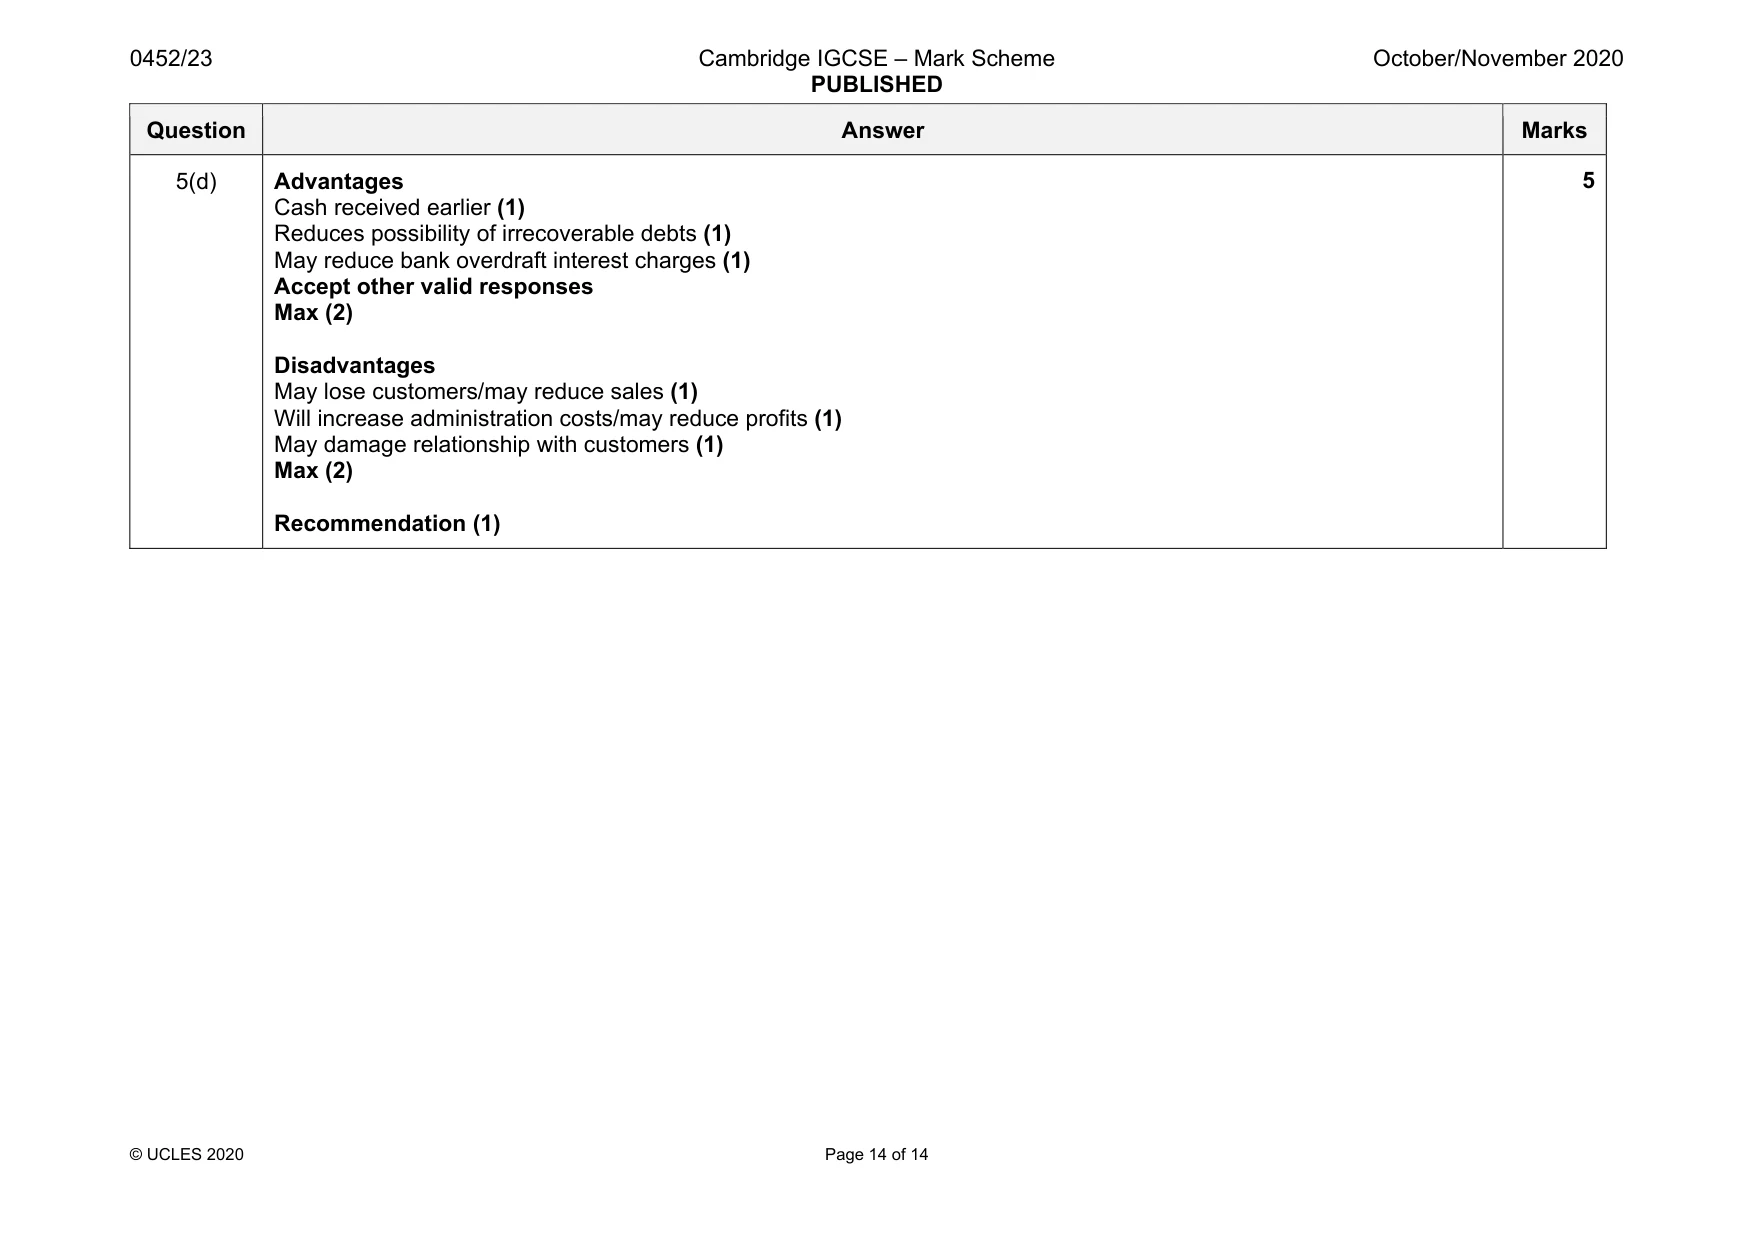
Mark scheme: 5(a) Effect on profit for the year Effect on working capital Repairs to office equipment had been entered in the office equipment account Overstated No effect No adjustment had been made for insurance prepaid Understated (1) Understated (1) An irrecoverable debt had not been written off Overstated (1) Overstated (1) No record had been made of additional capital introduced in cash No effect (1) Understated (1) Closing inventory had been overstated Overstated (1) Overstated (1) 8 5(b)(i) Aziz has more current assets/more inventory/more trade receivables/more cash (1) Aziz has less current liabilities/trade payables/bank overdraft (1) 2 5(b)(ii) Aziz has less inventory (1) Aziz has higher current ratio (1) 2 5(b)(iii) Aziz has higher profit for the year (1) Aziz has lower capital employed (1) Aziz has lower non-current liabilities (1) 2 5(c) Nazim has lower sales (1) Nazim has higher inventory (1) Max 1 1 Question Answer Marks 5(d) Advantages Cash received earlier (1) Reduces possibility of irrecoverable debts (1) May reduce bank overdraft interest charges (1) Accept other valid responses Max (2) Disadvantages May lose customers/may reduce sales (1) Will increase administration costs/may reduce profits (1) May damage relationship with customers (1) Max (2) Recommendation (1) 5
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2020 Oct/Nov, Paper 2 · Variant 3. A higher threshold means an easier paper — the bar moves with how the cohort did.