Cambridge IGCSE Accounting 0452 — 2020 Oct/Nov Paper 2 · Variant 2
0452/22/O/N/20 · 5 questions · 100 marks · ≈113 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper20 pages
Mark scheme14 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Dev owns a business selling furniture
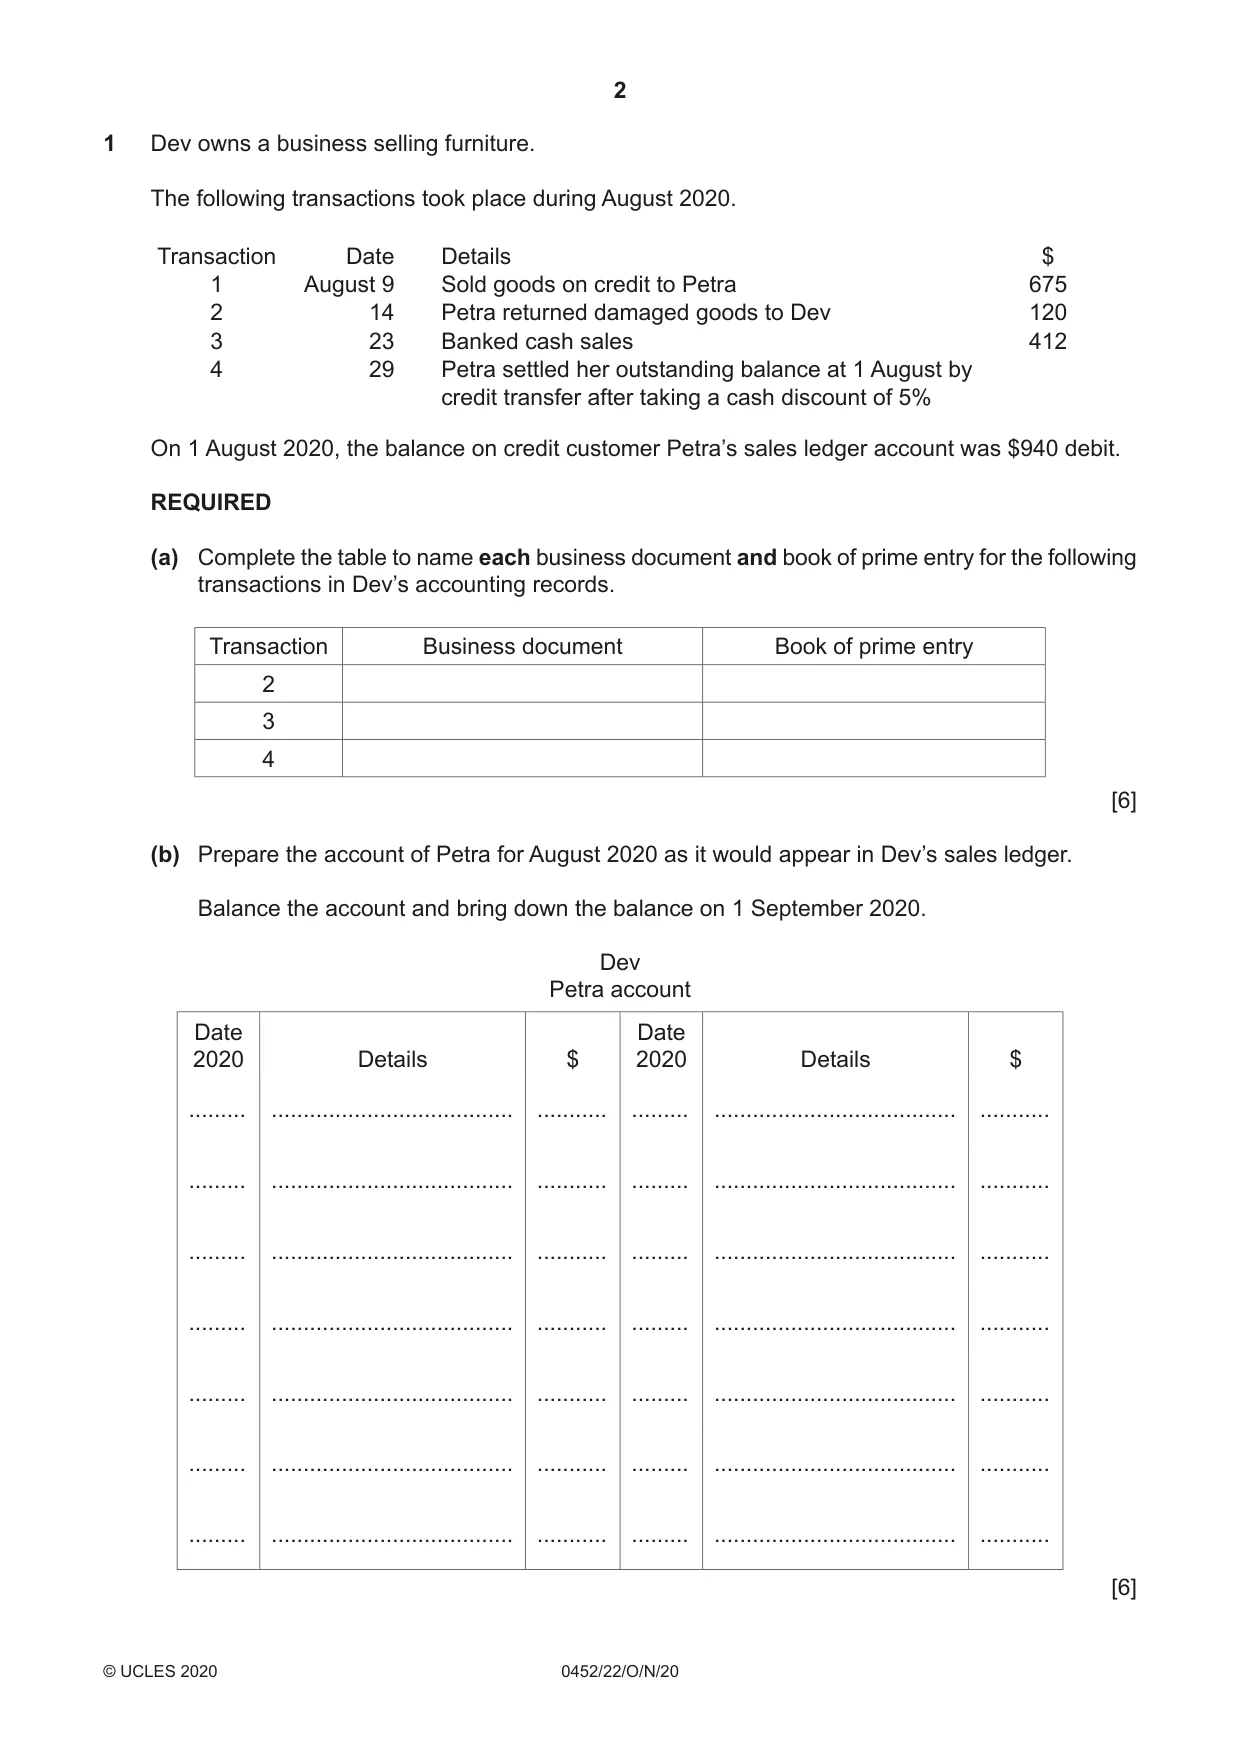
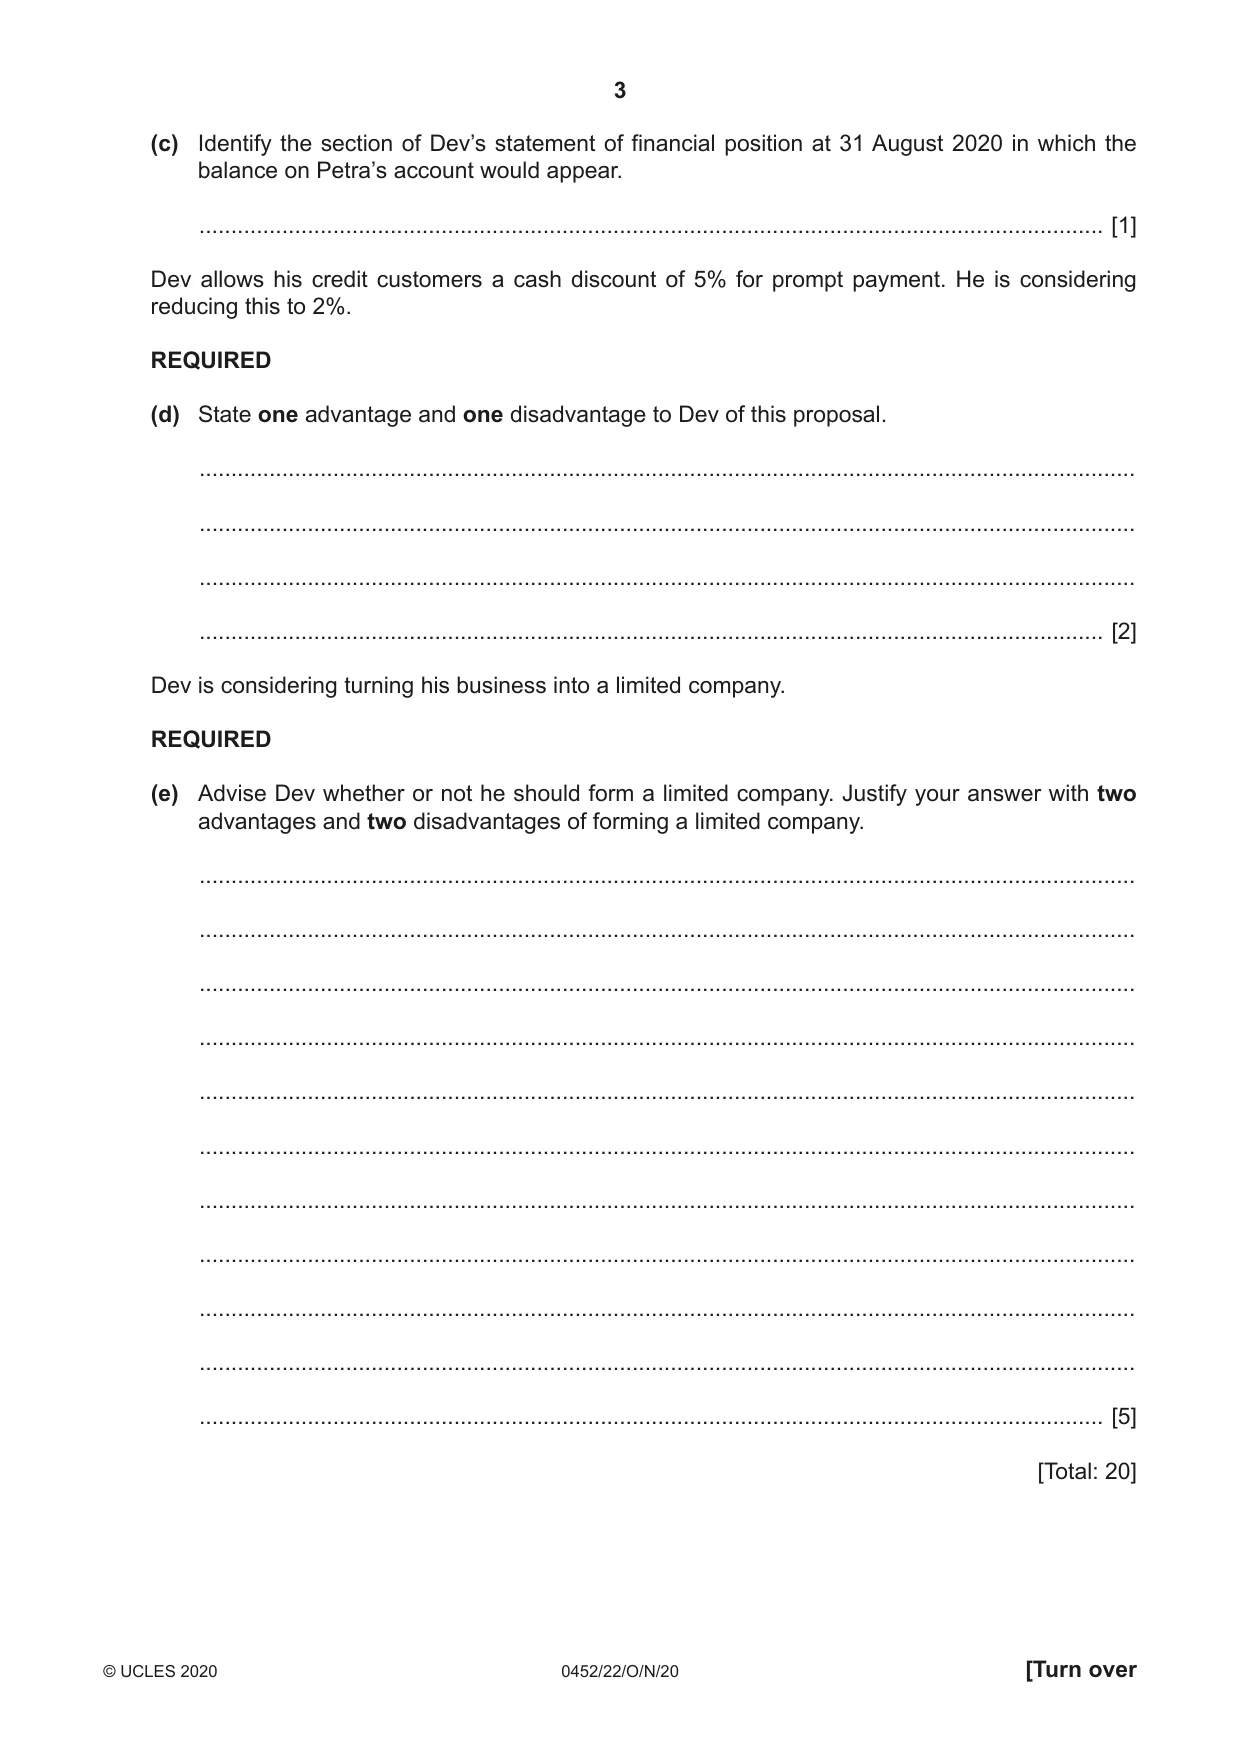
1 Dev owns a business selling furniture. The following transactions took place during August 2020. Transaction Date Details $ 1 August 9 Sold goods on credit to Petra 675 2 14 Petra returned damaged goods to Dev 120 3 23 Banked cash sales 412 4 29 Petra settled her outstanding balance at 1 August by credit transfer after taking a cash discount of 5% On 1 August 2020, the balance on credit customer Petra’s sales ledger account was $940 debit. REQUIRED (a) Complete the table to name each business document and book of prime entry for the following transactions in Dev’s accounting records. Transaction Business document Book of prime entry 2 3 4 [6] (b) Prepare the account of Petra for August 2020 as it would appear in Dev’s sales ledger. Balance the account and bring down the balance on 1 September 2020. Dev Petra account Date Date 2020 Details $ 2020 Details $ ......... ...................................... ........... ......... ...................................... ........... ......... ...................................... ........... ......... ...................................... ........... ......... ...................................... ........... ......... ...................................... ........... ......... ...................................... ........... ......... ...................................... ........... ......... ...................................... ........... ......... ...................................... ........... ......... ...................................... ........... ......... ...................................... ........... ......... ...................................... ........... ......... ...................................... ........... [6] (c) Identify the section of Dev’s statement of financial position at 31 August 2020 in which the balance on Petra’s account would appear. .............................................................................................................................................. [1] Dev allows his credit customers a cash discount of 5% for prompt payment. He is considering reducing this to 2%. REQUIRED (d) State one advantage and one disadvantage to Dev of this proposal. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [2] Dev is considering turning his business into a limited company. REQUIRED (e) Advise Dev whether or not he should form a limited company. Justify your answer with two advantages and two disadvantages of forming a limited company. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [5] [Total: 20]
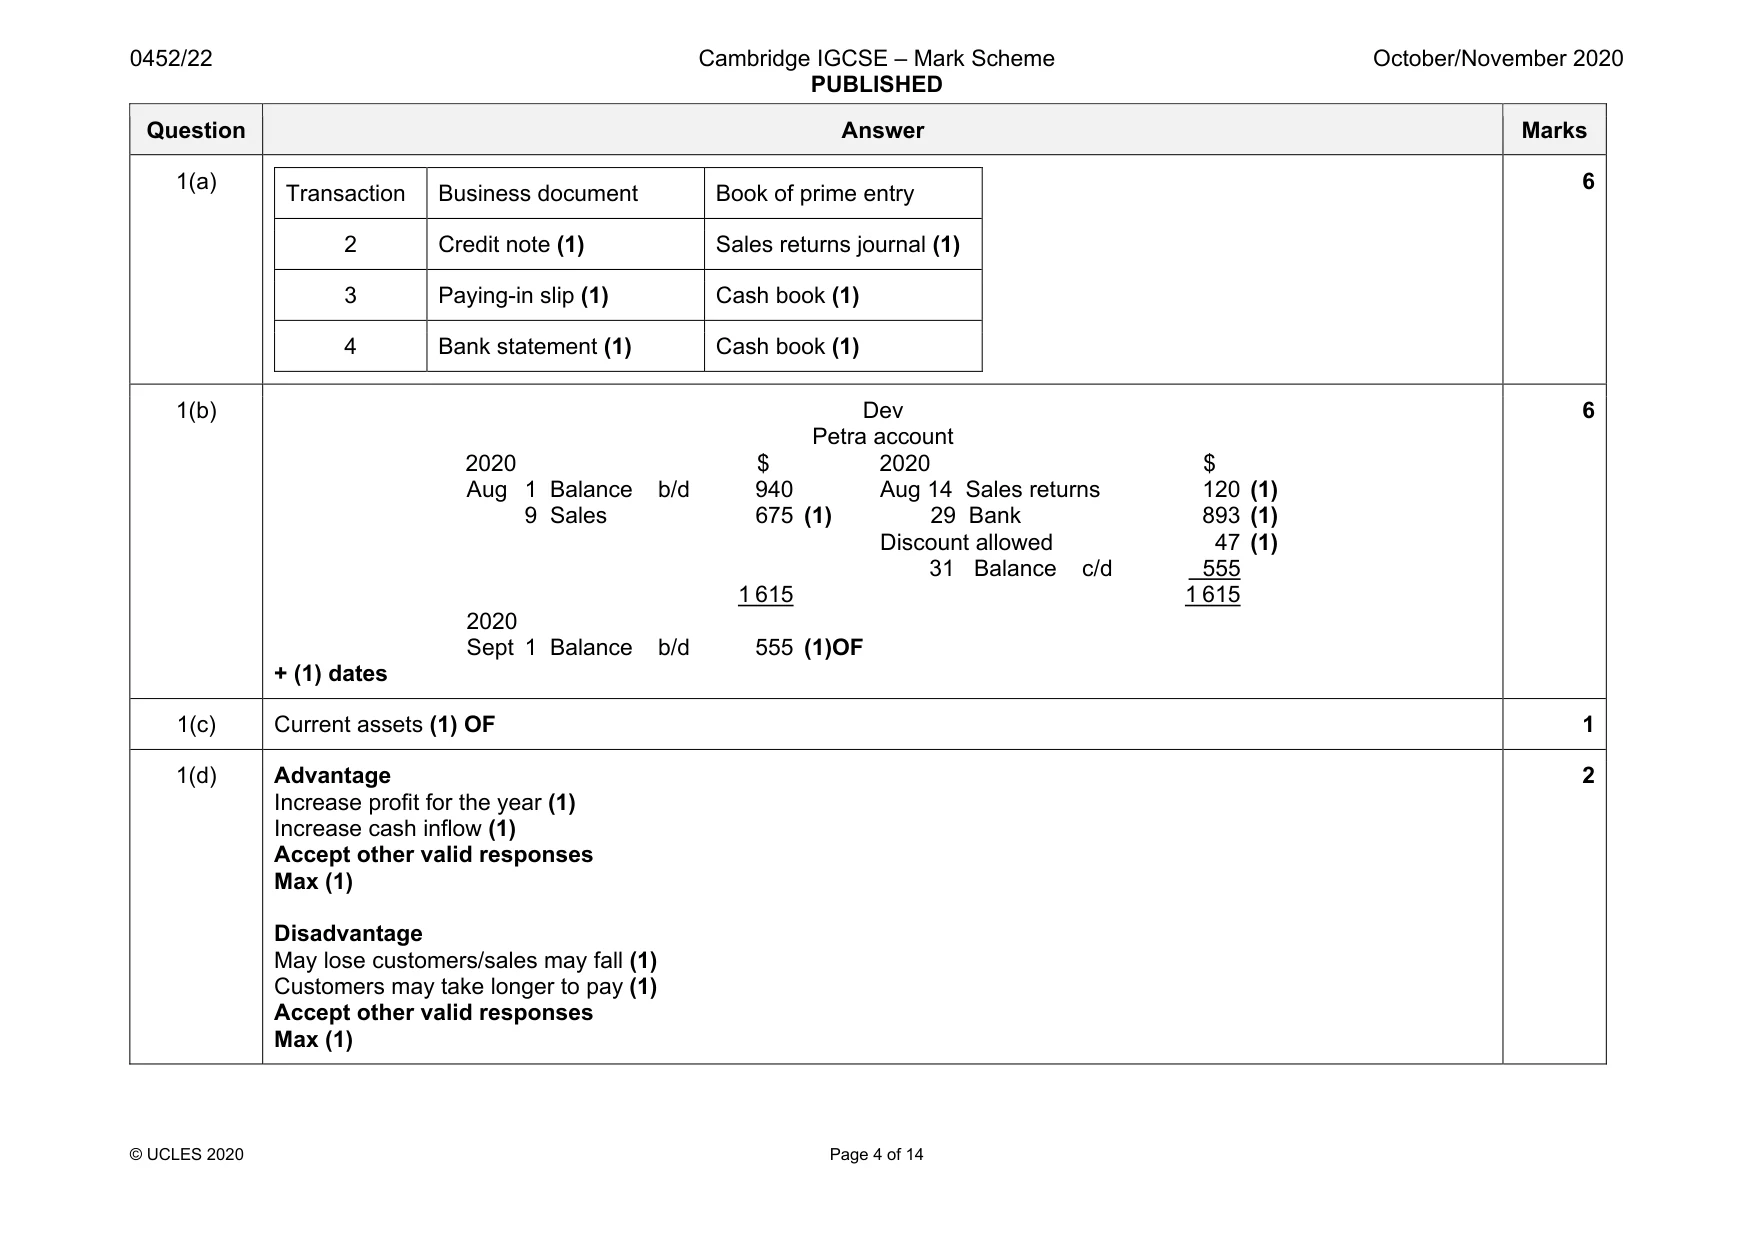
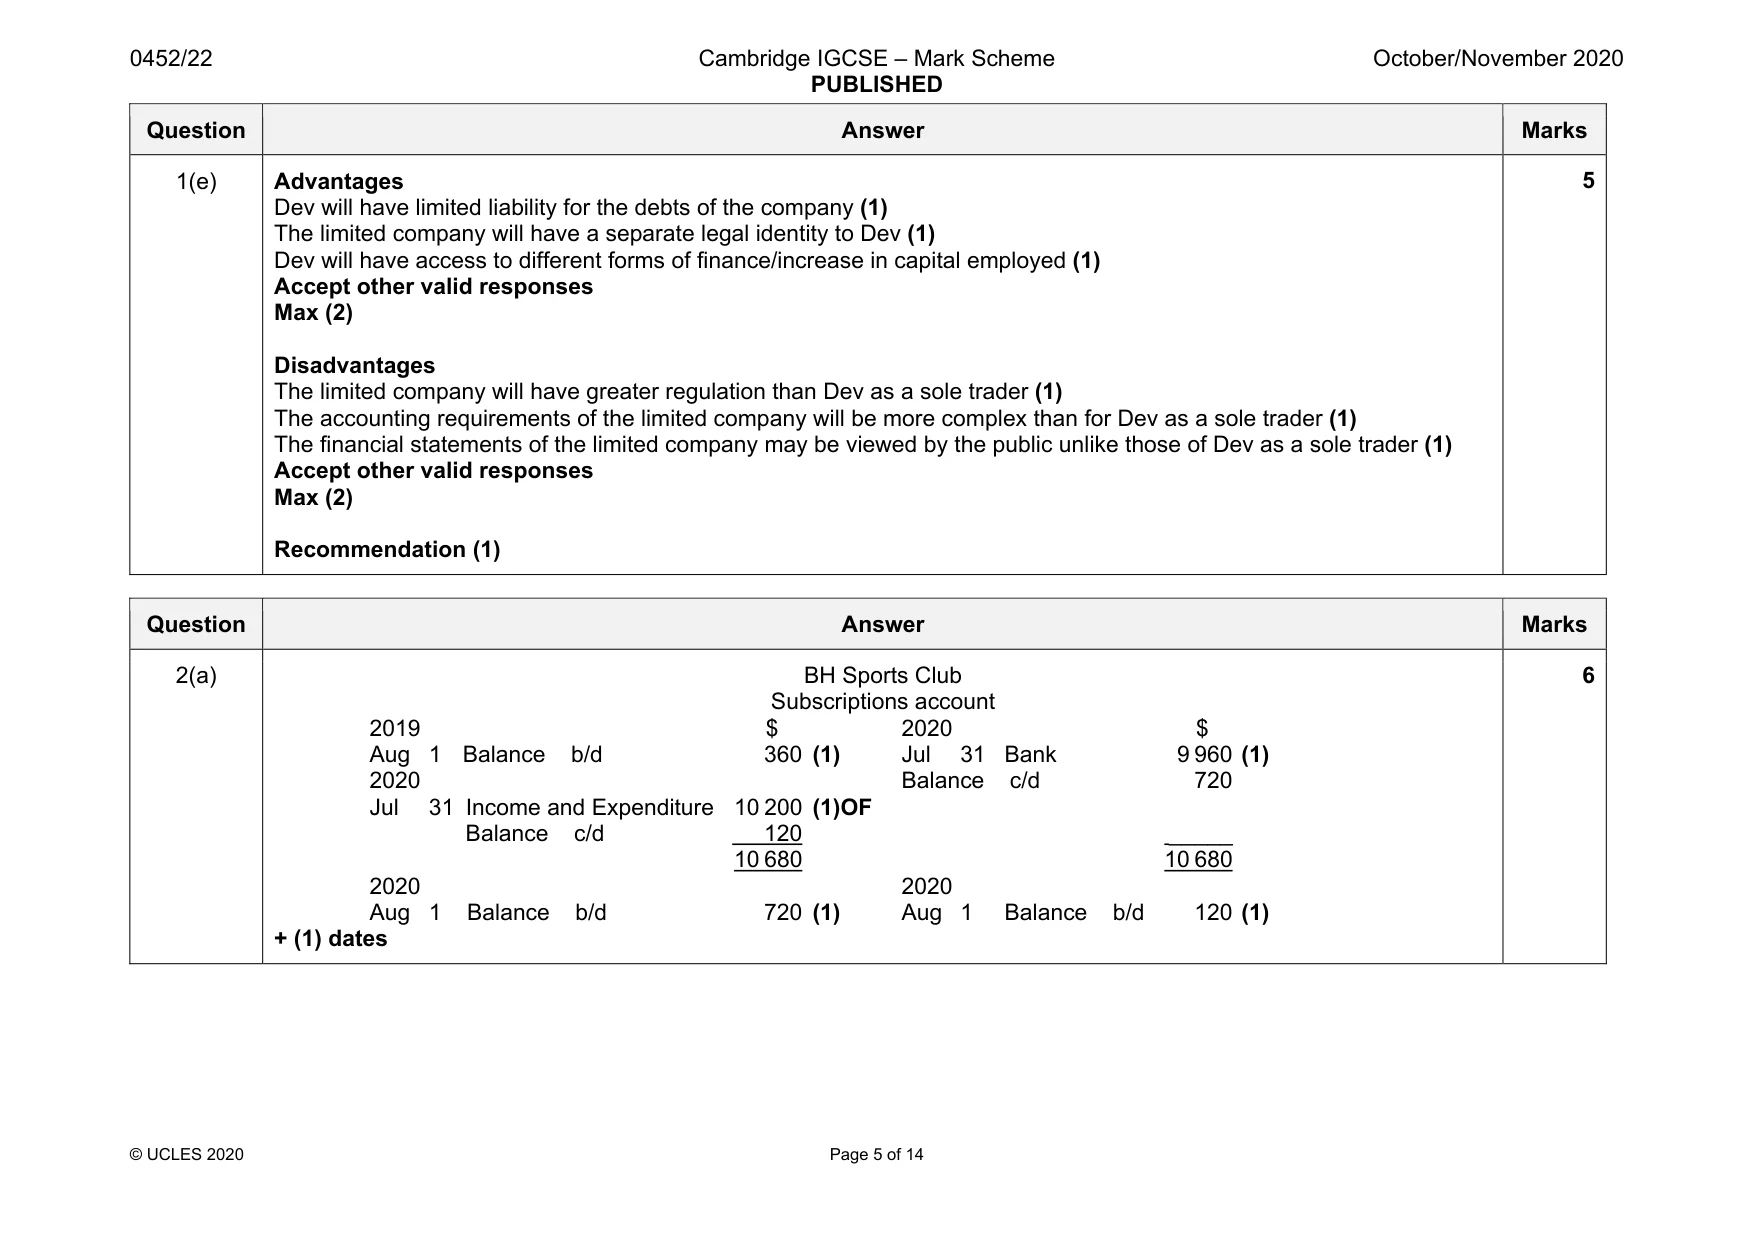
Mark scheme: 1(a) Transaction Business document Book of prime entry 2 Credit note (1) Sales returns journal (1) 3 Paying-in slip (1) Cash book (1) 4 Bank statement (1) Cash book (1) 6 1(b) Dev Petra account 2020 $ 2020 $ Aug 1 Balance b/d 940 Aug 14 Sales returns 120 (1) 9 Sales 675 (1) 29 Bank 893 (1) Discount allowed 47 (1) 31 Balance c/d 555 1 615 1 615 2020 Sept 1 Balance b/d 555 (1)OF + (1) dates 6 1(c) Current assets (1) OF 1 1(d) Advantage Increase profit for the year (1) Increase cash inflow (1) Accept other valid responses Max (1) Disadvantage May lose customers/sales may fall (1) Customers may take longer to pay (1) Accept other valid responses Max (1) 2 Question Answer Marks 1(e) Advantages Dev will have limited liability for the debts of the company (1) The limited company will have a separate legal identity to Dev (1) Dev will have access to different forms of finance/increase in capital employed (1) Accept other valid responses Max (2) Disadvantages The limited company will have greater regulation than Dev as a sole trader (1) The accounting requirements of the limited company will be more complex than for Dev as a sole trader (1) The financial statements of the limited company may be viewed by the public unlike those of Dev as a sole trader (1) Accept other valid responses Max (2) Recommendation (1) 5
Q2 · BH Sports Club provides sporting facilities and a café for the use of its members and…
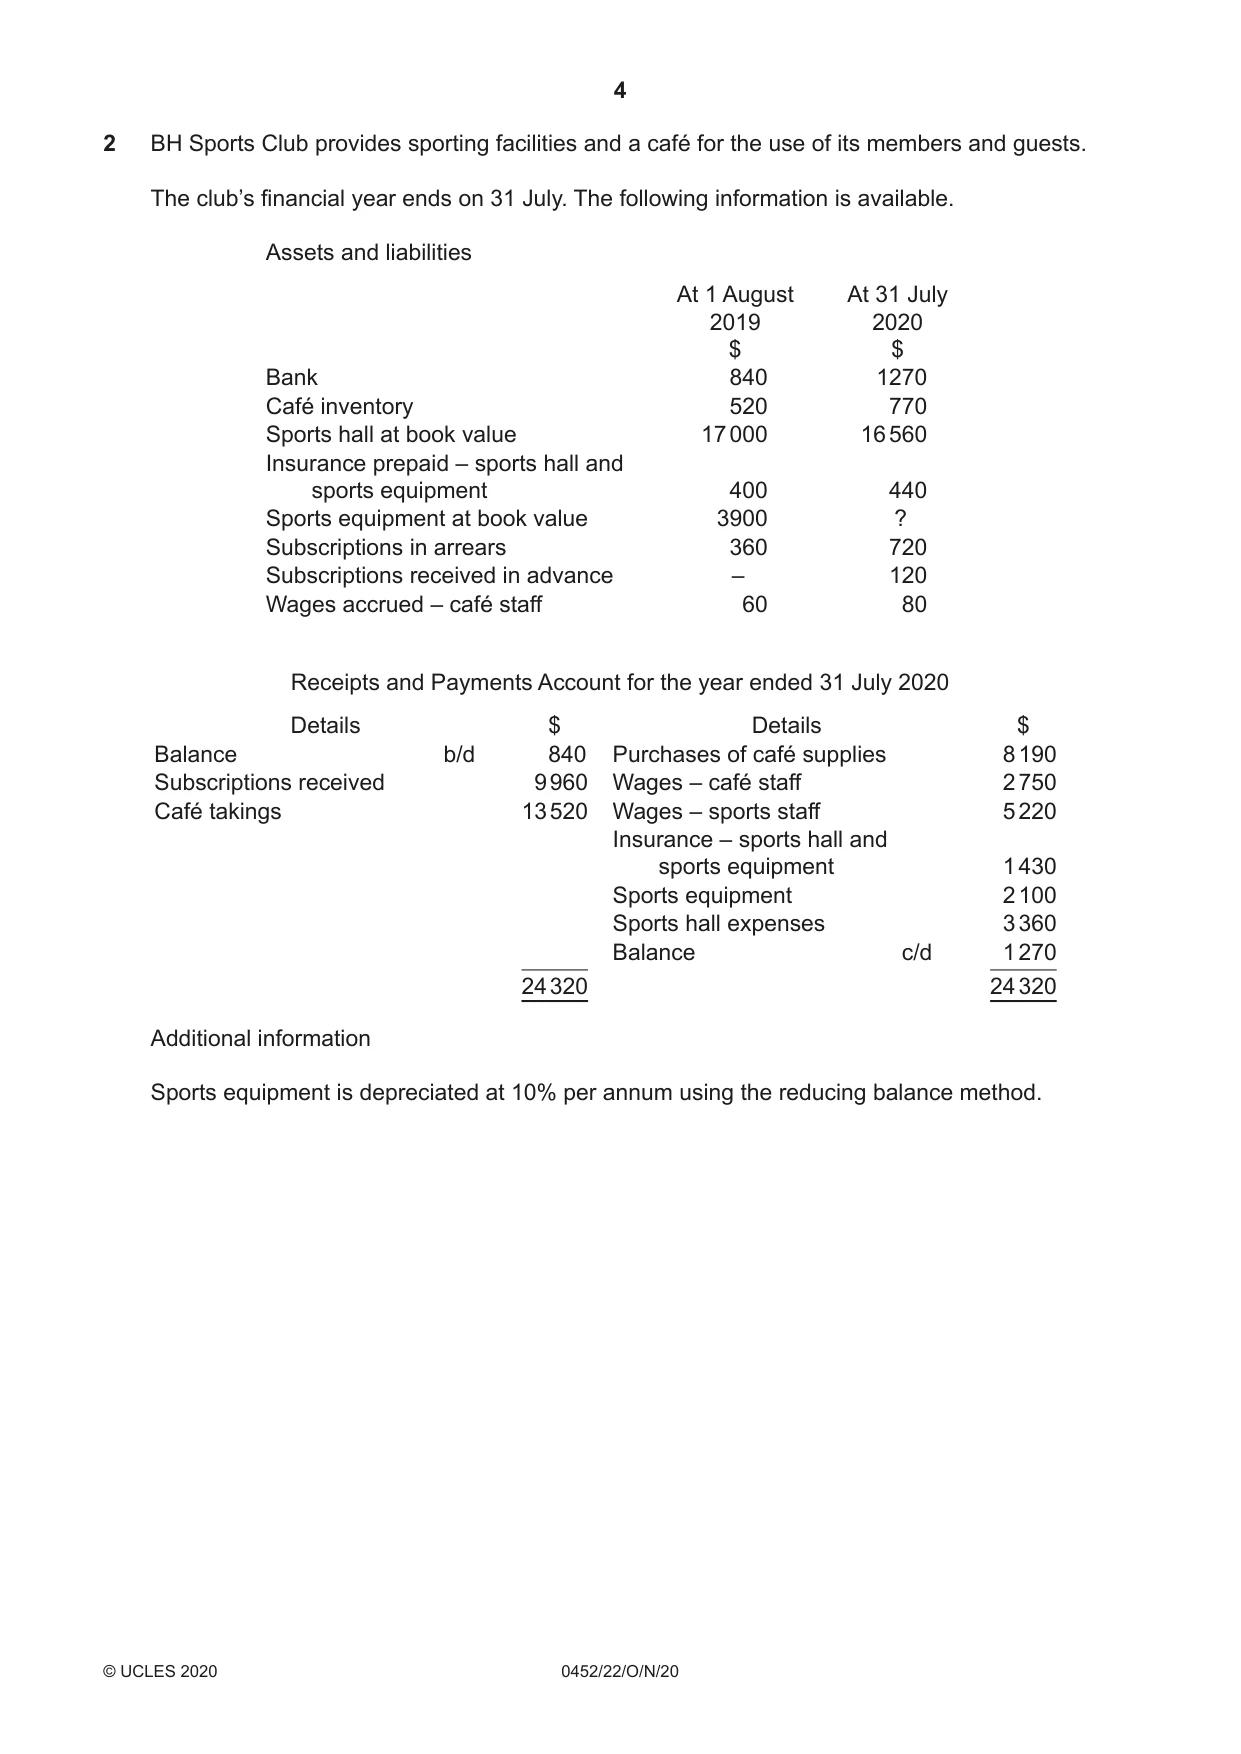
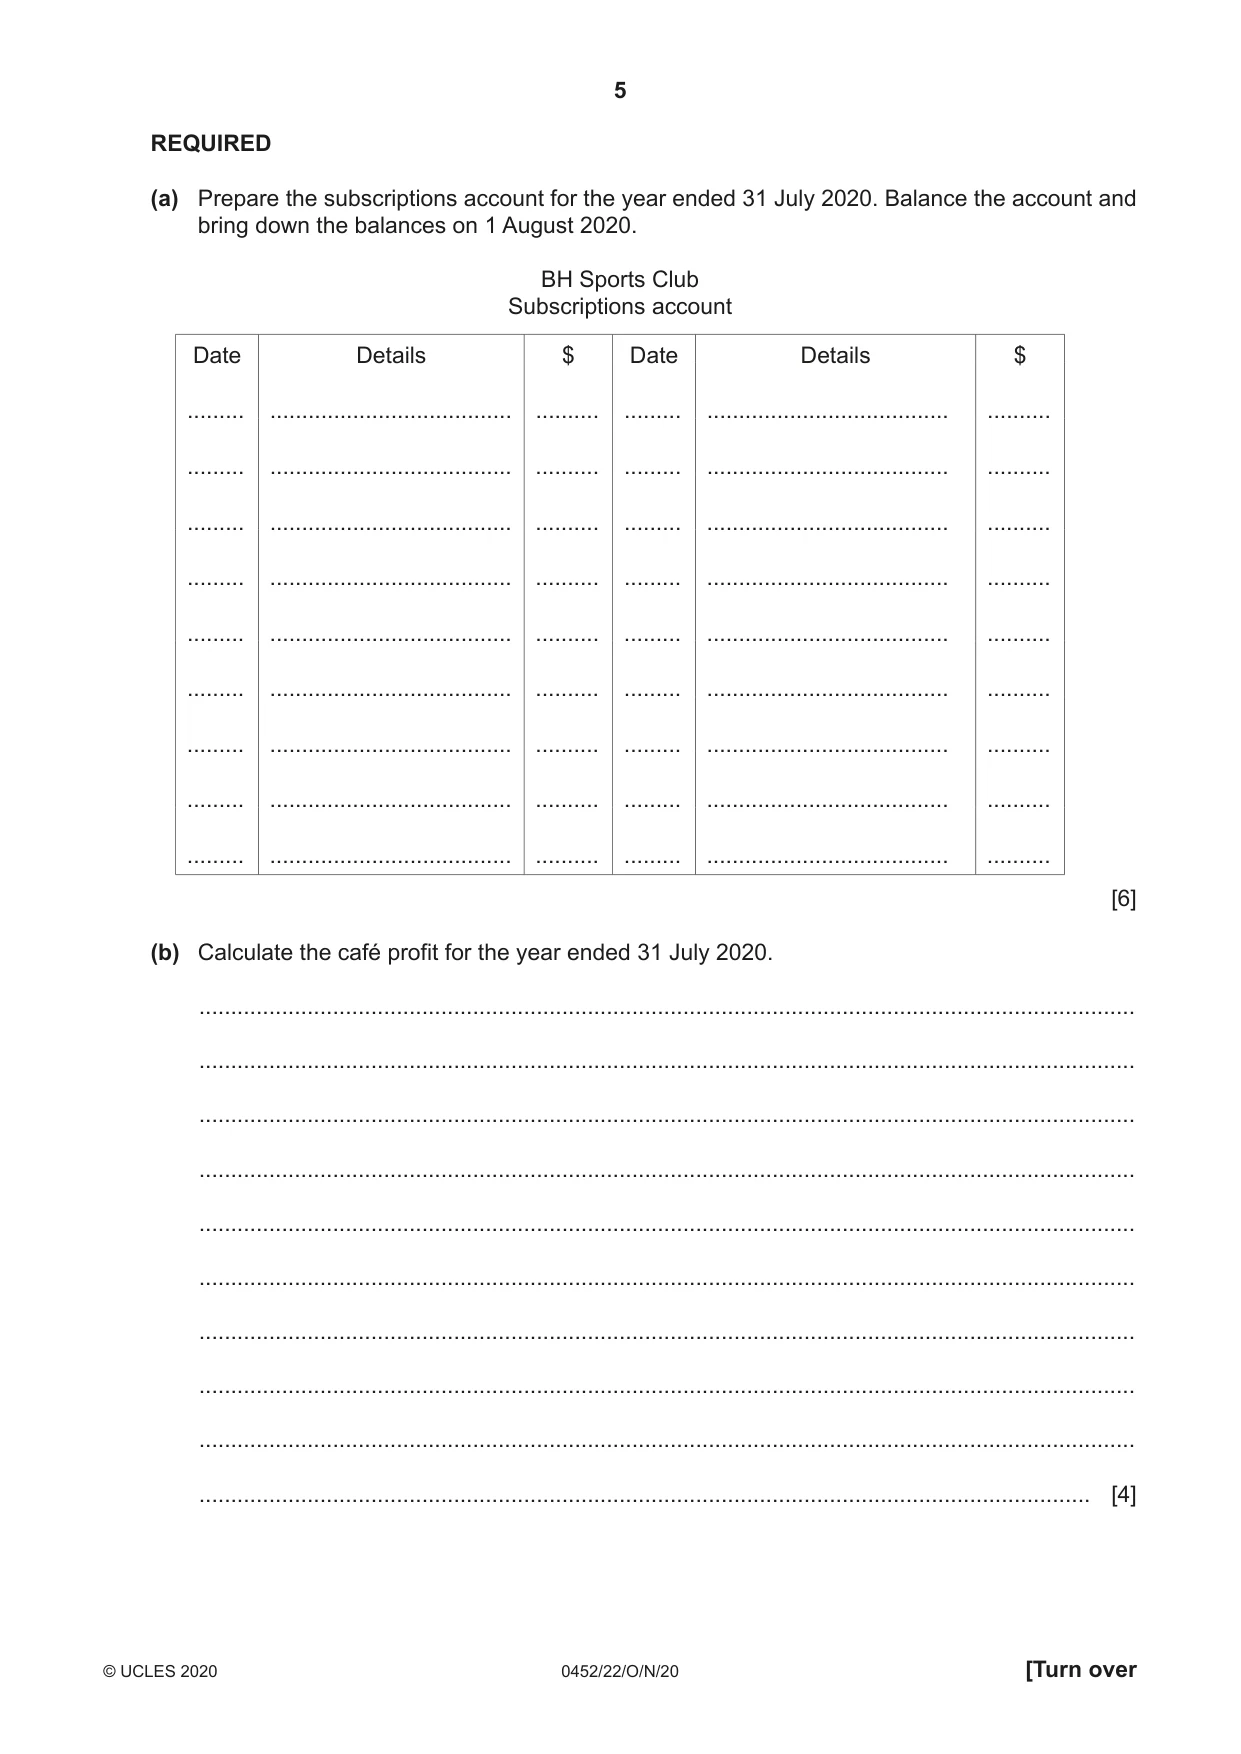
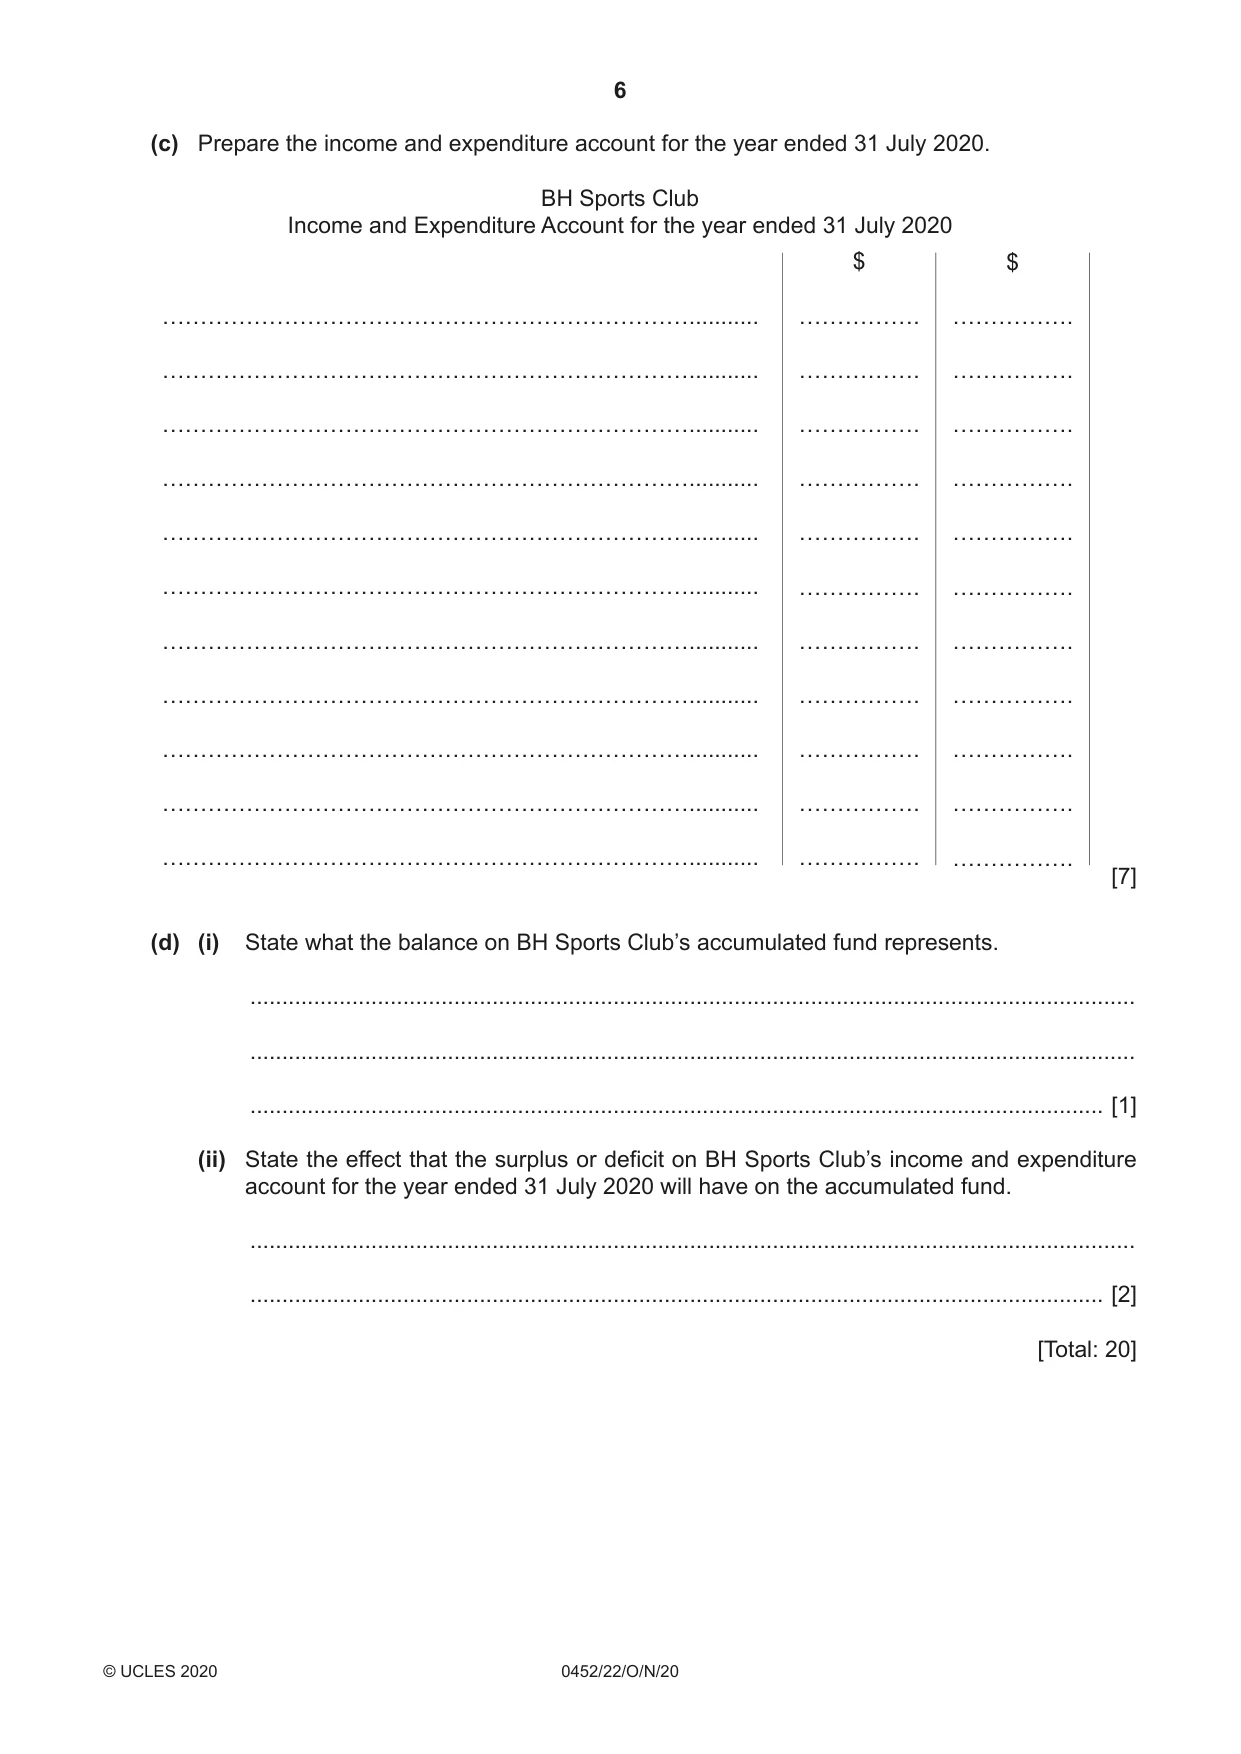
2 BH Sports Club provides sporting facilities and a café for the use of its members and guests. The club’s financial year ends on 31 July. The following information is available. Assets and liabilities At 1 August At 31 July 2019 2020 $ $ Bank 840 1270 Café inventory 520 770 Sports hall at book value 17 000 16 560 Insurance prepaid – sports hall and sports equipment 400 440 Sports equipment at book value 3900 ? Subscriptions in arrears 360 720 Subscriptions received in advance – 120 Wages accrued – café staff 60 80 Receipts and Payments Account for the year ended 31 July 2020 Details $ Details $ Balance b/d 840 Purchases of café supplies 8 190 Subscriptions received 9 960 Wages – café staff 2 750 Café takings 13 520 Wages – sports staff 5 220 Insurance – sports hall and sports equipment 1 430 Sports equipment 2 100 Sports hall expenses 3 360 Balance c/d 1 270 24 320 24 320 Additional information Sports equipment is depreciated at 10% per annum using the reducing balance method. REQUIRED (a) Prepare the subscriptions account for the year ended 31 July 2020. Balance the account and bring down the balances on 1 August 2020. BH Sports Club Subscriptions account Date Details $ Date Details $ ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... [6] (b) Calculate the café profit for the year ended 31 July 2020. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................ [4] (c) Prepare the income and expenditure account for the year ended 31 July 2020. BH Sports Club Income and Expenditure Account for the year ended 31 July 2020 $ $ ……………………………………………………………........... ……………. ……………. ……………………………………………………………........... ……………. ……………. ……………………………………………………………........... ……………. ……………. ……………………………………………………………........... ……………. ……………. ……………………………………………………………........... ……………. ……………. ……………………………………………………………........... ……………. ……………. ……………………………………………………………........... ……………. ……………. ……………………………………………………………........... ……………. ……………. ……………………………………………………………........... ……………. ……………. ……………………………………………………………........... ……………. ……………. ……………………………………………………………........... ……………. ……………. [7] (d) (i) State what the balance on BH Sports Club’s accumulated fund represents. ........................................................................................................................................... ........................................................................................................................................... ...................................................................................................................................... [1] (ii) State the effect that the surplus or deficit on BH Sports Club’s income and expenditure account for the year ended 31 July 2020 will have on the accumulated fund. ........................................................................................................................................... ...................................................................................................................................... [2] [Total: 20] PLEASE TURN OVER
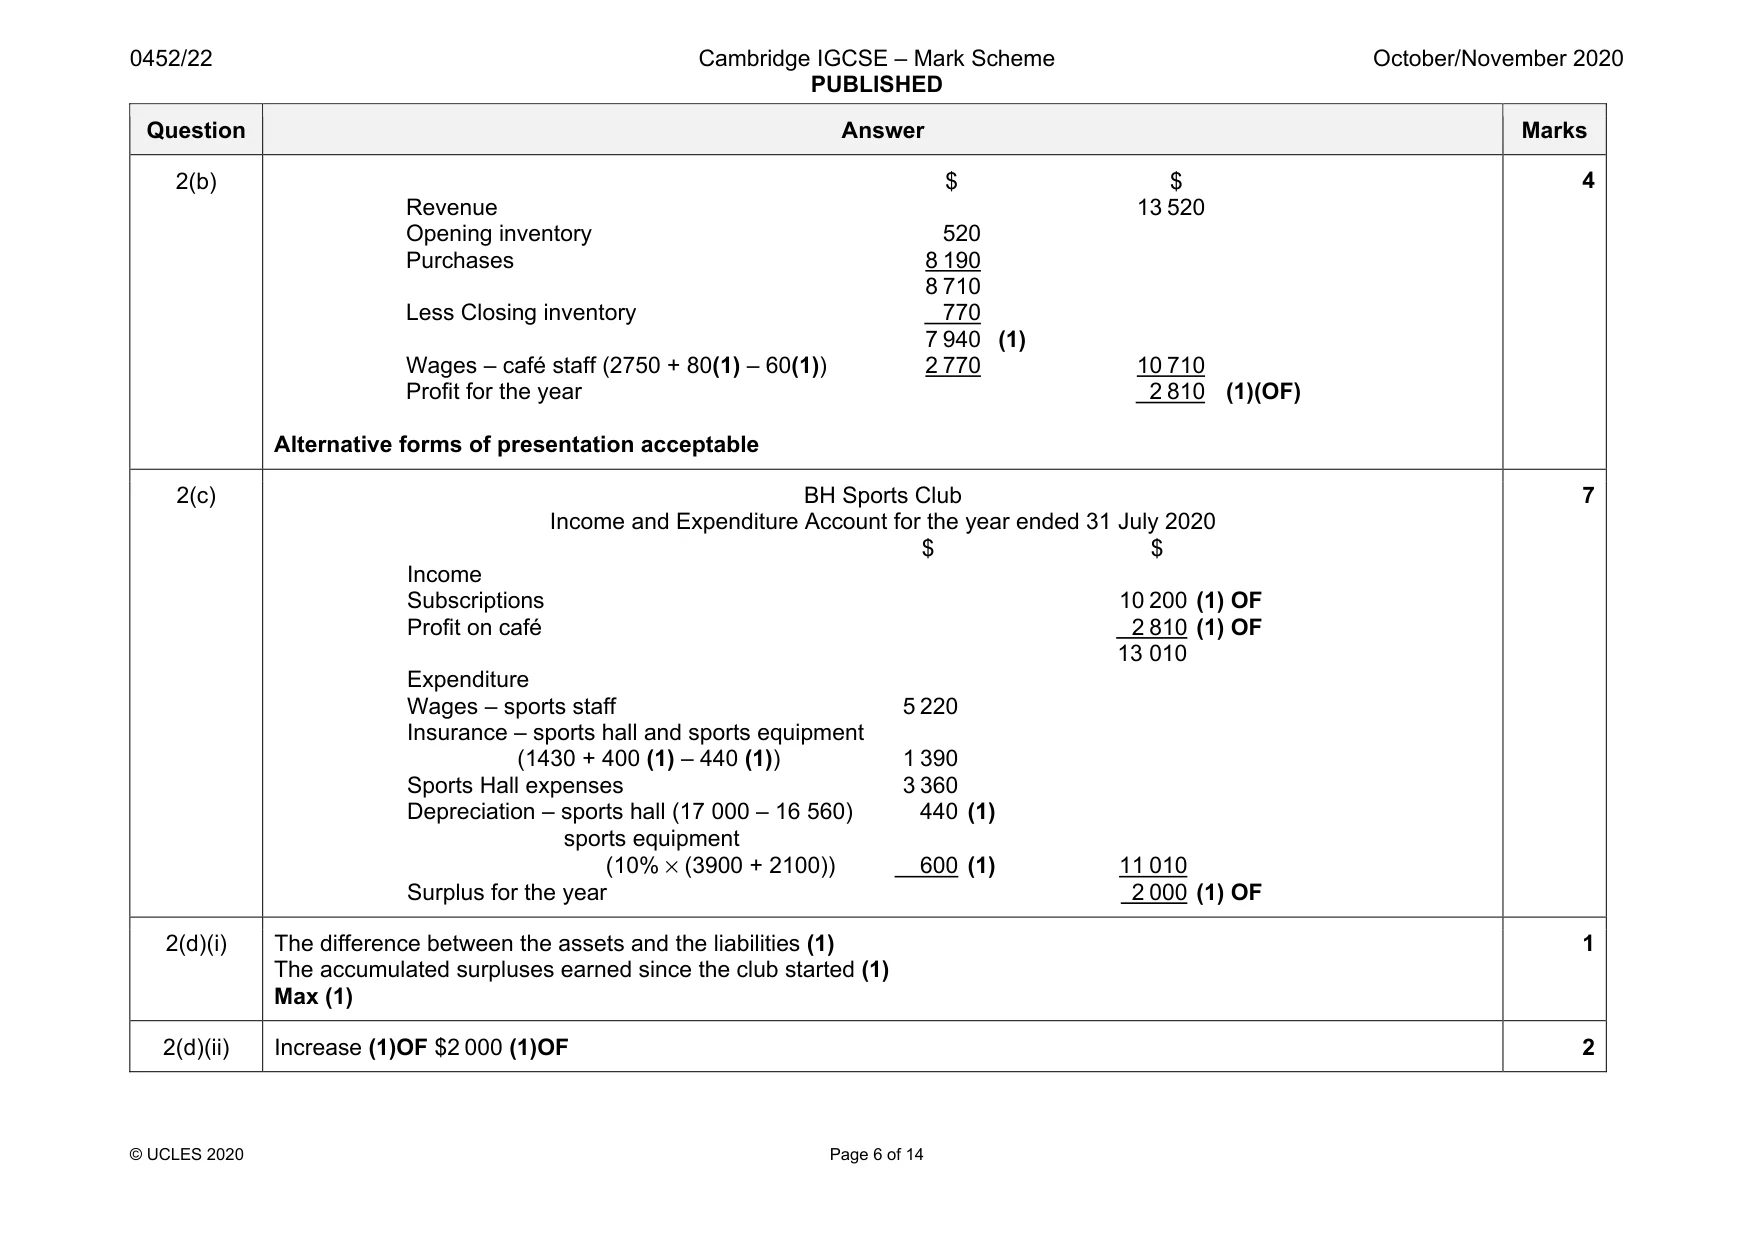
Mark scheme: 2(a) BH Sports Club Subscriptions account 2019 $ 2020 $ Aug 1 Balance b/d 360 (1) Jul 31 Bank 9 960 (1) 2020 Balance c/d 720 Jul 31 Income and Expenditure 10 200 (1)OF Balance c/d 120 _____ 10 680 10 680 2020 2020 Aug 1 Balance b/d 720 (1) Aug 1 Balance b/d 120 (1) + (1) dates Question Answer Marks 2(b) $ $ Revenue 13 520 Opening inventory 520 Purchases 8 190 8 710 Less Closing inventory 770 7 940 (1) Wages – café staff (2750 + 80(1) – 60(1)) 2 770 10 710 Profit for the year 2 810 (1)(OF) Alternative forms of presentation acceptable 4 2(c) BH Sports Club Income and Expenditure Account for the year ended 31 July 2020 $ $ Income Subscriptions 10 200 (1) OF Profit on café 2 810 (1) OF 13 010 Expenditure Wages – sports staff 5 220 Insurance – sports hall and sports equipment (1430 + 400 (1) – 440 (1)) 1 390 Sports Hall expenses 3 360 Depreciation – sports hall (17 000 – 16 560) 440 (1) sports equipment (10% × (3900 + 2100)) 600 (1) 11 010 Surplus for the year 2 000 (1) OF 7 2(d)(i) The difference between the assets and the liabilities (1) The accumulated surpluses earned since the club started (1) Max (1) 1 2(d)(ii) Increase (1)OF $2 000 (1)OF 2
Q3 · JP Limited’s financial year ended on 30 September 2020
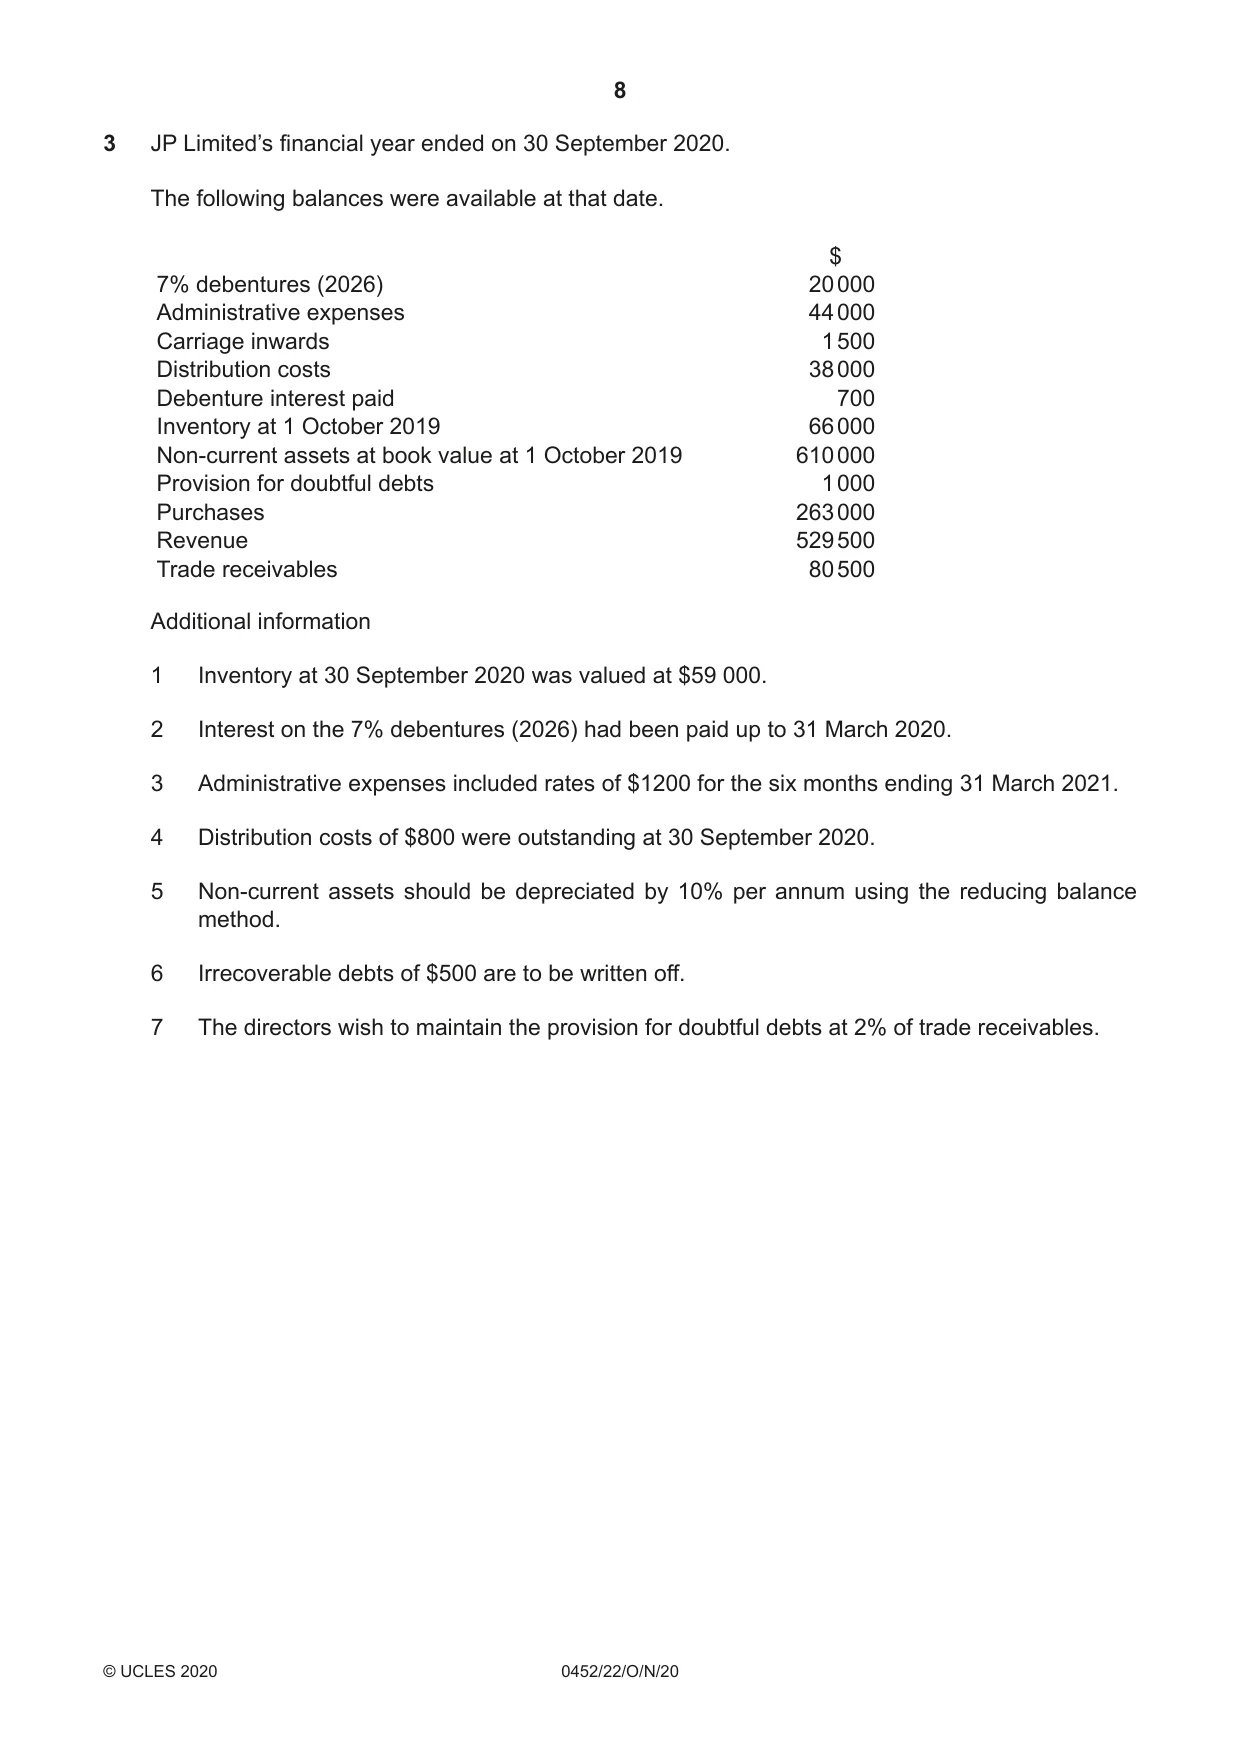
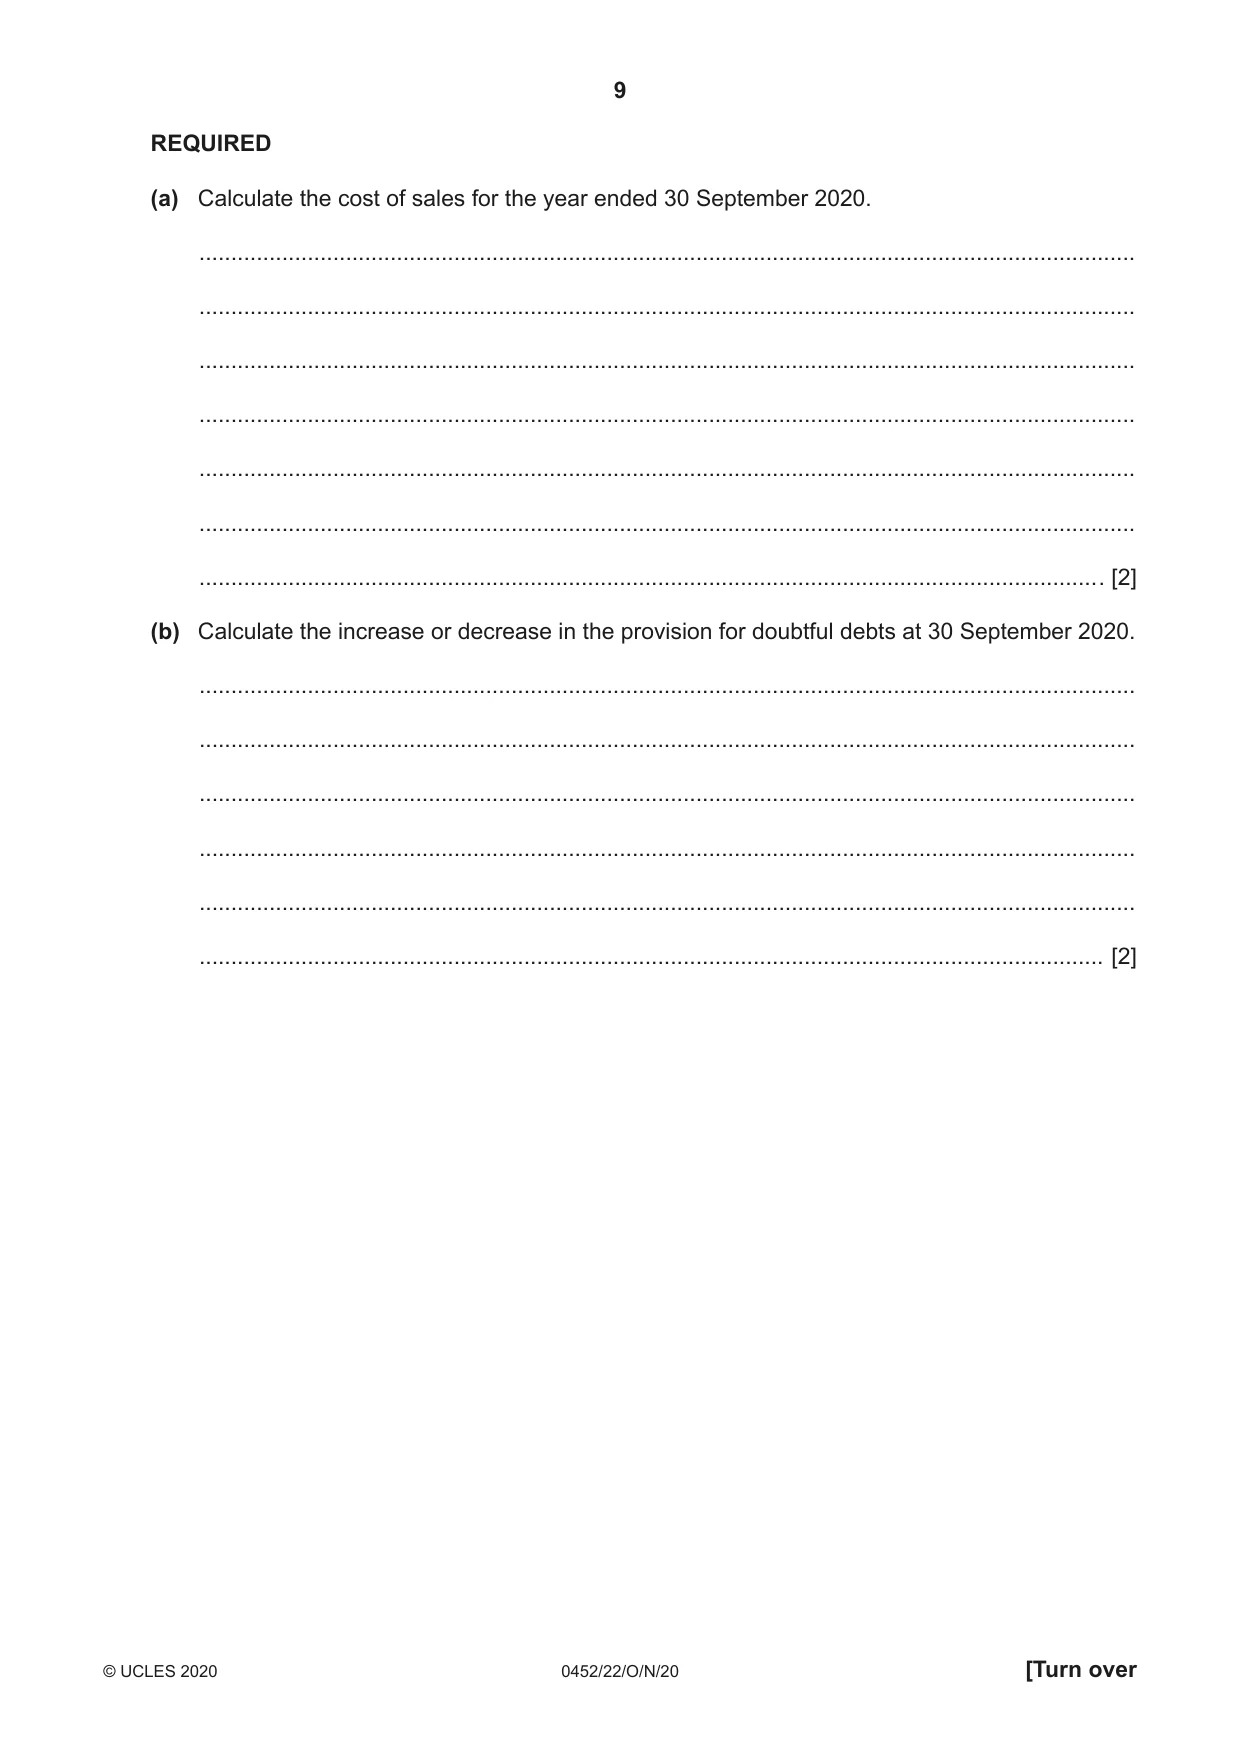
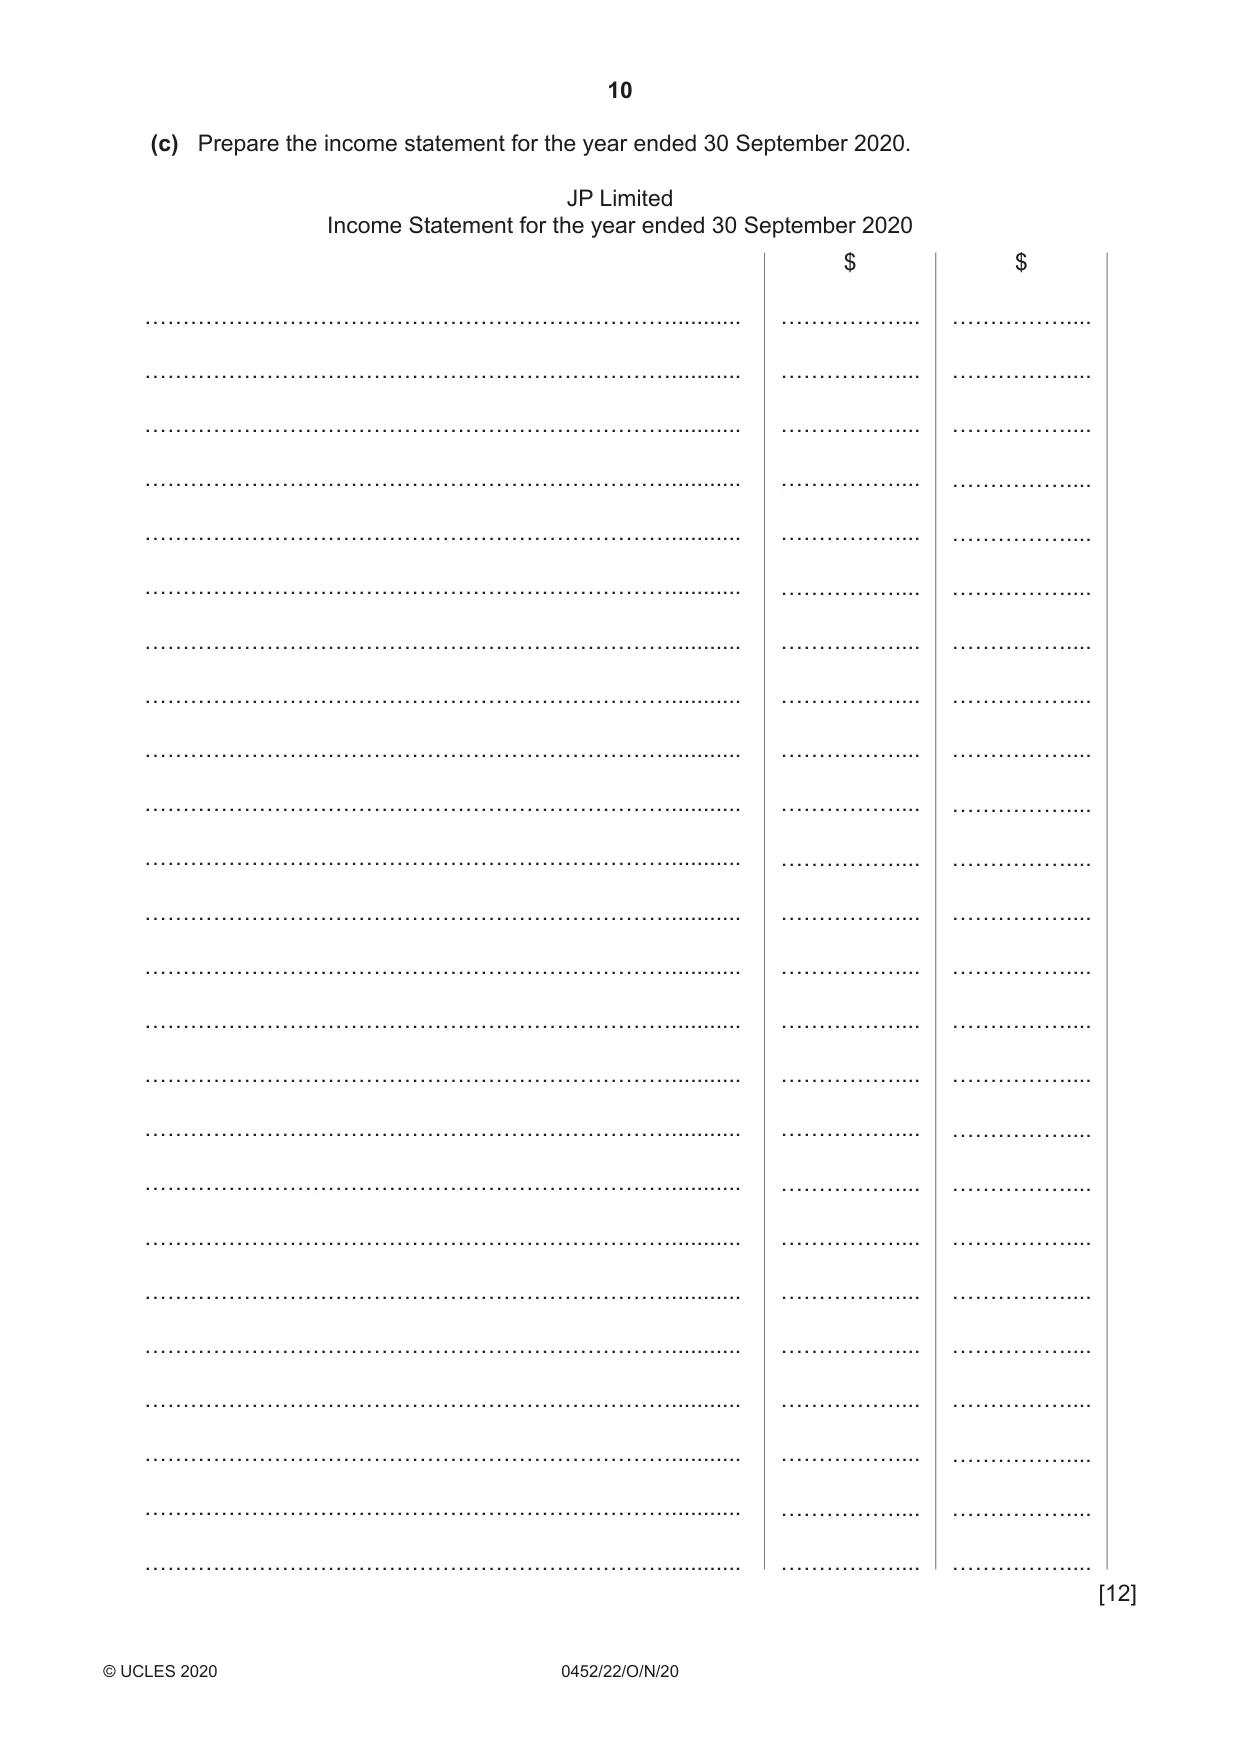
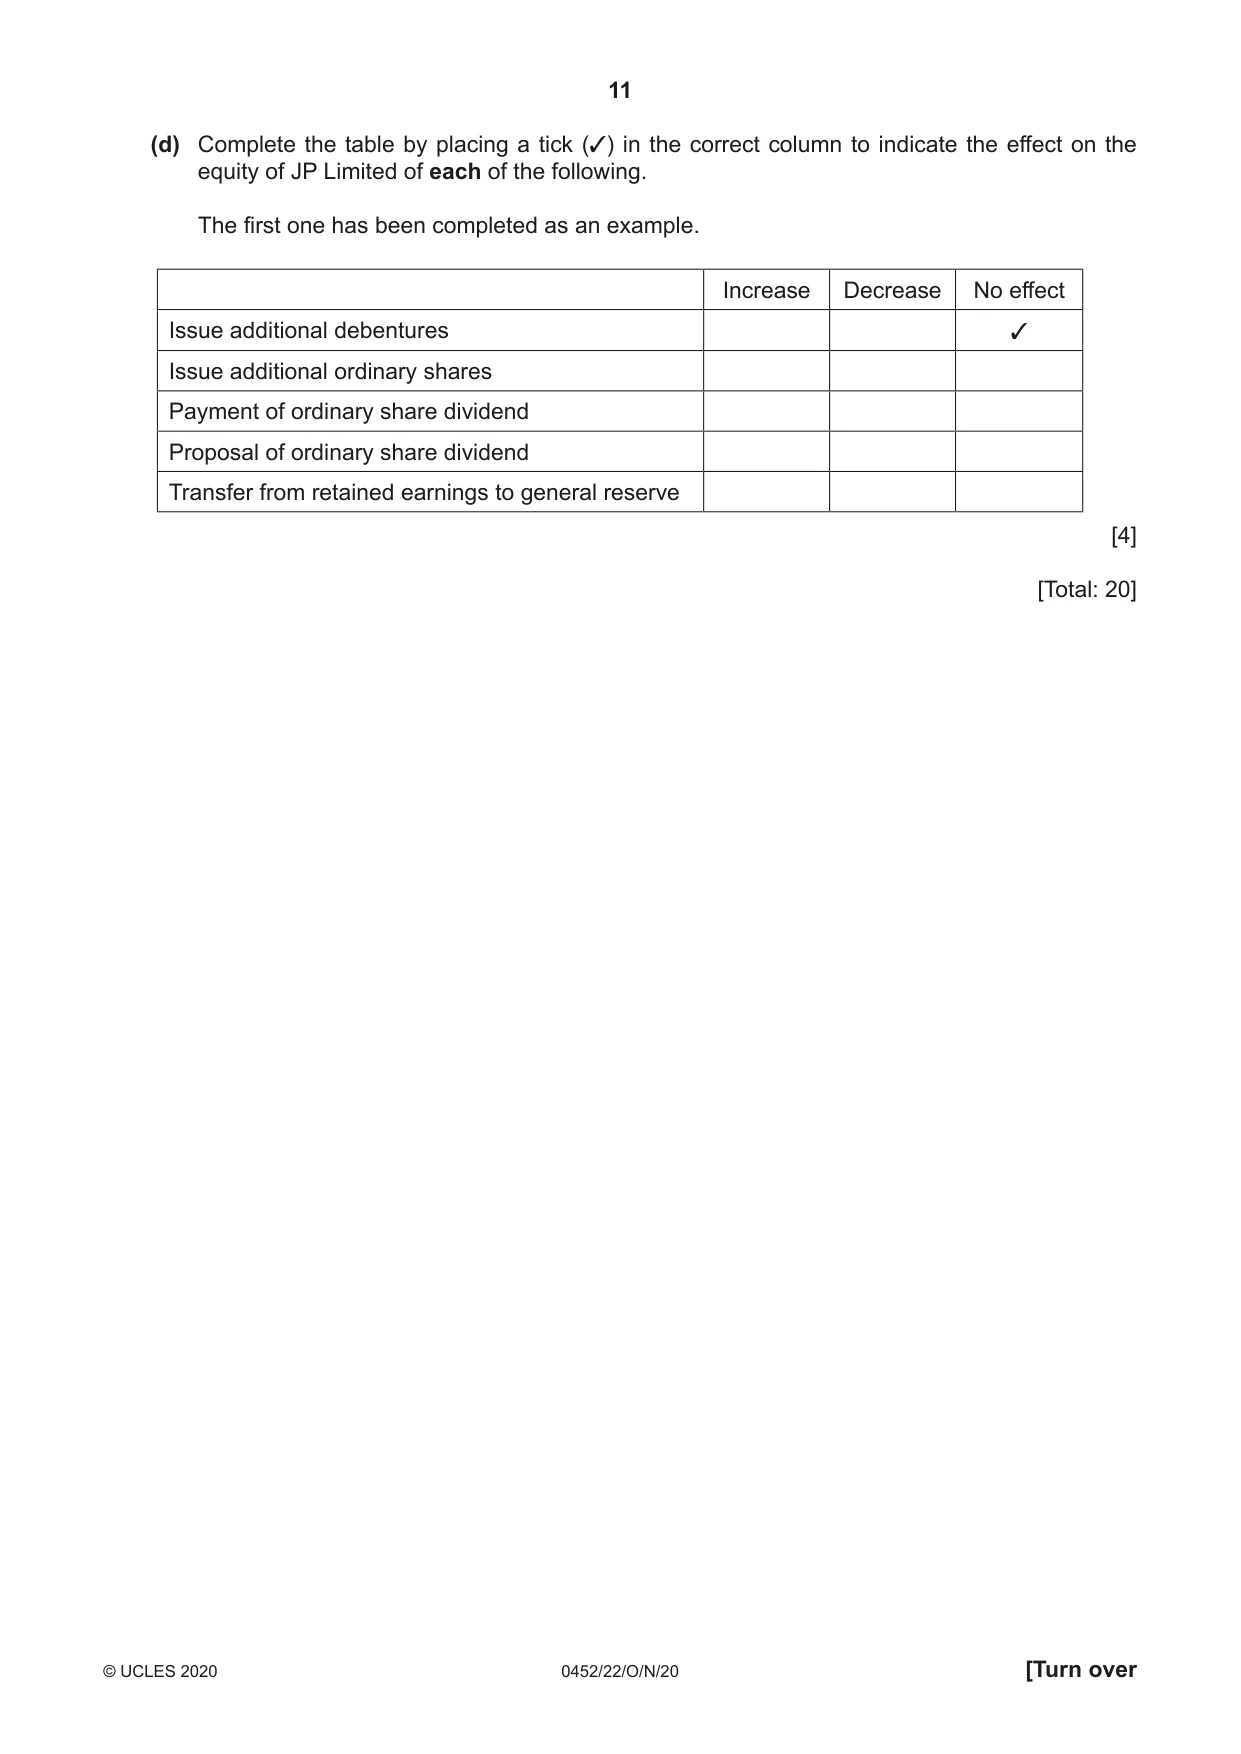
3 JP Limited’s financial year ended on 30 September 2020. The following balances were available at that date. $ 7% debentures (2026) 20 000 Administrative expenses 44 000 Carriage inwards 1 500 Distribution costs 38 000 Debenture interest paid 700 Inventory at 1 October 2019 66 000 Non-current assets at book value at 1 October 2019 610 000 Provision for doubtful debts 1 000 Purchases 263 000 Revenue 529 500 Trade receivables 80 500 Additional information 1 Inventory at 30 September 2020 was valued at $59 000. 2 Interest on the 7% debentures (2026) had been paid up to 31 March 2020. 3 Administrative expenses included rates of $1200 for the six months ending 31 March 2021. 4 Distribution costs of $800 were outstanding at 30 September 2020. 5 Non-current assets should be depreciated by 10% per annum using the reducing balance method. 6 Irrecoverable debts of $500 are to be written off. 7 The directors wish to maintain the provision for doubtful debts at 2% of trade receivables. REQUIRED (a) Calculate the cost of sales for the year ended 30 September 2020. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [2] (b) Calculate the increase or decrease in the provision for doubtful debts at 30 September 2020. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [2] (c) Prepare the income statement for the year ended 30 S JP Limited Income Statement for the year ended 30 S ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... ……………………………………………………………........... (d) Complete the table by placing a tick (✓) in the correct column to indicate the effect on the equity of JP Limited of each of the following. The first one has been completed as an example. Increase Decrease No effect Issue additional debentures ✓ Issue additional ordinary shares Payment of ordinary share dividend Proposal of ordinary share dividend Transfer from retained earnings to general reserve [4] [Total: 20]
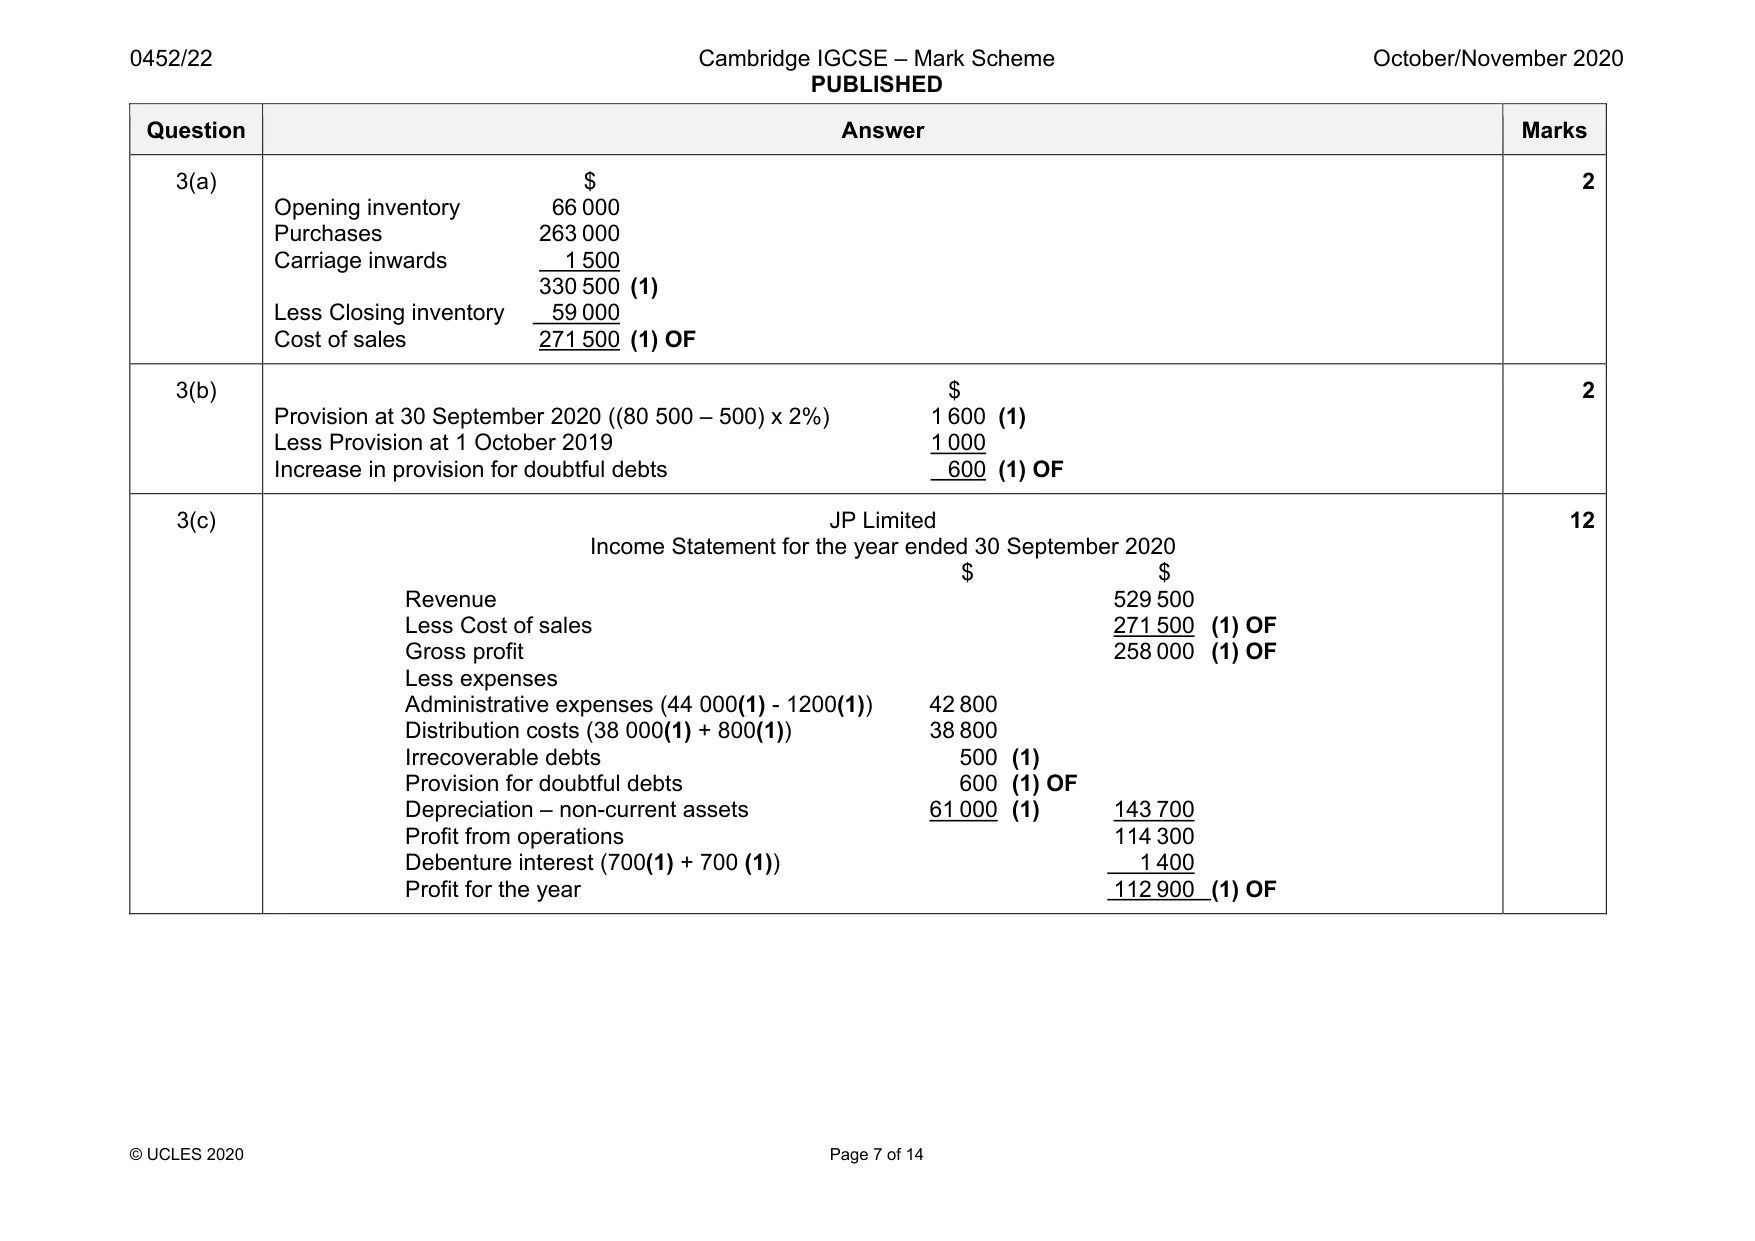
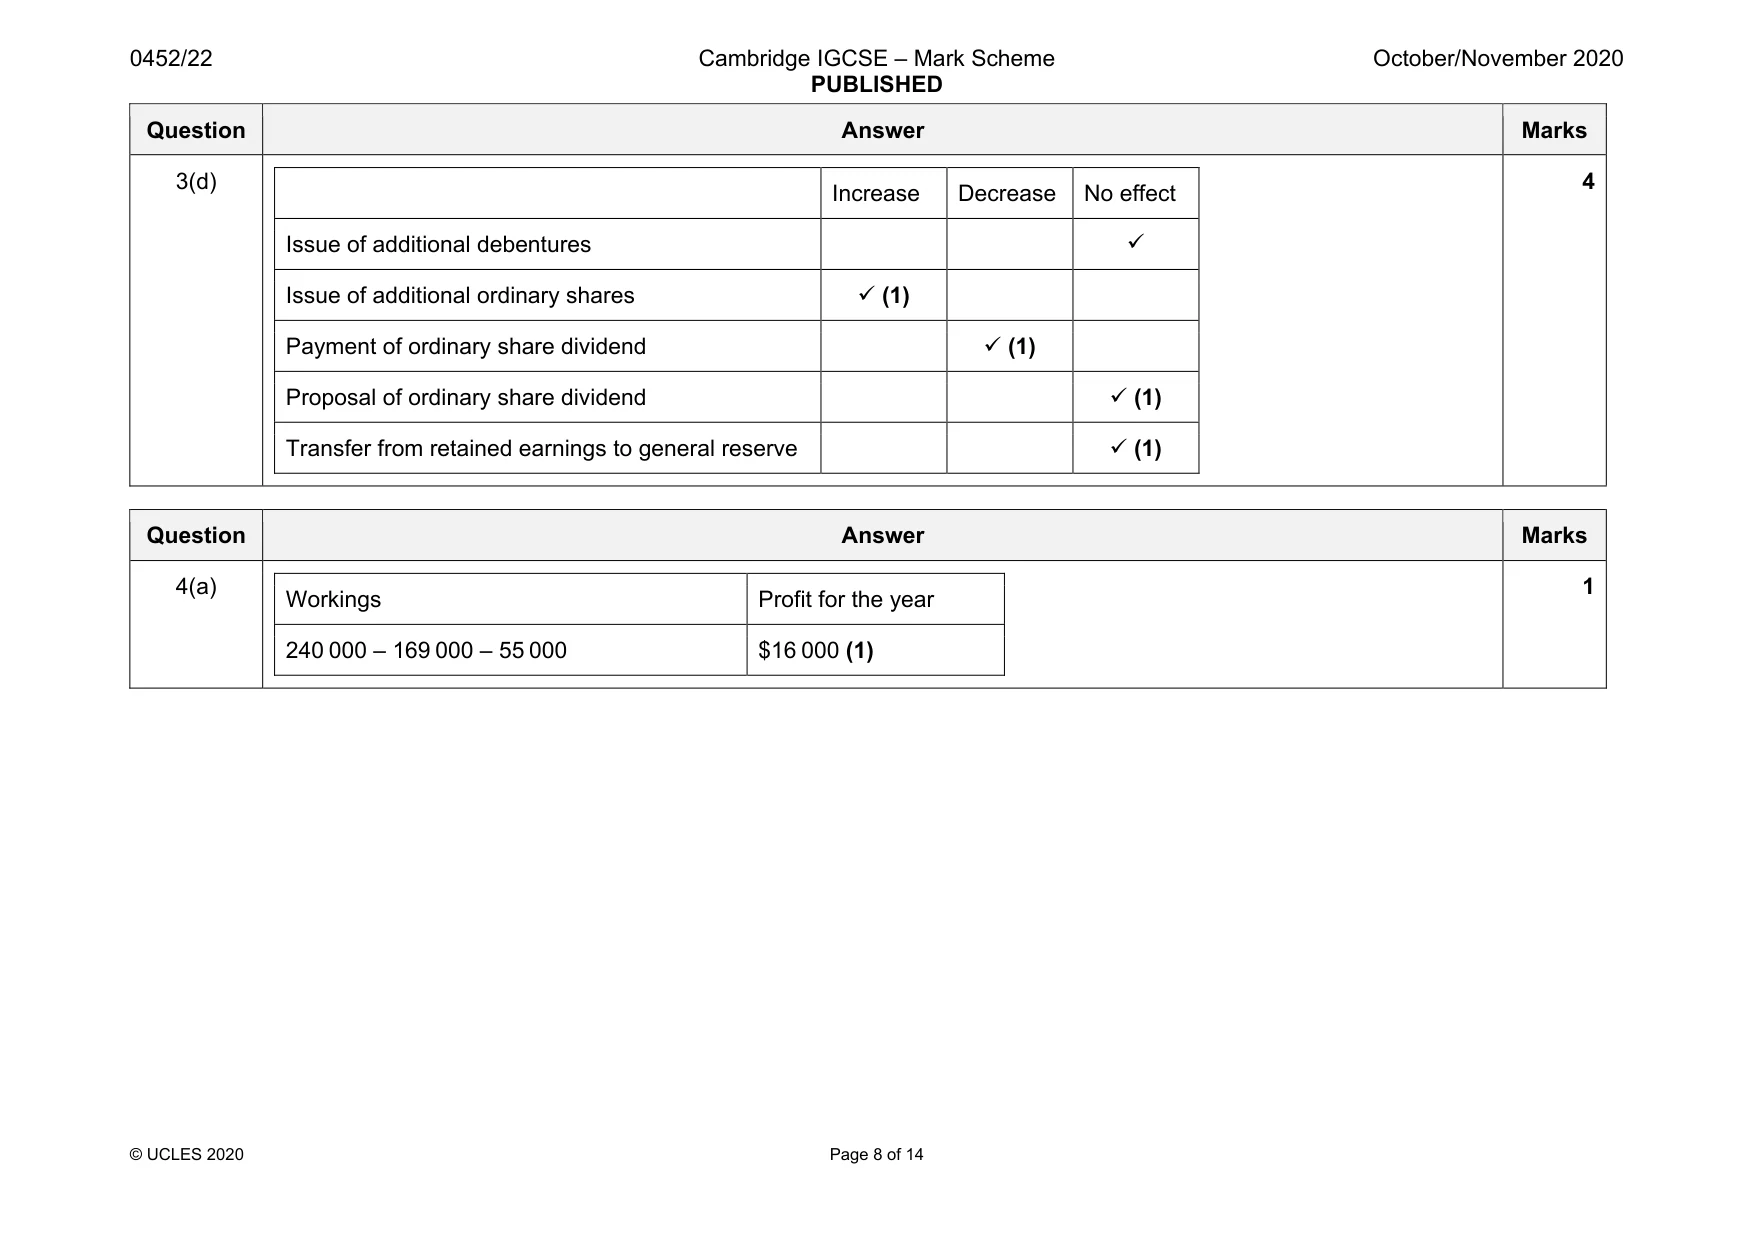
Mark scheme: 3(a) $ Opening inventory 66 000 Purchases 263 000 Carriage inwards 1 500 330 500 (1) Less Closing inventory 59 000 Cost of sales 271 500 (1) OF 2 3(b) $ Provision at 30 September 2020 ((80 500 – 500) x 2%) 1 600 (1) Less Provision at 1 October 2019 1 000 Increase in provision for doubtful debts 600 (1) OF 2 3(c) JP Limited Income Statement for the year ended 30 September 2020 $ $ Revenue 529 500 Less Cost of sales 271 500 (1) OF Gross profit 258 000 (1) OF Less expenses Administrative expenses (44 000(1) - 1200(1)) 42 800 Distribution costs (38 000(1) + 800(1)) 38 800 Irrecoverable debts 500 (1) Provision for doubtful debts 600 (1) OF Depreciation – non-current assets 61 000 (1) 143 700 Profit from operations 114 300 Debenture interest (700(1) + 700 (1)) 1 400 Profit for the year 112 900 (1) OF 12 Question Answer Marks 3(d) Increase Decrease No effect Issue of additional debentures Issue of additional ordinary shares (1) Payment of ordinary share dividend (1) Proposal of ordinary share dividend (1) Transfer from retained earnings to general reserve (1) 4
Q4 · Carlos owns a business selling computer equipment
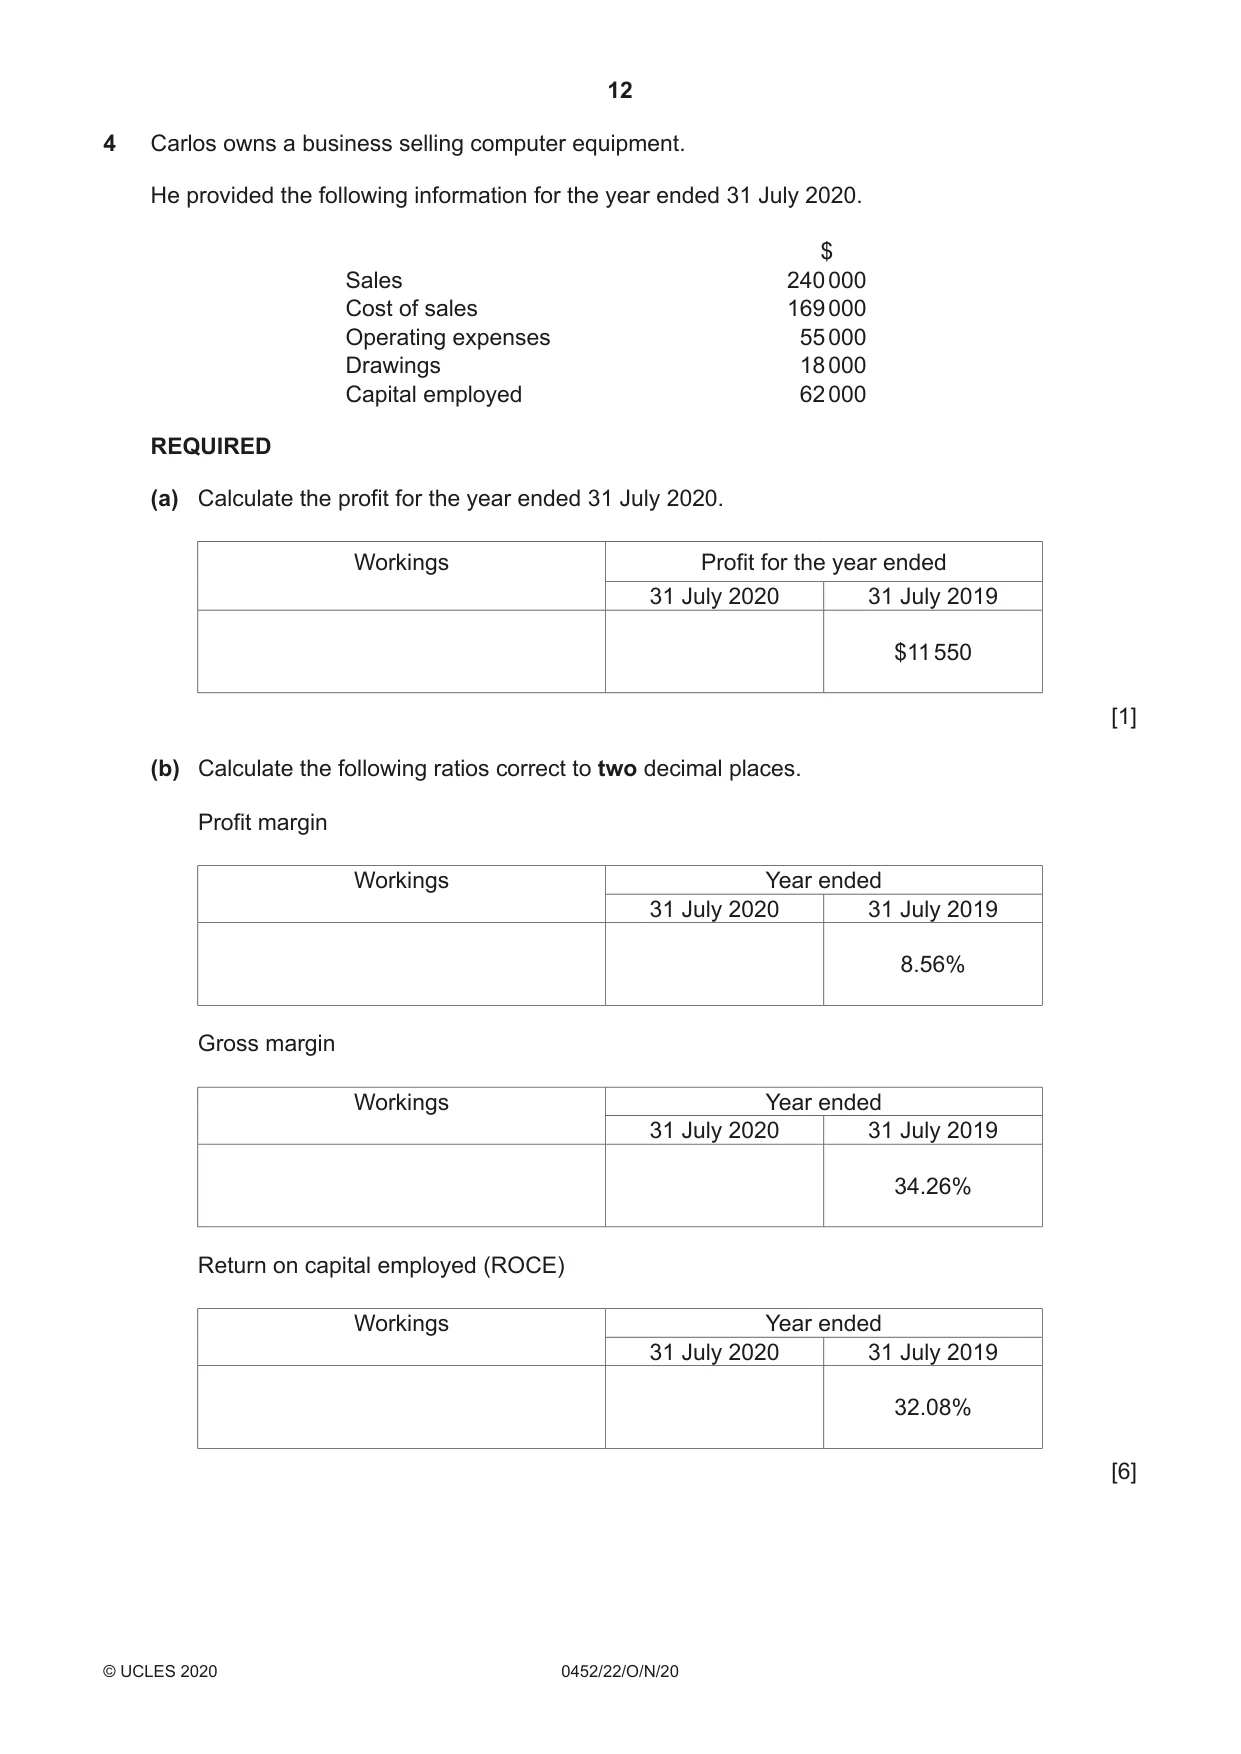
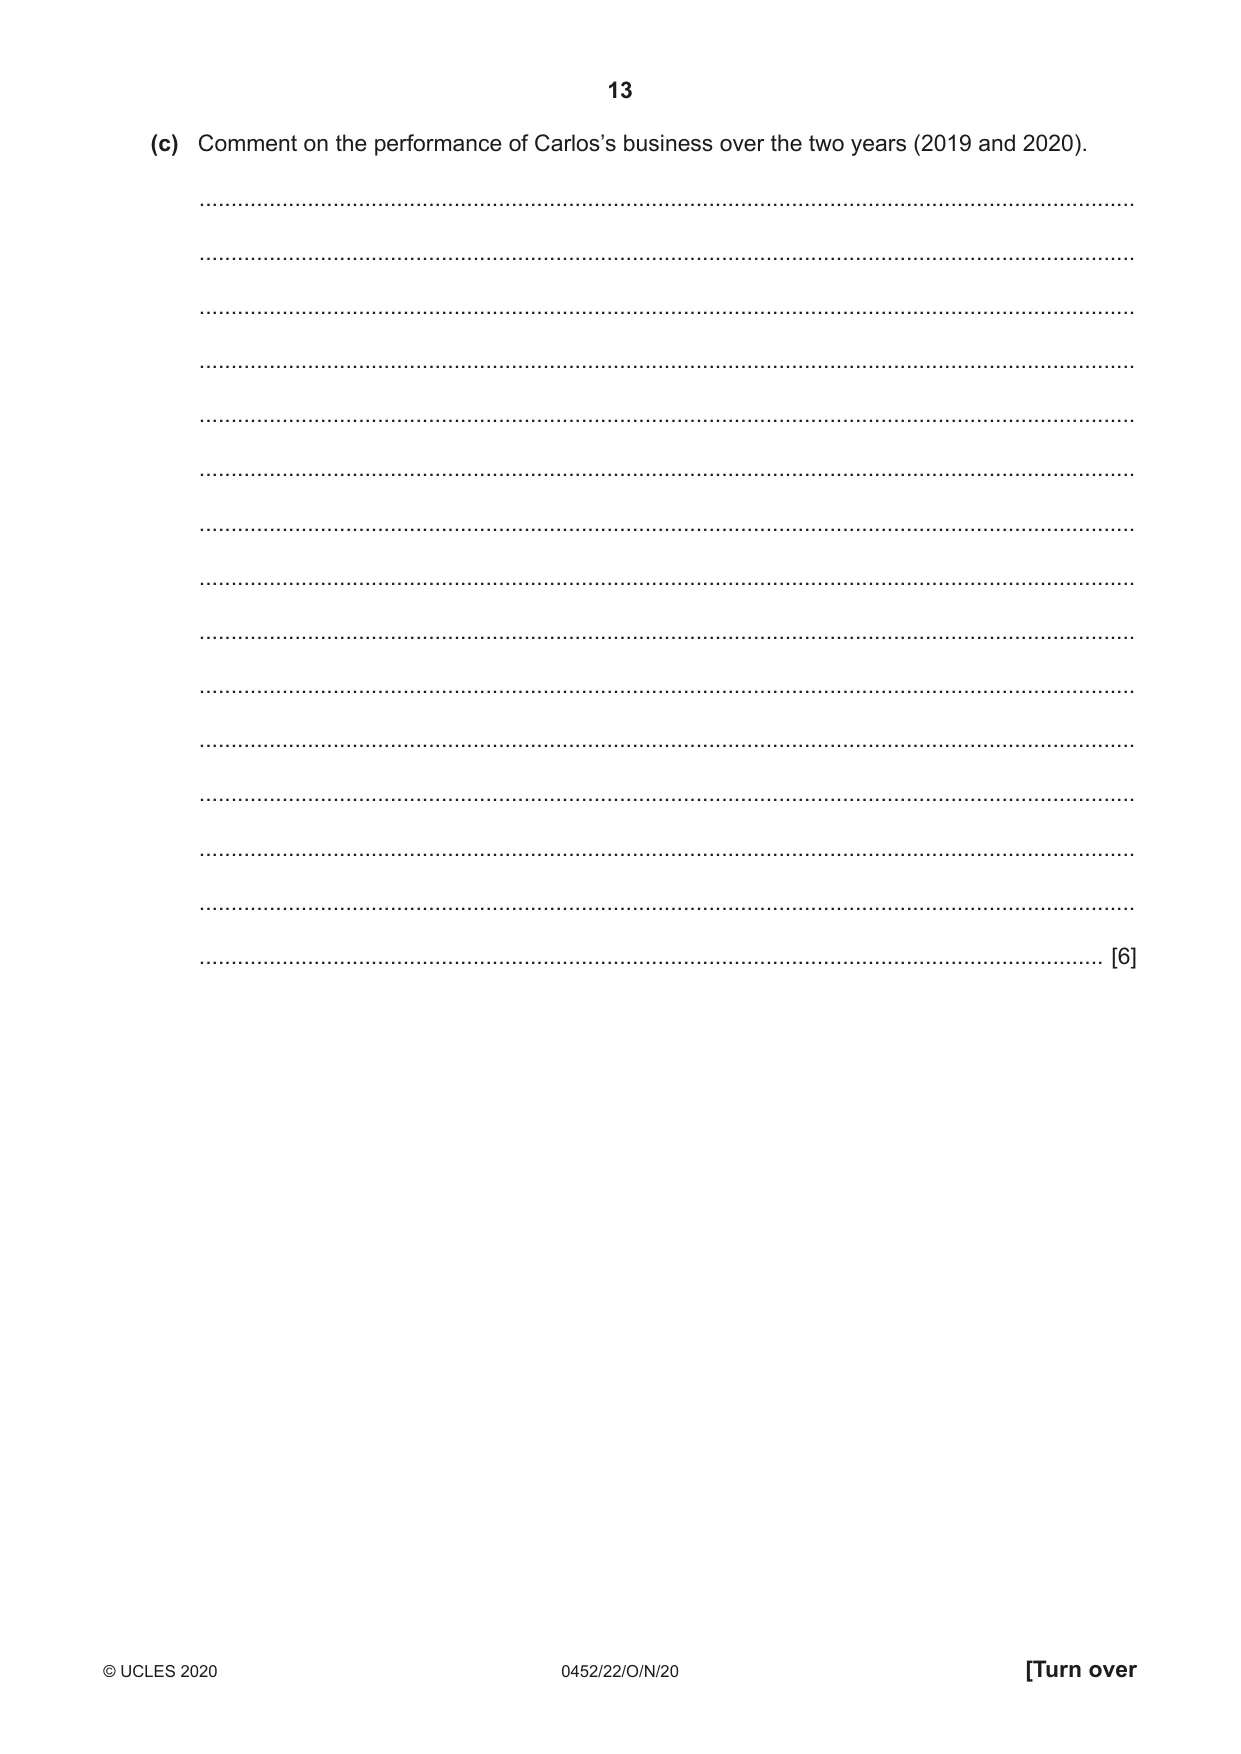
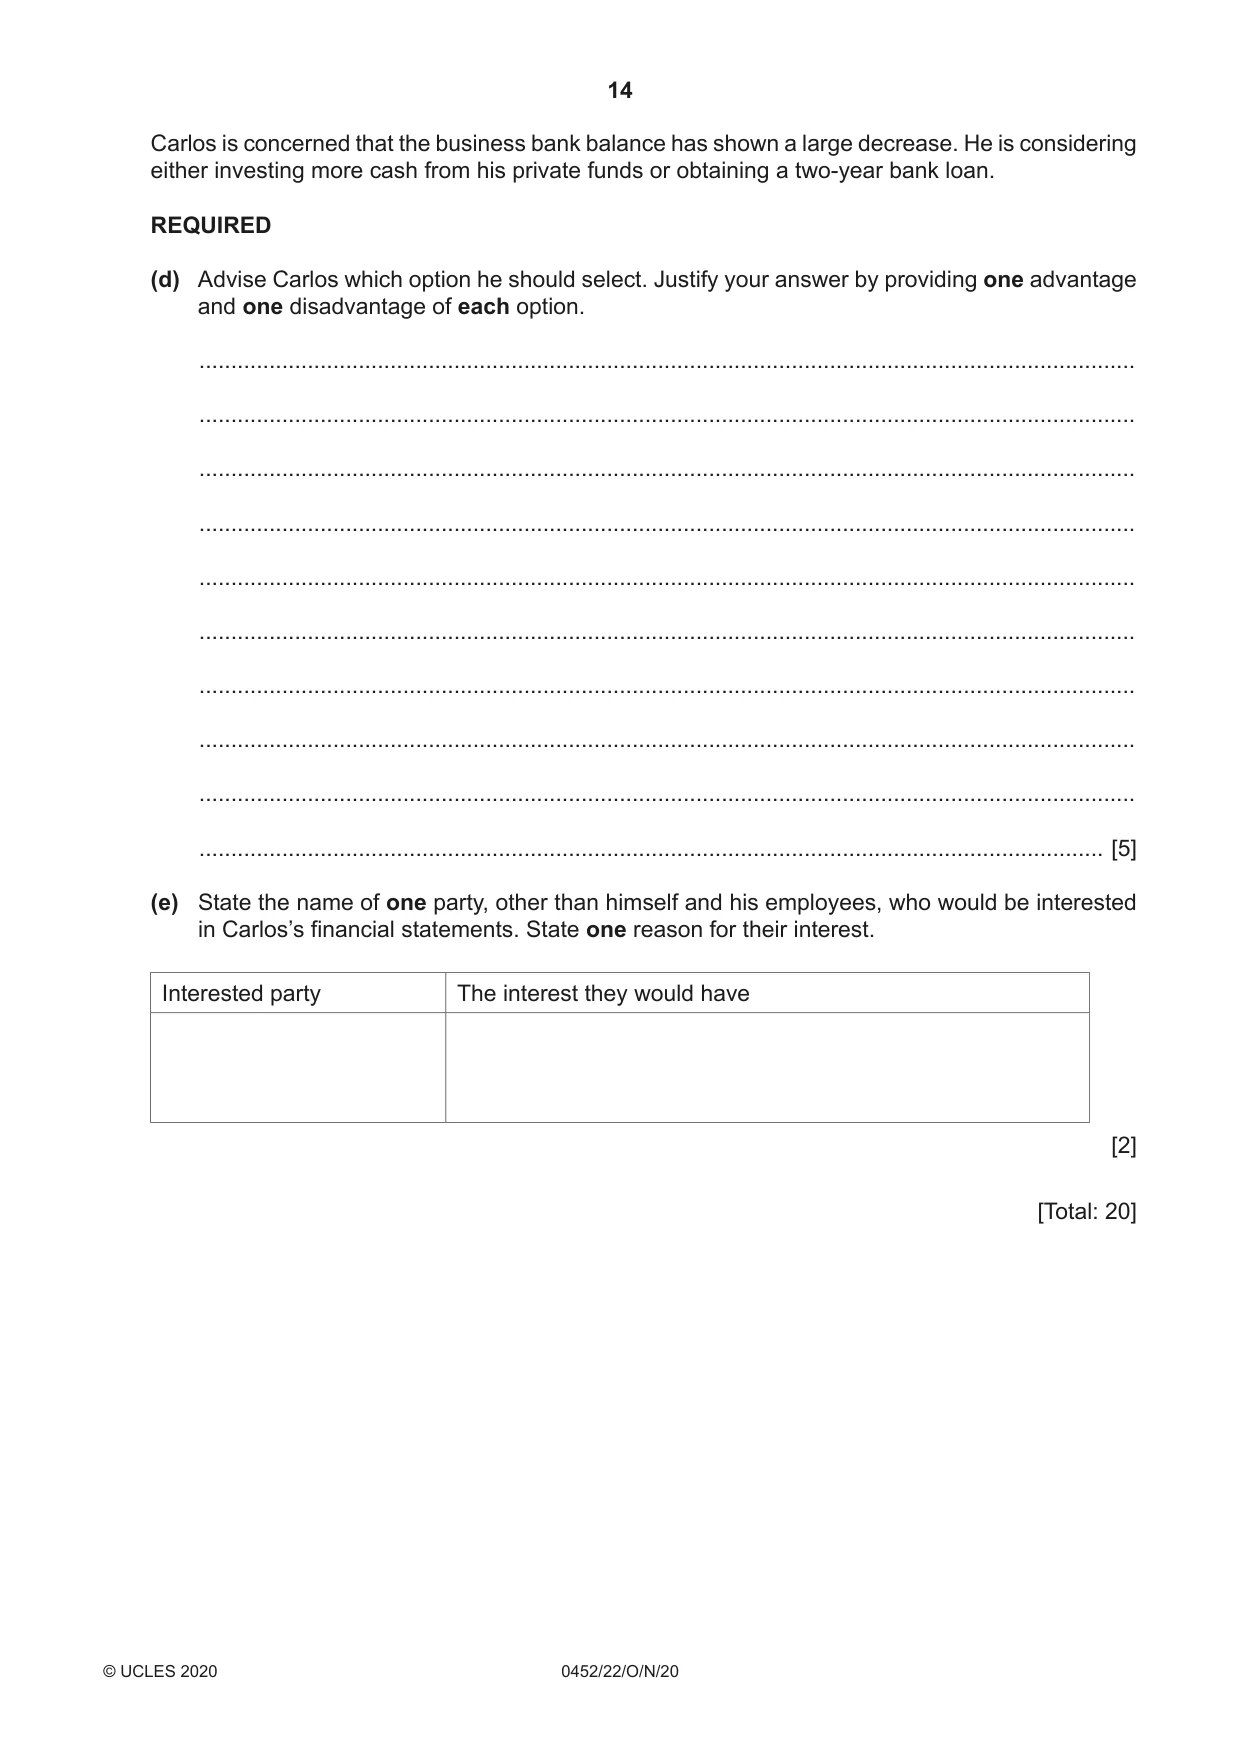
4 Carlos owns a business selling computer equipment. He provided the following information for the year ended 31 July 2020. $ Sales 240 000 Cost of sales 169 000 Operating expenses 55 000 Drawings 18 000 Capital employed 62 000 REQUIRED (a) Calculate the profit for the year ended 31 July 2020. Workings Profit for the year ended 31 July 2020 31 July 2019 $11 550 [1] (b) Calculate the following ratios correct to two decimal places. Profit margin Workings Year ended 31 July 2020 31 July 2019 8.56% Gross margin Workings Year ended 31 July 2020 31 July 2019 34.26% Return on capital employed (ROCE) Workings Year ended 31 July 2020 31 July 2019 32.08% [6] (c) Comment on the performance of Carlos’s business over the two years (2019 and 2020). ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [6] Carlos is concerned that the business bank balance has shown a large decrease. He is considering either investing more cash from his private funds or obtaining a two-year bank loan. REQUIRED (d) Advise Carlos which option he should select. Justify your answer by providing one advantage and one disadvantage of each option. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [5] (e) State the name of one party, other than himself and his employees, who would be interested in Carlos’s financial statements. State one reason for their interest. Interested party The interest they would have [2] [Total: 20] PLEASE TURN OVER
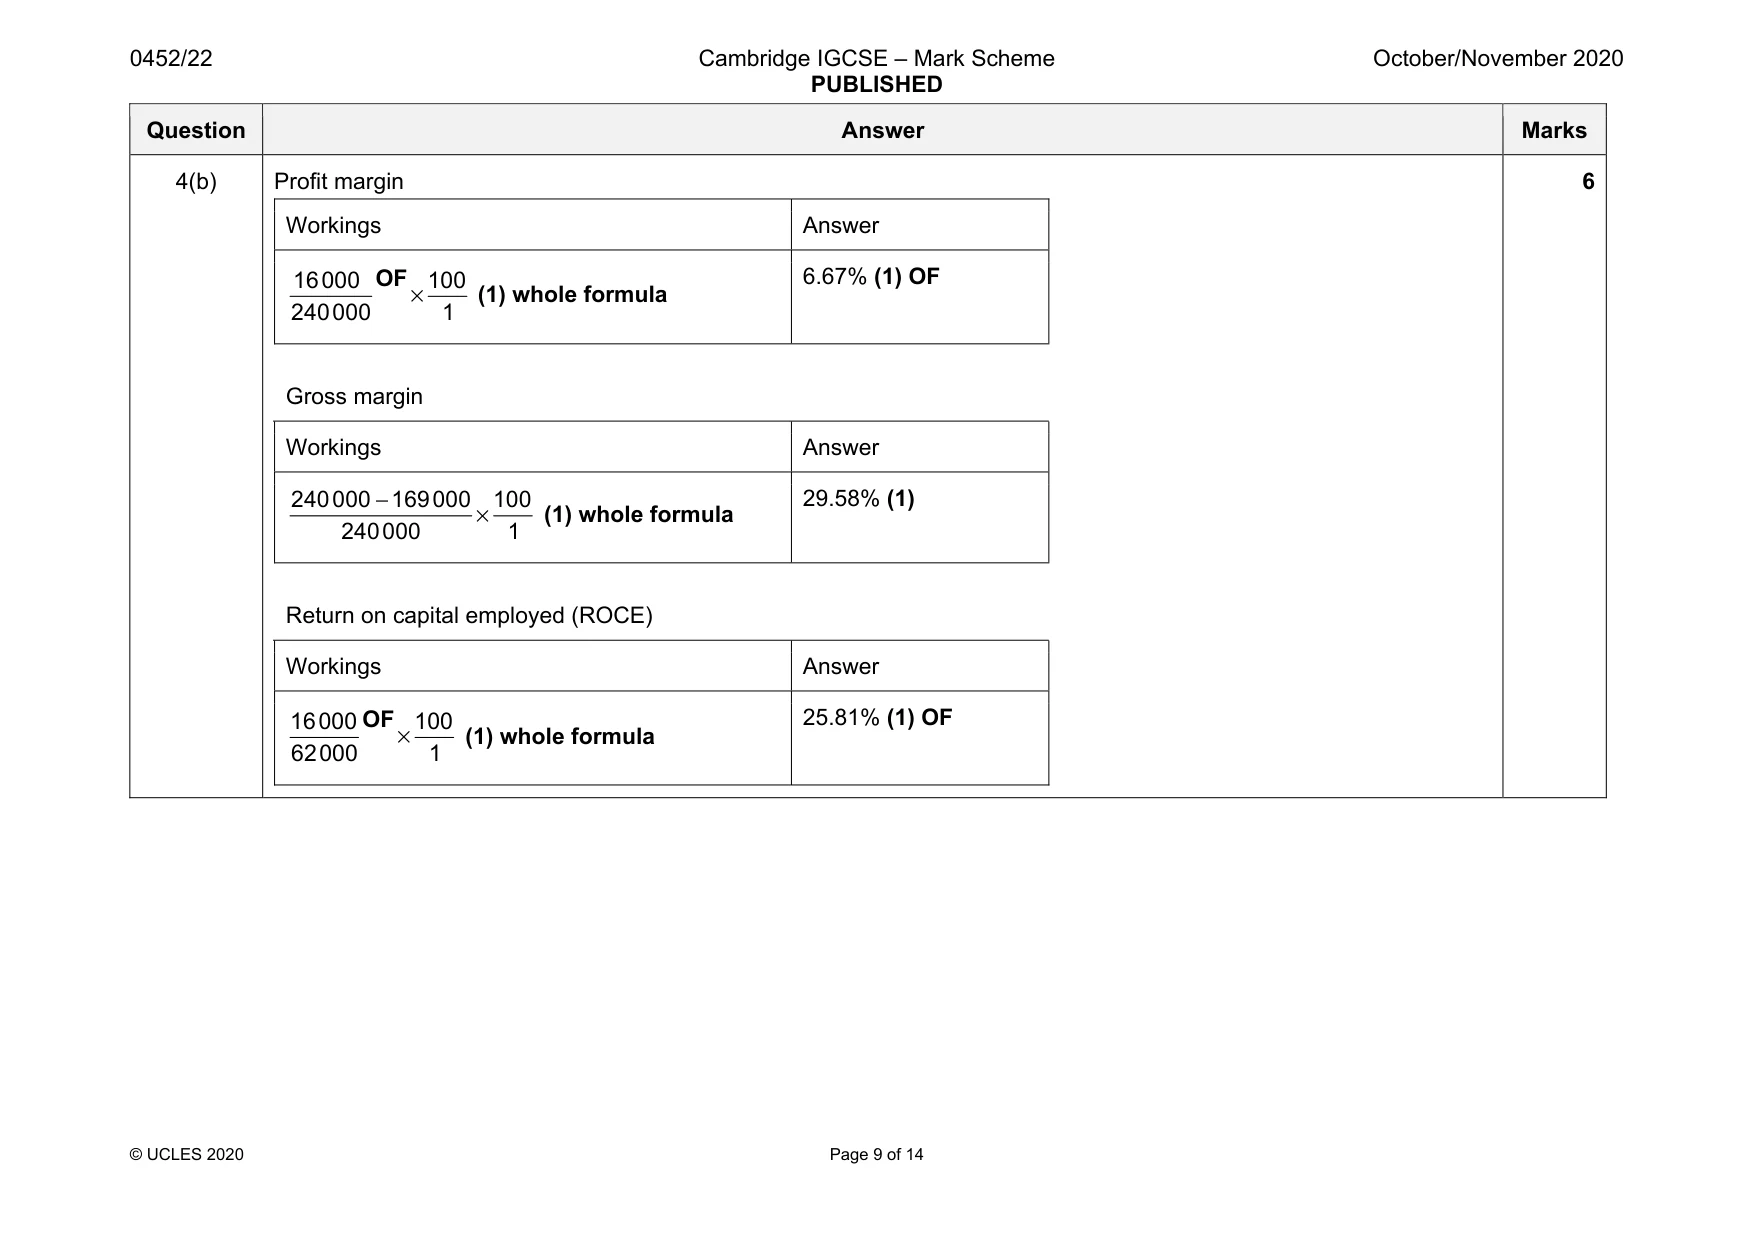
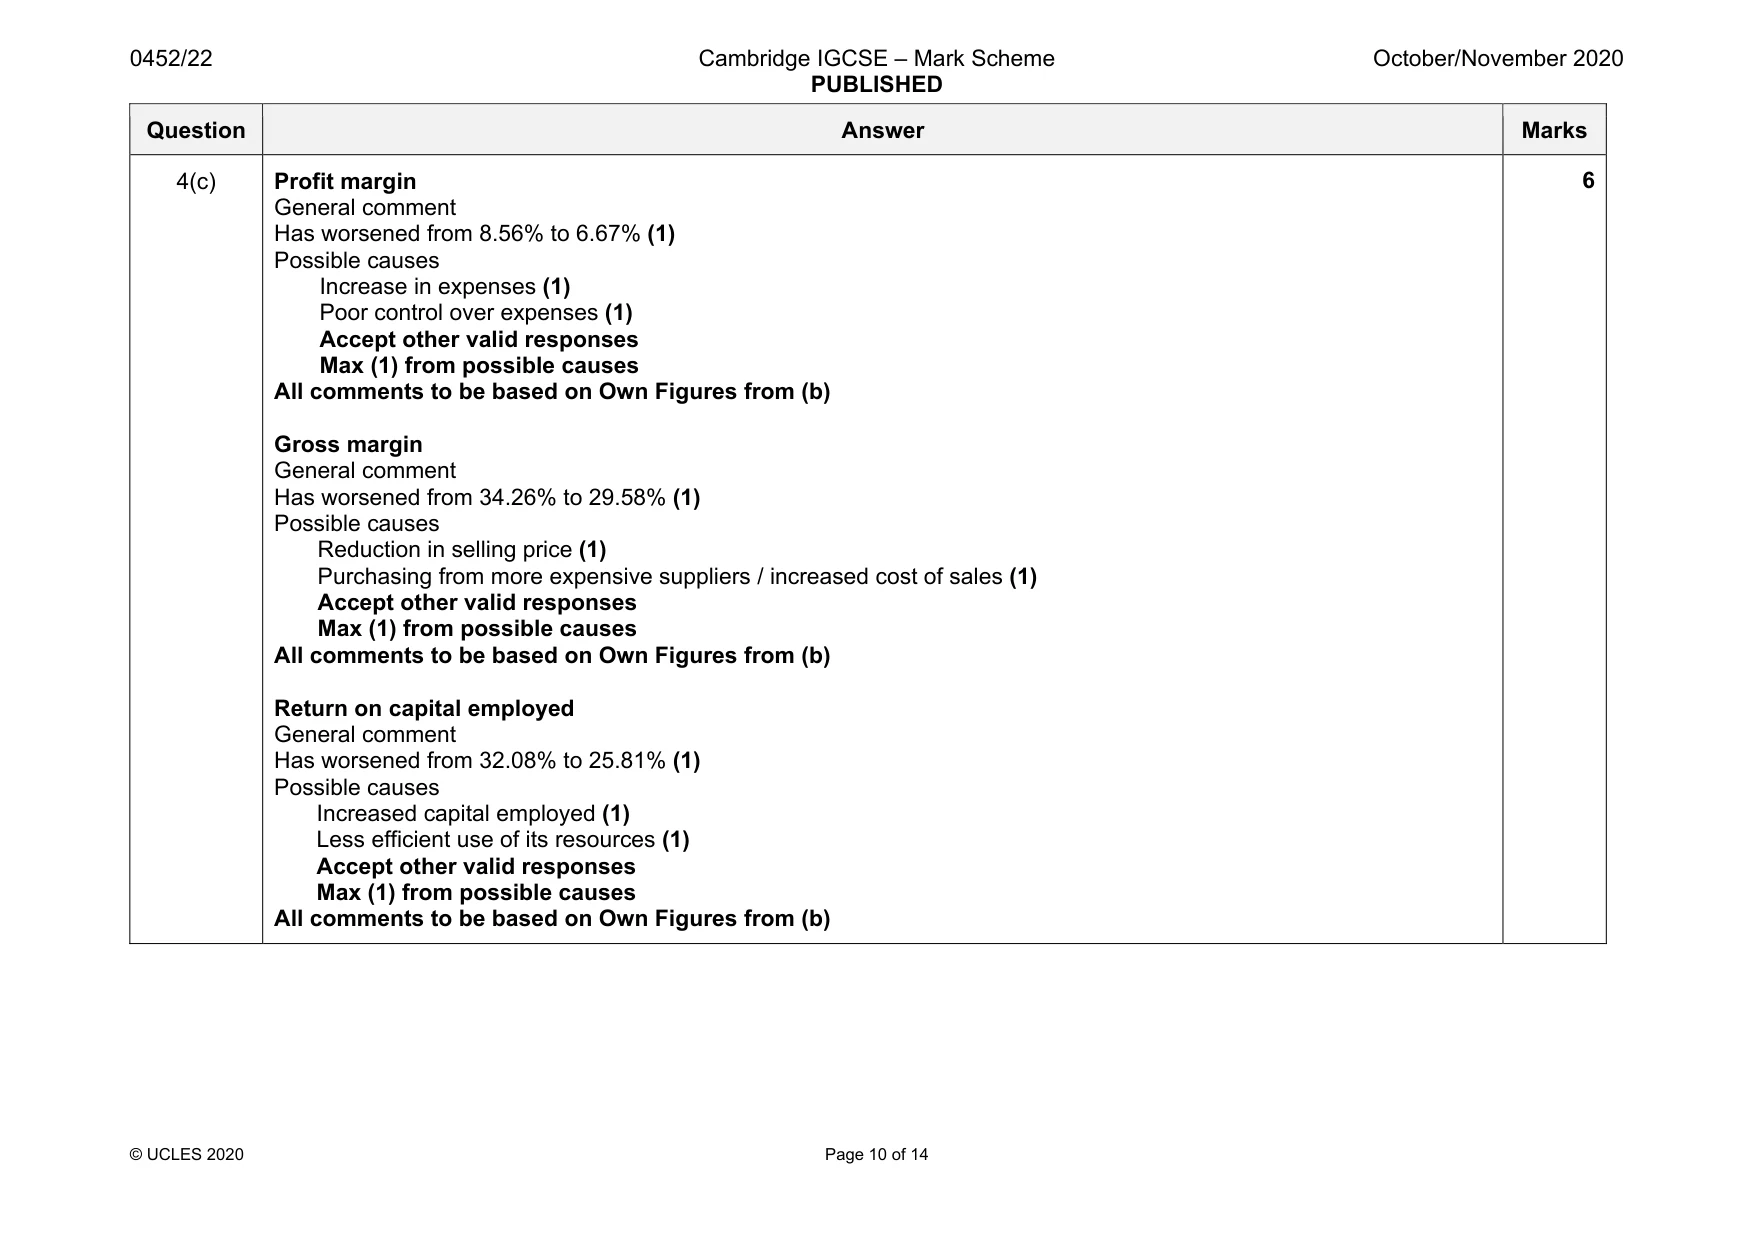
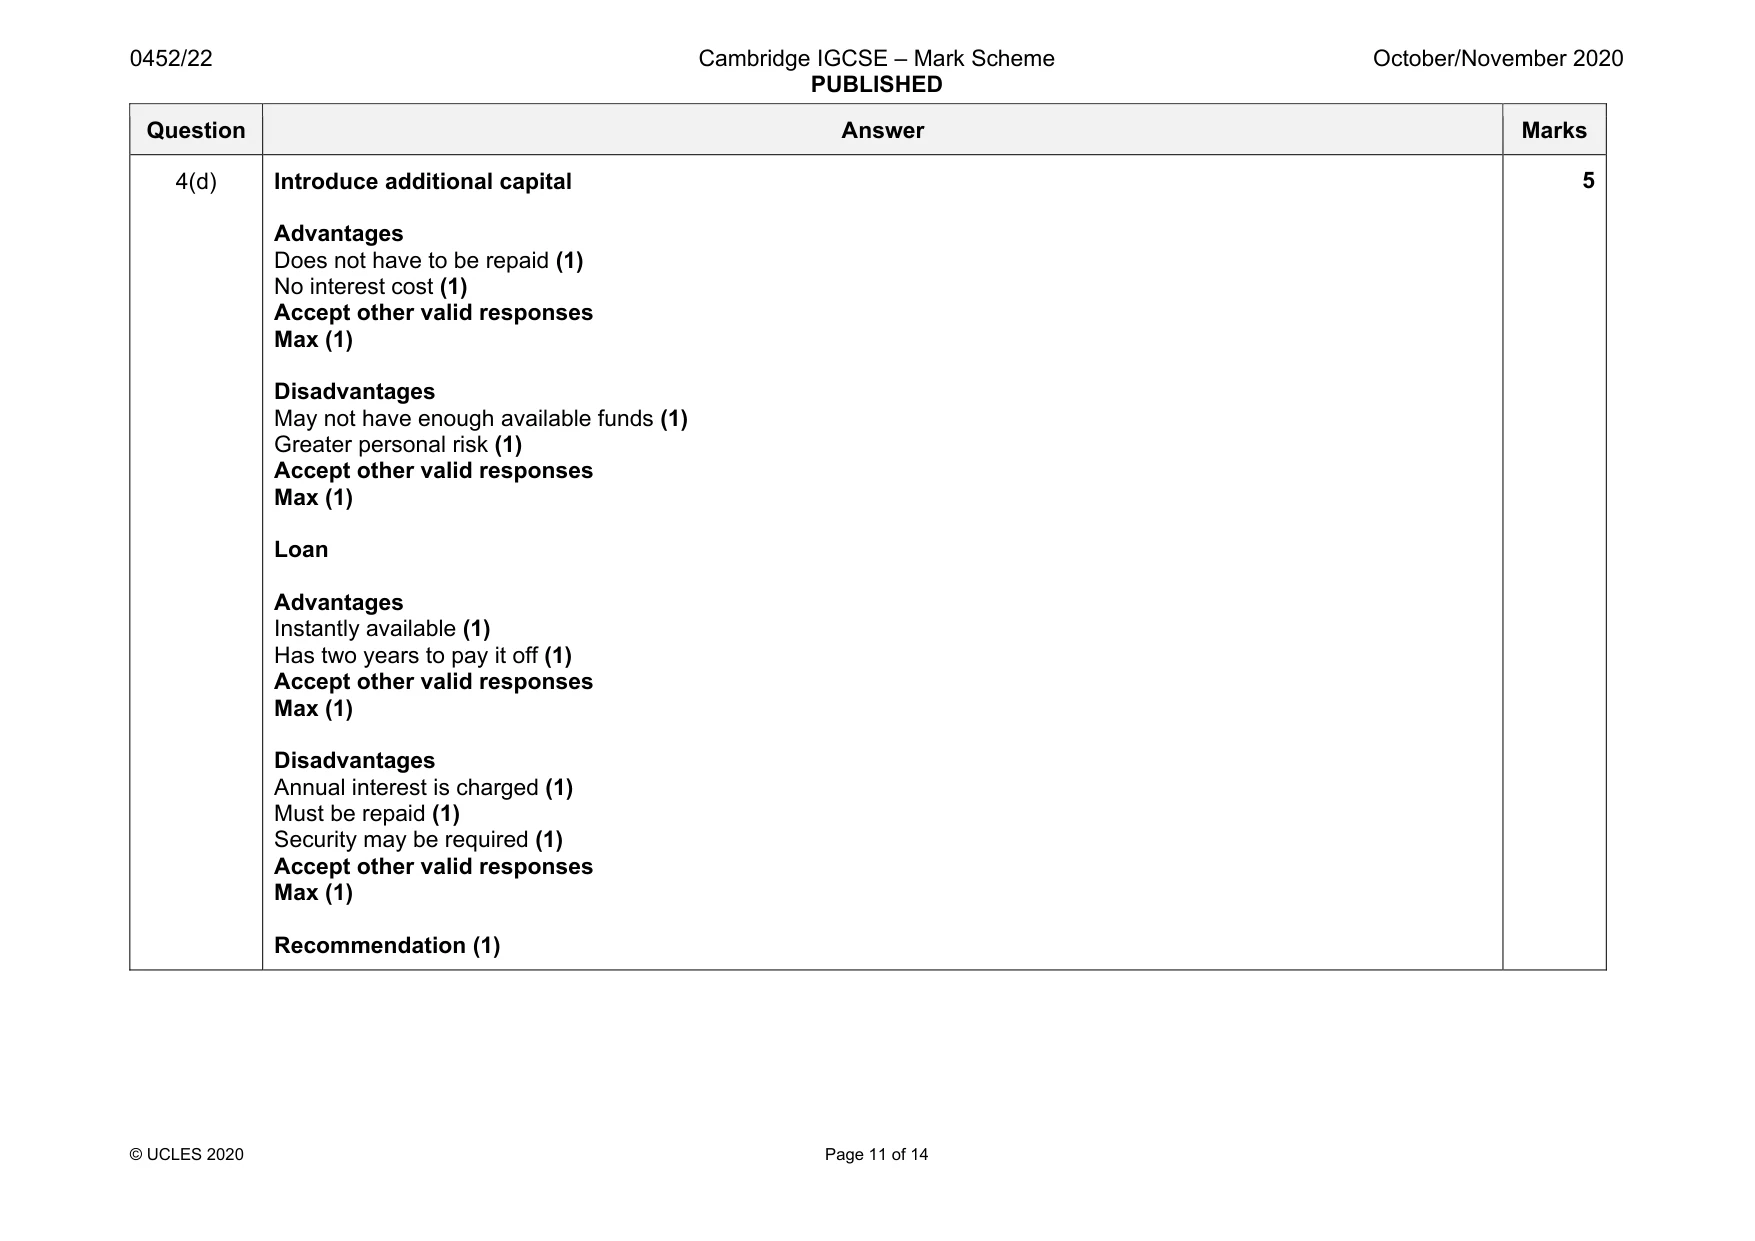
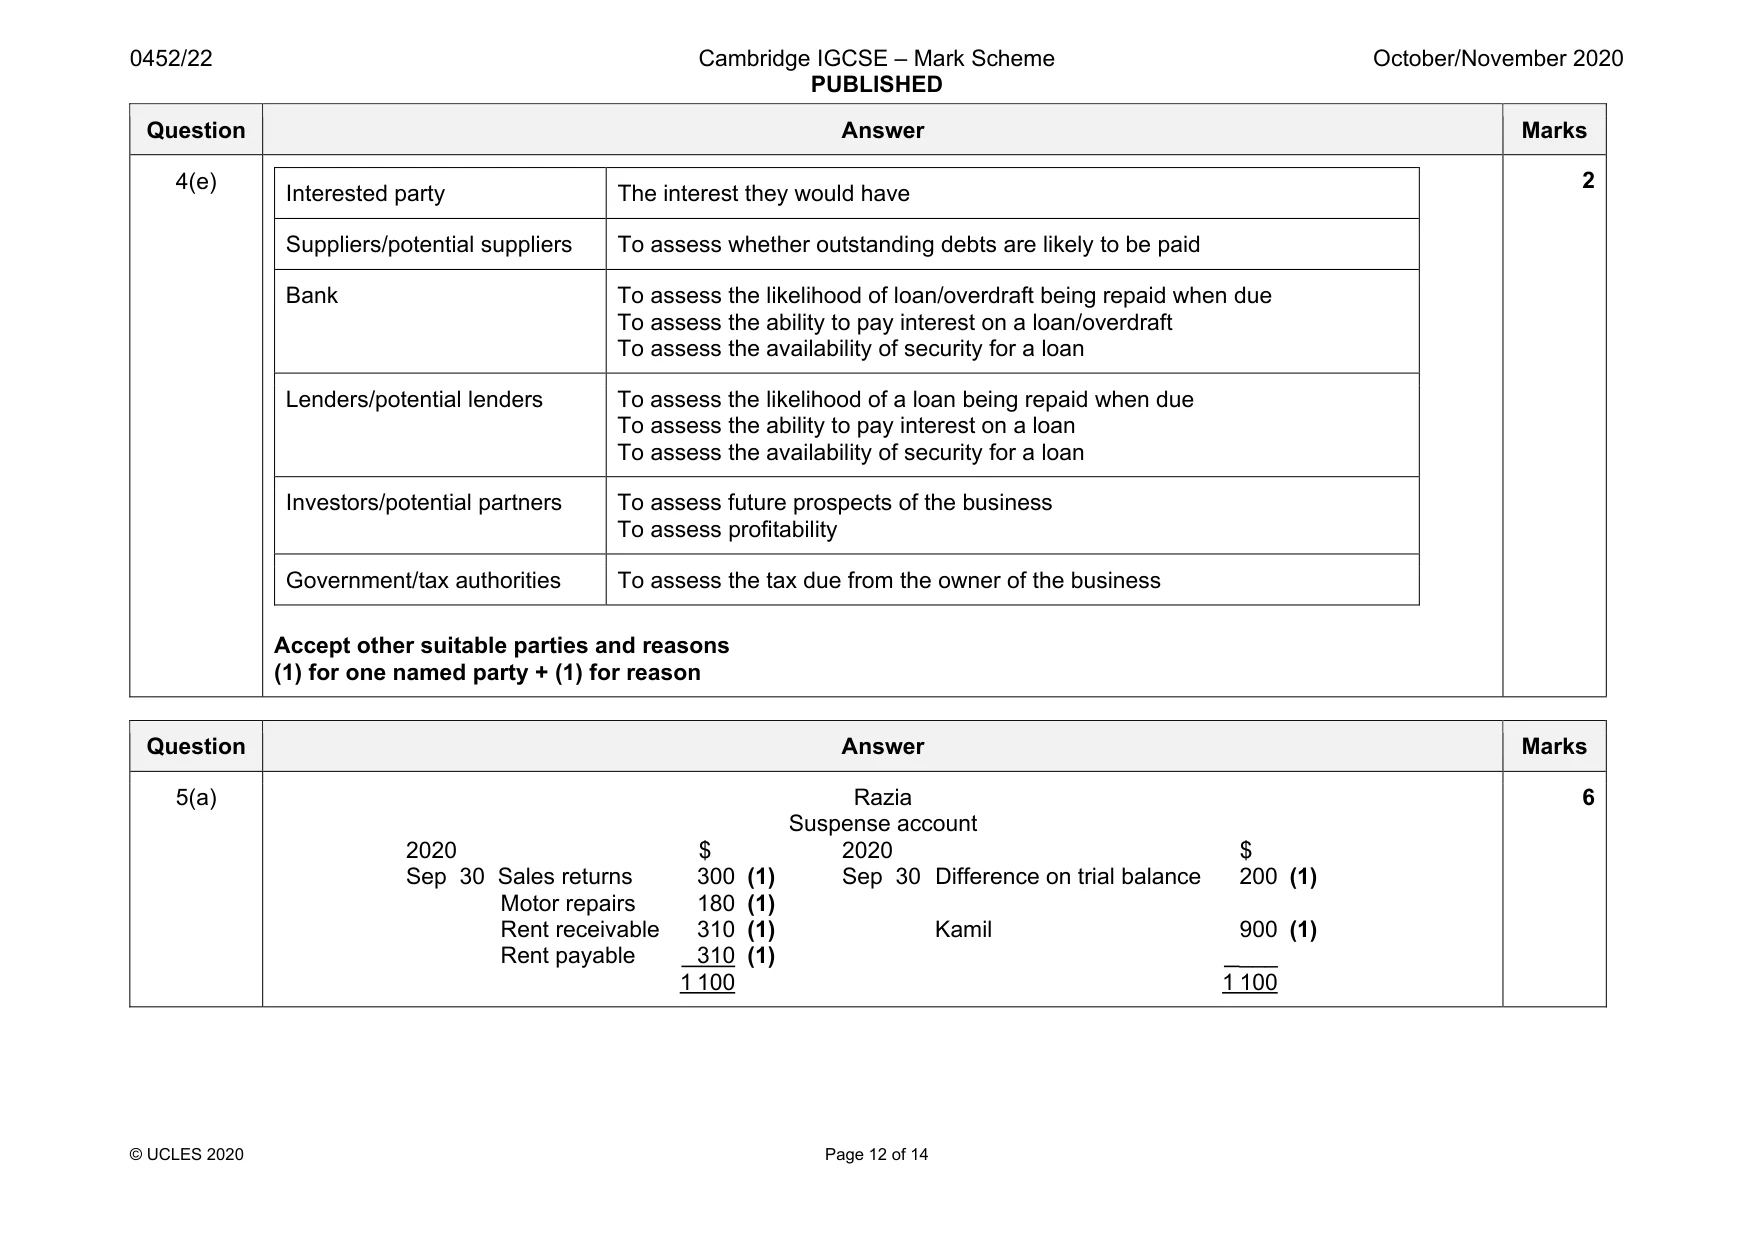
Mark scheme: 4(a) Workings Profit for the year 240 000 – 169 000 – 55 000 $16 000 (1) 1 Question Answer Marks 4(b) Profit margin Workings Answer × 16000 100 240000 1 OF (1) whole formula 6.67% (1) OF Gross margin Workings Answer − × 240000 169000 100 240000 1 (1) whole formula 29.58% (1) Return on capital employed (ROCE) Workings Answer × 16000 100 62000 1 OF (1) whole formula 25.81% (1) OF 6 Question Answer Marks 4(c) Profit margin General comment Has worsened from 8.56% to 6.67% (1) Possible causes Increase in expenses (1) Poor control over expenses (1) Accept other valid responses Max (1) from possible causes All comments to be based on Own Figures from (b) Gross margin General comment Has worsened from 34.26% to 29.58% (1) Possible causes Reduction in selling price (1) Purchasing from more expensive suppliers / increased cost of sales (1) Accept other valid responses Max (1) from possible causes All comments to be based on Own Figures from (b) Return on capital employed General comment Has worsened from 32.08% to 25.81% (1) Possible causes Increased capital employed (1) Less efficient use of its resources (1) Accept other valid responses Max (1) from possible causes All comments to be based on Own Figures from (b) 6 Question Answer Marks 4(d) Introduce additional capital Advantages Does not have to be repaid (1) No interest cost (1) Accept other valid responses Max (1) Disadvantages May not have enough available funds (1) Greater personal risk (1) Accept other valid responses Max (1) Loan Advantages Instantly available (1) Has two years to pay it off (1) Accept other valid responses Max (1) Disadvantages Annual interest is charged (1) Must be repaid (1) Security may be required (1) Accept other valid responses Max (1) Recommendation (1) 5 Question Answer Marks 4(e) Interested party The interest they would have Suppliers/potential suppliers To assess whether outstanding debts are likely to be paid Bank To assess the likelihood of loan/overdraft being repaid when due To assess the ability to pay interest on a loan/overdraft To assess the availability of security for a loan Lenders/potential lenders To assess the likelihood of a loan being repaid when due To assess the ability to pay interest on a loan To assess the availability of security for a loan Investors/potential partners To assess future prospects of the business To assess profitability Government/tax authorities To assess the tax due from the owner of the business Accept other suitable parties and reasons (1) for one named party + (1) for reason 2
Q5 · Razia’s financial year ends on 30 September
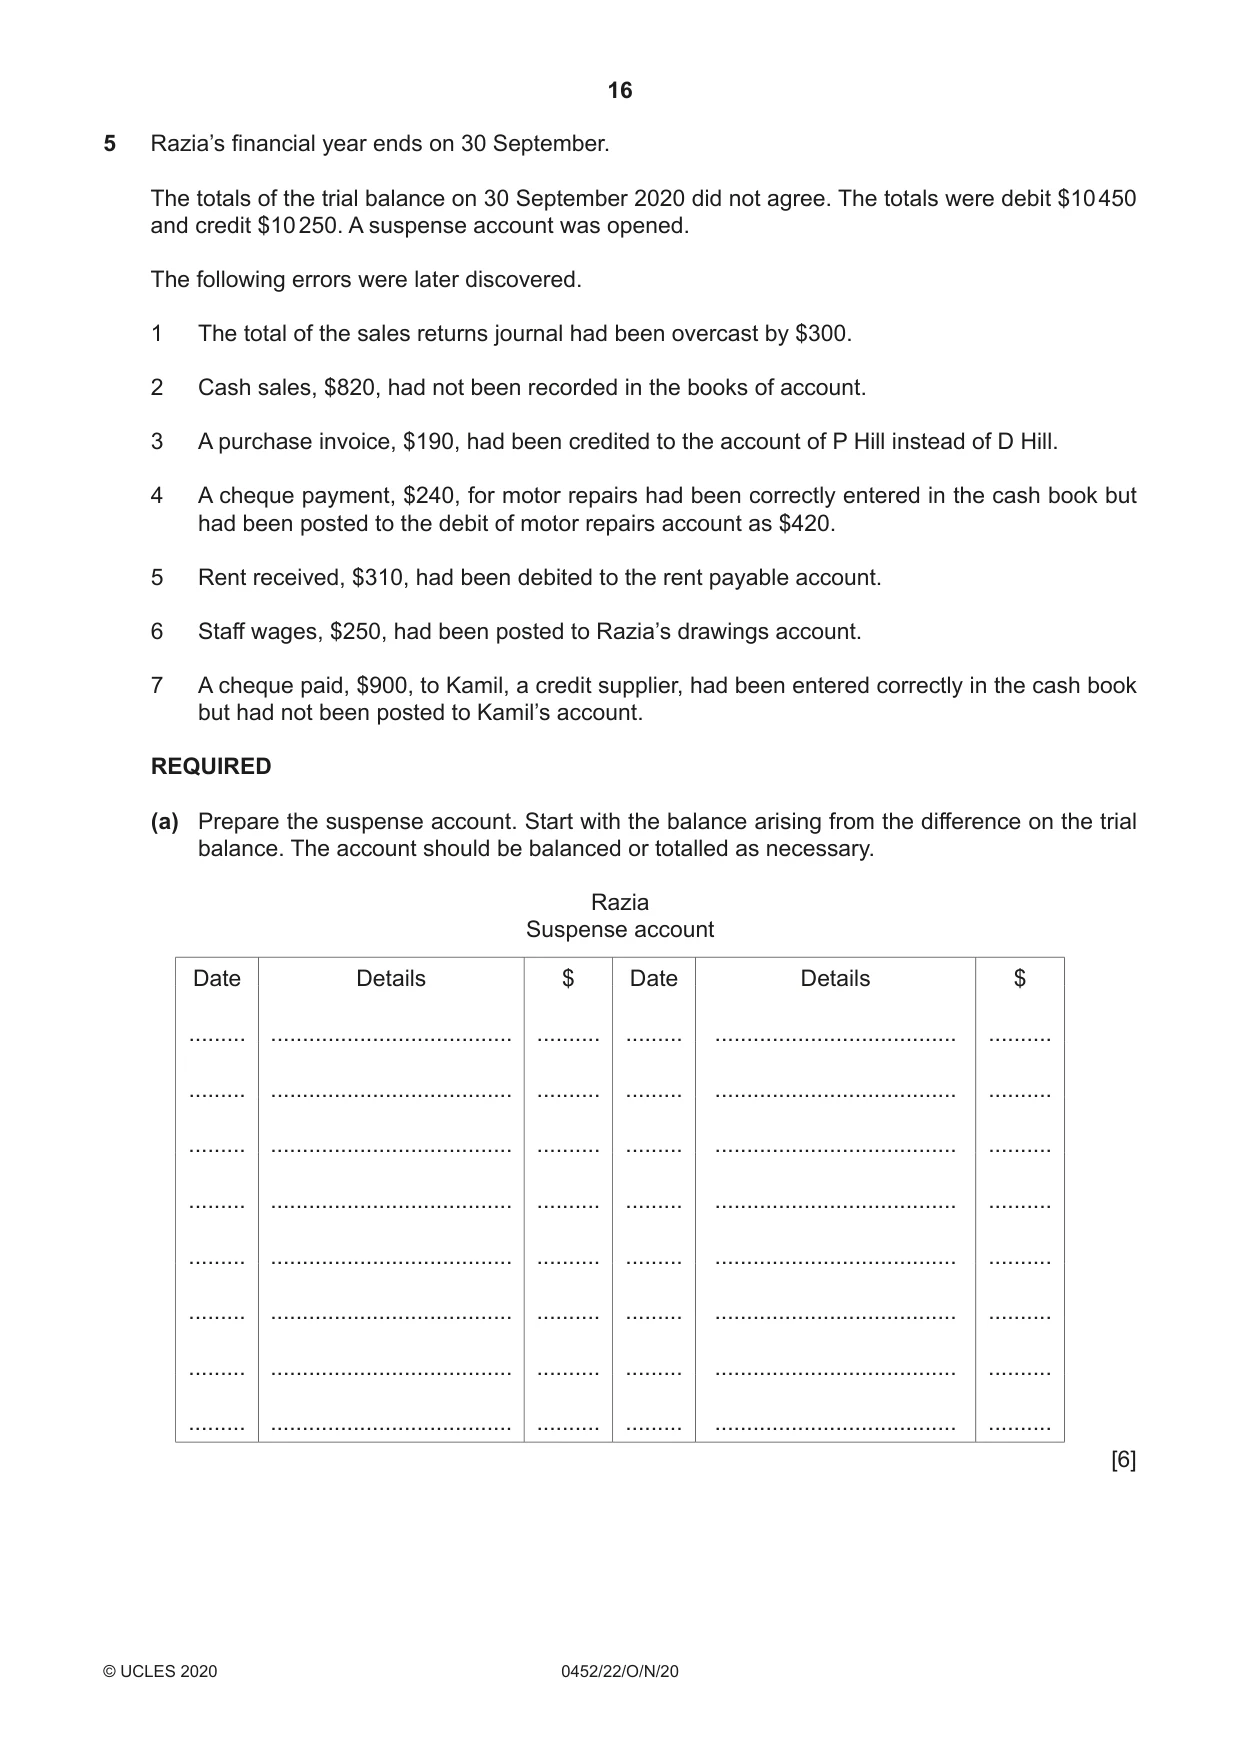
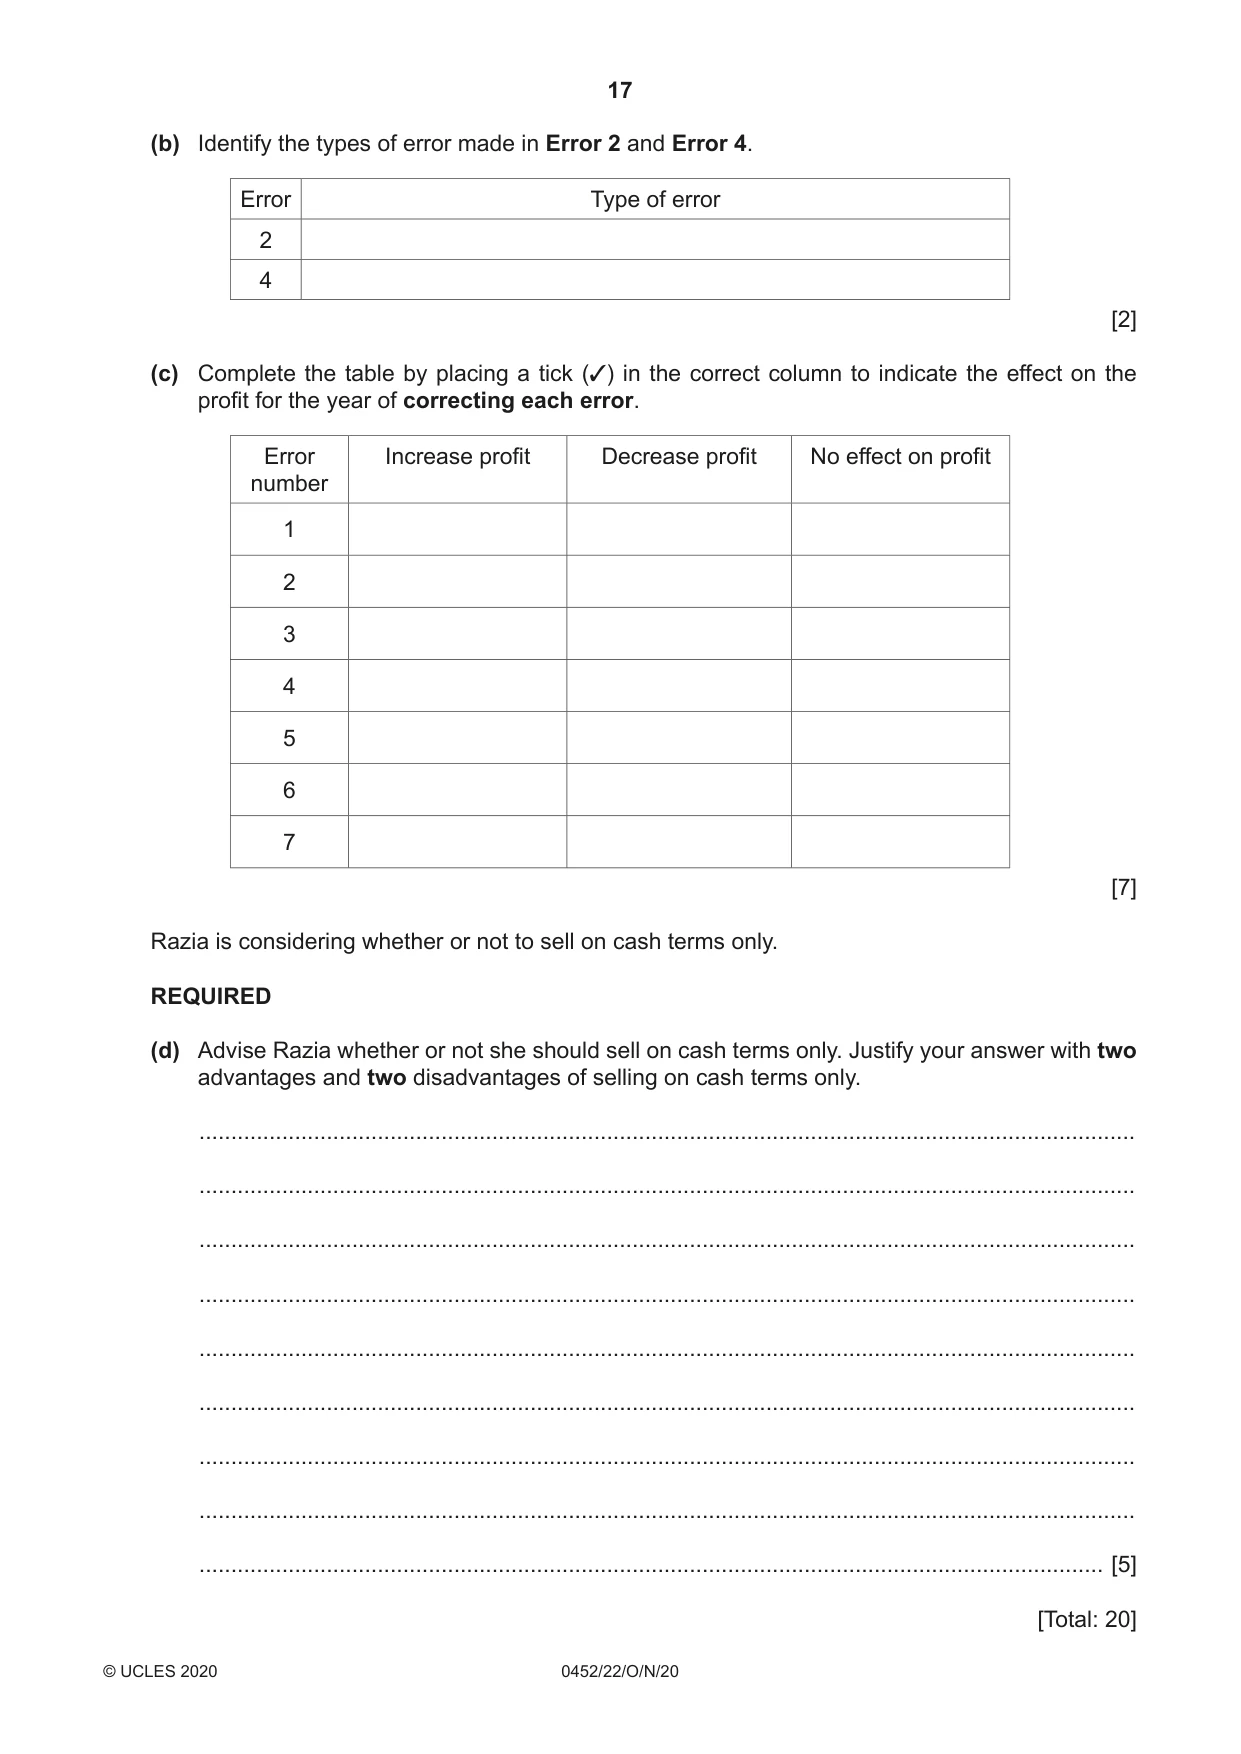
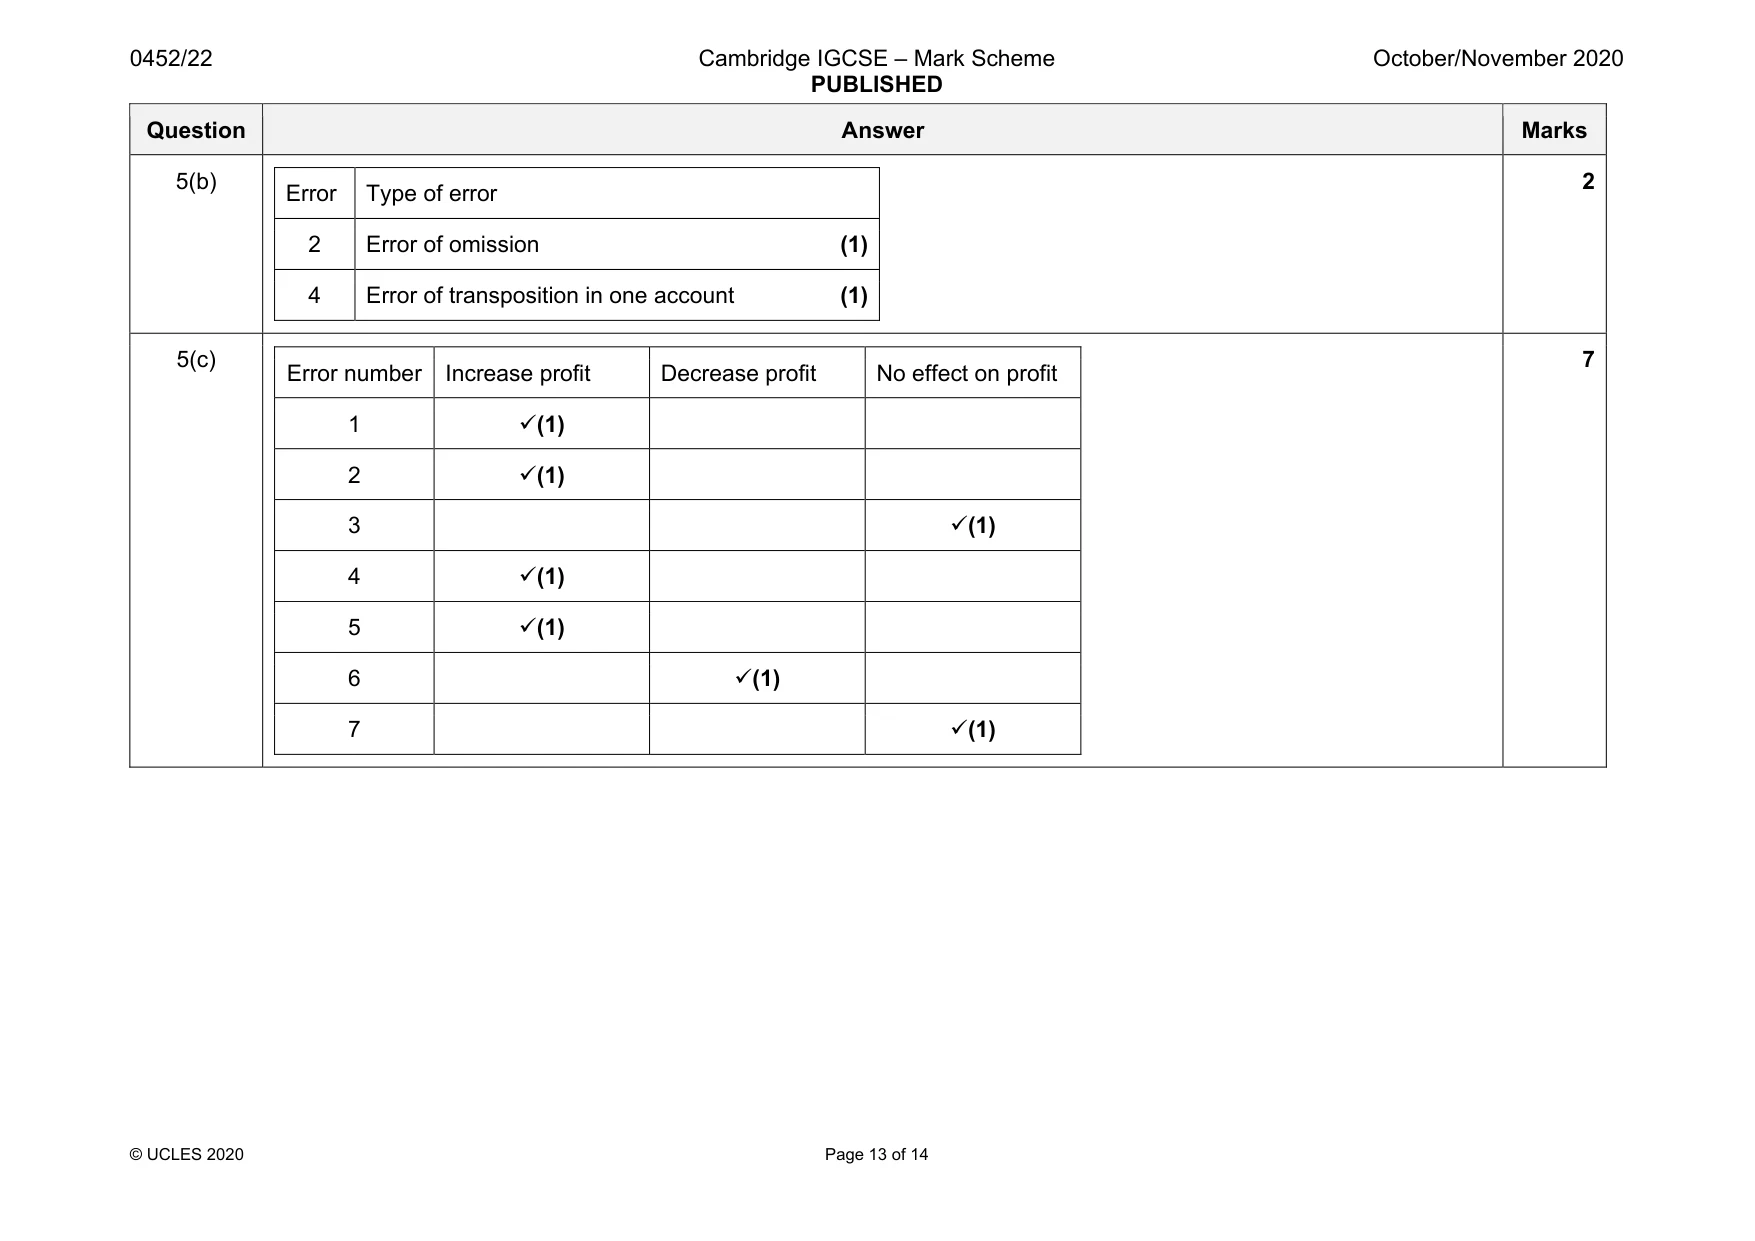
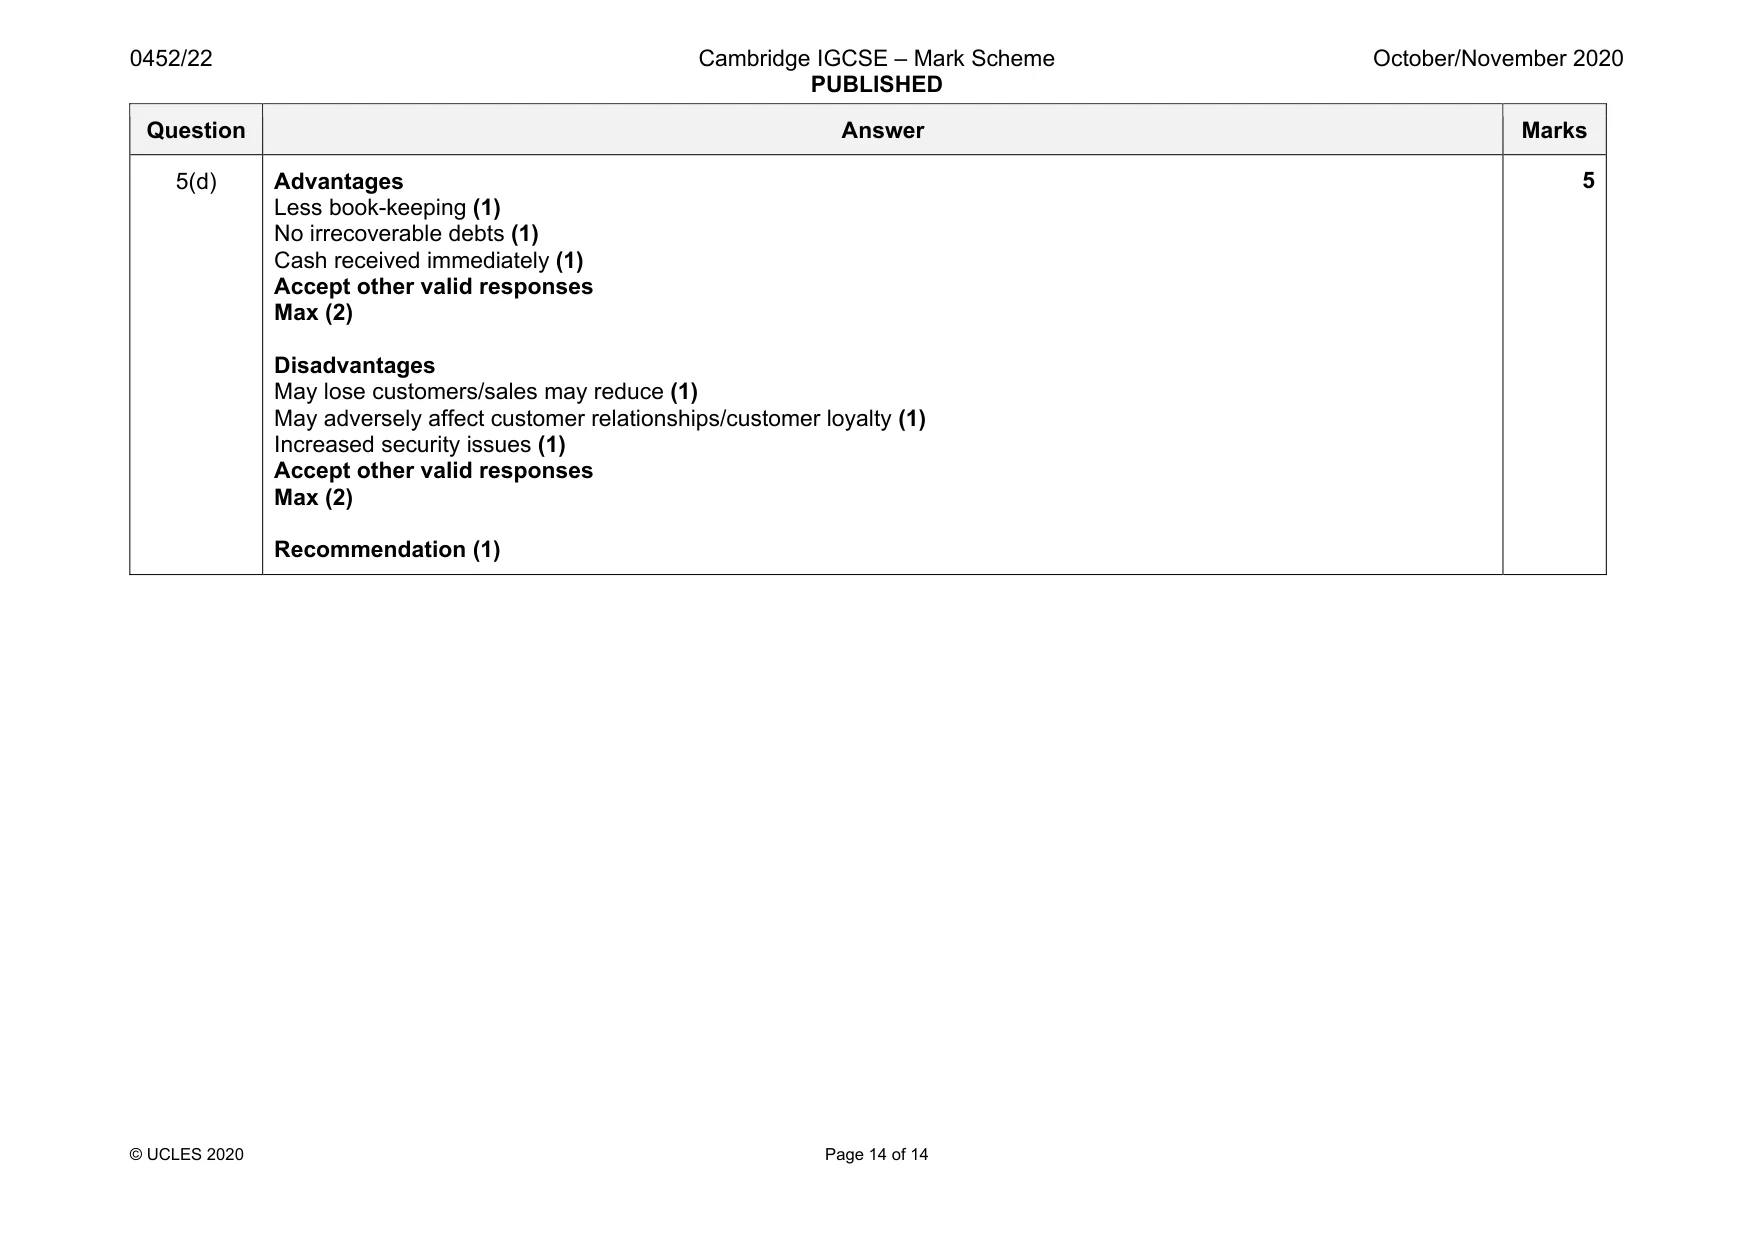
5 Razia’s financial year ends on 30 September. The totals of the trial balance on 30 September 2020 did not agree. The totals were debit $10 450 and credit $10 250. A suspense account was opened. The following errors were later discovered. 1 The total of the sales returns journal had been overcast by $300. 2 Cash sales, $820, had not been recorded in the books of account. 3 A purchase invoice, $190, had been credited to the account of P Hill instead of D Hill. 4 A cheque payment, $240, for motor repairs had been correctly entered in the cash book but had been posted to the debit of motor repairs account as $420. 5 Rent received, $310, had been debited to the rent payable account. 6 Staff wages, $250, had been posted to Razia’s drawings account. 7 A cheque paid, $900, to Kamil, a credit supplier, had been entered correctly in the cash book but had not been posted to Kamil’s account. REQUIRED (a) Prepare the suspense account. Start with the balance arising from the difference on the trial balance. The account should be balanced or totalled as necessary. Razia Suspense account Date Details $ Date Details $ ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... ......... ...................................... .......... [6] (b) Identify the types of error made in Error 2 and Error 4. Error Type of error 2 4 [2] (c) Complete the table by placing a tick (✓) in the correct column to indicate the effect on the profit for the year of correcting each error. Error Increase profit Decrease profit No effect on profit number 1 2 3 4 5 6 7 [7] Razia is considering whether or not to sell on cash terms only. REQUIRED (d) Advise Razia whether or not she should sell on cash terms only. Justify your answer with two advantages and two disadvantages of selling on cash terms only. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... .............................................................................................................................................. [5] [Total: 20]
Mark scheme: 5(a) Razia Suspense account 2020 $ 2020 $ Sep 30 Sales returns 300 (1) Sep 30 Difference on trial balance 200 (1) Motor repairs 180 (1) Rent receivable 310 (1) Kamil 900 (1) Rent payable 310 (1) ___ 1 100 1 100 6 Question Answer Marks 5(b) Error Type of error 2 Error of omission (1) 4 Error of transposition in one account (1) 2 5(c) Error number Increase profit Decrease profit No effect on profit 1 (1) 2 (1) 3 (1) 4 (1) 5 (1) 6 (1) 7 (1) 7 Question Answer Marks 5(d) Advantages Less book-keeping (1) No irrecoverable debts (1) Cash received immediately (1) Accept other valid responses Max (2) Disadvantages May lose customers/sales may reduce (1) May adversely affect customer relationships/customer loyalty (1) Increased security issues (1) Accept other valid responses Max (2) Recommendation (1) 5
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2020 Oct/Nov, Paper 2 · Variant 2. A higher threshold means an easier paper — the bar moves with how the cohort did.