Cambridge IGCSE Accounting 0452 — 2019 Oct/Nov Paper 2 · Variant 3
0452/23/O/N/19 · 5 questions · 120 marks · ≈135 min
The question paper and its mark scheme, free to read here and free to download. This is Cambridge’s own paper, exactly as it was sat.
Question paper24 pages

Mark scheme17 pages
Answers below. Sit the paper first if you are practising.
Questions as text
Q1 · Sophie employs a book‑keeper to maintain her accounting records
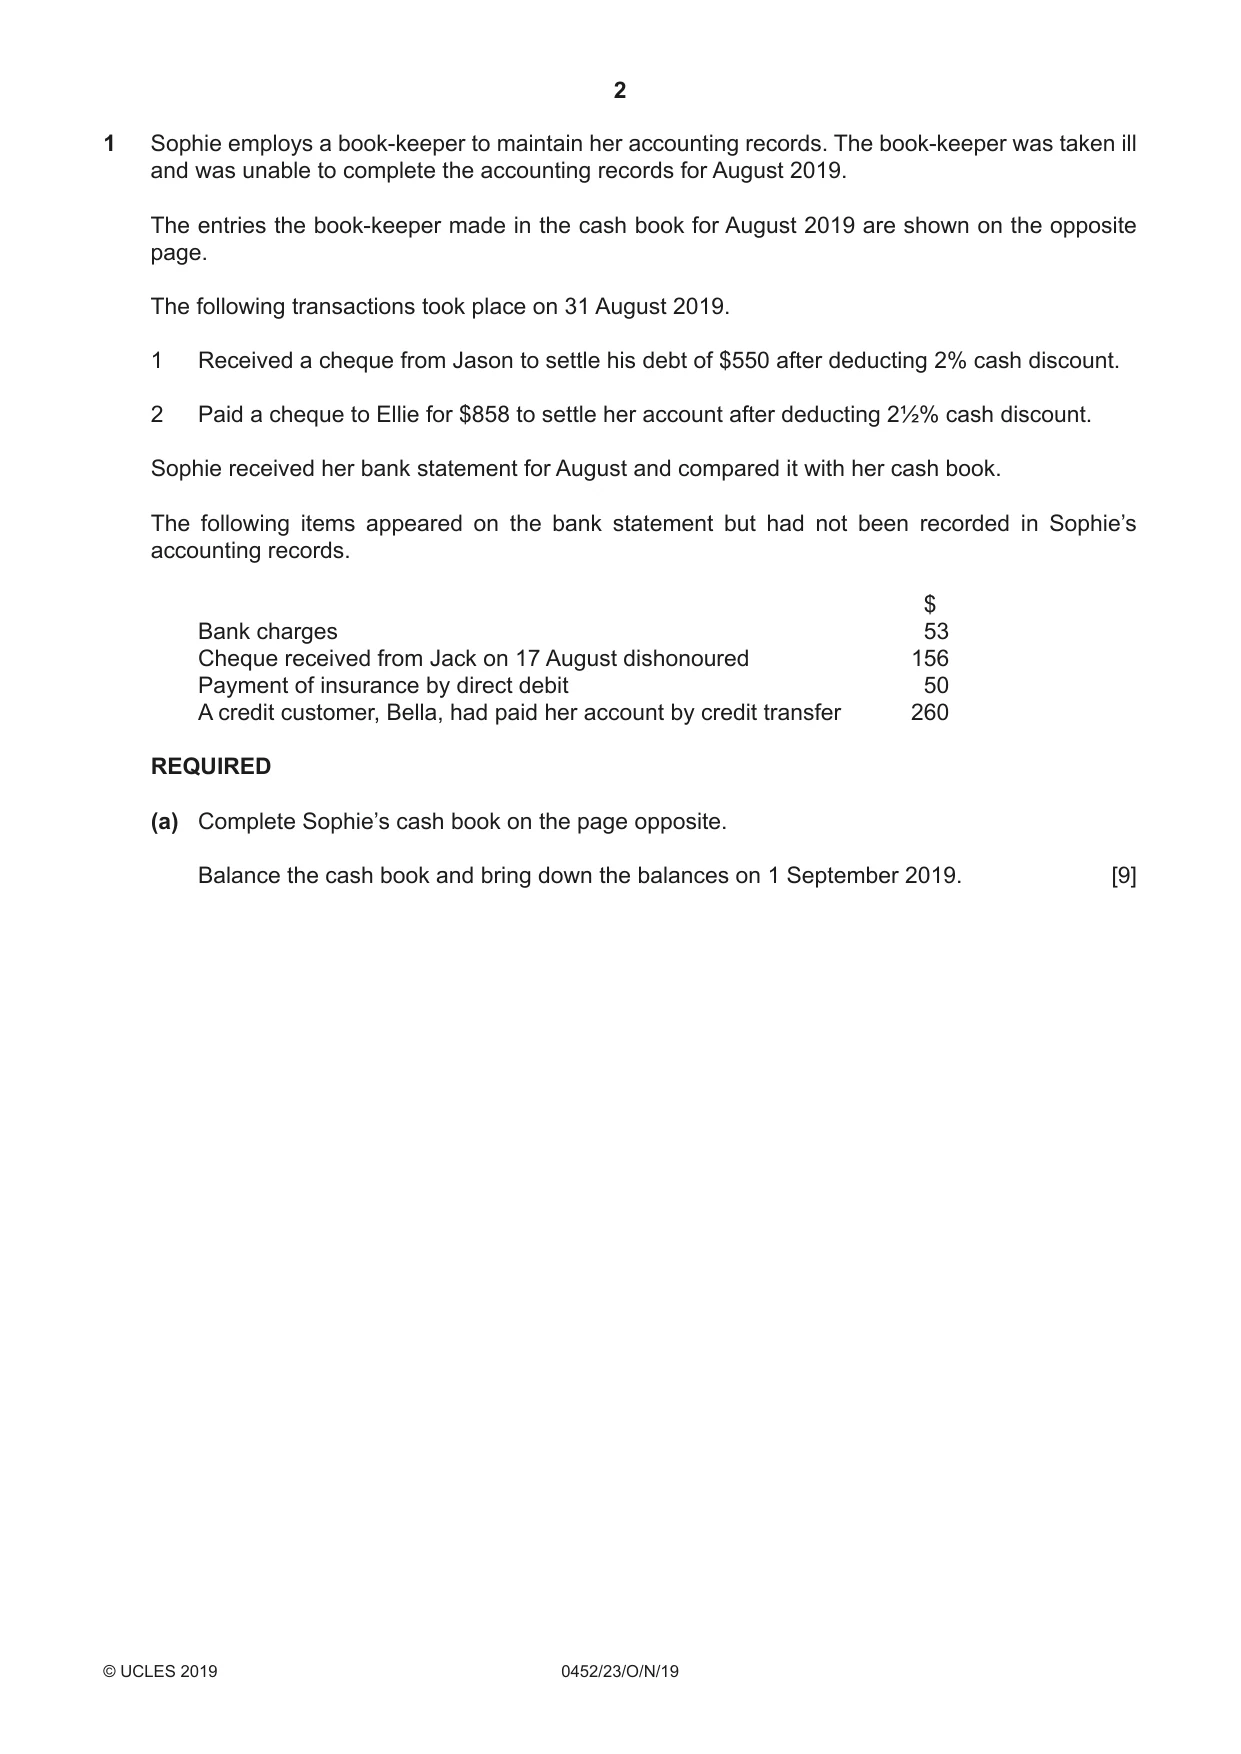
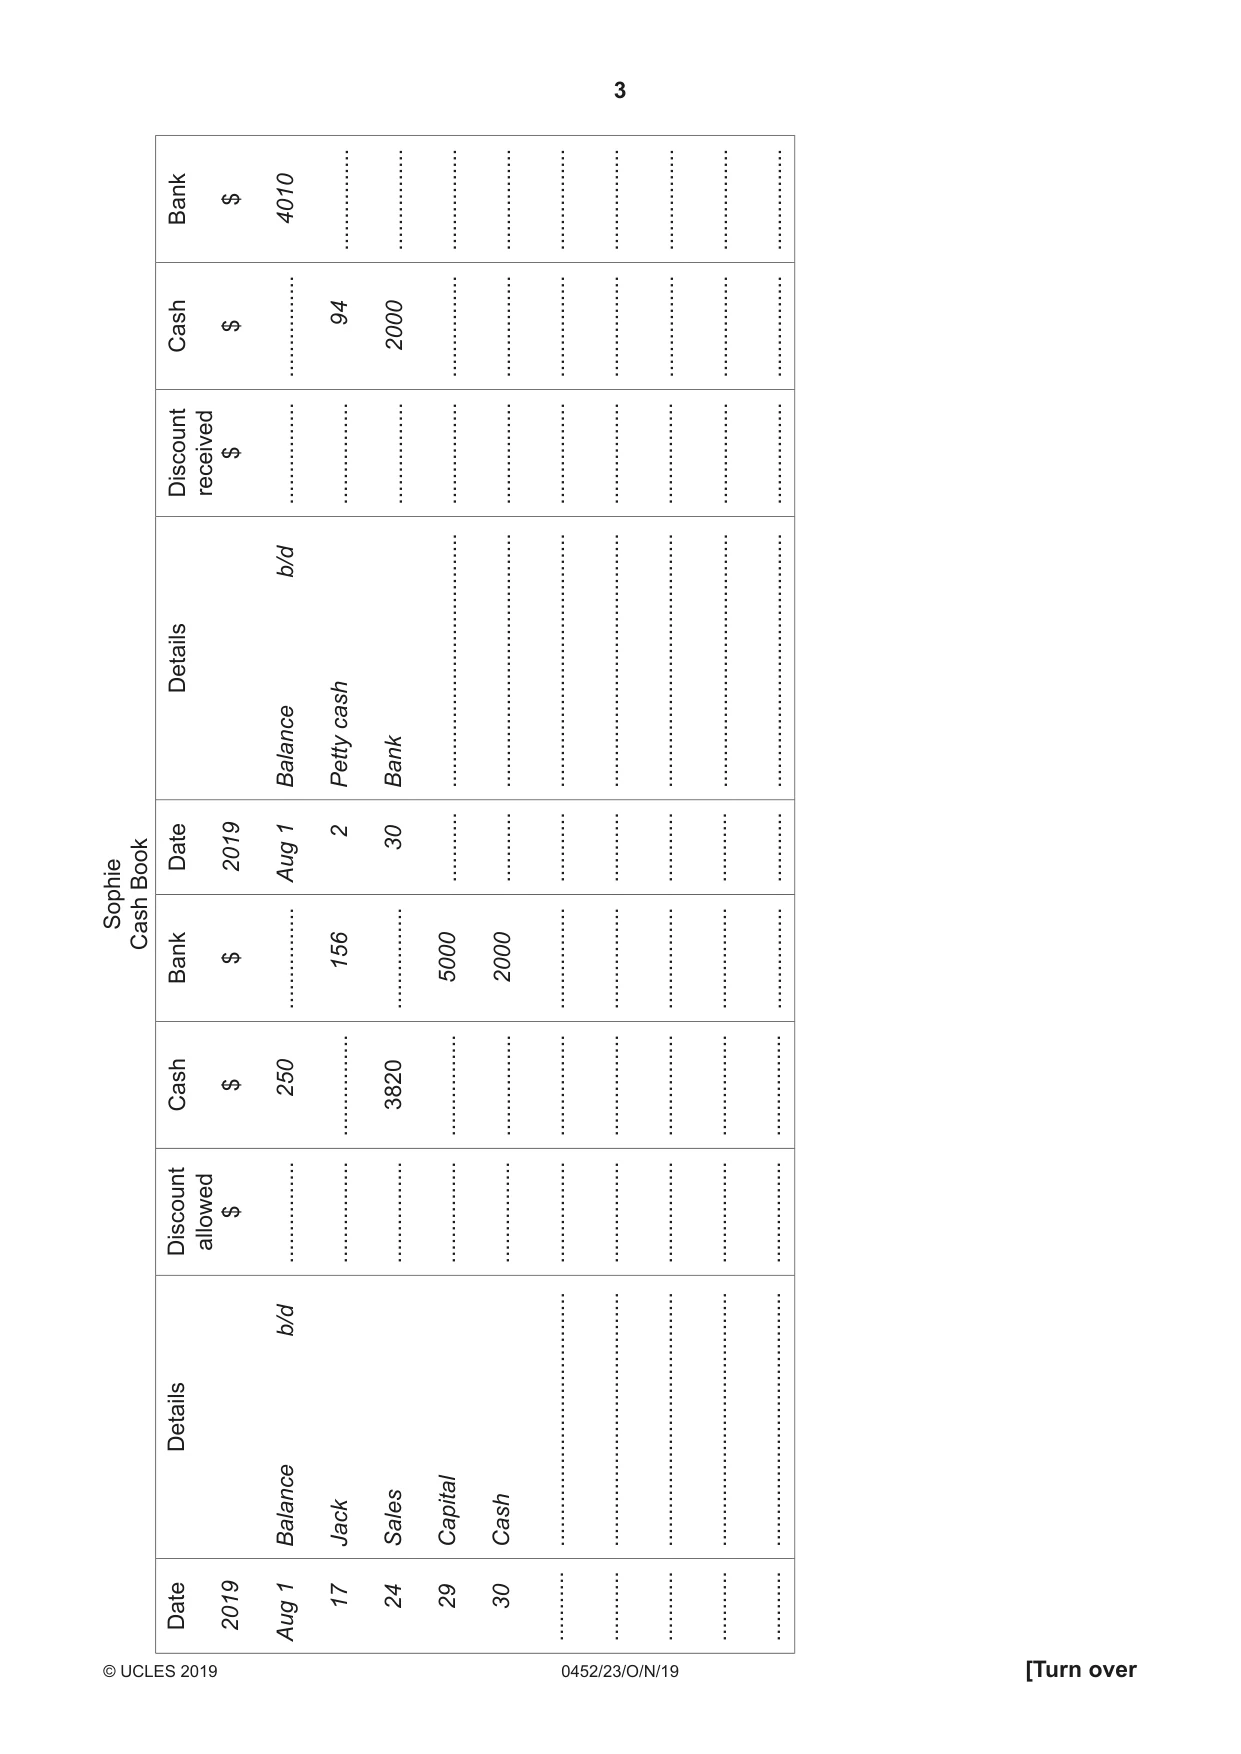
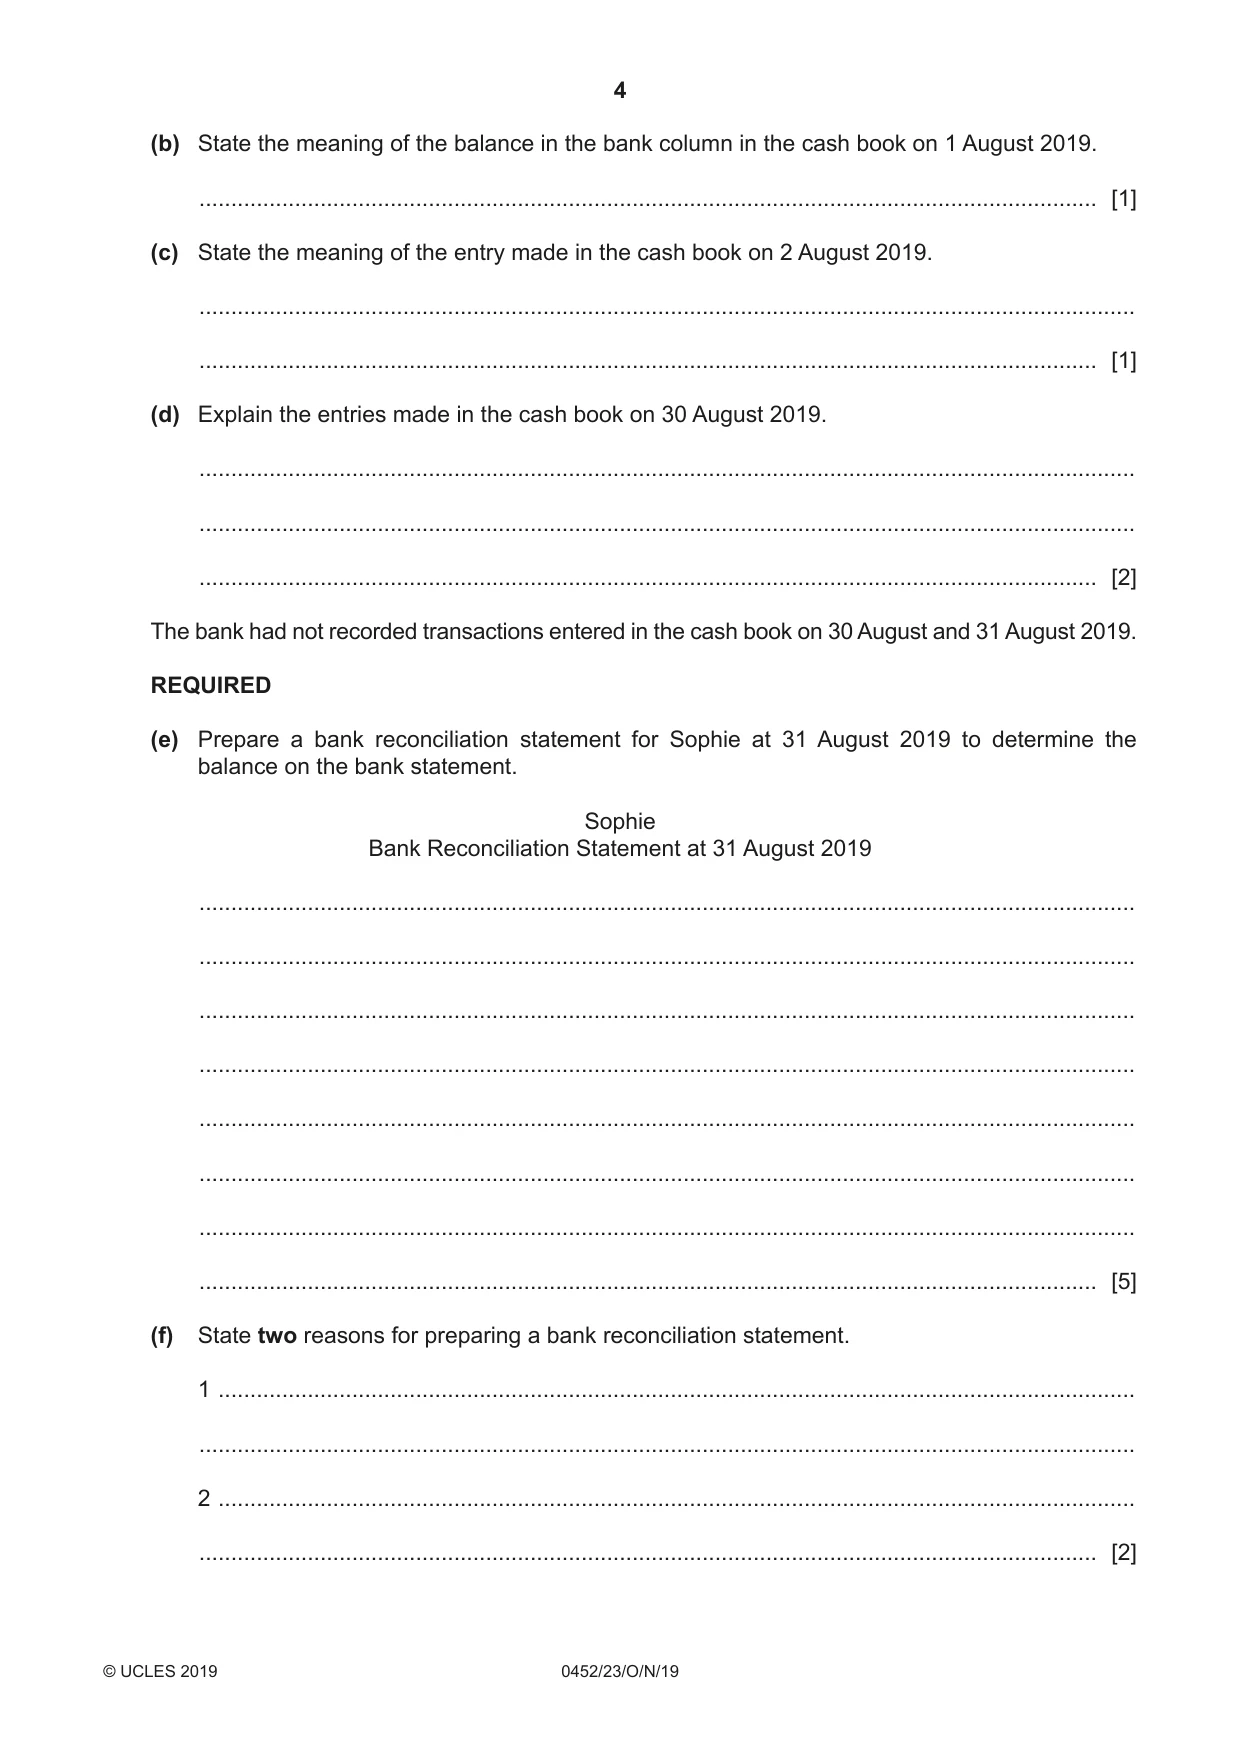
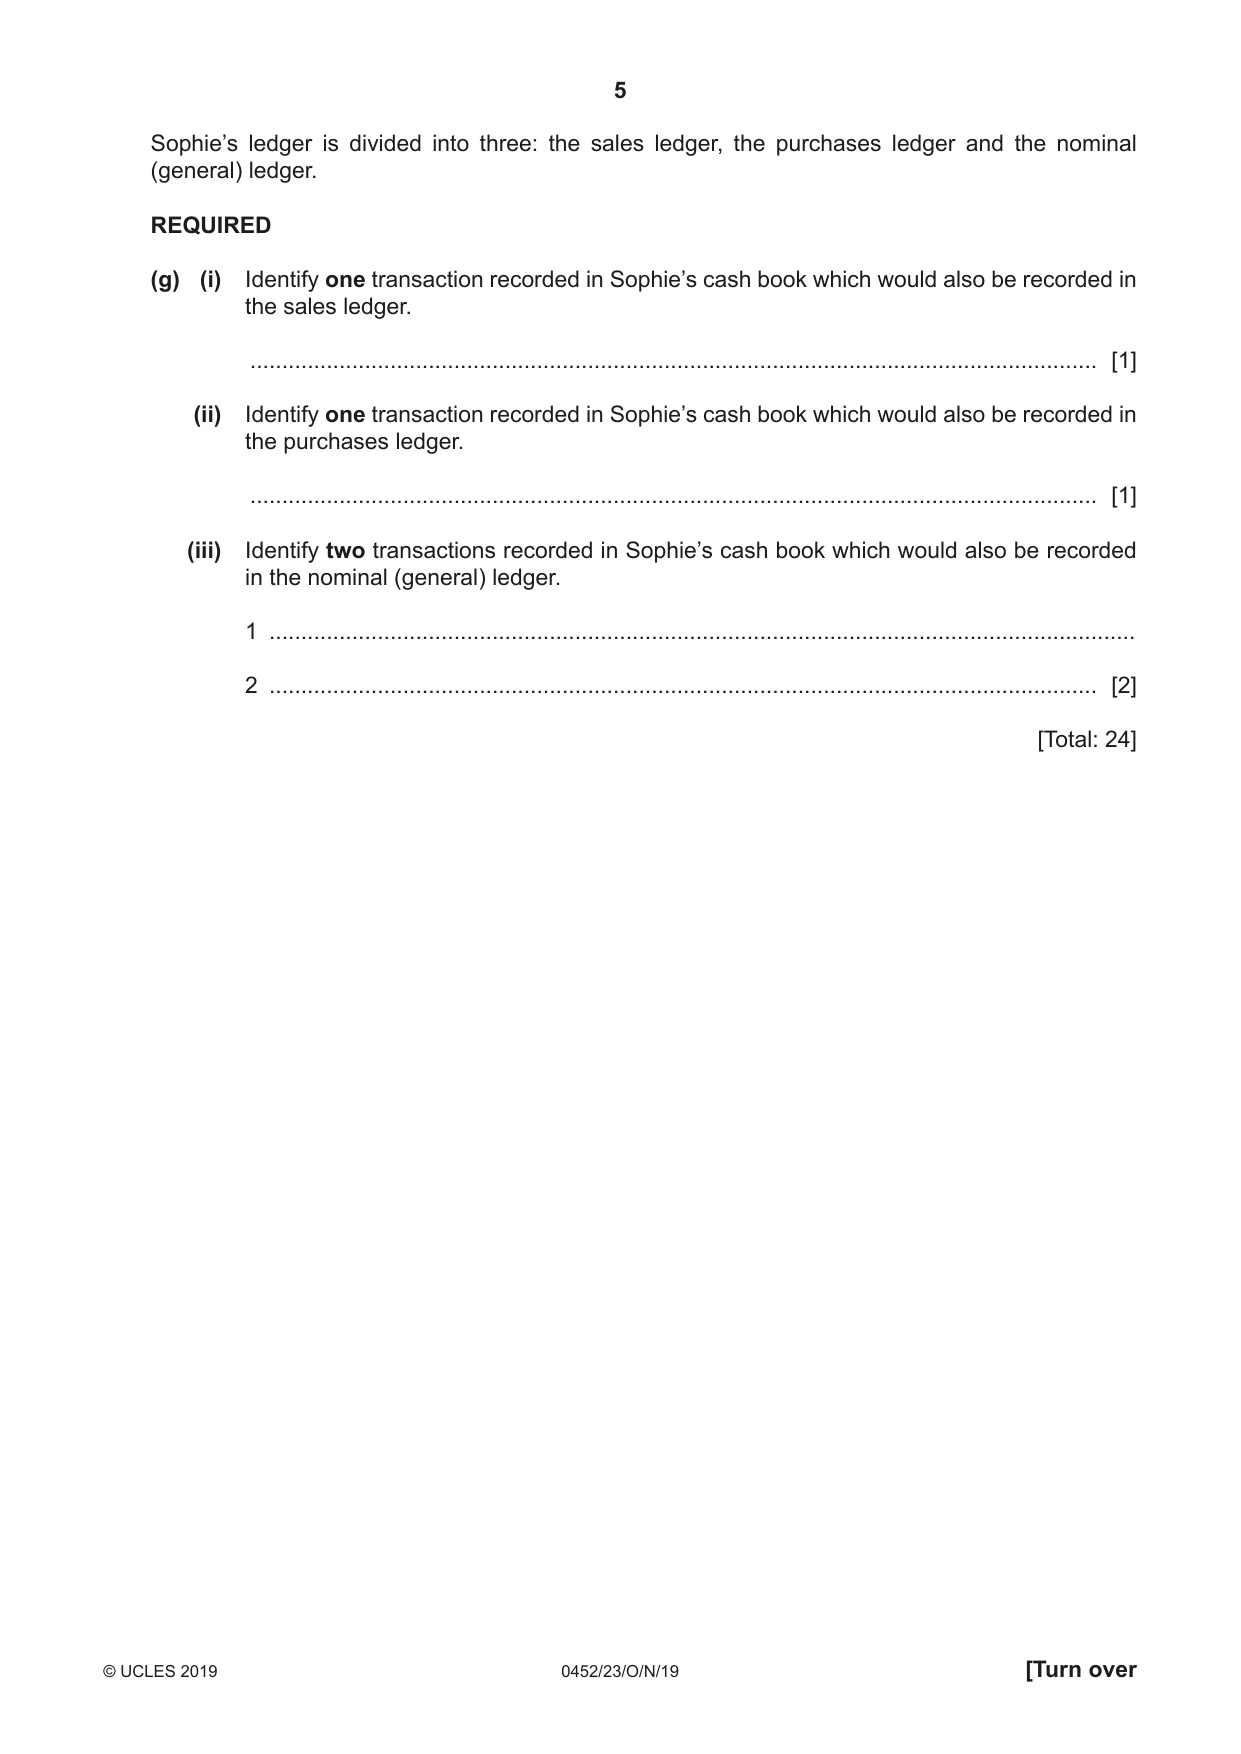
1 Sophie employs a book‑keeper to maintain her accounting records. The book‑keeper was taken ill and was unable to complete the accounting records for August 2019. The entries the book‑keeper made in the cash book for August 2019 are shown on the opposite page. The following transactions took place on 31 August 2019. 1 Received a cheque from Jason to settle his debt of $550 after deducting 2% cash discount. 2 Paid a cheque to Ellie for $858 to settle her account after deducting 2½% cash discount. Sophie received her bank statement for August and compared it with her cash book. The following items appeared on the bank statement but had not been recorded in Sophie’s accounting records. $ Bank charges 53 Cheque received from Jack on 17 August dishonoured 156 Payment of insurance by direct debit 50 A credit customer, Bella, had paid her account by credit transfer 260 REQUIRED (a) Complete Sophie’s cash book on the page opposite. Balance the cash book and bring down the balances on 1 September 2019. [9] $ Bank 4010 ................ ................ ................ ................ ................ ................ ................ ................ ................ 94 $ Cash 2000 ................ ................ ................ ................ ................ ................ ................ ................ $ Discountreceived ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ b/d Details cash Balance Petty Bank ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ ........................................ Date 2019 1 2 30 Aug ........... ........... ........... ........... ........... ........... ........... Book Sophie Cash $ Bank 156 5000 2000 ................ ................ ................ ................ ................ ................ ................ $ Cash 250 3820 ................ ................ ................ ................ ................ ................ ................ ................ $ Discountallowed ................ ................ ................ ................ ................ ................ ................ ................ ................ ................ b/d Details Balance Jack Sales Capital Cash ........................................ ........................................ ........................................ ........................................ ........................................ (b) State the meaning of the balance in the bank column in the cash book on 1 August 2019. ............................................................................................................................................. [1] (c) State the meaning of the entry made in the cash book on 2 August 2019. ................................................................................................................................................... ............................................................................................................................................. [1] (d) Explain the entries made in the cash book on 30 August 2019. ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] The bank had not recorded transactions entered in the cash book on 30 August and 31 August 2019. REQUIRED (e) Prepare a bank reconciliation statement for Sophie at 31 August 2019 to determine the balance on the bank statement. Sophie Bank Reconciliation Statement at 31 August 2019 ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] (f) State two reasons for preparing a bank reconciliation statement. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ............................................................................................................................................. [2] Sophie’s ledger is divided into three: the sales ledger, the purchases ledger and the nominal (general) ledger. REQUIRED (g) (i) Identify one transaction recorded in Sophie’s cash book which would also be recorded in the sales ledger. ..................................................................................................................................... [1] (ii) Identify one transaction recorded in Sophie’s cash book which would also be recorded in the purchases ledger. ..................................................................................................................................... [1] (iii) Identify two transactions recorded in Sophie’s cash book which would also be recorded in the nominal (general) ledger. 1 ........................................................................................................................................ 2 .................................................................................................................................. [2] [Total: 24]
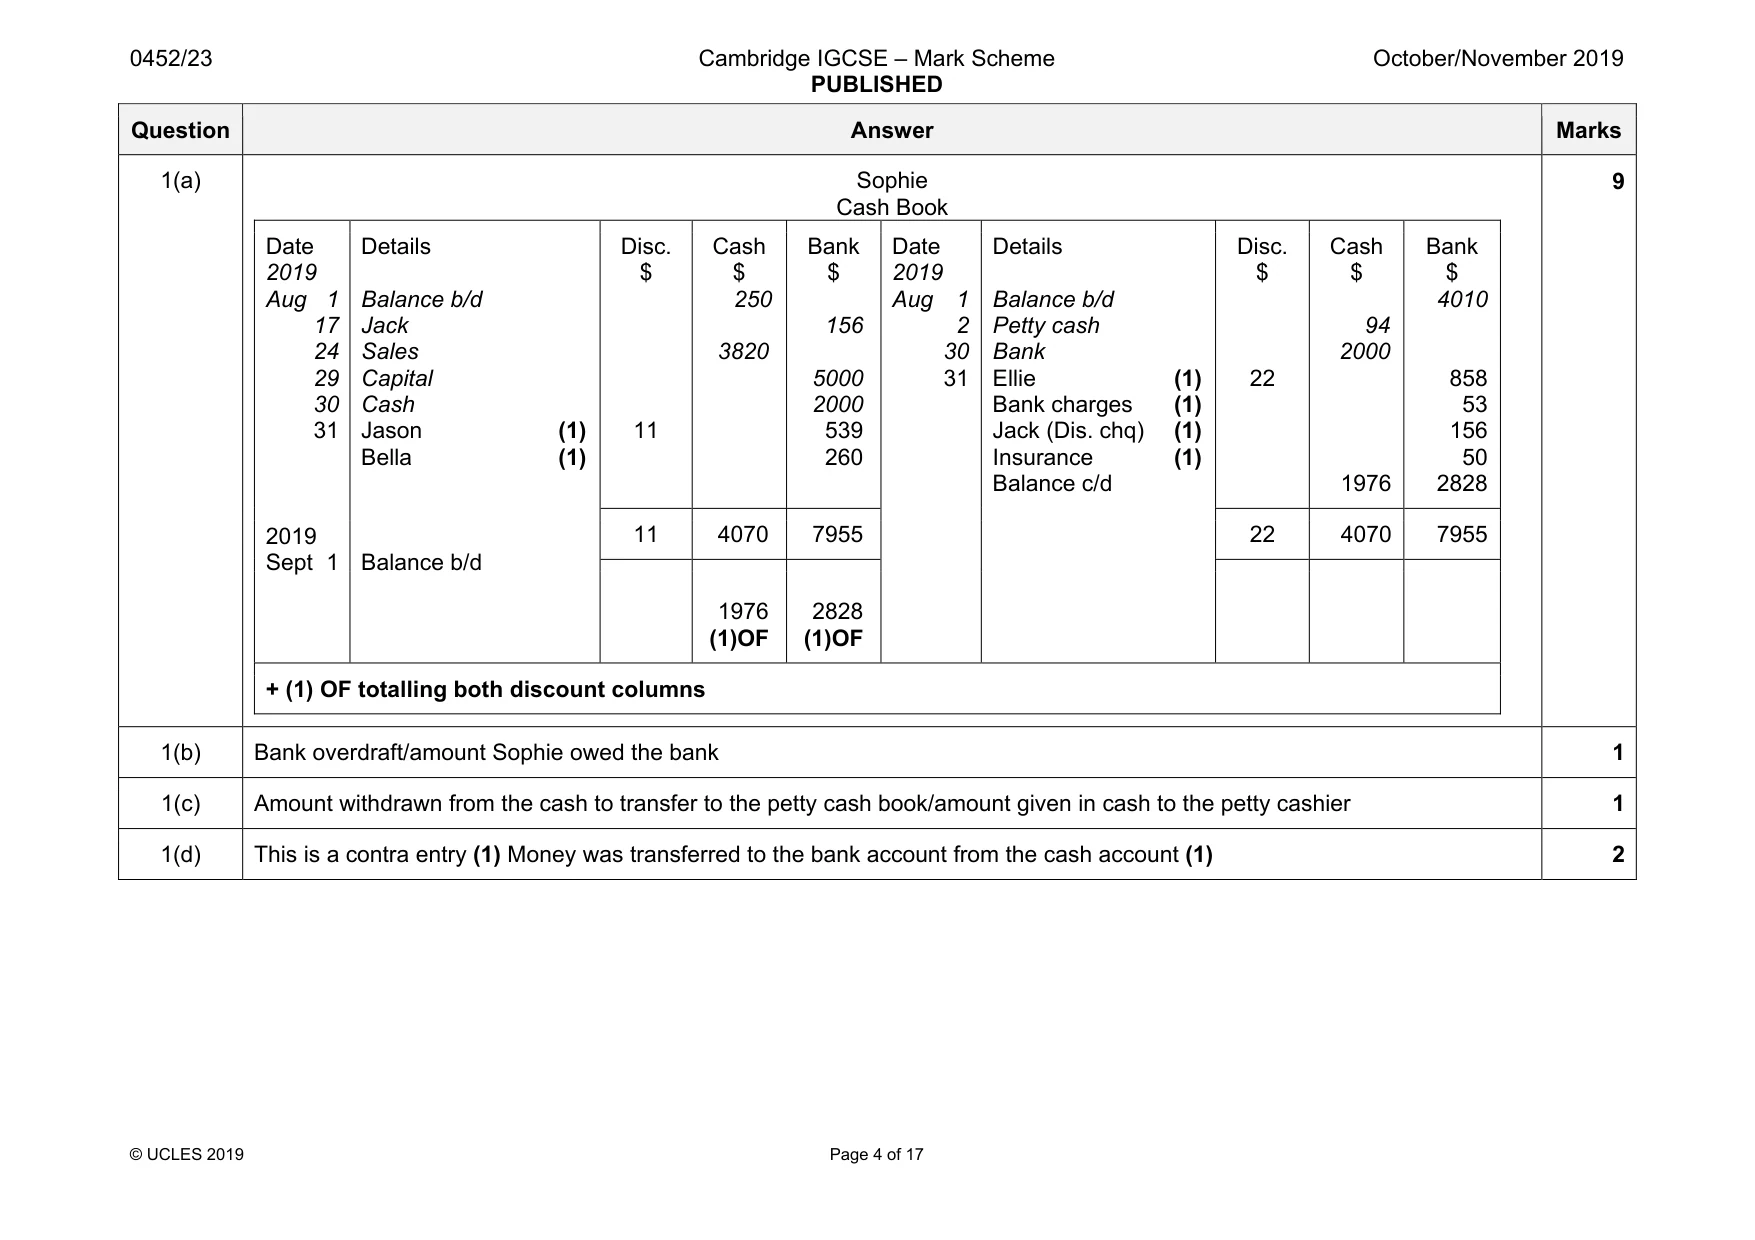
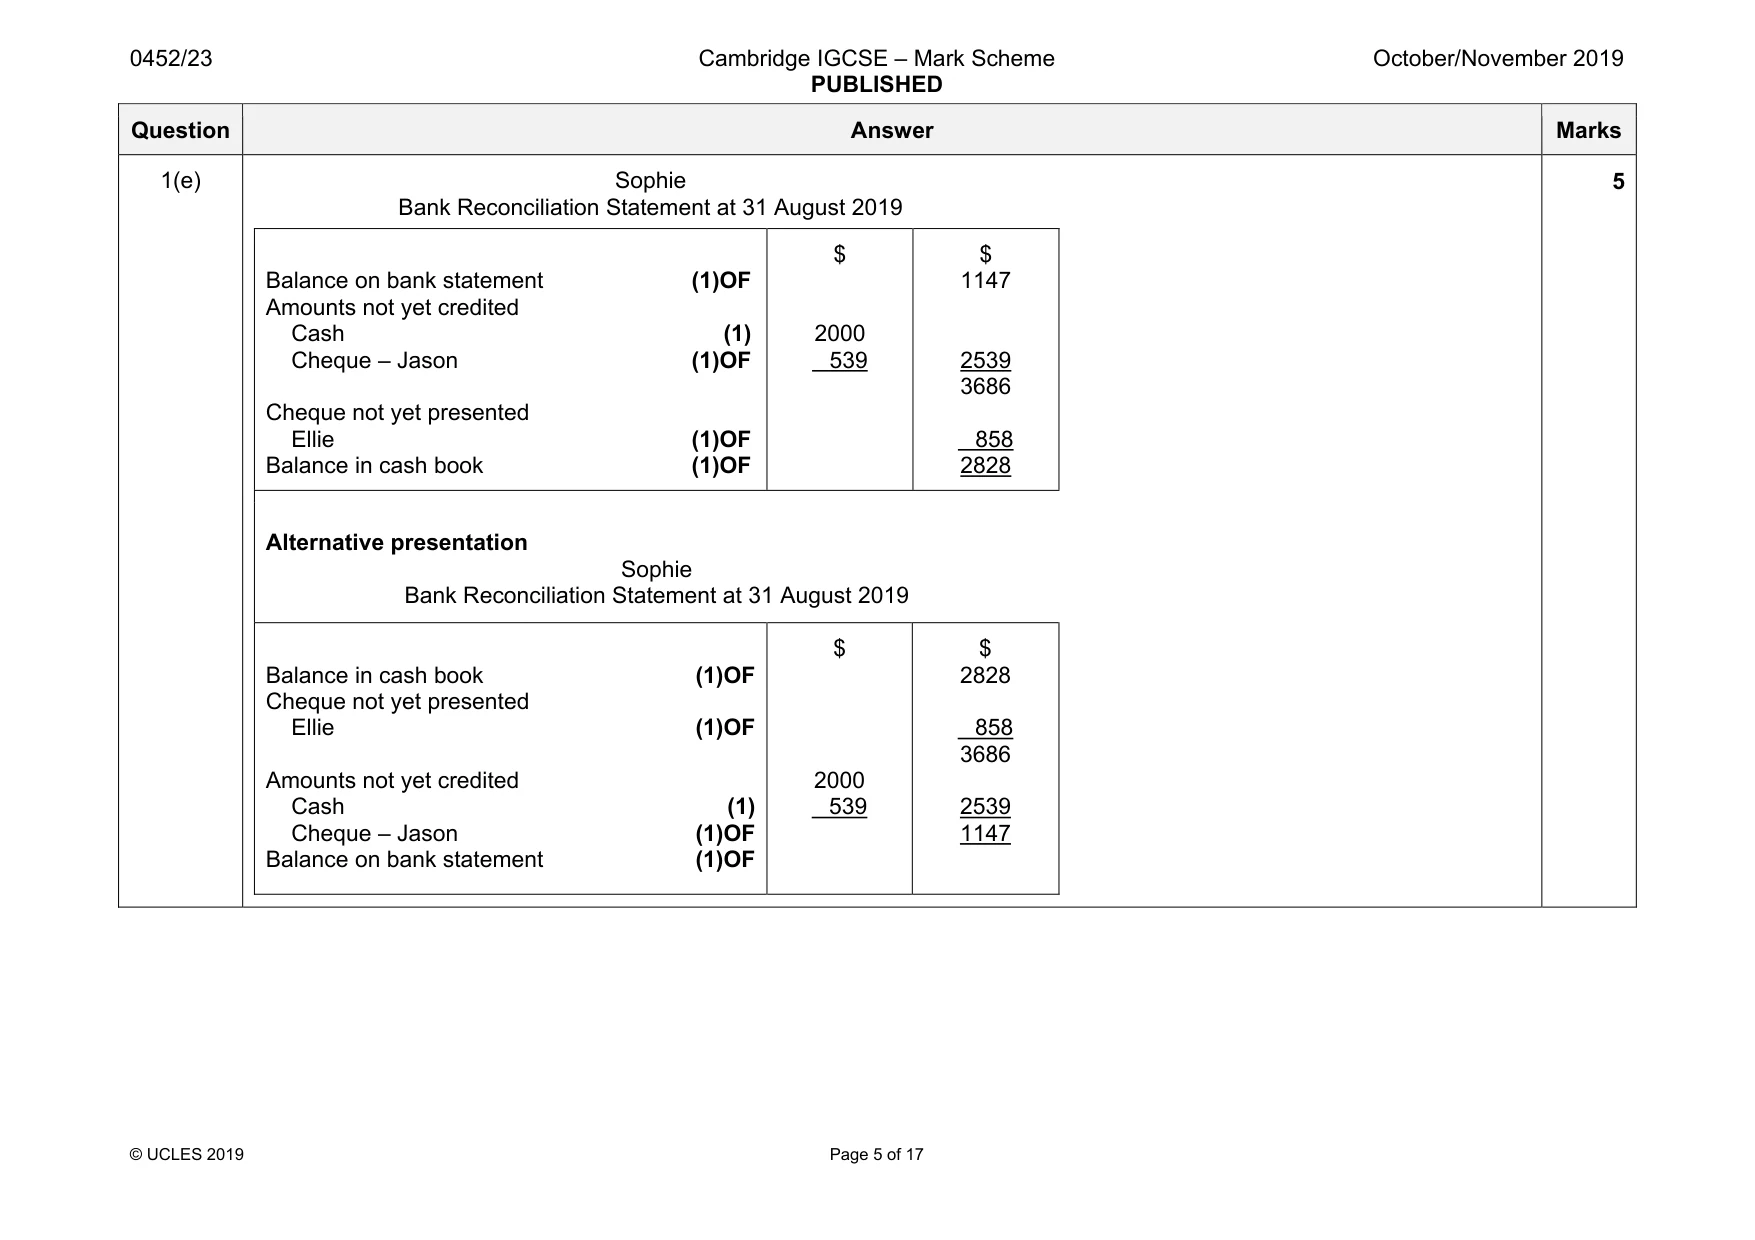
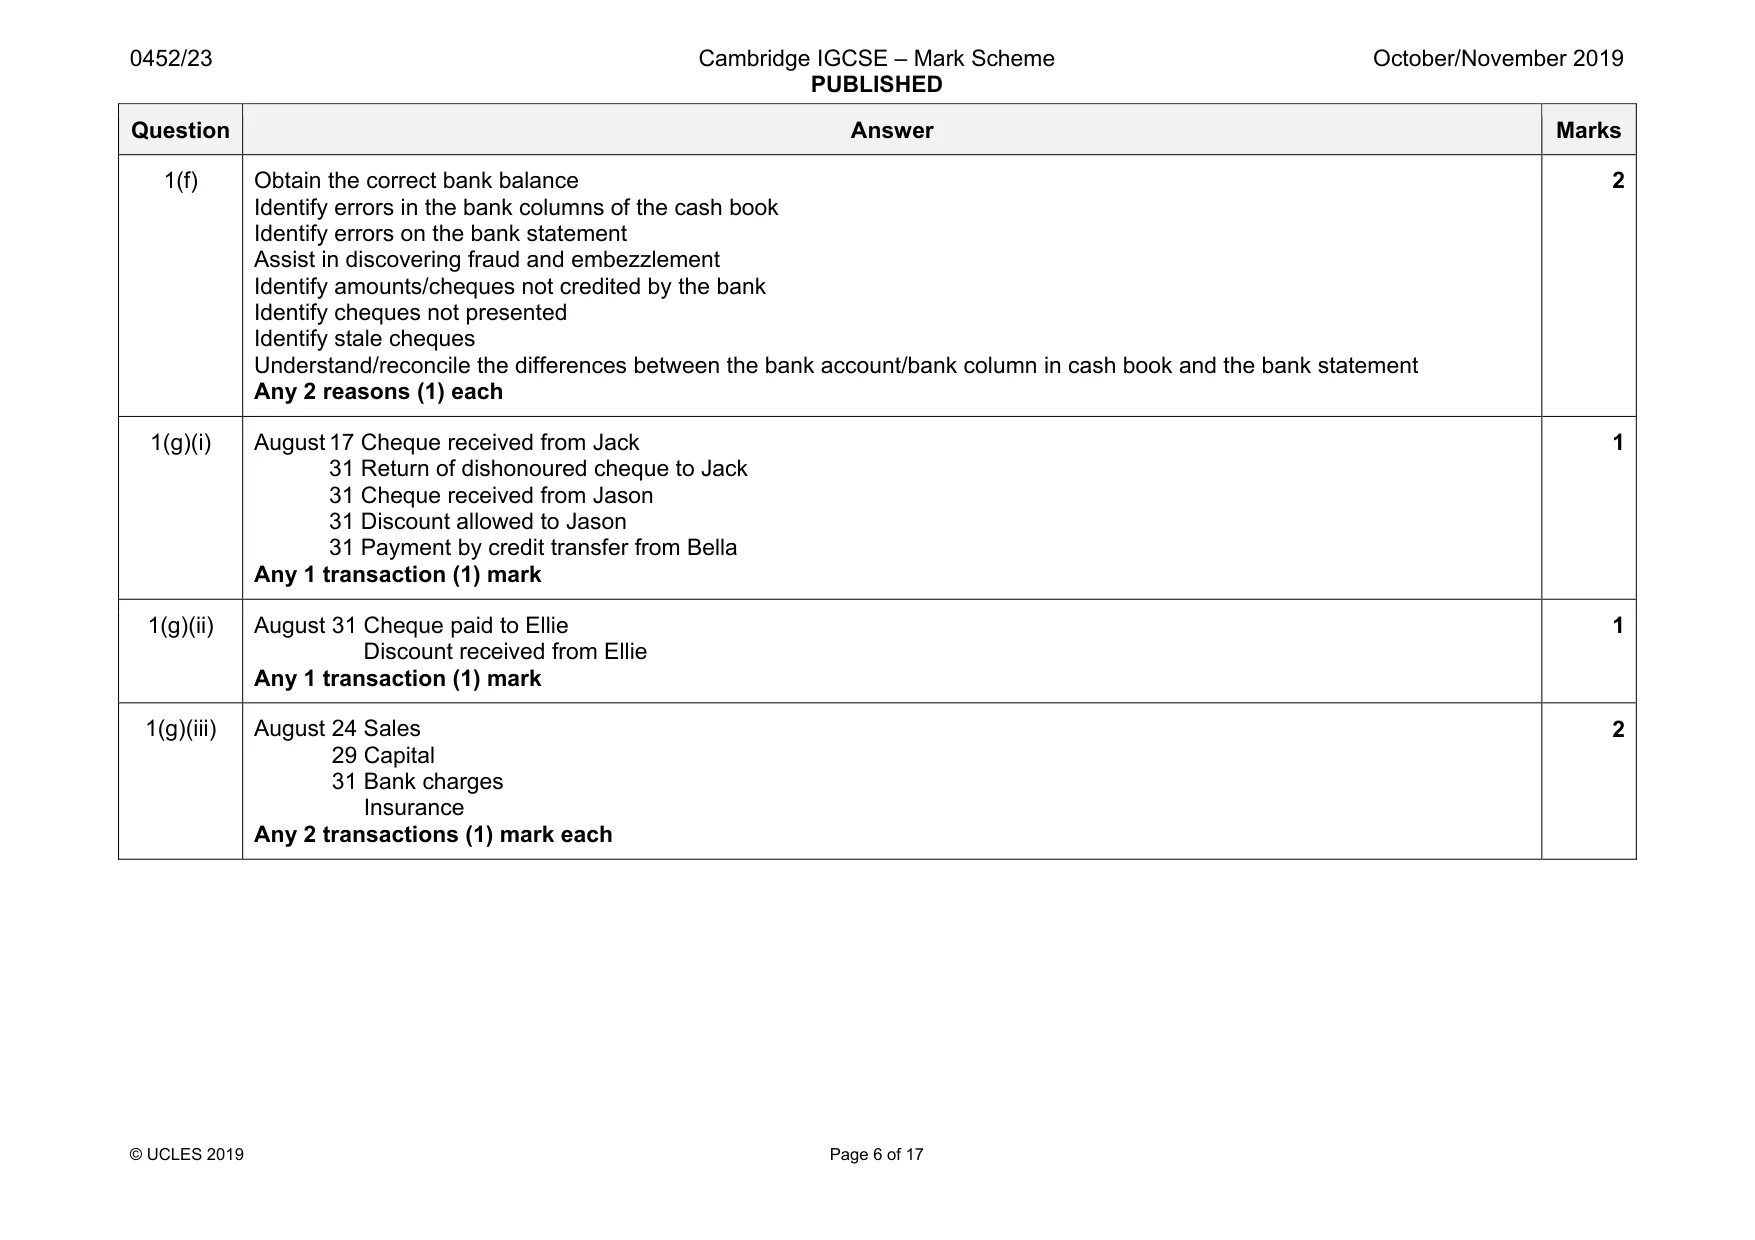
Mark scheme: 1(a) Sophie Cash Book Date 2019 Aug 1 17 24 29 30 31 2019 Sept 1 Details Balance b/d Jack Sales Capital Cash Jason (1) Bella (1) Balance b/d Disc. $ 11 Cash $ 250 3820 Bank $ 156 5000 2000 539 260 Date 2019 Aug 1 2 30 31 Details Balance b/d Petty cash Bank Ellie (1) Bank charges (1) Jack (Dis. chq) (1) Insurance (1) Balance c/d Disc. $ 22 Cash $ 94 2000 1976 Bank $ 4010 858 53 156 50 2828 11 4070 7955 22 4070 7955 1976 (1)OF 2828 (1)OF + (1) OF totalling both discount columns 9 1(b) Bank overdraft/amount Sophie owed the bank 1 1(c) Amount withdrawn from the cash to transfer to the petty cash book/amount given in cash to the petty cashier 1 1(d) This is a contra entry (1) Money was transferred to the bank account from the cash account (1) 2 Question Answer Marks 1(e) Sophie Bank Reconciliation Statement at 31 August 2019 Balance on bank statement (1)OF Amounts not yet credited Cash (1) Cheque – Jason (1)OF Cheque not yet presented Ellie (1)OF Balance in cash book (1)OF $ 2000 539 $ 1147 2539 3686 858 2828 Alternative presentation Sophie Bank Reconciliation Statement at 31 August 2019 Balance in cash book (1)OF Cheque not yet presented Ellie (1)OF Amounts not yet credited Cash (1) Cheque – Jason (1)OF Balance on bank statement (1)OF $ 2000 539 $ 2828 858 3686 2539 1147 5 Question Answer Marks 1(f) Obtain the correct bank balance Identify errors in the bank columns of the cash book Identify errors on the bank statement Assist in discovering fraud and embezzlement Identify amounts/cheques not credited by the bank Identify cheques not presented Identify stale cheques Understand/reconcile the differences between the bank account/bank column in cash book and the bank statement Any 2 reasons (1) each 2 1(g)(i) August 17 Cheque received from Jack 31 Return of dishonoured cheque to Jack 31 Cheque received from Jason 31 Discount allowed to Jason 31 Payment by credit transfer from Bella Any 1 transaction (1) mark 1 1(g)(ii) August 31 Cheque paid to Ellie August 31 Discount received from Ellie Any 1 transaction (1) mark 1 1(g)(iii) August 24 Sales 29 Capital 31 Bank charges Insurance Any 2 transactions (1) mark each 2
Q2 · The financial year of CS Limited ends on 30 September
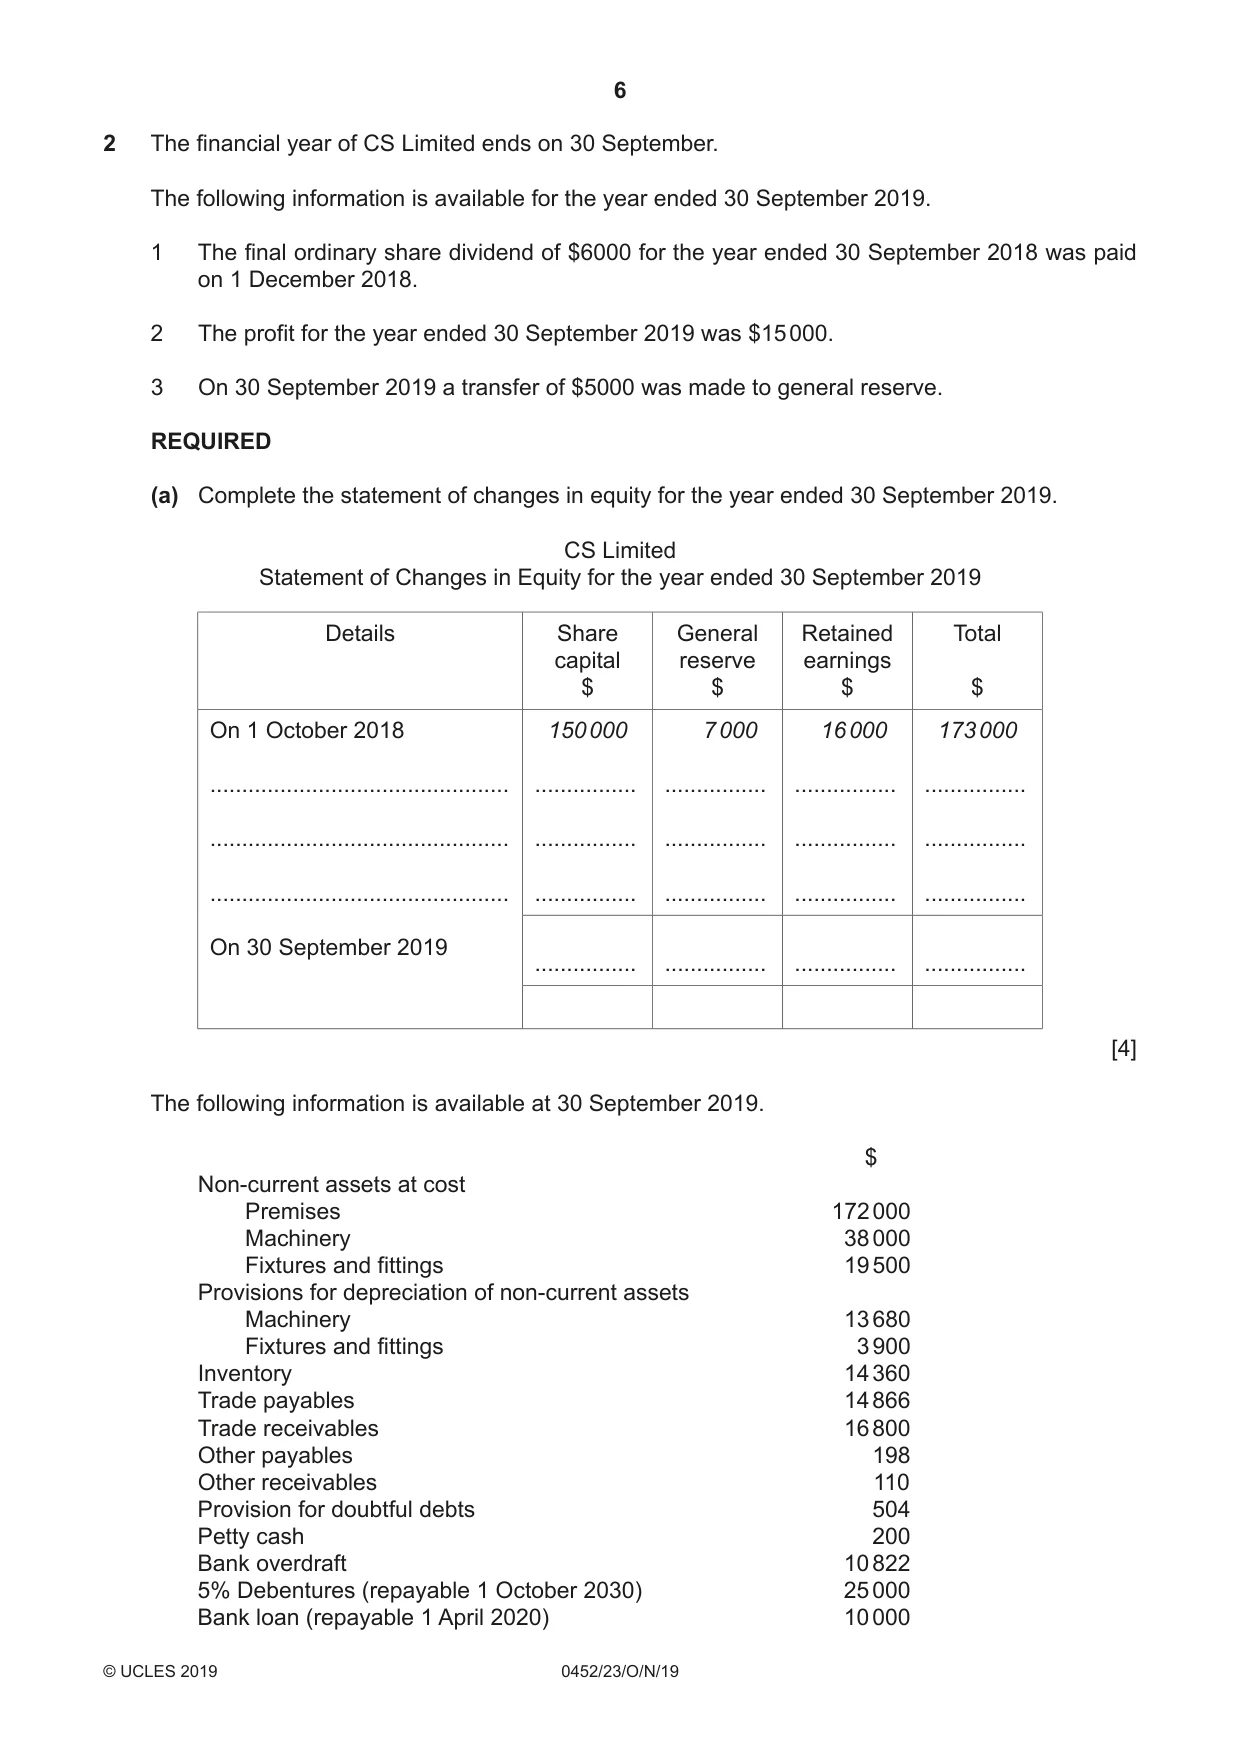
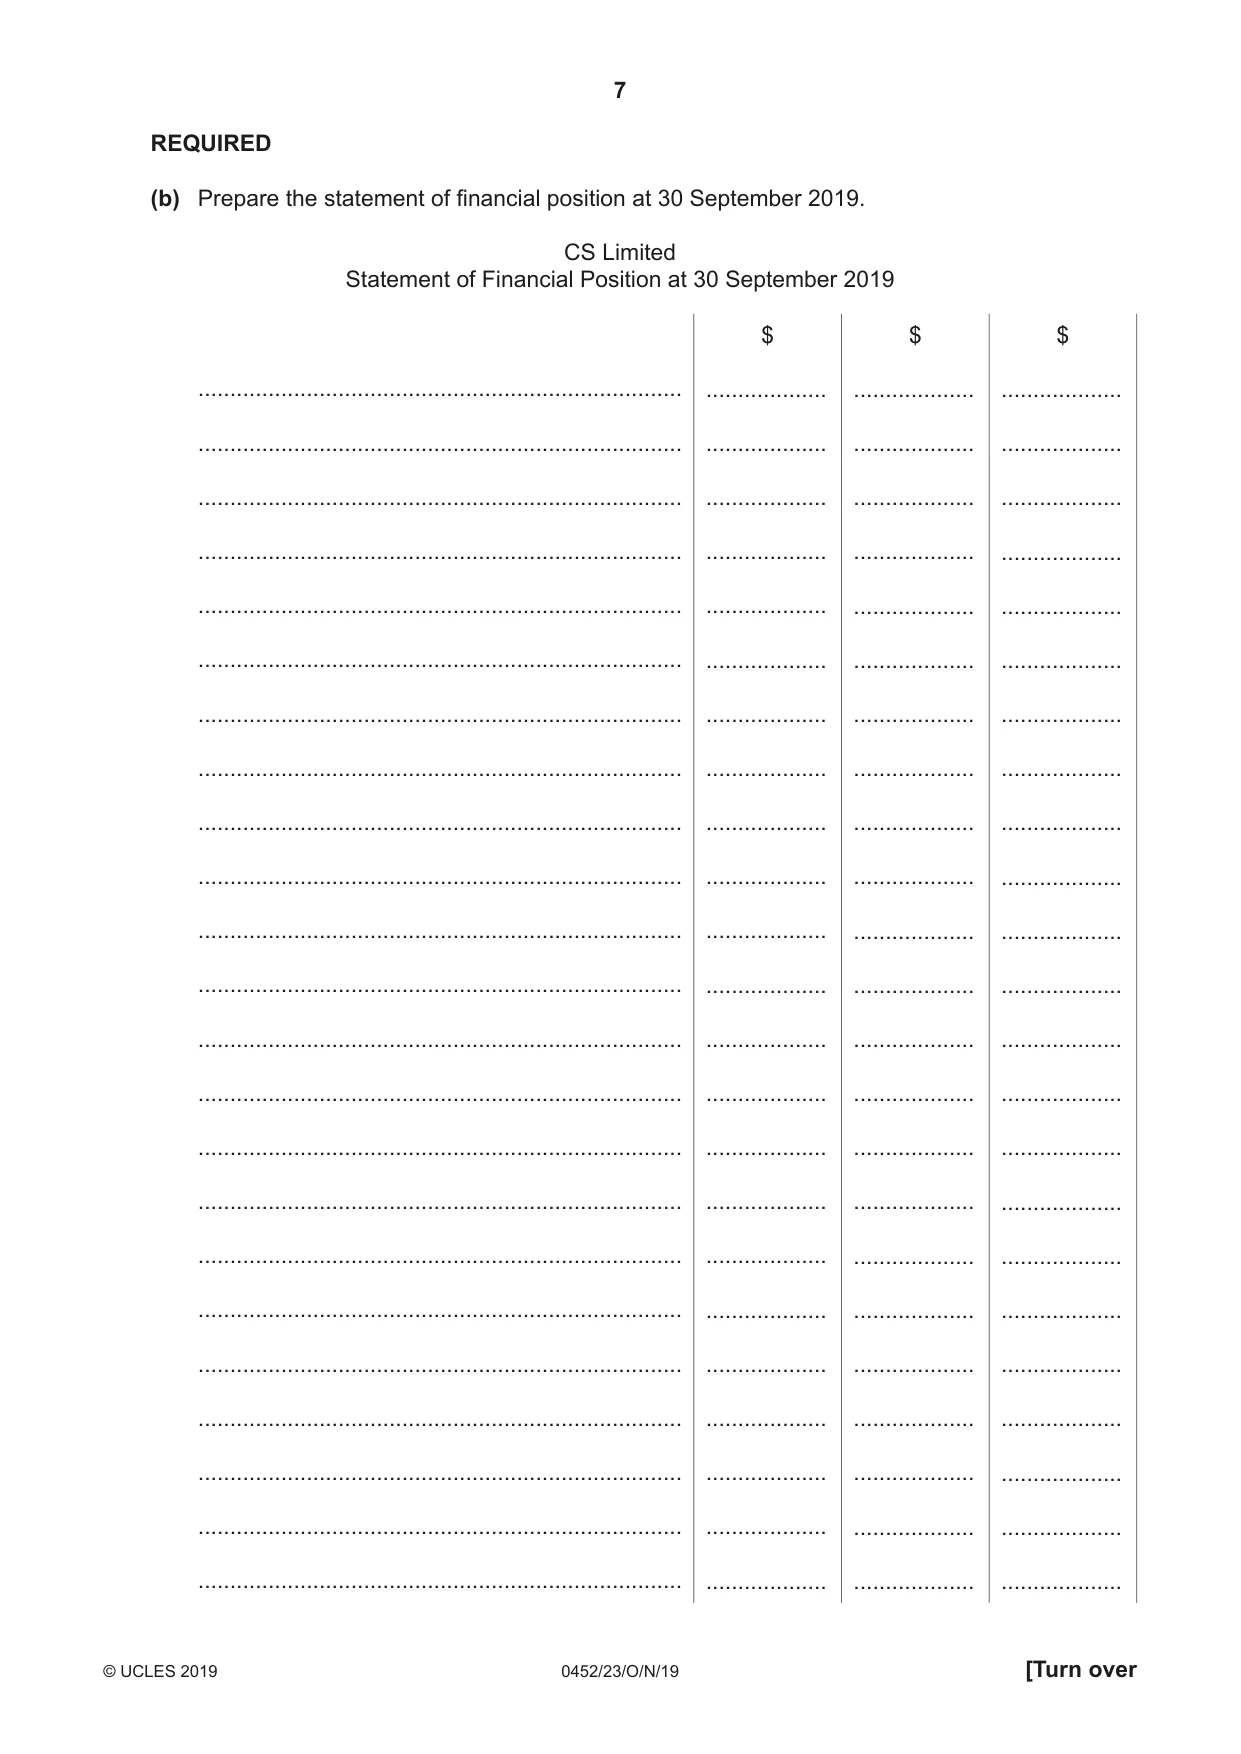
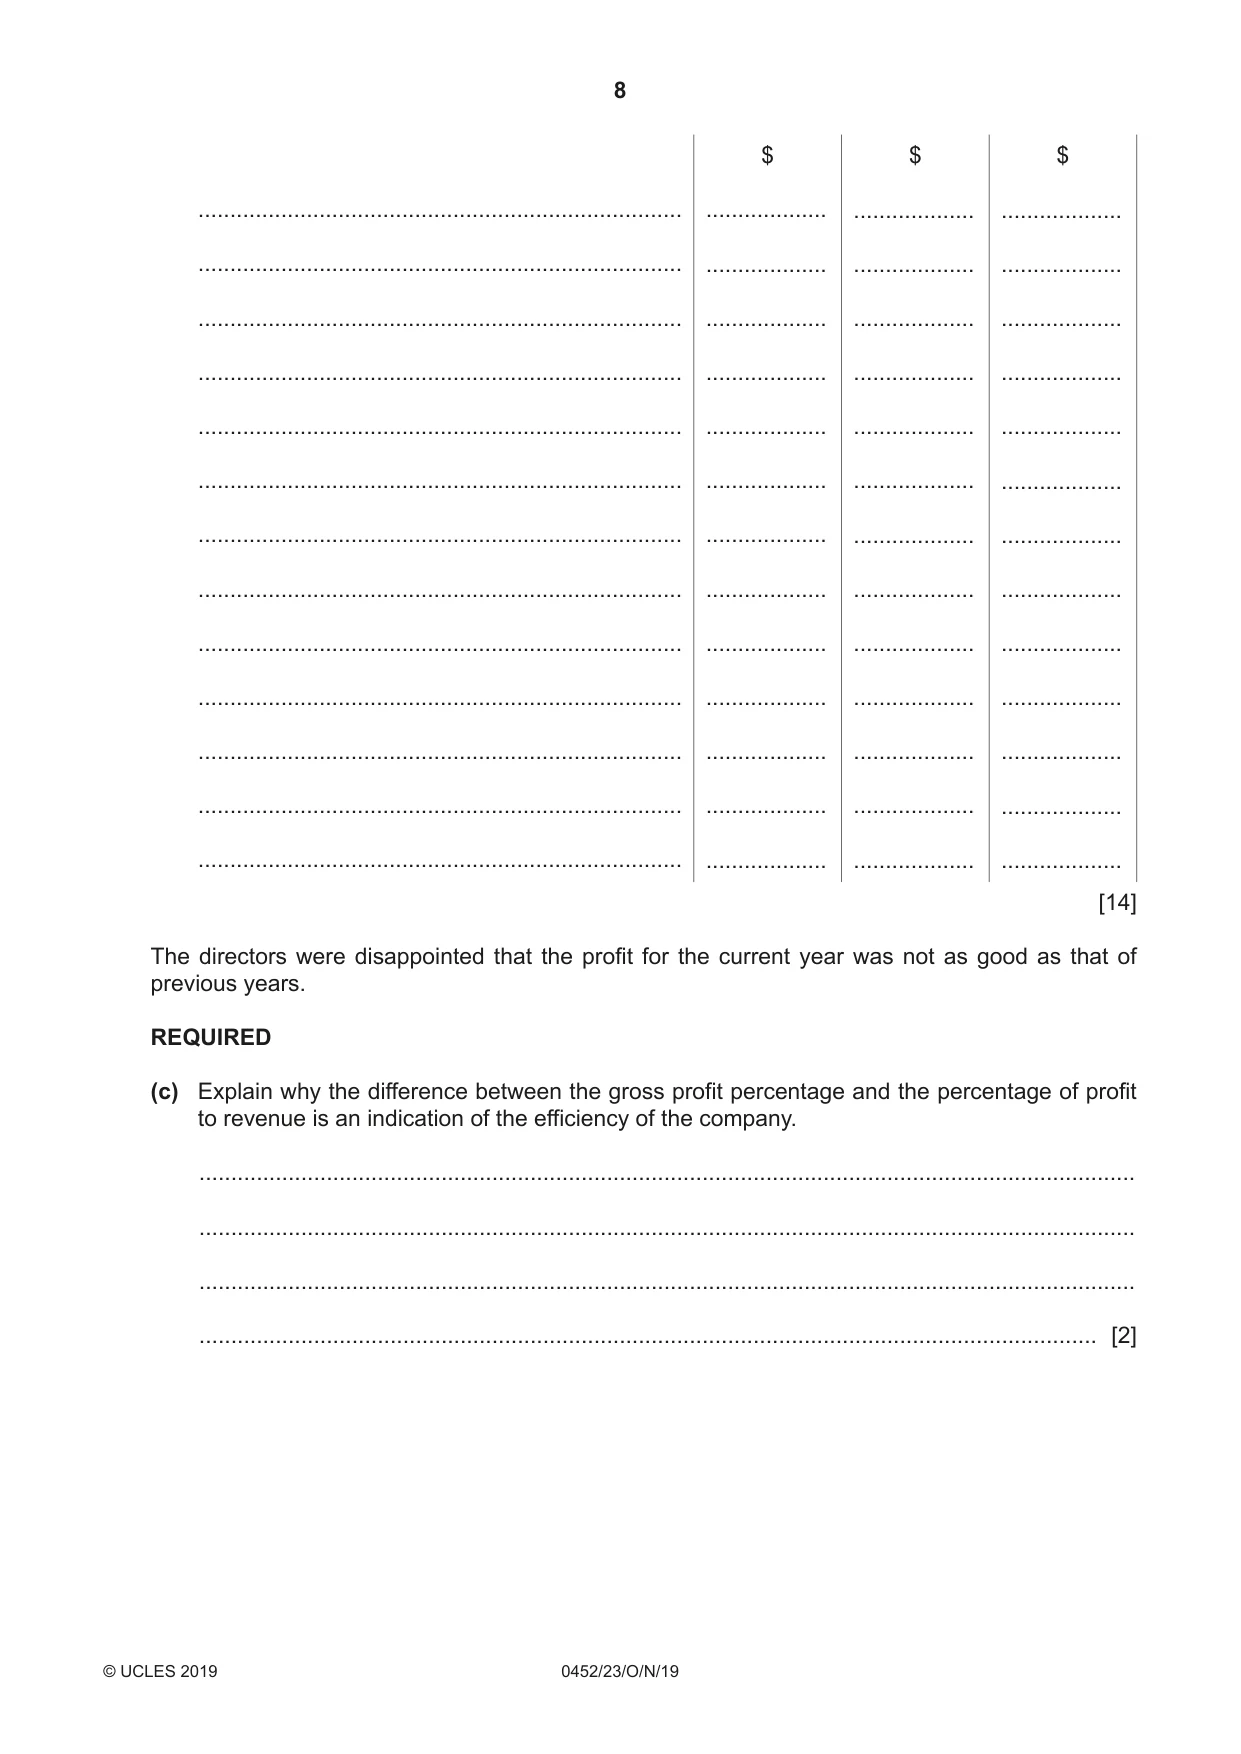
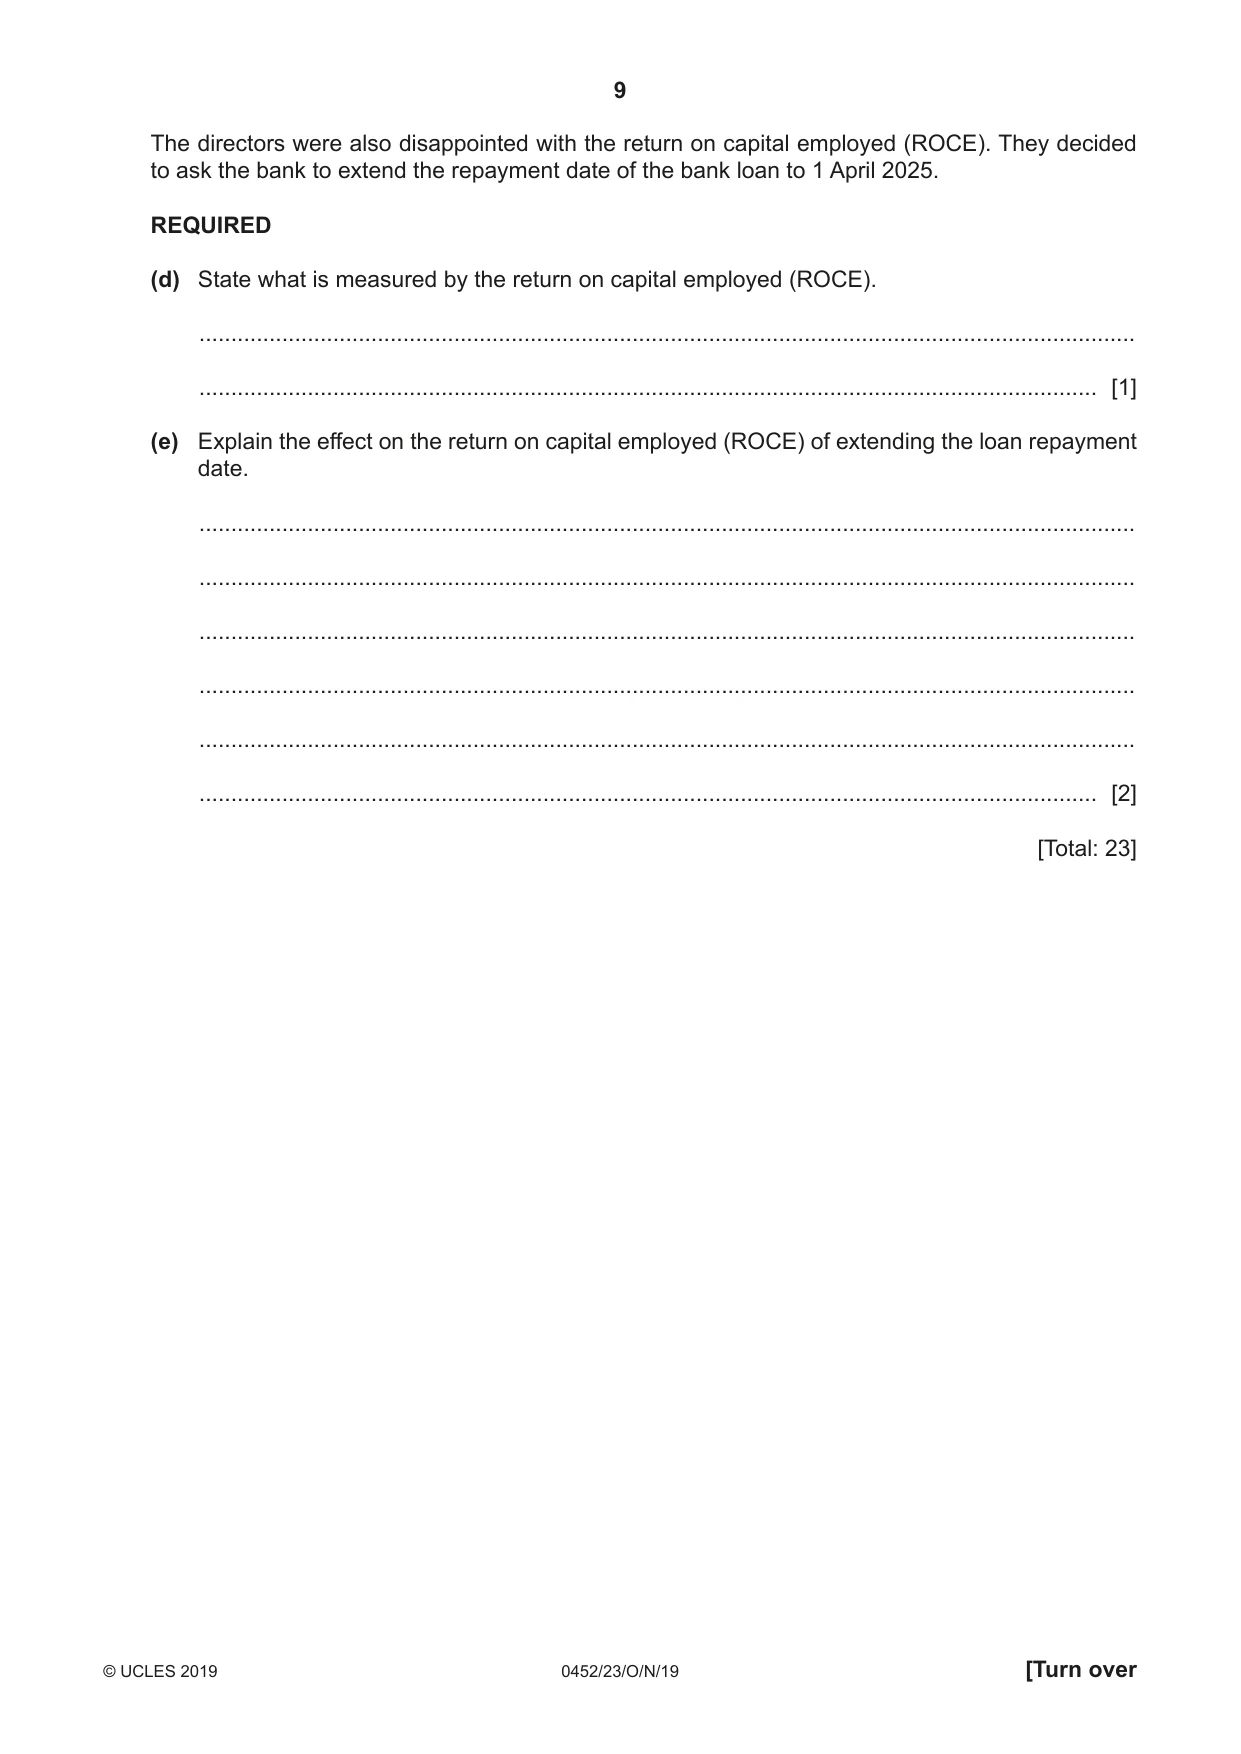
2 The financial year of CS Limited ends on 30 September. The following information is available for the year ended 30 September 2019. 1 The final ordinary share dividend of $6000 for the year ended 30 September 2018 was paid on 1 December 2018. 2 The profit for the year ended 30 September 2019 was $15 000. 3 On 30 September 2019 a transfer of $5000 was made to general reserve. REQUIRED (a) Complete the statement of changes in equity for the year ended 30 September 2019. CS Limited Statement of Changes in Equity for the year ended 30 September 2019 Details Share General Retained Total capital reserve earnings $ $ $ $ On 1 October 2018 150 000 7 000 16 000 173 000 ............................................... ................ ................ ................ ................ ............................................... ................ ................ ................ ................ ............................................... ................ ................ ................ ................ On 30 September 2019 ................ ................ ................ ................ [4] The following information is available at 30 September 2019. $ Non‑current assets at cost Premises 172 000 Machinery 38 000 Fixtures and fittings 19 500 Provisions for depreciation of non‑current assets Machinery 13 680 Fixtures and fittings 3 900 Inventory 14 360 Trade payables 14 866 Trade receivables 16 800 Other payables 198 Other receivables 110 Provision for doubtful debts 504 Petty cash 200 Bank overdraft 10 822 5% Debentures (repayable 1 October 2030) 25 000 Bank loan (repayable 1 April 2020) 10 000 REQUIRED (b) Prepare the statement of financial position at 30 CS Limited Statement of Financial Position at ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ $ $ $ ............................................................................ ................... ................... ................... ............................................................................ ................... ................... ................... ............................................................................ ................... ................... ................... ............................................................................ ................... ................... ................... ............................................................................ ................... ................... ................... ............................................................................ ................... ................... ................... ............................................................................ ................... ................... ................... ............................................................................ ................... ................... ................... ............................................................................ ................... ................... ................... ............................................................................ ................... ................... ................... ............................................................................ ................... ................... ................... ............................................................................ ................... ................... ................... ............................................................................ ................... ................... ................... [14] The directors were disappointed that the profit for the current year was not as good as that of previous years. REQUIRED (c) Explain why the difference between the gross profit percentage and the percentage of profit to revenue is an indication of the efficiency of the company. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] The directors were also disappointed with the return on capital employed (ROCE). They decided to ask the bank to extend the repayment date of the bank loan to 1 April 2025. REQUIRED (d) State what is measured by the return on capital employed (ROCE). ................................................................................................................................................... ............................................................................................................................................. [1] (e) Explain the effect on the return on capital employed (ROCE) of extending the loan repayment date. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] [Total: 23]
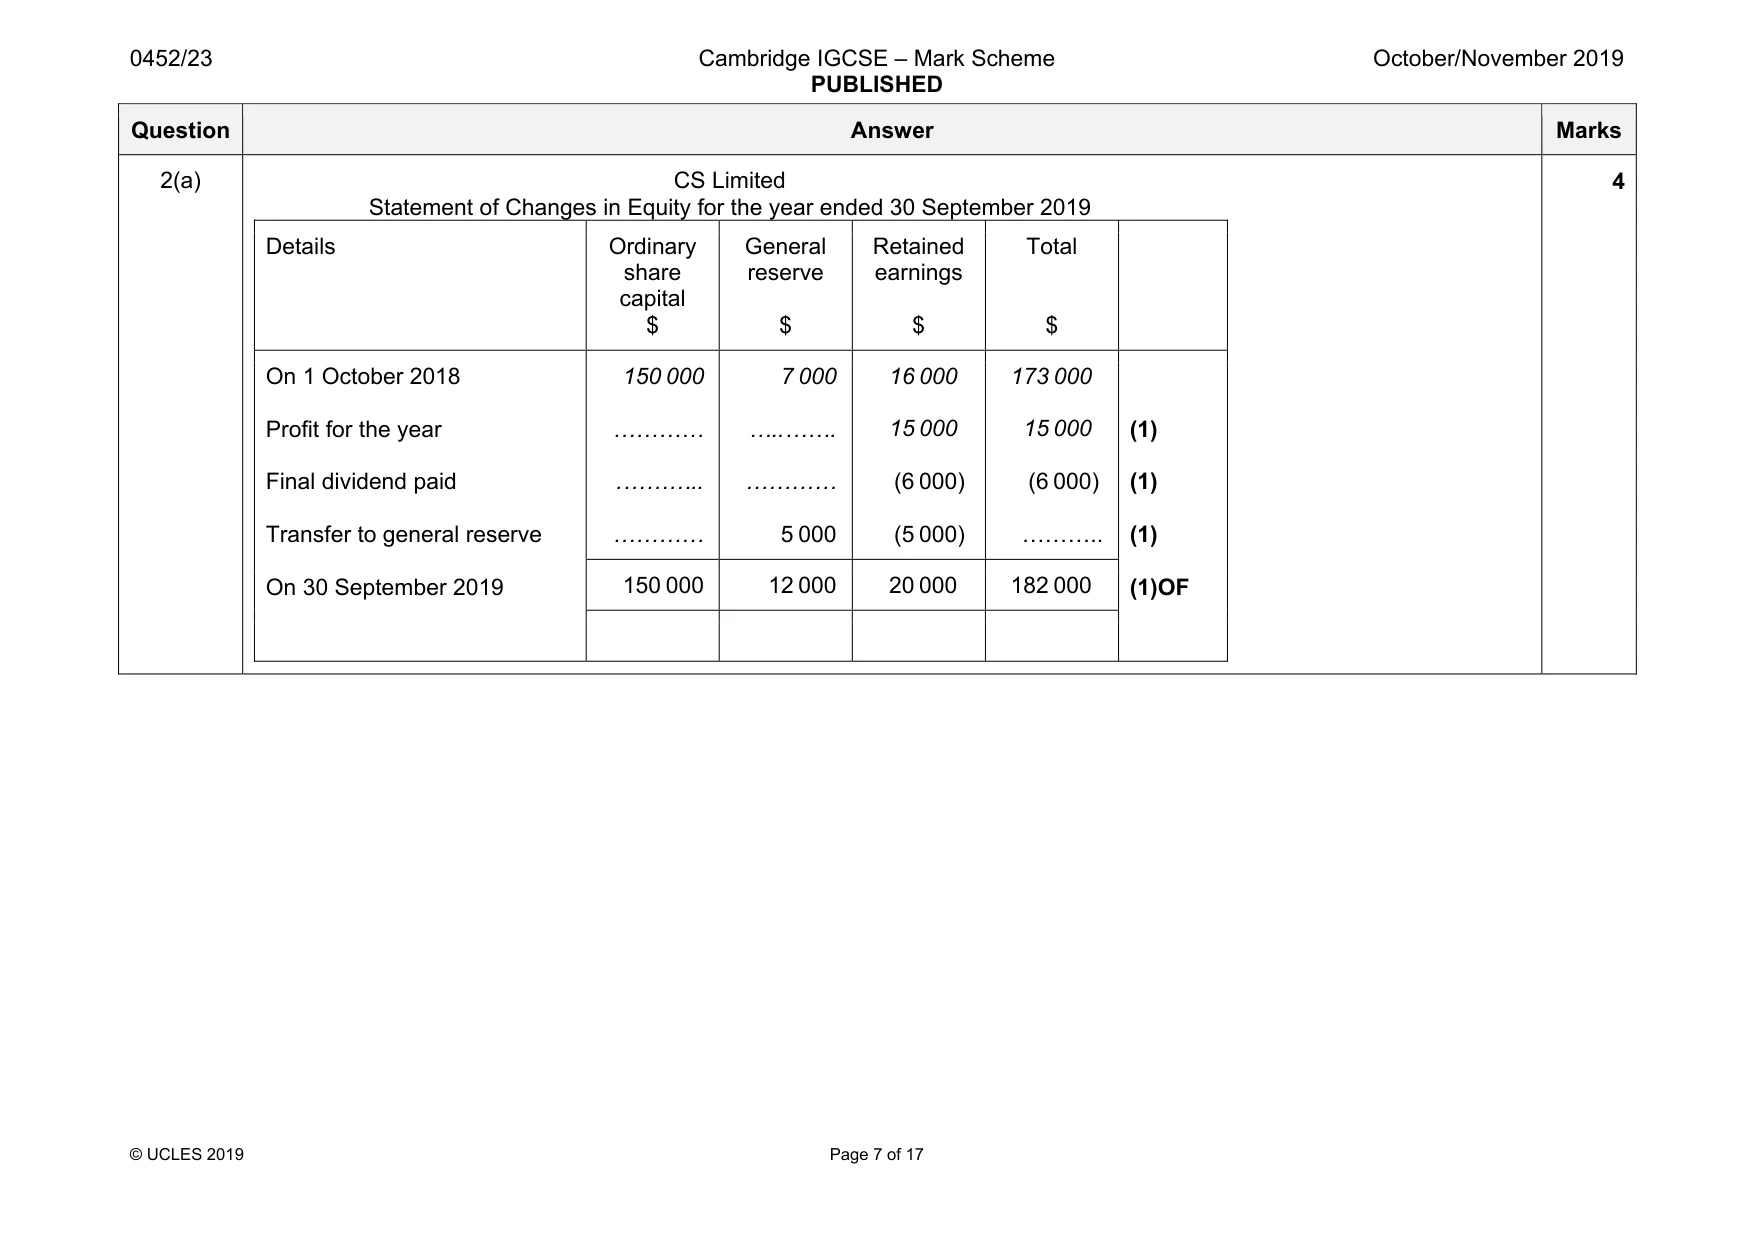
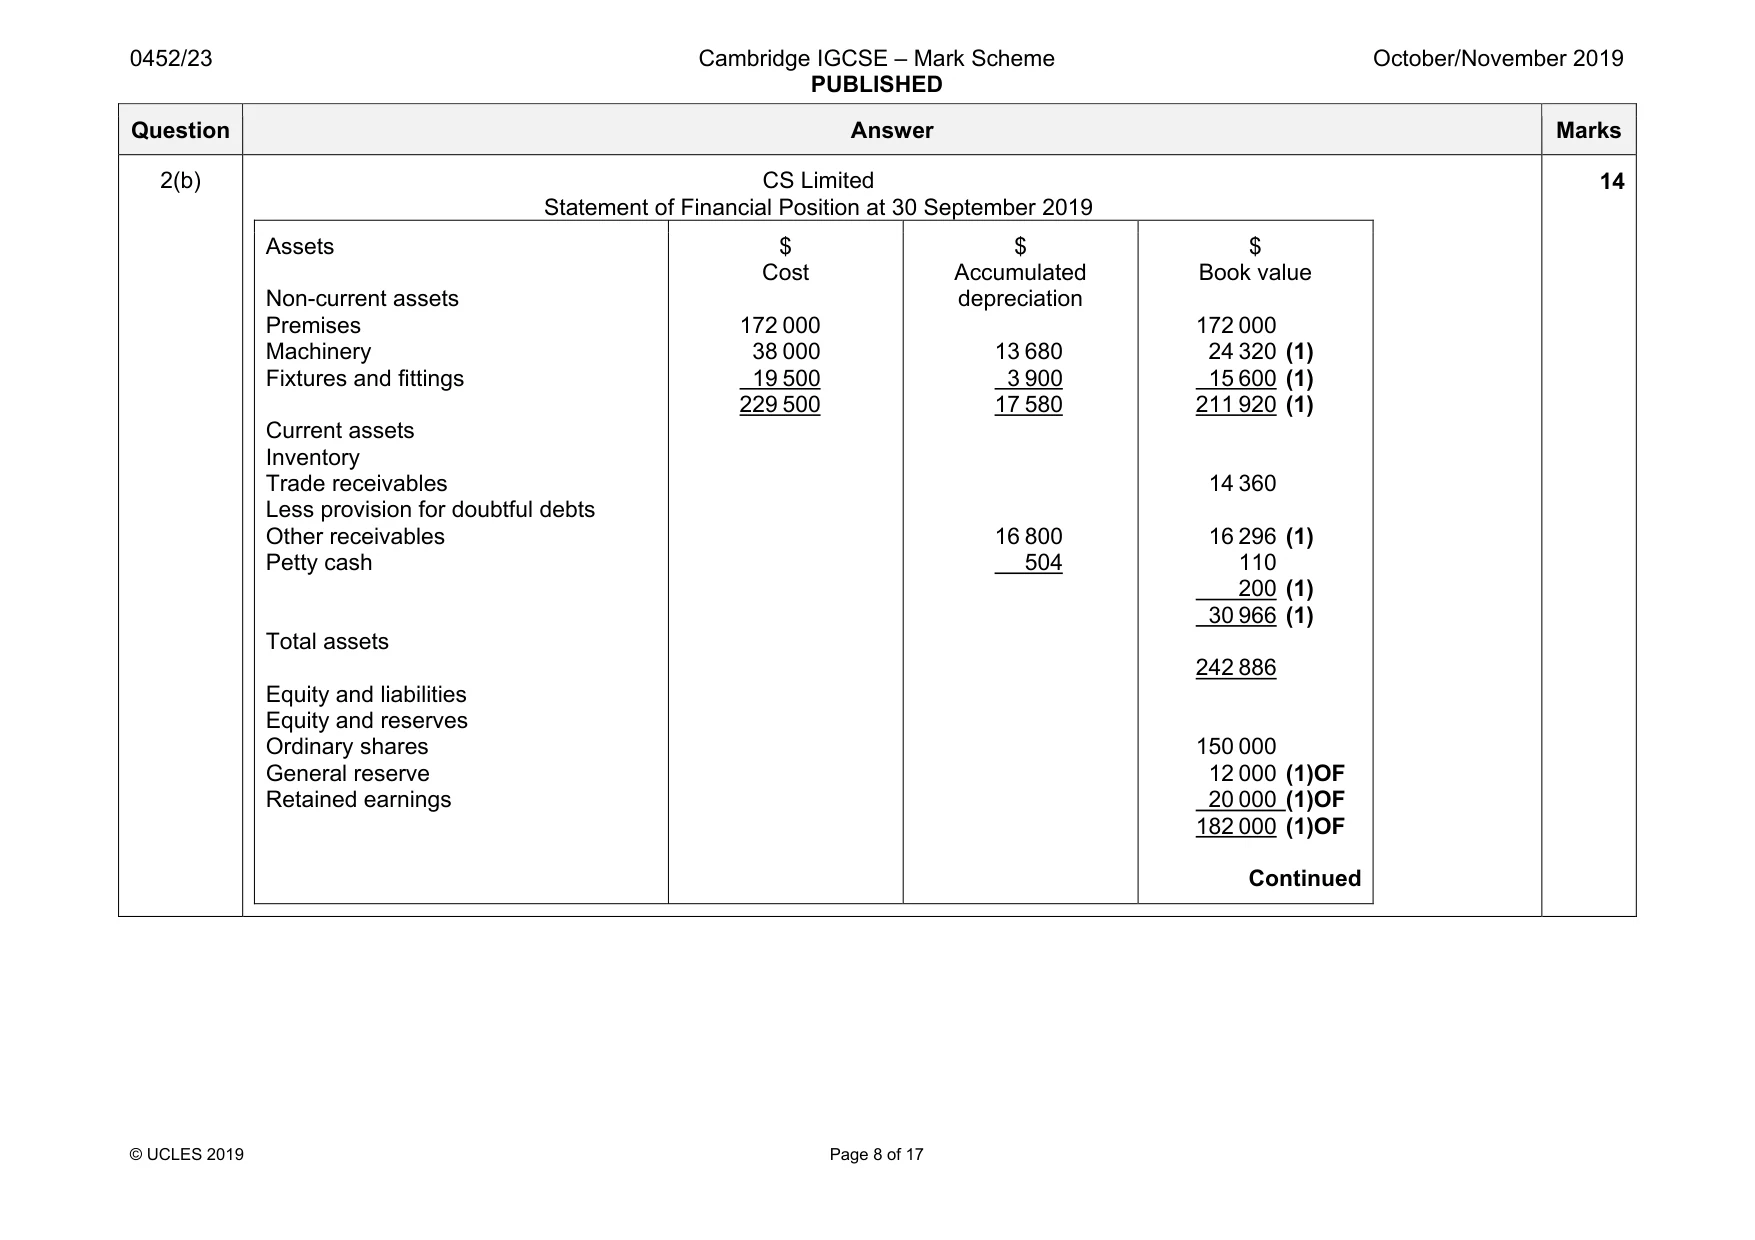
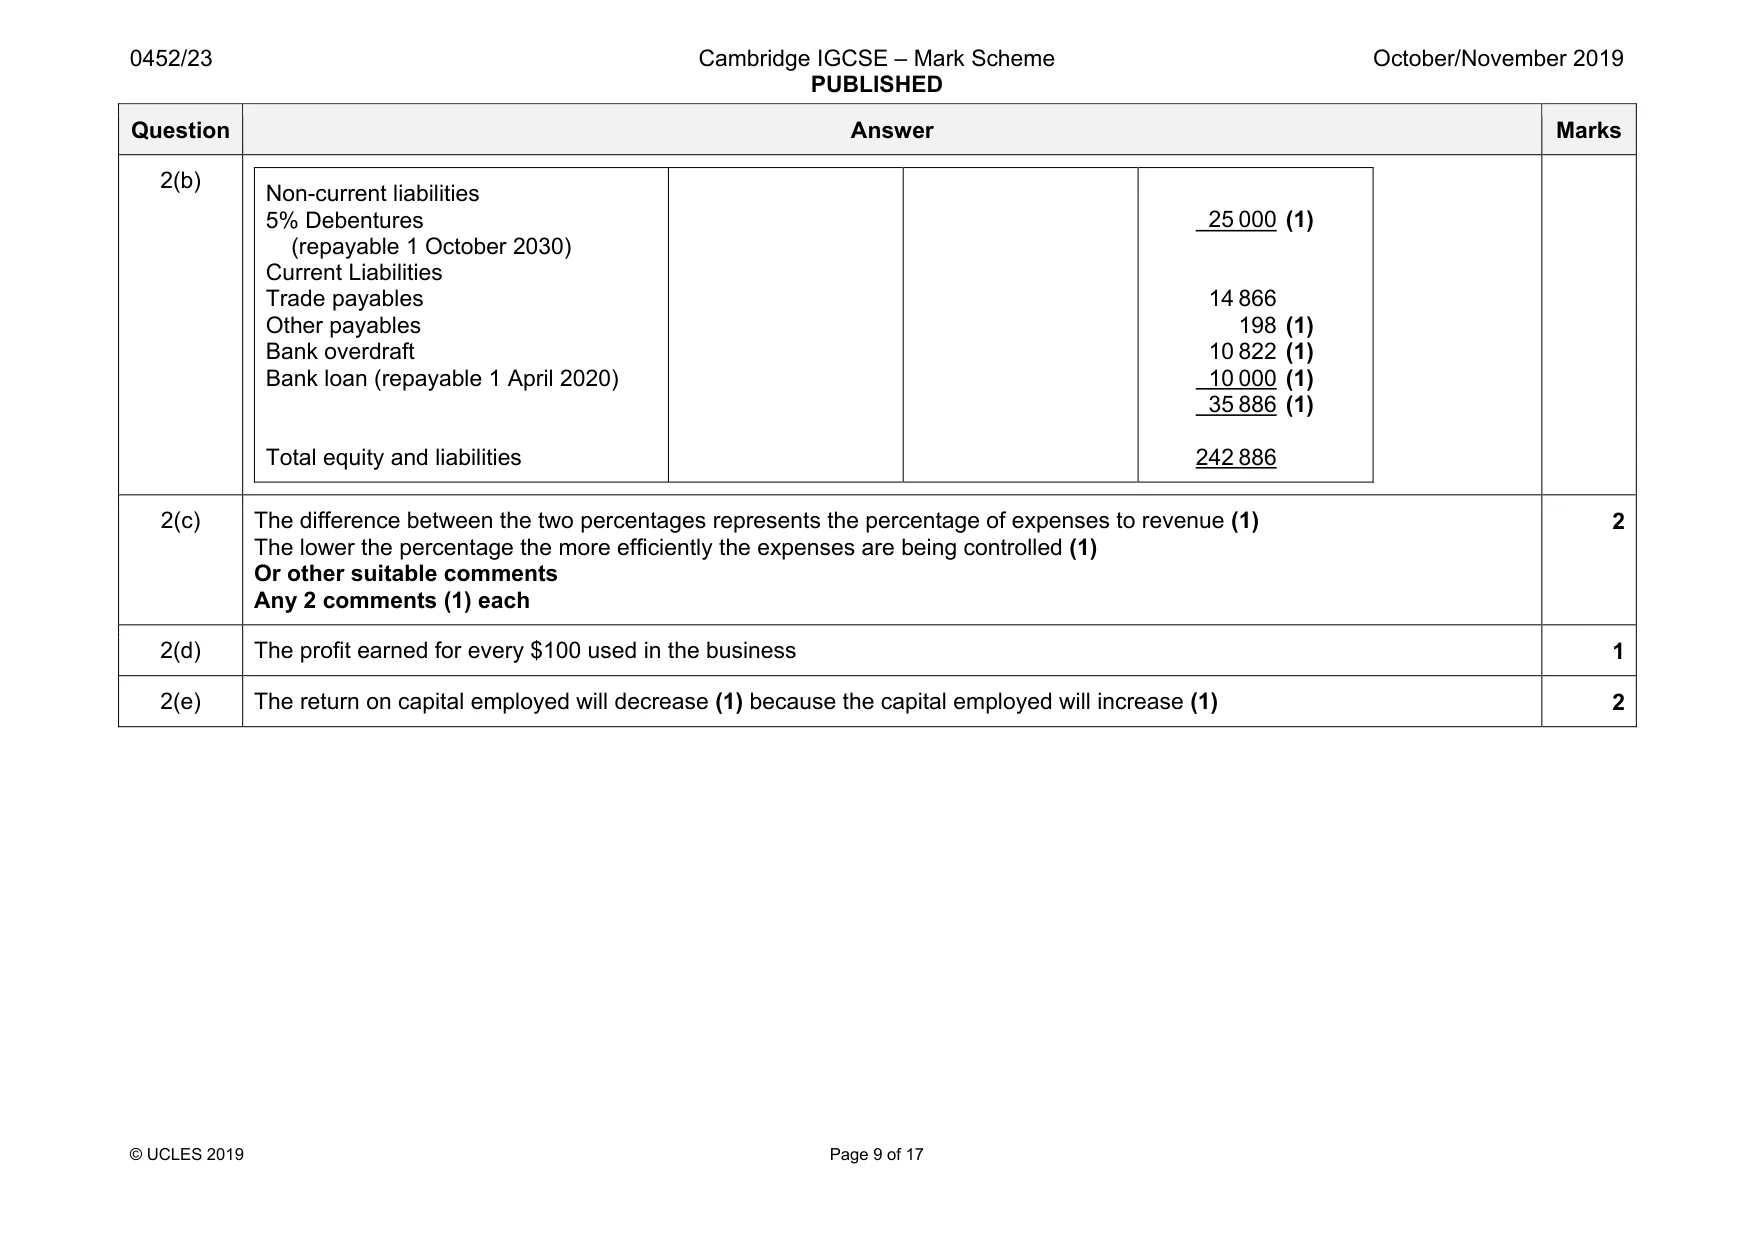
Mark scheme: 2(a) CS Limited Statement of Changes in Equity for the year ended 30 September 2019 Details Ordinary share capital $ General reserve $ Retained earnings $ Total $ On 1 October 2018 Profit for the year Final dividend paid Transfer to general reserve On 30 September 2019 150 000 «««« .«««.. «««« 7 000 «..««. «««« 5 000 16 000) 15 000) (6 000) (5 000) 173 000) 15 000) (6 000) «««.. (1) (1) (1) (1)OF 150 000 12 000 20 000) 182 000) 4 Question Answer Marks 2(b) CS Limited Statement of Financial Position at 30 September 2019 Assets Non-current assets Premises Machinery Fixtures and fittings Current assets Inventory Trade receivables Less provision for doubtful debts Other receivables Petty cash Total assets Equity and liabilities Equity and reserves Ordinary shares General reserve Retained earnings $ Cost 172 000 38 000 19 500 229 500 $ Accumulated depreciation 13 680 3 900 17 580 16 800 504 $ Book value 172 000 24 320 (1) 15 600 (1) 211 920 (1) 14 360 16 296 (1) 110 200 (1) 30 966 (1) 242 886 150 000 12 000 (1)OF 20 000 (1)OF 182 000 (1)OF Continued 14 Question Answer Marks 2(b) Non-current liabilities 5% Debentures (repayable 1 October 2030) Current Liabilities Trade payables Other payables Bank overdraft Bank loan (repayable 1 April 2020) Total equity and liabilities 25 000 (1) 14 866 198 (1) 10 822 (1) 10 000 (1) 35 886 (1) 242 886 2(c) The difference between the two percentages represents the percentage of expenses to revenue (1) The lower the percentage the more efficiently the expenses are being controlled (1) Or other suitable comments Any 2 comments (1) each 2 2(d) The profit earned for every $100 used in the business 1 2(e) The return on capital employed will decrease (1) because the capital employed will increase (1) 2
Q3 · Yabani is a manufacturer
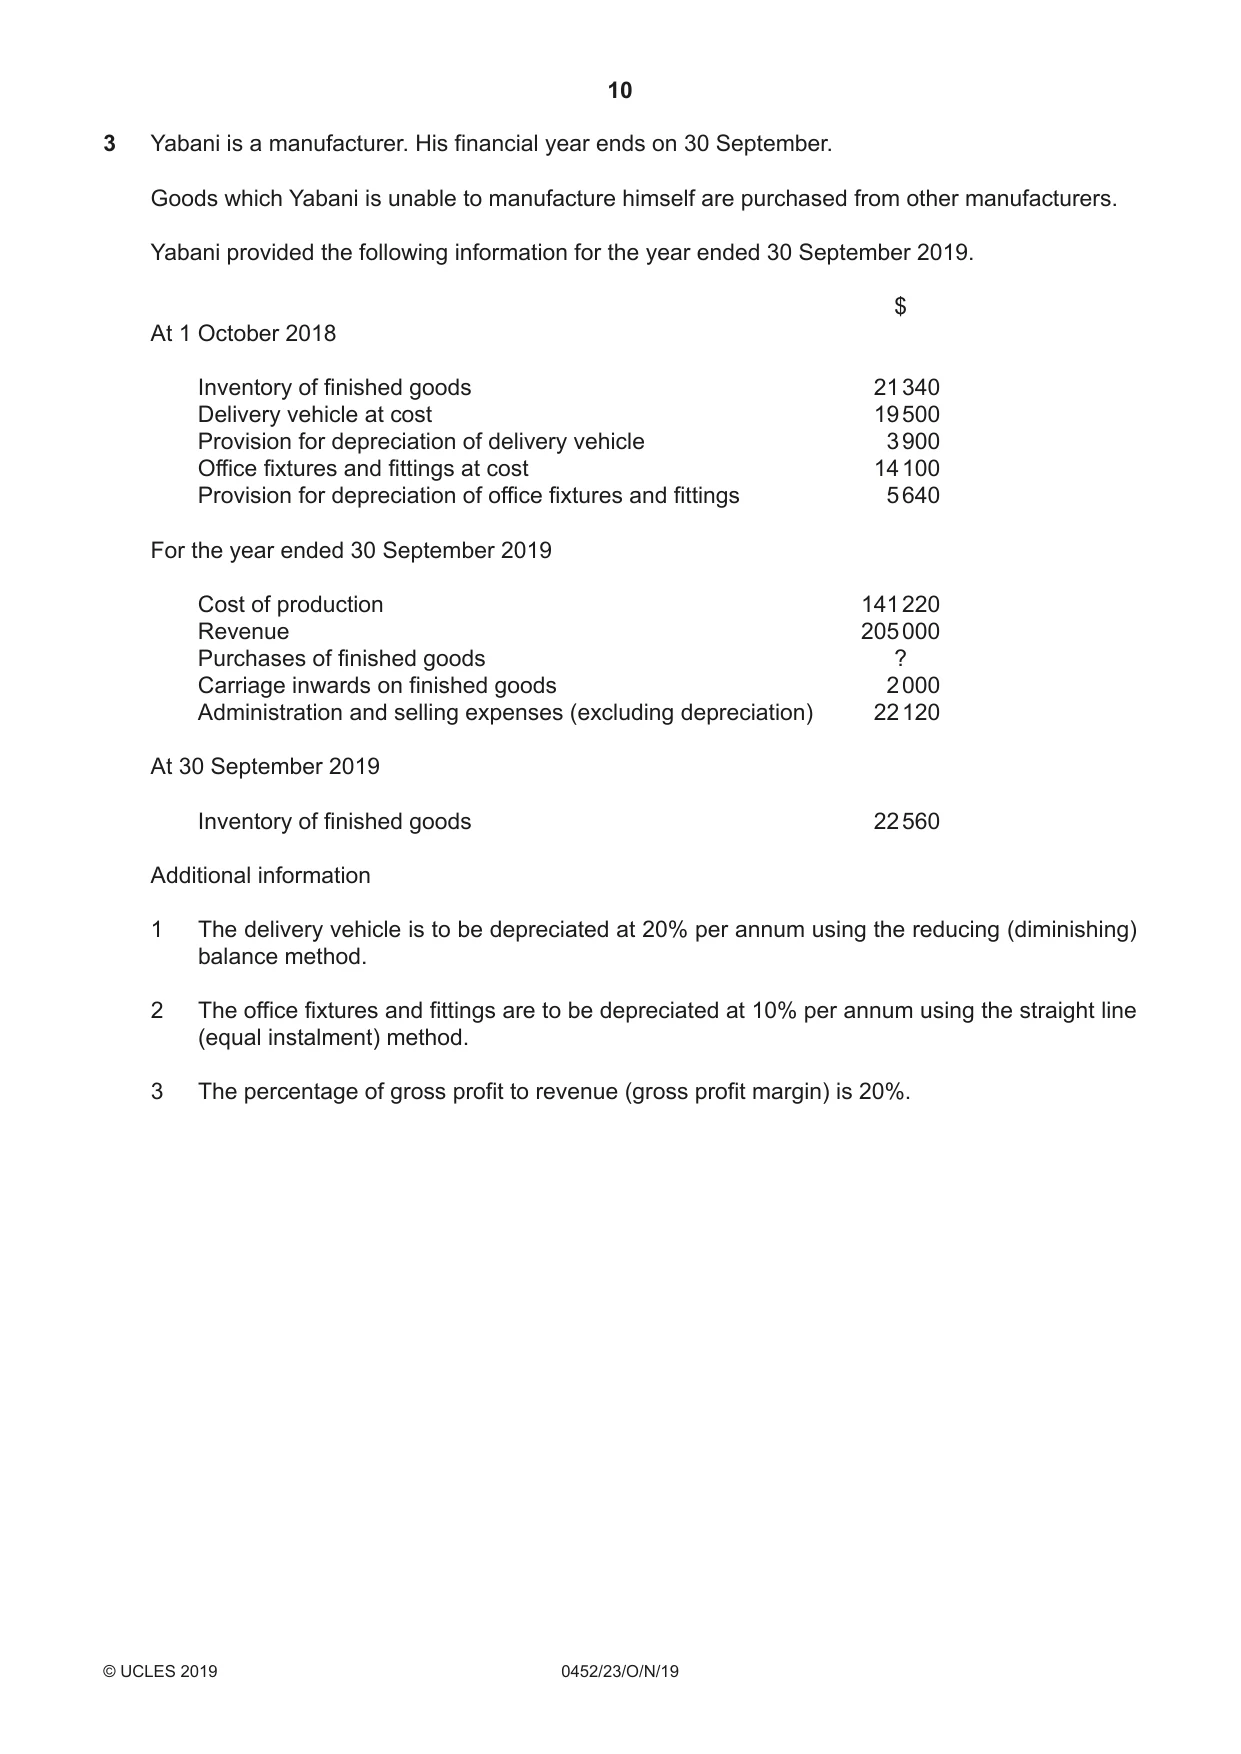
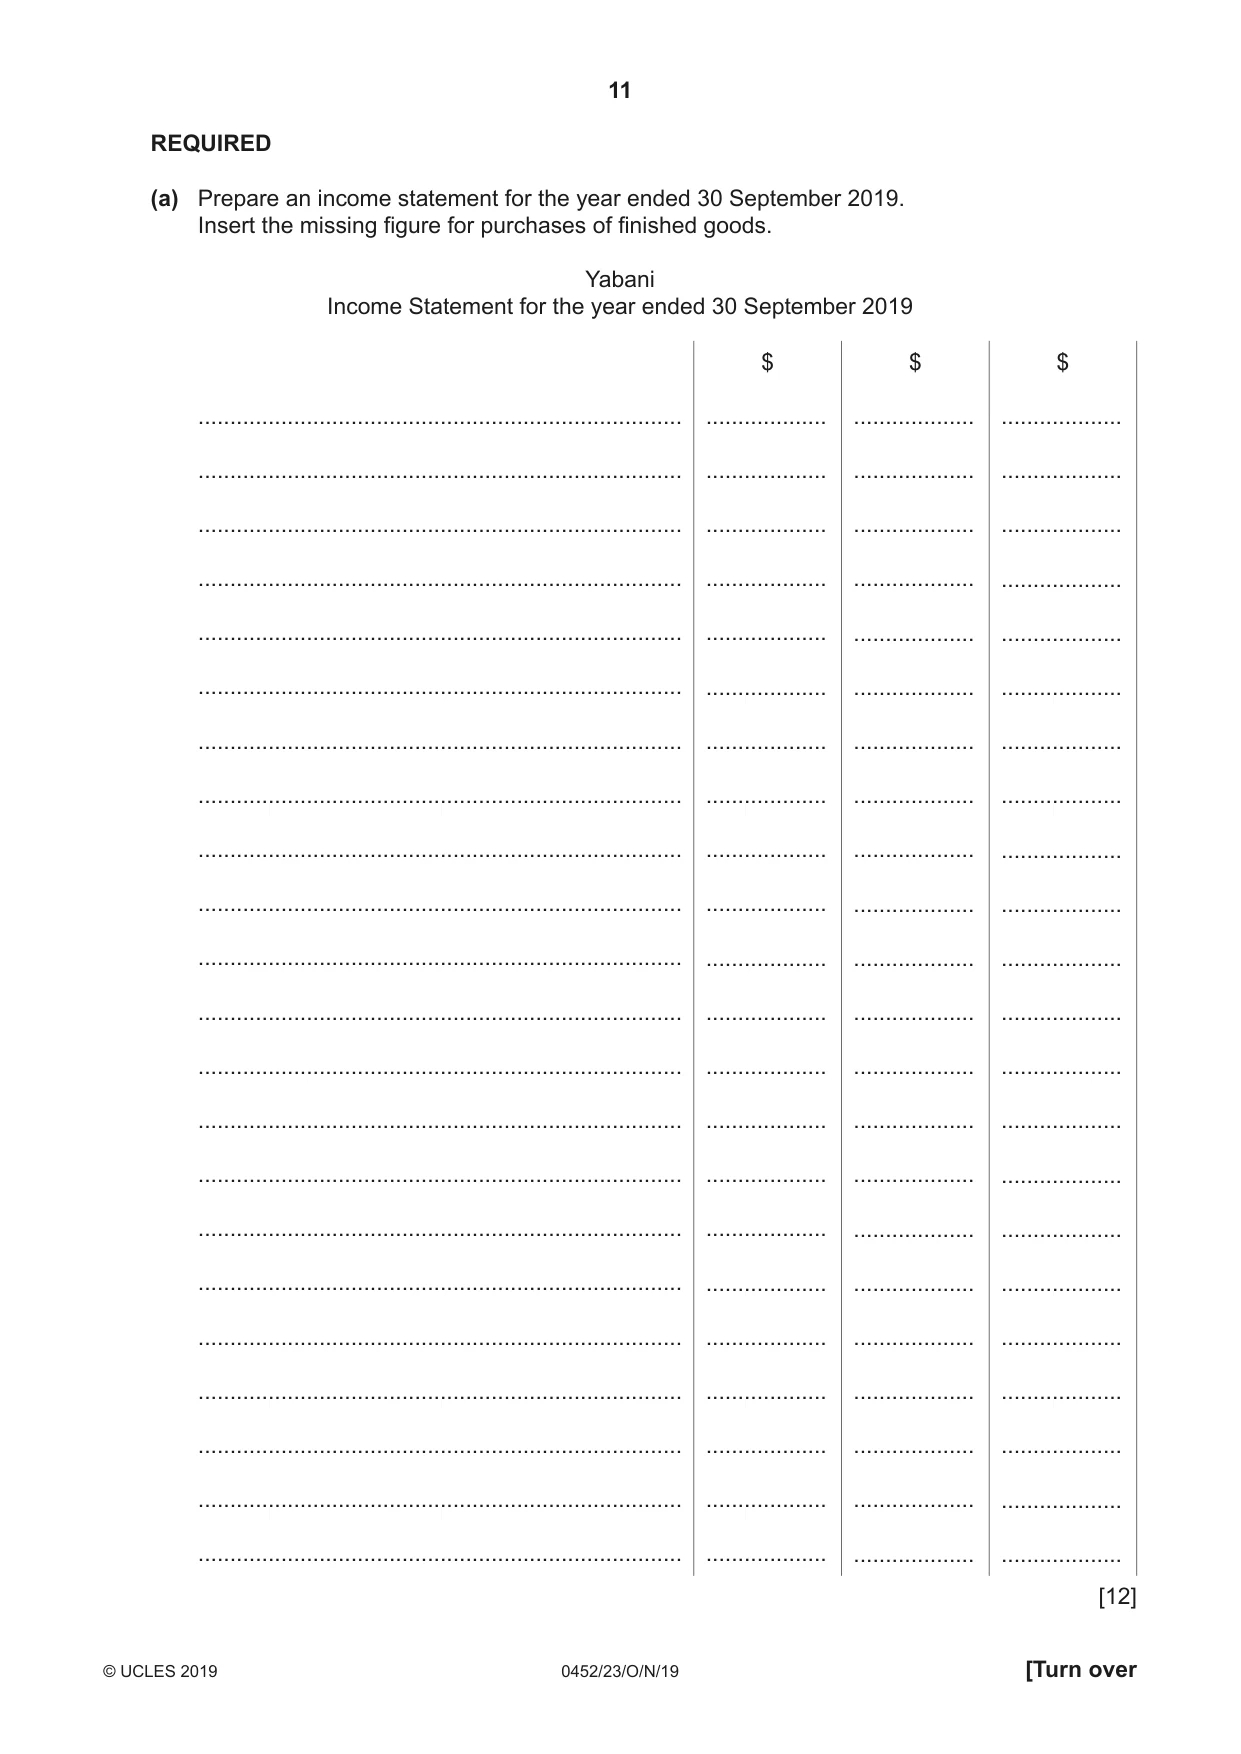
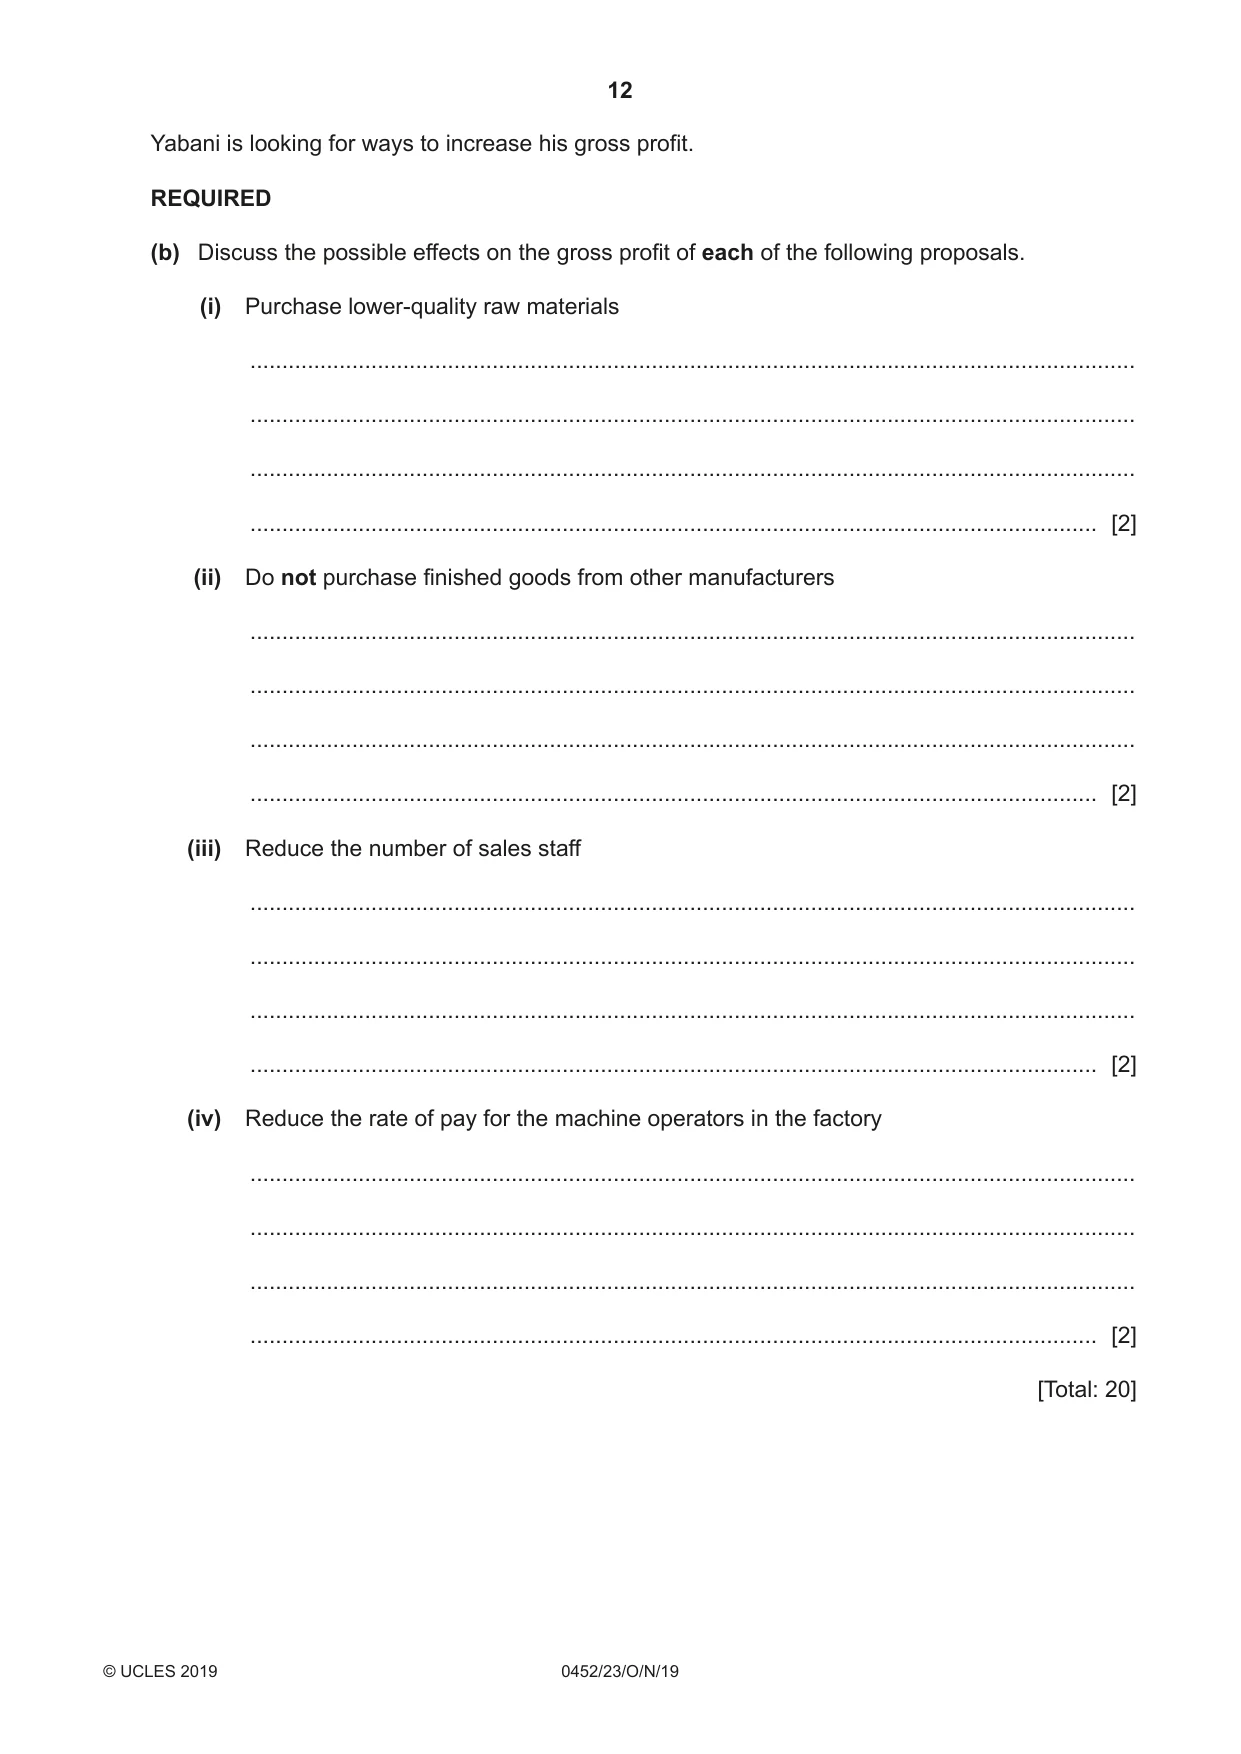
3 Yabani is a manufacturer. His financial year ends on 30 September. Goods which Yabani is unable to manufacture himself are purchased from other manufacturers. Yabani provided the following information for the year ended 30 September 2019. $ At 1 October 2018 Inventory of finished goods 21 340 Delivery vehicle at cost 19 500 Provision for depreciation of delivery vehicle 3 900 Office fixtures and fittings at cost 14 100 Provision for depreciation of office fixtures and fittings 5 640 For the year ended 30 September 2019 Cost of production 141 220 Revenue 205 000 Purchases of finished goods ? Carriage inwards on finished goods 2 000 Administration and selling expenses (excluding depreciation) 22 120 At 30 September 2019 Inventory of finished goods 22 560 Additional information 1 The delivery vehicle is to be depreciated at 20% per annum using the reducing (diminishing) balance method. 2 The office fixtures and fittings are to be depreciated at 10% per annum using the straight line (equal instalment) method. 3 The percentage of gross profit to revenue (gross profit margin) is 20%. REQUIRED (a) Prepare an income statement for the year ended Insert the missing figure for purchases of finishe Yabani Income Statement for the year end ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ ............................................................................ Yabani is looking for ways to increase his gross profit. REQUIRED (b) Discuss the possible effects on the gross profit of each of the following proposals. (i) Purchase lower‑quality raw materials ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] (ii) Do not purchase finished goods from other manufacturers ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] (iii) Reduce the number of sales staff ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] (iv) Reduce the rate of pay for the machine operators in the factory ........................................................................................................................................... ........................................................................................................................................... ........................................................................................................................................... ..................................................................................................................................... [2] [Total: 20]
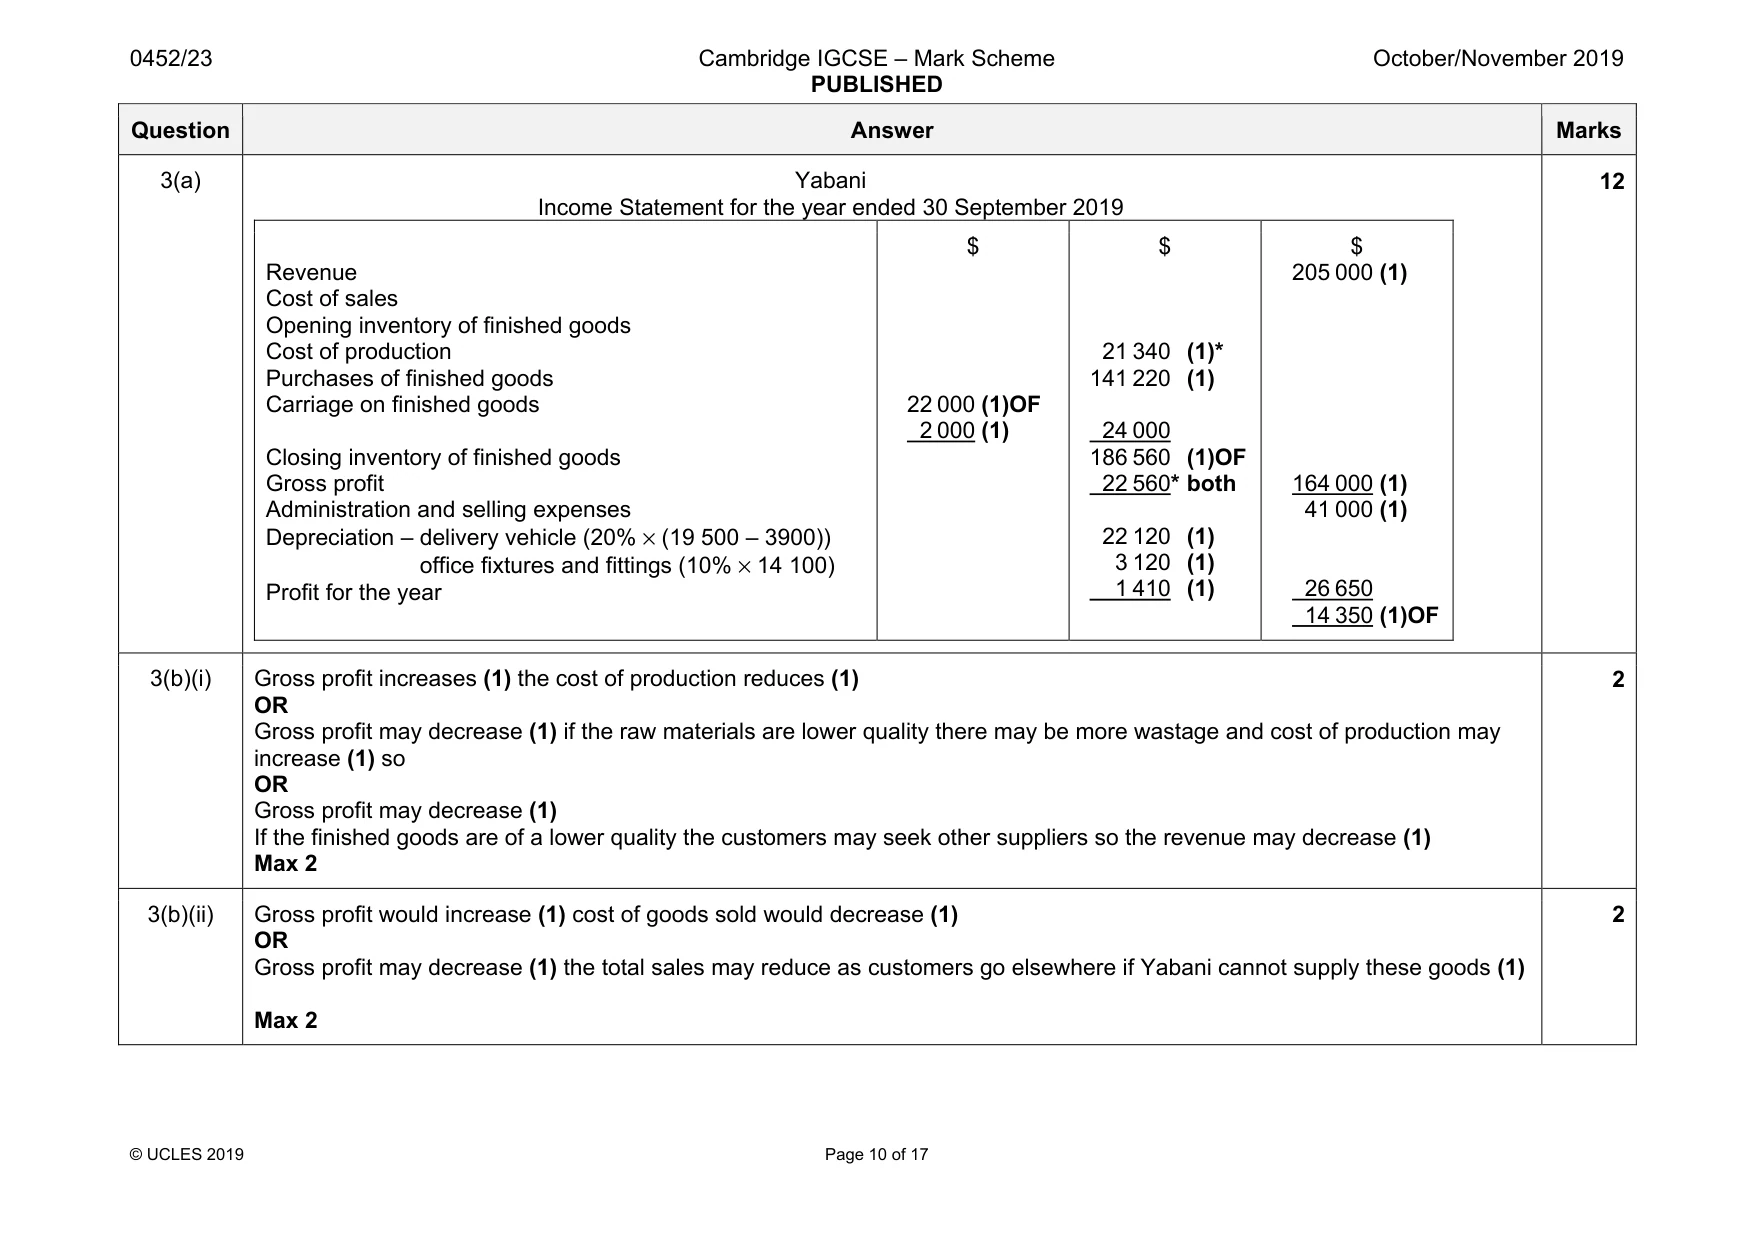
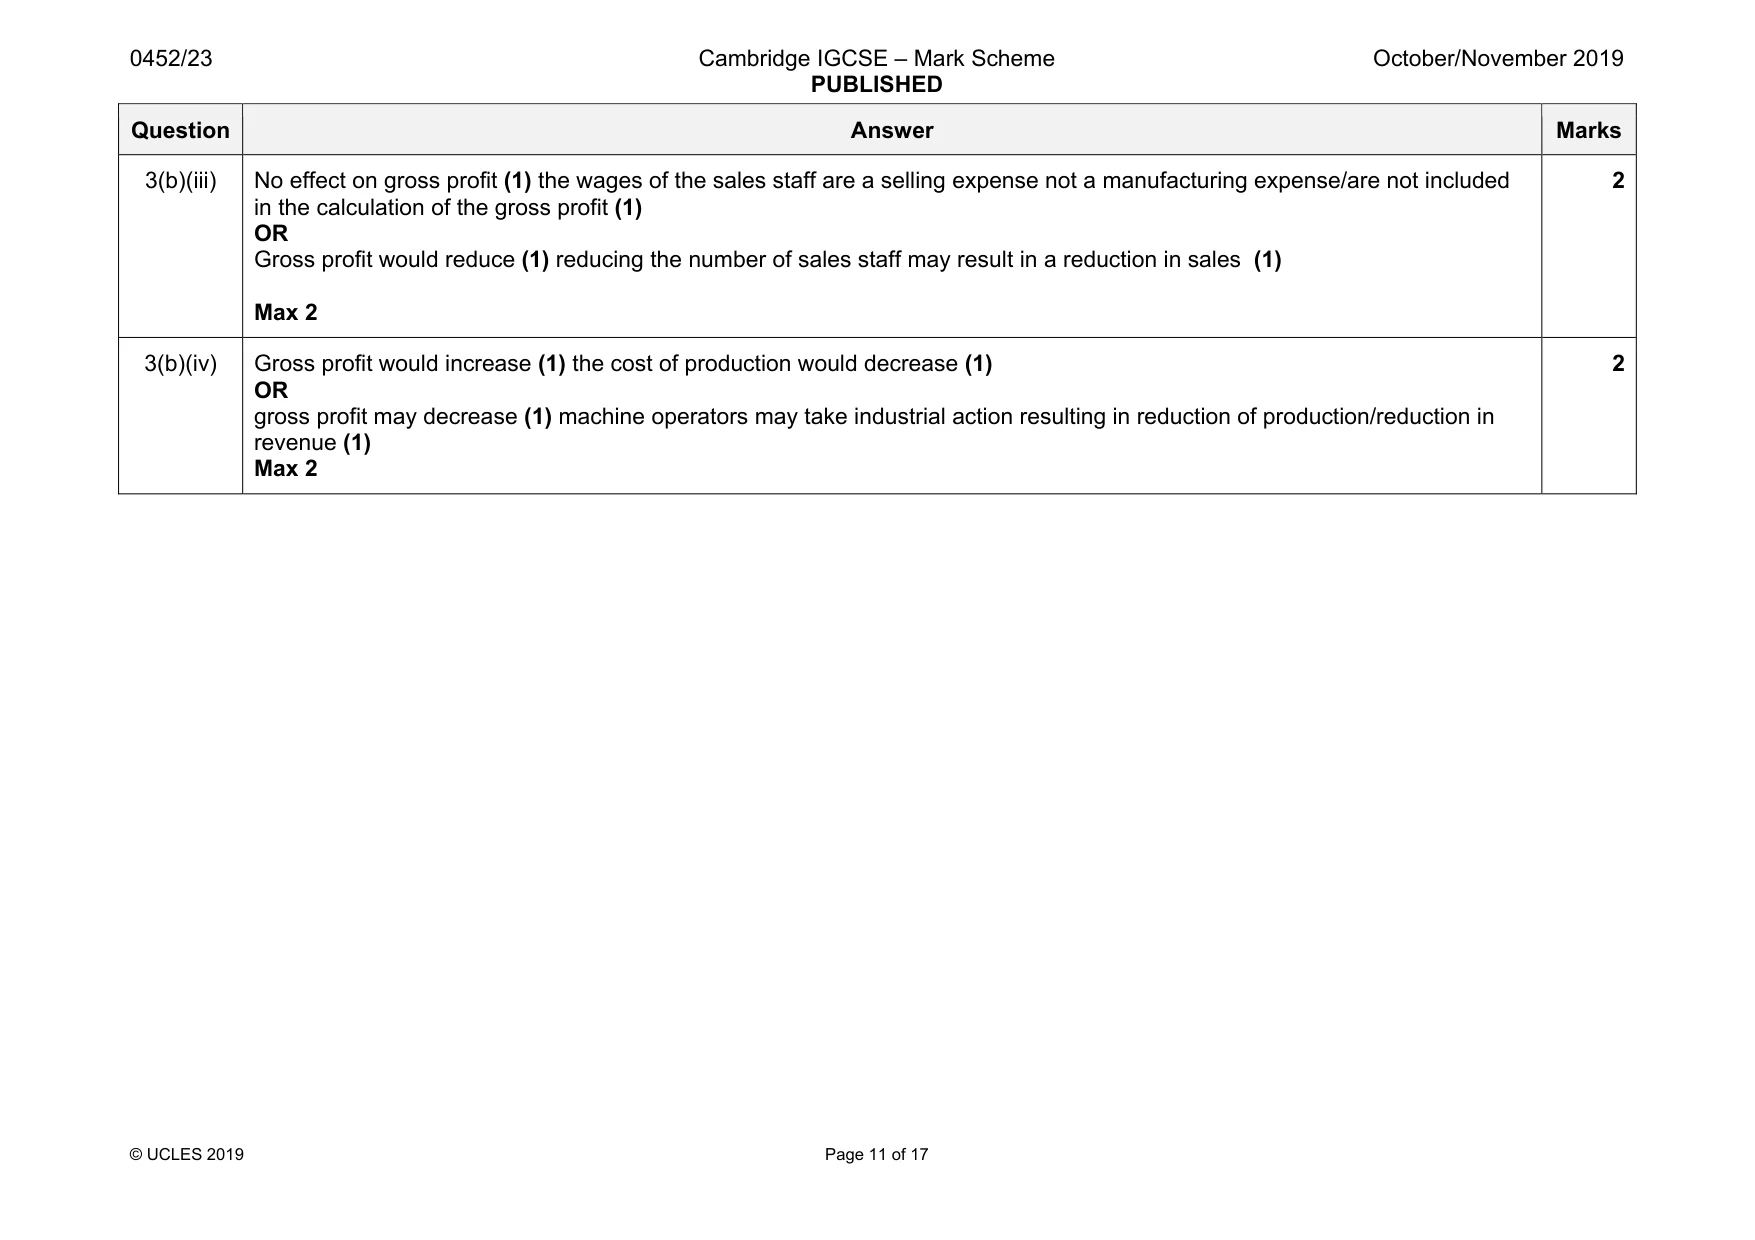
Mark scheme: 3(a) Yabani Income Statement for the year ended 30 September 2019 Revenue Cost of sales Opening inventory of finished goods Cost of production Purchases of finished goods Carriage on finished goods Closing inventory of finished goods Gross profit Administration and selling expenses Depreciation – delivery vehicle (20% × (19 500 – 3900)) office fixtures and fittings (10% × 14 100) Profit for the year $ 22 000 (1)OF 2 000 (1) $ 21 340* (1)* 141 220* (1) 24 000* 186 560* (1)OF 22 560* both 22 120* (1) 3 120* (1) 1 410* (1) $ 205 000 (1) 164 000 (1) 41 000 (1) 26 650 14 350 (1)OF 12 3(b)(i) Gross profit increases (1) the cost of production reduces (1) OR Gross profit may decrease (1) if the raw materials are lower quality there may be more wastage and cost of production may increase (1) so OR Gross profit may decrease (1) If the finished goods are of a lower quality the customers may seek other suppliers so the revenue may decrease (1) Max 2 2 3(b)(ii) Gross profit would increase (1) cost of goods sold would decrease (1) OR Gross profit may decrease (1) the total sales may reduce as customers go elsewhere if Yabani cannot supply these goods (1) Max 2 2 Question Answer Marks 3(b)(iii) No effect on gross profit (1) the wages of the sales staff are a selling expense not a manufacturing expense/are not included in the calculation of the gross profit (1) OR Gross profit would reduce (1) reducing the number of sales staff may result in a reduction in sales (1) Max 2 2 3(b)(iv) Gross profit would increase (1) the cost of production would decrease (1) OR gross profit may decrease (1) machine operators may take industrial action resulting in reduction of production/reduction in revenue (1) Max 2 2
Q4 · Ishaq started a business on 1 August 2018
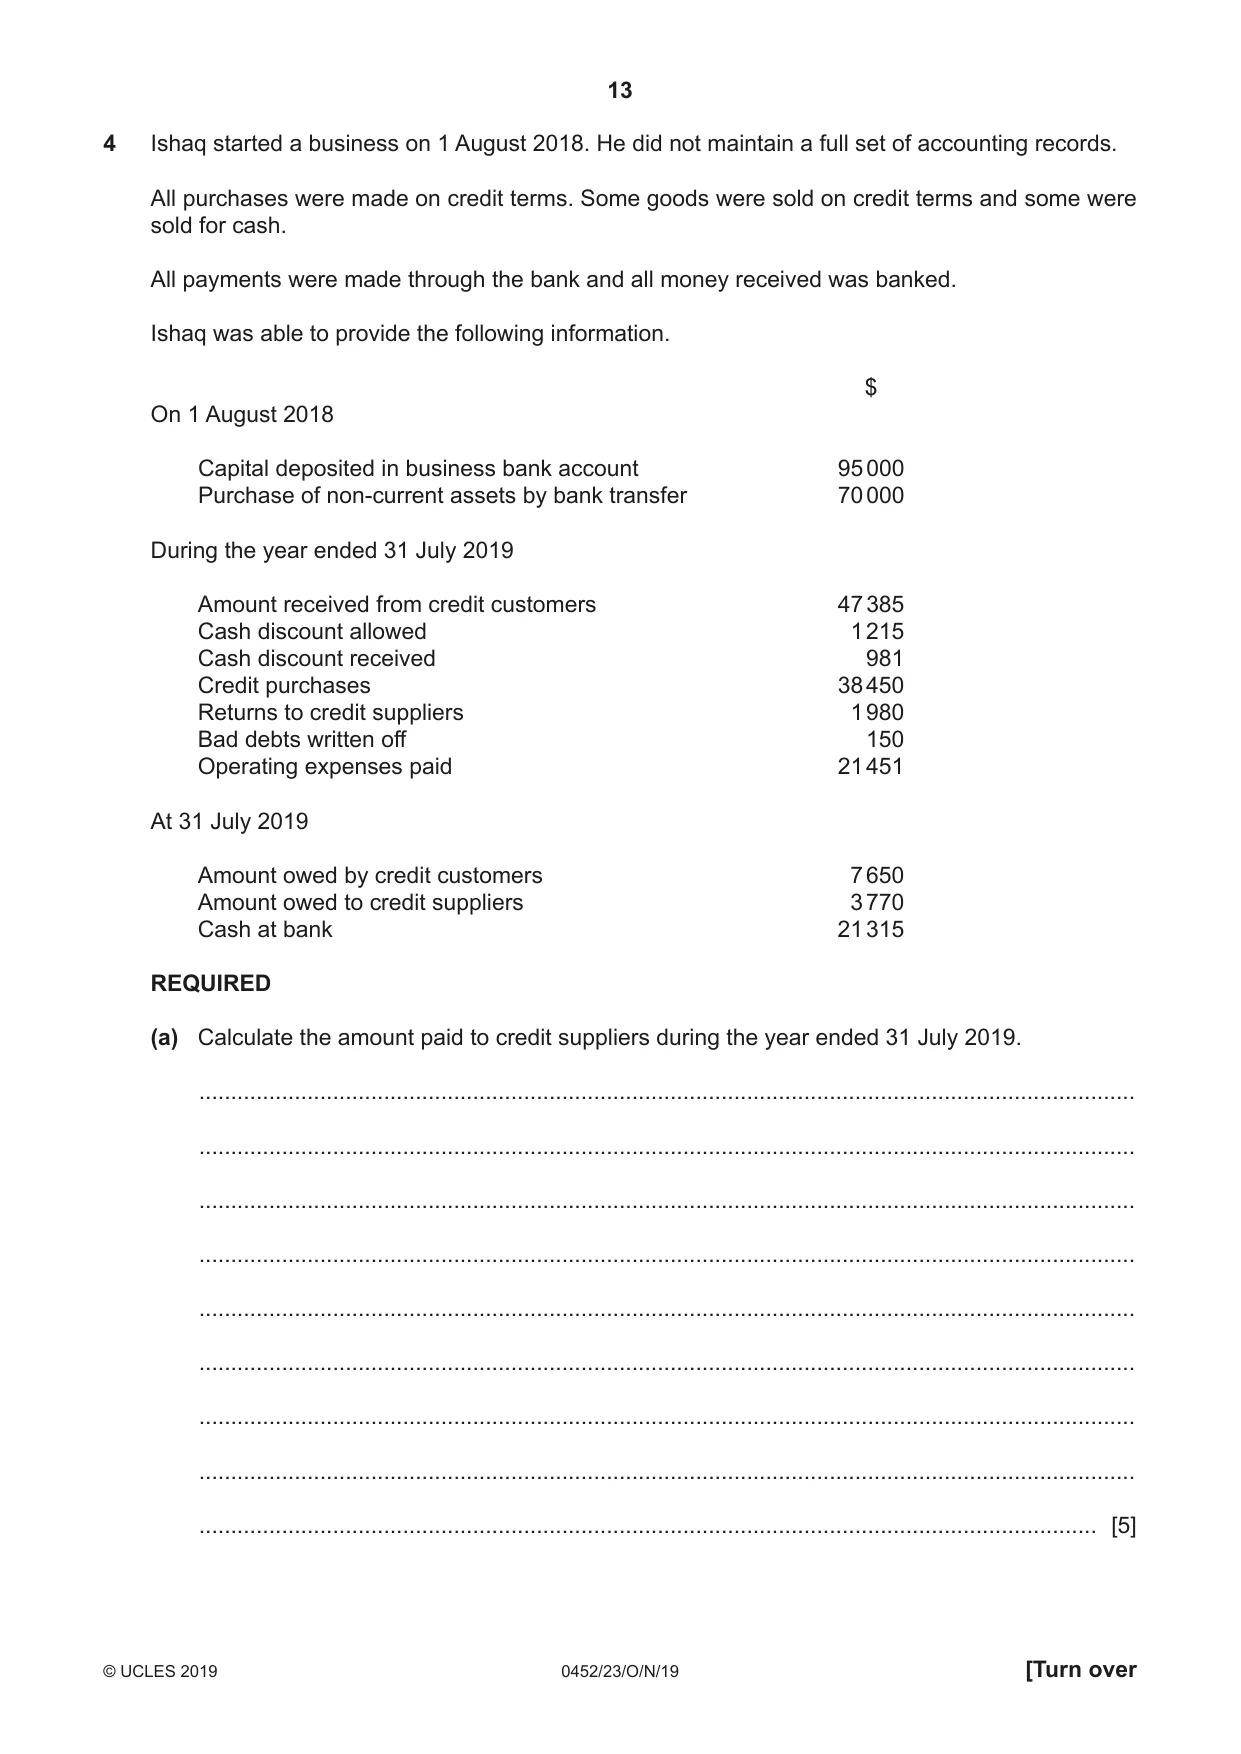
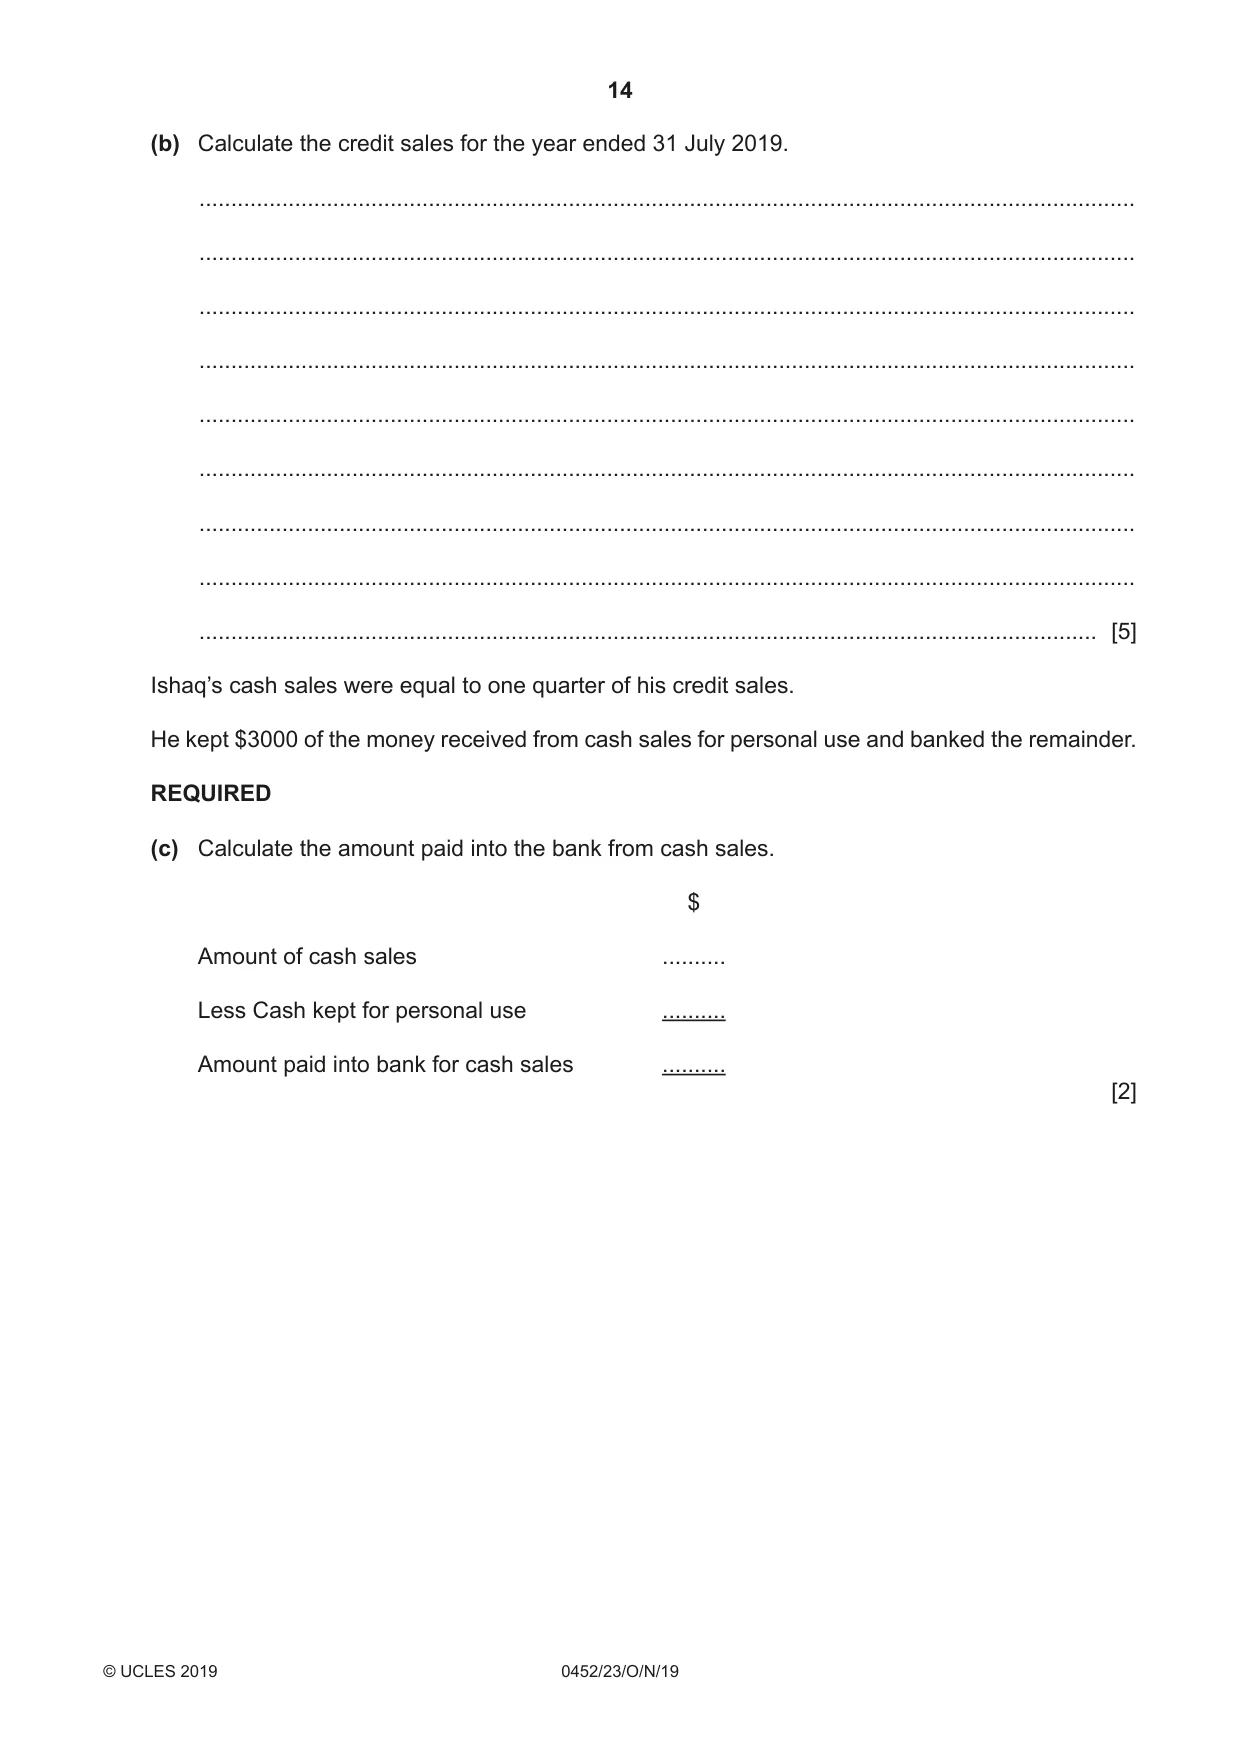
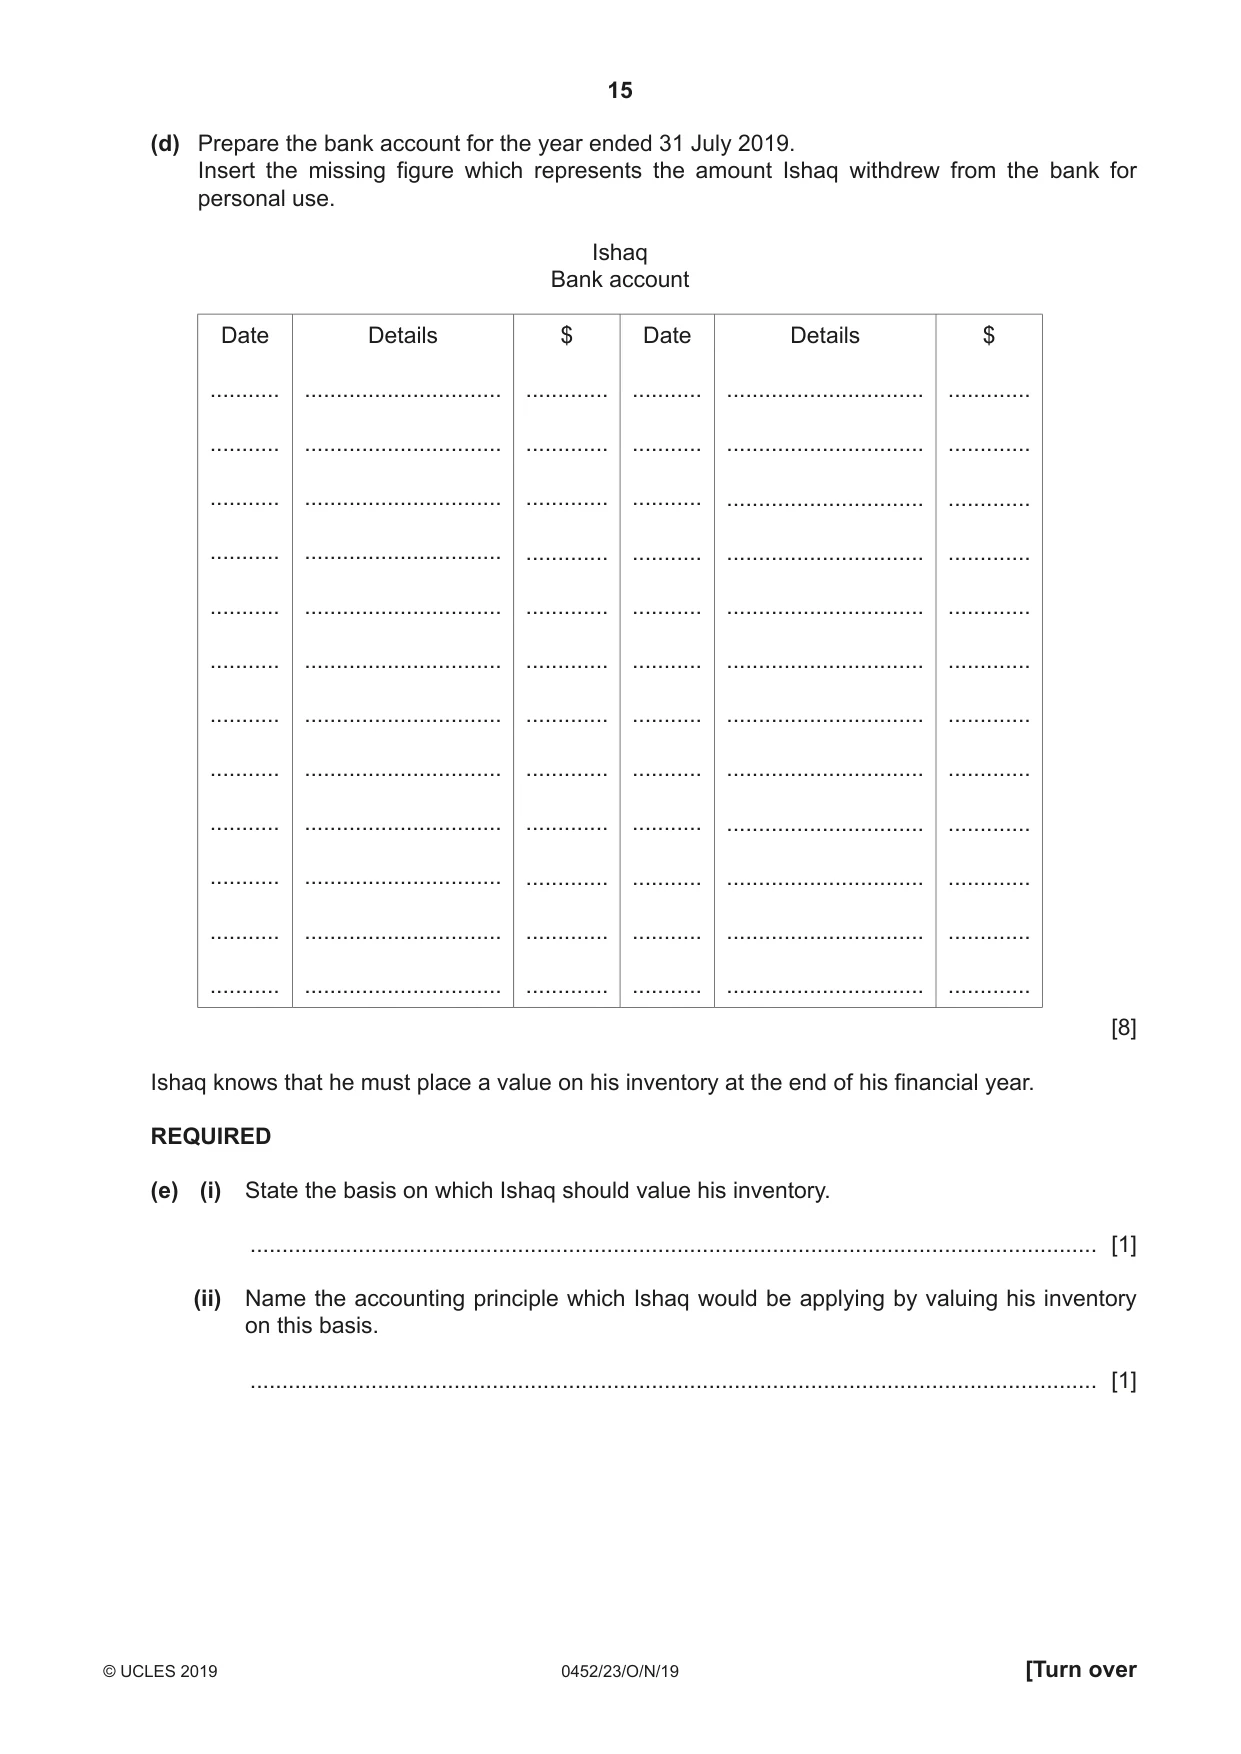
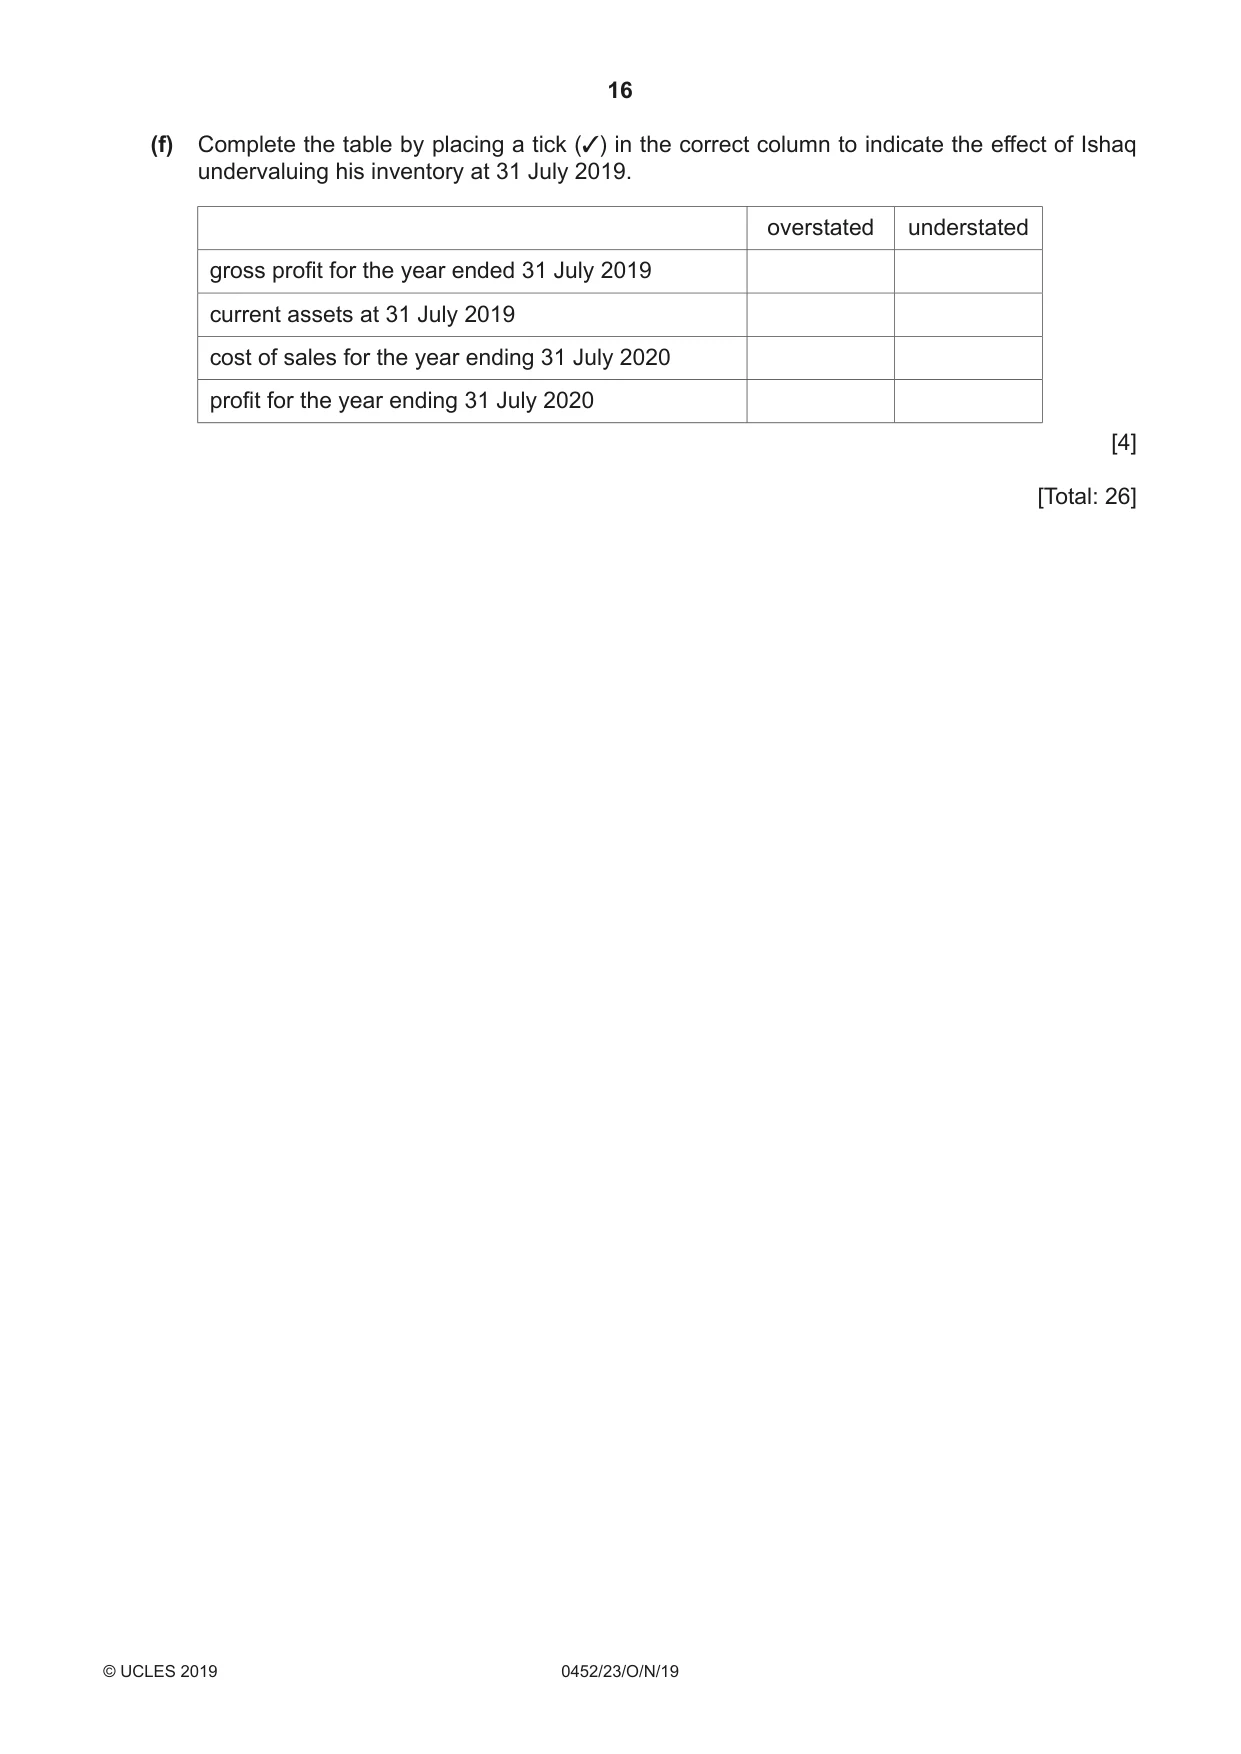
4 Ishaq started a business on 1 August 2018. He did not maintain a full set of accounting records. All purchases were made on credit terms. Some goods were sold on credit terms and some were sold for cash. All payments were made through the bank and all money received was banked. Ishaq was able to provide the following information. $ On 1 August 2018 Capital deposited in business bank account 95 000 Purchase of non‑current assets by bank transfer 70 000 During the year ended 31 July 2019 Amount received from credit customers 47 385 Cash discount allowed 1 215 Cash discount received 981 Credit purchases 38 450 Returns to credit suppliers 1 980 Bad debts written off 150 Operating expenses paid 21 451 At 31 July 2019 Amount owed by credit customers 7 650 Amount owed to credit suppliers 3 770 Cash at bank 21 315 REQUIRED (a) Calculate the amount paid to credit suppliers during the year ended 31 July 2019. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] (b) Calculate the credit sales for the year ended 31 July 2019. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [5] Ishaq’s cash sales were equal to one quarter of his credit sales. He kept $3000 of the money received from cash sales for personal use and banked the remainder. REQUIRED (c) Calculate the amount paid into the bank from cash sales. $ Amount of cash sales .......... Less Cash kept for personal use .......... Amount paid into bank for cash sales .......... [2] (d) Prepare the bank account for the year ended 31 July 2019. Insert the missing figure which represents the amount Ishaq withdrew from the bank for personal use. Ishaq Bank account Date Details $ Date Details $ ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. [8] Ishaq knows that he must place a value on his inventory at the end of his financial year. REQUIRED (e) (i) State the basis on which Ishaq should value his inventory. ..................................................................................................................................... [1] (ii) Name the accounting principle which Ishaq would be applying by valuing his inventory on this basis. ..................................................................................................................................... [1] (f) Complete the table by placing a tick (3) in the correct column to indicate the effect of Ishaq undervaluing his inventory at 31 July 2019. overstated understated gross profit for the year ended 31 July 2019 current assets at 31 July 2019 cost of sales for the year ending 31 July 2020 profit for the year ending 31 July 2020 [4] [Total: 26] PLEASE TURN OVER
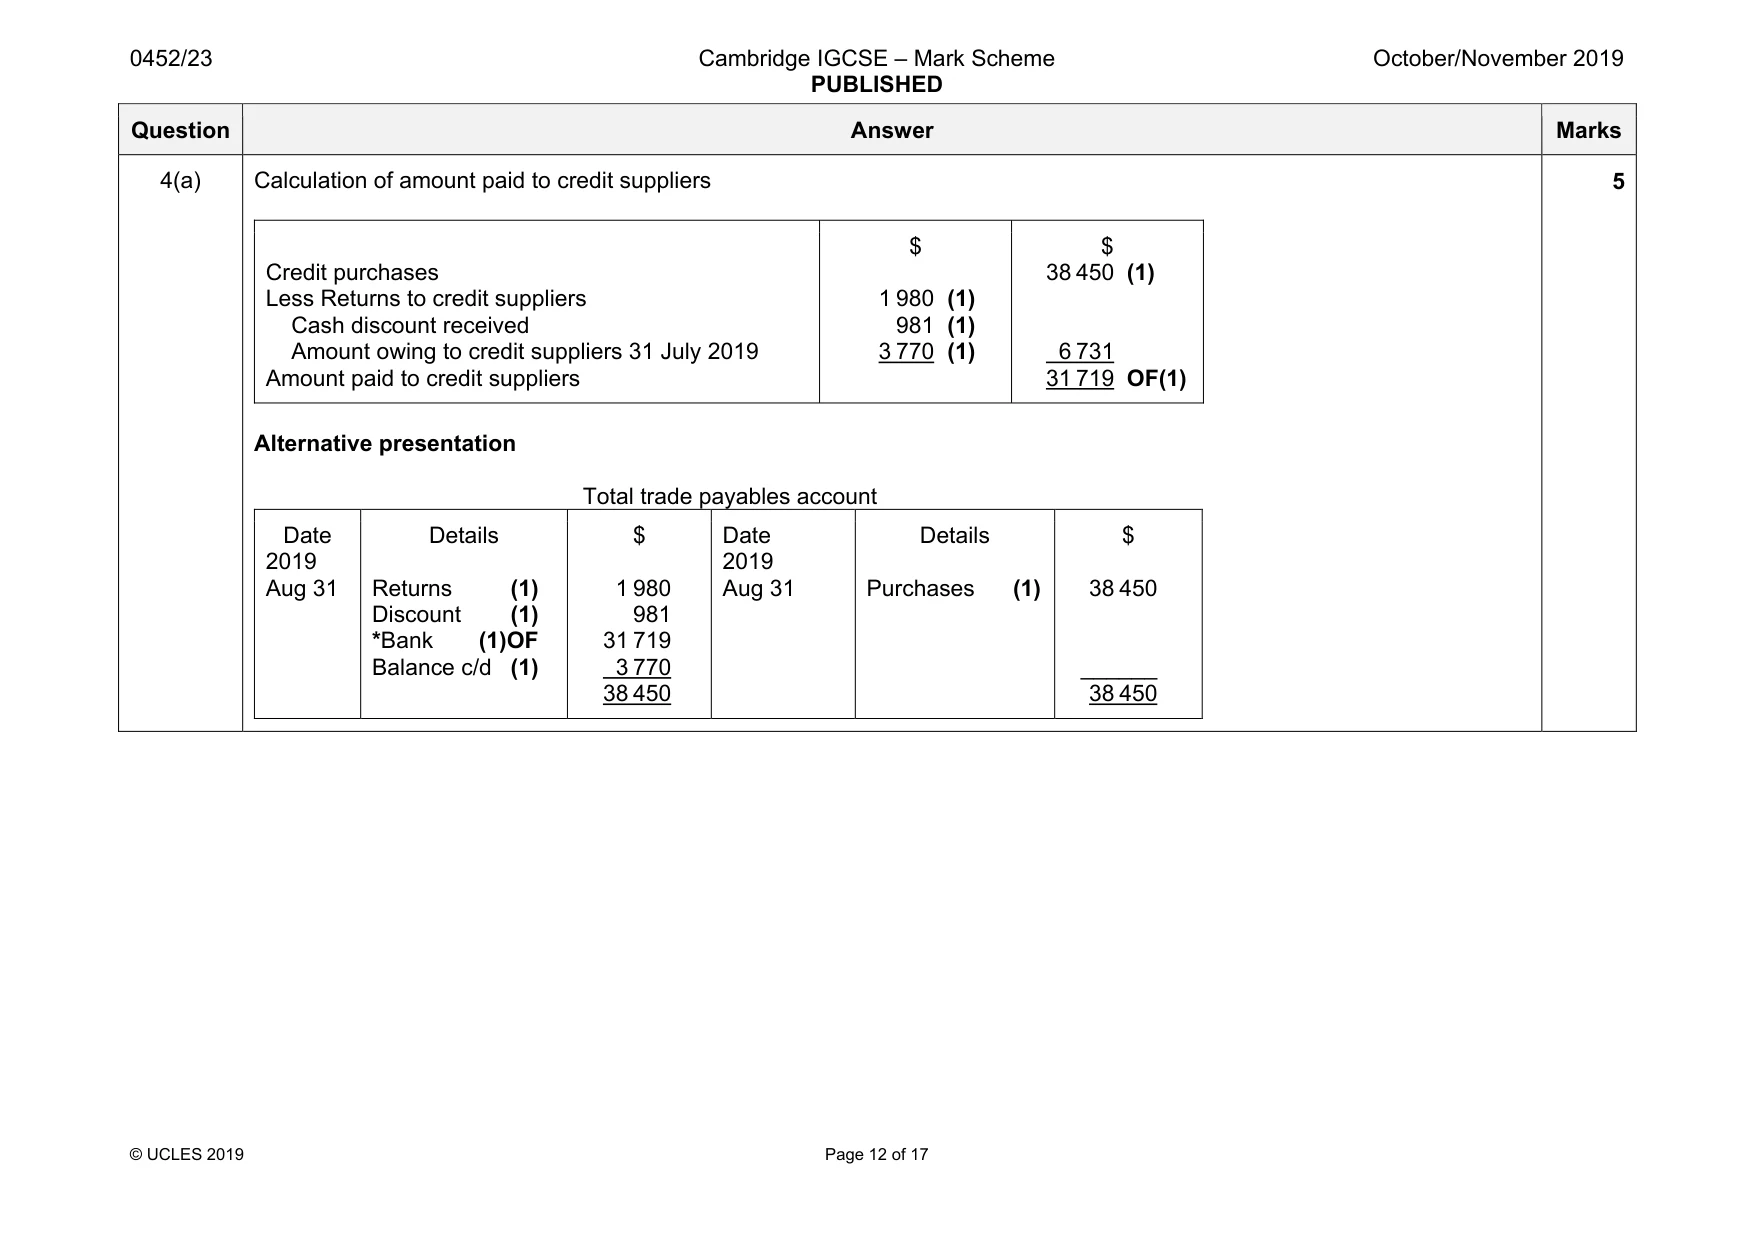
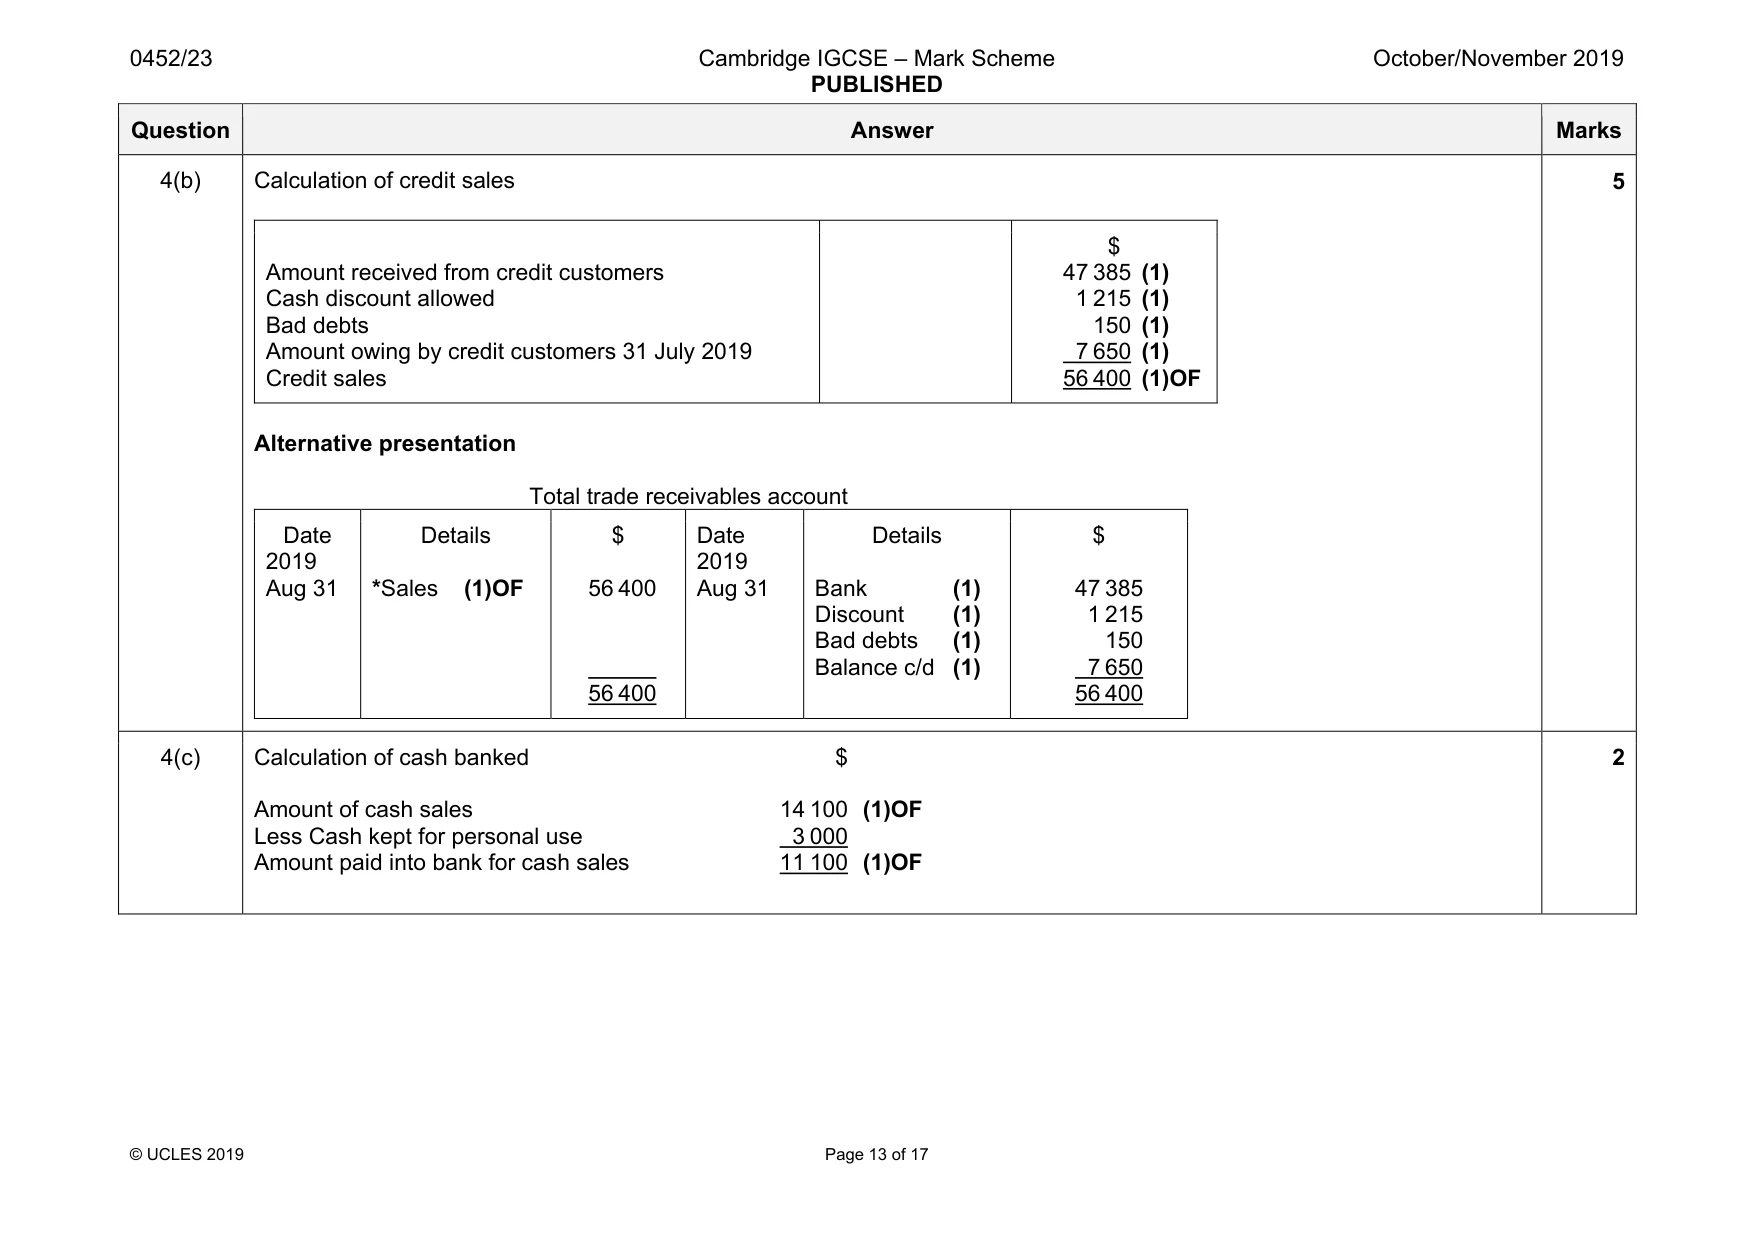
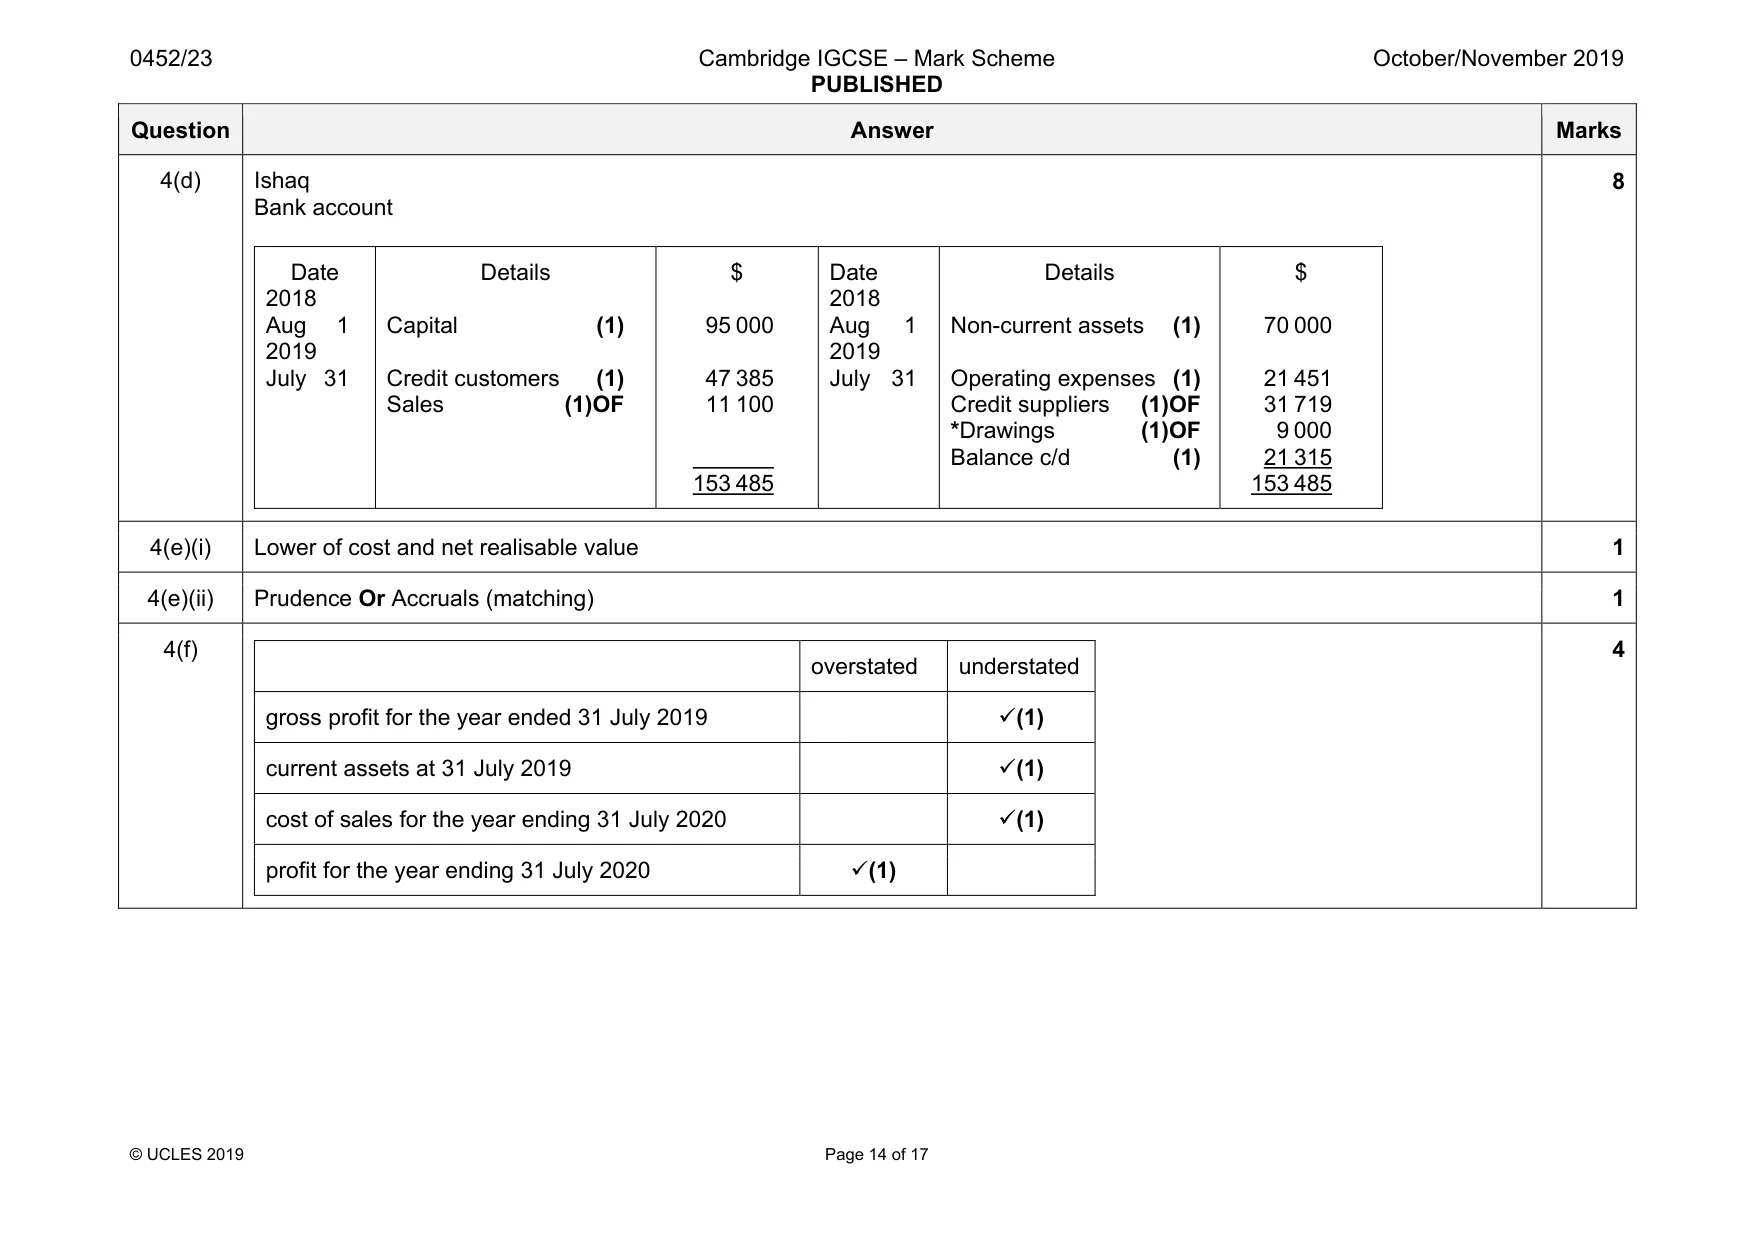
Mark scheme: 4(a) Calculation of amount paid to credit suppliers Credit purchases Less Returns to credit suppliers Cash discount received Amount owing to credit suppliers 31 July 2019 Amount paid to credit suppliers $ 1 980 (1) 981 (1) 3 770 (1) $ 38 450 (1) 6 731 31 719 OF(1) Alternative presentation Total trade payables account Date 2019 Aug 31 Details Returns (1) Discount (1) *Bank (1)OF Balance c/d (1) $ 1 980 981 31 719 3 770 38 450 Date 2019 Aug 31 Details Purchases (1) $ 38 450 ______ 38 450 5 Question Answer Marks 4(b) Calculation of credit sales Amount received from credit customers Cash discount allowed Bad debts Amount owing by credit customers 31 July 2019 Credit sales $ 47 385 (1) 1 215 (1) 150 (1) 7 650 (1) 56 400 (1)OF Alternative presentation Total trade receivables account Date 2019 Aug 31 Details *Sales (1)OF $ 56 400 56 400 Date 2019 Aug 31 Details Bank (1) Discount (1) Bad debts (1) Balance c/d (1) $ 47 385 1 215 150 7 650 56 400 5 4(c) Calculation of cash banked $ Amount of cash sales 14 100 (1)OF Less Cash kept for personal use 3 000 Amount paid into bank for cash sales 11 100 (1)OF 2 Question Answer Marks 4(d) Ishaq Bank account Date 2018 Aug 1 2019 July 31 Details Capital (1) Credit customers (1) Sales (1)OF $ 95 000 47 385 11 100 153 485 Date 2018 Aug 1 2019 July 31 Details Non-current assets (1) Operating expenses (1) Credit suppliers (1)OF *Drawings (1)OF Balance c/d (1) $ 70 000 21 451 31 719 9 000 21 315 153 485 8 4(e)(i) Lower of cost and net realisable value 1 4(e)(ii) Prudence Or Accruals (matching) 1 4(f) overstated understated gross profit for the year ended 31 July 2019 9(1) current assets at 31 July 2019 9(1) cost of sales for the year ending 31 July 2020 9(1) profit for the year ending 31 July 2020 9(1) 4
Q5 · Lili is a clothing wholesaler
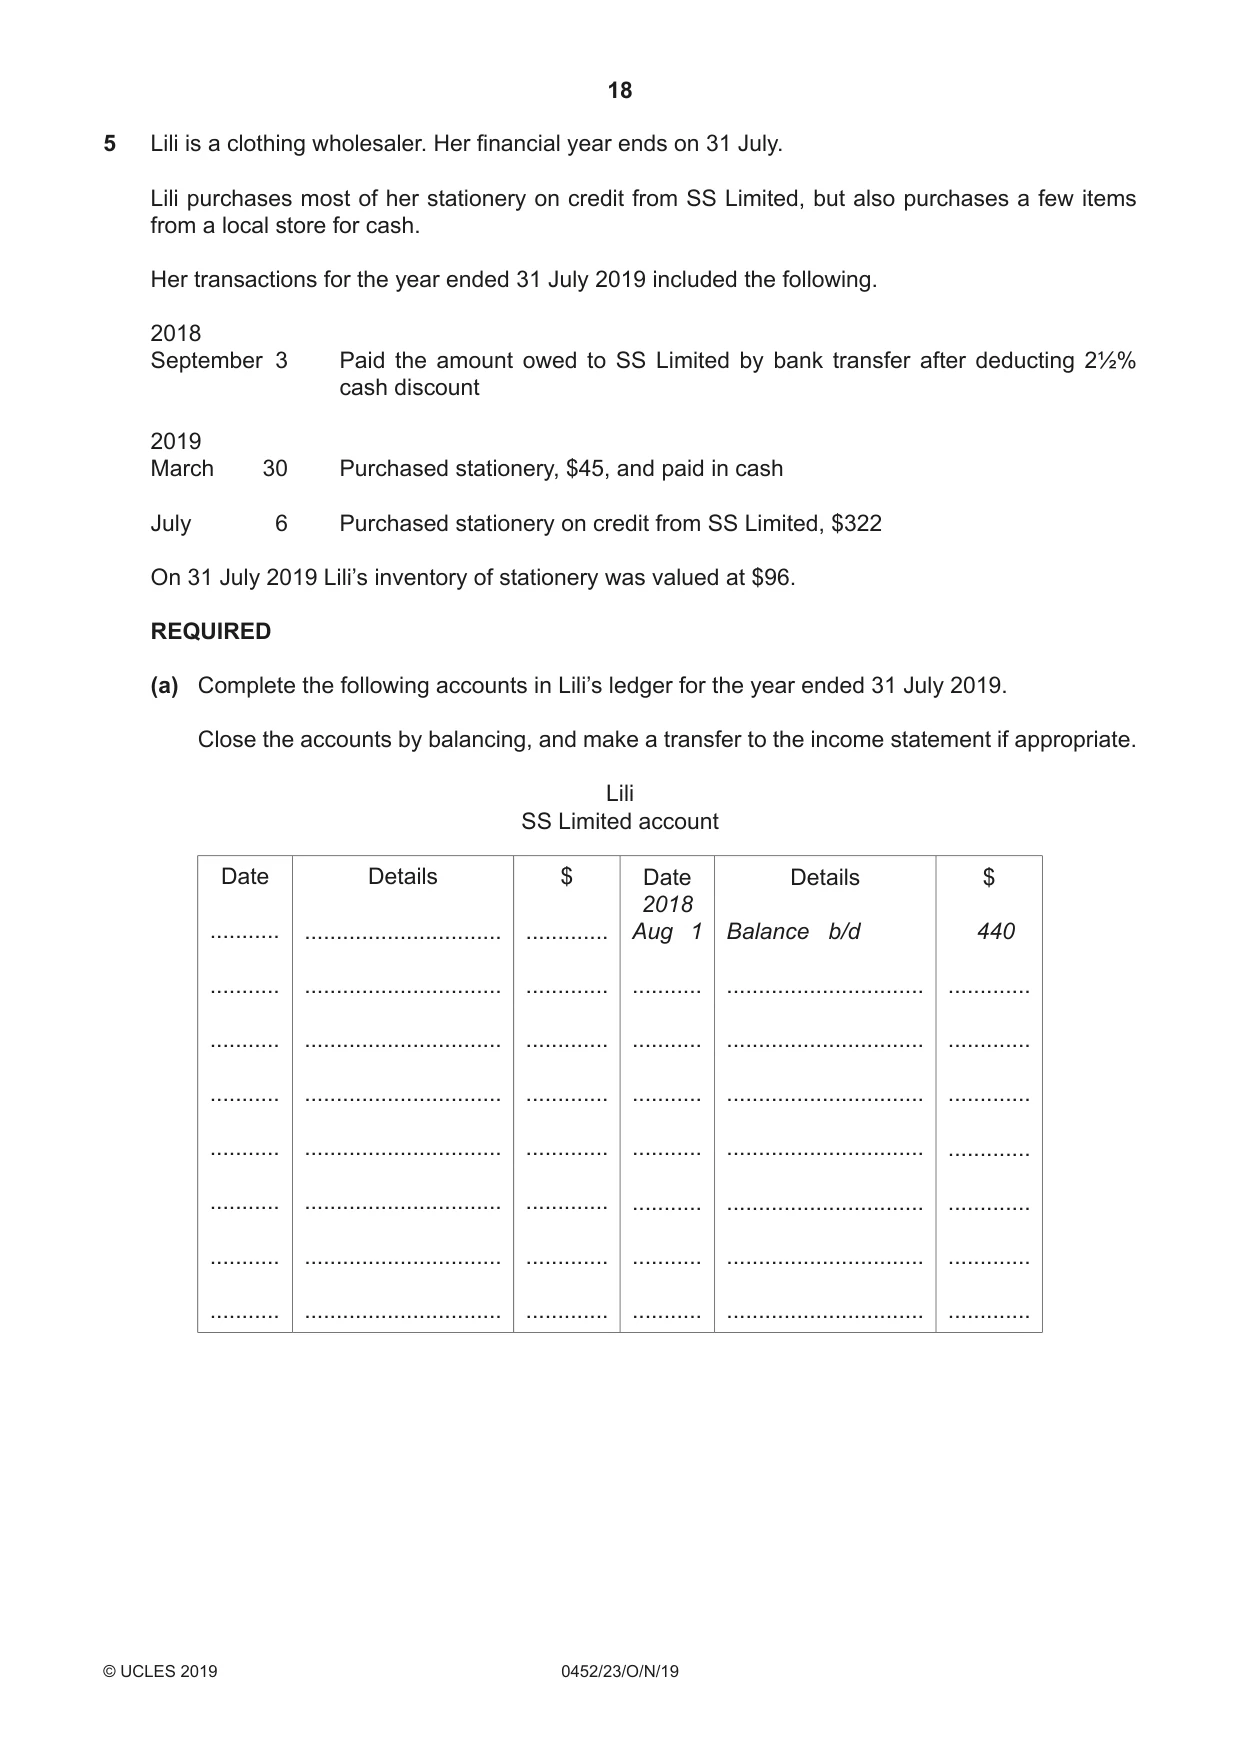
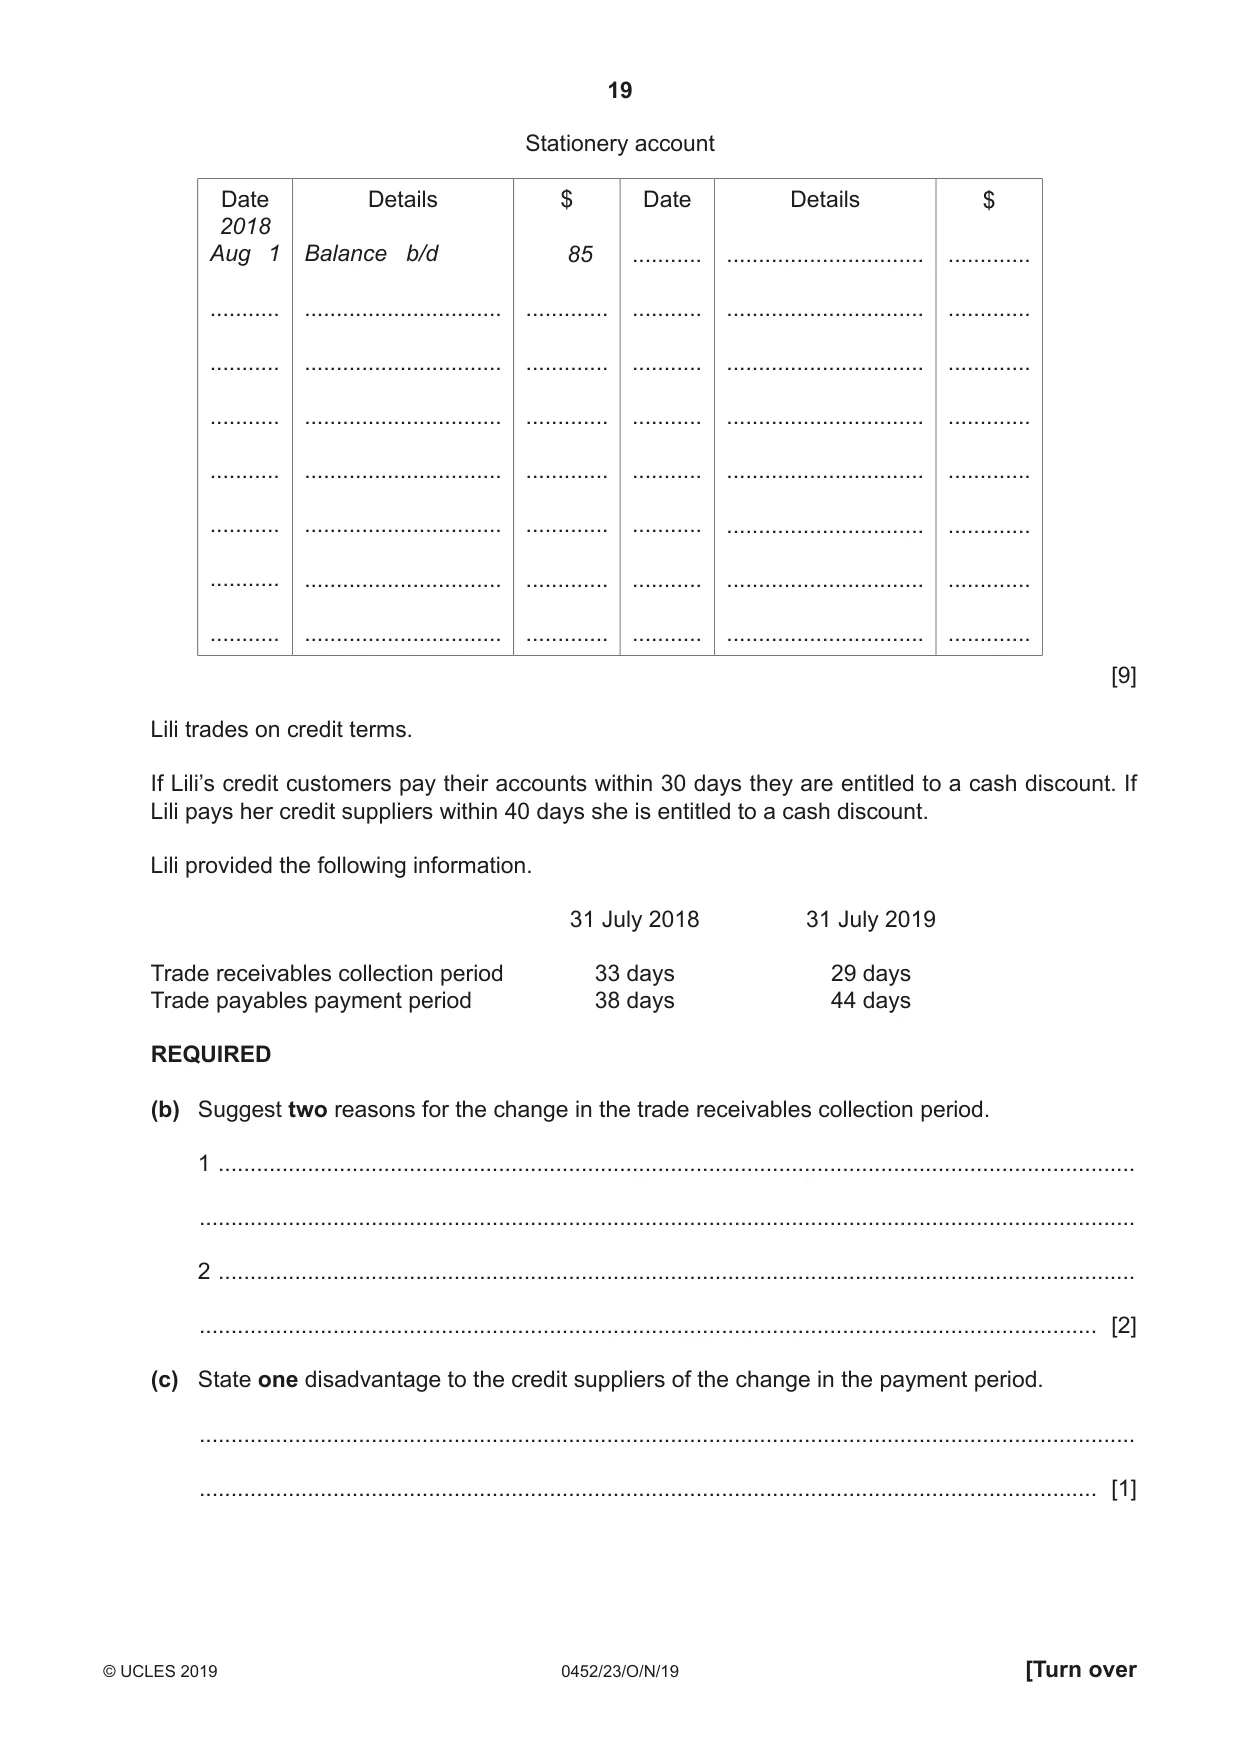
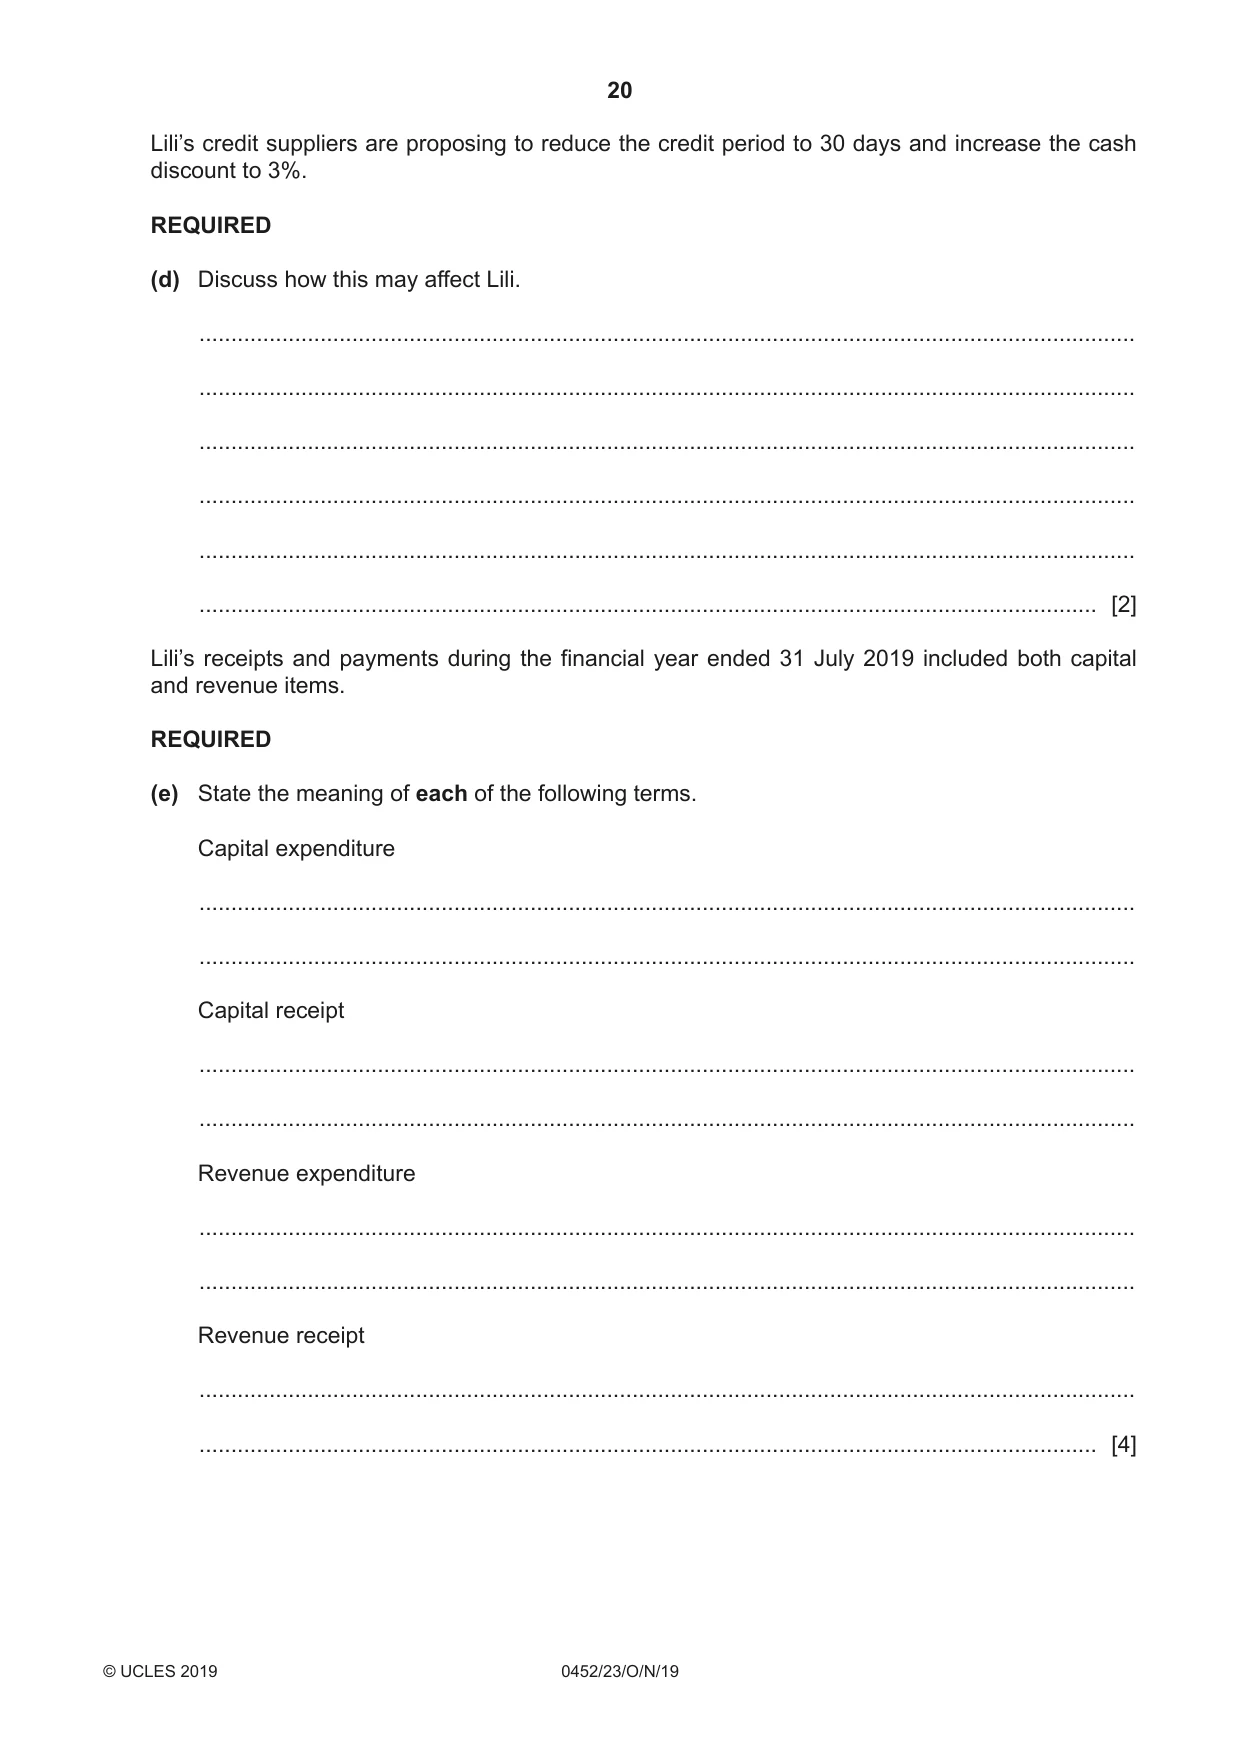
5 Lili is a clothing wholesaler. Her financial year ends on 31 July. Lili purchases most of her stationery on credit from SS Limited, but also purchases a few items from a local store for cash. Her transactions for the year ended 31 July 2019 included the following. 2018 September 3 Paid the amount owed to SS Limited by bank transfer after deducting 2½% cash discount 2019 March 30 Purchased stationery, $45, and paid in cash July 6 Purchased stationery on credit from SS Limited, $322 On 31 July 2019 Lili’s inventory of stationery was valued at $96. REQUIRED (a) Complete the following accounts in Lili’s ledger for the year ended 31 July 2019. Close the accounts by balancing, and make a transfer to the income statement if appropriate. Lili SS Limited account Date Details $ Date Details $ 2018 ........... ............................... ............. Aug 1 Balance b/d 440 ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. Stationery account Date Details $ Date Details $ 2018 Aug 1 Balance b/d 85 ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. ........... ............................... ............. [9] Lili trades on credit terms. If Lili’s credit customers pay their accounts within 30 days they are entitled to a cash discount. If Lili pays her credit suppliers within 40 days she is entitled to a cash discount. Lili provided the following information. 31 July 2018 31 July 2019 Trade receivables collection period 33 days 29 days Trade payables payment period 38 days 44 days REQUIRED (b) Suggest two reasons for the change in the trade receivables collection period. 1 ................................................................................................................................................ ................................................................................................................................................... 2 ................................................................................................................................................ ............................................................................................................................................. [2] (c) State one disadvantage to the credit suppliers of the change in the payment period. ................................................................................................................................................... ............................................................................................................................................. [1] Lili’s credit suppliers are proposing to reduce the credit period to 30 days and increase the cash discount to 3%. REQUIRED (d) Discuss how this may affect Lili. ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ................................................................................................................................................... ............................................................................................................................................. [2] Lili’s receipts and payments during the financial year ended 31 July 2019 included both capital and revenue items. REQUIRED (e) State the meaning of each of the following terms. Capital expenditure ................................................................................................................................................... ................................................................................................................................................... Capital receipt ................................................................................................................................................... ................................................................................................................................................... Revenue expenditure ................................................................................................................................................... ................................................................................................................................................... Revenue receipt ................................................................................................................................................... ............................................................................................................................................. [4]
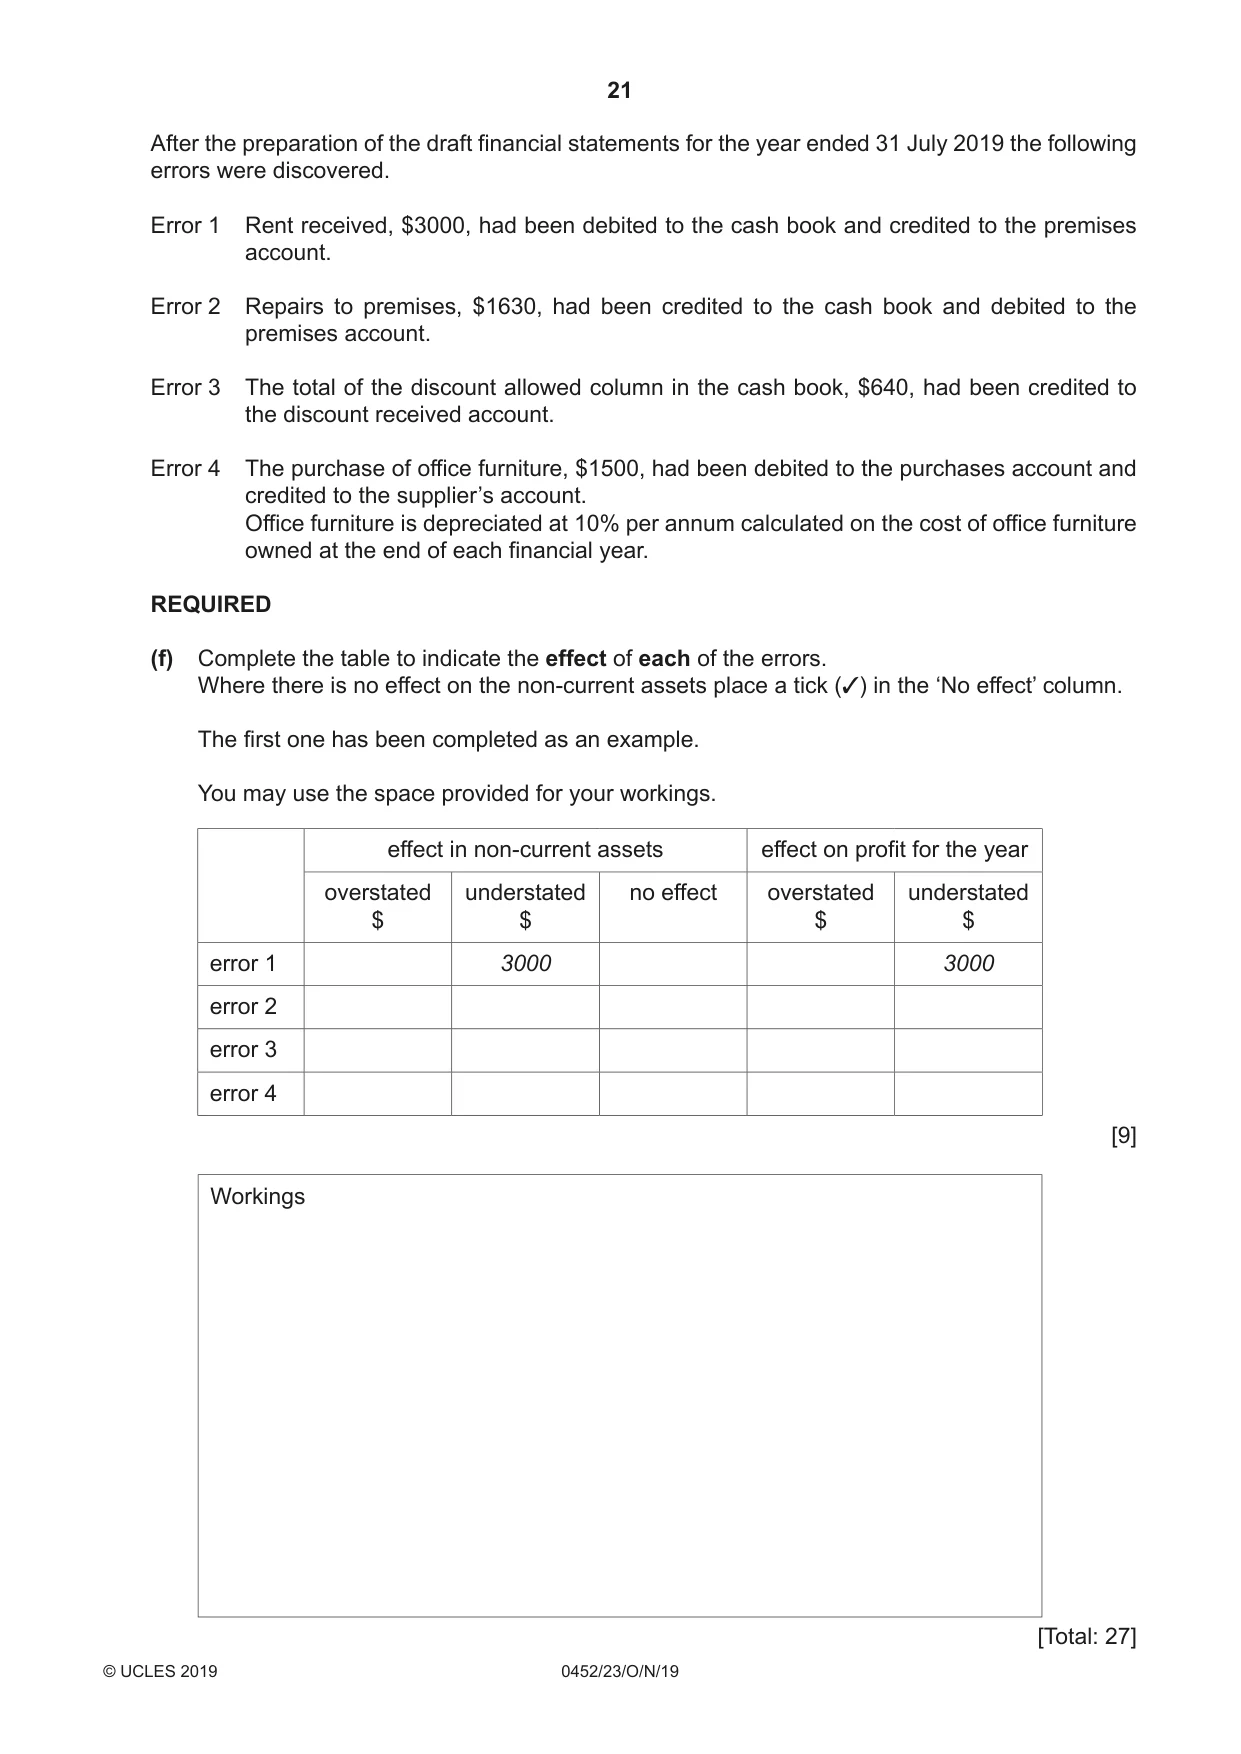
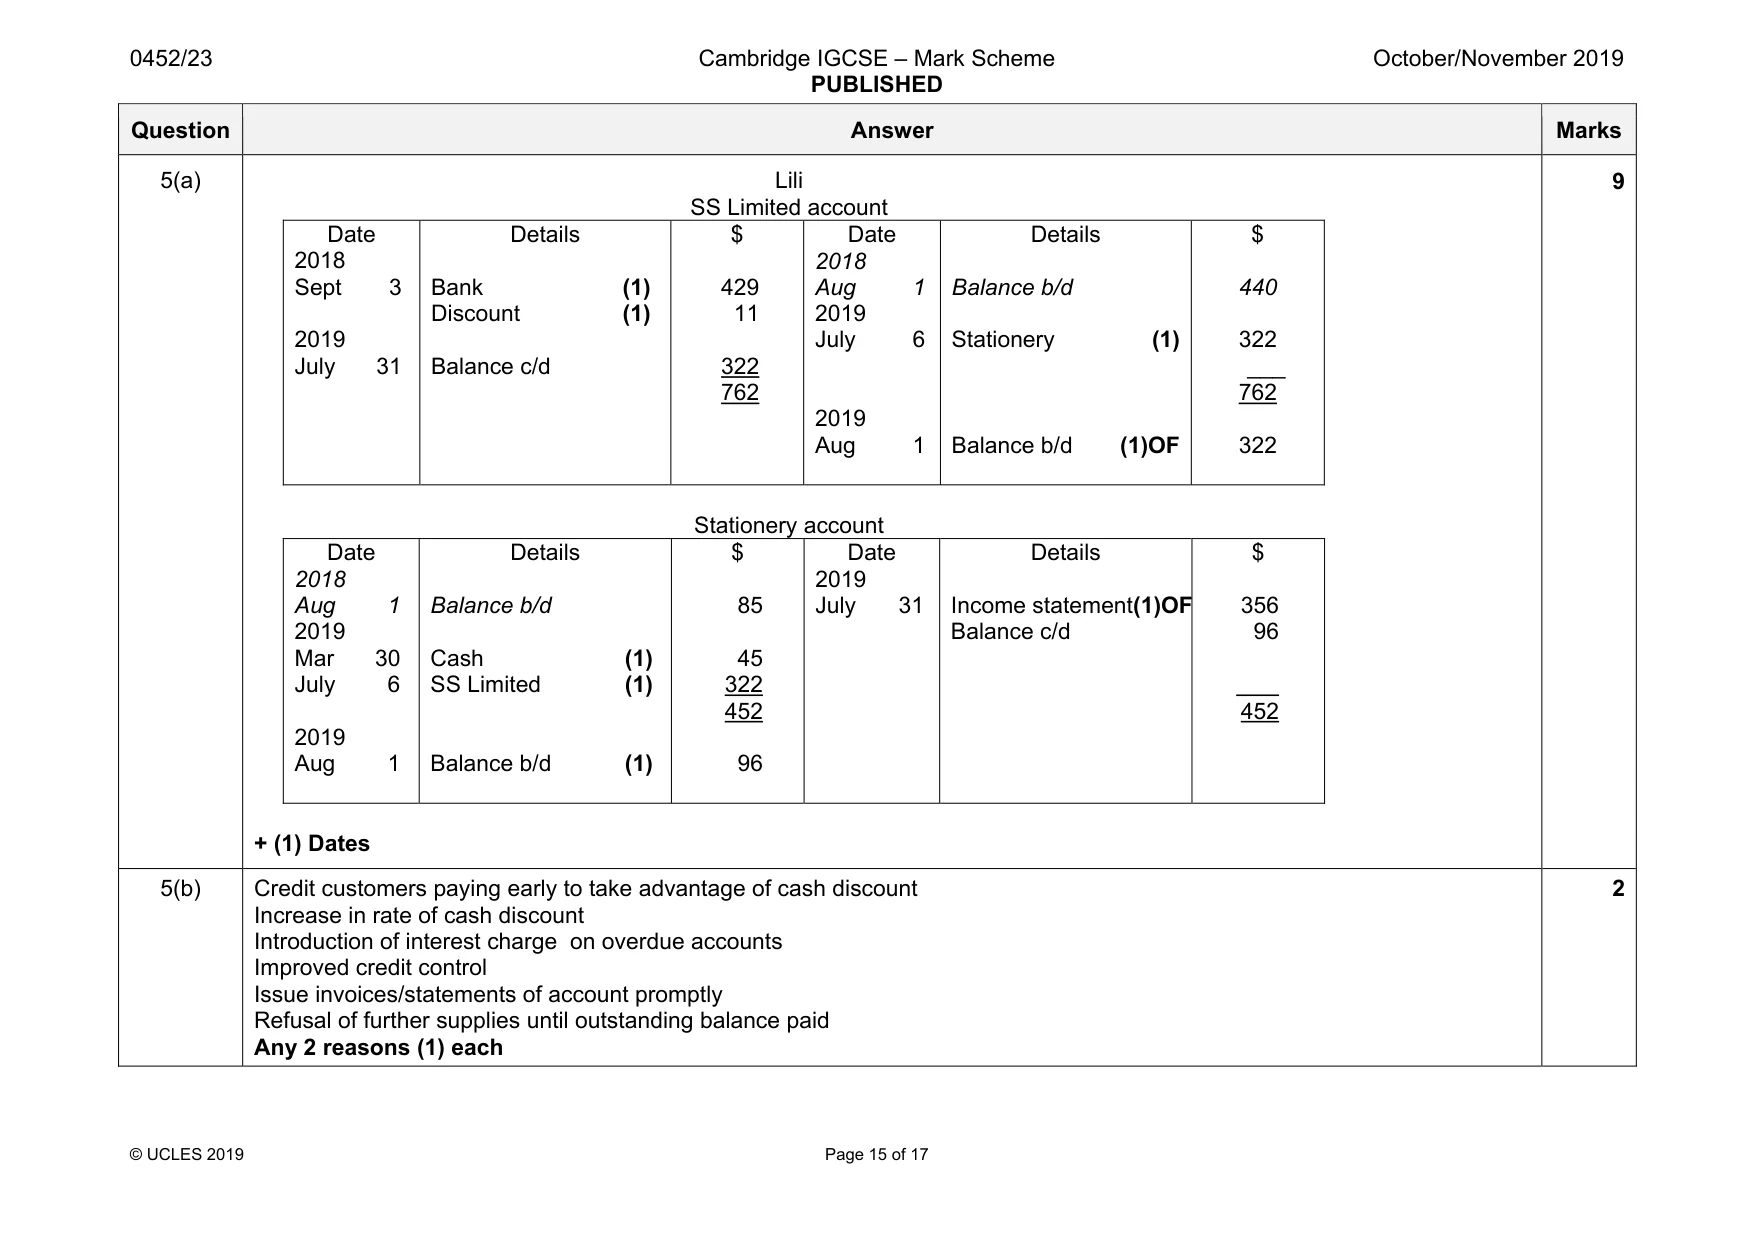
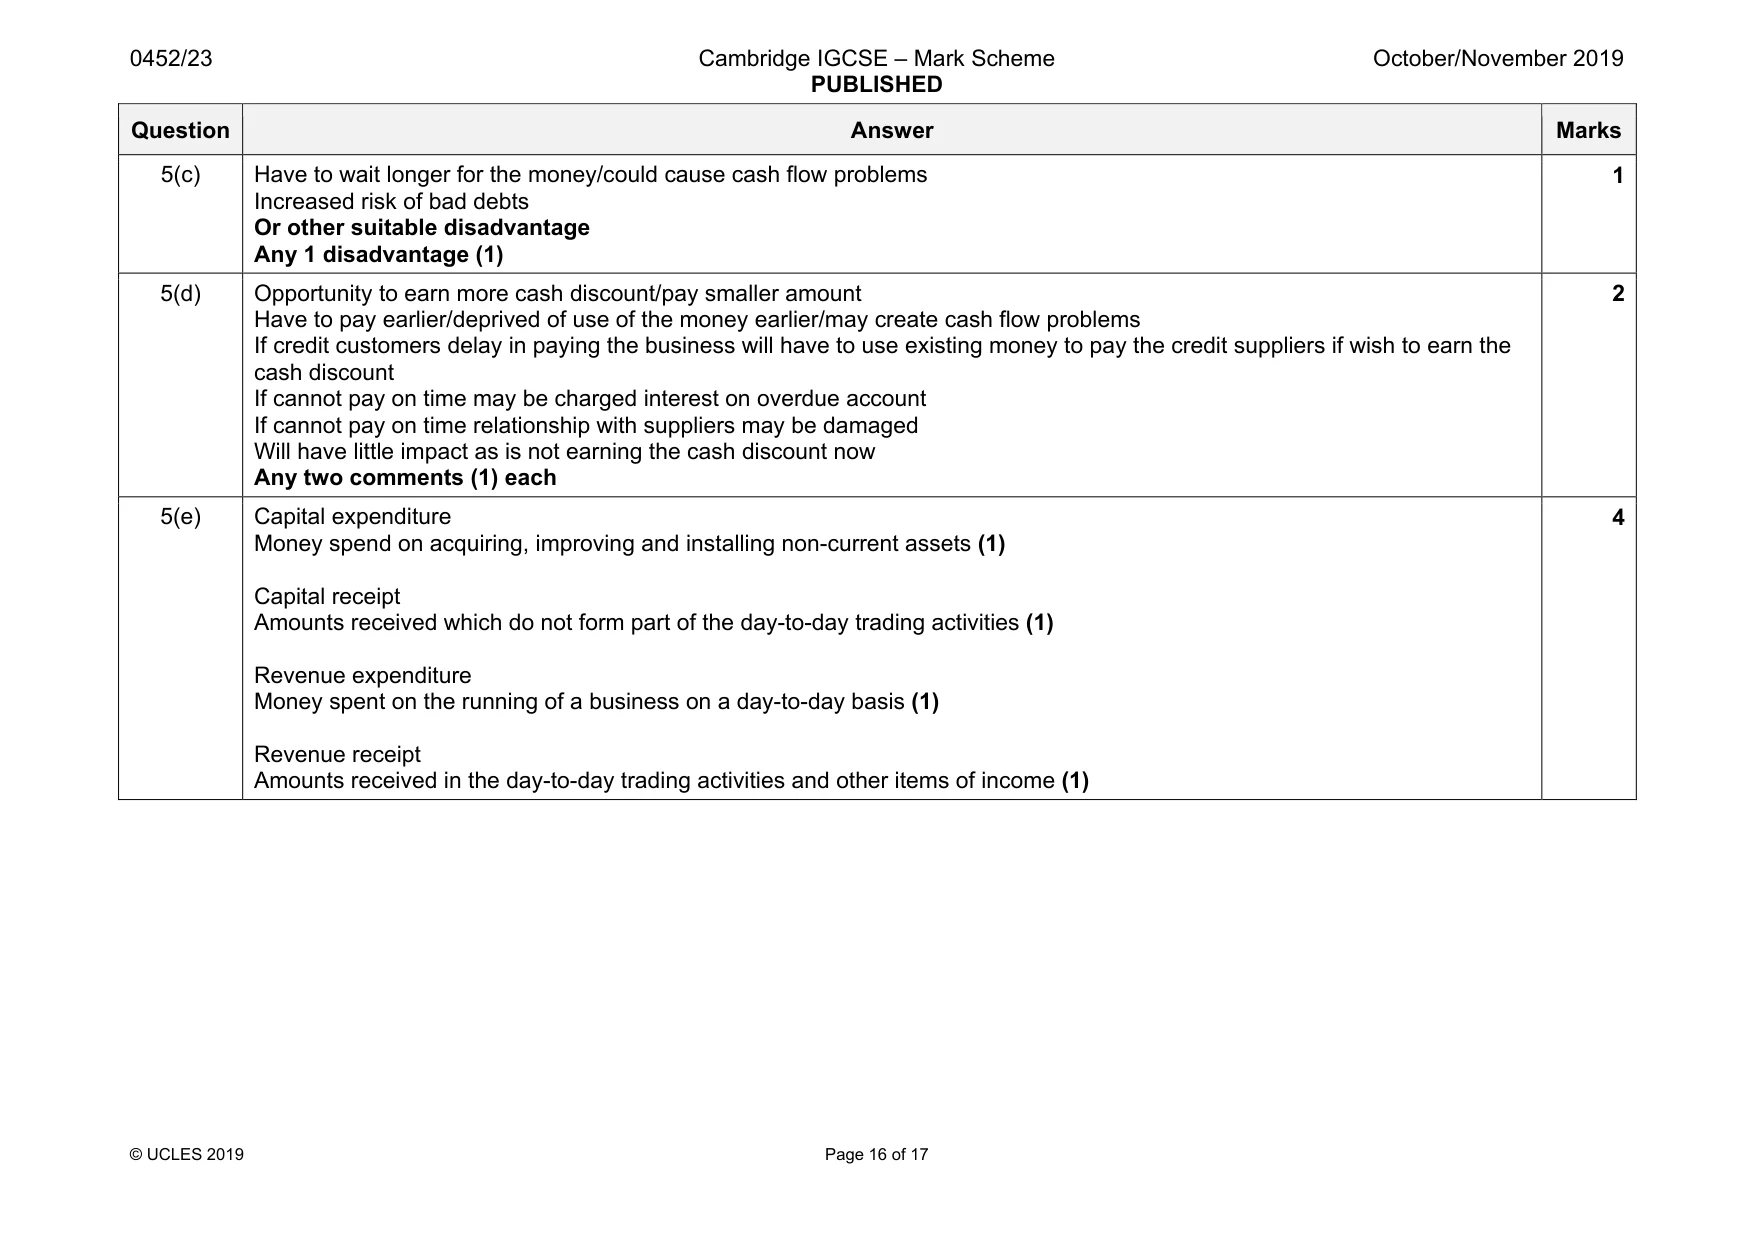
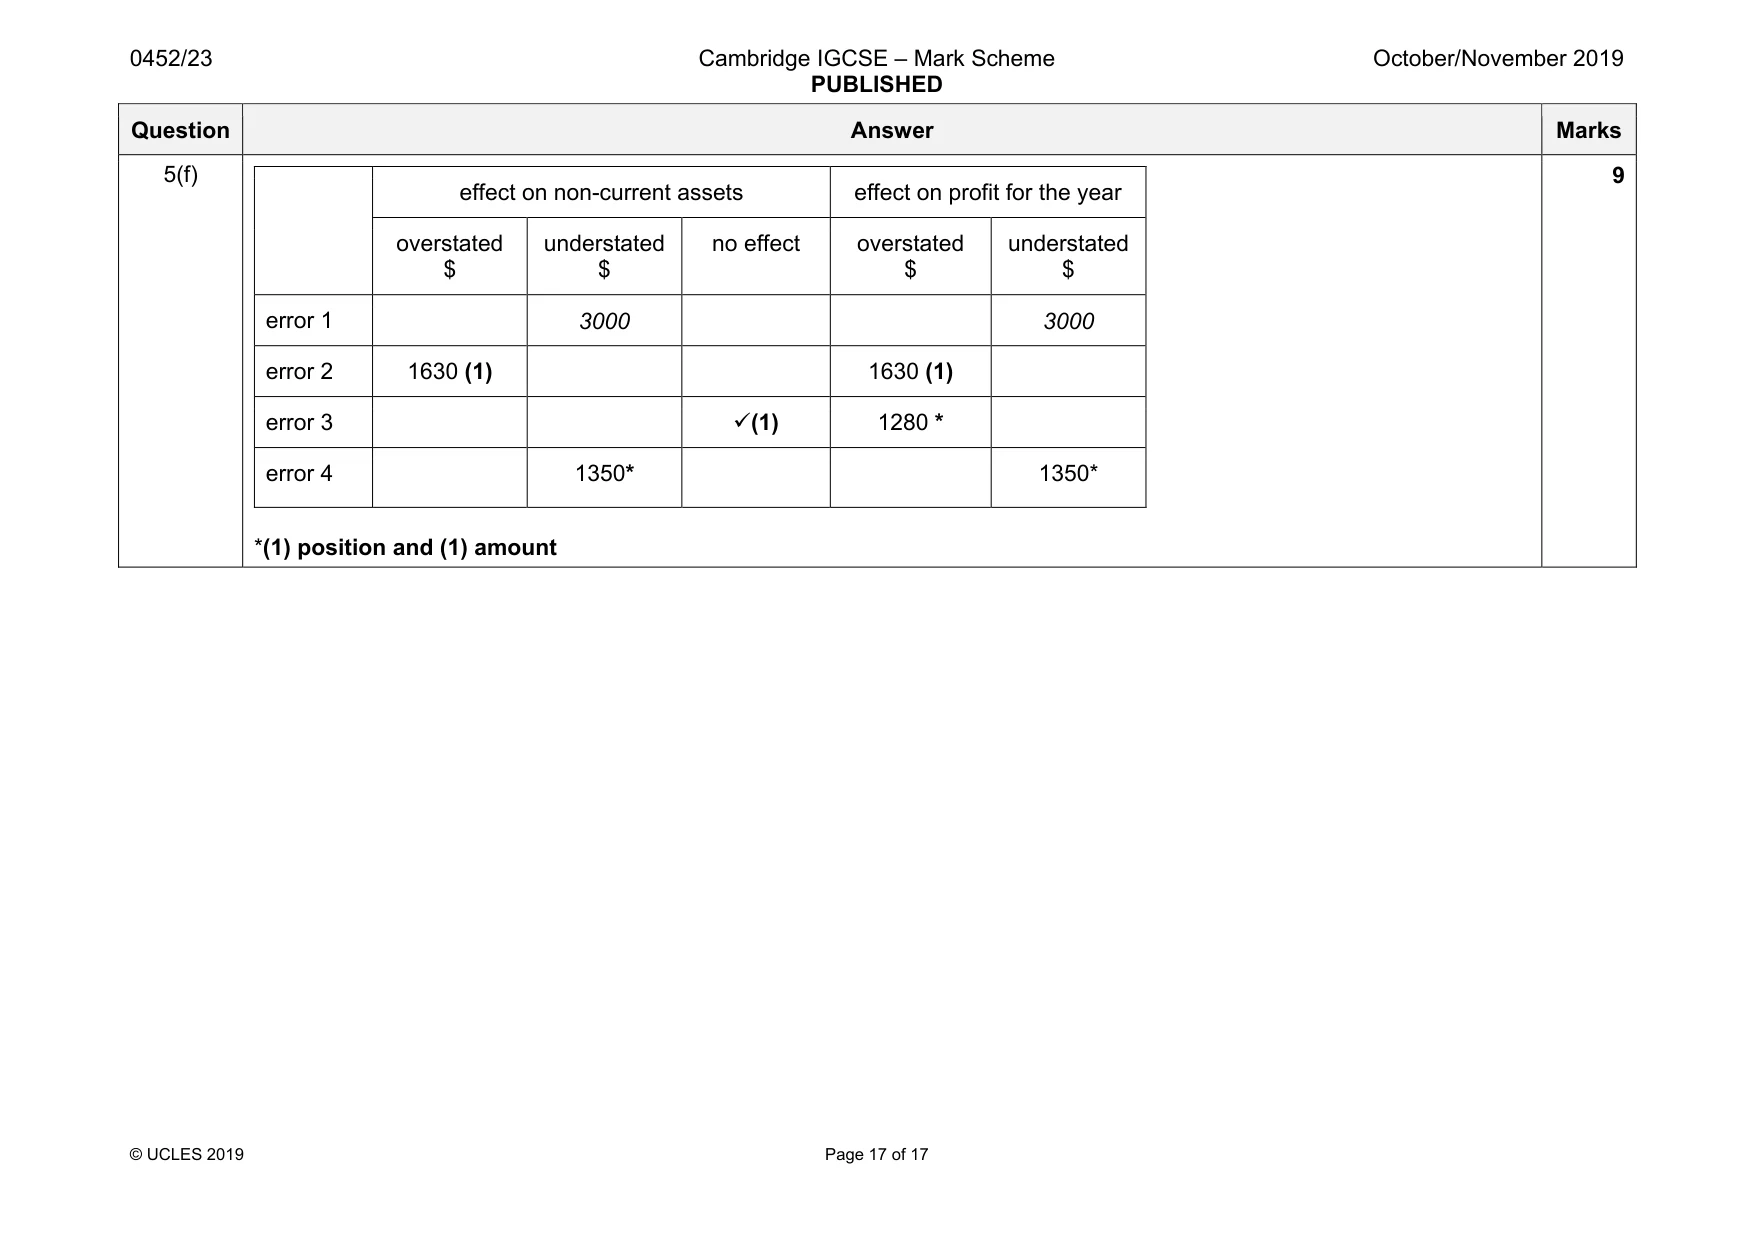
Mark scheme: 5(a) Lili SS Limited account Date 2018 Sept 3 2019 July 31 Details Bank (1) Discount (1) Balance c/d $ 429 11 322 762 Date 2018 Aug 1 2019 July 6 2019 Aug 1 Details Balance b/d Stationery (1) Balance b/d (1)OF $ 440 322 ___ 762 322 Stationery account Date 2018 Aug 1 2019 Mar 30 July 6 2019 Aug 1 Details Balance b/d Cash (1) SS Limited (1) Balance b/d (1) $ 85 45 322 452 96 Date 2019 July 31 Details Income statement(1)OF Balance c/d $ 356 96 452 + (1) Dates 9 5(b) Credit customers paying early to take advantage of cash discount Increase in rate of cash discount Introduction of interest charge on overdue accounts Improved credit control Issue invoices/statements of account promptly Refusal of further supplies until outstanding balance paid Any 2 reasons (1) each 2 Question Answer Marks 5(c) Have to wait longer for the money/could cause cash flow problems Increased risk of bad debts Or other suitable disadvantage Any 1 disadvantage (1) 1 5(d) Opportunity to earn more cash discount/pay smaller amount Have to pay earlier/deprived of use of the money earlier/may create cash flow problems If credit customers delay in paying the business will have to use existing money to pay the credit suppliers if wish to earn the cash discount If cannot pay on time may be charged interest on overdue account If cannot pay on time relationship with suppliers may be damaged Will have little impact as is not earning the cash discount now Any two comments (1) each 2 5(e) Capital expenditure Money spend on acquiring, improving and installing non-current assets (1) Capital receipt Amounts received which do not form part of the day-to-day trading activities (1) Revenue expenditure Money spent on the running of a business on a day-to-day basis (1) Revenue receipt Amounts received in the day-to-day trading activities and other items of income (1) 4 Question Answer Marks 5(f) effect on non-current assets effect on profit for the year overstated $ understated $ no effect overstated $ understated $ error 1 3000 3000 error 2 1630 (1) 1630 (1) error 3 9(1) 1280 * error 4 1350* 1350* *(1) position and (1) amount 9
What was in this paper
The subtopics covered by these 5 questions, and how many questions each got. Open one in a new tab to see every Cambridge question on it.
What you needed in this session
Cambridge’s own grade thresholds for 2019 Oct/Nov, Paper 2 · Variant 3. A higher threshold means an easier paper — the bar moves with how the cohort did.